Aerie Pharmaceuticals — Investor Presentation (April 2022)
25 slides from Aerie Pharmaceuticals's investor presentation, Apr 11, 2022
Slide 1: An Emerging Leader in Ophthalmology
Exhibit 99.1 AERIE An Emerging Leader in Ophthalmology Ap r i l 2 0 2 2 For Investor Use Only 1
Slide 2: Disclaimer
Disclaimer The information in this presentation regarding Aerie Pharmaceuticals, Inc. (the “Company” or “Aerie”) does not contain all of the information that a potential investor should review before investing in Aerie shares. The descriptions of Aerie in this presentation are qualified in their ent
Slide 3: An Emerging Leader in Ophthalmology
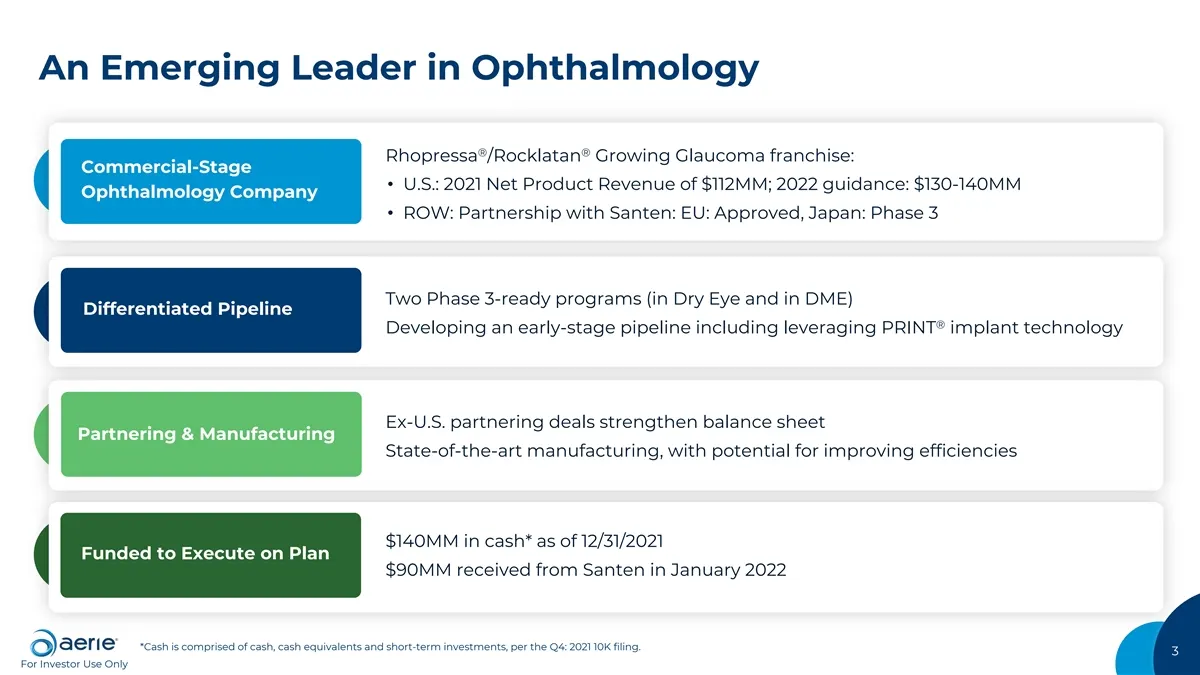
An Emerging Leader in Ophthalmology ® ® Rhopressa /Rocklatan Growing Glaucoma franchise: Commercial-Stage • U.S.: 2021 Net Product Revenue of $112MM; 2022 guidance: $130-140MM Ophthalmology Company • ROW: Partnership with Santen: EU: Approved, Japan: Phase 3 Two Phase 3-ready programs (in Dry Eye an
Slide 4: Novel Mechanisms for Products/Pipeline
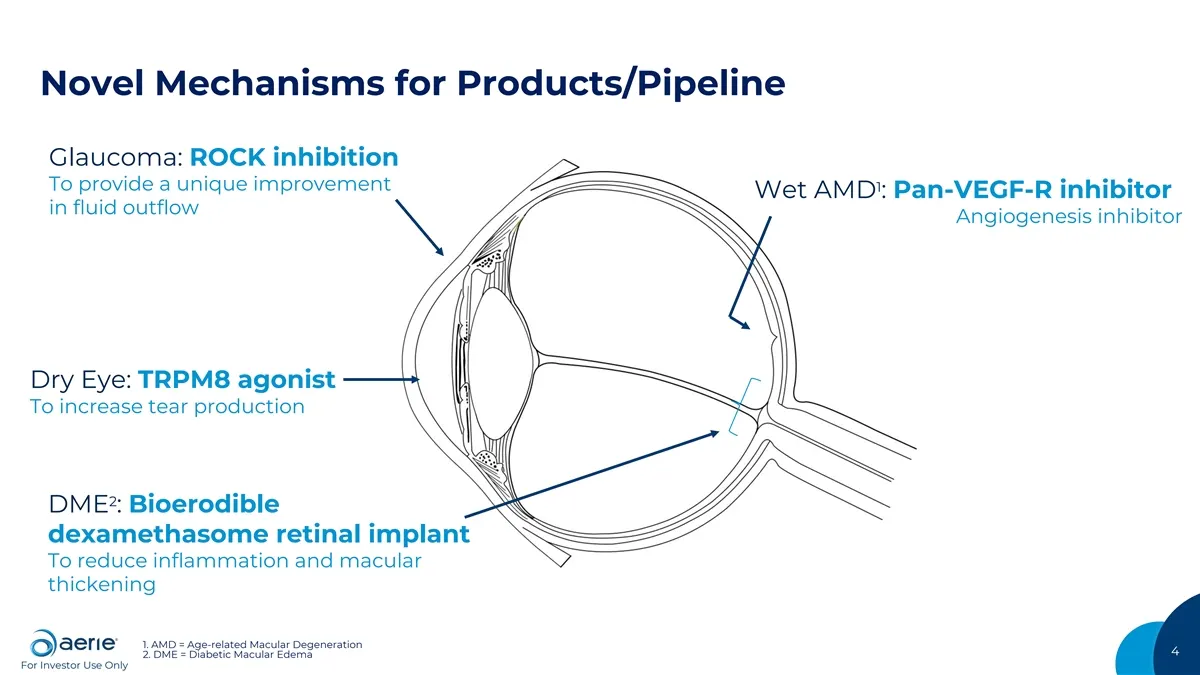
Novel Mechanisms for Products/Pipeline Glaucoma: ROCK inhibition To provide a unique improvement 1 Wet AMD : Pan-VEGF-R inhibitor in fluid outflow Angiogenesis inhibitor Dry Eye: TRPM8 agonist To increase tear production 2 DME : Bioerodible dexamethasome retinal implant To reduce inflammation and ma
Slide 5: Aerie Product Pipeline Targets Attractive Commercial Markets
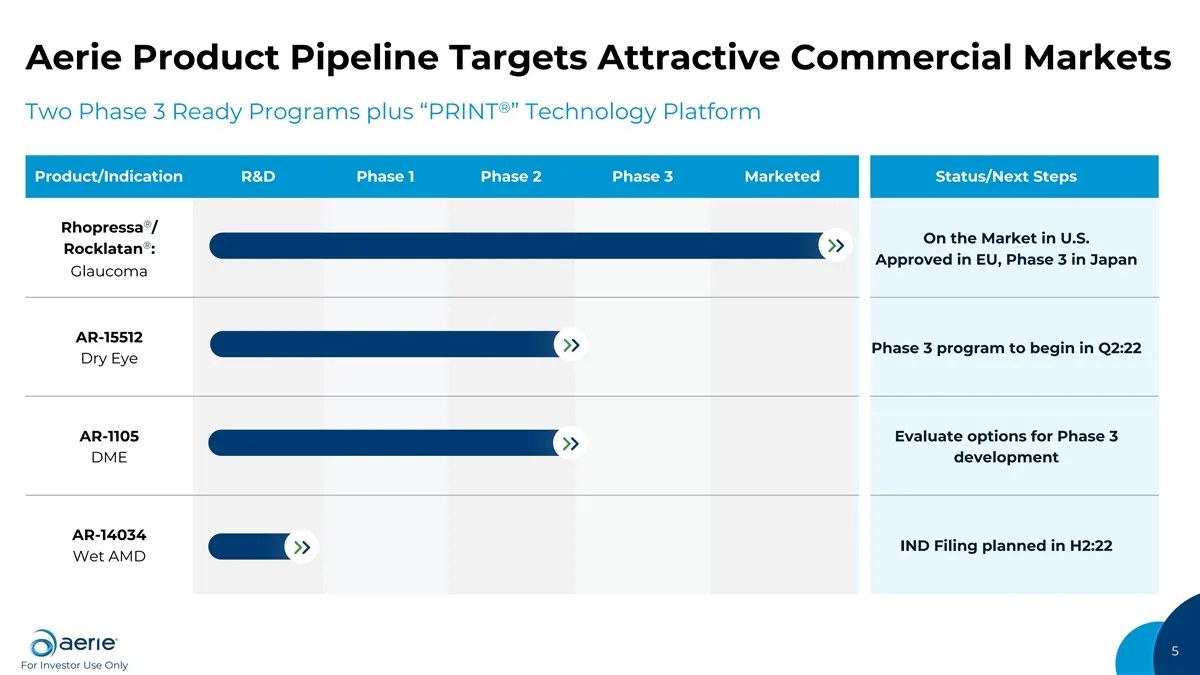
Aerie Product Pipeline Targets Attractive Commercial Markets ® Two Phase 3 Ready Programs plus “PRINT ” Technology Platform Product/Indication R&D Phase 1 Phase 2 Phase 3 Marketed Status/Next Steps ® Rhopressa / On the Market in U.S. ® Rocklatan : Approved in EU, Phase 3 in Japan Glaucoma AR-15512 P
Slide 6: Aerie 2.0: Strategic pillars for long-term success
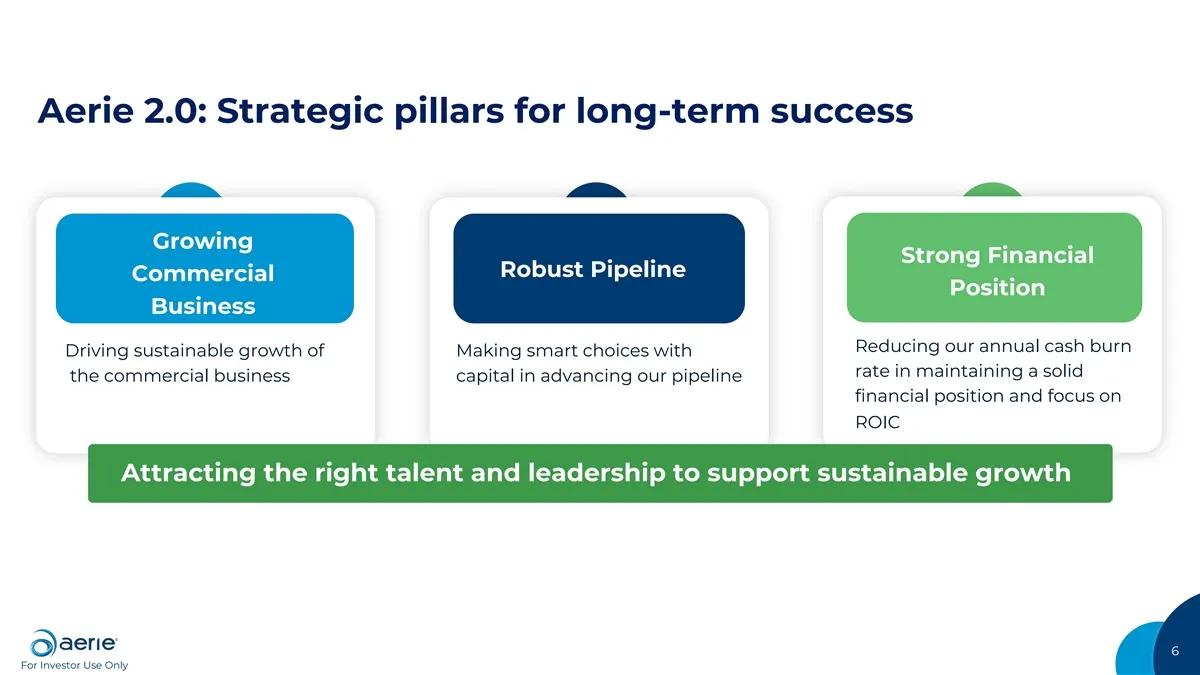
Aerie 2.0: Strategic pillars for long-term success Growing Strong Financial Robust Pipeline Commercial Position Business Reducing our annual cash burn Driving sustainable growth of Making smart choices with rate in maintaining a solid the commercial business capital in advancing our pipeline financi
Slide 7: Glaucoma: ~$3B U.S. Market
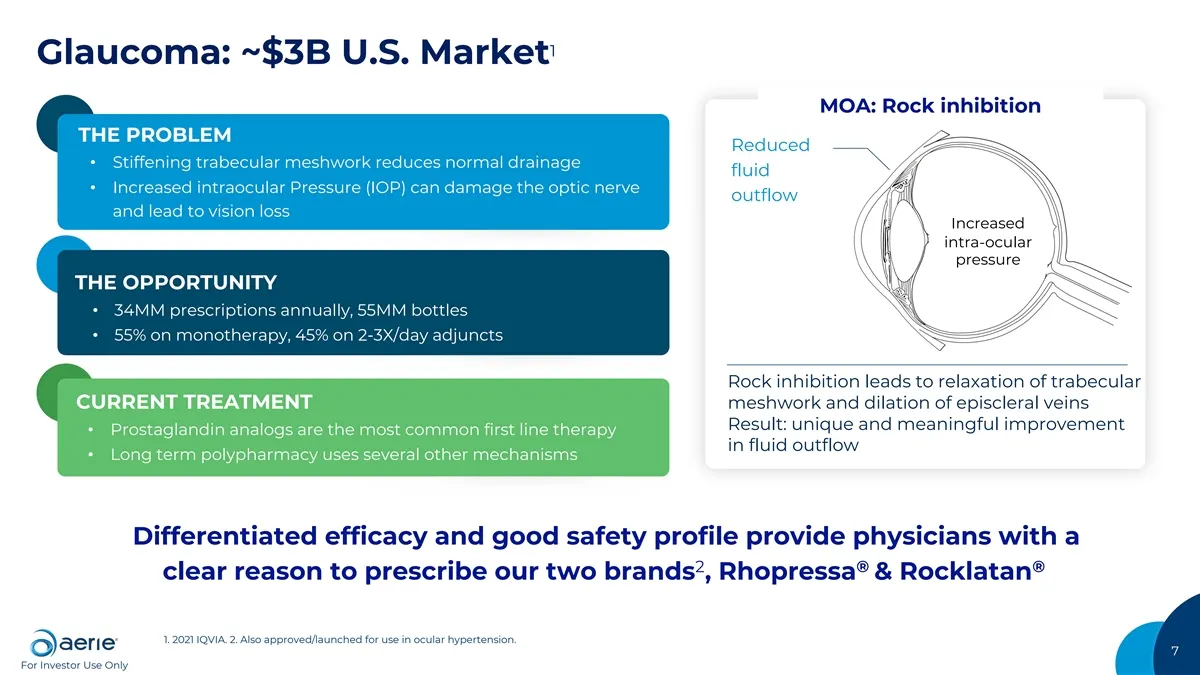
1 Glaucoma: ~$3B U.S. Market MOA: Rock inhibition THE PROBLEM Reduced • Stiffening trabecular meshwork reduces normal drainage fluid • Increased intraocular Pressure (IOP) can damage the optic nerve outflow and lead to vision loss Increased intra-ocular pressure THE OPPORTUNITY • 34MM prescriptions
Slide 8: Glaucoma Franchise
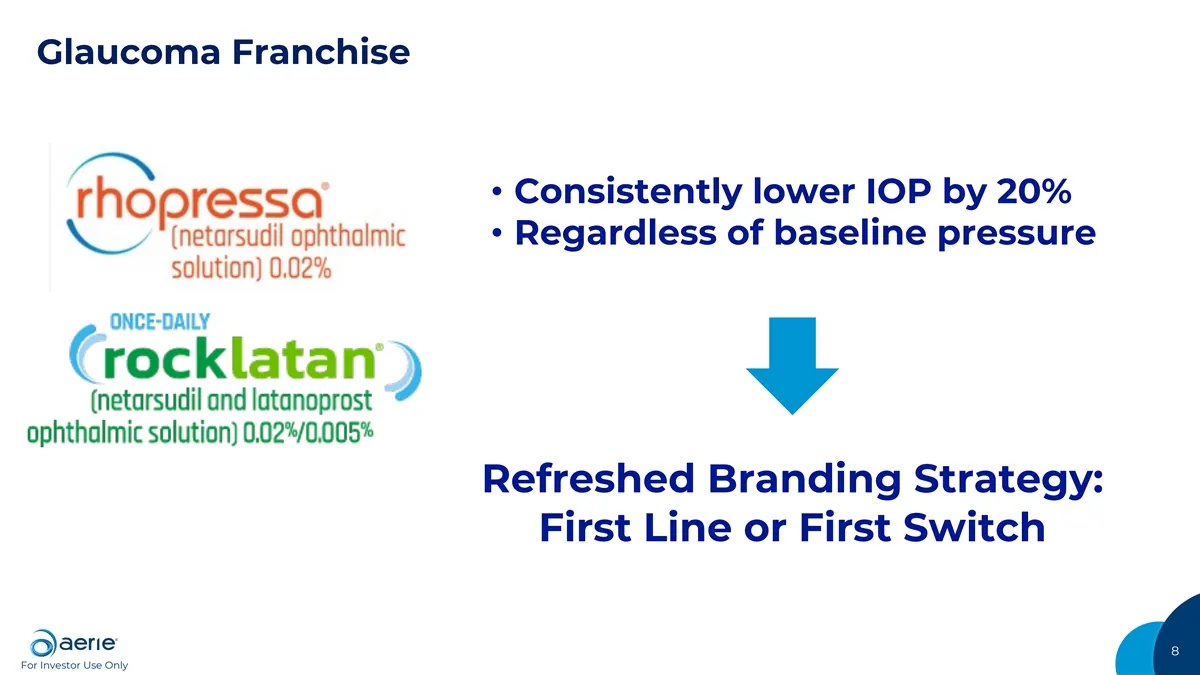
Glaucoma Franchise • Consistently lower IOP by 20% • Regardless of baseline pressure Refreshed Branding Strategy: First Line or First Switch 8 For Investor Use Only
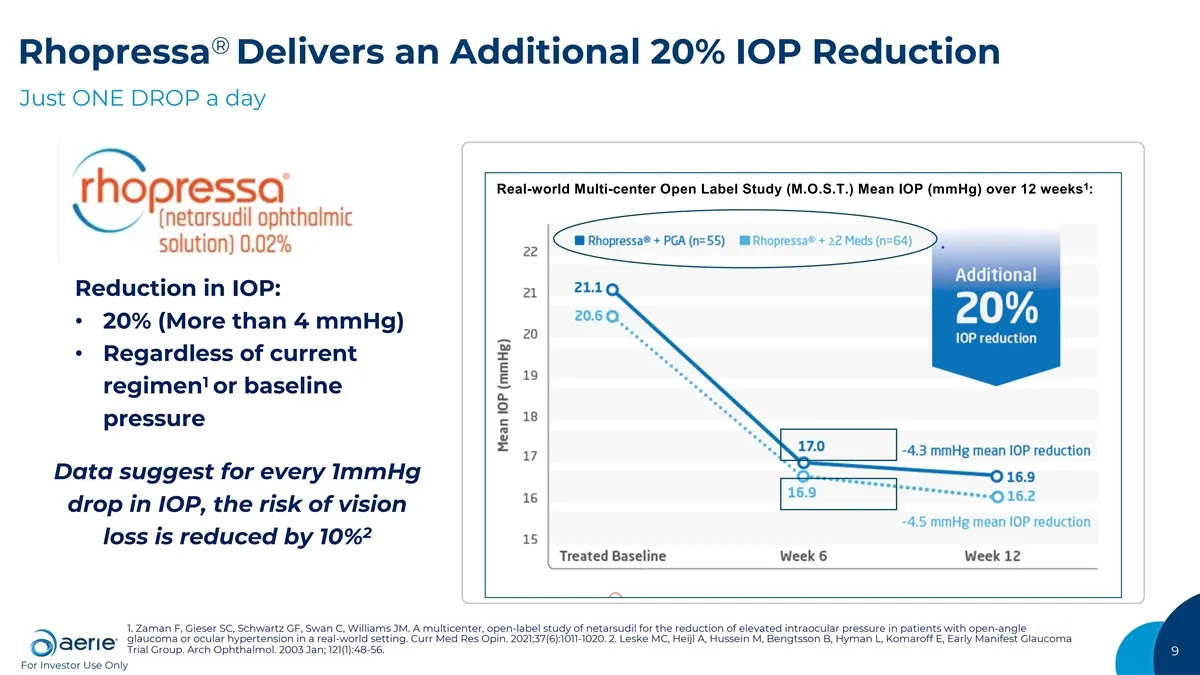
Slide 9: Rhopressa Delivers an Additional 20% IOP Reduction
® Rhopressa Delivers an Additional 20% IOP Reduction Just ONE DROP a day 1 Real-world Multi-center Open Label Study (M.O.S.T.) Mean IOP (mmHg) over 12 weeks : Reduction in IOP: • 20% (More than 4 mmHg) • Regardless of current 1 regimen or baseline pressure Data suggest for every 1mmHg drop in IOP, t
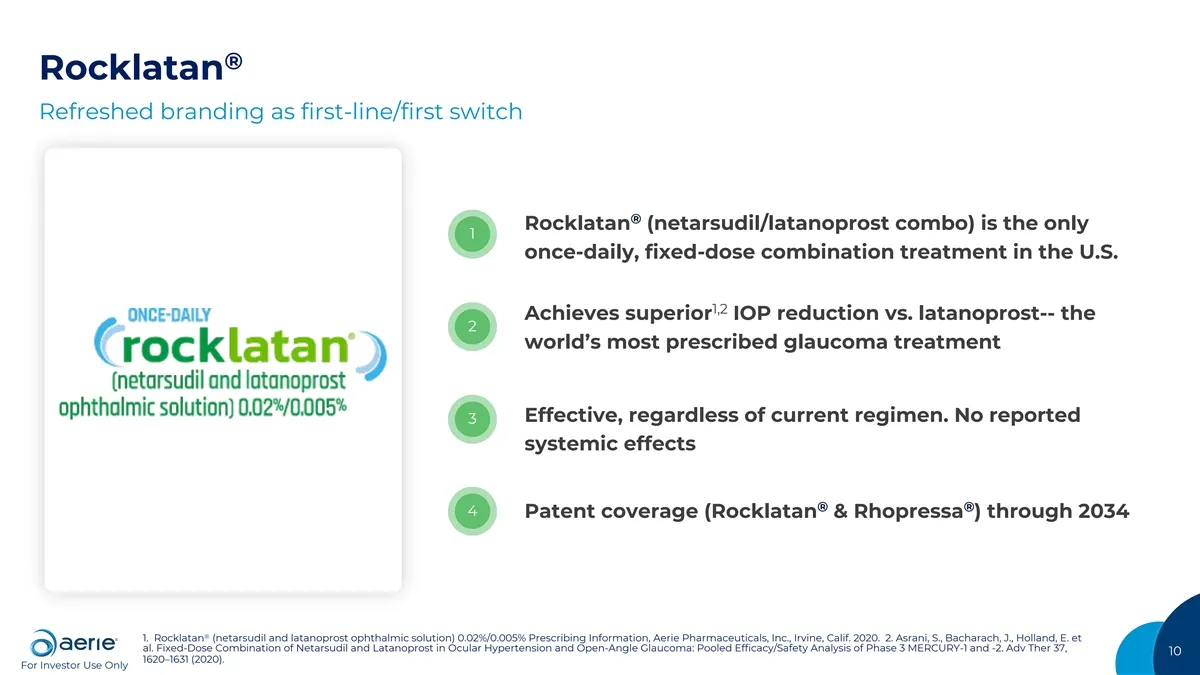
Slide 10: Rocklatan Refreshed branding as first-line/first switch
® Rocklatan Refreshed branding as first-line/first switch ® Rocklatan (netarsudil/latanoprost combo) is the only 1 once-daily, fixed-dose combination treatment in the U.S. 1,2 Achieves superior IOP reduction vs. latanoprost-- the 2 world’s most prescribed glaucoma treatment Effective, regardless of
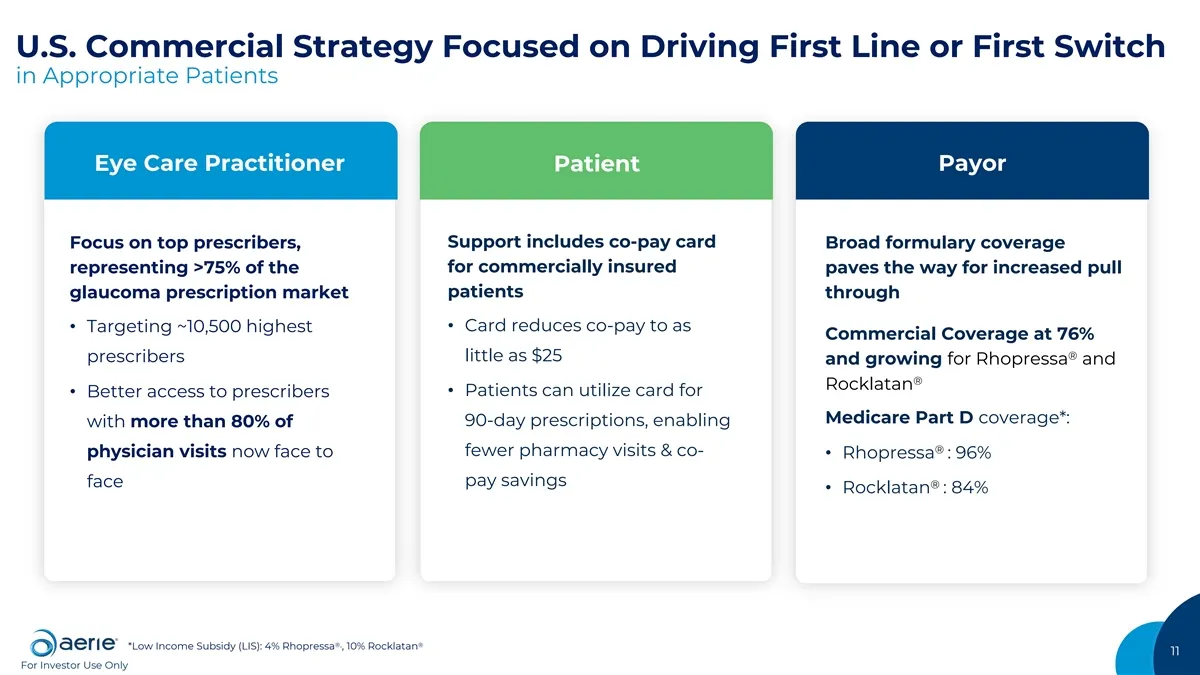
Slide 11: U.S. Commercial Strategy Focused on Driving First Line or First Switch
U.S. Commercial Strategy Focused on Driving First Line or First Switch in Appropriate Patients Eye Care Practitioner Patient Payor Support includes co-pay card Focus on top prescribers, Broad formulary coverage for commercially insured representing >75% of the paves the way for increased pull patien
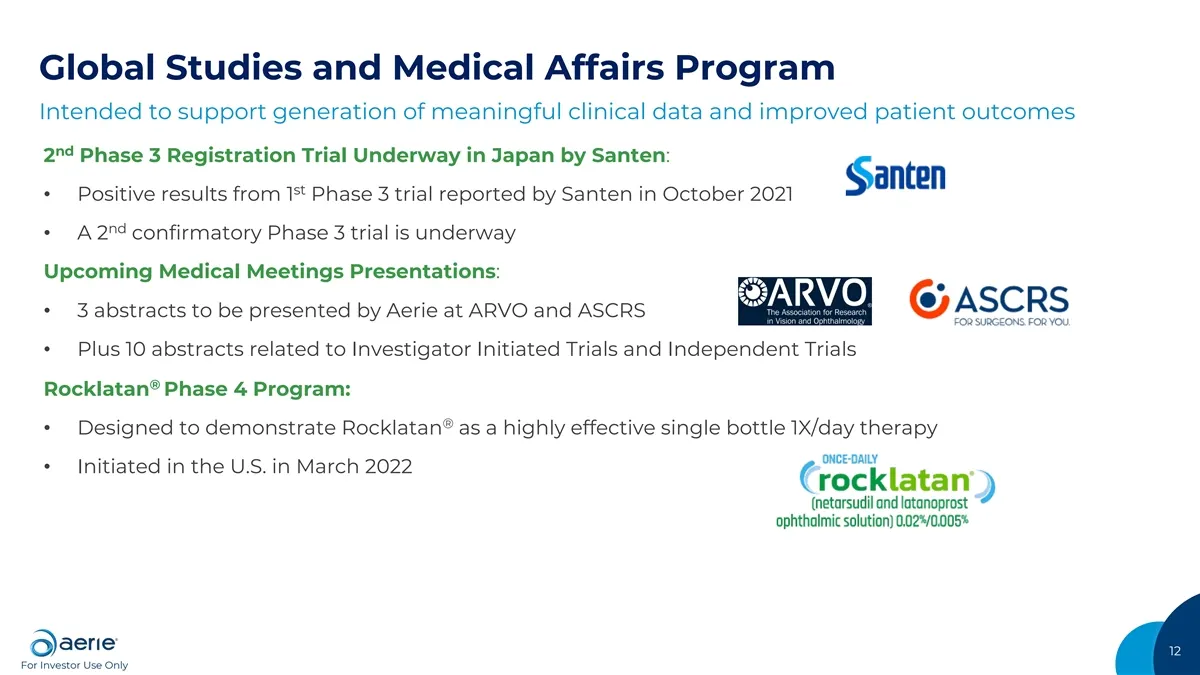
Slide 12: Global Studies and Medical Affairs Program
Global Studies and Medical Affairs Program Intended to support generation of meaningful clinical data and improved patient outcomes nd 2 Phase 3 Registration Trial Underway in Japan by Santen: st • Positive results from 1 Phase 3 trial reported by Santen in October 2021 nd • A 2 confirmatory Phase 3
Slide 13: Dry Eye: ~$1.6B U.S. Market
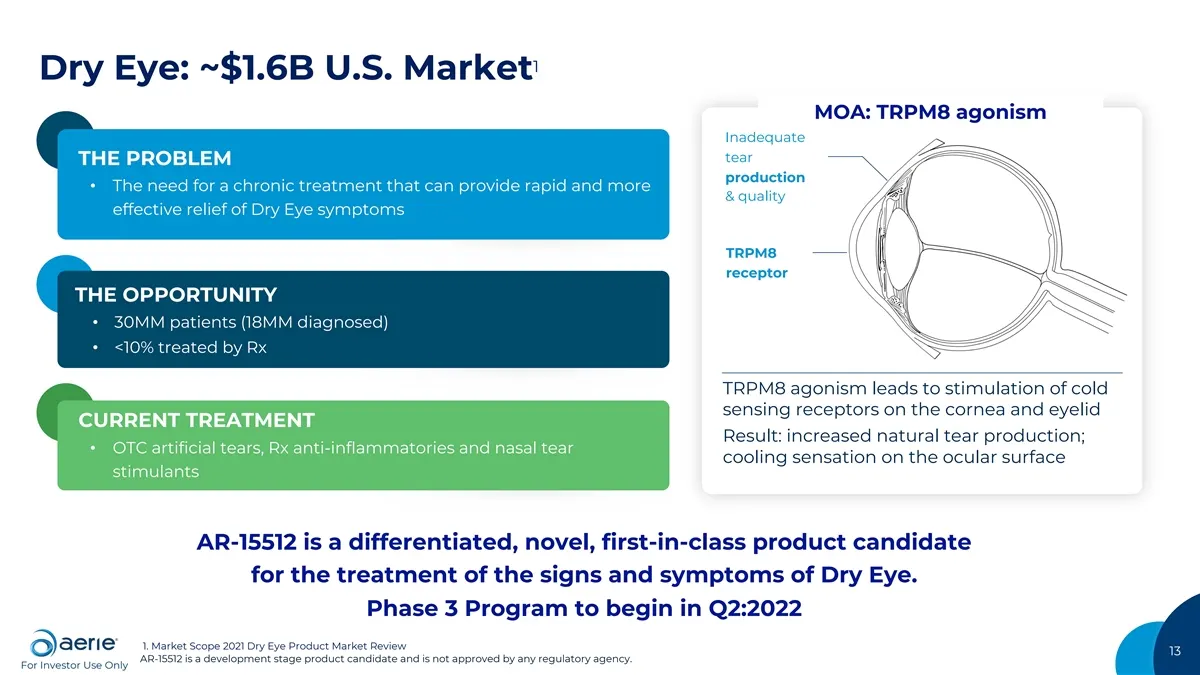
1 Dry Eye: ~$1.6B U.S. Market MOA: TRPM8 agonism Inadequate tear THE PROBLEM production • The need for a chronic treatment that can provide rapid and more & quality effective relief of Dry Eye symptoms TRPM8 receptor THE OPPORTUNITY • 30MM patients (18MM diagnosed) • <10% treated by Rx TRPM8 agonism
Slide 14: Phase 2b Sign: AR-15512 increase in tear production
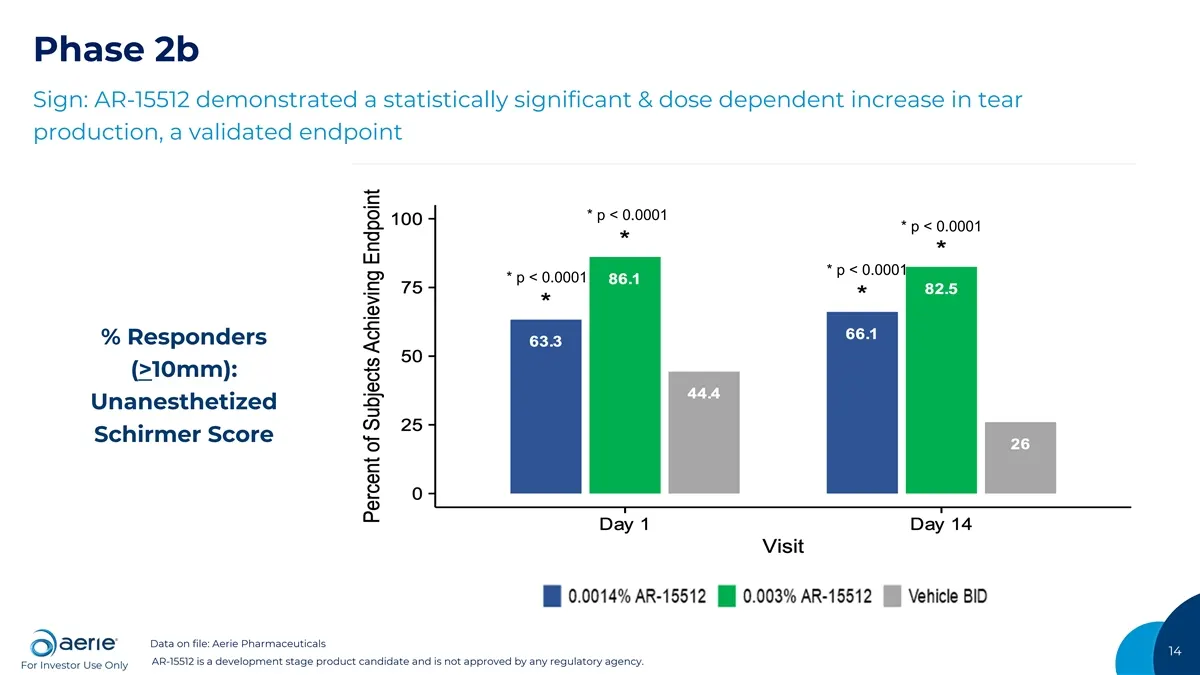
Phase 2b Sign: AR-15512 demonstrated a statistically significant & dose dependent increase in tear production, a validated endpoint * p < 0.0001 * p < 0.0001 * p < 0.0001 * p < 0.0001 % Responders (>10mm): Unanesthetized Schirmer Score Data on file: Aerie Pharmaceuticals 14 AR-15512 is a development
Slide 15: Phase 2b Symptoms: AR-15512 improvement at Day 14
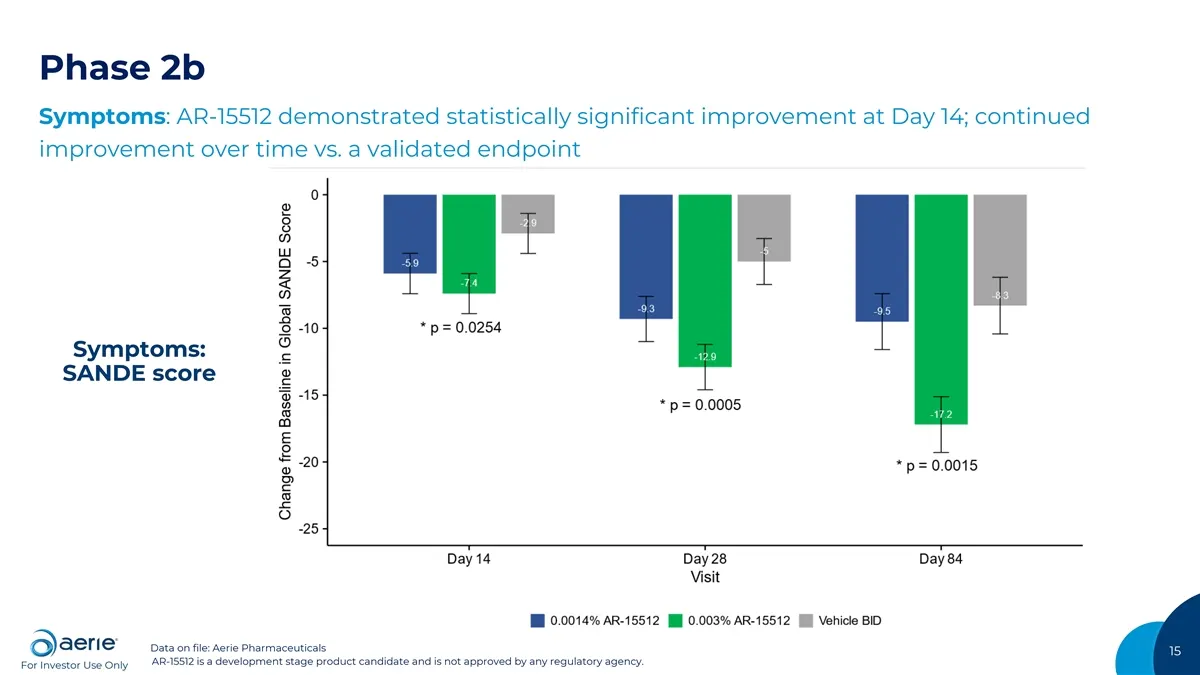
Phase 2b Symptoms: AR-15512 demonstrated statistically significant improvement at Day 14; continued improvement over time vs. a validated endpoint Symptoms: SANDE score Data on file: Aerie Pharmaceuticals 15 AR-15512 is a development stage product candidate and is not approved by any regulatory agen
Slide 16: Totality of AR-15512 Phase 2b Data Support Next Steps
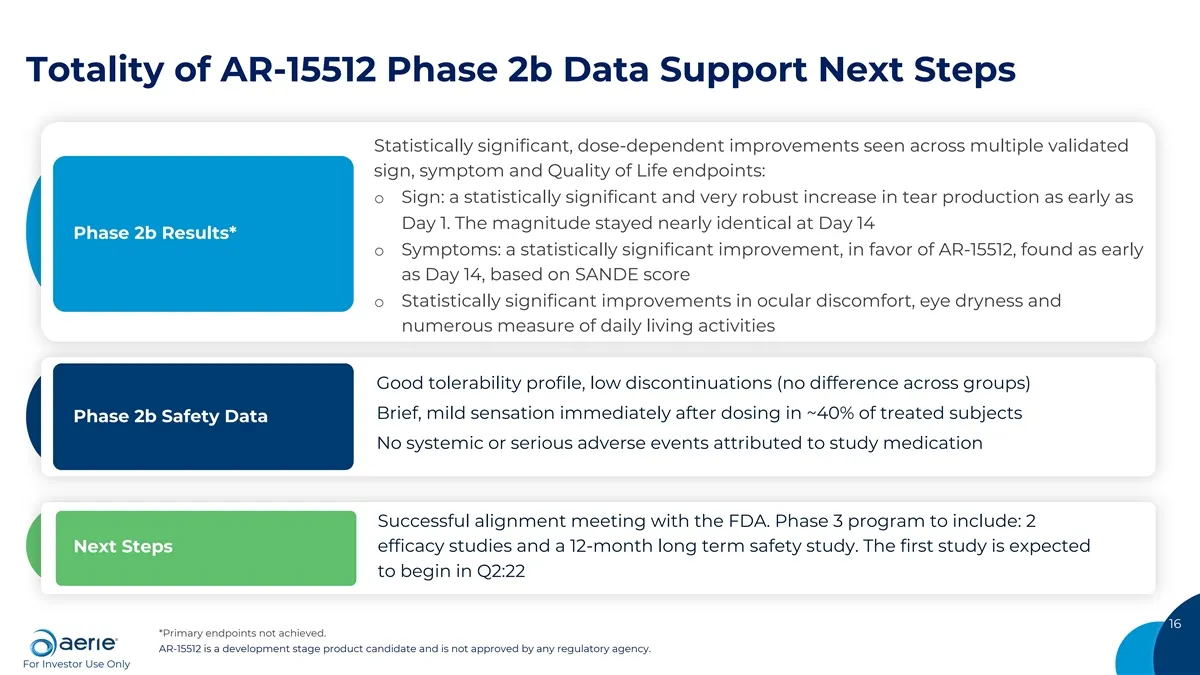
Totality of AR-15512 Phase 2b Data Support Next Steps Statistically significant, dose-dependent improvements seen across multiple validated sign, symptom and Quality of Life endpoints: o Sign: a statistically significant and very robust increase in tear production as early as Day 1. The magnitude st
Slide 17: DME: ~$2B U.S. Market
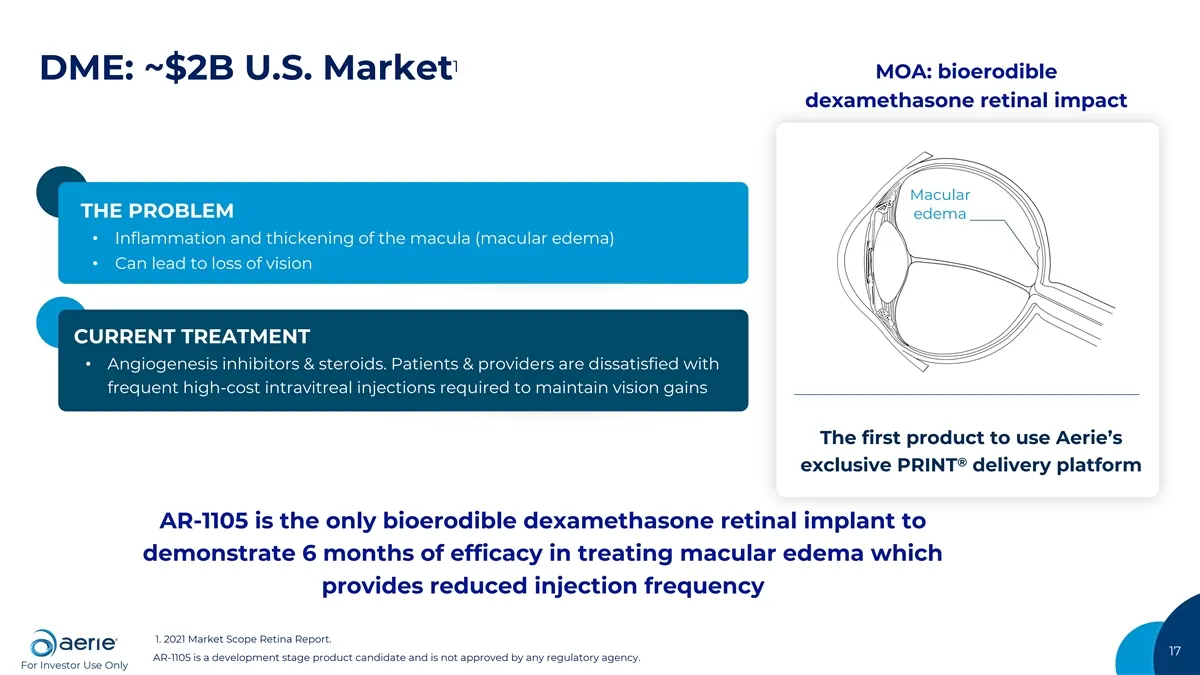
1 MOA: bioerodible DME: ~$2B U.S. Market dexamethasone retinal impact Macular THE PROBLEM edema • Inflammation and thickening of the macula (macular edema) • Can lead to loss of vision CURRENT TREATMENT • Angiogenesis inhibitors & steroids. Patients & providers are dissatisfied with frequent high-co
Slide 18: AR-1105 demonstrated at least 6 months of efficacy
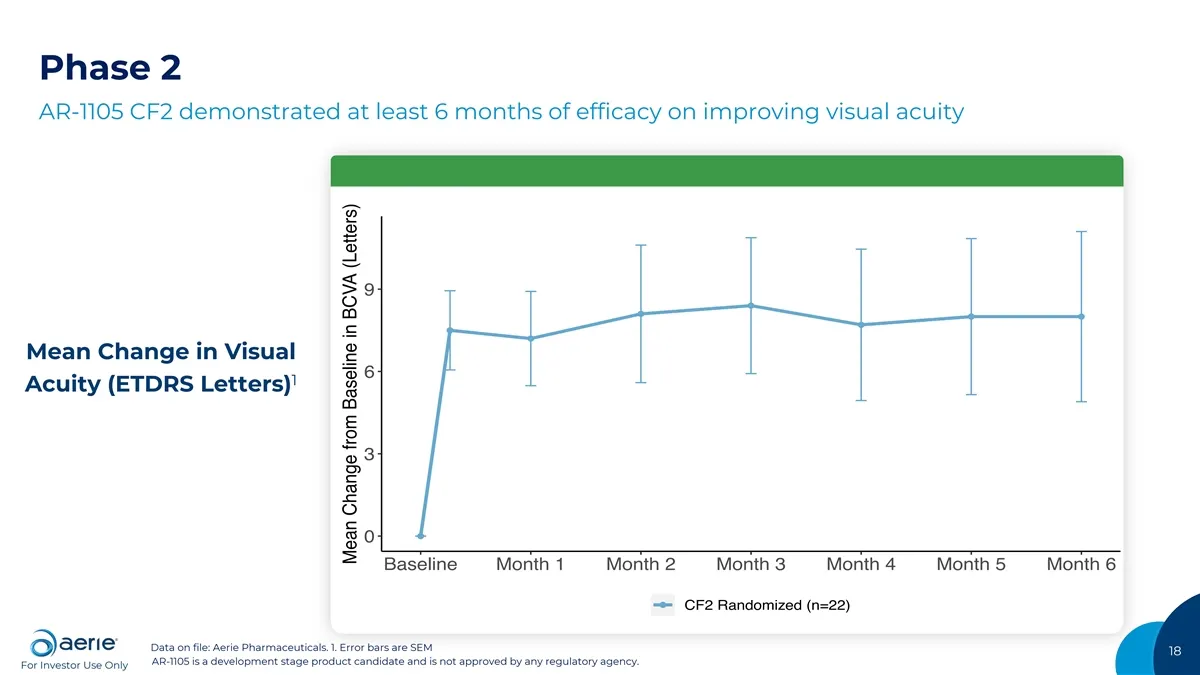
Phase 2 AR-1105 CF2 demonstrated at least 6 months of efficacy on improving visual acuity 9 Mean Change in Visual 6 1 Acuity (ETDRS Letters) 3 0 Baseline Month 1 Month 2 Month 3 Month 4 Month 5 Month 6 CF2 Randomized (n=22) Data on file: Aerie Pharmaceuticals. 1. Error bars are SEM 18 AR-1105 is a d
Slide 19: AR-1105 Phase 2 Proof-of-Concept Data Support Next Steps
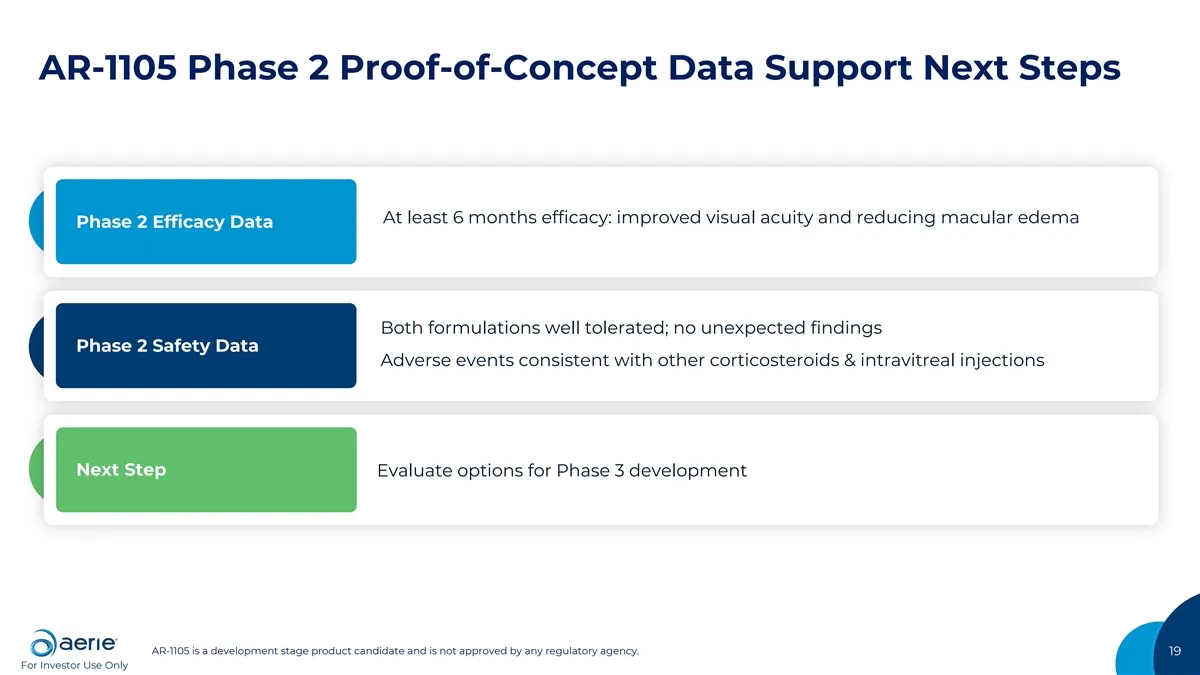
AR-1105 Phase 2 Proof-of-Concept Data Support Next Steps At least 6 months efficacy: improved visual acuity and reducing macular edema Phase 2 Efficacy Data Both formulations well tolerated; no unexpected findings Phase 2 Safety Data Adverse events consistent with other corticosteroids & intravitrea
Slide 20: Wet AMD: ~$4B U.S. Market
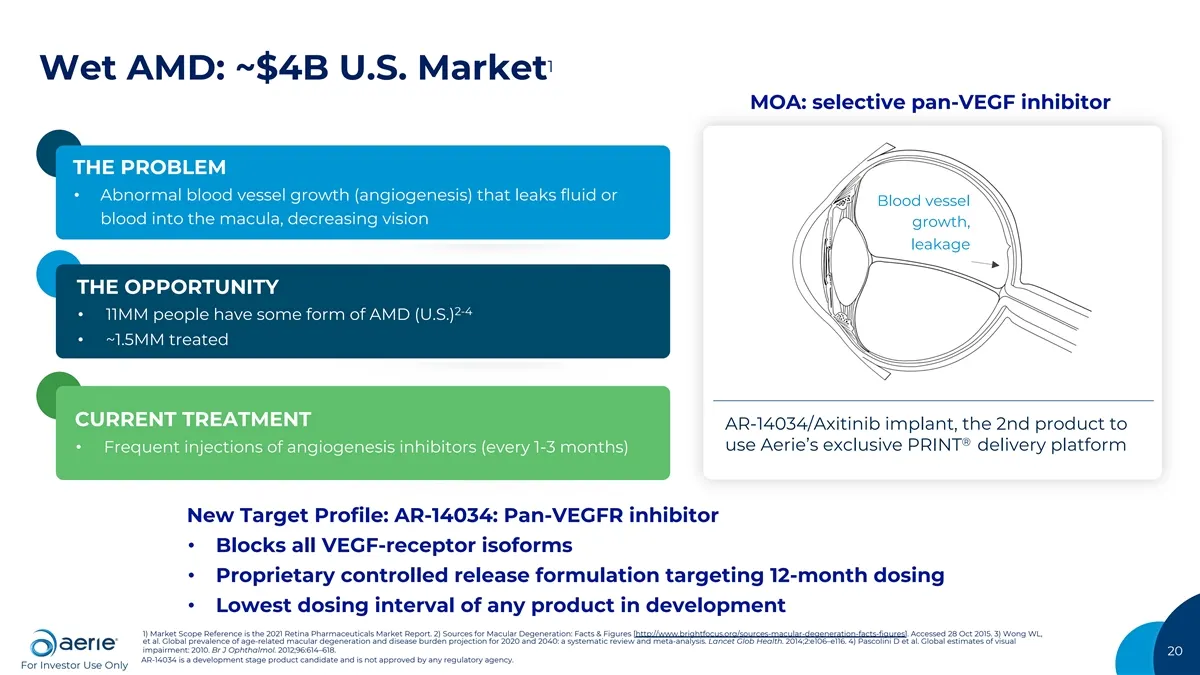
1 Wet AMD: ~$4B U.S. Market MOA: selective pan-VEGF inhibitor THE PROBLEM • Abnormal blood vessel growth (angiogenesis) that leaks fluid or Blood vessel blood into the macula, decreasing vision growth, leakage THE OPPORTUNITY 2-4 • 11MM people have some form of AMD (U.S.) • ~1.5MM treated CURRENT TR
Slide 21: Positive AR-14034 Preclinical Data Support Planned IND Filing
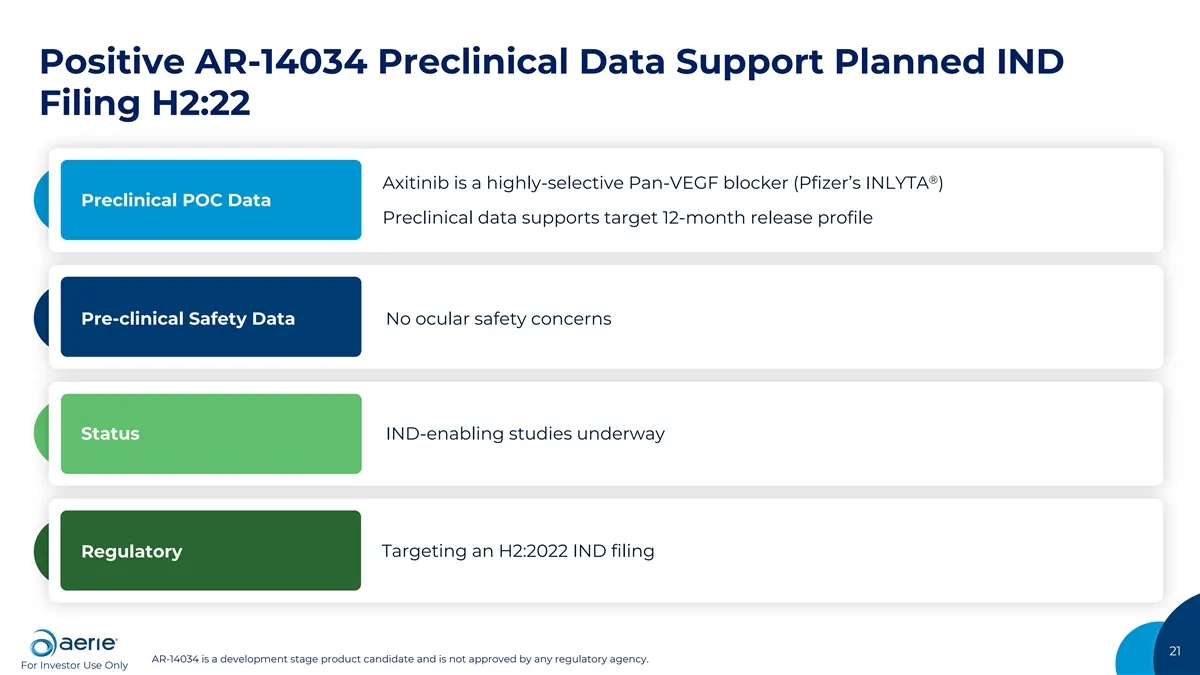
Positive AR-14034 Preclinical Data Support Planned IND Filing H2:22 ® Axitinib is a highly-selective Pan-VEGF blocker (Pfizer’s INLYTA ) Preclinical POC Data Preclinical data supports target 12-month release profile Pre-clinical Safety Data No ocular safety concerns Status IND-enabling studies under
Slide 22: Partnership Opportunities
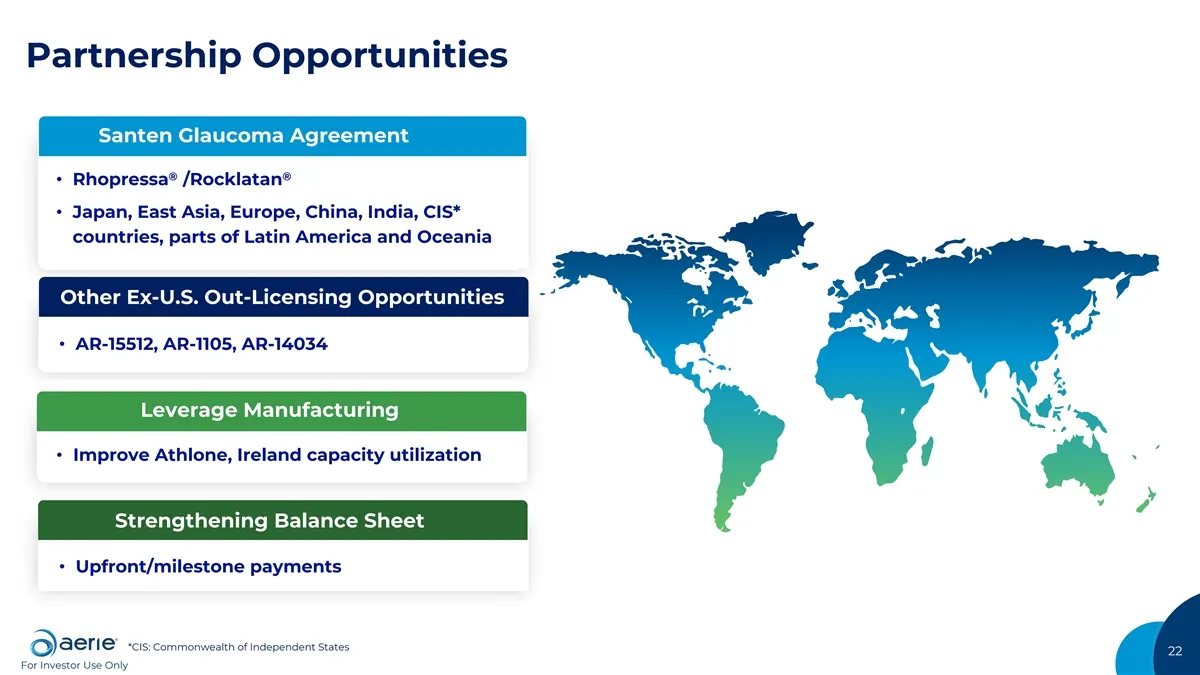
Partnership Opportunities Santen Glaucoma Agreement ® ® • Rhopressa /Rocklatan • Japan, East Asia, Europe, China, India, CIS* countries, parts of Latin America and Oceania Other Ex-U.S. Out-Licensing Opportunities • AR-15512, AR-1105, AR-14034 Leverage Manufacturing • Improve Athlone, Ireland capaci
Slide 23: Key 2022 Milestones
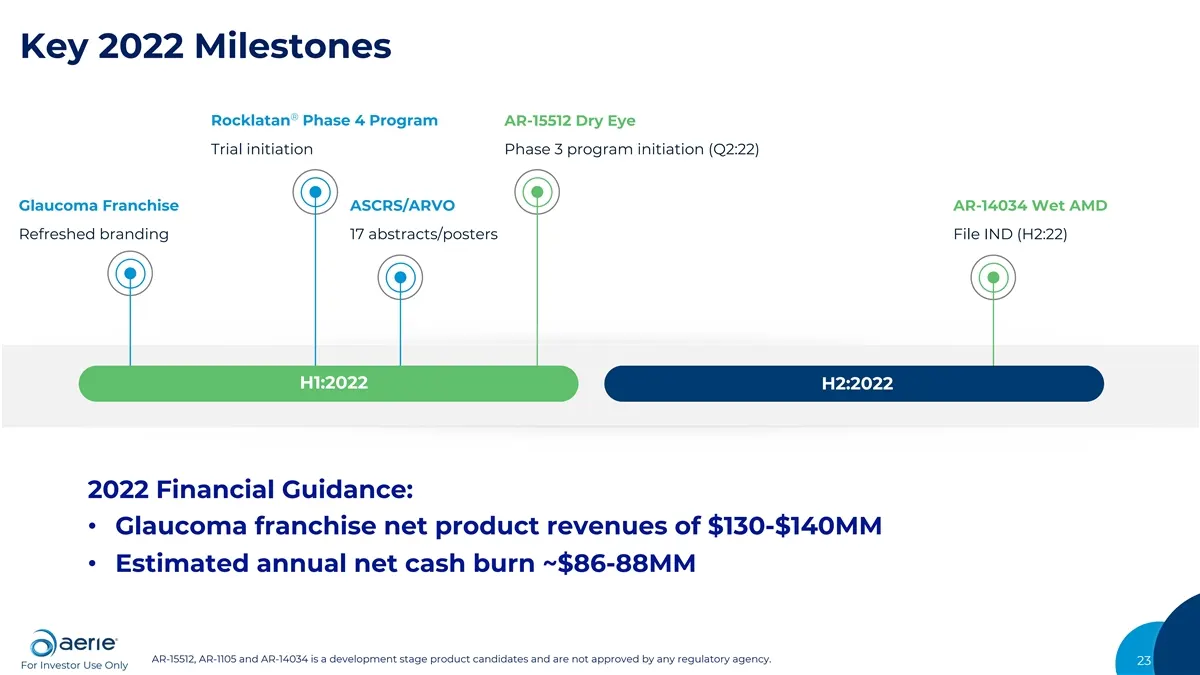
Key 2022 Milestones ® Rocklatan Phase 4 Program AR-15512 Dry Eye Trial initiation Phase 3 program initiation (Q2:22) Glaucoma Franchise ASCRS/ARVO AR-14034 Wet AMD Refreshed branding 17 abstracts/posters File IND (H2:22) H1:2022 H2:2022 2022 Financial Guidance: • Glaucoma franchise net product reven
Slide 24: Aerie 2.0: Strategic pillars for long-term success
Aerie 2.0: Strategic pillars for long-term success Growing Strong Financial Robust Pipeline Commercial Position Business Reducing our annual cash burn Driving sustainable growth of Making smart choices with rate in maintaining a solid the commercial business capital in advancing our pipeline financi
Slide 25: An Emerging Leader in Ophthalmology
An Emerging Leader in Ophthalmology Carolyn McAuliffe Hans Vitzthum ir@aeriepharma.com www.aeriepharma.com For Investor Use Only
Source: SEC EDGAR · 8-K filed Apr 11, 2022
More decks from Aerie Pharmaceuticals Inc.
 Investor Presentation (September 2022)30 slides · Sep 13, 2022
 Merger or Acquisition (August 2022)30 slides · Aug 23, 2022
 Investor Presentation (June 2022)30 slides · Jun 8, 2022
 Investor Presentation (May 2022)28 slides · May 25, 2022
 Investor Presentation (January 2022)33 slides · Jan 5, 2022
 OIS Glaucoma Innovation Summit 202116 slides · Oct 21, 2021