Duke Realty — Citi Global Property CEO Conference 2014
47 slides from Duke Realty's conference presentation, Mar 3, 2014
Slide 1: Citi Global Property CEO Conference
Exhibit 99.1 Citi Global Property CEO Conference March 3-5, 2014 RELIABLE. ANSWERS.
Slide 2: Contents
Contents Asset Strategy 4 Industrial Portfolio 9 Office Portfolio 17 Medical Office Portfolio 20 Development Capabilities 26 Operating Strategy 33 Capital Strategy 37 Why Duke Realty 42 RELIABLE. ANSWERS. © 2014 Duke Realty Corporation 2
Slide 3: Three-Pronged Strategy for Success
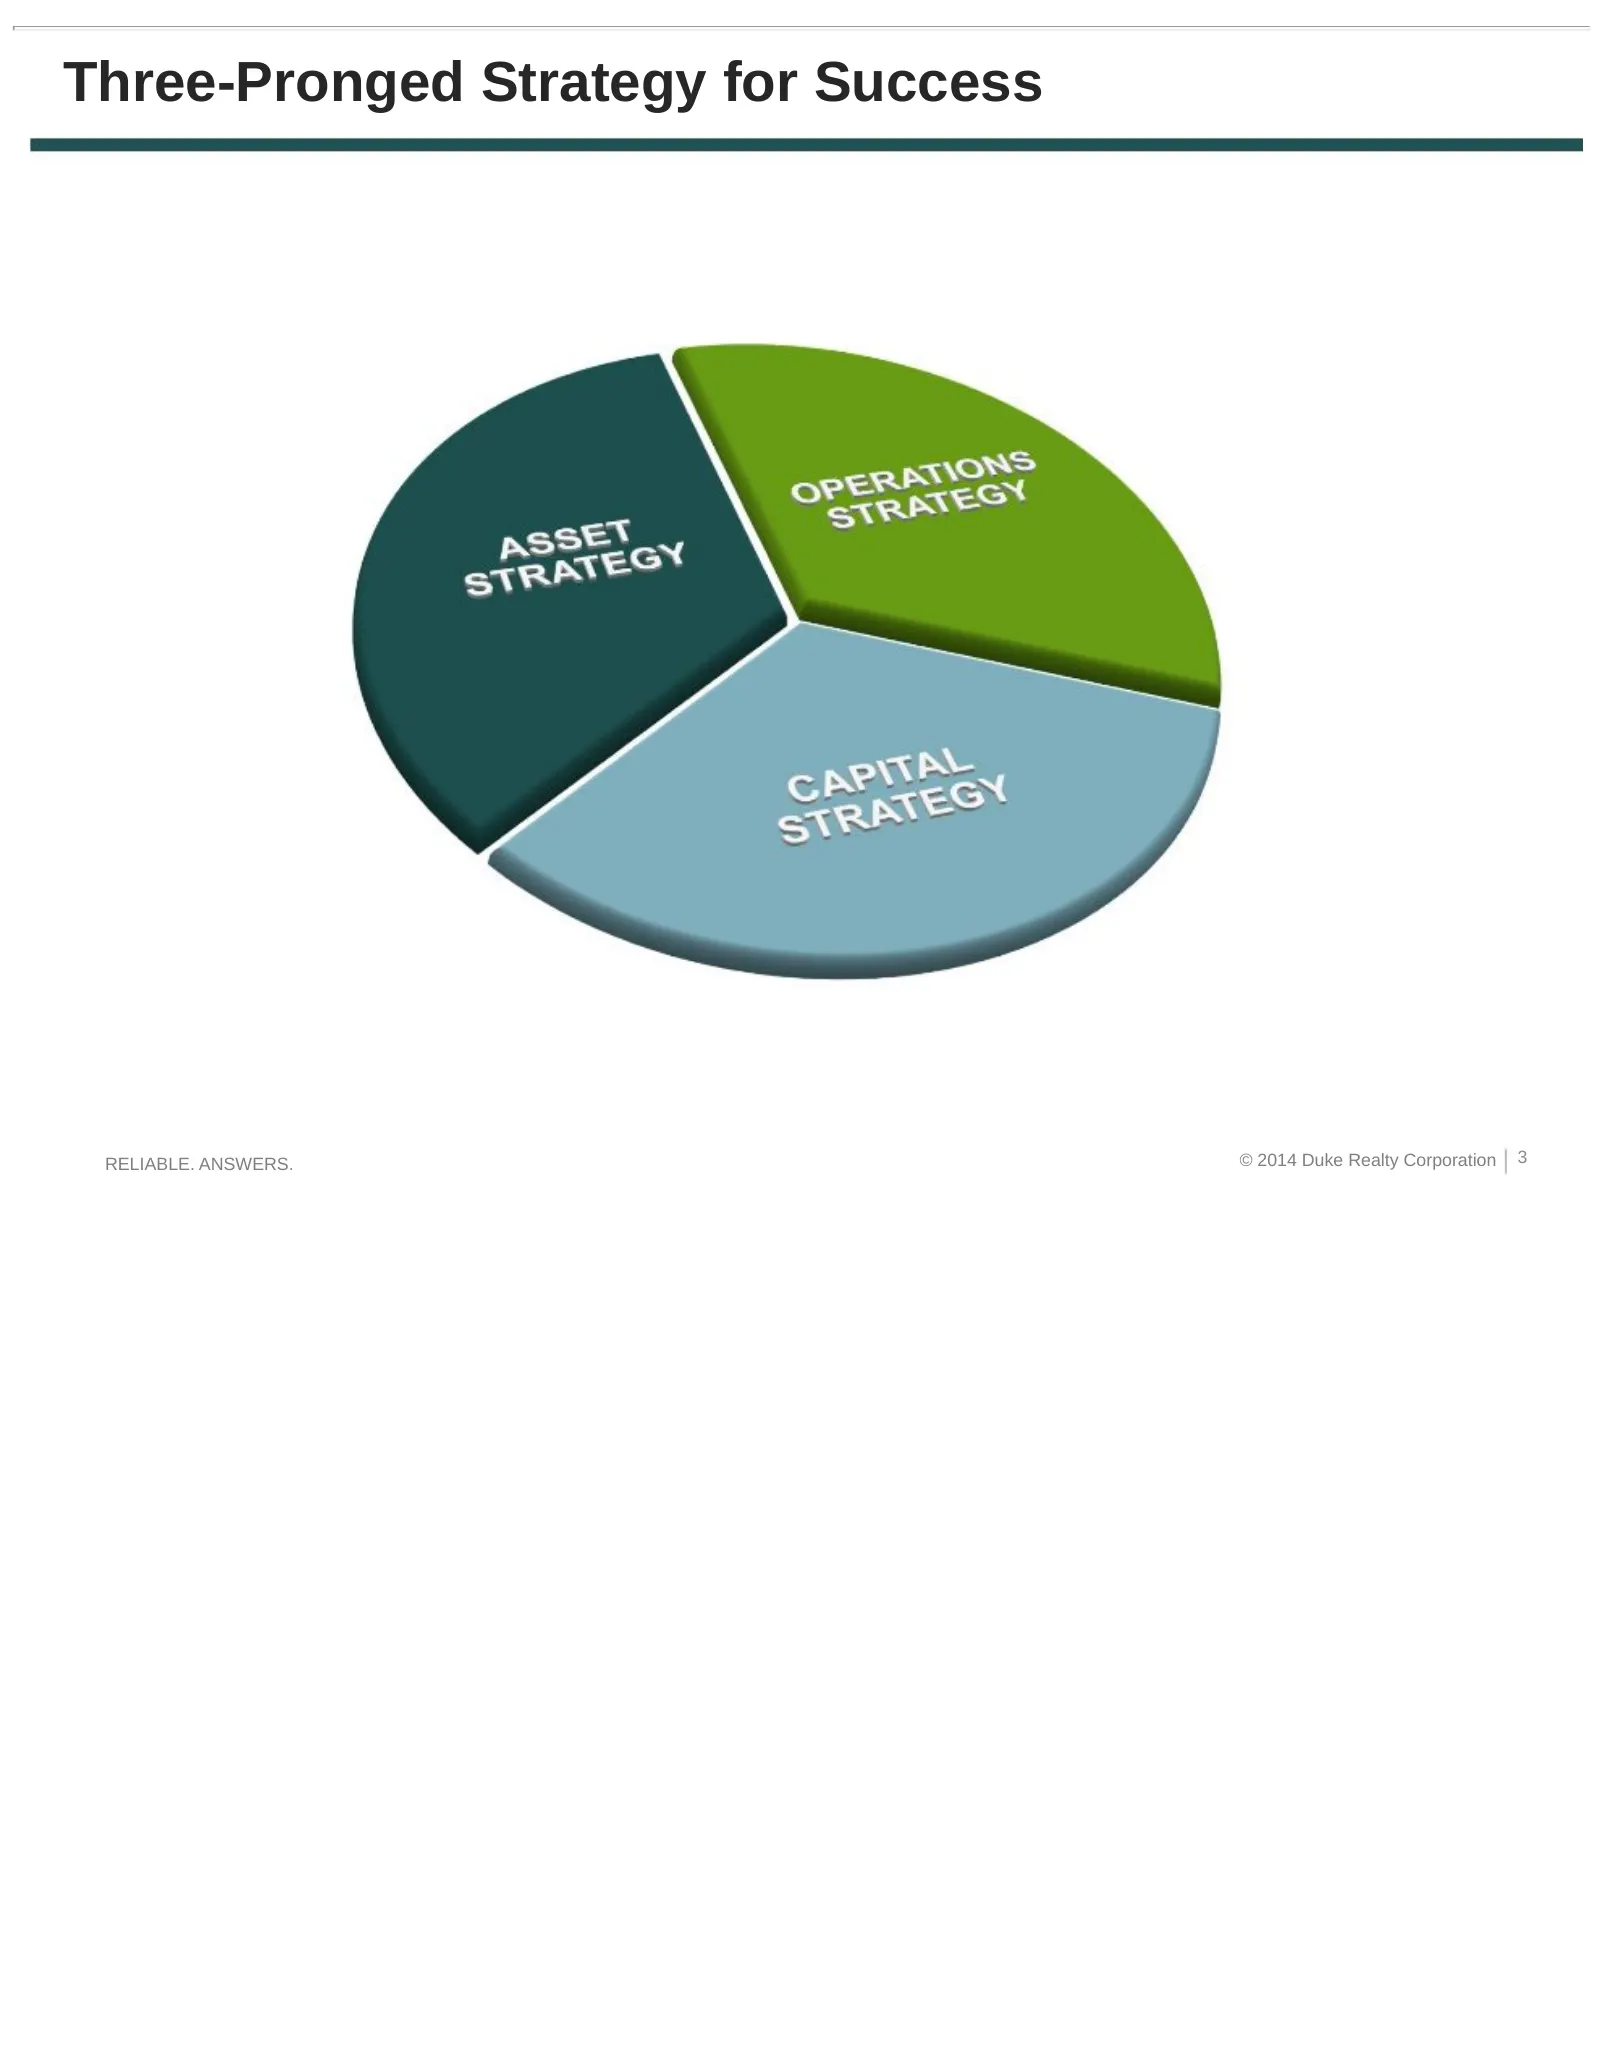
Three-Pronged Strategy for Success RELIABLE. ANSWERS. © 2014 Duke Realty Corporation 3
Slide 4: Asset Strategy
ASSET STRATEGY 4
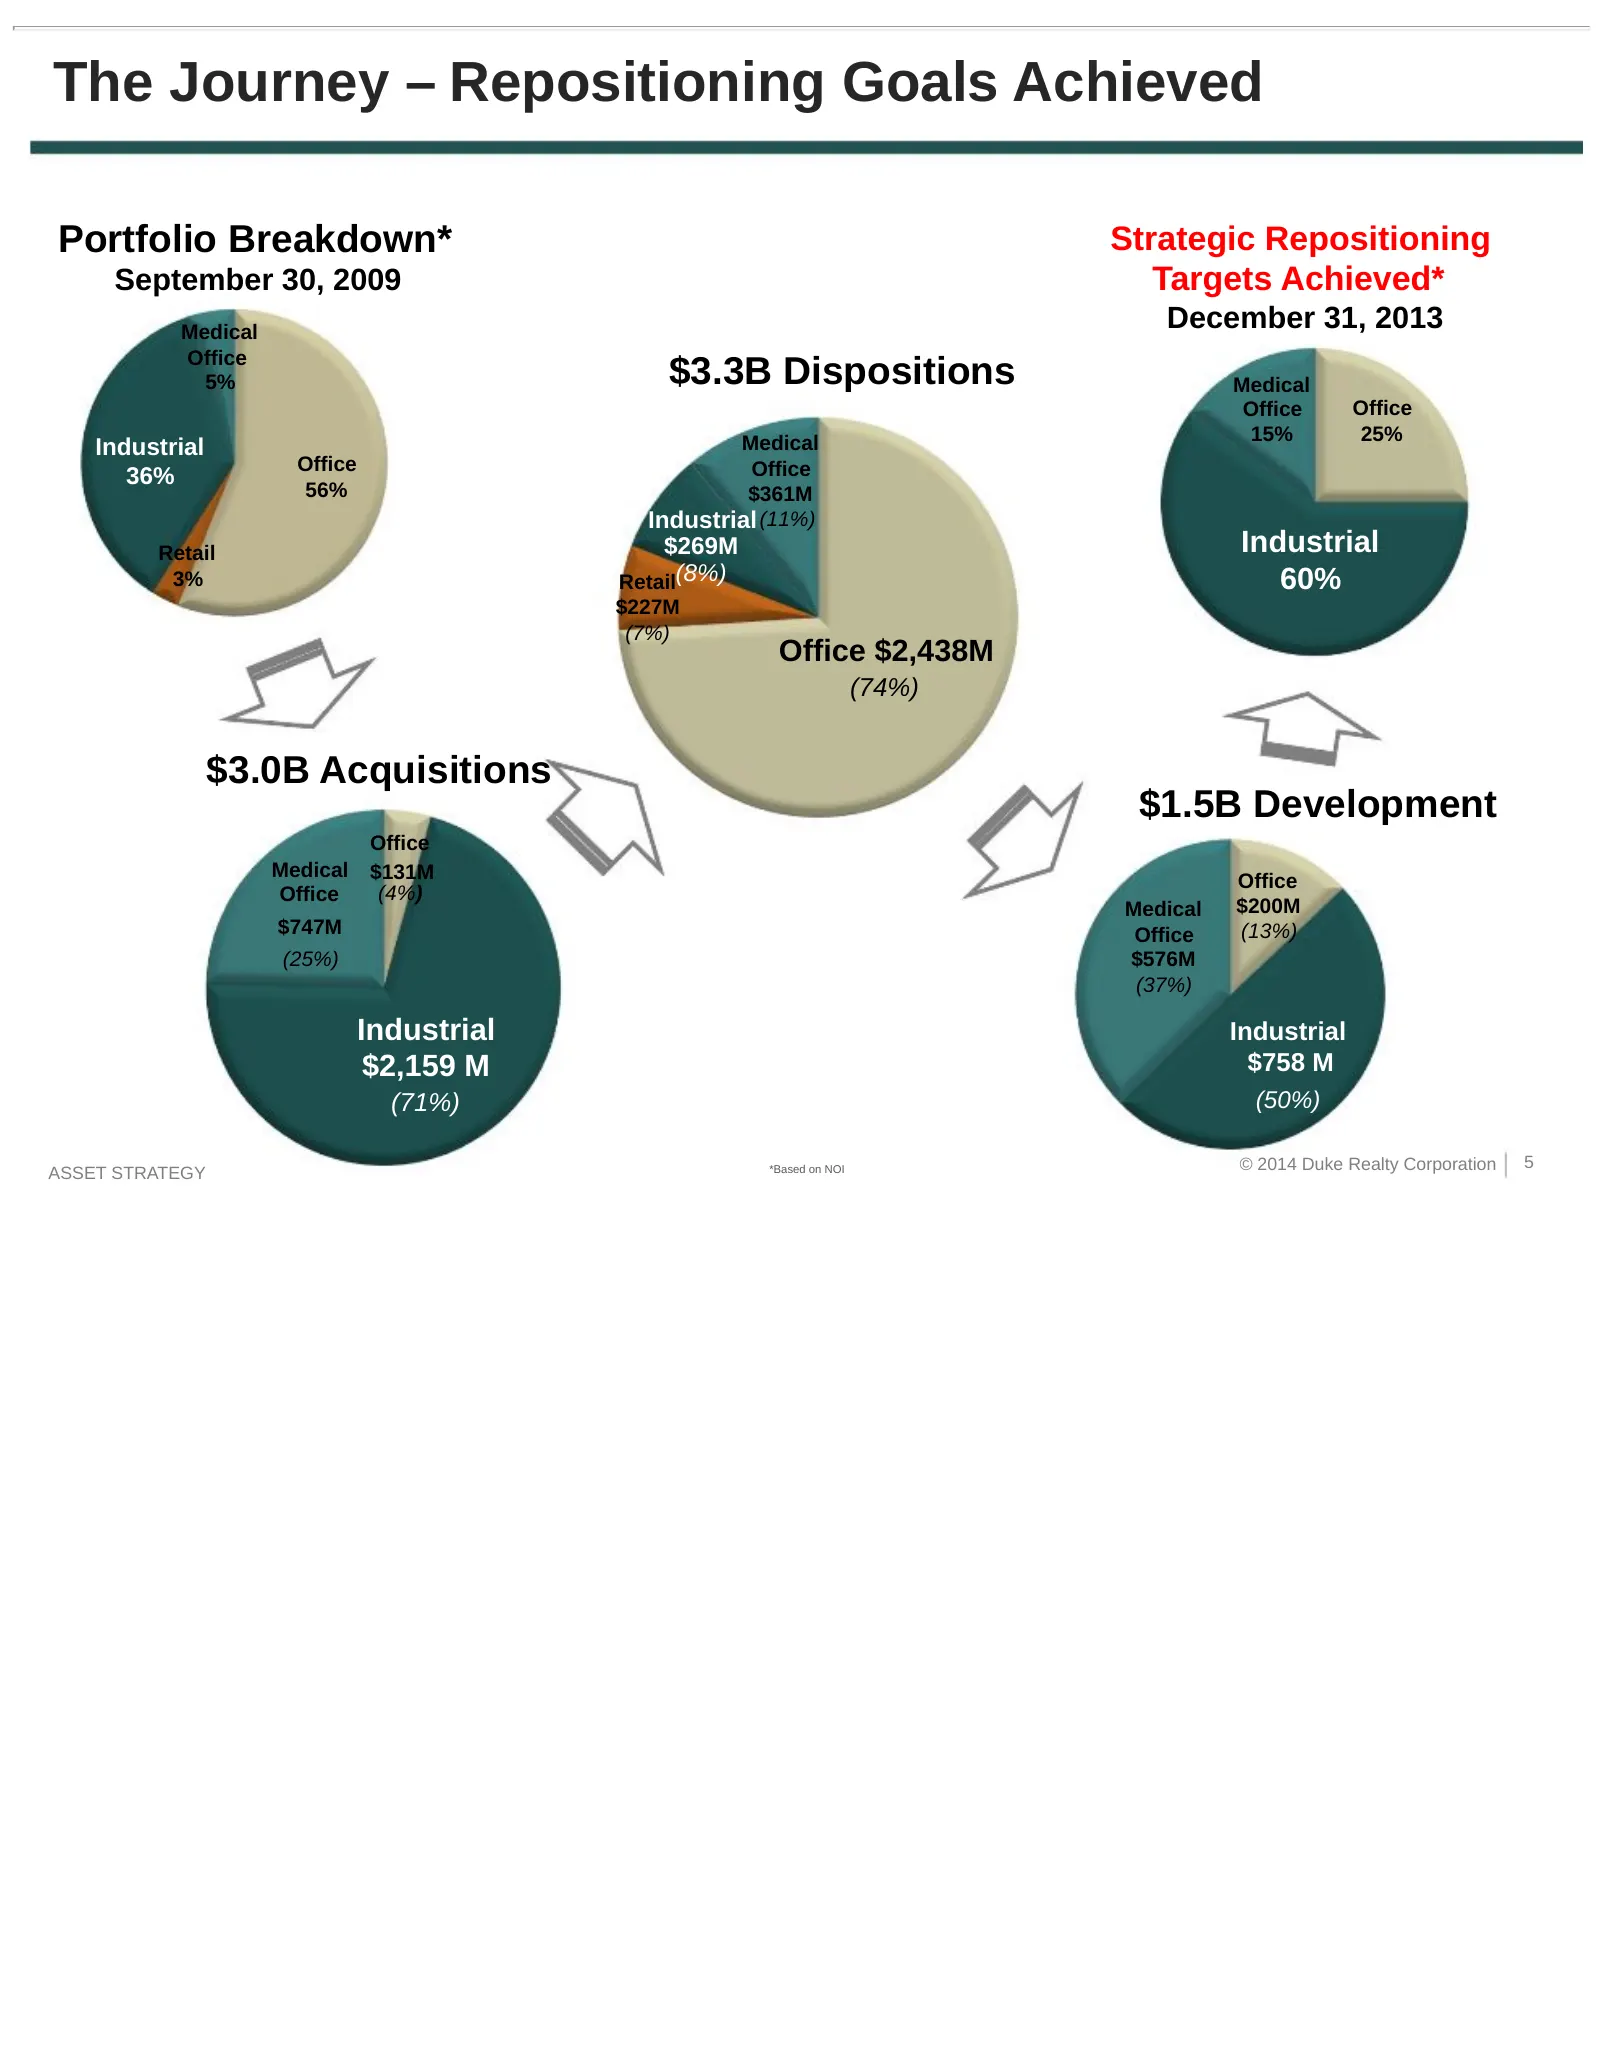
Slide 5: The Journey – Repositioning Goals Achieved
The Journey – Repositioning Goals Achieved Portfolio Breakdown* Strategic Repositioning September 30, 2009 Targets Achieved* Medical December 31, 2013 Office 5% $3.3B Dispositions Medical Office Office Medical 15% 25% Industrial Office Office 36% 56% $361M Industrial (11%) Retail $269M Industrial 3%
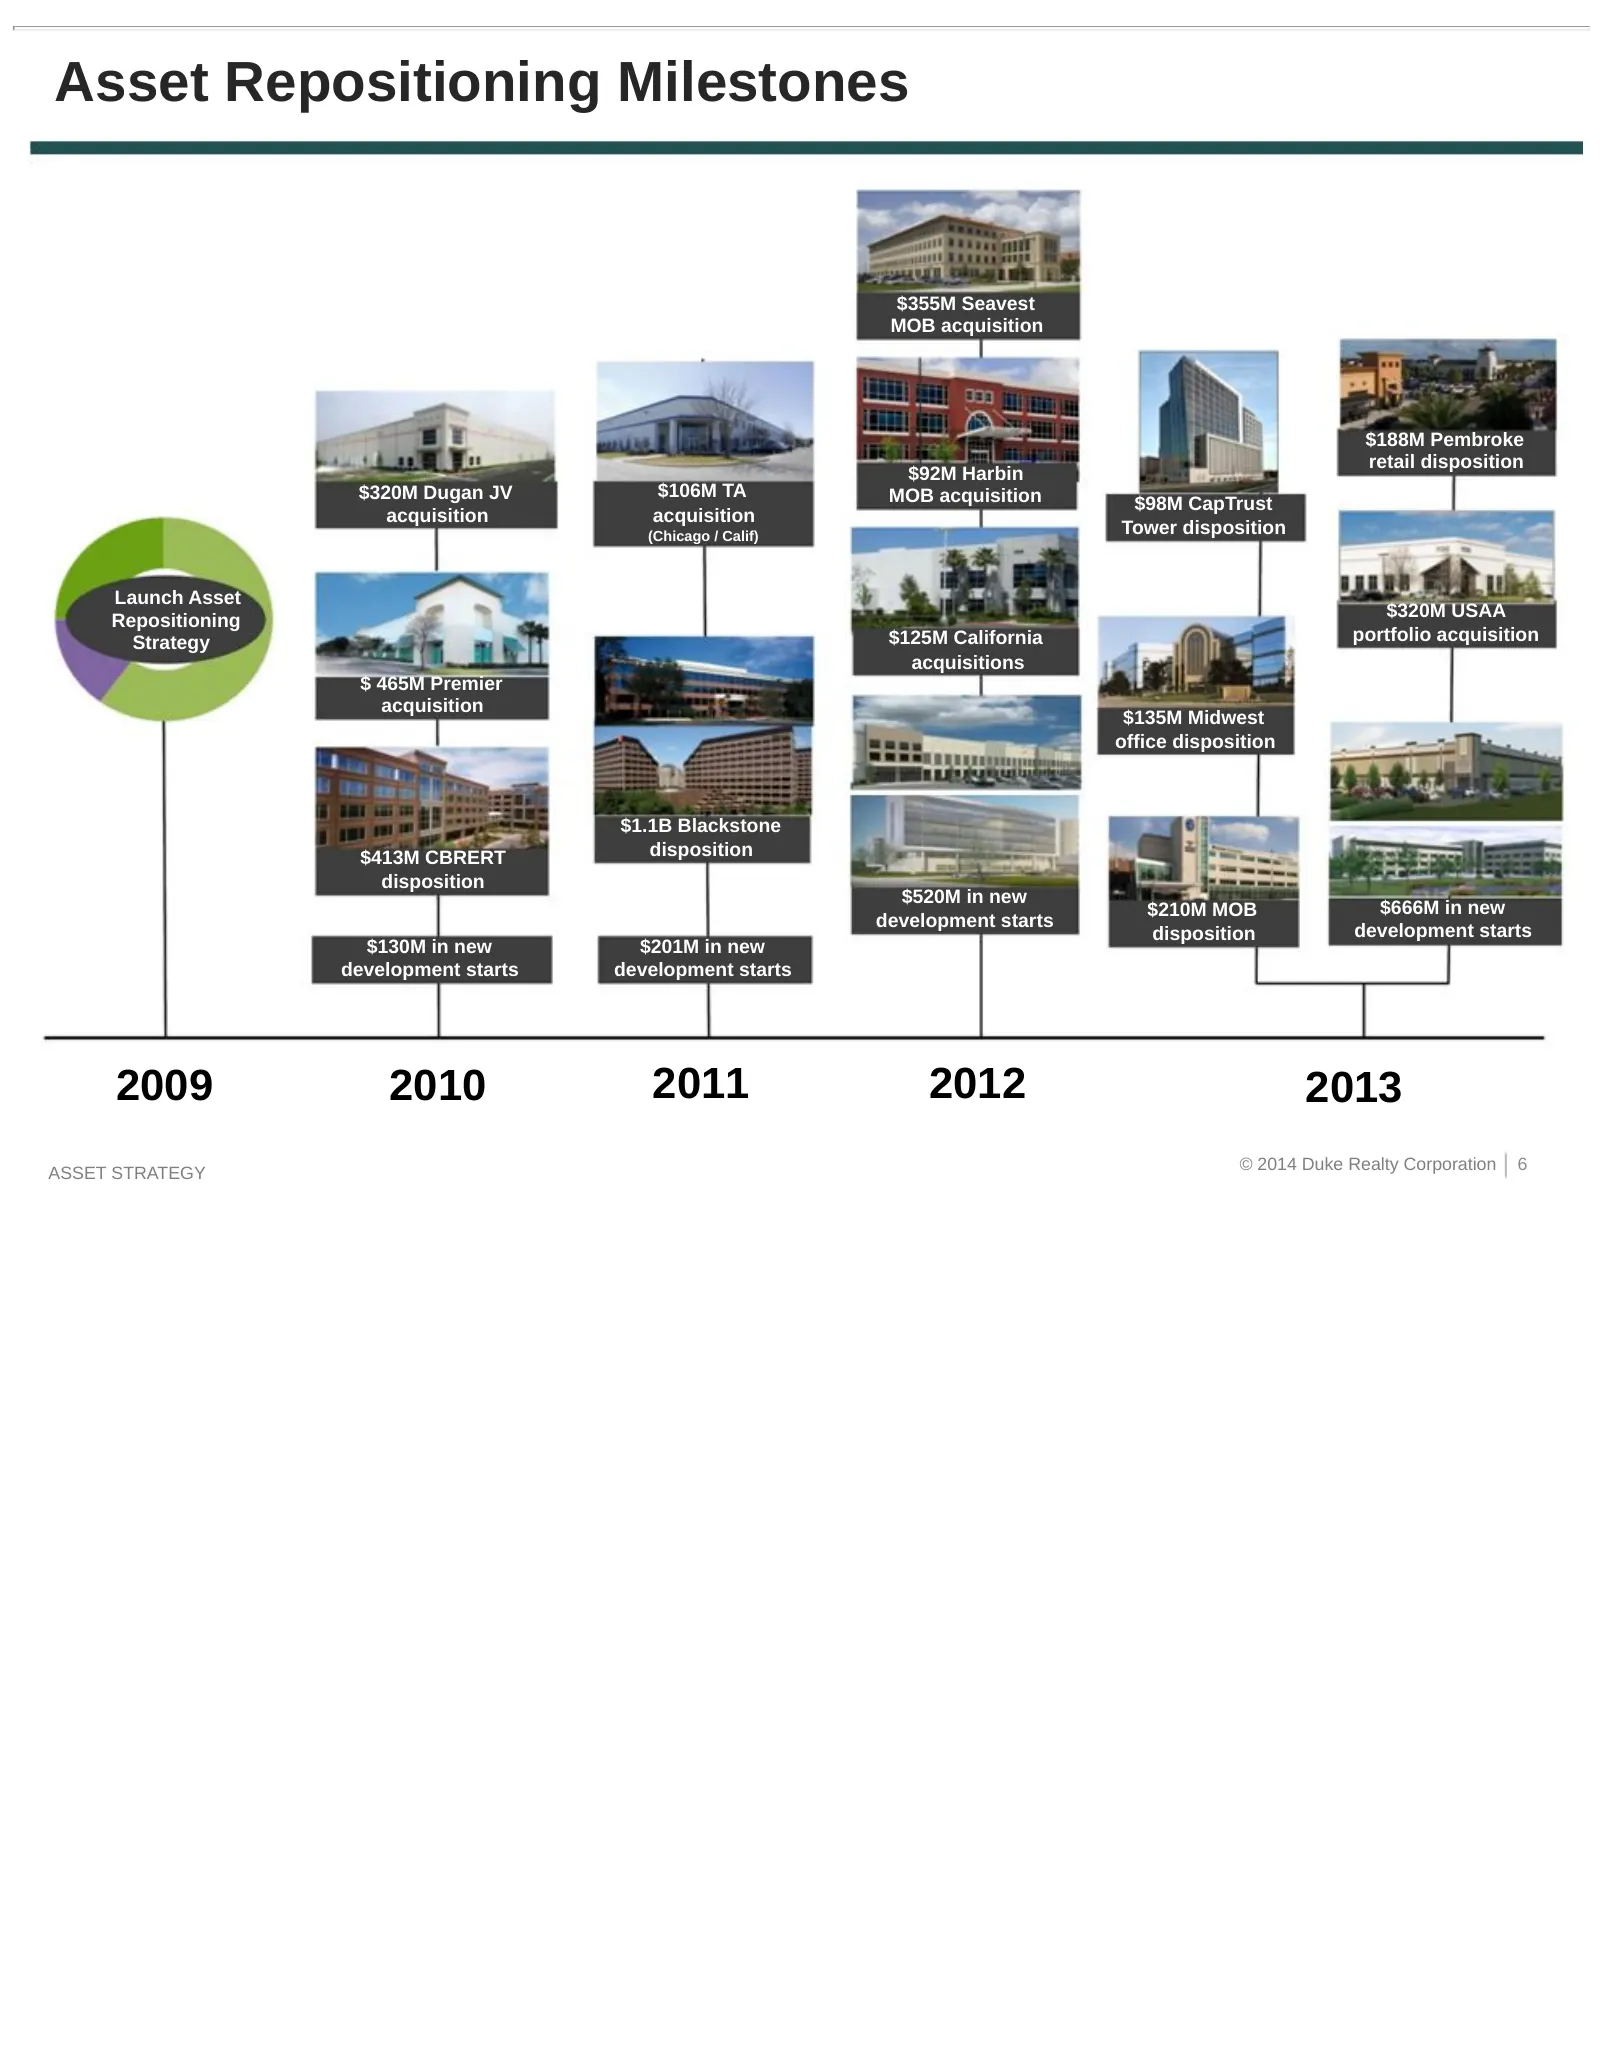
Slide 6: Asset Repositioning Milestones
Asset Repositioning Milestones $355M Seavest MOB acquisition $188M Pembroke retail disposition $92M Harbin $320M Dugan JV $106M TA MOB acquisition $98M CapTrust acquisition acquisition (Chicago / Calif) Tower disposition Launch Asset $320M USAA Repositioning Strategy $125M California portfolio acqui
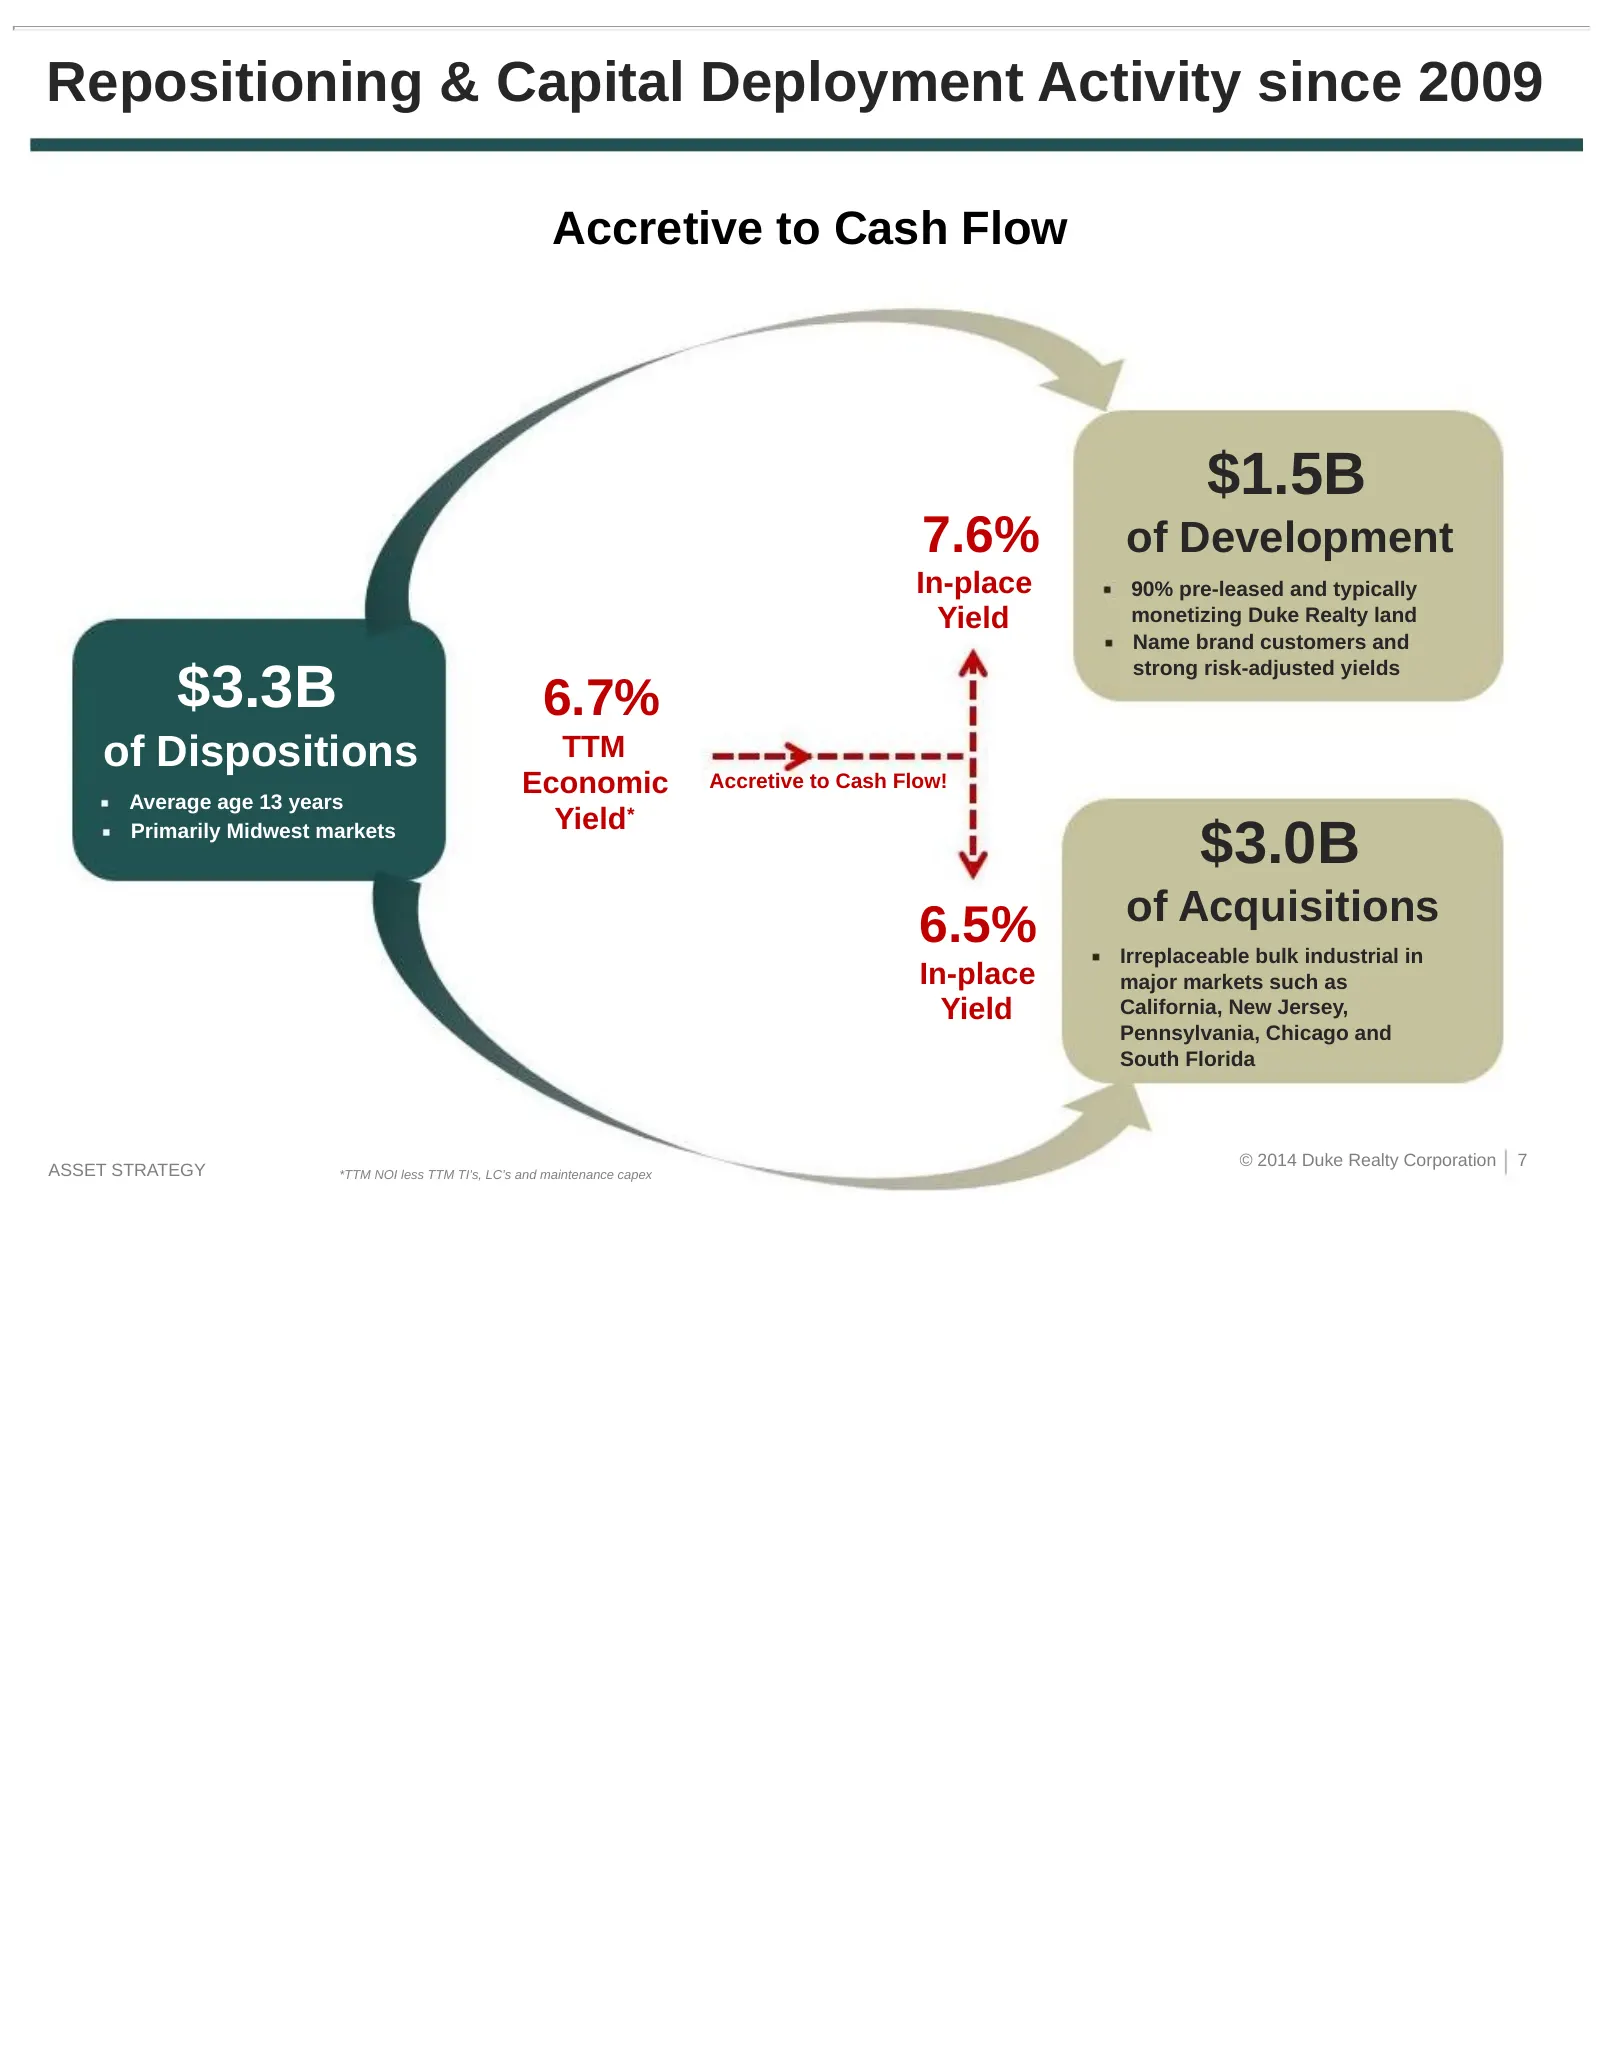
Slide 7: Repositioning & Capital Deployment Activity since 2009
Repositioning & Capital Deployment Activity since 2009 Accretive to Cash Flow $1.5B 7.6% of Development In-place 90% pre-leased and typically Yield monetizing Duke Realty land Name brand customers and $3.3B strong risk-adjusted yields 6.7% of Dispositions TTM Economic Accretive to Cash Flow! Average
Slide 8: Superior Asset Quality
Superior Asset Quality Highest quality portfolio of large, modern bulk industrial assets in key distribution markets Best in class MOB development platform and portfolio, with newest properties and highest hospital system credit Suburban office portfolio now less than 25%, with NOI growth opportunit
Slide 9: Asset Strategy: Industrial Portfolio
ASSET STRATEGY INDUSTRIAL PORTFOLIO 9
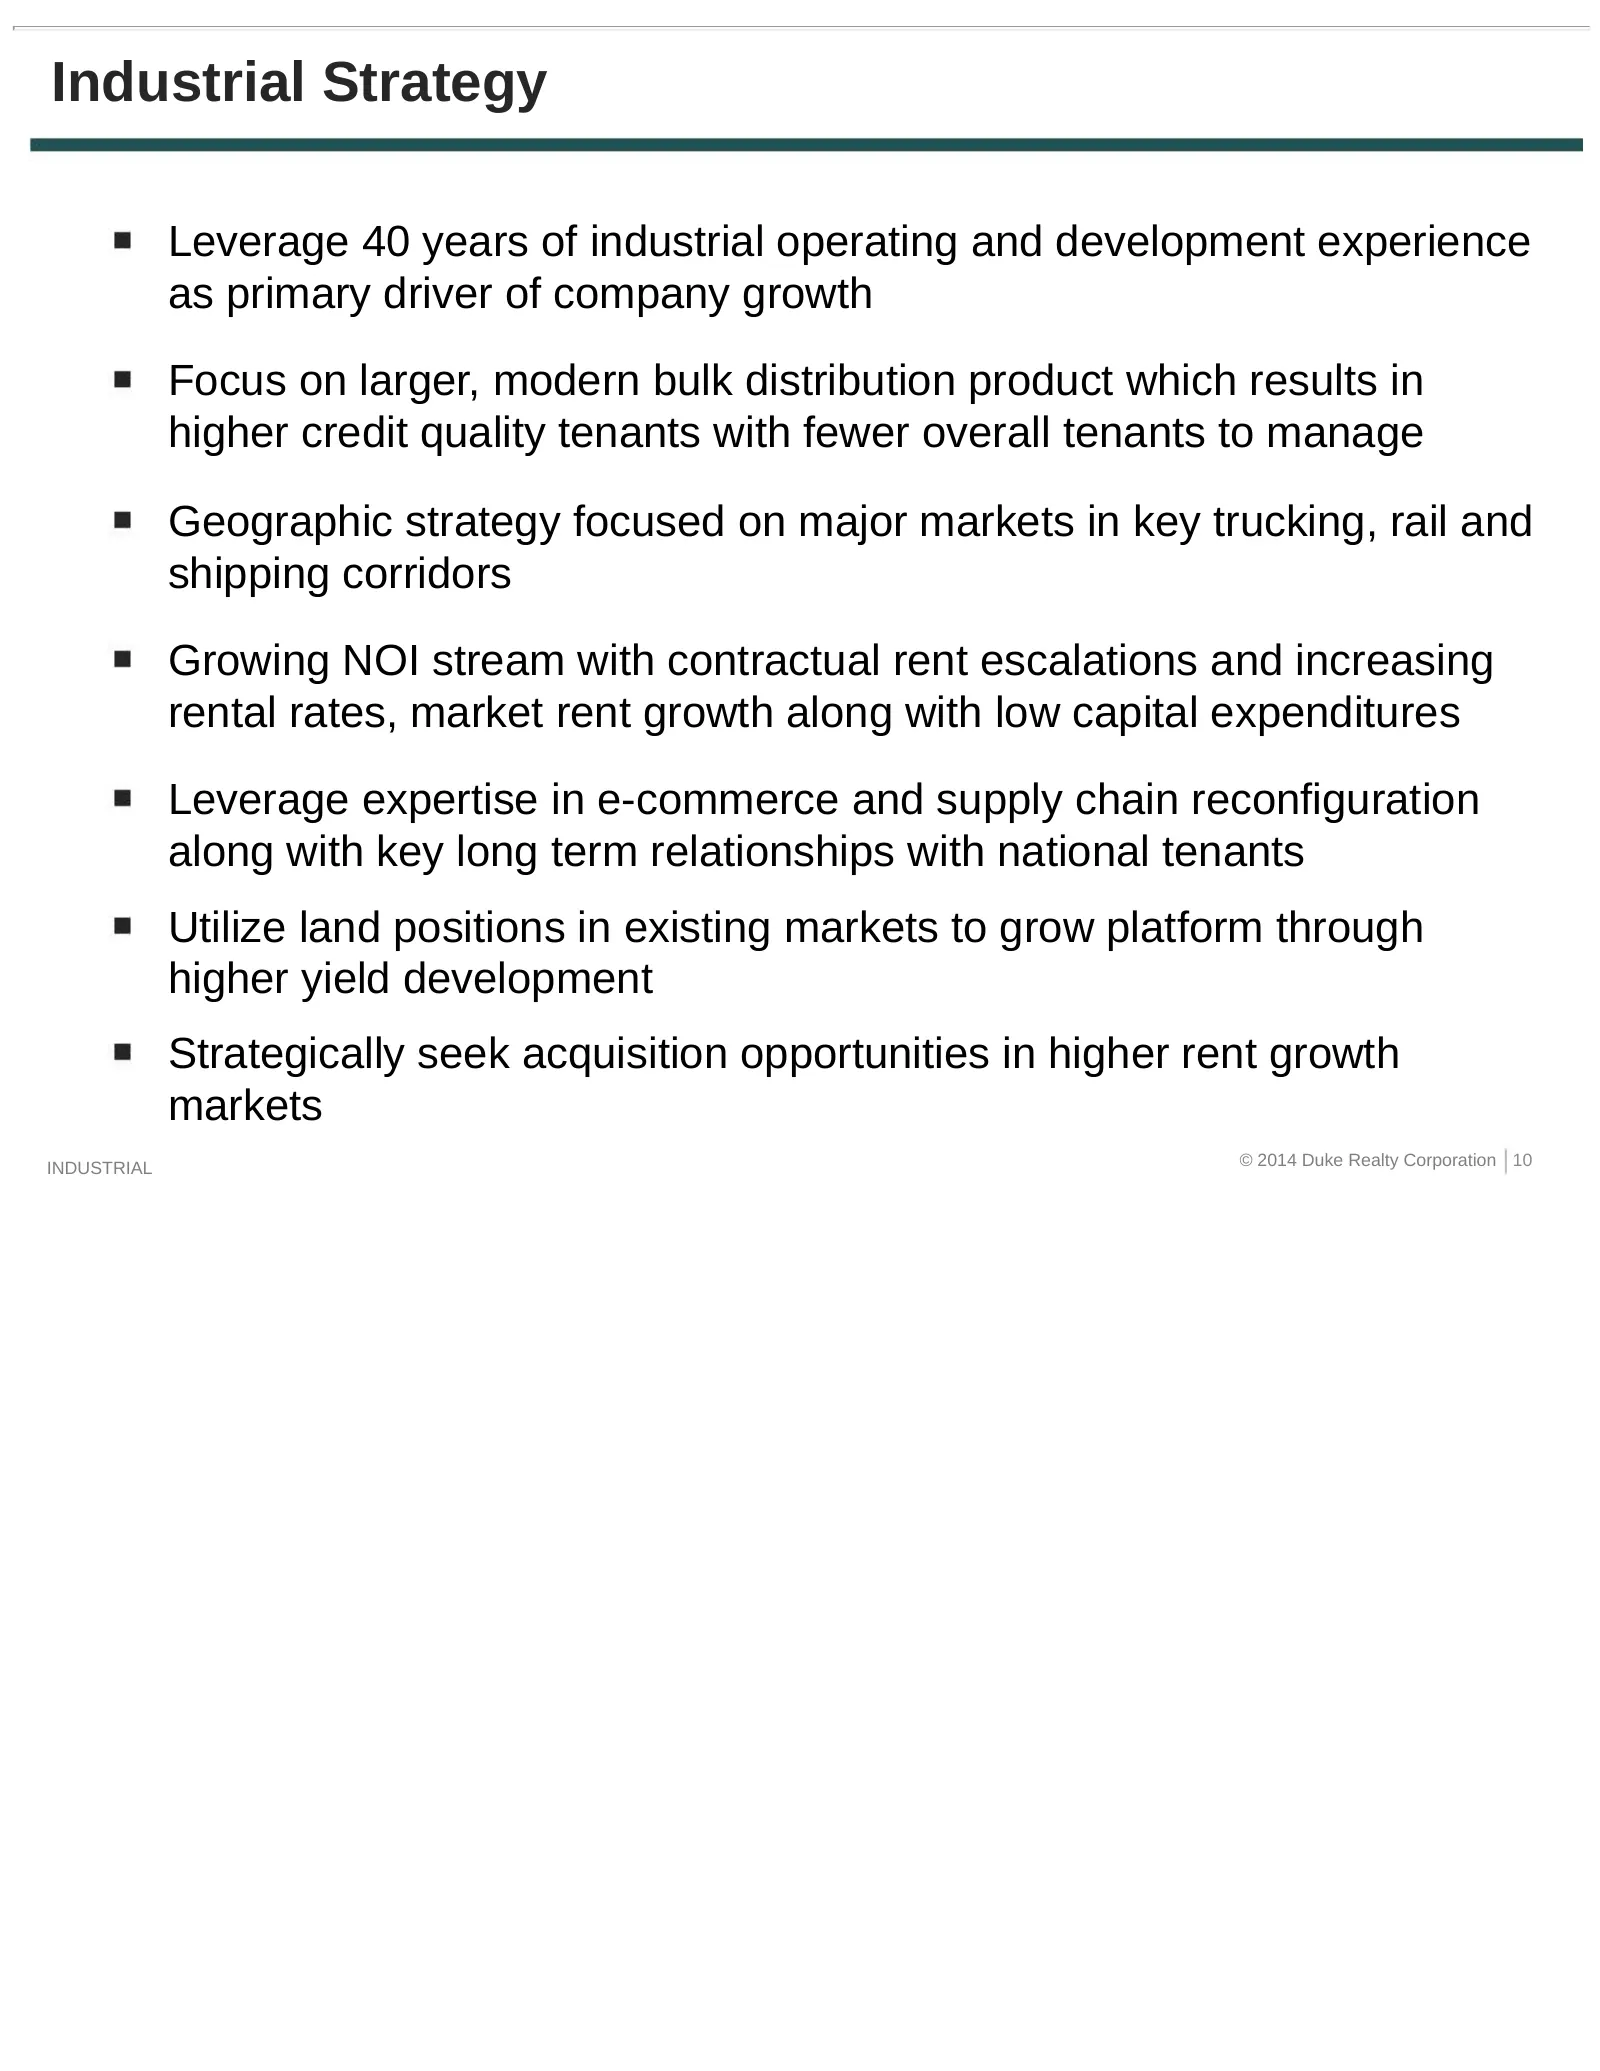
Slide 10: Industrial Strategy
Industrial Strategy Leverage 40 years of industrial operating and development experience as primary driver of company growth Focus on larger, modern bulk distribution product which results in higher credit quality tenants with fewer overall tenants to manage Geographic strategy focused on major mark
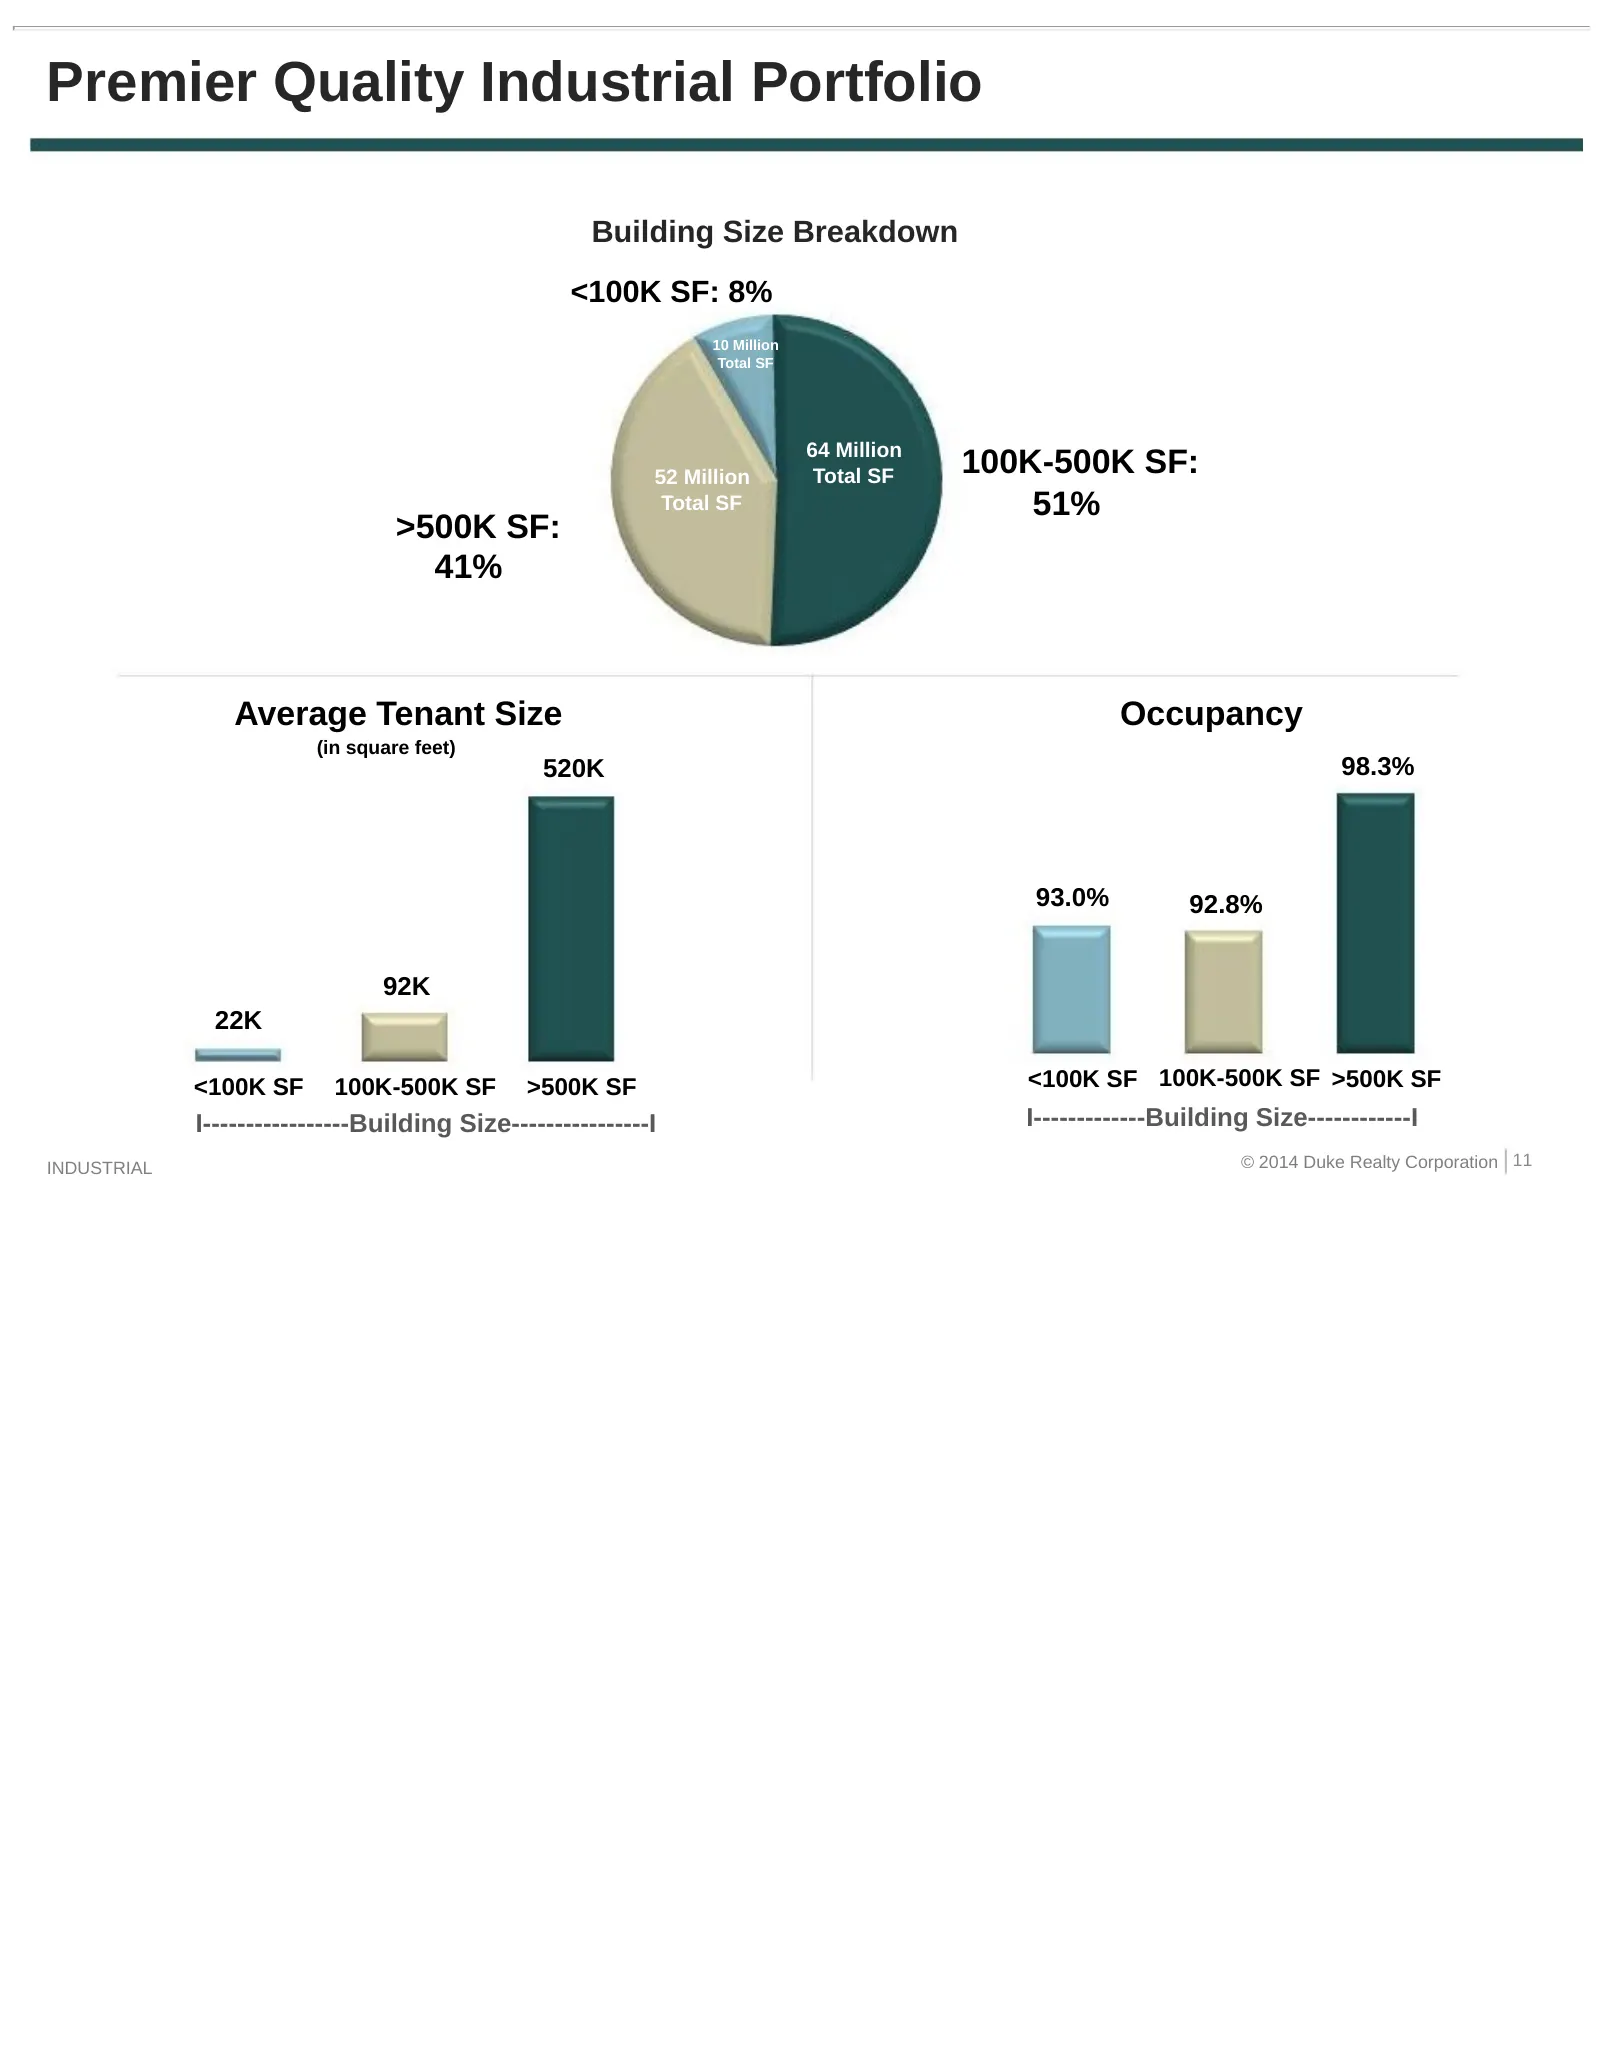
Slide 11: Premier Quality Industrial Portfolio
Premier Quality Industrial Portfolio Building Size Breakdown <100K SF: 8% 10 Million Total SF 64 Million 52 Million Total SF 100K-500K SF: Total SF 51% >500K SF: 41% Average Tenant Size Occupancy (in square feet) 520K 98.3% 93.0% 92.8% 92K 22K <100K SF 100K-500K SF >500K SF <100K SF 100K-500K SF >50
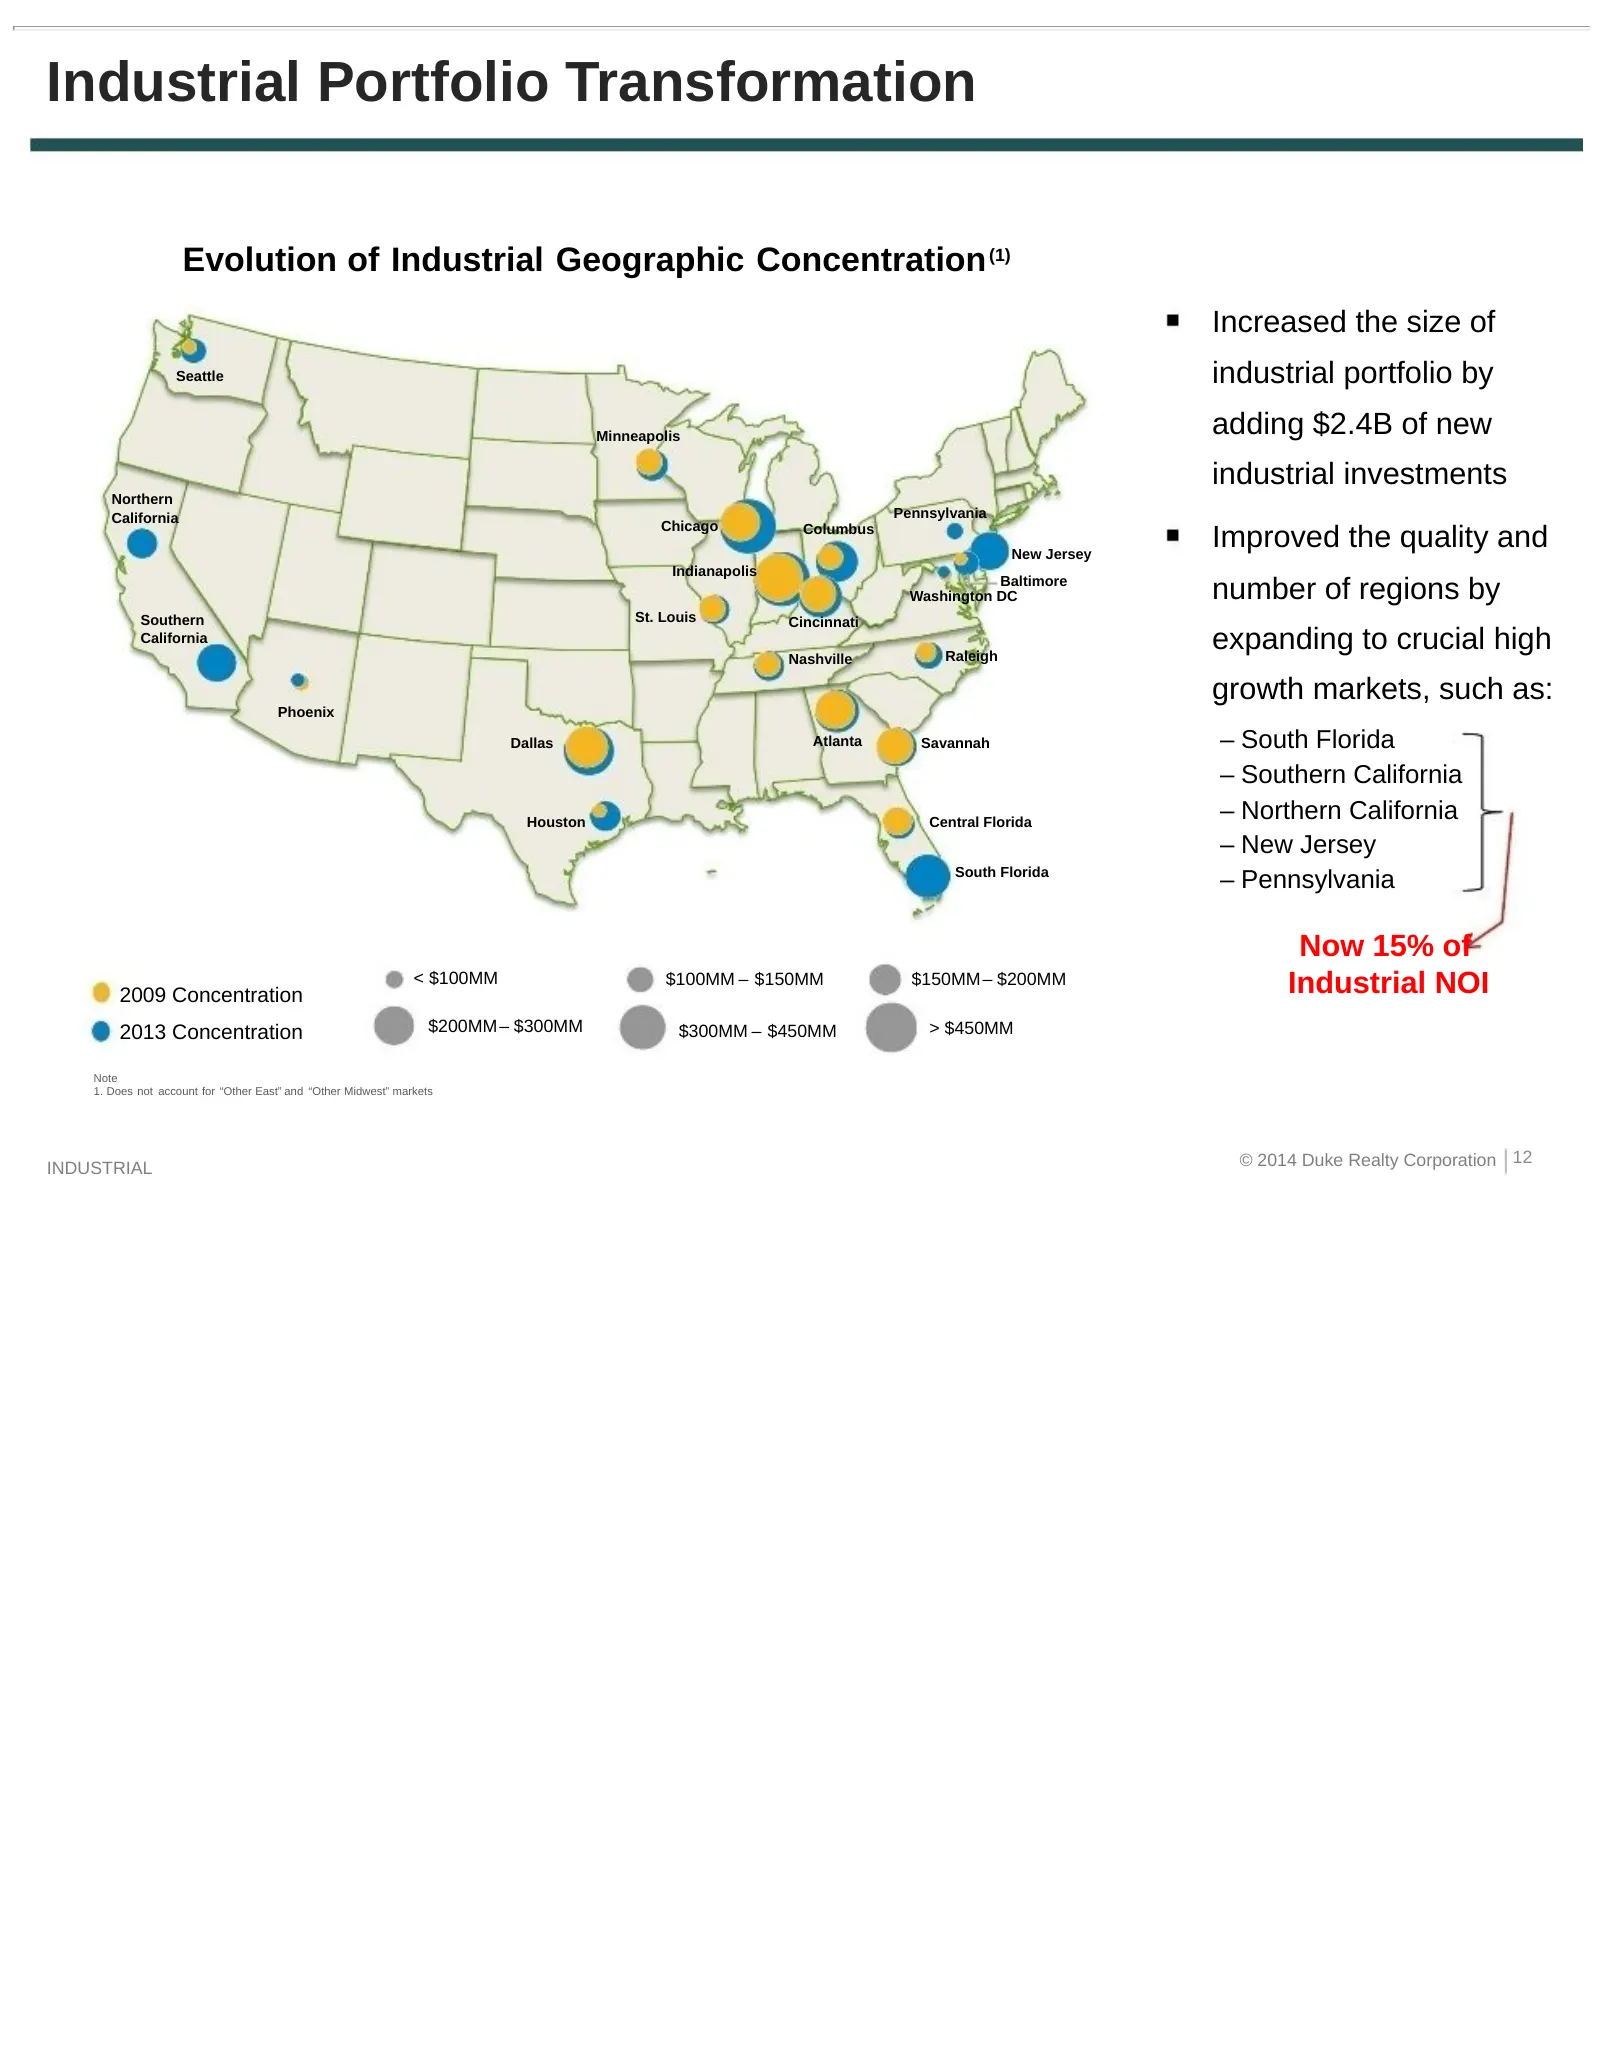
Slide 12: Industrial Portfolio Transformation
Industrial Portfolio Transformation Evolution of Industrial Geographic Concentration (1) Increased the size of Seattle industrial portfolio by Minneapolis adding $2.4B of new industrial investments Northern California Pennsylvania Chicago Columbus New Jersey Improved the quality and Indianapolis Bal
Slide 13: Best in Class Domestic Industrial Portfolio
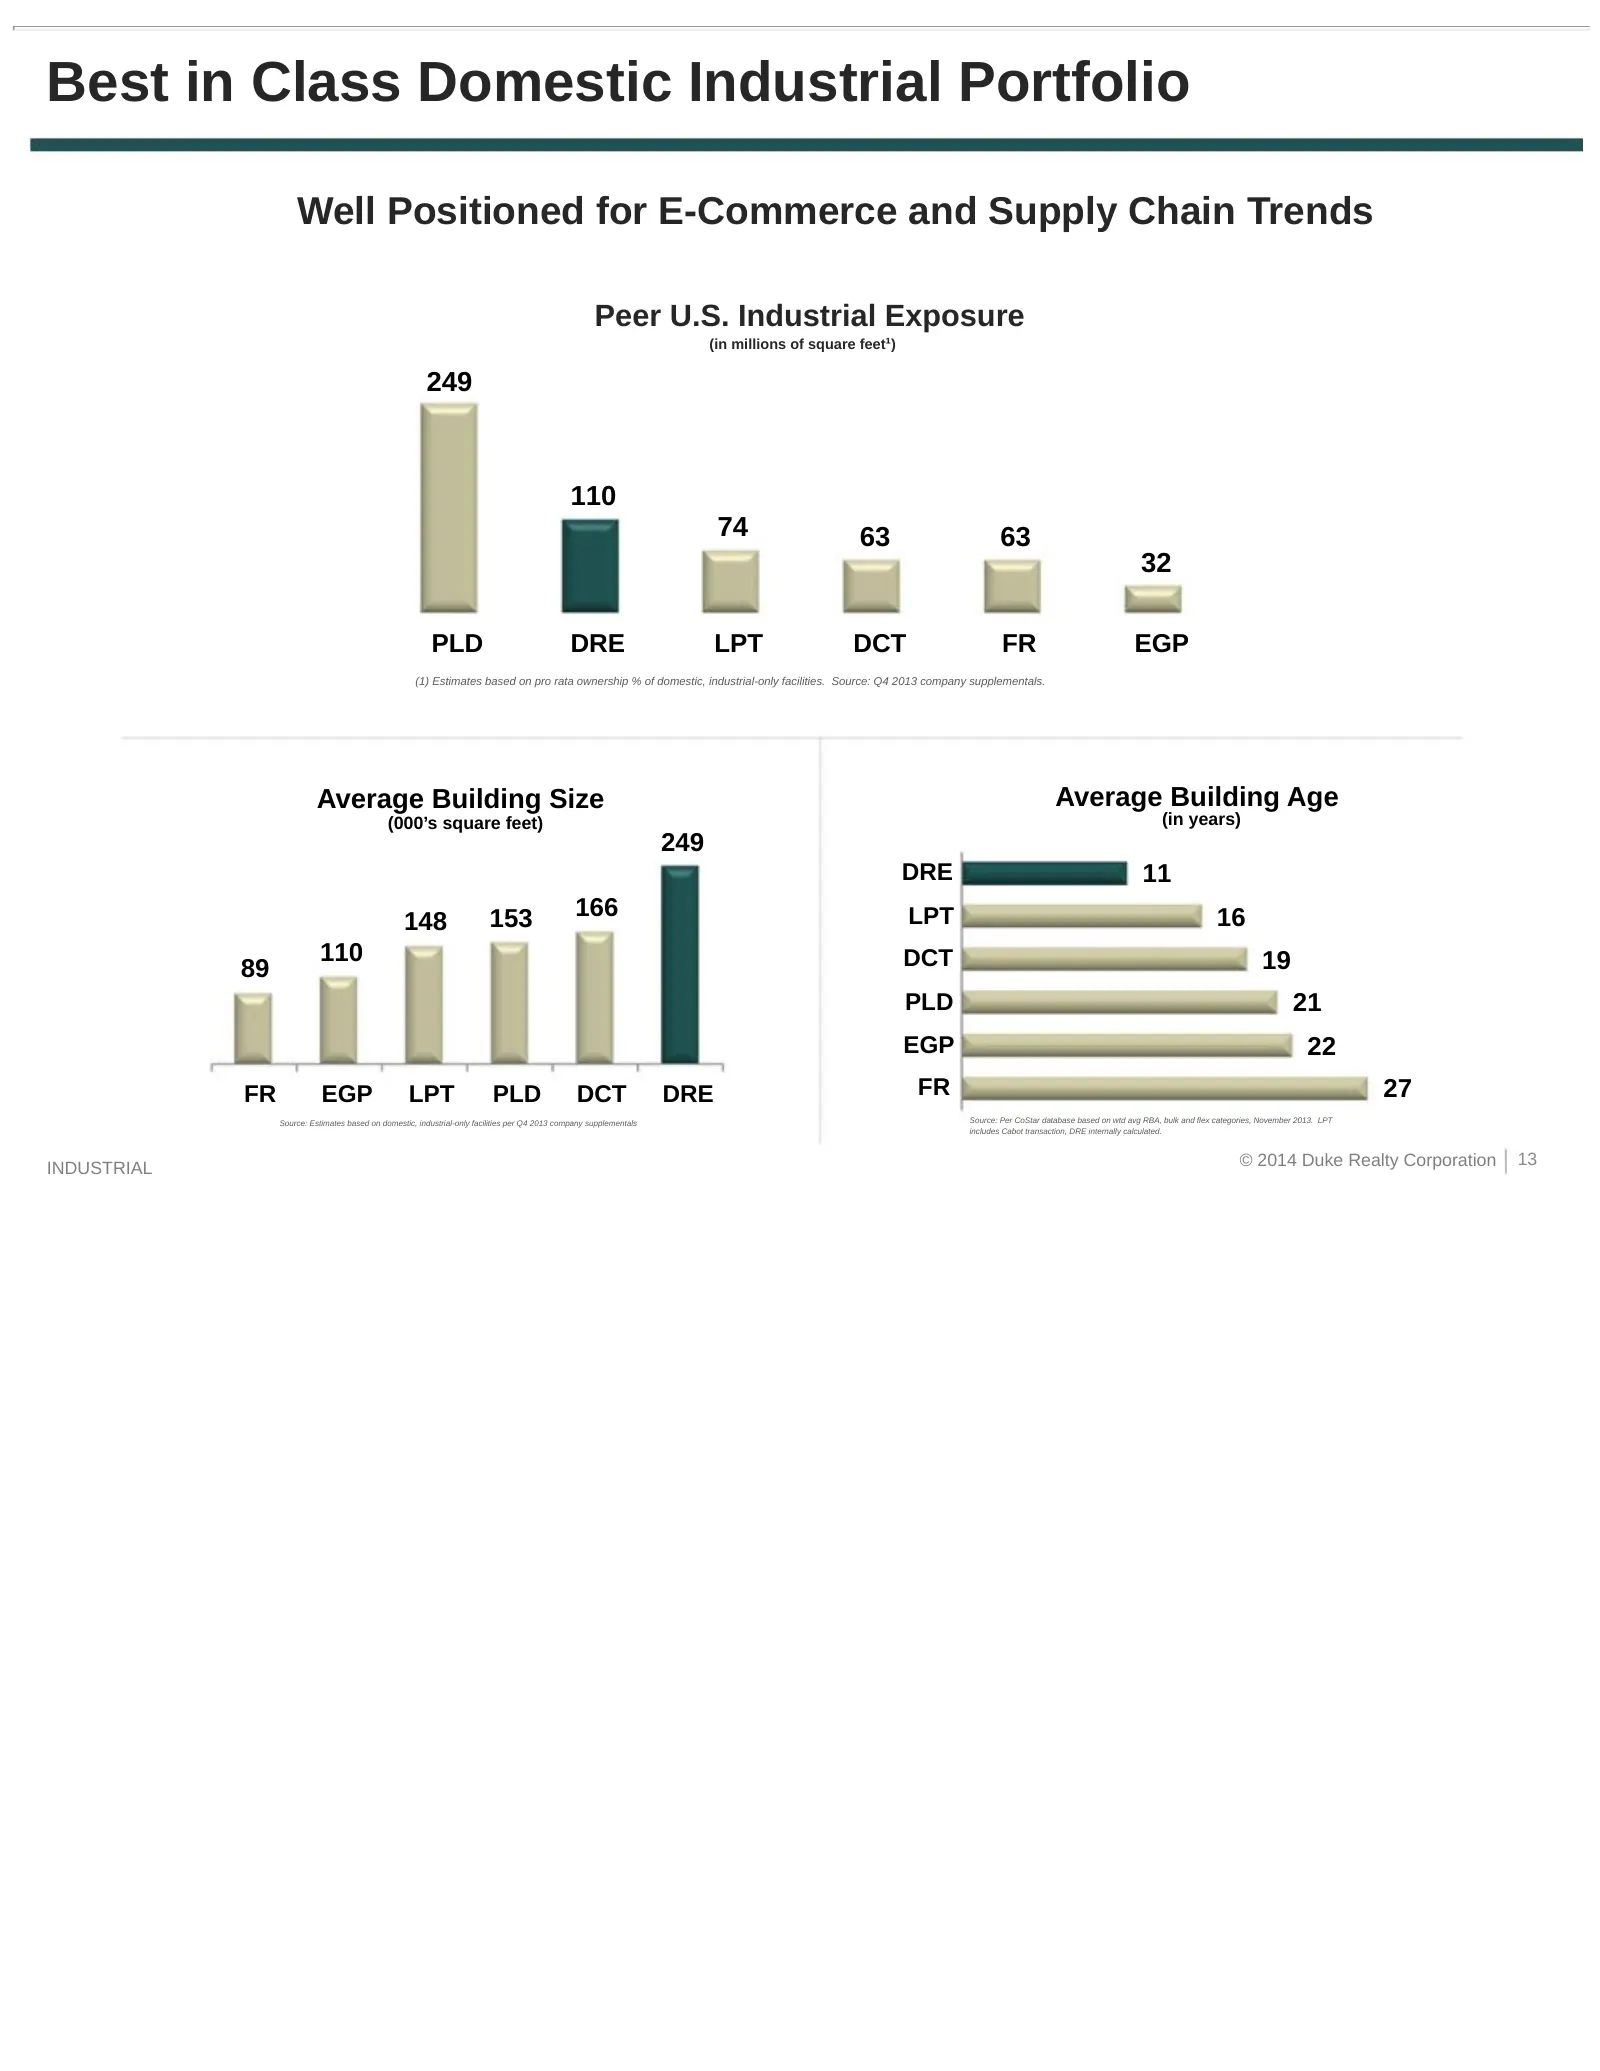
Best in Class Domestic Industrial Portfolio Well Positioned for E-Commerce and Supply Chain Trends Peer U.S. Industrial Exposure (in millions of square feet¹) 249 110 74 63 63 32 PLD DRE LPT DCT FR EGP (1) Estimates based on pro rata ownership % of domestic, industrial-only facilities. Source: Q4 20
Slide 14: Industrial Portfolio Significantly Outperforms Market
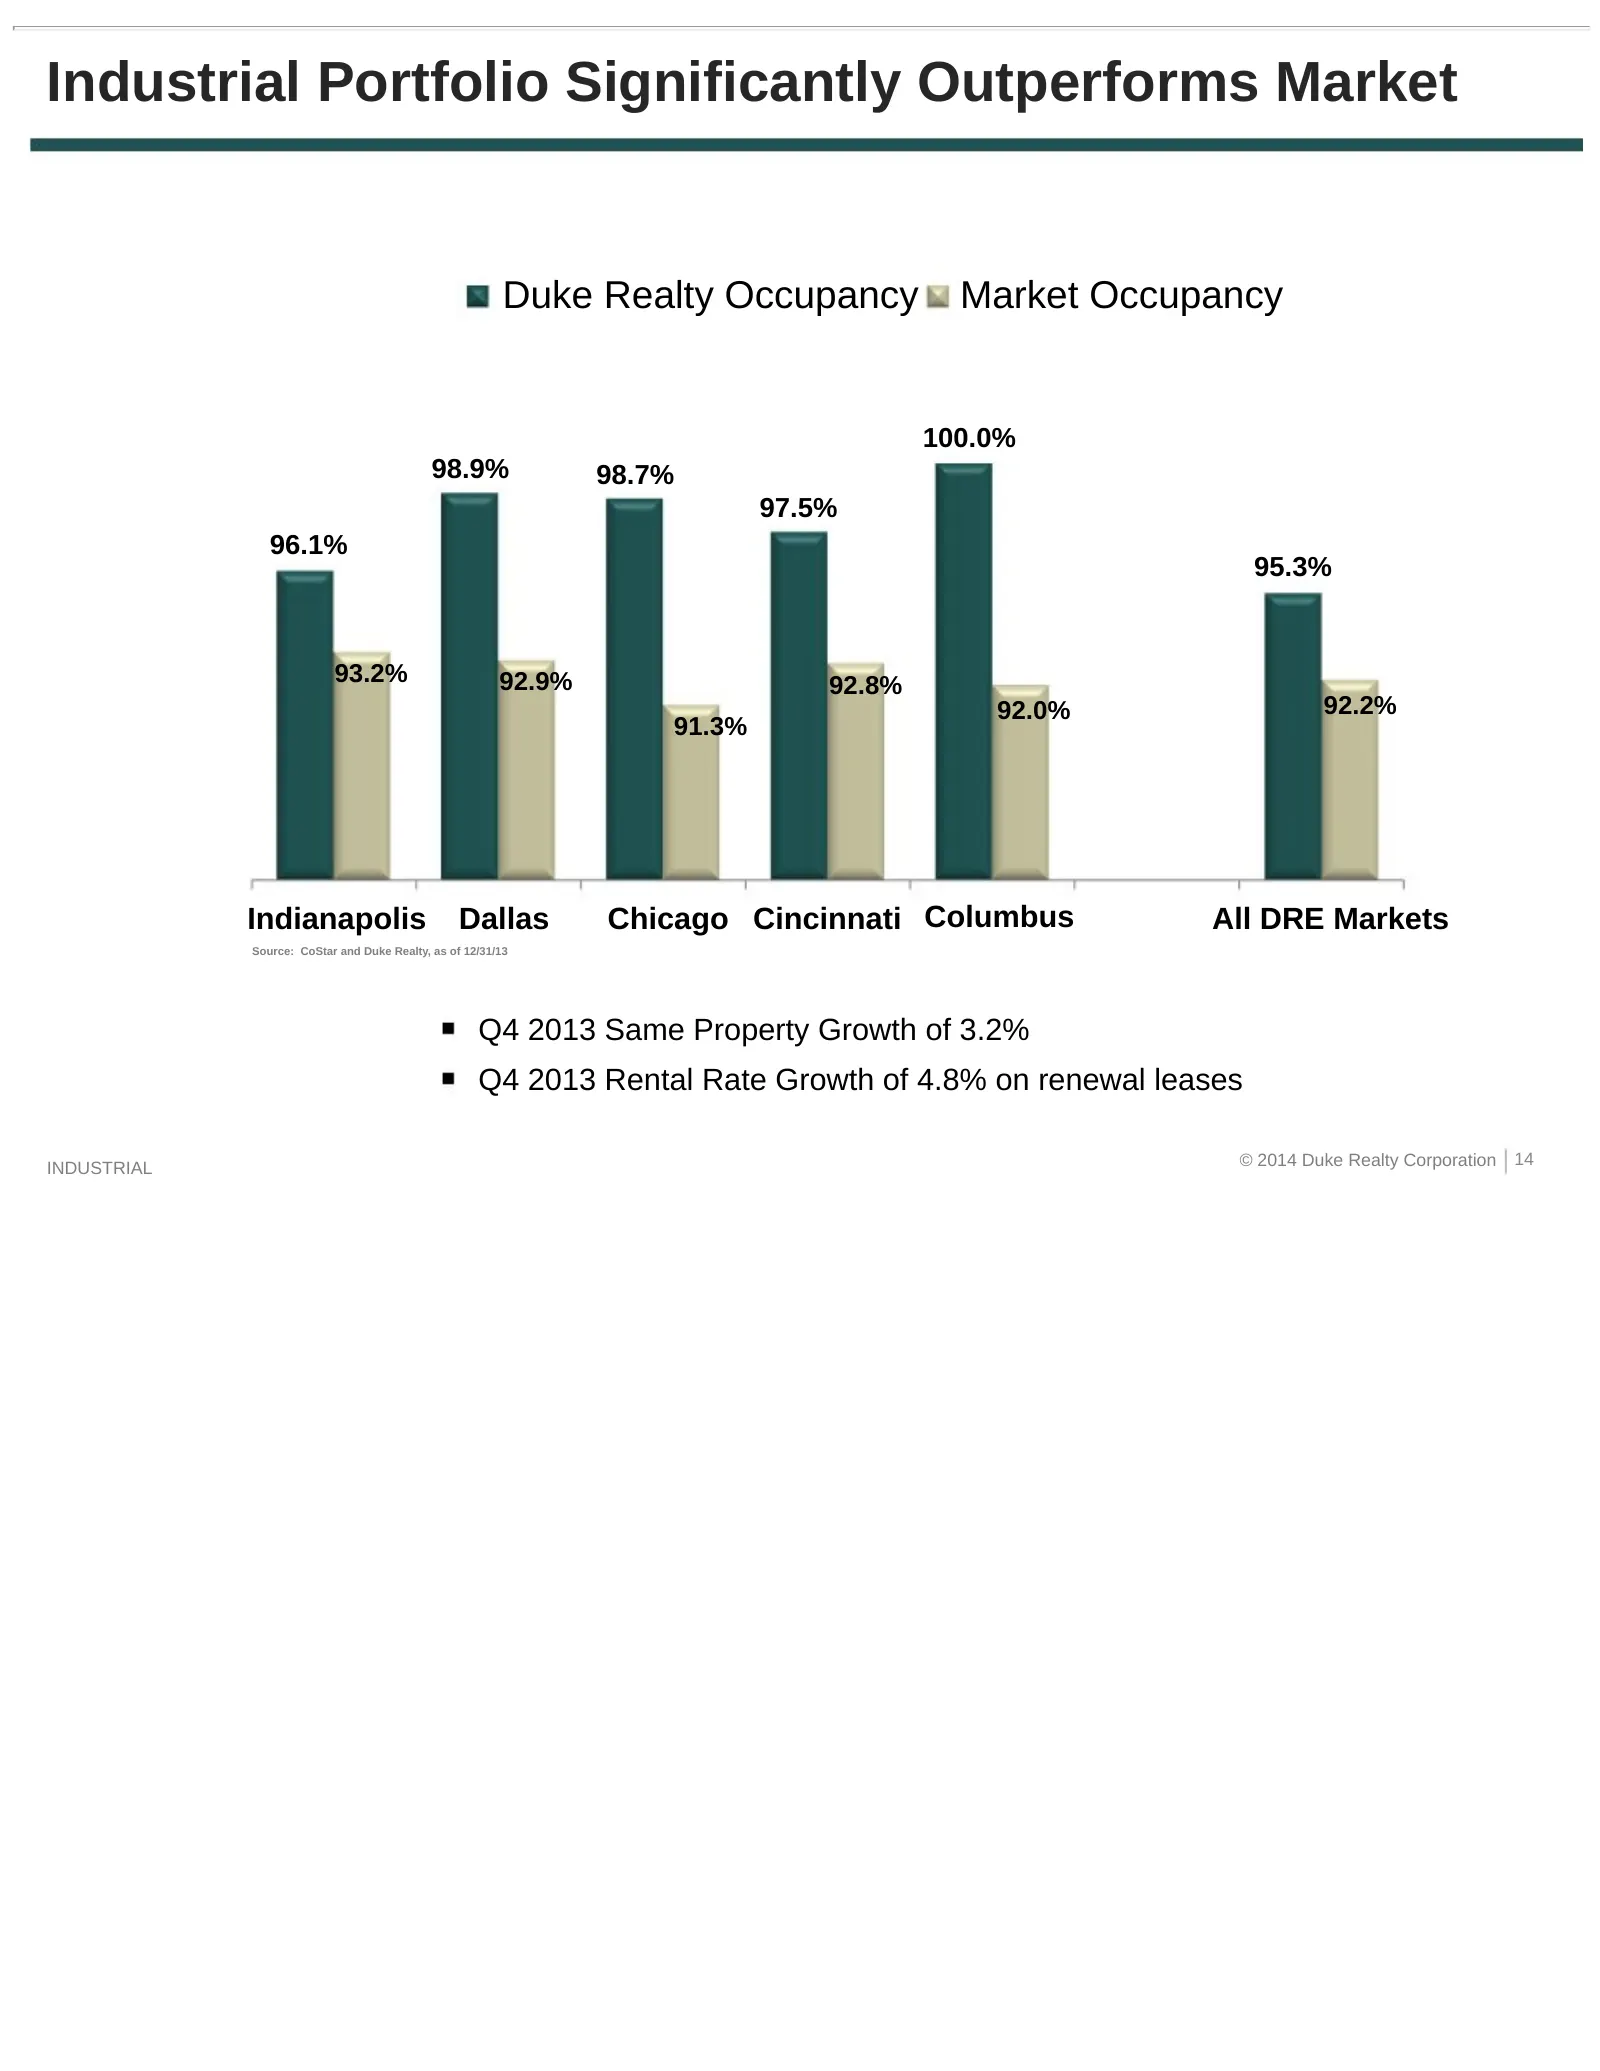
Industrial Portfolio Significantly Outperforms Market Duke Realty Occupancy Market Occupancy 100.0% 98.9% 98.7% 97.5% 96.1% 95.3% 93.2% 92.9% 92.8% 92.0% 92.2% 91.3% Indianapolis Dallas Chicago Cincinnati Columbus All DRE Markets Source: CoStar and Duke Realty, as of 12/31/13 Q4 2013 Same Property G
Slide 15: Big Box: Strong Rent Growth & E-Commerce Trends
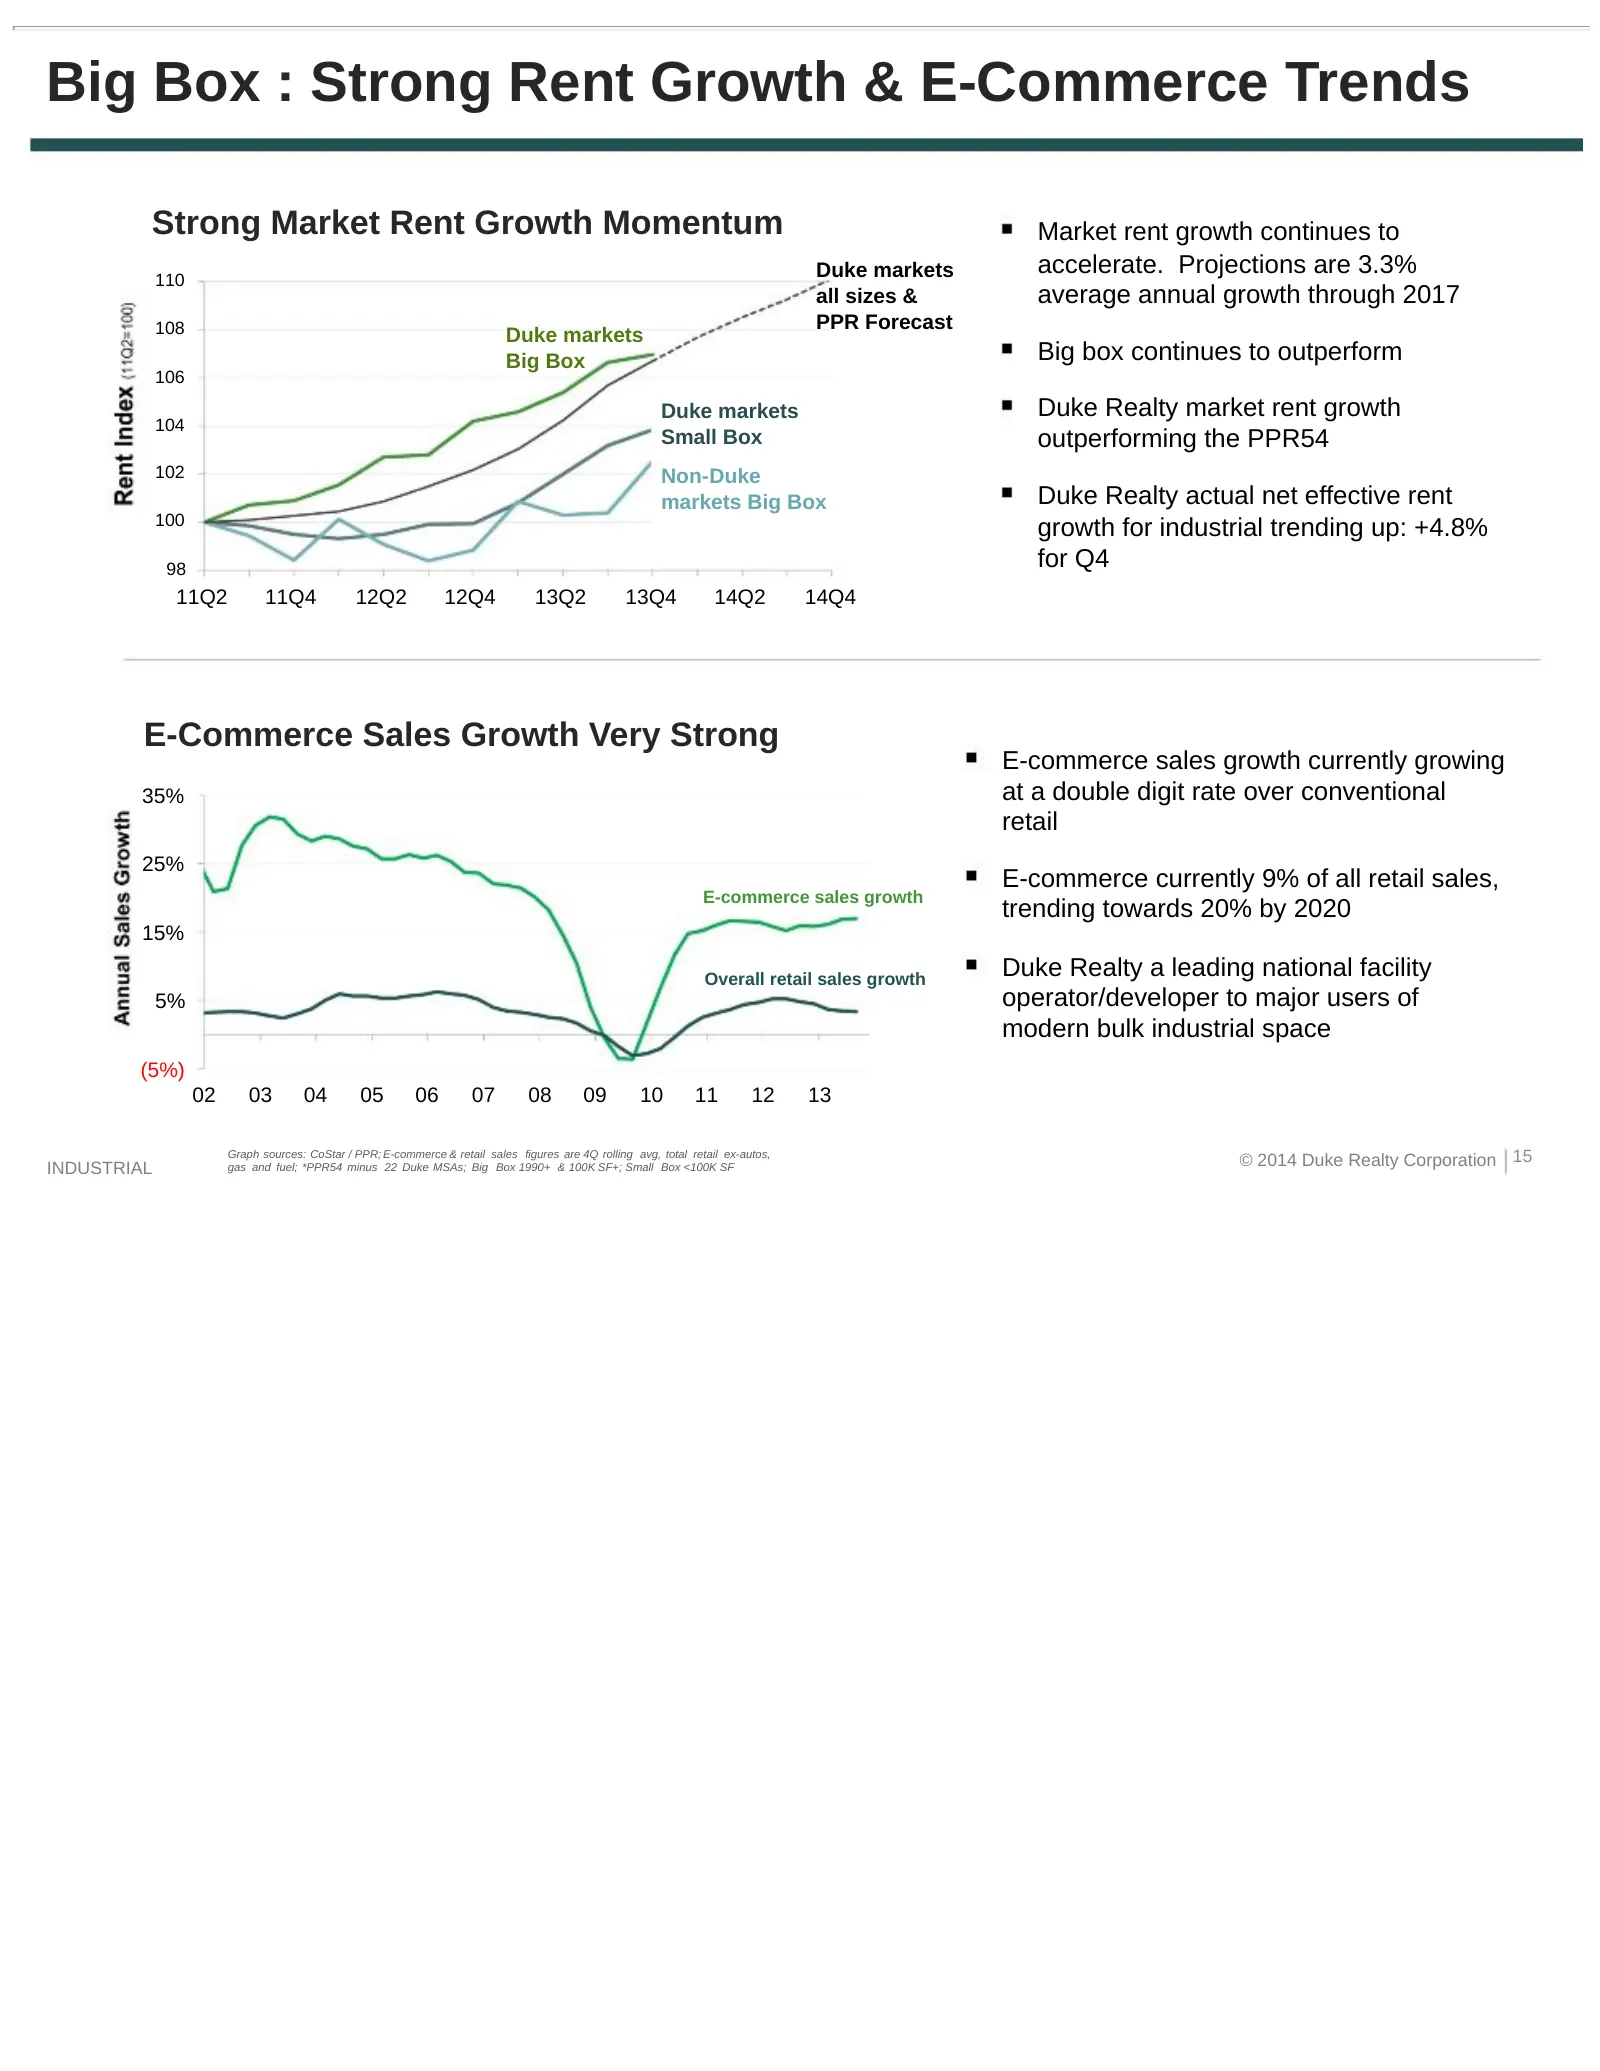
Big Box : Strong Rent Growth & E-Commerce Trends Strong Market Rent Growth Momentum Market rent growth continues to 110 Duke markets accelerate. Projections are 3.3% all sizes & average annual growth through 2017 108 PPR Forecast Duke markets Big Box Big box continues to outperform 106 Duke markets
Slide 16: Select 2013 Industrial Acquisitions
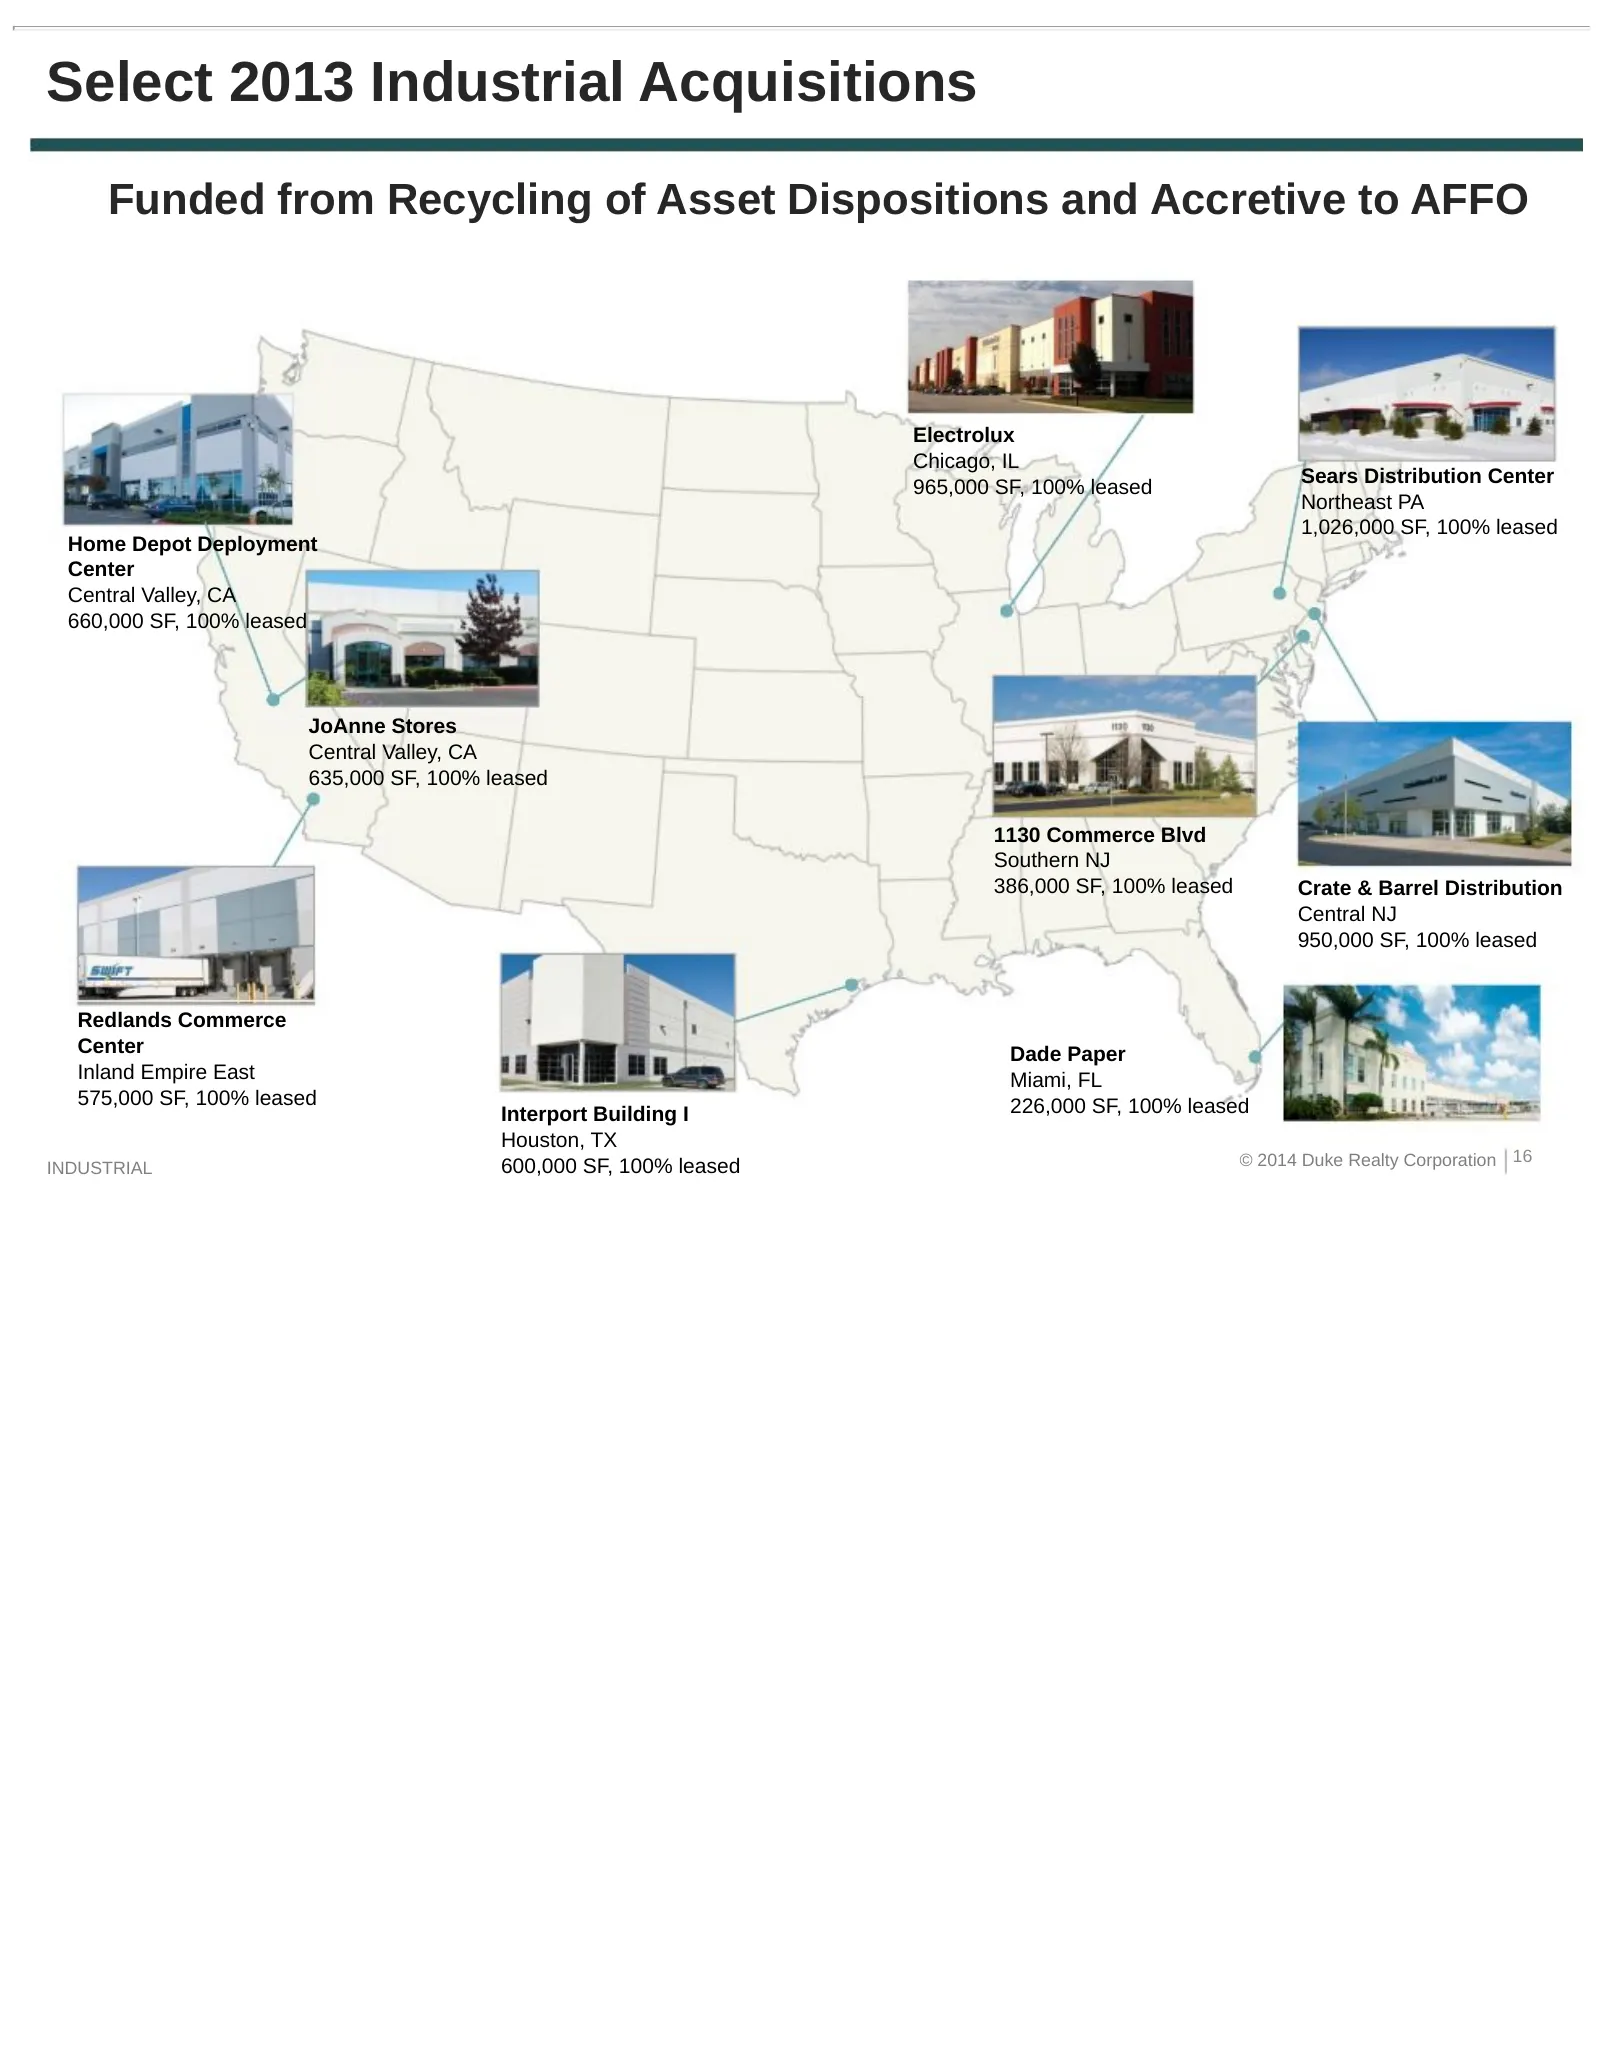
Select 2013 Industrial Acquisitions Funded from Recycling of Asset Dispositions and Accretive to AFFO Electrolux Chicago, IL Sears Distribution Center 965,000 SF, 100% leased Northeast PA 1,026,000 SF, 100% leased Home Depot Deployment Center Central Valley, CA 660,000 SF, 100% leased JoAnne Stores
Slide 17: Asset Strategy: Office Portfolio
ASSET STRATEGY OFFICE PORTFOLIO 17
Slide 18: Office Strategy
Office Strategy Reached 25% target at year-end 2013 according to plan Continue to sell older, non-strategic assets Develop remaining office land bank primarily with build to suit projects Own highest quality assets in high growth office markets Capitalize on improving economy and quality assets by l
Slide 19: Office Portfolio Transformation
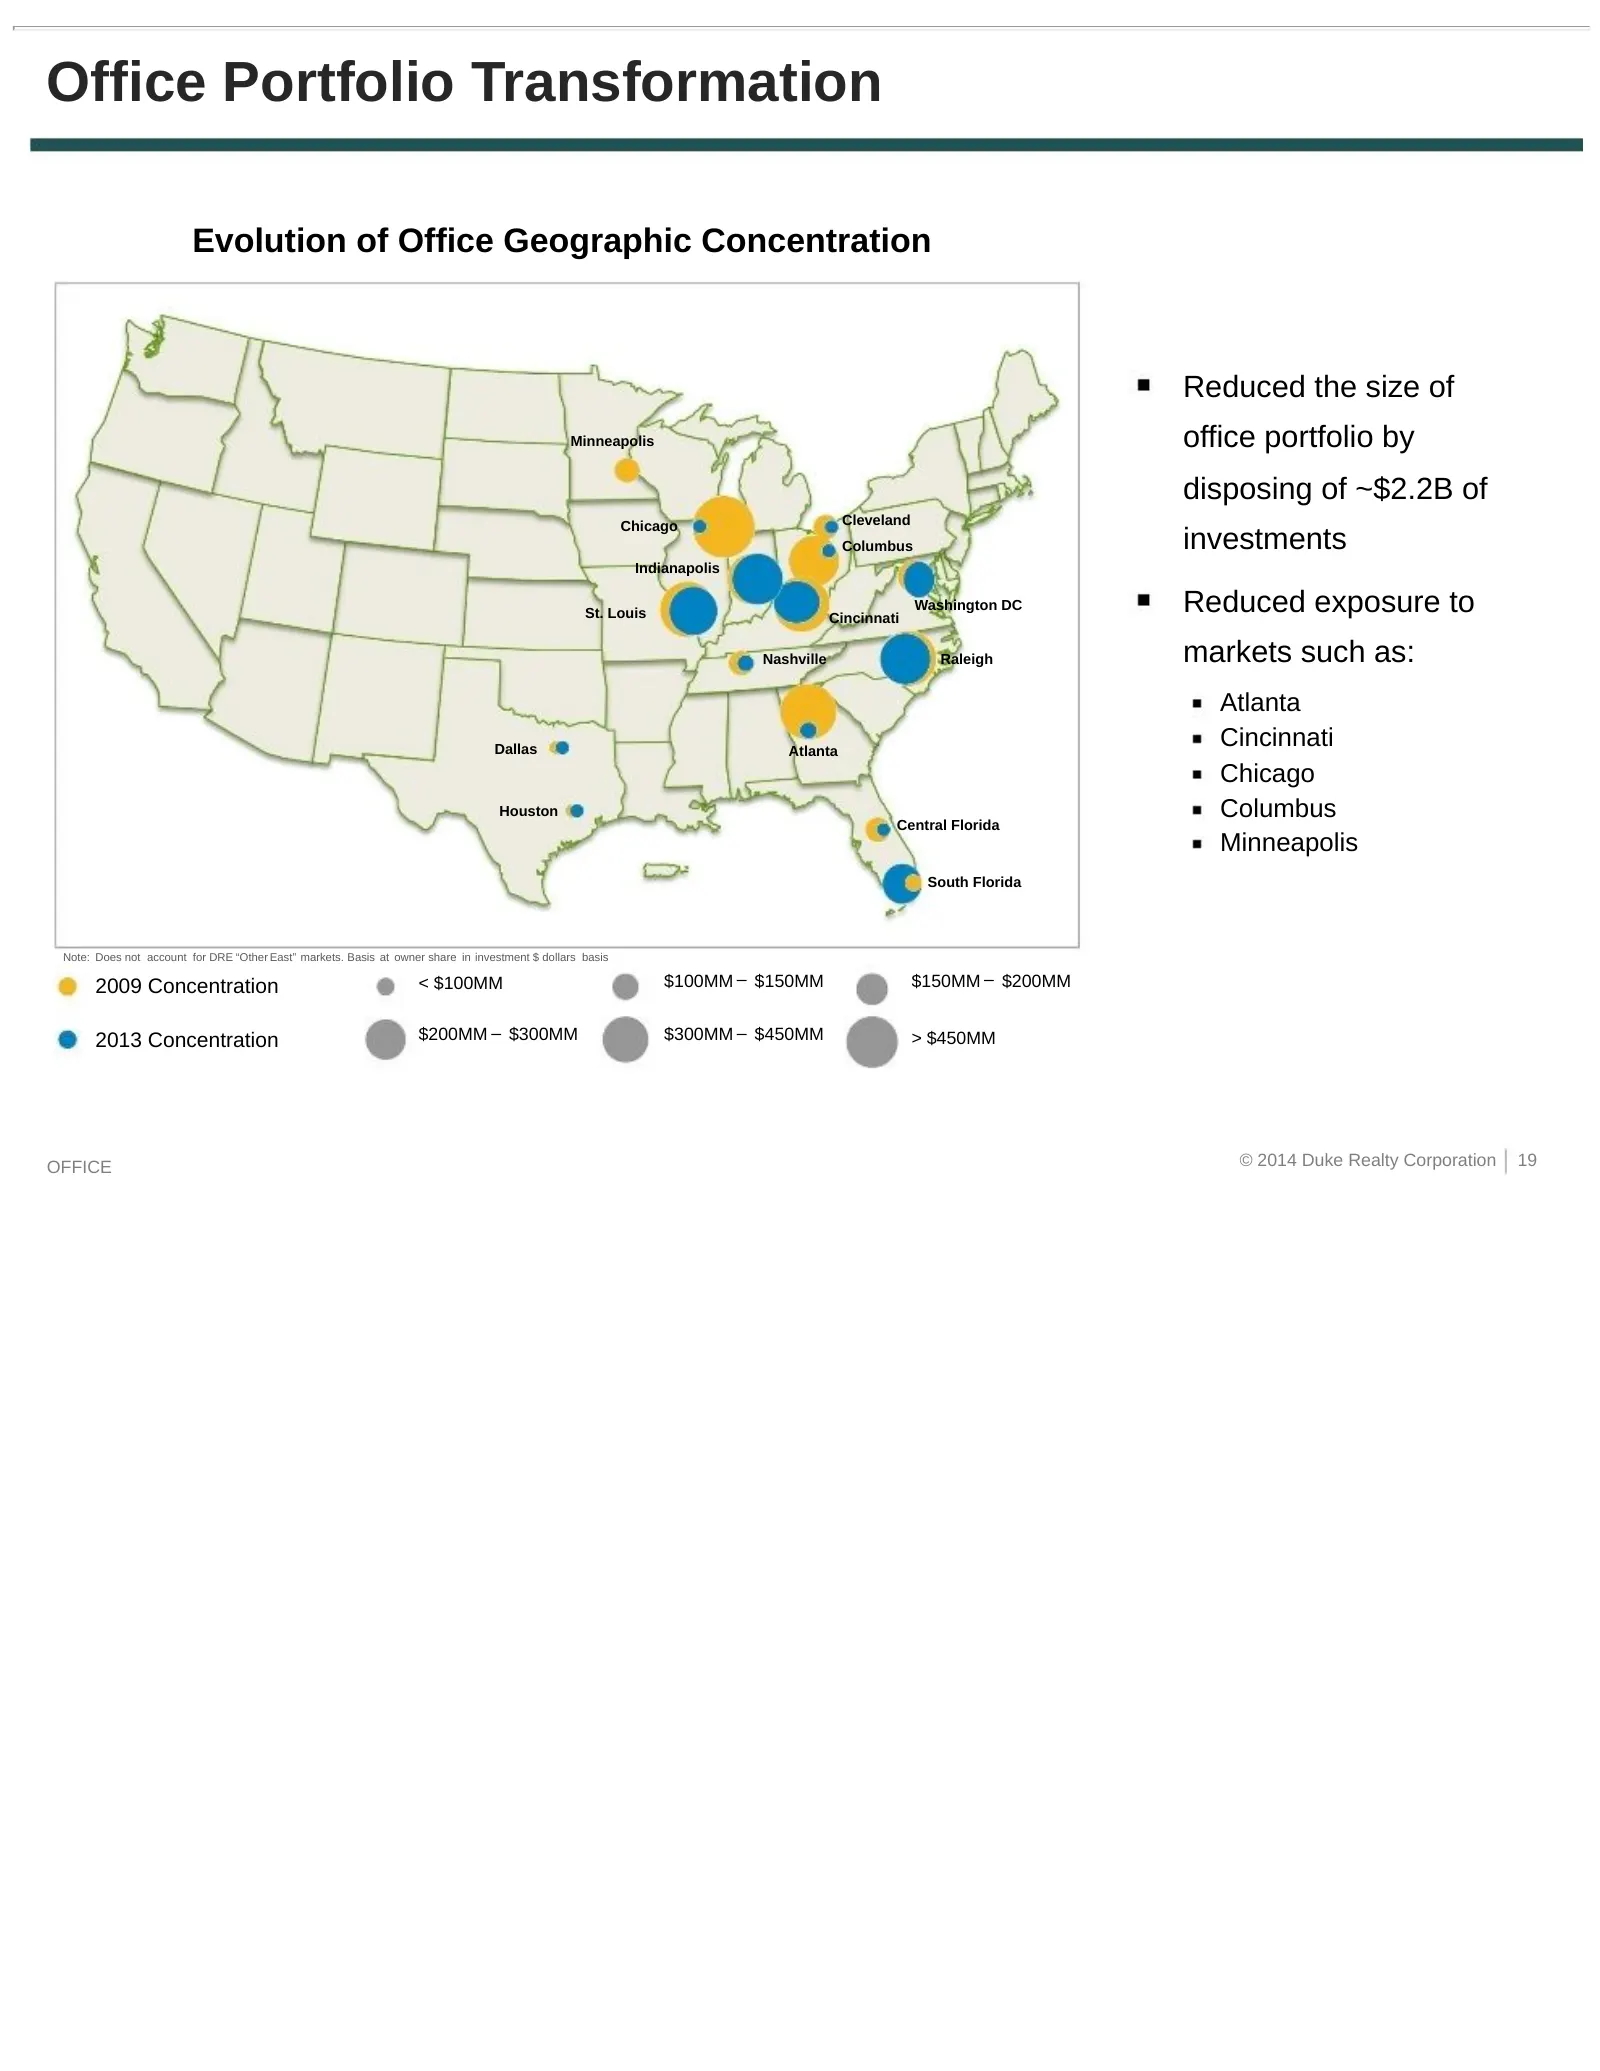
Office Portfolio Transformation Evolution of Office Geographic Concentration Reduced the size of Minneapolis office portfolio by disposing of ~$2.2B of Chicago Cleveland Columbus investments Indianapolis St. Louis Cincinnati Washington DC Reduced exposure to Nashville Raleigh markets such as: Atlant
Slide 20: Asset Strategy: Medical Office Portfolio
ASSET STRATEGY MEDICAL OFFICE PORTFOLIO 20
Slide 21: Medical Office Platform Enhances Risk-adjusted Returns
Medical Office Platform Enhances Risk-adjusted Returns Growth industry, recession resistant asset class Best in class development team able to produce consistent development opportunities through economic cycles Substantially all on-campus or aligned with major hospital systems Long term leases aver
Slide 22: Very Well Positioned for Strong Industry Demand Trends
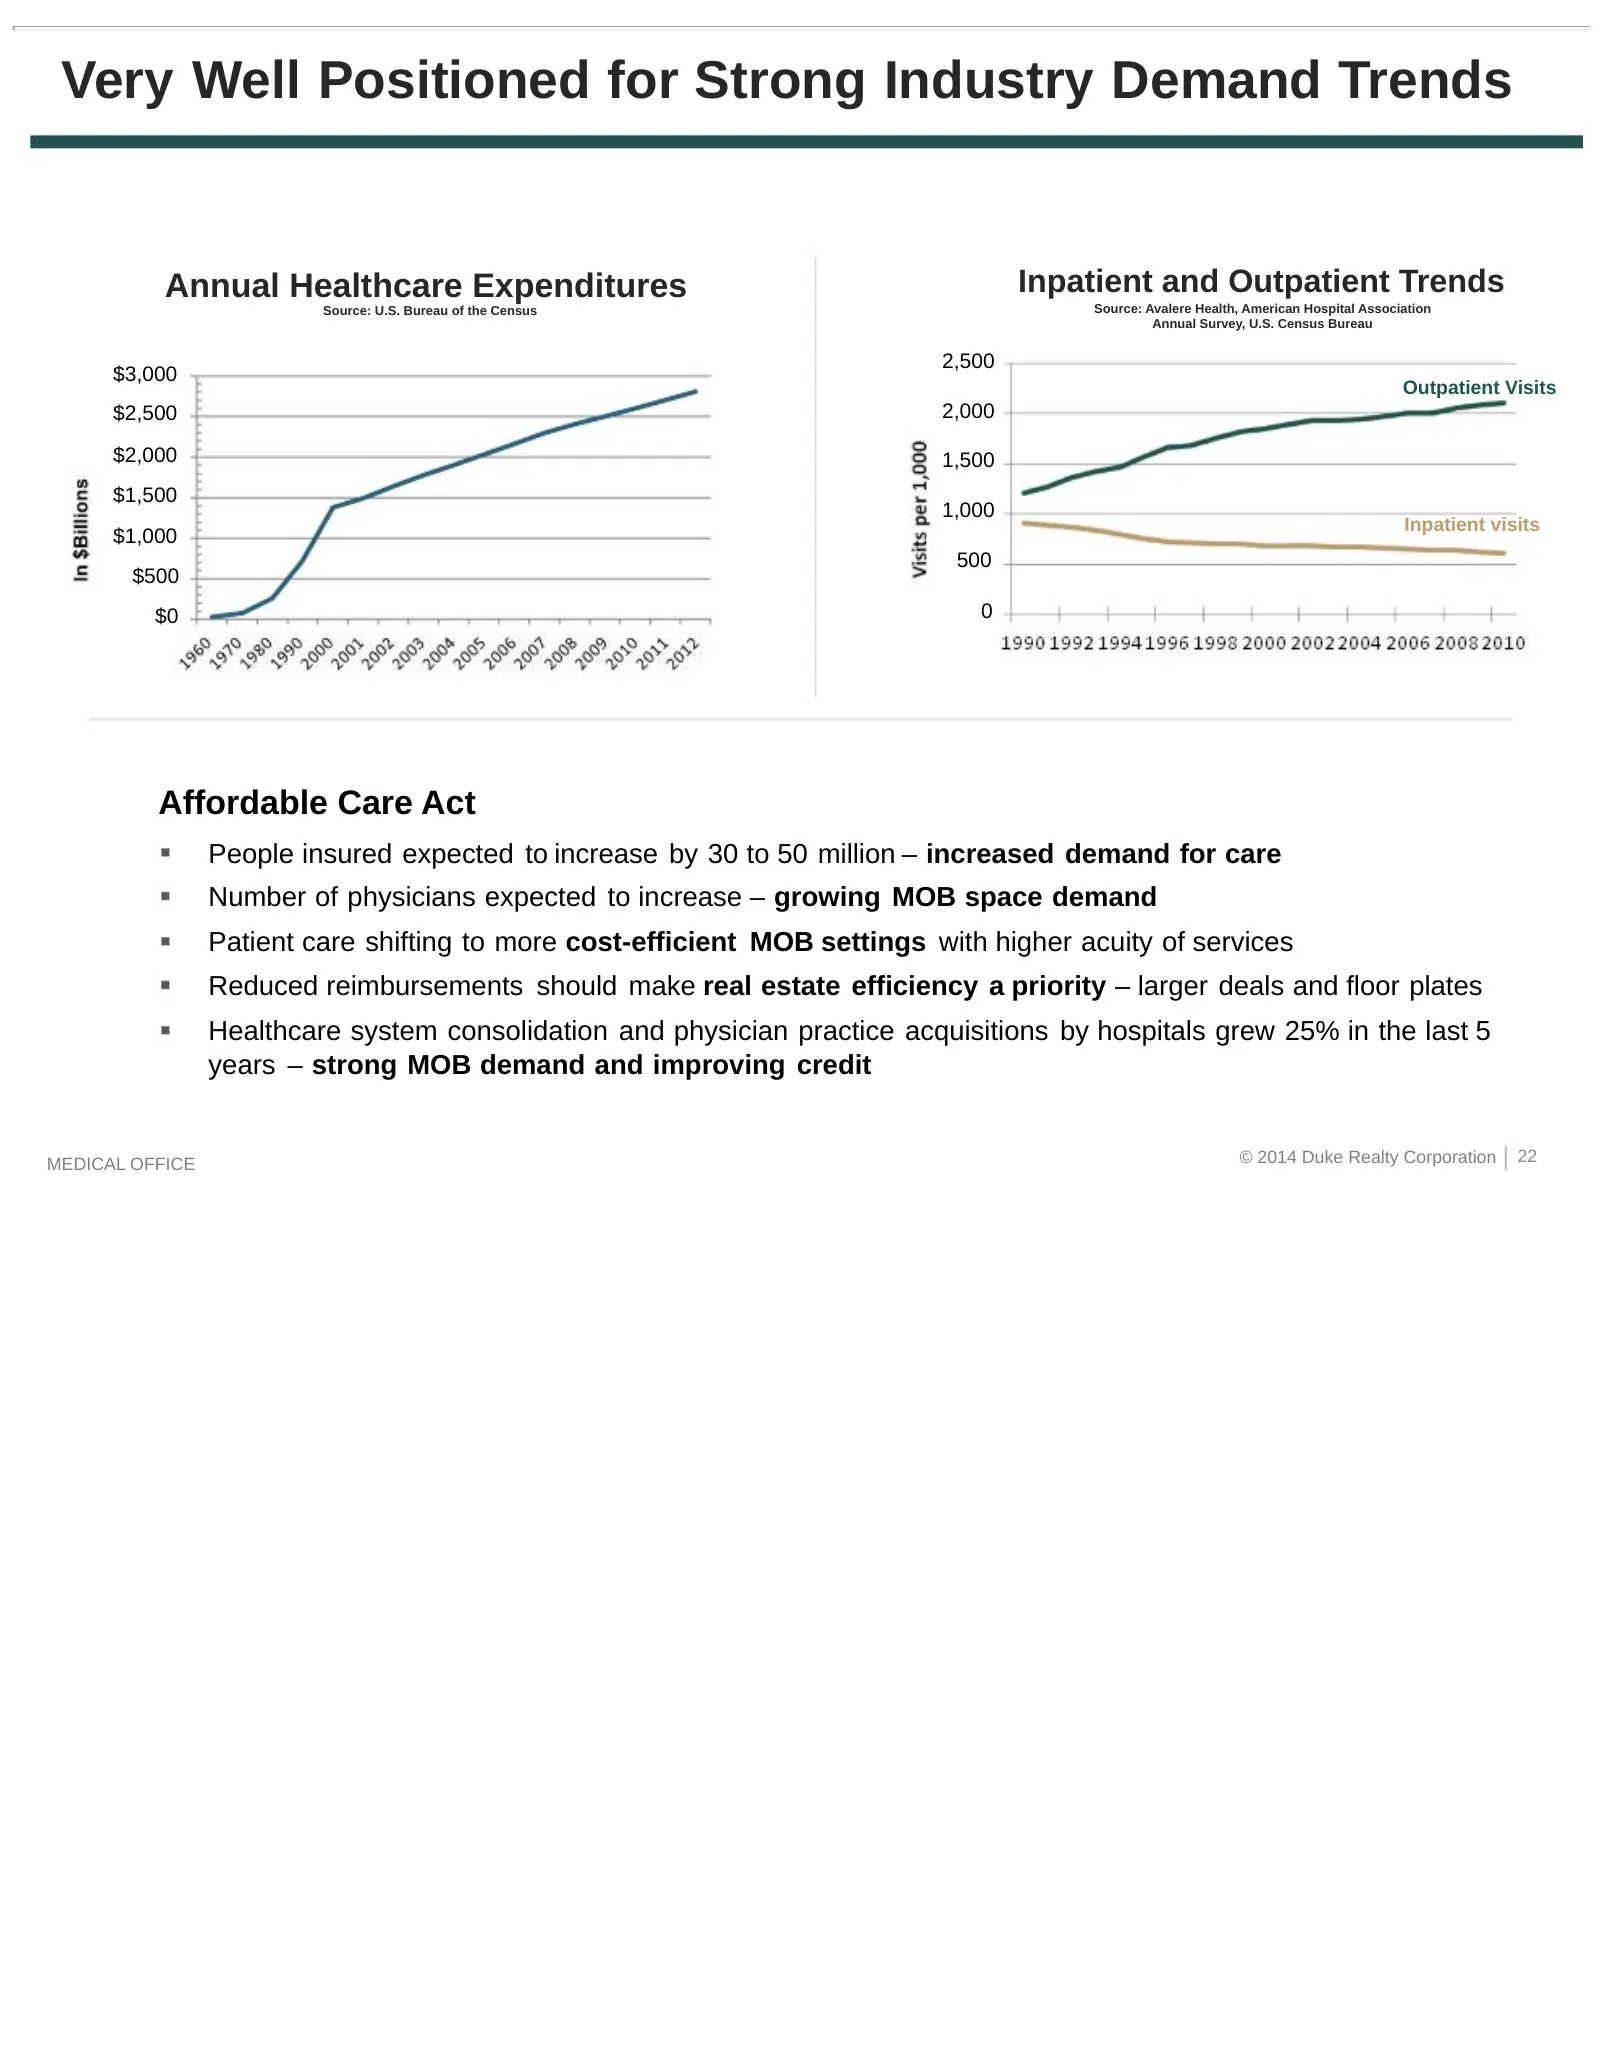
Very Well Positioned for Strong Industry Demand Trends Annual Healthcare Expenditures Inpatient and Outpatient Trends Source: U.S. Bureau of the Census Source: Avalere Health, American Hospital Association Annual Survey, U.S. Census Bureau 2,500 $3,000 Outpatient Visits $2,500 2,000 $2,000 1,500 $1,
Slide 23: Medical Office Portfolio
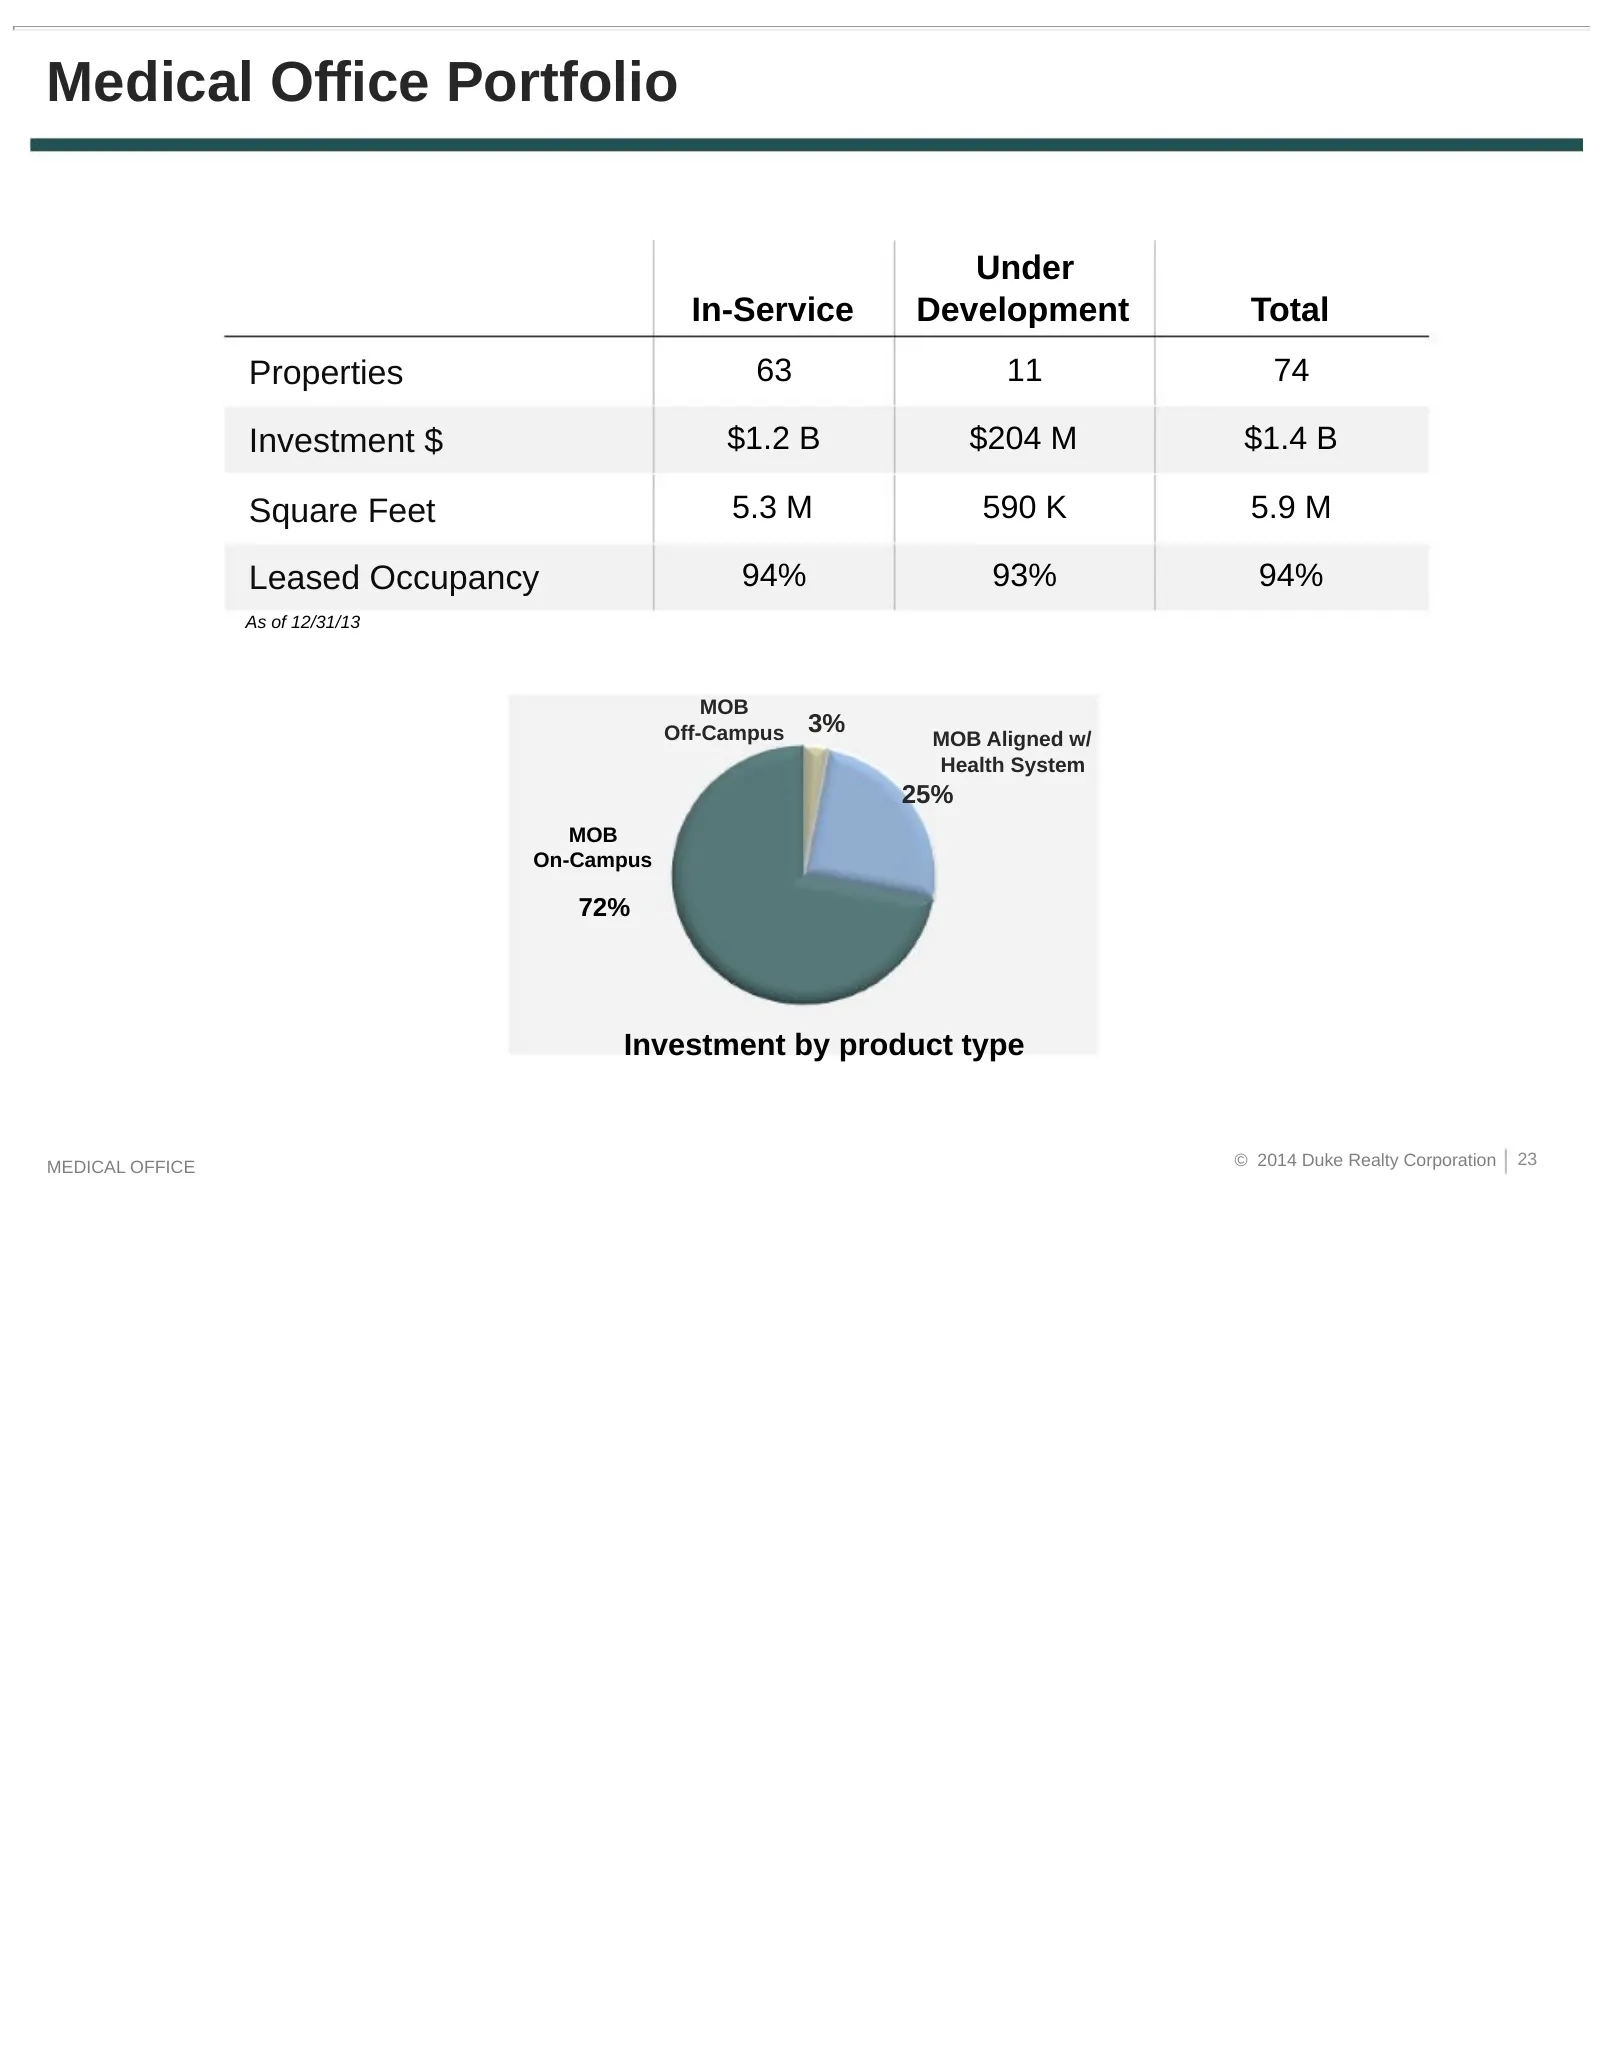
Medical Office Portfolio Under In-Service Development Total Properties 63 11 74 Investment $ $1.2 B $204 M $1.4 B Square Feet 5.3 M 590 K 5.9 M Leased Occupancy 94% 93% 94% As of 12/31/13 MOB Off-Campus 3% MOB Aligned w/ Health System 25% MOB On-Campus 72% Investment by product type MEDICAL OFFICE ©
Slide 24: Top Health System Relationships
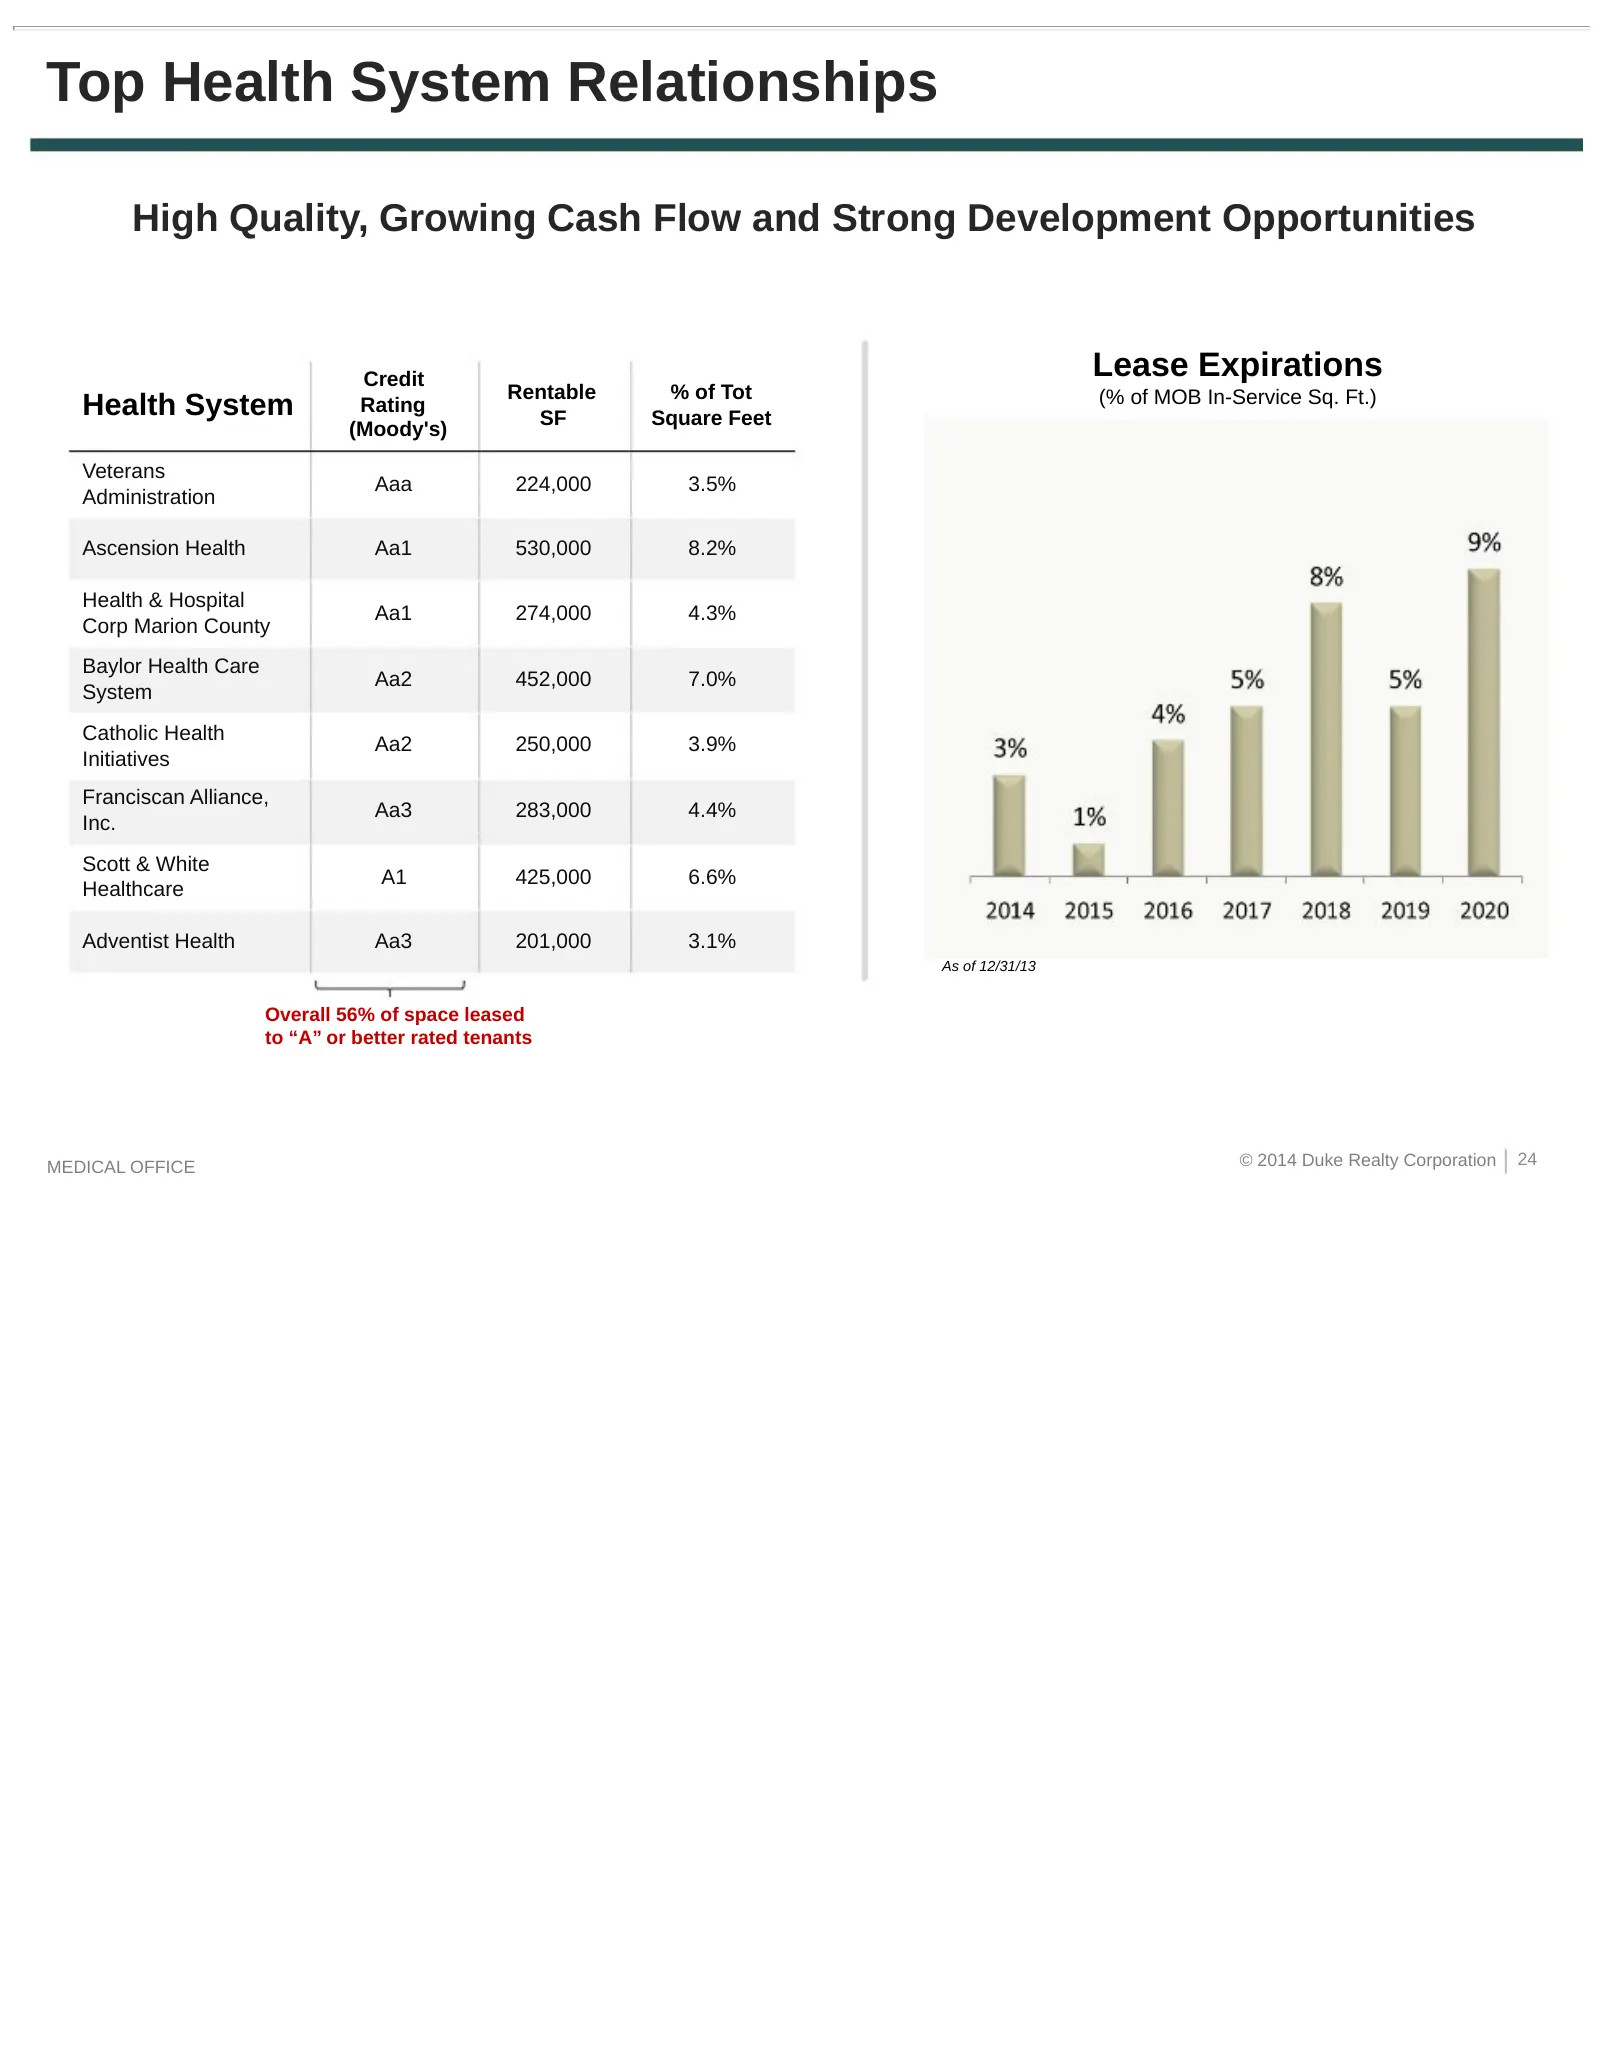
Top Health System Relationships High Quality, Growing Cash Flow and Strong Development Opportunities Credit Lease Expirations Rentable % of Tot (% of MOB In-Service Sq. Ft.) Health System Rating SF Square Feet (Moody's) Veterans Aaa 224,000 3.5% Administration Ascension Health Aa1 530,000 8.2% Healt
Slide 25: Best in Class Medical Office Platform Peer Comparison
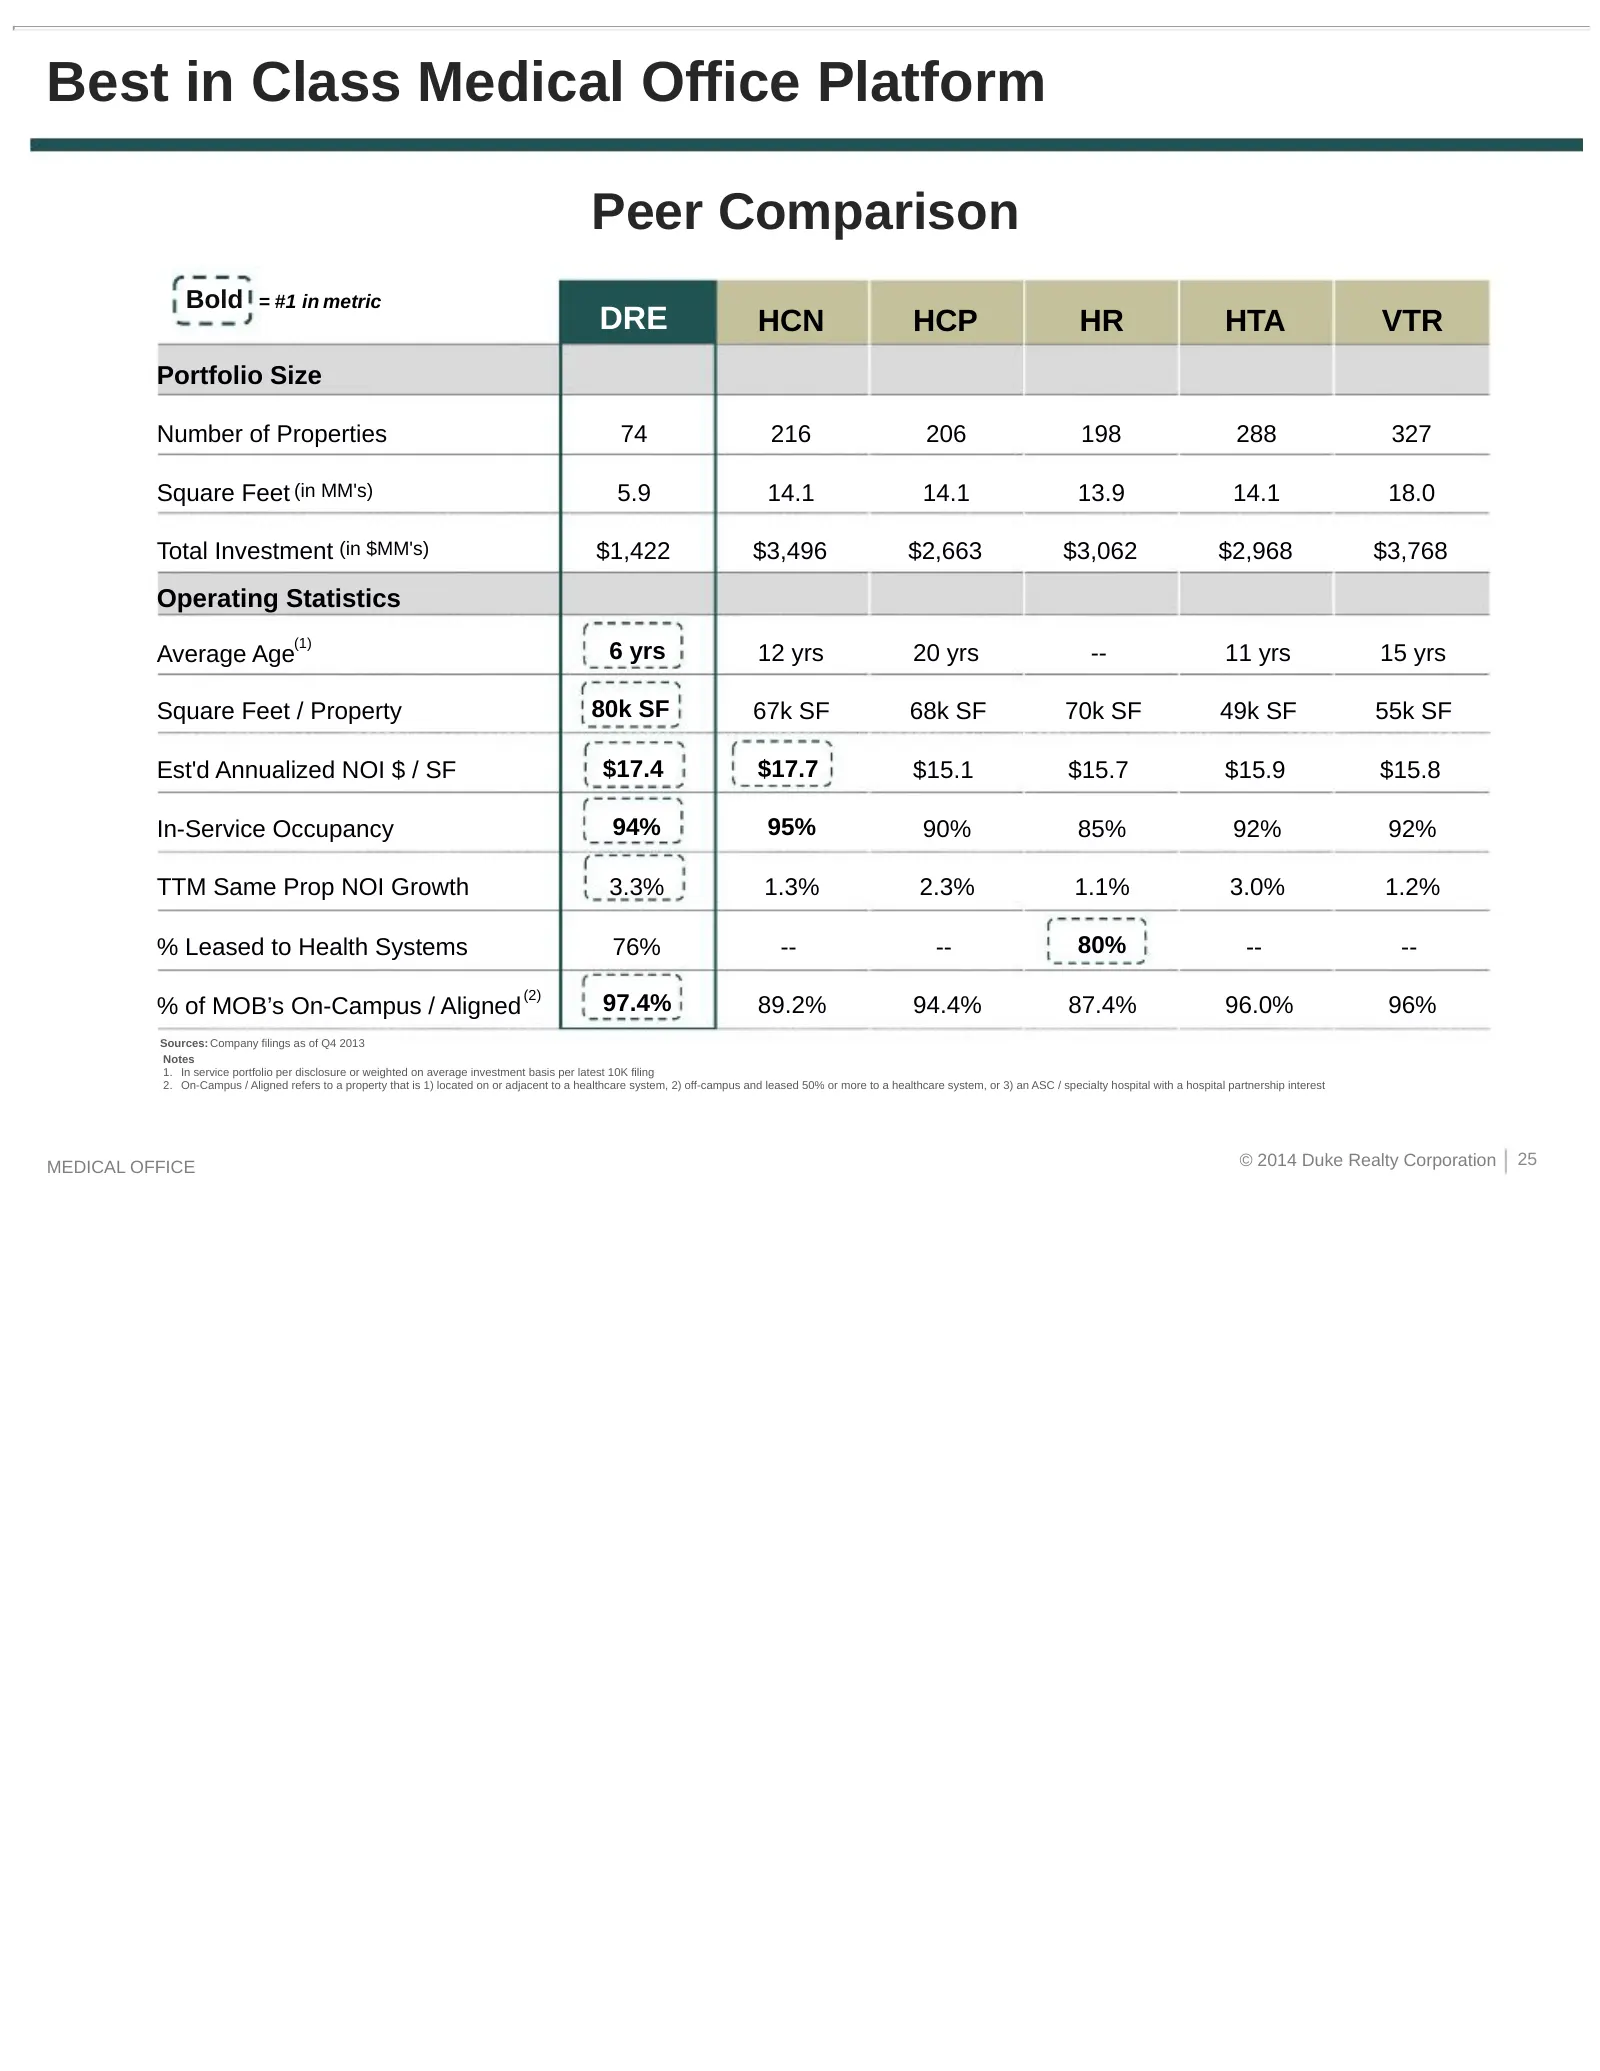
Best in Class Medical Office Platform Peer Comparison Bold = #1 in metric DRE HCN HCP HR HTA VTR Portfolio Size Number of Properties 74 216 206 198 288 327 Square Feet (in MM's) 5.9 14.1 14.1 13.9 14.1 18.0 Total Investment (in $MM's) $1,422 $3,496 $2,663 $3,062 $2,968 $3,768 Operating Statistics (1
Slide 26: Asset Strategy: Development Capabilities
ASSET STRATEGY DEVELOPMENT CAPABILITIES 26
Slide 27: Development Strategic Advantages
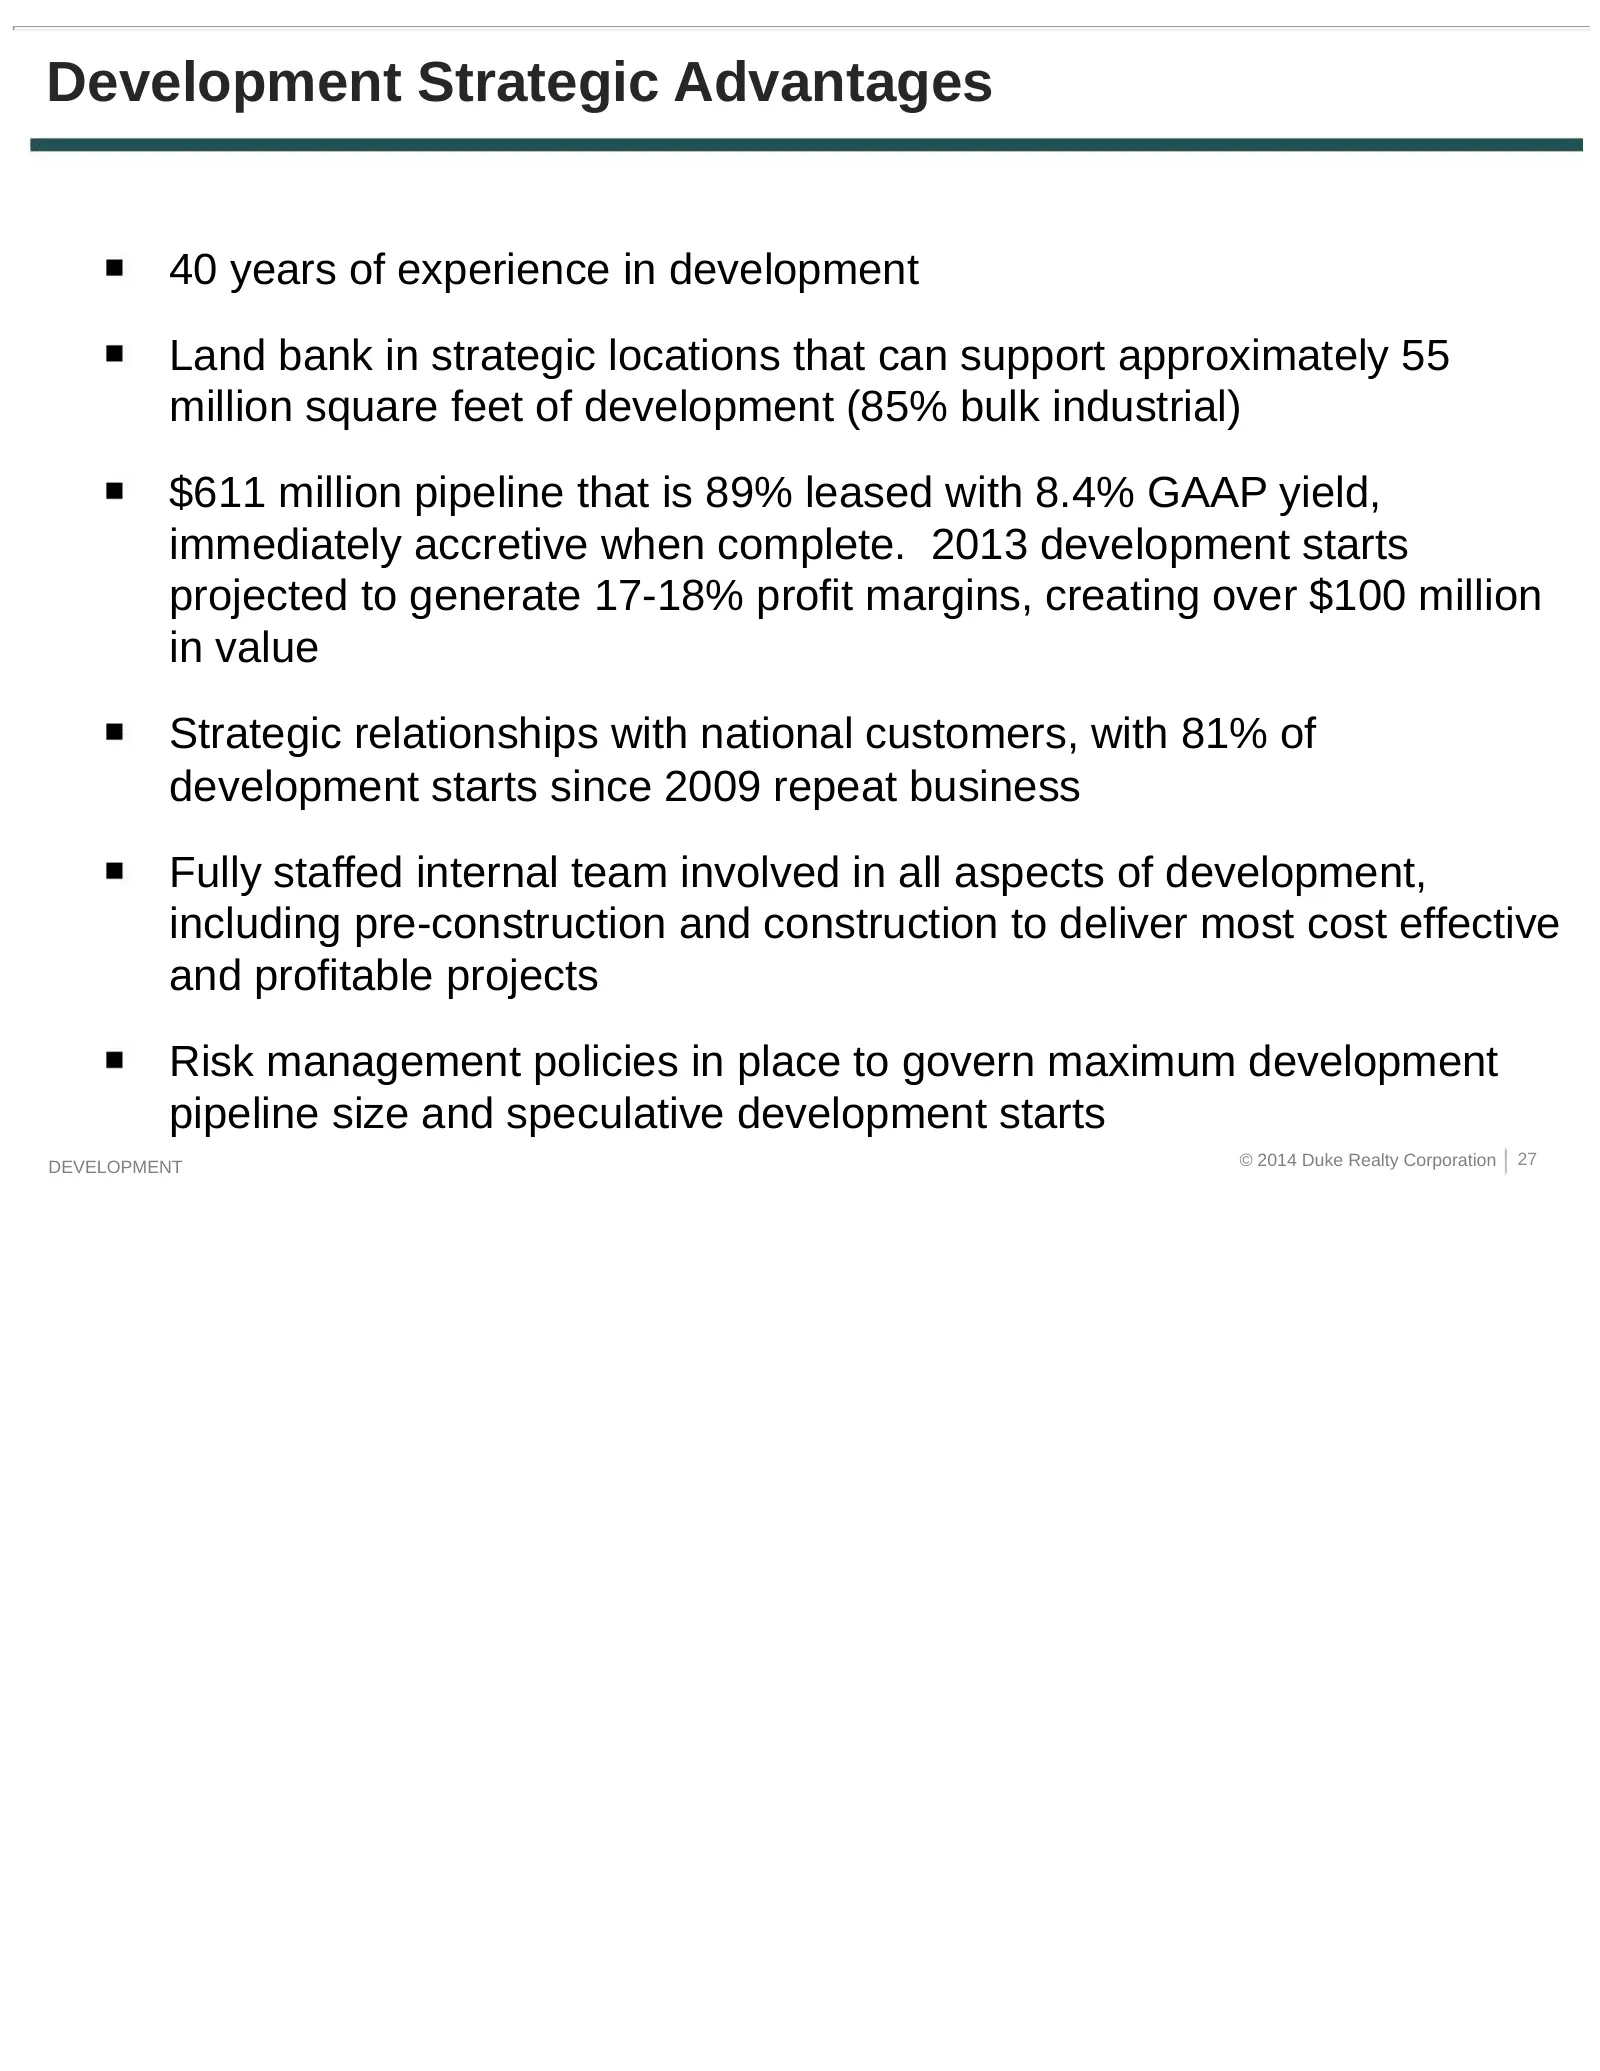
Development Strategic Advantages 40 years of experience in development Land bank in strategic locations that can support approximately 55 million square feet of development (85% bulk industrial) $611 million pipeline that is 89% leased with 8.4% GAAP yield, immediately accretive when complete. 2013
Slide 28: Strong Relative Development Pipeline
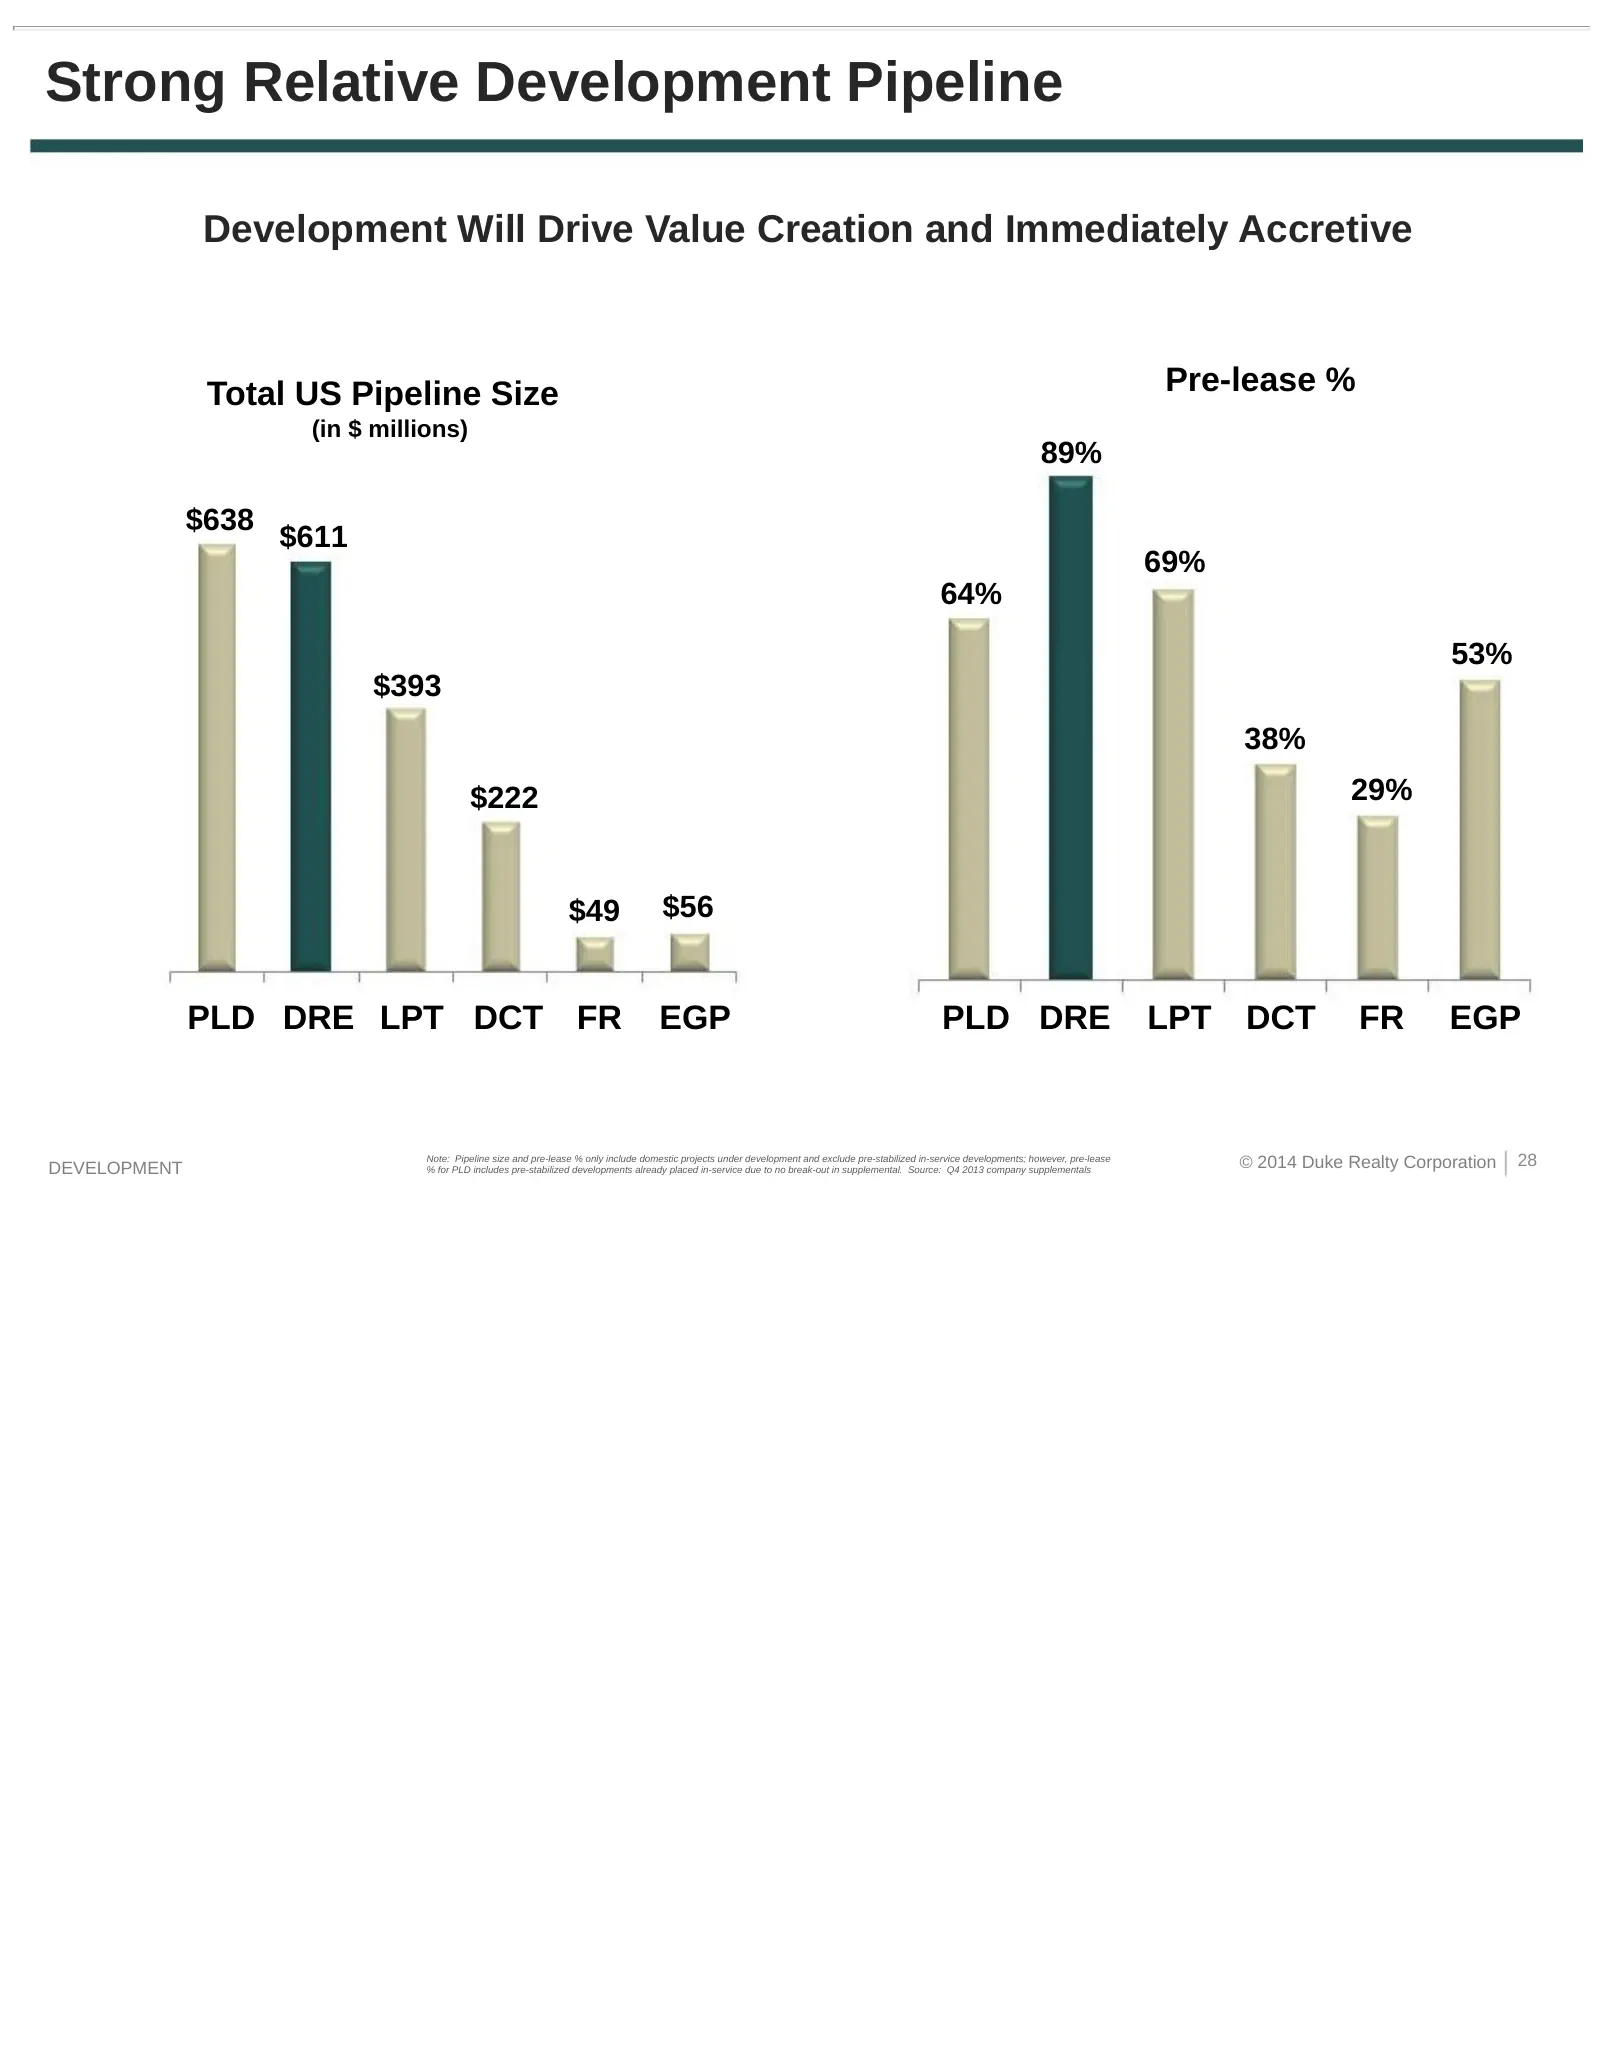
Strong Relative Development Pipeline Development Will Drive Value Creation and Immediately Accretive Total US Pipeline Size Pre-lease % (in $ millions) 89% $638 $611 69% 64% 53% $393 38% $222 29% $49 $56 PLD DRE LPT DCT FR EGP PLD DRE LPT DCT FR EGP DEVELOPMENT Note: Pipeline size and pre-lease % on
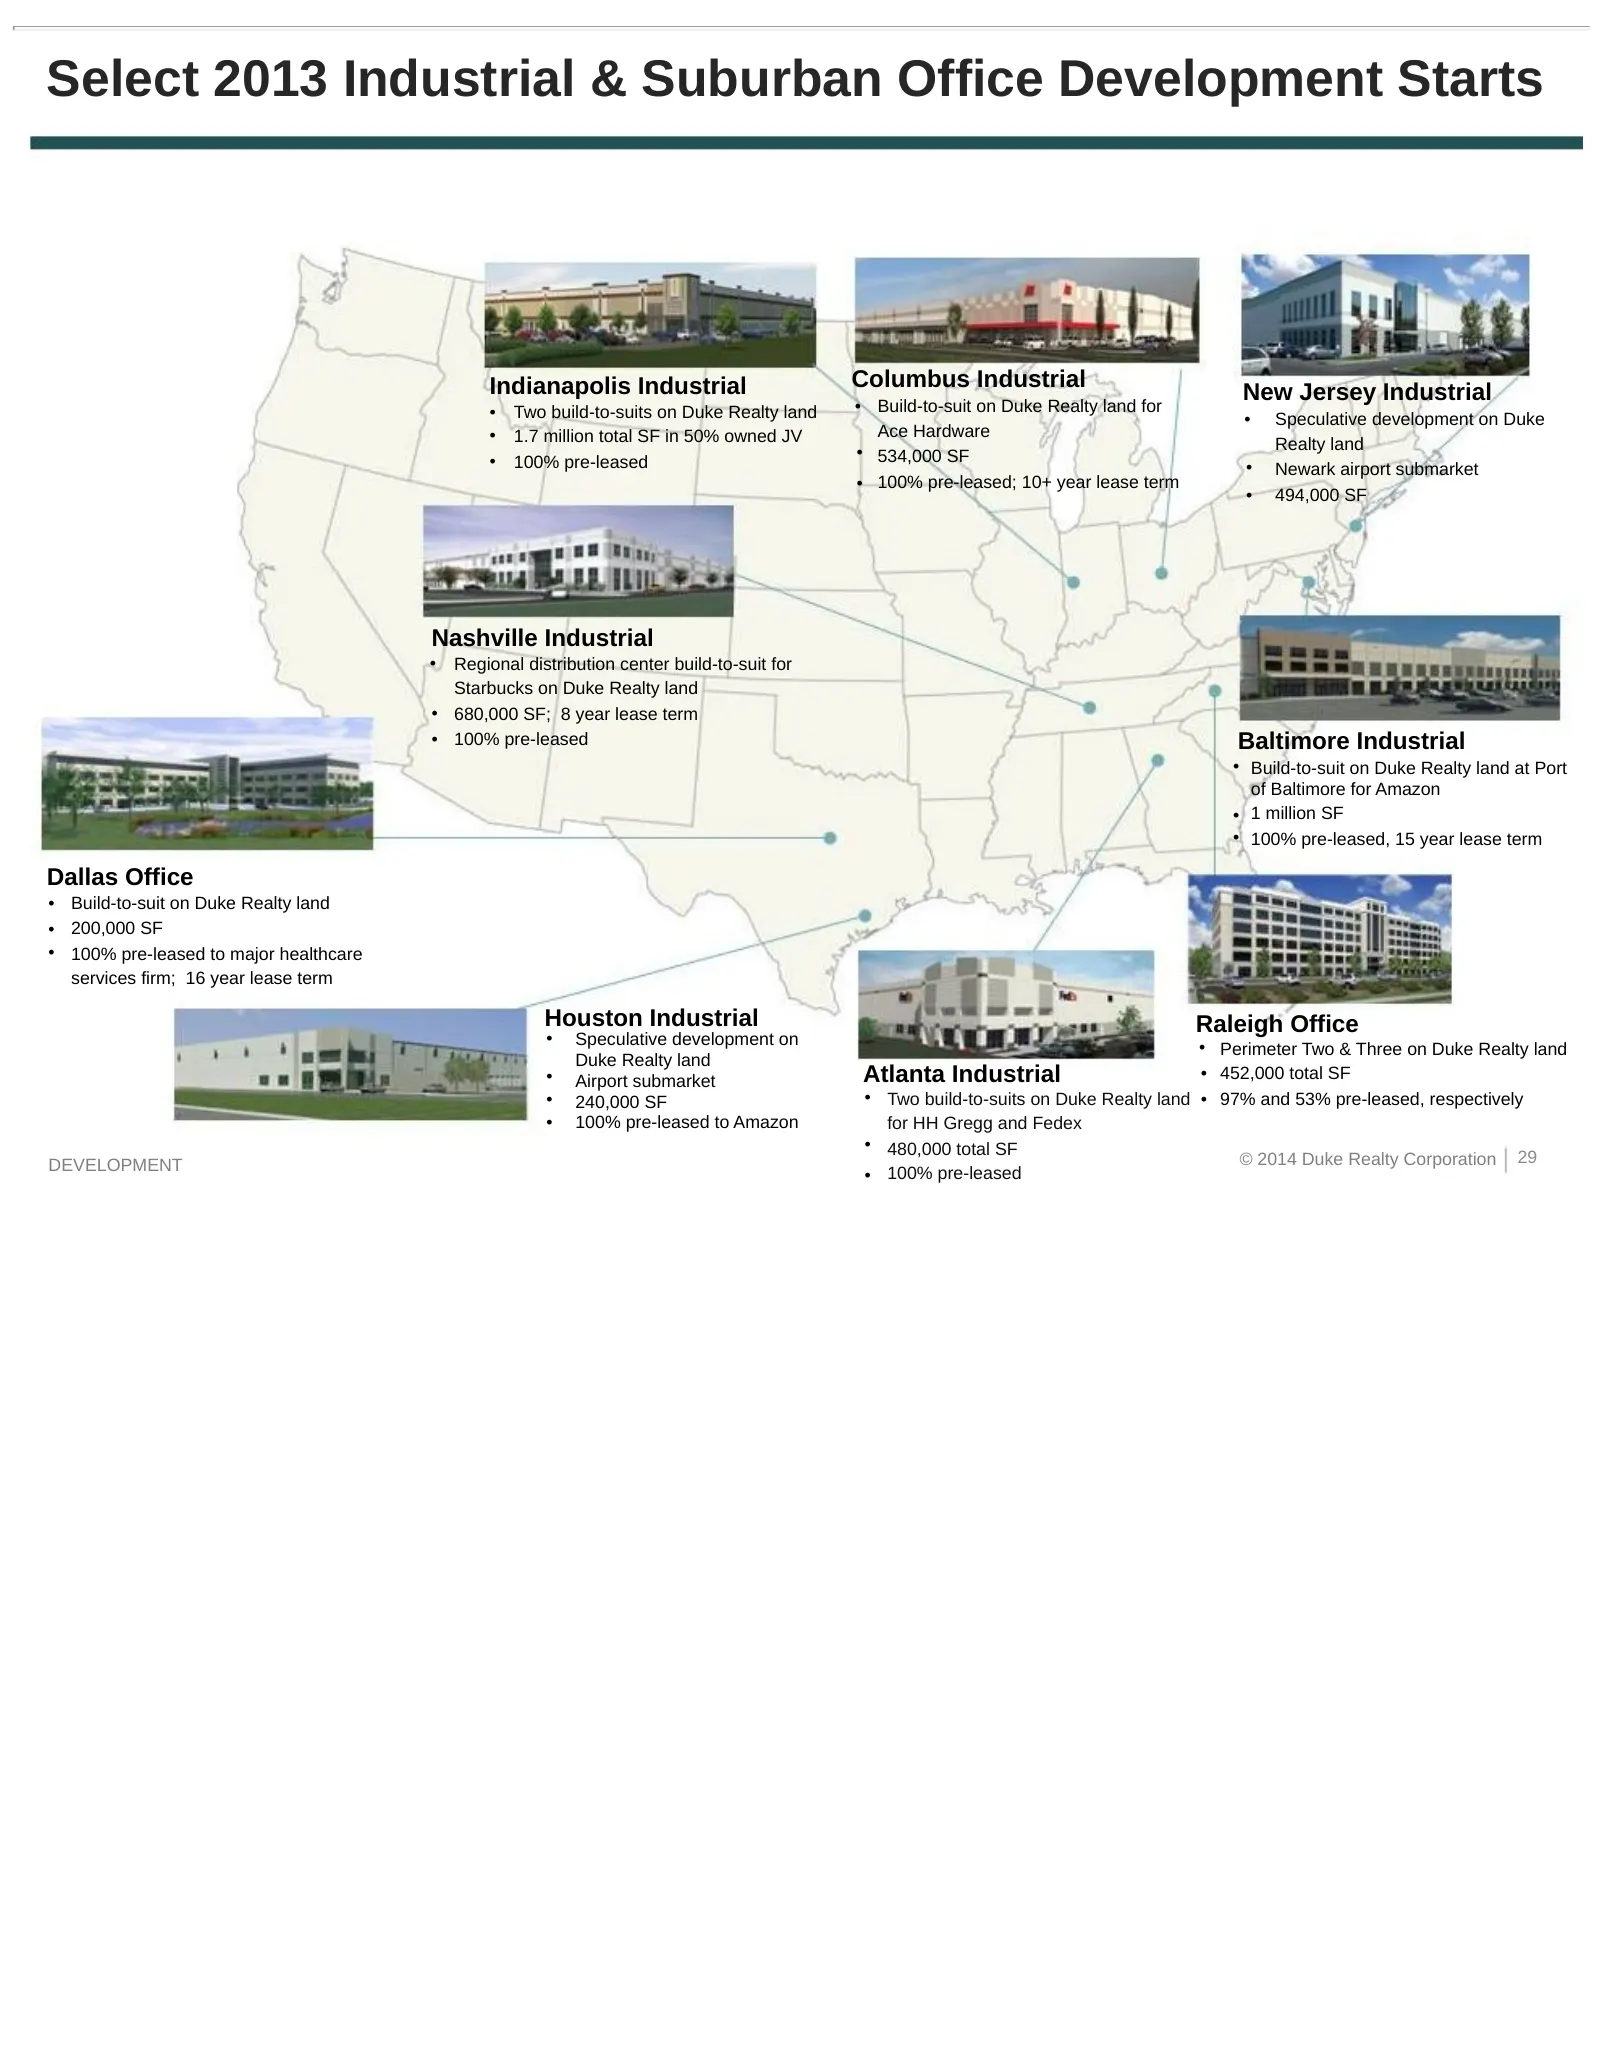
Slide 29: Select 2013 Industrial & Suburban Office Development Starts
Select 2013 Industrial & Suburban Office Development Starts Indianapolis Industrial Columbus Industrial • Build-to-suit on Duke Realty land for New Jersey Industrial • Two build-to-suits on Duke Realty land • Speculative development on Duke • 1.7 million total SF in 50% owned JV Ace Hardware • 534,0
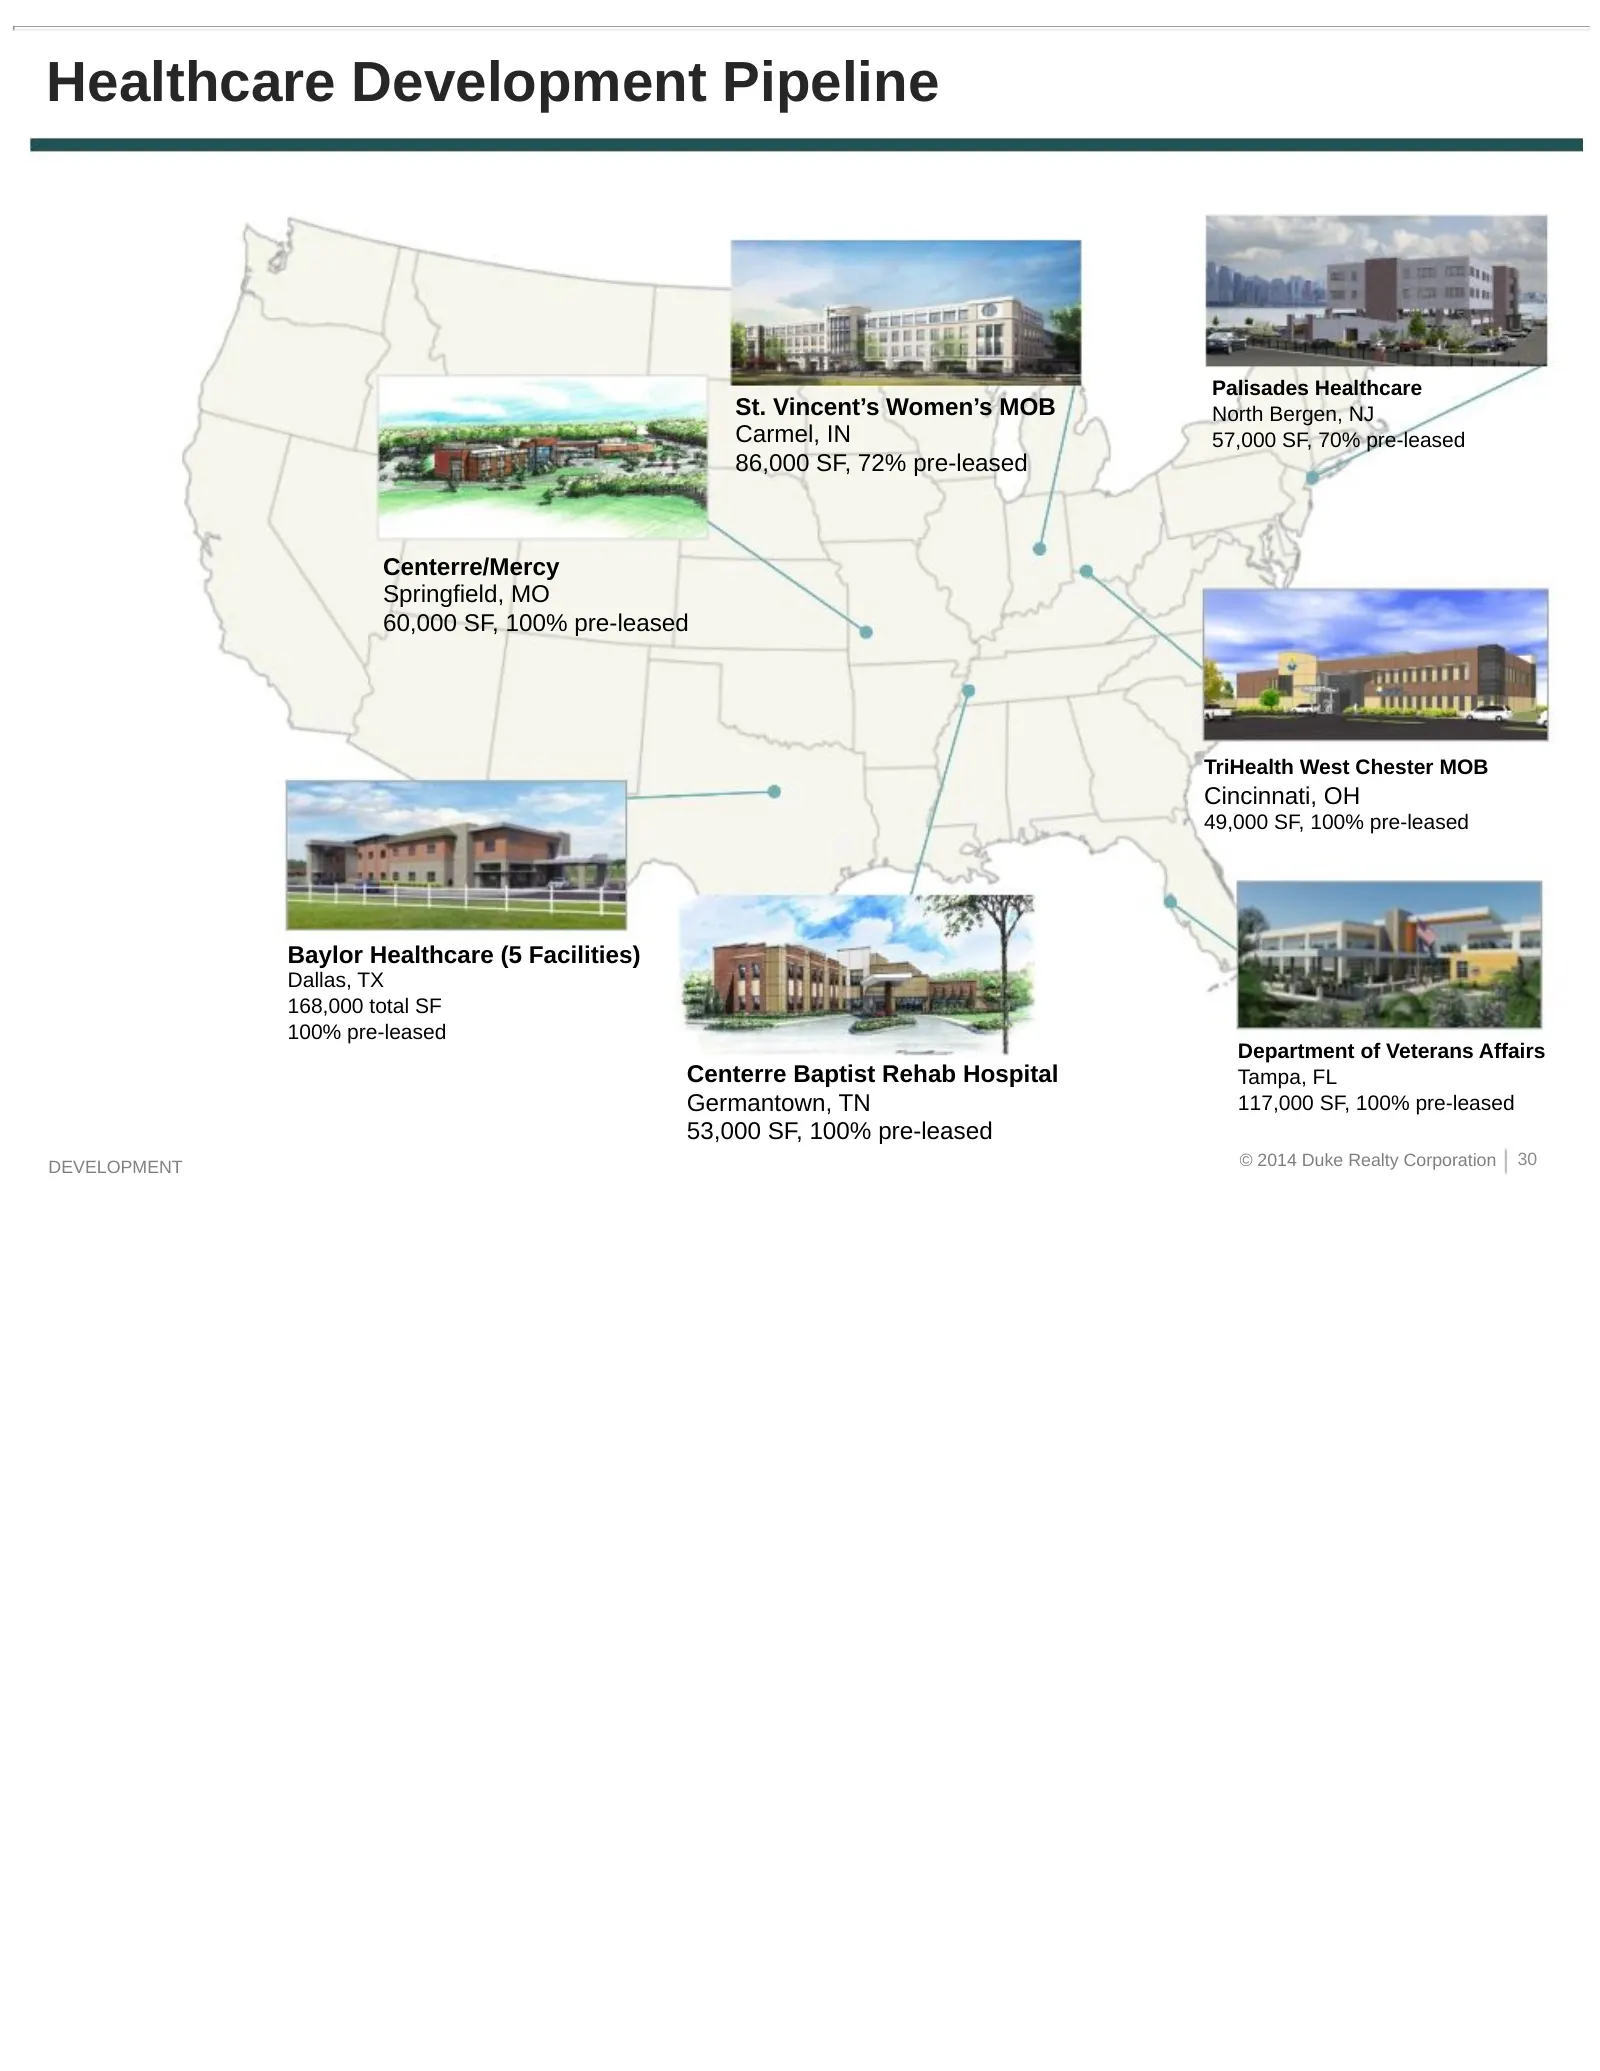
Slide 30: Healthcare Development Pipeline
Healthcare Development Pipeline Palisades Healthcare St. Vincent’s Women’s MOB North Bergen, NJ Carmel, IN 57,000 SF, 70% pre-leased 86,000 SF, 72% pre-leased Centerre/Mercy Springfield, MO 60,000 SF, 100% pre-leased TriHealth West Chester MOB Cincinnati, OH 49,000 SF, 100% pre-leased Baylor Healthc
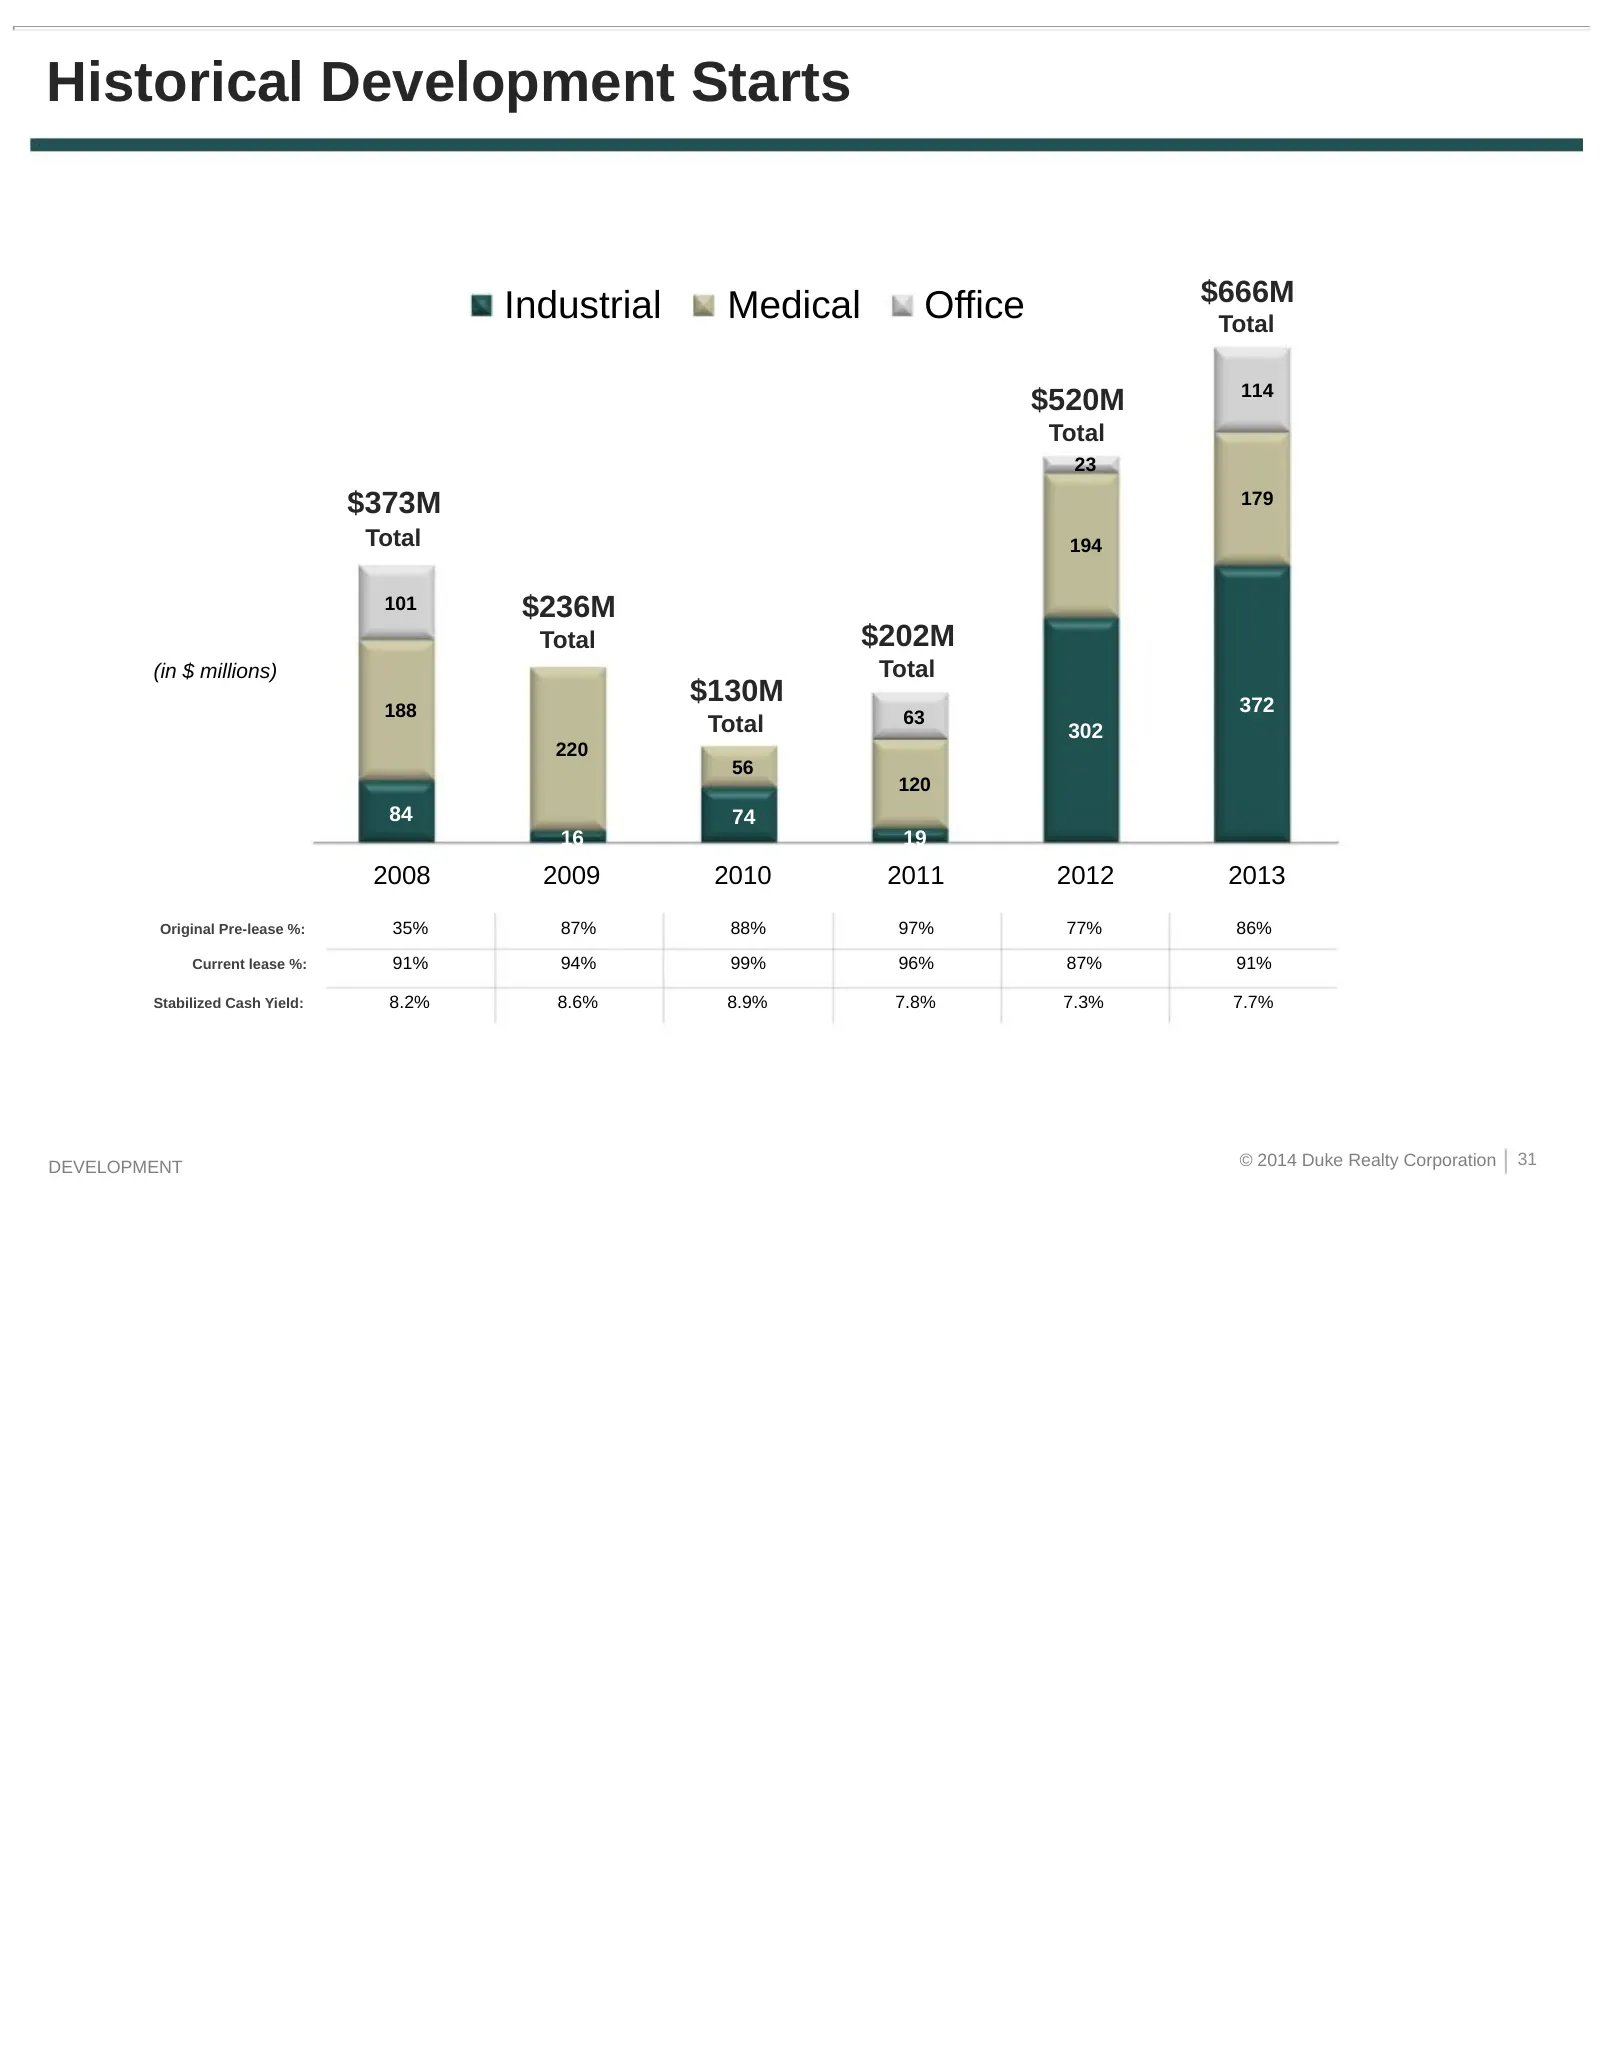
Slide 31: Historical Development Starts
Historical Development Starts $666M Industrial Medical Office Total 114 $520M Total 23 $373M 179 Total 194 101 $236M Total $202M (in $ millions) Total $130M 372 188 63 Total 302 220 56 120 84 74 16 19 2008 2009 2010 2011 2012 2013 Original Pre-lease %: 35% 87% 88% 97% 77% 86% Current lease %: 91% 94
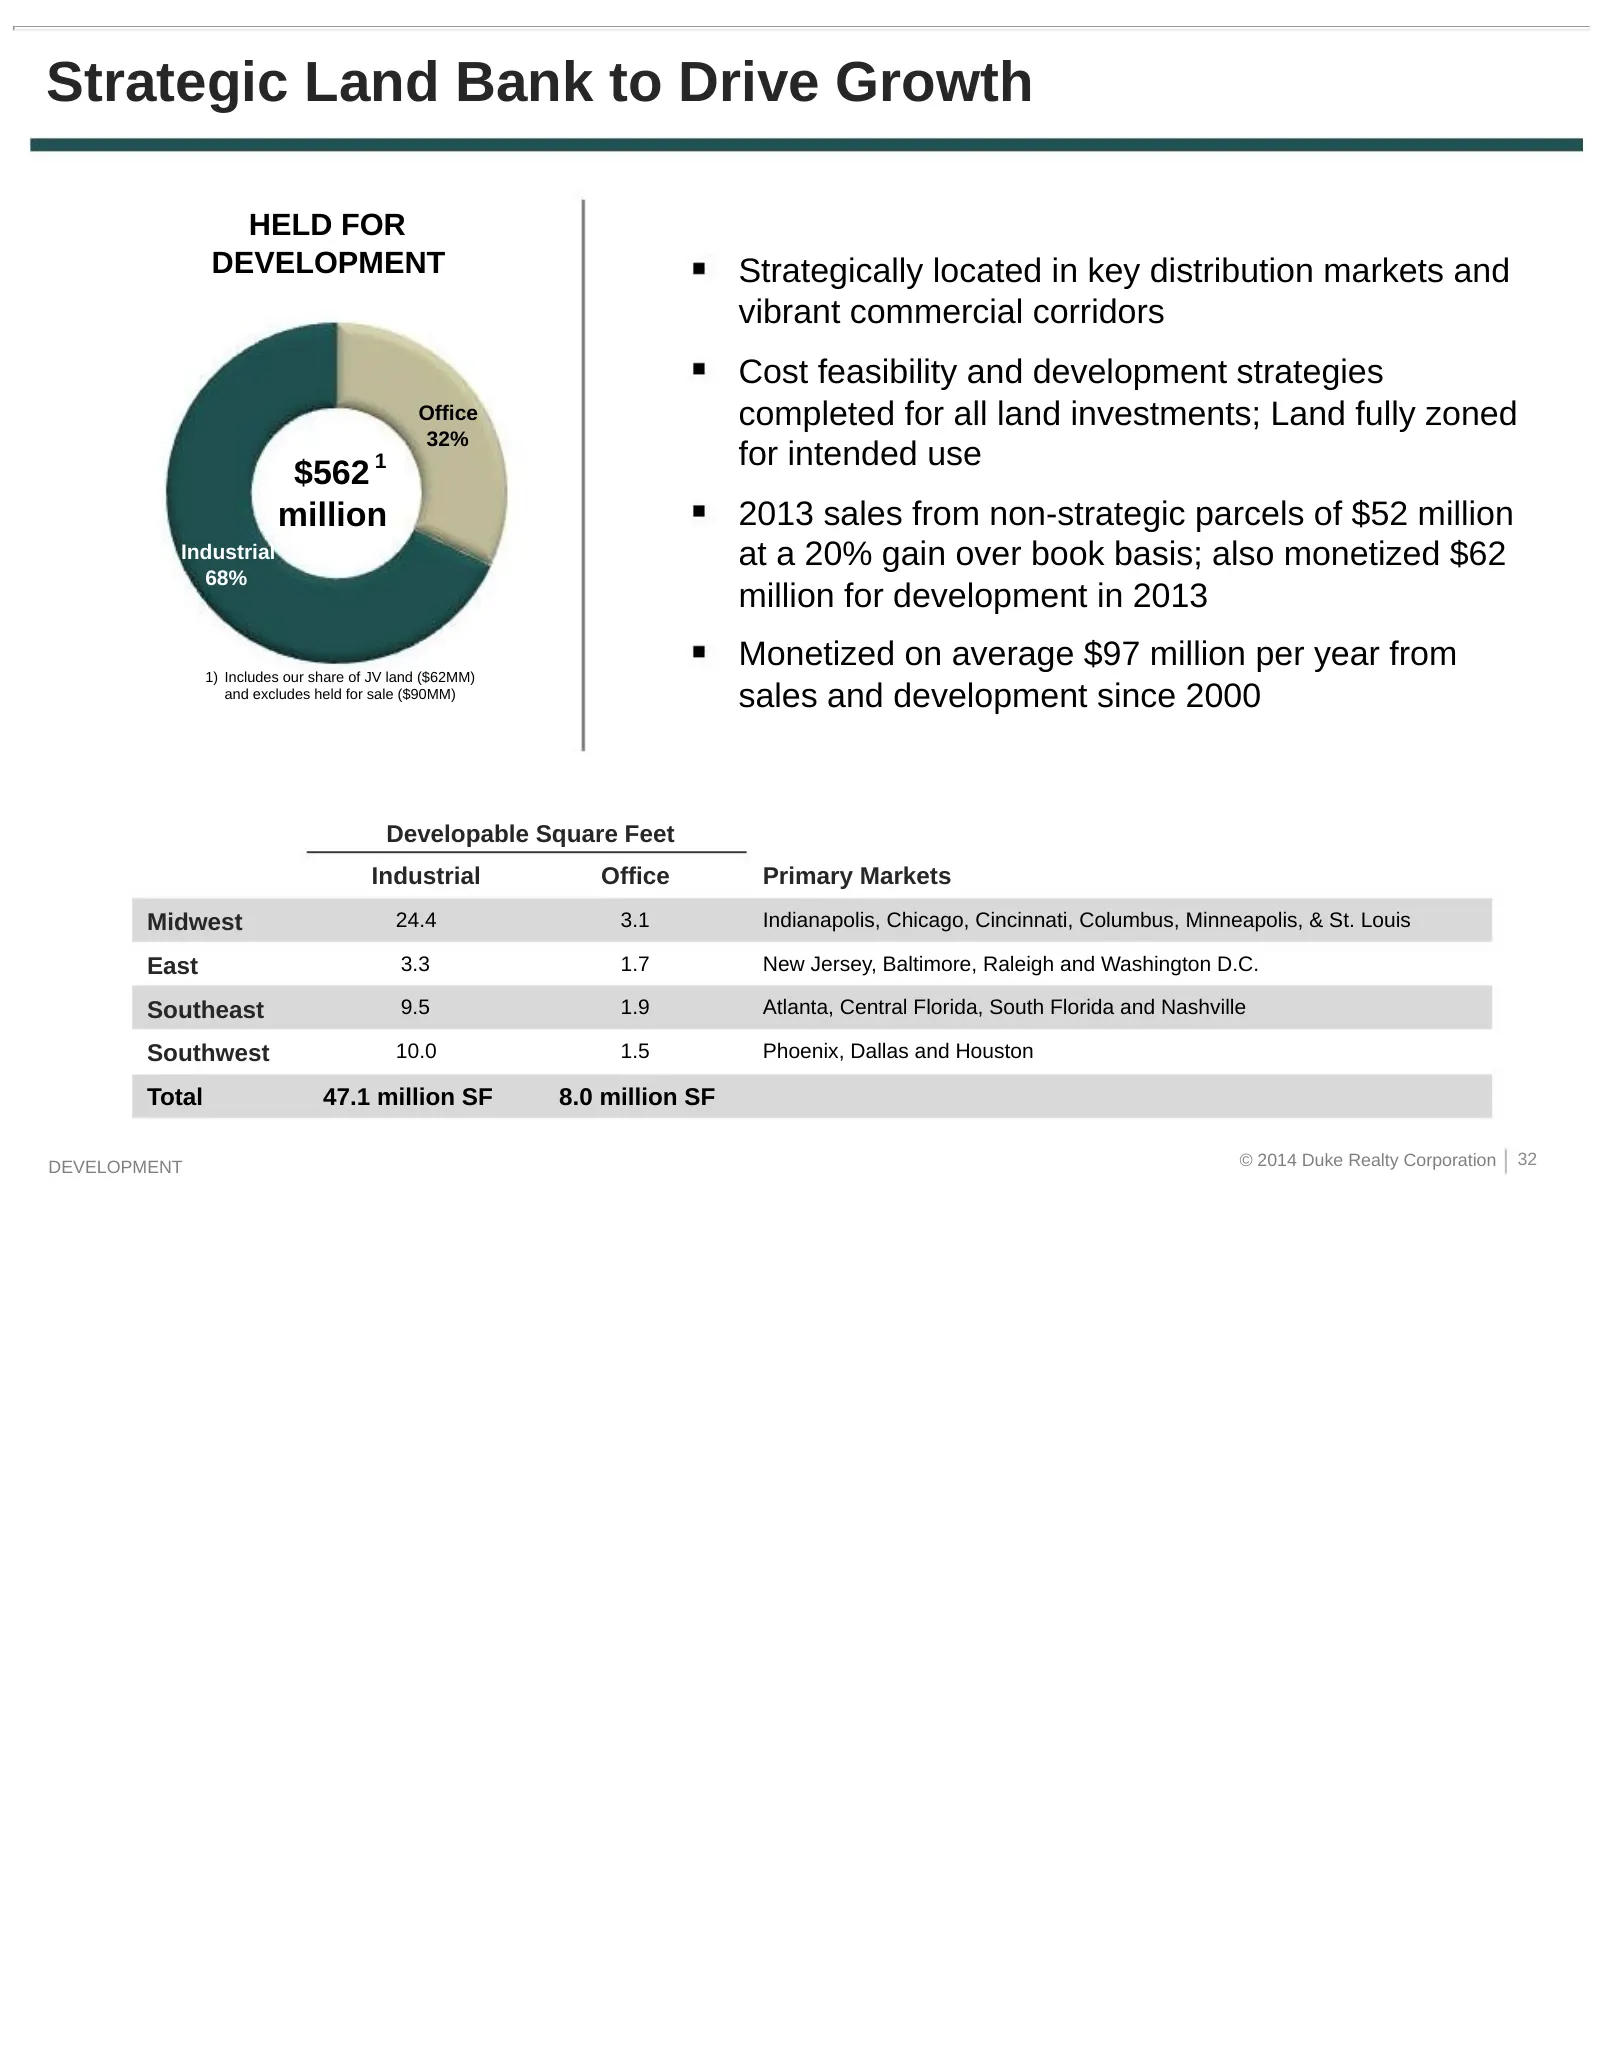
Slide 32: Strategic Land Bank to Drive Growth
Strategic Land Bank to Drive Growth HELD FOR DEVELOPMENT Strategically located in key distribution markets and vibrant commercial corridors Cost feasibility and development strategies Office completed for all land investments; Land fully zoned 32% for intended use $562 1 million 2013 sales from non-
Slide 33: Operating Strategy
> O pu <x o~ _ ie) O < - <x o LL oO Oo Vass say iairall ME ae Gil wica ua X Py r a
Slide 34: Operational Success and Future Growth Opportunities
Operational Success and Future Growth Opportunities Completed asset repositioning into higher quality, higher rental rate growth assets with minimal FFO per share dilution and annual growth in AFFO per share (6% CAGR) Proven same property NOI outperformance, well positioned for continuing same prope
Slide 35: Historical Occupancy Supports Additional Upside
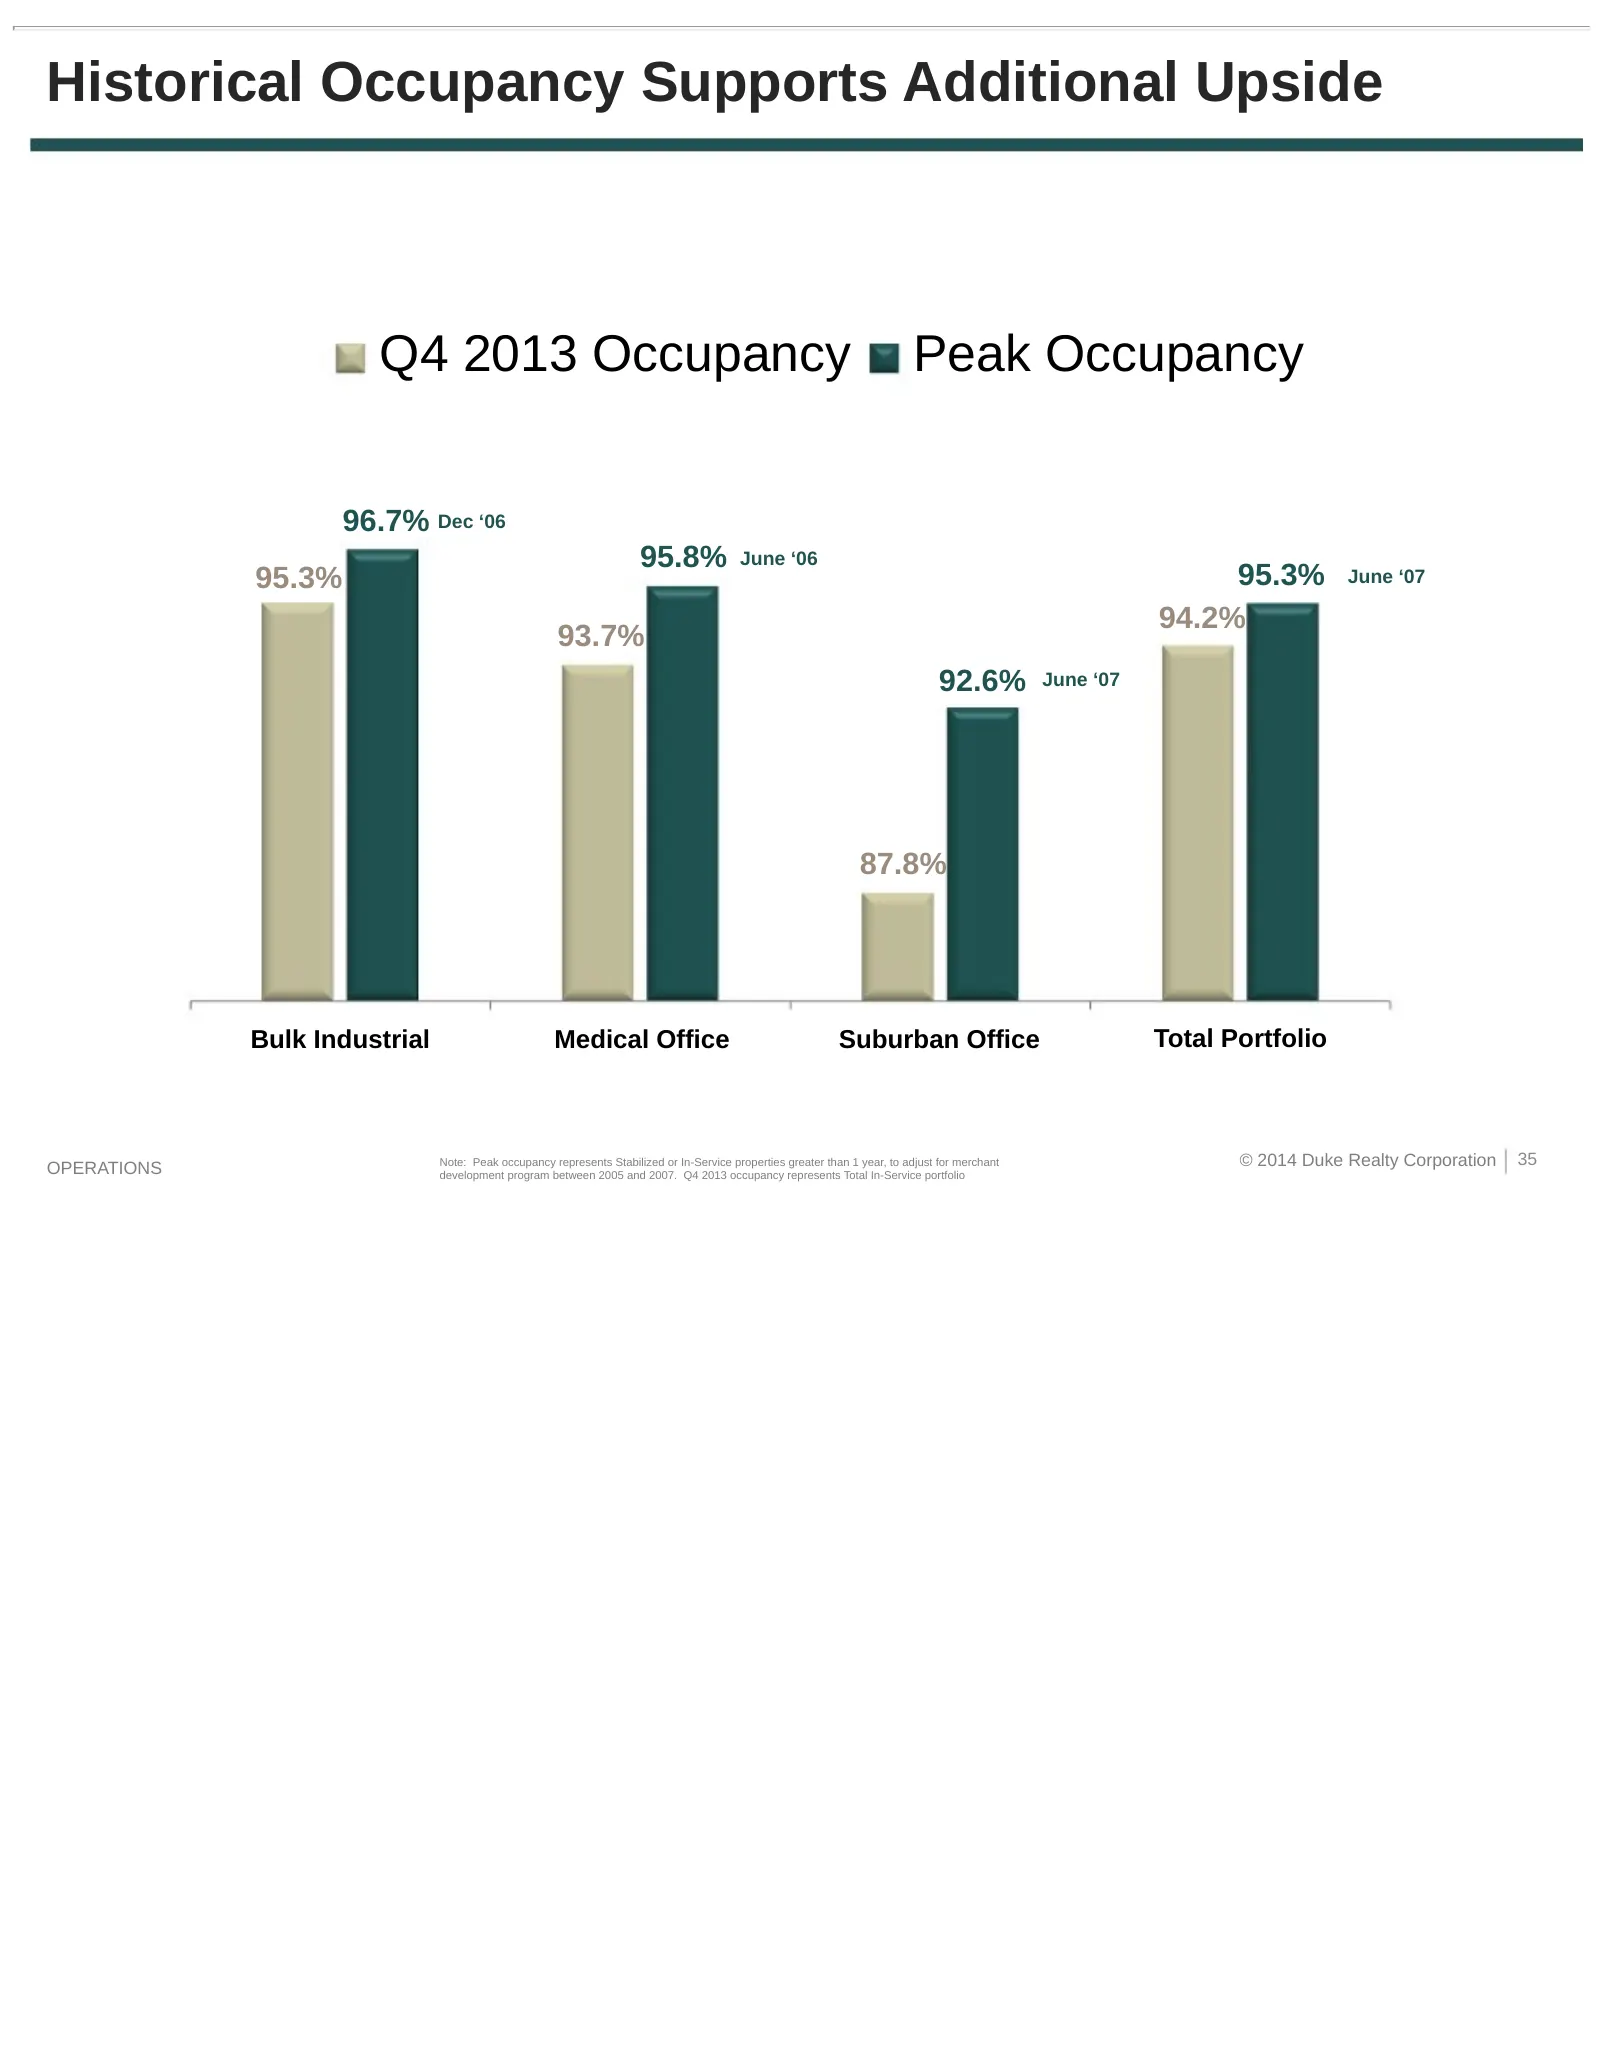
Historical Occupancy Supports Additional Upside Q4 2013 Occupancy Peak Occupancy 96.7% Dec ‘06 95.8% June ‘06 95.3% 95.3% June ‘07 94.2% 93.7% 92.6% June ‘07 87.8% Bulk Industrial Medical Office Suburban Office Total Portfolio Note: Peak occupancy represents Stabilized or In-Service properties great
Slide 36: Improving Operating Performance
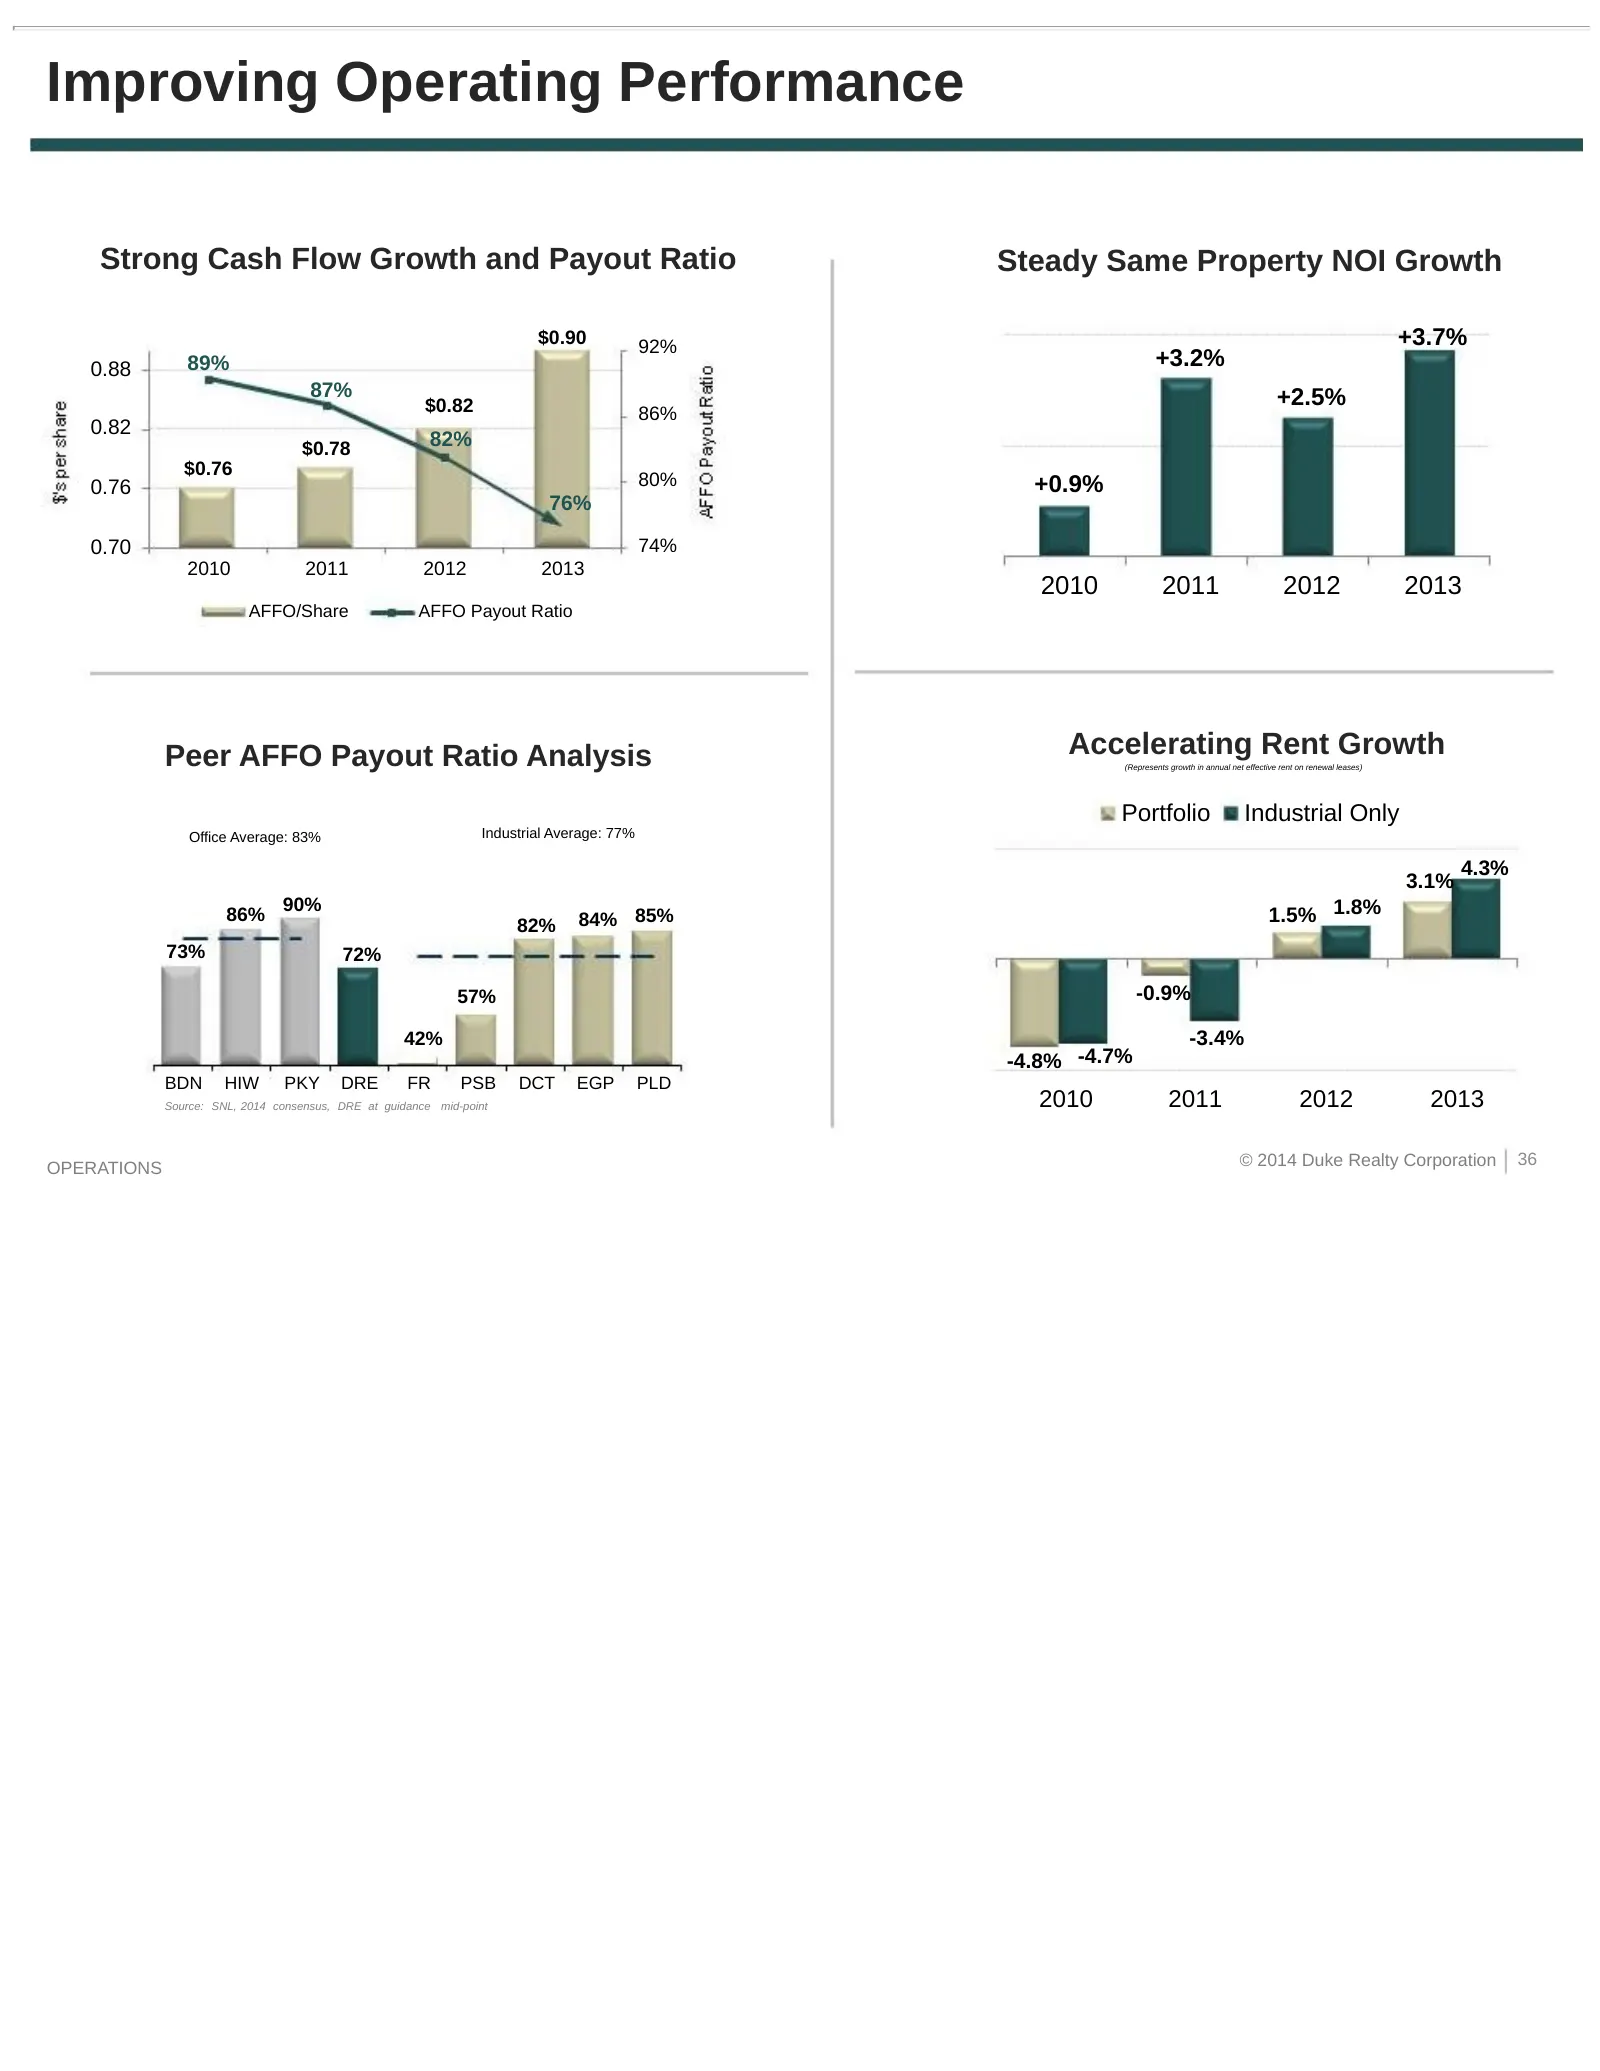
Improving Operating Performance Strong Cash Flow Growth and Payout Ratio Steady Same Property NOI Growth $0.90 92% +3.7% 0.88 89% +3.2% 87% +2.5% $0.82 86% 0.82 $0.78 82% $0.76 0.76 80% +0.9% 76% 0.70 74% 2010 2011 2012 2013 2010 2011 2012 2013 AFFO/Share AFFO Payout Ratio Peer AFFO Payout Ratio Ana
Slide 37: Capital Strategy
11 ‘orate wy ae = Si i uo = Hi i i ' Sn: | i # a CAPITAL STRATEGY
Slide 38: Balance Sheet Quality
Balance Sheet Quality Achieved original leverage goals established in 2009 Continue to delever through assets sales and equity to fund highly pre- leased development pipeline Improved portfolio quality generating cash flow growth and improved coverage metrics Well balanced annual debt maturities Sig
Slide 39: Key Capital Metrics
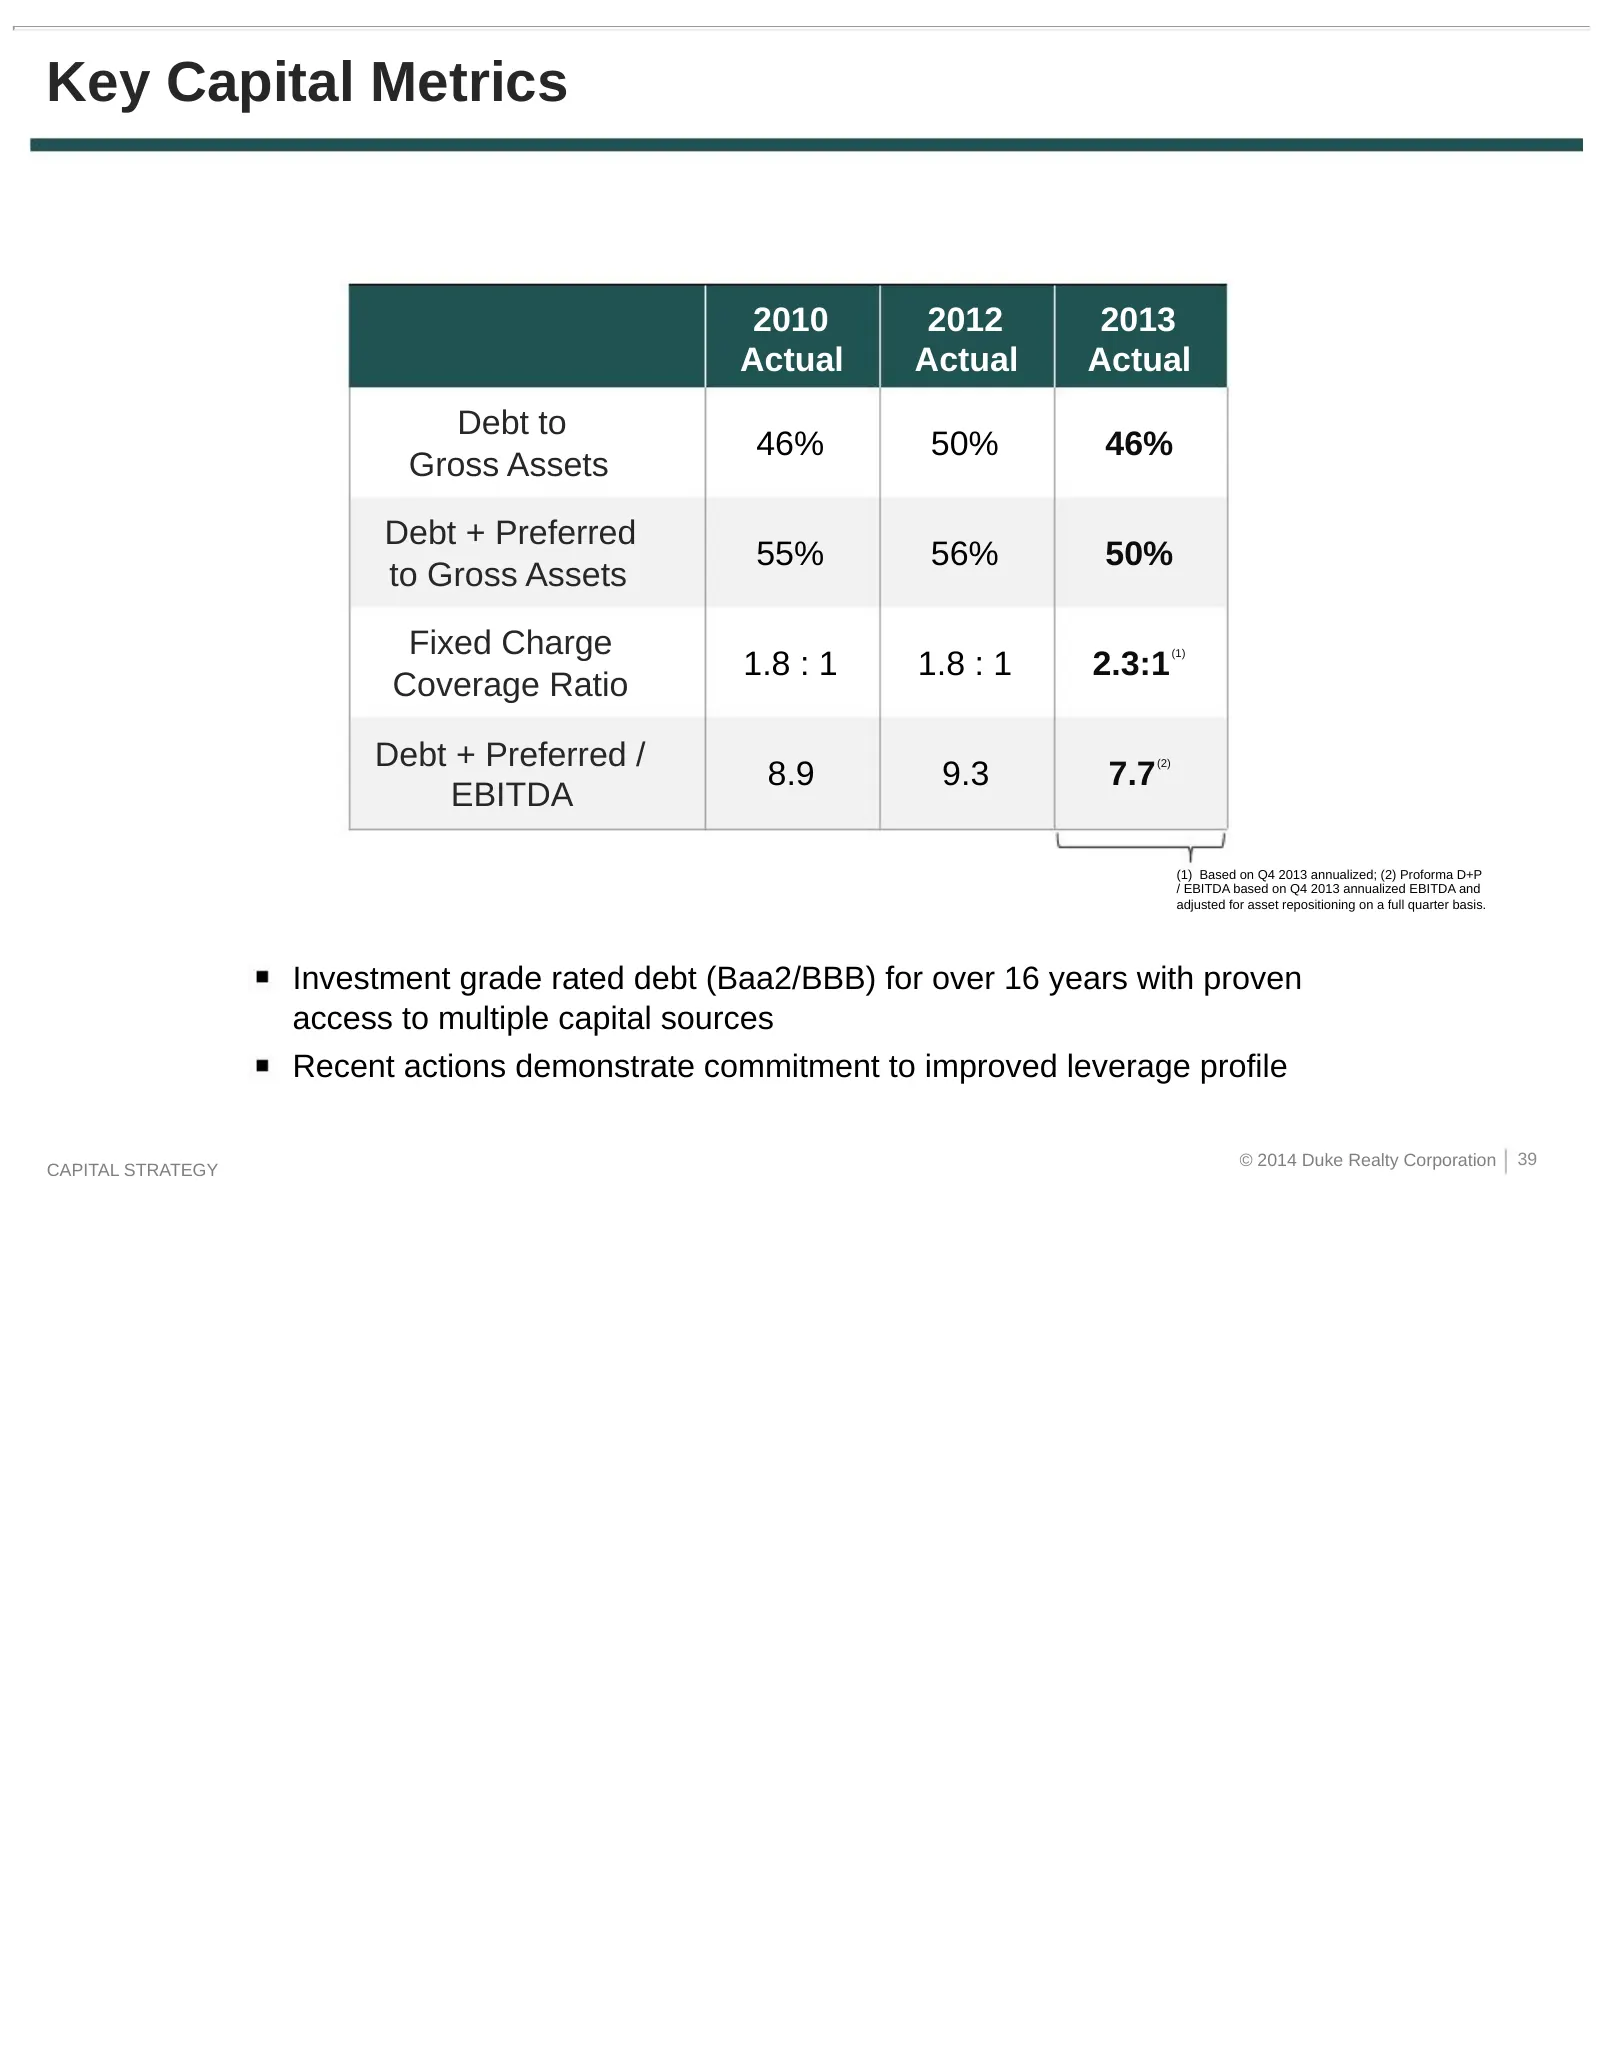
Key Capital Metrics 2010 2012 2013 Actual Actual Actual Debt to 46% 50% 46% Gross Assets Debt + Preferred 55% 56% 50% to Gross Assets Fixed Charge 1.8 : 1 1.8 : 1 2.3:1 (1) Coverage Ratio Debt + Preferred / 8.9 9.3 7.7 (2) EBITDA (1) Based on Q4 2013 annualized; (2) Proforma D+P / EBITDA based on Q4
Slide 40: Balanced Debt Maturities
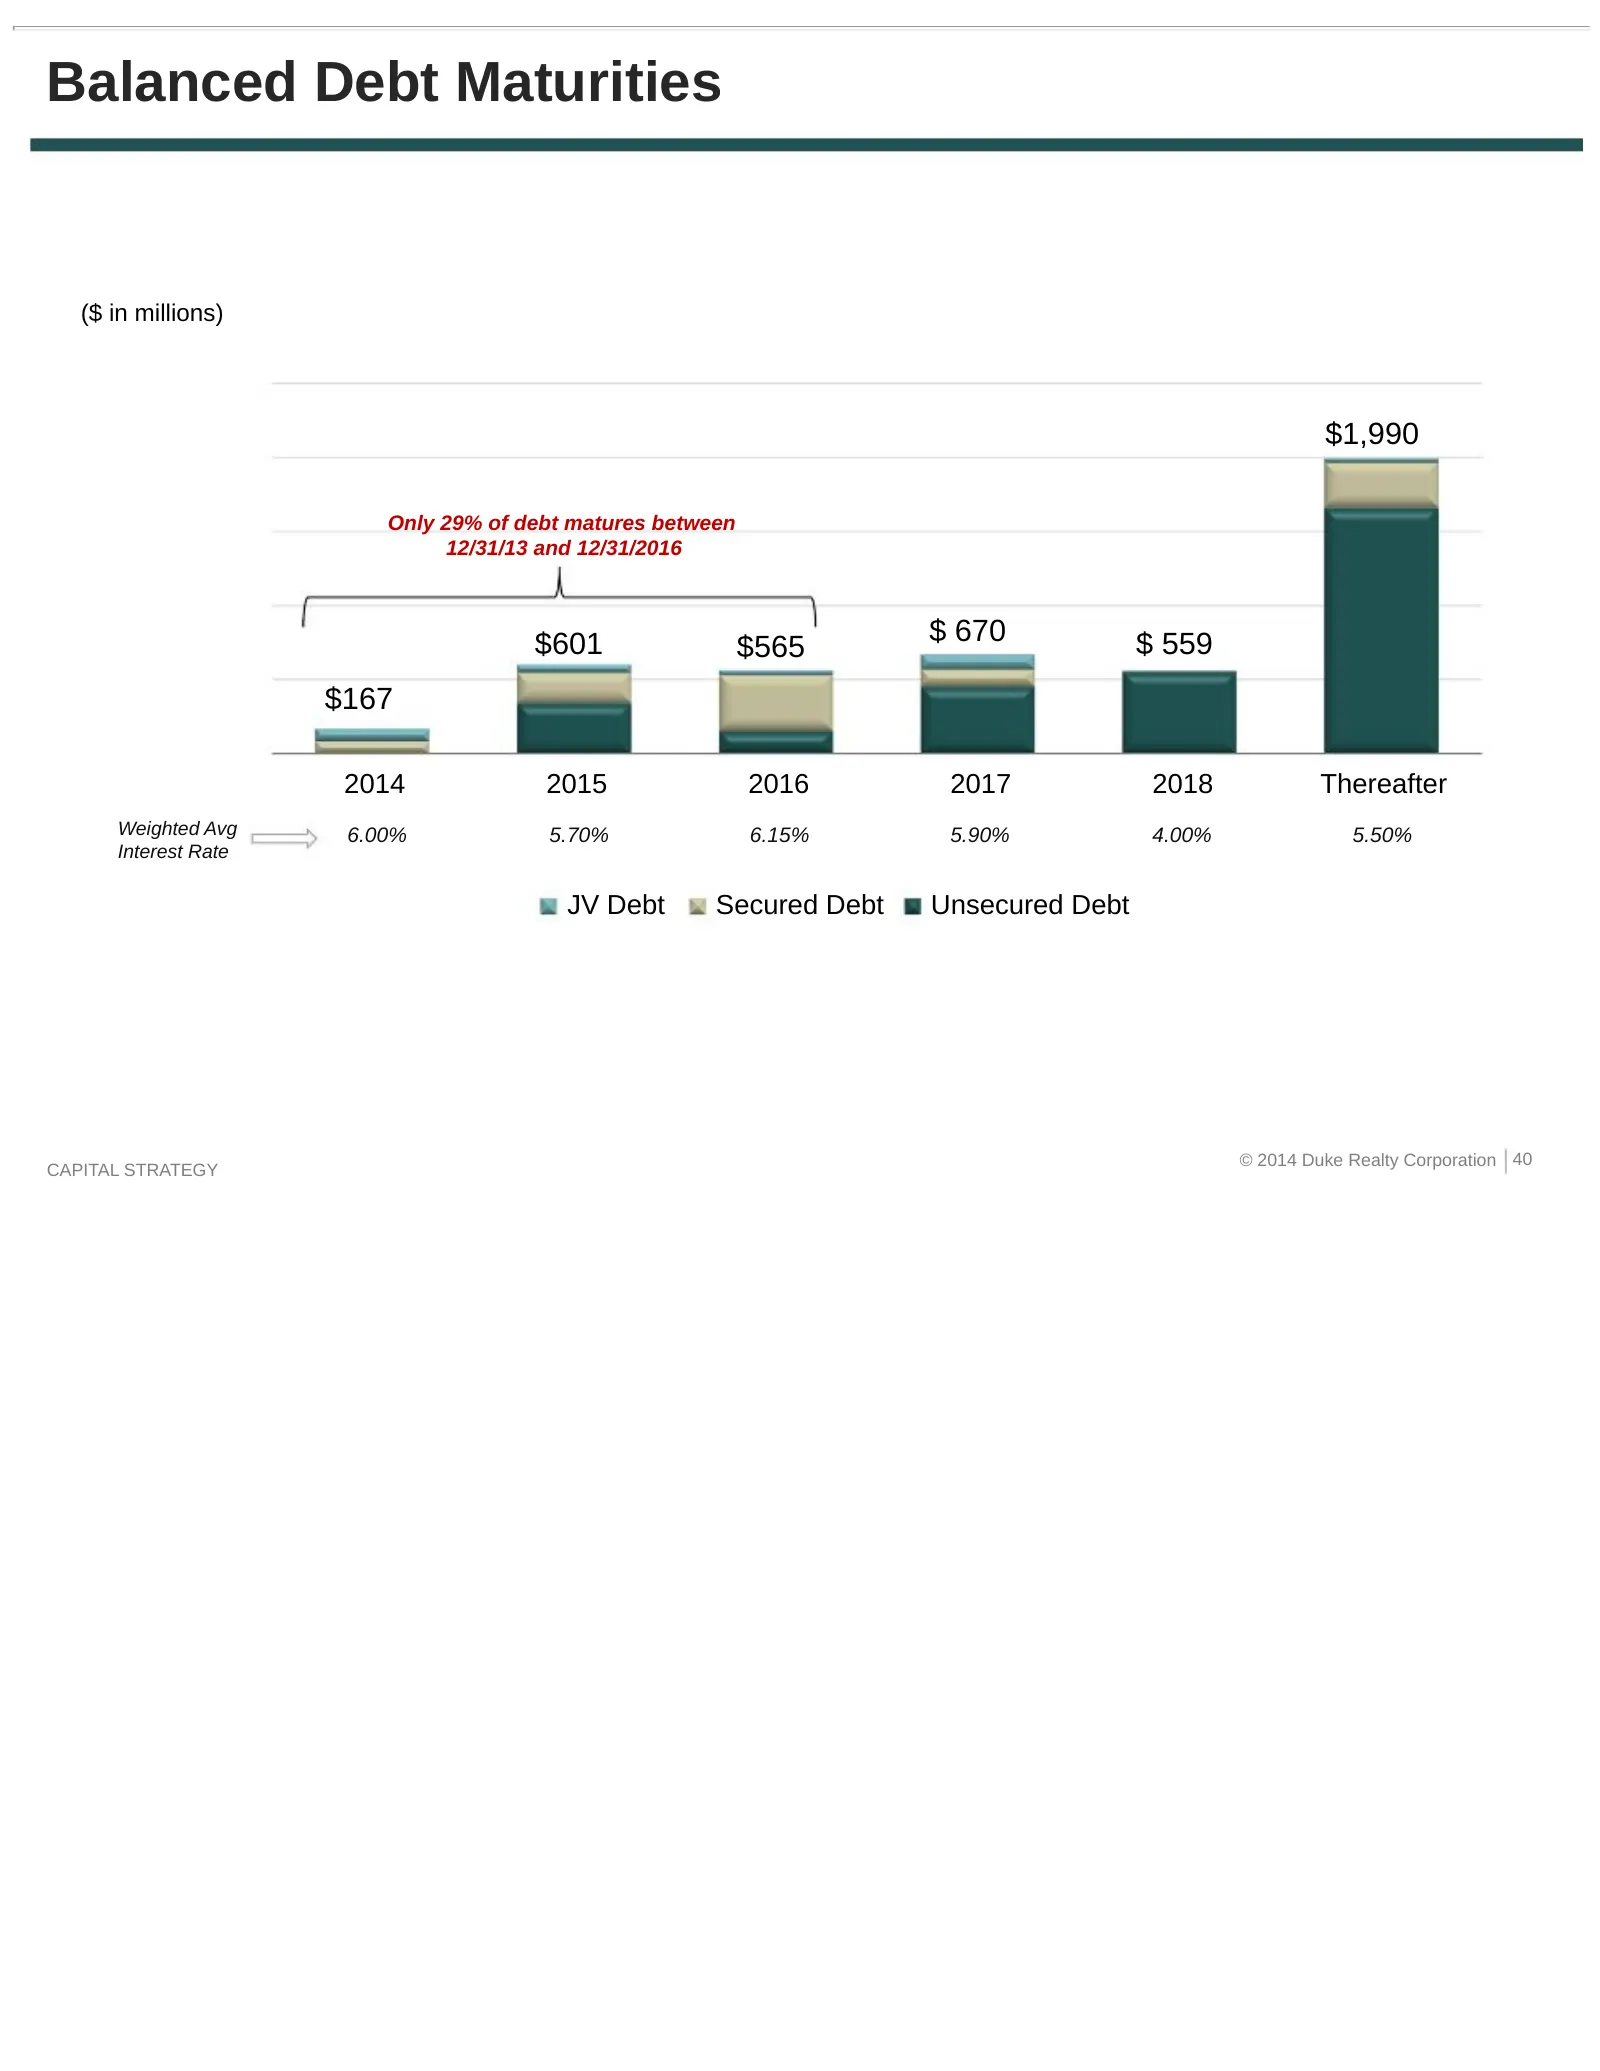
Balanced Debt Maturities ($ in millions) $1,990 Only 29% of debt matures between 12/31/13 and 12/31/2016 $601 $ 670 $ 559 $565 $167 2014 2015 2016 2017 2018 Thereafter Weighted Avg 6.00% 5.70% 6.15% 5.90% 4.00% 5.50% Interest Rate JV Debt Secured Debt Unsecured Debt © 2014 Duke Realty Corporation 40
Slide 41: Duke Realty Peer Debt Metrics
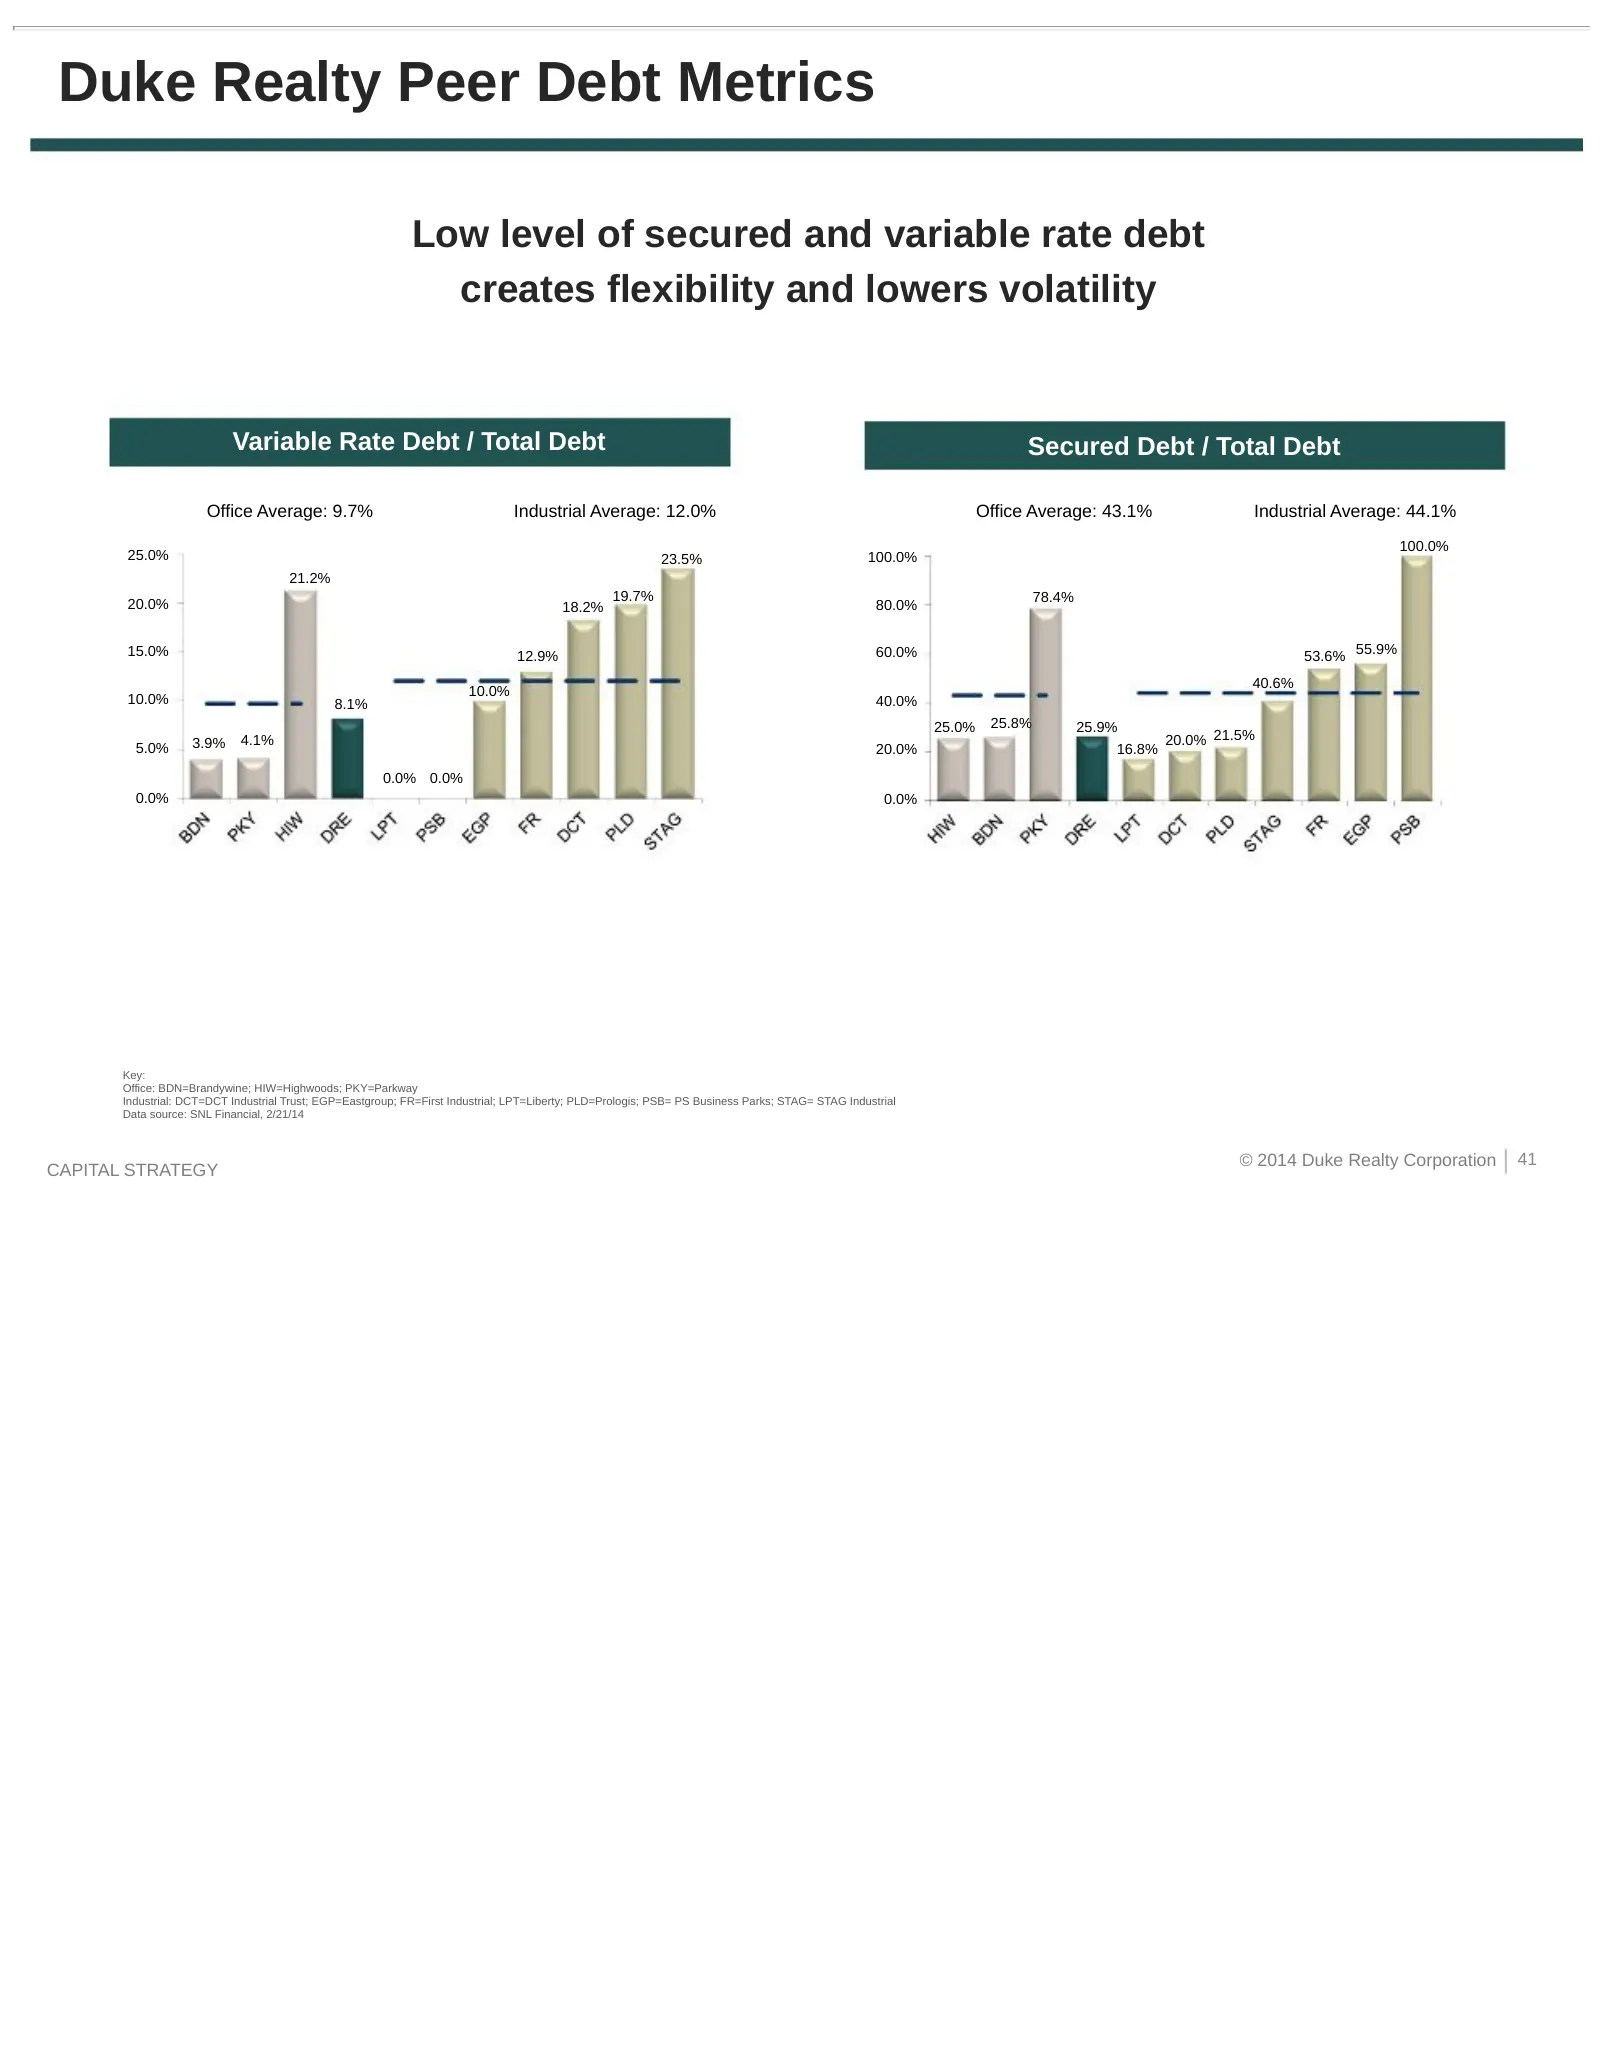
Duke Realty Peer Debt Metrics Low level of secured and variable rate debt creates flexibility and lowers volatility Variable Rate Debt / Total Debt Secured Debt / Total Debt Office Average: 9.7% Industrial Average: 12.0% Office Average: 43.1% Industrial Average: 44.1% 100.0% 25.0% 23.5% 100.0% 21.2%
Slide 42: Why Duke Realty
WHY DUKE REALTY RELIABLE. ANSWERS. © 2014 Duke Realty Corporation 42
Slide 43: Duke Realty Score Card
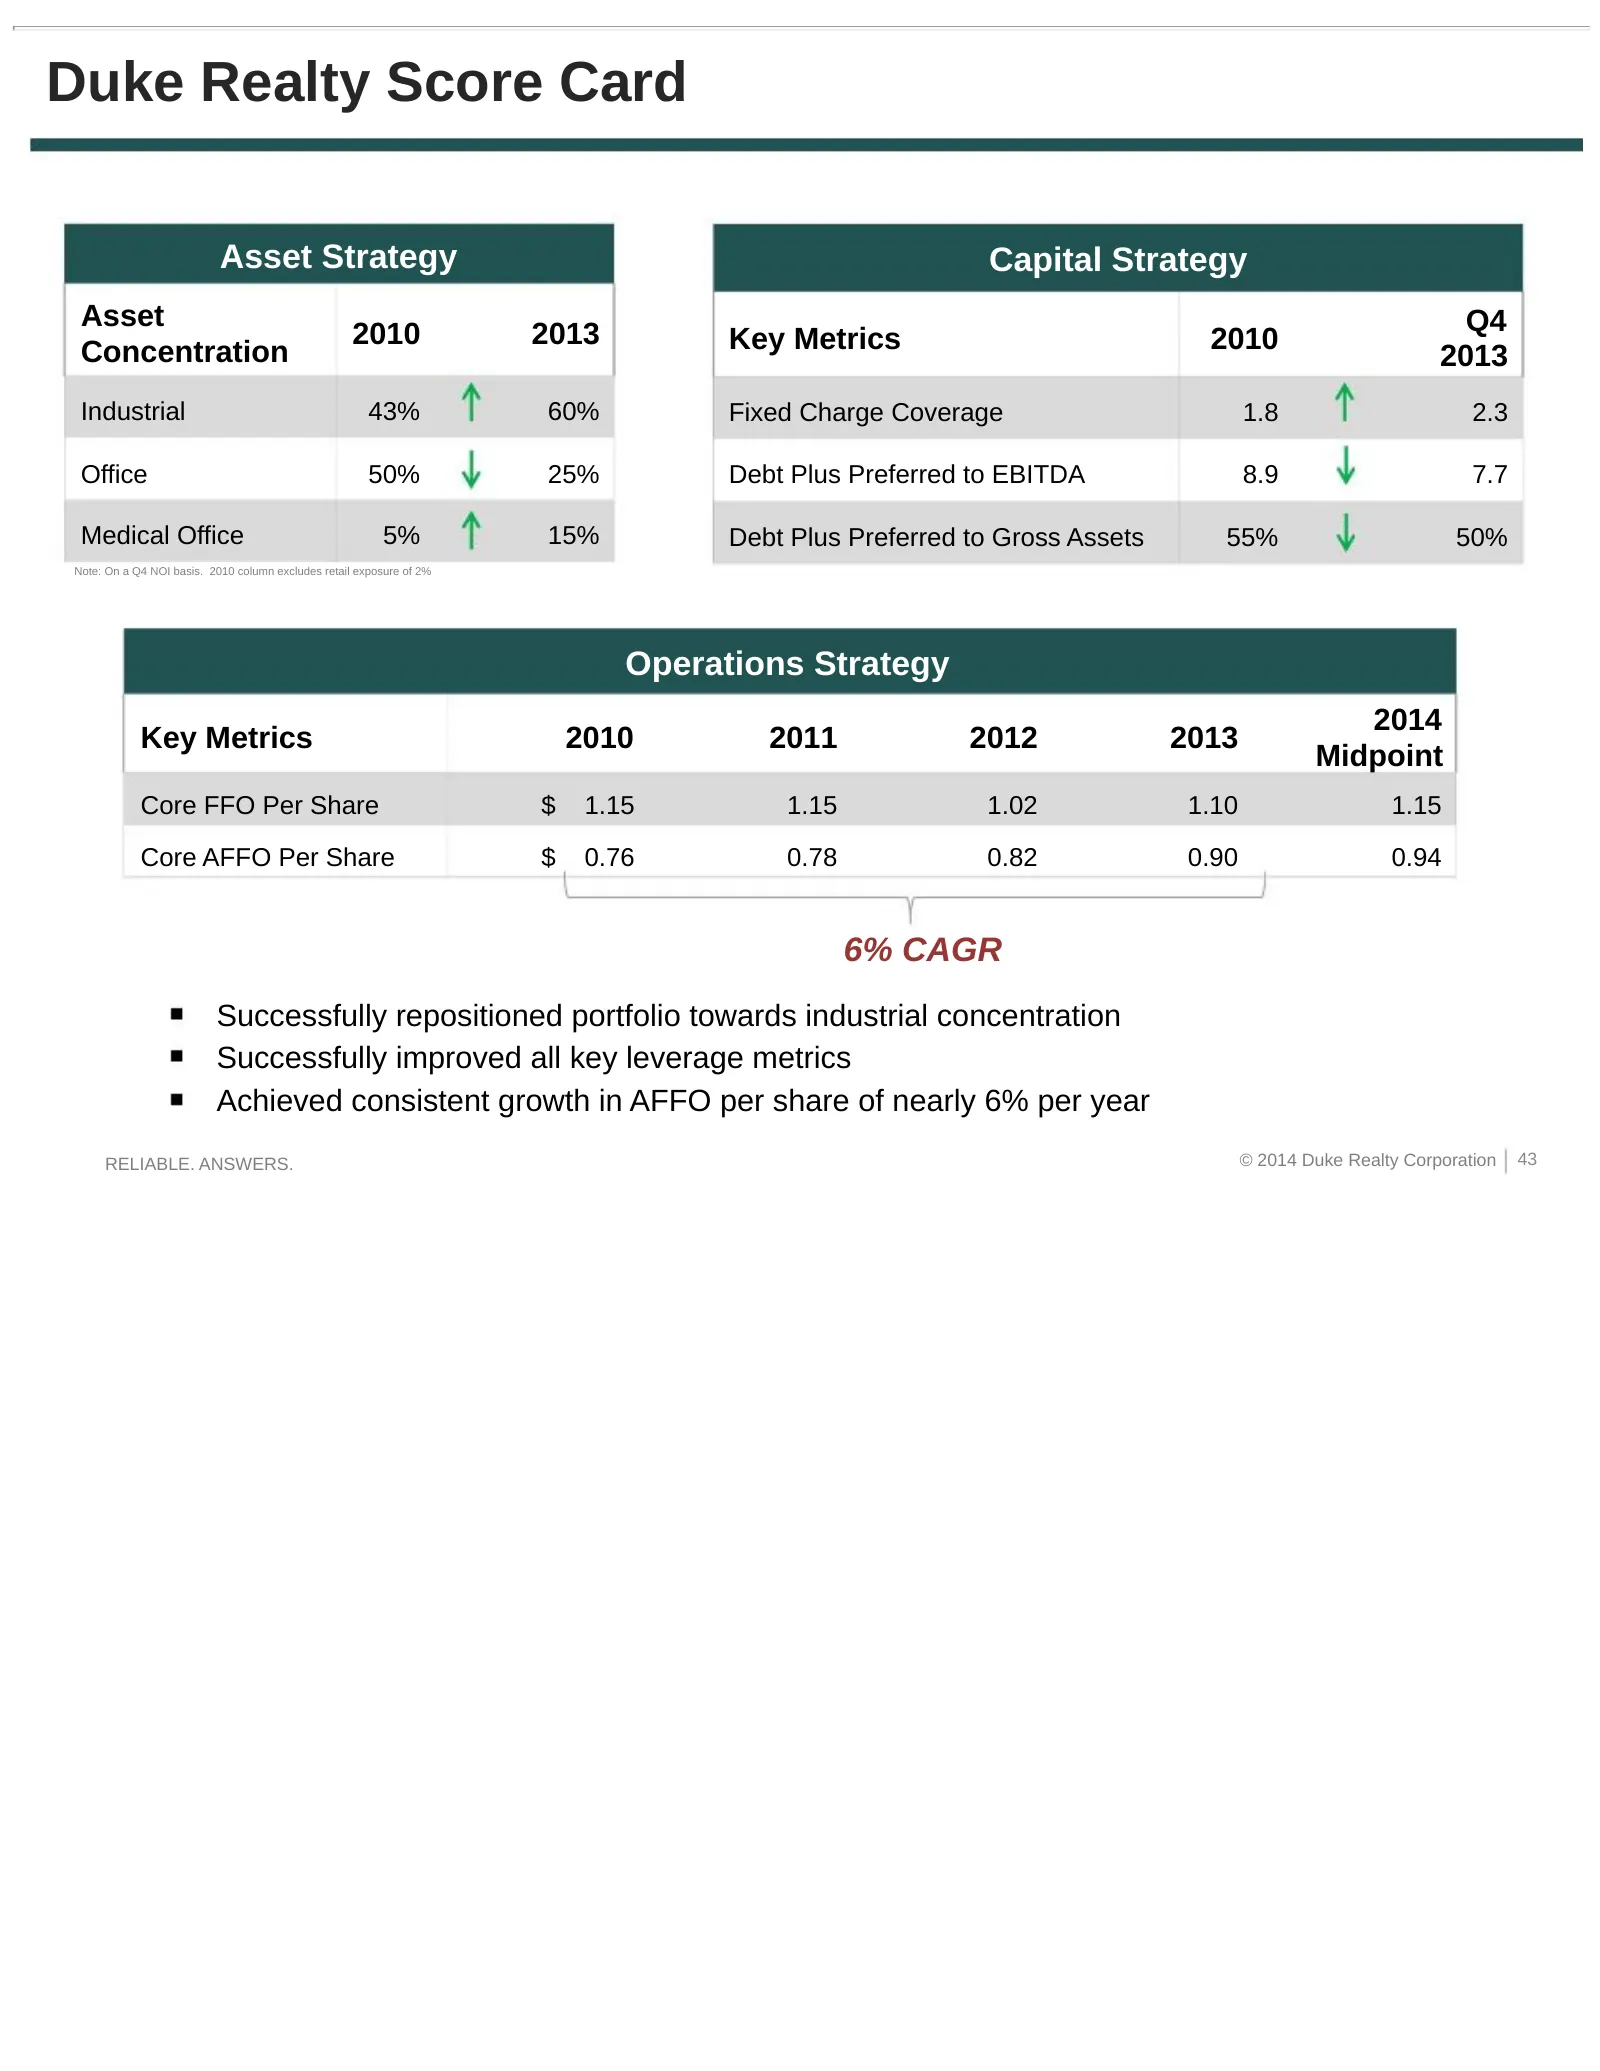
Duke Realty Score Card Asset Strategy Capital Strategy Asset Q4 2010 2013 Key Metrics 2010 Concentration 2013 Industrial 43% 60% Fixed Charge Coverage 1.8 2.3 Office 50% 25% Debt Plus Preferred to EBITDA 8.9 7.7 Medical Office 5% 15% Debt Plus Preferred to Gross Assets 55% 50% Note: On a Q4 NOI basi
Slide 44: Valuation Statistics – Undervalued on Relative Basis
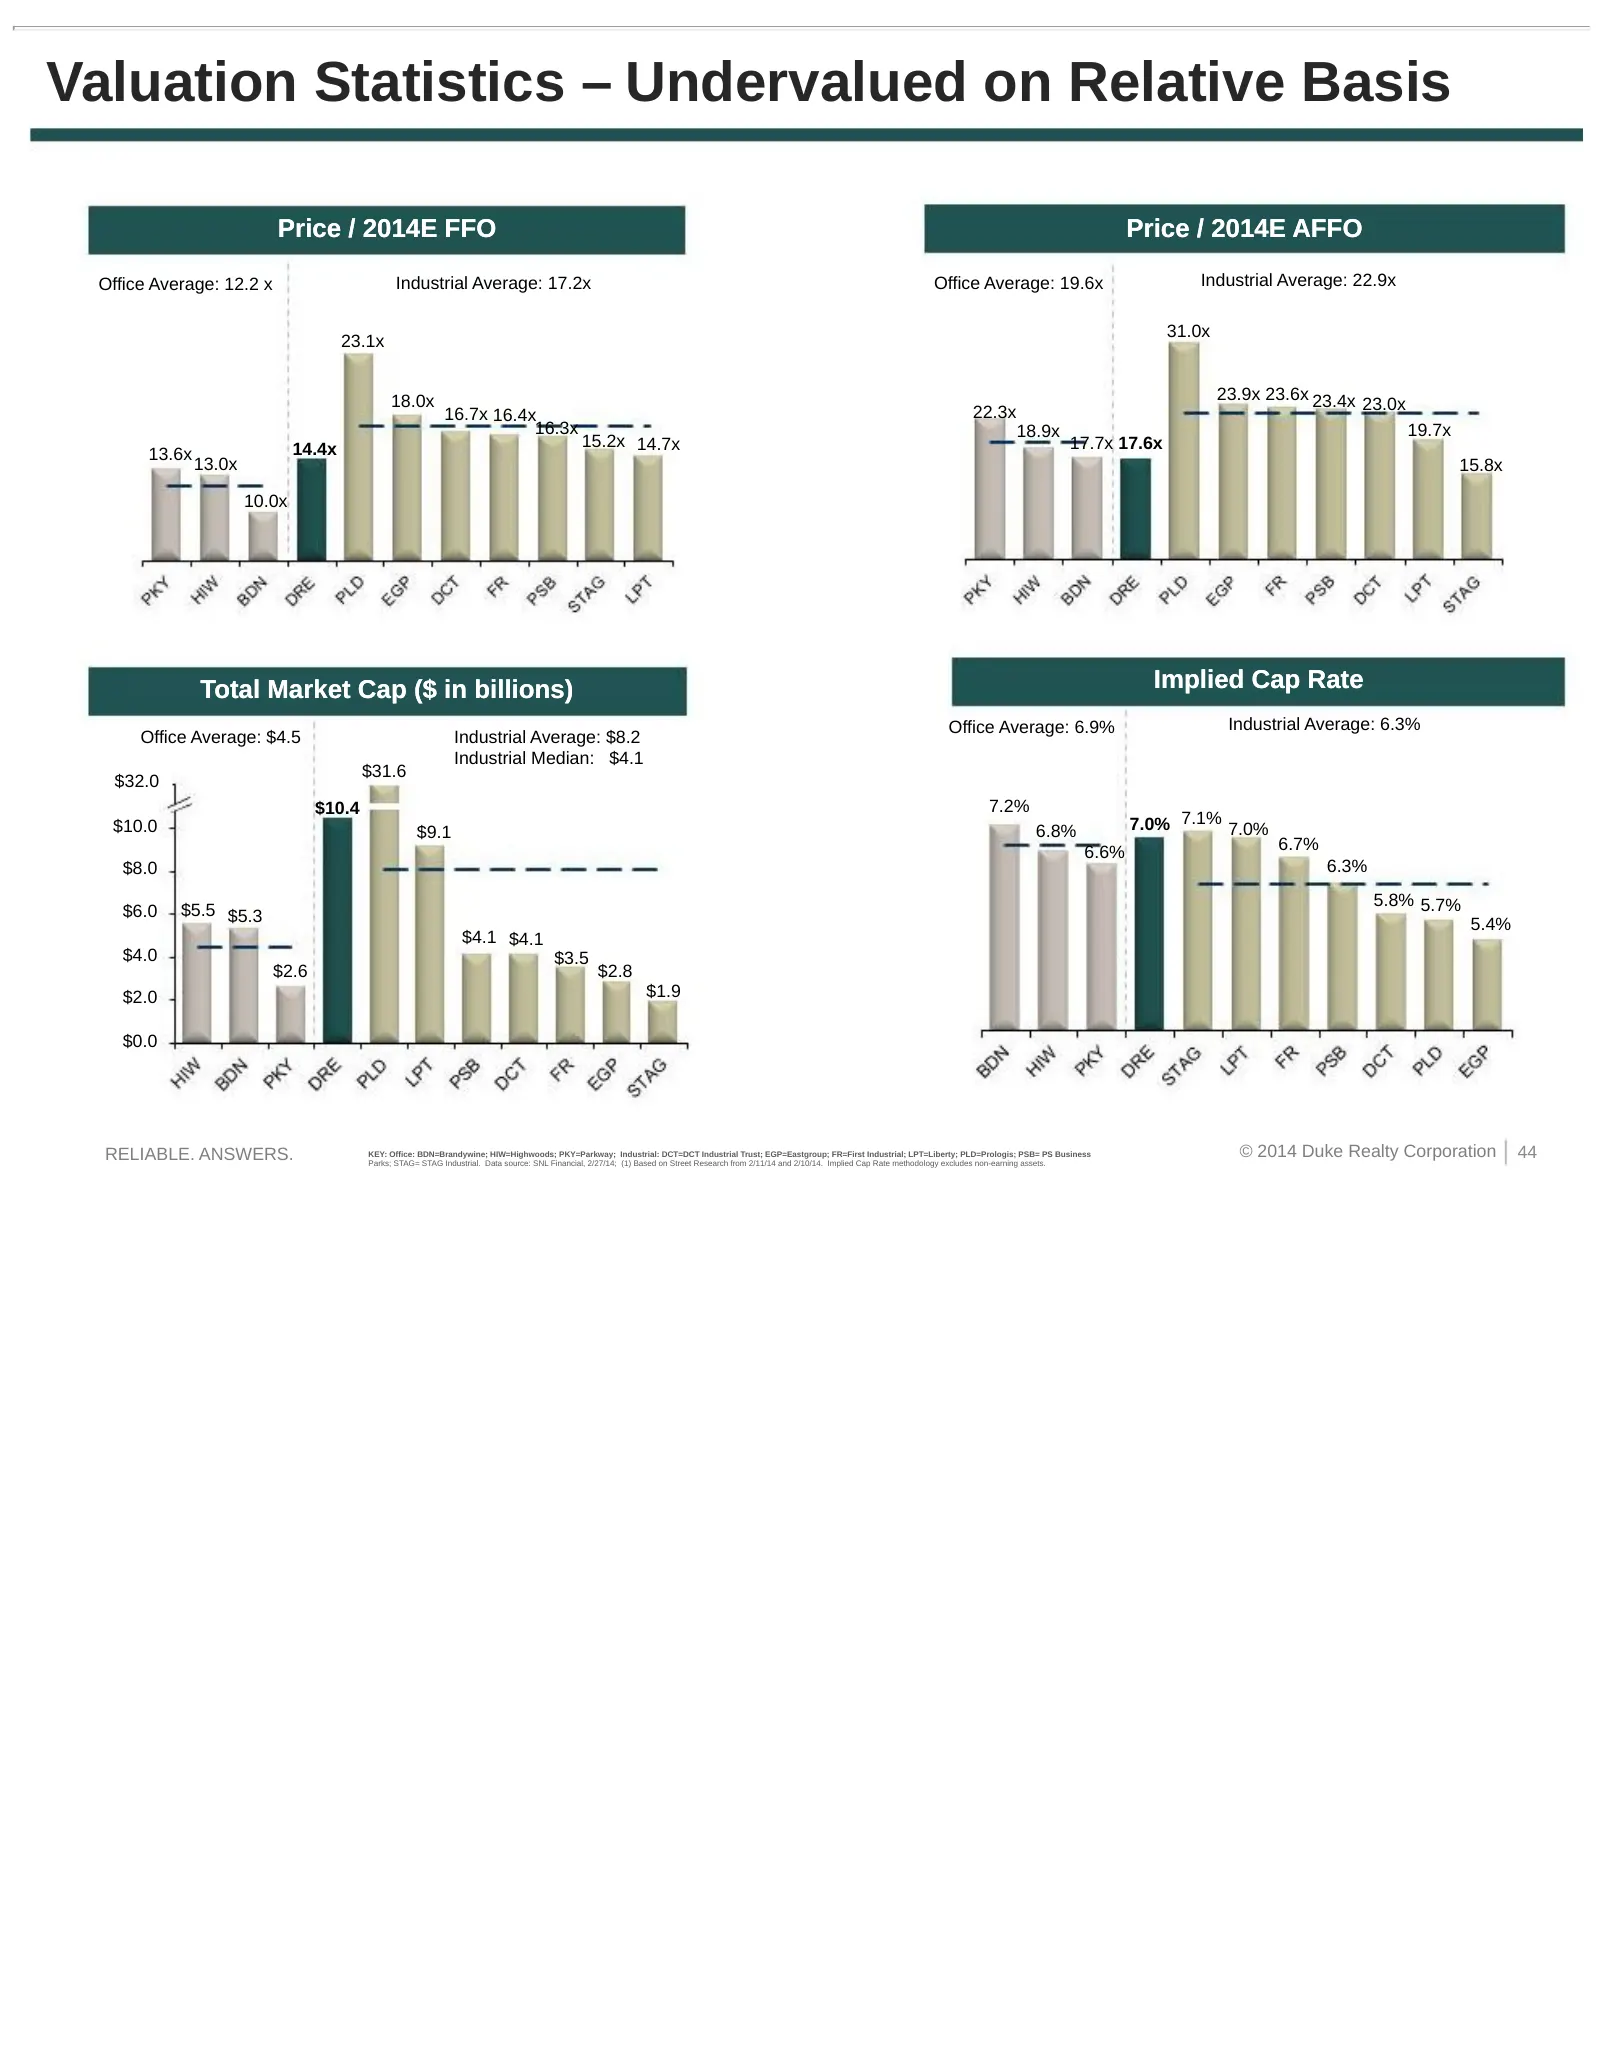
Valuation Statistics – Undervalued on Relative Basis Price / 2014E FFO Price / 2014E AFFO Office Average: 12.2 x Industrial Average: 17.2x Office Average: 19.6x Industrial Average: 22.9x 31.0x 23.1x 18.0x 23.9x 23.6x 23.4x 22.3x 23.0x 16.7x 16.4x 16.3x 18.9x 19.7x 14.4x 15.2x 14.7x 17.7x 17.6x 13.6x
Slide 45: 2014 Range of Estimates
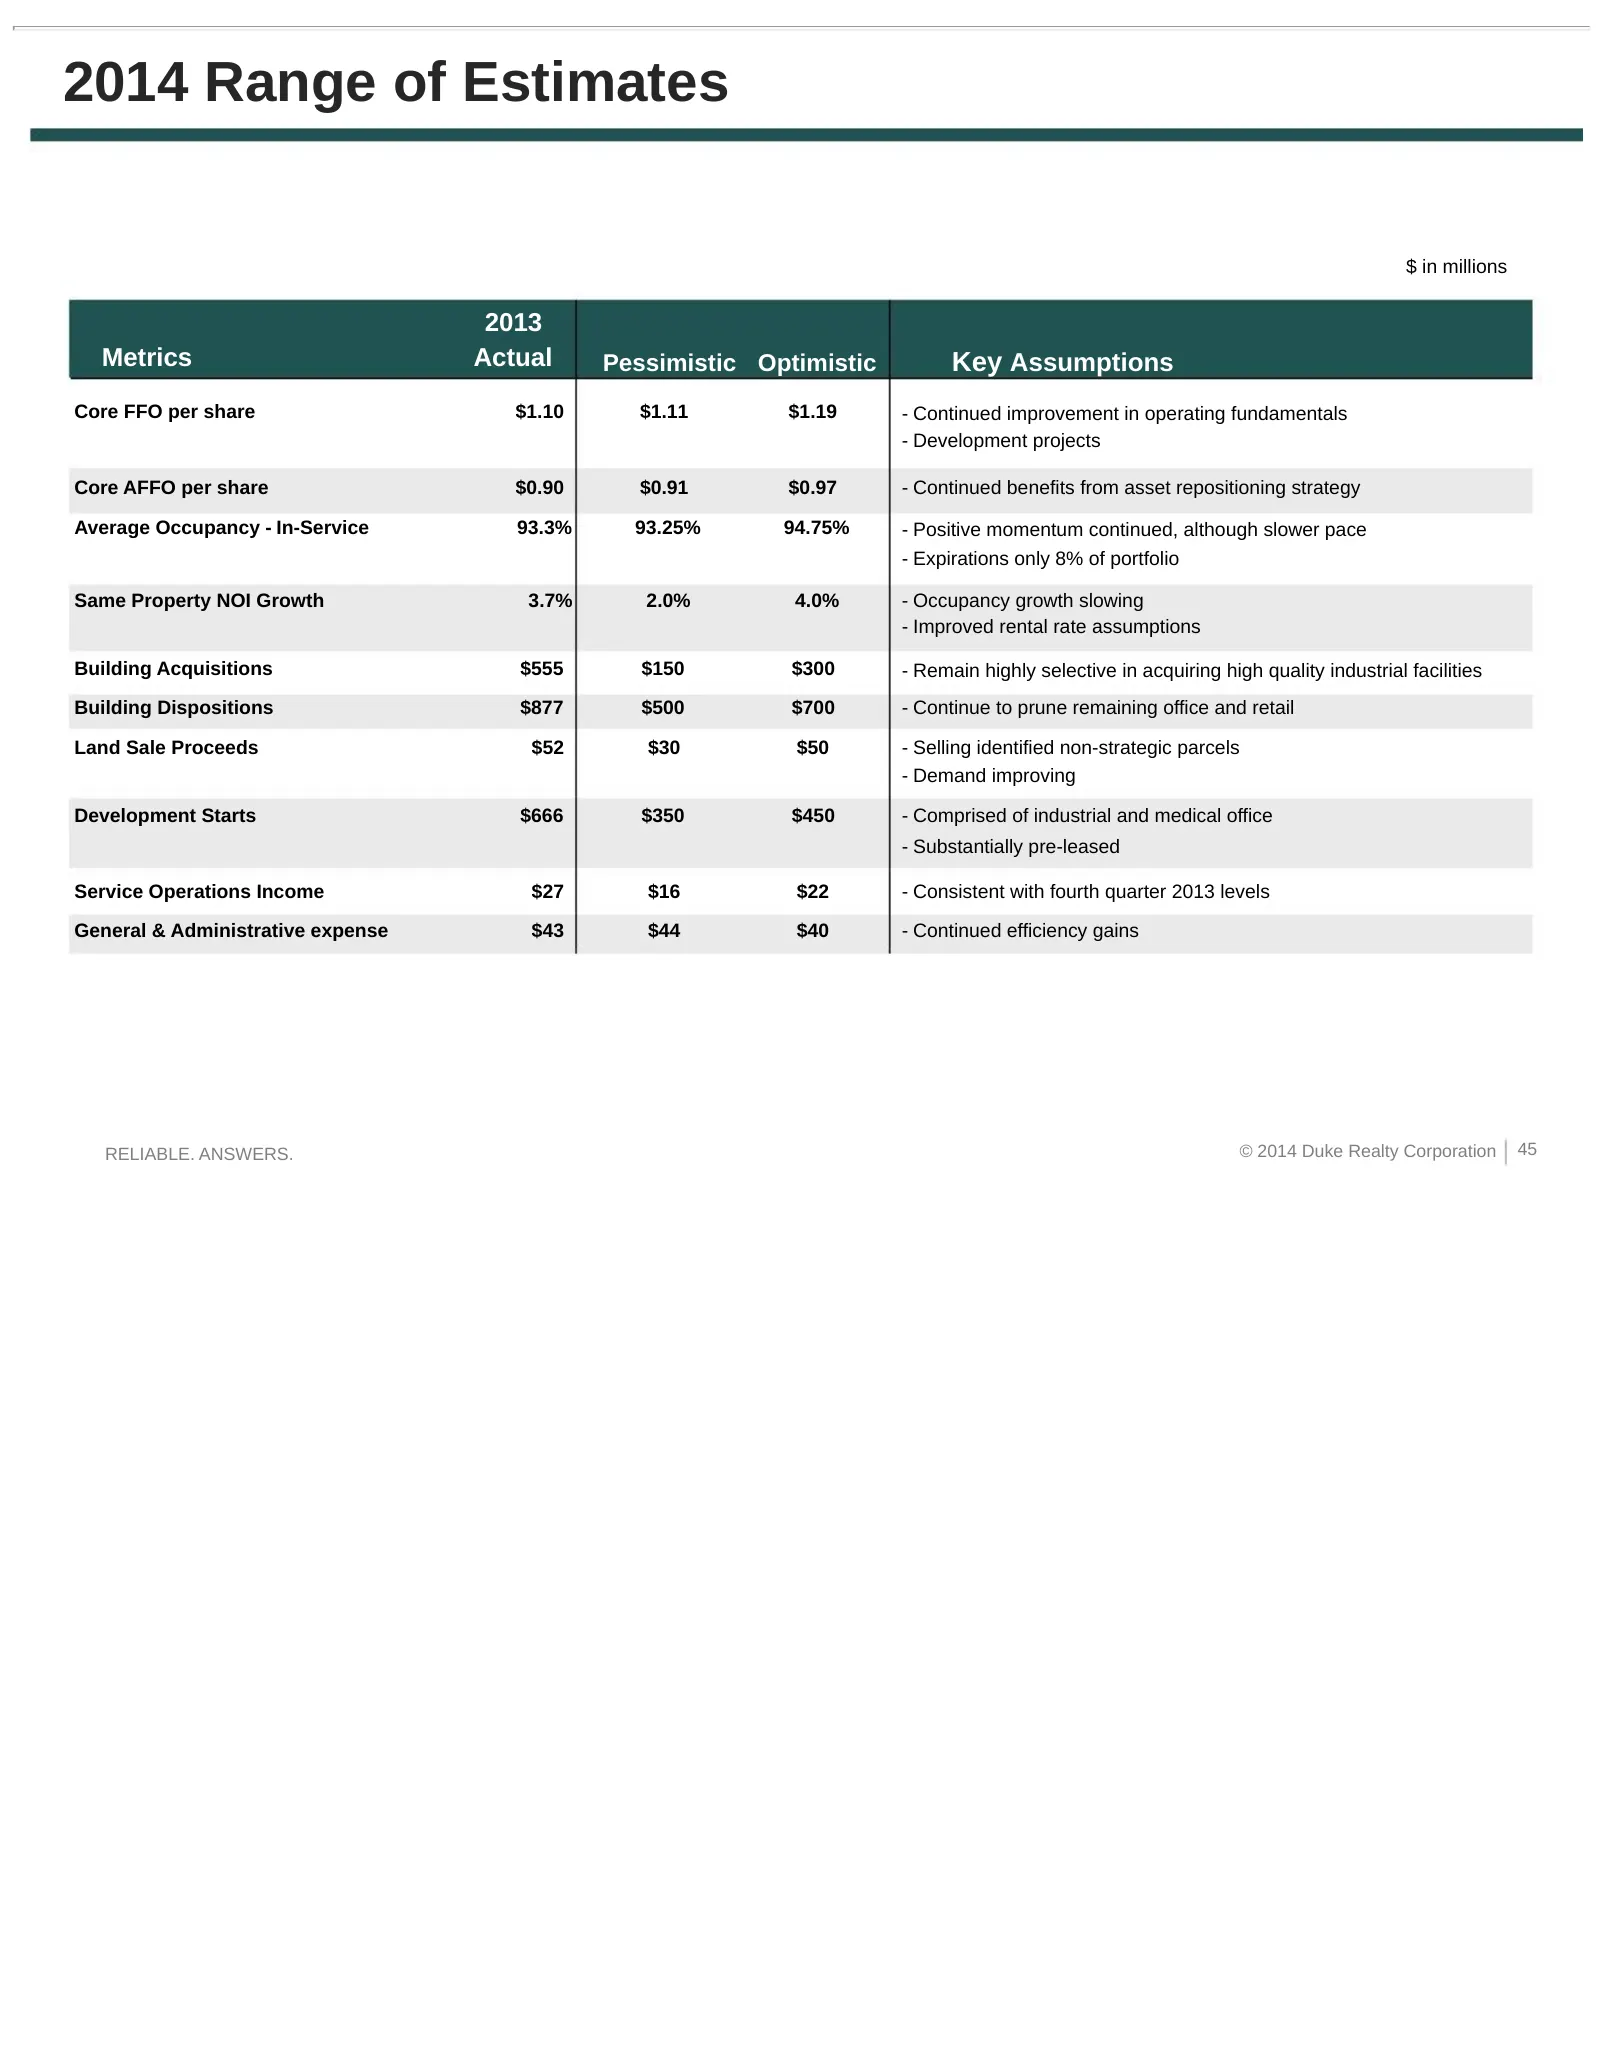
2014 Range of Estimates $ in millions 2013 Metrics Actual Pessimistic Optimistic Key Assumptions Core FFO per share $1.10 $1.11 $1.19 - Continued improvement in operating fundamentals - Development projects Core AFFO per share $0.90 $0.91 $0.97 - Continued benefits from asset repositioning strategy
Slide 46: Why Duke Realty?
Why Duke Realty? Talent and Leadership with Proven Ability to Execute Superior Asset Quality Strategically Located Land Bank and Experienced Development Capabilities Proven Operational Success and Future Growth Opportunities Balance Sheet Strength Relative Value vs. Peers Top Tier to Corporate Gover
Slide 47: Forward-Looking Statement
Forward-Looking Statement This slide presentation contains statements that constitute “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934 as amended by the Private Securities Litigation Reform Act of 1995. These forward-looking statem
Source: SEC EDGAR · 8-K filed Mar 3, 2014
More decks from Duke Realty Corporation
 Merger or Acquisition (June 2022)14 slides · Jun 13, 2022
 Investor Presentation (June 2021)58 slides · Jun 7, 2021
 Investor Presentation (May 2021)44 slides · May 10, 2021
 Investor Presentation (February 2021)58 slides · Feb 22, 2021
 NAREIT REITworld Virtual Investor Conference 202056 slides · Nov 16, 2020
 B of A Securities 2020 Global Real Estate Conference56 slides · Sep 15, 2020