Santander Consumer USA Holdings Inc
Santander Consumer USA — Investor Day (May 2015)
45 slides from Santander Consumer USA's investor day presentation, May 13, 2015
Slide 1: SCUSA ABS Investor Day – Capital Markets, Originations and Servicing
Exhibit 99.1 SCUSA ABS May 13, Investor Capital 2015 DayMarkets – Originations and Servicing
Slide 2: Important Information – Forward-Looking Statements
2 IMPORTANT Forward-Looking This forecasts, phrases words Factors” materially reduced; and automobile to the business; incorrect, place should business only by attract law. CFPB, uncertainties is presentation speak undue subject or not All such and or (d) such phrases. and its objectives, from adver
Slide 3: Agenda
3 I. Corporate AGENDA II. III.Originations ServicingOverview and Underwriting
Slide 4: Table of Contents – Corporate Overview
4 TABLE SCUSA Auto 1Q15: HIGHLIGHTS Income Loan Highlights and OF OVERVIEW ABS CONTENTS Operating Platforms Origination Expenses –Summary CORPORATE Trends Funding SCUSA and OVERVIEW Liquidity Key Compliance Program Elements
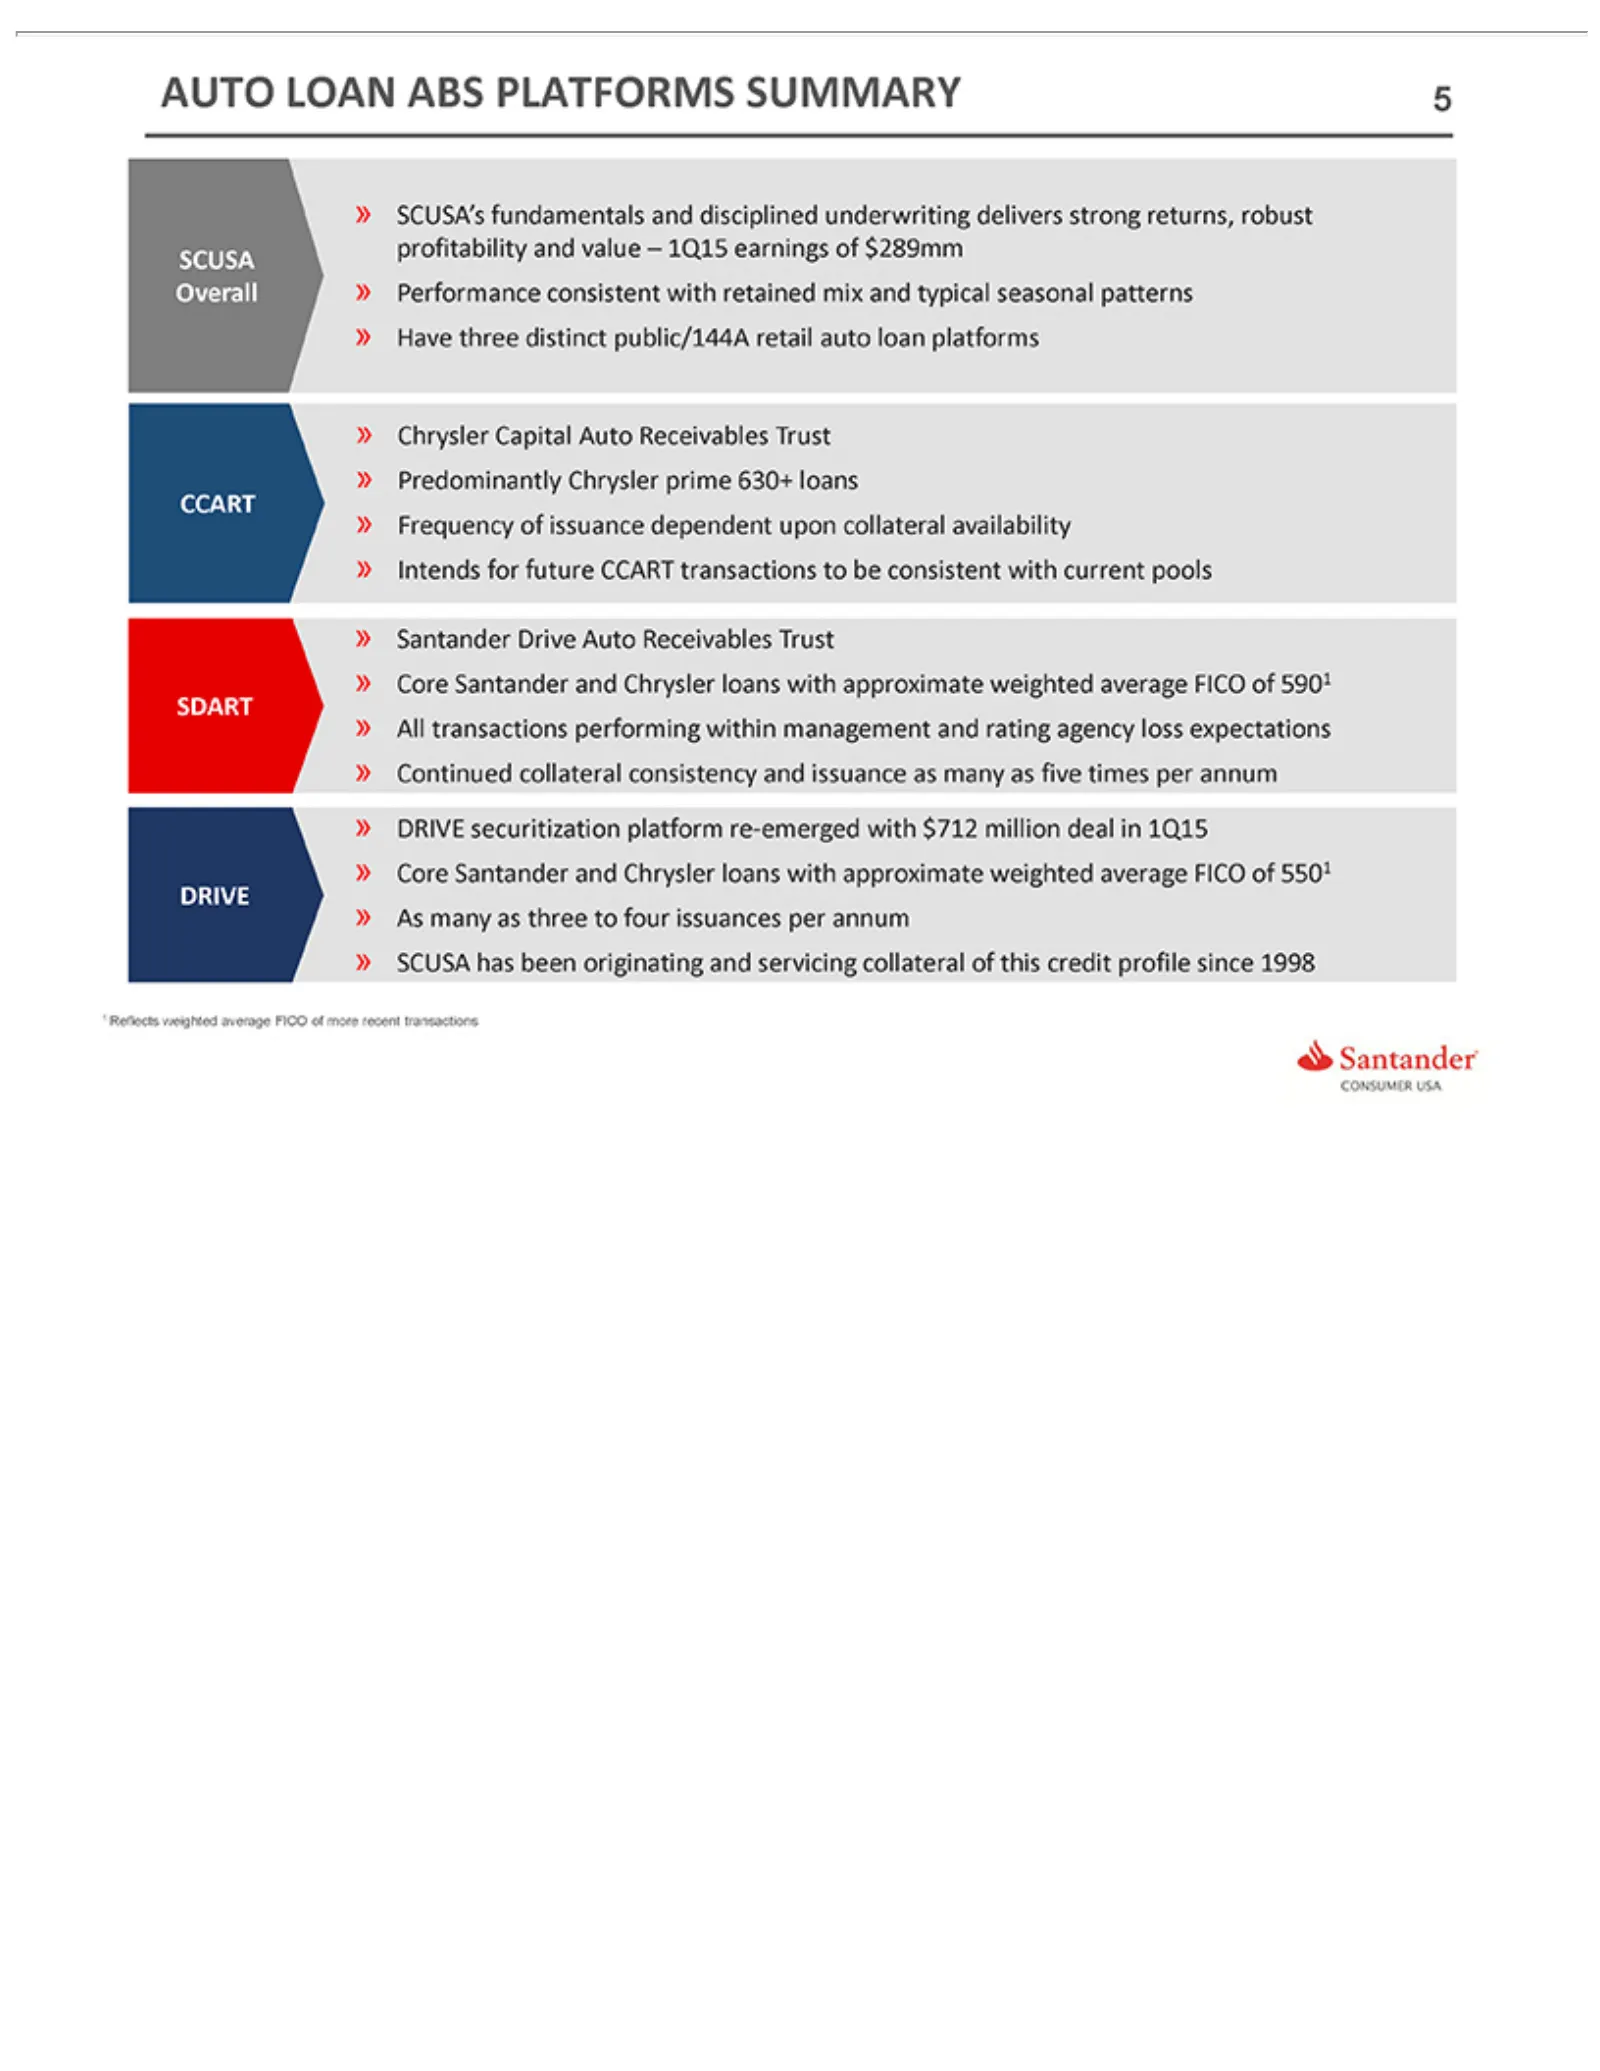
Slide 5: SCUSA Auto Loan ABS Platforms Summary
5 AUTO SCUSA CCART SDART DRIVE » 1 All As SCUSA’s Performance Have Chrysler Predominantly Frequency Intends Santander Continued DRIVE Core SCUSA many transactions Santander LOAN three Reflects Overall for securitization has Capital as fundamentals Drive collateral of distinct future three been ABS c
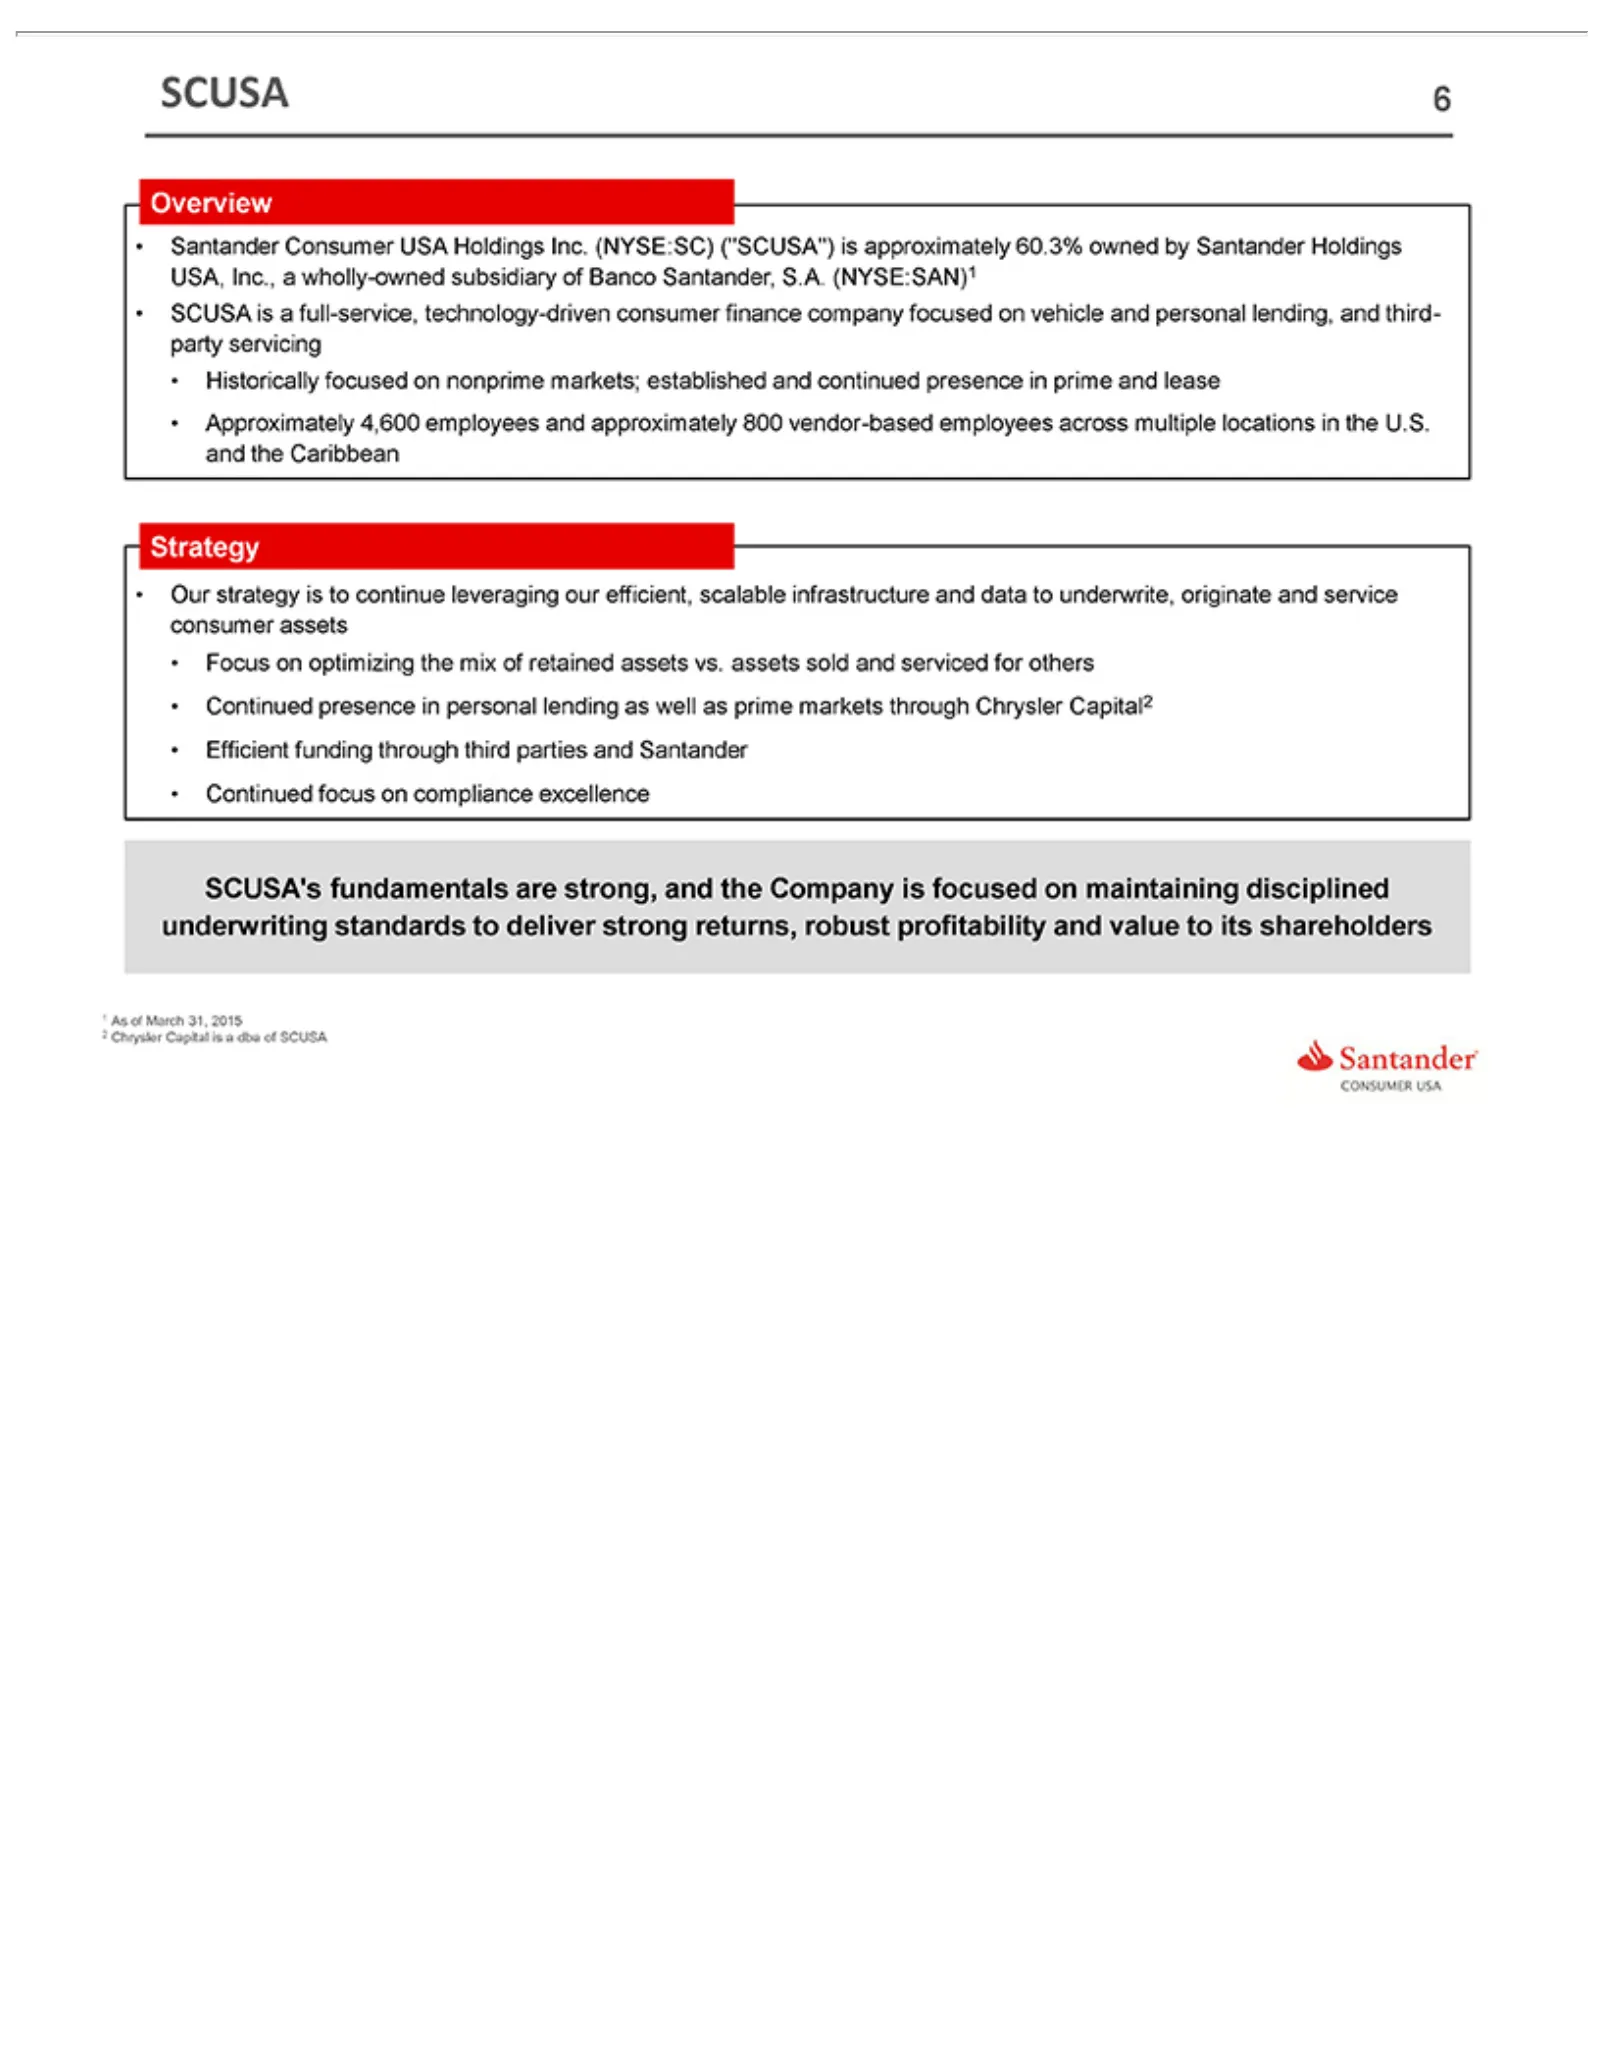
Slide 6: Overview of SCUSA
••6 Overview SCUSA Santander (NYSE:SAN)1 SCUSA HistoricallyConsumer onisfunding Approximately •Strategy Our strategy Focus a focused full-service, 4,600 is to optimizing USA on Holdings employees continue the mix ofandand leveraging Inc. technology-driven nonprime (NYSE:SC) markets; consumer establi
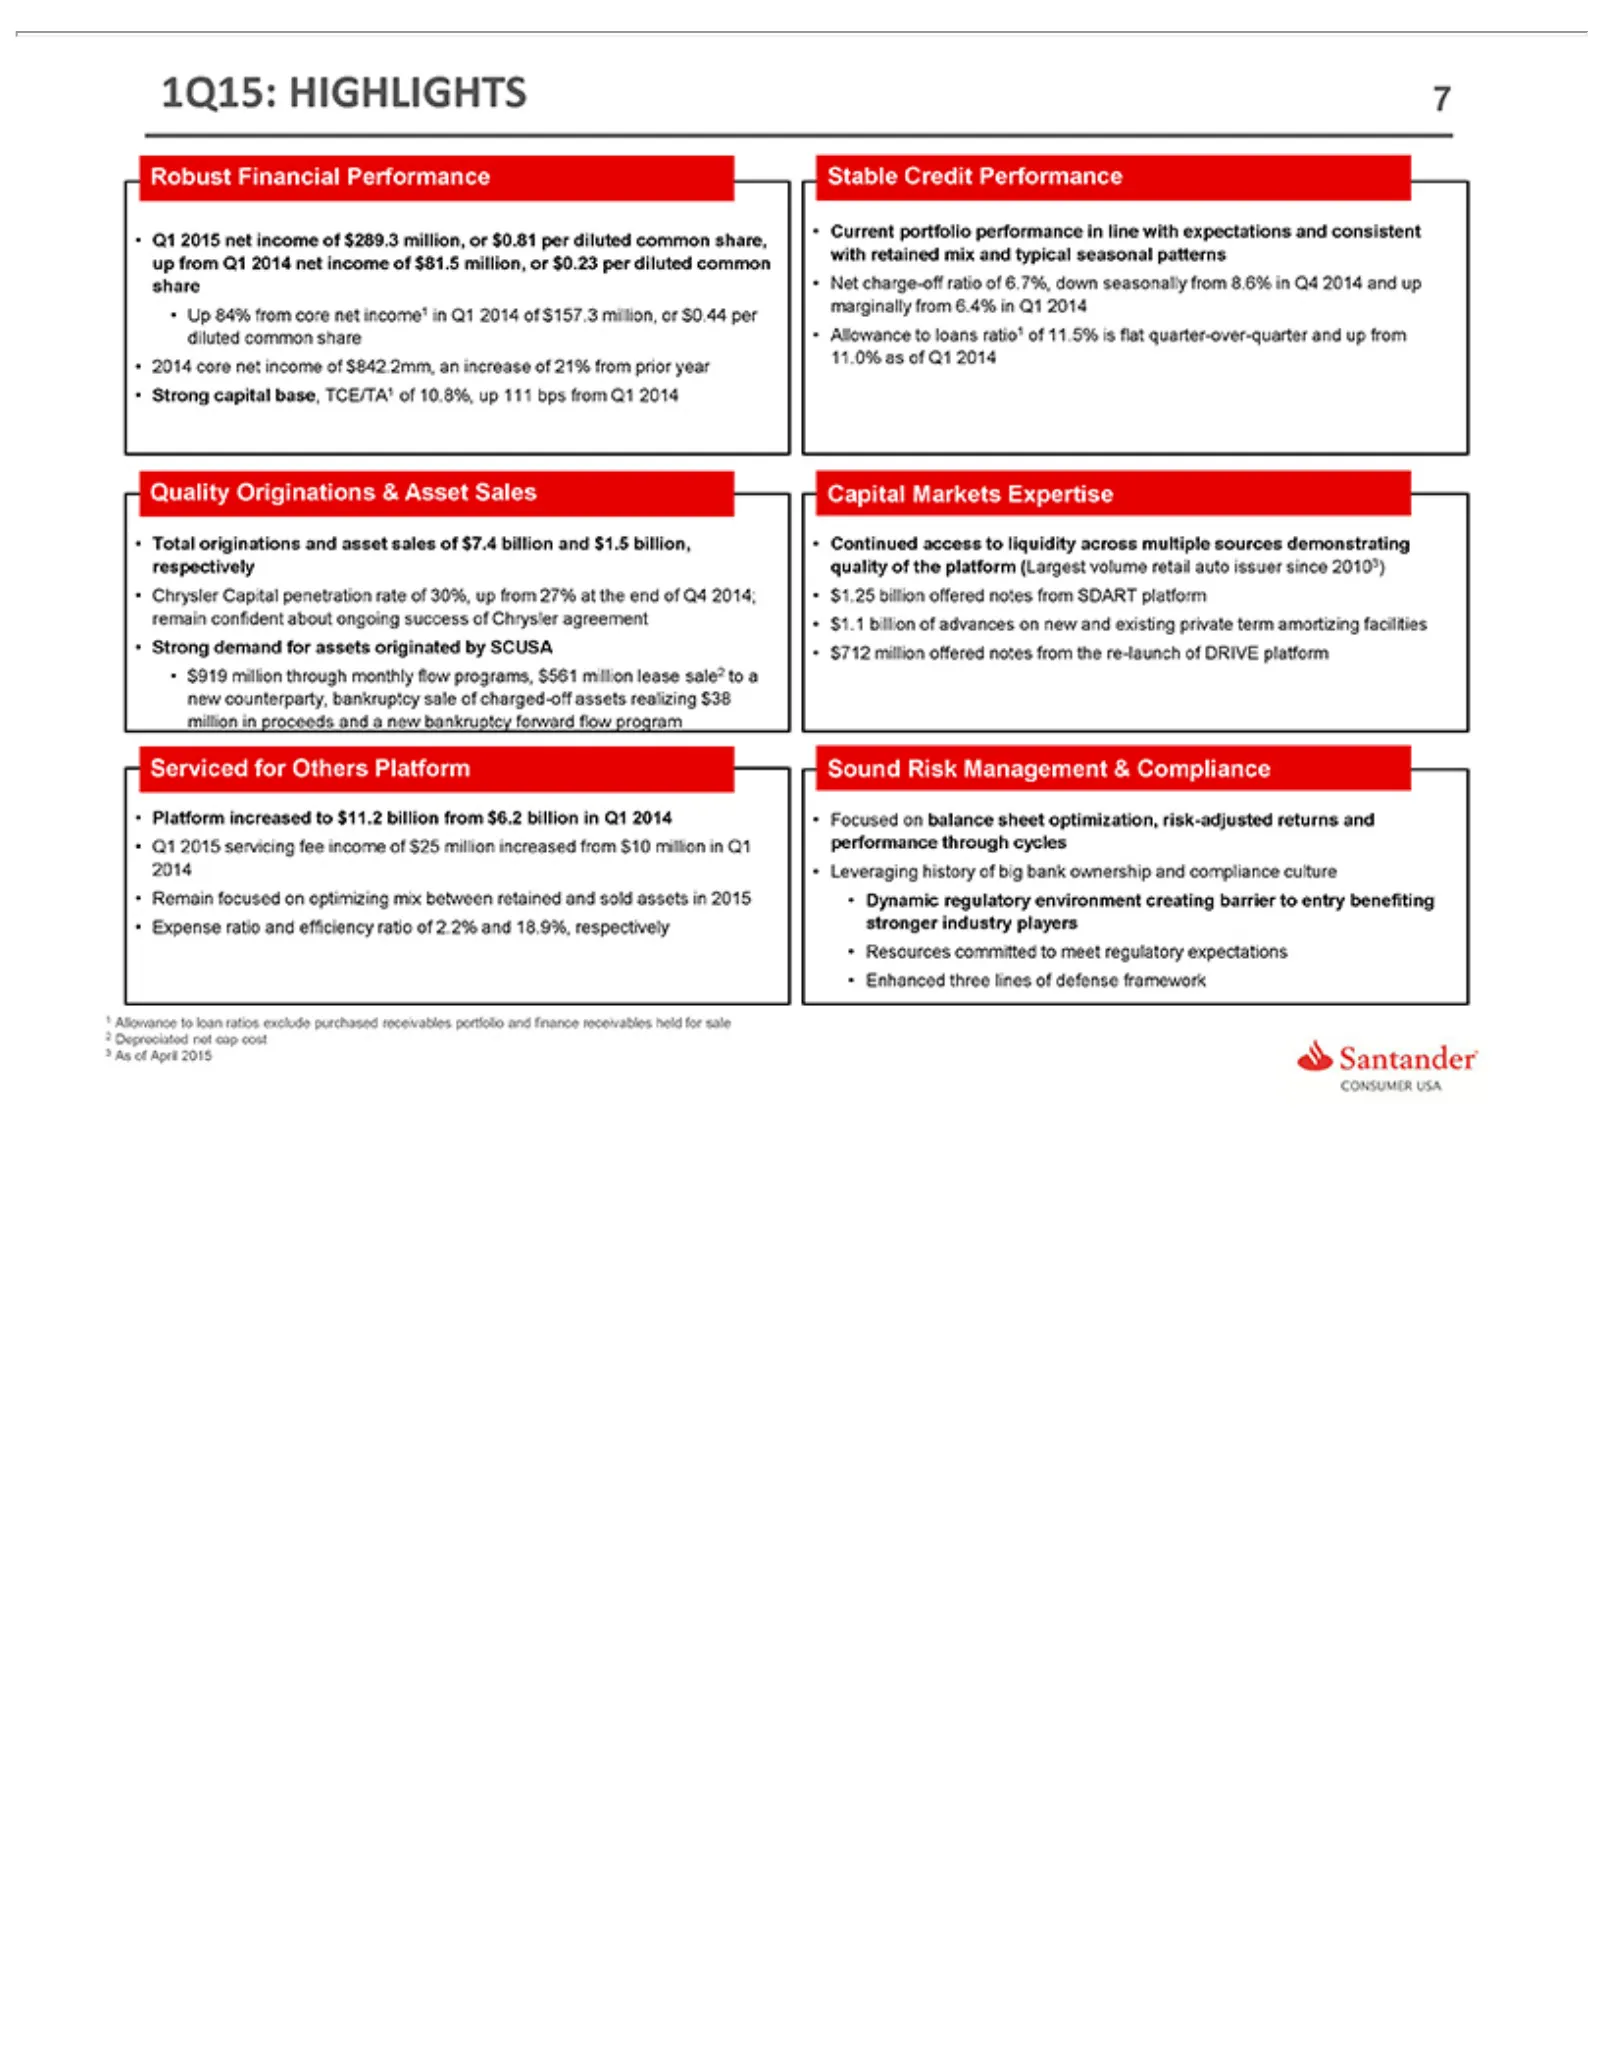
Slide 7: 1Q15 Highlights
7 1Q15: ••Robust Q1 Up HIGHLIGHTS 20142015 Financial 84% core net netincome from Performance core income netofof$289.3 income1 million, $842.2mm, inofQ1 or an2014$0.81 of increase per $157.3 diluted of27% 21% million, from common share, or respectively $0.44 prior per up remain fromcommon diluted Q1
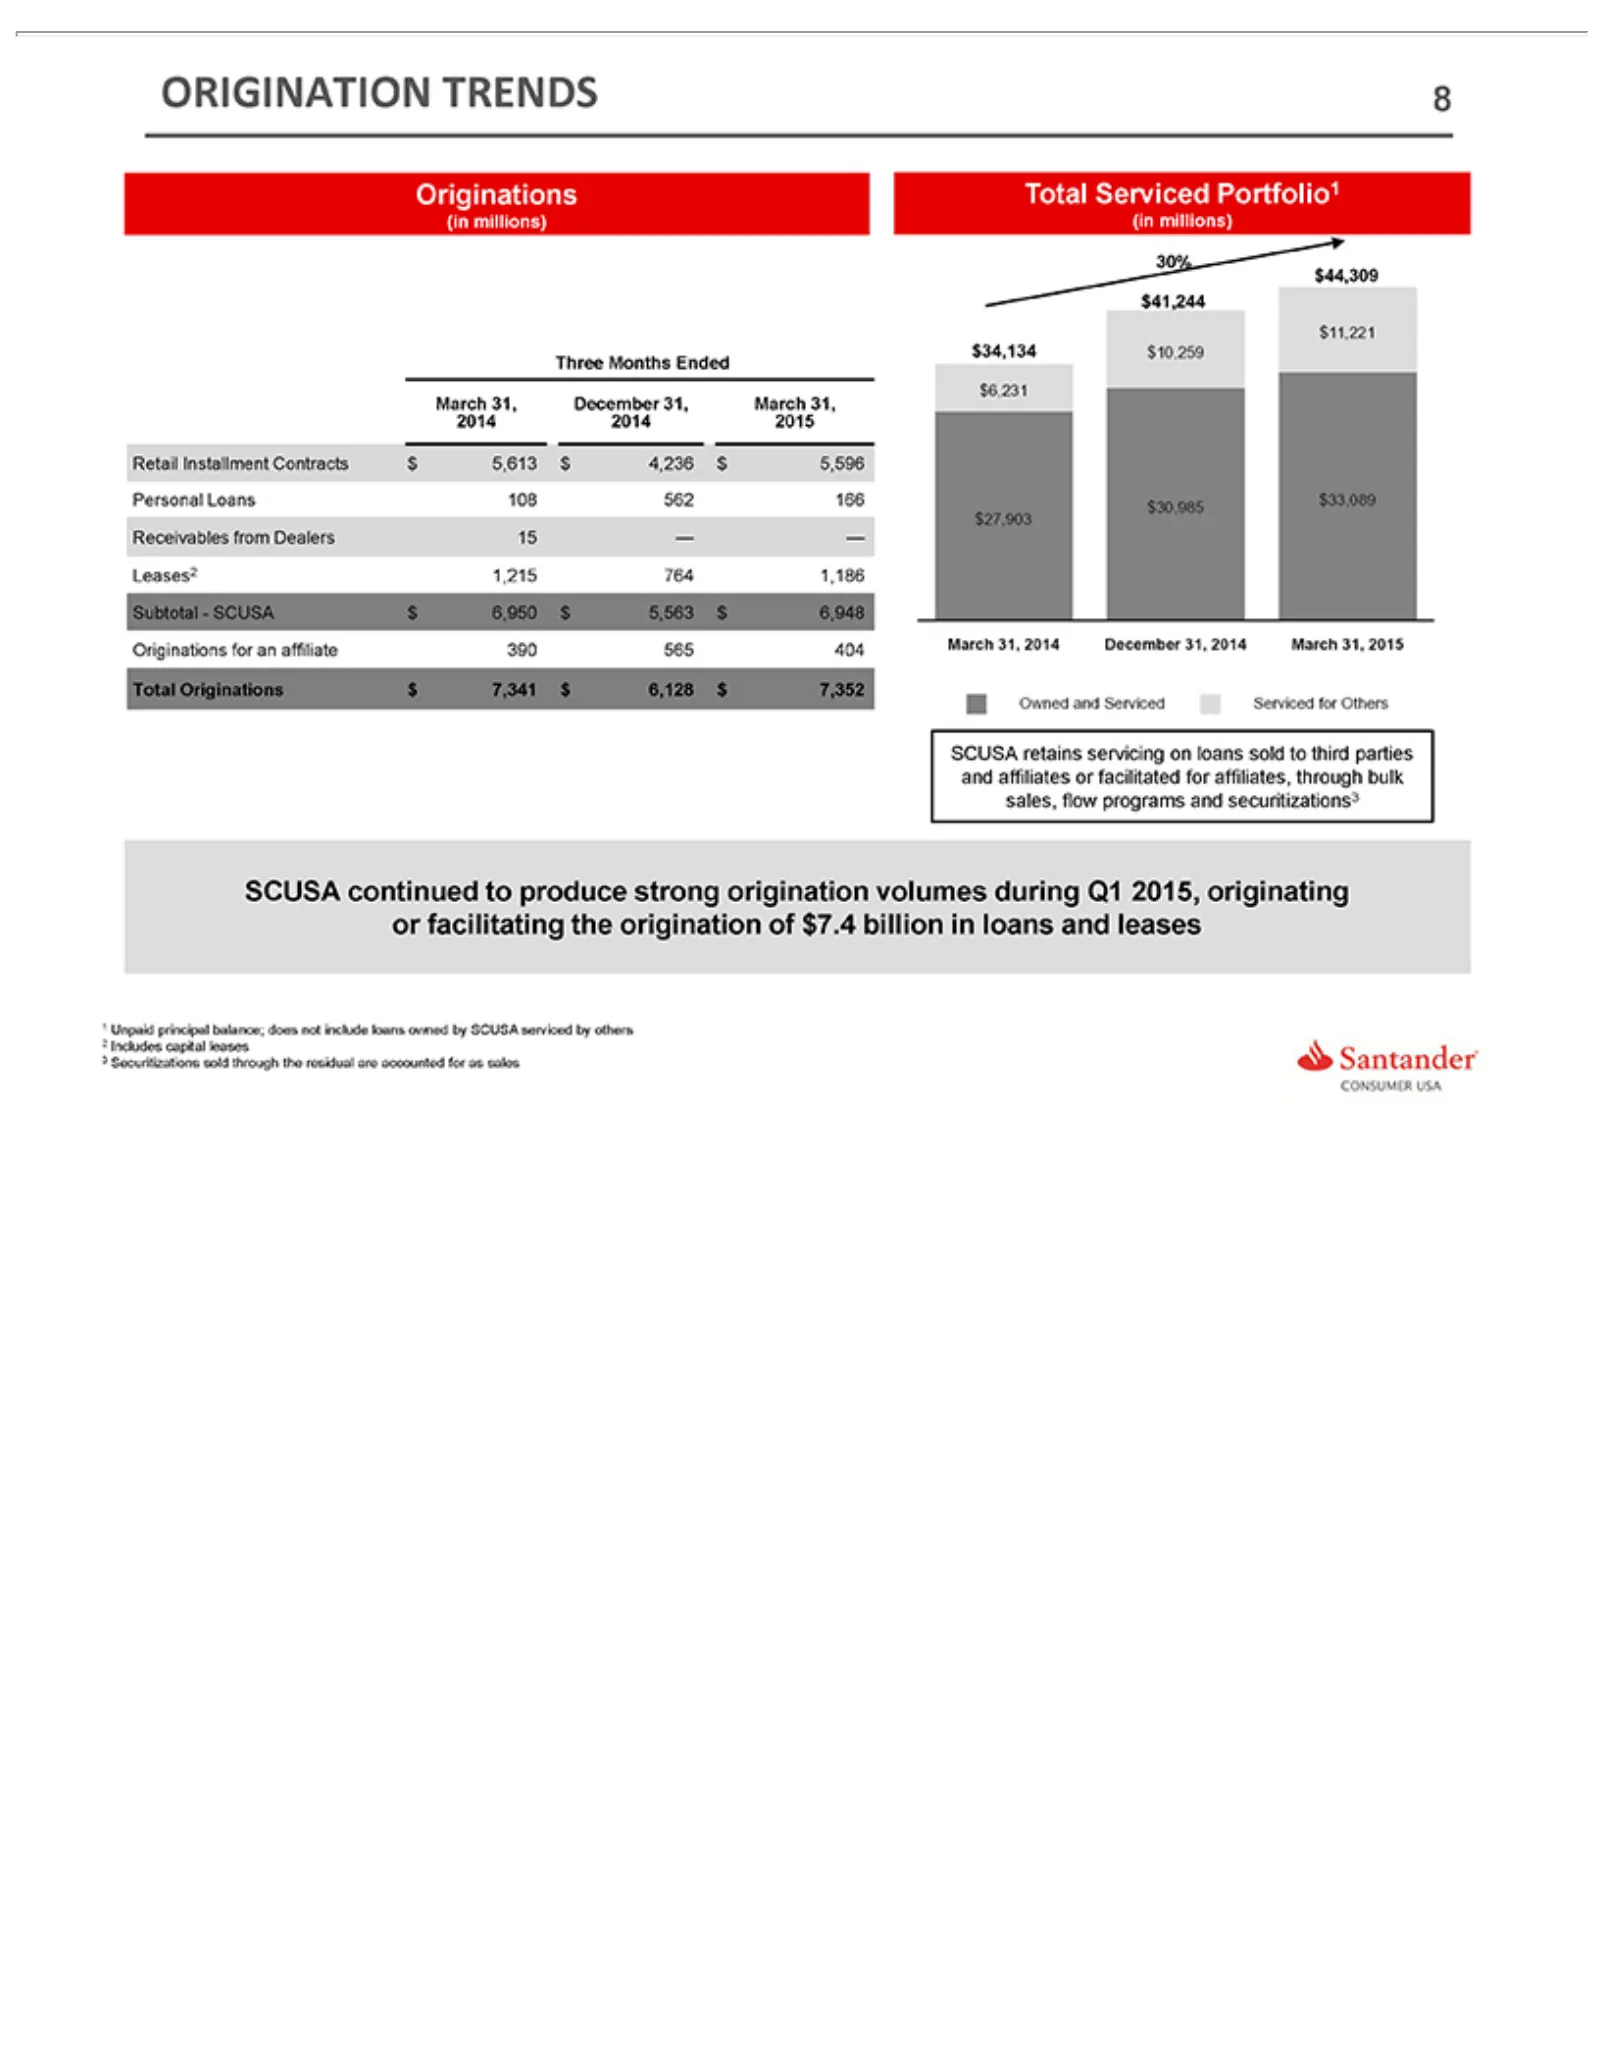
Slide 8: Origination Trends
8 ORIGINATION (in Three March 2014 Retail Personal Receivables Leases2 Subtotal—SCUSA Originations Total 30% SCUSA 1 2 3 Unpaid millions) $44,309 2014 Originations Months Installment 31, Includes retains continued 1,215 Loans principal December 2015 from (in Total for $41,244 Ended 764 servicing 108
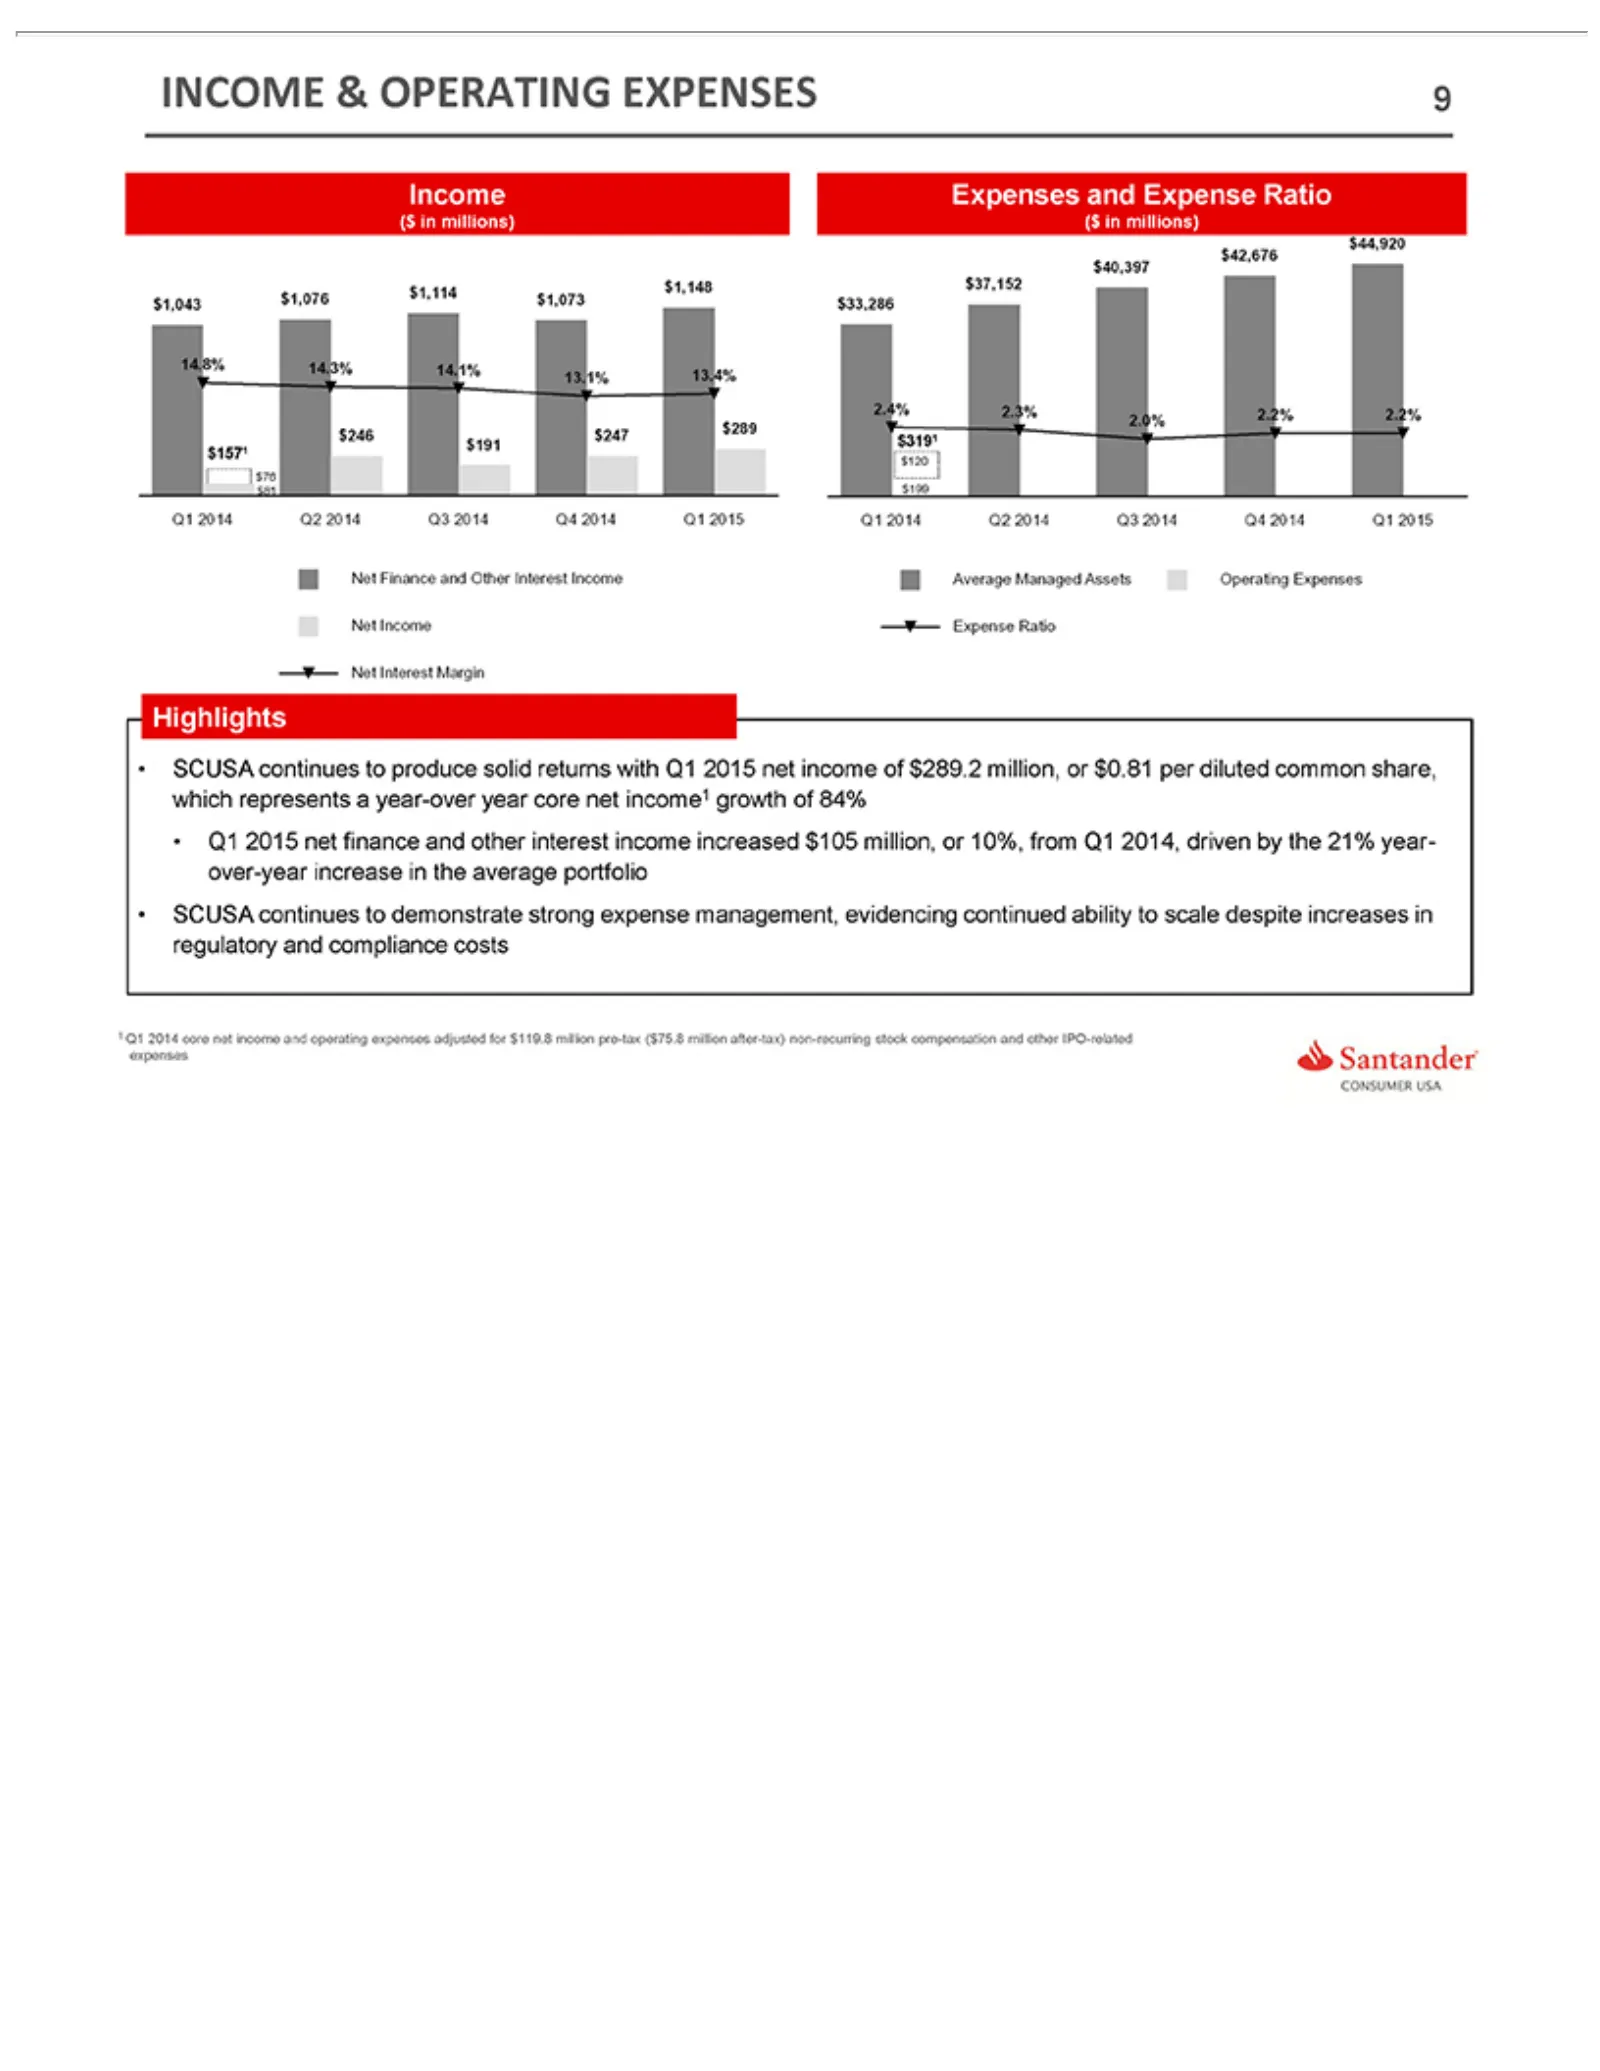
Slide 9: Income and Operating Expenses
INCOME 9 ($ Income $3191 $81 •$76 •Highlights 1 inSCUSA Q1SCUSA $199 millions) Q1$1571 Expenses & 2015 2014 continues OPERATING $120 net core and Expense to and finance continues net to incomeproduce EXPENSES Ratio other and solid ($ returns in 9 expenses interest demonstrate strong operating millio
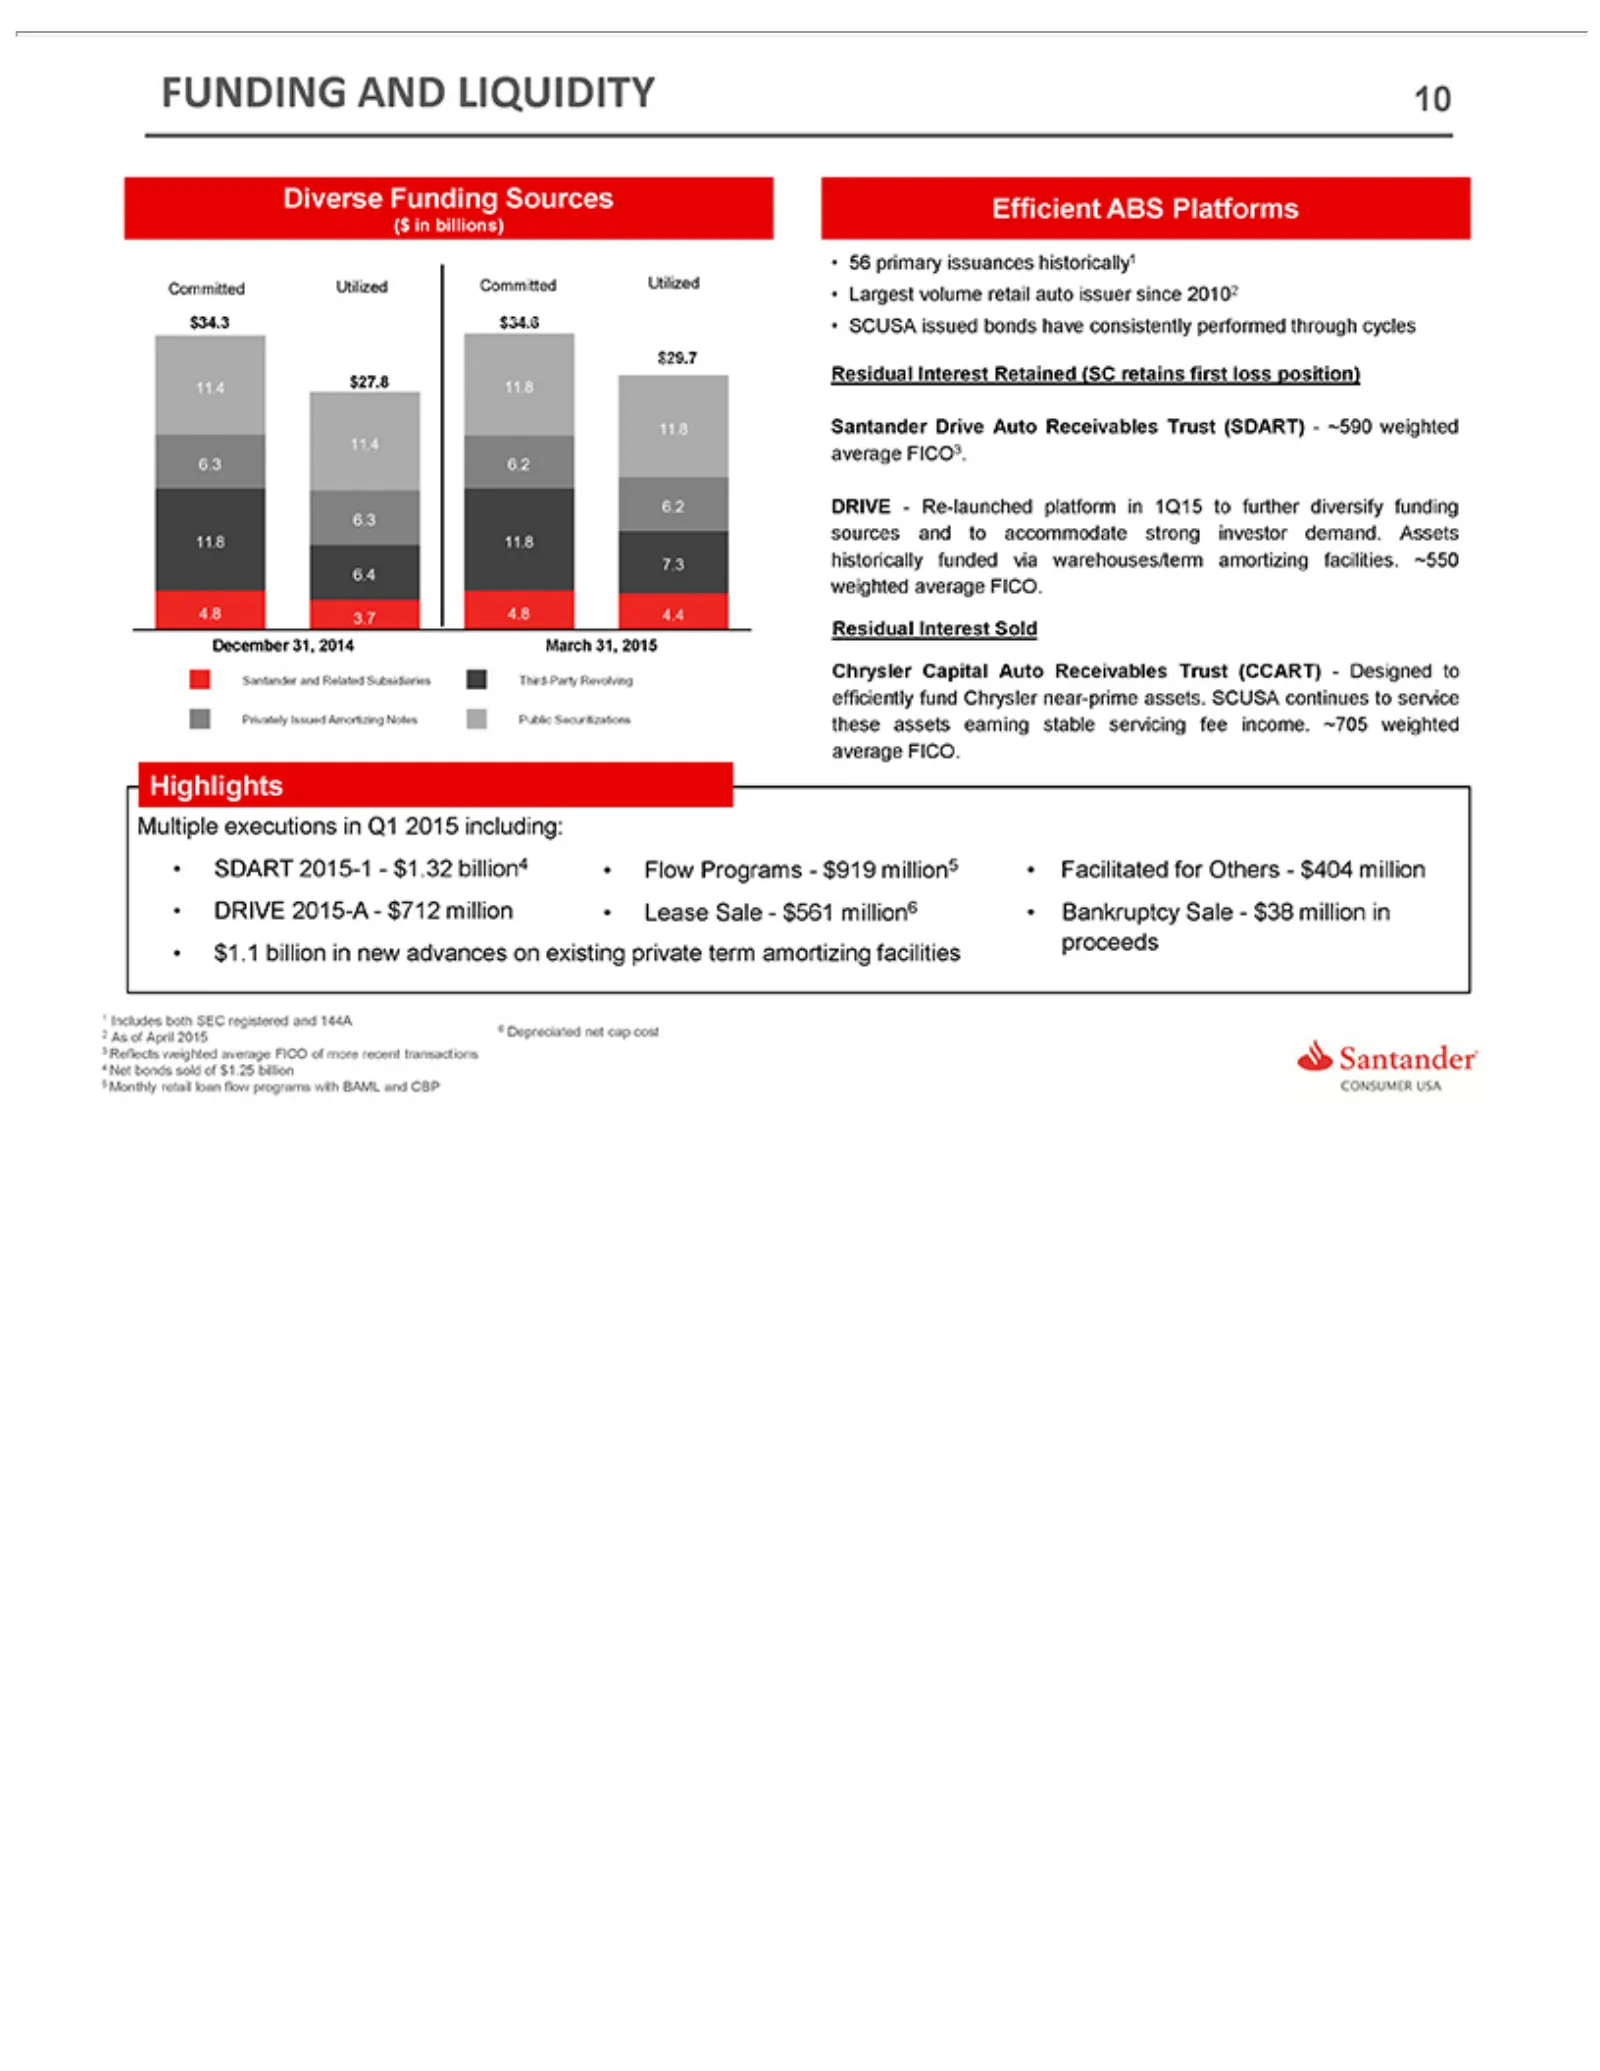
Slide 10: Diverse Funding Sources and Liquidity
FUNDING 10 Diverse ($ •Efficient in$1.1 DRIVE 56billions) Residual Chrysler weighted Multiple primary •Highlights 1 SDART DRIVE-Funding Largest SCUSA Santander ABSANDPlatforms Capital billion Includes issuances volume issued executions Interest Sources inLIQUIDITY Re-launched average 2015-1—$1.32 Dr
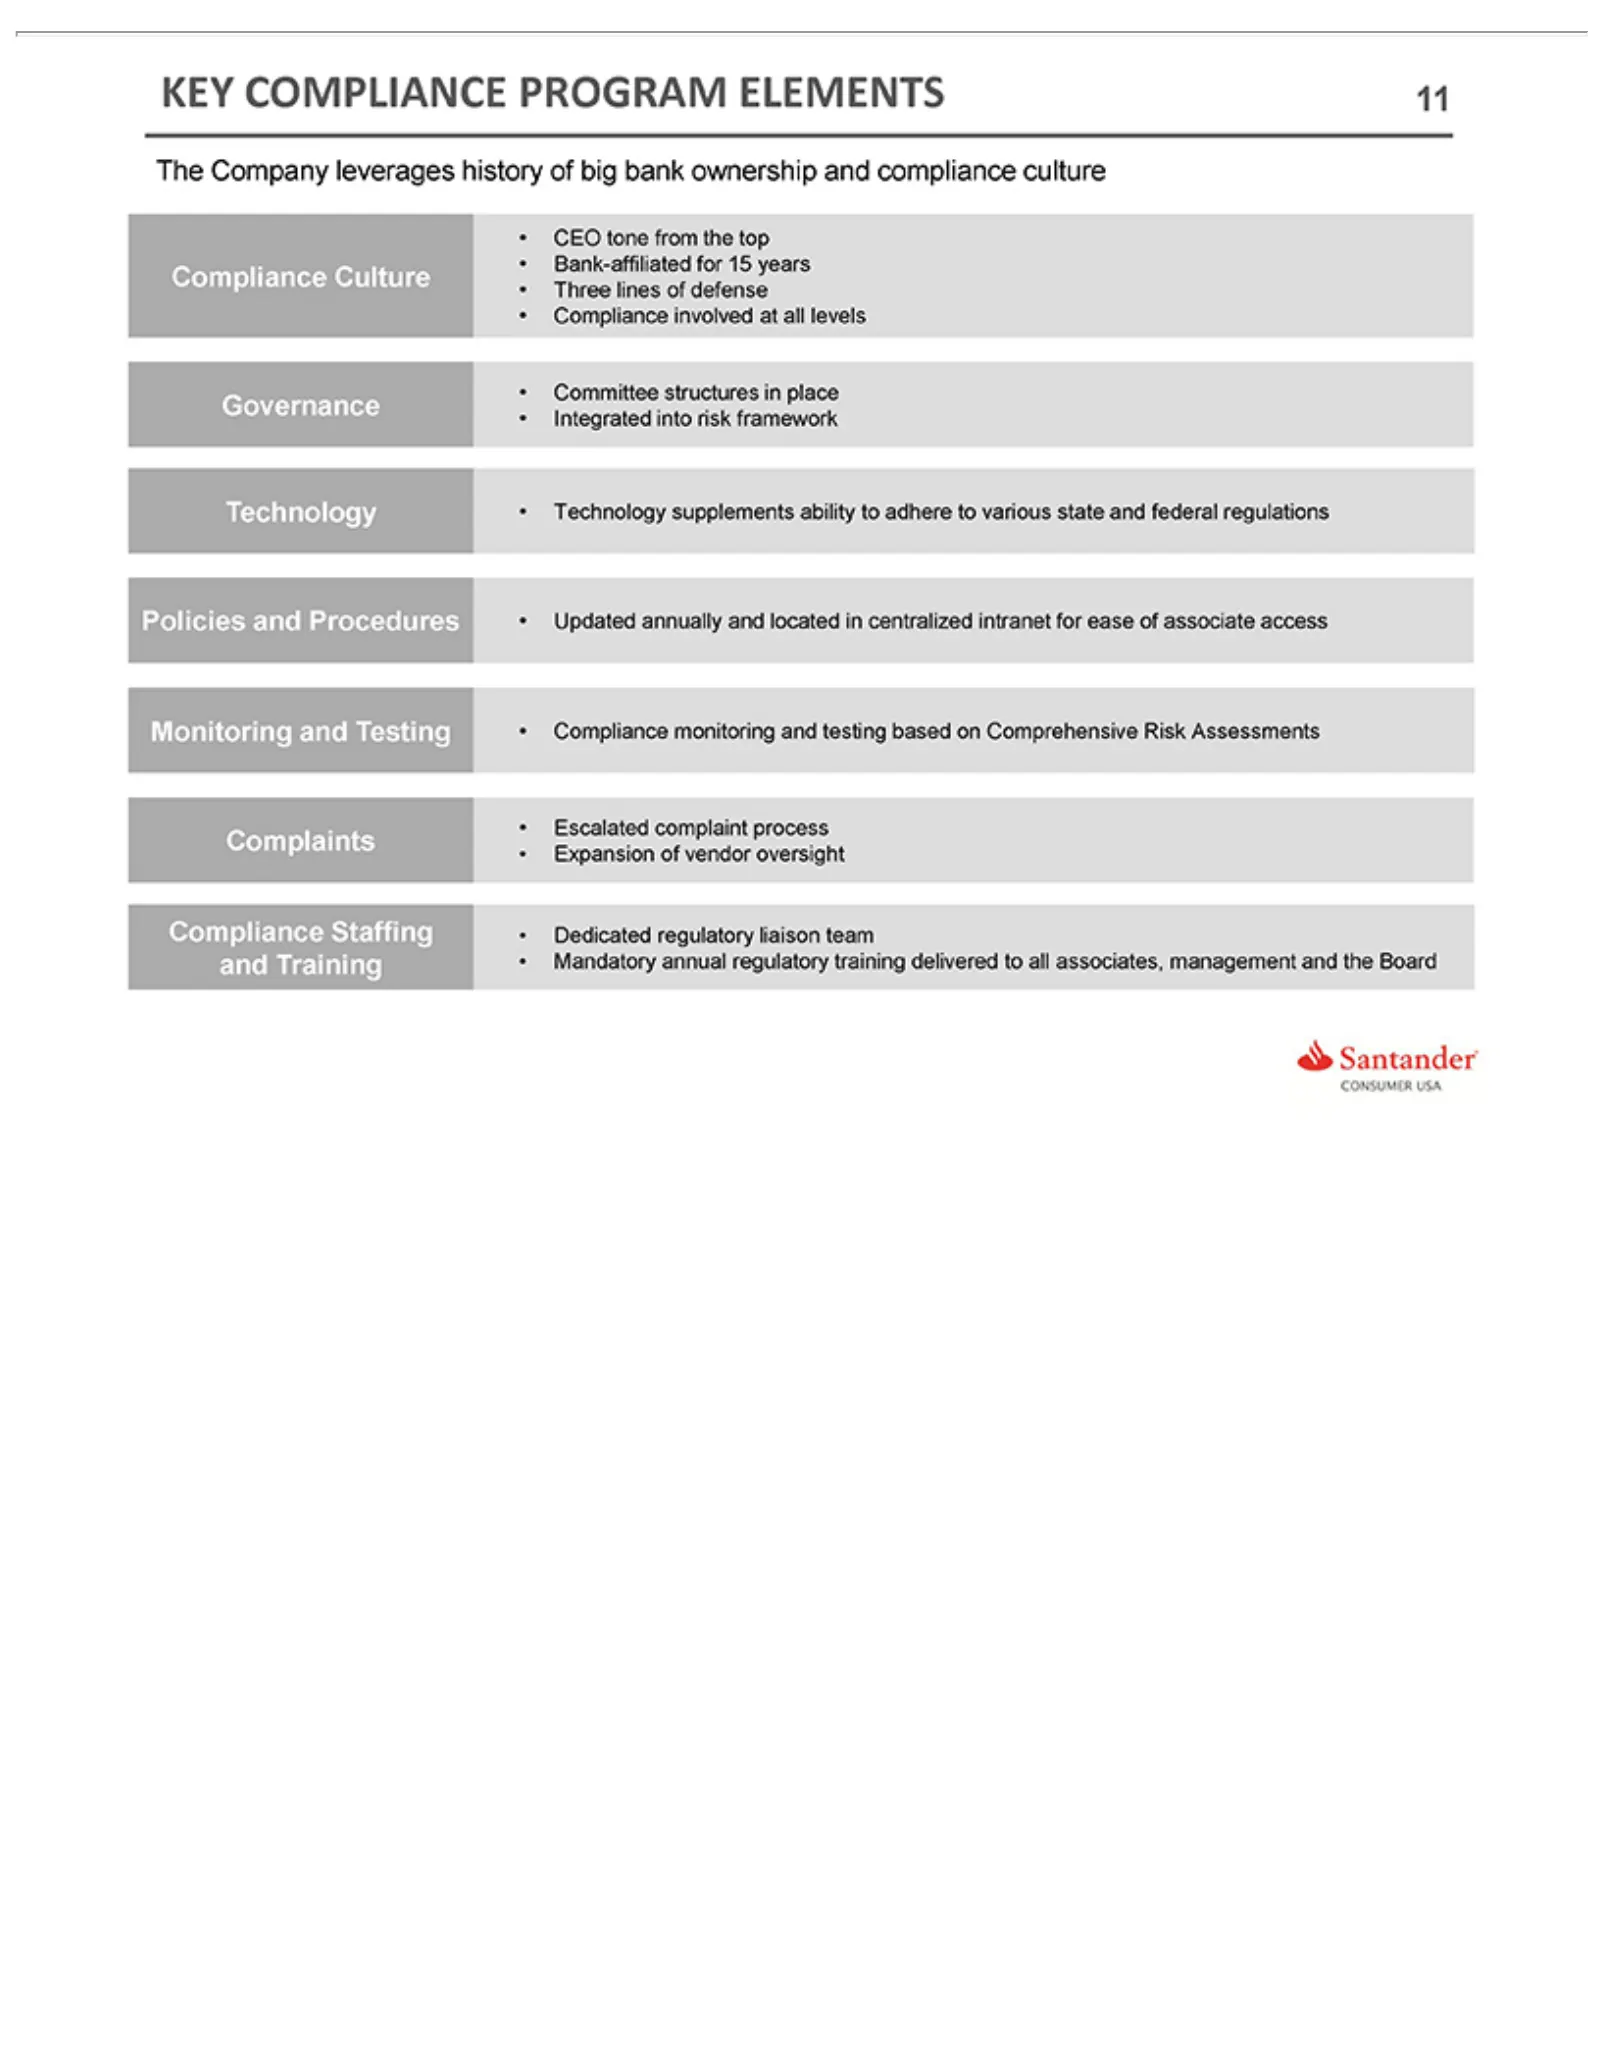
Slide 11: Key Compliance Program Elements
KEY 11 •The CEO Company COMPLIANCE tone from leverages Bank-affiliated •Compliance Three lines thePROGRAM for top 15 history years of big ELEMENTS bank ownership and compliance culture Committee Governance Policies •Monitoring Escalated and Complaints Expansion Compliance •Culture Compliance Integra
Slide 12: Agenda
I. Corporate AGENDA 12 II. III.Originations ServicingOverview and Underwriting
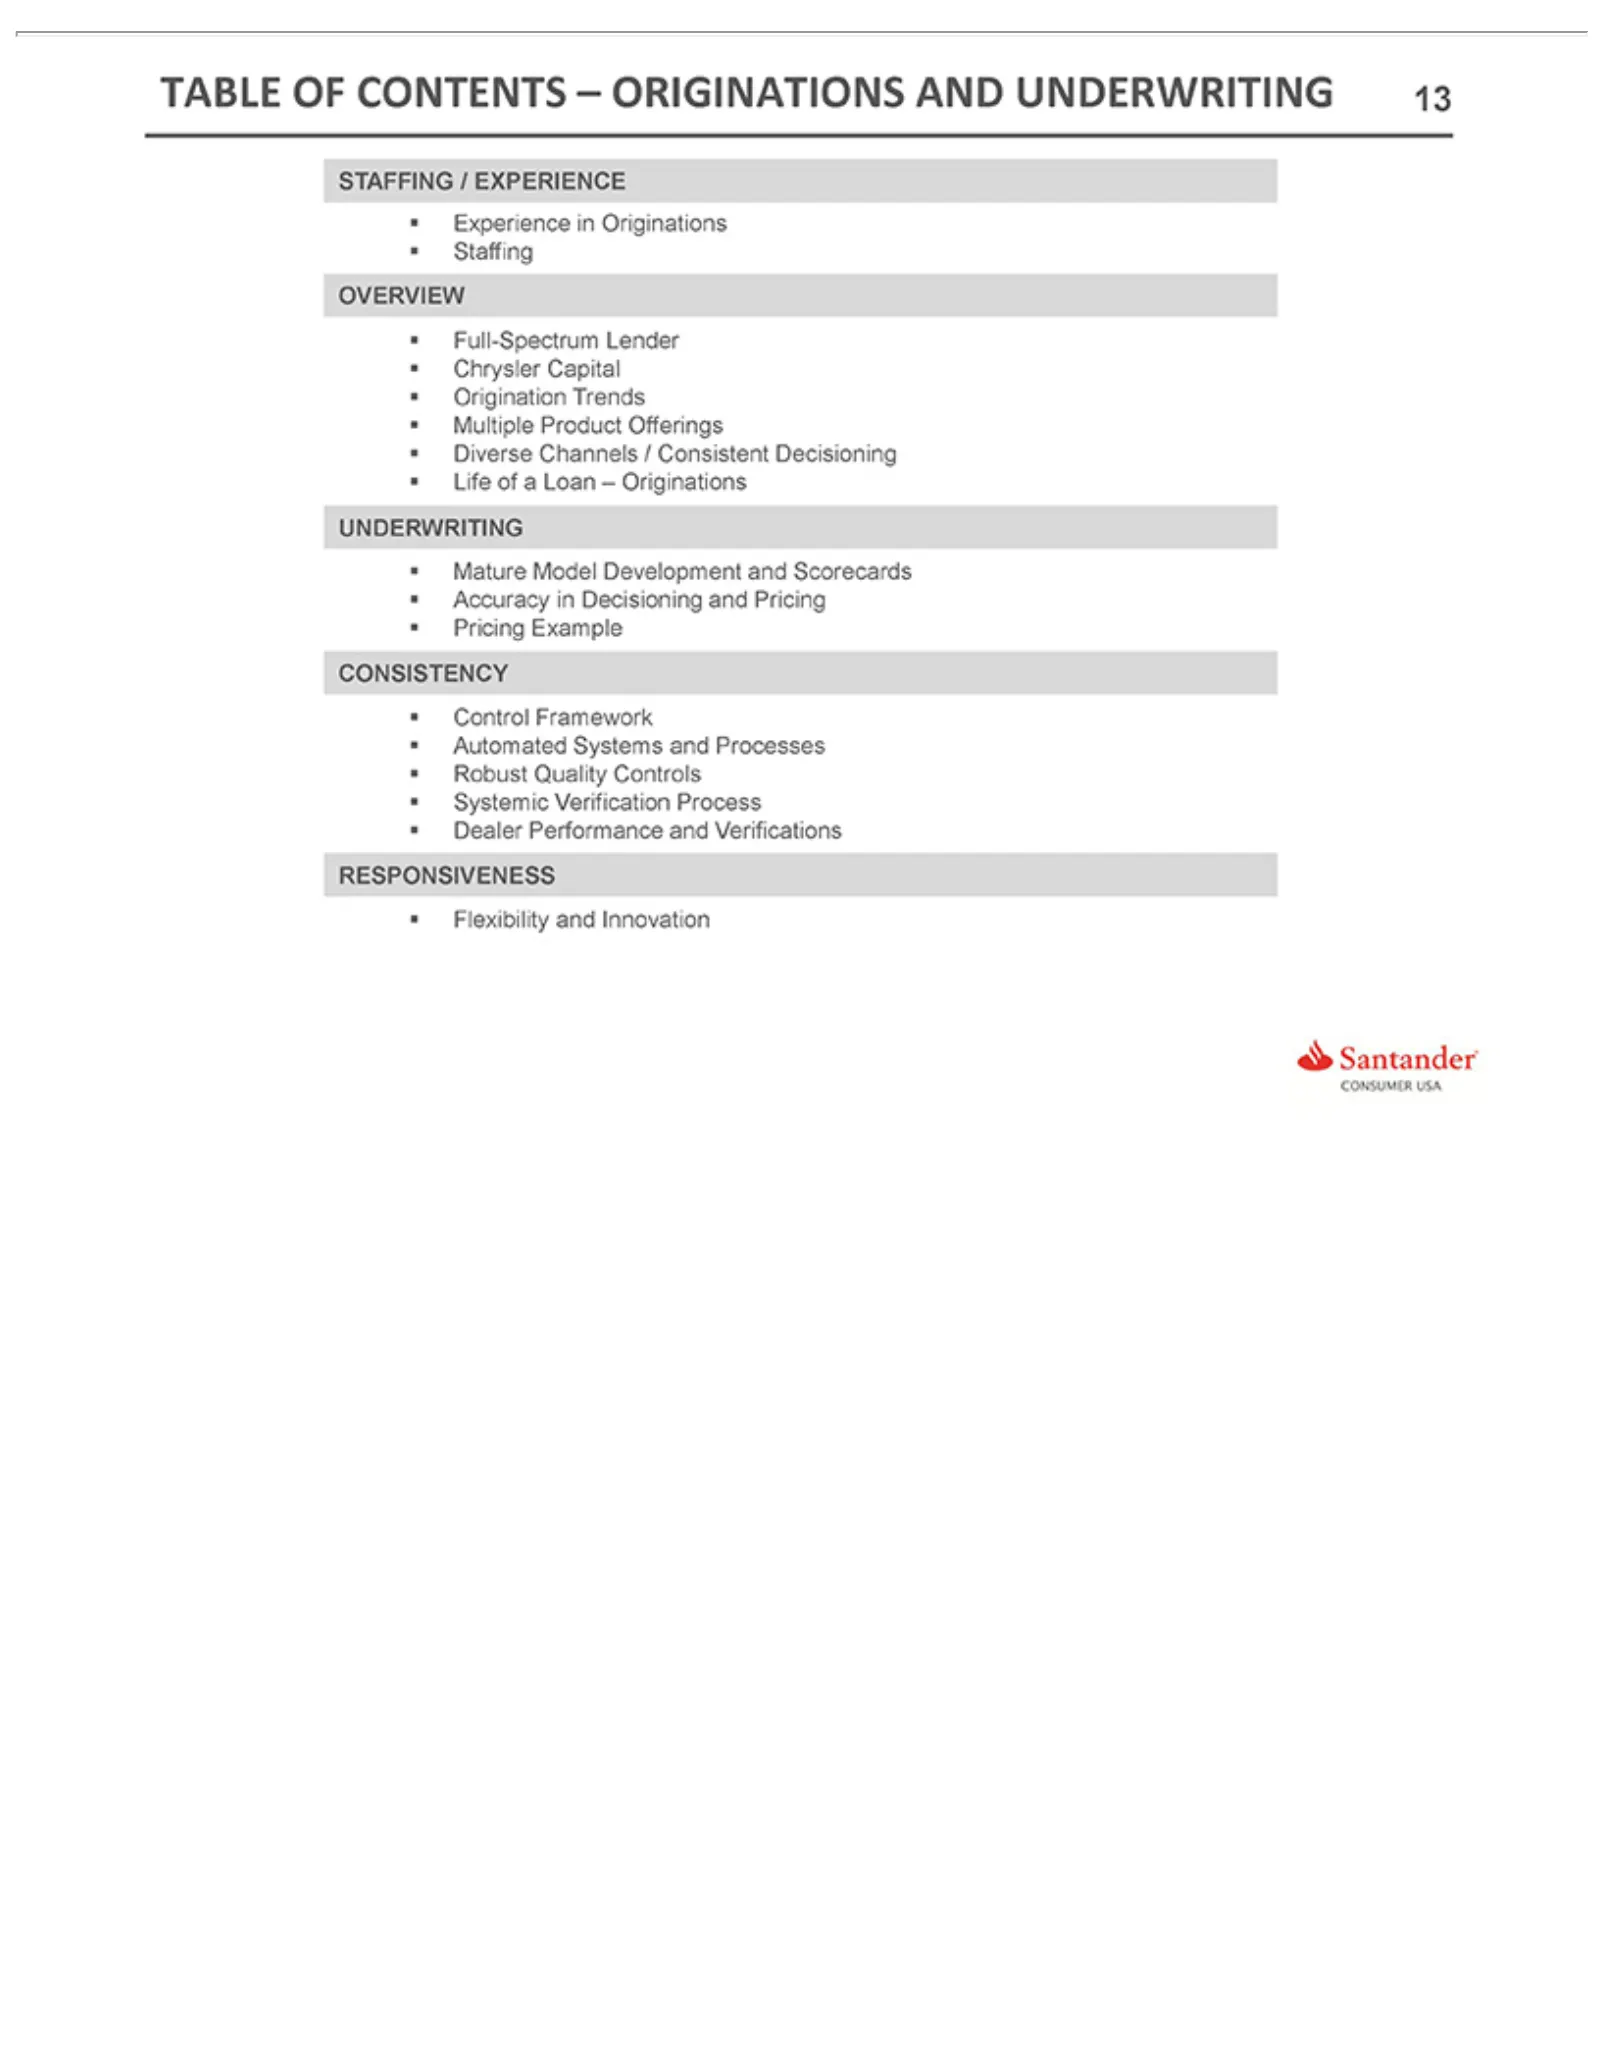
Slide 13: Table of Contents – Originations and Underwriting
TABLEModel 13 STAFFING Experience Full-Spectrum OVERVIEW Diverse Mature UNDERWRITING Control CONSISTENCY Automated Flexibility RESPONSIVENESS Framework Channels OFand Systems in CONTENTS / EXPERIENCE Originations Development Lender Innovation / Consistent and Chrysler Processes – Staffing ORIGINATIO
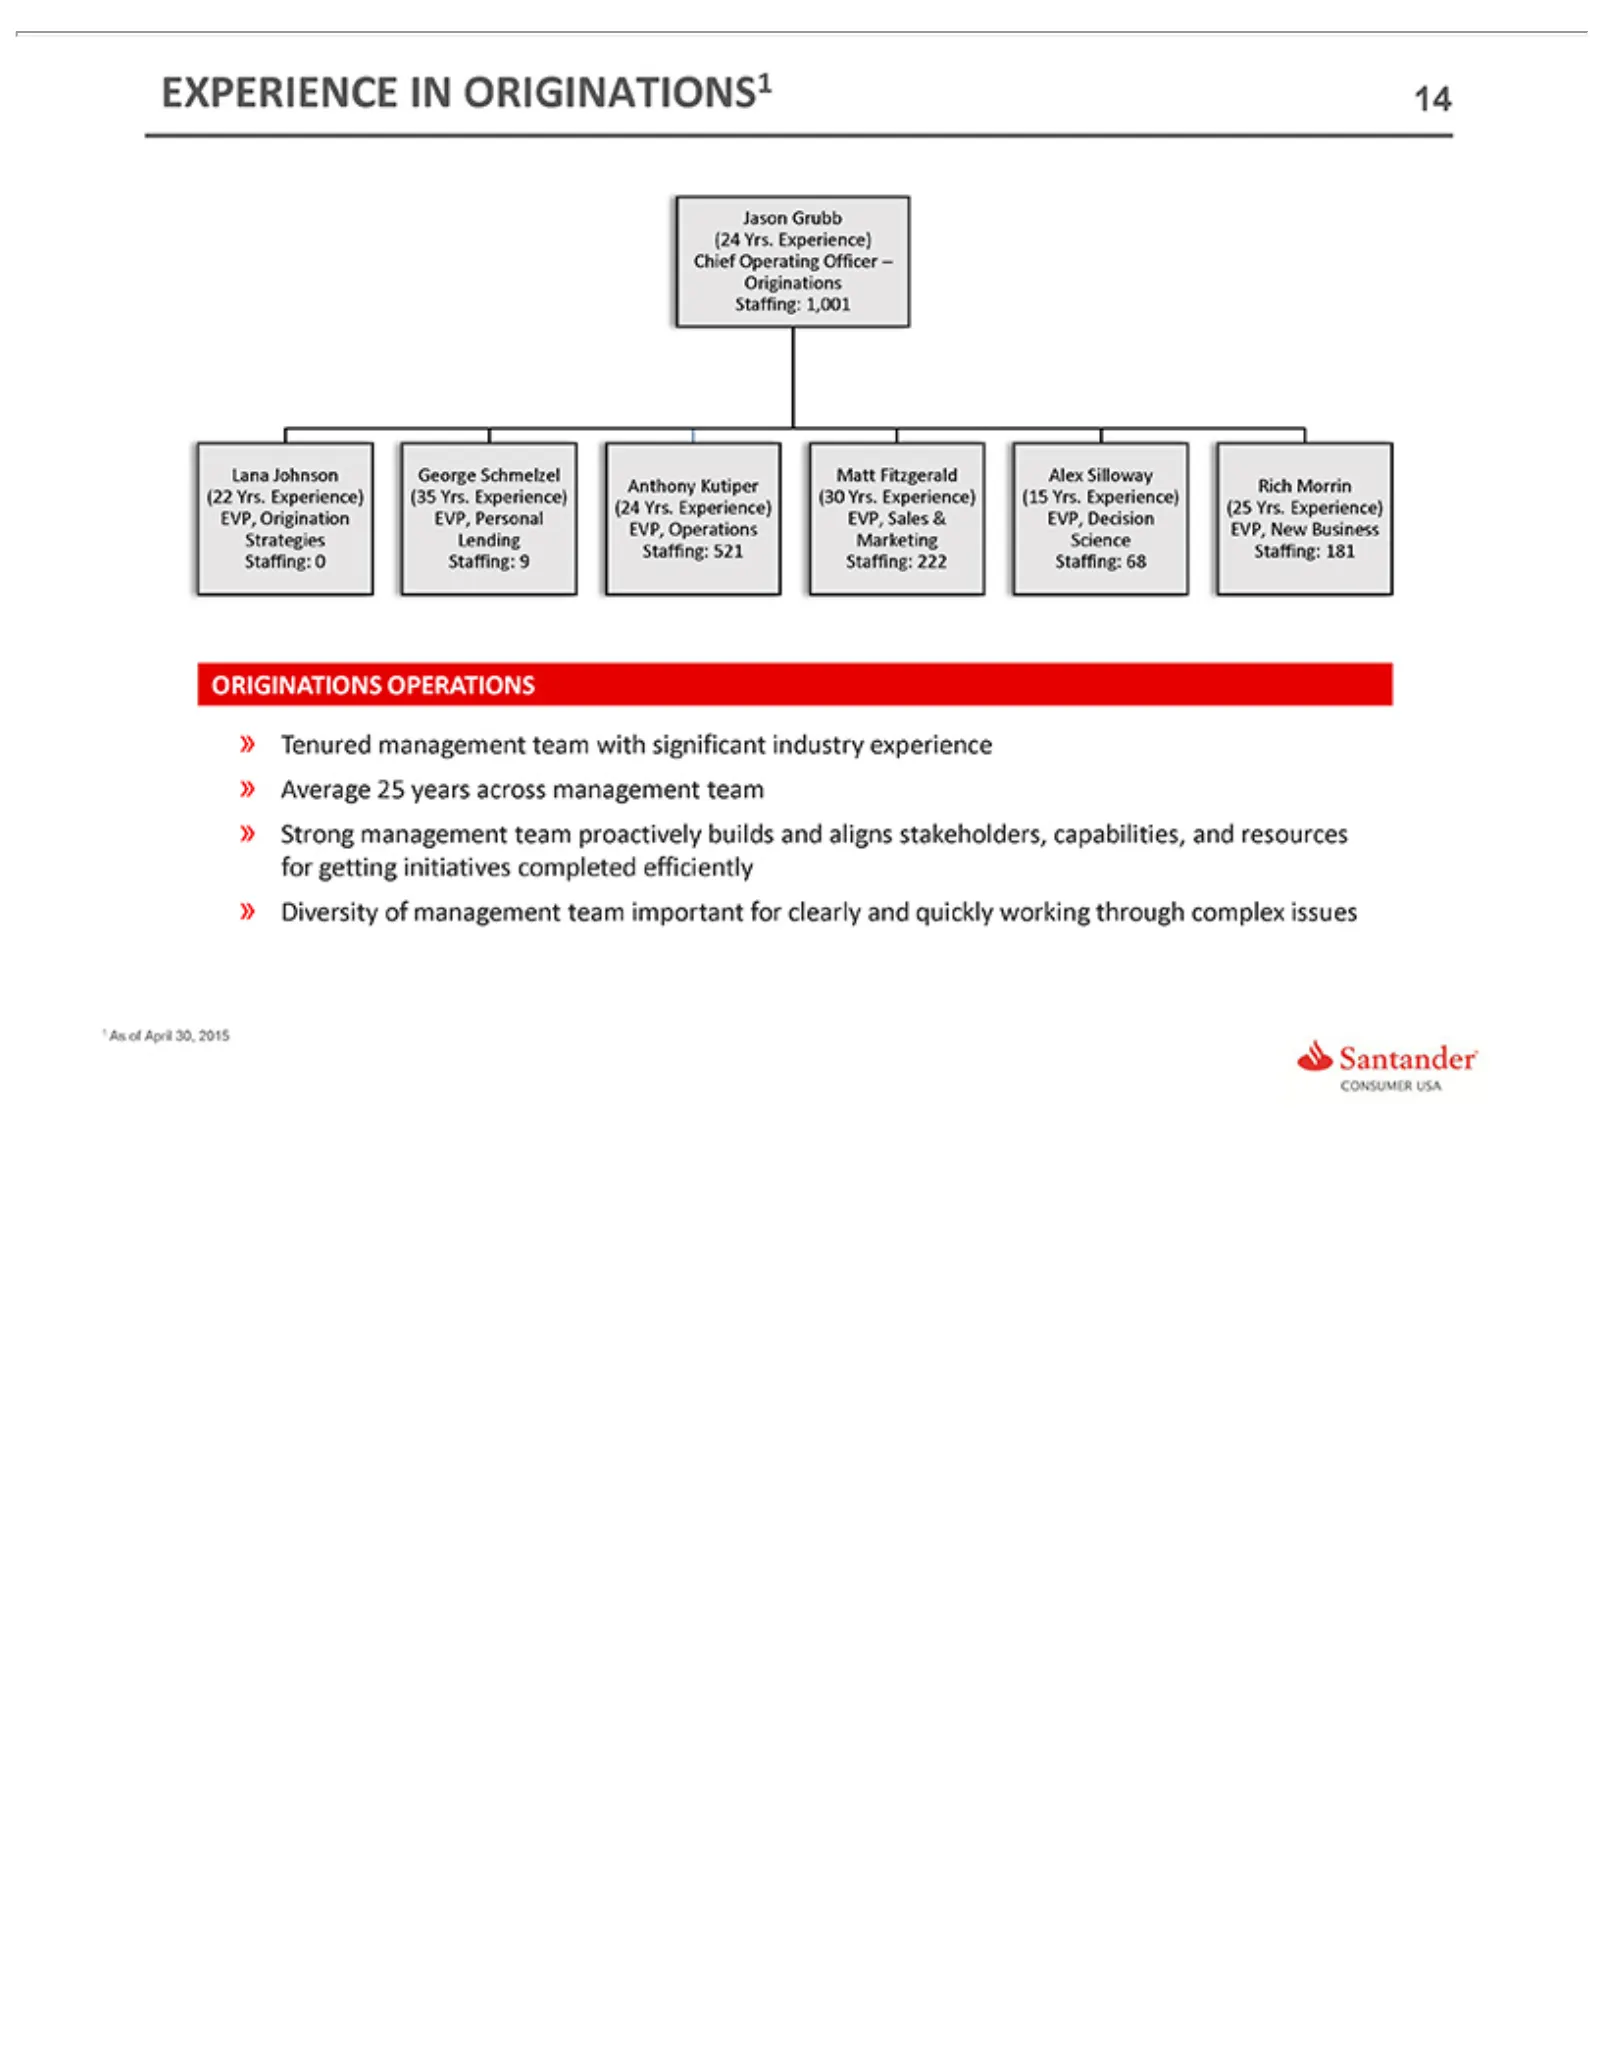
Slide 14: Experience in Originations
EXPERIENCE 14 Jason Lana George Anthony Matt Alex Rich ORIGINATIONS » 1 Average Tenured Strong Diversity Morrin Fitzgerald Silloway Johnson Grubb Schmelzel As management Kutiper management 25 of of(25 (24 years April (22 management (15 IN (30 Yrs. (24 OPERATIONS Yrs. Yrs. (35 ORIGINATIONS1 across 30
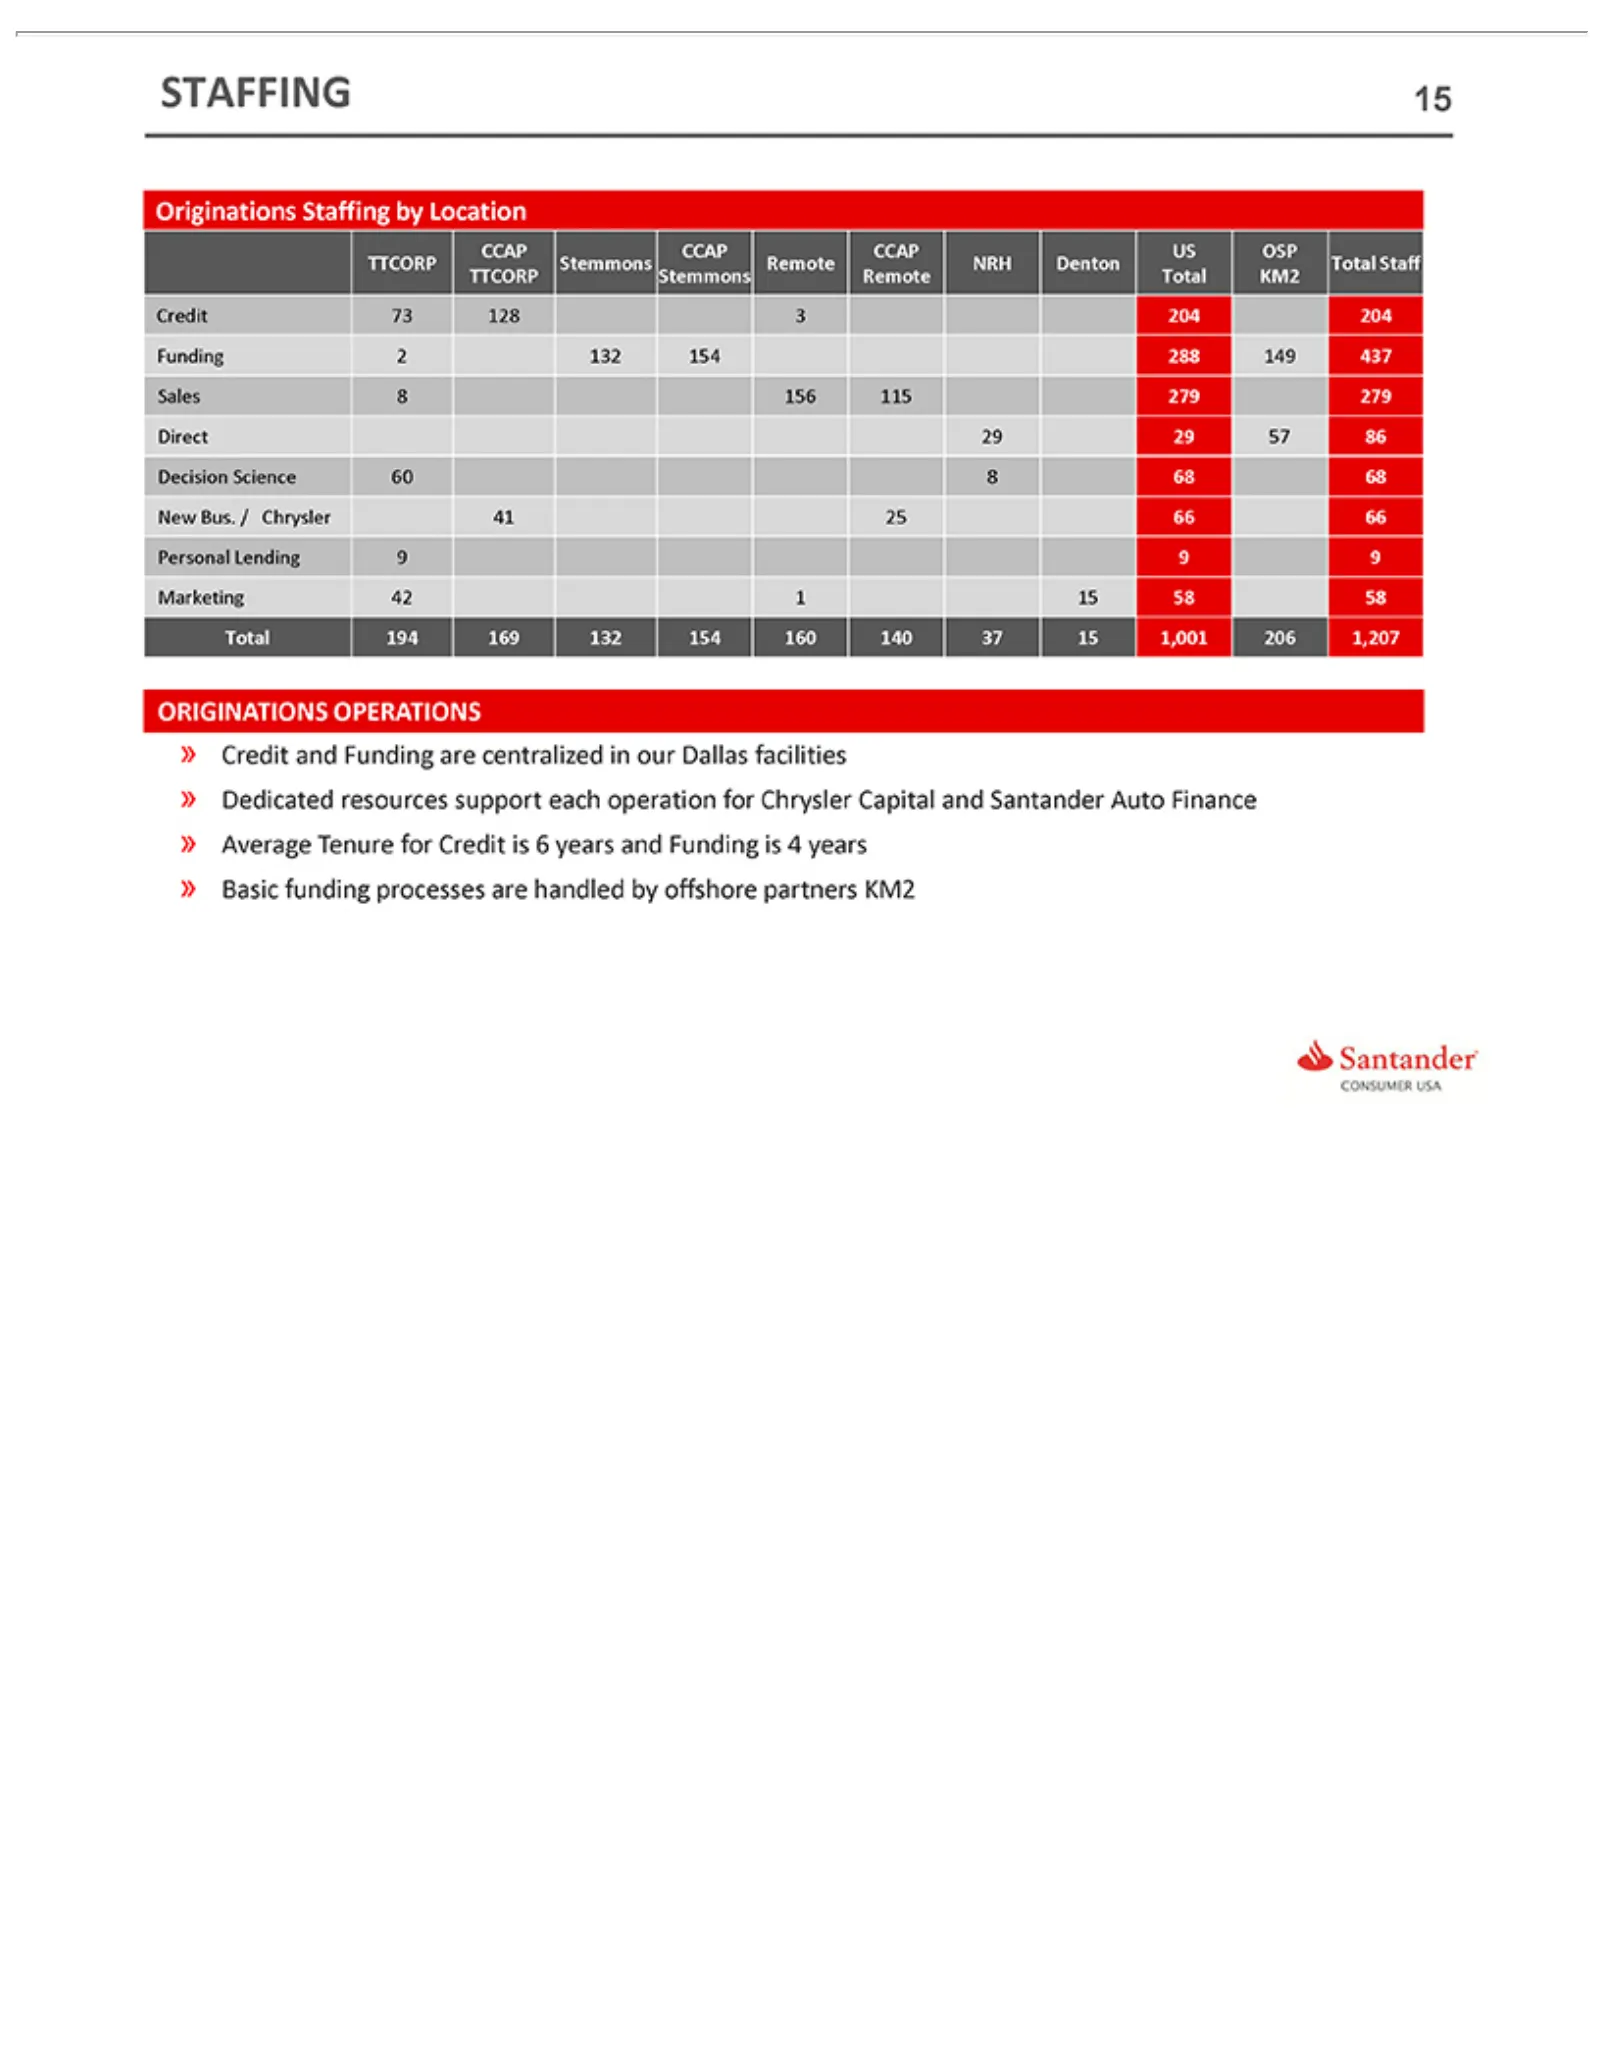
Slide 15: Originations Staffing
Originations STAFFING 15 CCAP TTCORP Credit Funding Sales Direct Decision New Personal Marketing Total ORIGINATIONS » Average Credit Dedicated Basic Bus. 194 829 73 CCAP 156 funding and 2Lending Science 29 128 169 Stemmons /Tenure 132 42 Chrysler 115 resources Funding 57 Staffing CCAP 13132 154 15 8
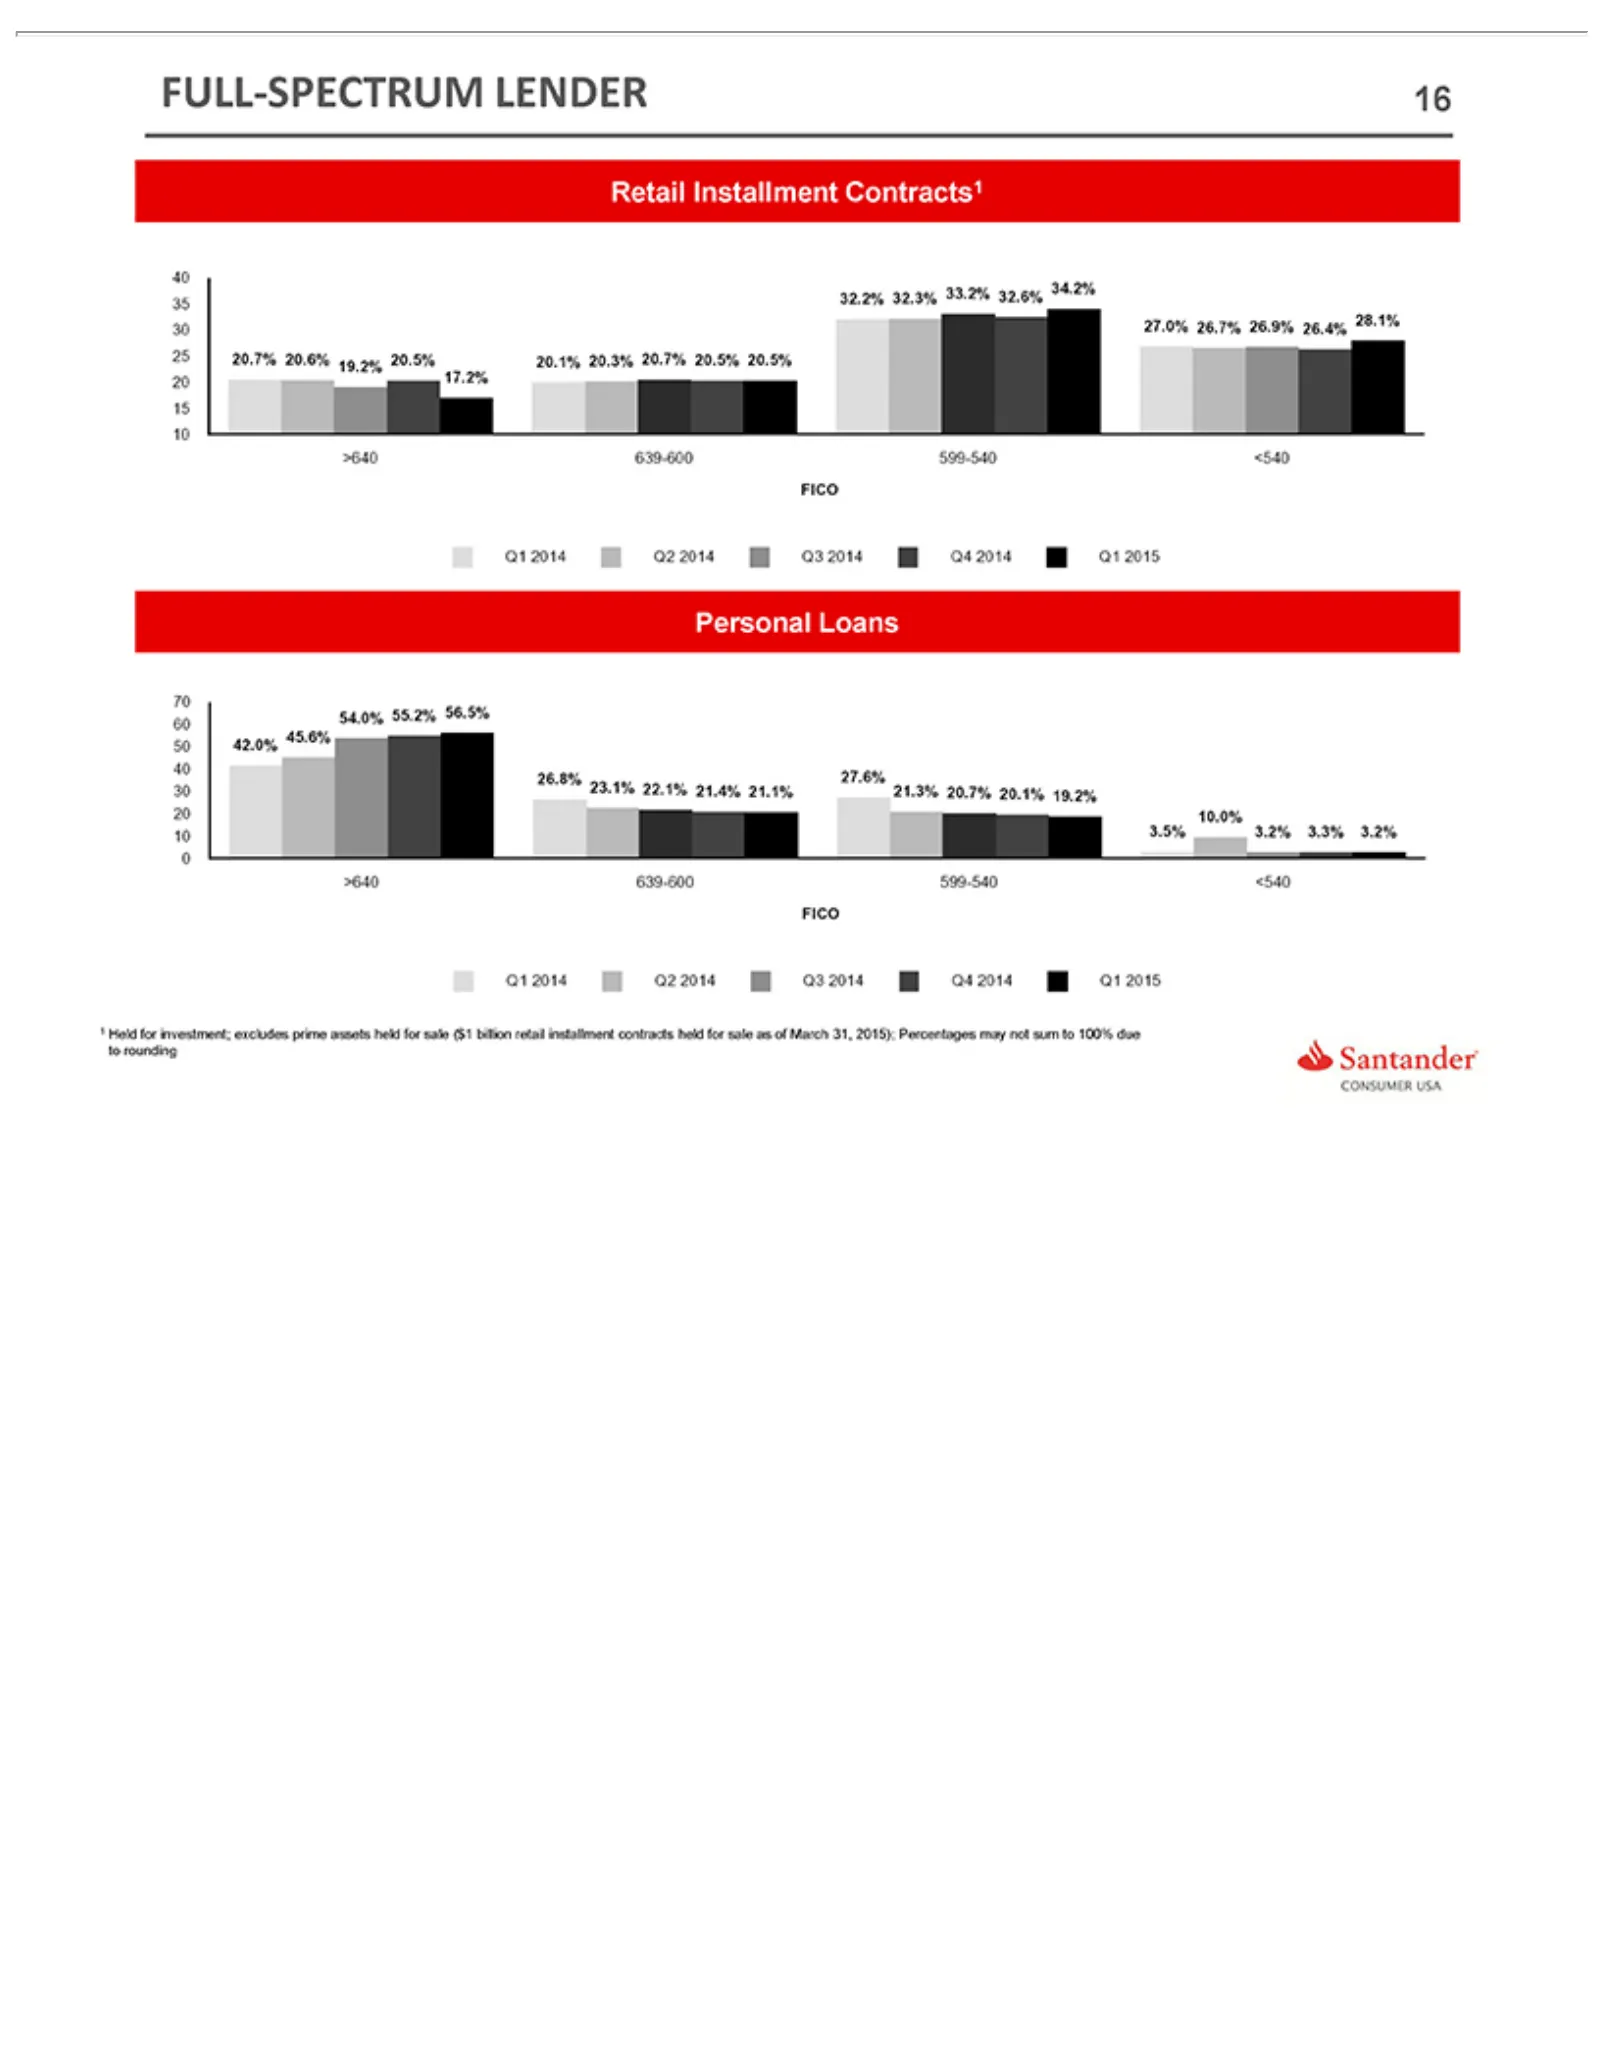
Slide 16: Full-Spectrum Lender
FULL-SPECTRUM 16 Retail Personal 1Held Installment forLoans investment; Contracts1 LENDER excludes prime assets held for sale ($1 billion retail installment contracts held for sale as of March 31,2015); Percentages may not sum to 100% due to rounding
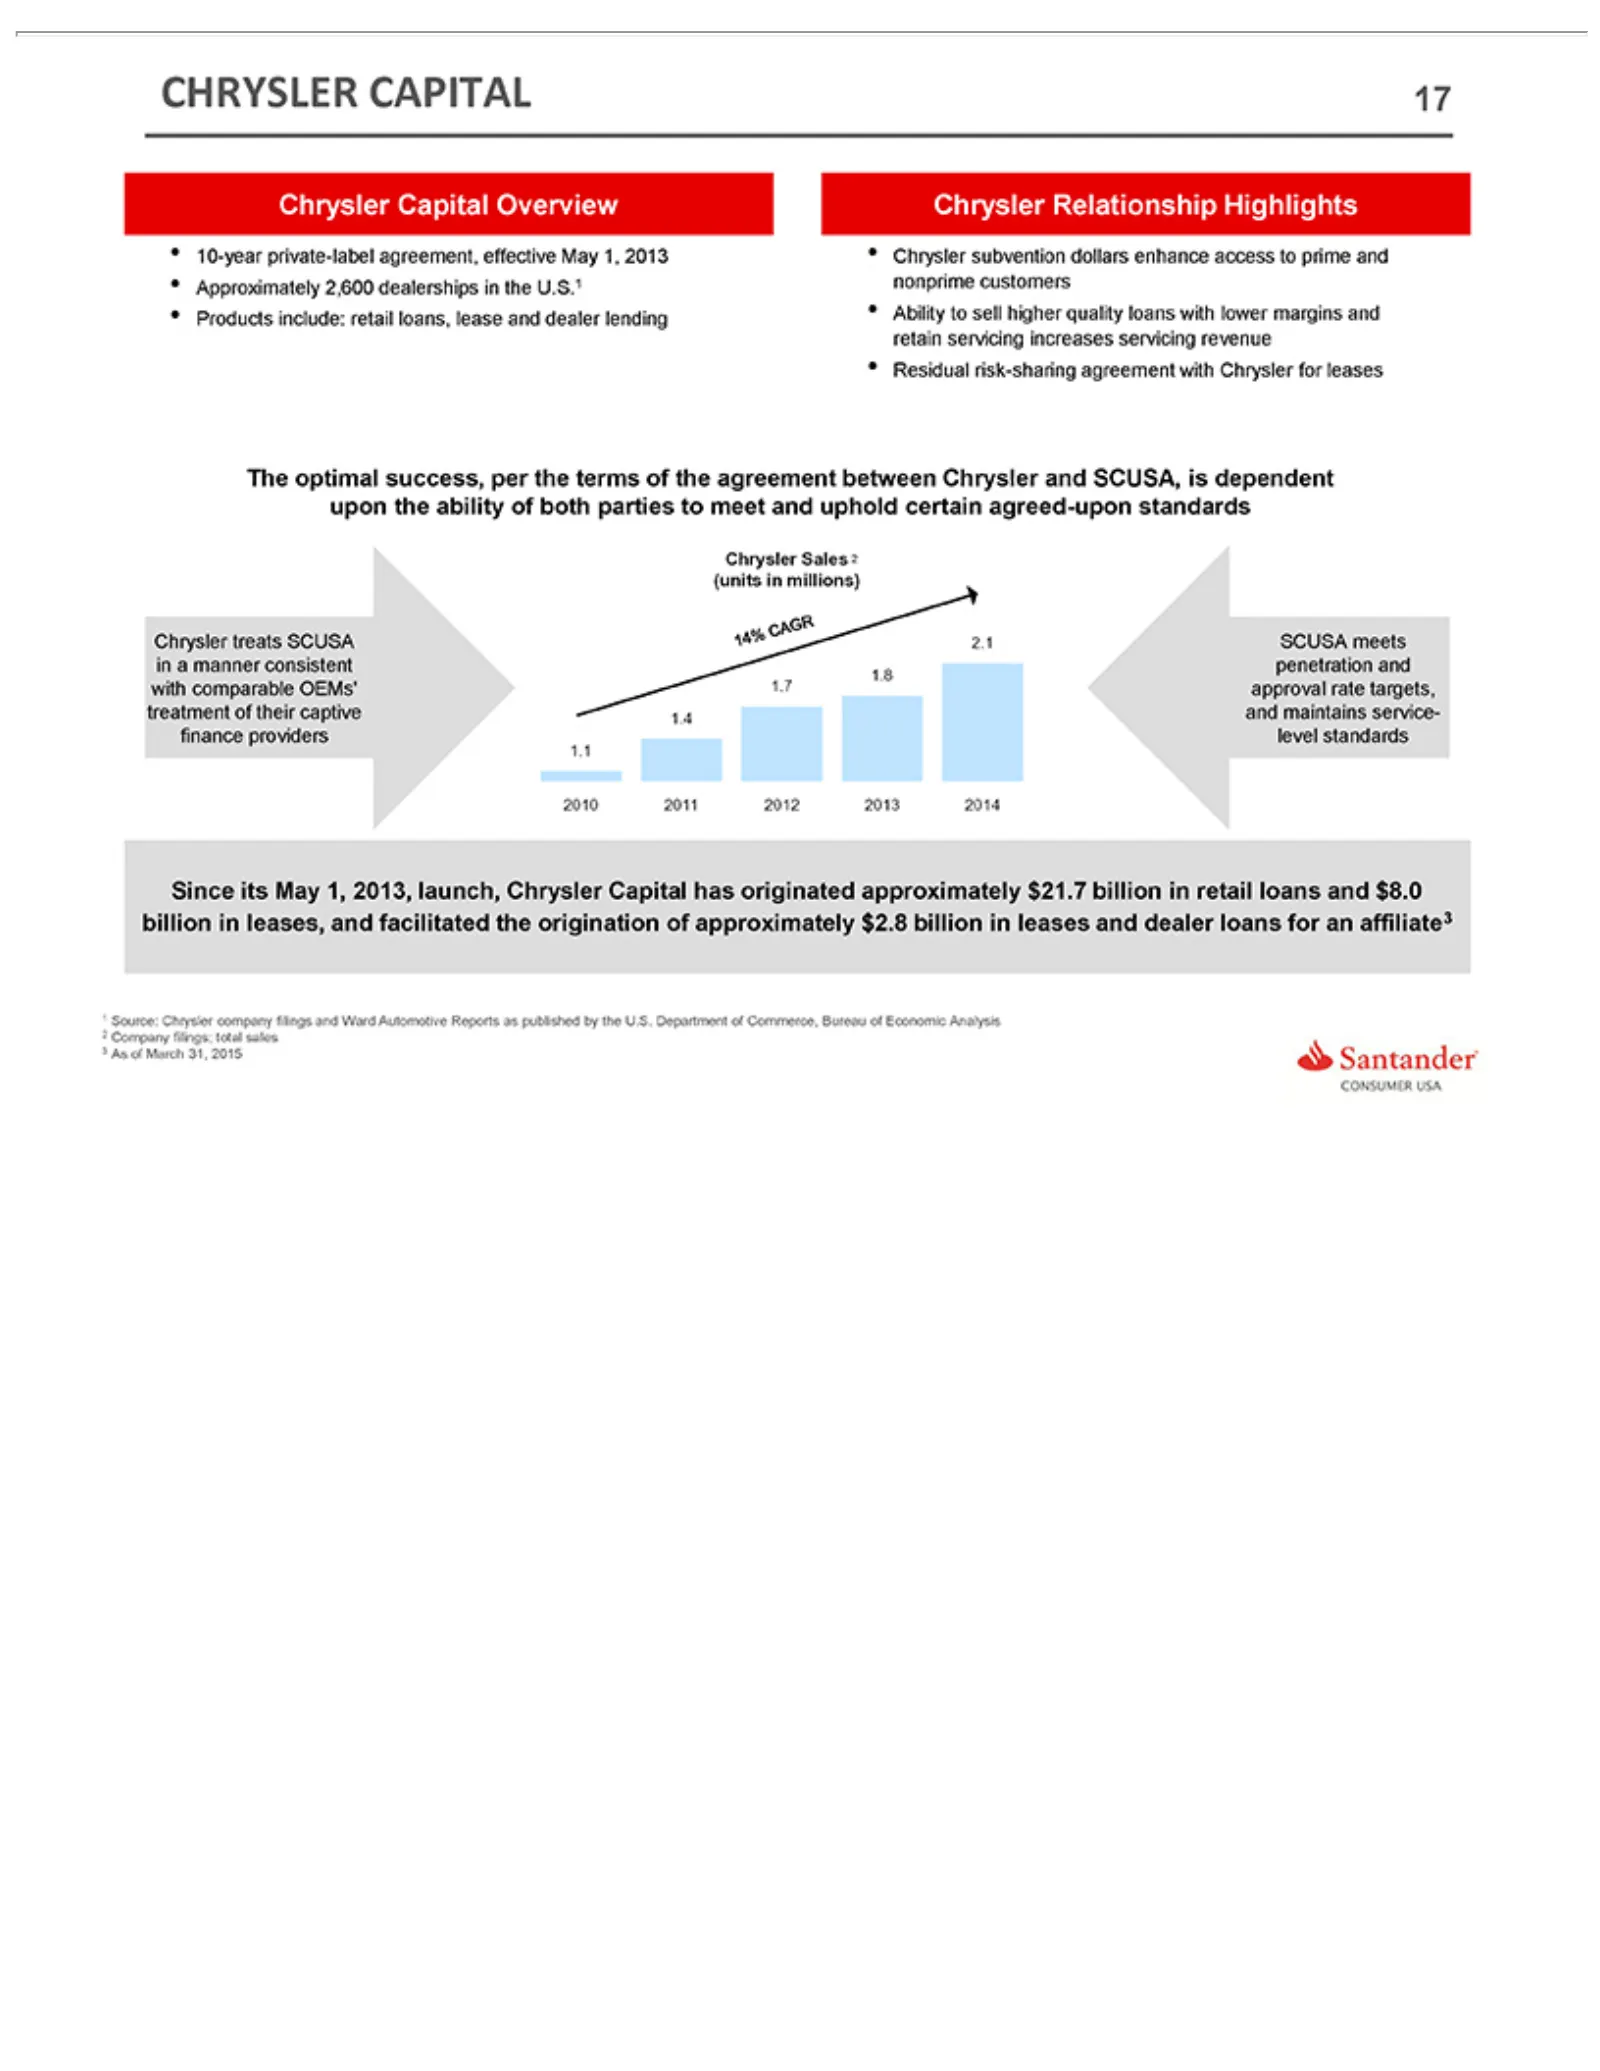
Slide 17: Chrysler Capital Overview
CHRYSLER 17 •10-year 3As The Approximately •Chrysler private-label AbilityCapital Products Residual Chrysler SCUSA Since leases 1Source: 2Company optimal ofits and March meets May treatsCAPITAL Overview include: Relationship subvention tosuccess, sell SCUSA 2,600 2013, loans 2015agreement, retail hi
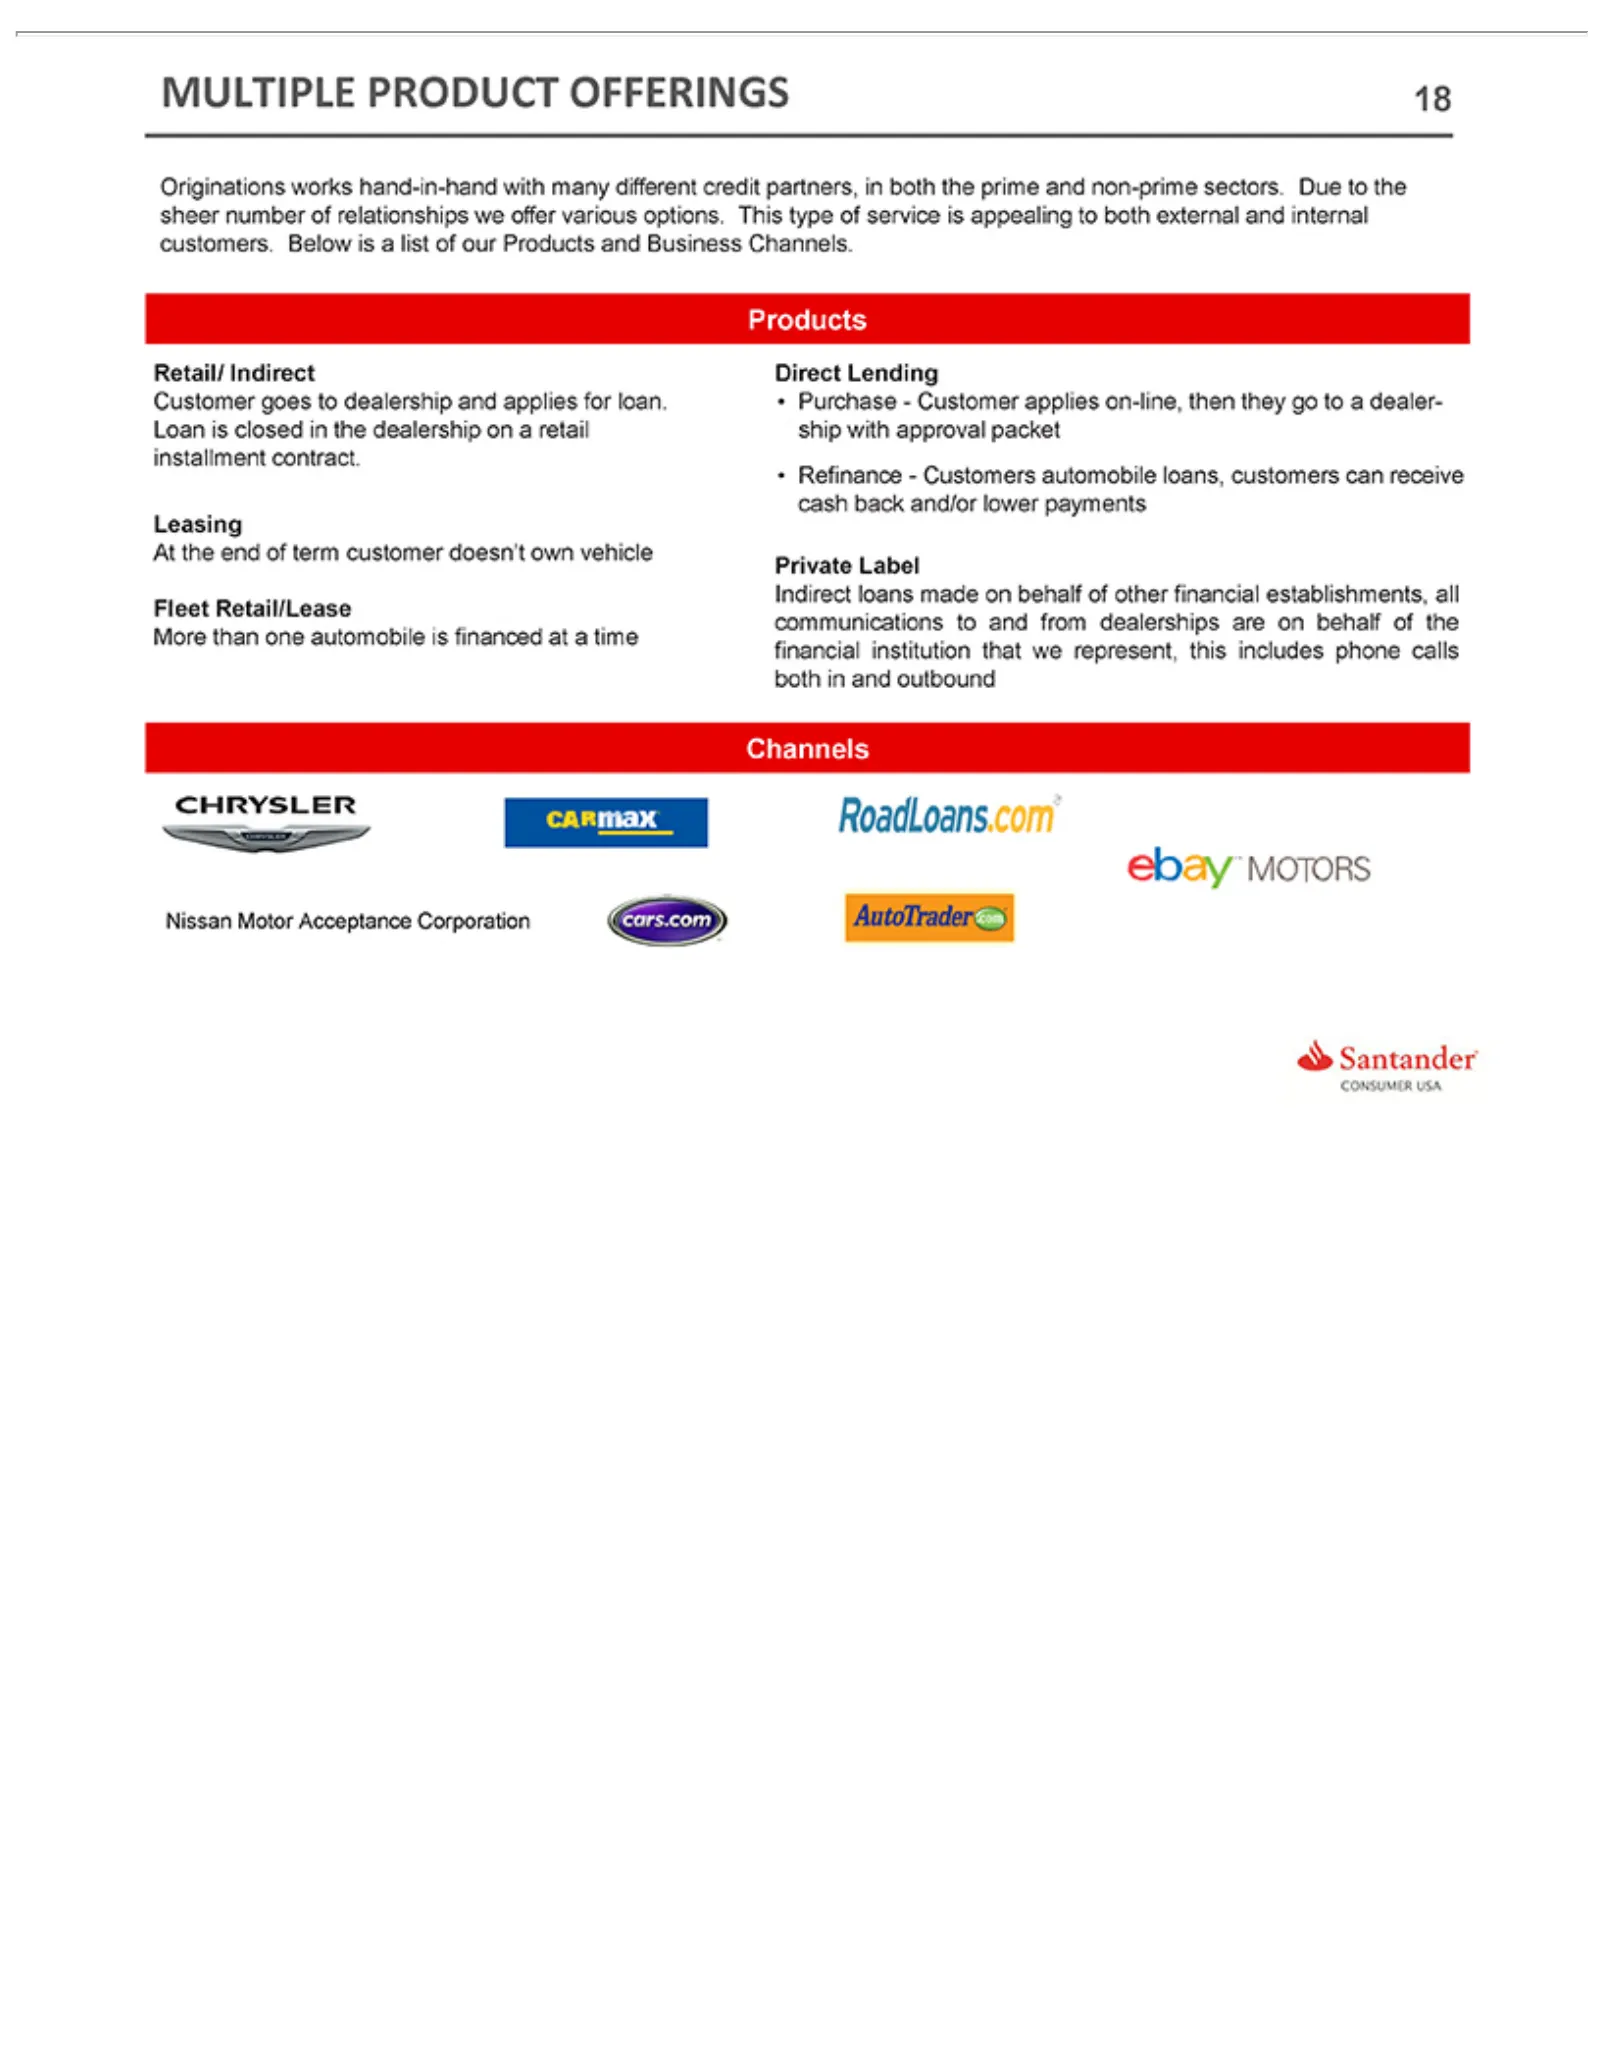
Slide 18: Multiple Product Offerings
MULTIPLE 18 Originations is Retail/ Products Customer At Leasing Fleet More •Direct appealing the Purchase Retail/Lease than end Lending Indirect goes one ofto Refinance Channels Private Indirect and Nissan outbound Motor Label loansPRODUCT works -Customer term automobile both to dealership customer
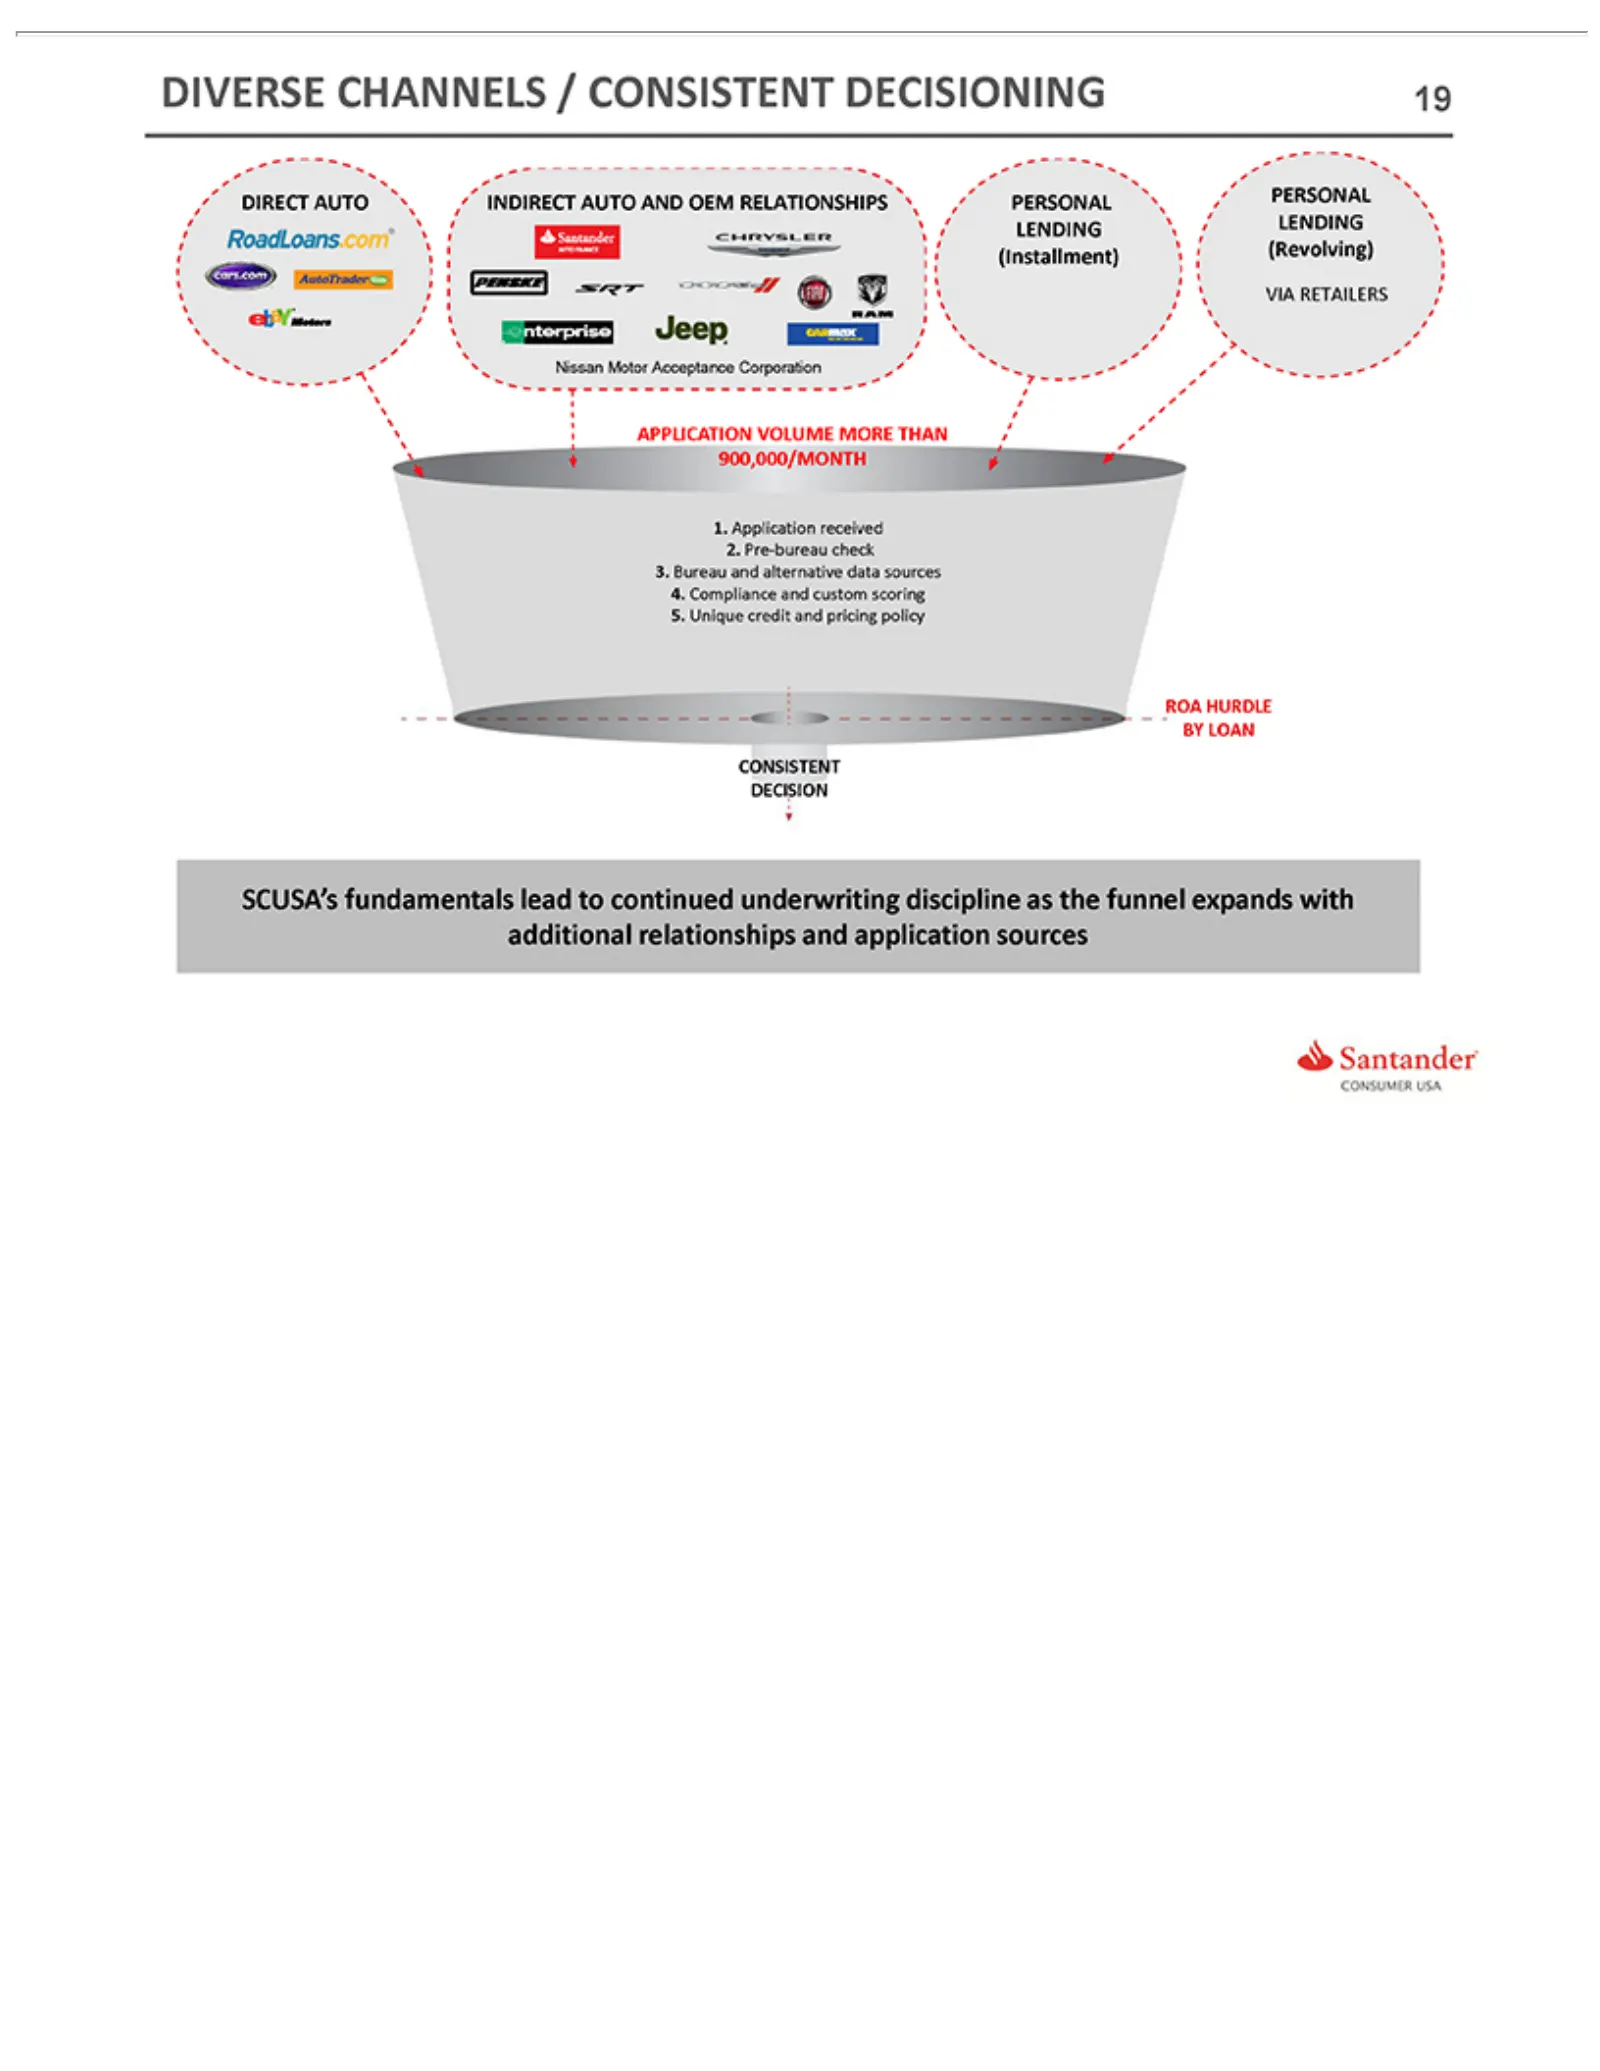
Slide 19: Diverse Origination Channels
DIVERSE 19 DIRECT (Installment) VIA Nissan APPLICATION 1. ROA CONSISTENT SCUSA’s Application RETAILERS HURDLE Motor AUTO fundamentals CHANNELS (Revolving) Acceptance received DECISION BY VOLUME INDIRECT LOAN 2. lead / Pre-bureau Corporation CONSISTENT MORE to AUTO continued THAN AND check underwriti
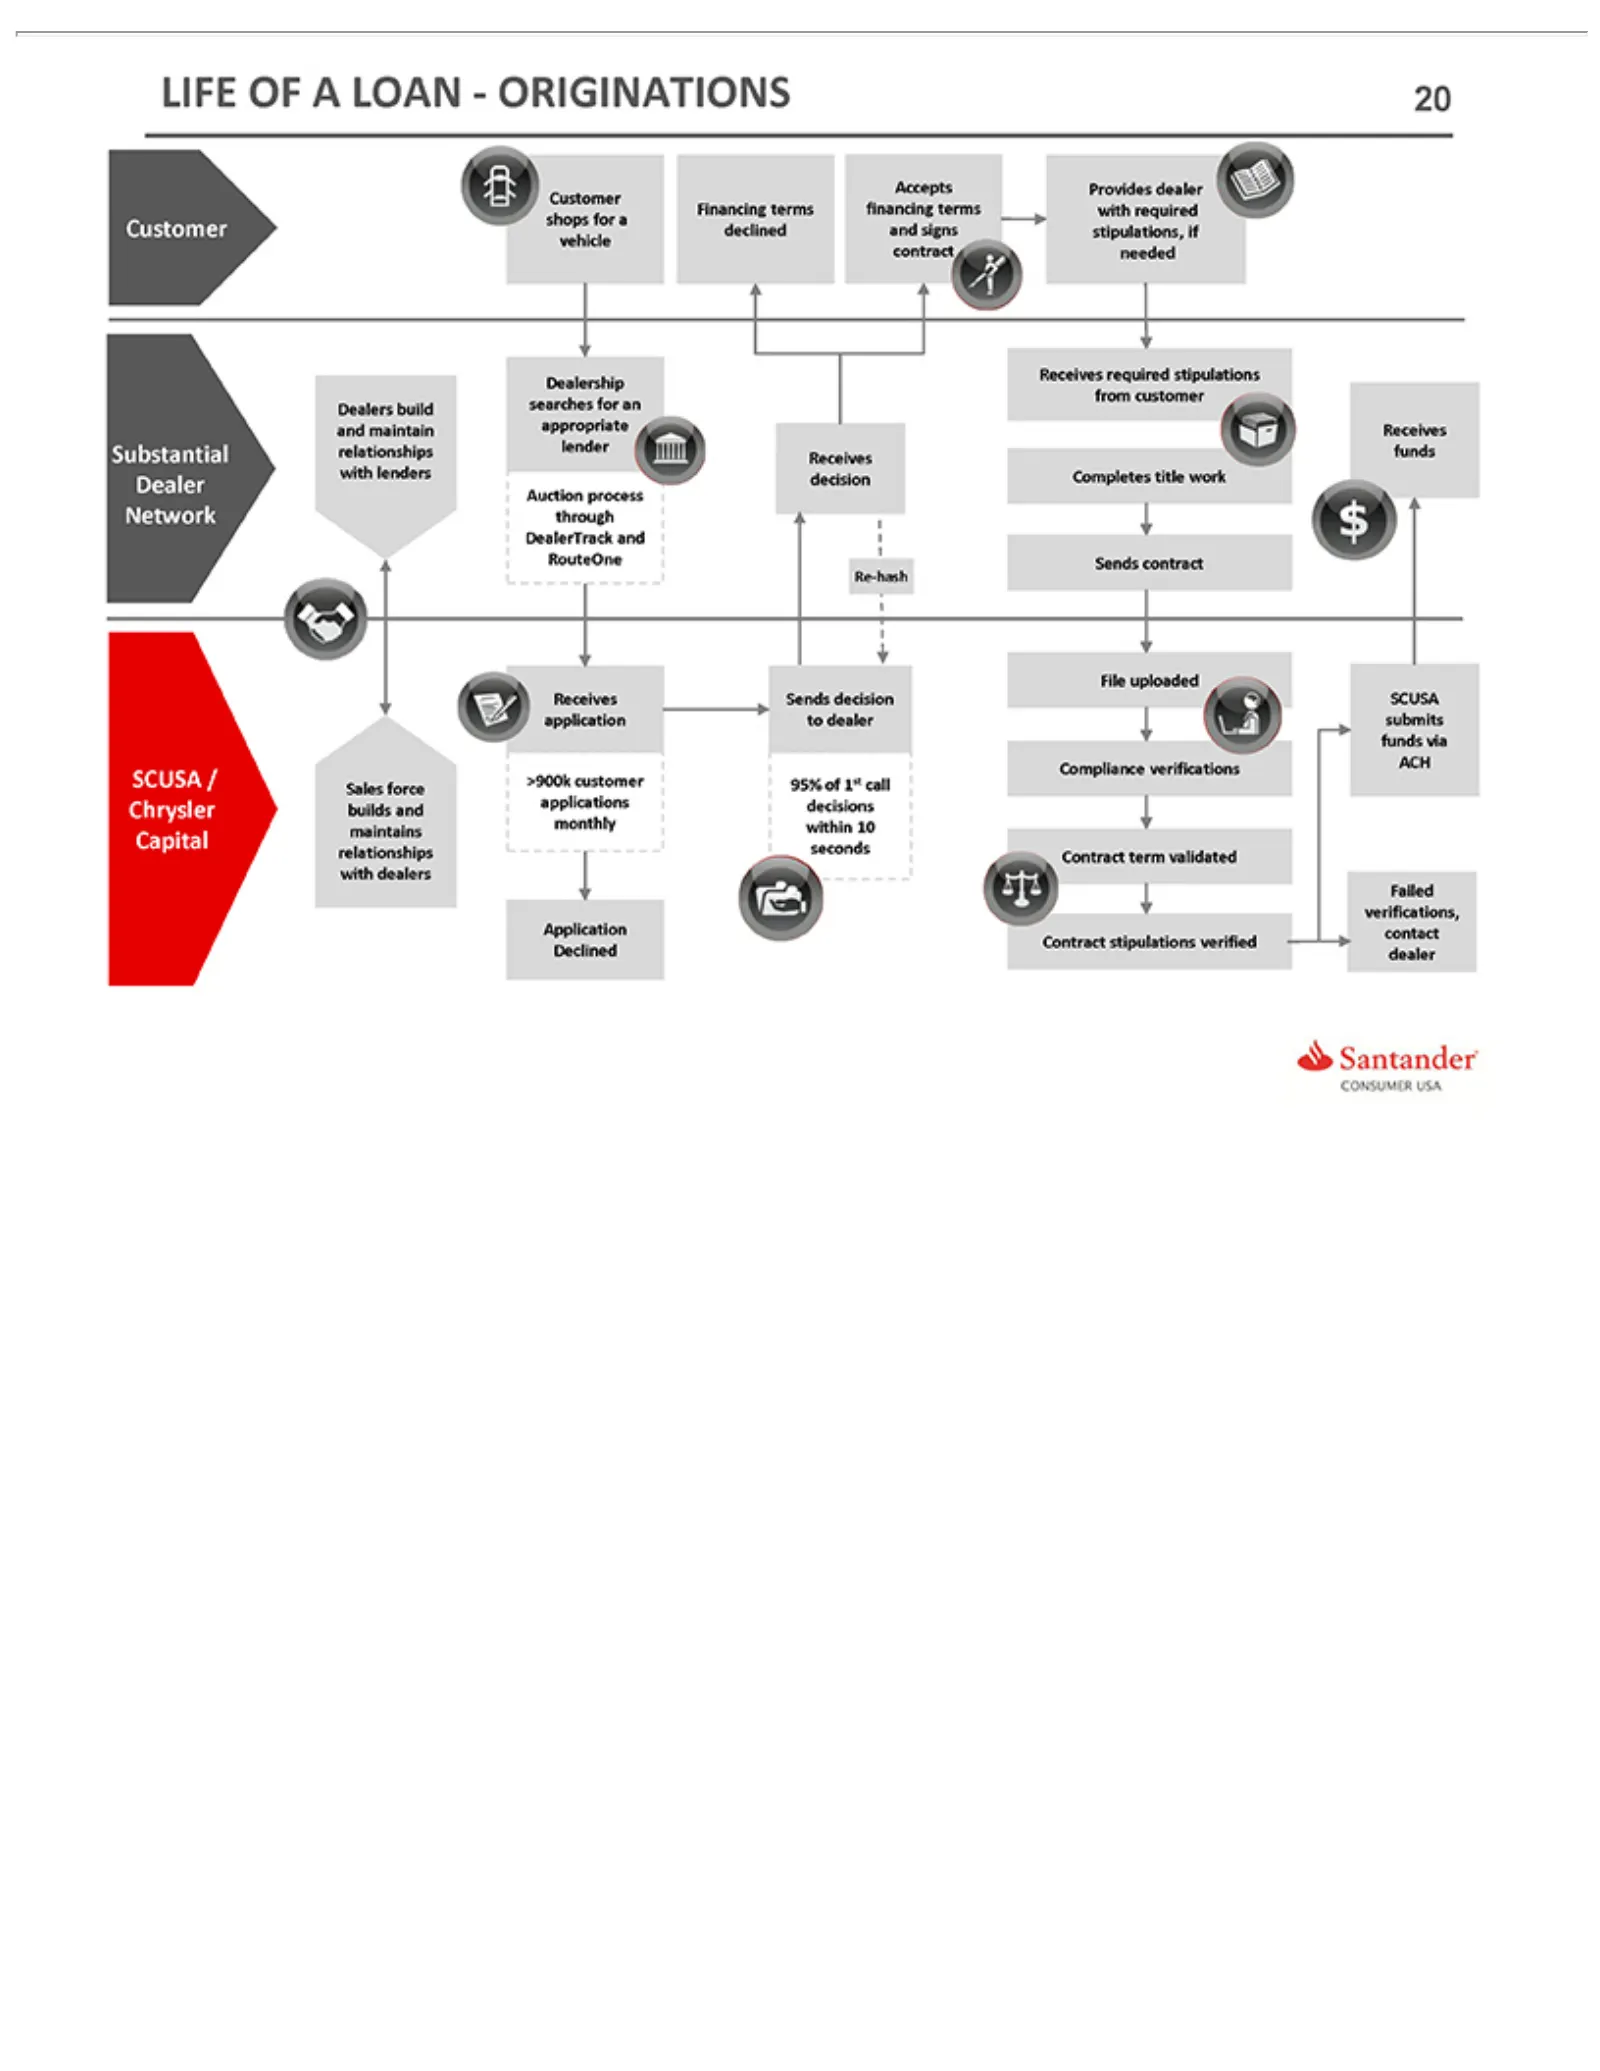
Slide 20: Life of a Loan – Originations
LIFEmaintain Customer shops declined contract vehicle Dealership from Dealers and Auction DealerTrack through RouteOne File Re-hash Receives application funds Compliance Sales builds force maintains relationships with Application verifications, Failed Contract Declined uploaded lenders dealers custo
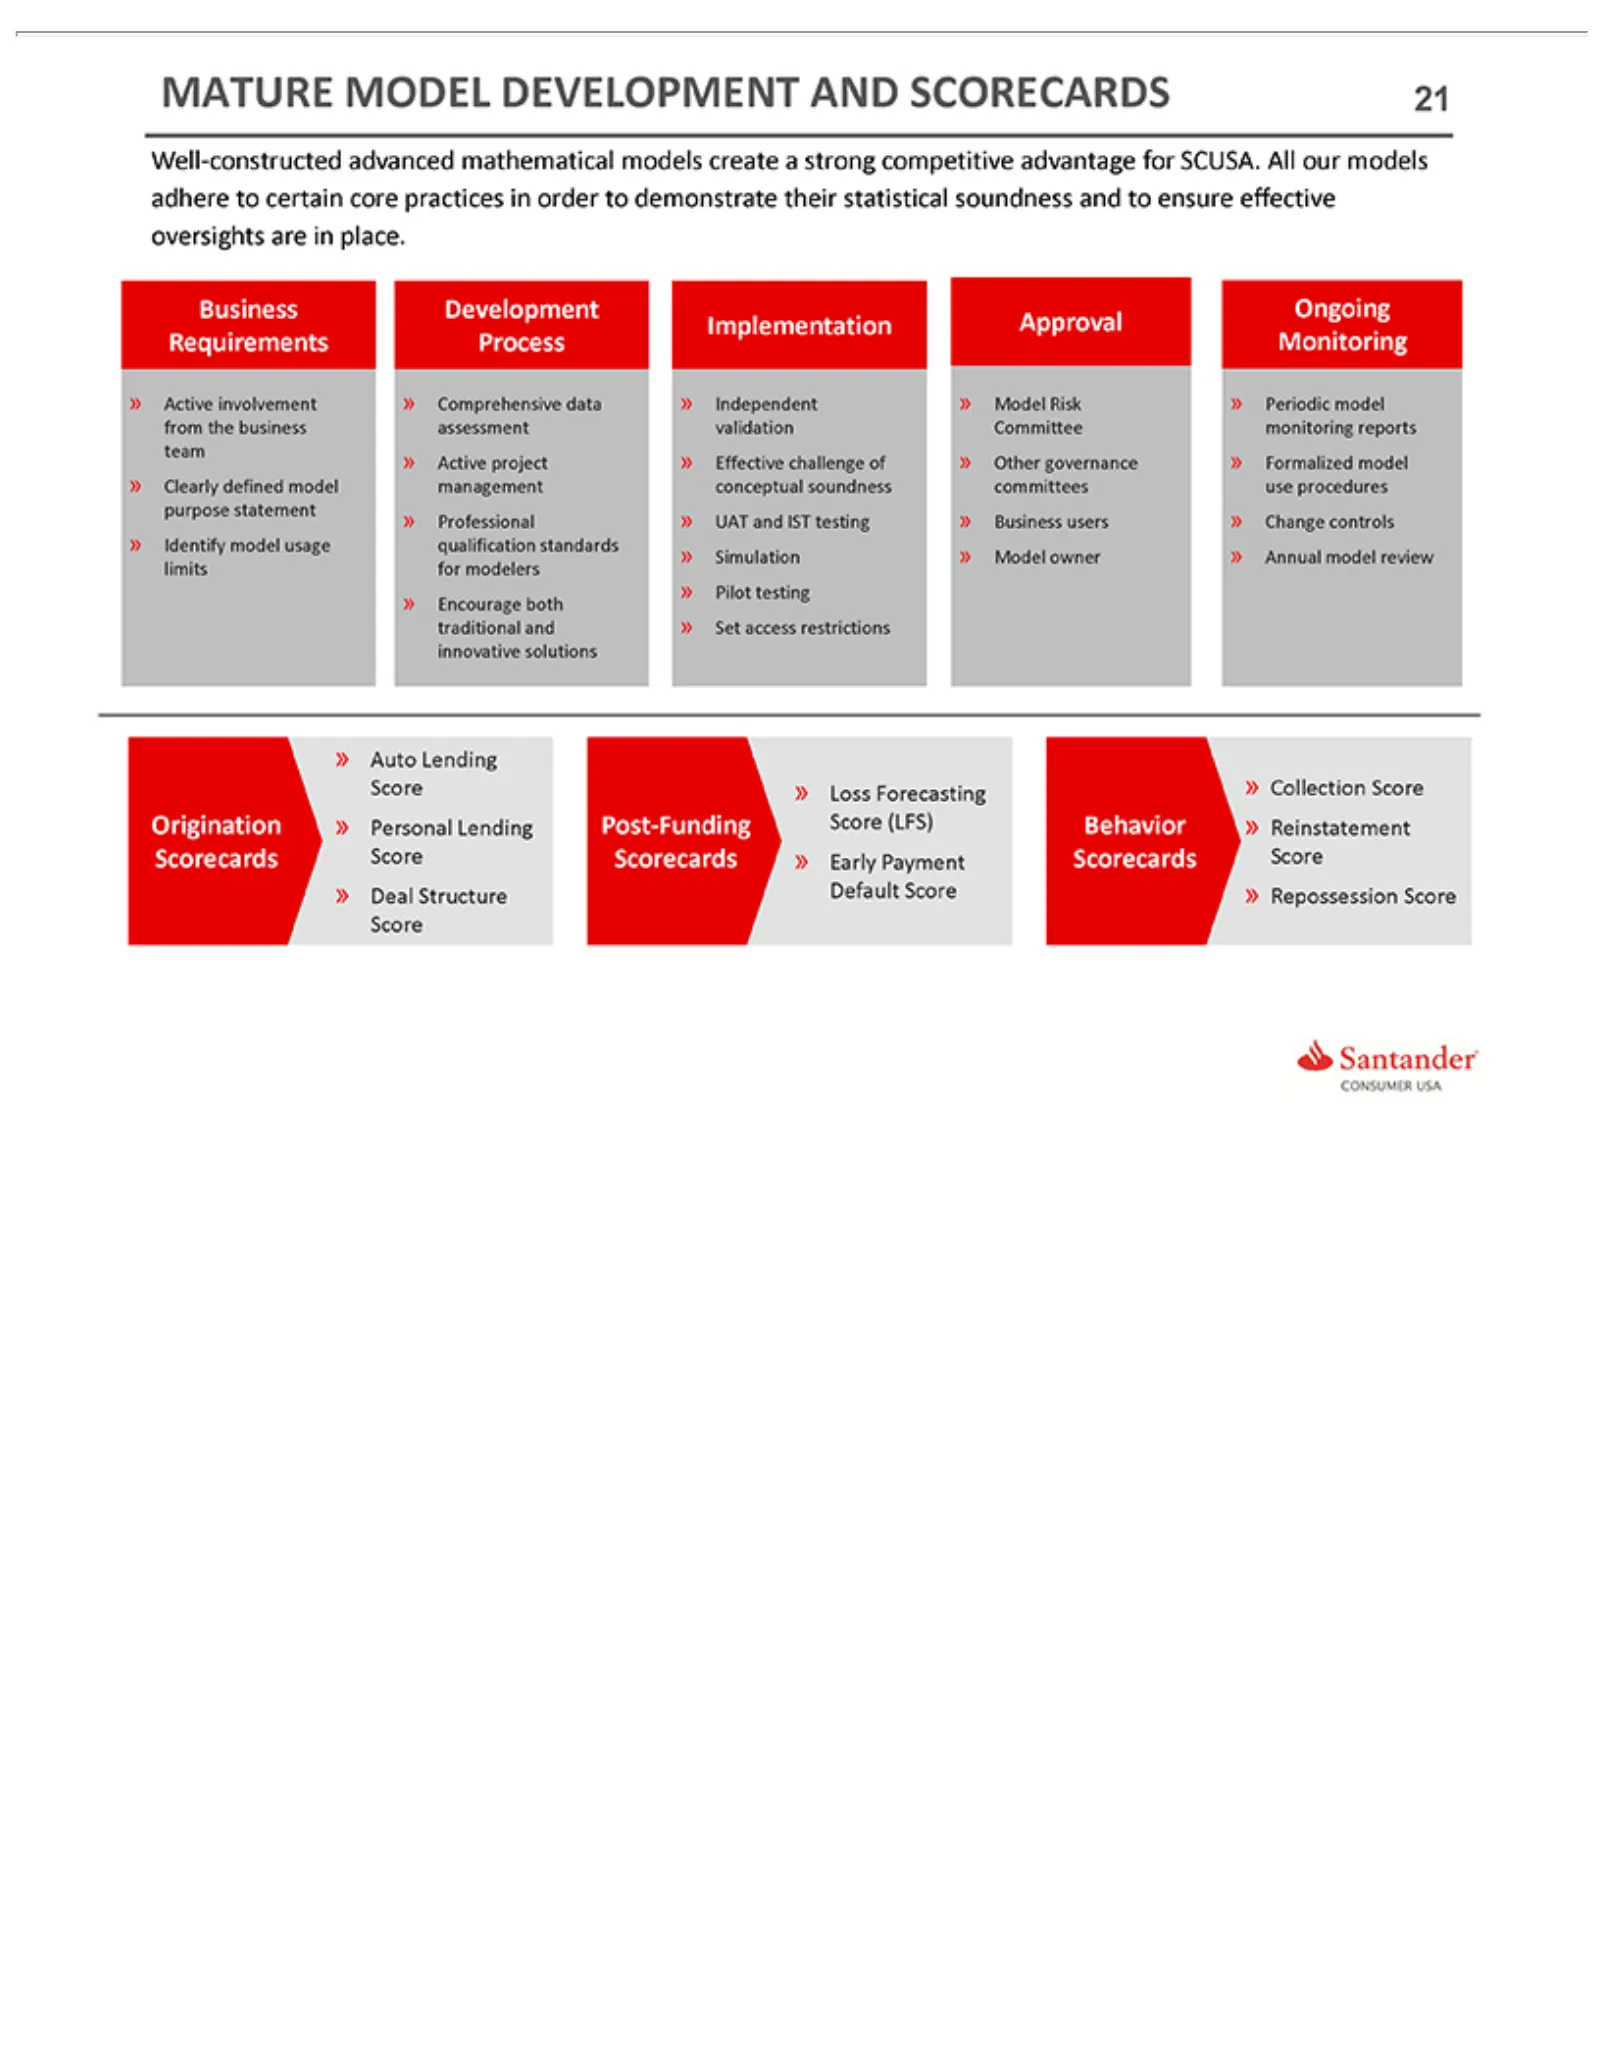
Slide 21: Mature Model Development Process
MATURE 21 Well-constructed and Business Development Implementation Approval Ongoing Origination Post-Funding Behavior Scorecards » Active Annual Auto Clearly Identify Comprehensive Professional Encourage Independent Effective UAT Simulation Pilot Set Other Business Model Periodic Formalized Change D
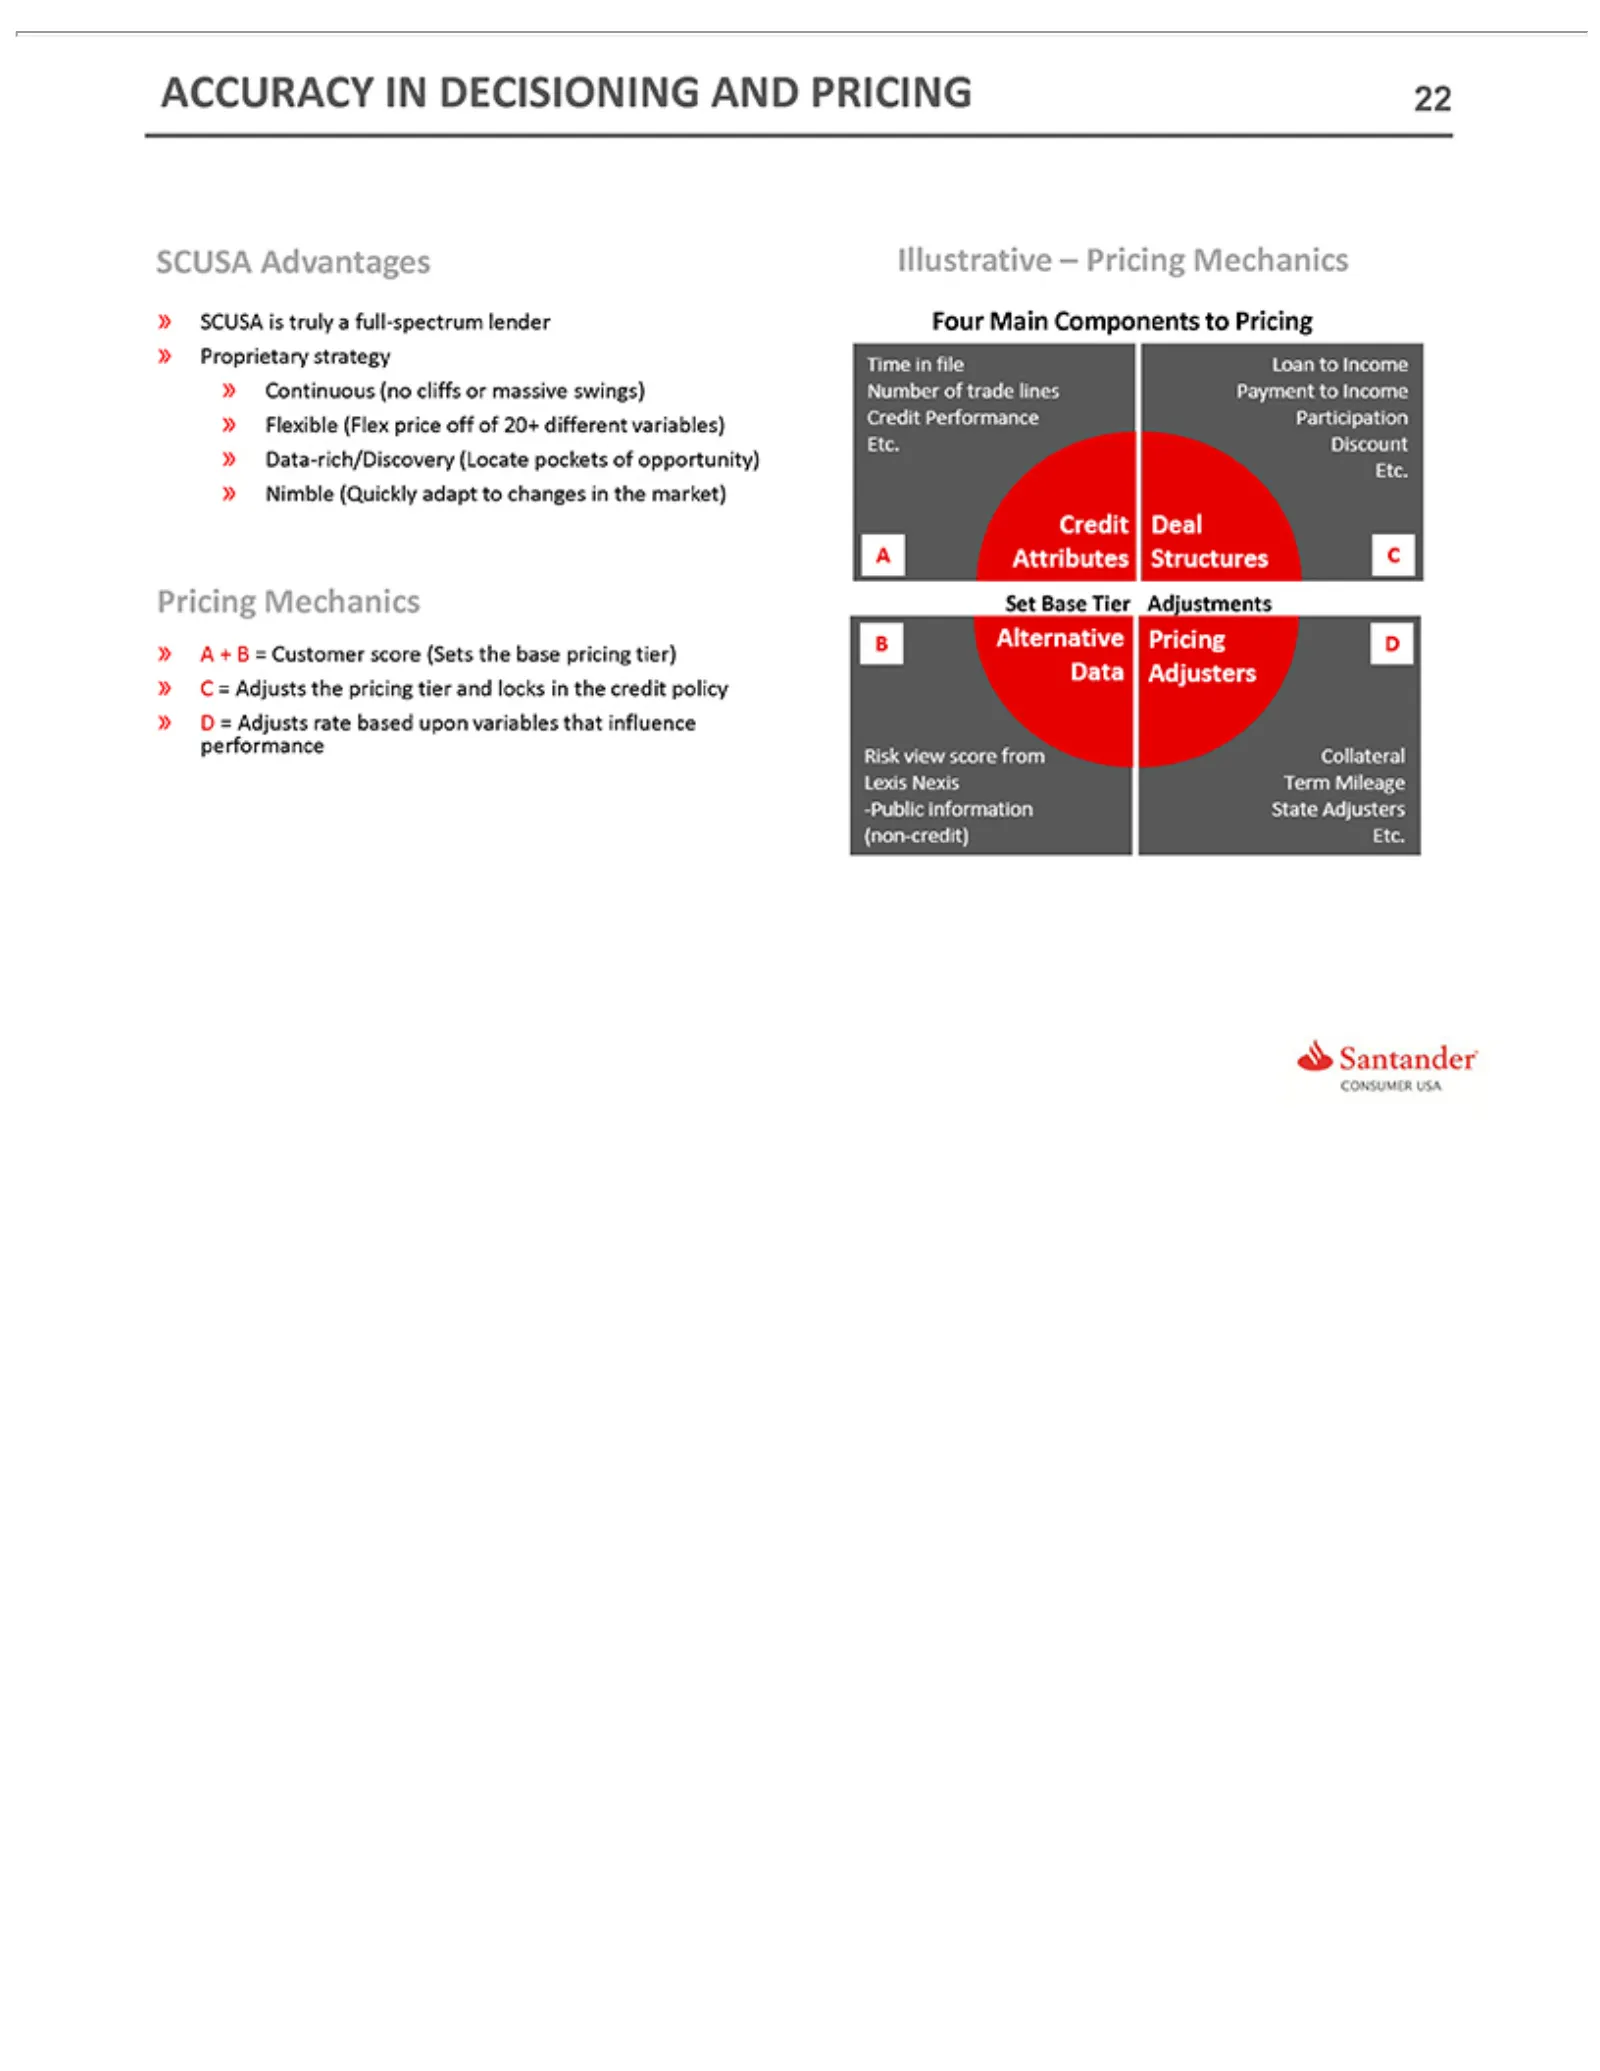
Slide 22: Accuracy in Decisioning and Pricing
ACCURACY 22 SCUSA Pricing » Illustrative Four Set ASCUSA Proprietary Continuous Flexible Data-rich/Discovery Nimble C D Base + =Main B Adjusts Mechanics = Advantages Tier (Quickly Customer is (Flex Components –truly Pricing strategy Adjustments (no the IN rate price DECISIONING cliffs pricing abased
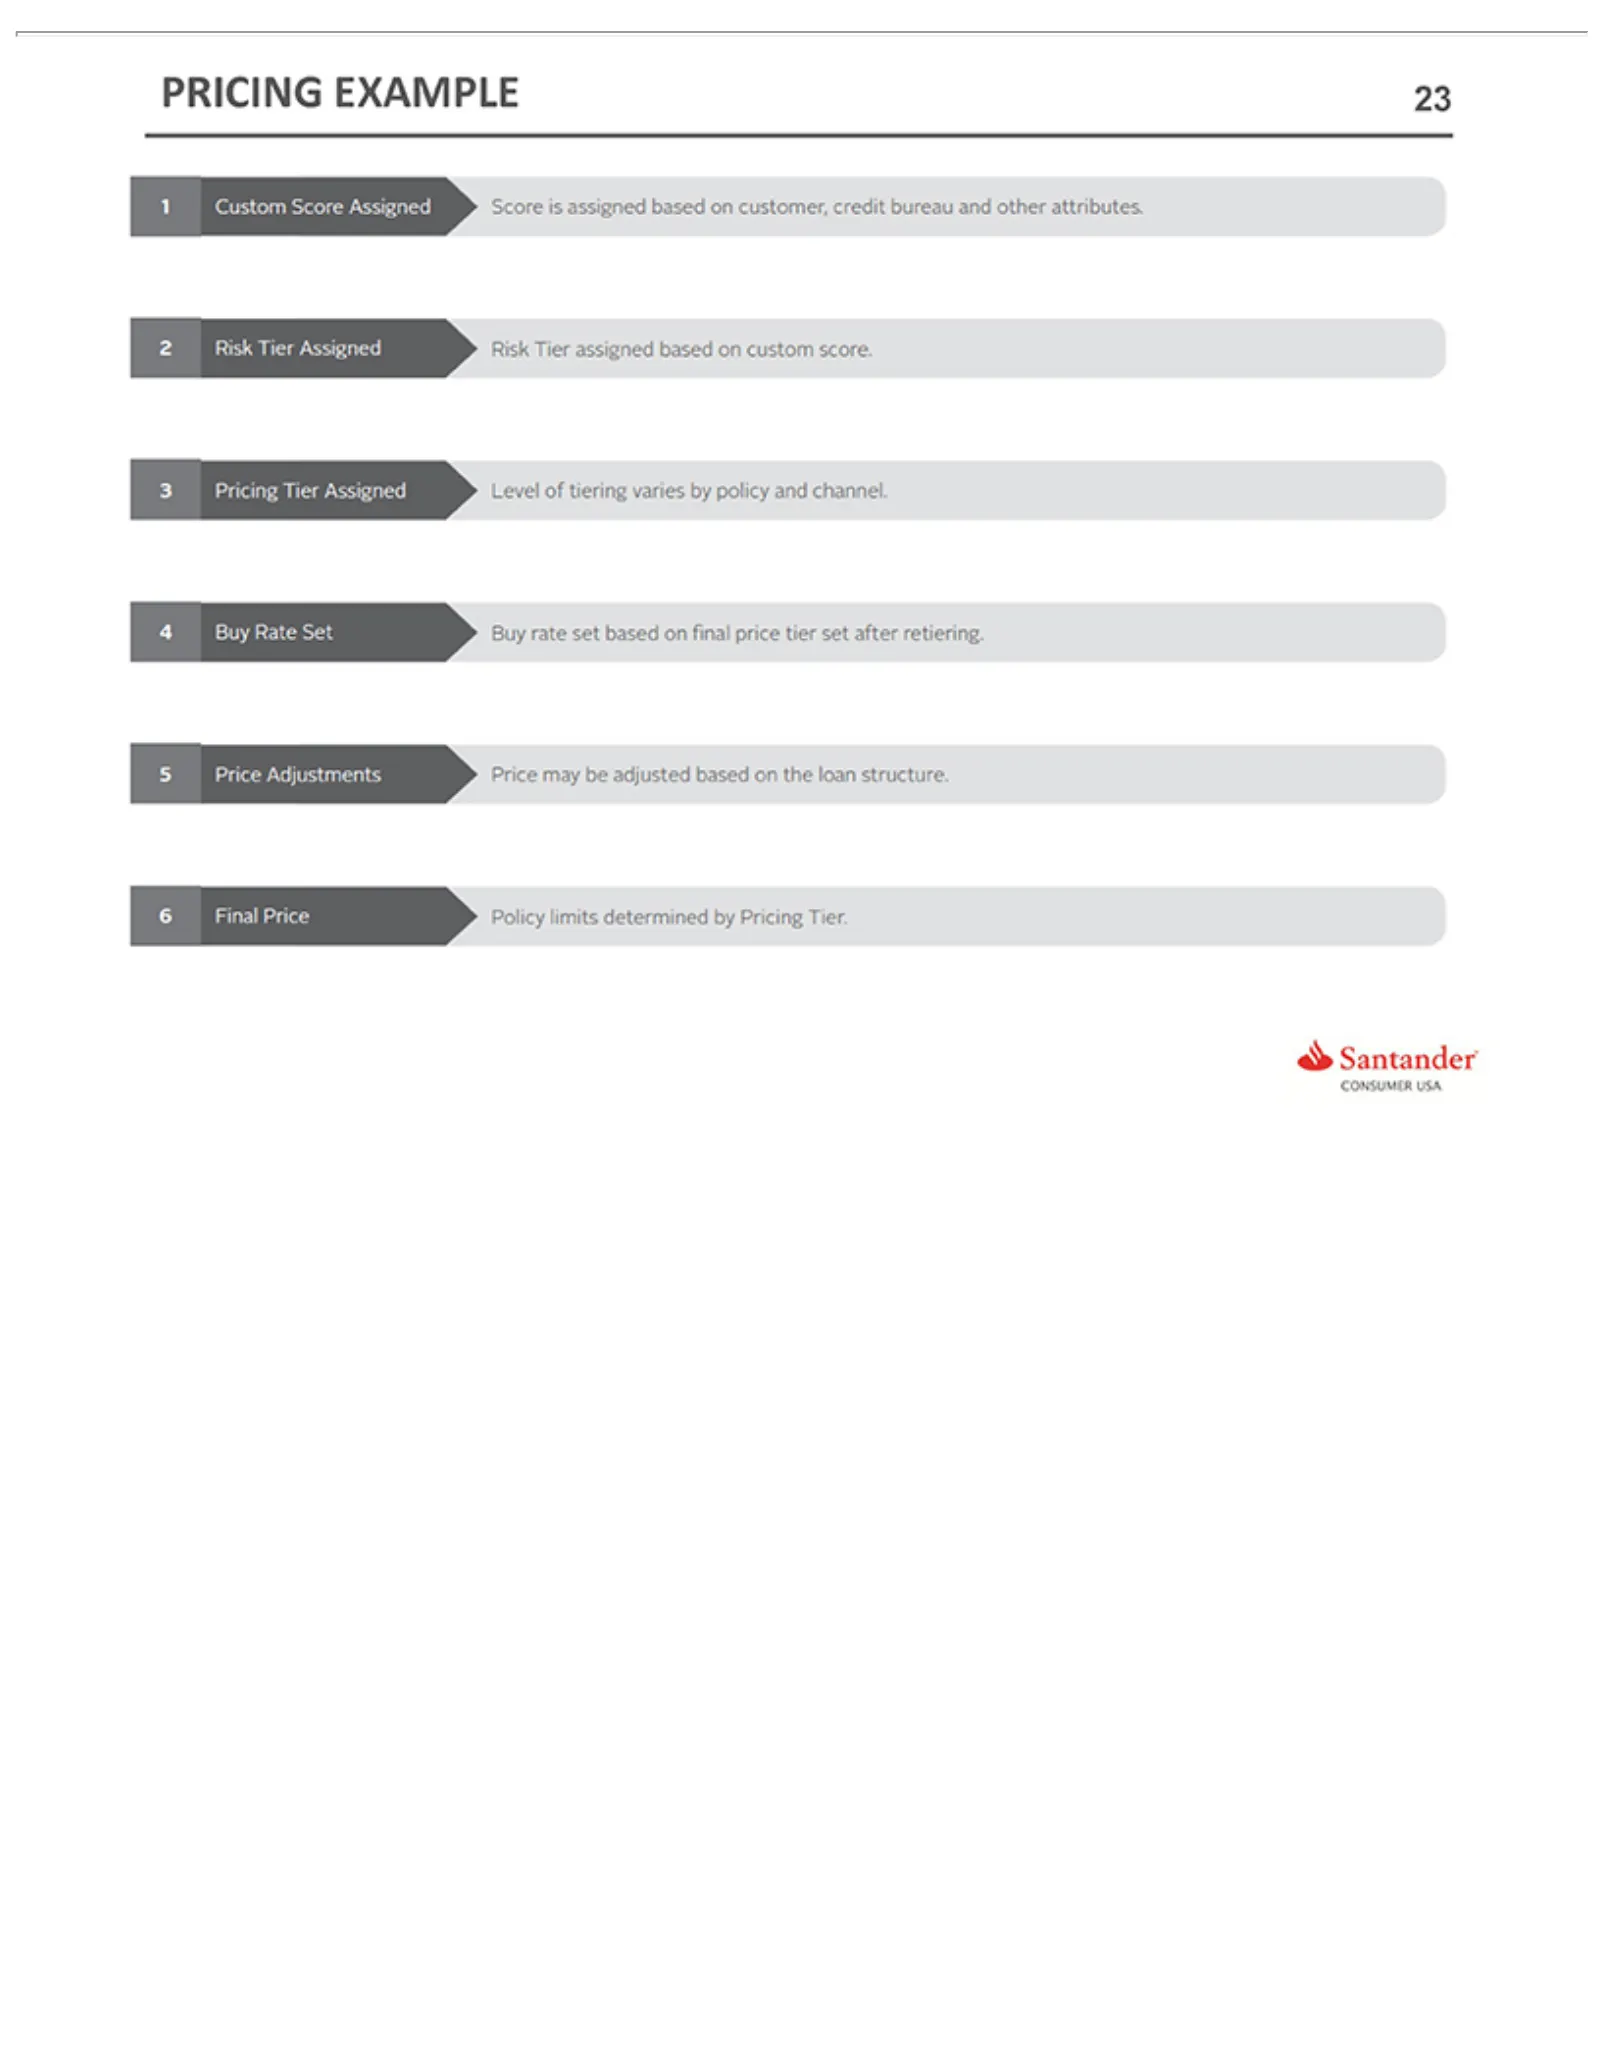
Slide 23: Pricing Example
PRICING EXAMPLE 23 ——_ > Score is assigned based on customer, credit bureau and other attributes. Risk Tier assigned based on custom score. Level of tiering varies by policy and channel. Buy rate set based on final price tier set after retiering. Price may be adjusted based on the loan structure. ce
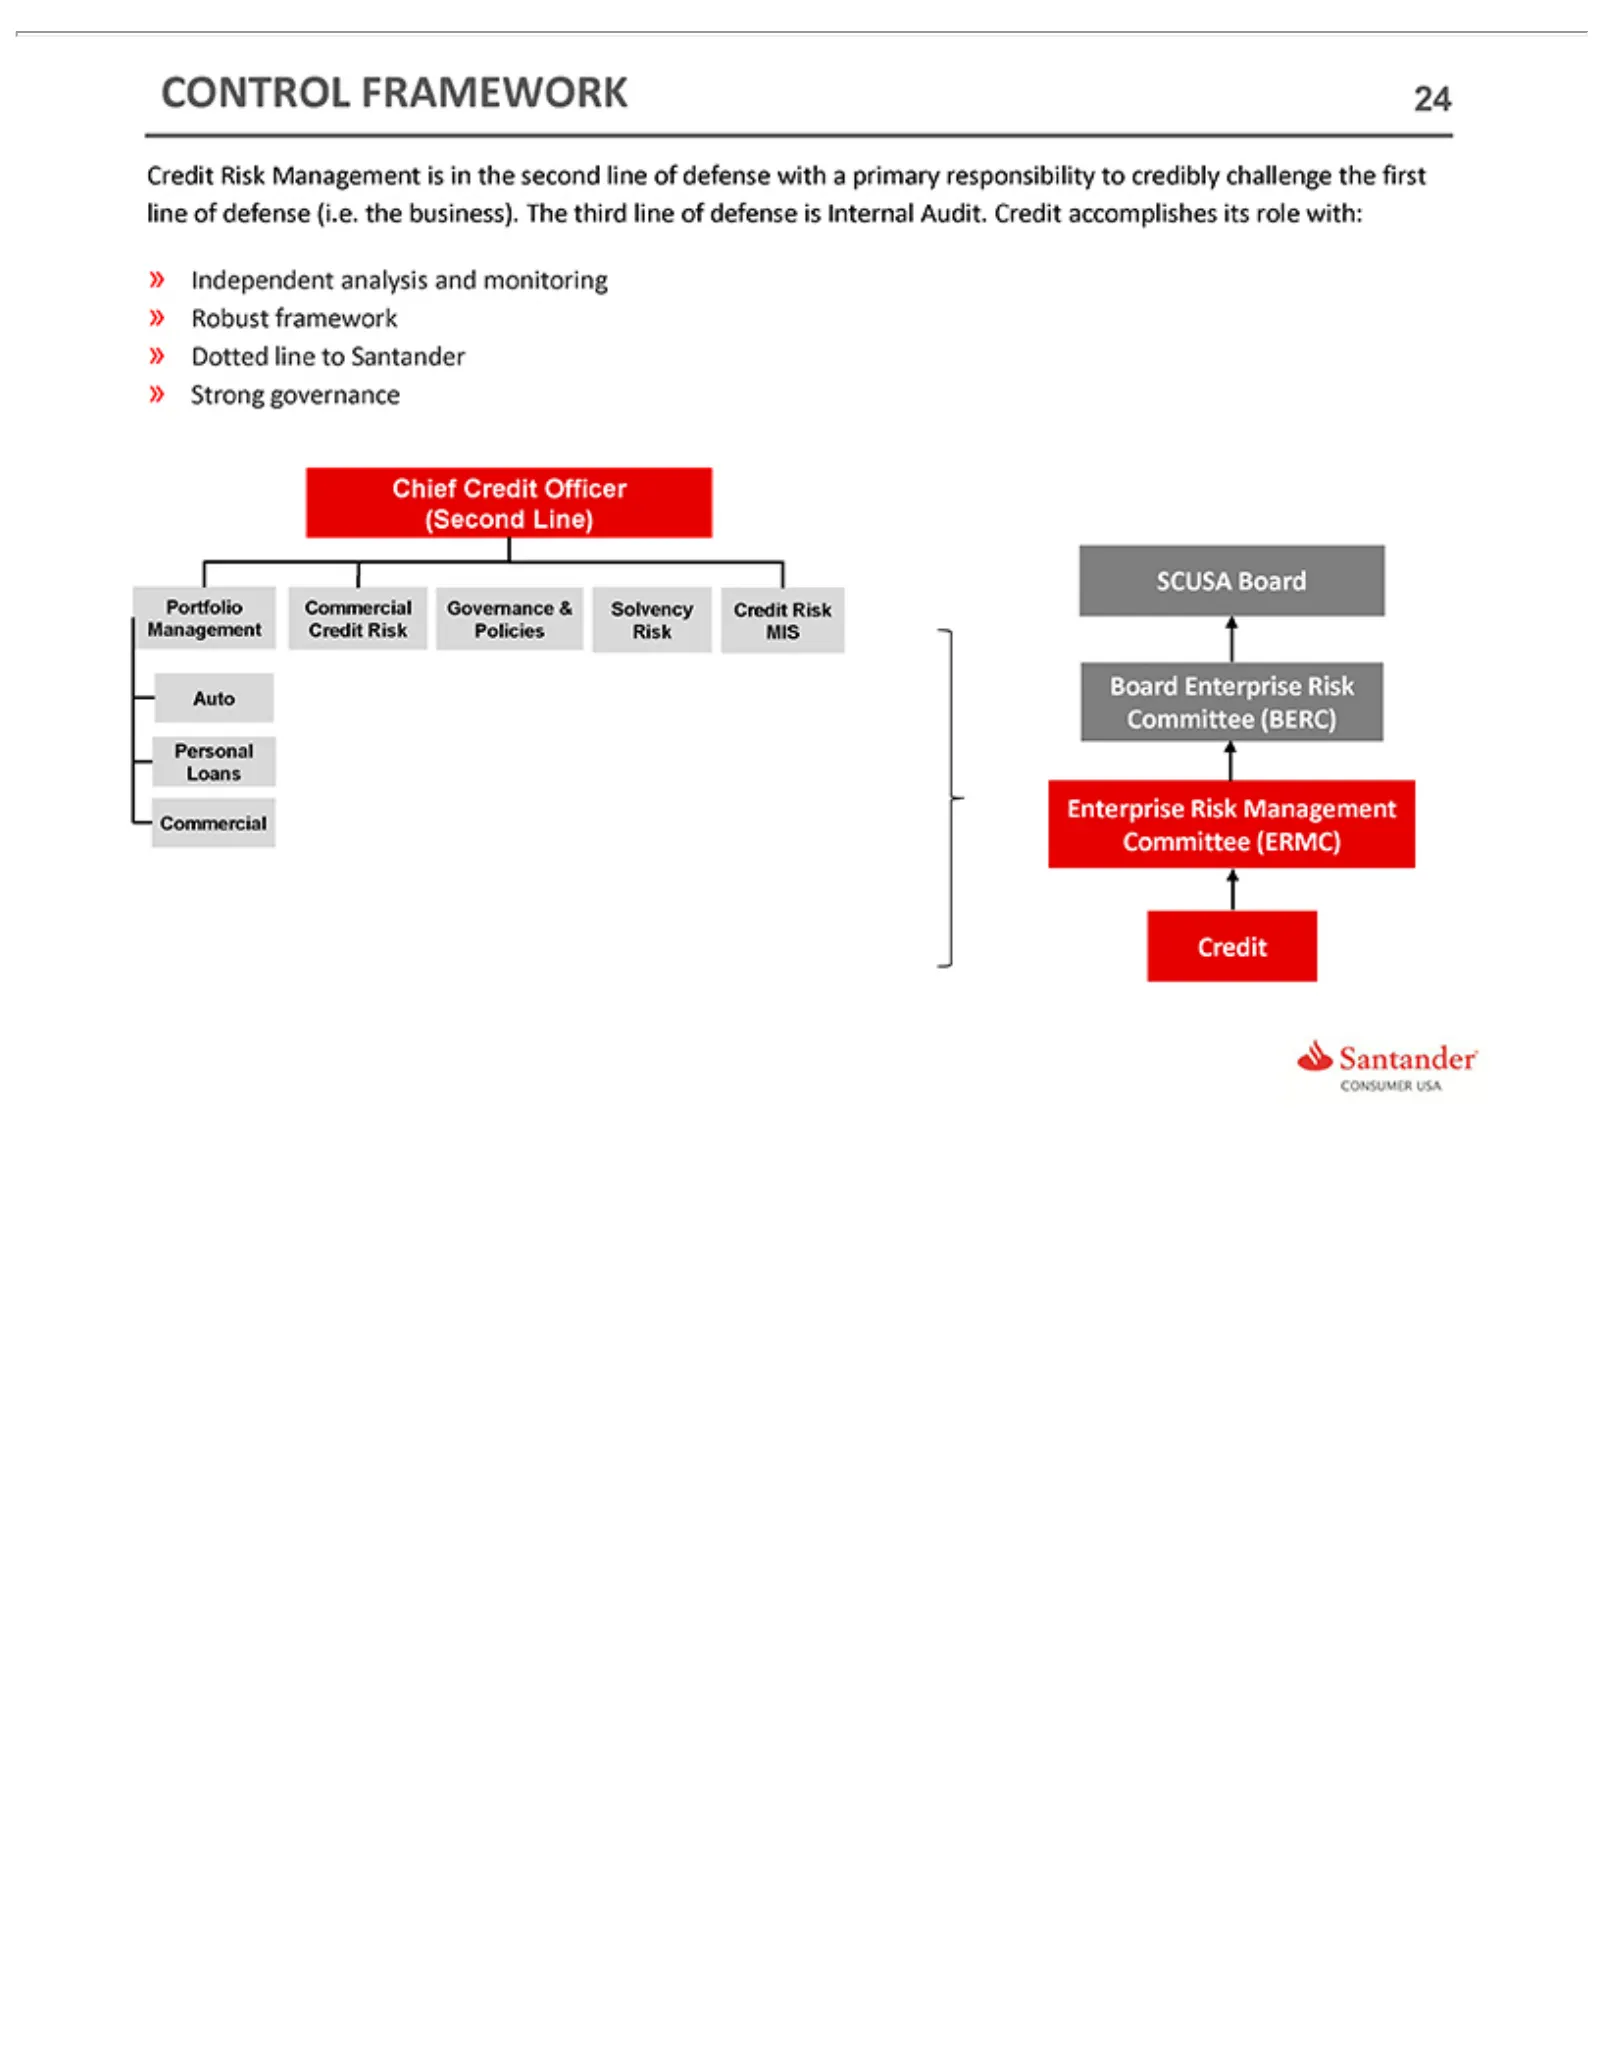
Slide 24: Control Framework
CONTROL 24 accomplishes » Chief Portfolio Auto SCUSA Board Enterprise Credit Independent Robust Dotted Strong Personal Credit Enterprise Risk Board governance line Commercial framework Risk Management FRAMEWORK Officer to its analysis Loans Management Santander role Risk (Second with: Commercial Gov
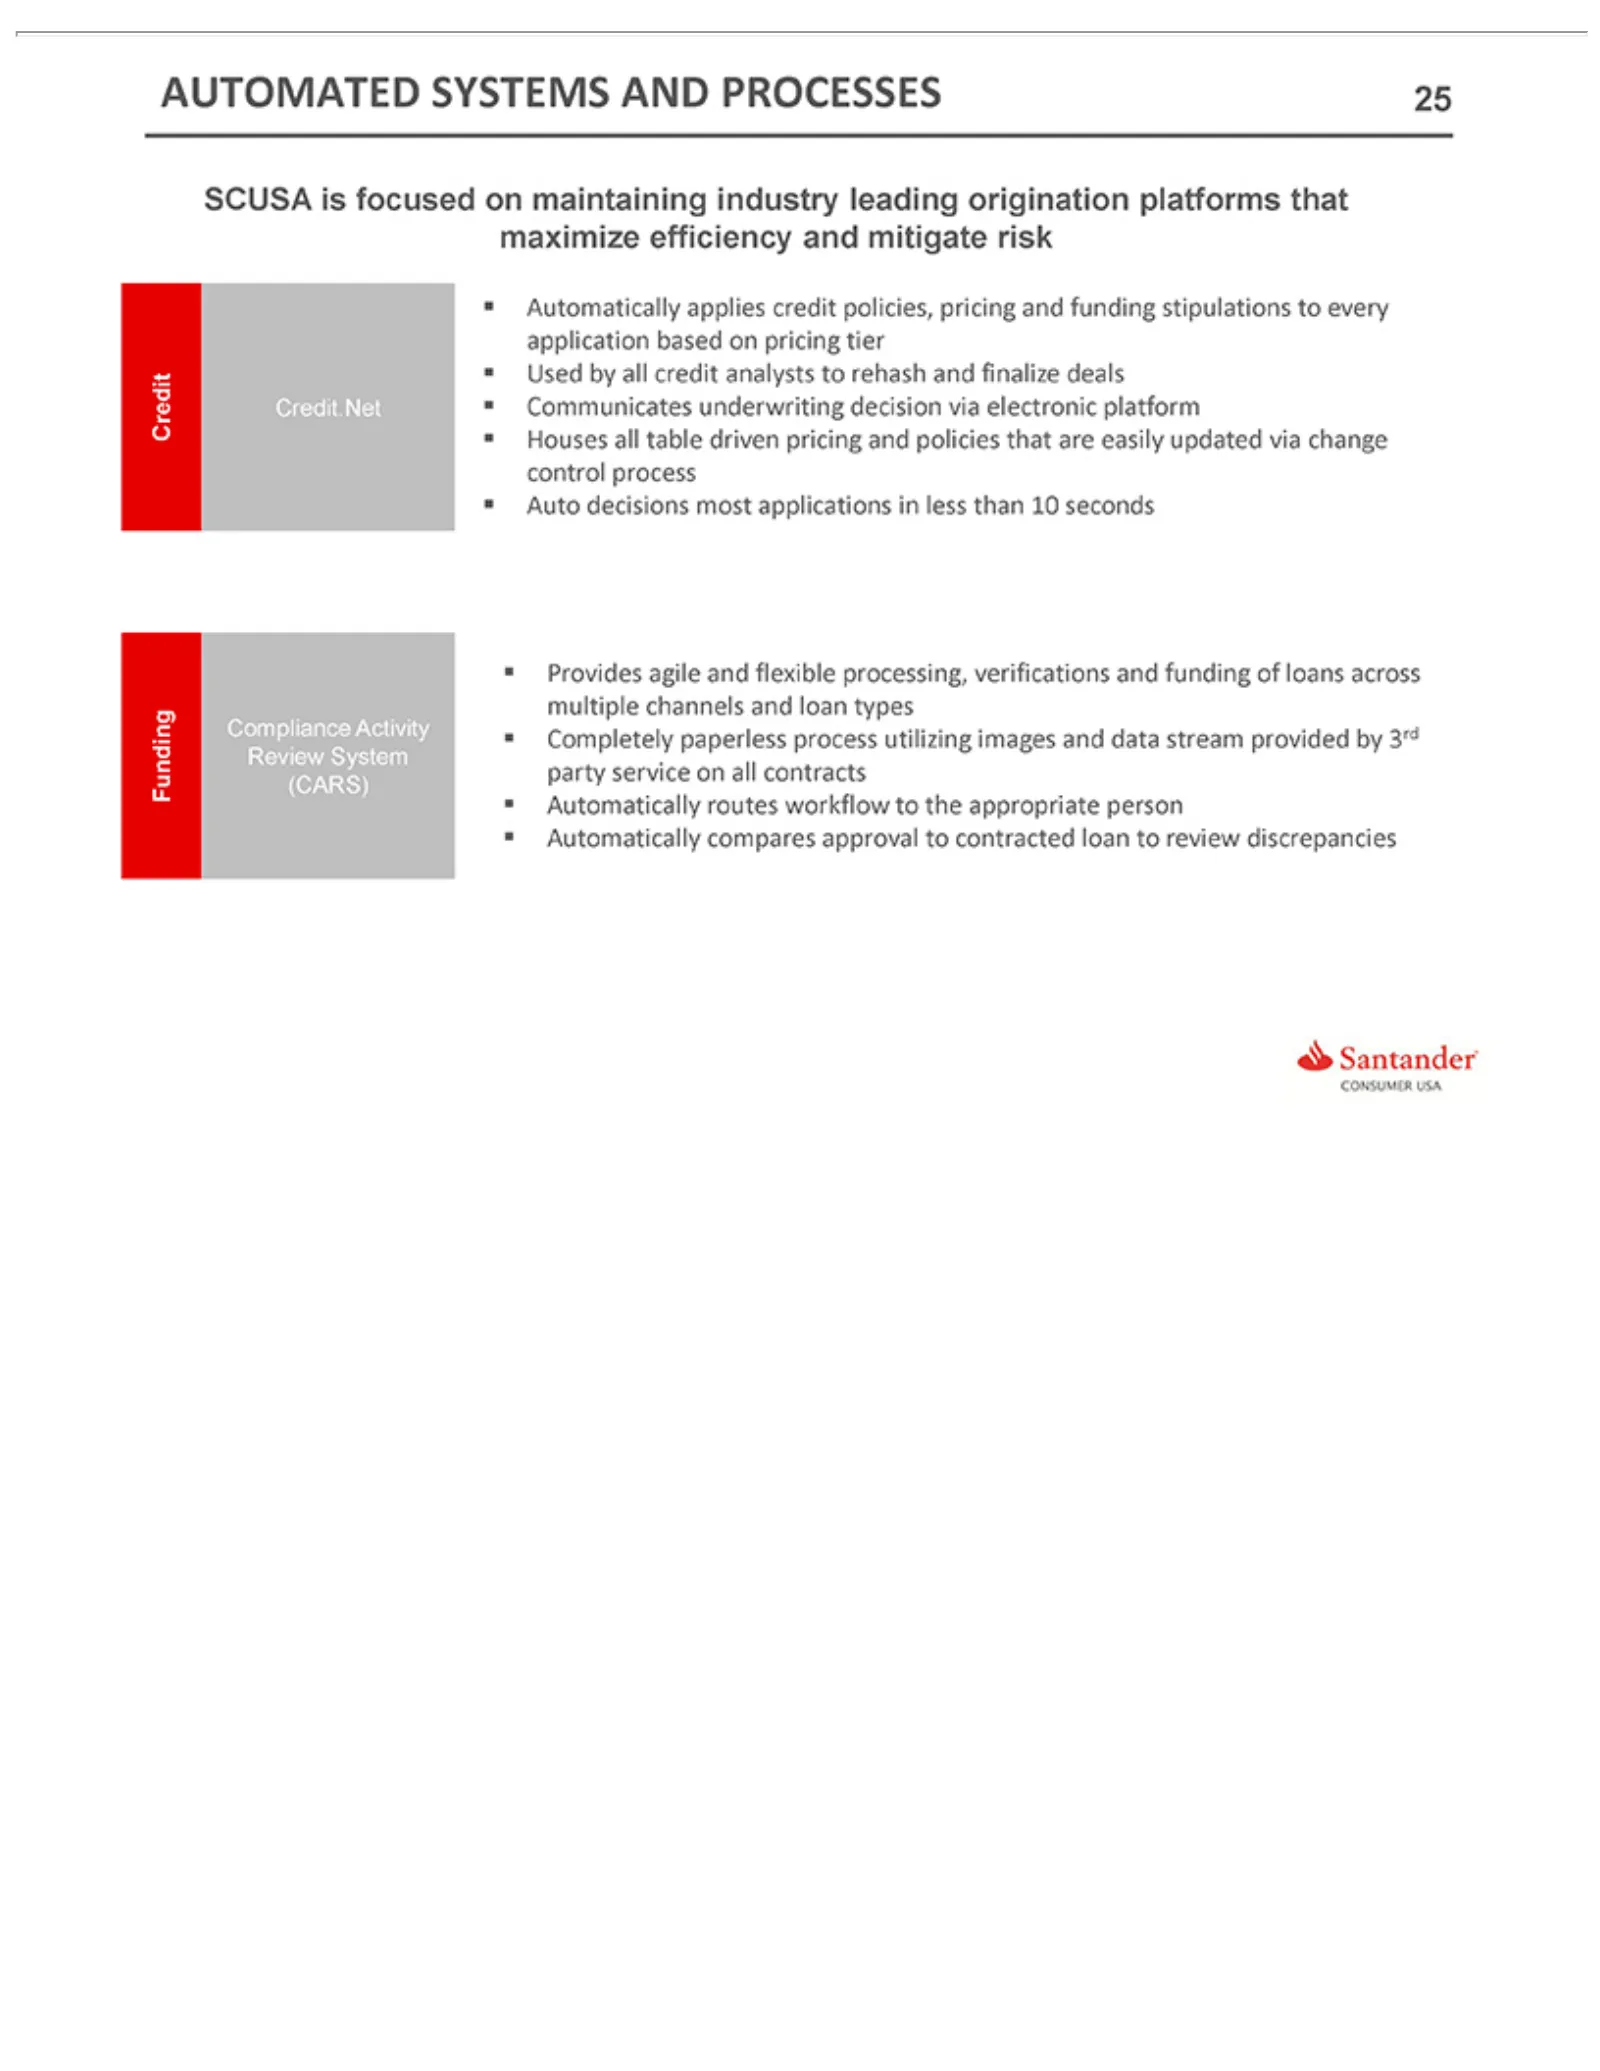
Slide 25: Automated Systems and Processes
AUTOMATED 25 SCUSA Credit Automatically decision Compliance Funding Provides serviceCredit. on is via (CARS) agile all focused Activity electronic contracts Net and applies SYSTEMS flexible onReview maintaining credit platform Automatically processing, AND policies, System Houses PROCESSES industry
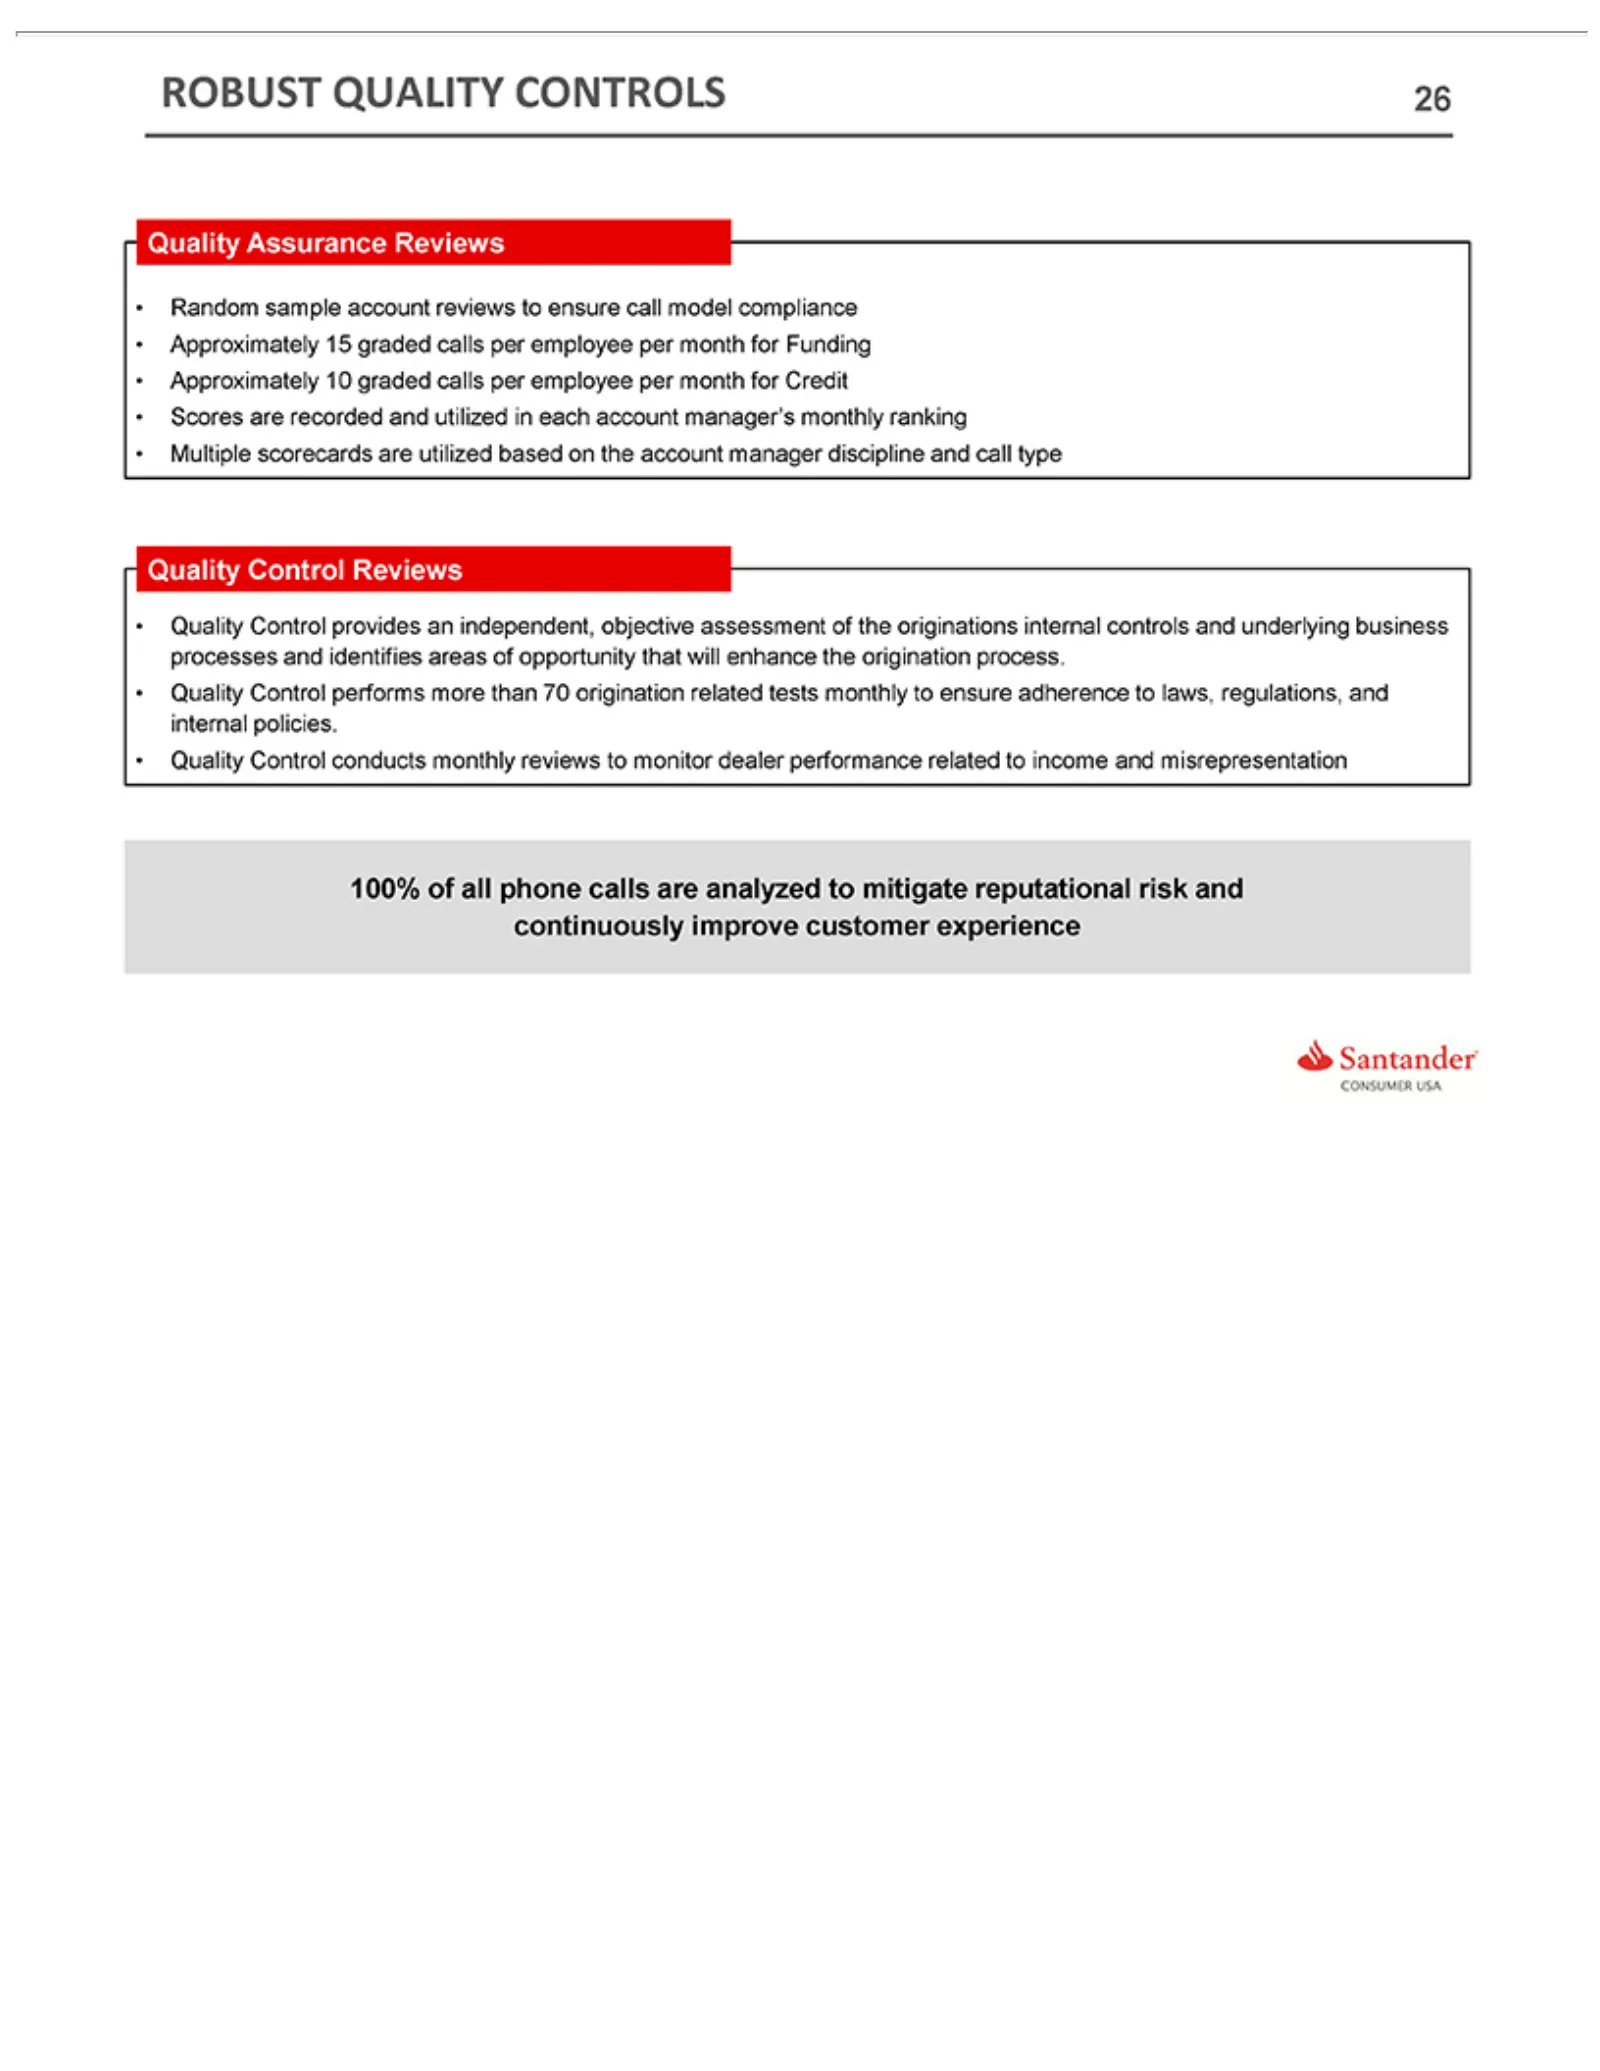
Slide 26: Robust Quality Controls
ROBUST 26 ••Quality Random Assurance QUALITY aresample Approximately Scores Reviews account 15 10 recordedCONTROLS graded and reviews calls utilized intoreviews per ensure employee each call account model per monthcompliance manager’s Funding fortests Credit monthly Multiple •Quality origination Qua
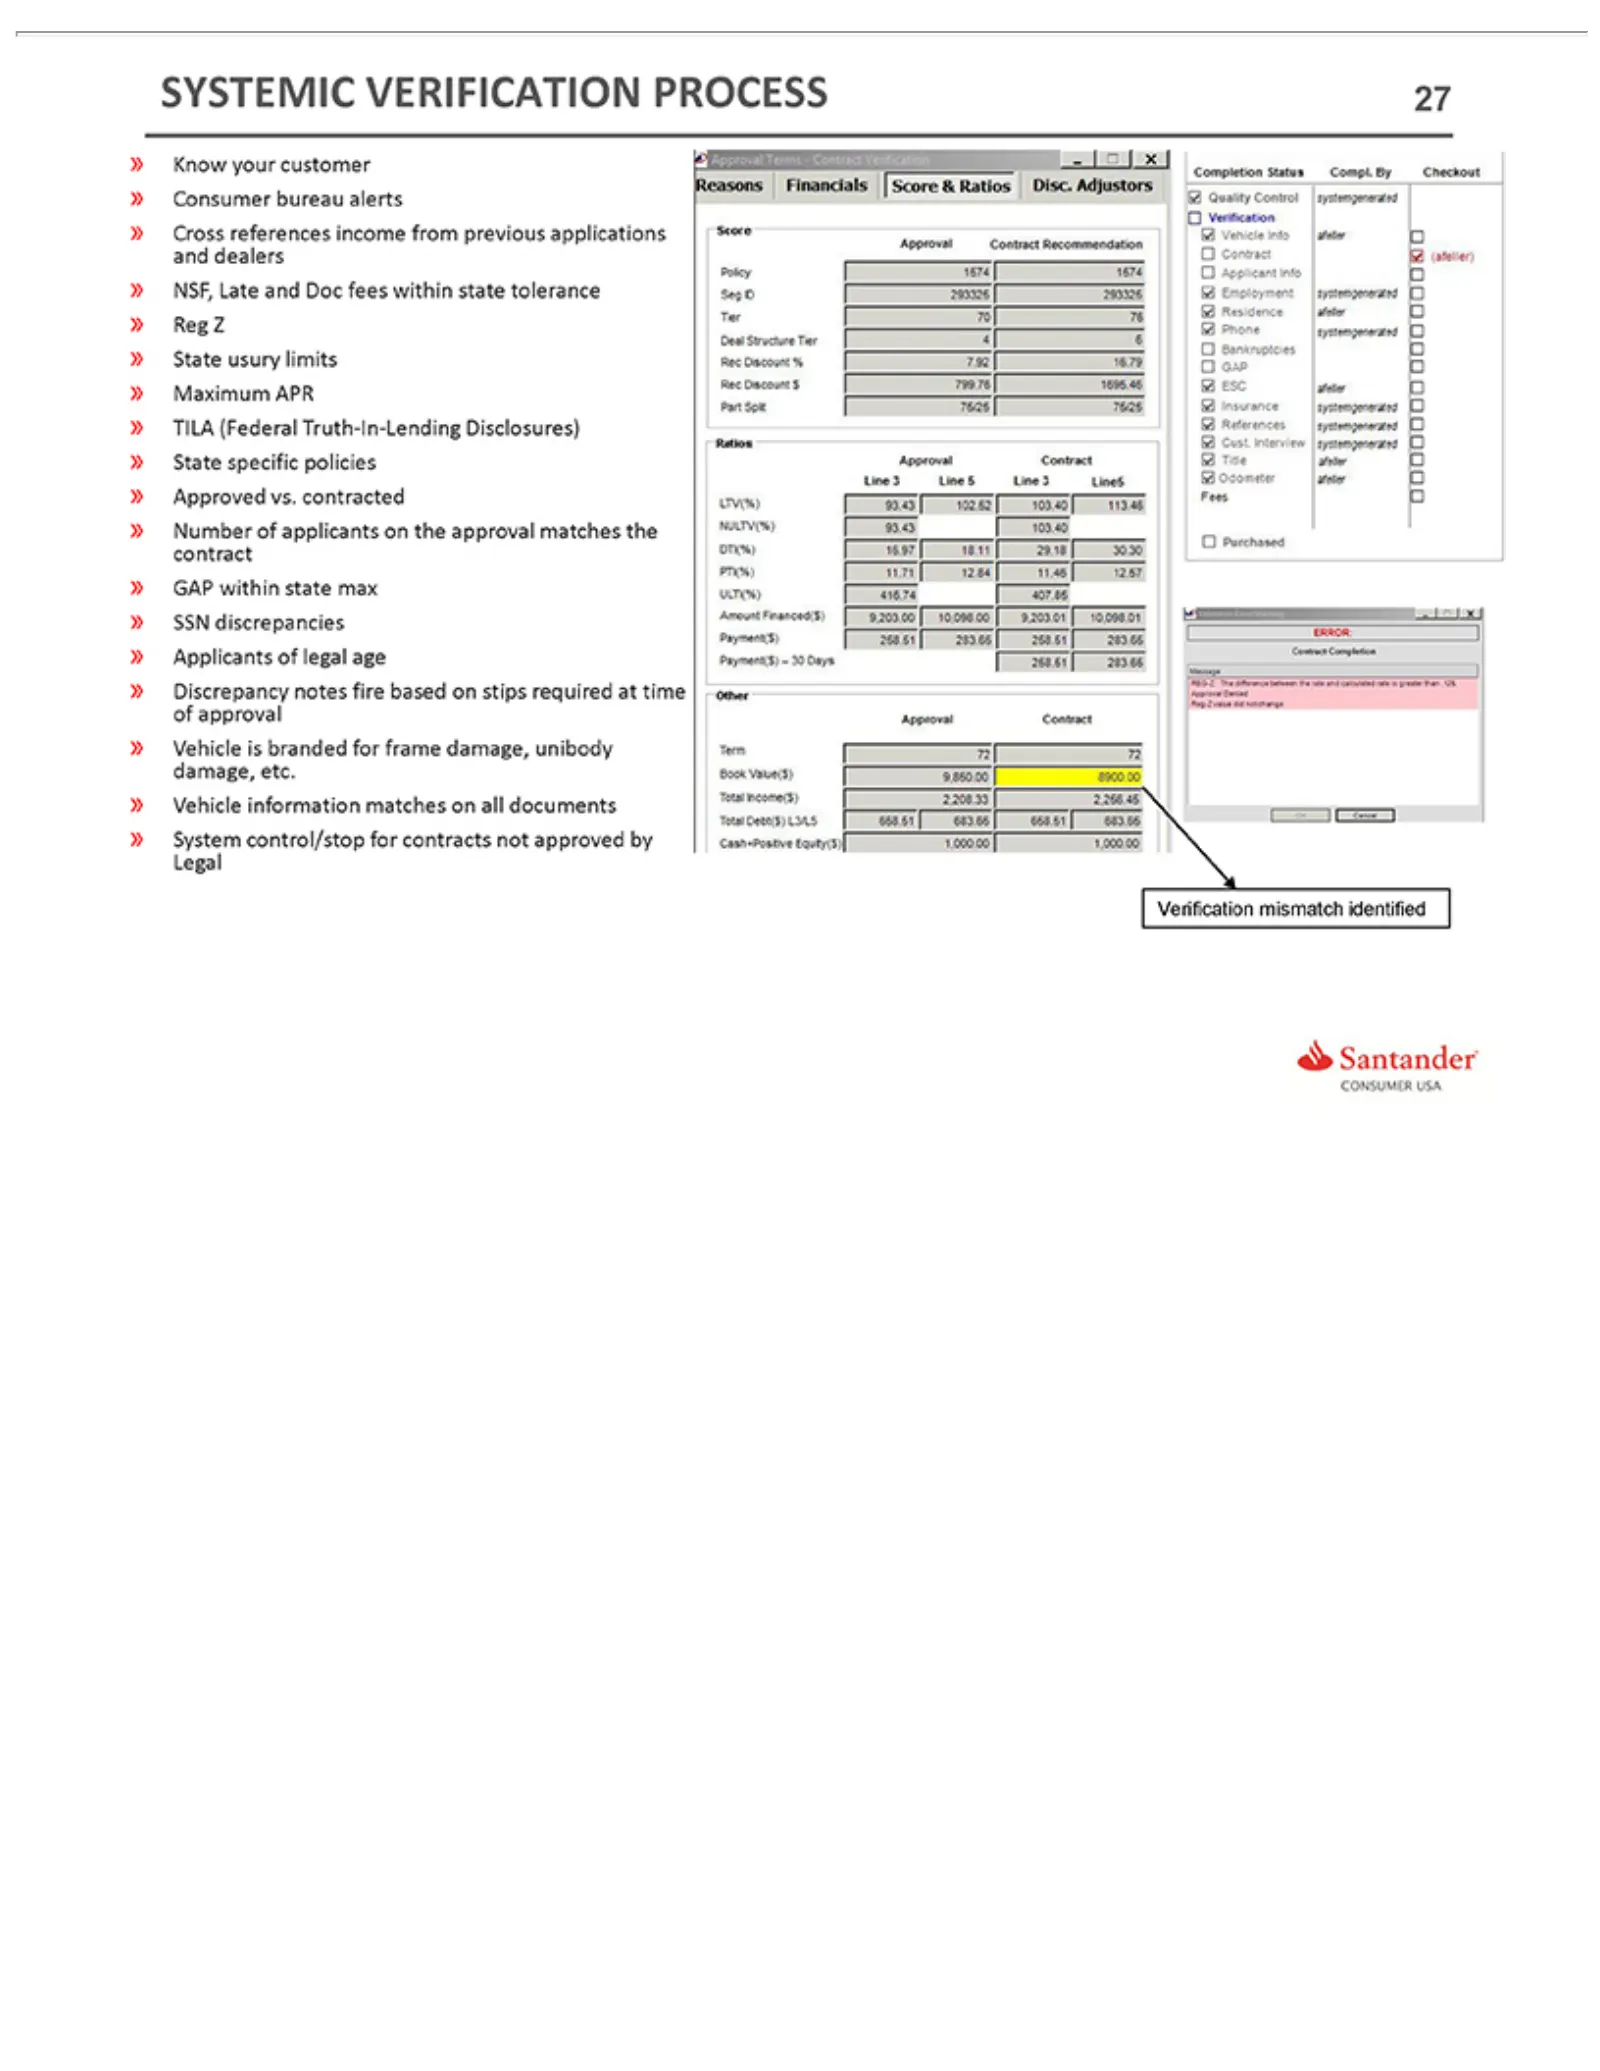
Slide 27: Systemic Verification Process
SYSTEMIC 27 » Approved Applicants TILA Vehicle Know Consumer Cross NSF, Reg Maximum State Number GAP SSN Discrepancy System Zdiscrepancies within usury specific Late (Federal references your control/stop isofbranded information vs. and bureau APR VERIFICATION of applicants limits customer state note
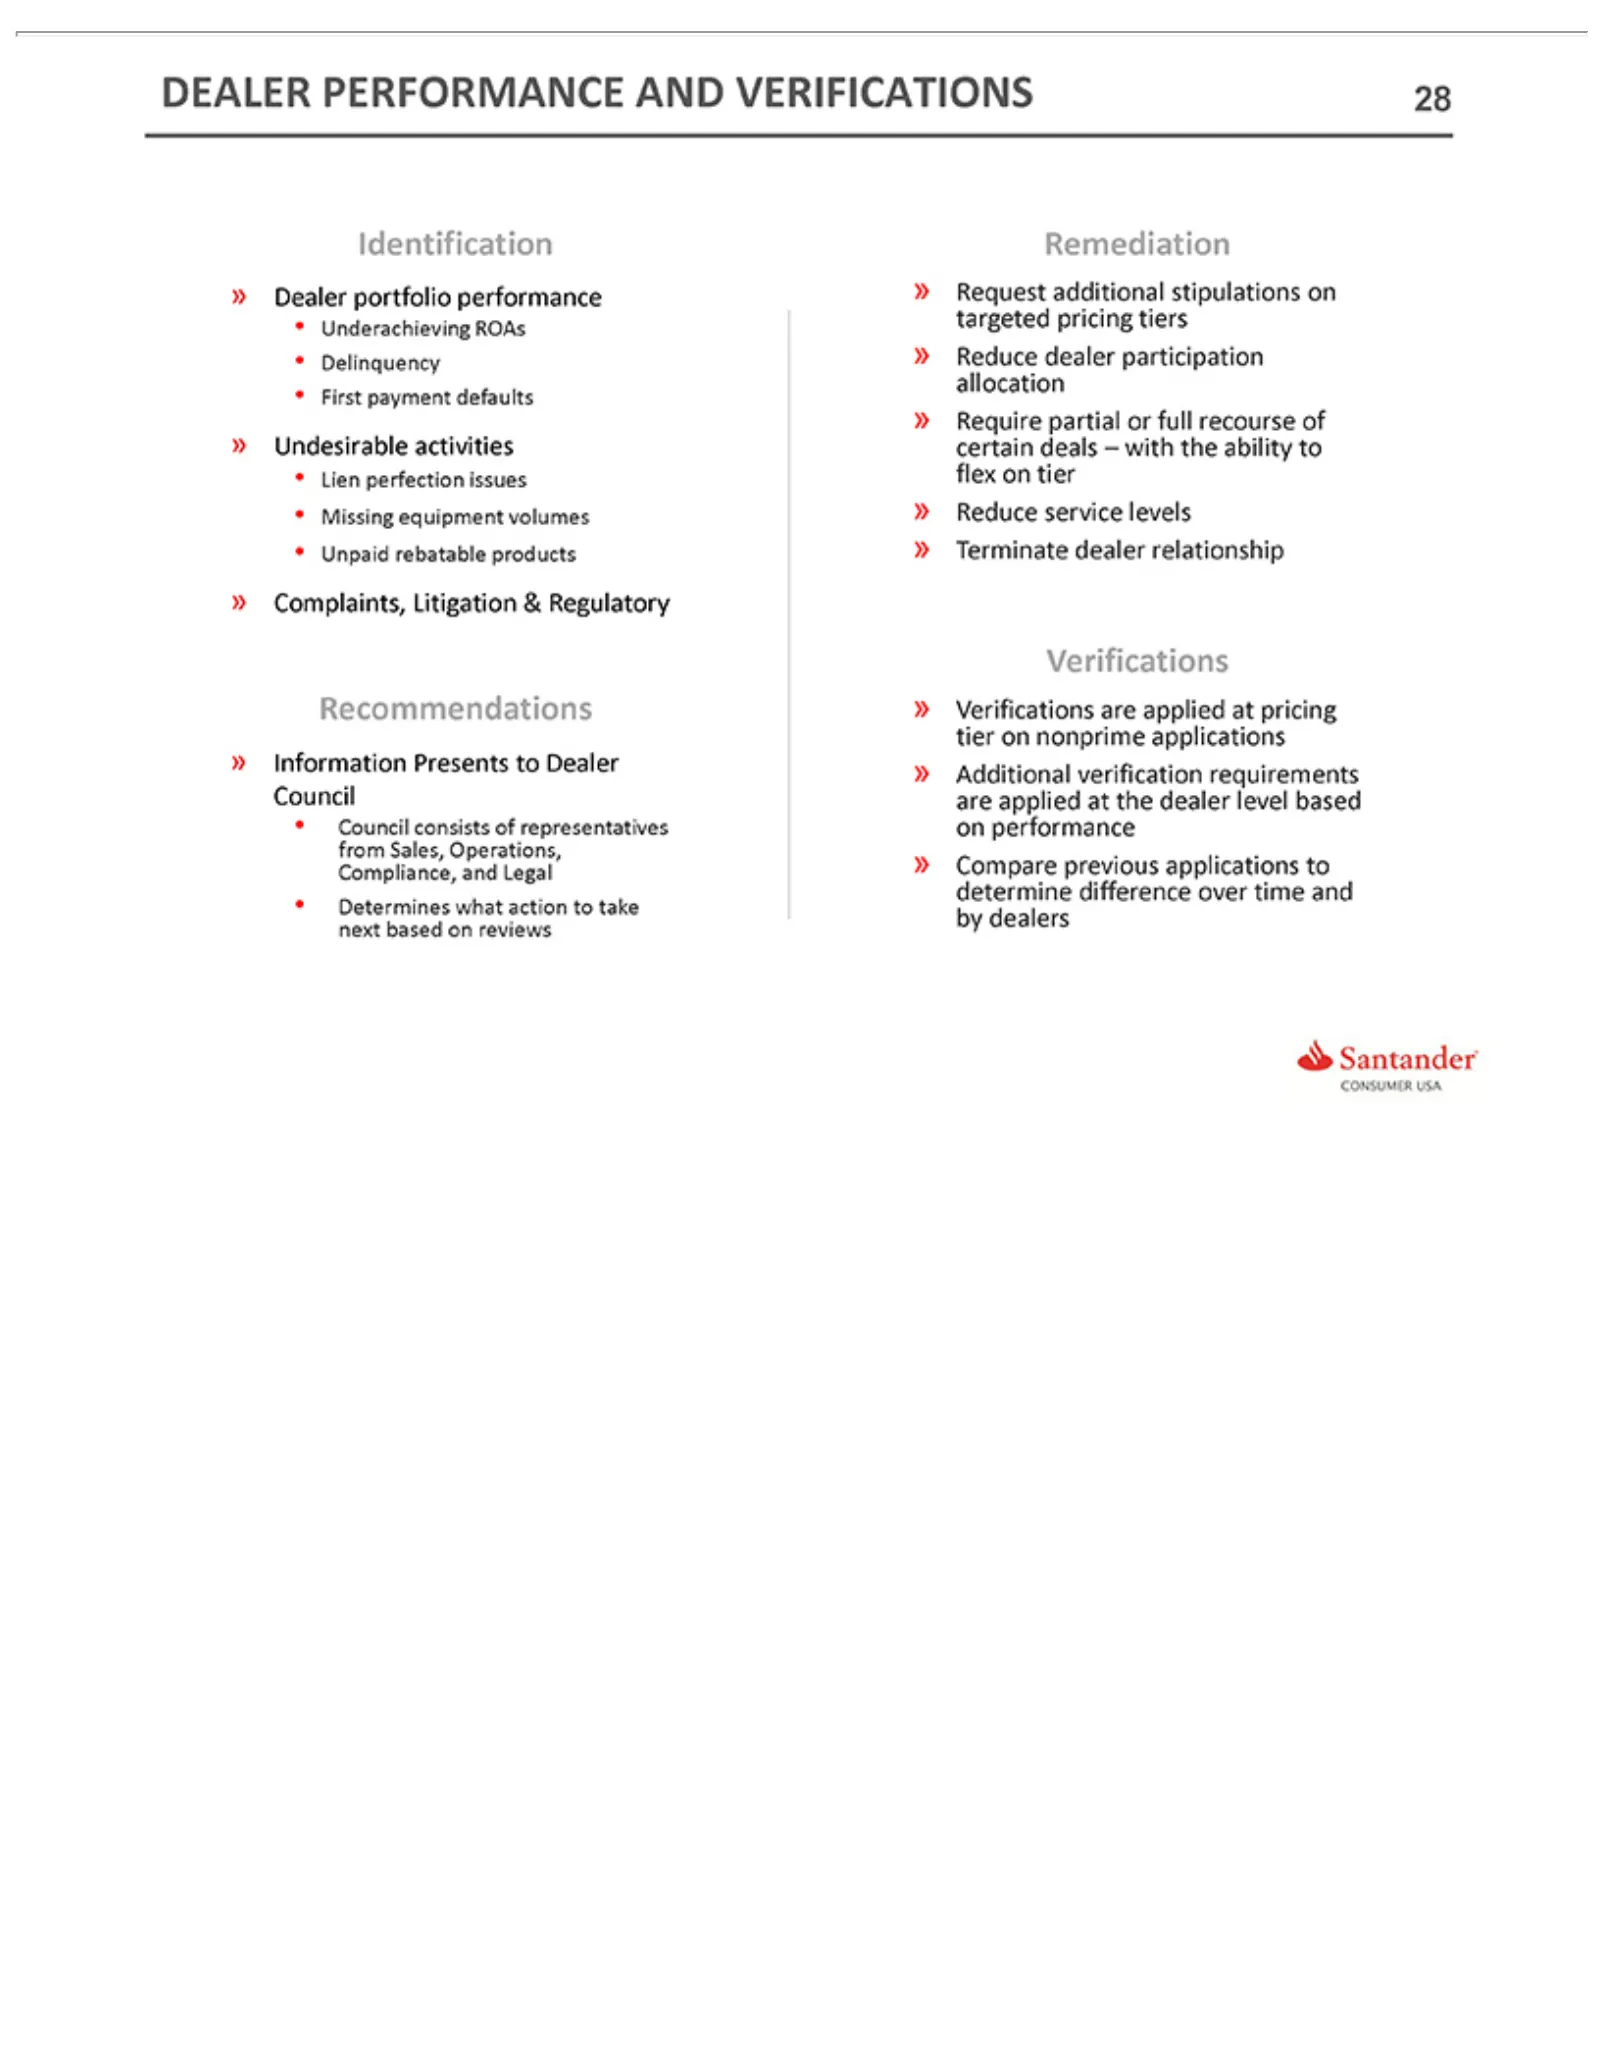
Slide 28: Dealer Performance and Verifications
DEALER 28 » •Identification •» Dealer Underachieving First portfolio PERFORMANCE Delinquency payment Undesirable Lien perfection Missing performance ROAs defaults activities equipmentissuesvolumes AND VERIFICATIONS » Unpaid Information Council rebatable •Recommendations Complaints, Determines Remedi
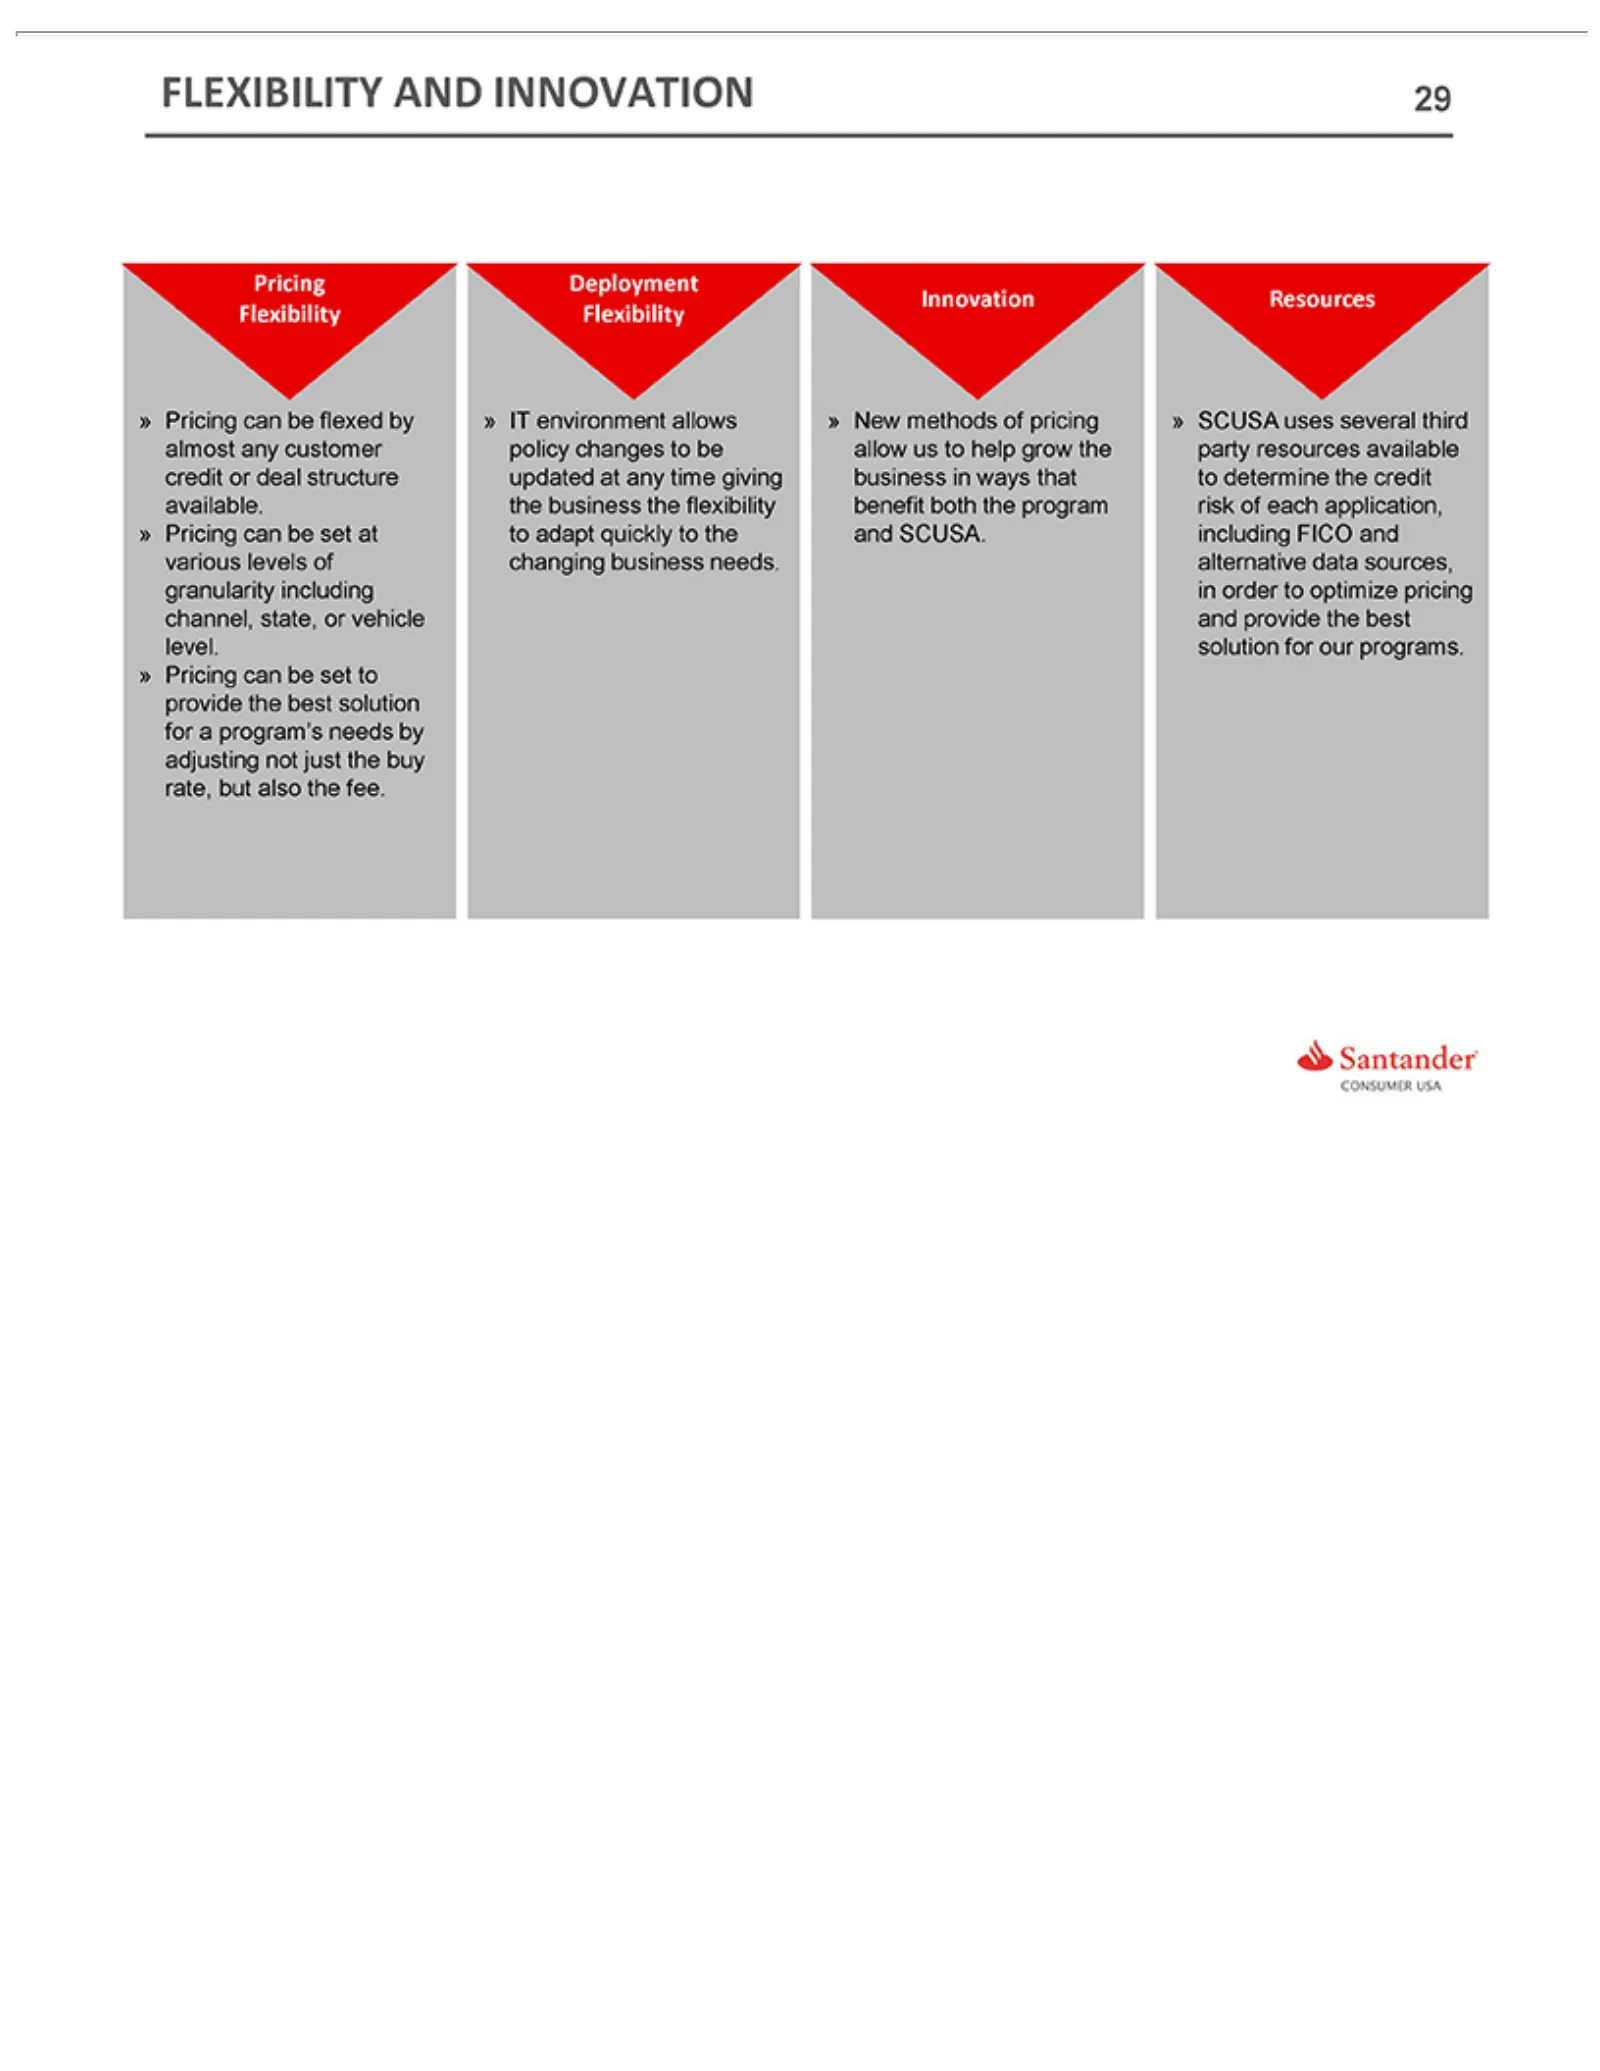
Slide 29: Flexibility and Innovation
FLEXIBILITY 29 Pricing Deployment Innovation » Resources solution Pricing IT New SCUSA environment methods Flexibility for can uses our Flexibility beseveral AND programs. of flexed set allows pricing atINNOVATION to various provide third bypolicy allow almost party levels the changes usany resource
Slide 30: Agenda
I. Corporate AGENDA 30 II. III.Originations ServicingOverview and Underwriting
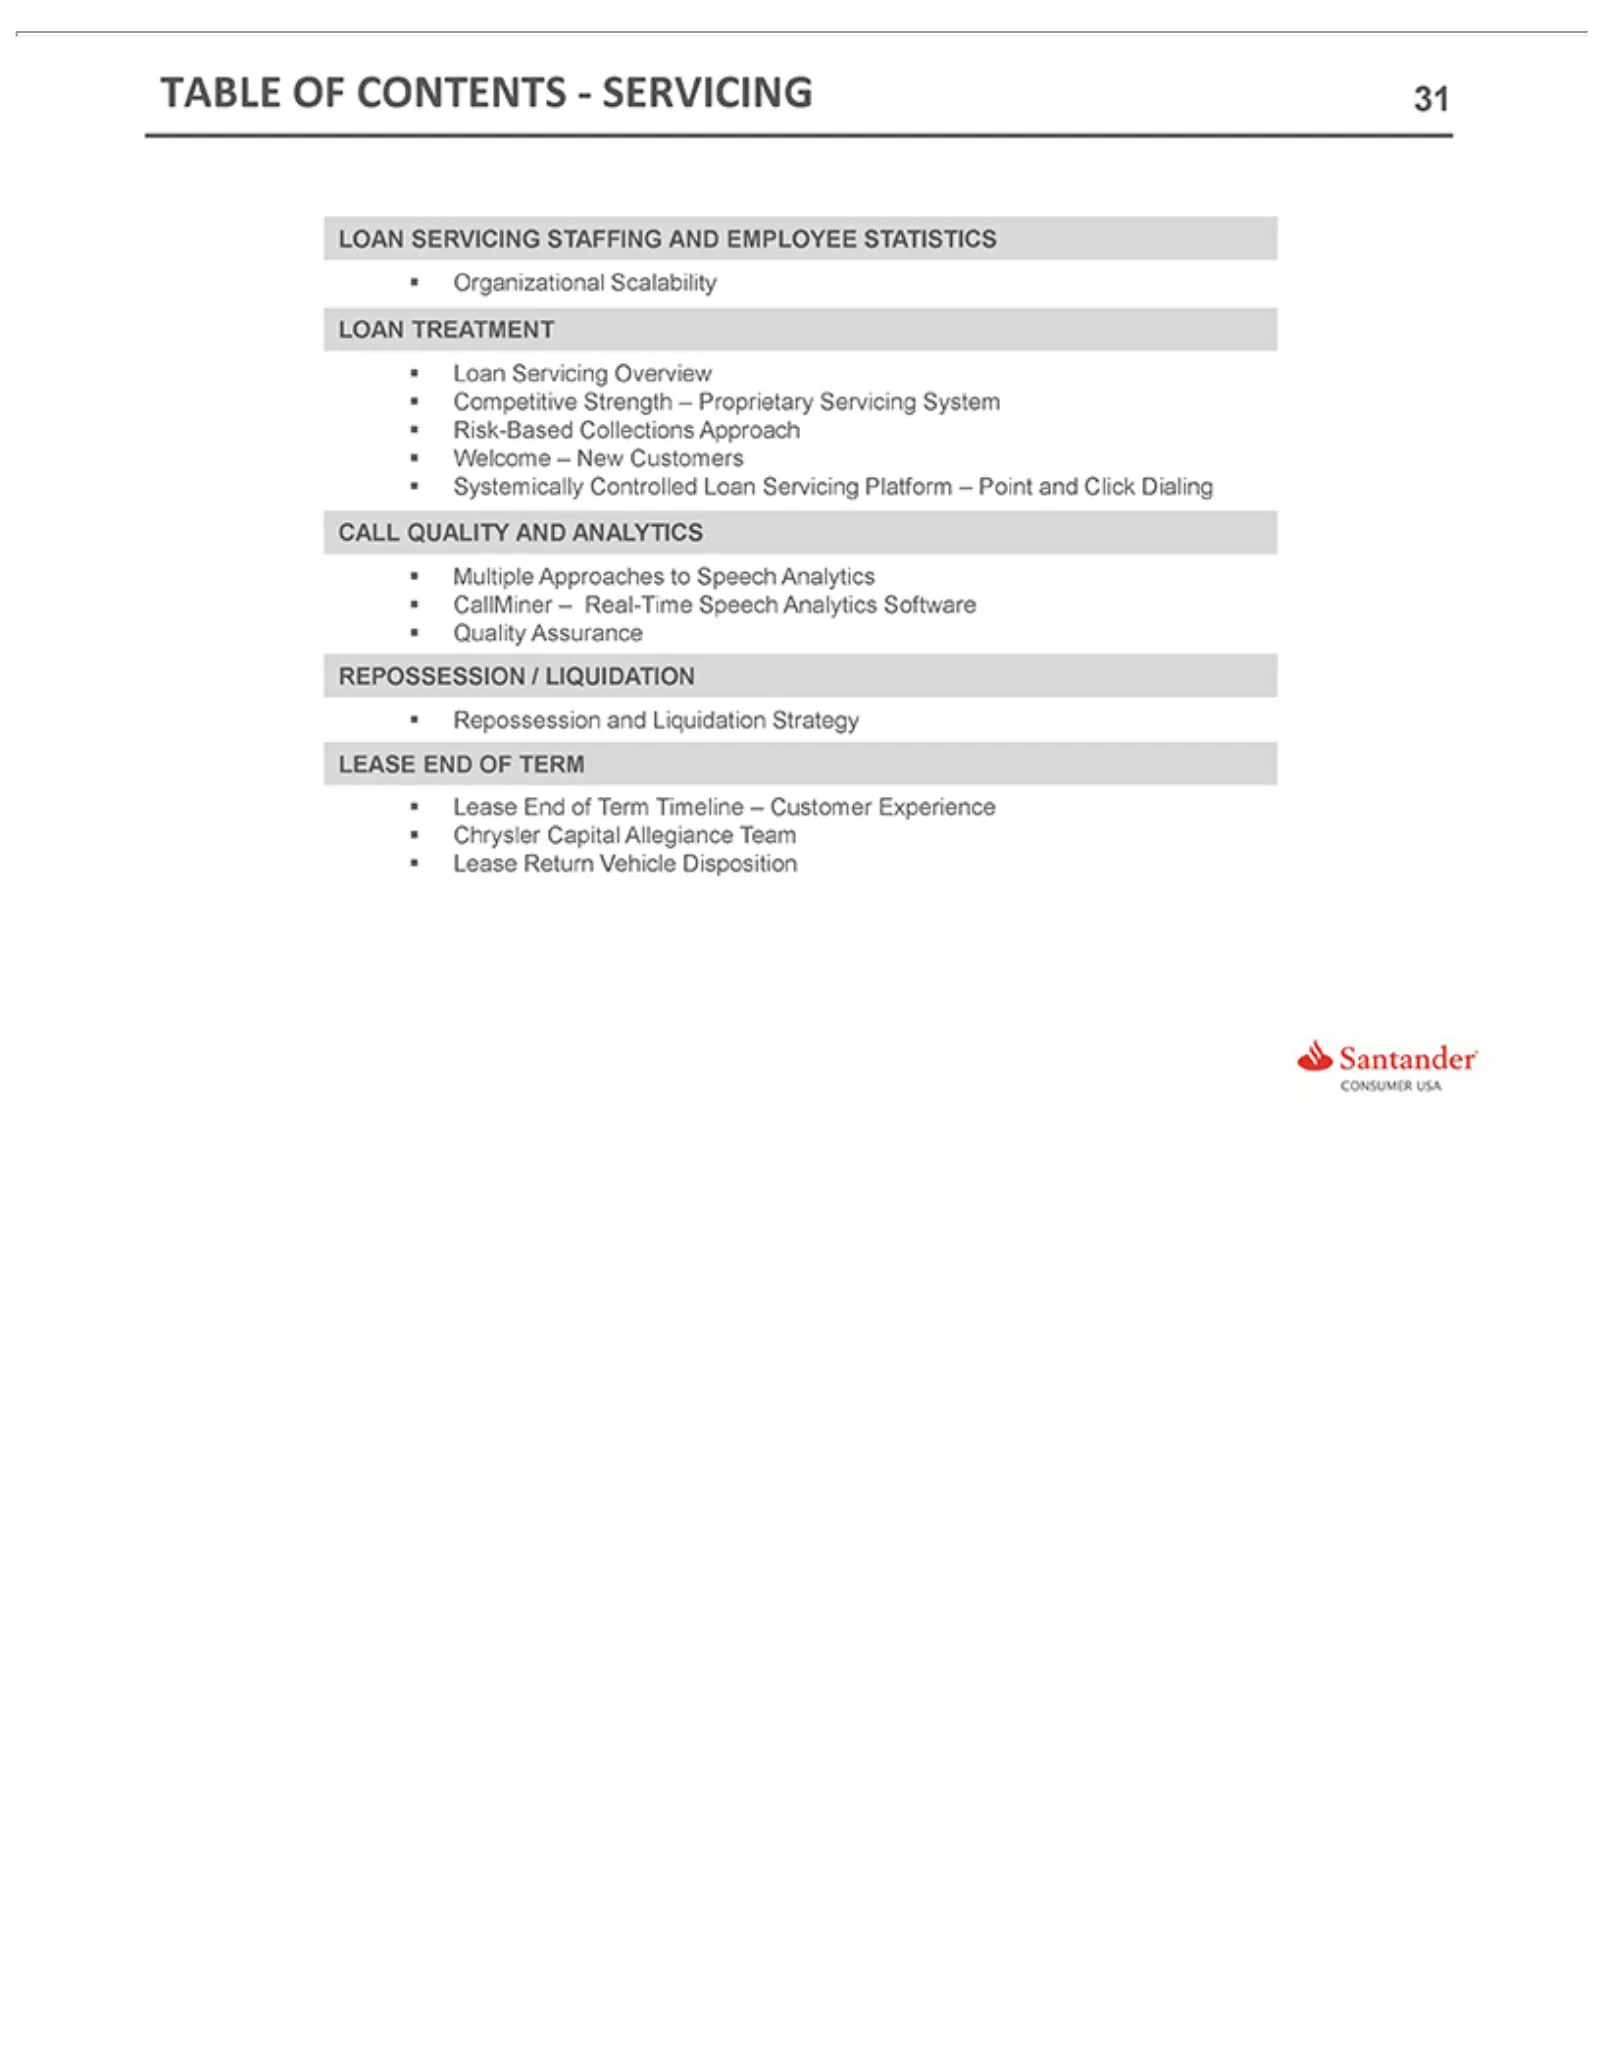
Slide 31: Table of Contents – Servicing
TABLE 31 LOAN CALL REPOSSESSION LEASE n Organizational Loan Competitive Systemically Multiple CallMiner Repossession LeaseQUALITY TREATMENT SERVICING Servicing End END OFApproaches CONTENTS—SERVICING –ofOF Real-Time Strength Controlled Term and Scalability Overview TERM /AND LIQUIDATION Liquidation
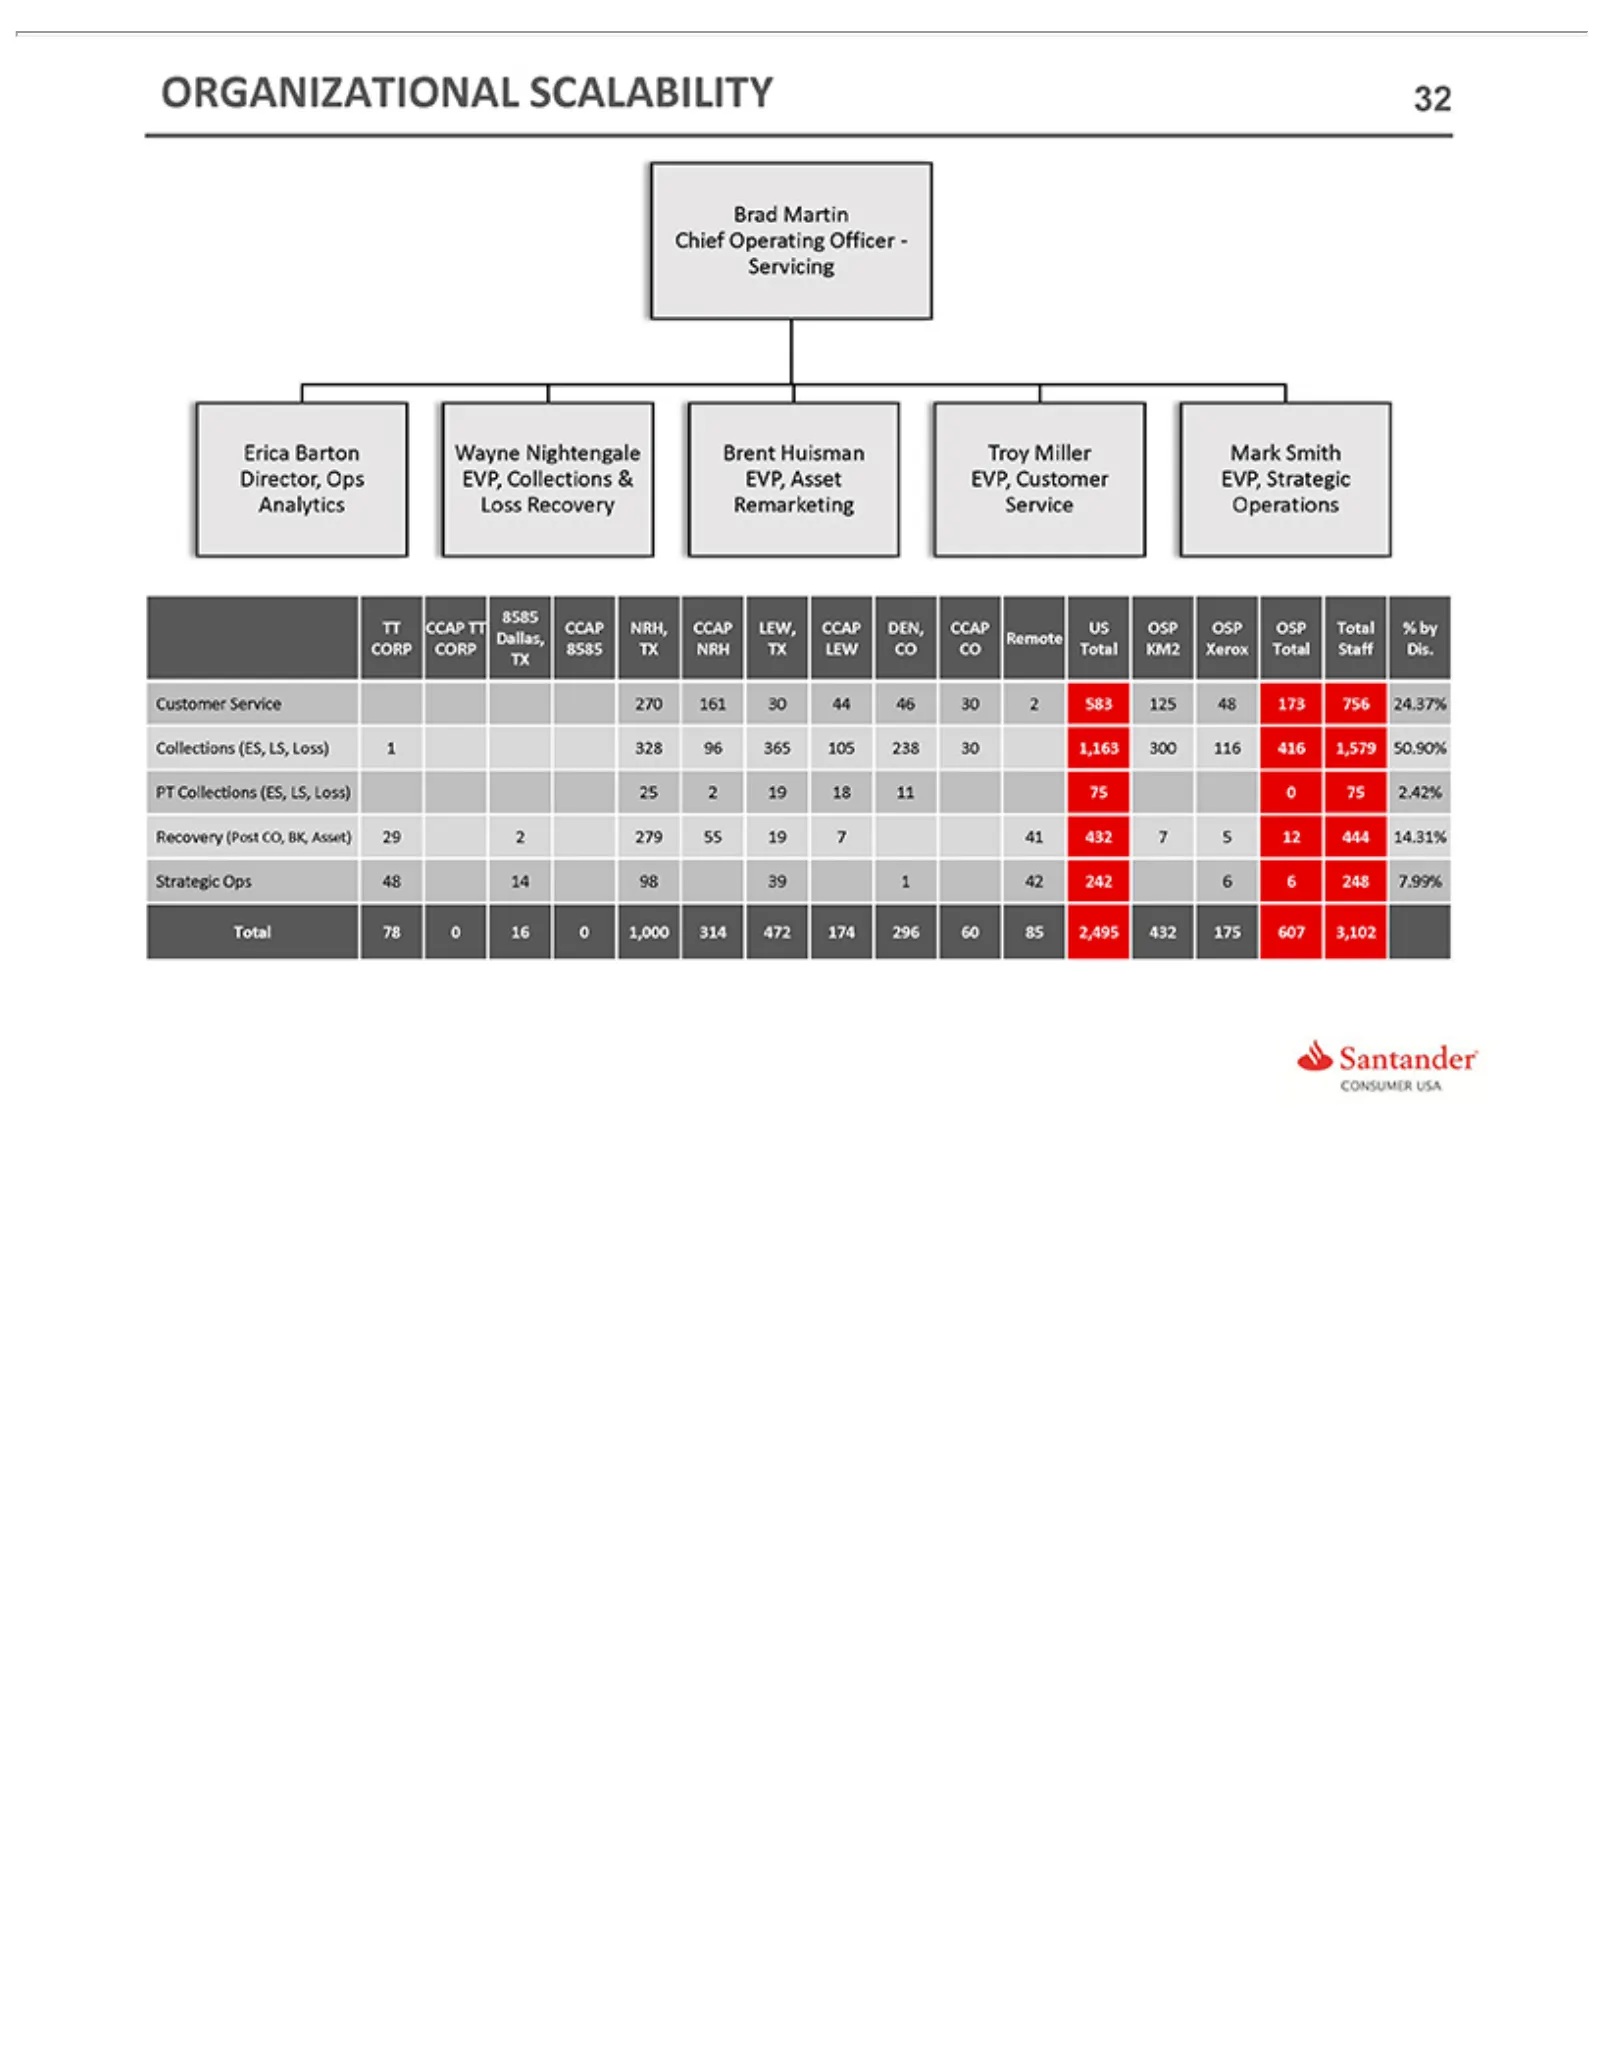
Slide 32: Organizational Scalability and Staffing
ORGANIZATIONAL Brad 32 Erica Wayne Brent Troy Mark TT 8585 Dallas, CORP Customer TX Collections PT Recovery Strategic Total Collections CCAP Miller Martin 78 Barton Smith Huisman CORP Nightengale Remote 0Ops (Post Service TT 16(ES, EVP, EVP, Chief Director, 08585 48 CCAP (ES, 1,000 EVP, CO, LS, 14 C
Slide 33: Loan Servicing Overview
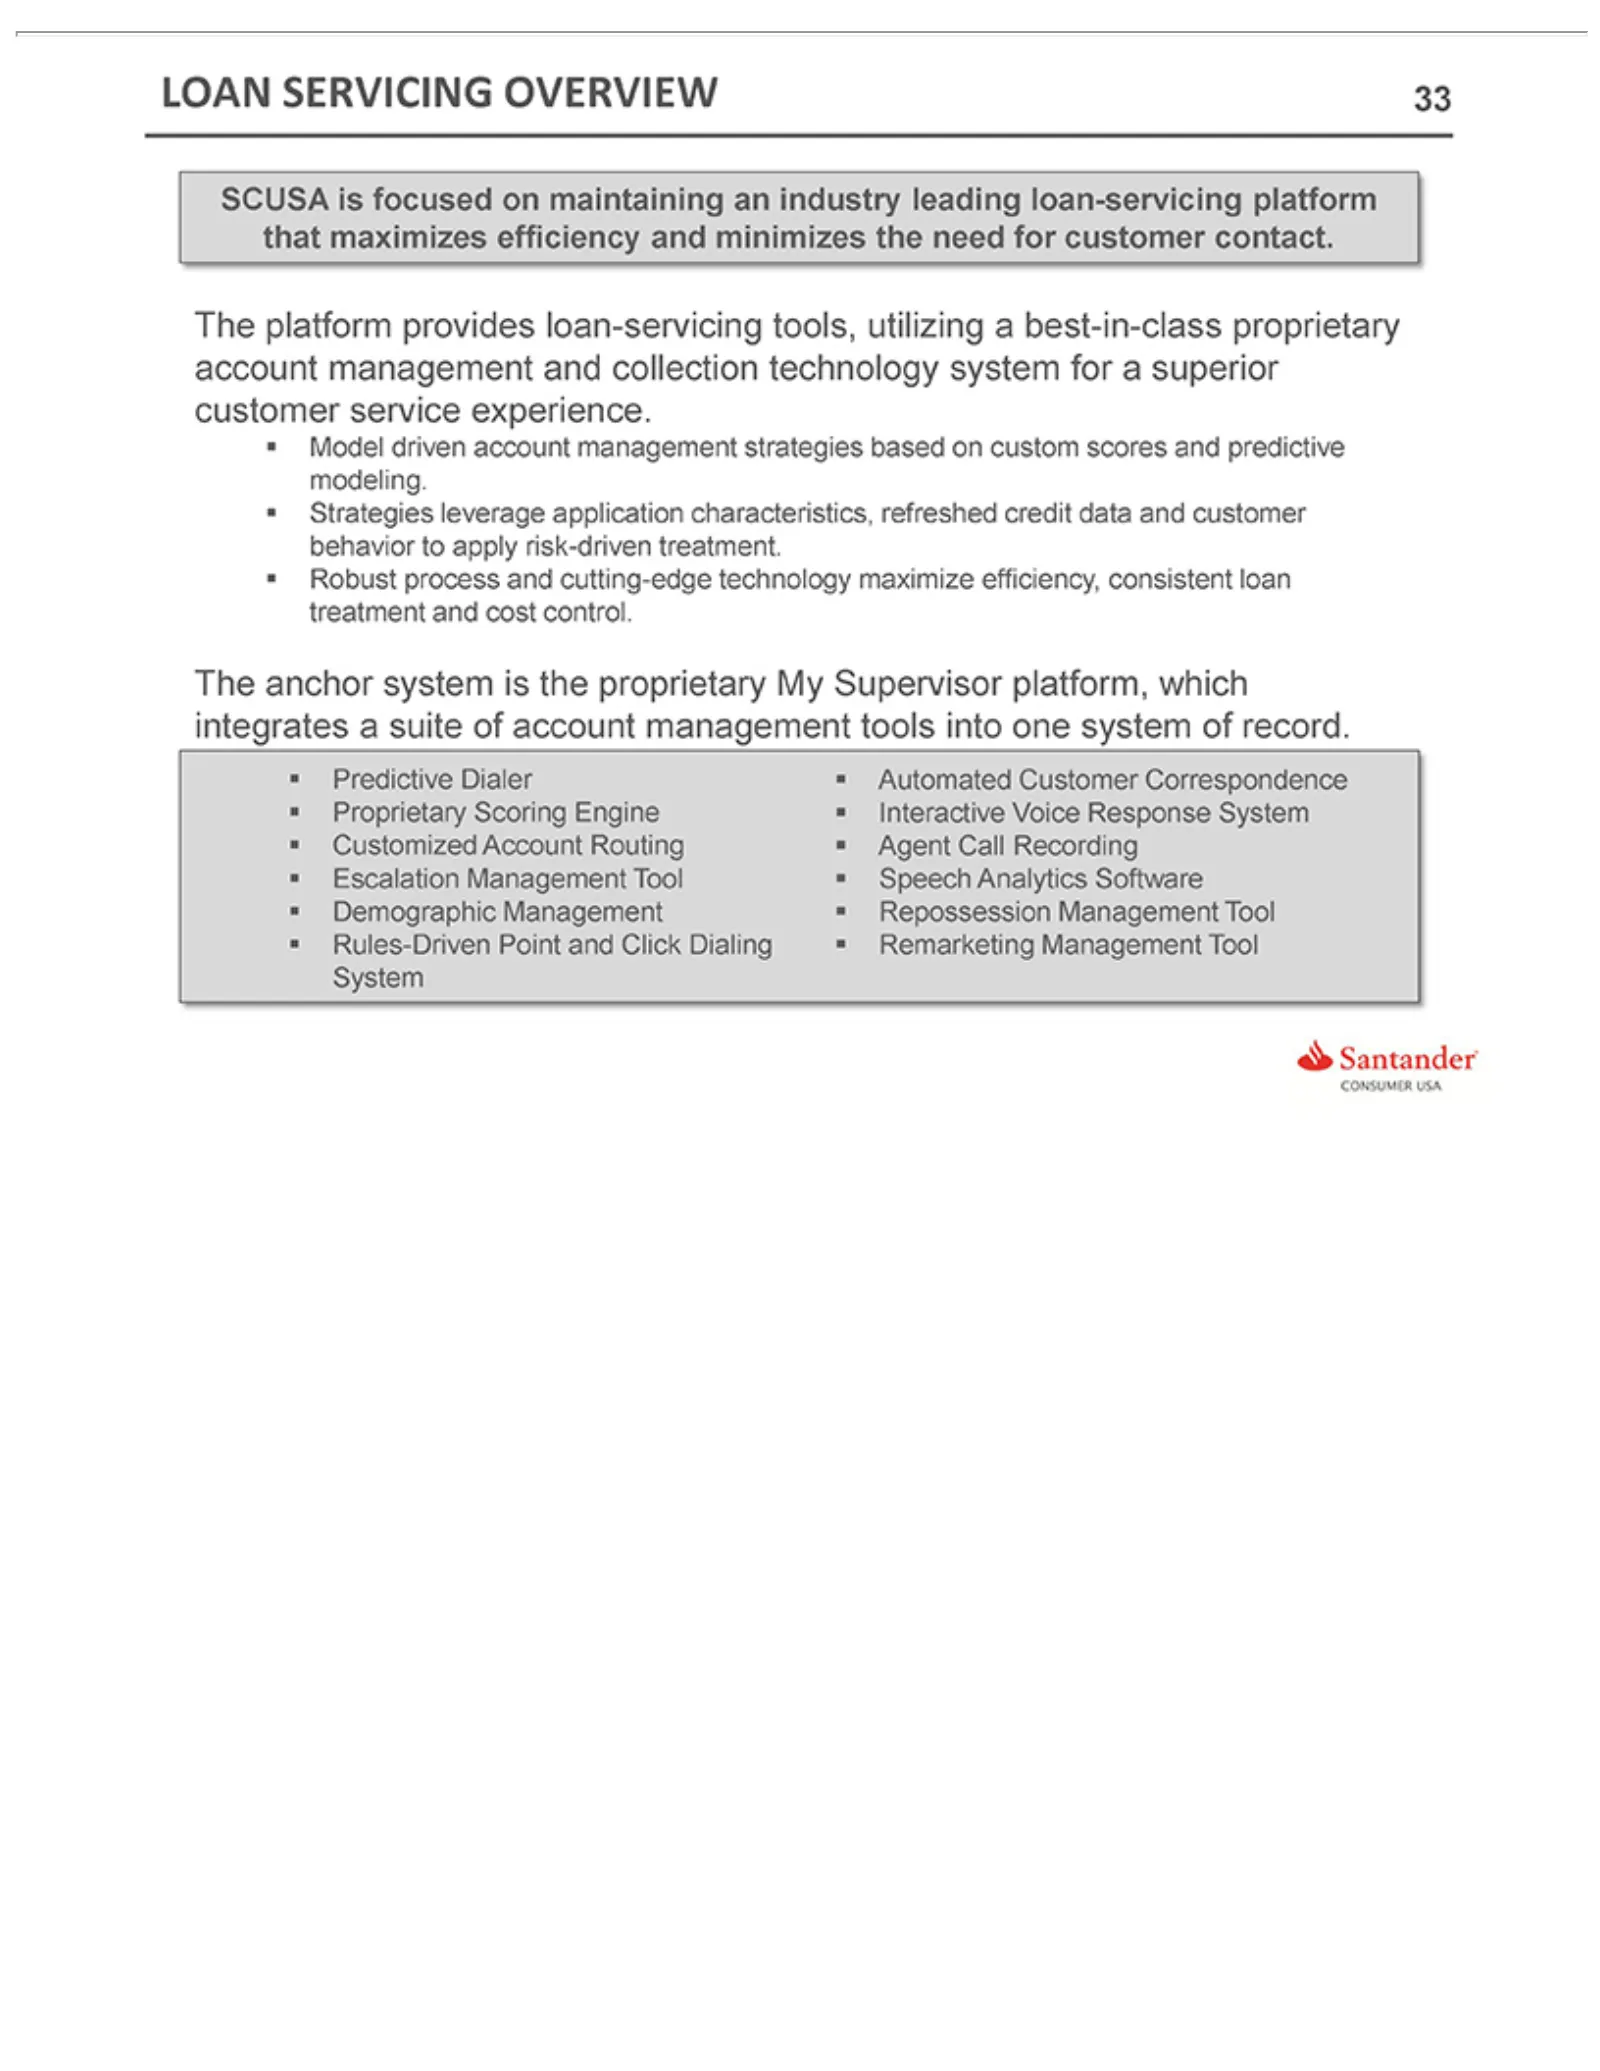
LOAN SCUSA 33 The n System Model Strategies Robust Predictive Proprietary Customized Escalation Demographic Rules-Driven platform anchor SERVICING isdriven process focused system leverage Dialer Management provides Scoring Account Point account Management and on nisAutomated OVERVIEW application the
Slide 34: Competitive Strength – Proprietary Servicing System
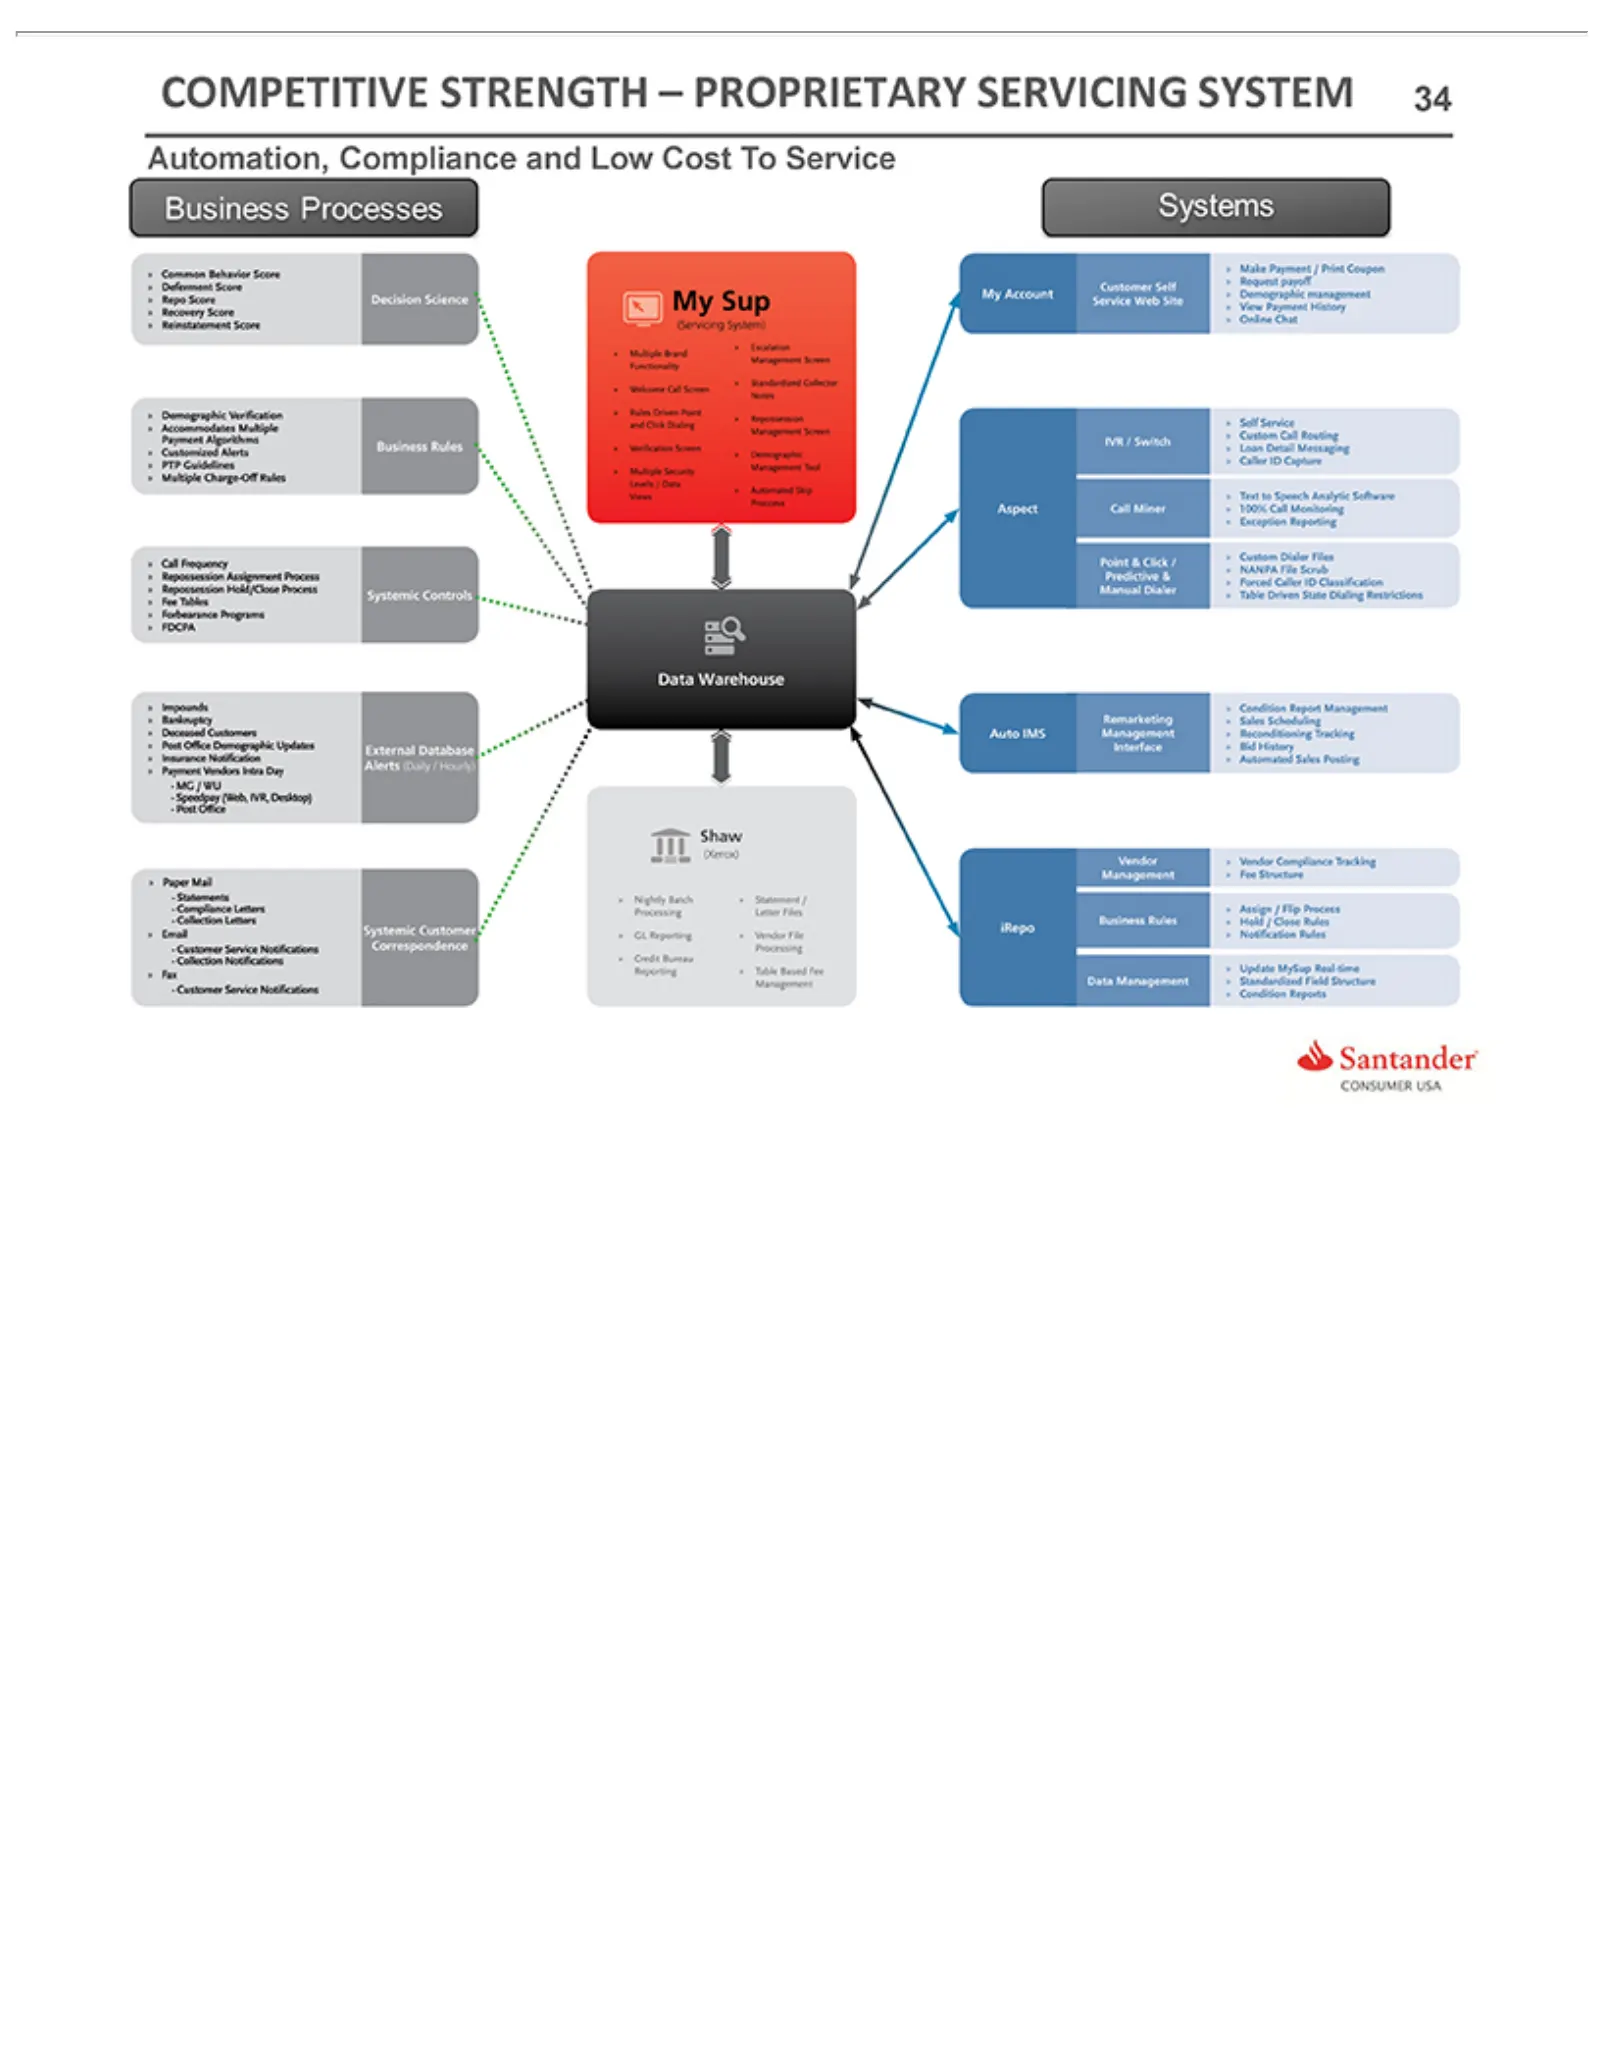
COMPETITIVE Automation, Compliance STRENGTHand Low – PROPRIETARY Cost To ServiceSERVICING SYSTEM 34
Slide 35: Risk-Based Collections Approach
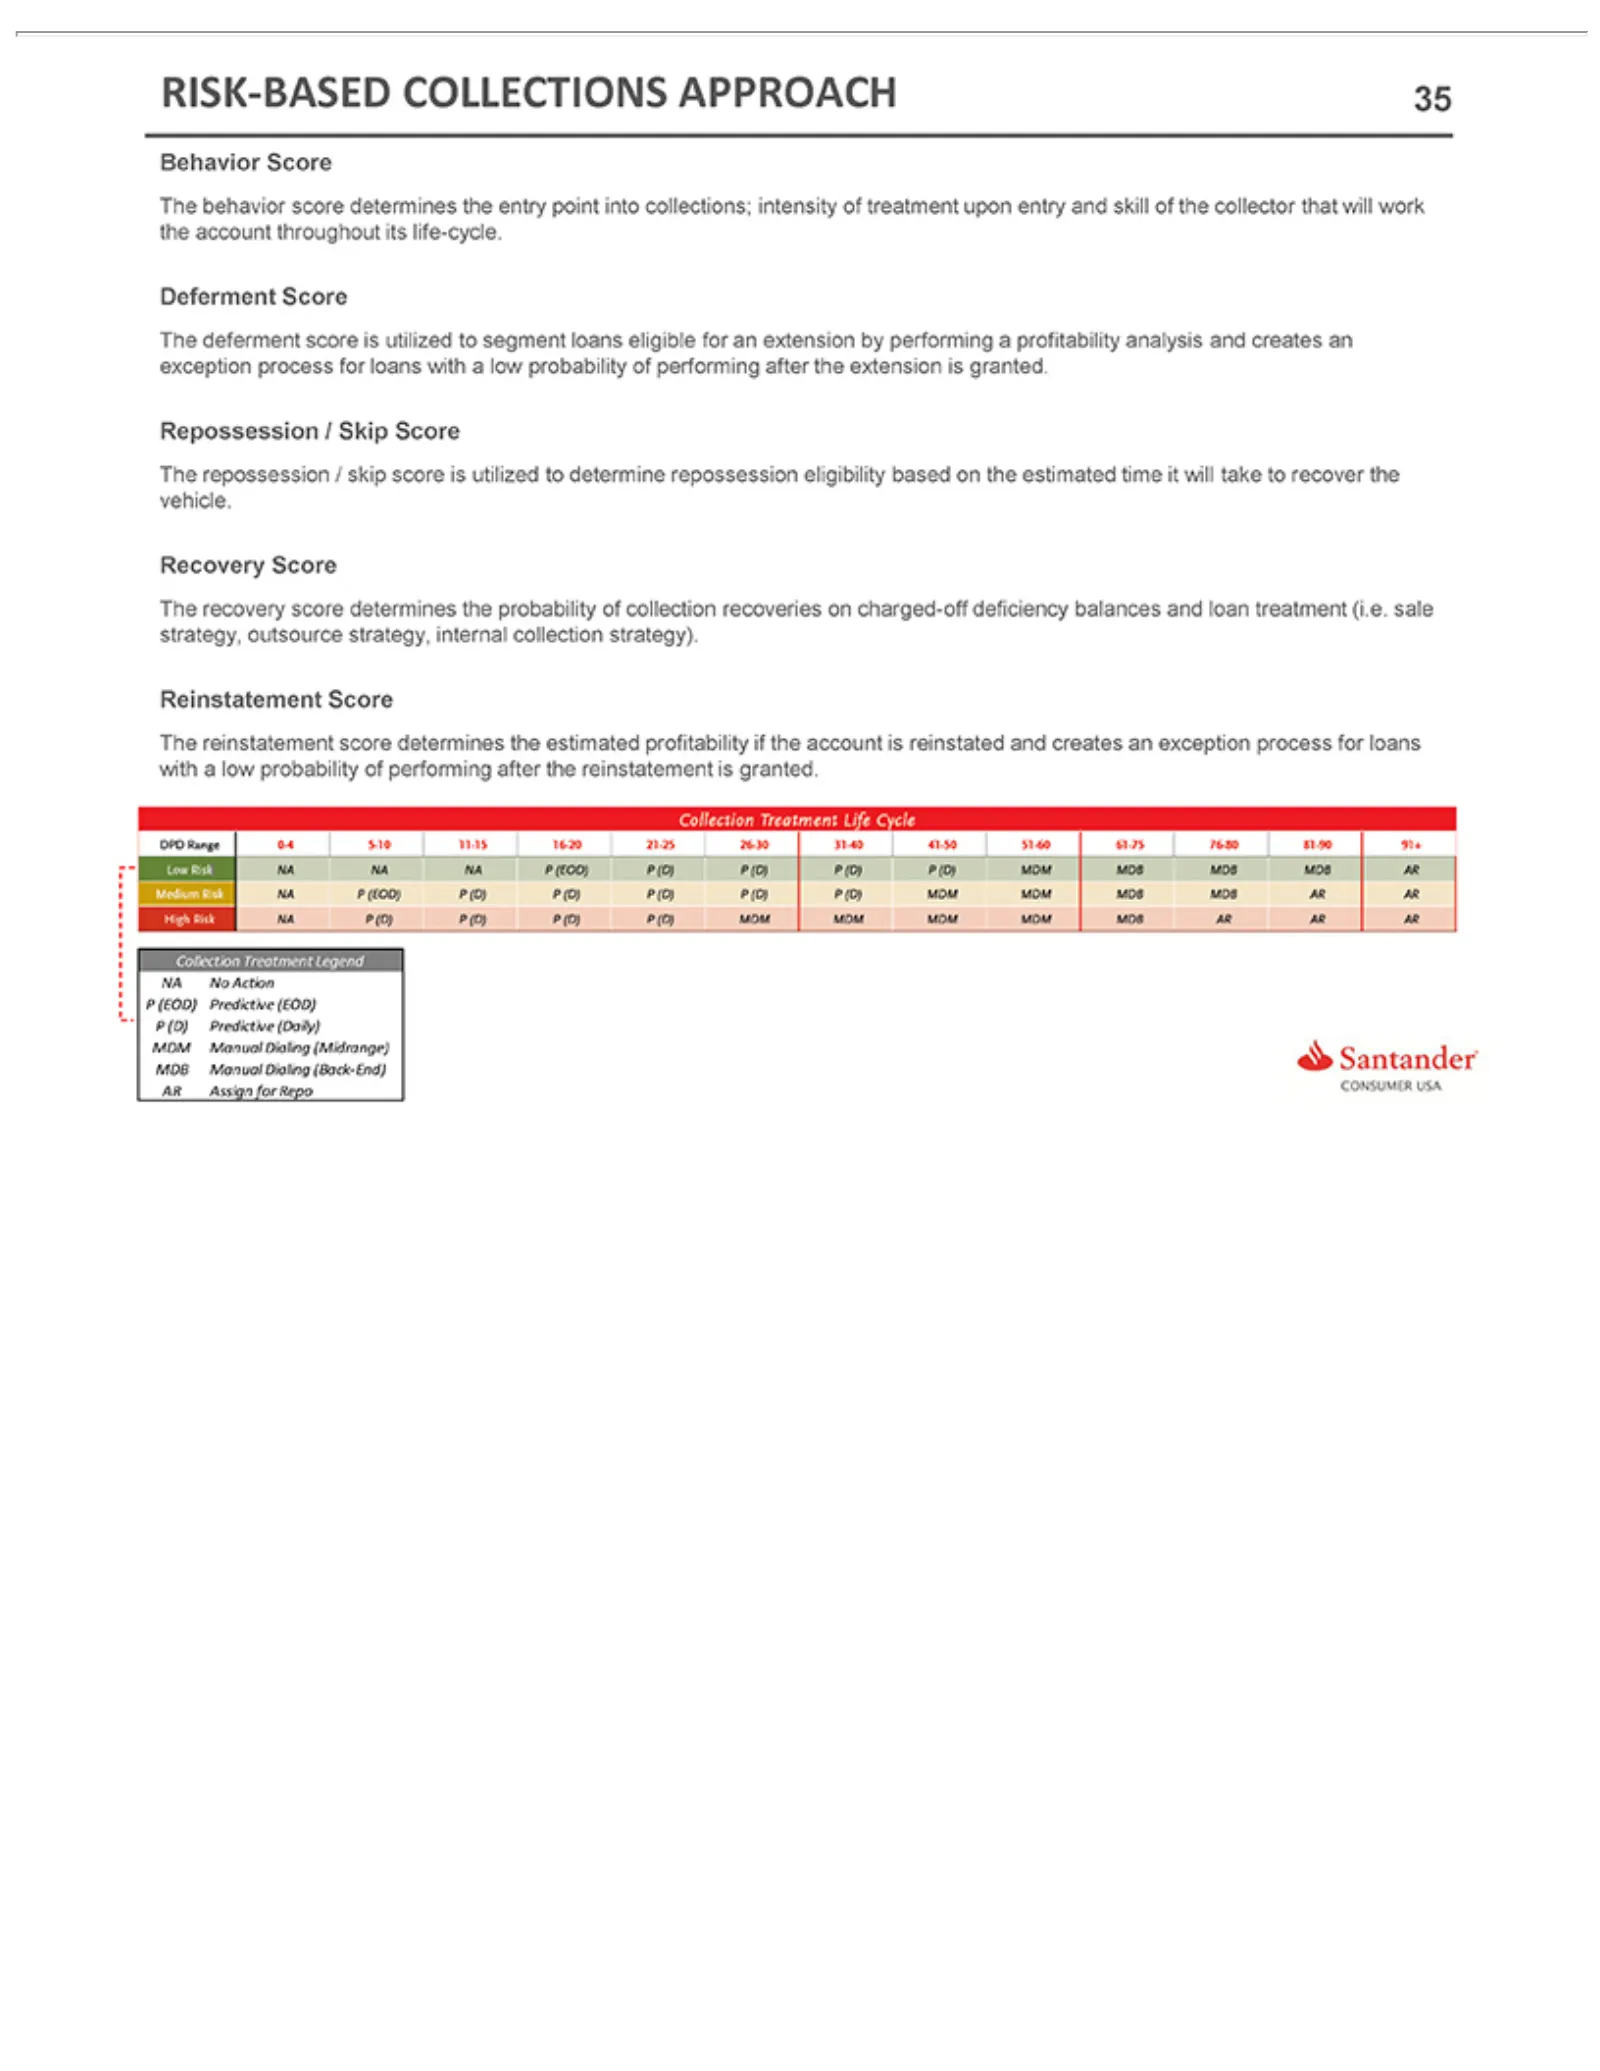
RISK-BASED Behavior Deferment the Repossession Recovery Reinstatement The granted. Collection No NA P Predictive MDM Manual MDB Assign AR(EOD) (D) Action extension behavior deferment repossession recovery reinstatement for Dialing Score Score (EOD) (Daily) Treatment Repo Score score is / Score score
Slide 36: Welcome New Customers
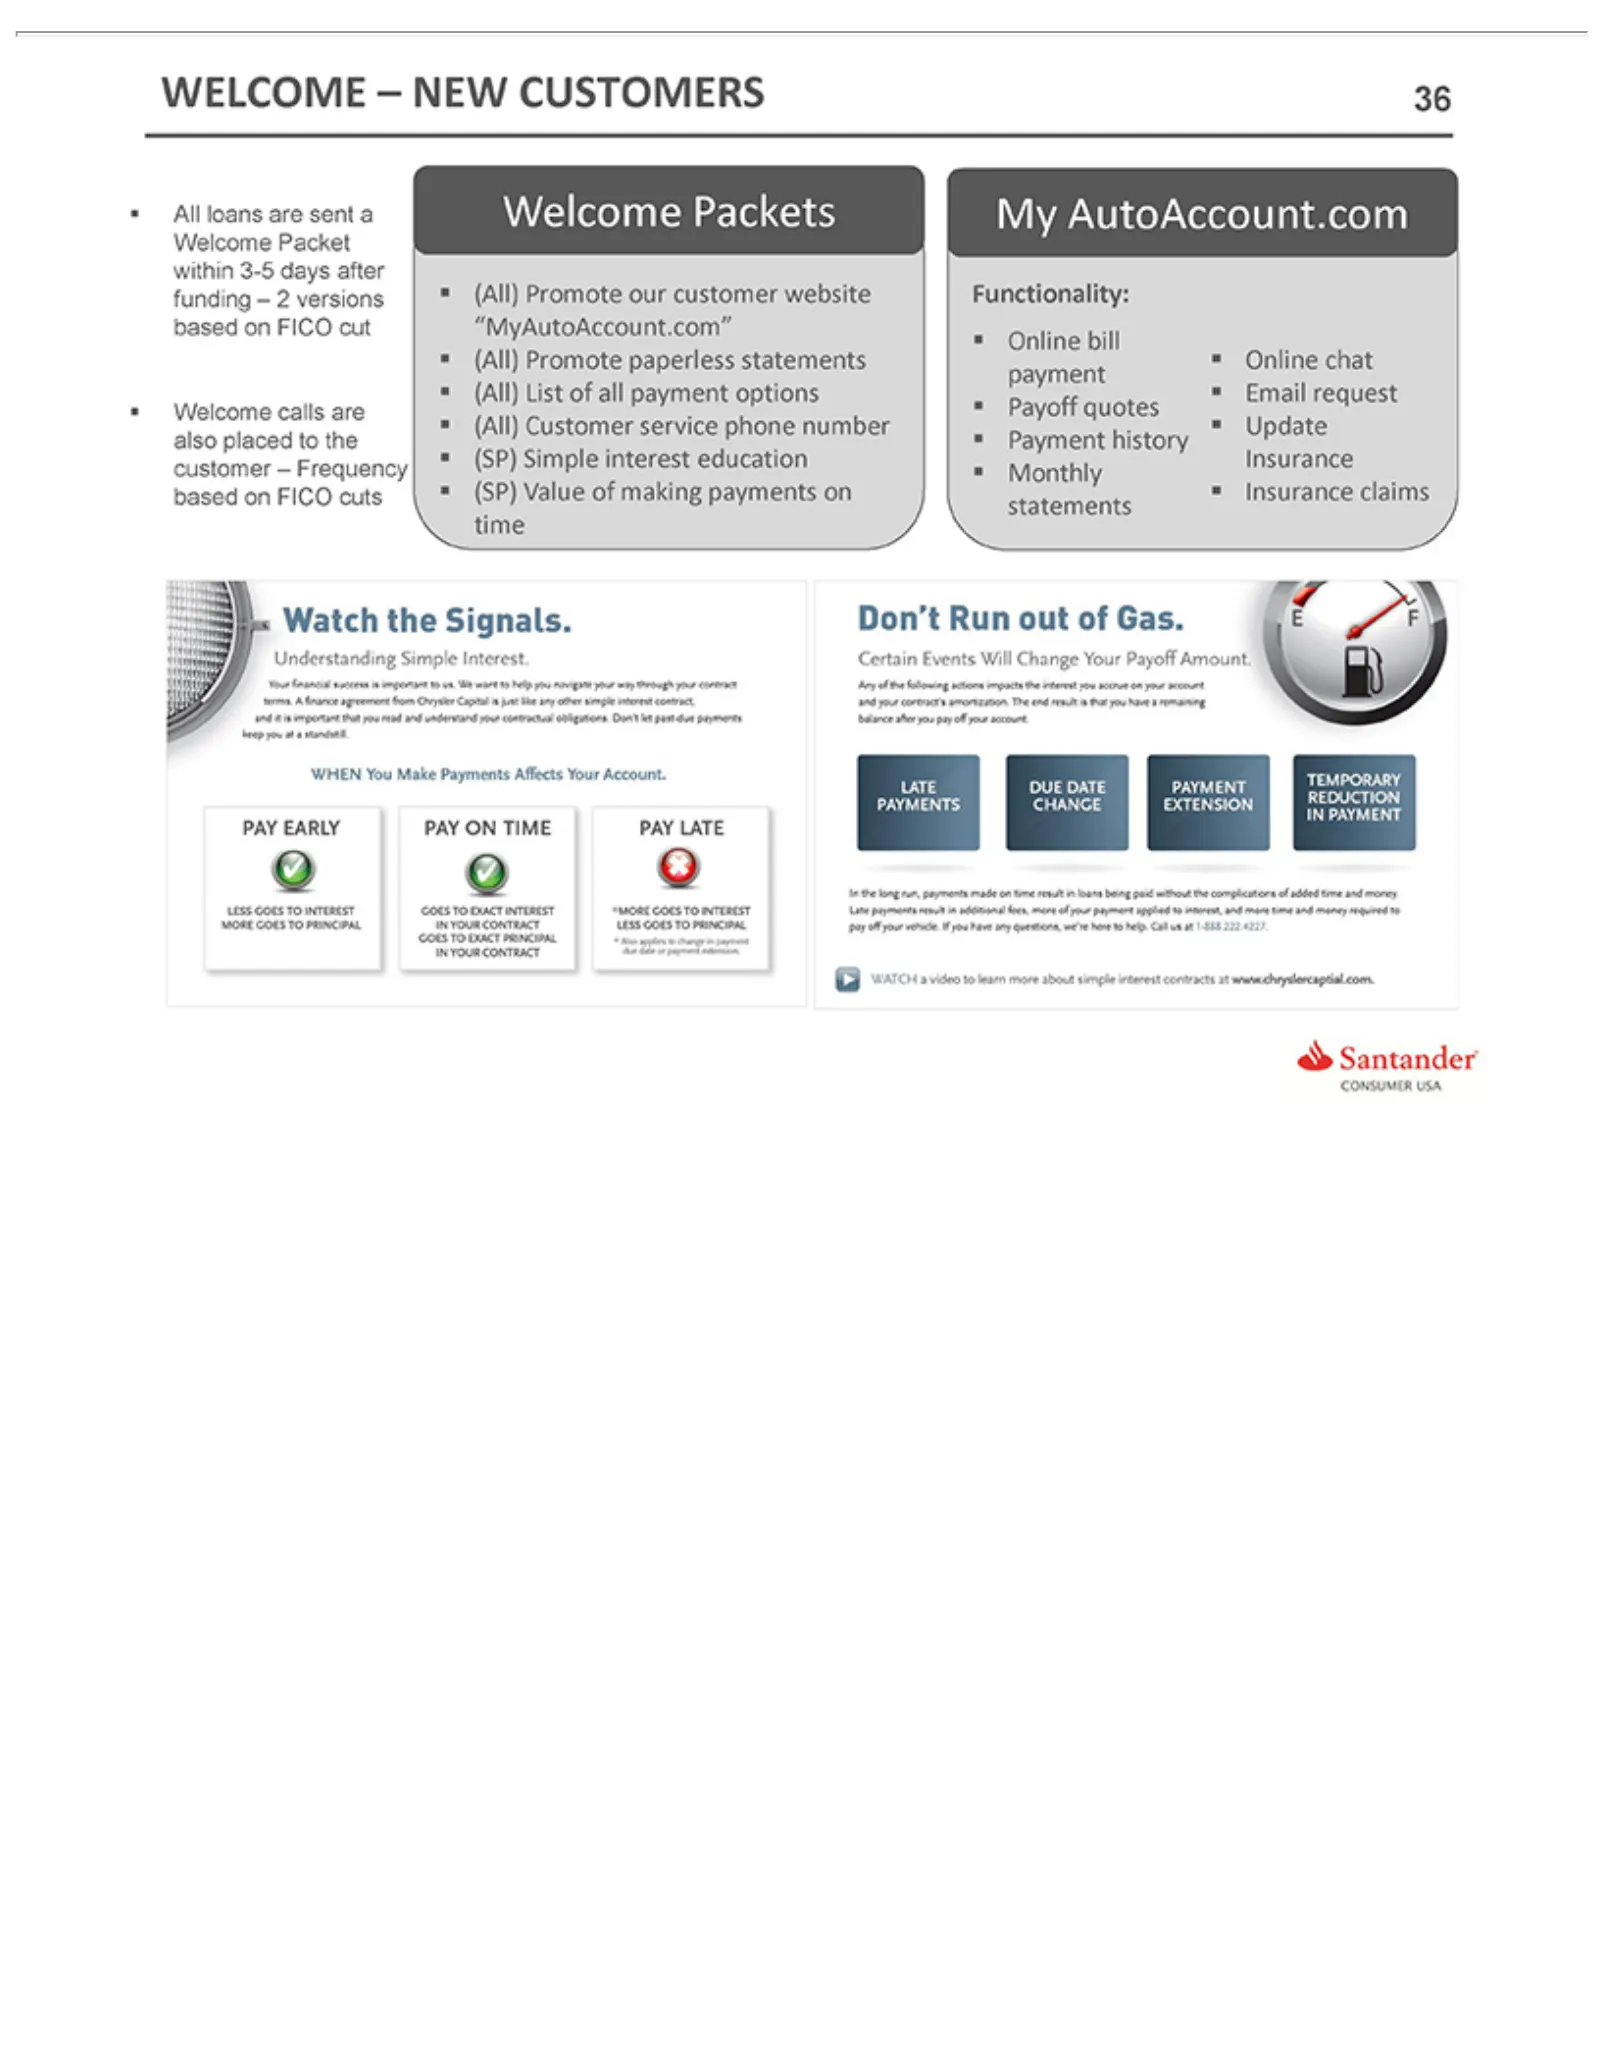
WELCOME All Welcome (All) “MyAutoAccount.com” My n Functionality: Online Online loans AutoAccount.com Promote chat bill are calls Packets Email –paymentn sent our paperless NEW areacustomer request also Welcome CUSTOMERS placed Payoff statements Update website Packet to quotesn the Insurance (All) c
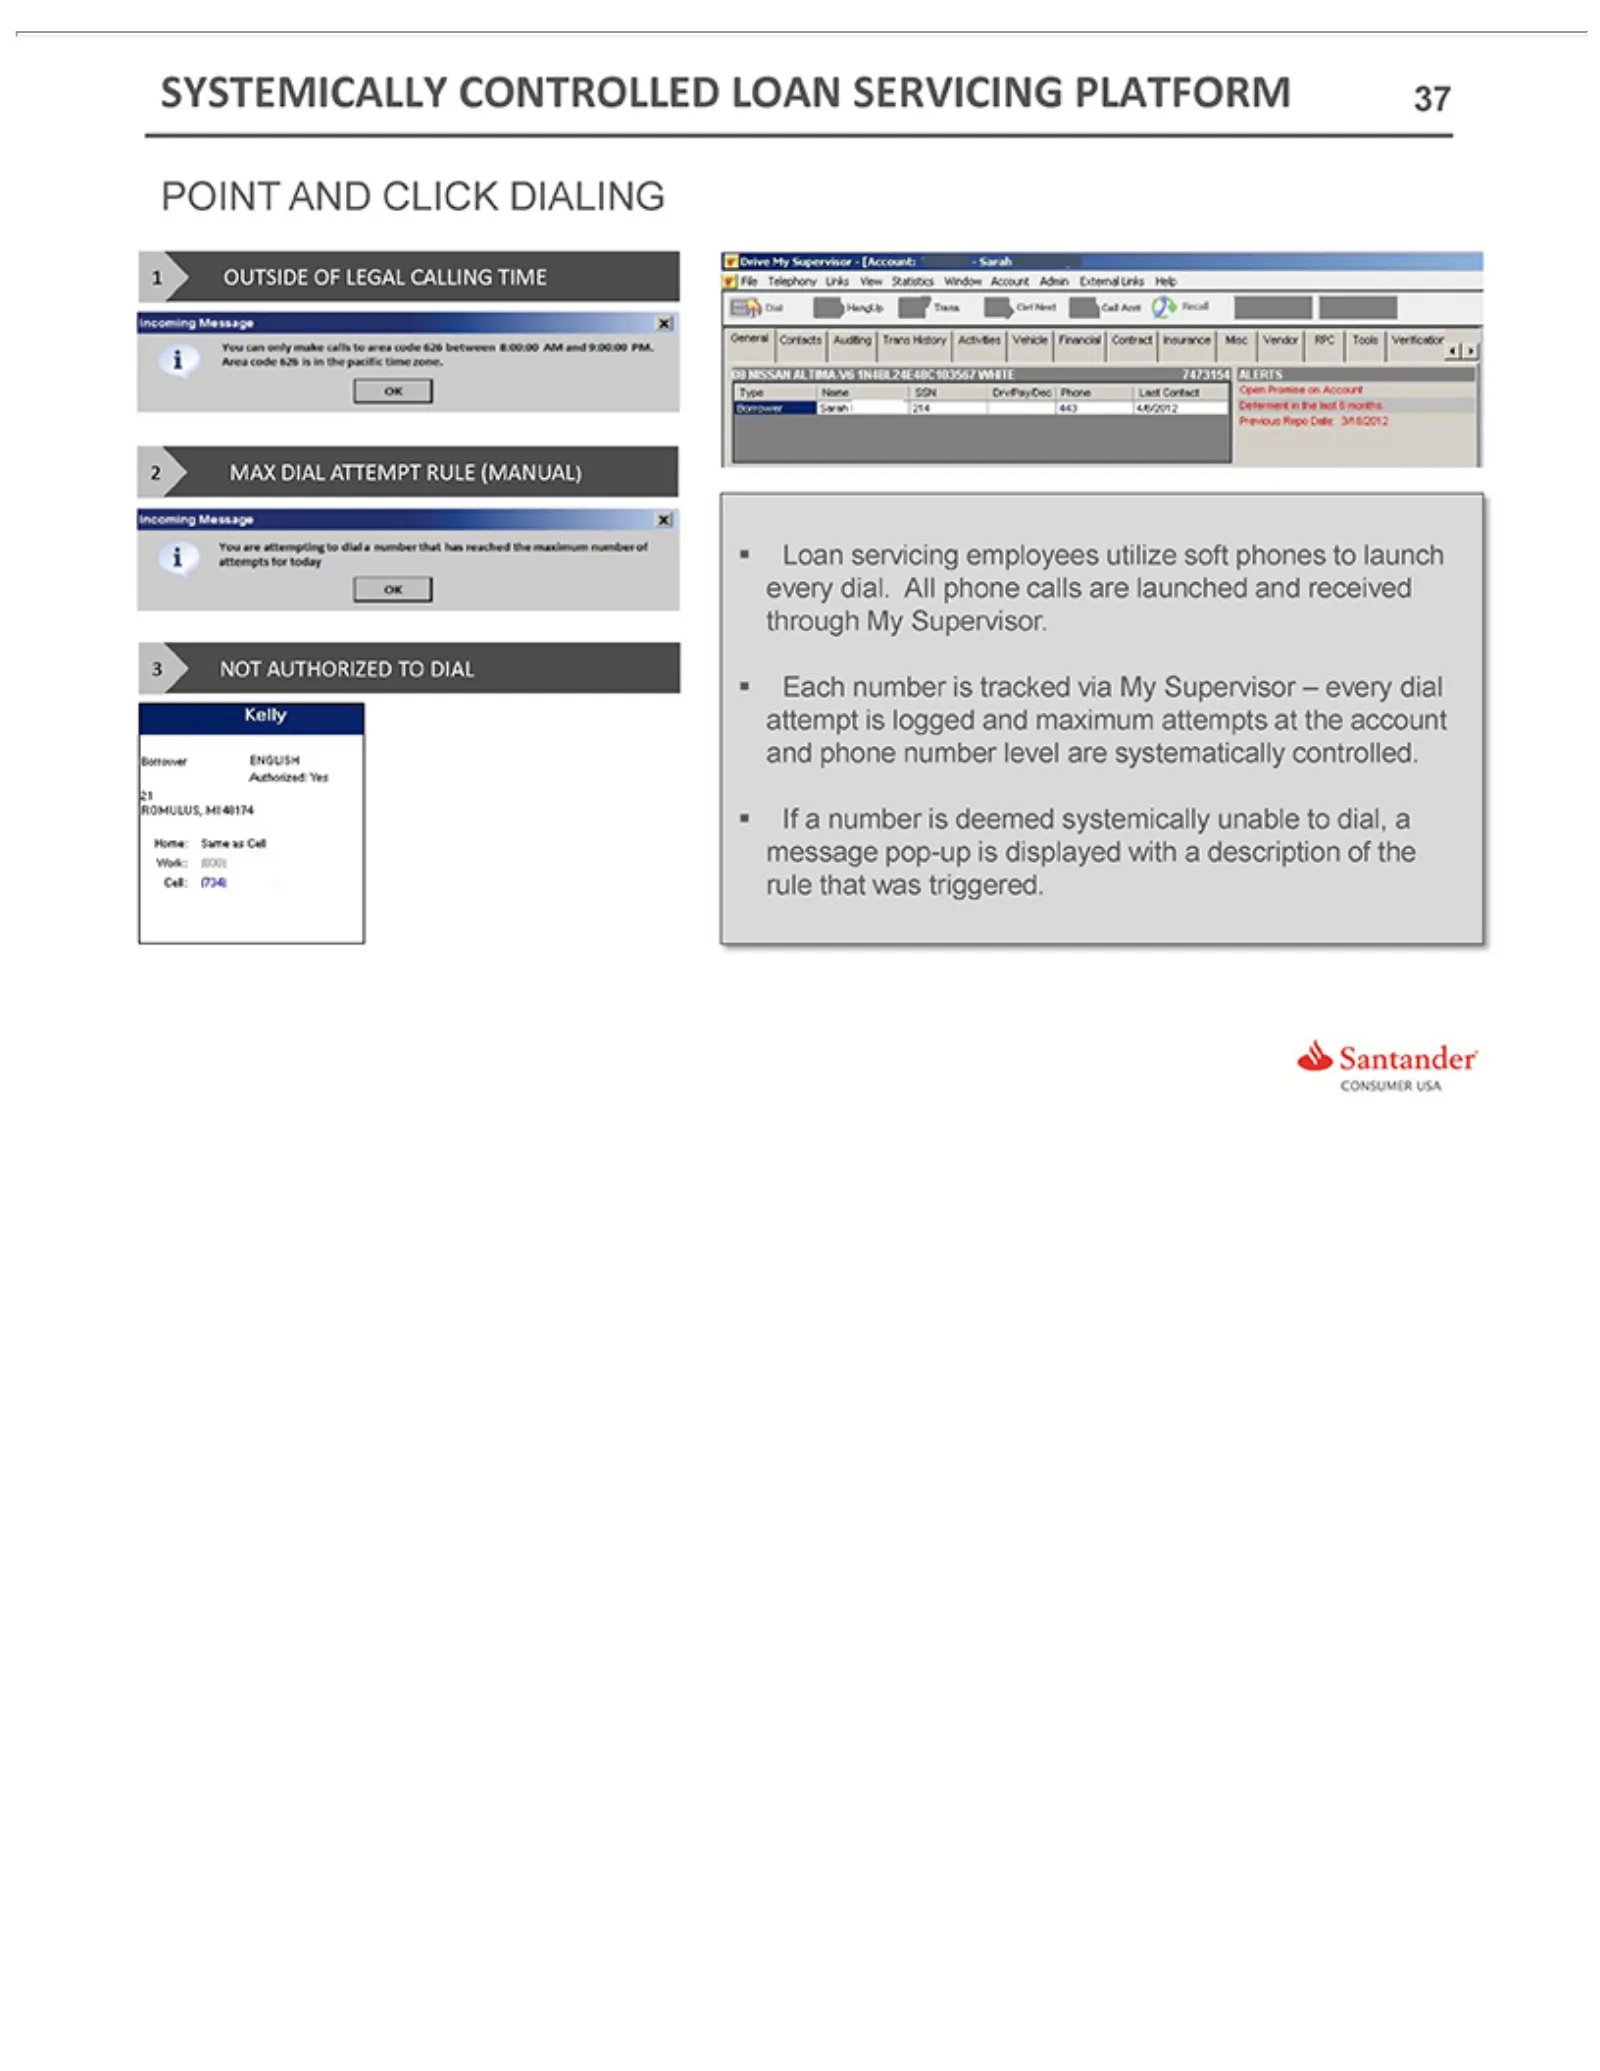
Slide 37: Systemically Controlled Loan Servicing Platform
SYSTEMICALLY POINT every through attempt and n message rule Loan Each If aphone that number dial. number servicing AND is My was pop-up logged number All Supervisor. triggered. CLICK isphone isdeemed isemployees and tracked displayed level CONTROLLED calls DIALING maximum are systemically via are sy
Slide 38: Multiple Approaches to Speech Analytics
MULTIPLE One detect Real-time Post-call n Allows Targeted Real-time Events Can Reduces element monitor changes that Mining for Speech head Quality alerts APPROACHES automated of trigger compliance inspeech count voice Analytics allow Assurance. alerts needs analytics tone Call us are elements toand
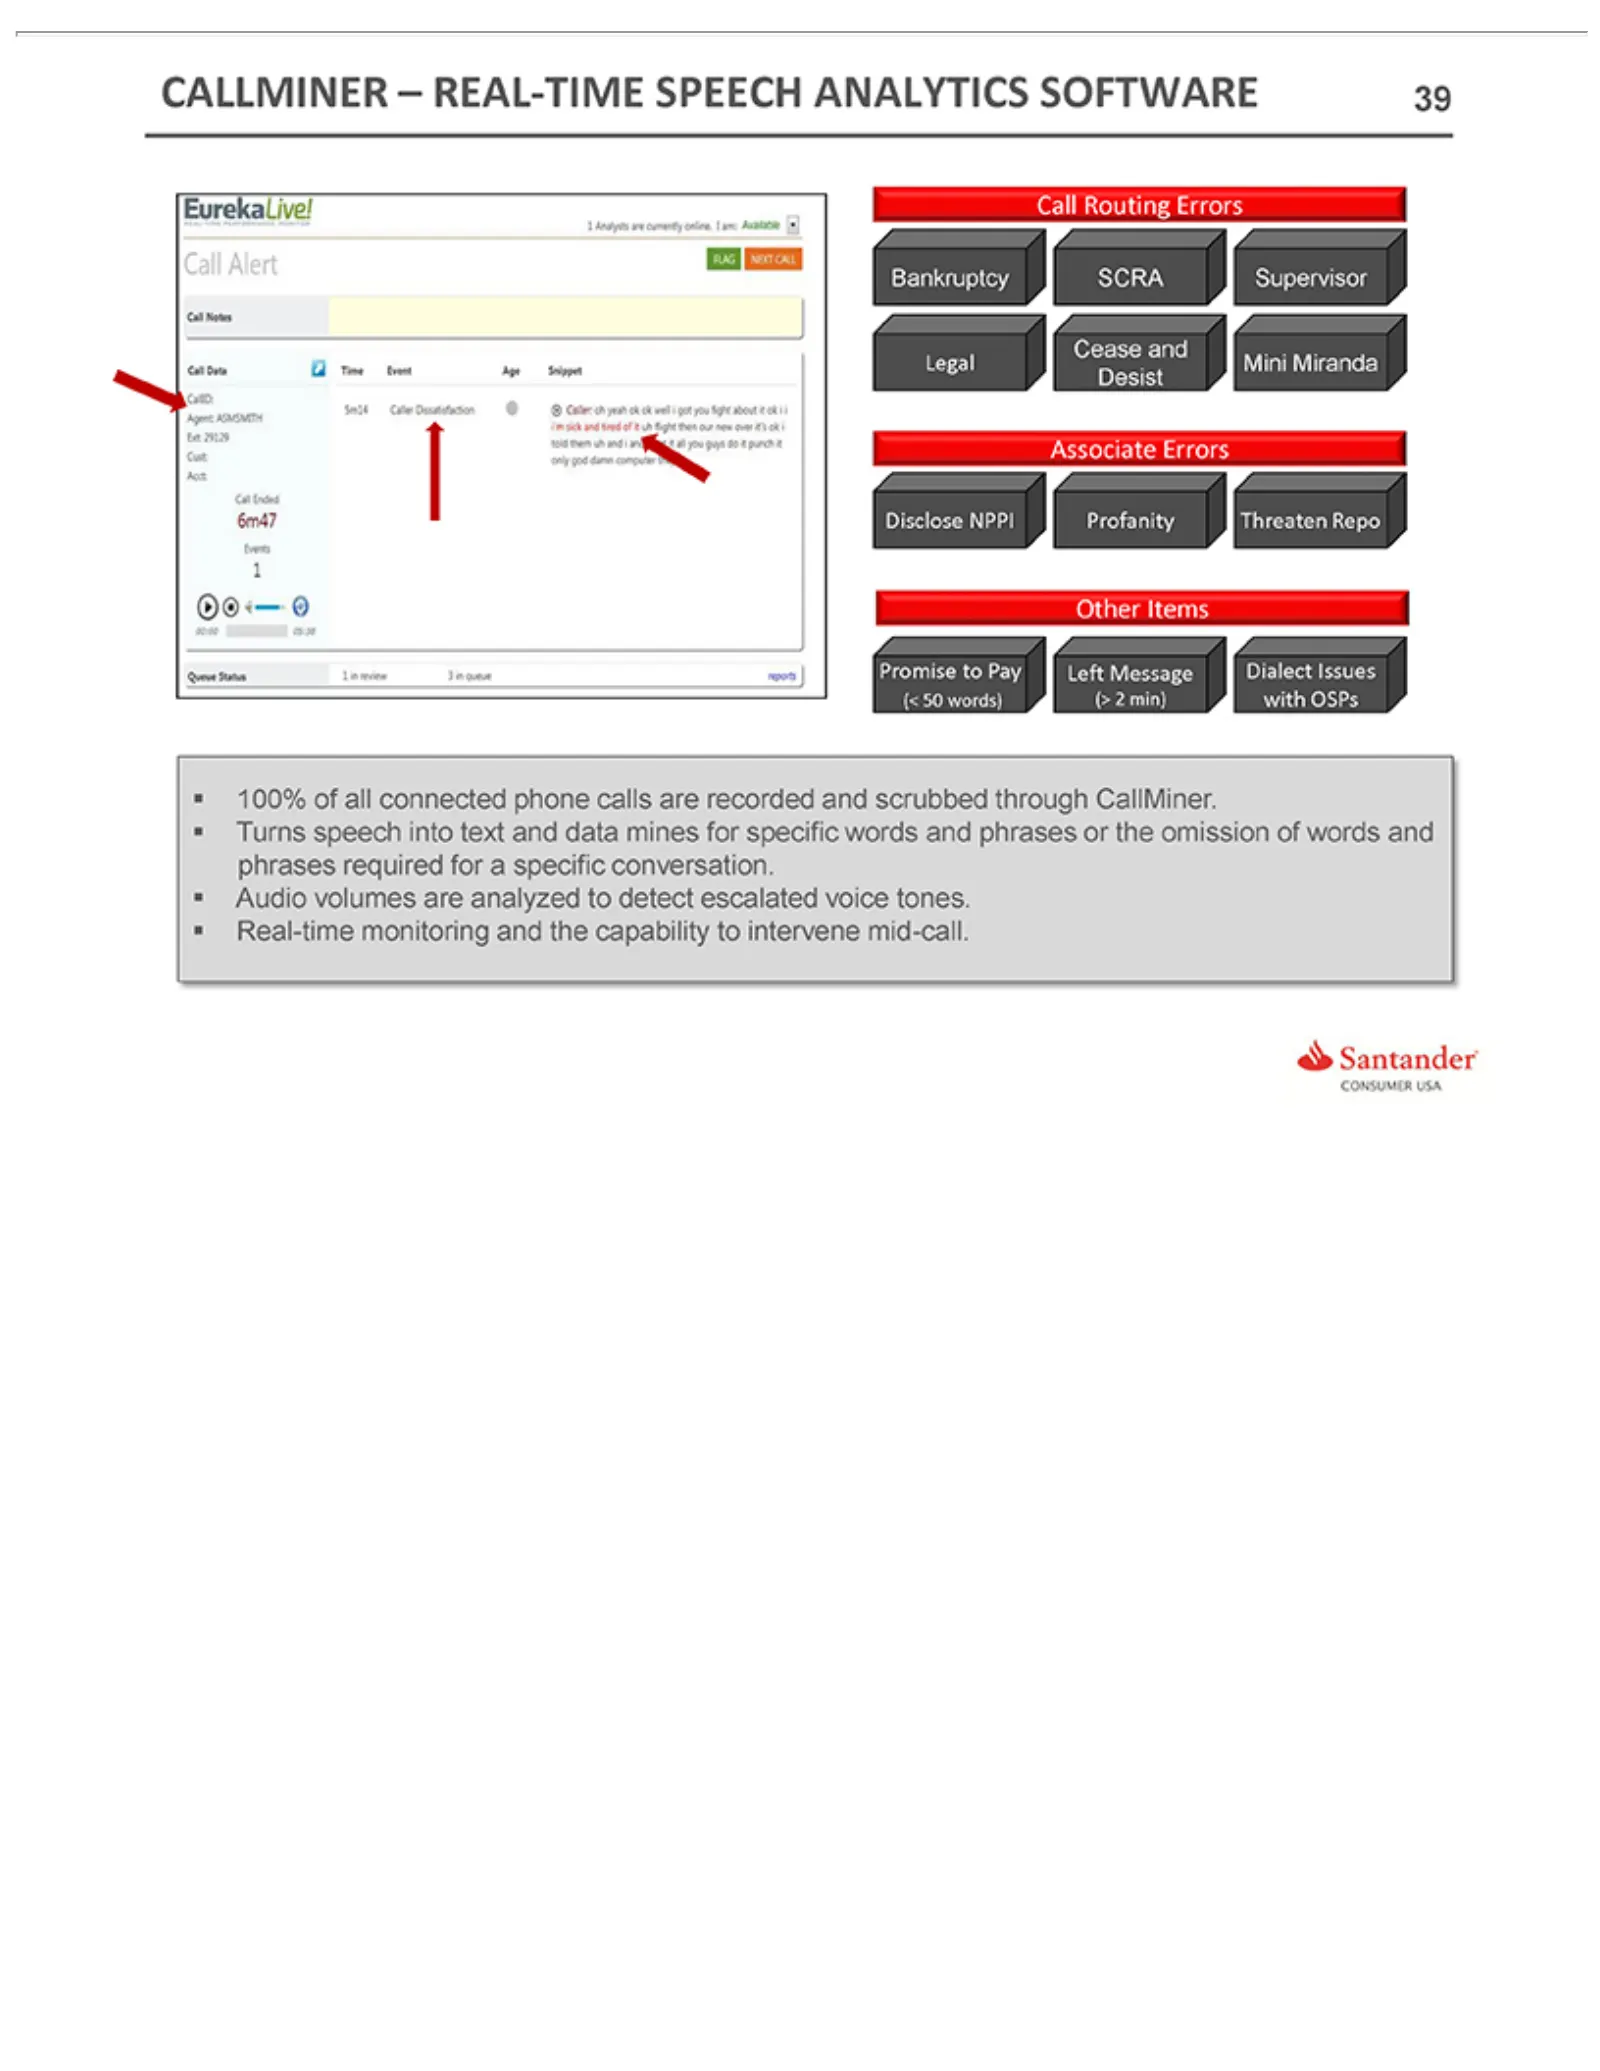
Slide 39: CallMiner Real-Time Speech Analytics Software
CALLMINER Call Bankruptcy Cease Legal Associate Disclose Other Promise > 100% Turns Audio 50 Routing words) Mini Items speech of and volumes to all NPPI Errors Pay Miranda connected SCRA (> Errors into –Profanity 2Left are REAL-TIME min) text Supervisor analyzed Message Desist and with phone Threate
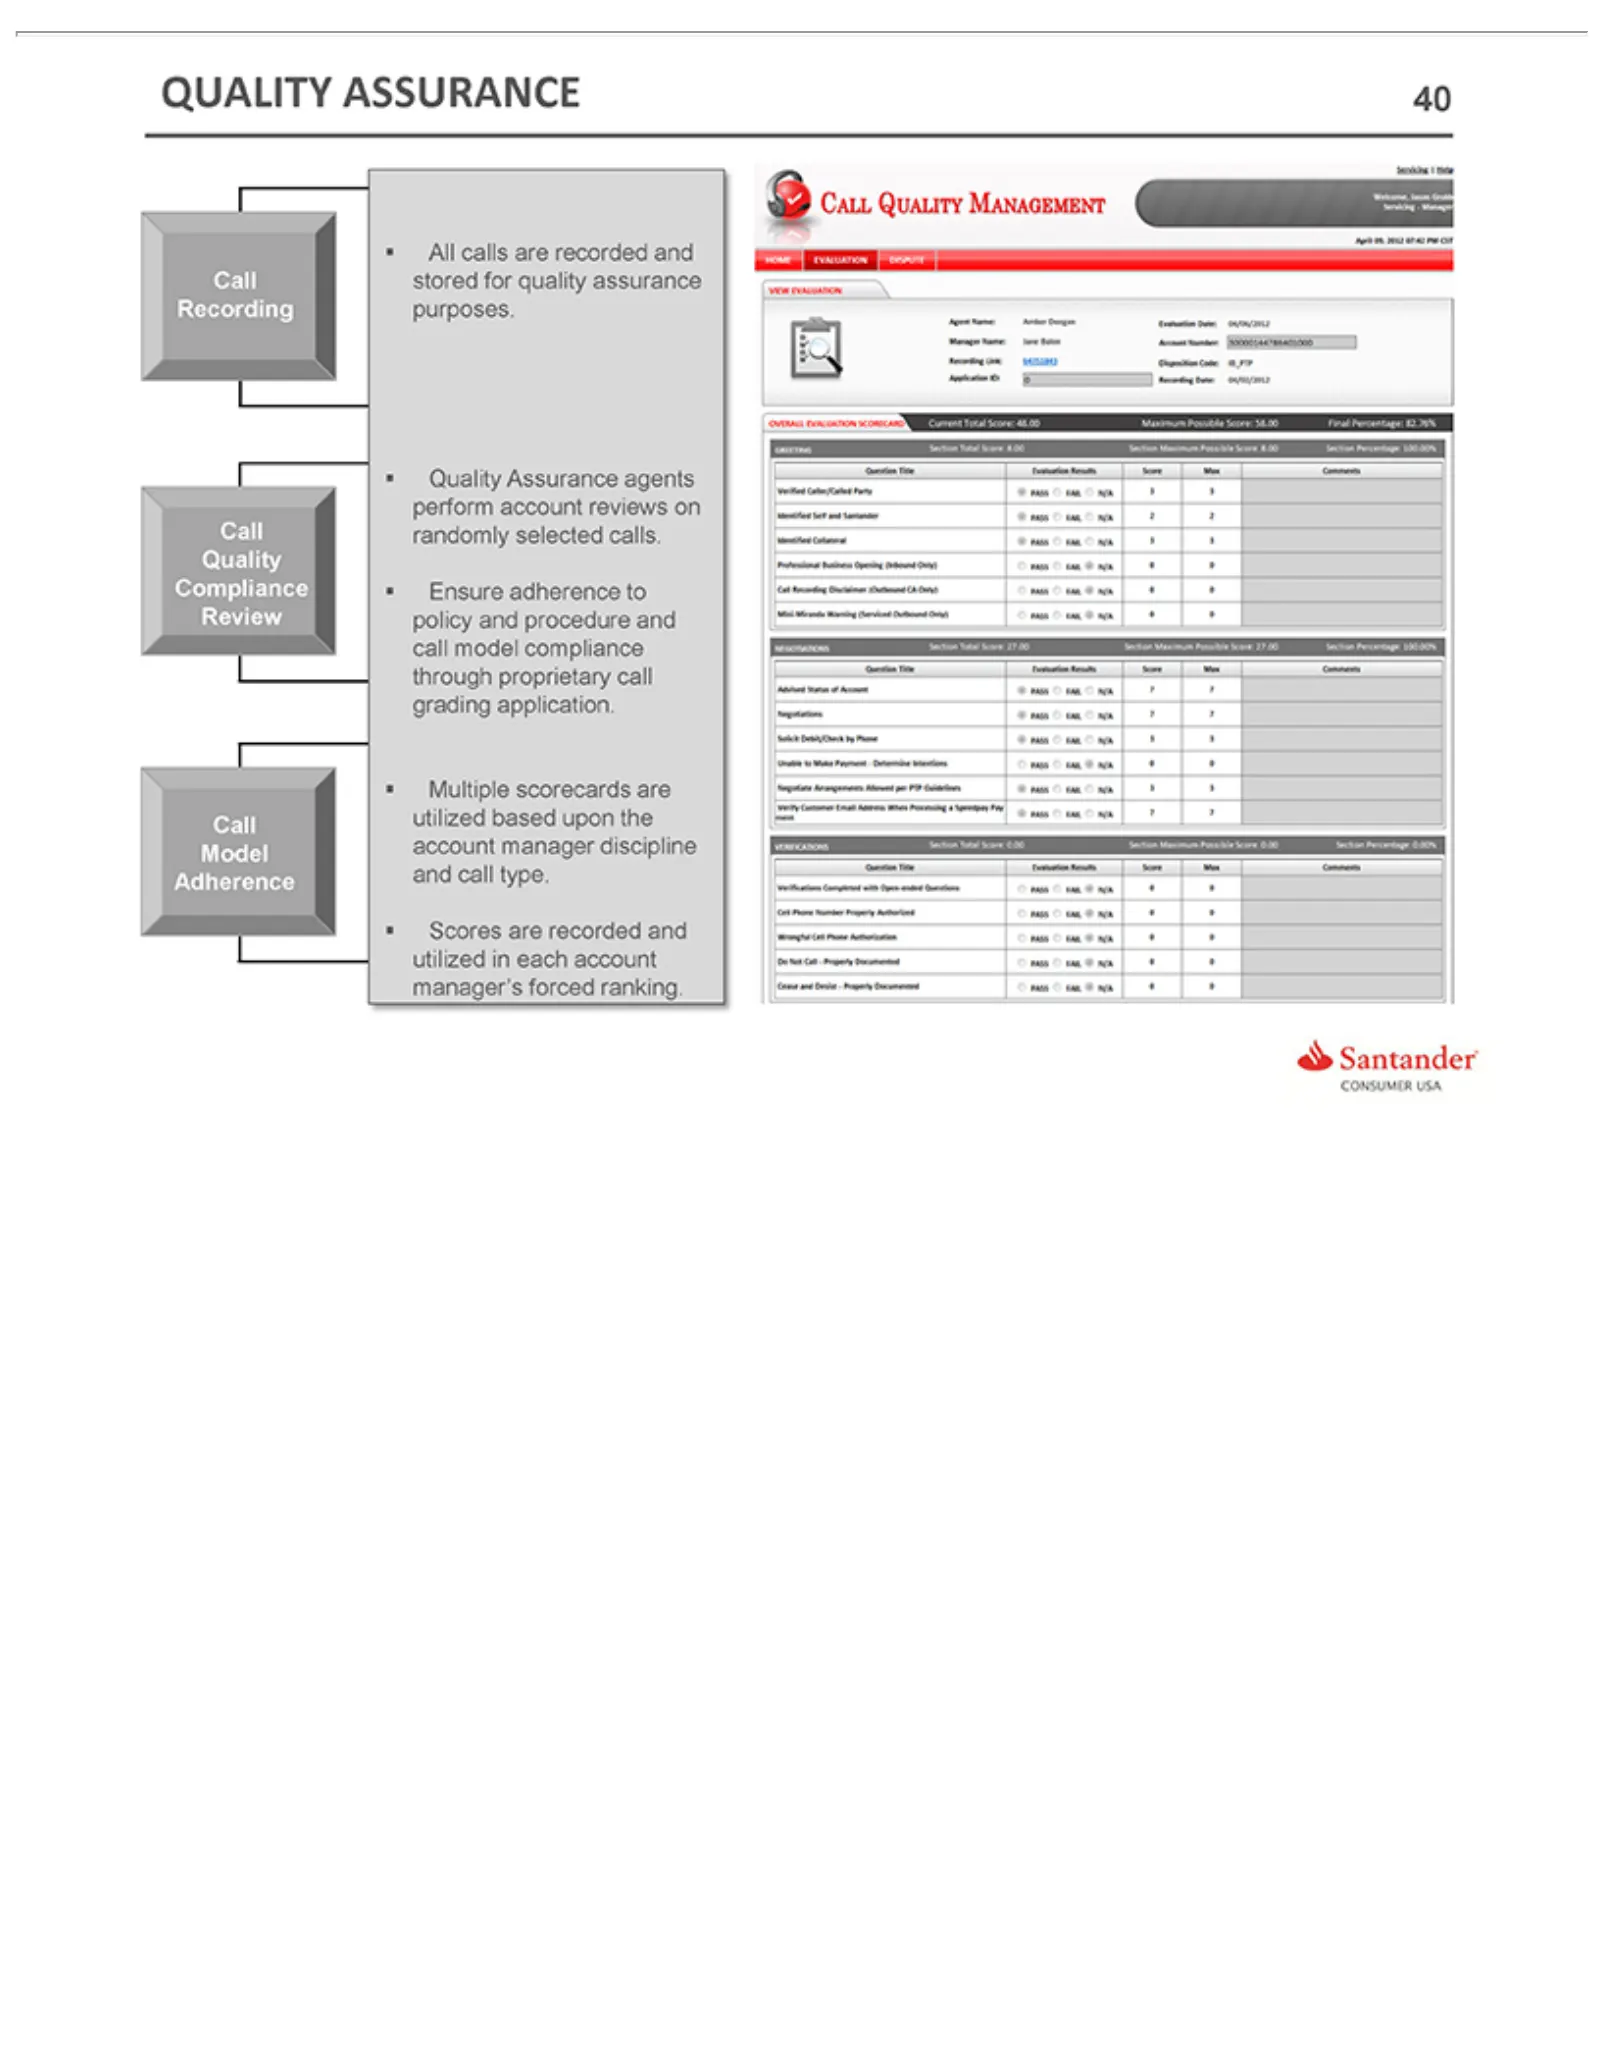
Slide 40: Quality Assurance
QUALITY Recording Compliance Quality n All Quality Multiple Scores callsare Assurance are purposes. scorecards ASSURANCE nrecorded recorded Ensureagents adherence and are and Call utilized 40 perform Call utilized stored toinReview account each based foraccount quality policy reviews upon and assura
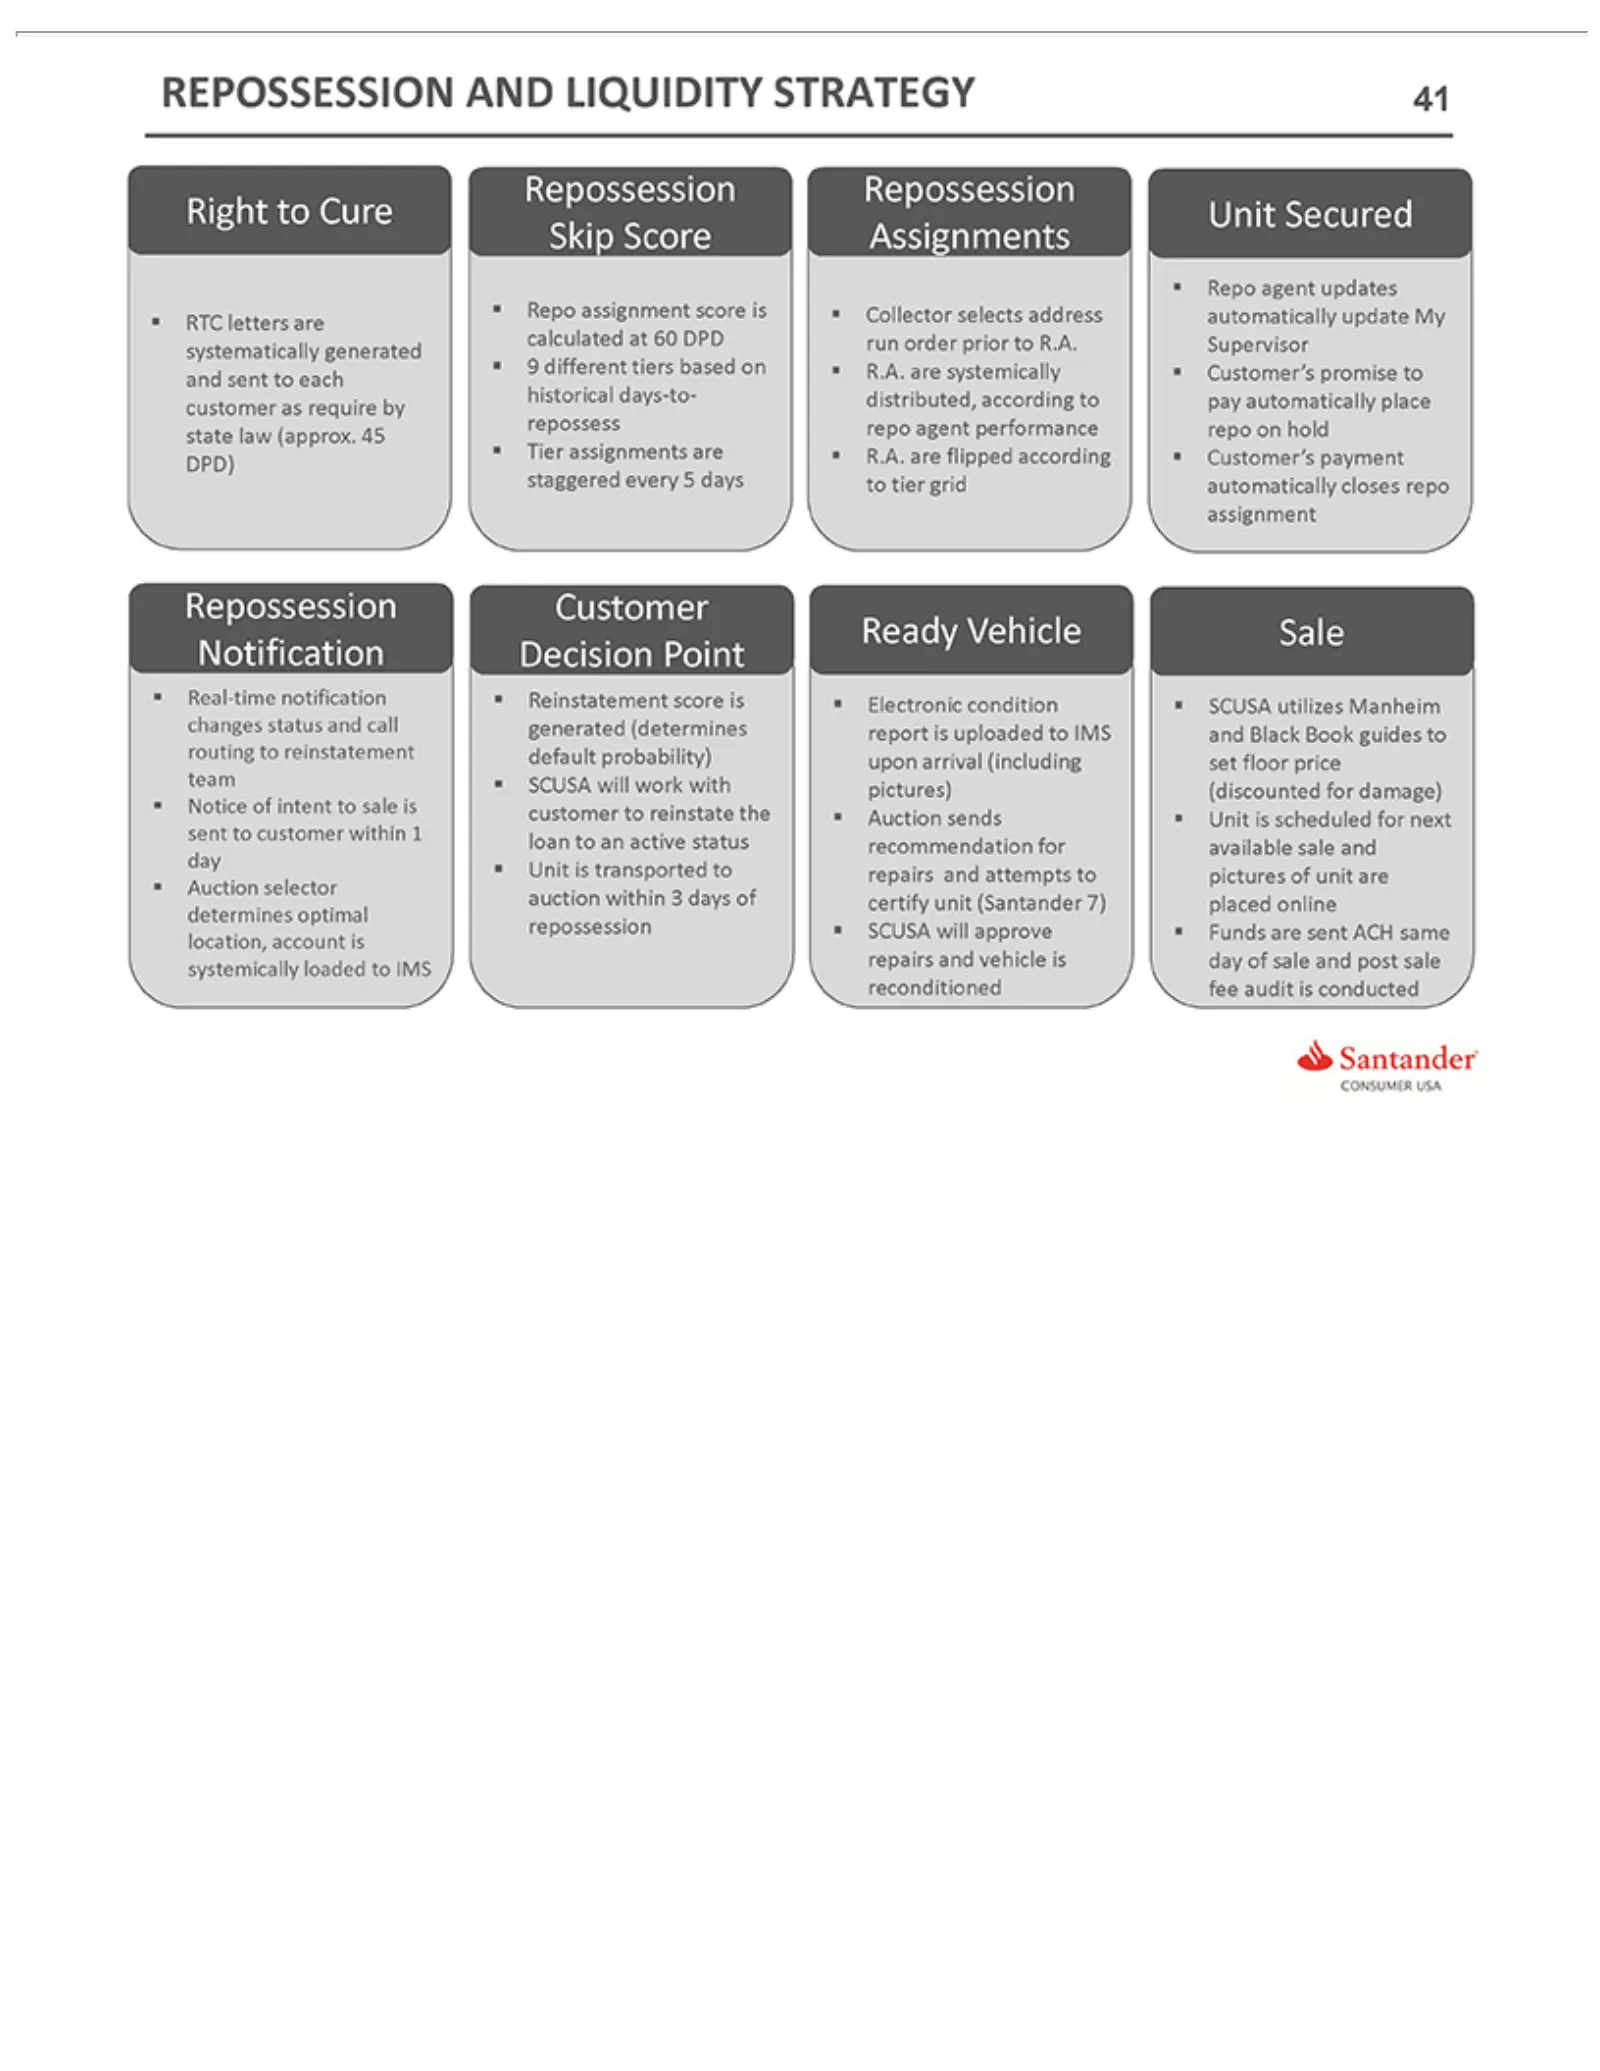
Slide 41: Repossession and Liquidation Strategy
REPOSSESSION Right Skip Repo R.A. hold Repossession Ready Notification Real-time Black Unit Auction vehicle state is Score are agent assignment to Book Vehicle transported isselector sends Cure systemically systemically law notification Assignments updates guides Decision Repossession Customer Unit
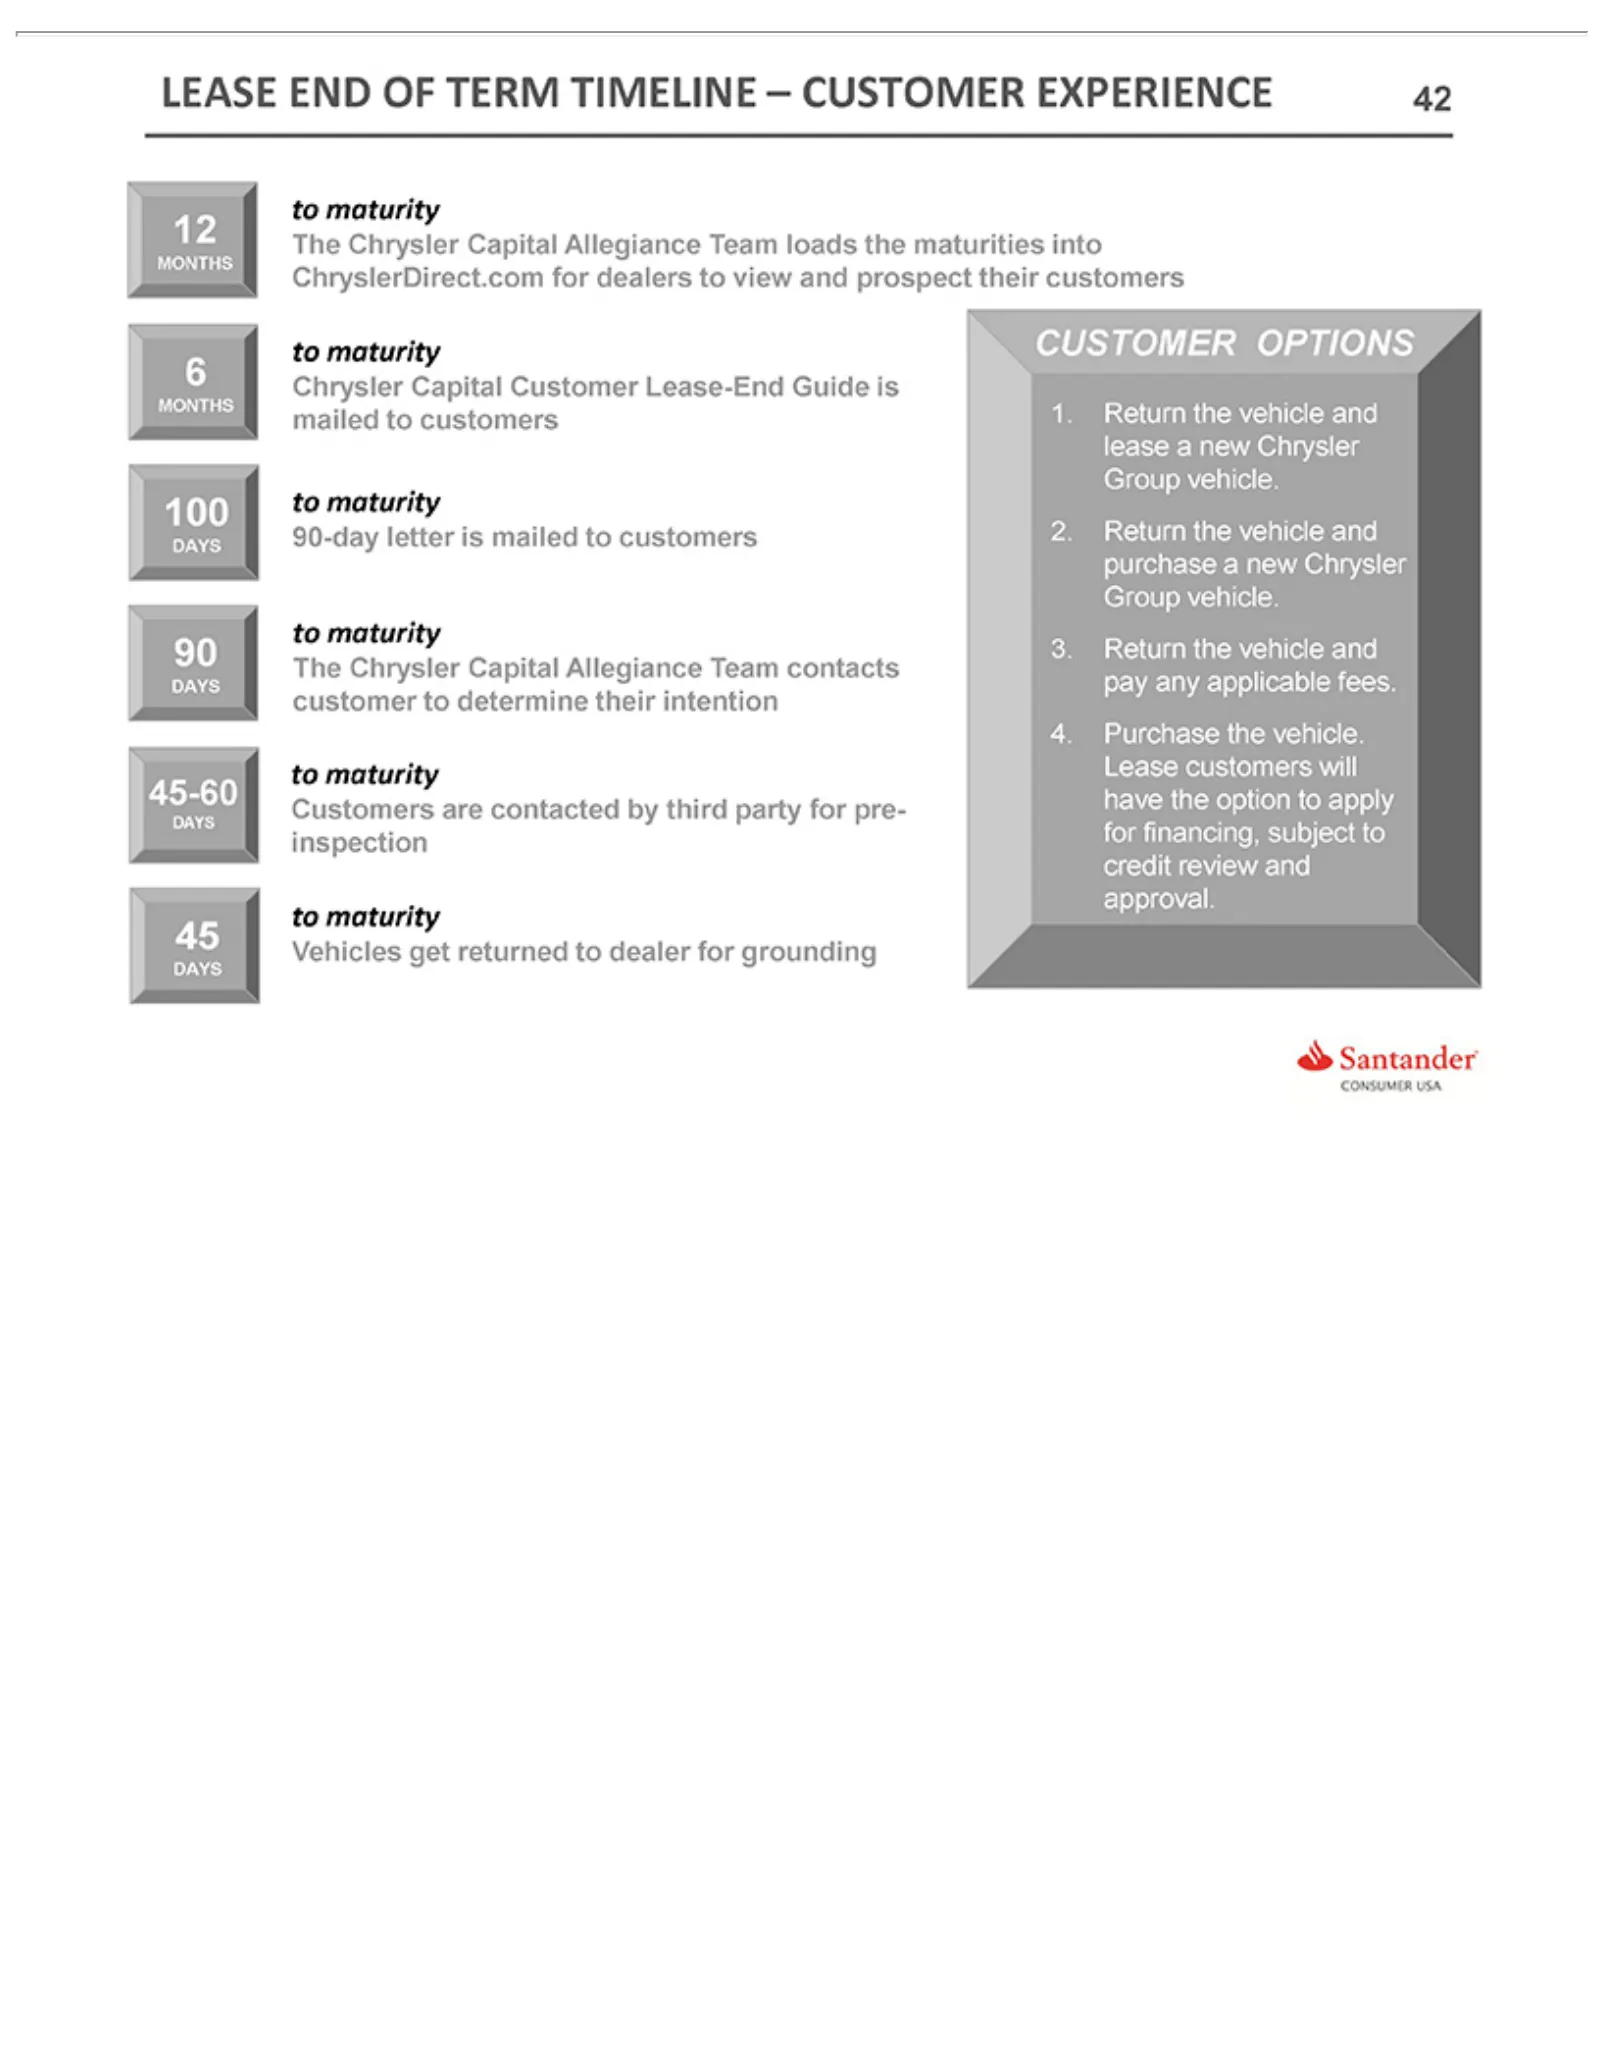
Slide 42: Lease End of Term Customer Experience
LEASE Chrysler 90-day The Customers to Vehicles M 6 MONTHS 12 CUSTOMER 45 45-60 90 DAYS 100 1. 2. 3. 4. ONTHS Return Purchase maturity Chrysler letter END get Capital the are the returned is vehicle Capital OF OPTIONS contacted mailed vehicle. Customer TERM and Allegiance totodealer Lease by TIMELIN
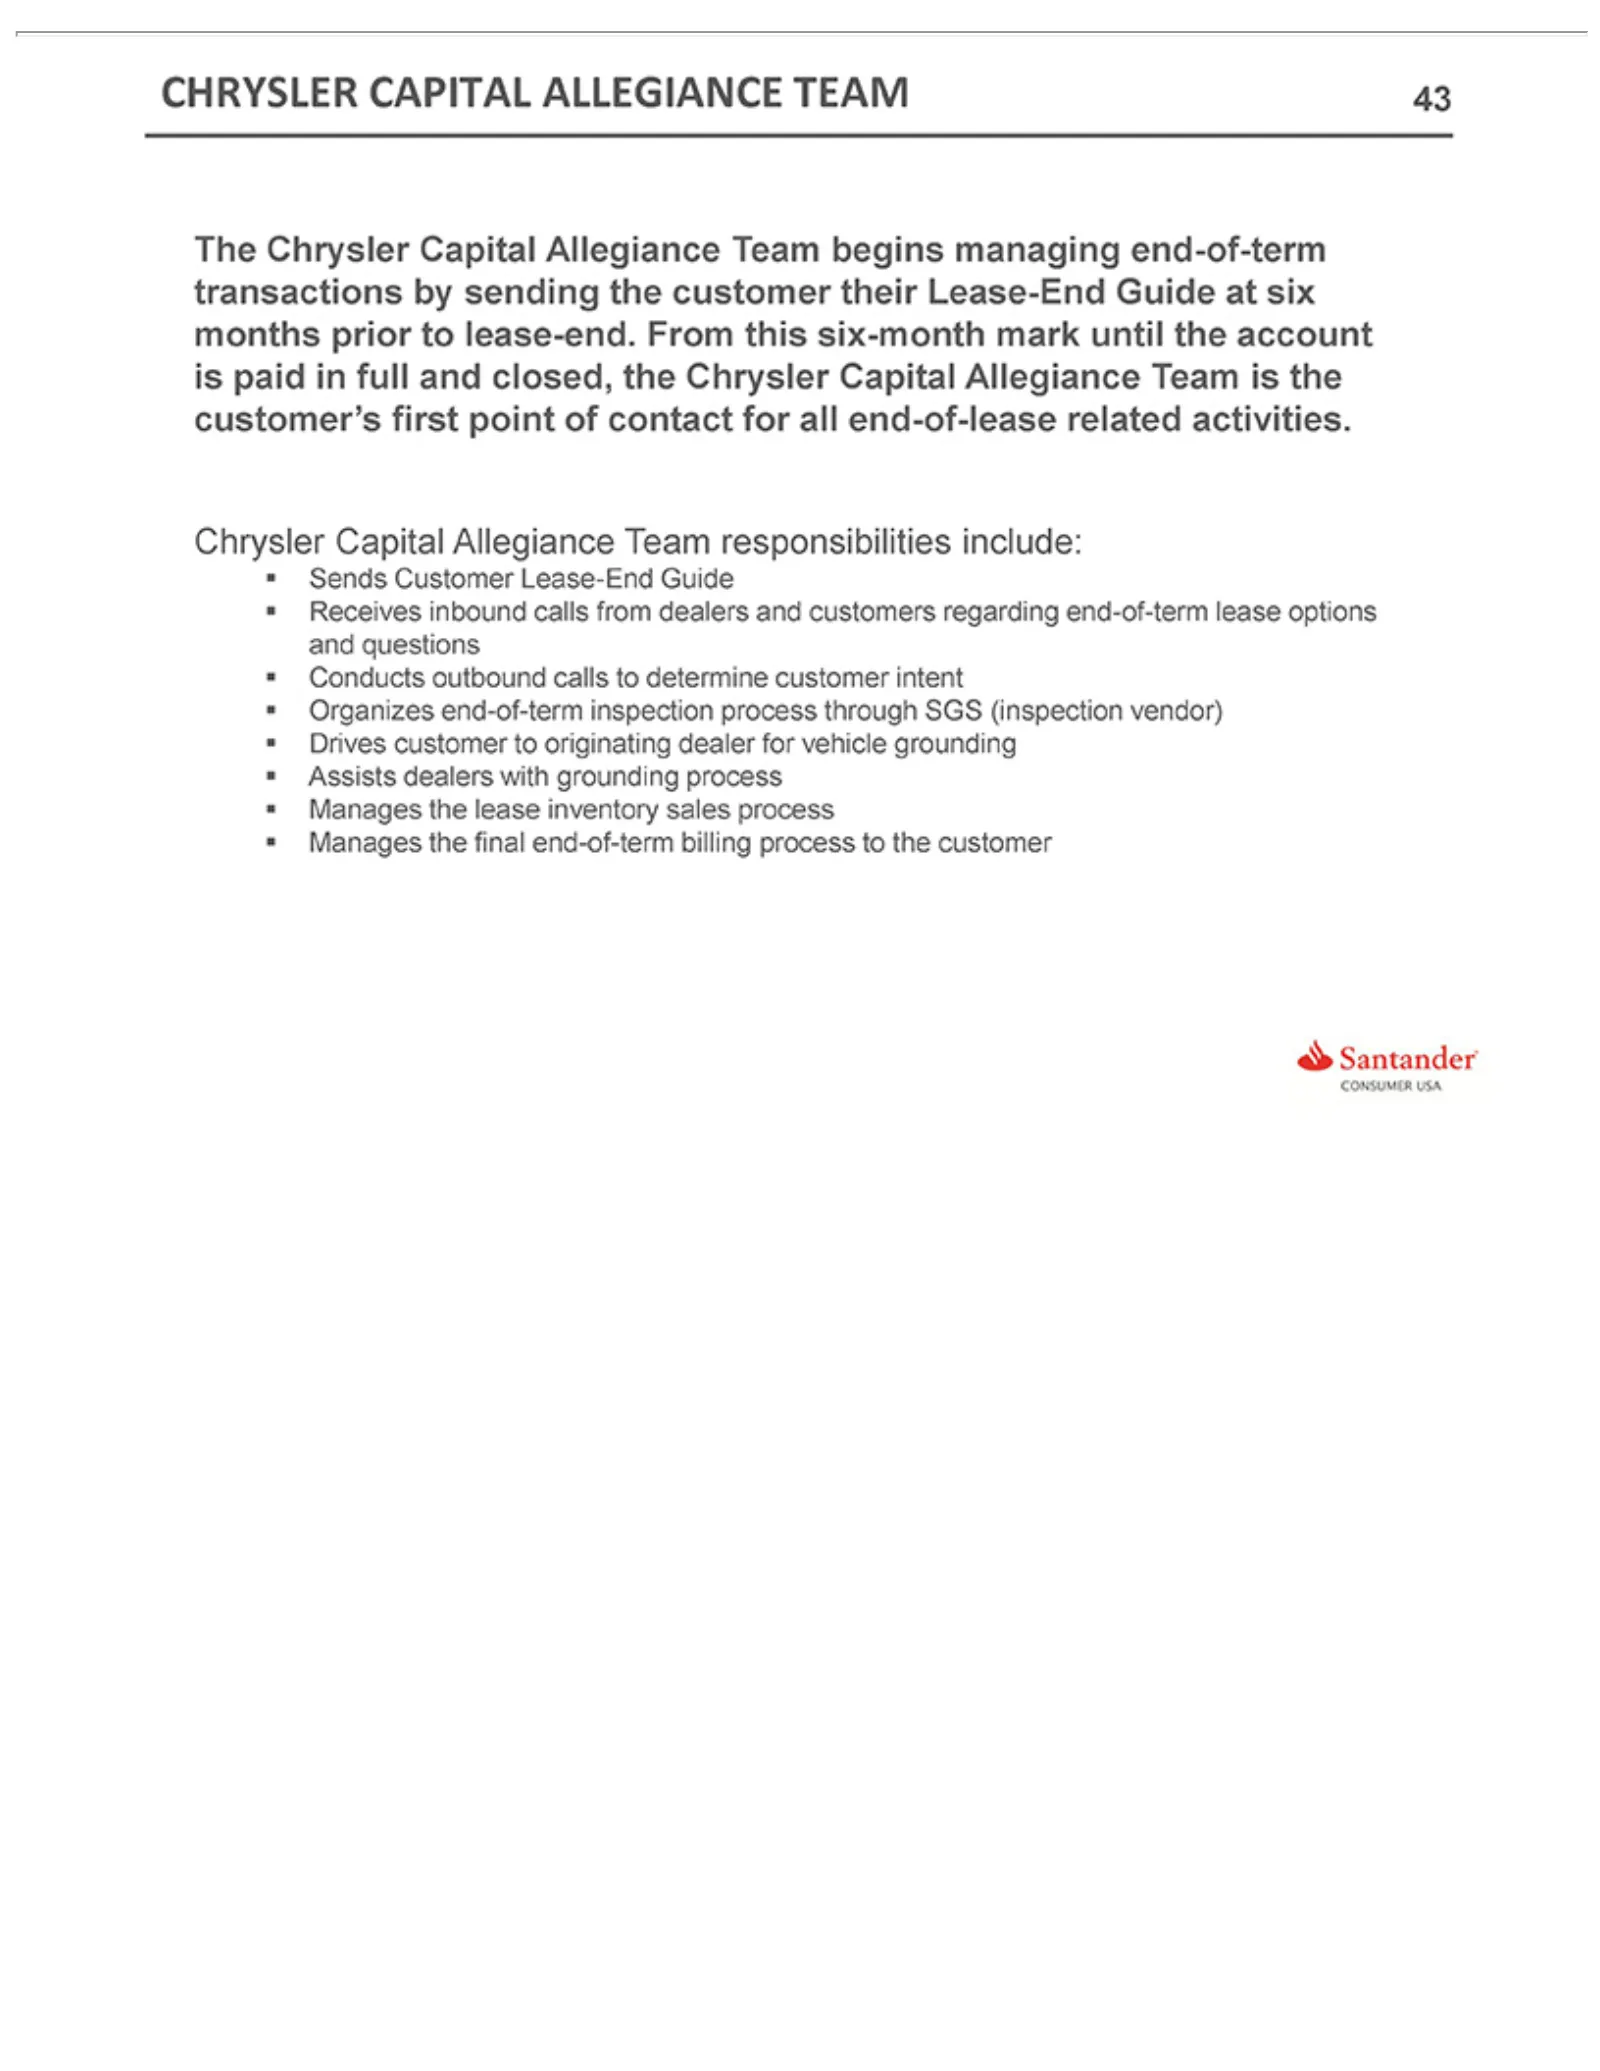
Slide 43: Chrysler Capital Allegiance Team
CHRYSLER The account Chrysler n process the Sends Receives final Chrysler through is Customer end-of-term Capital paid inbound CAPITAL Capital inSGS Allegiance full Lease-End calls billing Allegiance (inspection and ALLEGIANCE from closed, Team process Guide dealers Team vendor)n the responsibilitie
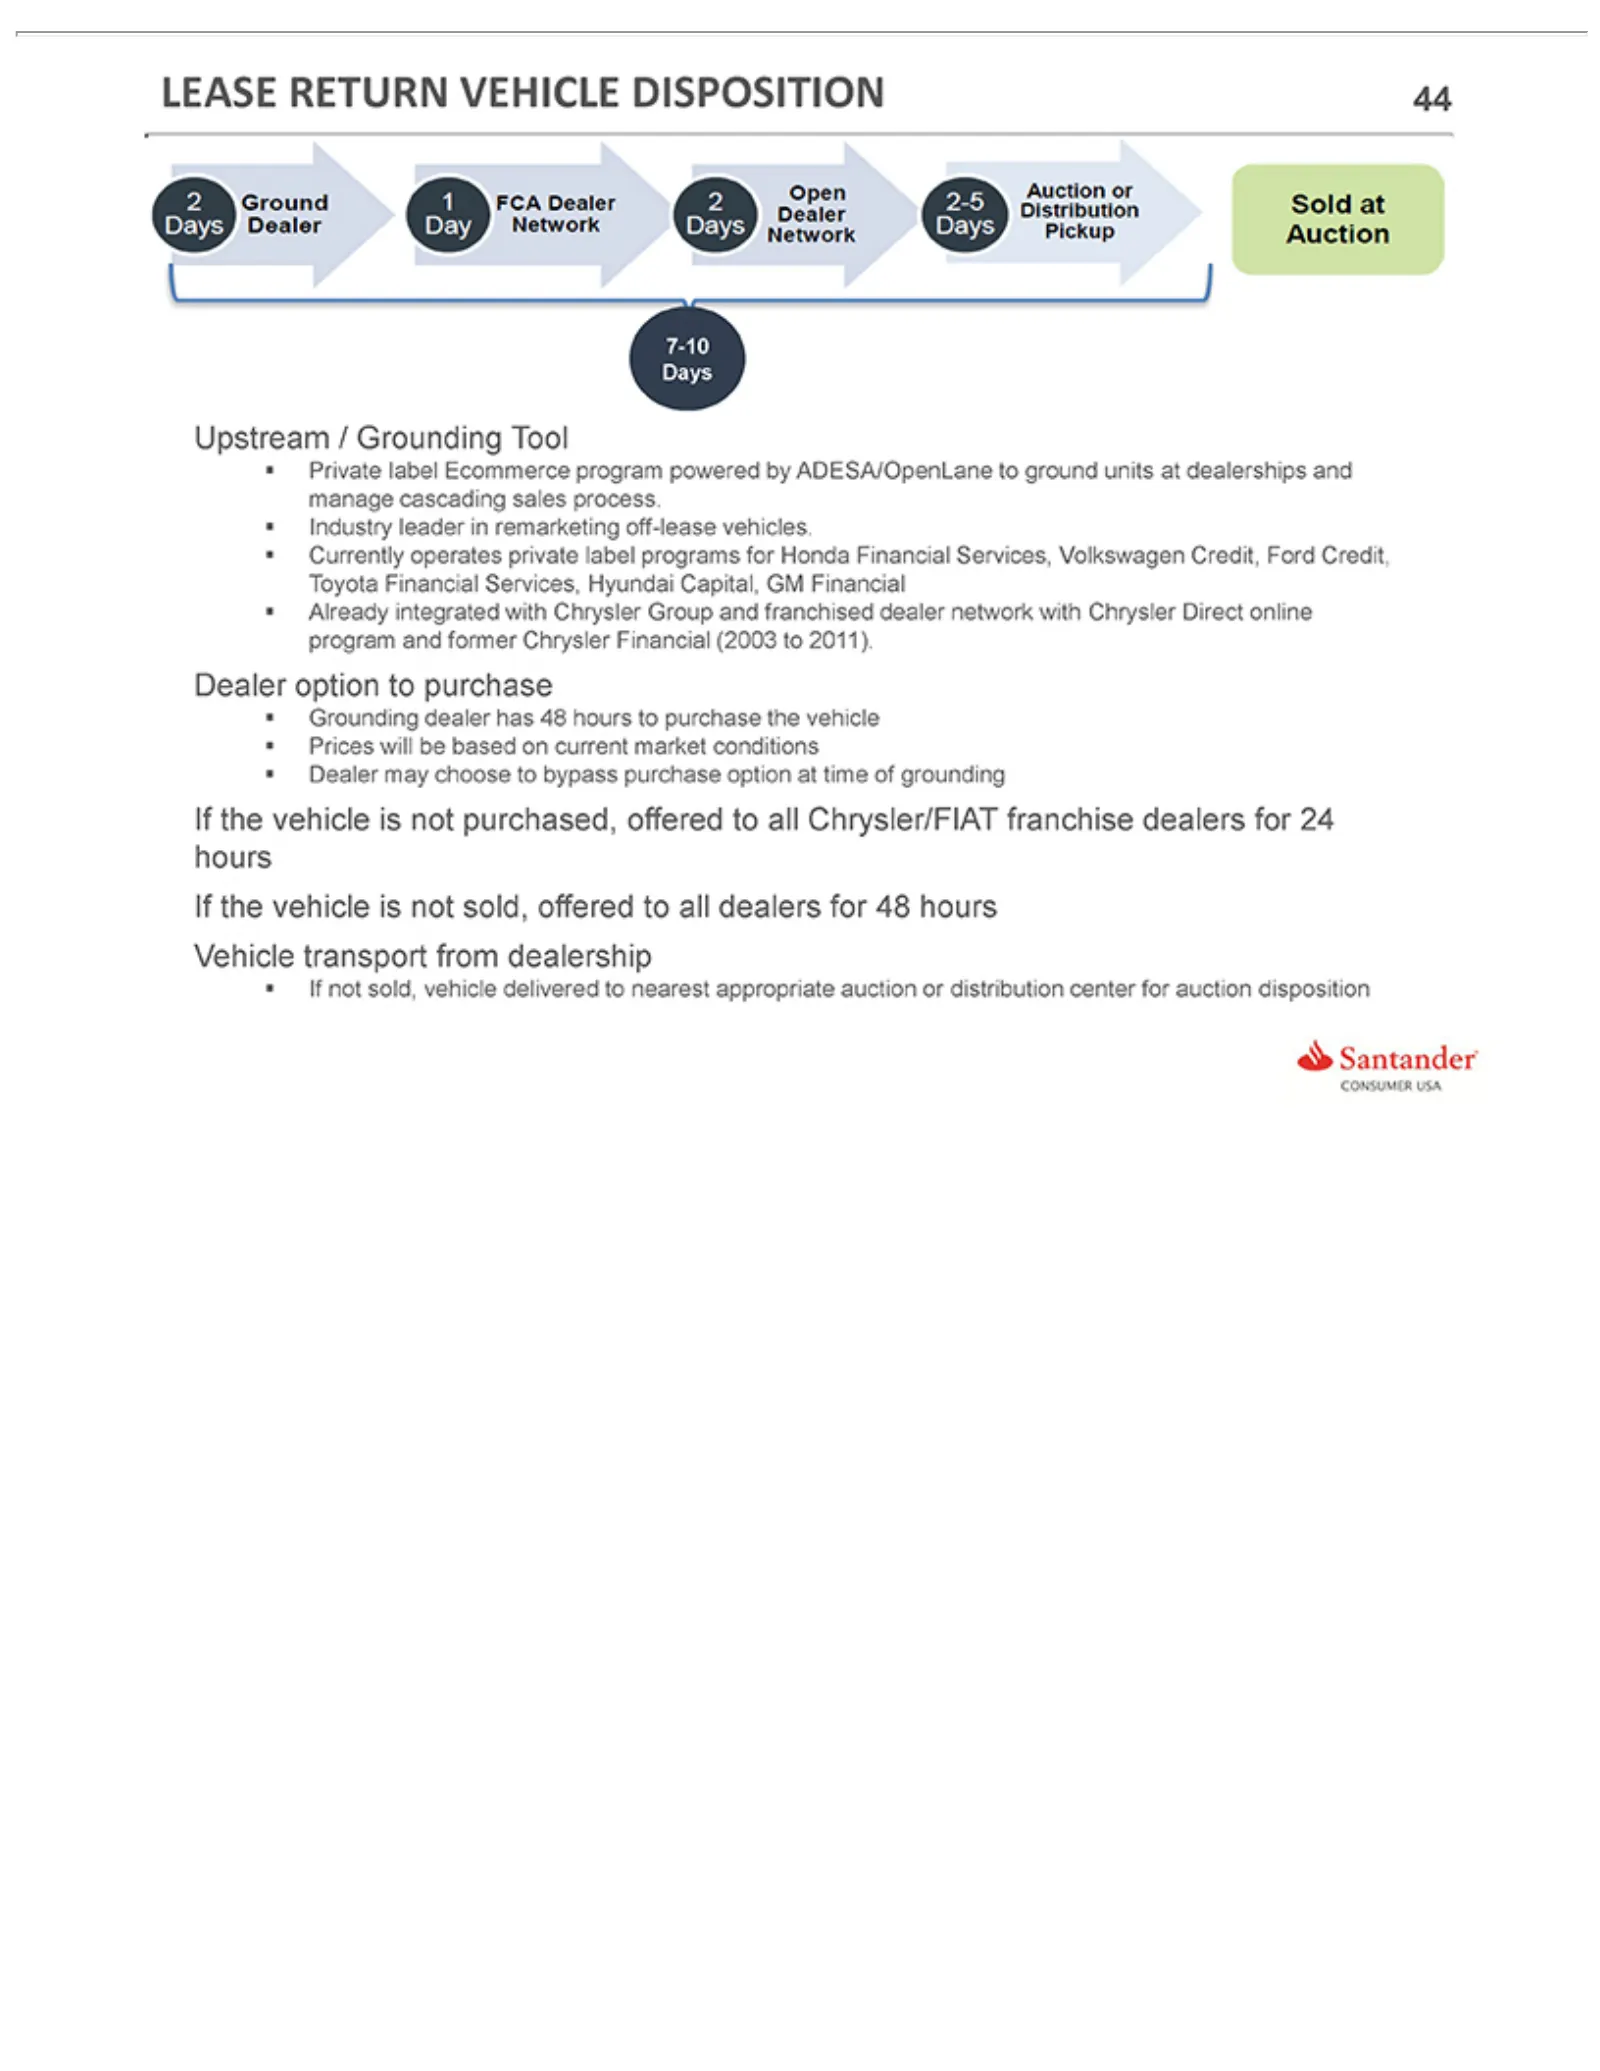
Slide 44: Lease Return Vehicle Disposition
LEASE Upstream Chrysler Dealer If n Private Industry Currently Grounding Dealer If thenot vehicle option sold, RETURN may Group label /leader Grounding operates dealer vehicle is choose toEcommerce not and purchase inVEHICLE purchased, has remarketing franchised private delivered toTool 48 bypass ho
Slide 45: Santander Consumer USA
«> Santander CONSUMER USA
Source: SEC EDGAR · 8-K filed May 13, 2015
More decks from Santander Consumer USA Holdings Inc
 Q3 2021 Earnings Presentation24 slides · Oct 27, 2021
 Q2 2021 Earnings Presentation24 slides · Jul 28, 2021
 Q1 2021 Earnings Presentation24 slides · Apr 28, 2021
 FY2020 Earnings Presentation28 slides · Feb 3, 2021
 Q3 2020 Earnings Presentation25 slides · Oct 28, 2020
 Q2 2020 Earnings Presentation26 slides · Jul 29, 2020