Cosan S.A. · BMFBOVESPA:CSAN3
Cosan — Merger or Acquisition (February 2010)
20 slides from Cosan's merger presentation, Feb 1, 2010
Slide 1: Joint Venture between Cosan and Shell
Joint Venture between Cosan and Shell February 1st, 2010
Slide 2: Disclaimer
Disclaimer Forward Looking Statements This presentation contains estimates and forward-looking statements regarding our strategy and opportunities for future growth. Such information is mainly based on our current expectations and estimates or projections of future events and trends, which affect or
Slide 3: Agenda
Agenda 1. Deal Rationale 2. Transaction Overview 3. Joint Venture 4. Next Steps 3
Slide 4: 1. Deal Rationale
1. Deal Rationale
Slide 5: Deal Rationale
Deal Rationale Association of two companies which are leaders in their respective core businesses • Cosan: world’s leading producer of sugar and sugarcane ethanol • Shell: global leading energy and petrochemical player Creation of a Joint Venture of unparalleled growth potential in sugar and biofuel
Slide 6: 2. Transaction Overview
2. Transaction Overview
Slide 7: Transaction Overview
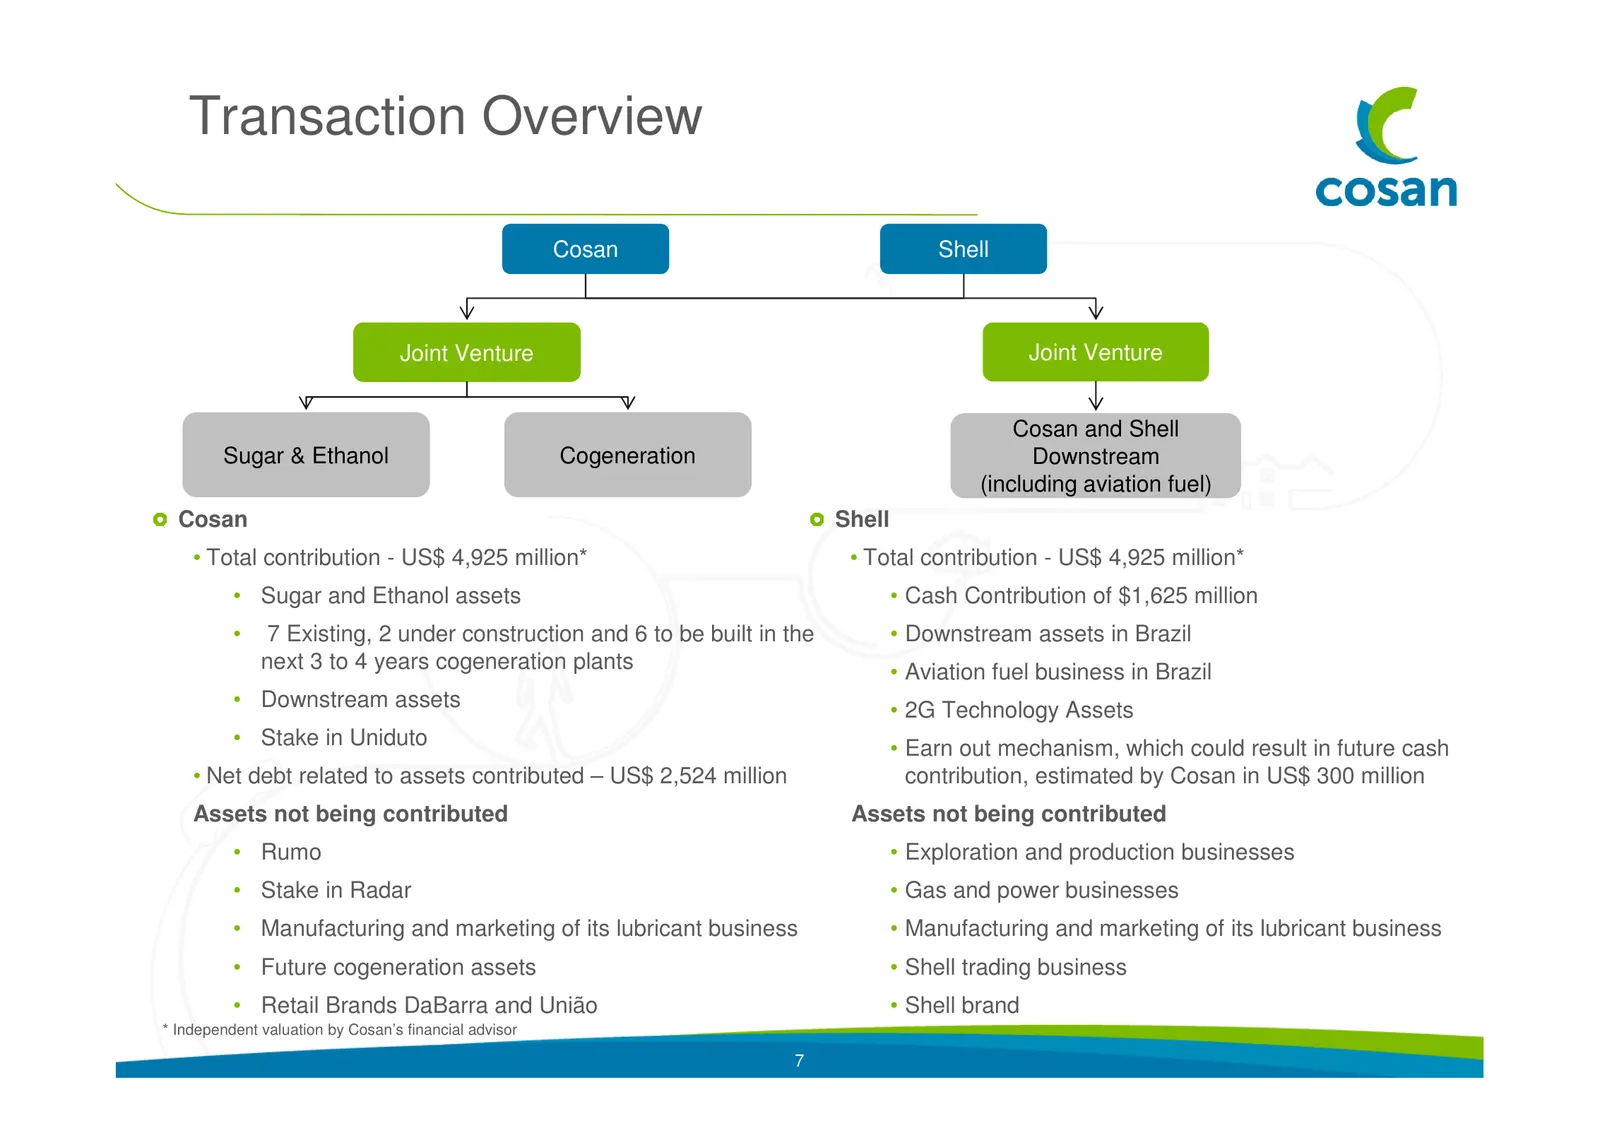
Transaction Overview Cosan Shell Joint Venture Joint Venture Cosan and Shell Sugar & Ethanol Cogeneration Downstream (including aviation fuel) Cosan Shell • Total contribution - US$ 4,925 million* • Total contribution - US$ 4,925 million* • Sugar and Ethanol assets • Cash Contribution of $1,625 mill
Slide 8: Scope of the Joint Venture
Scope of the Joint Venture Production and sale of sugarcane ethanol and ethanol-based products in Brazil Continuing development of ethanol’s first-generation technology in Brazil, and second-generation technology through international partnerships Production and sale of electricity, steam and other
Slide 9: 3. Joint Venture
3. Joint Venture
Slide 10: Leading global market position in S&E
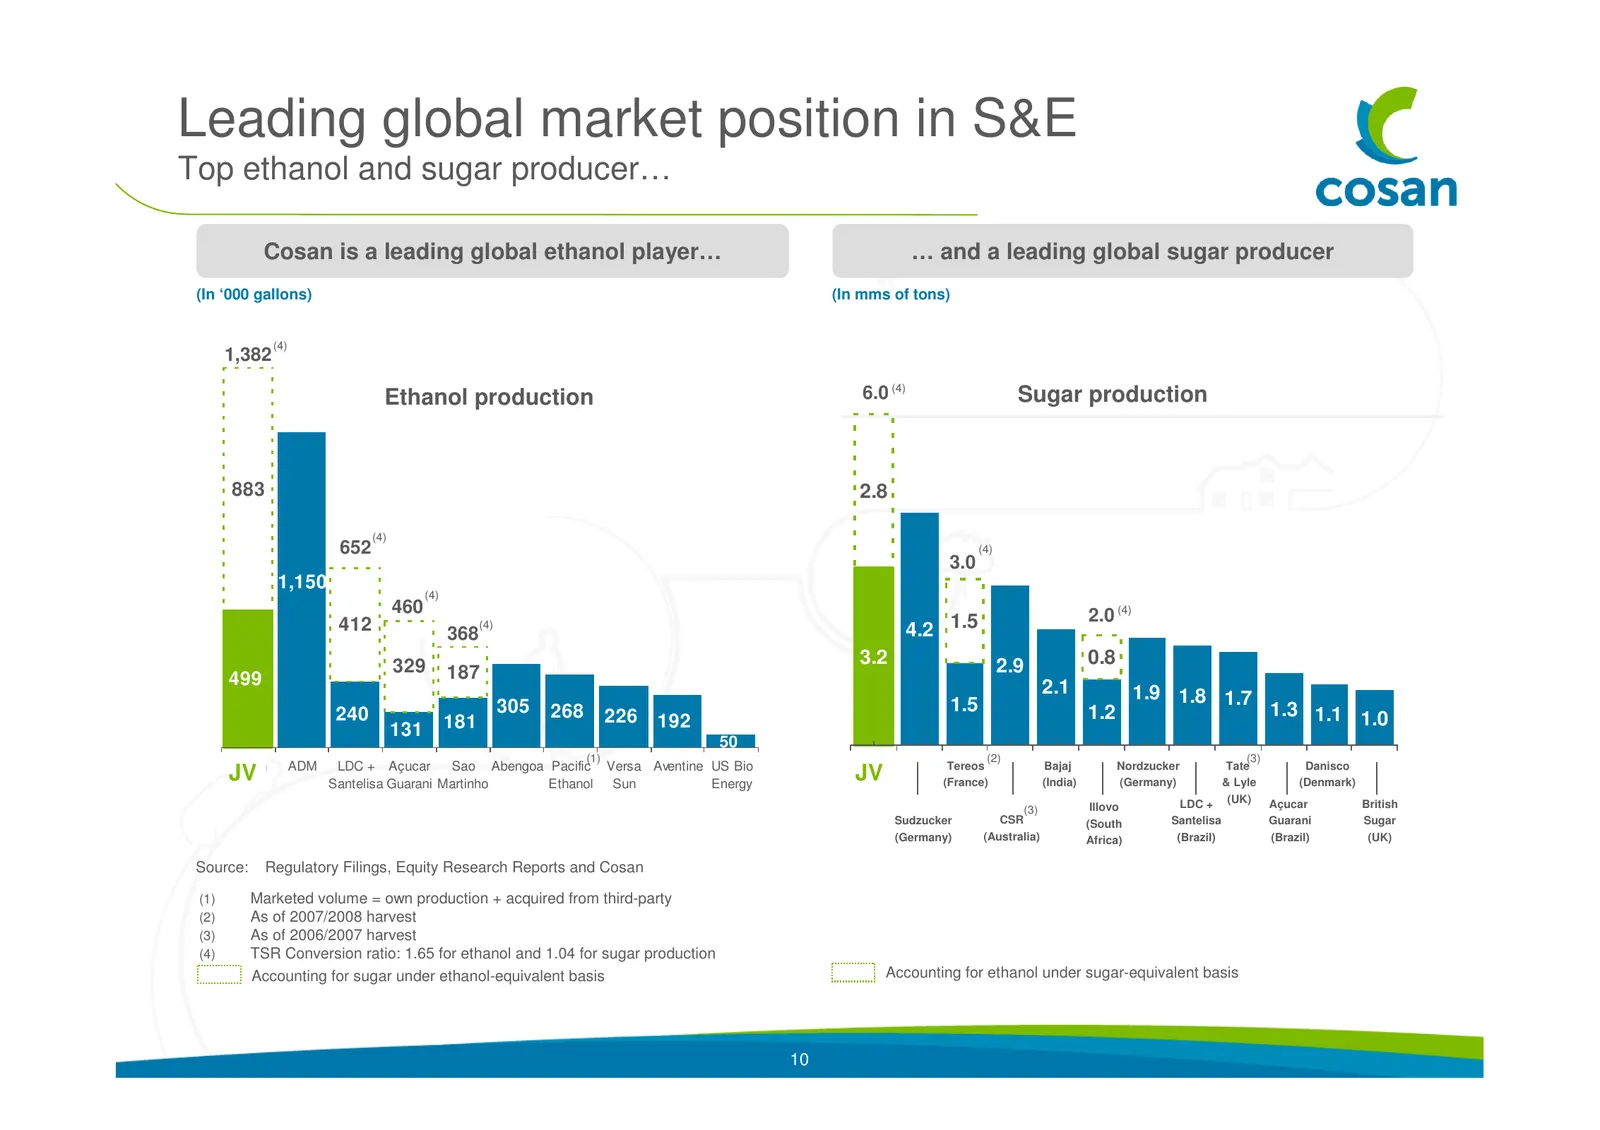
Leading global market position in S&E Top ethanol and sugar producer… Cosan is a leading global ethanol player… … and a leading global sugar producer (In ‘000 gallons) (In mms of tons) (4) 1,382 Ethanol production 6.0 (4) Sugar production 883 2.8 (4) 652 (4) 3.0 1,150 (4) 460 2.0 (4) 412 368 (4) 4.2
Slide 11: Leading global market position in S&E
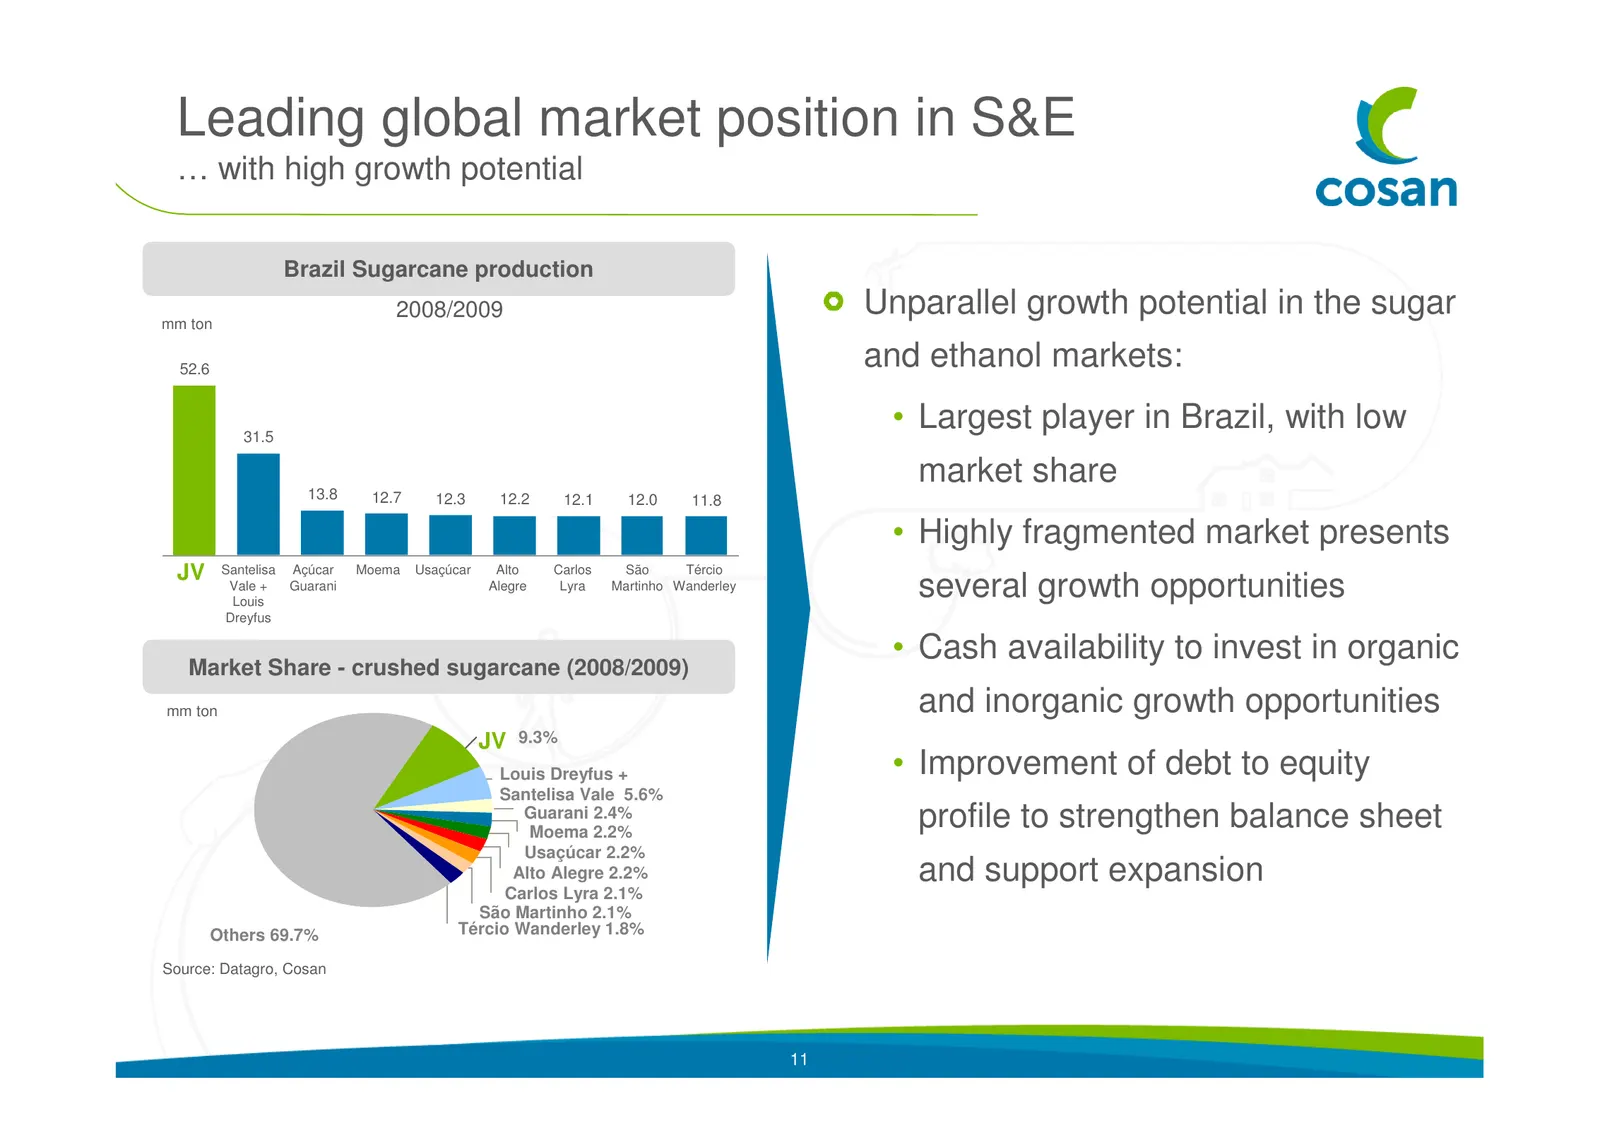
Leading global market position in S&E … with high growth potential Brazil Sugarcane production mm ton 2008/2009 Unparallel growth potential in the sugar 52.6 and ethanol markets: 31.5 • Largest player in Brazil, with low market share 13.8 12.7 12.3 12.2 12.1 12.0 11.8 • Highly fragmented market pres
Slide 12: Creation of a major fuels distributor in Brazil
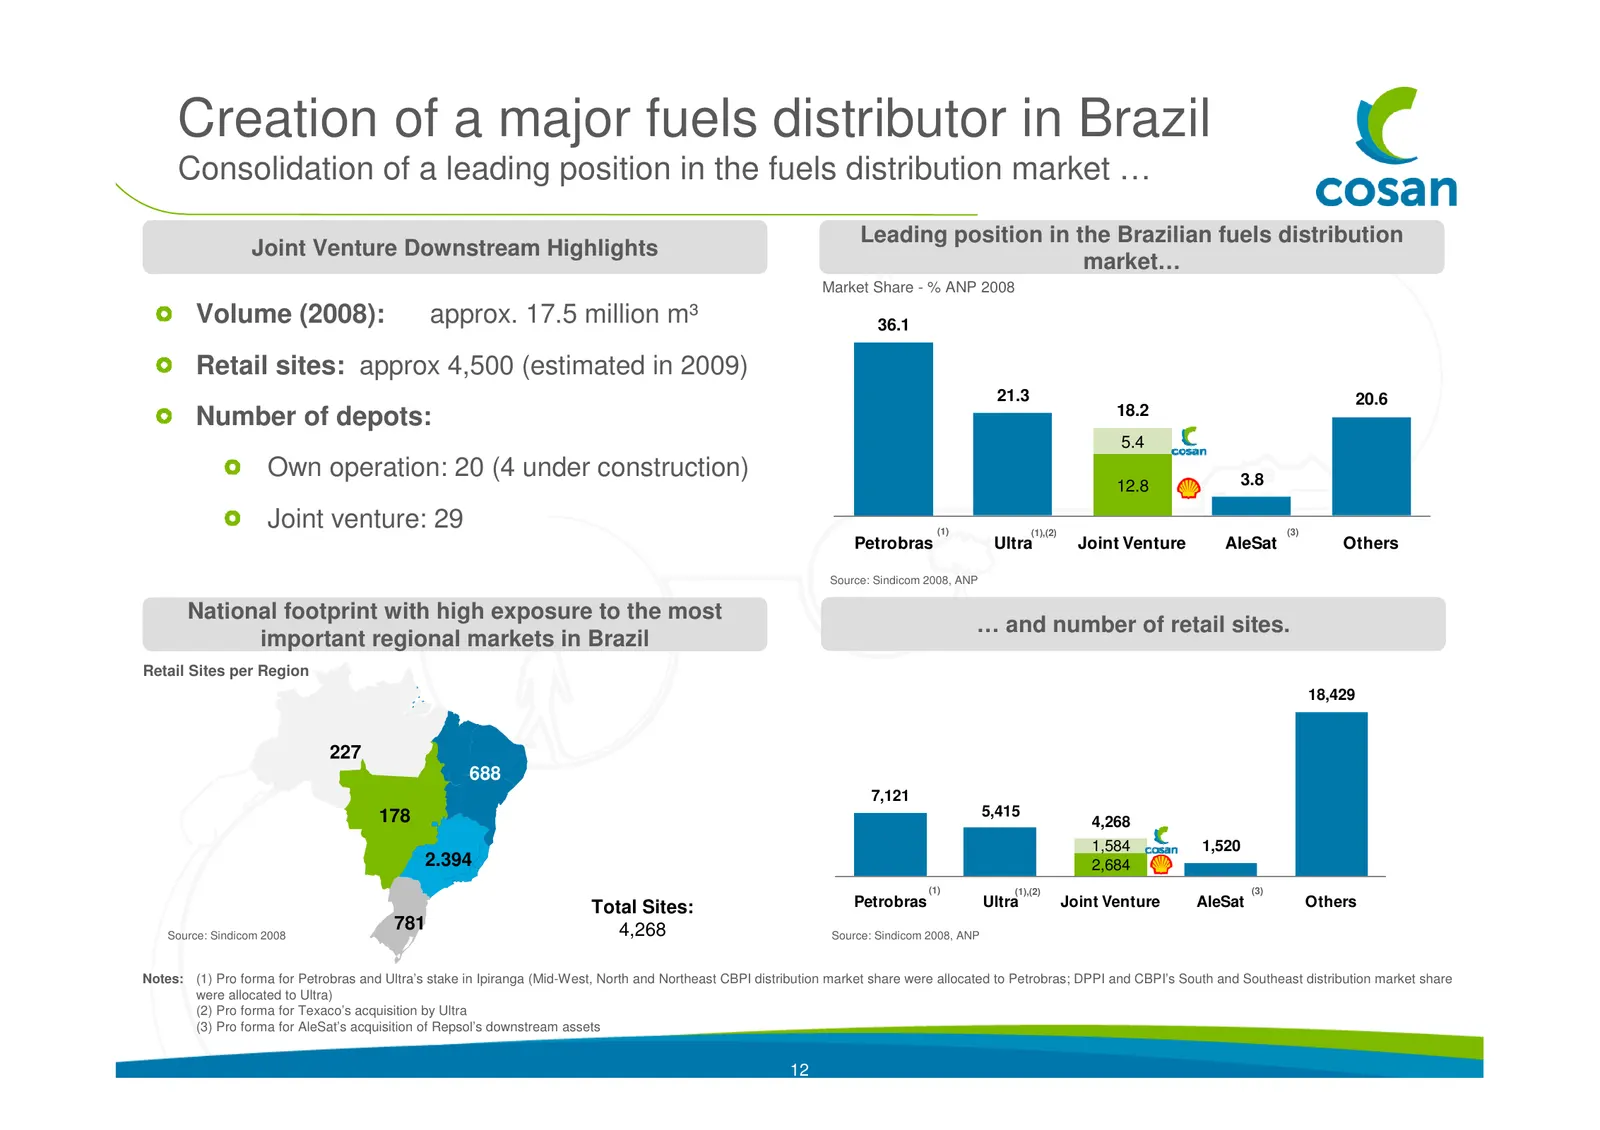
Creation of a major fuels distributor in Brazil Consolidation of a leading position in the fuels distribution market … Leading position in the Brazilian fuels distribution Joint Venture Downstream Highlights market… Market Share - % ANP 2008 Volume (2008): approx. 17.5 million m³ 36.1 Retail sites:
Slide 13: Creation of a major fuels distributor in Brazil
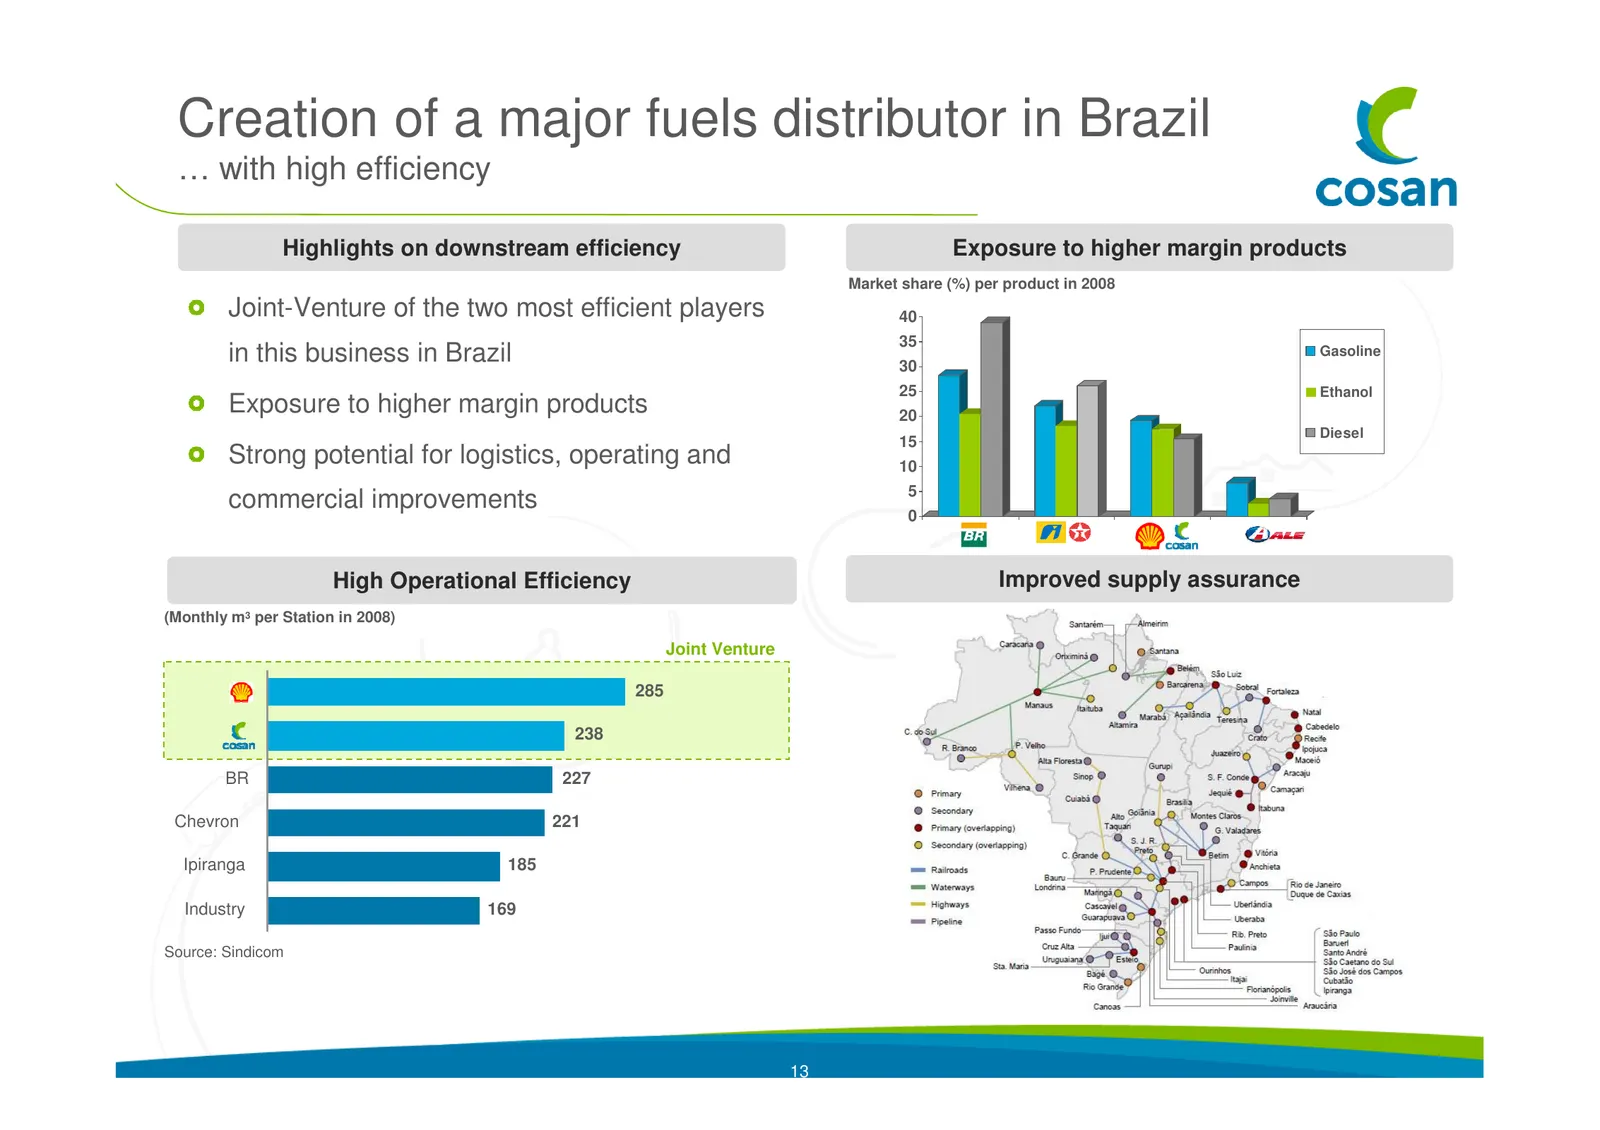
Creation of a major fuels distributor in Brazil … with high efficiency Highlights on downstream efficiency Exposure to higher margin products Market share (%) per product in 2008 Joint-Venture of the two most efficient players 40 35 in this business in Brazil 30 Gasoline 25 Ethanol Exposure to highe
Slide 14: Access to state of the art technology
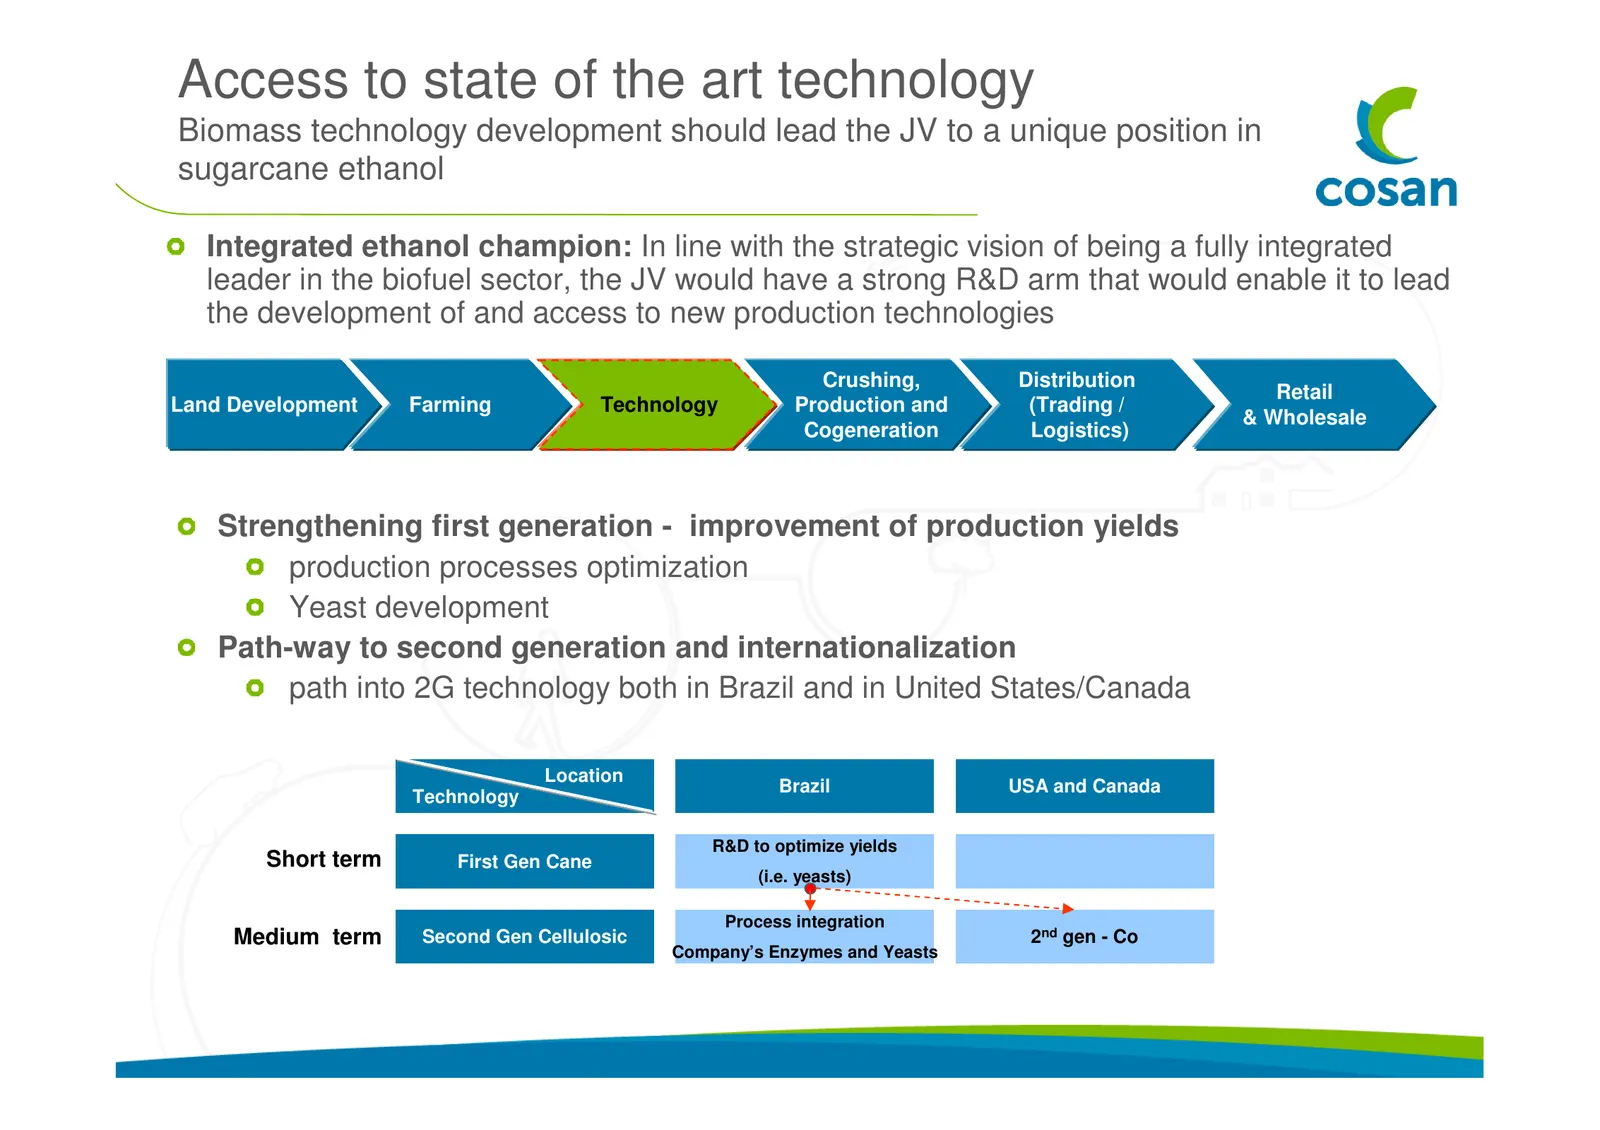
Access to state of the art technology Biomass technology development should lead the JV to a unique position in sugarcane ethanol Integrated ethanol champion: In line with the strategic vision of being a fully integrated leader in the biofuel sector, the JV would have a strong R&D arm that would ena
Slide 15: Shared values and strong commitment to sustainable development
Shared values and strong commitment to sustainable development Integration of economic, environmental and social considerations into the decision- making process Economic • Commitment to long-term profitability Environment • CO2 reduction commitment - Brazilian ethanol produced from sugarcane reduce
Slide 16: Strong synergy potential
Strong synergy potential Substantial value creation through synergies Benefits arising from the potential association of Cosan and Shell: • Increased competitiveness in the biofuels and fuels distribution businesses • Broader access to ethanol consumer markets • Substantial growth perspectives • Bui
Slide 17: 4. Next Steps
4. Next Steps
Slide 18: Next Steps
Next Steps Cosan and Shell have signed a non-binding MoU for a mutual exclusivity period of 180 days to conclude negotiations towards a JV Agreement Both parties to perform due-diligence Finalize deal structure, negotiate and sign JV Agreement 18
Slide 19: Remarks
Remarks Mark Williams, Royal Dutch Shell’s Downstream Director, said: “Today’s announcement demonstrates the continued importance of Brazil to Shell. We're looking forward to joining with a leading company in Brazil to meet the needs of retail and commercial fuels customers in that growing market. “
Slide 20: Contacts
Contacts Marcelo Martins CFO and IR Officer Luiz Felipe Jansen IR Manager ri@cosan.com.br 20
Source: Internet Archive copy of cosan.com.br
More decks from Cosan S.A.
 Q2 2026 Earnings Presentation8 slides · Aug 17, 2026
 Q1 2026 Earnings Presentation8 slides · May 15, 2026
 Q4 2025 Earnings Presentation9 slides · Mar 10, 2026
 Q3 2025 Earnings Presentation8 slides · Nov 17, 2025
 IPO Roadshow (October 2025)13 slides · October 2025
 Q1 2025 Earnings Presentation18 slides · May 16, 2025