Talisman Mining Limited · ASX:TLM
Talisman Mining — Investor Presentation (April 2017)
36 slides from Talisman Mining's investor presentation, April 2017
Slide 1: Monty: A High-Grade Development with Outstanding Returns
Focused Australian mineral resources company Monty: A High-Grade Development with Outstanding Returns Monty Project (Springfield Joint Venture) Feasibility Study Results, April 2017 Focused Australian mineral resources company 1
Slide 2: Disclaimer
Disclaimer This presentation has been prepared by Talisman Mining Limited. This document contains background information about Talisman Mining Ltd current at the date of this presentation. The presentation is in summary form, has not been independently verified and does not purport be all inclusive
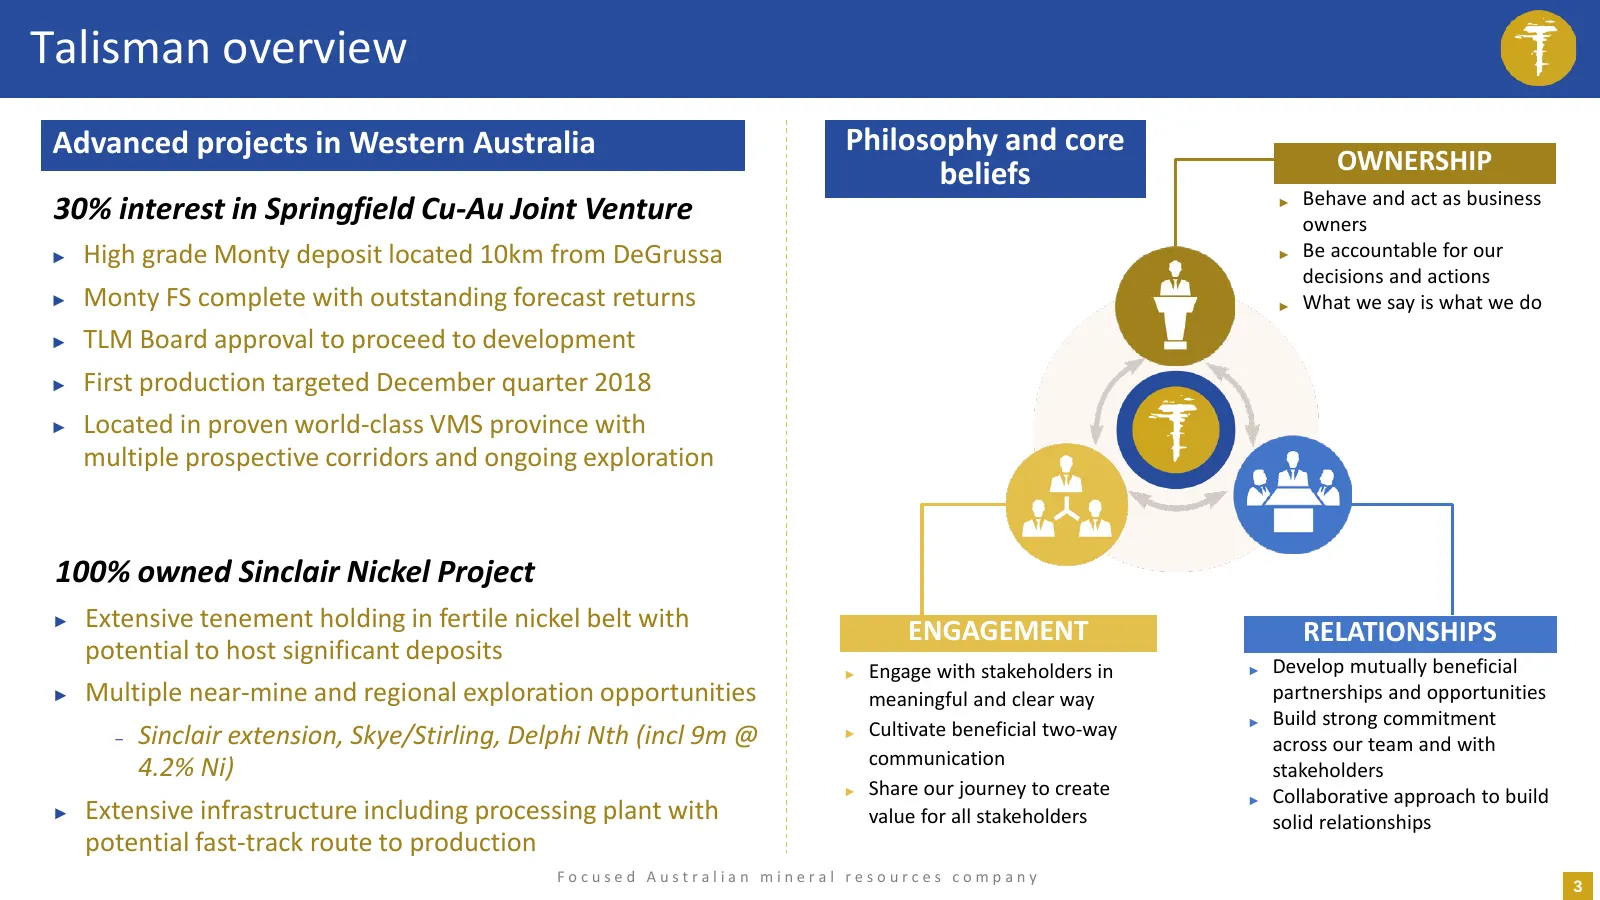
Slide 3: Talisman overview
Talisman overview Advanced projects in Western Australia Philosophy and core beliefs OWNERSHIP Behave and act as business 30% interest in Springfield Cu-Au Joint Venture ► owners ► High grade Monty deposit located 10km from DeGrussa ► Be accountable for our decisions and actions ► Monty FS complete
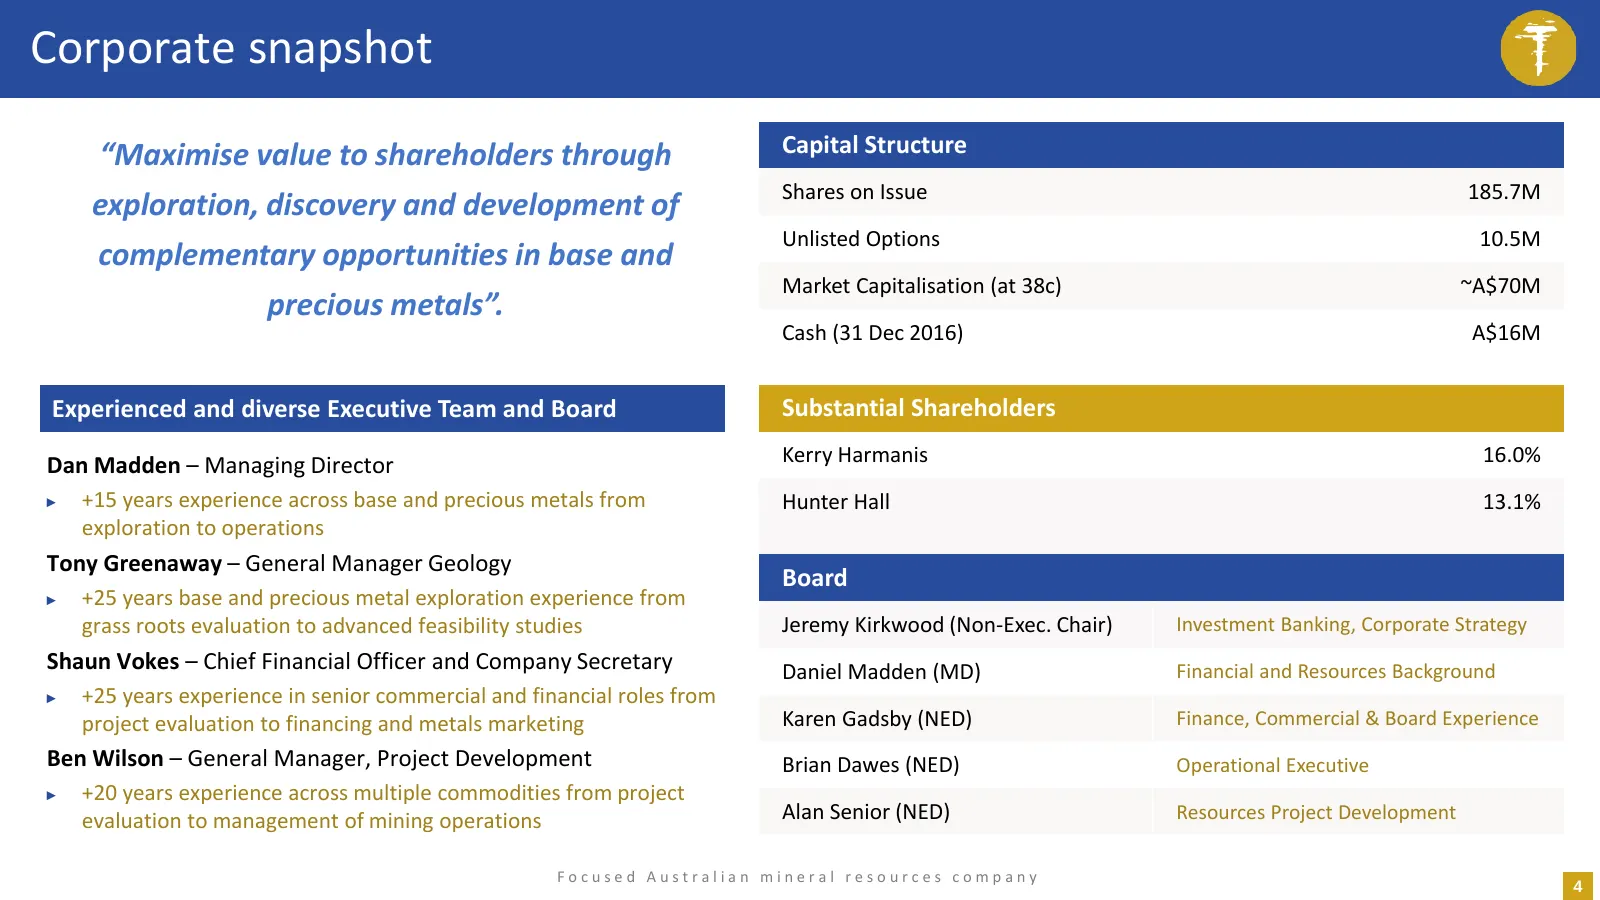
Slide 4: Corporate snapshot
Corporate snapshot “Maximise value to shareholders through Capital Structure Shares on Issue 185.7M exploration, discovery and development of Unlisted Options 10.5M complementary opportunities in base and Market Capitalisation (at 38c) ~A$70M precious metals”. Cash (31 Dec 2016) A$16M Experienced an
Slide 5: Springfield JV (30% Talisman)
Springfield JV (30% Talisman) Home to the Monty deposit and a proven world-class VMS province F o c u s e d A u s t r a l Ii a n m i n e r a l r e s o u r c e s c o m p a n y 5
Slide 6: Springfield Cu-Au Joint Venture
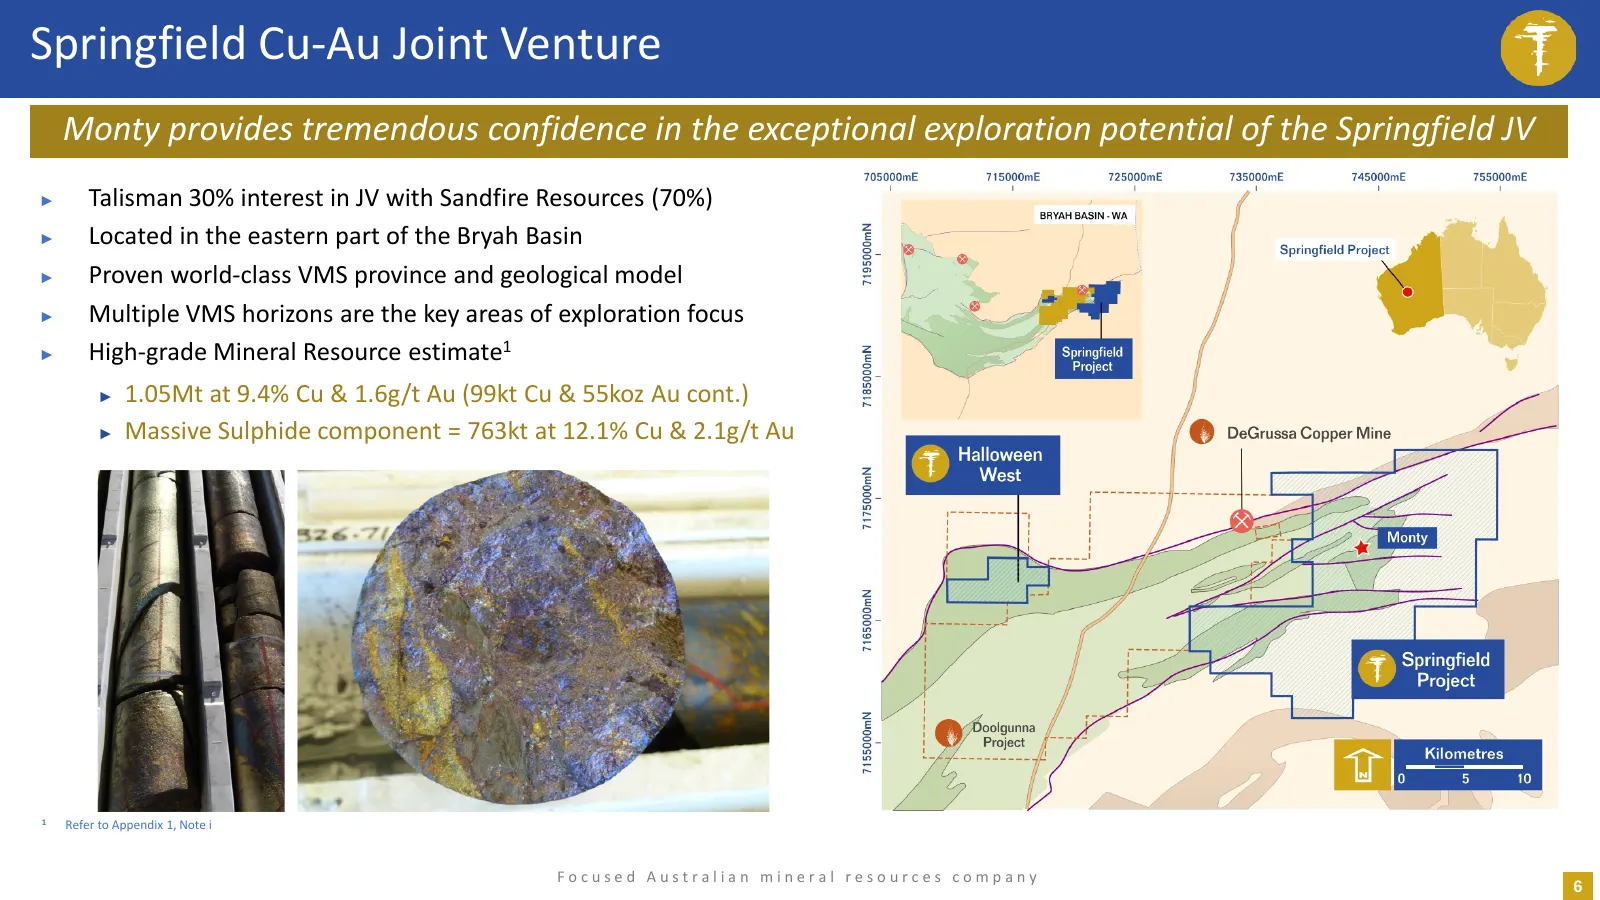
Springfield Cu-Au Joint Venture Monty provides tremendous confidence in the exceptional exploration potential of the Springfield JV ► Talisman 30% interest in JV with Sandfire Resources (70%) ► Located in the eastern part of the Bryah Basin ► Proven world-class VMS province and geological model ► Mu
Slide 7: The Monty Project: High grade, high value
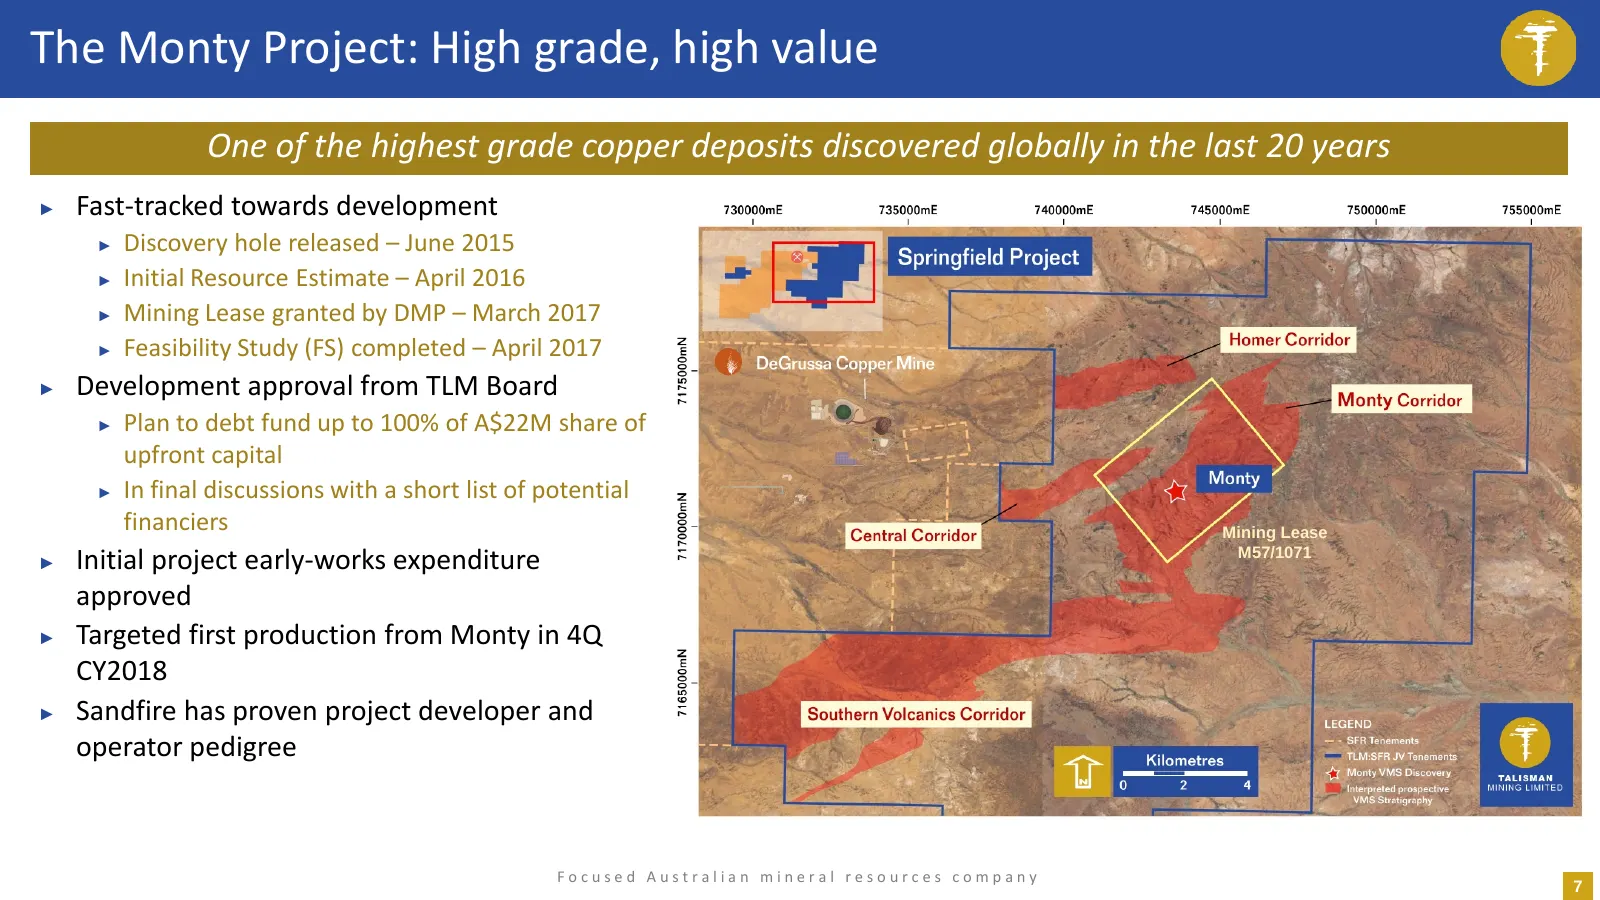
The Monty Project: High grade, high value One of the highest grade copper deposits discovered globally in the last 20 years ► Fast-tracked towards development ► Discovery hole released – June 2015 ► Initial Resource Estimate – April 2016 ► Mining Lease granted by DMP – March 2017 ► Feasibility Study
Slide 8: Key Monty Feasibility Study outcomes (TLM 30% basis)
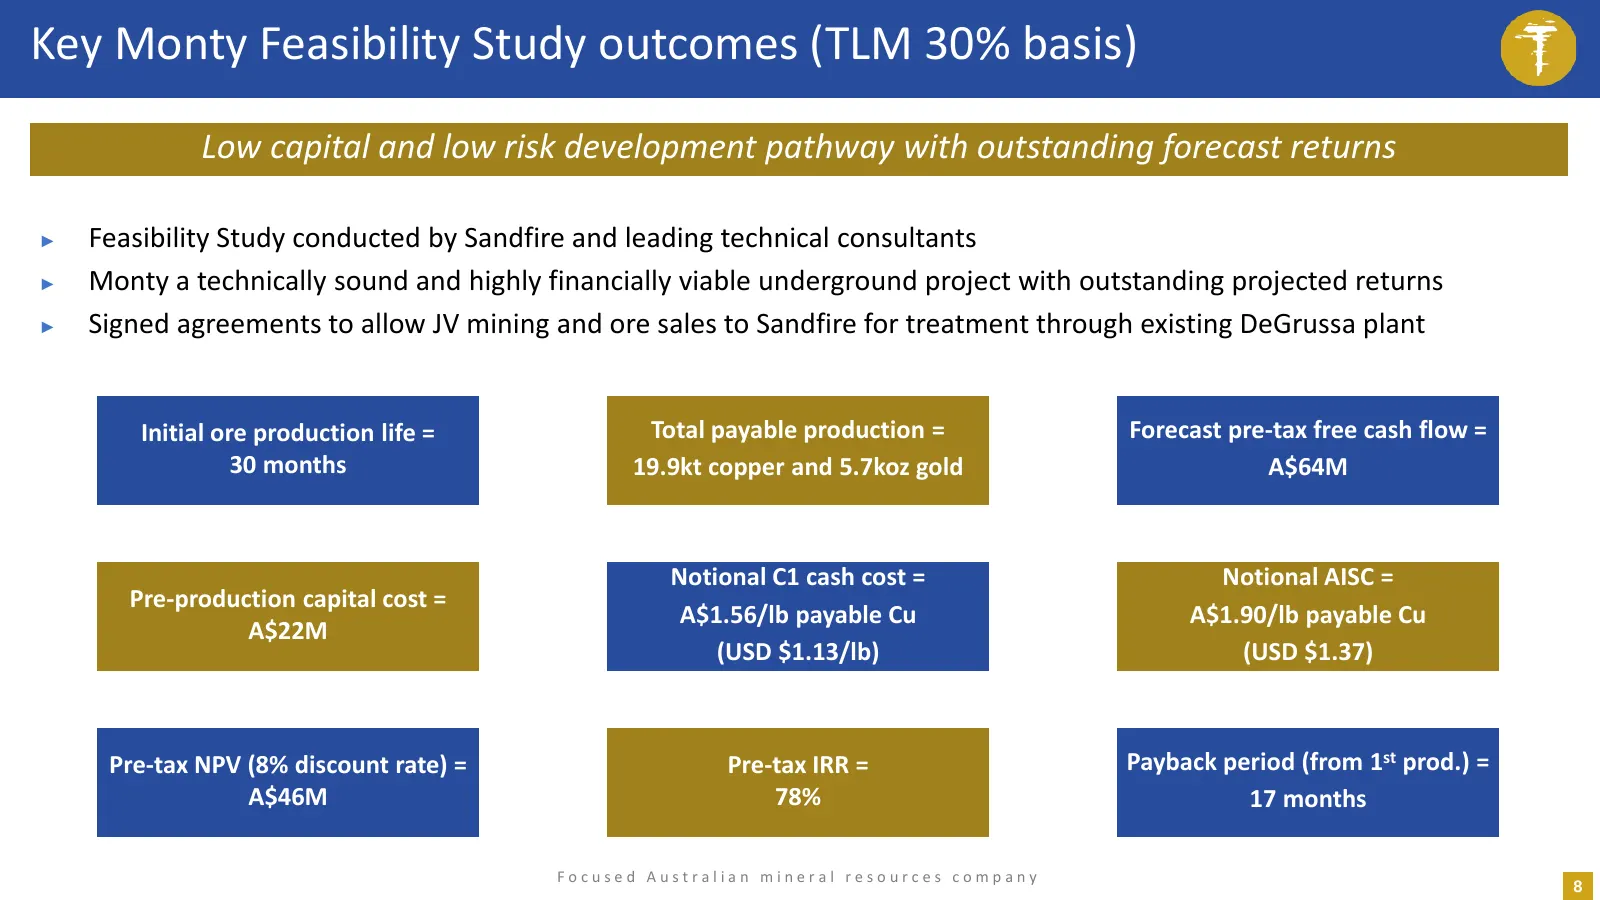
Key Monty Feasibility Study outcomes (TLM 30% basis) Low capital and low risk development pathway with outstanding forecast returns ► Feasibility Study conducted by Sandfire and leading technical consultants ► Monty a technically sound and highly financially viable underground project with outstandi
Slide 9: Maiden Monty Ore Reserve estimate
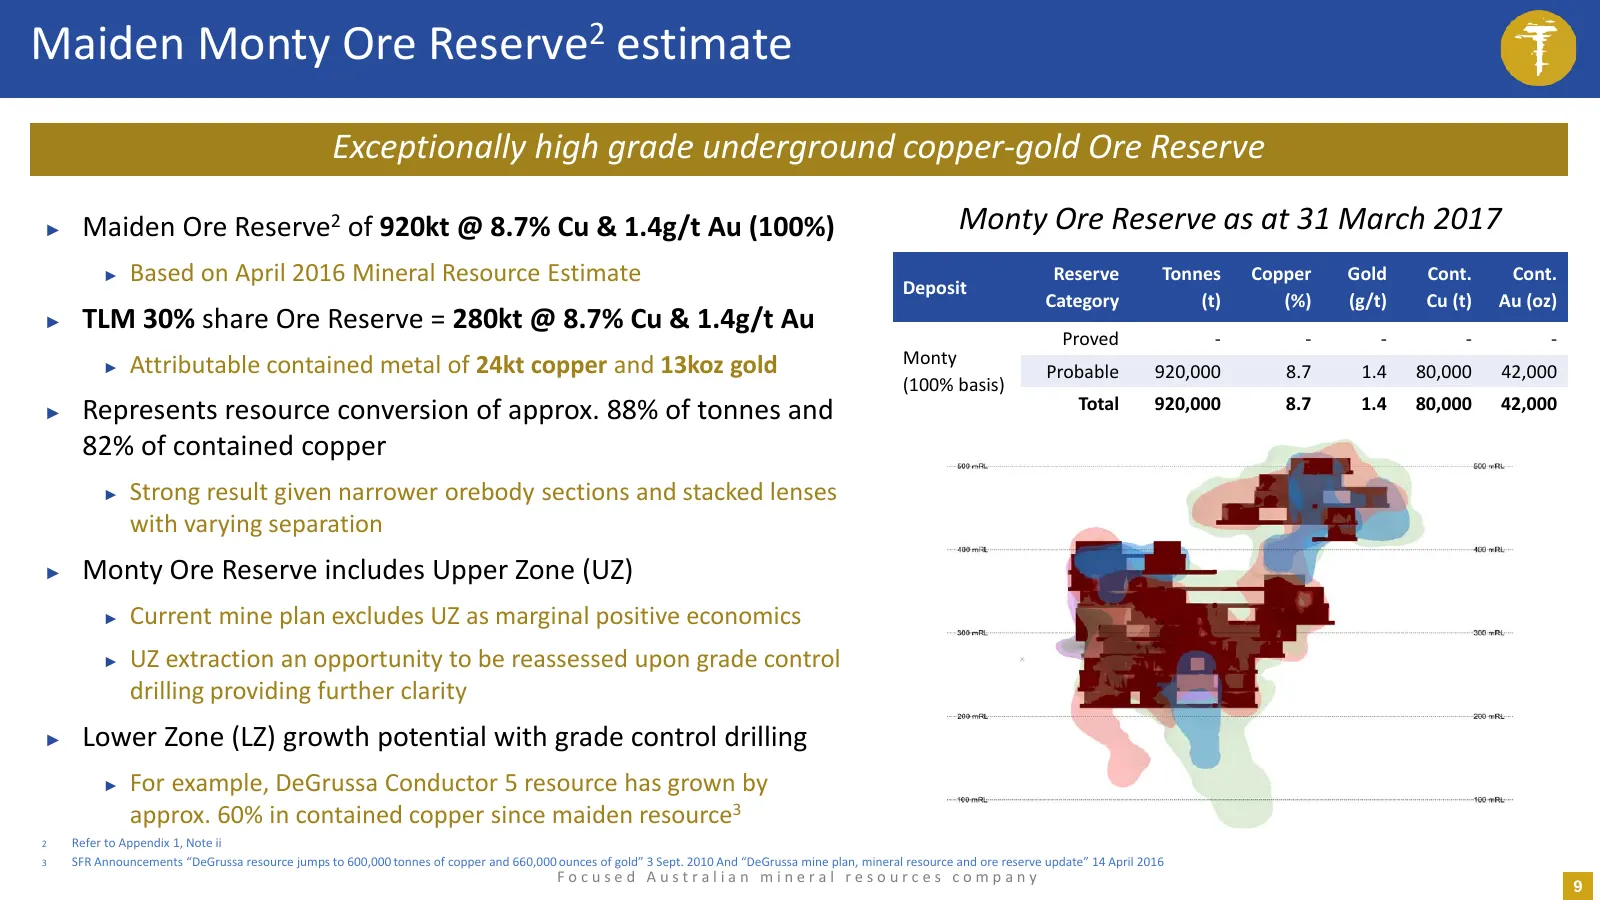
Maiden Monty Ore Reserve2 estimate Exceptionally high grade underground copper-gold Ore Reserve ► Maiden Ore Reserve2 of 920kt @ 8.7% Cu & 1.4g/t Au (100%) Monty Ore Reserve as at 31 March 2017 ► Based on April 2016 Mineral Resource Estimate Deposit Reserve Tonnes Copper Gold Cont. Cont. Category (t
Slide 10: World class mineral concentration
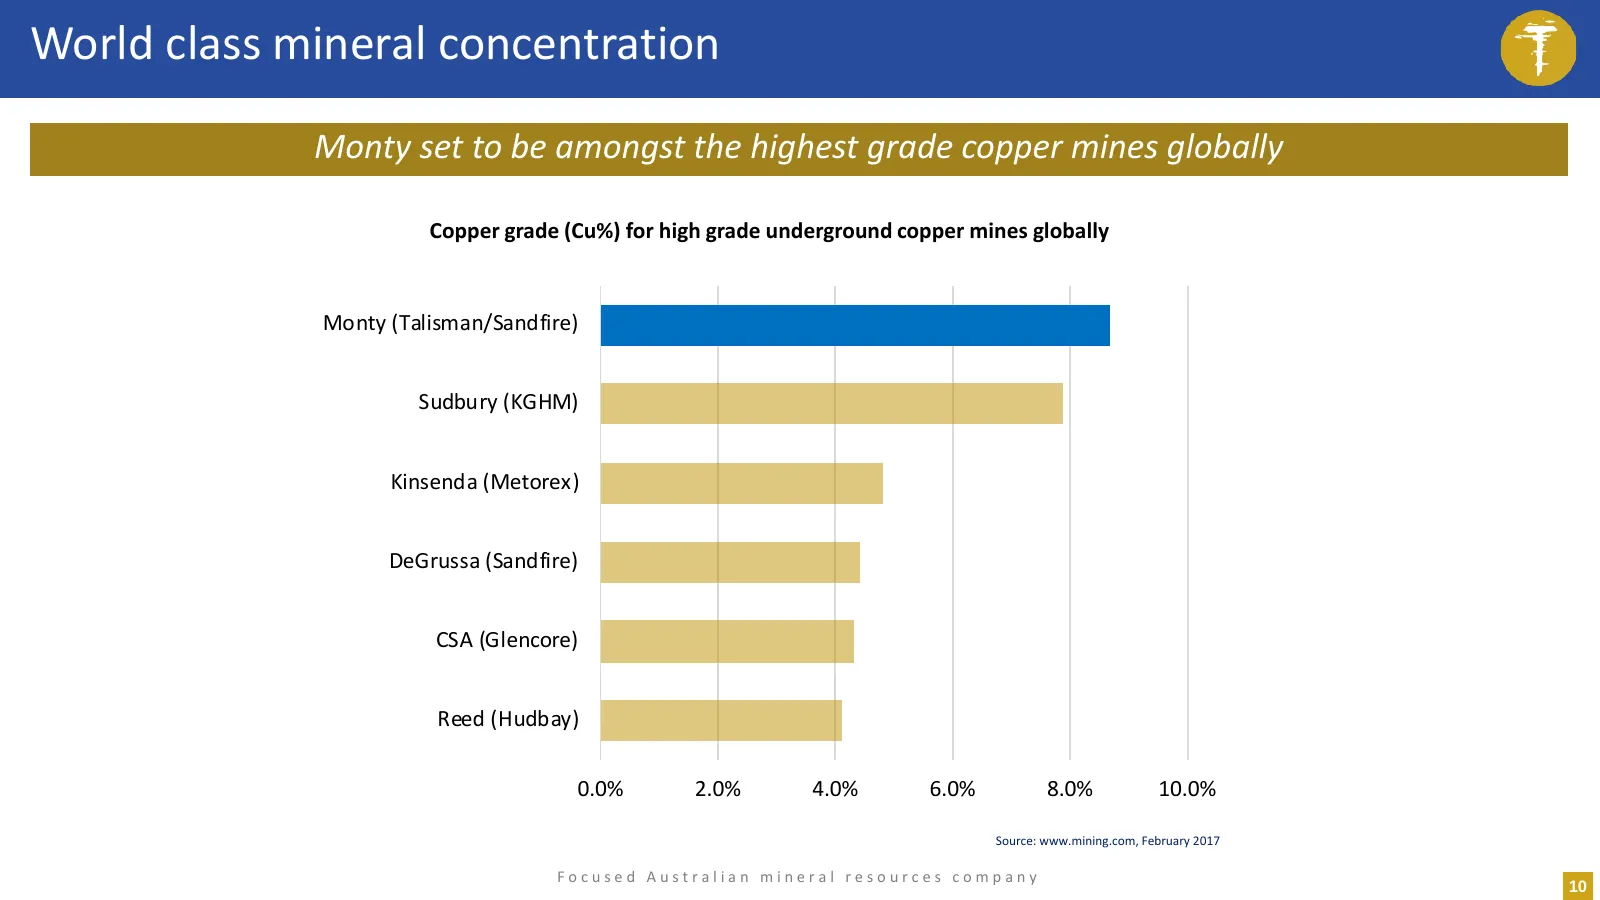
World class mineral concentration Monty set to be amongst the highest grade copper mines globally Copper grade (Cu%) for high grade underground copper mines globally Monty (Talisman/Sandfire) Sudbury (KGHM) Kinsenda (Metorex) DeGrussa (Sandfire) CSA (Glencore) Reed (Hudbay) 0.0% 2.0% 4.0% 6.0% 8.0%
Slide 11: Strong upside potential for Monty mineral inventory
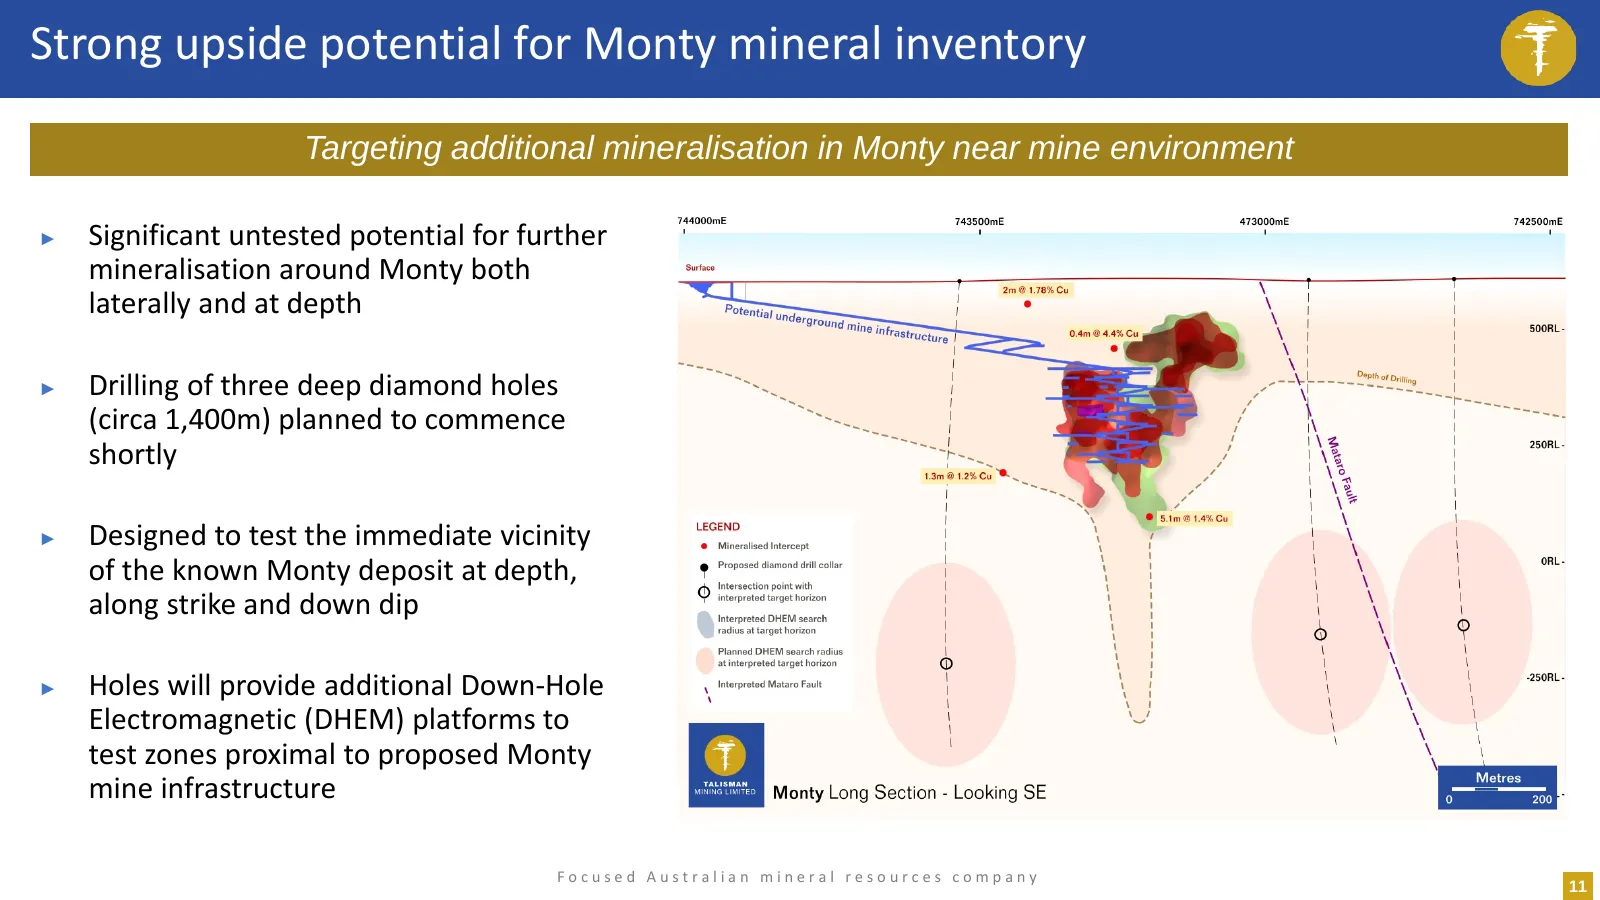
Strong upside potential for Monty mineral inventory Targeting additional mineralisation in Monty near mine environment ► Significant untested potential for further mineralisation around Monty both laterally and at depth ► Drilling of three deep diamond holes (circa 1,400m) planned to commence shortl
Slide 12: Key agreements with Sandfire
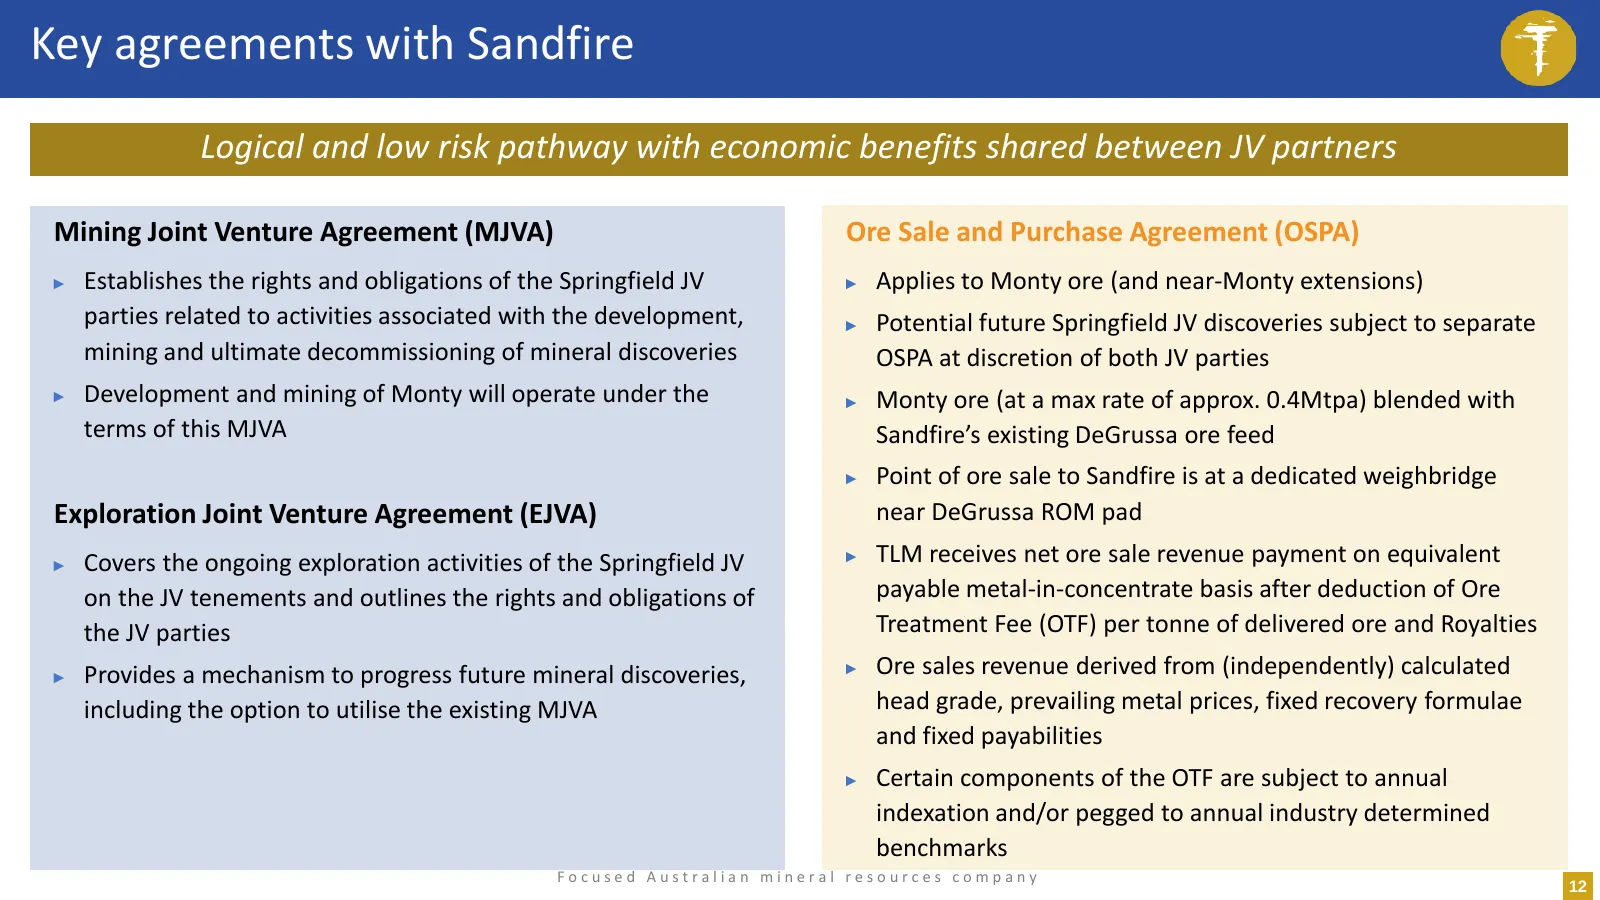
Key agreements with Sandfire Logical and low risk pathway with economic benefits shared between JV partners Mining Joint Venture Agreement (MJVA) Ore Sale and Purchase Agreement (OSPA) ► Establishes the rights and obligations of the Springfield JV ► Applies to Monty ore (and near-Monty extensions) p
Slide 13: Underground mining and ore haulage
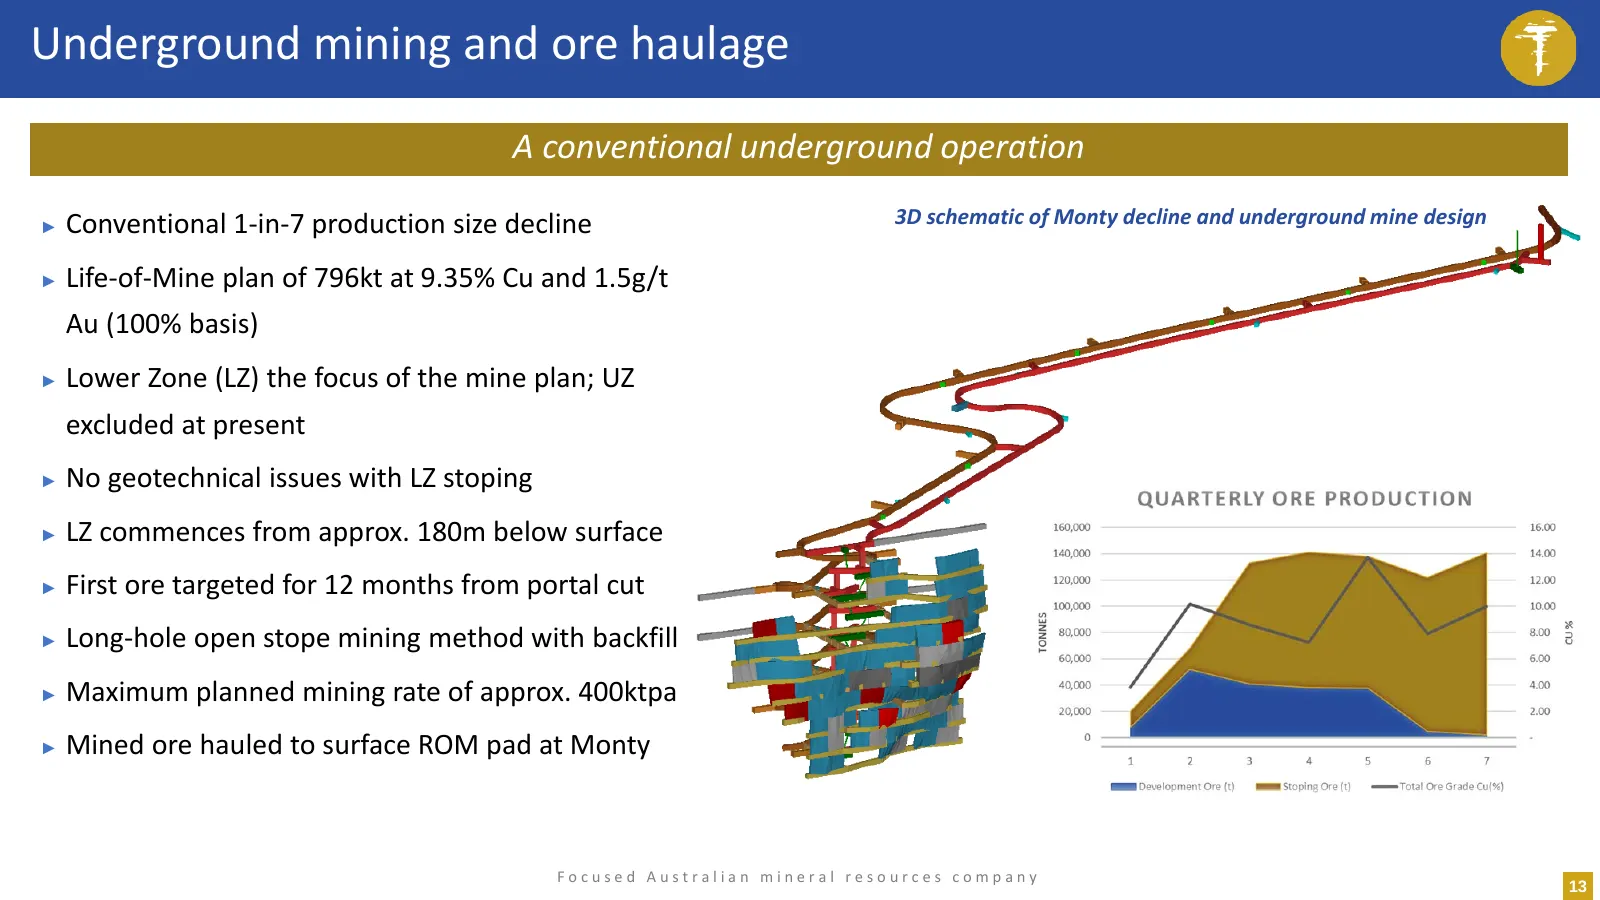
Underground mining and ore haulage A conventional underground operation ► Conventional 1-in-7 production size decline 3D schematic of Monty decline and underground mine design ► Life-of-Mine plan of 796kt at 9.35% Cu and 1.5g/t Au (100% basis) ► Lower Zone (LZ) the focus of the mine plan; UZ exclude
Slide 14: Monty Surface Infrastructure
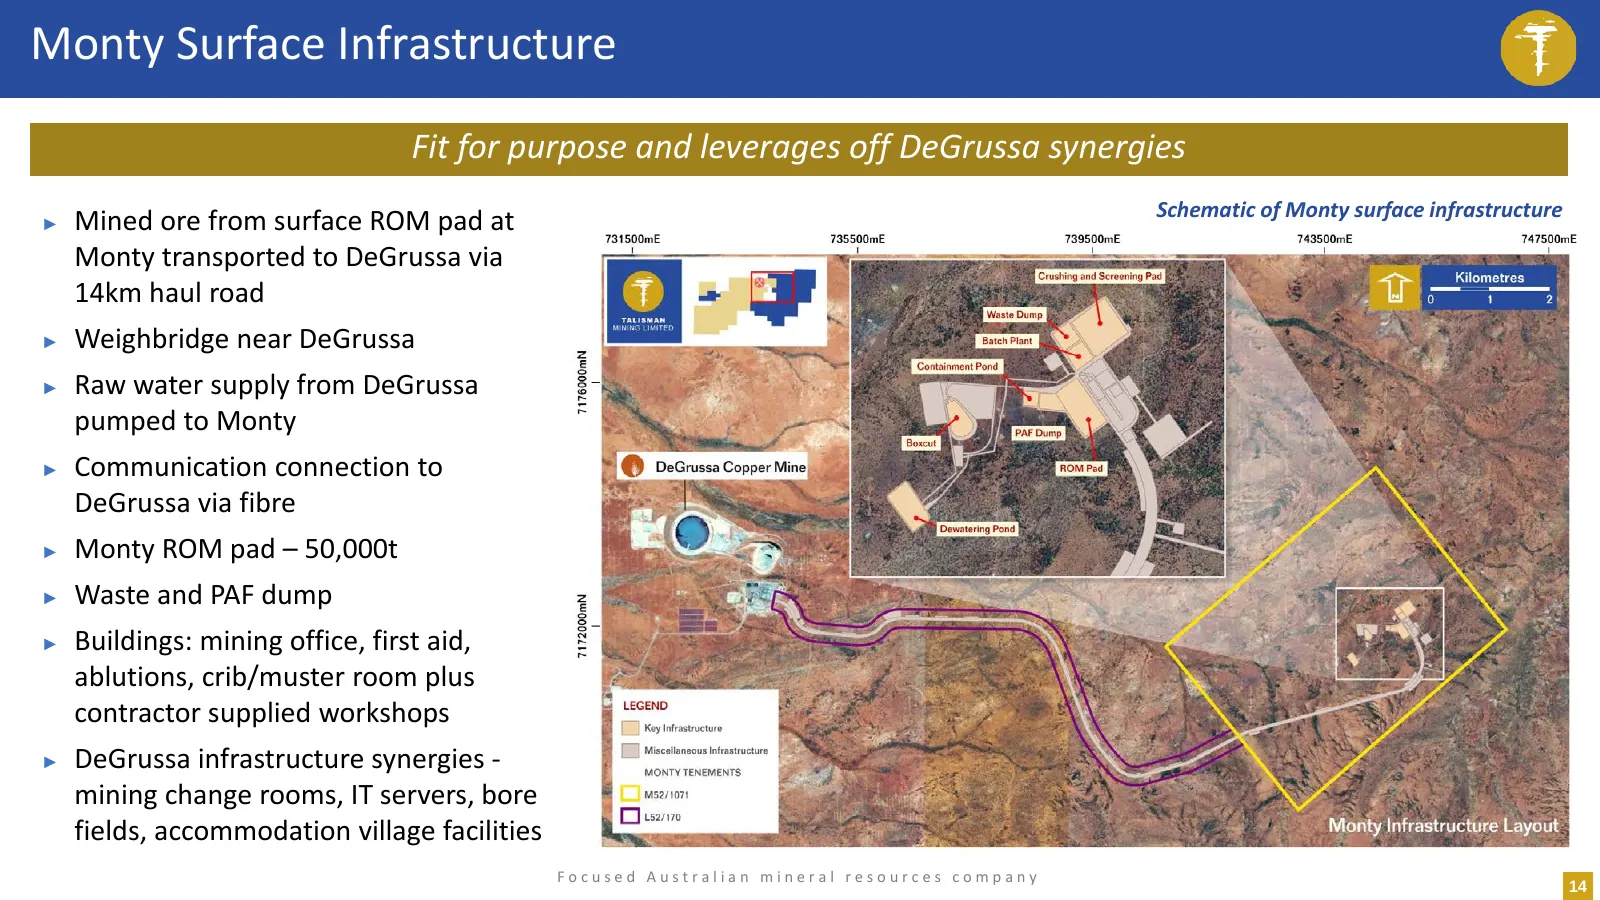
Monty Surface Infrastructure Fit for purpose and leverages off DeGrussa synergies Schematic of Monty surface infrastructure ► Mined ore from surface ROM pad at Monty transported to DeGrussa via 14km haul road ► Weighbridge near DeGrussa ► Raw water supply from DeGrussa pumped to Monty ► Communicatio
Slide 15: The OSPA maximises simplicity and minimises dispute risk
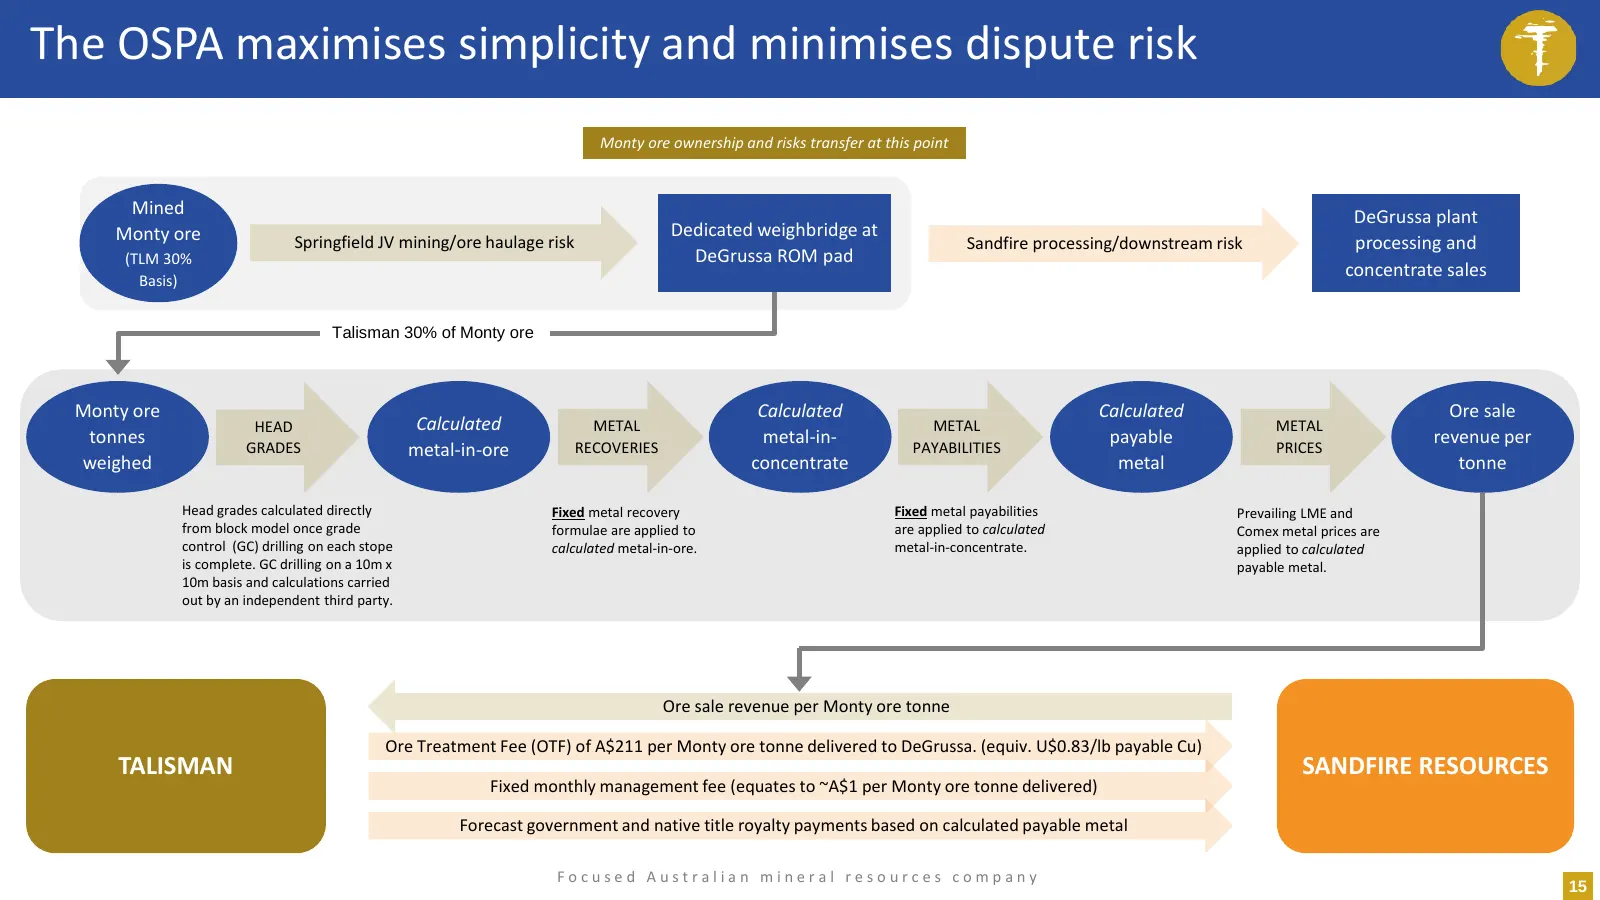
The OSPA maximises simplicity and minimises dispute risk Monty ore ownership and risks transfer at this point Mined DeGrussa plant Monty ore Dedicated weighbridge at Springfield JV mining/ore haulage risk Sandfire processing/downstream risk processing and (TLM 30% DeGrussa ROM pad Basis) concentrate
Slide 16: Key OSPA benefits for Talisman
Key OSPA benefits for Talisman A low capital, exposure minimising and high returning development route for Talisman ► OSPA limited to Monty deposit and near-Monty extensions ► Maintain optionality in relation to any future discoveries on the Springfield JV ► No plant build requirement ► Highly attra
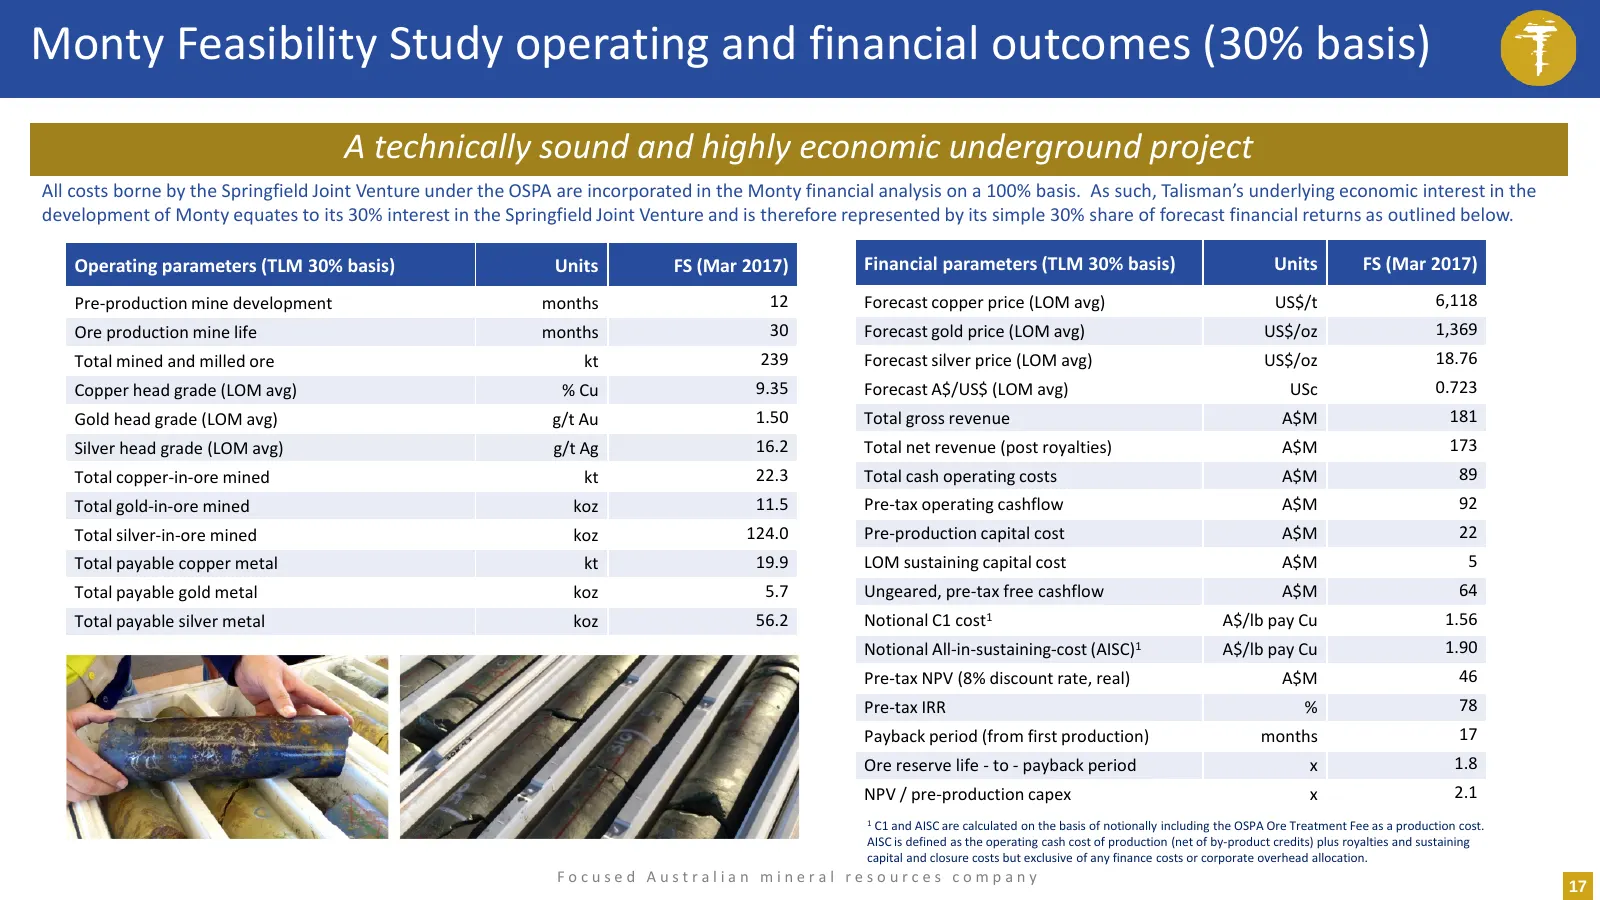
Slide 17: Monty Feasibility Study operating and financial outcomes (30% basis)
Monty Feasibility Study operating and financial outcomes (30% basis) A technically sound and highly economic underground project All costs borne by the Springfield Joint Venture under the OSPA are incorporated in the Monty financial analysis on a 100% basis. As such, Talisman’s underlying economic i
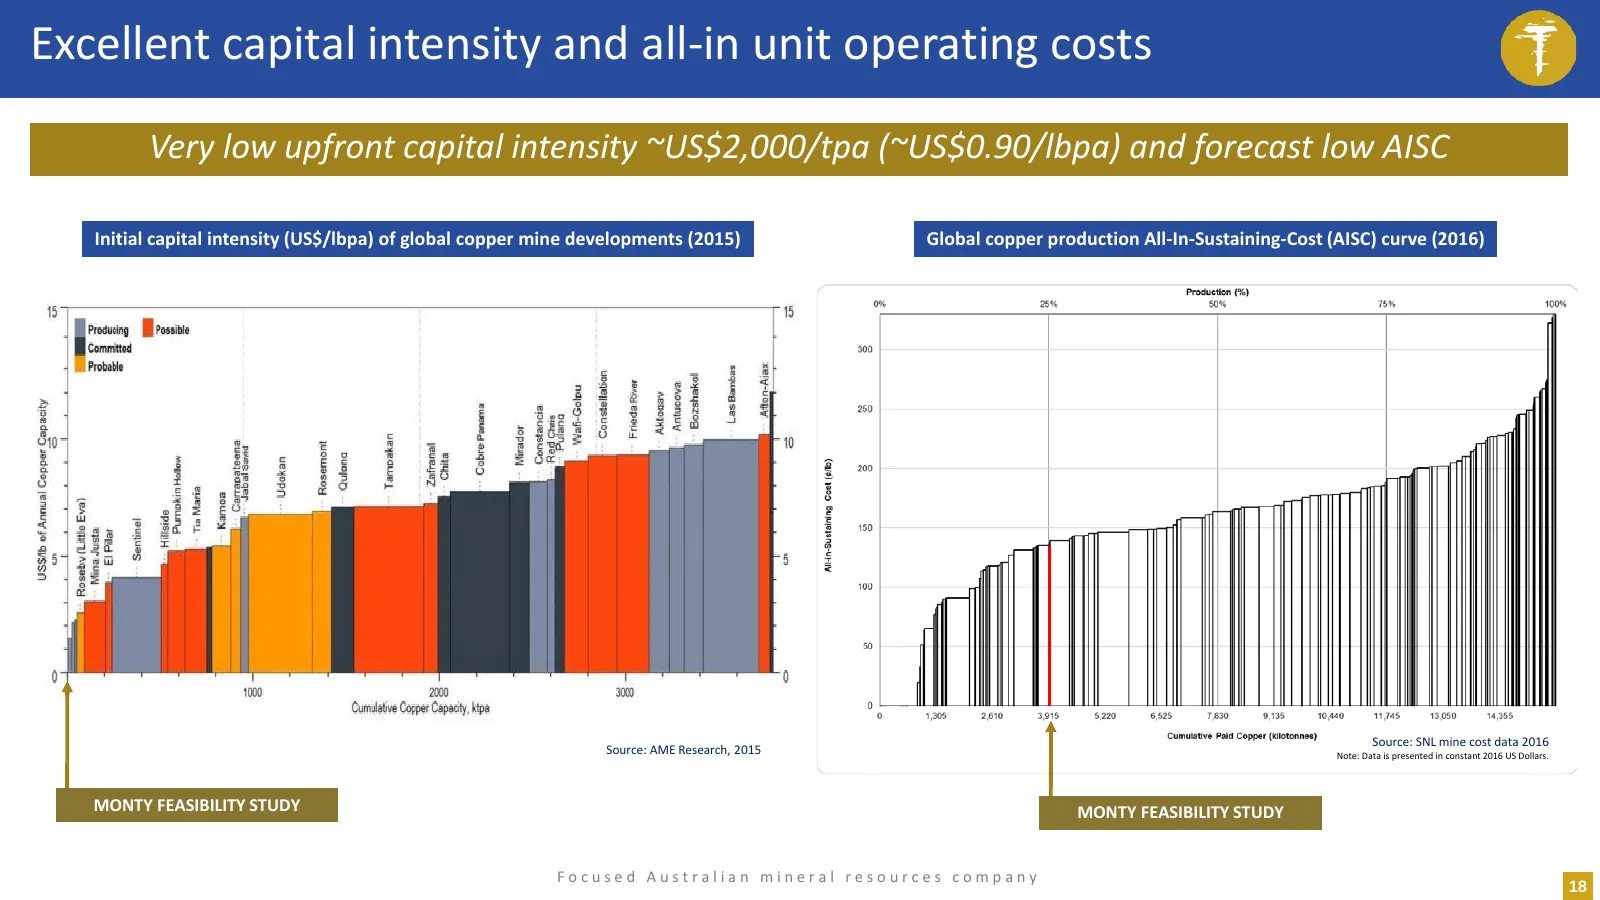
Slide 18: Excellent capital intensity and all-in unit operating costs
Excellent capital intensity and all-in unit operating costs Very low upfront capital intensity ~US$2,000/tpa (~US$0.90/lbpa) and forecast low AISC Initial capital intensity (US$/lbpa) of global copper mine developments (2015) Global copper production All-In-Sustaining-Cost (AISC) curve (2016) Source
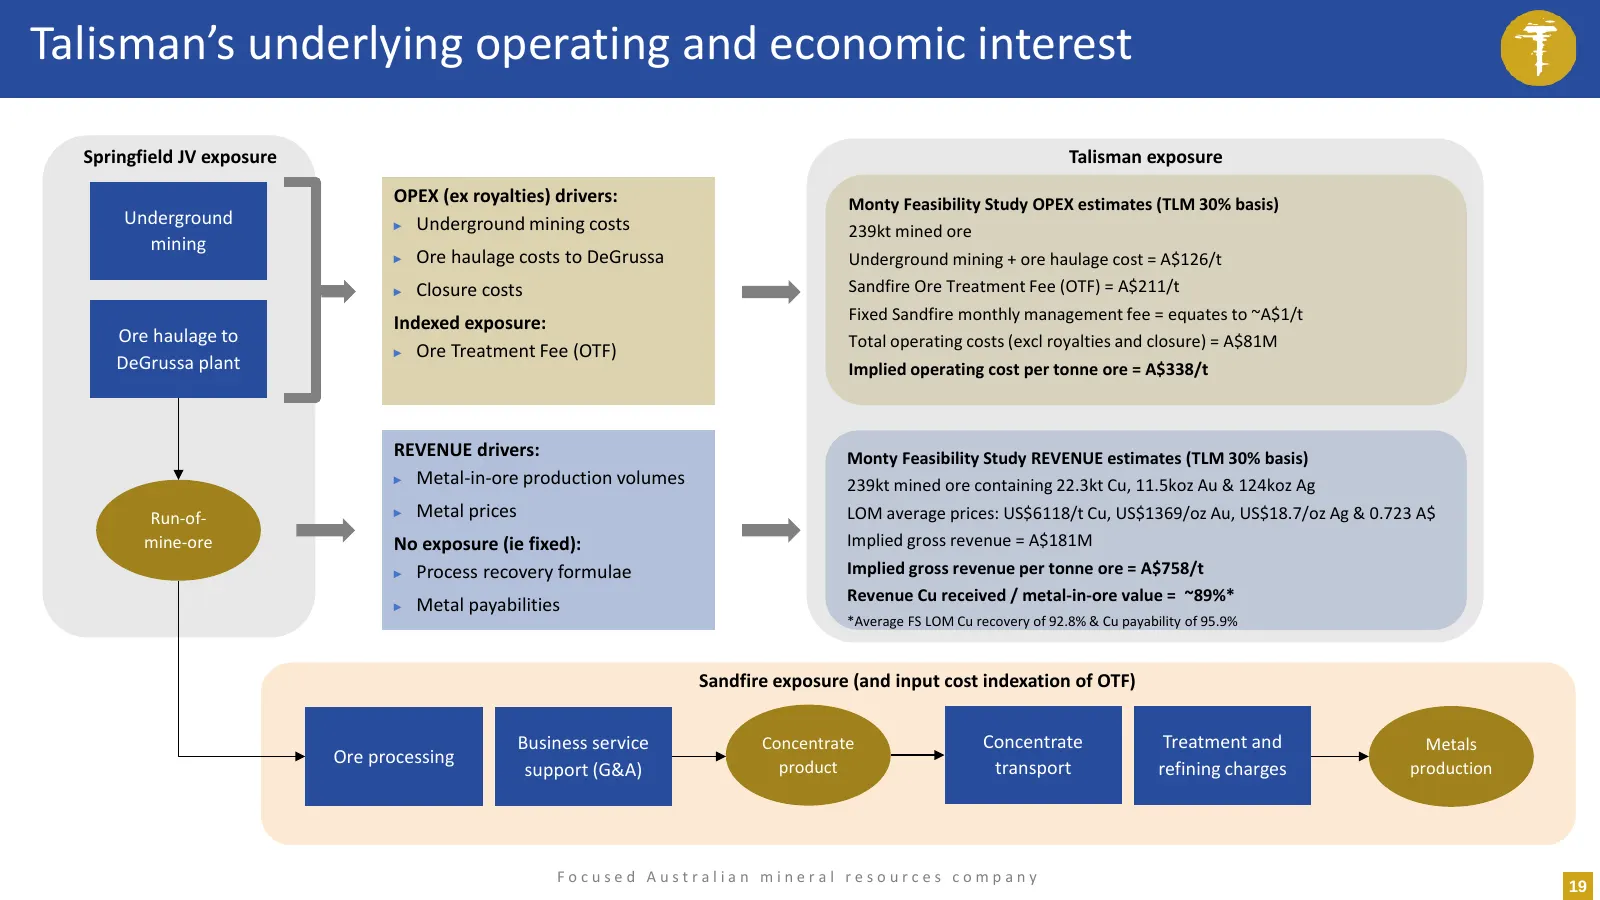
Slide 19: Talisman's underlying operating and economic interest
Talisman’s underlying operating and economic interest Springfield JV exposure Talisman exposure OPEX (ex royalties) drivers: Monty Feasibility Study OPEX estimates (TLM 30% basis) Underground ► Underground mining costs 239kt mined ore mining ► Ore haulage costs to DeGrussa Underground mining + ore h
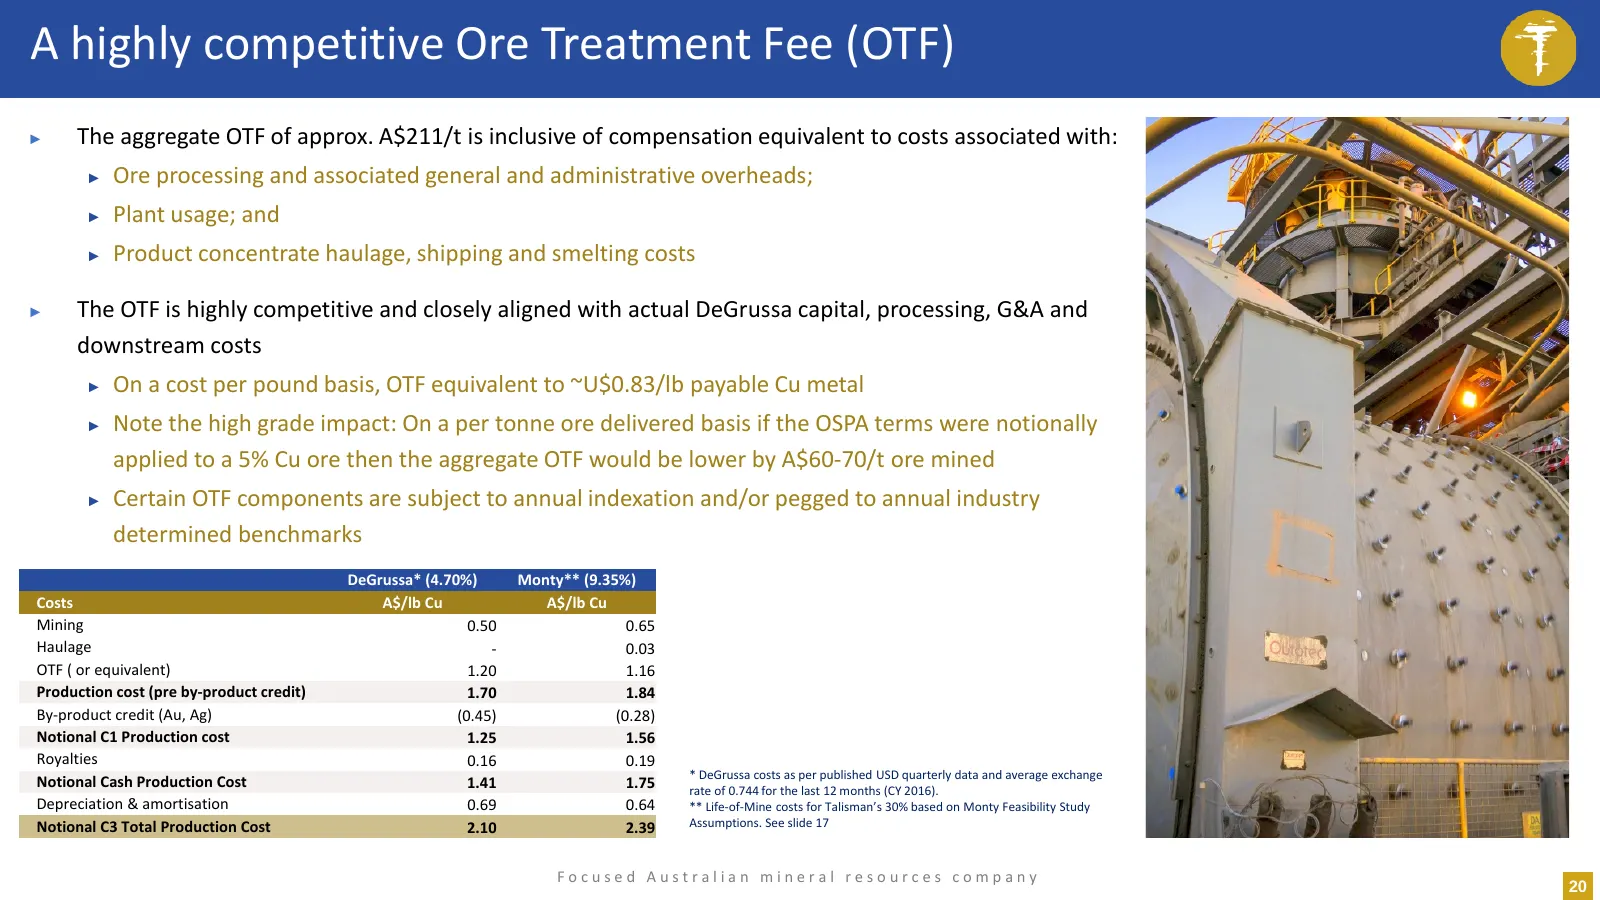
Slide 20: A highly competitive Ore Treatment Fee (OTF)
A highly competitive Ore Treatment Fee (OTF) ► The aggregate OTF of approx. A$211/t is inclusive of compensation equivalent to costs associated with: ► Ore processing and associated general and administrative overheads; ► Plant usage; and ► Product concentrate haulage, shipping and smelting costs ►
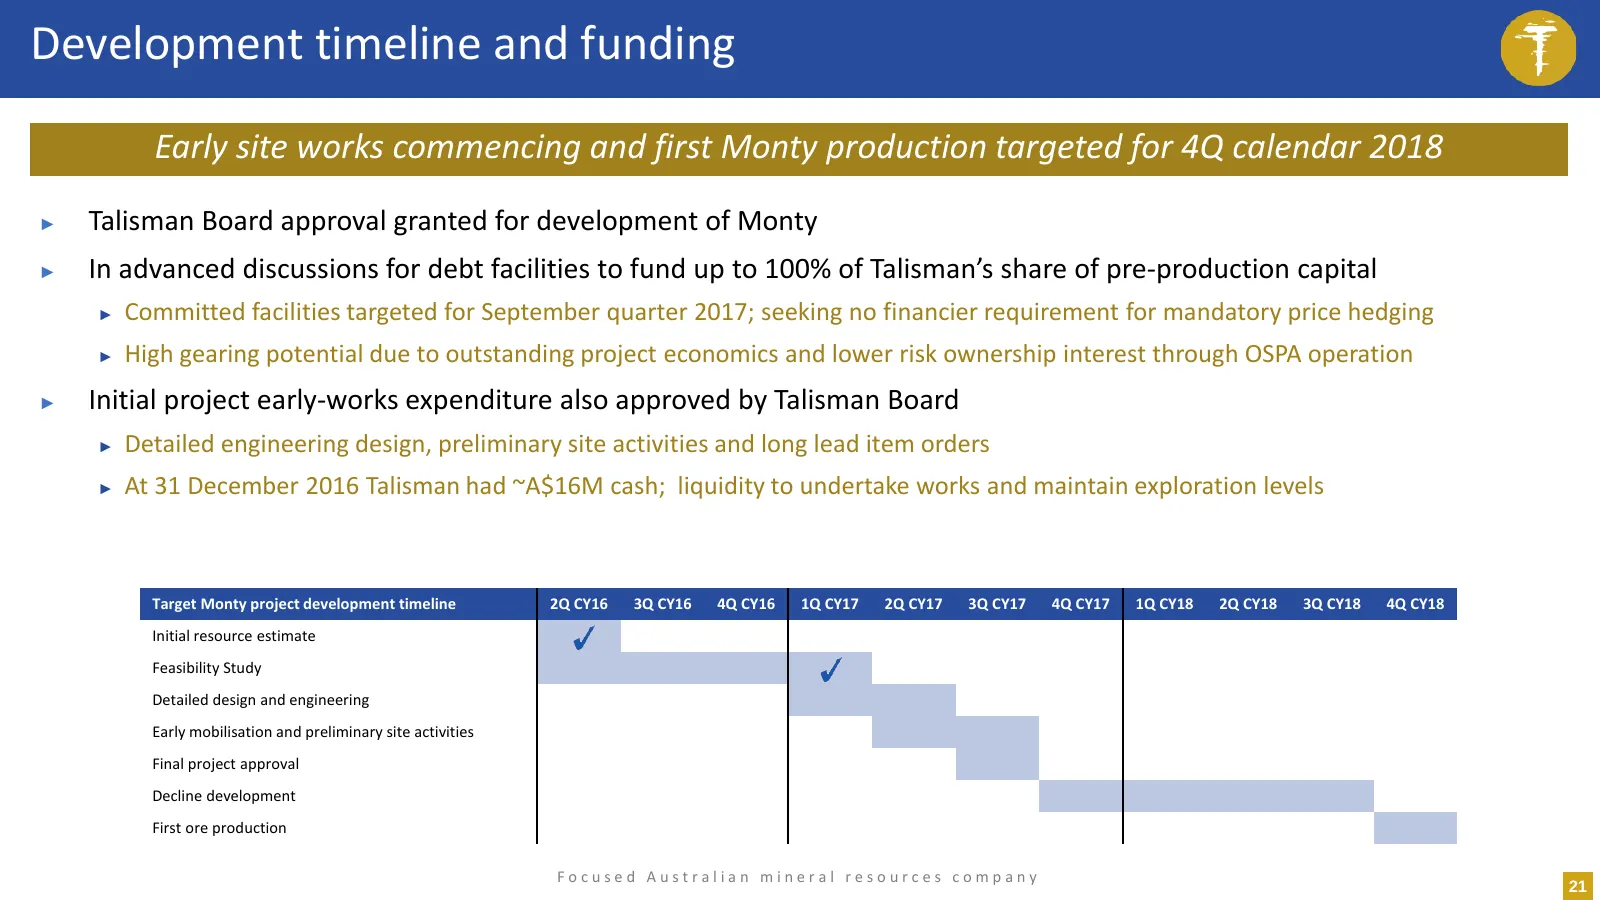
Slide 21: Development timeline and funding
Development timeline and funding Early site works commencing and first Monty production targeted for 4Q calendar 2018 ► Talisman Board approval granted for development of Monty ► In advanced discussions for debt facilities to fund up to 100% of Talisman’s share of pre-production capital ► Committed
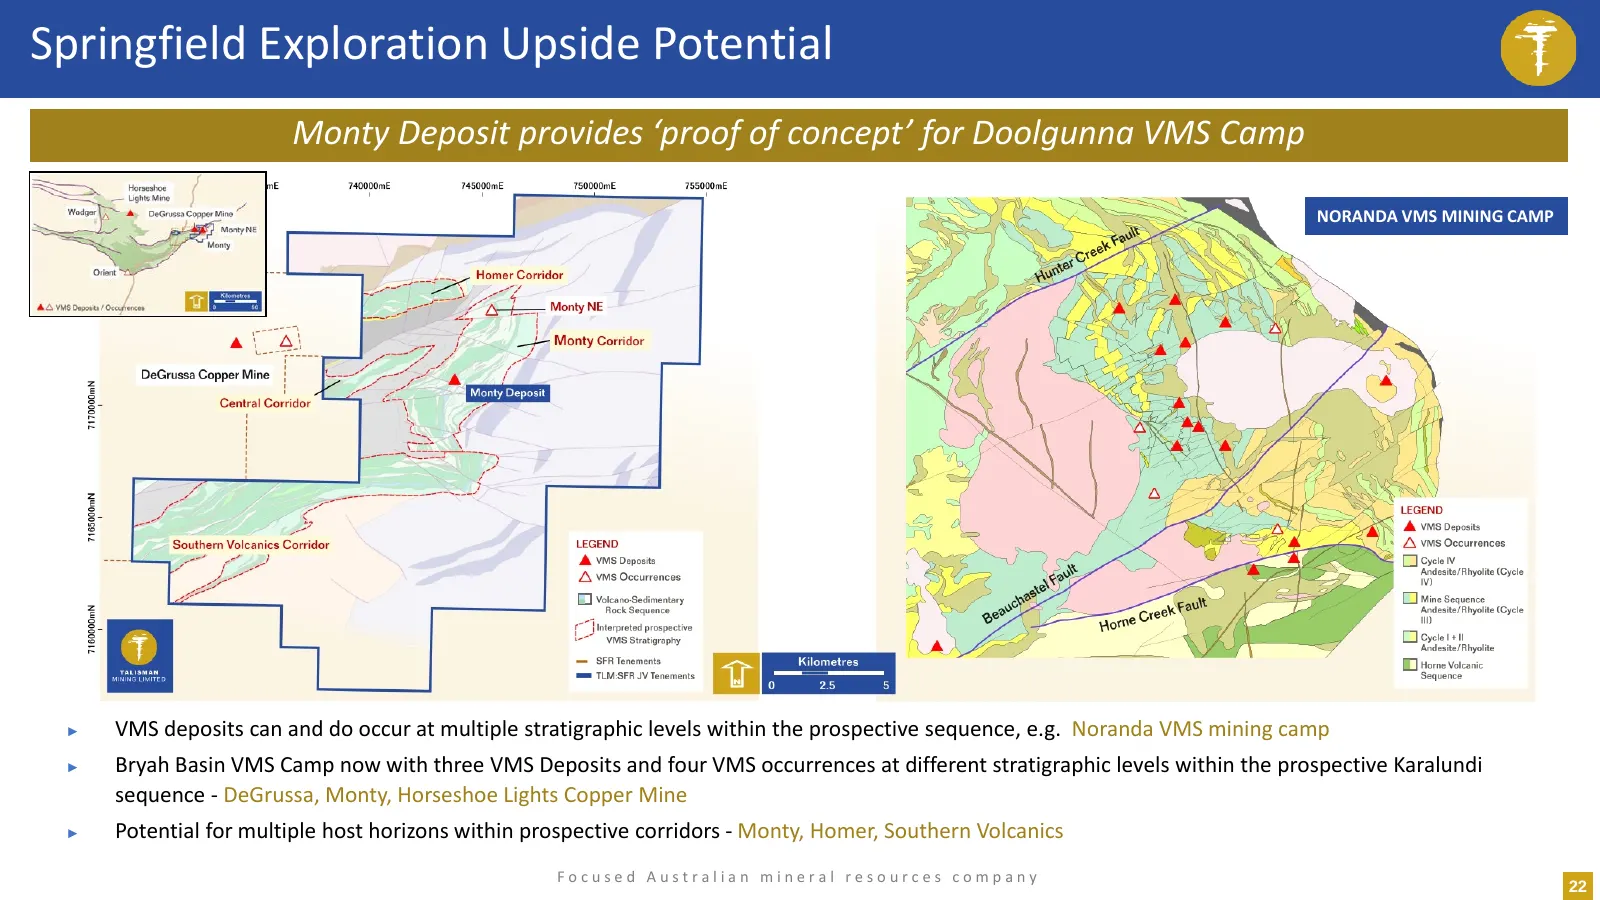
Slide 22: Springfield Exploration Upside Potential
Springfield Exploration Upside Potential Monty Deposit provides ‘proof of concept’ for Doolgunna VMS Camp NORANDA VMS MINING CAMP ► VMS deposits can and do occur at multiple stratigraphic levels within the prospective sequence, e.g. Noranda VMS mining camp ► Bryah Basin VMS Camp now with three VMS D
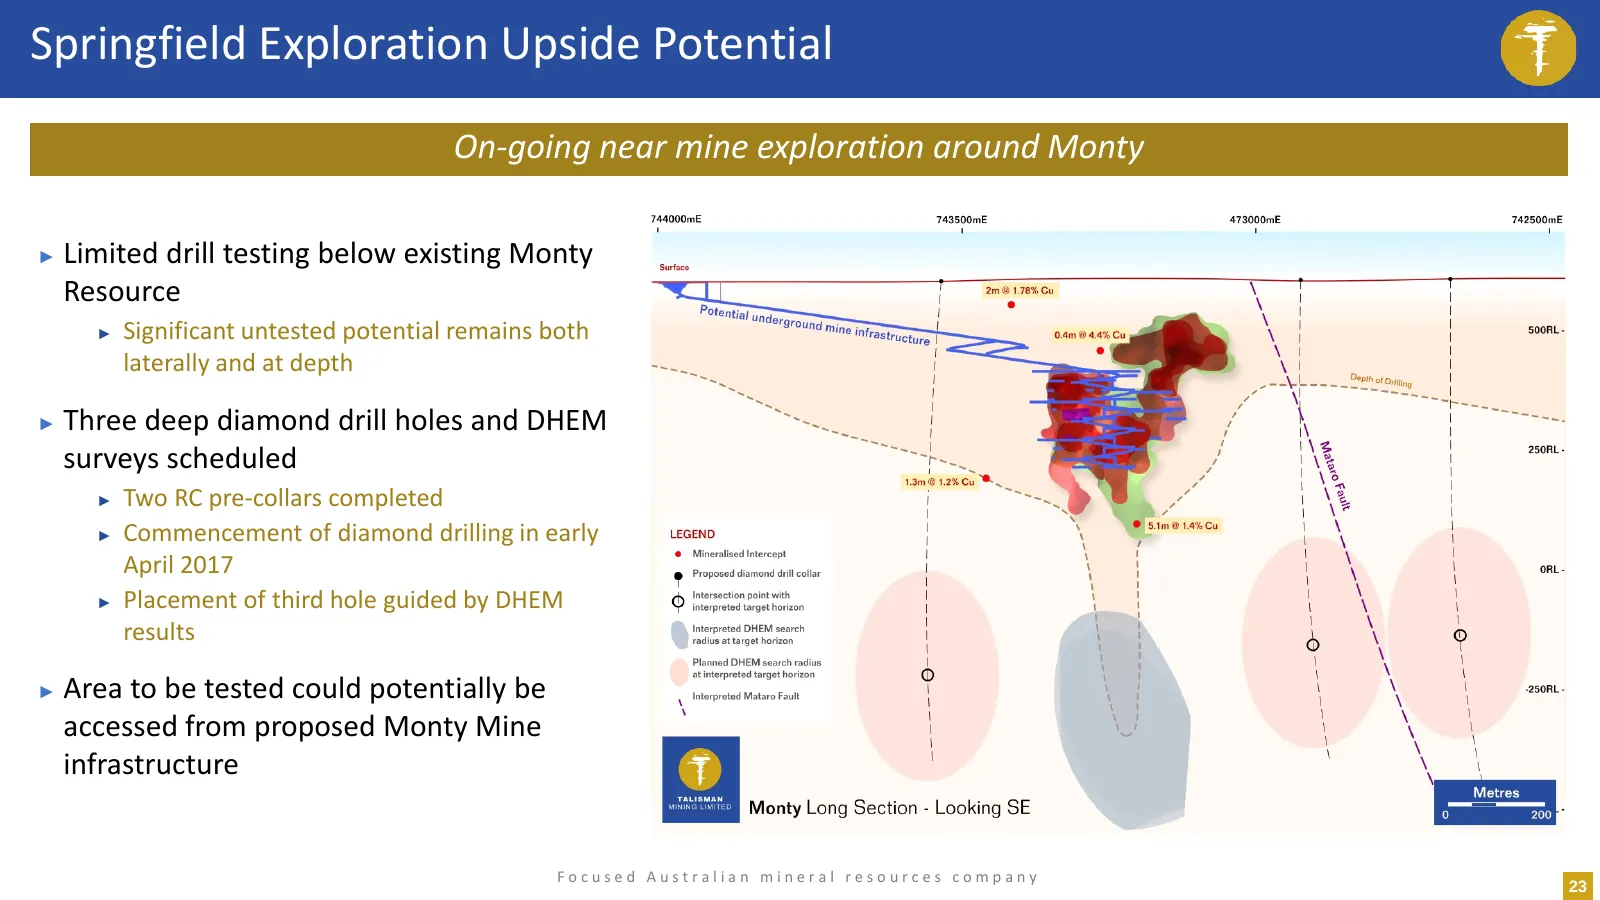
Slide 23: Springfield Exploration Upside Potential
Springfield Exploration Upside Potential On-going near mine exploration around Monty ► Limited drill testing below existing Monty Resource ► Significant untested potential remains both laterally and at depth ► Three deep diamond drill holes and DHEM surveys scheduled ► Two RC pre-collars completed ►
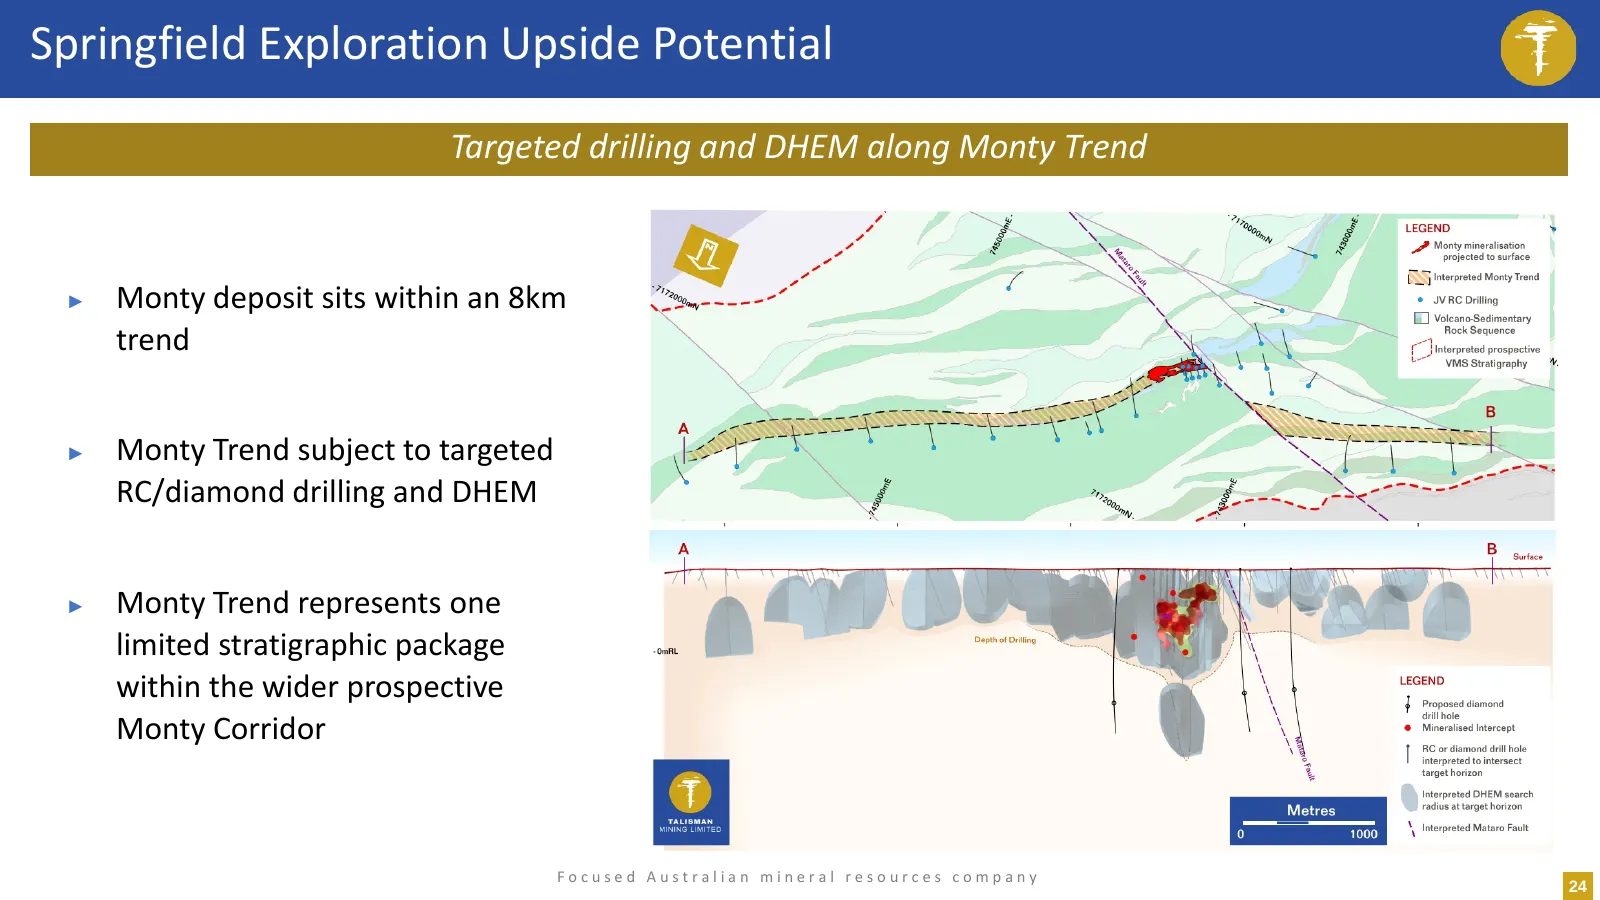
Slide 24: Springfield Exploration Upside Potential
Springfield Exploration Upside Potential Targeted drilling and DHEM along Monty Trend ► Monty deposit sits within an 8km trend ► Monty Trend subject to targeted 8km RC/diamond drilling and DHEM ► Monty Trend represents one limited stratigraphic package within the wider prospective Monty Corridor Foc
Slide 25: Springfield Exploration Upside Potential
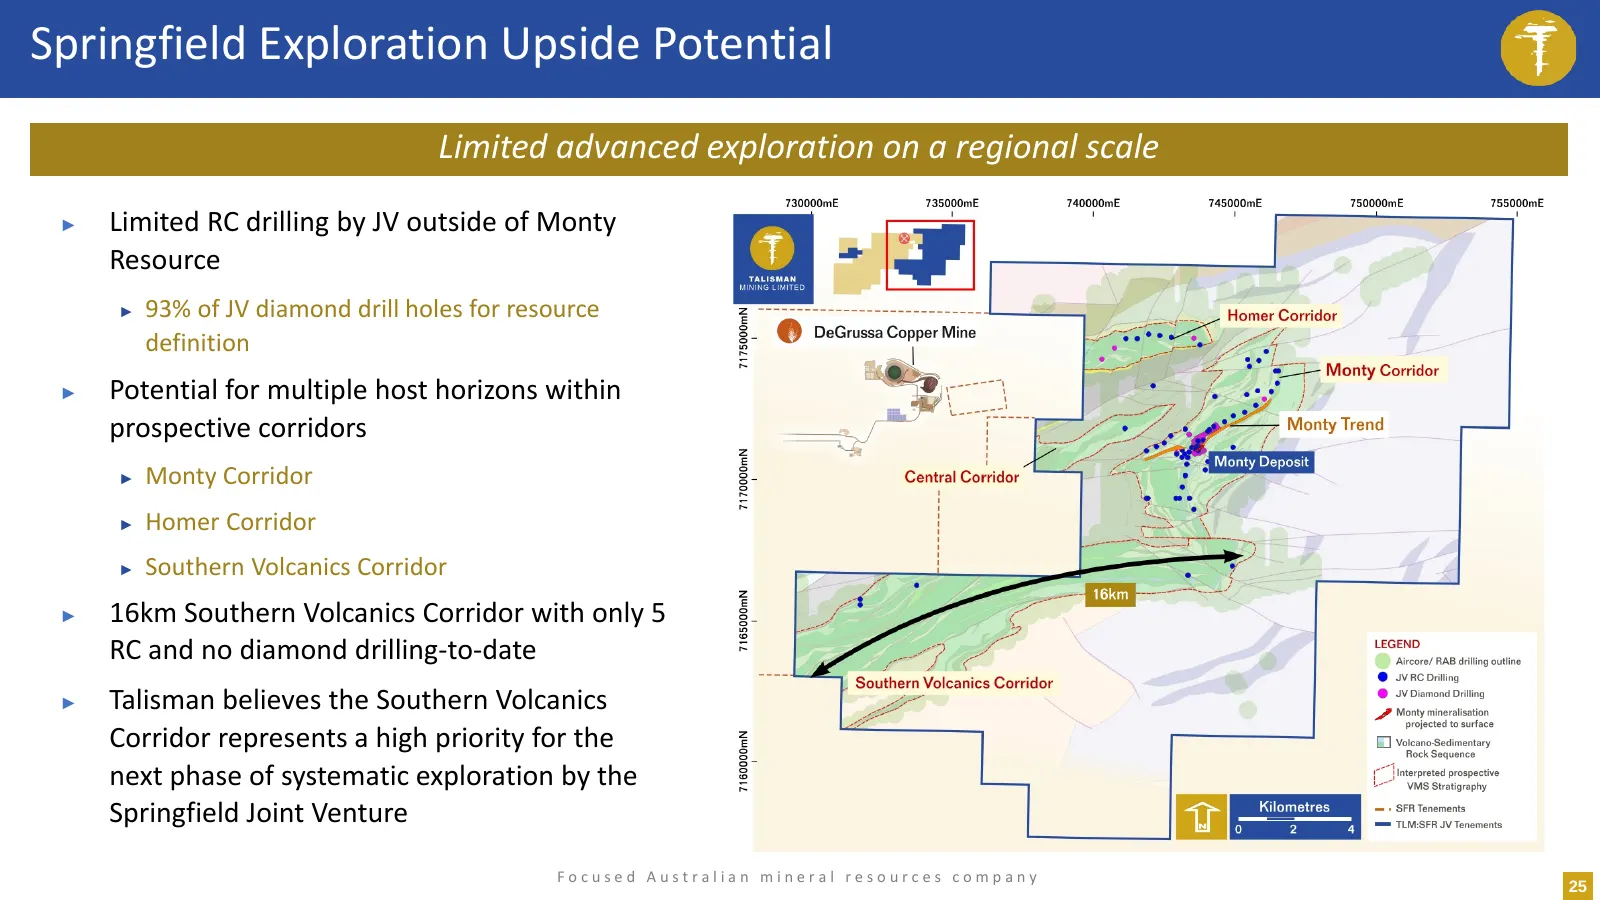
Springfield Exploration Upside Potential Limited advanced exploration on a regional scale ► Limited RC drilling by JV outside of Monty Resource ► 93% of JV diamond drill holes for resource definition ► Potential for multiple host horizons within prospective corridors ► Monty Corridor ► Homer Corrido
Slide 26: The Monty project and the Springfield JV
The Monty project and the Springfield JV Monty is a low risk, high returning copper project with outstanding potential upside [Photo] ► Low capital, low risk development path via ore sales to Sandfire ► Outstanding projected returns (TLM 30% basis) of A$64M pre-tax free cashflow, A$46M pre-tax NPV8
Slide 27: Sinclair Nickel Project
Sinclair Nickel Project Advanced opportunity in a proven nickel province F o c u s e d A u s t r a l Ii a n m i n e r a l r e s o u r c e s c o m p a n y 27
Slide 28: Sinclair: A low cost, fast track nickel production option
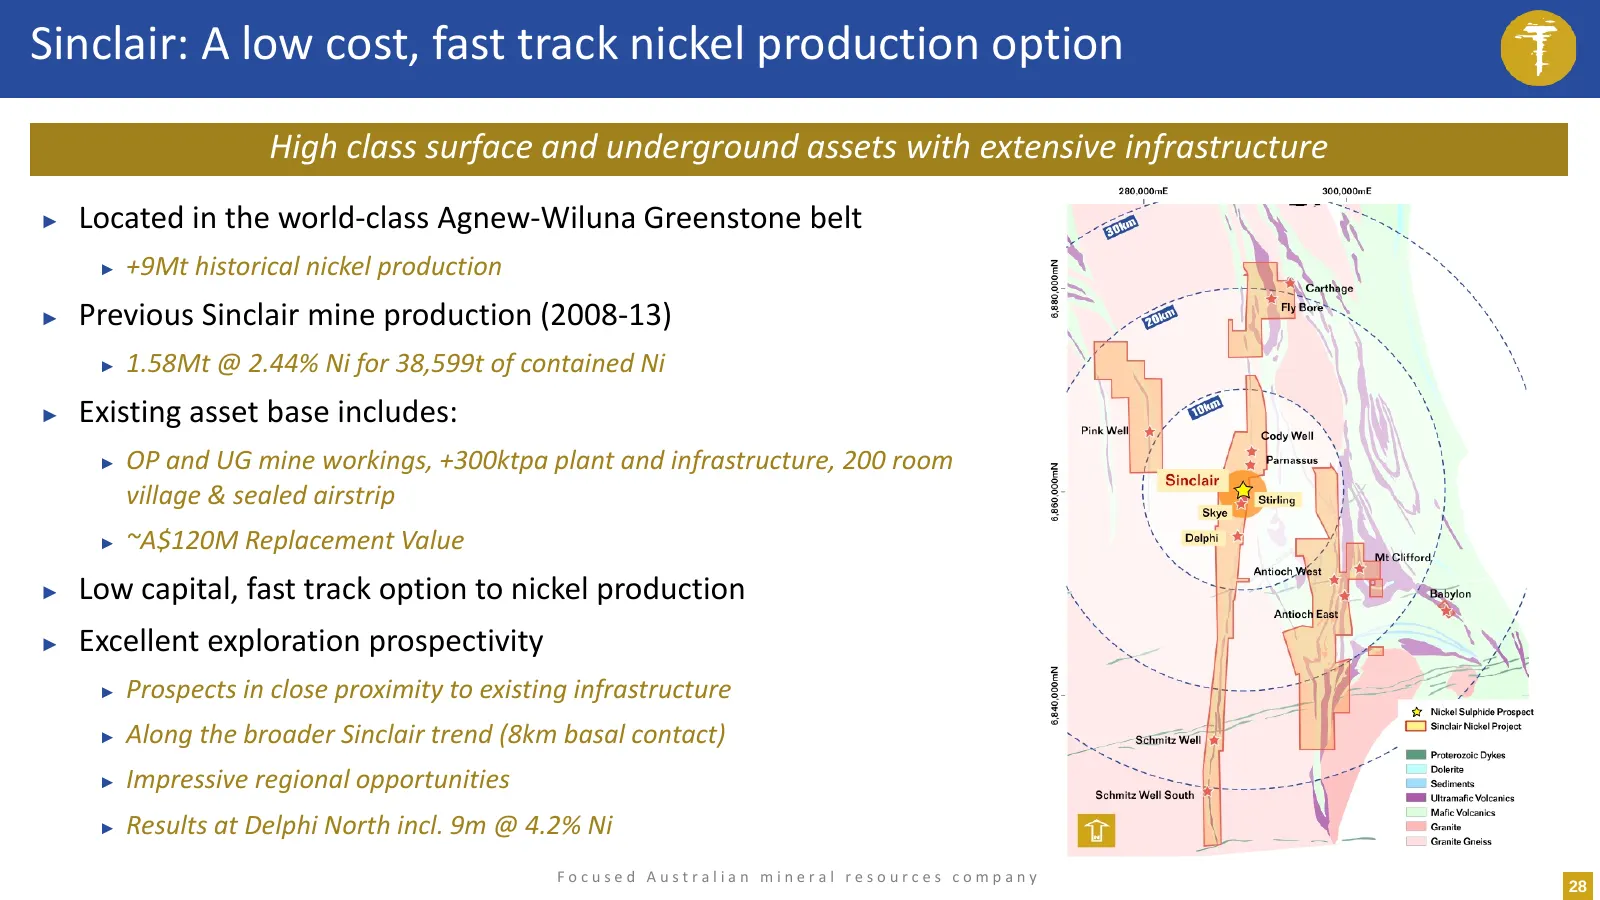
Sinclair: A low cost, fast track nickel production option High class surface and underground assets with extensive infrastructure ► Located in the world-class Agnew-Wiluna Greenstone belt ► +9Mt historical nickel production ► Previous Sinclair mine production (2008-13) ► 1.58Mt @ 2.44% Ni for 38,599
Slide 29: Sinclair: Regional and near-mine exploration potential
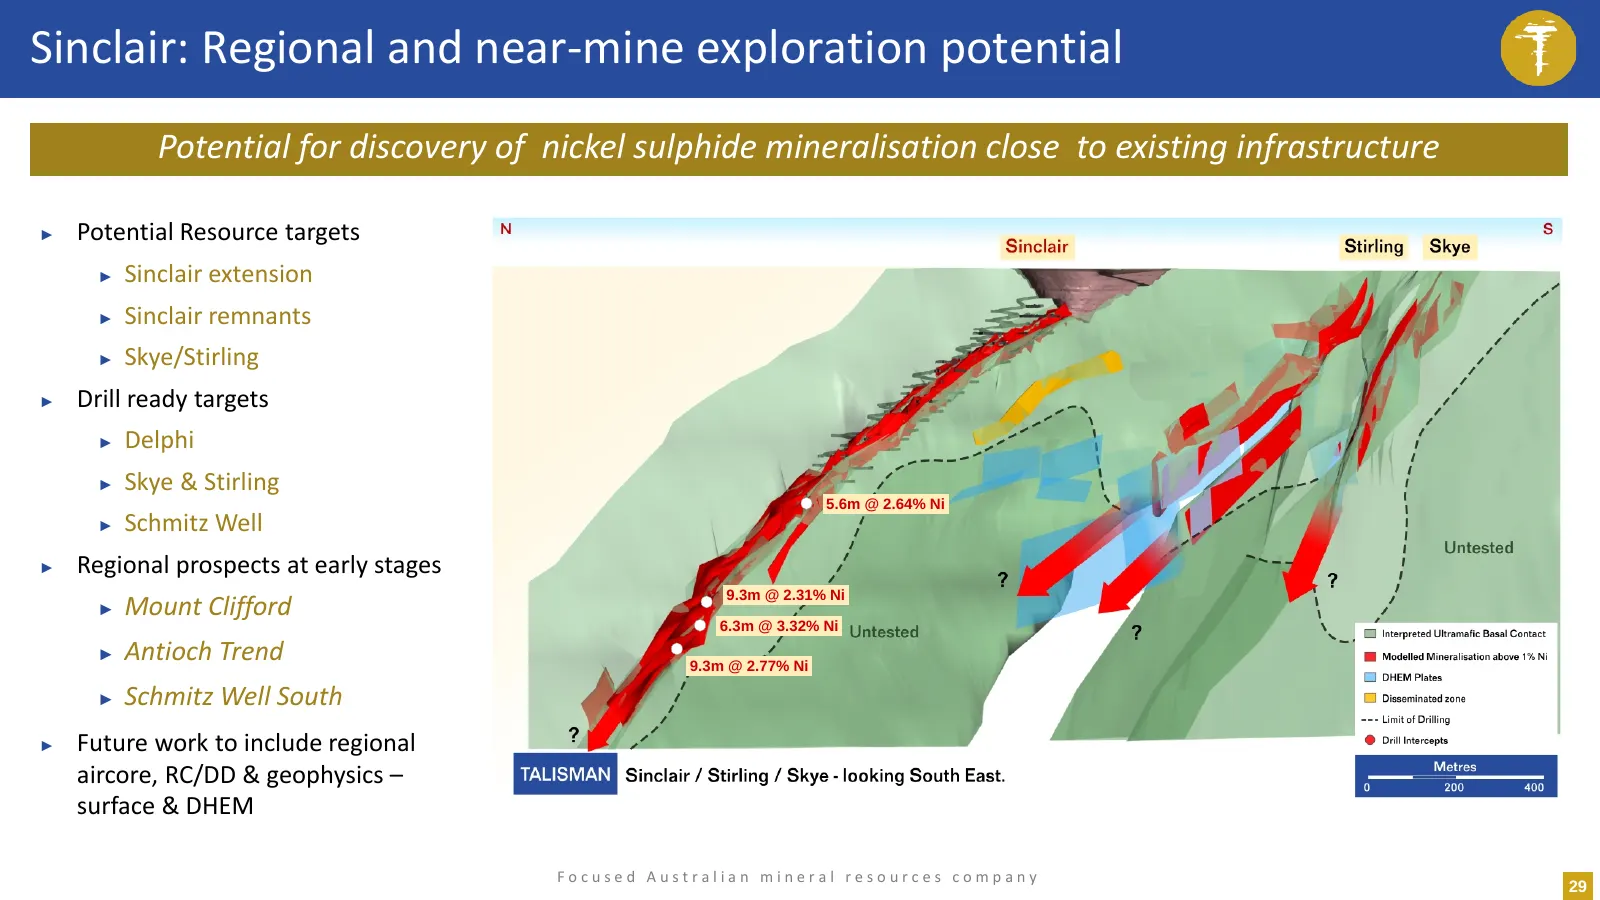
Sinclair: Regional and near-mine exploration potential Potential for discovery of nickel sulphide mineralisation close to existing infrastructure ► Potential Resource targets ► Sinclair extension ► Sinclair remnants ► Skye/Stirling ► Drill ready targets ► Delphi ► Skye & Stirling 5.6m @ 2.64% Ni ► S
Slide 30: The Talisman Investment Case
The Talisman Investment Case Emerging metals producer with exceptional prospectivity F o c u s e d A u s t r a l Ii a n m i n e r a l r e s o u r c e s c o m p a n y 30
Slide 31: The Talisman investment case
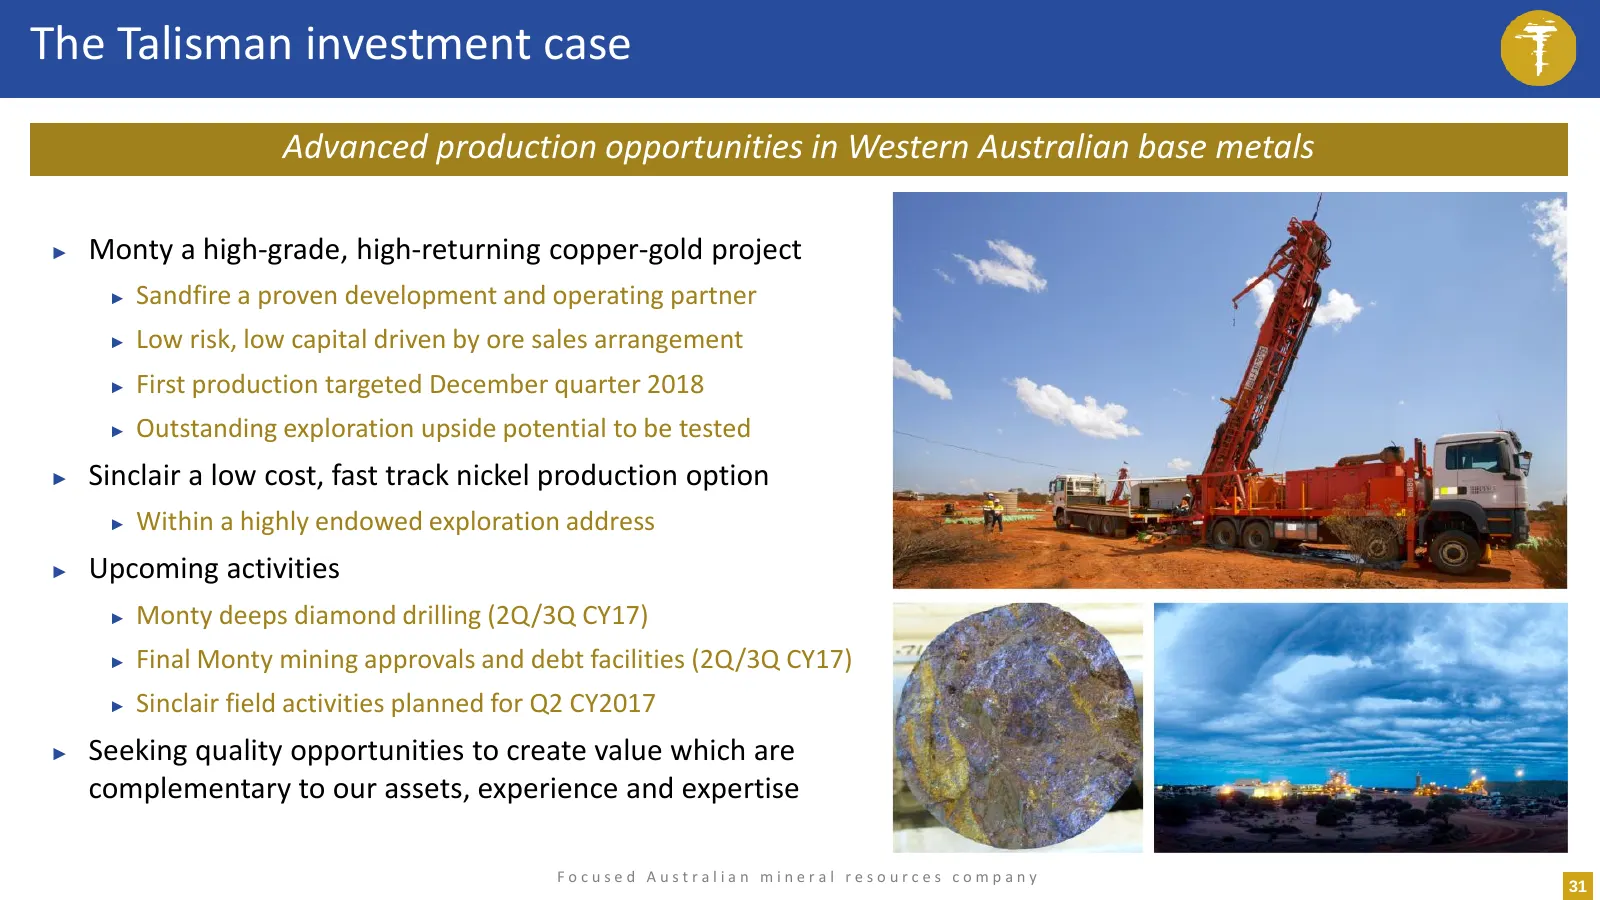
The Talisman investment case Advanced production opportunities in Western Australian base metals [Photo] ► Monty a high-grade, high-returning copper-gold project ► Sandfire a proven development and operating partner ► Low risk, low capital driven by ore sales arrangement ► First production targeted
Slide 32: THANK YOU
Focused Australian mineral resources company THANK YOU Monty: A High-Grade Development with Outstanding Returns Monty Project (Springfield Joint Venture) Feasibility Study Results, April 2017 Focused Australian mineral resources company 32
Slide 33: Appendix 1: Competent Persons' Statements
Appendix 1: Competent Persons’ Statements Note i: Mineral Resources Information in this presentation that relates to the Monty JORC Mineral Resource estimate is information previously published by Sandfire Resources NL (“Sandfire”) and is available on the Sandfire and ASX websites (see announcement
Slide 34: Appendix 2
Focused Australian mineral resources company Appendix 2 Additional Monty Feasibility Study detail Focused Australian mineral resources company 34
Slide 35: Monty Mineral Resources
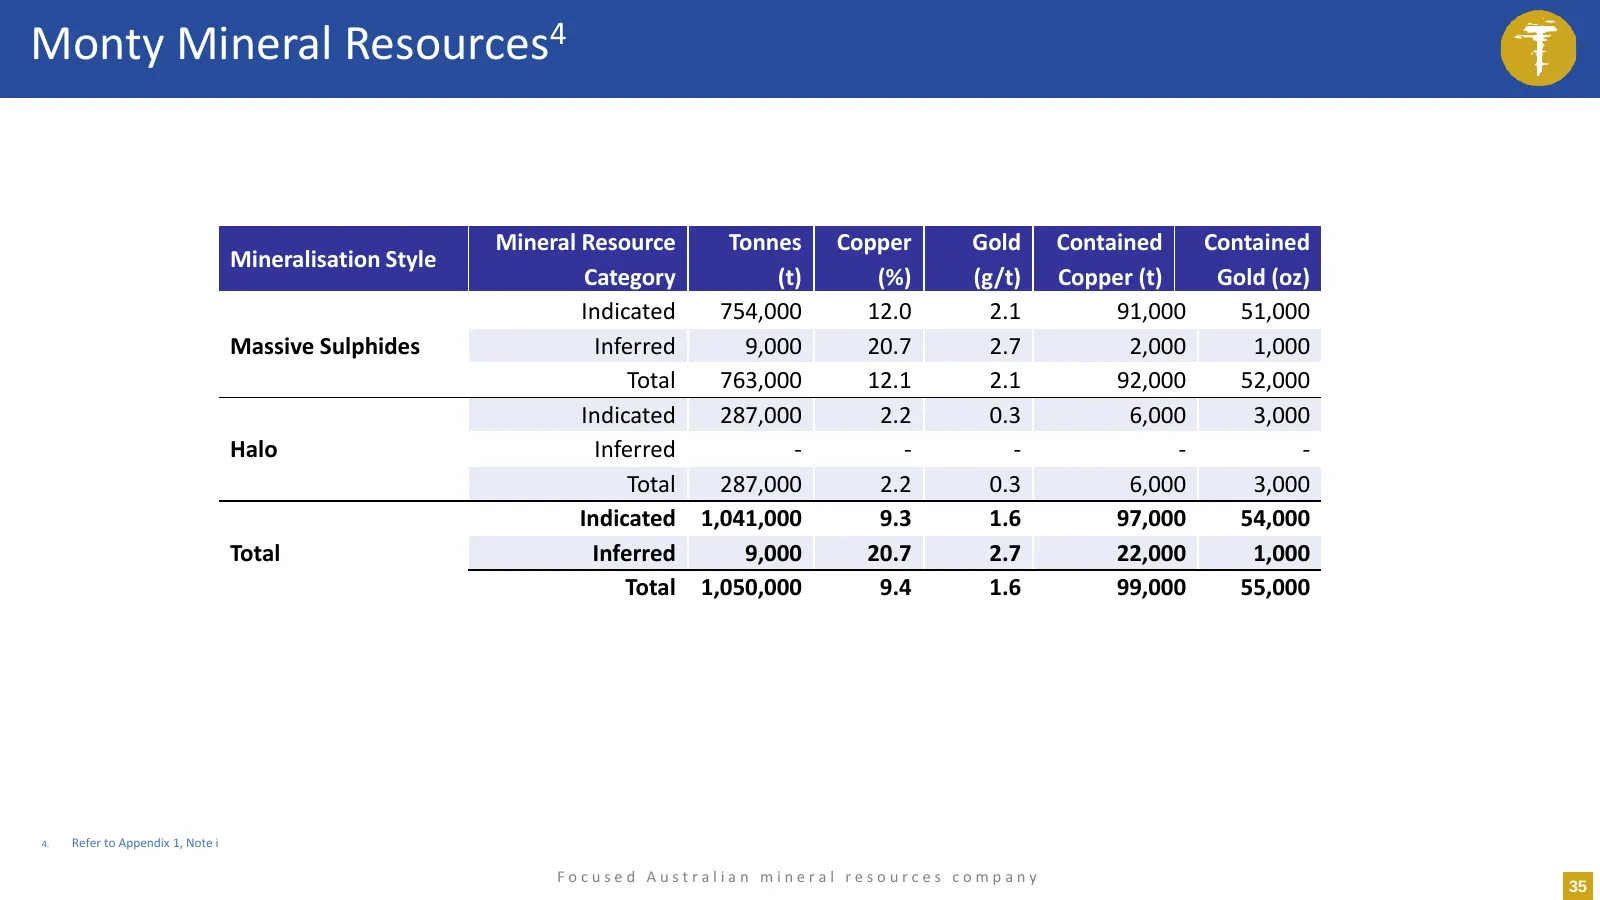
Monty Mineral Resources4 Mineral Resource Tonnes Copper Gold Contained Contained Mineralisation Style Category (t) (%) (g/t) Copper (t) Gold (oz) Indicated 754,000 12.0 2.1 91,000 51,000 Massive Sulphides Inferred 9,000 20.7 2.7 2,000 1,000 Total 763,000 12.1 2.1 92,000 52,000 Indicated 287,000 2.2
Slide 36: Capital and operating cost detail
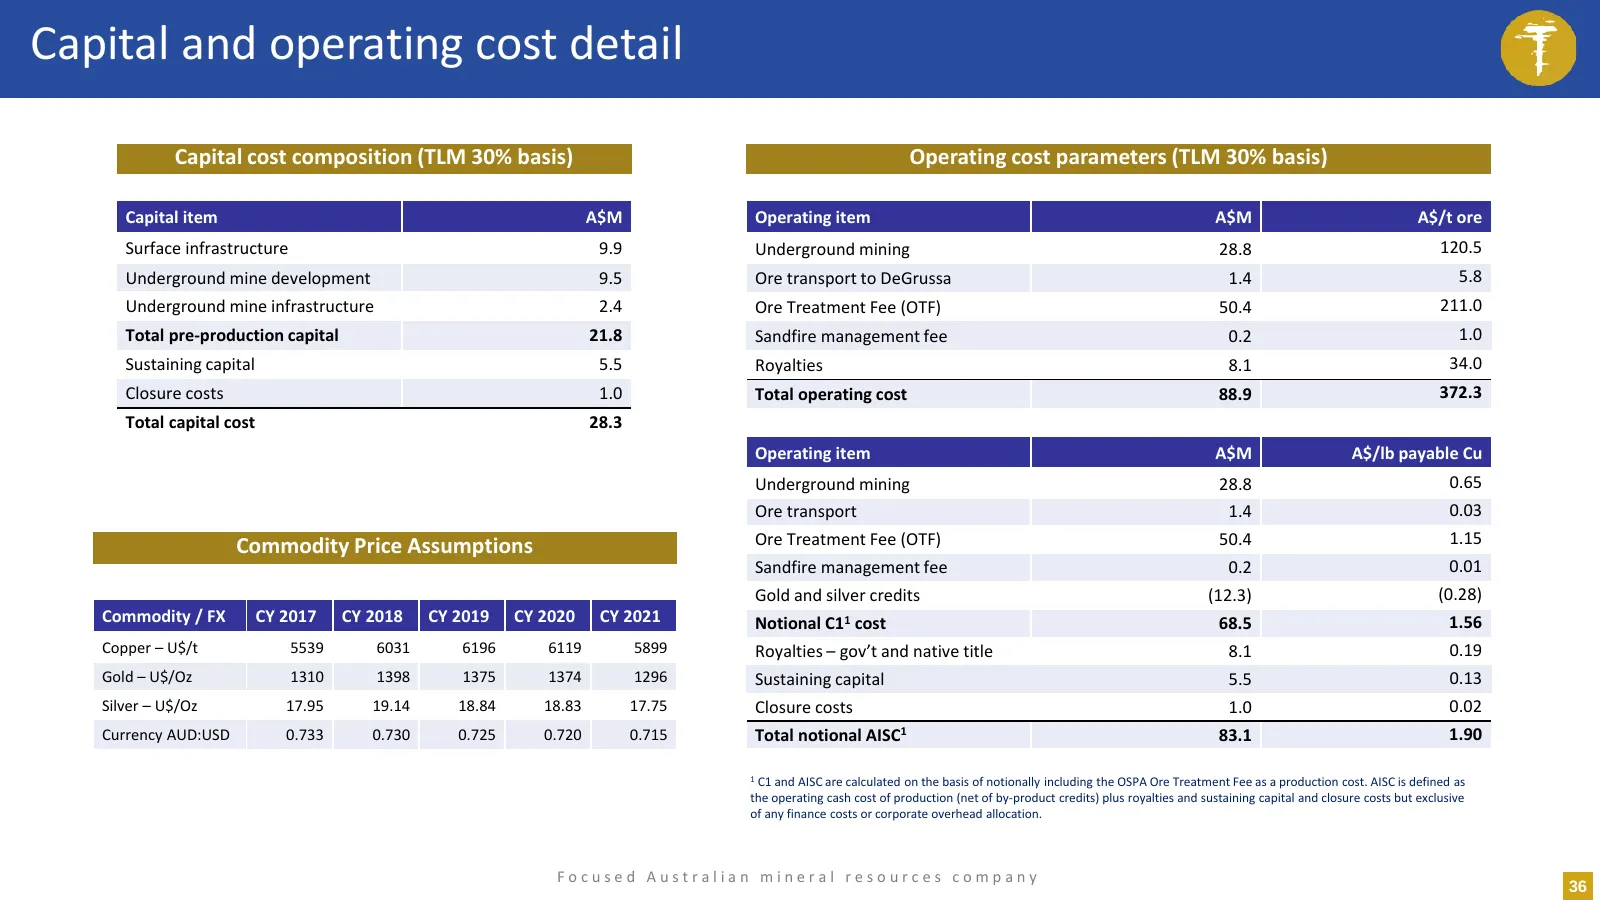
Capital and operating cost detail Capital cost composition (TLM 30% basis) Operating cost parameters (TLM 30% basis) Capital item A$M Operating item A$M A$/t ore Surface infrastructure 9.9 Underground mining 28.8 120.5 Underground mine development 9.5 Ore transport to DeGrussa 1.4 5.8 Underground mi
Source: Internet Archive copy of talismanmining.com.au
More decks from Talisman Mining Limited
 Resource Rising Stars Investor Conference 202622 slides · Sep 8, 2026
 Investor Presentation (July 2026)22 slides · Jul 8, 2026
 RRS Summer Series December 202515 slides · Dec 2, 2025
 Shareholder Meeting (November 2025)17 slides · Nov 6, 2025
 Diggers and Dealers 202517 slides · Aug 4, 2025
 RRS Gather Round April 202516 slides · Apr 10, 2025