Thales SA · EURONEXT:HO
Thales SA — Investor Day (November 2024)
104 slides from Thales SA's investor day presentation, Nov 14, 2024
Slide 1: Capital Markets Day
Capital Markets Day N o v e m b e r 1 4 th, 2 0 2 4 www.thalesgroup.com
Slide 2: CEO Perspective
CEO PERSPECTIVE PATRICE CAINE
Slide 3: Our Journey So Far | Today
~ OUR JOURNEY SO FAR | TODAY
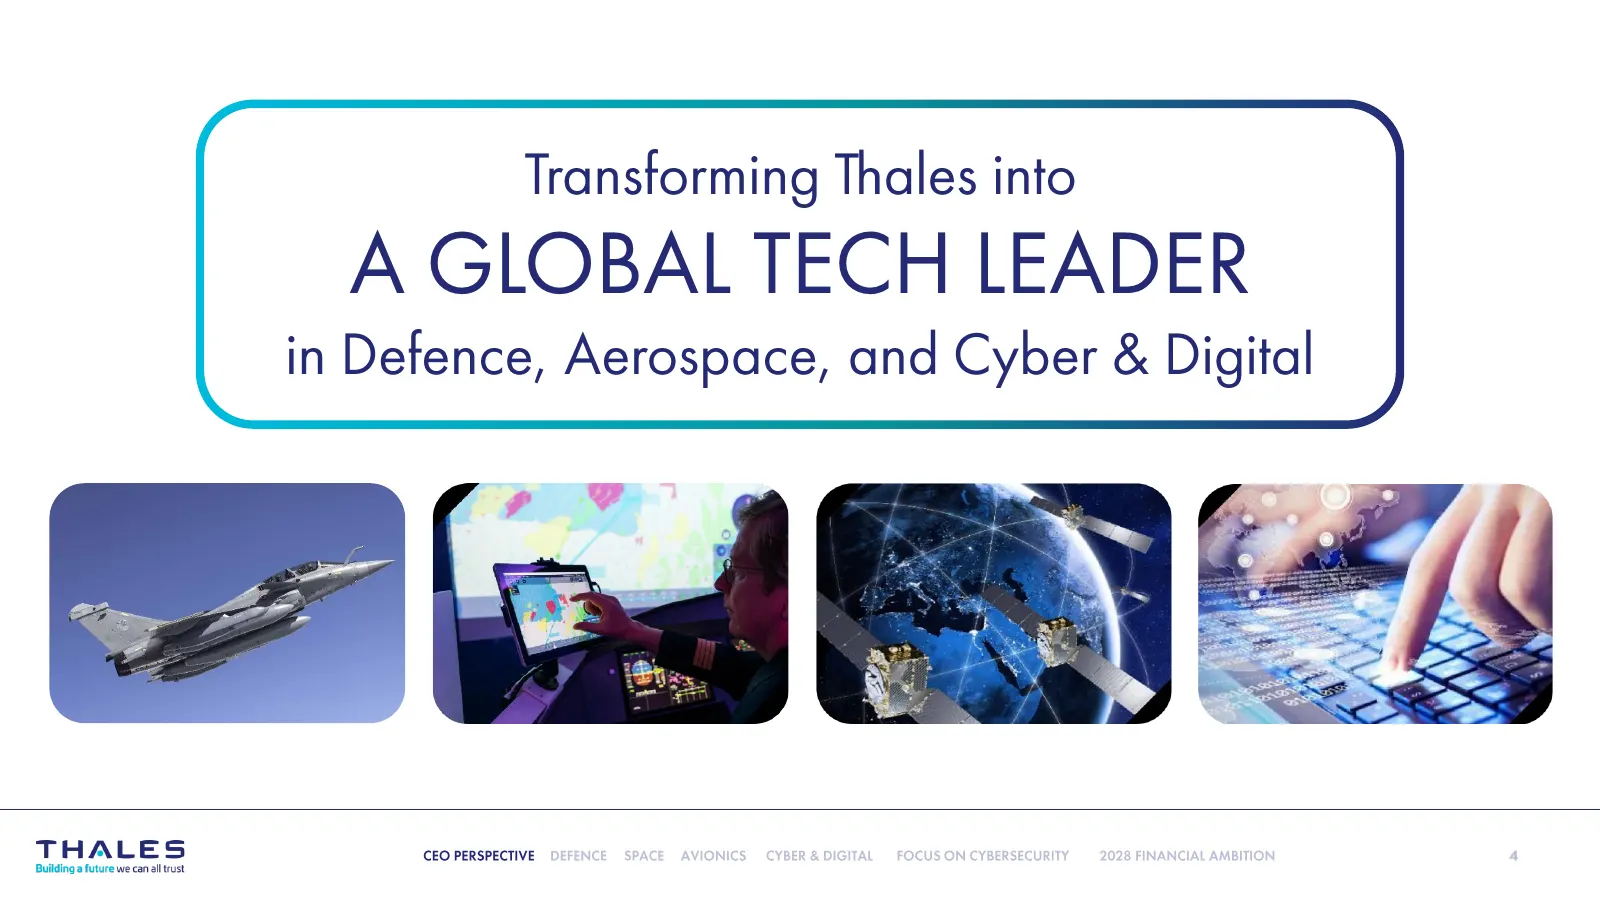
Slide 4: Transforming Thales into a global tech leader
Transforming Thales into A GLOBAL TECH LEADER in Defence, Aerospace, and Cyber & Digital Building a future we can alltust
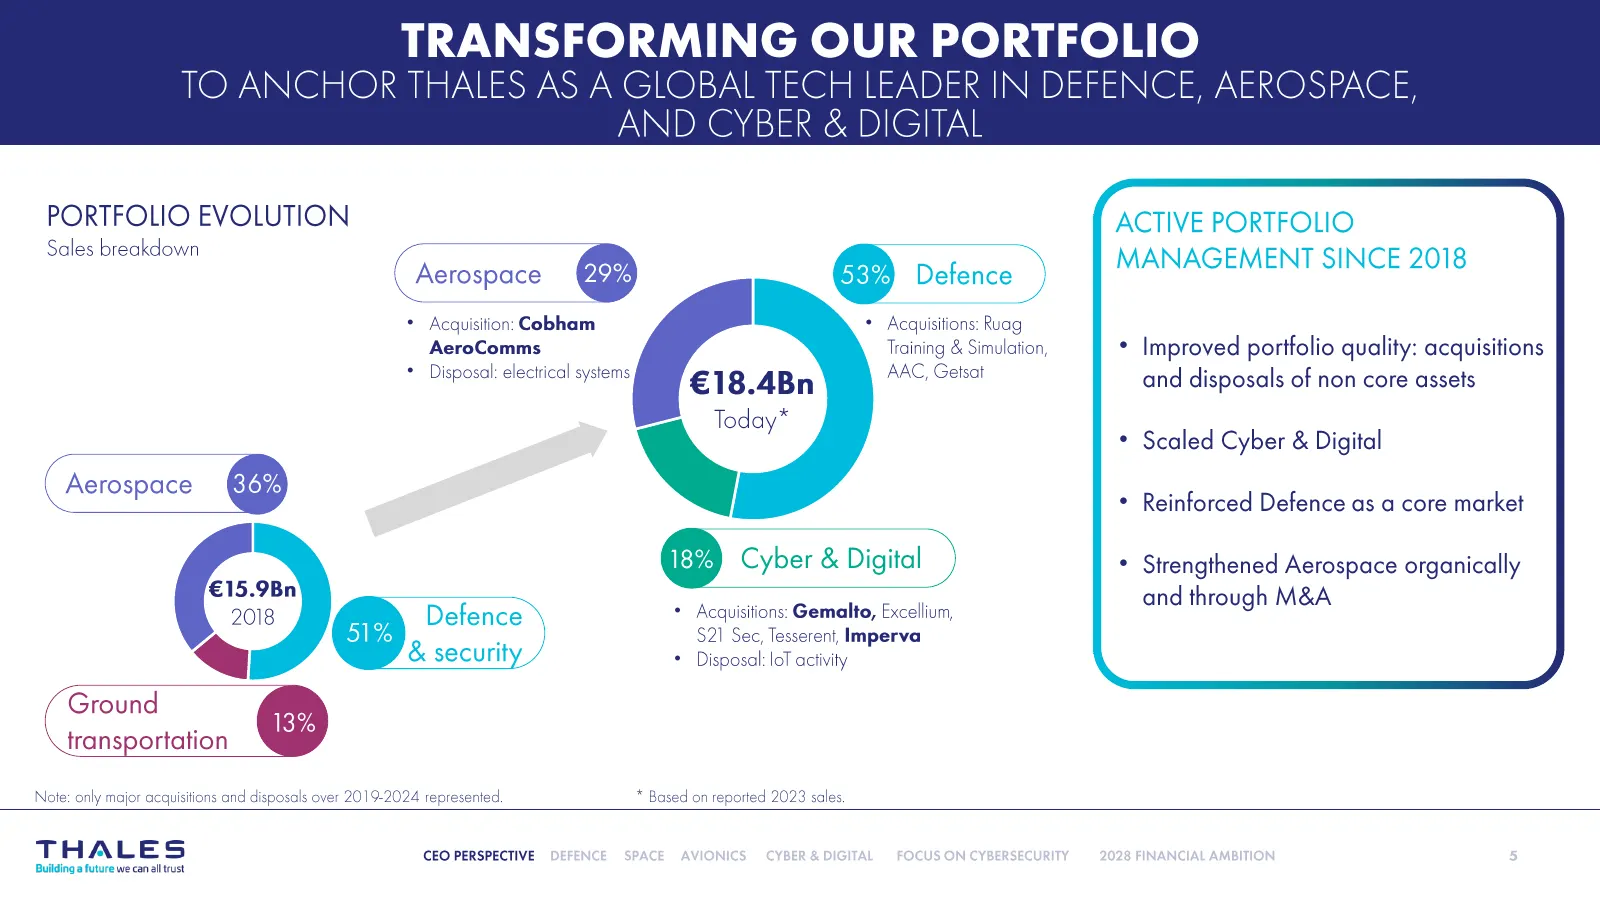
Slide 5: Transforming our portfolio to anchor Thales
TRANSFORMING OUR PORTFOLIO TO ANCHOR THALES AND CYBER & DIGITAL A GLOBAL TECH LEADER IN DEFENCE, AEROSPACE, PORTFOLIO EVOLUTION Sales breakdown 7 ( Aerospace NL @ veience ) @ eience ) * Acquisition: = @ * Acquisitions: Ruag AeroComms * Disposal: electrical systems AAC, Getsat €18.4Bn \ 7 seopace Q)
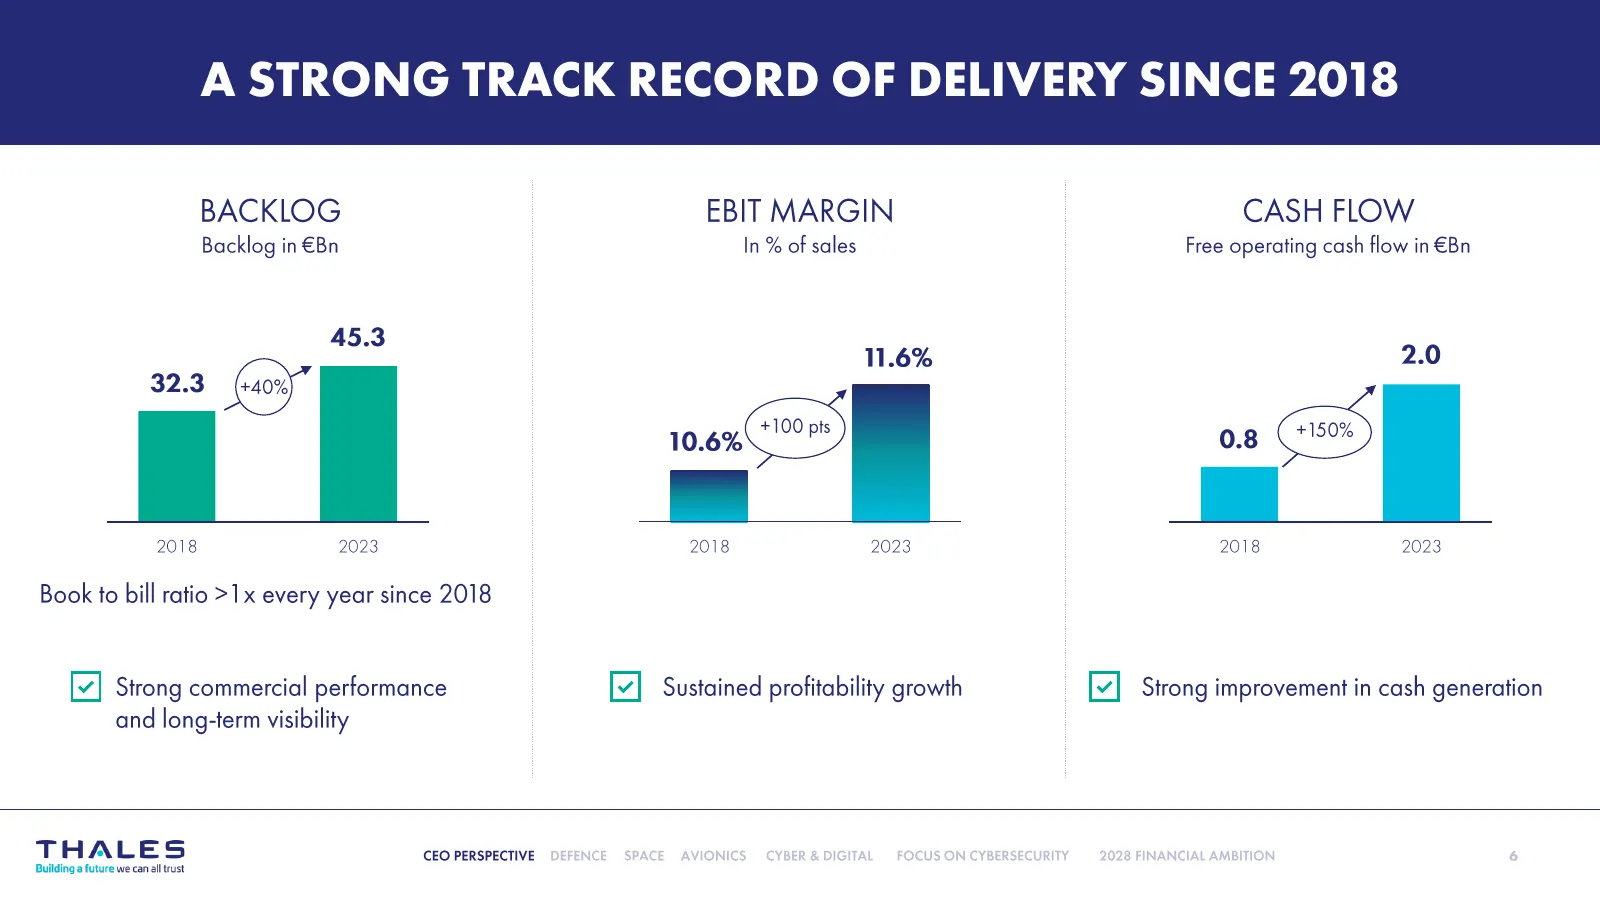
Slide 6: A strong track record of delivery since 2018
A STRONG TRACK RECORD OF DELIVERY SINCE 2018 BACKLOG Backlog in €Bn 45.3 32.3 ; 2018 2023 Book to bill ratio >1x every year since 2018 ¥| Strong commercial performance and long-term visibility EBIT MARGIN In % of sales 2018 2023 ¥| Sustained profitability growth CASH FLOW Free operating cash flow in
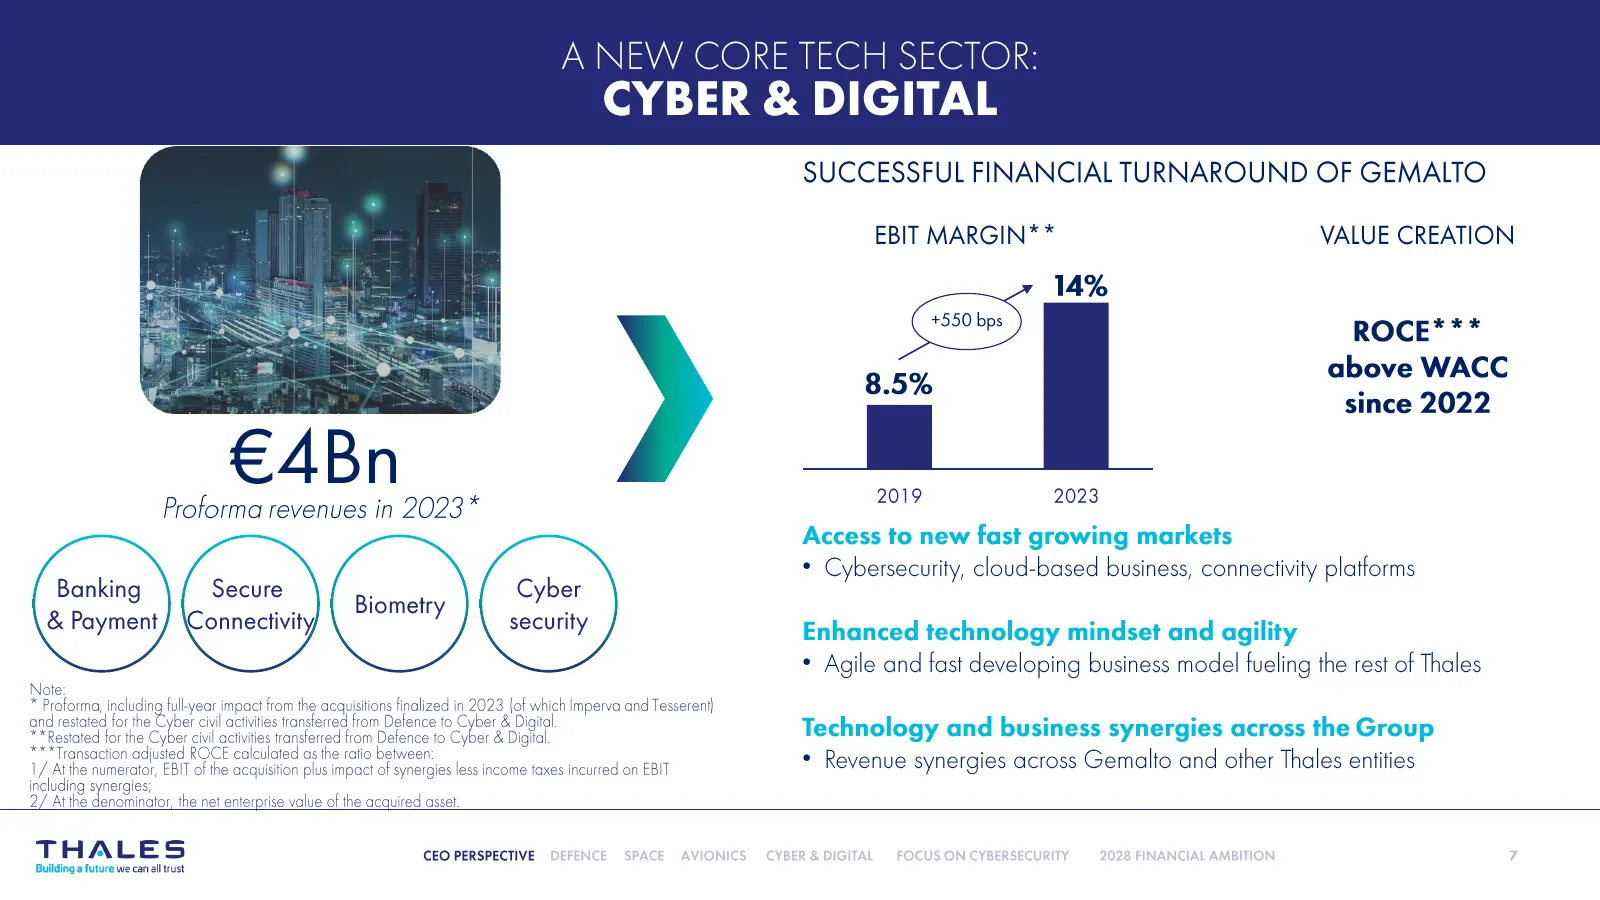
Slide 7: A new core tech sector: Cyber & Digital
A NEW CORE TECH SECTOR: CYBER & DIGITAL SUCCESSFUL FINANCIAL TURNAROUND OF GEMALTO EBIT MARGIN * * VALUE CREATION ROCE*** above WACC since 2022 ‘ y €ABn Proforma revenues in 2023 * 2019 2023 * Cybersecurity, cloud-based business, connectivity platforms Banking Secure Cyber CPE ON * Agile and fast de
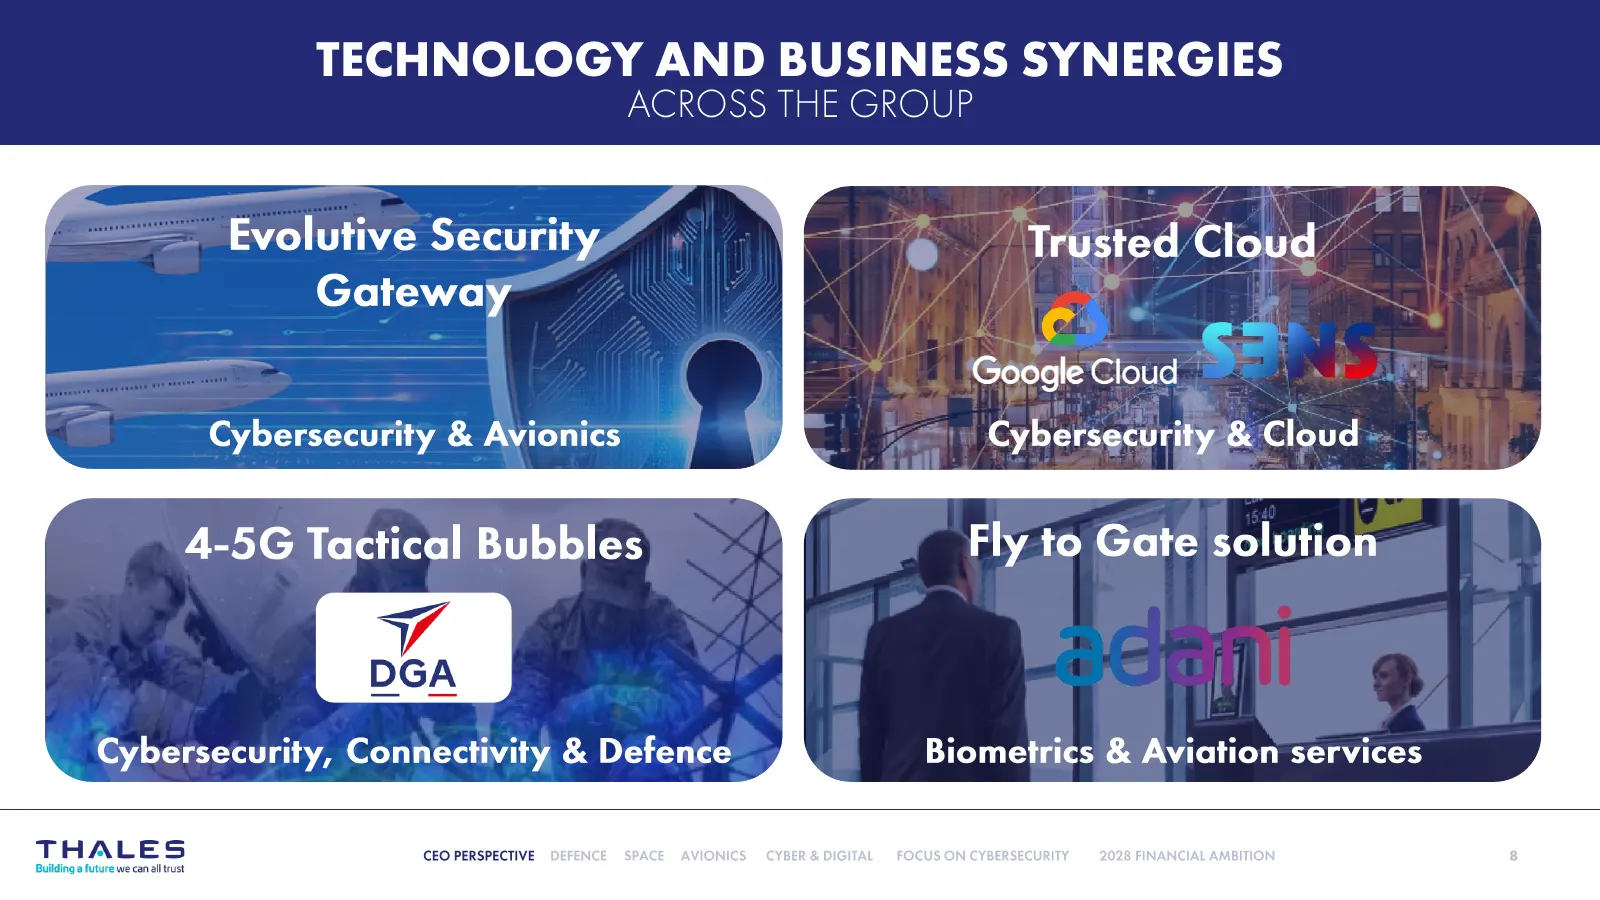
Slide 8: Technology and business synergies across the group
TECHNOLOGY AND BUSINESS SYNERGIES ACROSS THE GROUP Evolutive Security, Trusted Cloud Gateway £2" §> Google Cloud Cybersecurity & Avionics Cybersecurity & Cloud 4-5G Tactical Bubbles Fly to Gate solution DGA Cybersecurity, Connectivity & Defence Biometrics & Aviation services CEO PERSPECTIVE
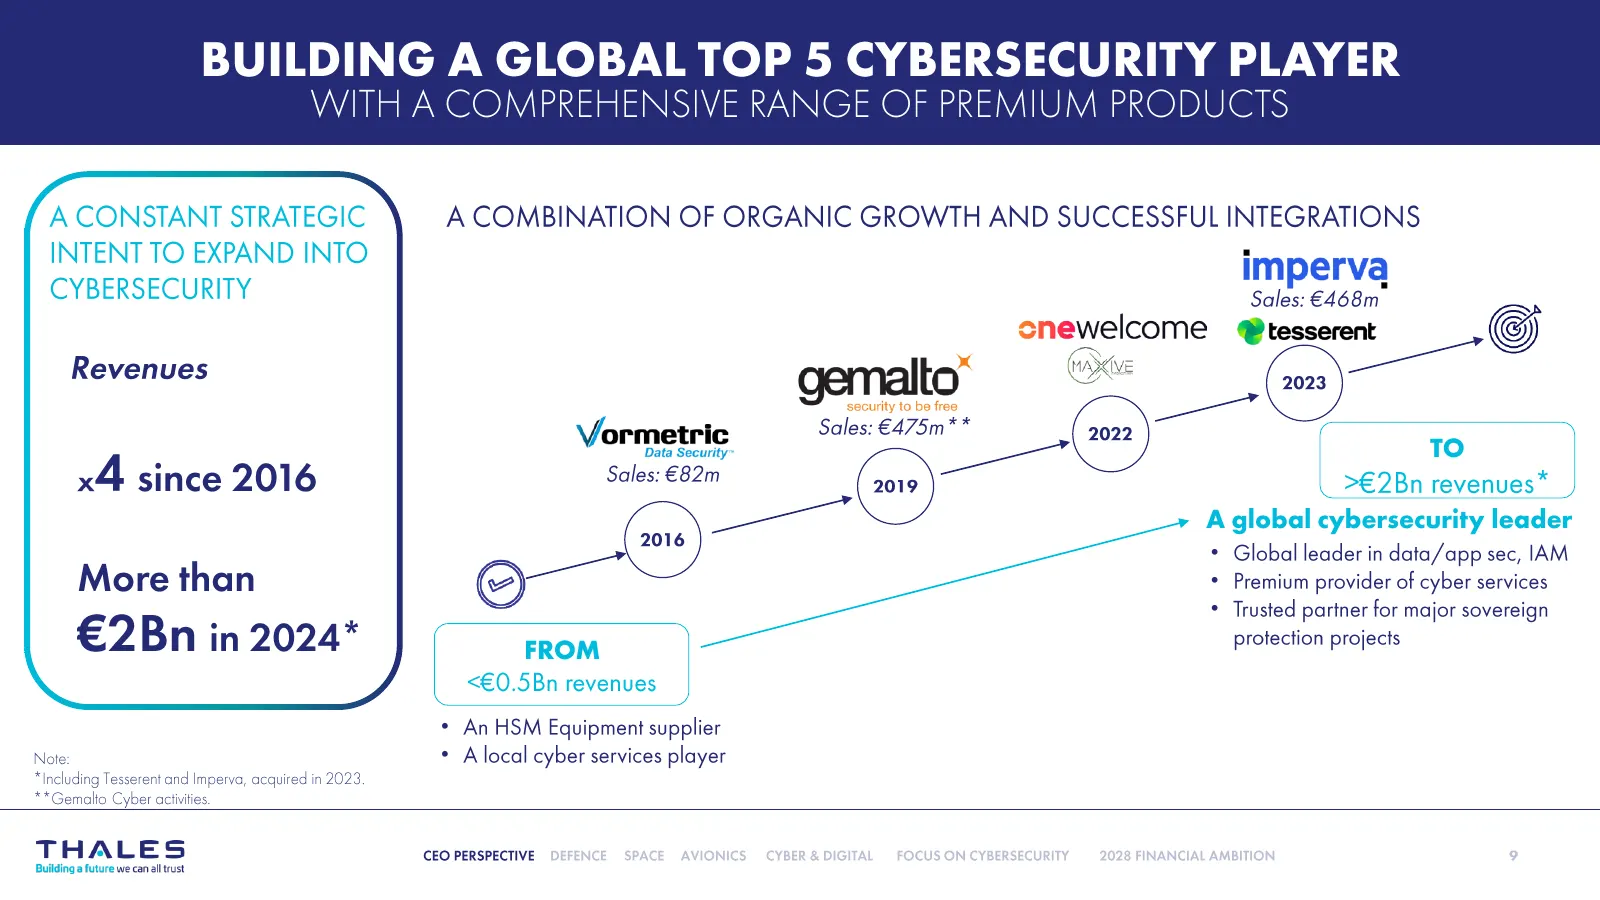
Slide 9: Building a global top cybersecurity player
BUILDING A GLOBAL TOP 5 CYBERSECURITY PLAYER WITH A COMPREHENSIVE RANGE OF PREMIUM PRODUCTS A CONSTANT STRATEGIC A COMBINATION OF ORGANIC GROWTH AND SUCCESSFUL INTEGRATIONS INTENT TO EXPAND INTO CYBERSECURITY imperva cnewelcome @tesserent © Revenues gemalto* @ ive (+2) oe ‘security to be free Vormet
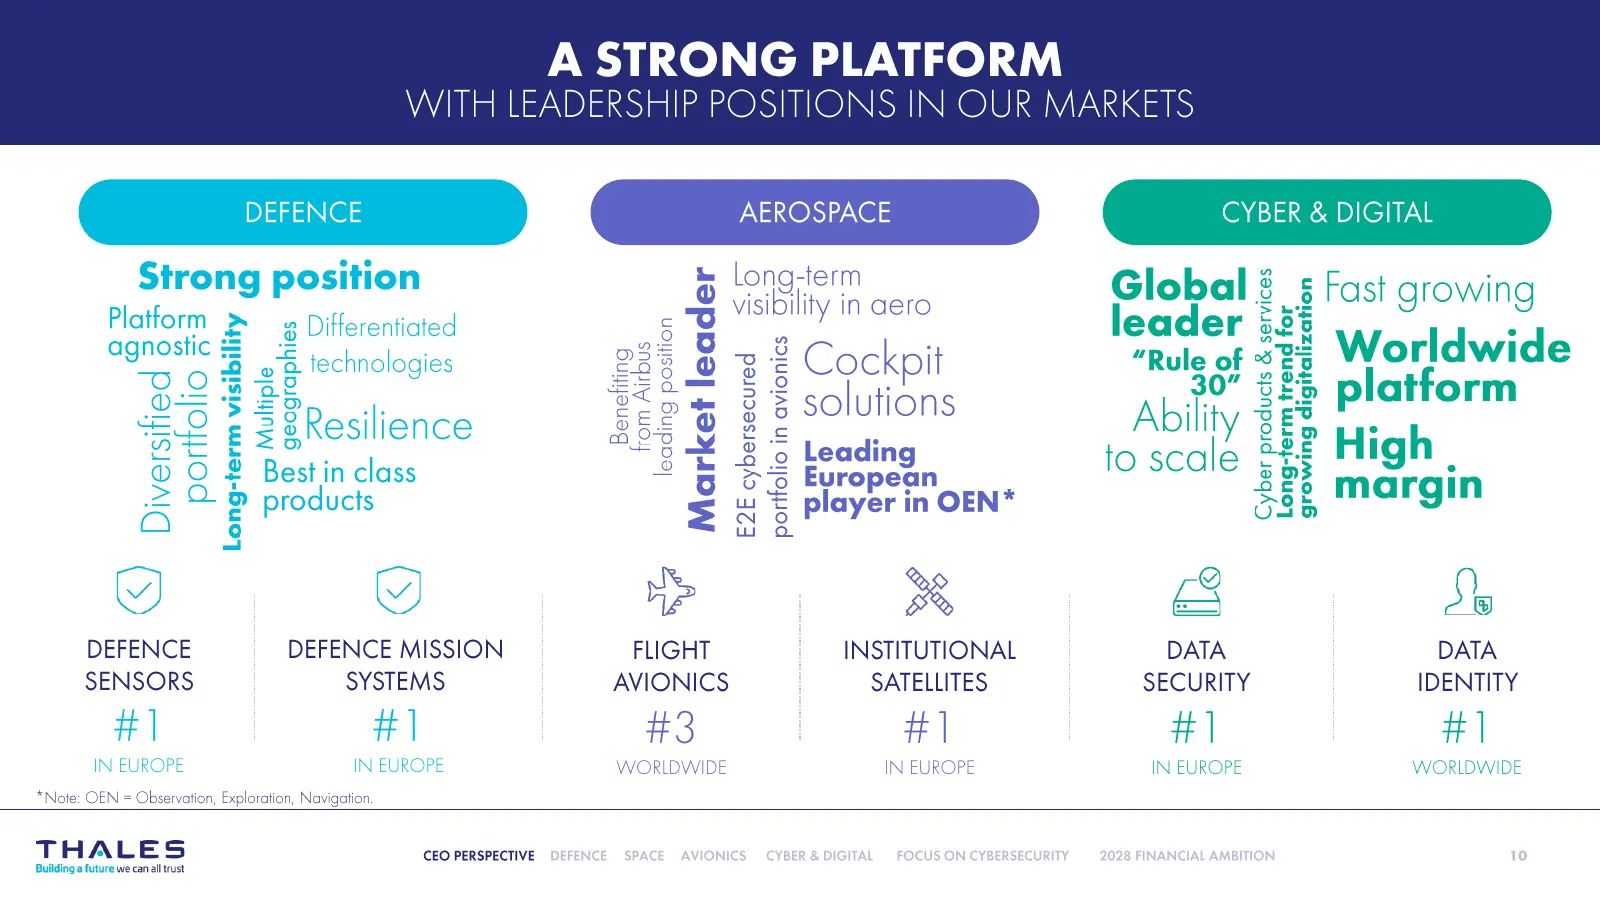
Slide 10: A strong platform with leadership positions
A STRONG PLATFORM WITH LEADERSHIP POSITIONS IN OUR MARKETS AEROSPACE CYBER & DIGITAL & Long-term 3 ; © visibility i In AelO Global 3 8 Fast growing so. leader 33: Word id ® = Cockpit “Rule of 23's lat wide 5g solutions Ability 3=2 P atrorm 2c Sen 7 42 eading | to scale 238 High | = w = player in OEN
Slide 11: Strategic Priorities
\ STRATEGIC PRIORITIES _ TOMORROW
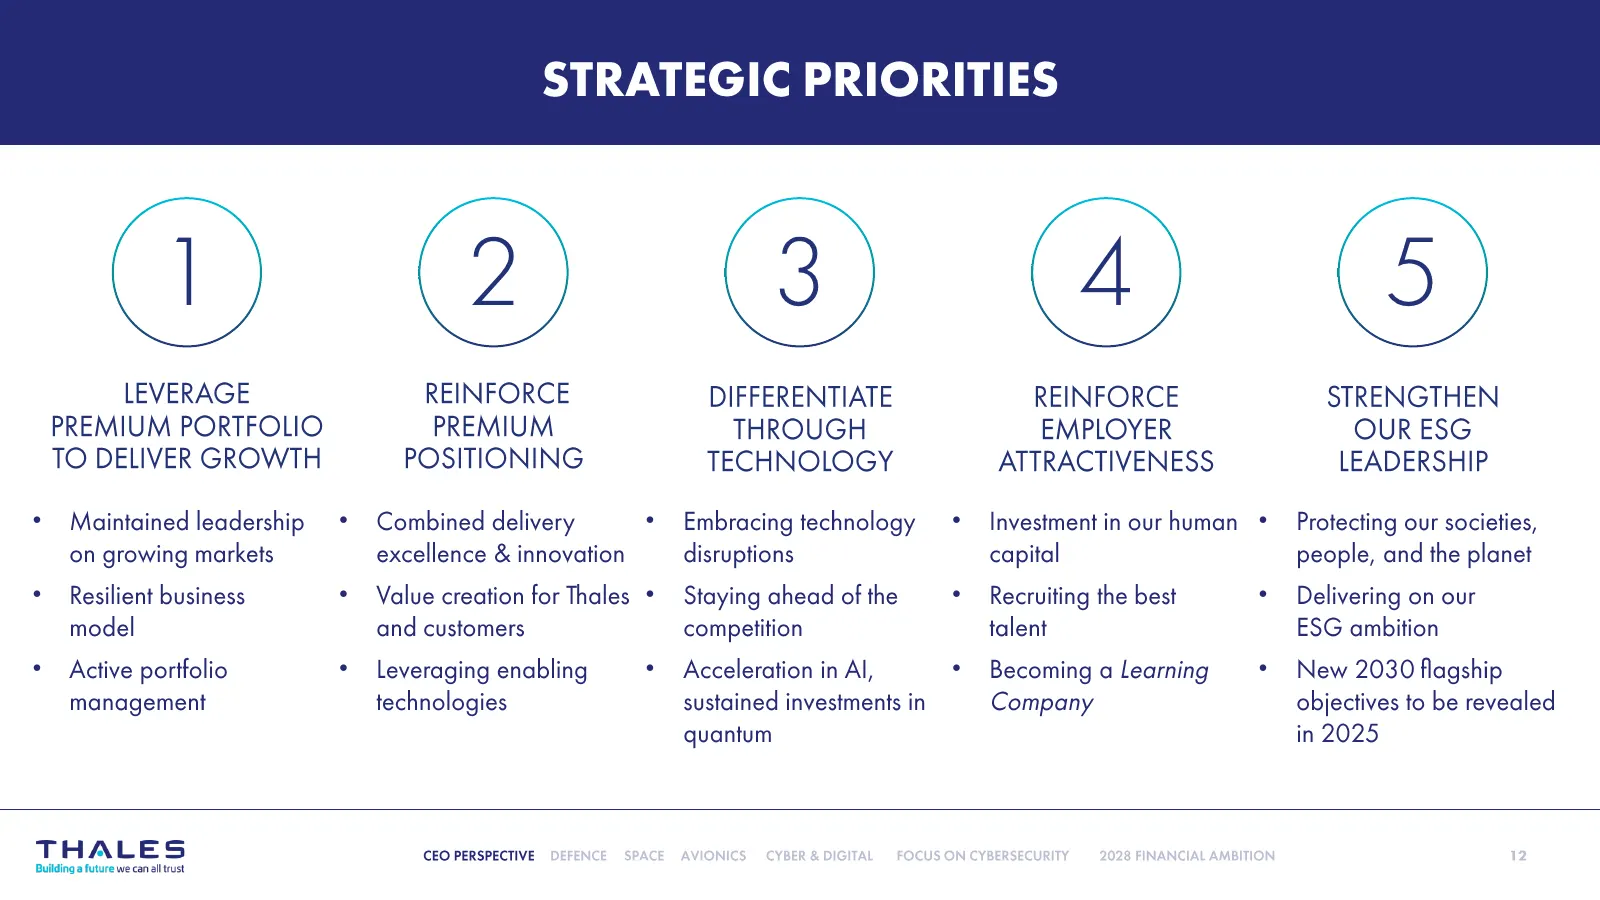
Slide 12: Strategic priorities
STRATEGIC PRIORITIES D&O #& ®& LEVERAGE REINFORCE DIFFERENTIATE REINFORCE STRENGTHEN PREMIUM PORTFOLIO PREMIUM THROUGH EMPLOYER OUR ESG TO DELIVER GROWTH POSITIONING TECHNOLOGY ATTRACTIVENESS LEADERSHIP * Maintained leadership * Combined delivery * Embracing technology * Investmentin ourhuman * Prot
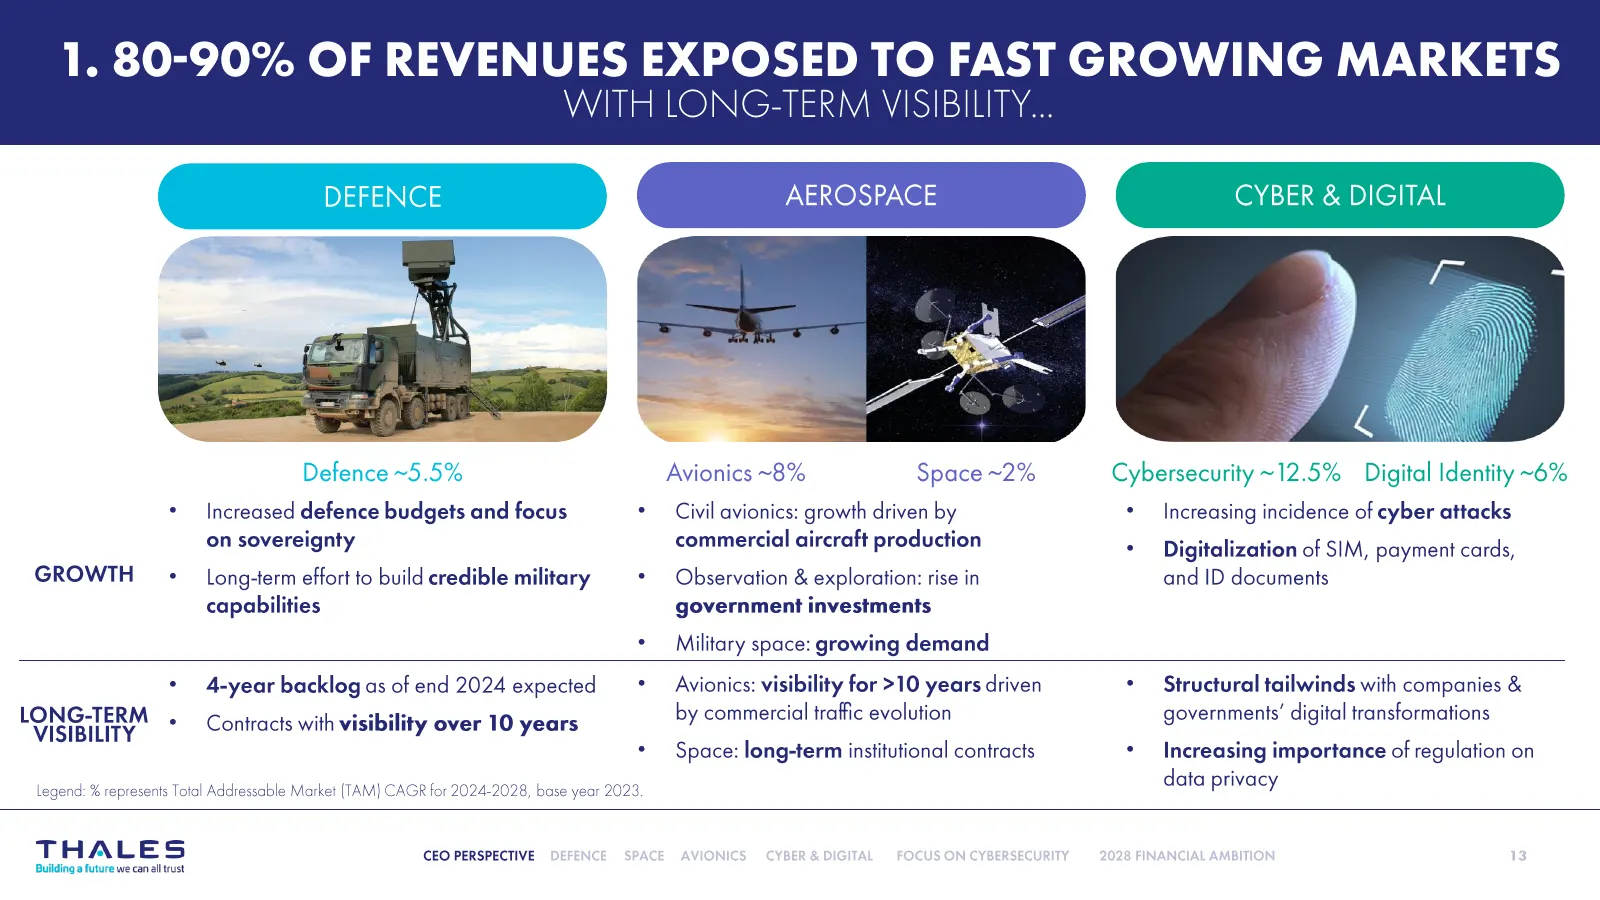
Slide 13: 80-90% of revenues exposed to fast growing markets
1. 80-90% OF REVENUES EXPOSED TO FAST GROWING MARKETS WITH LONG-TERM VISIBILITY... AEROSPACE Increased defence budgets and focus on sovereignty Avionics ~8% Civil avionics: growth driven by commercial aircraft production Space ~2% Increasing incidence of cyber attacks Digitalization of SIM, payment
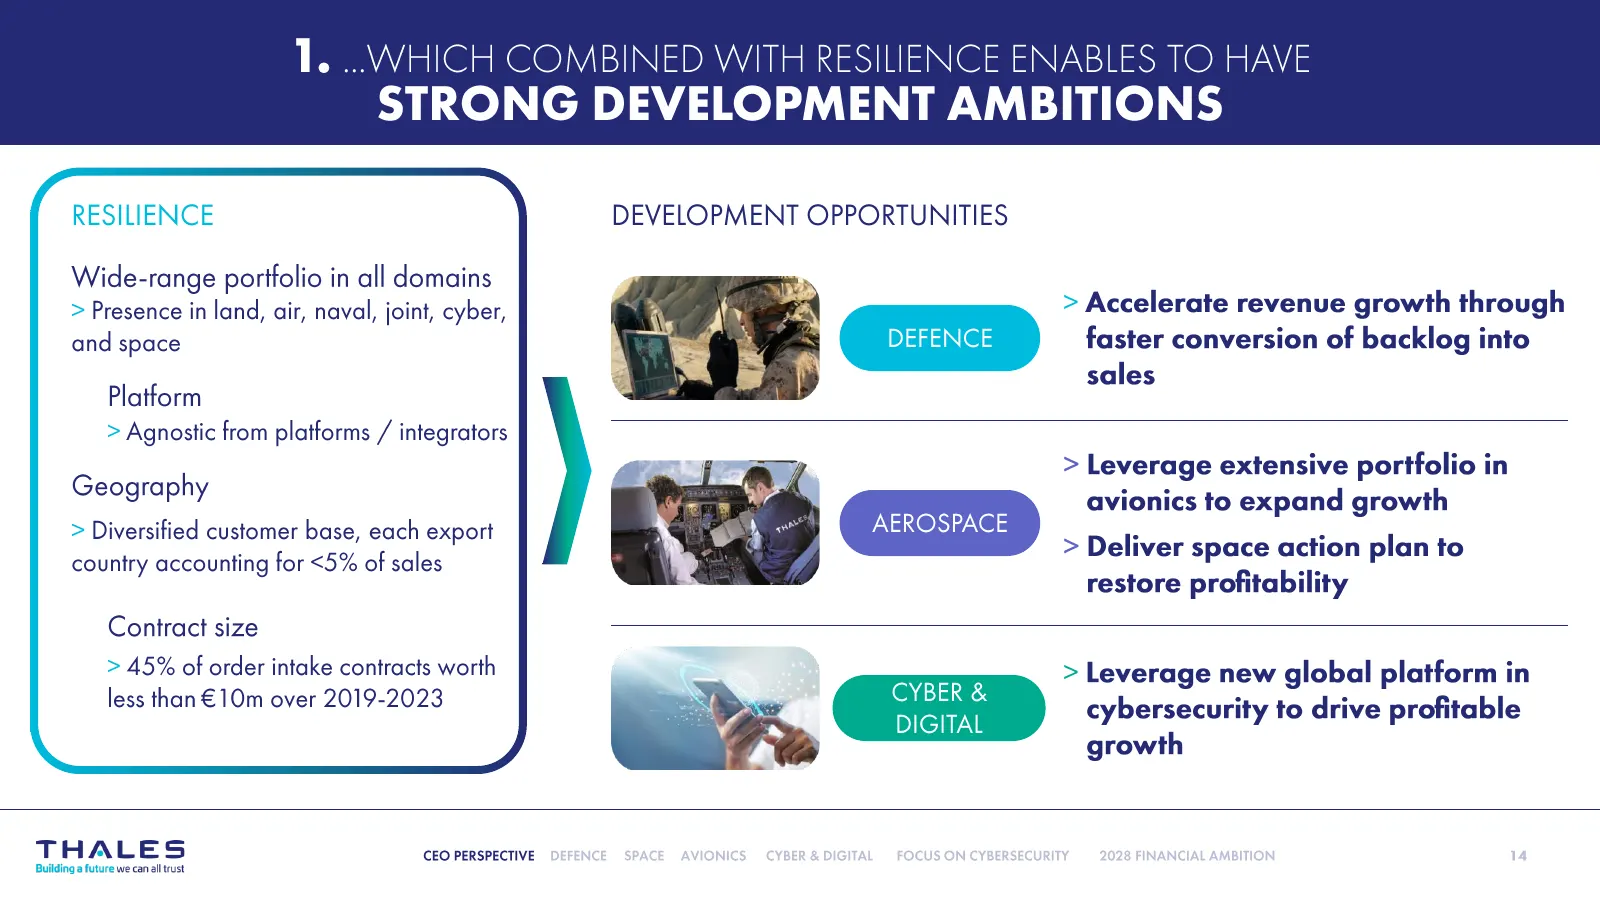
Slide 14: Resilience enabling strong development ambitions
T. ..WHICH COMBINED WITH RESILIENCE ENABLES TO HAVE STRONG DEVELOPMENT AMBITIONS DEVELOPMENT OPPORTUNITIES Wide-range portfolio in all domains Presence in land, air, naval, joint, cyber, and space Accelerate revenue growth through faster conversion of backlog into sales Platform Agnostic from platfo
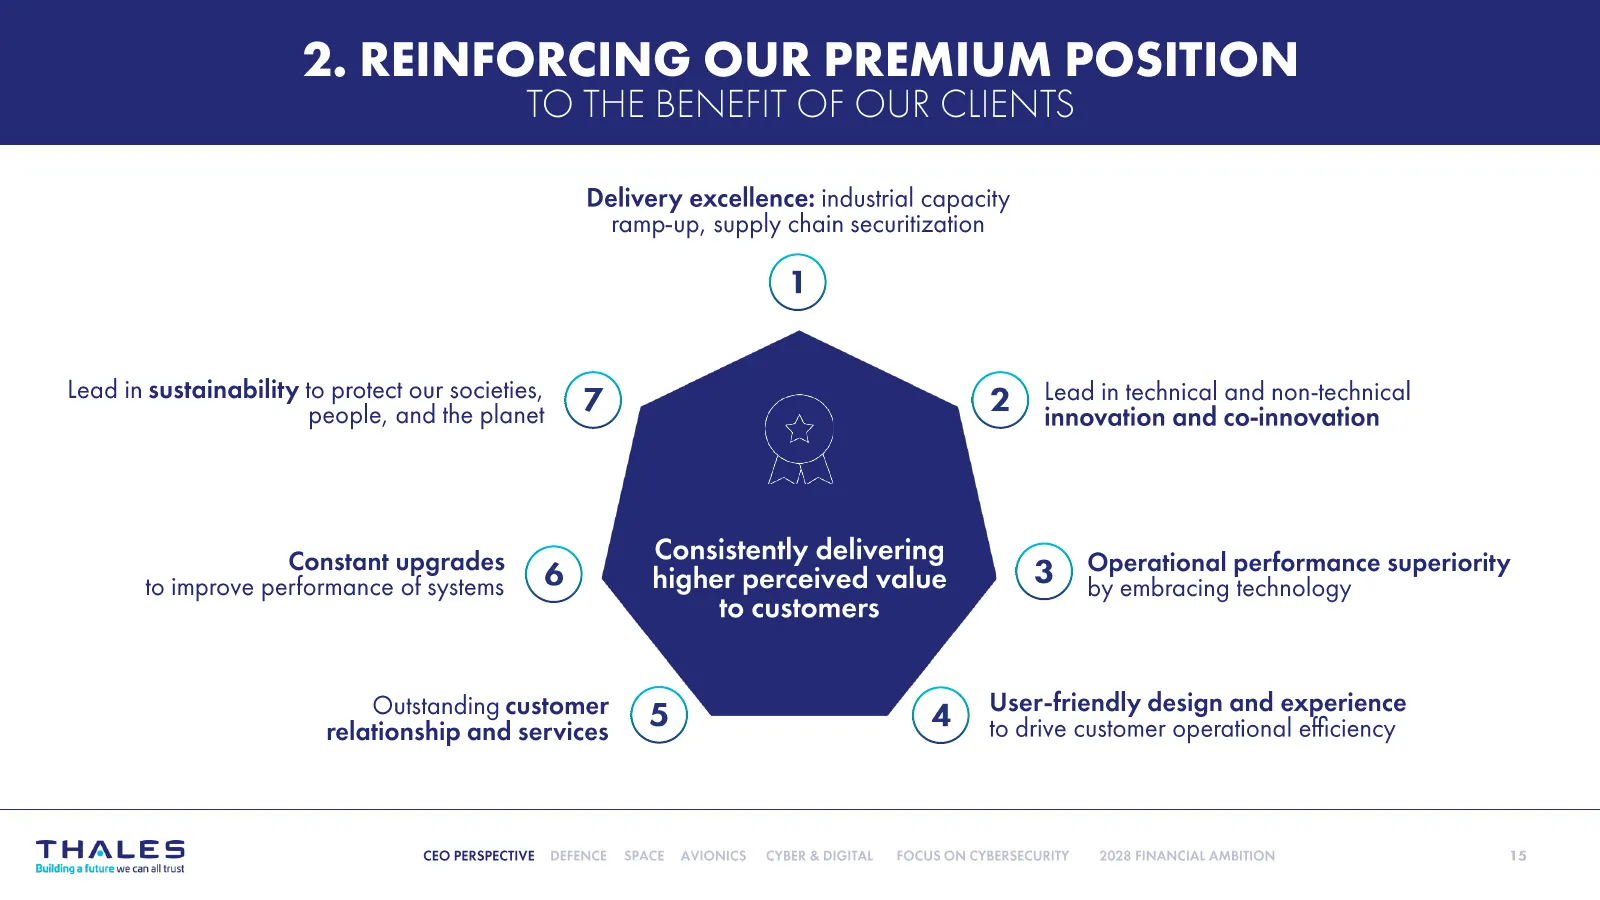
Slide 15: Reinforcing our premium position
2. REINFORCING OUR PREMIUM POSITION TO THE BENEFIT OF OUR CLIENTS Delivery excellence: industrial capacity ramp-up, supply chain securitization ® Lead in sustainability to protect our societies, (7) ur socie (2) Lead in technical and non-technical people, and the planet innovation and co-innovation
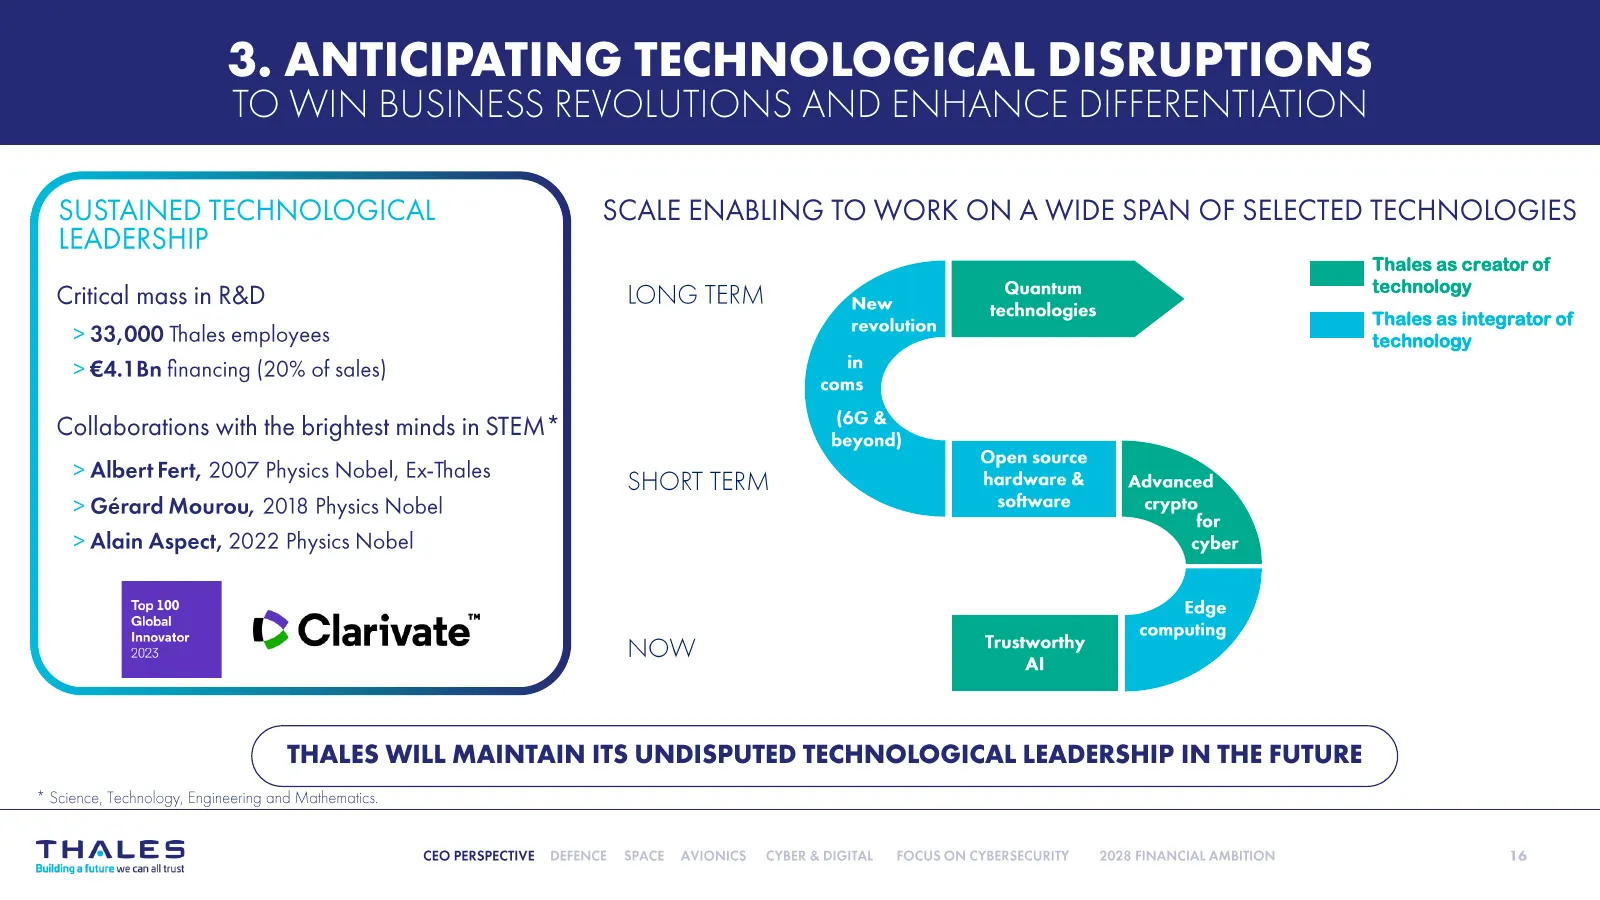
Slide 16: Thales as creator and integrator of technology
Thales as creator of technology Thales as integrator of technology
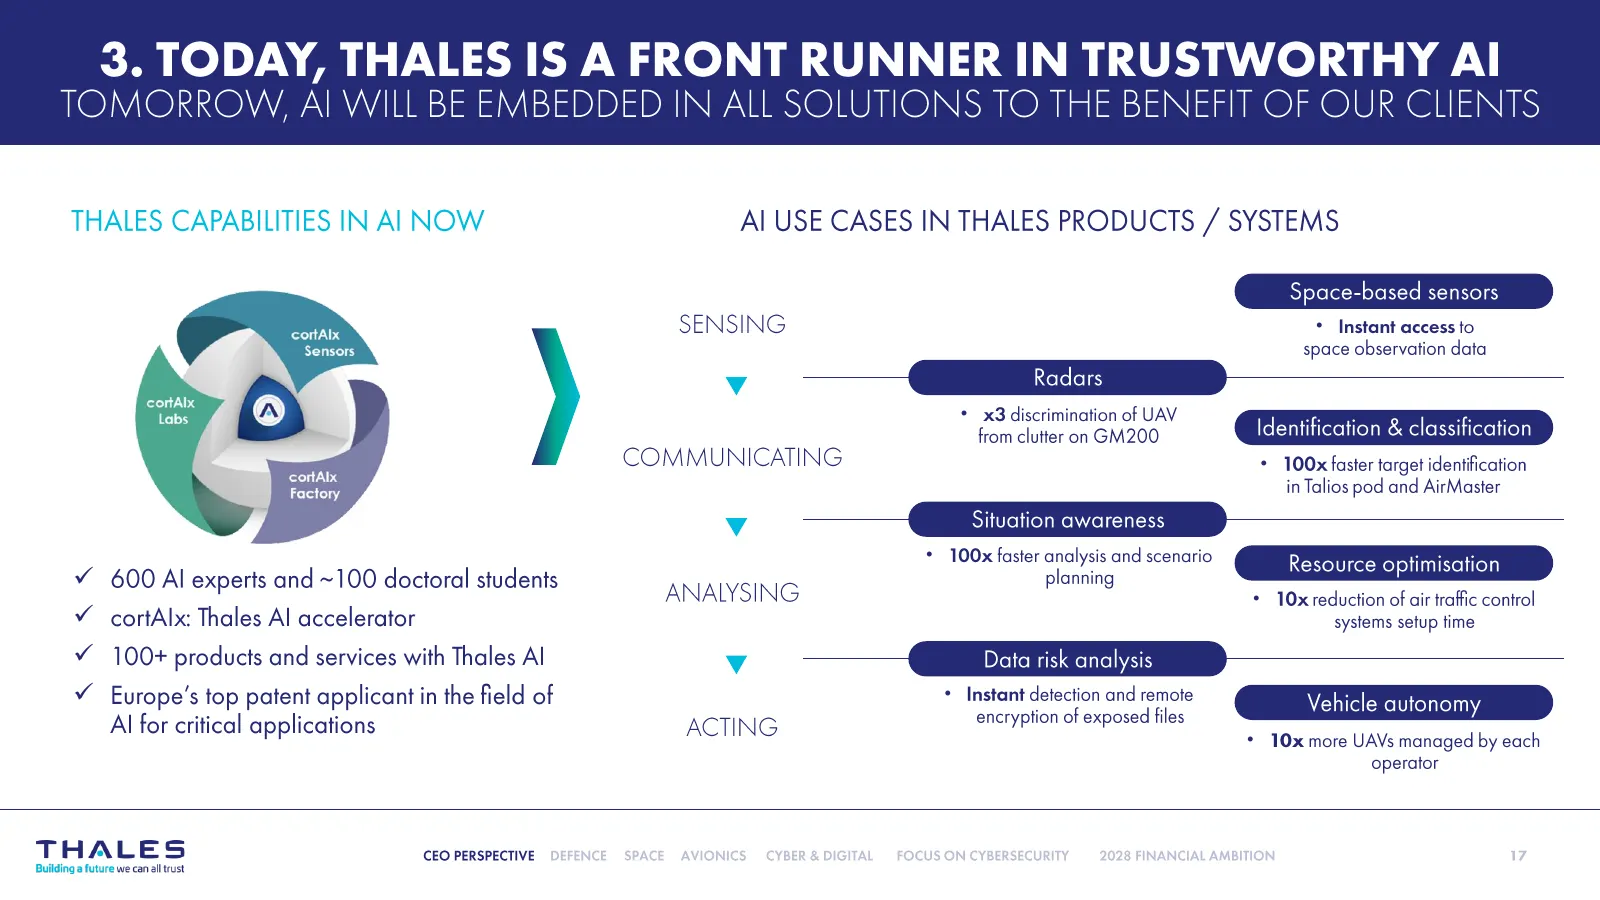
Slide 17: Thales a front runner in trustworthy AI
3. TODAY, THALES IS A FRONT RUNNER IN TRUSTWORTHY Al TOMORROW, Al WILL BE EMBEDDED IN ALL SOLUTIONS TO THE BENEFIT OF OUR CLIENTS THALES CAPABILITIES IN Al NOW Al USE CASES IN THALES PRODUCTS / SYSTEMS Space-based sensors SENSING * Instant access to space observation data ee cs * x3 discri ti f UAV
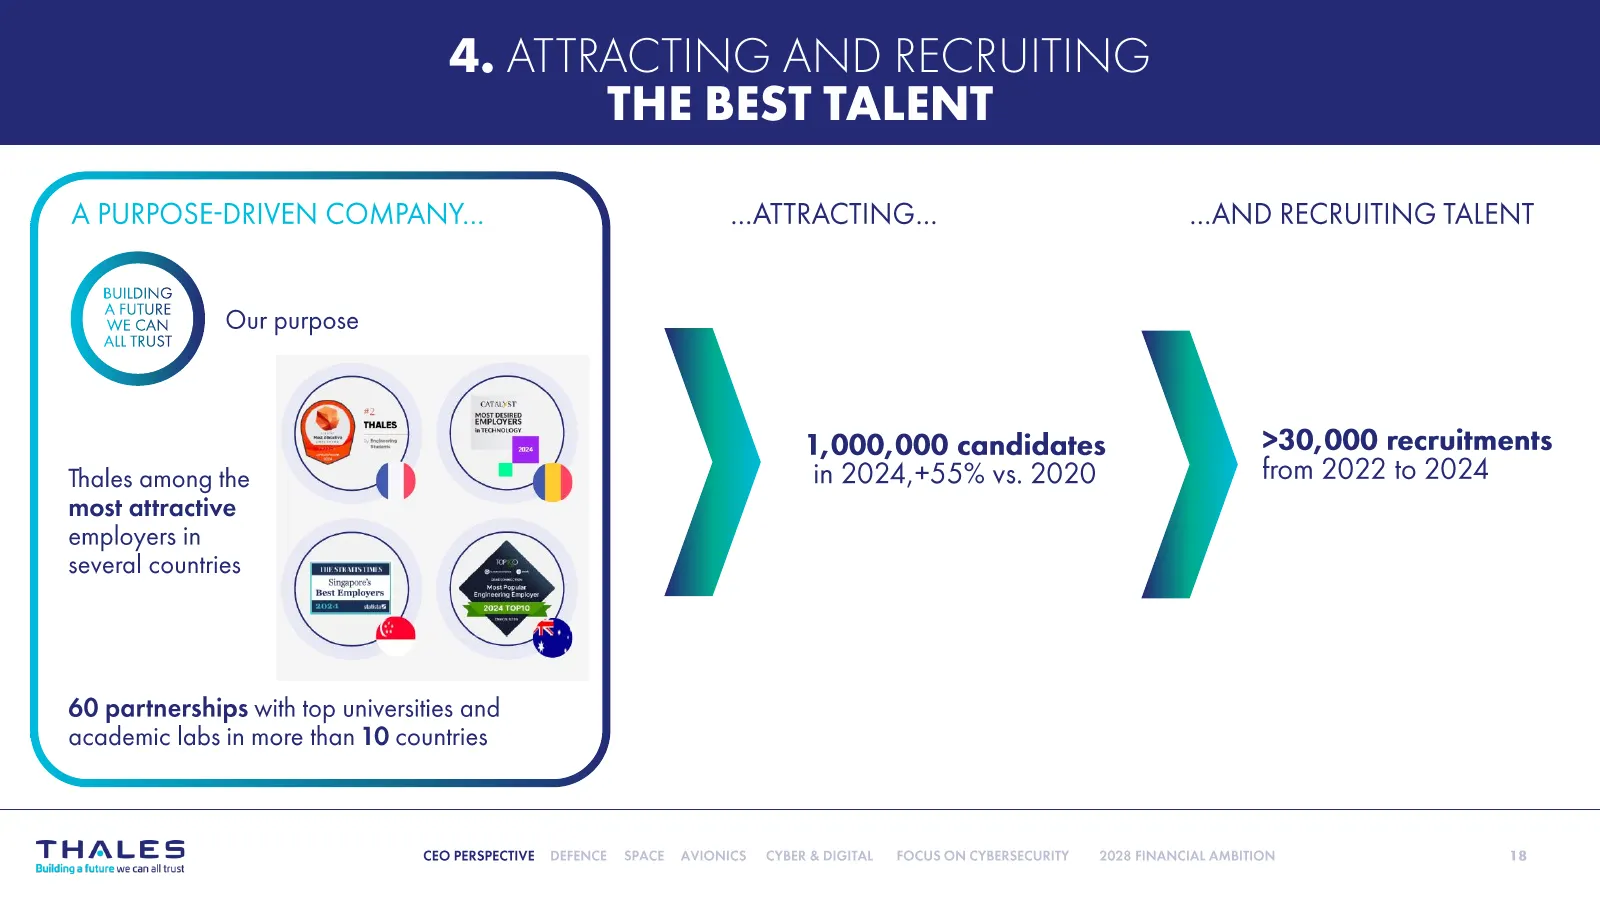
Slide 18: Attracting and recruiting the best talent
4. ATTRACTING AND RECRUITING THE BEST TALENT A PURPOSE-DRIVEN COMPANY... . ATTRACTING... .-AND RECRUITING TALENT BUILDING A FUTURE WE CAN Our purpose ALL TRUST 1,000,000 candidates >30,000 recruitments Thales among the in 2024,+55% vs. 2020 from 2022 to 2024 most attractive employers in several coun
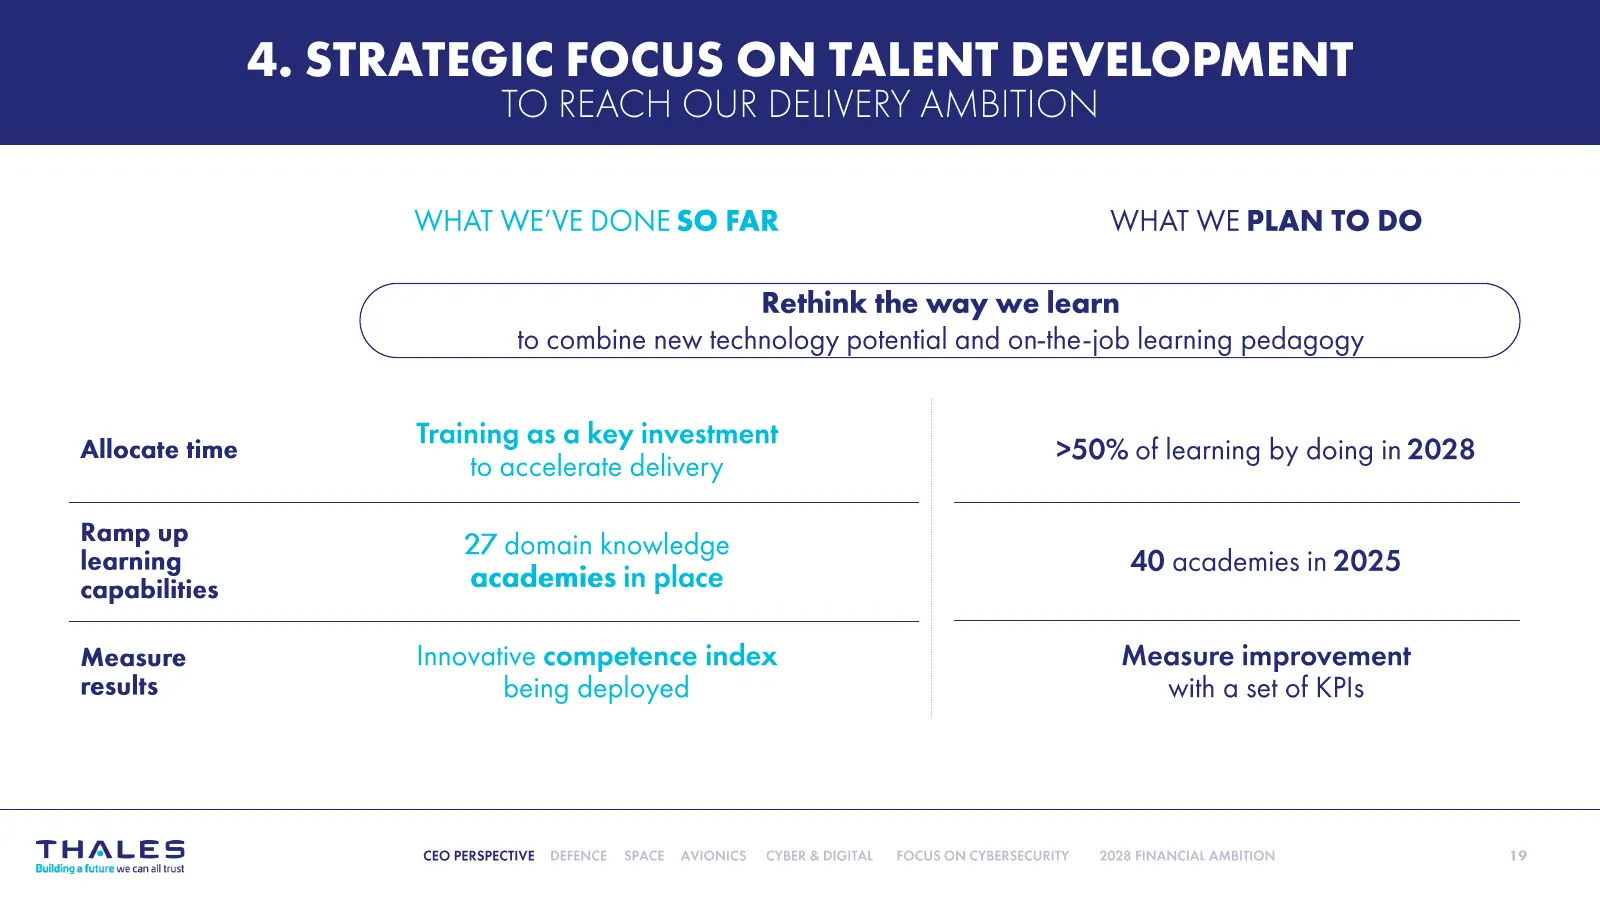
Slide 19: Strategic focus on talent development
4. STRATEGIC FOCUS ON TALENT DEVELOPMENT TO REACH OUR DELIVERY AMBITION WHAT WE'VE DONE SO FAR WHAT WE PLAN TO DO C Rethink the way we learn ) to combine new technology potential and on-the-job learning pedagogy Training as a key investment Allocate time : to accelerate delivery >50% of learning by
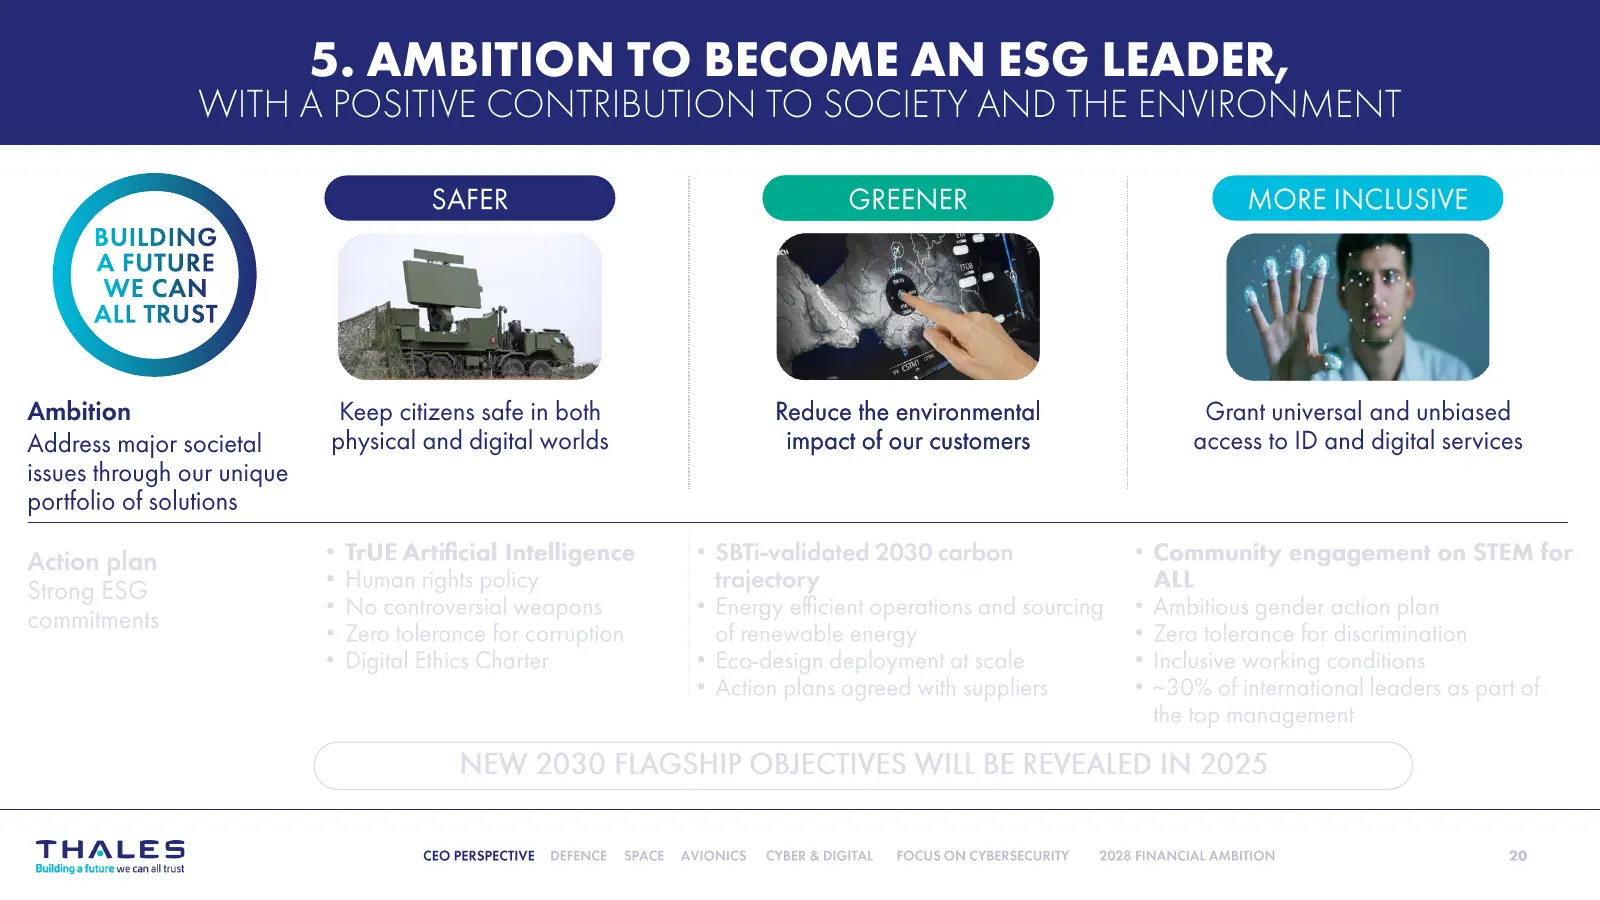
Slide 20: Ambition to become an ESG leader
5. AMBITION TO BECOME AN ESG LEADER, WITH A POSITIVE CONTRIBUTION TO SOCIETY AND THE ENVIRONMENT SAFER GREENER MORE INCLUSIVE 4 @ = BUILDING A FUTURE WE CAN ALL TRUST Ambition Keep citizens safe in both Address major societal physical and digital worlds issues through our unique portfolio of solutio
Slide 21: Ambition to become an ESG leader through internal actions
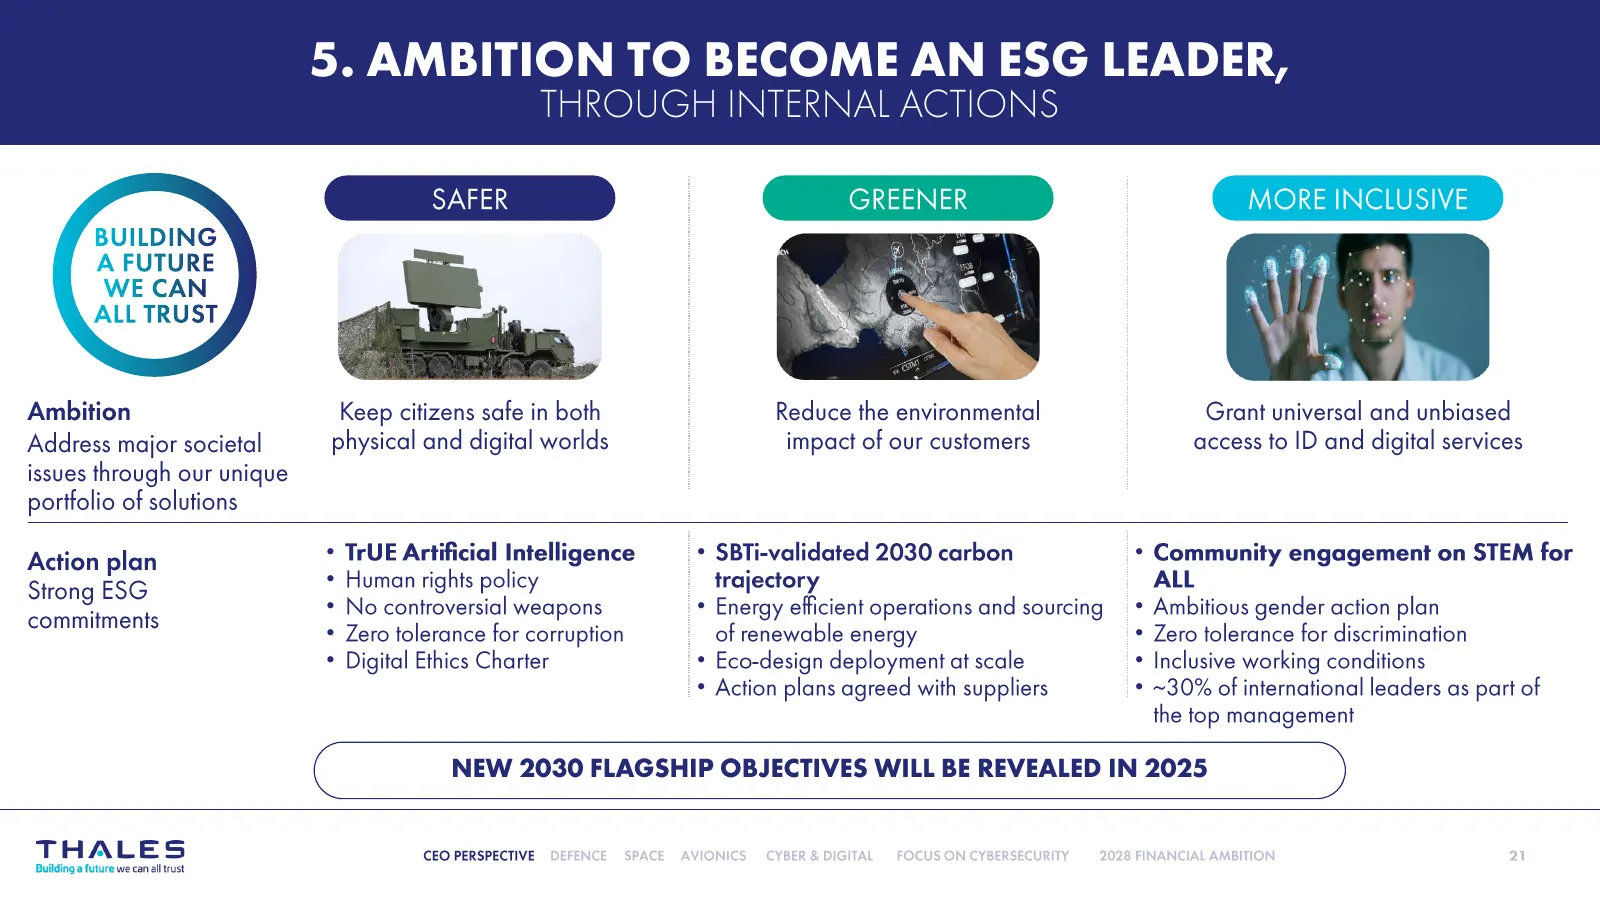
5. AMBITION TO BECOME AN ESG LEADER, THROUGH INTERNAL ACTIONS ILDING FUTURE E CAN L TRUST Ambition Keep citizens safe in both Reduce the environmental Grant universal and unbiased Address major societal physical and digital worlds impact of our customers access to ID and digital services issues thro
Slide 22: Medium-term group financial targets
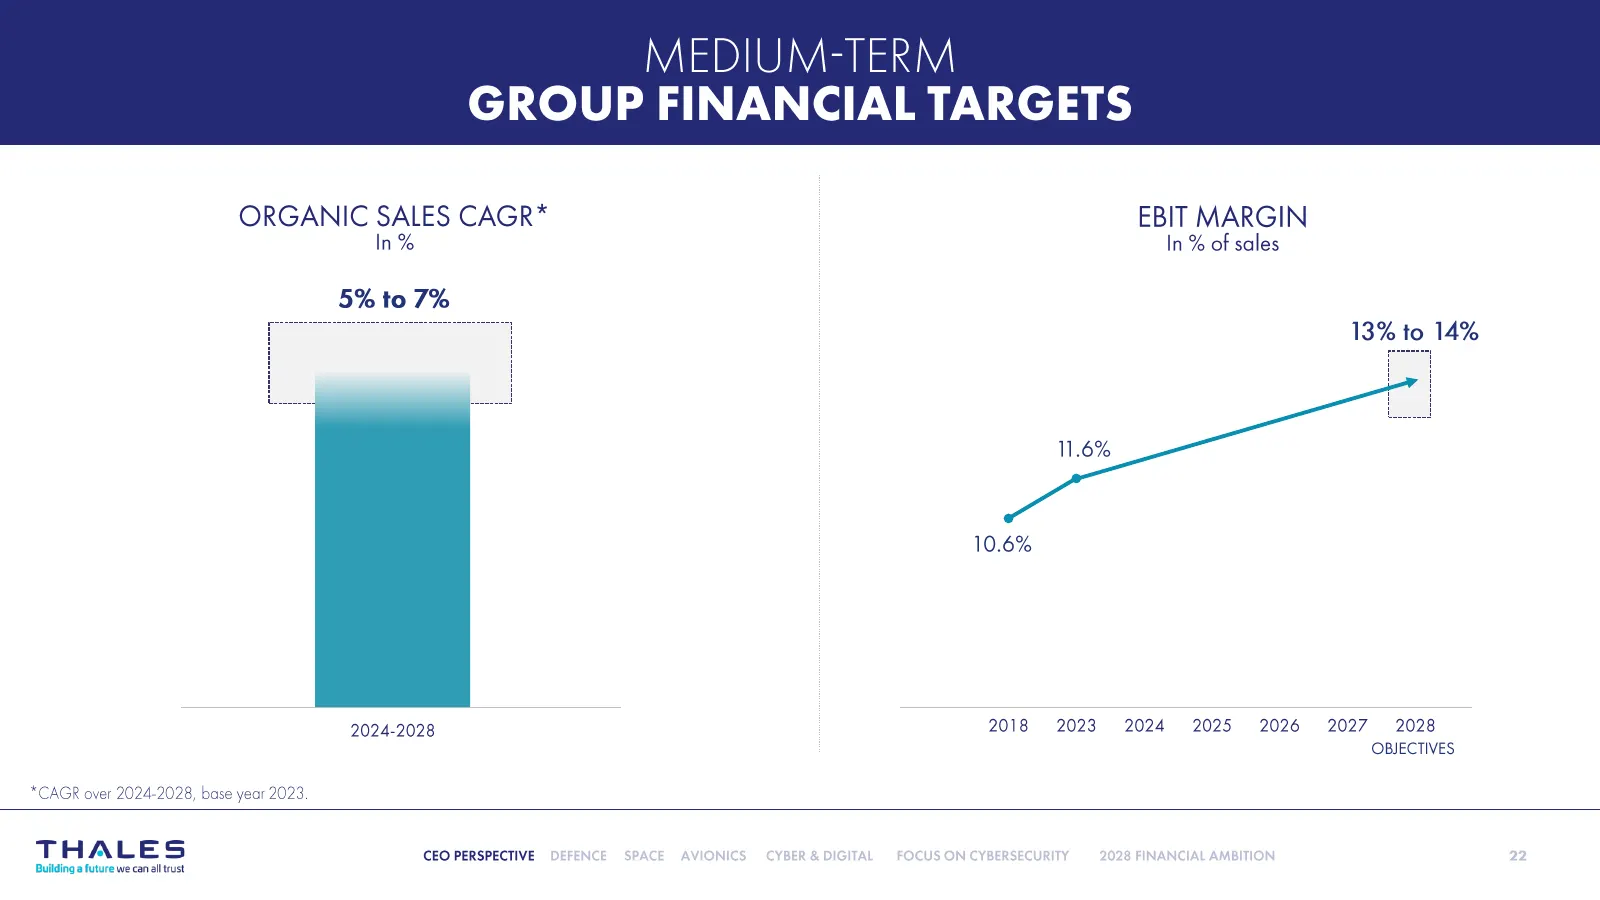
MEDIUM-TERM GROUP FINANCIAL TARGETS ORGANIC SALES CAGR* EBIT MARGIN In % In % of sales 5% to 7% 13% to 14% 10.6% 2024-2028 2018 2023 2024 2025 2026 2027 2028 OBJECTIVES *CAGR over 2024-2028, base year 2023. THALES CEO PERSPECTIVE Building a future we can alltust
Slide 23: Balanced capital allocation
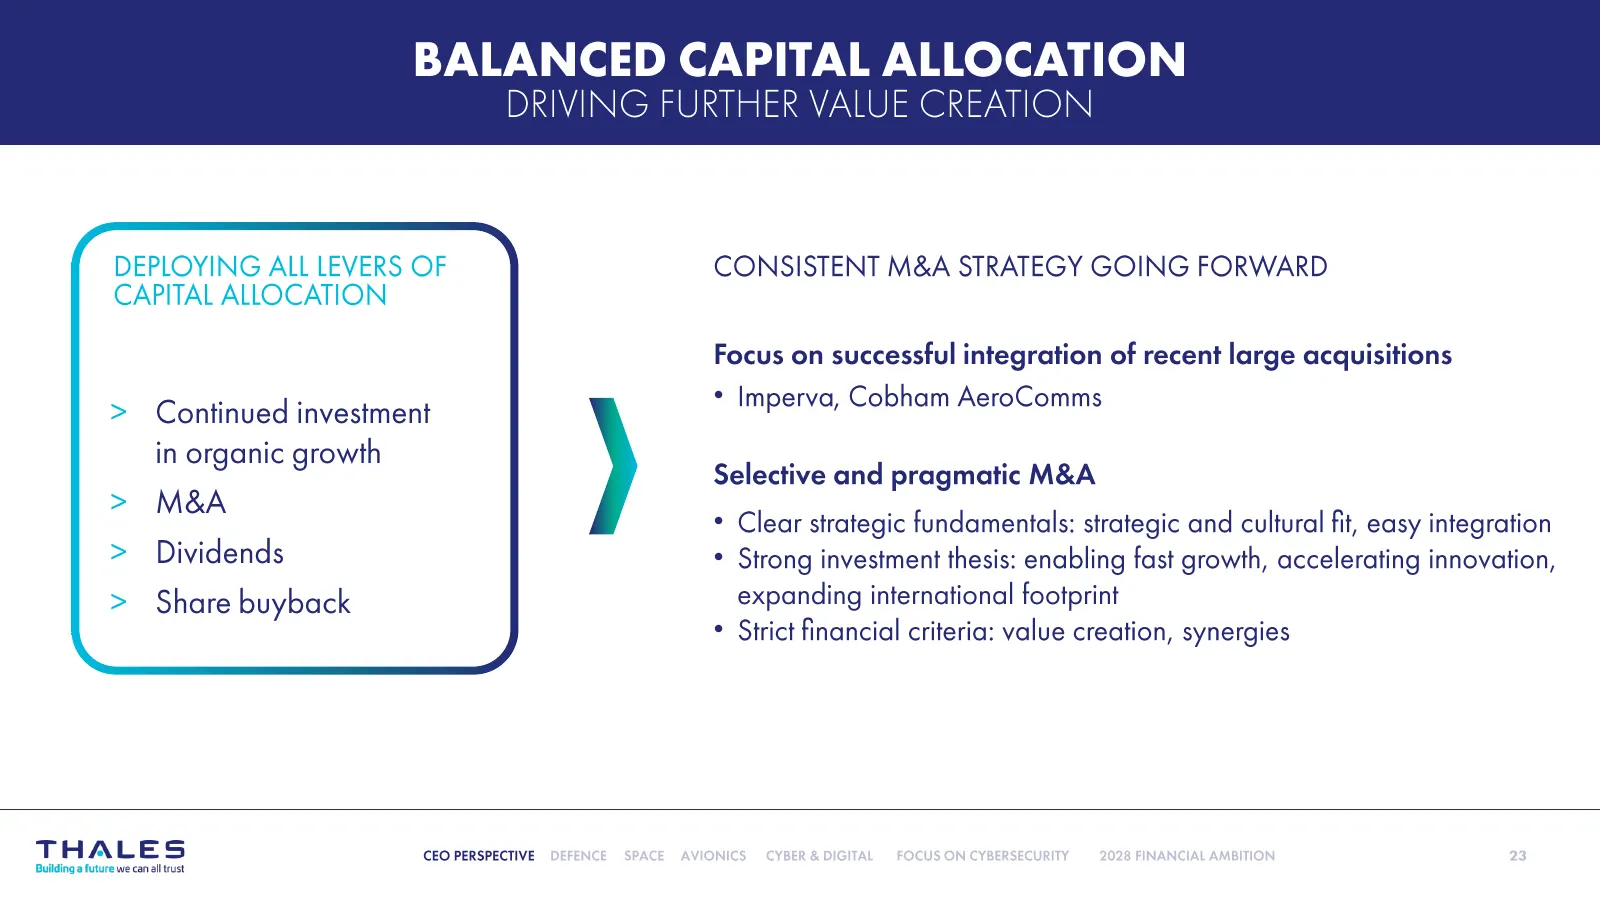
BALANCED CAPITAL ALLOCATION DRIVING FURTHER VALUE CREATION DEPLOYING ALL LEVERS OF CAPITAL ALLOCATION Continued investment in organic growth M&A Dividends Share buyback CONSISTENT M&A STRATEGY GOING FORWARD Focus on successful integration of recent large acquisitions * Imperva, Cobham AeroComms Sele
Slide 24: In summary: Thales, a global tech leader
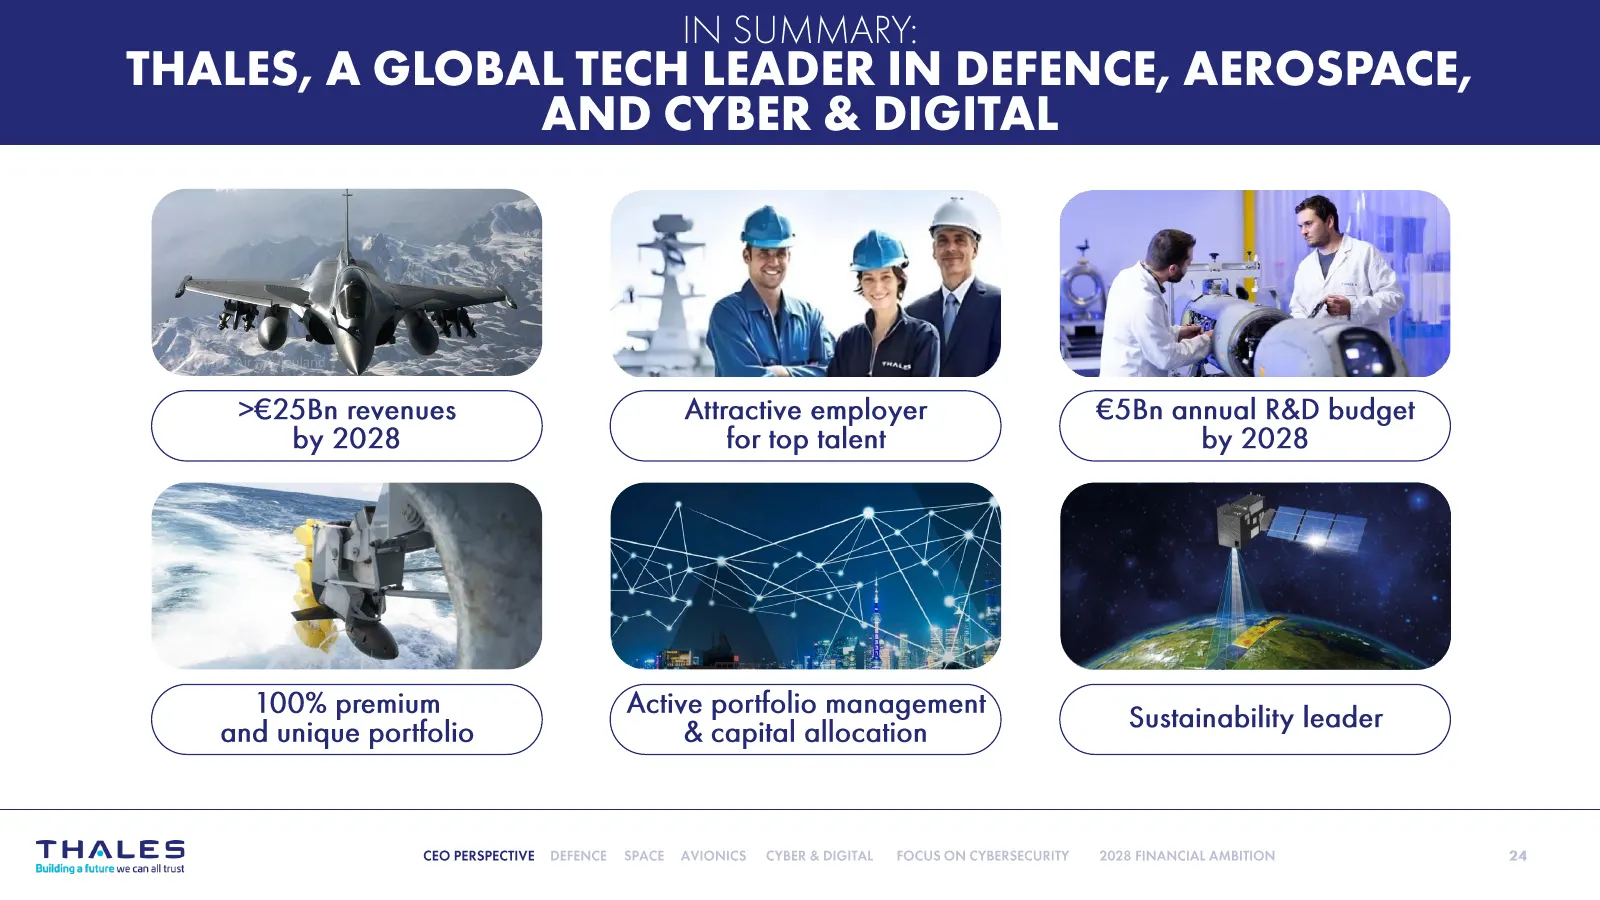
IN SUMMARY: THALES, A GLOBAL TECH LEADER IN DEFENCE, AEROSPACE, AND CYBER & DIGITAL Attractive employer €5Bn annual R&D budget by 2028 for top talent by 2028 100% premium Active portfolio management a, C and unique portfolio +) (A & capital allocation Sustainability leader CEO PERSPECTIVE
Slide 25: Business Reviews: Defence
BUSINESS REVIEWS DEFENCE Hervé Dammann Executive Vice-President, Land and Air Systems
Slide 26: 2018-2020 2020-2022 2022-2023
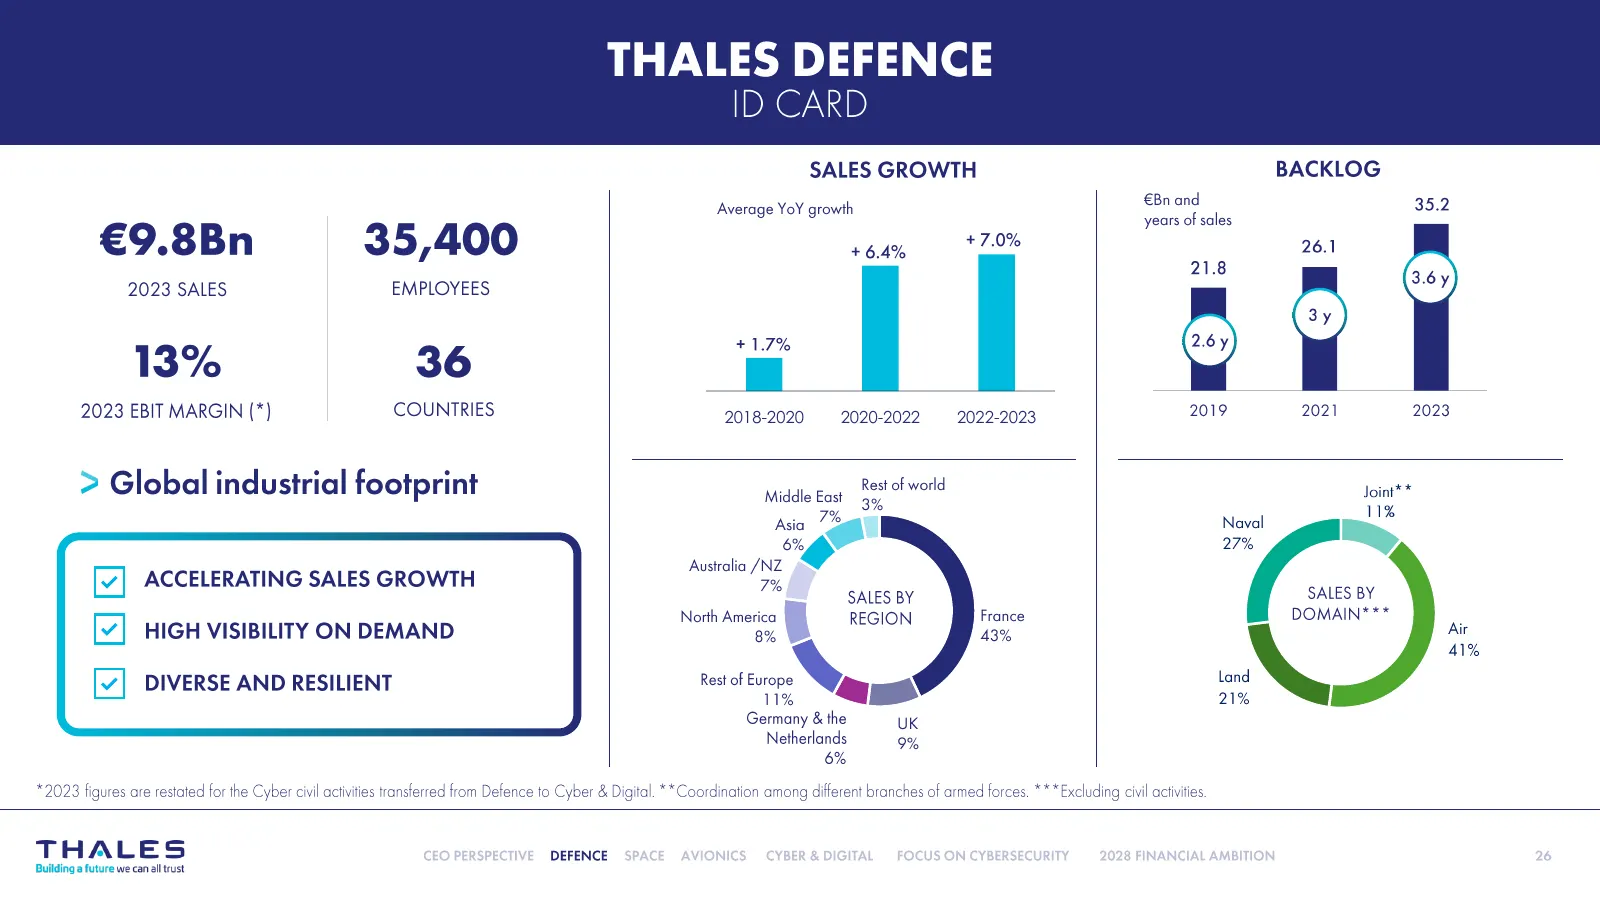
2018-2020 2020-2022 2022-2023
Slide 27: Unique position across all the value chain
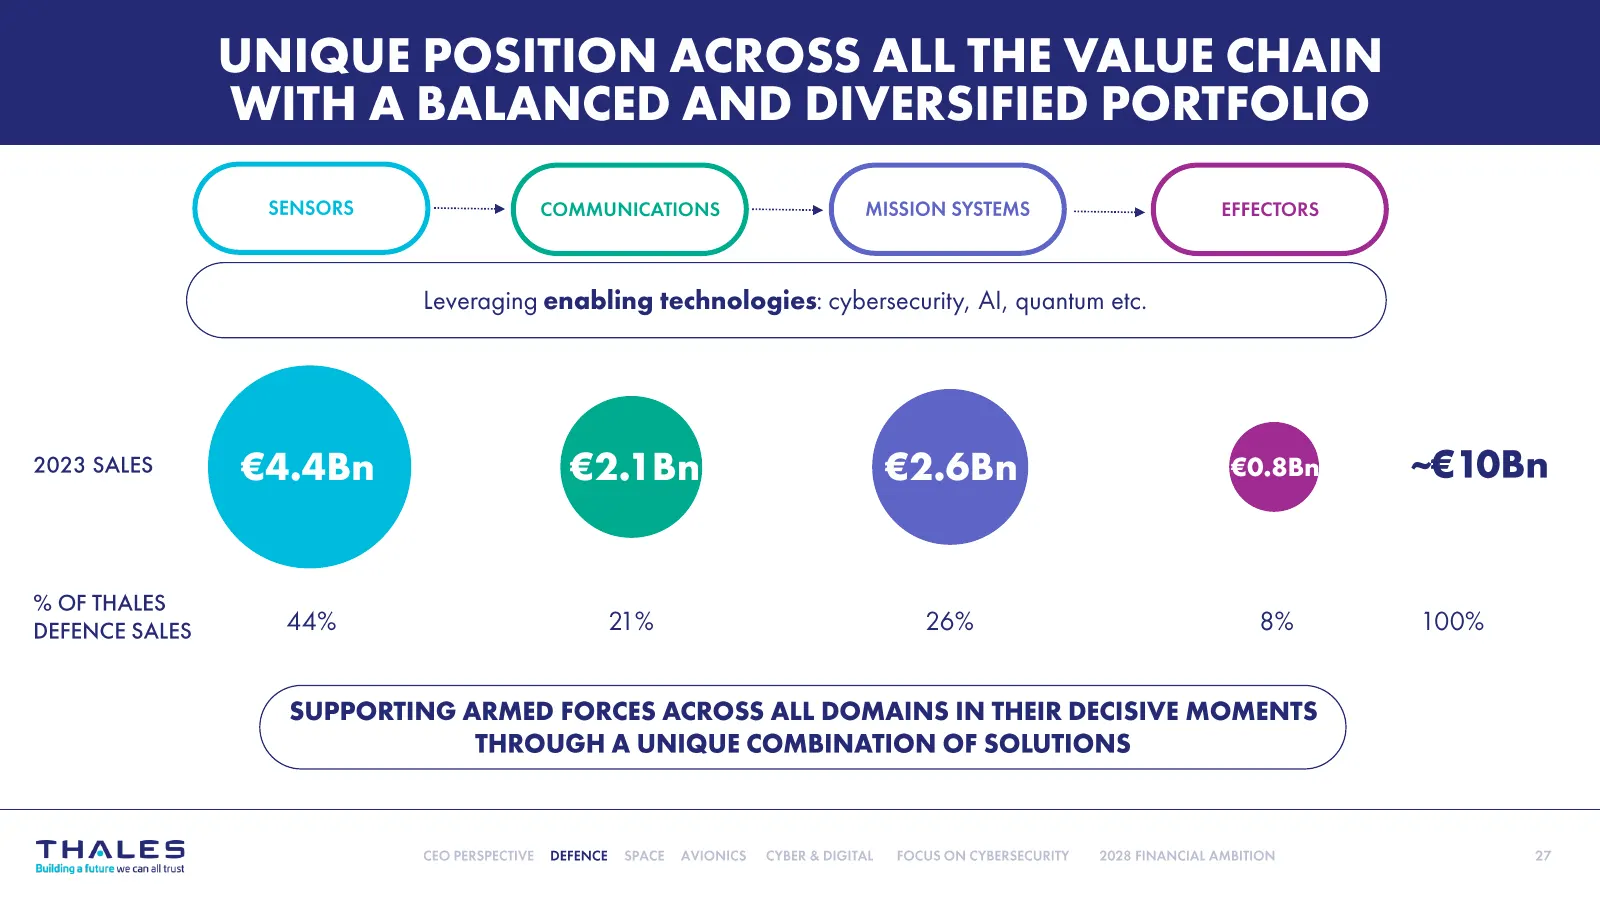
UNIQUE POSITION ACROSS ALL THE VALUE CHAIN WITH A BALANCED AND DIVERSIFIED PORTFOLIO ’ SENSORS ~~ ~ COMMUNICATIONS J -+(mssonstens) — C EFFECTORS ) Leveraging enabling technologies: cybersecurity, Al, quantum etc. ) 2023 SALES €4.4Bn So S €0.8B: ~€10Bn % OF THALES 5 5 5 5 Reaasieeey ti 44% 21% 26% 8
Slide 28: Securing airspace sovereignty
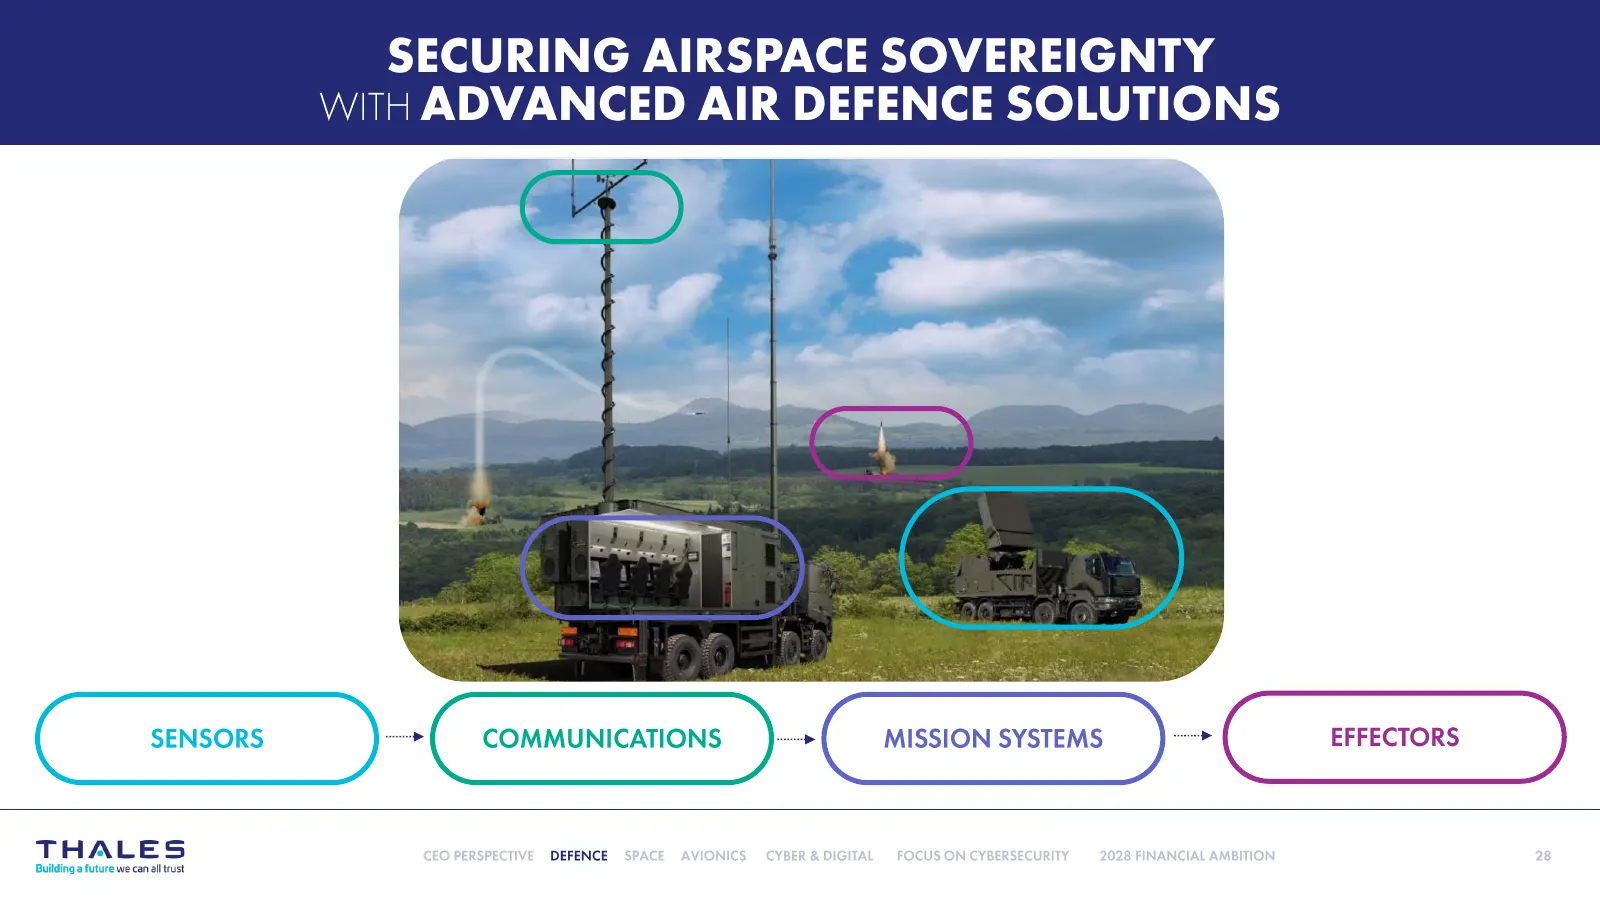
SECURING AIRSPACE SOVEREIGNTY WITH ADVANCED AIR DEFENCE SOLUTIONS > COMMUNICATIONS > id EFFECTORS THALES DEFENCE
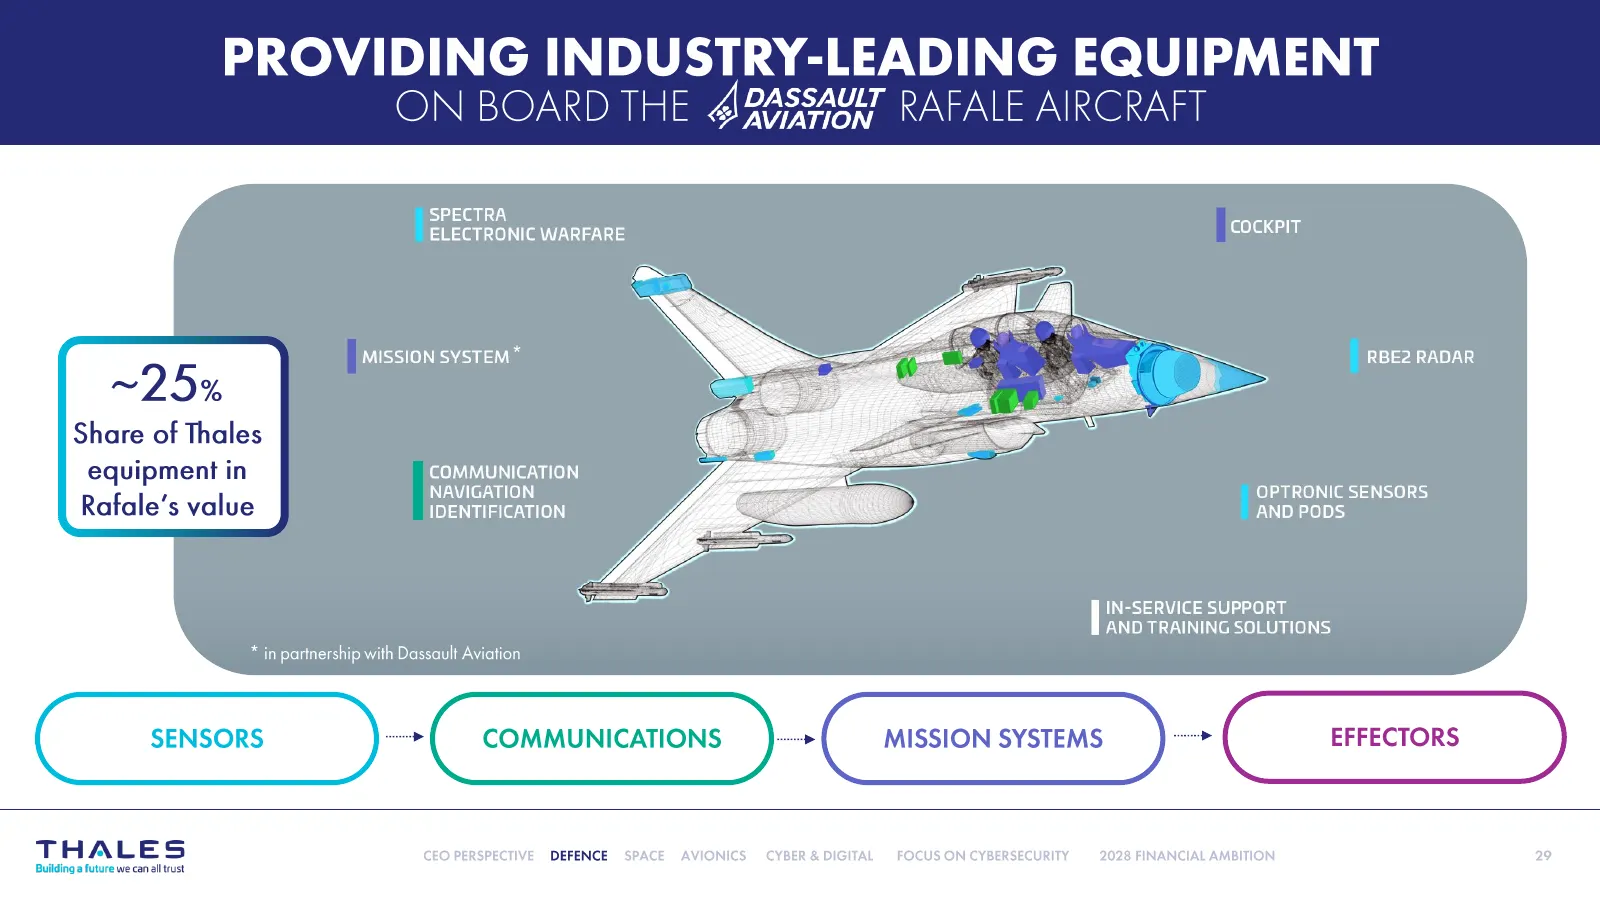
Slide 29: Providing industry-leading equipment on board Rafale
PROVIDING INDUSTRY-LEADING EQUIPMENT ON BOARD THE J RQSSAULT RAFALE AIRCRAFT SPECTRA ELECTRONIC WARFARE COCKPIT MISSION SYSTEM* a= i a= RBE2 RADAR ~25% Share of Thales equipment in COMMUNICATION ; NAVIGATION OPTRONIC SENSORS Rafale’s value IDENTIFICATION y AND PODS IN-SERVICE SUPPORT AND TRAINING SO
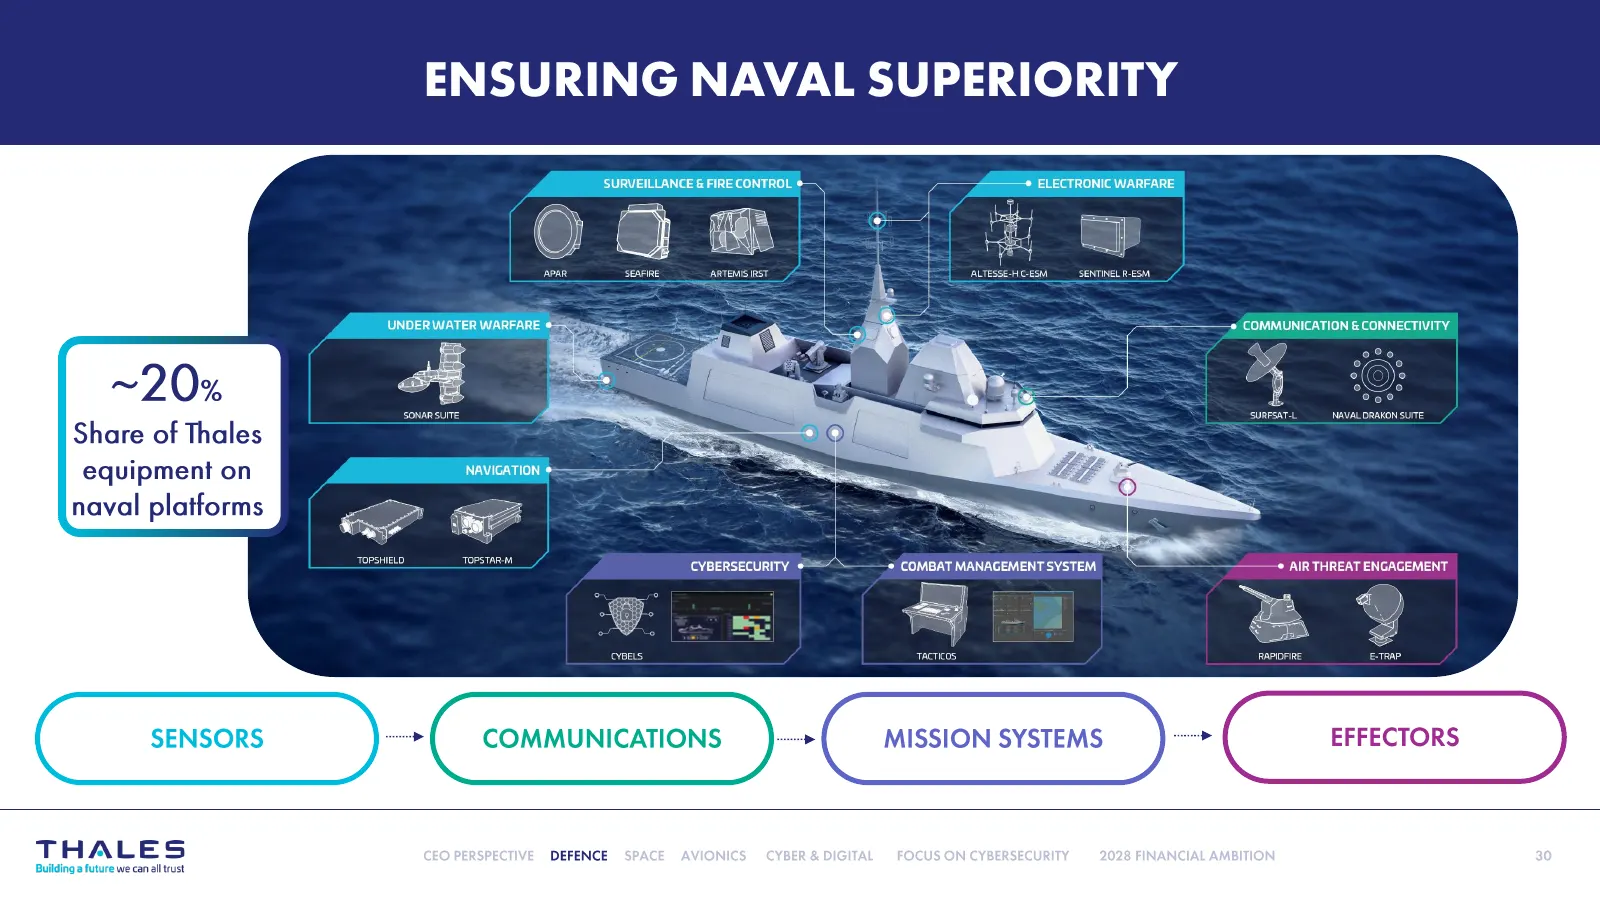
Slide 30: Ensuring naval superiority
ENSURING NAVAL SUPERIORITY ‘SURVEILLANCE & FIRE CONTROL, ; -* ELECTRONIC WARFARE 2 = ca ~20% 1 Share of Thales equipment on naval platforms CYBERSECURITY © DEFENCE
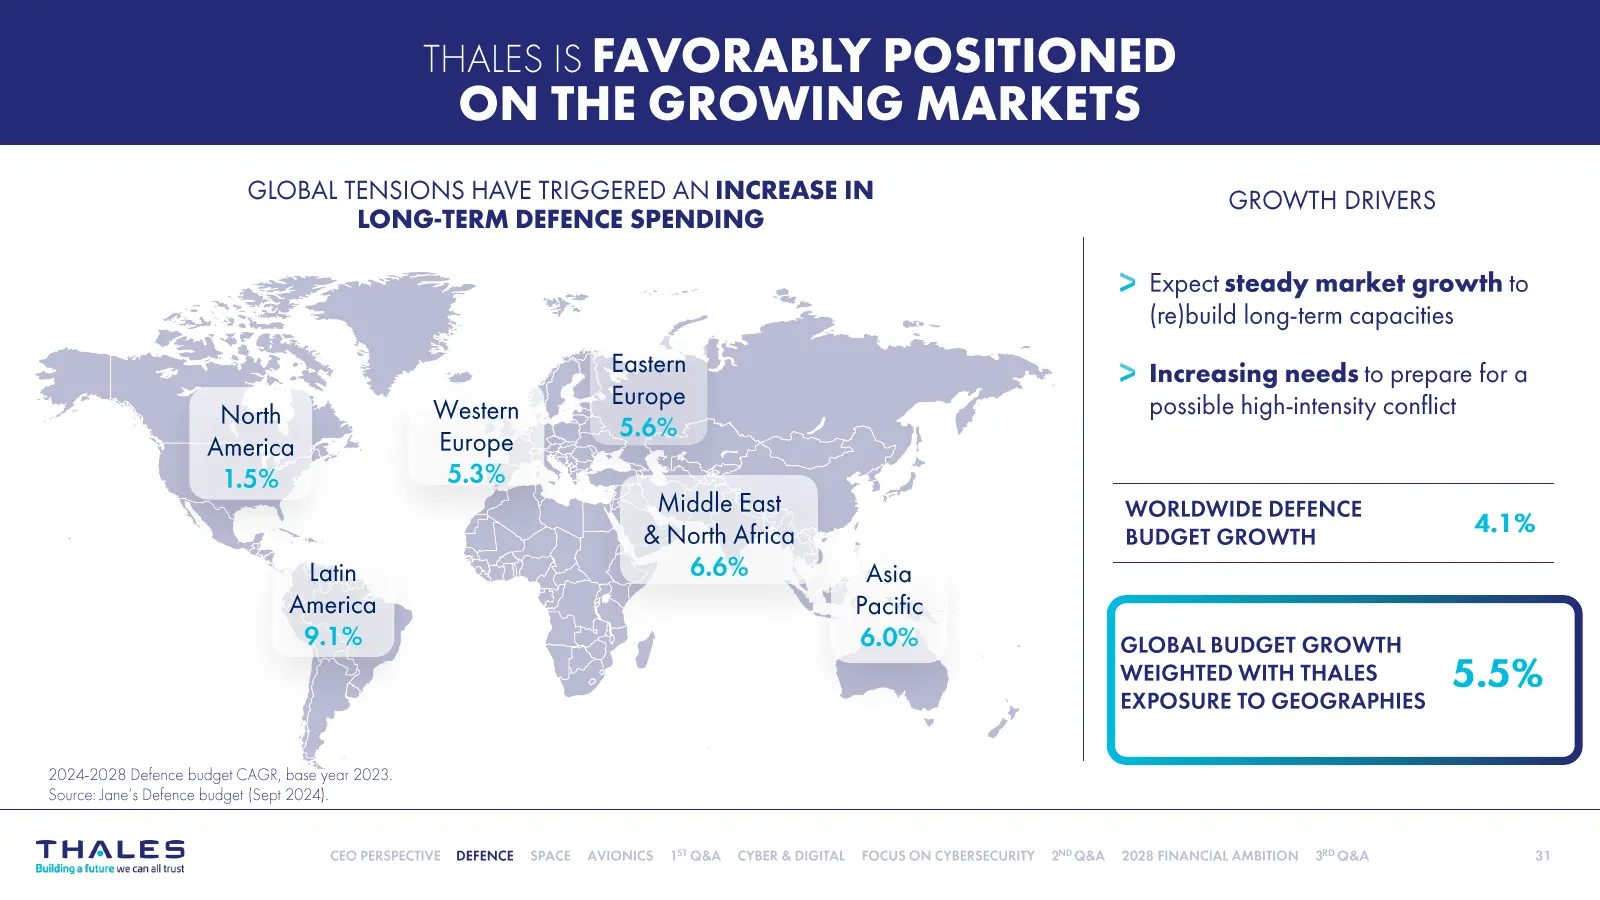
Slide 31: Thales favorably positioned on growing markets
THALES IS FAVORABLY POSITIONED ON THE GROWING MARKETS GLOBAL TENSIONS HAVE TRIGGERED AN INCREASE IN LONG-TERM DEFENCE SPENDING North America 1.5% Latin America 9.1% Jon Western Europe 5.3% Eastern Europe 5.6% Middle East & North Africa 6.6% Asia Pacific 6.0% GROWTH DRIVERS > Expect steady market gro
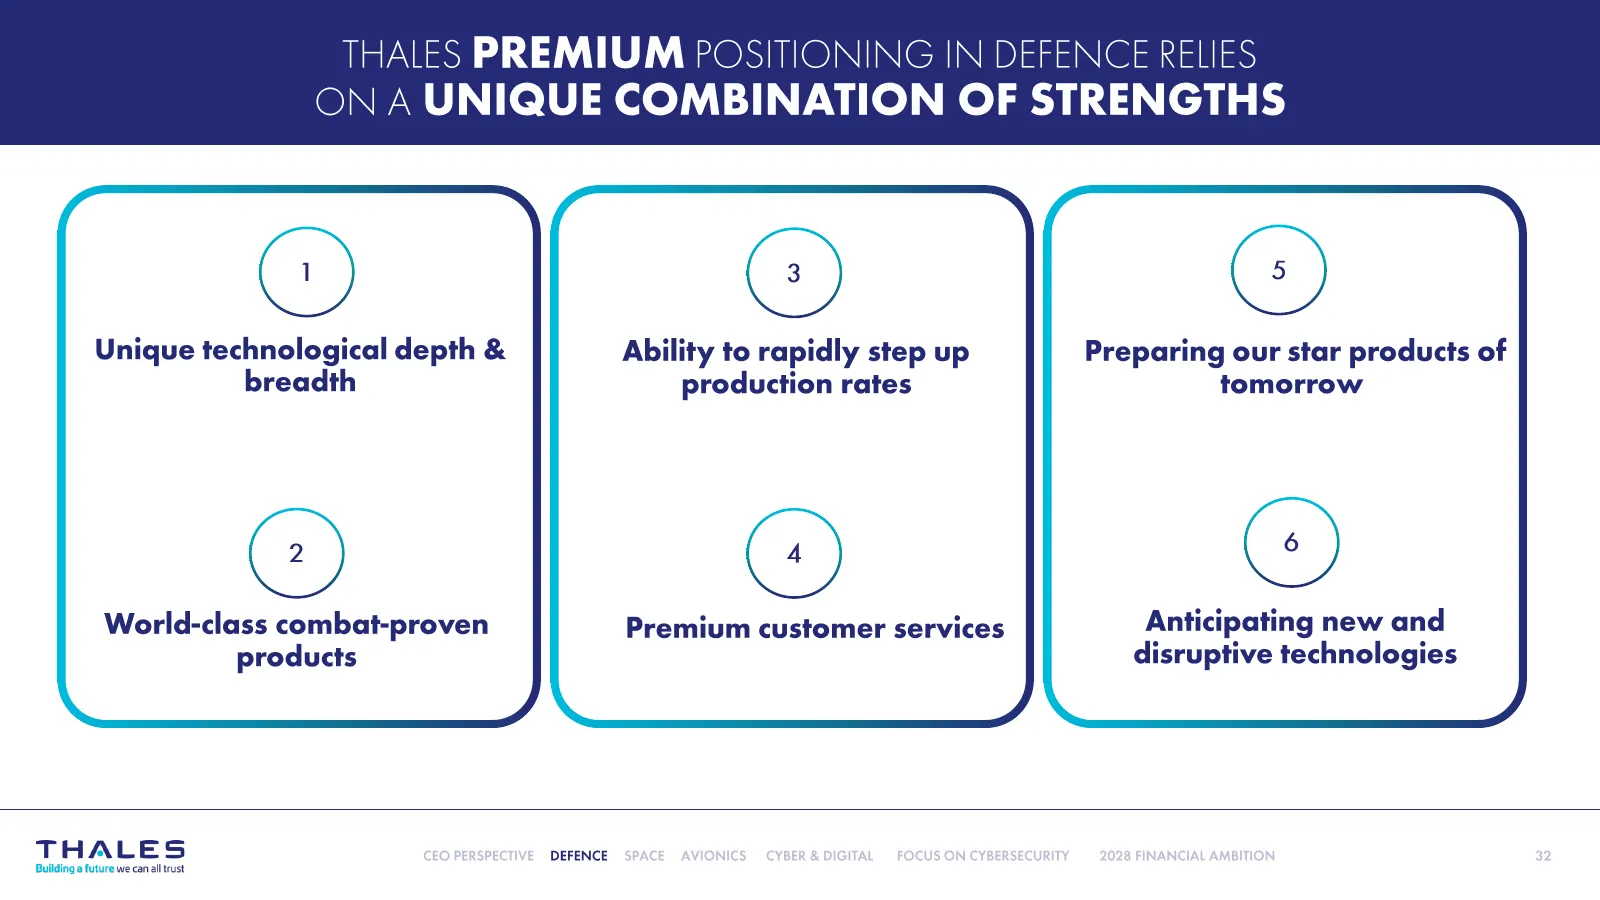
Slide 32: Premium positioning in Defence
THALES PREMIUM POSITIONING IN DEFENCE RELIES ON A UNIQUE COMBINATION OF STRENGTHS Q) @) @) Unique technological depth & Ability to rapidly step up Preparing our star products of breadth production rates tomorrow ©) @) ©) World-class combat-proven Premium customer services Anticipating new and produc
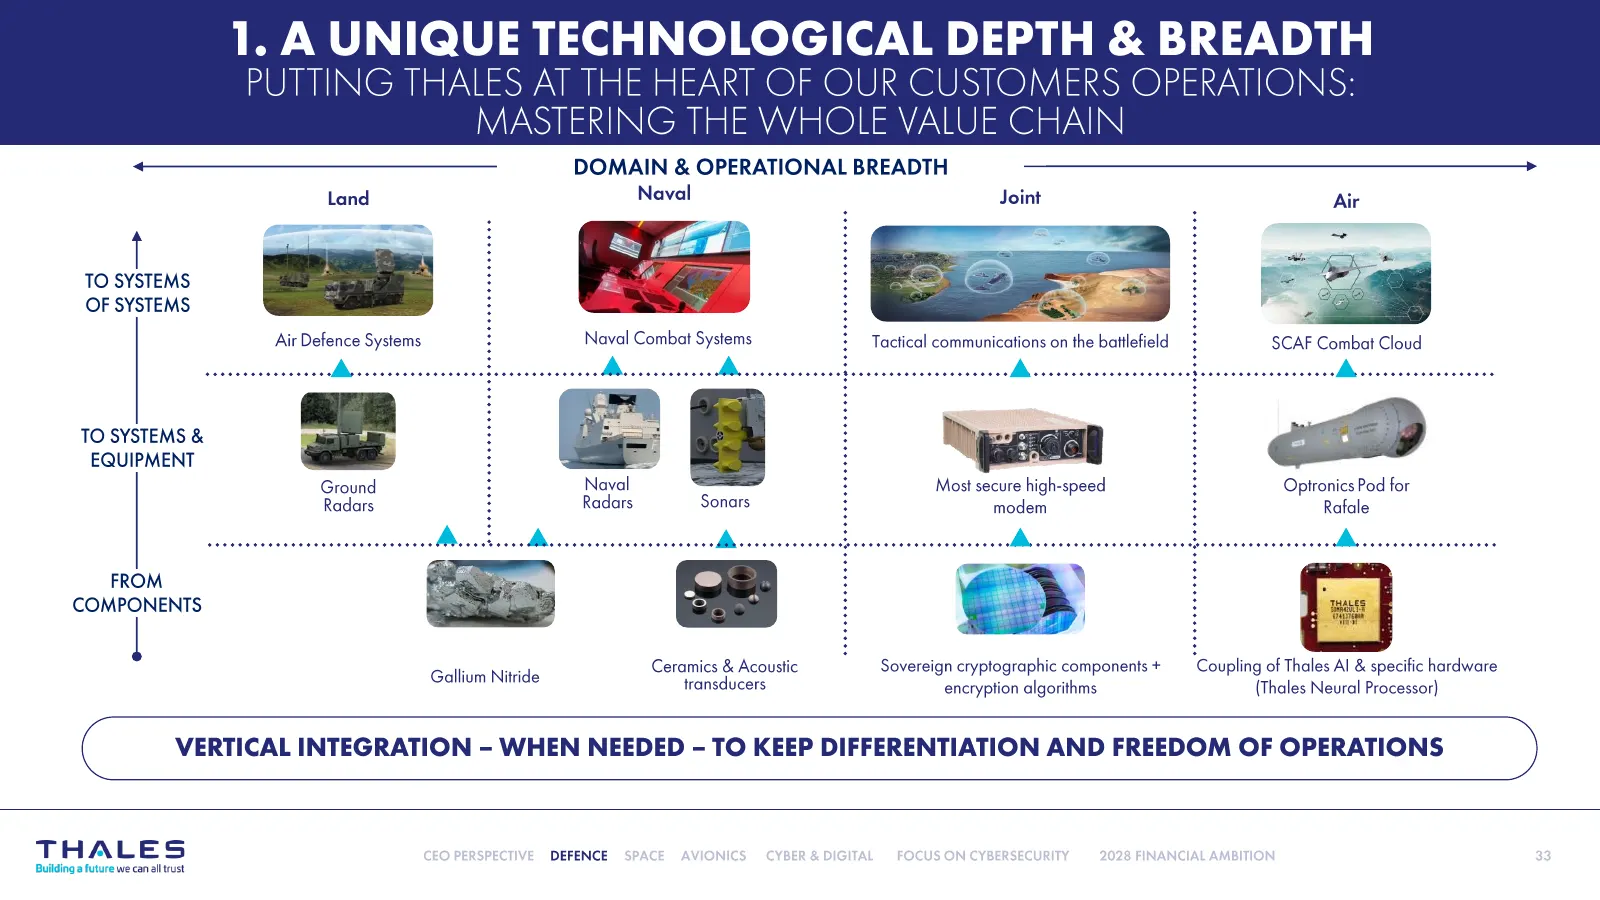
Slide 33: Unique technological depth and breadth
1. A UNIQUE TECHNOLOGICAL DEPTH & BREADTH PUTTING THALES AT THE HEART OF OUR CUSTOMERS OPERATION MASTERING THE WHOLE VALUE CHAIN DOMAIN & OPERATIONAL BREADTH Land Naval Air TO SYSTEMS OF SYSTEMS Air Defence ra TO SYSTEMS & EQUIPMENT FROM COMPONENTS ° Ceramics & Acoustic ~—-Sovereign cryptographic co
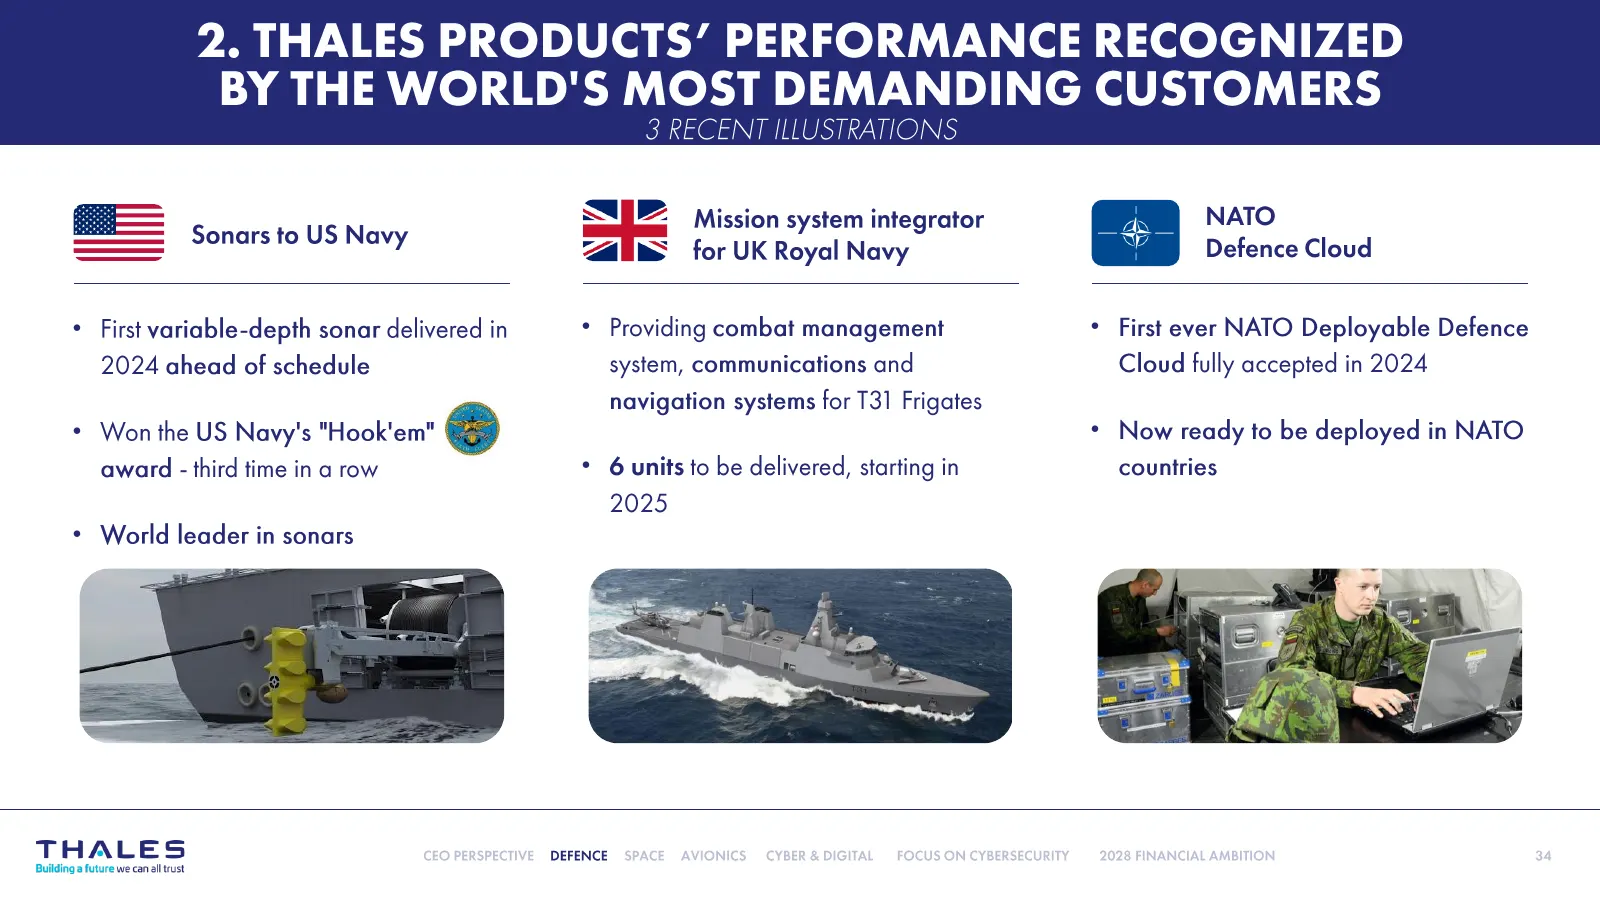
Slide 34: Products' performance recognized by demanding customers
2. THALES PRODUCTS’ PERFORMANCE RECOGNIZED BY THE WORLD'S MOST DEMANDING CUSTOMERS 3 RECENT | ATIONS SZ Mission system integrator shy NATO pee Sonars to US Navy “als for UK Royal Navy Defence Cloud * First variable-depth sonar delivered in * Providing combat management * First ever NATO Deployable D
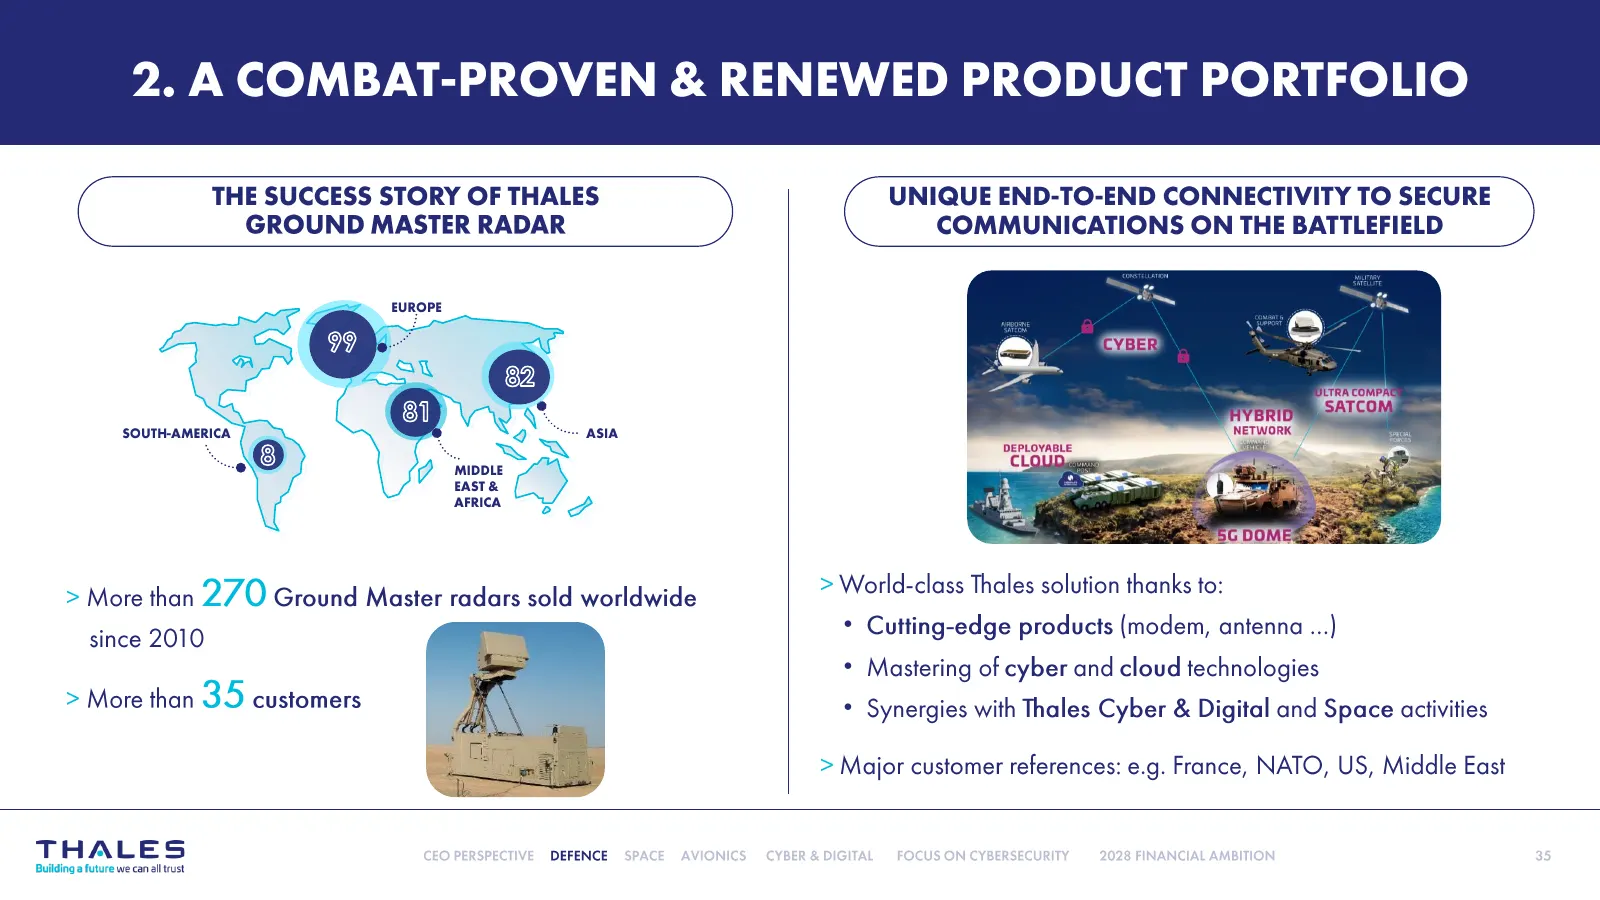
Slide 35: A combat-proven and renewed product portfolio
2. A COMBAT-PROVEN & RENEWED PRODUCT PORTFOLIO ) THE SUCCESS STORY OF THALES GROUND MASTER RADAR EUROPE o- 81 ° SOUTH-AMERICA ~~ ASIA a) “jap EAST & AFRICA More than Ground Master radars sold worldwide since 2010 More than customers UNIQUE END-TO-END CONNECTIVITY TO SECURE COMMUNICATIONS ON THE BATT
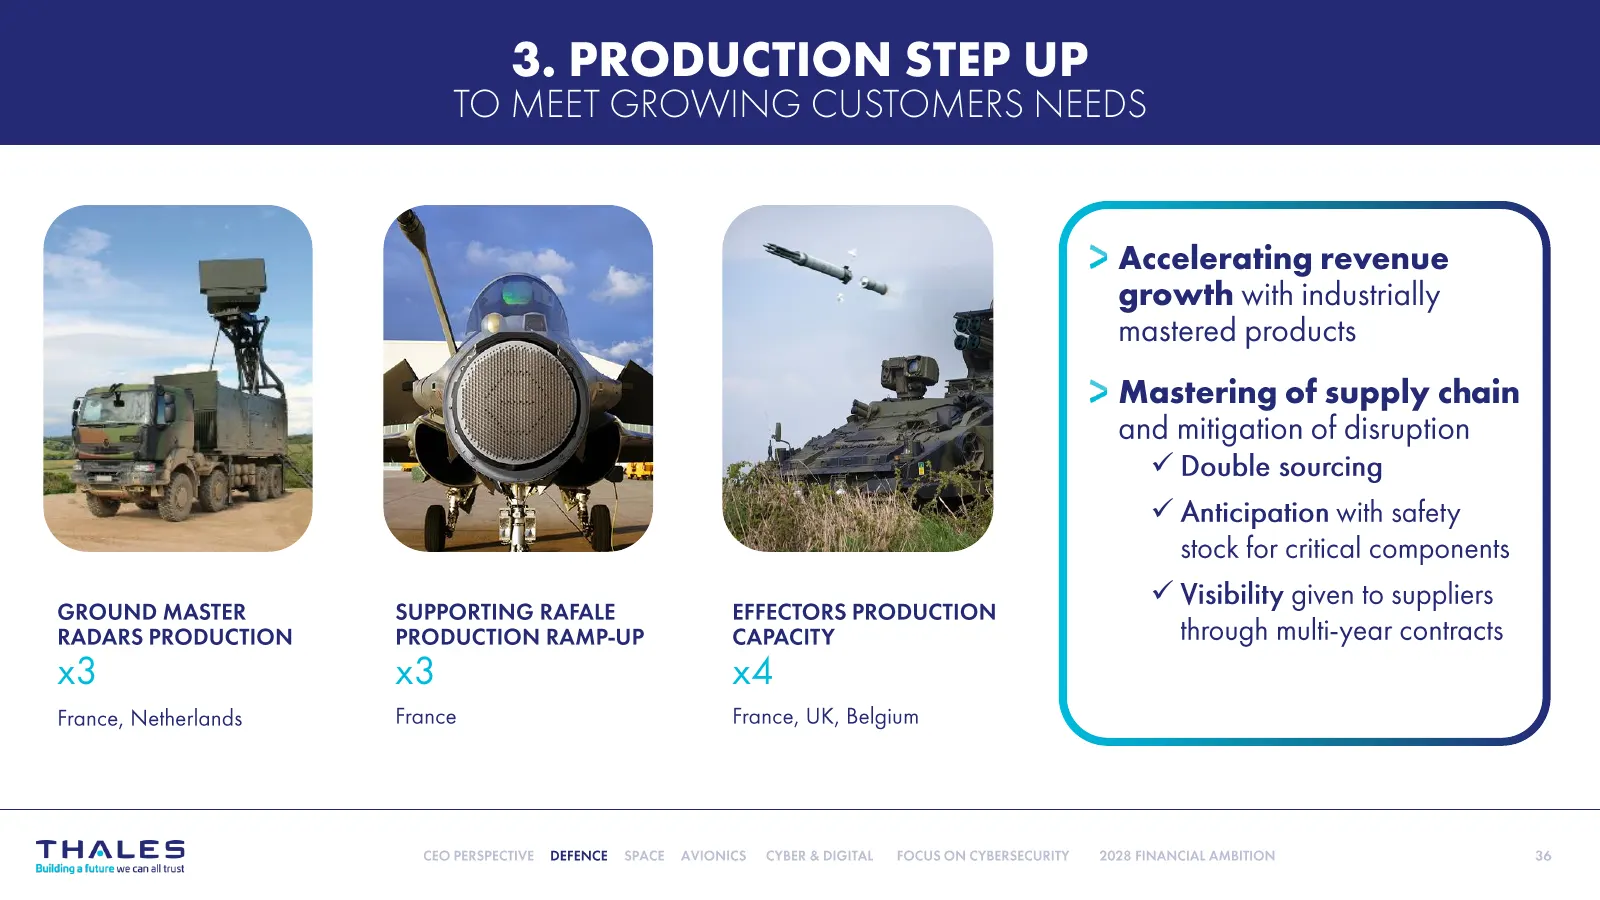
Slide 36: Production step up
3. PRODUCTION STEP UP TO MEET GROWING CUSTOMERS NEEDS Accelerating revenue growth with industrially mastered products Mastering of supply chain and mitigation of disruption Y Double sourcing Y Anticipation with safety stock for critical components V Vieibility oi . GROUND MASTER SUPPORTING RAFALE EF
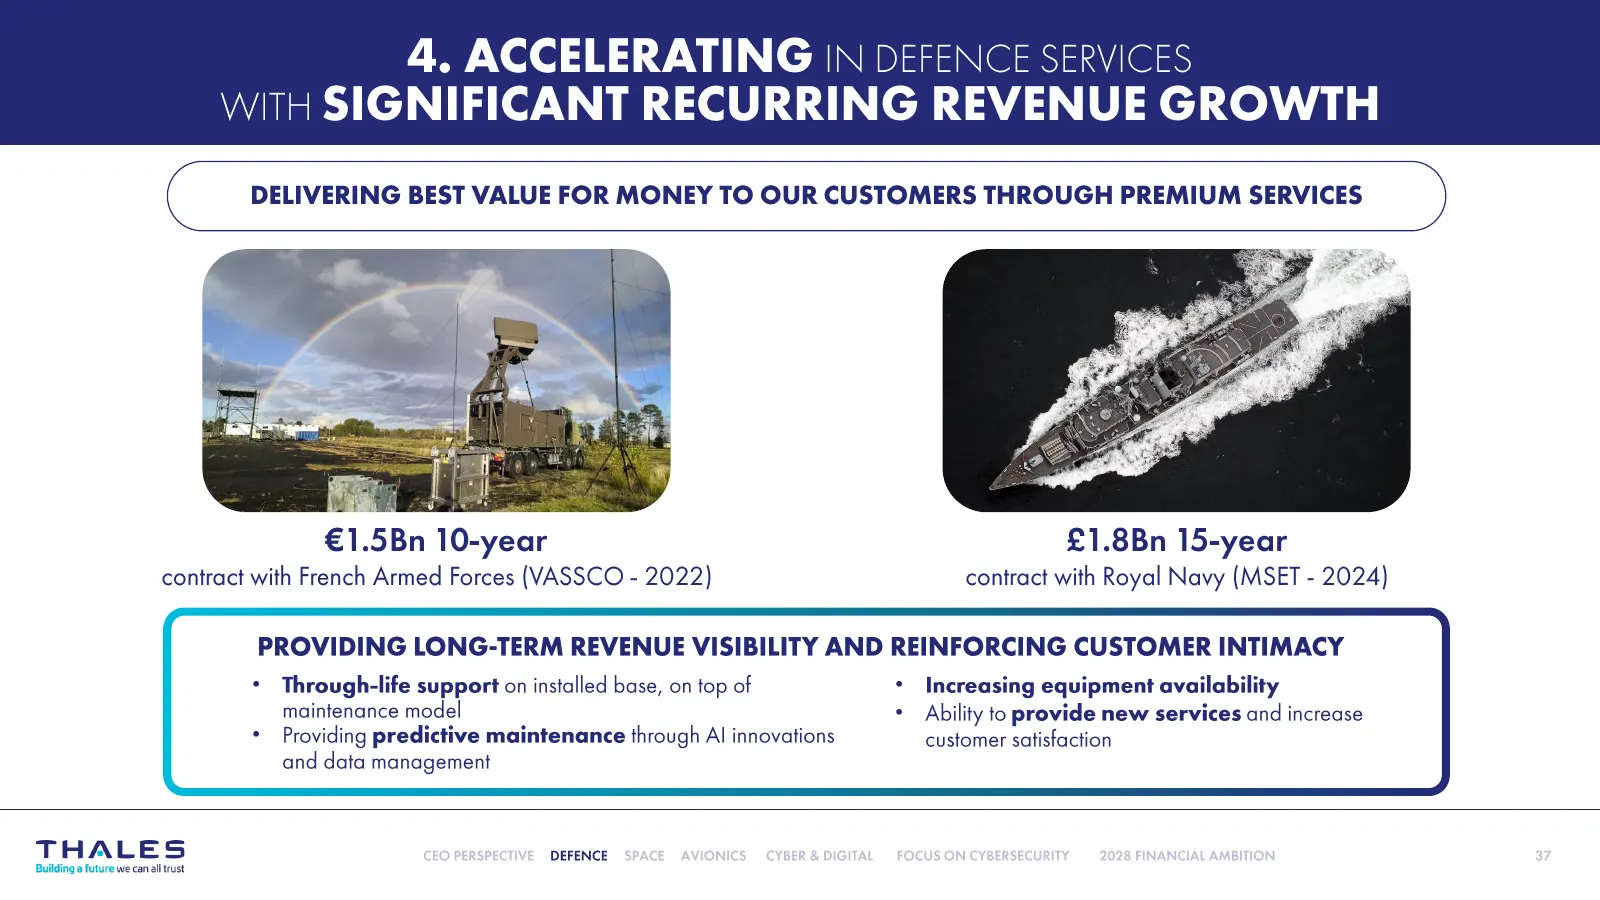
Slide 37: Accelerating in defence services
4. ACCELERATING IN DEFENCE SERVICES WITH SIGNIFICANT RECURRING REVENUE GROWTH C DELIVERING BEST VALUE FOR MONEY TO OUR CUSTOMERS THROUGH PREMIUM SERVICES ) €1.5Bn 10-year contract with French Armed Forces (VASSCO - 2022) £1.8Bn 15-year contract with Royal Navy (MSET - 2024) PROVIDING LONG-TERM REVEN
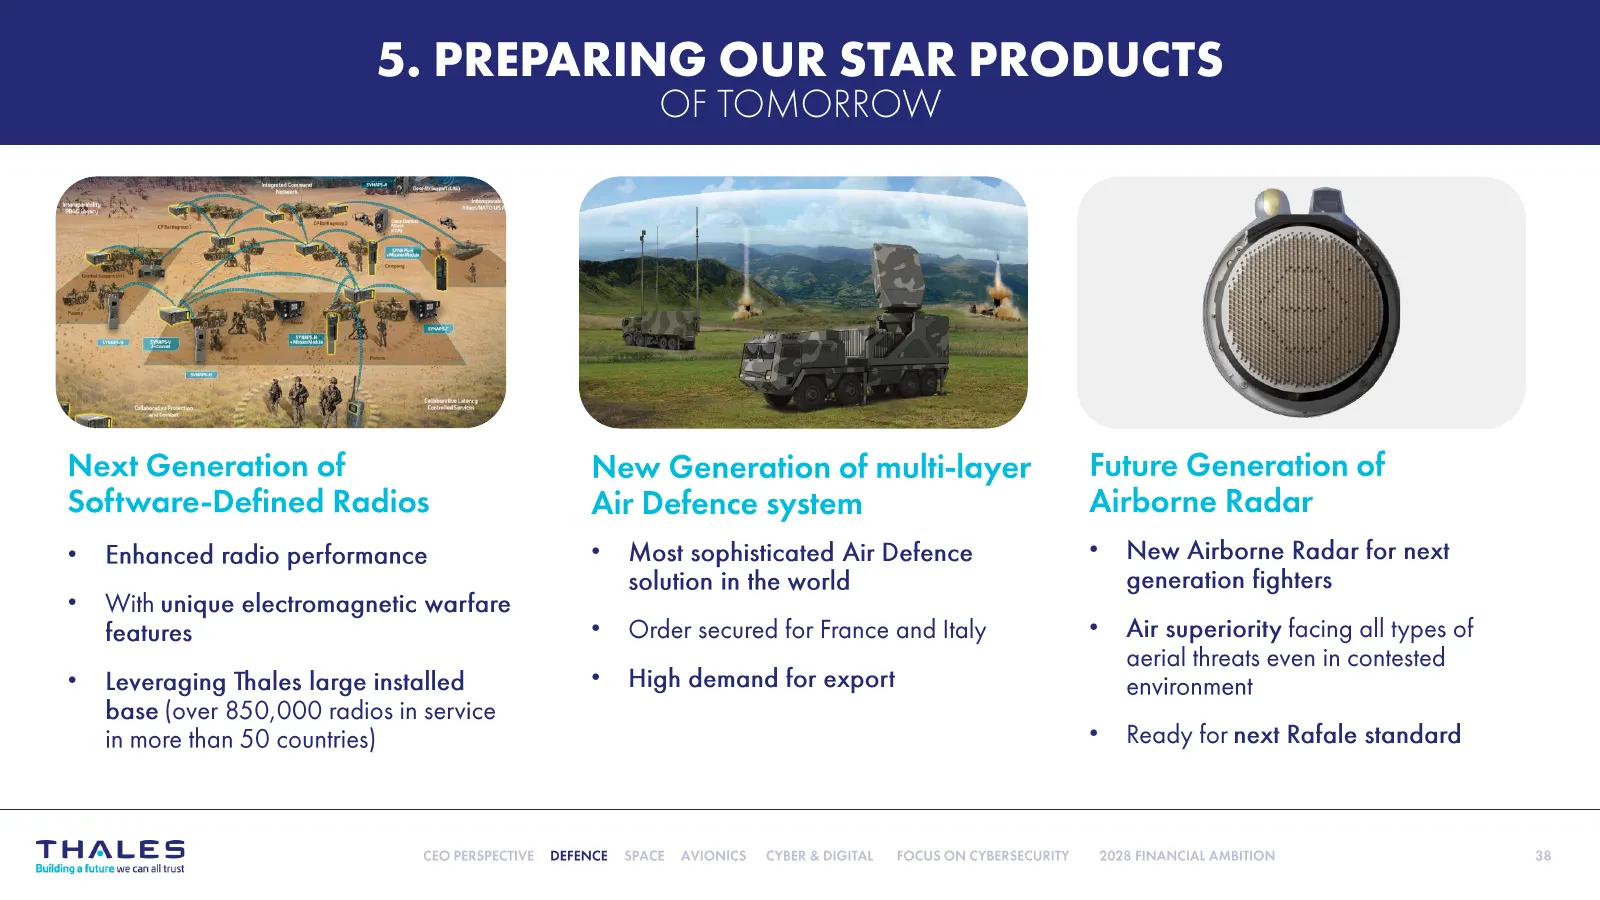
Slide 38: Preparing our star products of tomorrow
5. PREPARING OUR STAR PRODUCTS OF TOMORROW Next Generation of New Generation of multi-layer Future Generation of Software-Defined Radios Air Defence system Airborne Radar * Enhanced radio performance * Most sophisticated Air Defence * New Airborne Radar for next solution in the world generation figh
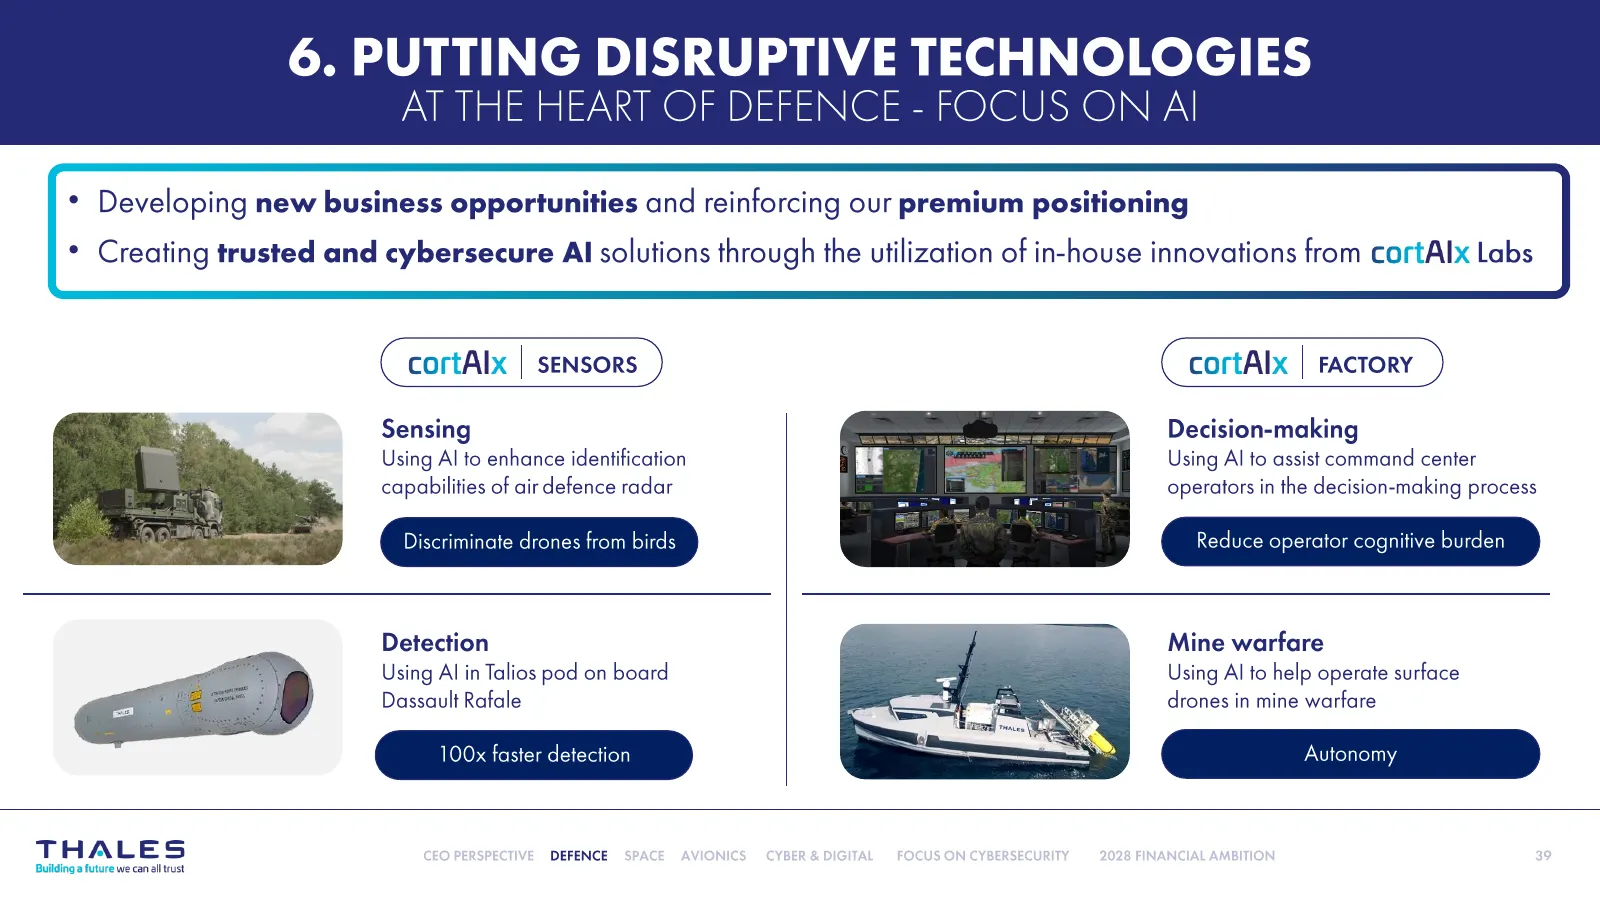
Slide 39: Putting disruptive technologies at the heart of defence
6. PUTTING DISRUPTIVE TECHNOLOGIES AT THE HEART OF DEFENCE - FOCUS ON Al * Developing new business opportunities and reinforcing our premium positioning * Creating trusted and cybersecure Al solutions through the utilization of in-house innovations from cortAlx Labs cortAlx | sensors Sensing Using A
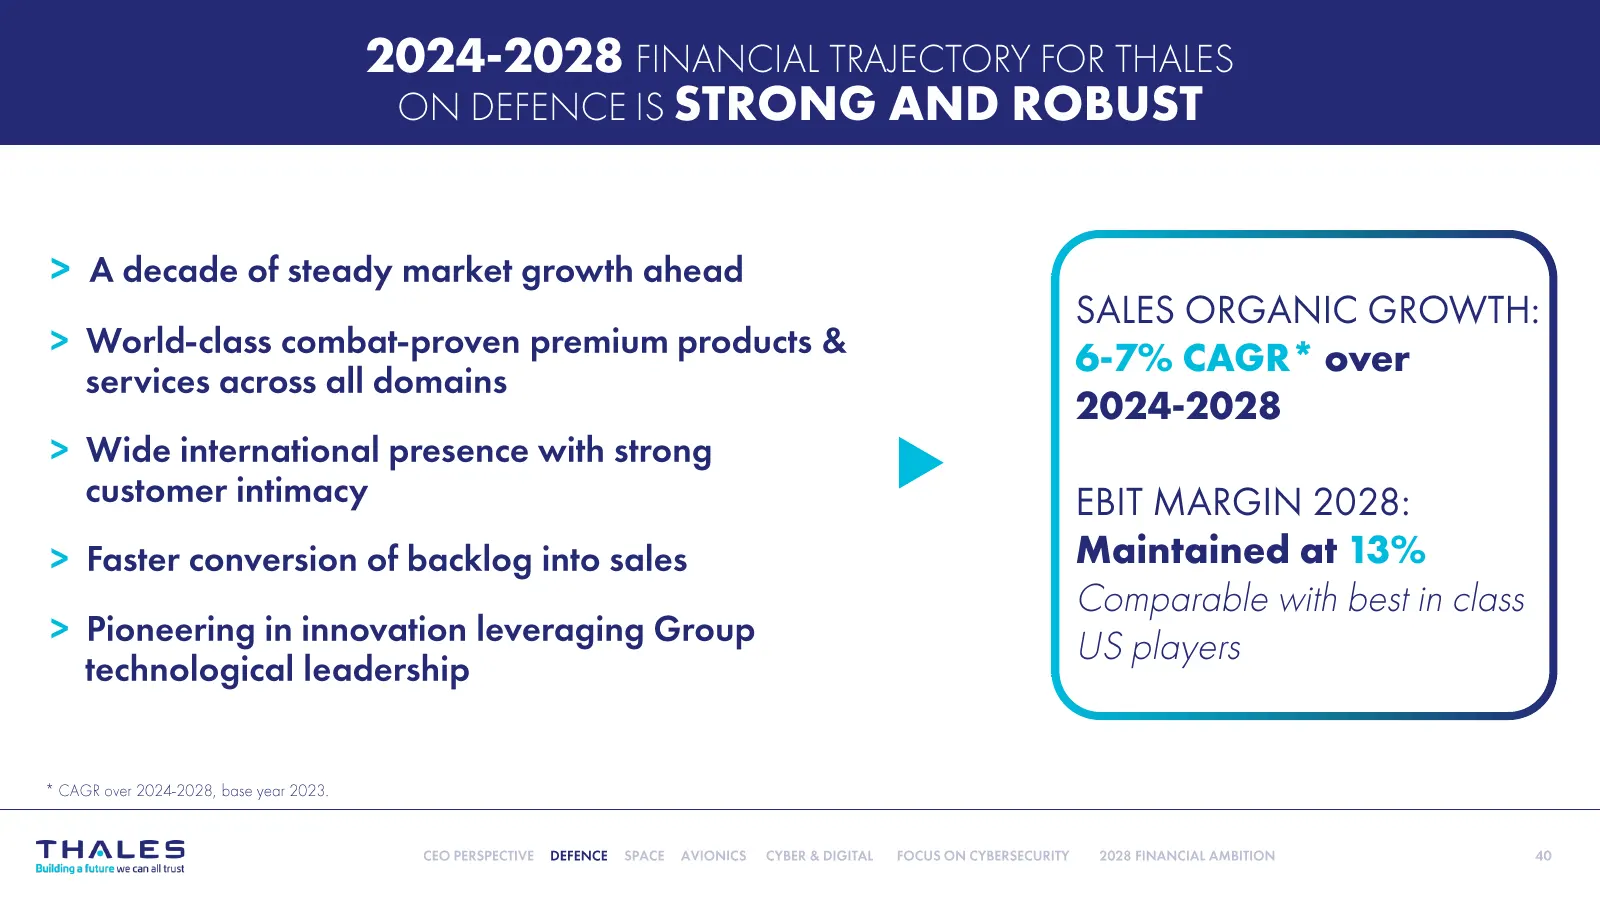
Slide 40: 2024-2028 financial trajectory on Defence
2024-2028 FINANCIAL TRAJECTORY FOR THALES ON DEFENCE |S STRONG AND ROBUST > A decade of steady market growth ahead SALES ORGANIC GROWTH: > World-class combat-proven premium products & 6-7% CAGR* over services across all domains 2024-2028 > Wide international presence with strong > customer infimacy
Slide 41: Business Reviews: Space
BUSINESS REVIEWS EAC Herve Derrey Executive Vice-President, Space
Slide 42: Thales Space ID card
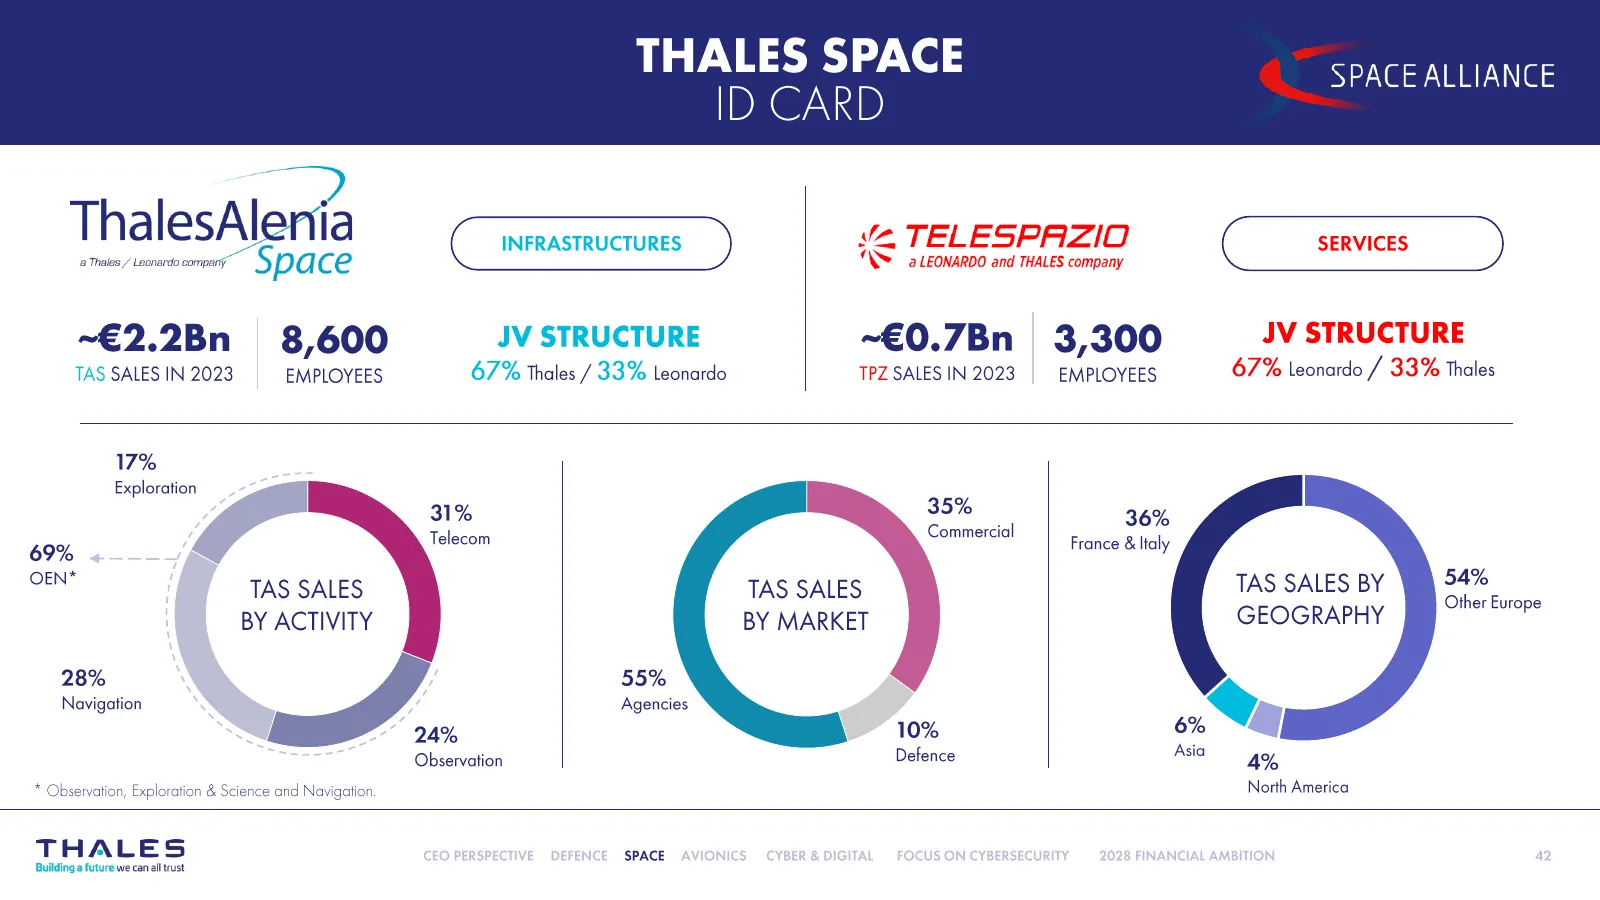
THALES SPACE ID CARD SPACE ALLIANCE ThalesAle a ce Teueseqzio ‘Thales / Leonard compen Space 4% a LEONARDO and THALES company SERVICES ~€2.2Bn 8,600 JV STRUCTURE ~€0.7Bn 3,300 JV STRUCTURE TAS SALES IN 2023 EMPLOYEES 67% Thales / 33% Leonardo TPZ SALES IN 2023 | EMPLOYEES 67% leonardo / 33% Thales 1
Slide 43: Focus on profitability while pursuing growth
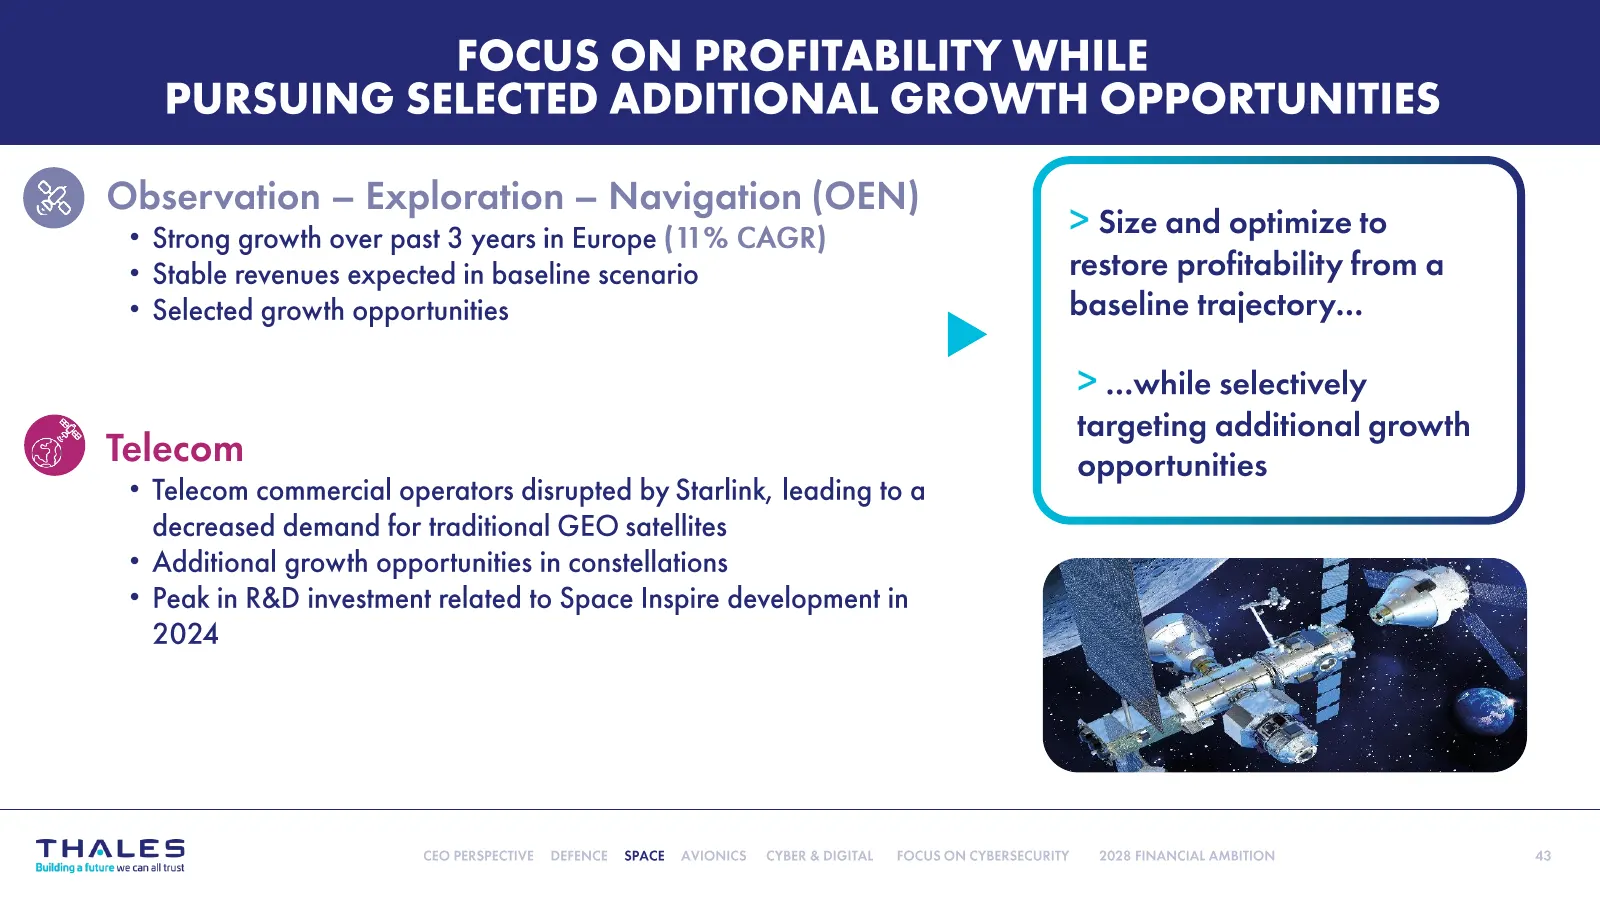
FOCUS ON PROFITABILITY WHILE PURSUING SELECTED ADDITIONAL GROWTH OPPORTUNITIES Observation — Exploration — Navigation (OEN) . a * Strong growth over past 3 years in Europe (11% CAGR) Size and optimize to * Stable revenues expected in baseline scenario restore profitability from a * Selected growth o
Slide 44: Observation - Exploration - Navigation markets
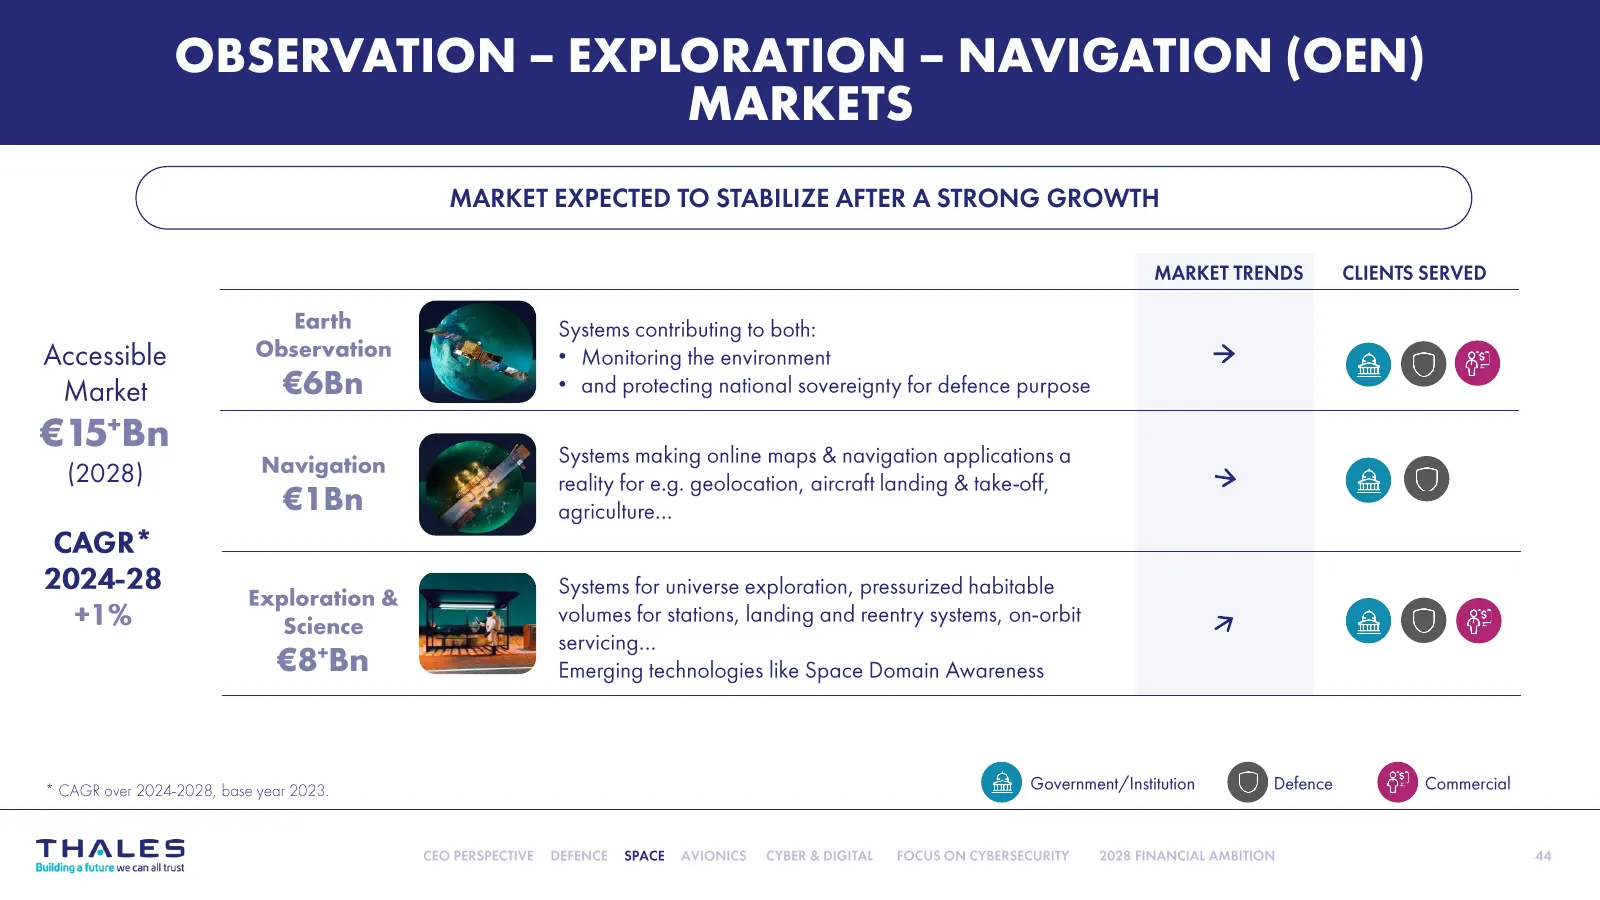
OBSERVATION - EXPLORATION - NAVIGATION (OEN) MARKETS C MARKET EXPECTED TO STABILIZE AFTER A STRONG GROWTH +) MARKETTRENDS — CLIENTS SERVED Earth = Systems contributing to both: Accessible Observation * Monitoring the environment > Market €6Bn * and protecting national sovereignty for defence purpose
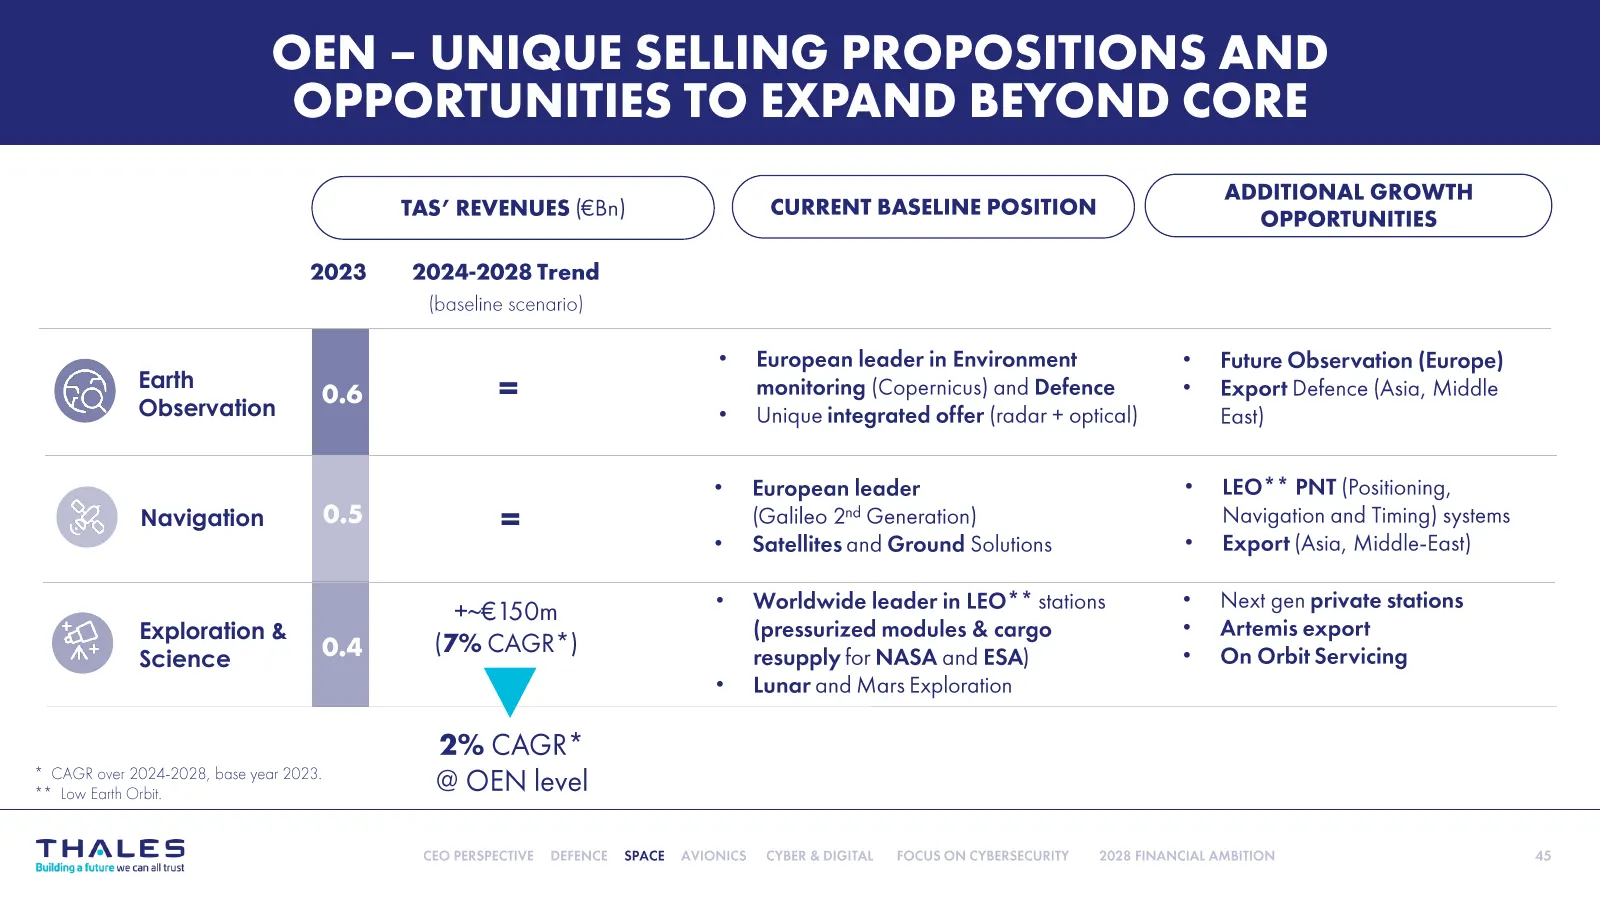
Slide 45: Earth Observation, Navigation, Exploration & Science
• • Earth • Observation • • • Navigation • • • • Exploration & • Science • •
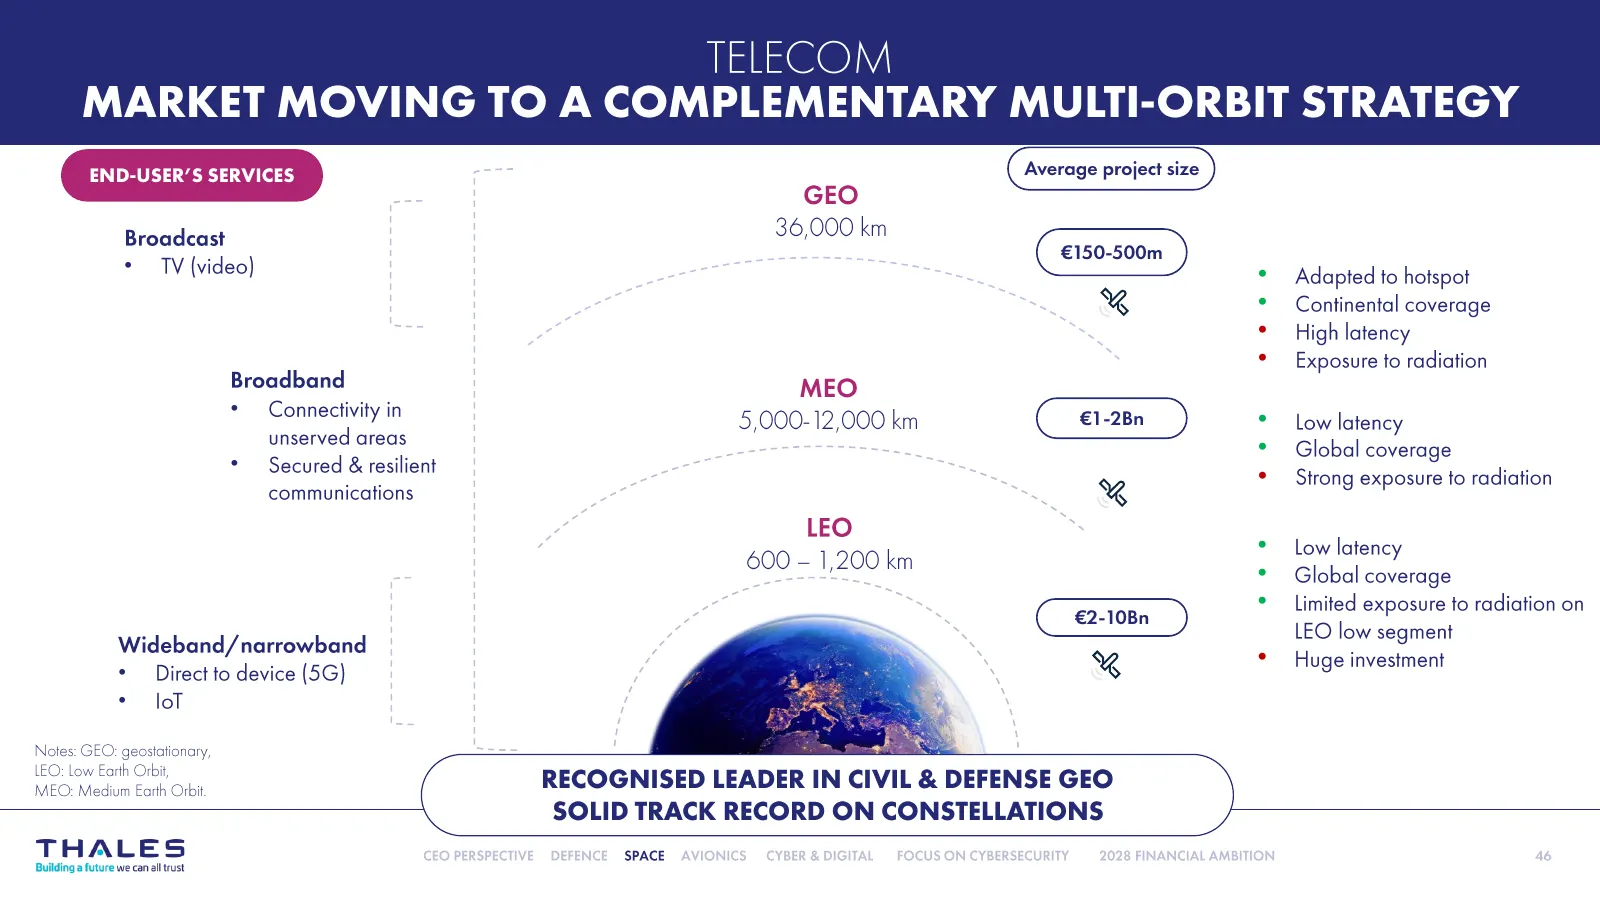
Slide 46: Telecom: multi-orbit strategy
TELECOM MARKET MOVING TO A COMPLEMENTARY MULTI-ORBIT STRATEGY GEO Broadcast 36,000 km * TV (video) % Adapted to hotspot Continental coverage High latency Exposure to radiation Broadband MEO * Connectivity in 5,000- 12,000 km * Low latency unserved areas * Global coverage * Strong exposure to radiati
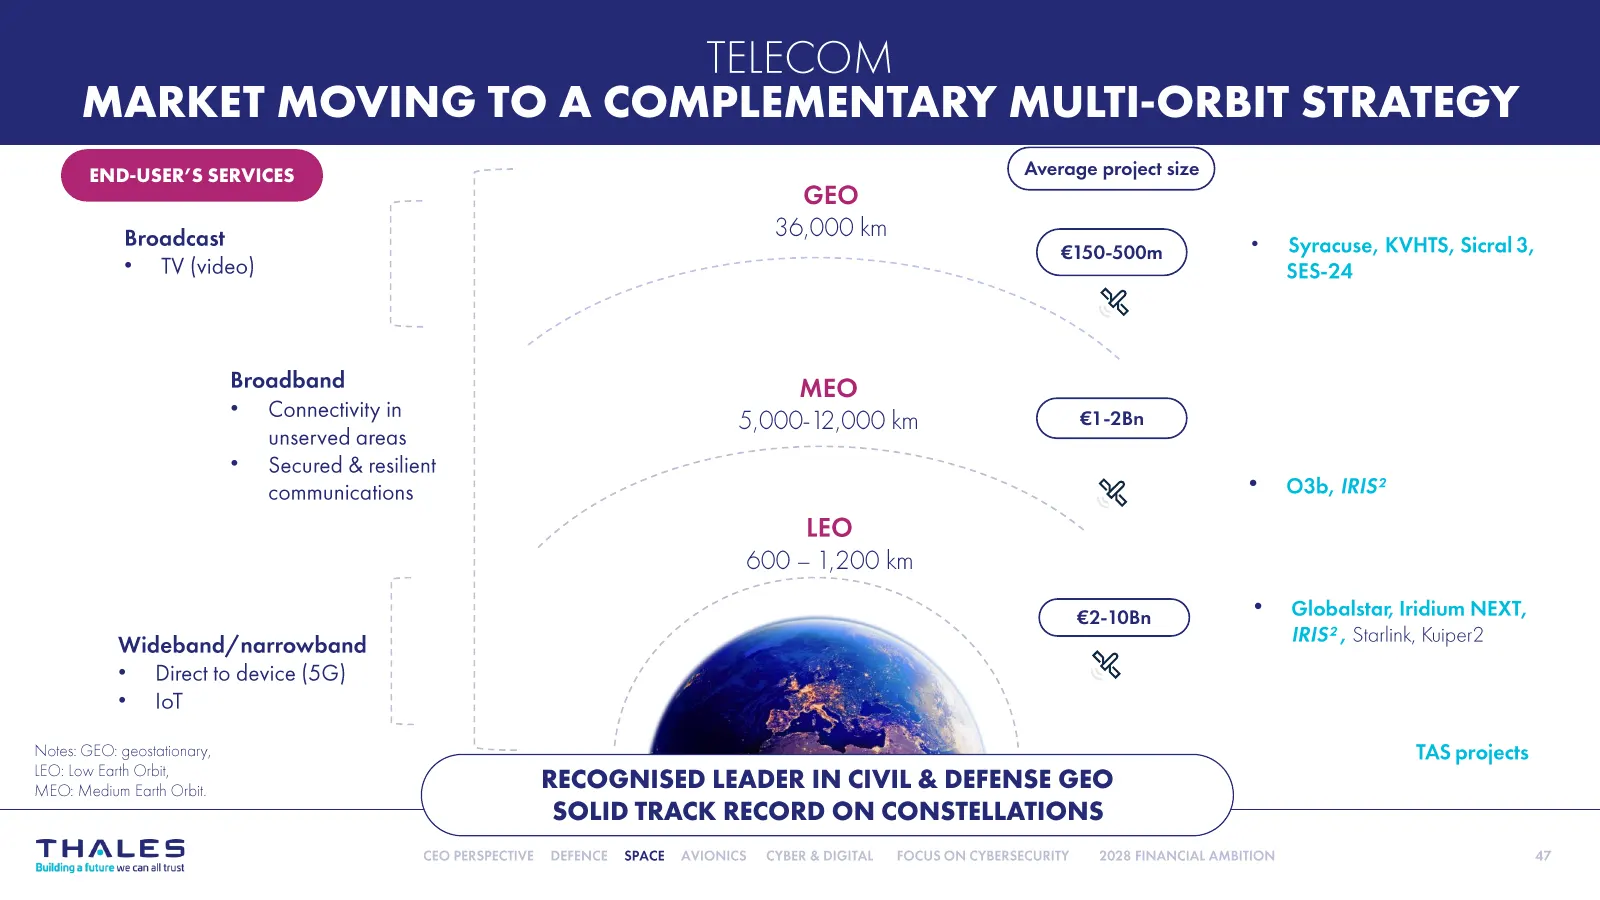
Slide 47: Telecom: multi-orbit strategy
TELECOM MARKET MOVING TO A COMPLEMENTARY MULTI-ORBIT STRATEGY GEO 36,000 ki Broadcast ‘ m * Syracuse, KVHTS, Sicral 3, * TV (video) SES-24 % Broadband MEO Connectivity in 5,000- 12,000 km unserved areas Secured & resilient communications % * O3b, IRIS? LEO 600 — 1,200 km _ ° ~~ Globalstar, Iridium N
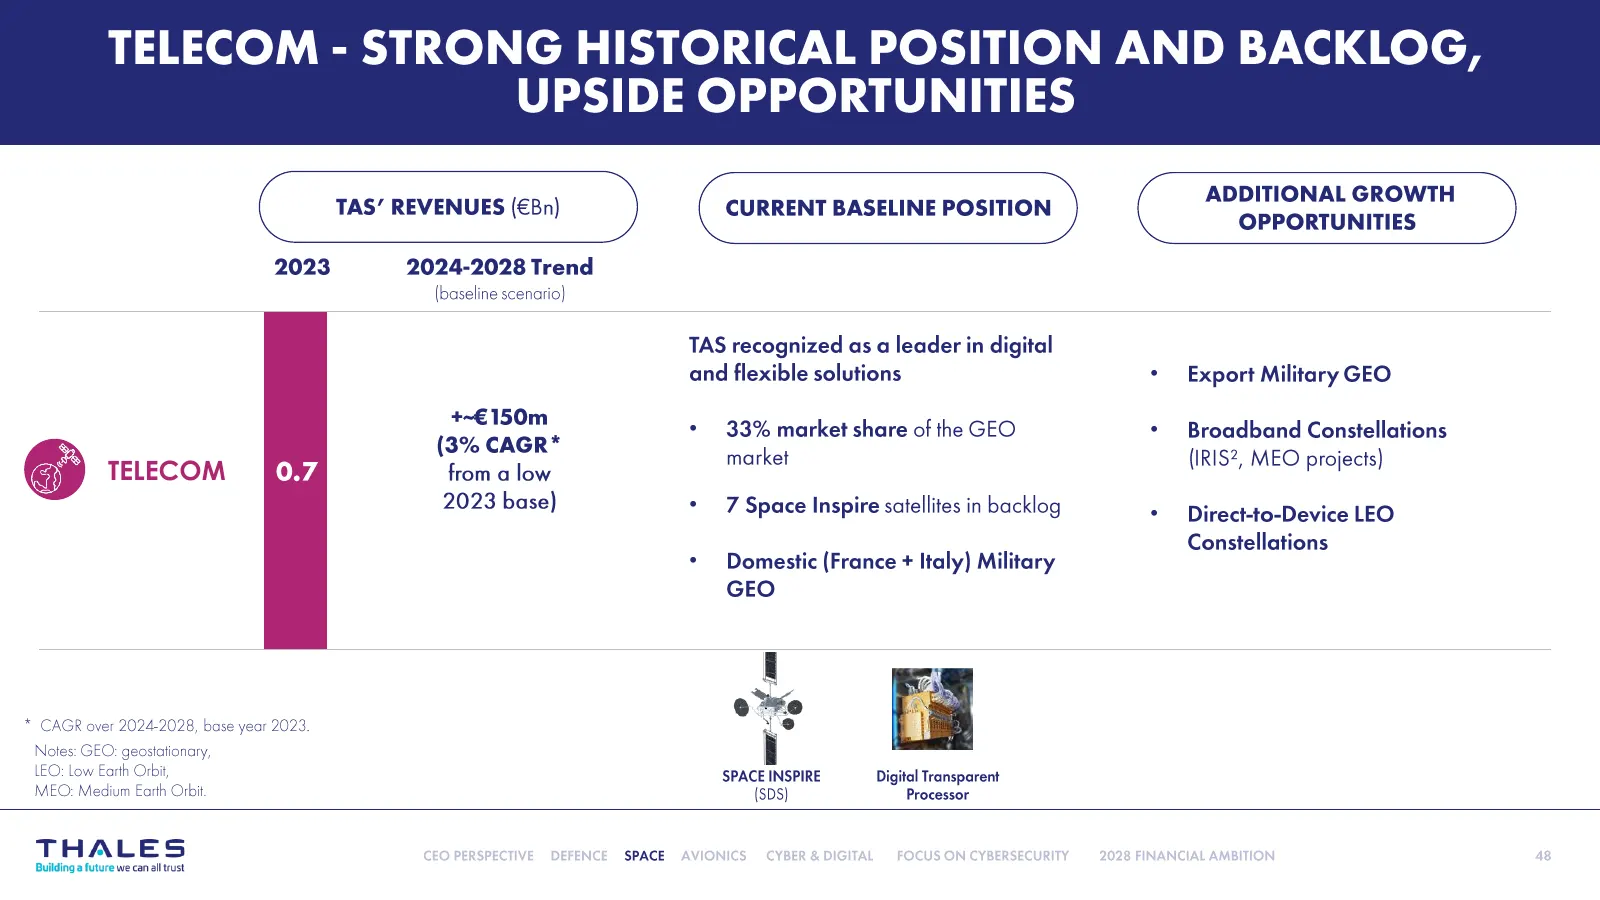
Slide 48: Telecom - strong backlog, upside opportunities
TELECOM - STRONG HISTORICAL POSITION AND BACKLOG, UPSIDE OPPORTUNITIES , ADDITIONAL GROWTH C TAS’ REVENUES (€Bn) +) ( curren BASELINE POSITION ) C OPPORTUNITIES ) 2023 2024-2028 Trend (baseline scenario} TAS recognized as a leader in digital and flexible solutions + Export Military GEO secnene 33% m
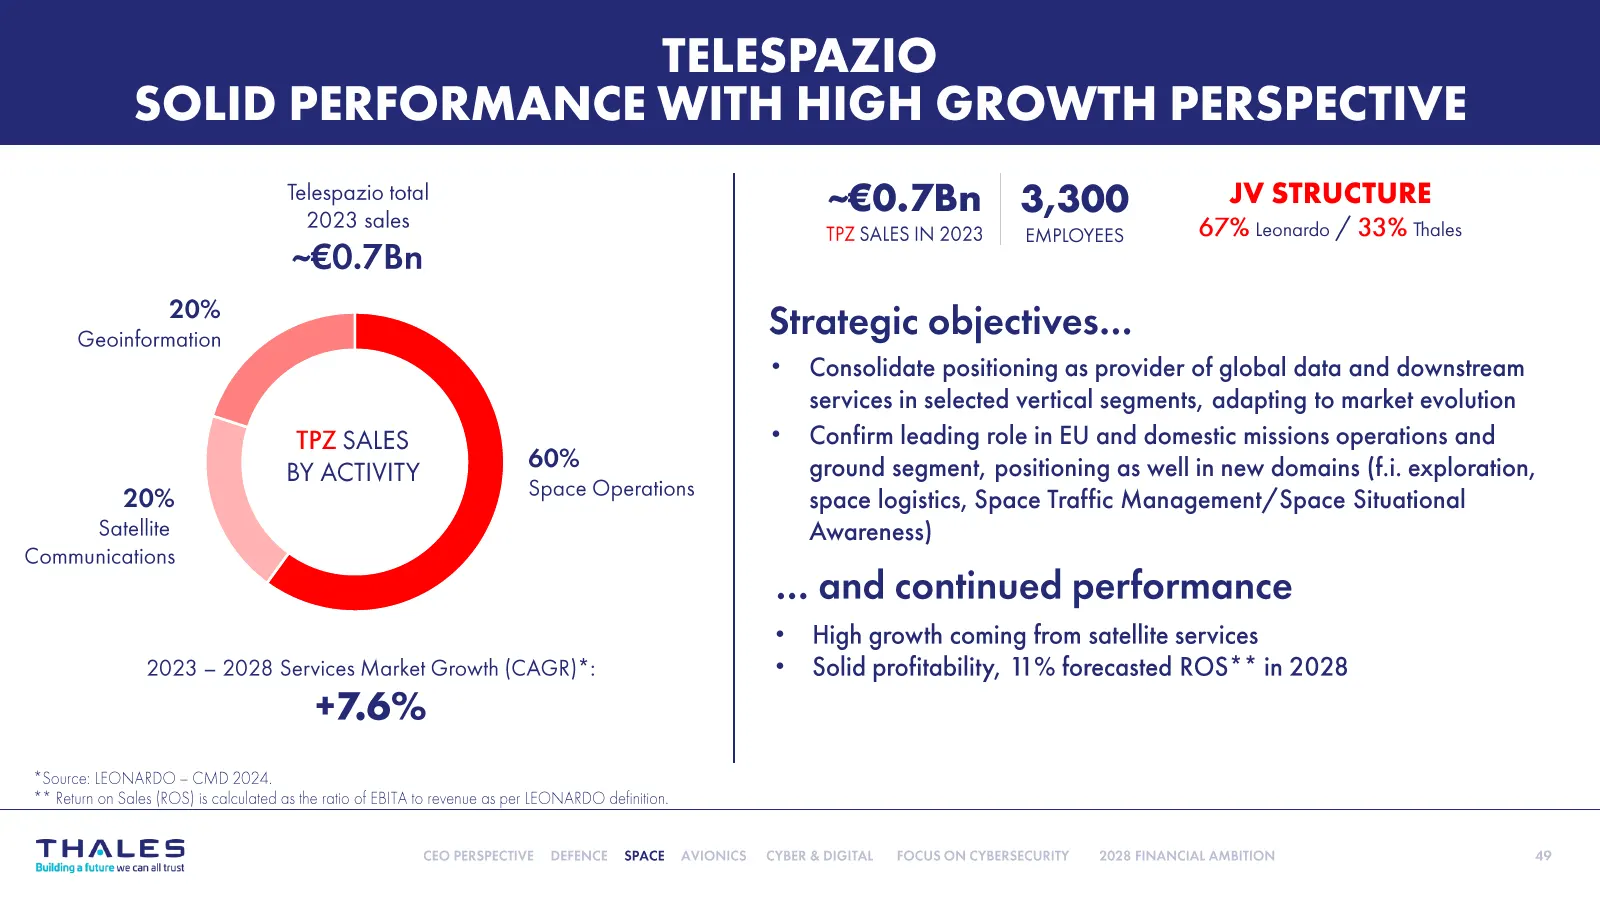
Slide 49: Telespazio
TELESPAZIO SOLID PERFORMANCE WITH HIGH GROWTH PERSPECTIVE Telespazio total ~€0.7Bn 3,300 JV STRUCTURE 2023 sales TPZSALES IN 2023 EMPLOYEES 67% teonardo / 33% Thales ~€0.7Bn 20% Geoinformation Strategic objectives... * Consolidate positioning as provider of global data and downstream services in sel
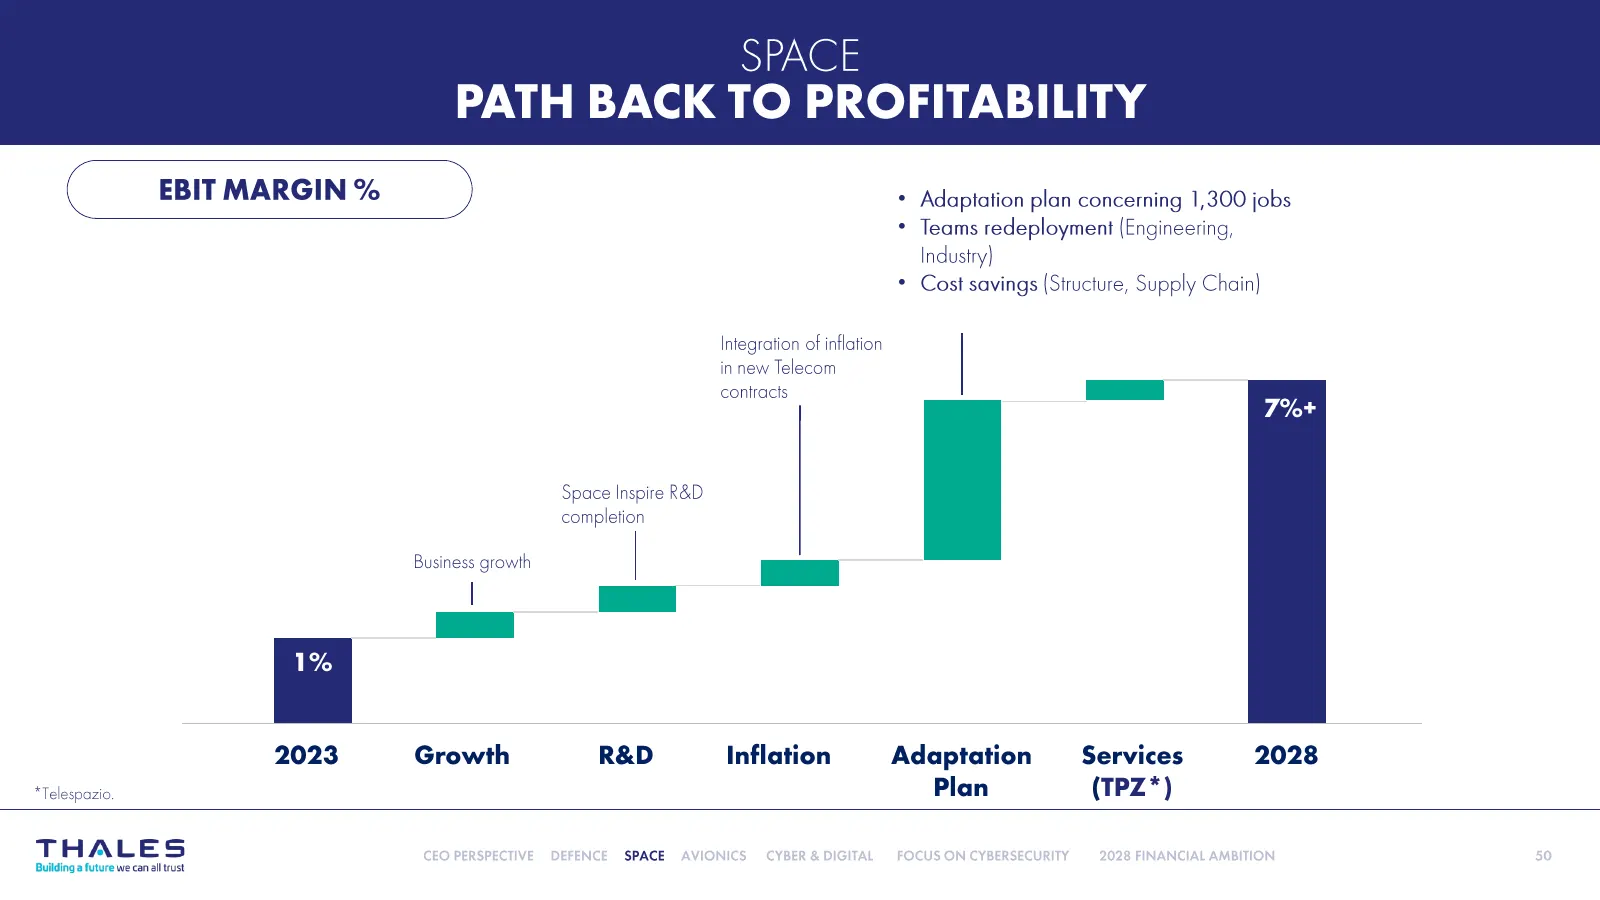
Slide 50: Space: path back to profitability
SPACE PATH BACK TO PROFITABILITY C EBIT MARGIN % yy * Adaptation plan concerning 1,300 jobs * Teams redeployment (Engineering, Industry) * Cost savings (Structure, Supply Chain) Integration of inflation in new Telecom contracts Le Space Inspire R&D completion 7 | 2023 Growth R&D Inflation Adaptation
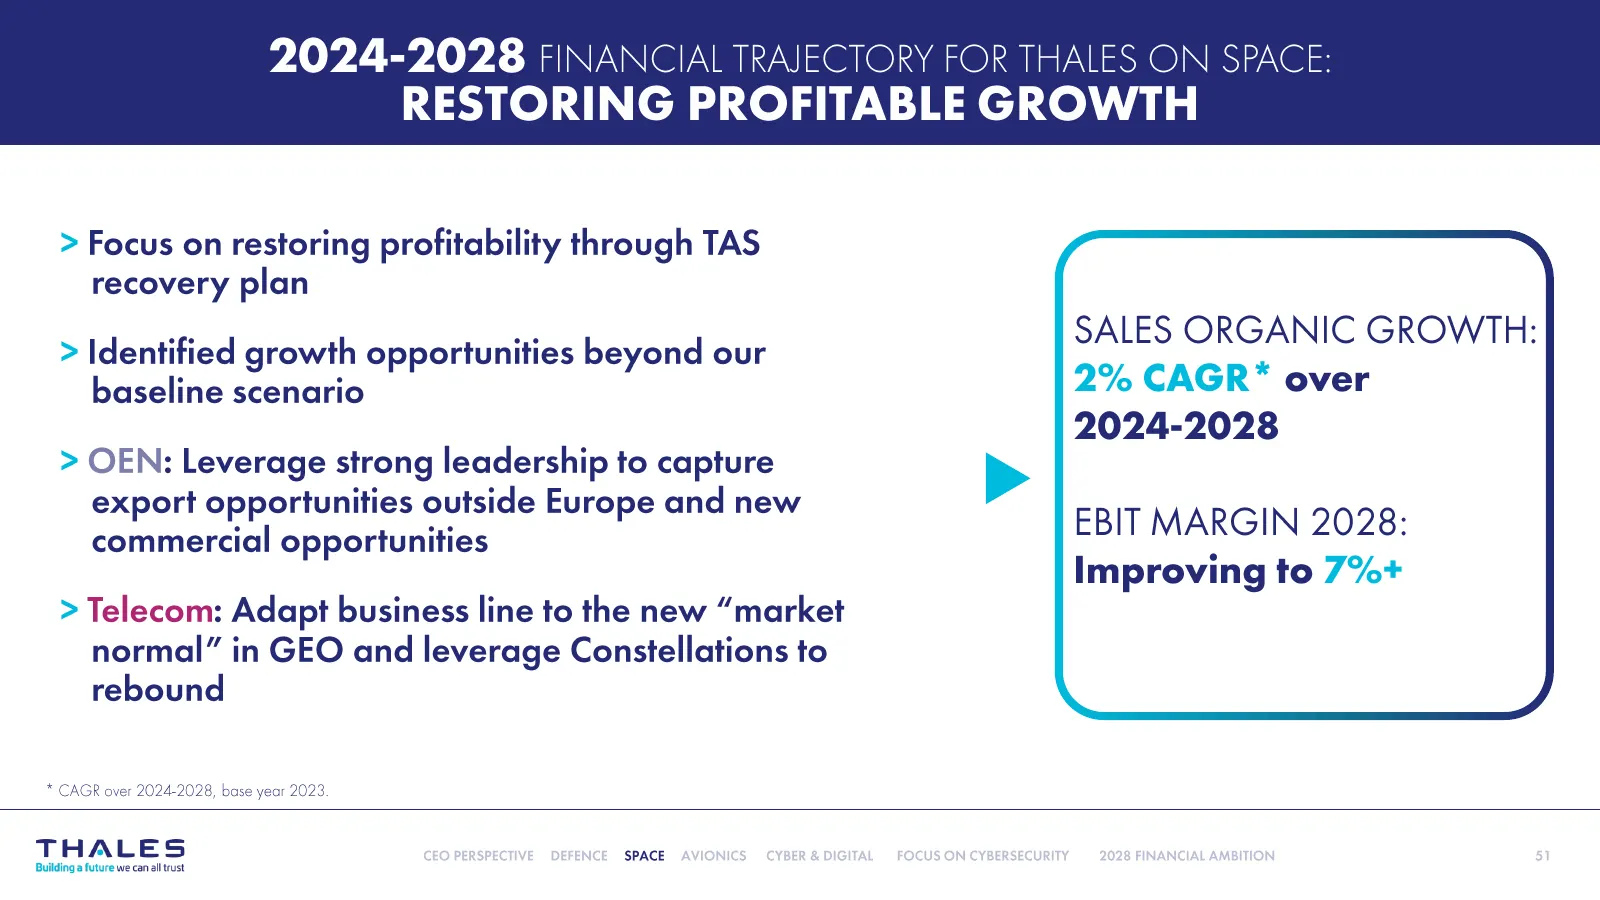
Slide 51: 2024-2028 financial trajectory on Space
2024-2028 FINANCIAL TRAJECTORY FOR THALES ON SPACE: RESTORING PROFITABLE GROWTH > Focus on restoring profitability through TAS recovery plan SALES ORGANIC GROWTH: 2% CAGR* over 2024-2028 > Identified growth opportunities beyond our baseline scenario > OEN: Leverage strong leadership to capture expor
Slide 52: Business Reviews: Avionics
BUSINESS REVIEWS AVIONICS Yannick Assoua id Executive Vice-President, Avionics
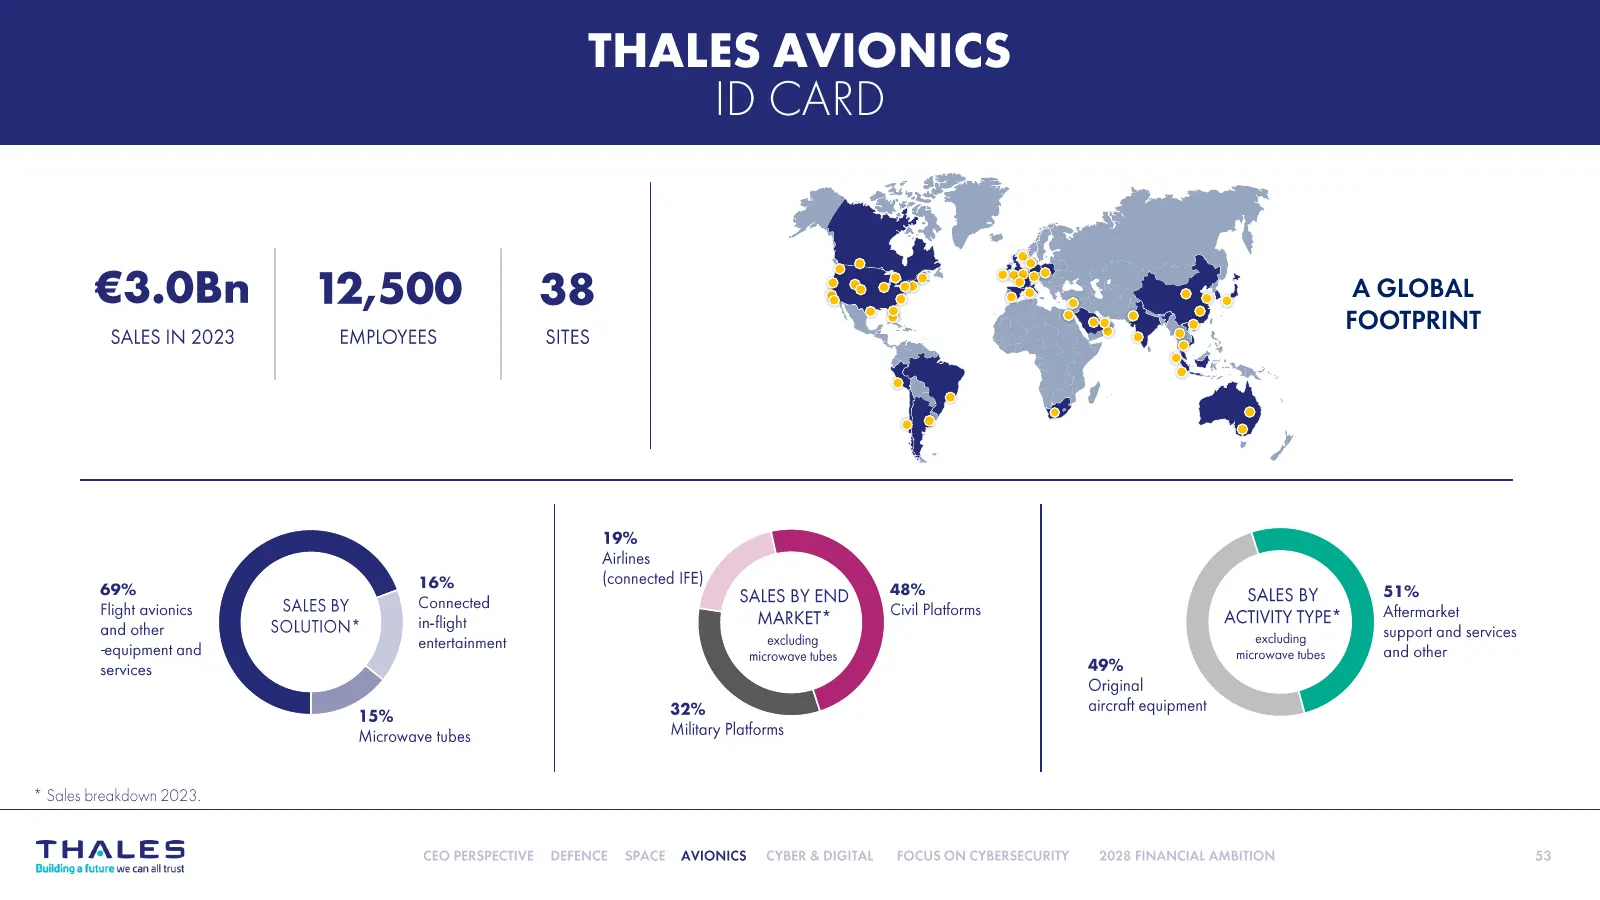
Slide 53: Thales Avionics ID card
THALES AVIONICS ID CARD i A GLOBAL FOOTPRINT €3.0Bn 12,500 38 SALES IN 2023 EMPLOYEES SITES 19% Airlines 16% (connected IFE) » , ae SALES BY Connected SALES BY END Wy 48% SALES BY 51% Flight avionics . ; NMARKET™ Civil Plaorms ACES Be WB Atomonkt and other SOLUTION in wish . cluding Juding support a
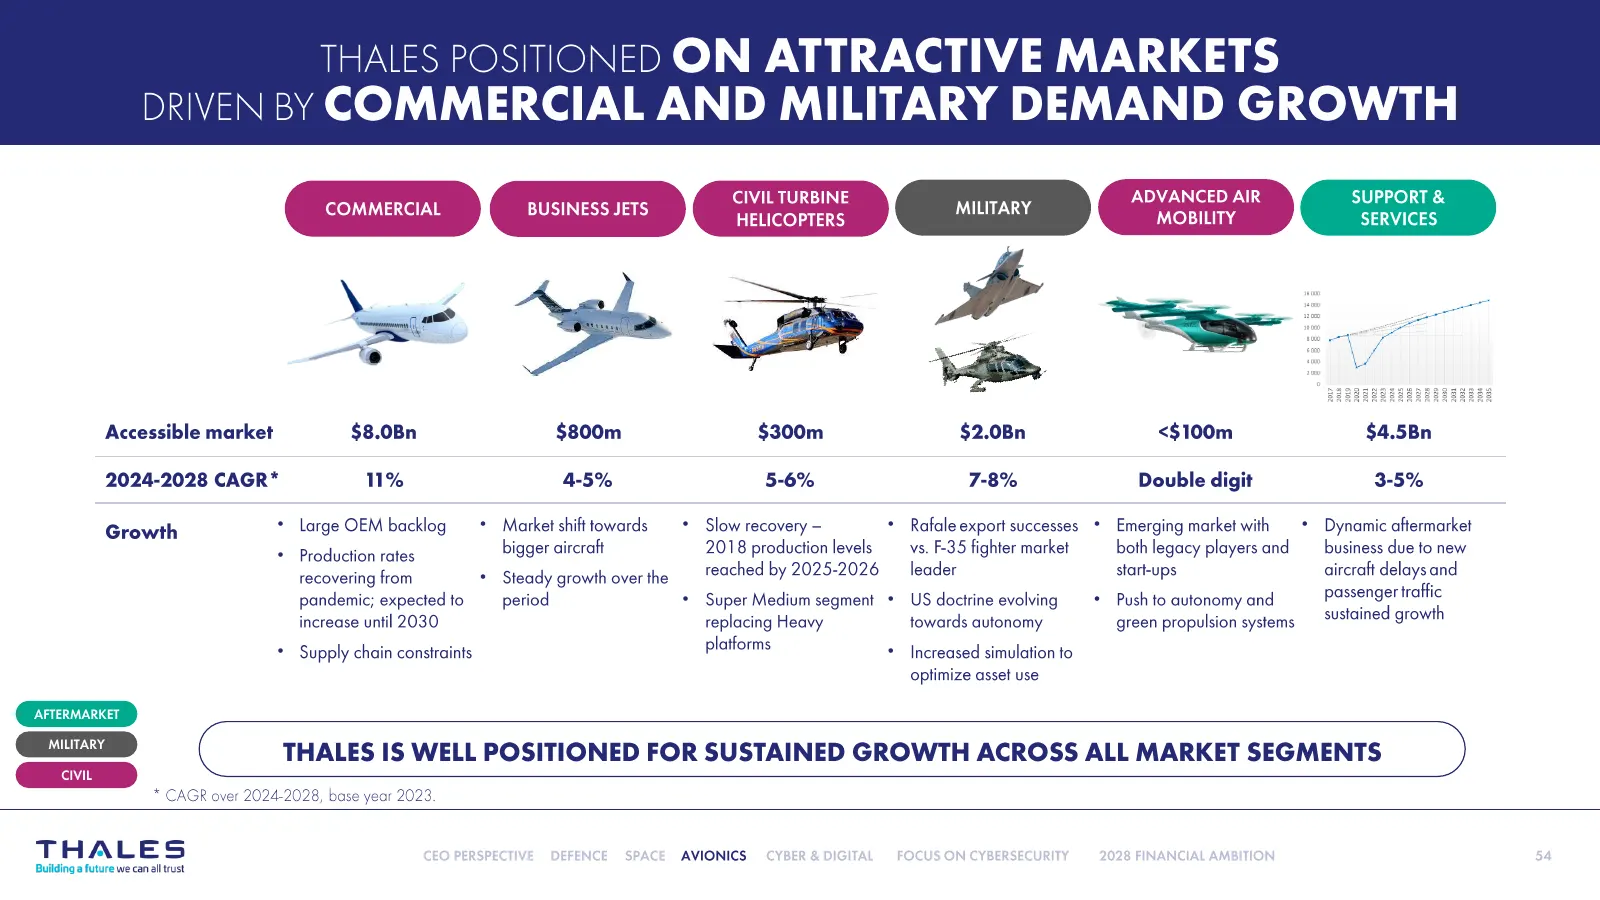
Slide 54: Thales positioned on attractive markets
THALES POSITIONED ON ATTRACTIVE MARKETS DRIVEN BY COMMERCIAL AND MILITARY DEMAND GROWTH \ee Ahk ae Accessible market $8.0Bn $800m $300m $2.0Bn <$100m $4.5Bn 2024-2028 CAGR* 1% 4-5% 5-6% 7-8% Double digit 3-5% Growth * Large OEM backlog = * “Market shifttowards ~*~ Slow recovery — * Rafale export suc
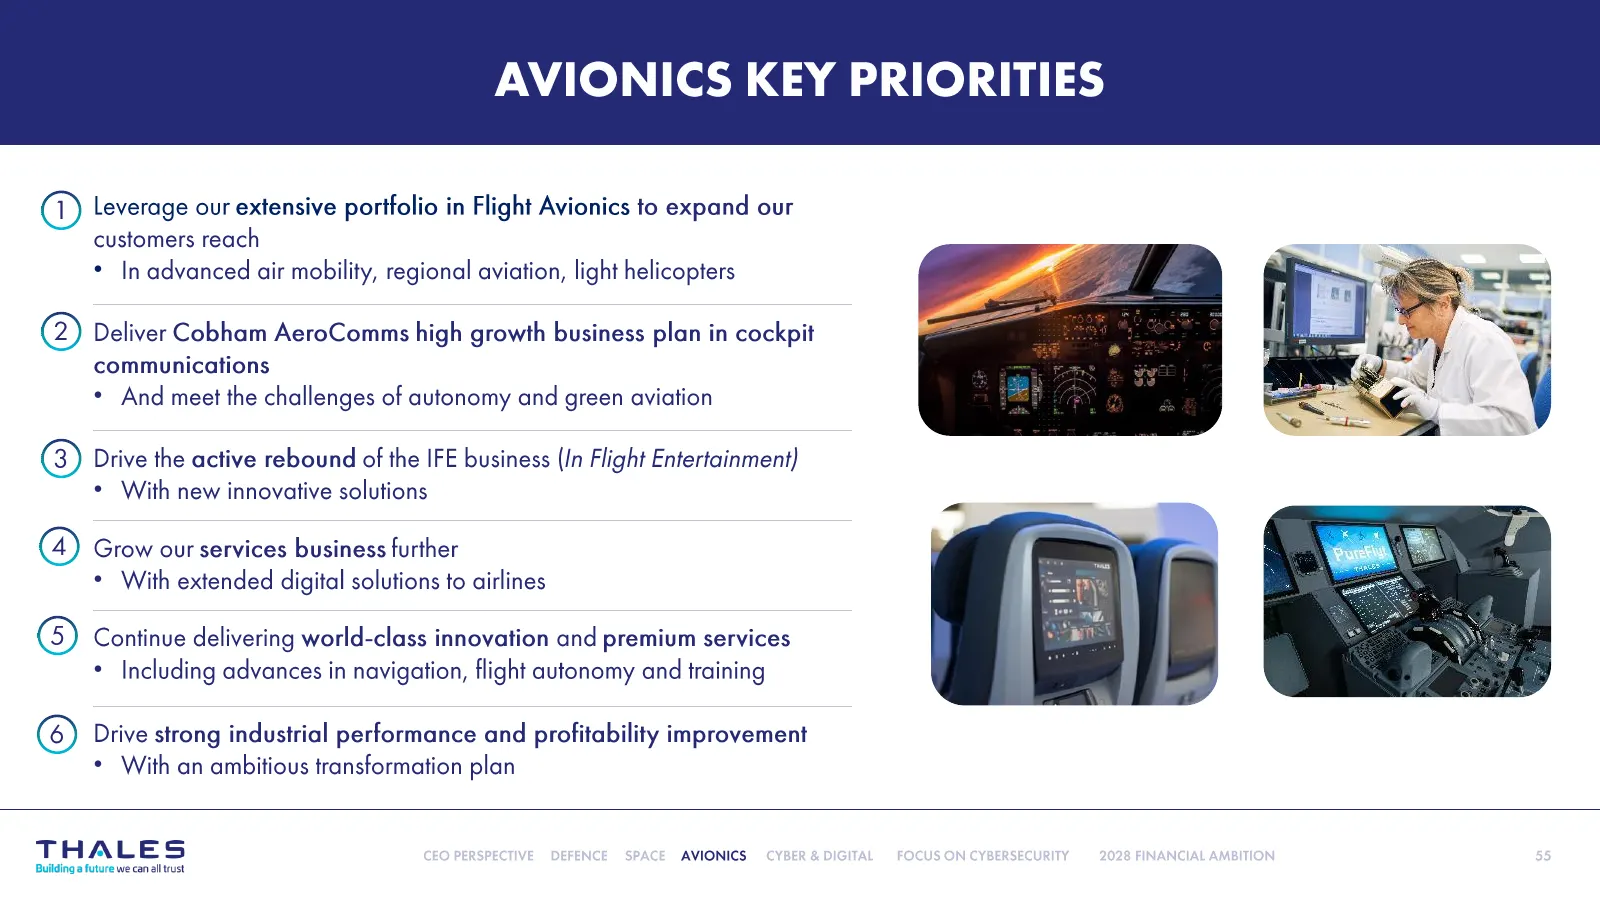
Slide 55: Avionics key priorities
AVIONICS KEY PRIORITIES @ Leverage our extensive portfolio in Flight Avionics to expand our customers reach * In advanced air mobility, regional aviation, light helicopters @ Deliver Cobham AeroComms high growth business plan in cockpit communications * And meet the challenges of autonomy and green
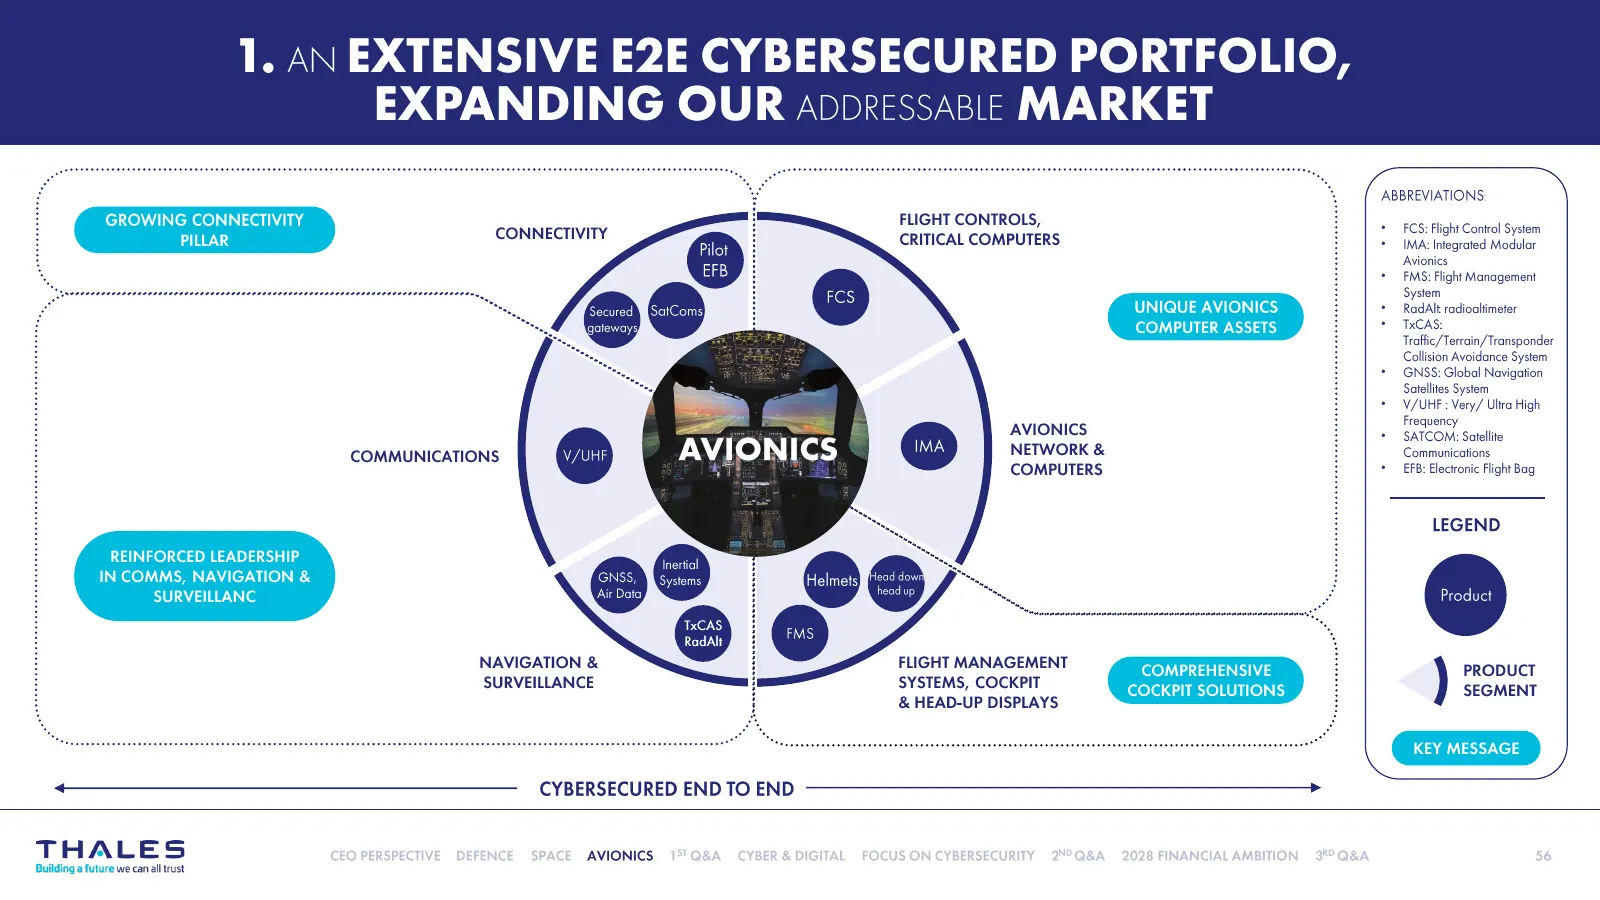
Slide 56: Extensive E2E cybersecured portfolio
1. AN EXTENSIVE E2E CYBERSECURED PORTFOLIO, EXPANDING OUR AppressAsle MARKET ABBREVIATIONS FCS: Flight Control System IMA: Integrated Modular Avionics FMS: Flight Management System RadAlt radioaliimeter TXCAS: Trafic/Terrain/ Transponder Collision Avoidance System GNSS: Global Navigation Satellites
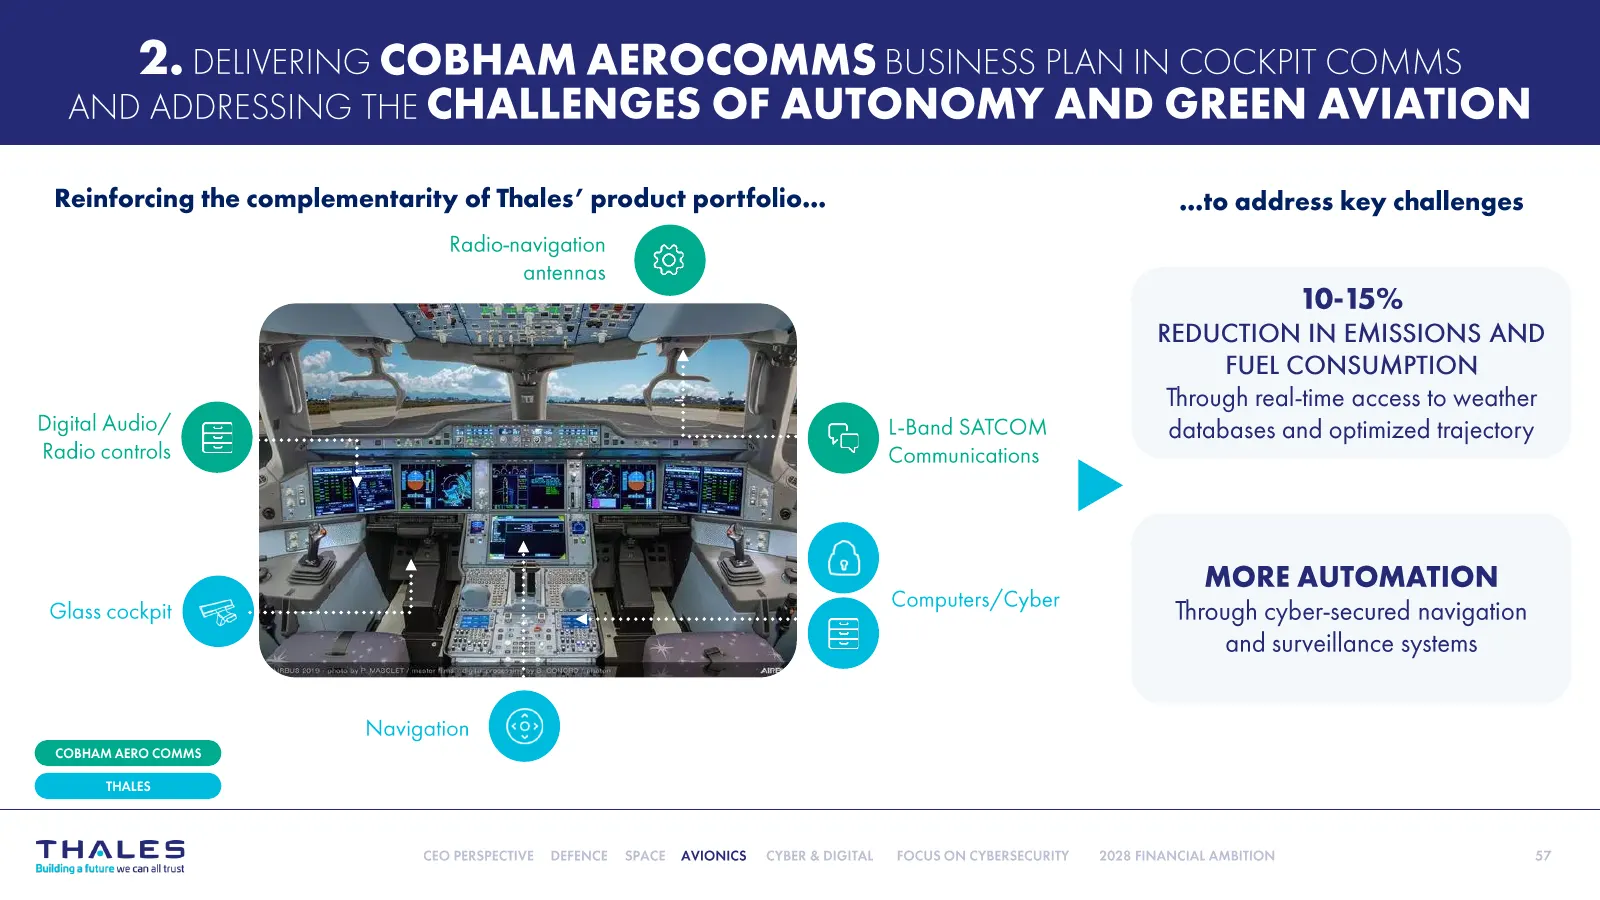
Slide 57: Delivering Cobham AeroComms business plan
2. DELIVERING COBHAM AEROCOMMS BUSINESS PLAN IN COCKPIT COMMS AND ADDRESSING THE CHALLENGES OF AUTONOMY AND GREEN AVIATION Reinforcing the complementarity of Thales’ product portfolio... ..to address key challenges 10-15% REDUCTION IN EMISSIONS AND FUEL CONSUMPTION Through real-time access to weathe
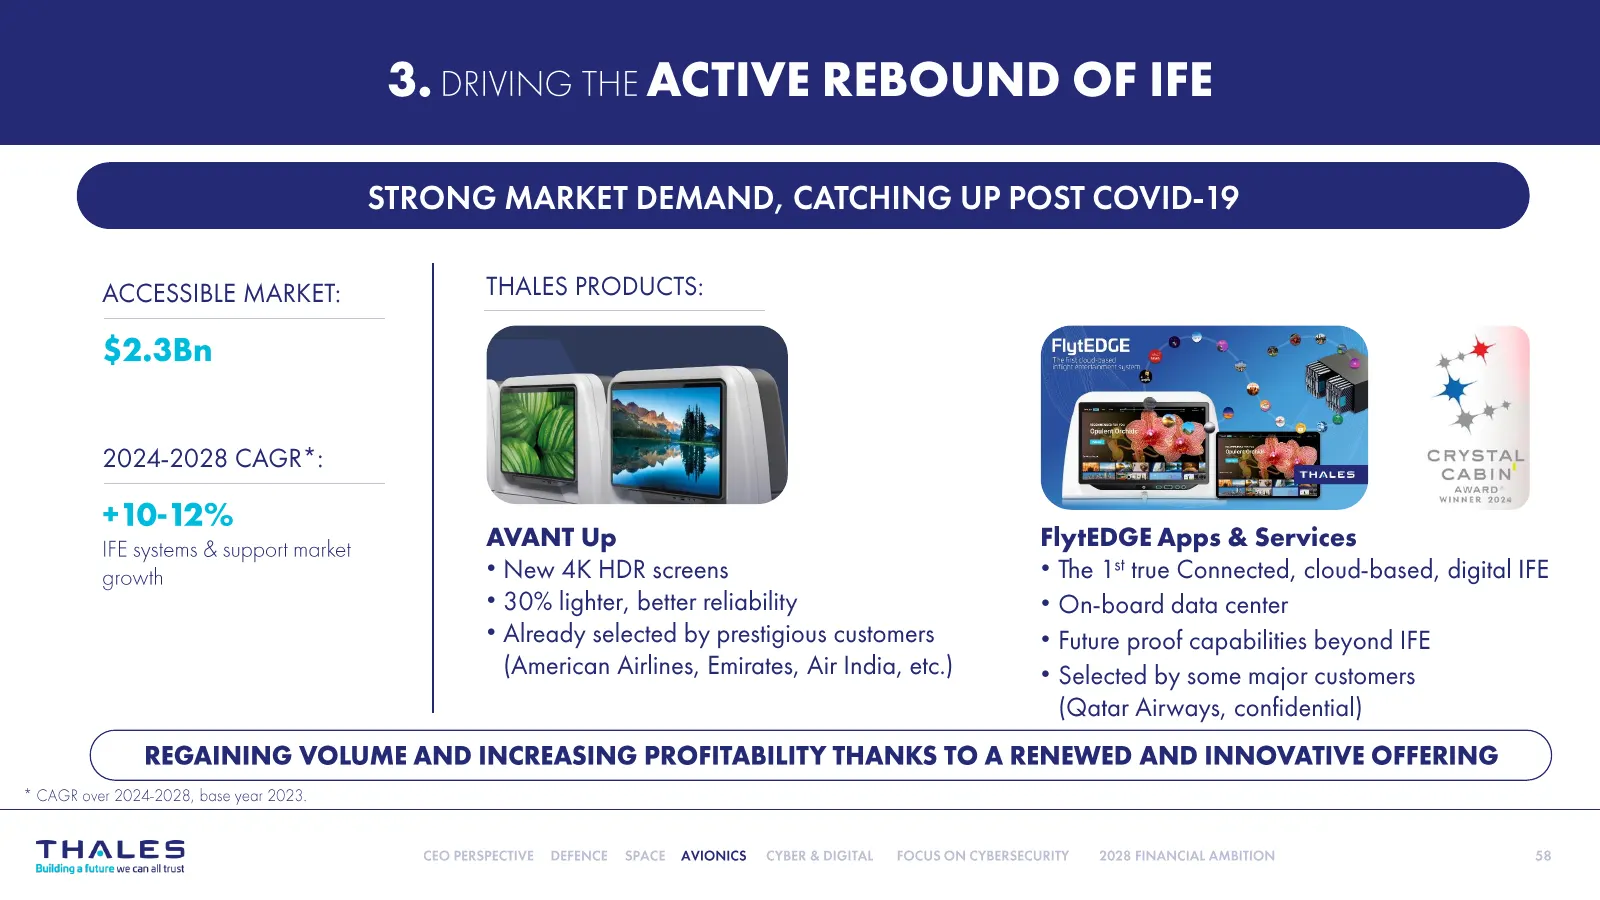
Slide 58: Driving the active rebound of IFE
3. DRIVING THE ACTIVE REBOUND OF IFE RONG MARKET DEMAN ACCESSIBLE MARKET: THALES PRODUCTS: at Ae 2024-2028 CAGR*: CRYSTAL CABIN IFE systems & support morket AVANT Up FlytEDGE Apps & Services growth * New 4K HDR screens * The 1* true Connected, cloud-based, digital IFE * 30% lighter, better reliabili
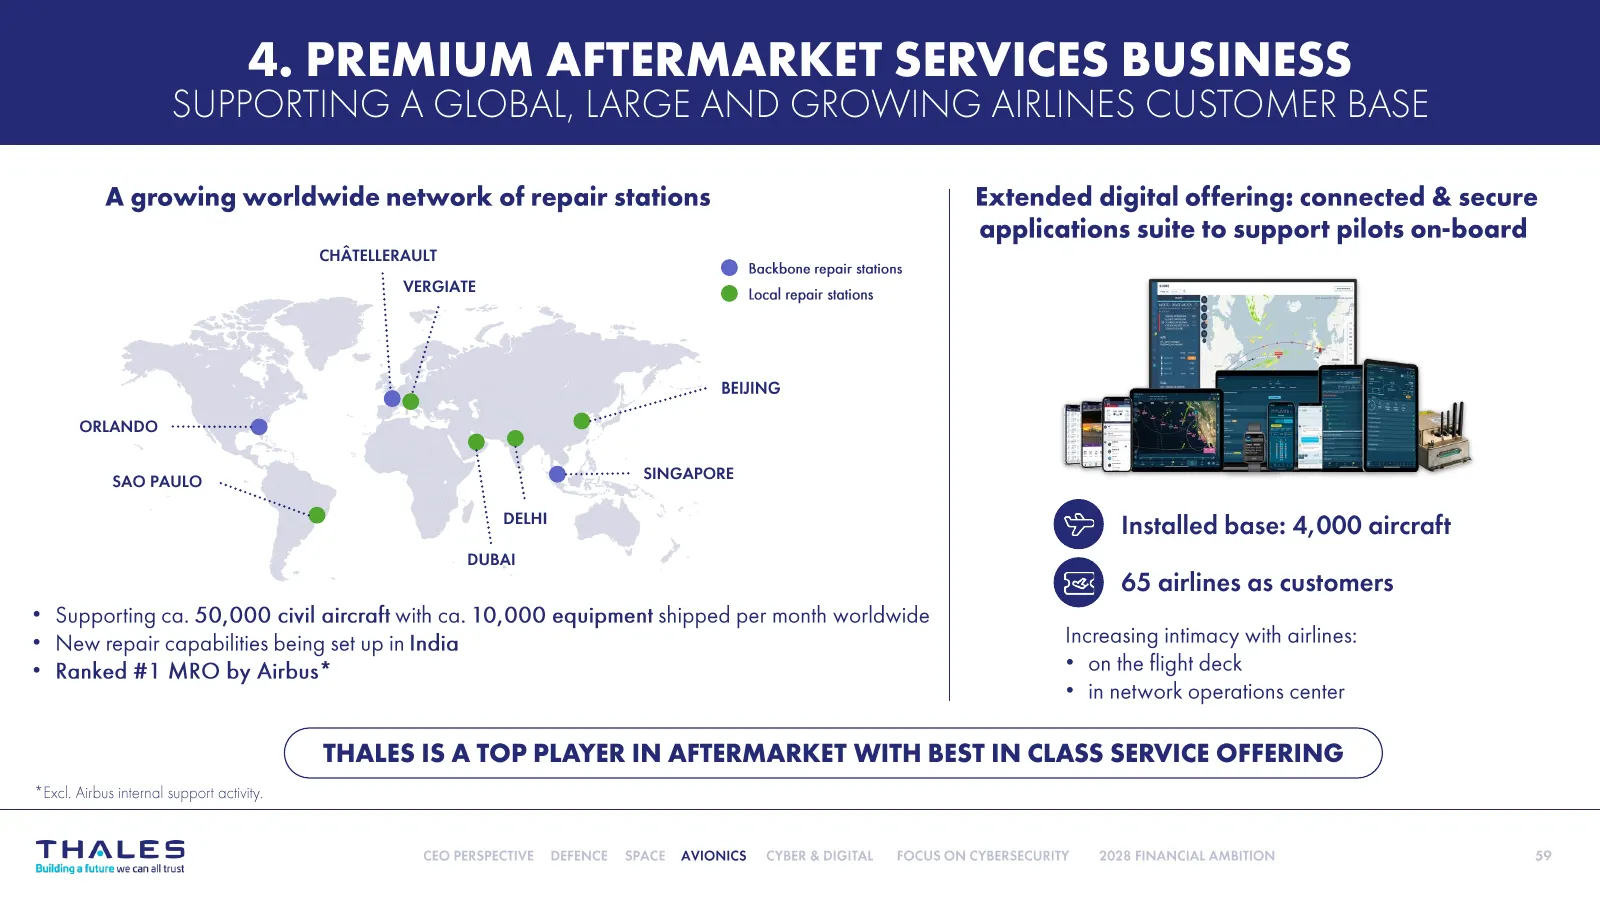
Slide 59: Premium aftermarket services business
4. PREMIUM AFTERMARKET SERVICES BUSINESS SUPPORTING A GLOBAL, LARGE AND GROWING AIRLINES CUSTOMER BASE A growing worldwide network of repair stations CHATELLERAULT : @ Backbone repair stations b VERGIATE @ Local repair stations BEVING ORLANDO. veeessessseeee @ SAO PAULO... SINGAPORE DUBAI * Supporti
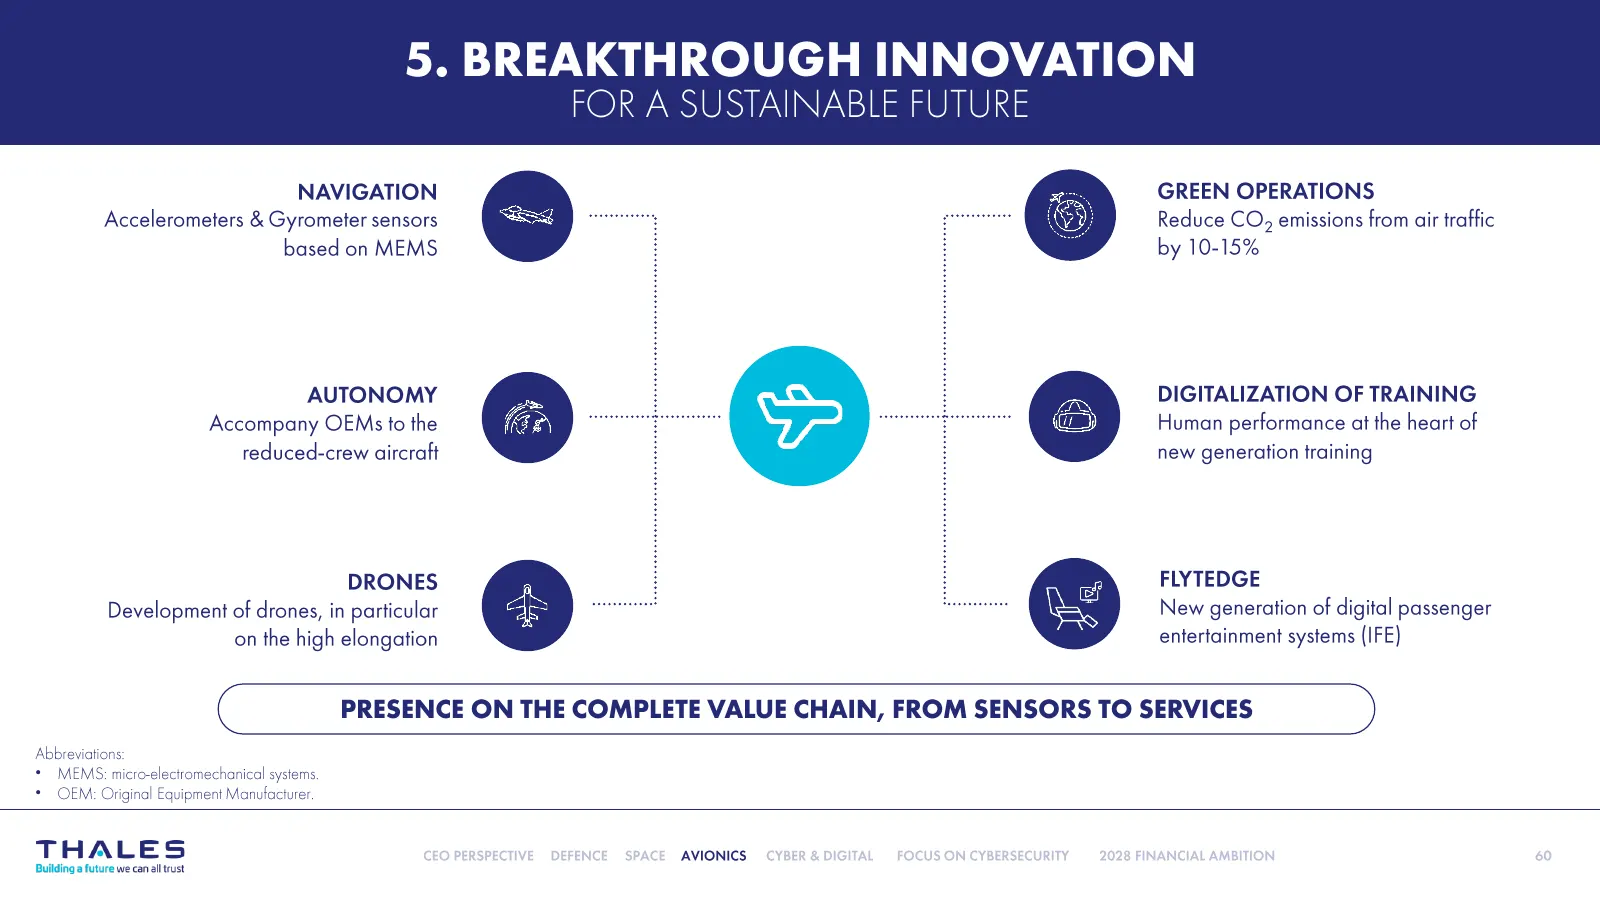
Slide 60: Breakthrough innovation for a sustainable future
5. BREAKTHROUGH INNOVATION FOR A SUSTAINABLE FUTURE NAVIGATION Accelerometers & Gyrometer sensors based on MEMS AUTONOMY Accompany OEMs to the reduced-crew aircraft DRONES Development of drones, in particular on the high elongation GREEN OPERATIONS Reduce CO, emissions from air traffic by 10-15% DIG
Slide 61: Accelerating Thales Avionics transformation plan
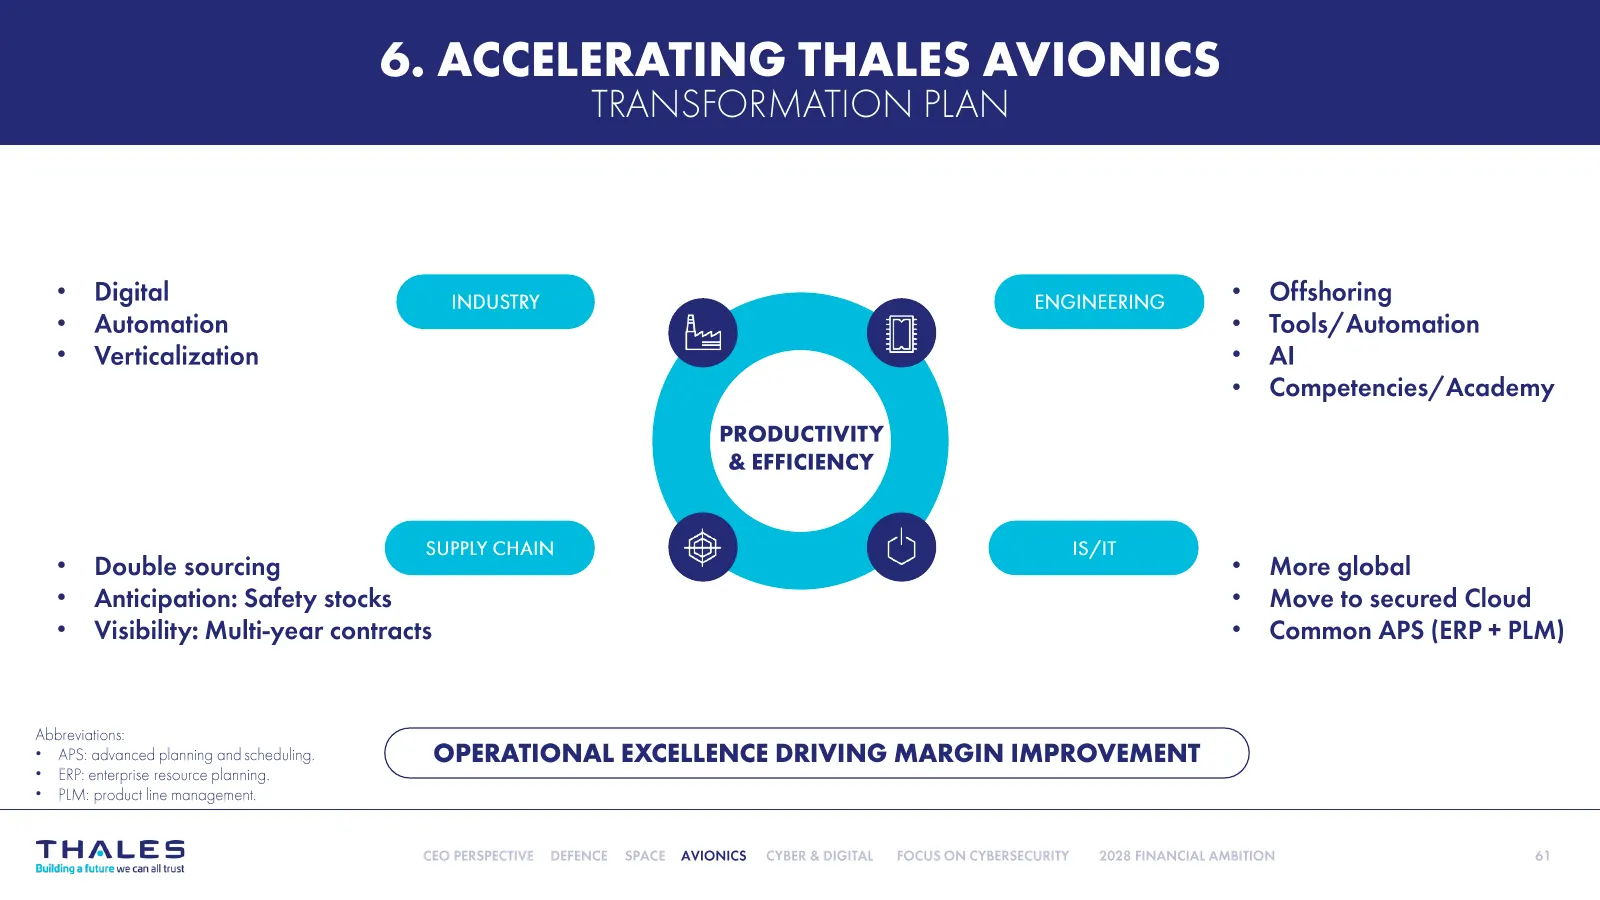
6. ACCELERATING THALES AVIONICS TRANSFORMATION PLAN * Digital * Offshoring + Automation * Tools/Automation * Verticalization ° Al * Competencies/Academy PRODUCTIVITY & EFFICIENCY . SUPPLY CHAIN * Double sourcing * More global * Anticipation: Safety stocks * Move to secured Cloud * Visibility: Multi-
Slide 62: 2024-2028 financial trajectory on Avionics
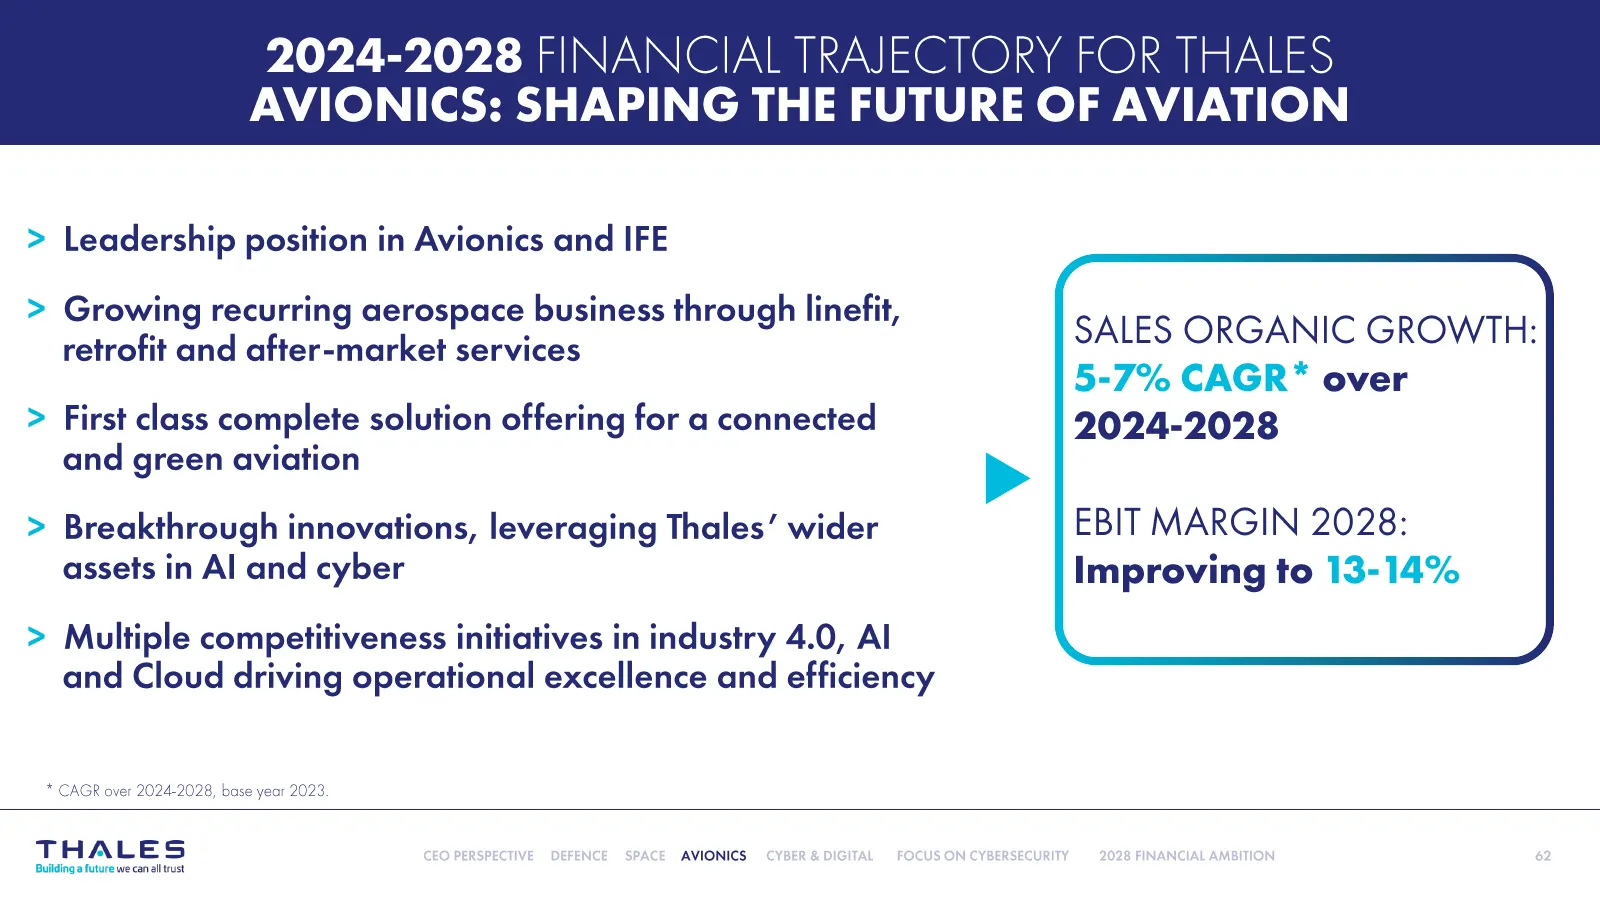
2024-2028 FINANCIAL TRAJECTORY FOR THALES AVIONICS: SHAPING THE FUTURE OF AVIATION > Leadership position in Avionics and IFE > Growing recurring aerospace business through linefit, . retrofit and after-market services SALES ORGANIC GROWTH: 5-7% CAGR* over > First class complete solution offering for
Slide 63: Business Reviews: Cyber & Digital
BUSINESS REVIEWS CYBER & DIGITAL Philippe Vallée Executive Vice-President, Cyber and Digital Sébastien Cano Senior Vice-President, Cloud Protection & Licensing (Cybersecurity Products) 63
Slide 64: Cyber & Digital ID card
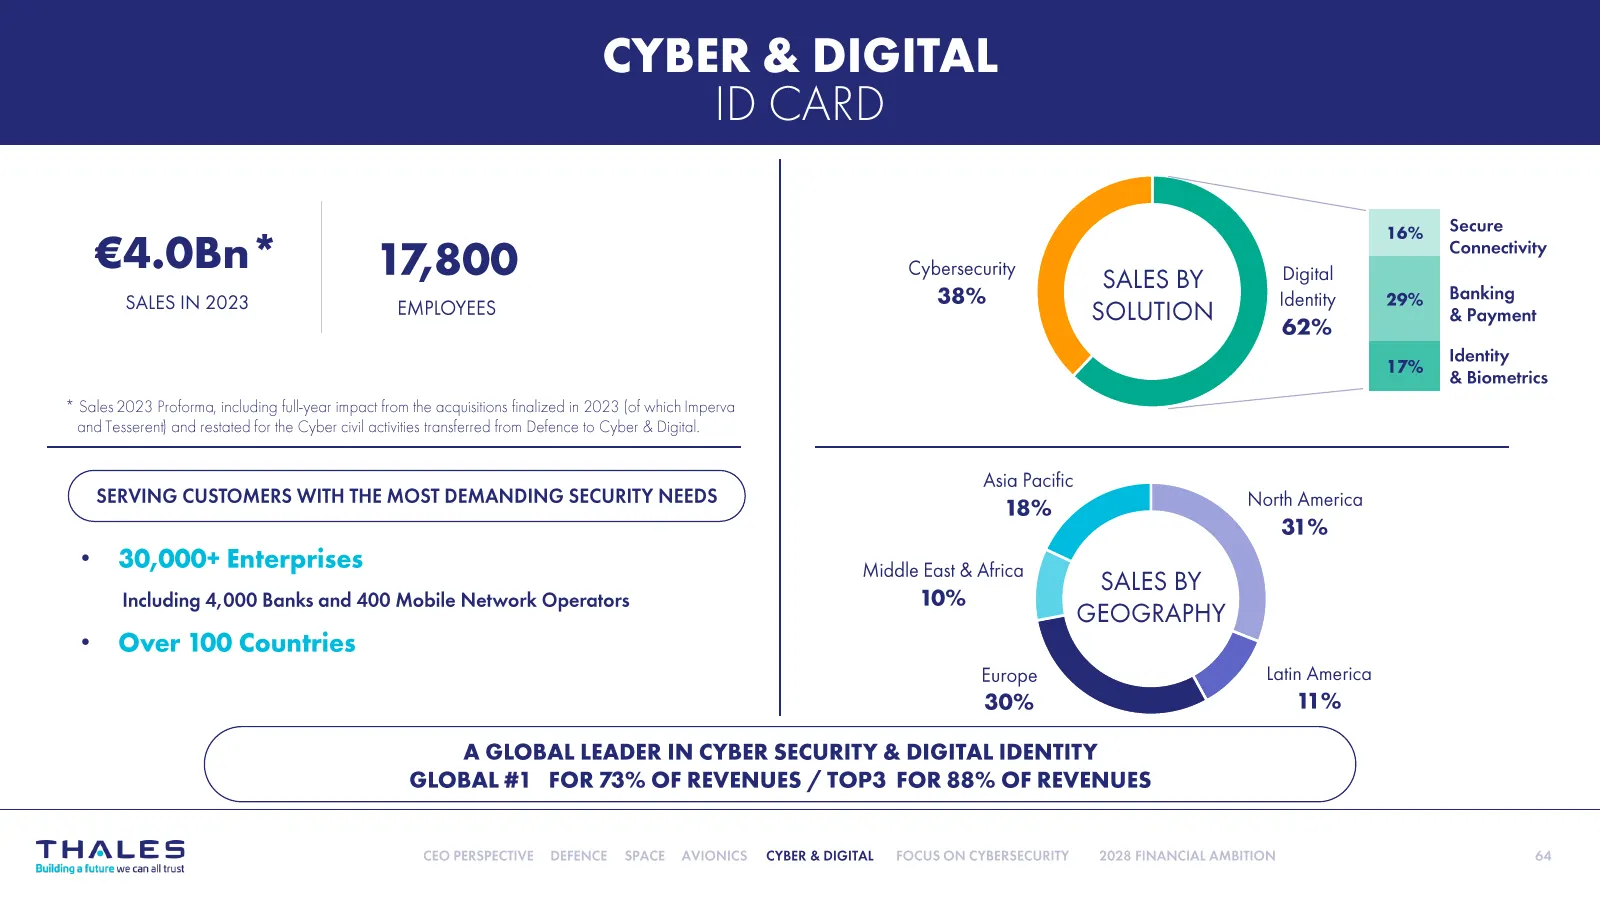
CYBER & DIGITAL ID CARD ‘x 16% Secure Connectivity €4.0Bn* —_17,800 me Ge ee ba SALES IN 2028 EMPLOYEES 38% SOLUTION J ety & Payment fo Identity & Biometrics Asia Pacifi C SERVING CUSTOMERS WITH THE MOST DEMANDING SECURITY NeEDs ) “18% North America 31% . 30,000+ Enterprises Middle East & Africa SAL
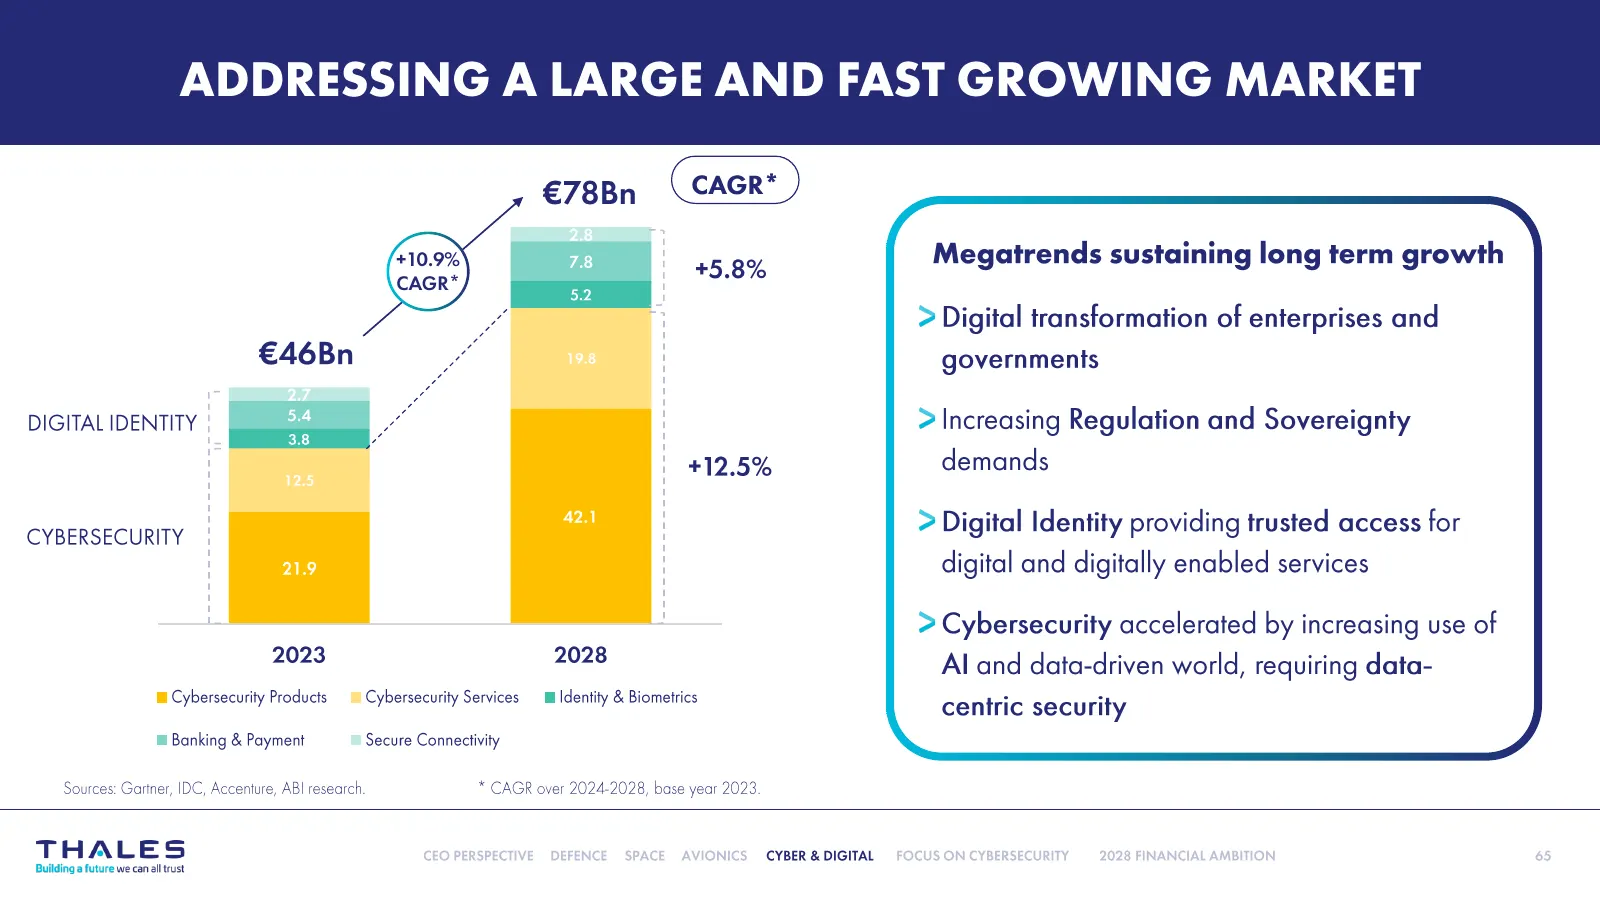
Slide 65: Addressing a large and fast growing market
ADDRESSING A LARGE AND FAST GROWING MARKET +5.8% €46Bn DIGITAL IDENTITY +12.5% CYBERSECURITY 2023 2028 Cybersecurity Products" Cybersecurity Services mi Identity & Biometrics = Banking & Payment Secure Connectivity Sources: Gariner, IDC, Accenture, ABI research * CAGR over 2024-2028, base year 2023
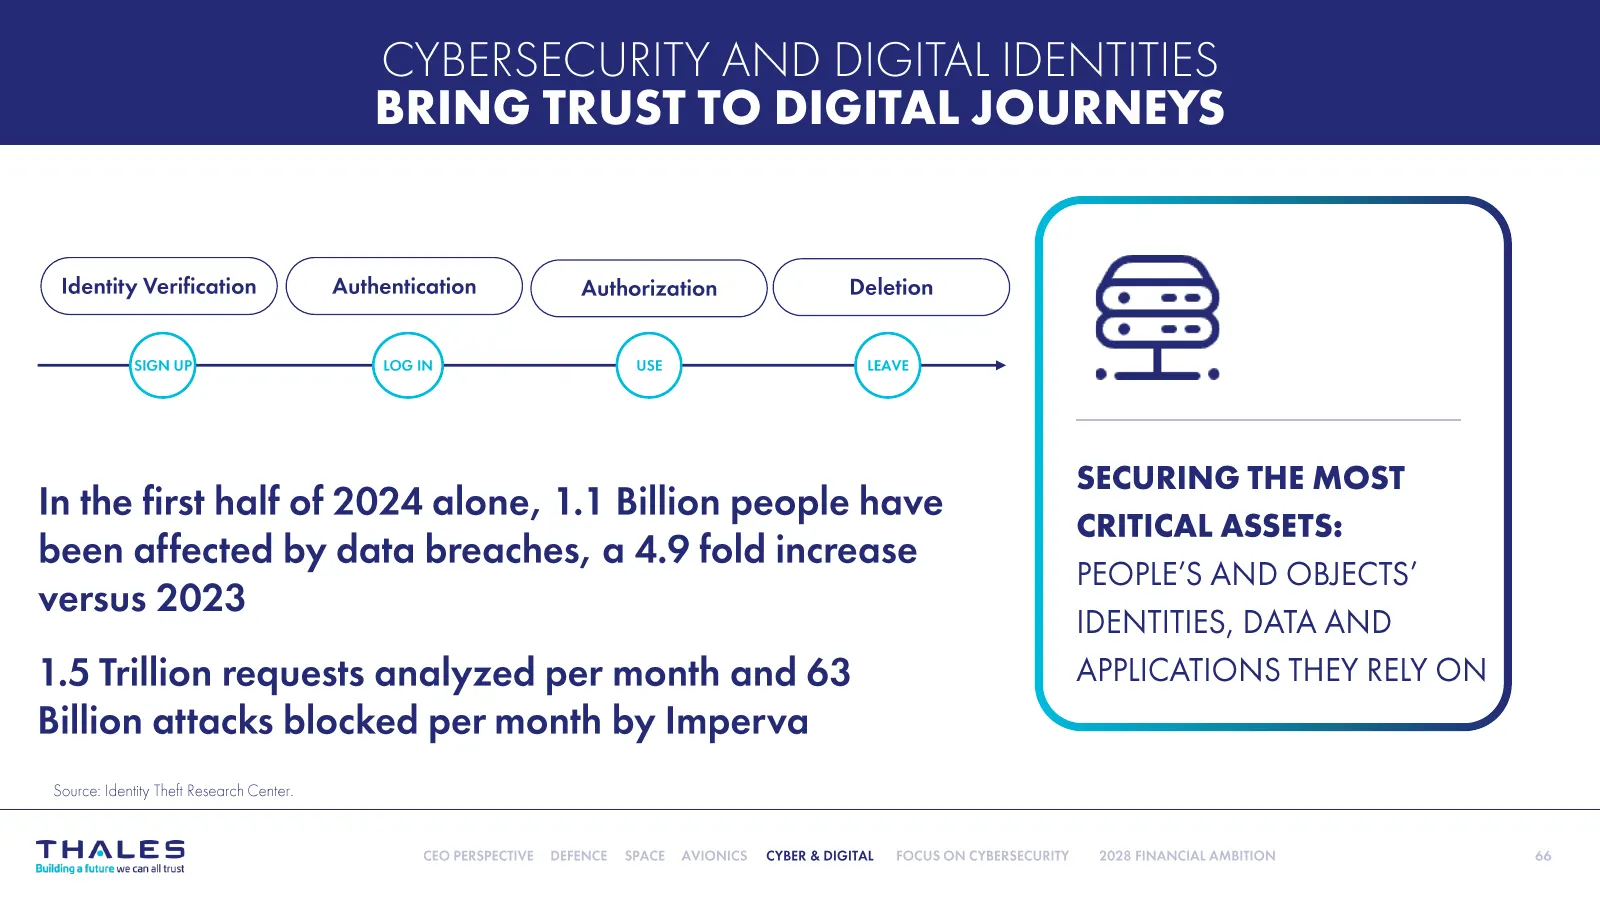
Slide 66: Cybersecurity and digital identities bring trust
CYBERSECURITY AND DIGITAL IDENTITIES BRING TRUST TO DIGITAL JOURNEYS (tent Verification ) (_ Authentication dC Authorization YC Deletion ) Q ey) Na ey . ore SECURING THE MOST In the first half of 2024 alone, 1.1 Billion people have been affected by data breaches, a 4.9 fold increase CRITICAL ASSETS:
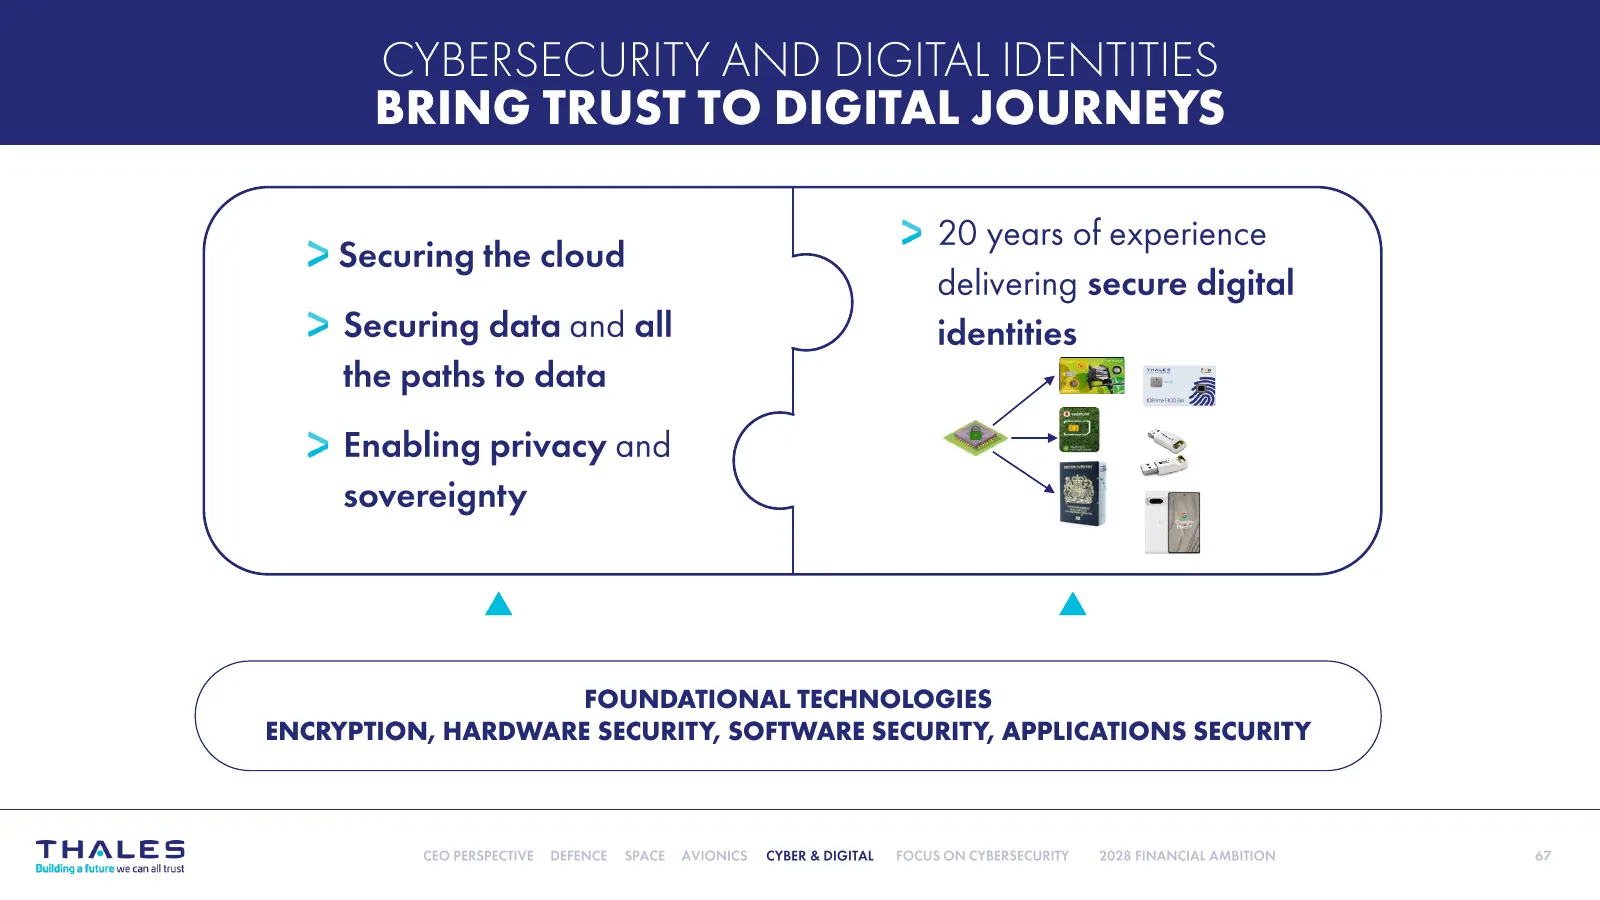
Slide 67: Cybersecurity and digital identities bring trust
CYBERSECURITY AND DIGITAL IDENTITIES BRING TRUST TO DIGITAL JOURNEYS > Securing the cloud > 20 years of experience delivering secure digital > Securing data and all identities the paths to data / = = & > Enabling privacy and C ~ ; S sovereignty 8 a: A A FOUNDATIONAL TECHNOLOGIES ENCRYPTION, HARDWARE
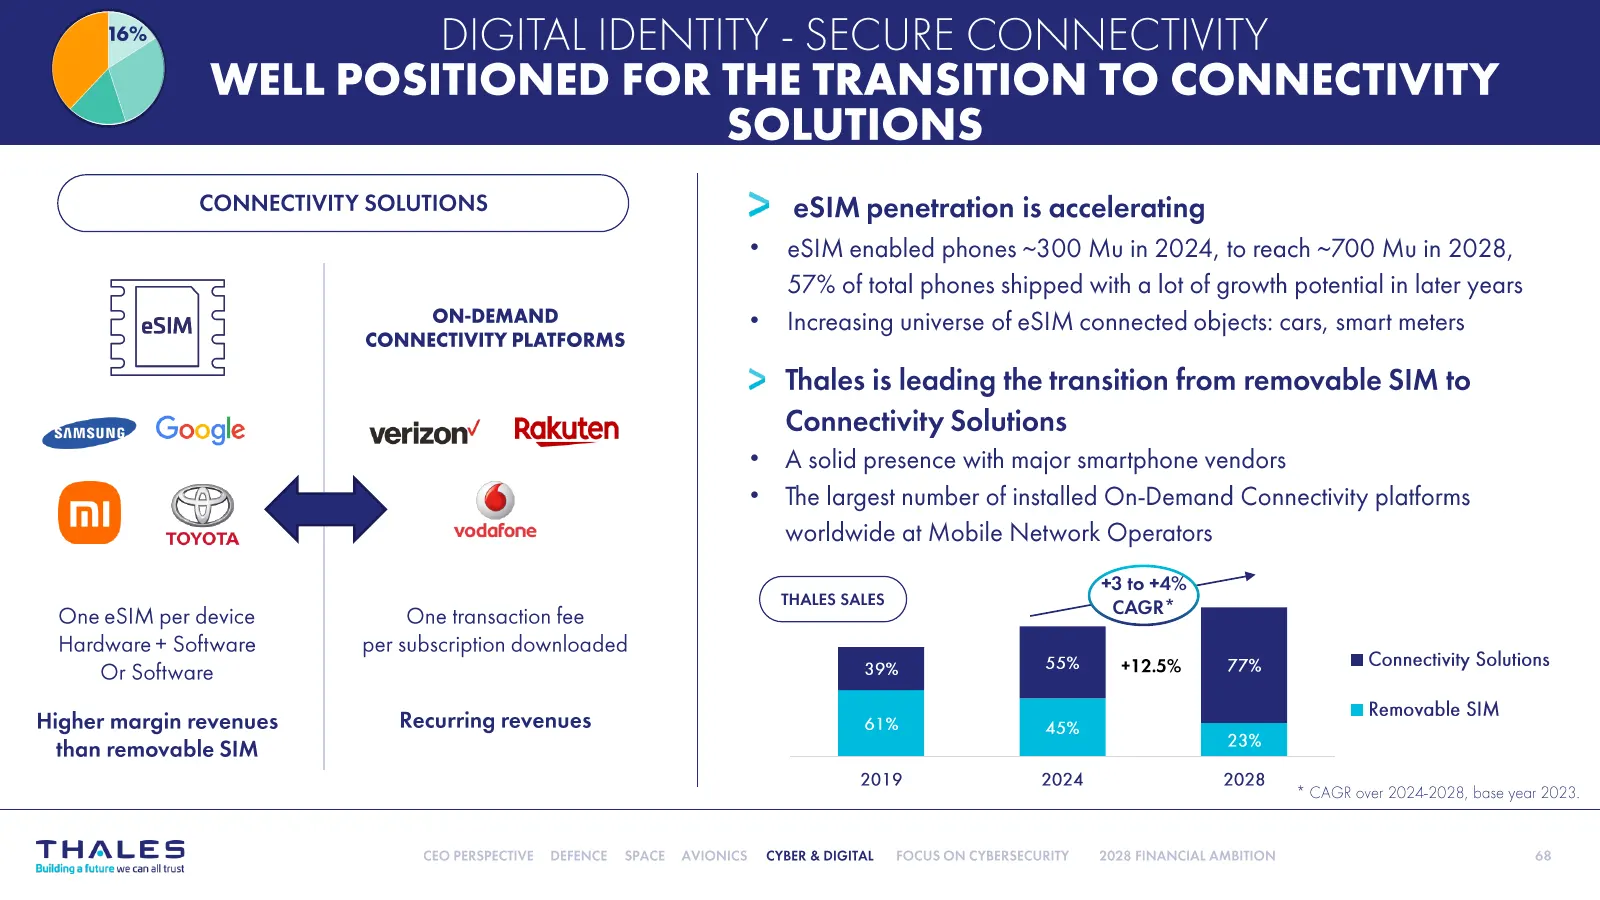
Slide 68: Digital identity - secure connectivity
DIGITAL IDENTITY - SECURE CONNECTIVITY WELL POSITIONED FOR THE TRANSITION TO CONNECTIVITY SOLUTIONS C CONNECTIVITY SOLUTIONS ) oO Google @D ee TOYOTA 2. One eSIM per device Hardware + Software Or Software ON-DEMAND CONNECTIVITY PLATFORMS verizon’ Rakuten One transaction fee per subscription download
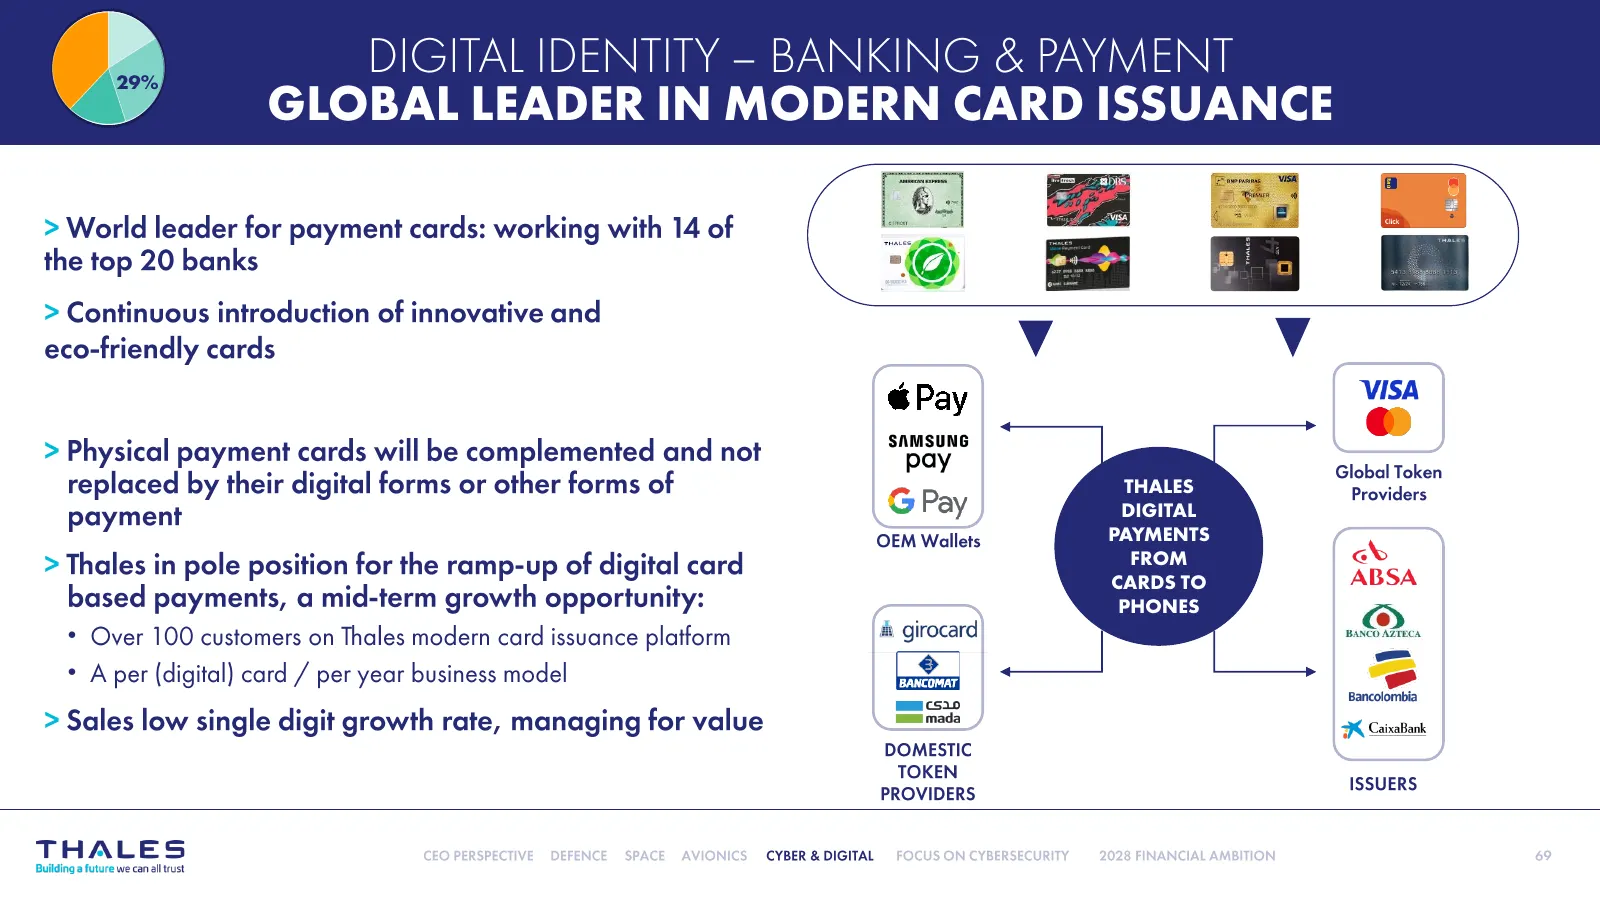
Slide 69: Digital identity - banking & payment
D> DIGITAL IDENTITY - BANKING & PAYMENT GLOBAL LEADER IN MODERN CARD ISSUANCE > World leader for payment cards: working with 14 of i ay = wet o = = > Continuous introduction of innovative and eco-friendly cards Vv Pay VISA Lo) > Physical payment cards will be complemented and not say” Aare Pay Globa
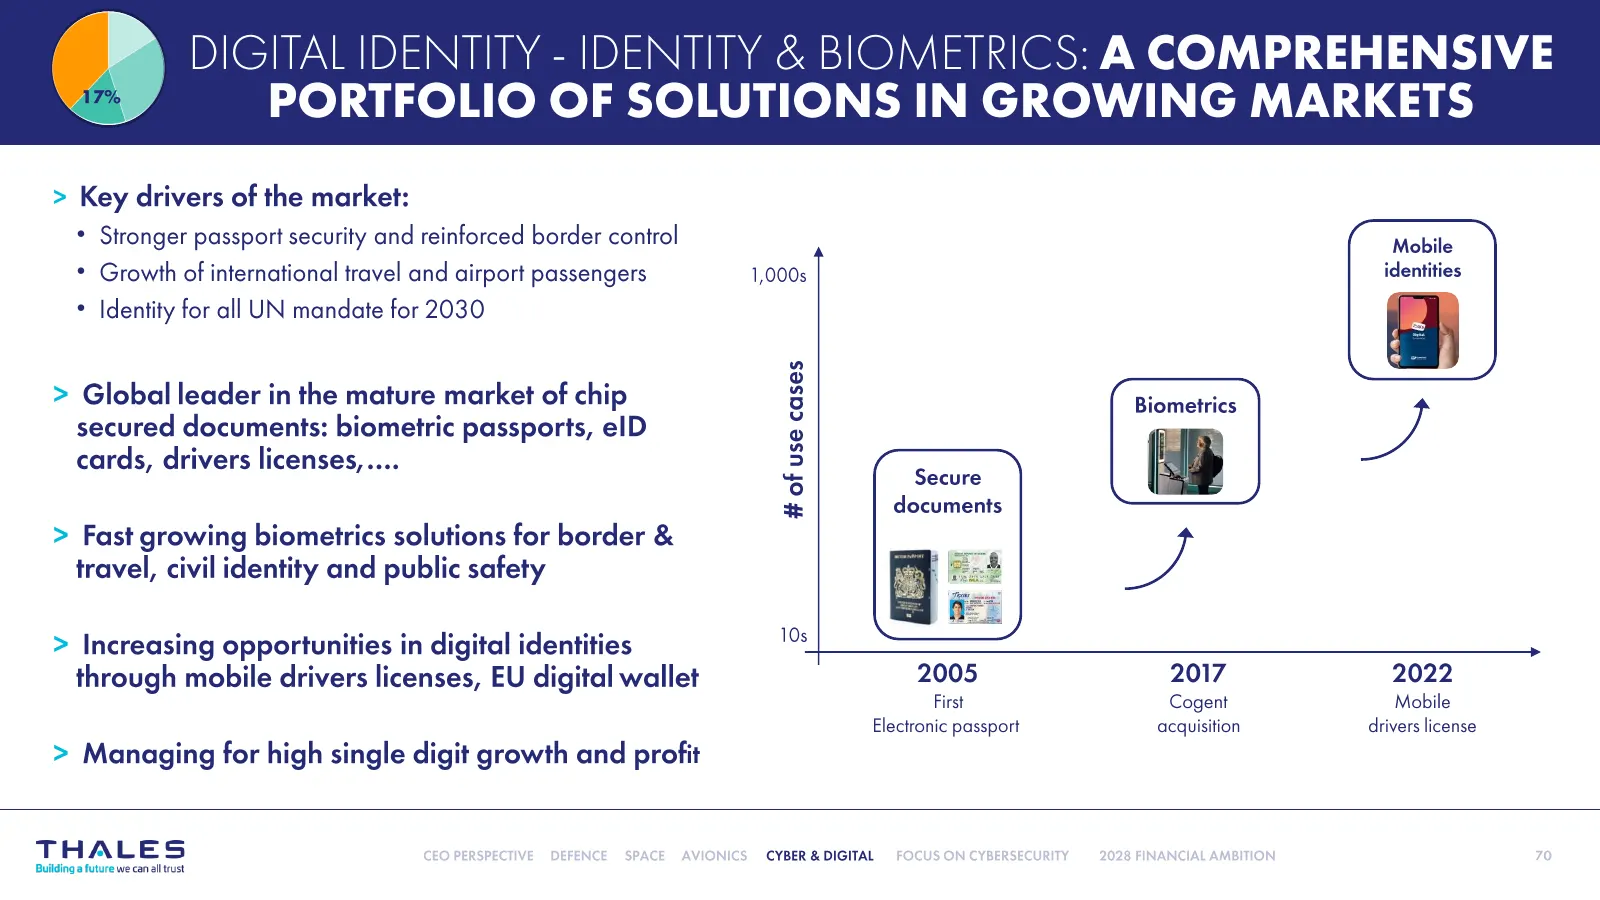
Slide 70: Digital identity - identity & biometrics
D> DIGITAL IDENTITY - IDENTITY & BIOMETRICS: A COMPREHENSIVE PORTFOLIO OF SOLUTIONS IN GROWING MARKETS > Key drivers of the market: * Stronger passport security and reinforced border control * Growth of international travel and airport passengers * Identity for all UN mandate for 2030 > Global leade
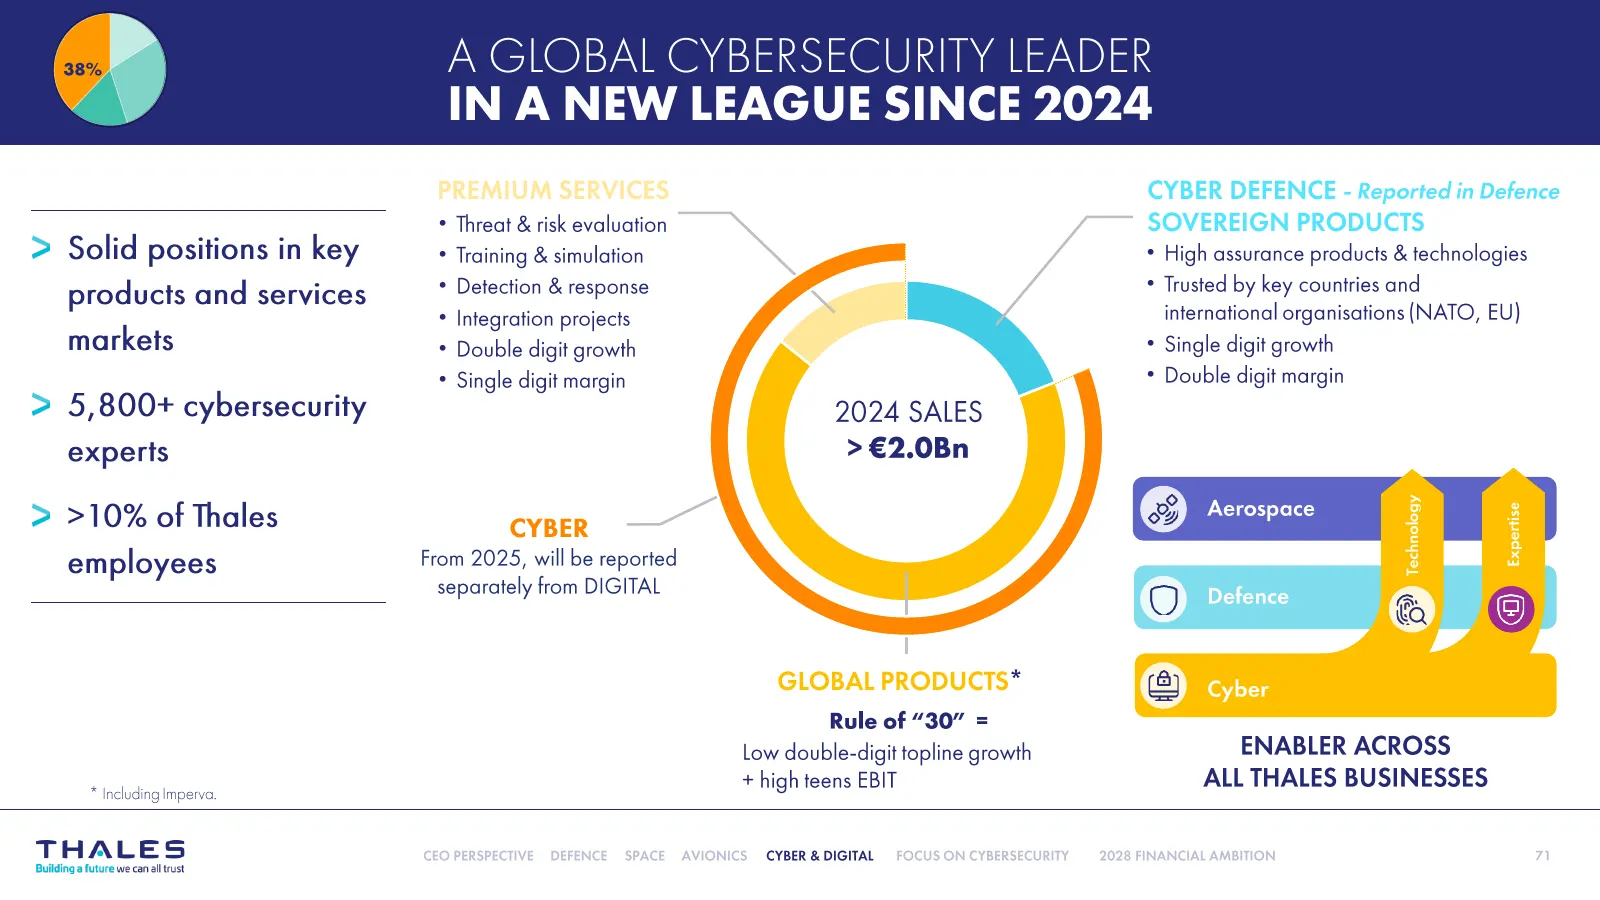
Slide 71: A global cybersecurity leader
A GLOBAL CYBERSECURITY LEADER IN A NEW LEAGUE SINCE 2024 > Solid positions in key products and services markets > 5,800+ cybersecurity experts > >10% of Thales employees * Including Imperva. PREMIUM SERVICES * Threat & risk evaluation * Training & simulation * Detection & response * Integration proj
Slide 72: Focus on Cybersecurity Global Products
BUSINESS REVIEWS FOCUS ON CYBERSECURITY GLOBAL PRODUCTS Sébastien Cano Senior Vice-President, Cloud Protection & Licensing
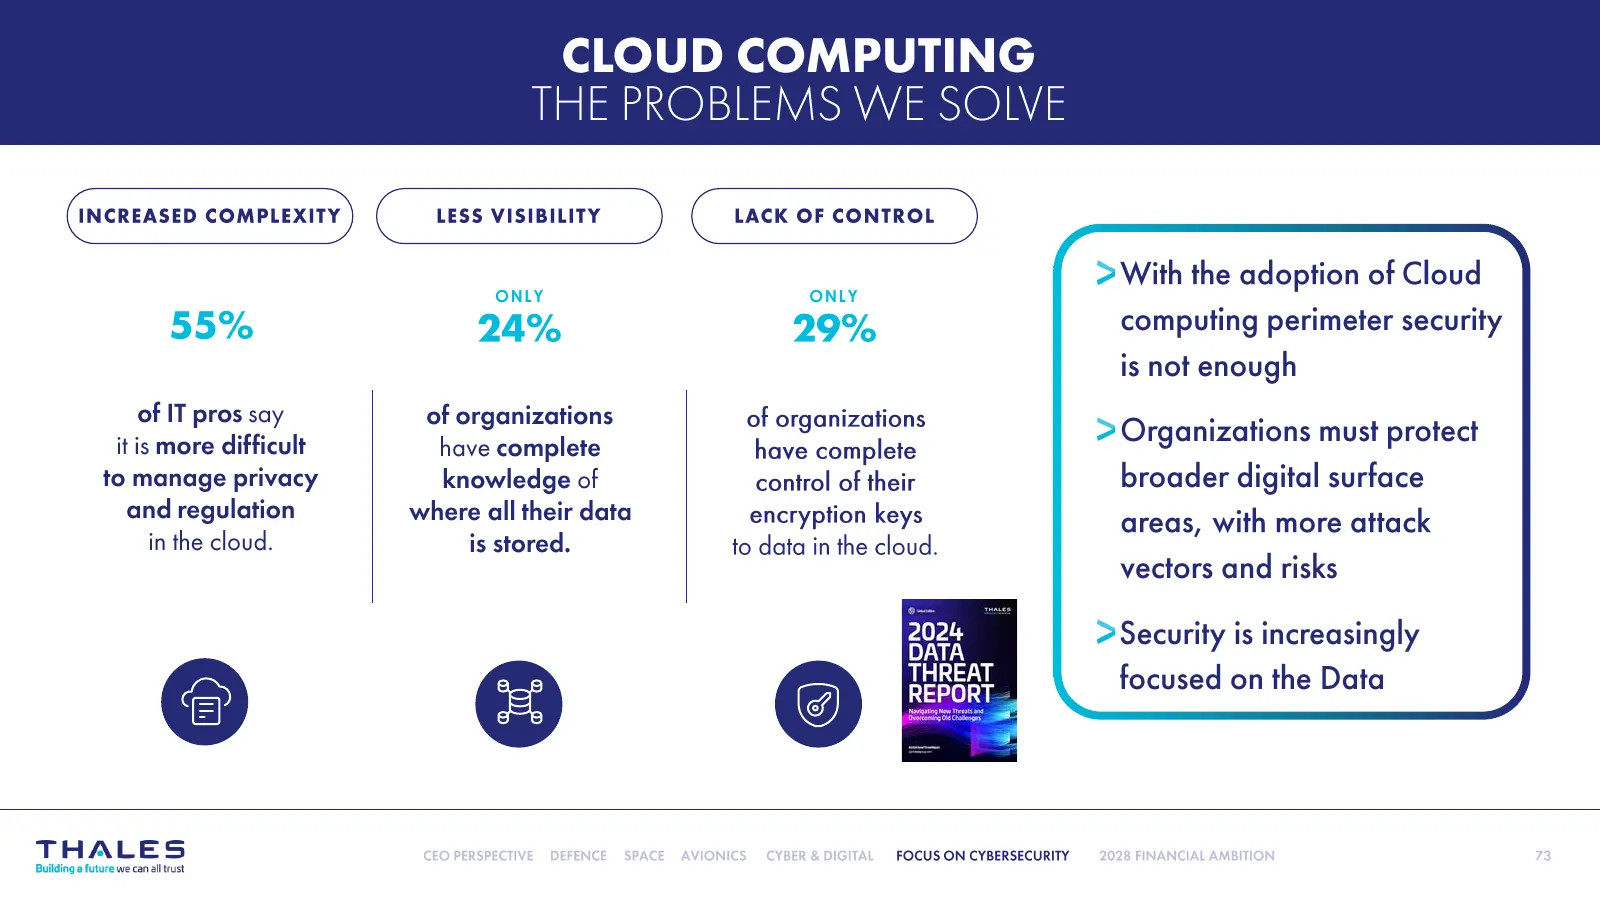
Slide 73: Cloud computing: the problems we solve
CLOUD COMPUTING THE PROBLEMS WE SOLVE ((nereasep COMPLEXITY) C LESS VISIBILITY +) C LACK OF CONTROL ) > With the adoption of Cloud ONLY ONLY : . : 55% 24% 29% computing perimeter security is not enough of IT pros say of organizations of organizations > Organizations must protect itis more difficult
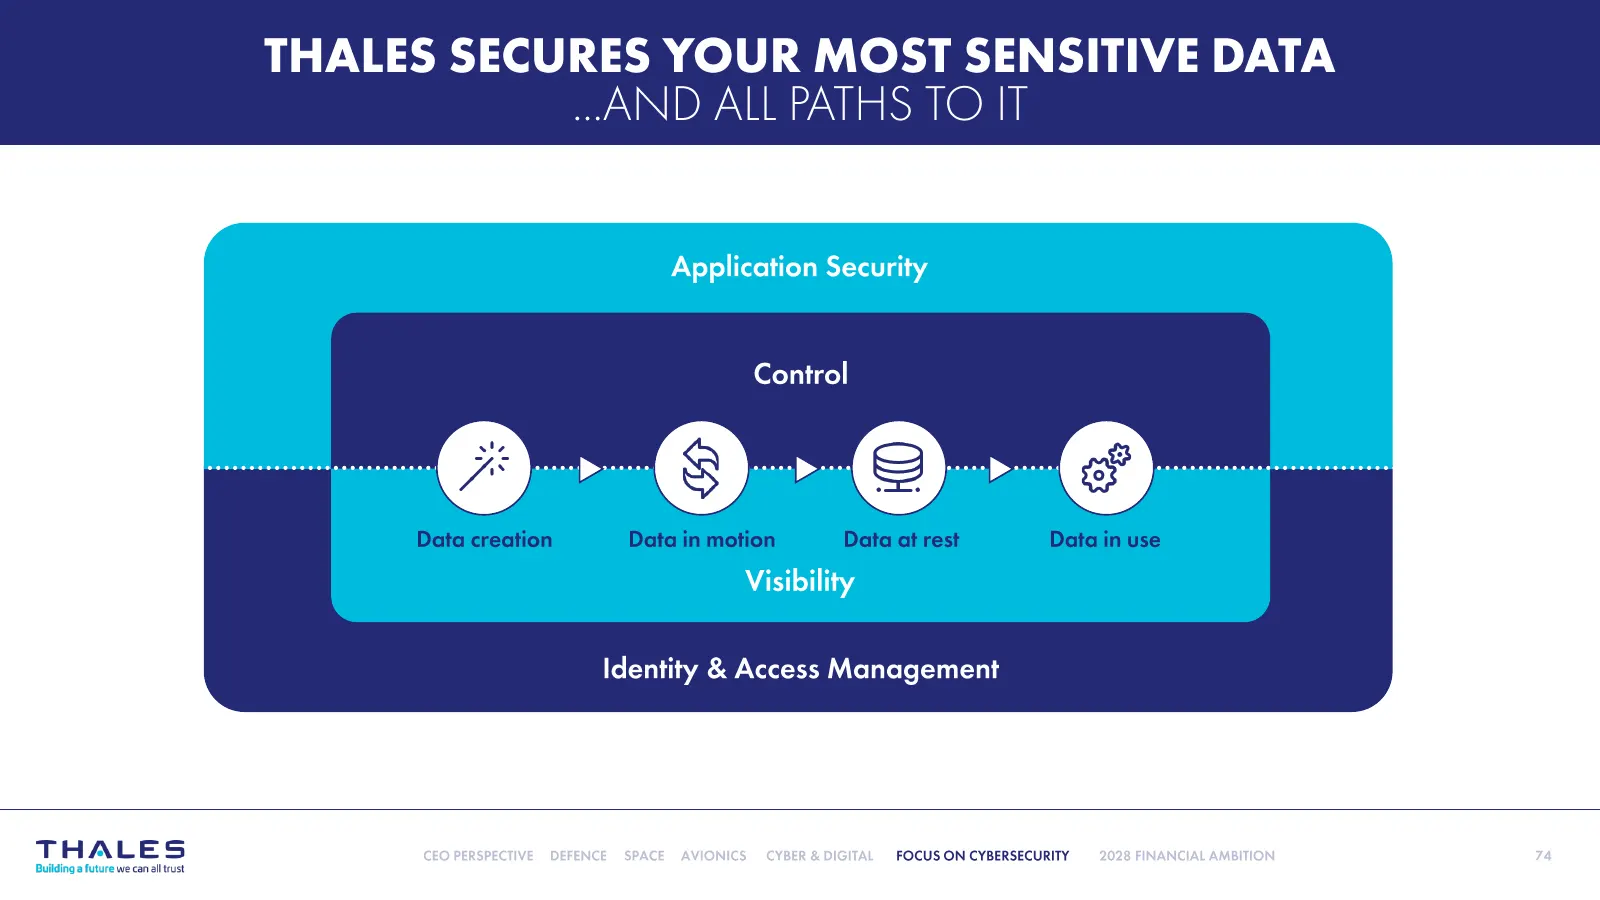
Slide 74: Thales secures your most sensitive data
THALES SECURES YOUR MOST SENSITIVE DATA AND ALL PATHS TO IT Data creation Data in motion Data at rest Data in use Identity & Access Management THALES
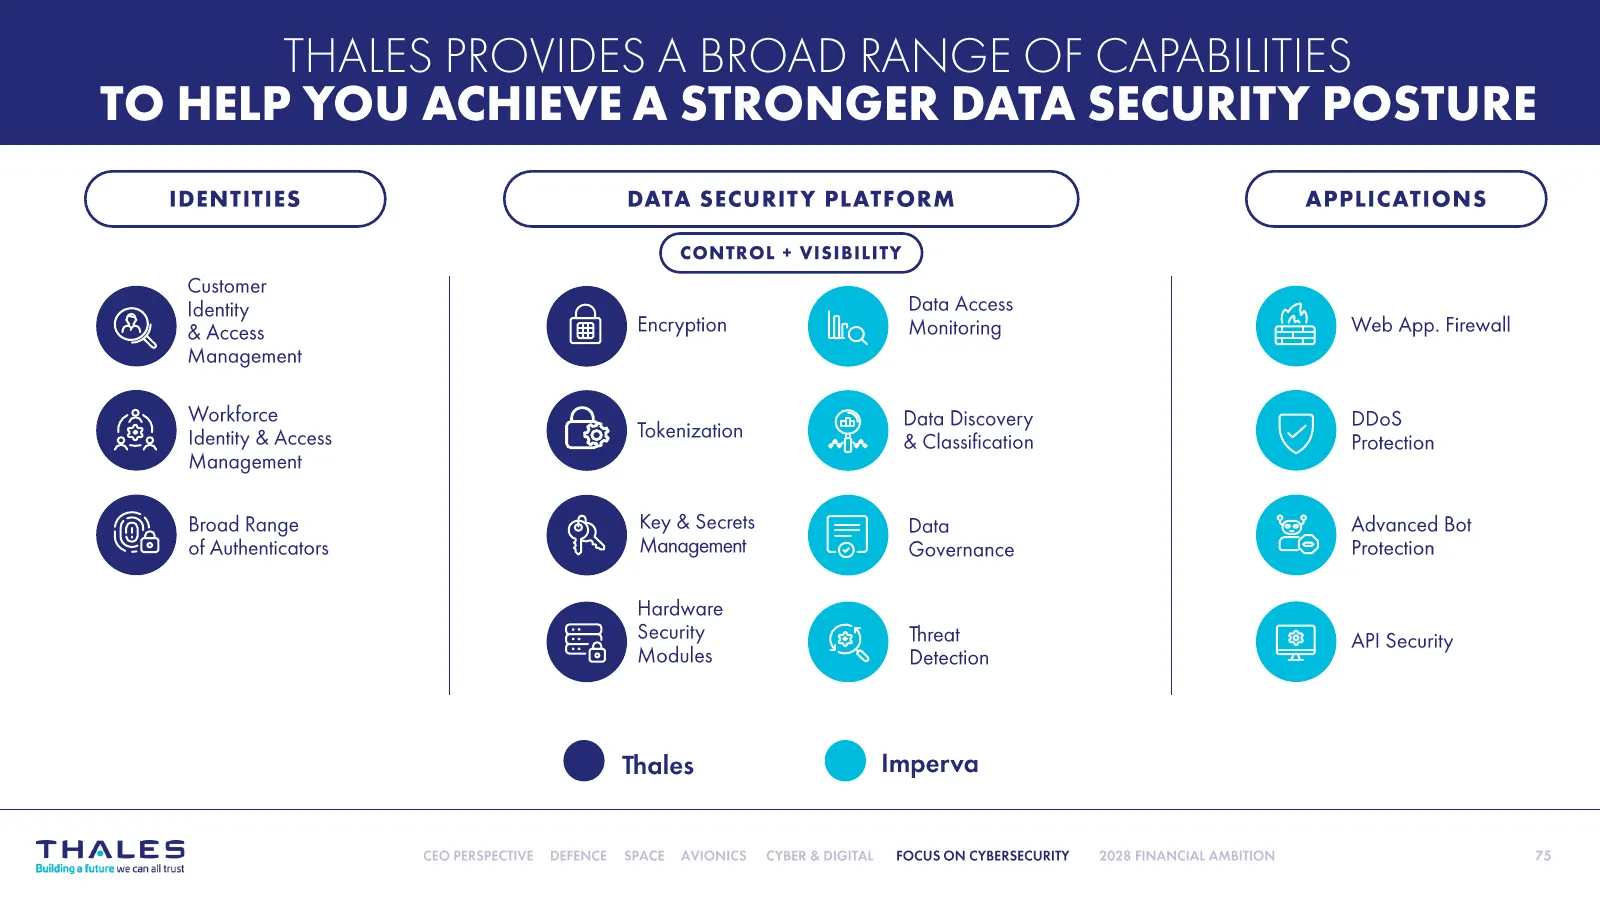
Slide 75: Broad range of capabilities for data security
THALES PROVIDES A BROAD RANGE OF CAPABILITIES TO HELP YOU ACHIEVE A STRONGER DATA SECURITY POSTURE IDENTITIES C DATA SECURITY PLATFORM ) CONTROL + VISIBILITY APPLICATIONS Customer Data A. Identit a jata Access @ & Access oO Encryption @ Monitoring & Web App. Firewall Management kforce Data Di: DDoS
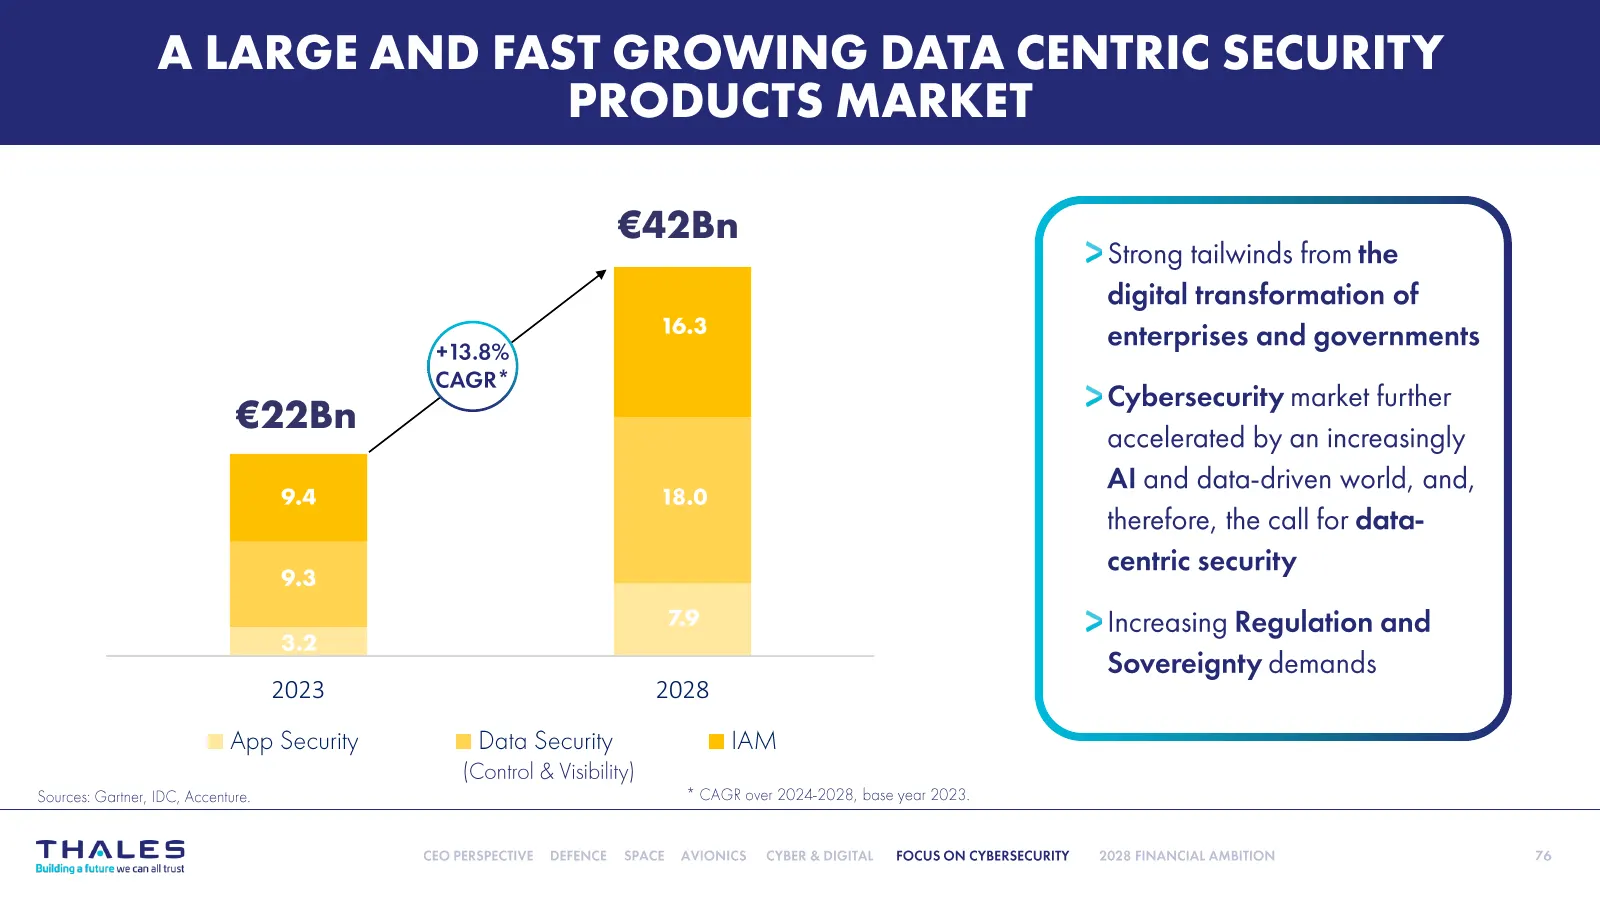
Slide 76: Large and fast growing data centric security market
A LARGE AND FAST GROWING DATA CENTRIC SECURITY PRODUCTS MARKET > Strong tailwinds from the digital transformation of enterprises and governments > Cybersecurity market further €22Bn ; . accelerated by an increasingly AG Al and data-driven world, and, therefore, the call for data- centric security 79
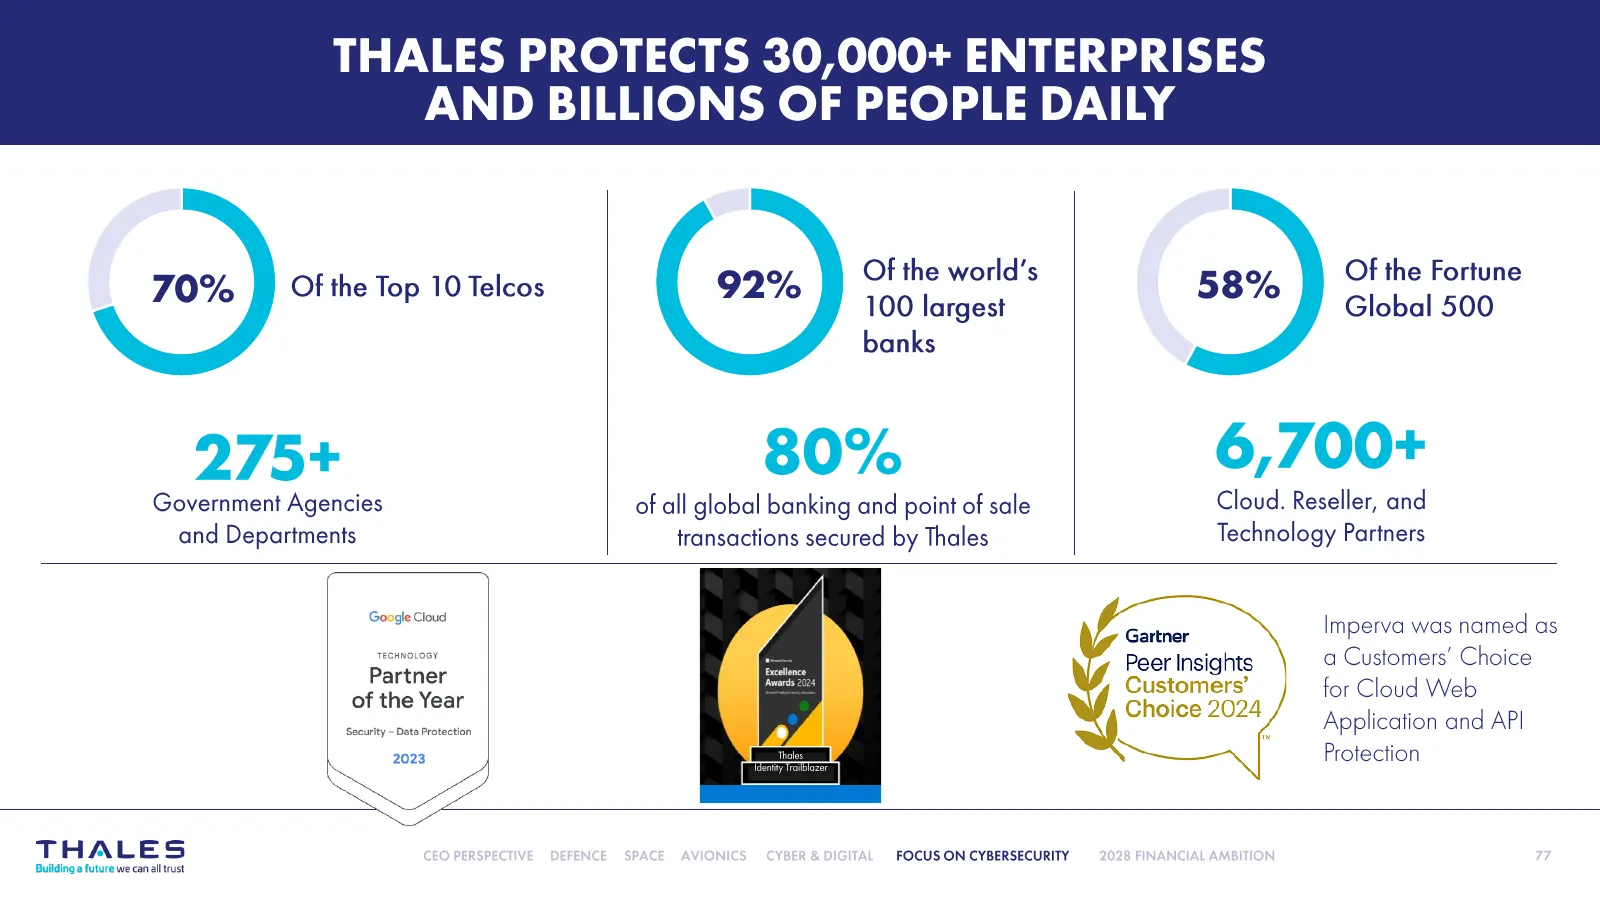
Slide 77: Thales protects 30,000+ enterprises
THALES PROTECTS 30,000+ ENTERPRISES AND BILLIONS OF PEOPLE DAILY 70% |) Of the Top 10 Telcos 275+ Government Agencies and Departments ° Of the world’s 92% 100 largest banks 80% of all global banking and point of sale transactions secured by Thales ° Of the Fortune 58% Global 500 6,700+ Cloud. Resell
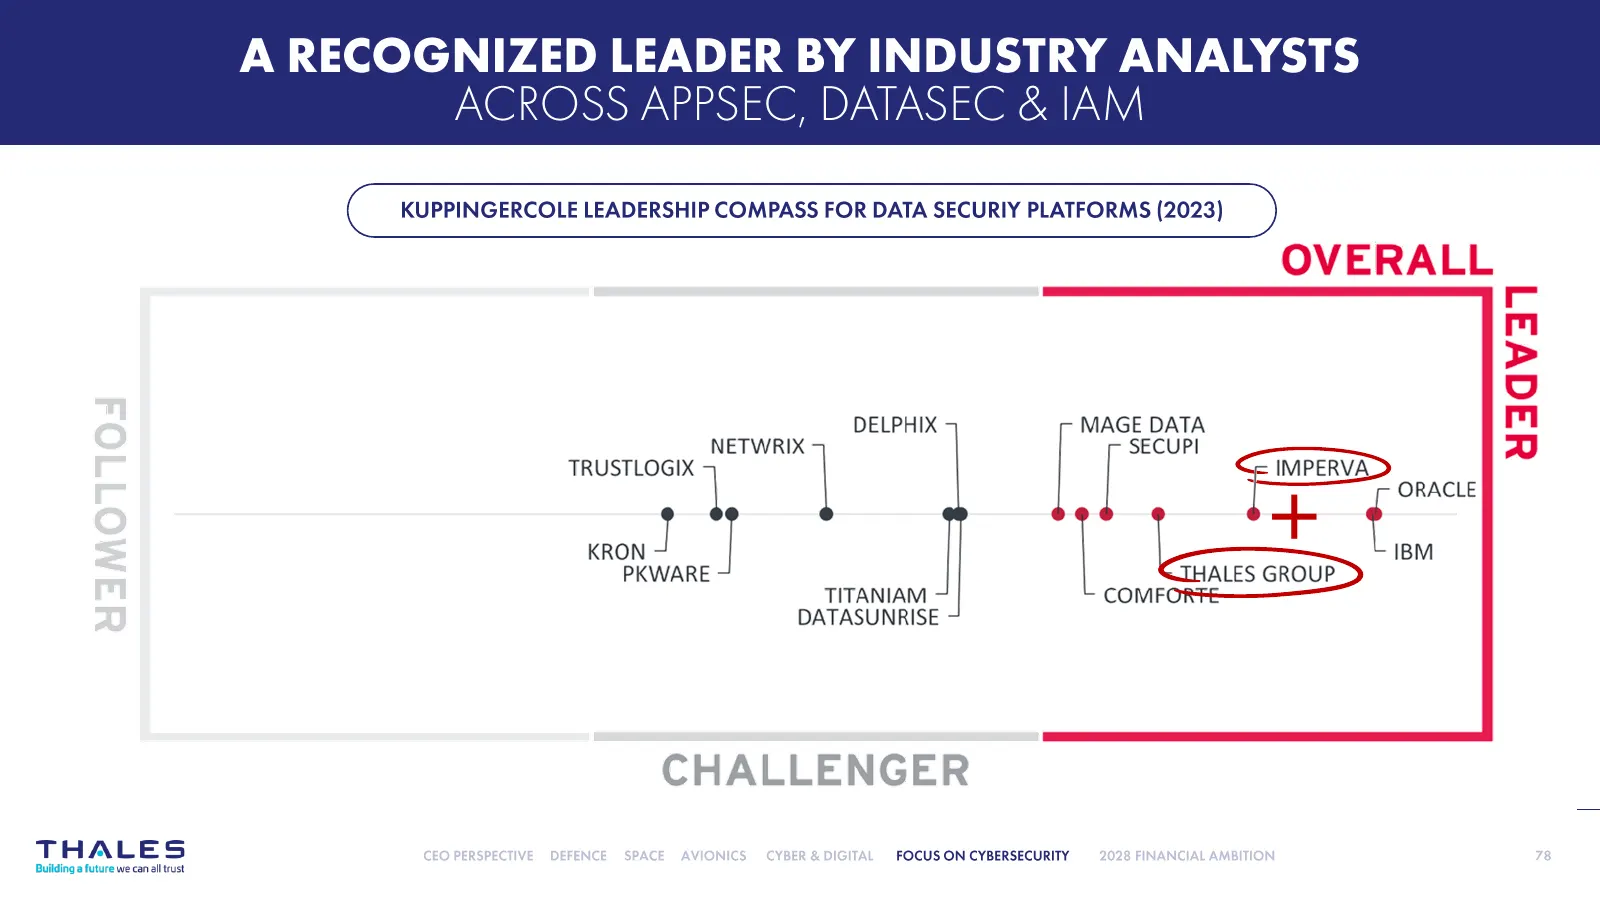
Slide 78: Recognized leader by industry analysts
A RECOGNIZED LEADER BY INDUSTRY ANALYSTS ACROSS APPSEC, DATASEC & IAM C KUPPINGERCOLE LEADERSHIP COMPASS FOR DATA SECURIY PLATFORMS (2023) ) OVERALL Yyaqval DELPHIX MAGE DATA NETWRIX SECUPI TRUSTLOGIX < IMPERVA> ] ‘ ORACLE KRON J i IBM PKWARE ALES GROUP TITANIAM COMF DATASUNRISE CHALLENGER THALES FO
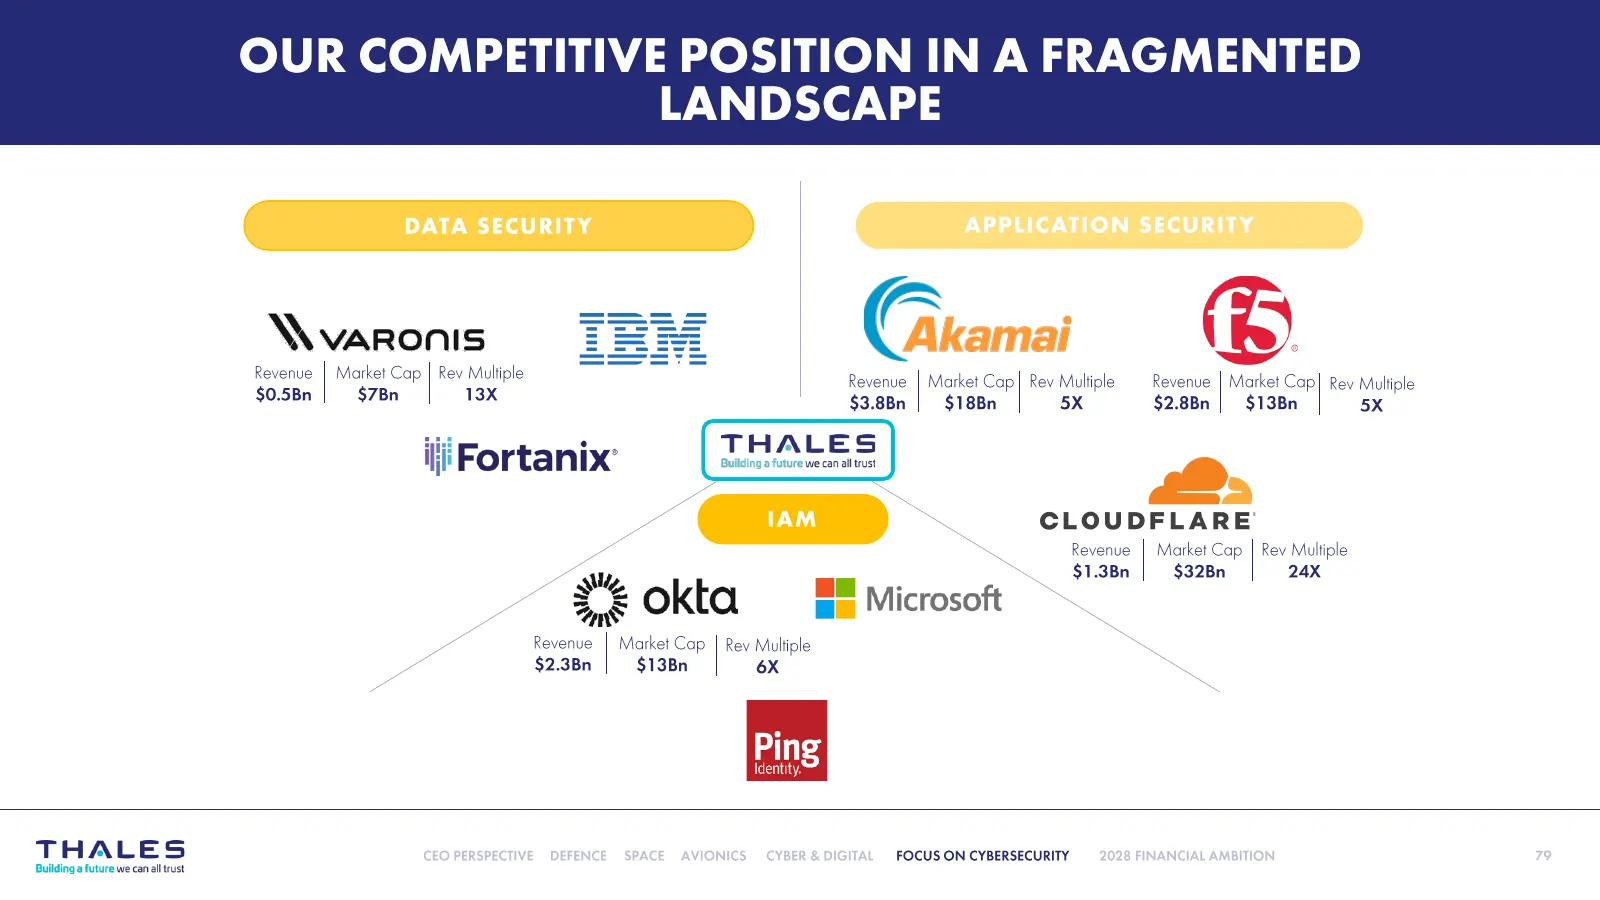
Slide 79: Our competitive position in a fragmented landscape
OUR COMPETITIVE POSITION IN A FRAGMENTED LANDSCAPE Gieamai ® Nvaronis Revenue | Market Cap | Rev Multiple revenue | Market Cop) Rev Mulliole 8 Market C Revenue | Market Cap| Rev Multiple Revenue | Market Cap] Rev Multiple $0.5Bn | $7Bn 13X §3.8Bn | $18Bn 5X §2.8Bn | $13Bn 5X bil . ij Fortanix in : =
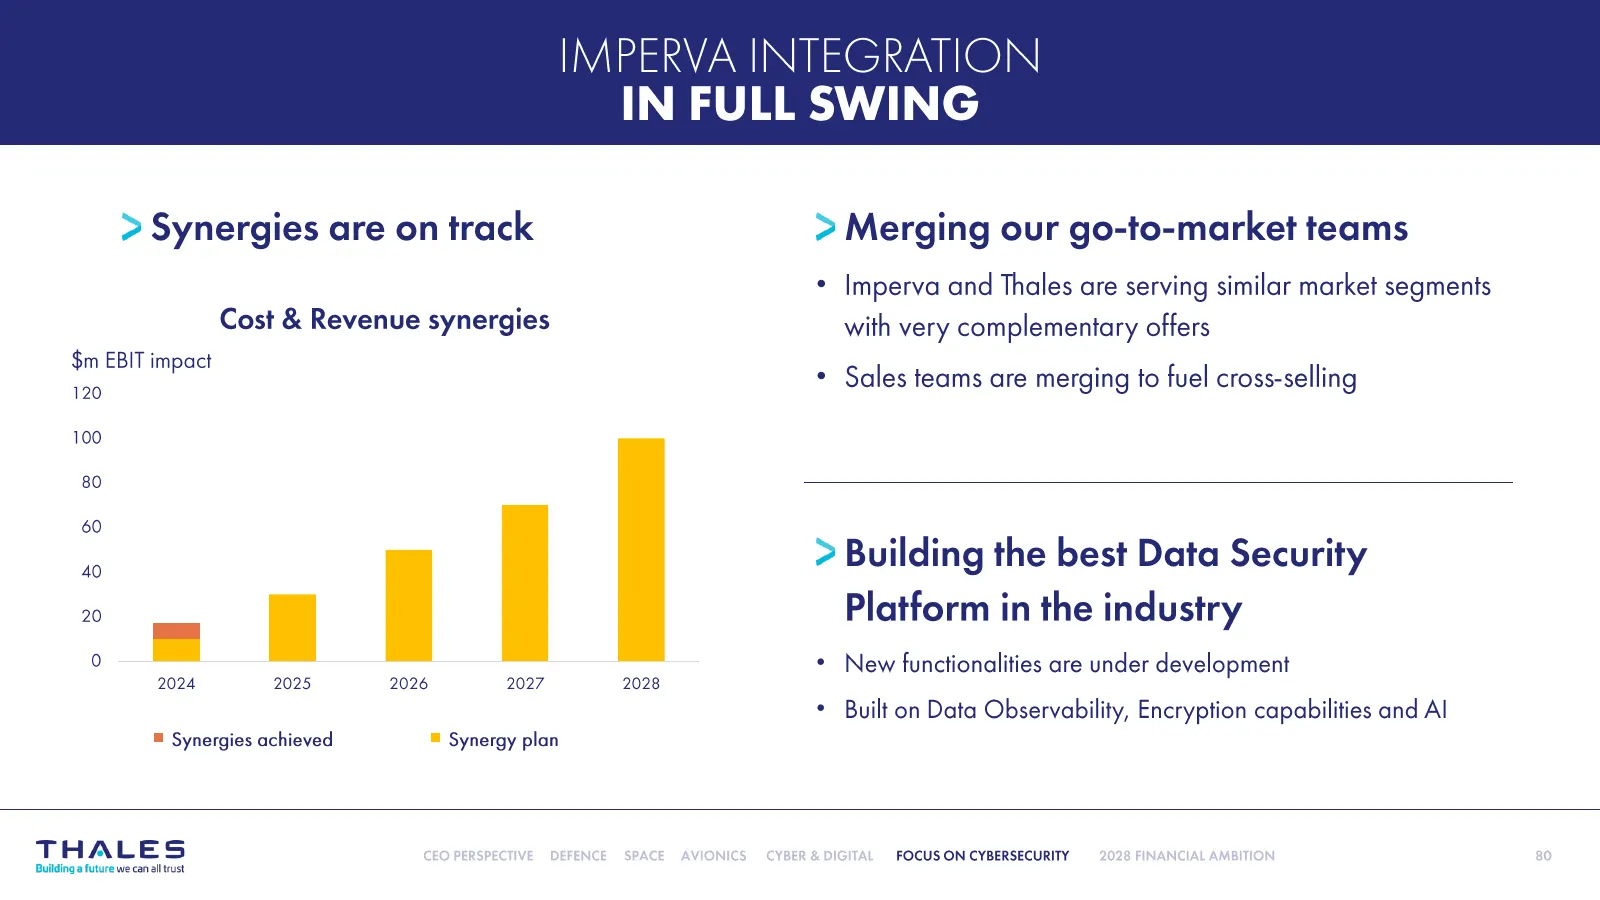
Slide 80: Imperva integration in full swing
IMPERVA INTEGRATION IN FULL SWING > Synergies are on track > Merging our go-to-market teams * Imperva and Thales are serving similar market segments Cost & Revenue synergies with very complementary offers $m EBIT impact © Sal . fuel Ik 120 ales teams are merging to tuel cross-selling 100 80 60 . . .
Slide 81: Strategy to deliver Rule of 30
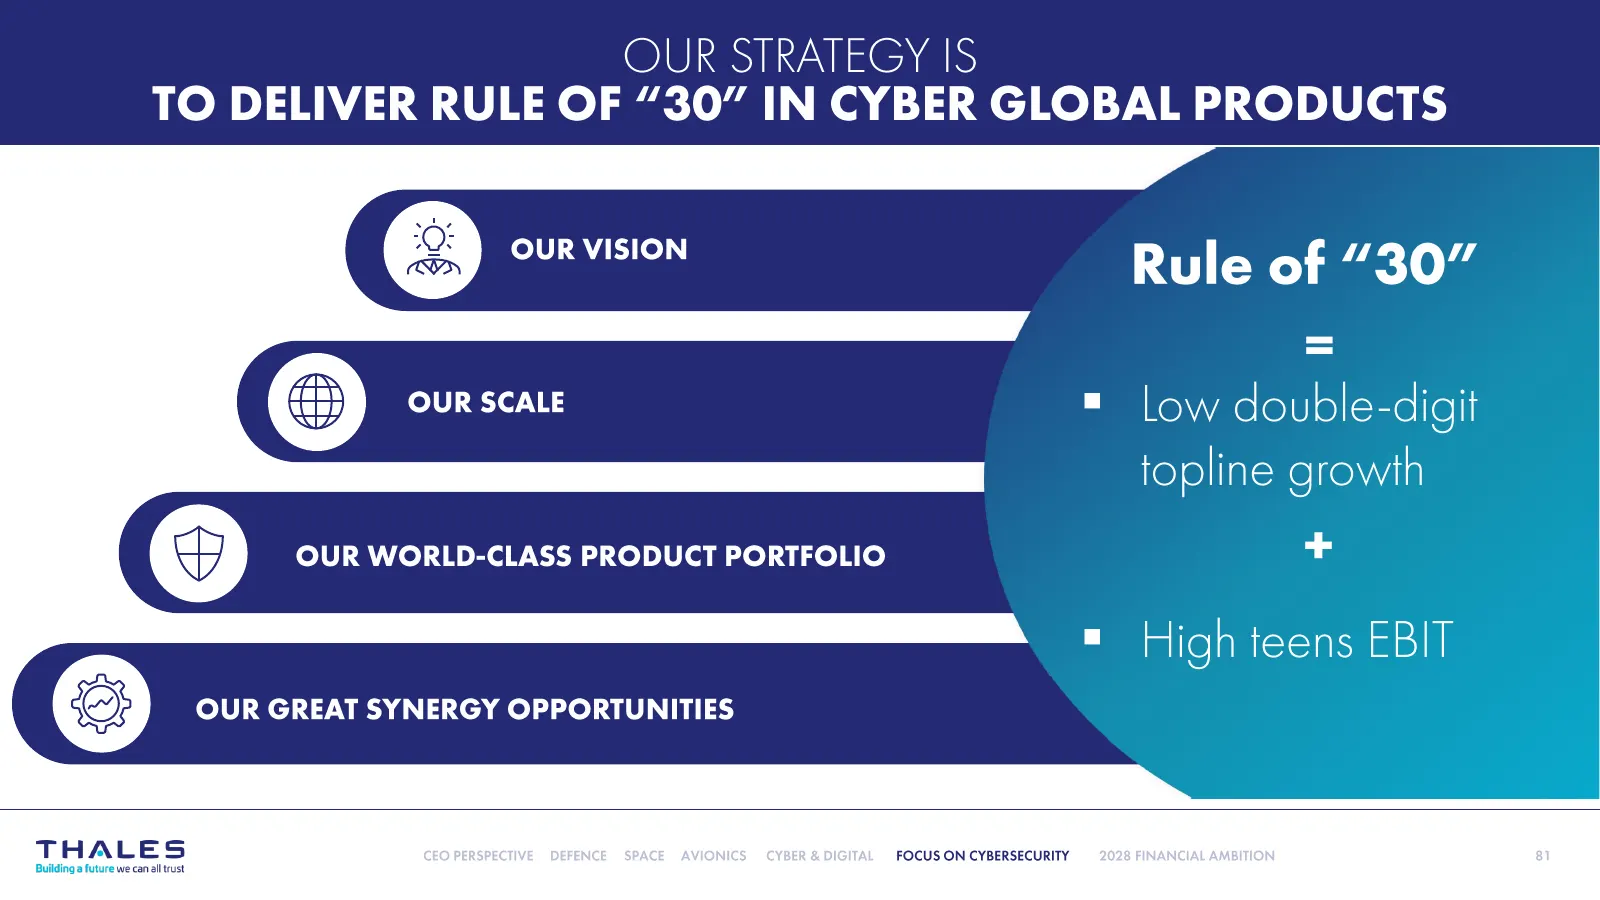
OUR STRATEGY IS TO DELIVER RULE OF “30” IN CYBER GLOBAL PRODUCTS Rule of “30” 30% OUR VISION OUR SCALE ) OUR WORLD-CLASS PRODUCT PORTFOLIO = Low double-digit topline growth + = High teens EBIT OUR GREAT SYNERGY OPPORTUNITIES FOCUS
Slide 82: Cloud based platform driving recurring revenues
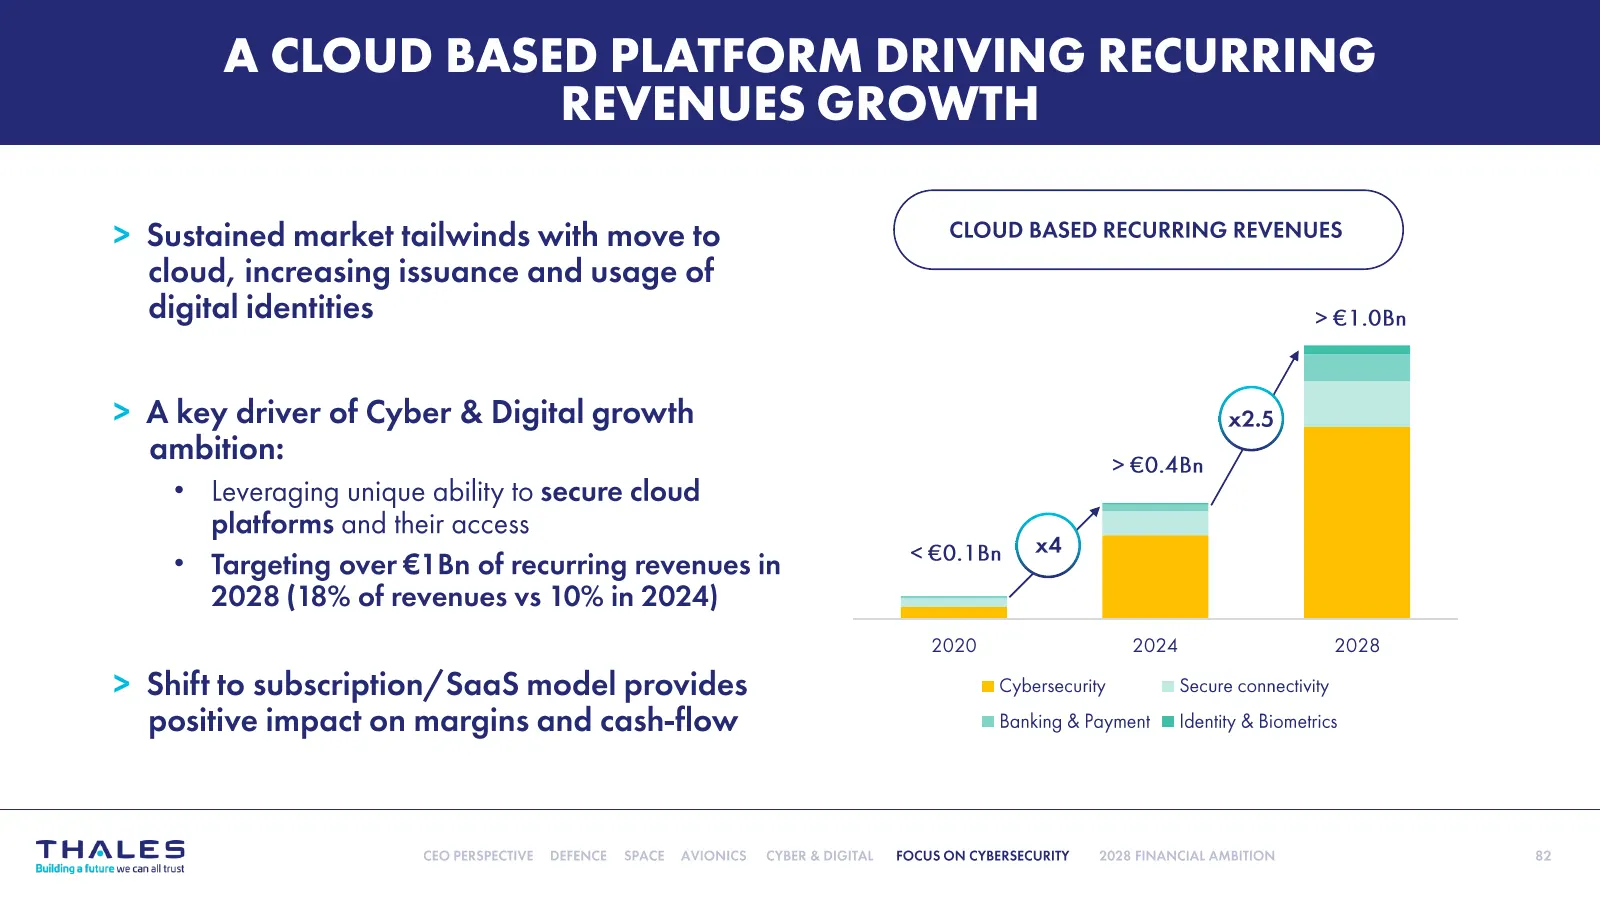
A CLOUD BASED PLATFORM DRIVING RECURRING REVENUES GROWTH > Sustained market tailwinds with move to C CLOUD BASED RECURRING REVENUES ) cloud, increasing issuance and usage of digital identities > €1.0Bn > Akey driver of Cyber & Digital growth ambition: > €0.4Bn * Leveraging unique ability to secure c
Slide 83: 2024-2028 financial trajectory for Cyber & Digital
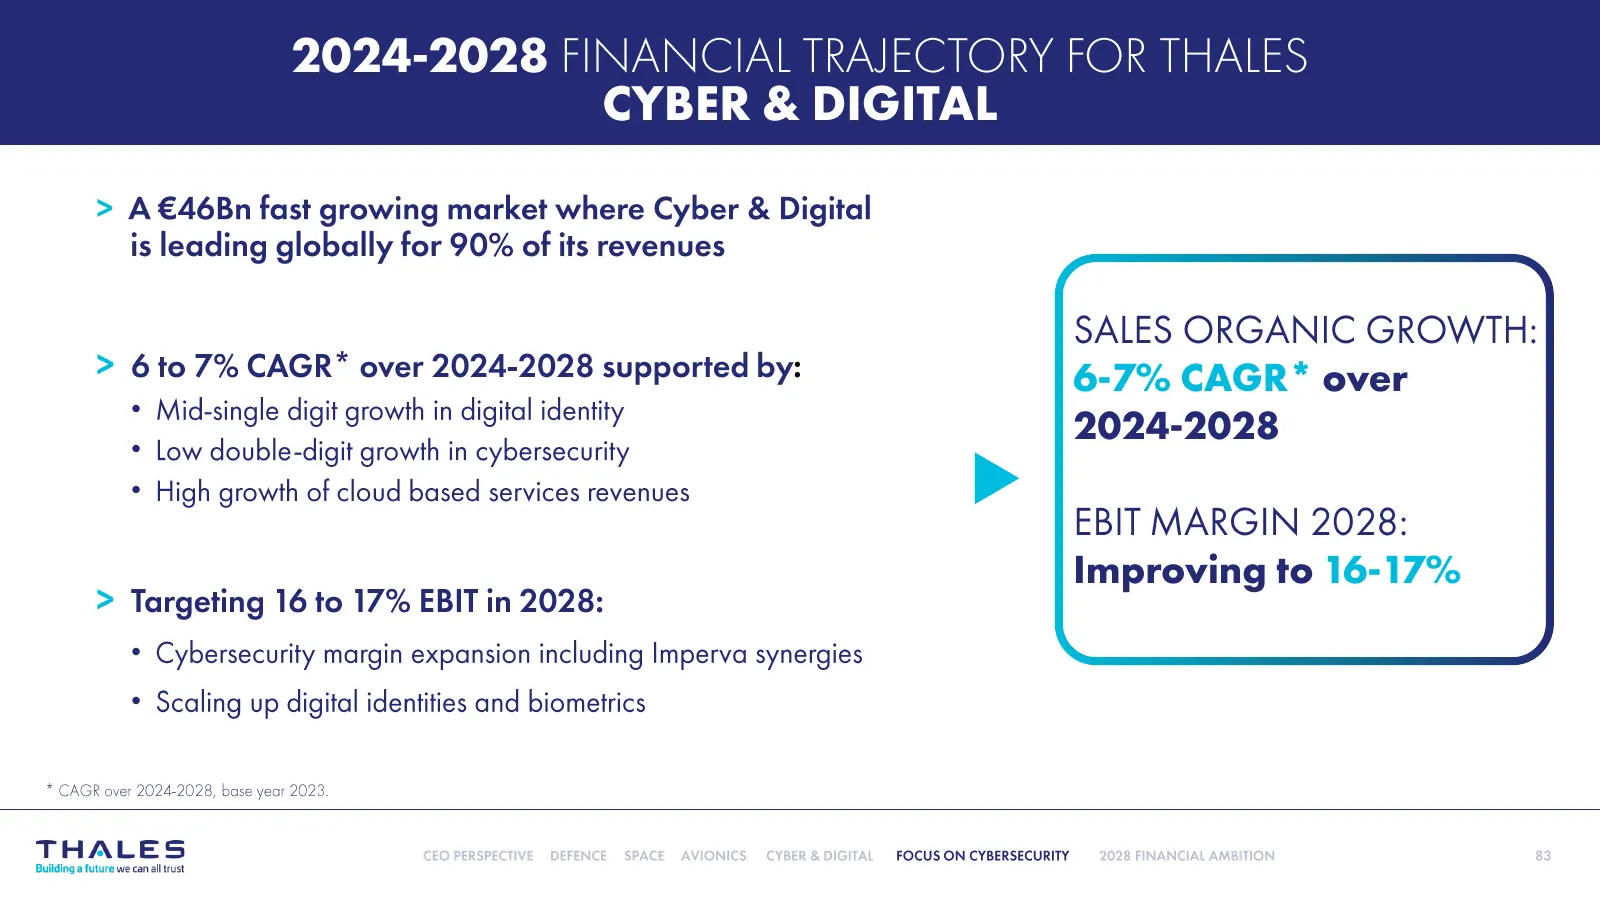
2024-2028 FINANCIAL TRAJECTORY FOR THALES CYBER & DIGITAL > A €46Bn fast growing market where Cyber & Digital is leading globally for 90% of its revenues SALES ORGANIC GROWTH: > 6to 7% CAGR* over 2024-2028 supported by: 6-7% CAGR* over * Mid-single digit growth in digital identity 2024-2028 * Low do
Slide 84: 2028 Financial Ambition
2028 FINANCIAL AMBITION Pascal Bouchiat Senior Executive Vice-President, Chief Financial Officer
Slide 85: • • •
• • •
Slide 86: • • •
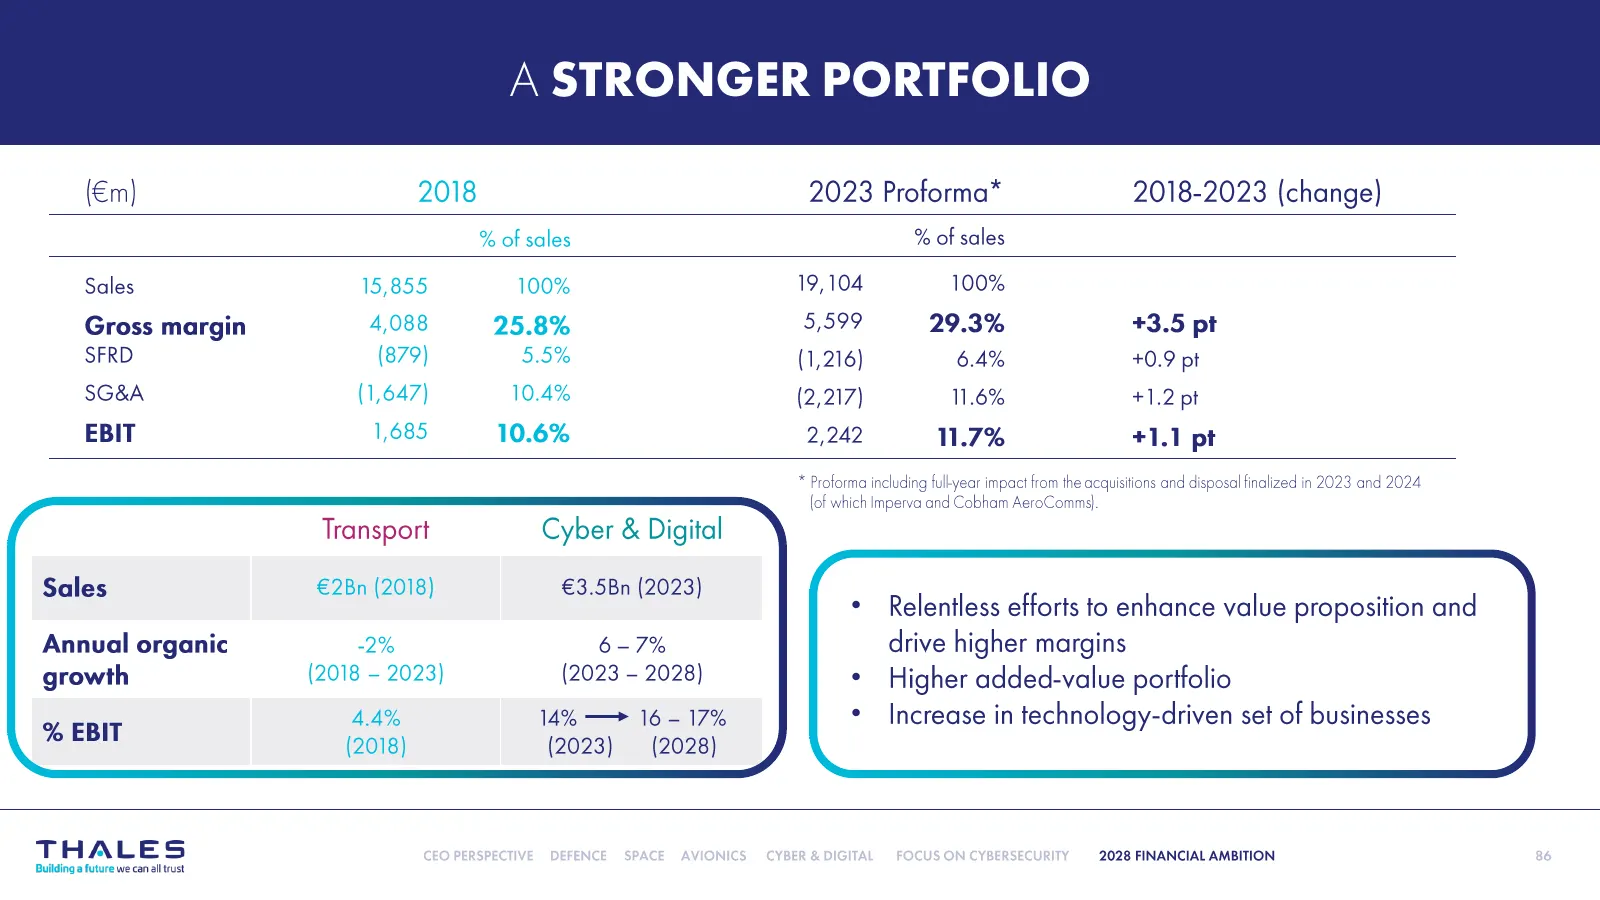
• • •
Slide 87: • • • •
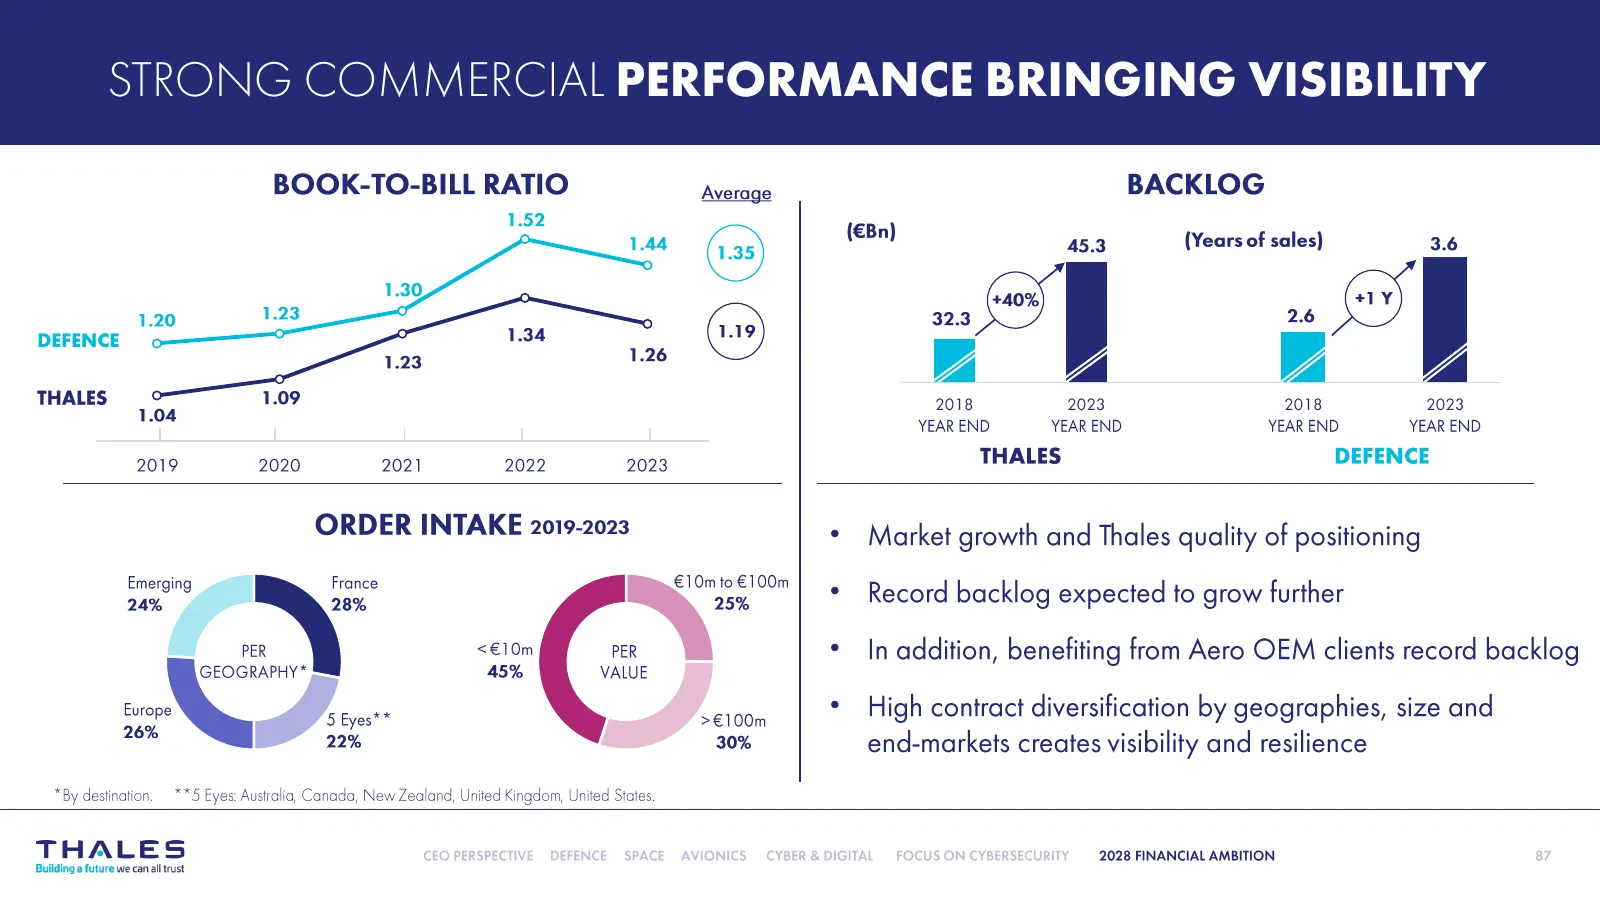
• • • •
Slide 88: • • • • •
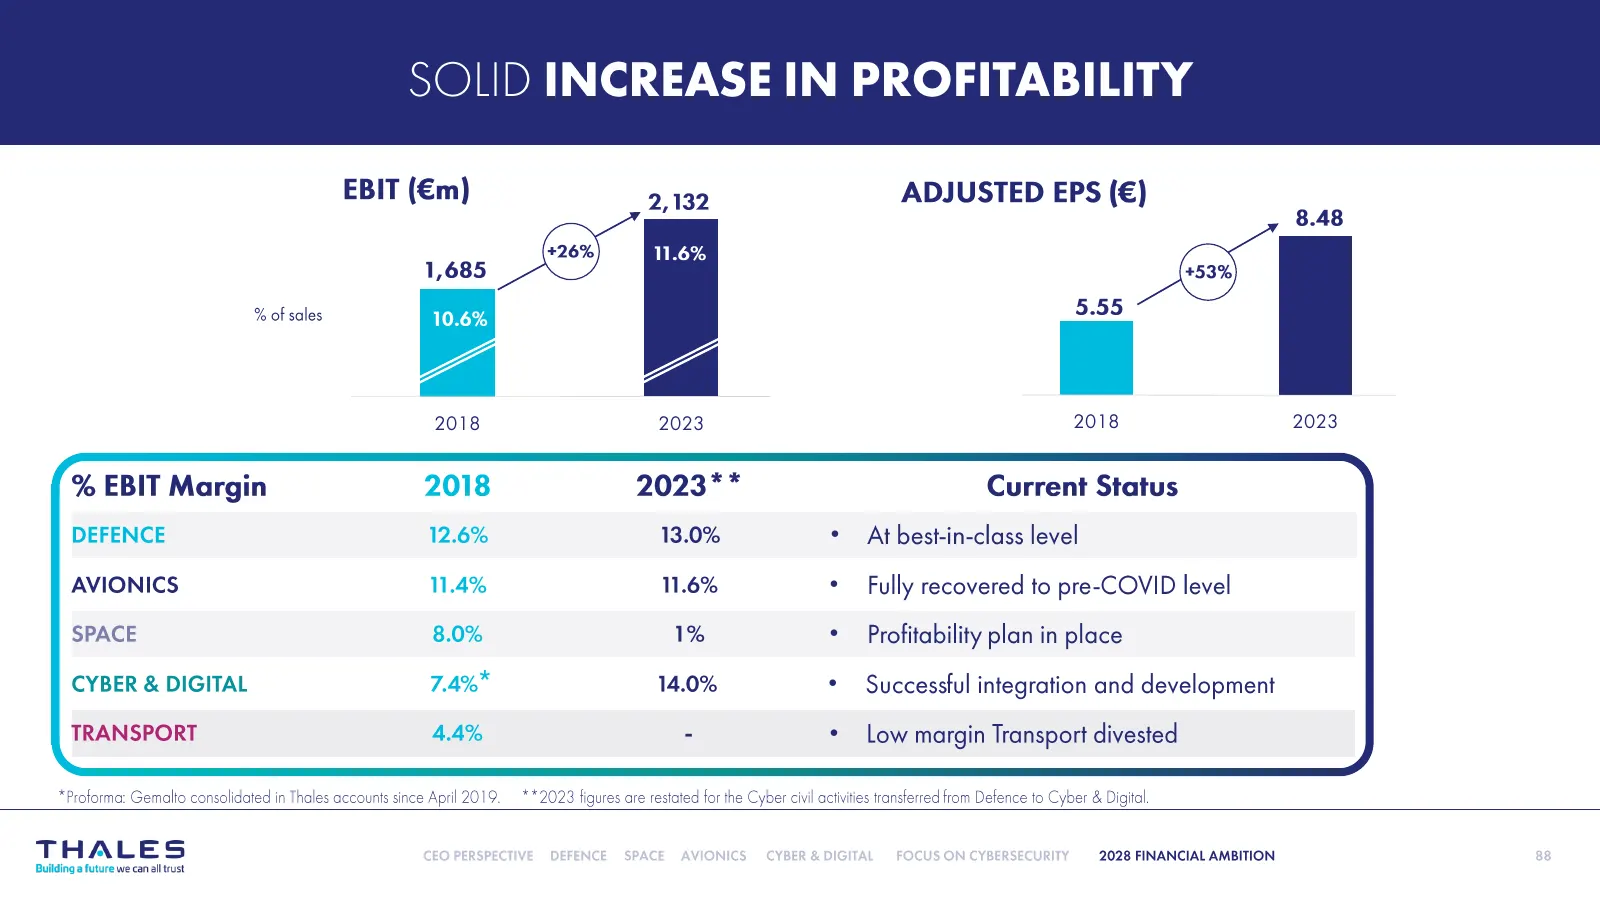
• • • • •
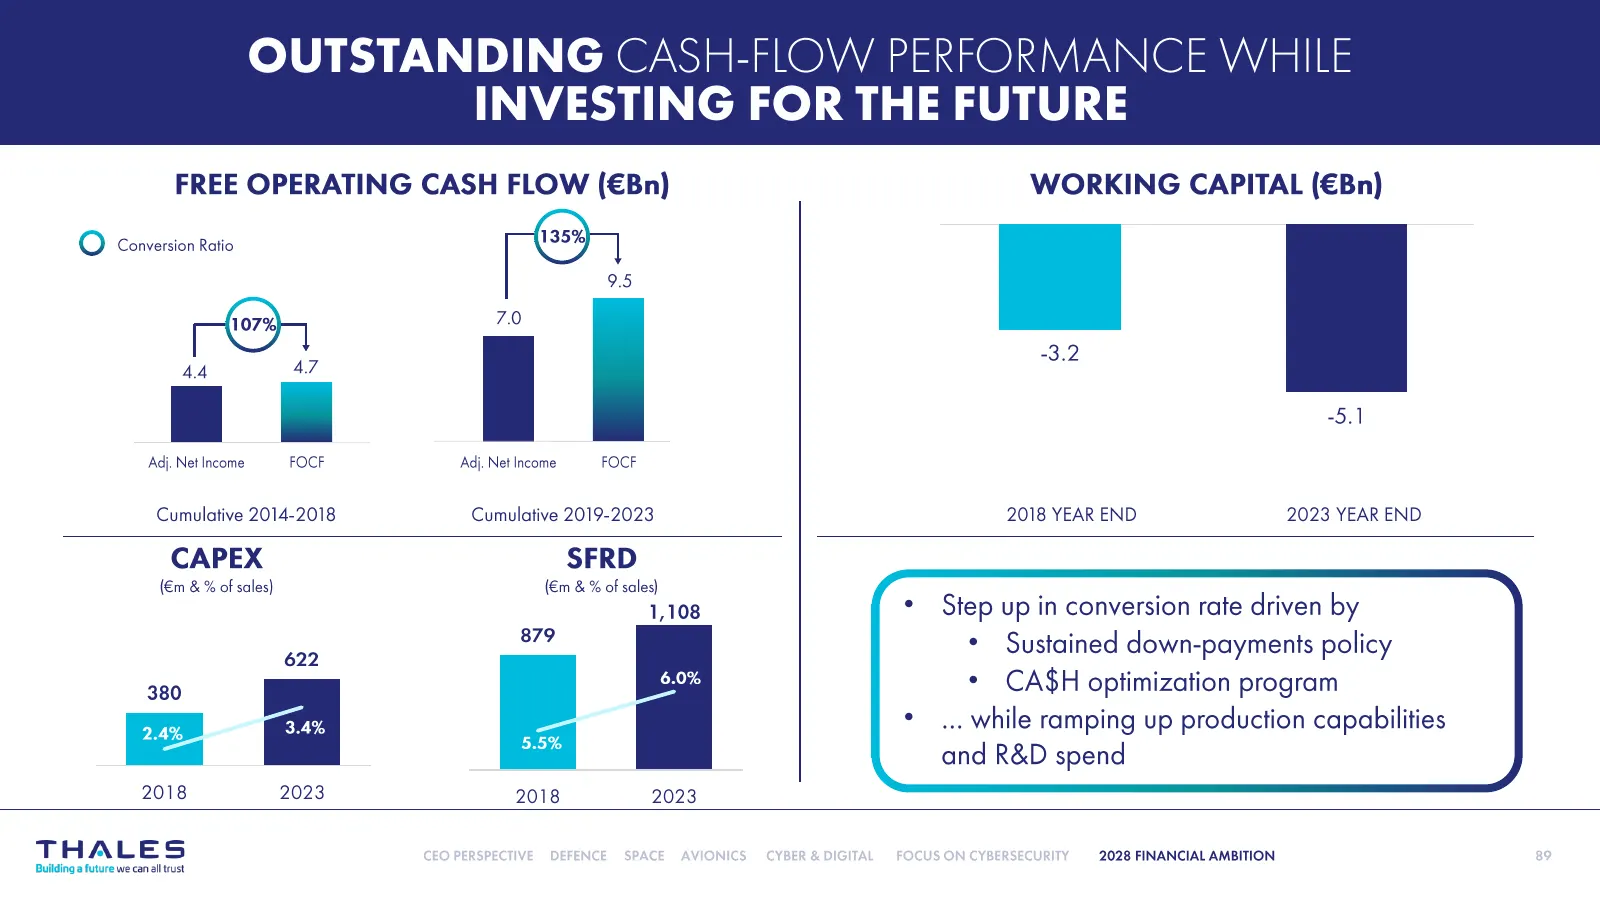
Slide 89: • • • •
• • • •
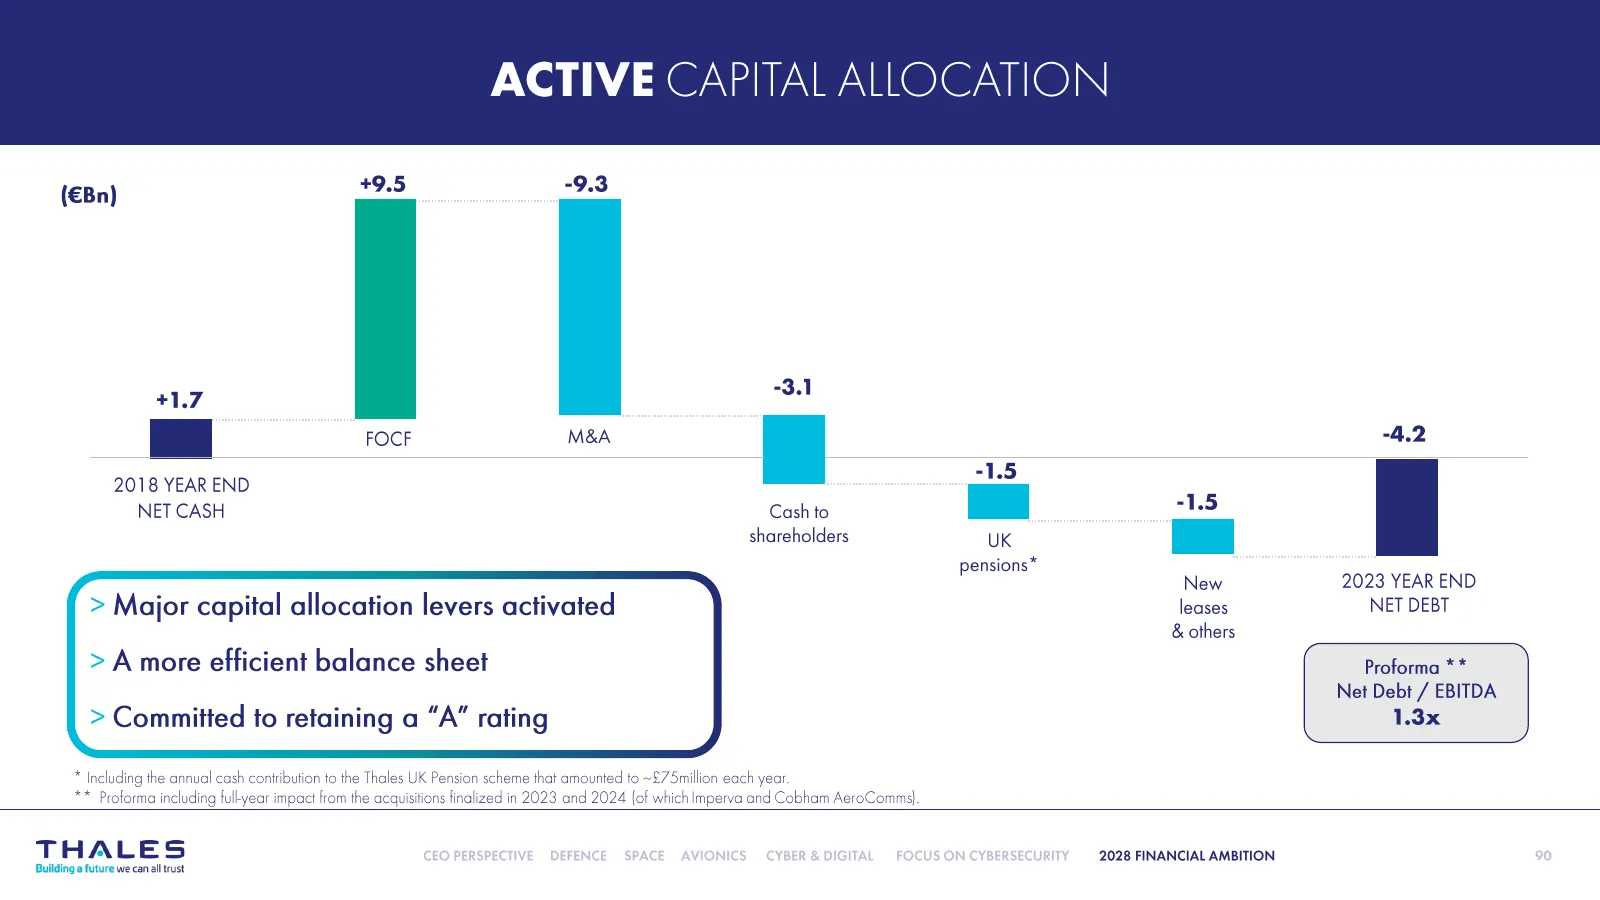
Slide 90: Active capital allocation
Slide 91: Still a large potential to unleash
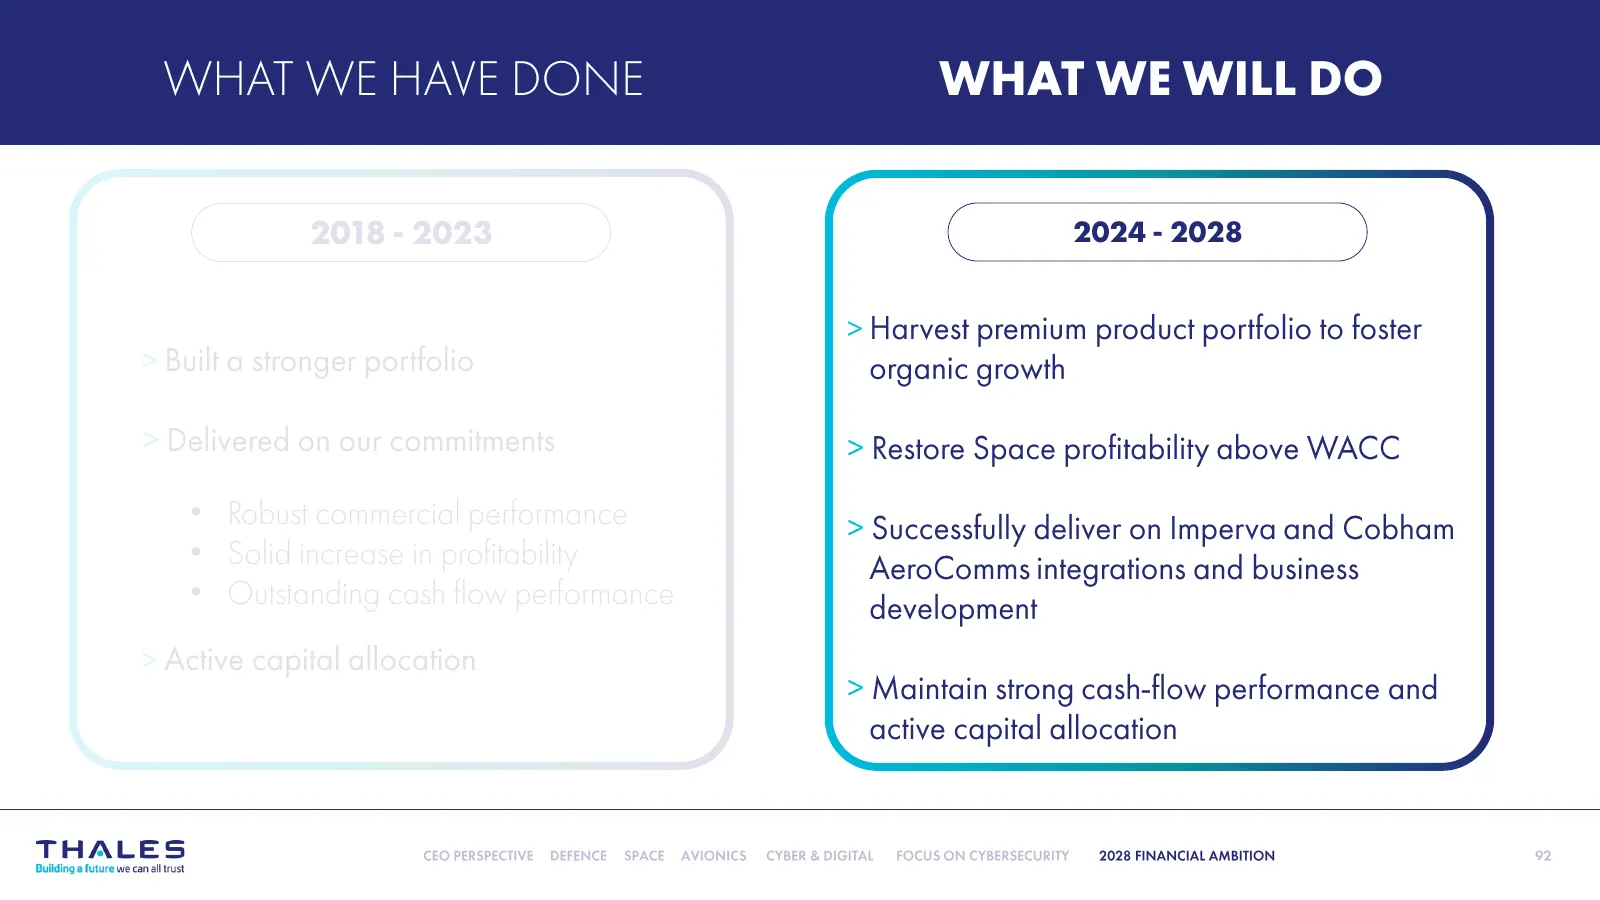
Slide 92: • • •
• • •
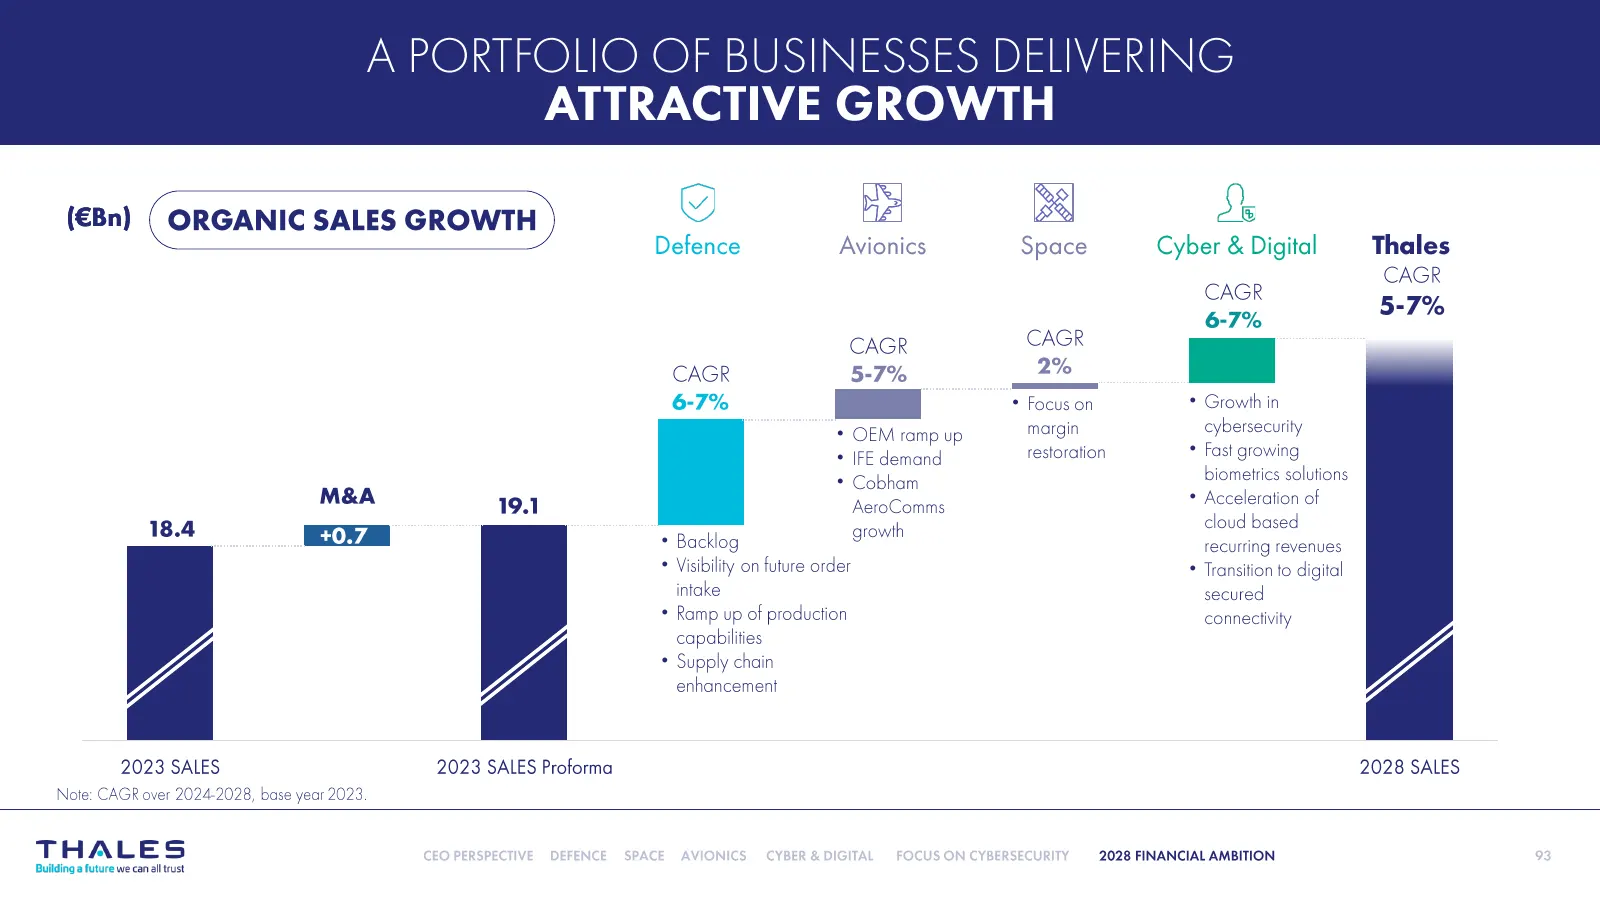
Slide 93: • • • • • • • • • • • •
• • • • • • • • • • • •
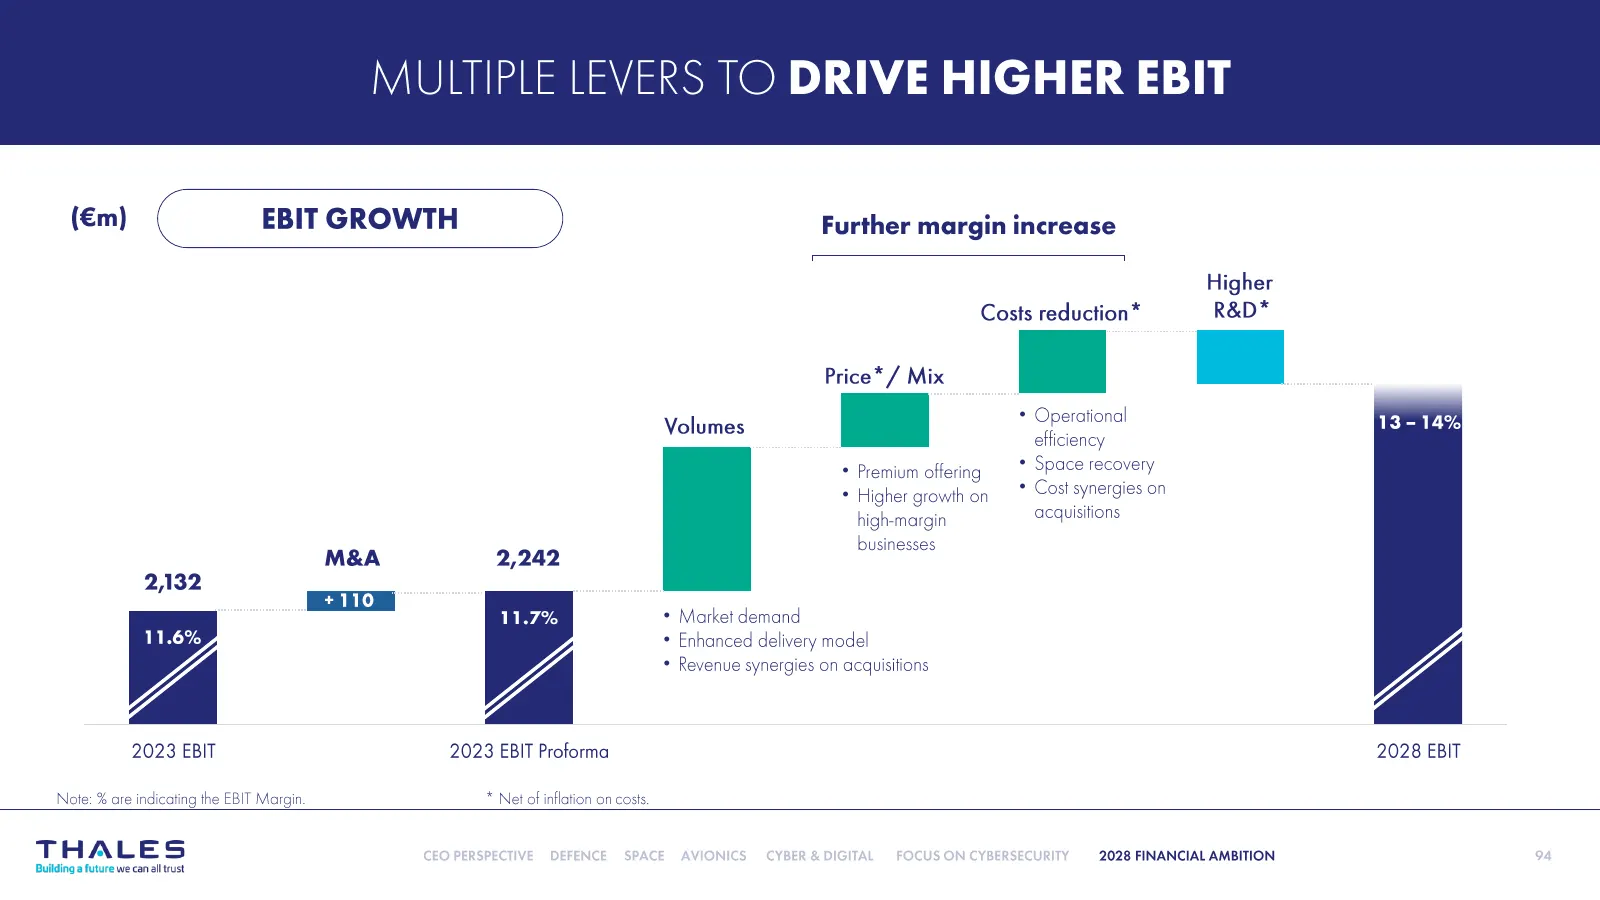
Slide 94: • • • • • • • •
• • • • • • • •
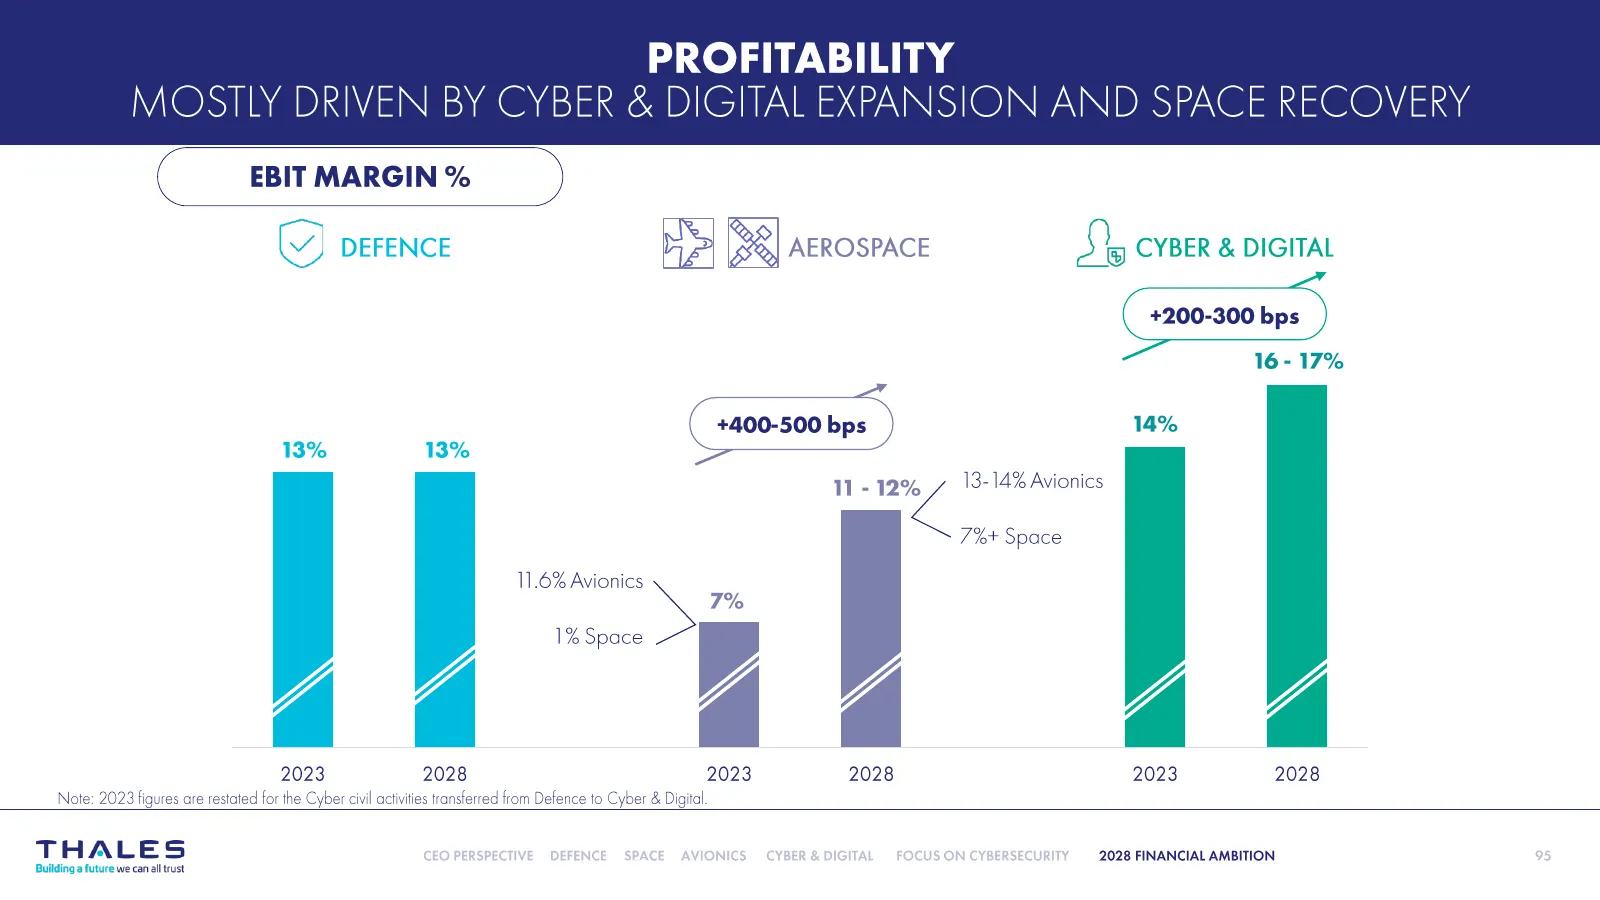
Slide 95: Profitability mostly driven by Cyber & Digital and Space recovery
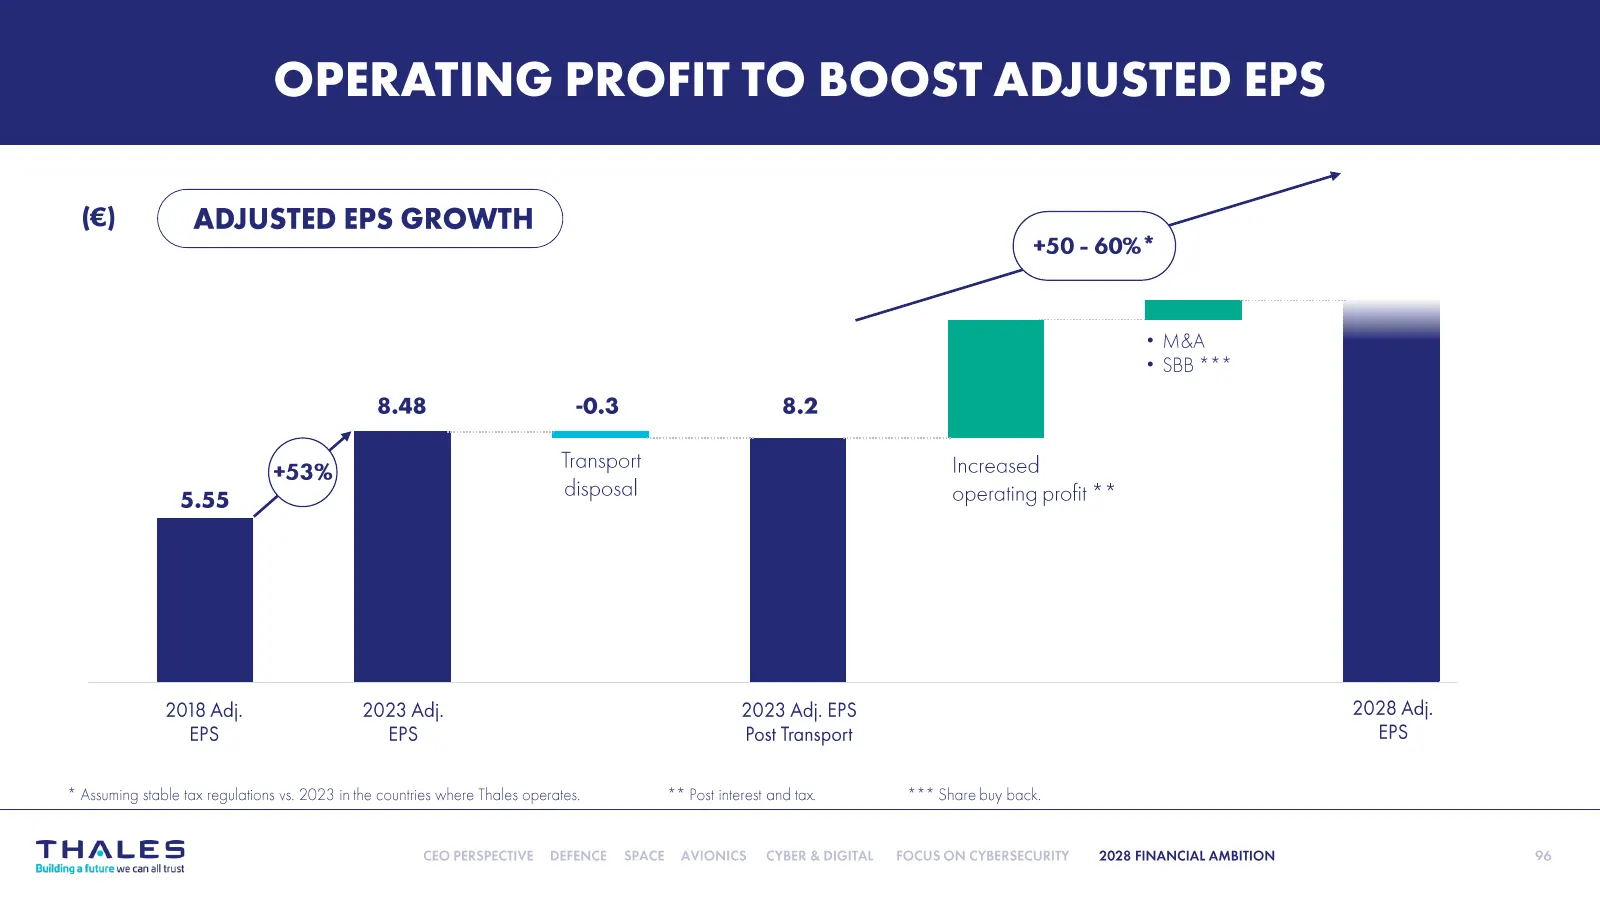
Slide 96: • •
• •
Slide 97: • • • • • •
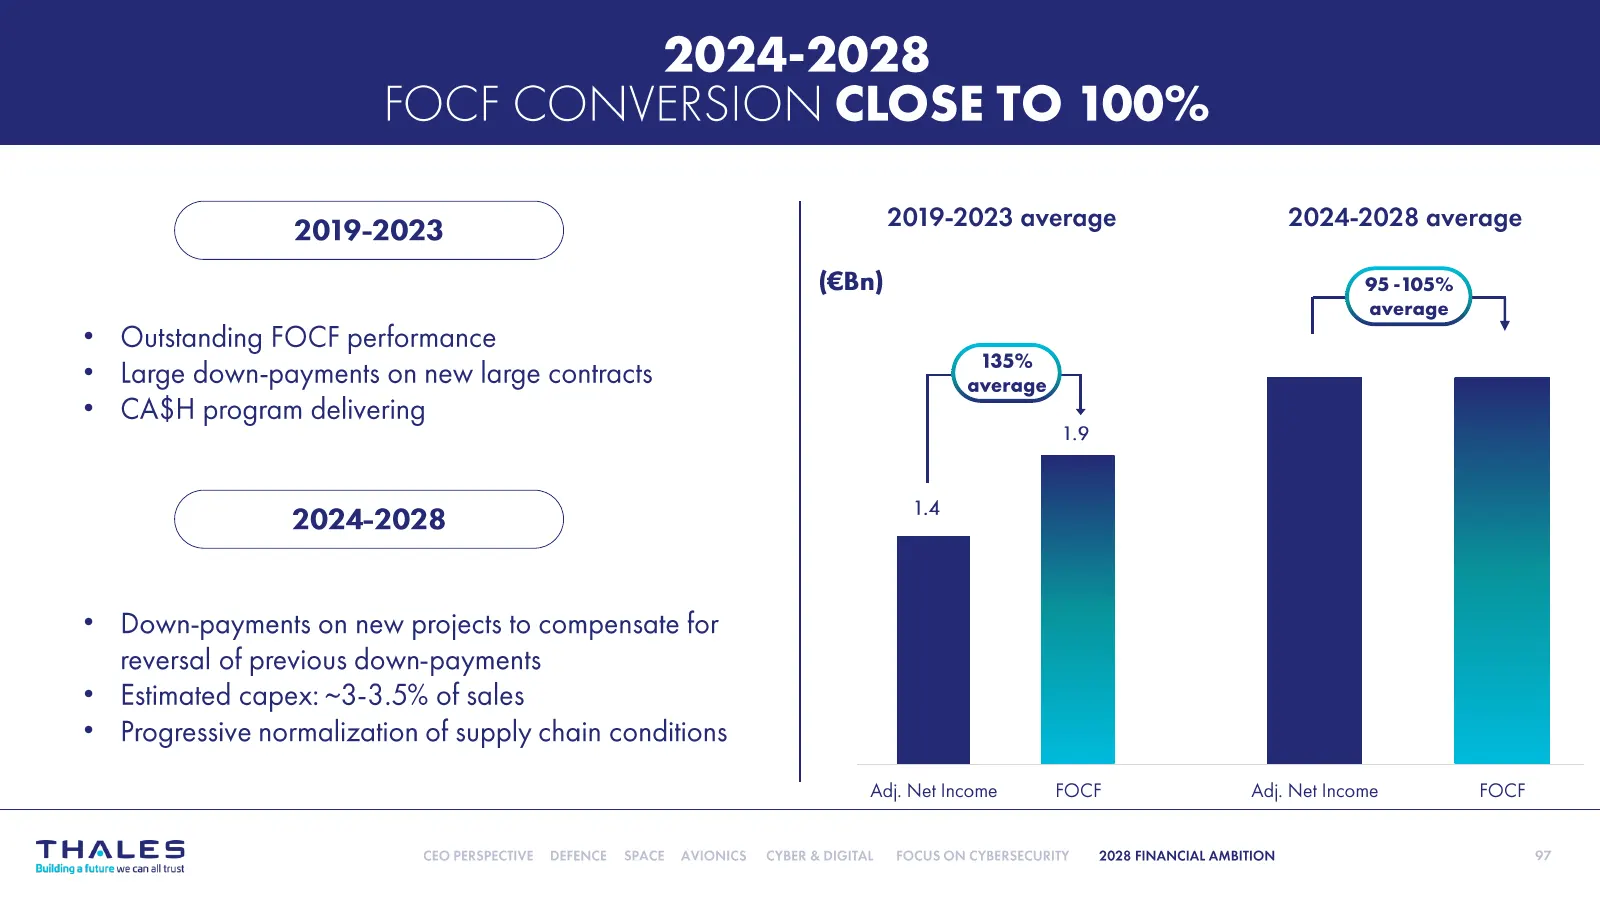
• • • • • •
Slide 98: • • • • • • • • • • • • • •
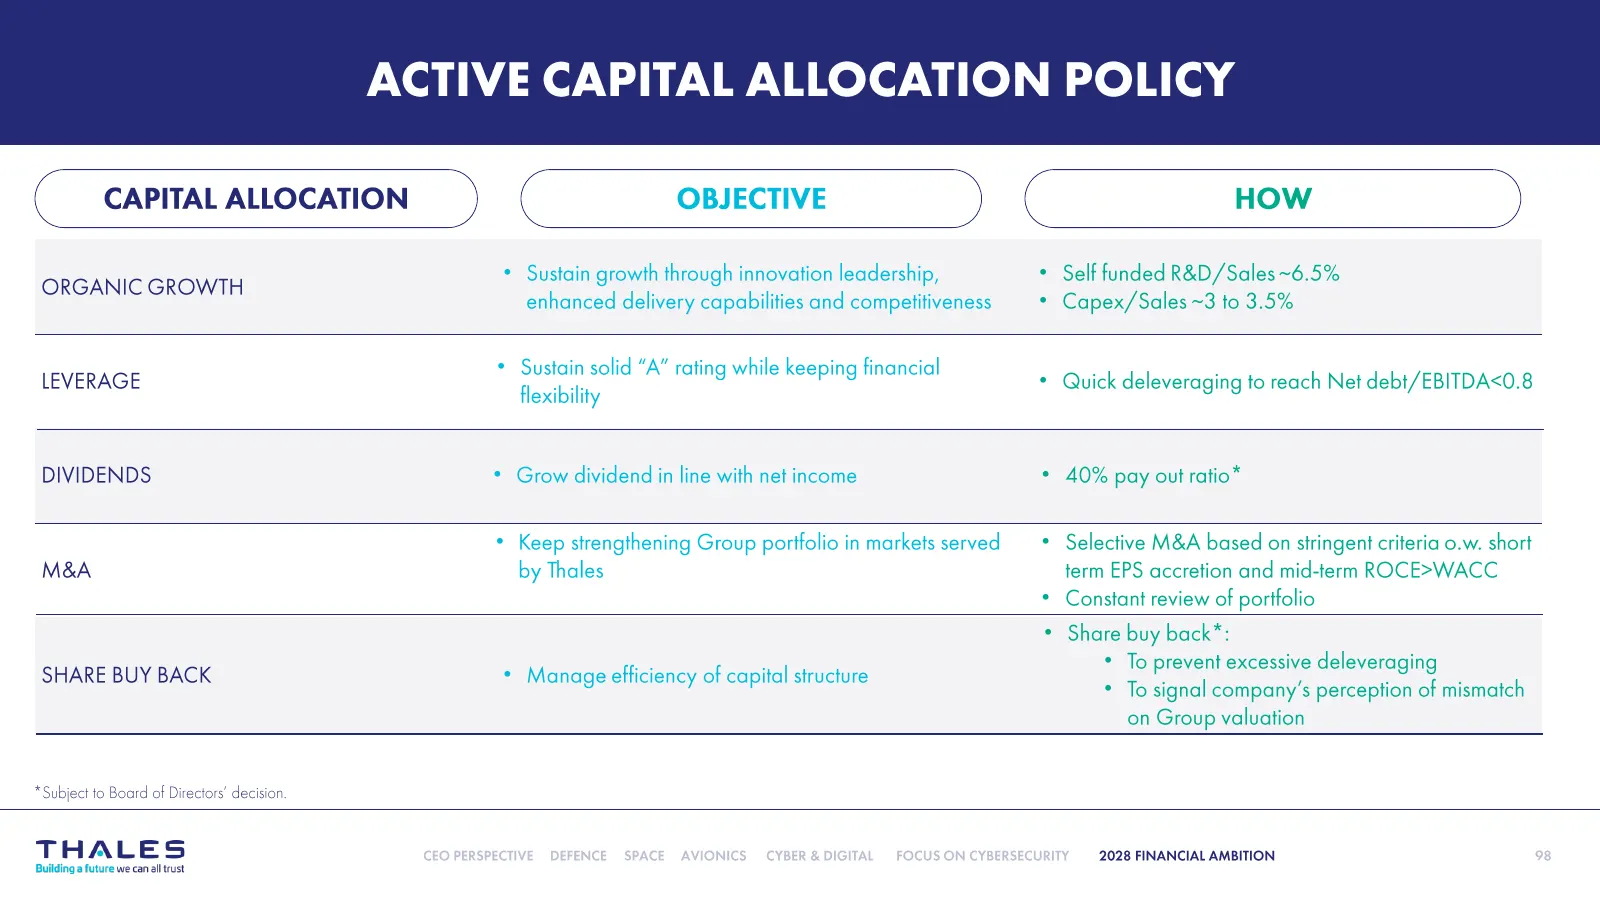
• • • • • • • • • • • • • •
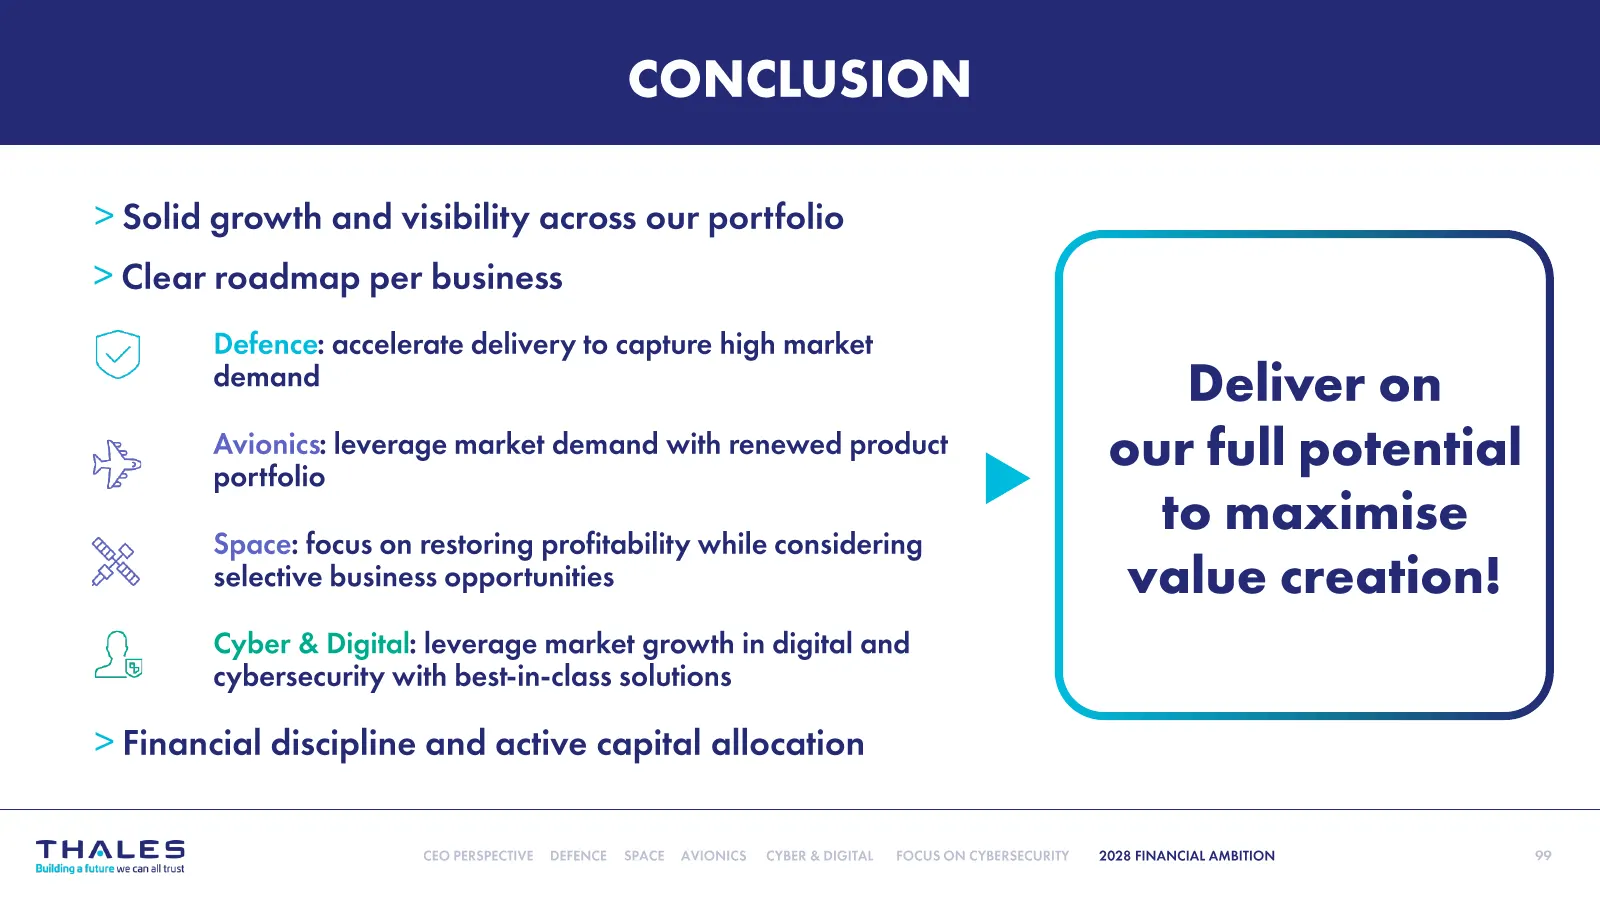
Slide 99: Conclusion
Slide 100: > : > > > > > : > > :
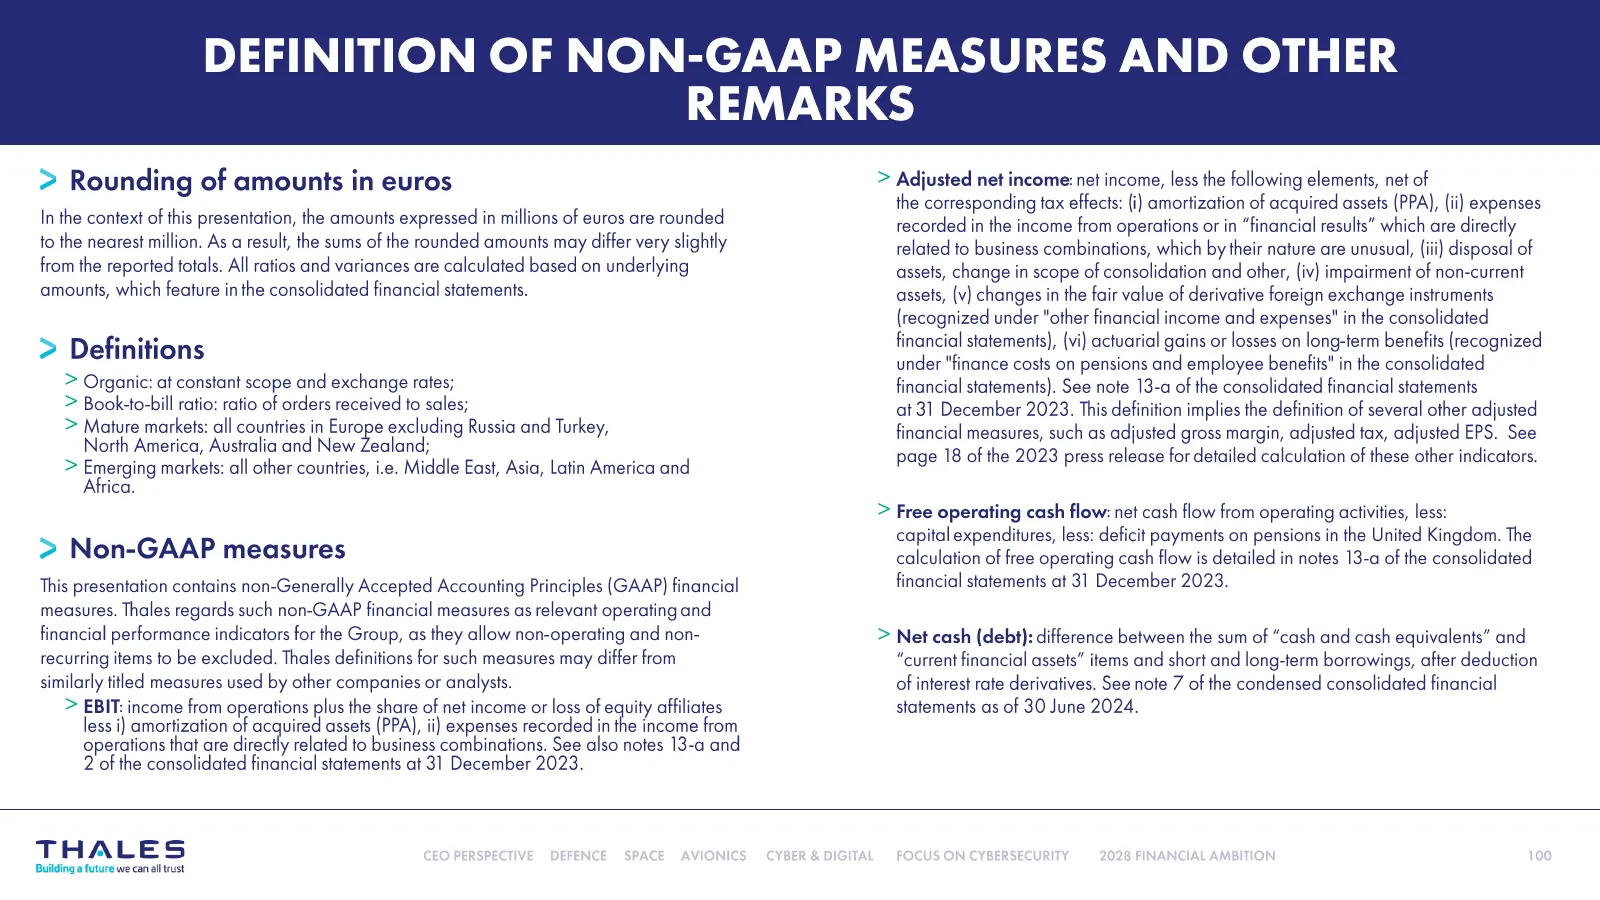
> : > > > > > : > > :
Slide 101: Disclaimer
Slide 102: Appendix
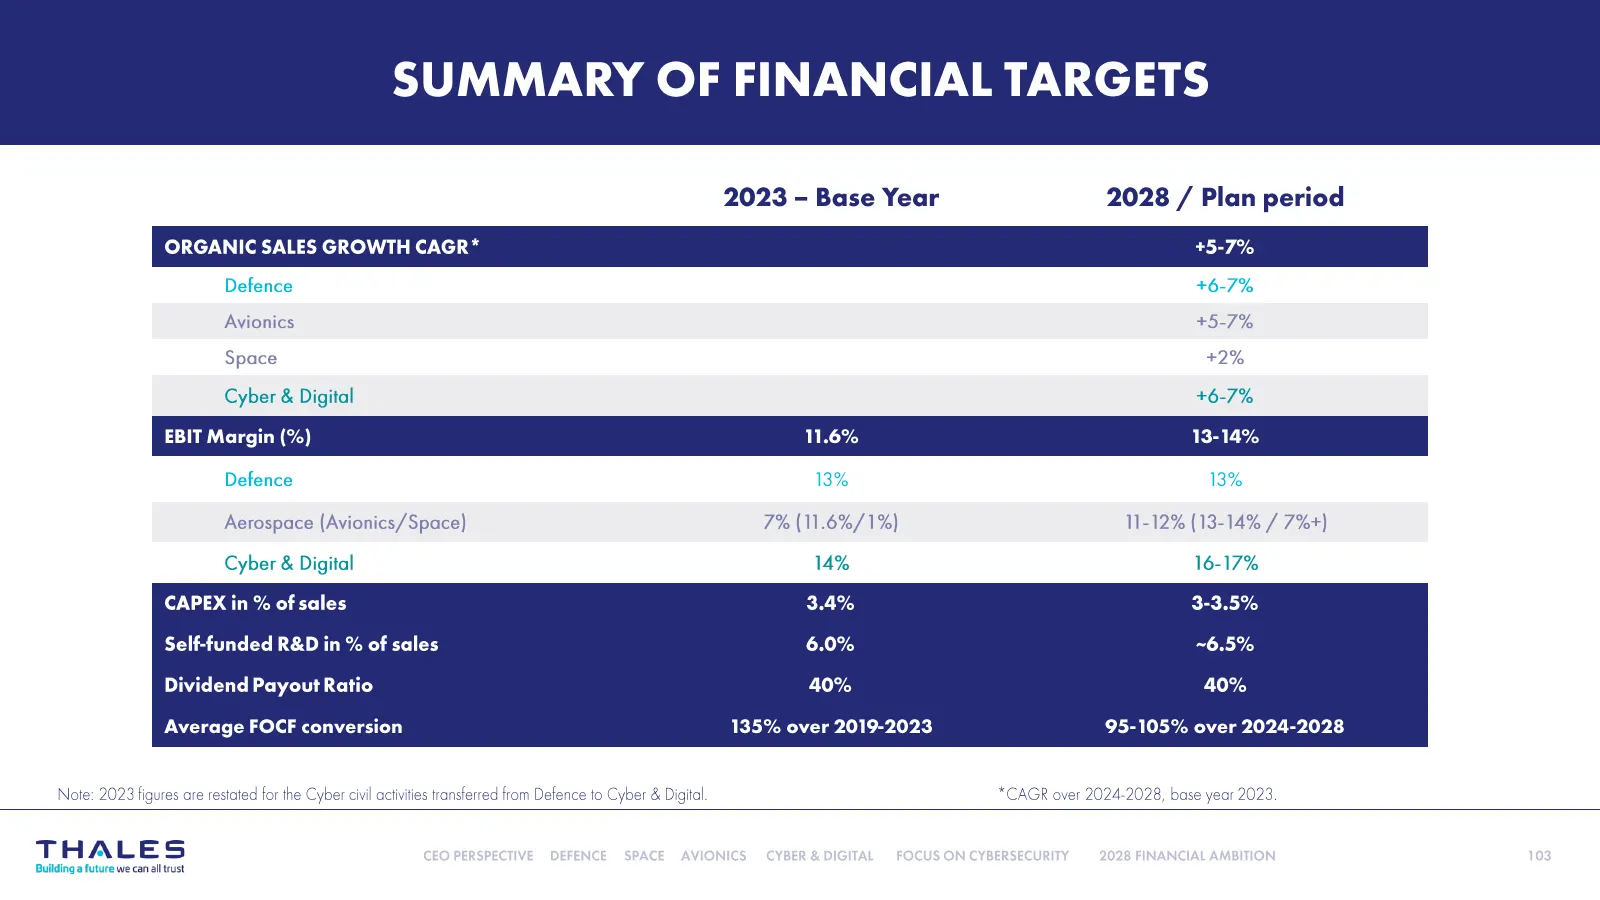
Slide 103: Summary of financial targets
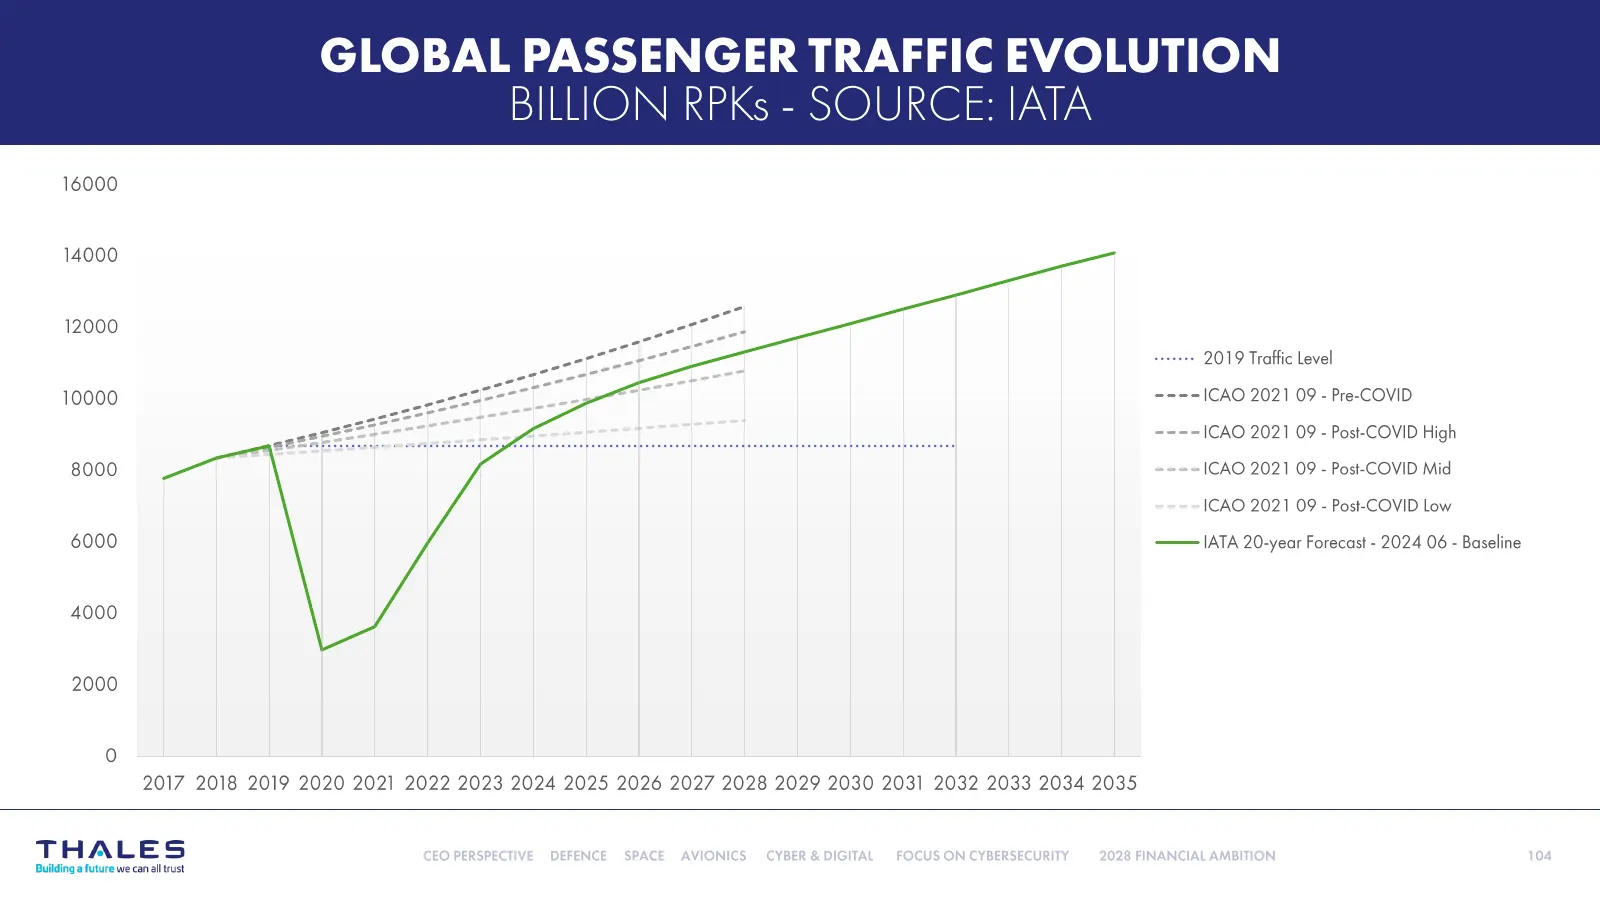
Slide 104: Global passenger traffic evolution
Source: Internet Archive copy of thalesgroup.com
More decks from Thales SA
 Fact Sheet (2026)1 slide · Jul 27, 2026
 H1 2026 Earnings Presentation26 slides · Jul 23, 2026
 Merger or Acquisition (July 2026)15 slides · Jul 6, 2026
 Investor Presentation (May 2026)66 slides · May 2026
 Q1 2026 Earnings Presentation17 slides · Apr 21, 2026
 FY2025 Earnings Presentation33 slides · Mar 3, 2026