Volex plc · LSE:VLX
Volex — FY2014/15 Earnings Presentation
23 slides from Volex's earnings presentation, June 2015
Slide 1: Volex – Preliminary Results 2014/15
Volex – Preliminary Results 2014/15 Christoph Eisenhardt, CEO Daren Morris, CFO June 2015 ©Volex 2015 1
Slide 2: Disclaimer
This Presentation has been prepared by Volex PLC (the “Company”) in connection with the publication of the Company's preliminary results for the fifty-three weeks to April 5 2015. This Presentation does not constitute or form part of any offer or invitation to sell or issue, or any solicitation of a
Slide 3: Key Summary
Key Summary • Return to profitable growth • Revenue growth of 6% with stable margins • Near doubling of operating profits from $4.5million to $8.8million • Operating cash flow positive • De-risked the balance sheet Volex Transformation Plan completed – 2015/16 focus on continued growth and operation
Slide 4: Volex has returned to profitable growth (1)
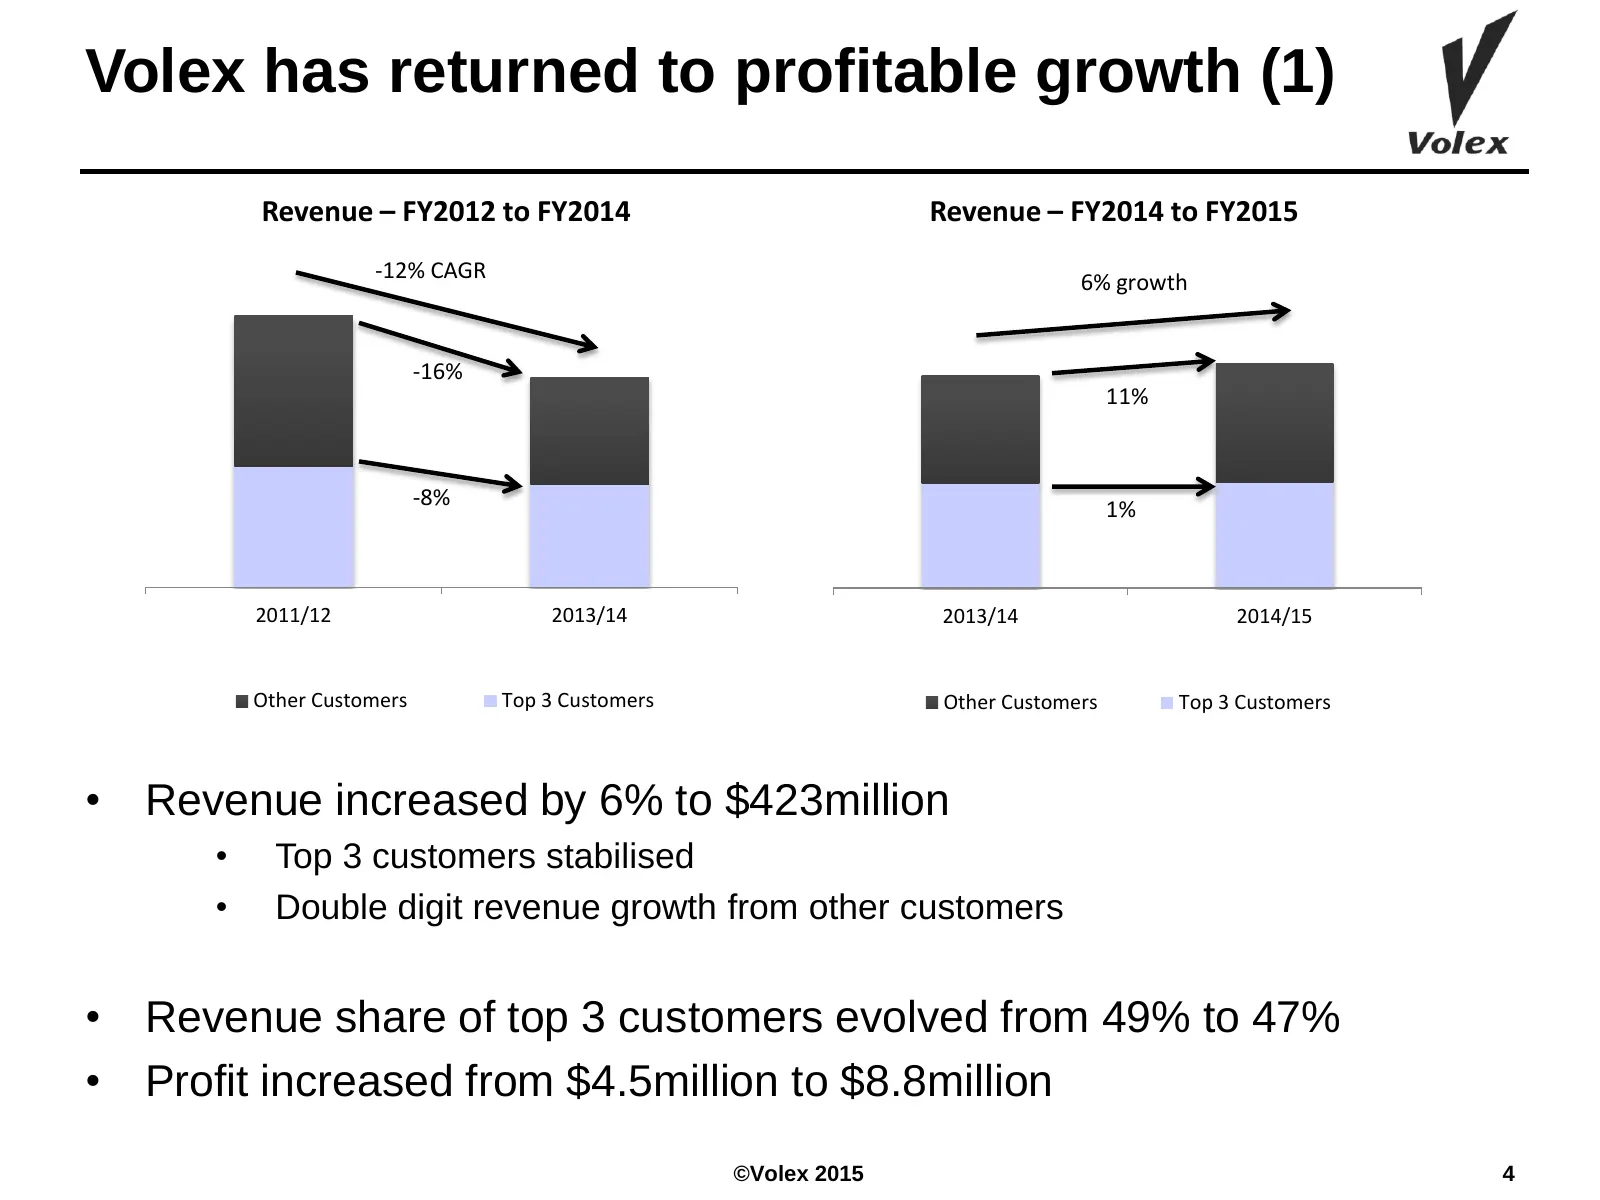
Volex has returned to profitable growth (1) Revenue – FY2012 to FY2014 Revenue – FY2014 to FY2015 -12% CAGR 6% growth -16% 11% -8% 1% 2011/12 2013/14 2013/14 2014/15 Other Customers Top 3 Customers Other Customers Top 3 Customers • Revenue increased by 6% to $423million • Top 3 customers stabilised
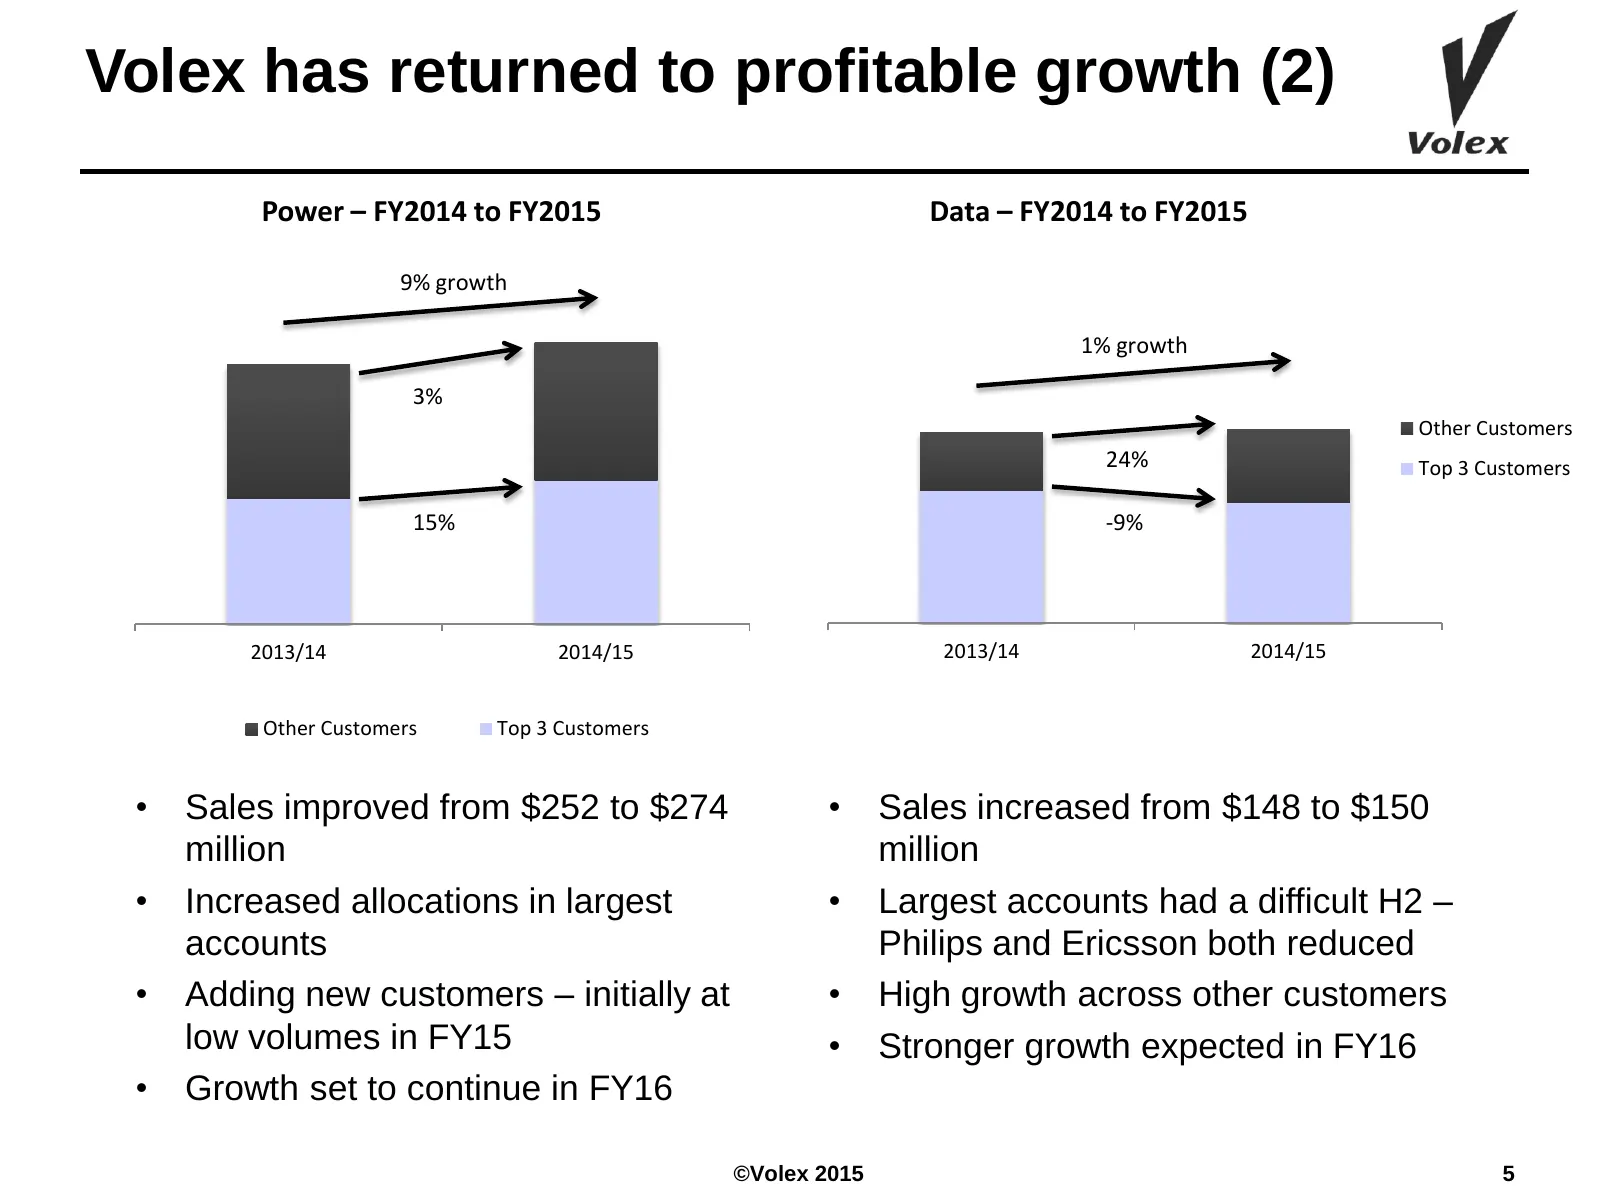
Slide 5: Volex has returned to profitable growth (2)
Volex has returned to profitable growth (2) Power – FY2014 to FY2015 Data – FY2014 to FY2015 9% growth 1% growth 3% Other Customers 24% Top 3 Customers 15% -9% 2013/14 2014/15 2013/14 2014/15 Other Customers Top 3 Customers • Sales improved from $252 to $274 • Sales increased from $148 to $150 milli
Slide 6: Sales Bridge
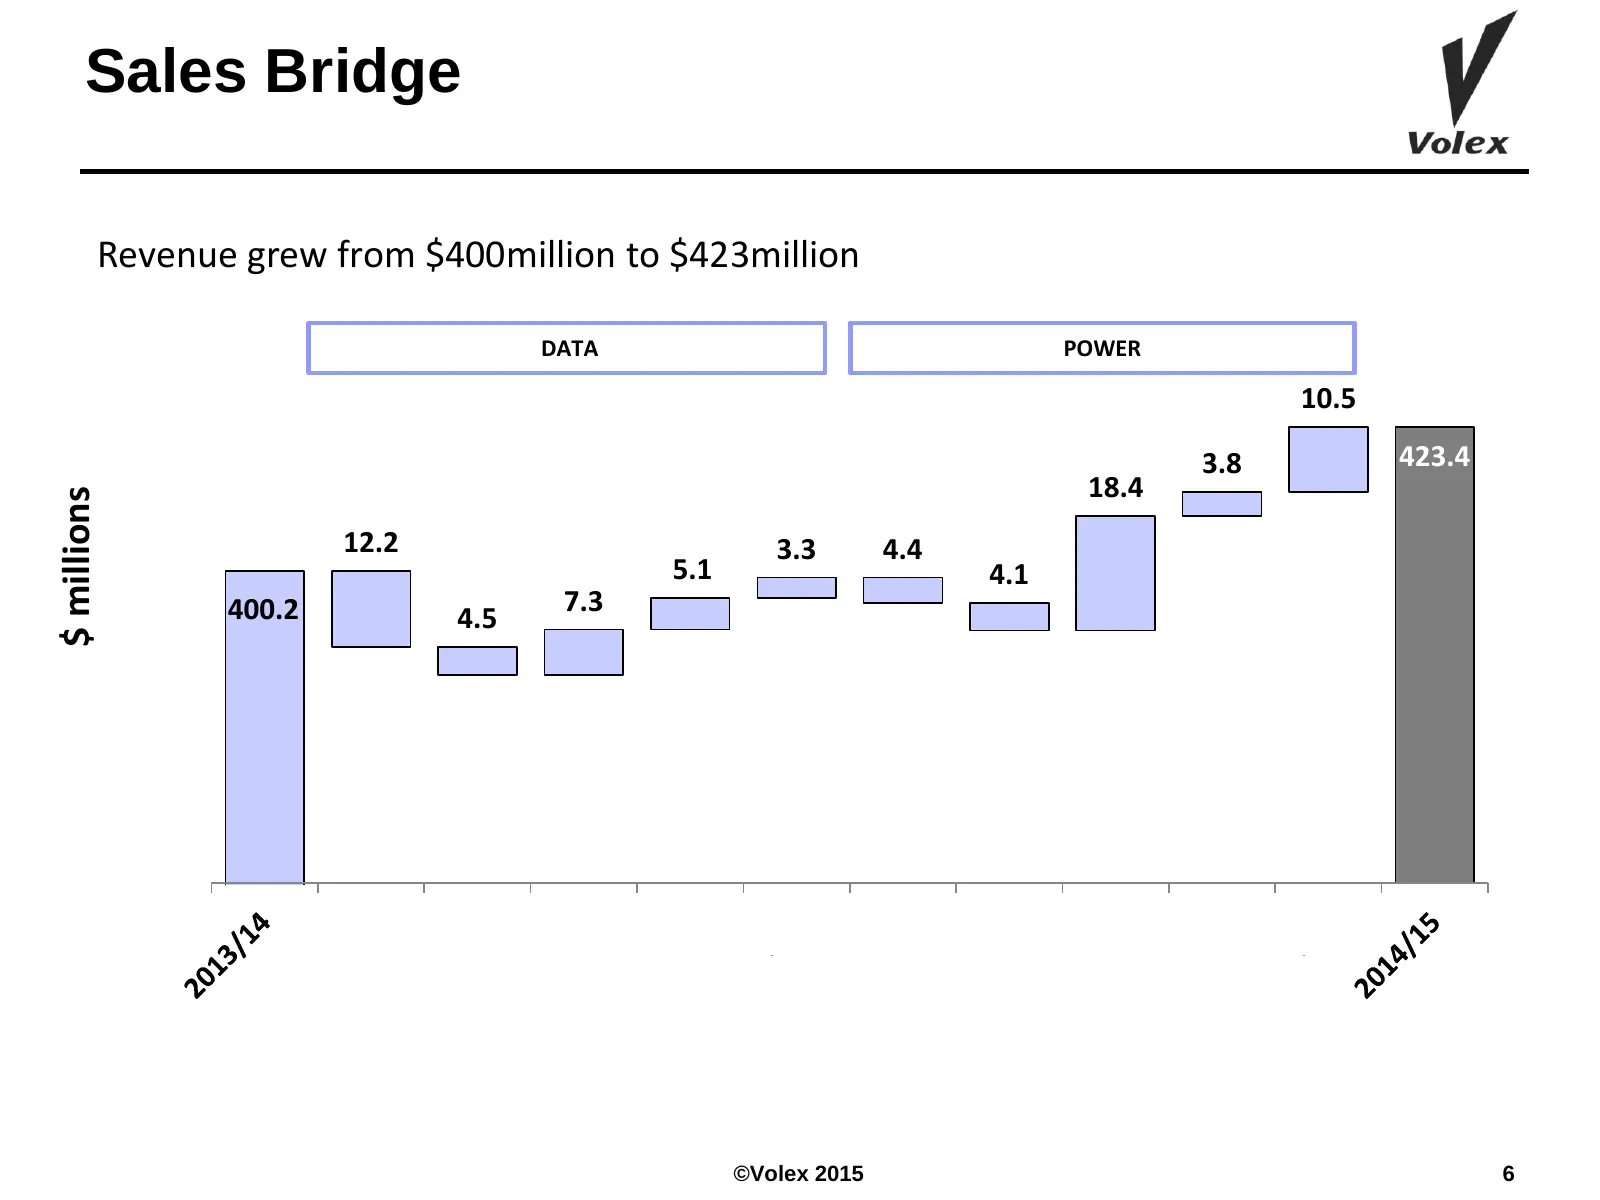
Sales Bridge Revenue grew from $400million to $423million DATA POWER 10.5 3.8 423.4 18.4 $ millions 12.2 3.3 4.4 5.1 4.1 400.2 7.3 4.5 ©Volex 2015 6
Slide 7: Operational Priorities for FY16
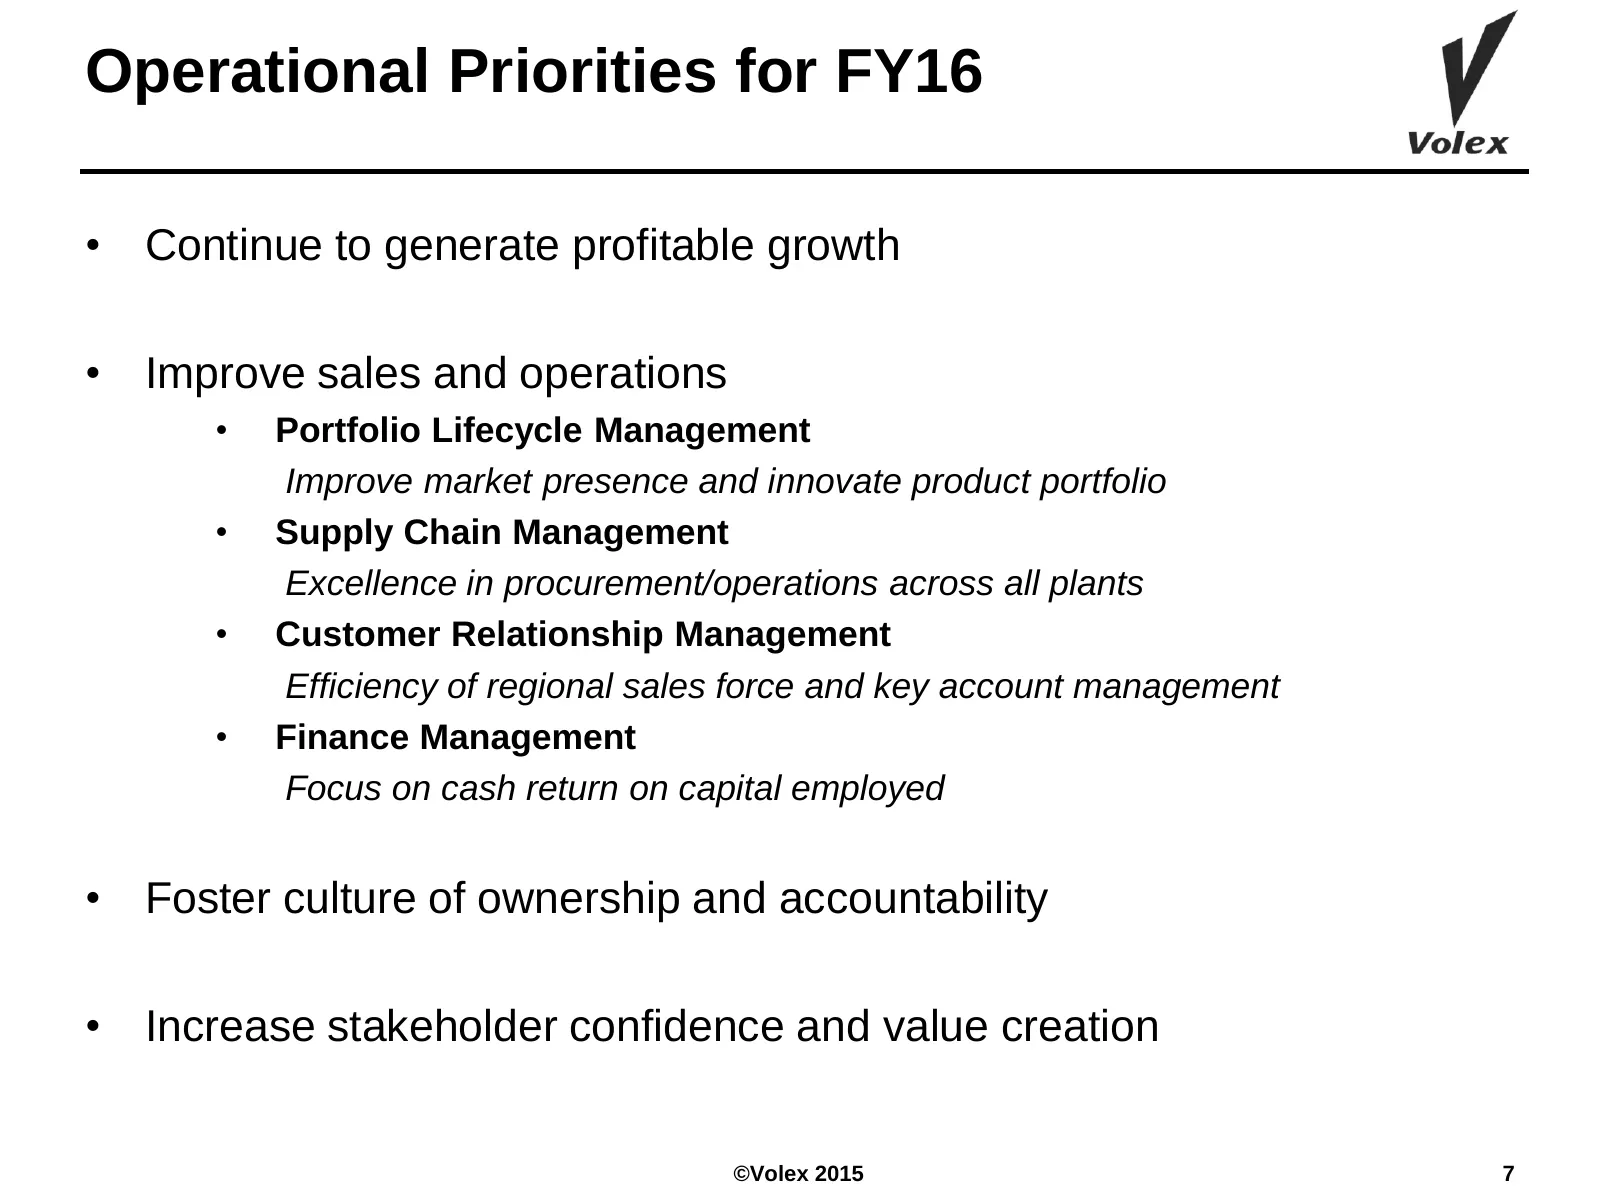
Operational Priorities for FY16 • Continue to generate profitable growth • Improve sales and operations • Portfolio Lifecycle Management Improve market presence and innovate product portfolio • Supply Chain Management Excellence in procurement/operations across all plants • Customer Relationship Man
Slide 8: Financial Review
Financial Review ©Volex 2015 8
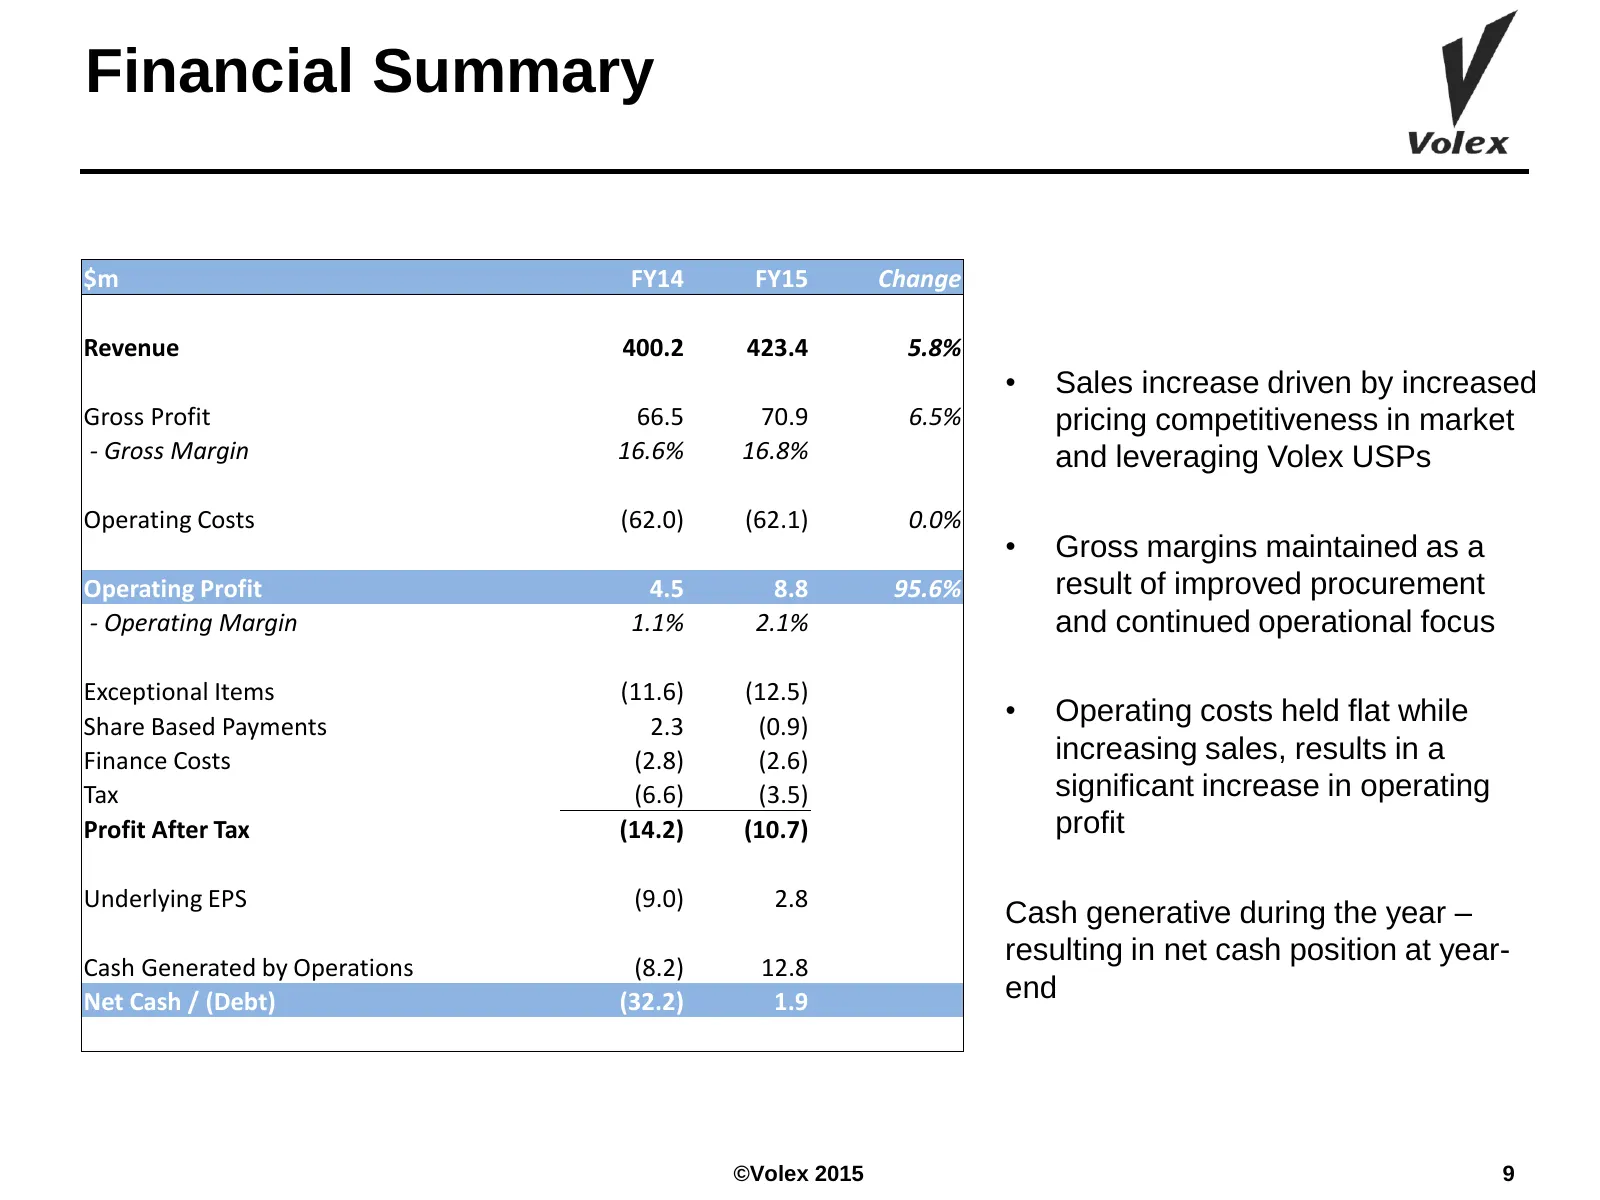
Slide 9: Financial Summary
Financial Summary $m FY14 FY15 Change Revenue 400.2 423.4 5.8% • Sales increase driven by increased Gross Profit 66.5 70.9 6.5% pricing competitiveness in market - Gross Margin 16.6% 16.8% and leveraging Volex USPs Operating Costs (62.0) (62.1) 0.0% • Gross margins maintained as a Operating Profit 4
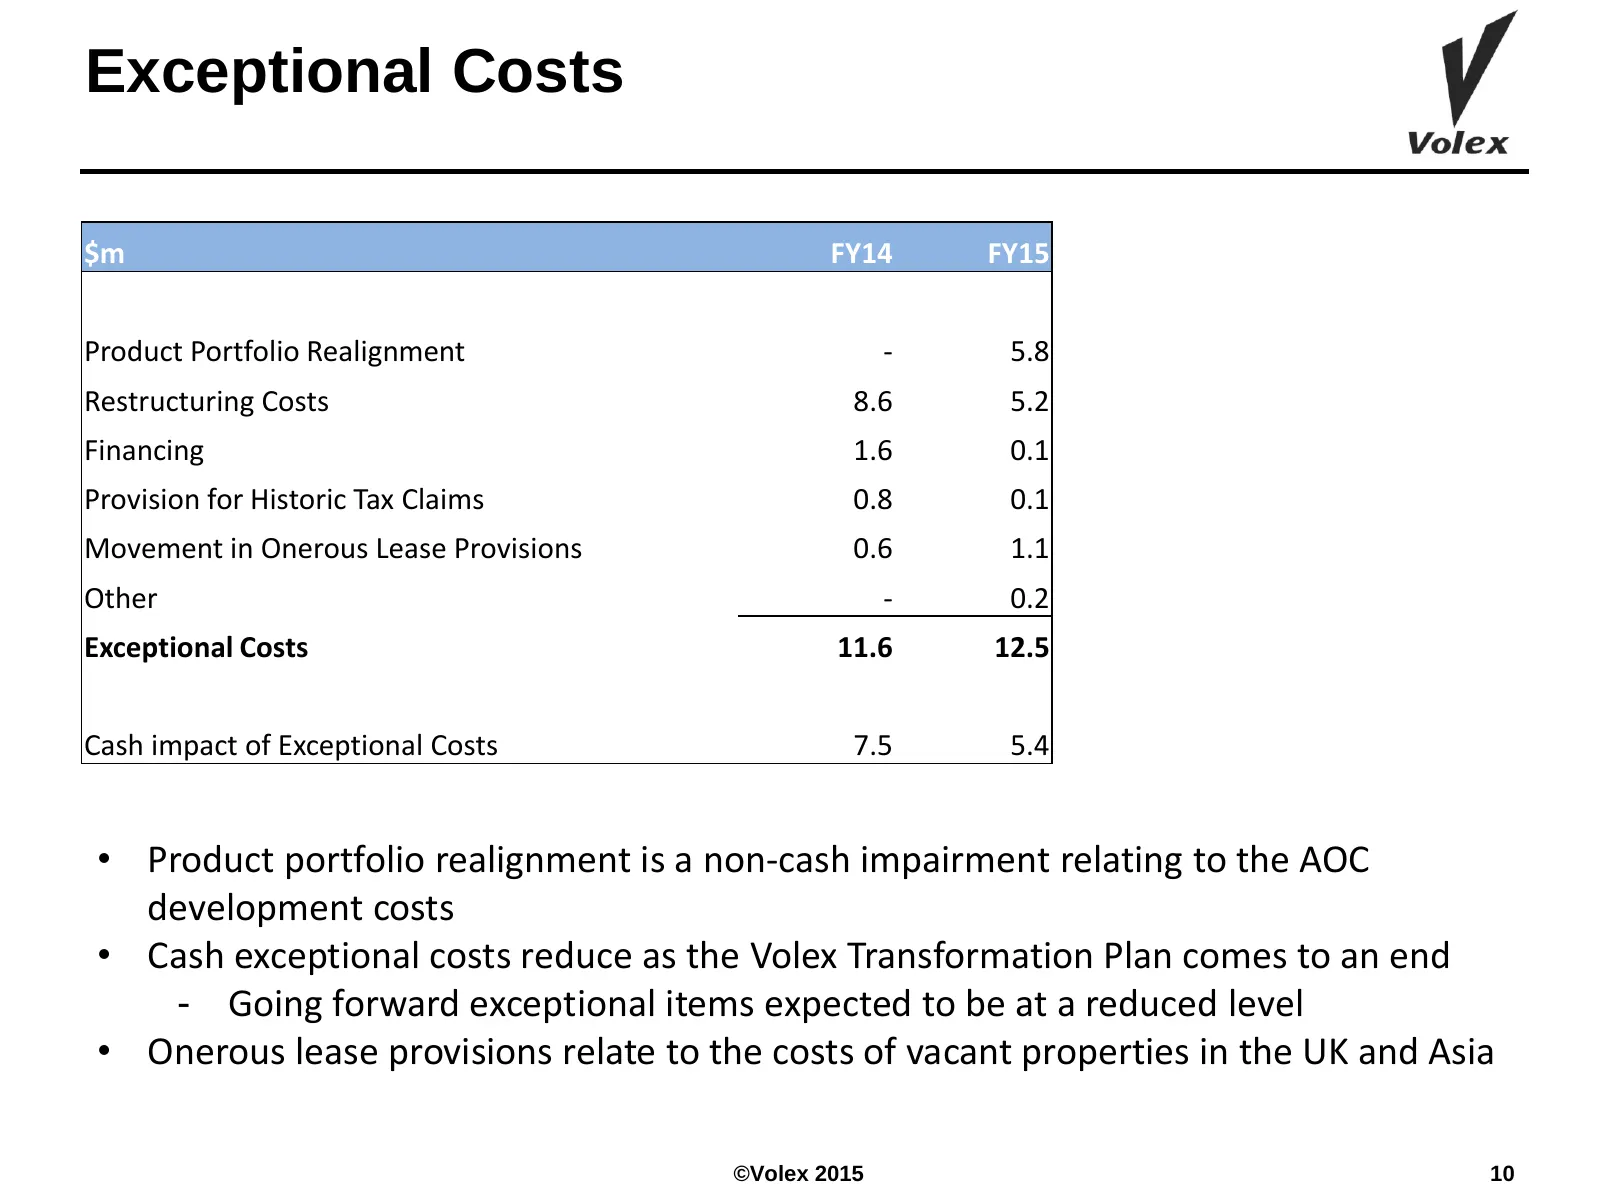
Slide 10: Exceptional Costs
Exceptional Costs $m FY14 FY15 Product Portfolio Realignment - 5.8 Restructuring Costs 8.6 5.2 Financing 1.6 0.1 Provision for Historic Tax Claims 0.8 0.1 Movement in Onerous Lease Provisions 0.6 1.1 Other - 0.2 Exceptional Costs 11.6 12.5 Cash impact of Exceptional Costs 7.5 5.4 • Product portfolio
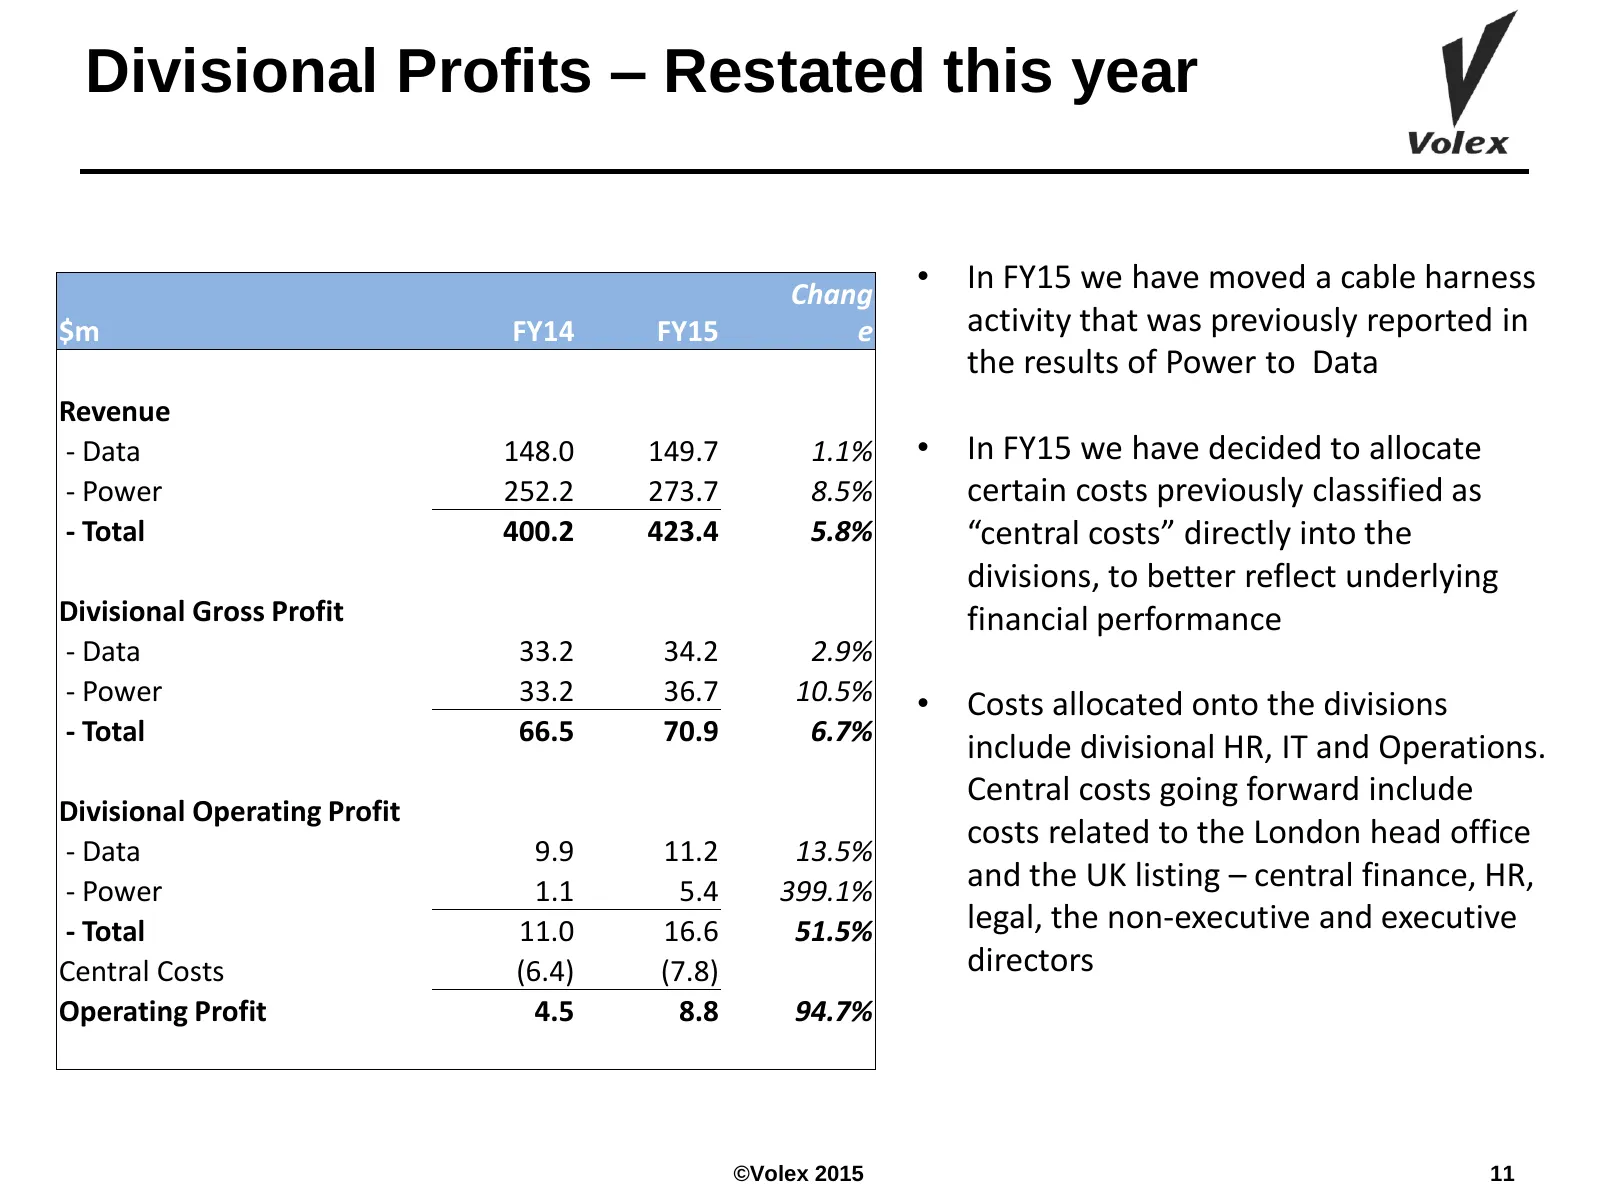
Slide 11: Divisional Profits – Restated this year
Divisional Profits – Restated this year Chang • In FY15 we have moved a cable harness $m FY14 FY15 e activity that was previously reported in the results of Power to Data Revenue - Data 148.0 149.7 1.1% • In FY15 we have decided to allocate - Power 252.2 273.7 8.5% certain costs previously classifie
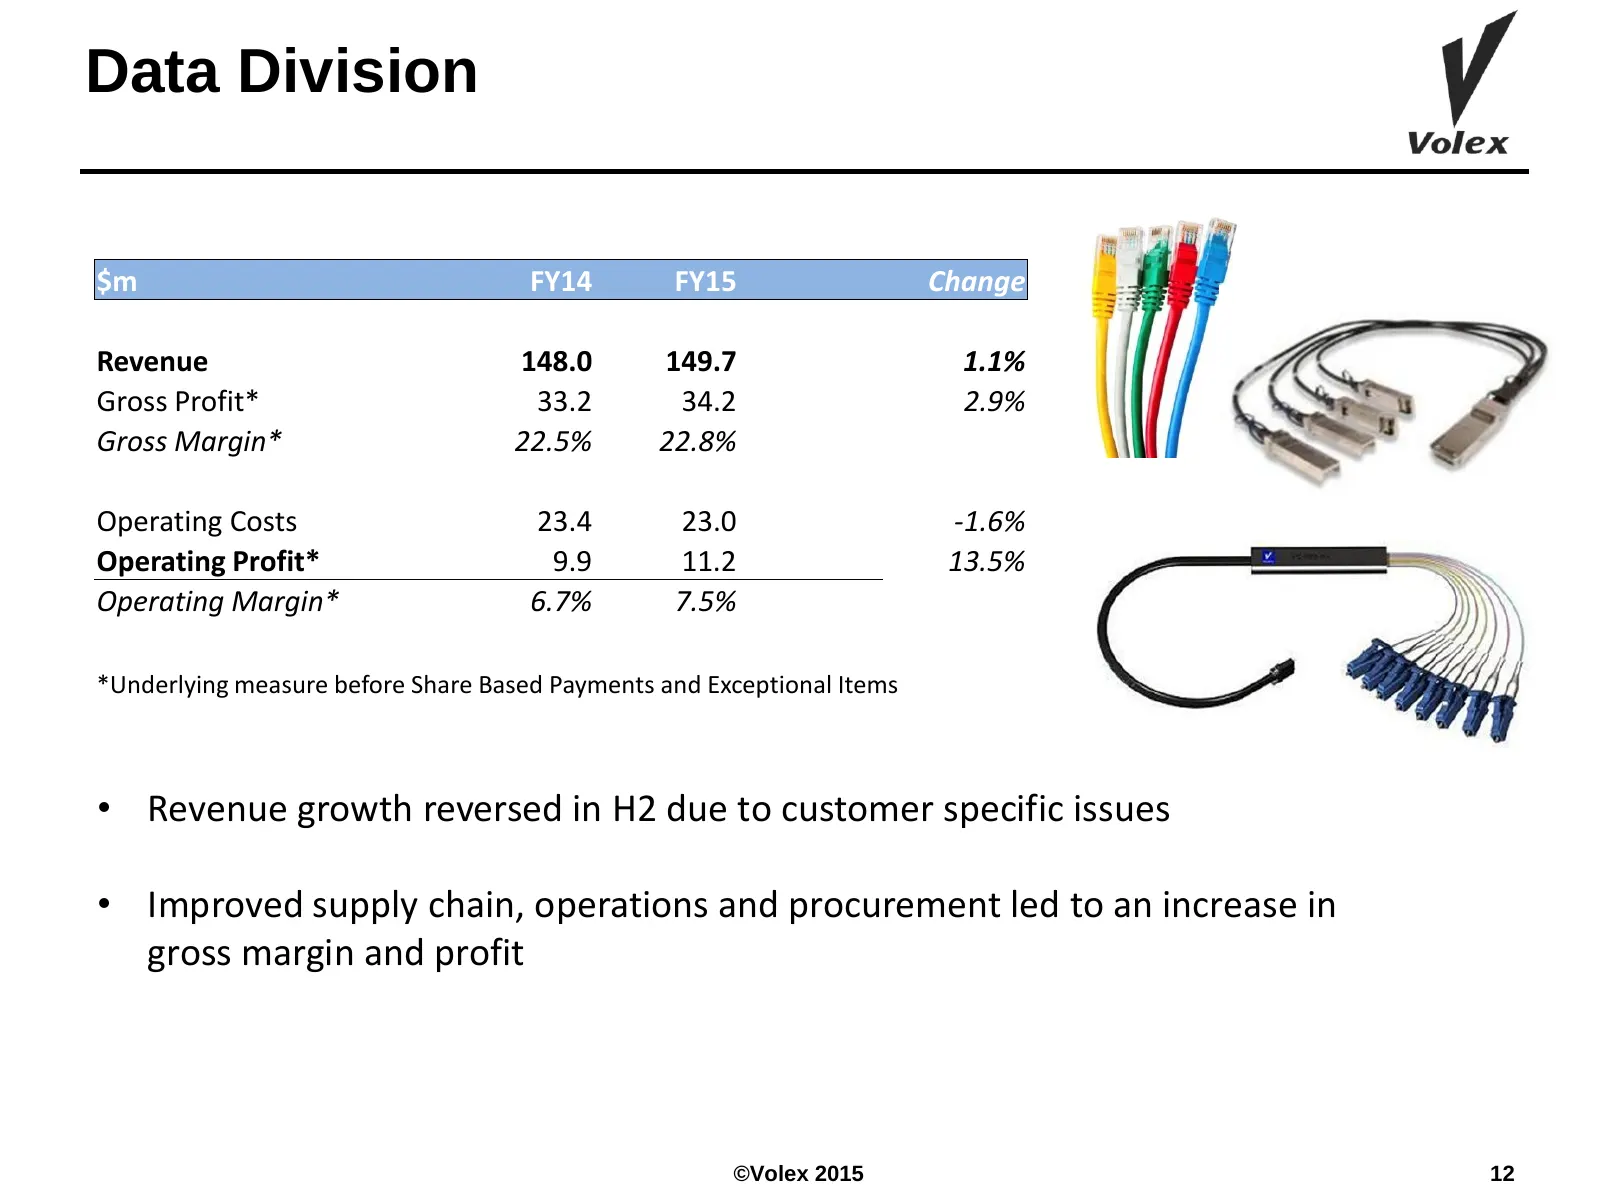
Slide 12: Data Division
Data Division $m FY14 FY15 Change Revenue 148.0 149.7 1.1% Gross Profit* 33.2 34.2 2.9% Gross Margin* 22.5% 22.8% Operating Costs 23.4 23.0 -1.6% Operating Profit* 9.9 11.2 13.5% Operating Margin* 6.7% 7.5% *Underlying measure before Share Based Payments and Exceptional Items • Revenue growth revers
Slide 13: Power Division
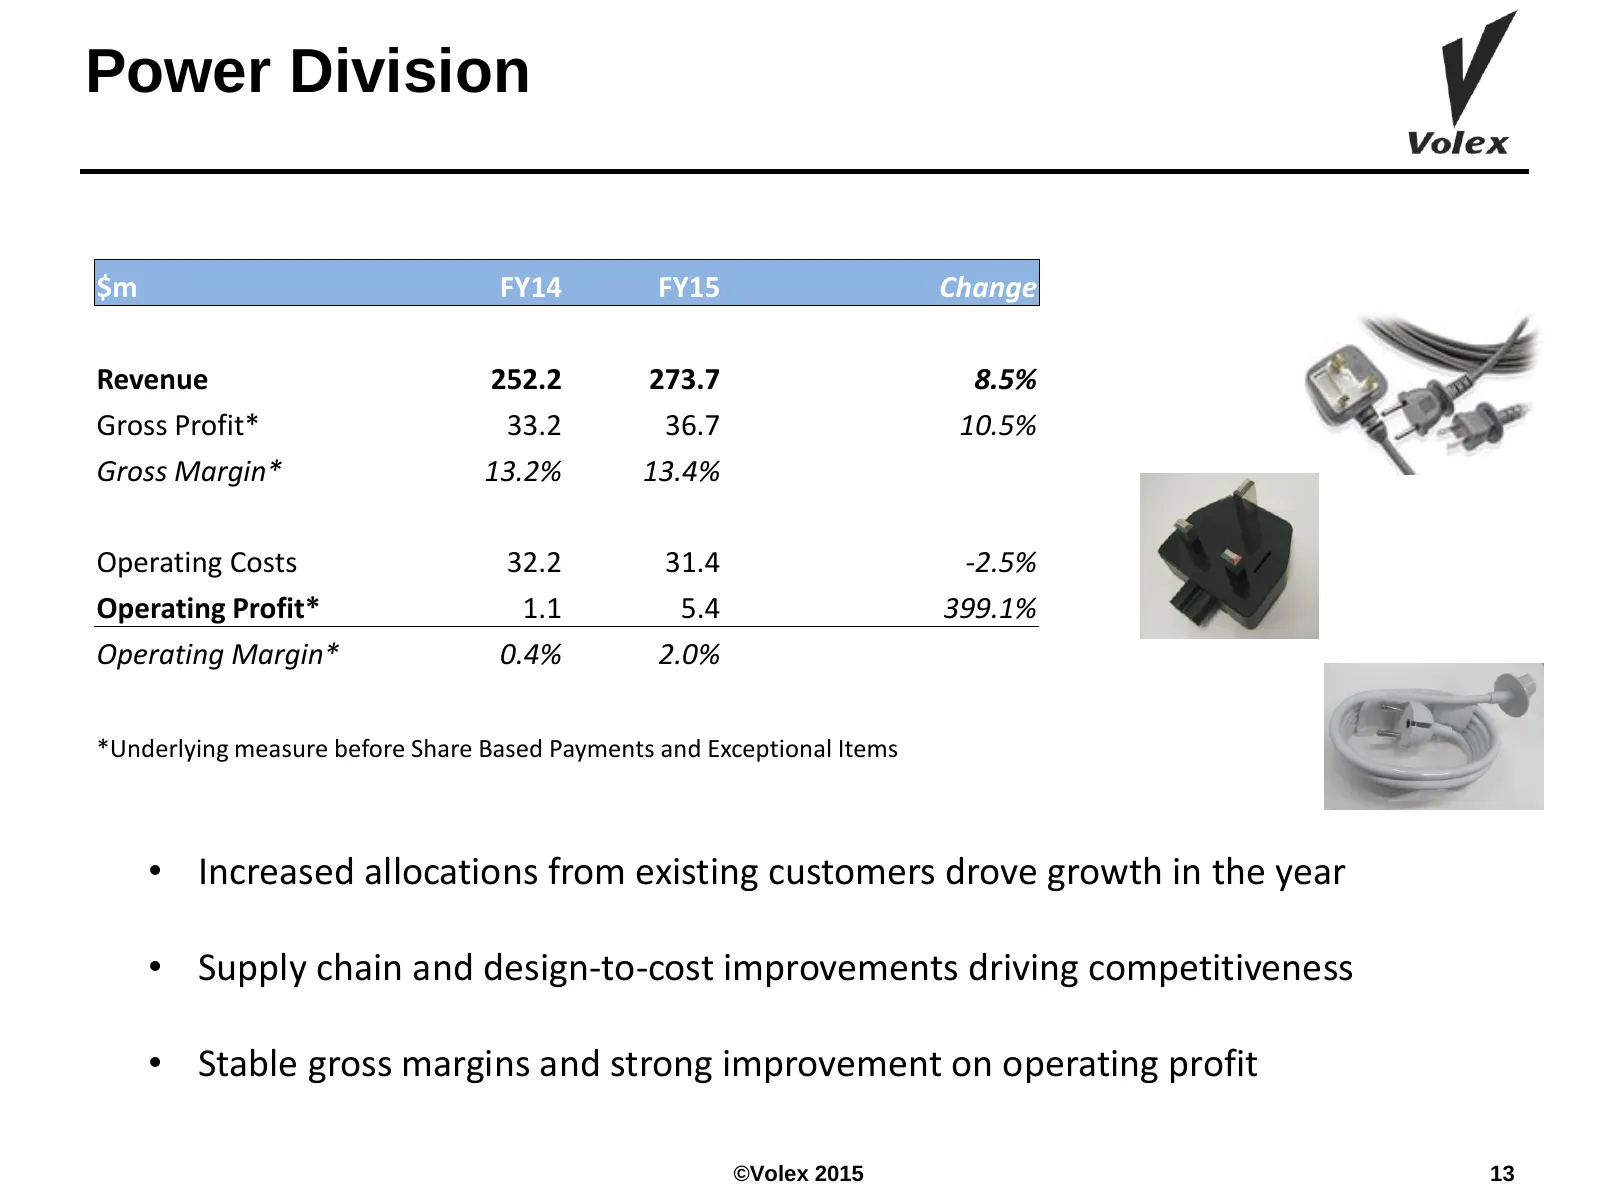
Power Division $m FY14 FY15 Change Revenue 252.2 273.7 8.5% Gross Profit* 33.2 36.7 10.5% Gross Margin* 13.2% 13.4% Operating Costs 32.2 31.4 -2.5% Operating Profit* 1.1 5.4 399.1% Operating Margin* 0.4% 2.0% *Underlying measure before Share Based Payments and Exceptional Items • Increased allocatio
Slide 14: Cash Flow
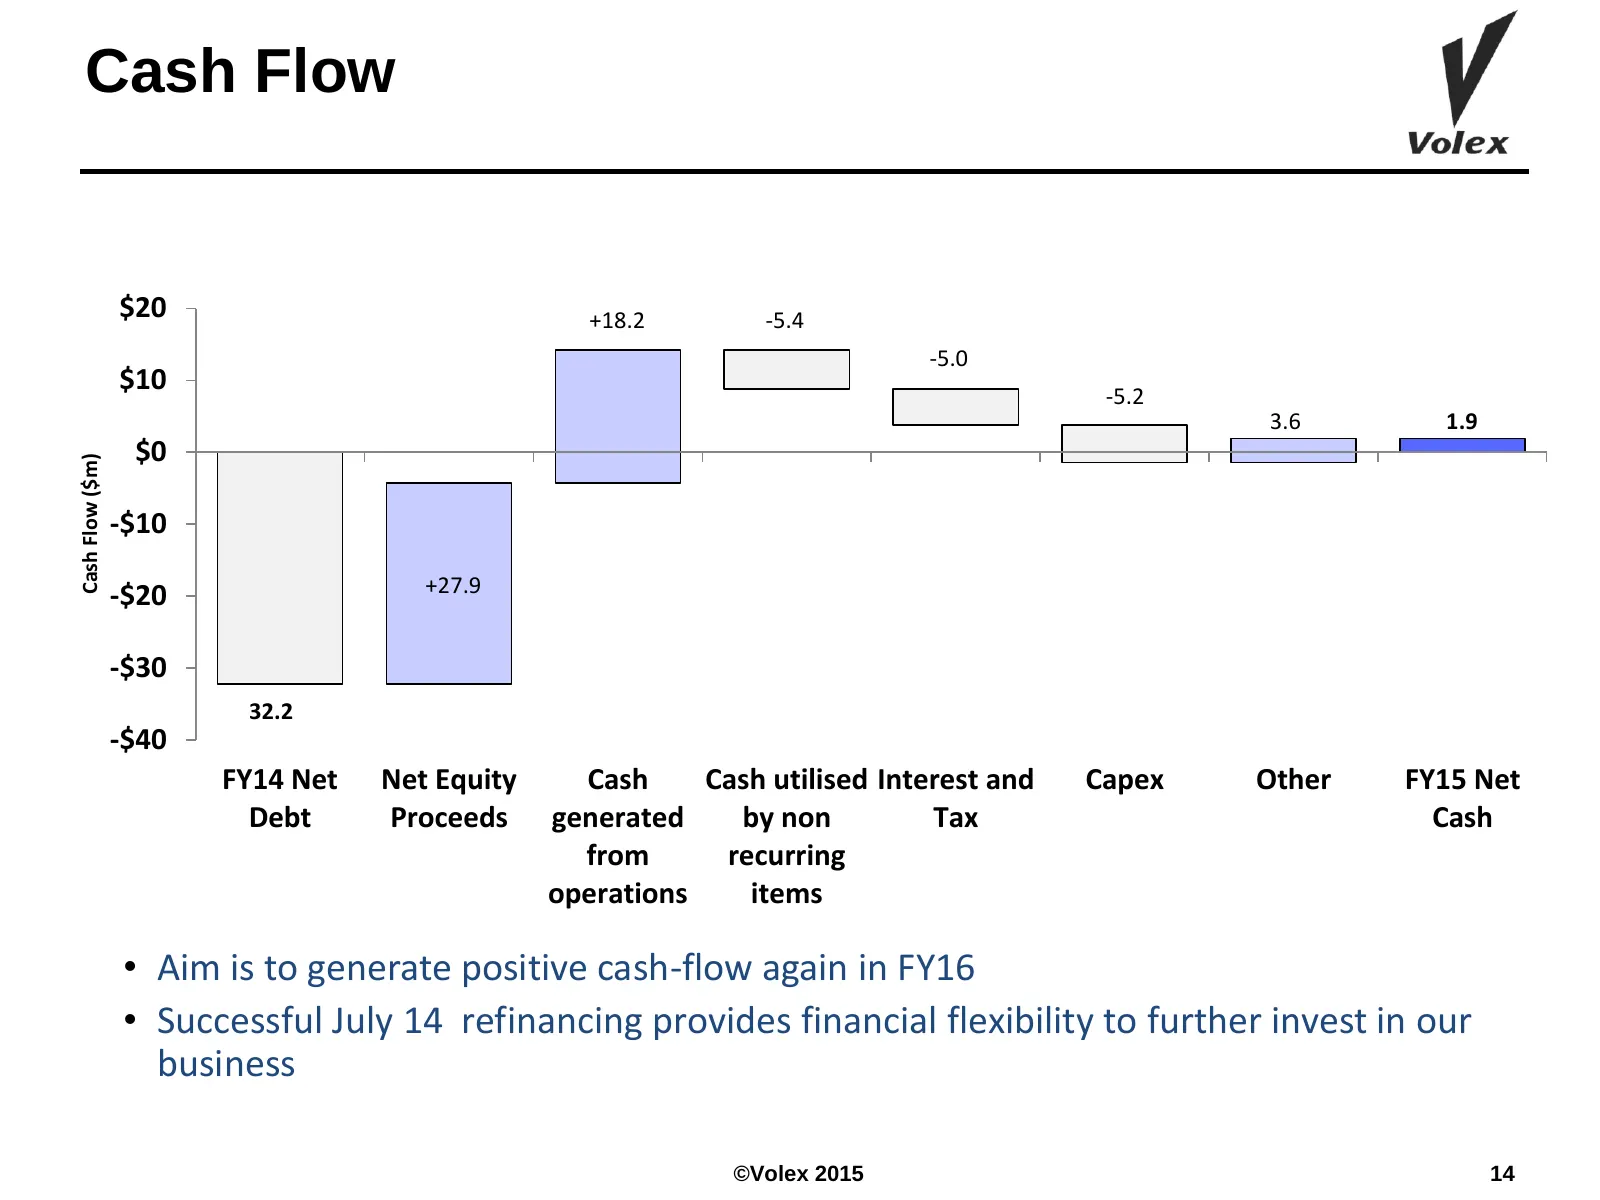
Cash Flow $20 +18.2 -5.4 -5.0 $10 -5.2 3.6 1.9 $0 Cash Flow ($m) 1.9 -$10 -$20 +27.9 -$30 32.2 -$40 FY14 Net Net Equity Cash Cash utilised Interest and Capex Other FY15 Net Debt Proceeds generated by non Tax Cash from recurring operations items • Aim is to generate positive cash-flow again in FY16 •
Slide 15: Balance Sheet
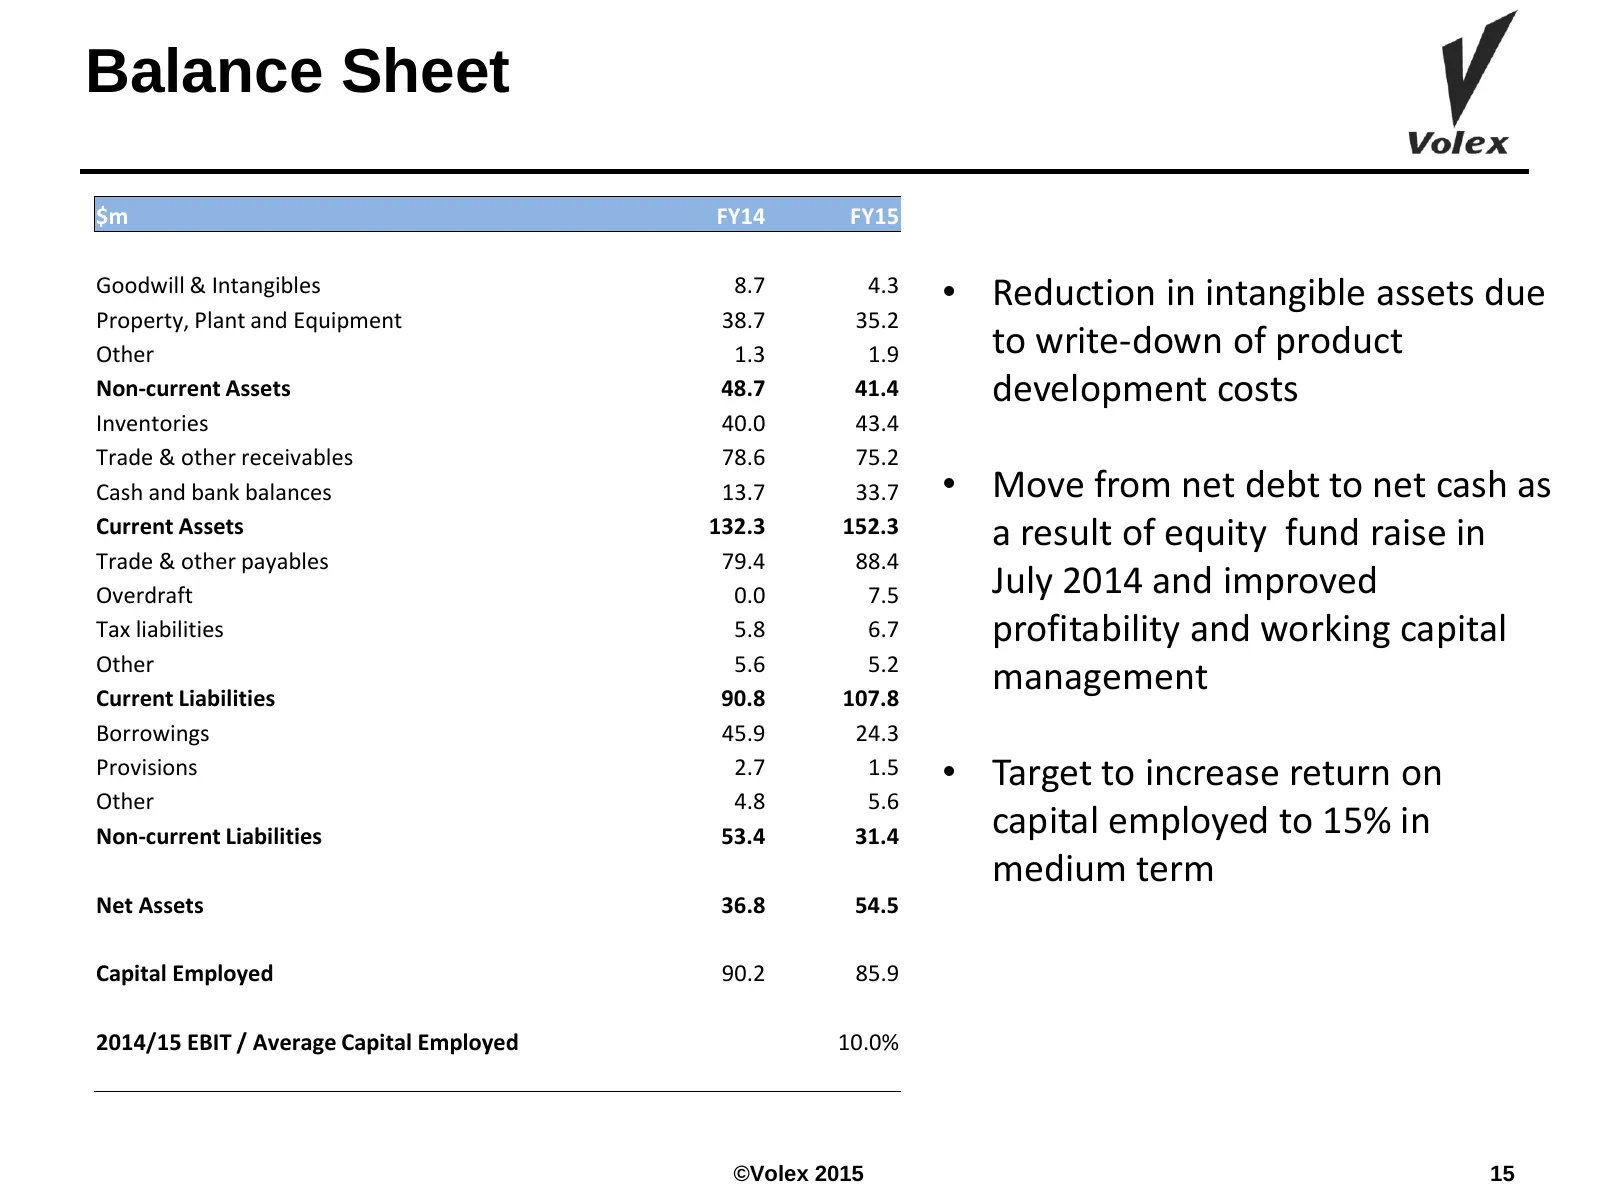
Balance Sheet $m FY14 FY15 Goodwill & Intangibles 8.7 4.3 • Reduction in intangible assets due Property, Plant and Equipment 38.7 35.2 Other 1.3 1.9 to write-down of product Non-current Assets 48.7 41.4 development costs Inventories 40.0 43.4 Trade & other receivables 78.6 75.2 Cash and bank balance
Slide 16: Outlook
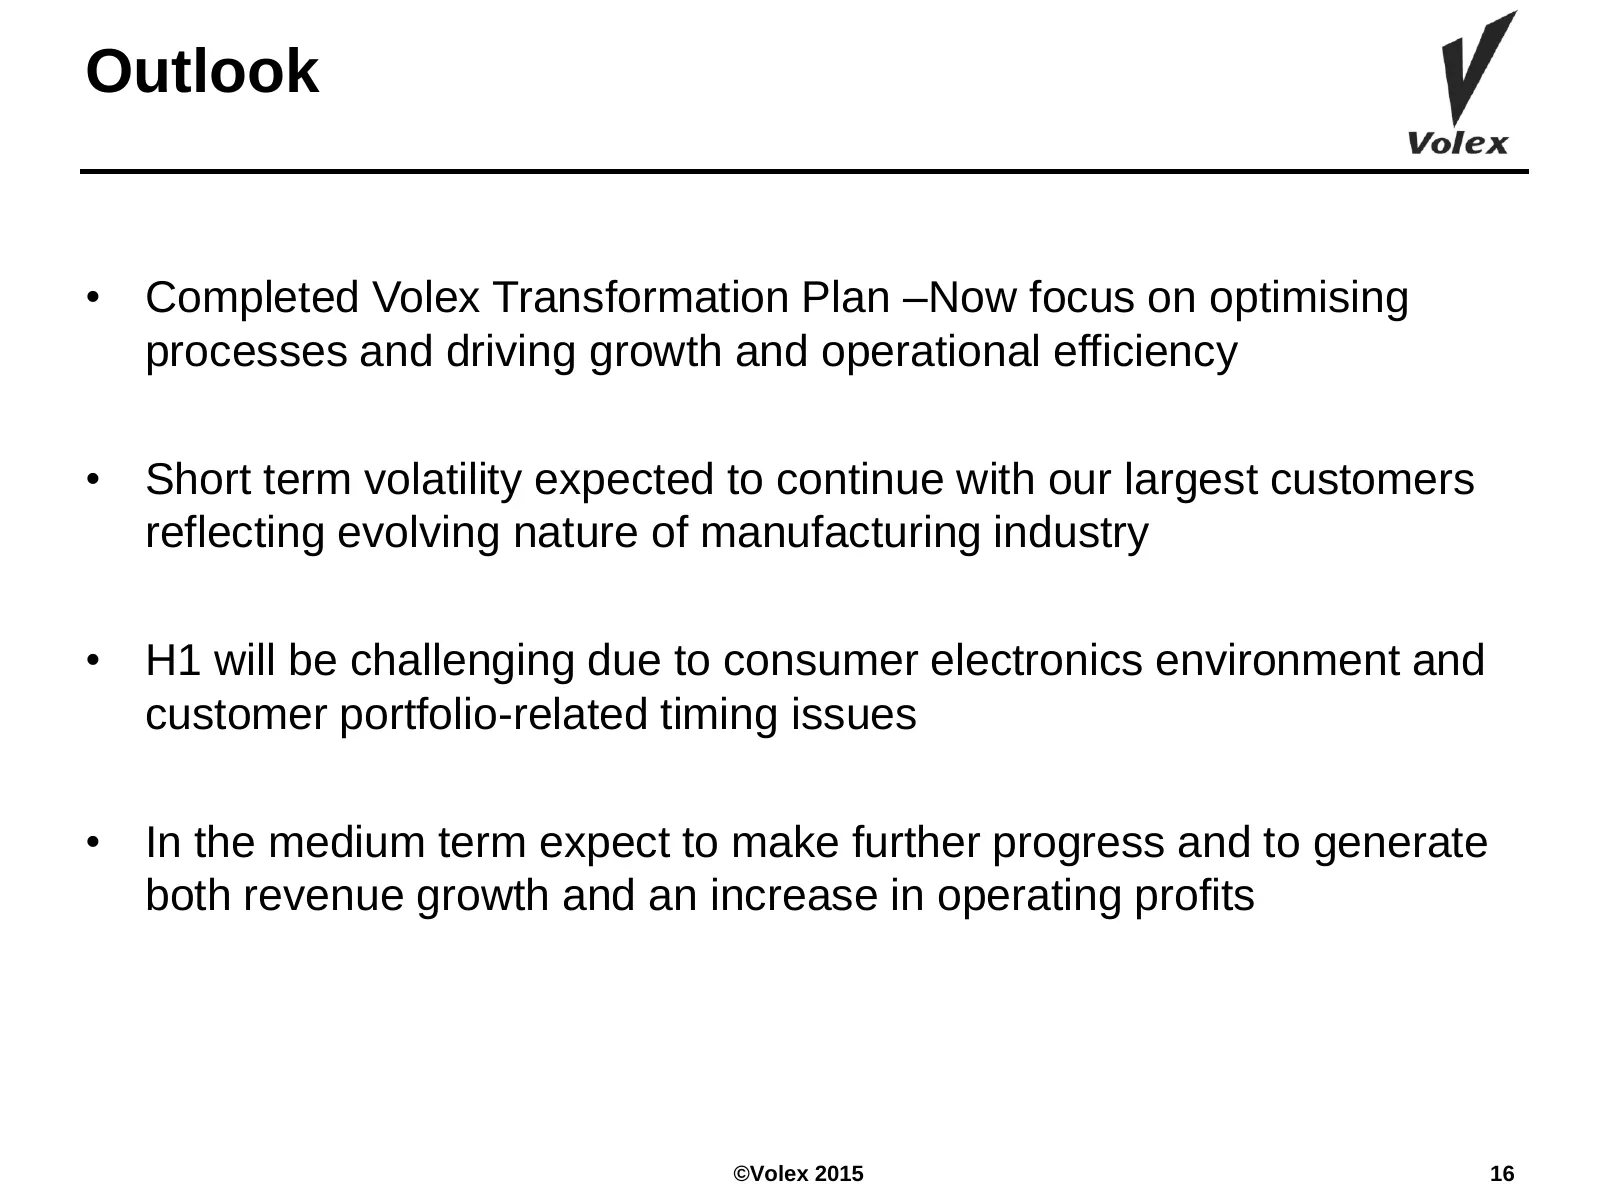
Outlook • Completed Volex Transformation Plan –Now focus on optimising processes and driving growth and operational efficiency • Short term volatility expected to continue with our largest customers reflecting evolving nature of manufacturing industry • H1 will be challenging due to consumer electro
Slide 17: Strategy and Operating Review
Strategy and Operating Review ©Volex 2015 17
Slide 18: Power Division - Summary
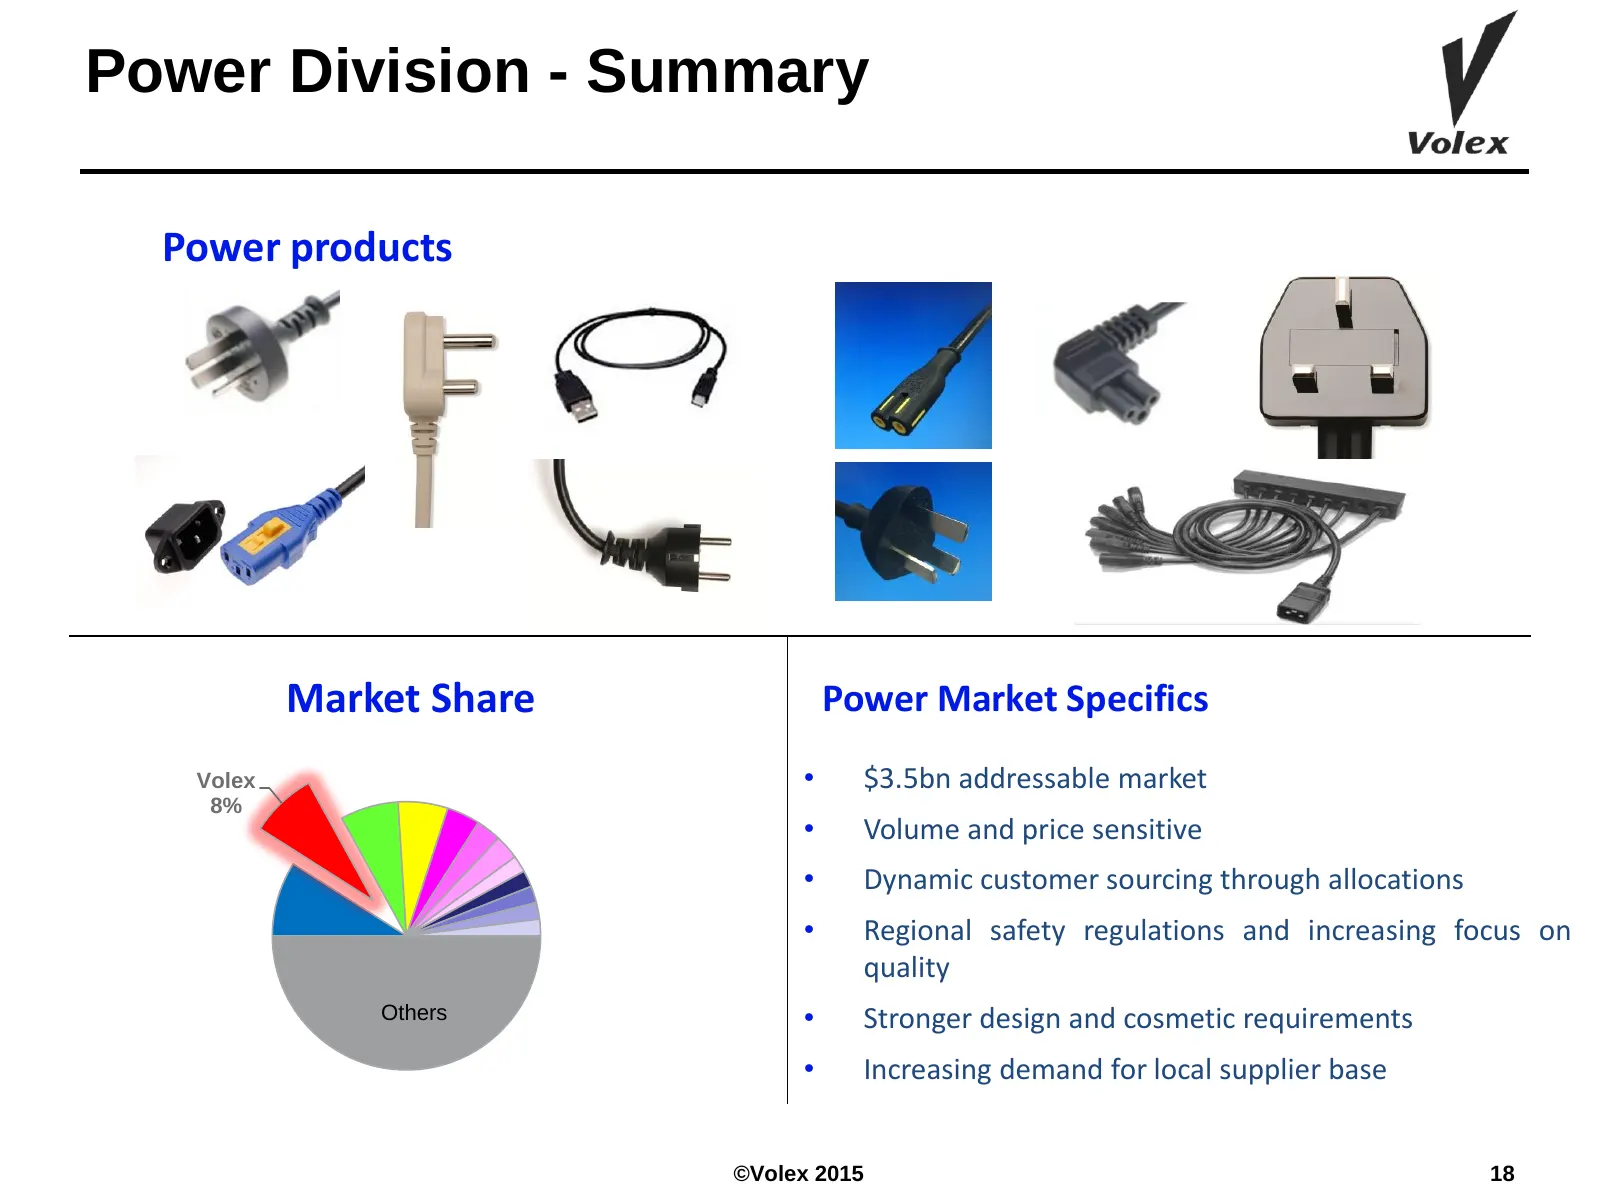
Power Division - Summary Power products Market Share Power Market Specifics Volex • $3.5bn addressable market 8% • Volume and price sensitive • Dynamic customer sourcing through allocations • Regional safety regulations and increasing focus on quality Others • Stronger design and cosmetic requiremen
Slide 19: Power Division – strategy to drive sales
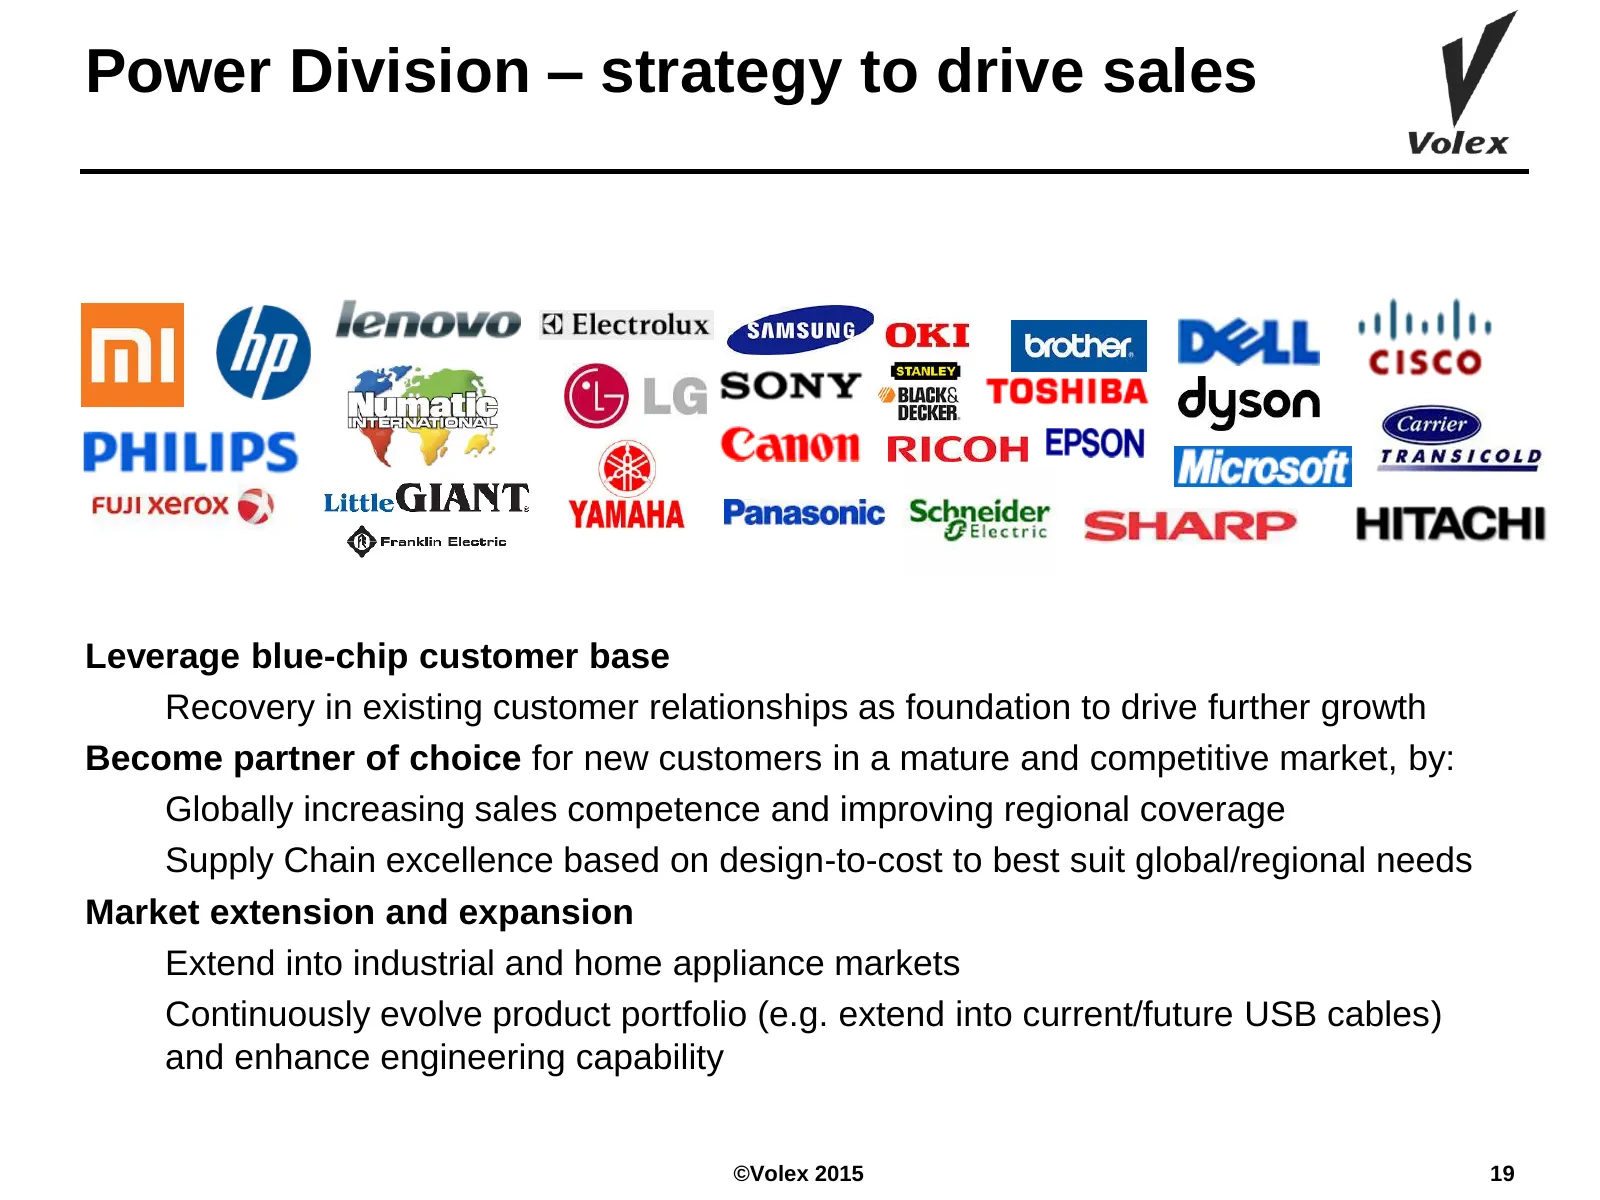
Power Division – strategy to drive sales Leverage blue-chip customer base Recovery in existing customer relationships as foundation to drive further growth Become partner of choice for new customers in a mature and competitive market, by: Globally increasing sales competence and improving regional c
Slide 20: Data Division - Summary
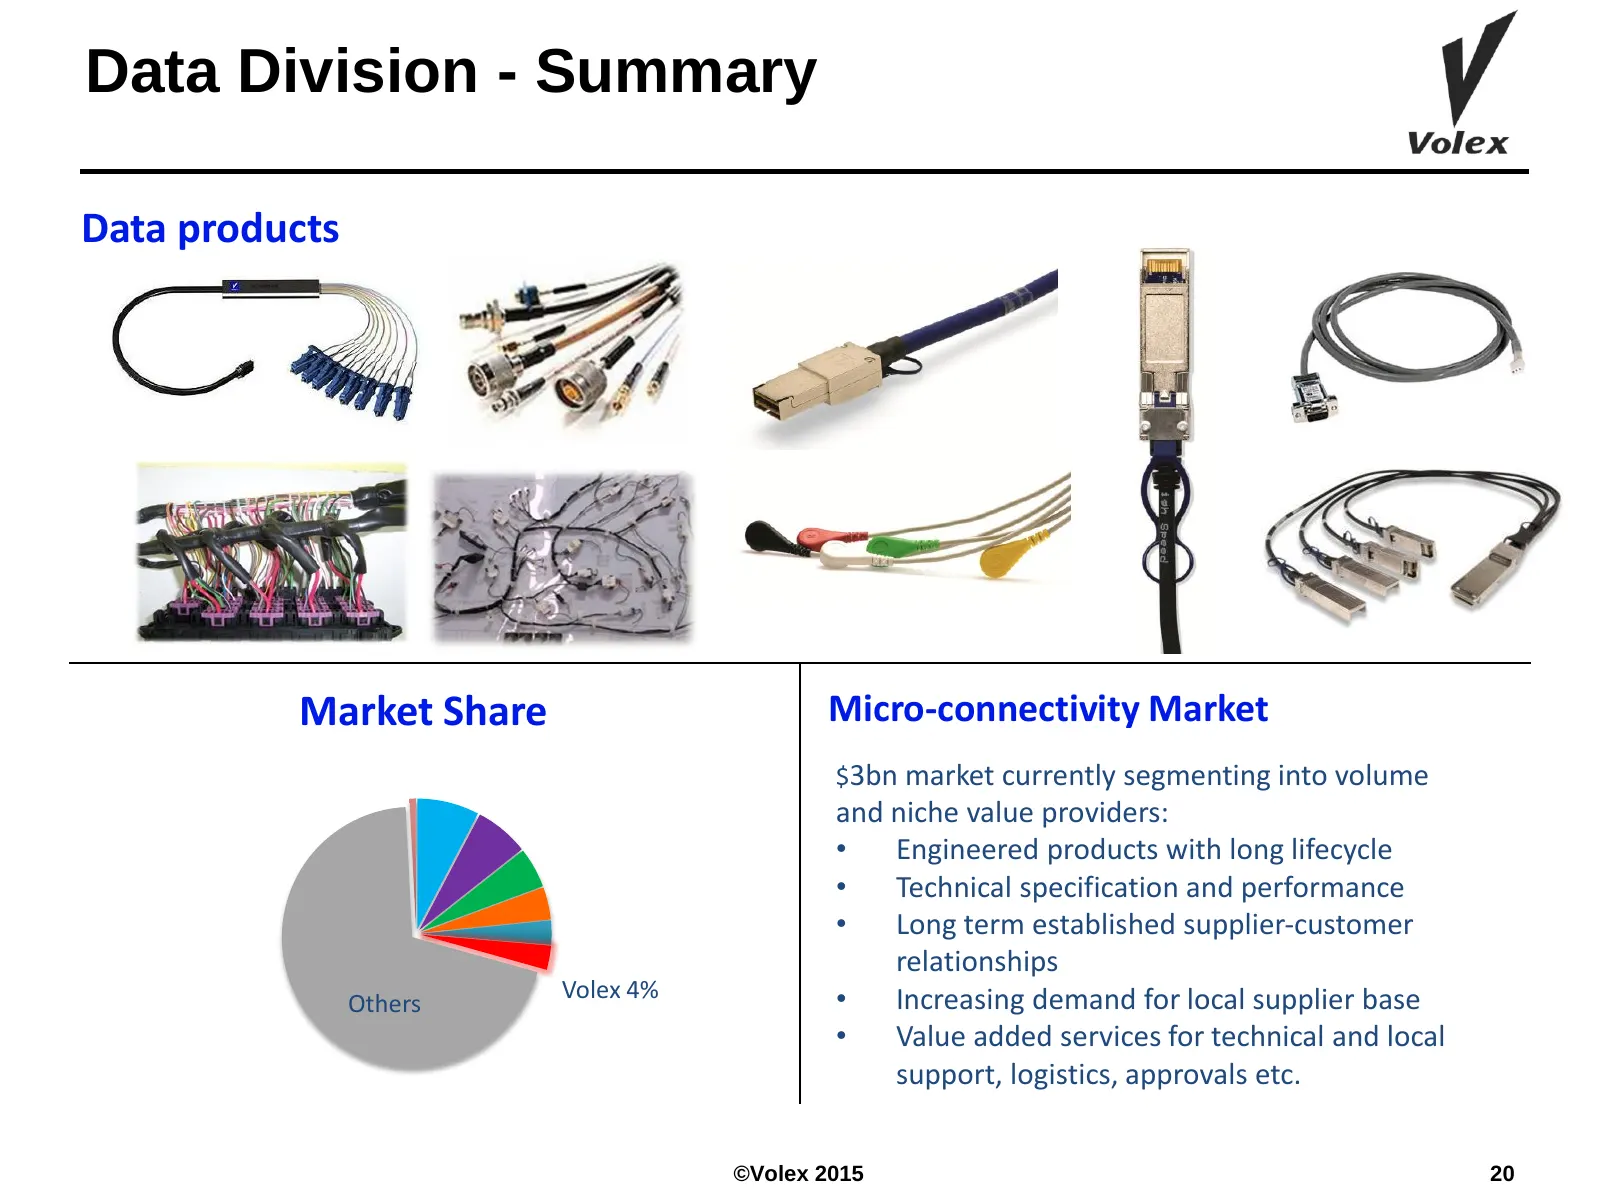
Data Division - Summary Data products Market Share Micro-connectivity Market $3bn market currently segmenting into volume and niche value providers: • Engineered products with long lifecycle • Technical specification and performance • Long term established supplier-customer relationships Volex 4% •
Slide 21: Data Division – shaping the future
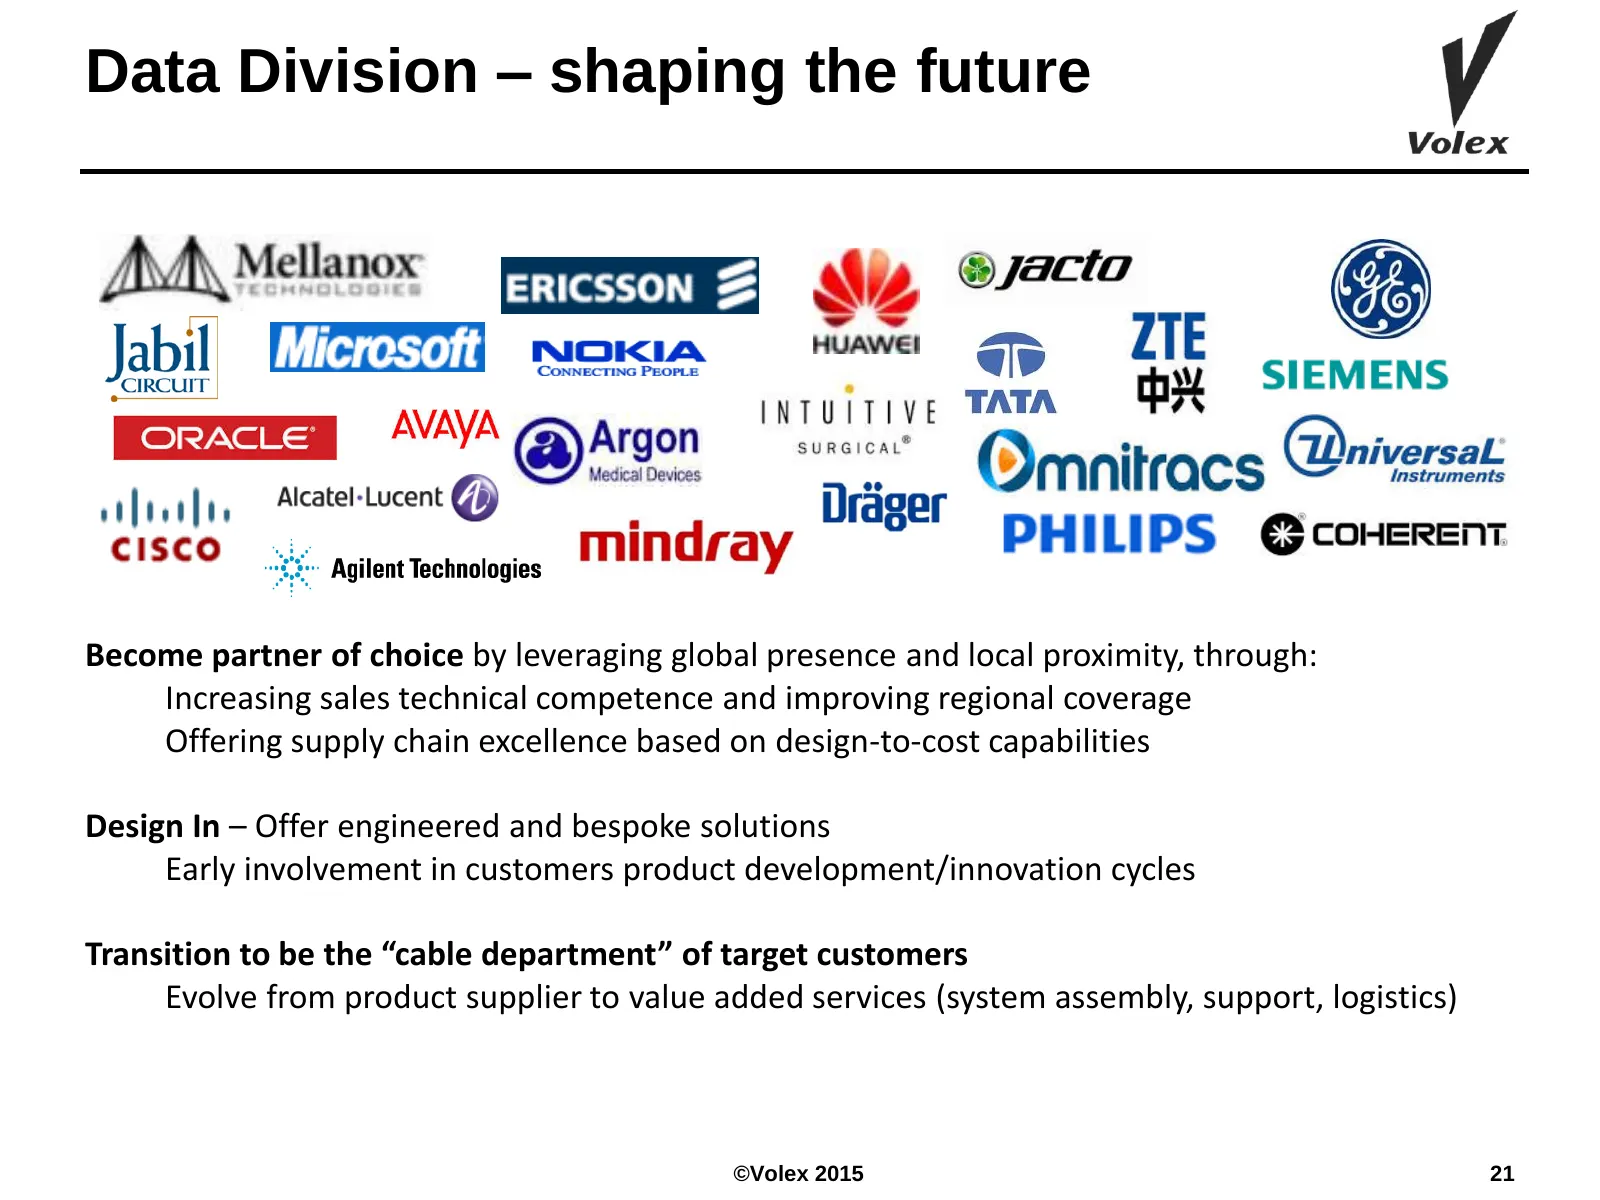
Data Division – shaping the future Become partner of choice by leveraging global presence and local proximity, through: Increasing sales technical competence and improving regional coverage Offering supply chain excellence based on design-to-cost capabilities Design In – Offer engineered and bespoke
Slide 22: Strategy – increasing revenue and profits
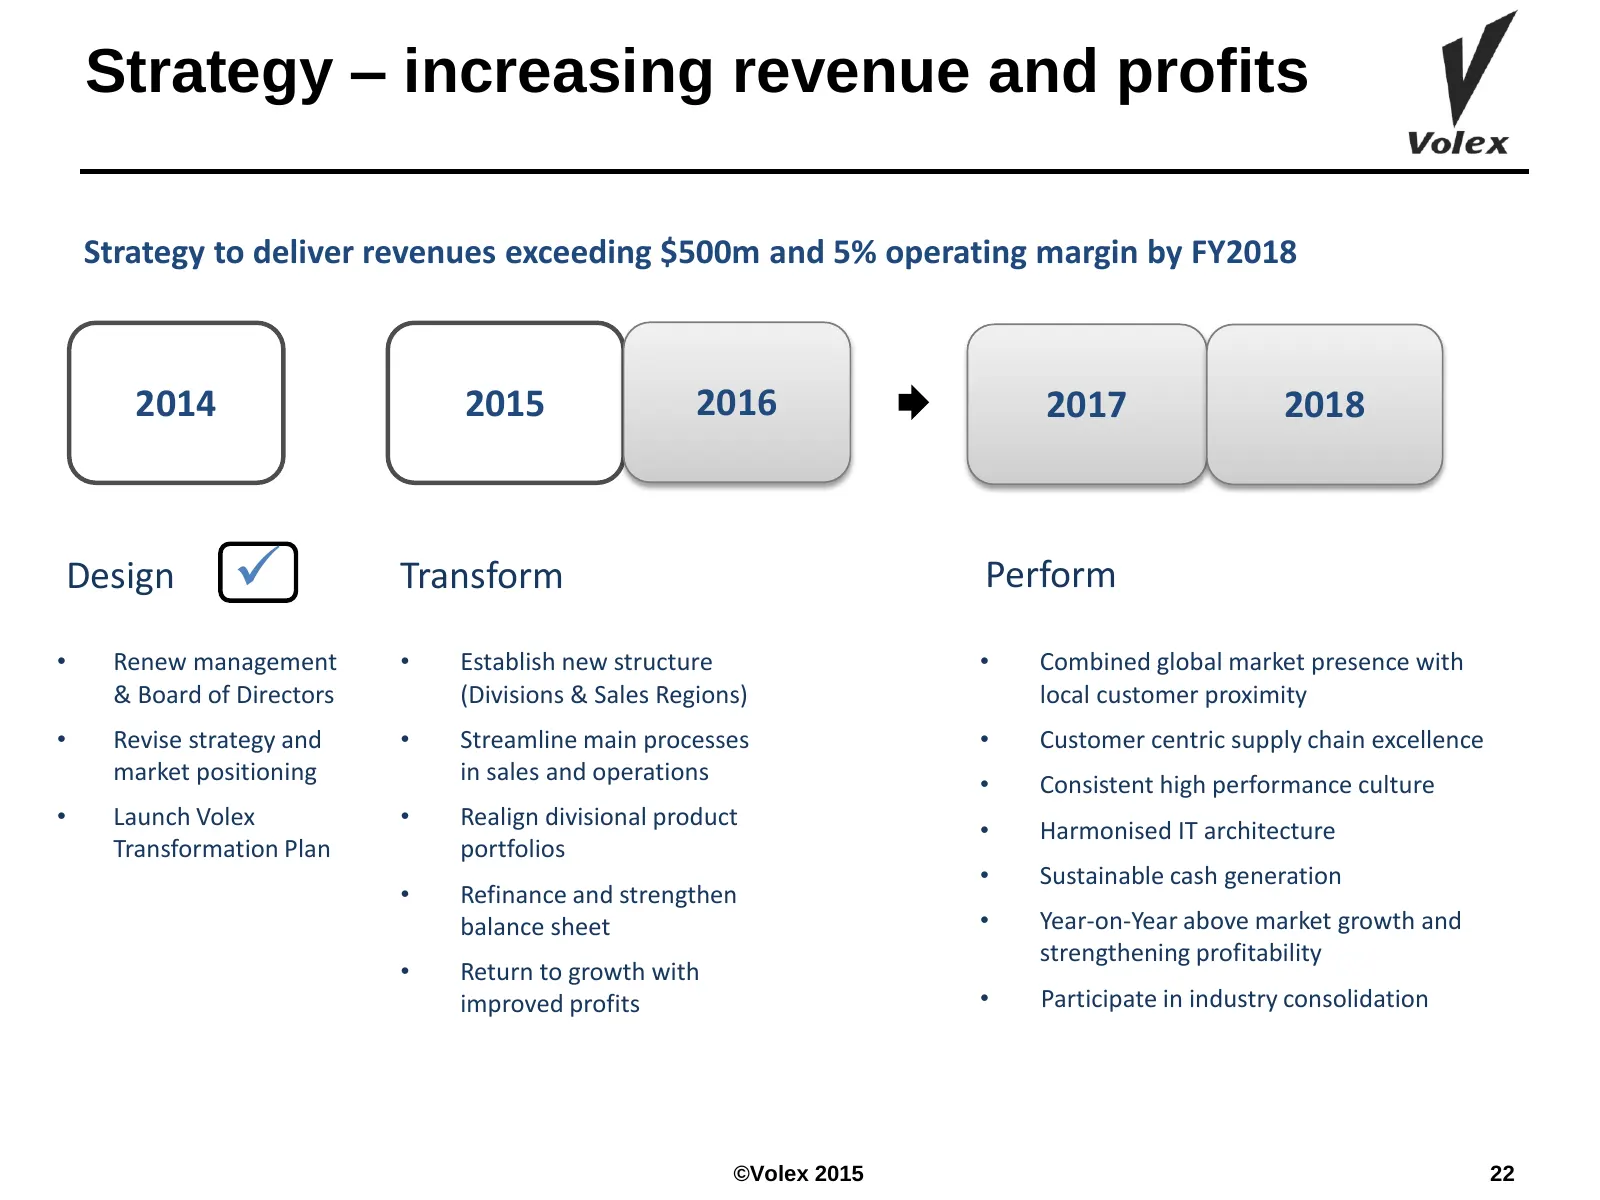
Strategy – increasing revenue and profits Strategy to deliver revenues exceeding $500m and 5% operating margin by FY2018 2014 2015 2016 2017 2018 Design Transform Perform • Renew management • Establish new structure • Combined global market presence with & Board of Directors (Divisions & Sales Reg
Slide 23: Strategic Priorities to FY18
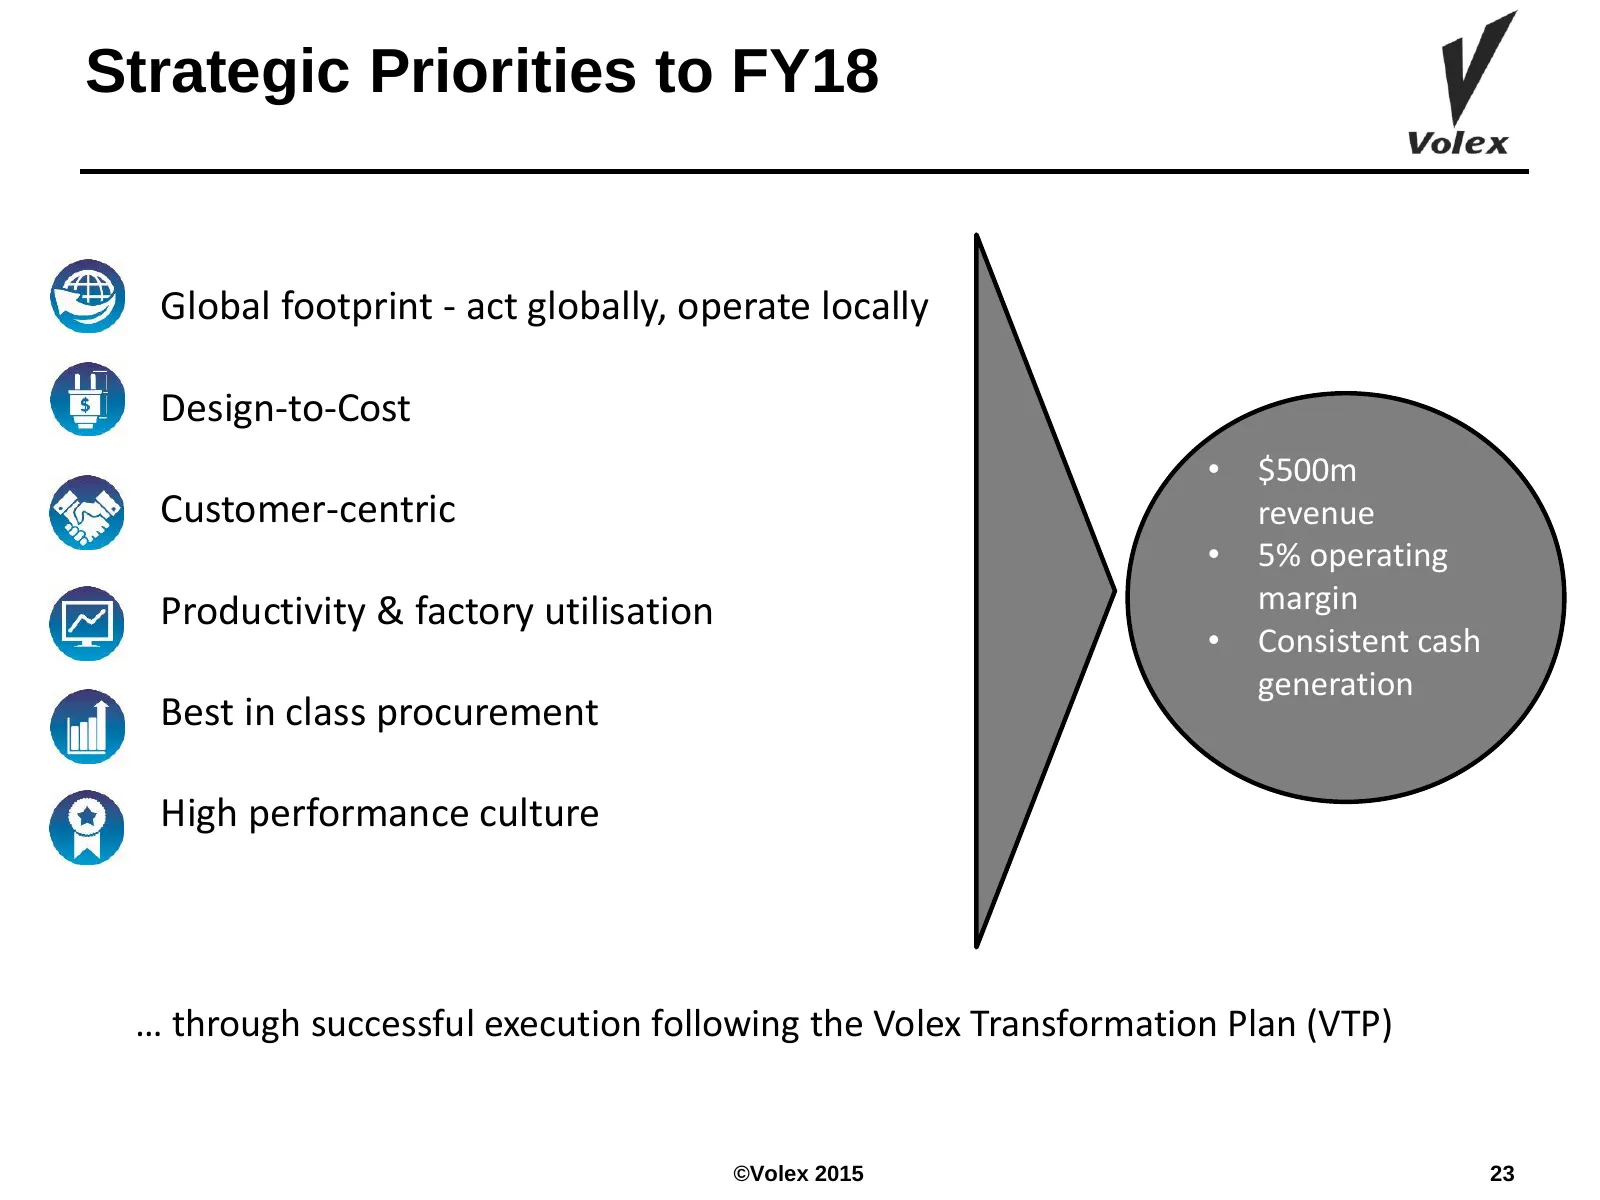
Strategic Priorities to FY18 Global footprint - act globally, operate locally Design-to-Cost • $500m Customer-centric revenue • 5% operating Productivity & factory utilisation margin • Consistent cash generation Best in class procurement High performance culture … through successful execution follow
Source: company website
More decks from Volex plc
 H1 FY2027 Earnings Presentation29 slides · Nov 12, 2026
 FY2026 Earnings Presentation34 slides · June 2026
 Investor Day (April 2026)67 slides · April 2026
 H1 FY2026 Earnings Presentation29 slides · Nov 12, 2025
 FY2025 Earnings Presentation38 slides · Jun 26, 2025
 H1 2025 Earnings Presentation26 slides · Nov 15, 2024