Novelis — Shareholder Meeting (October 2006)
24 slides from Novelis's shareholder meeting presentation, Oct 27, 2006
Slide 1: Business Overview
nl Novelis Business Overview William T. Monahan, Chairman and Interim CEO Annual Meeting of Shareholders, Oct. 26, 2006 This presentation is available on our web site at www.novelis.com
Slide 2: Safe Harbor Statement
Wyn Safe Harbor Statement sill ‘Statements made in this presentation which describe Novelis’inlentions, expectations, bebefs or predictons may be forward-ooking statements with the meaning of secures laws. Fonvardlookng statements may include siatements preceded by, followed by, or including the wor
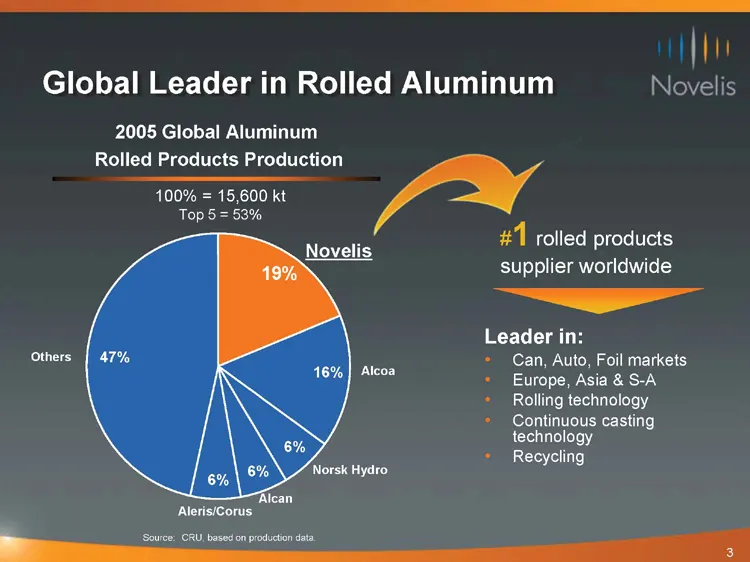
Slide 3: Global Leader in Rolled Aluminum
iy | {i Global Leader in Rolled Aluminum Novelis 2005 Global Aluminum Rolled Products Production 100% = 15,600 kt Top 5 = 53% #1 rolled products supplier worldwide a Leader in: Can, Auto, Foil markets Europe, Asia & S-A Rolling technology Continuous casting technology » Recycling Novelis Others ce:
Slide 4: Internal and External Challenges
Internal and External Challenges Novelis ° Extraordinary run-up in metal prices — Tested the business model — Required new hedging approach ° Debt structure ~— Assumed lower metal prices » Accounting review ~ Delayed financial filings EN — ————— re
Slide 5: Strengthening the Organization
AYU Strengthening the Organization Novelis ° Enhanced finance team — CFO, Rick Dobson — Controller, Bob Patterson ° Expanded and strengthened Board of Directors ~— Chairman, Bill Monahan — New Directors: * Kevin Twomey * Edward Blechschmidt » John Watson EN — ————— ee
Slide 6: Enhancing our Competitiveness
{hu Enhancing our Competitiveness Novelis Employees worldwide are strengthening our competitiveness and setting the stage for creation of shareholder value by: * Improving our operational efficiency * Strengthening our service to customers * Enhancing our product portfolio * Generating cash to de-le
Slide 7: Restructuring
AYU Restructuring Novelis Restructuring of manufacturing operations is a top priority. Since the spin-off we have: * Closed plants in U.K., Belgium, Italy * Sold operation in France » Reorganized two facilities in Germany * Streamlining European central management and R&D » Reviewing strategic alter
Slide 8: Improving Operational Efficiency
Ayn Improving Operational Efficiency Novelis Lean Six Sigma will contribute over $30 million to free cash flow in 2006 through working capital initiatives alone: * NA. consolidated ingot specifications, leading to decreased finished goods inventory » Europe decreased customer lead times, improved de
Slide 9: De-leveraging the Capital Structure
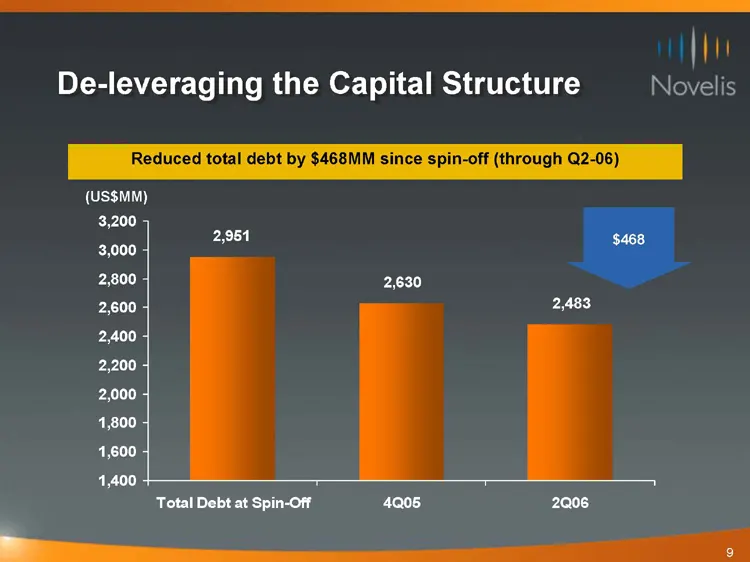
II! De-leveraging the Capital Structure Novelis Reduced total debt by $468MM since spin-off (through Q2-06) (ussMM) 3,200 3,000 2,800 2,630 2,600 2,483 2,400 2,200 2,000 1,800 1,600 1,400 + 4005 Total Debt at Spin-Off 2Q06 2,951 $468
Slide 10: Enhancing Our Position in Asia
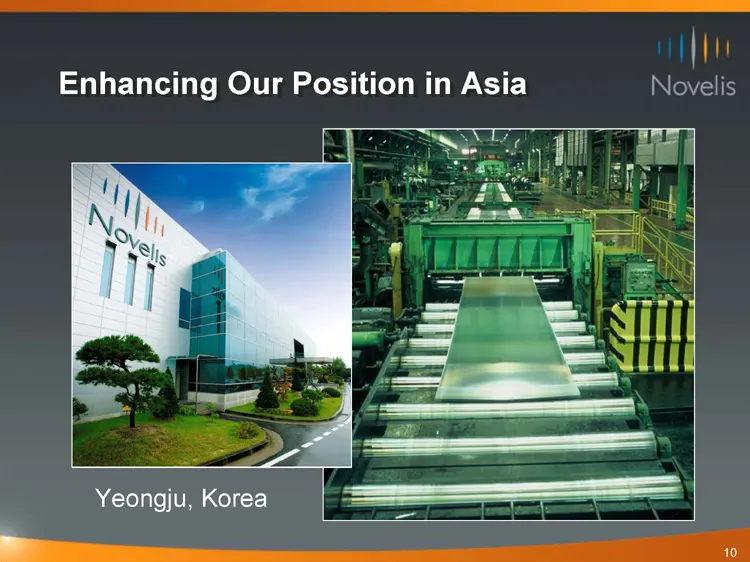
fin Enhancing Our Position in Asia Novelis
Slide 11: Focus on Innovation
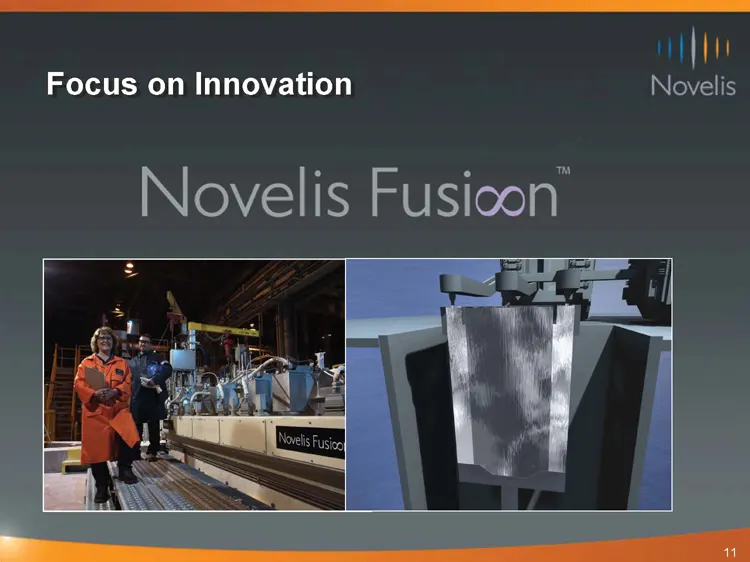
Focus on Innovation Novelis Novelis Fusioon”
Slide 12: Jaguar XK
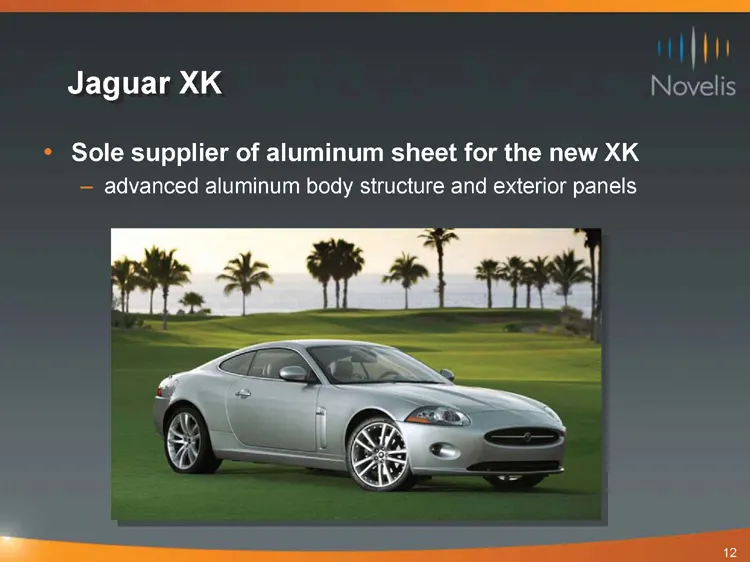
i] | {i Jaguar XK Novelis ° Sole supplier of aluminum sheet for the new XK — advanced aluminum body structure and exterior panels
Slide 13: Audi Q7
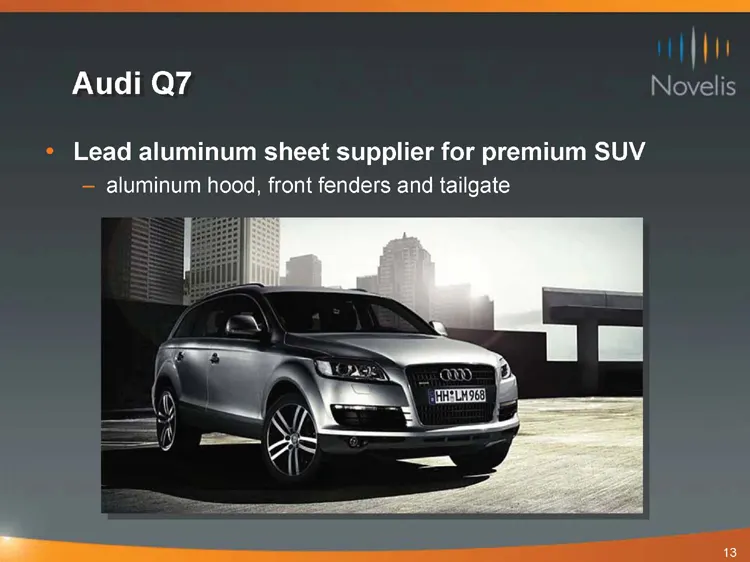
vi[i Audi Q7 Novelis » Lead aluminum sheet supplier for premium SUV — aluminum hood, front fenders and tailgate
Slide 14: 2005 Financial Highlights
AYU 2005 Financial Highlights Novelis ° Net sales up 8% to $8.4 billion ° RP shipments up over 3% to 2.87 million tonnes ° Net income $90 MM compared with $55 MM ° EPS $1.21 compared with $0.74
Slide 15: 2006 First Half Highlights
AYU 2006 First Half Highlights Novelis * Total rolled product shipments increased 3.5% to 1.49 million tonnes ° Strong cash flows enable $147 MM debt reduction for six months; total reduction of over $450 MM « Expect full-year loss before taxes of $240-$285 MM ° All-time best performance in health a
Slide 16: 2007 Outlook
a 2007 Outlook Novelis e Anticipate return to positive earnings before taxes * Elimination of half the metal price ceiling exposure « Expect increased RP shipments and cost reductions * Total free cash flow expected between $150-$200 MM * Cash flow and debt reduction primary areas of focus Free Cash
Slide 17: Long-term Targets
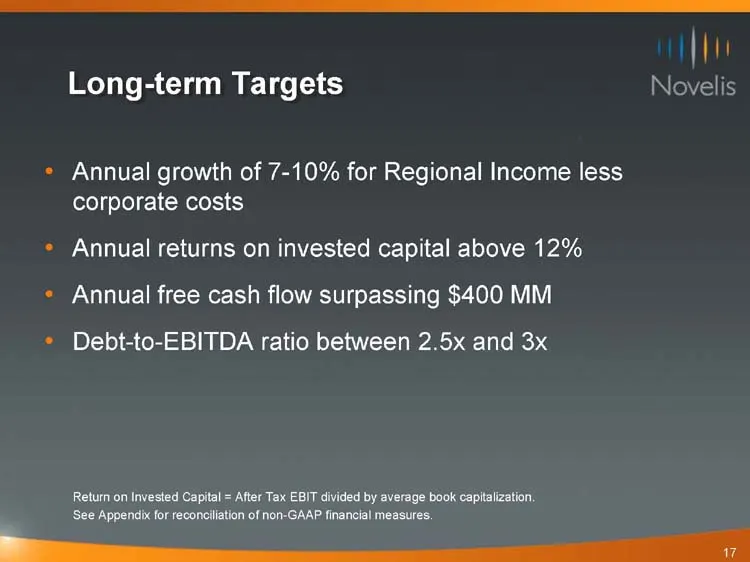
a Long-term Targets Novelis * Annual growth of 7-10% for Regional Income less corporate costs ° Annual returns on invested capital above 12% ° Annual free cash flow surpassing $400 MM * Debt-to-EBITDA ratio between 2.5x and 3x Return on Invested Capital = After Tax EBIT divided by average book capit
Slide 18: Concluding Remarks
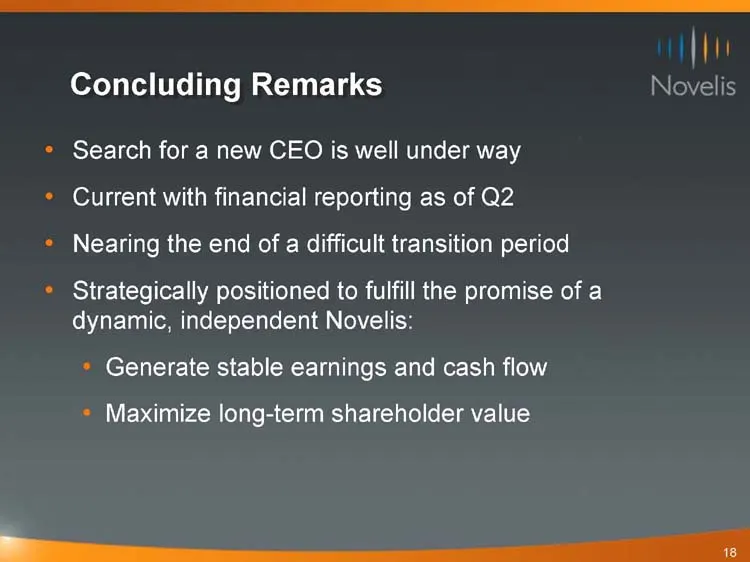
Concluding Remarks ° Search for a new CEO is well under way ° Current with financial reporting as of Q2 ° Nearing the end of a difficult transition period ° Strategically positioned to fulfill the promise of a dynamic, independent Novelis: » Generate stable earnings and cash flow » Maximize long-ter
Slide 19: Appendix
[ih Novelis
Slide 20: Appendix
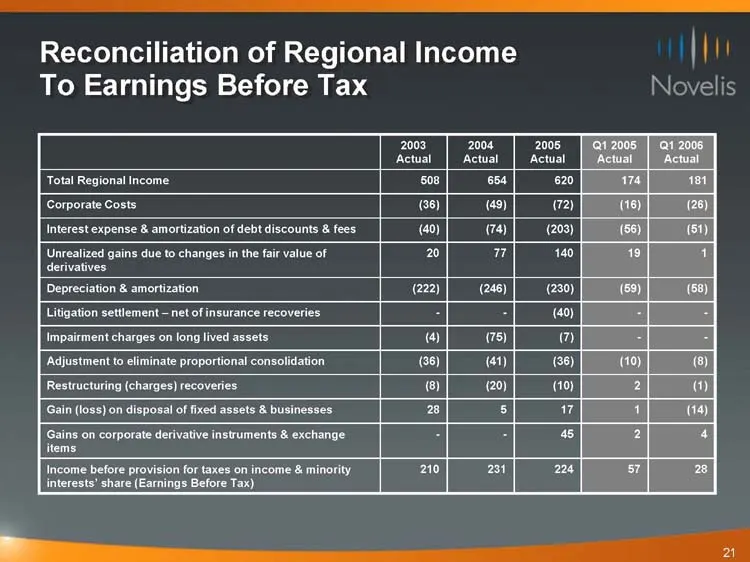
Slide 21: Reconciliation of Regional Income
Reconciliation of Regional Income To Earnings Before Tax 72003 2008 2005 | ai2005 | ai 2006 Actual | Actual | Actual | Actual | Actual Total Regional Income 608 654 620 174 181 Corporate Costs 65) (49) (72) (16) (26) Interest expense & amortization of debt discounts & fees (40) (74) | _ (203) (56) (
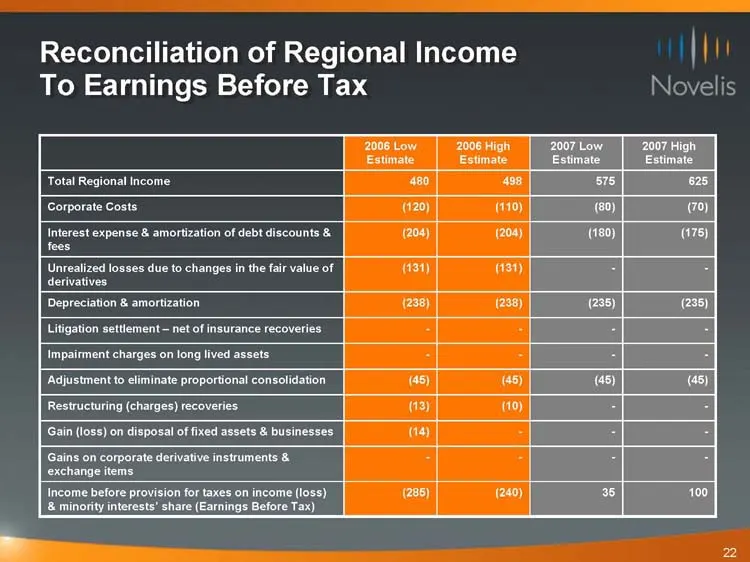
Slide 22: Reconciliation of Regional Income
Reconciliation of Regional Income To Earnings Before Tax 2006Low | 2006High | 2007Low | 2007 High Estimate Estimate Estimate Estimate Total Regional income 480 438 575 625 Corporate Costs ro) (110) (60) a) Interest expense & amortization of debt discounts & (204) (208) (180) (175) fees Unrealized lo
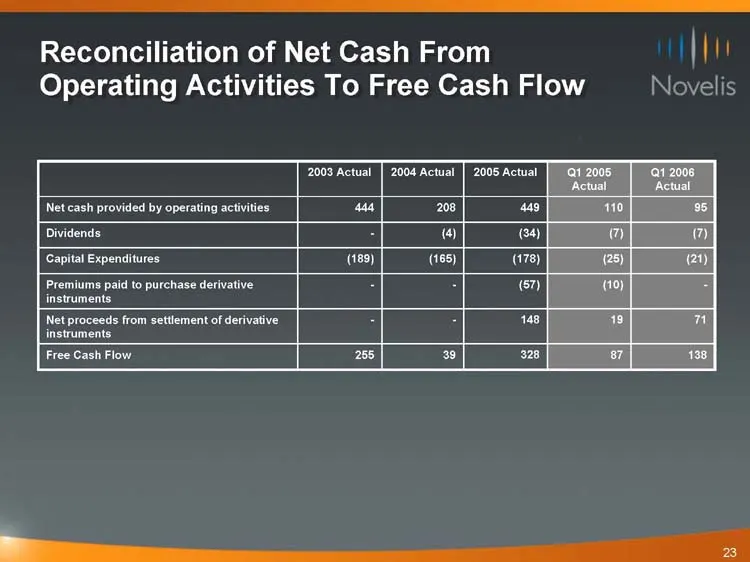
Slide 23: Reconciliation of Net Cash From Operating Activities To Free Cash Flow
Reconciliation of Net Cash From Operating Activities To Free Cash Flow Novel 2003 Actual | 2004 Actual | 2005 Actual [juuGH2008 uy] yan 2008 Actual ‘Actual Net cash provided by operating activities 4 208 449 110 a Dividends @ 4) a @ Capital Expenditures (189) (165) (178) (25) (21) Premiums paid to p
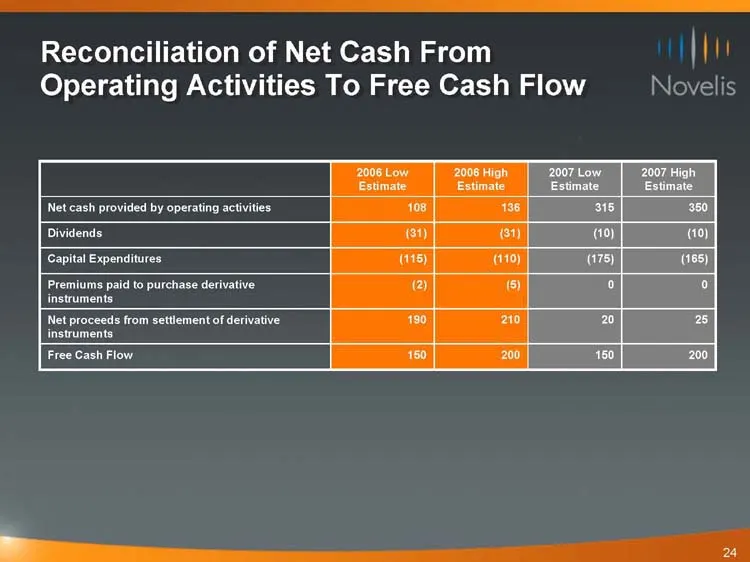
Slide 24: Business Overview (duplicate text version)
[LOGO OF NOVELIS] Business Overview William T. Monahan, Chairman and Interim CEO Annual Meeting of Shareholders, Oct. 26, 2006 [GRAPHIC APPEARS HERE] This presentation is available on our web site at www.novelis.com Safe Harbor Statement [LOGO OF NOVELIS] Statements made in this presentation which d
Source: SEC EDGAR · 8-K filed Oct 27, 2006
More decks from Novelis Inc.
 Q2 FY2027 Earnings Presentation20 slides · Nov 5, 2026
 Q2 FY2027 Earnings Presentation31 slides · Nov 5, 2026
 Q1 FY2027 Earnings Presentation21 slides · Aug 5, 2026
 Q1 FY2027 Earnings Presentation31 slides · Aug 5, 2026
 Q4 FY2026 Earnings Presentation33 slides · May 19, 2026
 Q3 FY2026 Earnings Presentation33 slides · Feb 11, 2026