Endeavour International — Credit Suisse High Yield Conference 2012
26 slides from Endeavour International's conference presentation, Oct 5, 2012
Slide 1: Credit Suisse High Yield Conference
Exhibit 99.1 Credit Suisse High Yield Conference October 4 - 5, 2012
Slide 2: Forward-looking statements and SEC reserves cautionary note
This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and potenti
Slide 3: Endeavour At A Glance
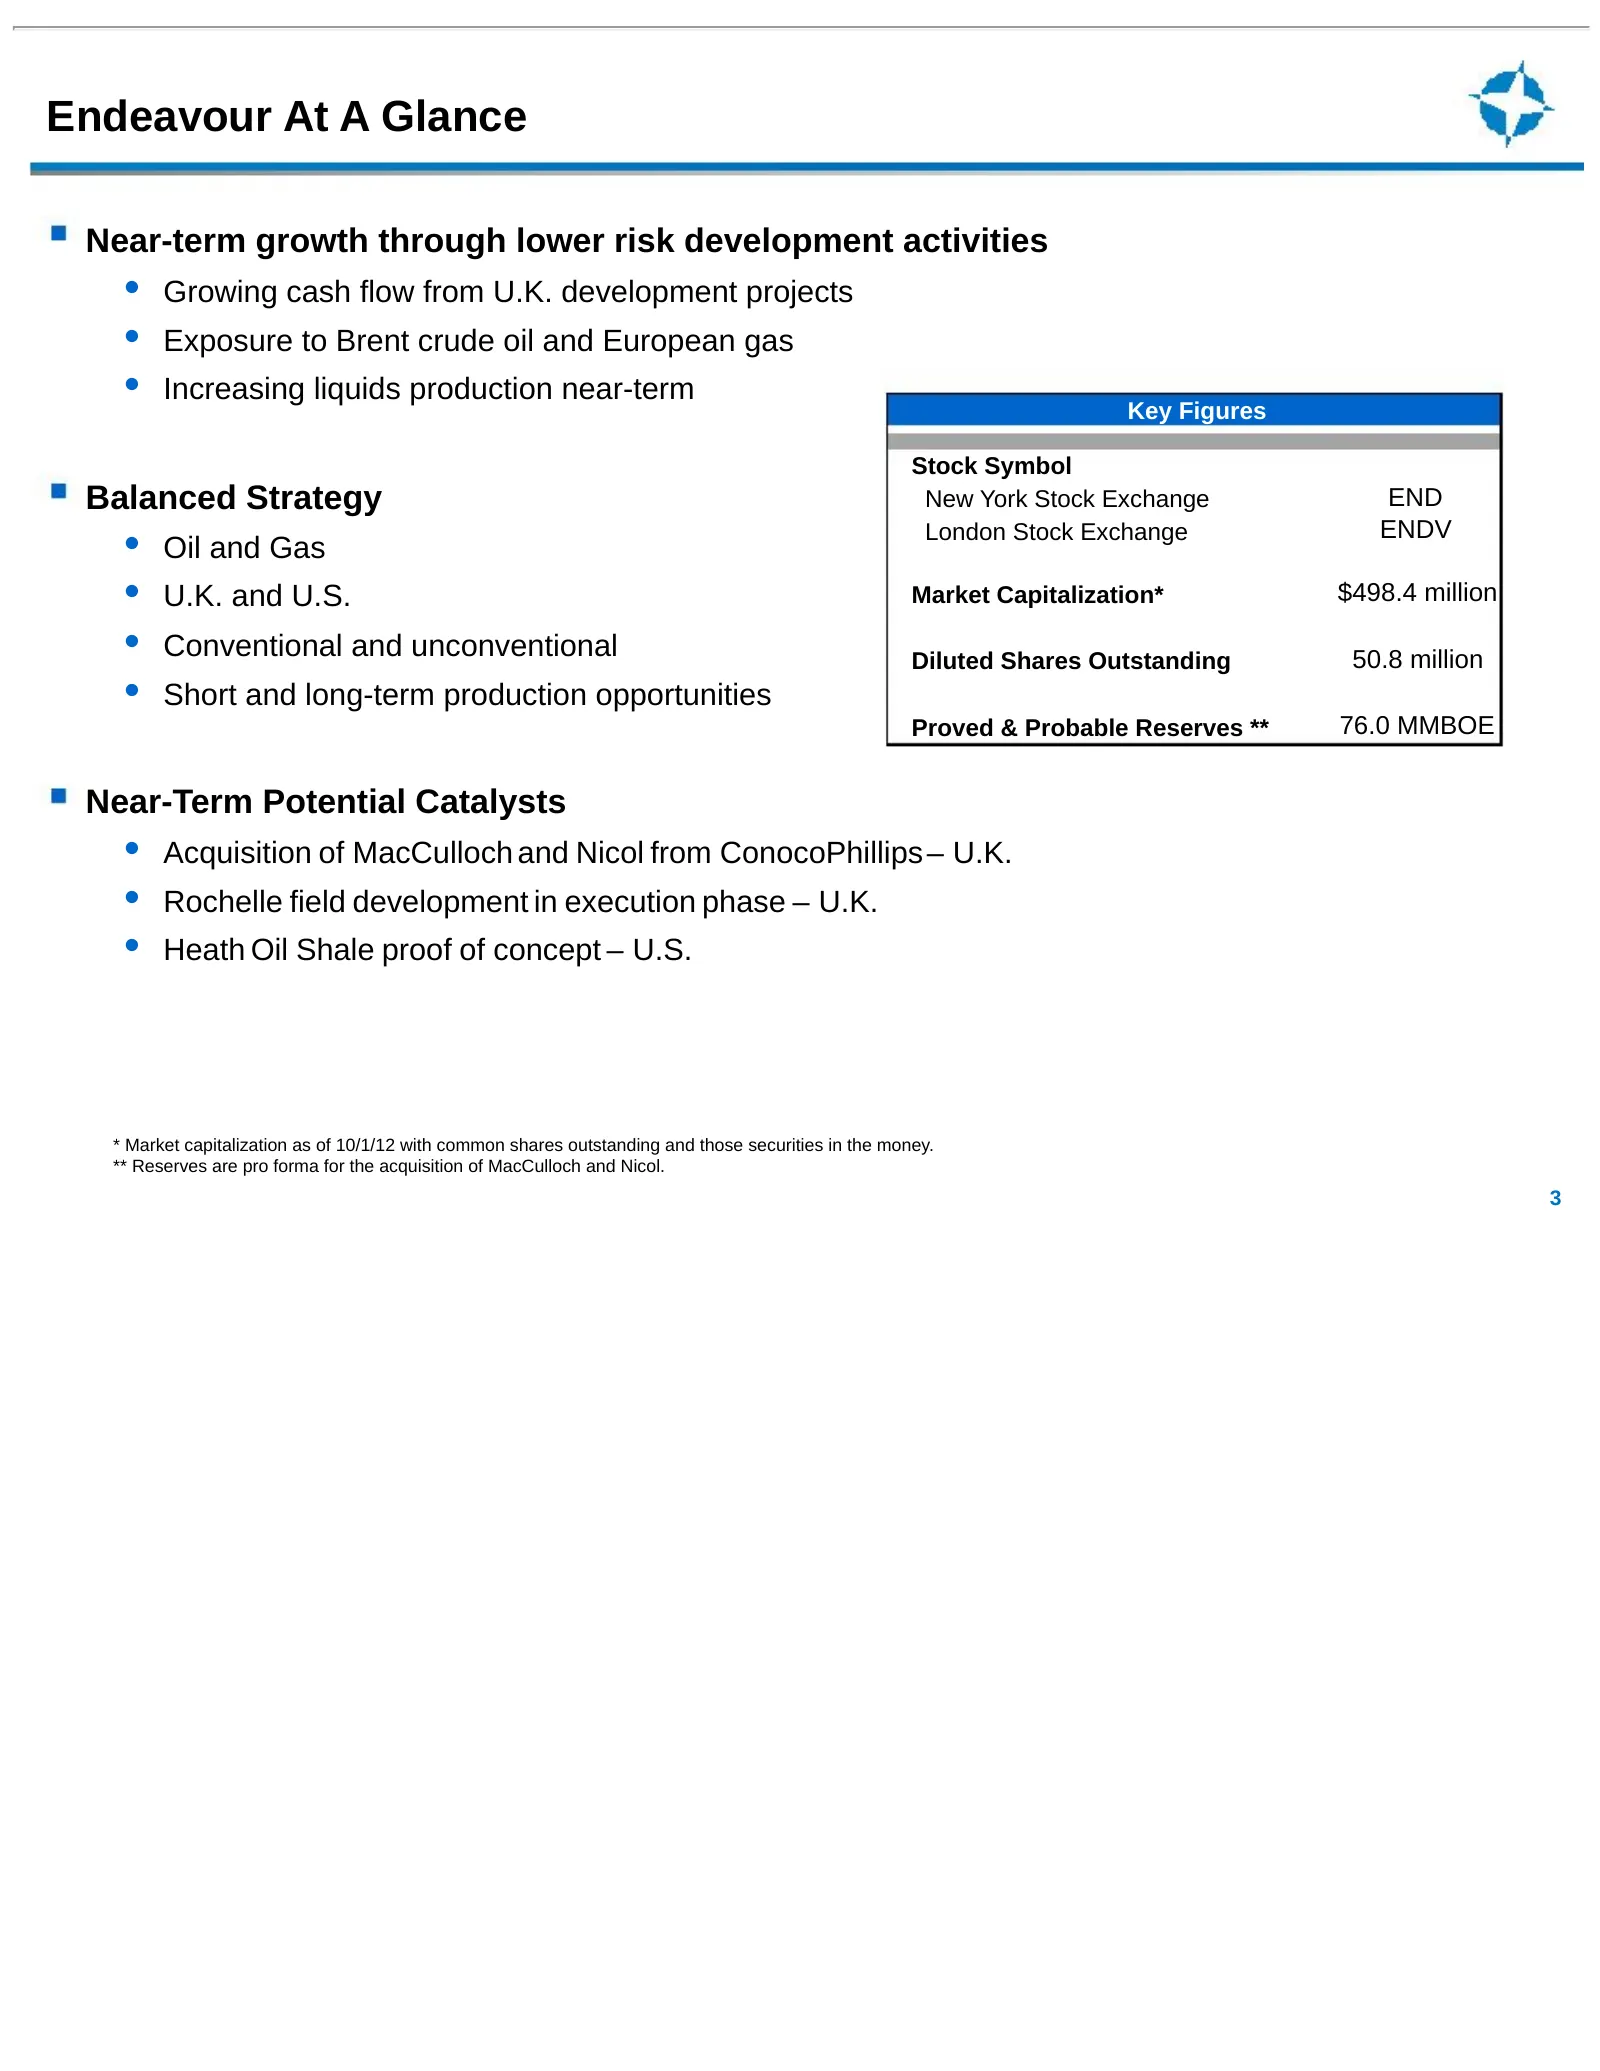
Endeavour At A Glance Near-term growth through lower risk development activities • Growing cash flow from U.K. development projects • Exposure to Brent crude oil and European gas • Increasing liquids production near-term Key Figures Stock Symbol Balanced Strategy New York Stock Exchange END ENDV • O
Slide 4: Significant Production Growth – Acquisition and Near-Term Projects
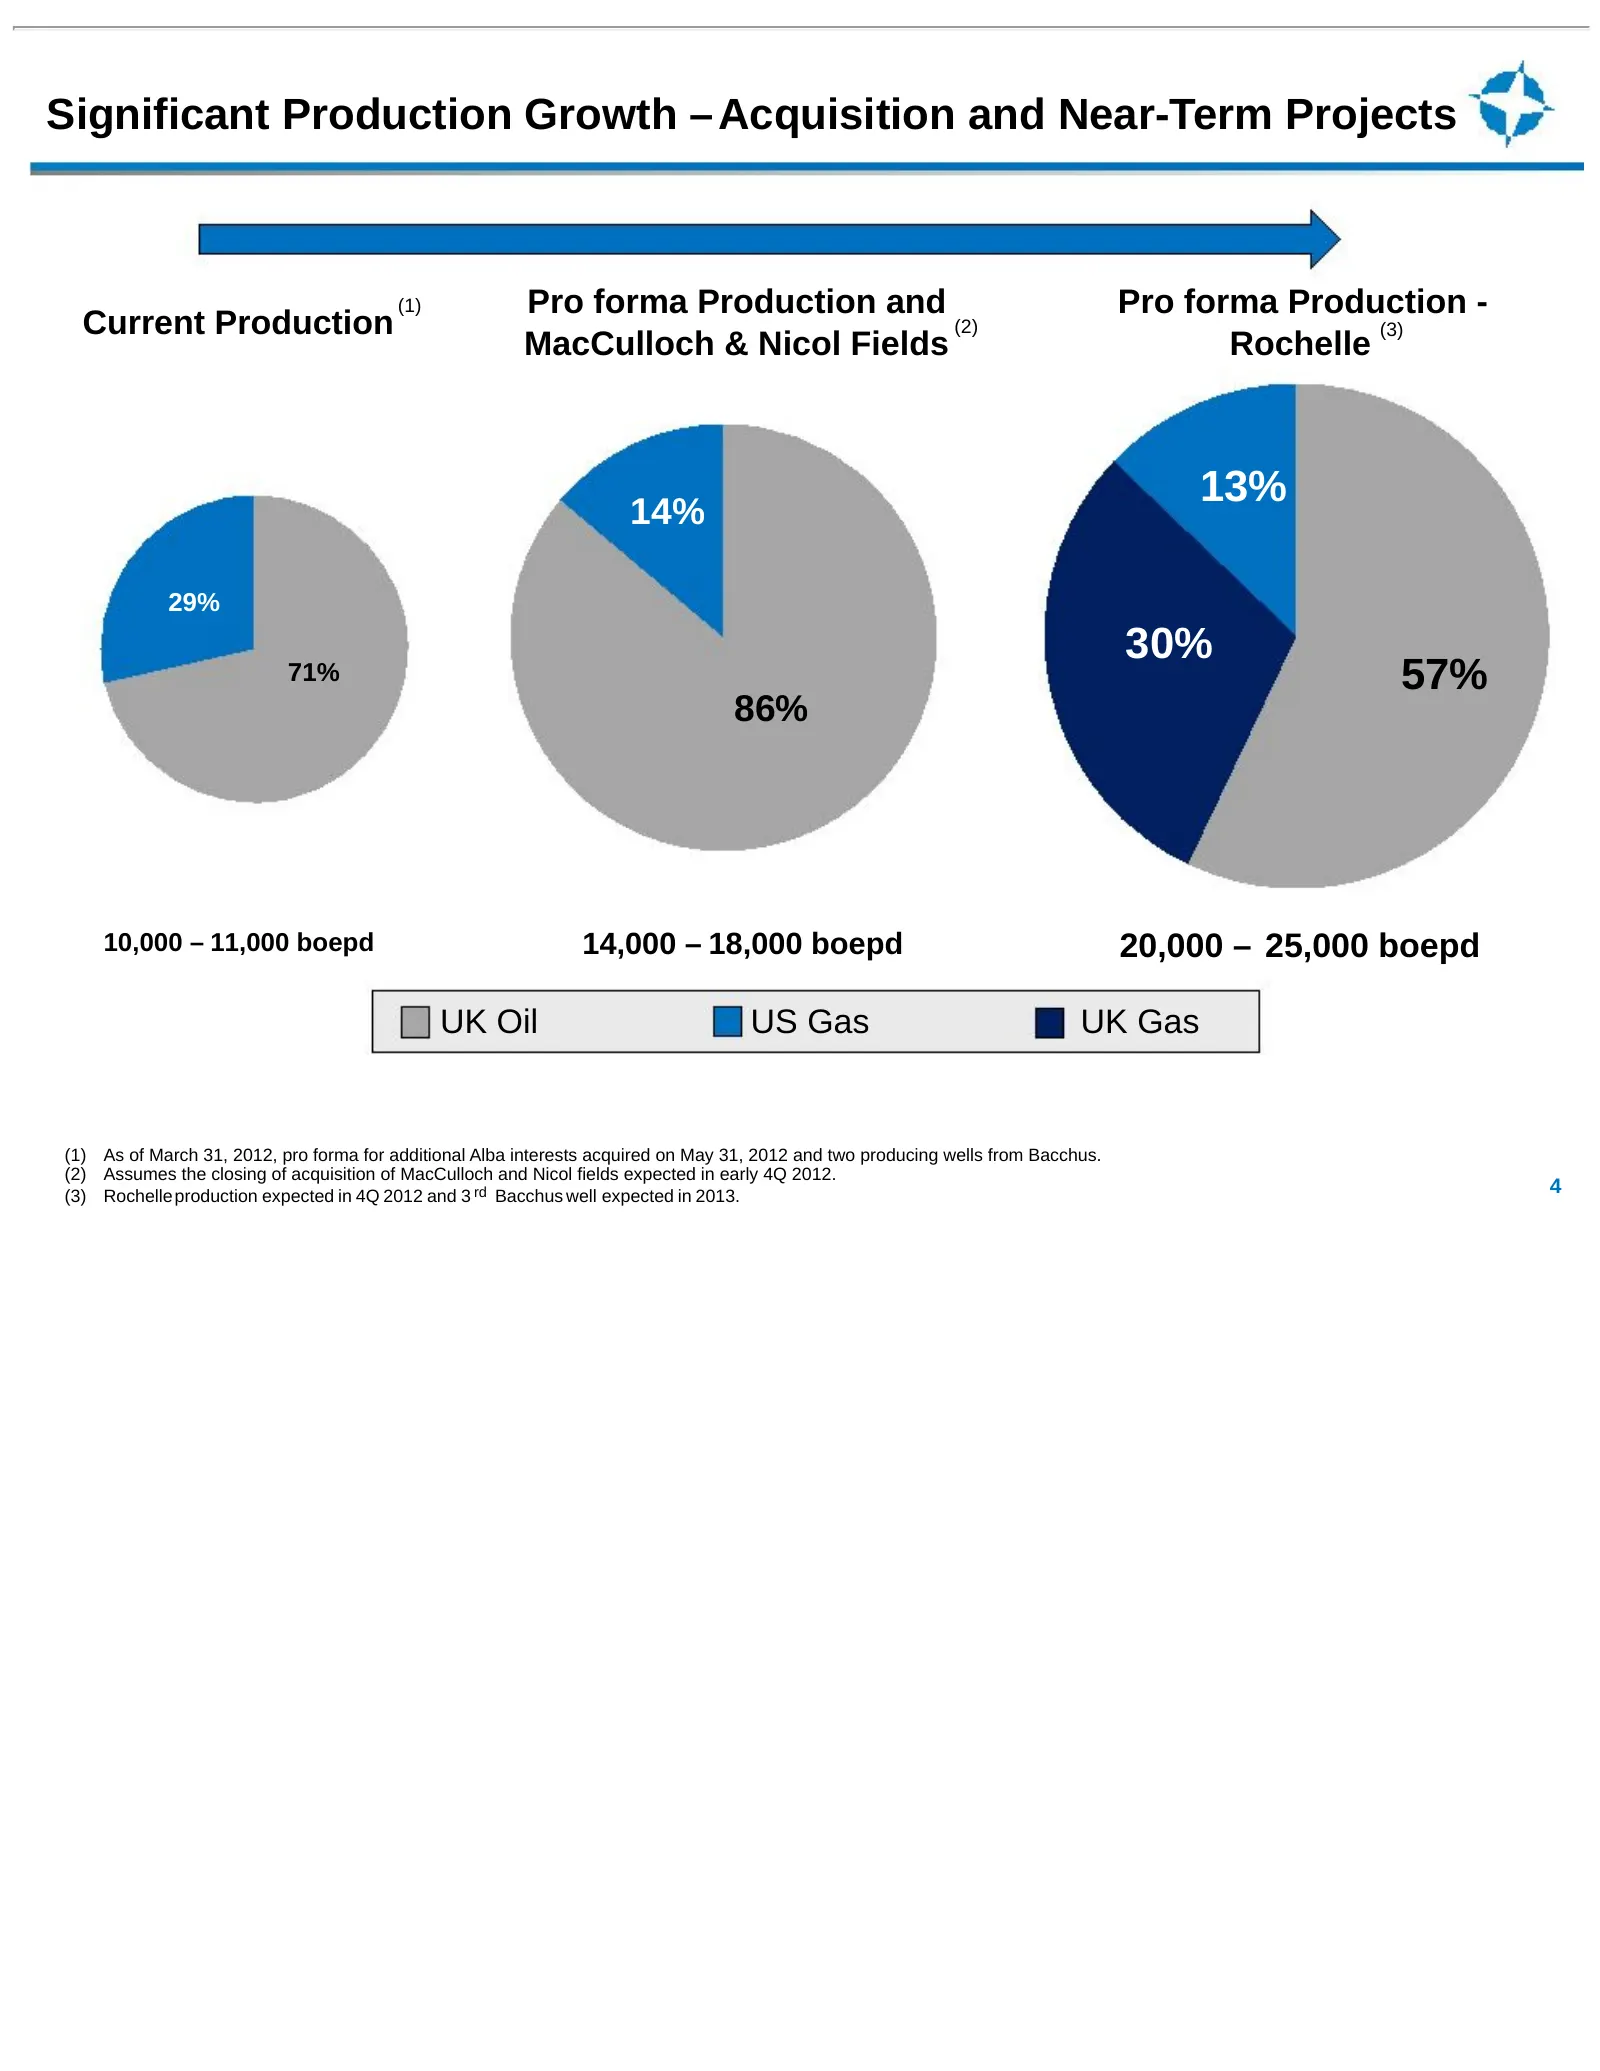
Significant Production Growth –Acquisition and Near-Term Projects (1) Pro forma Production and Pro forma Production - Current Production (2) (3) MacCulloch & Nicol Fields Rochelle 13% 14% 29% 30% 71% 57% 86% 10,000 – 11,000 boepd 14,000 – 18,000 boepd 20,000 – 25,000 boepd UK Oil US Gas UK Gas (1) A
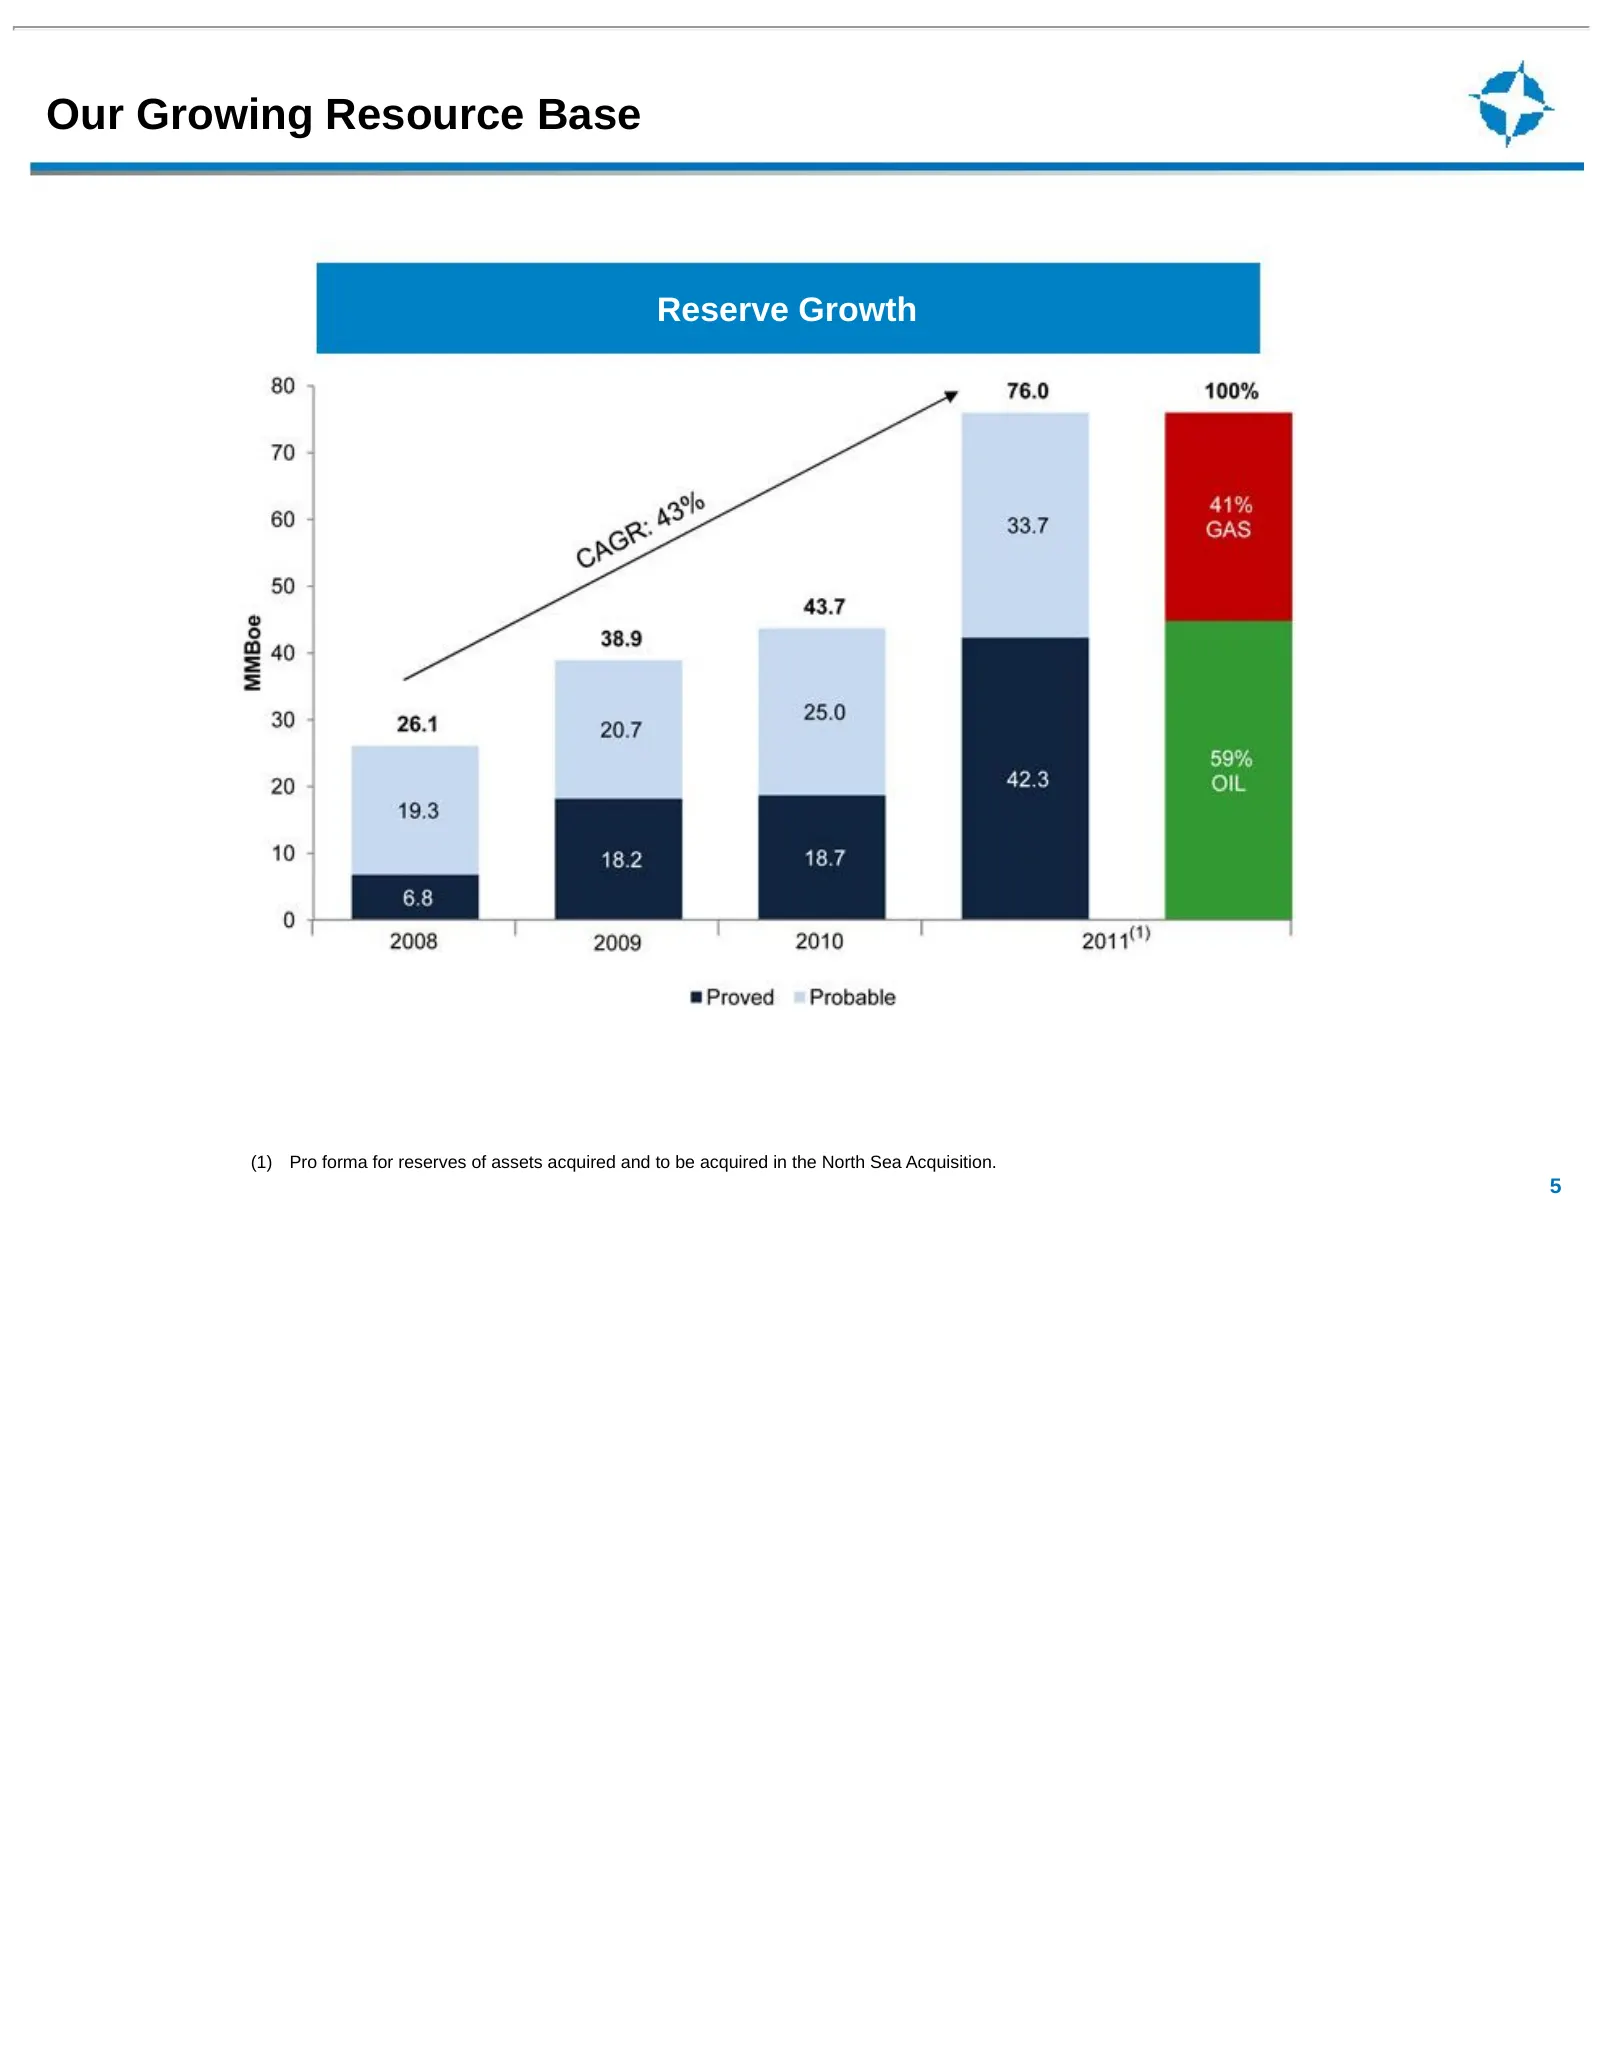
Slide 5: Our Growing Resource Base
Our Growing Resource Base Reserve Growth (1) Pro forma for reserves of assets acquired and to be acquired in the North Sea Acquisition. 5
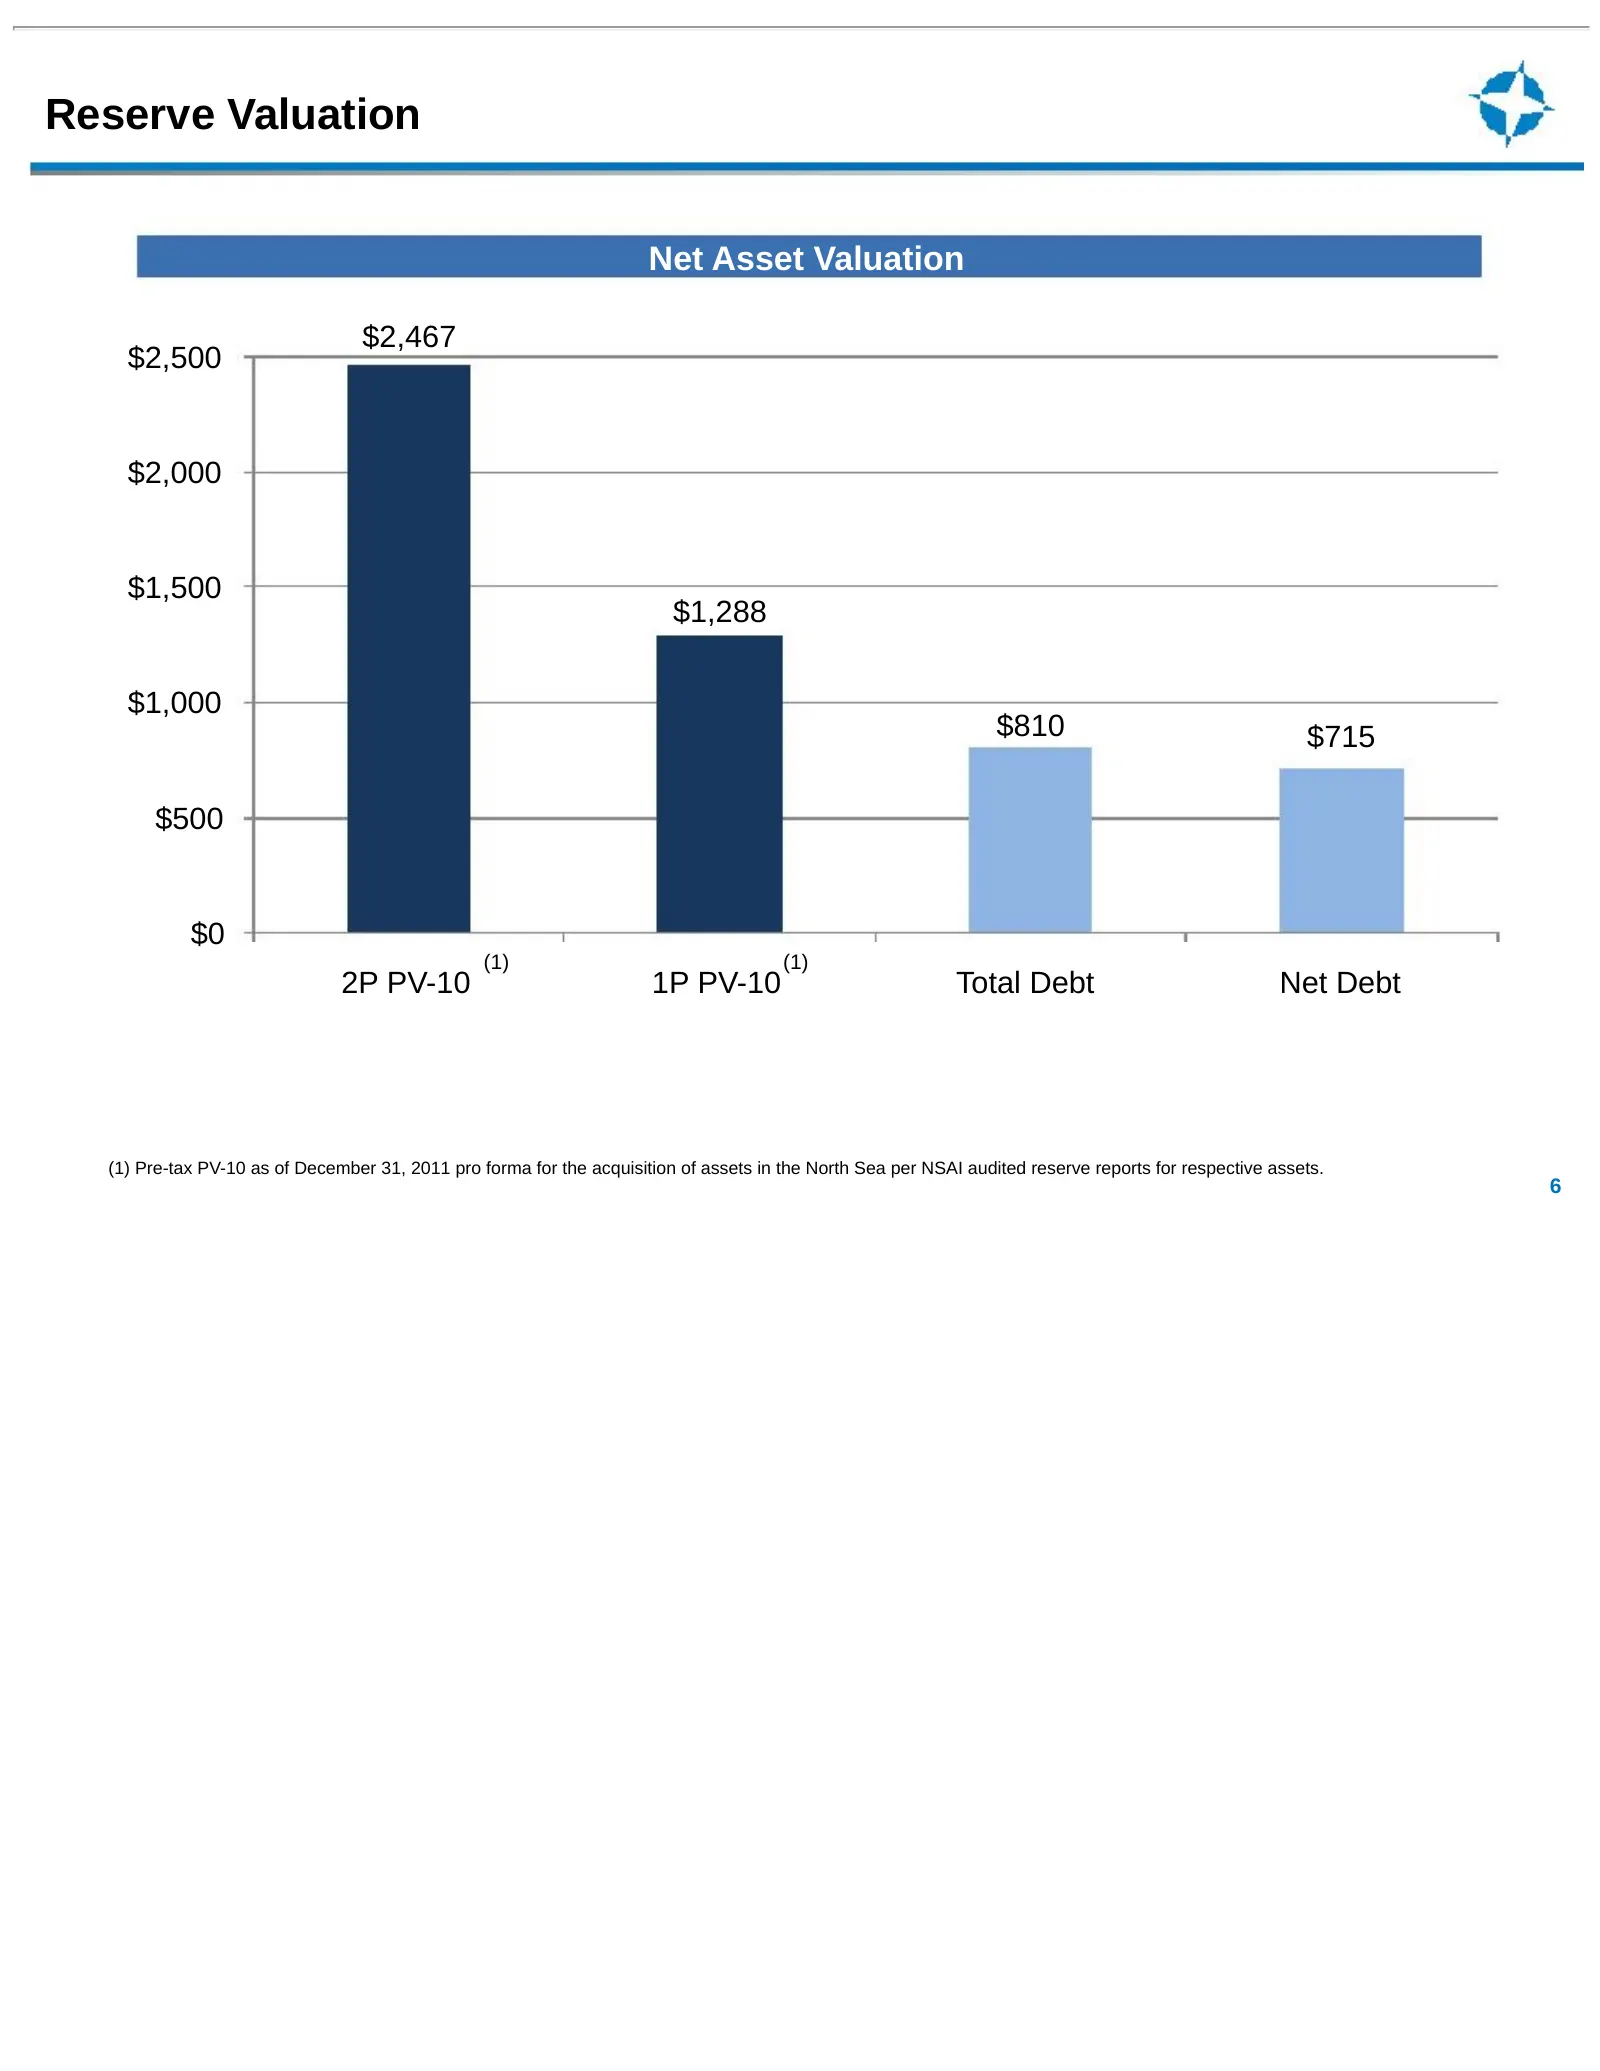
Slide 6: Reserve Valuation
Reserve Valuation Net Asset Valuation $2,467 $2,500 $2,000 $1,500 $1,288 $1,000 $810 $715 $500 $0 (1) (1) 2P PV-10 1P PV-10 Total Debt Net Debt (1) Pre-tax PV-10 as of December 31, 2011 pro forma for the acquisition of assets in the North Sea per NSAI audited reserve reports for respective assets. 6
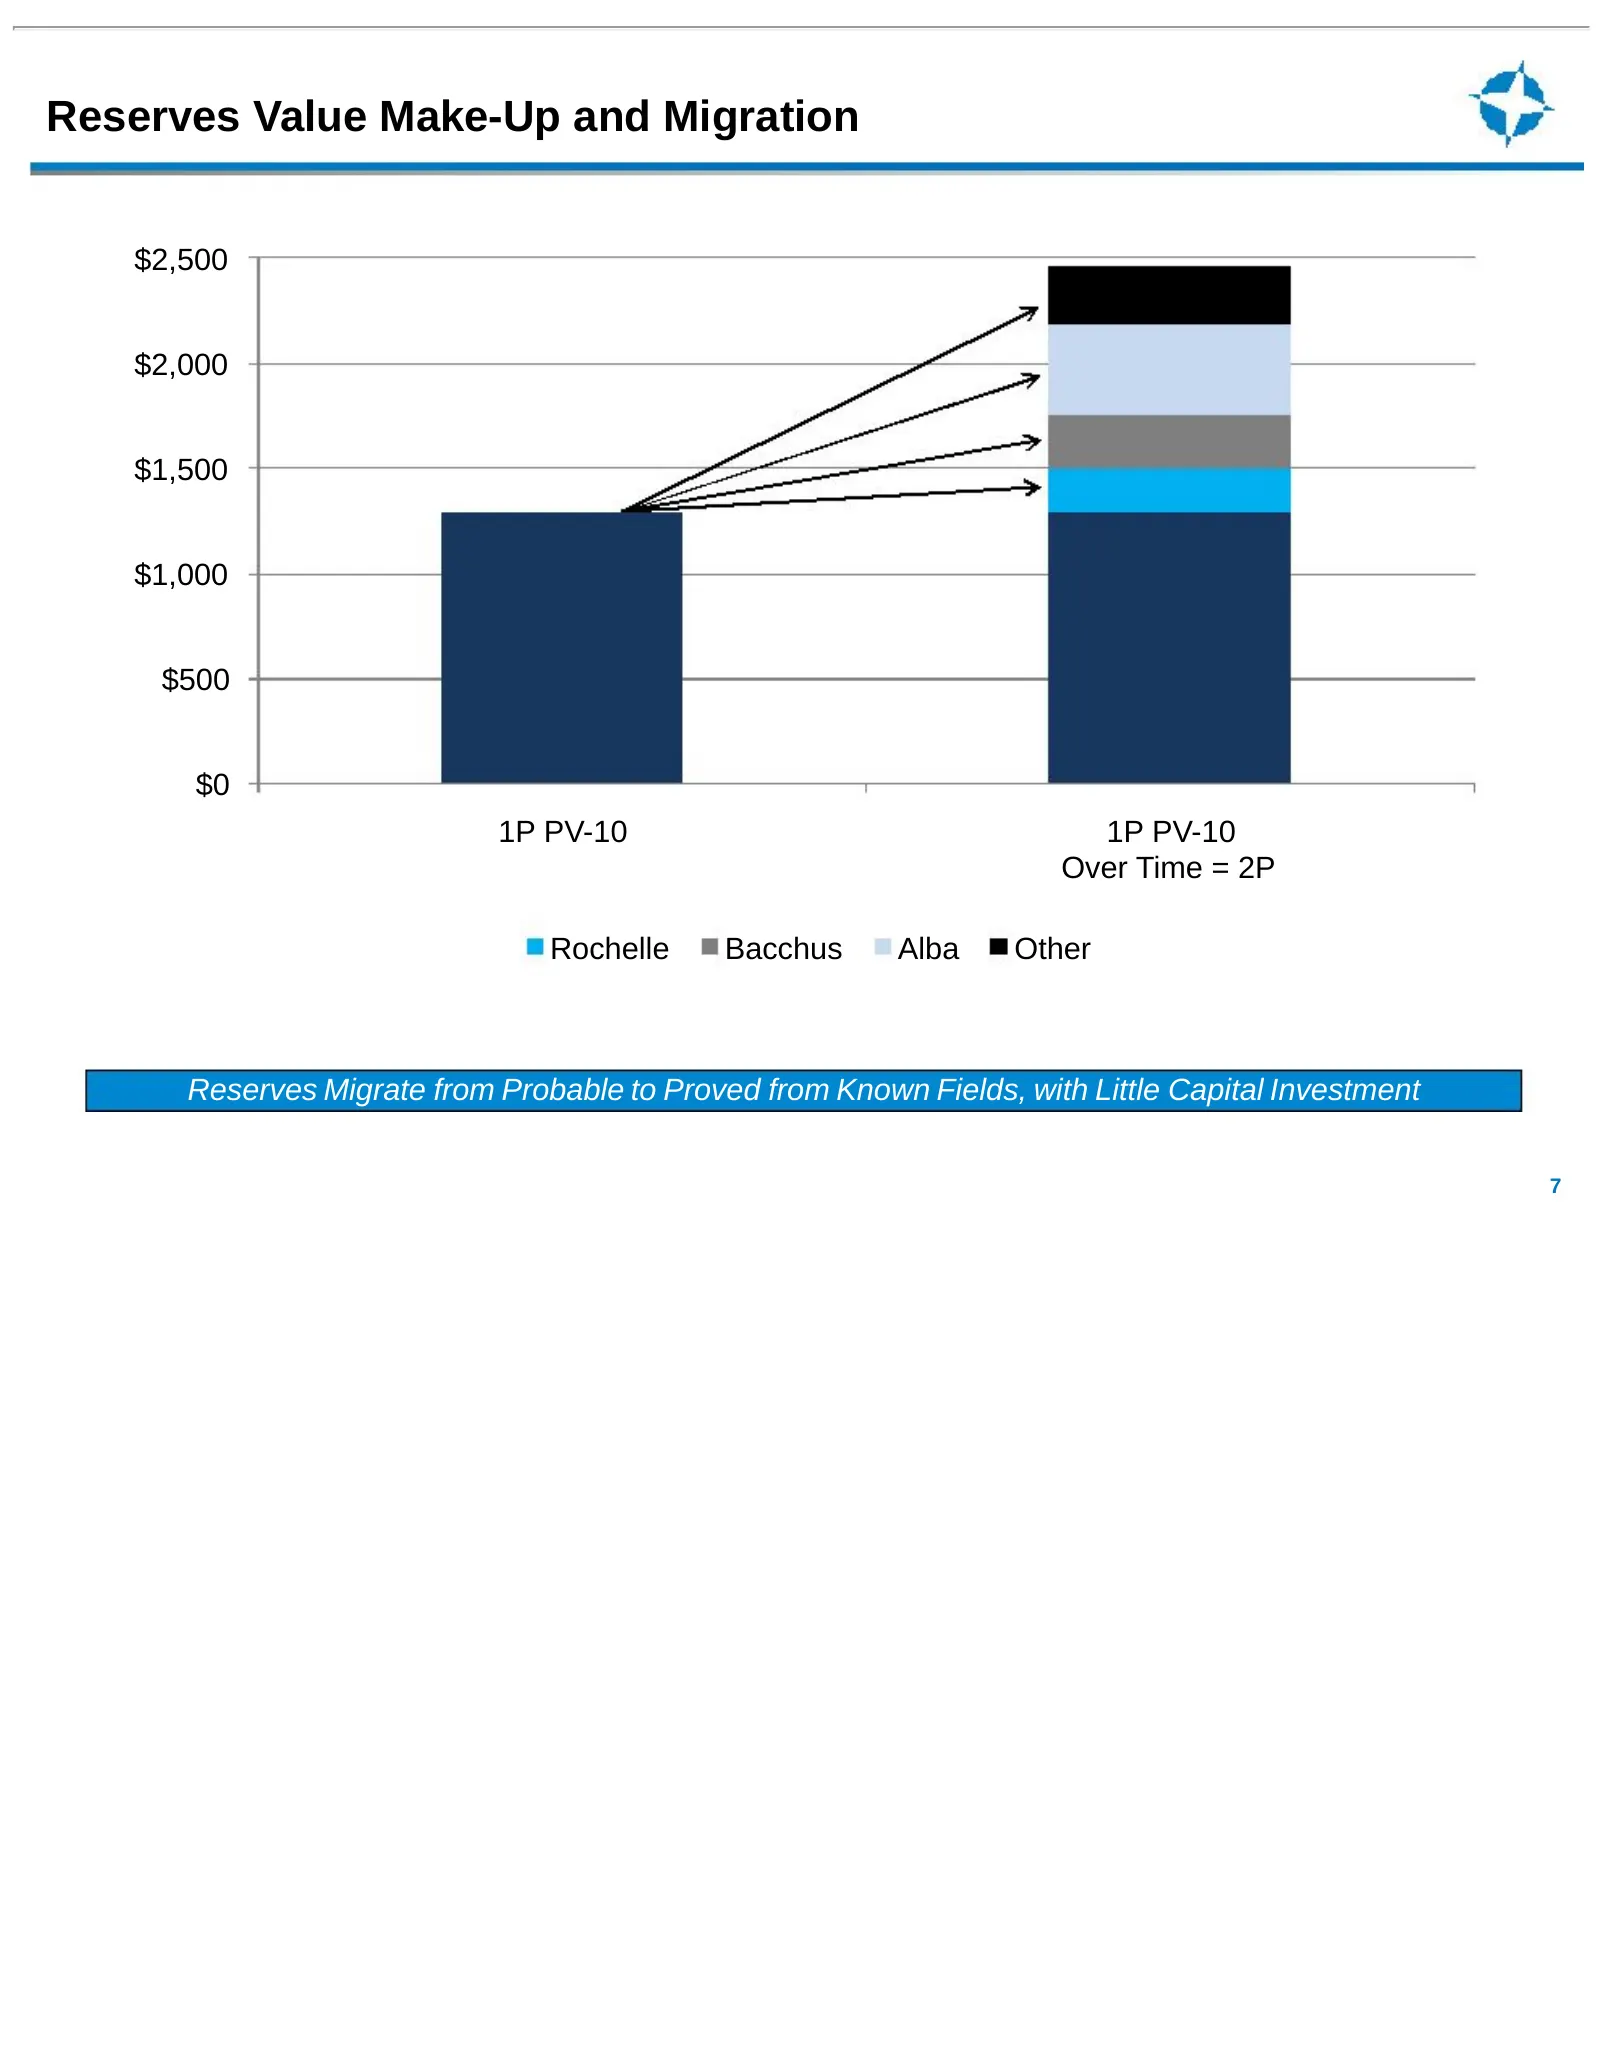
Slide 7: Reserves Value Make-Up and Migration
Reserves Value Make-Up and Migration $2,500 $2,000 $1,500 $1,000 $500 $0 1P PV-10 1P PV-10 Over Time = 2P Rochelle Bacchus Alba Other Reserves Migrate from Probable to Proved from Known Fields, with Little Capital Investment 7
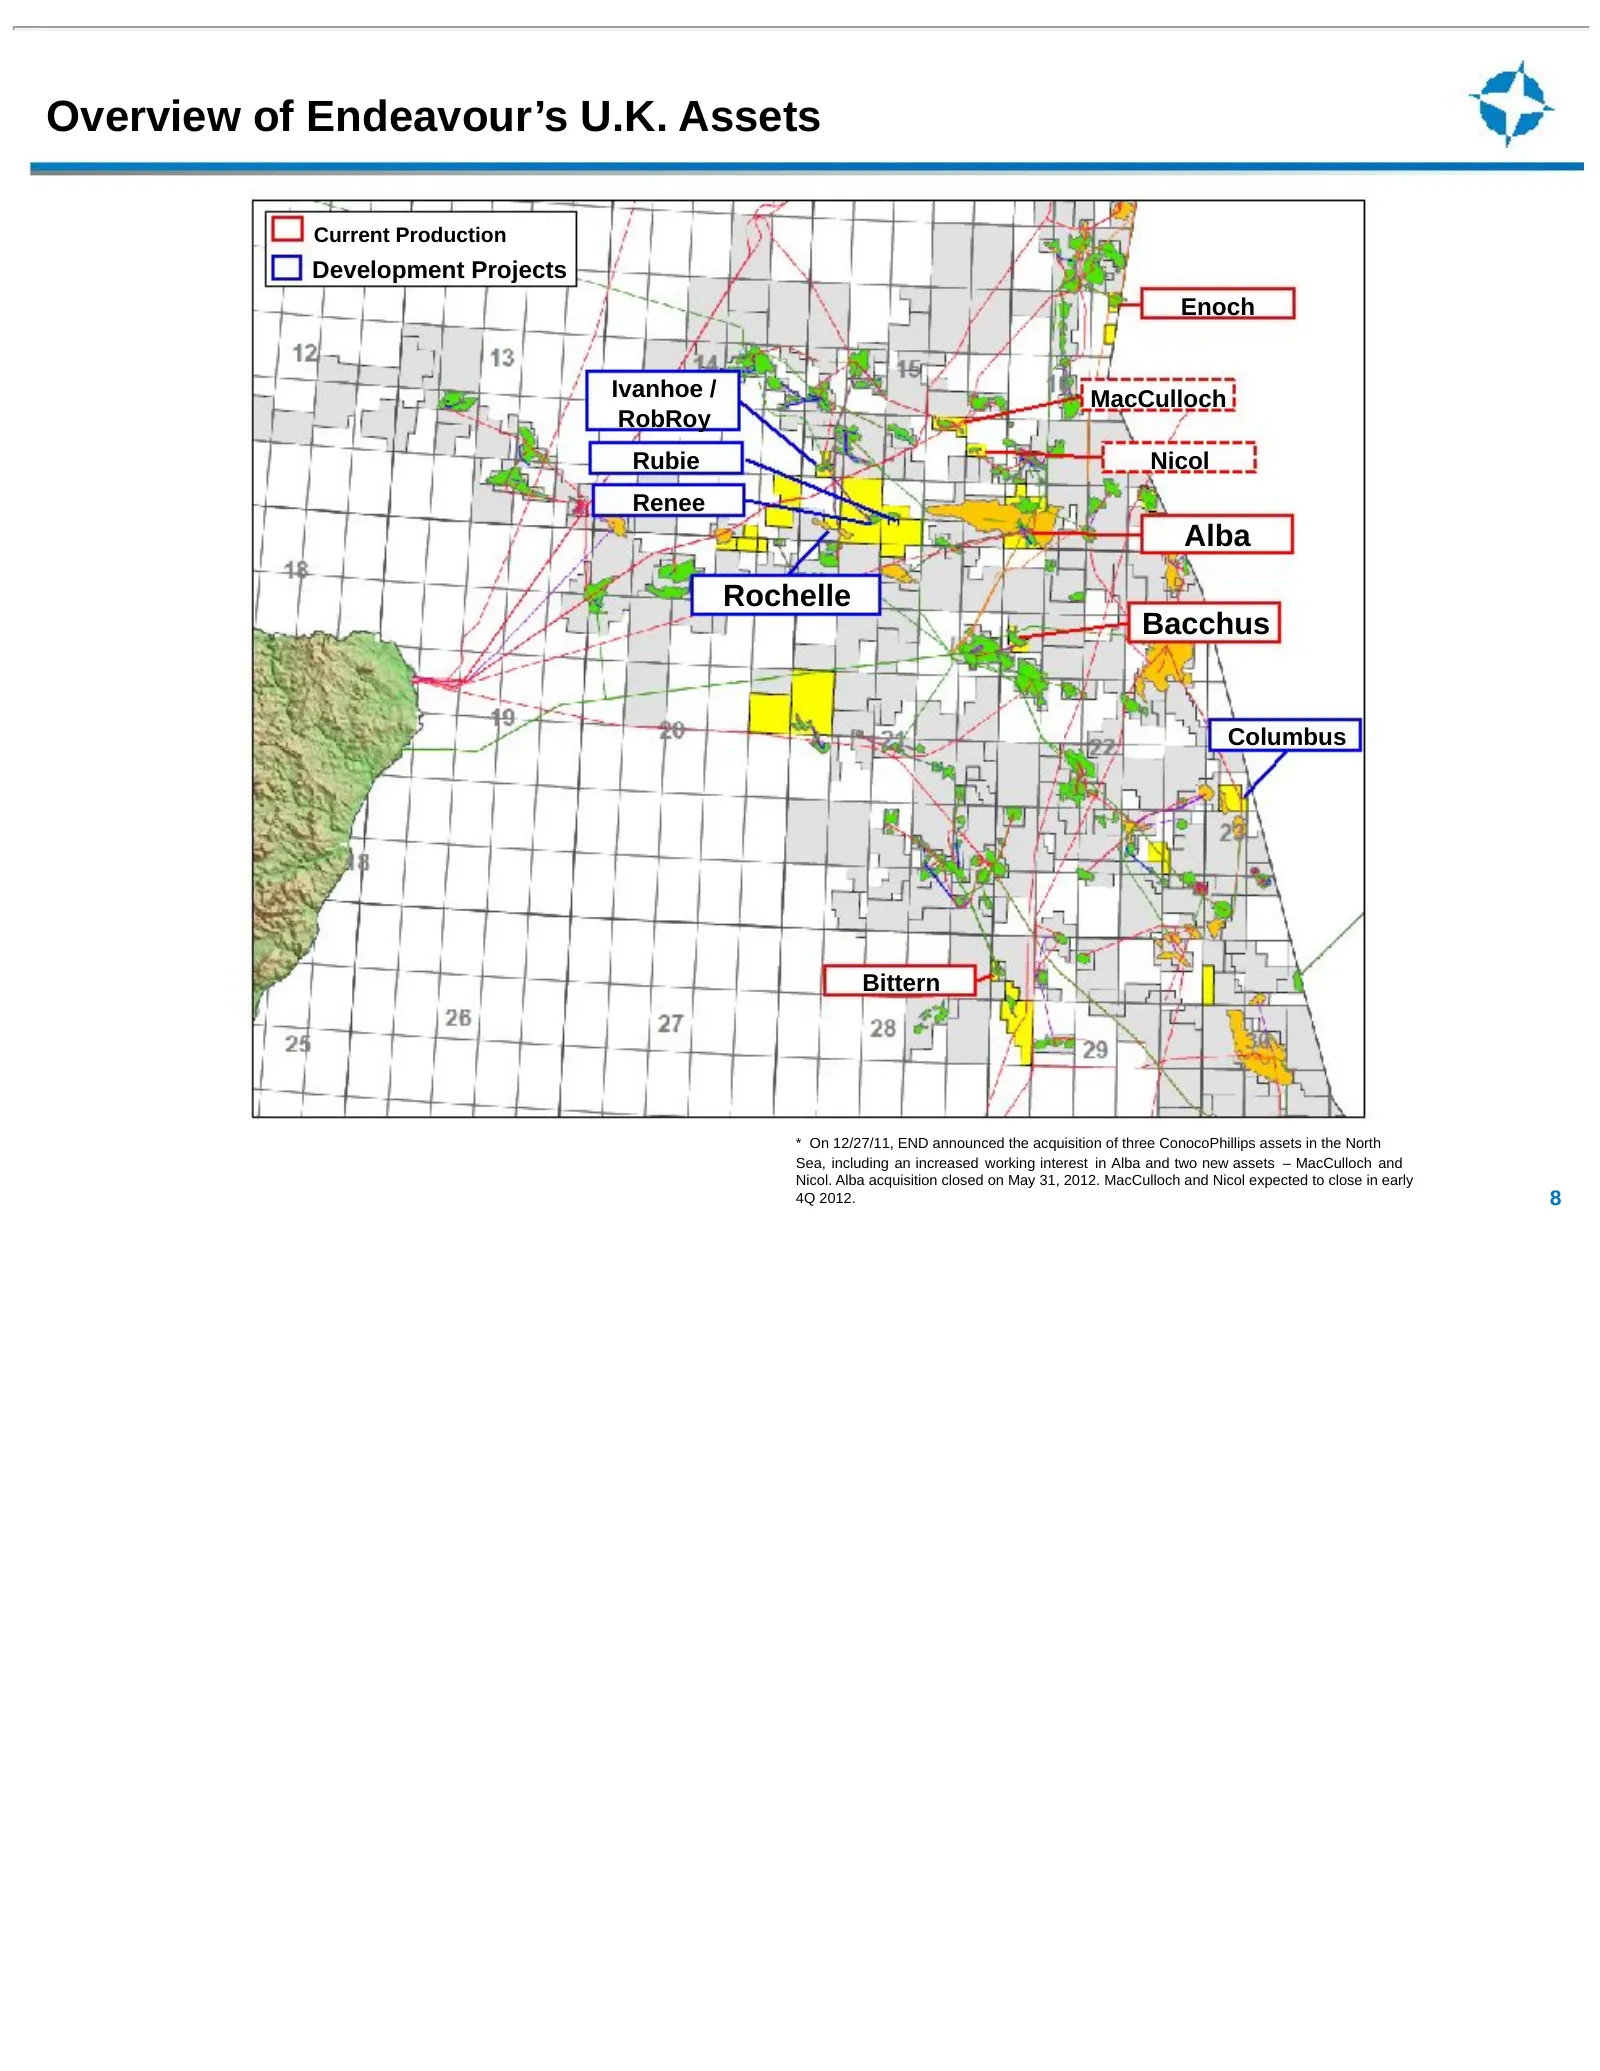
Slide 8: Overview of Endeavour's U.K. Assets
Overview of Endeavour’s U.K. Assets Current Production Development Projects Enoch Ivanhoe / MacCulloch RobRoy Rubie Nicol Renee Alba Rochelle Bacchus Columbus Bittern * On 12/27/11, END announced the acquisition of three ConocoPhillips assets in the North Sea, including an increased working interest
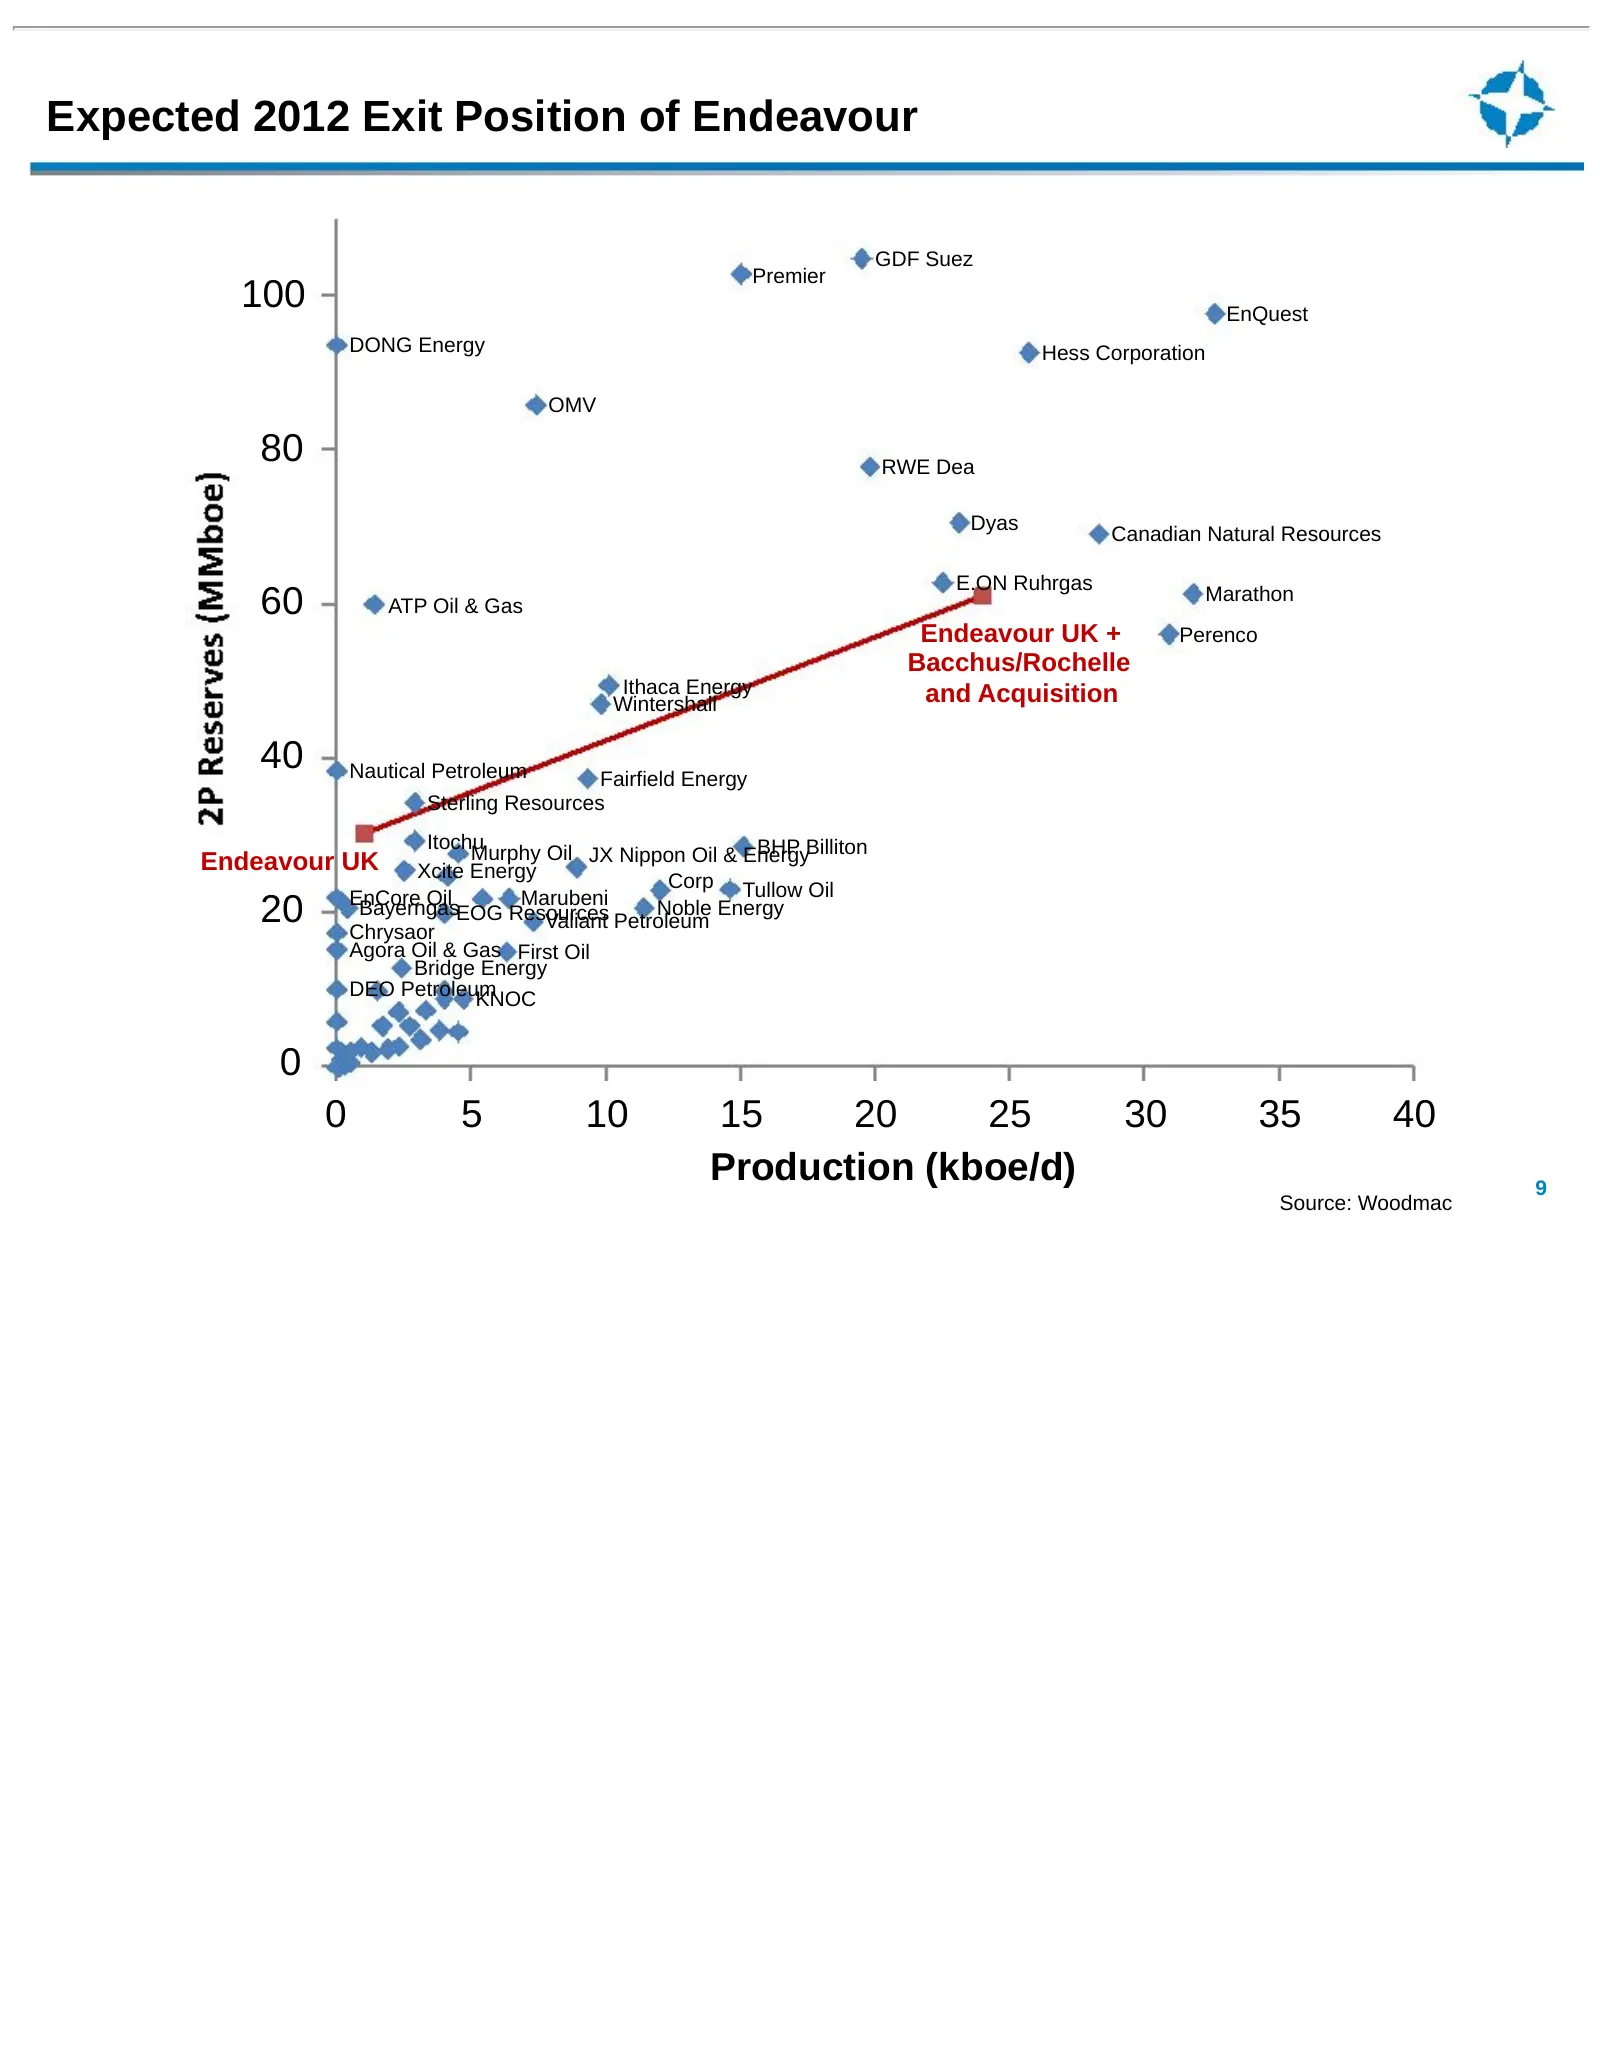
Slide 9: Expected 2012 Exit Position of Endeavour
Expected 2012 Exit Position of Endeavour GDF Suez Premier 100 EnQuest DONG Energy Hess Corporation OMV 80 RWE Dea Dyas Canadian Natural Resources E.ON Ruhrgas 60 ATP Oil & Gas Marathon Endeavour UK + Perenco Bacchus/Rochelle Ithaca Energy and Acquisition Wintershall 40 Nautical Petroleum Fairfield E
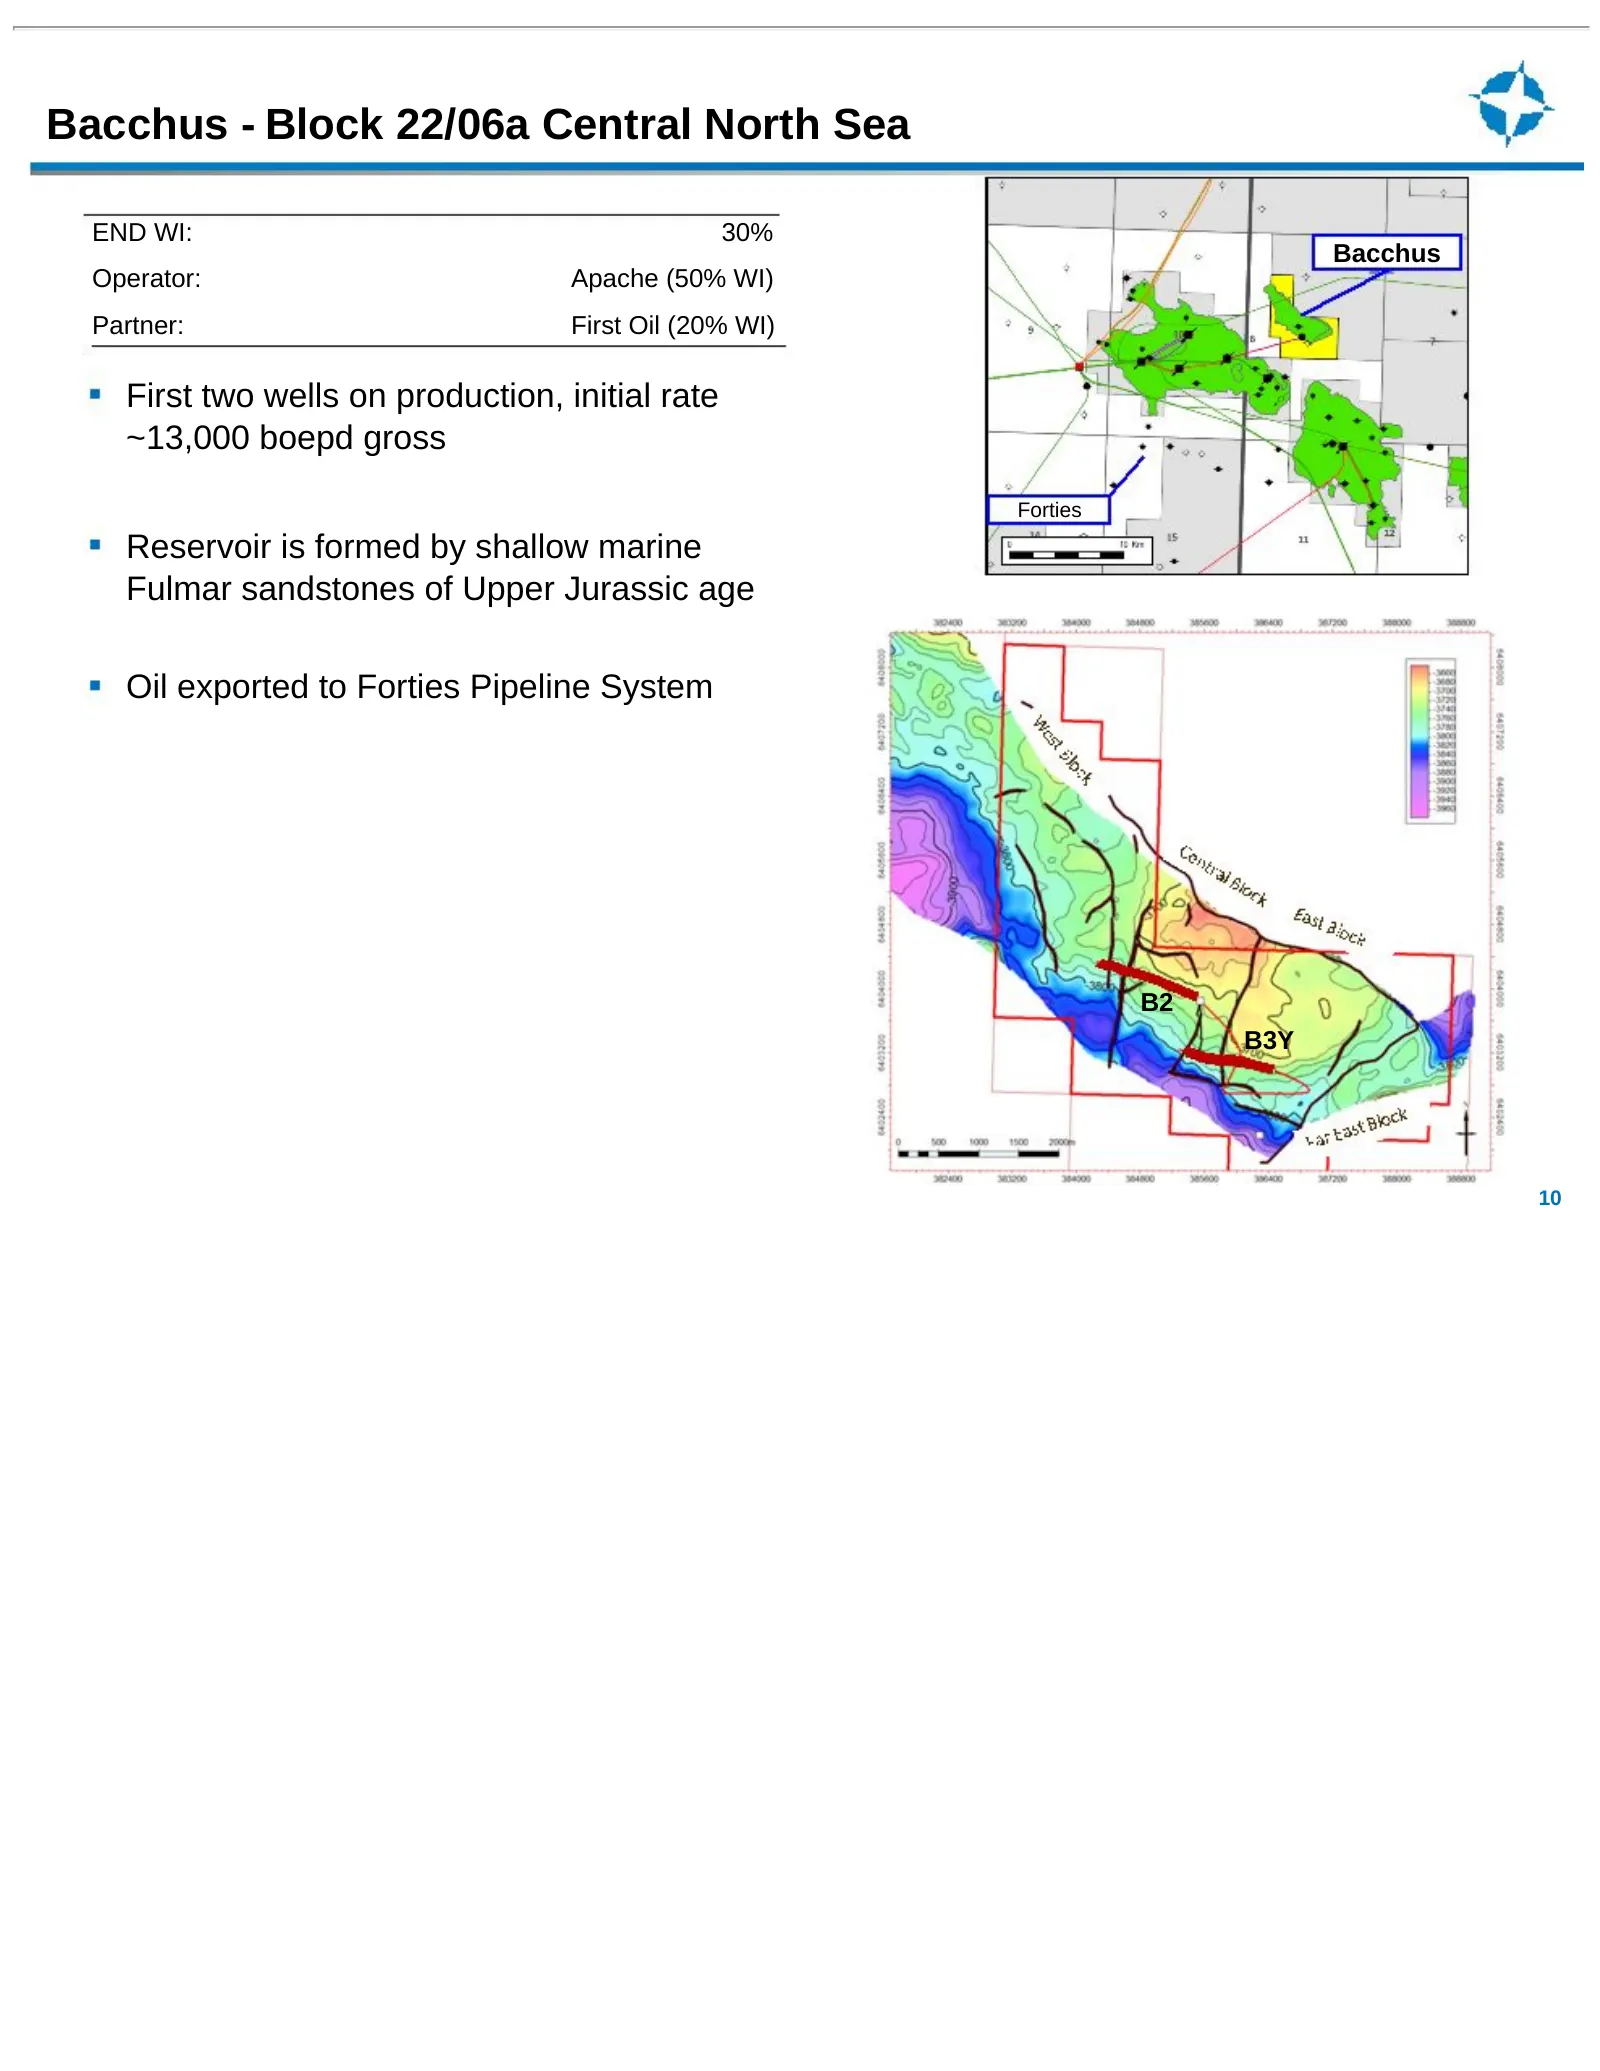
Slide 10: Bacchus - Block 22/06a Central North Sea
Bacchus - Block 22/06a Central North Sea END WI: 30% Bacchus Operator: Apache (50% WI) Partner: First Oil (20% WI) First two wells on production, initial rate ~13,000 boepd gross Forties Reservoir is formed by shallow marine Fulmar sandstones of Upper Jurassic age Oil exported to Forties Pipeline Sy
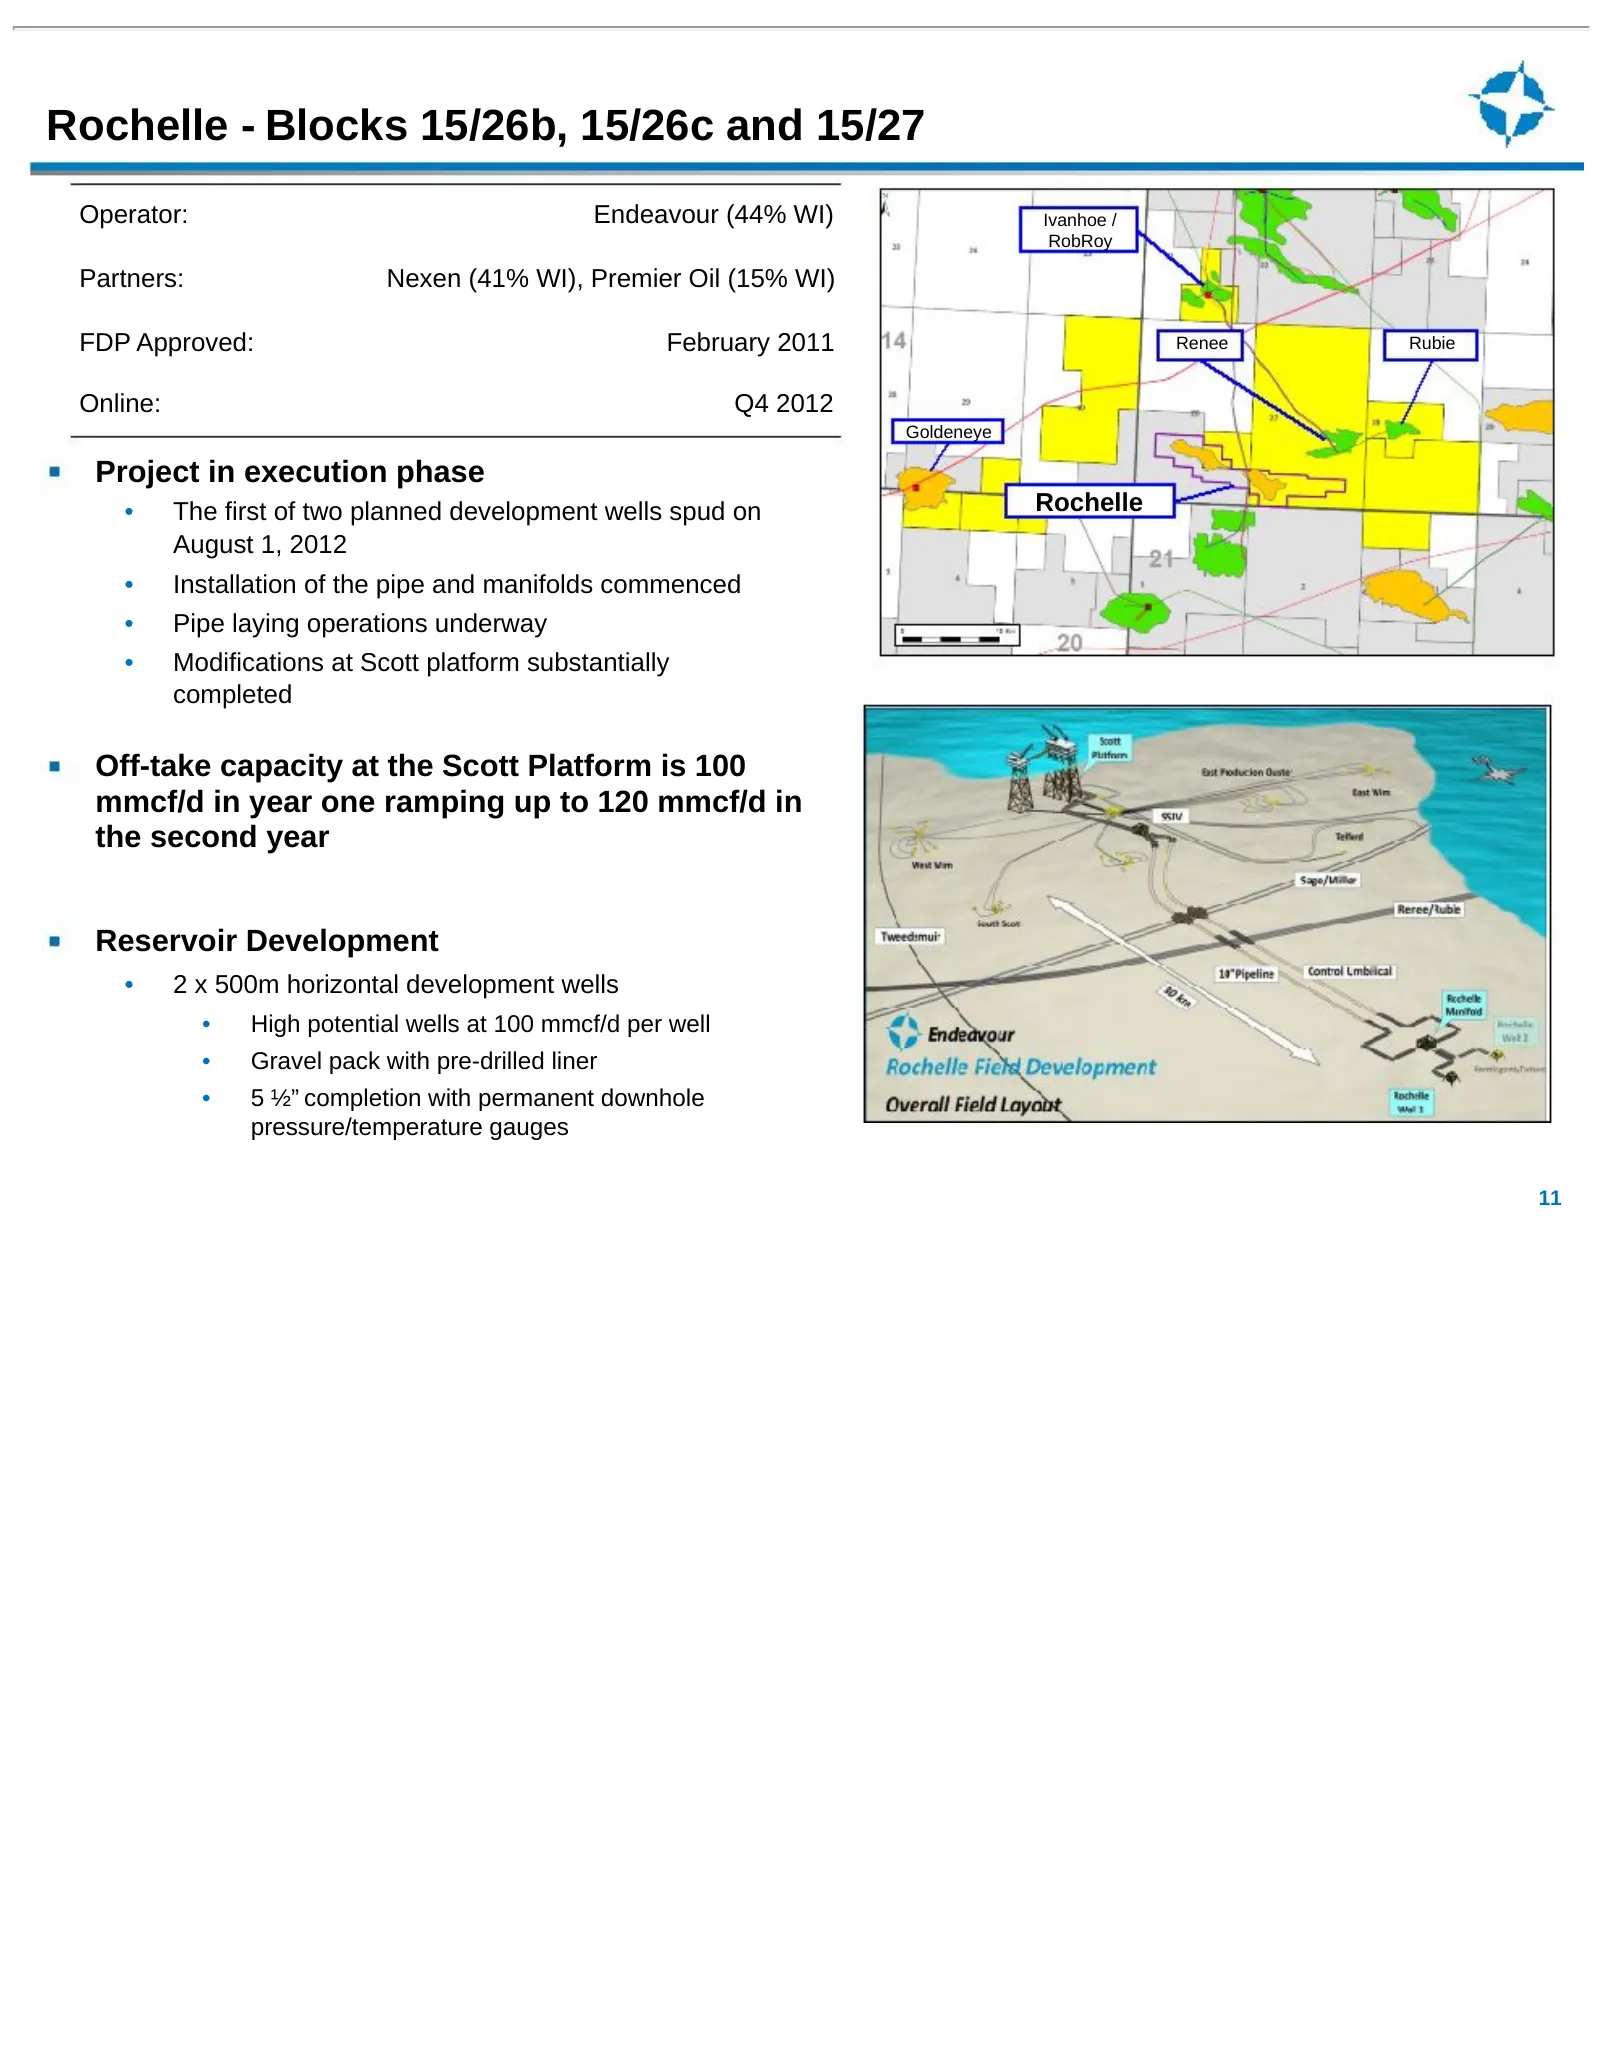
Slide 11: Rochelle - Blocks 15/26b, 15/26c and 15/27
Rochelle - Blocks 15/26b, 15/26c and 15/27 Operator: Endeavour (44% WI) Ivanhoe / RobRoy Partners: Nexen (41% WI), Premier Oil (15% WI) FDP Approved: February 2011 Renee Rubie Online: Q4 2012 Goldeneye Project in execution phase • The first of two planned development wells spud on Rochelle August 1,
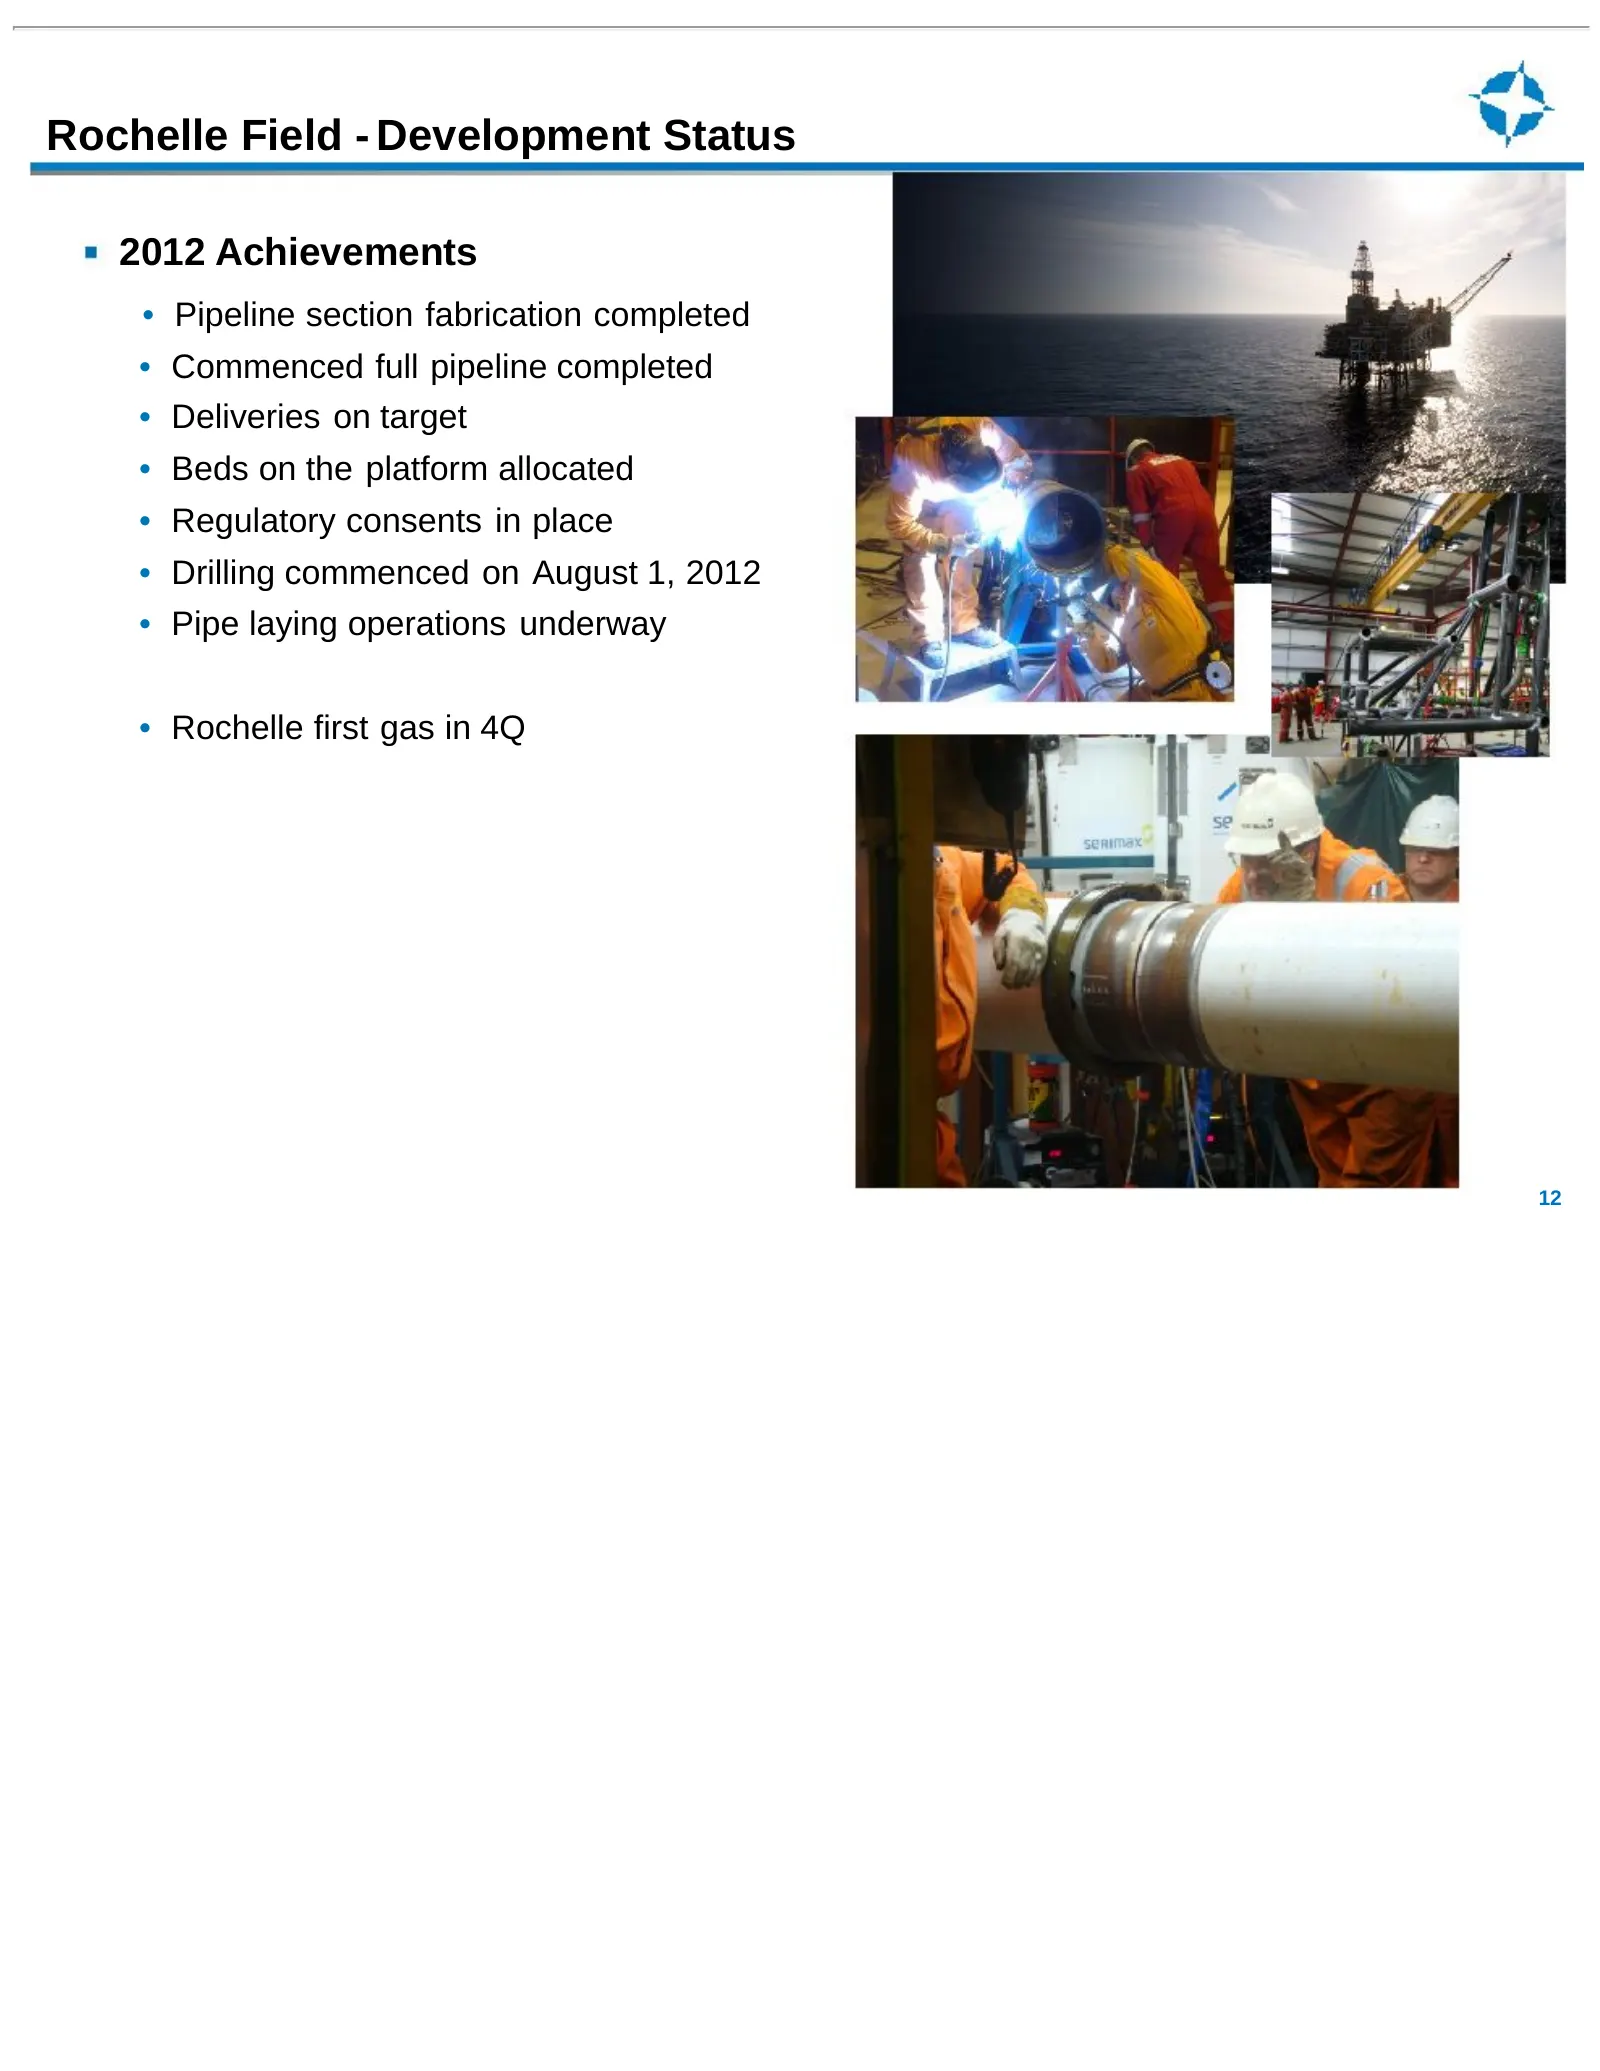
Slide 12: Rochelle Field - Development Status
Rochelle Field - Development Status 2012 Achievements • Pipeline section fabrication completed • Commenced full pipeline completed • Deliveries on target • Beds on the platform allocated • Regulatory consents in place • Drilling commenced on August 1, 2012 • Pipe laying operations underway • Rochell
Slide 13: Alba Field Overview - Block 16/26a
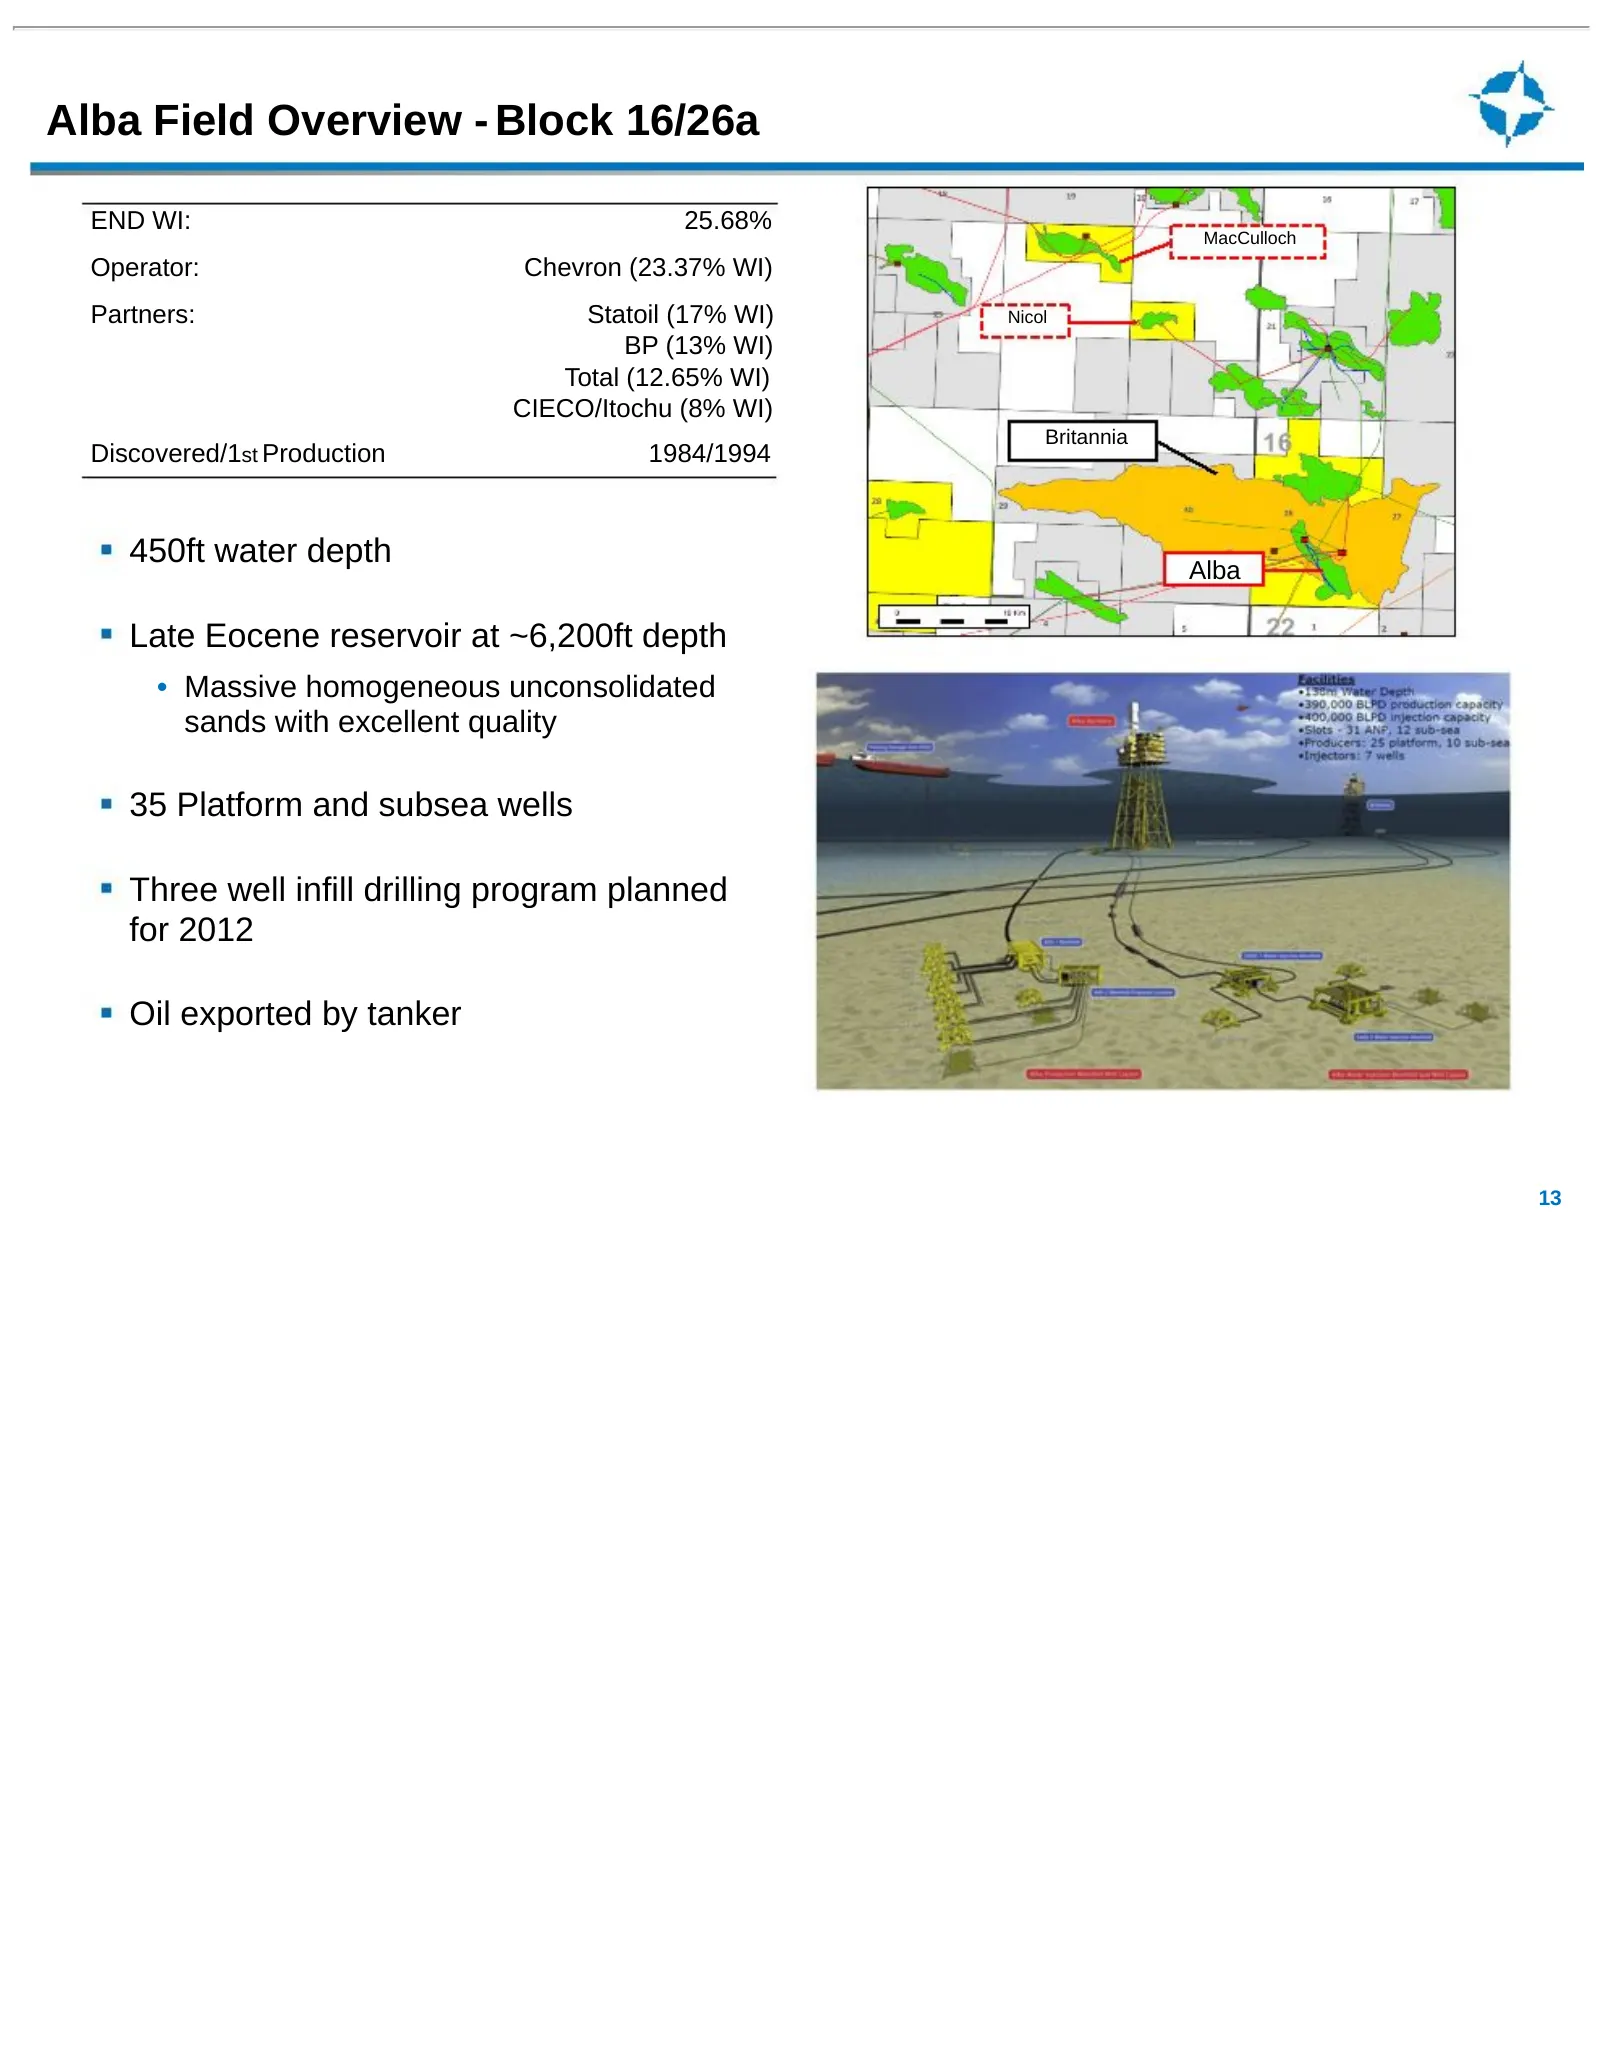
Alba Field Overview - Block 16/26a END WI: 25.68% MacCulloch Operator: Chevron (23.37% WI) Partners: Statoil (17% WI) Nicol BP (13% WI) Total (12.65% WI) CIECO/Itochu (8% WI) Britannia Discovered/1st Production 1984/1994 450ft water depth Alba Late Eocene reservoir at ~6,200ft depth • Massive homoge
Slide 14: Alba Field - Future Development
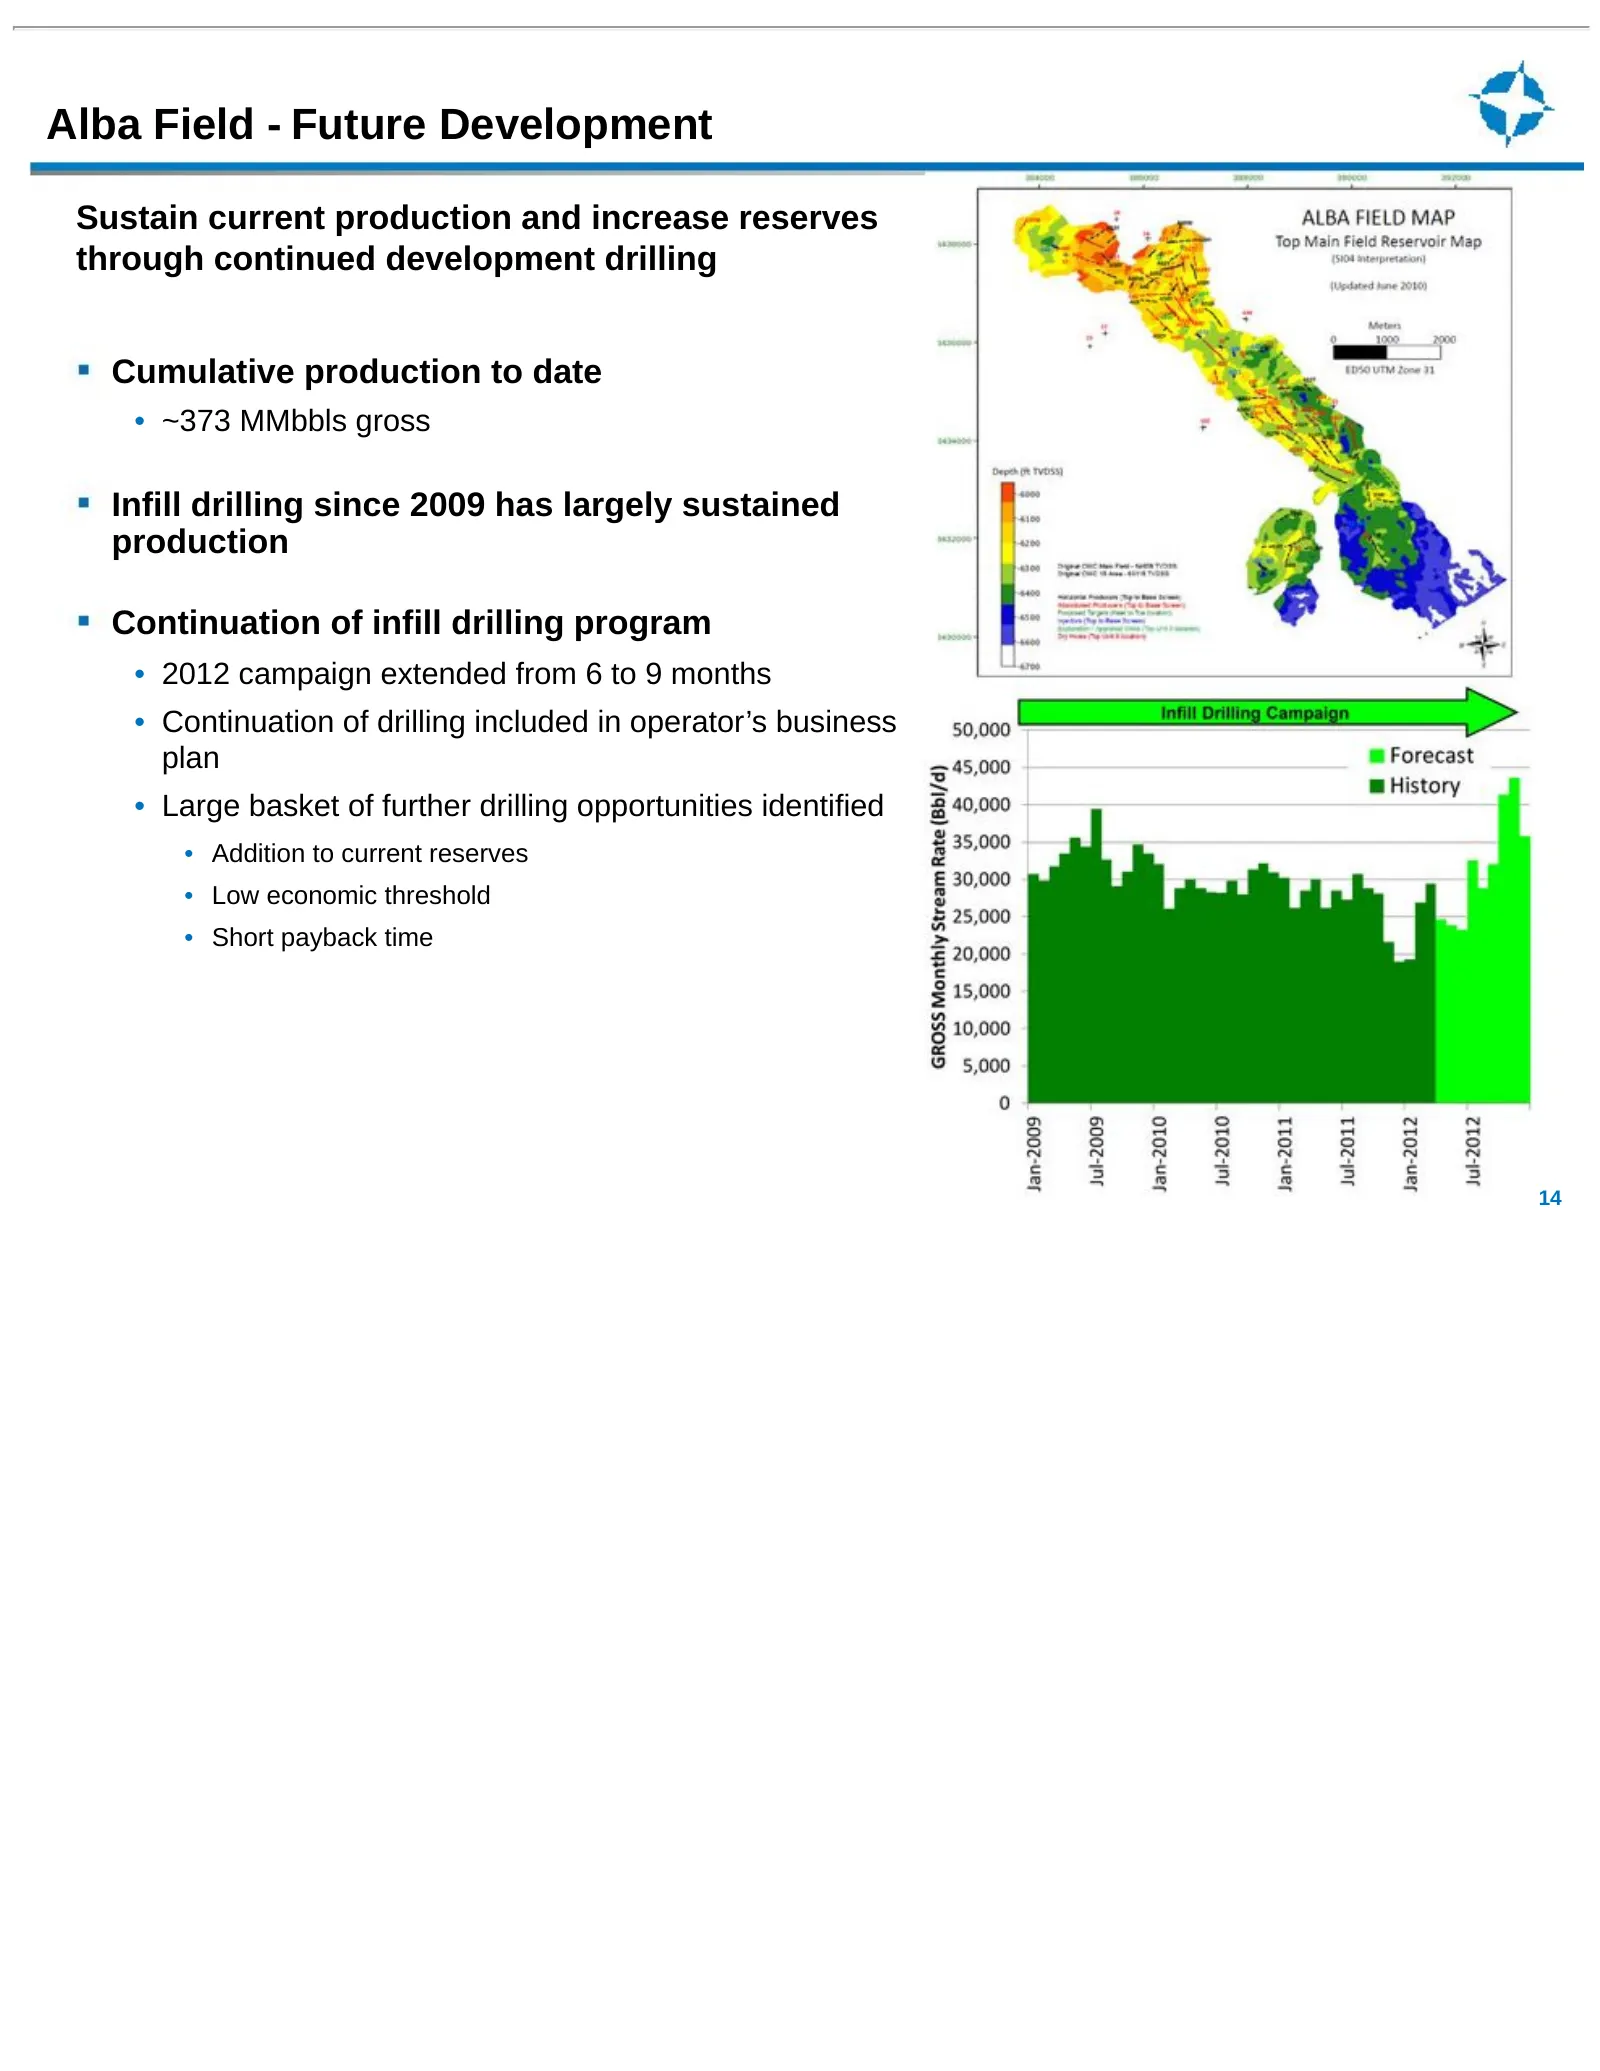
Alba Field - Future Development Sustain current production and increase reserves through continued development drilling Cumulative production to date • ~373 MMbbls gross Infill drilling since 2009 has largely sustained production Continuation of infill drilling program • 2012 campaign extended from
Slide 15: MacCulloch Field Overview - Block 15/24b
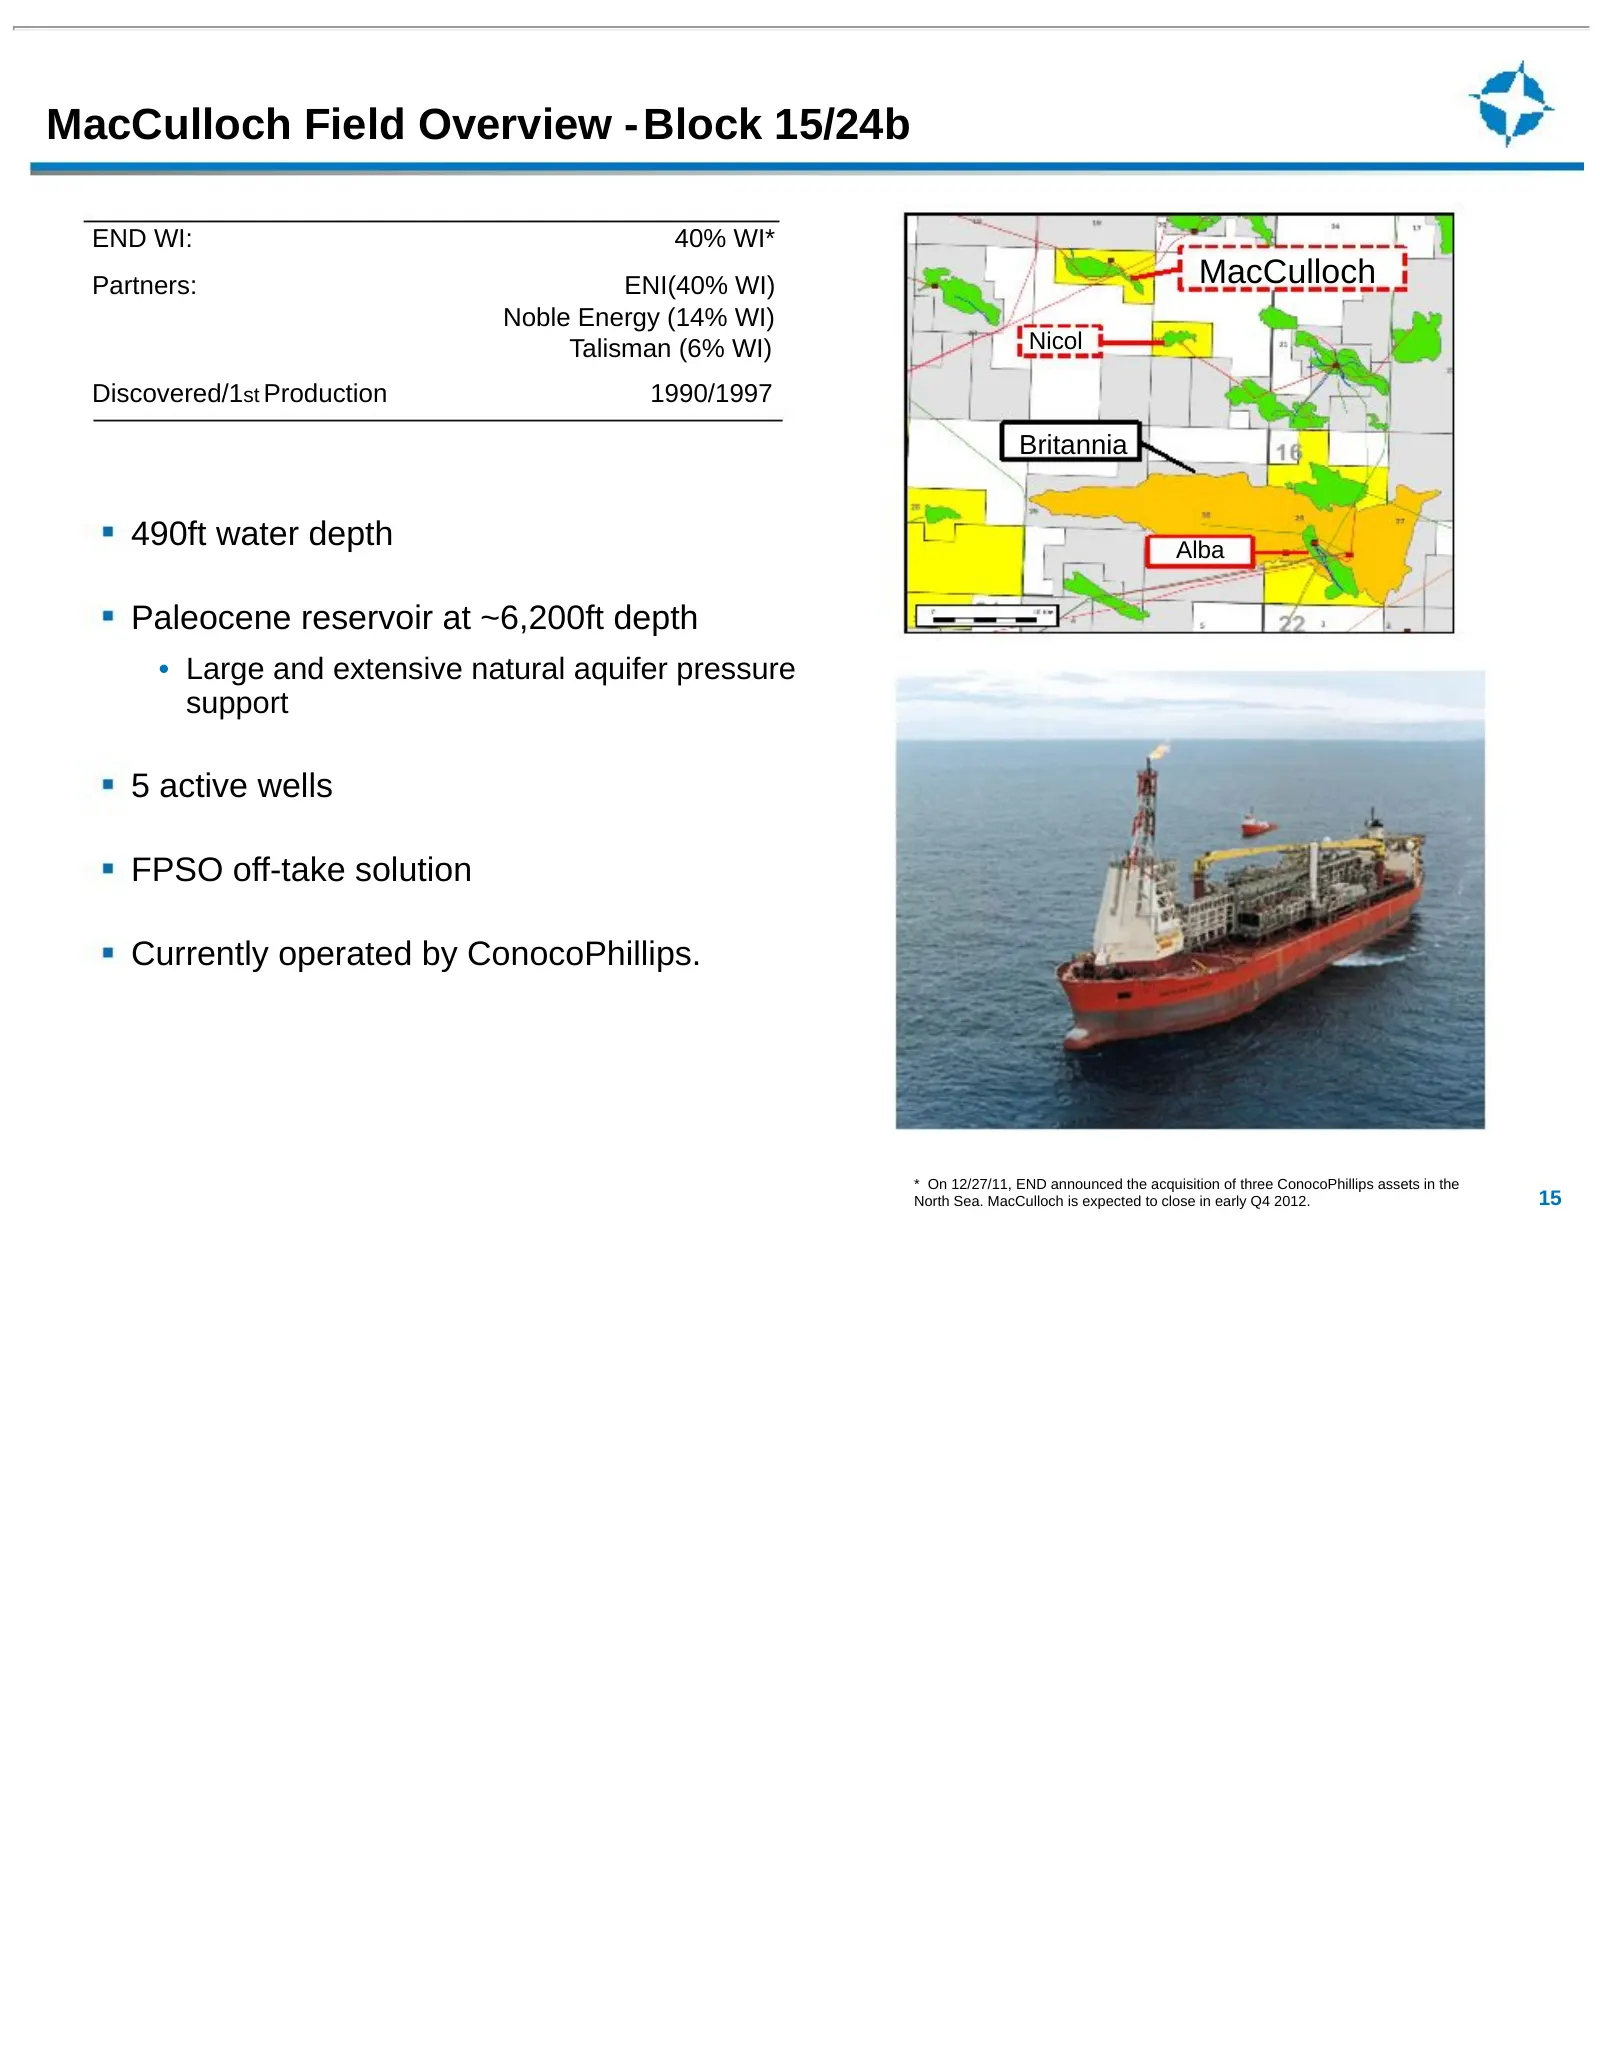
MacCulloch Field Overview - Block 15/24b END WI: 40% WI* Partners: ENI(40% WI) MacCulloch Noble Energy (14% WI) Talisman (6% WI) Nicol Discovered/1st Production 1990/1997 Britannia 490ft water depth Alba Paleocene reservoir at ~6,200ft depth • Large and extensive natural aquifer pressure support 5 a
Slide 16: MacCulloch Field - Details
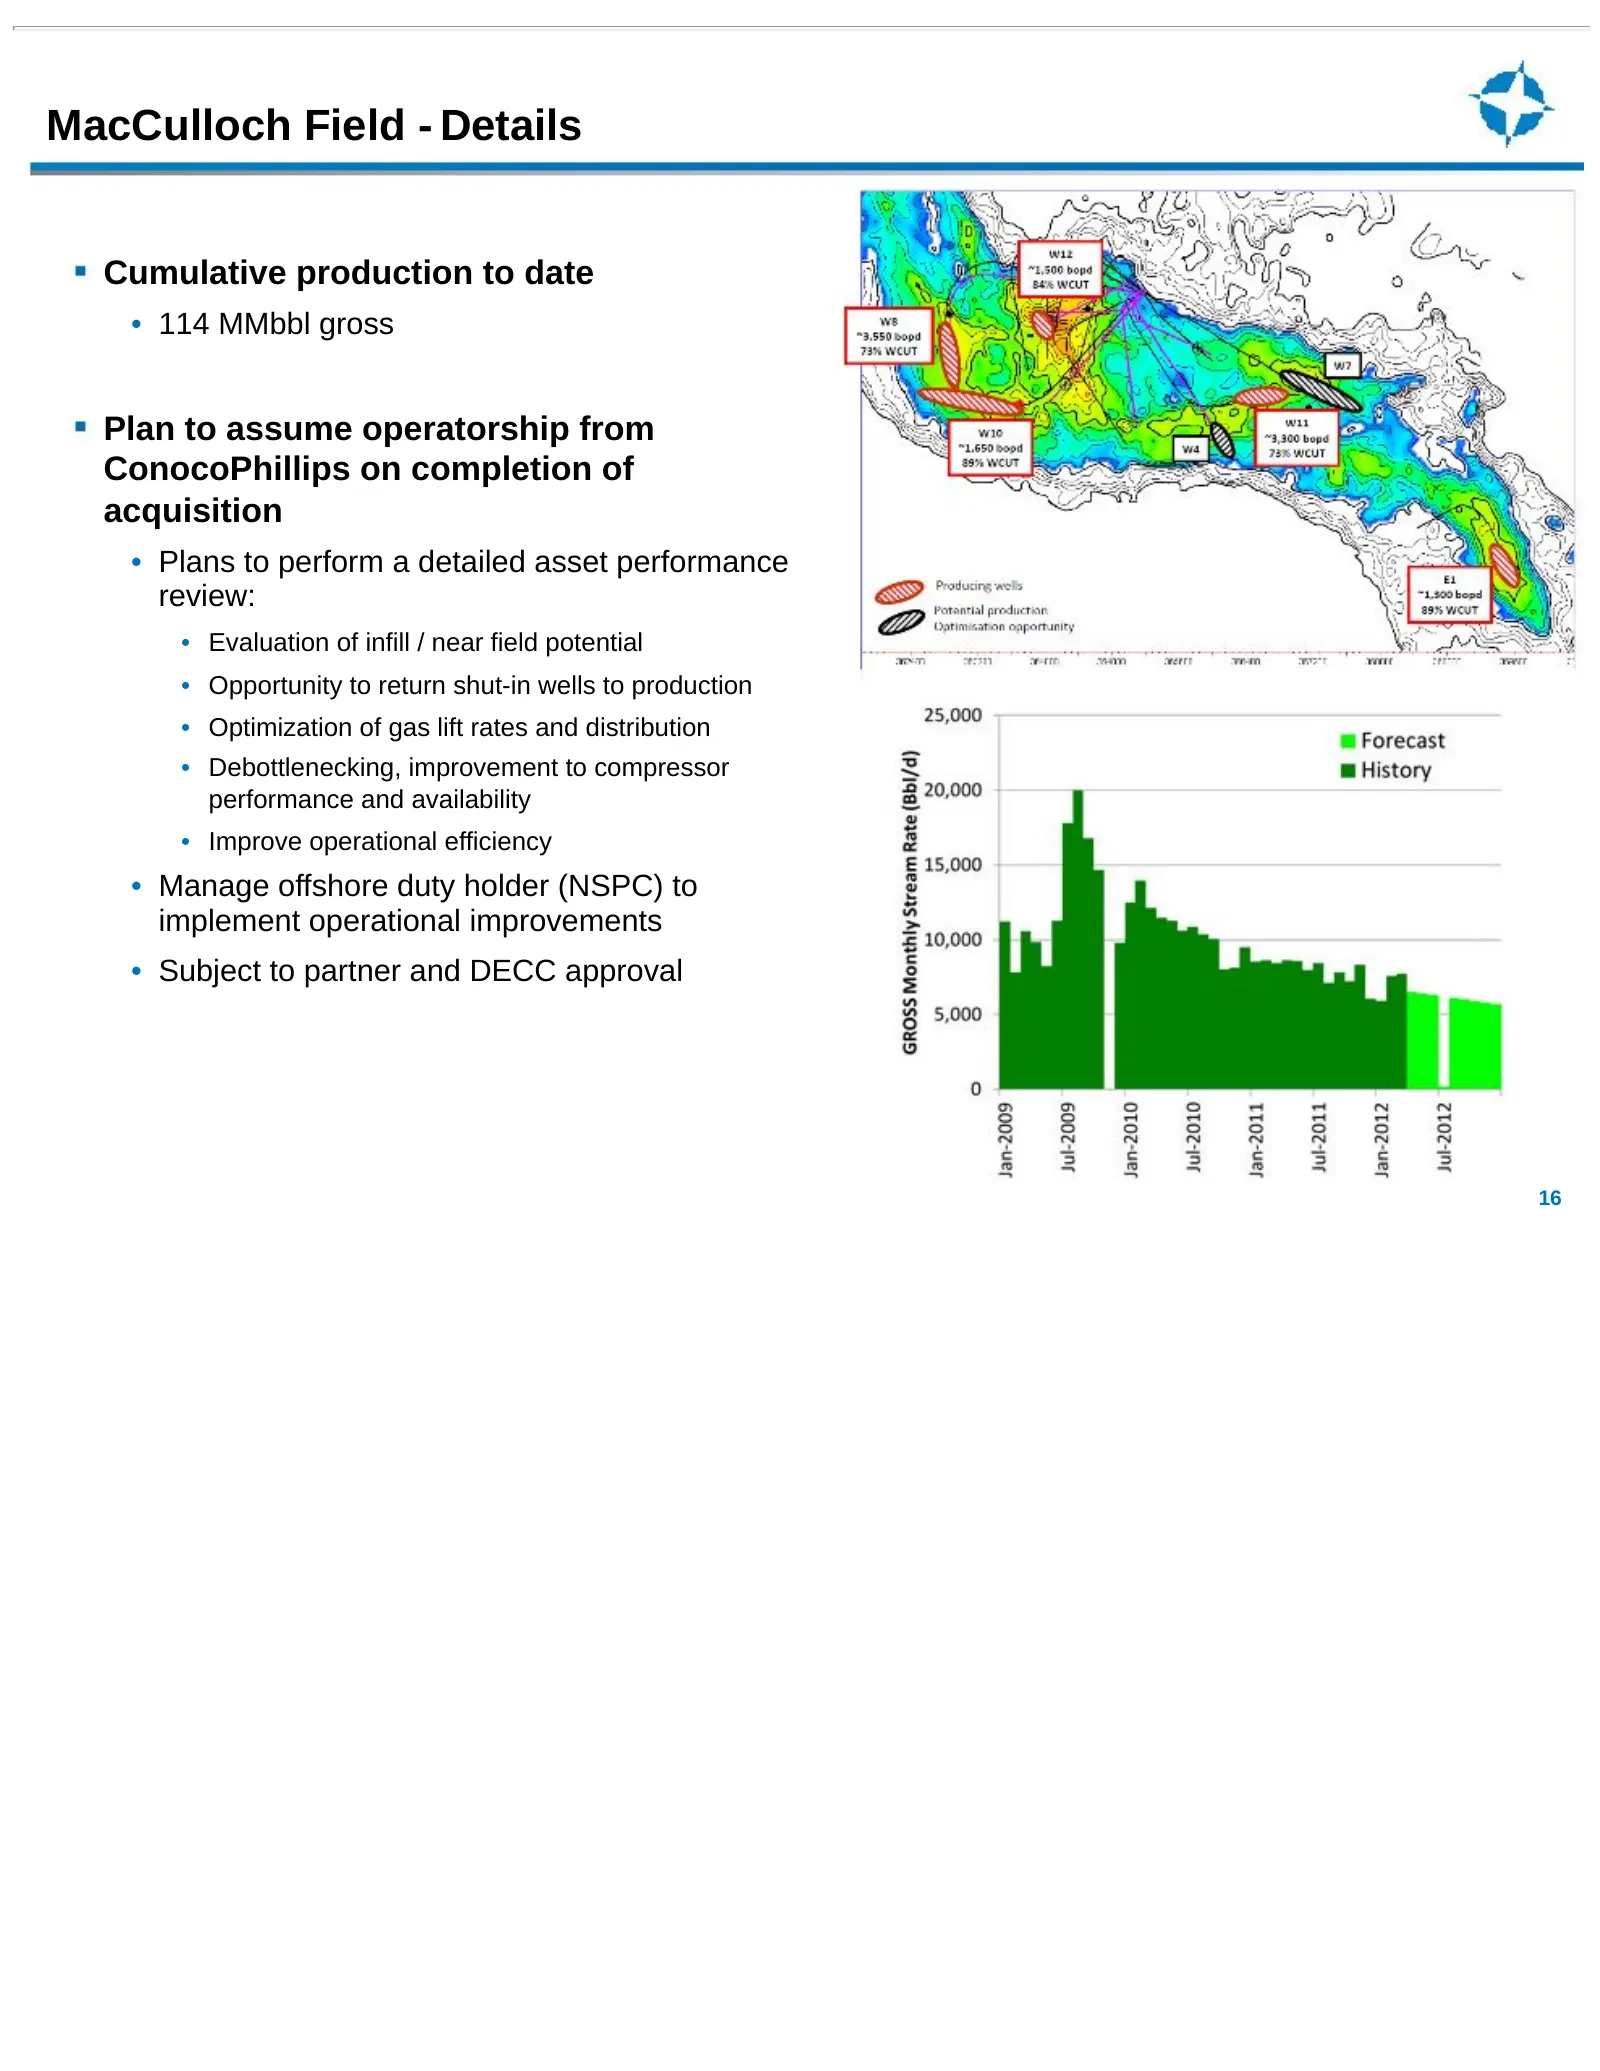
MacCulloch Field - Details Cumulative production to date • 114 MMbbl gross Plan to assume operatorship from ConocoPhillips on completion of acquisition • Plans to perform a detailed asset performance review: • Evaluation of infill / near field potential • Opportunity to return shut-in wells to produ
Slide 17: Overview of Endeavour's US Assets
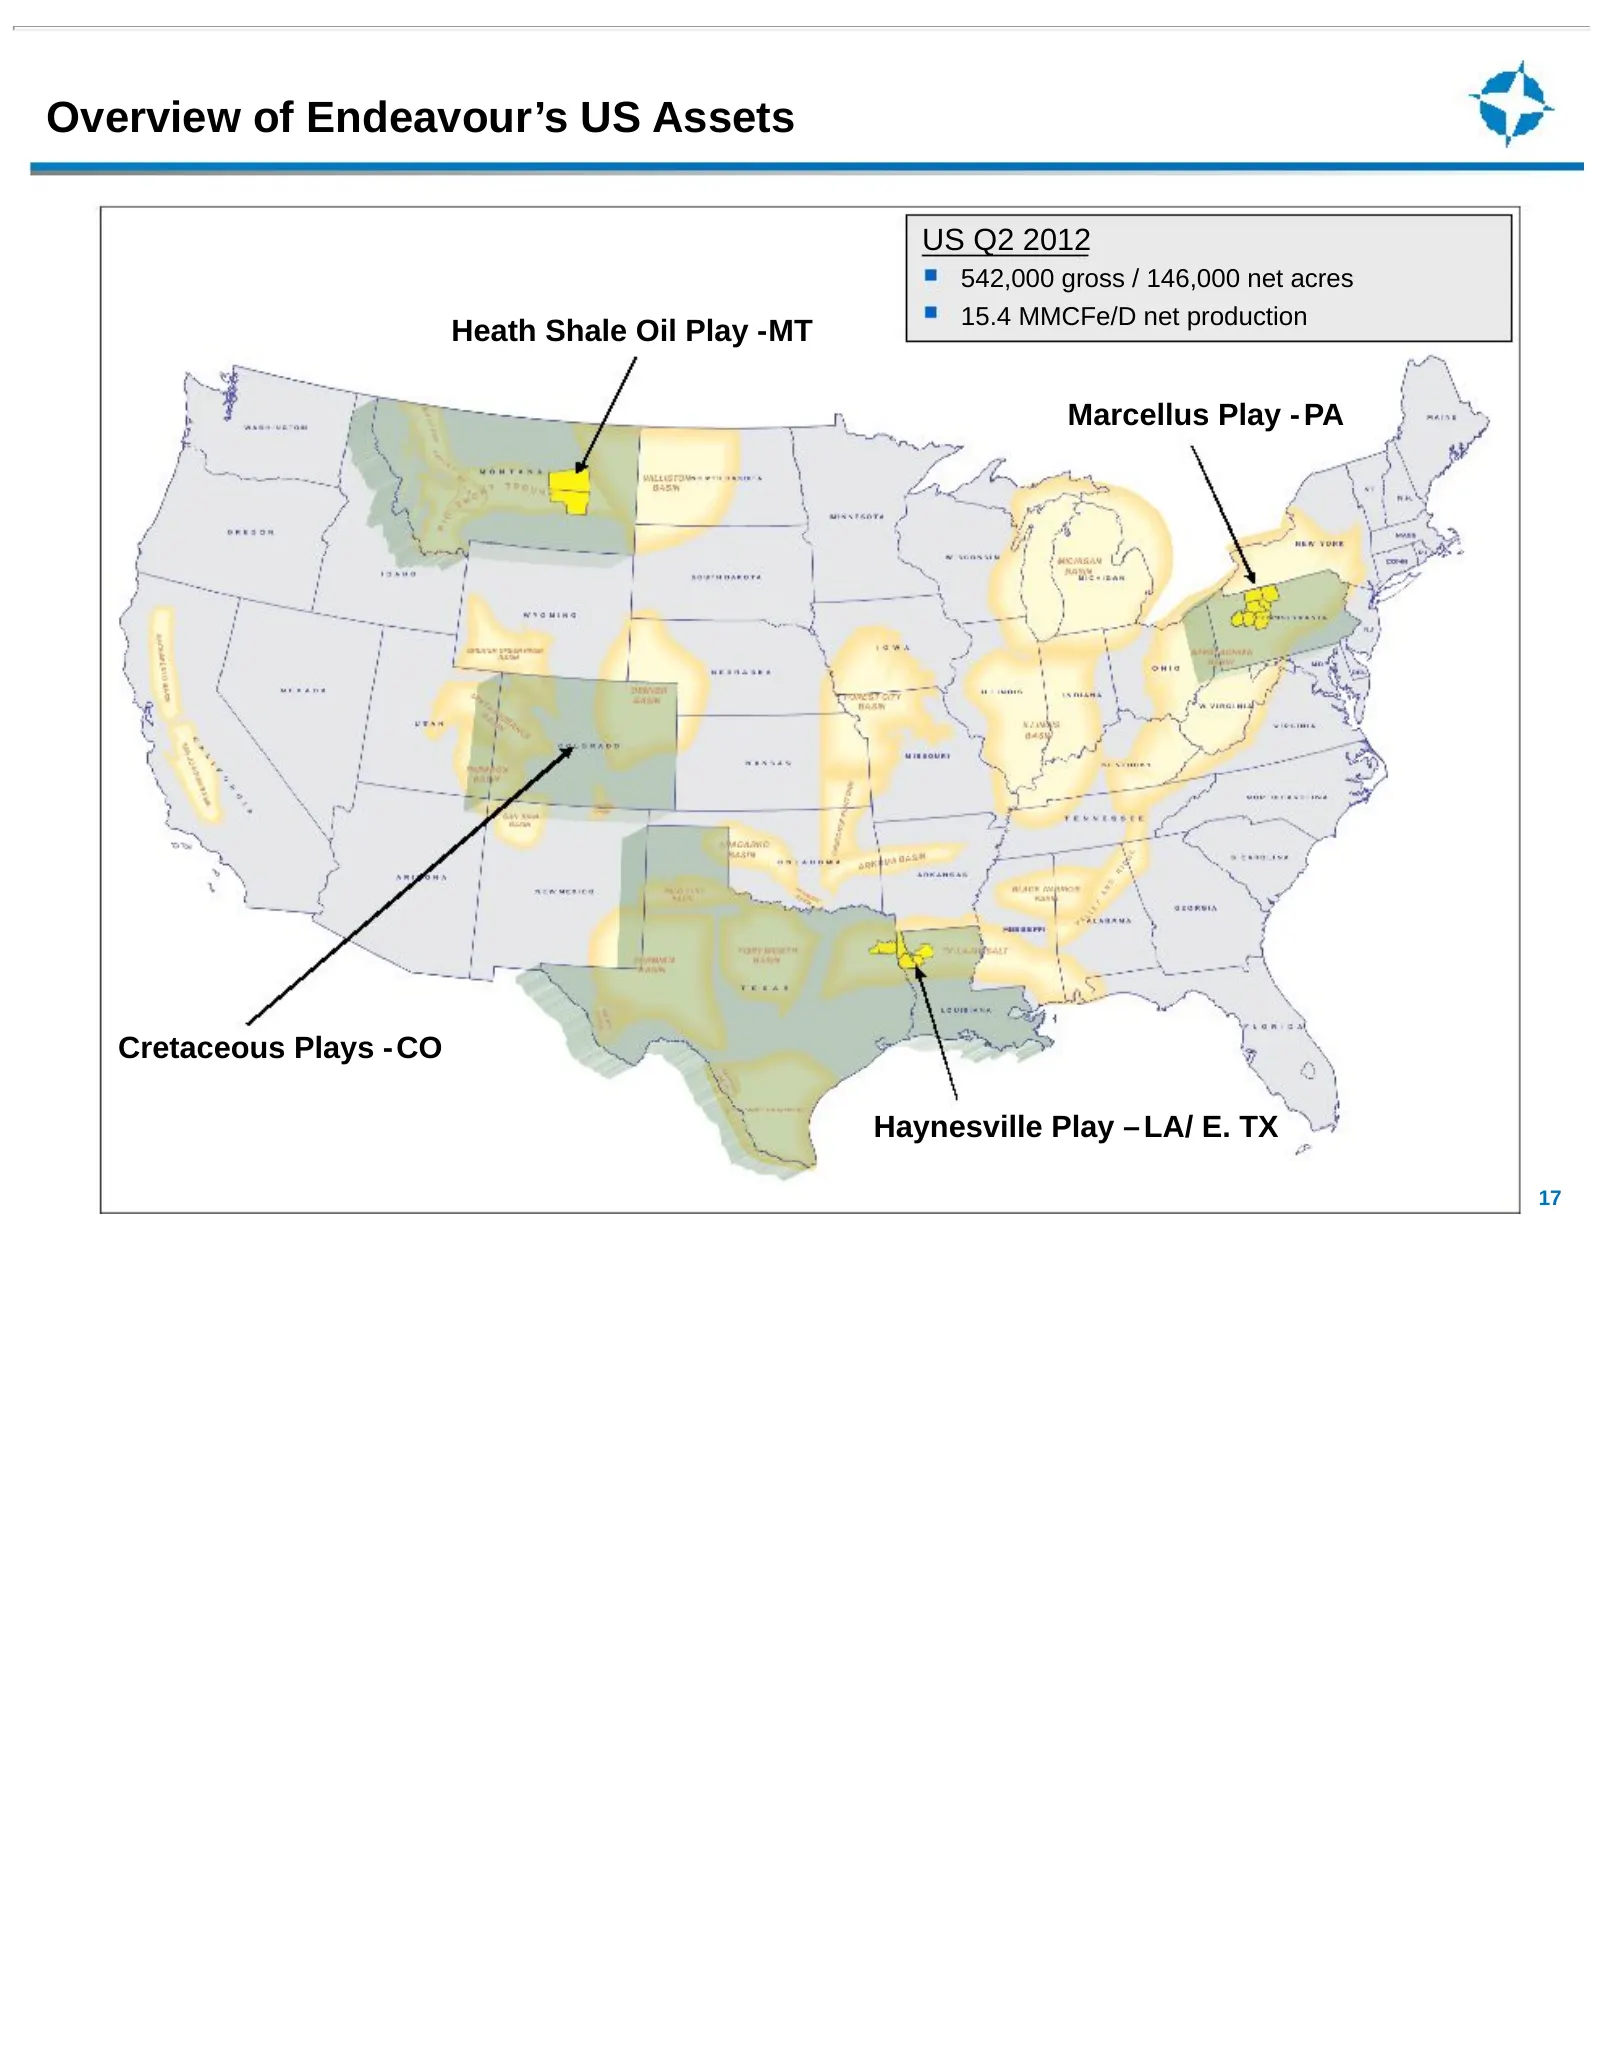
Overview of Endeavour’s US Assets US Q2 2012 542,000 gross / 146,000 net acres 15.4 MMCFe/D net production Heath Shale Oil Play -MT Marcellus Play - PA Cretaceous Plays - CO Haynesville Play – LA/ E. TX 17
Slide 18: Heath Shale 'Tight Oil' Play in Central Montana
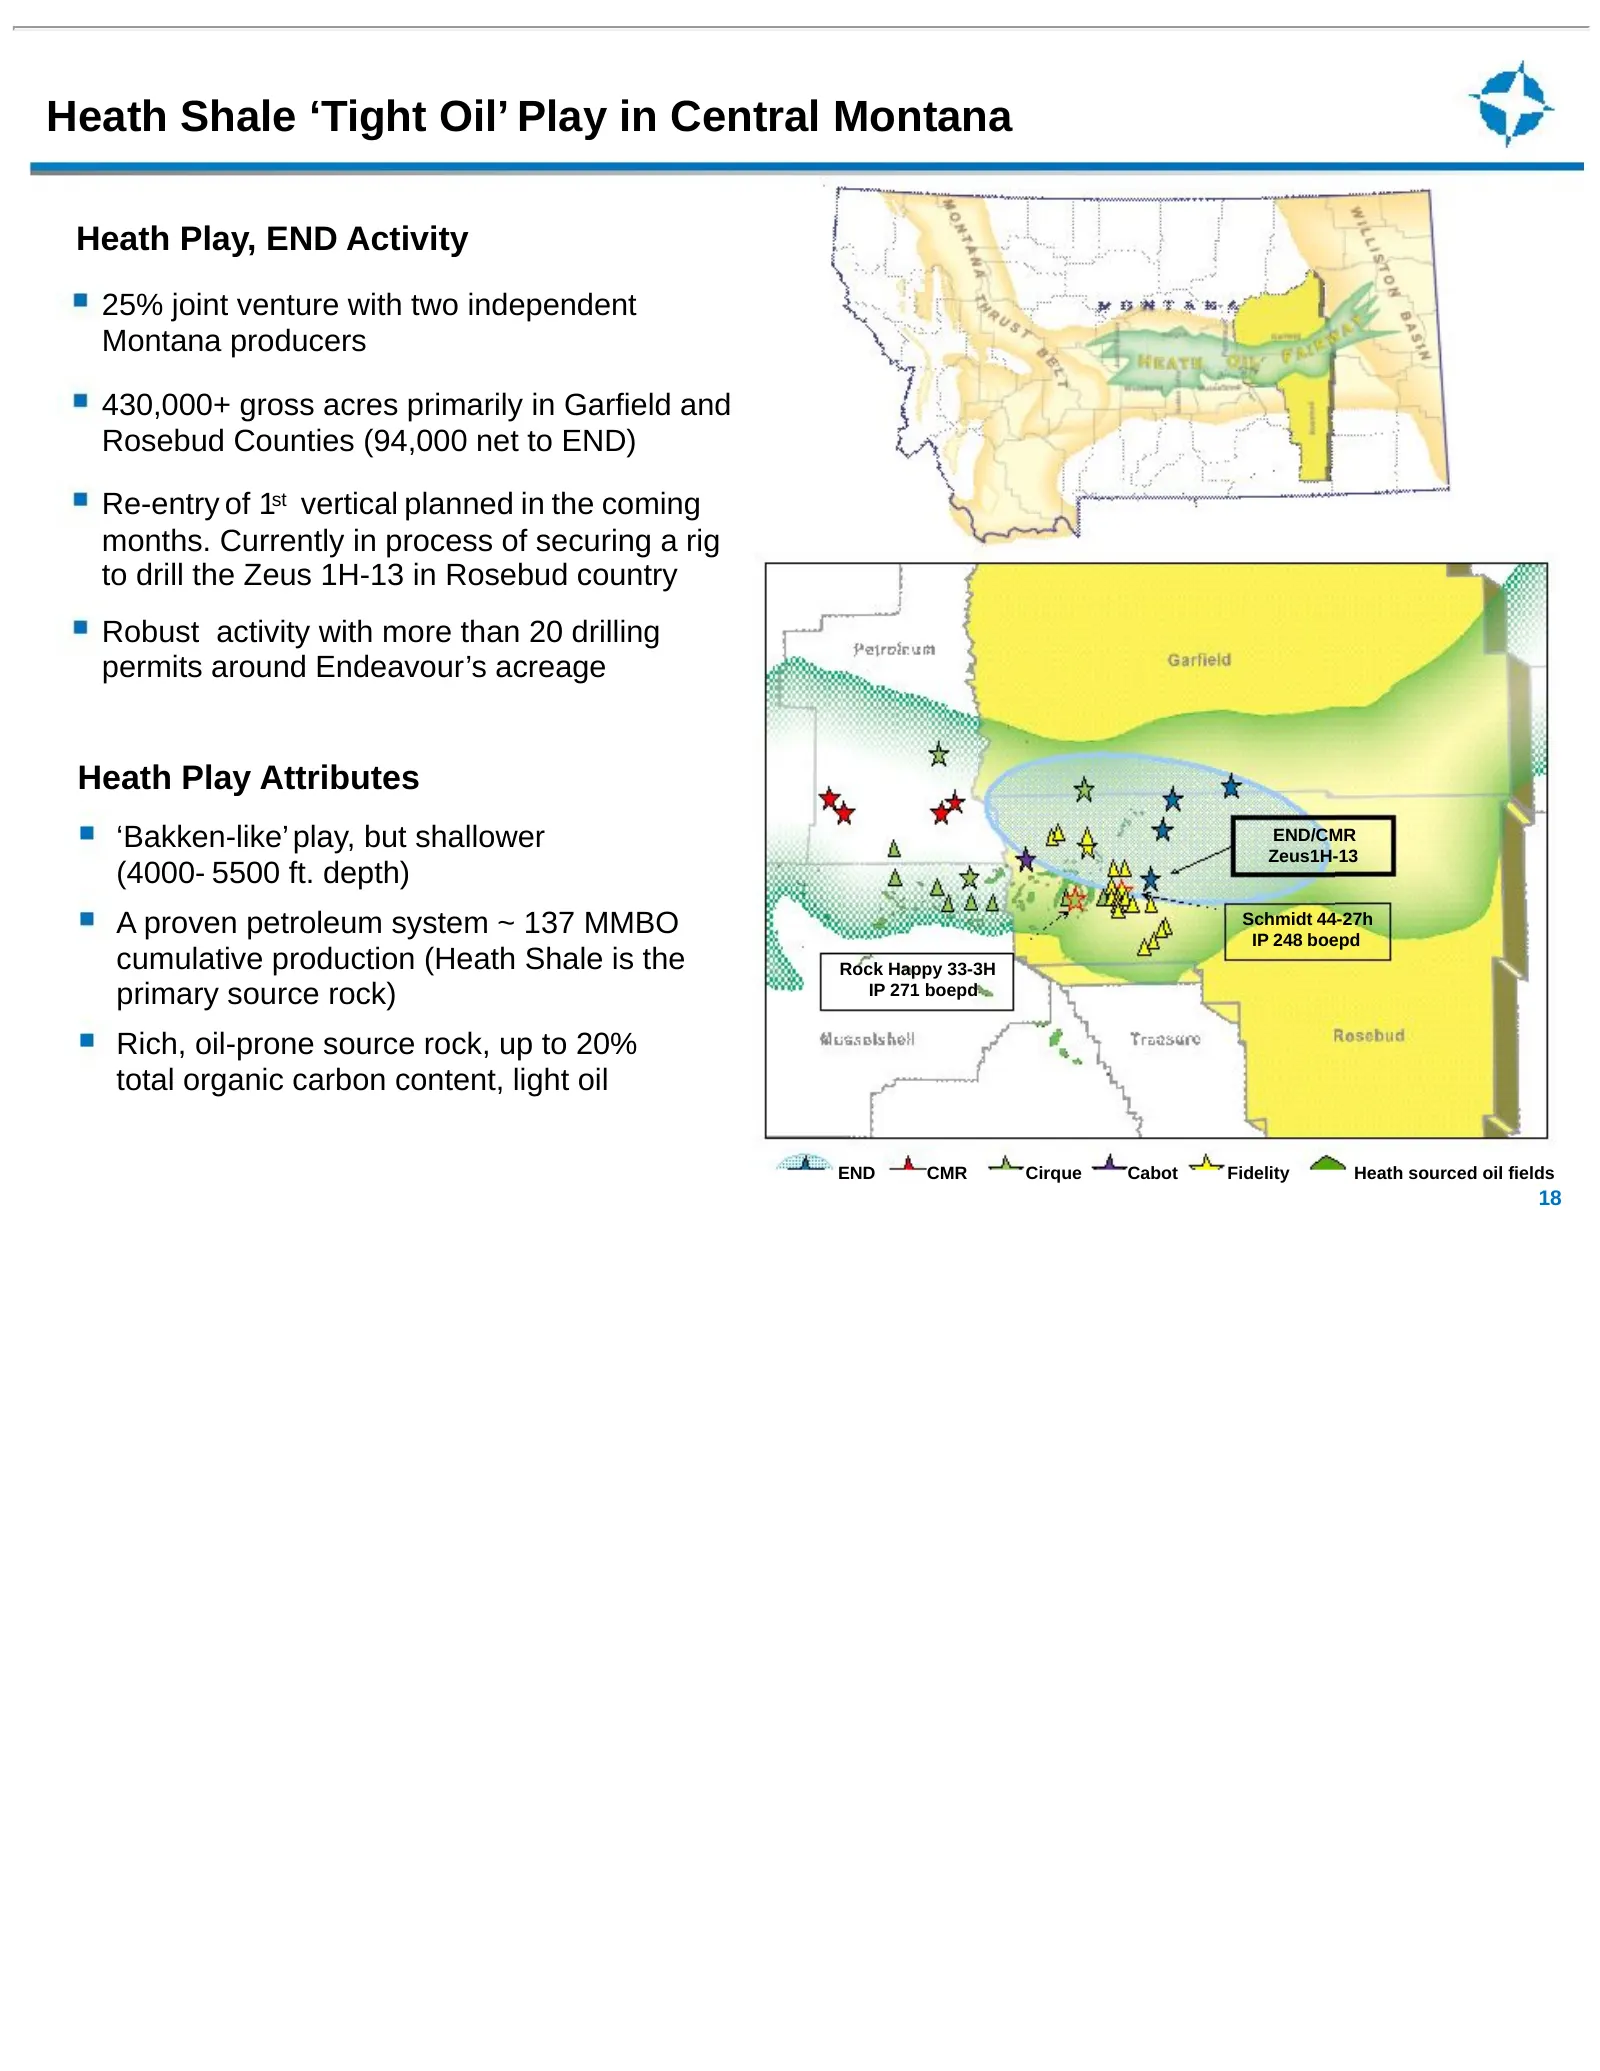
Heath Shale ‘Tight Oil’ Play in Central Montana Heath Play, END Activity 25% joint venture with two independent Montana producers 430,000+ gross acres primarily in Garfield and Rosebud Counties (94,000 net to END) Re-entry of 1st vertical planned in the coming months. Currently in process of securin
Slide 19: The Haynesville and Marcellus Plays
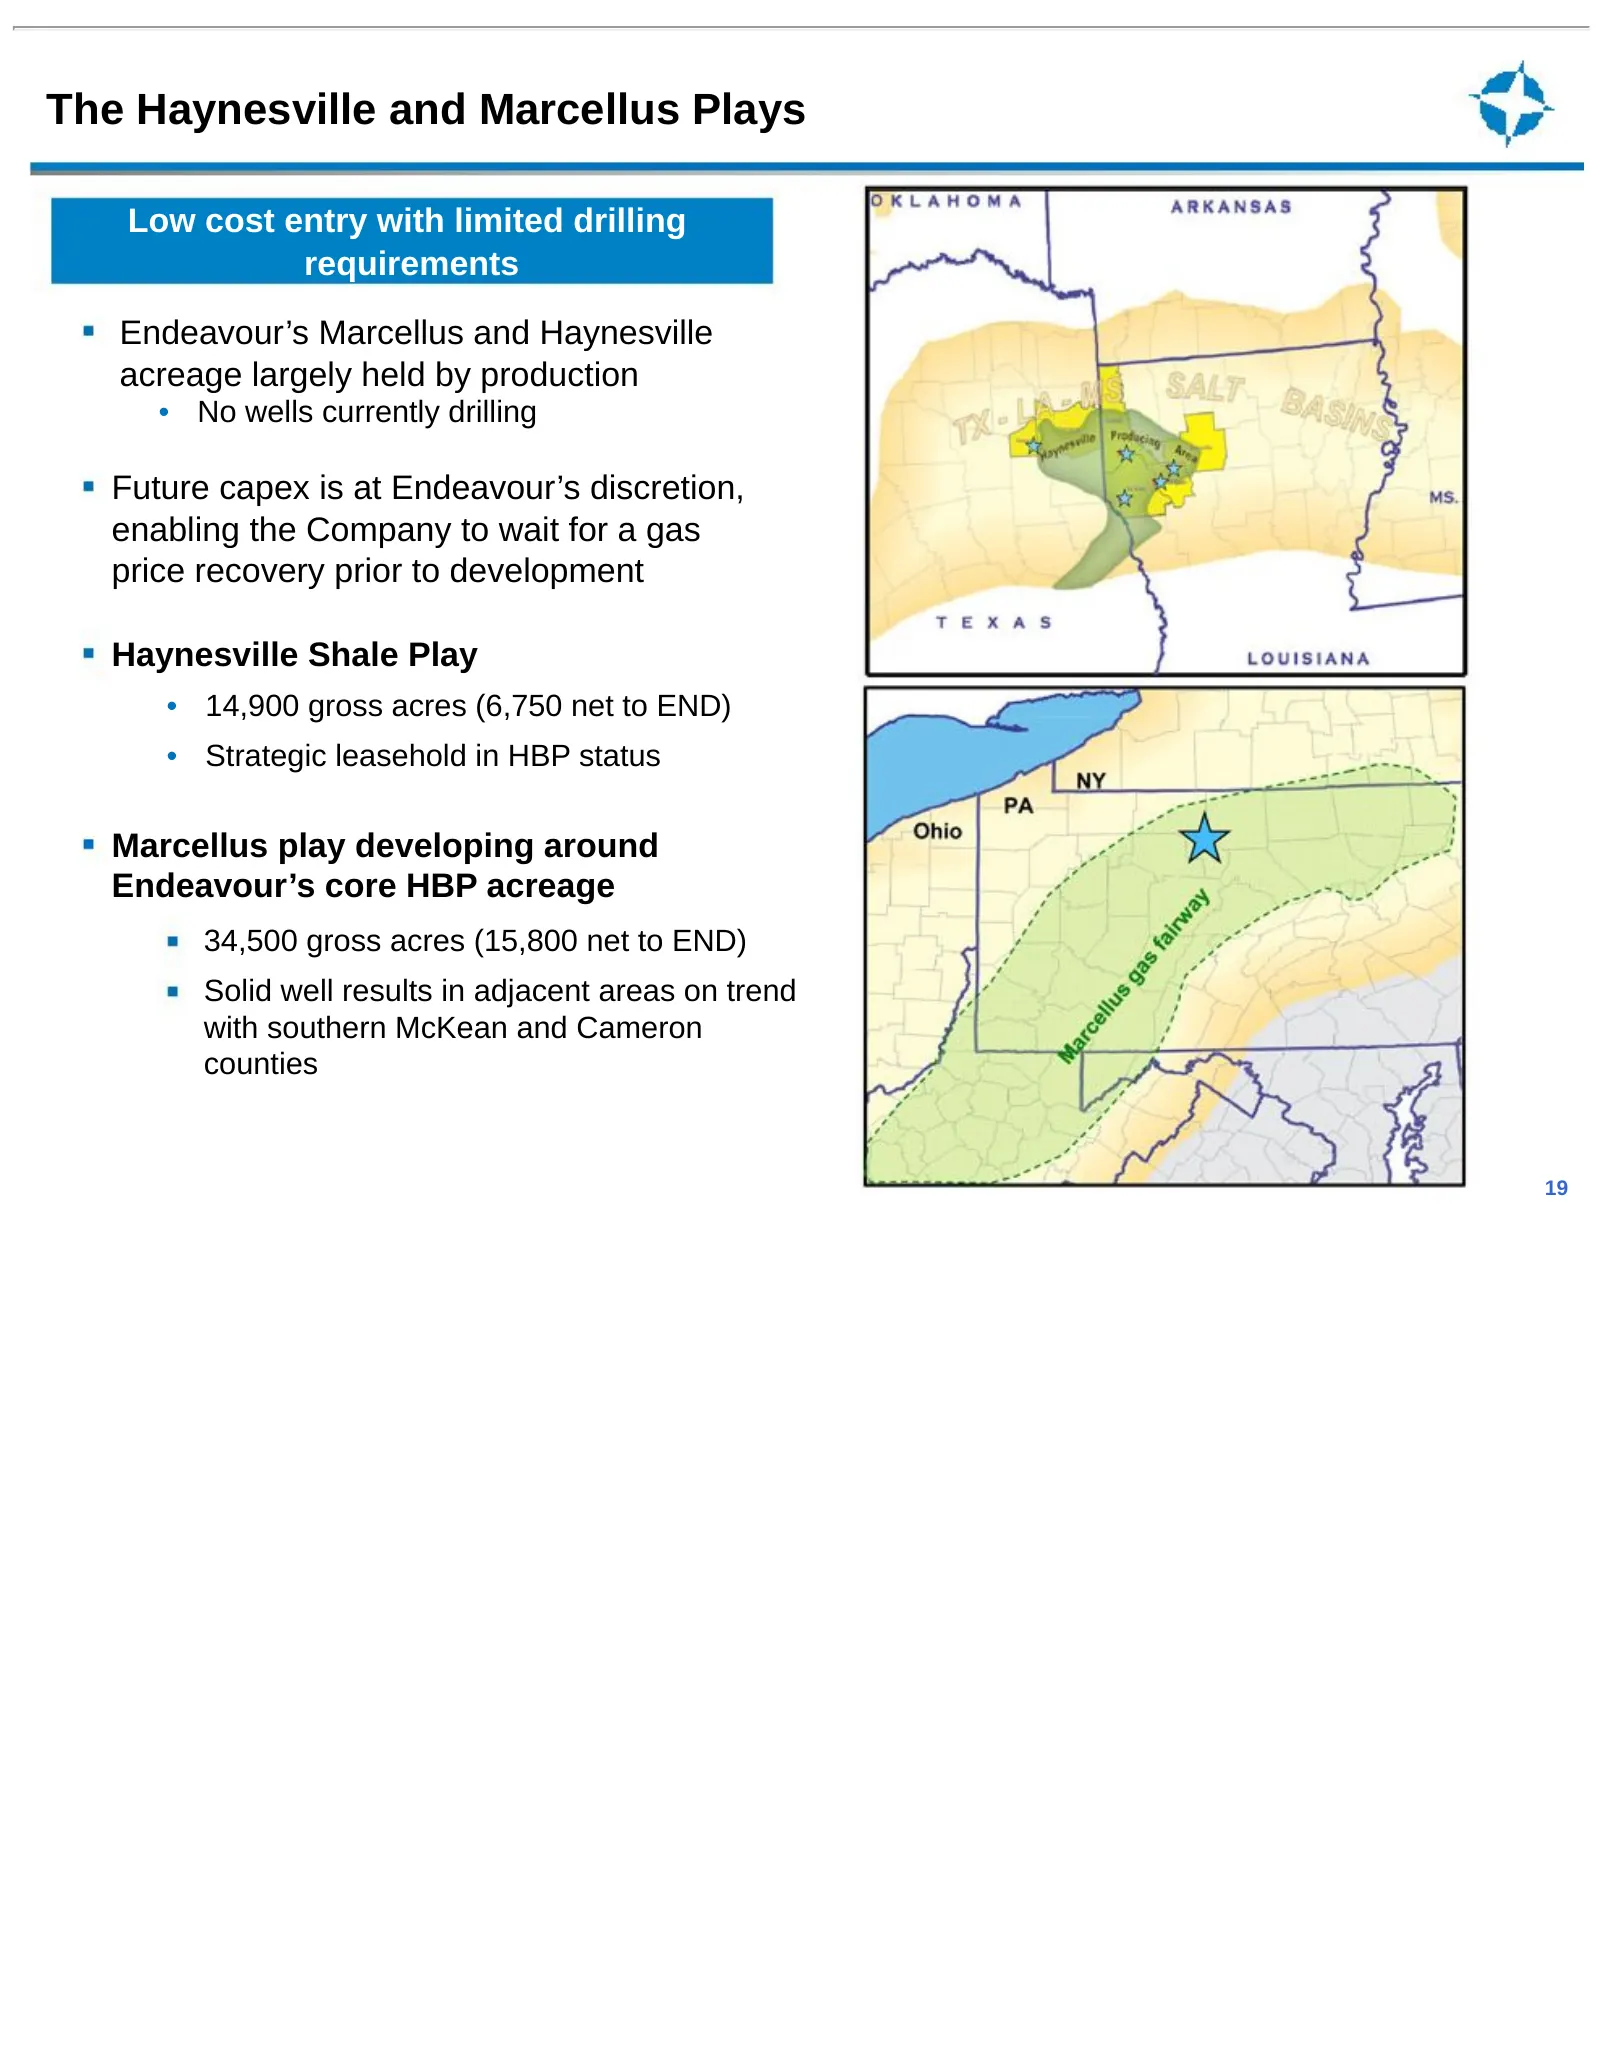
The Haynesville and Marcellus Plays Low cost entry with limited drilling requirements Endeavour’s Marcellus and Haynesville acreage largely held by production • No wells currently drilling Future capex is at Endeavour’s discretion, enabling the Company to wait for a gas price recovery prior to devel
Slide 20: Financial Philosophy
Financial Philosophy Maintain disciplined, conservative approach to capital spending • Allocate capital to optimize and grow our asset base, making appropriate adjustments in sustained periods of lower commodity prices • Capital budget is expected to be fully funded from operations • Focus on assets
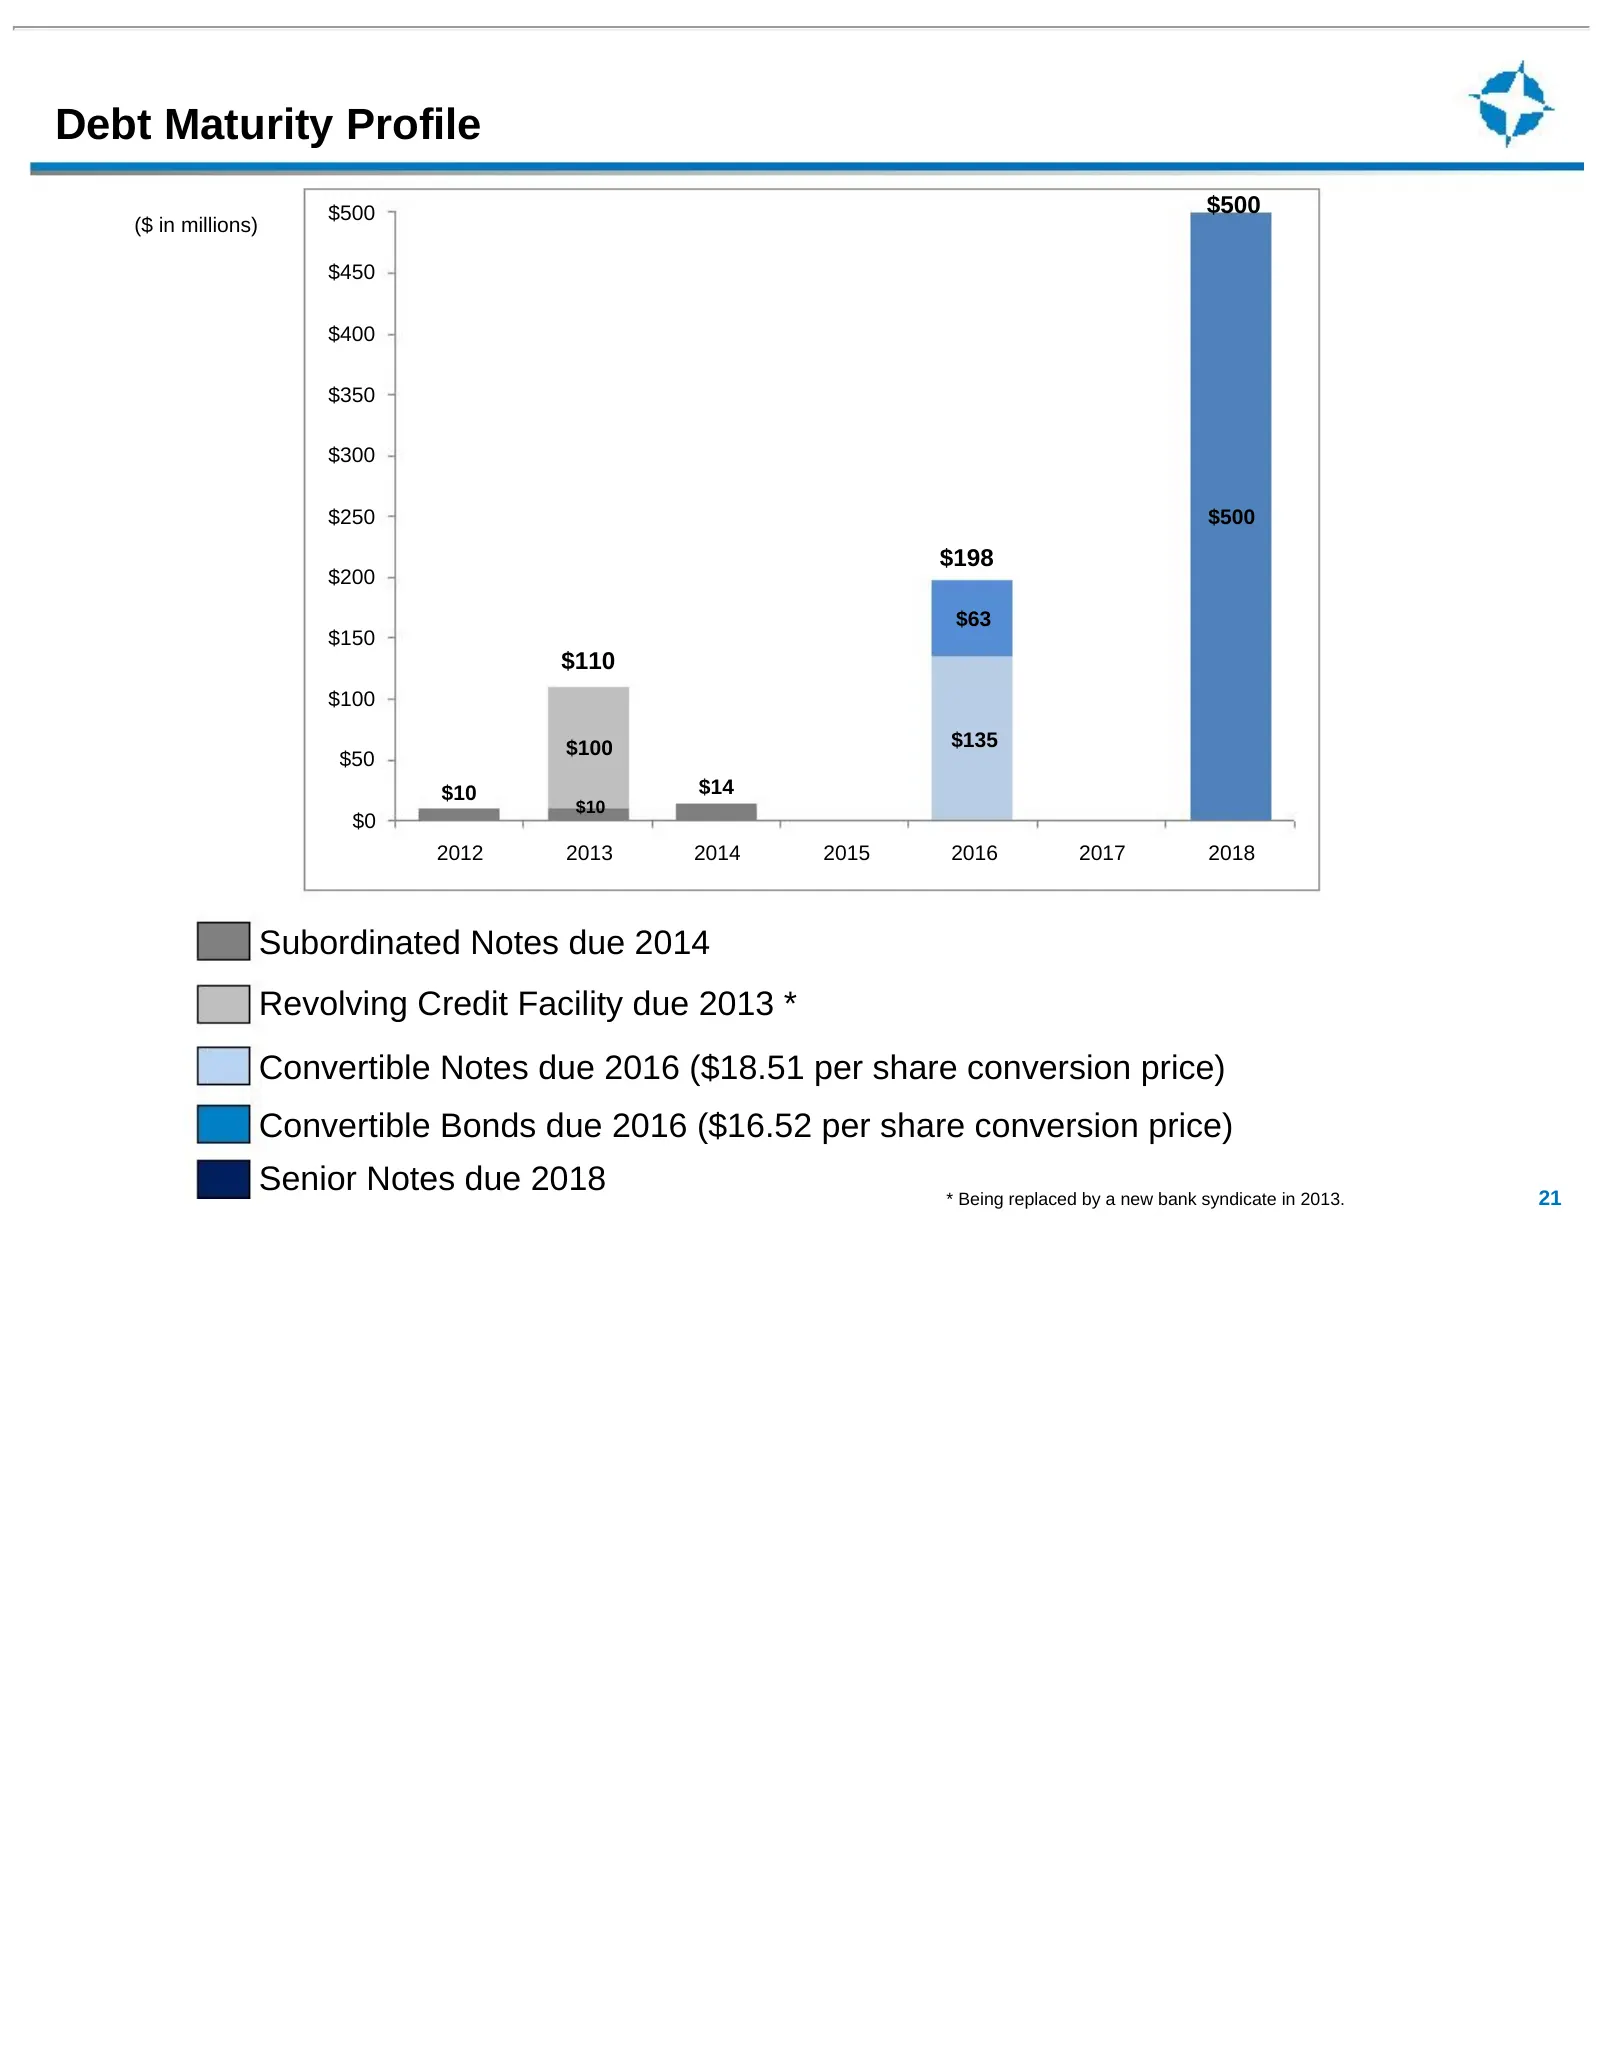
Slide 21: Debt Maturity Profile
Debt Maturity Profile $500 $500 ($ in millions) $450 $400 (1) $350 $300 $250 $500 $198 $200 $63 $150 $110 $100 $100 $135 $50 $10 $14 $10 $0 2012 2013 2014 2015 2016 2017 2018 Subordinated Notes due 2014 Revolving Credit Facility due 2013 * Convertible Notes due 2016 ($18.51 per share conversion pric
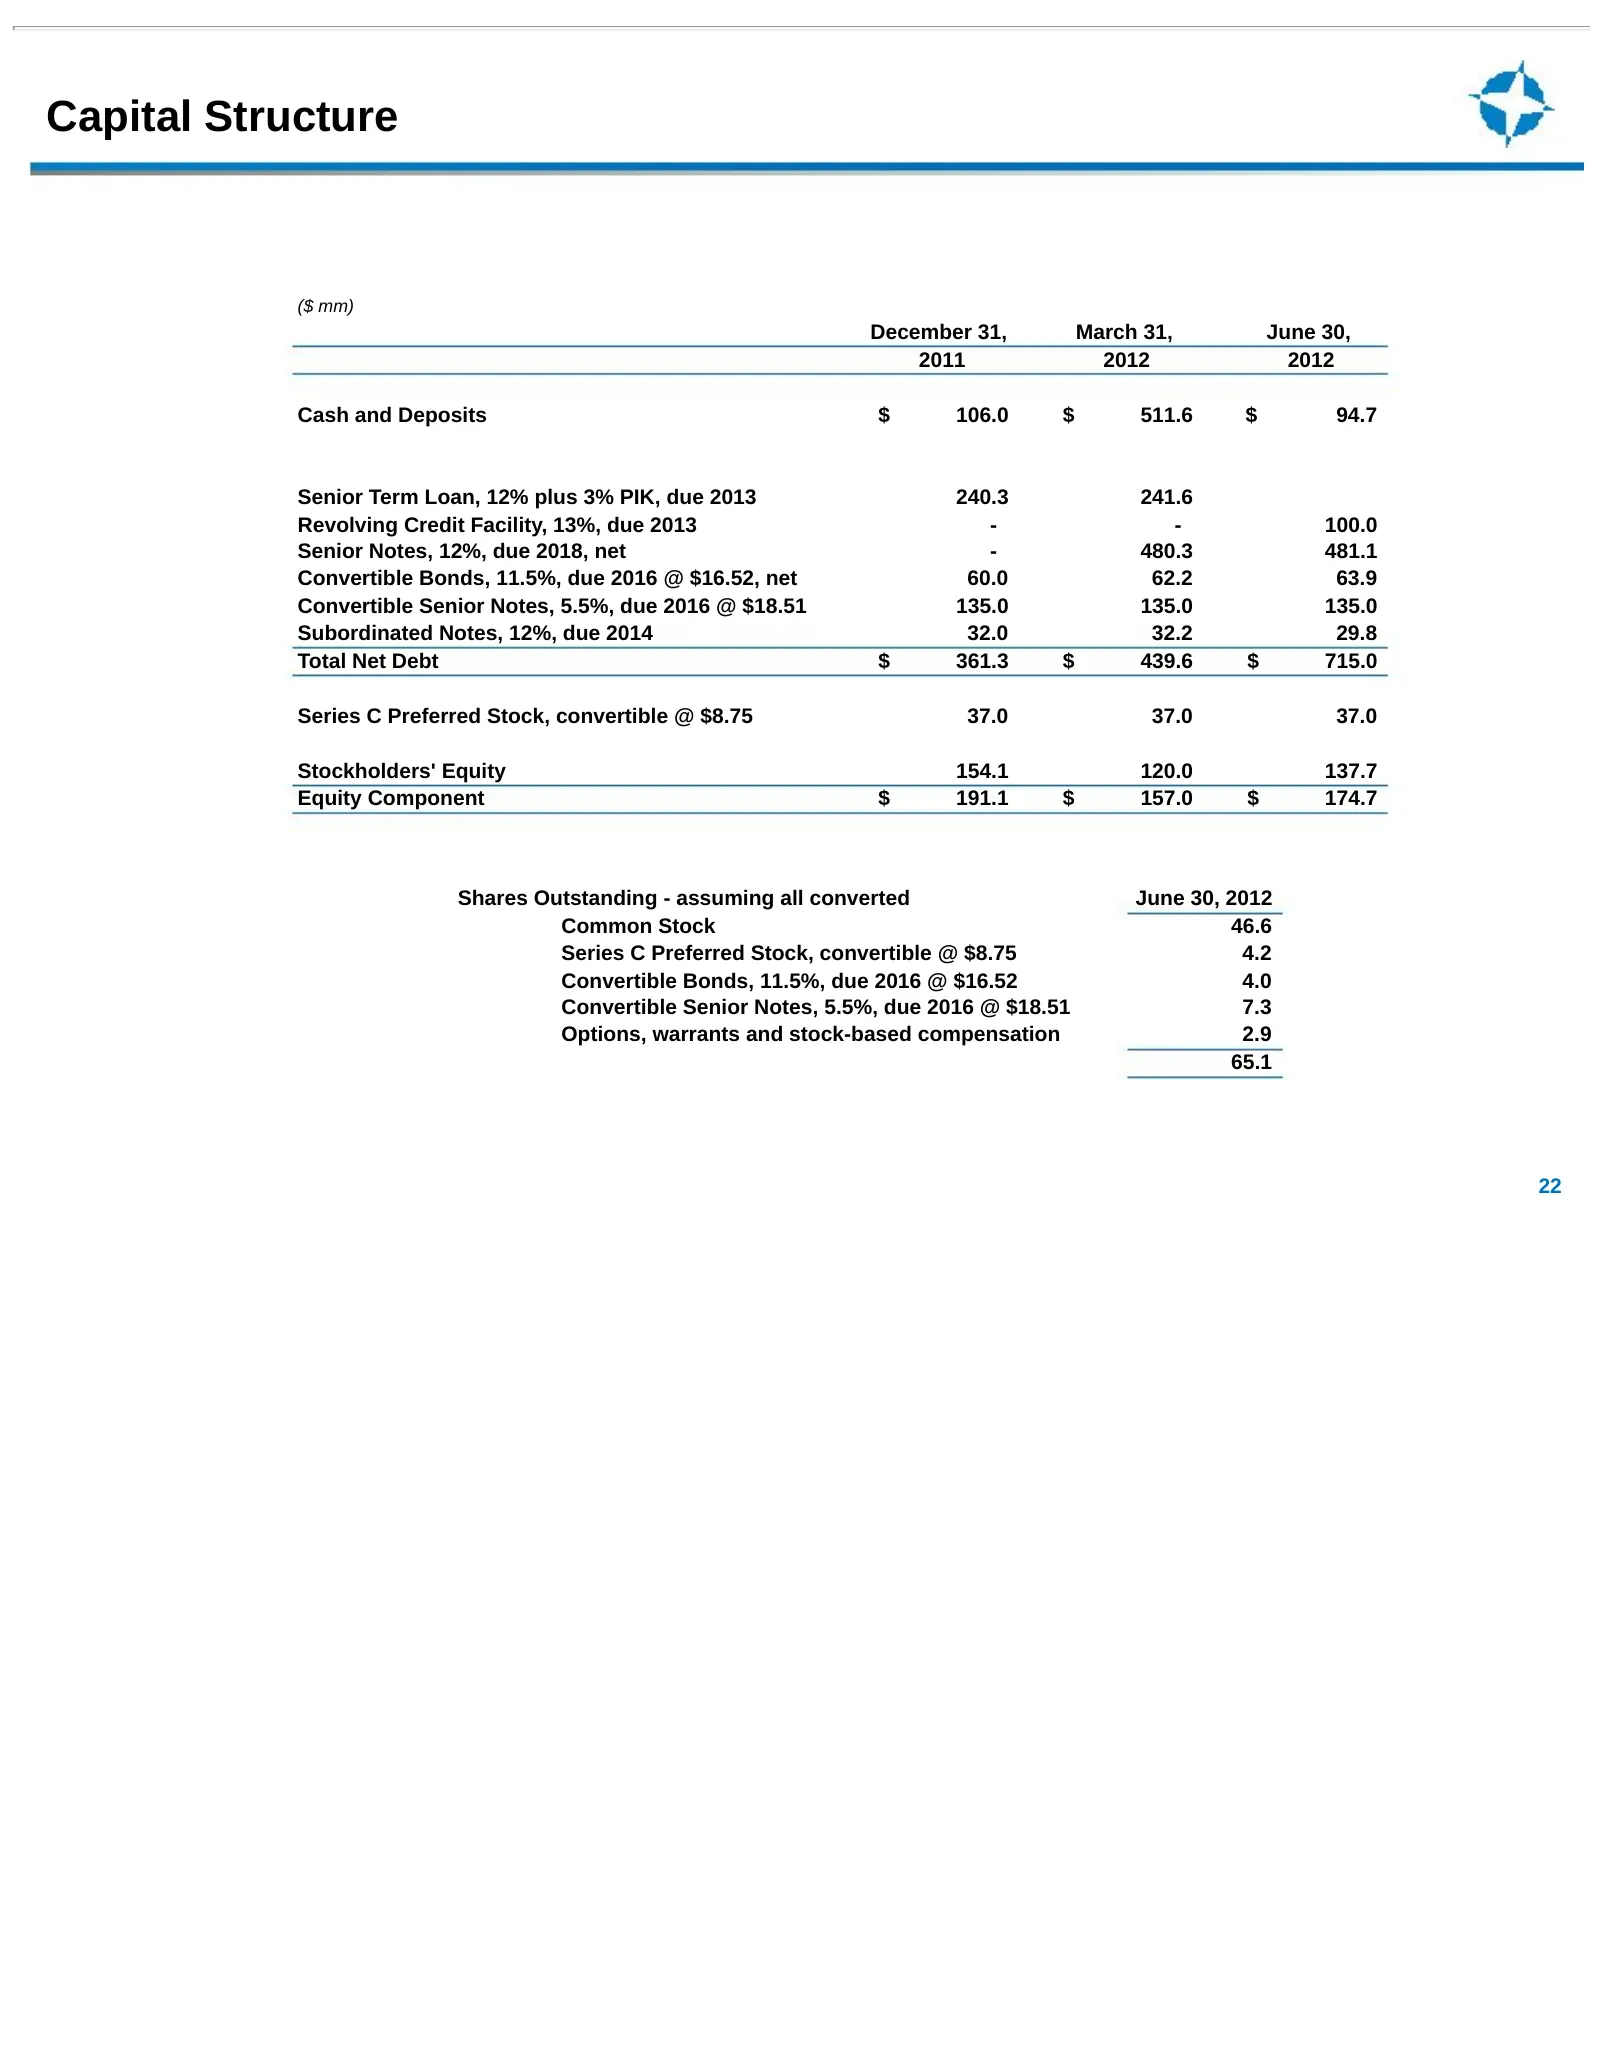
Slide 22: Capital Structure
Capital Structure ($ mm) December 31, March 31, June 30, 2011 2012 2012 Cash and Deposits $ 106.0 $ 511.6 $ 94.7 Senior Term Loan, 12% plus 3% PIK, due 2013 240.3 241.6 Revolving Credit Facility, 13%, due 2013 - - 100.0 Senior Notes, 12%, due 2018, net - 480.3 481.1 Convertible Bonds, 11.5%, due 201
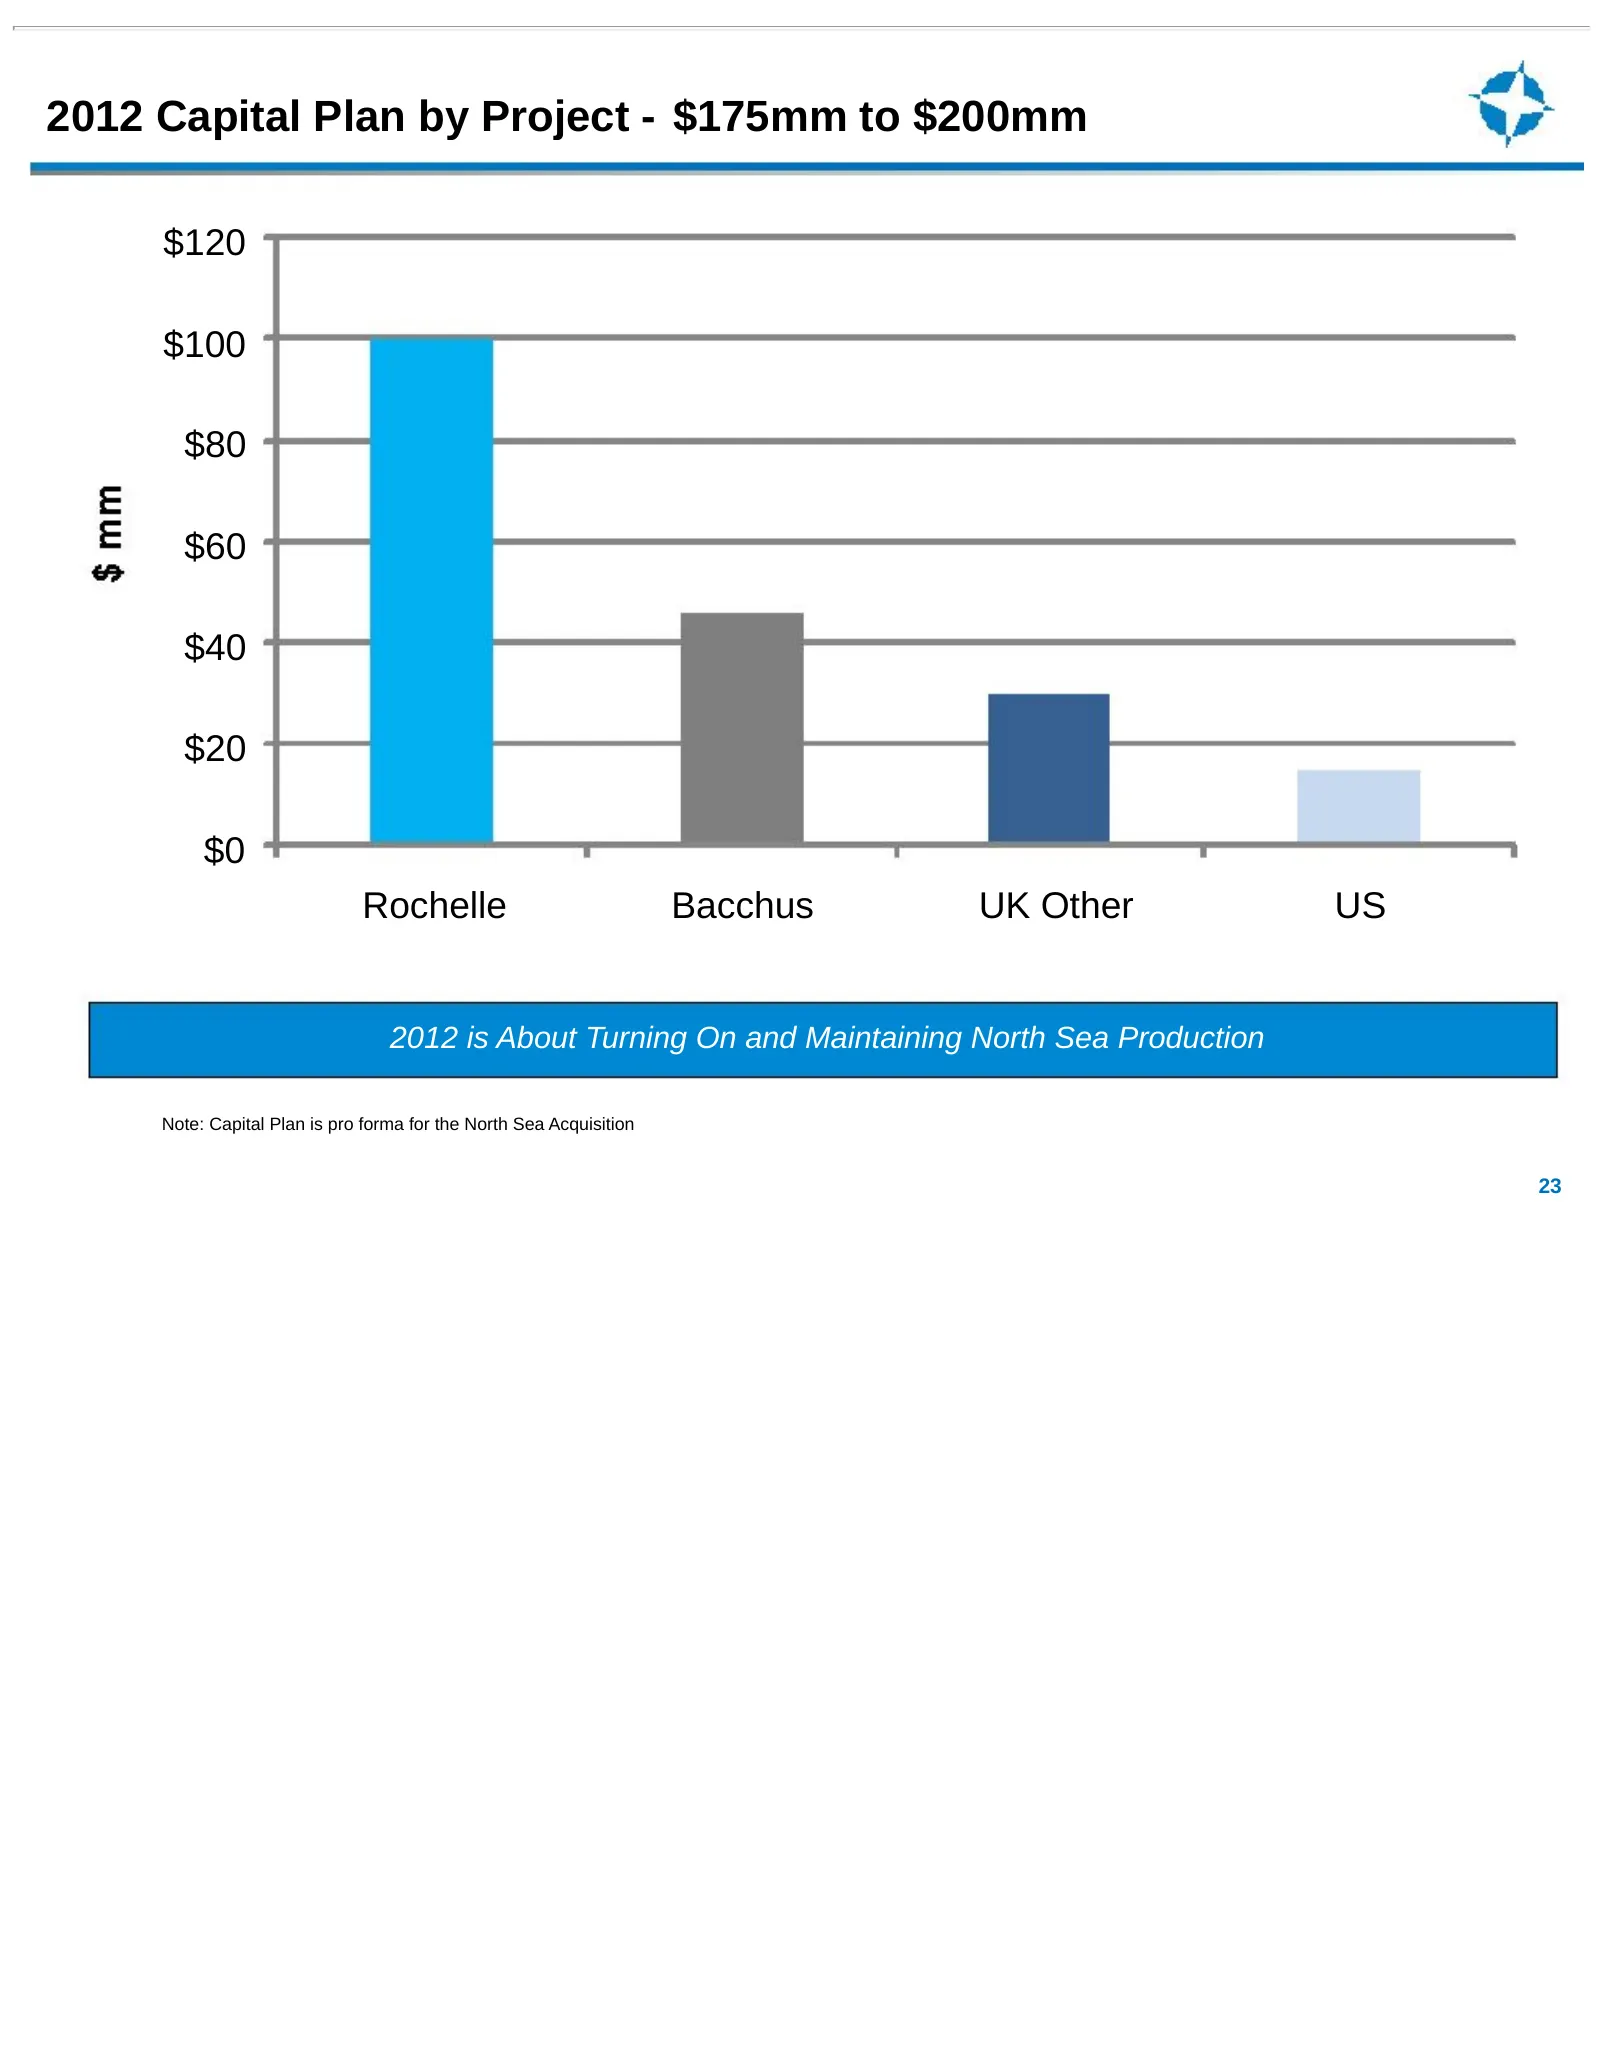
Slide 23: 2012 Capital Plan by Project - $175mm to $200mm
2012 Capital Plan by Project - $175mm to $200mm $120 $100 $80 $60 $40 $20 $0 Rochelle Bacchus UK Other US 2012 is About Turning On and Maintaining North Sea Production Note: Capital Plan is pro forma for the North Sea Acquisition 23
Slide 24: Key Credit Highlights
Key Credit Highlights Balanced business strategy based on the low risk exploitational development of proven petroleum systems with current technology North Sea acquisition has significantly increase production and cash flow Significant production growth expected in 2013 from known developments Produ
Slide 25: Corporate Focus
Corporate Focus North Sea Asset Acquisition • Closed acquisition of Alba interests on May 31, 2012 • Closing on the acquisition of MacCulloch and Nicol field interests expected in early 4Q Bacchus Development On-line • First two wells on production with field performance at 13,000 boepd gross and ab
Slide 26: Investor Contacts
NYSE:END LSE:ENDV www.endeavourcorp.com INVESTOR CONTACTS: Mike Kirksey Darcey Matthews Chief Financial Officer Director of Investor Relations 713.307.8788 / +44.207.451.2381 713.307.8711 mike.kirksey@endeavourcorp.com darcey.matthews@endeavourcorp.com
Source: SEC EDGAR · 8-K filed Oct 5, 2012
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014