McBride plc · LSE:MCB
McBride — FY2012-13 Earnings Presentation
32 slides from McBride's earnings presentation, Sep 3, 2013
Slide 1: McBride plc Preliminary Results Presentation
McBride plc Preliminary Results Presentation 3 September 2013 Passionate about Private Label
Slide 2: Summary
Summary Chris Bull – Chief Executive Officer Passionate about Private Label 2
Slide 3: Introduction
Introduction • A challenging year with a revenue decline in contract manufacturing as expected and intensified branded competition • Product launch programme successfully executed with Private Label revenue returning to growth in the second half • Adjusted operating profit(1) down 19% • Net debt of
Slide 4: Financial review
Financial review Richard Armitage - Chief Finance Officer Passionate about Private Label 4
Slide 5: Financial headlines
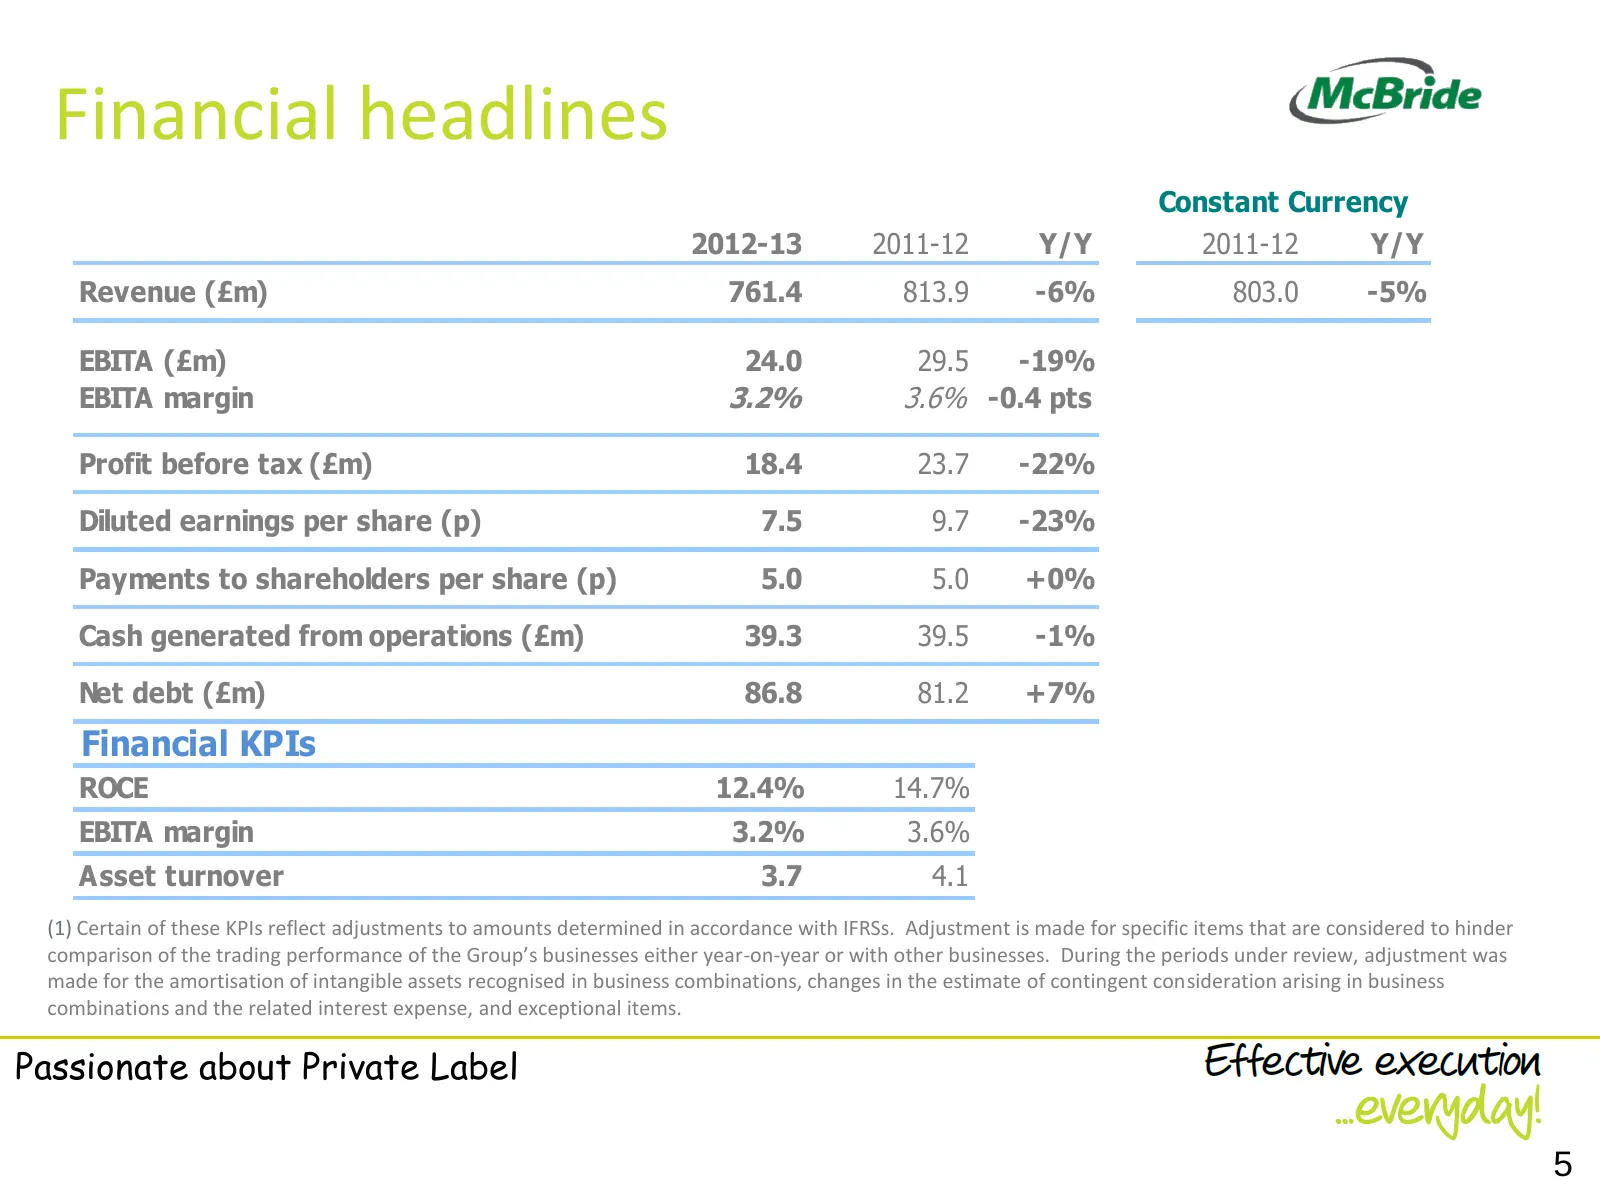
Financial headlines Constant Currency 2012-13 2011-12 Y/Y 2011-12 Y/Y Revenue (£m) 761.4 813.9 -6% 803.0 -5% EBITA (£m) 24.0 29.5 -19% EBITA margin 3.2% 3.6% -0.4 pts Profit before tax (£m) 18.4 23.7 -22% Diluted earnings per share (p) 7.5 9.7 -23% Payments to shareholders per share (p) 5.0 5.0 +0%
Slide 6: Income statement
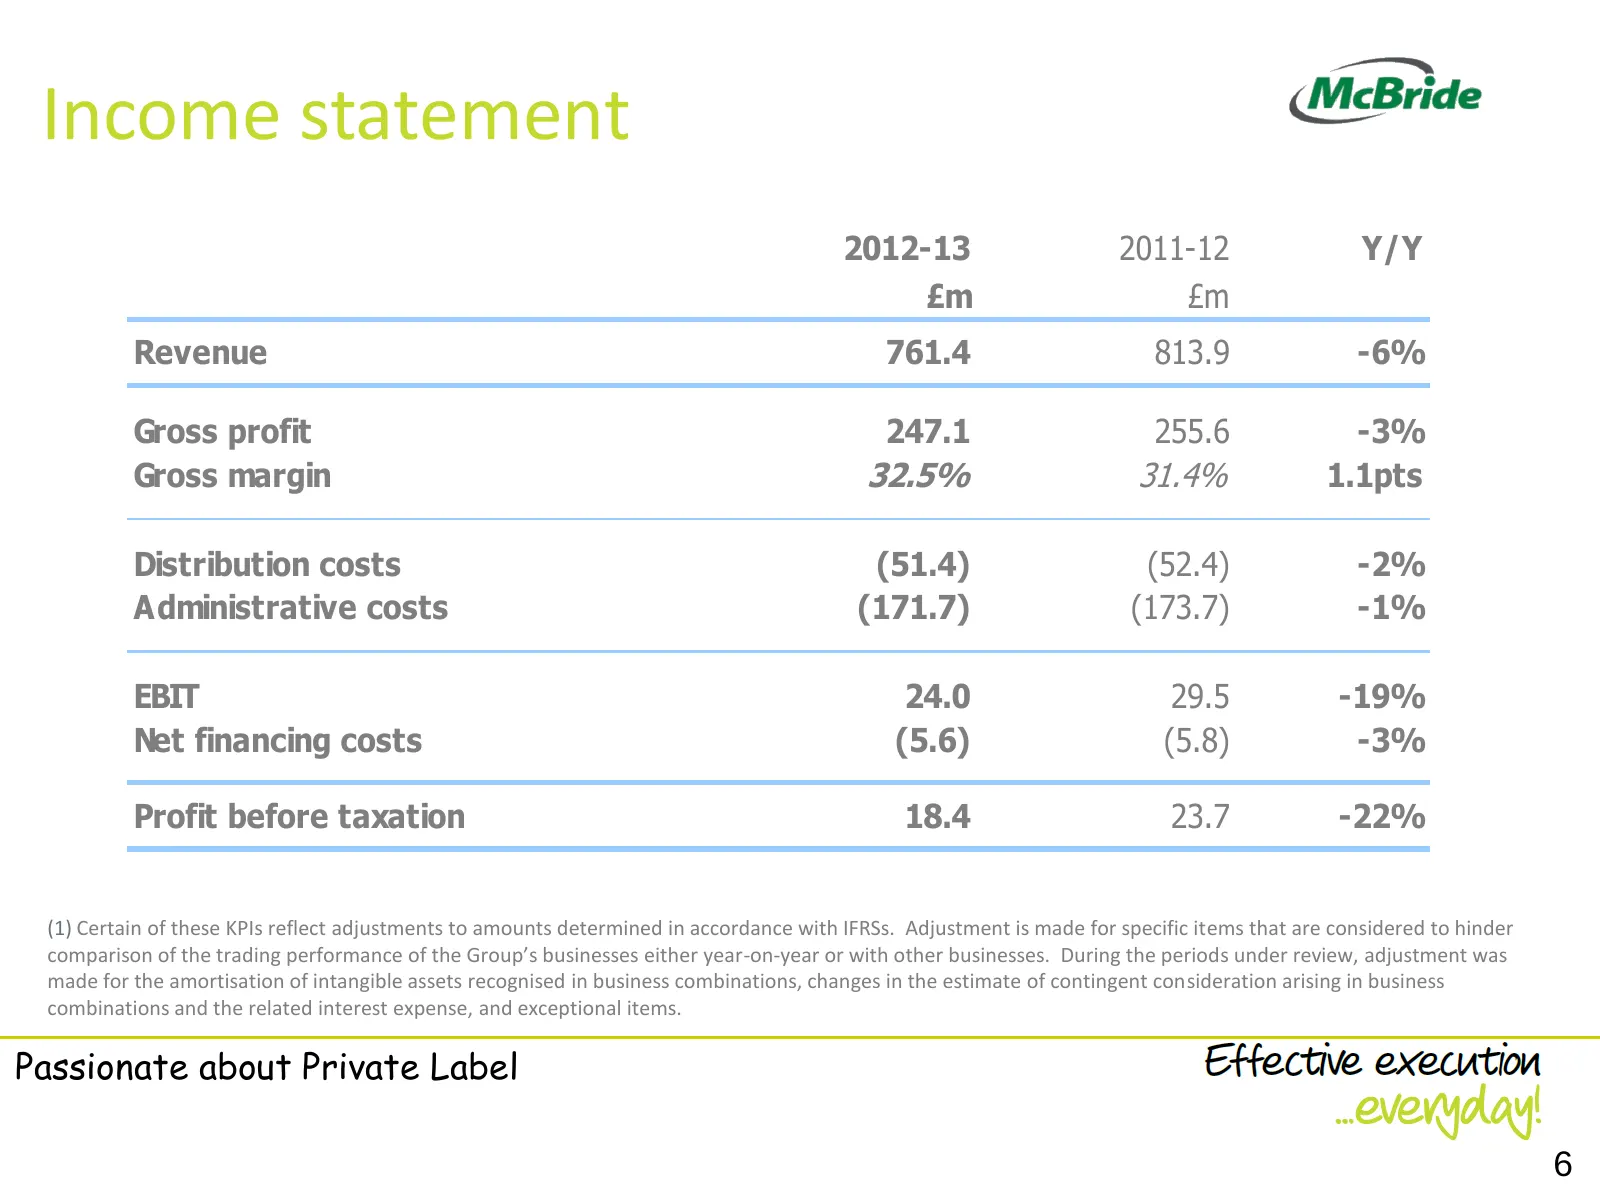
Income statement 2012-13 2011-12 Y/Y £m £m Revenue 761.4 813.9 -6% Gross profit 247.1 255.6 -3% Gross margin 32.5% 31.4% 1.1pts Distribution costs (51.4) (52.4) -2% Administrative costs (171.7) (173.7) -1% EBIT 24.0 29.5 -19% Net financing costs (5.6) (5.8) -3% Profit before taxation 18.4 23.7 -22%
Slide 7: Regional performance – Revenue
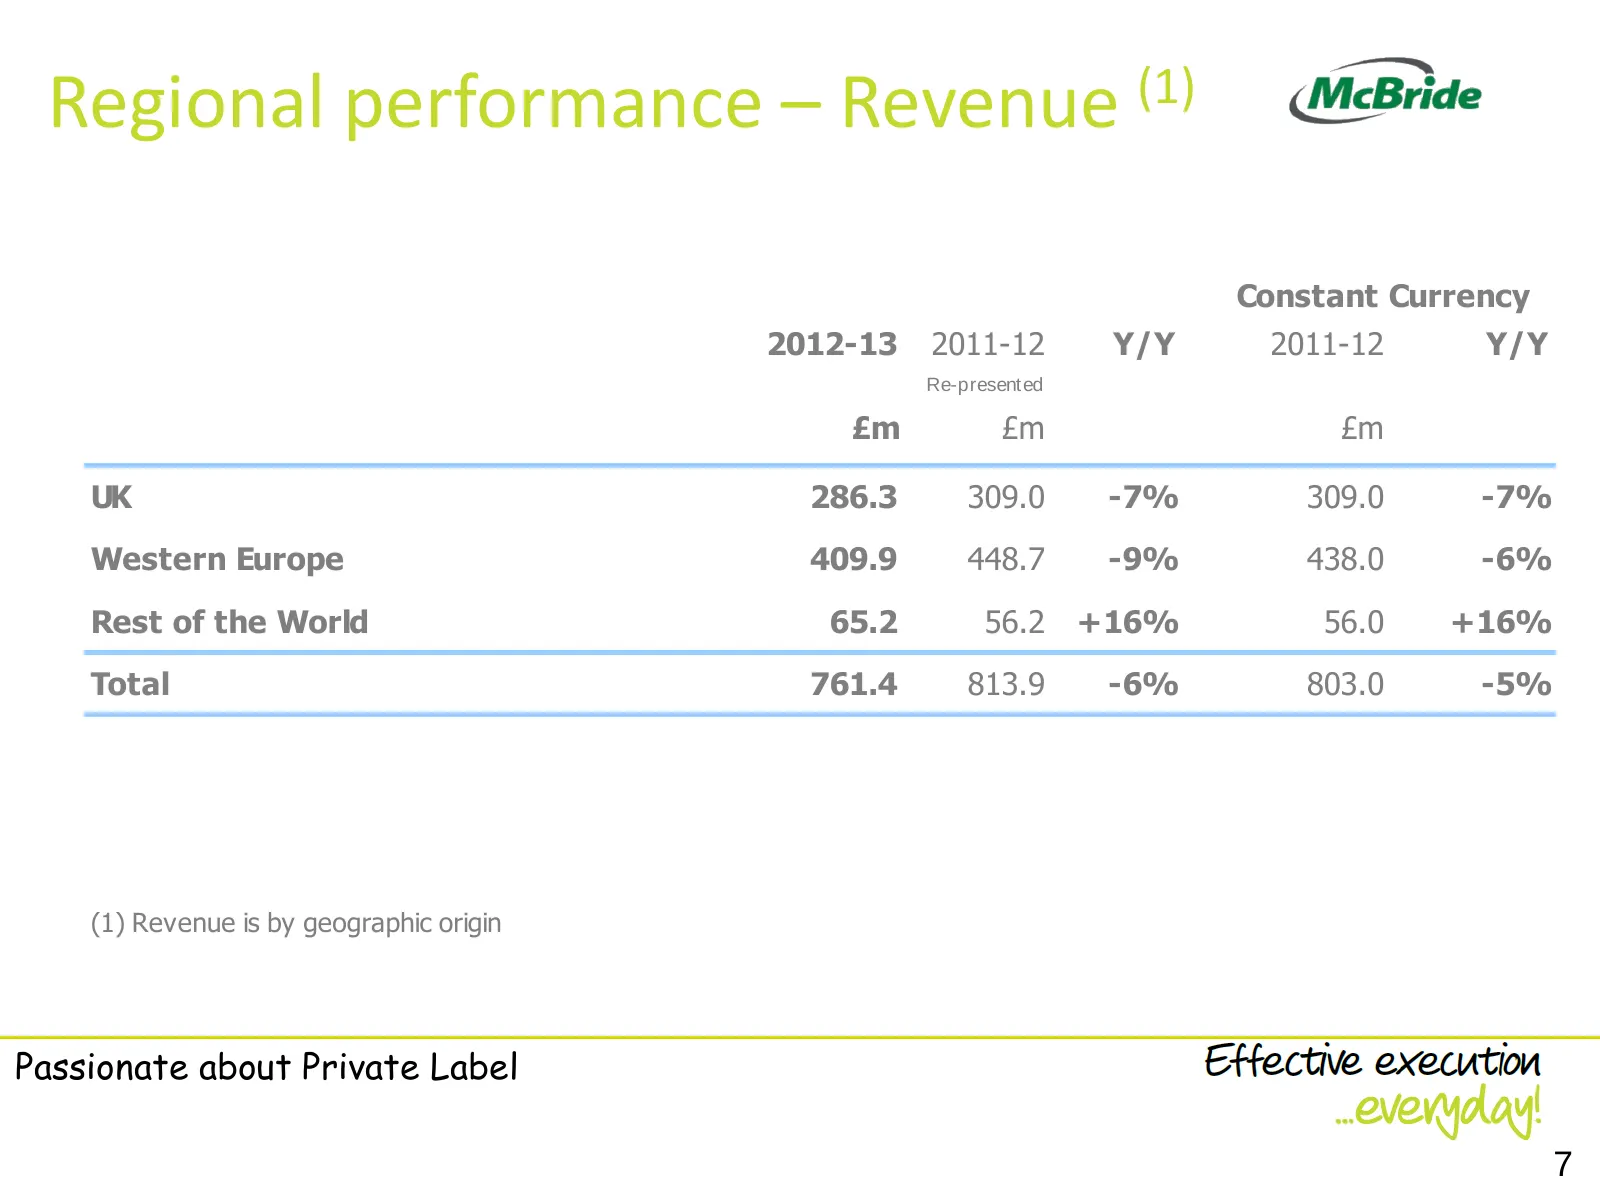
Regional performance – Revenue (1) Constant Currency 2012-13 2011-12 Y/Y 2011-12 Y/Y Re-presented £m £m £m UK 286.3 309.0 -7% 309.0 -7% Western Europe 409.9 448.7 -9% 438.0 -6% Rest of the World 65.2 56.2 +16% 56.0 +16% Total 761.4 813.9 -6% 803.0 -5% (1) Revenue is by geographic origin Passionate a
Slide 8: Regional performance – Operating profit
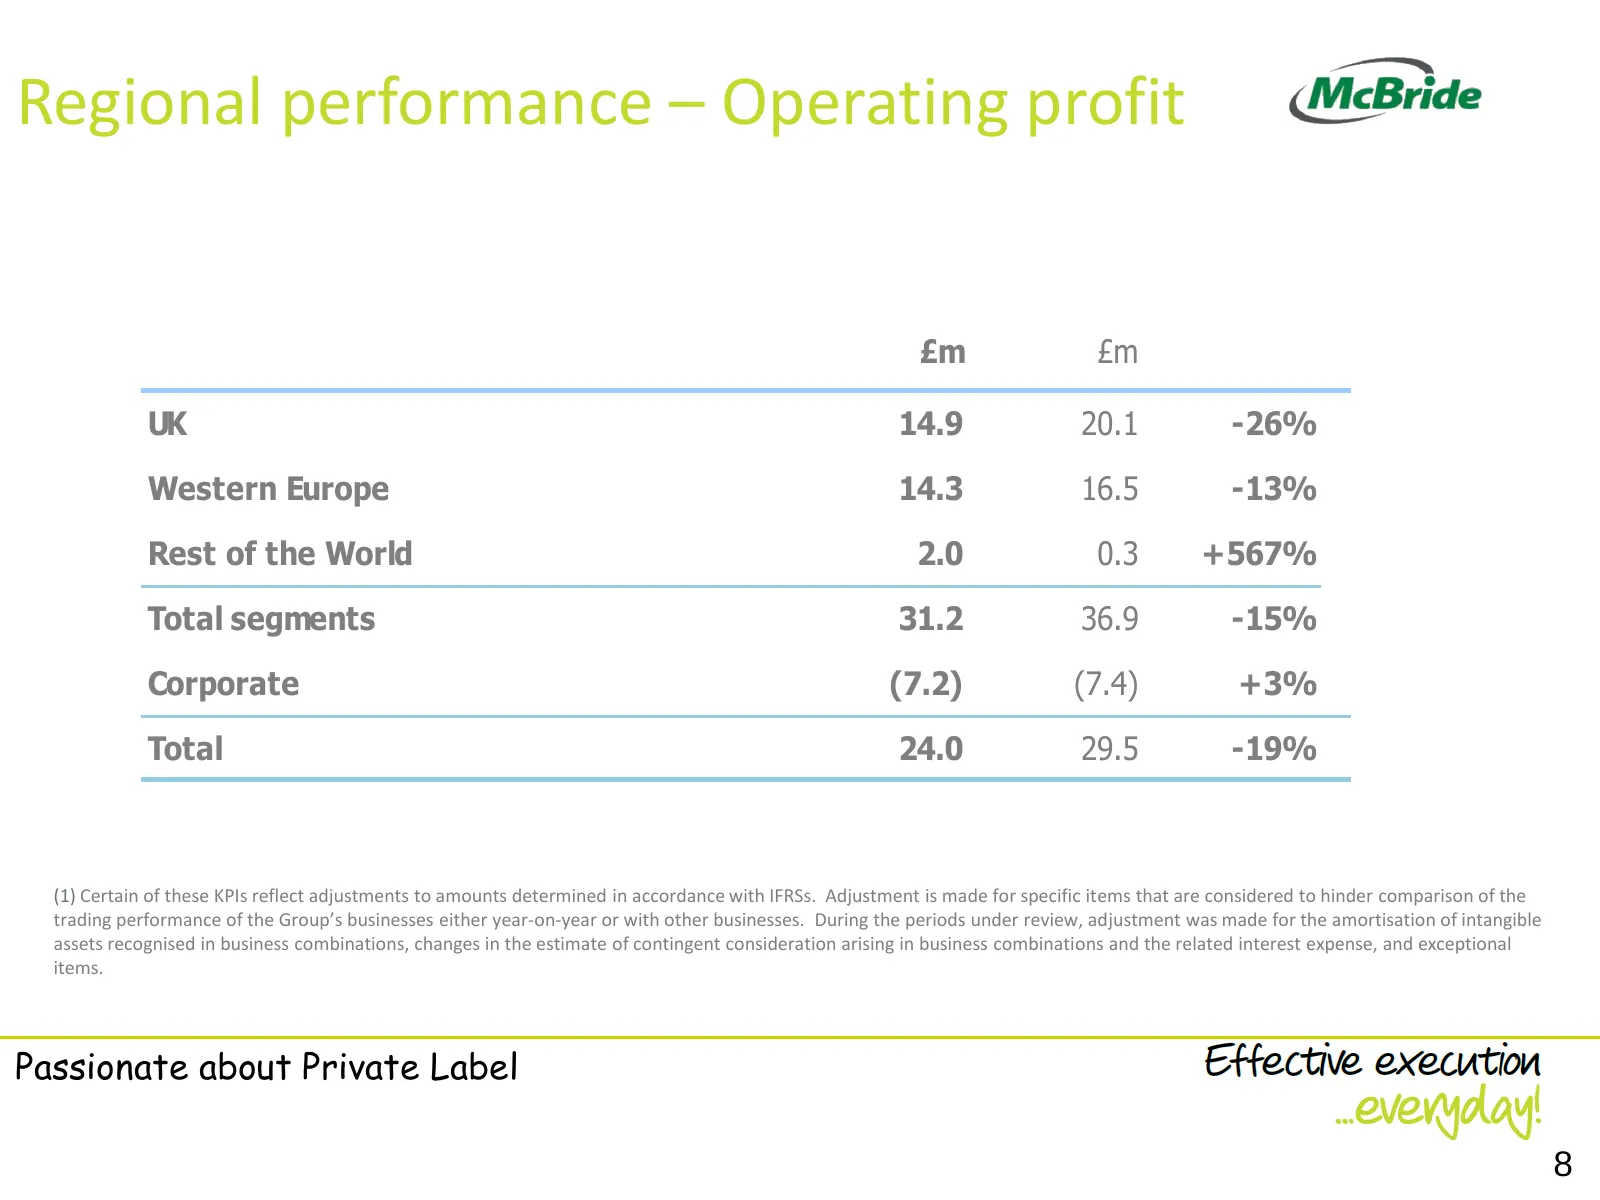
Regional performance – Operating profit £m £m UK 14.9 20.1 -26% Western Europe 14.3 16.5 -13% Rest of the World 2.0 0.3 +567% Total segments 31.2 36.9 -15% Corporate (7.2) (7.4) +3% Total 24.0 29.5 -19% (1) Certain of these KPIs reflect adjustments to amounts determined in accordance with IFRSs. Adj
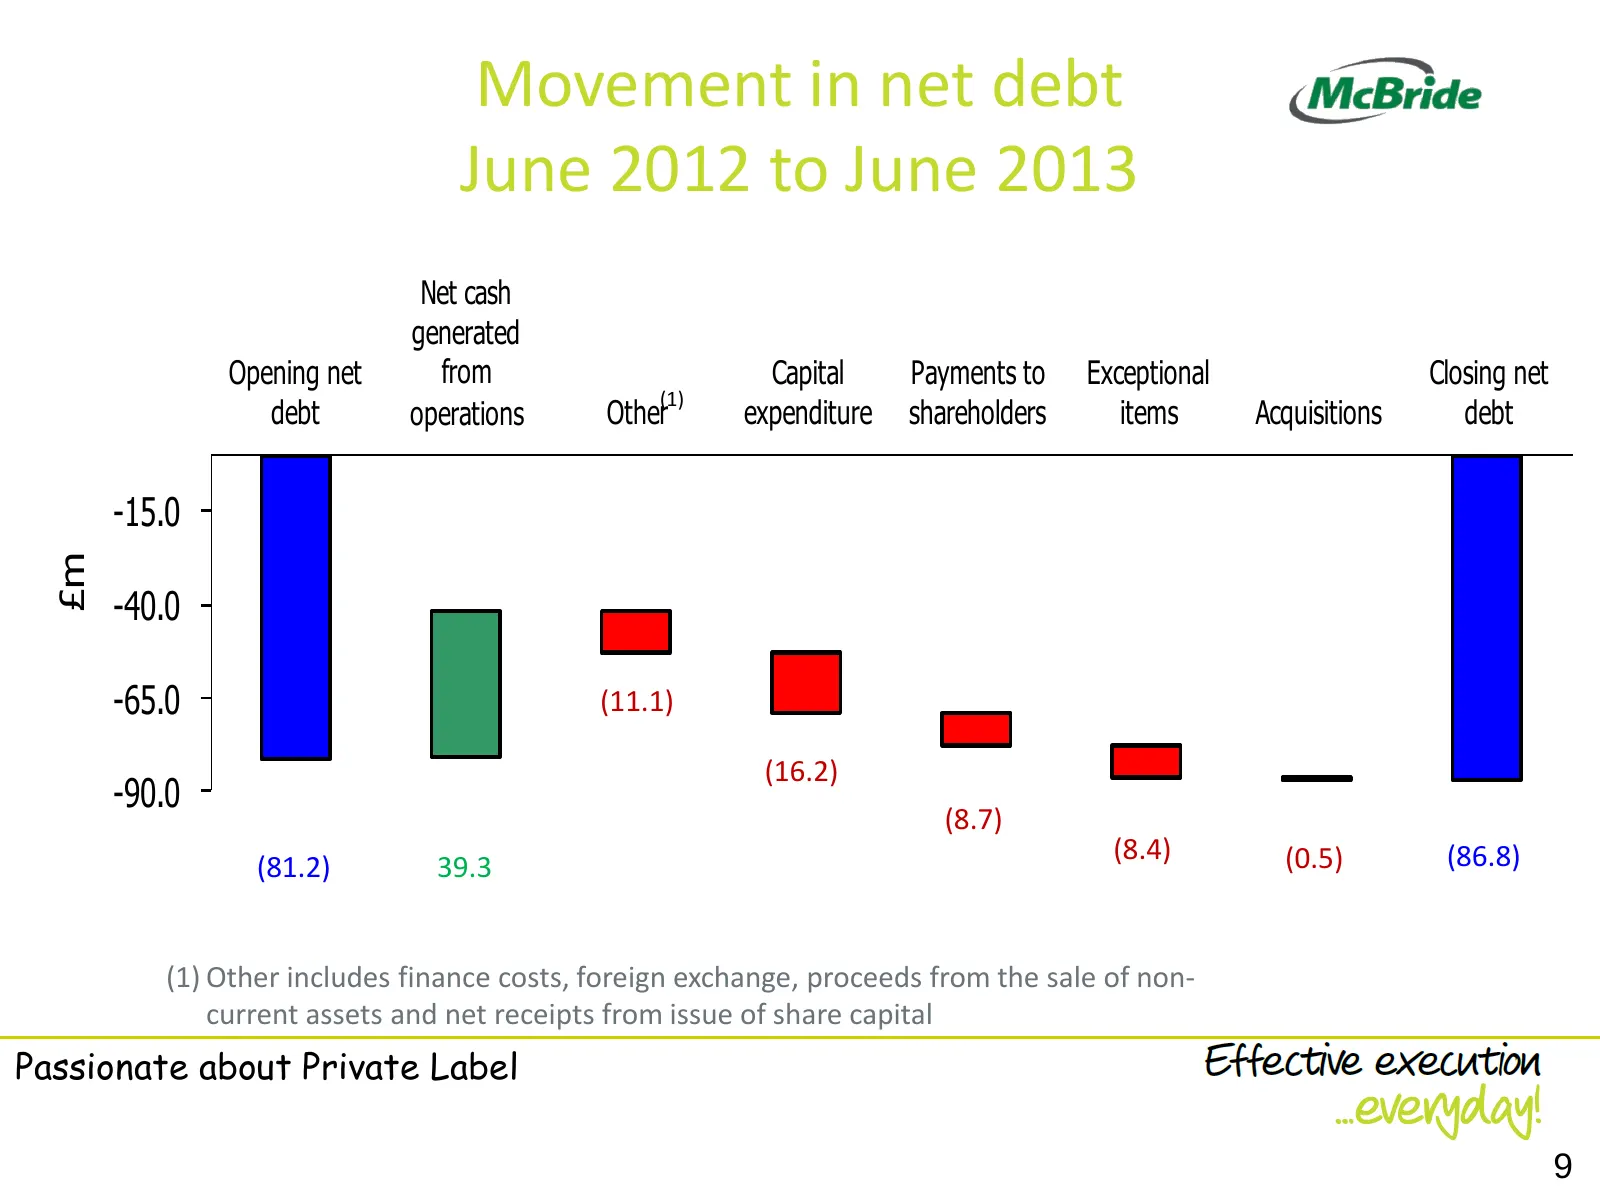
Slide 9: Movement in net debt June 2012 to June 2013
Movement in net debt June 2012 to June 2013 Net cash generated Opening net from Capital Payments to Exceptional Closing net (1) debt operations Other expenditure shareholders items Acquisitions debt -15.0 £m -40.0 -65.0 (11.1) (16.2) -90.0 (8.7) (8.4) (0.5) (86.8) (81.2) 39.3 (1) Other includes fina
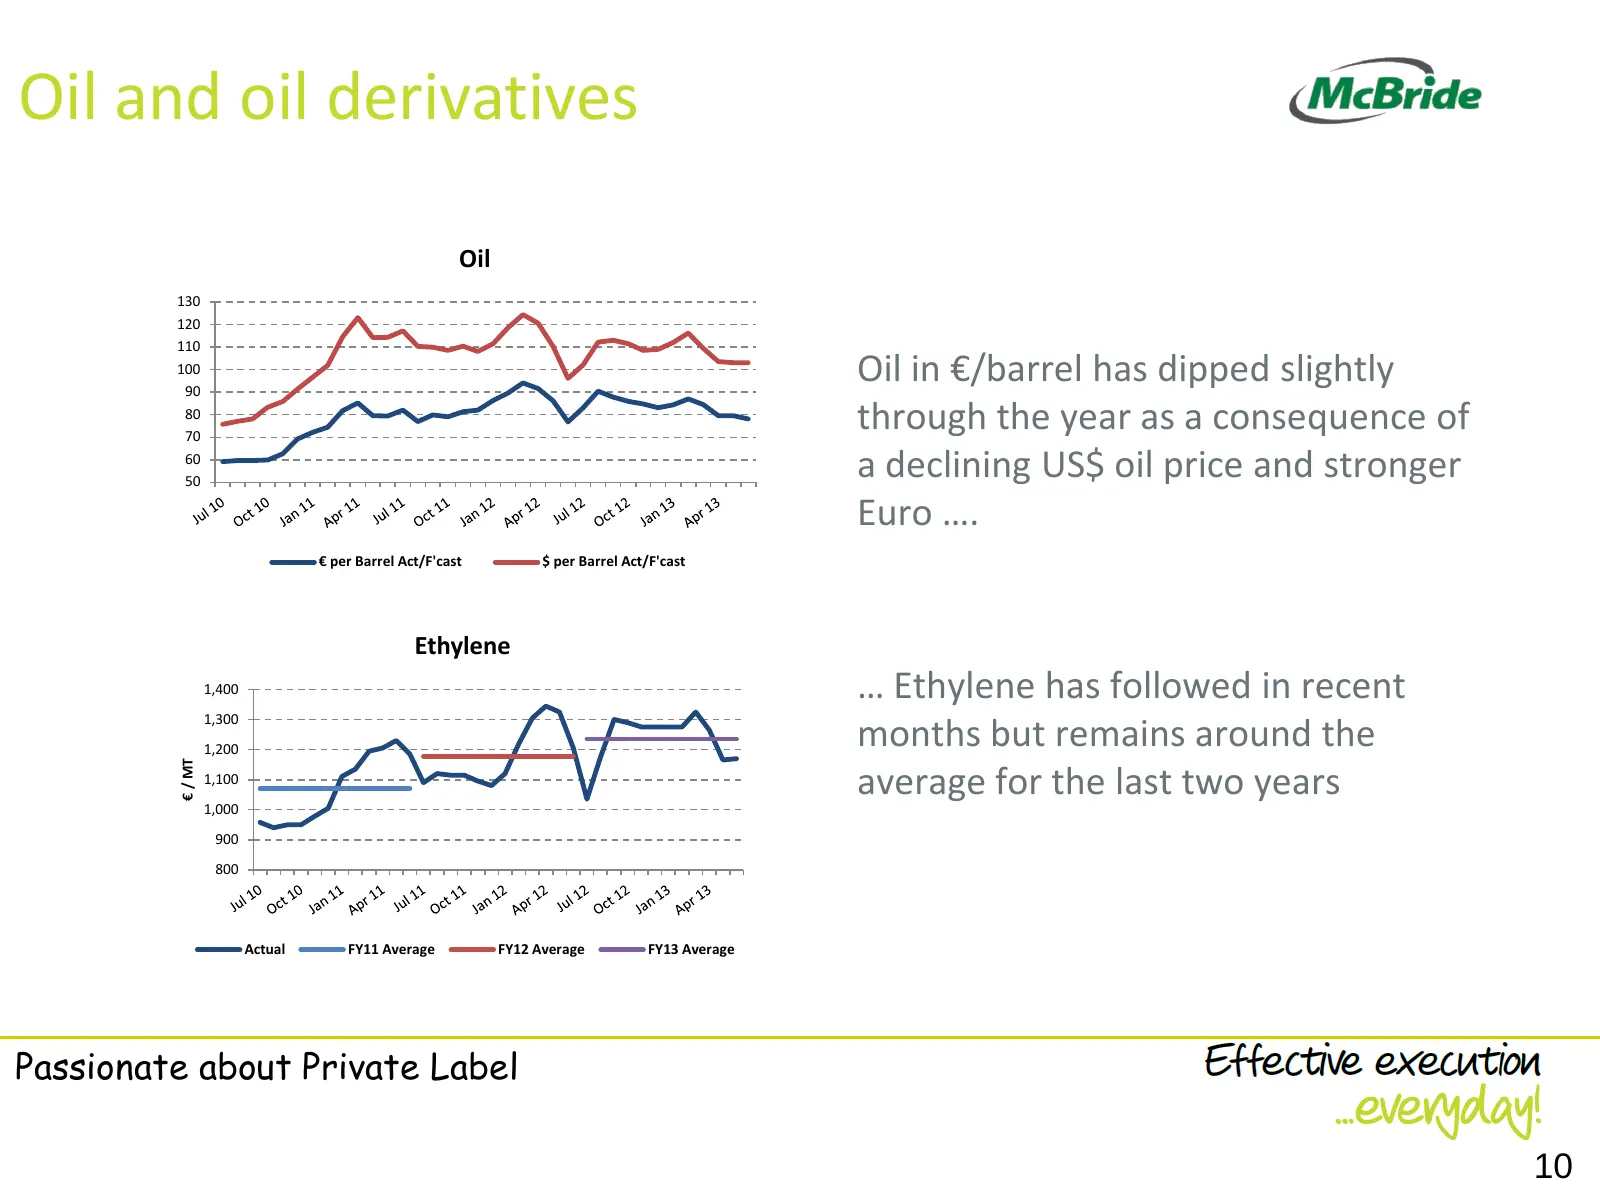
Slide 10: Oil and oil derivatives
Oil and oil derivatives Oil 130 120 110 100 90 Oil in €/barrel has dipped slightly 80 70 through the year as a consequence of 60 50 a declining US$ oil price and stronger Euro …. € per Barrel Act/F'cast $ per Barrel Act/F'cast Ethylene 1,400 … Ethylene has followed in recent 1,300 1,200 months but r
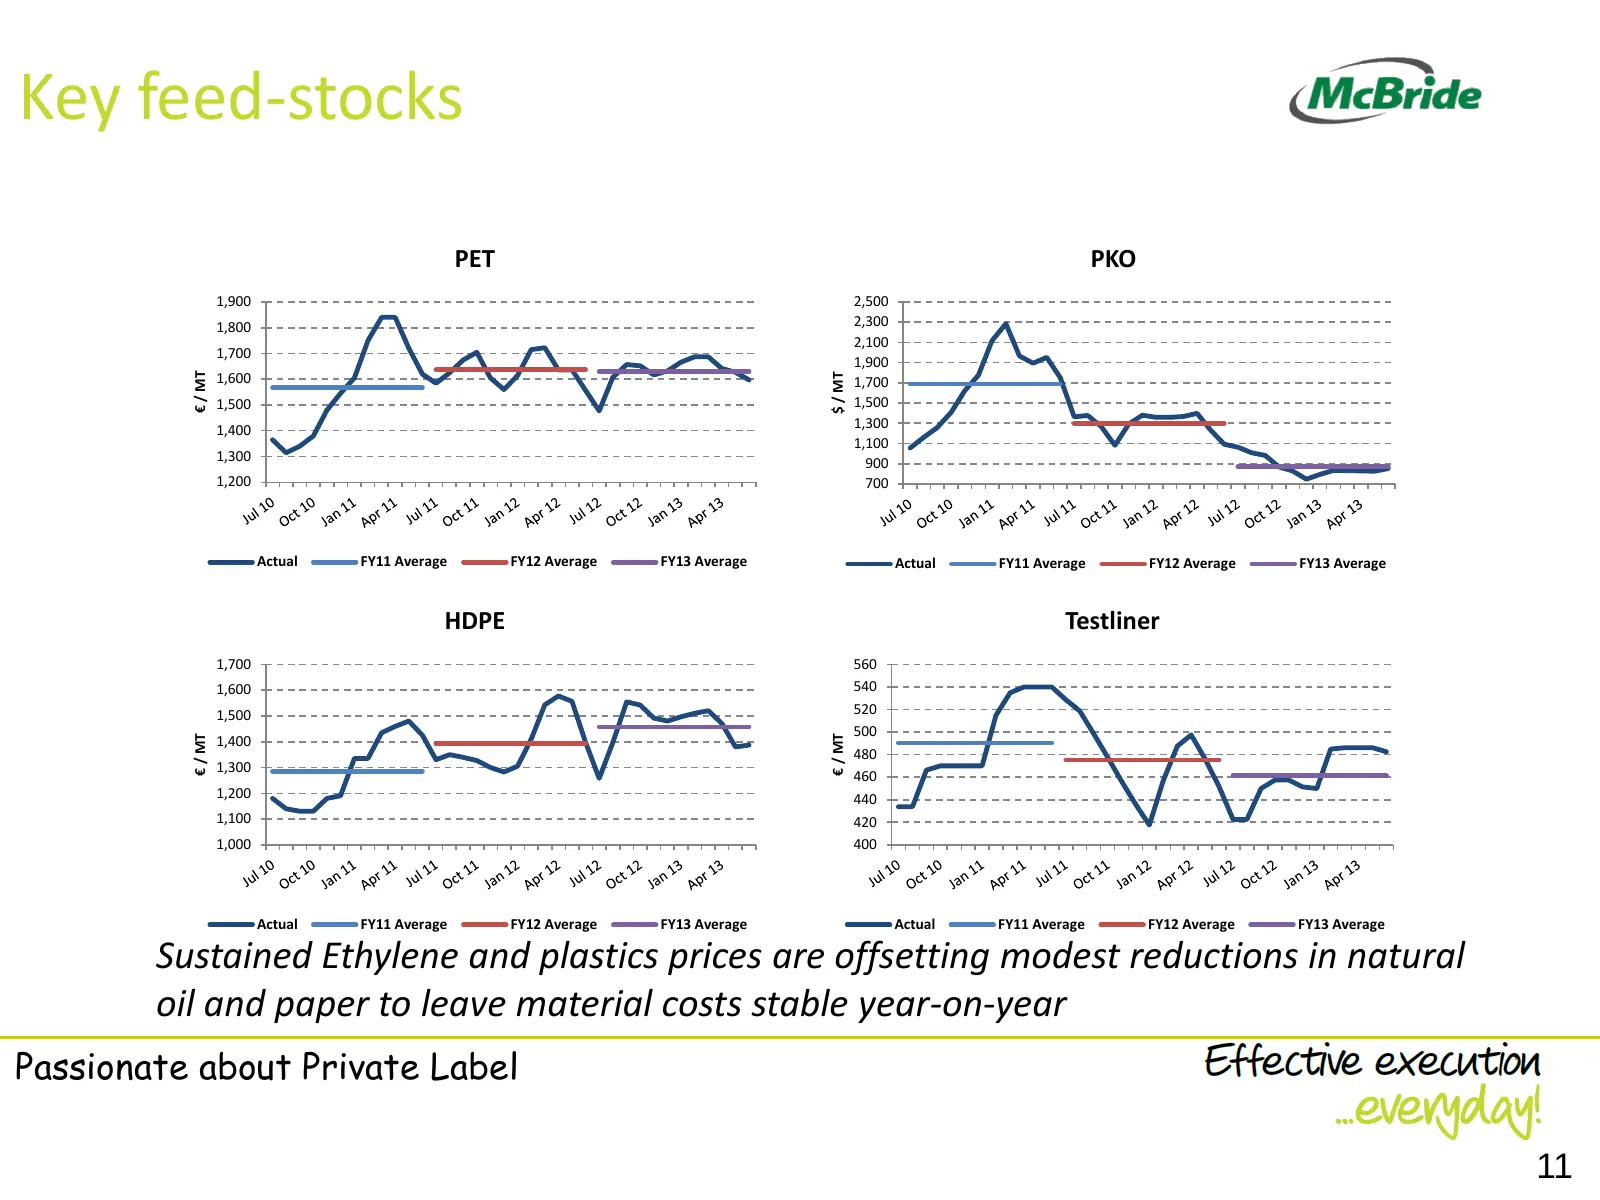
Slide 11: Key feed-stocks
Key feed-stocks PET PKO 1,900 2,500 1,800 2,300 2,100 1,700 1,900 € / MT $ / MT 1,600 1,700 1,500 1,500 1,400 1,300 1,100 1,300 900 1,200 700 Actual FY11 Average FY12 Average FY13 Average Actual FY11 Average FY12 Average FY13 Average HDPE Testliner 1,700 560 1,600 540 1,500 520 500 € / MT € / MT 1,4
Slide 12: Cost management to accelerate
Cost management to accelerate • A wide range of projects will underpin the delivery of 2013/14 results: • Optimisation of the Supply Chain for Western Continental Europe • The first phase of a programme to reduce Group distribution costs • Significant savings from the consolidation of Group function
Slide 13: Summary
Summary Chris Bull – Chief Executive Officer Passionate about Private Label 13
Slide 14: What we have achieved so far
What we have achieved so far • Successful delivery of our product launch programme; Core and Future Growth categories up to 49% of Private Label sales (2012:47%) • Strong growth in Germany and Poland; • Year two Operational Excellence savings achieved and restructuring savings targets delivered; • R
Slide 15: Tough trading conditions across Europe in the Household sector
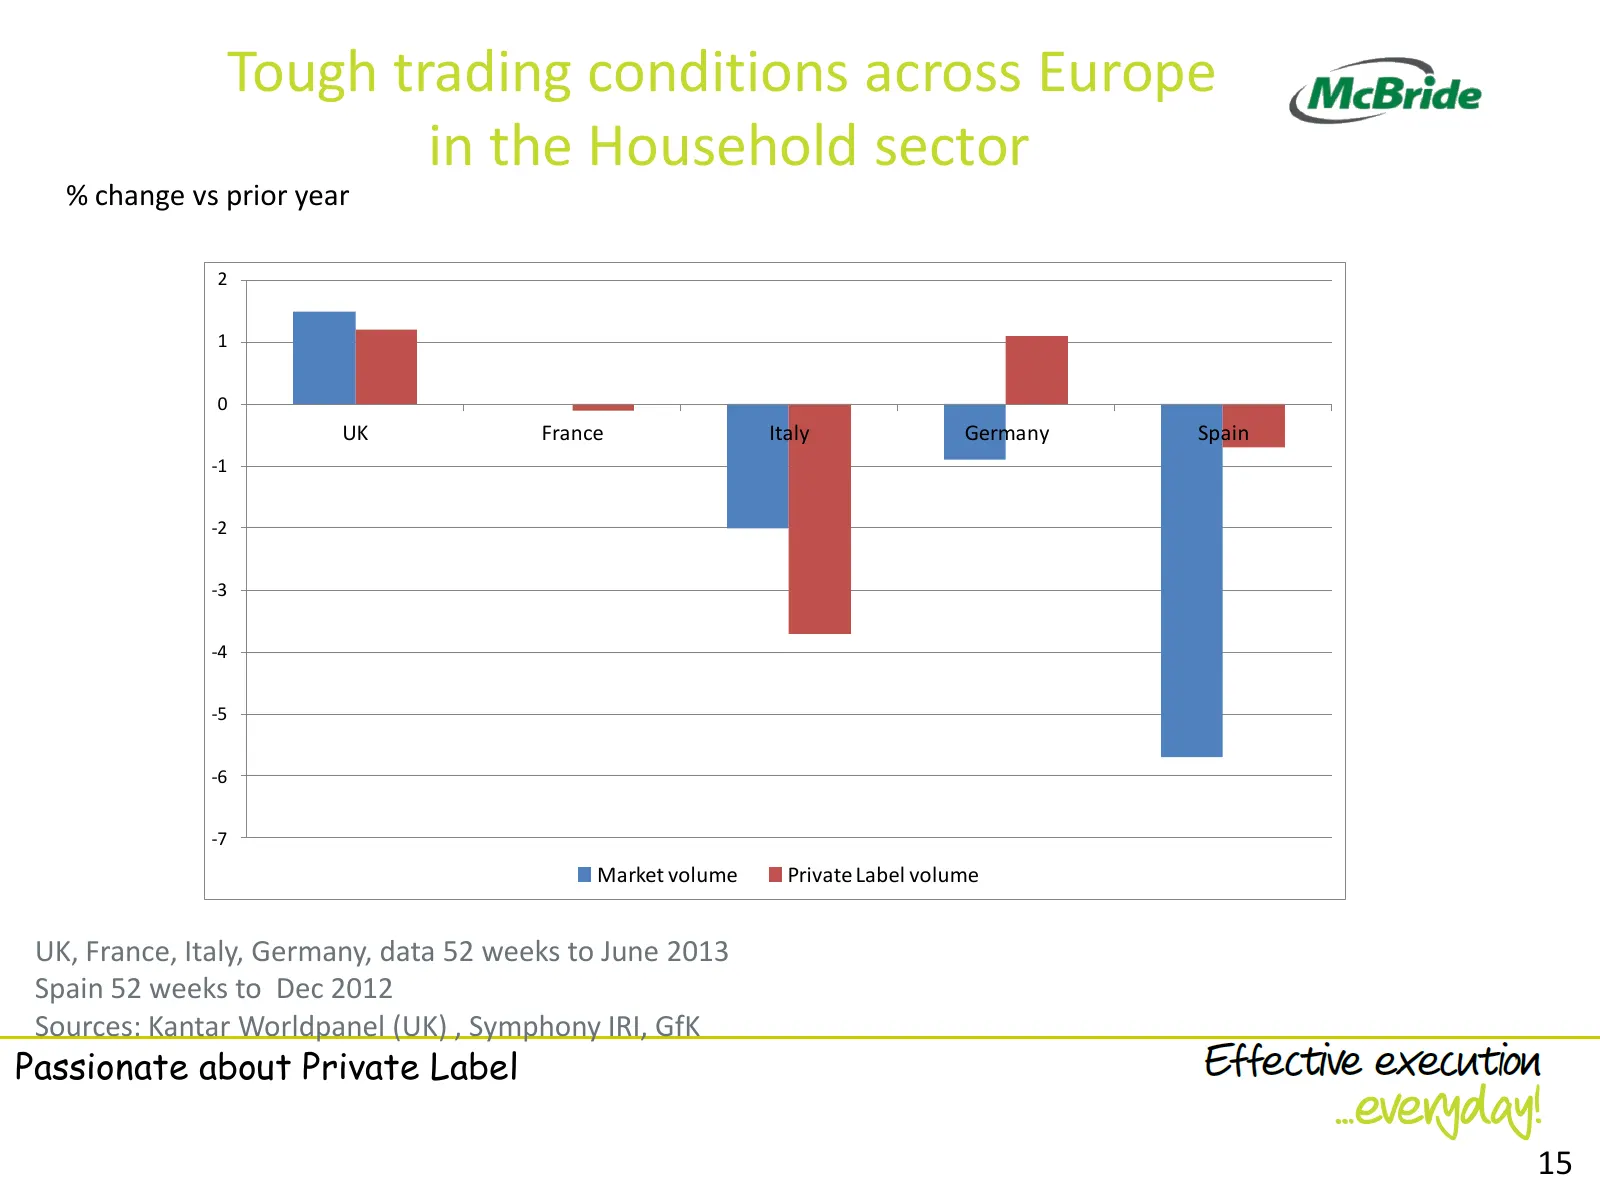
Tough trading conditions across Europe in the Household sector % change vs prior year 2 1 0 UK France Italy Germany Spain -1 -2 -3 -4 -5 -6 -7 Market volume Private Label volume UK, France, Italy, Germany, data 52 weeks to June 2013 Spain 52 weeks to Dec 2012 Sources: Kantar Worldpanel (UK) , Sympho
Slide 16: Private Label Household volume shares 2013 vs 2012
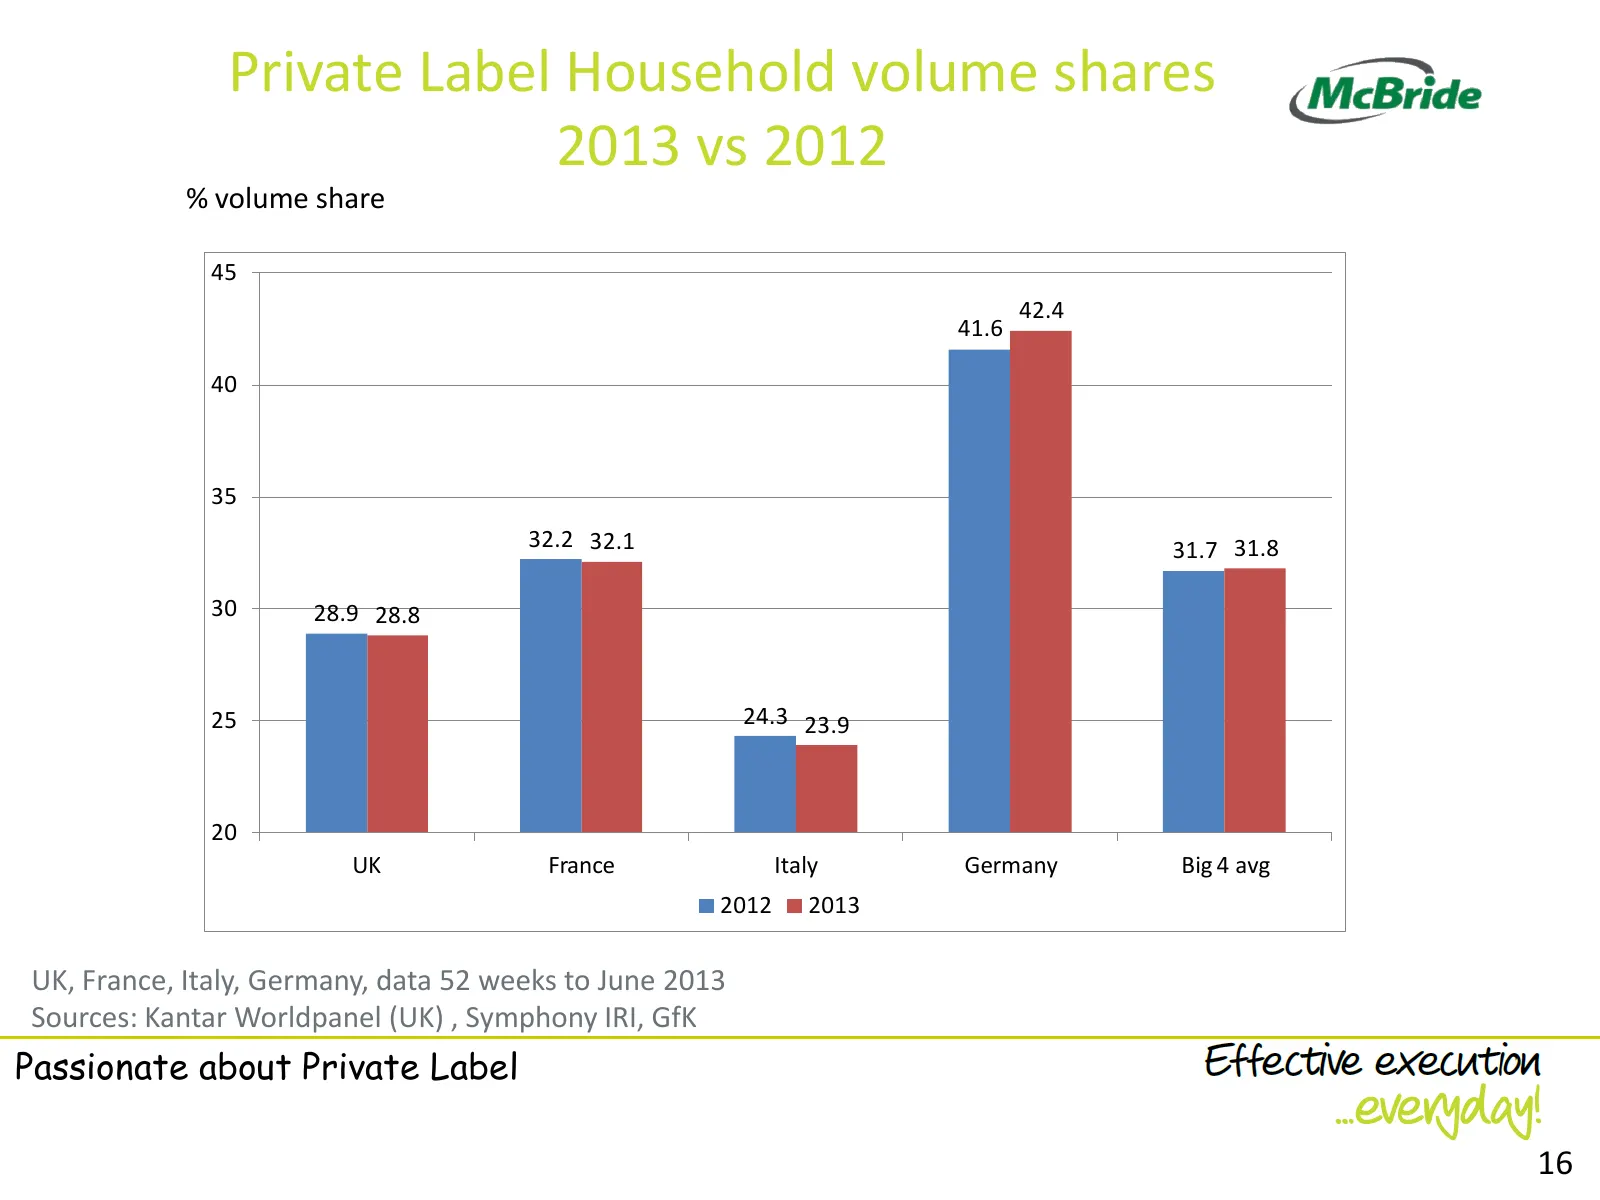
Private Label Household volume shares 2013 vs 2012 % volume share 45 42.4 41.6 40 35 32.2 32.1 31.7 31.8 30 28.9 28.8 25 24.3 23.9 20 UK France Italy Germany Big 4 avg 2012 2013 UK, France, Italy, Germany, data 52 weeks to June 2013 Sources: Kantar Worldpanel (UK) , Symphony IRI, GfK Passionate abou
Slide 17: Household and Personal Care products on promotion to end March 2013
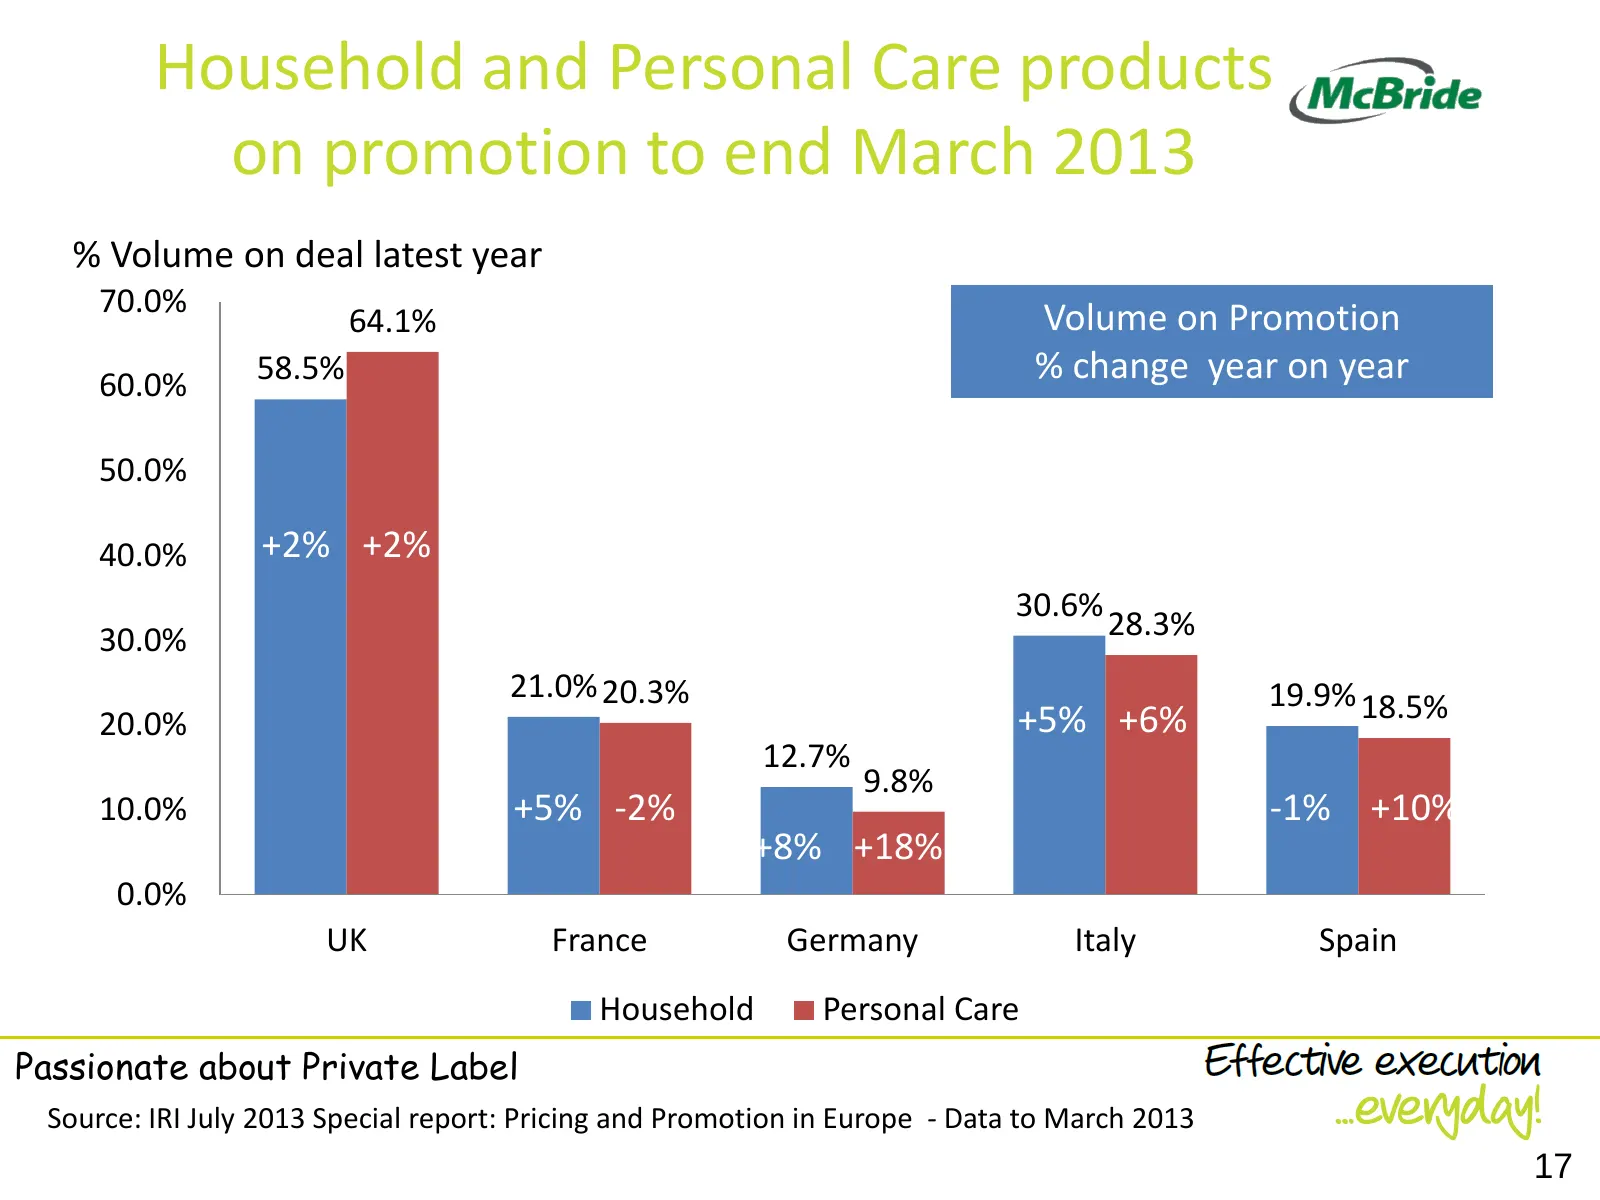
Household and Personal Care products on promotion to end March 2013 % Volume on deal latest year 70.0% 64.1% Volume on Promotion 60.0% 58.5% % change year on year 50.0% 40.0% +2% +2% 30.6% 30.0% 28.3% 21.0% 20.3% 19.9% 18.5% 20.0% +5% +6% 12.7% 9.8% 10.0% +5% -2% -1% +10% +8% +18% 0.0% UK France Ger
Slide 18: Where we are achieving growth
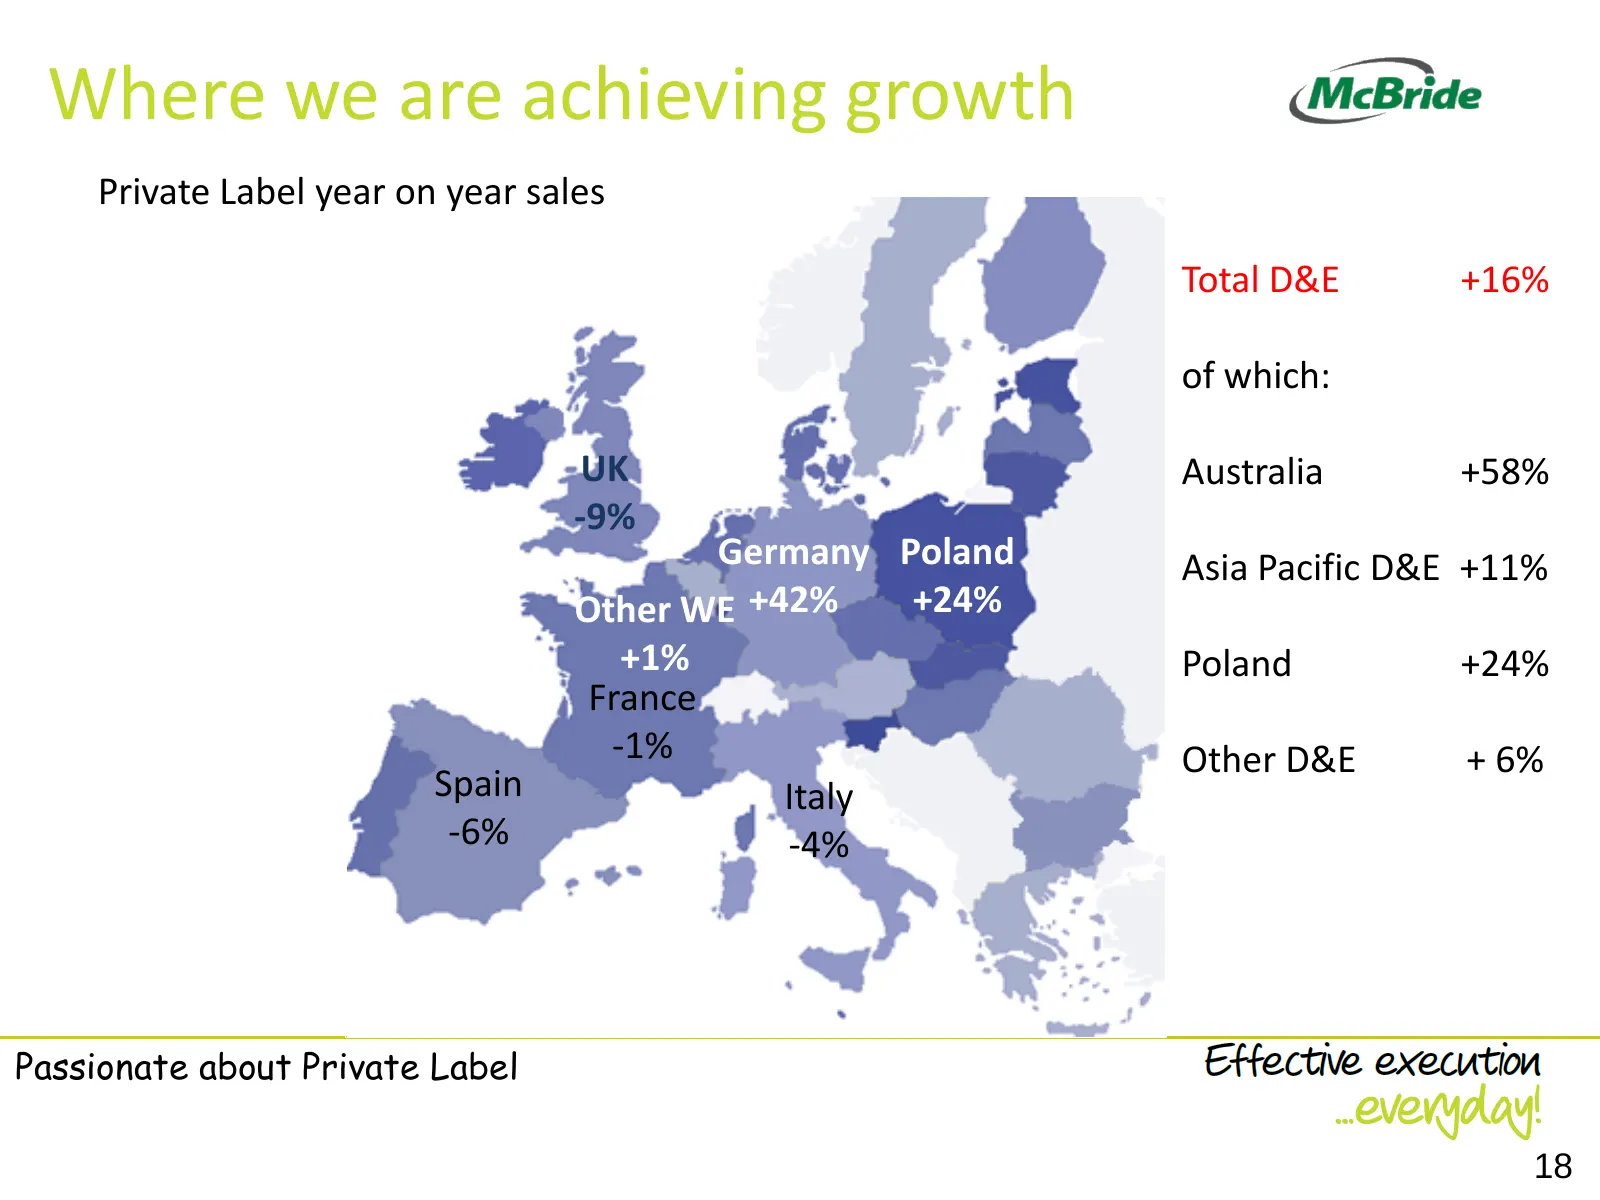
Where we are achieving growth Private Label year on year sales Total D&E +16% of which: UK Australia +58% -9% Germany Poland Asia Pacific D&E +11% Other WE +42% +24% +1% Poland +24% France -1% Other D&E + 6% Spain Italy -6% -4% Passionate about Private Label 18
Slide 19: Growth through NPD
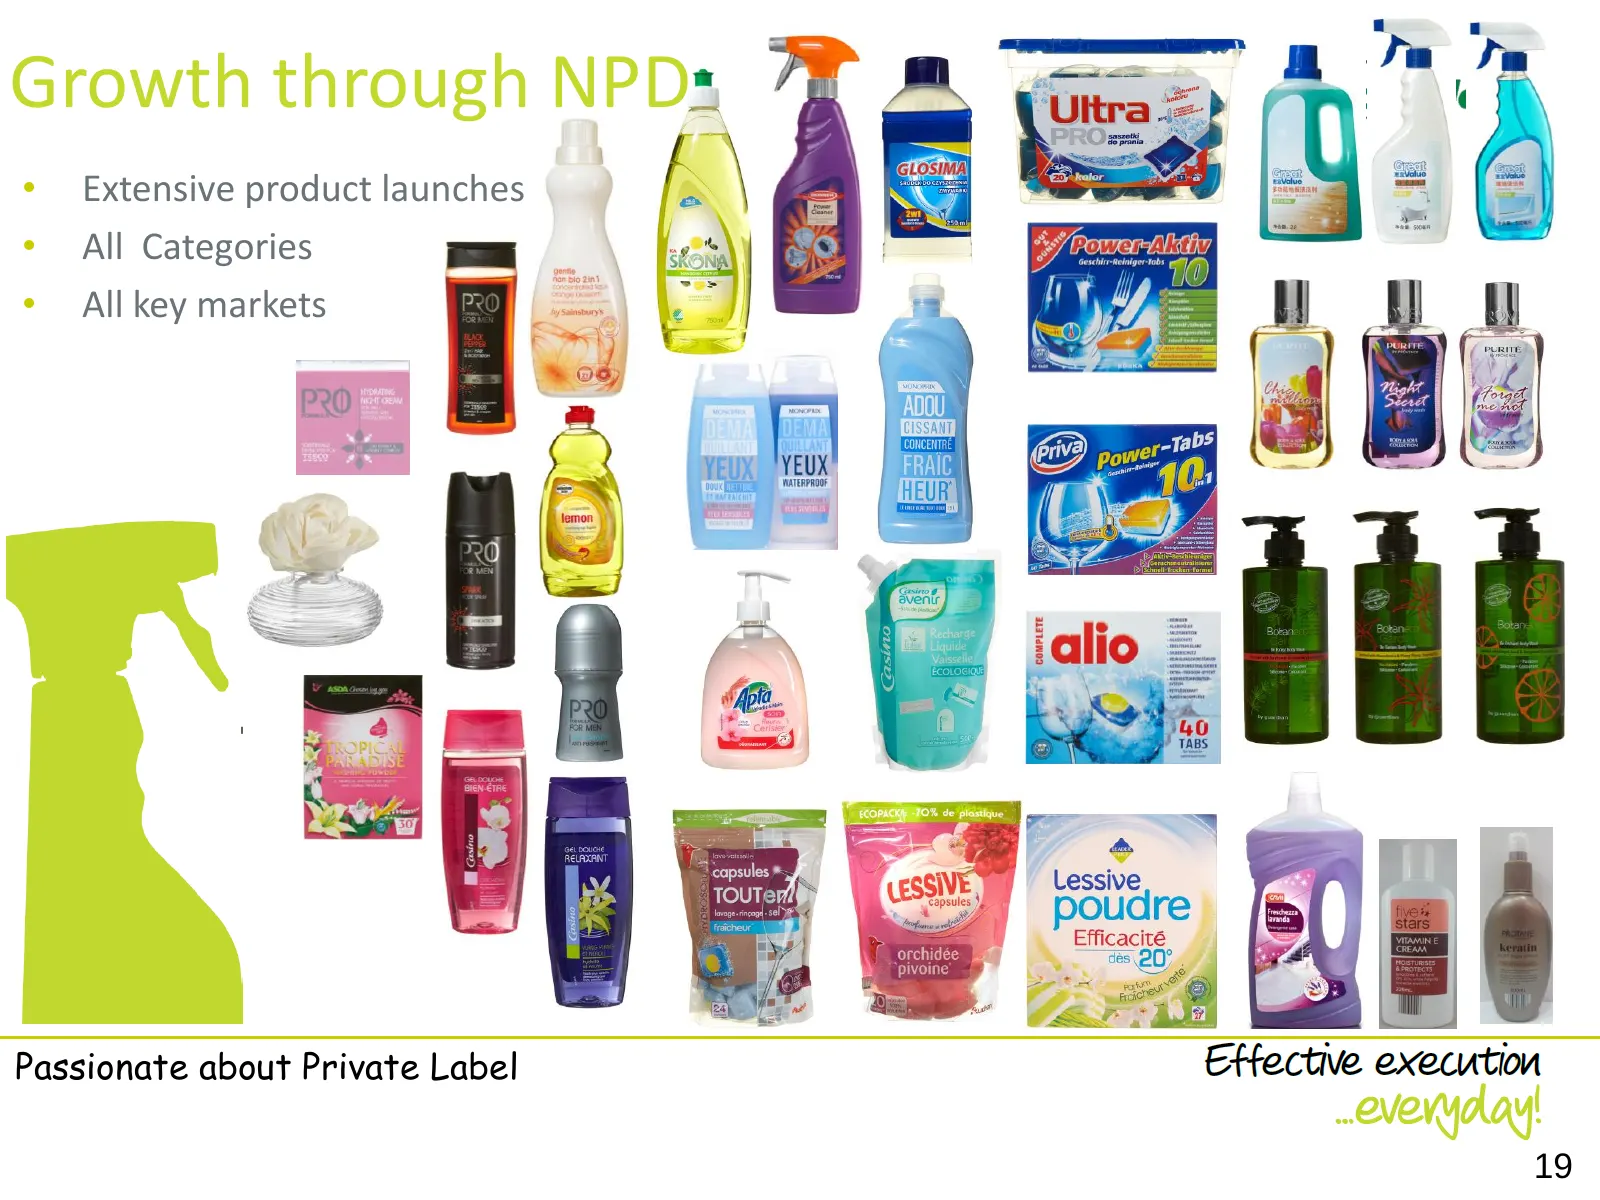
Growth through NPD • Extensive product launches • All Categories • All key markets Passionate about Private Label 19
Slide 20: Driving EDLP In Asda Laundry powders
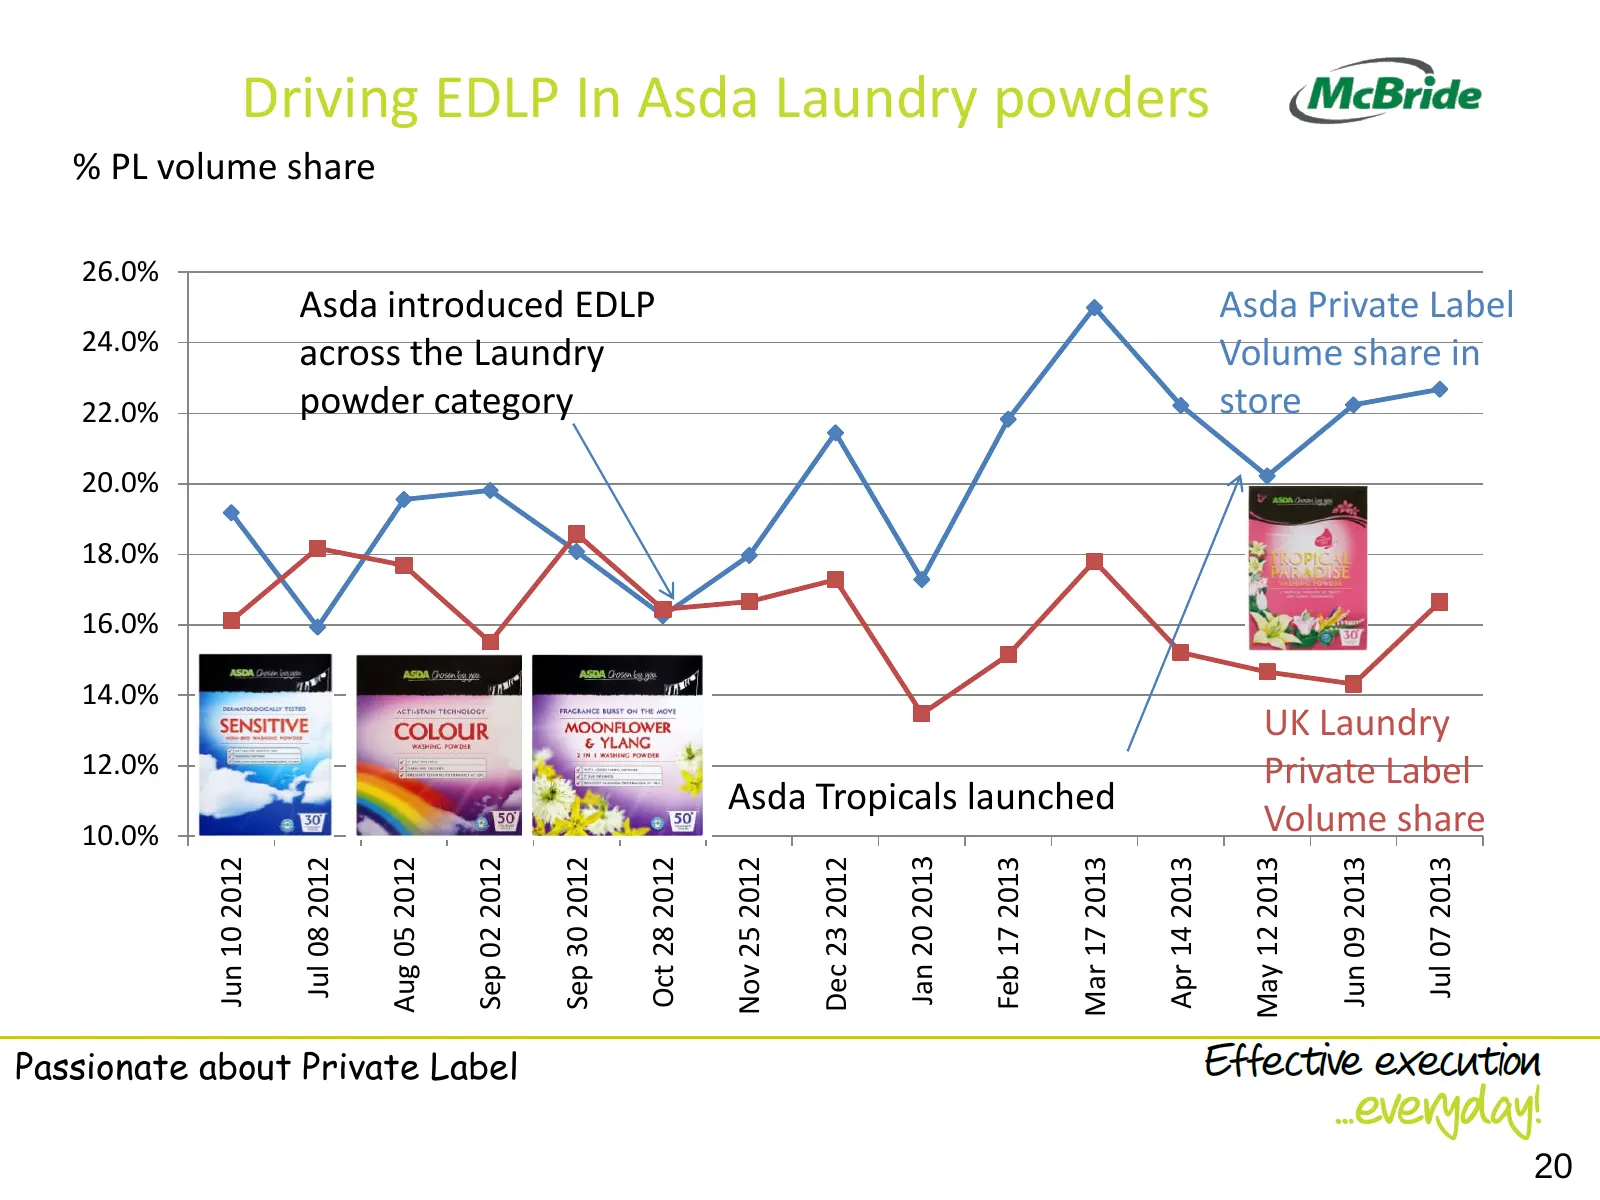
Driving EDLP In Asda Laundry powders % PL volume share 26.0% Asda introduced EDLP Asda Private Label 24.0% across the Laundry Volume share in 22.0% powder category store 20.0% 18.0% 16.0% 14.0% UK Laundry 12.0% Private Label Asda Tropicals launched 10.0% Volume share Jan 20 2013 Oct 28 2012 Aug 05 2
Slide 21: Investment Plans
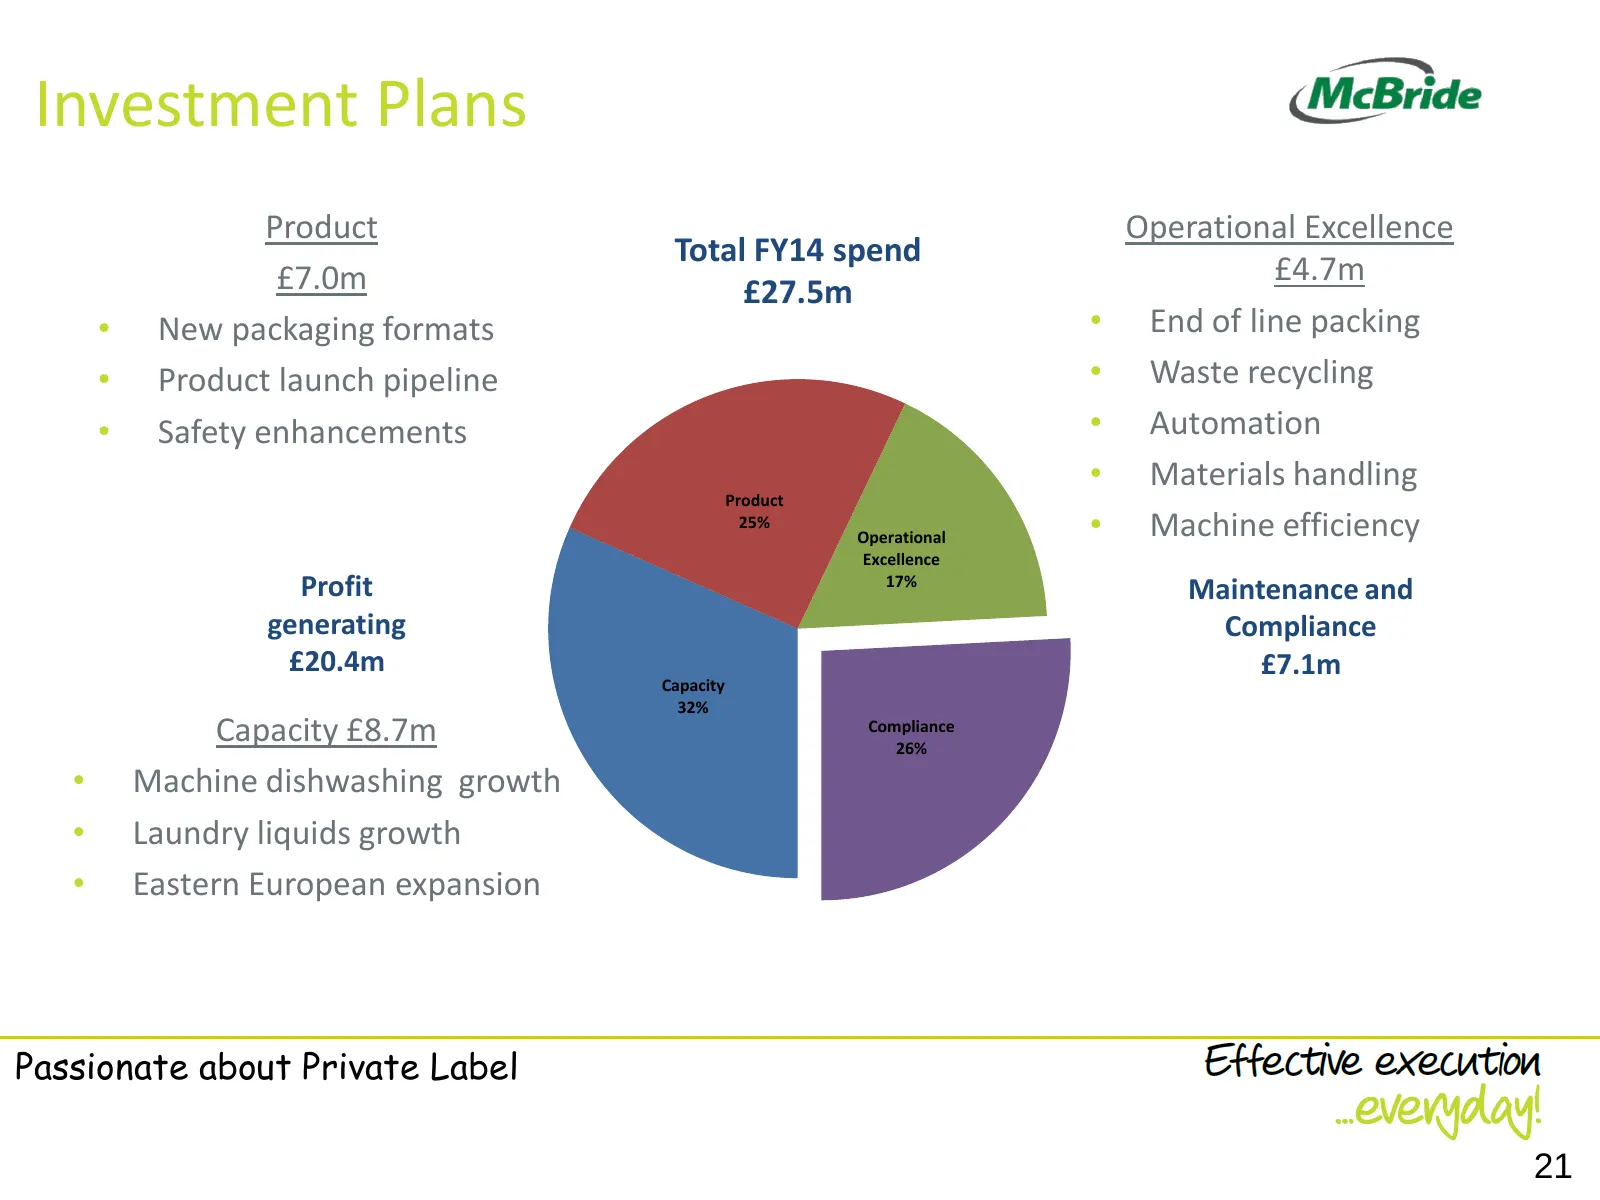
Investment Plans Product Operational Excellence Total FY14 spend £7.0m £4.7m £27.5m • New packaging formats • End of line packing • Product launch pipeline • Waste recycling • Safety enhancements • Automation • Materials handling Product 25% Operational • Machine efficiency Excellence Profit 17% Mai
Slide 22: Key Priorities for 2014
Key Priorities for 2014 • Drive Group revenue by building our new product launch pipeline • Leverage our unique capabilities to grow substantially in the mass markets of Central and Eastern Europe; and build for the future in Asia Pacific • Restore profitability in UK and Western Europe through sele
Slide 23: Passionate about Private Label
Passionate about Private Label 23
Slide 24: Q&A
Q&A Passionate about Private Label 24
Slide 25: Appendix
Appendix Passionate about Private Label 25
Slide 26: UK Household Private label Value and Volume share Jan – June 2013
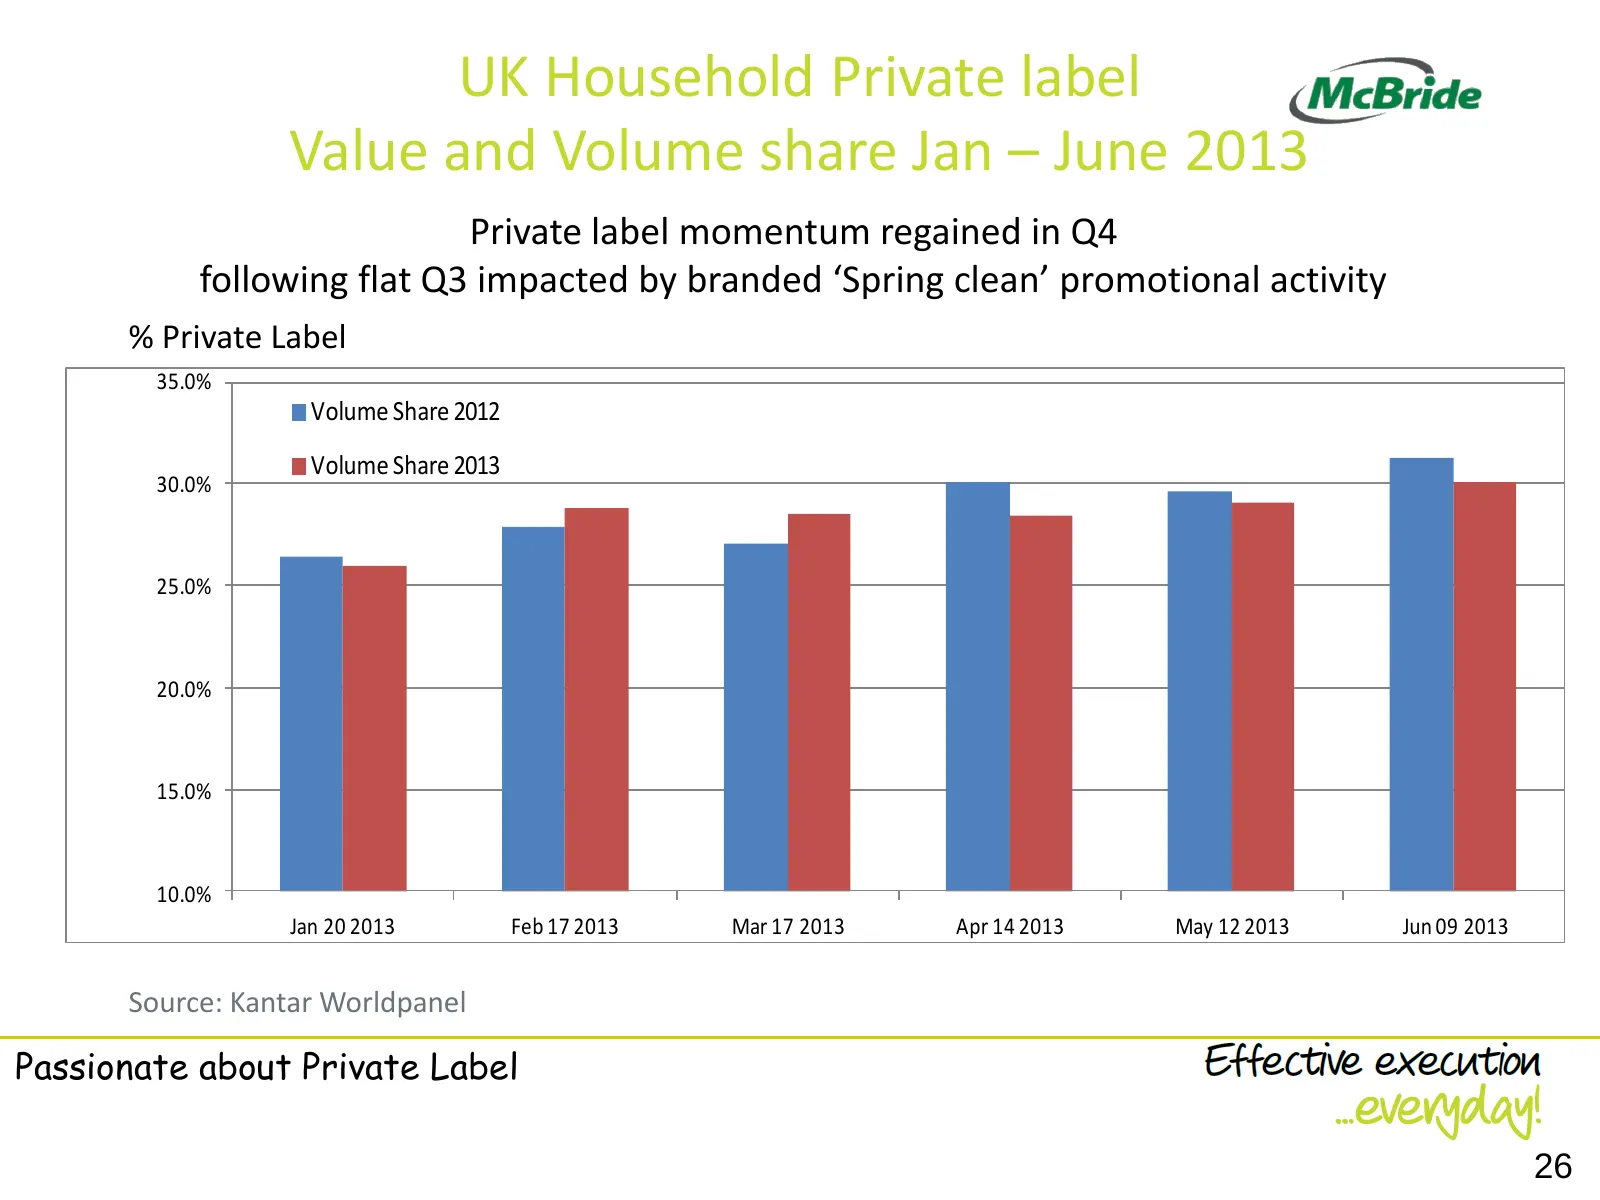
UK Household Private label Value and Volume share Jan – June 2013 Private label momentum regained in Q4 following flat Q3 impacted by branded ‘Spring clean’ promotional activity % Private Label 35.0% Volume Share 2012 Volume Share 2013 30.0% 25.0% 20.0% 15.0% 10.0% Jan 20 2013 Feb 17 2013 Mar 17 201
Slide 27: Our planned business
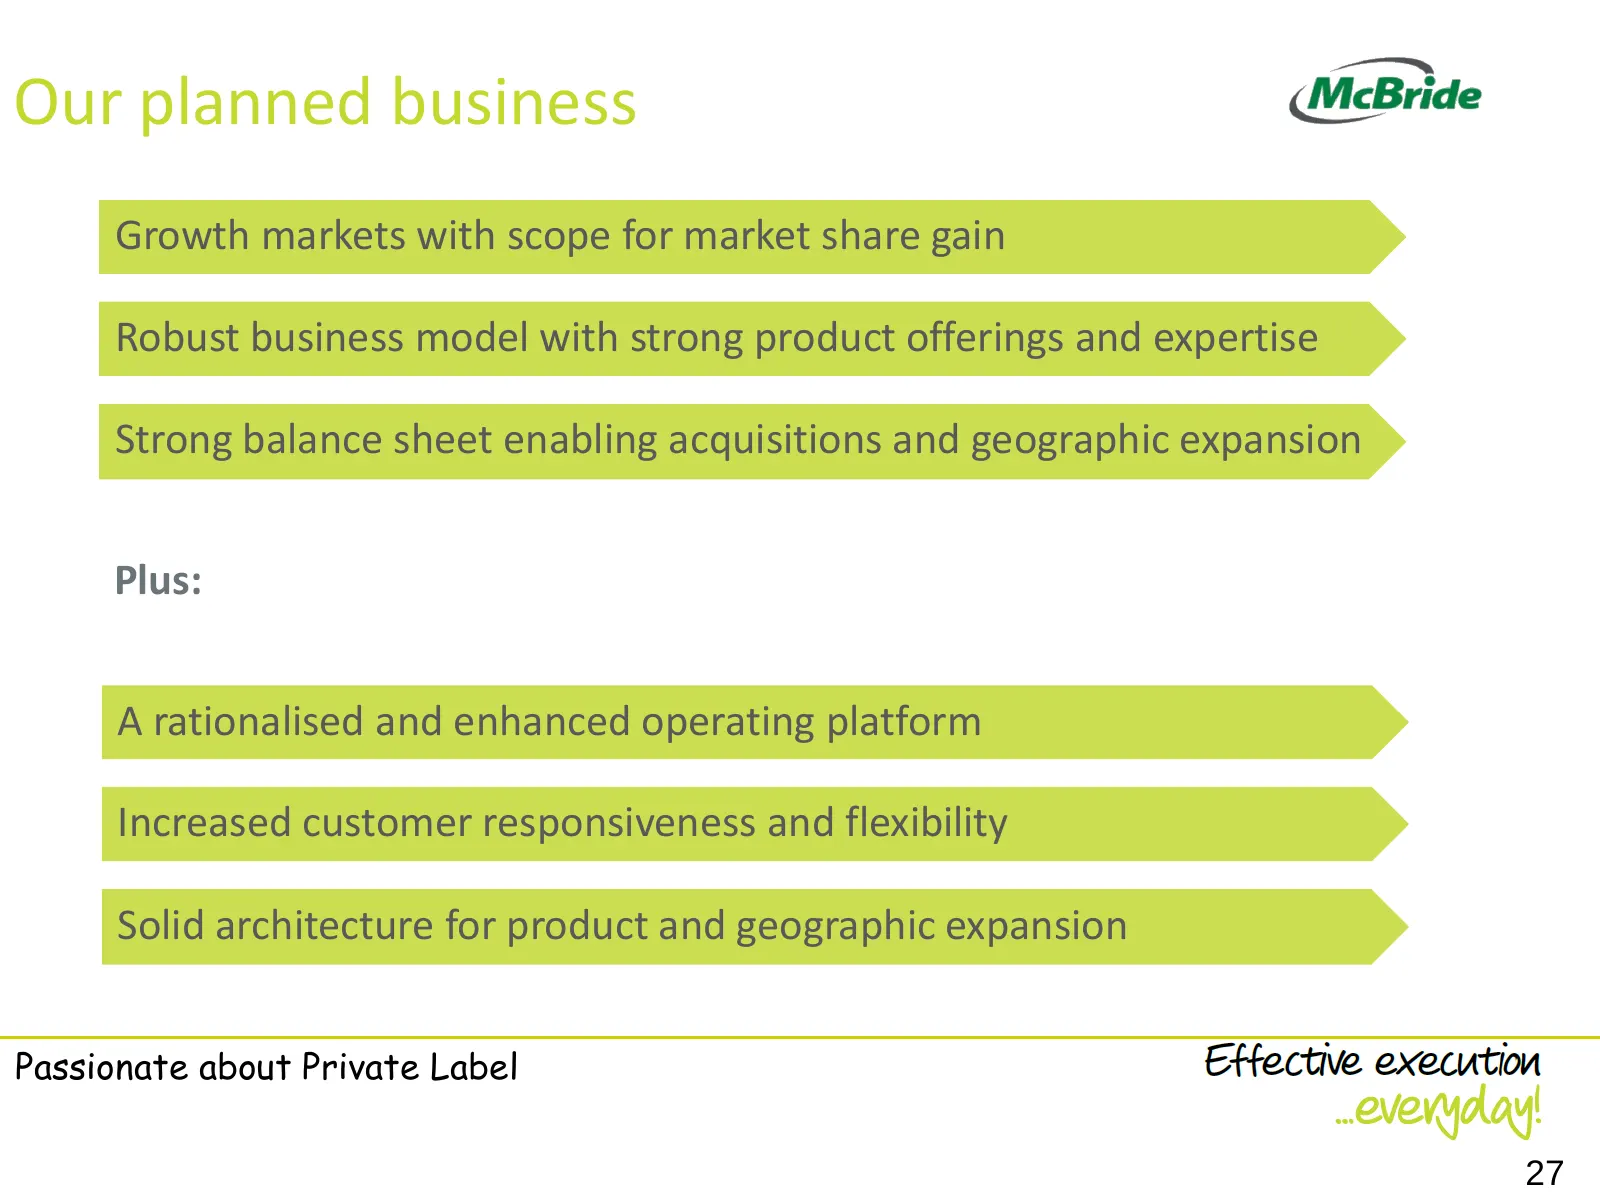
Our planned business Growth markets with scope for market share gain Robust business model with strong product offerings and expertise Strong balance sheet enabling acquisitions and geographic expansion Plus: A rationalised and enhanced operating platform Increased customer responsiveness and flexib
Slide 28: Business model
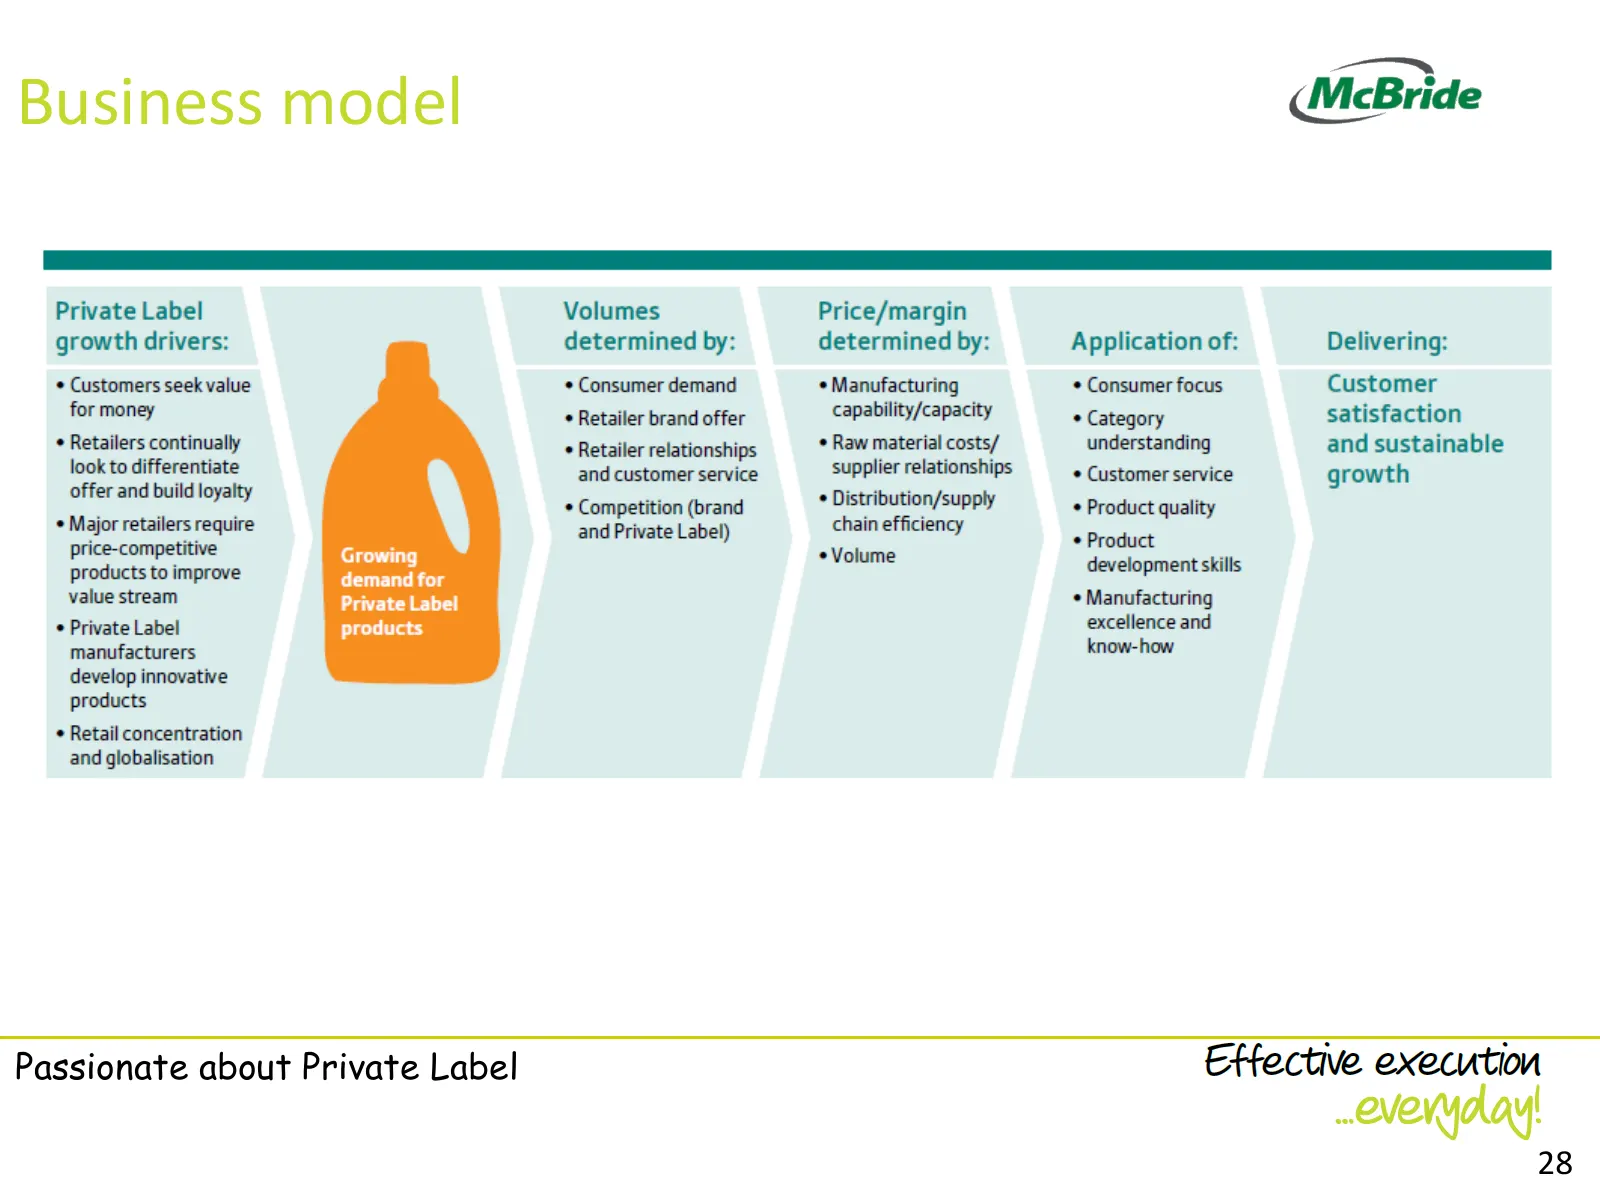
Business model Passionate about Private Label 28
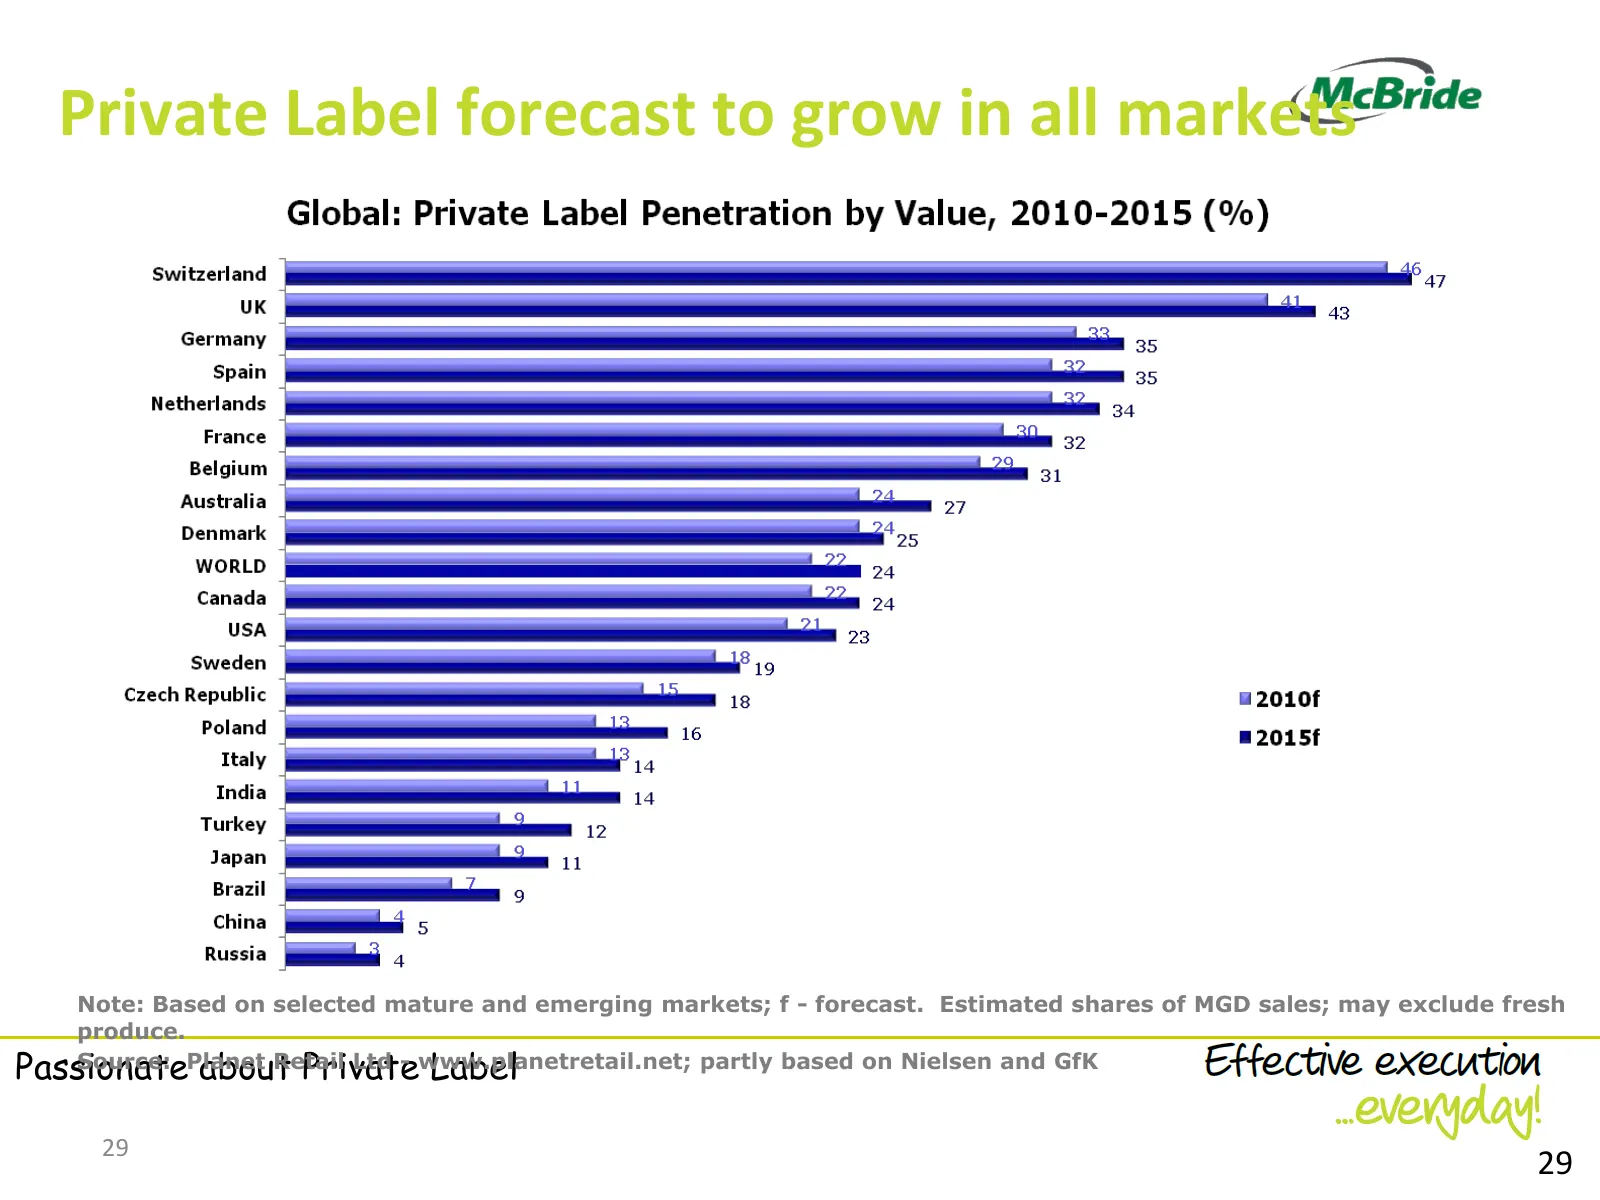
Slide 29: Private Label forecast to grow in all markets
Private Label forecast to grow in all markets Note: Based on selected mature and emerging markets; f - forecast. Estimated shares of MGD sales; may exclude fresh produce. Passionate about Private Label Source: Planet Retail Ltd - www.planetretail.net; partly based on Nielsen and GfK 29 29
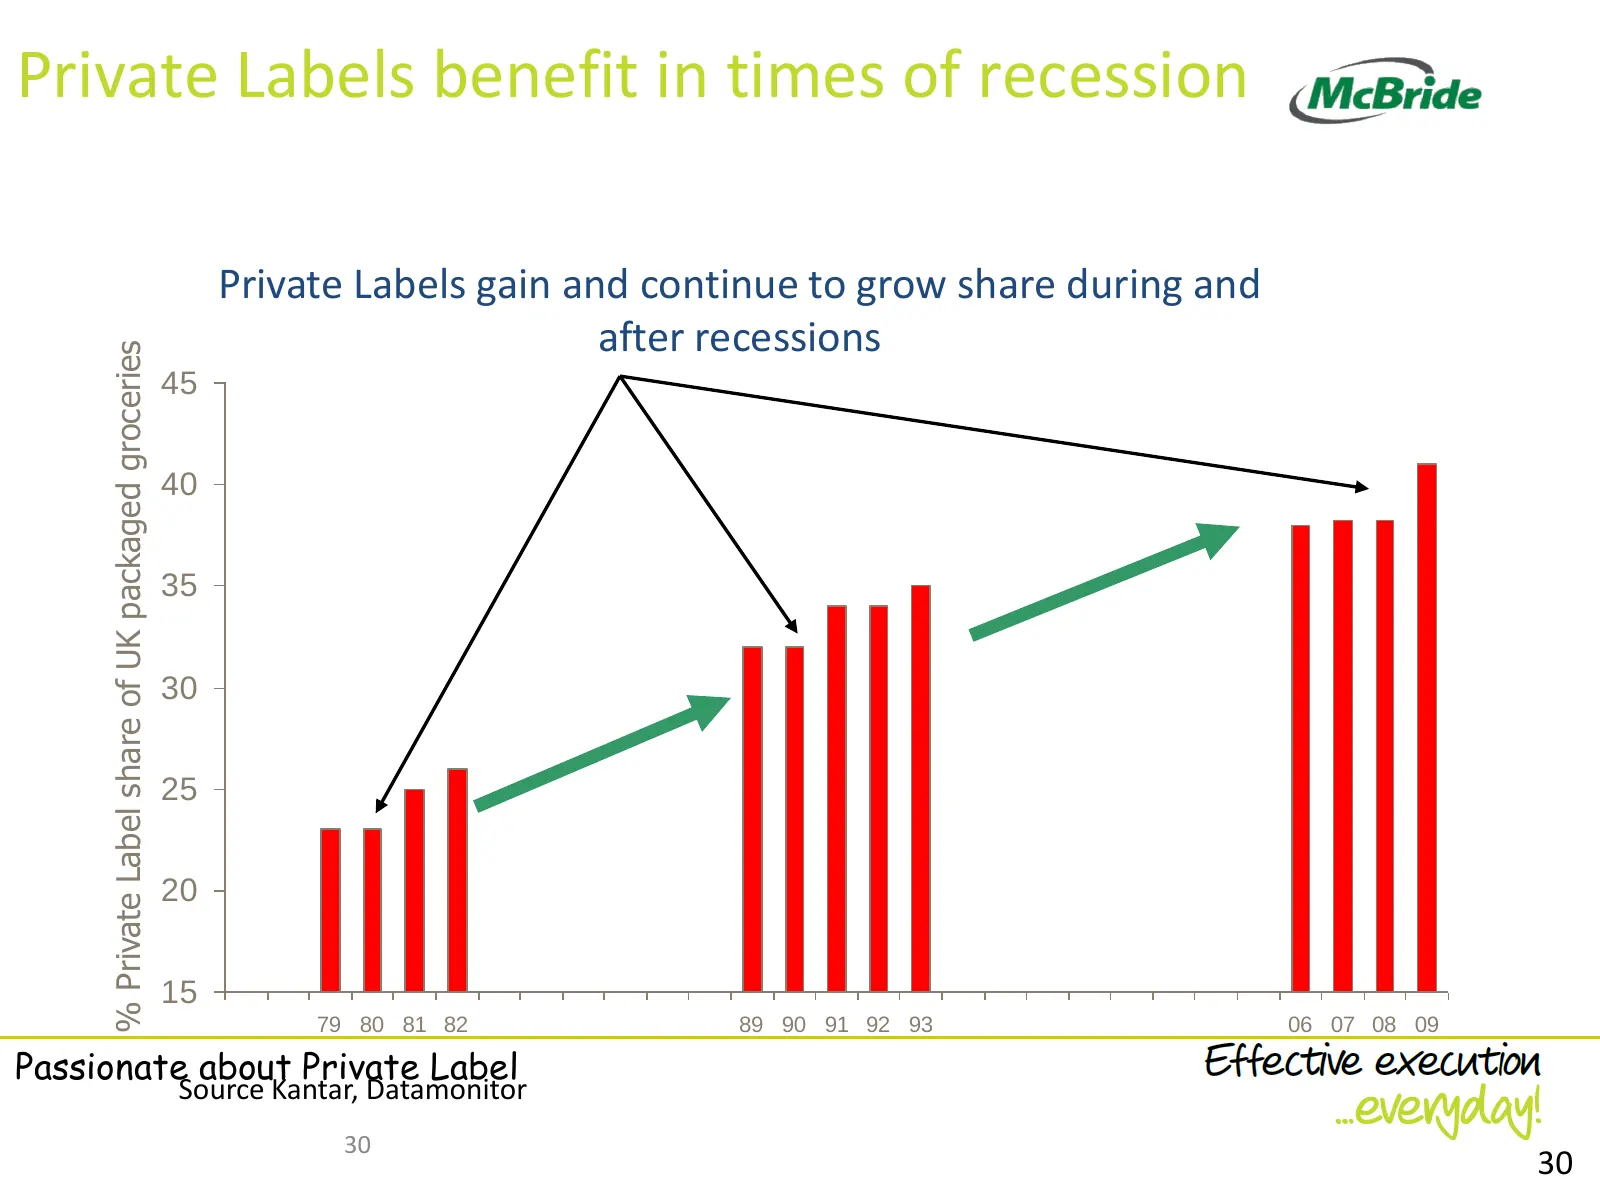
Slide 30: % Private Label share of UK packaged groceries
Private Labels benefit in times of recession Private Labels gain and continue to grow share during and after recessions % Private Label share of UK packaged groceries 45 40 35 30 25 20 15 79 80 81 82 89 90 91 92 93 06 07 08 09 Passionate about Private Label Source Kantar, Datamonitor 30 30
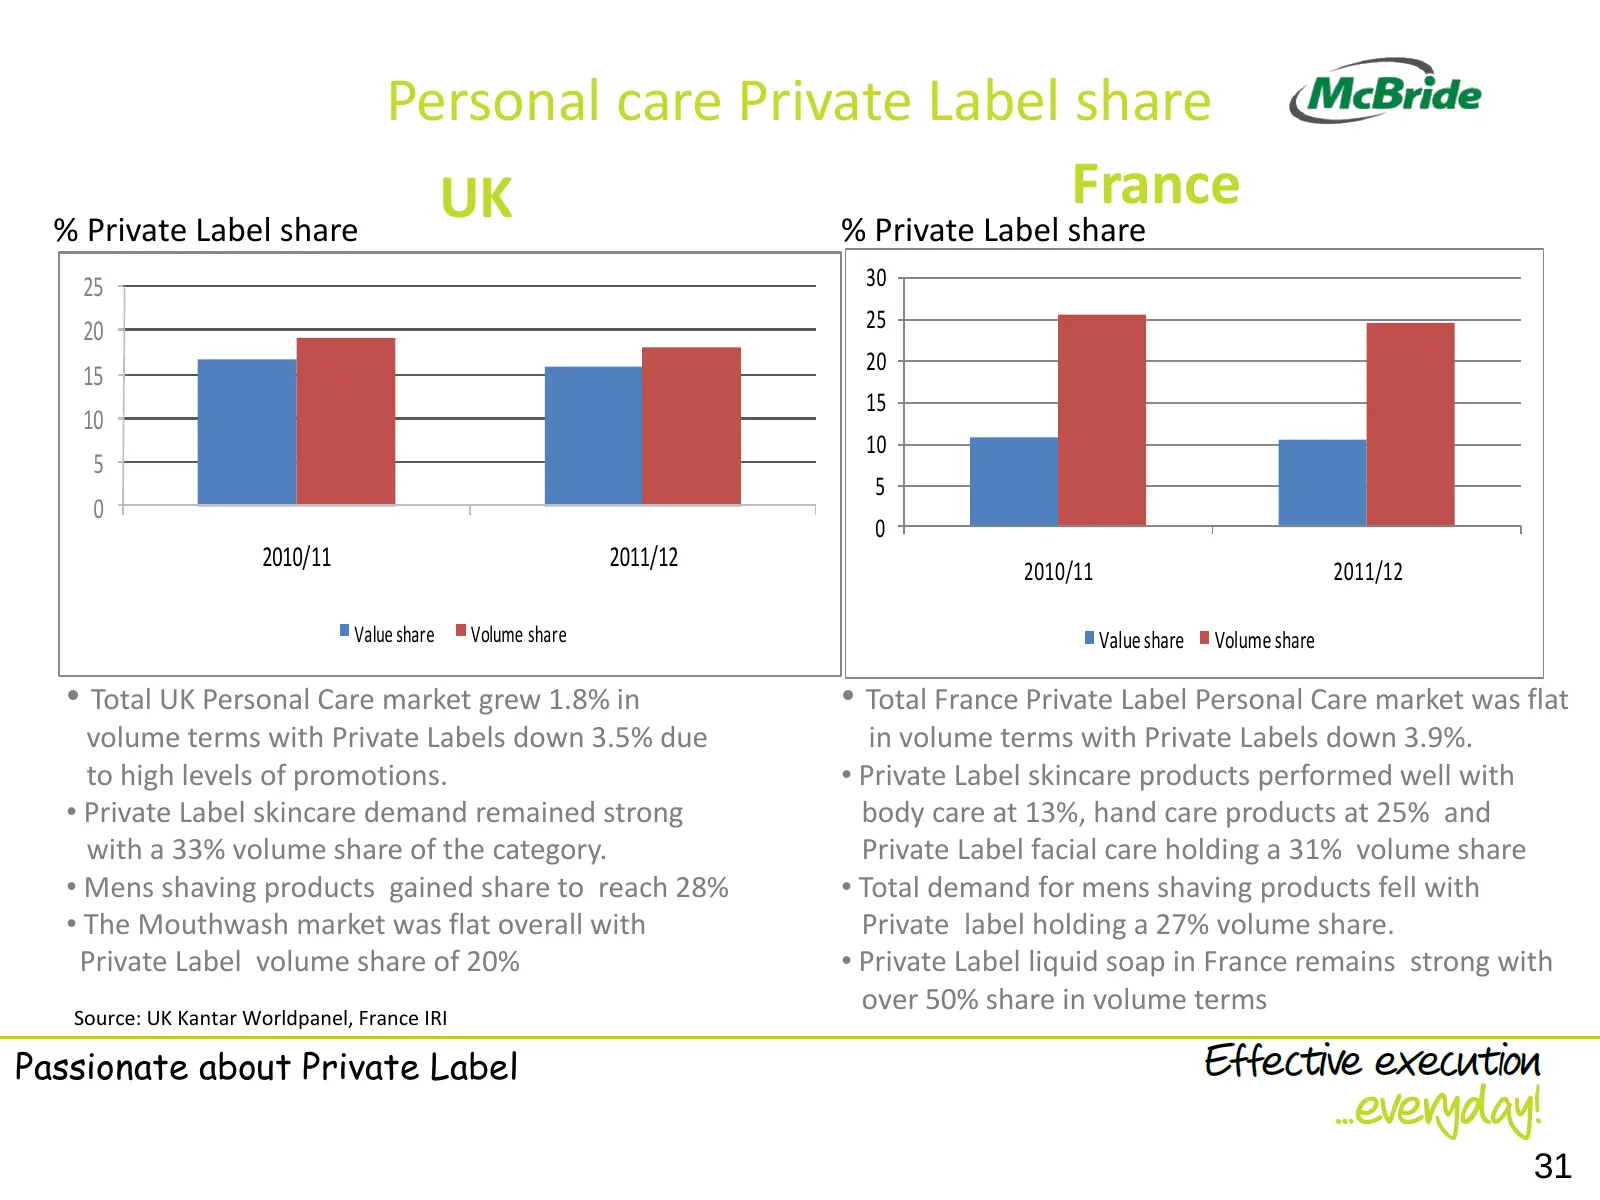
Slide 31: Personal care Private Label share France UK
Personal care Private Label share UK France % Private Label share % Private Label share 25 30 20 25 20 15 15 10 10 5 5 0 0 2010/11 2011/12 2010/11 2011/12 Value share Volume share Value share Volume share • Total UK Personal Care market grew 1.8% in • Total France Private Label Personal Care market
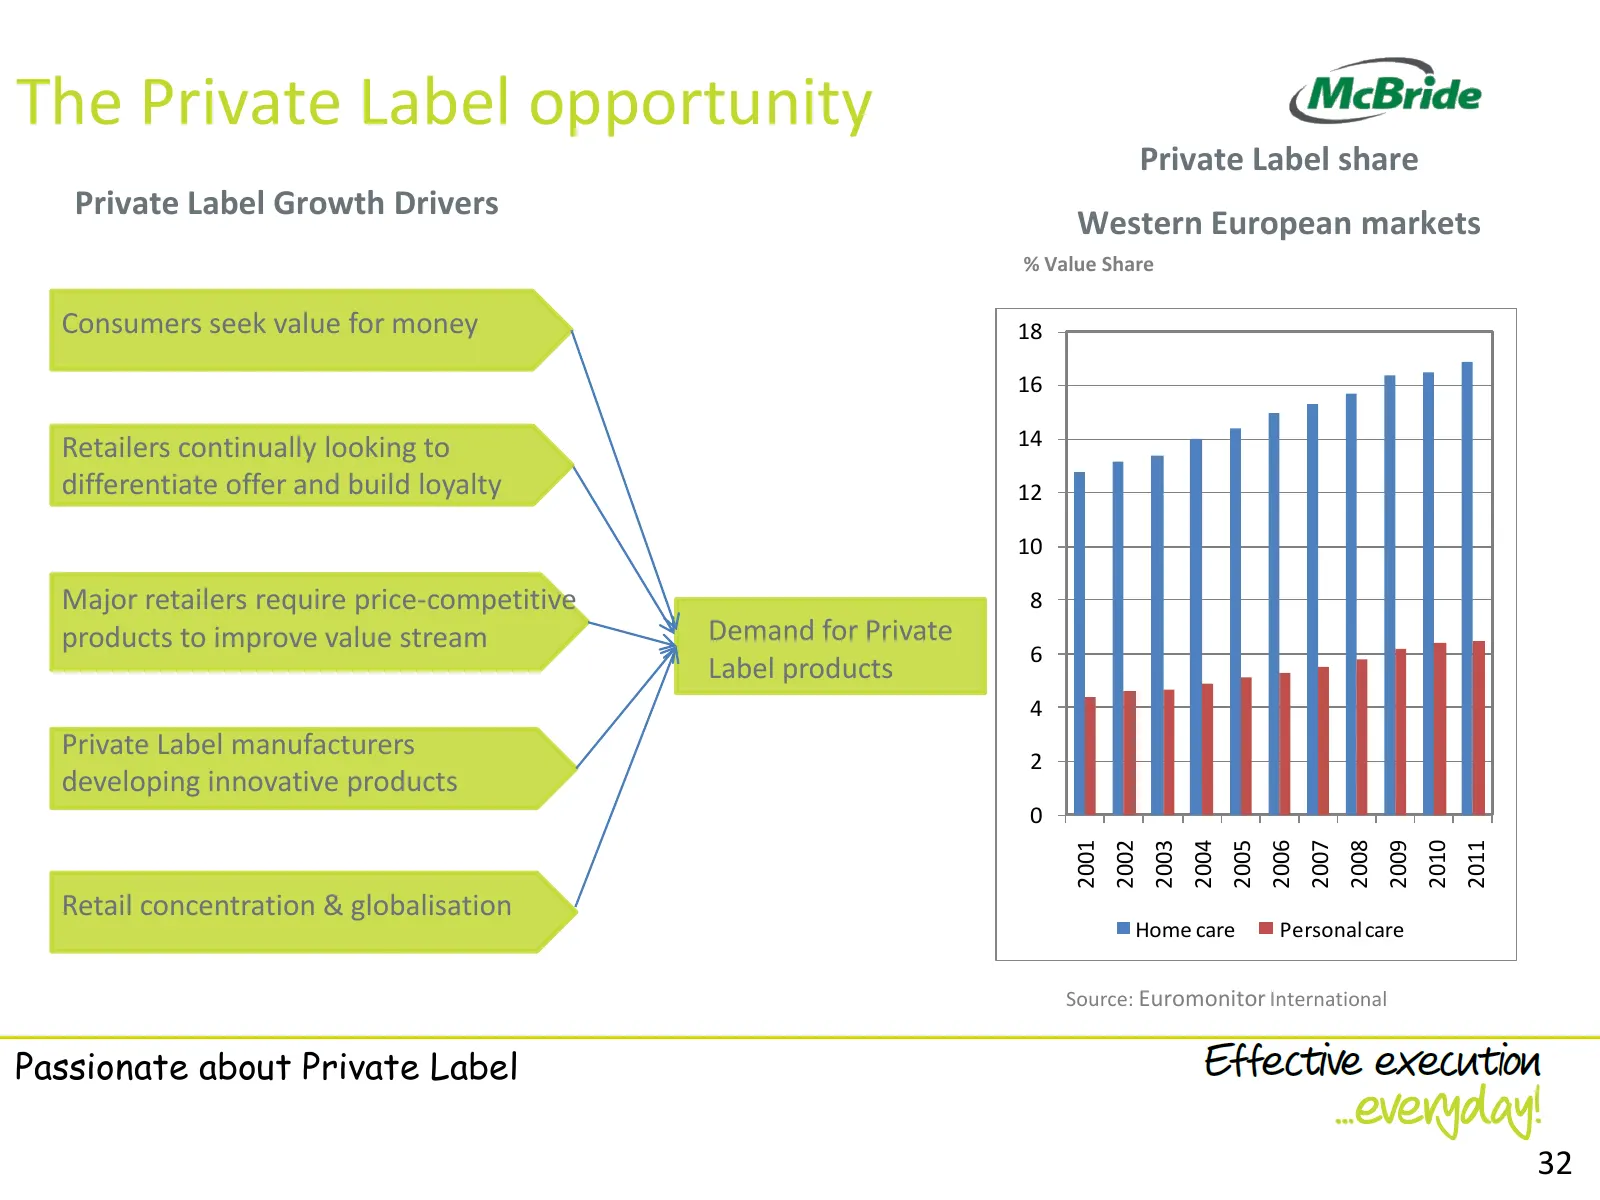
Slide 32: The Private Label opportunity
The Private Label opportunity Private Label share Private Label Growth Drivers Western European markets % Value Share Consumers seek value for money 18 16 Retailers continually looking to 14 differentiate offer and build loyalty 12 10 Major retailers require price-competitive 8 products to improve v
Source: Internet Archive copy of mcbride.co.uk
More decks from McBride plc
 FY2026 Earnings Presentation28 slides · Sep 15, 2026
 H1 FY26 Earnings Presentation22 slides · Feb 26, 2026
 FY2025 Earnings Presentation23 slides · Sep 18, 2025
 H1 FY2025 Earnings Presentation30 slides · Feb 25, 2025
 FY2024 Earnings Presentation30 slides · Sep 17, 2024
 Investor Day (March 2024)65 slides · Mar 13, 2024