K+s AG · XETR:SDF
K+s — K+S Aktiengesellschaft — German Investment Conference 2005 (HVB, Munich)
34 slides from K+s's conference presentation, Sep 28, 2005
Slide 1: Experience growth. German Investment Conference
K+S Group - 28 September 2005 Experience growth. German Investment Conference HVB, Munich 28 September 2005
Slide 2: Growth Lies at the Heart of Our Vision
K+S Group Growth Lies at the Heart of Our Vision K+S is one of the world‘s leading suppliers of speciality and standard fertilizers, plant care and salt products. Achieving healthy and sustained growth is our goal as a company and a challenge at the same time. We offer agriculture, industry and priv
Slide 3: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 4: Business Model
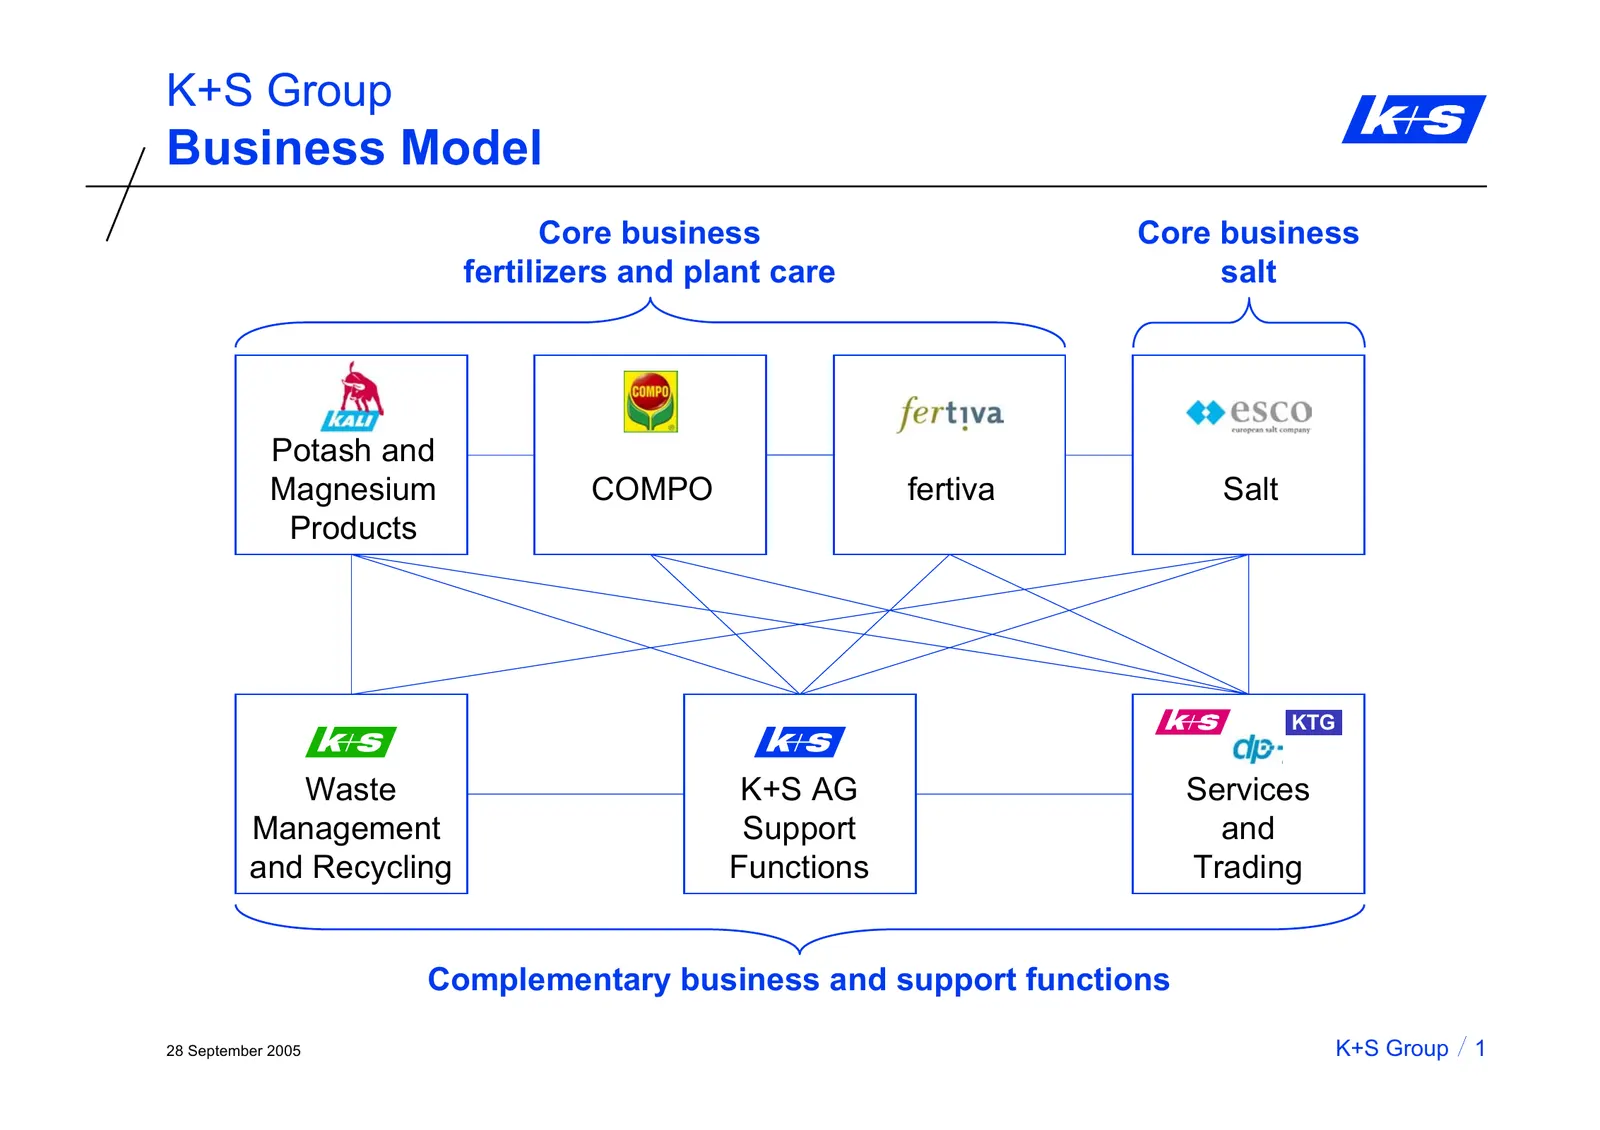
K+S Group Business Model Core business Core business fertilizers and plant care salt Potash and Magnesium COMPO fertiva Salt Products KTG Waste K+S AG Services Management Support and and Recycling Functions Trading Complementary business and support functions 28 September 2005 K+S Group 1
Slide 5: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 6: Fertilizer Business
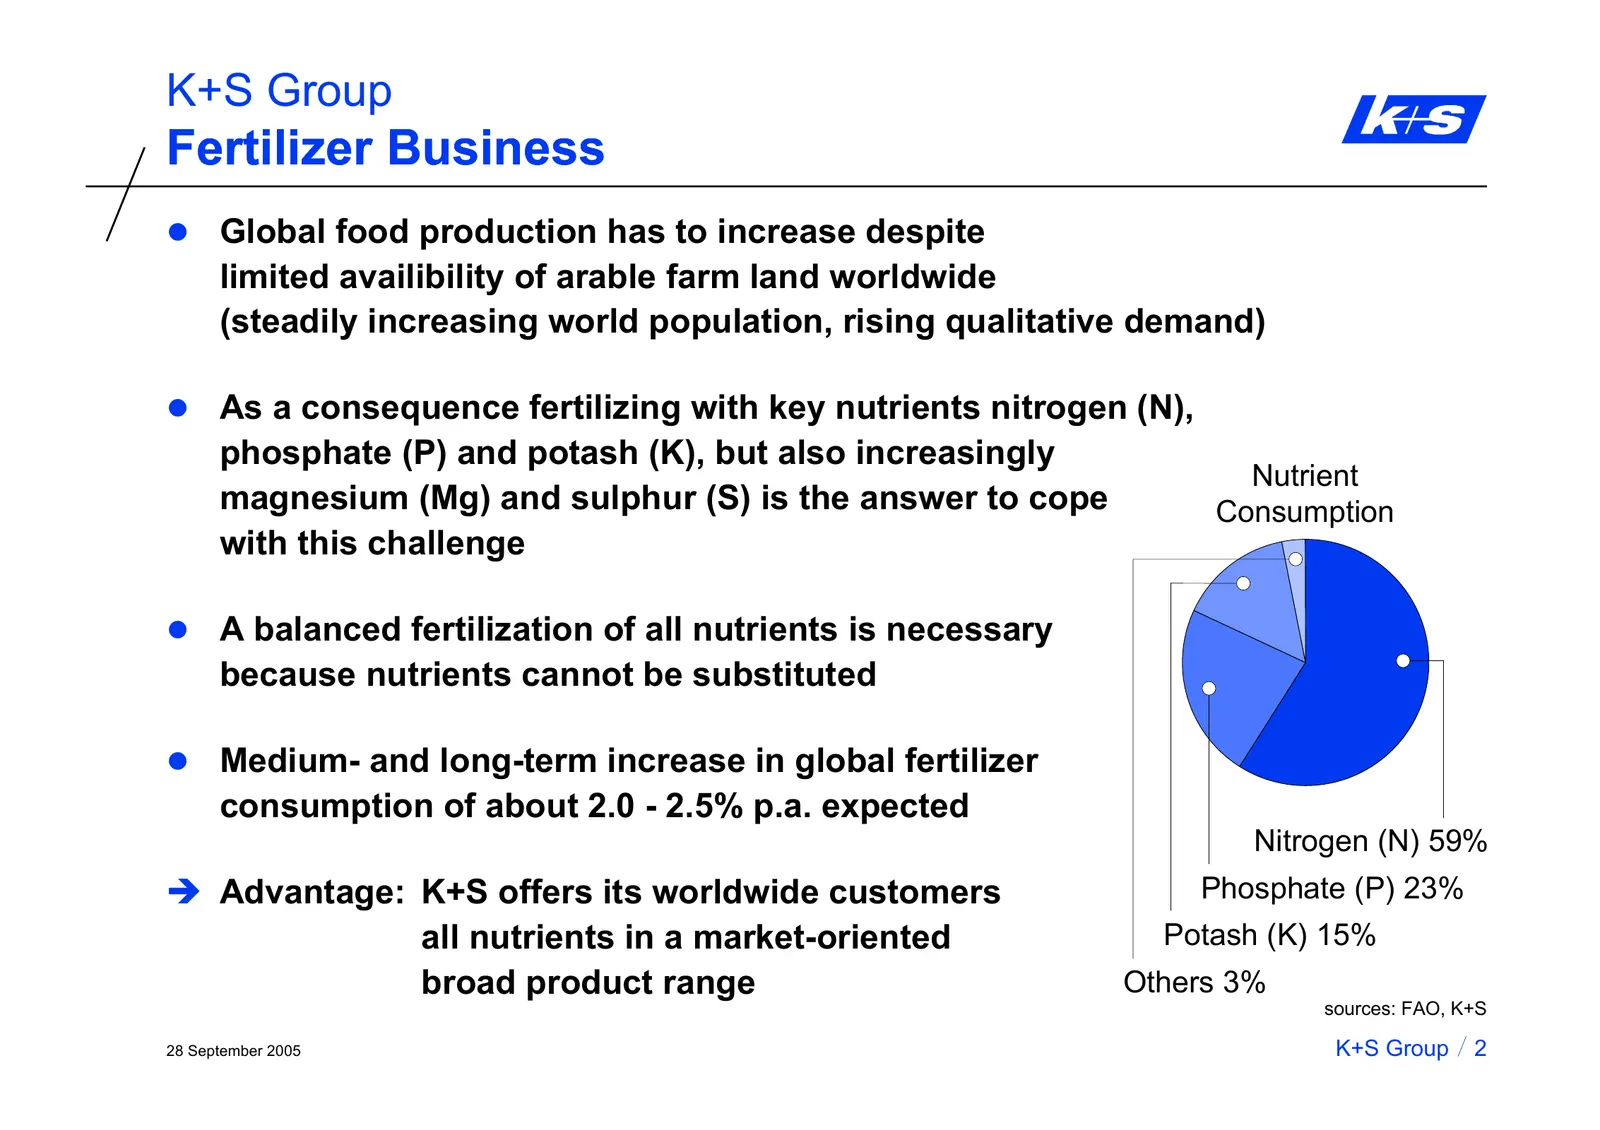
K+S Group Fertilizer Business z Global food production has to increase despite limited availibility of arable farm land worldwide (steadily increasing world population, rising qualitative demand) z As a consequence fertilizing with key nutrients nitrogen (N), phosphate (P) and potash (K), but also i
Slide 7: World Potash Capacity, Production and Demand
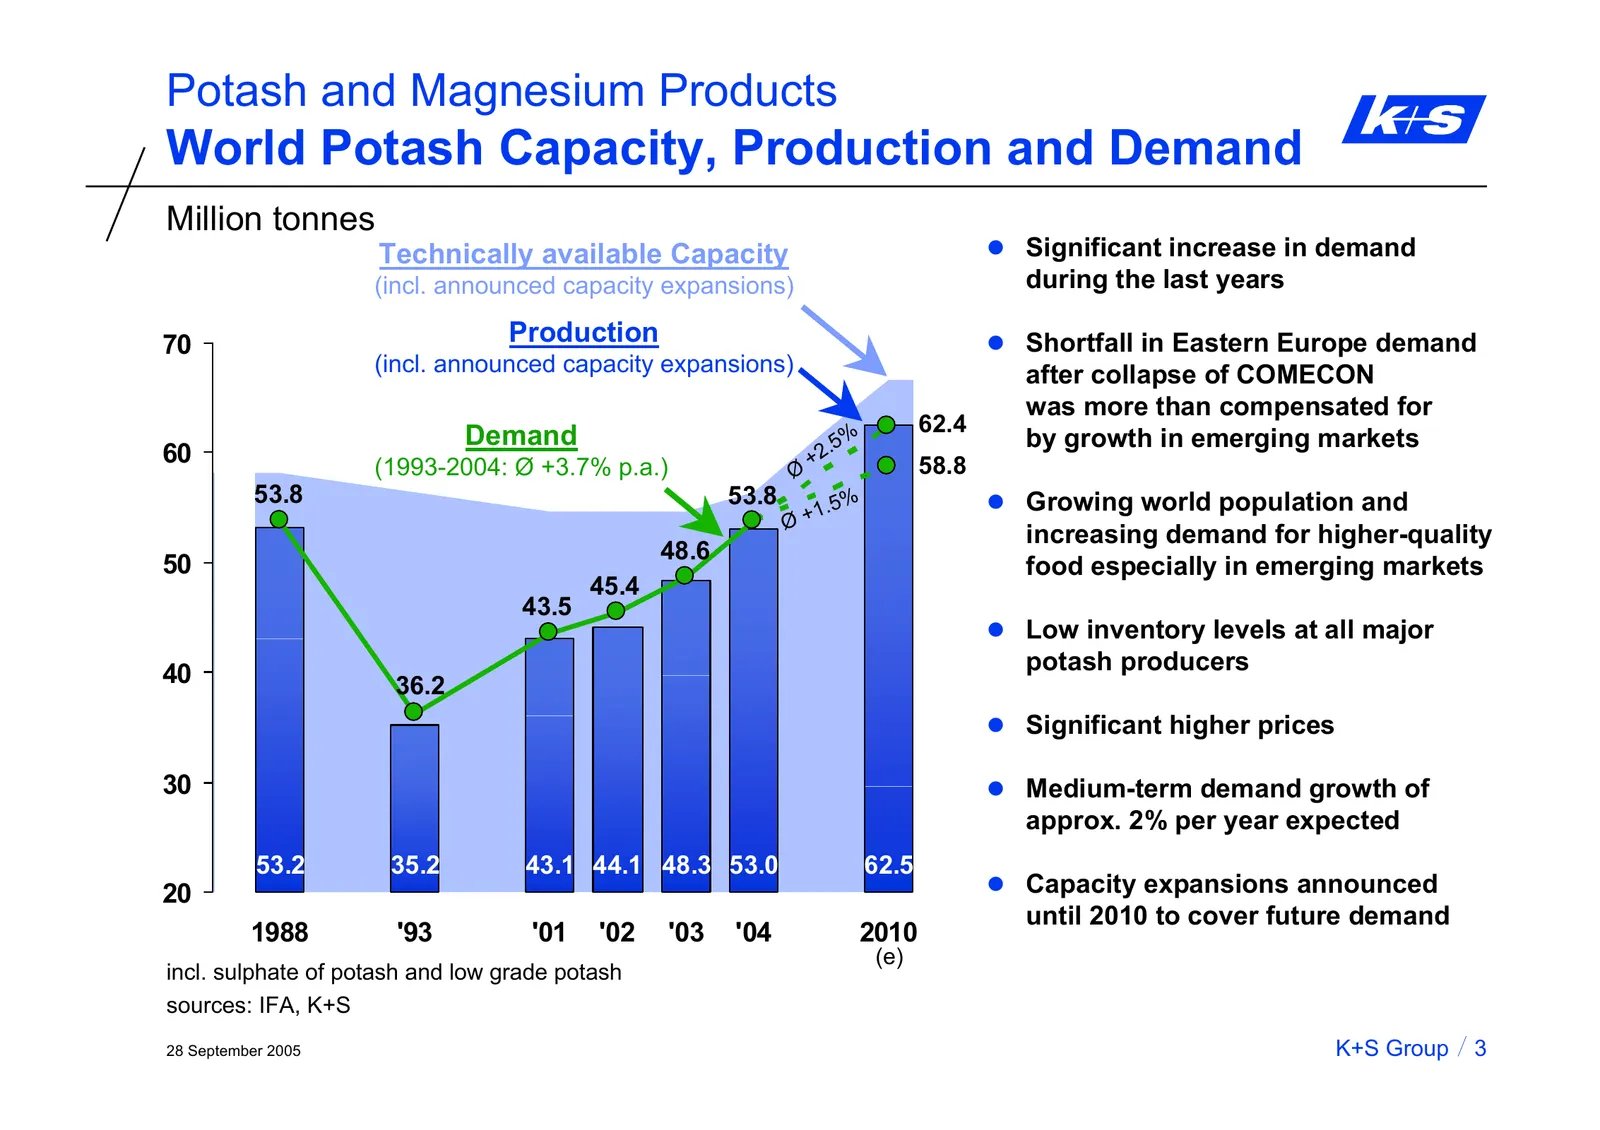
Potash and Magnesium Products World Potash Capacity, Production and Demand Million tonnes Technically available Capacity z Significant increase in demand (incl. announced capacity expansions) during the last years 70 Production z Shortfall in Eastern Europe demand (incl. announced capacity expansion
Slide 8: Agricultural Potash Consumption by Region
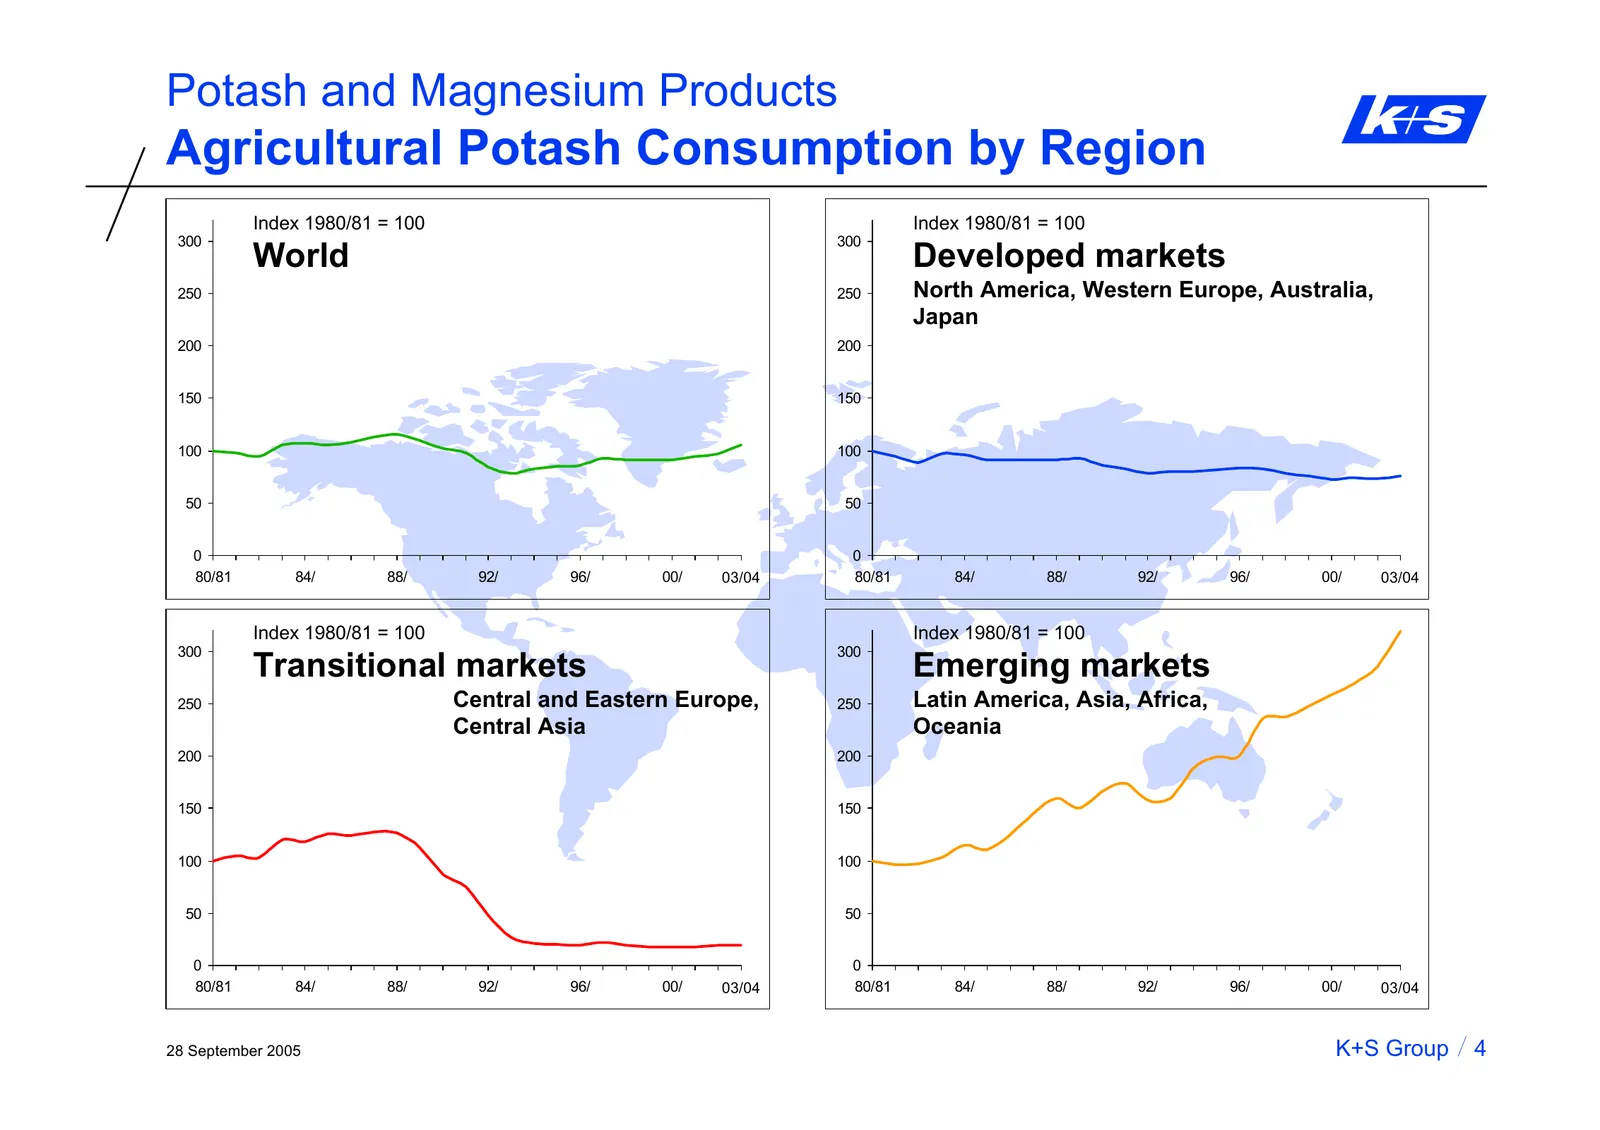
Potash and Magnesium Products Agricultural Potash Consumption by Region Index 1980/81 = 100 Index 1980/81 = 100 300 300 World Developed markets 250 250 North America, Western Europe, Australia, Japan 200 200 150 150 100 100 50 50 0 0 80/81 84/ 88/ 92/ 96/ 00/ 03/04 80/81 84/ 88/ 92/ 96/ 00/ 03/04 In
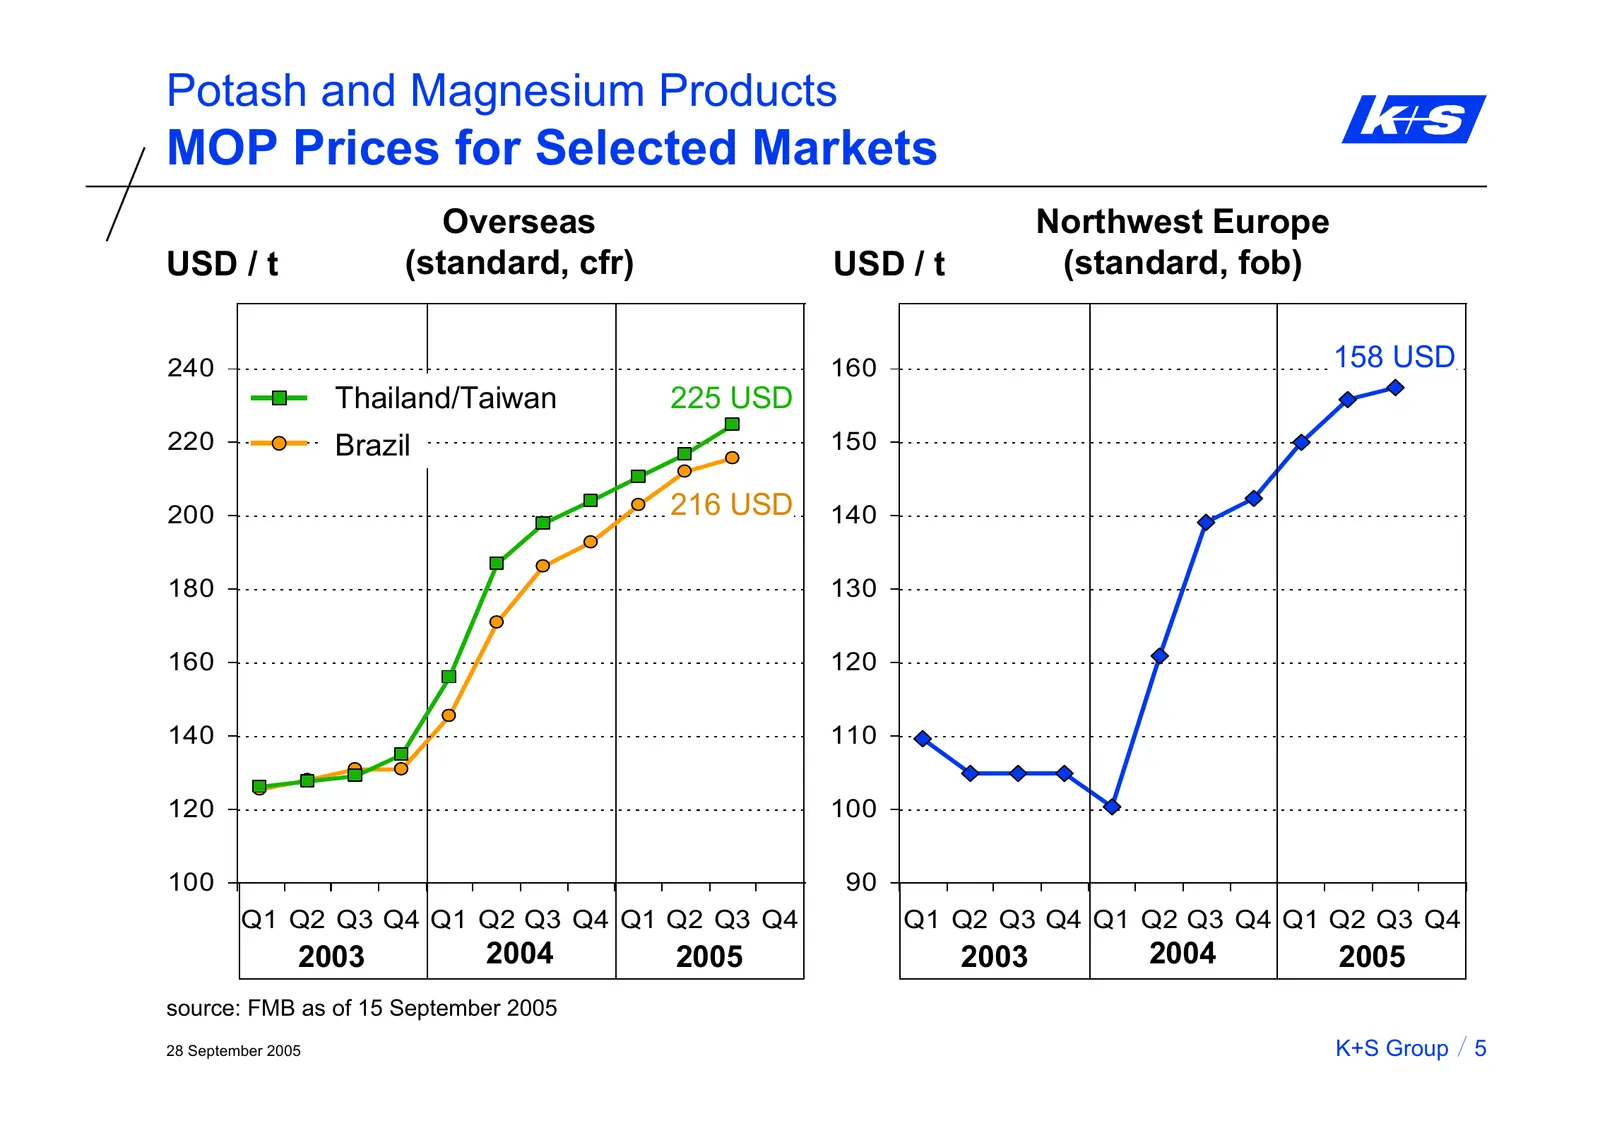
Slide 9: MOP Prices for Selected Markets
Potash and Magnesium Products MOP Prices for Selected Markets Overseas Northwest Europe USD / t (standard, cfr) USD / t (standard, fob) 240 160 158 USD Thailand/Taiwan 225 USD 220 Brazil 150 200 216 USD 140 180 130 160 120 140 110 120 100 100 90 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2
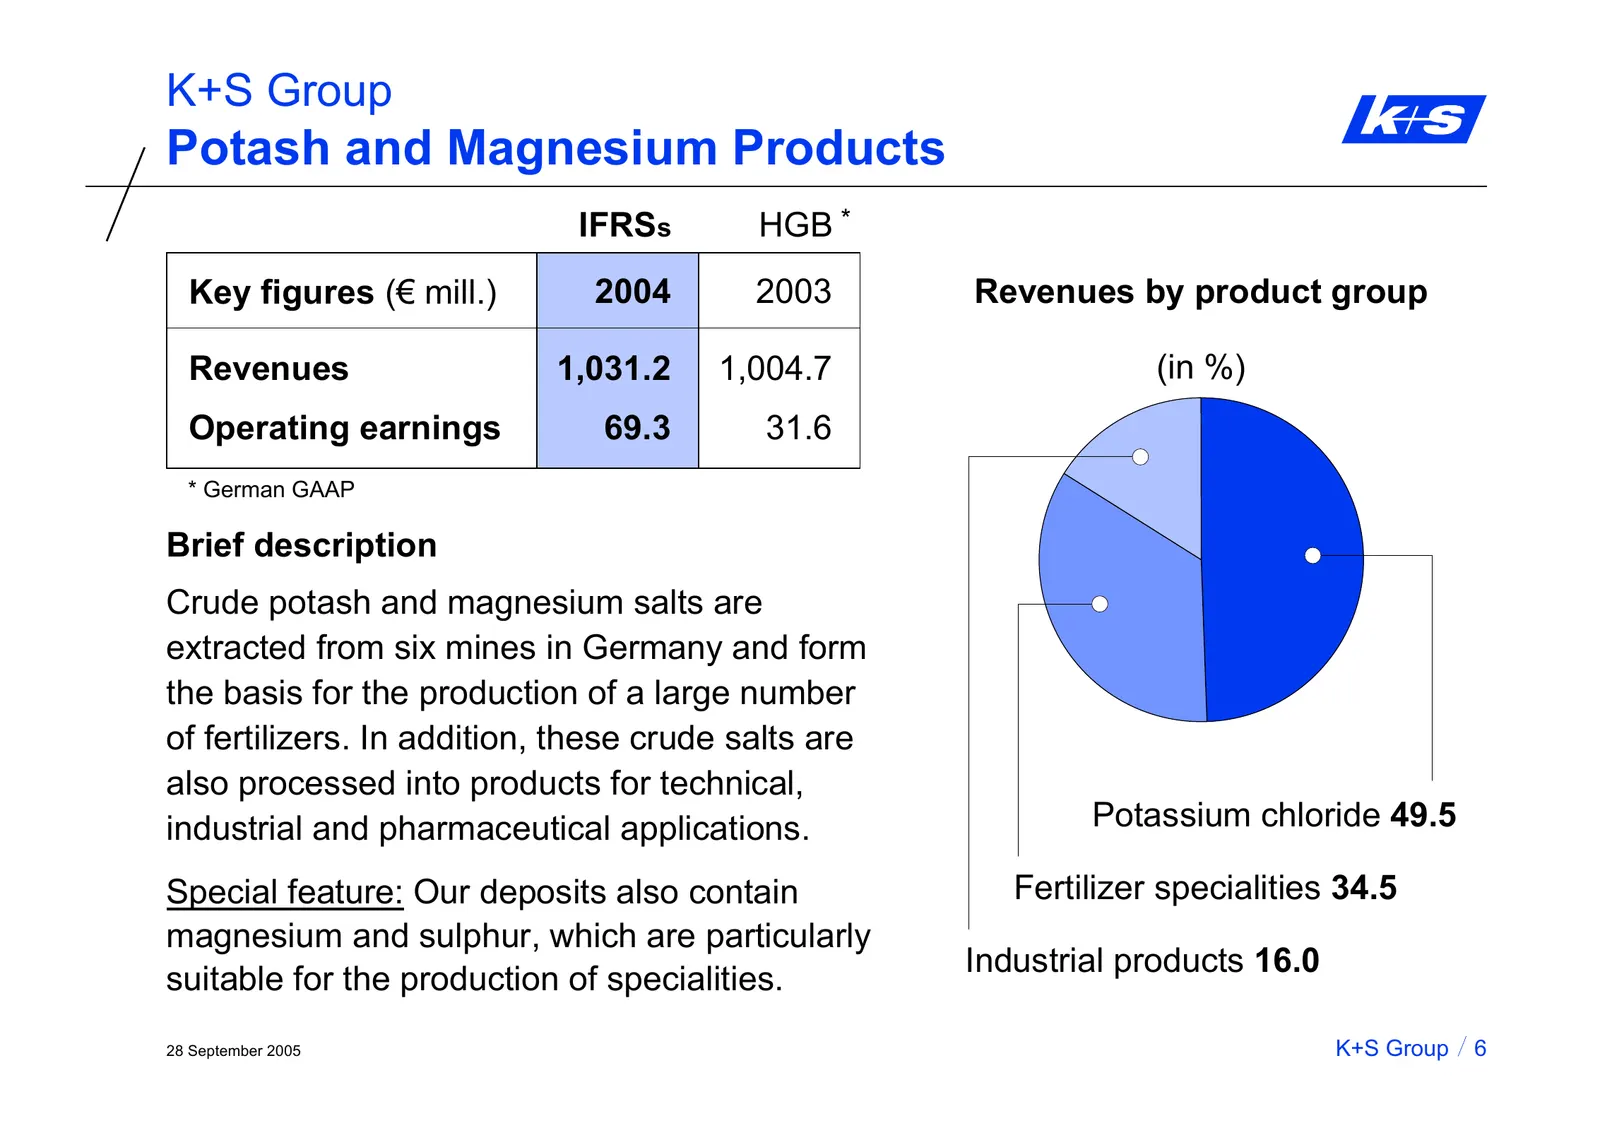
Slide 10: Potash and Magnesium Products
K+S Group Potash and Magnesium Products IFRSs HGB * Key figures (€ mill.) 2004 2003 Revenues by product group Revenues 1,031.2 1,004.7 (in %) Operating earnings 69.3 31.6 * German GAAP Brief description Crude potash and magnesium salts are extracted from six mines in Germany and form the basis for t
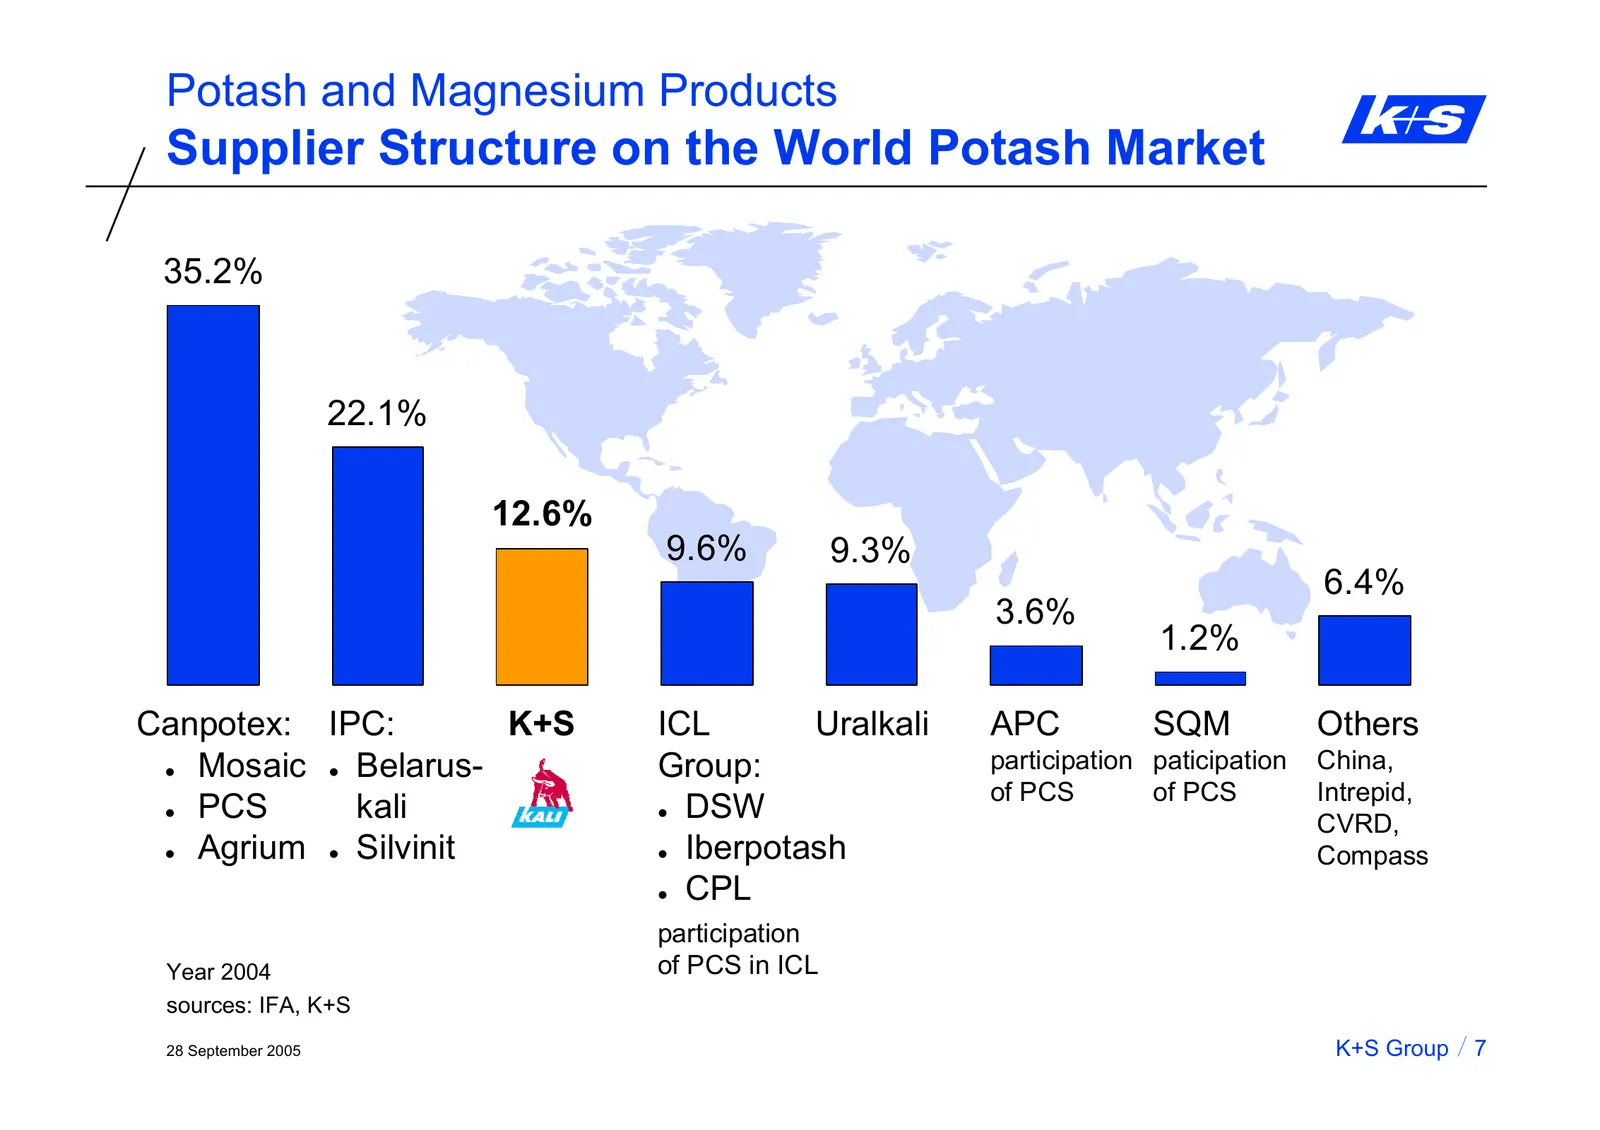
Slide 11: Supplier Structure on the World Potash Market
Potash and Magnesium Products Supplier Structure on the World Potash Market 35.2% 22.1% 12.6% 9.6% 9.3% 6.4% 3.6% 1.2% Canpotex: IPC: K+S ICL Uralkali APC SQM Others z Mosaic Belarus- z Group: participation paticipation China, of PCS of PCS Intrepid, z PCS kali z DSW CVRD, z Agrium Silvinit z z Iber
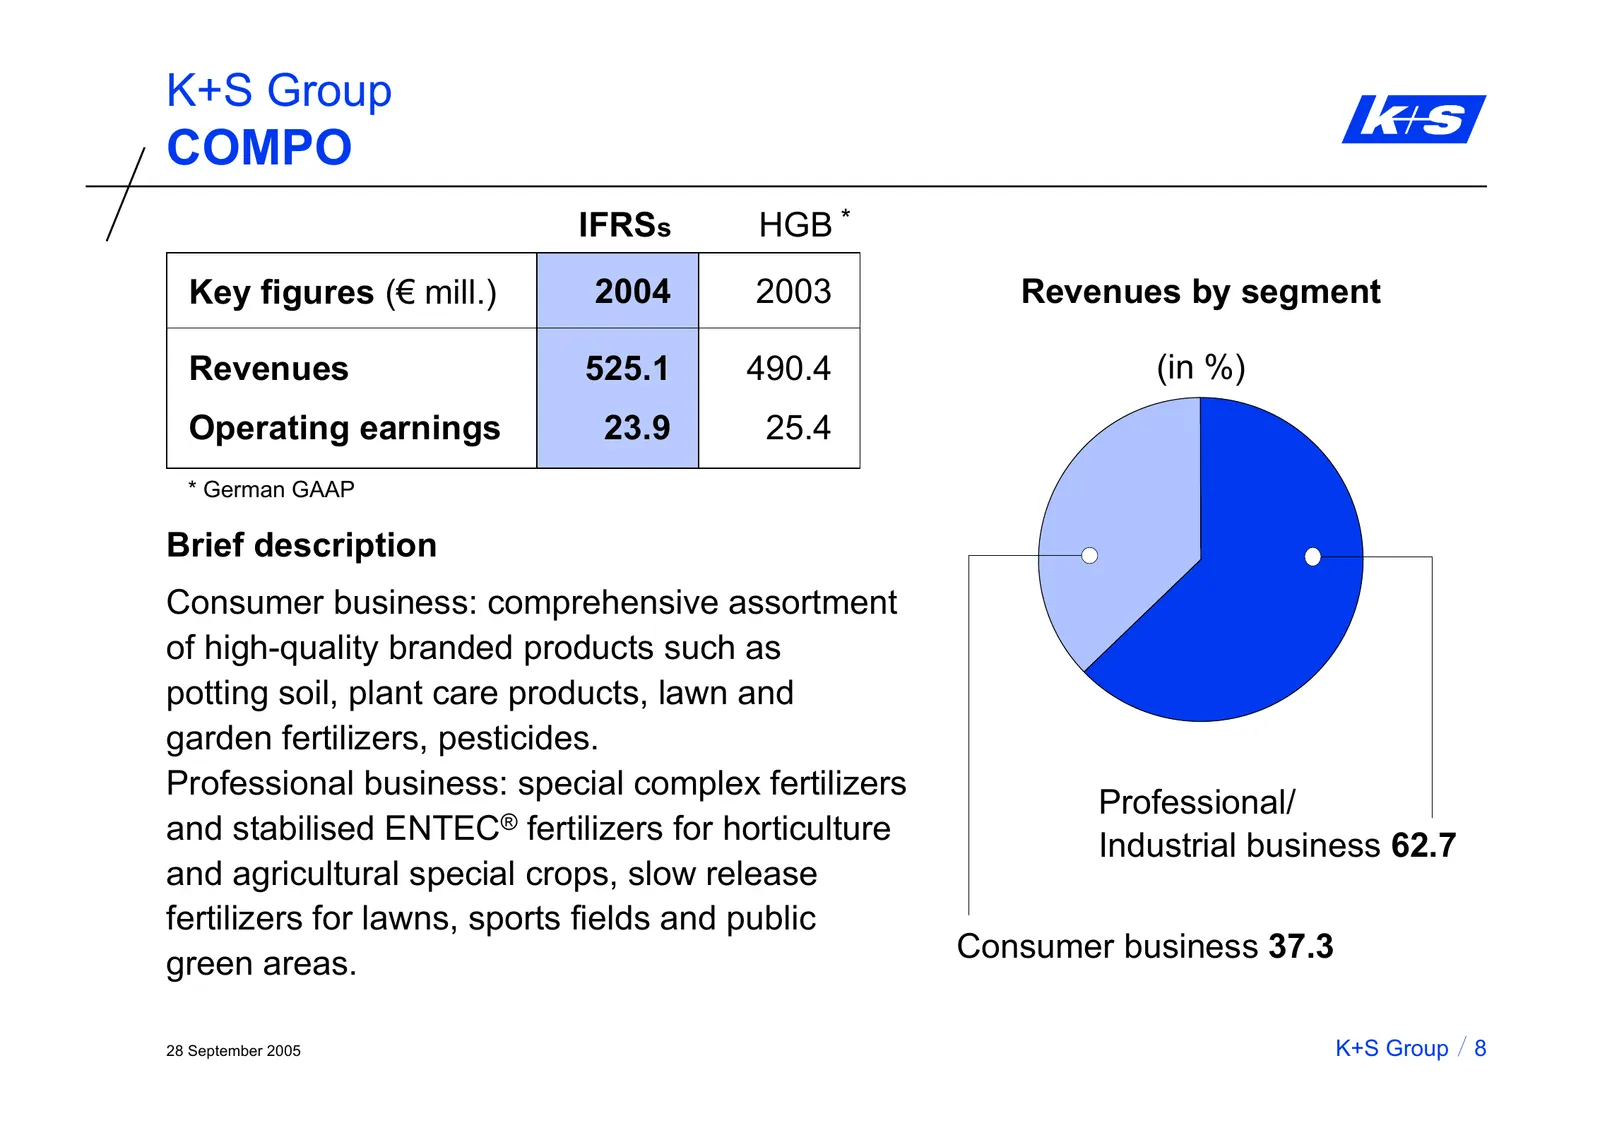
Slide 12: COMPO
K+S Group COMPO IFRSs HGB * Key figures (€ mill.) 2004 2003 Revenues by segment Revenues 525.1 490.4 (in %) Operating earnings 23.9 25.4 * German GAAP Brief description Consumer business: comprehensive assortment of high-quality branded products such as potting soil, plant care products, lawn and ga
Slide 13: fertiva
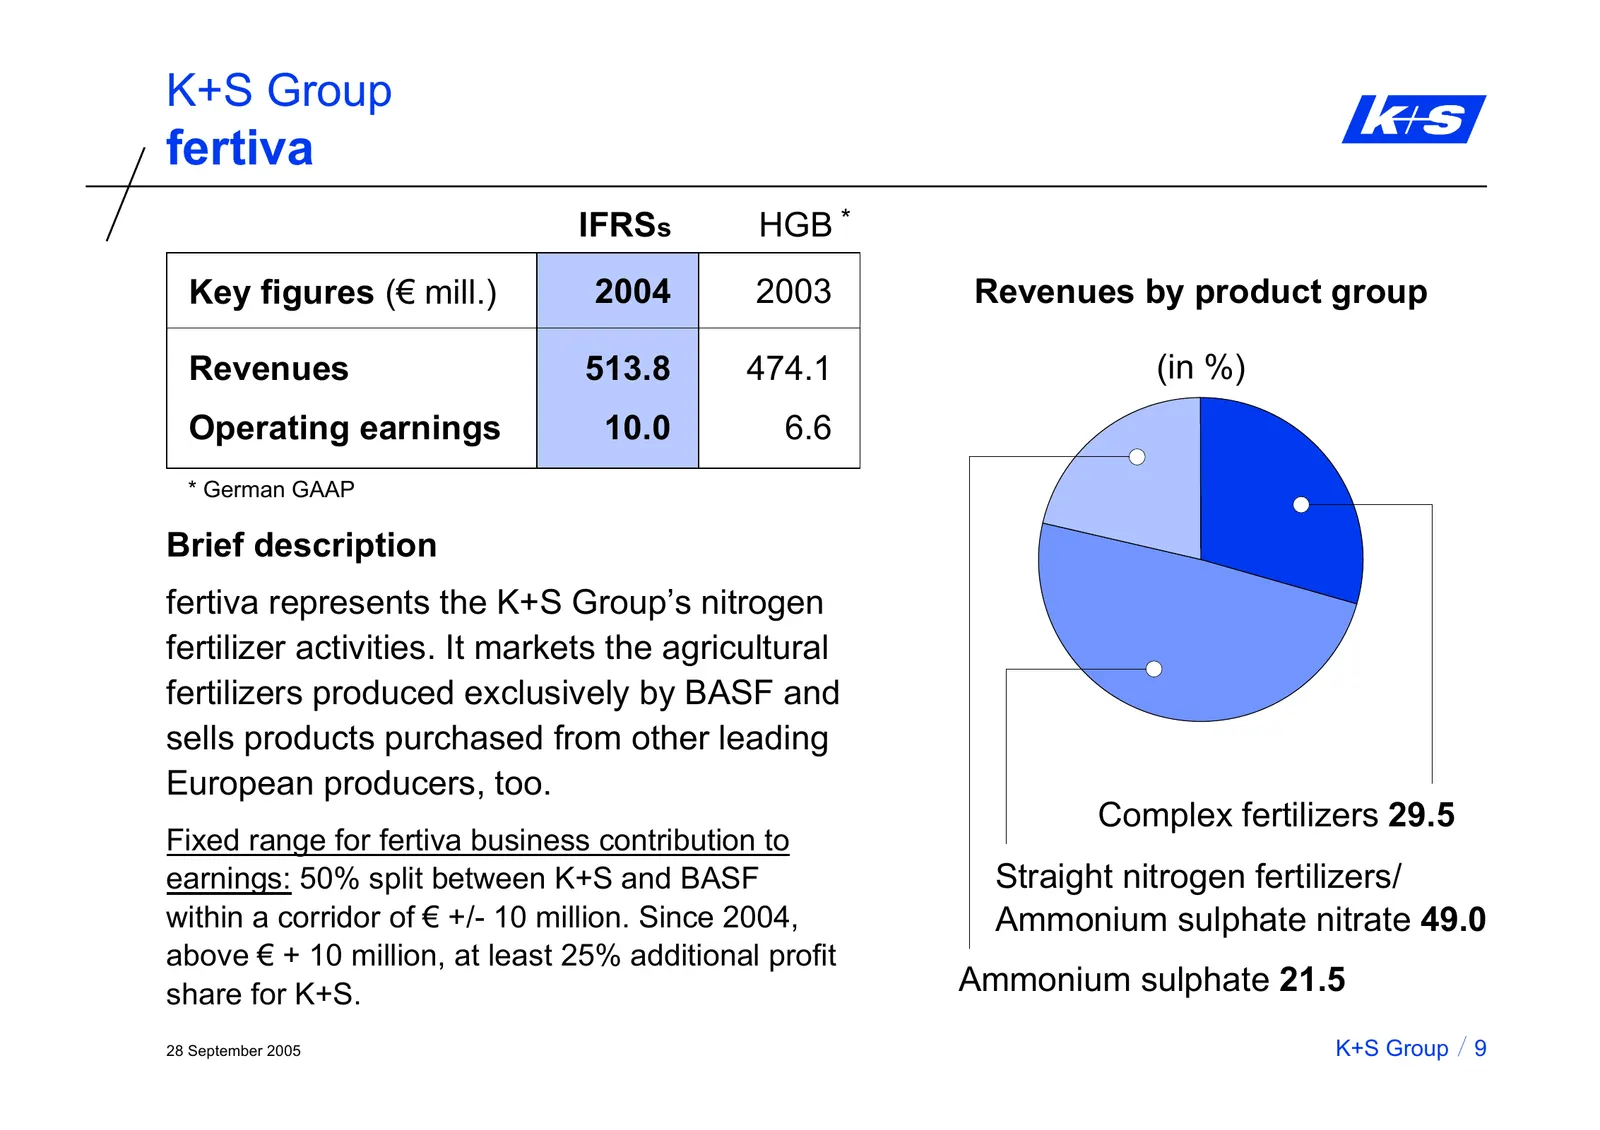
K+S Group fertiva IFRSs HGB * Key figures (€ mill.) 2004 2003 Revenues by product group Revenues 513.8 474.1 (in %) Operating earnings 10.0 6.6 * German GAAP Brief description fertiva represents the K+S Group’s nitrogen fertilizer activities. It markets the agricultural fertilizers produced exclusiv
Slide 14: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 15: Salt
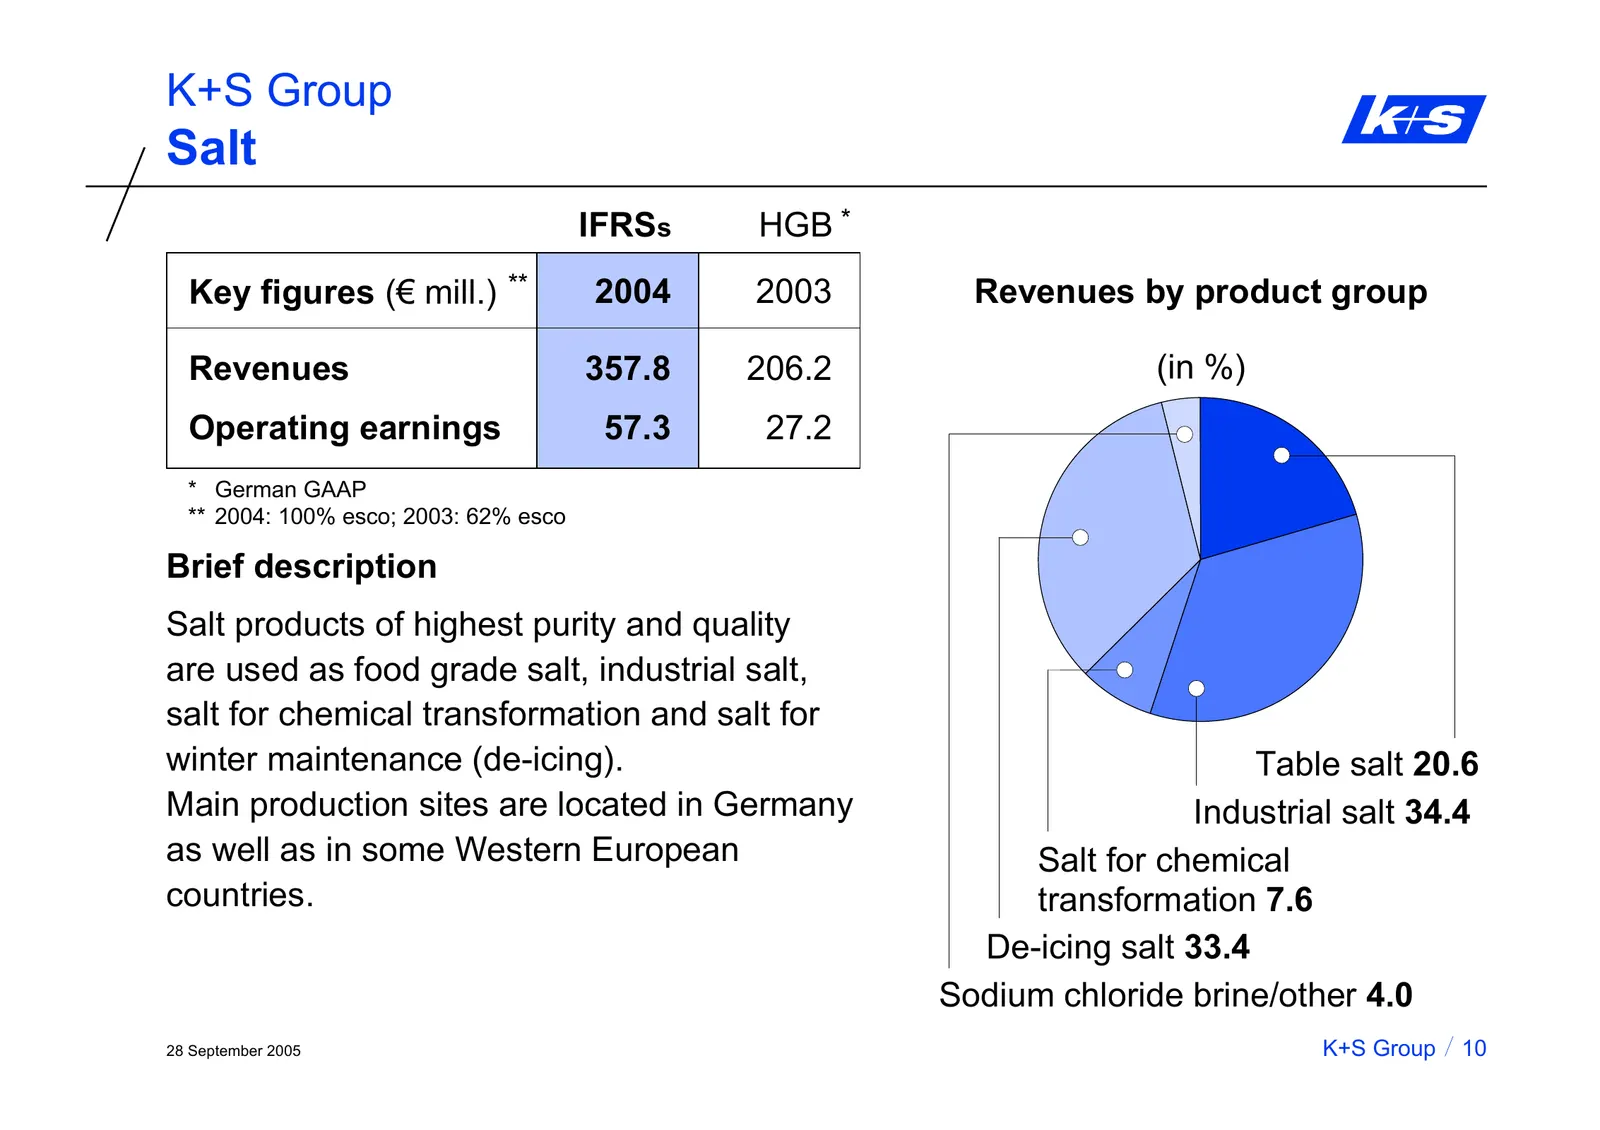
K+S Group Salt IFRSs HGB * Key figures (€ mill.) ** 2004 2003 Revenues by product group Revenues 357.8 206.2 (in %) Operating earnings 57.3 27.2 * German GAAP ** 2004: 100% esco; 2003: 62% esco Brief description Salt products of highest purity and quality are used as food grade salt, industrial salt
Slide 16: Main European Crystallized Salt Suppliers
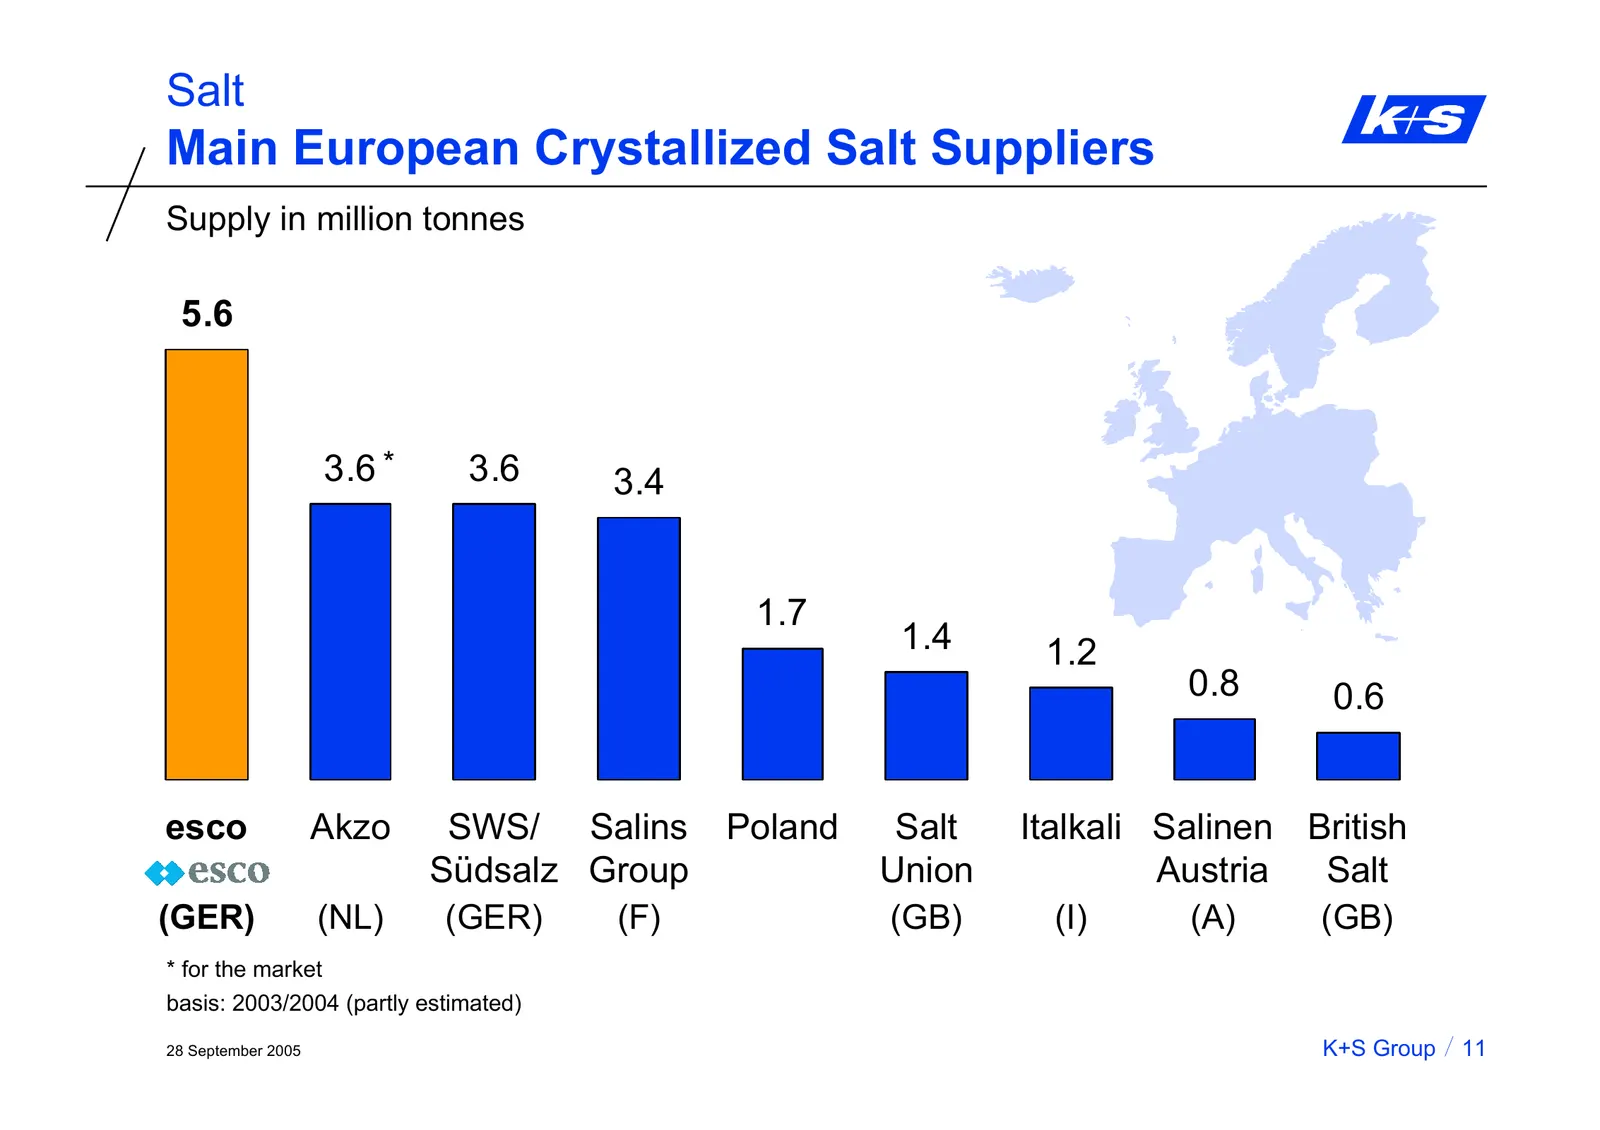
Salt Main European Crystallized Salt Suppliers Supply in million tonnes 5.6 3.6 * 3.6 3.4 1.7 1.4 1.2 0.8 0.6 esco Akzo SWS/ Salins Poland Salt Italkali Salinen British Südsalz Group Union Austria Salt (GER) (NL) (GER) (F) (GB) (I) (A) (GB) * for the market basis: 2003/2004 (partly estimated) 28 Sep
Slide 17: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 18: K+S is the Leading Player in its Markets
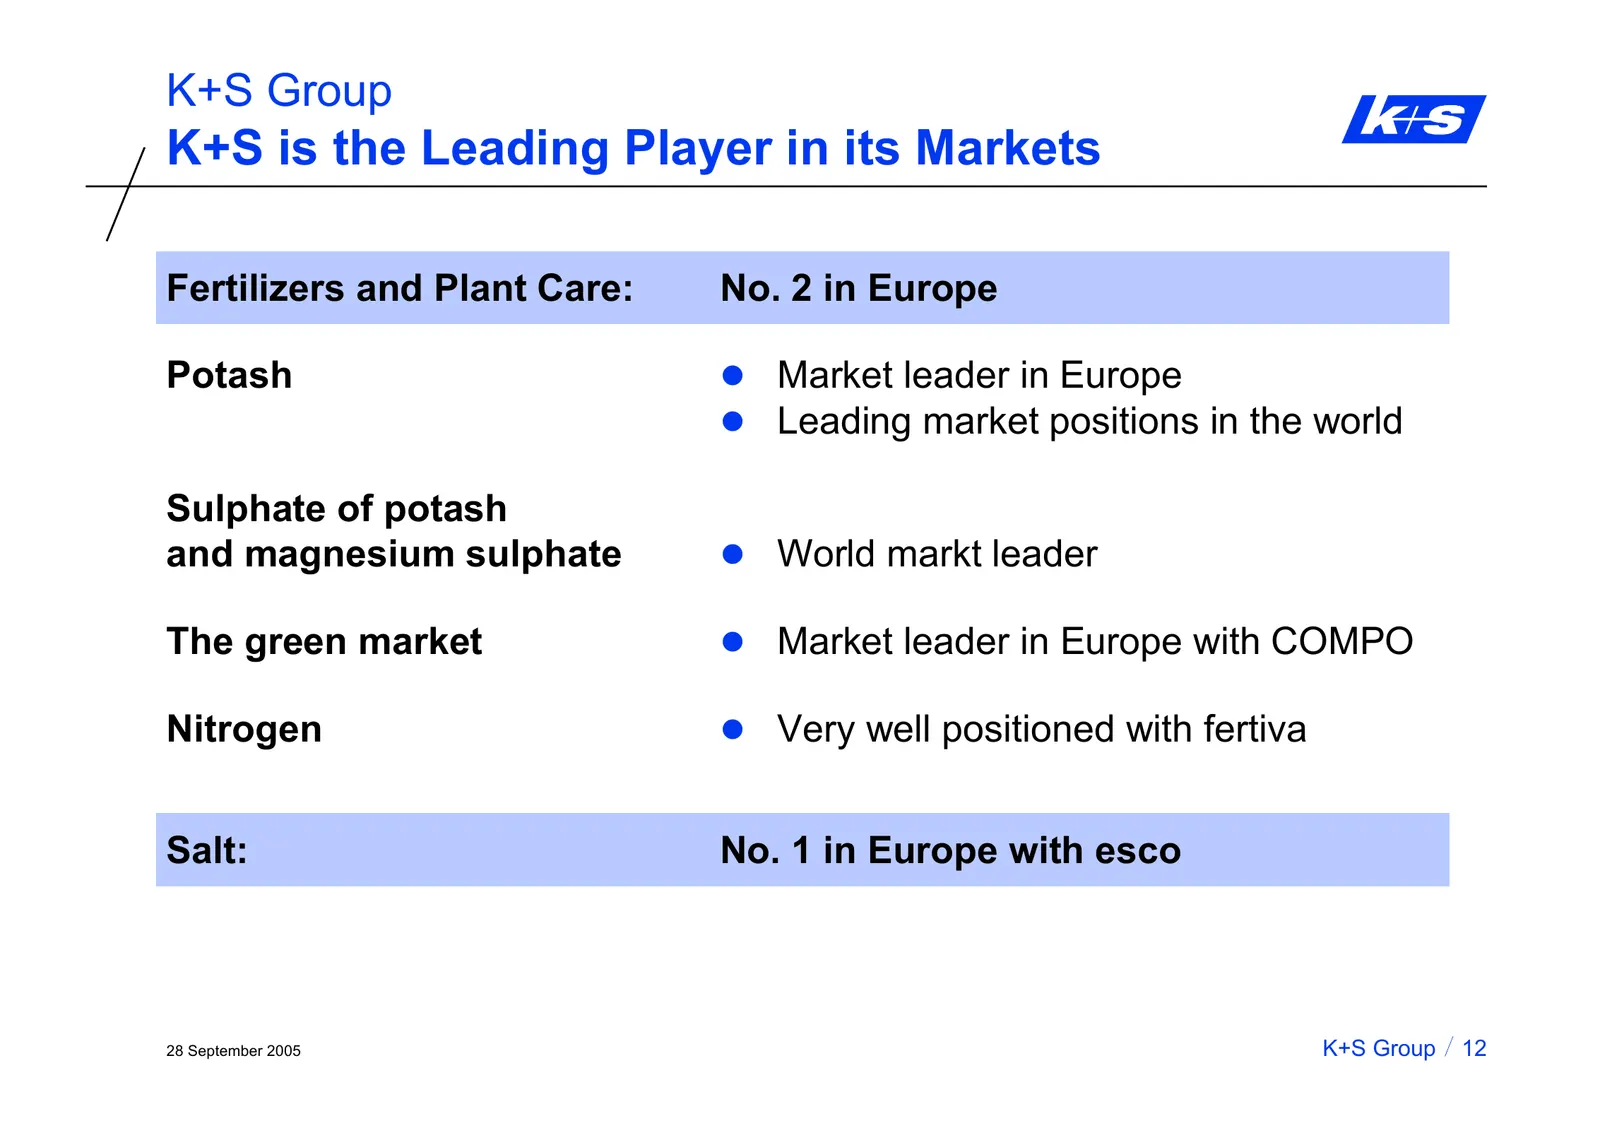
K+S Group K+S is the Leading Player in its Markets Fertilizers and Plant Care: No. 2 in Europe Potash z Market leader in Europe z Leading market positions in the world Sulphate of potash and magnesium sulphate z World markt leader The green market z Market leader in Europe with COMPO Nitrogen z Very
Slide 19: Strategy
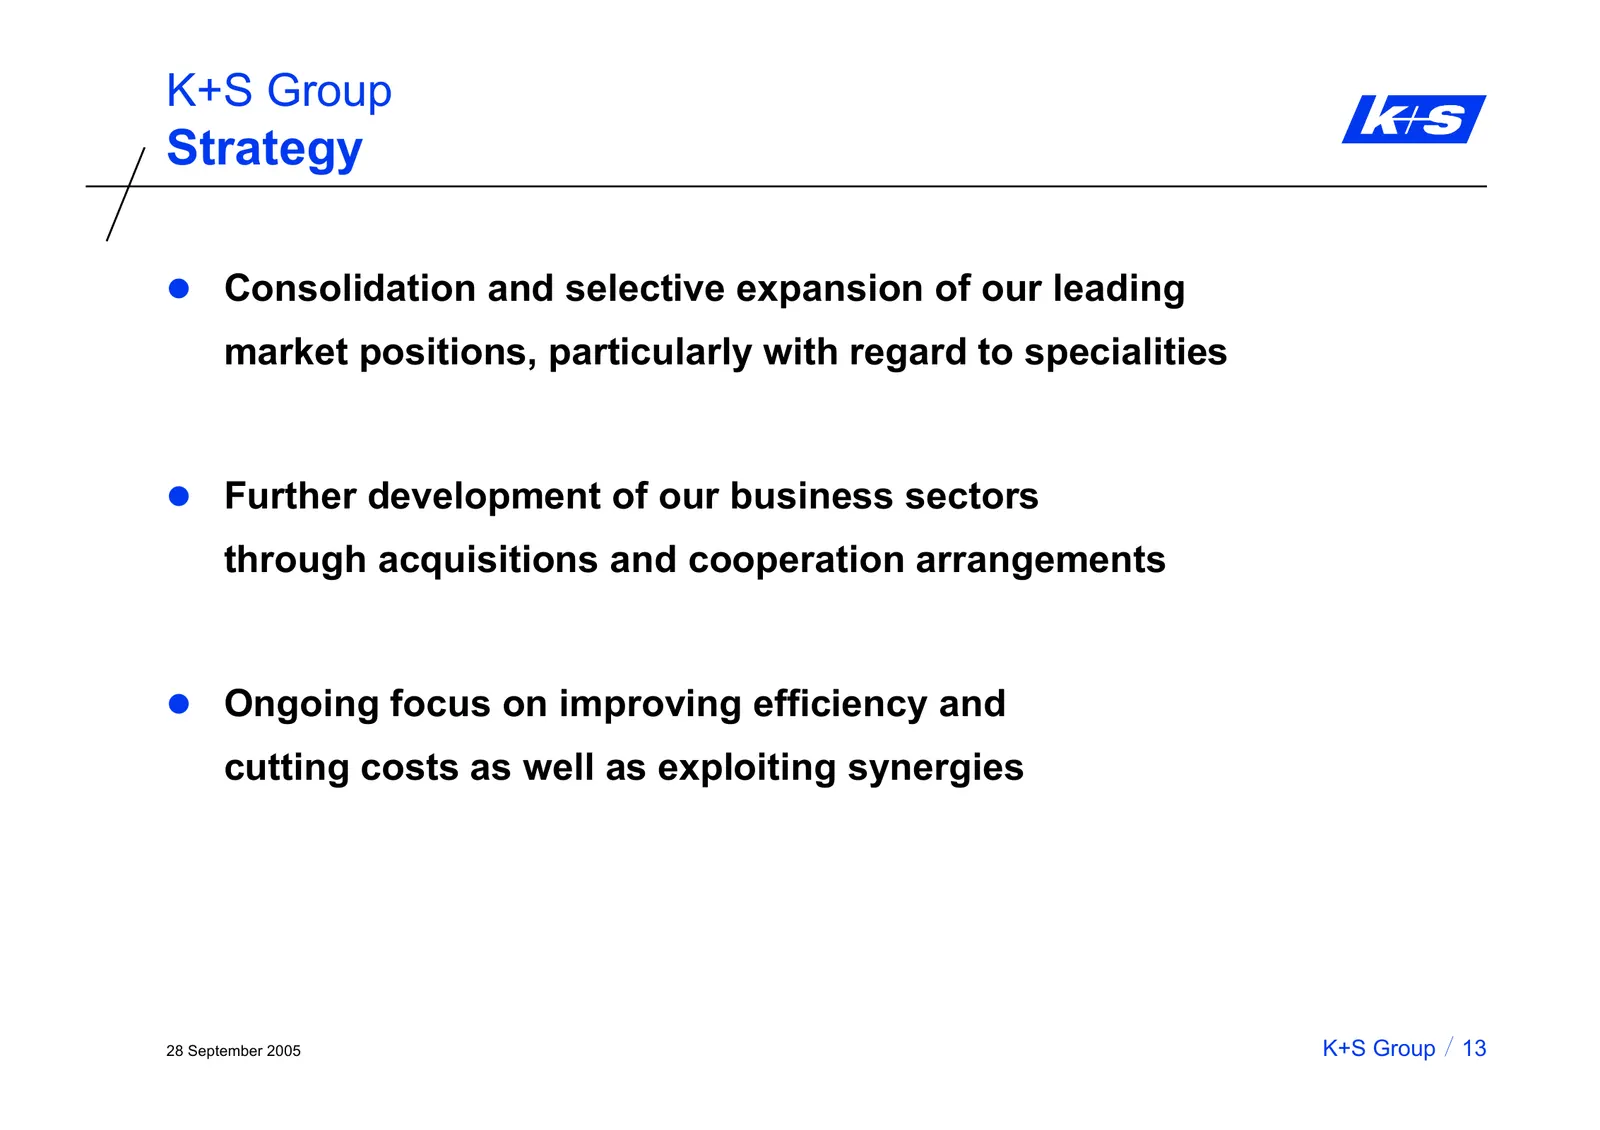
K+S Group Strategy z Consolidation and selective expansion of our leading market positions, particularly with regard to specialities z Further development of our business sectors through acquisitions and cooperation arrangements z Ongoing focus on improving efficiency and cutting costs as well as ex
Slide 20: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 21: Revenues and Earnings as of 30 June
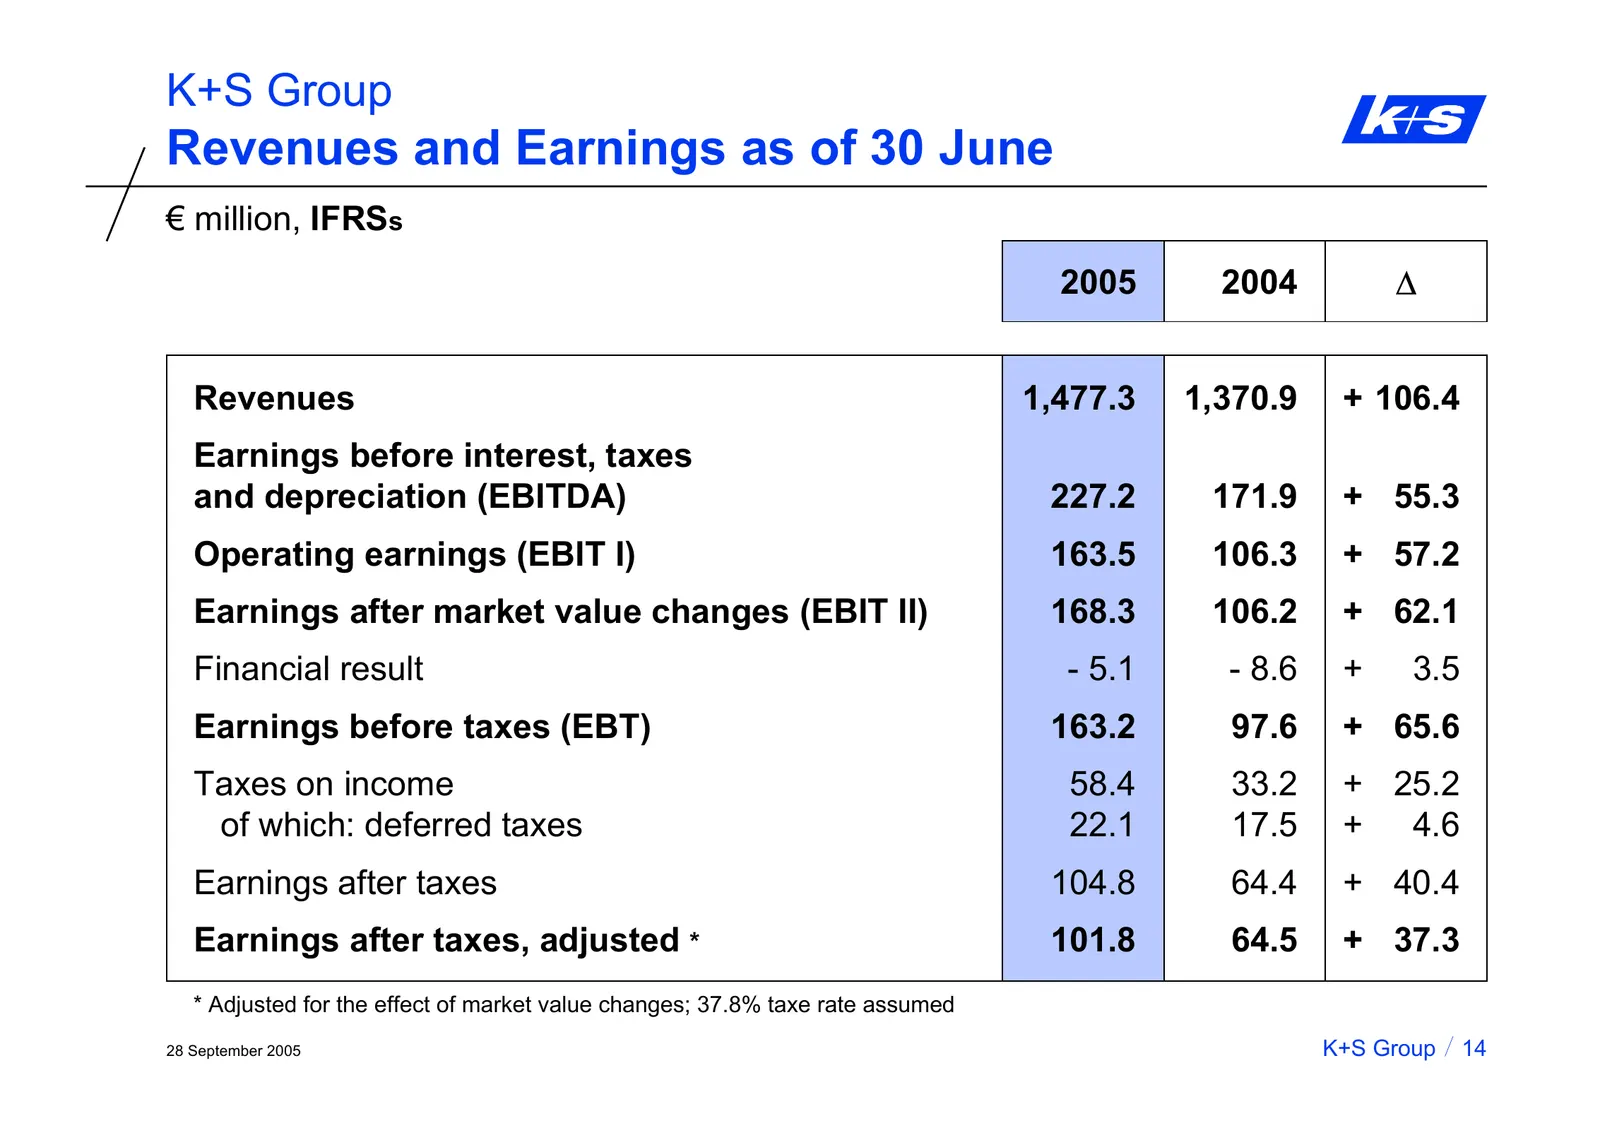
K+S Group Revenues and Earnings as of 30 June € million, IFRSs 2005 2004 ∆ Revenues 1,477.3 1,370.9 + 106.4 Earnings before interest, taxes and depreciation (EBITDA) 227.2 171.9 + 55.3 Operating earnings (EBIT I) 163.5 106.3 + 57.2 Earnings after market value changes (EBIT II) 168.3 106.2 + 62.1 Fin
Slide 22: Development of Cash Flow
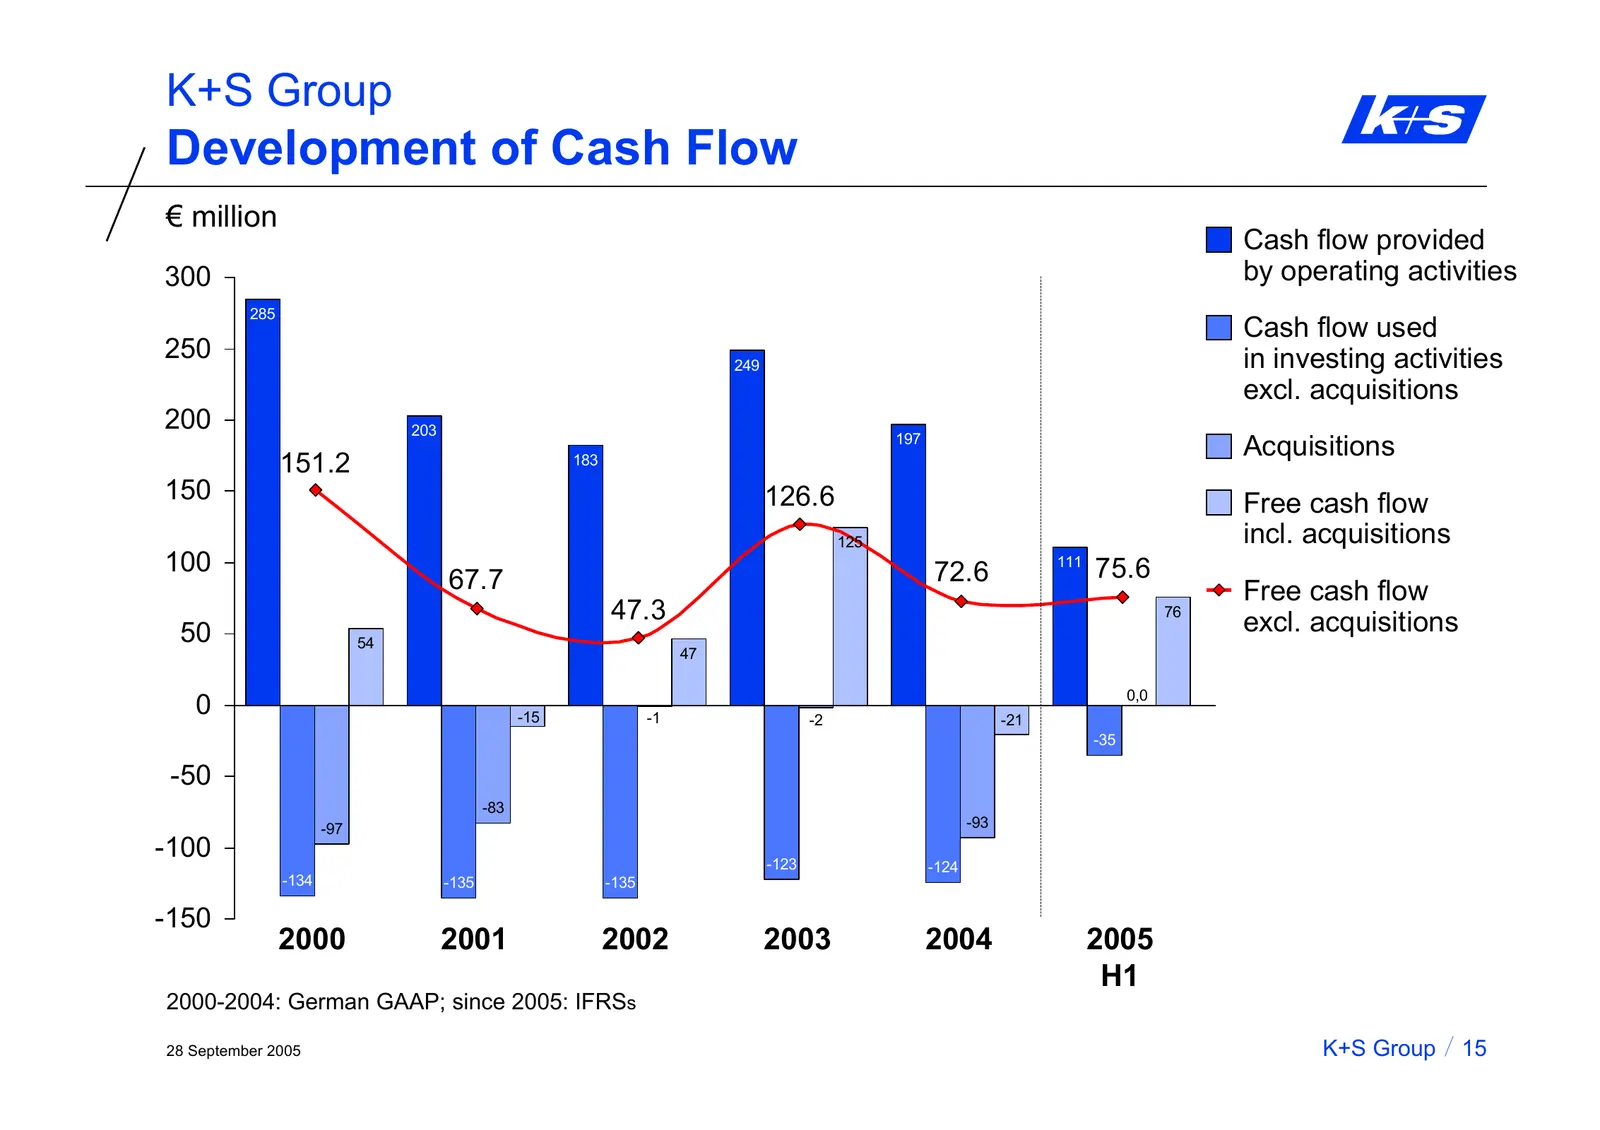
K+S Group Development of Cash Flow € million Cash flow provided 300 by operating activities 285 Cash flow used 250 249 in investing activities excl. acquisitions 200 203 197 Acquisitions 151.2 183 150 126.6 Free cash flow 125 incl. acquisitions 100 72.6 111 75.6 67.7 Free cash flow 47.3 76 excl. acq
Slide 23: Balance Sheet Key Data as of 30 June
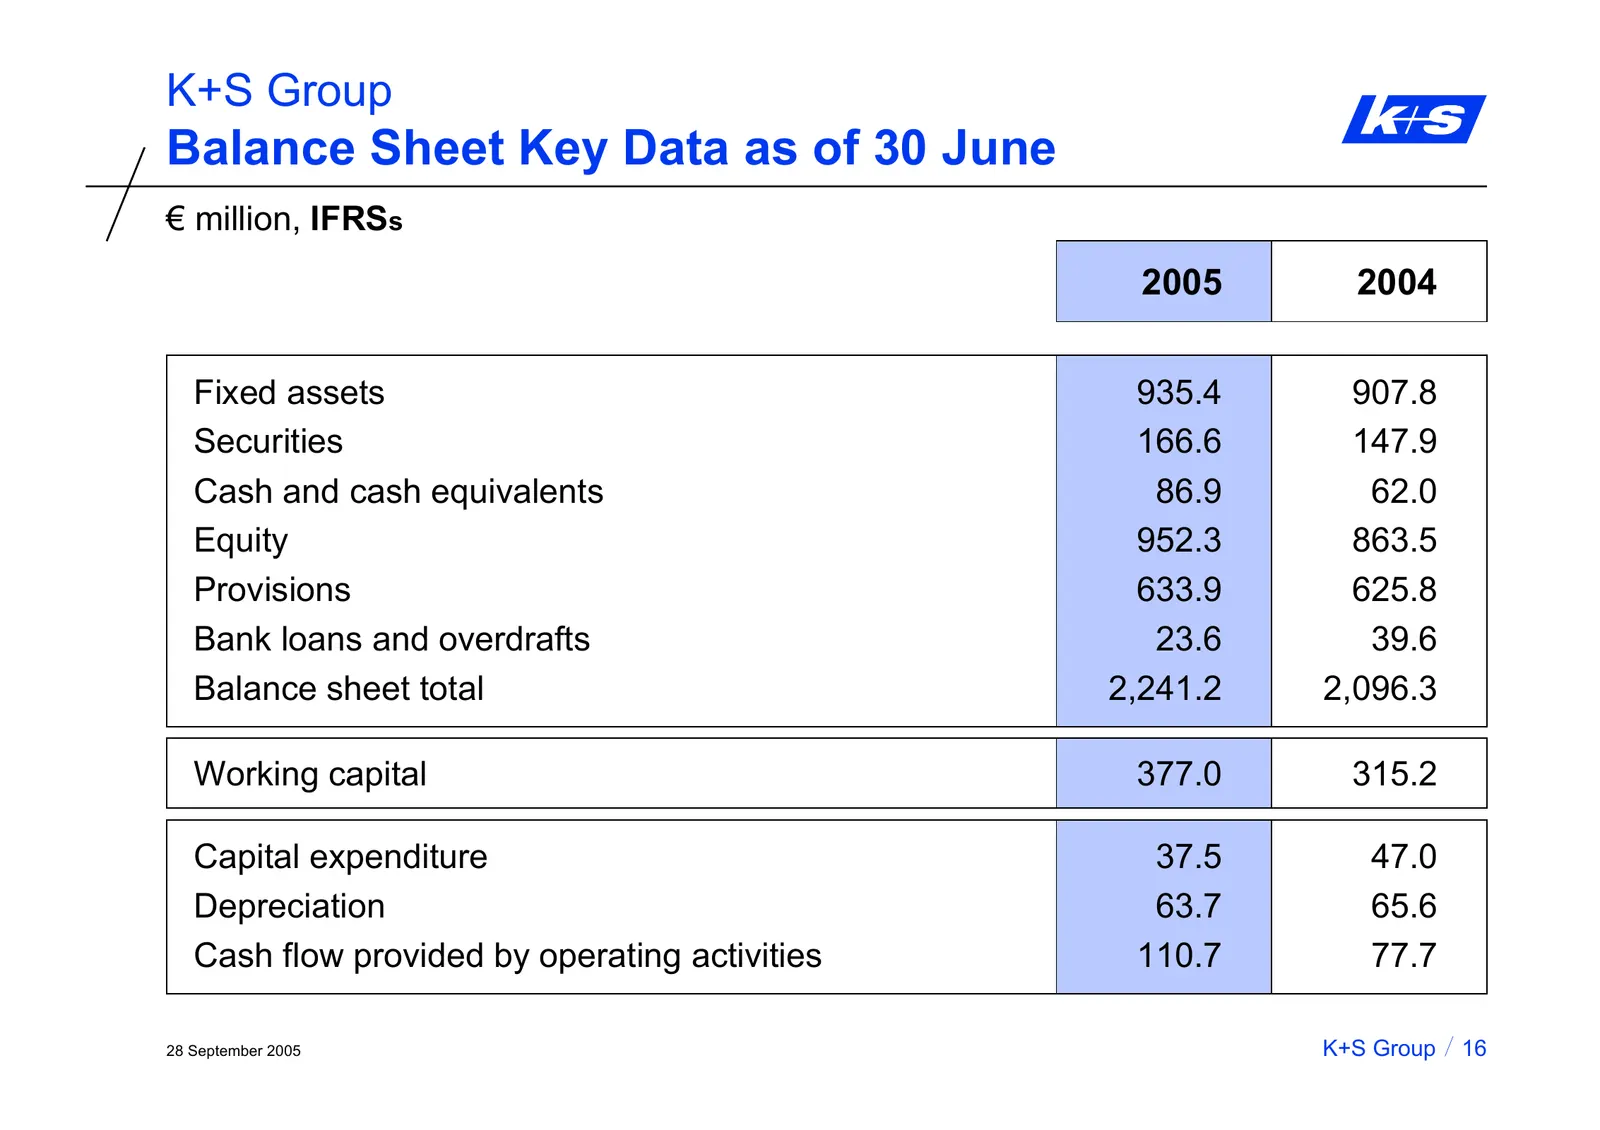
K+S Group Balance Sheet Key Data as of 30 June € million, IFRSs 2005 2004 Fixed assets 935.4 907.8 Securities 166.6 147.9 Cash and cash equivalents 86.9 62.0 Equity 952.3 863.5 Provisions 633.9 625.8 Bank loans and overdrafts 23.6 39.6 Balance sheet total 2,241.2 2,096.3 Working capital 377.0 315.2
Slide 24: Free Cash Flow Use
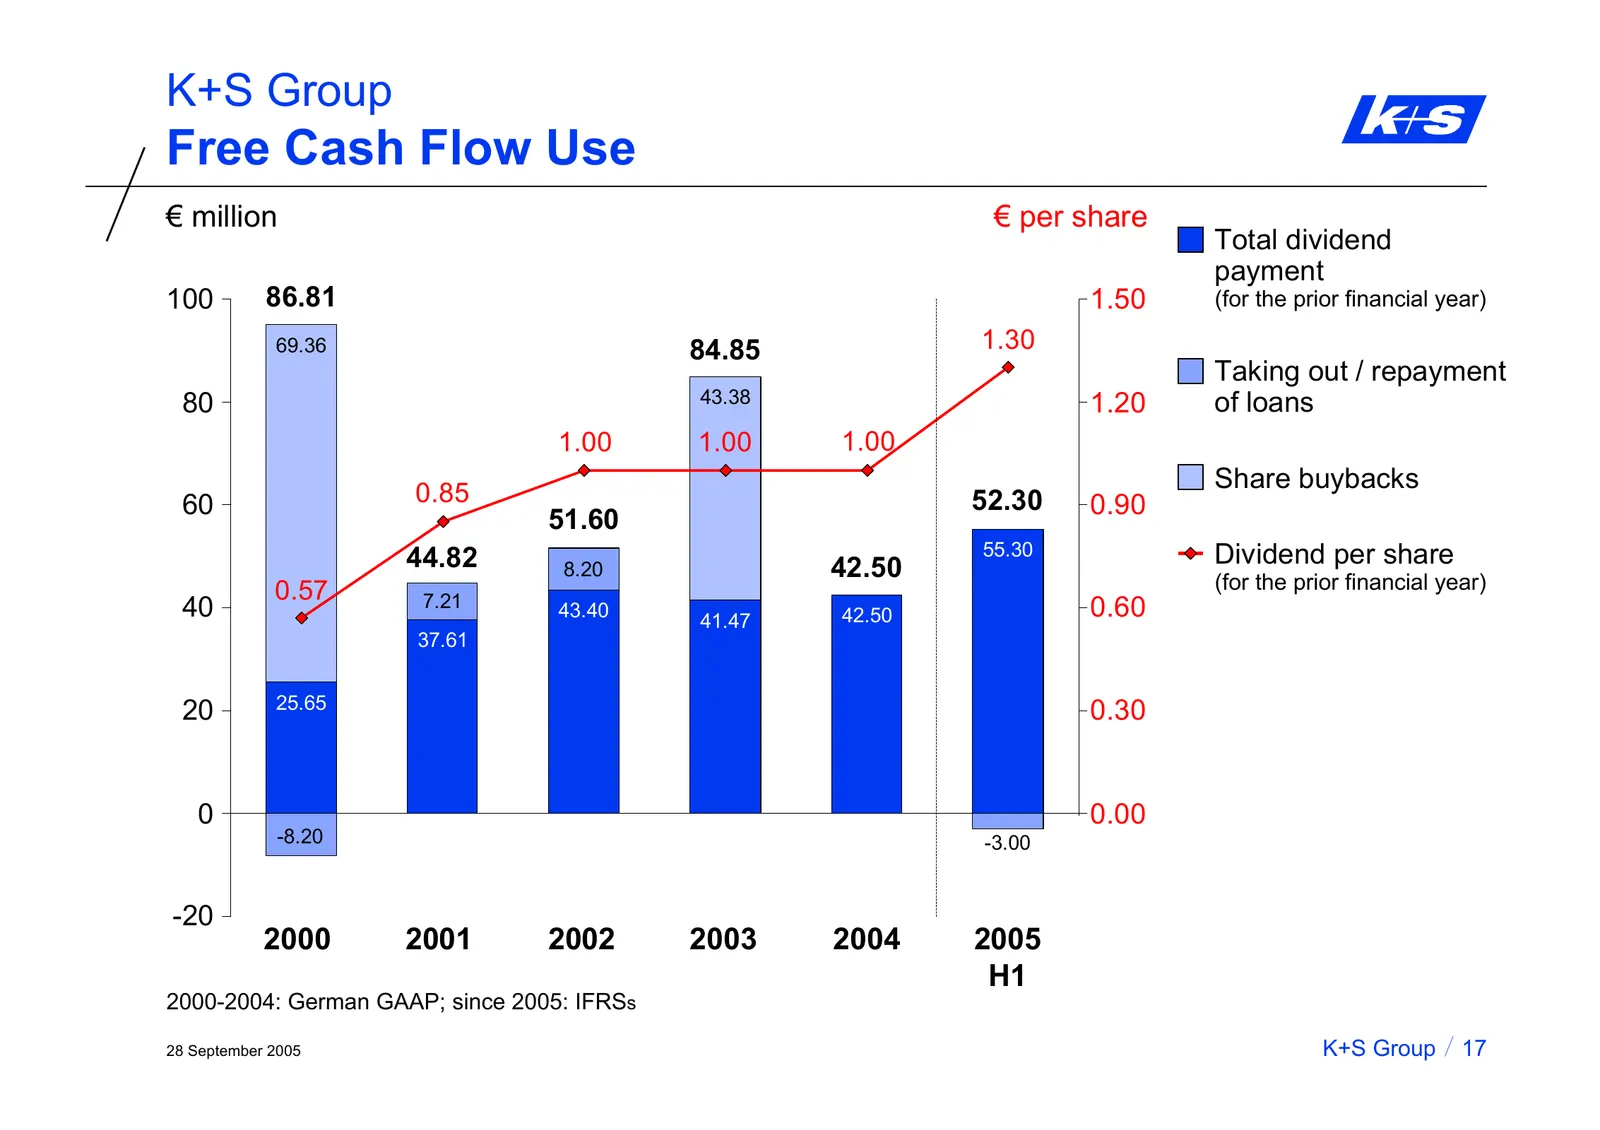
K+S Group Free Cash Flow Use € million € per share Total dividend payment 100 100 86.81 1.50 1,50 (for the prior financial year) 69.36 84.85 1.30 Taking out / repayment 80 80 43.38 1.20 1,20 of loans 1.00 1.00 1.00 Share buybacks 60 60 0.85 52.30 0.90 0,90 51.60 44.82 8.20 42.50 55.30 Dividend per s
Slide 25: Outlook for the Year 2005 (on IFRS Basis)
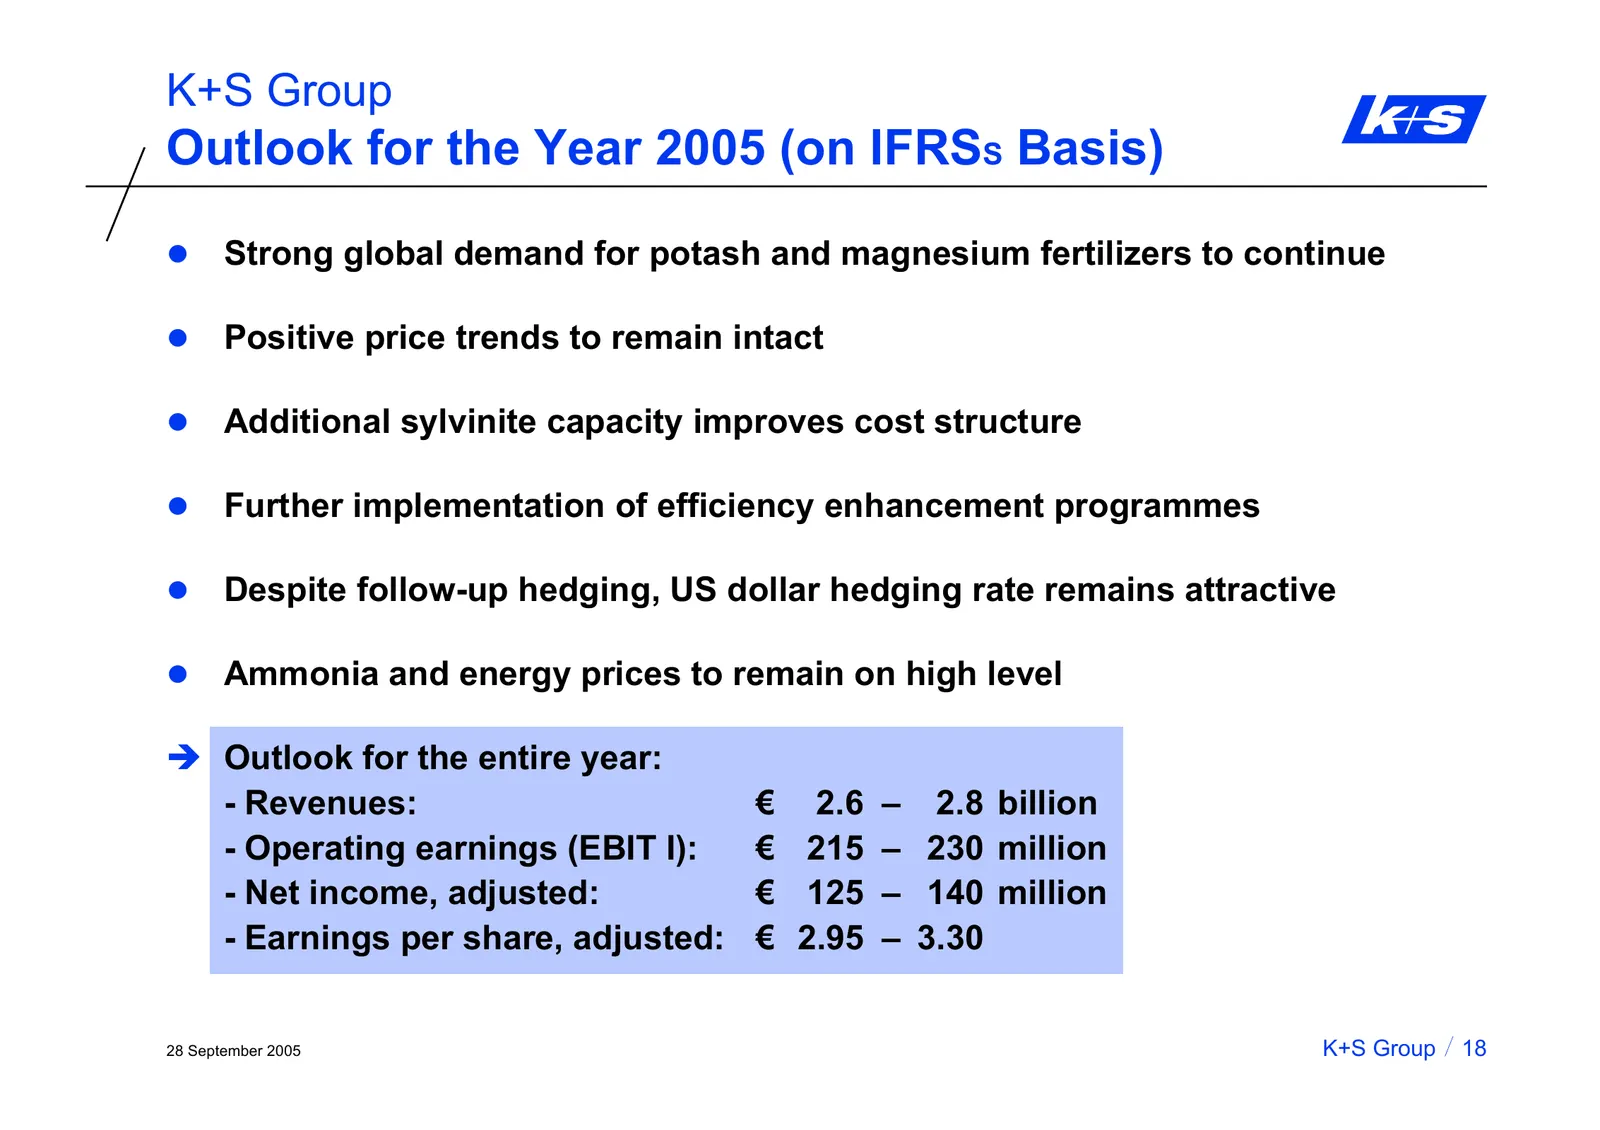
K+S Group Outlook for the Year 2005 (on IFRSS Basis) z Strong global demand for potash and magnesium fertilizers to continue z Positive price trends to remain intact z Additional sylvinite capacity improves cost structure z Further implementation of efficiency enhancement programmes z Despite follow
Slide 26: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 27: K+S Share Price Compared with DAX and MDAX
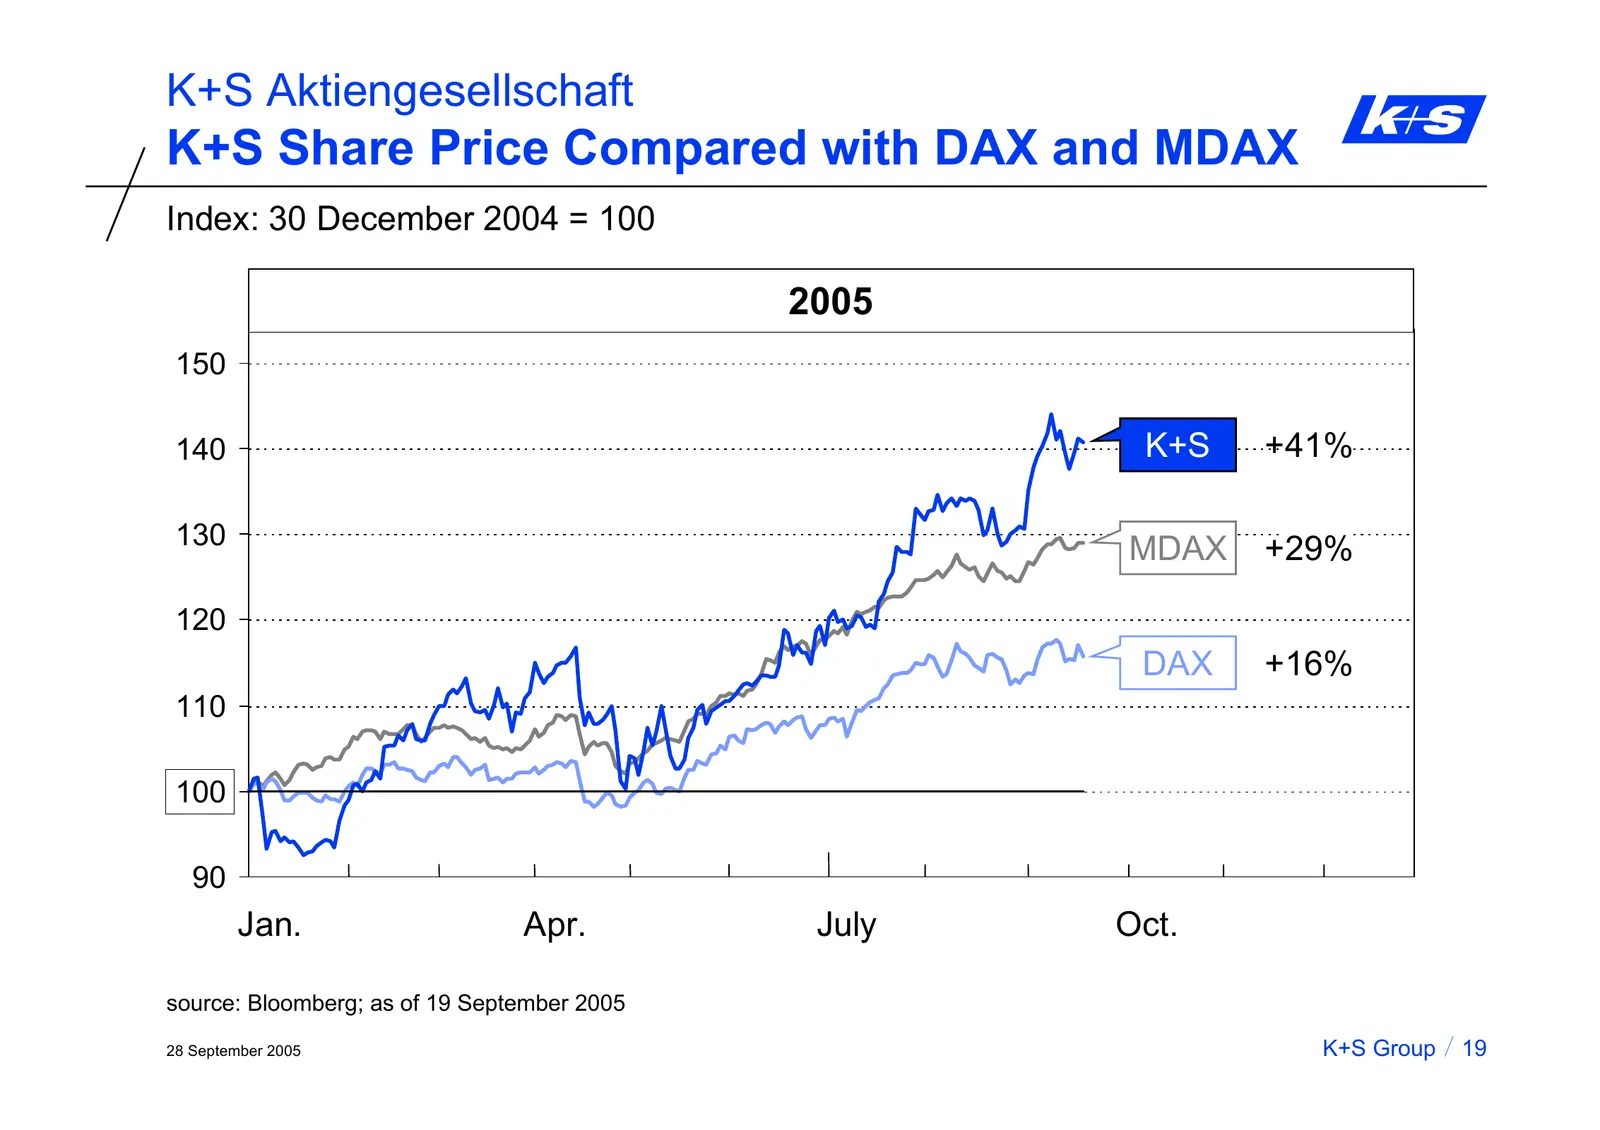
K+S Aktiengesellschaft K+S Share Price Compared with DAX and MDAX Index: 30 December 2004 = 100 2005 150 140 K+S +41% 130 +29% MDAX 120 DAX +16% 110 100 90 Jan. Apr. July Oct. source: Bloomberg; as of 19 September 2005 28 September 2005 K+S Group 19
Slide 28: Experience growth.
www.k-plus-s.com Experience growth. K+S Aktiengesellschaft Investor Relations Bertha-von-Suttner-Straße 7 phone: +49 (0)561 / 9301-1460 34131 Kassel (Germany) fax: +49 (0)561 / 9301-2425 phone: +49 (0)561 / 9301-0 email: investor-relations@k-plus-s.com fax: +49 (0)561 / 9301-1753 28 September 2005 K
Slide 29: Content
K+S Group Content A. The K+S Group Business Model B. Core Business Segments: - Fertilizers and Plant Care - Salt C. Strategy D. Financial Data and Outlook E. K+S Share Appendix 28 September 2005 K+S Group
Slide 30: USD Currency Management 2004-2008
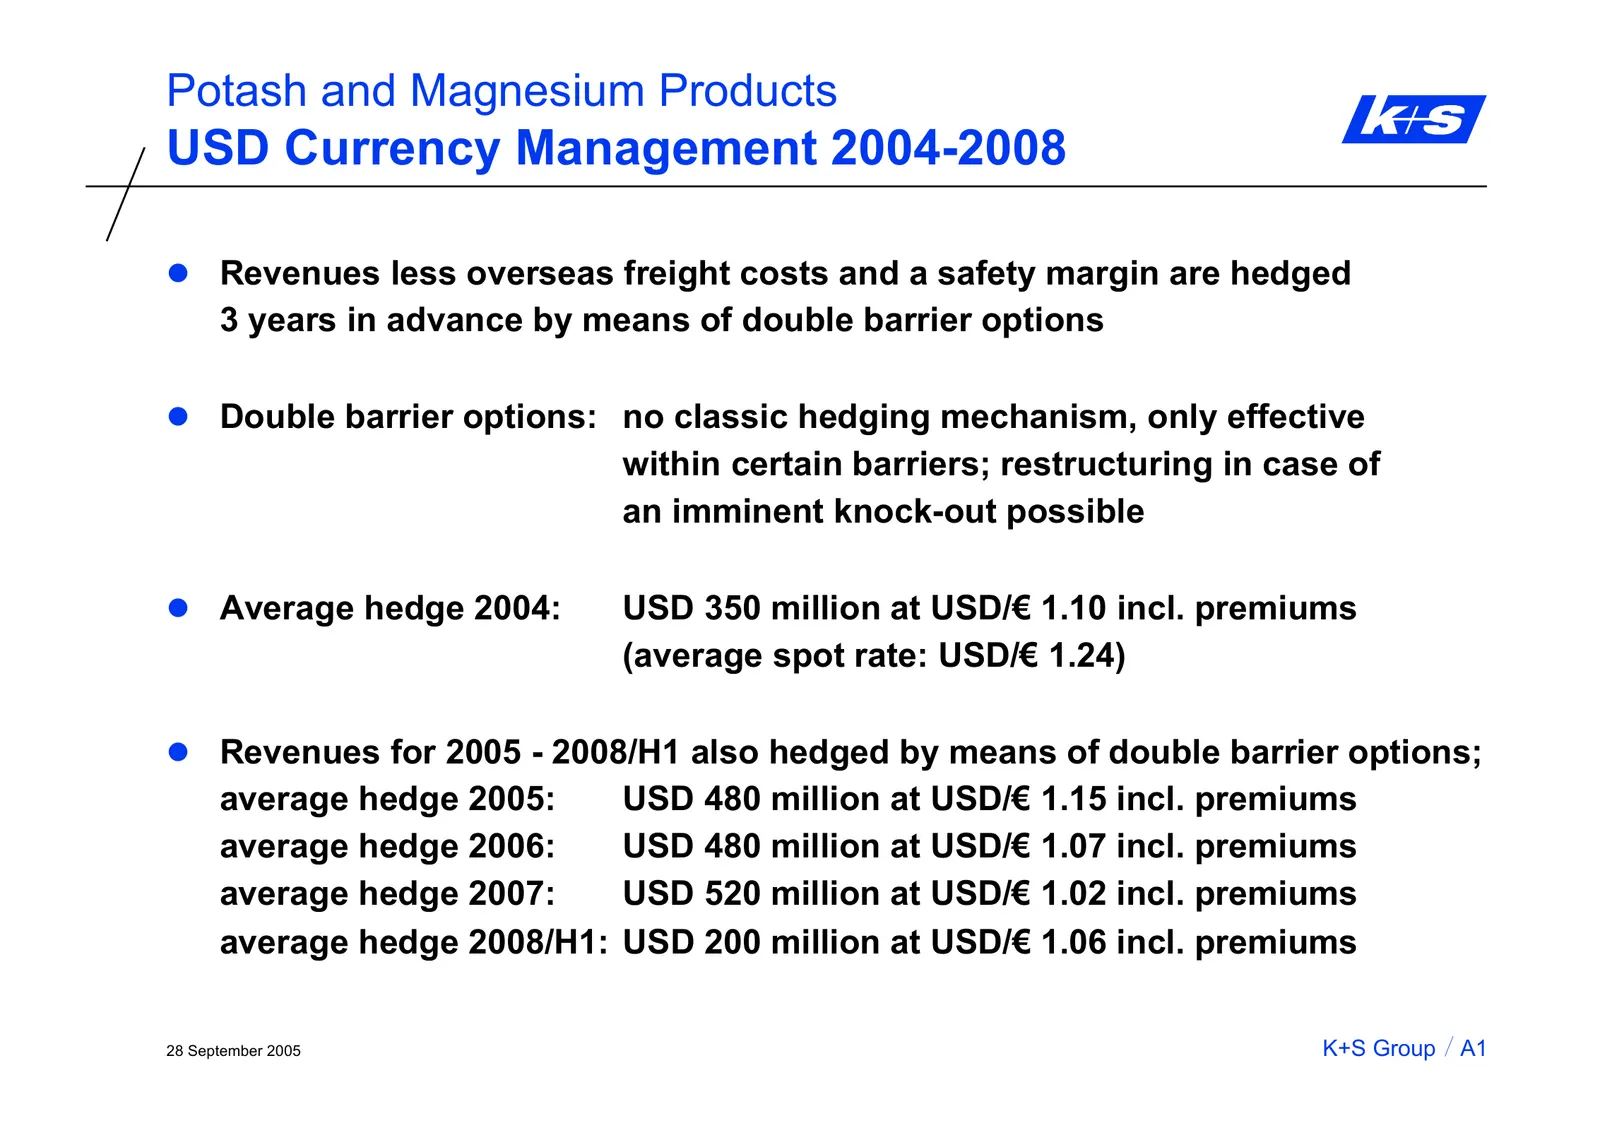
Potash and Magnesium Products USD Currency Management 2004-2008 z Revenues less overseas freight costs and a safety margin are hedged 3 years in advance by means of double barrier options z Double barrier options: no classic hedging mechanism, only effective within certain barriers; restructuring in
Slide 31: USD Double Barrier Option System
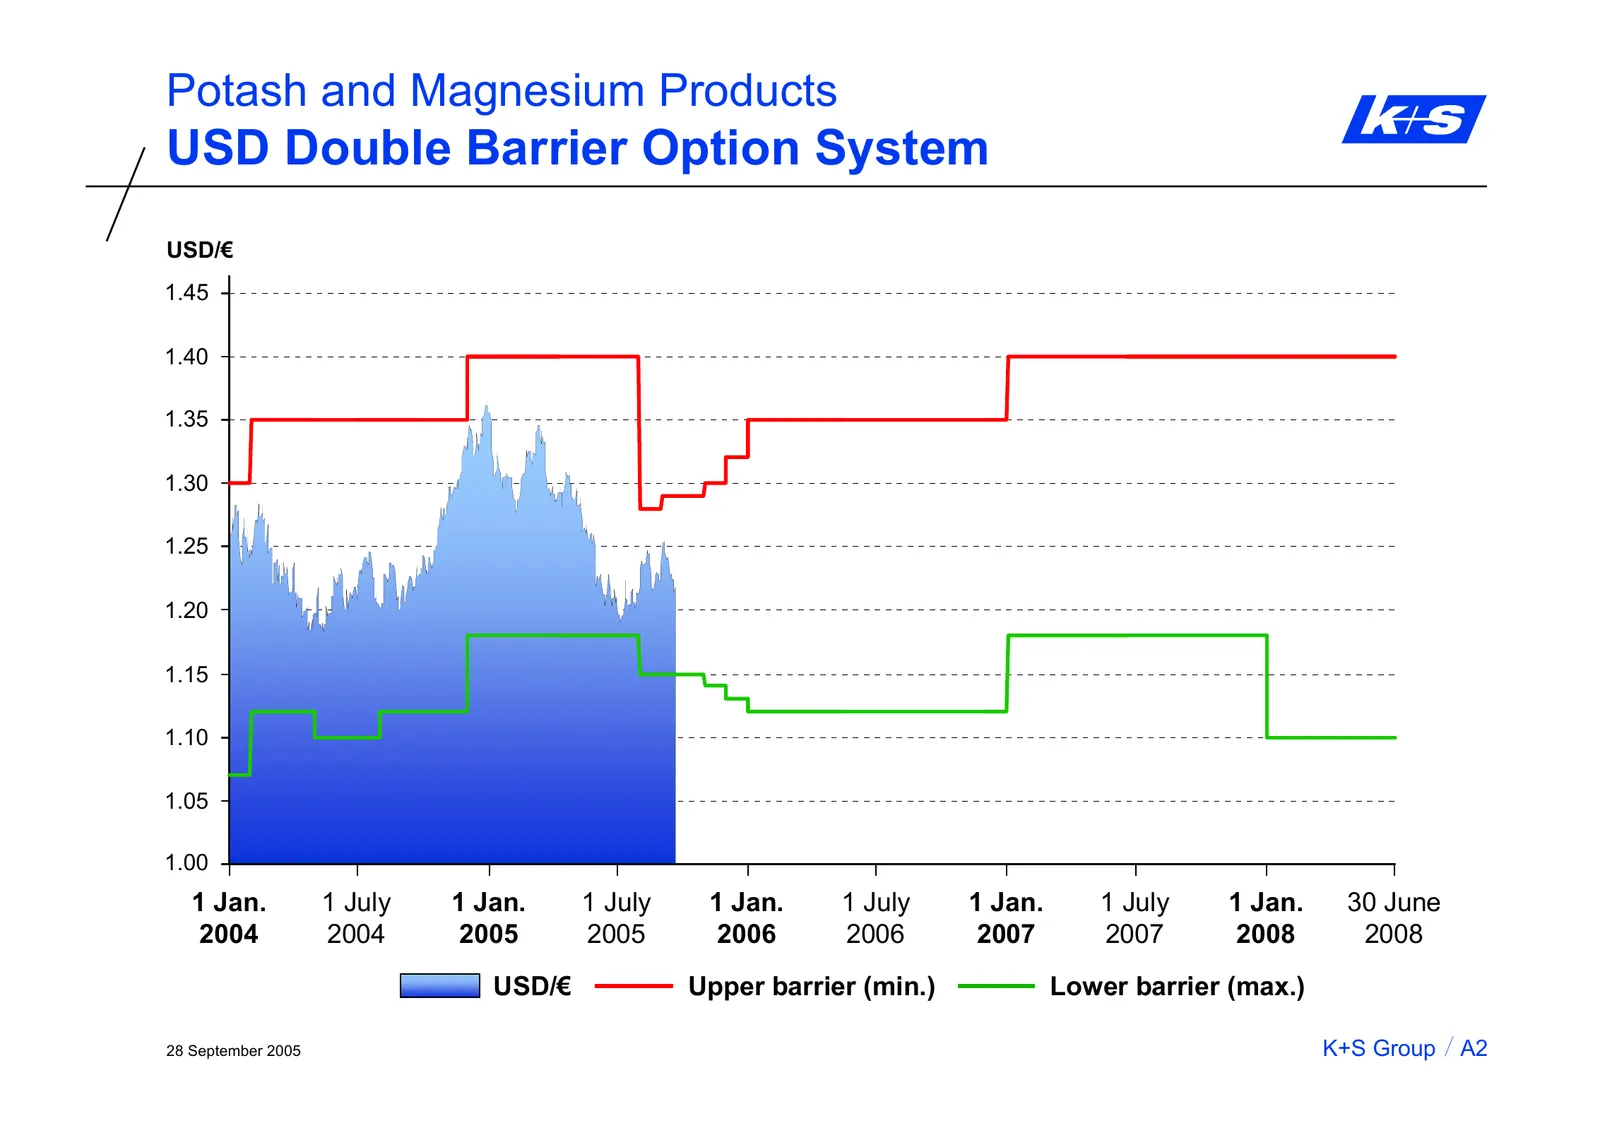
Potash and Magnesium Products 1,60 USD Double Barrier Option System 1,55 1,50 USD/€ 1,45 1.45 1,40 1.40 1,35 1.35 1,30 1.30 1,25 1.25 1,20 1.20 1,15 1.15 1,10 1.10 1,05 1.05 1,00 1.00 1 Jan. 1 July 1 Jan. 1 July 1 Jan. 1 July 1 Jan. 1 July 1 Jan. 30 June 2004 2004 2005 2005 2006 2006 2007 2007 2008
Slide 32: Financial Calendar
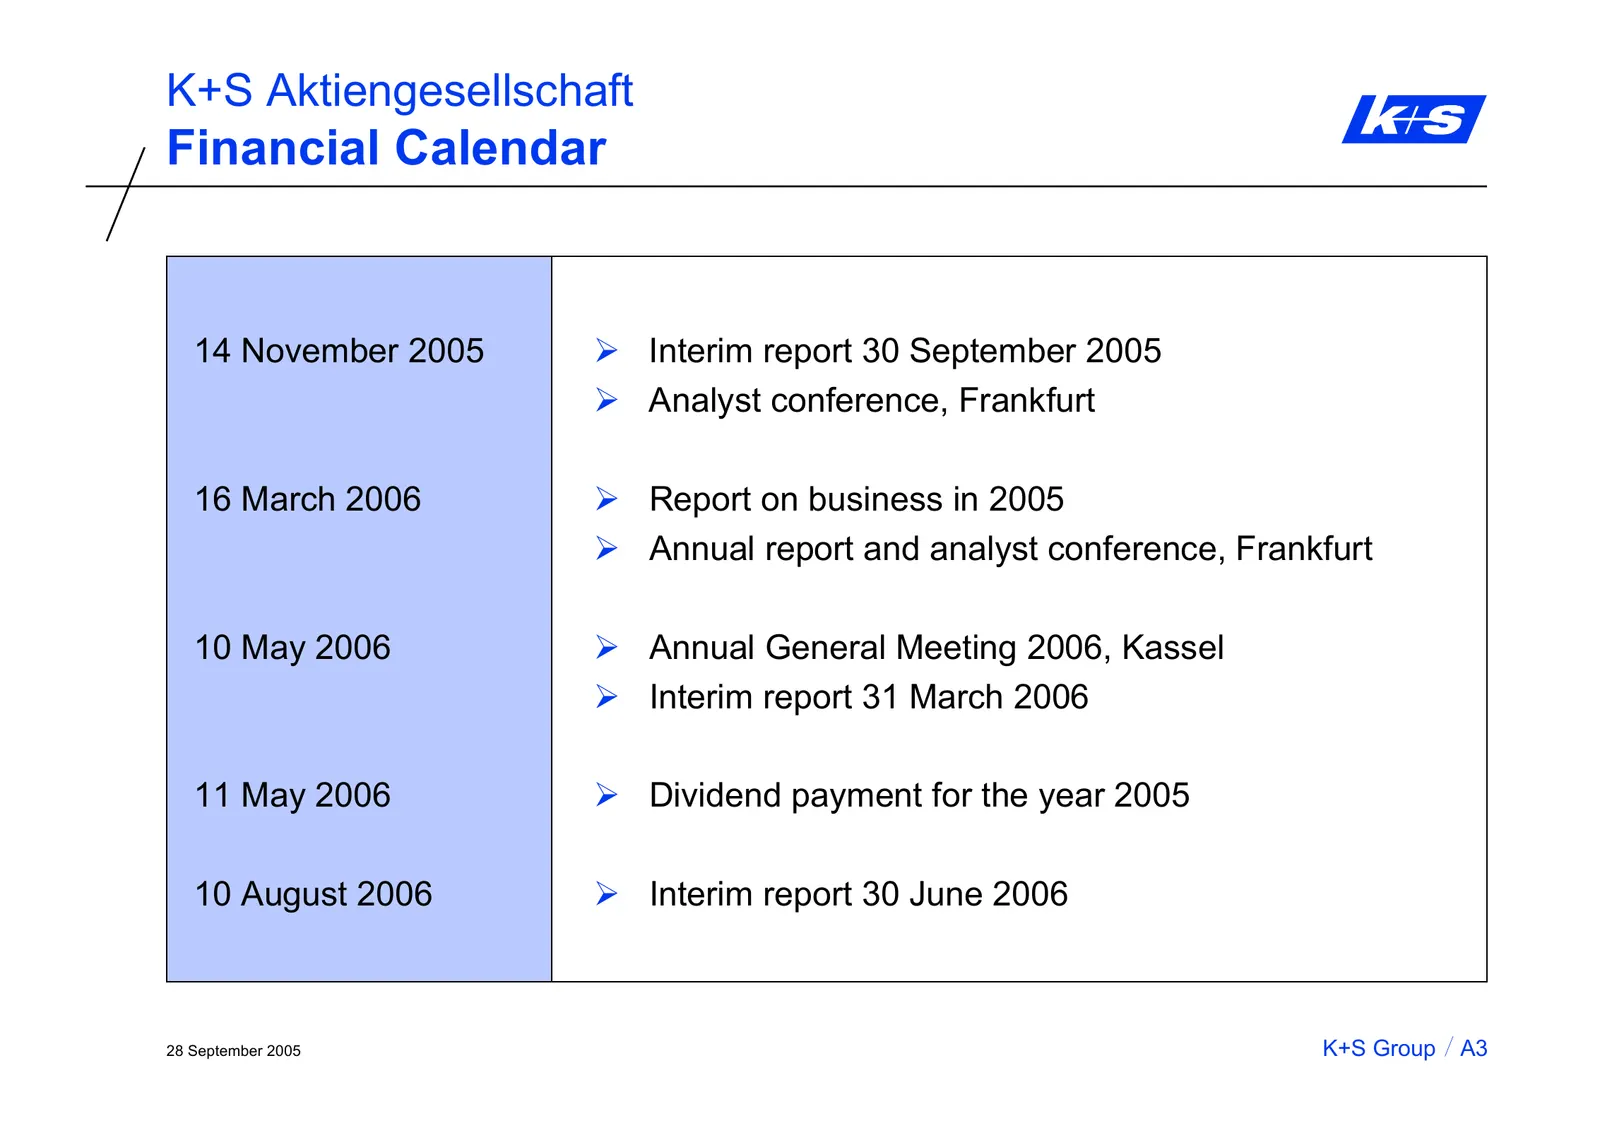
K+S Aktiengesellschaft Financial Calendar 14 November 2005 ¾ Interim report 30 September 2005 ¾ Analyst conference, Frankfurt 16 March 2006 ¾ Report on business in 2005 ¾ Annual report and analyst conference, Frankfurt 10 May 2006 ¾ Annual General Meeting 2006, Kassel ¾ Interim report 31 March 2006
Slide 33: Forward-Looking Statements
K+S Group Forward-Looking Statements This presentation contains facts and forecasts that relate to the future development of the K+S Group and its companies. The forecasts are estimates that we have made on the basis of all information available to us at this moment in time. Should the assumptions u
Slide 34: Experience growth.
www.k-plus-s.com Experience growth. K+S Aktiengesellschaft Investor Relations Bertha-von-Suttner-Straße 7 phone: +49 (0)561 / 9301-1460 34131 Kassel (Germany) fax: +49 (0)561 / 9301-2425 phone: +49 (0)561 / 9301-0 email: investor-relations@k-plus-s.com fax: +49 (0)561 / 9301-1753 28 September 2005 K
Source: Internet Archive copy of k-plus-s.com
More decks from K+s AG
 Investor Presentation (October 2026)100 slides · October 2026
 Q2 2026 Earnings Presentation9 slides · Aug 12, 2026
 Investor Presentation (August 2026)102 slides · August 2026
 Q1 2026 Earnings Presentation11 slides · May 11, 2026
 Investor Presentation (May 2026)89 slides · May 2026
 Q4 2025 Earnings Presentation11 slides · Mar 13, 2026