Mapletree Logistics Trust · SGX:M44U
Mapletree Logistics Trust — Q1 FY2015/16 Earnings Presentation
38 slides from Mapletree Logistics Trust's earnings presentation, Jul 20, 2015
Slide 1: 1Q FY2015/16 Financial Results
1Q FY2015/16 Financial Results 20 July 2015
Slide 2: Disclaimer
Disclaimer This Presentation is focused on comparing results for the three months ended 30 Jun 2015 versus results achieved in the three months ended 30 Jun 2014 and versus results achieved in the previous quarter ended 31 Mar 2015. This shall be read in conjunction with Mapletree Logistics Trust’s
Slide 3: Agenda
Agenda 1Q FY15/16 Highlights Financial Review Capital Management Business Review Outlook 2
Slide 4: 1Q FY15/16 Highlights
1Q FY15/16 Highlights
Slide 5: 1Q FY15/16 Highlights
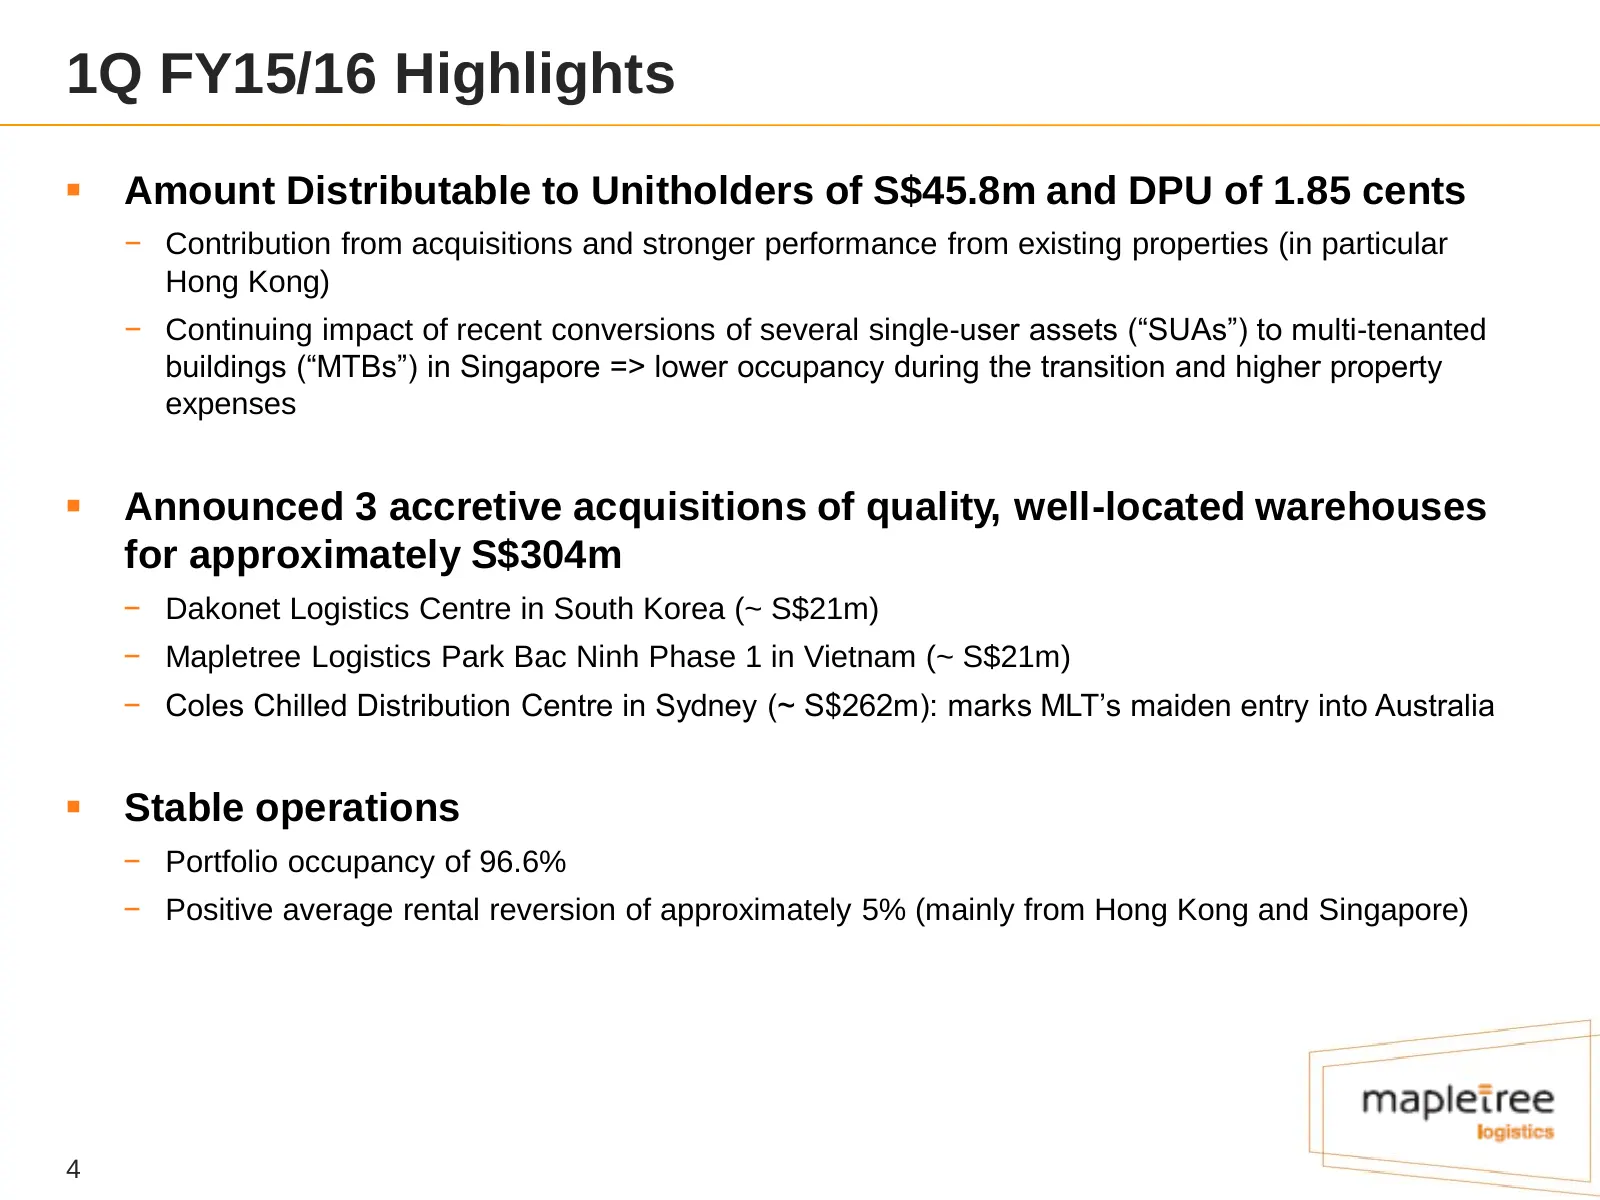
1Q FY15/16 Highlights Amount Distributable to Unitholders of S$45.8m and DPU of 1.85 cents − Contribution from acquisitions and stronger performance from existing properties (in particular Hong Kong) − Continuing impact of recent conversions of several single-user assets (“SUAs”) to multi-tenanted
Slide 6: Financial Review
Financial Review
Slide 7: 1Q FY15/16 vs. 1Q FY14/15 (Year-on-Year)
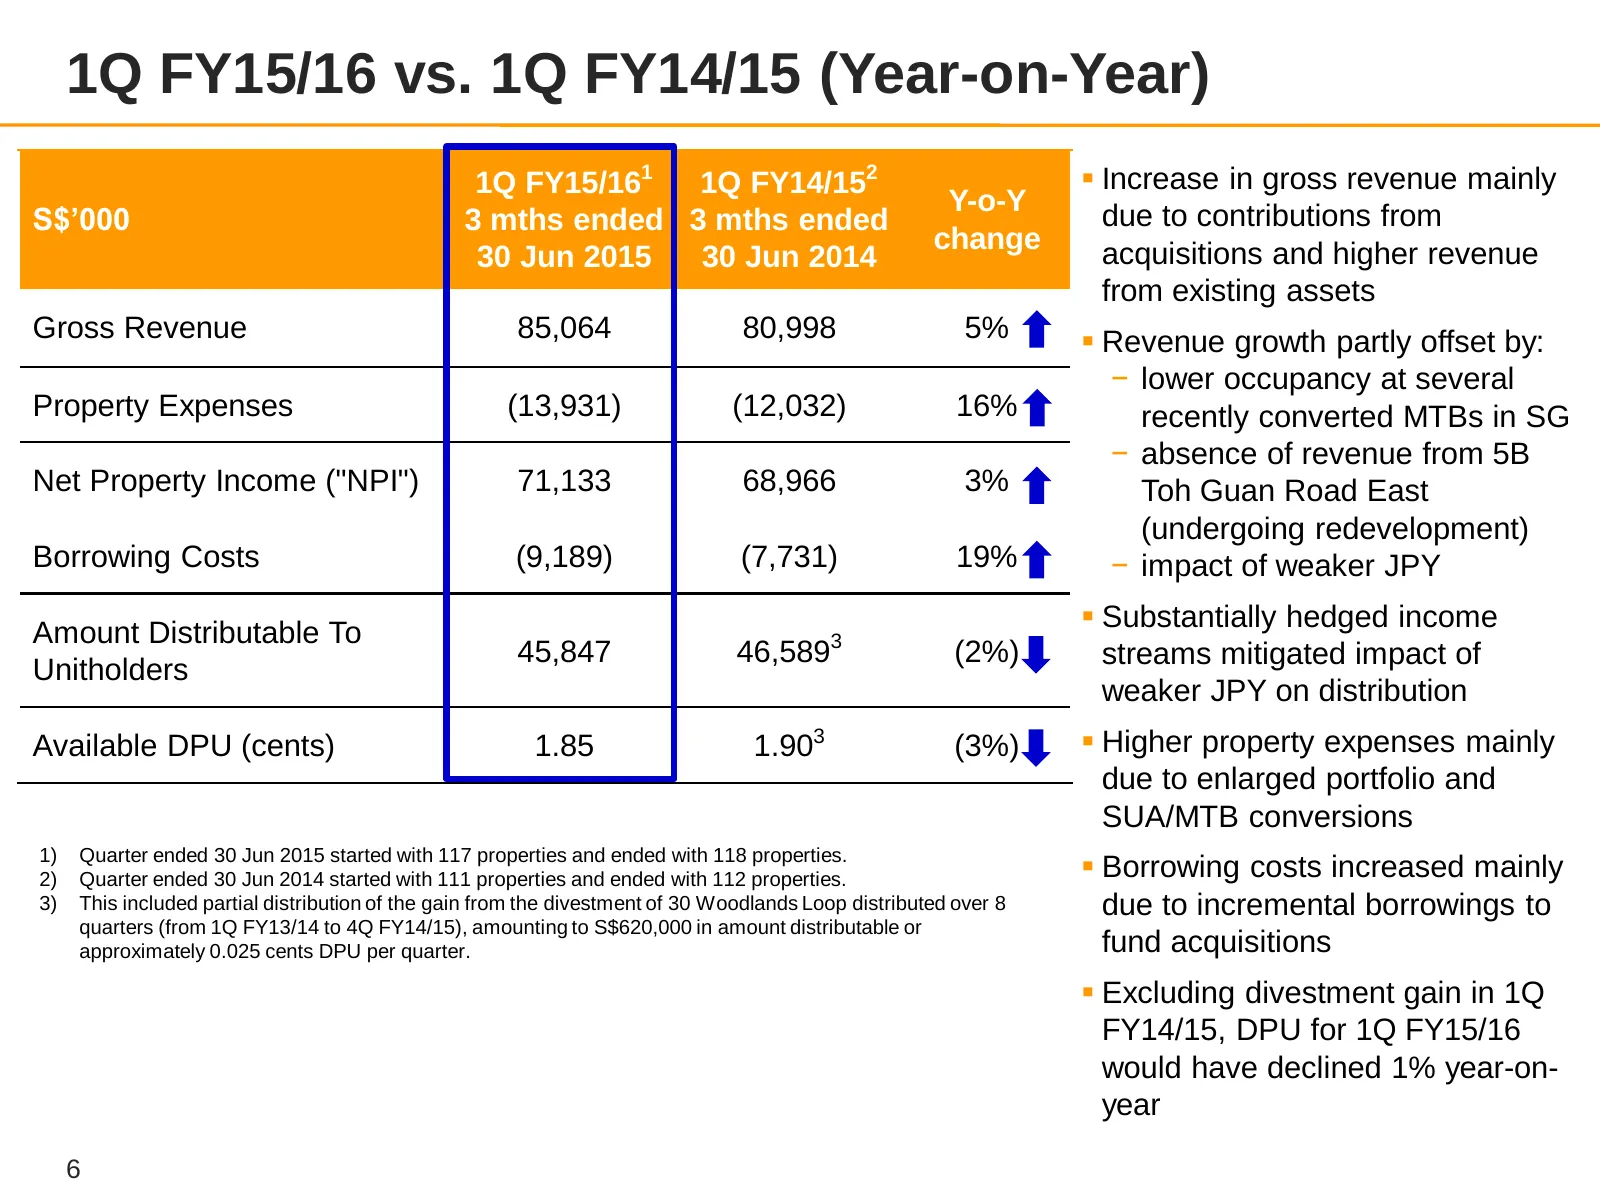
1Q FY15/16 vs. 1Q FY14/15 (Year-on-Year) 1Q FY15/161 1Q FY14/152 Increase in gross revenue mainly Y-o-Y S$’000 3 mths ended 3 mths ended due to contributions from change acquisitions and higher revenue 30 Jun 2015 30 Jun 2014 from existing assets Gross Revenue 85,064 80,998 5% Revenue growth par
Slide 8: 1Q FY15/16 vs. 4Q FY14/15 (Quarter-on-Quarter)
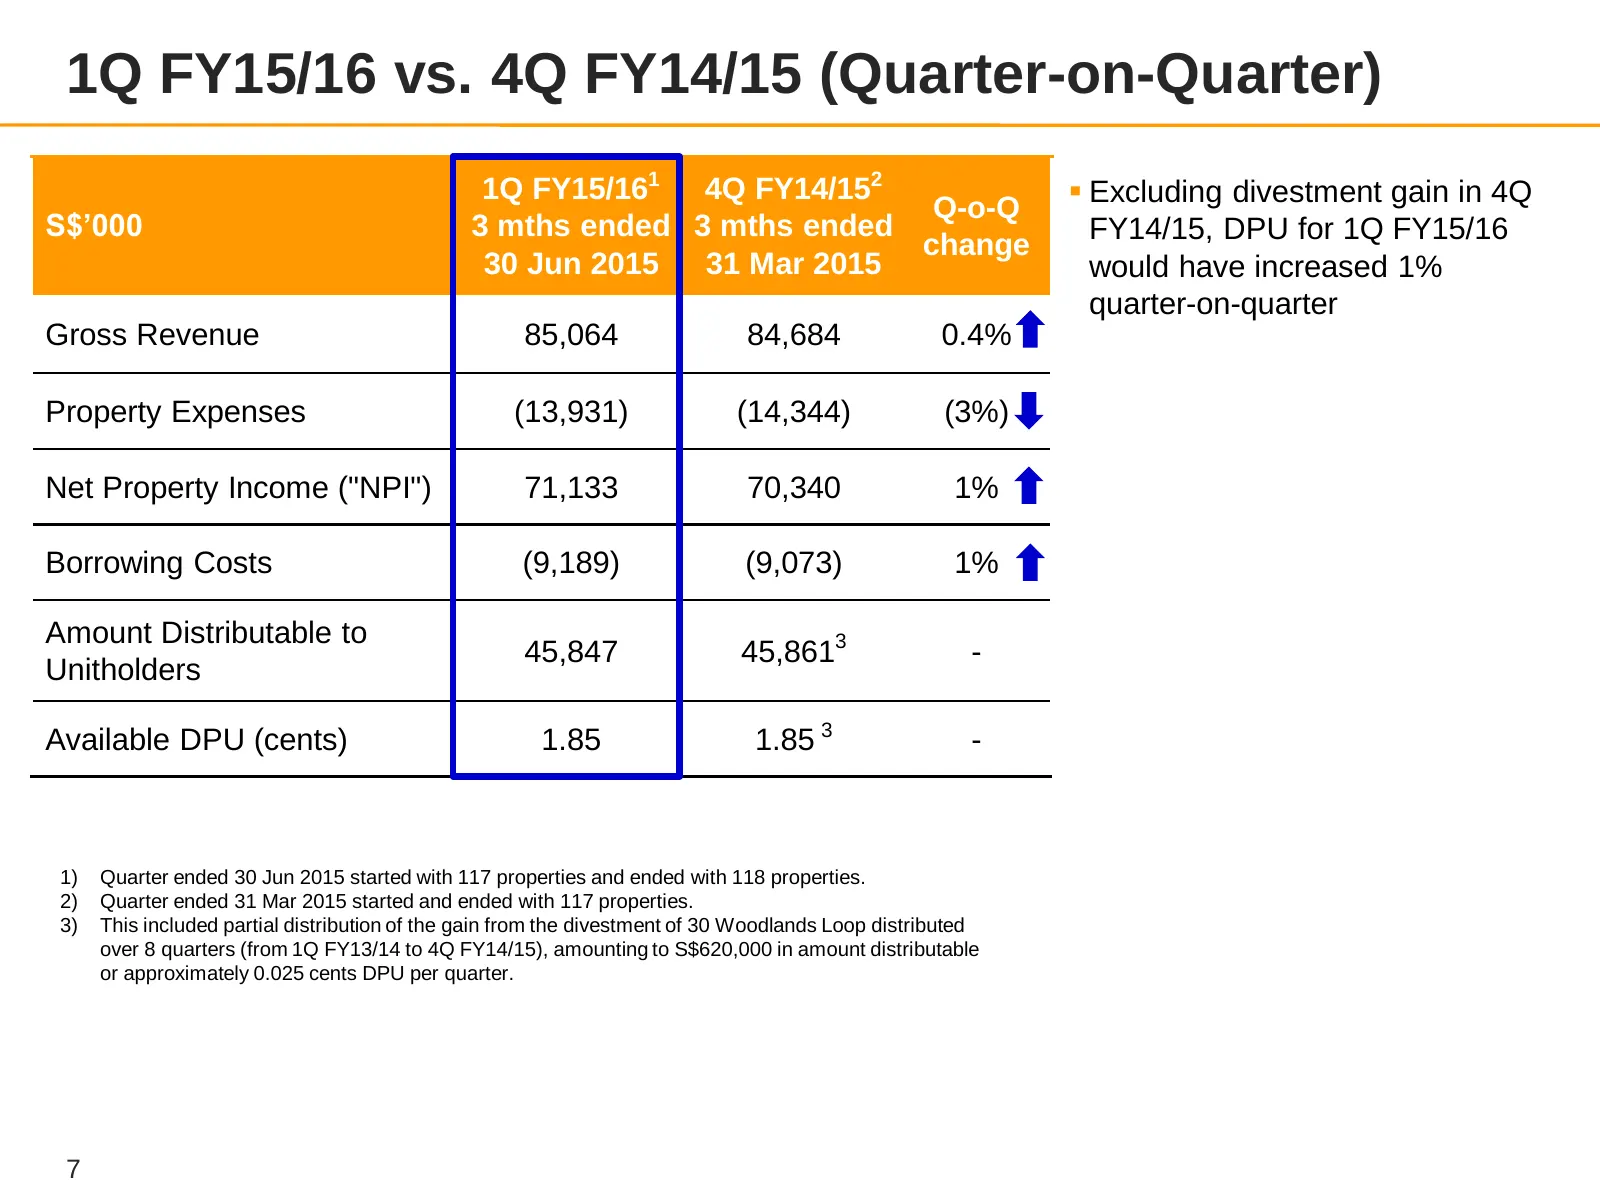
1Q FY15/16 vs. 4Q FY14/15 (Quarter-on-Quarter) 1Q FY15/161 4Q FY14/152 Excluding divestment gain in 4Q Q-o-Q S$’000 3 mths ended 3 mths ended FY14/15, DPU for 1Q FY15/16 change 30 Jun 2015 31 Mar 2015 would have increased 1% quarter-on-quarter Gross Revenue 85,064 84,684 0.4% Property Expenses (13
Slide 9: Healthy Balance Sheet
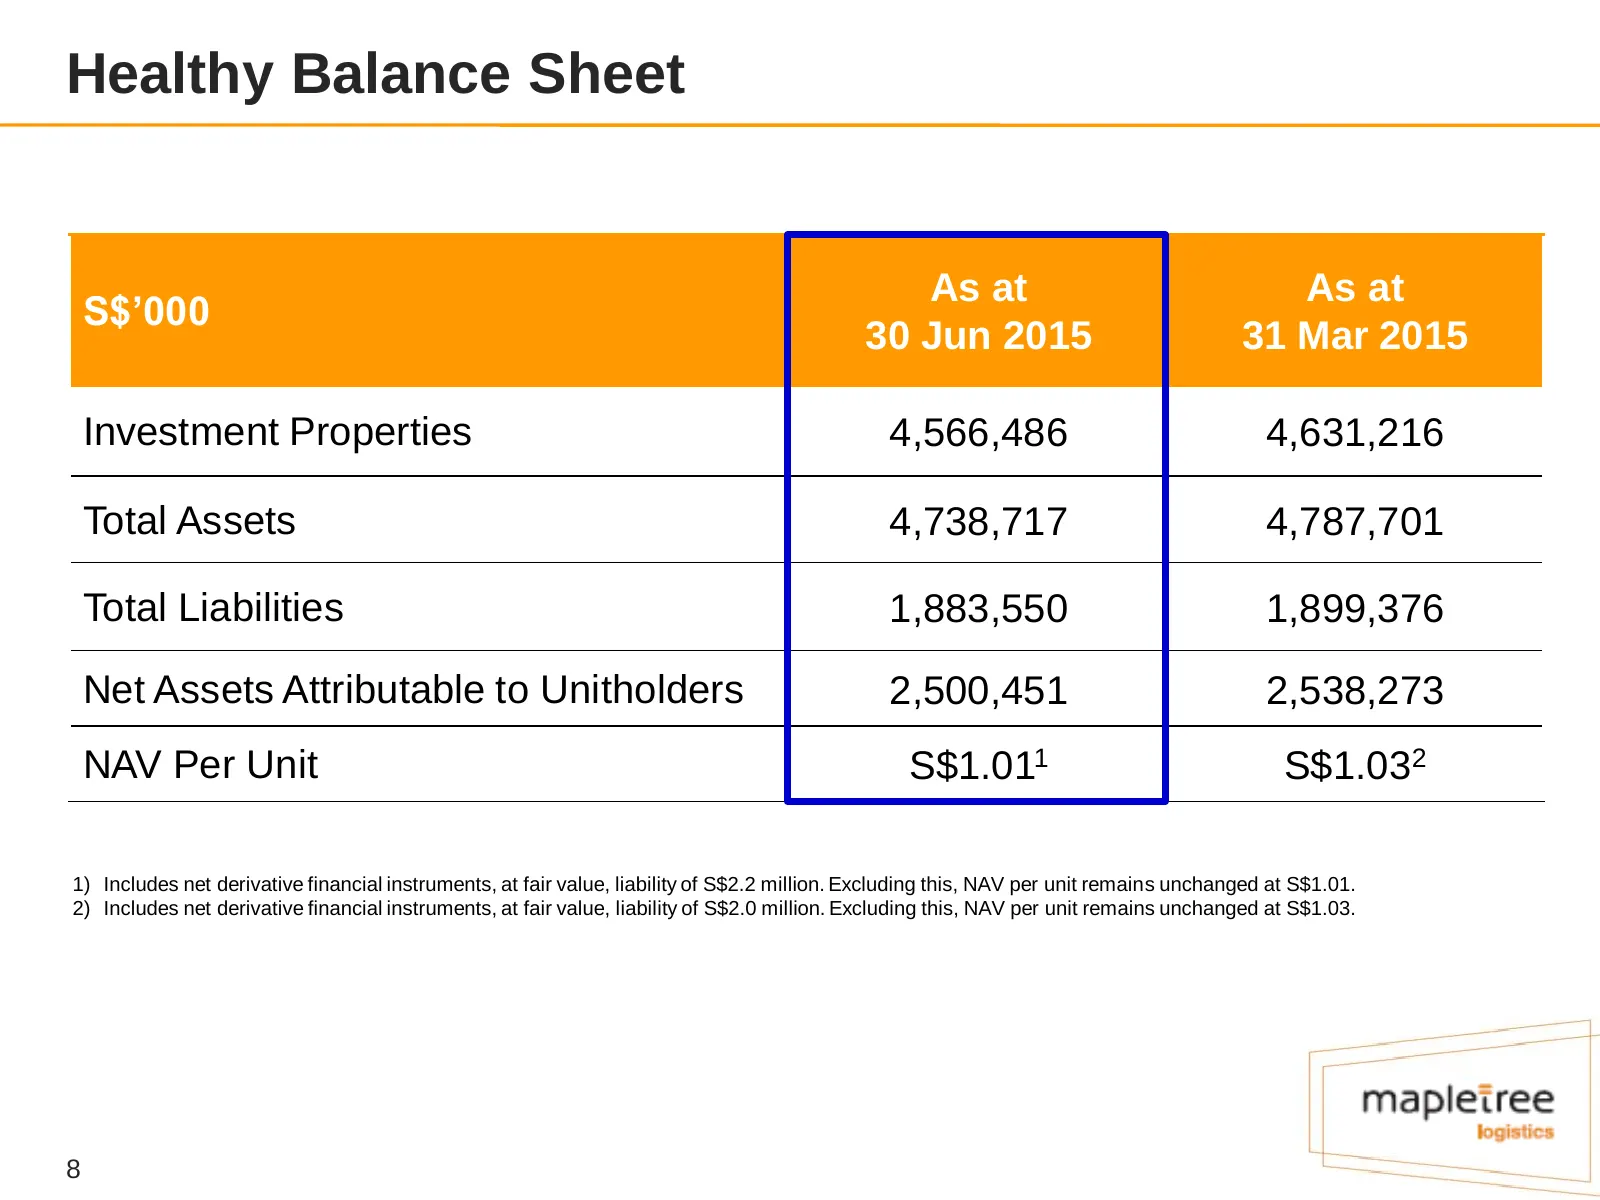
Healthy Balance Sheet As at As at S$’000 30 Jun 2015 31 Mar 2015 Investment Properties 4,566,486 4,631,216 Total Assets 4,738,717 4,787,701 Total Liabilities 1,883,550 1,899,376 Net Assets Attributable to Unitholders 2,500,451 2,538,273 NAV Per Unit S$1.011 S$1.032 1) Includes net derivative financi
Slide 10: 1Q FY15/16 Distribution
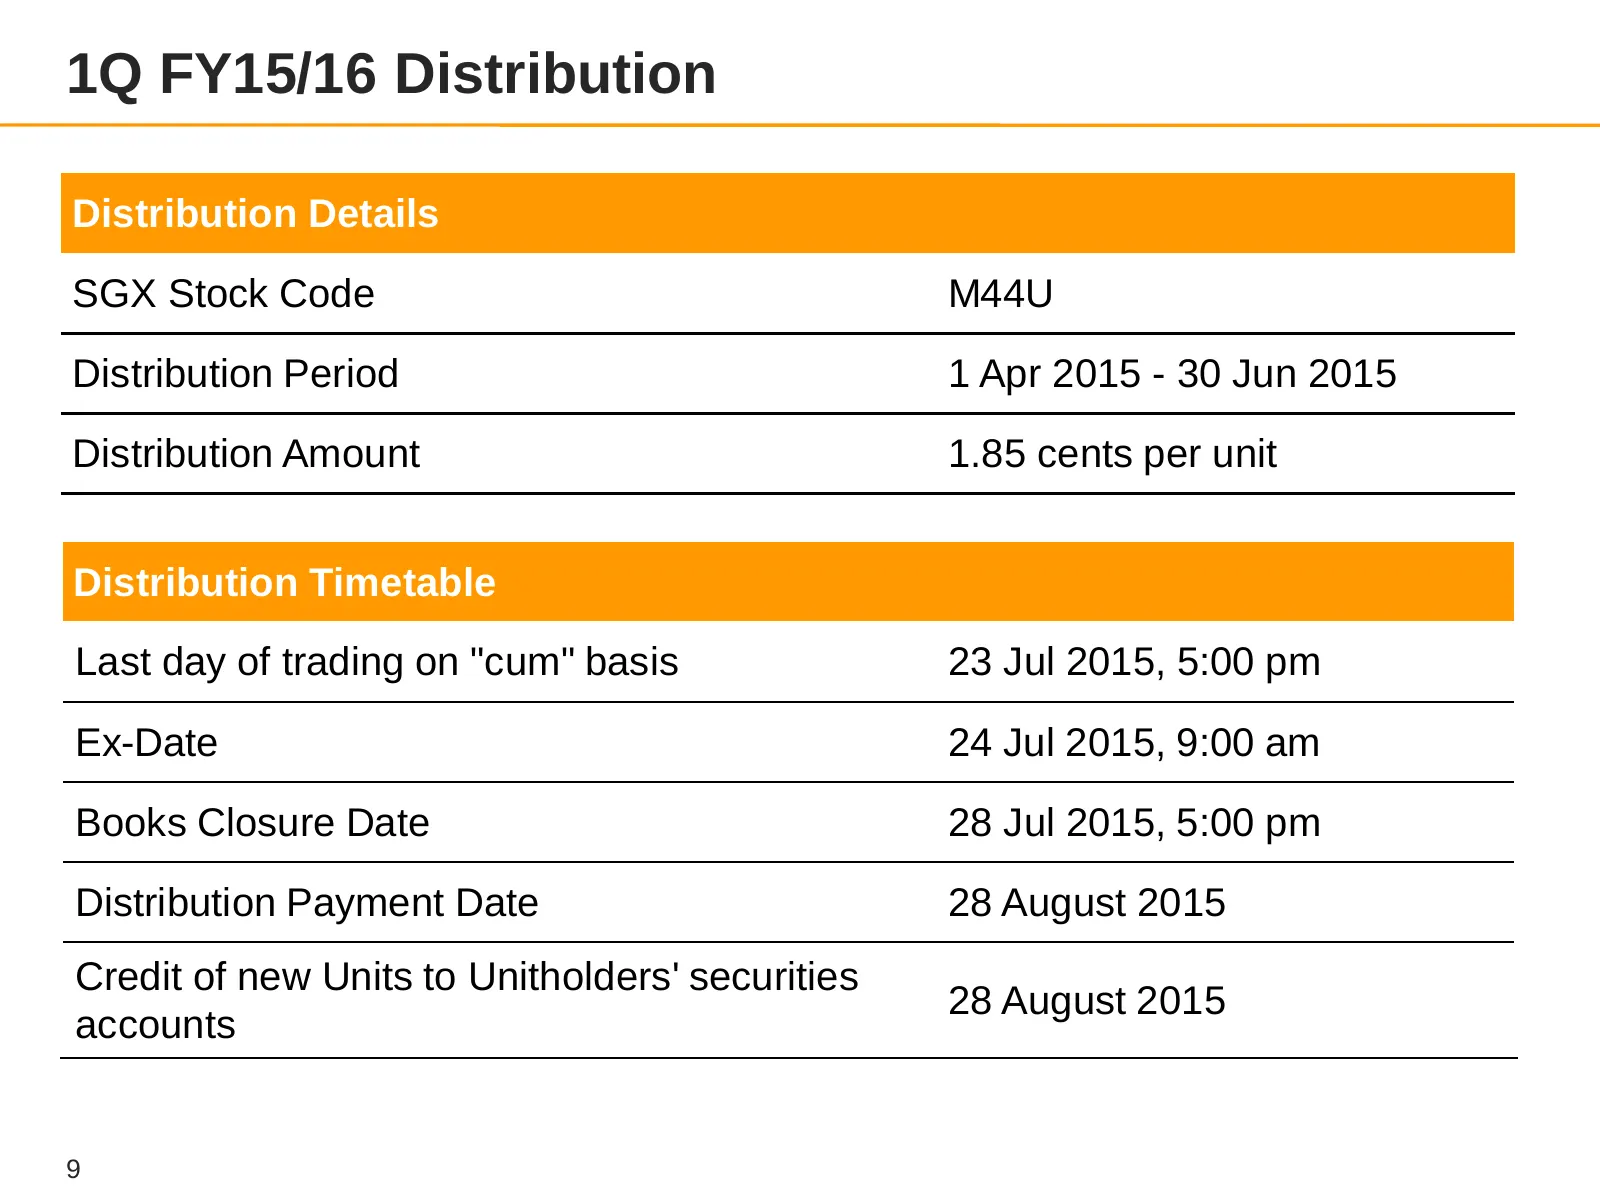
1Q FY15/16 Distribution Distribution Details SGX Stock Code M44U Distribution Period 1 Apr 2015 - 30 Jun 2015 Distribution Amount 1.85 cents per unit Distribution Timetable Last day of trading on "cum" basis 23 Jul 2015, 5:00 pm Ex-Date 24 Jul 2015, 9:00 am Books Closure Date 28 Jul 2015, 5:00 pm Di
Slide 11: Capital Management
Capital Management
Slide 12: Prudent Capital Management
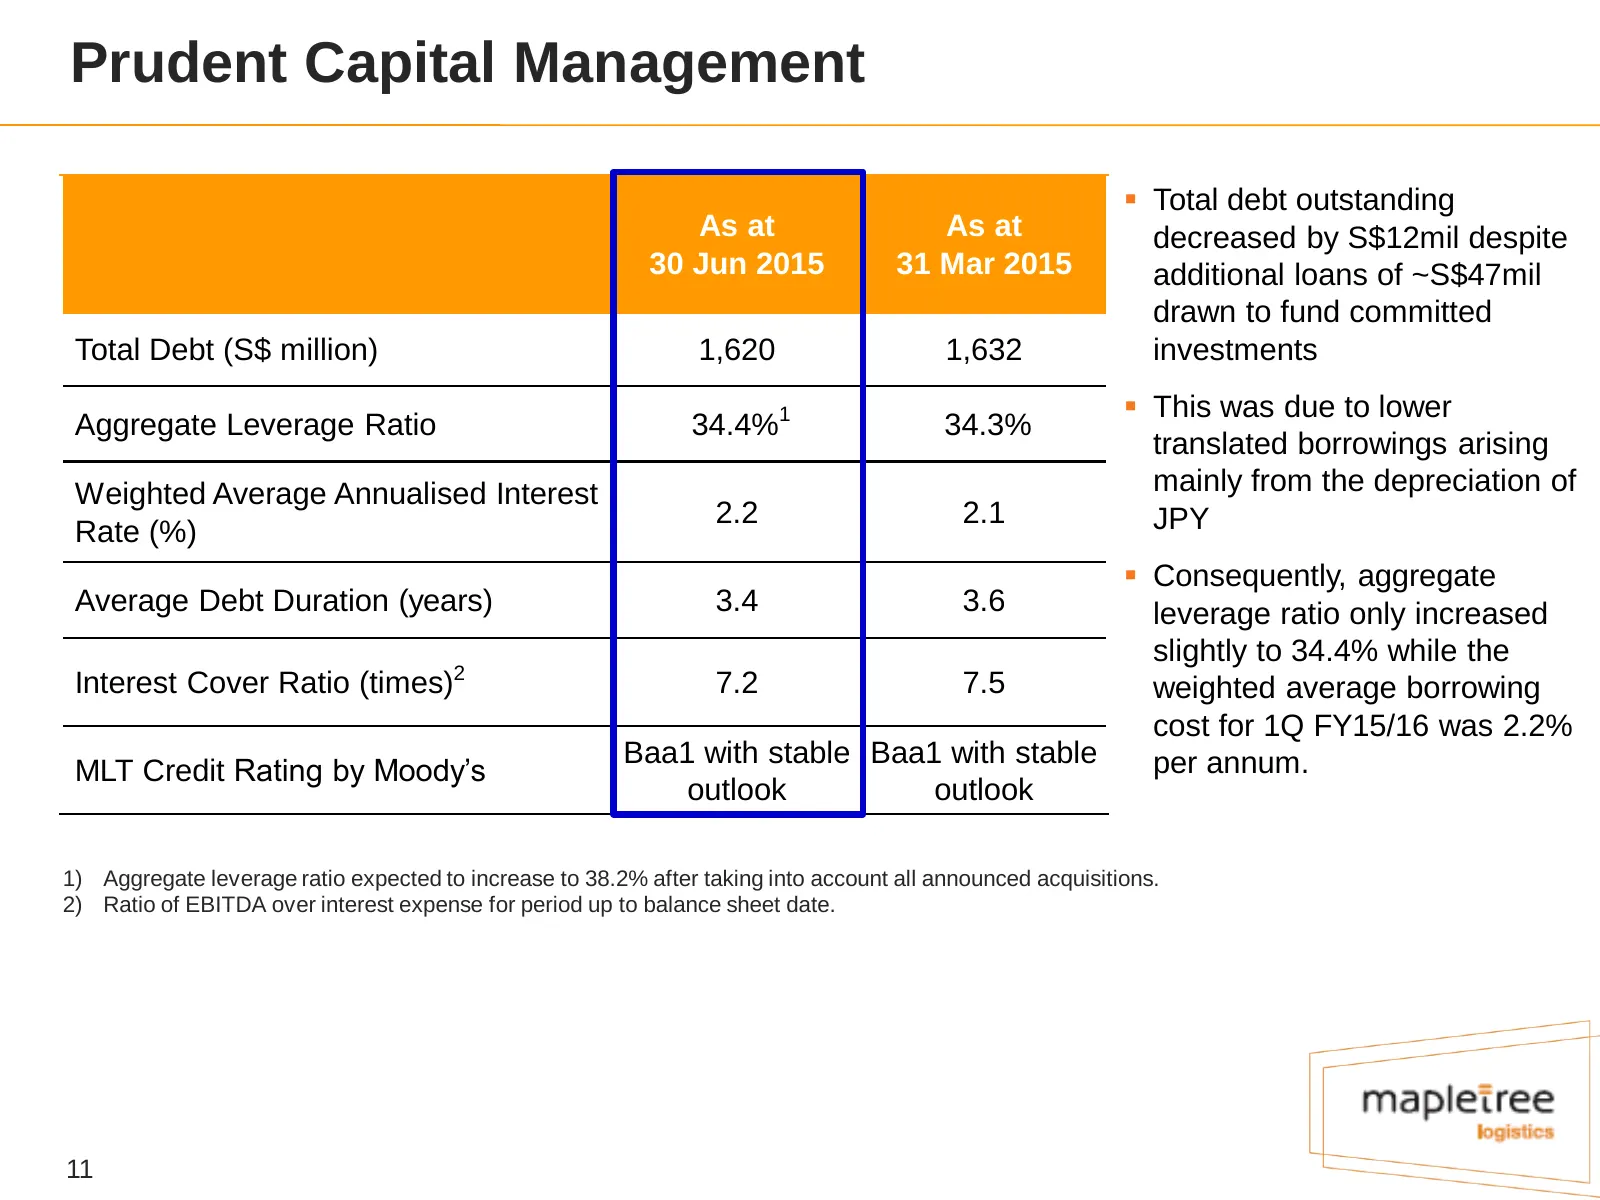
Prudent Capital Management Total debt outstanding As at As at decreased by S$12mil despite 30 Jun 2015 31 Mar 2015 additional loans of ~S$47mil drawn to fund committed Total Debt (S$ million) 1,620 1,632 investments This was due to lower Aggregate Leverage Ratio 34.4%1 34.3% translated borrowing
Slide 13: Debt Maturity Profile (By Currency) as at 30 Jun 2015
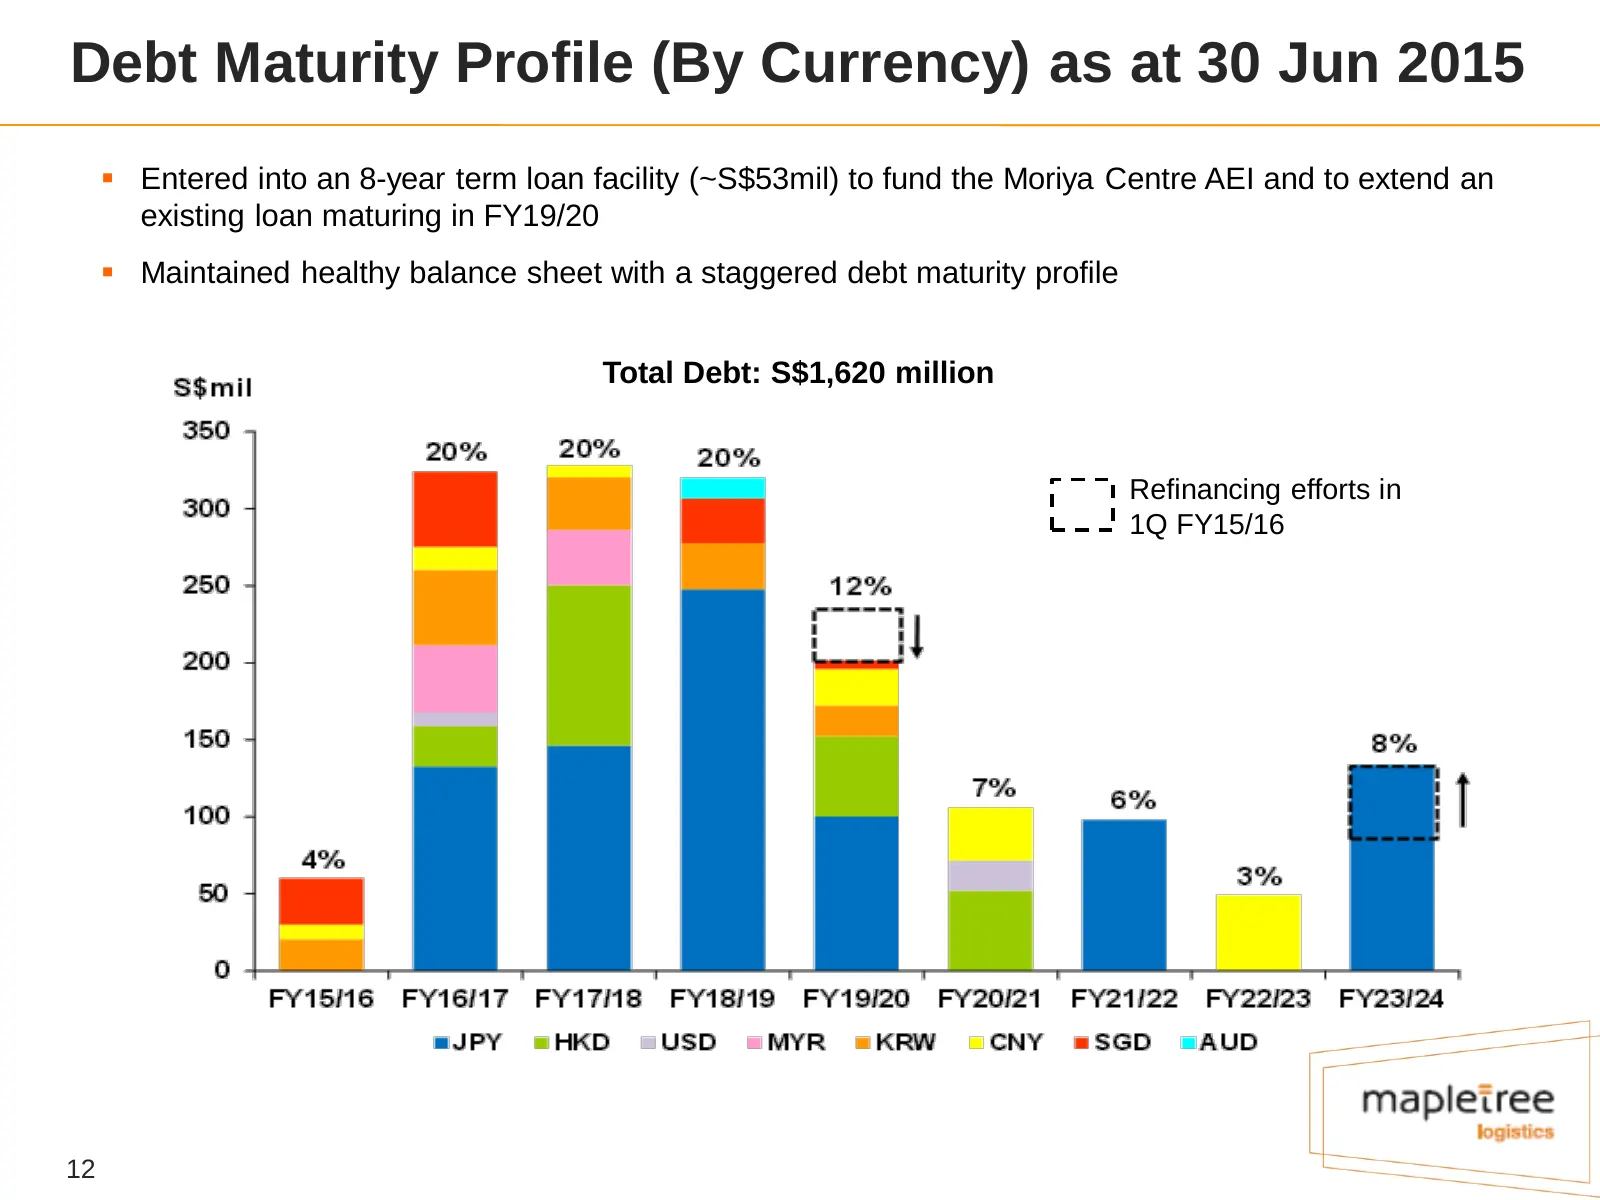
Debt Maturity Profile (By Currency) as at 30 Jun 2015 Entered into an 8-year term loan facility (~S$53mil) to fund the Moriya Centre AEI and to extend an existing loan maturing in FY19/20 Maintained healthy balance sheet with a staggered debt maturity profile Total Debt: S$1,620 million Refinanc
Slide 14: Interest Rate Risk Management
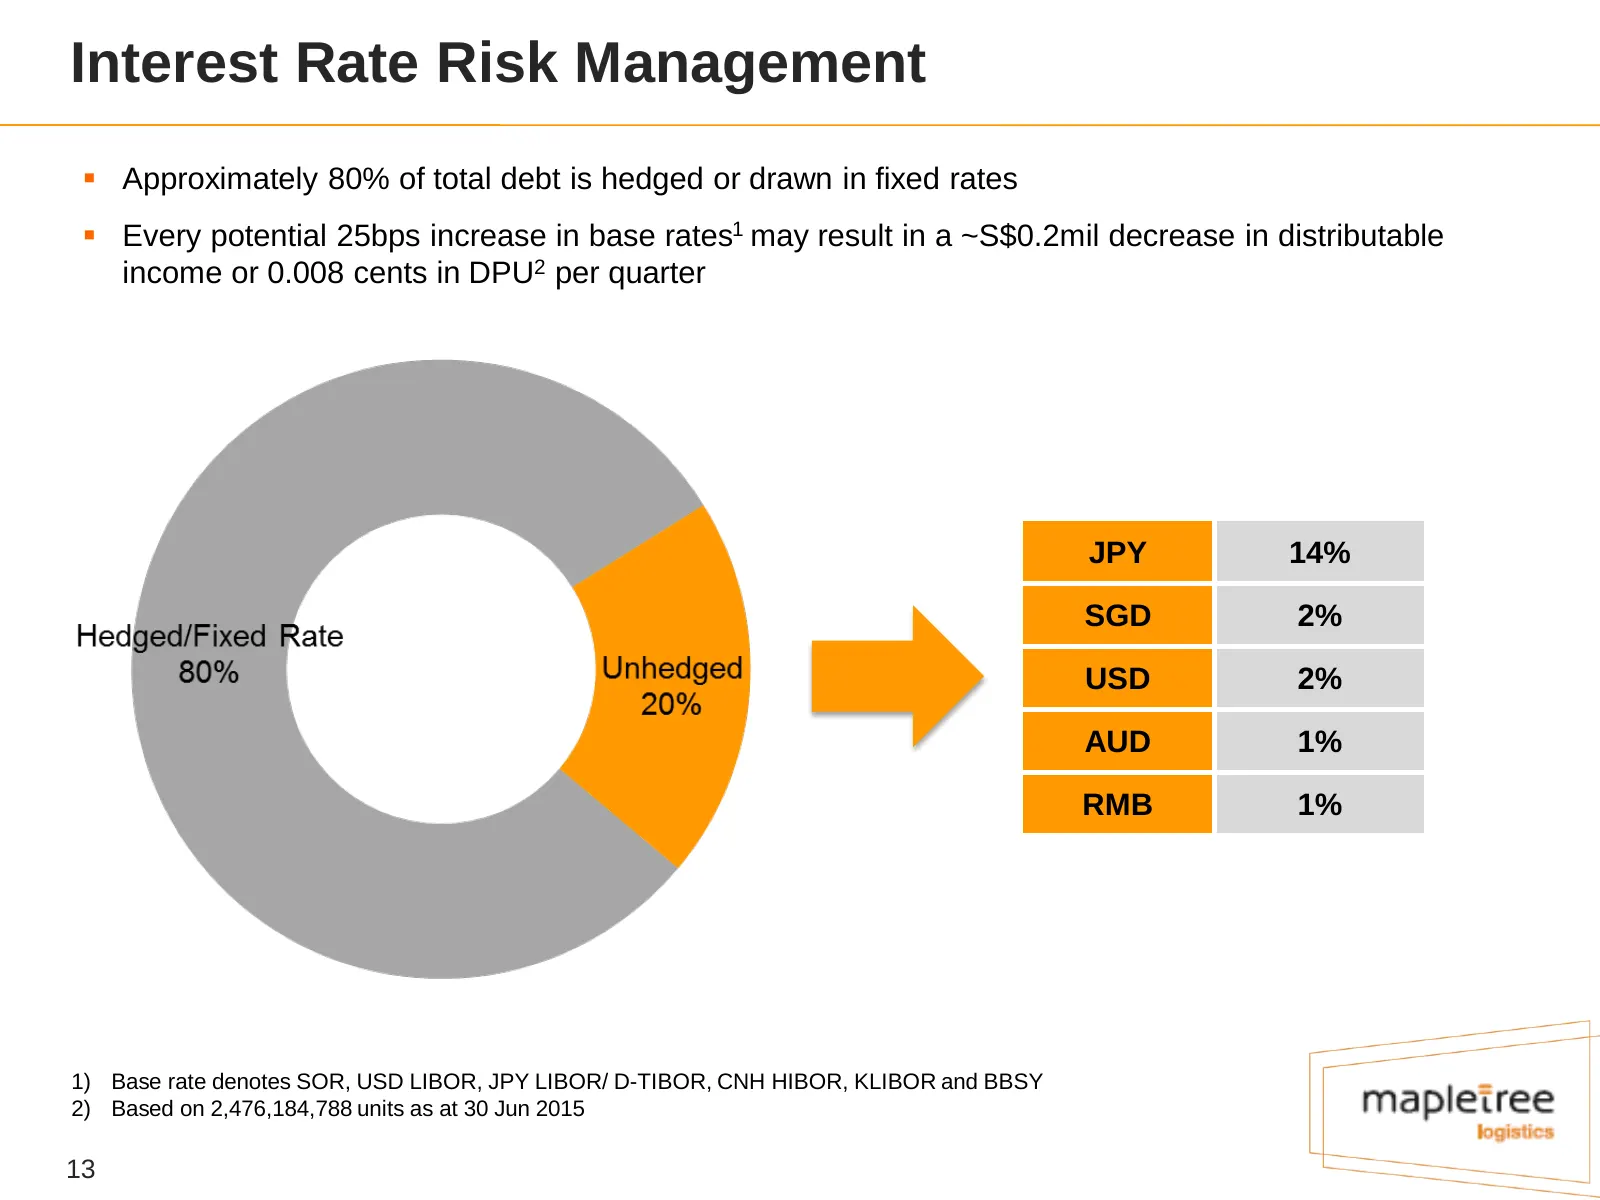
Interest Rate Risk Management Approximately 80% of total debt is hedged or drawn in fixed rates Every potential 25bps increase in base rates1 may result in a ~S$0.2mil decrease in distributable income or 0.008 cents in DPU2 per quarter JPY 14% SGD 2% USD 2% AUD 1% RMB 1% 1) Base rate denotes SOR
Slide 15: Forex Risk Management
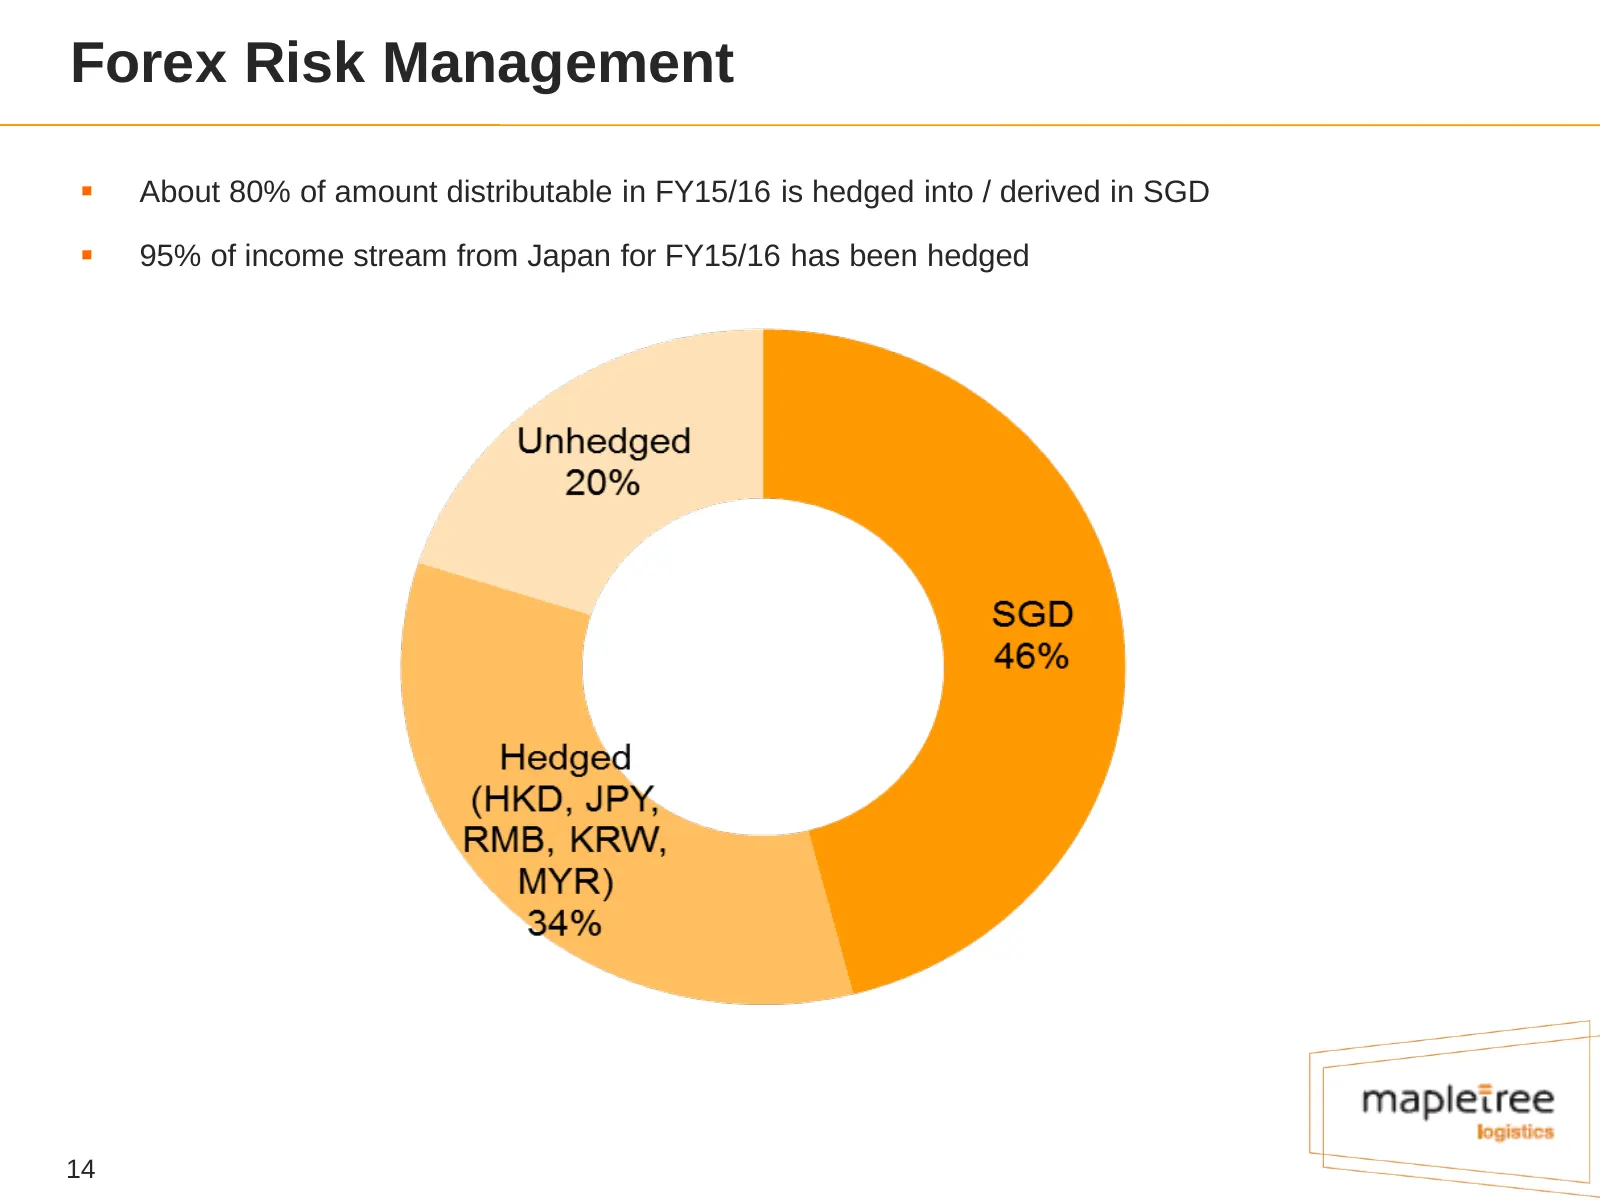
Forex Risk Management About 80% of amount distributable in FY15/16 is hedged into / derived in SGD 95% of income stream from Japan for FY15/16 has been hedged 14
Slide 16: Business Review
Business Review
Slide 17: Investment Highlights in 1Q FY15/16
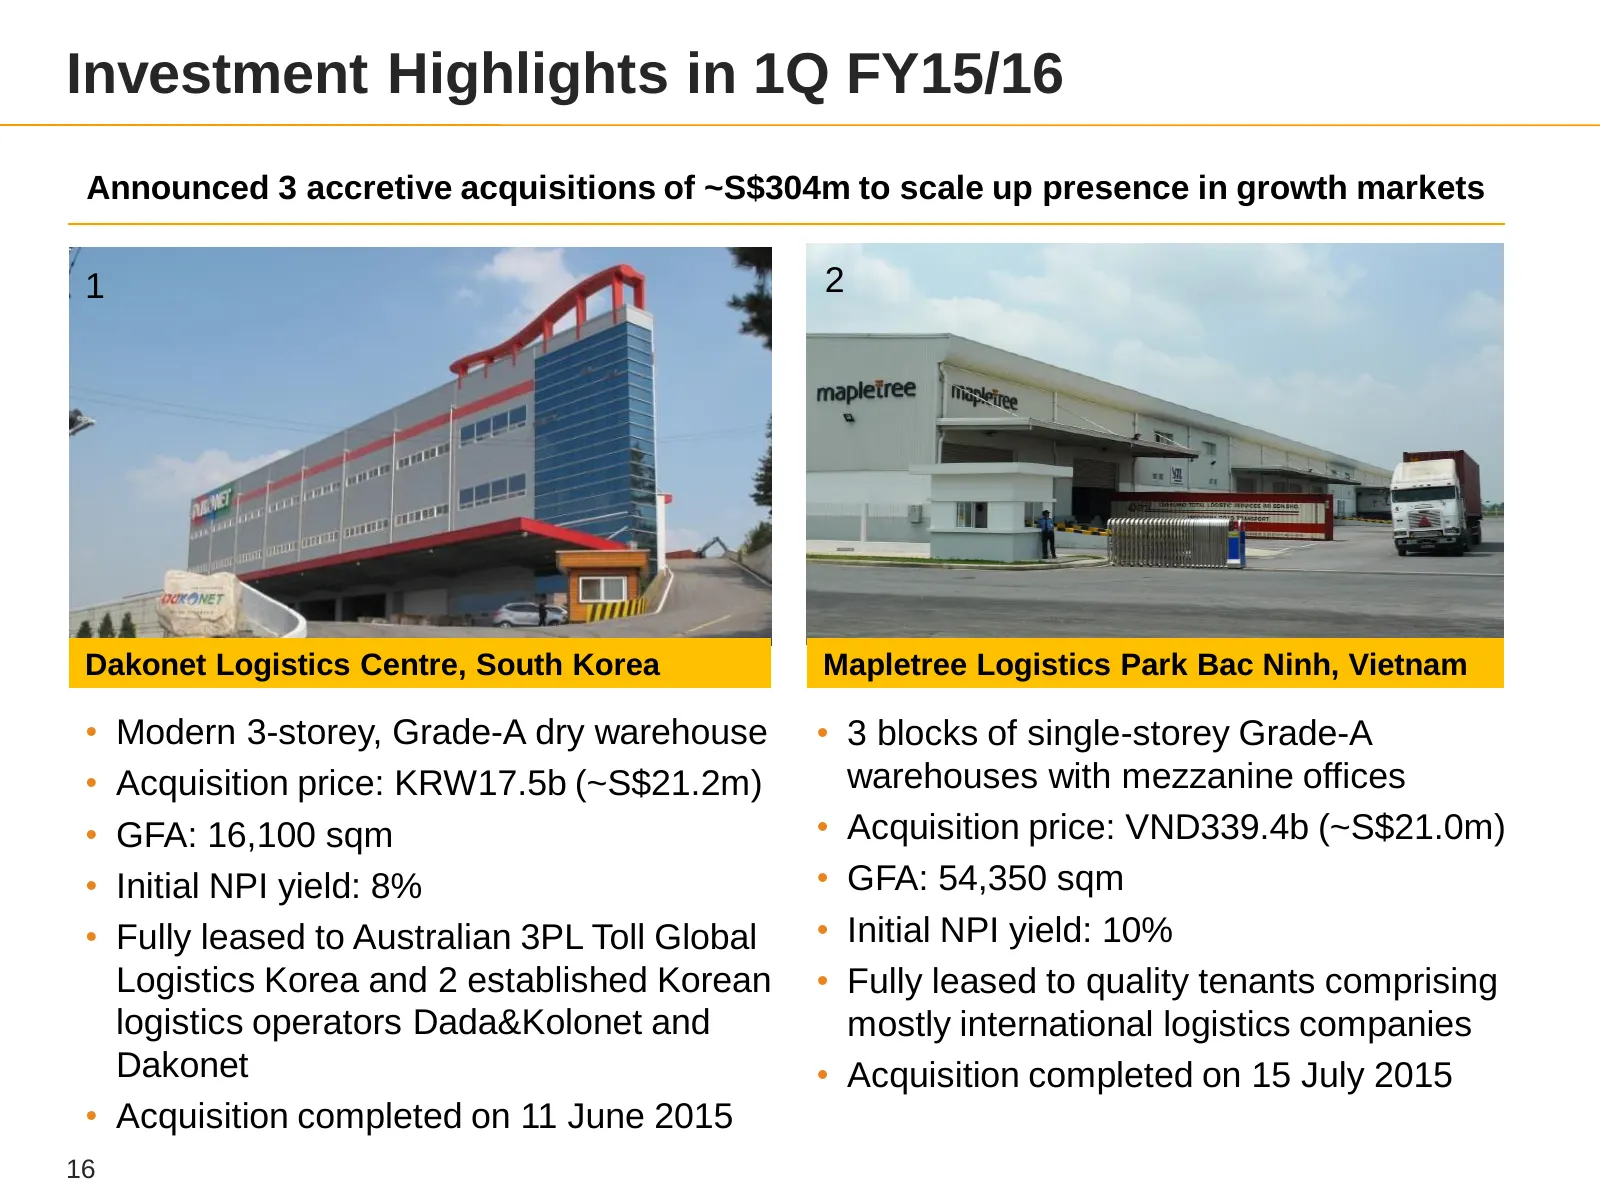
Investment Highlights in 1Q FY15/16 Announced 3 accretive acquisitions of ~S$304m to scale up presence in growth markets 1 2 Dakonet Logistics Centre, South Korea Mapletree Logistics Park Bac Ninh, Vietnam • Modern 3-storey, Grade-A dry warehouse • 3 blocks of single-storey Grade-A • Acquisition pri
Slide 18: Investment Highlights in 1Q FY15/16
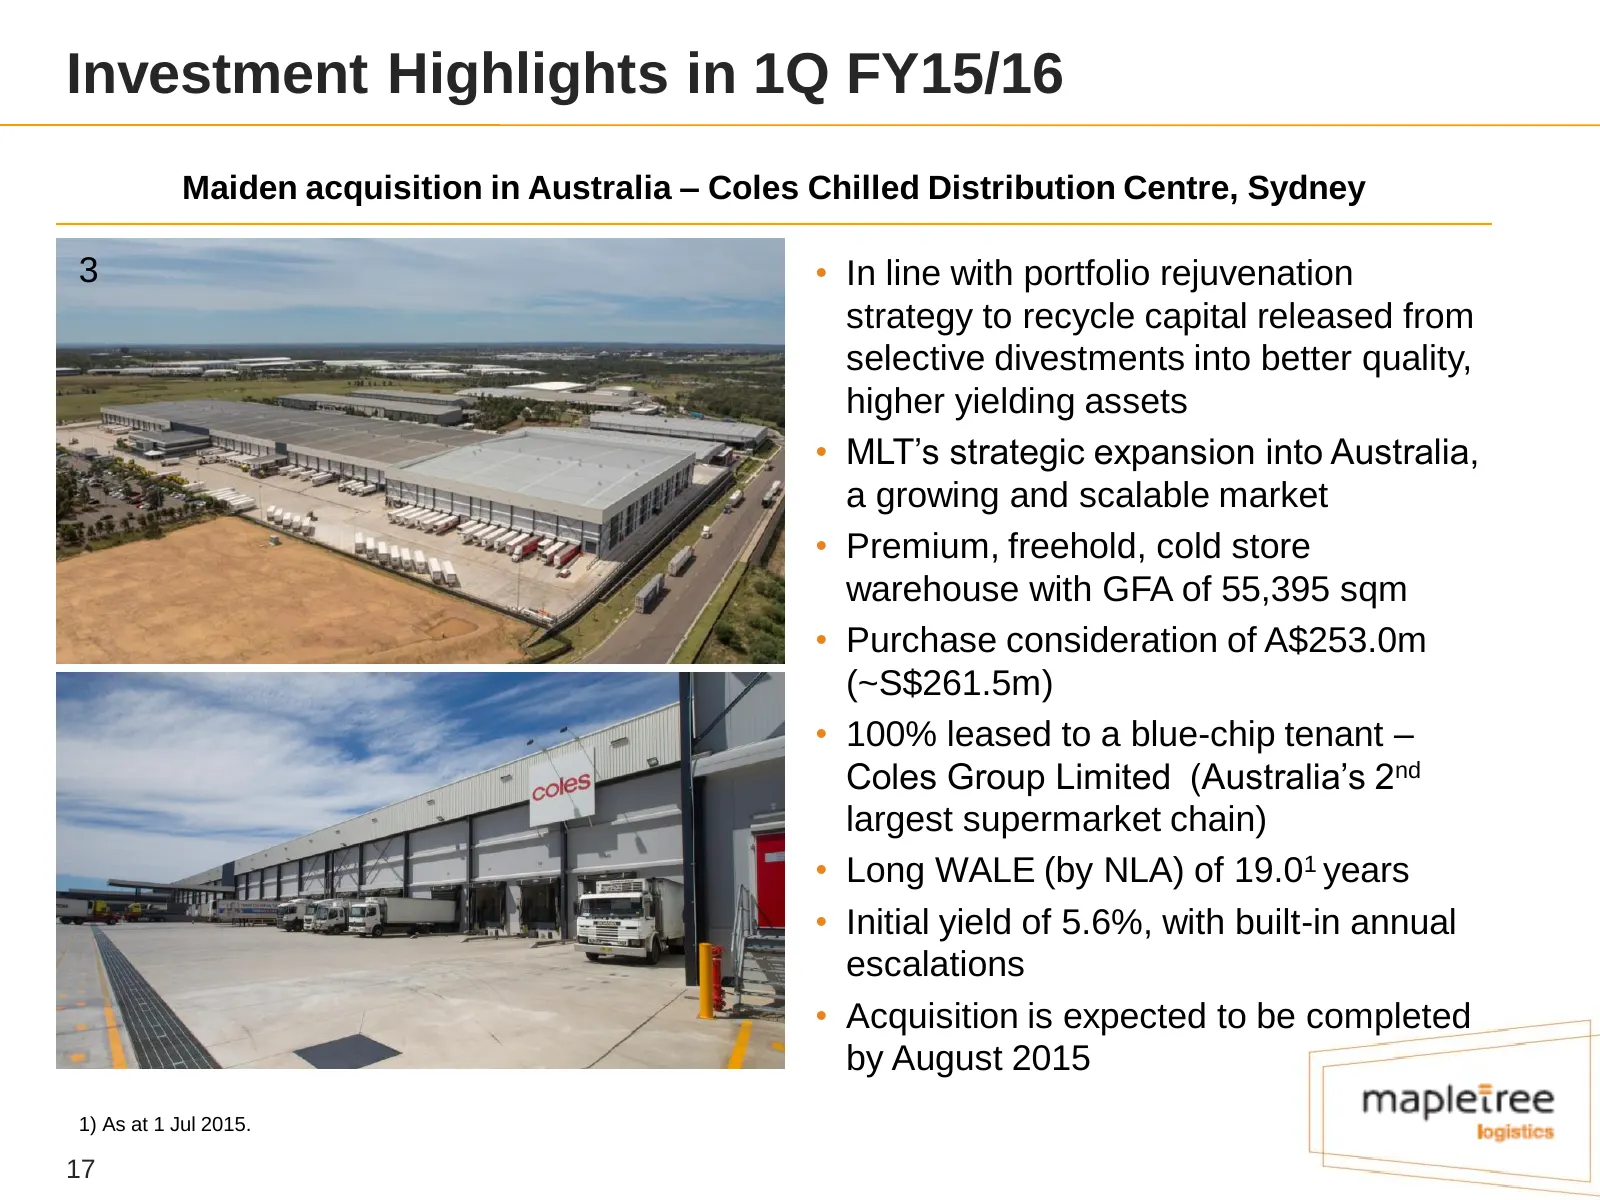
Investment Highlights in 1Q FY15/16 Maiden acquisition in Australia – Coles Chilled Distribution Centre, Sydney 3 • In line with portfolio rejuvenation strategy to recycle capital released from selective divestments into better quality, higher yielding assets • MLT’s strategic expansion into Austral
Slide 19: Portfolio Rejuvenation: Redevelopment 5B Toh Guan Road East
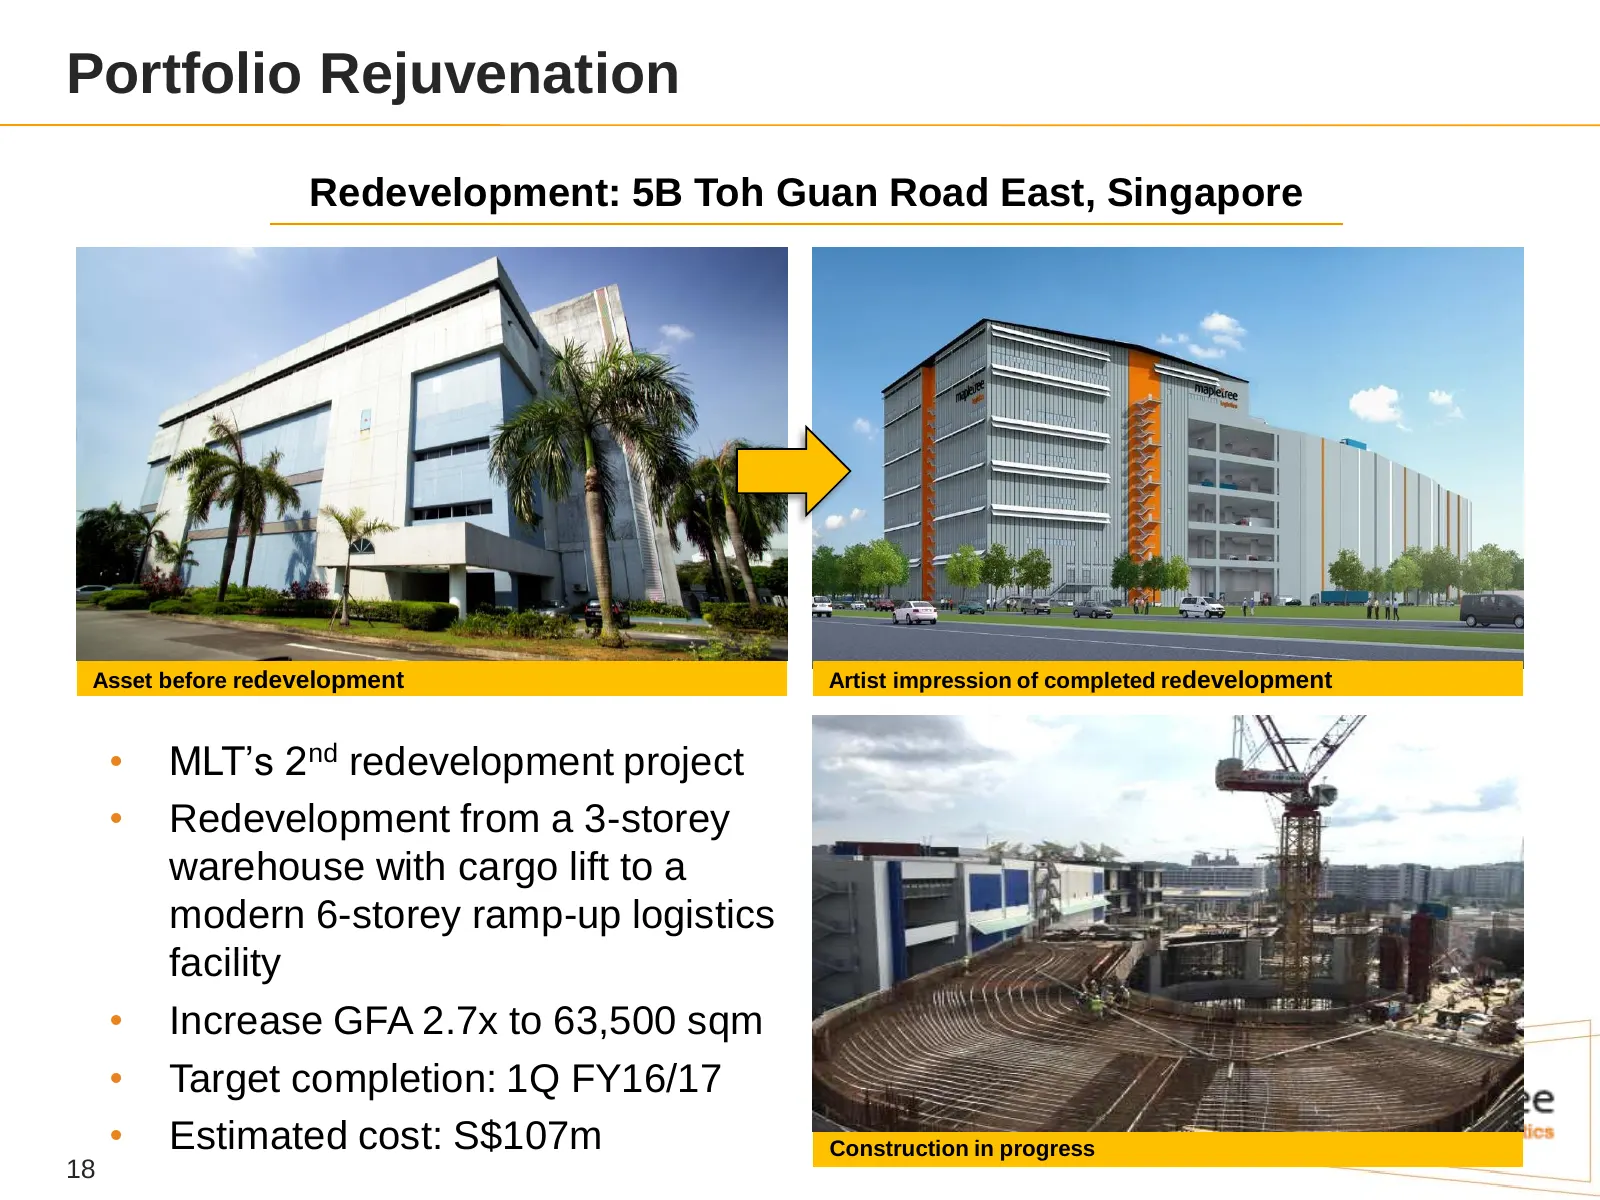
Portfolio Rejuvenation Redevelopment: 5B Toh Guan Road East, Singapore Asset before redevelopment Artist impression of completed redevelopment • MLT’s 2nd redevelopment project • Redevelopment from a 3-storey warehouse with cargo lift to a modern 6-storey ramp-up logistics facility • Increase GFA 2.
Slide 20: Portfolio Rejuvenation: Redevelopment Pioneer Road
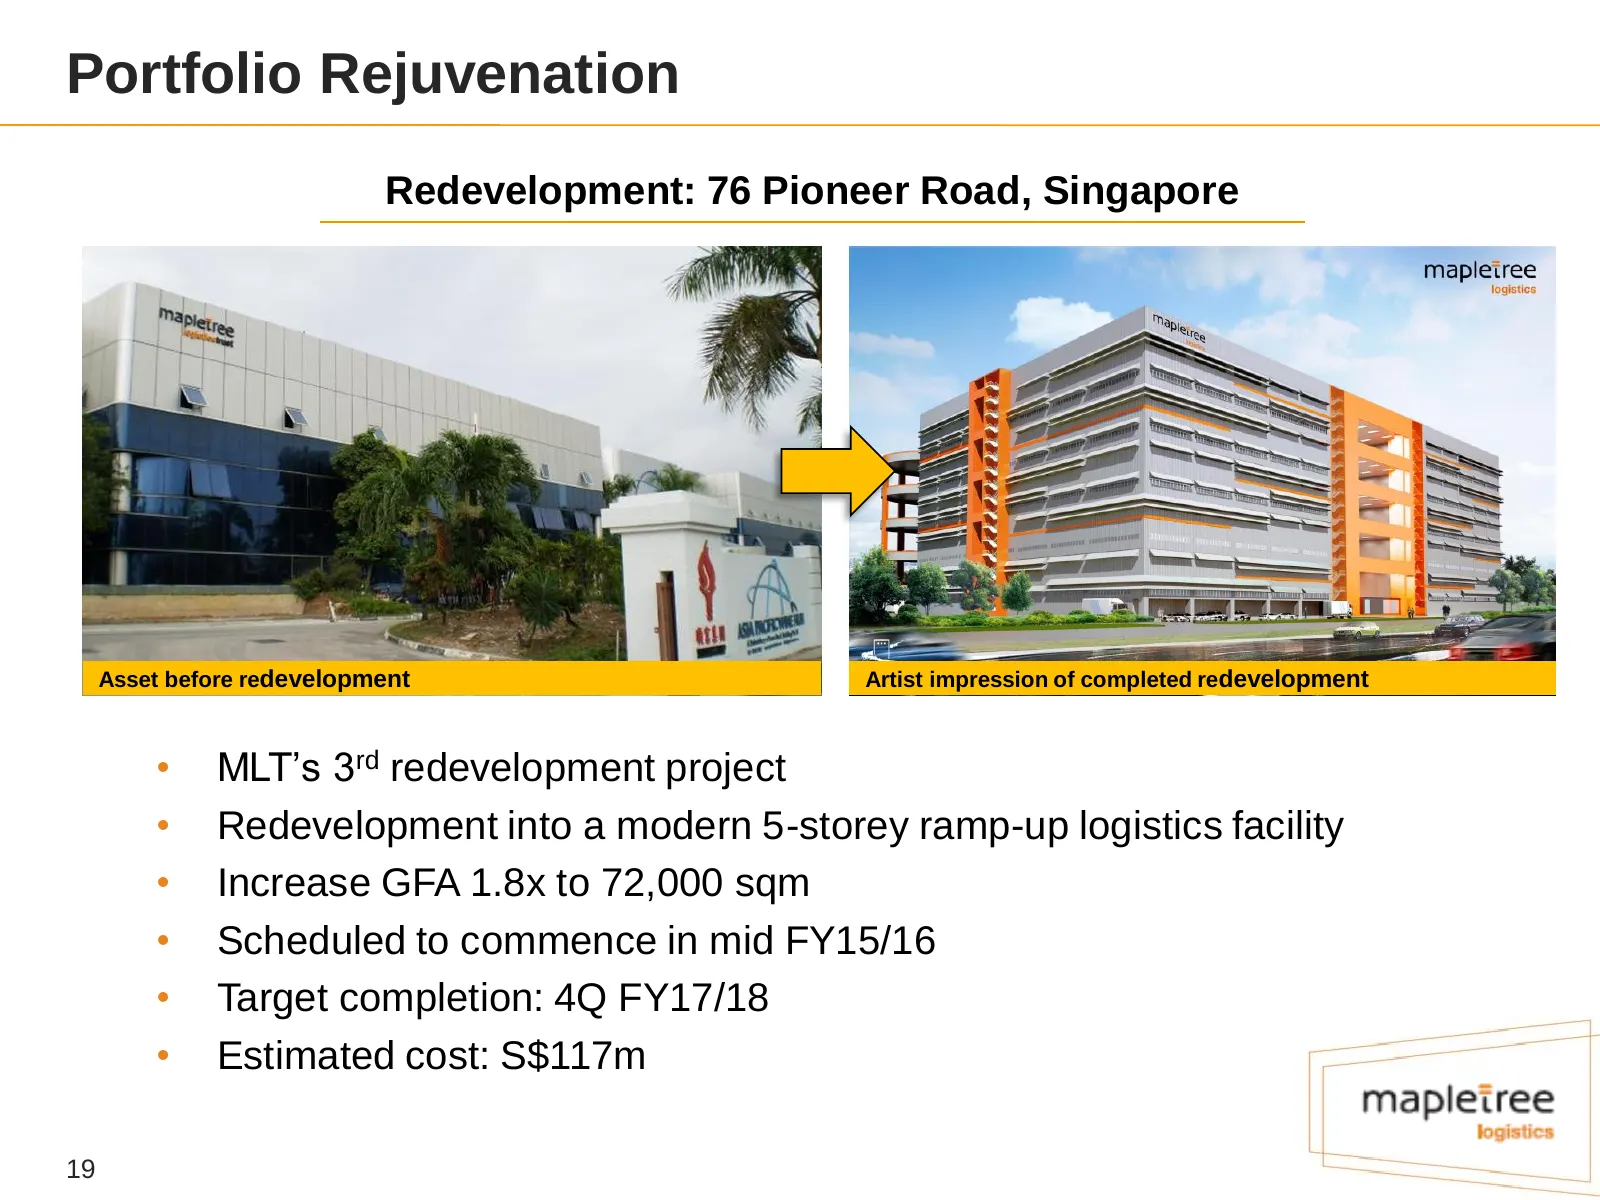
Portfolio Rejuvenation Redevelopment: 76 Pioneer Road, Singapore Asset before redevelopment Artist impression of completed redevelopment • MLT’s 3rd redevelopment project • Redevelopment into a modern 5-storey ramp-up logistics facility • Increase GFA 1.8x to 72,000 sqm • Scheduled to commence in mi
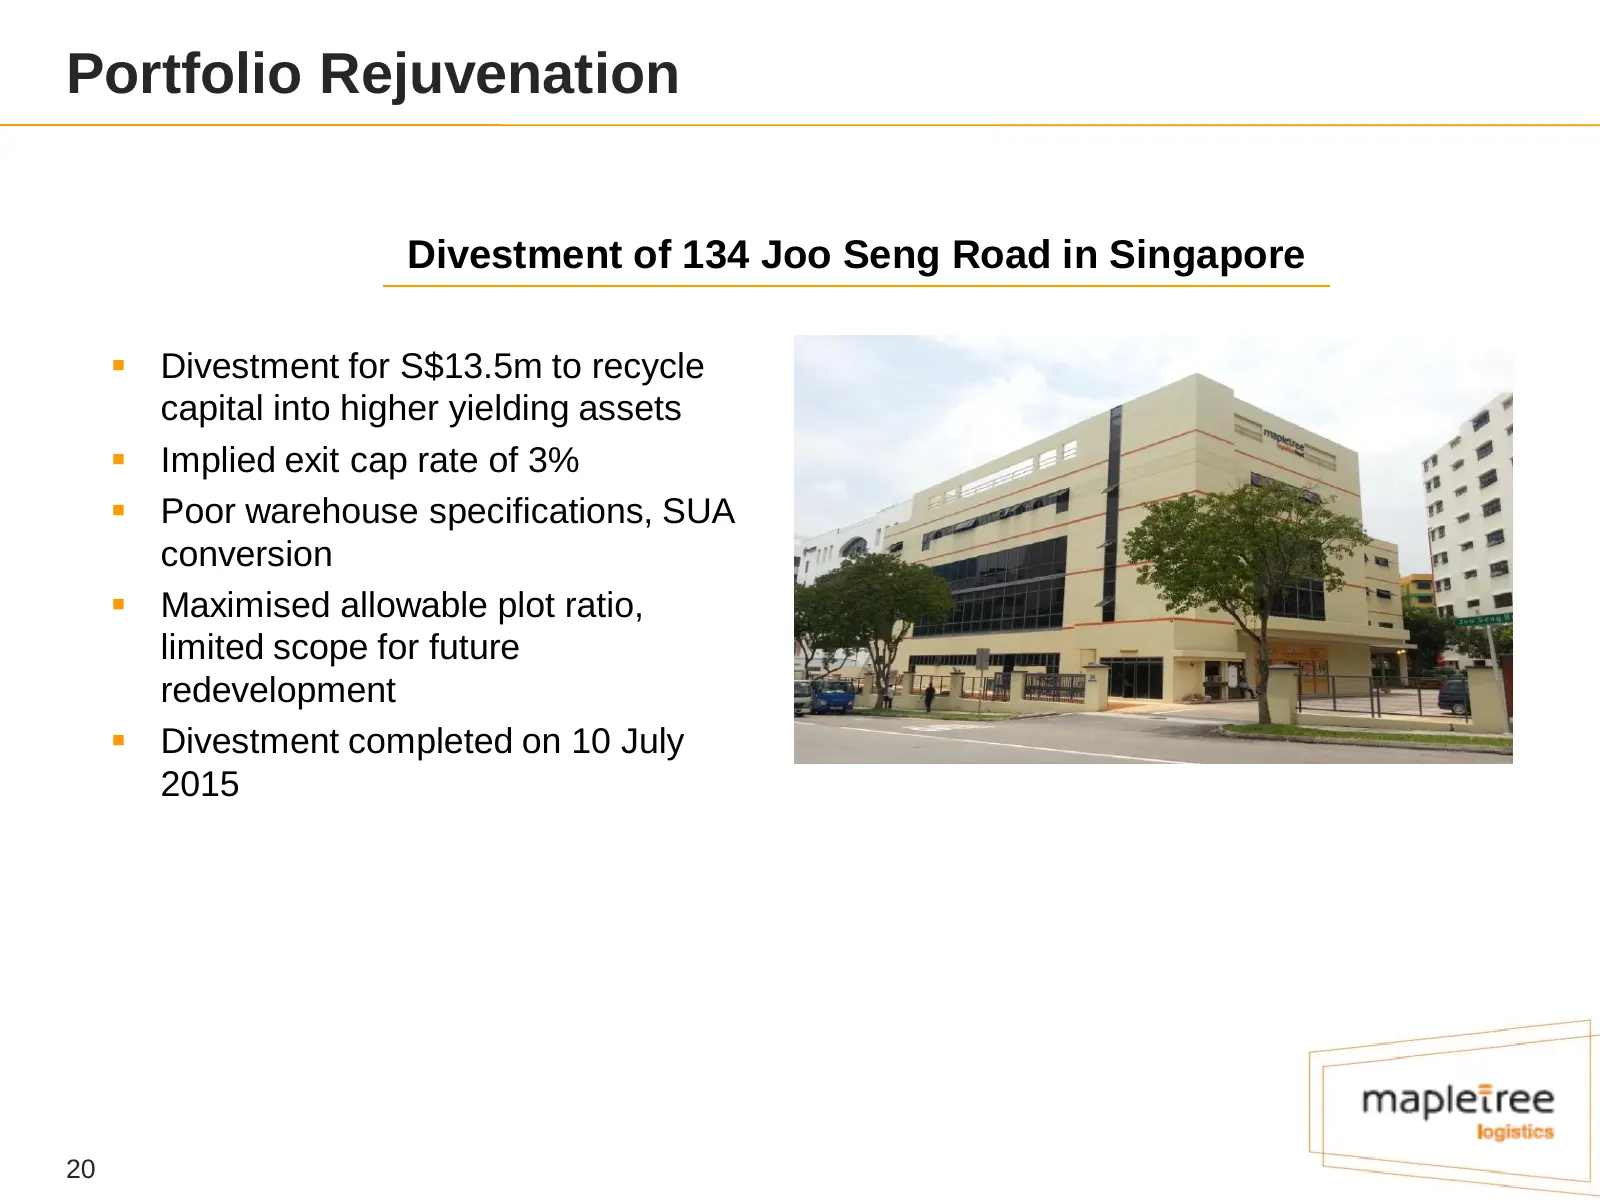
Slide 21: Portfolio Rejuvenation: Divestment of Joo Seng Road
Portfolio Rejuvenation Divestment of 134 Joo Seng Road in Singapore Divestment for S$13.5m to recycle capital into higher yielding assets Implied exit cap rate of 3% Poor warehouse specifications, SUA conversion Maximised allowable plot ratio, limited scope for future redevelopment Divestm
Slide 22: Portfolio Highlights
Portfolio Highlights Active asset and lease management − Renewed/replaced 32% of leases (by NLA) due for expiry in FY15/16 − Positive average rental reversions of 5% mainly from Hong Kong and Singapore Stability from long leases − Weighted average lease term to expiry (by NLA) is about 4.1 years
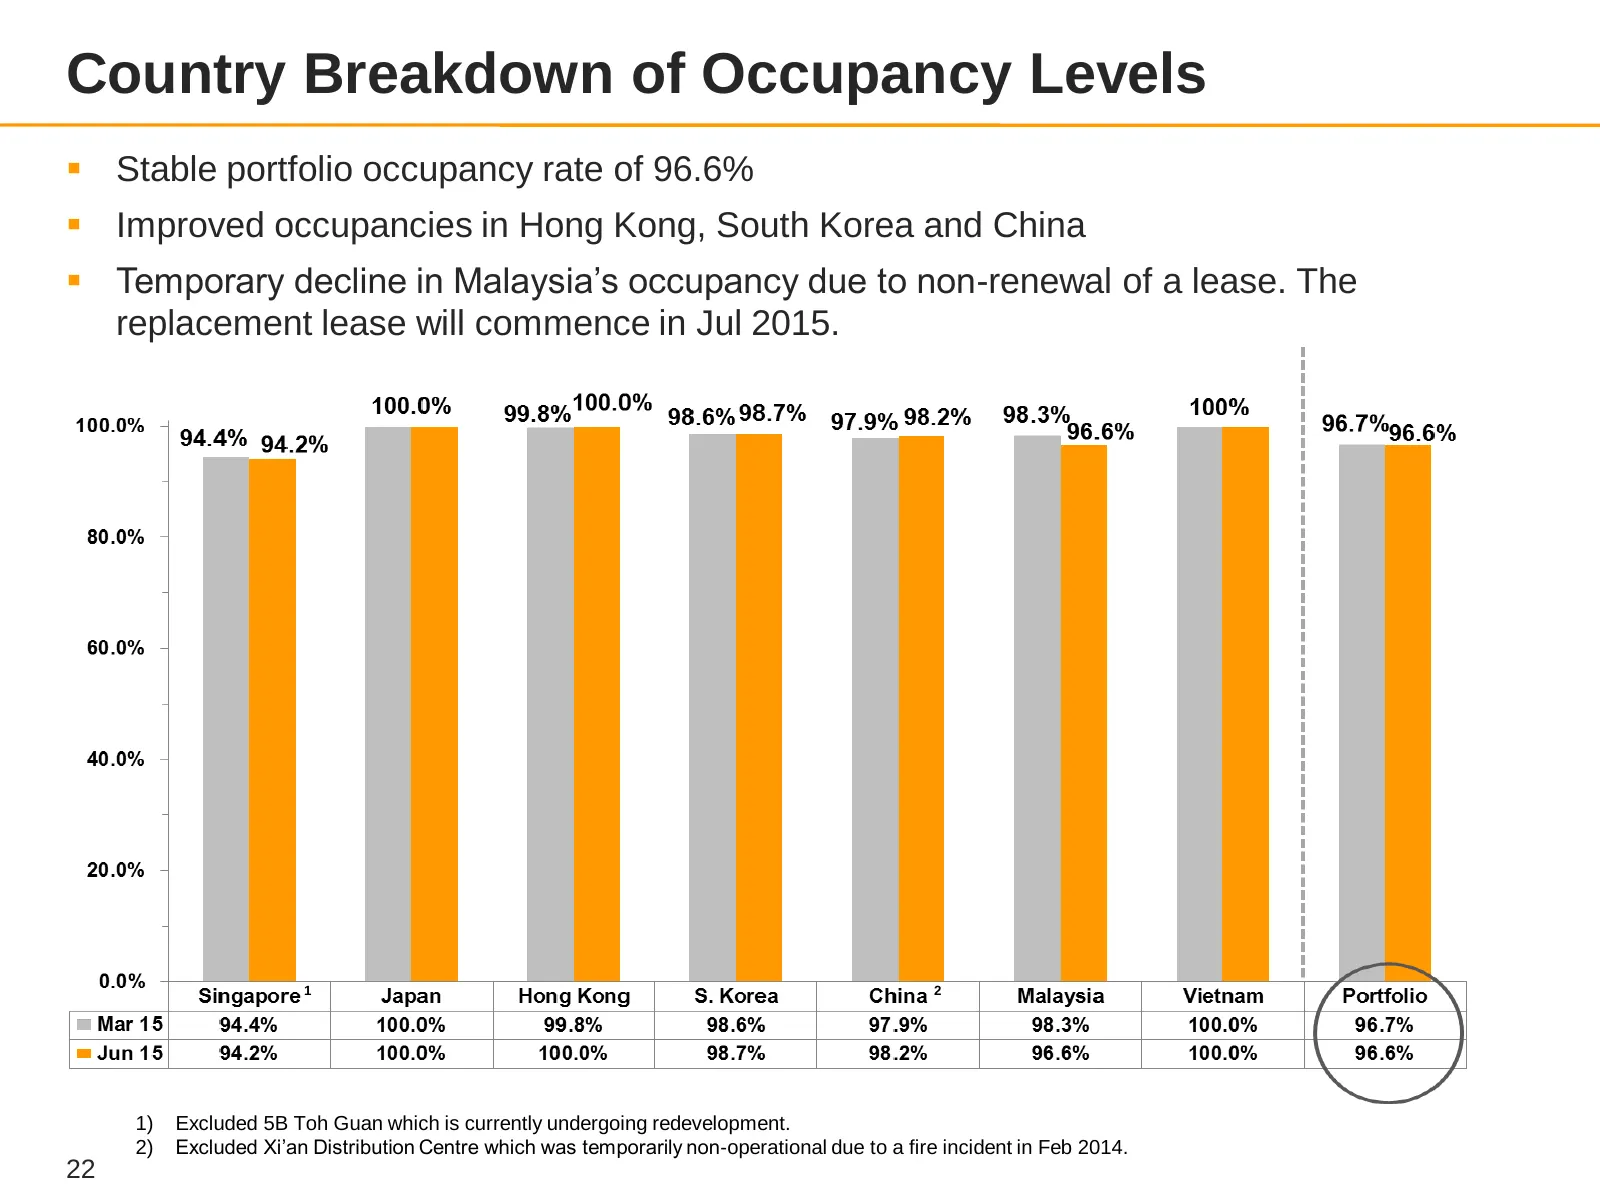
Slide 23: Country Breakdown of Occupancy Levels
Country Breakdown of Occupancy Levels Stable portfolio occupancy rate of 96.6% Improved occupancies in Hong Kong, South Korea and China Temporary decline in Malaysia’s occupancy due to non-renewal of a lease. The replacement lease will commence in Jul 2015. 1 2 1) Excluded 5B Toh Guan which is
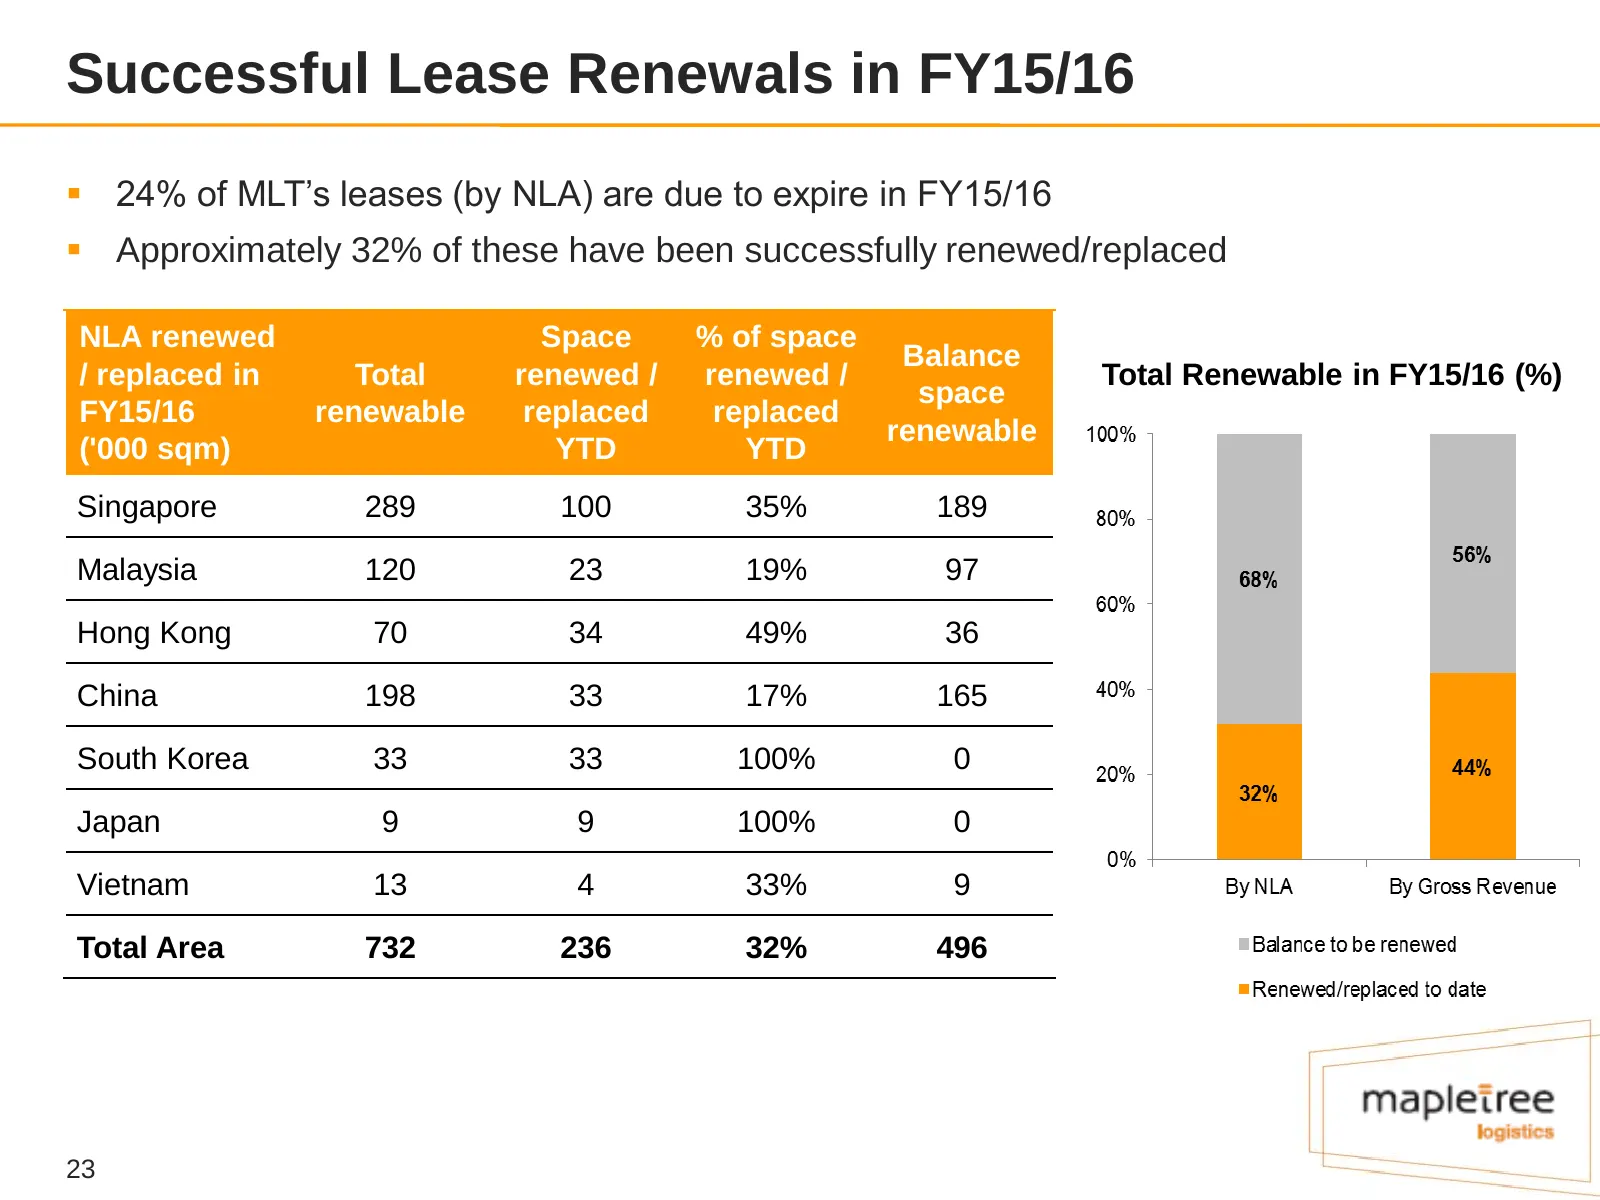
Slide 24: Successful Lease Renewals in FY15/16
Successful Lease Renewals in FY15/16 24% of MLT’s leases (by NLA) are due to expire in FY15/16 Approximately 32% of these have been successfully renewed/replaced NLA renewed Space % of space Balance / replaced in Total renewed / renewed / Total Renewable in FY15/16 (%) space FY15/16 renewable re
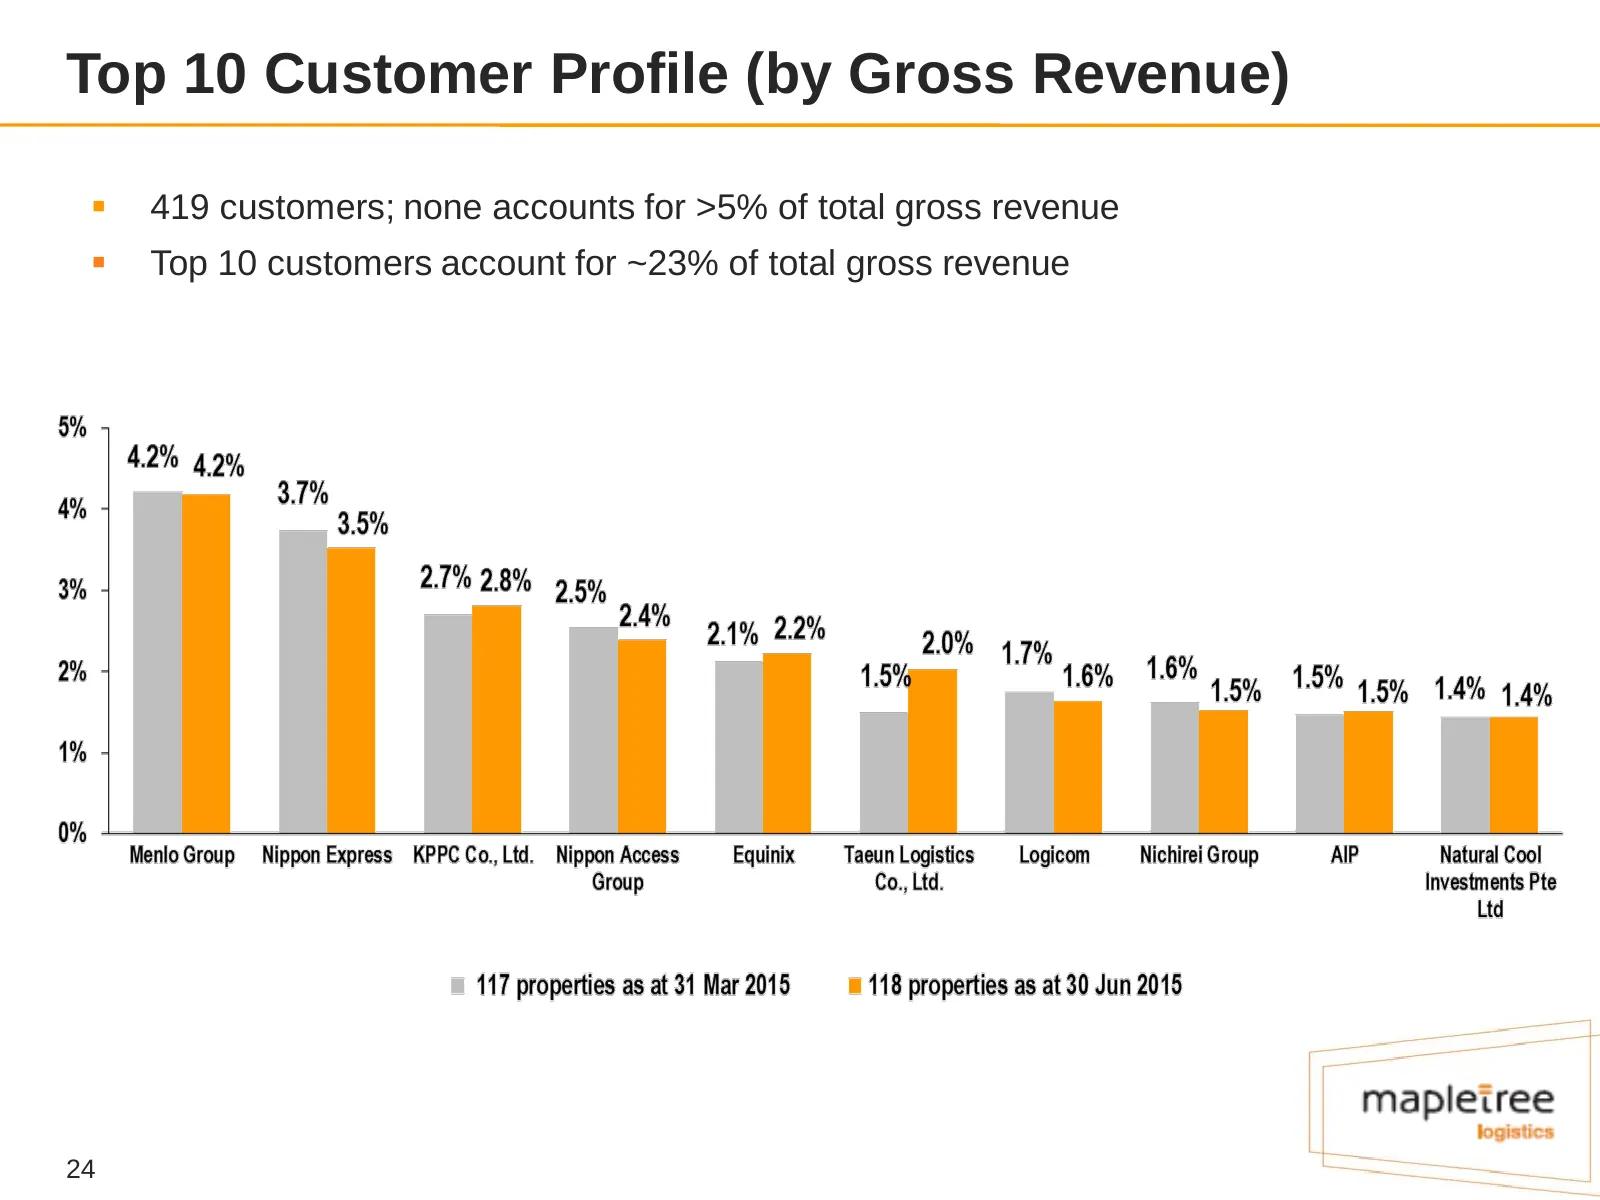
Slide 25: Top 10 Customer Profile (by Gross Revenue)
Top 10 Customer Profile (by Gross Revenue) 419 customers; none accounts for >5% of total gross revenue Top 10 customers account for ~23% of total gross revenue 24
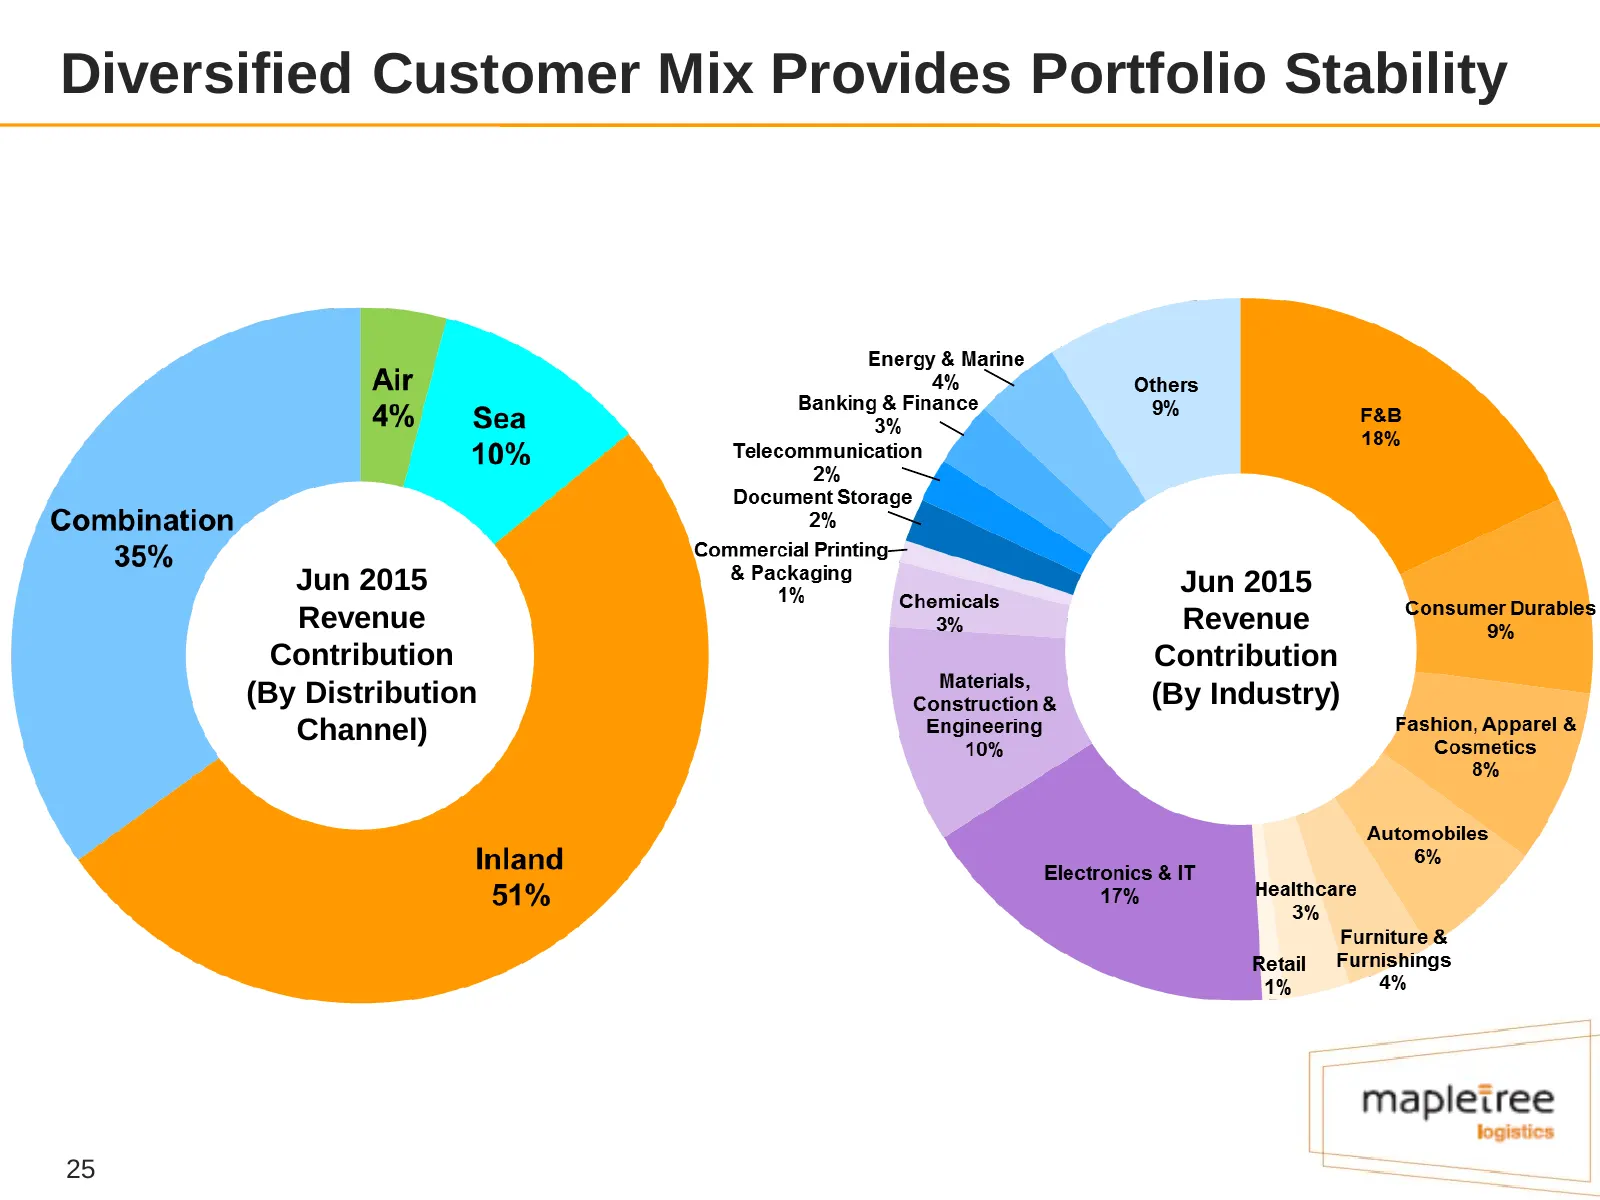
Slide 26: Diversified Customer Mix Provides Portfolio Stability
Diversified Customer Mix Provides Portfolio Stability Jun 2015 Jun 2015 Revenue Revenue Contribution Contribution (By Distribution (By Industry) Channel) 25
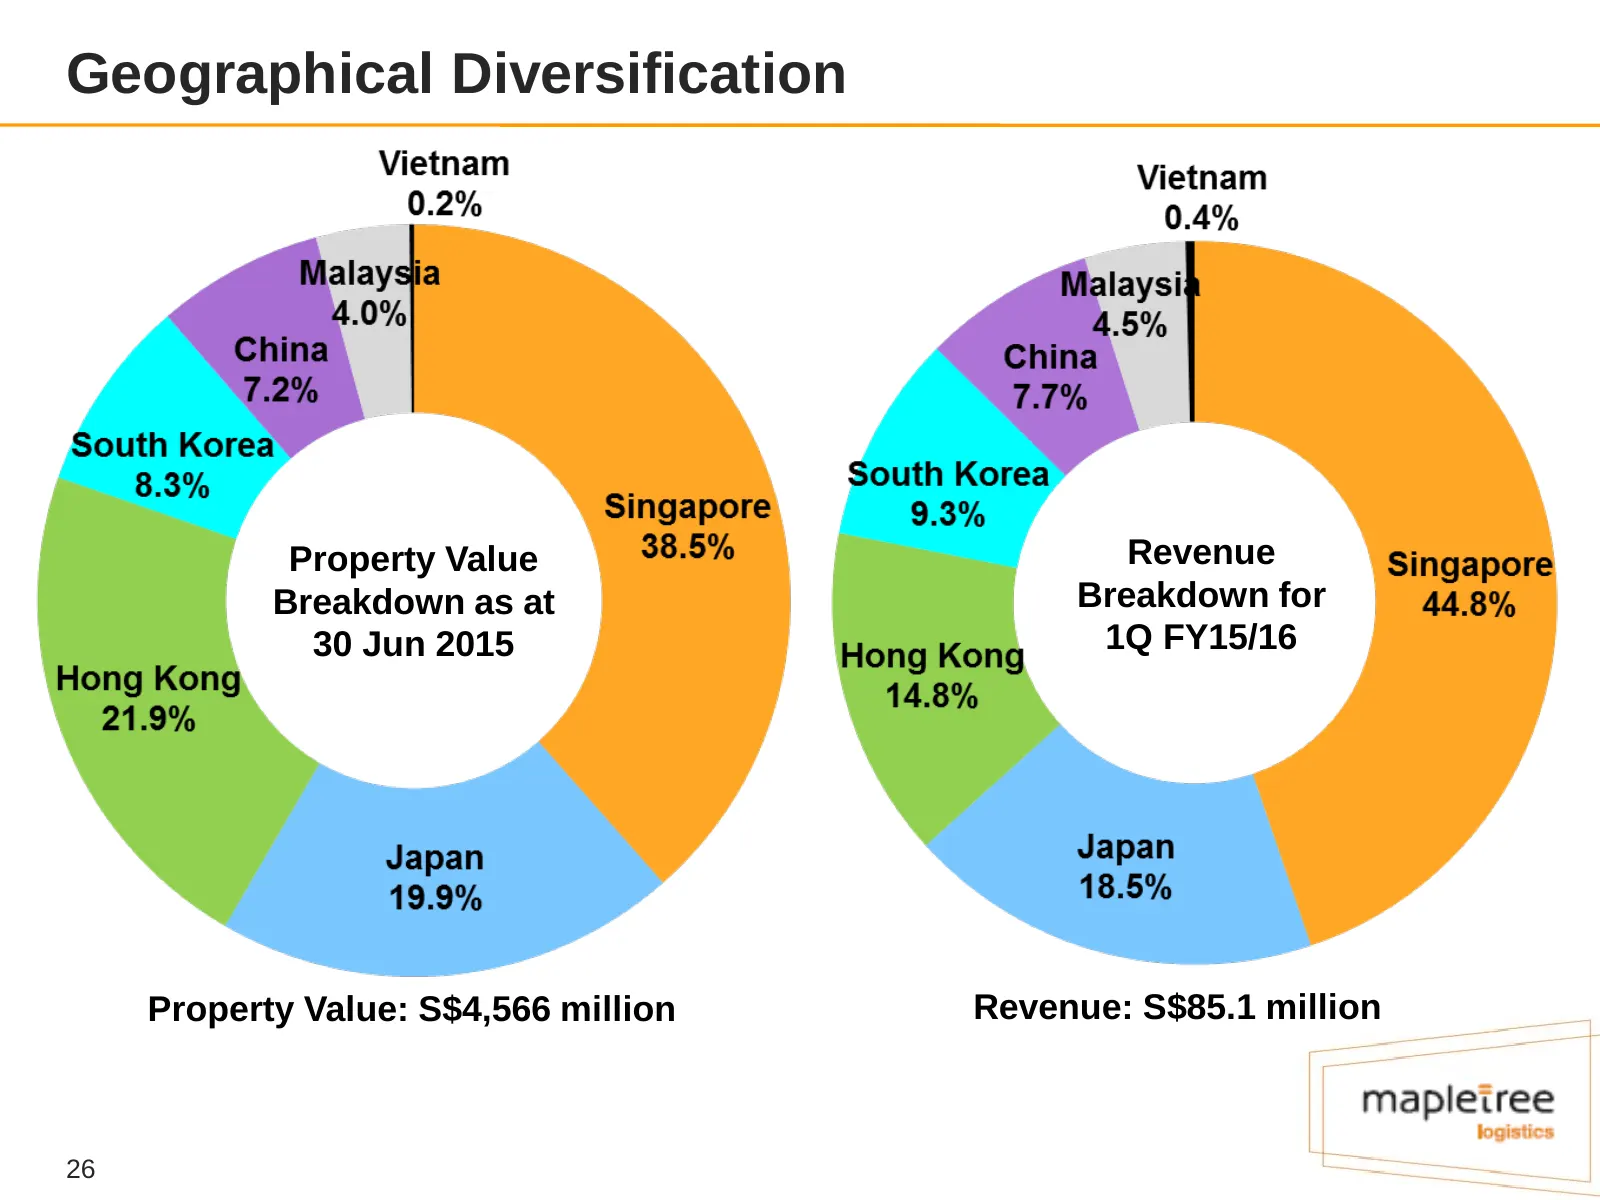
Slide 27: Geographical Diversification
Geographical Diversification Property Value Revenue Breakdown as at Breakdown for 30 Jun 2015 1Q FY15/16 Property Value: S$4,566 million Revenue: S$85.1 million 26
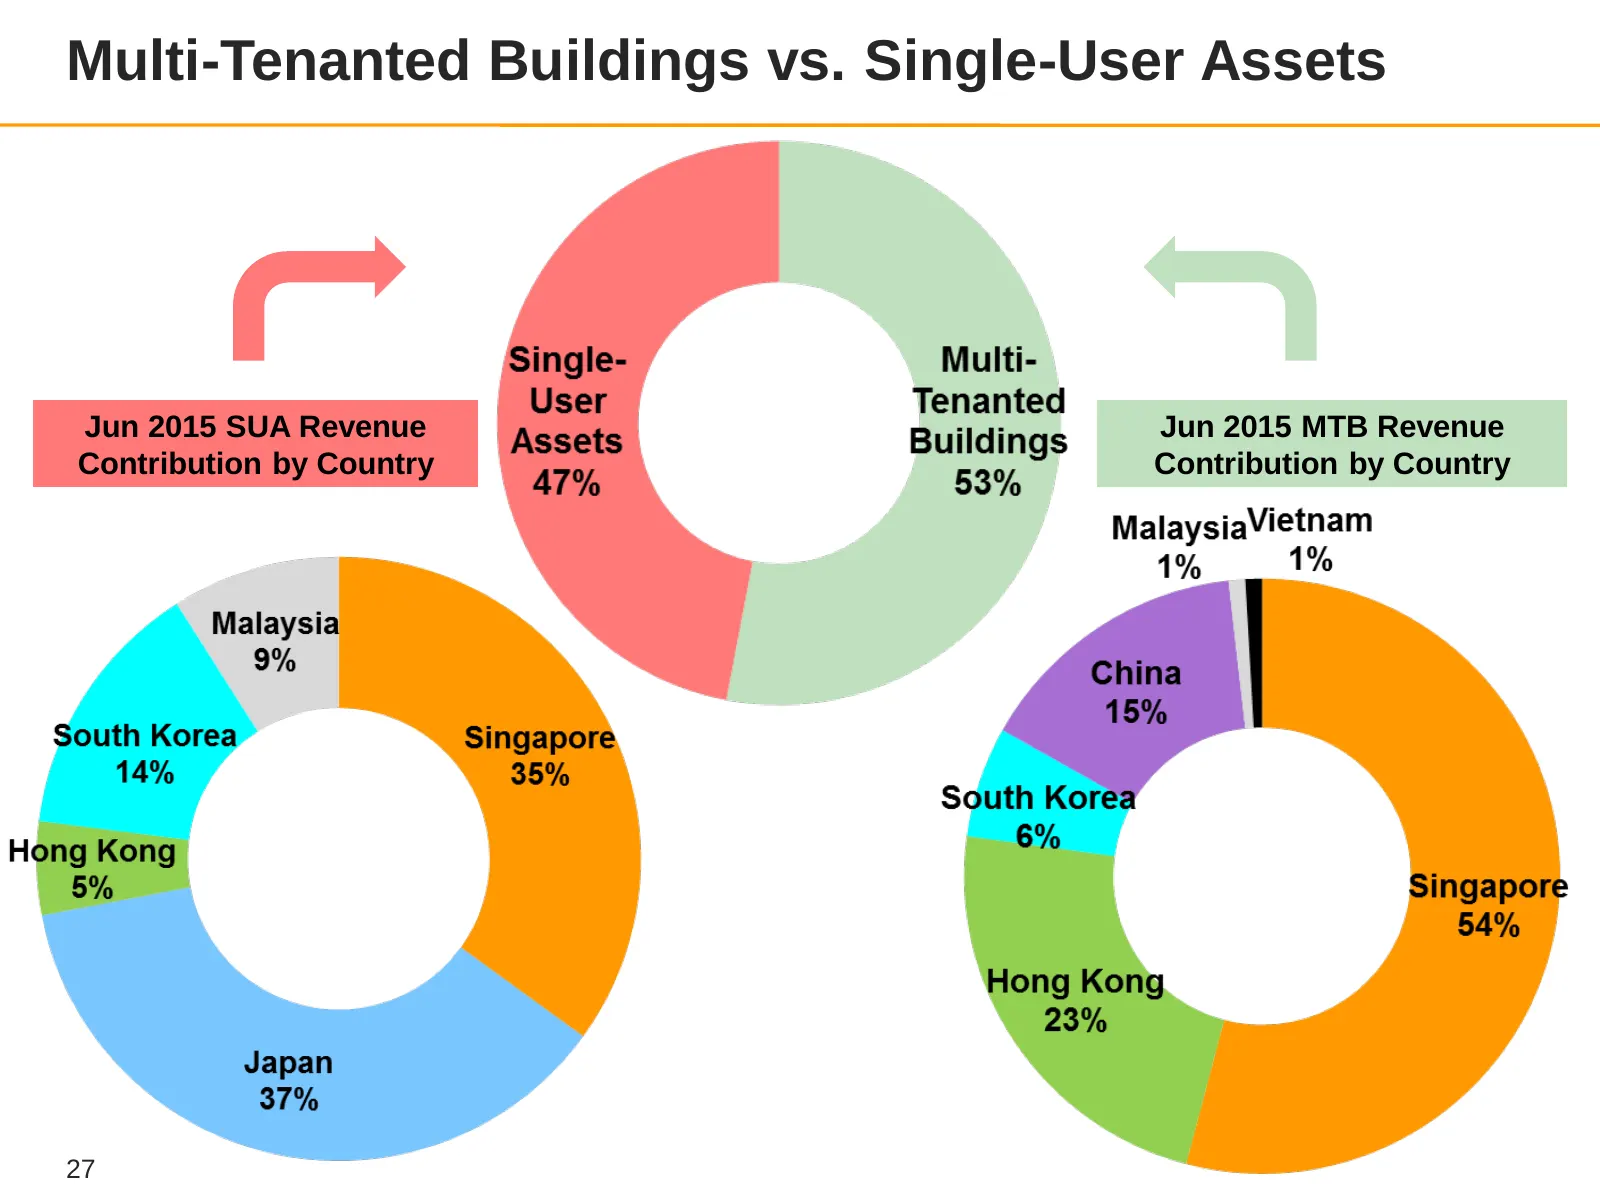
Slide 28: Multi-Tenanted Buildings vs. Single-User Assets
Multi-Tenanted Buildings vs. Single-User Assets Jun 2015 SUA Revenue Jun 2015 MTB Revenue Contribution by Country Contribution by Country 27
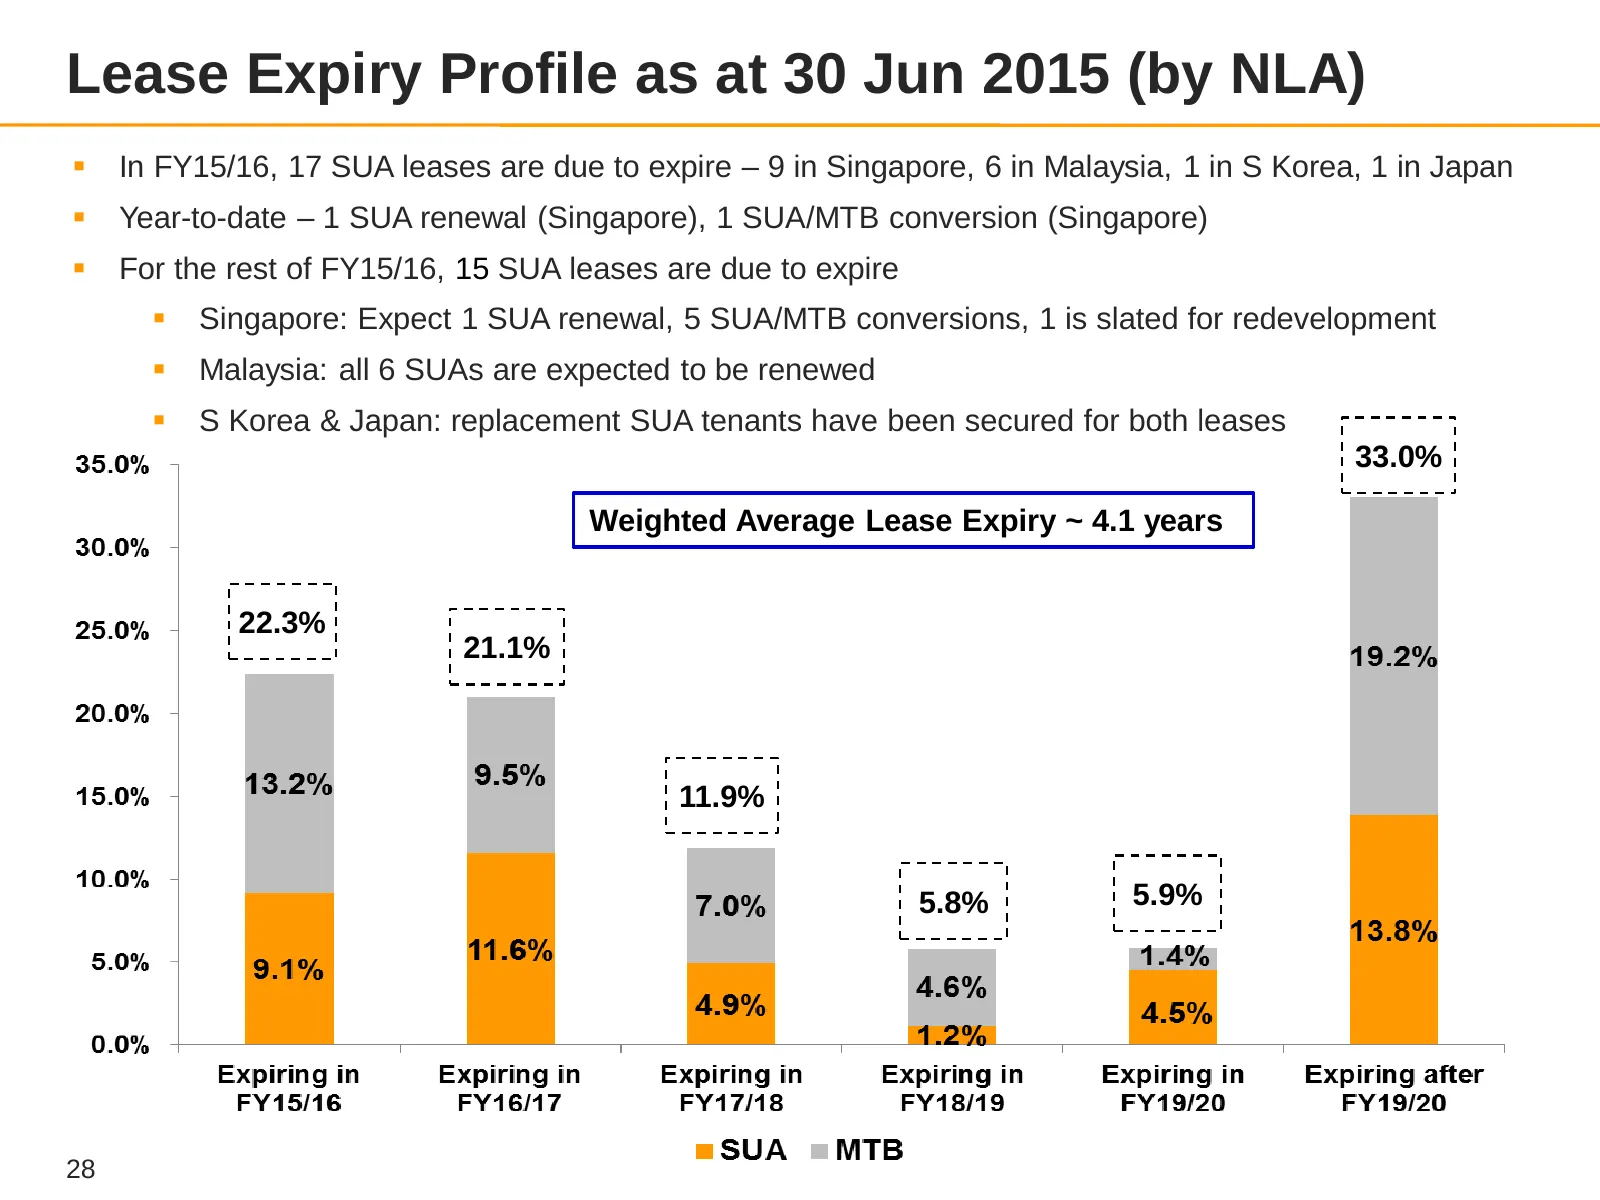
Slide 29: Lease Expiry Profile as at 30 Jun 2015 (by NLA)
Lease Expiry Profile as at 30 Jun 2015 (by NLA) In FY15/16, 17 SUA leases are due to expire – 9 in Singapore, 6 in Malaysia, 1 in S Korea, 1 in Japan Year-to-date – 1 SUA renewal (Singapore), 1 SUA/MTB conversion (Singapore) For the rest of FY15/16, 15 SUA leases are due to expire Singapore:
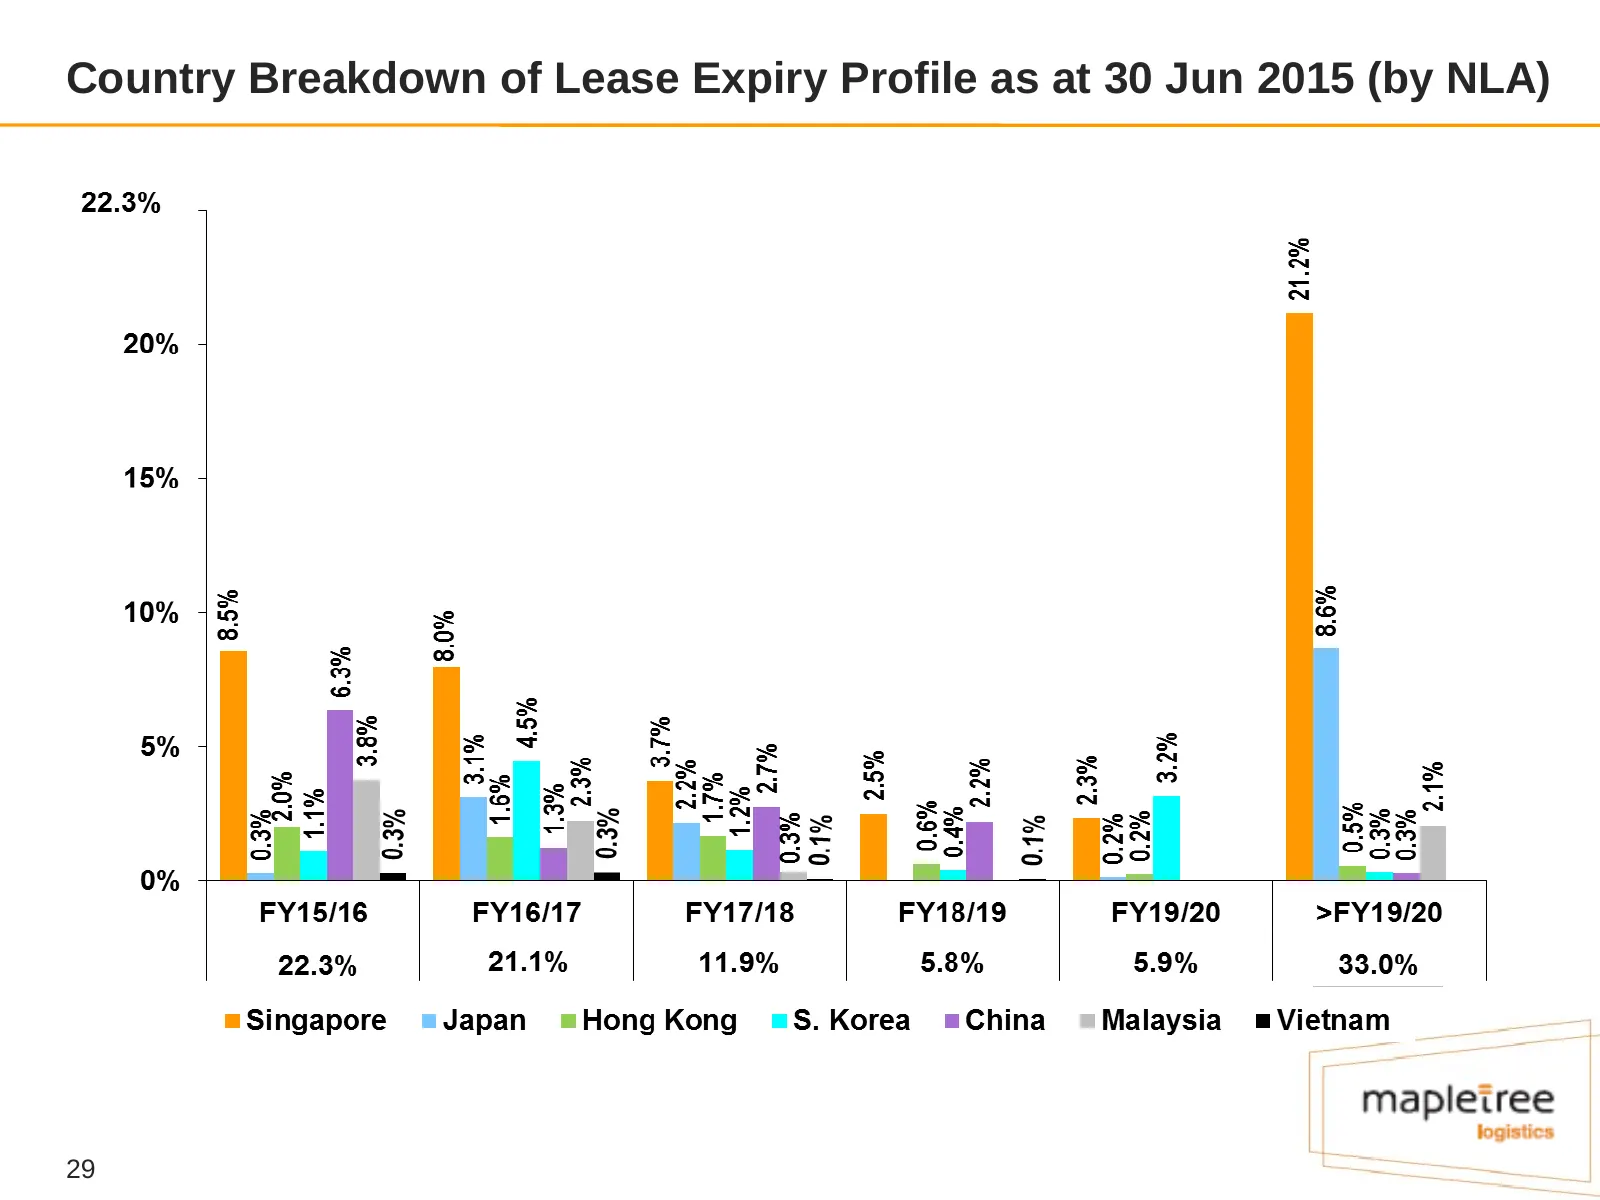
Slide 30: Country Breakdown of Lease Expiry Profile as at 30 Jun 2015
Country Breakdown of Lease Expiry Profile as at 30 Jun 2015 (by NLA) 29
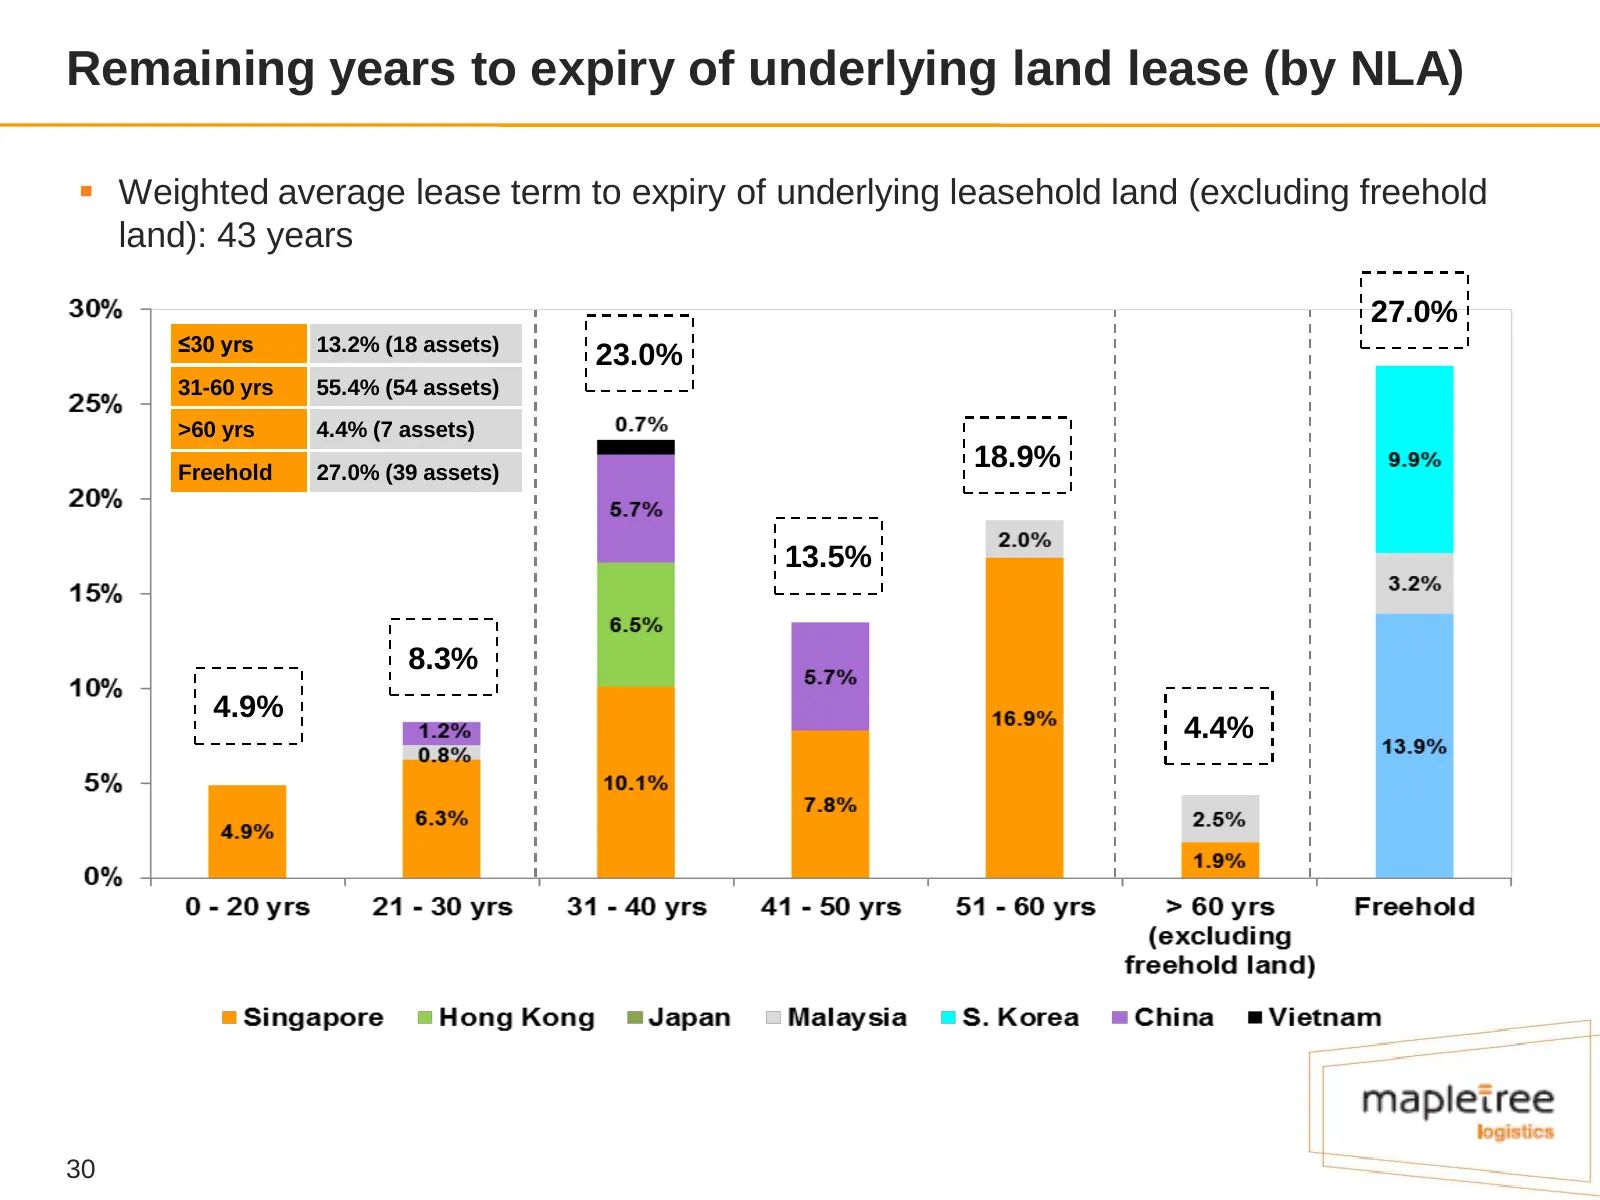
Slide 31: Remaining years to expiry of underlying land lease (by NLA)
Remaining years to expiry of underlying land lease (by NLA) Weighted average lease term to expiry of underlying leasehold land (excluding freehold land): 43 years 27.0% ≤30 yrs 13.2% (18 assets) 23.0% 31-60 yrs 55.4% (54 assets) >60 yrs 4.4% (7 assets) Freehold 27.0% (39 assets) 18.9% 13.5% 8.3% 4
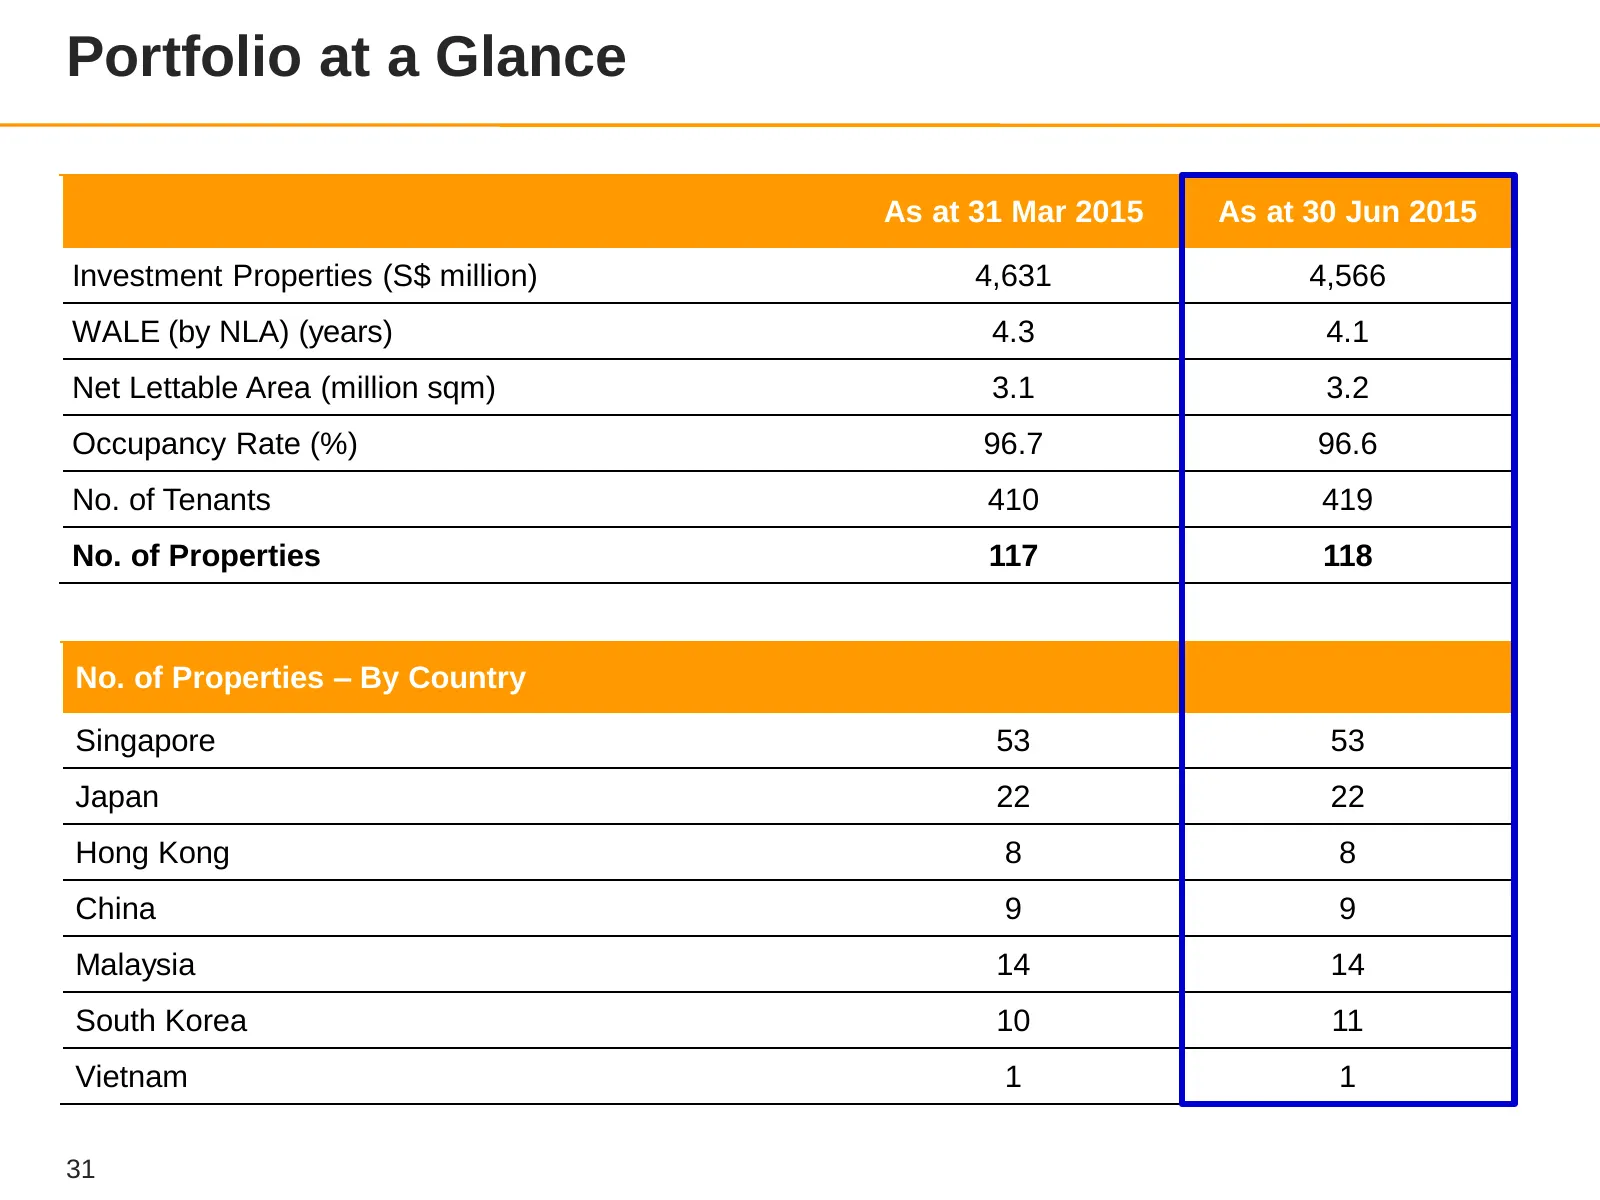
Slide 32: Portfolio at a Glance
Portfolio at a Glance As at 31 Mar 2015 As at 30 Jun 2015 Investment Properties (S$ million) 4,631 4,566 WALE (by NLA) (years) 4.3 4.1 Net Lettable Area (million sqm) 3.1 3.2 Occupancy Rate (%) 96.7 96.6 No. of Tenants 410 419 No. of Properties 117 118 No. of Properties – By Country Singapore 53 53
Slide 33: Outlook
Outlook
Slide 34: Outlook
Outlook Demand for logistics space in Asia has remained stable, although customers are generally cautious about capacity expansion Maintain focus on active asset & lease management − Manage transition of SUA conversions to MTBs − Short term pressure on portfolio occupancy and property expenses d
Slide 35: Thank You
Thank You
Slide 36: Appendix
Appendix
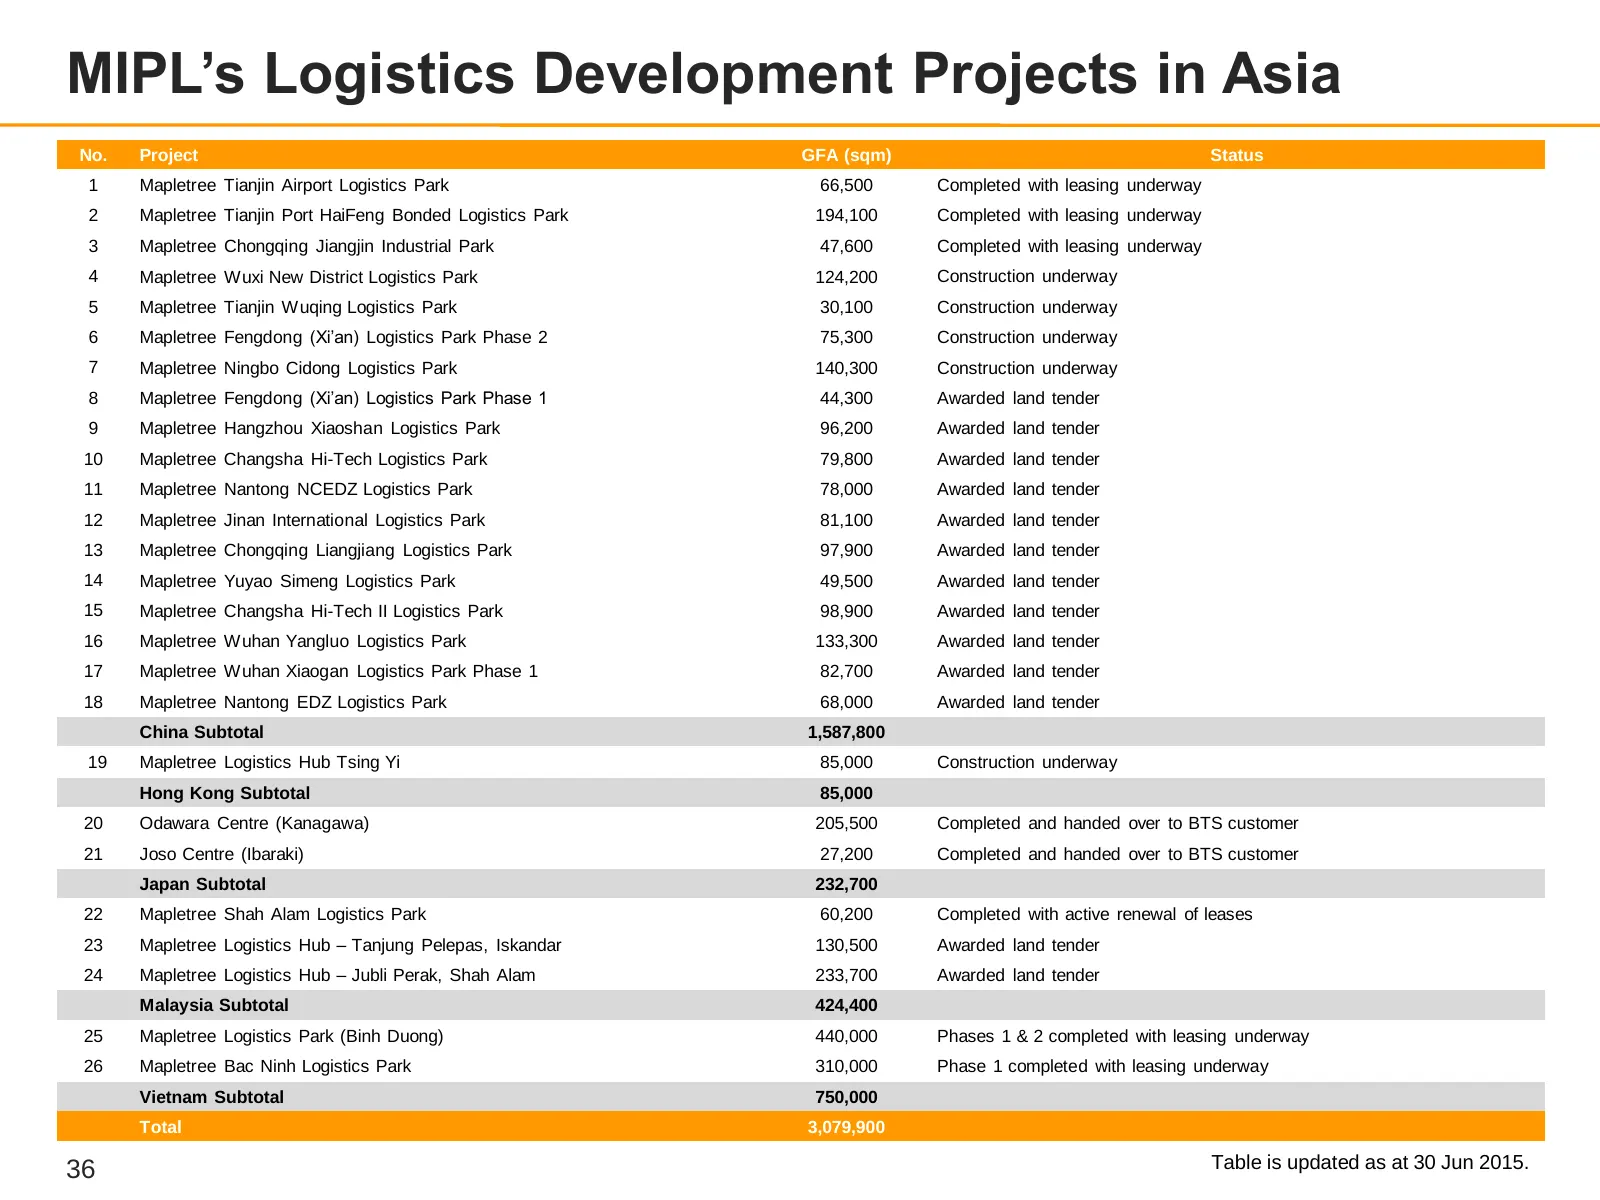
Slide 37: MIPL's Logistics Development Projects in Asia
MIPL’s Logistics Development Projects in Asia No. Project GFA (sqm) Status 1 Mapletree Tianjin Airport Logistics Park 66,500 Completed with leasing underway 2 Mapletree Tianjin Port HaiFeng Bonded Logistics Park 194,100 Completed with leasing underway 3 Mapletree Chongqing Jiangjin Industrial Park 4
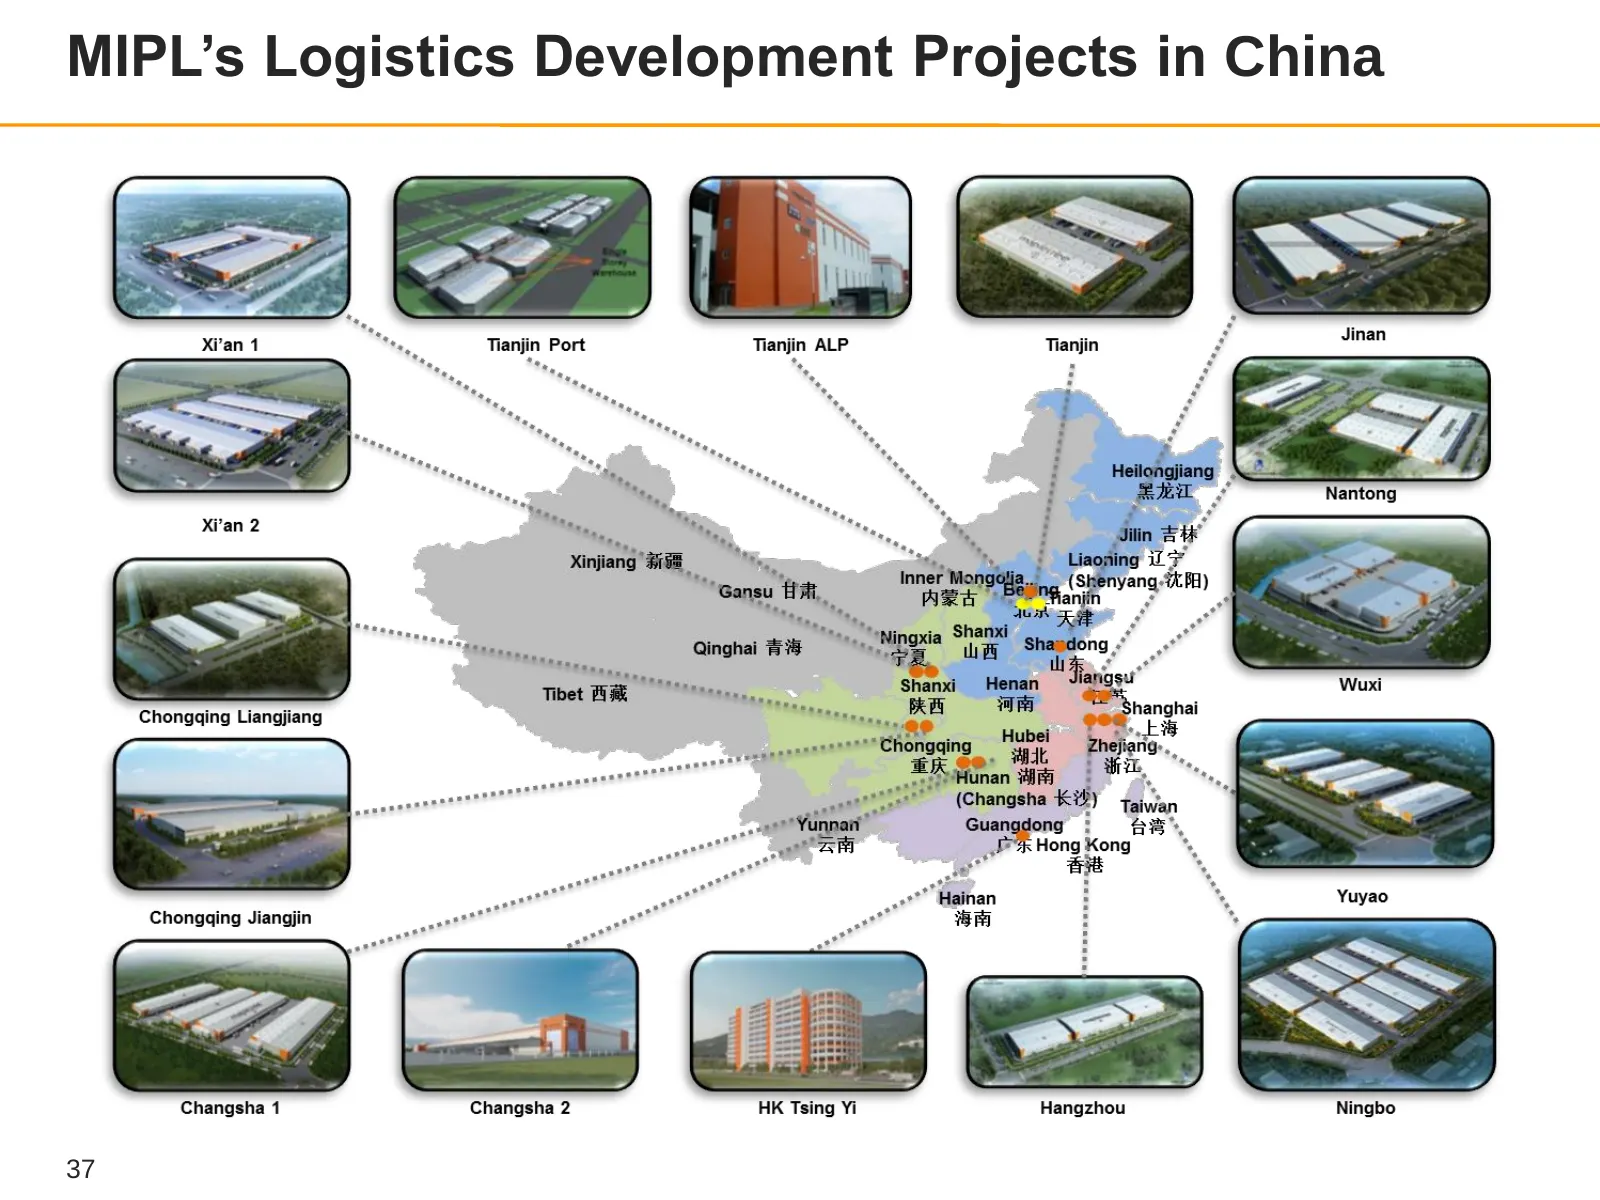
Slide 38: MIPL's Logistics Development Projects in China
MIPL’s Logistics Development Projects in China 37
Source: Internet Archive copy of investor.mapletreelogisticstrust.com
More decks from Mapletree Logistics Trust
 Shareholder Meeting (July 2023)24 slides · Jul 20, 2023
 Shareholder Meeting (July 2022)25 slides · Jul 18, 2022
 Merger or Acquisition (November 2021)48 slides · Nov 22, 2021
 Shareholder Meeting (November 2020)39 slides · Nov 23, 2020
 FY2015/16 Earnings Presentation42 slides · Apr 29, 2016
 H1 FY14/15 Earnings Presentation36 slides · Oct 20, 2014