Endeavour International — Canaccord Adams conference August 2007
34 slides from Endeavour International's conference presentation, Aug 9, 2007
Slide 1: "A New Course" Canaccord Adams August 2007
"A New Course" Canaccord Adams August 2007
Slide 2: Forward-looking statements and cautionary notes
This is an oral presentation which is accompanied by slides. Investors are urged to review our SEC filings. This presentation contains certain forward-looking statements regarding various oil and gas discoveries, oil and gas exploration, development and production activities, anticipated and potenti
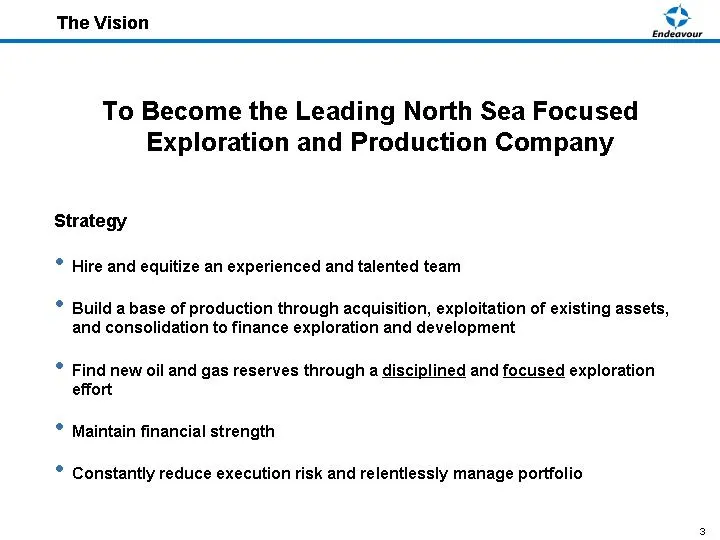
Slide 3: The Vision: Leading North Sea Focused E&P Company
To Become the Leading North Sea Focused Exploration and Production Company Strategy Hire and equitize an experienced and talented team Build a base of production through acquisition, exploitation of existing assets, and consolidation to finance exploration and development Find new oil and gas reserv
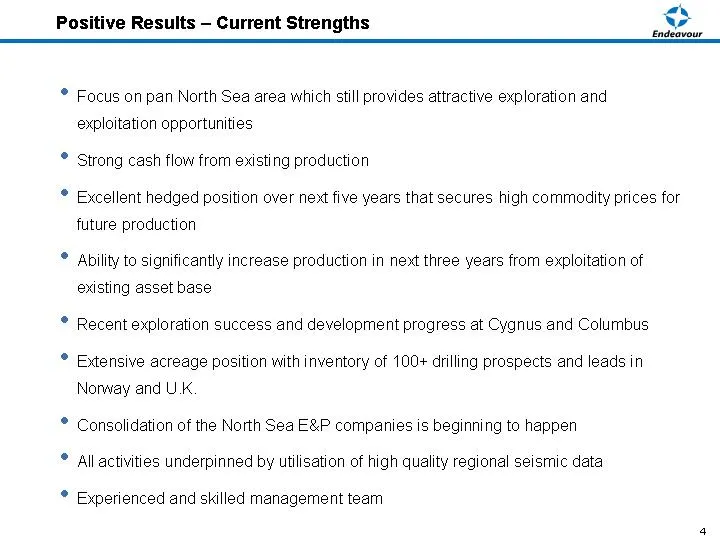
Slide 4: Positive Results - Current Strengths
Positive Results - Current Strengths Focus on pan North Sea area which still provides attractive exploration and exploitation opportunities Strong cash flow from existing production Excellent hedged position over next five years that secures high commodity prices for future production Ability to sig
Slide 5: Current Challenges
Current Challenges Disappointing exploration results in 2007 Continued high cost of exploration Slow down in exploration acreage turnover in UKCS Longer-than-expected development cycle times on discoveries
Slide 6: New Strategy
New Strategy Focus on developments and lower risk exploitation and exploration Cygnus Columbus Rochelle R-blocks Agat Reduce costs Replace exploration leadership, then restore disciplined and focused exploration effort Improve capital structure Continue to execute on existing assets
Slide 7: Comparative Analysis June 2007
Comparative Analysis June 2007
Slide 8: Net Asset Value
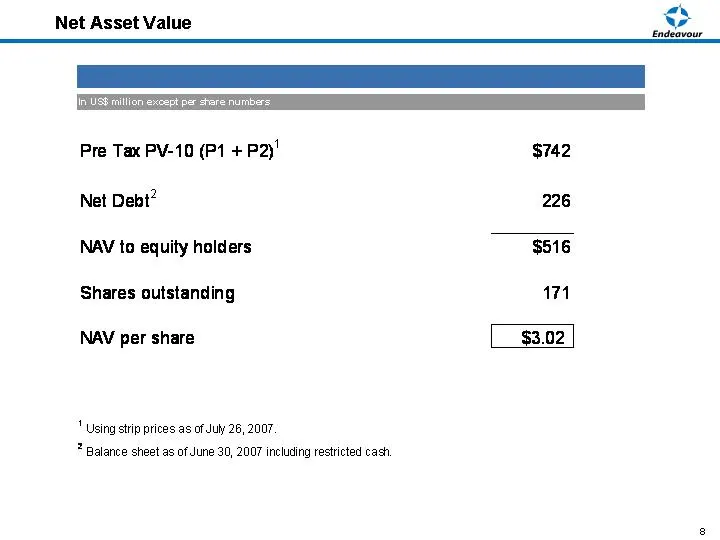
Net Asset Value Pre Tax PV-10 (P1 +P2)' Net Debt? NAV to equity holders Shares outstanding NAV per share " Using strip prices as of July 26, 2007. * Balance sheet as of June 30, 2007 incusing restricted cash 171 $3.02
Slide 9: Peer Comparisons
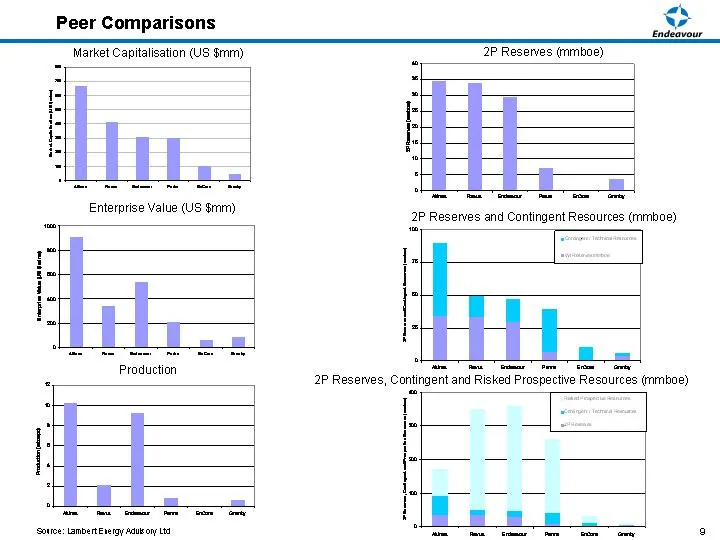
Peer Comparisons Peer Comparisons Market Capitalisation (US $mm) Enterprise Value (US $mm) Enterprise Value (US $mm) Production Production 2P Reserves (mmboe) 2P Reserves and Contingent Resources (mmboe) 2P Reserves and Contingent Resources (mmboe) 2P Reserves, Contingent and Risked Prospective Reso
Slide 10: Peer Comparison, continued
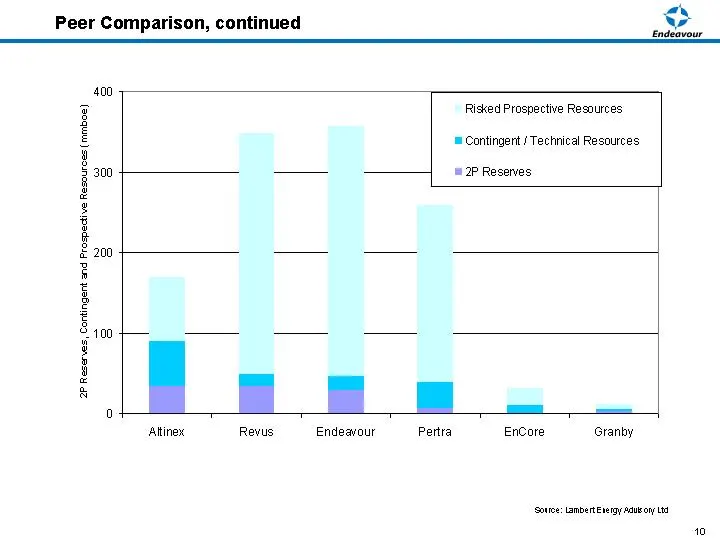
Peer Comparison, continued Peer Comparison, continued Source: Lambert Energy Advisory Ltd
Slide 11: Side by Side Peer Analysis
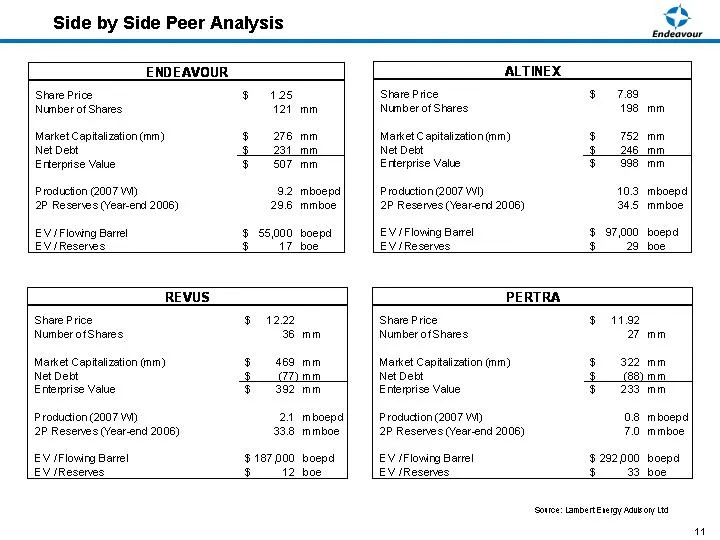
Side by Side Peer Analysis Source: Lambert Energy Advisory Ltd
Slide 12: On the Quest for Energy
moms On the Quest for Energy =
Slide 13: Company History
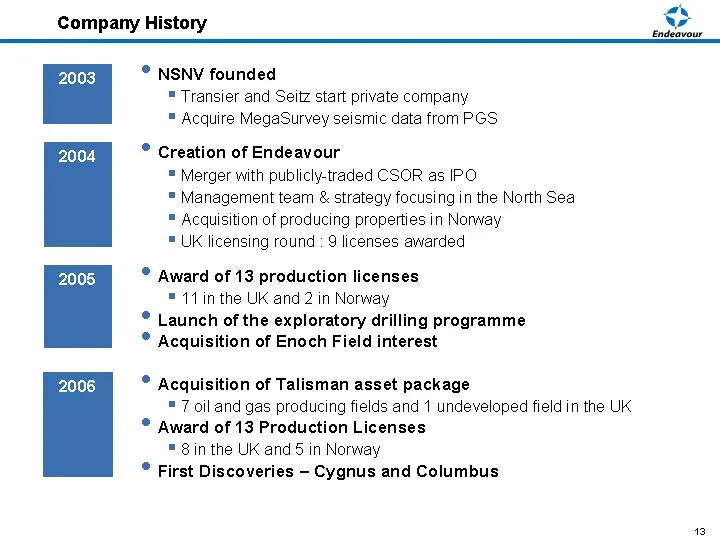
Company History NSNV founded Transier and Seitz start private company Acquire MegaSurvey seismic data from PGS Creation of Endeavour Merger with publicly-traded CSOR as IPO Management team & strategy focusing in the North Sea Acquisition of producing properties in Norway UK licensing round : 9 licen
Slide 14: Endeavour Today
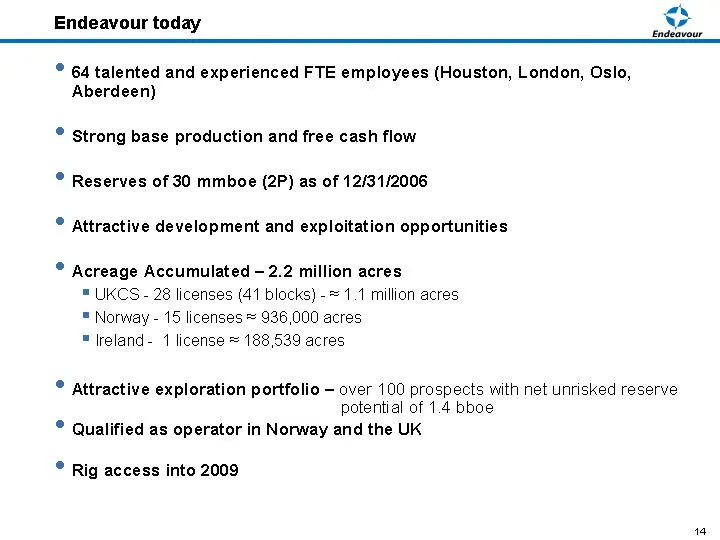
Endeavour today 64 talented and experienced FTE employees (Houston, London, Oslo, Aberdeen) Strong base production and free cash flow Reserves of 30 mmboe (2P) as of 12/31/2006 Attractive development and exploitation opportunities Acreage Accumulated - 2.2 million acres UKCS - 28 licenses (41 blocks
Slide 15: Deep Technical Team
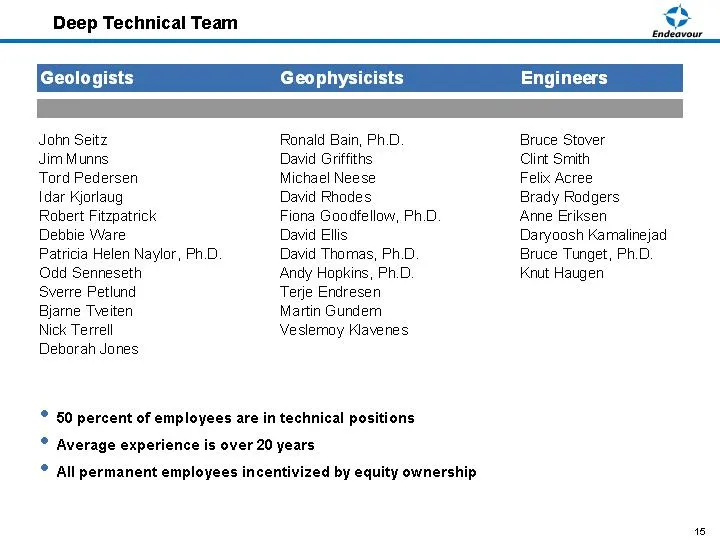
Deep Technical Team 50 percent of employees are in technical positions Average experience is over 20 years All permanent employees incentivized by equity ownership
Slide 16: Asset Overview
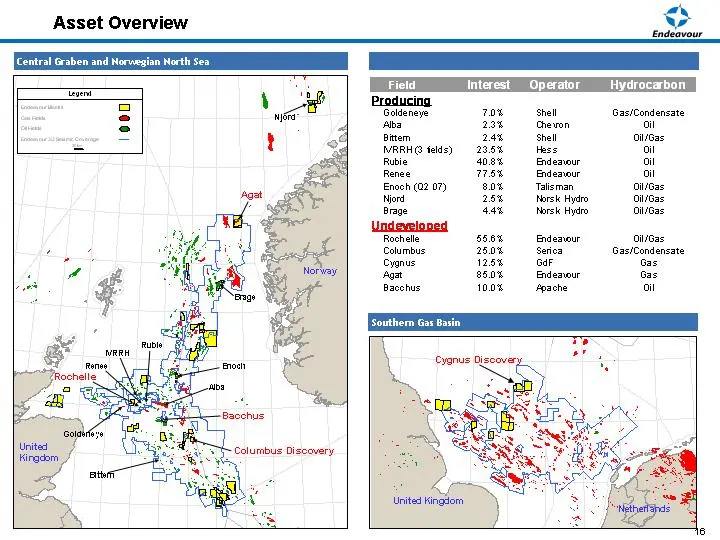
Asset Overview Central Graben and Norwegian North Sea Cygnus Discovery United Kingdom Netherlands Southern Gas Basin Renee IVRRH Rubie Alba Rochelle Goldeneye Enoch Brage Agat Njord Bittern Columbus Discovery United Kingdom Norway Bacchus
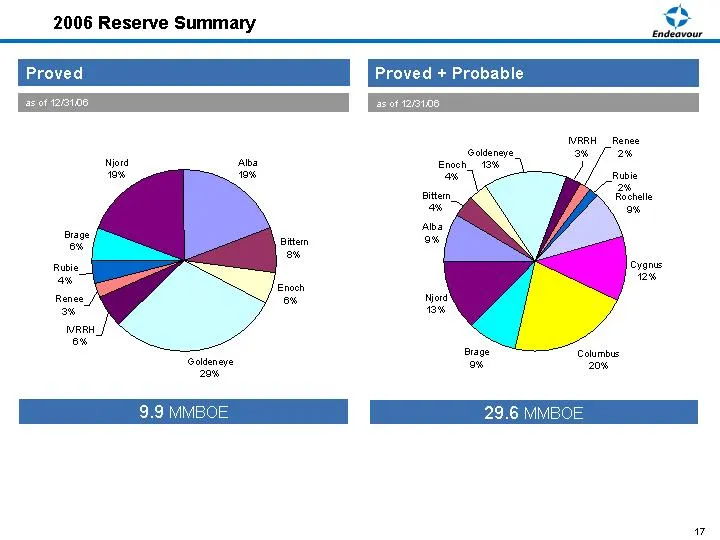
Slide 17: 2006 Reserve Summary
2006 Reserve Summary 9.9 MMBOE Proved Proved + Probable as of 12/31/06 as of 12/31/06 29.6 MMBOE
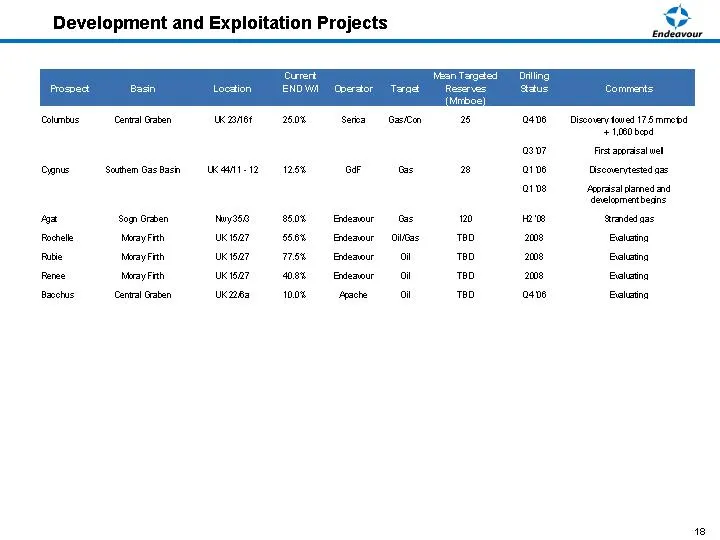
Slide 18: Development and Exploitation Projects
Development and Exploitation Projects
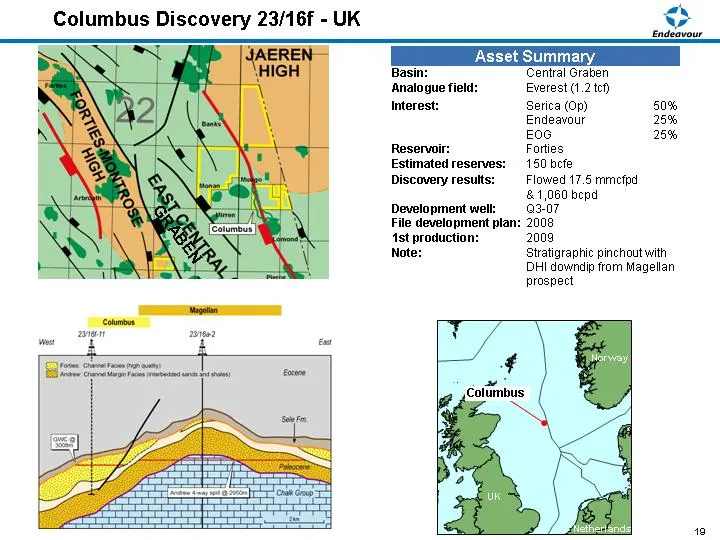
Slide 19: Columbus Discovery 23/16f - UK Asset Summary
Columbus Discovery 23/16f - UK Asset Summary UK Norway Netherlands Columbus Basin: Central Graben Analogue field: Everest (1.2 tcf) Interest: Serica (Op) 50% Endeavour 25% EOG 25% Reservoir: Forties Estimated reserves: 150 bcfe Discovery results: Flowed 17.5 mmcfpd & 1,060 bcpd Development well: Q3-
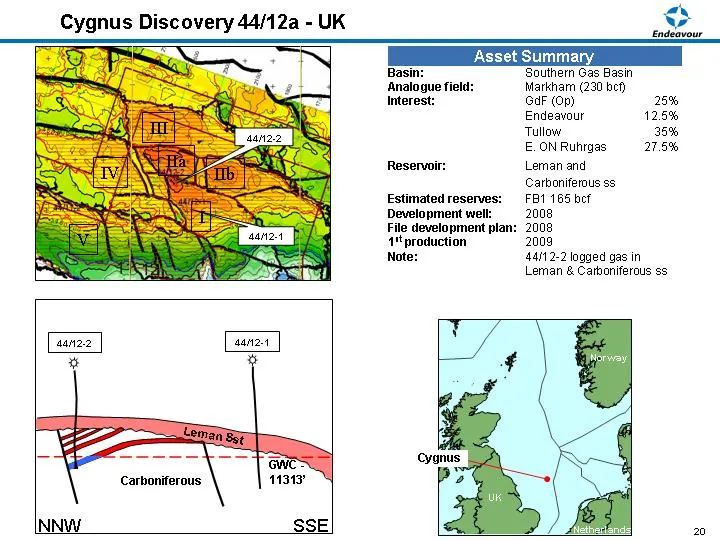
Slide 20: Cygnus Discovery 44/12a - UK Asset Summary
Cygnus Discovery 44/12a - UK Asset Summary UK Norway Netherlands Cygnus Basin: Southern Gas Basin Analogue field: Markham (230 bcf) Interest: GdF (Op) 25% Endeavour 12.5% Tullow 35% E. ON Ruhrgas 27.5% Reservoir: Leman and Carboniferous ss Estimated reserves: FB1 165 bcf Development well: 2008 File
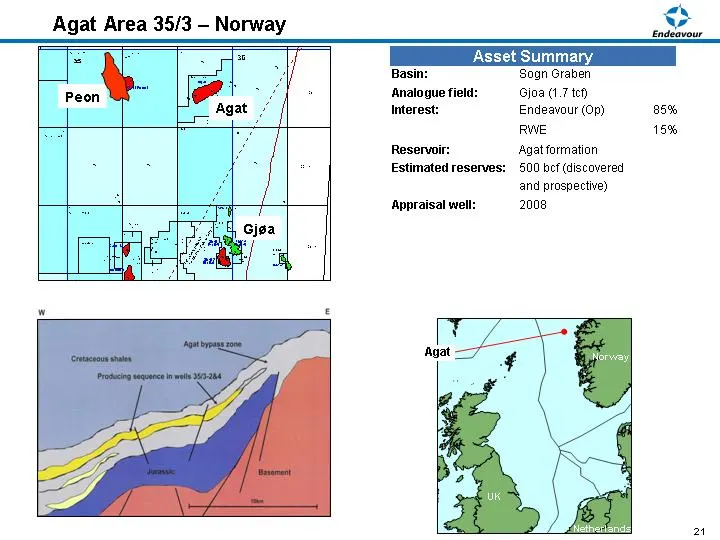
Slide 21: Agat Area 35/3 - Norway Asset Summary
Agat Area 35/3 - Norway Asset Summary UK Norway Netherlands UK Norway Netherlands Agat Basin: Sogn Graben Analogue field: Gjoa (1.7 tcf) Interest: Endeavour (Op) 85% RWE 15% Reservoir: Agat formation Estimated reserves: 500 bcf (discovered and prospective) Appraisal well: 2008 Peon Agat Gjoa
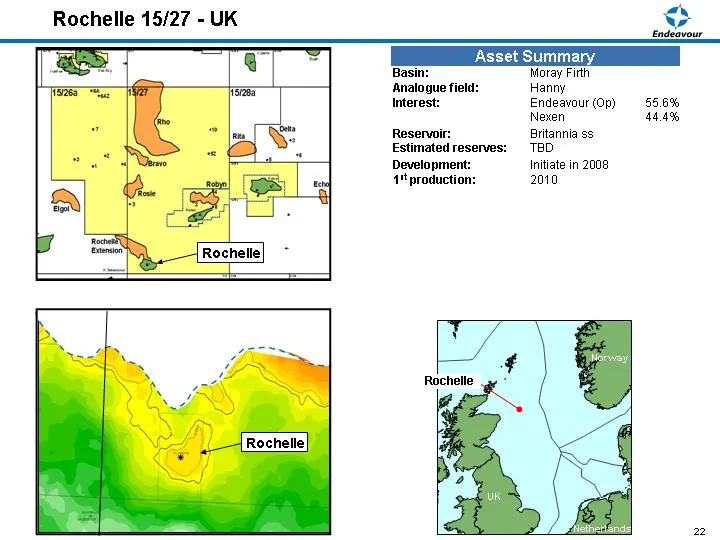
Slide 22: Rochelle 15/27 - UK Asset Summary
Rochelle 15/27 - UK Asset Summary UK Norway Netherlands Rochelle Basin: Moray Firth Analogue field: Hanny Interest: Endeavour (Op) 55.6% Nexen 44.4% Reservoir: Britannia ss Estimated reserves: TBD Development: Initiate in 2008 1st production: 2010 Rochelle Rochelle
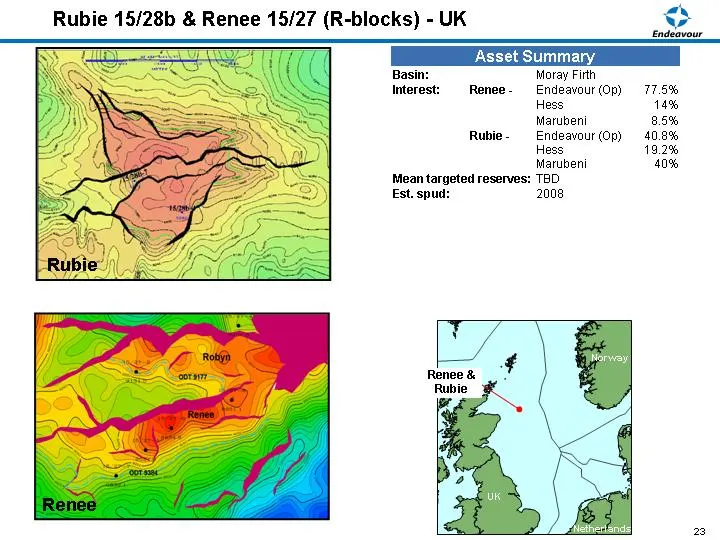
Slide 23: Rubie 15/28b & Renee 15/27 (R-blocks) - UK Asset Summary
Rubie 15/28b & Renee 15/27 (R-blocks) - UK Asset Summary UK Norway Netherlands Renee & Rubie Basin: Moray Firth Interest: Renee - Endeavour (Op) 77.5% Hess 14% Marubeni 8.5% Rubie - Endeavour (Op) 40.8% Hess 19.2% Marubeni 40% Mean targeted reserves: TBD Est. spud: 2008 Rubie Renee
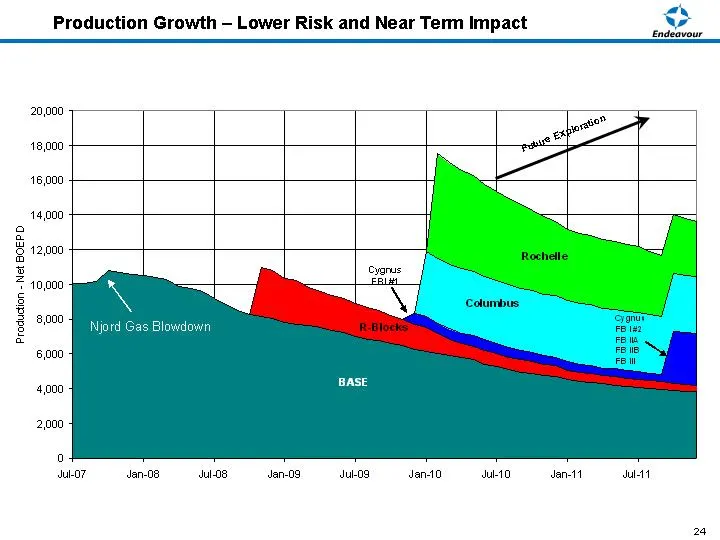
Slide 24: Production Growth - Lower Risk and Near Term Impact; Future Exploration
Production Growth - Lower Risk and Near Term Impact Future Exploration
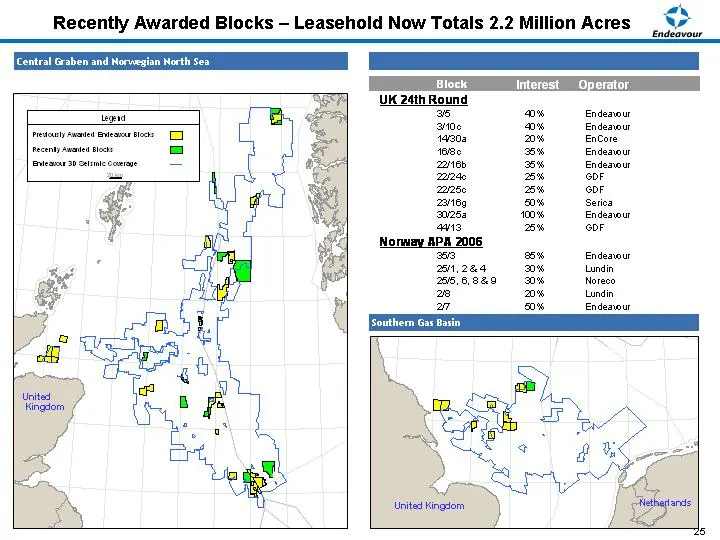
Slide 25: Recently Awarded Blocks - Leasehold Now Totals 2.2 Million Acres
Recently Awarded Blocks - Leasehold Now Totals 2.2 Million Acres Central Graben and Norwegian North Sea United Kingdom Netherlands Southern Gas Basin United Kingdom
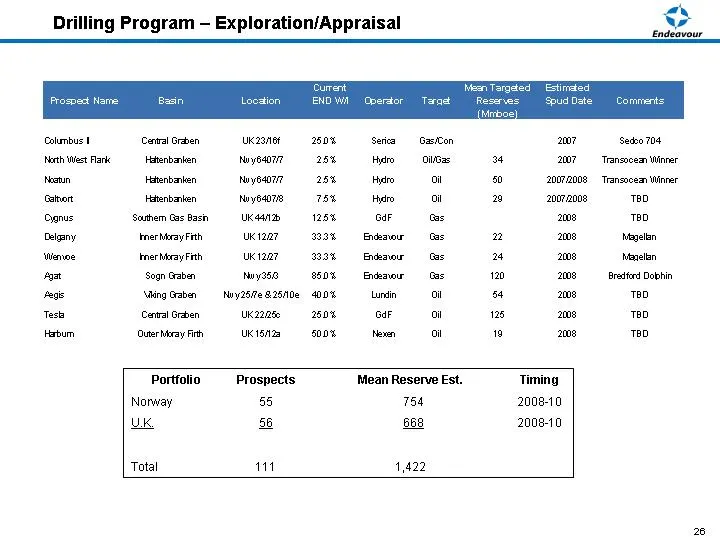
Slide 26: Drilling Program - Exploration/Appraisal Portfolio
Drilling Program - Exploration/Appraisal Portfolio Prospects Mean Reserve Est. Timing Norway 55 754 2008-10 U.K. 56 668 2008-10 Total 111 1,422
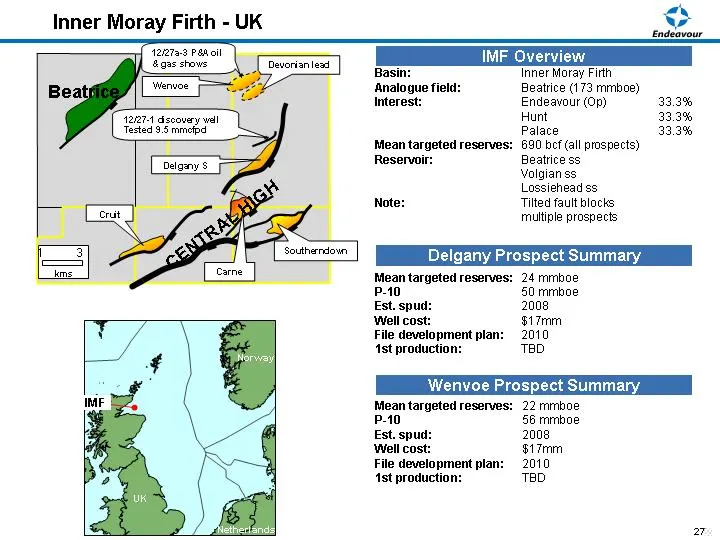
Slide 27: Inner Moray Firth - UK Prospect Summary
Inner Moray Firth - UK Mean targeted reserves: 22 mmboe P-10 56 mmboe Est. spud: 2008 Well cost: $17mm File development plan: 2010 1st production: TBD Basin: Inner Moray Firth Analogue field: Beatrice (173 mmboe) Interest: Endeavour (Op) 33.3% Hunt 33.3% Palace 33.3% Mean targeted reserves: 690 bcf
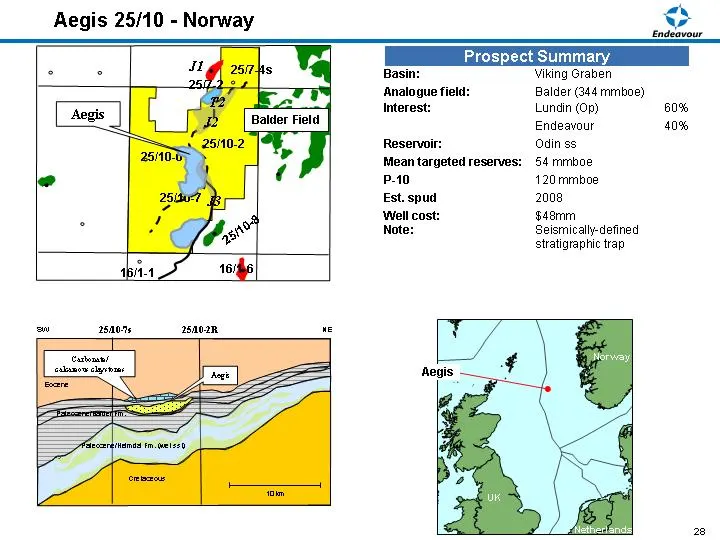
Slide 28: Aegis 25/10 - Norway Prospect Summary
Aegis 25/10 - Norway Prospect Summary UK Norway Netherlands Aegis Basin: Viking Graben Analogue field: Balder (344 mmboe) Interest: Lundin (Op) 60% Endeavour 40% Reservoir: Odin ss Mean targeted reserves: 54 mmboe P-10 120 mmboe Est. spud 2008 Well cost: $48mm Note: Seismically-defined stratigraphic
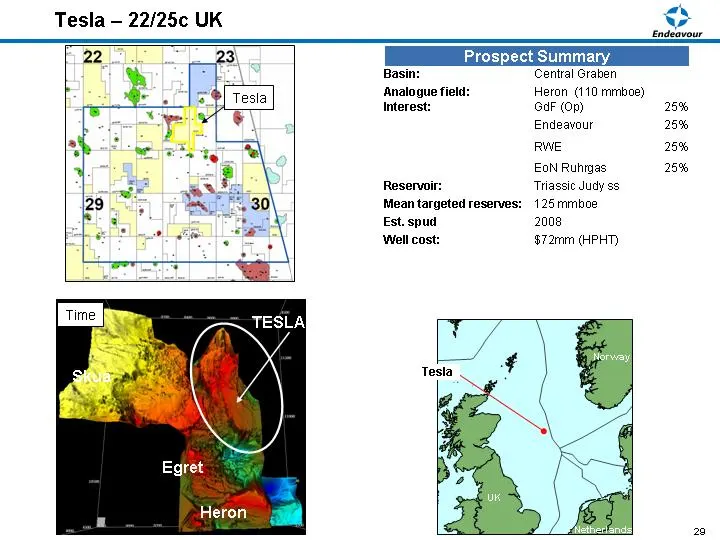
Slide 29: Tesla - 22/25c UK Prospect Summary
Tesla - 22/25c UK Prospect Summary UK Norway Netherlands Tesla Basin: Central Graben Analogue field: Heron (110 mmboe) Interest: GdF (Op) 25% Endeavour 25% RWE 25% EoN Ruhrgas 25% Reservoir: Triassic Judy ss Mean targeted reserves: 125 mmboe Est. spud 2008 Well cost: $72mm (HPHT) Tesla Tesla Skua Eg
Slide 30: Endeavour - On the Quest for Energy
q - Endeavour moms On the Quest for Energy =
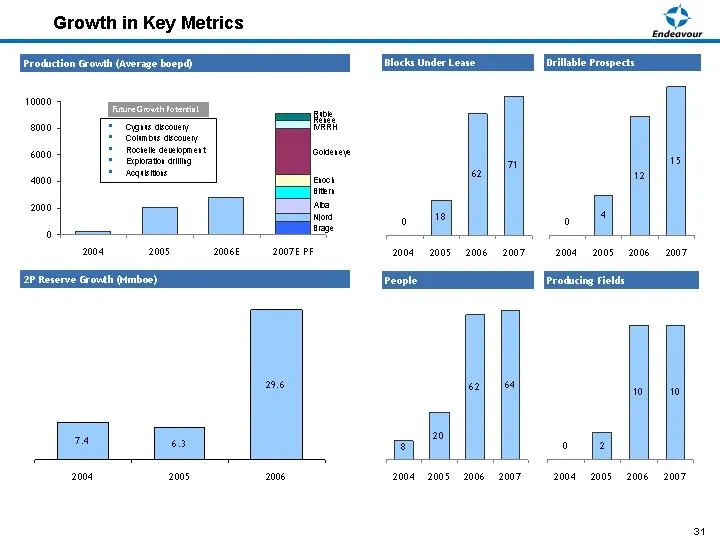
Slide 31: Growth in Key Metrics
Growth in Key Metrics Brage Njord Alba Bittern Enoch Goldeneye IVRRH Renee Rubie 2004 249 2005 2071 2006E 2790 2007E PF 989 587 1145 939 862 3448 587 39 503 Production Growth (Average boepd) Rubie Renee IVRRH Goldeneye Enoch Bittern Alba Blocks under lease 2004 0 2005 18 2006 62 2007 71 Drilling pro
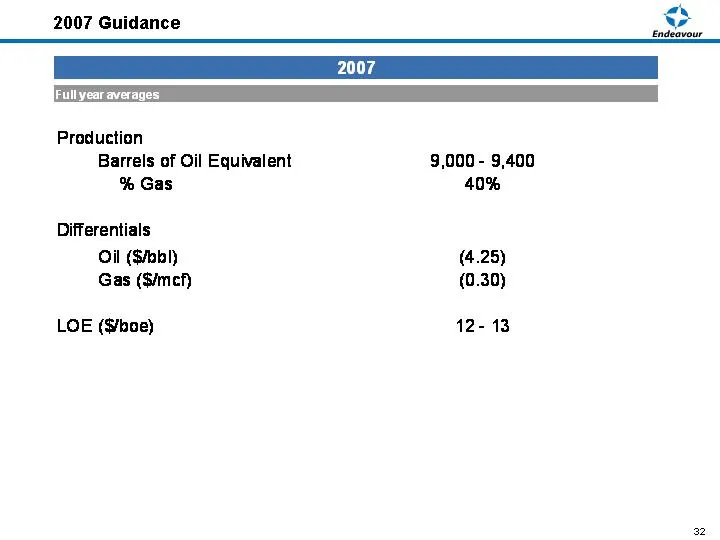
Slide 32: 2007 Guidance
2007 Guidance > 2007 [Full year averages Full year averages Production Barrels of Oil Equivalent 9,000 - 9,400 % Gas 40% Differentials Oil (S/obI) (4.25) Gas (S/mef) (0.30) LOE (#boe) 12-13 32
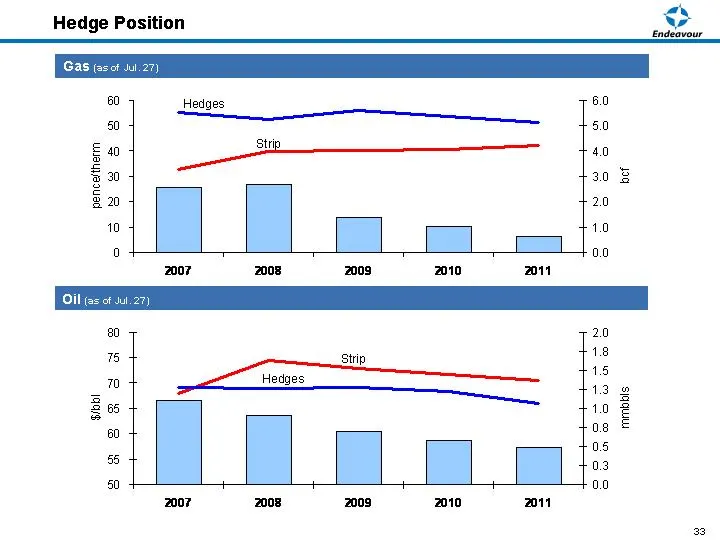
Slide 33: Hedge Position
Hedge Position Gas (as of Jul. 27) Oil (as of Jul. 27)
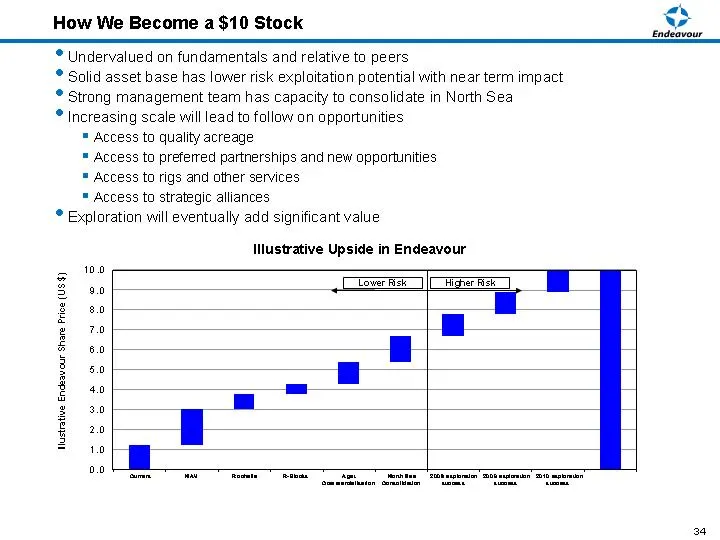
Slide 34: How We Become a $10 Stock
How We Become a $10 Stock Illustrative Upside in Endeavour Undervalued on fundamentals and relative to peers Solid asset base has lower risk exploitation potential with near term impact Strong management team has capacity to consolidate in North Sea Increasing scale will lead to follow on opportunit
Source: SEC EDGAR · 8-K filed Aug 9, 2007
More decks from Endeavour International Corp
 Presentation (May 2015)5 slides · May 7, 2015
 Corporate Update (February 2015)23 slides · Feb 27, 2015
 Debt Investor Presentation (October 2014)16 slides · Oct 14, 2014
 Q2 2014 Earnings Presentation12 slides · Aug 5, 2014
 Proxy Contest (May 2014)45 slides · May 8, 2014
 Q1 2014 Earnings Presentation12 slides · May 7, 2014