Vanguard Natural Resources LLC
Vanguard Natural Resources — Investor Presentation (October 2016)
75 slides from Vanguard Natural Resources's investor presentation, Oct 7, 2016
Slide 1: Management Presentation October 7, 2016
Management Presentation October 7, 2016
Slide 2: Forward Looking Statements
36 32 87 89 89 89 83 141 213 168 177 182 Statements made by representatives of Vanguard Natural Resources, LLC during the course of this presentation that are not historical facts are forward looking statements. These statements are based on certain assumptions and expectations made by the Company w
Slide 3: Agenda
36 32 87 89 89 89 83 141 213 168 177 182 Company Overview Asset and Operations Overview Northern Division Overview Pinedale Overview & Upside Piceance Overview & Upside East Central Division Overview Arkoma Woodford Overview & Upside Southern Division Overview East Haynesville Fiel
Slide 4: Company Overview
36 32 87 89 89 89 83 141 213 168 177 182 Company Overview 4
Slide 5: Management Team
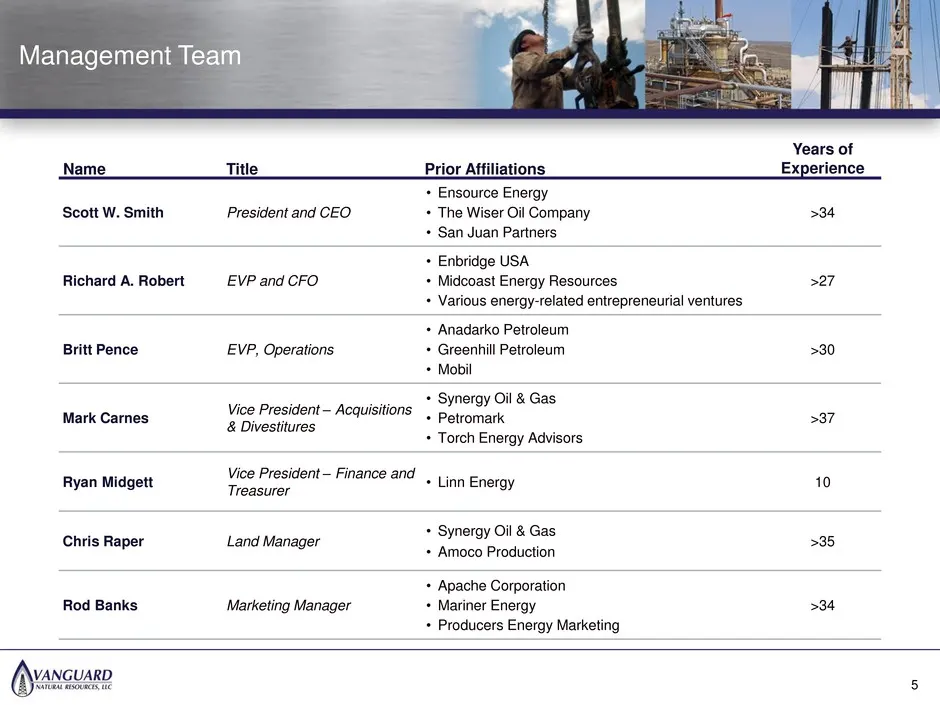
36 32 87 89 89 89 83 141 213 168 177 182 Name Title Prior Affiliations Years of Experience Scott W. Smith President and CEO • Ensource Energy • The Wiser Oil Company • San Juan Partners >34 Richard A. Robert EVP and CFO • Enbridge USA • Midcoast Energy Resources • Various energy-related entrepreneur
Slide 6: Company Highlights
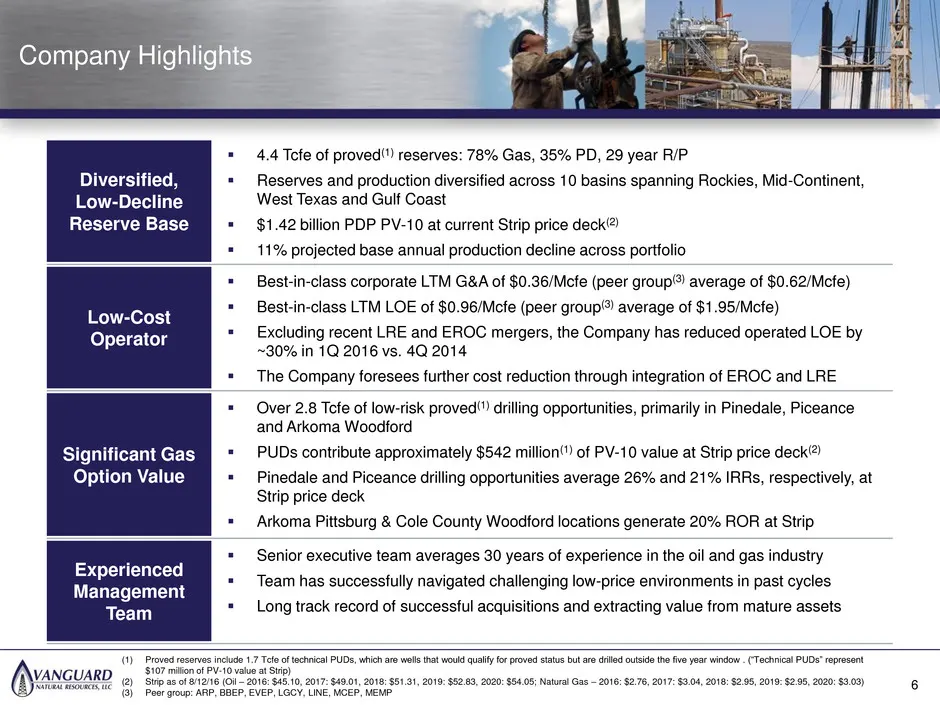
36 32 87 89 89 89 83 141 213 168 177 182 Company Highlights Low-Cost Operator Diversified, Low-Decline Reserve Base Experienced Management Team Significant Gas Option Value 4.4 Tcfe of proved(1) reserves: 78% Gas, 35% PD, 29 year R/P Reserves and production diversified across 10 basins spanning
Slide 7: Asset Profile
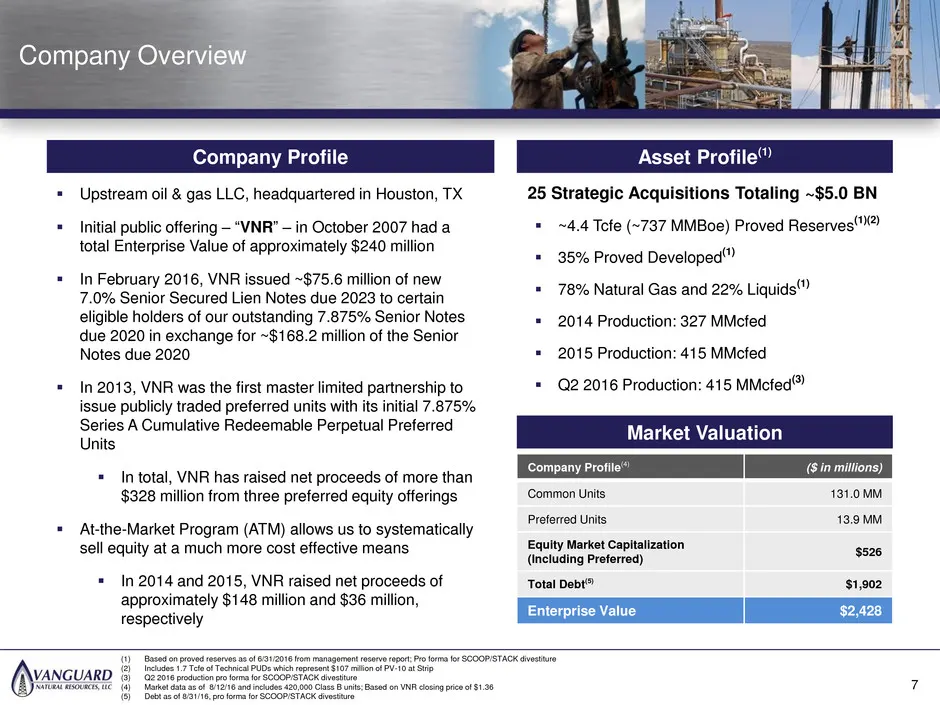
36 32 87 89 89 89 83 141 213 168 177 182 Asset Profile(1) 7 Upstream oil & gas LLC, headquartered in Houston, TX Initial public offering – “VNR” – in October 2007 had a total Enterprise Value of approximately $240 million In February 2016, VNR issued ~$75.6 million of new 7.0% Senior Secured L
Slide 8: Organizational Structure
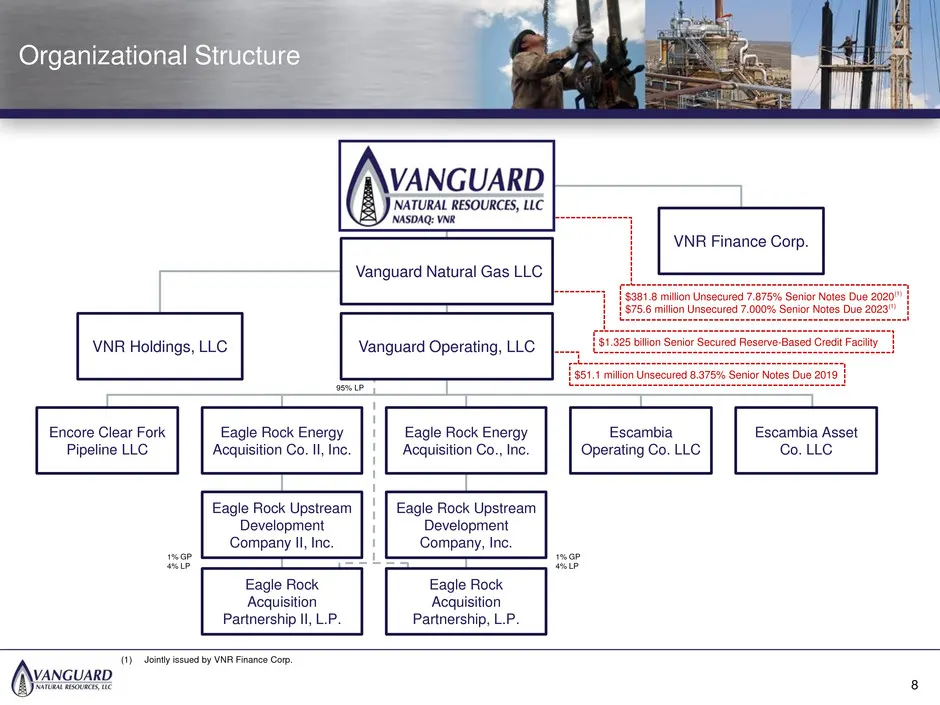
36 32 87 89 89 89 83 141 213 168 177 182 Organizational Structure Vanguard Natural Gas LLC VNR Finance Corp. Vanguard Operating, LLC VNR Holdings, LLC Encore Clear Fork Pipeline LLC Eagle Rock Energy Acquisition Co. II, Inc. Eagle Rock Upstream Development Company II, Inc. Eagle Rock Acquisition Par
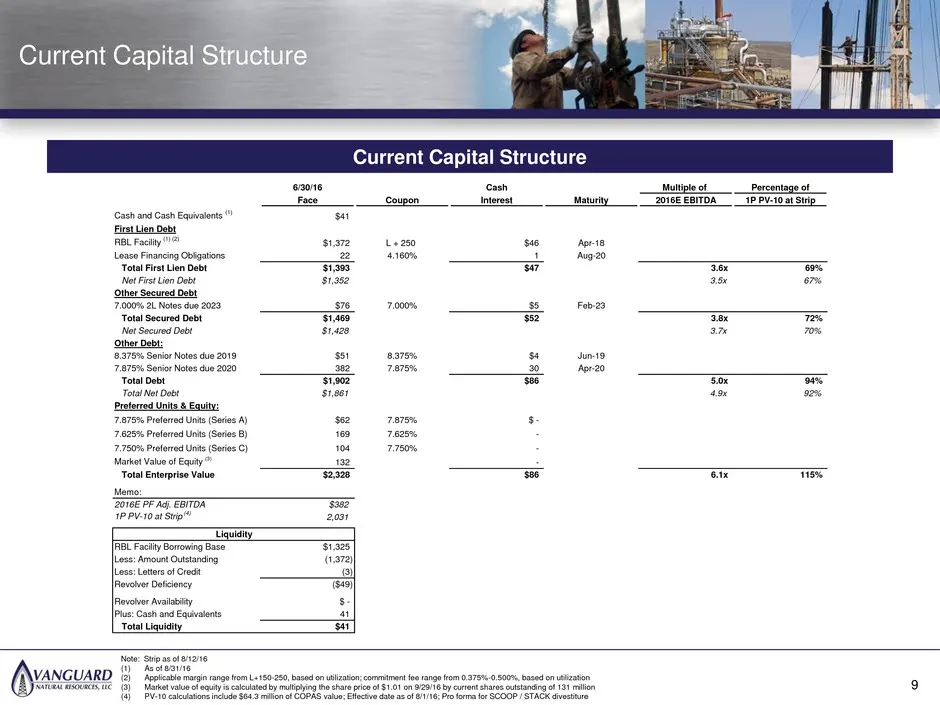
Slide 9: Current Capital Structure
36 32 87 89 89 89 83 141 213 168 177 182 Current Capital Structure Current Capital Structure 1 9 Note: Strip as of 8/12/16 (1) As of 8/31/16 (2) Applicable margin range from L+150-250, based on utilization; commitment fee range from 0.375%-0.500%, based on utilization (3) Market value of equity is c
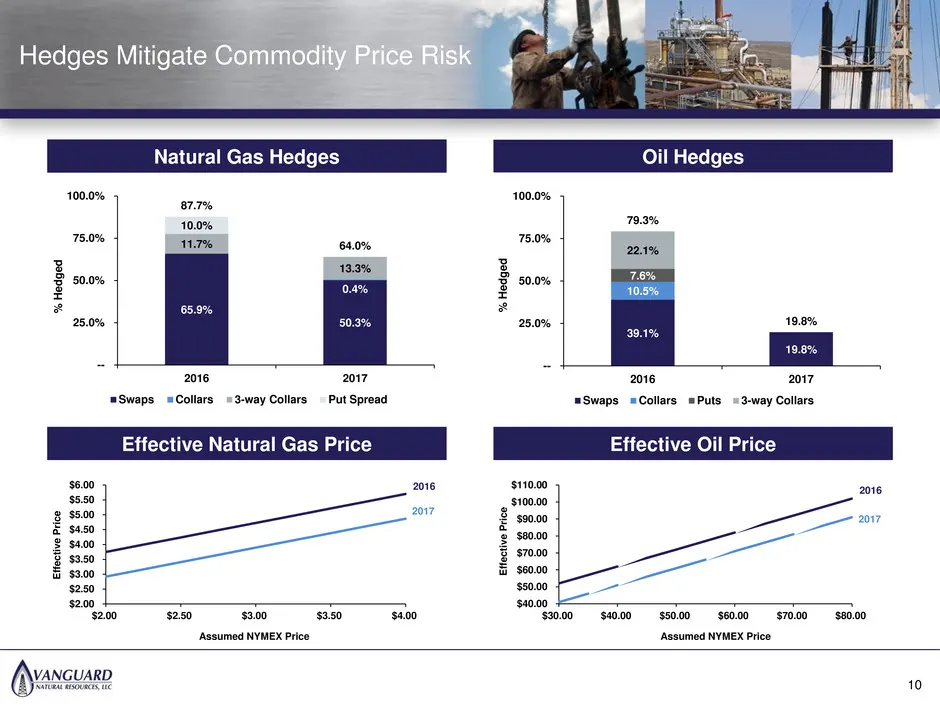
Slide 10: Hedges Mitigate Commodity Price Risk
36 32 87 89 89 89 83 141 213 168 177 182 Hedges Mitigate Commodity Price Risk Oil Hedges Natural Gas Hedges 39.1% 19.8% 10.5% 7.6% 22.1% 79.3% 19.8% -- 25.0% 50.0% 75.0% 100.0% 2016 2017 Swaps Collars Puts 3-way Collars % Hed ge d Effective Oil Price Effective Natural Gas Price 10 $2.00 $2.50 $3.00
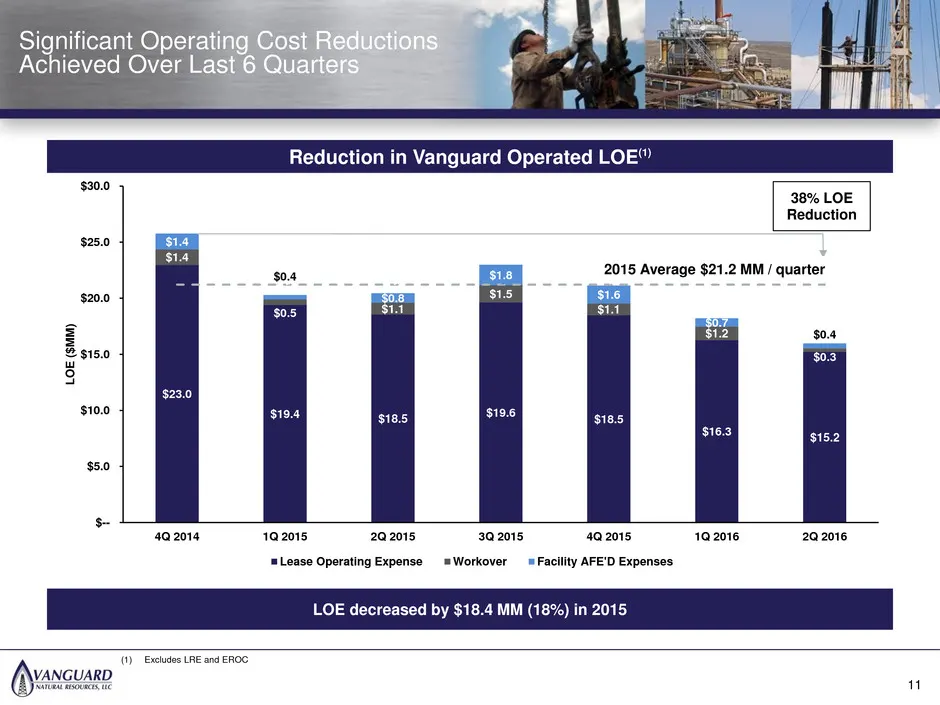
Slide 11: Significant Operating Cost Reductions Achieved Over Last 6 Quarters
36 32 87 89 89 89 83 141 213 168 177 182 Significant Operating Cost Reductions Achieved Over Last 6 Quarters 11 (1) Excludes LRE and EROC Reduction in Vanguard Operated LOE(1) LOE decreased by $18.4 MM (18%) in 2015 $23.0 $19.4 $18.5 $19.6 $18.5 $16.3 $15.2 $1.4 $0.5 $1.1 $1.5 $1.1 $1.2 $0.3 $1.4 $0
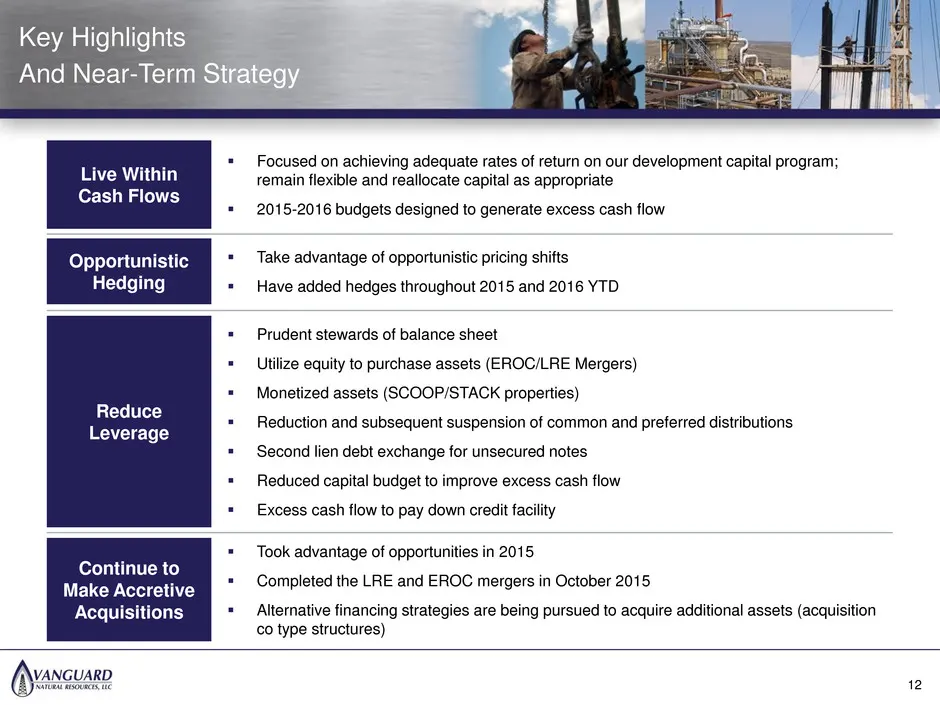
Slide 12: Key Highlights And Near-Term Strategy
36 32 87 89 89 89 83 141 213 168 177 182 Key Highlights And Near-Term Strategy Opportunistic Hedging Live Within Cash Flows Continue to Make Accretive Acquisitions Reduce Leverage Focused on achieving adequate rates of return on our development capital program; remain flexible and reallocate capit
Slide 13: Asset and Operations Overview
36 32 87 89 89 89 83 141 213 168 177 182 Asset and Operations Overview 13
Slide 14: Geographically Diversified Reserve Base
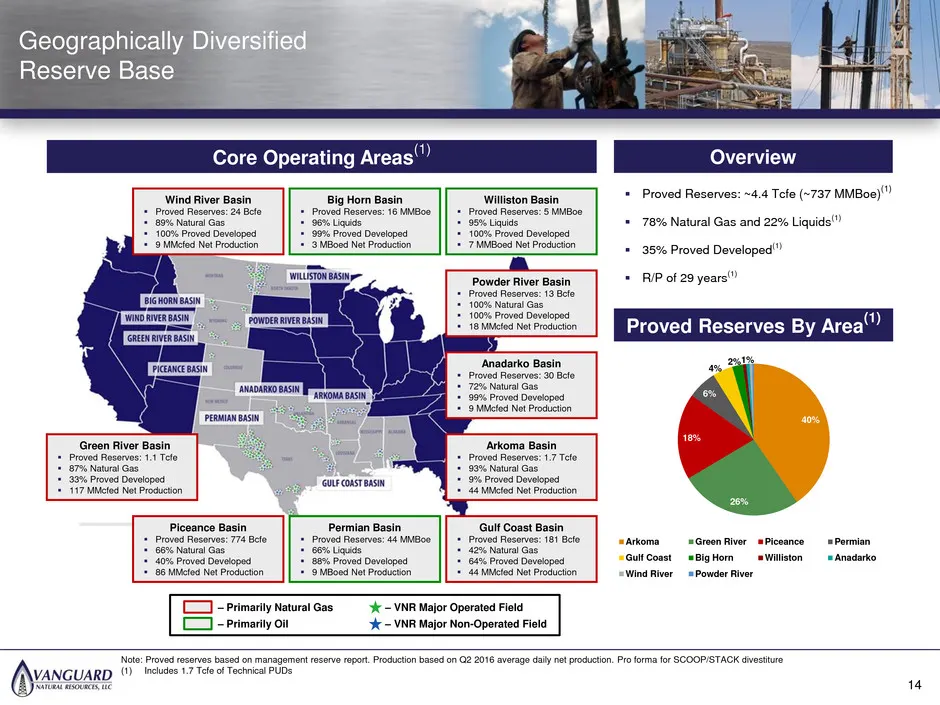
36 32 87 89 89 89 83 141 213 168 177 182 Geographically Diversified Reserve Base Core Operating Areas (1) Overview Proved Reserves By Area (1) 14 Green River Basin Proved Reserves: 1.1 Tcfe 87% Natural Gas 33% Proved Developed 117 MMcfed Net Production Piceance Basin Proved Reserves: 774 B
Slide 15: Low-Risk Proved Reserve Base with Significant PDP Component
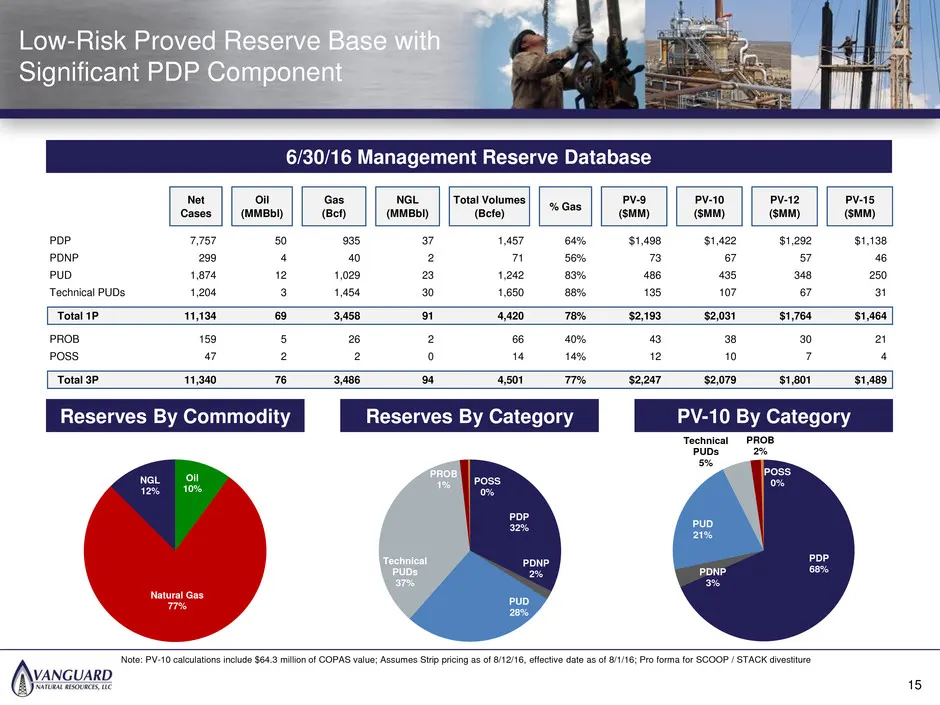
36 32 87 89 89 89 83 141 213 168 177 182 6/30/16 Management Reserve Database Low-Risk Proved Reserve Base with Significant PDP Component Reserves By Commodity Reserves By Category PV-10 By Category Note: PV-10 calculations include $64.3 million of COPAS value; Assumes Strip pricing as of 8/12/16, ef
Slide 16: Meaningful Inventory of Low-Risk Drilling Opportunities Shifted to PUDs
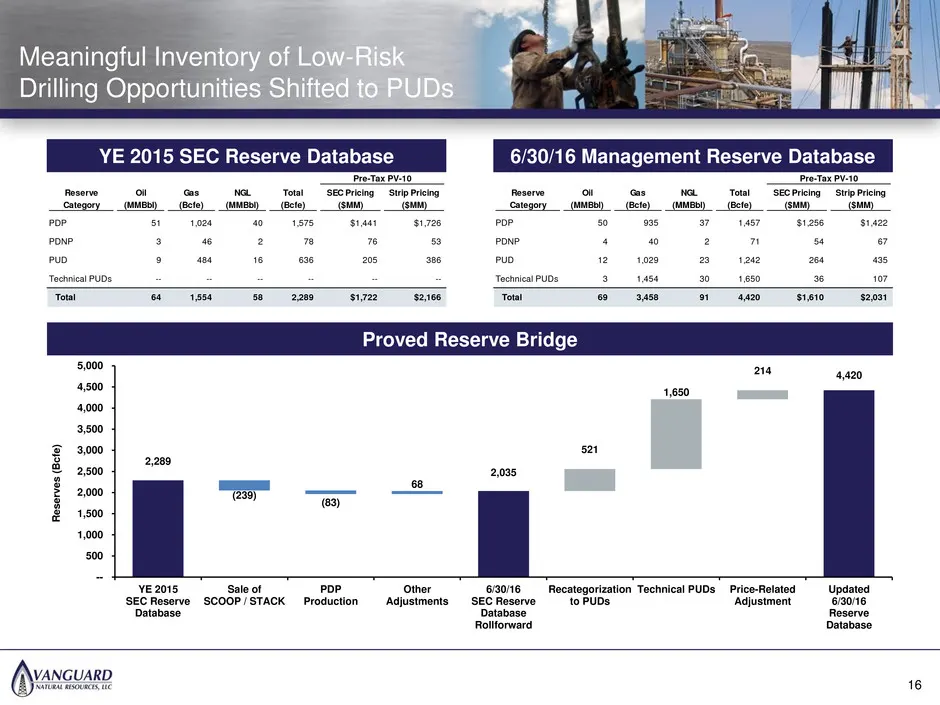
36 32 87 89 89 89 83 141 213 168 177 182 Meaningful Inventory of Low-Risk Drilling Opportunities Shifted to PUDs YE 2015 SEC Reserve Database Proved Reserve Bridge 6/30/16 Management Reserve Database 16 19 2,289 2,035 4,420 (239) (83) 68 521 1,650 214 -- 500 1,000 1,500 2,000 2,500 3,000 3,500 4,000
Slide 17: Low-Decline Base Production
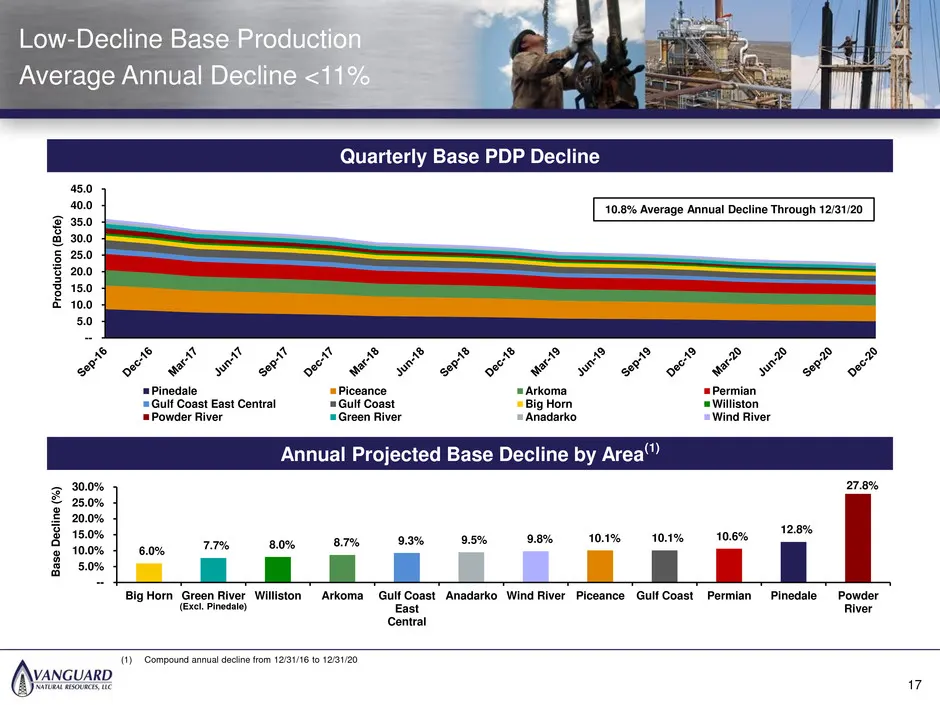
36 32 87 89 89 89 83 141 213 168 177 182 Low-Decline Base Production Average Annual Decline <11% Annual Projected Base Decline by Area(1) Quarterly Base PDP Decline (1) Compound annual decline from 12/31/16 to 12/31/20 17 -- 5.0 10.0 15.0 20.0 25.0 30.0 35.0 40.0 45.0 Produc tion (Bc fe) Pinedale Pi
Slide 18: Ability to Grow Collateral Value While Spending Within Cash Flow
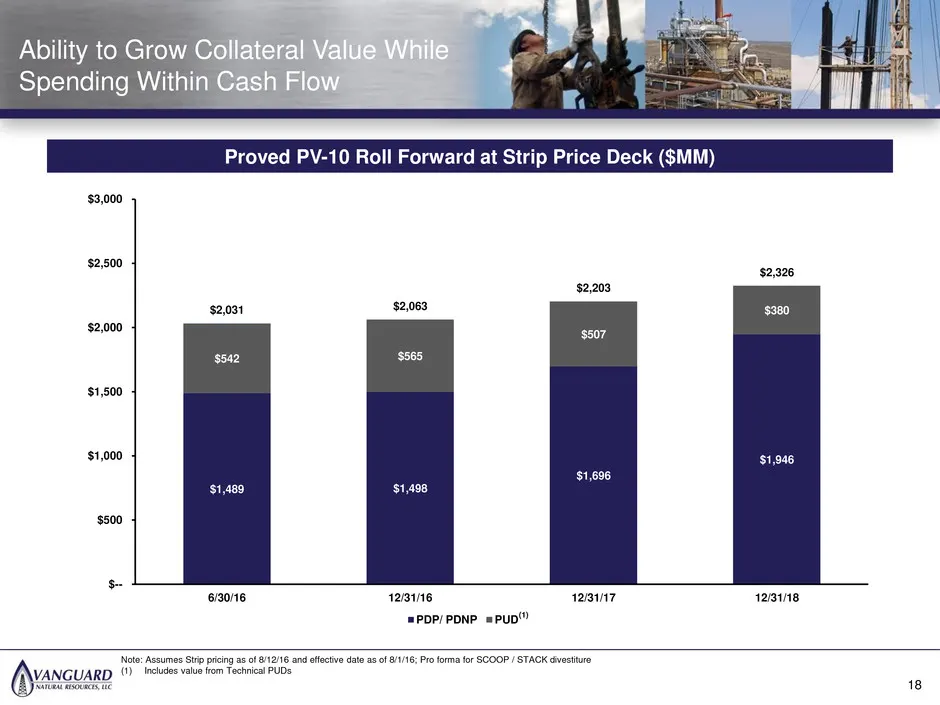
36 32 87 89 89 89 83 141 213 168 177 182 Ability to Grow Collateral Value While Spending Within Cash Flow Proved PV-10 Roll Forward at Strip Price Deck ($MM) 18 21 $1,489 $1,498 $1,696 $1,946 $542 $565 $507 $380$2,031 $2,063 $2,203 $2,326 $-- $500 $1,000 $1,500 $2,000 $2,500 $3,000 6/30/16 12/31/16
Slide 19: Significant Inventory of High-Quality, Organic Growth Opportunities
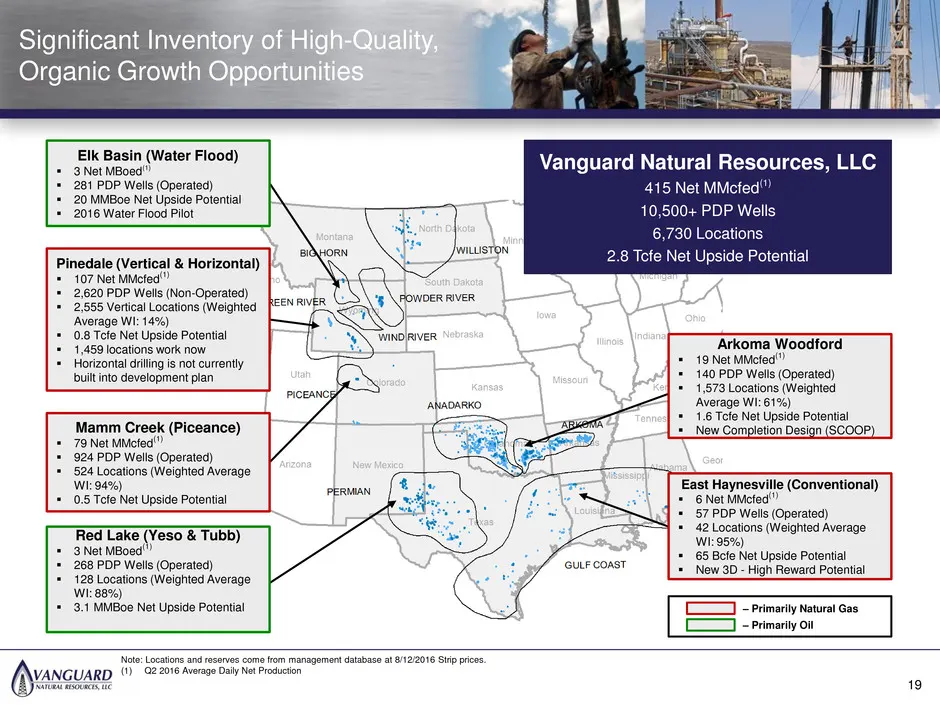
36 32 87 89 89 89 83 141 213 168 177 182 Significant Inventory of High-Quality, Organic Growth Opportunities Note: Locations and reserves come from management database at 8/12/2016 Strip prices. (1) Q2 2016 Average Daily Net Production – Primarily Natural Gas – Primarily Oil 19 Vanguard Natural Reso
Slide 20: Macro Gas Outlook
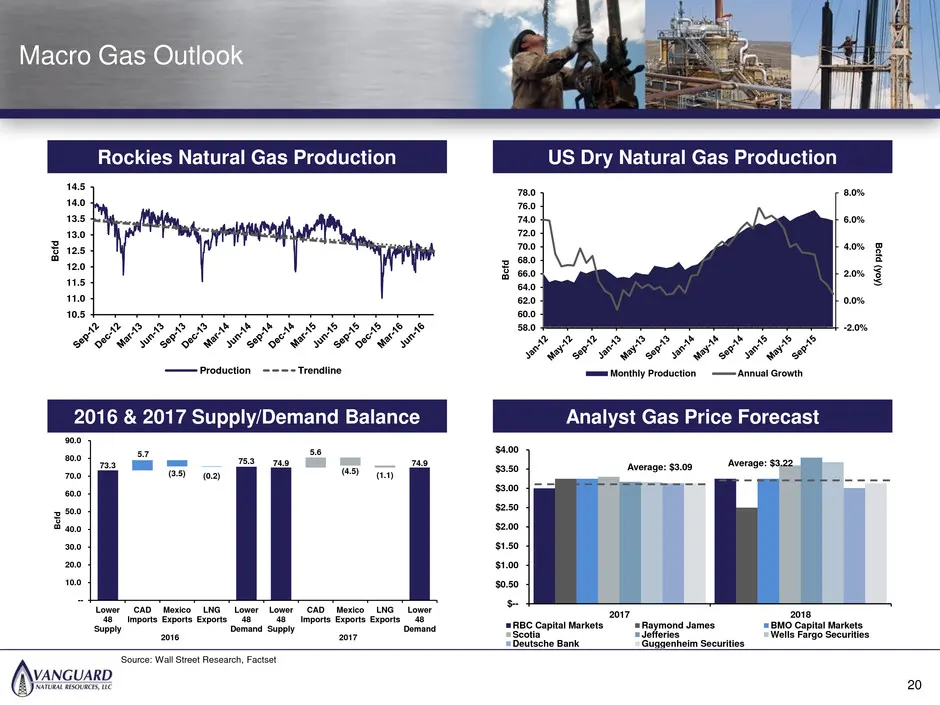
36 32 87 89 89 89 83 141 213 168 177 182 Macro Gas Outlook 20 2016 & 2017 Supply/Demand Balance Analyst Gas Price Forecast Rockies Natural Gas Production US Dry Natural Gas Production Source: Wall Street Research, Factset $-- $0.50 $1.00 $1.50 $2.00 $2.50 $3.00 $3.50 $4.00 2017 2018 RBC Capital Mark
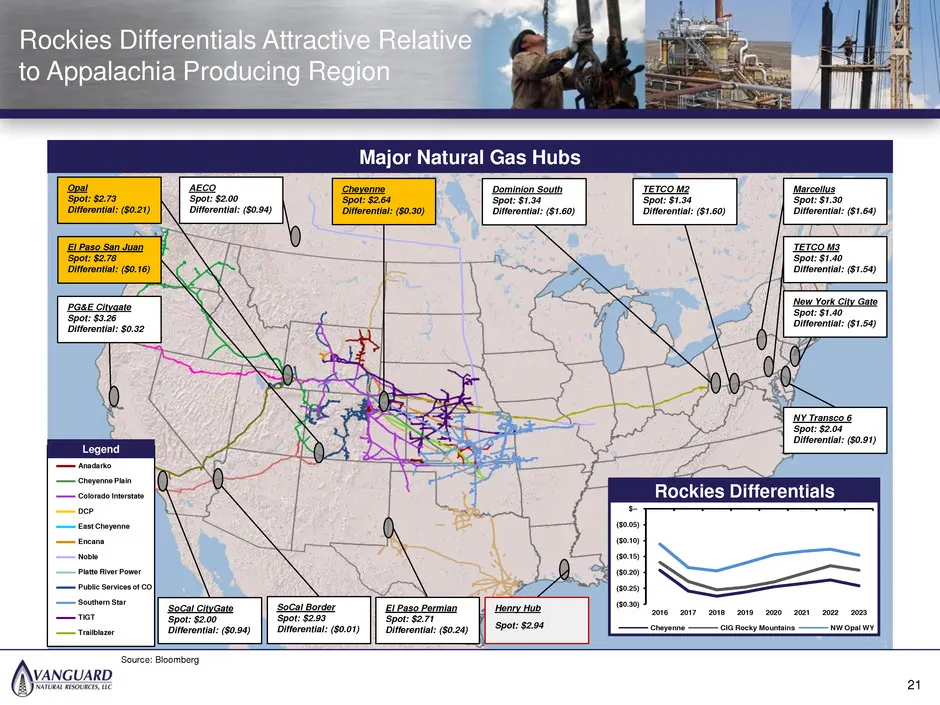
Slide 21: Rockies Differentials Attractive Relative to Appalachia
36 32 87 89 89 89 83 141 213 168 177 182 Rockies Differentials Attractive Relative to Appalachia Producing Region Source: Bloomberg Major Natural Gas Hubs El Paso Permian Spot: $2.71 Differential: ($0.24) SoCal CityGate Spot: $2.00 Differential: ($0.94) SoCal Border Spot: $2.93 Differential: ($0.01)
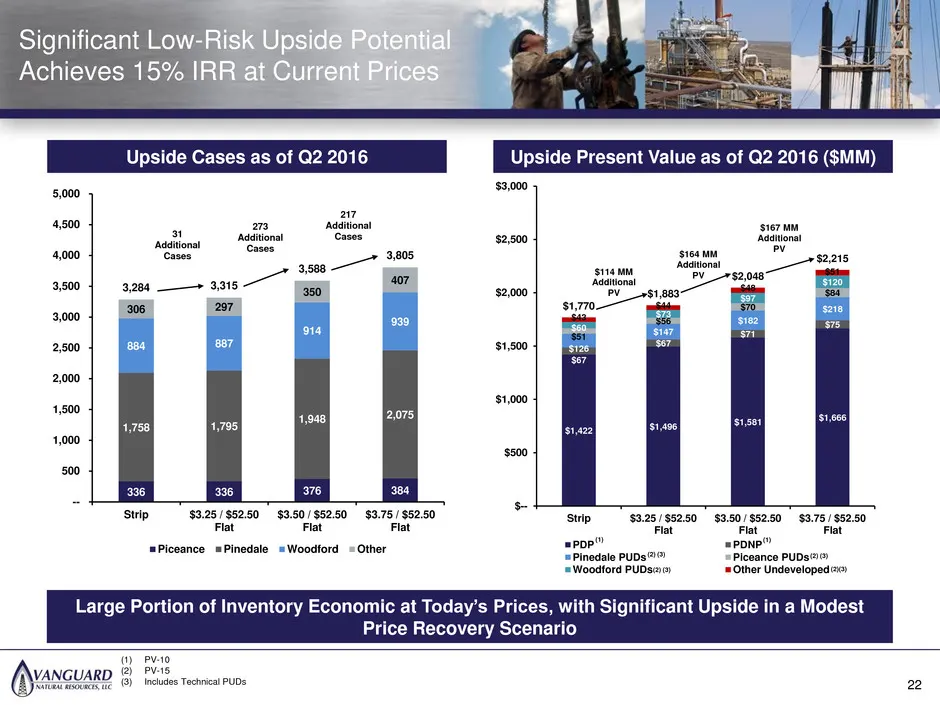
Slide 22: Significant Low-Risk Upside Potential Achieves 15% IRR at Current Prices
36 32 87 89 89 89 83 141 213 168 177 182 Significant Low-Risk Upside Potential Achieves 15% IRR at Current Prices 22 Upside Present Value as of Q2 2016 ($MM) Upside Cases as of Q2 2016 Large Portion of Inventory Economic at Today’s Prices, with Significant Upside in a Modest Price Recovery Scenario
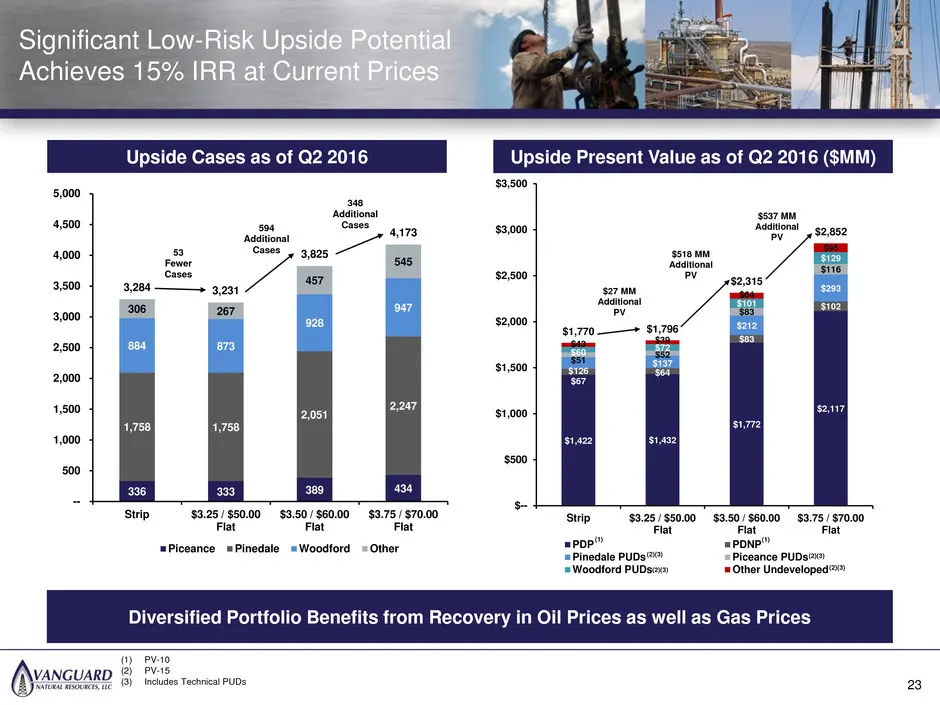
Slide 23: Significant Low-Risk Upside Potential Achieves 15% IRR at Current Prices
36 32 87 89 89 89 83 141 213 168 177 182 Significant Low-Risk Upside Potential Achieves 15% IRR at Current Prices 23 Upside Present Value as of Q2 2016 ($MM) Upside Cases as of Q2 2016 Diversified Portfolio Benefits from Recovery in Oil Prices as well as Gas Prices (1) PV-10 (2) PV-15 (3) Includes T
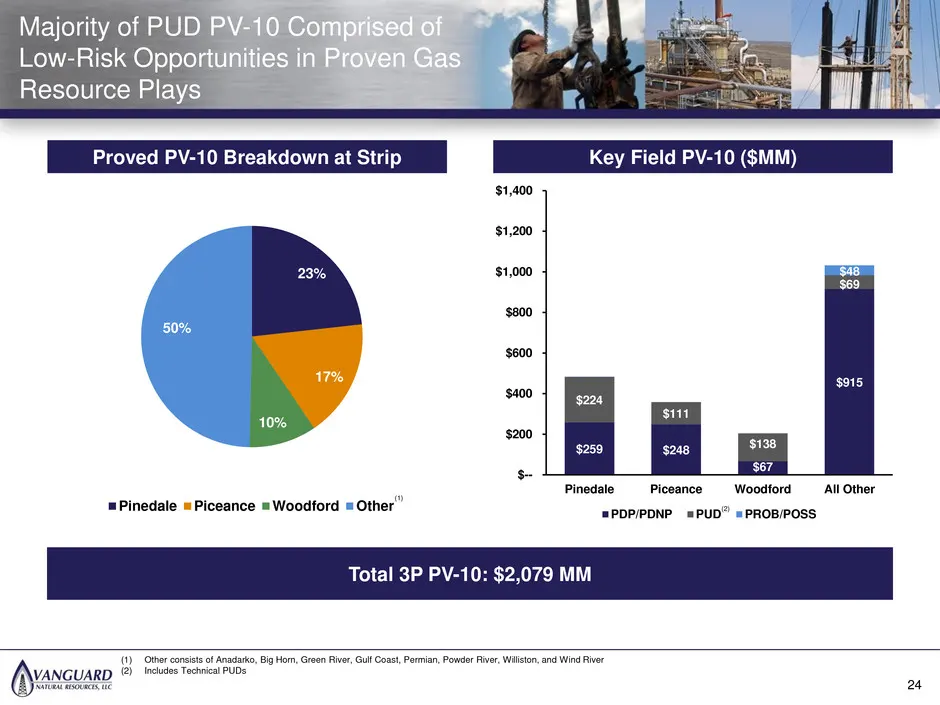
Slide 24: Majority of PUD PV-10 Comprised of Low-Risk Opportunities
36 32 87 89 89 89 83 141 213 168 177 182 23% 17% 10% 50% Pinedale Piceance Woodford Other Majority of PUD PV-10 Comprised of Low-Risk Opportunities in Proven Gas Resource Plays Key Field PV-10 ($MM) Proved PV-10 Breakdown at Strip 24 Total 3P PV-10: $2,079 MM $259 $248 $67 $915 $224 $111 $138 $69 $4
Slide 25: Northern Division Overview
36 32 87 89 89 89 83 141 213 168 177 182 Northern Division Overview 25
Slide 26: Northern Division Overview
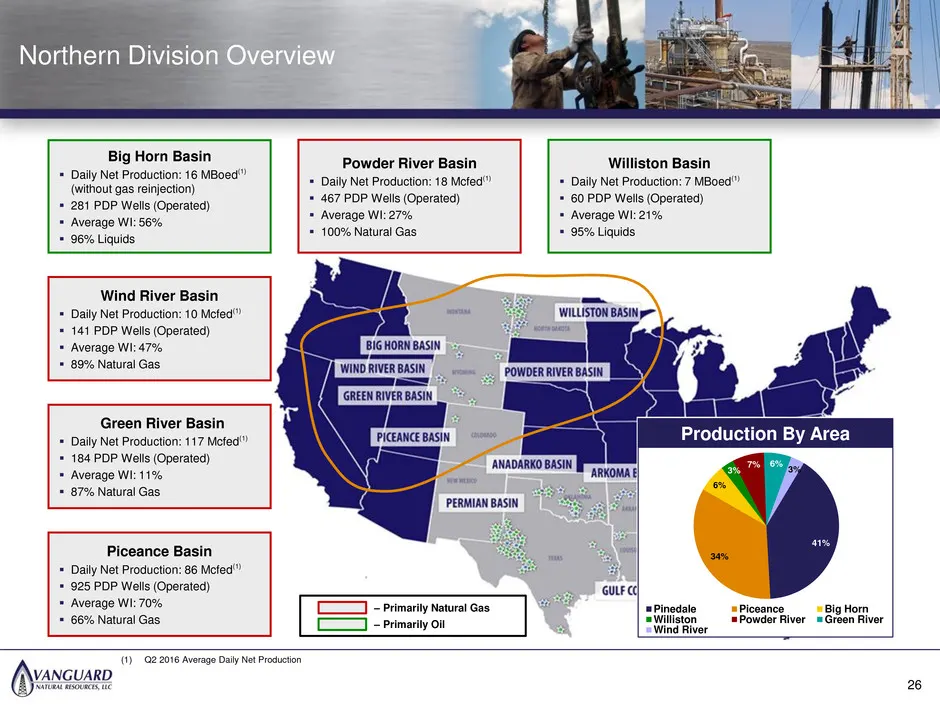
36 32 87 89 89 89 83 141 213 168 177 182 Northern Division Overview – Primarily Natural Gas – Primarily Oil Production By Area Production By Area 41% 34% 6% 3% 7% 6% 3% Pinedale Piceance Big Horn Williston Powder River Green River Wind River 26 (1) Q2 2016 Average Daily Net Production Piceance Basin
Slide 27: Pinedale Overview & Upside
36 32 87 89 89 89 83 141 213 168 177 182 Pinedale Overview & Upside 27
Slide 28: Pinedale Field Overview
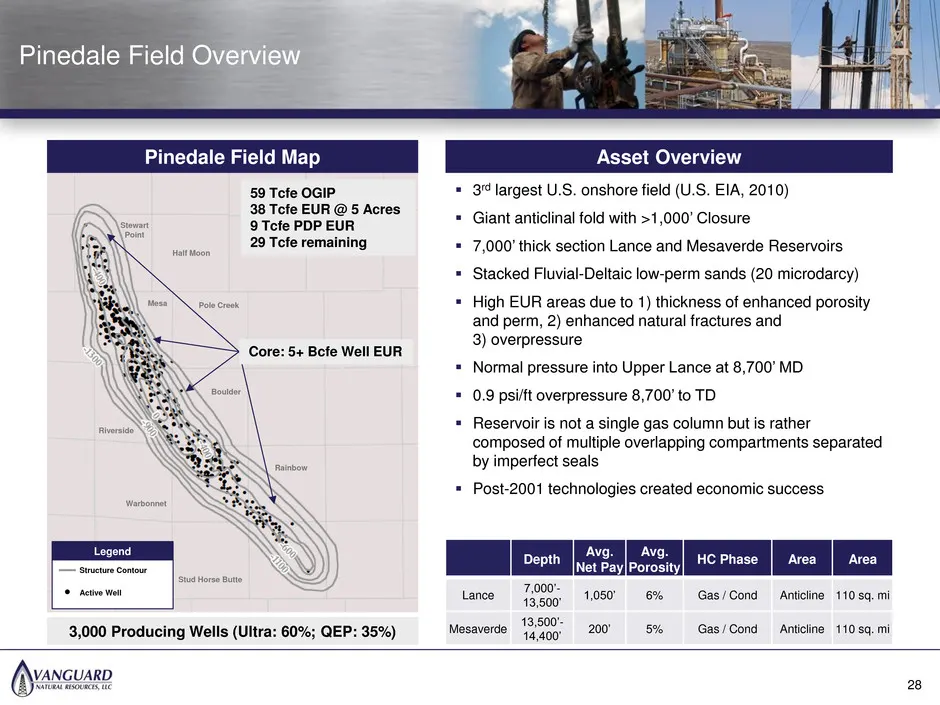
36 32 87 89 89 89 83 141 213 168 177 182 Pinedale Field Overview 3rd largest U.S. onshore field (U.S. EIA, 2010) Giant anticlinal fold with >1,000’ Closure 7,000’ thick section Lance and Mesaverde Reservoirs Stacked Fluvial-Deltaic low-perm sands (20 microdarcy) High EUR areas due to 1) th
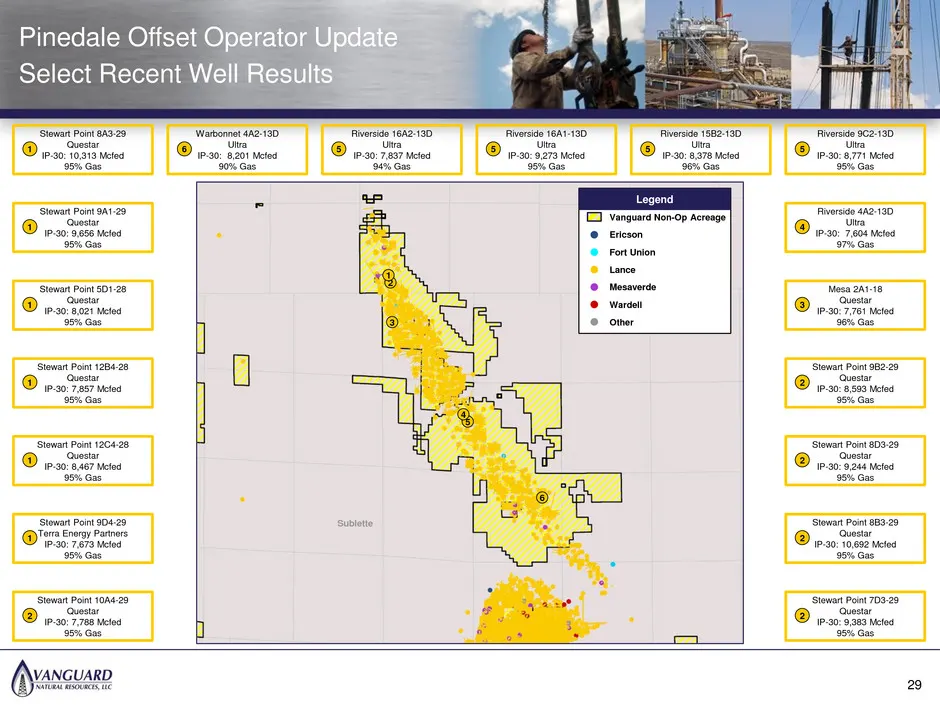
Slide 29: Sublette Pinedale Offset Operator Update
36 32 87 89 89 89 83 141 213 168 177 182 Sublette 2 1 3 5 4 6 Pinedale Offset Operator Update Select Recent Well Results Stewart Point 8A3-29 Questar IP-30: 10,313 Mcfed 95% Gas 1 Legend Vanguard Non-Op Acreage Ericson Fort Union Lance Mesaverde Wardell Other Stewart Point 9A1-29 Questar IP-30: 9,65
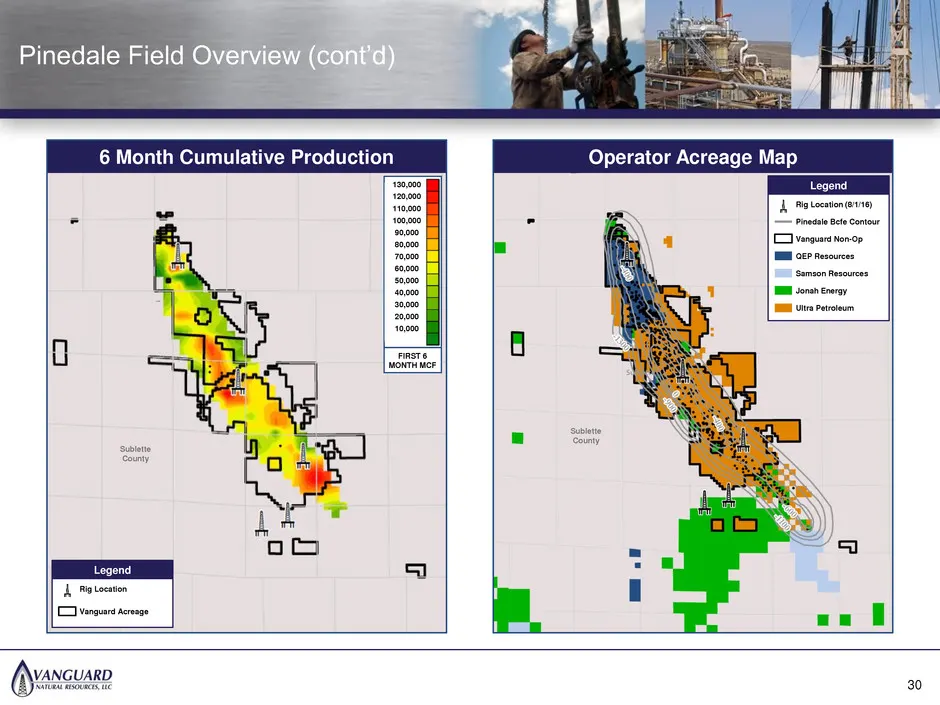
Slide 30: Pinedale Field Overview (cont'd)
36 32 87 89 89 89 83 141 213 168 177 182 Pinedale Field Overview (cont’d) 6 Month Cumulative Production Operator Acreage Map 30 Legend Rig Location (8/1/16) Pinedale Bcfe Contour Vanguard Non-Op QEP Resources Samson Resources Jonah Energy Ultra Petroleum Sublette County Sublette County Legend Rig Lo
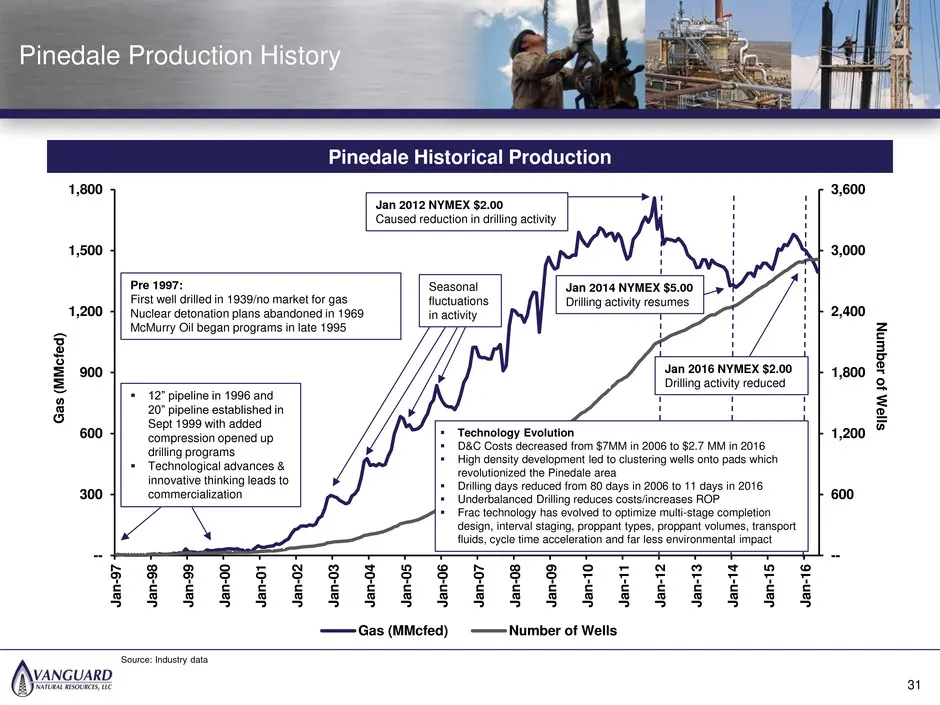
Slide 31: Pinedale Production History
36 32 87 89 89 89 83 141 213 168 177 182 -- 600 1,200 1,800 2,400 3,000 3,600 -- 300 600 900 1,200 1,500 1,800 Ja n- 97 Ja n- 98 Ja n- 99 Ja n- 00 Ja n- 01 Ja n- 02 Ja n- 03 Ja n- 04 Ja n- 05 Ja n- 06 Ja n- 07 Ja n- 08 Ja n- 09 Ja n- 10 Ja n- 11 Ja n- 12 Ja n- 13 Ja n- 14 Ja n- 15 Ja n- 16 Num be r
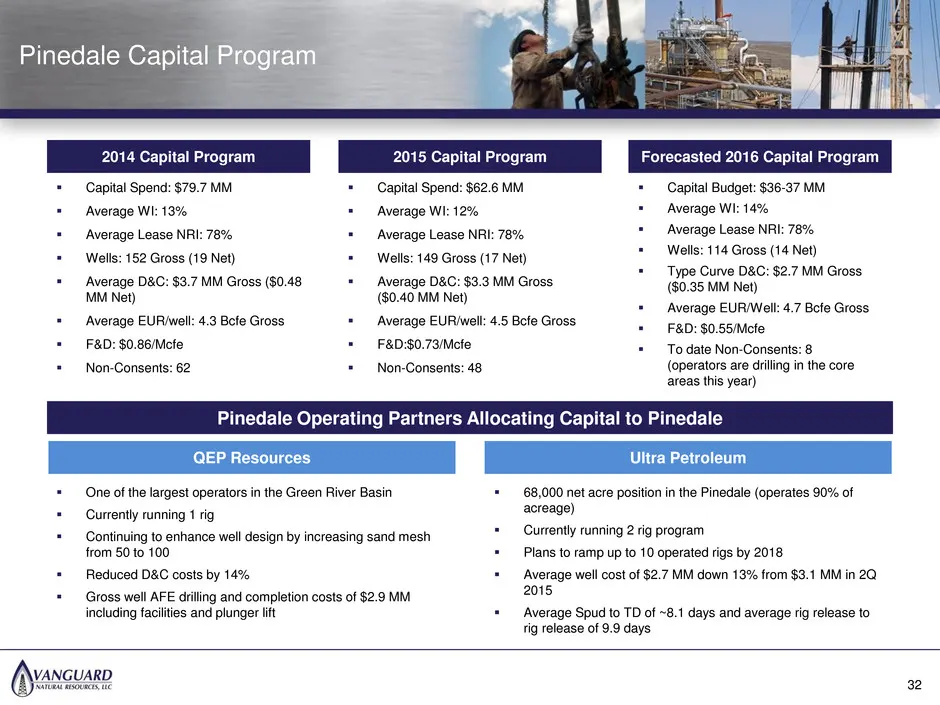
Slide 32: Pinedale Capital Program
36 32 87 89 89 89 83 141 213 168 177 182 Pinedale Capital Program Capital Spend: $79.7 MM Average WI: 13% Average Lease NRI: 78% Wells: 152 Gross (19 Net) Average D&C: $3.7 MM Gross ($0.48 MM Net) Average EUR/well: 4.3 Bcfe Gross F&D: $0.86/Mcfe Non-Consents: 62 Forecasted 2016 Capit
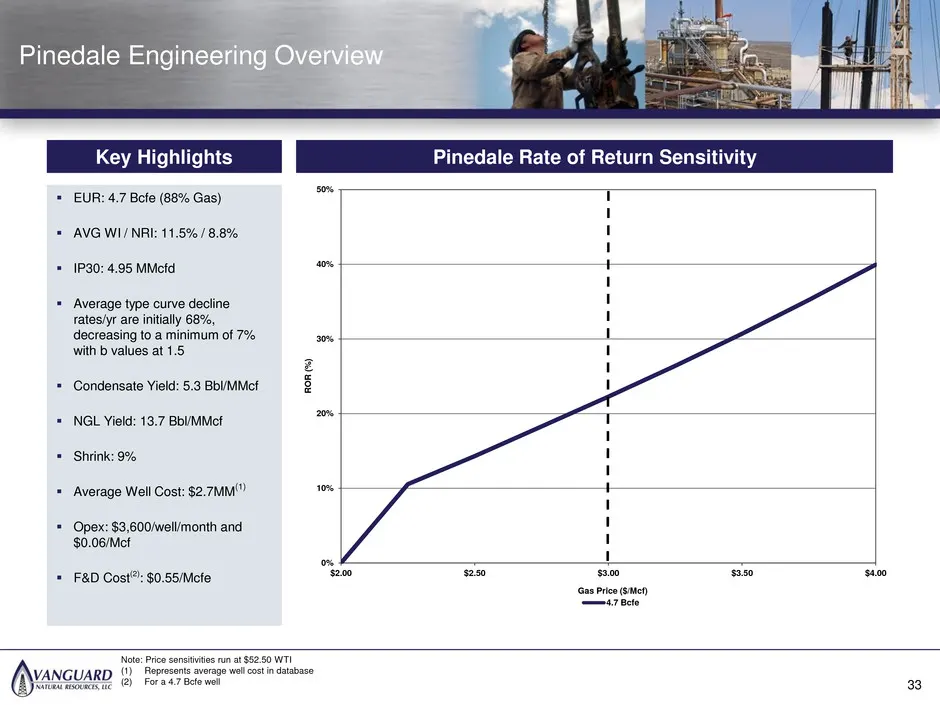
Slide 33: Pinedale Engineering Overview
36 32 87 89 89 89 83 141 213 168 177 182 EUR: 4.7 Bcfe (88% Gas) AVG WI / NRI: 11.5% / 8.8% IP30: 4.95 MMcfd Average type curve decline rates/yr are initially 68%, decreasing to a minimum of 7% with b values at 1.5 Condensate Yield: 5.3 Bbl/MMcf NGL Yield: 13.7 Bbl/MMcf Shrink: 9% Av
Slide 34: Piceance Overview & Upside
36 32 87 89 89 89 83 141 213 168 177 182 Piceance Overview & Upside 34
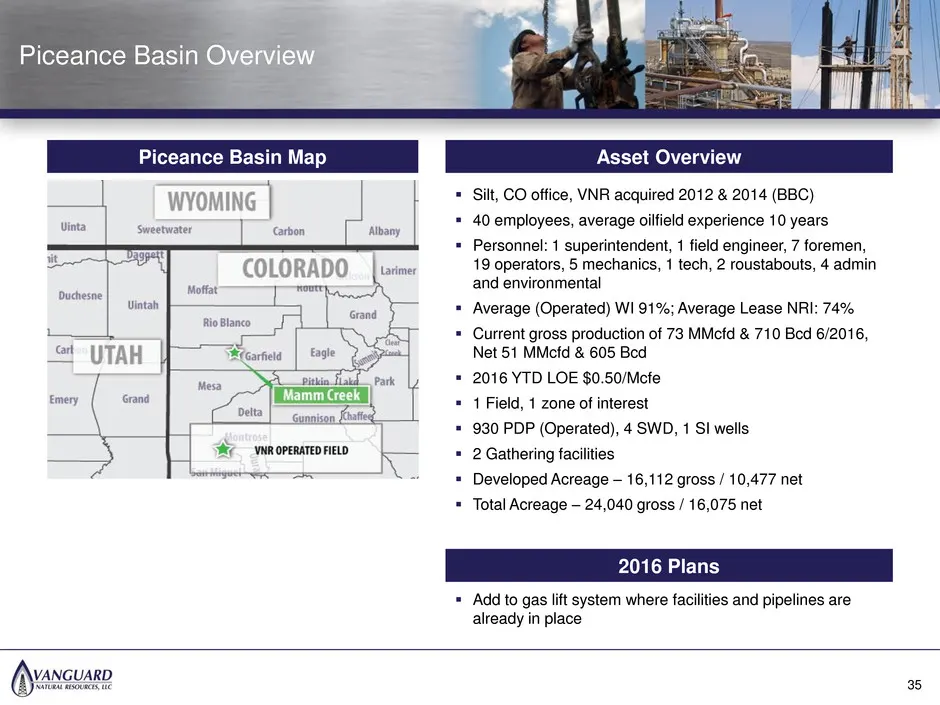
Slide 35: Piceance Basin Overview
36 32 87 89 89 89 83 141 213 168 177 182 Piceance Basin Overview Piceance Basin Map Asset Overview Add to gas lift system where facilities and pipelines are already in place 2016 Plans 35 Silt, CO office, VNR acquired 2012 & 2014 (BBC) 40 employees, average oilfield experience 10 years Perso
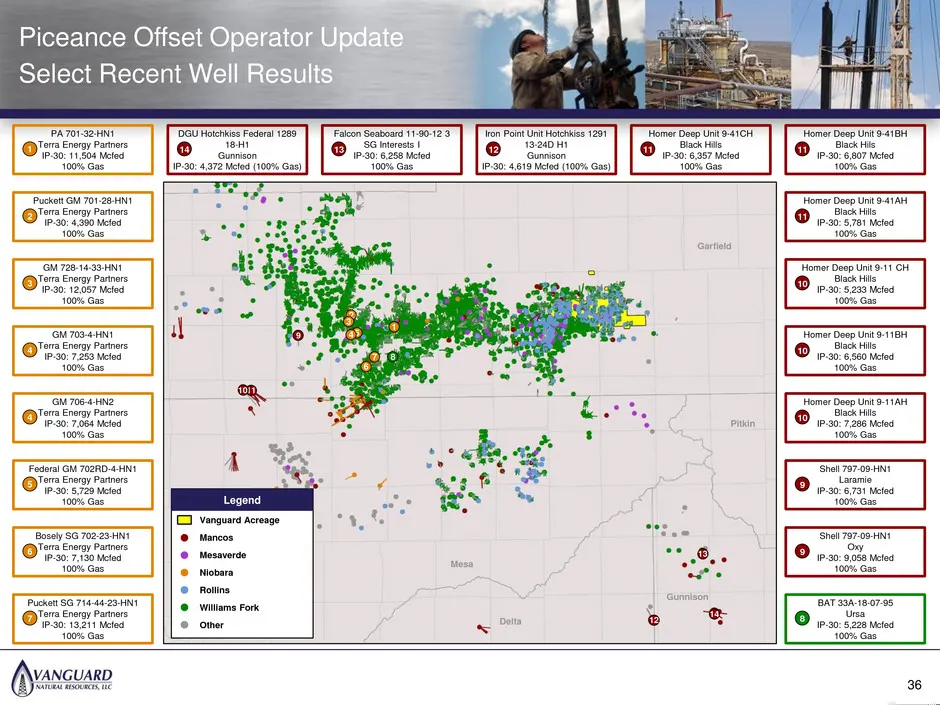
Slide 36: Piceance Offset Operator Update
36 32 87 89 89 89 83 141 213 168 177 182 1 2 3 5 4 7 6 8 9 11 10 13 14 12 Mesa Delta Gunnison Garfield Pitkin Piceance Offset Operator Update Select Recent Well Results Legend Vanguard Acreage Mancos Mesaverde Niobara Rollins Williams Fork Other PA 701-32-HN1 Terra Energy Partners IP-30: 11,504 Mcfe
Slide 37: Piceance Basin Overview (cont'd)
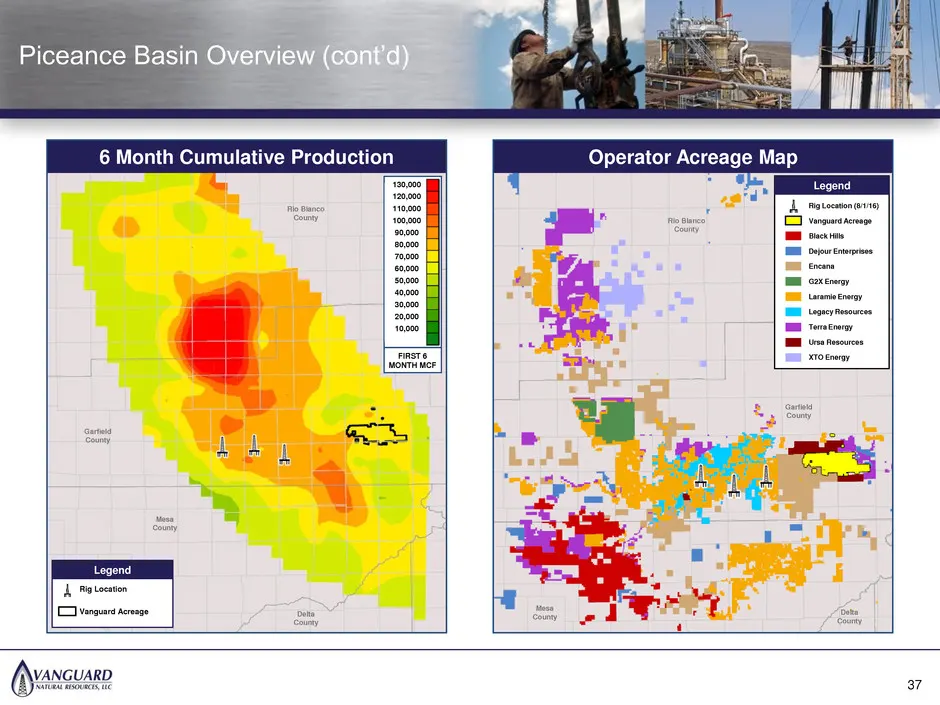
36 32 87 89 89 89 83 141 213 168 177 182 Piceance Basin Overview (cont’d) 6 Month Cumulative Production Operator Acreage Map 37 Legend Rig Location (8/1/16) Vanguard Acreage Black Hills Dejour Enterprises Encana G2X Energy Laramie Energy Legacy Resources Terra Energy Ursa Resources XTO Energy Garfie
Slide 38: Mamm Creek (Piceance) Overview
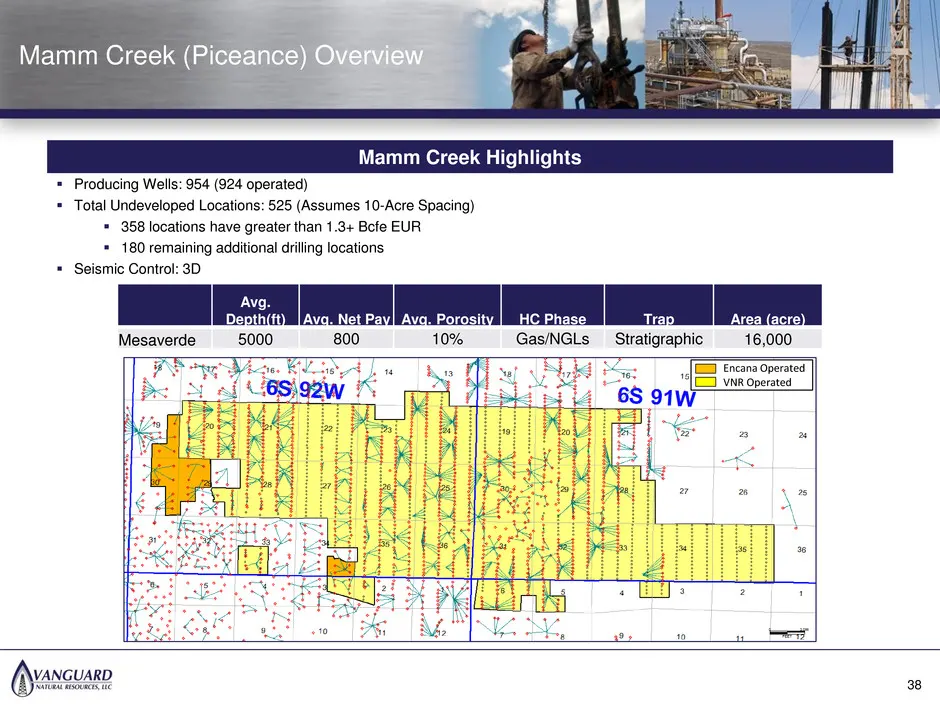
36 32 87 89 89 89 83 141 213 168 177 182 Producing Wells: 954 (924 operated) Total Undeveloped Locations: 525 (Assumes 10-Acre Spacing) 358 locations have greater than 1.3+ Bcfe EUR 180 remaining additional drilling locations Seismic Control: 3D Avg. Depth(ft) Avg. Net Pay Avg. Porosity HC
Slide 39: Piceance Completion Improvements
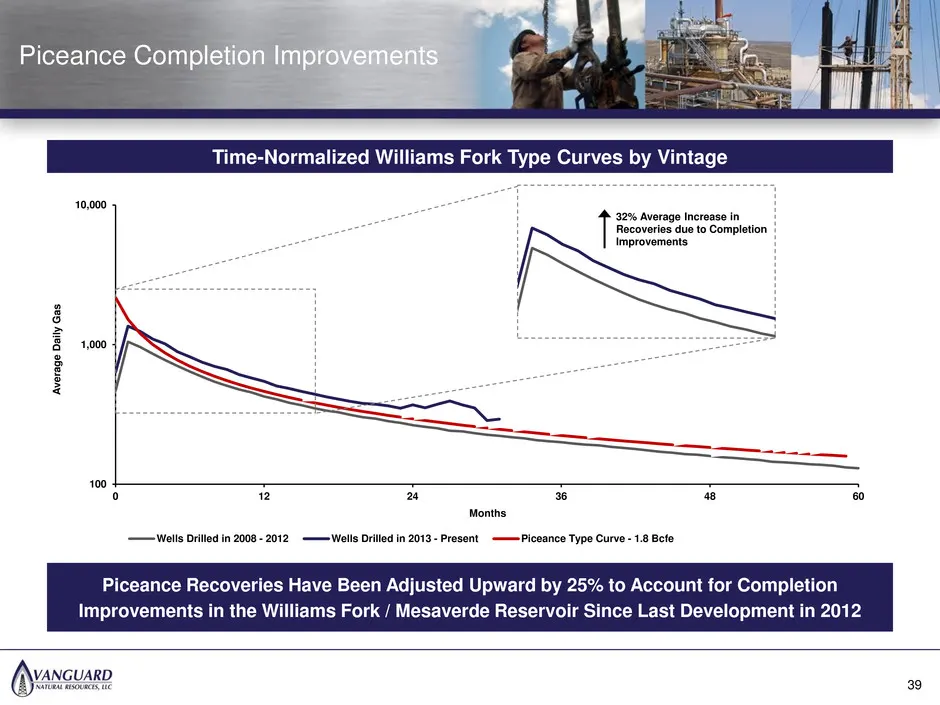
36 32 87 89 89 89 83 141 213 168 177 182 100 1,000 10,000 0 12 24 36 48 60 Av era ge Da ily Ga s Months Wells Drilled in 2008 - 2012 Wells Drilled in 2013 - Present Piceance Type Curve - 1.8 Bcfe Piceance Recoveries Have Been Adjusted Upward by 25% to Account for Completion Improvements in the Willi
Slide 40: Mamm Creek Engineering Overview
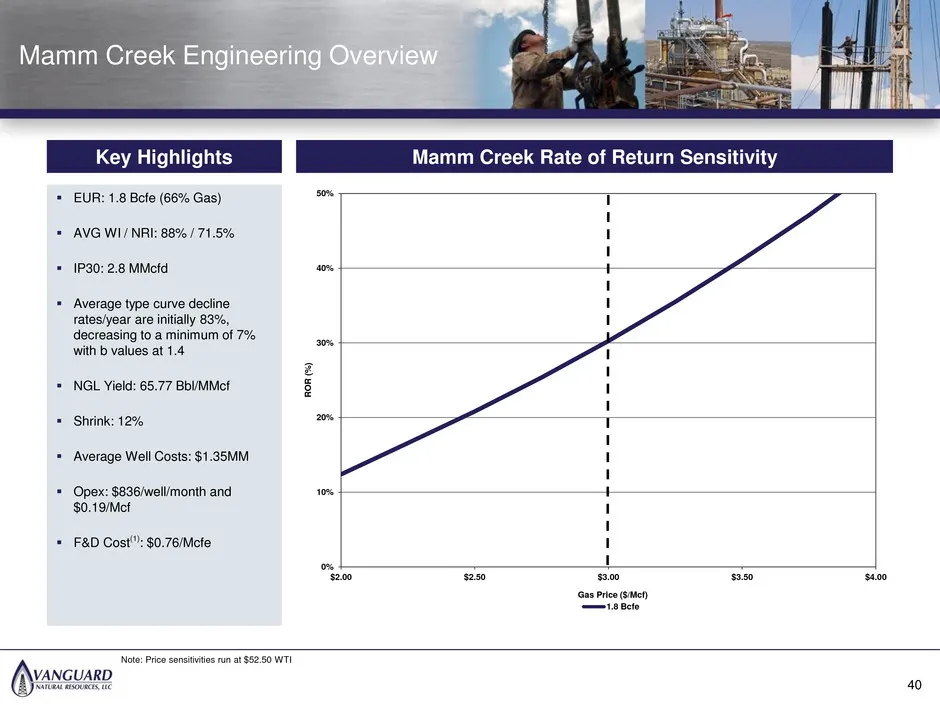
36 32 87 89 89 89 83 141 213 168 177 182 EUR: 1.8 Bcfe (66% Gas) AVG WI / NRI: 88% / 71.5% IP30: 2.8 MMcfd Average type curve decline rates/year are initially 83%, decreasing to a minimum of 7% with b values at 1.4 NGL Yield: 65.77 Bbl/MMcf Shrink: 12% Average Well Costs: $1.35MM Ope
Slide 41: East Central Division Overview
36 32 87 89 89 89 83 141 213 168 177 182 East Central Division Overview 41
Slide 42: East Central Region Overview
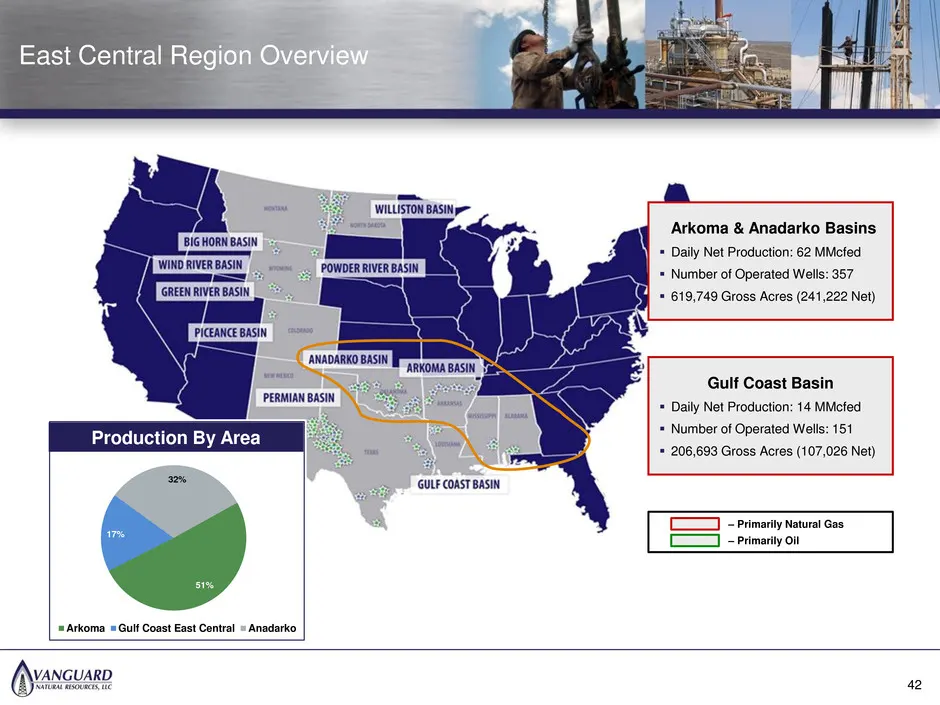
36 32 87 89 89 89 83 141 213 168 177 182 East Central Region Overview Gulf Coast Basin Daily Net Production: 14 MMcfed Number of Operated Wells: 151 206,693 Gross Acres (107,026 Net) Production By Area Pro i Arkoma & Anadarko Basins Daily Net Production: 62 MMcfed Number of Operated Wells:
Slide 43: Arkoma Overview
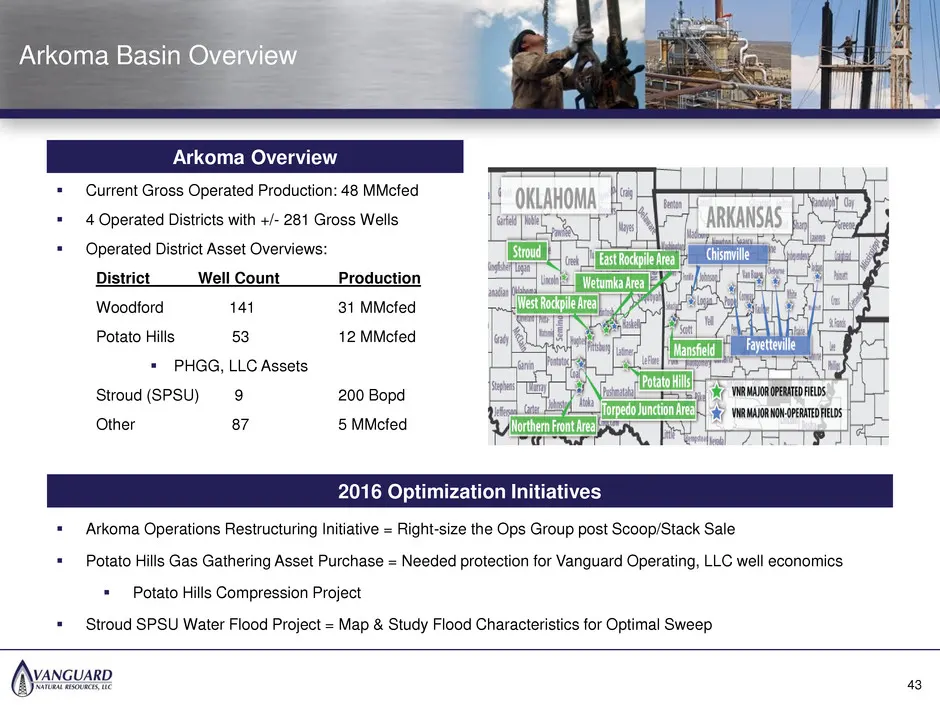
36 32 87 89 89 89 83 141 213 168 177 182 Arkoma Overview 2016 Optimization Initiatives Arkoma Operations Restructuring Initiative = Right-size the Ops Group post Scoop/Stack Sale Potato Hills Gas Gathering Asset Purchase = Needed protection for Vanguard Operating, LLC well economics Potato Hil
Slide 44: Anadarko Basin Overview
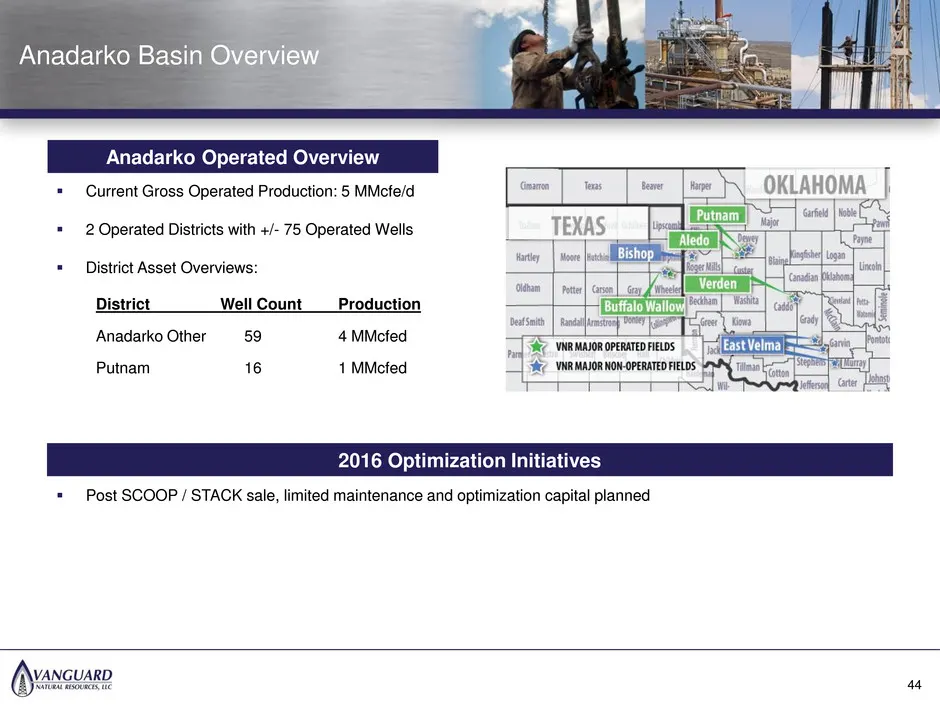
36 32 87 89 89 89 83 141 213 168 177 182 Current Gross Operated Production: 5 MMcfe/d 2 Operated Districts with +/- 75 Operated Wells District Asset Overviews: District Well Count Production Anadarko Other 59 4 MMcfed Putnam 16 1 MMcfed Anadarko Operated Overview Anadarko Basin Overview 44 201
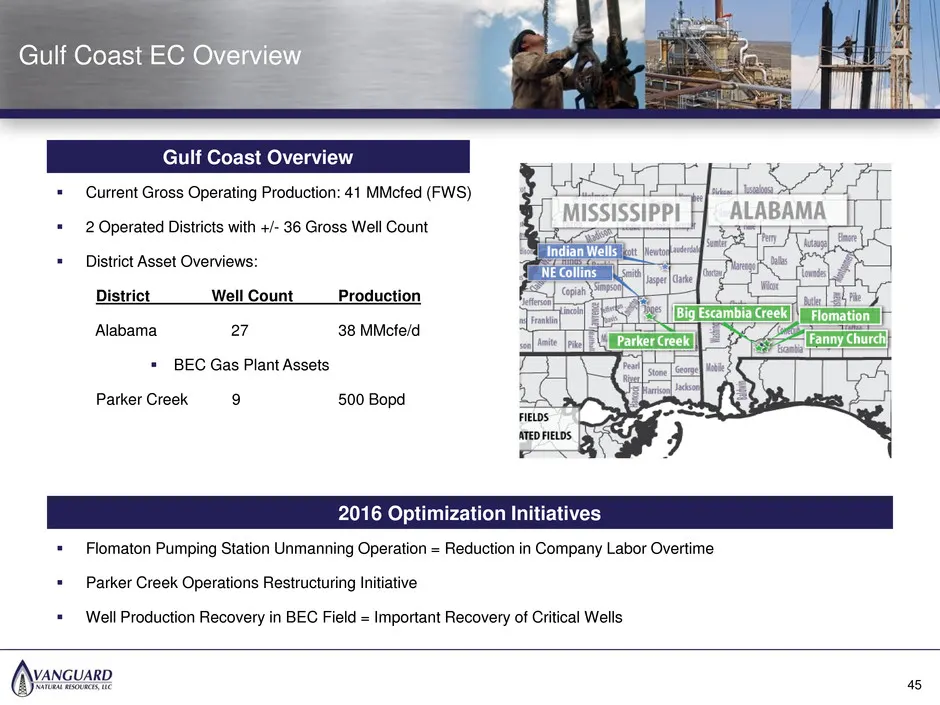
Slide 45: Gulf Coast EC Overview
36 32 87 89 89 89 83 141 213 168 177 182 Current Gross Operating Production: 41 MMcfed (FWS) 2 Operated Districts with +/- 36 Gross Well Count District Asset Overviews: District Well Count Production Alabama 27 38 MMcfe/d BEC Gas Plant Assets Parker Creek 9 500 Bopd Gulf Coast Overview 2016
Slide 46: Arkoma Woodford Overview & Upside
36 32 87 89 89 89 83 141 213 168 177 182 Arkoma Woodford Overview & Upside 46
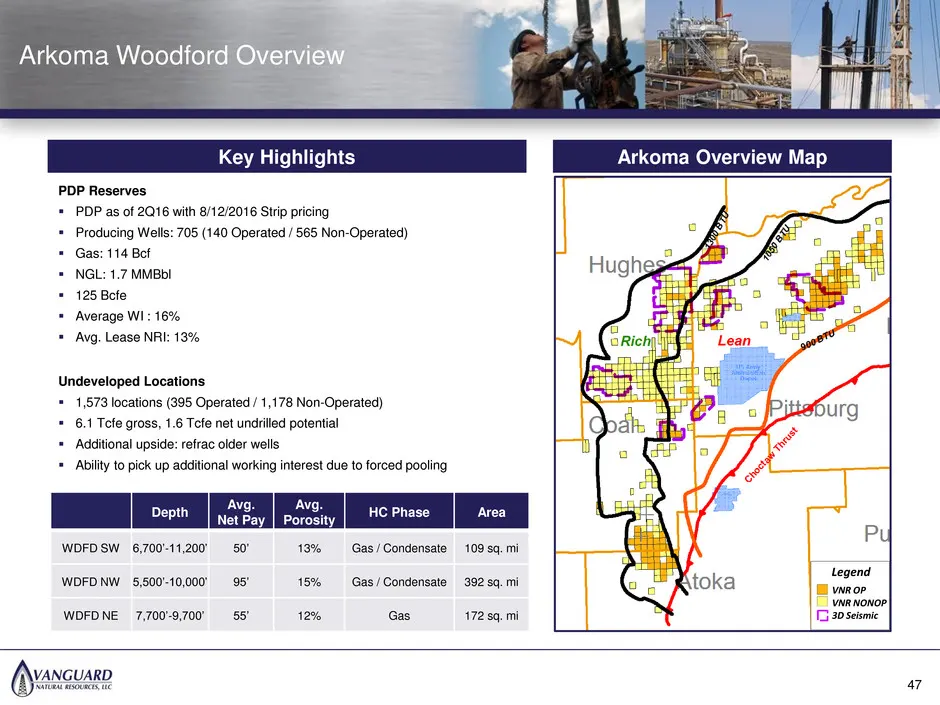
Slide 47: Arkoma Woodford Overview
36 32 87 89 89 89 83 141 213 168 177 182 Depth Avg. Net Pay Avg. Porosity HC Phase Area WDFD SW 6,700’-11,200’ 50’ 13% Gas / Condensate 109 sq. mi WDFD NW 5,500’-10,000’ 95’ 15% Gas / Condensate 392 sq. mi WDFD NE 7,700’-9,700’ 55’ 12% Gas 172 sq. mi Arkoma Woodford Overview 54 Key Highlights Arkoma
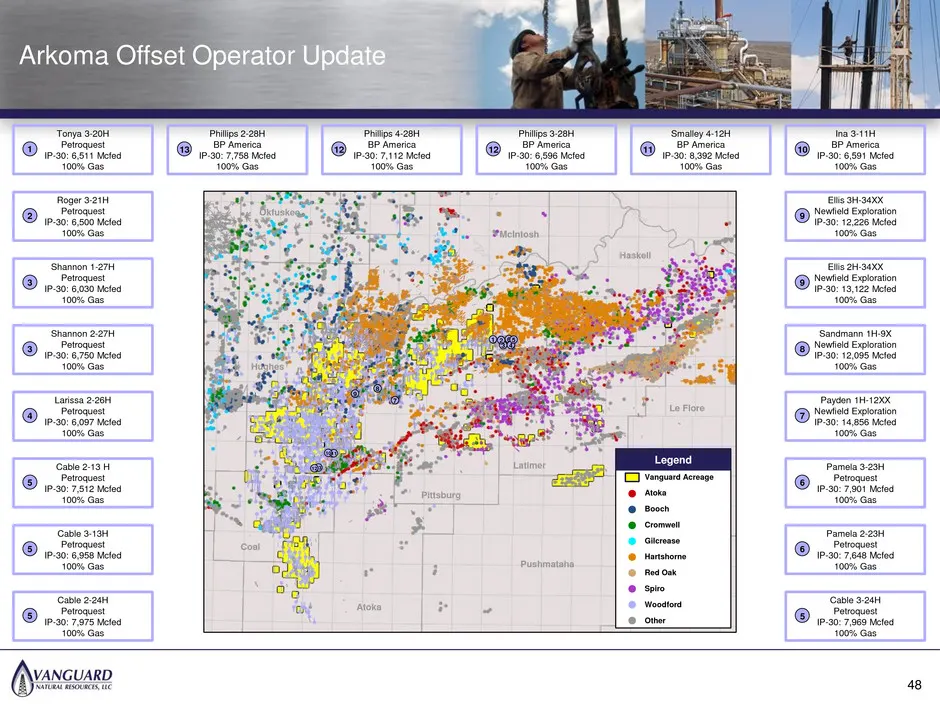
Slide 48: Arkoma Offset Operator Update
36 32 87 89 89 89 83 141 213 168 177 182 6 11 10 13 12 1 3 2 4 5 7 8 9 Pushmataha Atoka Pittsburg Latimer Le Flore Haskell McIntosh Hughes Coal Okfuskee Arkoma Offset Operator Update Legend Vanguard Acreage Atoka Booch Cromwell Gilcrease Hartshorne Red Oak Spiro Woodford Other Tonya 3-20H Petroquest
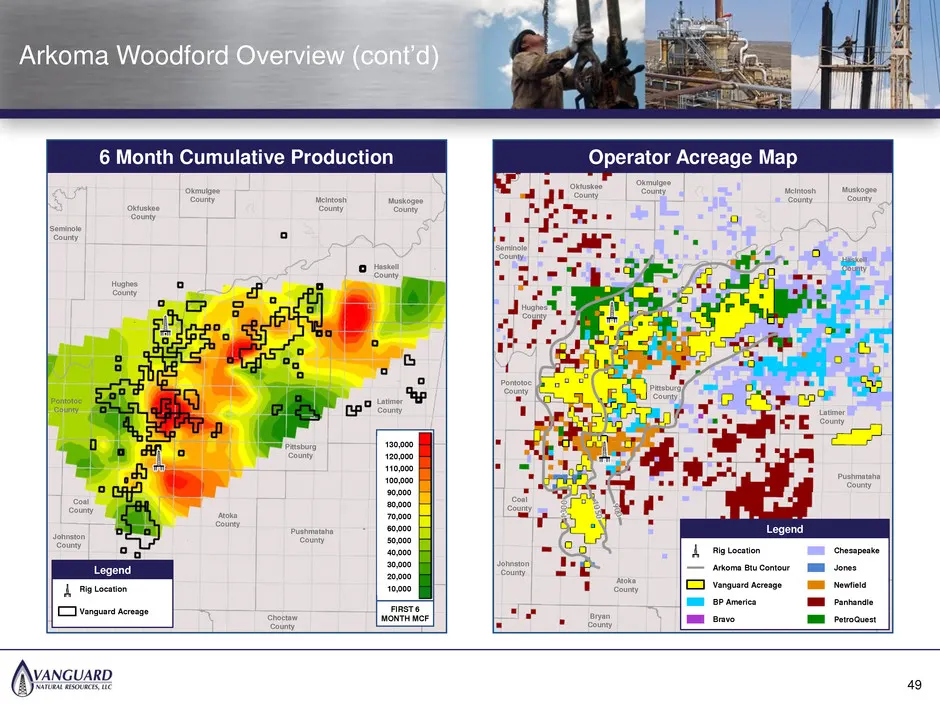
Slide 49: Arkoma Woodford Overview (cont'd)
36 32 87 89 89 89 83 141 213 168 177 182 49 Arkoma Woodford Overview (cont’d) Operator Acreage Map 6 Month Cumulative Production Rig Location Arkoma Btu Contour Vanguard Acreage BP America Bravo Legend Chesapeake Jones Newfield Panhandle PetroQuest Muskogee County Okmulgee County Okfuskee County McI
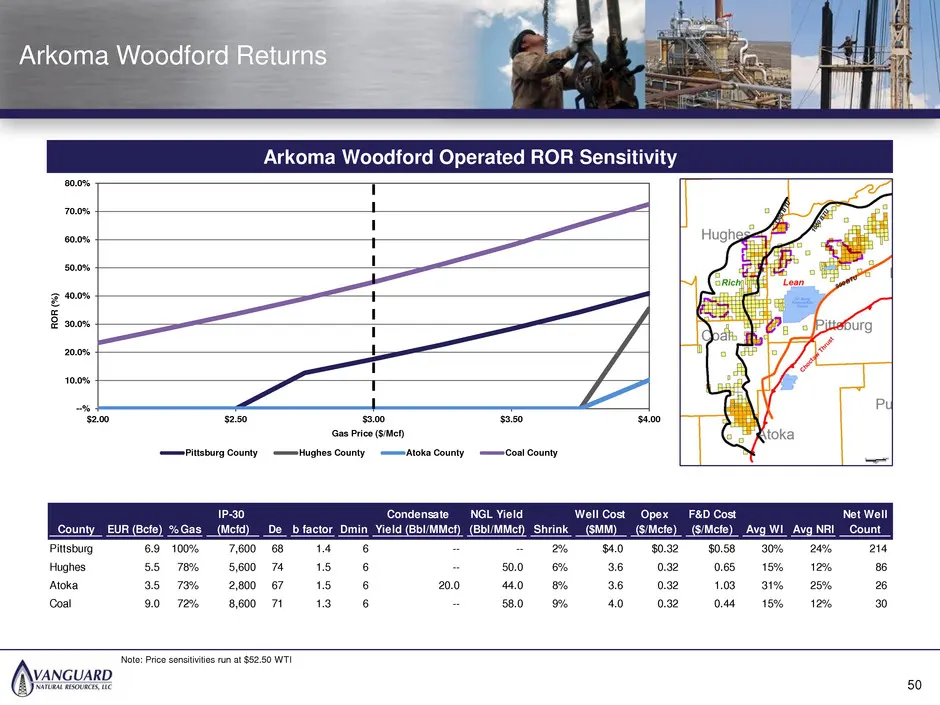
Slide 50: Arkoma Woodford Returns
36 32 87 89 89 89 83 141 213 168 177 182 --% 10.0% 20.0% 30.0% 40.0% 50.0% 60.0% 70.0% 80.0% $2.00 $2.50 $3.00 $3.50 $4.00 RO R ( %) Gas Price ($/Mcf) Pittsburg County Hughes County Atoka County Coal County Arkoma Woodford Returns Arkoma Woodford Operated ROR Sensitivity 64 50 Note: Price sensitivit
Slide 51: Southern Division Overview
36 32 87 89 89 89 83 141 213 168 177 182 Southern Division Overview 51
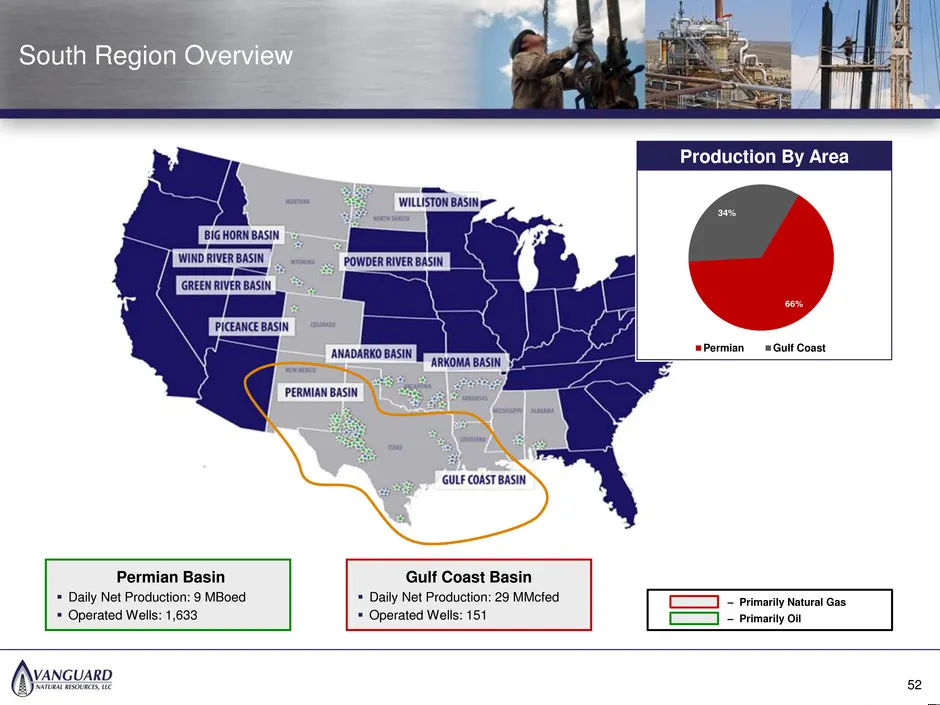
Slide 52: South Region Overview
36 32 87 89 89 89 83 141 213 168 177 182 South Region Overview Gulf Coast Basin Daily Net Production: 29 MMcfed Operated Wells: 151 Permian Basin Daily Net Production: 9 MBoed Operated Wells: 1,633 – Primarily Natural Gas – Primarily Oil Production By Area 66% 34% Permian Gulf Coast Producti
Slide 53: Permian Overview
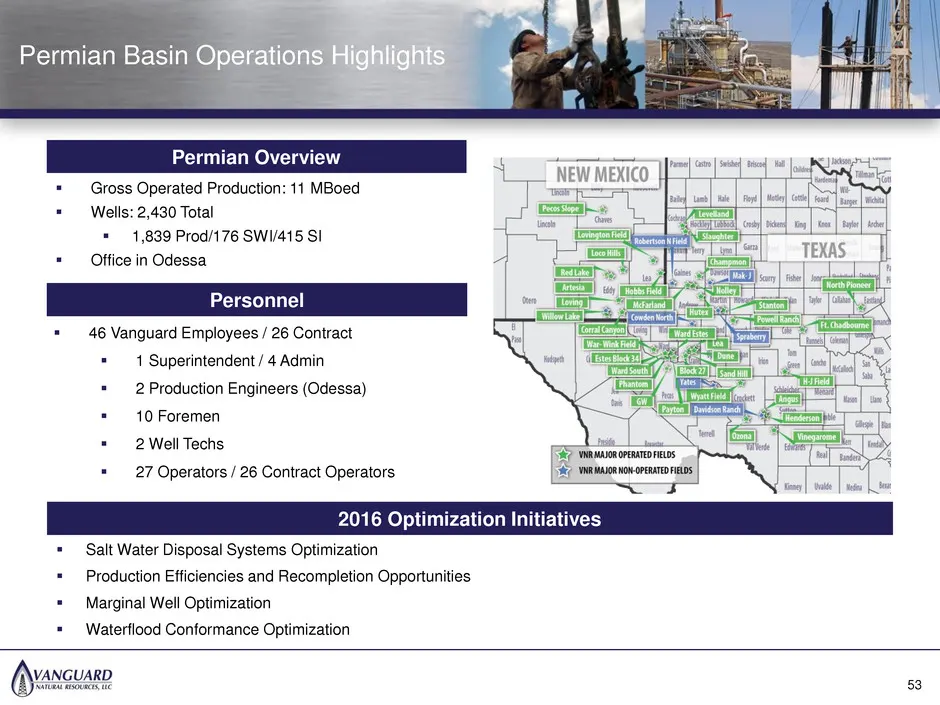
36 32 87 89 89 89 83 141 213 168 177 182 Gross Operated Production: 11 MBoed Wells: 2,430 Total 1,839 Prod/176 SWI/415 SI Office in Odessa Permian Overview OPERATIONS MAP Personnel 46 Vanguard Employees / 26 Contract 1 Superintendent / 4 Admin 2 Production Engineers (Odessa) 10 Forem
Slide 54: New Mexico Operations Highlights
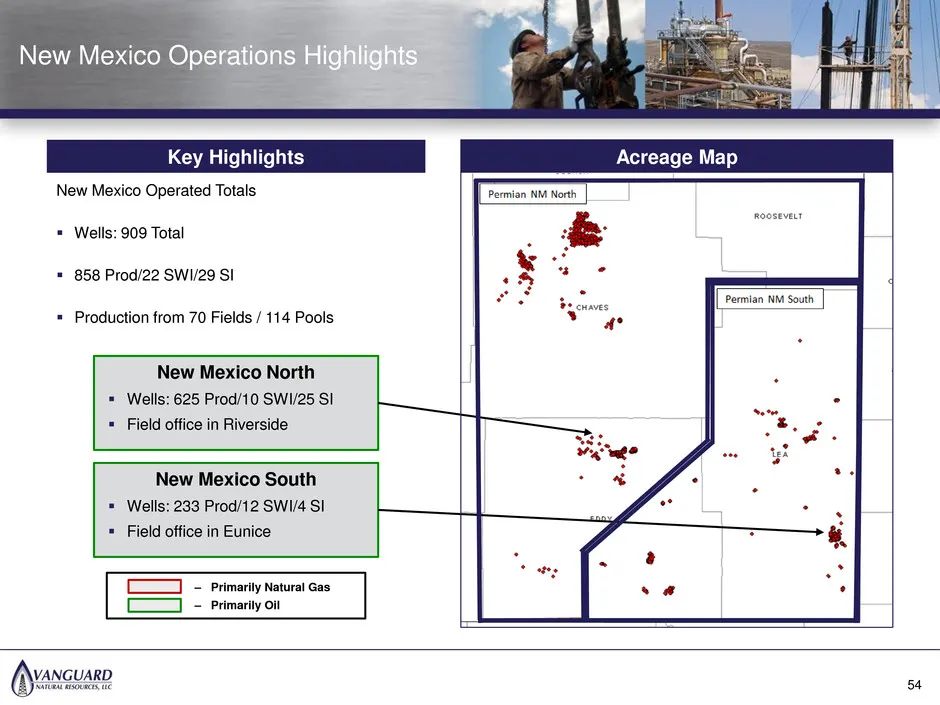
36 32 87 89 89 89 83 141 213 168 177 182 New Mexico North Wells: 625 Prod/10 SWI/25 SI Field office in Riverside New Mexico South Wells: 233 Prod/12 SWI/4 SI Field office in Eunice New Mexico Operated Totals Wells: 909 Total 858 Prod/22 SWI/29 SI Production from 70 Fields / 114 Pools N
Slide 55: Permian Texas Operations Highlights
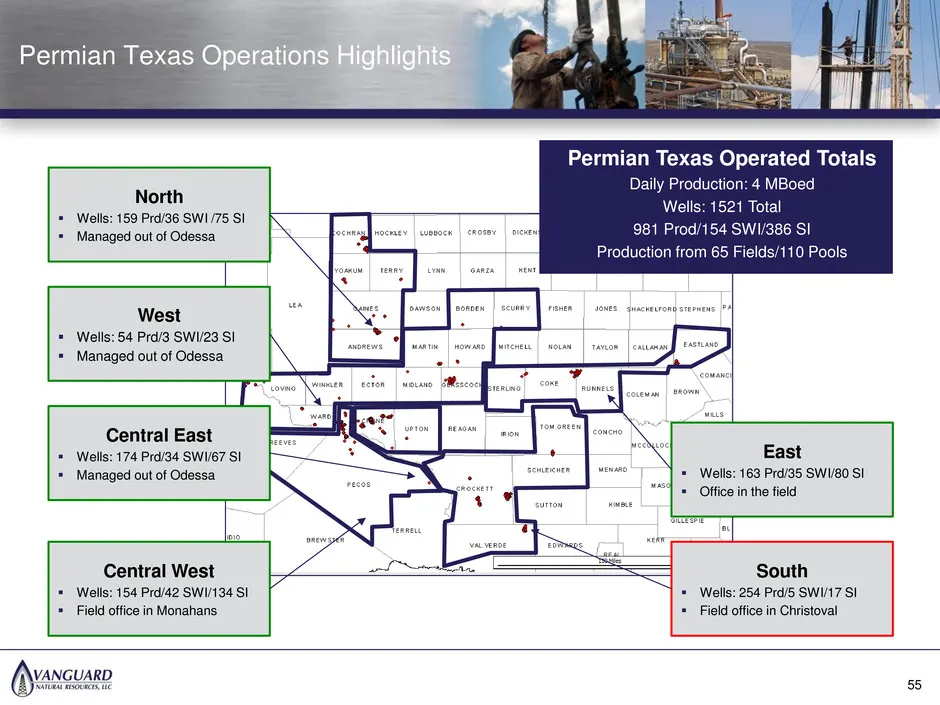
36 32 87 89 89 89 83 141 213 168 177 182 North Wells: 159 Prd/36 SWI /75 SI Managed out of Odessa Central West Wells: 154 Prd/42 SWI/134 SI Field office in Monahans Central East Wells: 174 Prd/34 SWI/67 SI Managed out of Odessa West Wells: 54 Prd/3 SWI/23 SI Managed out of Odessa Eas
Slide 56: Glasscock County Acreage Opportunity
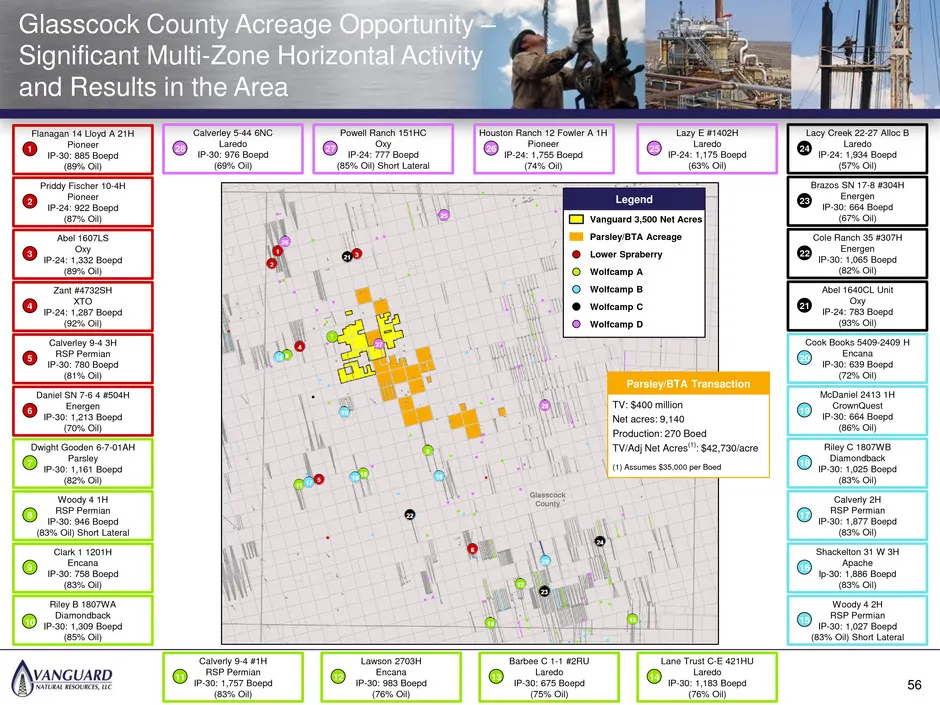
36 32 87 89 89 89 83 141 213 168 177 182 Glasscock County Glasscock County Acreage Opportunity – Significant Multi-Zone Horizontal Activity and Results in the Area Legend Vanguard 3,500 Net Acres Parsley/BTA Acreage Lower Spraberry Wolfcamp A Wolfcamp B Wolfcamp C Wolfcamp D Flanagan 14 Lloyd A 21H
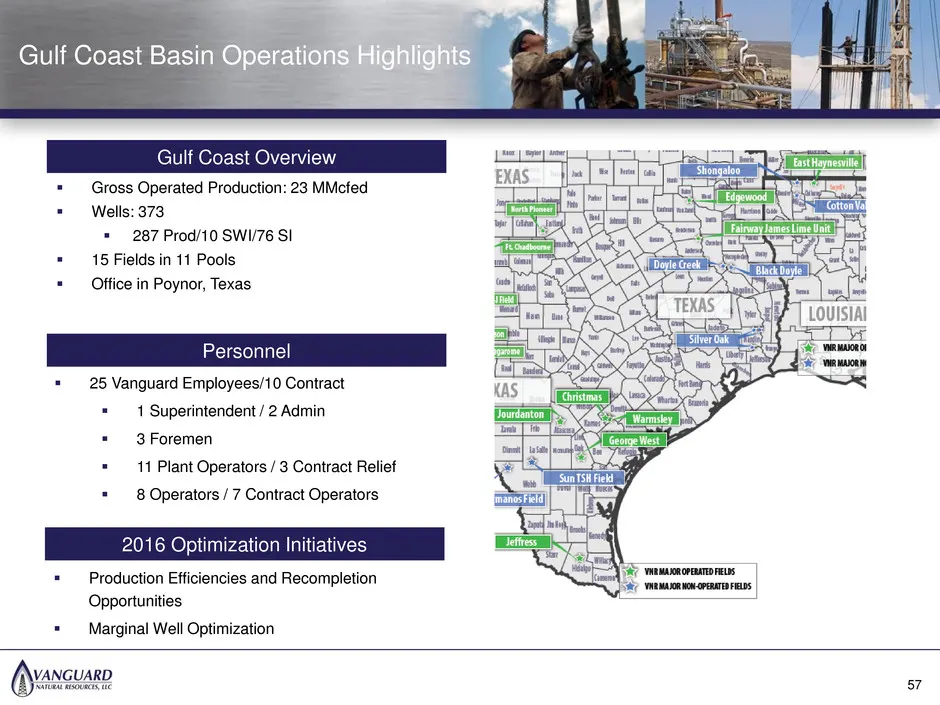
Slide 57: Gulf Coast Overview
36 32 87 89 89 89 83 141 213 168 177 182 Gross Operated Production: 23 MMcfed Wells: 373 287 Prod/10 SWI/76 SI 15 Fields in 11 Pools Office in Poynor, Texas Gulf Coast Overview Personnel Production Efficiencies and Recompletion Opportunities Marginal Well Optimization 57 Gulf Coast Bas
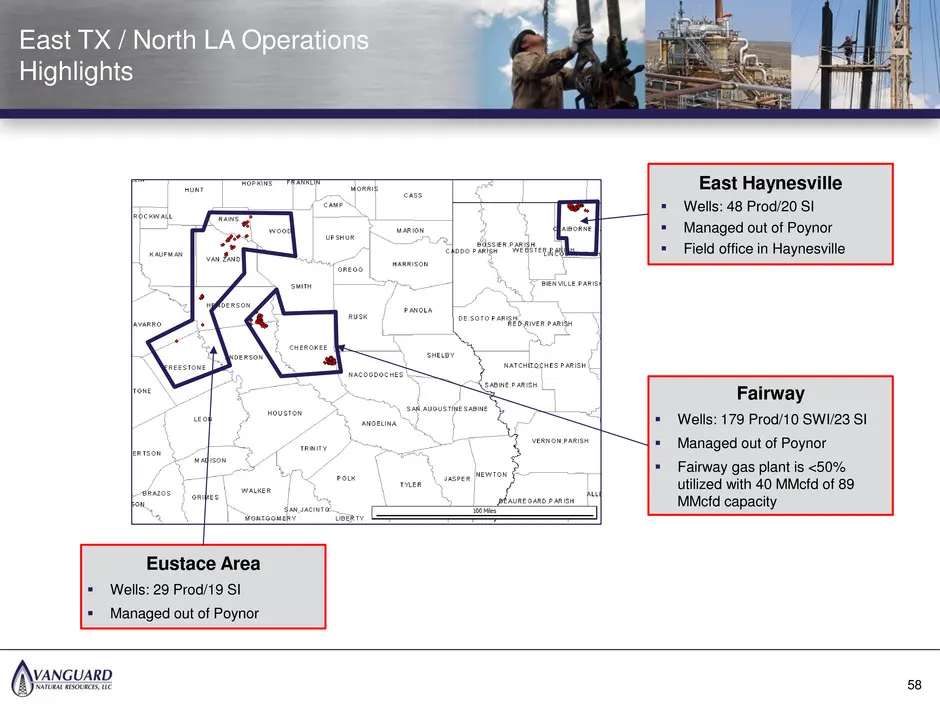
Slide 58: East TX / North LA Operations Highlights
36 32 87 89 89 89 83 141 213 168 177 182 East Haynesville Wells: 48 Prod/20 SI Managed out of Poynor Field office in Haynesville Fairway Wells: 179 Prod/10 SWI/23 SI Managed out of Poynor Fairway gas plant is <50% utilized with 40 MMcfd of 89 MMcfd capacity Eustace Area Wells: 29 Prod/
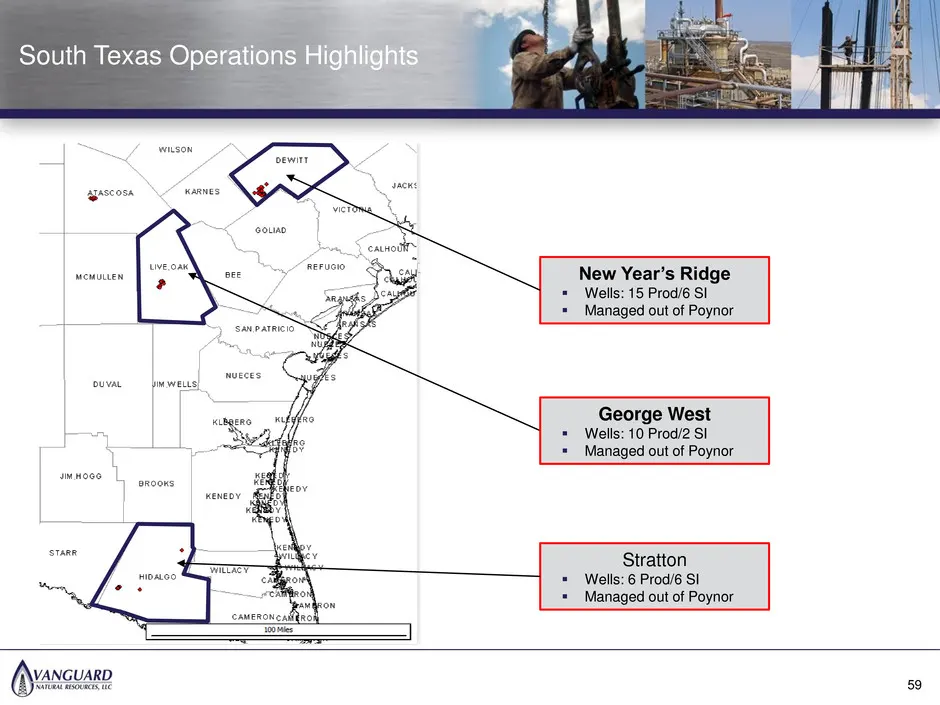
Slide 59: South Texas Operations Highlights
36 32 87 89 89 89 83 141 213 168 177 182 New Year’s Ridge Wells: 15 Prod/6 SI Managed out of Poynor George West Wells: 10 Prod/2 SI Managed out of Poynor Stratton Wells: 6 Prod/6 SI Managed out of Poynor South Texas Operations Highlights 59
Slide 60: East Haynesville Field Overview & Upside
36 32 87 89 89 89 83 141 213 168 177 182 East Haynesville Field Overview & Upside 60
Slide 61: East Haynesville Field Overview
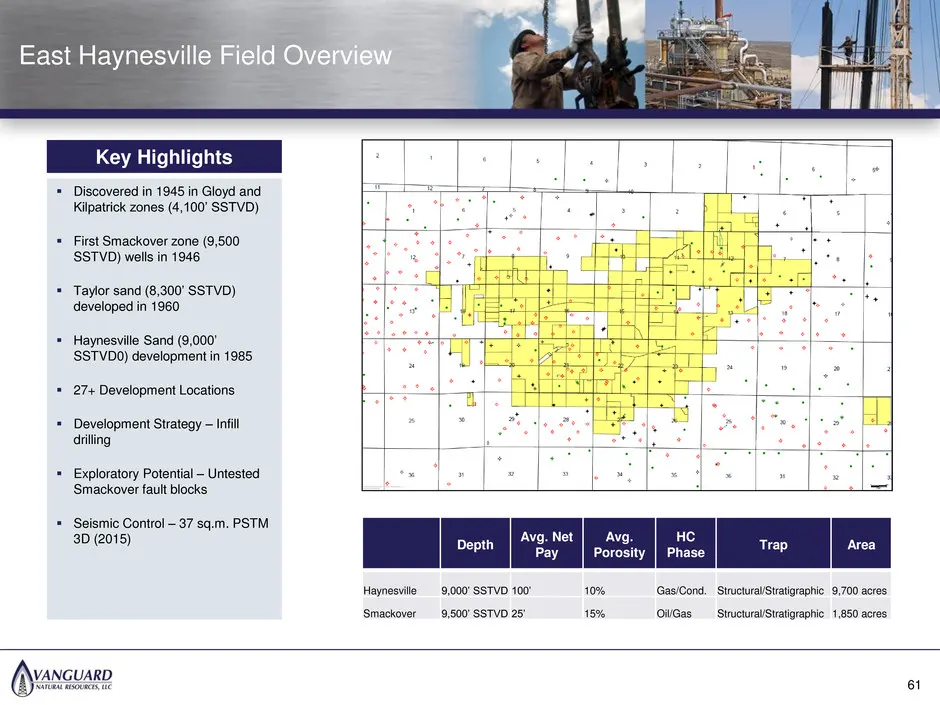
36 32 87 89 89 89 83 141 213 168 177 182 Depth Avg. Net Pay Avg. Porosity HC Phase Trap Area Haynesville 9,000’ SSTVD 100’ 10% Gas/Cond. Structural/Stratigraphic 9,700 acres Smackover 9,500’ SSTVD 25’ 15% Oil/Gas Structural/Stratigraphic 1,850 acres East Haynesville Field Overview Key Highlights D
Slide 62: Haynesville Sand Type Curve
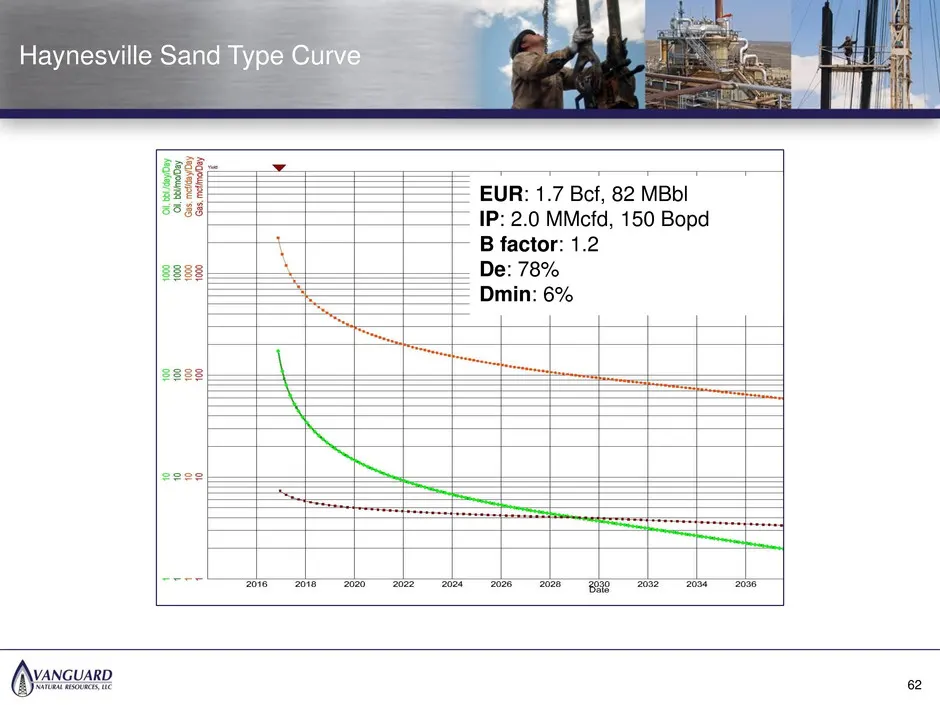
36 32 87 89 89 89 83 141 213 168 177 182 EUR: 1.7 Bcf, 82 MBbl IP: 2.0 MMcfd, 150 Bopd B factor: 1.2 De: 78% Dmin: 6% 62 Haynesville Sand Type Curve
Slide 63: Haynesville Sand Economics
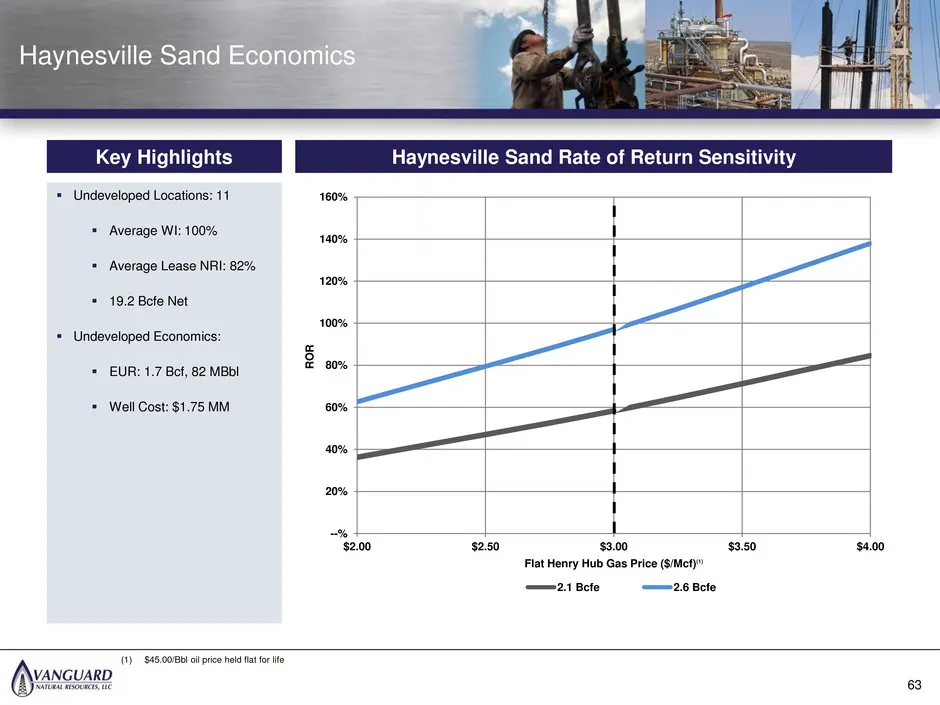
36 32 87 89 89 89 83 141 213 168 177 182 Haynesville Sand Economics (1) $45.00/Bbl oil price held flat for life Haynesville Sand Rate of Return Sensitivity Key Highlights Undeveloped Locations: 11 Average WI: 100% Average Lease NRI: 82% 19.2 Bcfe Net Undeveloped Economics: EUR: 1.7 Bcf,
Slide 64: Smackover Type Curve
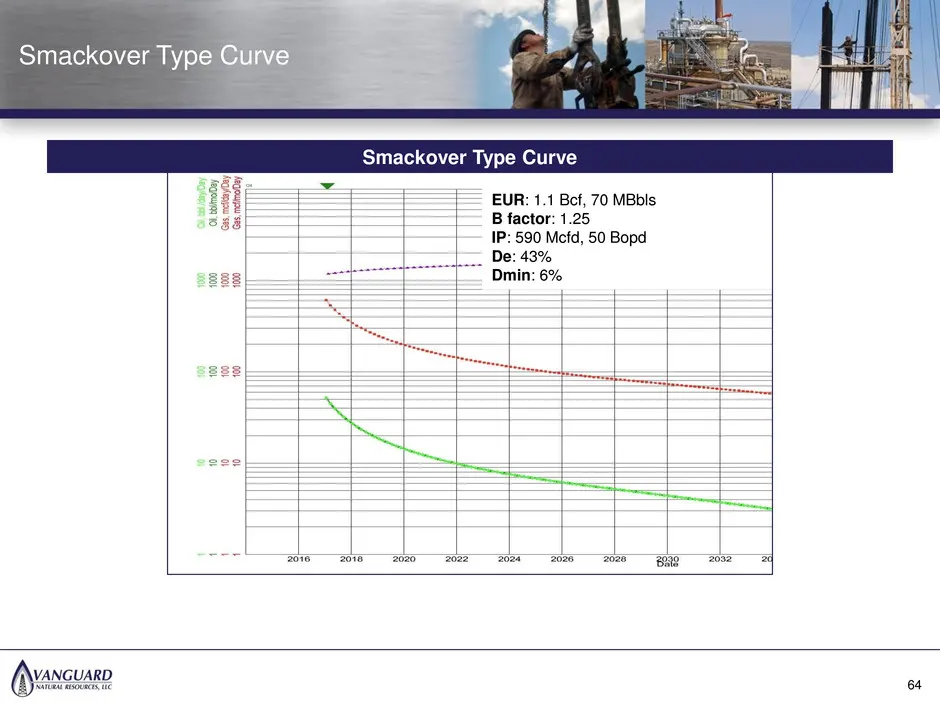
36 32 87 89 89 89 83 141 213 168 177 182 EUR: 1.1 Bcf, 70 MBbls B factor: 1.25 IP: 590 Mcfd, 50 Bopd De: 43% Dmin: 6% Smackover Type Curve Smackover Type Curve 64
Slide 65: Smackover Economics
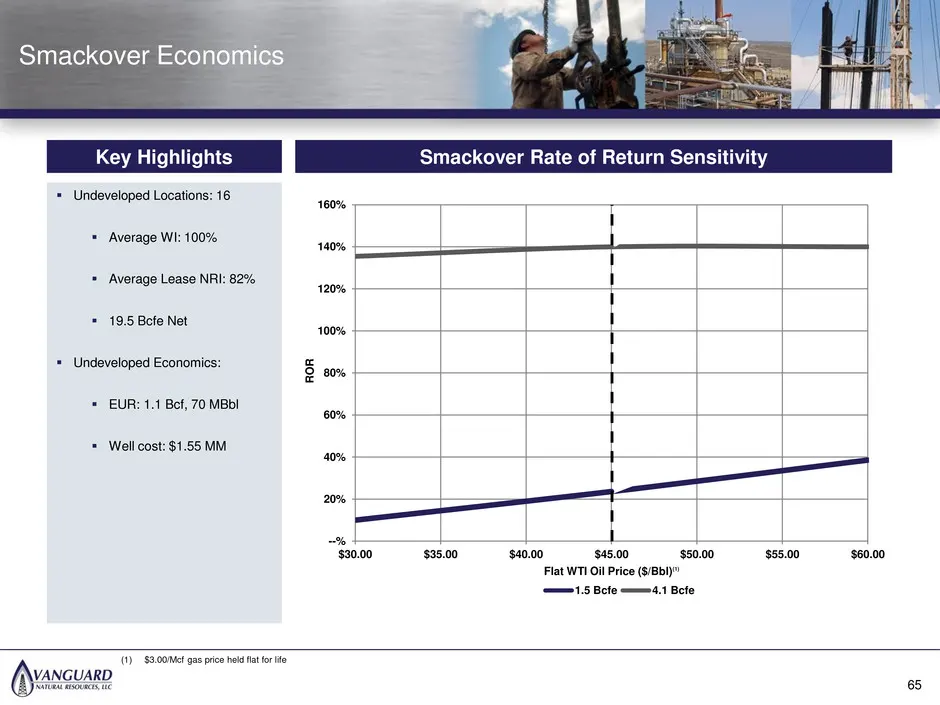
36 32 87 89 89 89 83 141 213 168 177 182 Smackover Economics (1) $3.00/Mcf gas price held flat for life 84 Smackover Rate of Return Sensitivity Key Highlights Undeveloped Locations: 16 Average WI: 100% Average Lease NRI: 82% 19.5 Bcfe Net Undeveloped Economics: EUR: 1.1 Bcf, 70 MBbl We
Slide 66: Red Lake Overview & Upside
36 32 87 89 89 89 83 141 213 168 177 182 Red Lake Overview & Upside 66
Slide 67: Red Lake Field – Permian Basin
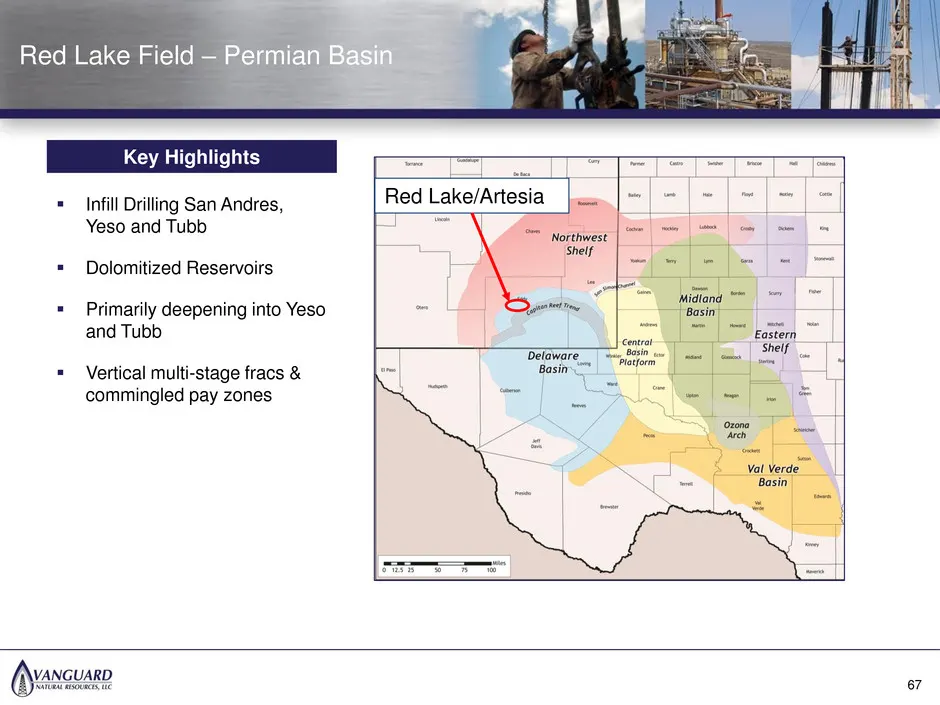
36 32 87 89 89 89 83 141 213 168 177 182 Infill Drilling San Andres, Yeso and Tubb Dolomitized Reservoirs Primarily deepening into Yeso and Tubb Vertical multi-stage fracs & commingled pay zones Red Lake/Artesia Red Lake Field – Permian Basin Key Highlights 67
Slide 68: Red Lake Type Curve
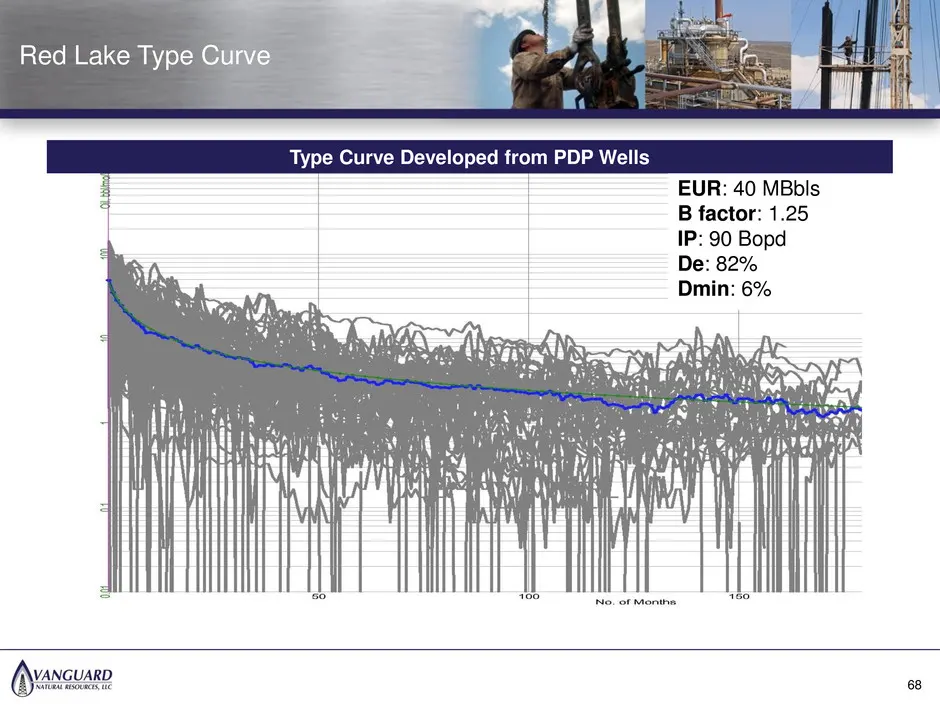
36 32 87 89 89 89 83 141 213 168 177 182 EUR: 40 MBbls B factor: 1.25 IP: 90 Bopd De: 82% Dmin: 6% Red Lake Type Curve 68 Type Curve Developed from PDP Wells
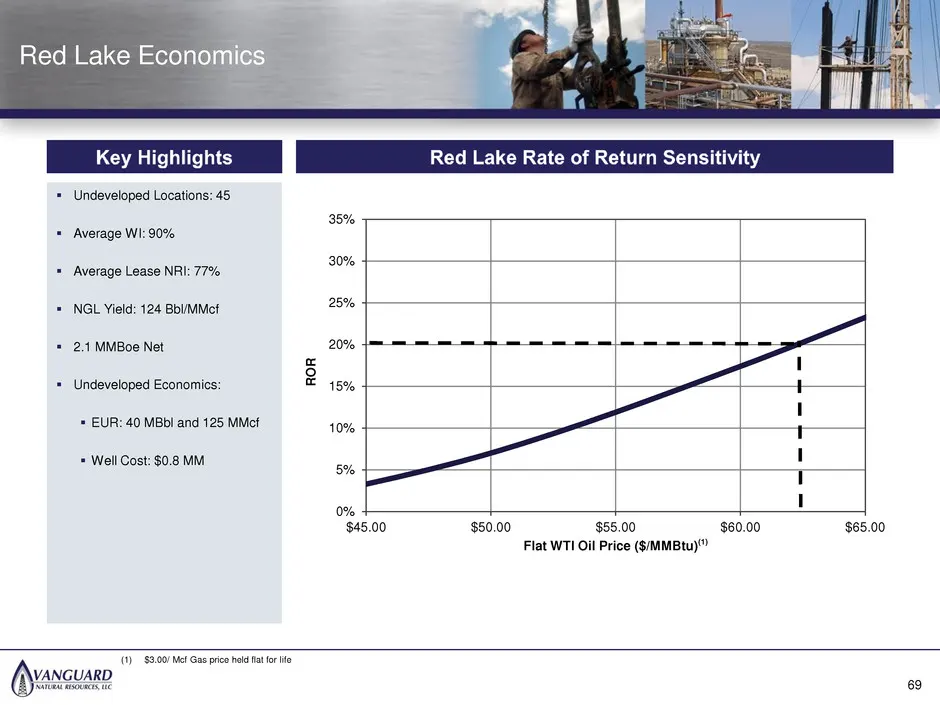
Slide 69: Red Lake Economics
36 32 87 89 89 89 83 141 213 168 177 182 Red Lake Economics (1) $3.00/ Mcf Gas price held flat for life Undeveloped Locations: 45 Average WI: 90% Average Lease NRI: 77% NGL Yield: 124 Bbl/MMcf 2.1 MMBoe Net Undeveloped Economics: EUR: 40 MBbl and 125 MMcf Well Cost: $0.8 MM 0% 5% 10%
Slide 70: Business Plan Overview
36 32 87 89 89 89 83 141 213 168 177 182 Business Plan Overview 70
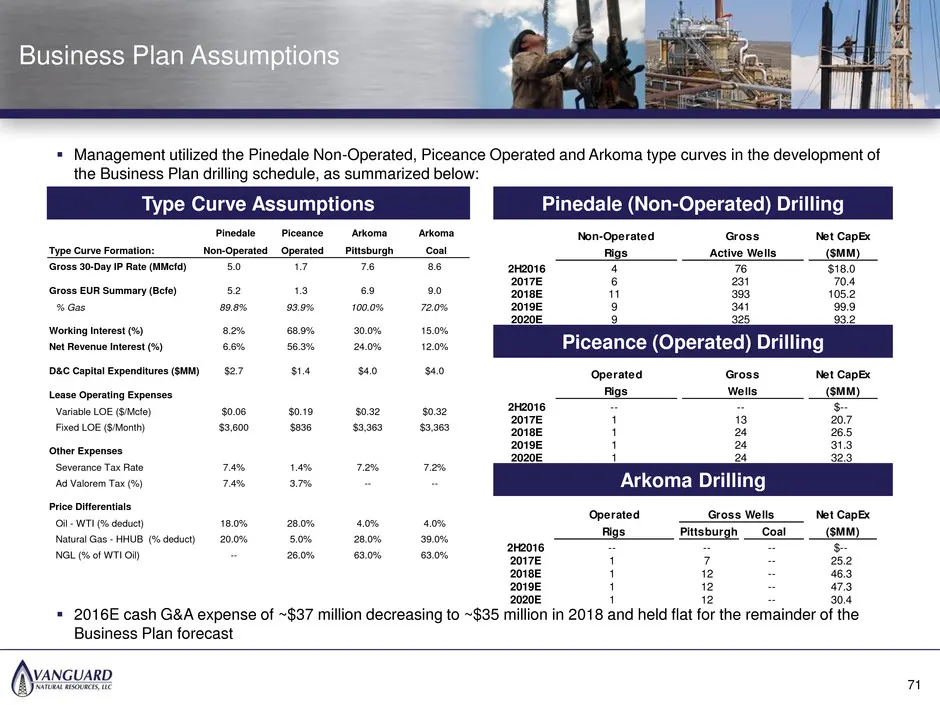
Slide 71: Business Plan Assumptions
36 32 87 89 89 89 83 141 213 168 177 182 Business Plan Assumptions Management utilized the Pinedale Non-Operated, Piceance Operated and Arkoma type curves in the development of the Business Plan drilling schedule, as summarized below: Pinedale Piceance Arkoma Arkoma Type Curve Formation: Non-Opera
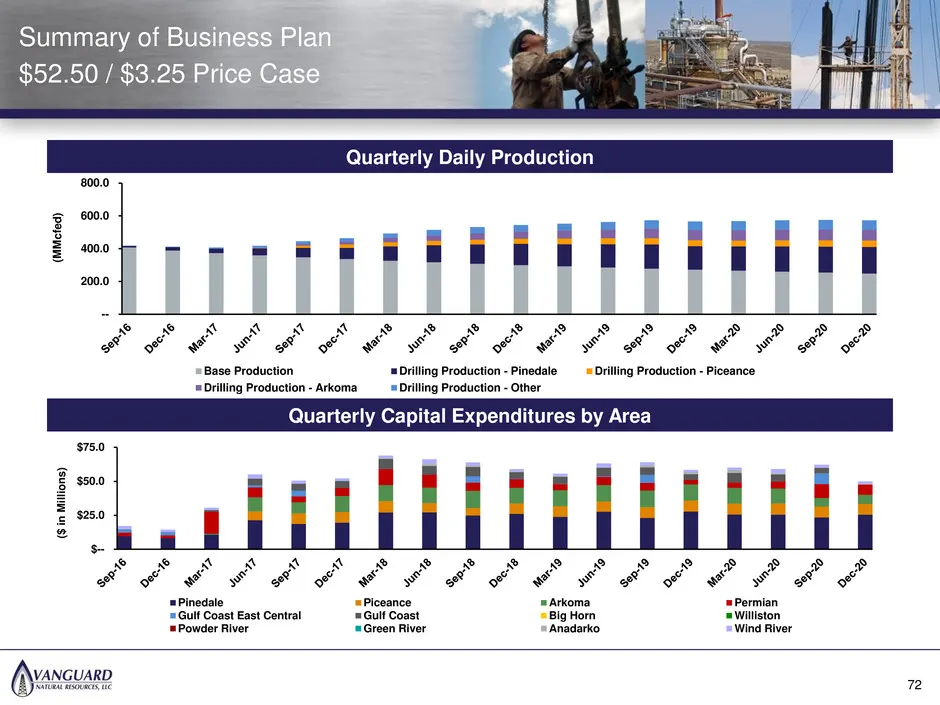
Slide 72: Summary of Business Plan
36 32 87 89 89 89 83 141 213 168 177 182 Summary of Business Plan $52.50 / $3.25 Price Case Quarterly Daily Production Quarterly Capital Expenditures by Area 72 -- 200.0 400.0 600.0 800.0 (MM cfed ) Base Production Drilling Production - Pinedale Drilling Production - Piceance Drilling Production - A
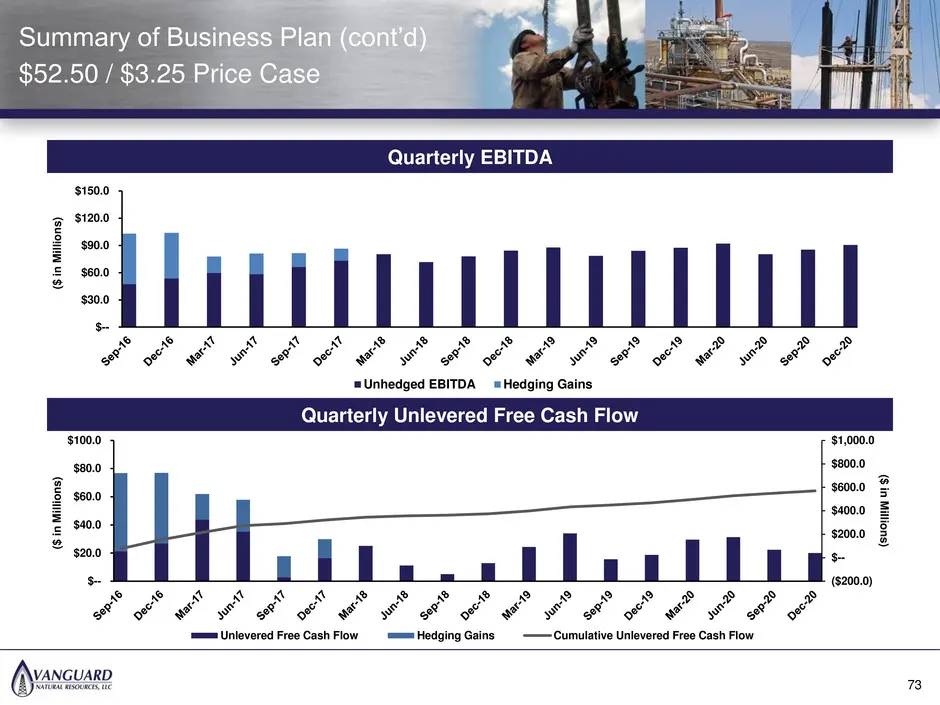
Slide 73: Summary of Business Plan (cont'd)
36 32 87 89 89 89 83 141 213 168 177 182 Summary of Business Plan (cont’d) $52.50 / $3.25 Price Case Quarterly EBITDA Quarterly Unlevered Free Cash Flow 73 $-- $30.0 $60.0 $90.0 $120.0 $150.0 ($ in Mill ions ) Unhedged EBITDA Hedging Gains ($200.0) $-- $200.0 $400.0 $600.0 $800.0 $1,000.0 $-- $20.0
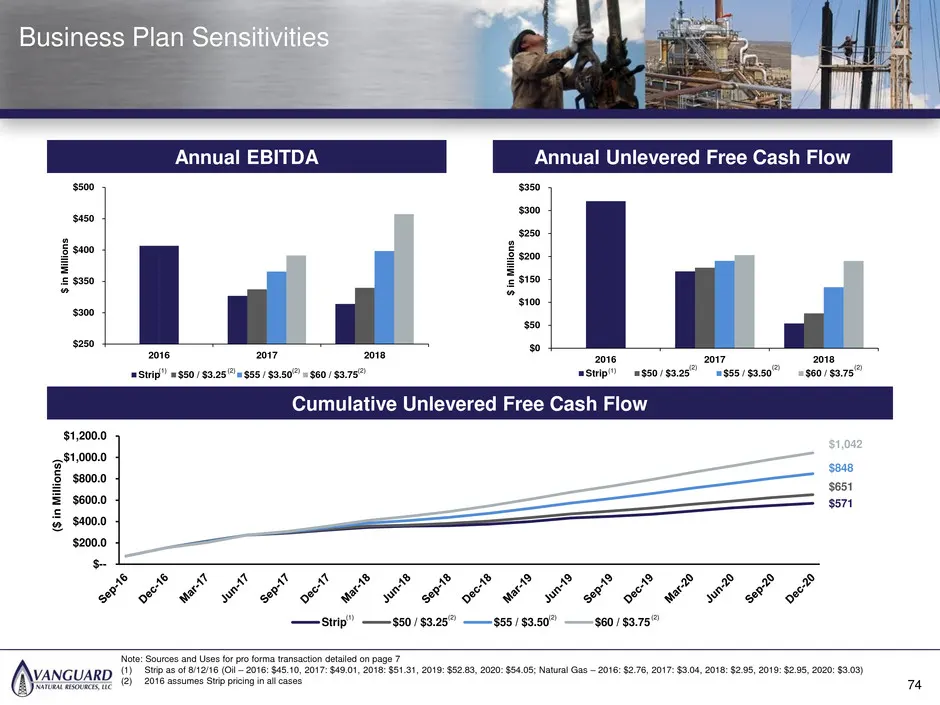
Slide 74: Business Plan Sensitivities
36 32 87 89 89 89 83 141 213 168 177 182 Business Plan Sensitivities Annual EBITDA Annual Unlevered Free Cash Flow 74 Cumulative Unlevered Free Cash Flow $250 $300 $350 $400 $450 $500 2016 2017 2018 $ i n M illi on s Strip $50 / $3.25 $55 / $3.50 $60 / $3.75 $0 $50 $100 $150 $200 $250 $300 $350 2016
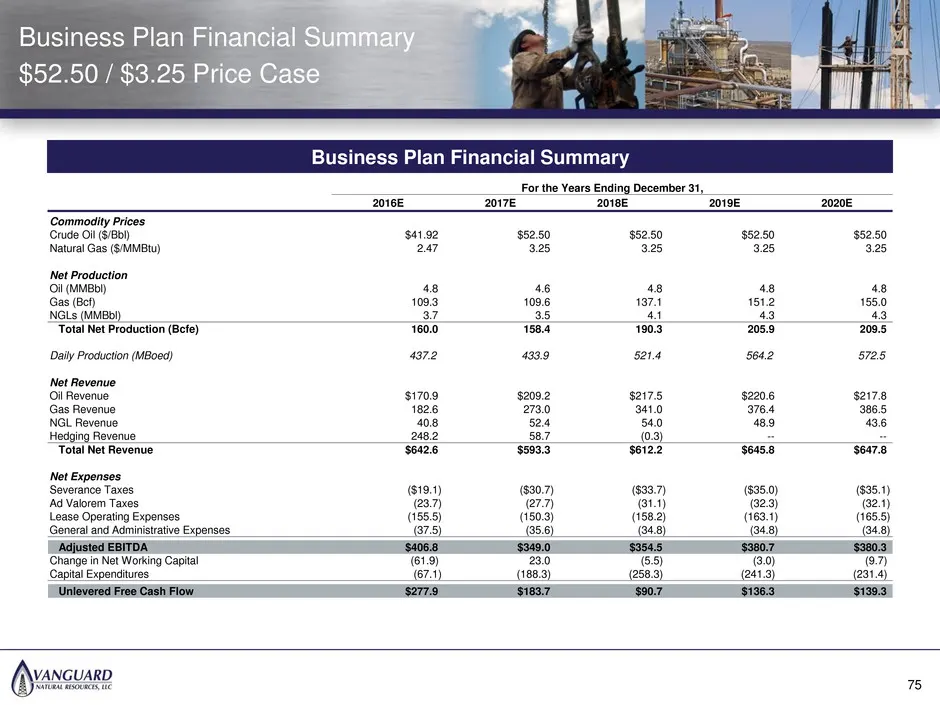
Slide 75: Business Plan Financial Summary
36 32 87 89 89 89 83 141 213 168 177 182 Business Plan Financial Summary $52.50 / $3.25 Price Case Business Plan Financial Summary 75 For the Years Ending December 31, 2016E 2017E 2018E 2019E 2020E Commodity Prices Crude Oil ($/Bbl) $41.92 $52.50 $52.50 $52.50 $52.50 Natural Gas ($/MMBtu) 2.47 3.25
Source: SEC EDGAR · 8-K filed Oct 7, 2016
More decks from Vanguard Natural Resources LLC
 Debt Investor Presentation (April 2019)14 slides · Apr 1, 2019
 Investor Presentation (August 2018)26 slides · Aug 13, 2018
 Presentation (May 2017)6 slides · May 25, 2017
 Technical Presentation (May 2017)5 slides · May 25, 2017
 Debt Investor Presentation (May 2017)10 slides · May 25, 2017
 Investor Presentation (February 2017)61 slides · Feb 2, 2017