International Coal — Bear Stearns Commodities & Capital Goods Conference (November 2007)
29 slides from International Coal's conference presentation, Nov 29, 2007
Slide 1: Mining Opportunities
Mining Opportunities Exhibit 99.1 Bennett K. Hatfield President and CEO November 29, 2007 Bear Stearns Commodities & Capital Goods Conference
Slide 2: Forward-Looking Statements
Mining Opportunities Statements that are not historical fact are forward-looking statements and may involve a number of risks and uncertainties. We have used the words “anticipate” “believe,” “could,” “estimate,” “expect,” “intend,” “may,” “plan,” “predict,” “project” and similar terms and phrases,
Slide 3: Summary Statistics
Mining Opportunities Summary Statistics Well-positioned with operations in 3 of 4 largest US coal producing regions Extensive reserve base (69% owned) supports internal growth opportunity Growth strategy targeted toward higher margin metallurgical and premium steam coal markets 100% union free workf
Slide 4: Current and Future Operations
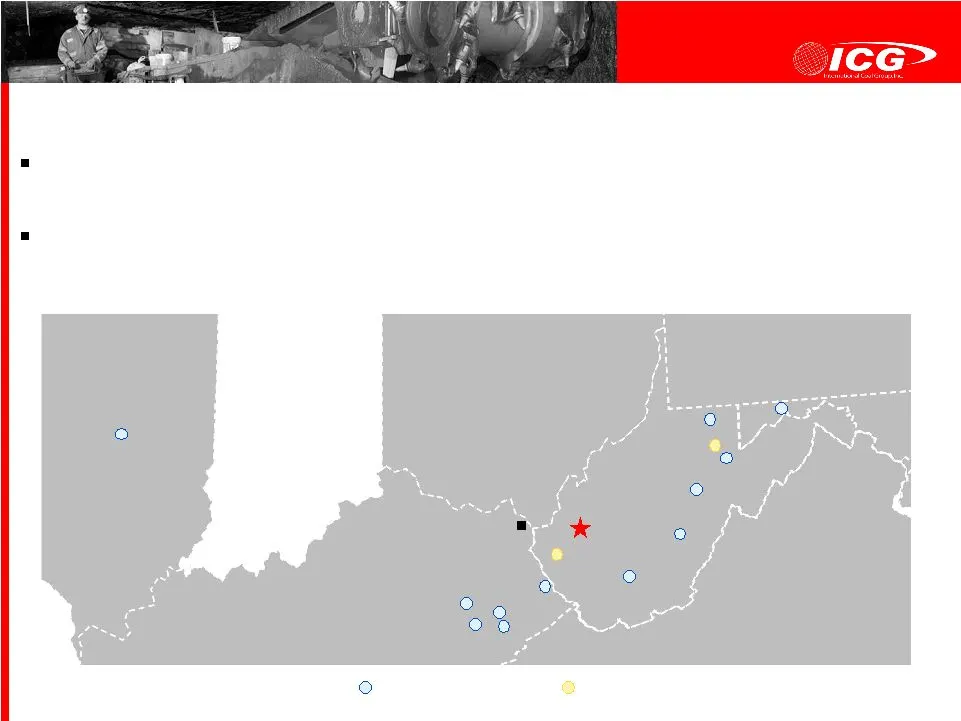
Mining Opportunities 12 active mining complexes - 7 in Central Appalachia, 4 in Northern Appalachia, and 1 in Illinois Basin 3 mine complexes (Raven, Sentinel and Beckley) opened within last 12 months; Tygart #1 expected to open by late 2009 Current and Future Operations Illinois Illinois Kentucky O
Slide 5: High Caliber Reserve Base
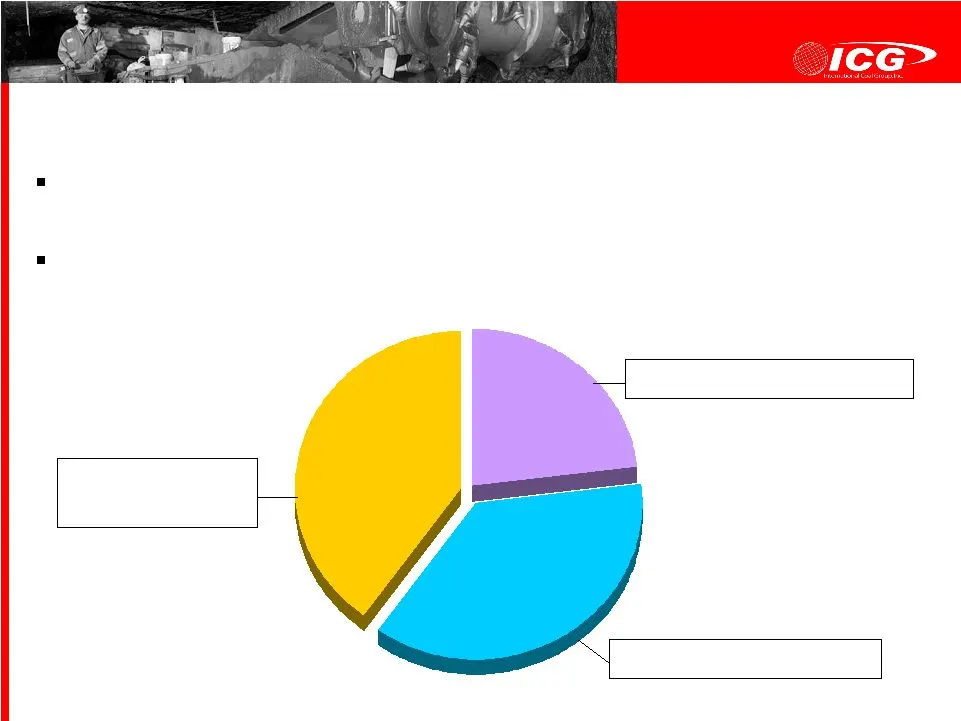
Mining Opportunities ICG controls 958 million tons of high-quality coal reserves that are primarily high BTU, low sulfur steam and metallurgical coal 54% of Appalachian region reserves are metallurgical quality High Caliber Reserve Base CAPP, 223 million tons NAPP, 355 million tons Illinois Basin, 3
Slide 6: Total Reserve Profile: Owned vs. Leased
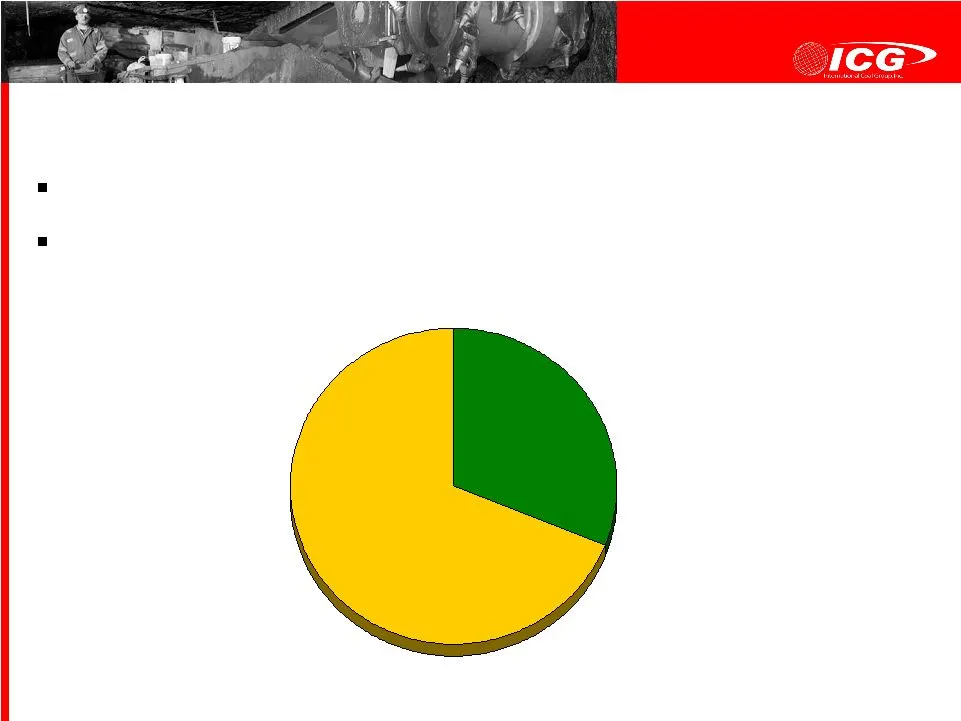
Mining Opportunities 31% Total Reserve Profile: Owned vs. Leased 69% Leased 294 million tons ICG ownership % is largest among publicly traded peers Peer group median ownership is less than 30% Owned 664 million tons
Slide 7: Production Outlook – Selective Growth
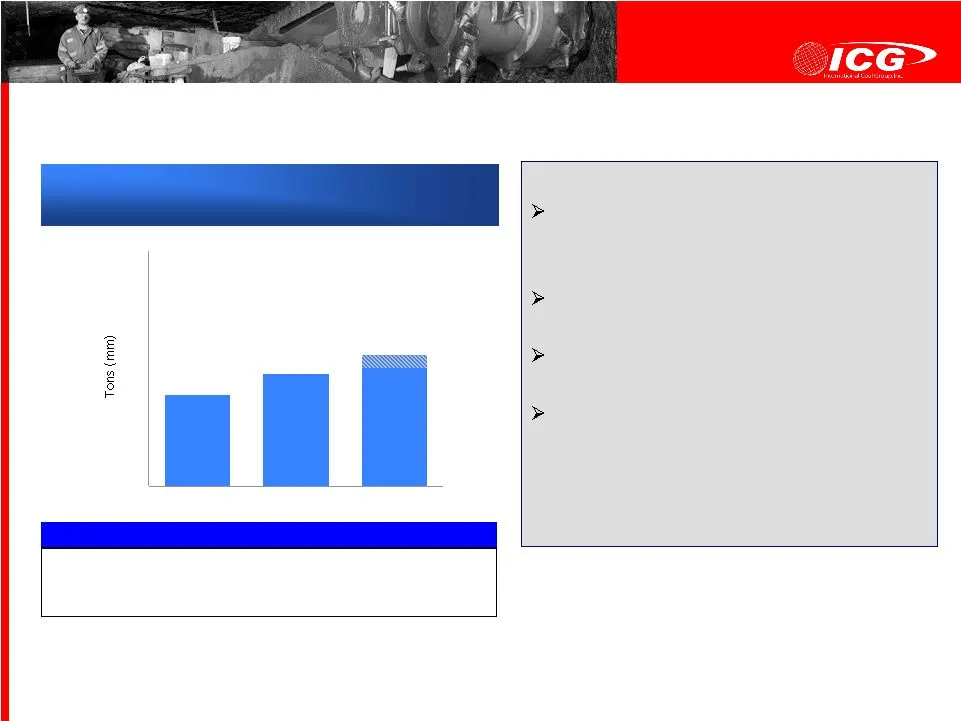
Mining Opportunities Projected Production Production by Region Note: 1 2005 pro forma for acquisition of Anker / CoalQuest 2 Per management guidance as of October 24, 2007 16.5 14.9 17-18 Production Outlook – Selective Growth CAPP 66% 68% 67% NAPP 19% 19% 21% ILB 15% 13% 12% Target projects that cre
Slide 8: Raven Complex (Kite, KY)
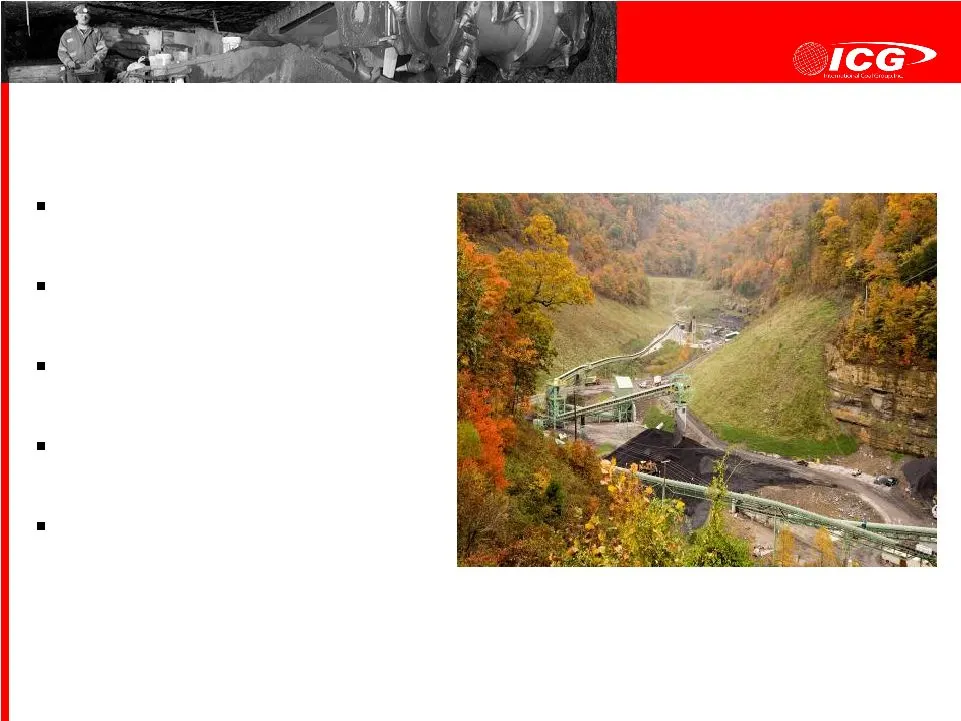
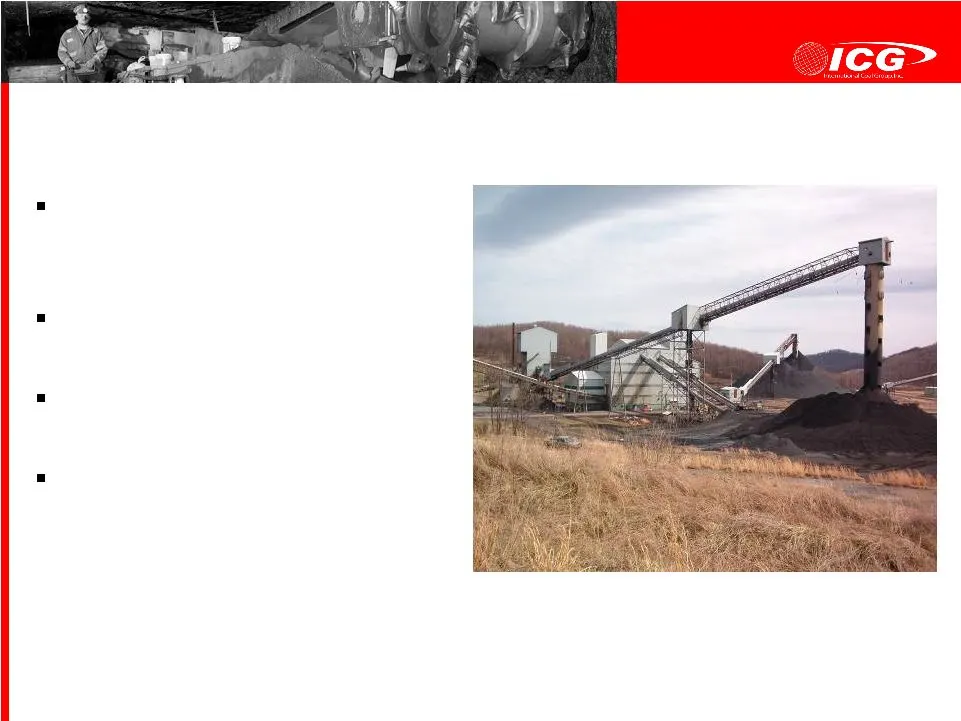
Mining Opportunities Began shipments in October Two underground mines now operating 1.2 million tons/year of high quality steam coal Full production expected by early 2008 Target market is the southeastern utility sector Raven Complex (Kite, KY)
Slide 9: Sentinel Mine (Philippi, WV)
Mining Opportunities Resumed production in late 2006 after 8-month construction outage 2 of 3 planned sections are now in production 1.5 million tons/year run rate expected by 1 st quarter 2008 Increasing shift to high volatile met market generates significant margin increase Sentinel Mine (Philippi
Slide 10: Beckley Complex (Eccles, WV)
Mining Opportunities Production commenced September 2007 One of 3 planned sections now producing 1.4 million tons/year of low vol met coal Full production expected by mid-2008 Strong interest from both export and domestic steelmakers Beckley Complex (Eccles, WV)
Slide 11: Tygart #1 Complex (Taylor County, WV)
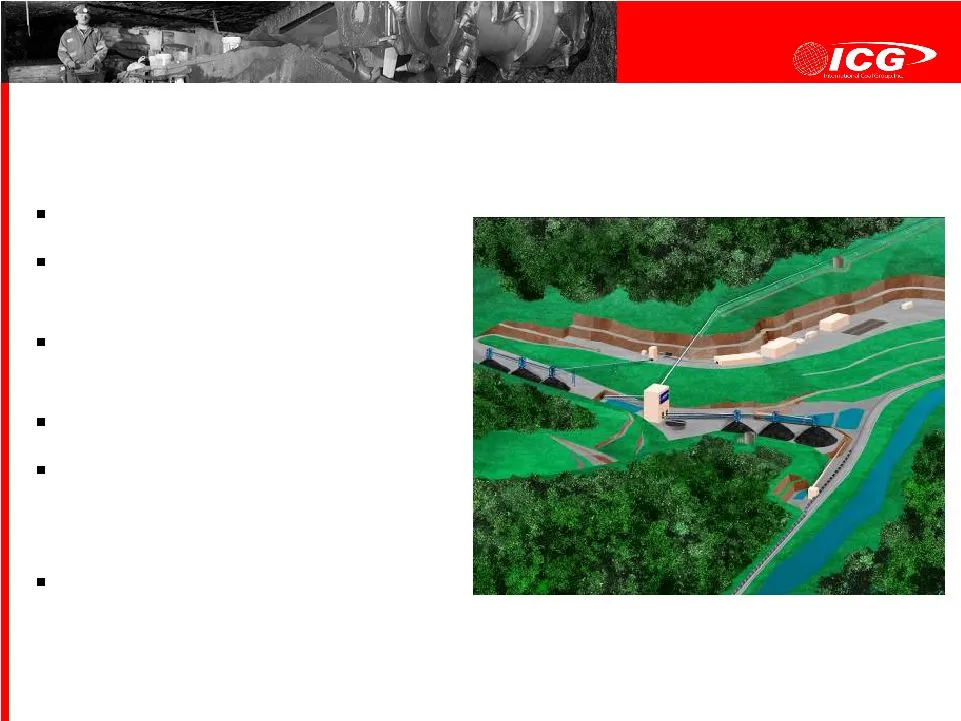
Mining Opportunities Site development: 2007-2008 Major construction of shafts and slope: 2008-2009 Planned production start-up in late 2009 3.5 million tons/year Quality well suited to either premium utility or high volatile met coal markets Underground longwall mine Tygart #1 Complex (Taylor County
Slide 12: Increasing Metallurgical Coal Production
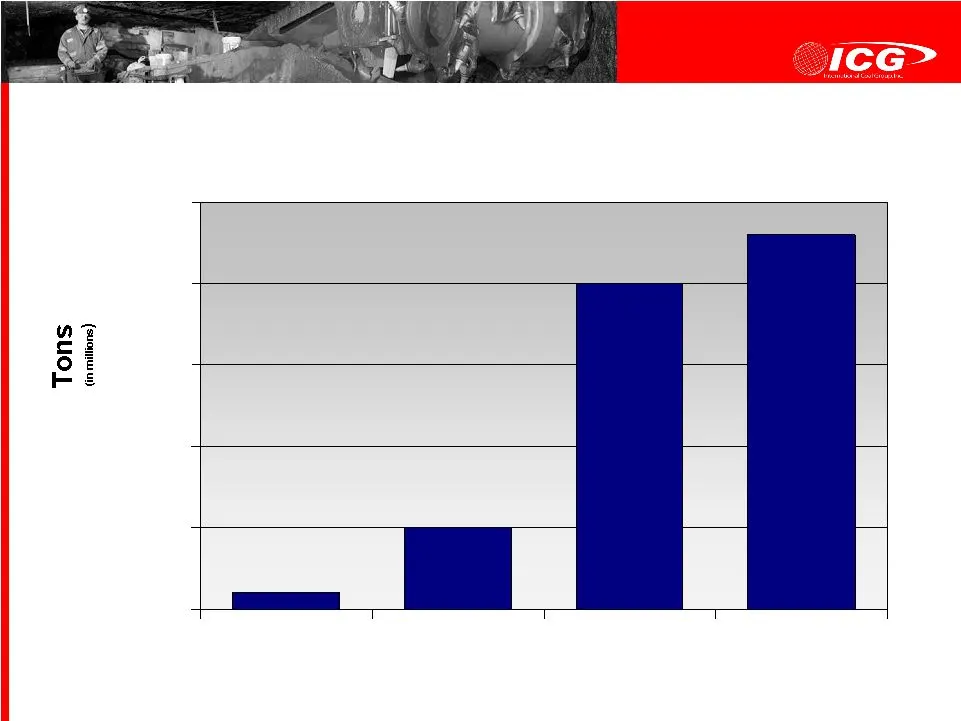
Mining Opportunities 2.3 2.0 0.5 0.1 0.0 0.5 1.0 1.5 2.0 2.5 Increasing Metallurgical Coal Production Est. Est.
Slide 13: Favorable Sales Position
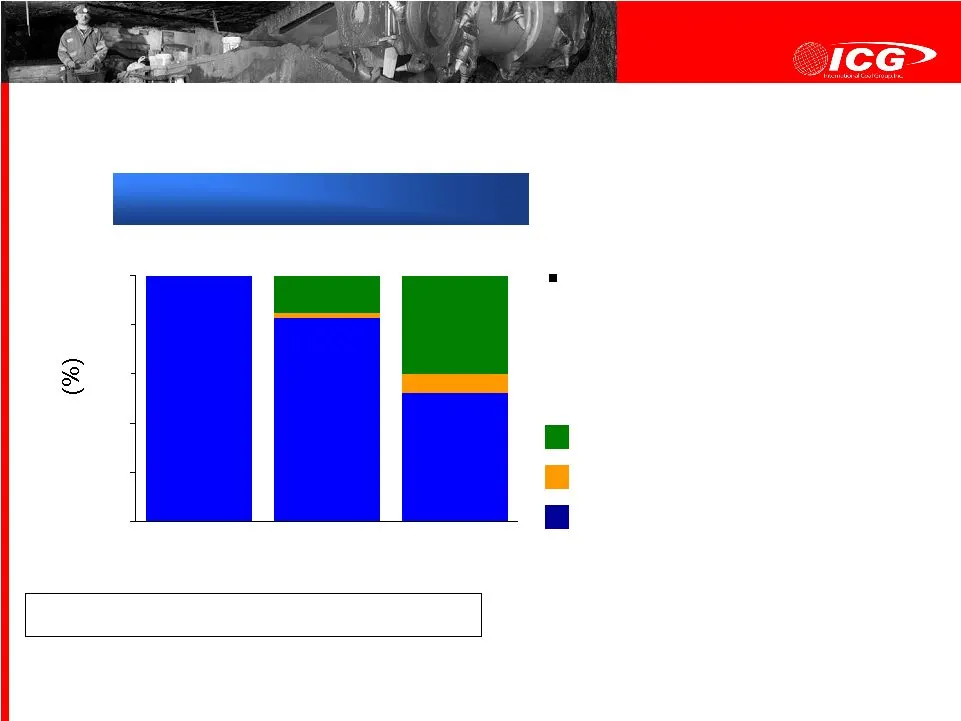
Mining Opportunities Committed Tonnage 100 83 52 2 8 15 40 Projected Sales 19-20 19-21 na (mm tons) Strong committed sales level for 2008-09, yet substantial room for upside from market improvement Note: Committed tonnages for 2008-2009 are estimated as of 11/26/07 Per management guidance as of Octo
Slide 14: ICG Export Sales Climbing Sharply
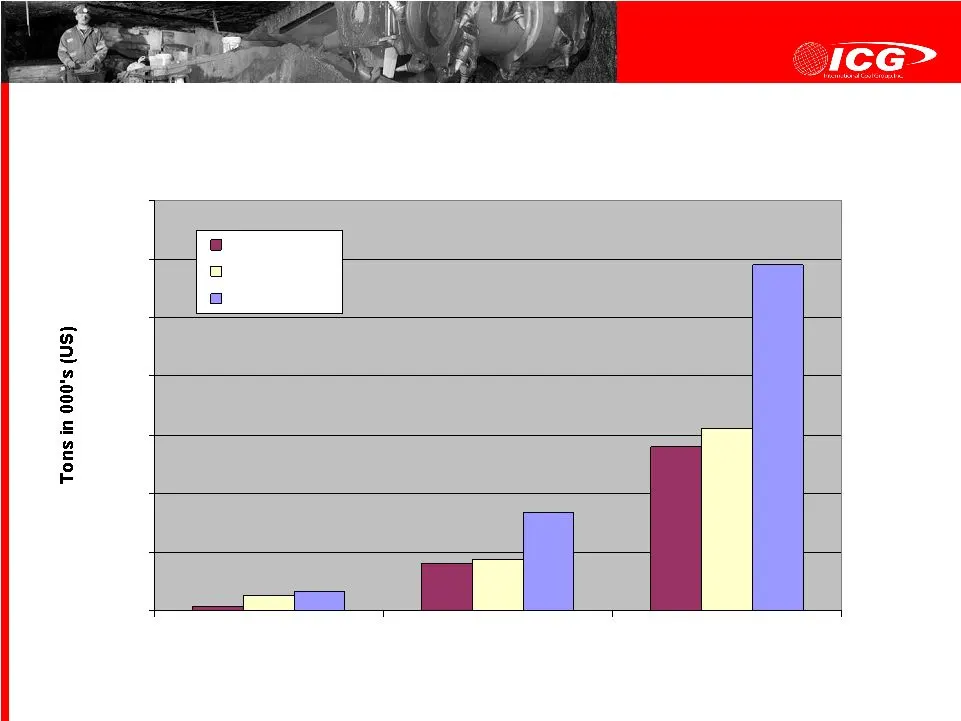
Mining Opportunities 1,000 1,500 2,000 2,500 3,000 3,500 2006 Actual 2007 Estimate 2008 Estimate Year Thermal Met Total Exports ICG Export Sales Climbing Sharply
Slide 15: Low Legacy Liabilities
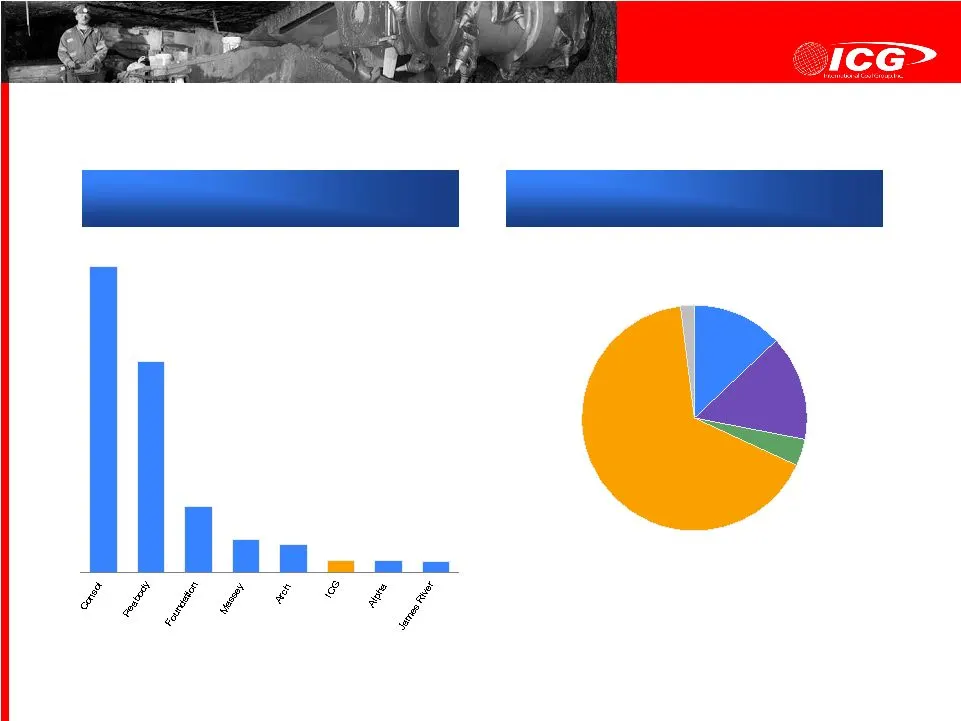
Mining Opportunities ICG Legacy Liabilities Total Legacy Liabilities ¹ ($ in millions) 3,574 2,455 Reclamation 66% Rockefeller 4% Workers Comp 2% FAS 106 13% Black lung 15% Source: Company Reports as of 12/31/06 Total: $141mm Notes: Legacy liabilities include post retirement benefits, black lung, re
Slide 16: ADDCAR – Expanding Opportunities
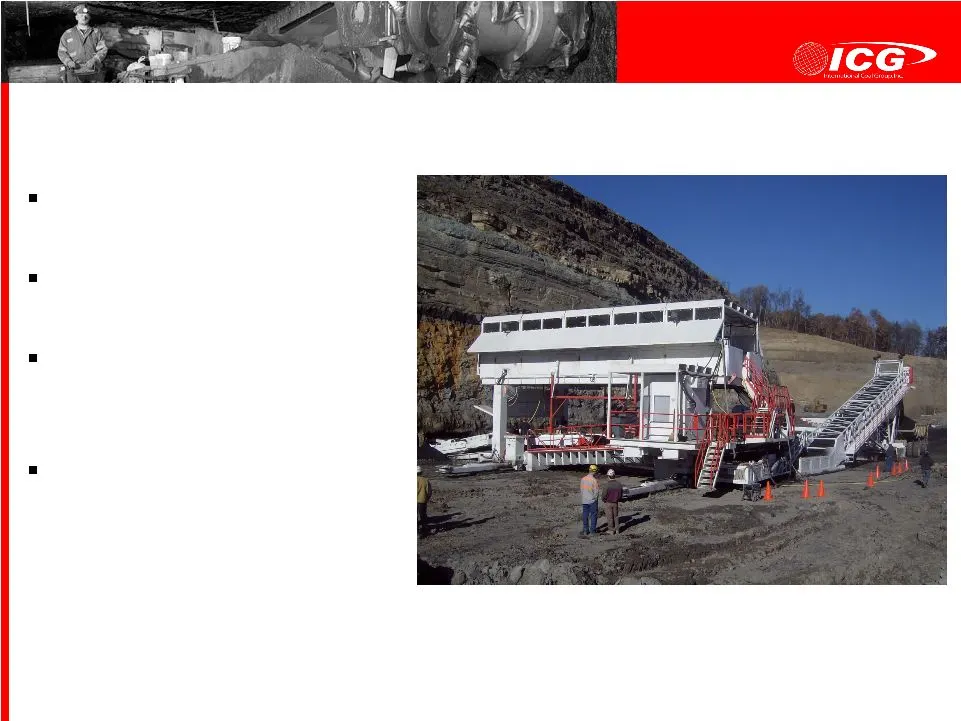
Mining Opportunities Manufactures highwall mining systems Enjoys exclusive U.S. patent rights Introduced new narrow- bench system into marketplace Q2 2007 Significant growth potential for both domestic and international markets ADDCAR – Expanding Opportunities
Slide 17: Update on Financial Matters
Mining Opportunities Update on Financial Matters
Slide 18: ICG Is Navigating a Critical Transition in 2007
Mining Opportunities Key components: – Complete ramp-up of strategic development projects representing 4.1 million annual tons of new production for 2008 and beyond • Focus on high-margin met coal operations • Secure margins on new production to replace approximately $30 million of margin contribute
Slide 19: Financial Performance Summary
Mining Opportunities ($ in millions) Tons sold 19.4 14.6 13.9 Revenue $891.6 $664.9 $644.2 % Growth 37.1% 29.7% (3.1%) Avg. coal rev/ton sold $43.05 $43.04 $42.46 EBITDA $71.7 $41.1 $57.9 % Margin 8.0% 6.2% 9.0% Year Ended December 31, 2006 September 30, 2006 September 30, 2007 Nine Months Ended Fin
Slide 20: Capital Expenditures
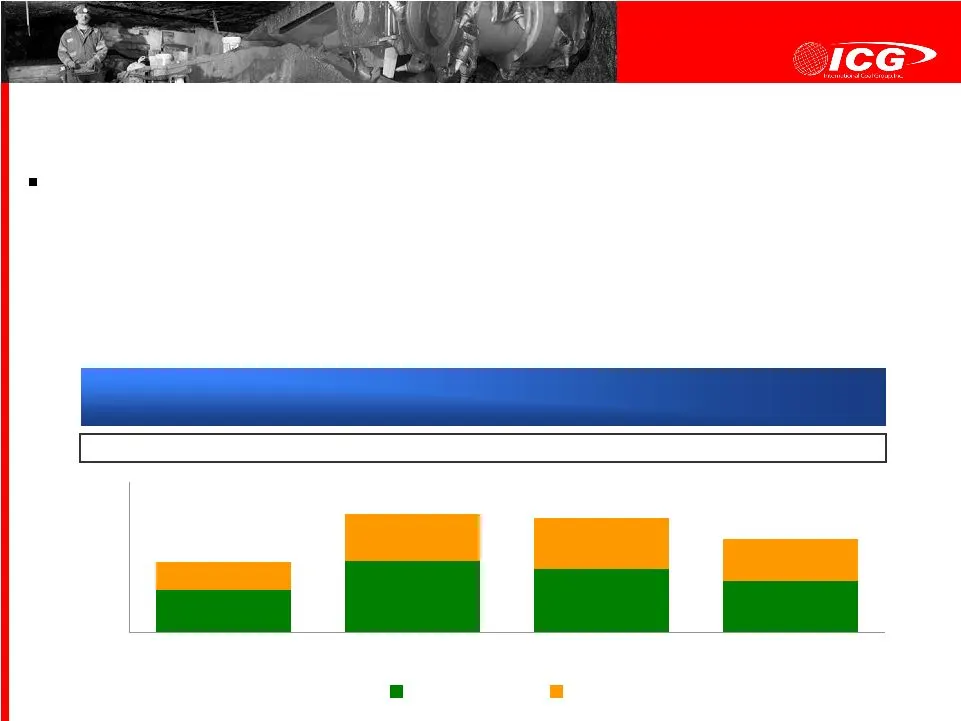
Mining Opportunities Capital Expenditures ($mm) 60% 60% 55% 55% Projected 2008 capital spending of $155 million includes: – Completion of the Sentinel and Beckley projects – Initial site development & slope construction at Tygart #1 complex – Continued upgrading of equipment & facilities at other IC
Slide 21: Update on Coal Markets
Mining Opportunities Update on Coal Markets
Slide 22: Near Term Trend - Continued Price Growth
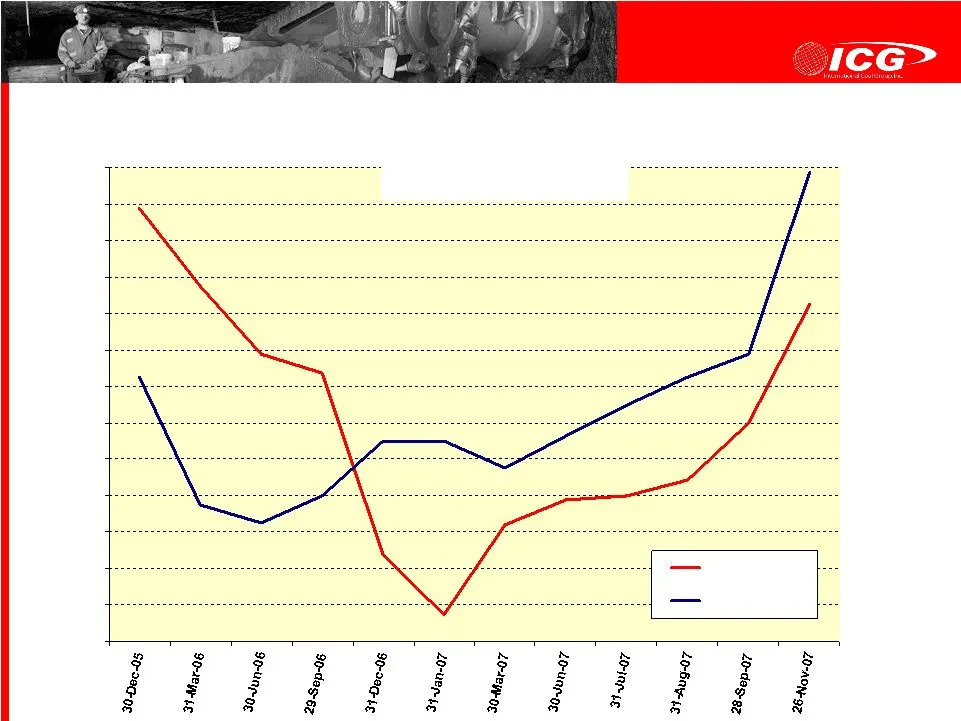
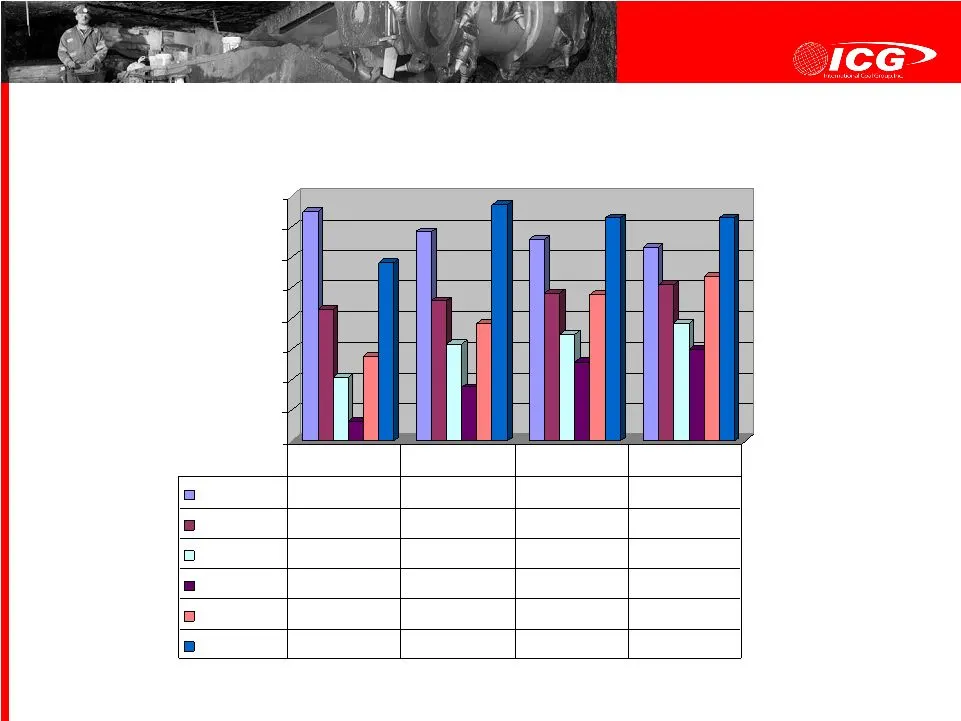
Mining Opportunities Near Term Trend - Continued Price Growth Electricity output up 2.8% YTD Domestic coal production in decline; down 13 million tons YTD per EIA Regulatory issues will further temper output - New MSHA regulations - Continued surface permitting delays Dramatic import / export change
Slide 23: Prompt Market Has Rebounded
Mining Opportunities Prompt Month Spot Prices End of Month Values per United $34.00 $36.00 $38.00 $40.00 $42.00 $44.00 $46.00 $48.00 $50.00 $52.00 $54.00 $56.00 $58.00 $60.00 CSX 12500 1.6# Pitt 8 13000 3.4# Prompt Market Has Rebounded
Slide 24: Term Prices Have Recovered
Mining Opportunities $35.00 $38.00 $41.00 $44.00 $47.00 $50.00 $53.00 $56.00 $59.00 CAPP 12500 <1% Forward Prices 31-Jan-06 $57.50 $55.50 $54.75 $54.00 30-Sep-06 $47.85 $48.75 $49.50 $50.25 31-Dec-06 $41.25 $44.50 $45.50 $46.50 31-Jan-07 $37.00 $40.25 $42.75 $44.00 31-Jul-07 $43.25 $46.50 $49.35 $51
Slide 25: Export Market Has Driven the Recovery
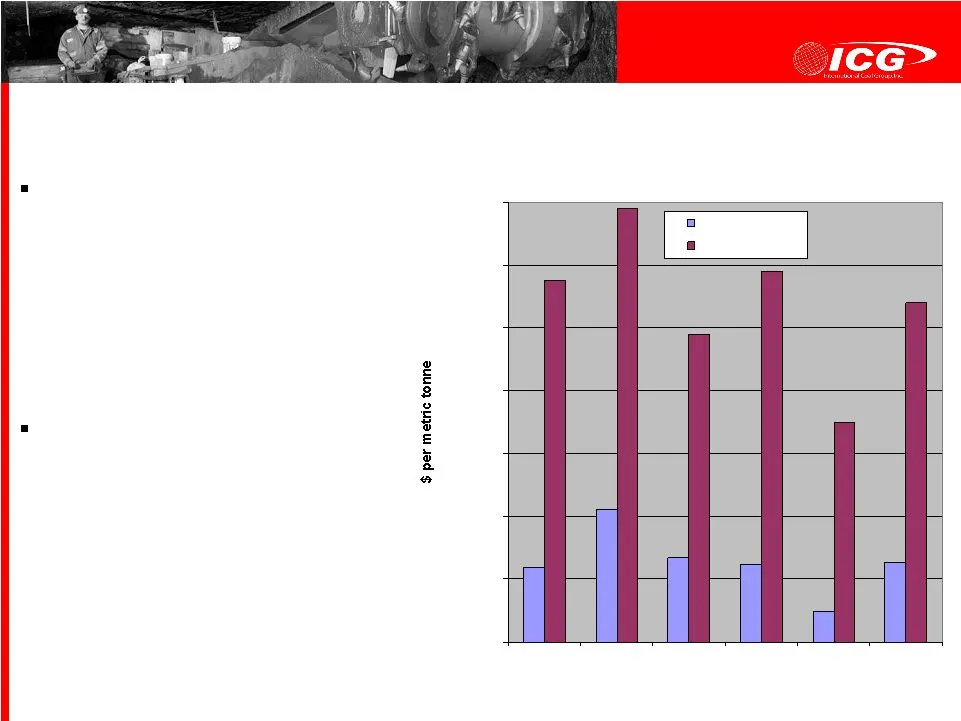
Mining Opportunities Prompt Qtr Index International FOB Vessel Prices $40.00 $50.00 $60.00 $70.00 $80.00 $90.00 $100.00 $110.00 South Africa Russia Australia Columbia Indonesia Average Origin Country March 2007 November 2007 Steam: Tremendous price momentum around the globe – Average price increase
Slide 26: Outlook for Coal Going Forward
Mining Opportunities Outlook for Coal Going Forward
Slide 27: US DOE Forecast
Mining Opportunities US DOE forecast * predicts electricity demand growth of 41% from 2007 to 2030, with coal’s portion increasing from 50% to 57% – Nuclear provides about 20% of electricity today, but maintaining that level requires building 35-40 new plants within years – an unlikely pace – Natura
Slide 28: General Outlook for the US Coal Industry
Mining Opportunities Continued growth in coal demand to supply US energy needs Build-out of scrubbers by Eastern utilities should generally favor Appalachian region coals over Powder River Basin – Higher BTU and lower transportation cost will be key economic advantages – Depletion of CAPP reserves s
Slide 29: Thank You!
Mining Opportunities Thank You!
Source: SEC EDGAR · 8-K filed Nov 29, 2007
More decks from International Coal Group Inc
 Howard Weil Energy Conference 201035 slides · Mar 22, 2010
 Simmons & Company Energy Conference and UBS Energy/Utility Conference 201031 slides · Mar 2, 2010
 UBS Boston Coal Conference 200937 slides · Dec 1, 2009
 Raymond James Coal Investors Conference 200831 slides · Dec 4, 2008
 Davenport Metals & Mining Symposium 200835 slides · Sep 16, 2008
 Howard Weil 36th Annual Energy Conference (April 2008)24 slides · Apr 7, 2008