Copano Energy L.L.C — Investor Presentation (December 2009)
62 slides from Copano Energy L.L.C's investor presentation, Dec 7, 2009
Slide 1: Investor Presentation
Investor Presentation NASDAQ: CPNO December 2009
Slide 2: Disclaimer
Disclaimer Statements made by representatives of Copano Energy, L.L.C. (“Copano”) during this presentation will include “forward-looking statements,” as defined in the federal securities laws. All statements that address activities, events or developments that Copano expects, believes or anticipates
Slide 3: Introduction to Copano
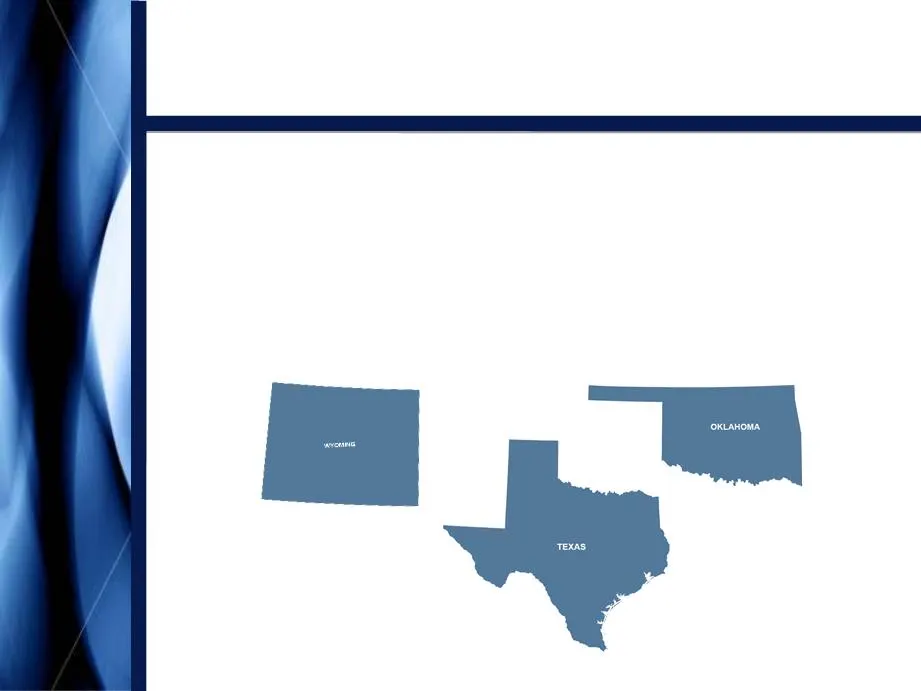
Introduction to Copano • Serves natural gas producers in three leading producing regions • Founded in 1992 - built through more than 50 acquisitions and major capital projects Texas South Texas and North Texas Oklahoma Central and Eastern Oklahoma Rocky Mountains Wyoming’s Powder River Basin
Slide 4: Key Metrics
Key Metrics • Service throughput volumes approximate 2 Bcf per day of natural gas (1) • Approximately 6,700 miles of active pipelines • 7 natural gas processing plants with over 1 Bcf/d of combined processing capacity • Equity market cap: $1.2 billion (2) • Enterprise value: $2.0 billion (2) • Copan
Slide 5: Copano's LLC Structure
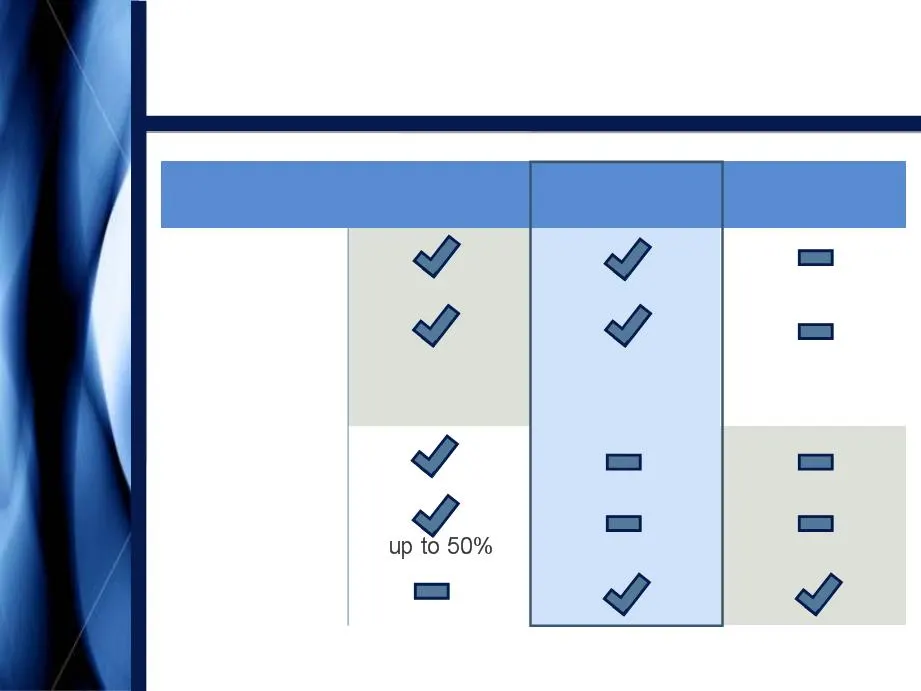
Characteristic Typical MLP Copano Energy Typical Corporation Non-Taxable Entity Tax Shield on Distributions Tax Reporting General Partner Incentive Distribution Rights Voting Rights Copano’s LLC Structure Schedule K-1 Schedule K-1 Form 1099
Slide 6: Throughput Volume Outlook
Throughput Volume Outlook Agenda Commodity Prices and Margin Sensitivities Capital Access Distribution Policy and Outlook
Slide 7: Total Volume Trends
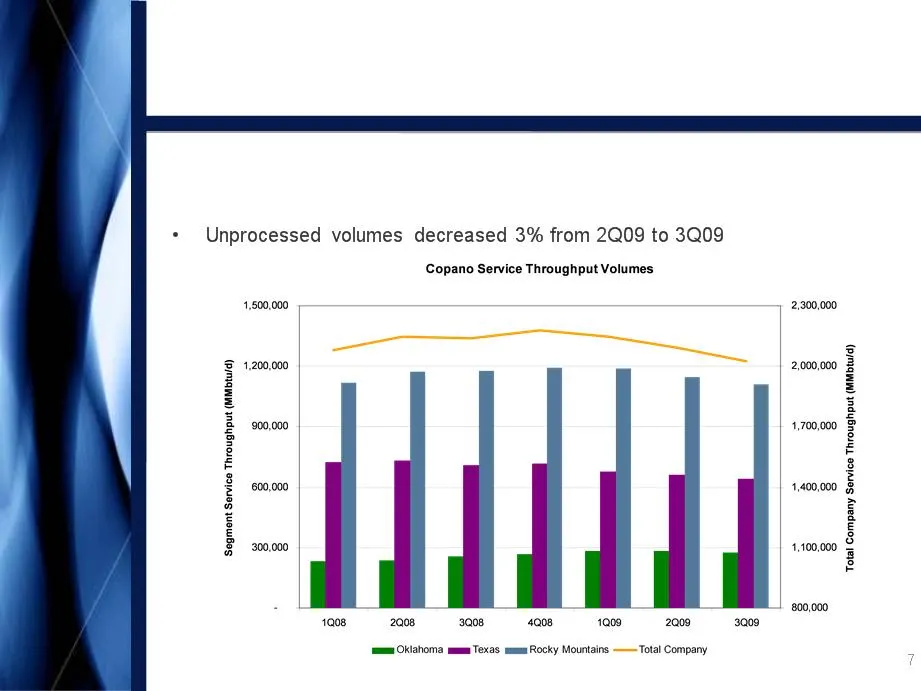
• Total service throughput volumes decreased 3% from 2Q09 to 3Q09 • Processed volumes decreased 2% from 2Q09 to 3Q09 Total Volume Trends Note: Includes affiliates, net of intercompany volumes.
Slide 8: YTD 2009 Oklahoma Prices
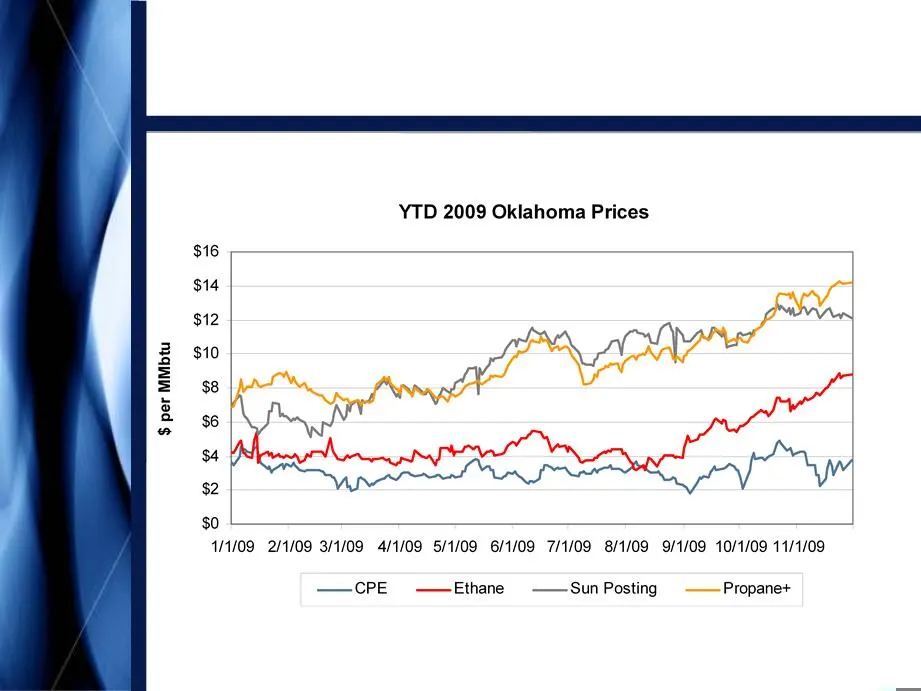
YTD 2009 Oklahoma Prices $ per MMbtu 2 g $0 1/1/09 2/1/09 3/1/09 4/1/09 5/1/09 6/1/09 7/1/09 8/1/09 9/1/09 10/1/09 11/1/09 CPE Ethane Sun Posting Propane+
Slide 9: Oklahoma Volume Outlook
• Rich gas (primarily Hunton de-watering play) – Drilling activity increasing due to current commodity prices and long-term price outlook – 3 rigs running currently in the Hunton and 12 rigs in other rich gas areas – High BTU gas, processing upgrade and low geologic risk enhance drilling economics,
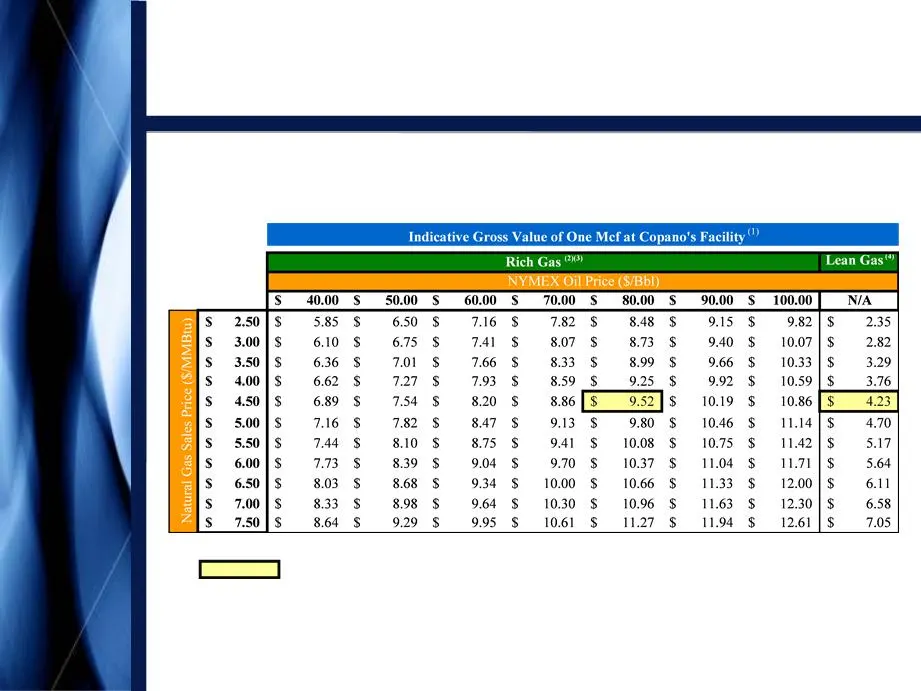
Slide 10: Oklahoma Rich Gas vs. Lean Gas
Oklahoma Rich Gas vs. Lean Gas (1) Full value prior to deduction of Copano’s margin. Excludes value of condensate and crude oil recovered by the producer at the wellhead. (2) Implied NGL prices are based on a three-year historical regression analysis. (3) Assumes 9 GPM gas with a Btu factor of 1.375
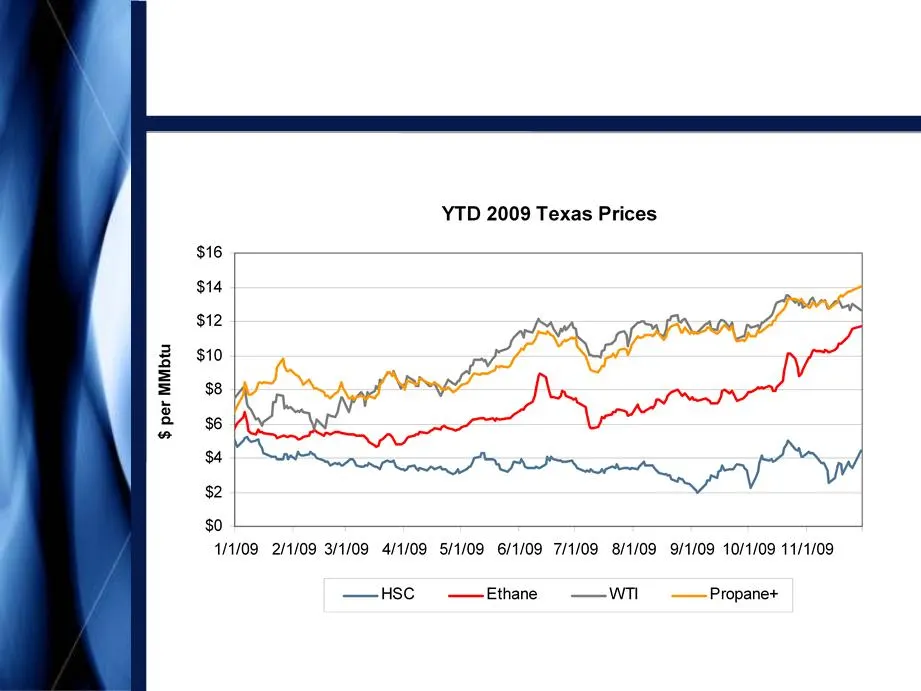
Slide 11: YTD 2009 Texas Prices
YTD 2009 Texas Prices $ per MMbtu ei 8 $0 1/1/09 2/1/09 3/1/09 4/1/09 5/1/09 6/1/09 7/1/09 8/1/09 9/1/09 10/1/09 11/1/09 ——HSC ——Ethane —wi ——Propane+
Slide 12: South Texas Volume Outlook
South Texas Volume Outlook • Despite reduced rig counts, activity in the traditional supply area continues • On November 13, 2009, Copano announced a joint venture with Kinder Morgan to provide gathering, transportation and processing services to gas producers in the Eagle Ford Shale • 4Q09 volumes
Slide 13: Texas Fractionation Strategy
Texas Fractionation Strategy • Capacity at NGL fractionation facilities along the Texas Gulf Coast has become constrained • For a portion of the second and third quarters of 2009, Copano realized lower revenue for sales of mixed NGLs from the tailgate of the Houston Central plant under a short term
Slide 14: North Texas Volume Outlook
North Texas Volume Outlook • Copano’s Saint Jo processing and treating plant placed in service in September 2009 – Eliminates the need for third-party processing – High efficiency and high recovery plant • 7 rigs running in the area with 12 rigs anticipated in early 2010 • Drilling economics are dri
Slide 15: Rocky Mountains Volume Outlook
Rocky Mountains Volume Outlook • Development of extensive acreage dedication will be driven by drilling economics and commodity prices • Timing of dewatering will also drive volume levels • 4Q09 volumes are expected to be flat vs. 3Q09 due to previously drilled wells • For Bighorn, 130 previously dr
Slide 16: Commodity Prices and Margin Sensitivities
Commodity Prices and Margin Sensitivities Commodity Prices and Margin Sensitivities Distribution Policy and Outlook Capital Access Throughput Volume Outlook
Slide 17: Oklahoma Natural Gas Price Outlook
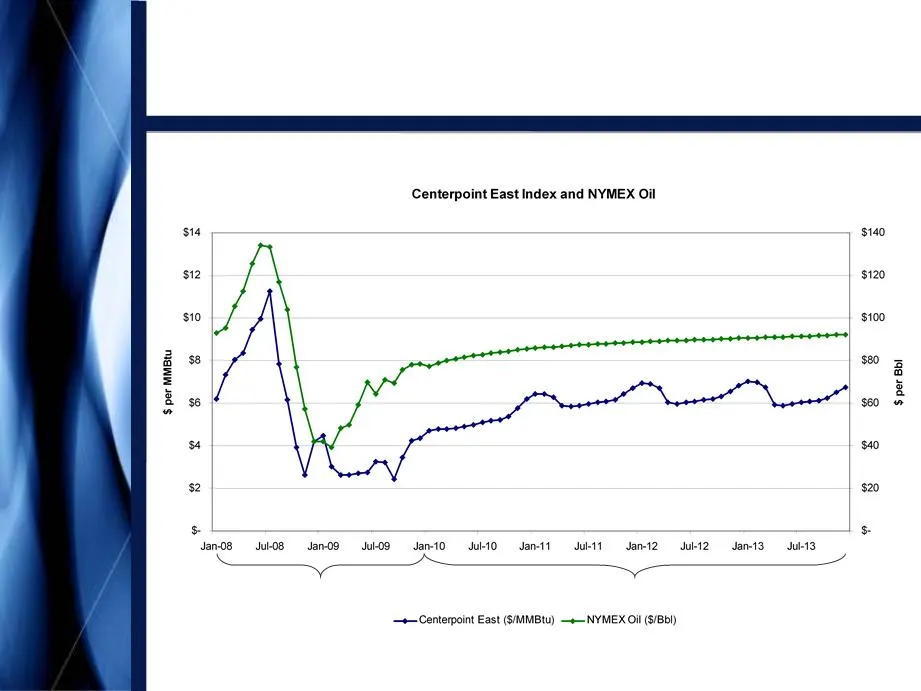
Actual Prices: 1/08 - 12/09 Forward Prices as of 12/1/09: 1/10 - 12/13 Oklahoma Natural Gas Price Outlook
Slide 18: South Texas Natural Gas Price Outlook
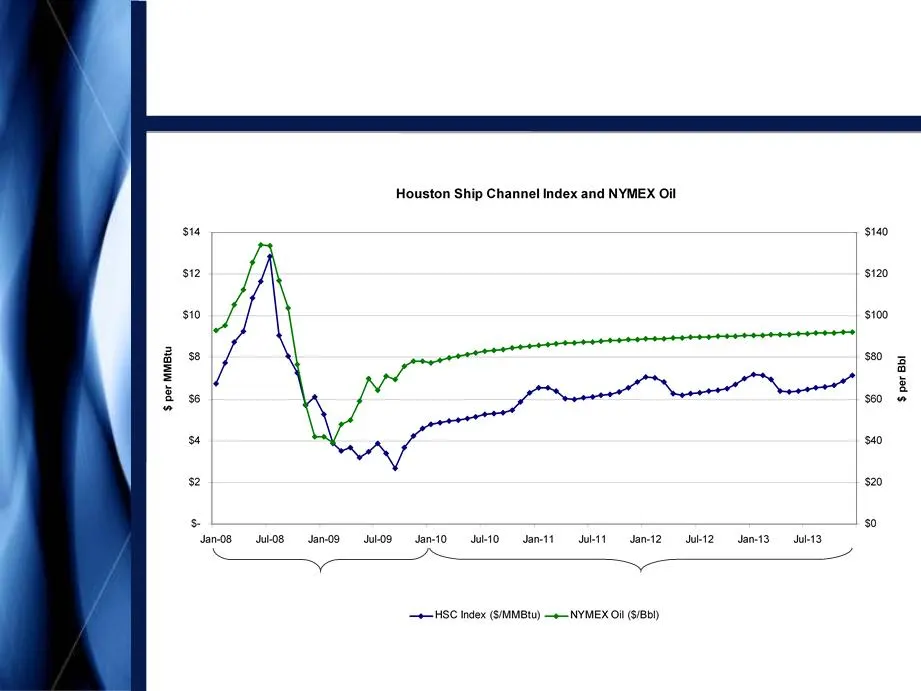
Actual Prices: 1/08 - 12/09 Forward Prices as of 12/1/09: 1/10 - 12/13 South Texas Natural Gas Price Outlook
Slide 19: Rocky Mountains Natural Gas Price Outlook
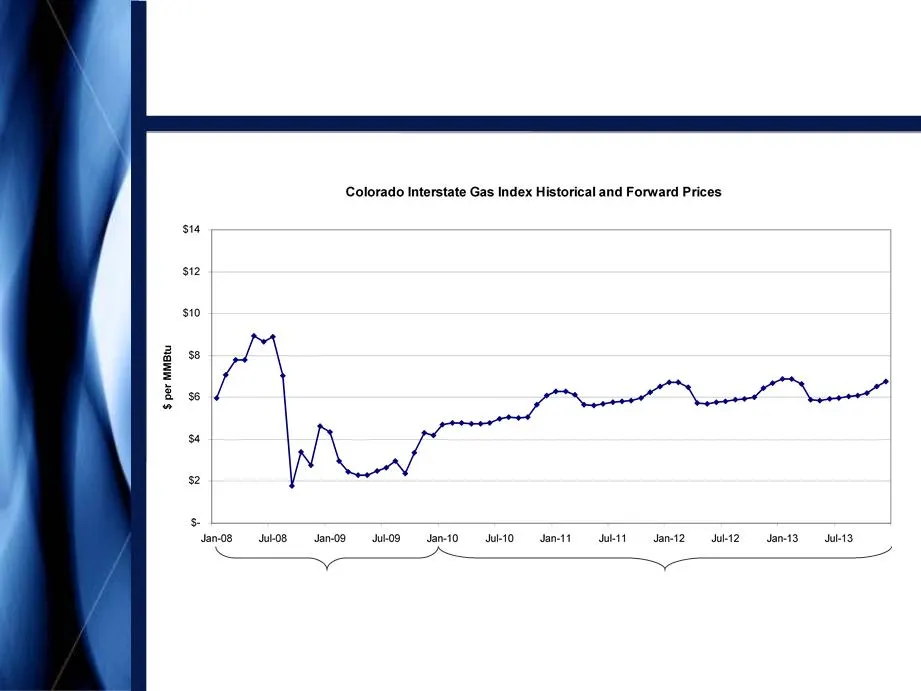
Actual Prices: 1/08 - 12/09 Forward Prices as of 12/1/09: 1/10 - 12/13 Rocky Mountains Natural Gas Price Outlook
Slide 20: Combined Commodity-Sensitive Segment Margins and Hedging Settlements
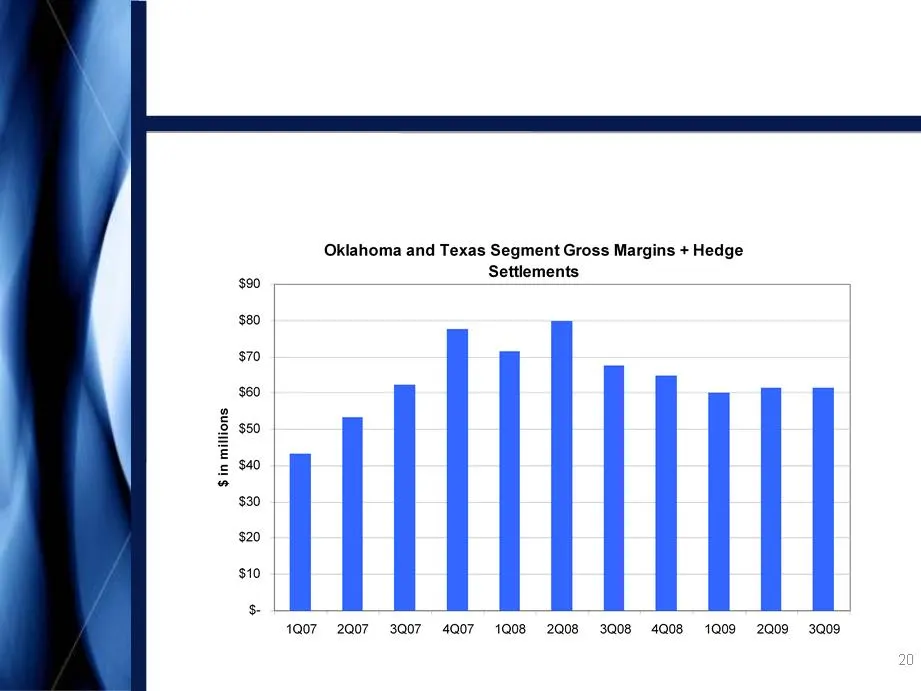
Combined Commodity-Sensitive Segment Margins and Hedging Settlements • Copano’s hedge portfolio supports cash flow stability based on combined segment gross margins and cash hedging settlements
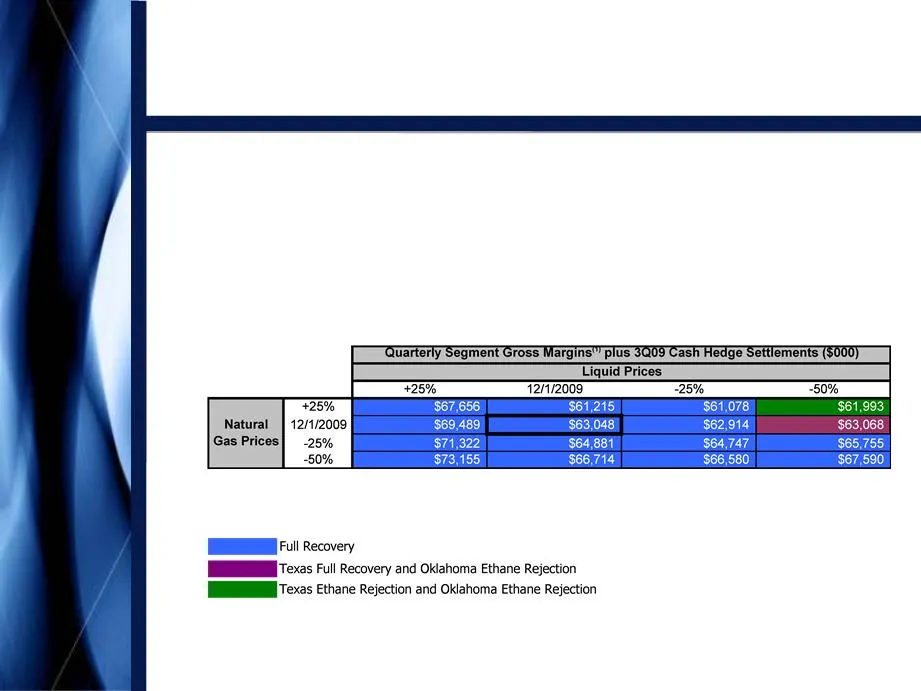
Slide 21: Commodity-Related Margin Sensitivities
Commodity-Related Margin Sensitivities Note: Please see Appendix for definitions of processing modes and additional details. • Matrix reflects 3Q09 wellhead and plant inlet volumes, adjusted using Copano’s 2009 planning model (1) Consists of Texas and Oklahoma Segment gross margins.
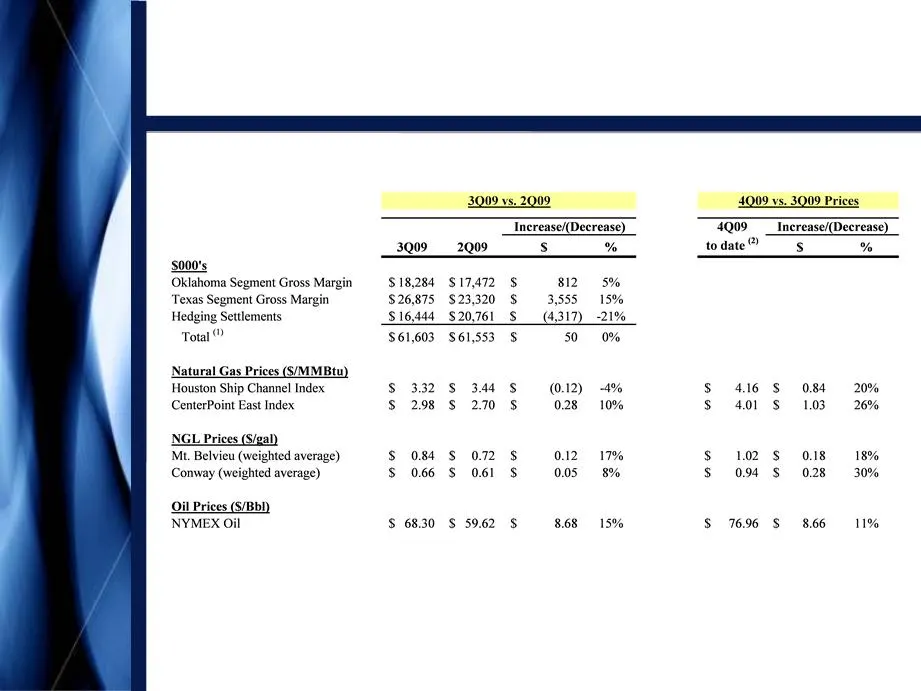
Slide 22: Combined Commodity-Sensitive Segment Margins and Hedging Settlements
Combined Commodity-Sensitive Segment Margins and Hedging Settlements (1) Does not include non-cash expenses included in Corporate and Other for purposes of calculating Total Segment Gross Margin. See Appendix for reconciliation of Total Segment Gross Margin. (2) Reflects prices as of 12/1/09.
Slide 23: Capital Access
Capital Access Capital Access Distribution Policy and Outlook Commodity Prices and Margin Sensitivities Throughput Volume Outlook
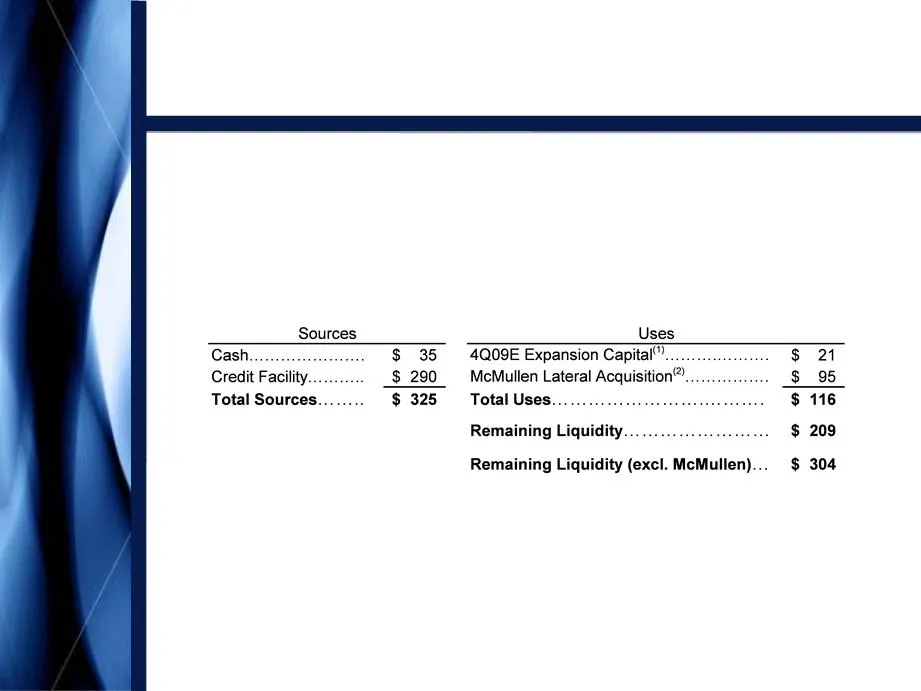
Slide 24: Capital Access
Capital Access • Copano has no need to access capital markets to support currently approved projects – At September 30, 2009: ($ in millions) • Debt access available • Equity access available privately – Would only make sense for accretive transactions or projects (1) Includes Copano’s net share for
Slide 25: Liquidity and Debt Facilities
Liquidity and Debt Facilities • At September 30, 2009: – Cash: $35 million – $550 million revolving credit facility • Approximately $290 million available • Remaining term: approximately 3.1 years • LIBOR + 175 bps – $582 million senior notes • $332,665,000 8 ⅛% due 2016 • $249,525,000 7 ¾% due 2018
Slide 26: Key Debt Terms and Covenants
• Senior Secured Revolving Credit Facility – $550 million facility with $100 million accordion – Maintenance tests: • 5x total debt to defined EBITDA (1) limitation § 3.99x at September 30, 2009 • Minimum required interest coverage 2.5x defined EBITDA § 3.41x at September 30, 2009 • Defined EBITDA a
Slide 27: Distribution Policy and Outlook
Distribution Policy and Outlook Distribution Policy and Outlook Capital Access Commodity Prices and Margin Sensitivities Throughput Volume Outlook
Slide 28: Distribution Track Record
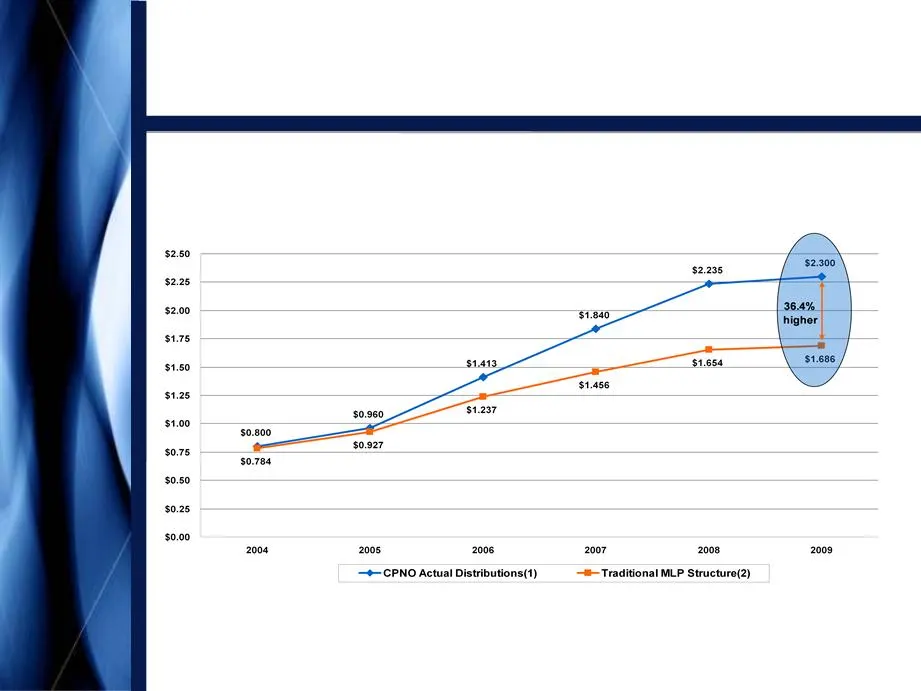
Distribution Track Record • On October 14, 2009, Copano announced a cash distribution for the third quarter of 2009 of $0.575 per common unit (3)(4) (5) (1) All pre-1Q 2007 distributions are adjusted to reflect Copano’s 3/30/07 two-for-one unit split. (2) Assumes generic MLP splits with 10%, 25% & 5
Slide 29: Distribution Outlook
Driver Potential 2011 - 2012 Annual Incremental Total DCF Impact (1) ($ in millions) Comments and Risk Factors Forward Commodity Prices (3Q09 vs. 2012 forward curve (2) and without hedges) $54 • Reflects December 2009 forward curve (2) • Future market conditions North Texas (2) $35 - $45 • Resource
Slide 30: Distribution Outlook
Driver Potential 2011 - 2012 Annual Incremental Total DCF Impact (1) ($ in millions) Comments and Risk Factors Oklahoma Volumes (2) $15 - $20 • Resource play • Drilling activity • Product prices Future Acquisitions and Major Projects TBD • Opportunities • Execution Distribution Outlook (1) Compared
Slide 31: #1 in Customer Satisfaction
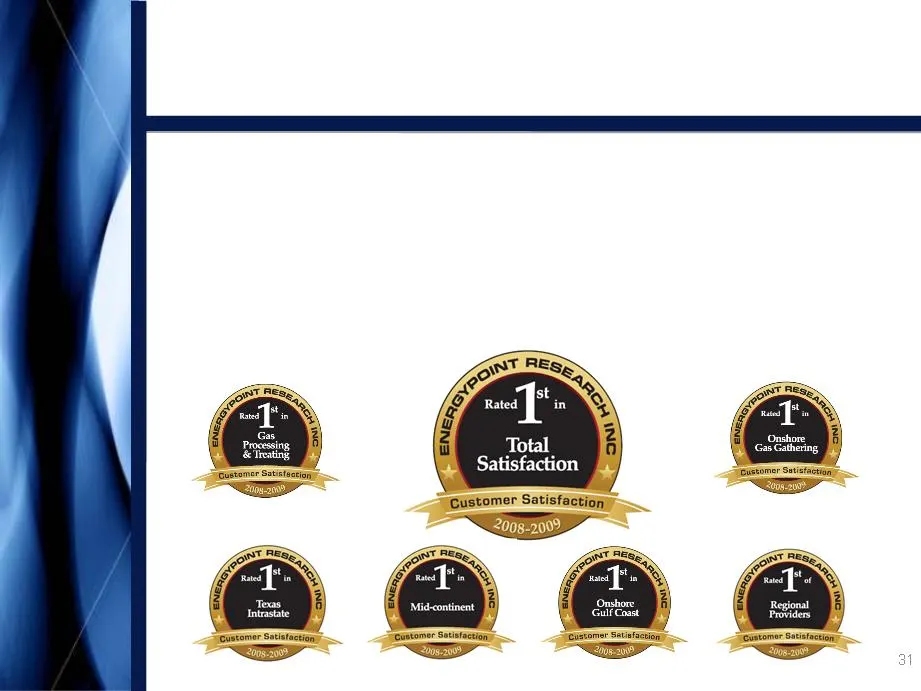
• On October 14, 2009, EnergyPoint Research, Inc. announced results of its Natural Gas Midstream Services Survey • Copano placed first overall among 16 midstream energy companies. Copano also rated first in many categories for gathering and processing/treating #1 in Customer Satisfaction
Slide 32: Conclusions
• Current cash flow trends remain solid • Forward market prices should drive increased drilling activity in our cost-competitive operating regions • Copano’s liquidity and access to capital remain strong • Copano continues to enjoy an abundant opportunity environment Conclusions
Slide 33: Appendix
Appendix
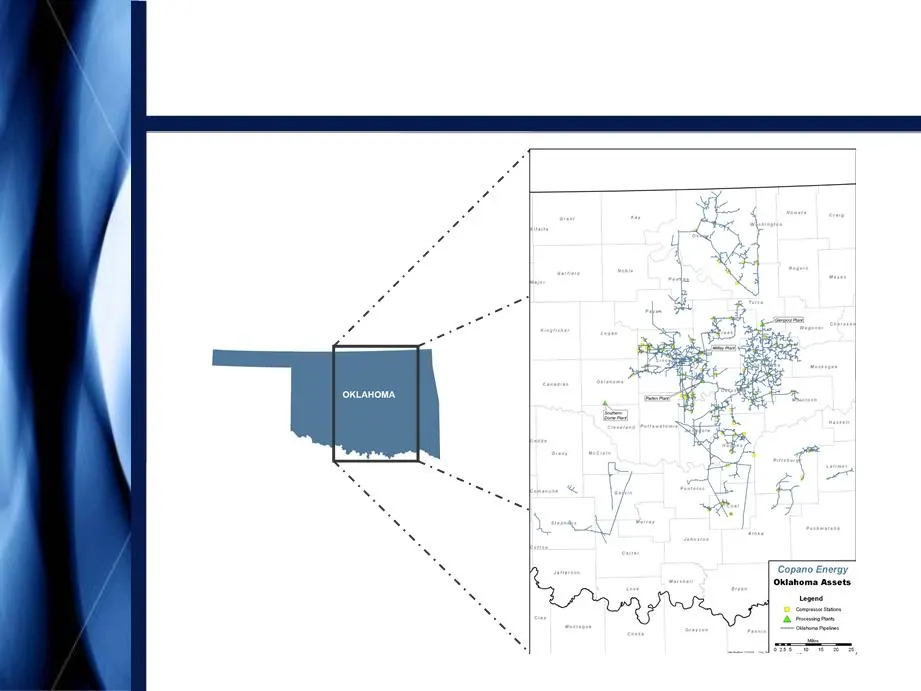
Slide 34: Oklahoma Assets
Oklahoma Assets Appendix
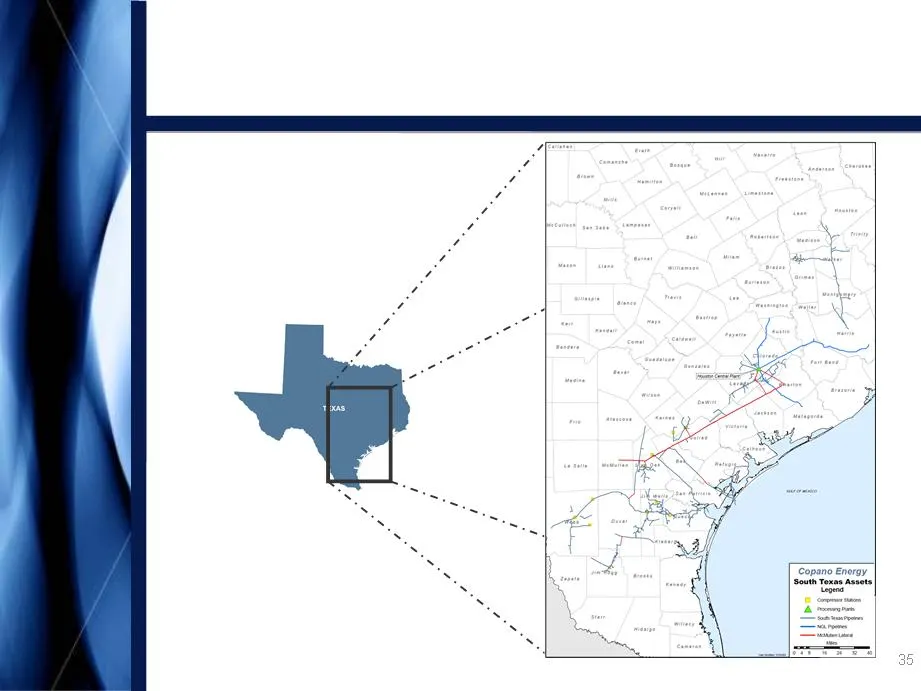
Slide 35: South Texas Assets
South Texas Assets Appendix (1) The McMullen Lateral acquisition remains subject to FERC approval. (1)
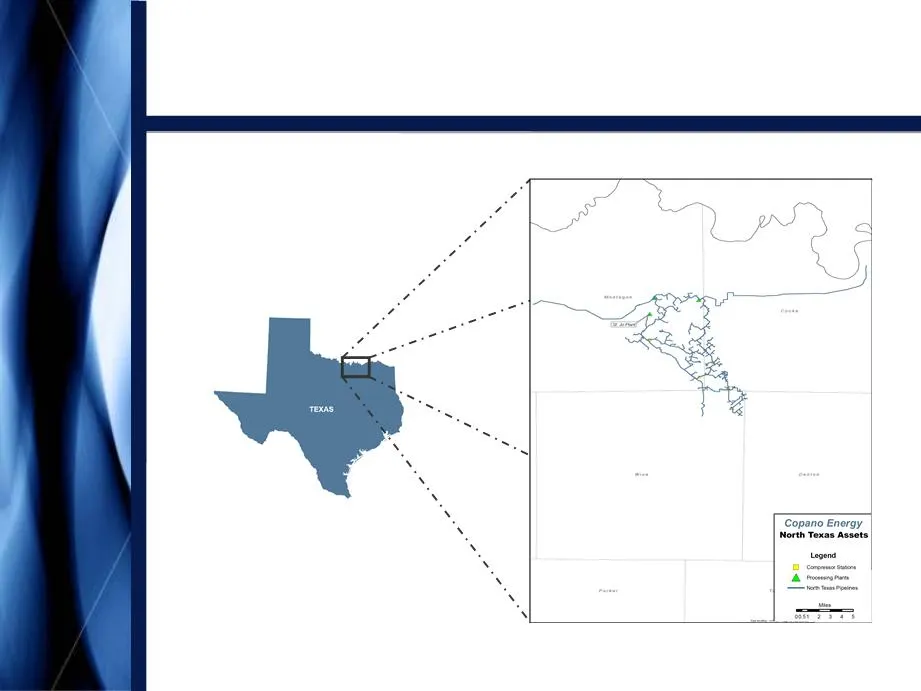
Slide 36: North Texas Assets
North Texas Assets Appendix
Slide 37: Rocky Mountains Assets
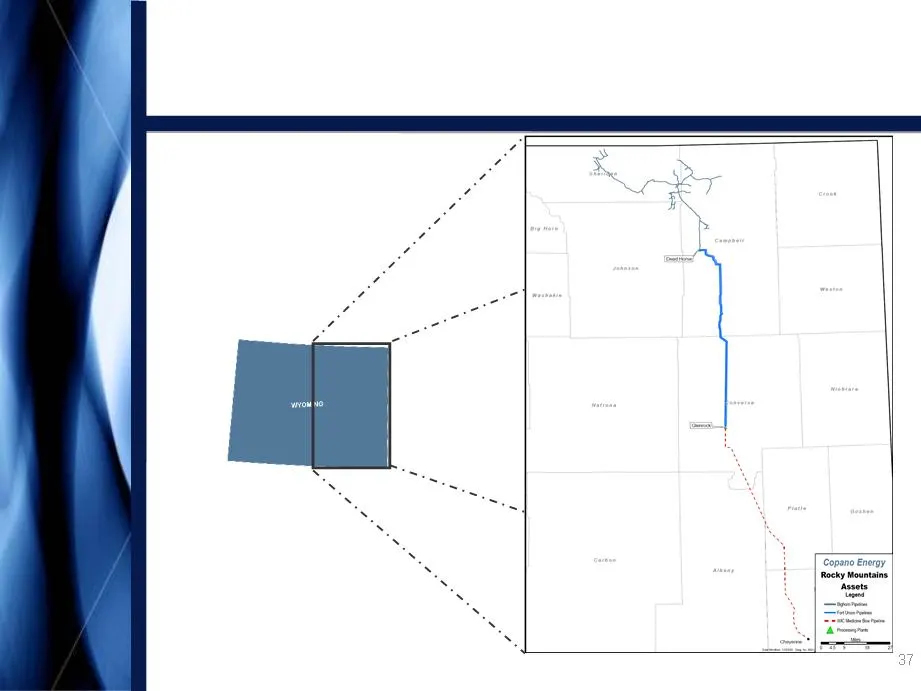
Rocky Mountains Assets Appendix
Slide 38: Processing Modes
Processing Modes • Full Recovery • Ethane Rejection • Conditioning Mode → Texas and Oklahoma - If the value of recovered NGLs exceeds the fuel and gas shrinkage costs of recovering NGLs → Texas - If the value of recovered NGLs is less than the fuel and gas shrinkage cost of recovering NGLs (availabl
Slide 39: Oklahoma Commercial Update
Oklahoma Commercial Update • Third Quarter 2009 – Total service throughput volumes: 260,000 MMBtu/d (1) – Unit margin: $0.76/MMBtu (2) – Margins from approximately 75% of contract volumes are directly correlated with NGL prices – Significant percentage of contract volumes (51%) contain fee-based com
Slide 40: Oklahoma Contract Mix
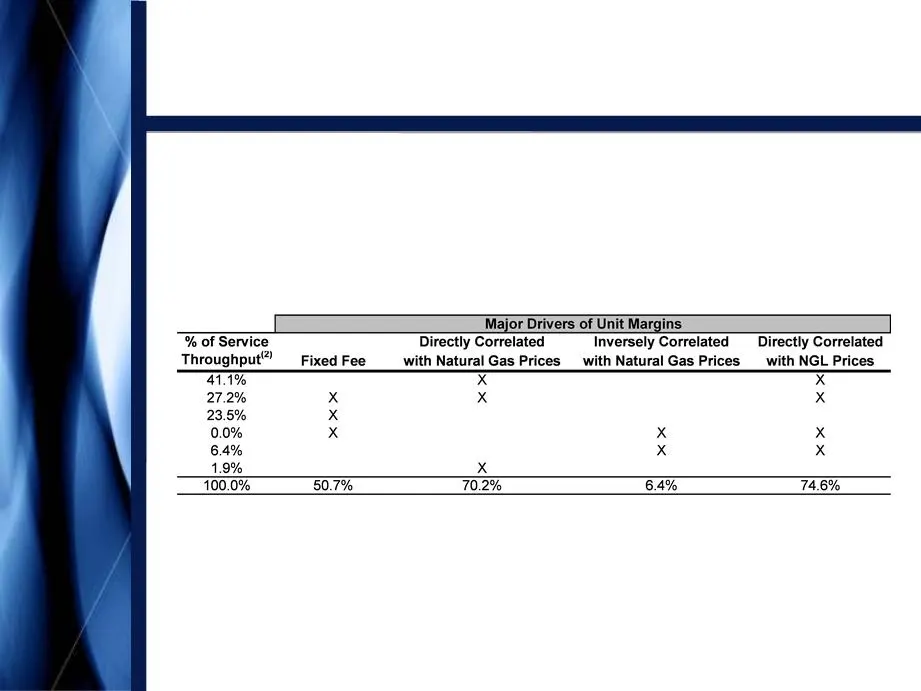
Oklahoma Contract Mix • Third quarter 2009 contract mix (1) (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Excludes 13,857 MMBtu/d service throughput for Southern Dome, a majority-owned affiliate. Appendix
Slide 41: Oklahoma Net Commodity Exposure
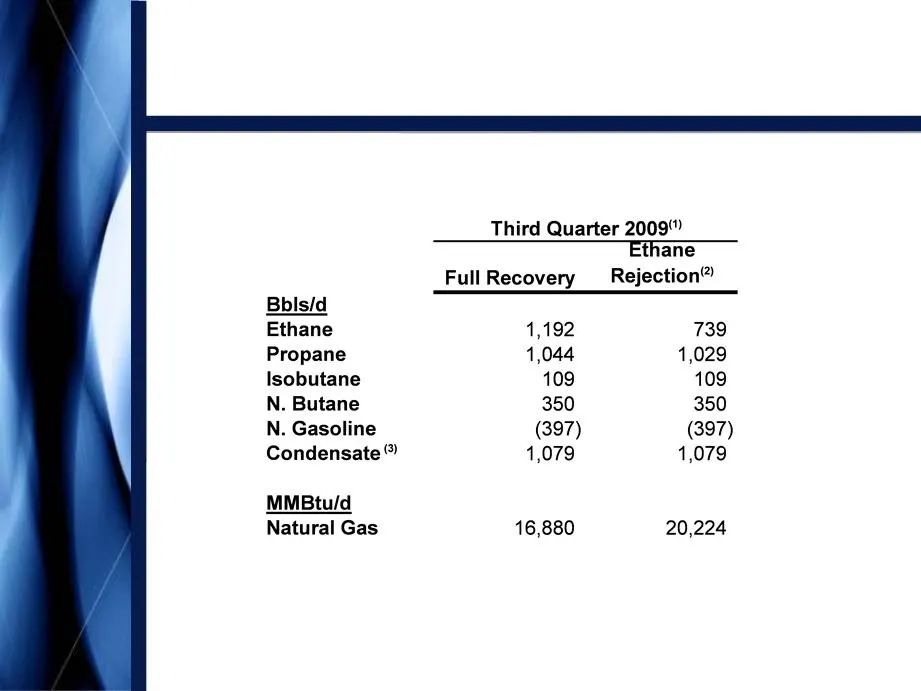
Oklahoma Net Commodity Exposure Note: See explanation of processing modes in this Appendix. Values reflect rounding. (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Ethane rejection at Paden plant is limited by nitrogen rejection facilities. (3) Reflec
Slide 42: Oklahoma Commodity Price Sensitivities
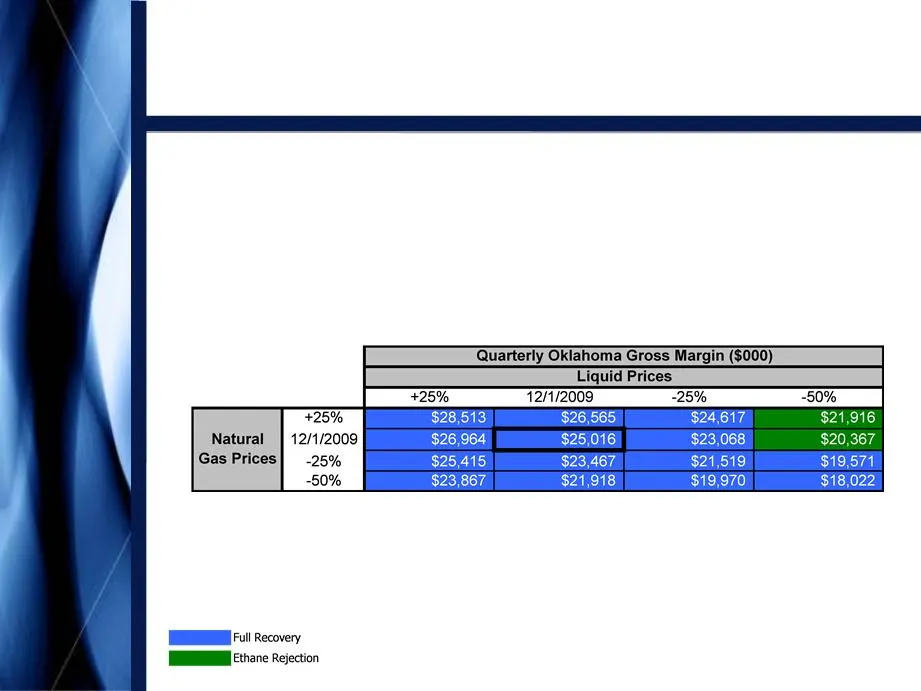
Oklahoma Commodity Price Sensitivities • Oklahoma segment gross margins excluding hedge settlements – Matrix reflects 3Q09 volumes, adjusted using Copano’s 2009 planning model Appendix
Slide 43: Texas Commercial Update
Texas Commercial Update • Third Quarter 2009 – Total service throughput volumes: 613,000 MMBtu/d (1) – Unit margin: $0.48/MMBtu (2) – Margins from approximately 85% of contract volumes are directly correlated with NGL prices – Approximately 91% of contract volumes have fee-based components, includin
Slide 44: Texas Contract Mix
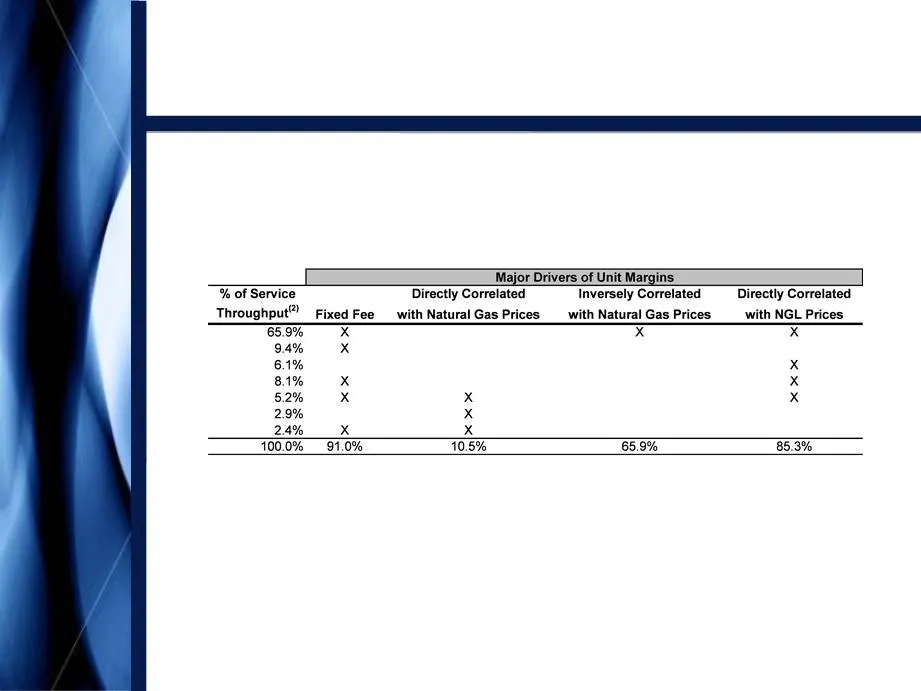
Texas Contract Mix • Third quarter 2009 contract mix (1) Appendix (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. (2) Excludes 72,985 MMBtu/d service throughput for Webb Duval, a majority-owned affiliate.
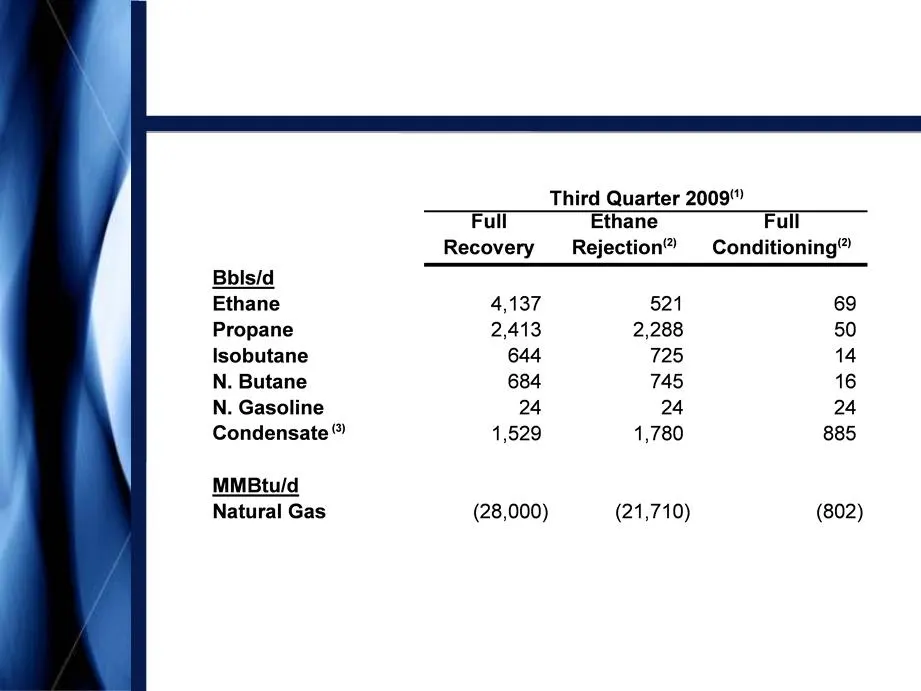
Slide 45: Texas Net Commodity Exposure
Texas Net Commodity Exposure Note: See explanation of processing modes in this Appendix. (1) Source: Copano Energy internal financial planning models for consolidated subsidiaries. Based on 3Q09 daily wellhead/plant inlet volumes. (2) Fractionation at Houston Central processing plant permits signifi
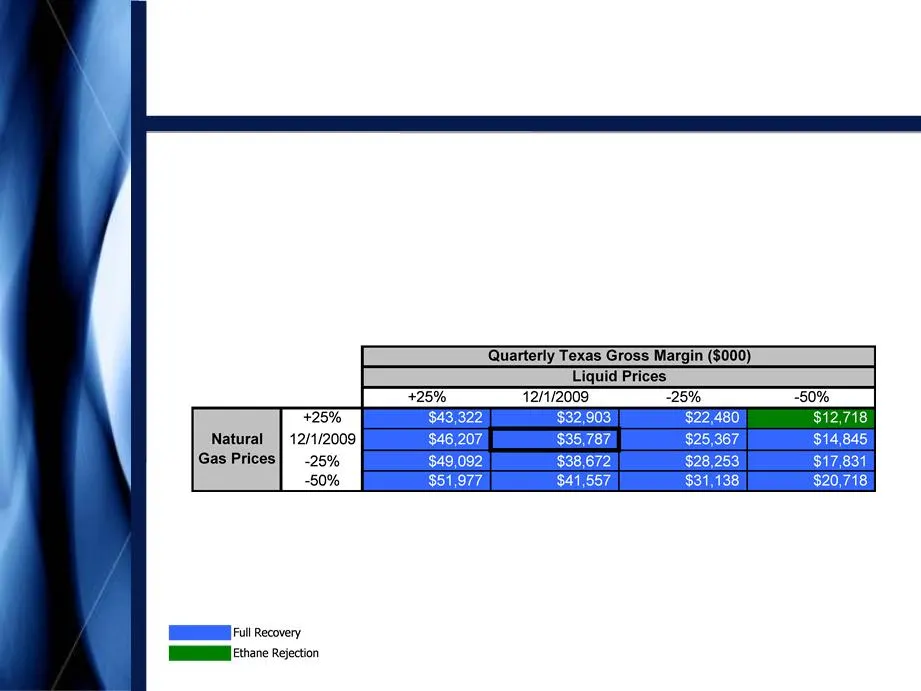
Slide 46: Texas Commodity Price Sensitivities
Texas Commodity Price Sensitivities • Texas segment gross margins excluding hedge settlements – Matrix reflects 3Q09 volumes and operating conditions, adjusted using Copano’s 2009 planning model Appendix
Slide 47: Rocky Mountains Commercial Update
Rocky Mountains Commercial Update • Third Quarter 2009 – Total service throughput volumes: • Consolidated affiliates (producer services): 157,000 MMBtu/d • Unconsolidated affiliates: § Bighorn: 190,000 MMBtu/d § Fort Union: 762,000 MMBtu/d • All Bighorn and Fort Union margins are fixed fee • Virtual
Slide 48: Rocky Mountains Sensitivities
Rocky Mountains Sensitivities Appendix Note: See this Appendix for reconciliation of Adjusted EBITDA. Values reflect rounding. (1) Impact on Adjusted EBITDA based on Copano’s interest in the unconsolidated affiliate. • Third Quarter 2009 – Adjusted EBITDA volume sensitivity (positive or negative imp
Slide 49: Rocky Mountains Takeaway Capacity Outlook
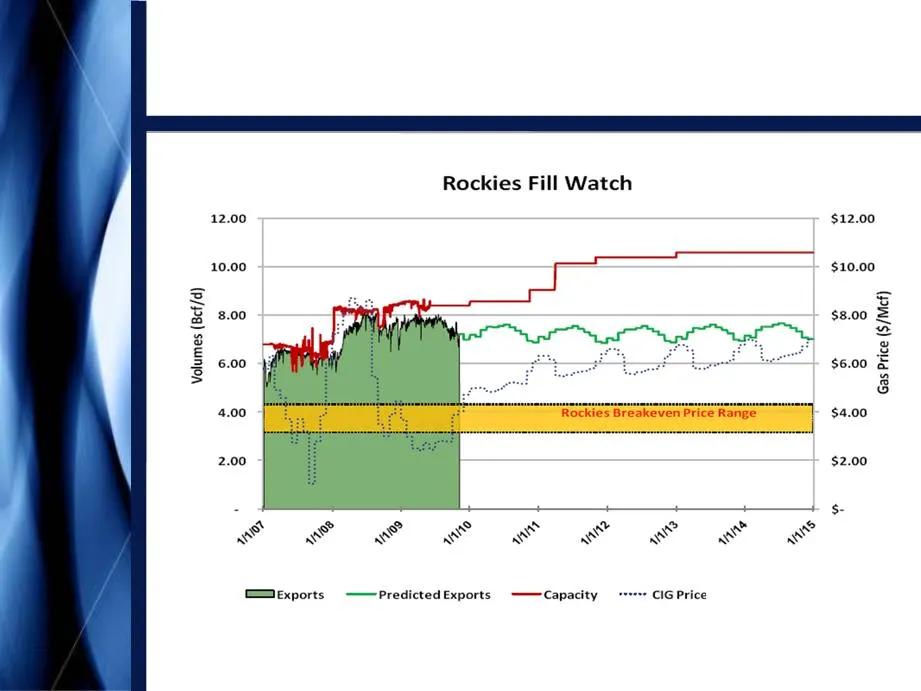
Rocky Mountains Takeaway Capacity Outlook Source: Bentek Energy, LLC (1) Historical and future prices as of 11/3/09. 12/1/09 spot: $4.09/Mcf (1) Appendix
Slide 50: Hedging Impact of Commodity Price Sensitivities
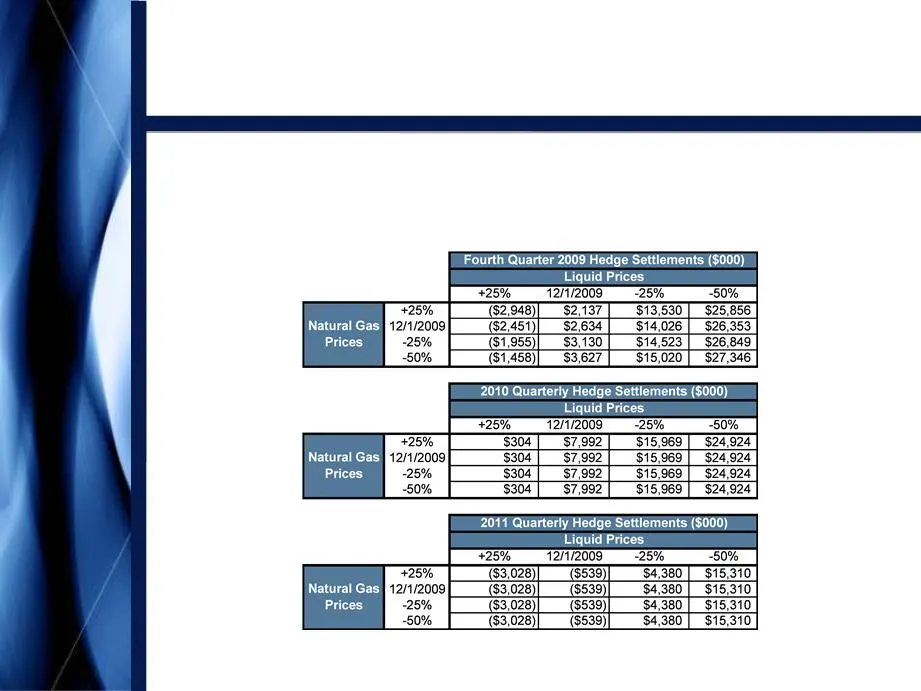
Hedging Impact of Commodity Price Sensitivities • Commodity hedging program supplements cash flow in 2009 through 2011 during less favorable commodity price periods Appendix Note: For calendar 2012, Copano currently has WTI crude puts of 300 barrels per day with a strike price of $79/Bbl.
Slide 51: Hedging Impact: Fourth Quarter 2009 NGLs
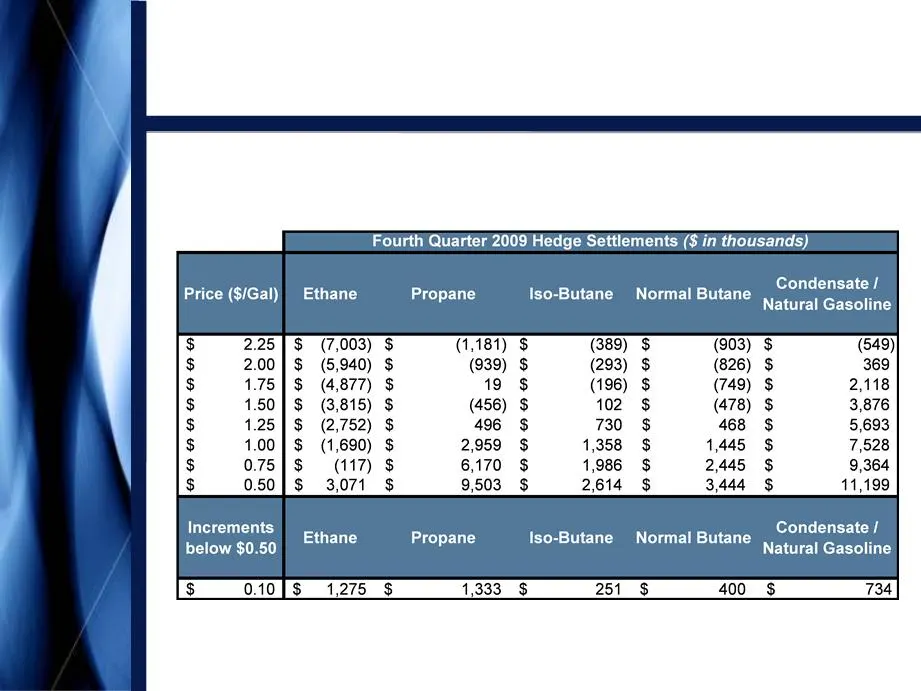
Hedging Impact • Fourth Quarter 2009 NGLs Hedge Settlement Matrix Note: All hedge instruments are reported in Copano’s SEC filings. Hedge settlements are based on monthly average Mt. Belvieu NGL and NYMEX WTI prices. Positive amounts reflect payments from hedge counterparties under swap and put opti
Slide 52: Hedging Impact: 2010 NGLs
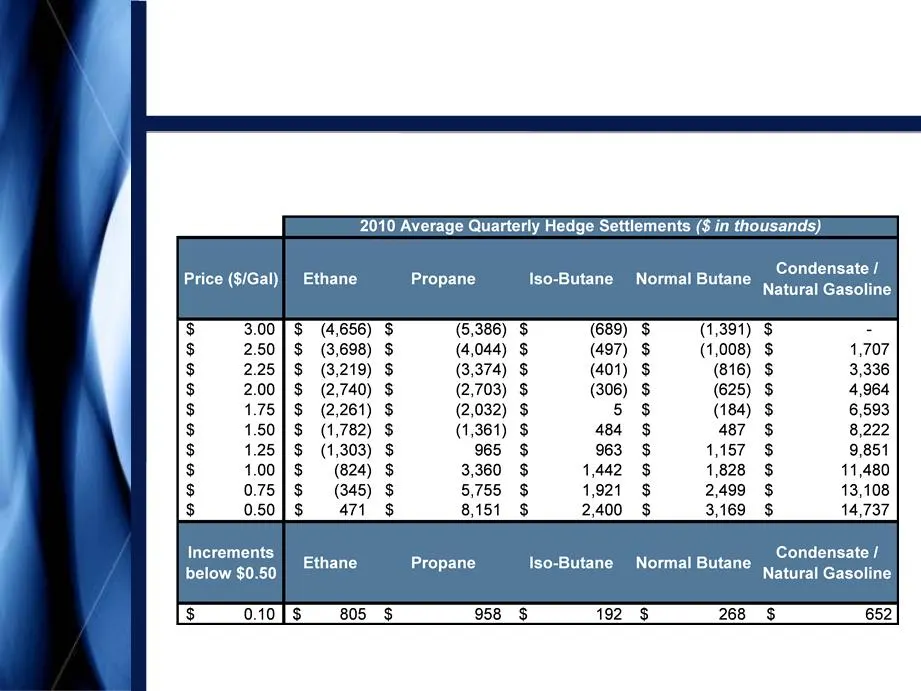
Hedging Impact • 2010 NGLs Hedge Settlement Matrix Note: All hedge instruments are reported in Copano’s SEC filings. Hedge settlements are based on monthly average Mt. Belvieu NGL and NYMEX WTI prices. Positive amounts reflect payments from hedge counterparties under swap and put option instruments.
Slide 53: Hedging Impact: 2011 NGLs
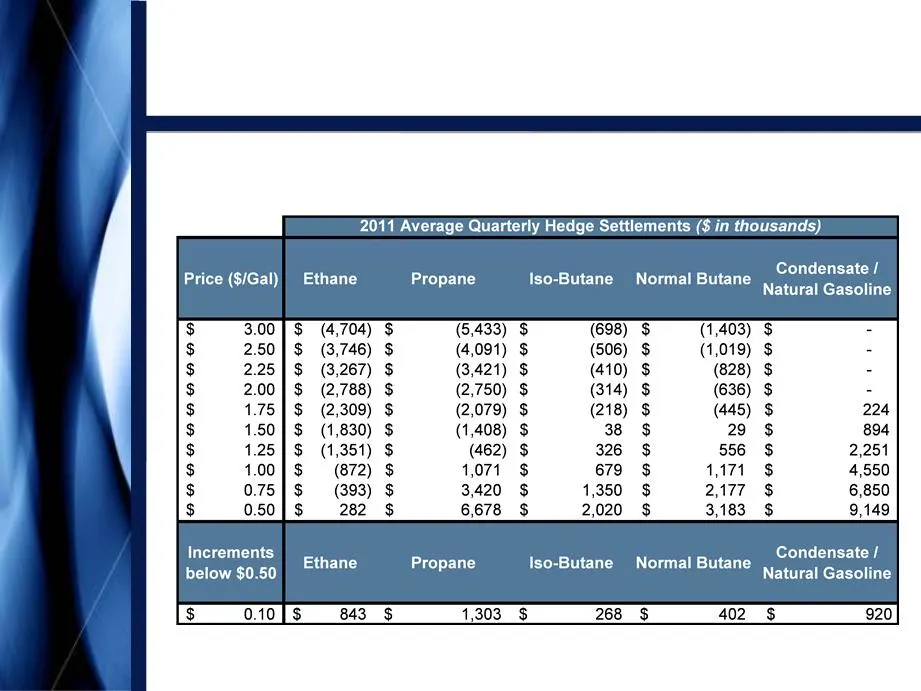
Hedging Impact • 2011 NGLs Hedge Settlement Matrix Note: All hedge instruments are reported in Copano’s SEC filings. Hedge settlements are based on monthly average Mt. Belvieu NGL and NYMEX WTI prices. Positive amounts reflect payments from hedge counterparties under swap and put option instruments.
Slide 54: Hedging Impact: 2012 NGLs
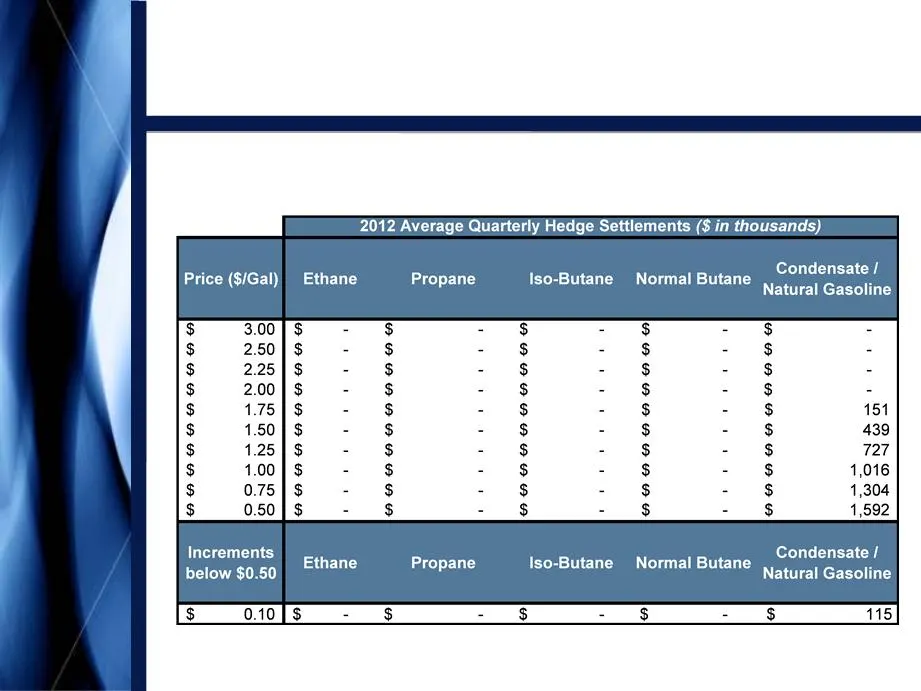
Hedging Impact • 2012 NGLs Hedge Settlement Matrix Note: All hedge instruments are reported in Copano’s SEC filings. Hedge settlements are based on monthly average Mt. Belvieu NGL and NYMEX WTI prices. Positive amounts reflect payments from hedge counterparties under swap and put option instruments.
Slide 55: Hedging Impact: 2009-2011 Natural Gas
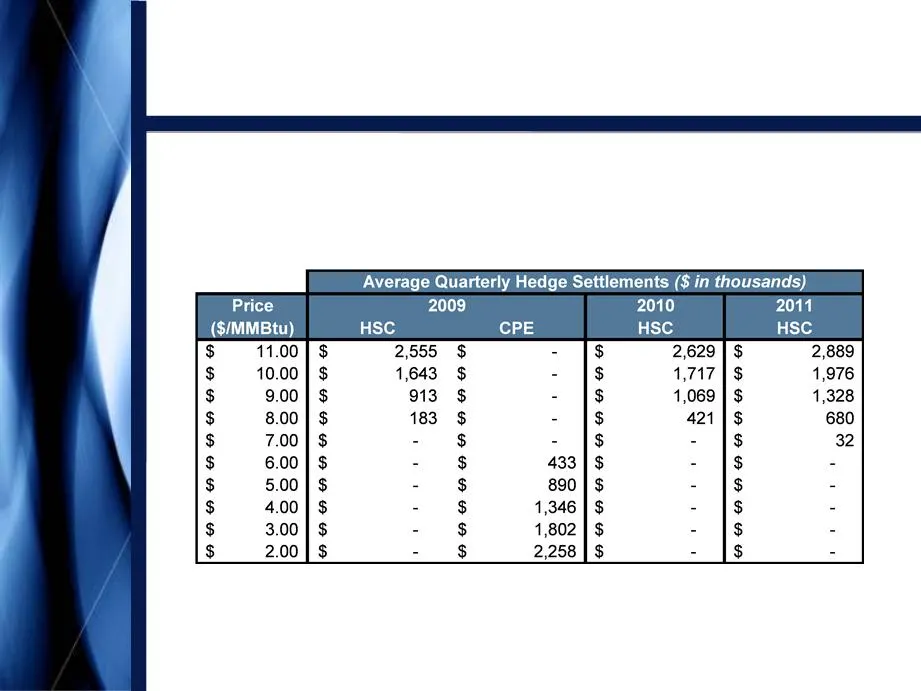
Hedging Impact • 2009 - 2011 Natural Gas Hedge Settlement Matrix Note: All hedge instruments are reported in Copano’s SEC filings. Hedge settlements are based on first of the month Houston Ship Channel and CenterPoint East natural gas prices. Positive amounts reflect payments from hedge counterparti
Slide 56: Credit Ratings
• At September 30, 2009: – Moody’s • Corporate Family Rating: Ba3 • Senior Unsecured Rating: B1 • Outlook: Stable – Standard & Poor’s • Corporate Credit Rating: BB- • Senior Unsecured Rating: B+ • Outlook: Stable Credit Ratings Appendix
Slide 57: Limited Liability Company Agreement
Limited Liability Company Agreement • Distributions based on “Available Cash” – Cash on hand at the end of a quarter less reserves established by the Board – Board may increase or decrease reserves quarterly • Since IPO and as of September 30, 2009: – Initial available cash and reserve at IPO: $20 m
Slide 58: Reconciliation of Non-GAAP Financial Measures
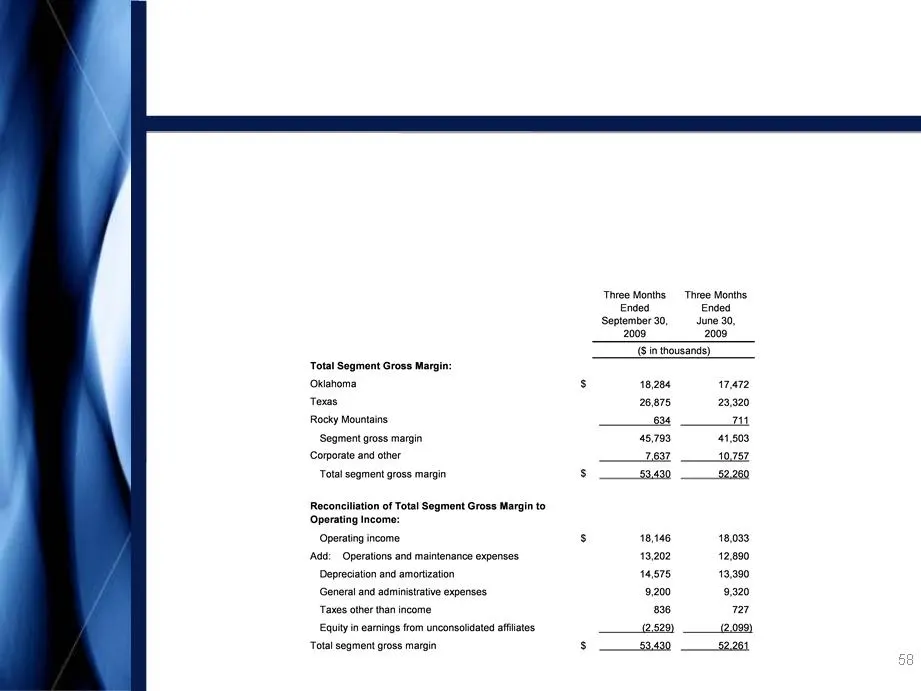
Reconciliation of Non-GAAP Financial Measures Segment Gross Margin and Total Segment Gross Margin • We define segment gross margin, with respect to a Copano operating segment, as segment revenue less cost of sales. Cost of sales includes the following: cost of natural gas and NGLs purchased from thi
Slide 59: Reconciliation of Non-GAAP Financial Measures: Adjusted EBITDA
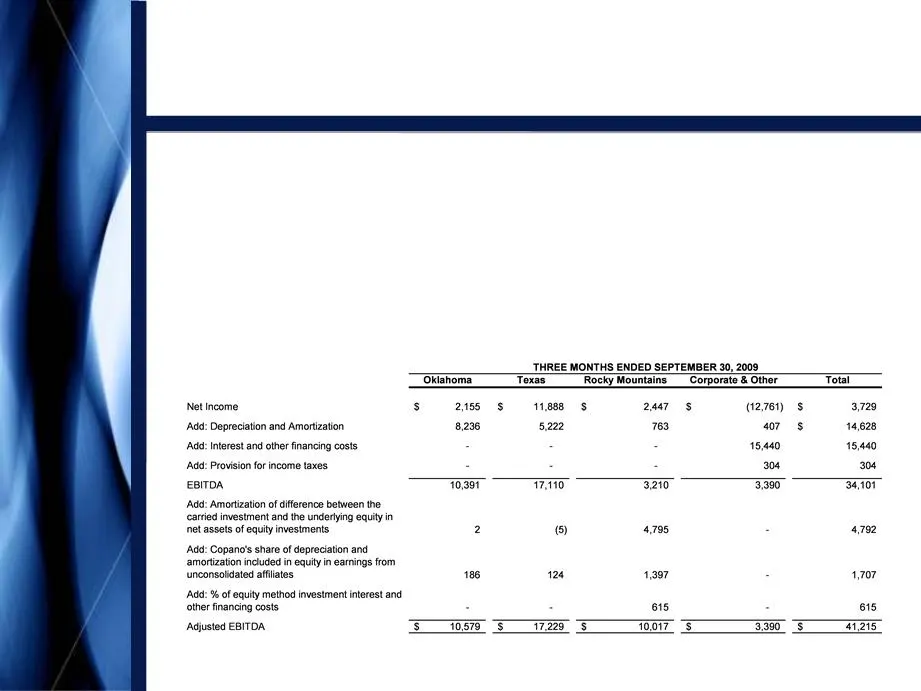
Reconciliation of Non-GAAP Financial Measures Adjusted EBITDA • We define EBITDA as net income (loss) plus interest expense, provision for income taxes and depreciation and amortization expense. Because a portion of our net income (loss) is attributable to equity in earnings (loss) from our equity i
Slide 60: Reconciliation of Non-GAAP Financial Measures: Consolidated EBITDA
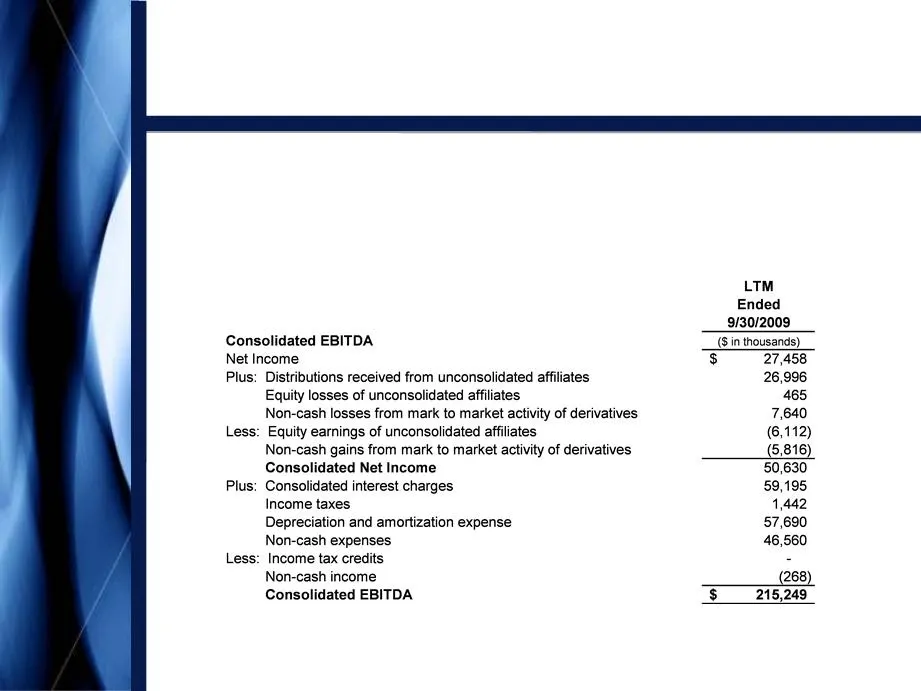
Reconciliation of Non-GAAP Financial Measures Consolidated EBITDA § EBITDA is also a financial measure that, with negotiated pro forma adjustments relating to acquisitions completed during the period, is reported to our lenders as Consolidated EBITDA and is used to compute our financial covenants un
Slide 61: Definitions of Non-GAAP Financial Measures
Definitions of Non-GAAP Financial Measures Total Distributable Cash Flow § We define total distributable cash flow as net income plus: (i) depreciation, amortization and impairment expense (including amortization expense relating to the option component of our risk management portfolio); (ii) cash d
Slide 62: December 2009
NASDAQ: CPNO December 2009
Source: SEC EDGAR · 8-K filed Dec 7, 2009
More decks from Copano Energy L.L.C.
 2012 RBC Capital Markets MLP Conference35 slides · Nov 15, 2012
 2012 Citi One-on-One MLP/Midstream Infrastructure Conference35 slides · Aug 21, 2012
 Investor Presentation (June 2012)34 slides · Jun 18, 2012
 NAPTP 2012 MLP Investor Conference34 slides · May 22, 2012
 Morgan Stanley MLP and Diversified Natural Gas Corporate Access Day 201245 slides · Mar 7, 2012
 2011 RBC Capital Markets MLP Conference42 slides · Nov 17, 2011