easyJet plc · LSE:EZJ
easyJet — H1 2018 Earnings Presentation
59 slides from easyJet's earnings presentation, May 2018
Slide 1: easyJet H1 2018 Analyst & Investor Presentation
easyJet Hi 2018 ANALYST & INVESTOR PRESENTATION
Slide 2: Introduction
introduction Johan Lundgren - Chief Executive Officer
Slide 3: Financial review
Financial review Andrew Findlay - Chief Financial Officer
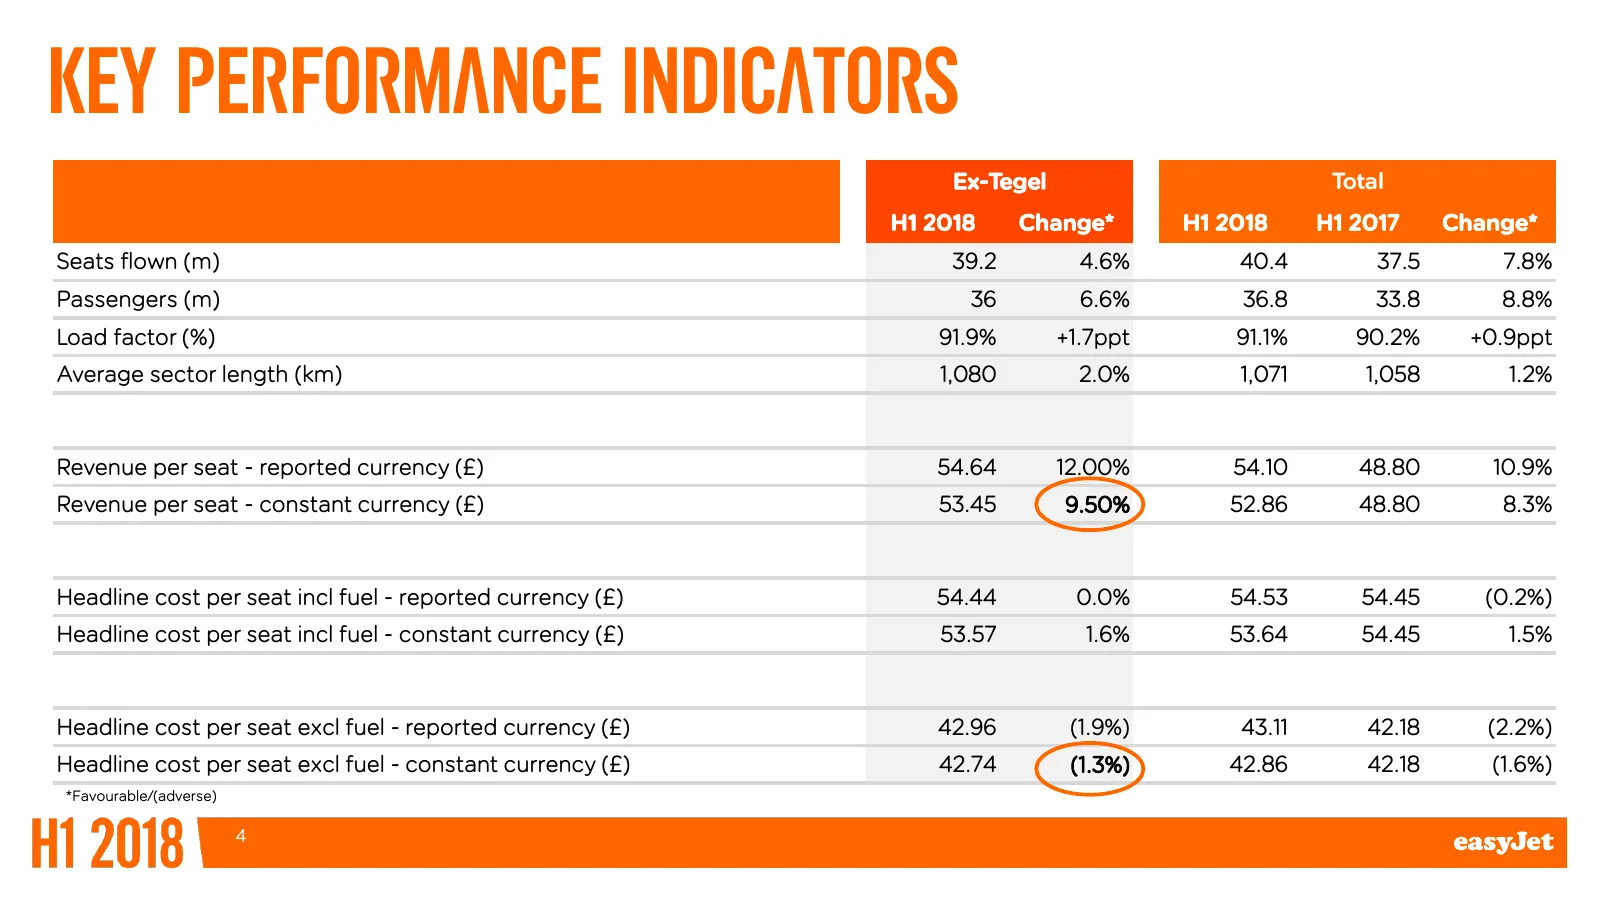
Slide 4: Key performance indicators
Key performance indicators Ex-Tegel Total H1 2018 Change* H1 2018 H1 2017 Change* Seats flown (m) 39.2 4.6% 40.4 37.5 7.8% Passengers (m) 36 6.6% 36.8 33.8 8.8% Load factor (%) 91.9% +1.7ppt 91.1% 90.2% +0.9ppt Average sector length (km) 1,080 2.0% 1,071 1,058 1.2% Revenue per seat - reported curren
Slide 5: Financial performance
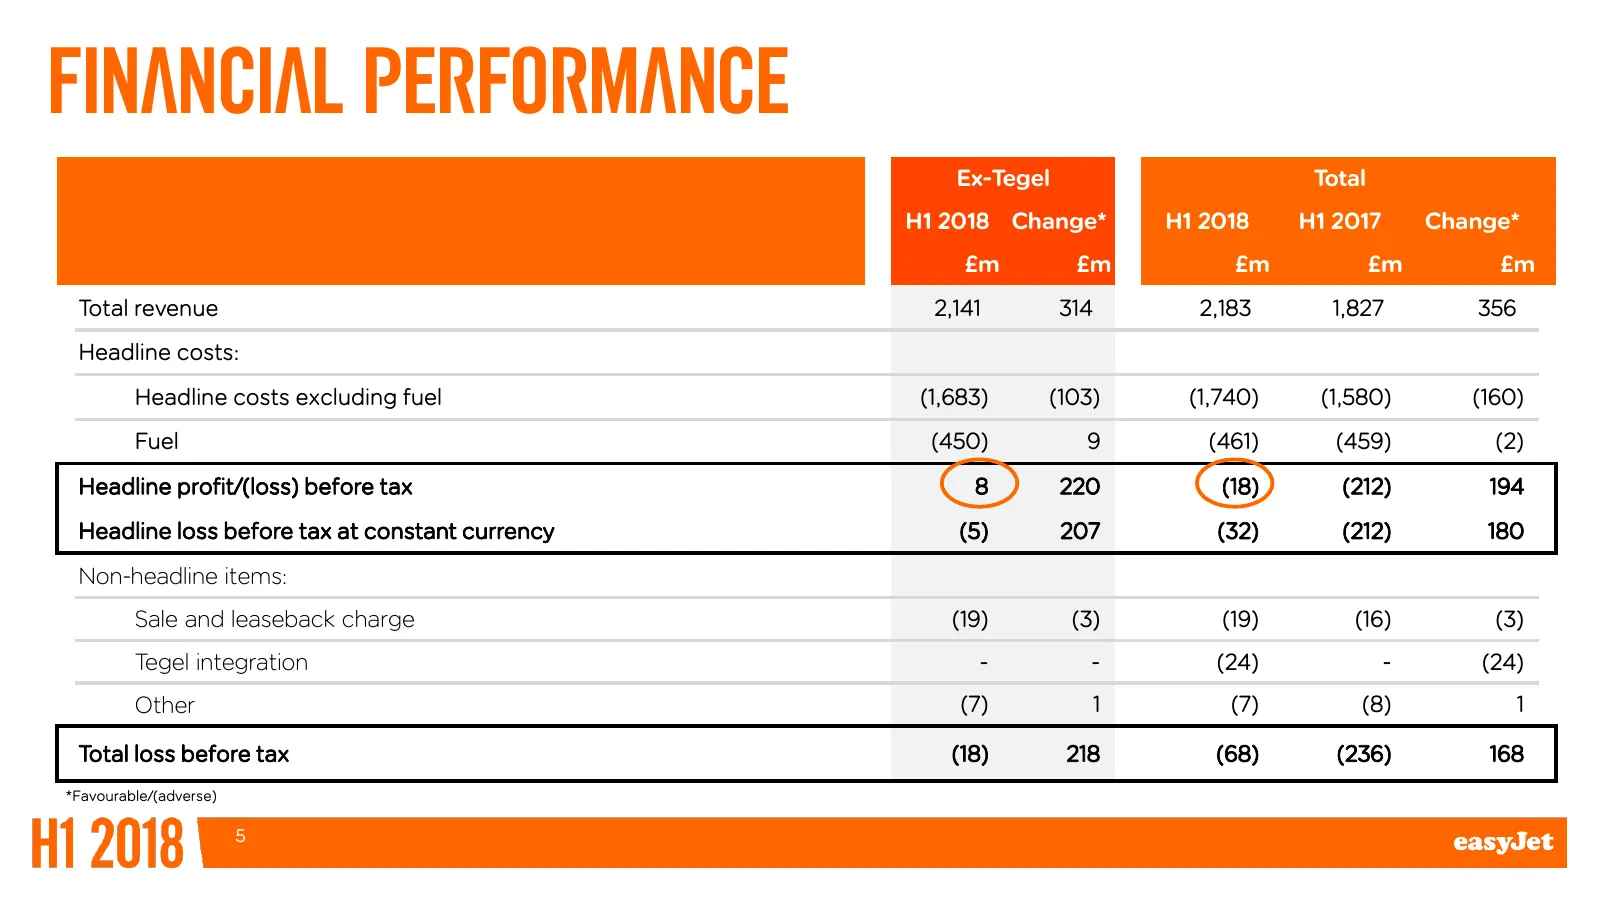
Financial performance Ex-Tegel Total H1 2018 Change* H1 2018 H1 2017 Change* £m £m £m £m £m Total revenue 2,141 314 2,183 1,827 356 Headline costs: Headline costs excluding fuel (1,683) (103) (1,740) (1,580) (160) Fuel (450) 9 (461) (459) (2) Headline profit/(loss) before tax 8 220 (18) (212) 194 He
Slide 6: Tegel operation
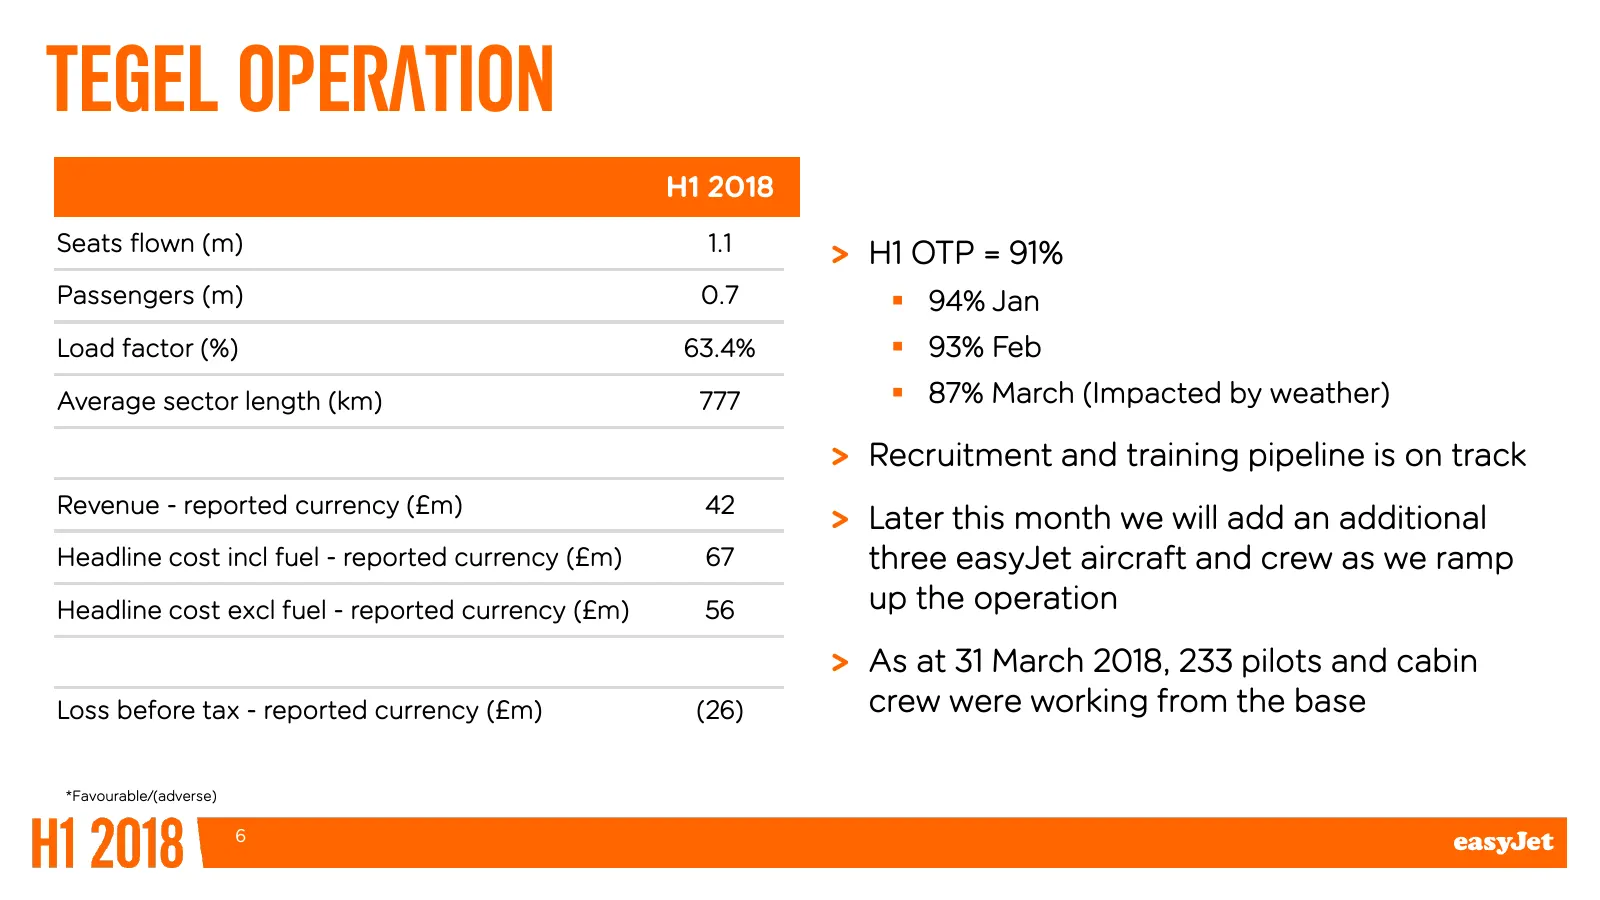
Tegel operation H1 2018 Seats flown (m) 1.1 > H1 OTP = 91% Passengers (m) 0.7 94% Jan Load factor (%) 63.4% 93% Feb Average sector length (km) 777 87% March (Impacted by weather) > Recruitment and training pipeline is on track Revenue - reported currency (£m) 42 > Later this month we will add
Slide 7: Revenue performance – ex-Tegel
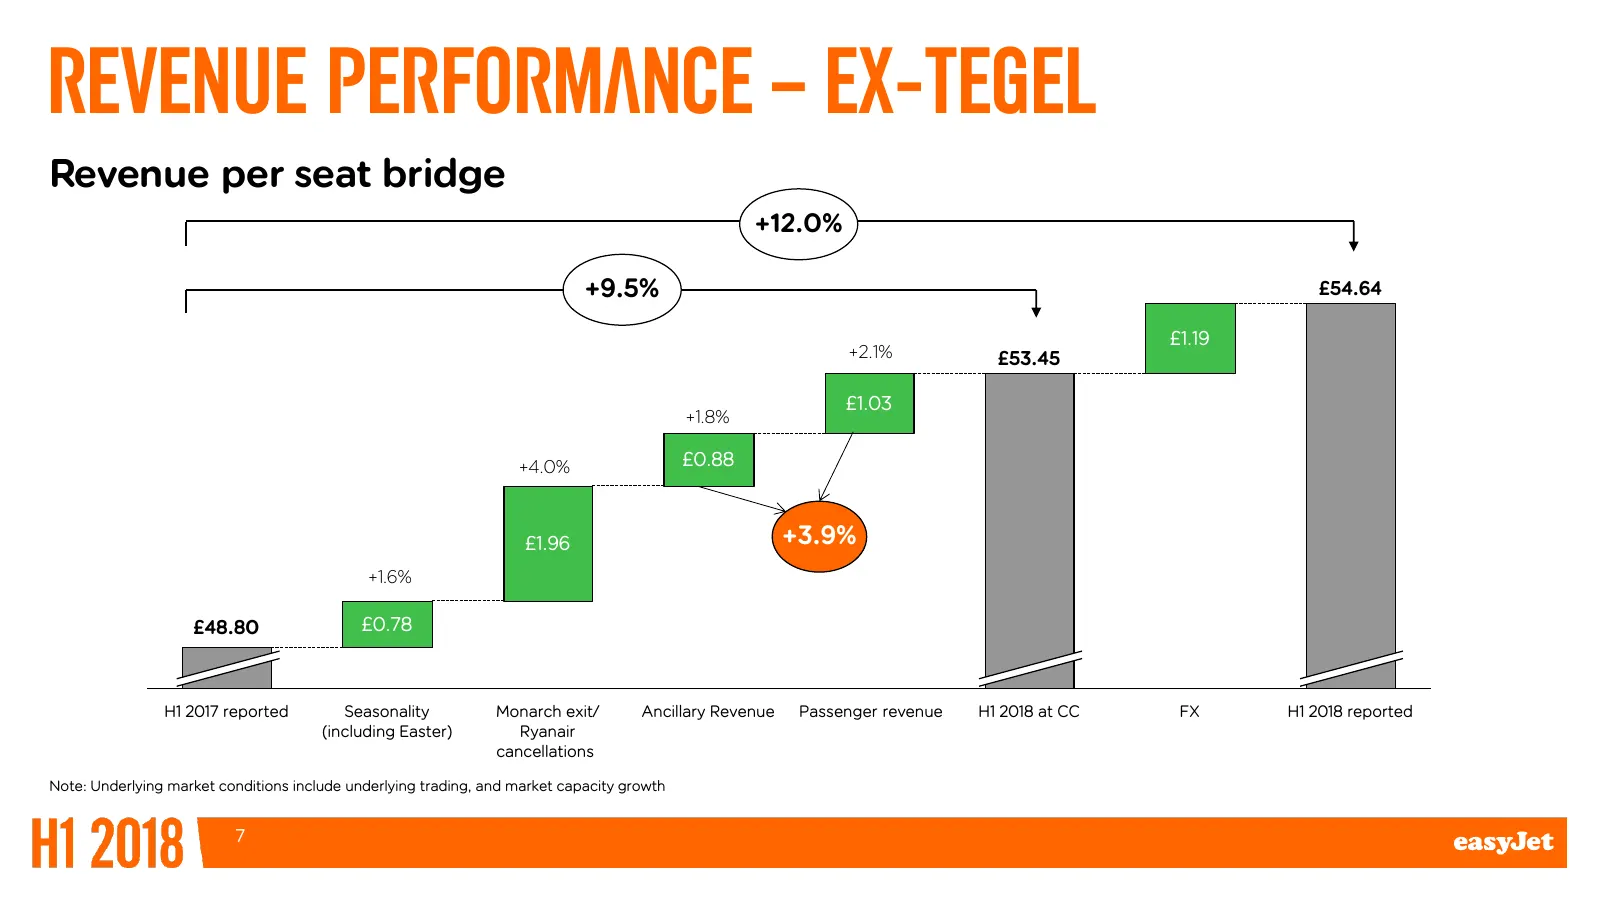
Revenue performance – ex-Tegel Revenue per seat bridge +12.0% +9.5% £54.64 £1.19 +2.1% £53.45 £1.03 +1.8% +4.0% £0.88 £1.96 +3.9% +1.6% £48.80 £0.78 H1 2017 reported Seasonality Monarch exit/ Ancillary Revenue Passenger revenue H1 2018 at CC FX H1 2018 reported (including Easter) Ryanair cancellatio
Slide 8: Headline cost per seat - ex-Tegel
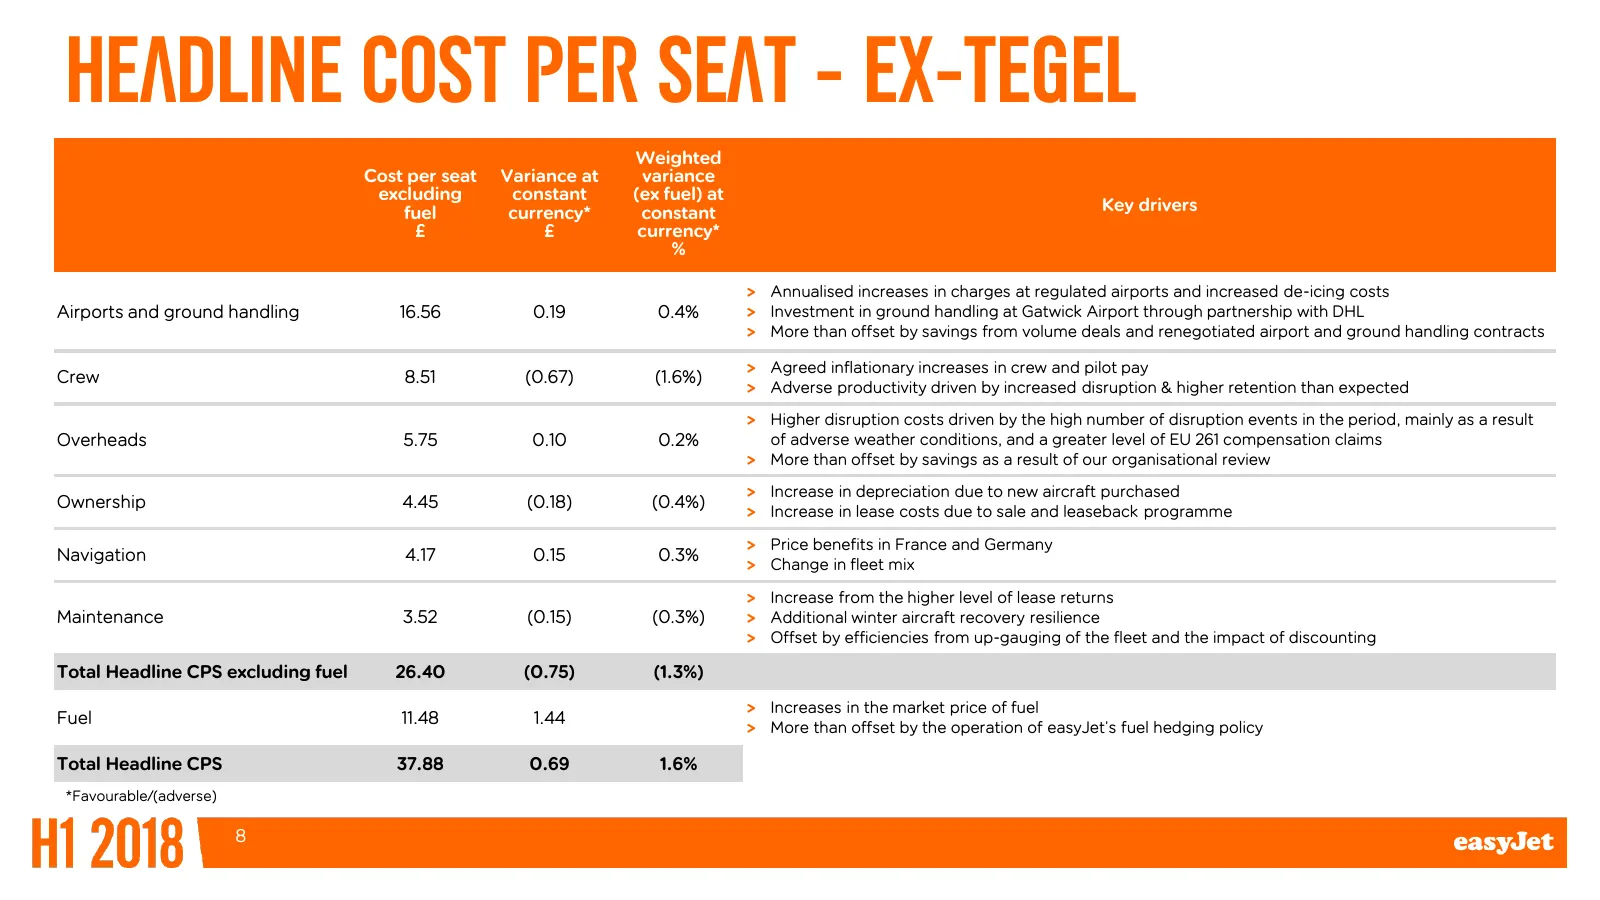
Headline cost per seat - ex-tegel Weighted Cost per seat Variance at variance excluding constant (ex fuel) at fuel currency* constant Key drivers £ £ currency* % > Annualised increases in charges at regulated airports and increased de-icing costs Airports and ground handling 16.56 0.19 0.4% > Invest
Slide 9: Disruption
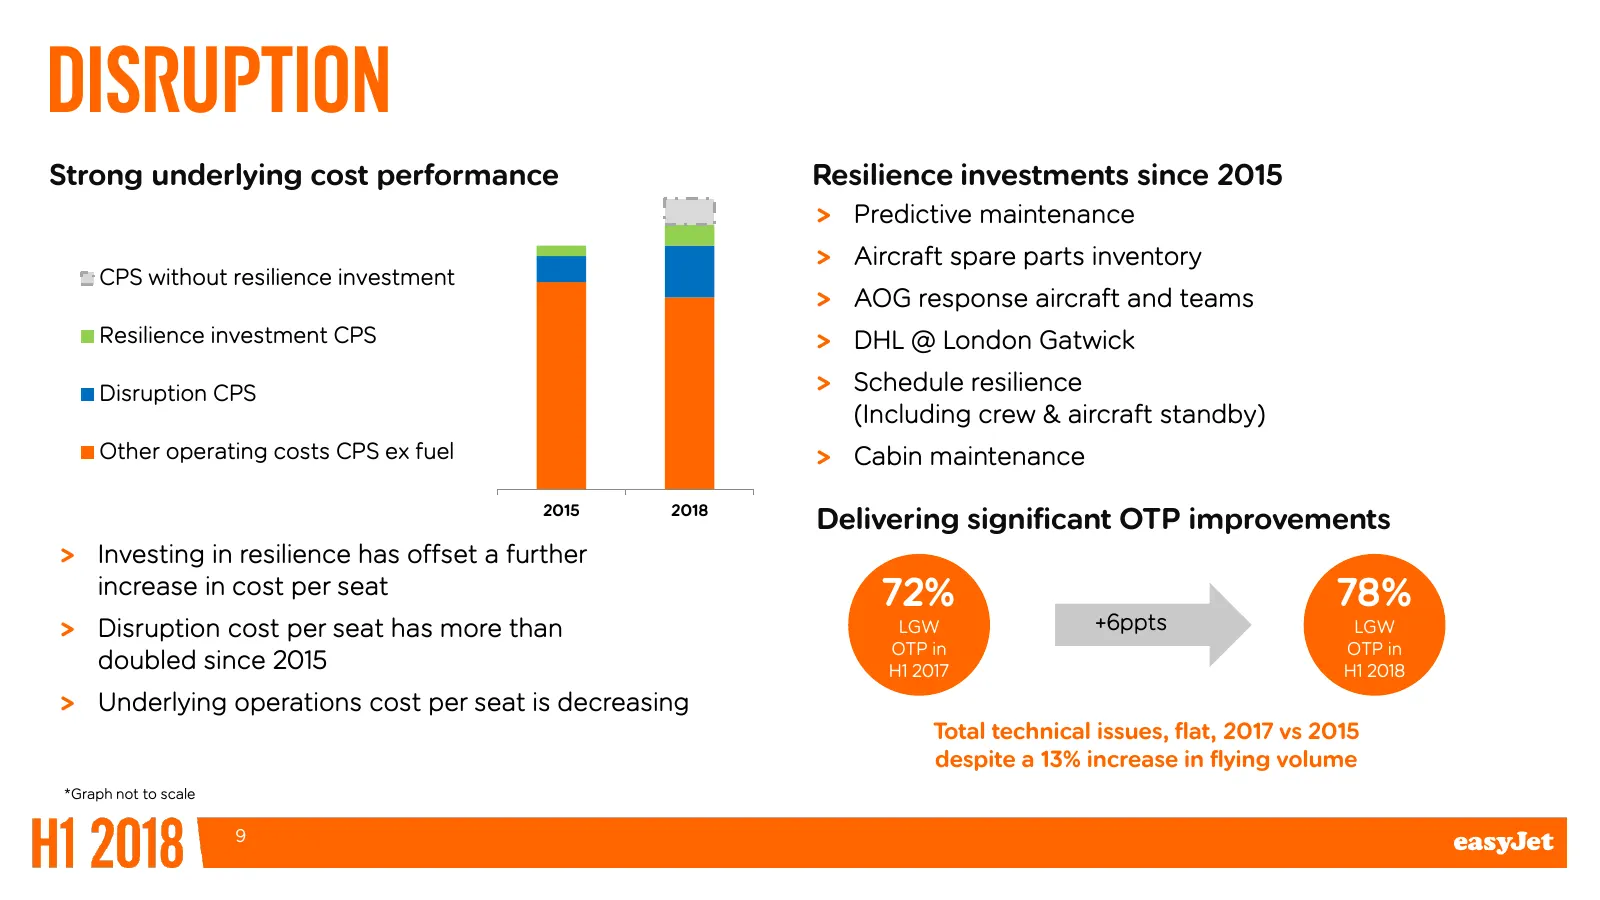
Disruption Strong underlying cost performance Resilience investments since 2015 > Predictive maintenance > Aircraft spare parts inventory CPS without resilience investment > AOG response aircraft and teams Resilience investment CPS > DHL @ London Gatwick Disruption CPS > Schedule resilience (Includi
Slide 10: Impact of fuel & currency
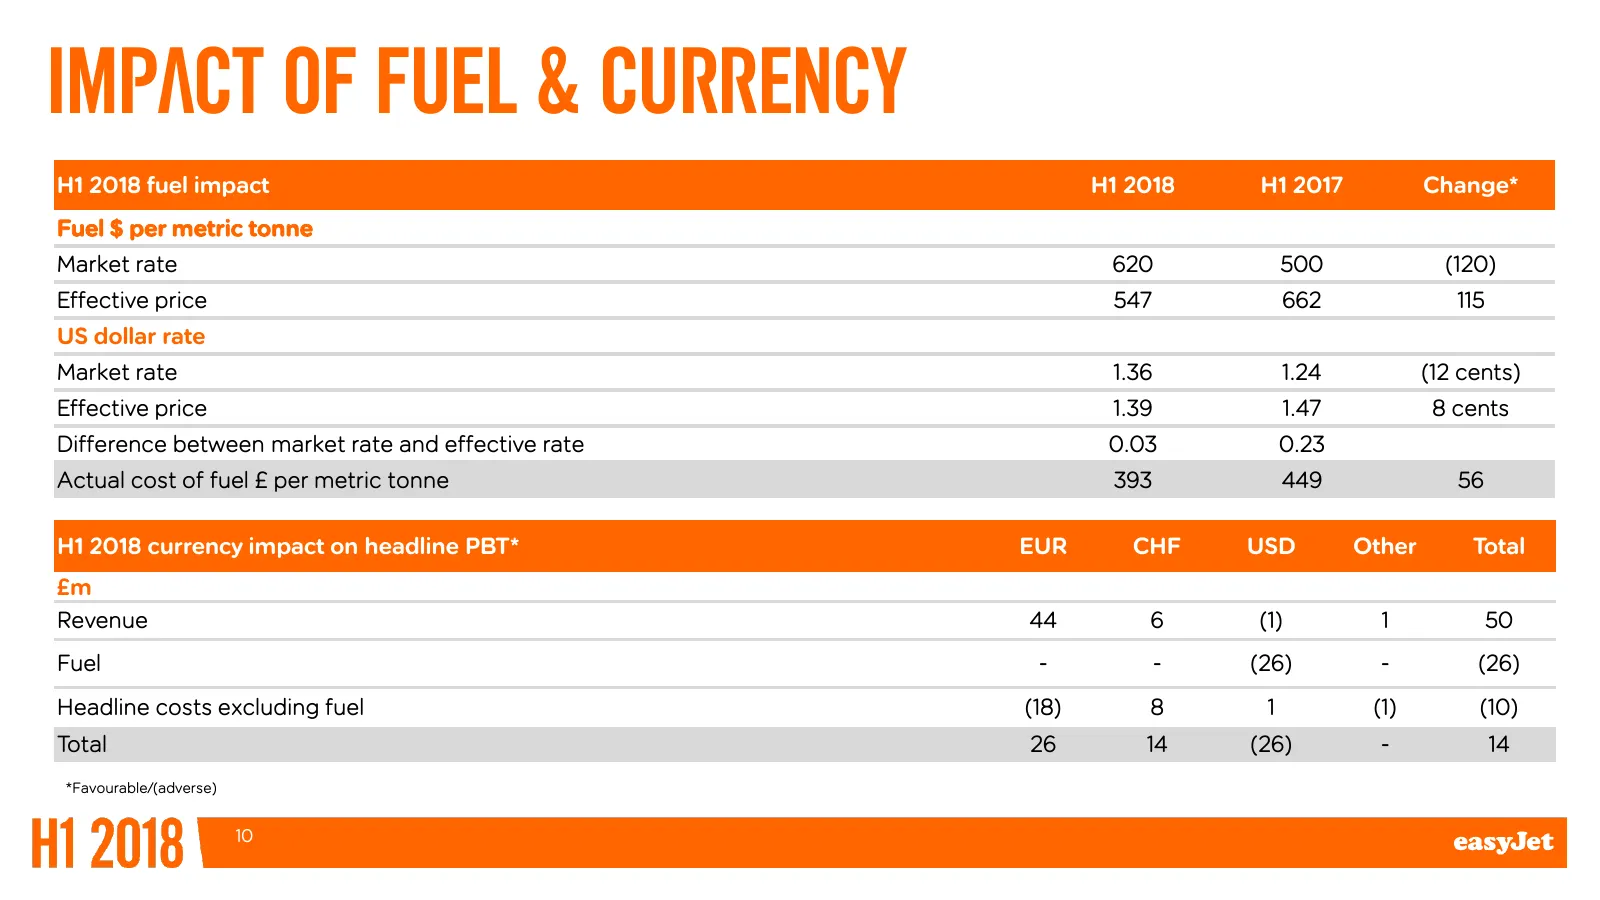
Impact of fuel & currency H1 2018 fuel impact H1 2018 H1 2017 Change* Fuel $ per metric tonne Market rate 620 500 (120) Effective price 547 662 115 US dollar rate Market rate 1.36 1.24 (12 cents) Effective price 1.39 1.47 8 cents Difference between market rate and effective rate 0.03 0.23 Actual cos
Slide 11: Strong cash generation
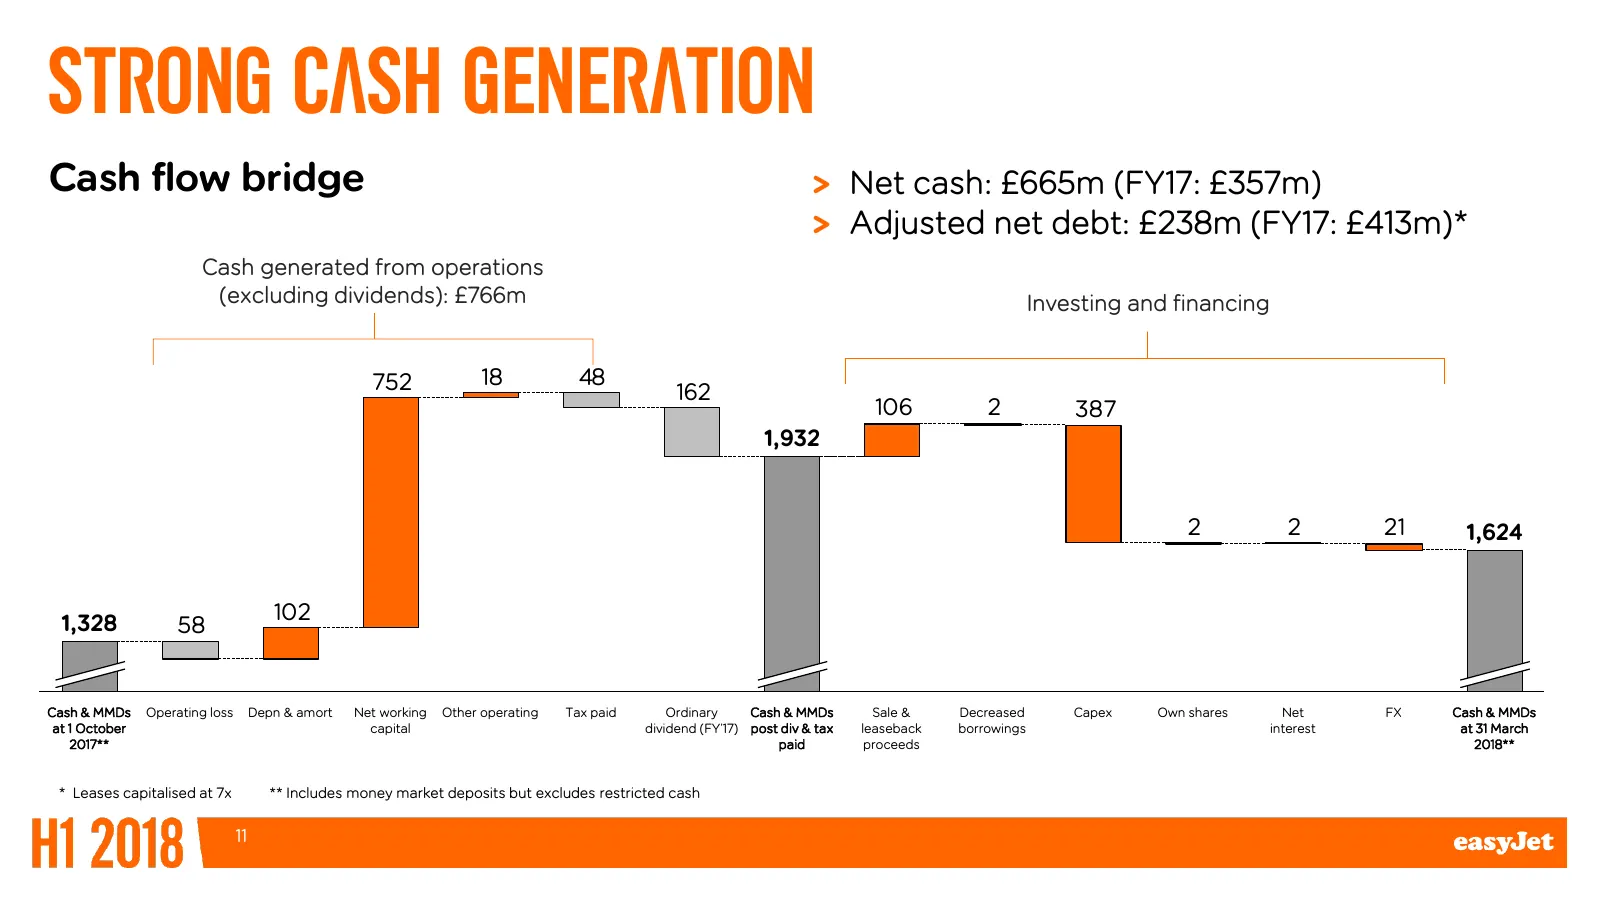
Strong cash generation Cash flow bridge > Net cash: £665m (FY17: £357m) > Adjusted net debt: £238m (FY17: £413m)* Cash generated from operations (excluding dividends): £766m Investing and financing 752 18 48 162 106 2 387 1,932 2 2 21 1,624 1,328 102 58 Cash & MMDs Operating loss Depn & amort Net wo
Slide 12: Strong balance sheet
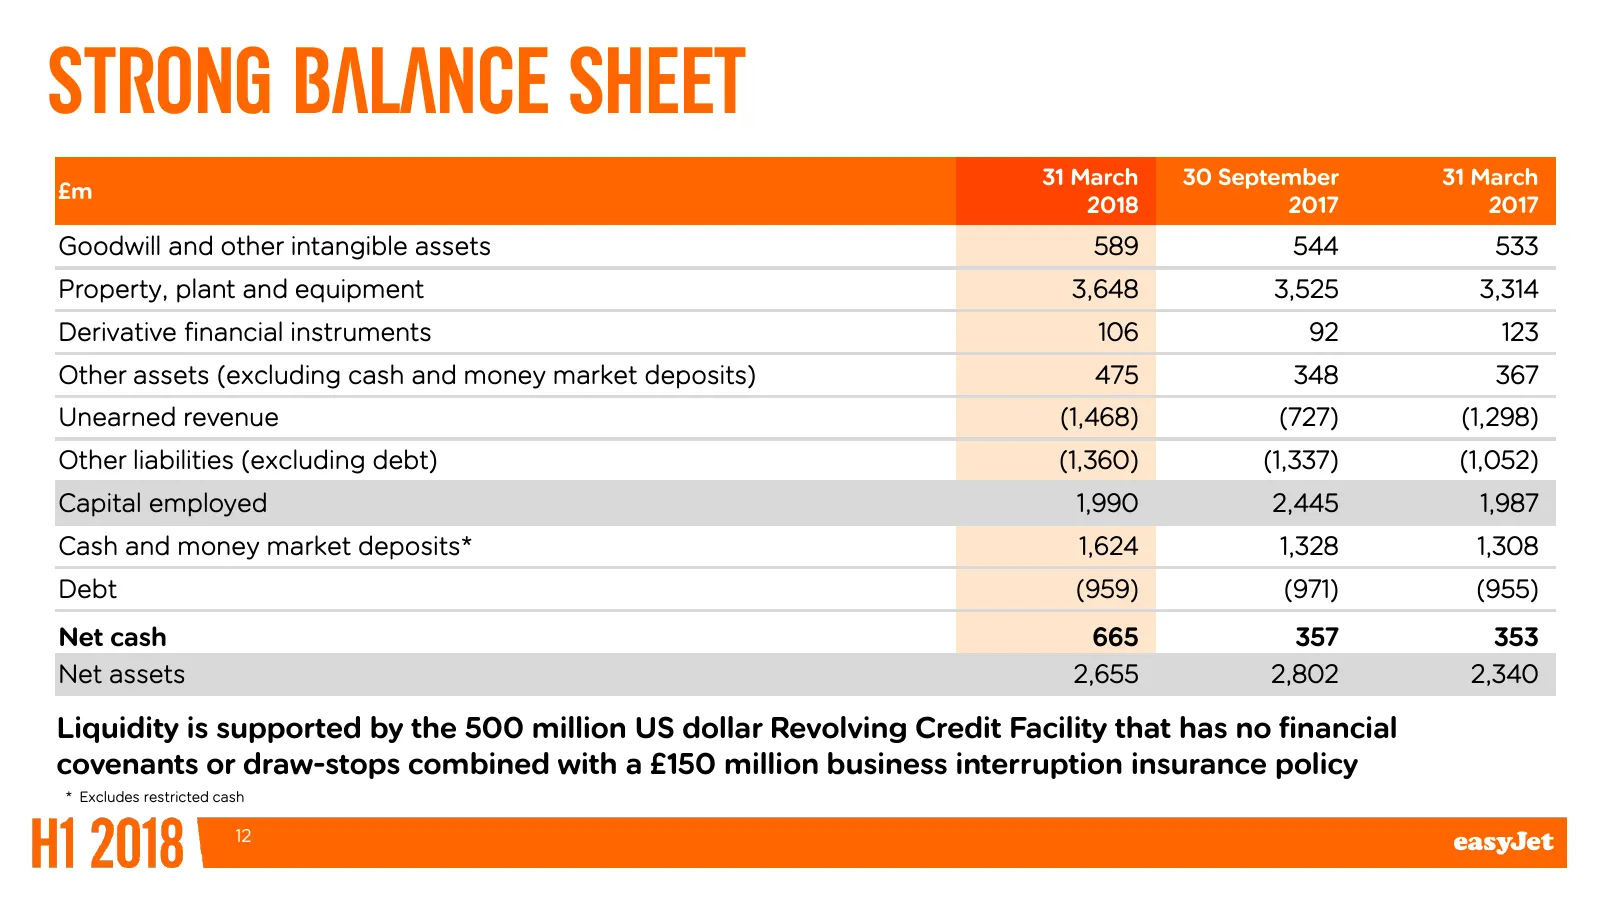
Strong balance sheet 31 March 30 September 31 March £m 2018 2017 2017 Goodwill and other intangible assets 589 544 533 Property, plant and equipment 3,648 3,525 3,314 Derivative financial instruments 106 92 123 Other assets (excluding cash and money market deposits) 475 348 367 Unearned revenue (1,4
Slide 13: H2 forward bookings
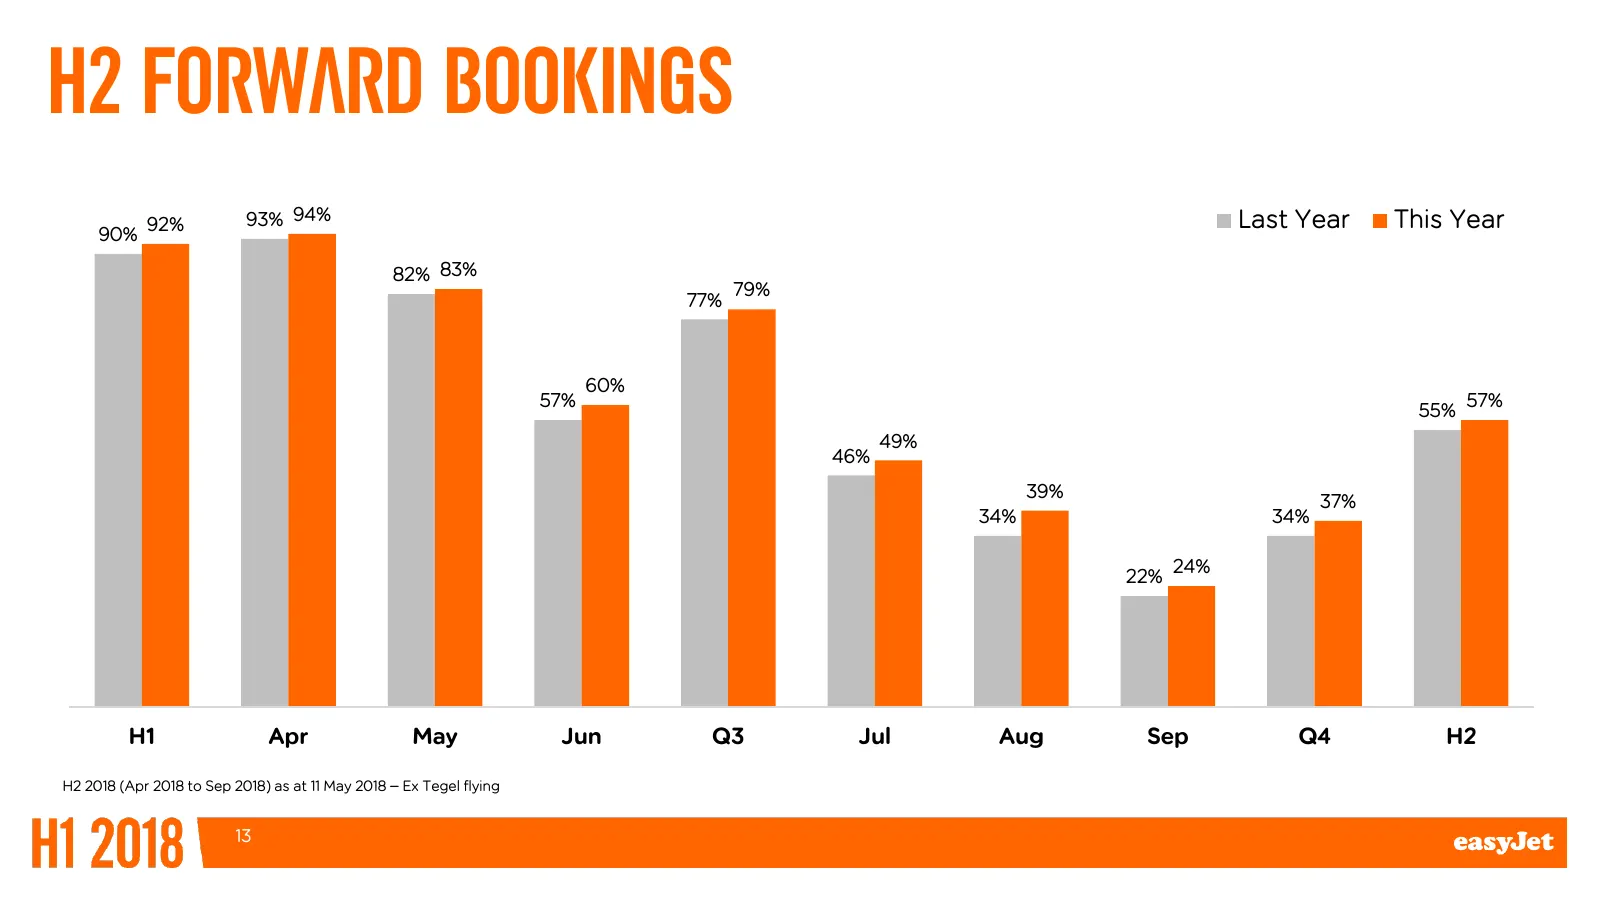
H2 forward bookings 92% 93% 94% Last Year This Year 90% 82% 83% 79% 77% 60% 57% 57% 55% 49% 46% 39% 37% 34% 34% 24% 22% H1 Apr May Jun Q3 Jul Aug Sep Q4 H2 H2 2018 (Apr 2018 to Sep 2018) as at 11 May 2018 – Ex Tegel flying 13
Slide 14: H2 capacity outlook
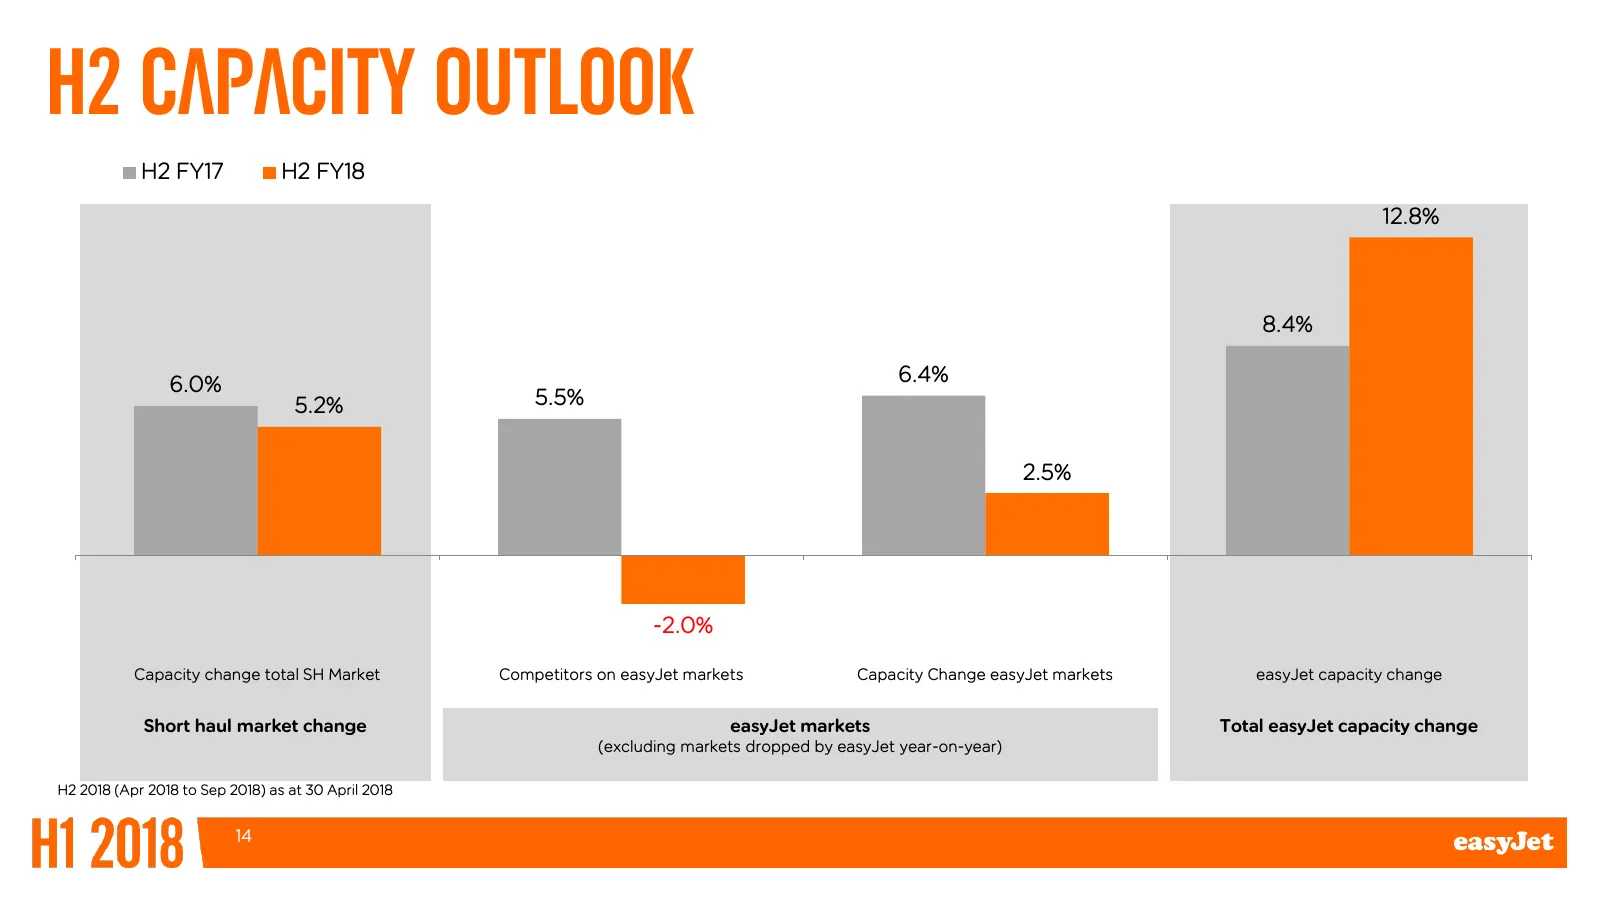
H2 capacity outlook H2 FY17 H2 FY18 12.8% 8.4% 6.0% 6.4% 5.2% 5.5% 2.5% -2.0% Capacity change total SH Market Competitors on easyJet markets Capacity Change easyJet markets easyJet capacity change Short haul market change easyJet markets Total easyJet capacity change (excluding markets dropped by ea
Slide 15: 2018 Outlook
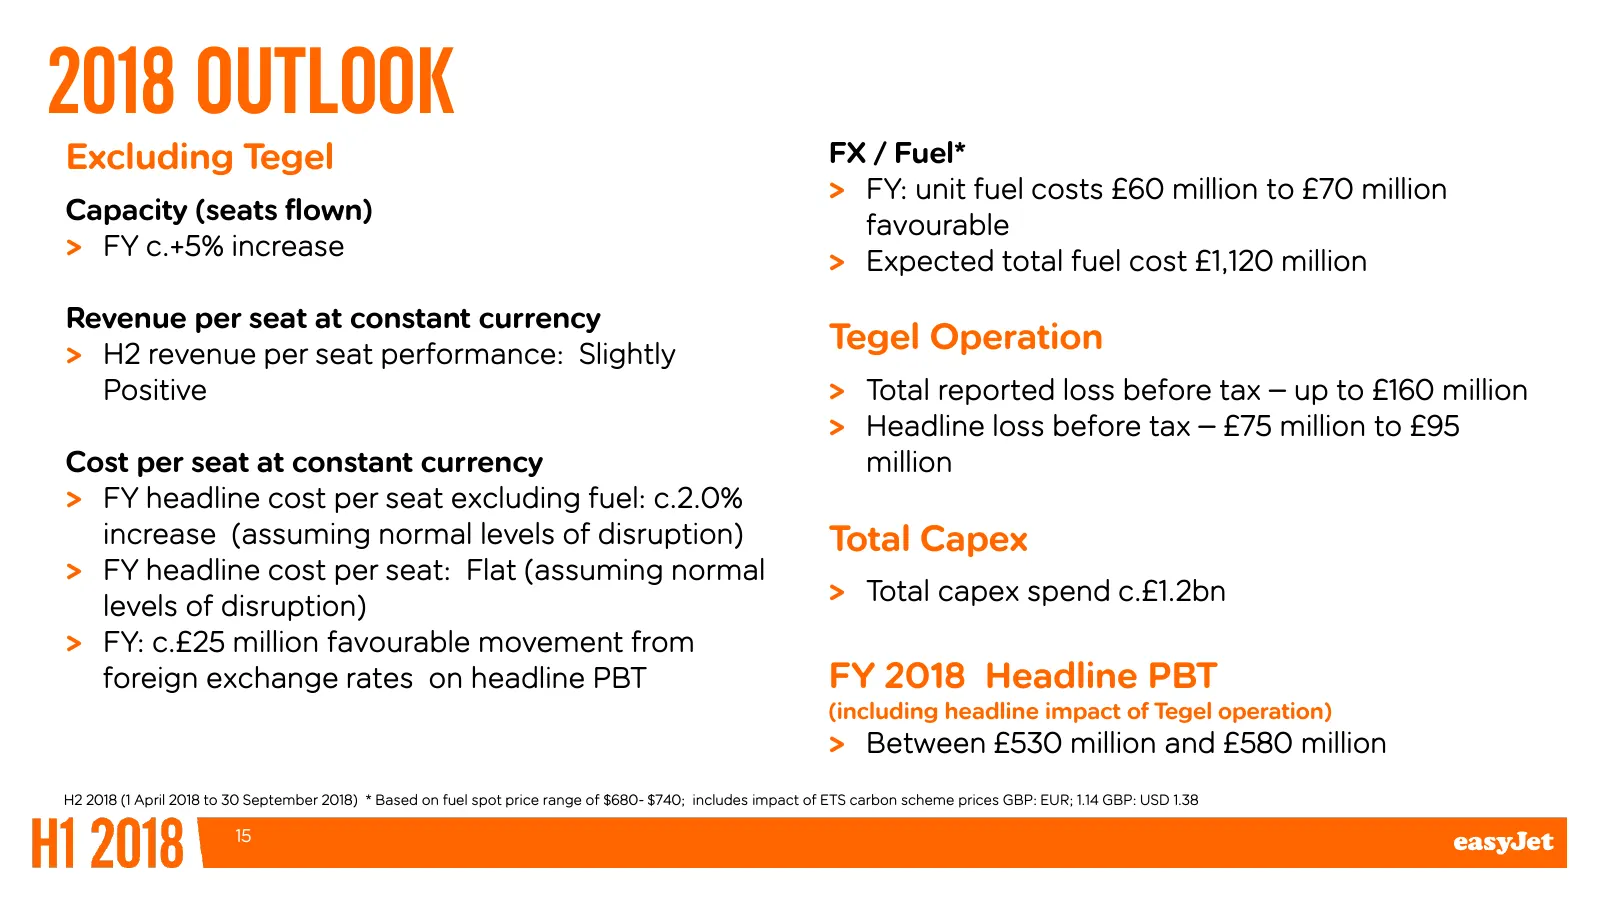
2018 Outlook FX / Fuel* Excluding Tegel > FY: unit fuel costs £60 million to £70 million Capacity (seats flown) favourable > FY c.+5% increase > Expected total fuel cost £1,120 million Revenue per seat at constant currency > H2 revenue per seat performance: Slightly Tegel Operation Positive > Total
Slide 16: Strategy outlook
Strategy outlook Johan Lundgren - Chief Executive Officer
Slide 17: Strength-to-strength
STRENGTH-T0-STRENGTH Hi 2018
Slide 18: Unique strengths & many opportunities
unique strengths & many opportunities 18
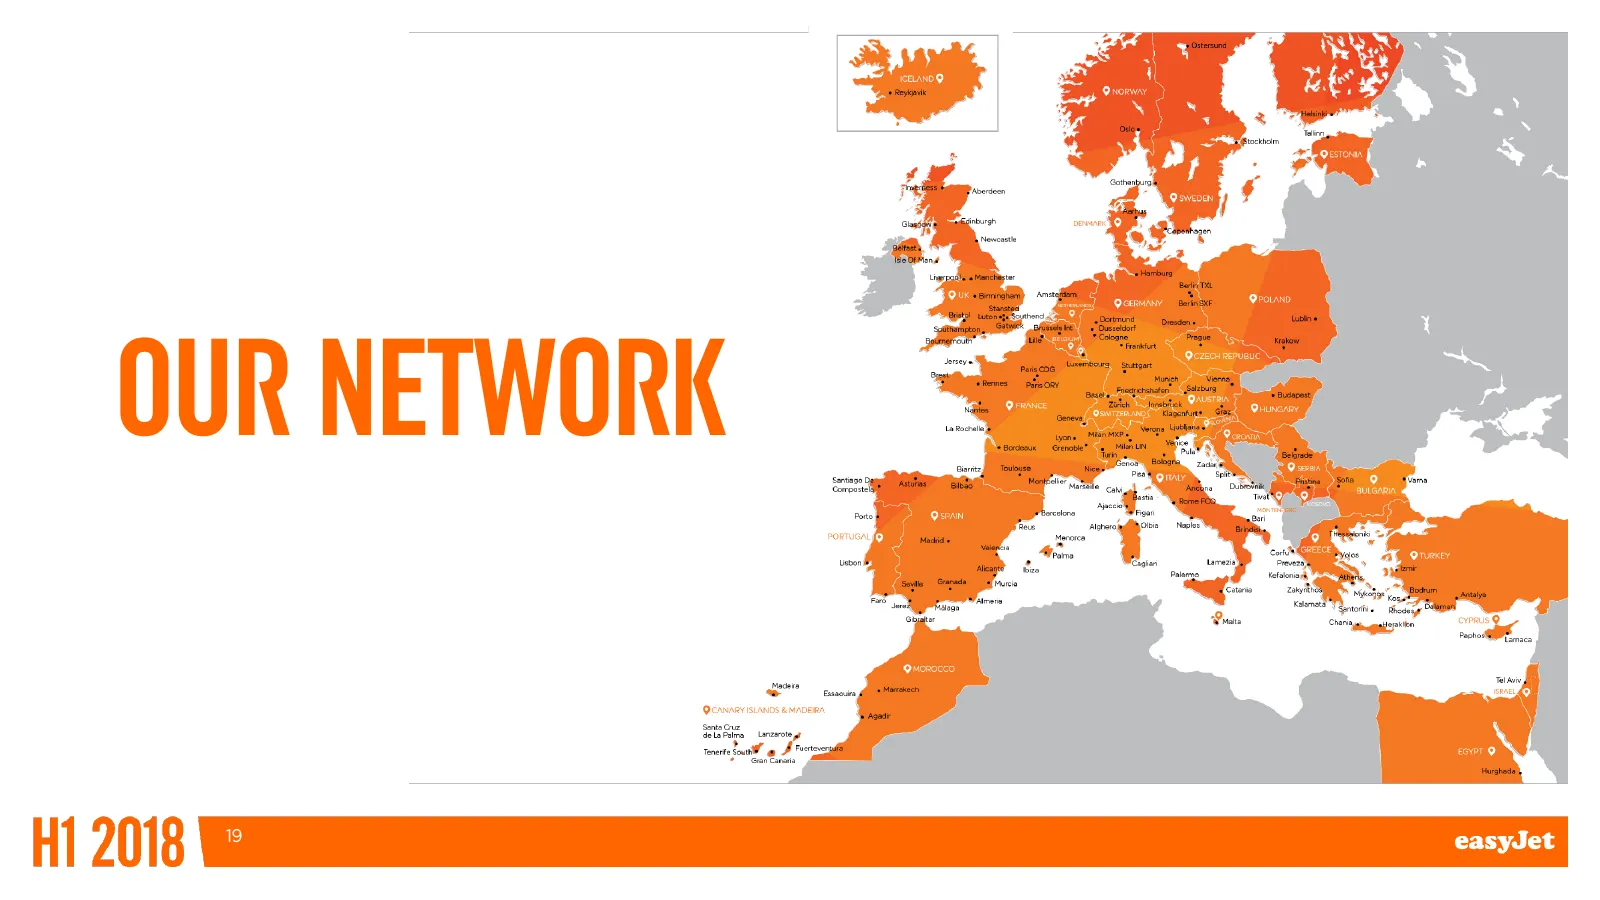
Slide 19: Our network
OURNETWORK & ] easyJet Hi 2018 &
Slide 20: Our cost base
Our COST Base 20
Slide 21: Scale
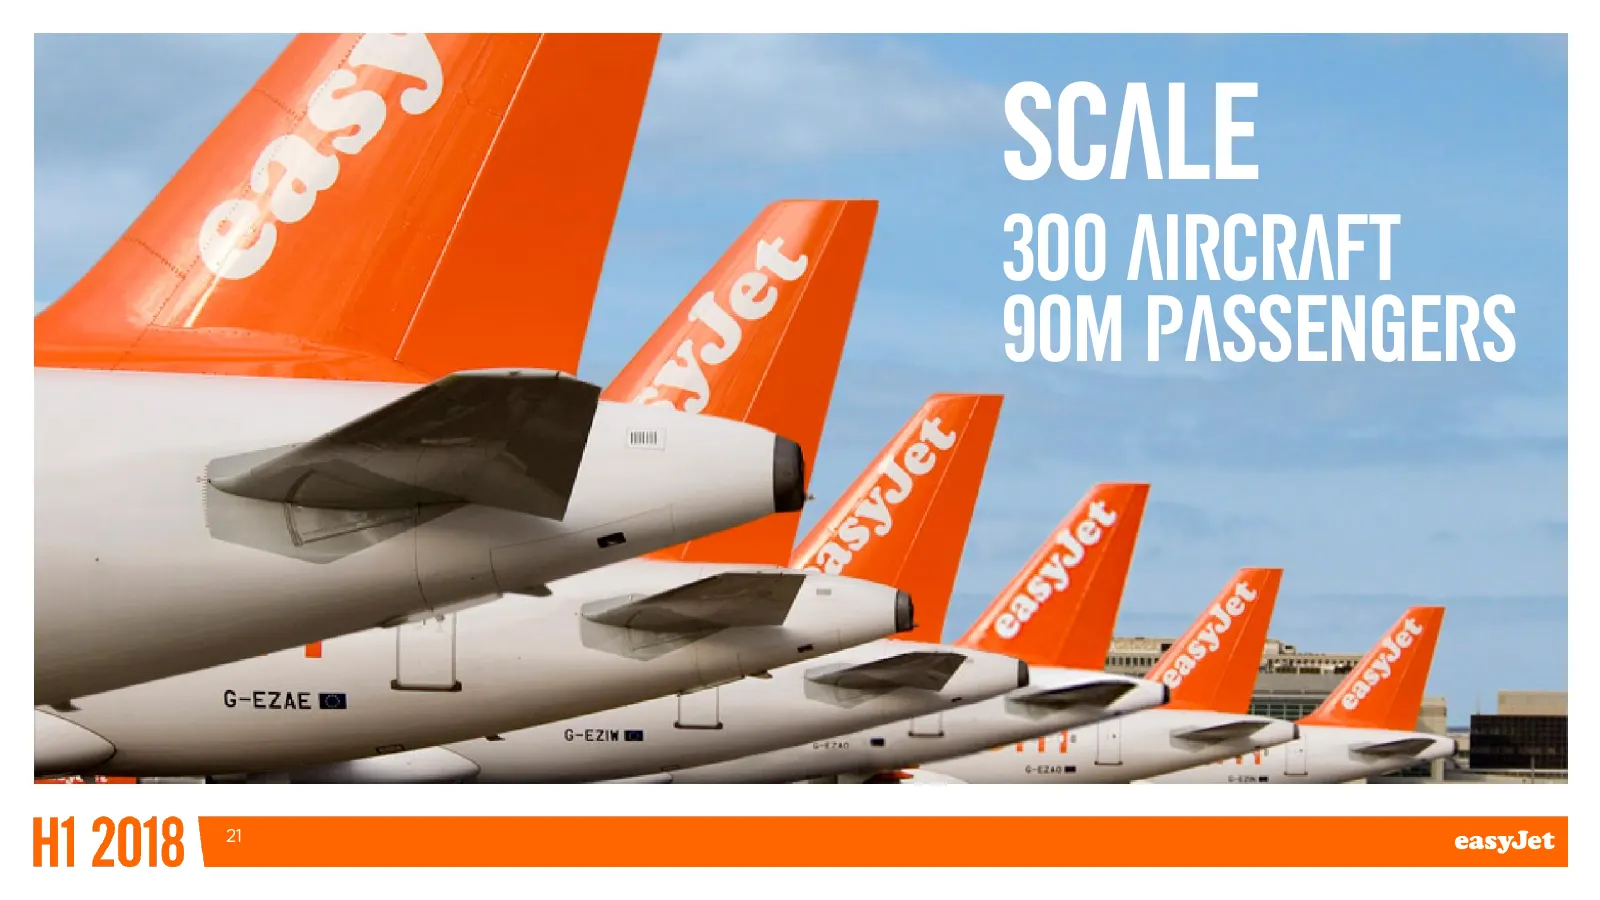
Scale 300 aircraft 90m passengers 21
Slide 22: People
a PEOPLE Hi 2018 &
Slide 23: Our brand
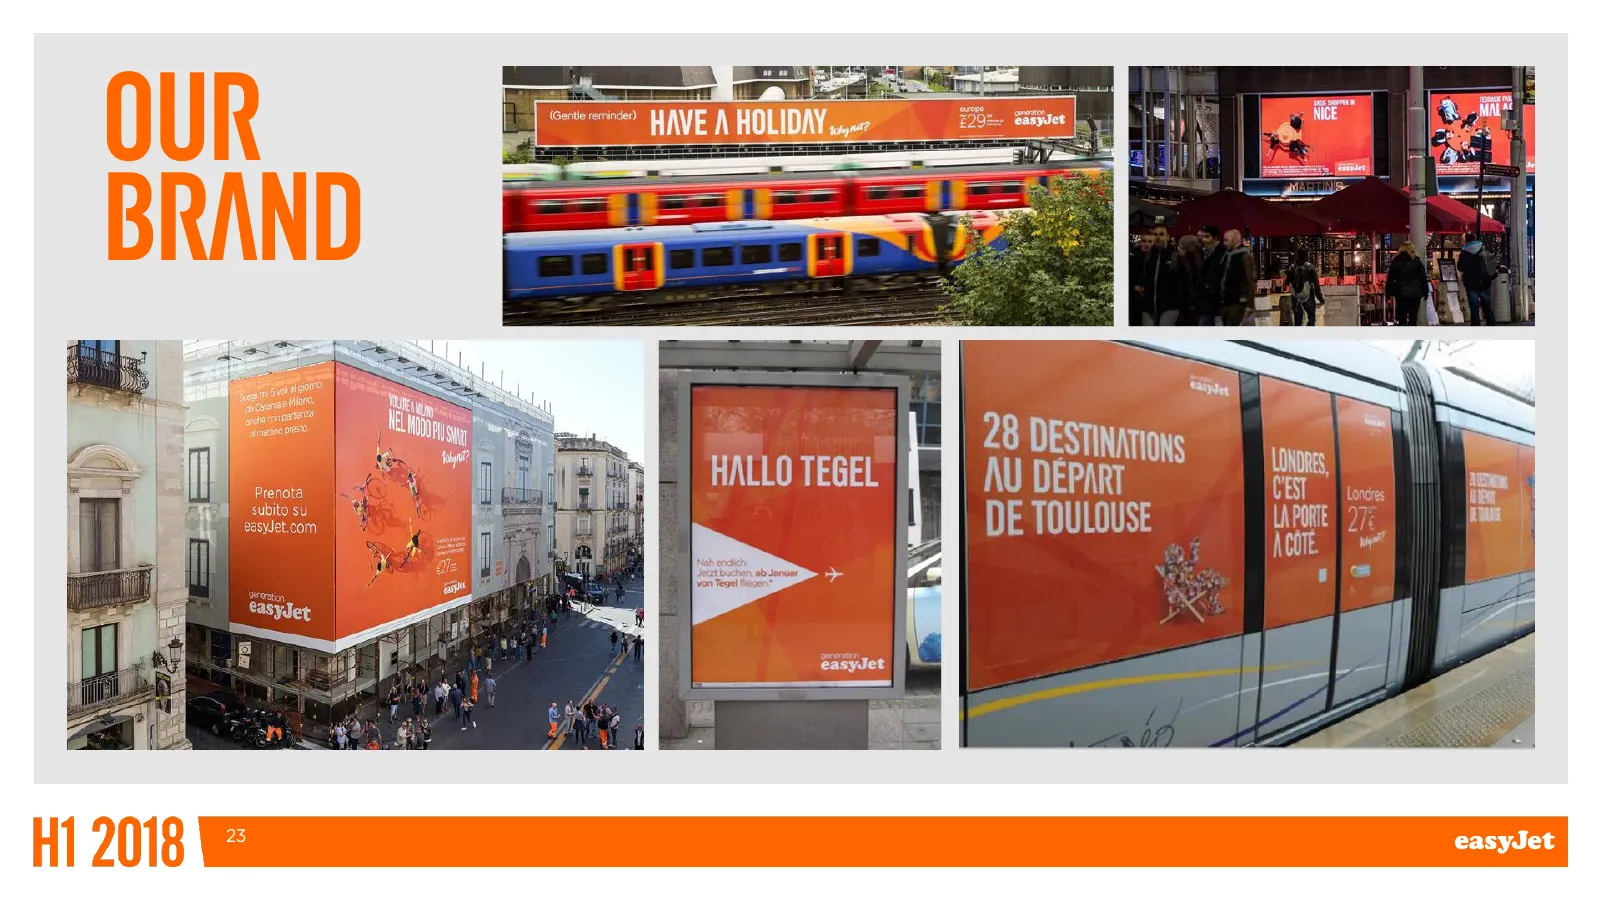
Our brand 23
Slide 24: Our brand position
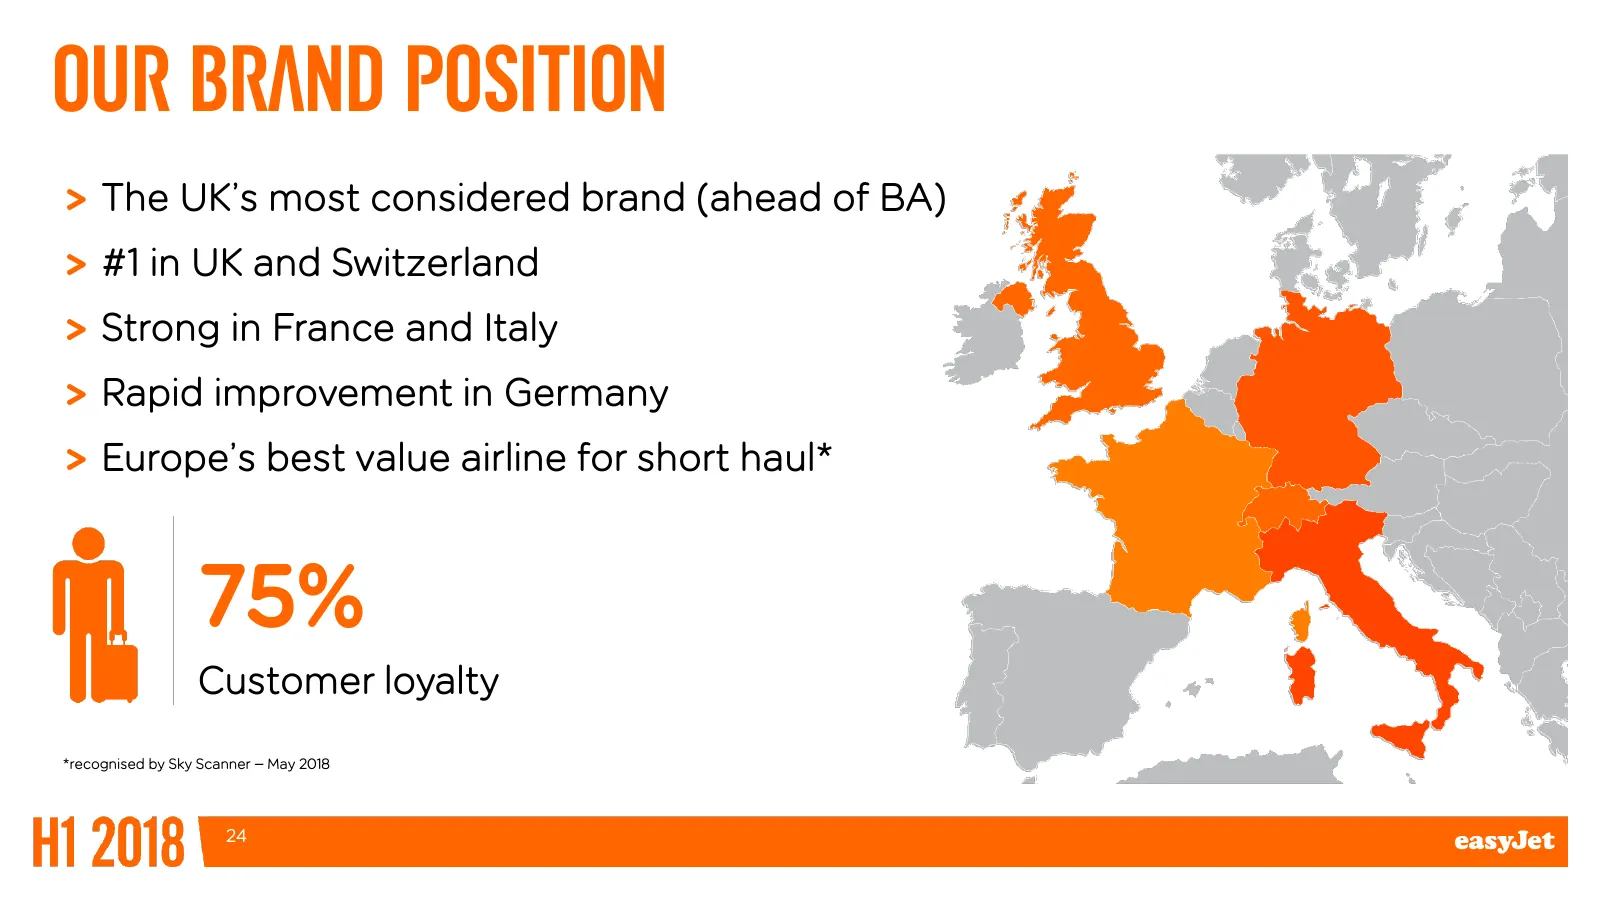
Our brand position > The UK’s most considered brand (ahead of BA) > #1 in UK and Switzerland > Strong in France and Italy > Rapid improvement in Germany > Europe’s best value airline for short haul* 75% Customer loyalty *recognised by Sky Scanner – May 2018 24
Slide 25: Data
Data To win in our industry you have to use data well 25
Slide 26: 26
26
Slide 27: easyJet holidays, business customers, loyalty
2D easyJet holidays im BUSINESS CUSTOMERS LOYALTY Hi 2018
Slide 28: Profit per seat increase our return
Profit per seat increase our return Increase the reward on capital employed to shareholders 28
Slide 29: Focus on profit per seat
Focus on profit per seat 29
Slide 30: easyJet holidays
easyJet holidays Hi 2018
Slide 31: Our destinations
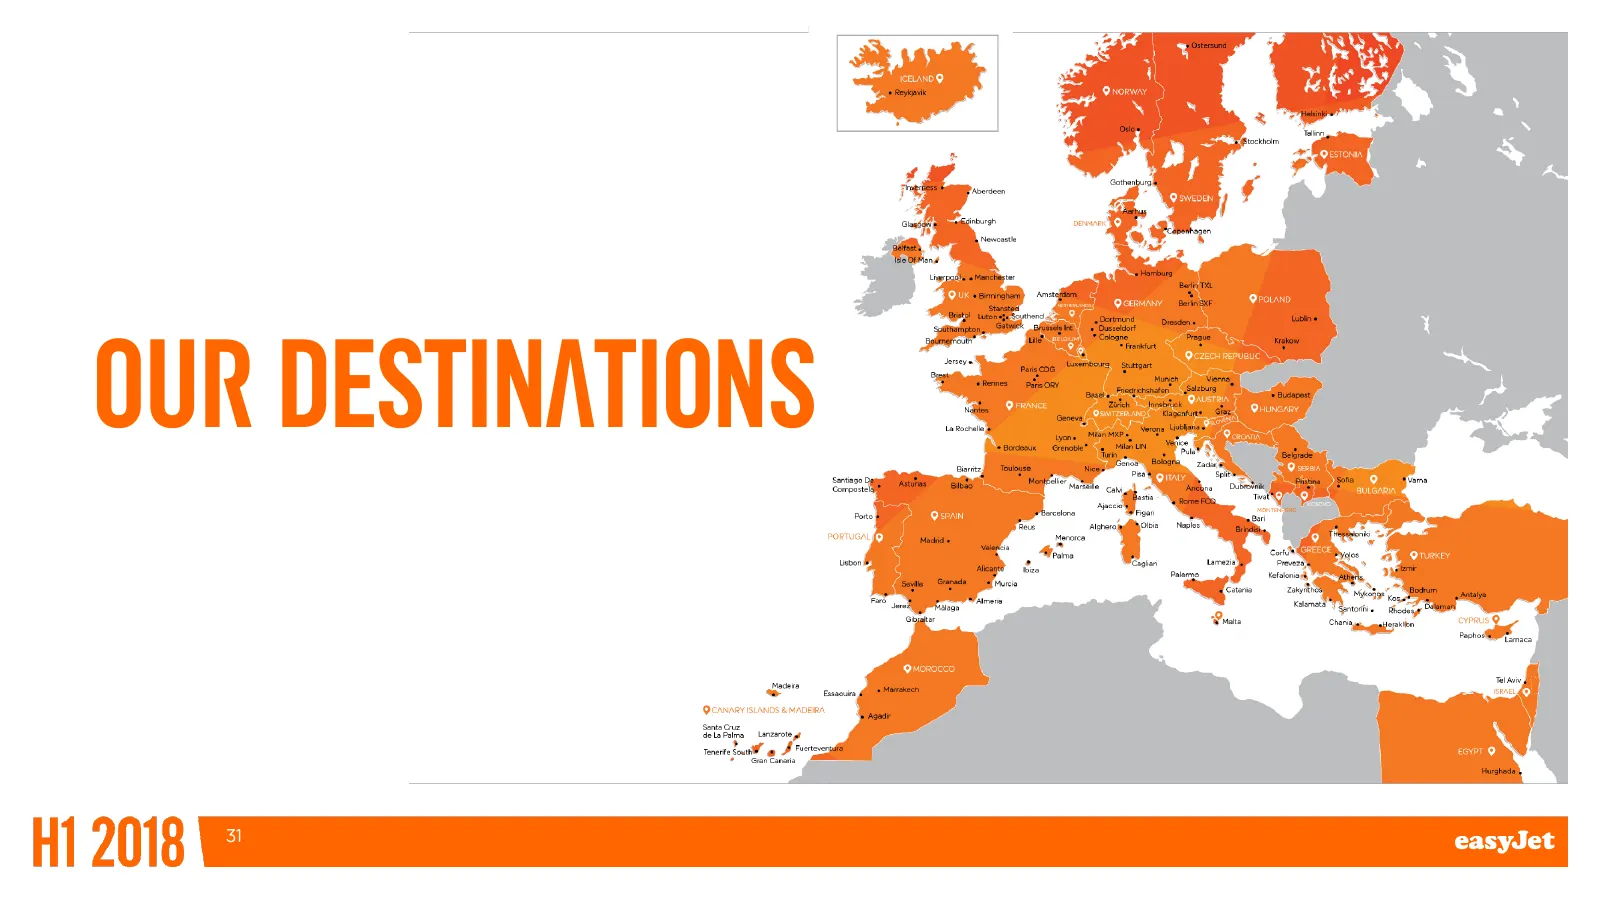
Our destinations 31
Slide 32: Cost advantage of 20%
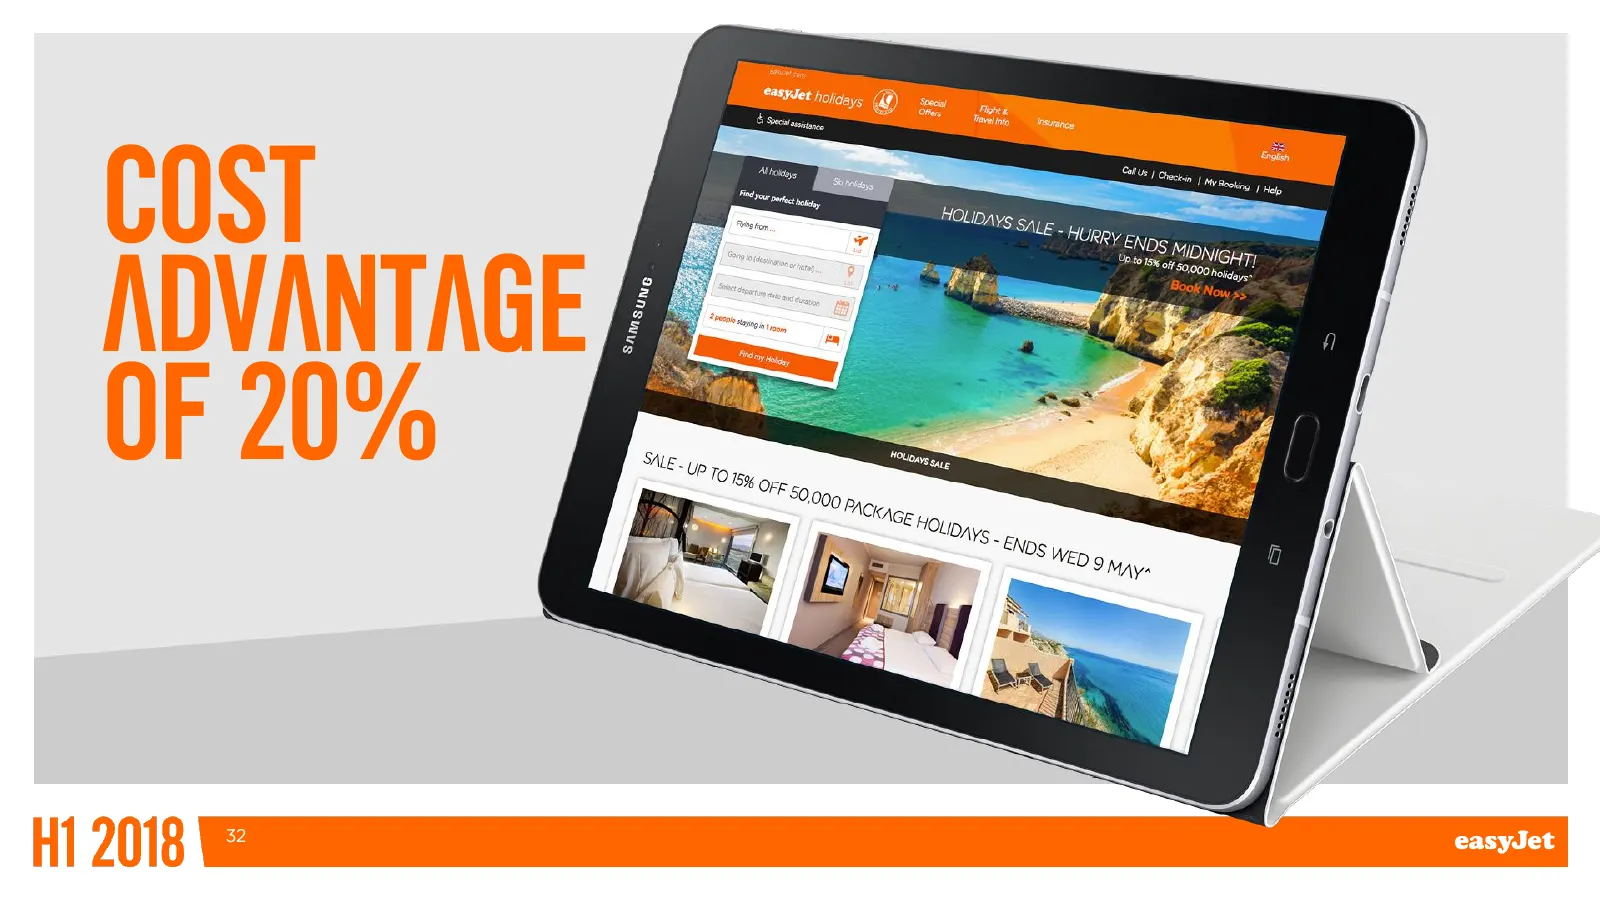
HOLIDA YS: SALE HURRY ENDS MIDNIGH Ty "080 15% of 5 2.000 hoidayas Now sf
Slide 33: easyJet holidays
easyJet holidays Hi 2018
Slide 34: Better value proposition
easyJet _ holidays BETTER VALUE PROPOSITION
Slide 35: Business travellers
Z e\ Bn } BUSINESS hy TRAVELLEROR Hi 2018 &
Slide 36: Over 13 million business passengers
over 13 million Business Passengers 36
Slide 37: Business travellers 92% more likely to fly again
Once business travellers try us, they are 92% more likely to fly with us again 37
Slide 38: Loyalty
Loyalty Returning customers book twice as many flights 38
Slide 39: 46% of customers only fly with us once a year
46% of our customers only fly with us once a year 39
Slide 40: Thank you
THANIX YOU.
Slide 41: Over 60 of our 90 million passengers are returning customers
over 60 of our 90 million passengers are returning customers 41
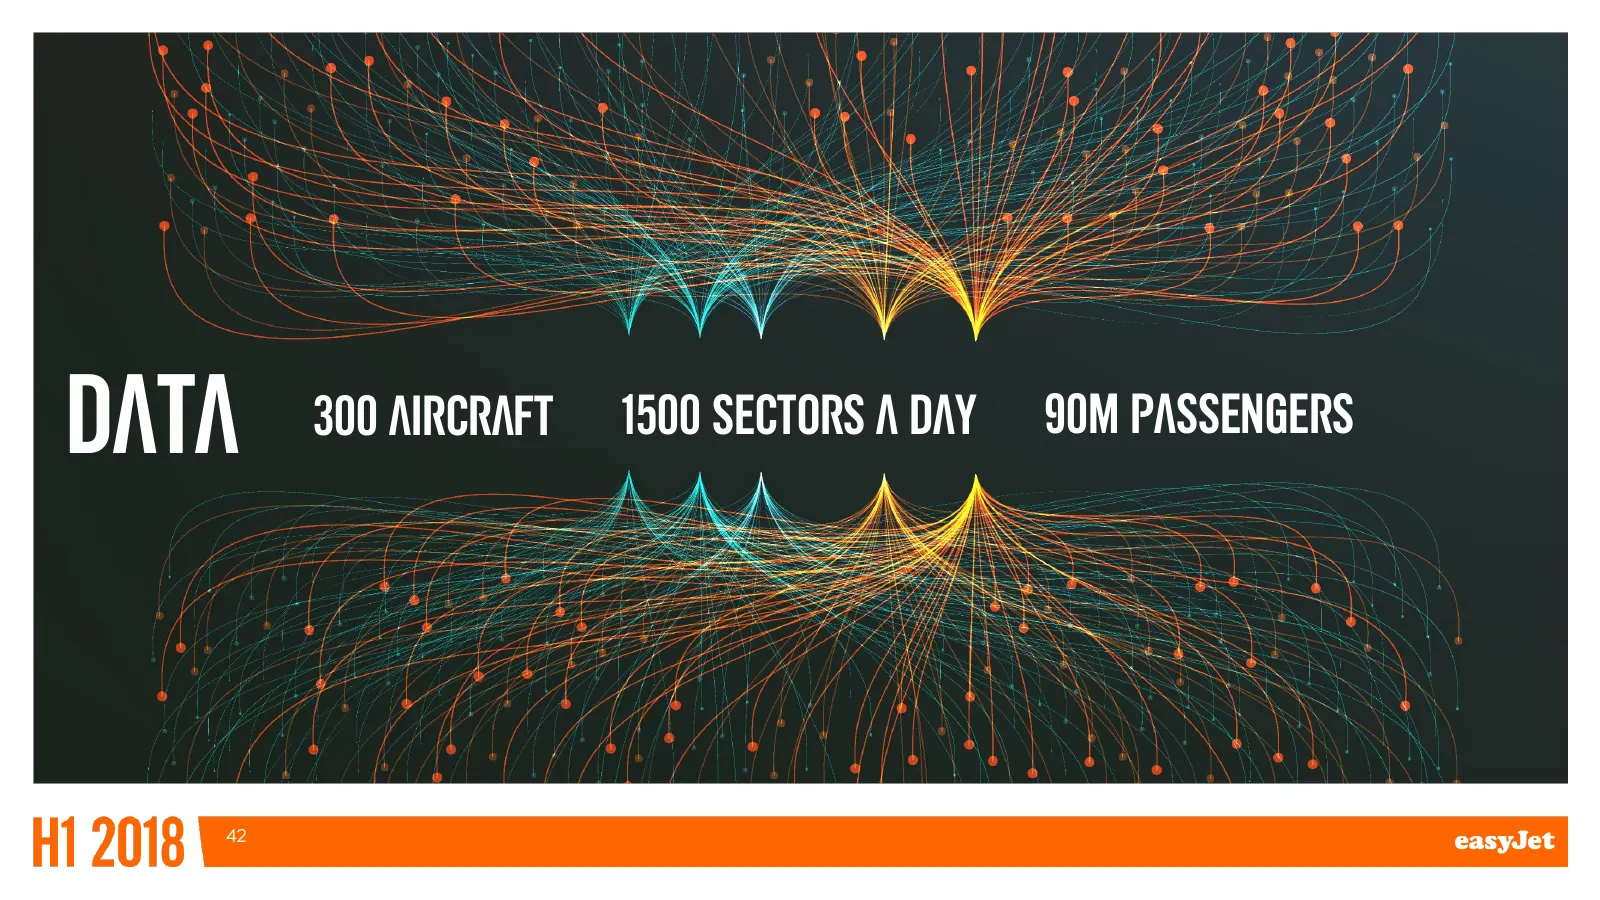
Slide 42: Data
DATA 300 aircraft 1500 sectors a day 90m passengers 42
Slide 43: Revenue
REVENUE Hi 2018
Slide 44: Improving cost & operational efficiency
improving cost & operational efficiency 44
Slide 45: Customer proposition & satisfaction
Customer proposition & satisfaction 45
Slide 46: Our people
} }: OUR PEOPLE Hi 2018
Slide 47: 86% friendliness and approachability
86% friendliness And approachability 47
Slide 48: 48
48
Slide 49: Disruption
ae. & Ge: HOAENNNNES fons € — = — a ae Ce “4 [|
Slide 50: H1 2018
= = = = a = => = Hl 2018 Cd
Slide 51: Q&A
q&a 51
Slide 52: Appendix
Appendix 52
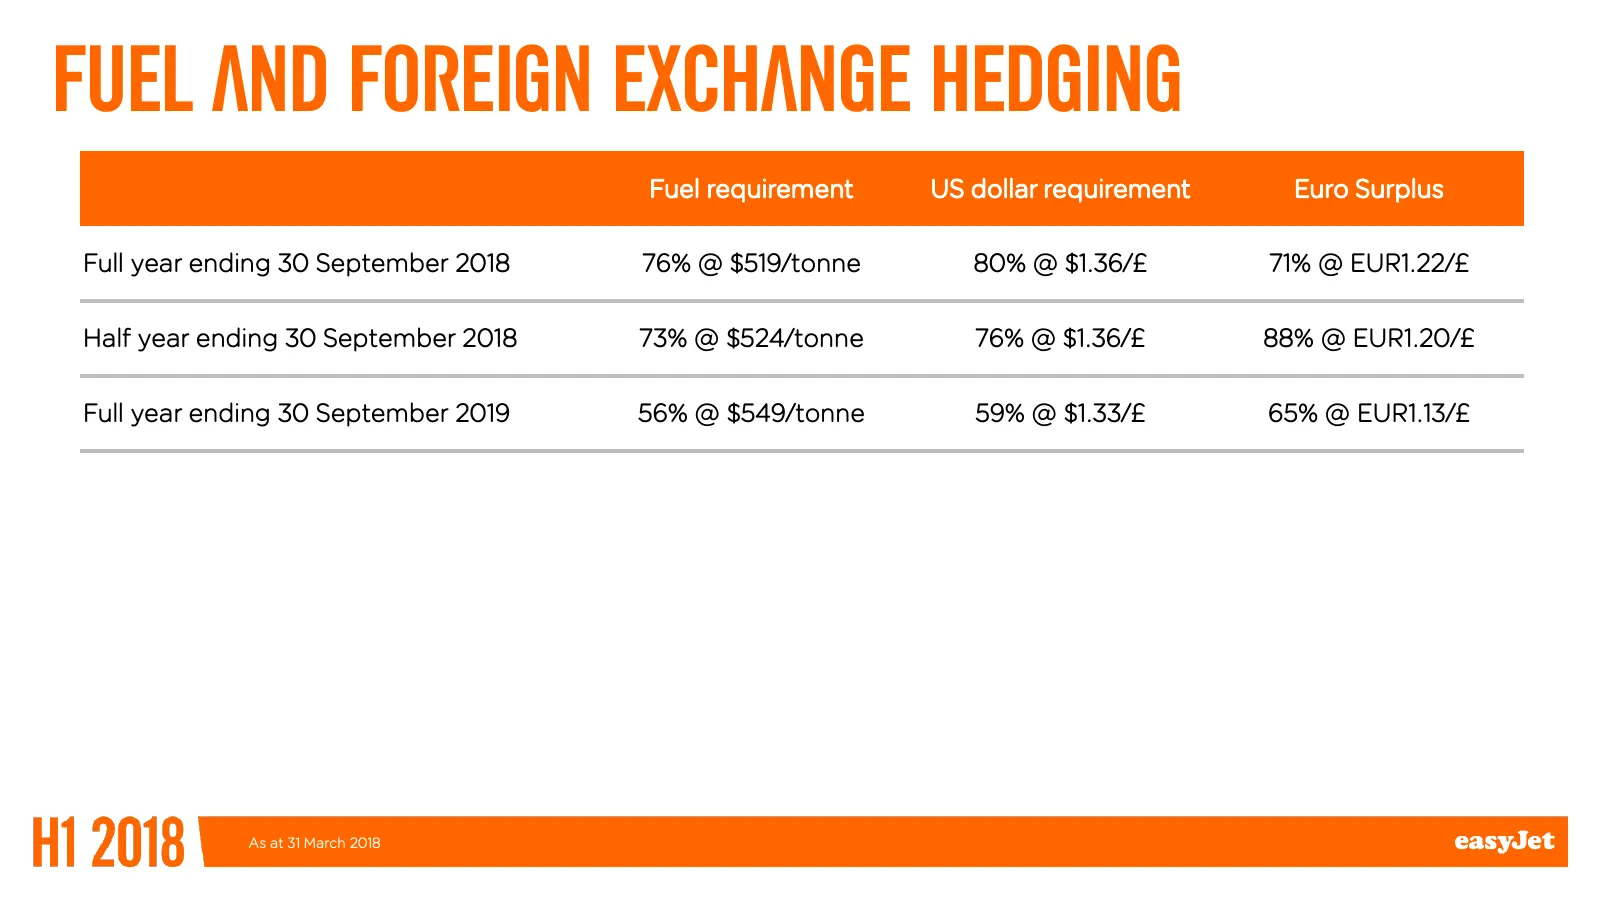
Slide 53: Fuel and foreign exchange hedging
Fuel and foreign exchange hedging Fuel requirement US dollar requirement Euro Surplus Full year ending 30 September 2018 76% @ $519/tonne 80% @ $1.36/£ 71% @ EUR1.22/£ Half year ending 30 September 2018 73% @ $524/tonne 76% @ $1.36/£ 88% @ EUR1.20/£ Full year ending 30 September 2019 56% @ $549/tonn
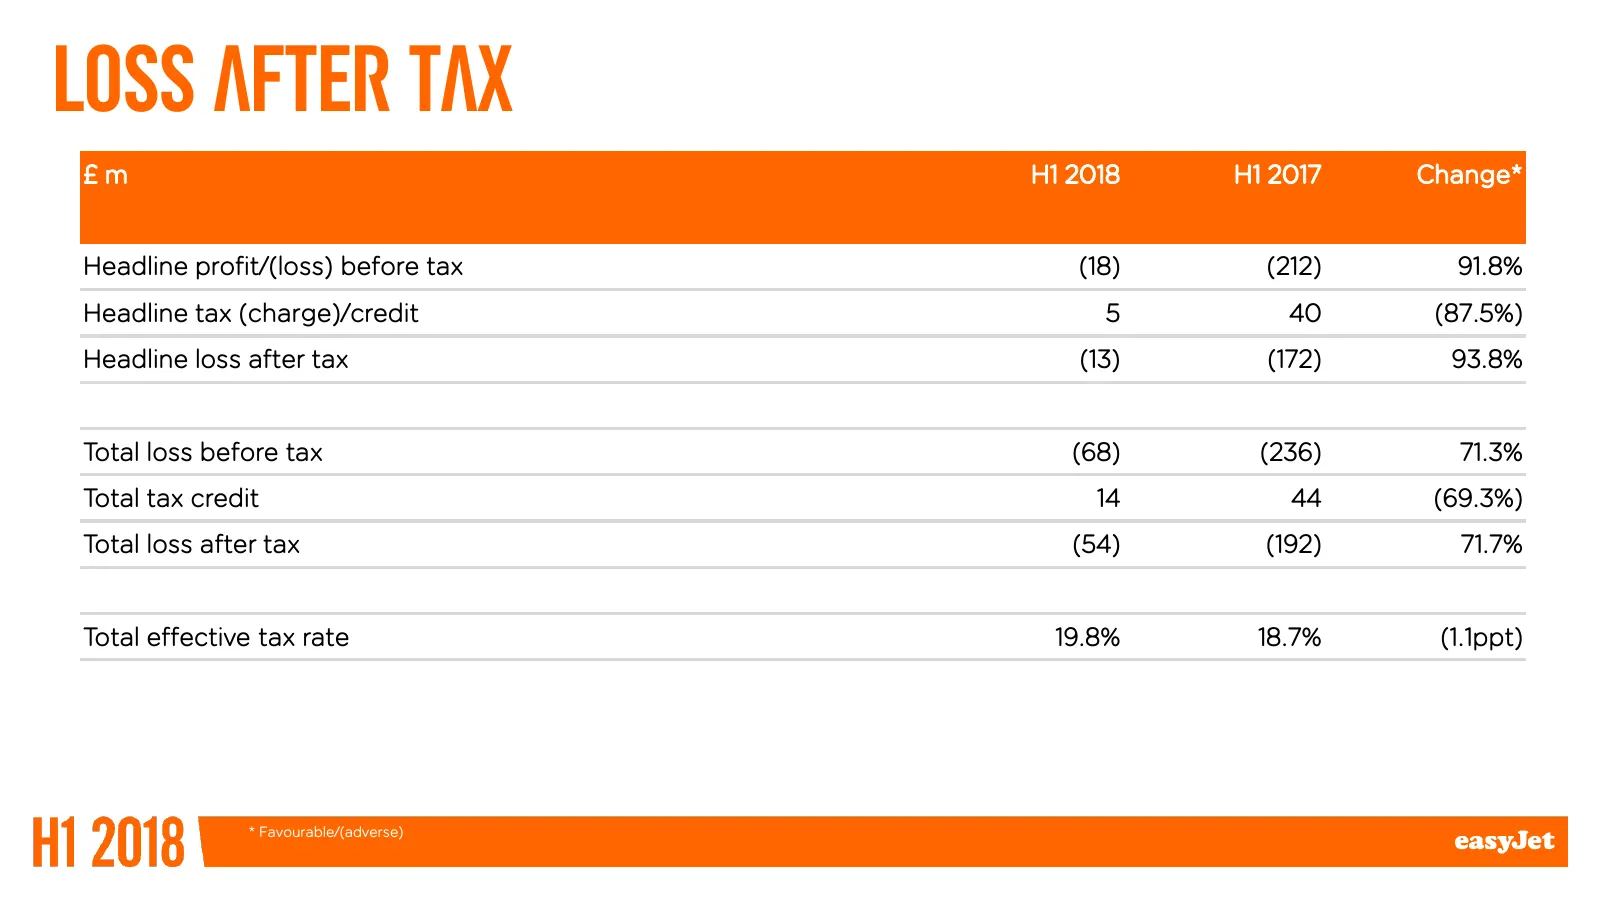
Slide 54: Loss after tax
Loss after tax £m H1 2018 H1 2017 Change* Headline profit/(loss) before tax (18) (212) 91.8% Headline tax (charge)/credit 5 40 (87.5%) Headline loss after tax (13) (172) 93.8% Total loss before tax (68) (236) 71.3% Total tax credit 14 44 (69.3%) Total loss after tax (54) (192) 71.7% Total effective
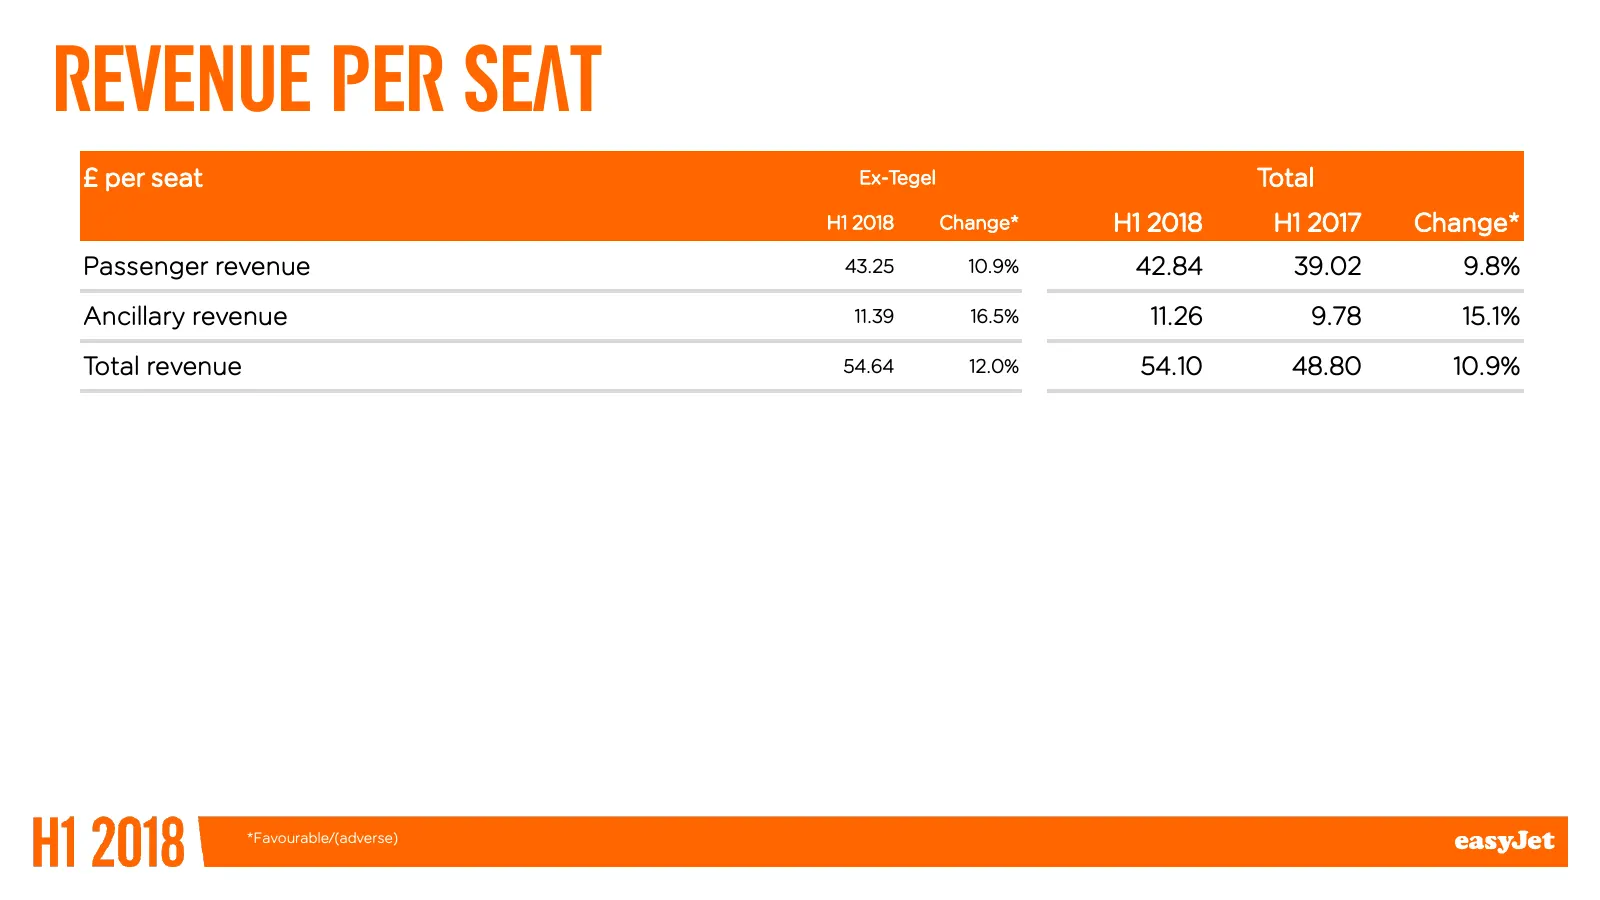
Slide 55: Revenue per seat
Revenue per seat £ per seat Ex-Tegel Total H1 2018 Change* H1 2018 H1 2017 Change* Passenger revenue 43.25 10.9% 42.84 39.02 9.8% Ancillary revenue 11.39 16.5% 11.26 9.78 15.1% Total revenue 54.64 12.0% 54.10 48.80 10.9% *Favourable/(adverse)
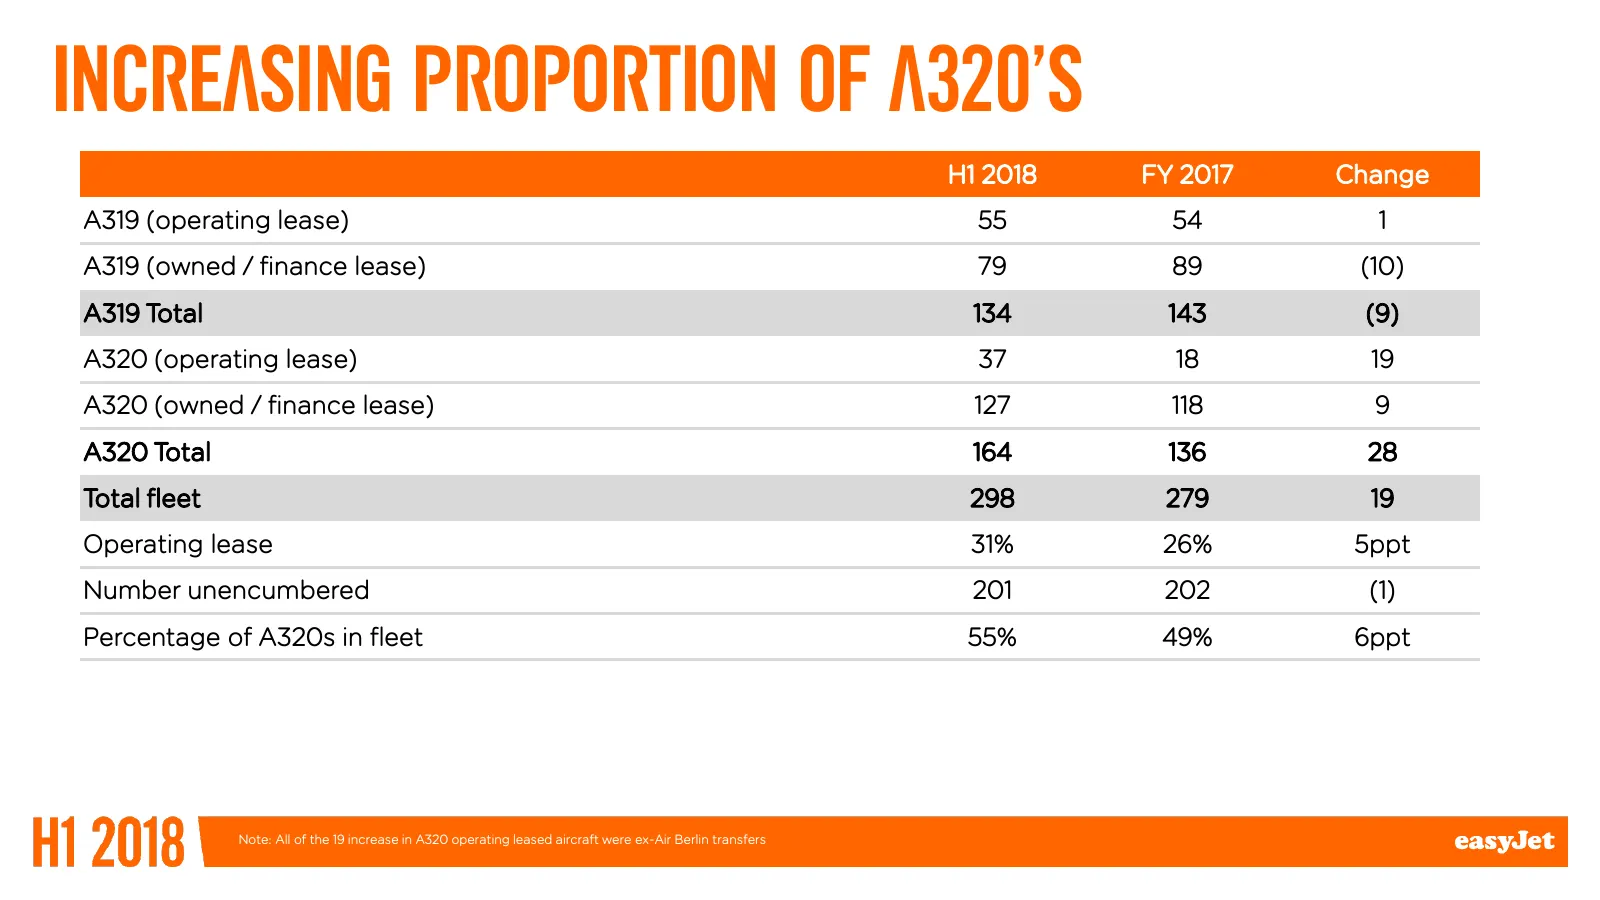
Slide 56: Increasing proportion of A320s
Increasing proportion of A320’s H1 2018 FY 2017 Change A319 (operating lease) 55 54 1 A319 (owned / finance lease) 79 89 (10) A319 Total 134 143 (9) A320 (operating lease) 37 18 19 A320 (owned / finance lease) 127 118 9 A320 Total 164 136 28 Total fleet 298 279 19 Operating lease 31% 26% 5ppt Number
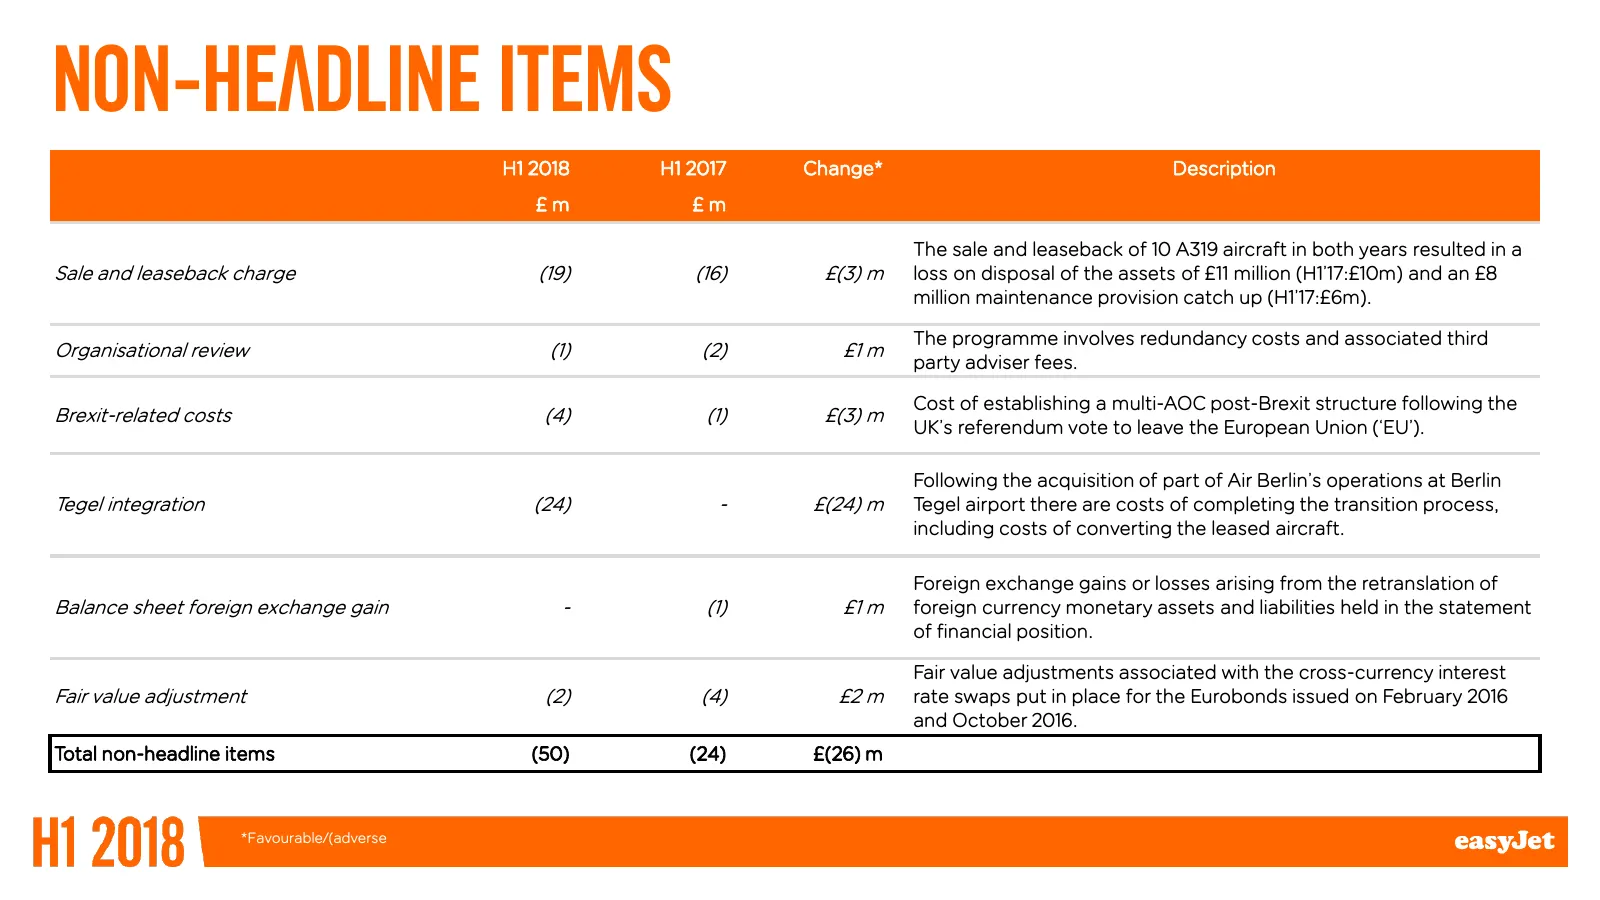
Slide 57: Non-headline items
Non-headline items H1 2018 H1 2017 Change* Description £m £m The sale and leaseback of 10 A319 aircraft in both years resulted in a Sale and leaseback charge (19) (16) £(3) m loss on disposal of the assets of £11 million (H1’17:£10m) and an £8 million maintenance provision catch up (H1’17:£6m). The
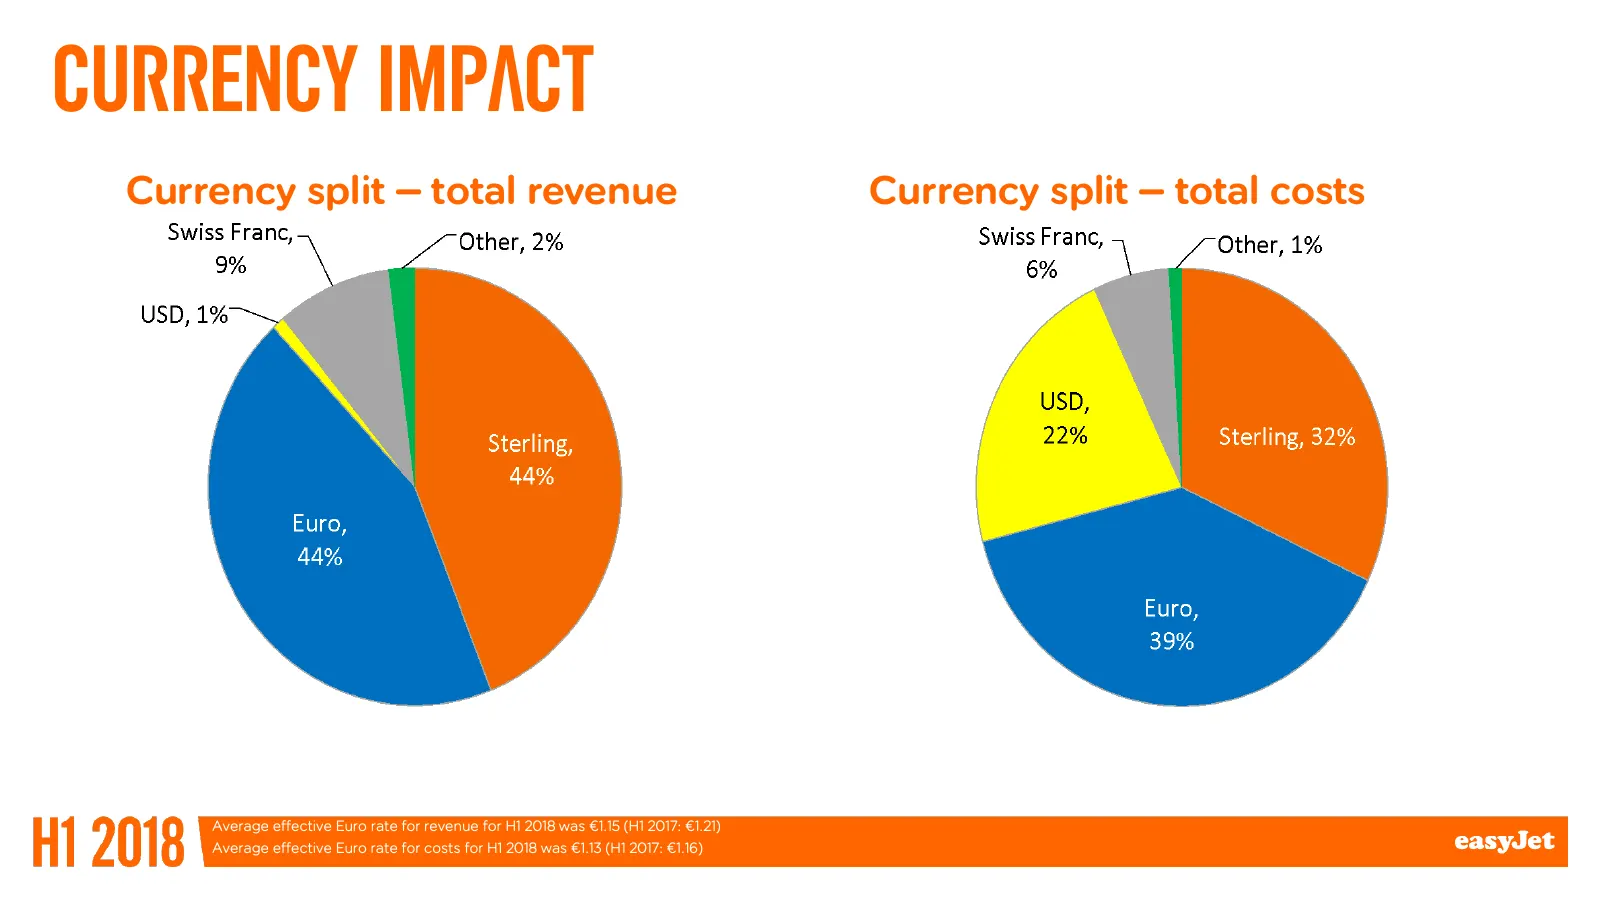
Slide 58: Currency impact
Currency impact Currency split – total revenue Currency split – total costs Average effective Euro rate for revenue for H1 2018 was €1.15 (H1 2017: €1.21) Average effective Euro rate for costs for H1 2018 was €1.13 (H1 2017: €1.16)
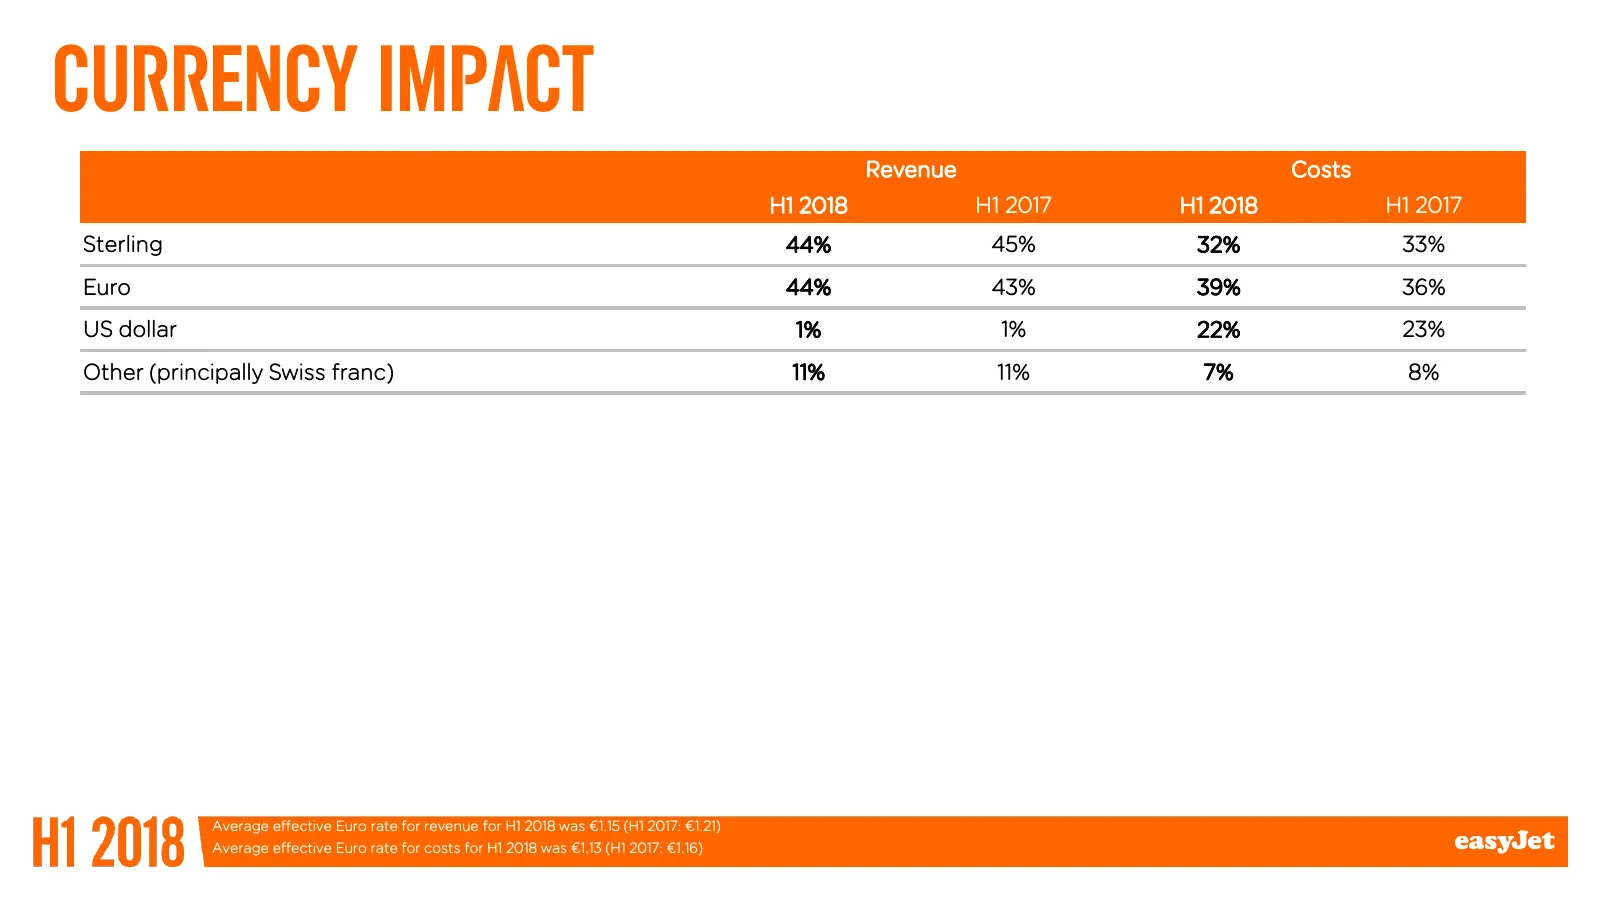
Slide 59: Currency impact
Currency impact Revenue Costs H1 2018 H1 2017 H1 2018 H1 2017 Sterling 44% 45% 32% 33% Euro 44% 43% 39% 36% US dollar 1% 1% 22% 23% Other (principally Swiss franc) 11% 11% 7% 8% Average effective Euro rate for revenue for H1 2018 was €1.15 (H1 2017: €1.21) Average effective Euro rate for costs for H
Source: company website
More decks from easyJet plc
 H1 2026 Earnings Presentation43 slides · May 21, 2026
 Investor Day (November 2025)24 slides · Nov 28, 2025
 FY2025 Earnings Presentation41 slides · Nov 25, 2025
 H1 2025 Earnings Presentation37 slides · May 22, 2025
 FY2024 Earnings Presentation34 slides · Nov 27, 2024
 Investor Day (June 2024)17 slides · Jun 20, 2024