Curo — Debt Investor Presentation (October 2022)
23 slides from Curo's debt investor presentation, Oct 17, 2022
Slide 1: ABS Investor Presentation October 17-18, 2022
ABS Investor Presentation O C T O B E R 1 7 - 1 8 , 2 0 2 2
Slide 2: Important Information
Important Information 2 F ORWARD-LOOKING S TA TEMENTS This presentation contains forward-looking statements. These forward-looking statements include projections, estimates and assumptions about various matters such as our growth strategy and opportunities presented in our addressable market. In add
Slide 3: CURO Company Overview
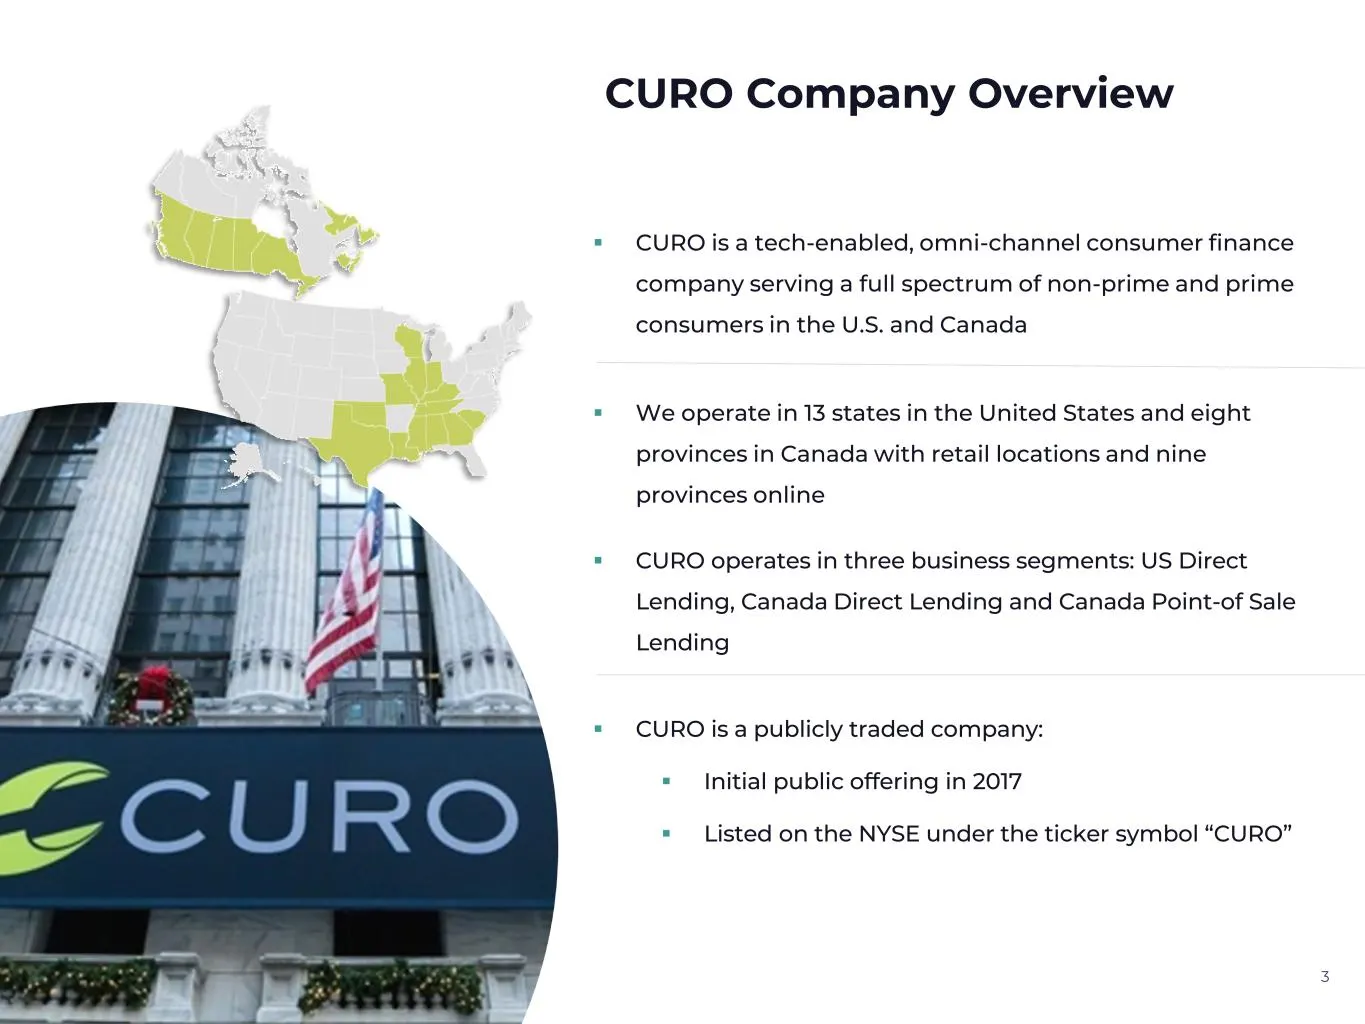
CURO Company Overview 3 CURO is a tech-enabled, omni-channel consumer finance company serving a full spectrum of non-prime and prime consumers in the U.S. and Canada We operate in 13 states in the United States and eight provinces in Canada with retail locations and nine provinces online CURO
Slide 4: CURO Business Segments
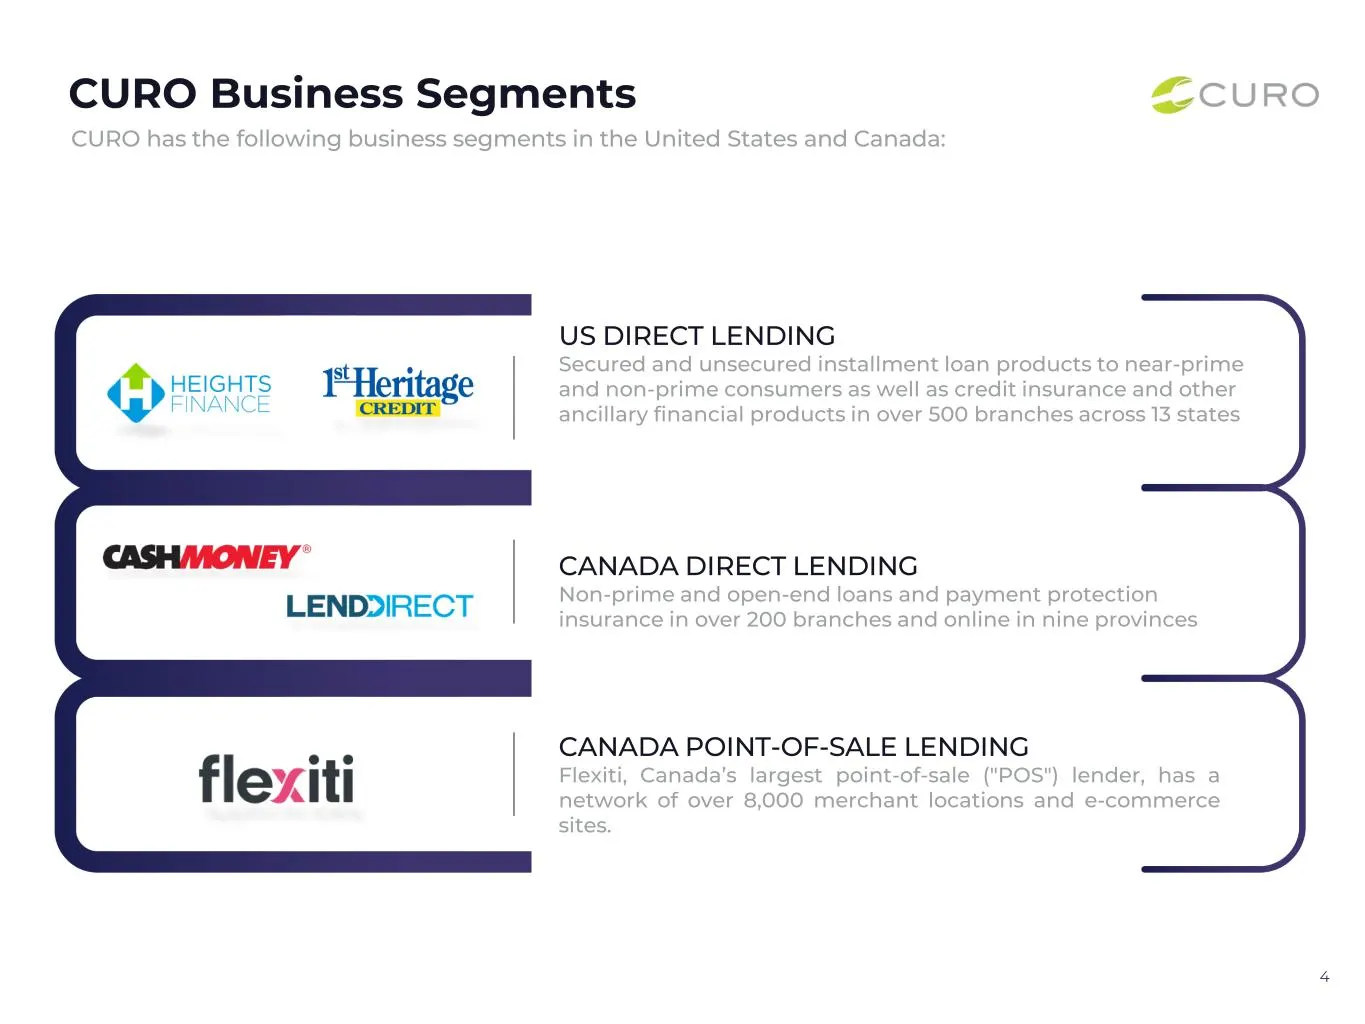
CURO Business Segments 4 CURO has the following business segments in the United States and Canada: US DIRECT LENDING Secured and unsecured installment loan products to near-prime and non-prime consumers as well as credit insurance and other ancillary financial products in over 500 branches across 13
Slide 5: CURO's Strategic Transformation
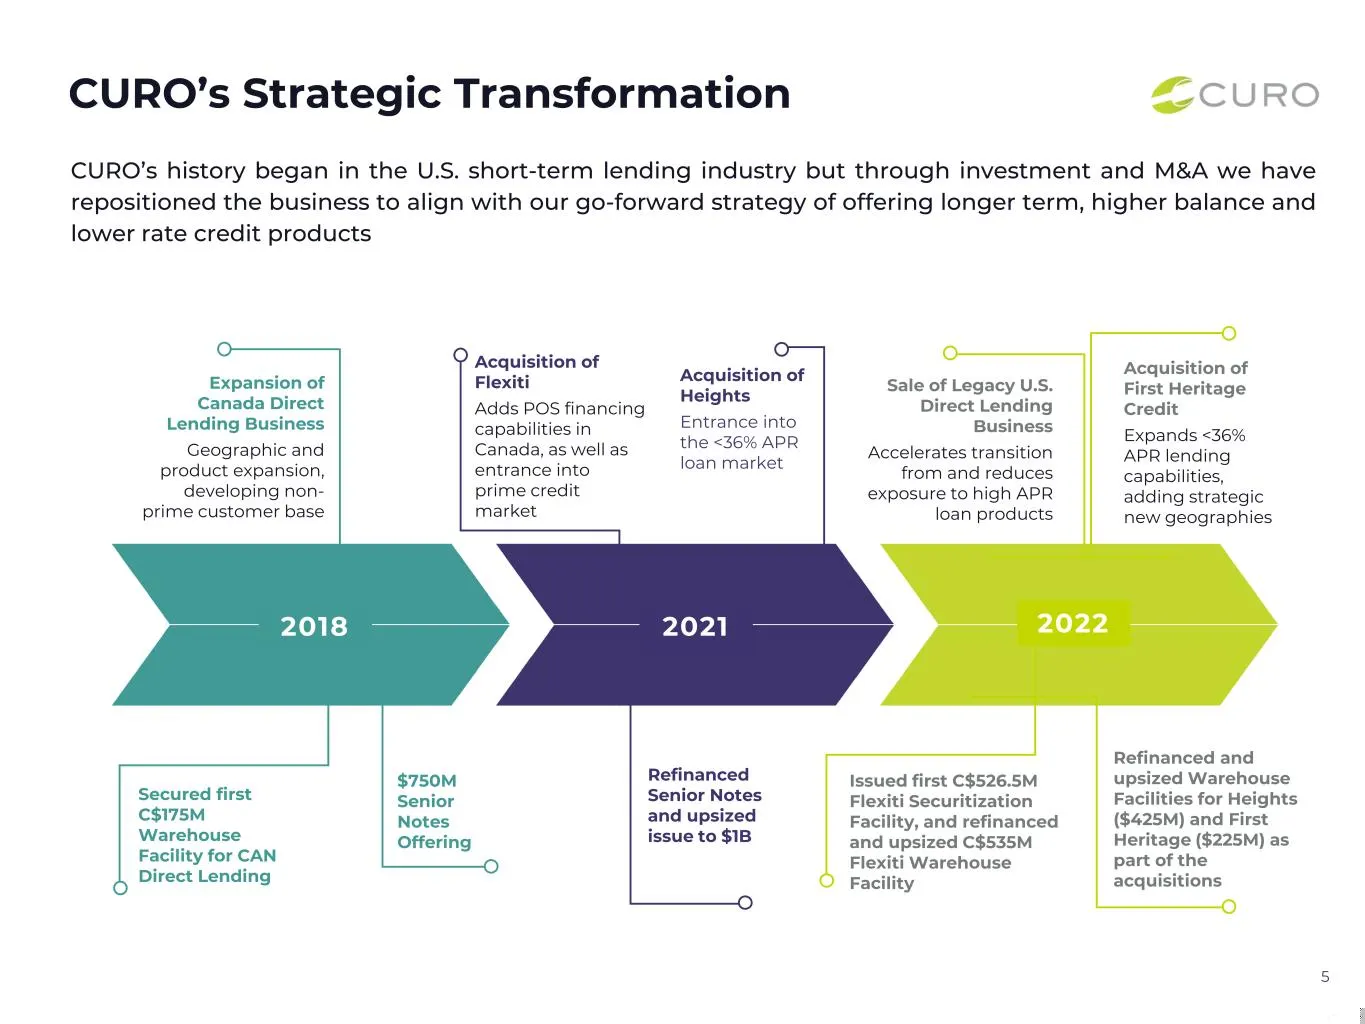
CURO’s Strategic Transformation 5 CURO’s history began in the U.S. short-term lending industry but through investment and M&A we have repositioned the business to align with our go-forward strategy of offering longer term, higher balance and lower rate credit products Expansion of Canada Direct Lend
Slide 6: CURO Company Highlights
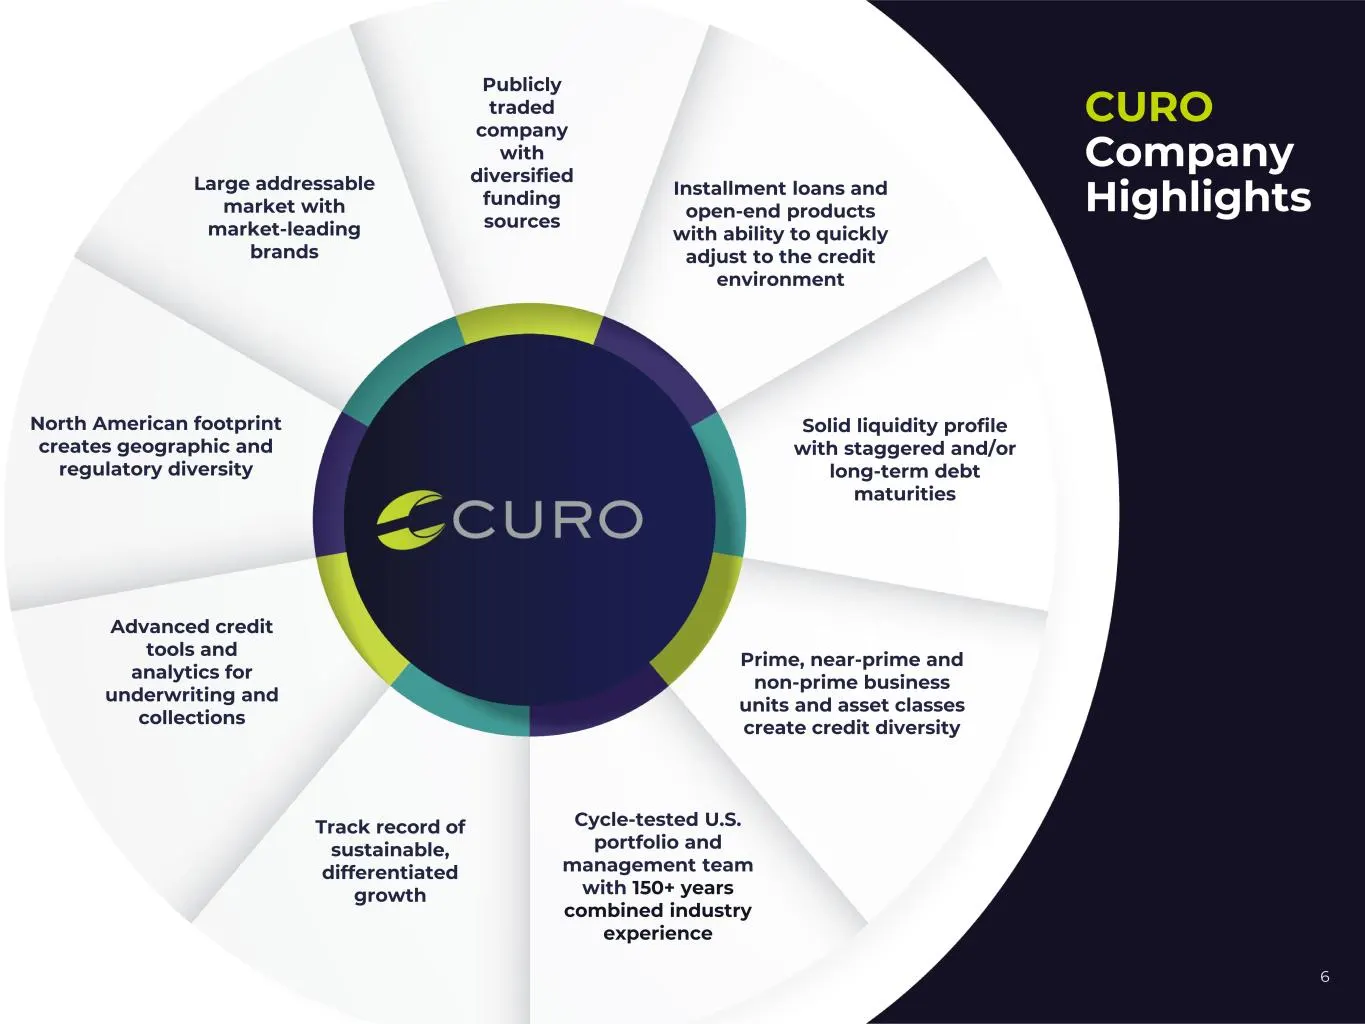
CURO Company Highlights Publicly traded company with diversified funding sources Solid liquidity profile with staggered and/or long-term debt maturities North American footprint creates geographic and regulatory diversity Prime, near-prime and non-prime business units and asset classes create credit
Slide 7: CURO Management Team
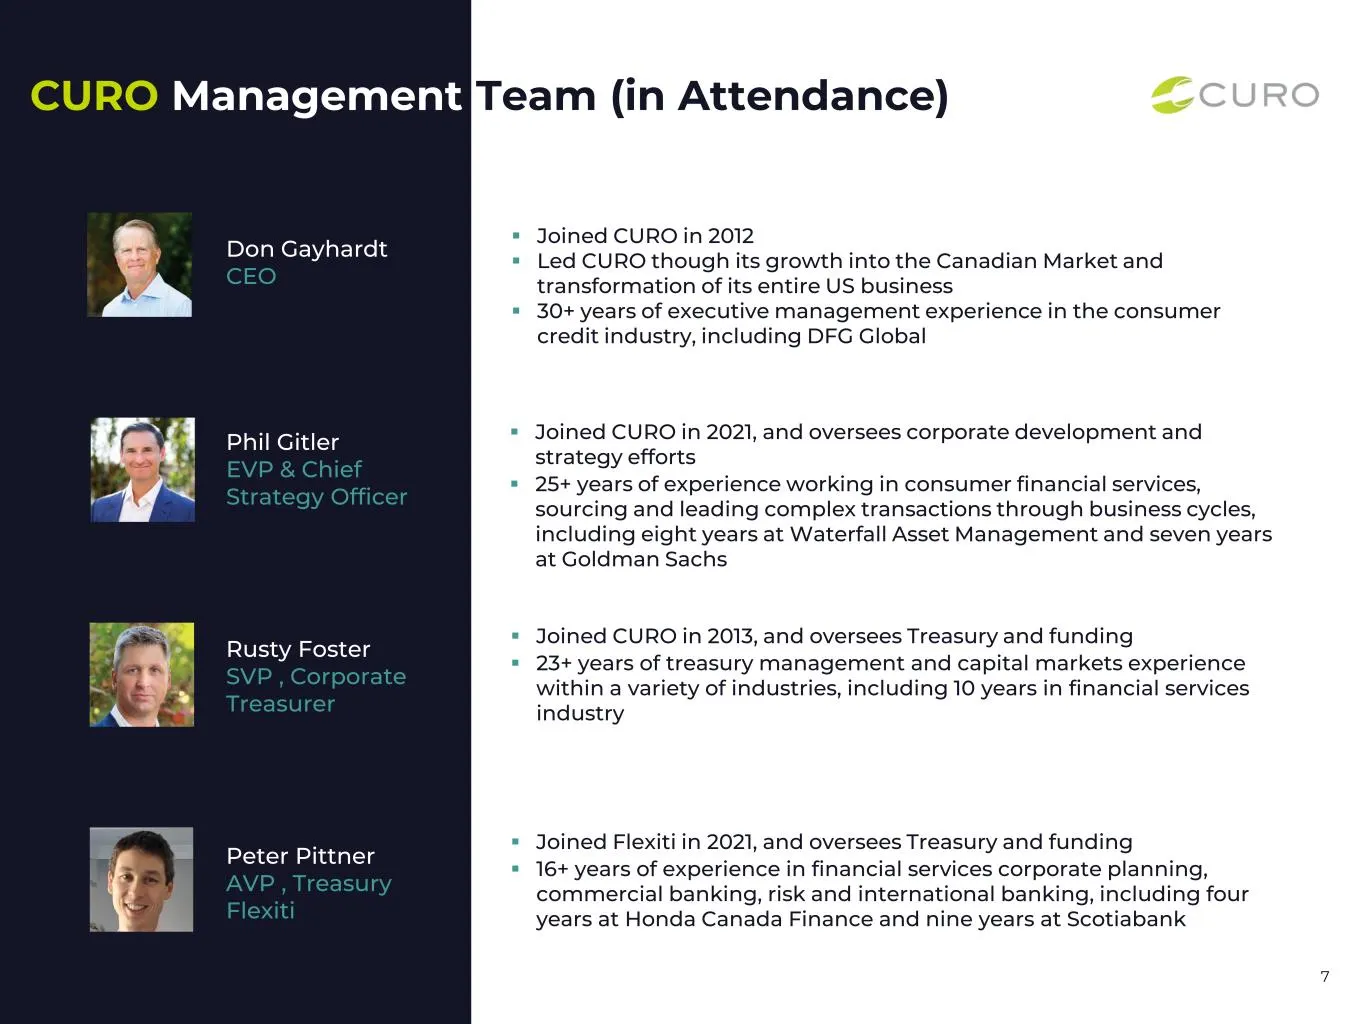
7 Joined CURO in 2012 Led CURO though its growth into the Canadian Market and transformation of its entire US business 30+ years of executive management experience in the consumer credit industry, including DFG Global Joined CURO in 2021, and oversees corporate development and strategy effor
Slide 8: Public Company Discipline
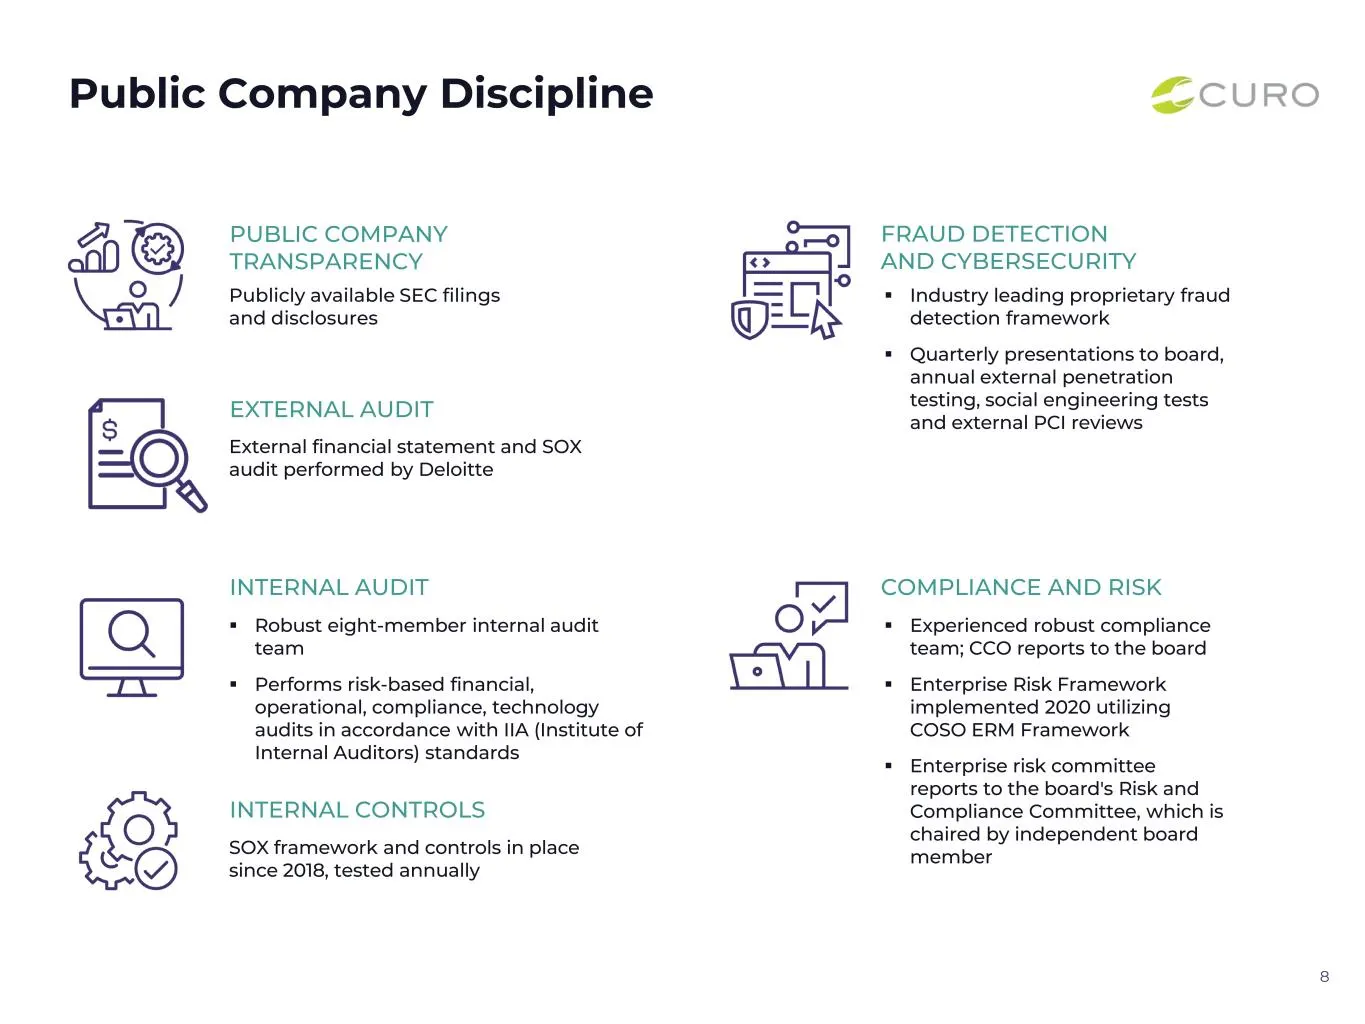
Public Company Discipline 8 PUBLIC COMPANY TRANSPARENCY Publicly available SEC filings and disclosures EXTERNAL AUDIT External financial statement and SOX audit performed by Deloitte COMPLIANCE AND RISK Experienced robust compliance team; CCO reports to the board Enterprise Risk Framework implem
Slide 9: CURO Business Segments - US Direct Lending
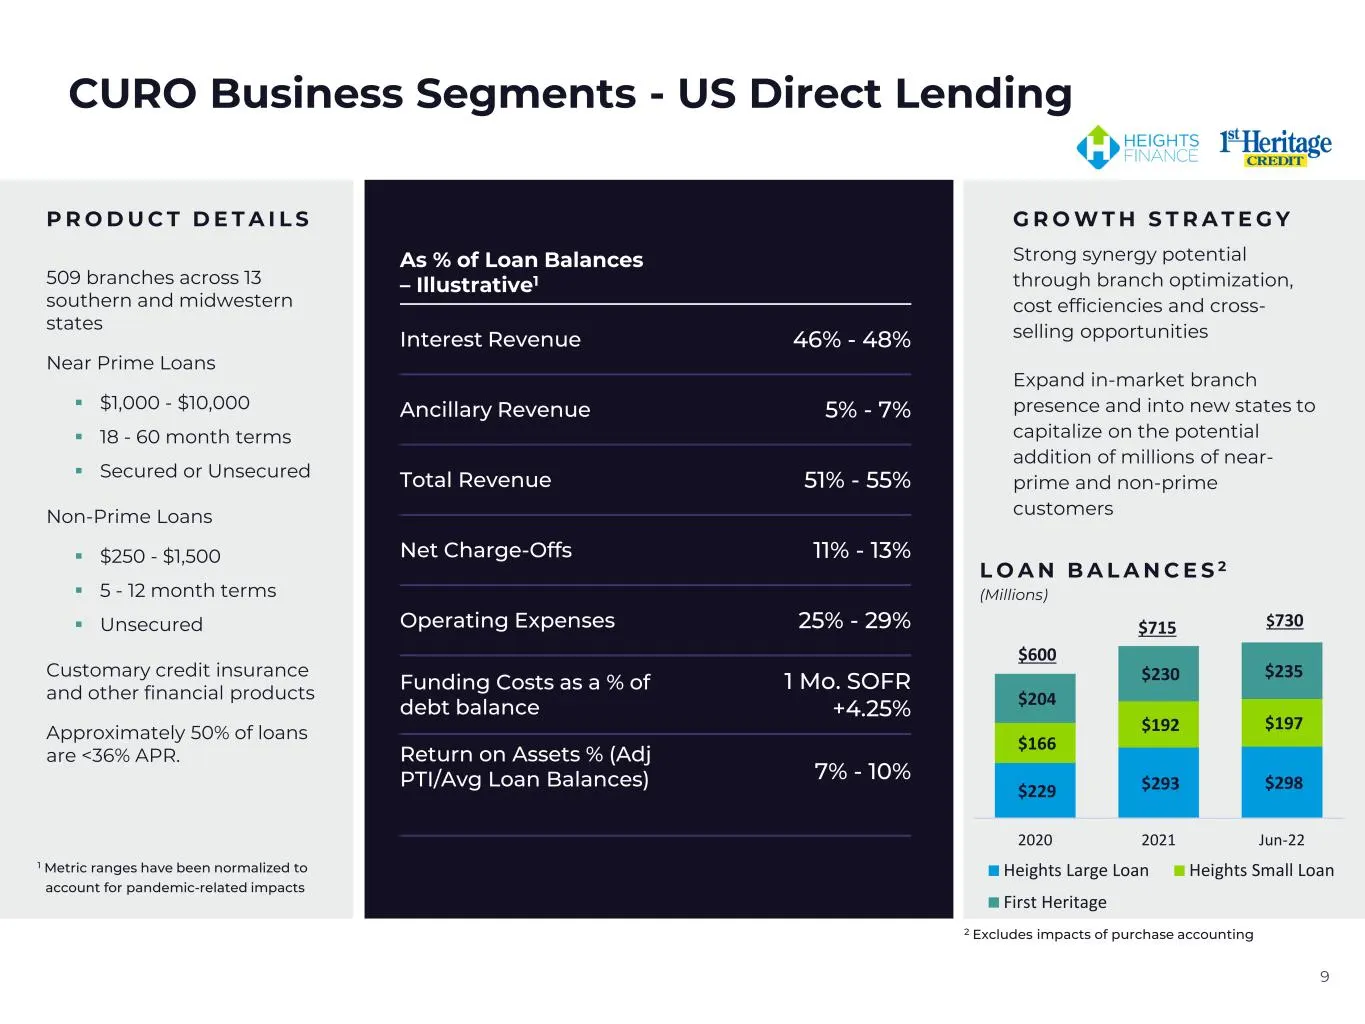
As % of Loan Balances – Illustrative1 Interest Revenue 46% - 48% Ancillary Revenue 5% - 7% Total Revenue 51% - 55% Net Charge-Offs 11% - 13% Operating Expenses 25% - 29% Funding Costs as a % of debt balance 1 Mo. SOFR +4.25% Return on Assets % (Adj PTI/Avg Loan Balances) 7% - 10% 509 branches across
Slide 10: CURO Business Segments - Canada Direct Lending
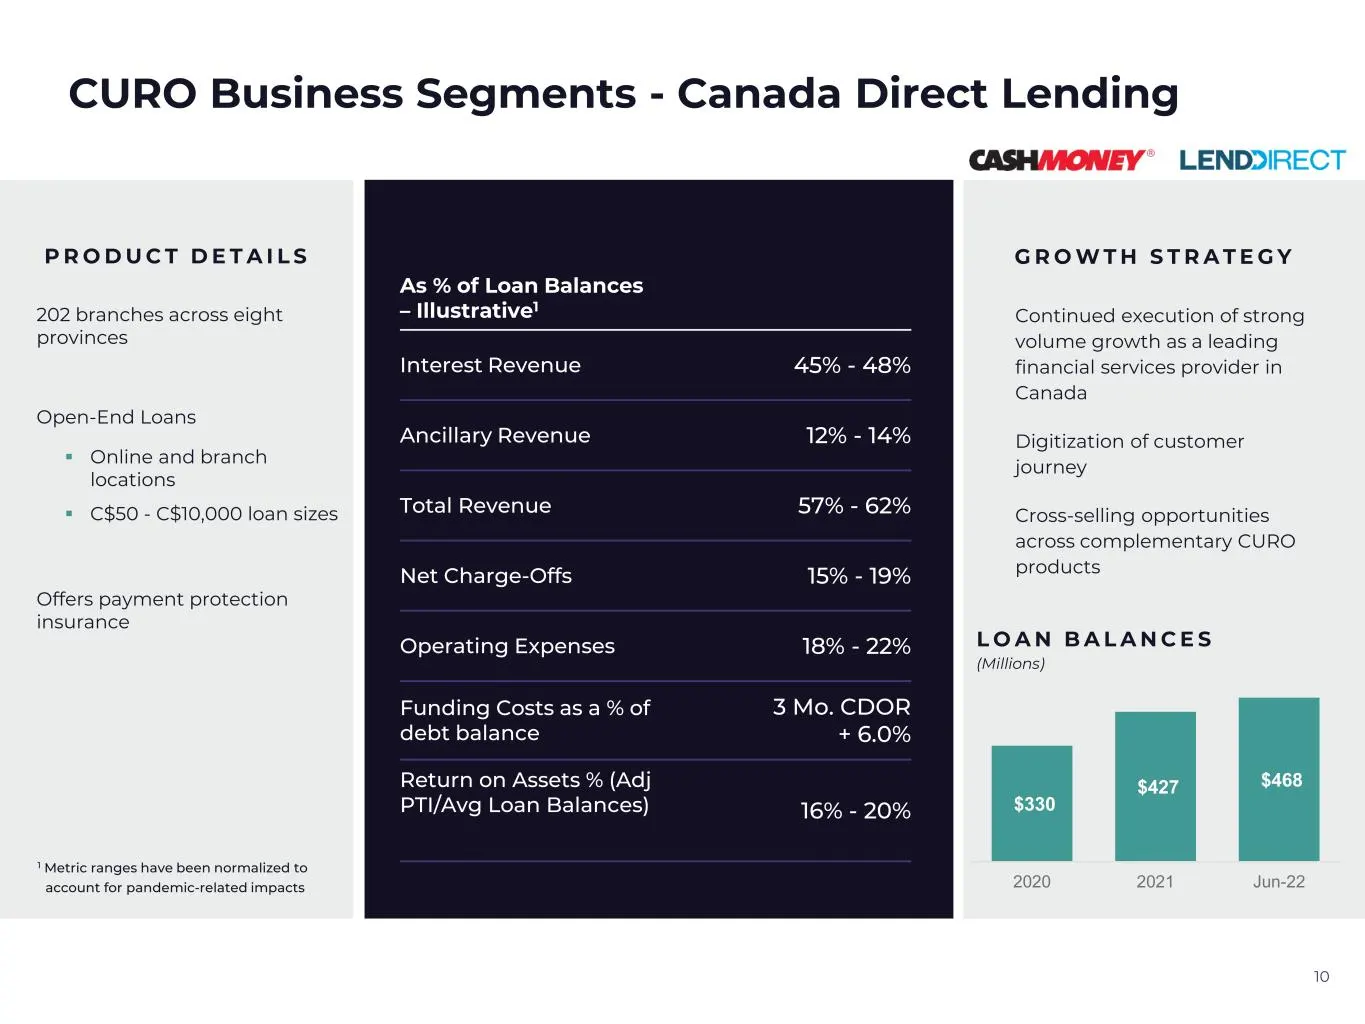
As % of Loan Balances – Illustrative1 Interest Revenue 45% - 48% Ancillary Revenue 12% - 14% Total Revenue 57% - 62% Net Charge-Offs 15% - 19% Operating Expenses 18% - 22% Funding Costs as a % of debt balance 3 Mo. CDOR + 6.0% Return on Assets % (Adj PTI/Avg Loan Balances) 16% - 20% 202 branches acr
Slide 11: CURO Business Segments - Canada Point-of-Sale
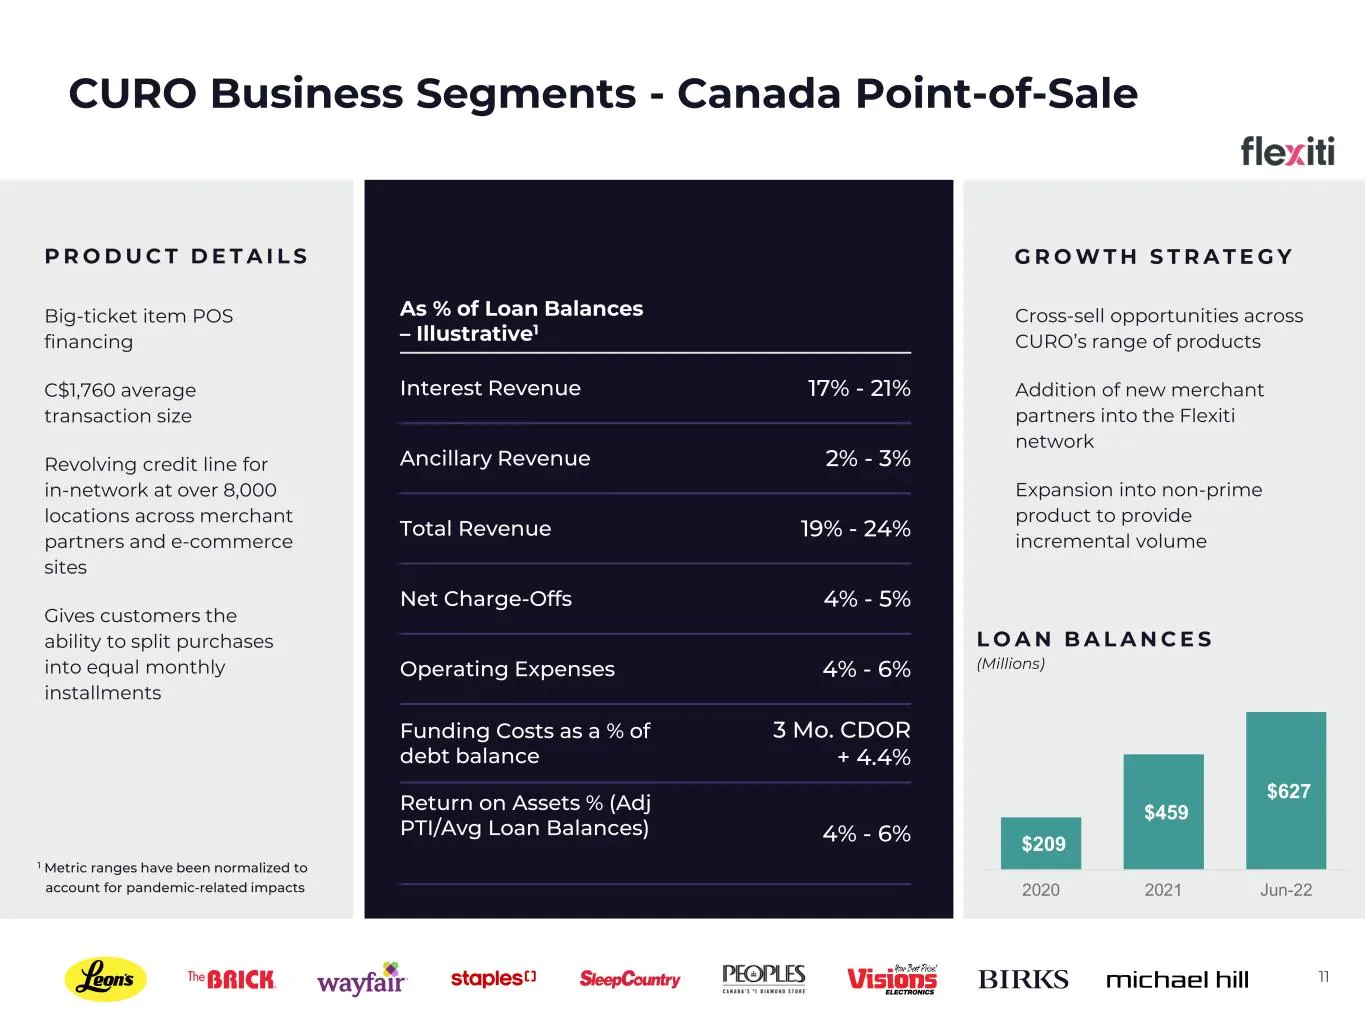
As % of Loan Balances – Illustrative1 Interest Revenue 17% - 21% Ancillary Revenue 2% - 3% Total Revenue 19% - 24% Net Charge-Offs 4% - 5% Operating Expenses 4% - 6% Funding Costs as a % of debt balance 3 Mo. CDOR + 4.4% Return on Assets % (Adj PTI/Avg Loan Balances) 4% - 6% Big-ticket item POS fina
Slide 12: Diversified Funding Sources
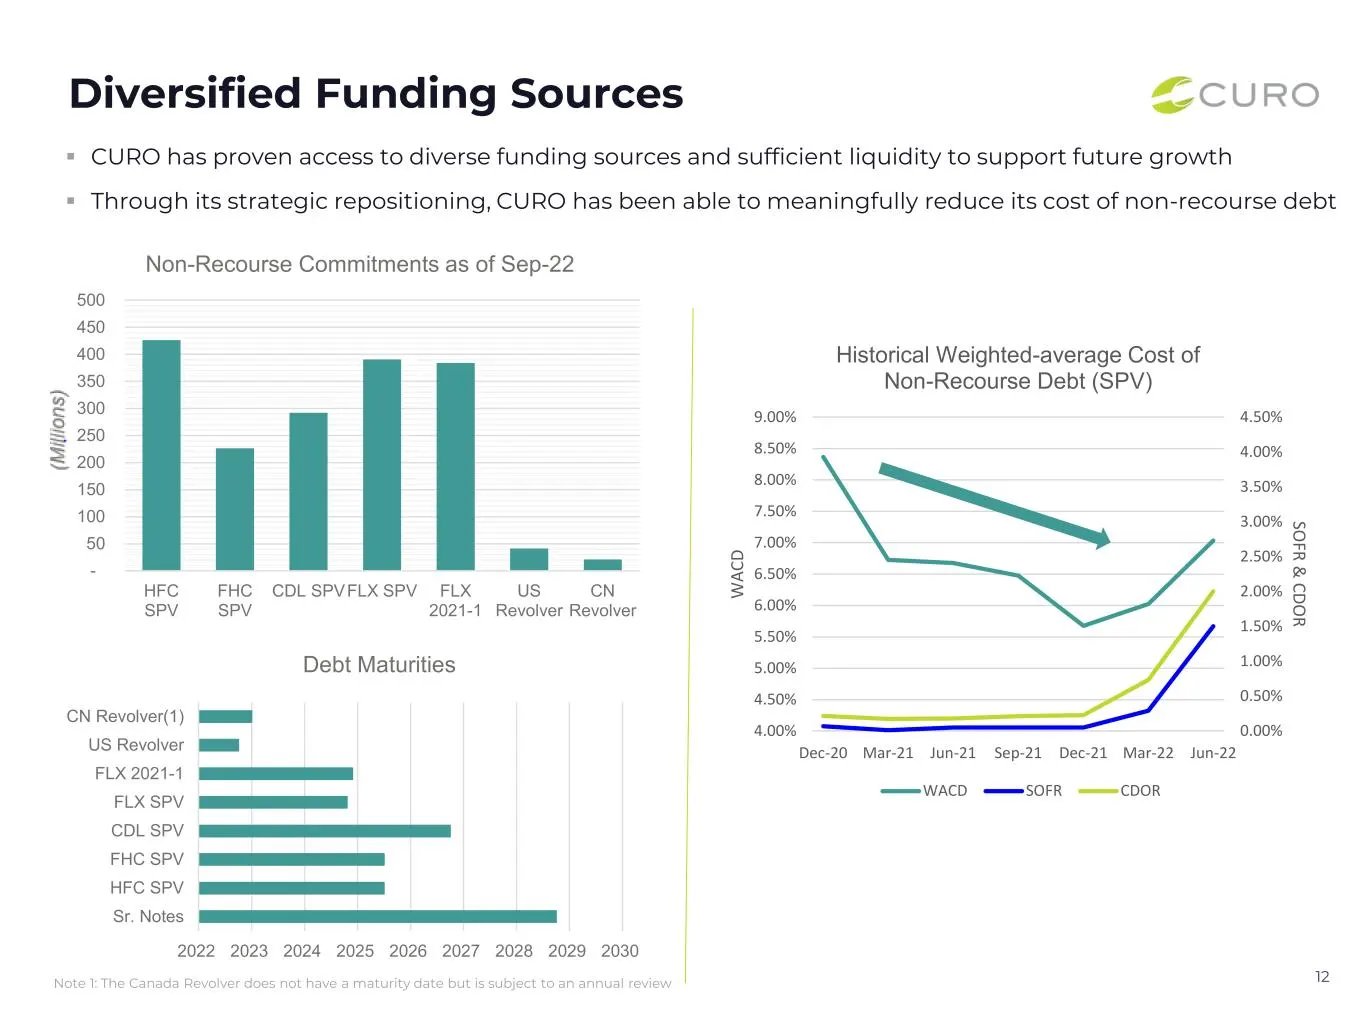
0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 4.00% 4.50% 4.00% 4.50% 5.00% 5.50% 6.00% 6.50% 7.00% 7.50% 8.00% 8.50% 9.00% Dec-20 Mar-21 Jun-21 Sep-21 Dec-21 Mar-22 Jun-22 SO FR & CDO R W AC D Historical Weighted-average Cost of Non-Recourse Debt (SPV) WACD SOFR CDOR 2022 2023 2024 2025 2026 2027
Slide 13: Heights Finance
Heights Finance 13
Slide 14: Company Overview
Company Overview 14 Leading consumer finance company operating as Heights Finance and Southern Management Company in over 400 branch locations across 11 southern and mid-western U.S. states Heights Finance predominately underwrites large loans (>$2,500) with primarily <36% APR Southern Managem
Slide 15: Heights Finance Overview
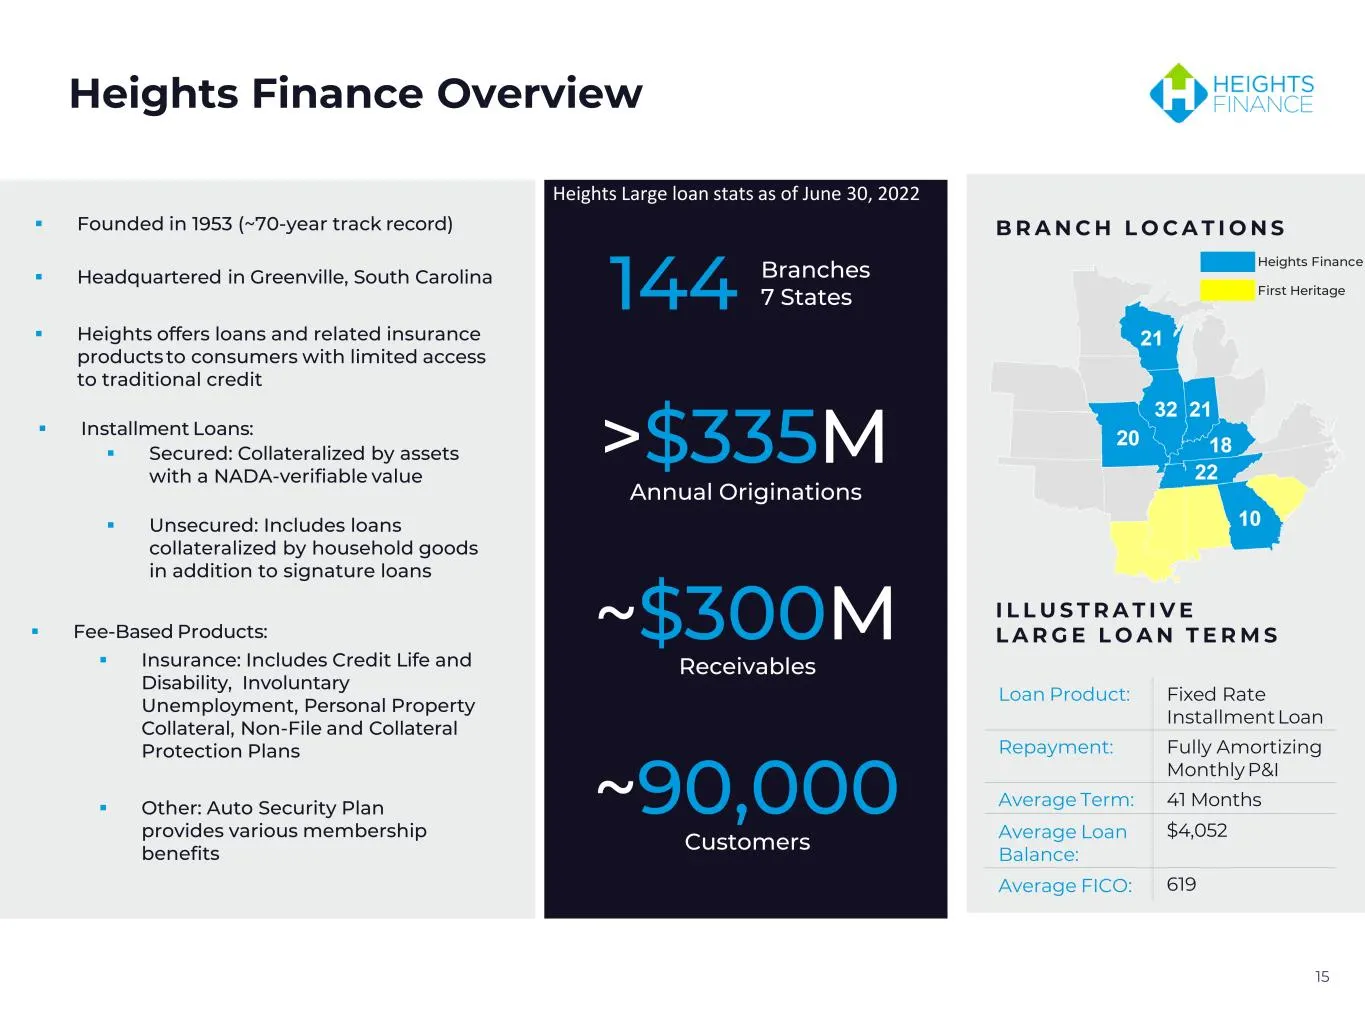
Heights Finance Overview 15 Loan Product: Fixed Rate Installment Loan Repayment: Fully Amortizing Monthly P&I Average Term: 41 Months Average Loan Balance: $4,052 Average FICO: 619 Founded in 1953 (~70-year track record) Headquartered in Greenville, South Carolina Heights offers loans and rela
Slide 16: Heights Finance Management Team
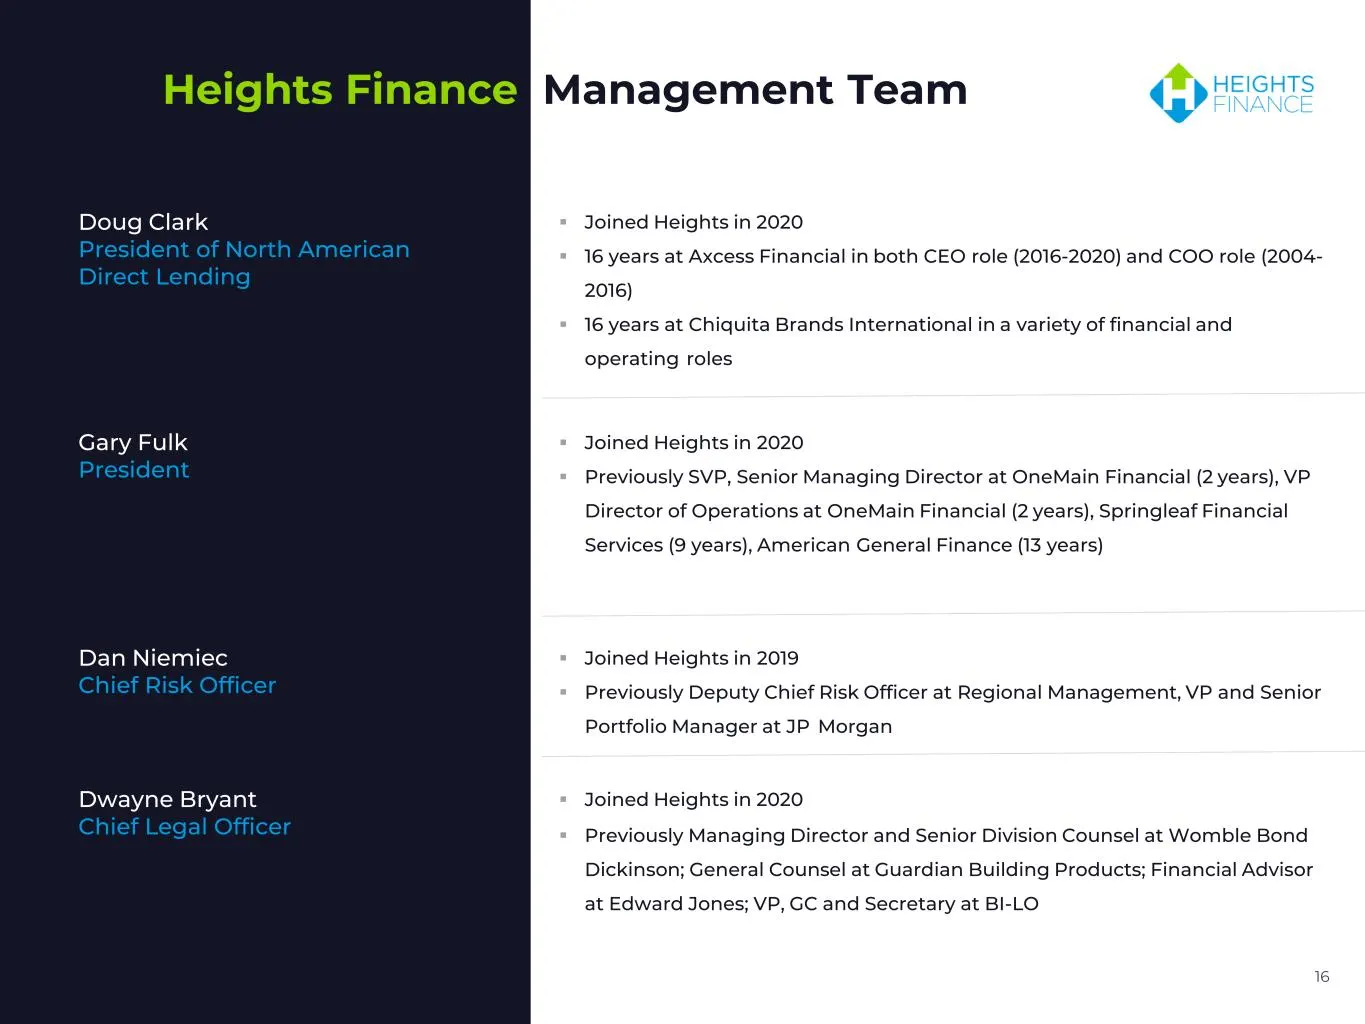
Heights Finance Management Team 16 Doug Clark President of North American Direct Lending Gary Fulk President Dan Niemiec Chief Risk Officer Dwayne Bryant Chief Legal Officer Joined Heights in 2020 16 years at Axcess Financial in both CEO role (2016-2020) and COO role (2004- 2016) 16 years at C
Slide 17: Heights Finance Company Highlights
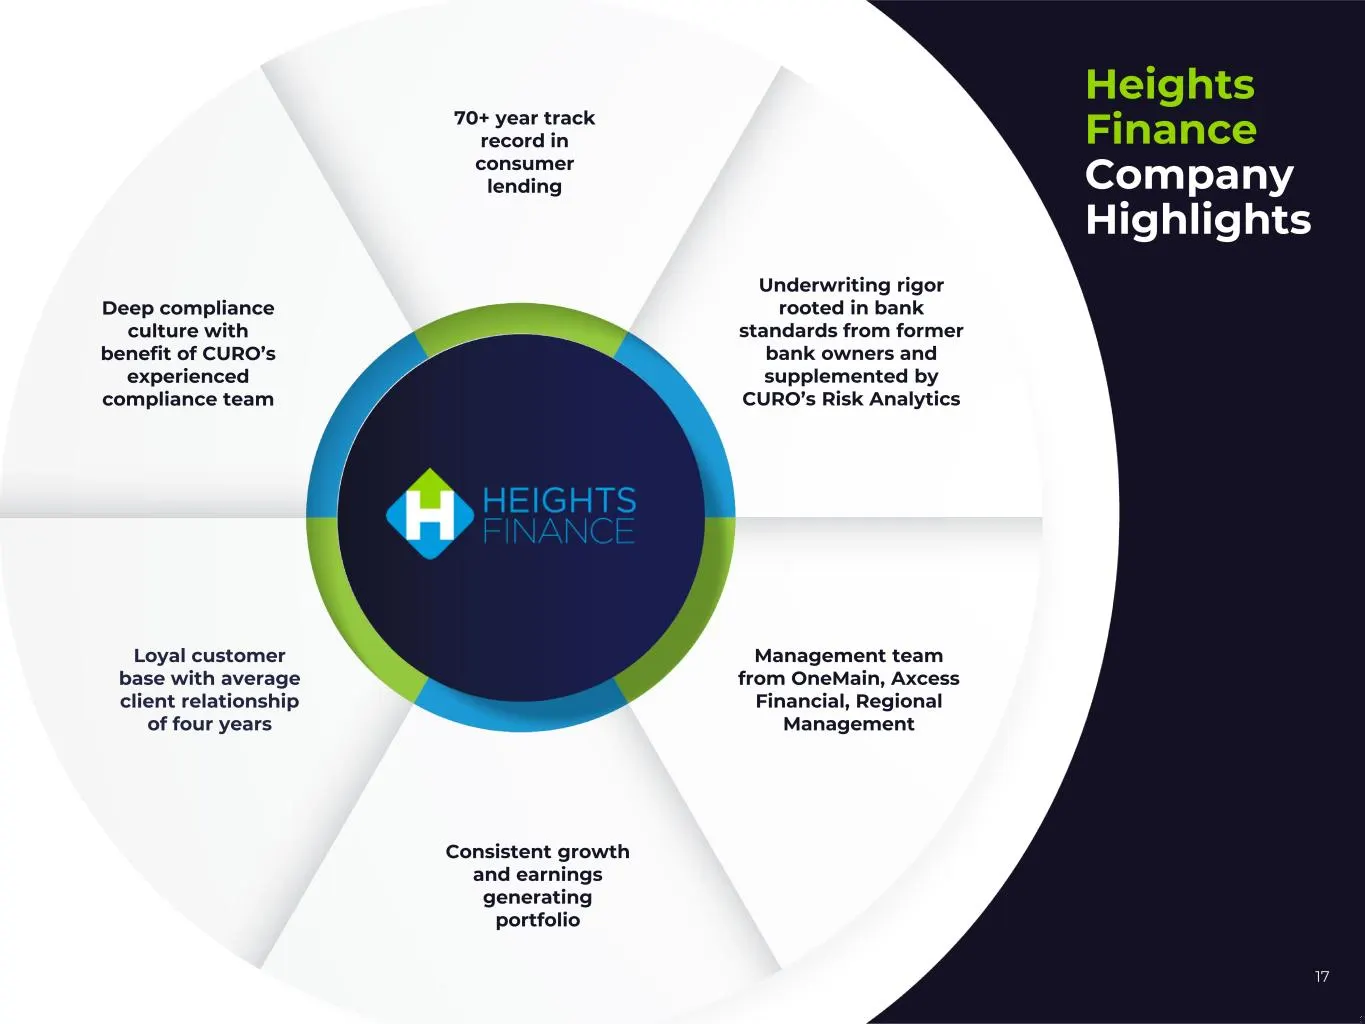
Heights Finance Company Highlights 70+ year track record in consumer lending Underwriting rigor rooted in bank standards from former bank owners and supplemented by CURO’s Risk Analytics Management team from OneMain, Axcess Financial, Regional Management Consistent growth and earnings generating por
Slide 18: Heights Large Loan Typical Customer
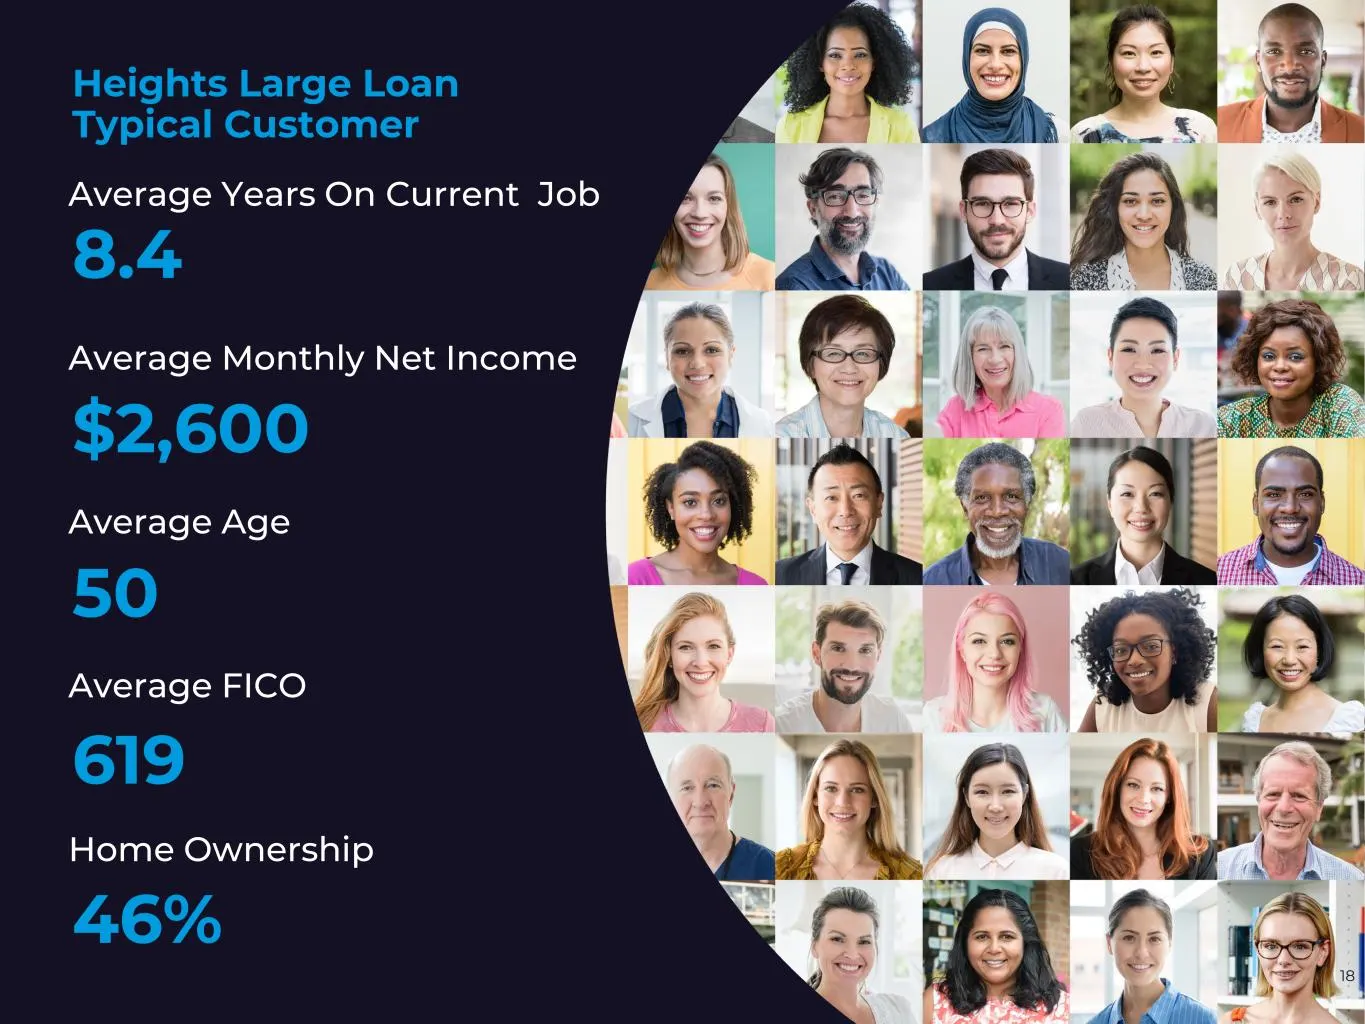
Average Years On Current Job Average Monthly Net Income Average Age Average FICO Home Ownership Heights Large Loan Typical Customer 8.4 $2,600 50 619 46% 18
Slide 19: Large Addressable US Consumer Market Remains Underserved
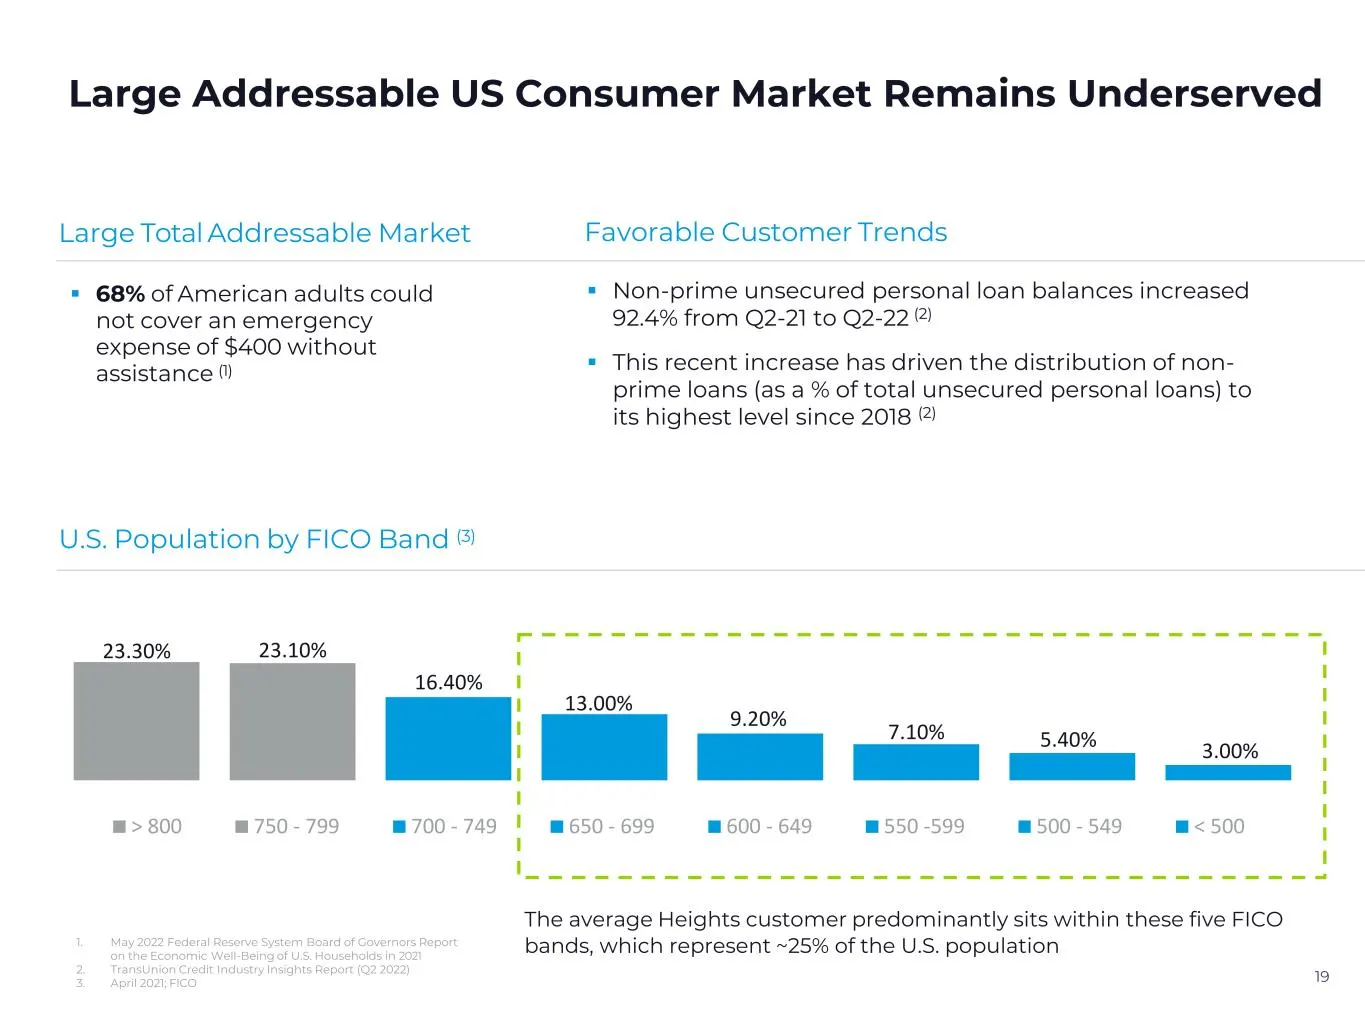
23.30% 23.10% 16.40% 13.00% 9.20% 7.10% 5.40% 3.00% > 800 750 - 799 700 - 749 650 - 699 600 - 649 550 -599 500 - 549 < 500 Large Addressable US Consumer Market Remains Underserved 19 Large Total Addressable Market Favorable Customer Trends 68% of American adults could not cover an emergency expens
Slide 20: Origination & Underwriting Process Flow
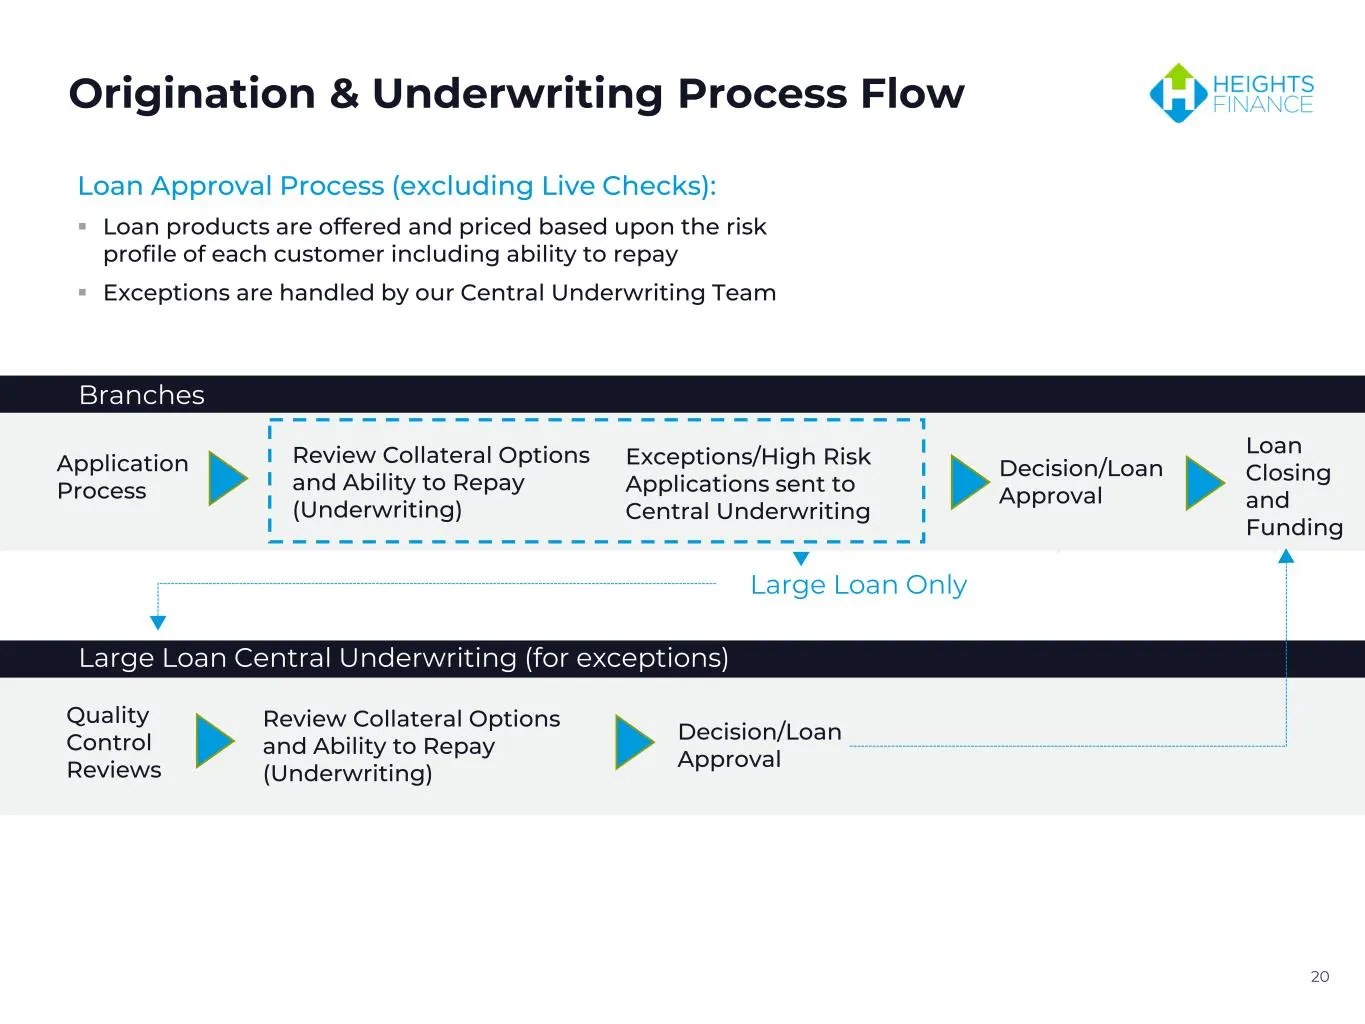
Origination & Underwriting Process Flow 20 Loan Approval Process (excluding Live Checks): Loan products are offered and priced based upon the risk profile of each customer including ability to repay Exceptions are handled by our Central Underwriting Team Application Process Review Collateral Opt
Slide 21: Underwriting Criterion
21 Johanna Underwriting Criterion Application Review Character Capacity Collateral Collateral Options Secured – Titled Unsecured (may include certain personal property) Verifications Identification Residence Employment Income Ability to Repay Net Disposable Income Underwriting
Slide 22: Servicing Process
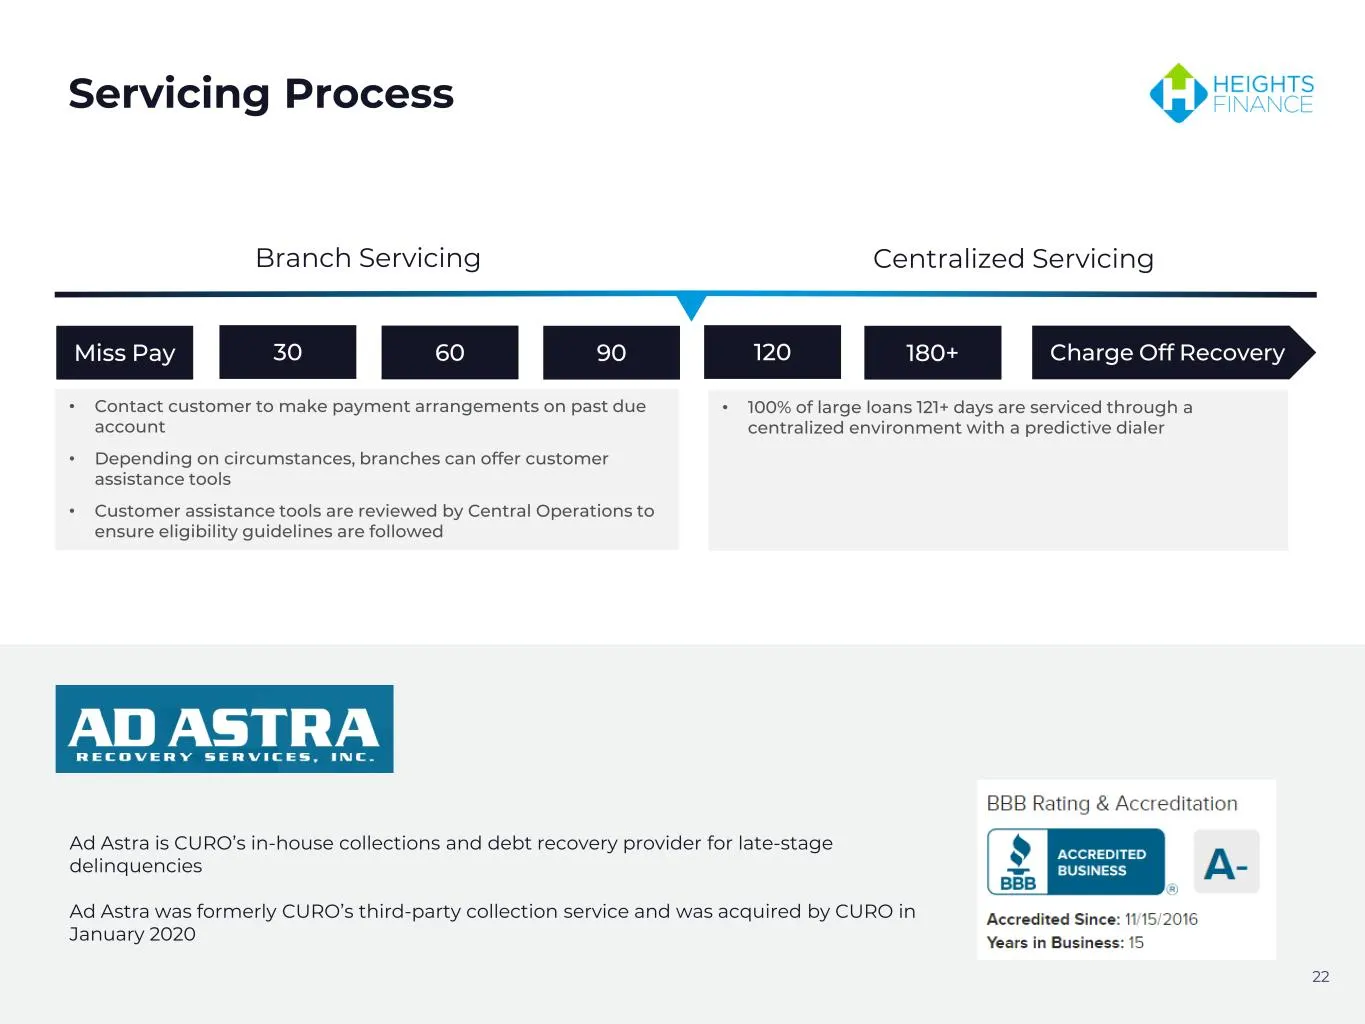
Servicing Process 22 Ad Astra is CURO’s in-house collections and debt recovery provider for late-stage delinquencies Ad Astra was formerly CURO’s third-party collection service and was acquired by CURO in January 2020 Centralized ServicingBranch Servicing Charge Off Recovery180+906030Miss Pay 120 •
Slide 23: CURO
4~CURO
Source: SEC EDGAR · 8-K filed Oct 17, 2022
More decks from Curo Group Holdings Corp
 Q4 2023 Earnings Presentation21 slides · Feb 12, 2024
 Investor Presentation (November 2023)15 slides · Nov 13, 2023
 Q3 2023 Earnings Presentation20 slides · Nov 2, 2023
 Debt Investor Presentation (October 2023)21 slides · Oct 23, 2023
 Investor Presentation (September 2023)15 slides · Sep 25, 2023
 Q2 2023 Earnings Presentation21 slides · Aug 3, 2023