Vodacom Group Limited · JSE:VOD
Vodacom — IPO Roadshow (March 2009)
35 slides from Vodacom's IPO roadshow presentation, March 2009
Slide 1: Vodacom Group Media Presentation
Vodacom Group (Pty) Ltd Media Presentation March 2009
Slide 2: Disclaimer
Disclaimer 7KLVSUHVHQWDWLRQKDVEHHQSUHSDUHGDQGLVVXHGE\9RGDFRP*URXS 3URSULHWDU\ /LPLWHG ³9RGDFRP´RUWKH³&RPSDQ\´ VROHO\IRU your information and for use at the presentation to research analysts to be made on or about 5 March 2009 in connection with WKHSURSRVHGOLVWLQJ WKH³/LVWLQJ´ RIWKH&RPSDQ\RQWKHPDLQER
Slide 3: Agenda
Agenda Transaction highlights Key investment highlights Vodacom growth strategy Conclusion and Q&A Media presentation March 2009 22
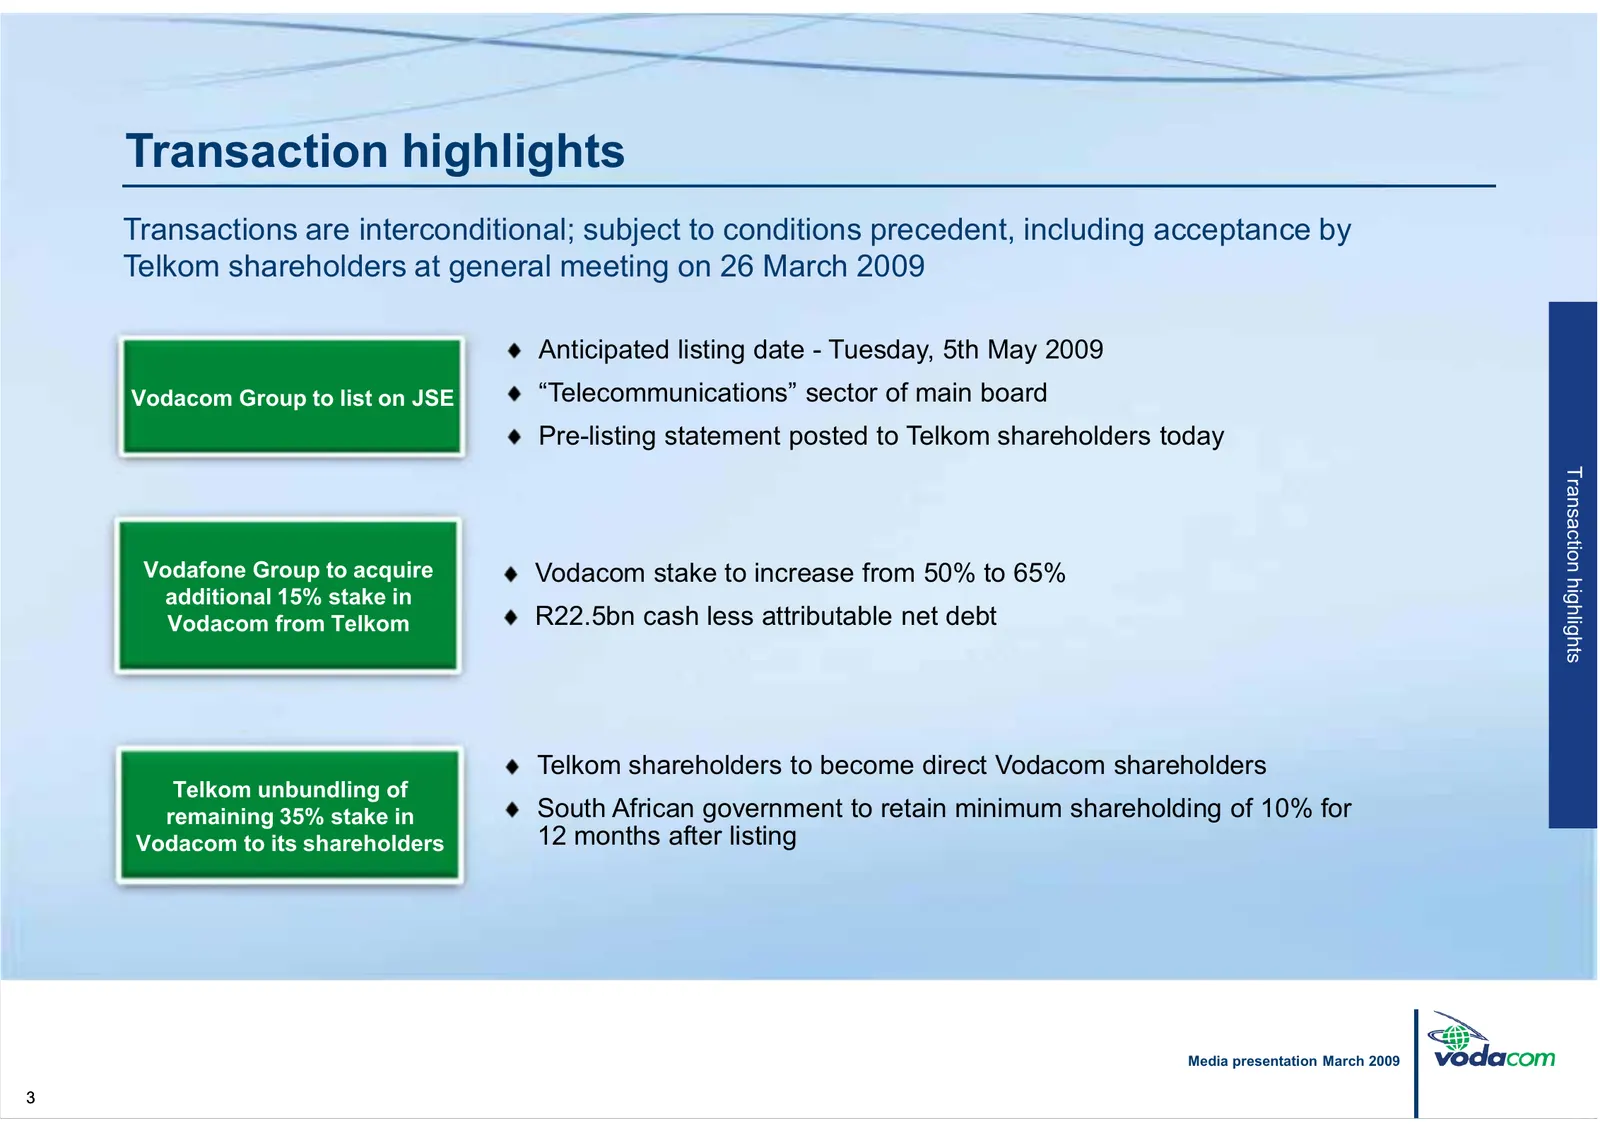
Slide 4: Transaction highlights
Transaction highlights Transactions are interconditional; subject to conditions precedent, including acceptance by Telkom shareholders at general meeting on 26 March 2009 Anticipated listing date - Tuesday, 5th May 2009 Vodacom Group to list on JSE ³7HOHFRPPXQLFDWLRQV´VHFWRURIPDLQERDUG Pre-listing s
Slide 5: Key investment highlights
Key investment highlights Media presentation March 2009 4
Slide 6: Key Vodacom investment highlights
Key Vodacom investment highlights Leading market positions Unique platform for growth Key investment highlights Established track record Proven management team supported by Vodafone Attractive balance between growth and returns Media presentation March 2009 5
Slide 7: Leading market positions
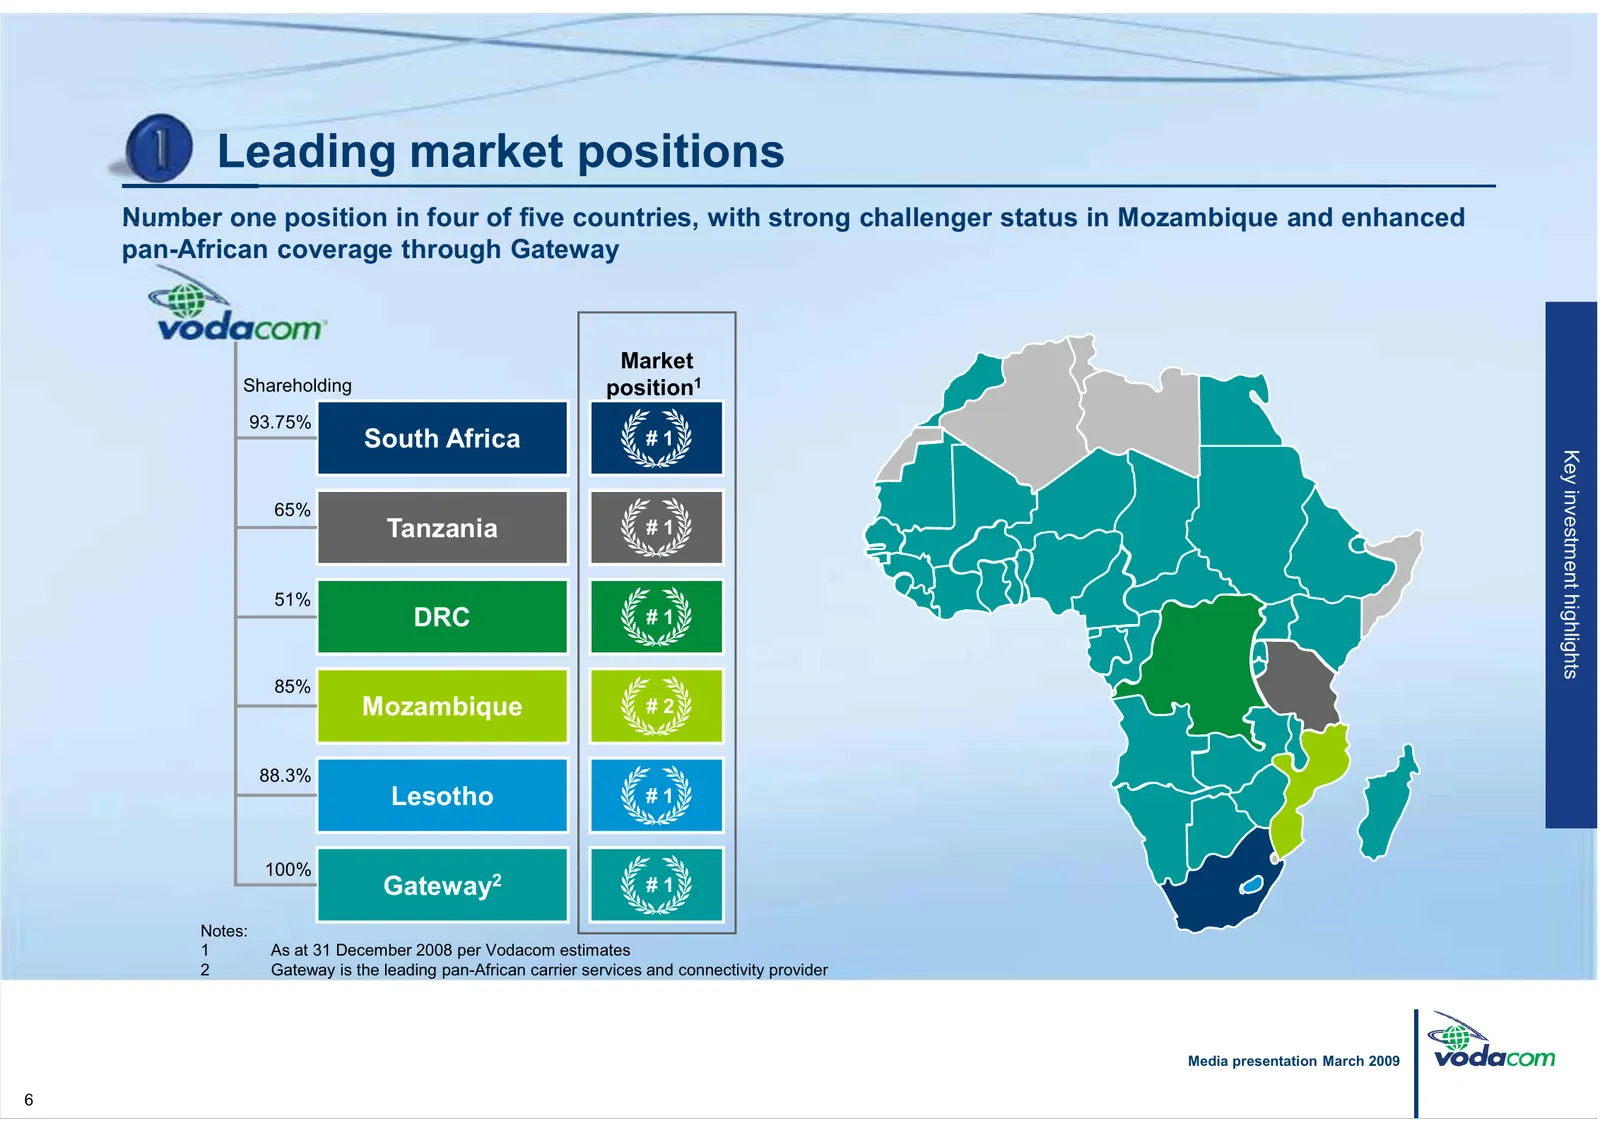
Leading market positions Number one position in four of five countries, with strong challenger status in Mozambique and enhanced pan-African coverage through Gateway Market Shareholding position1 93.75% South Africa #1 Key investment highlights 65% Tanzania #1 51% DRC #1 85% Mozambique #2 88.3% Leso
Slide 8: Platform for growth: attractive existing markets and region
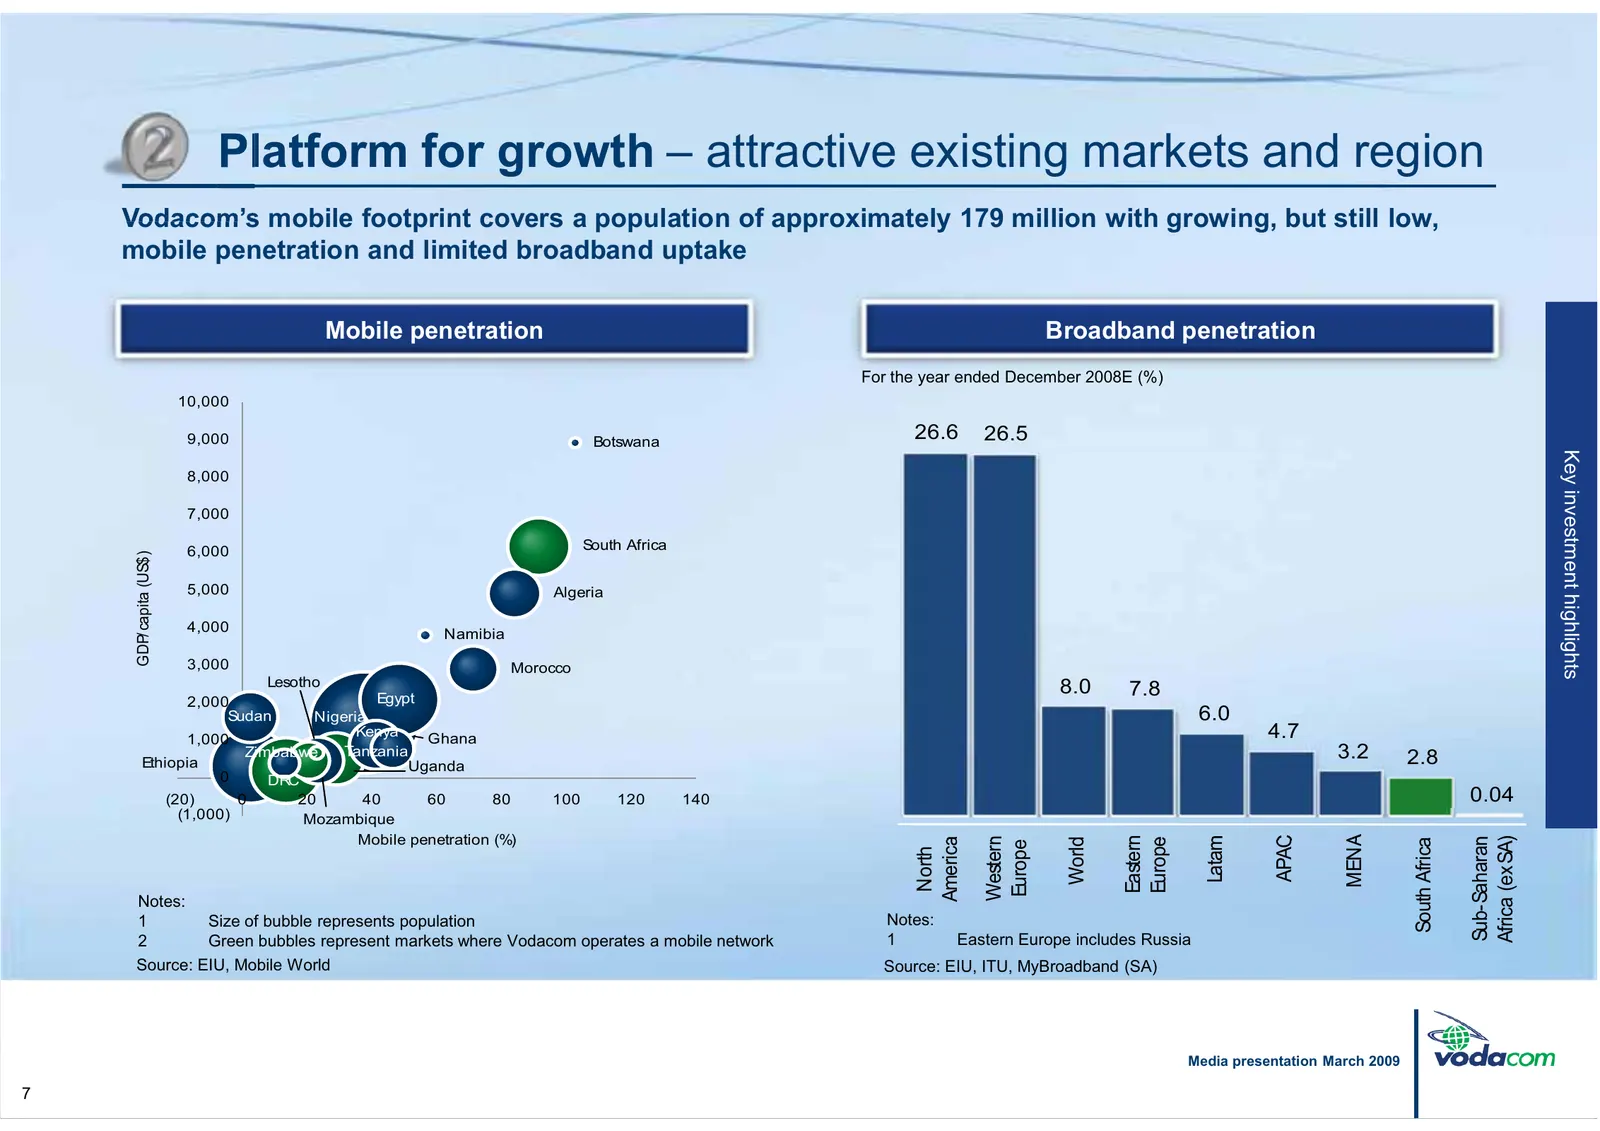
Platform for growth ± attractive existing markets and region 9RGDFRP¶VPRELOHIRRWSULQWFRYHUVDSRSXODWLRQRIDSSUR[LPDWHO\PLOOLRQZLWKJURZLQJEXWVWLOOlow, mobile penetration and limited broadband uptake Mobile penetration Broadband penetration For the year ended December 2008E (%) 10,000 9,000 Botswana 26.
Slide 9: Platform for growth: total communications provider
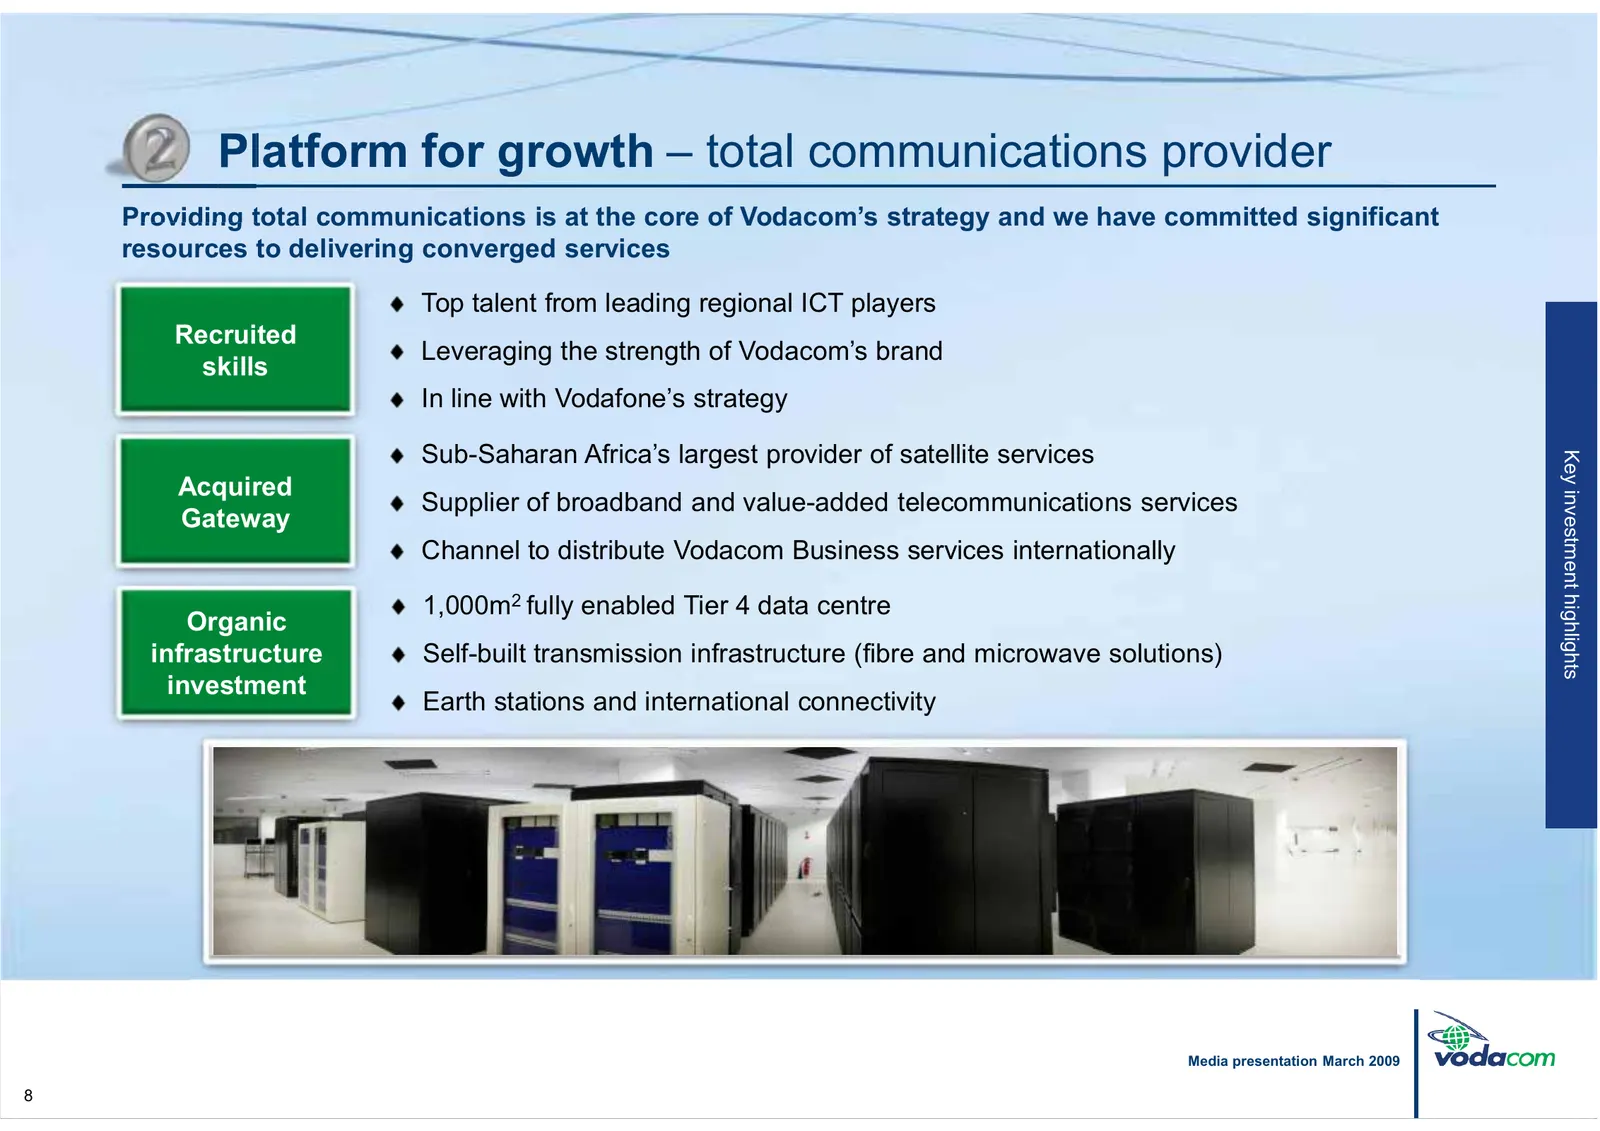
Platform for growth ± total communications provider Providing total communications is DWWKHFRUHRI9RGDFRP¶VVWUDWHJ\DQGZHKDYHFRPPLWWHGVLJQLILFDQW resources to delivering converged services Top talent from leading regional ICT players Recruited /HYHUDJLQJWKHVWUHQJWKRI9RGDFRP¶VEUDQG skills ,QOLQHZLWK9RG
Slide 10: Platform for growth: brand, distribution and customer care
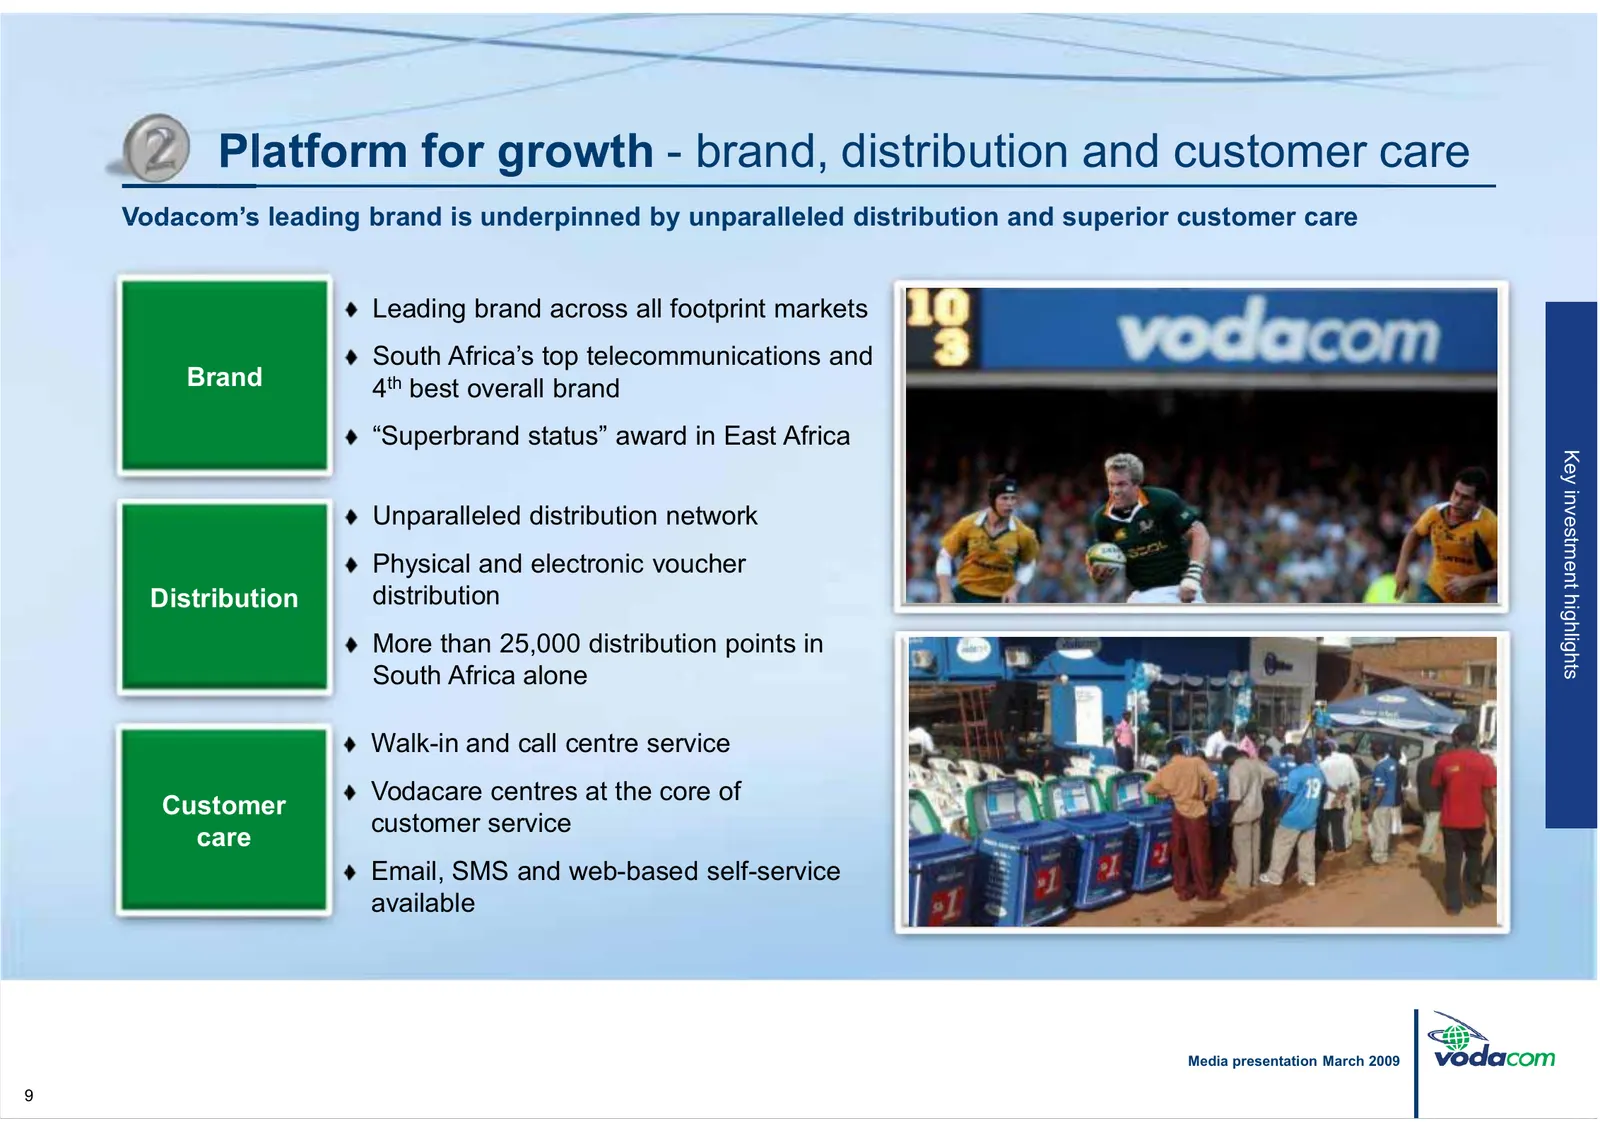
Platform for growth - brand, distribution and customer care 9RGDFRP¶VOHDGLQJEUDQGLVXQGHUSLQQHGE\XQSDUDOOHOHGGLVWULEXWLRQDQGVXSHULRUFXVWRPHUFDUH Leading brand across all footprint markets 6RXWK$IULFD¶VWRSWHOHFRPPXQLFDWLRQVDQG Brand 4th best overall brand ³Superbrand VWDWXV´DZDUGLQ(DVW$IULFD Key inves
Slide 11: Established track record: innovation
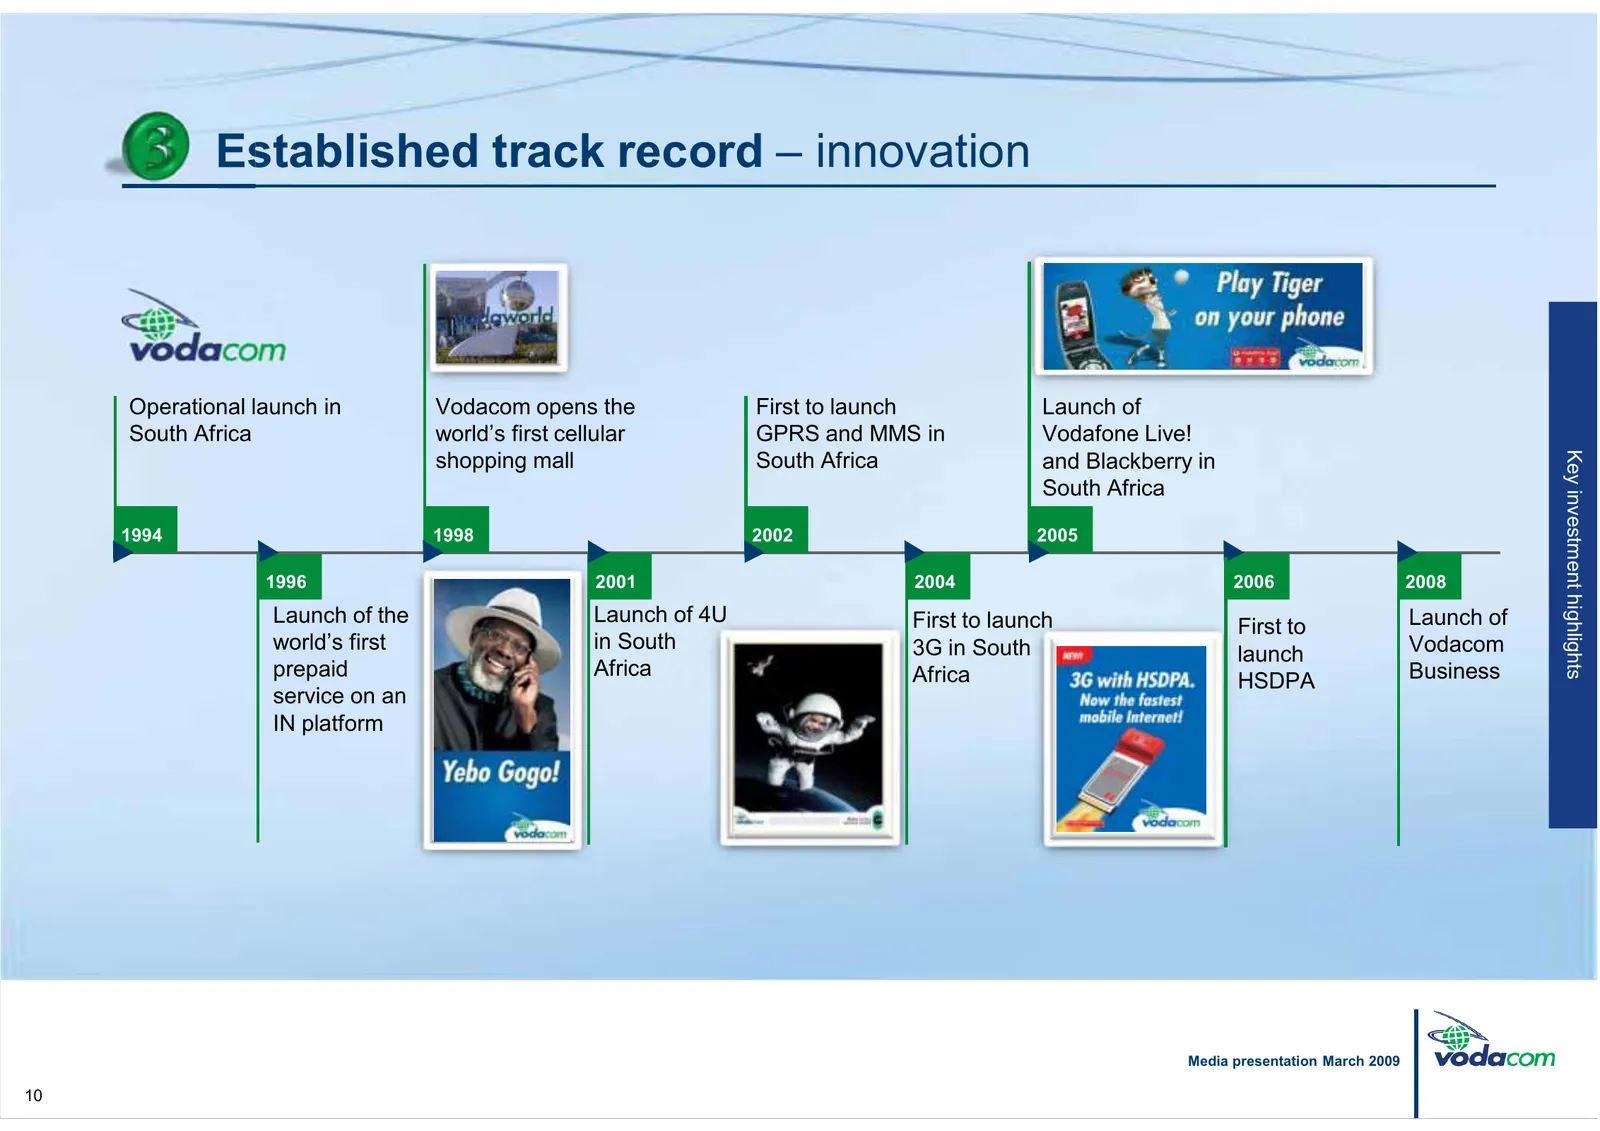
Established track record ± innovation Operational launch in Vodacom opens the First to launch Launch of South Africa ZRUOG¶VILUVWFHOOXODU GPRS and MMS in Vodafone Live! Key investment highlights shopping mall South Africa and Blackberry in South Africa 1994 1998 2002 2005 1996 2001 2004 2006 2008 La
Slide 12: Established track record: profitable growth
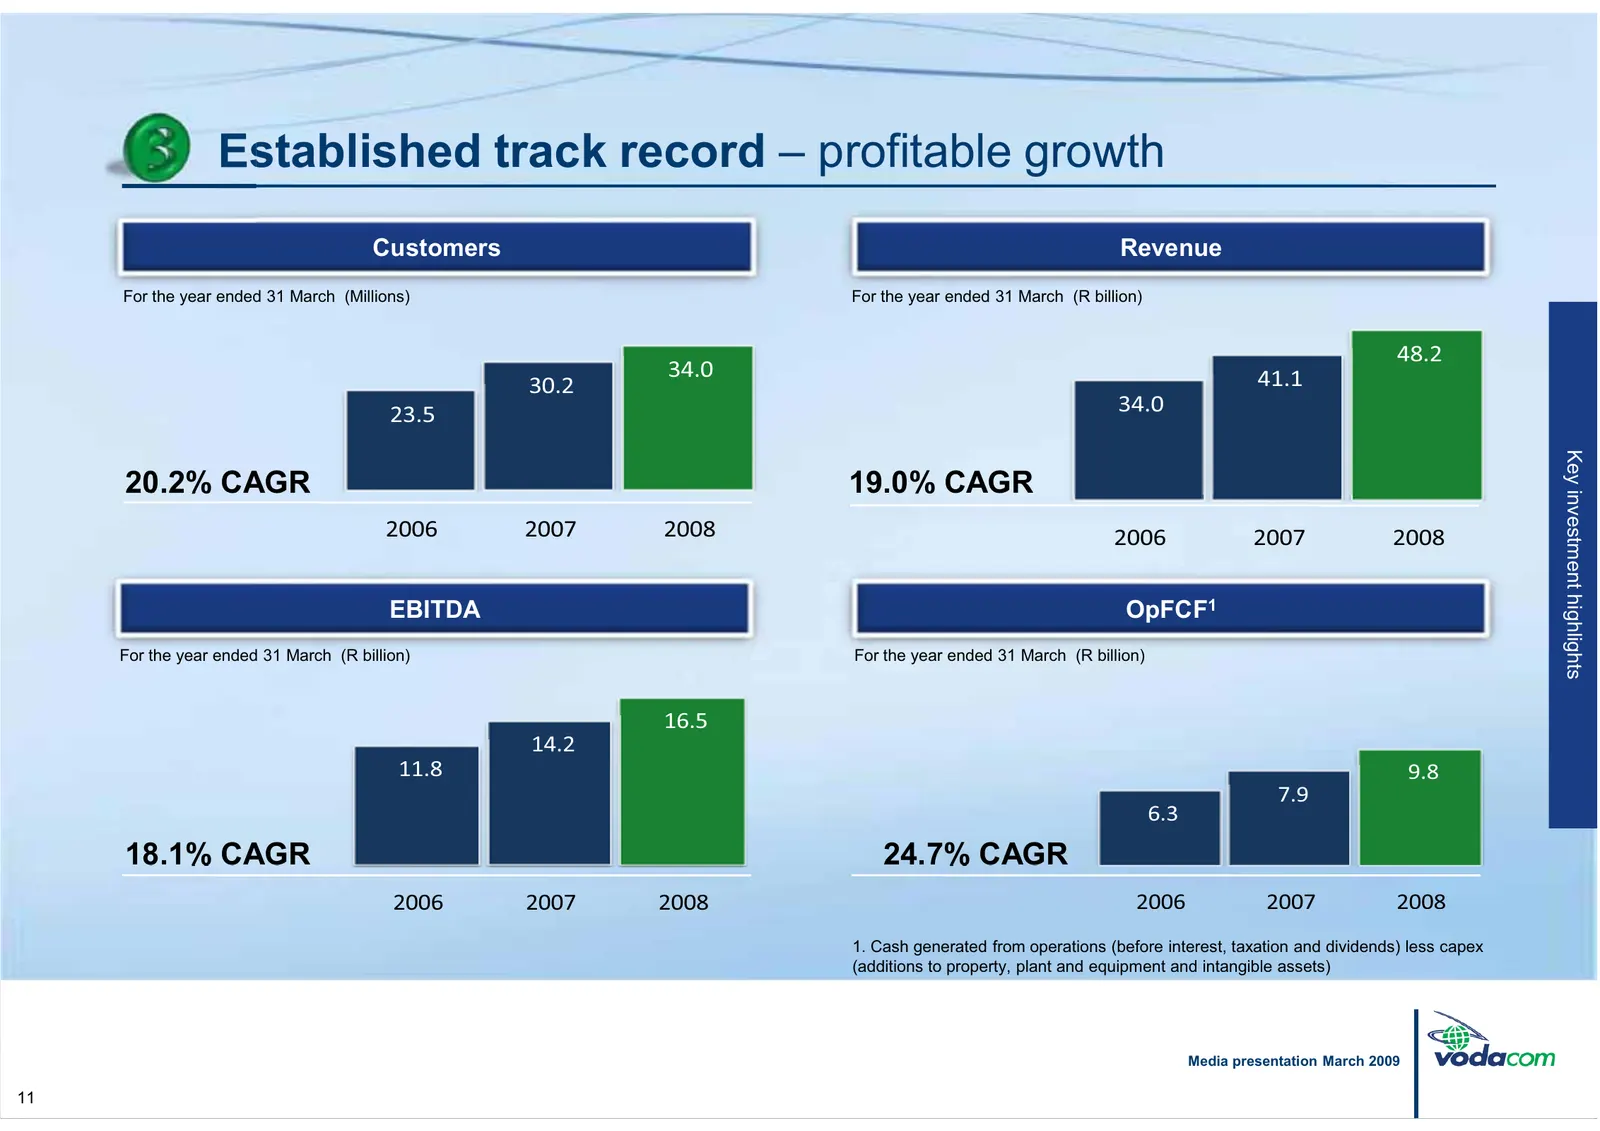
Established track record ± profitable growth Customers Revenue For the year ended 31 March (Millions) For the year ended 31 March (R billion) 48.2 34.0 41.1 30.2 23.5 34.0 Key investment highlights 20.2% CAGR 19.0% CAGR 2006 2007 2008 2006 2007 2008 EBITDA OpFCF1 For the year ended 31 March (R billi
Slide 13: Proven management team
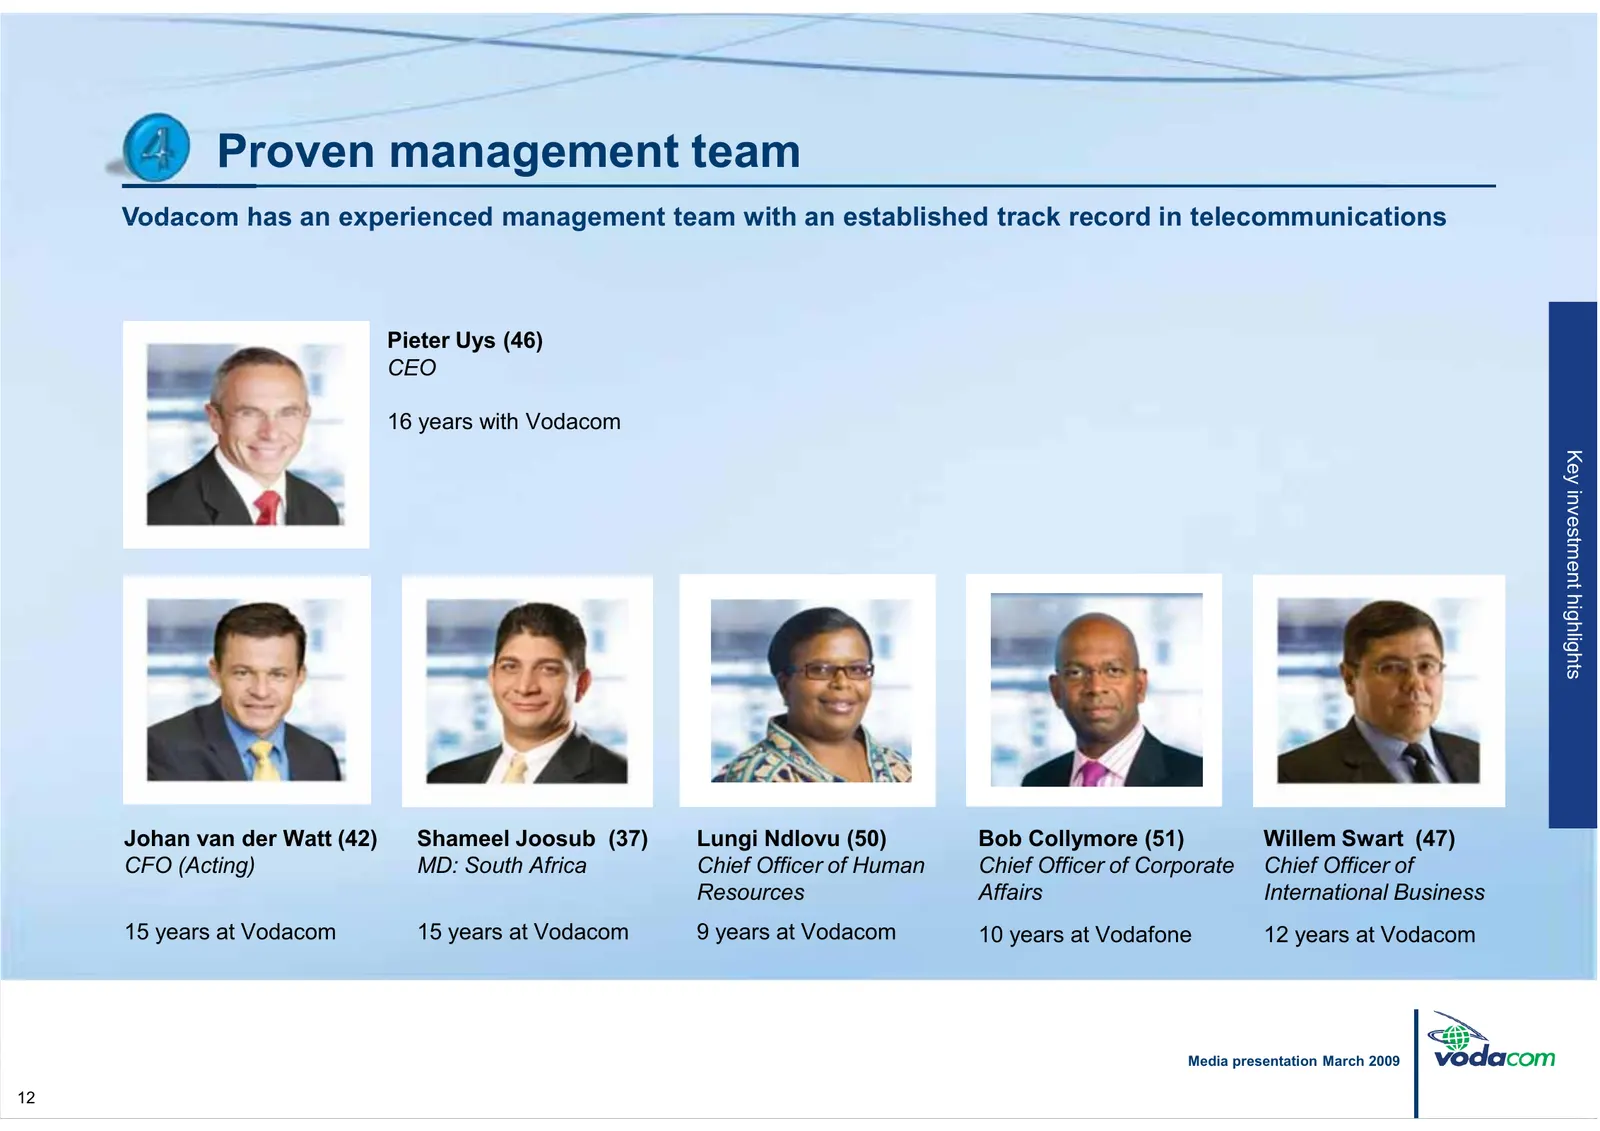
Proven management team Vodacom has an experienced management team with an established track record in telecommunications Pieter Uys (46) CEO 16 years with Vodacom Key investment highlights Johan van der Watt (42) Shameel Joosub (37) Lungi Ndlovu (50) Bob Collymore (51) Willem Swart (47) CFO (Acting)
Slide 14: Supported by Vodafone
Supported by Vodafone $FFHVVWR9RGDIRQH¶VH[SHUWLVHSURGXFWLQQRYDWLRQPDUNHWLQJDQGFHQWUDOLVHGprocurement supports 9RGDFRP¶VLQ-house strength :RUOG¶VOHDGLQJLQWHUQDWLRQDOPRELOHFRPPXQLFDWLRQVJURXSZLWK The Vodafone Group c. 280 million proportionate subscribers in 27 countries Key investment highlights $FFH
Slide 15: Experienced and well balanced Board
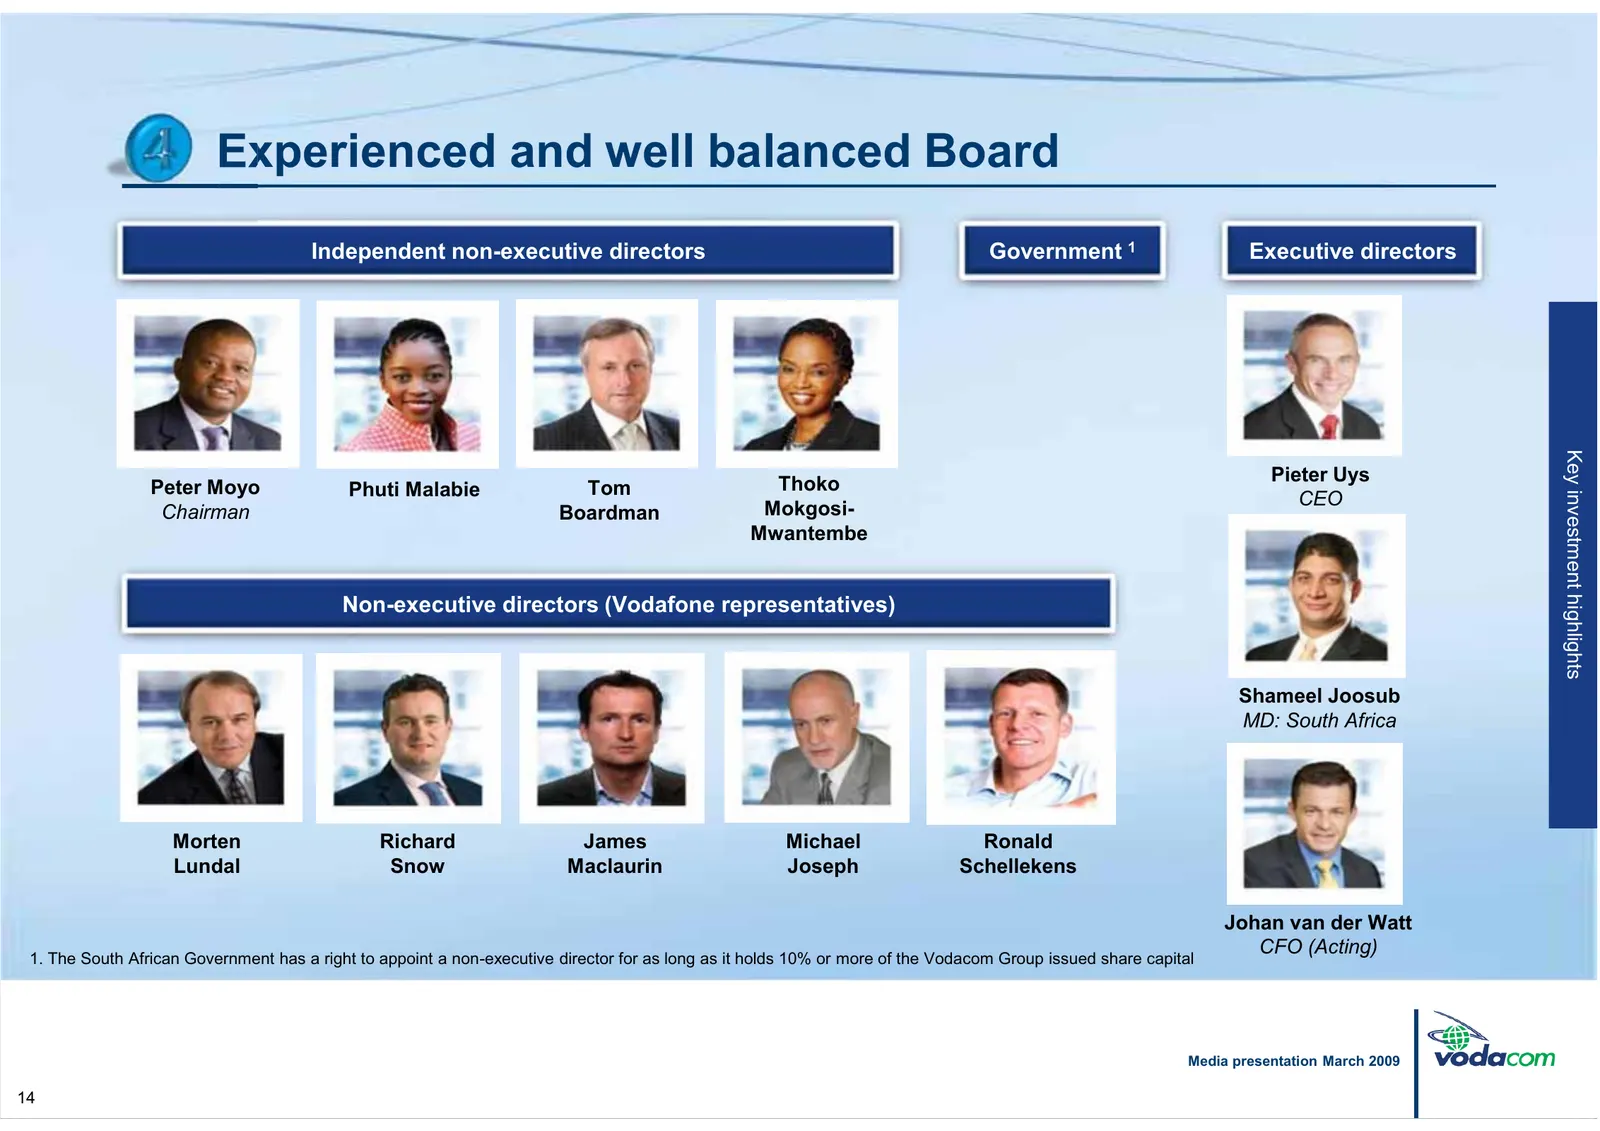
Experienced and well balanced Board Independent non-executive directors Government 1 Executive directors Key investment highlights Thoko Pieter Uys Peter Moyo Phuti Malabie Tom CEO Chairman Boardman Mokgosi- Mwantembe Non-executive directors (Vodafone representatives) Shameel Joosub MD: South Africa
Slide 16: Attractive balance between growth and returns
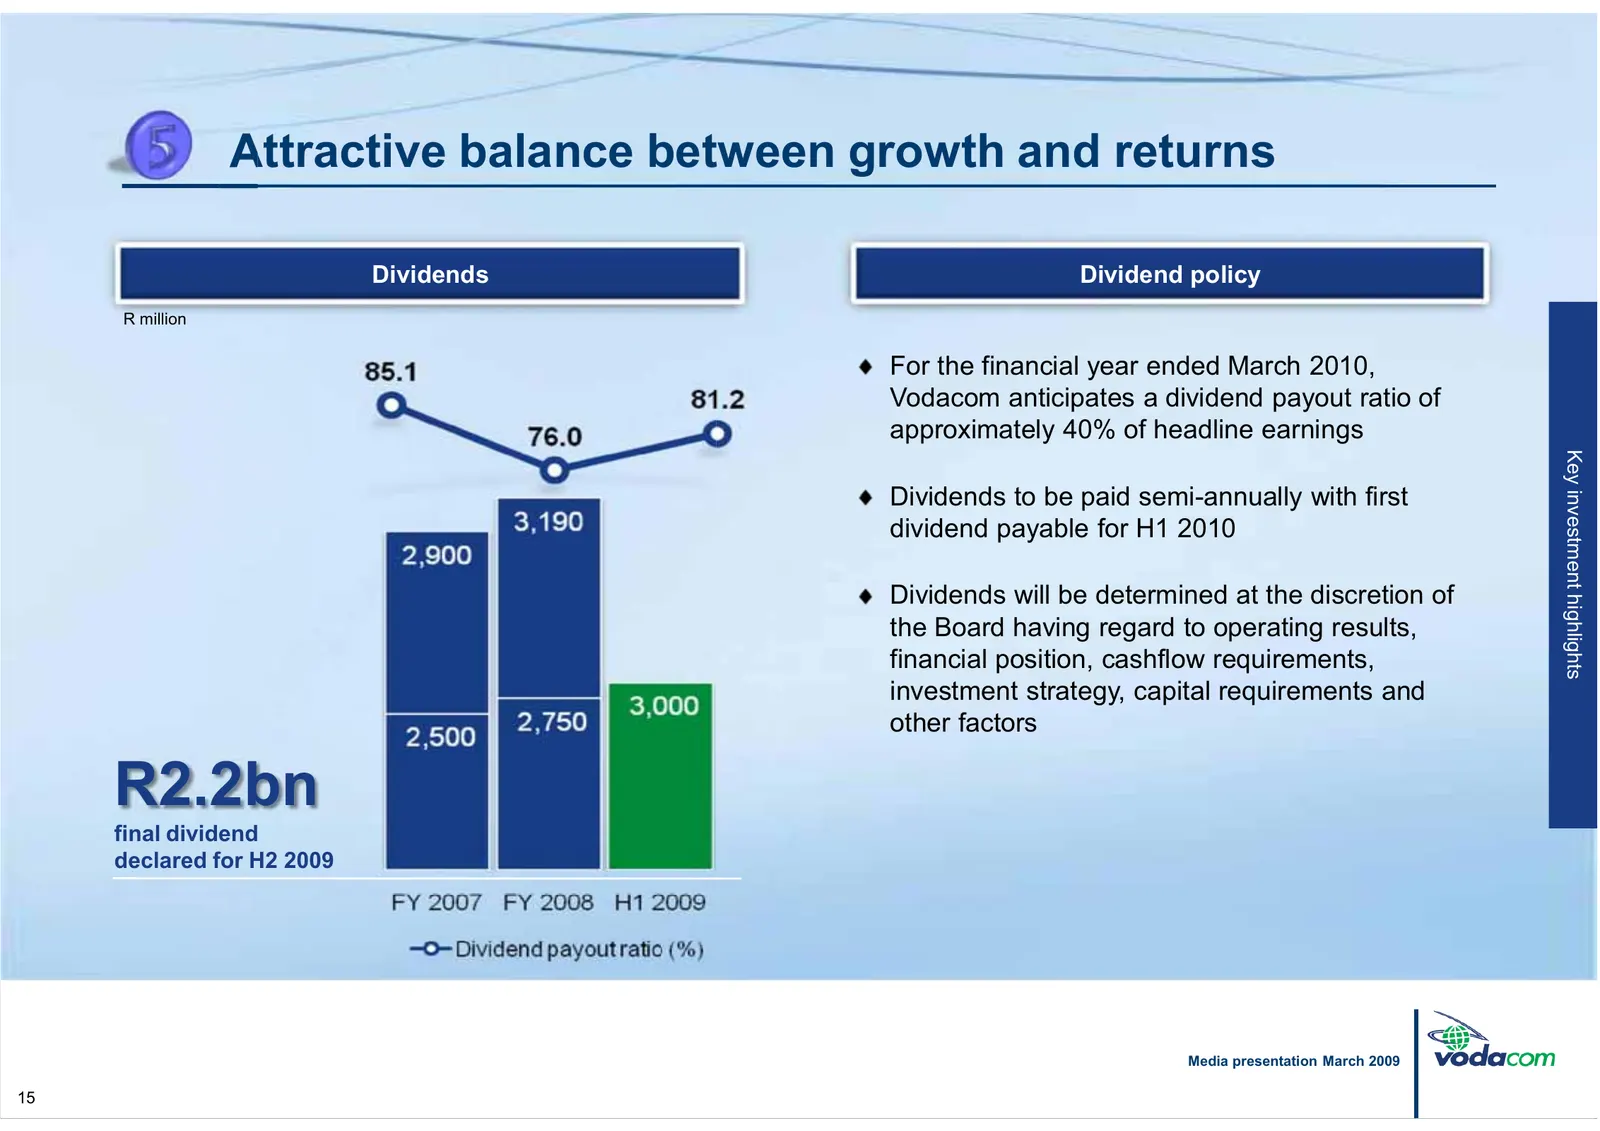
Attractive balance between growth and returns Dividends Dividend policy R million For the financial year ended March 2010, Vodacom anticipates a dividend payout ratio of approximately 40% of headline earnings Key investment highlights Dividends to be paid semi-annually with first dividend payable fo
Slide 17: Vodacom growth strategy
Vodacom growth strategy Media presentation March 2009 16
Slide 18: Vodacom's strategies for growth
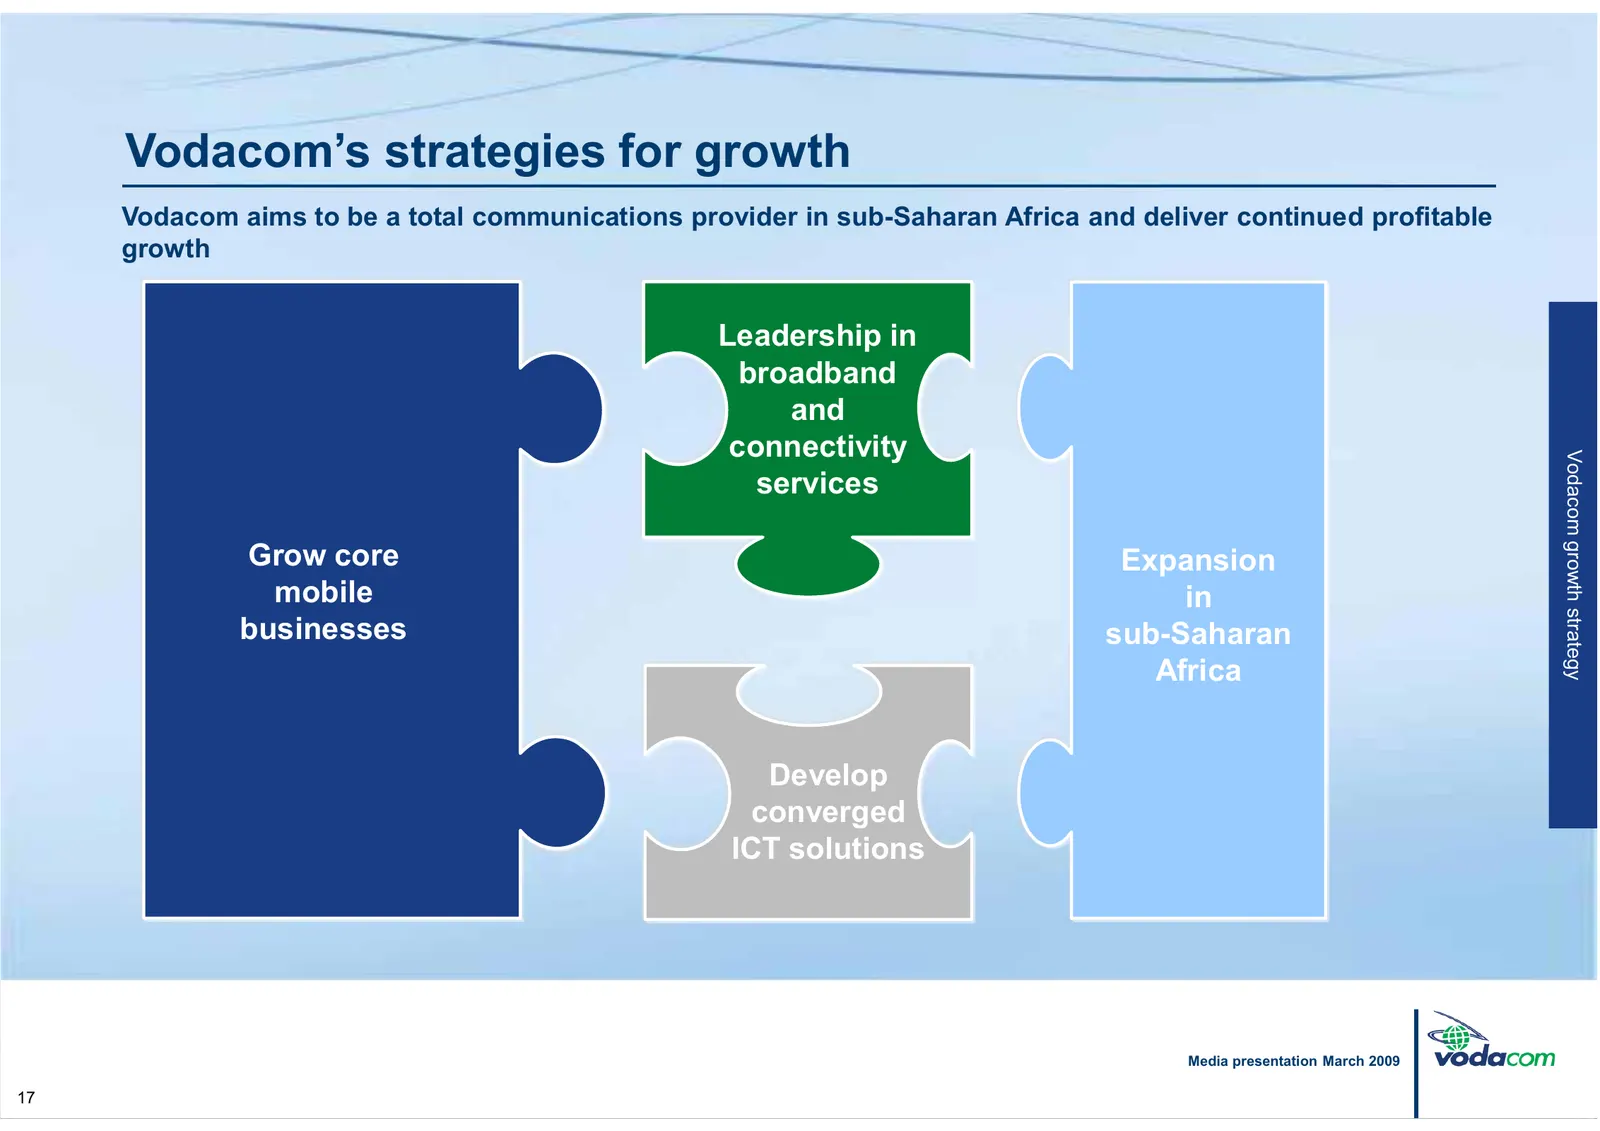
9RGDFRP¶VVWUDWHJLHVIRUJURZWK Vodacom aims to be a total communications provider in sub-Saharan Africa and deliver continued profitable growth Leadership in broadband and connectivity Vodacom growth strategy services Grow core Expansion mobile in businesses sub-Saharan Africa Develop converged ICT so
Slide 19: Strategies for growth: grow core mobile business
9RGDFRP¶VVWUDWHJLHVIRUJURZWK± grow core mobile business Vodacom aims to be a total communications provider in sub-Saharan Africa and deliver continued profitable growth Vodacom growth strategy Grow core mobile businesses Media presentation March 2009 18
Slide 20: How have we become market leaders?
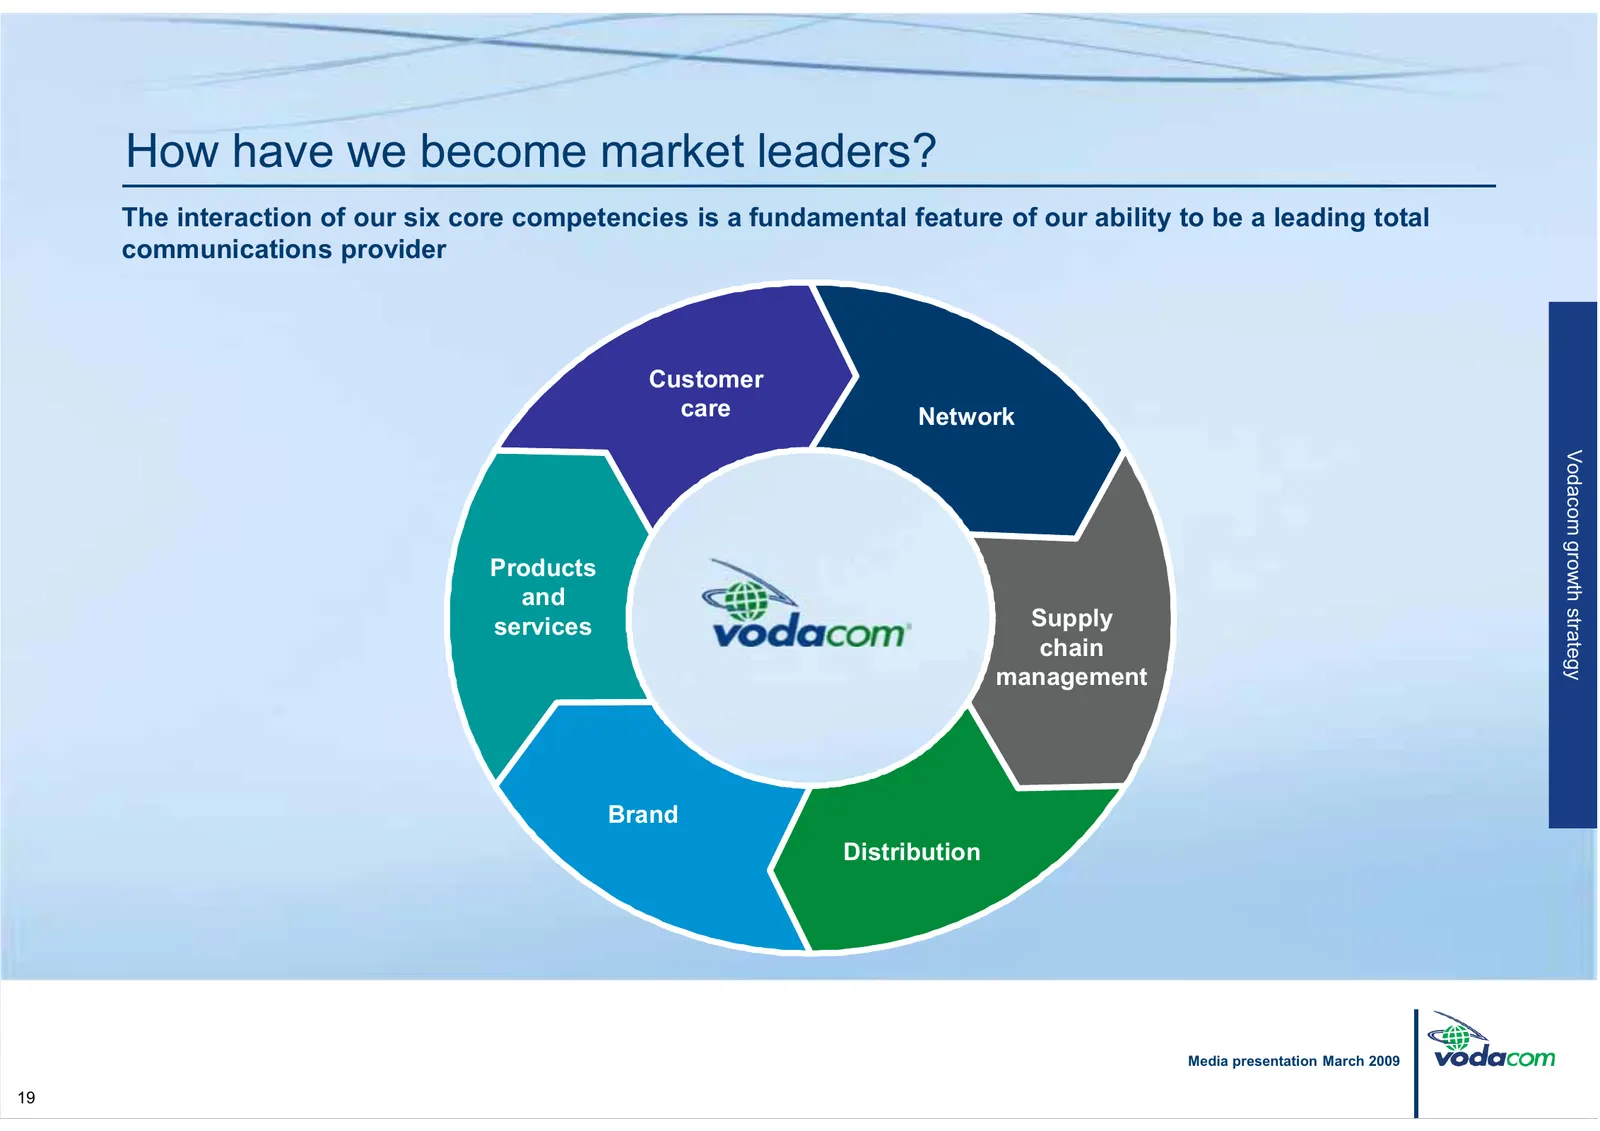
How have we become market leaders? The interaction of our six core competencies is a fundamental feature of our ability to be a leading total communications provider Customer care Network Vodacom STRATEGIC growth Products REVIEW and strategy services Supply chain management Brand Distribution Media
Slide 21: Growth strategies for existing mobile markets
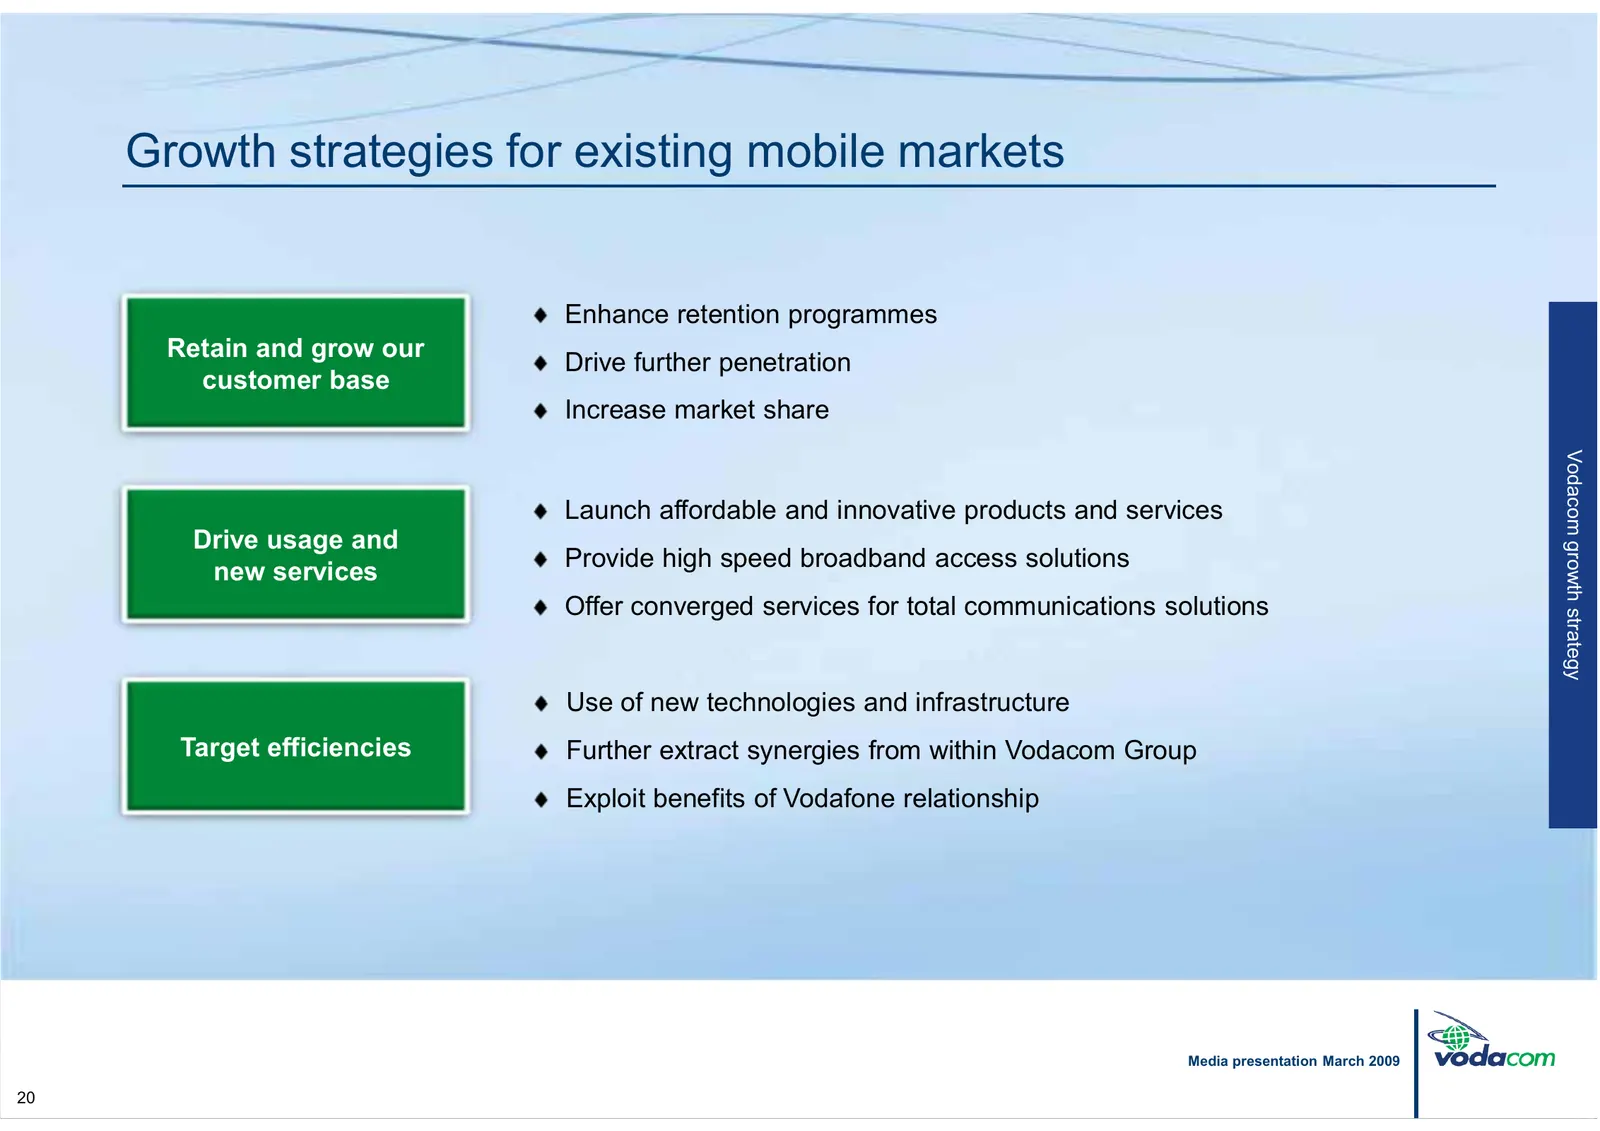
Growth strategies for existing mobile markets Enhance retention programmes Retain and grow our Drive further penetration customer base Increase market share Vodacom growth strategy Launch affordable and innovative products and services Drive usage and Provide high speed broadband access solutions ne
Slide 22: Strategies for growth: broadband leadership
9RGDFRP¶VVWUDWHJLHVIRUgrowth ± broadband leadership Vodacom aims to be a total communications provider in sub-Saharan Africa and deliver continued profitable growth Leadership in broadband and connectivity Vodacom growth strategy services Media presentation March 2009 21
Slide 23: Vodacom's strategy is to lead in broadband
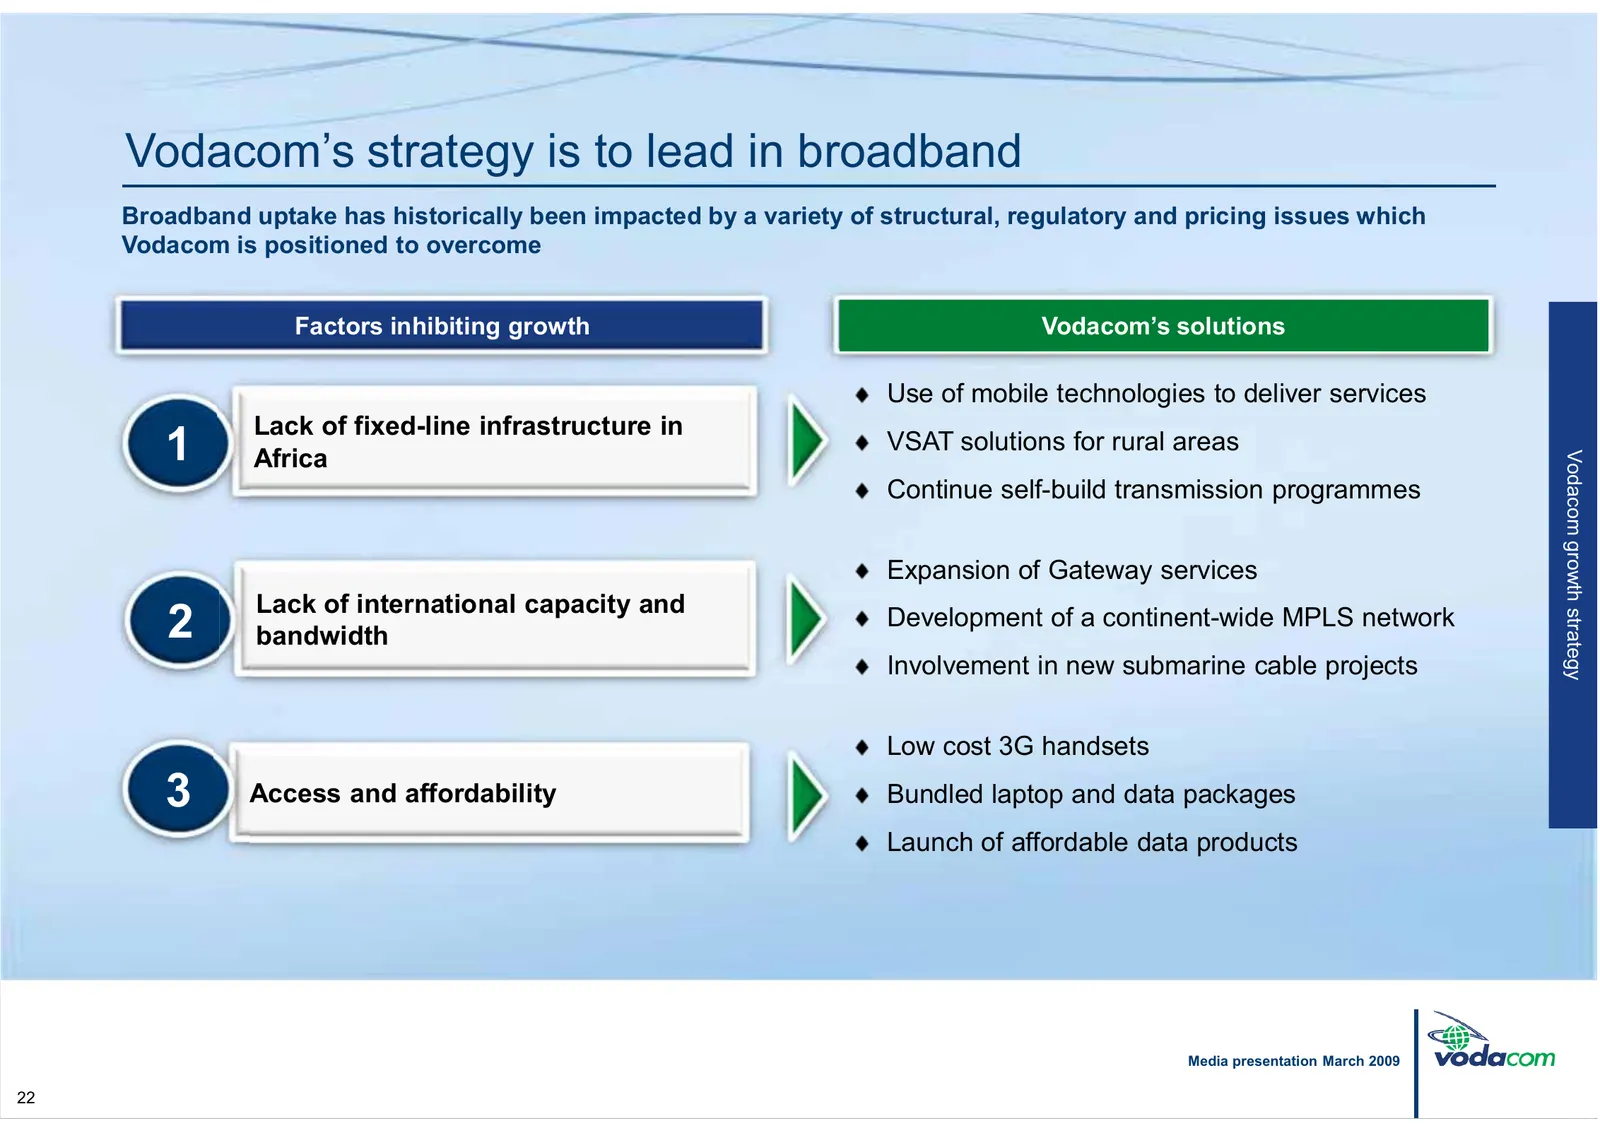
9RGDFRP¶VVWUDWHJ\LVWROHDGLQEURDGEDQG Broadband uptake has historically been impacted by a variety of structural, regulatory and pricing issues which Vodacom is positioned to overcome Factors inhibiting growth 9RGDFRP¶VVROXWLRQV Use of mobile technologies to deliver services Lack of fixed-line infras
Slide 24: Mobile can fill the African fixed-line void
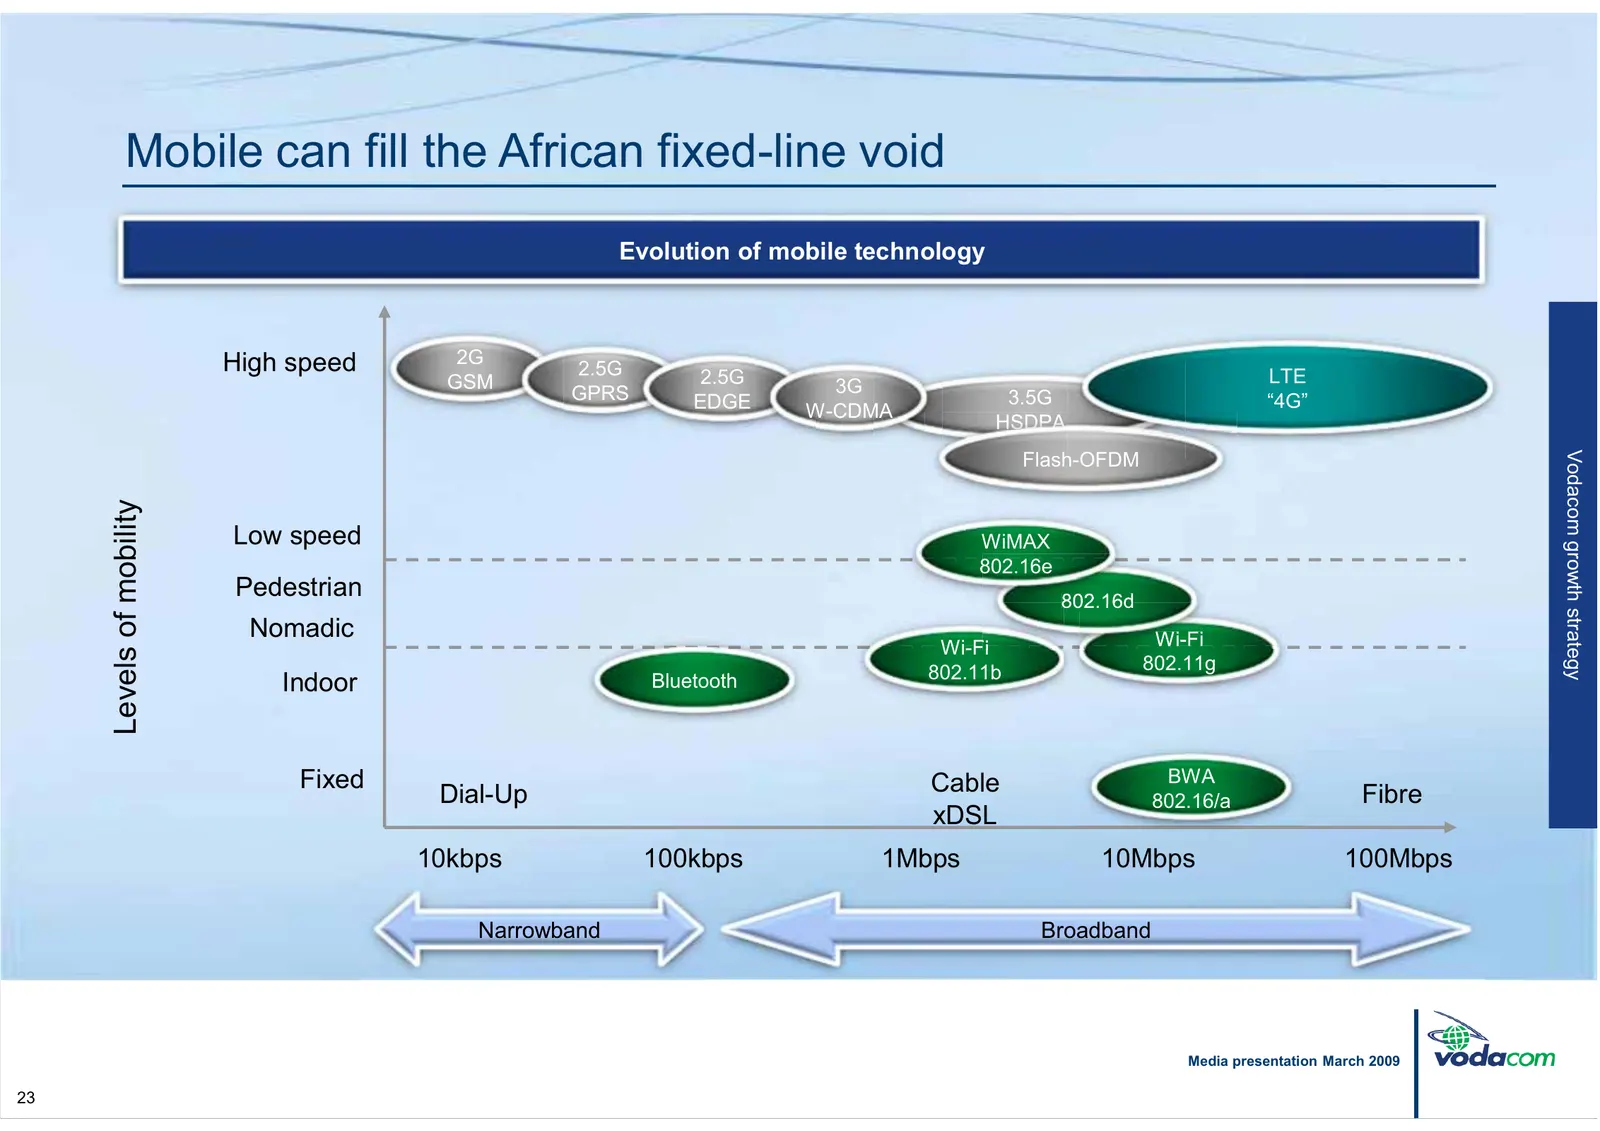
Mobile can fill the African fixed-line void Evolution of mobile technology High speed 2G 2.5G 2.5G LTE GSM 3G GPRS EDGE 3.5G ³*´ W-CDMA HSDPA Vodacom Flash-OFDM Levels of mobility GATEWAY Low speed WiMAX growth strategy 802.16e Pedestrian 802.16d Nomadic Wi-Fi Wi-Fi 802.11b 802.11g Indoor Bluetooth
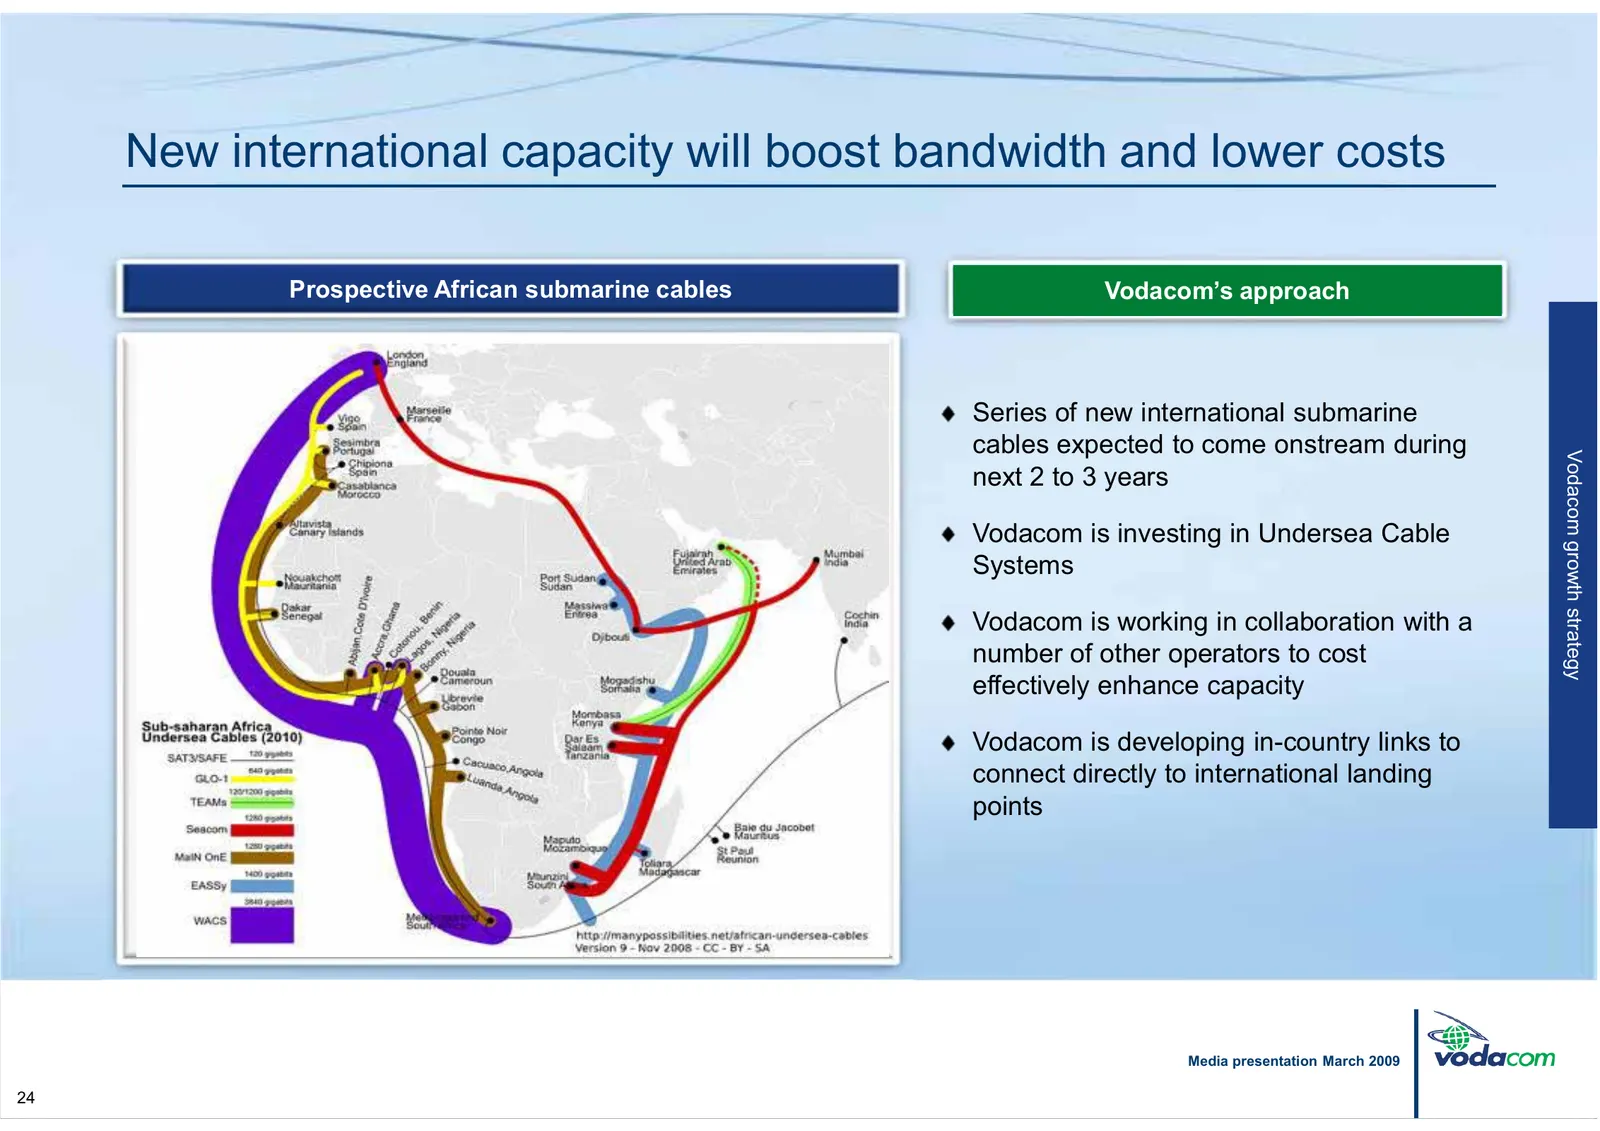
Slide 25: New international capacity will boost bandwidth and lower costs
New international capacity will boost bandwidth and lower costs Prospective African submarine cables 9RGDFRP¶Vapproach Series of new international submarine cables expected to come onstream during Vodacom next 2 to 3 years GATEWAY Vodacom is investing in Undersea Cable growth strategy Systems Vodaco
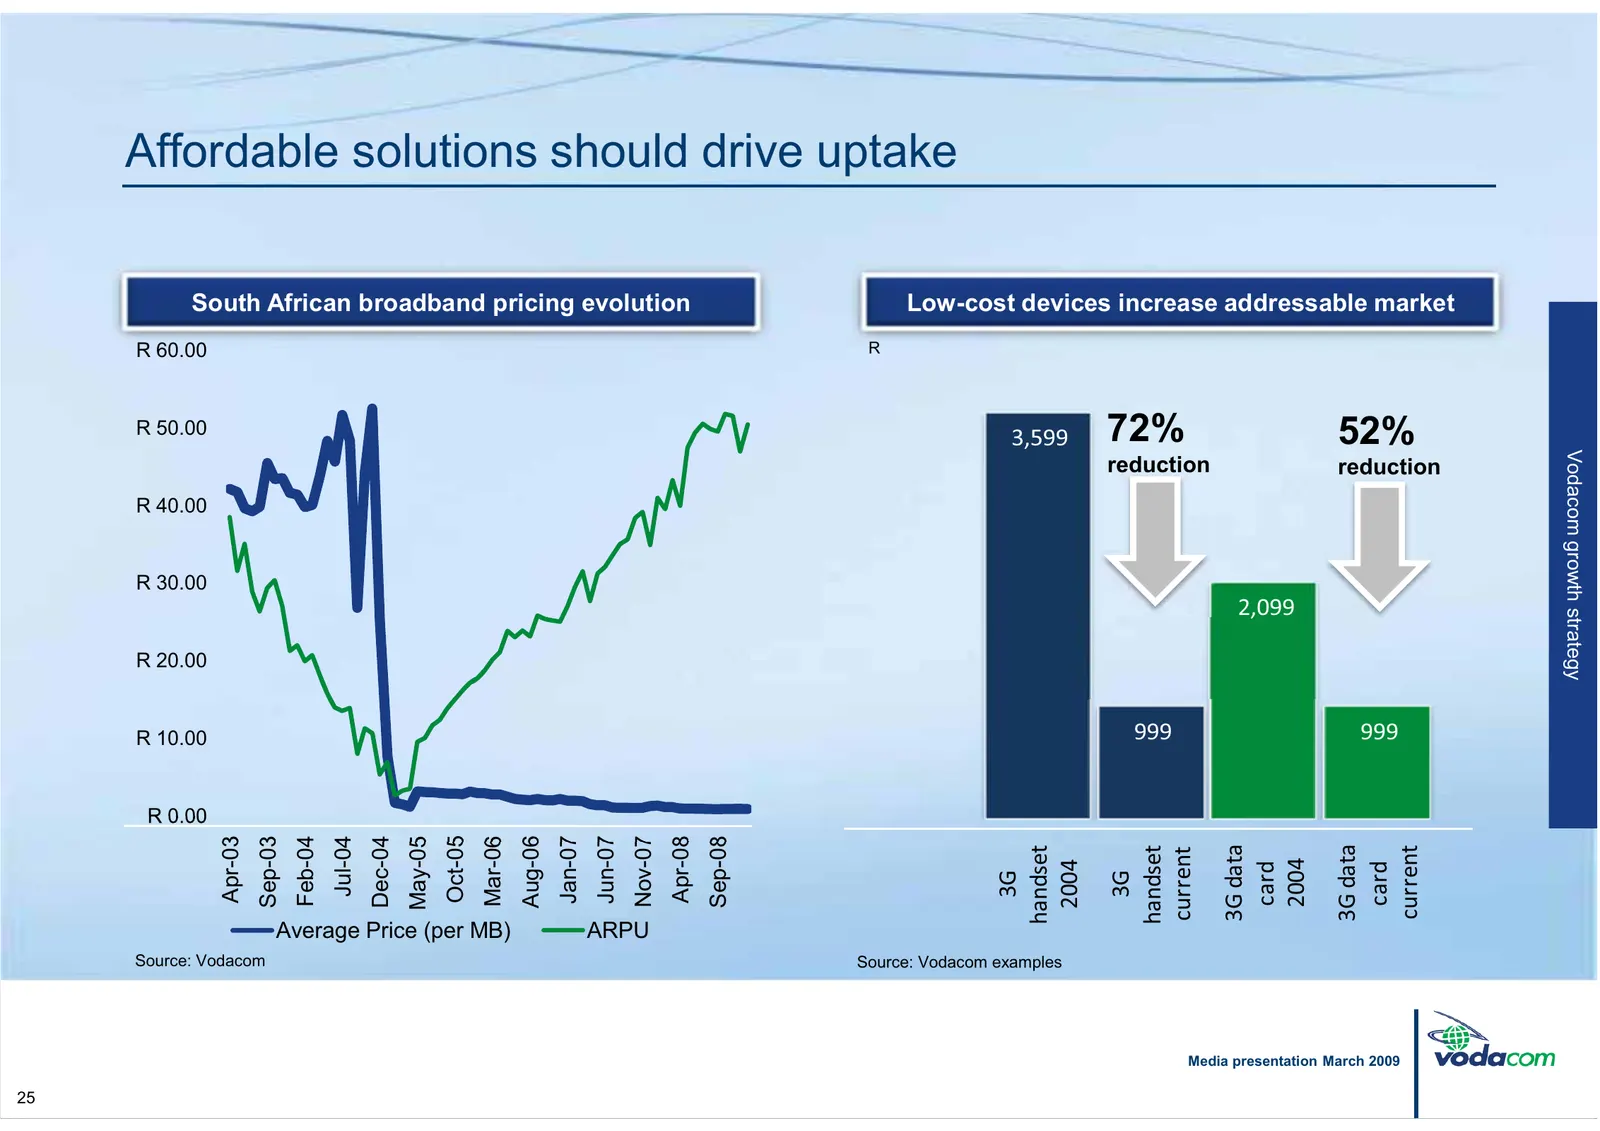
Slide 26: Affordable solutions should drive uptake
Affordable solutions should drive uptake South African broadband pricing evolution Low-cost devices increase addressable market R 60.00 R R 50.00 3,599 72% 52% Vodacom reduction reduction STRATEGIC R 40.00 growth R 30.00 REVIEW 2,099 strategy R 20.00 R 10.00 999 999 R 0.00 Oct-05 Aug-06 Jan-07 Jun-0
Slide 27: Strategies for growth: converged ICT solutions
9RGDFRP¶VVWUDWHJLHVIRUgrowth ± converged ICT solutions Vodacom aims to be a total communications provider in sub-Saharan Africa and deliver continued profitable growth Vodacom growth strategy Develop converged ICT solutions Media presentation March 2009 26
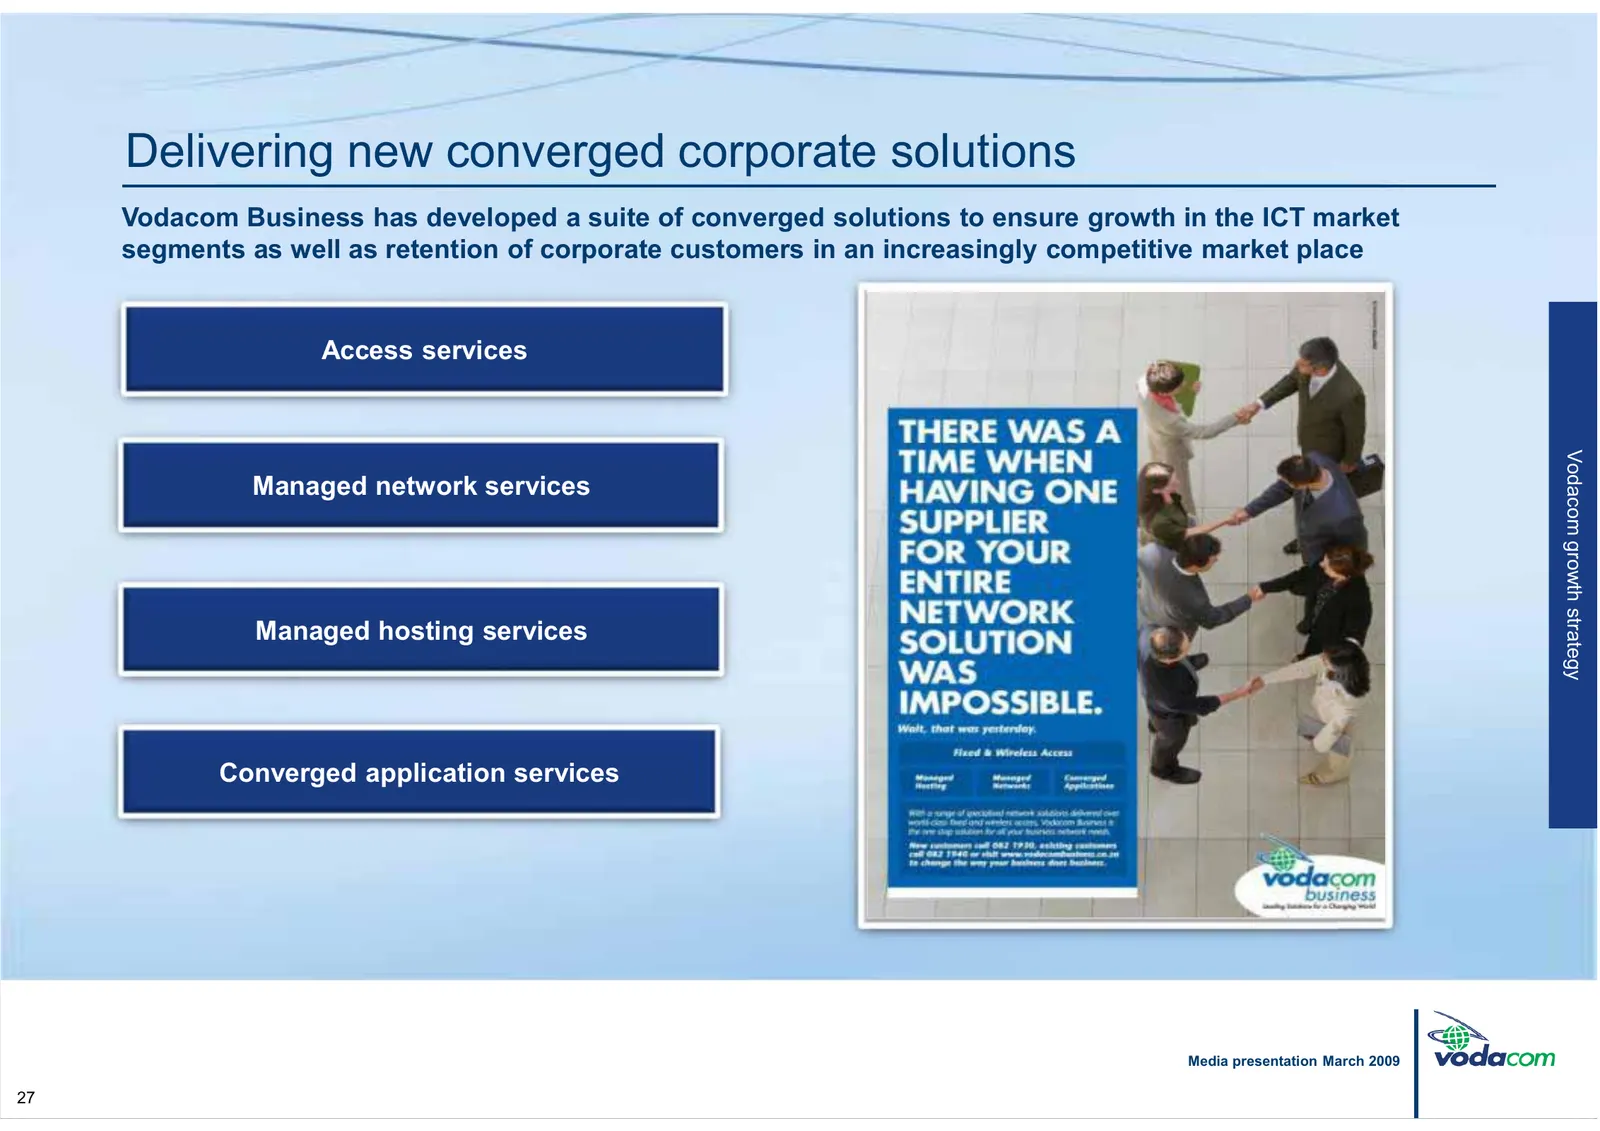
Slide 28: Delivering new converged corporate solutions
Delivering new converged corporate solutions Vodacom Business has developed a suite of converged solutions to ensure growth in the ICT market segments as well as retention of corporate customers in an increasingly competitive market place Access services Vodacom growth strategy Managed network servi
Slide 29: Delivering new converged consumer solutions
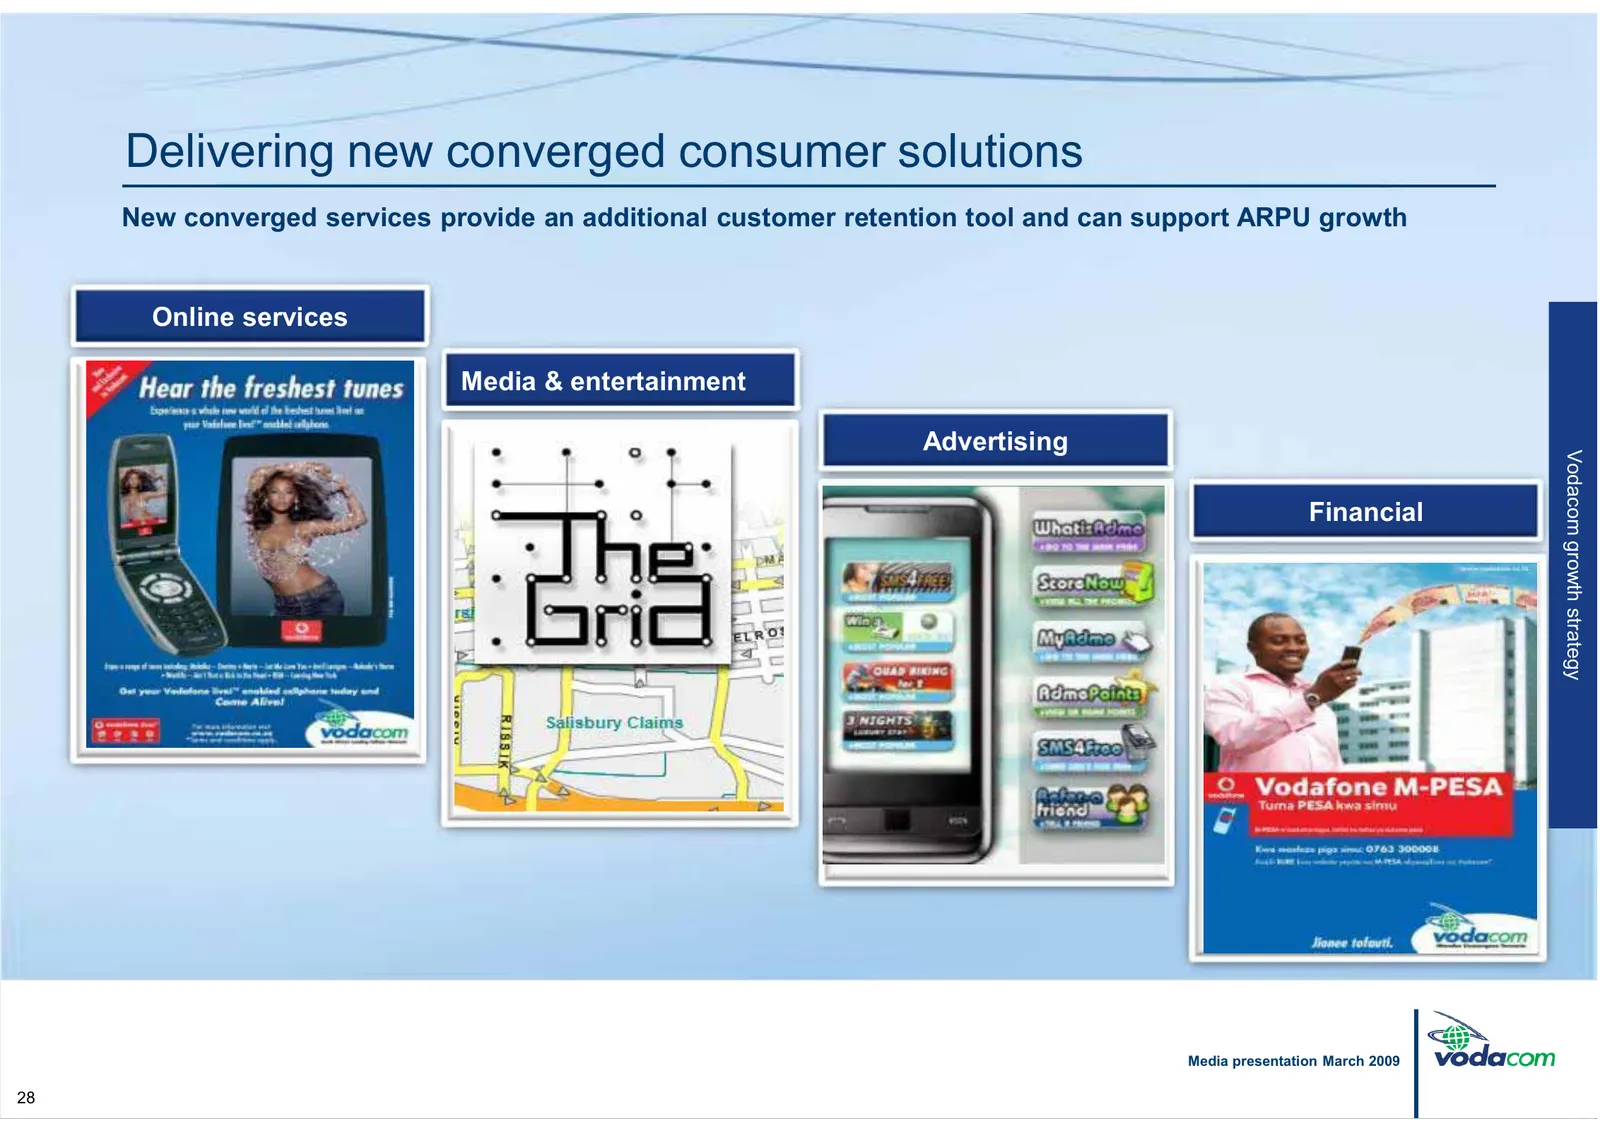
Delivering new converged consumer solutions New converged services provide an additional customer retention tool and can support ARPU growth Online services Media & entertainment Advertising Vodacom growth strategy Financial Media presentation March 2009 28
Slide 30: Strategies for growth: sub-Saharan Africa
9RGDFRP¶VVWUDWHJLHVIRUgrowth ± sub-Saharan Africa Vodacom aims to be a total communications provider in sub-Saharan Africa and deliver continued profitable growth Vodacom growth strategy Expansion in sub-Saharan Africa Media presentation March 2009 29
Slide 31: Africa remains an exciting telecommunications market
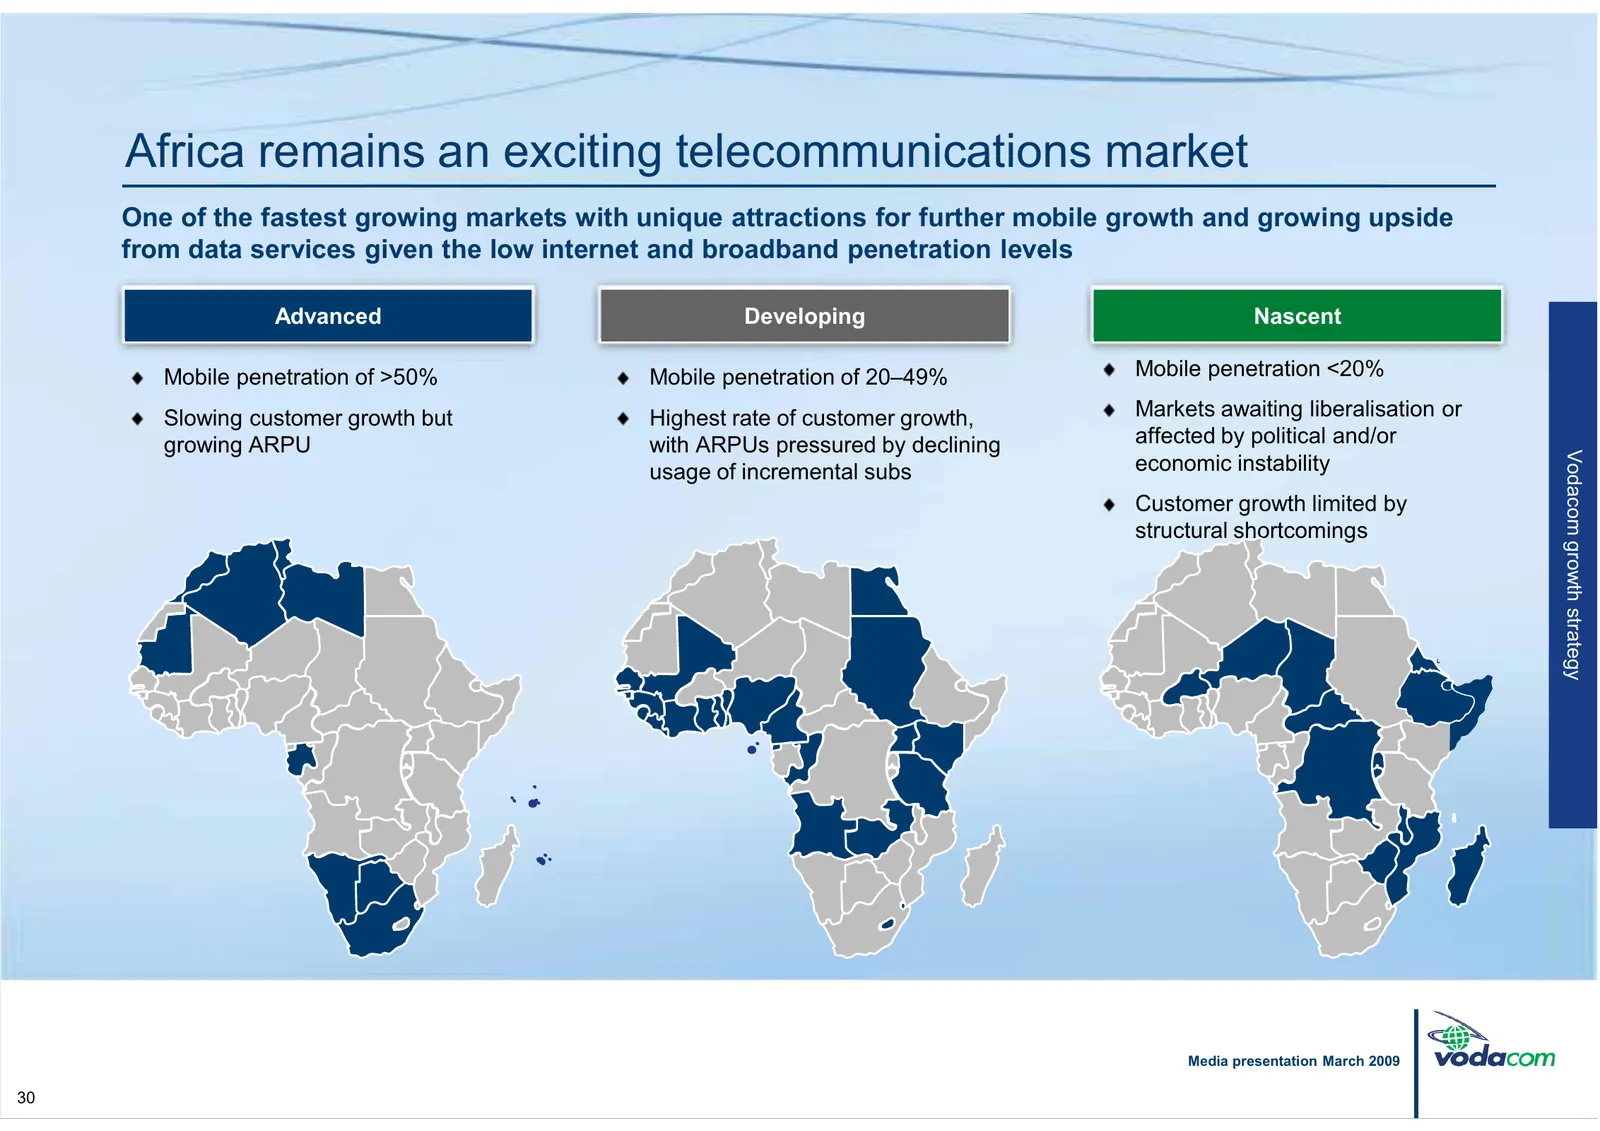
Africa remains an exciting telecommunications market One of the fastest growing markets with unique attractions for further mobile growth and growing upside from data services given the low internet and broadband penetration levels Advanced Developing Nascent Mobile penetration of >50% Mobile penetr
Slide 32: Gateway provides new market entry points
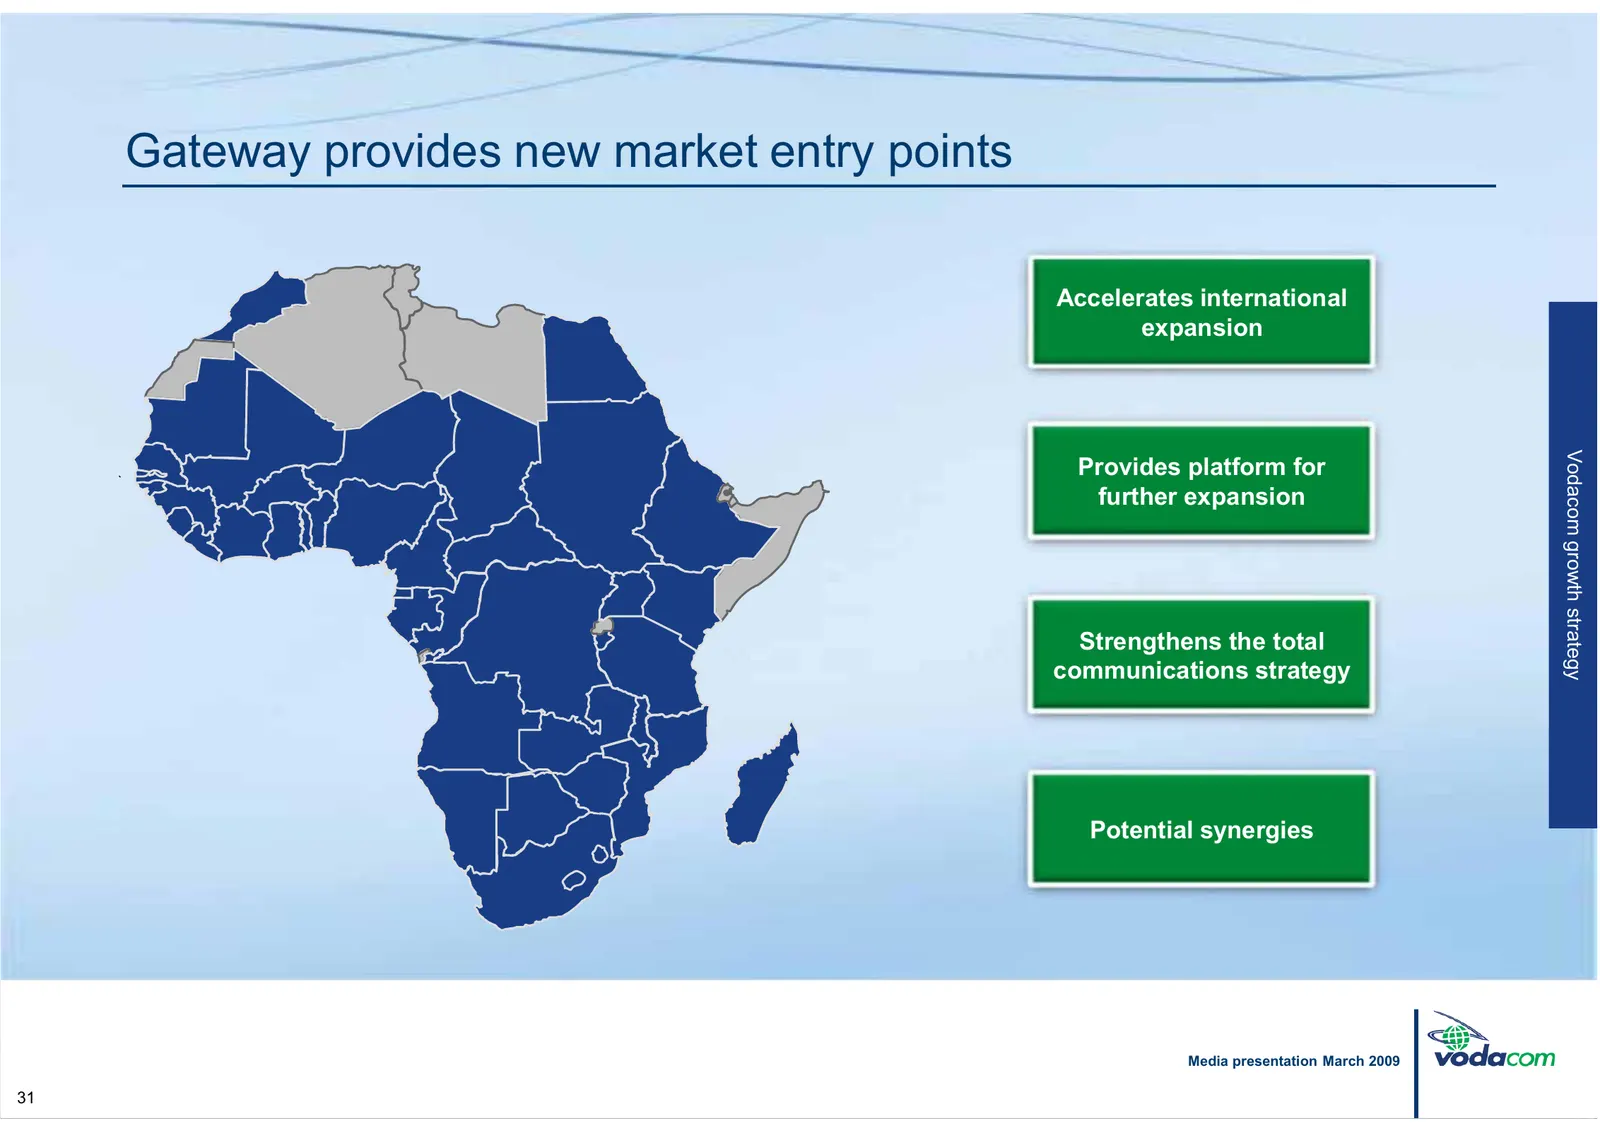
Gateway provides new market entry points Accelerates international expansion Vodacom Provides platform for STRATEGIC further expansion growth REVIEW strategy Strengthens the total communications strategy Potential synergies Media presentation March 2009 31
Slide 33: Conclusion and Q&A
Conclusion and Q&A Media presentation March 2009 32
Slide 34: Conclusion
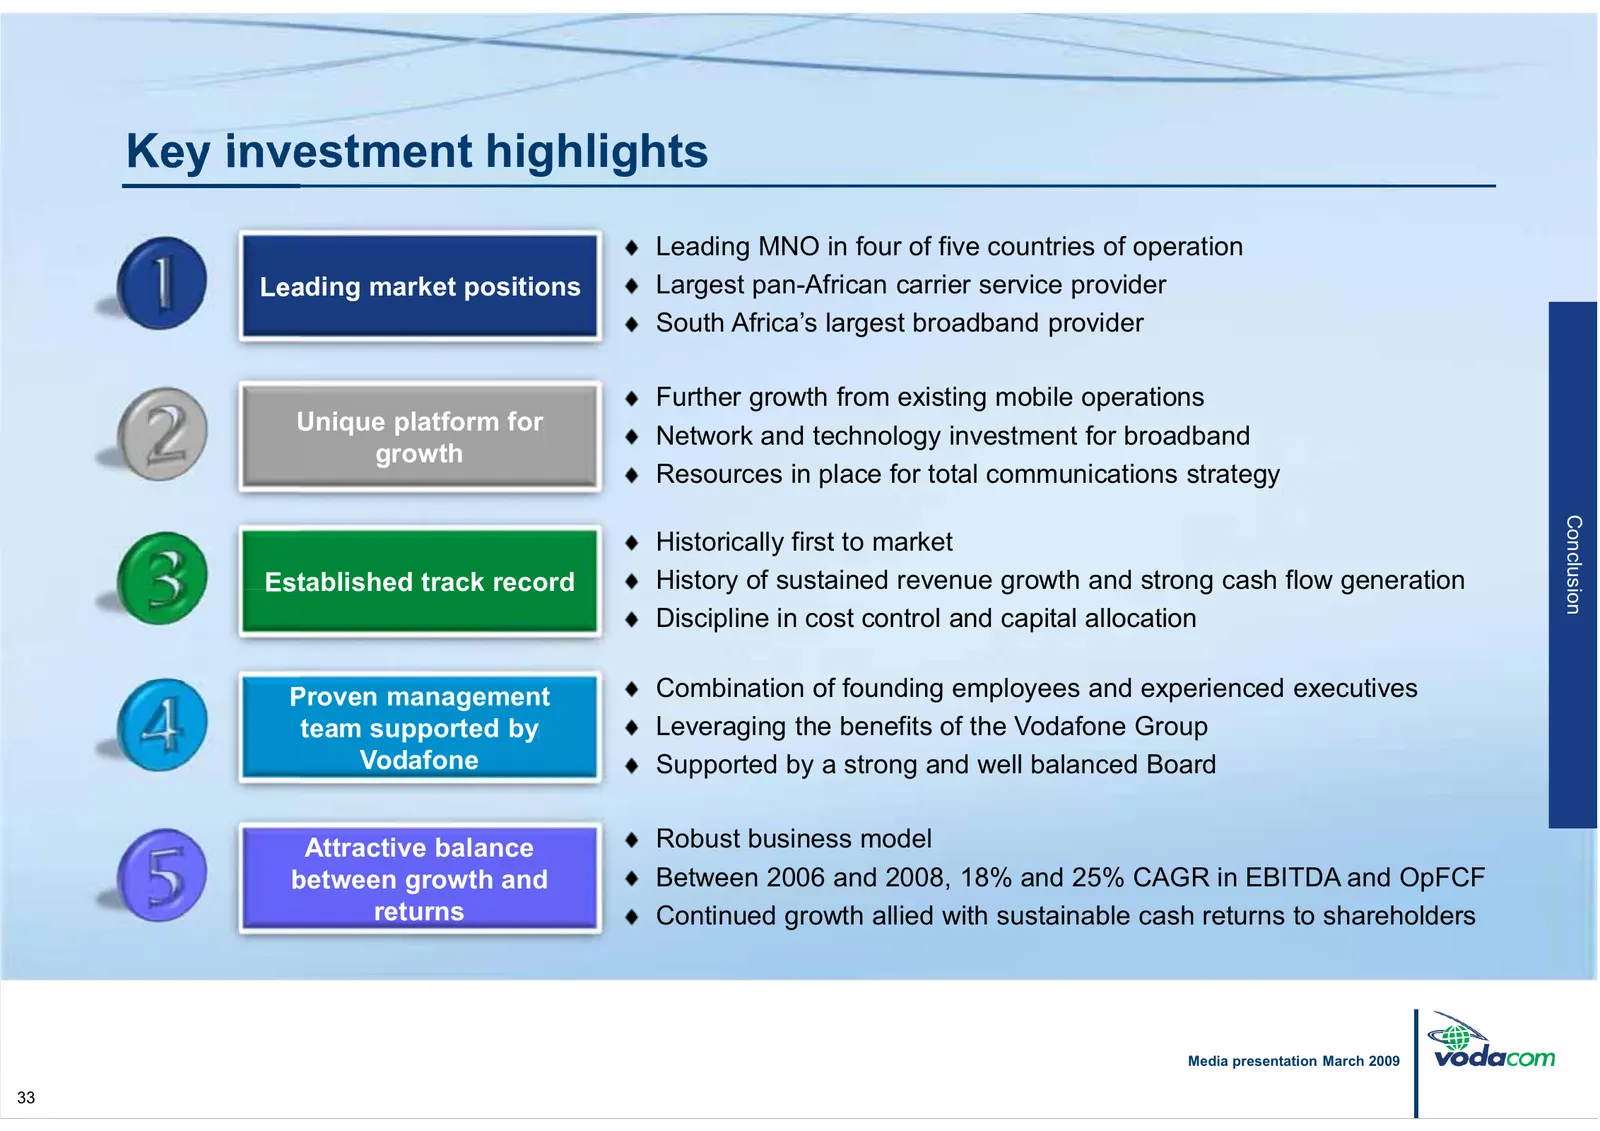
Key investment highlights Leading MNO in four of five countries of operation Leading market positions Largest pan-African carrier service provider 6RXWK$IULFD¶VODUJHVWEURDGEDQGprovider Further growth from existing mobile operations Unique platform for Network and technology investment for broadband
Slide 35: Q&A
Q&A Media presentation Media presentation March 2009 34
Source: Internet Archive copy of vodacom.com
More decks from Vodacom Group Limited
 H1 FY2027 Earnings Presentation40 slides · November 2026
 FY2026 Earnings Presentation39 slides · May 11, 2026
 Merger or Acquisition (December 2025)16 slides · Dec 4, 2025
 Q2 2026 Earnings Presentation39 slides · Nov 10, 2025
 FY2025 Earnings Presentation39 slides · May 19, 2025
 Investor Day (February 2025)34 slides · Feb 19, 2025