MMC Energy — Investor Presentation (September 2006)
20 slides from MMC Energy's investor presentation, Sep 18, 2006
Slide 1: MMC Energy Inc.
MMC Energy Inc. MMCN.OTC:BB NASDAQ
Slide 2: Disclaimer
Disclaimer This presentation material contains forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The opinions, forecasts, projections or other statements, other than statements o
Slide 3: Company Overview
Company Overview = MMC is an acquisition company targeting deep value power generating assets in the U.S. * Closed two acquisitions since January 2006 and one pending acquisition = MMC seeks to be a first mover and consolidator of unregulated power generation * Targeting smaller assets that are “bel
Slide 4: MMC History
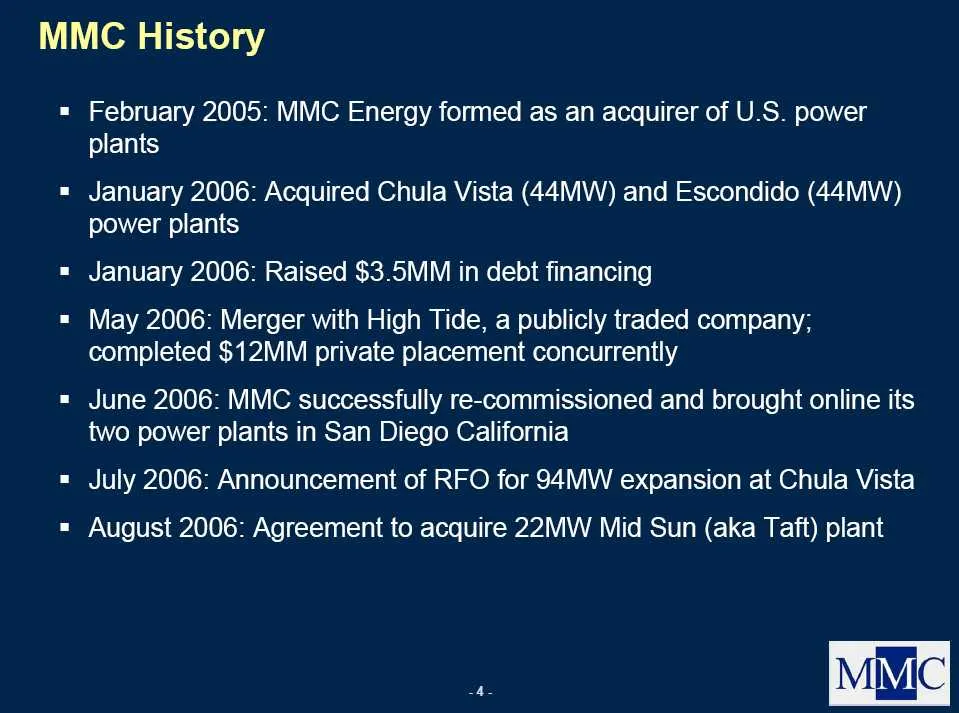
MMC History = February 2005: MMC Energy formed as an acquirer of U.S. power plants = January 2006: Acquired Chula Vista (44MW) and Escondido (44MW) power plants = January 2006: Raised $3.5MM in debt financing = May 2006: Merger with High Tide, a publicly traded company; completed $12MM private place
Slide 5: MMC Executive Management and Board
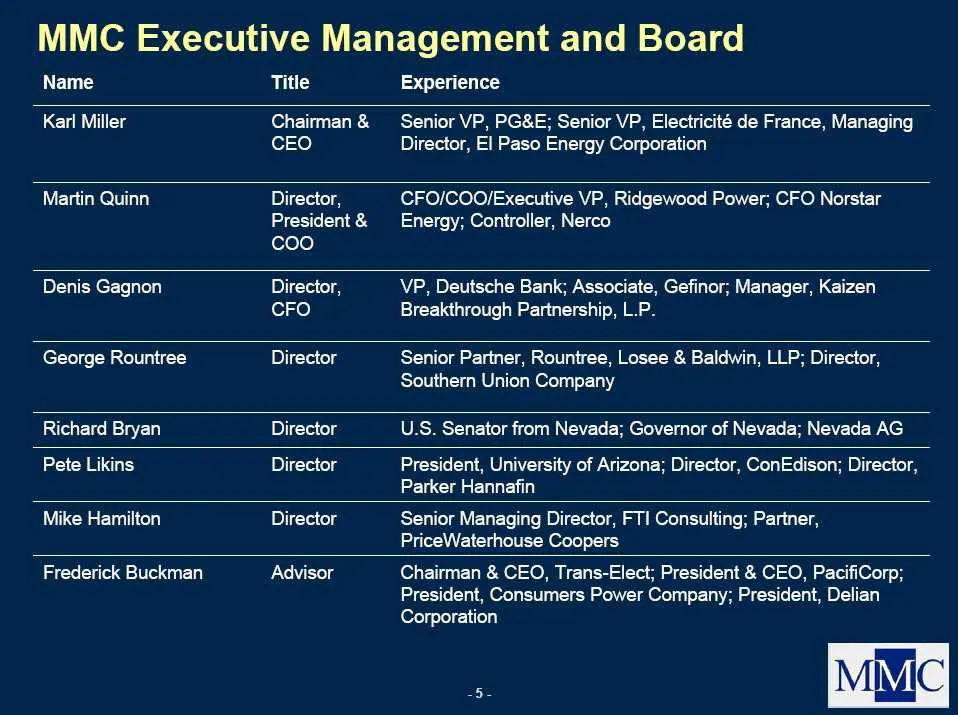
MMC Executive Management and Board Name Title Experience Karl Miller Chairman & Senior VP, PG&E; Senior VP, Electricité de France, Managing CEO Director, El Paso Energy Corporation Martin Quinn Director, CFO/COO/Executive VP, Ridgewood Power; CFO Norstar President & Energy; Controller, Nerco coo Den
Slide 6: Large and Fragmented U.S. Energy Market
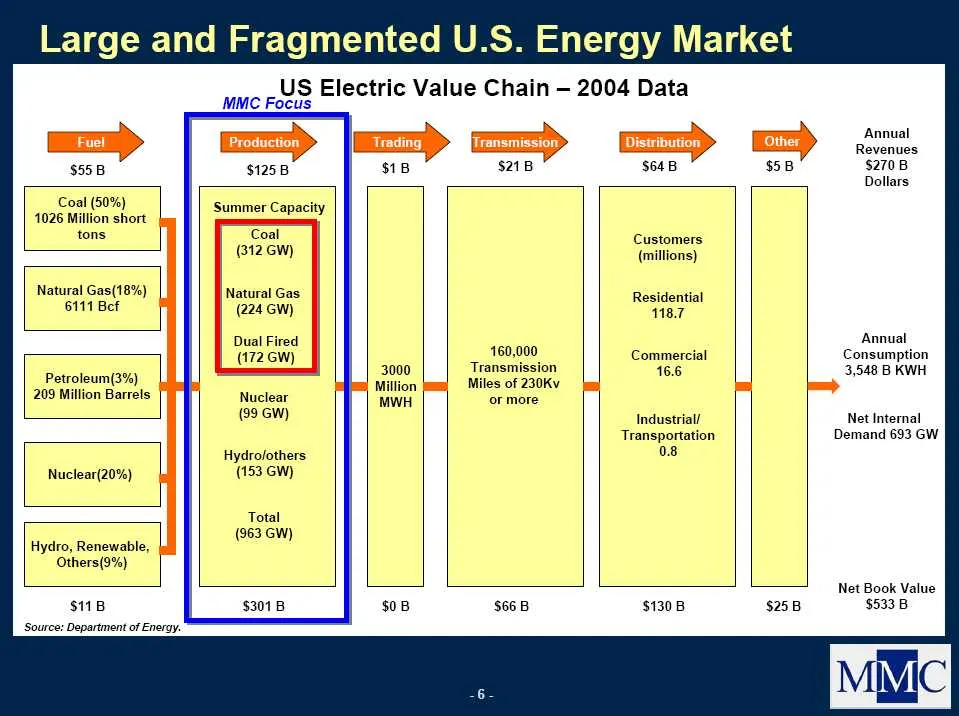
Large and Fragmented U.S. Energy Market US Electric Value Chain — 2004 Data MMC Focus Annual Revenues $55B $1258 : S708 Dollars Coal (50%) Summer Capacity Coal | Customers (312.G6Ww) (millions) Natural Gas(18%) Natural Gas Residential 6111 Bef (224 GW) 118.7 Dual Fired Annual (172 GW) 160,000 Commer
Slide 7: Creates Unique Buying Opportunity
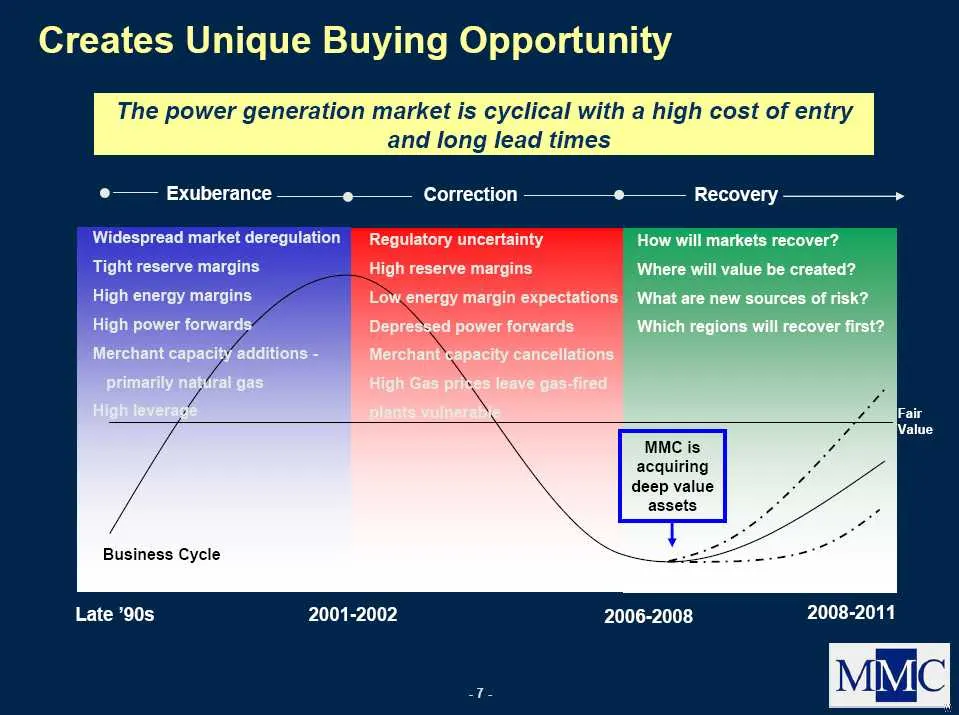
Creates Unique Buying Opportunity Exuberance © Correction 2 Recovery - Regulatory uncertainty How will markets recover? High reserve margins Where will value be created? Low energy margin expectations What are new sources of risk? acquiring deep value x assets Business Cycle Late 90s 2001-2002 2006-
Slide 8: Power Generation Industry: Over-Expansion
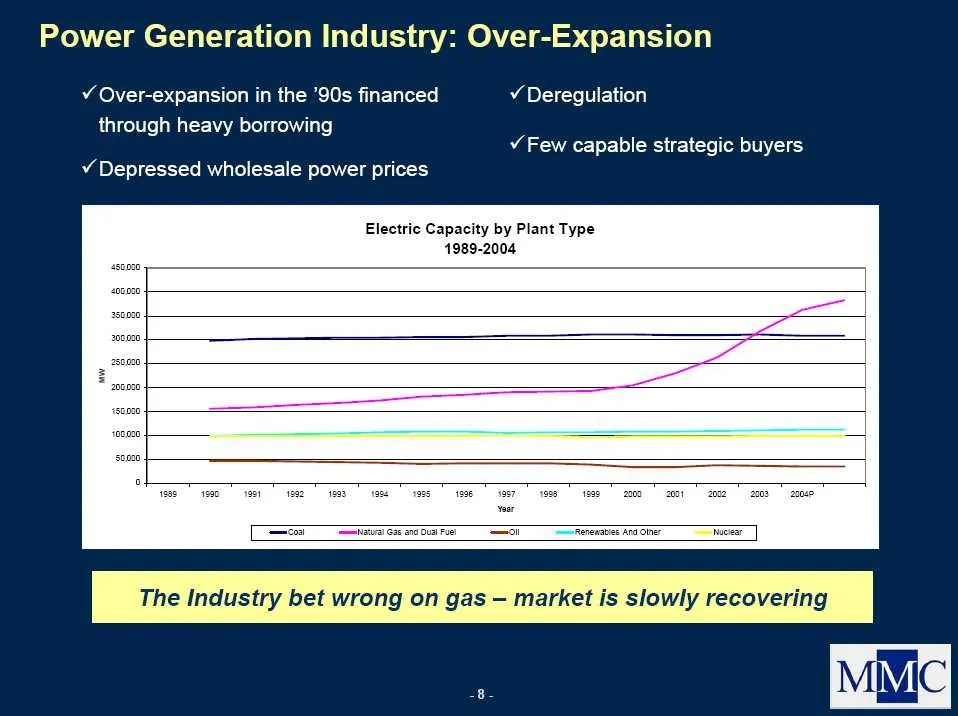
Power Generation Industry: Over-Expansion ¥ Over-expansion in the 90s financed ¥ Deregulation through heavy borrowing v Few capable strategic buyers v Depressed wholesale power prices Electric Capacity by Plant Type 1989-2004 rket i
Slide 9: Targeted Acquisitions Strategy
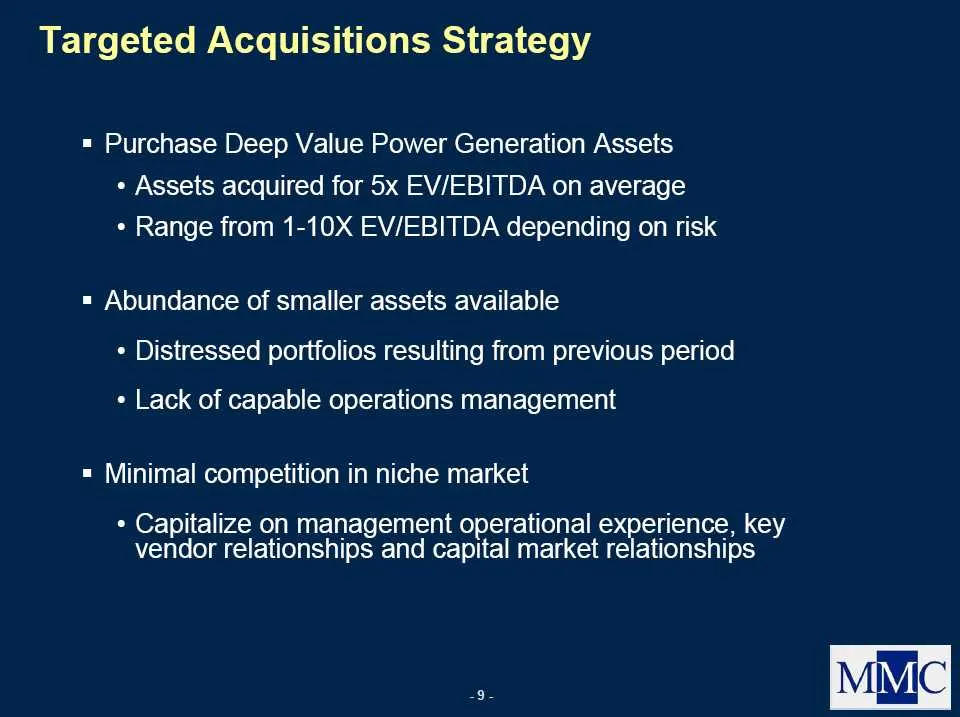
Targeted Acquisitions Strategy = Purchase Deep Value Power Generation Assets « Assets acquired for 5x EV/EBITDA on average « Range from 1-10X EV/EBITDA depending on risk = Abundance of smaller assets available + Distressed portfolios resulting from previous period « Lack of capable operations manage
Slide 10: Optimize Plants to Maximize Profitability
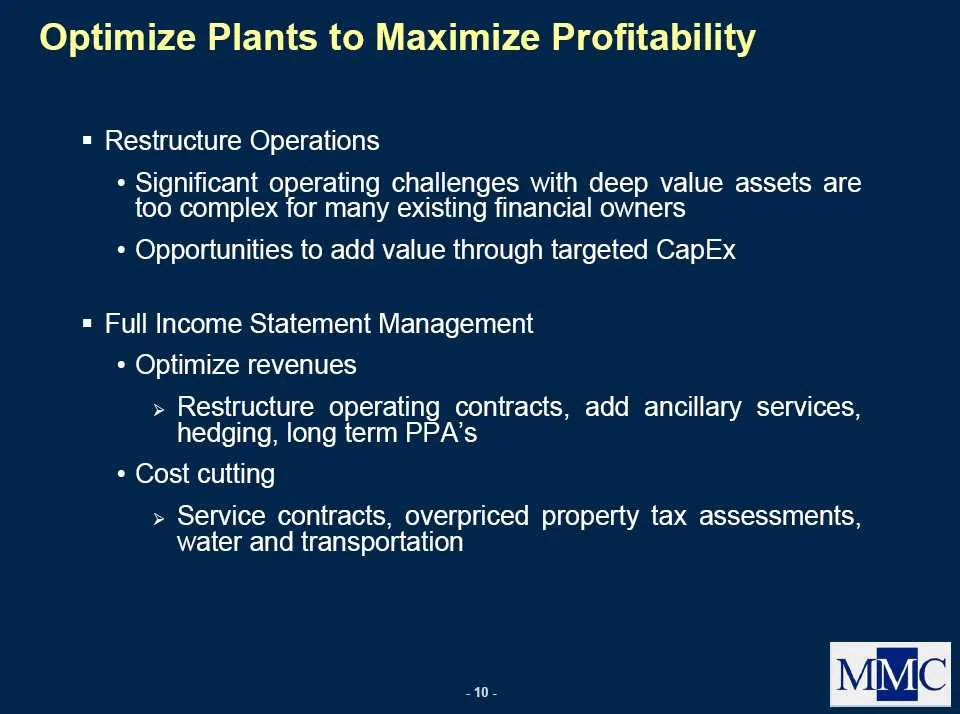
Optimize Plants to Maximize Profitability = Restructure Operations * Significant operating challenges with deep value assets are too complex for many existing financial owners * Opportunities to add value through targeted CapEx = Full Income Statement Management * Optimize revenues » Restructure ope
Slide 11: Risk/Return Optimization
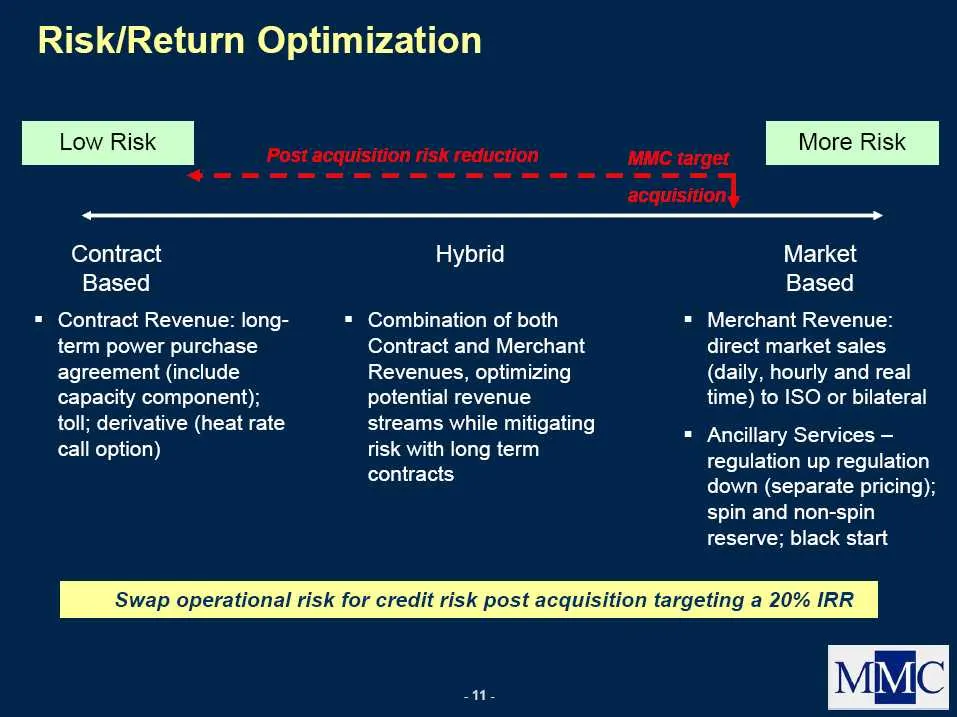
Risk/Return Optimization Post acquisition risk reduction MMC target ¢—_ ee ee ee ee ee ee ee ee Low acquisitic Contract Hybrid Market Based Based = Contract Revenue: long- = Combination of both = Merchant Revenue: term power purchase Contract and Merchant direct market sales agreement (include Reven
Slide 12: MMC Completed Acquisitions — 88MW
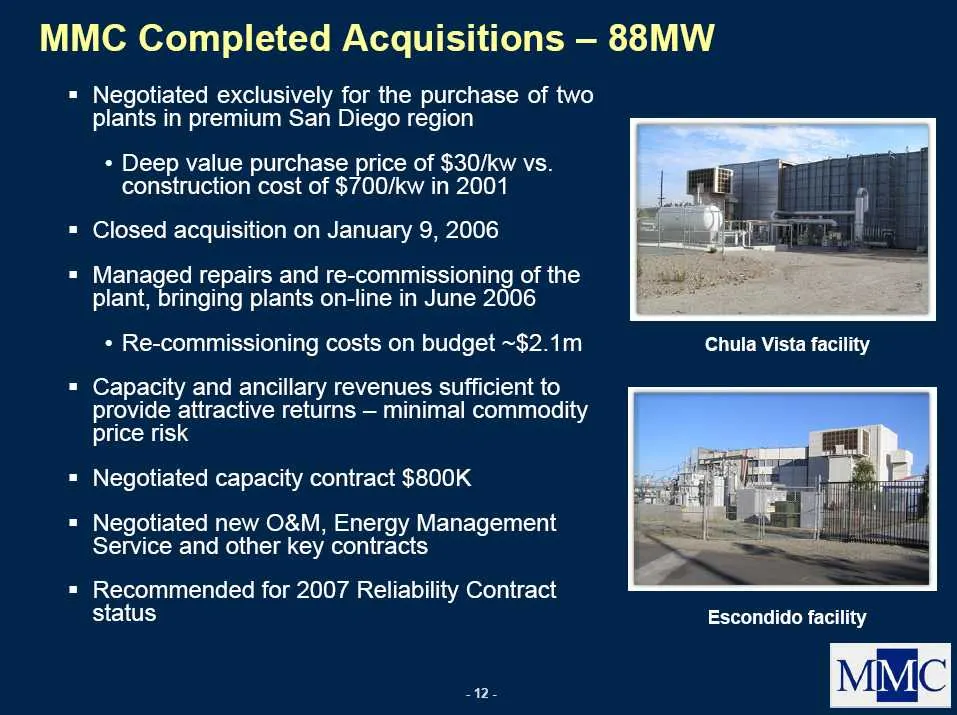
MMC Completed Acquisitions — 88MW = Negotiated exclusively for the purchase of two plants in premium San Diego region + Deep value purchase price of $30/kw vs. construction cost of $700/kw in 2001 = Closed acquisition on January 9, 2006 = Managed repairs and re-commissioning of the plant, bringing p
Slide 13: 94MW Chula Vista Expansion
94MW Chula Vista Expansion CPUC/CAISO mandate for new capacity in 2007 * Currently 44MW name plate capacity 50 MW expansion planned at Chula Vista with newer, efficient turbines * 2GELM-6000’s to be sourced and installed at Chula Vista site Total project cost of ~$60MM Commenced expansion of Chula V
Slide 14: MW Mid-Sun Transaction
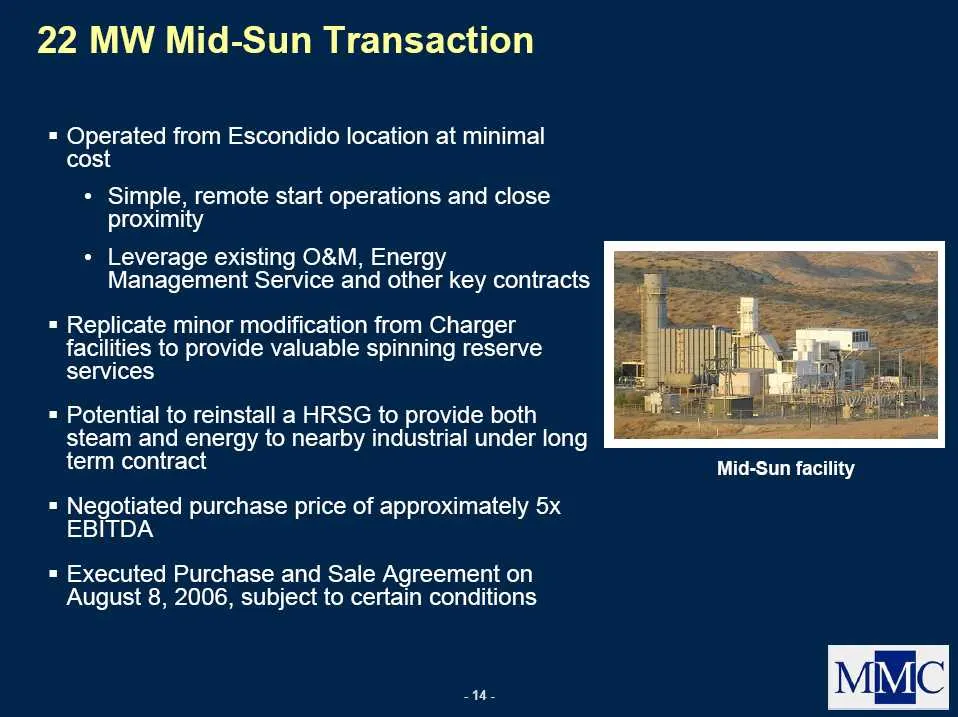
22 MW Mid-Sun Transaction = Operated from Escondido location at minimal cost + Simple, remote start operations and close proximity « Leverage existing O&M, Energy Management Service and other key contracts = Replicate minor modification from Charger facilities to provide valuable spinning reserve se
Slide 15: Financial Overview
Financial Overview
Slide 16: Per MW Economic Model
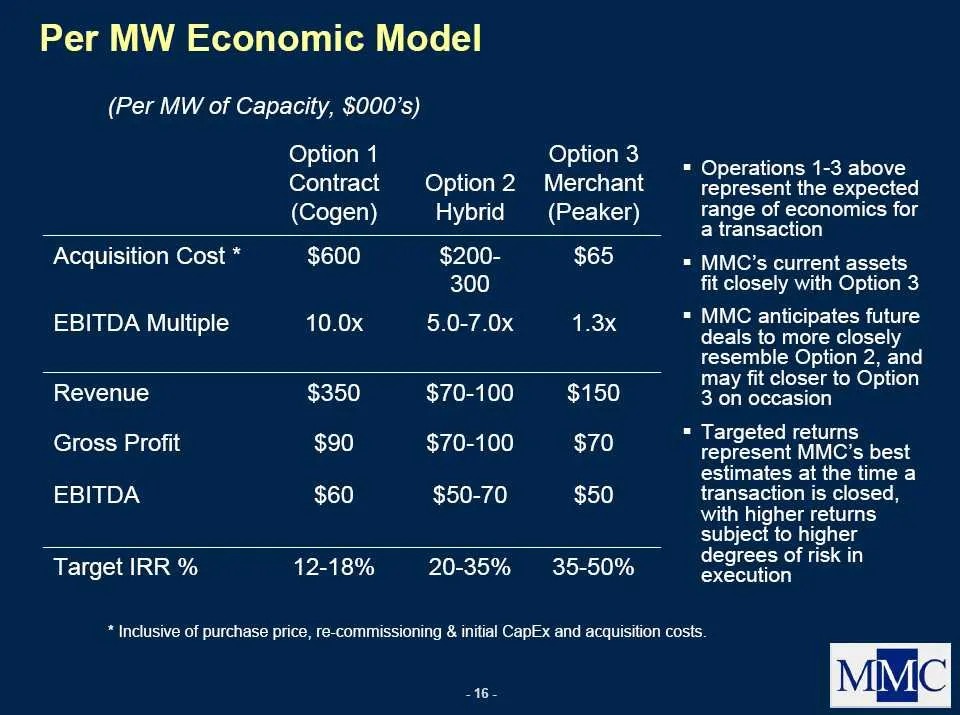
Per MW Economic Model (Per MW of Capacity, $000’s) Option 1 Option 3 Contract Option 2 Merchant (Cogen) Hybrid (Peaker) Acquisition Cost * $600 $200- $65 300 EBITDA Multiple 10.0x 5.0-7.0x 1.3x Revenue $350 $70-100 $150 Gross Profit $90 $70-100 $70 EBITDA $60 $50-70 $50 Target IRR % 12-18% 20-35% 35
Slide 17: Summary Balance Sheet
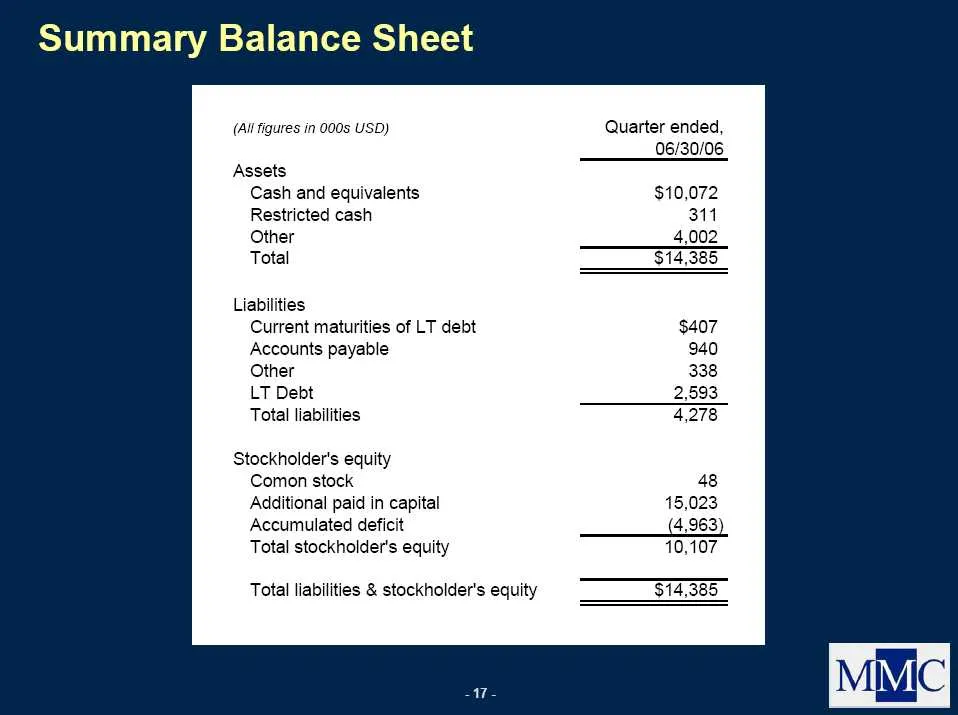
ry L Summary Balance Shee (All figures in 000s USD) Quarter ended, 06/30/06 Assets Cash and equivalents $10,072 Restricted cash 311 Other 4,002 Total Liabilities Current maturities of LT debt Accounts payable Other LT Debt Total liabilities Stockholder's equity Comon stock Additional paid in capital
Slide 18: Ownership Summary
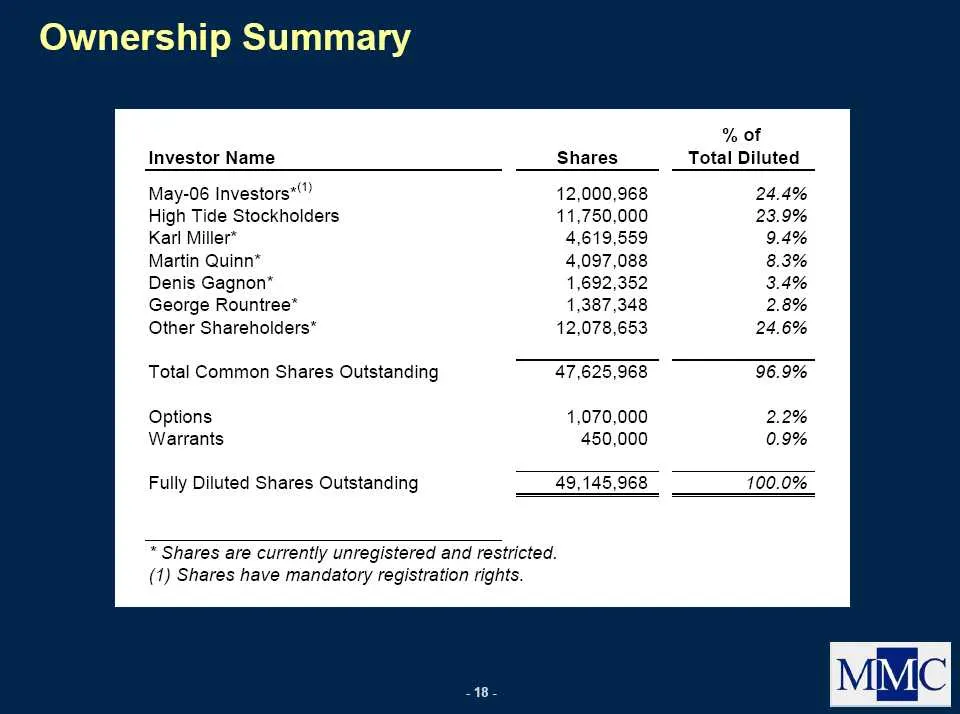
Ownership Summary Investor Name Shares % of Total Diluted May-06 Investors*”” 12,000,968 High Tide Stockholders 11,750,000 Karl Miller* 4,619,559 Martin Quinn* 4,097,088 Denis Gagnon” 1,692,352 George Rountree” 1,387,348 Other Shareholders” 12,078,653 Total Common Shares Outstanding 47,625,968 Optio
Slide 19: MMC Summary
MMC Summary MMC is an acquisition company targeting deep value power generating assets in the U.S. * Closed two acquisitions since January 2006 and one pending acquisition MMC seeks to be a first mover and consolidator of unregulated power generation * Targeting smaller assets that are “below the ra
Slide 20: MMC Energy Inc.
MMC Energy Inc. MMCN.OTC:BB NASDAQ
Source: SEC EDGAR · 8-K filed Sep 18, 2006