United Community Financial Corp
United Community Financial — Shareholder Meeting (August 2013)
20 slides from United Community Financial's shareholder meeting presentation, Aug 27, 2013
Slide 1: 2013 Annual Meeting
Exhibit 99 2013 Annual Meeting August 2013
Slide 2: Patrick W. Bevack, President and Chief Executive Officer
Patrick W. Bevack President and Chief Executive Officer
Slide 3: Forward-Looking Statement Disclosure
Forward-Looking Statement Disclosure When used in this presentation the words or phrases “will likely result,” “are expected to,” “will continue,” “is anticipated,” “estimate,” “project” or similar expressions are intended to identify “forward-looking statements” within the meaning of the Private Se
Slide 4: Non-GAAP Financial Measures
Non-GAAP Financial Measures This presentation contains financial information determined by methods other than those prescribed by accounting principles generally accepted in the United States of America ("GAAP"). Management uses these non-GAAP financial measures because it believes that they are use
Slide 5: Major Goals
Major Goals Established upon being named CEO Achieve termination of the Regulatory Orders at the Bank and Holding Company Establish a strong management team that works well together Improve asset quality and establish a strong credit culture Raise a sufficient amount of capital to strengthen the fin
Slide 6: Review of Financial Performance: Asset Quality
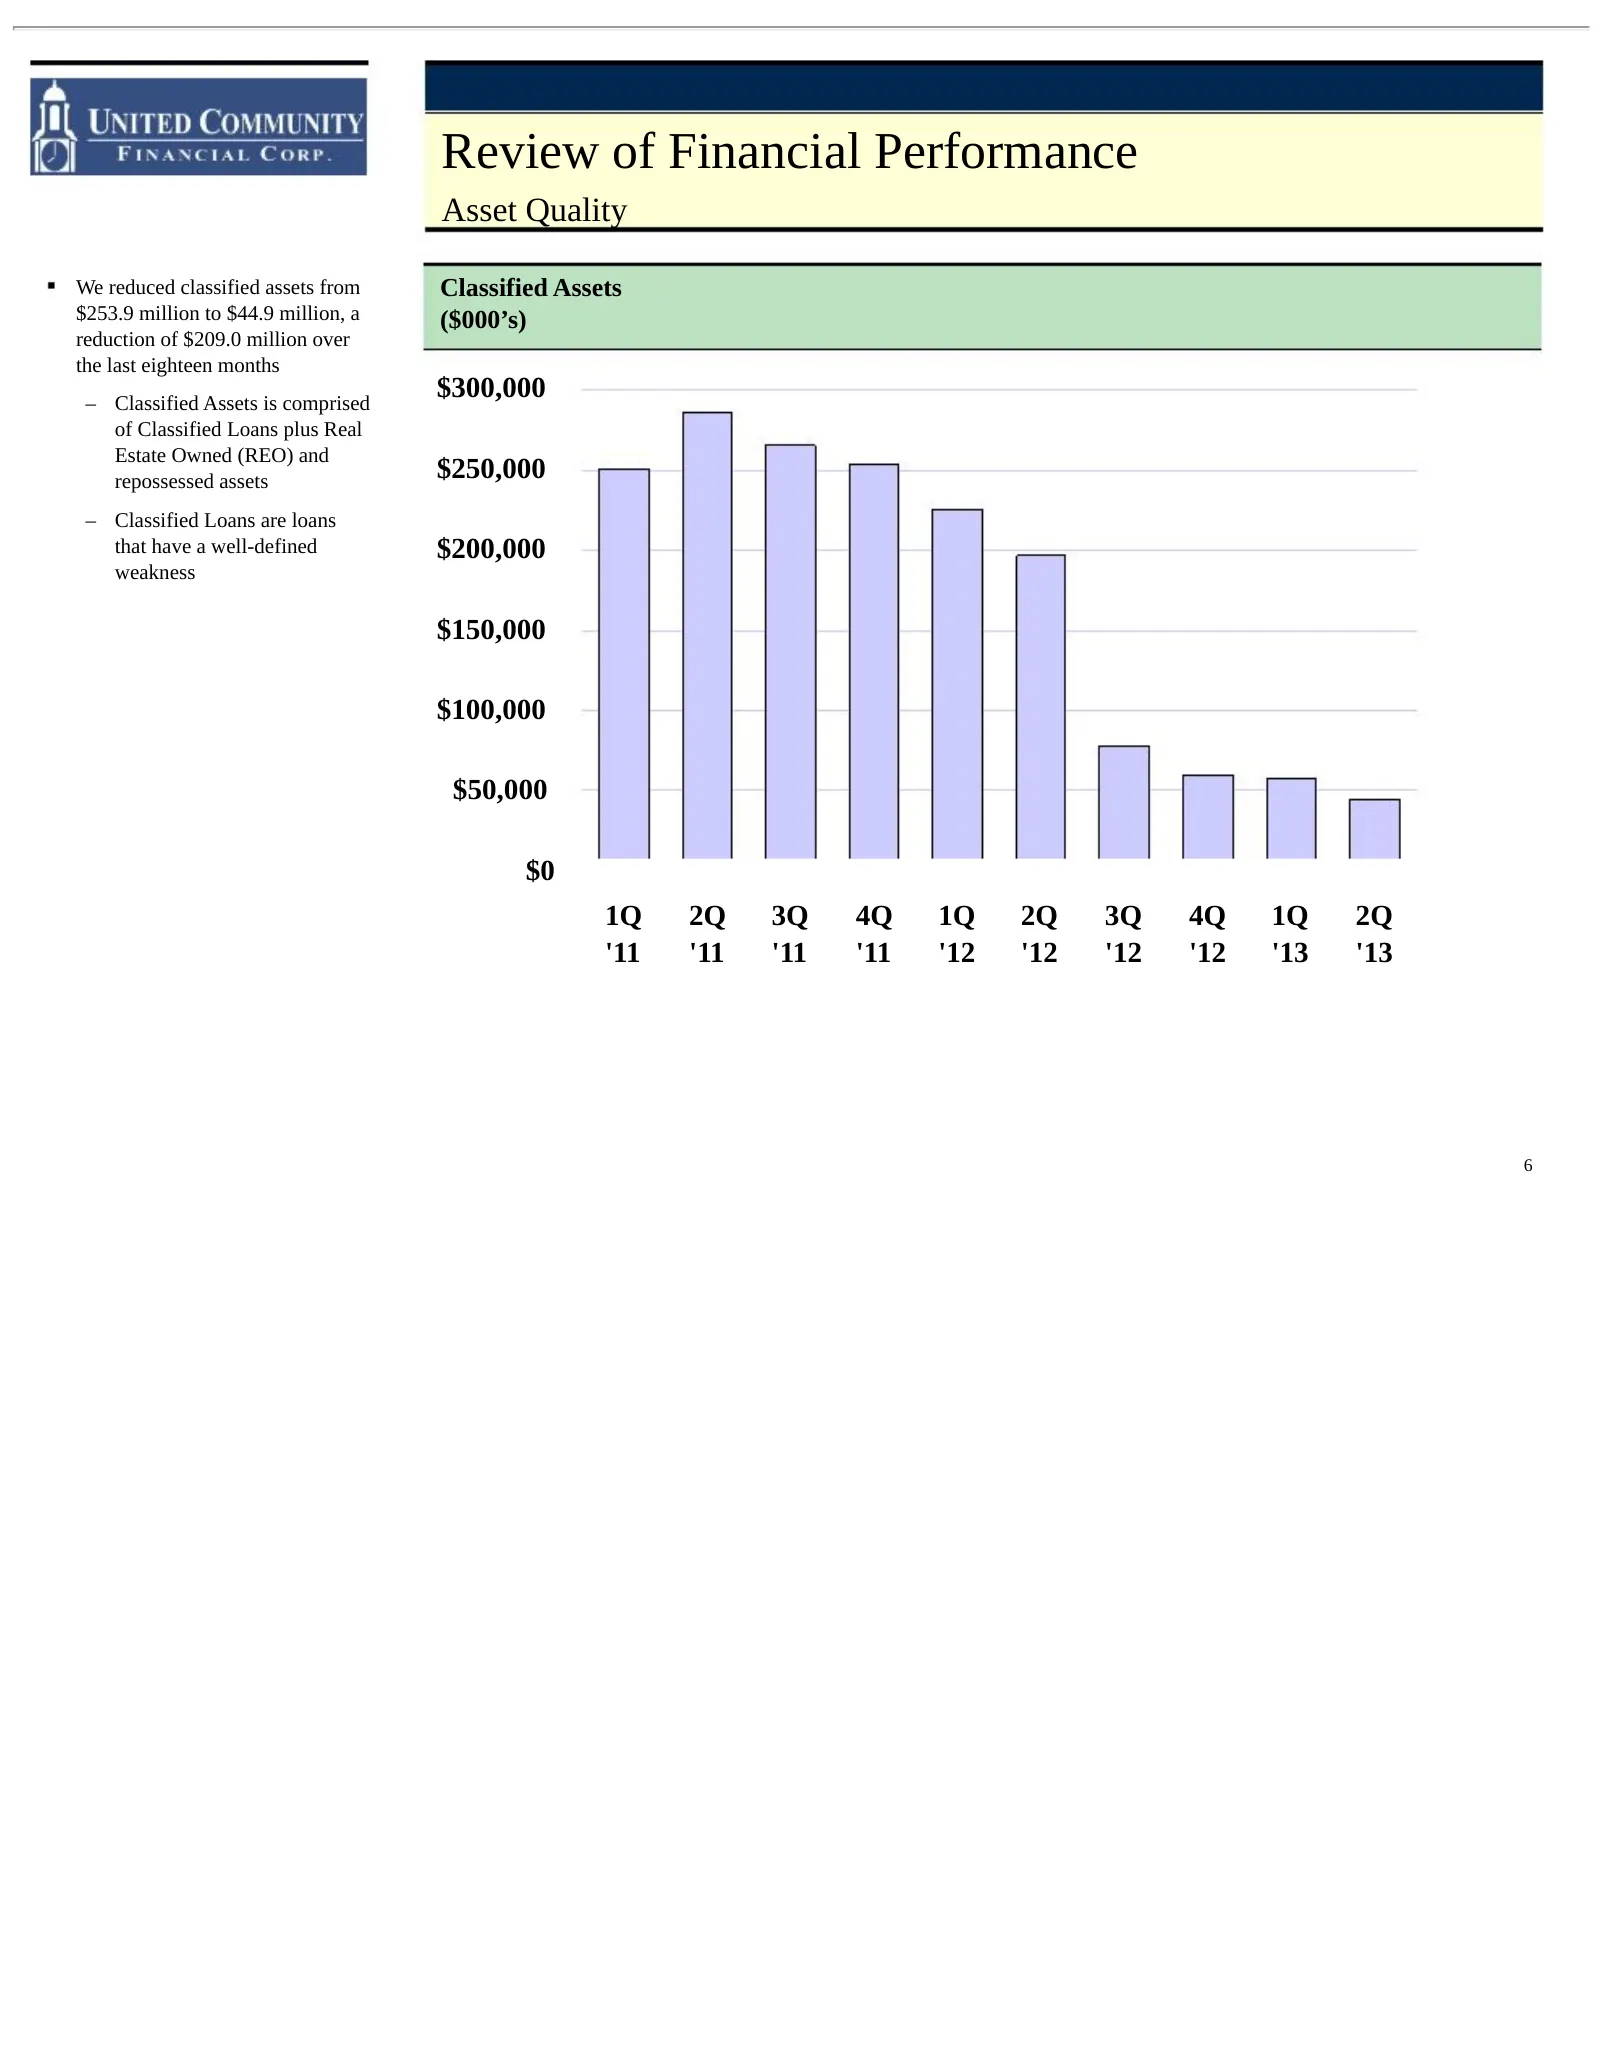
Review of Financial Performance Asset Quality We reduced classified assets from Classified Assets $253.9 million to $44.9 million, a ($000’s) reduction of $209.0 million over the last eighteen months – Classified Assets is comprised $300,000 of Classified Loans plus Real Estate Owned (REO) and repos
Slide 7: Review of Financial Performance (cont.): Asset Quality
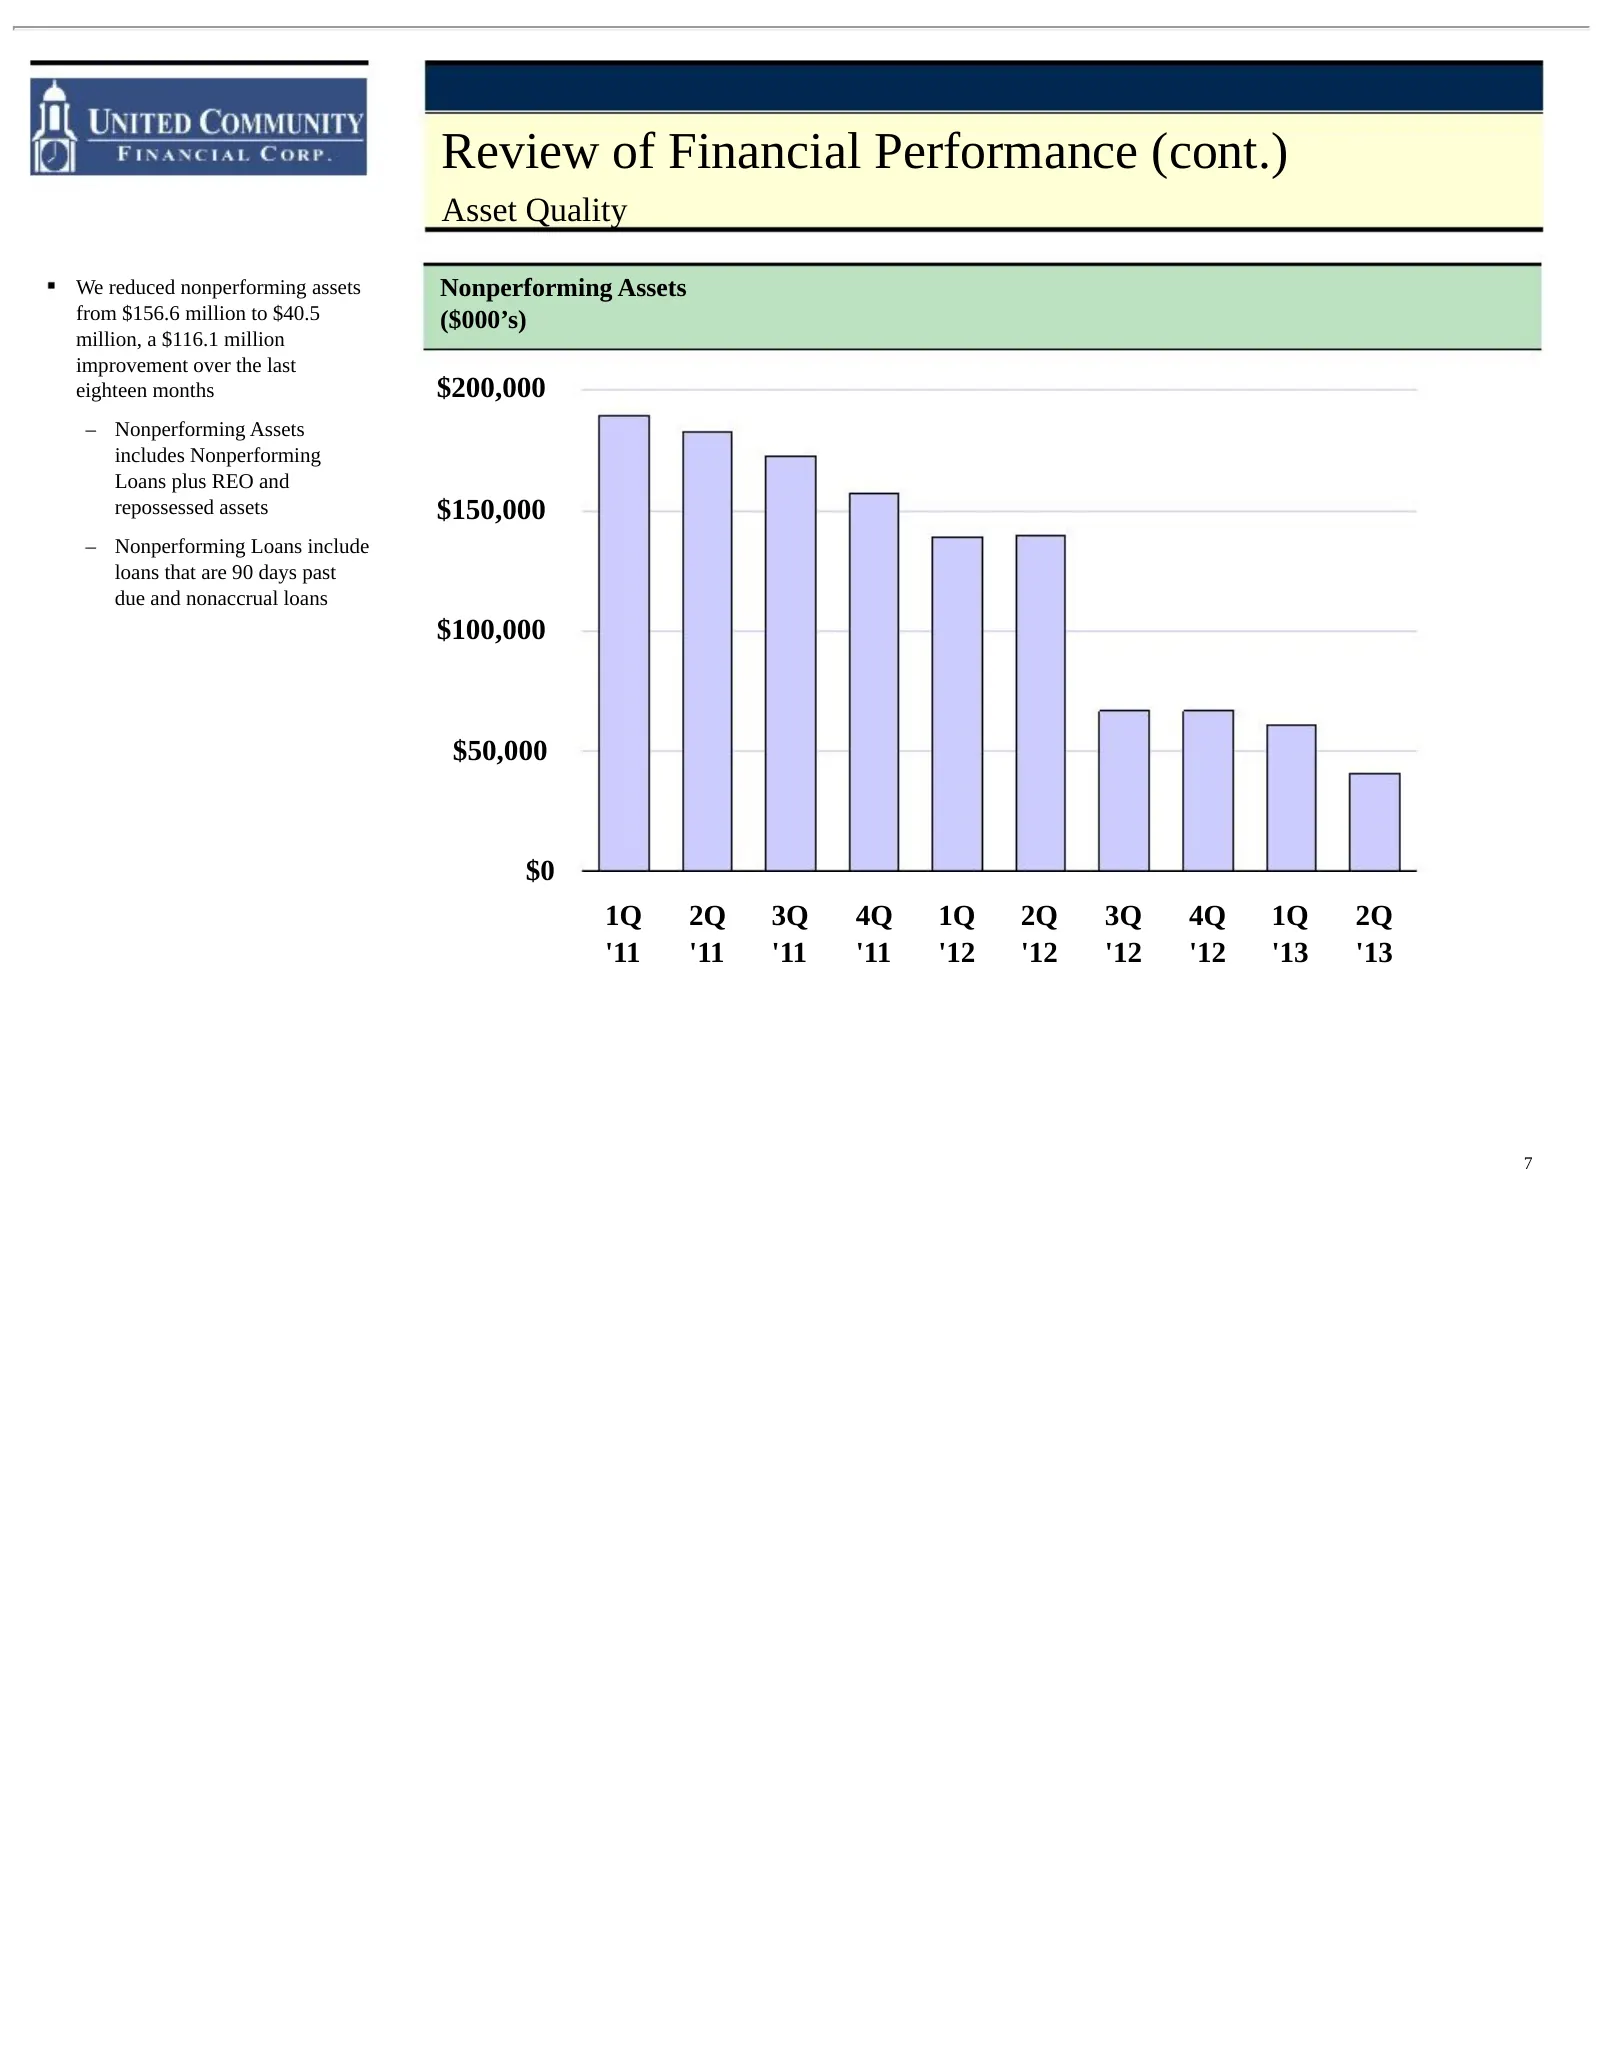
Review of Financial Performance (cont.) Asset Quality We reduced nonperforming assets Nonperforming Assets from $156.6 million to $40.5 ($000’s) million, a $116.1 million improvement over the last eighteen months $200,000 – Nonperforming Assets includes Nonperforming Loans plus REO and repossessed a
Slide 8: Review of Financial Performance (cont.): Stock Price
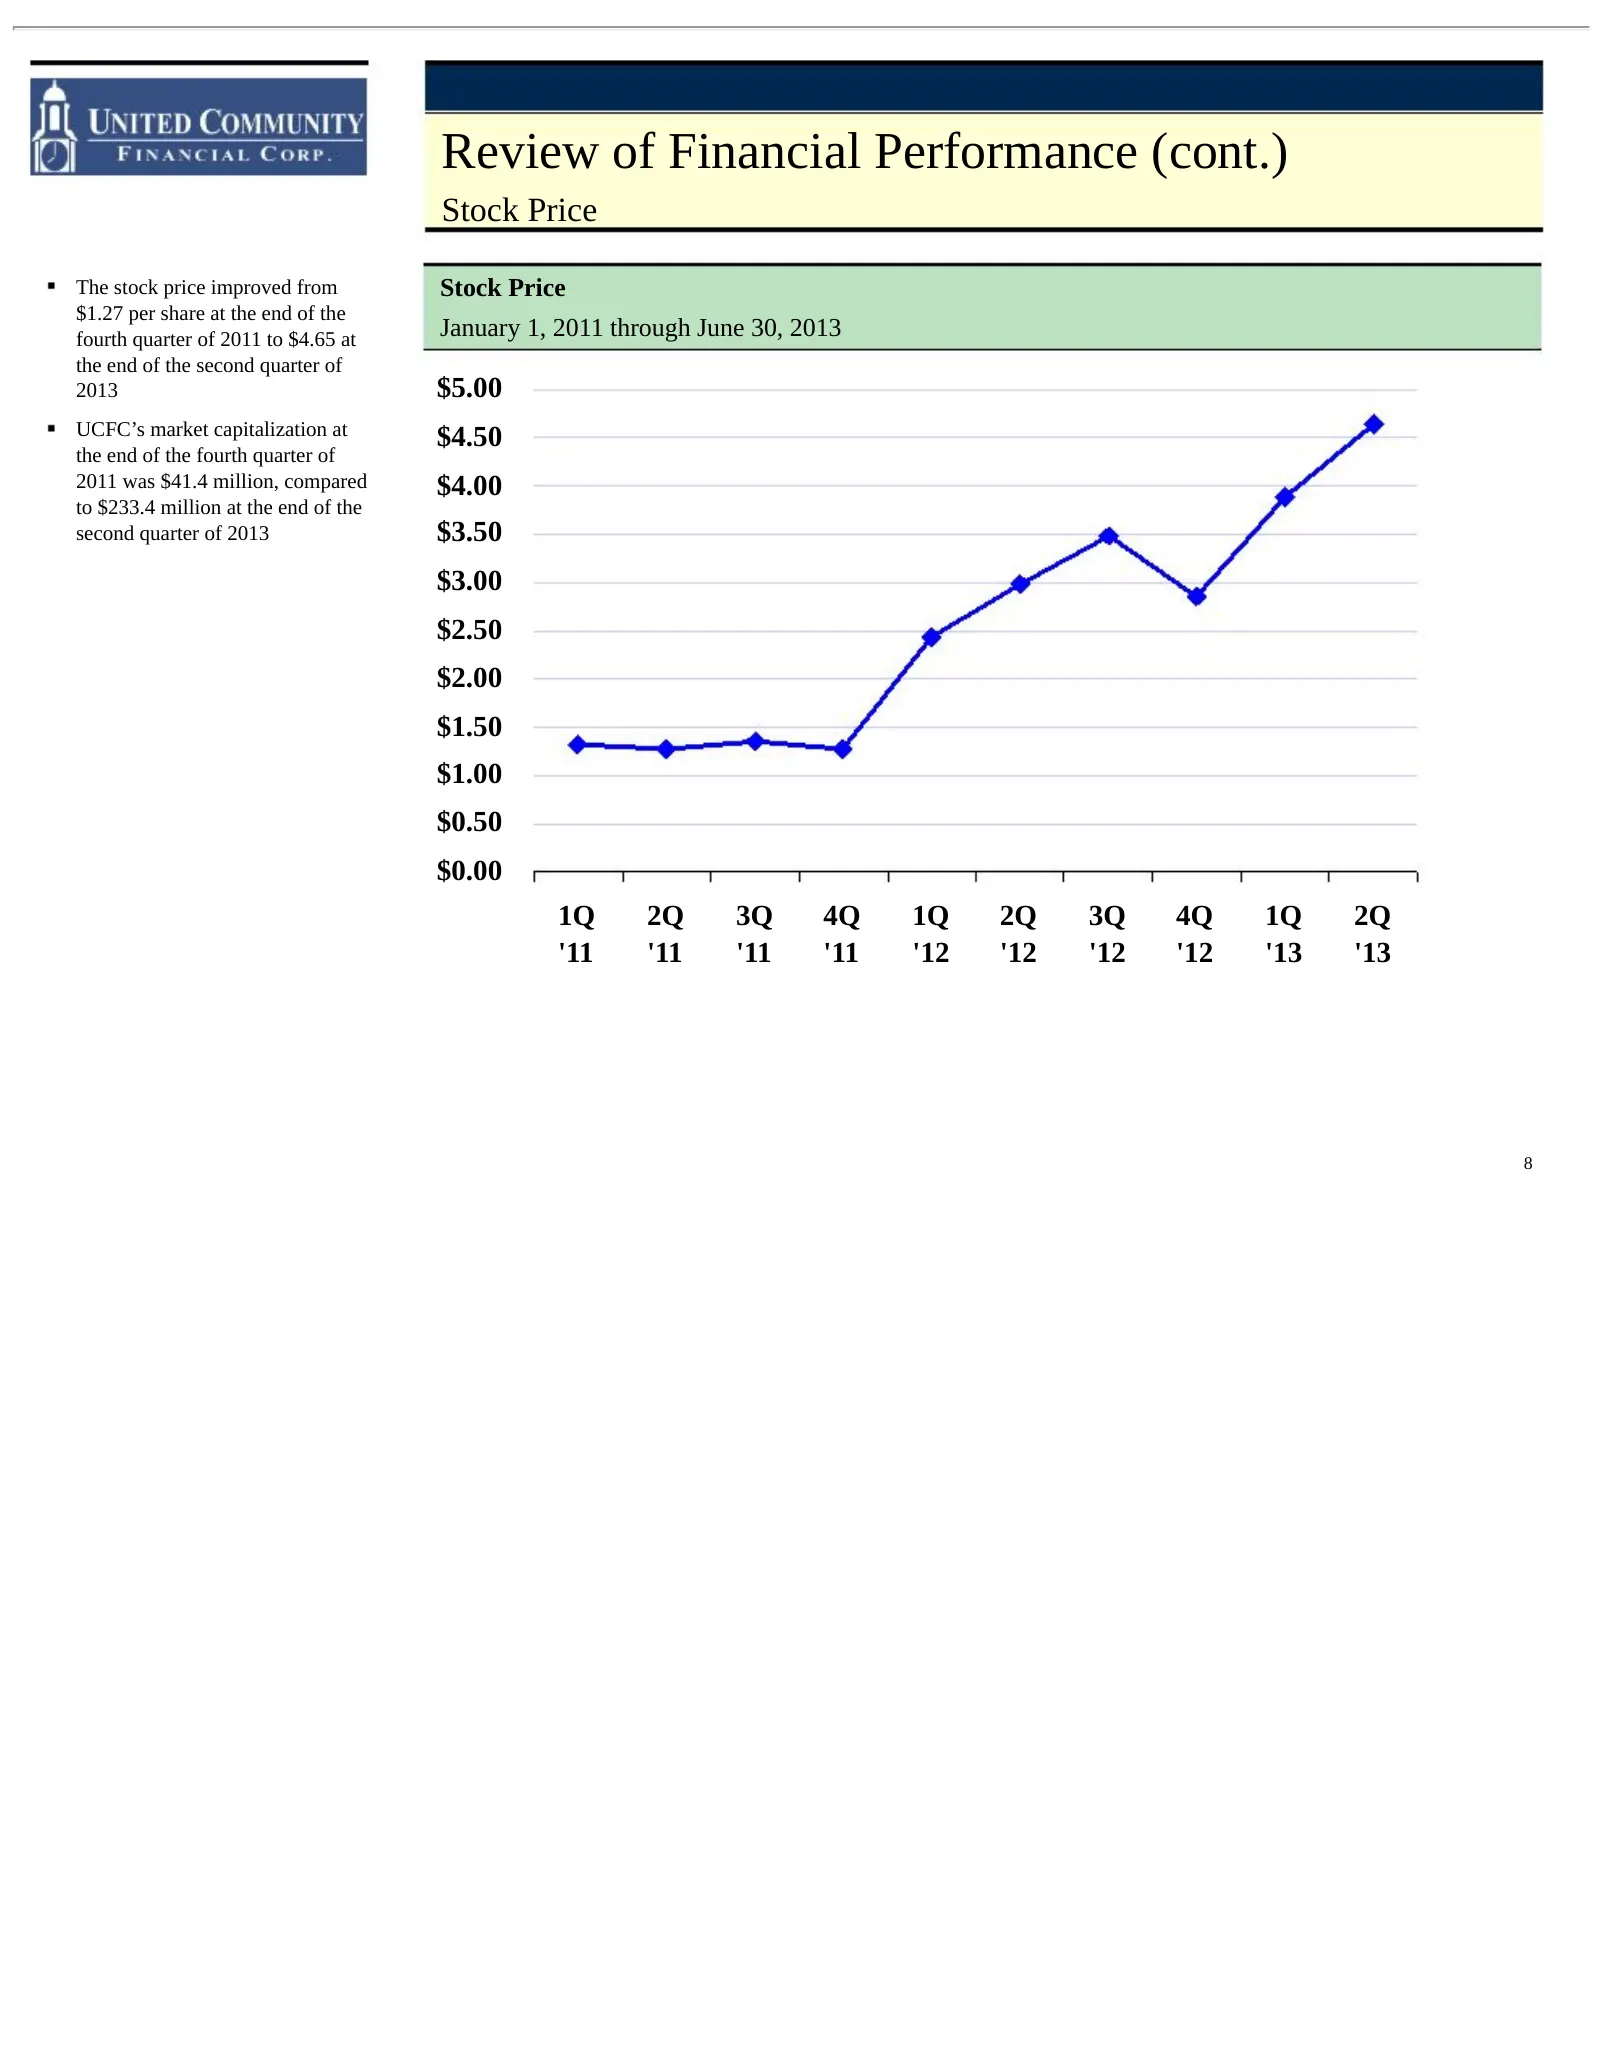
Review of Financial Performance (cont.) Stock Price The stock price improved from Stock Price $1.27 per share at the end of the fourth quarter of 2011 to $4.65 at January 1, 2011 through June 30, 2013 the end of the second quarter of 2013 $5.00 UCFC’s market capitalization at $4.50 the end of the fo
Slide 9: Review of Financial Performance (cont.): Stock Price
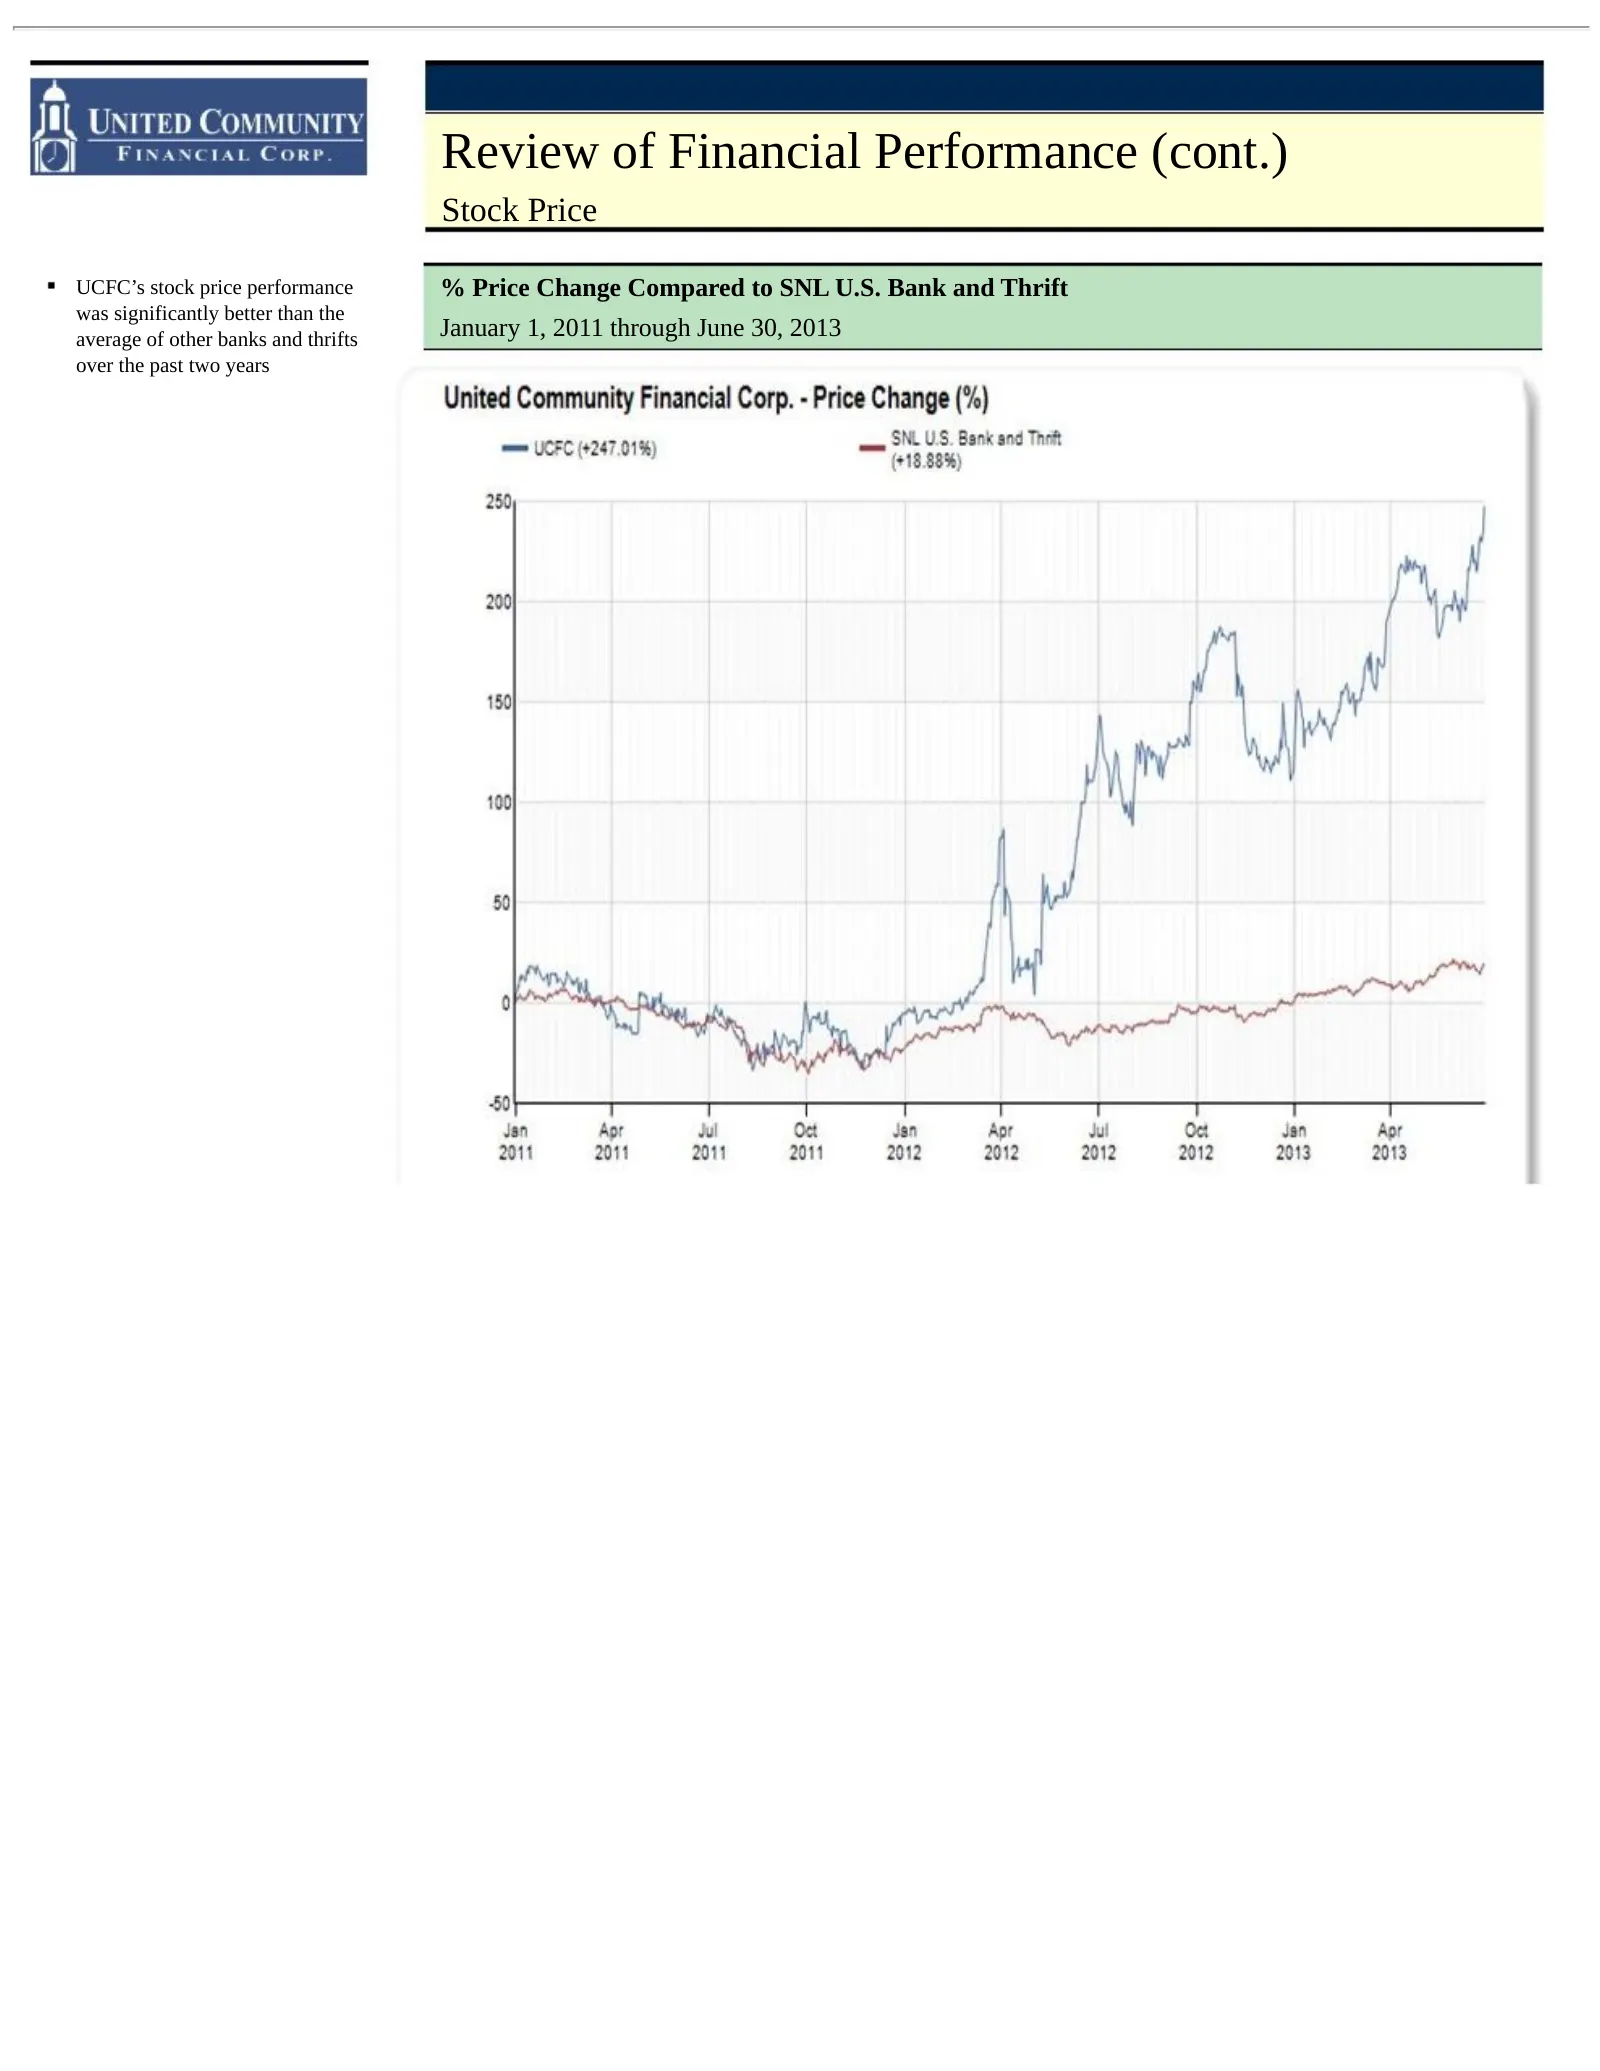
Review of Financial Performance (cont.) Stock Price UCFC’s stock price performance % Price Change Compared to SNL U.S. Bank and Thrift was significantly better than the average of other banks and thrifts January 1, 2011 through June 30, 2013 over the past two years
Slide 10: Top Performing Ohio Businesses
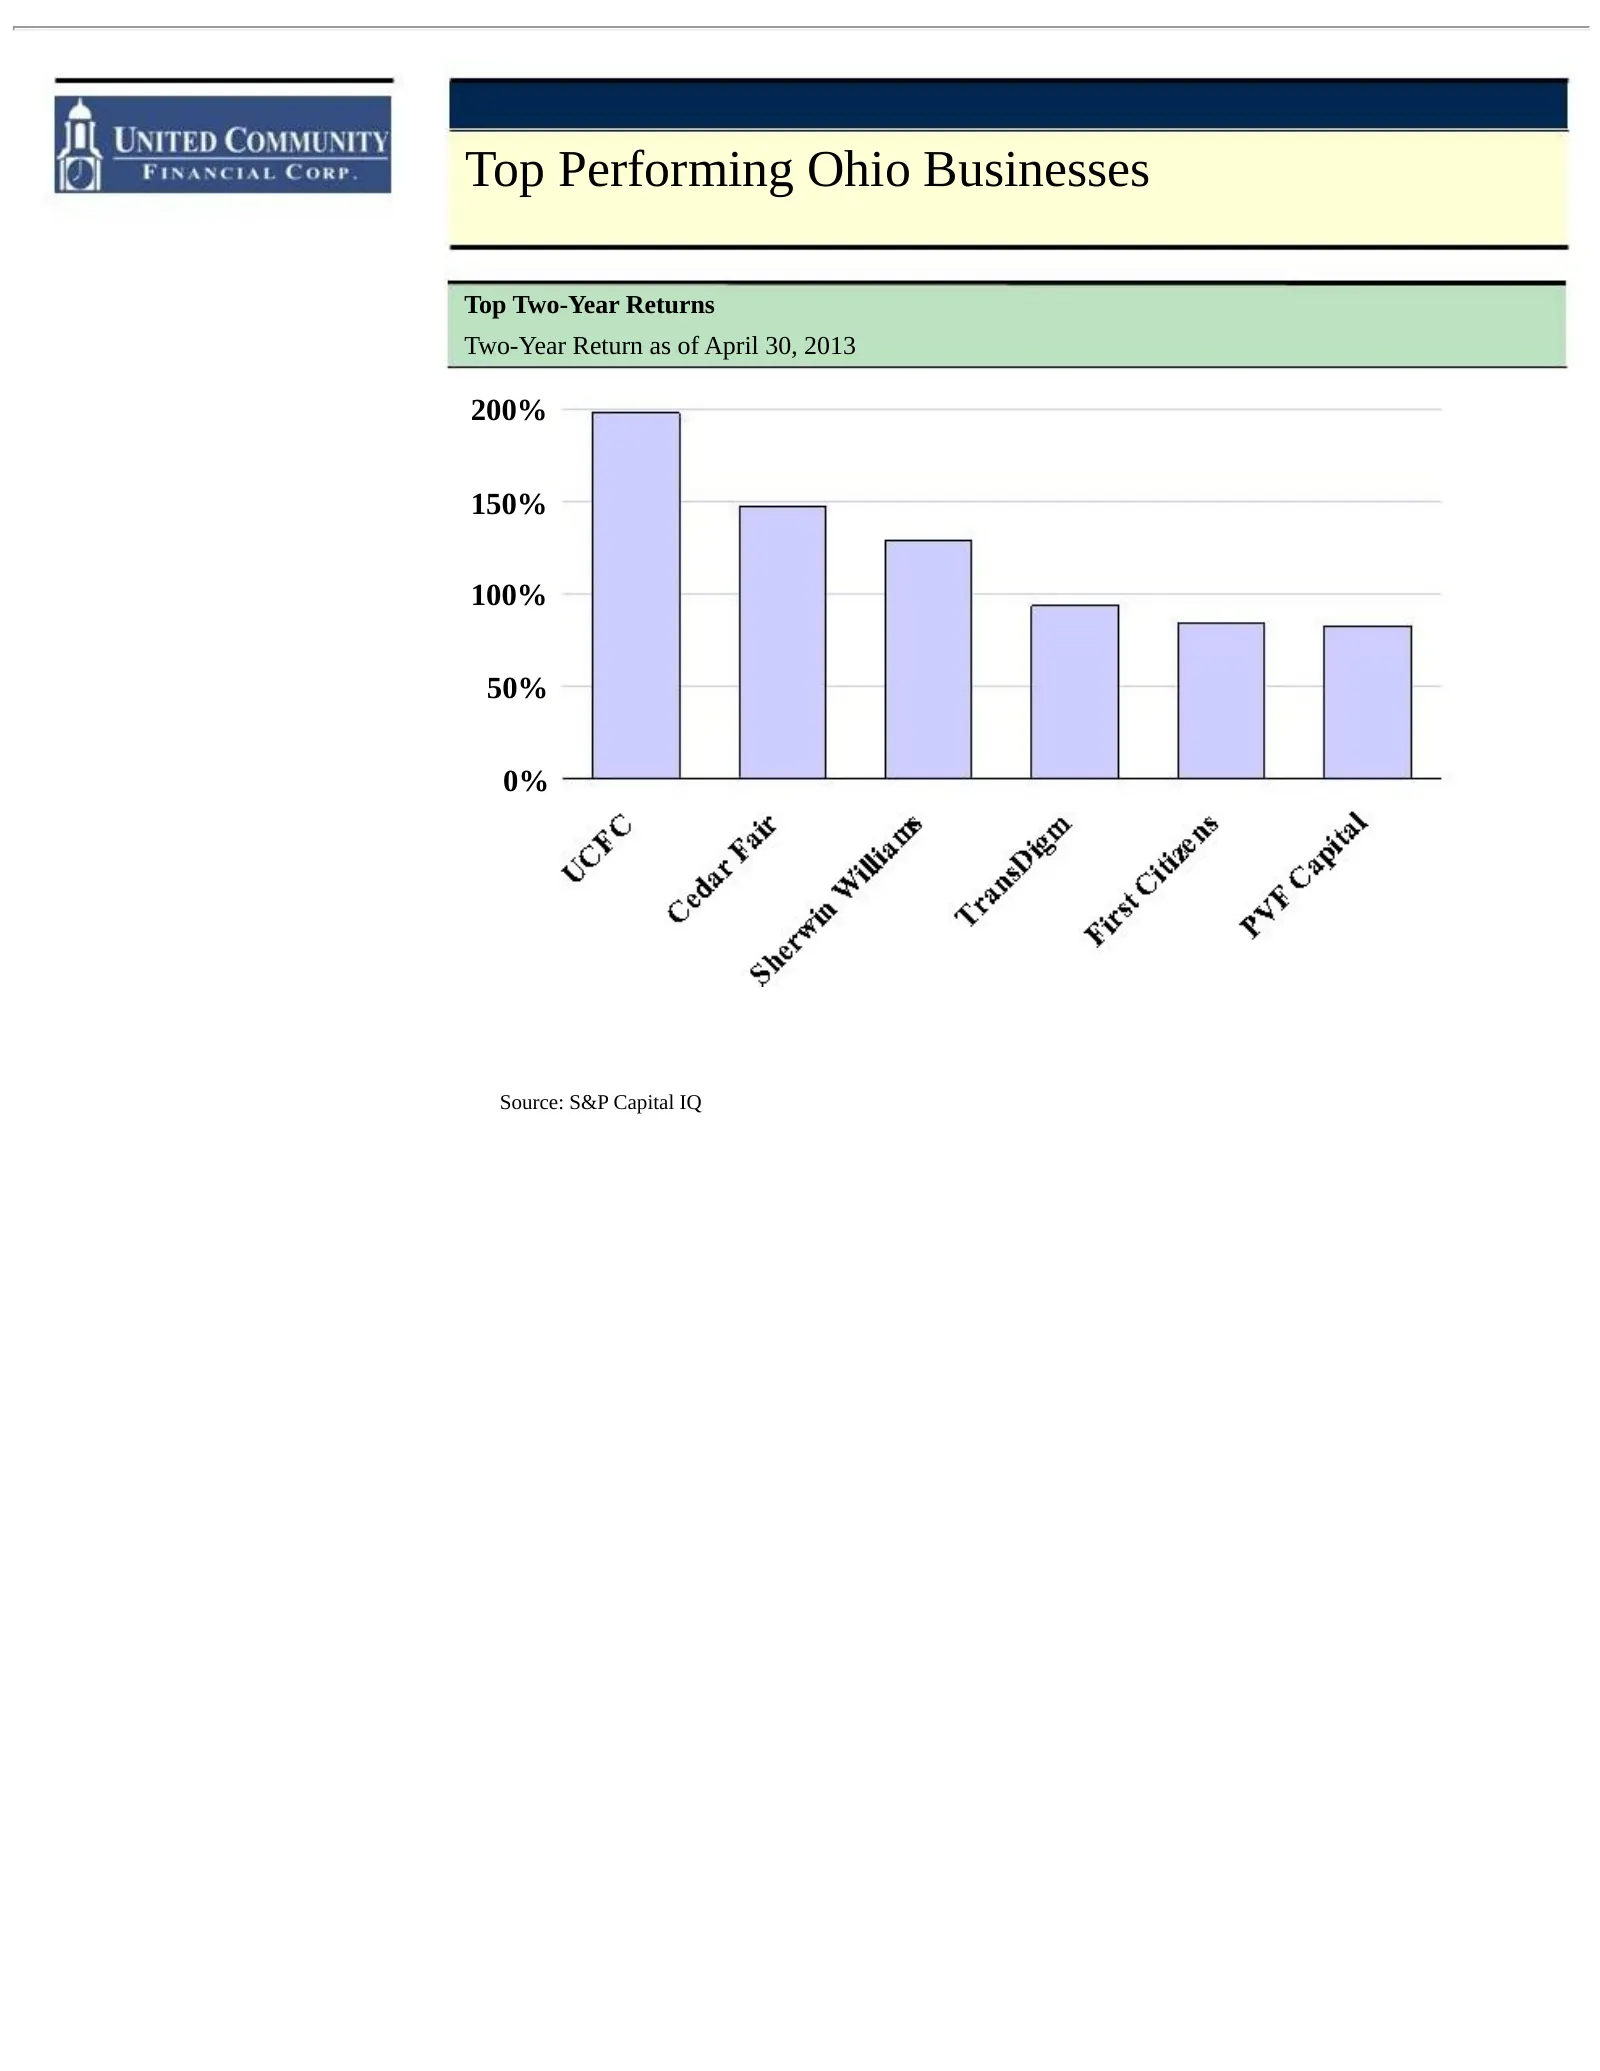
Top Performing Ohio Businesses Top Two-Year Returns Two-Year Return as of April 30, 2013 200% 150% 100% 50% 0% Source: S&P Capital IQ
Slide 11: James R. Reske, Chief Financial Officer and Treasurer
James R. Reske Chief Financial Officer and Treasurer
Slide 12: Operations: Branches and Loan Production Offices
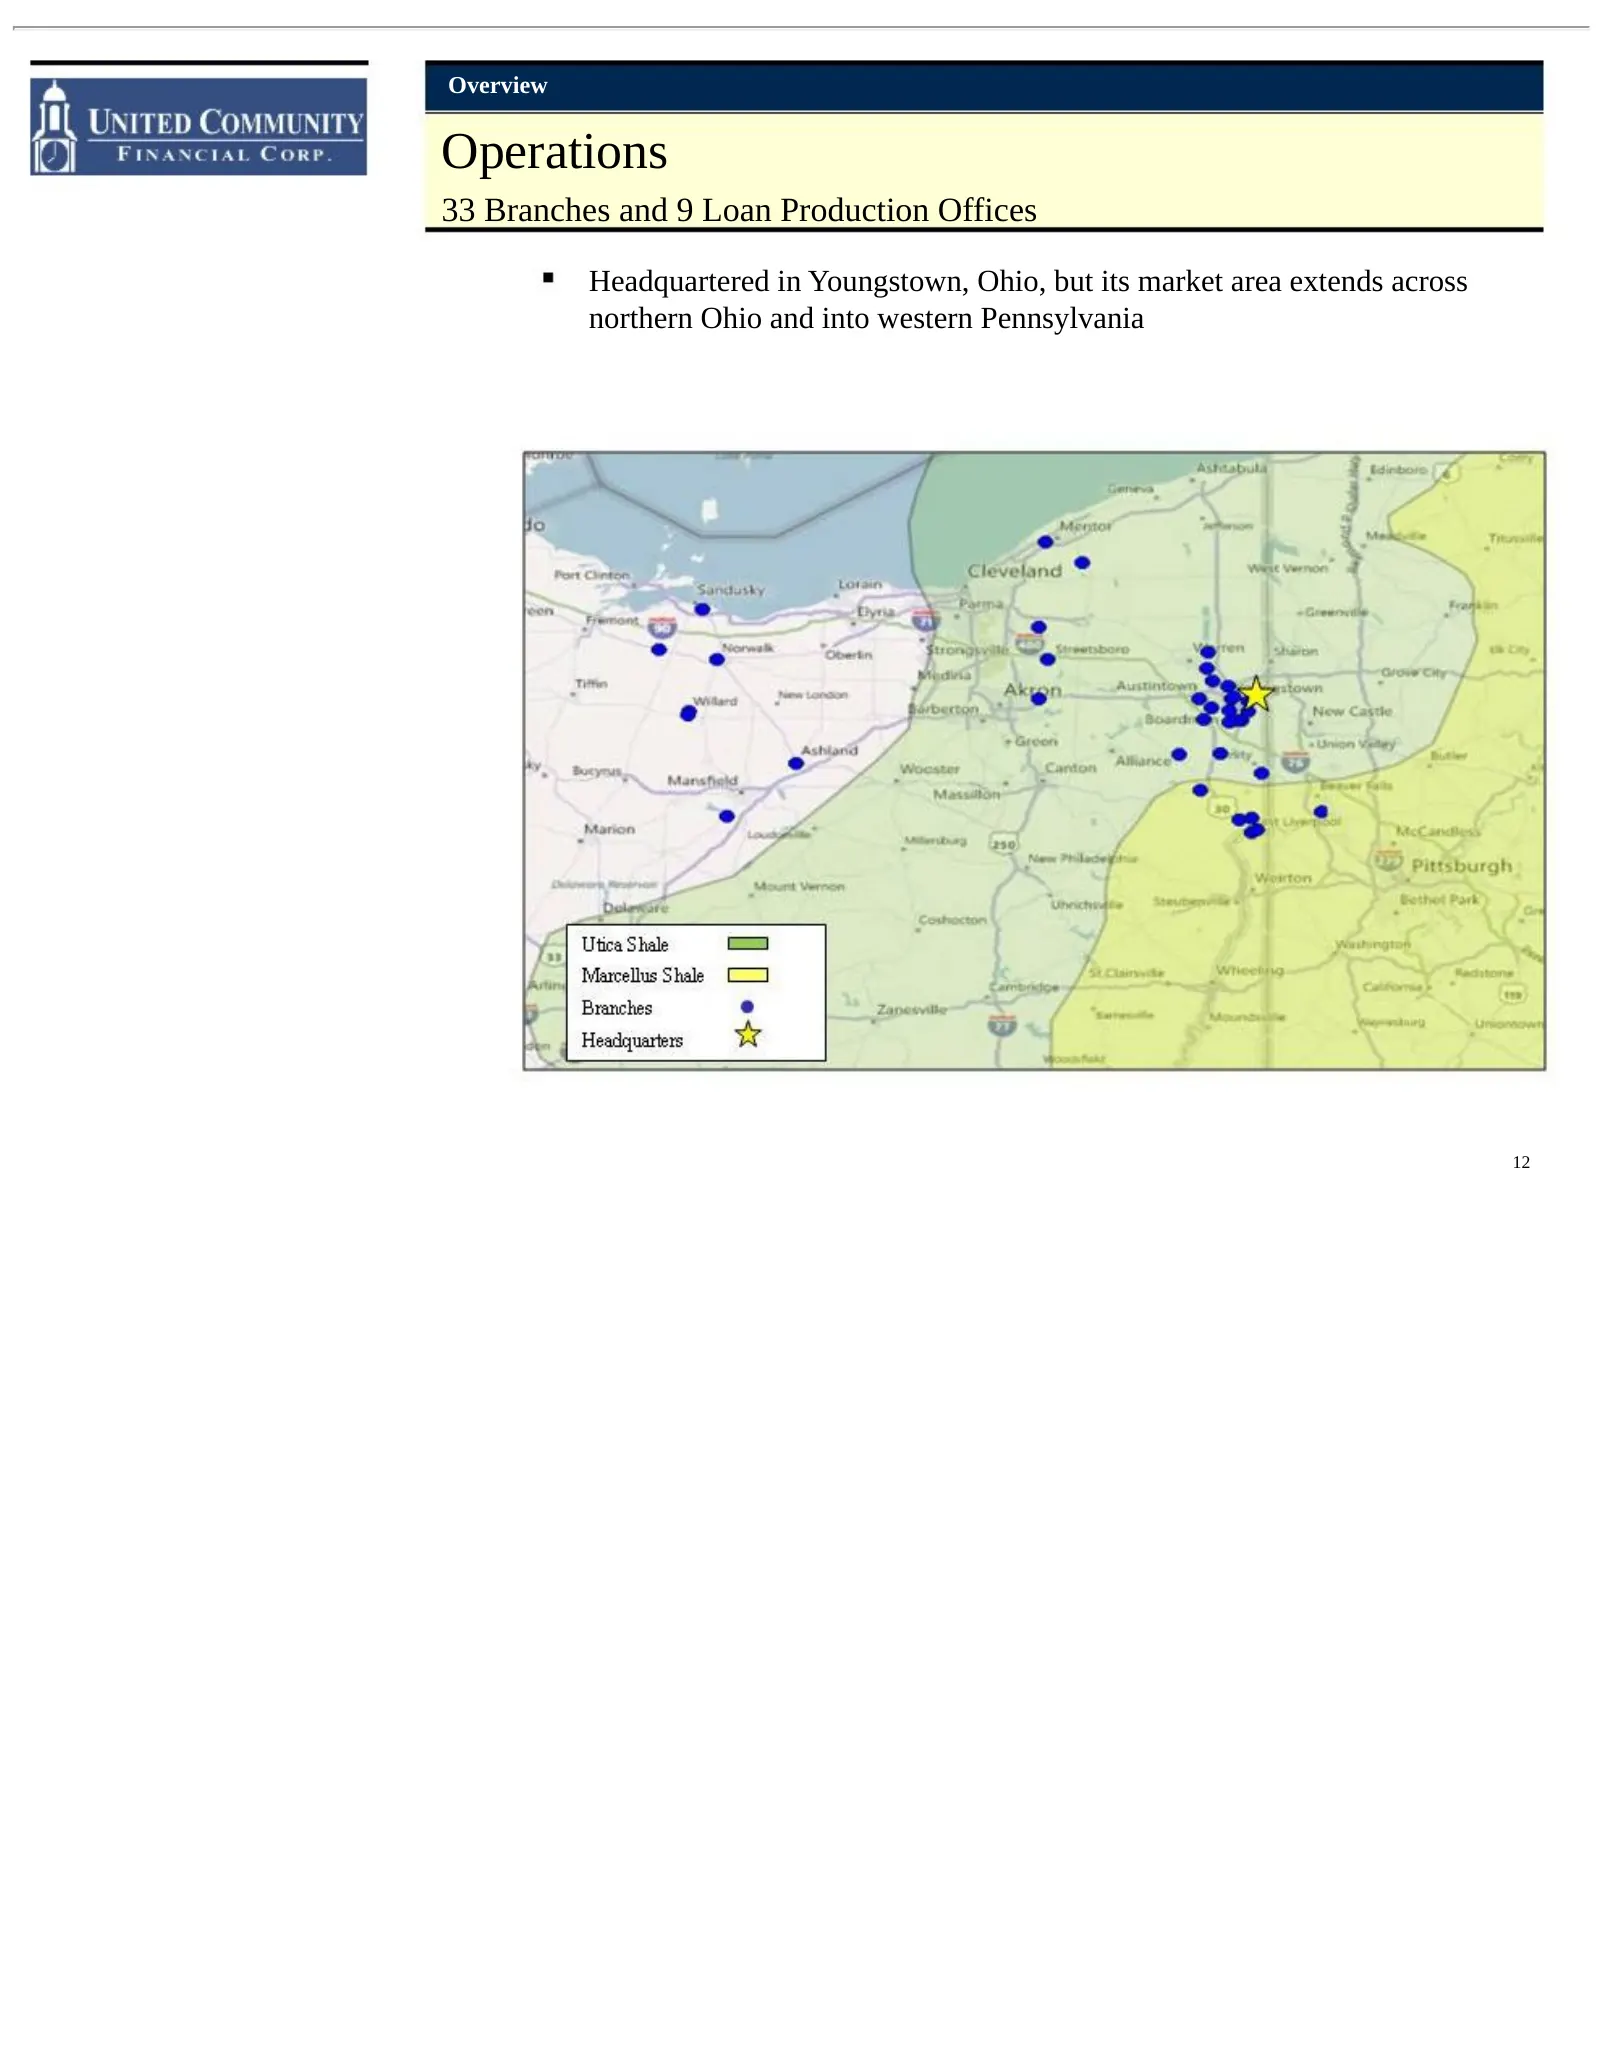
Overview Operations 33 Branches and 9 Loan Production Offices Headquartered in Youngstown, Ohio, but its market area extends across northern Ohio and into western Pennsylvania 12
Slide 13: Major Accomplishments
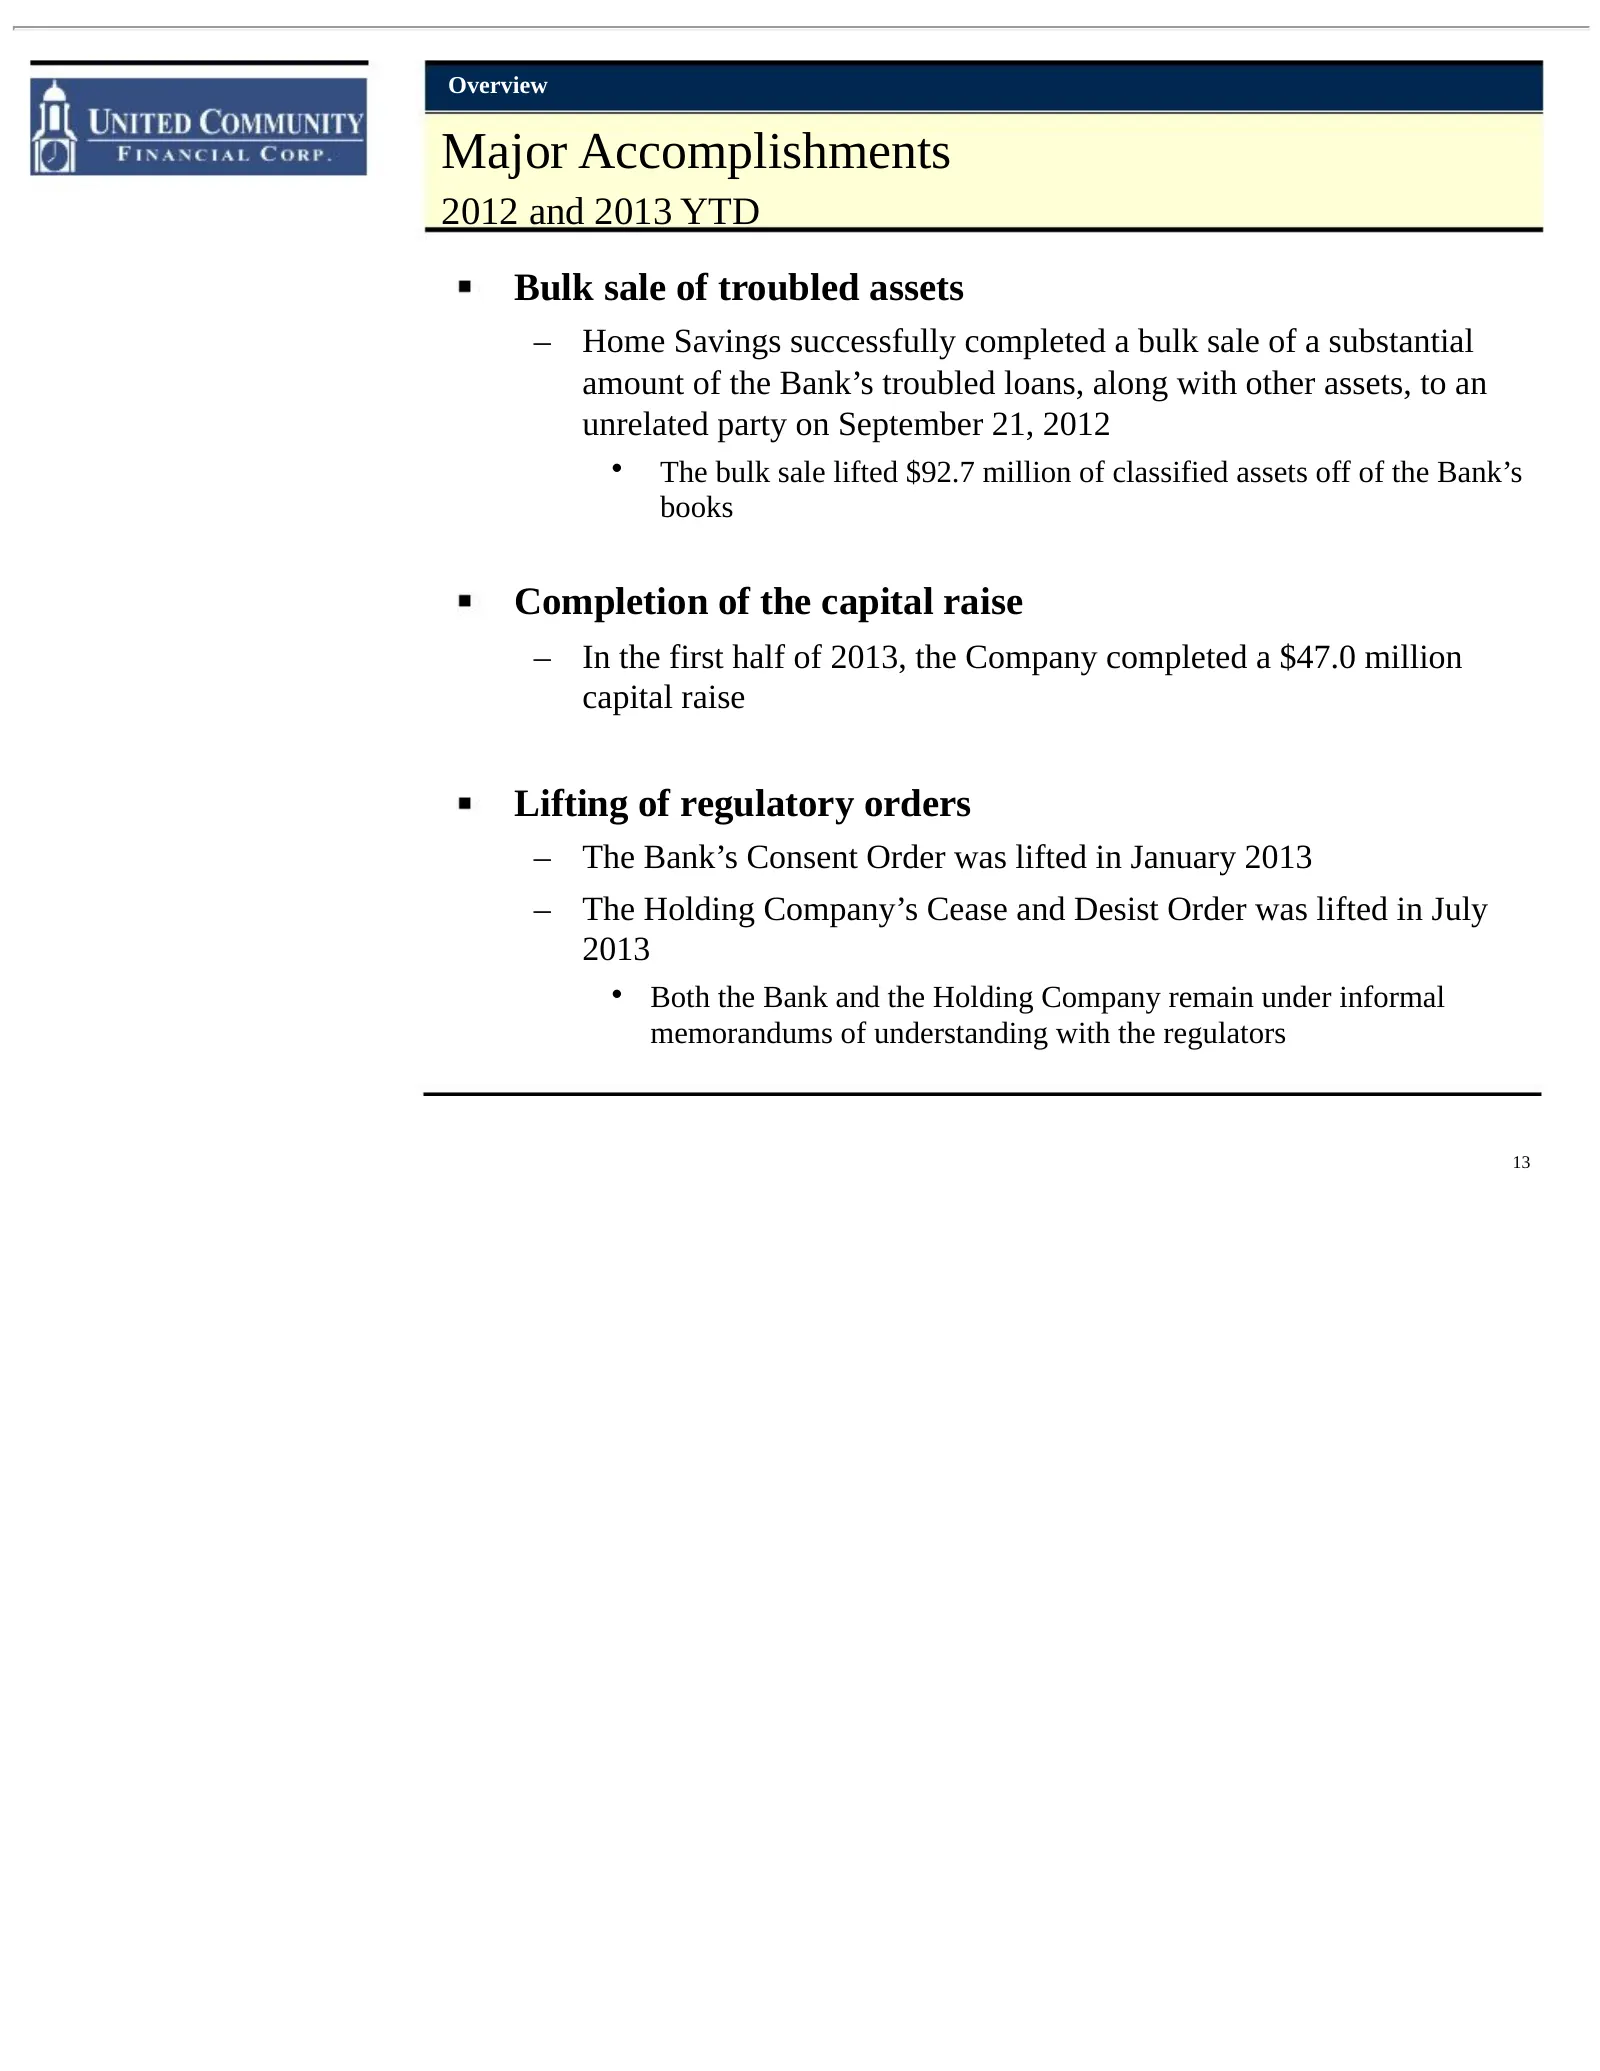
Overview Major Accomplishments 2012 and 2013 YTD Bulk sale of troubled assets – Home Savings successfully completed a bulk sale of a substantial amount of the Bank’s troubled loans, along with other assets, to an unrelated party on September 21, 2012 • The bulk sale lifted $92.7 million of classifie
Slide 14: Capital Ratios
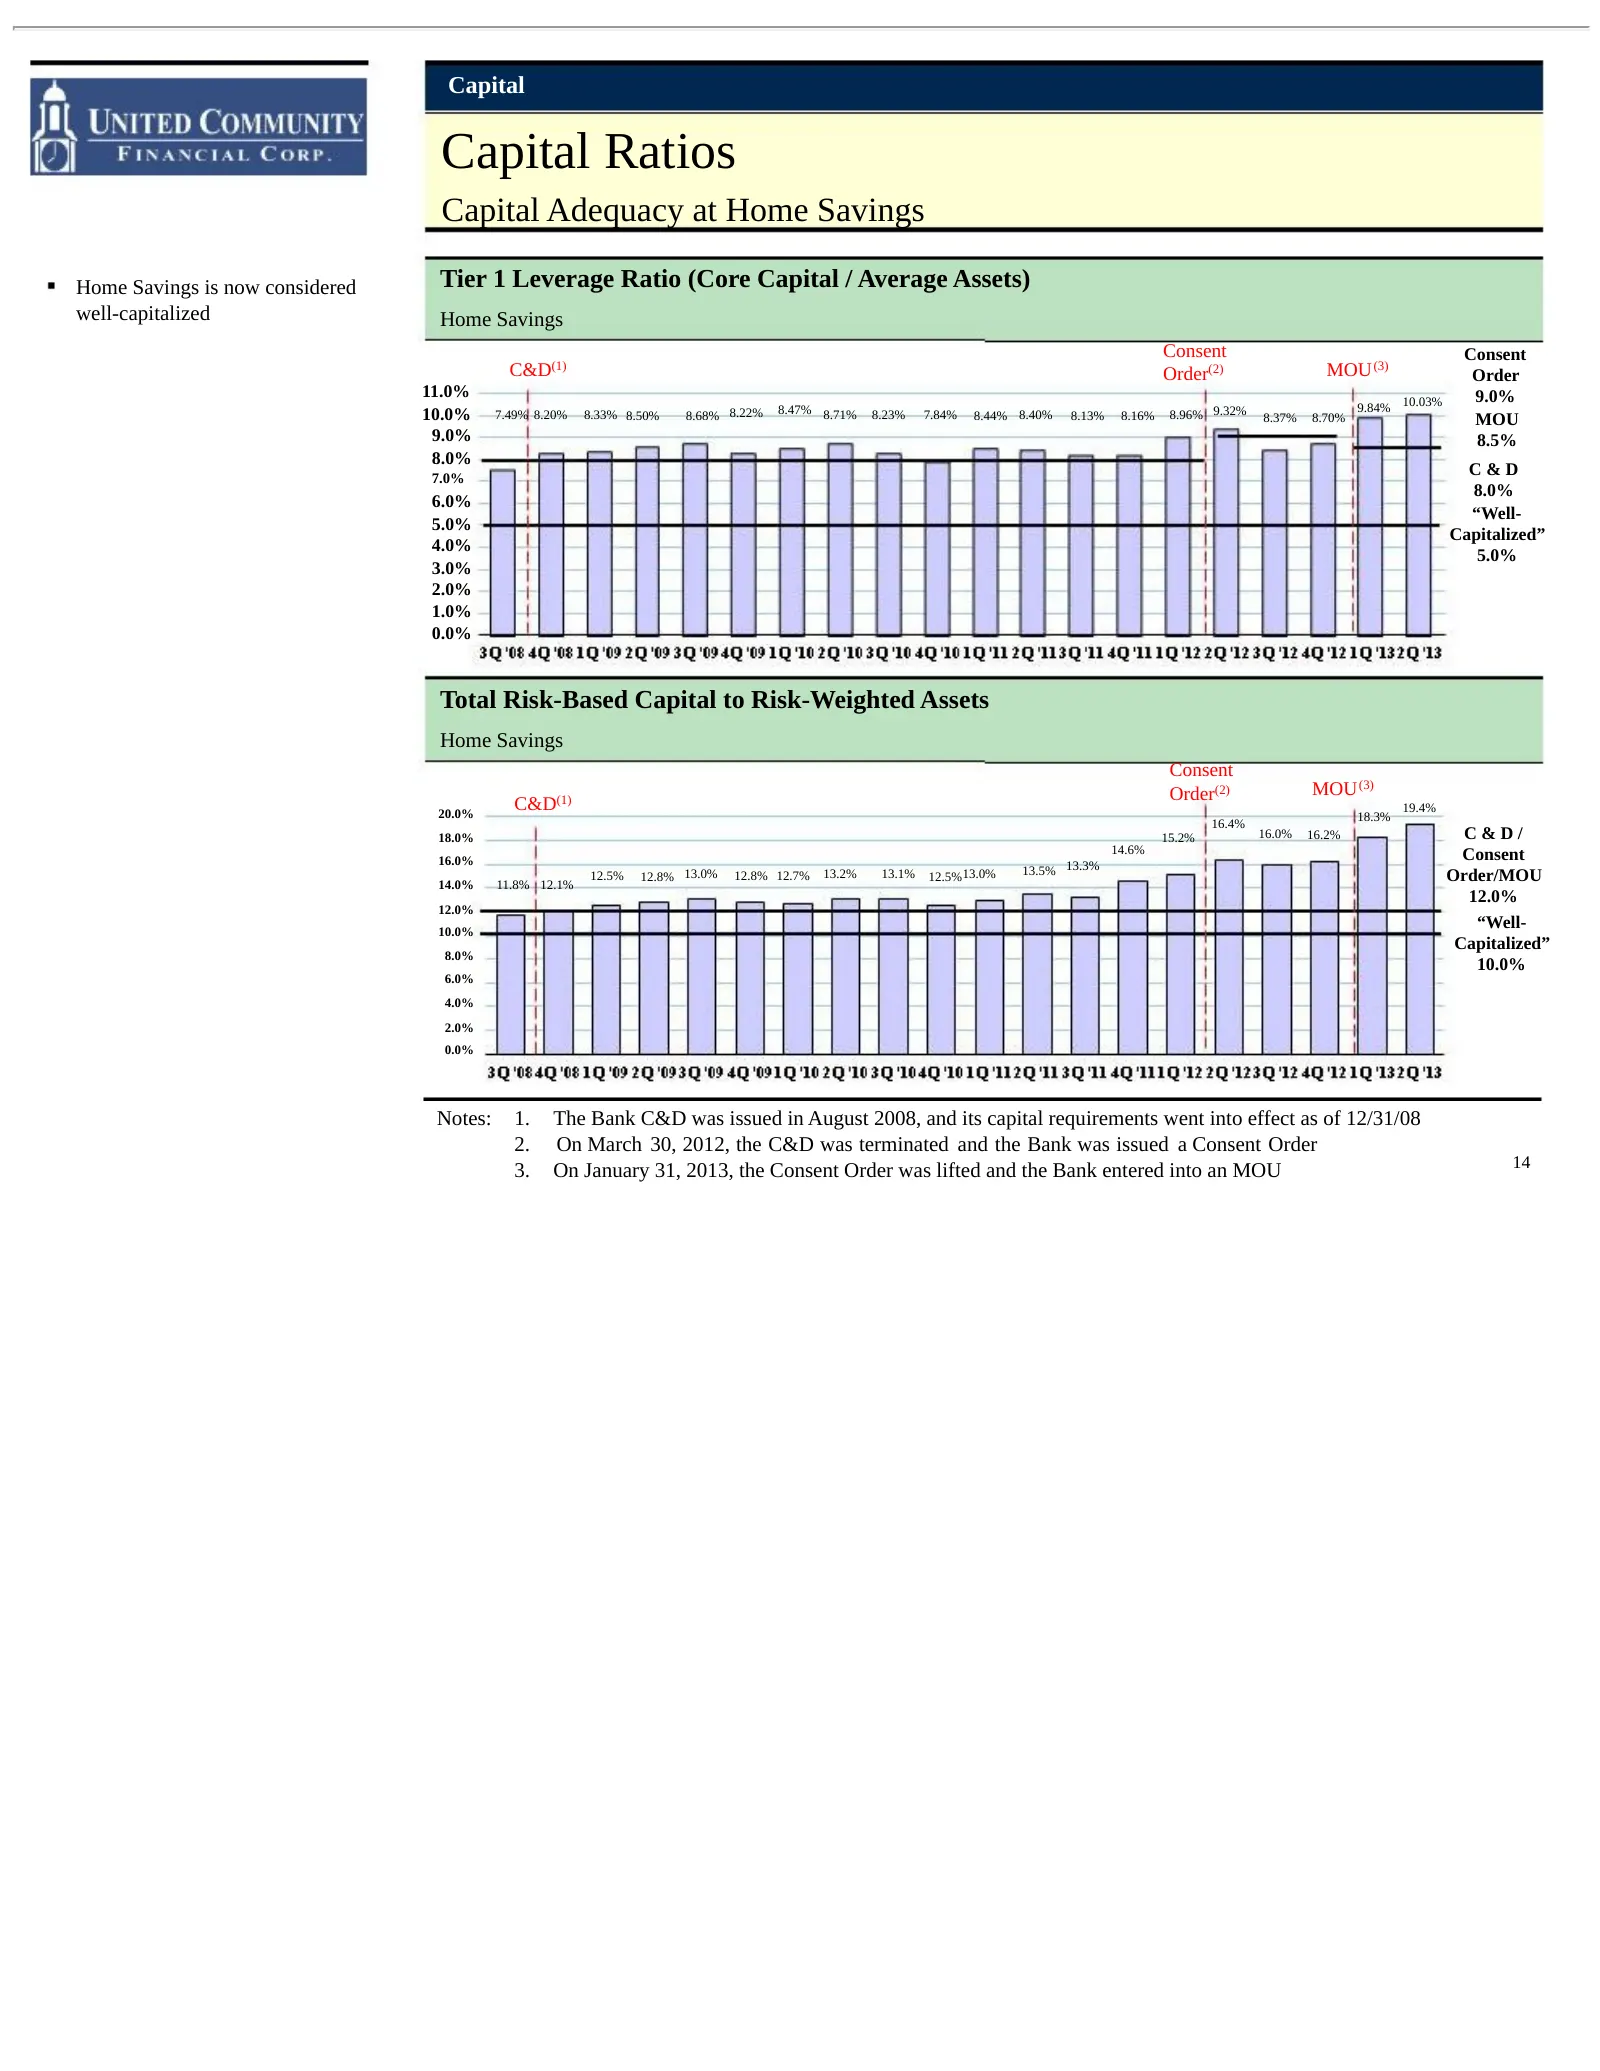
Capital Capital Ratios Capital Adequacy at Home Savings Home Savings is now considered Tier 1 Leverage Ratio (Core Capital / Average Assets) well-capitalized Home Savings Consent Consent C&D(1) Order(2) MOU (3) Order 11.0% 10.03% 9.0% 8.47% 8.71% 8.96% 9.32% 9.84% 10.0% 7.49% 8.20% 8.33% 8.50% 8.68%
Slide 15: Review of Financial Performance: Earnings
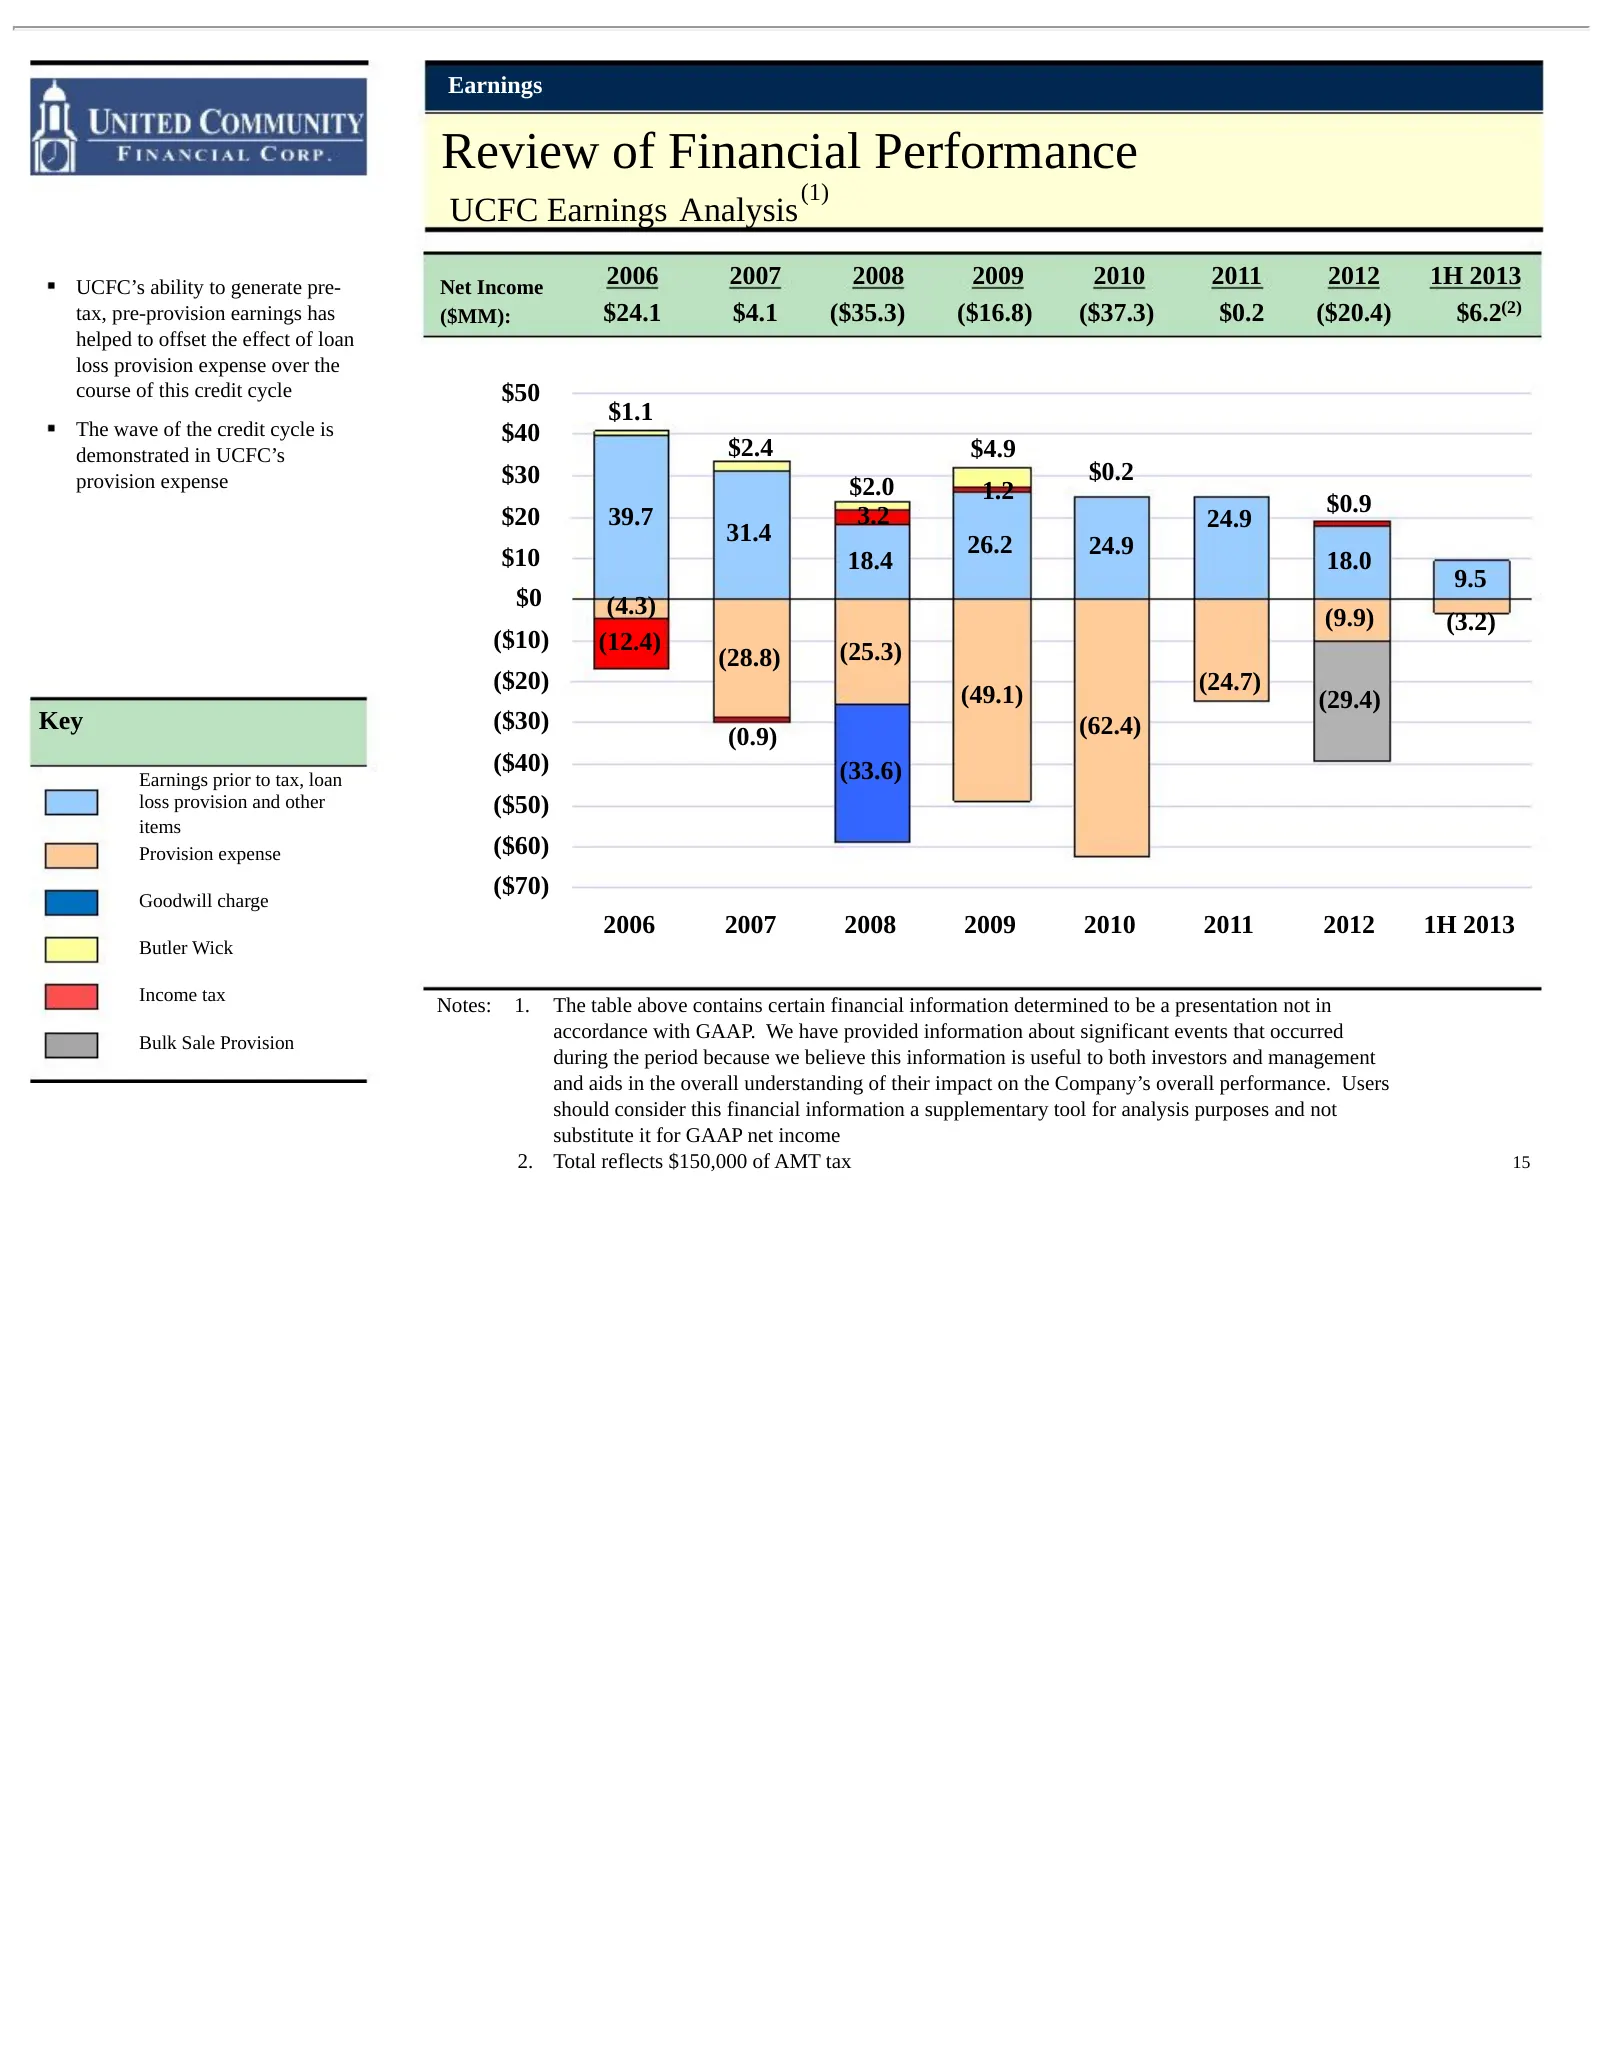
Earnings Review of Financial Performance (1) UCFC Earnings Analysis UCFC’s ability to generate pre- Net Income 2006 2007 2008 2009 2010 2011 2012 1H 2013 tax, pre-provision earnings has ($MM): $24.1 $4.1 ($35.3) ($16.8) ($37.3) $0.2 ($20.4) $6.2(2) helped to offset the effect of loan loss provision
Slide 16: Reductions in Real Estate Owned (REO)
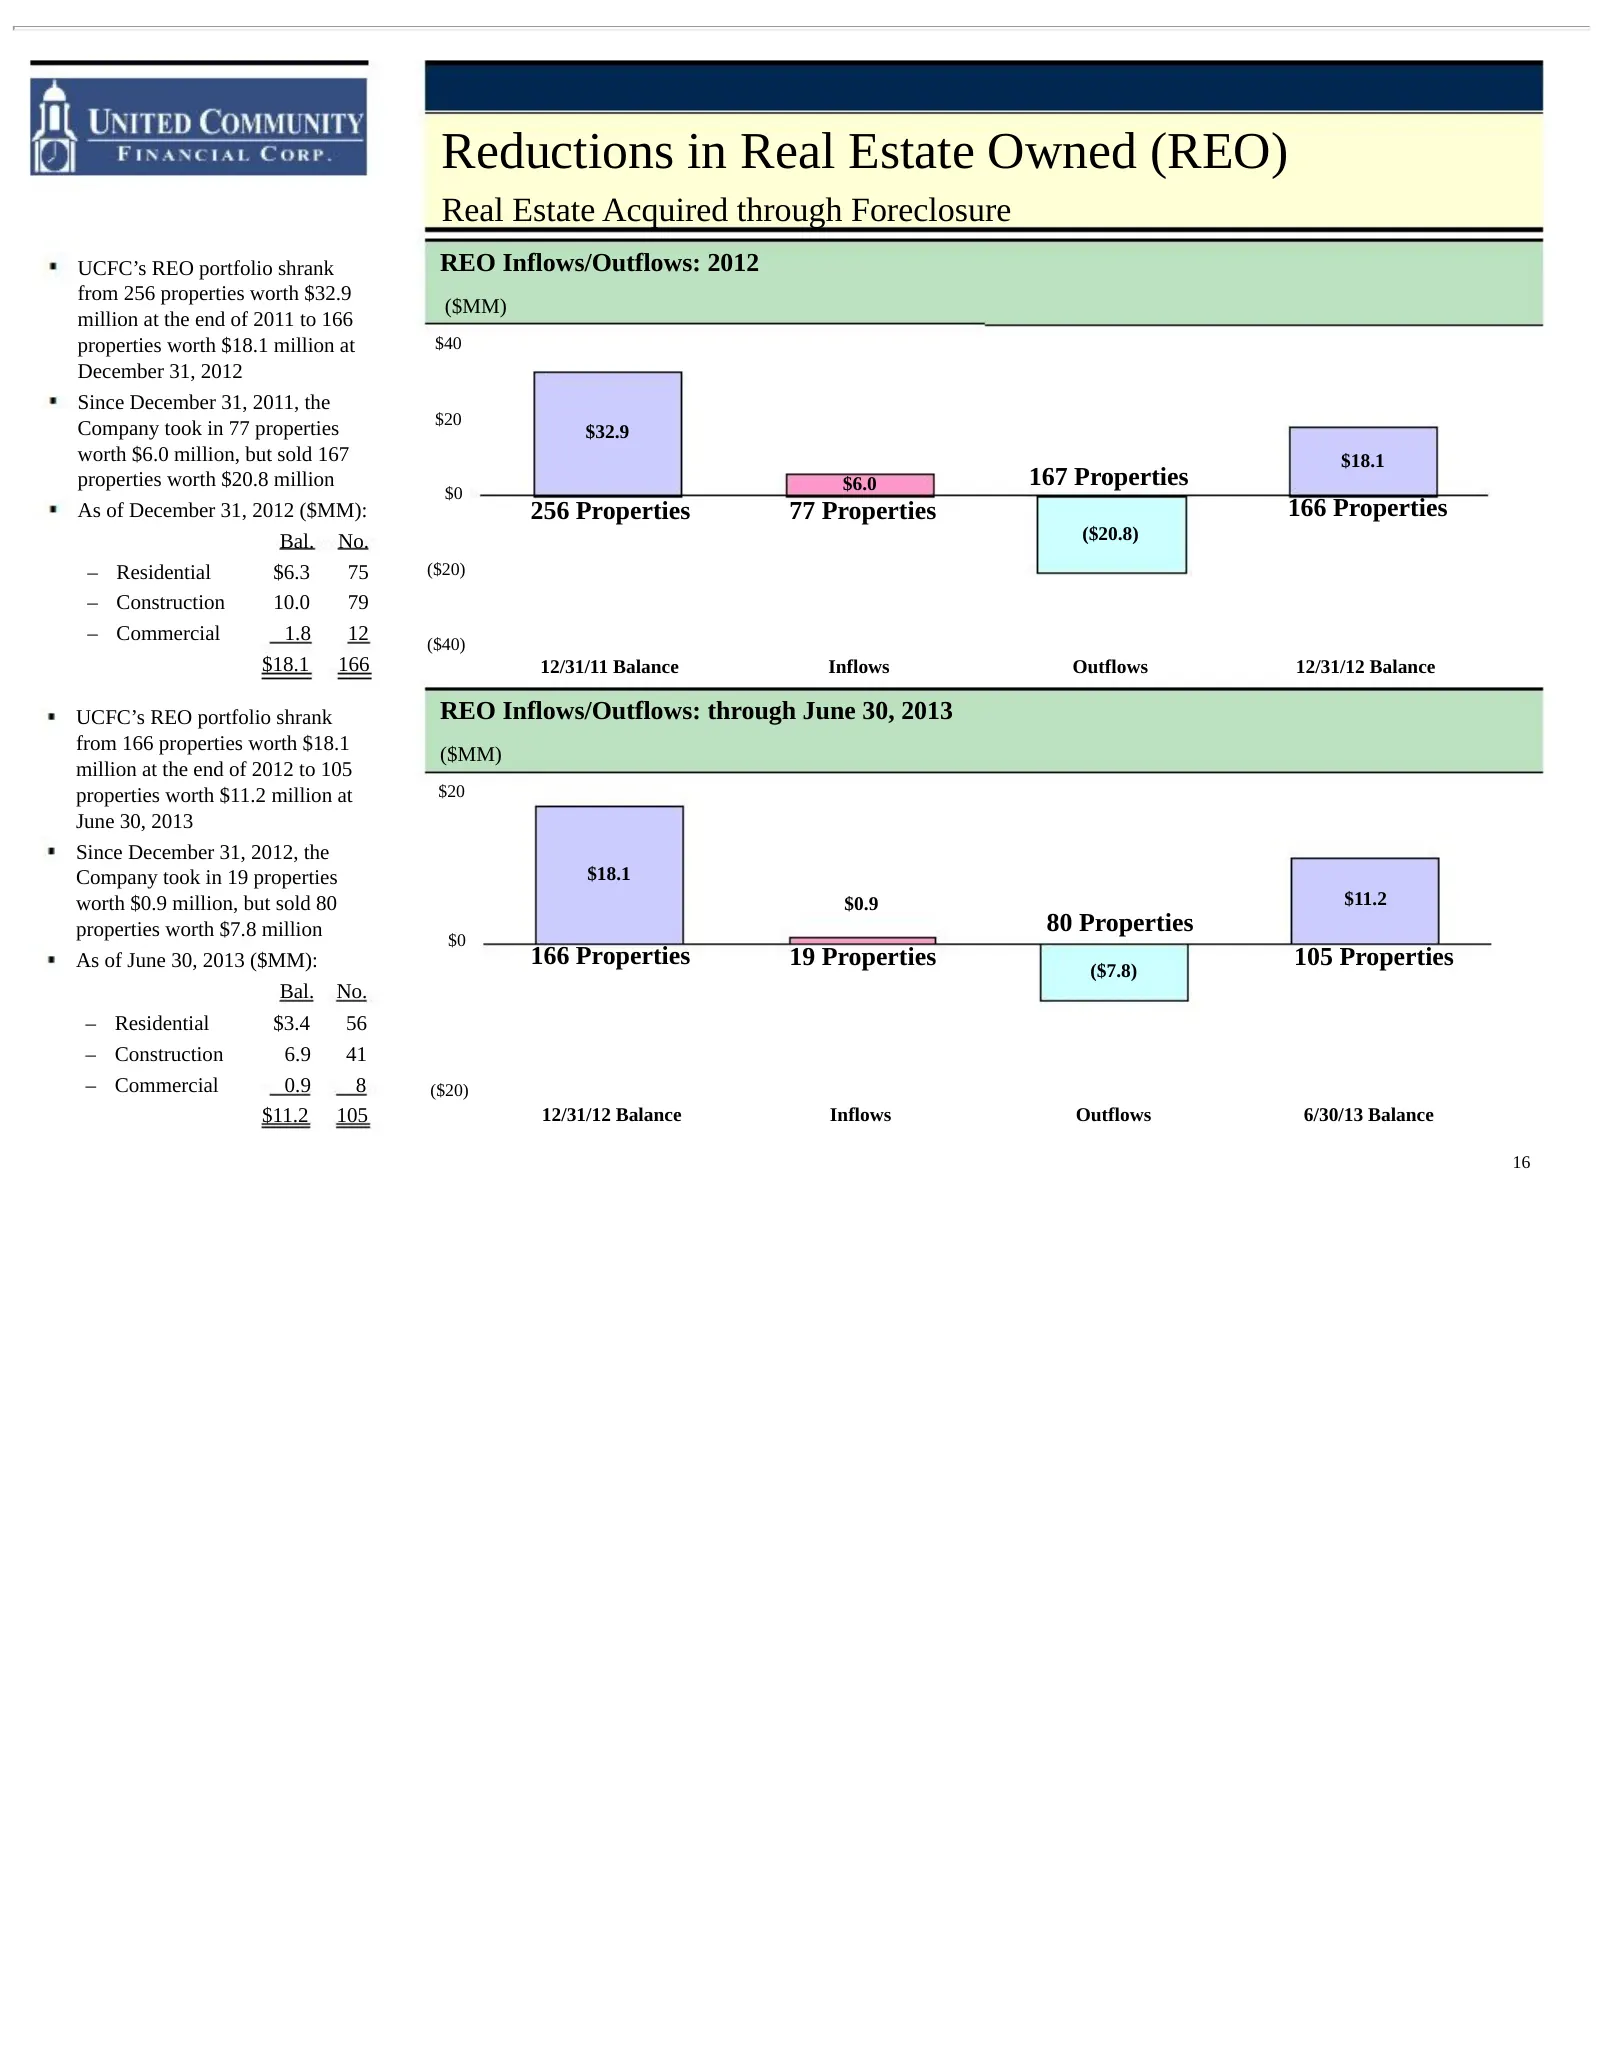
Reductions in Real Estate Owned (REO) Real Estate Acquired through Foreclosure UCFC’s REO portfolio shrank REO Inflows/Outflows: 2012 from 256 properties worth $32.9 ($MM) million at the end of 2011 to 166 properties worth $18.1 million at $40 December 31, 2012 Since December 31, 2011, the $20 Compa
Slide 17: Interest Rate Risk
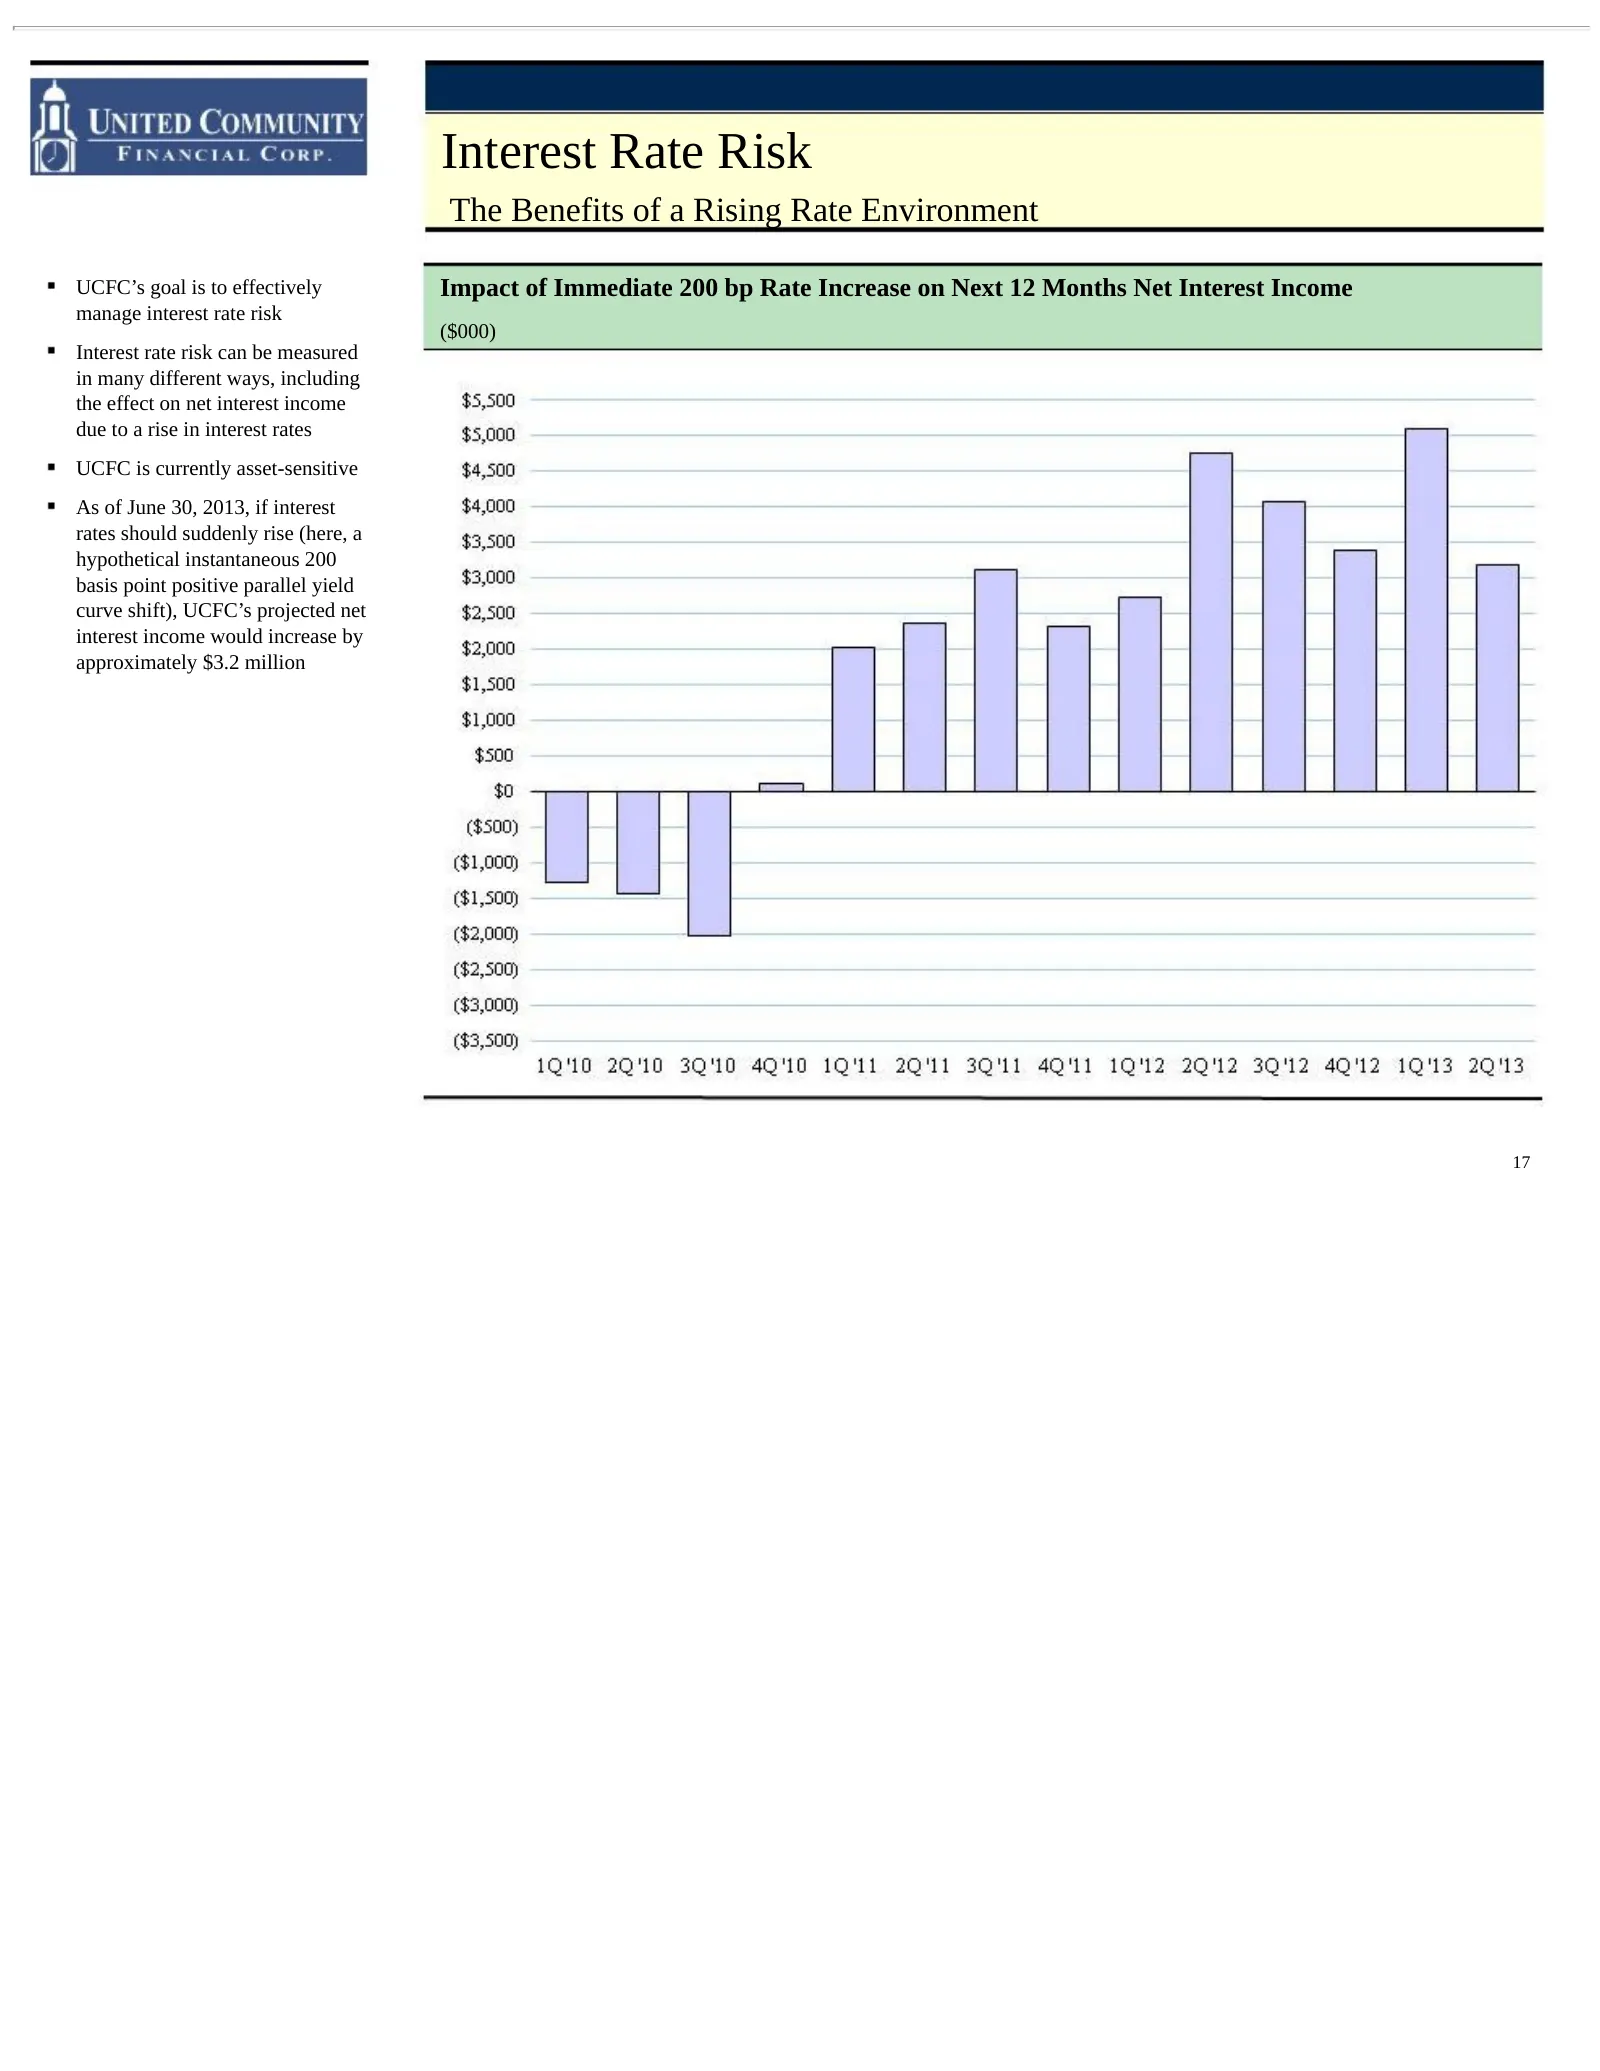
Interest Rate Risk The Benefits of a Rising Rate Environment UCFC’s goal is to effectively Impact of Immediate 200 bp Rate Increase on Next 12 Months Net Interest Income manage interest rate risk ($000) Interest rate risk can be measured in many different ways, including the effect on net interest i
Slide 18: Earning Assets
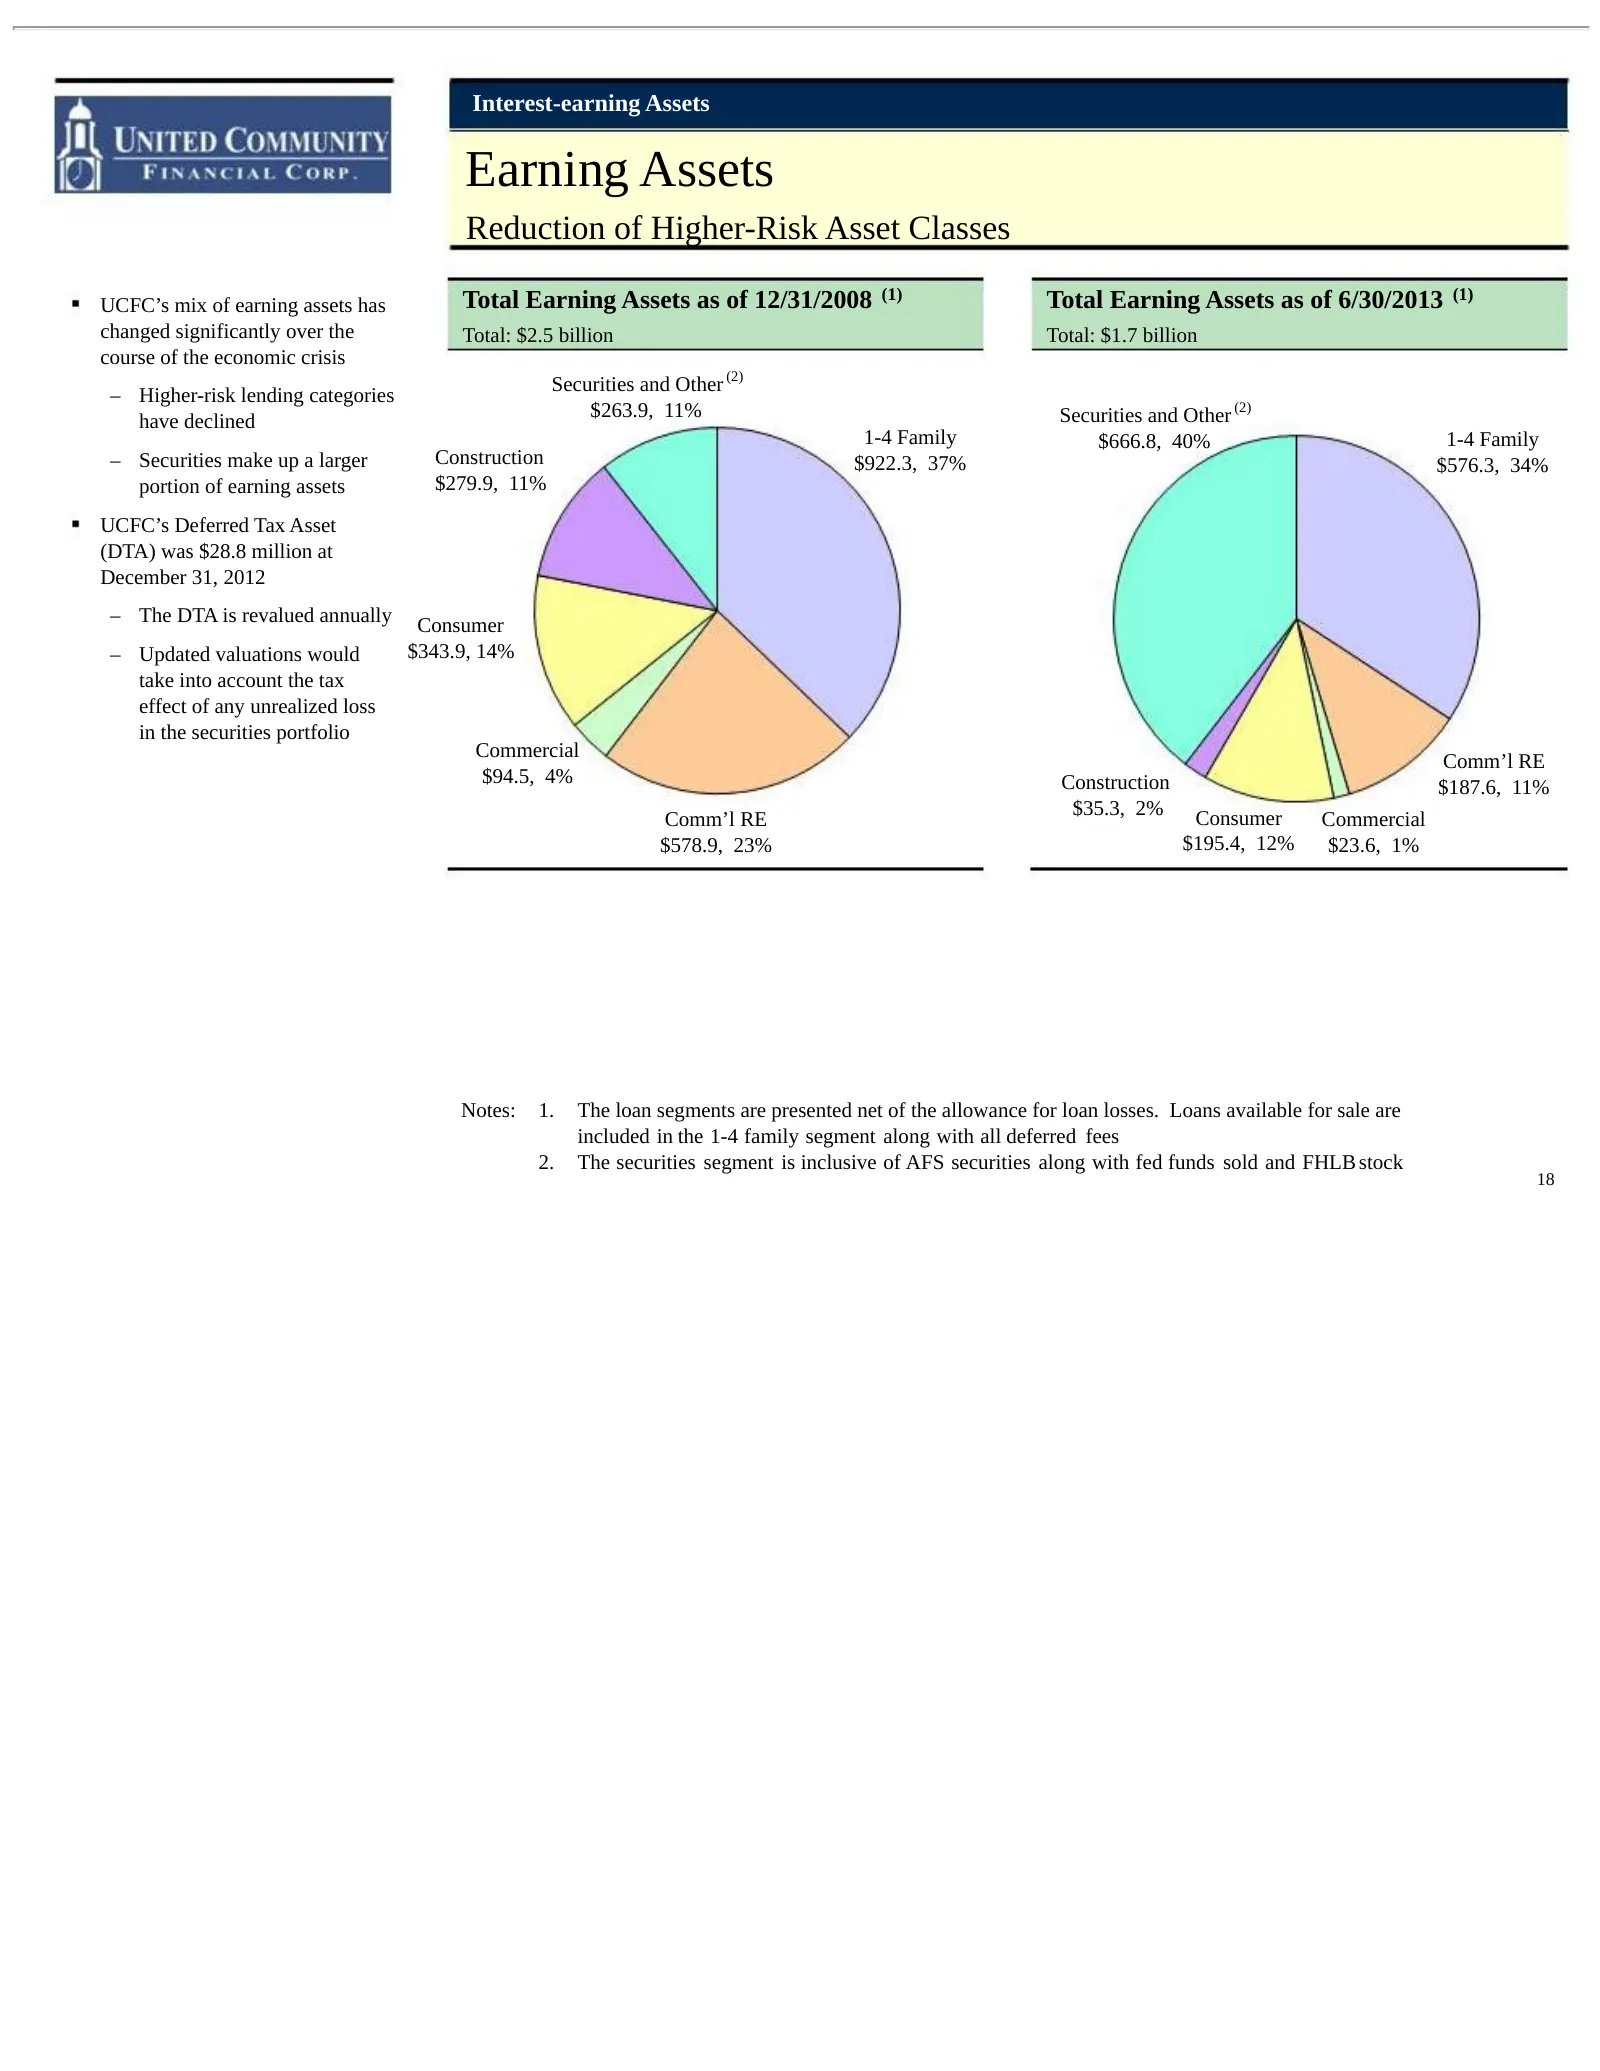
Interest-earning Assets Earning Assets Reduction of Higher-Risk Asset Classes UCFC’s mix of earning assets has Total Earning Assets as of 12/31/2008 (1) Total Earning Assets as of 6/30/2013 (1) changed significantly over the Total: $2.5 billion Total: $1.7 billion course of the economic crisis Secur
Slide 19: Deposits and Borrowings
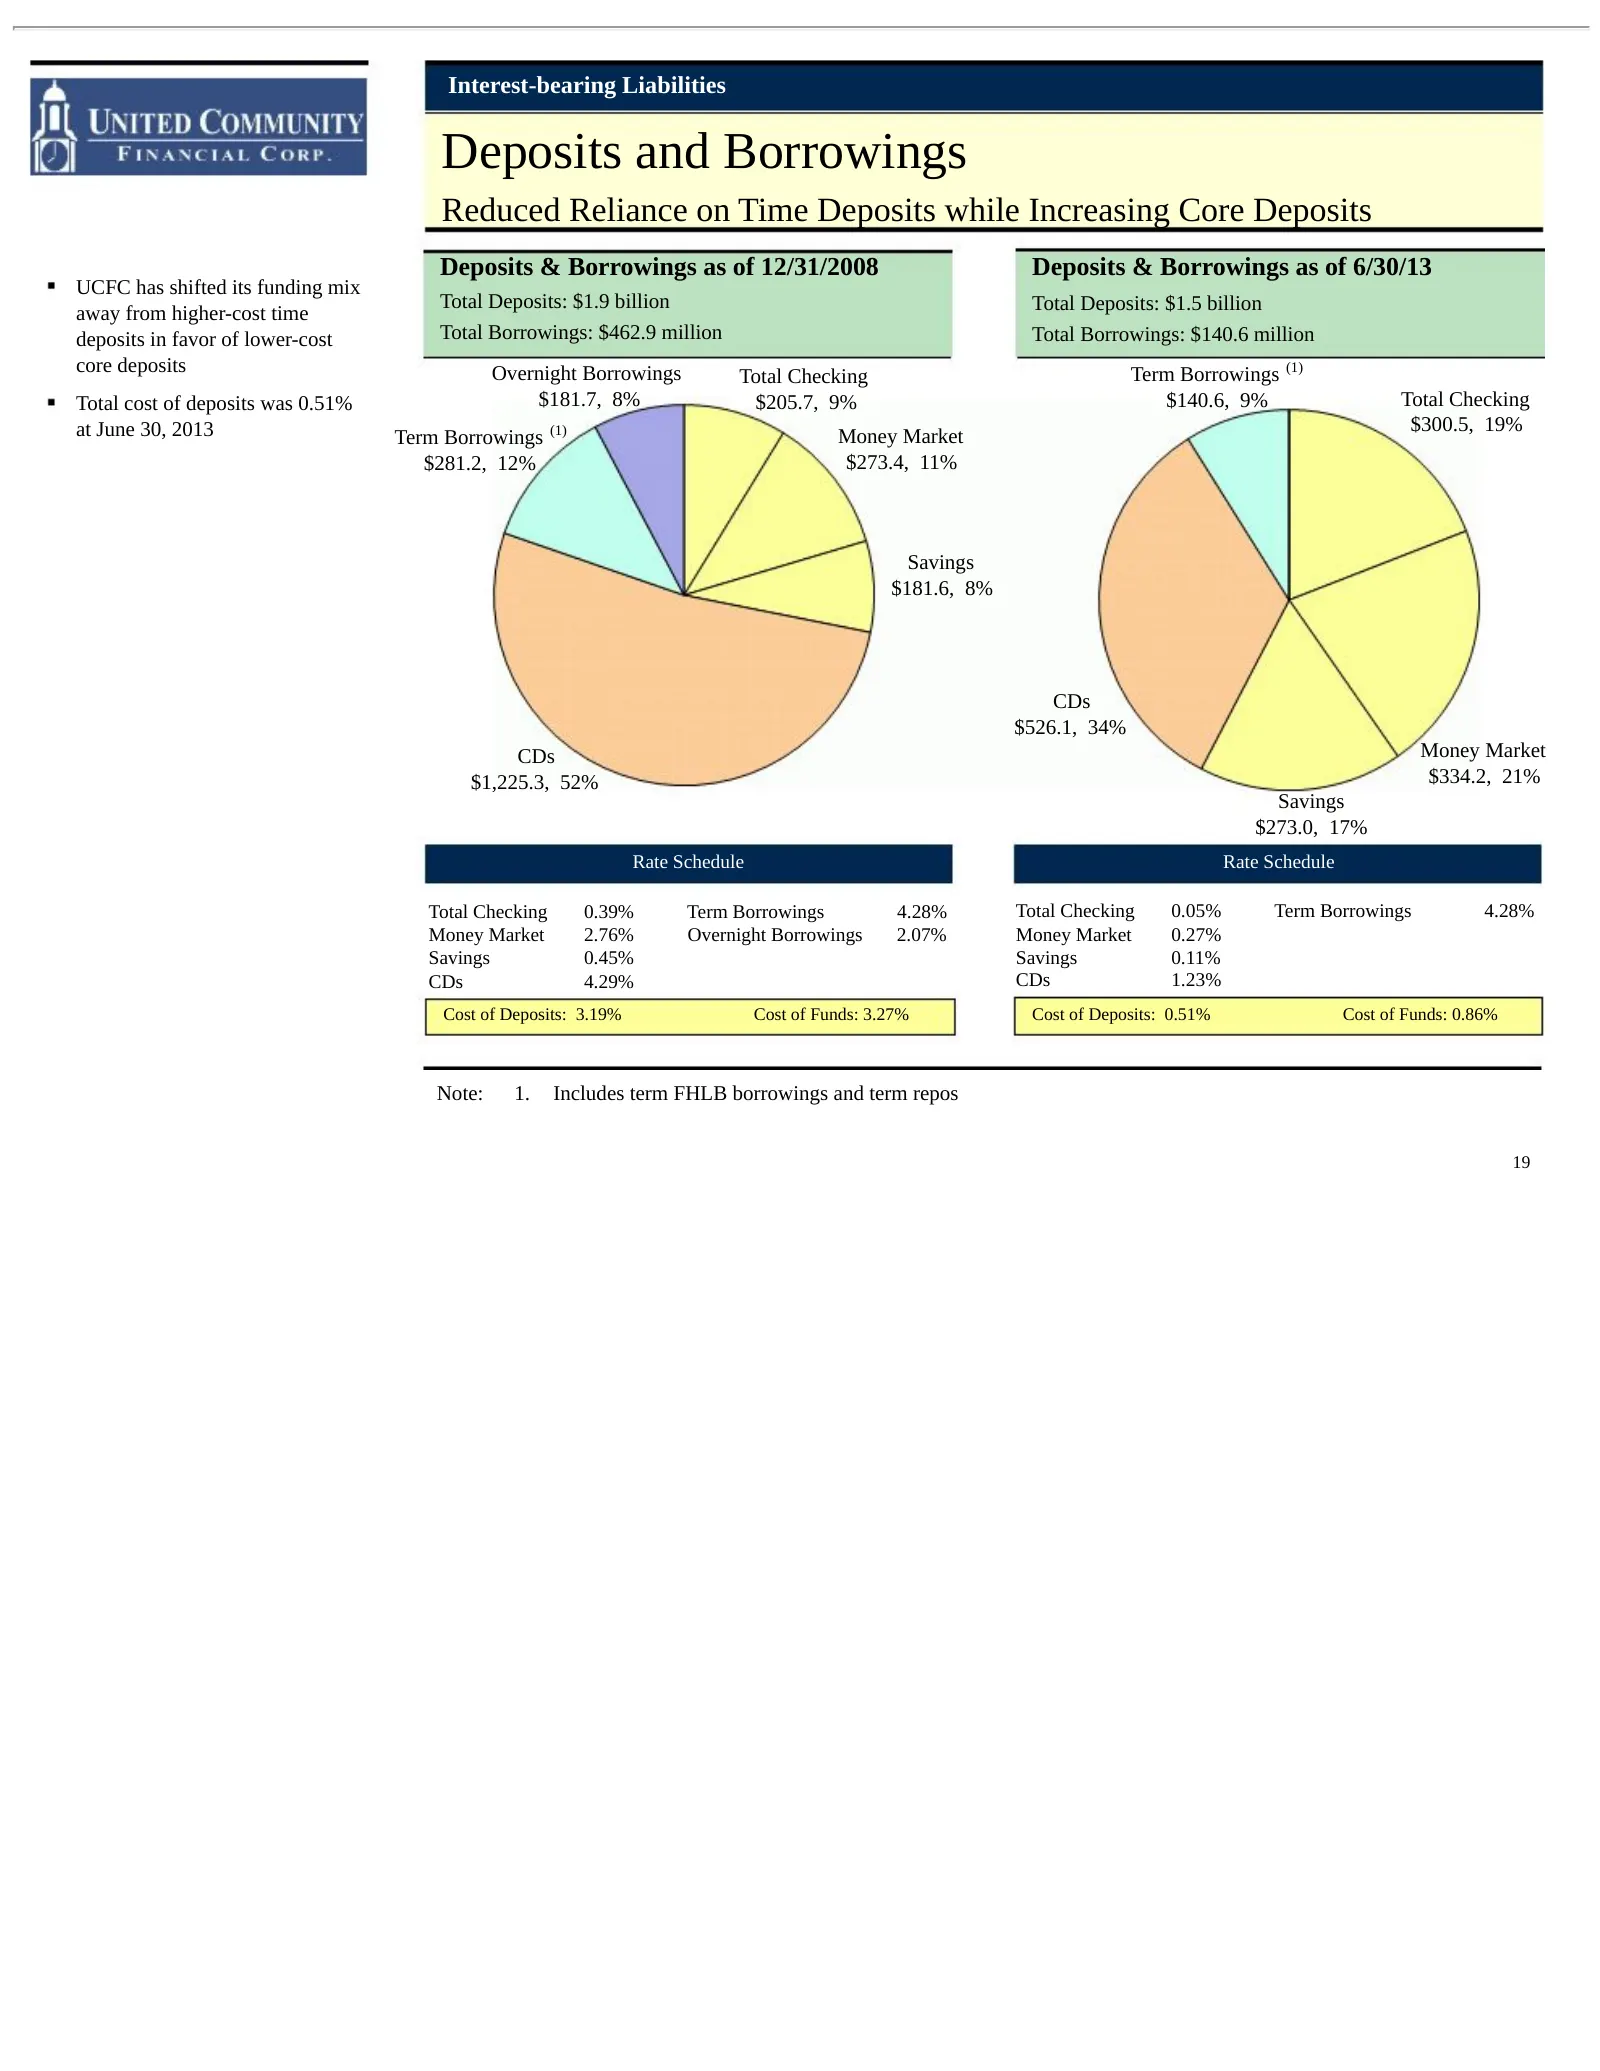
Interest-bearing Liabilities Deposits and Borrowings Reduced Reliance on Time Deposits while Increasing Core Deposits Deposits & Borrowings as of 12/31/2008 Deposits & Borrowings as of 6/30/13 UCFC has shifted its funding mix Total Deposits: $1.9 billion Total Deposits: $1.5 billion away from higher
Slide 20: Questions
Questions United Community Financial Corp. NASDAQ: UCFC www.UCFCONLINE.com www.HOMESAVINGS.com Headquarters 275 West Federal Street Youngstown, Ohio 44503 20
Source: SEC EDGAR · 8-K filed Aug 27, 2013
More decks from United Community Financial Corp
 Merger or Acquisition (September 2019)20 slides · Sep 9, 2019
 Merger or Acquisition (September 2016)15 slides · Sep 9, 2016
 Raymond James Presentation (October 2015)23 slides · Oct 30, 2015
 Shareholder Meeting (December 2012)27 slides · Dec 18, 2012
 Shareholder Meeting (April 2011)18 slides · Apr 28, 2011
 Investor Presentation (February 2010)22 slides · Feb 18, 2010