United Community Financial Corp
United Community Financial — Shareholder Meeting (December 2012)
27 slides from United Community Financial's shareholder meeting presentation, Dec 18, 2012
Slide 1: 2012 Annual Meeting
2012 Annual MeetingDecember 2012
Slide 2: Patrick W. Bevack, President and Chief Executive Officer
Patrick W. Bevack President and Chief Executive Officer
Slide 3: Forward-Looking Statement Disclosure
Forward-Looking Statement Disclosure 3 When used in this presentation the words or phrases "will likely result," "are expected to," "will continue," "is anticipated," "estimate," "project" or similar expressions are intended to identify "forward-looking statements" within the meaning of the Private
Slide 4: Non-GAAP Financial Measures
Non-GAAP Financial Measures 4 This presentation contains financial information determined by methods other than those prescribed by accounting principles generally accepted in the United States of America ("GAAP"). Management uses these non-GAAP financial measures because it believes that they are u
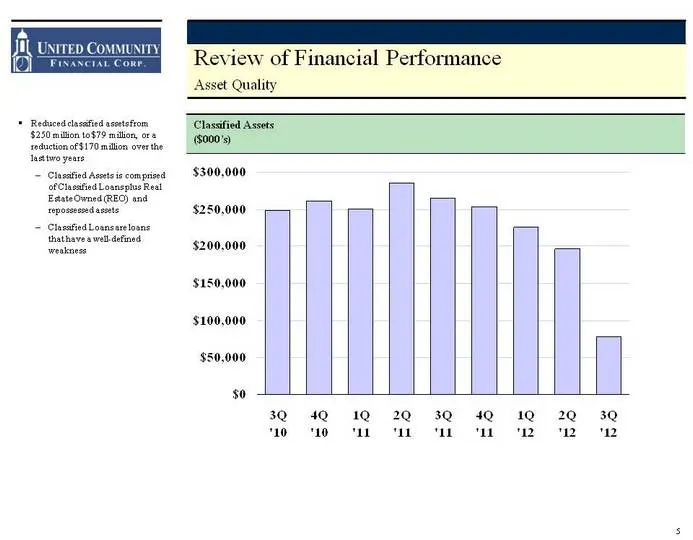
Slide 5: Review of Financial Performance: Asset Quality (Classified Assets)
Review of Financial Performance Asset Quality 3Q '10 4Q '10 1Q '11 2Q '11 3Q '11 4Q '11 1Q '12 2Q '12 3Q '12 East 249046 261708 251002 285532 264712 253914 225112 196617 78579 Classified Assets($000's) 5 Reduced classified assets from $250 million to $79 million, or a reduction of $170 million over
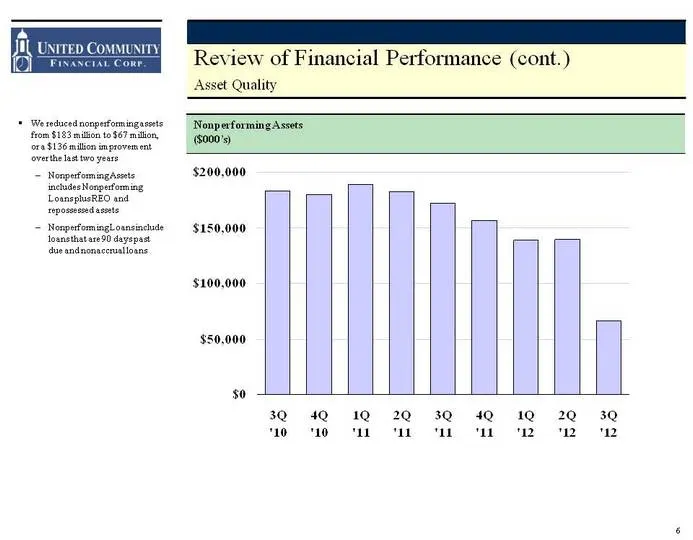
Slide 6: Review of Financial Performance: Nonperforming Assets
Review of Financial Performance (cont.) Asset Quality 3Q '10 4Q '10 1Q '11 2Q '11 3Q '11 4Q '11 1Q '12 2Q '12 3Q '12 East 183010 179867 188729 182774 172398 156581 138965 139307 66763 Nonperforming Assets($000's) 6 We reduced nonperforming assets from $183 million to $67 million, or a $136 million i
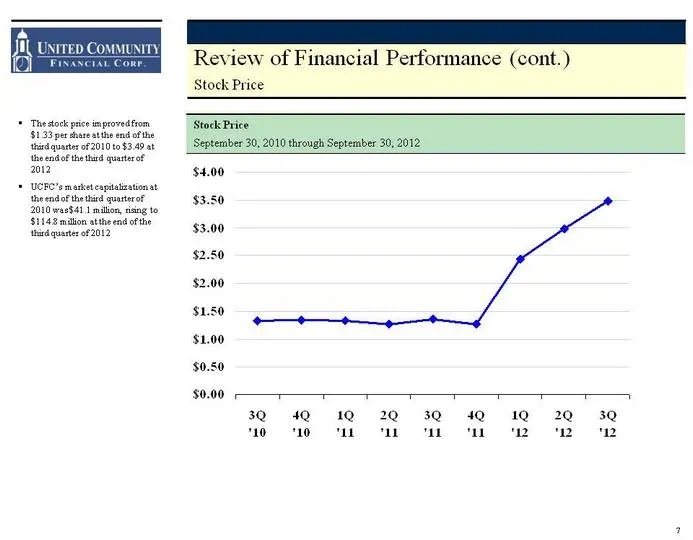
Slide 7: Review of Financial Performance: Stock Price
Review of Financial Performance (cont.) Stock Price 3Q '10 4Q '10 1Q '11 2Q '11 3Q '11 4Q '11 1Q '12 2Q '12 3Q '12 East 1.33 1.34 1.33 1.27 1.35 1.27 2.44 2.98 3.49 Stock PriceSeptember 30, 2010 through September 30, 2012 7 The stock price improved from $1.33 per share at the end of the third quarte
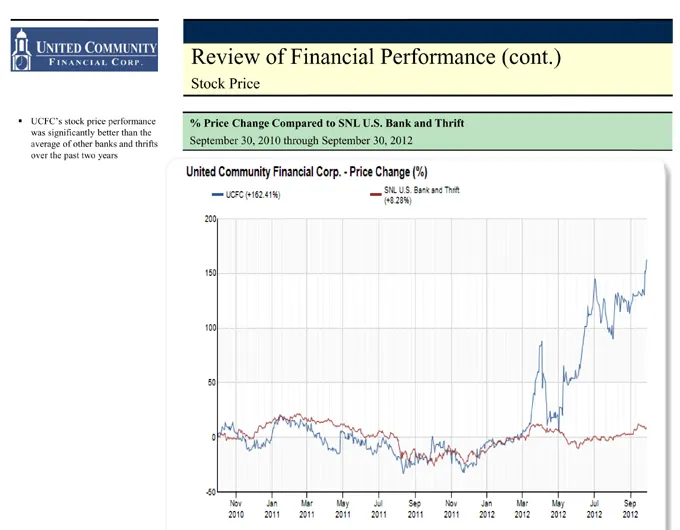
Slide 8: Stock Price % Change Compared to SNL U.S. Bank and Thrift
Review of Financial Performance (cont.) Stock Price % Price Change Compared to SNL U.S. Bank and Thrift September 30, 2010 through September 30, 2012 UCFC's stock price performance was significantly better than the average of other banks and thrifts over the past two years
Slide 9: James R. Reske, Chief Financial Officer and Treasurer
James R. Reske Chief Financial Officer and Treasurer
Slide 10: Operations: Branches and Loan Production Offices
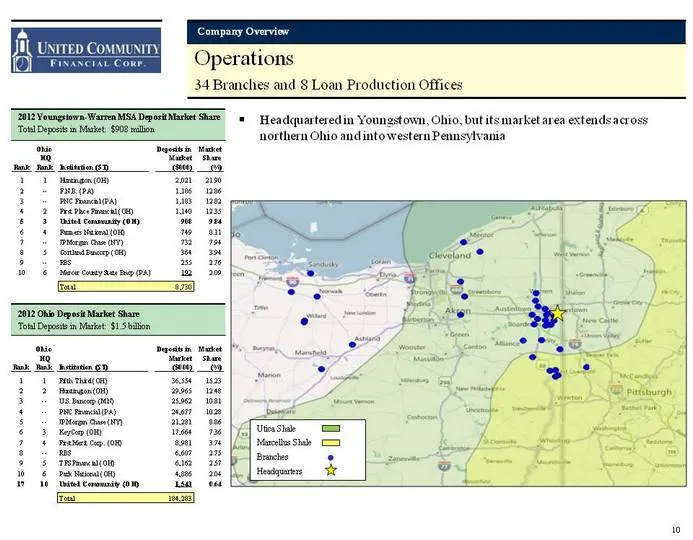
Operations 34 Branches and 8 Loan Production Offices Headquartered in Youngstown, Ohio, but its market area extends across northern Ohio and into western Pennsylvania Company Overview Utica Shale Marcellus Shale BranchesHeadquarters 2012 Ohio Deposit Market Share Total Deposits in Market: $1.5 billi
Slide 11: Bulk Loan Sale, Third Quarter 2012
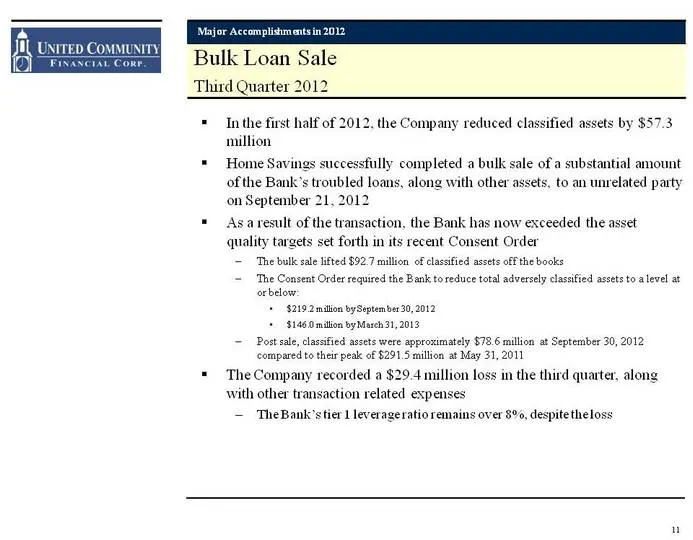
Bulk Loan Sale Third Quarter 2012 11 In the first half of 2012, the Company reduced classified assets by $57.3 million Home Savings successfully completed a bulk sale of a substantial amount of the Bank's troubled loans, along with other assets, to an unrelated party on September 21, 2012As a result
Slide 12: UCFC Earnings Analysis
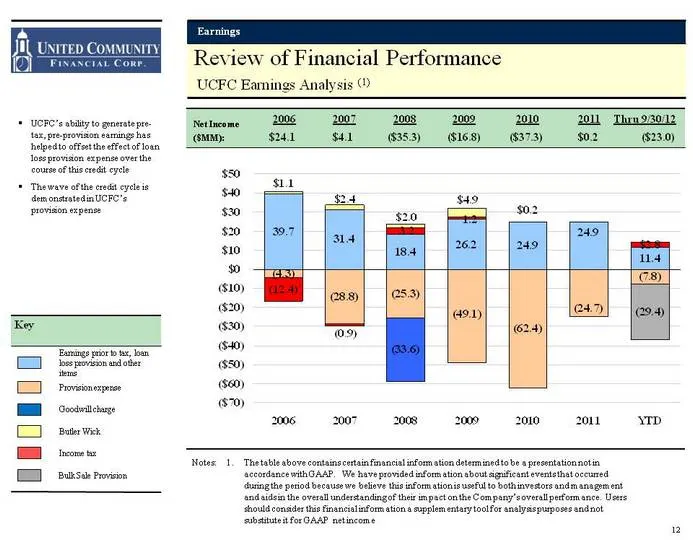
Review of Financial Performance UCFC Earnings Analysis (1) Earnings prior to tax, loan loss provision and other items Provision expense Goodwill charge Key Income tax UCFC's ability to generate pre- tax, pre-provision earnings has helped to offset the effect of loan loss provision expense over the c
Slide 13: Capital Ratios: Capital Adequacy at Home Savings
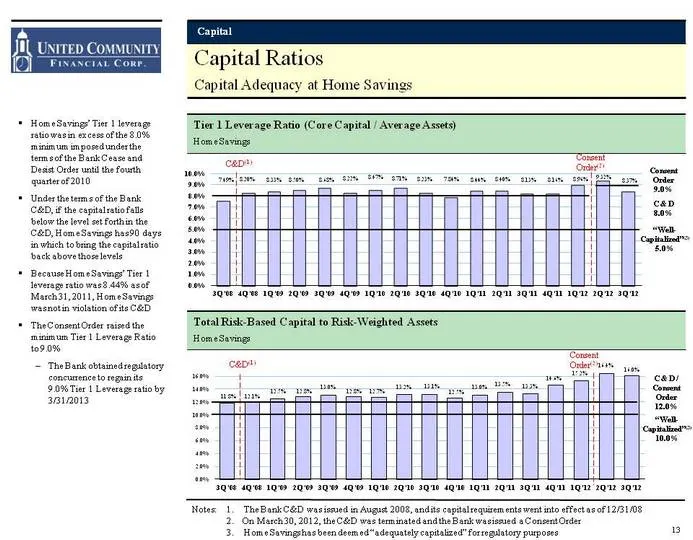
Capital Ratios Capital Adequacy at Home Savings (CHART) C & D 8.0% "Well- Capitalized"(3)5.0% Tier 1 Leverage Ratio (Core Capital / Average Assets)Home Savings Home Savings' Tier 1 leverage ratio was in excess of the 8.0% minimum imposed under the terms of the Bank Cease and Desist Order until the f
Slide 14: Loan Portfolios
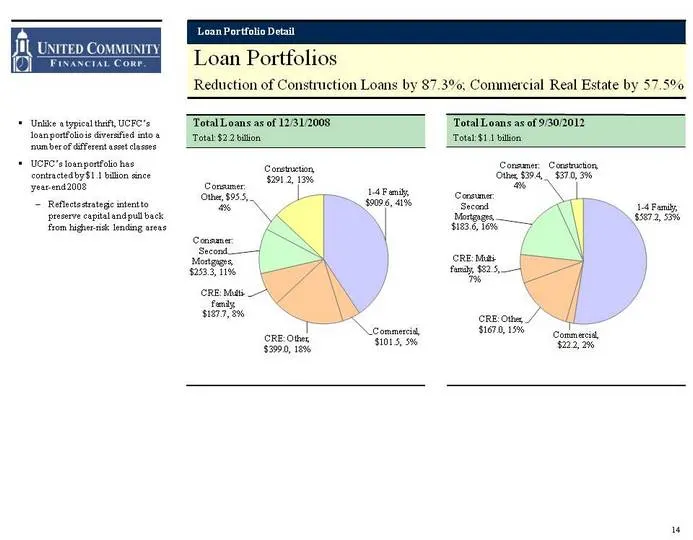
Loan Portfolios Reduction of Construction Loans by 87.3%; Commercial Real Estate by 57.5% Unlike a typical thrift, UCFC's loan portfolio is diversified into a number of different asset classesUCFC's loan portfolio has contracted by $1.1 billion since year-end 2008Reflects strategic intent to preserv
Slide 15: Funding Detail: De-Risking the Balance Sheet
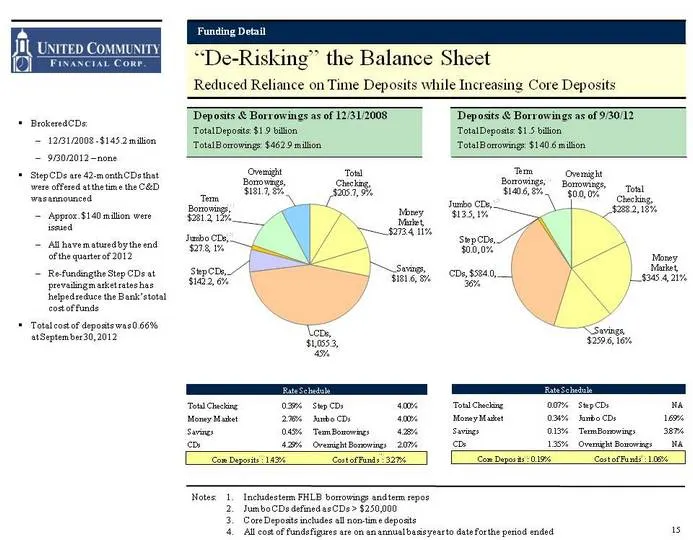
Brokered CDs:12/31/2008 - $145.2 million9/30/2012 - noneStep CDs are 42-month CDs that were offered at the time the C&D was announcedApprox. $140 million were issuedAll have matured by the end of the quarter of 2012Re-funding the Step CDs at prevailing market rates has helped reduce the Bank's total
Slide 16: Going Forward
Going Forward
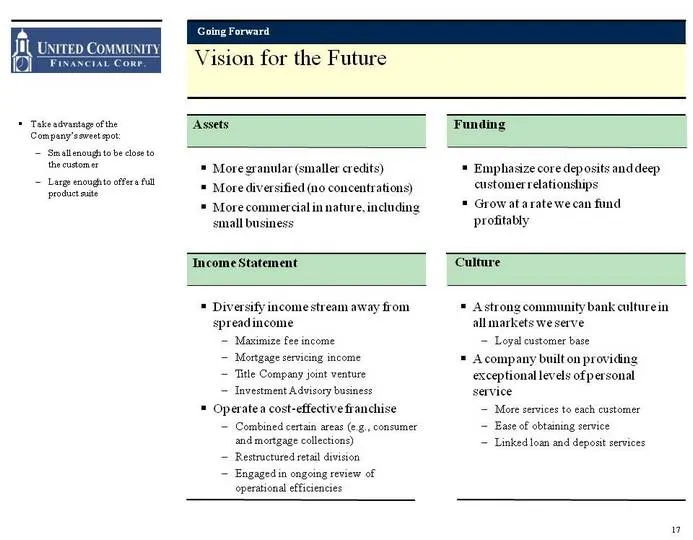
Slide 17: Vision for the Future
Diversify income stream away from spread incomeMaximize fee incomeMortgage servicing incomeTitle Company joint ventureInvestment Advisory businessOperate a cost-effective franchiseCombined certain areas (e.g., consumer and mortgage collections)Restructured retail divisionEngaged in ongoing review of
Slide 18: United Community Financial Corp. - Questions
United Community Financial Corp.NASDAQ: UCFCwww.UCFCONLINE.comwww.HOMESAVINGS.comHeadquarters275 West Federal StreetYoungstown, Ohio 44503 18 Questions
Slide 19: Appendix
Appendix
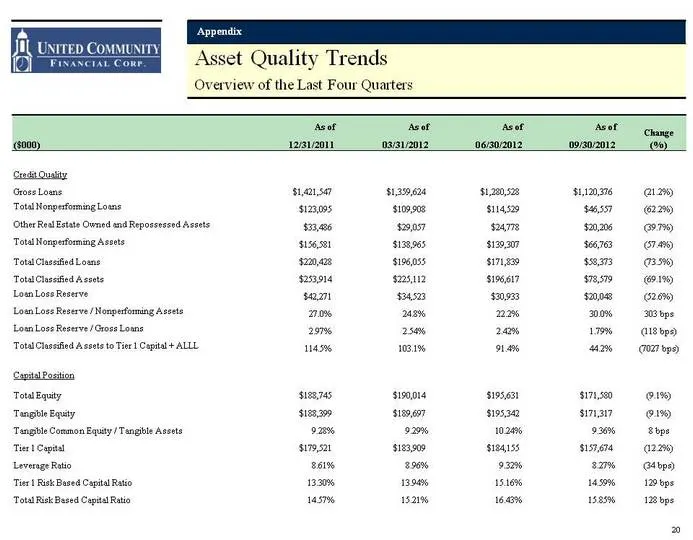
Slide 20: Asset Quality Trends: Overview of the Last Four Quarters
Asset Quality Trends Overview of the Last Four Quarters 20 Appendix
Slide 21: Asset Quality Trends ($000)
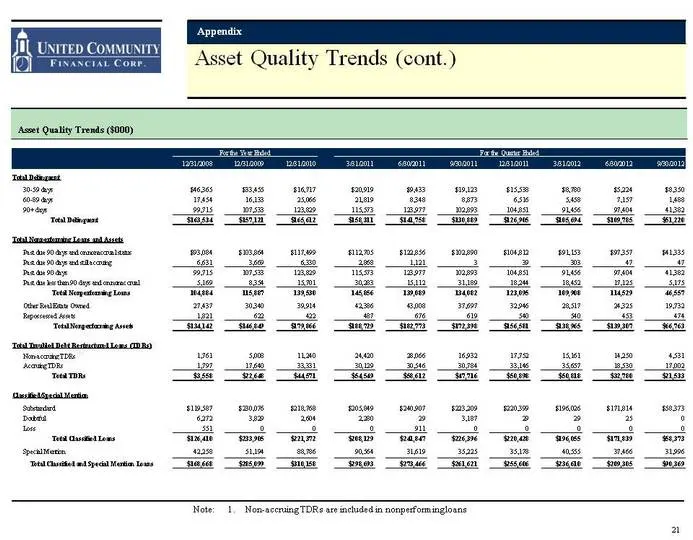
Asset Quality Trends ($000) Asset Quality Trends (cont.) Appendix 21 Note: 1. Non-accruing TDRs are included in nonperforming loans
Slide 22: Asset Quality - UCFC Consolidated
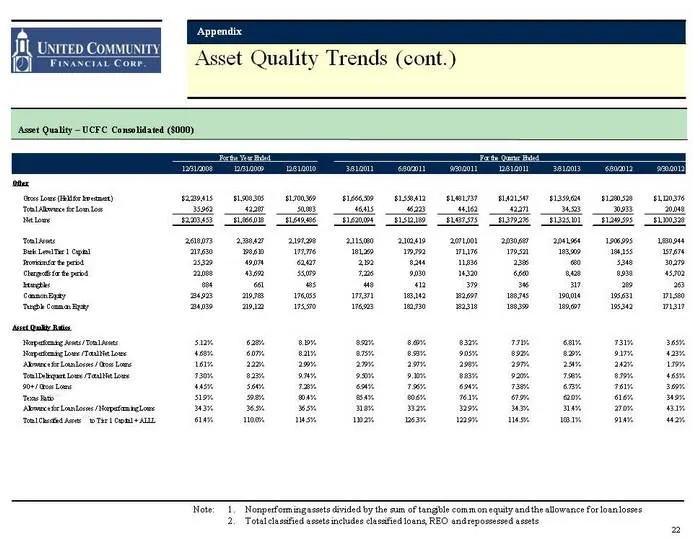
Asset Quality Trends (cont.) Appendix Asset Quality - UCFC Consolidated ($000) 22 Note: 1. Nonperforming assets divided by the sum of tangible common equity and the allowance for loan losses 2. Total classified assets includes classified loans, REO and repossessed assets
Slide 23: Mortgage Loan Delinquency Compared with State and National Averages
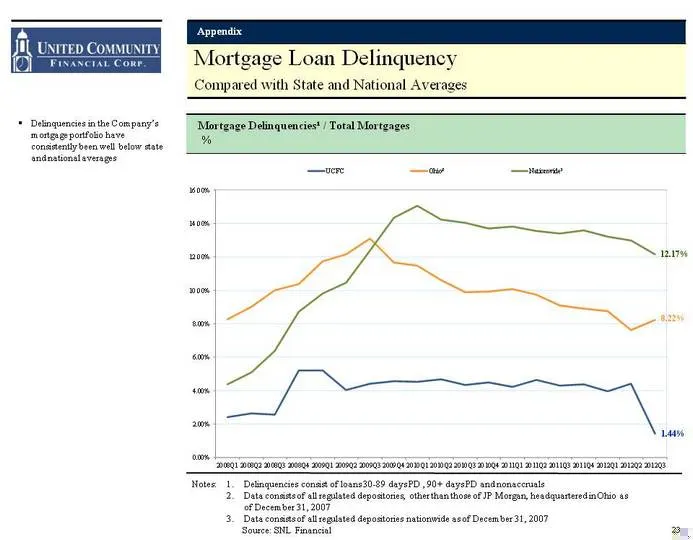
Mortgage Loan Delinquency Compared with State and National Averages Appendix Mortgage Delinquencies1 / Total Mortgages% 23 Delinquencies in the Company's mortgage portfolio have consistently been well below state and national averages 1.44% 8.22% 12.17% Notes: 1. Delinquencies consist of loans 30-89
Slide 24: De-Risking the Balance Sheet: Loan Concentrations
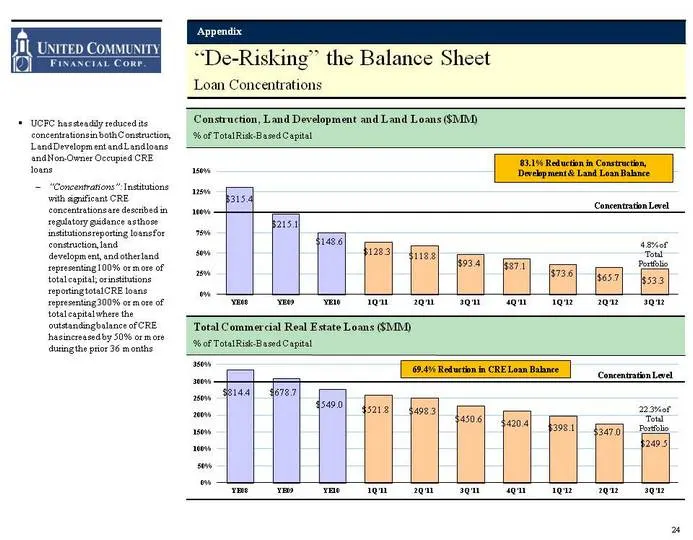
"De-Risking" the Balance Sheet Loan Concentrations Loan Concentrations Loan Concentrations Total Commercial Real Estate Loans ($MM)% of Total Risk-Based Capital UCFC has steadily reduced its concentrations in both Construction, Land Development and Land loans and Non-Owner Occupied CRE loans"Concent
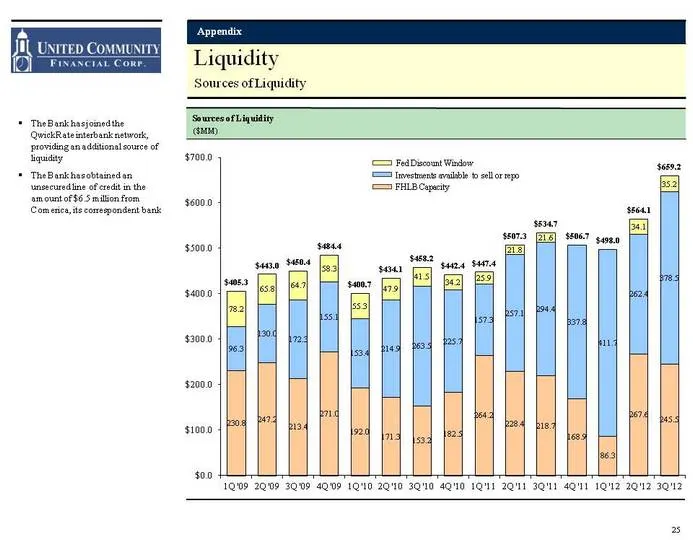
Slide 25: Liquidity: Sources of Liquidity
Liquidity Sources of Liquidity Sources of Liquidity Sources of Liquidity Sources of Liquidity Fed Discount Window Investments available to sell or repo FHLB Capacity The Bank has joined the QwickRate interbank network, providing an additional source of liquidityThe Bank has obtained an unsecured lin
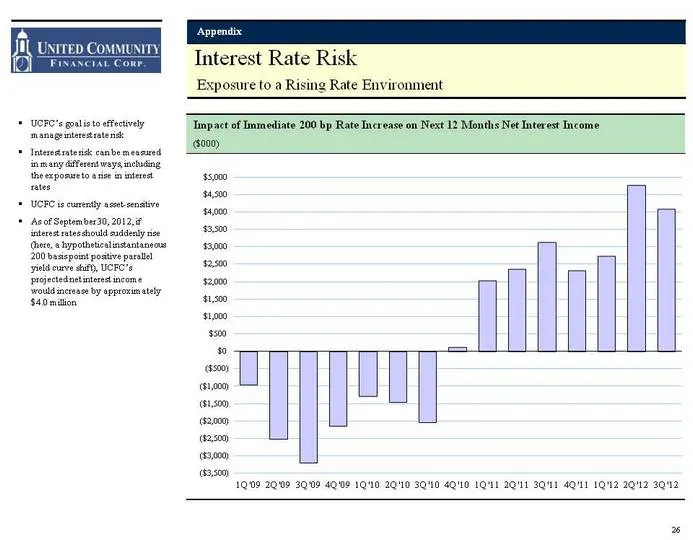
Slide 26: Interest Rate Risk: Exposure to a Rising Rate Environment
Interest Rate Risk Exposure to a Rising Rate Environment Exposure to a Rising Rate Environment Exposure to a Rising Rate Environment Impact of Immediate 200 bp Rate Increase on Next 12 Months Net Interest Income UCFC's goal is to effectively manage interest rate riskInterest rate risk can be measure
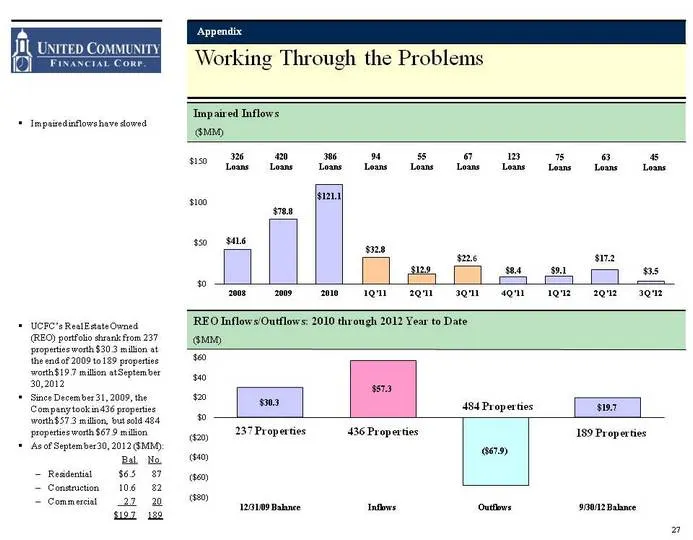
Slide 27: Working Through the Problems: REO Inflows/Outflows
Working Through the Problems REO Inflows/Outflows: 2010 through 2012 Year to Date ($MM) UCFC's Real Estate Owned (REO) portfolio shrank from 237 properties worth $30.3 million at the end of 2009 to 189 properties worth $19.7 million at September 30, 2012Since December 31, 2009, the Company took in 4
Source: SEC EDGAR · 8-K filed Dec 18, 2012
More decks from United Community Financial Corp
 Merger or Acquisition (September 2019)20 slides · Sep 9, 2019
 Merger or Acquisition (September 2016)15 slides · Sep 9, 2016
 Raymond James Presentation (October 2015)23 slides · Oct 30, 2015
 Shareholder Meeting (August 2013)20 slides · Aug 27, 2013
 Shareholder Meeting (April 2011)18 slides · Apr 28, 2011
 Investor Presentation (February 2010)22 slides · Feb 18, 2010