Gemfields Group Limited · JSE:GML
Gemfields — H1 FY2017 Earnings Presentation
34 slides from Gemfields's earnings presentation, Feb 20, 2017
Slide 1: Interim results for the six months ended 31 December 2016
A leading supplier of responsibly sourced coloured gemstones Interim results for the six months ended 31 December 2016 20 February 2017 Gemfields Plc
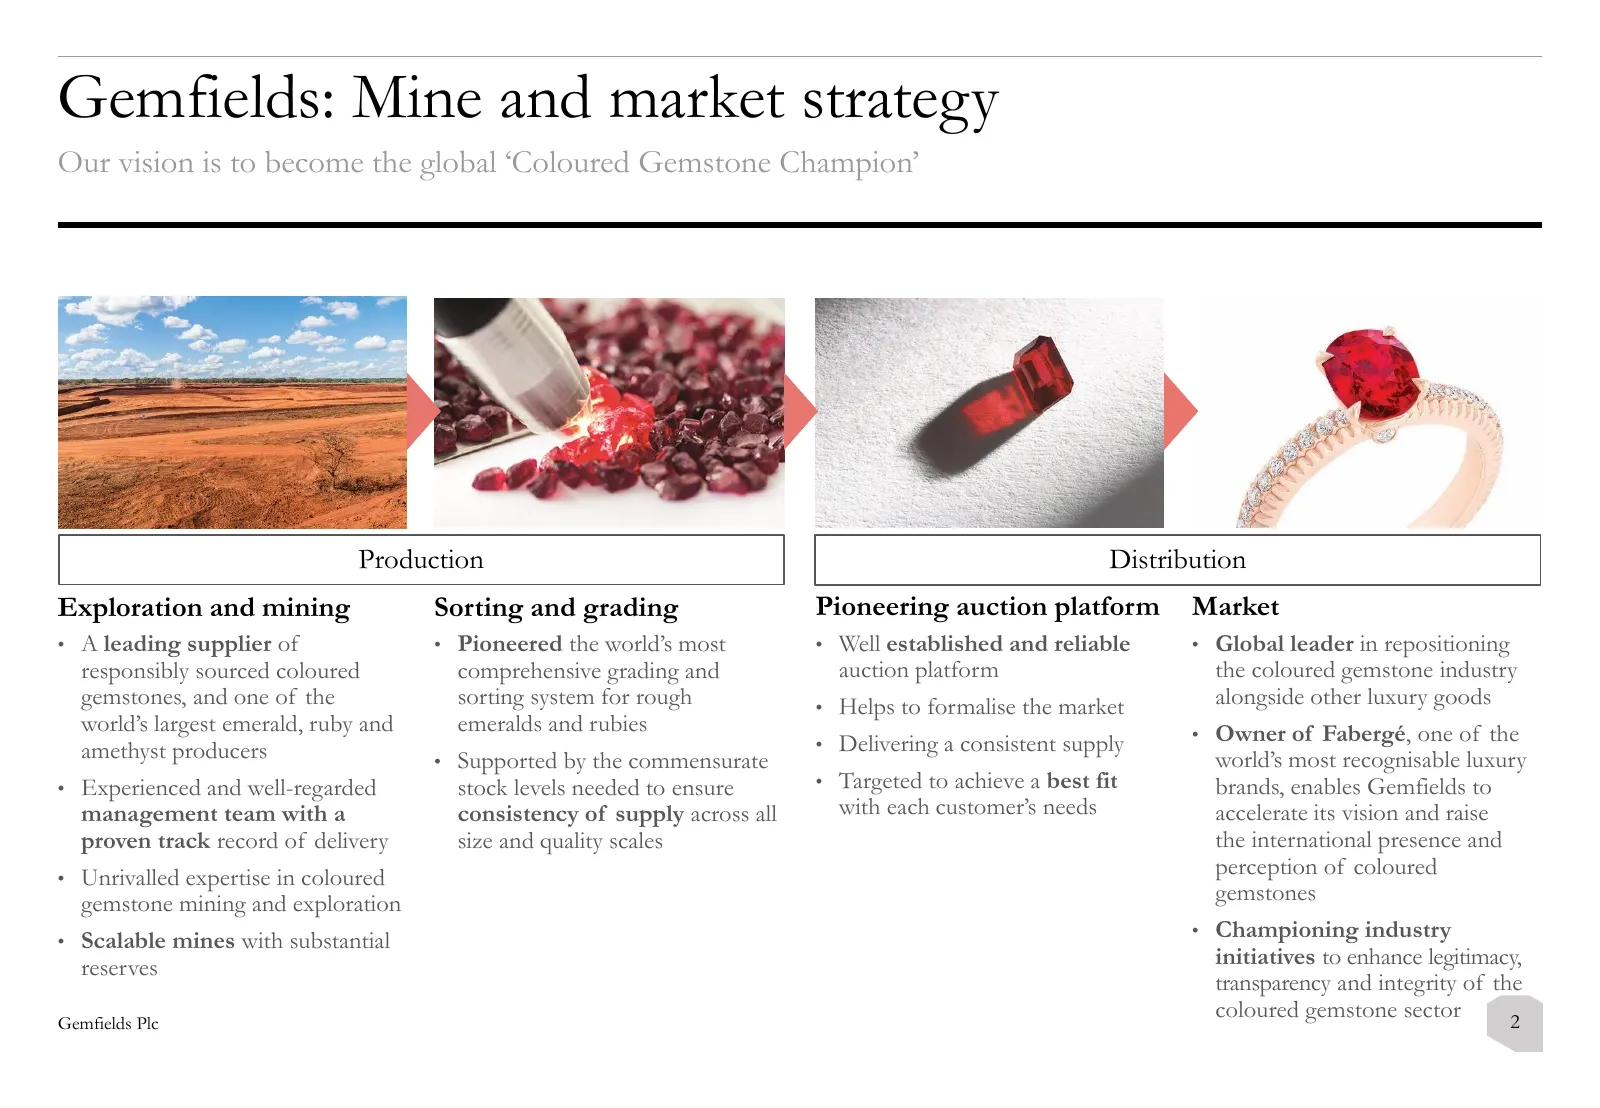
Slide 2: Gemfields: Mine and market strategy
Gemfields: Mine and market strategy Our vision is to become the global ‘Coloured Gemstone Champion’ Production Distribution Exploration and mining Sorting and grading Pioneering auction platform Market • A leading supplier of • Pioneered the world’s most • Well established and reliable • Global lead
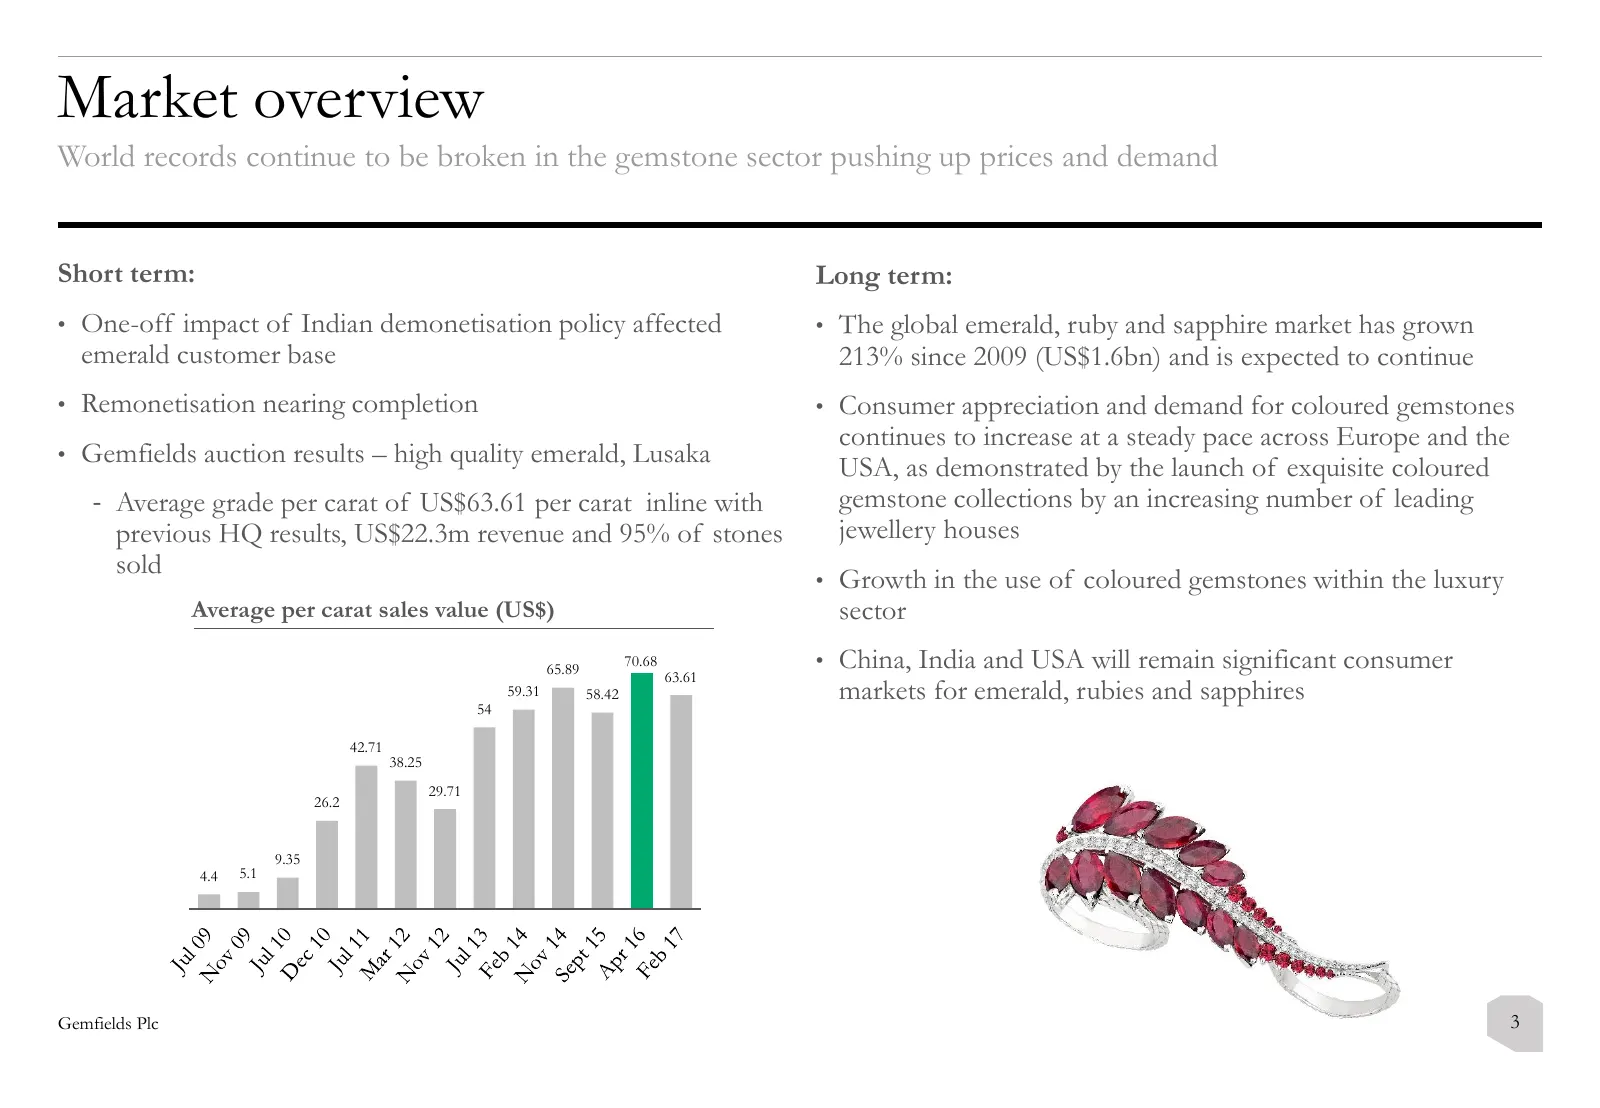
Slide 3: Market overview
Market overview World records continue to be broken in the gemstone sector pushing up prices and demand Short term: Long term: • One-off impact of Indian demonetisation policy affected • The global emerald, ruby and sapphire market has grown emerald customer base 213% since 2009 (US$1.6bn) and is ex
Slide 4: Financial Highlights
Financial Highlights Gemfields Plc 4
Slide 5: Financial highlights
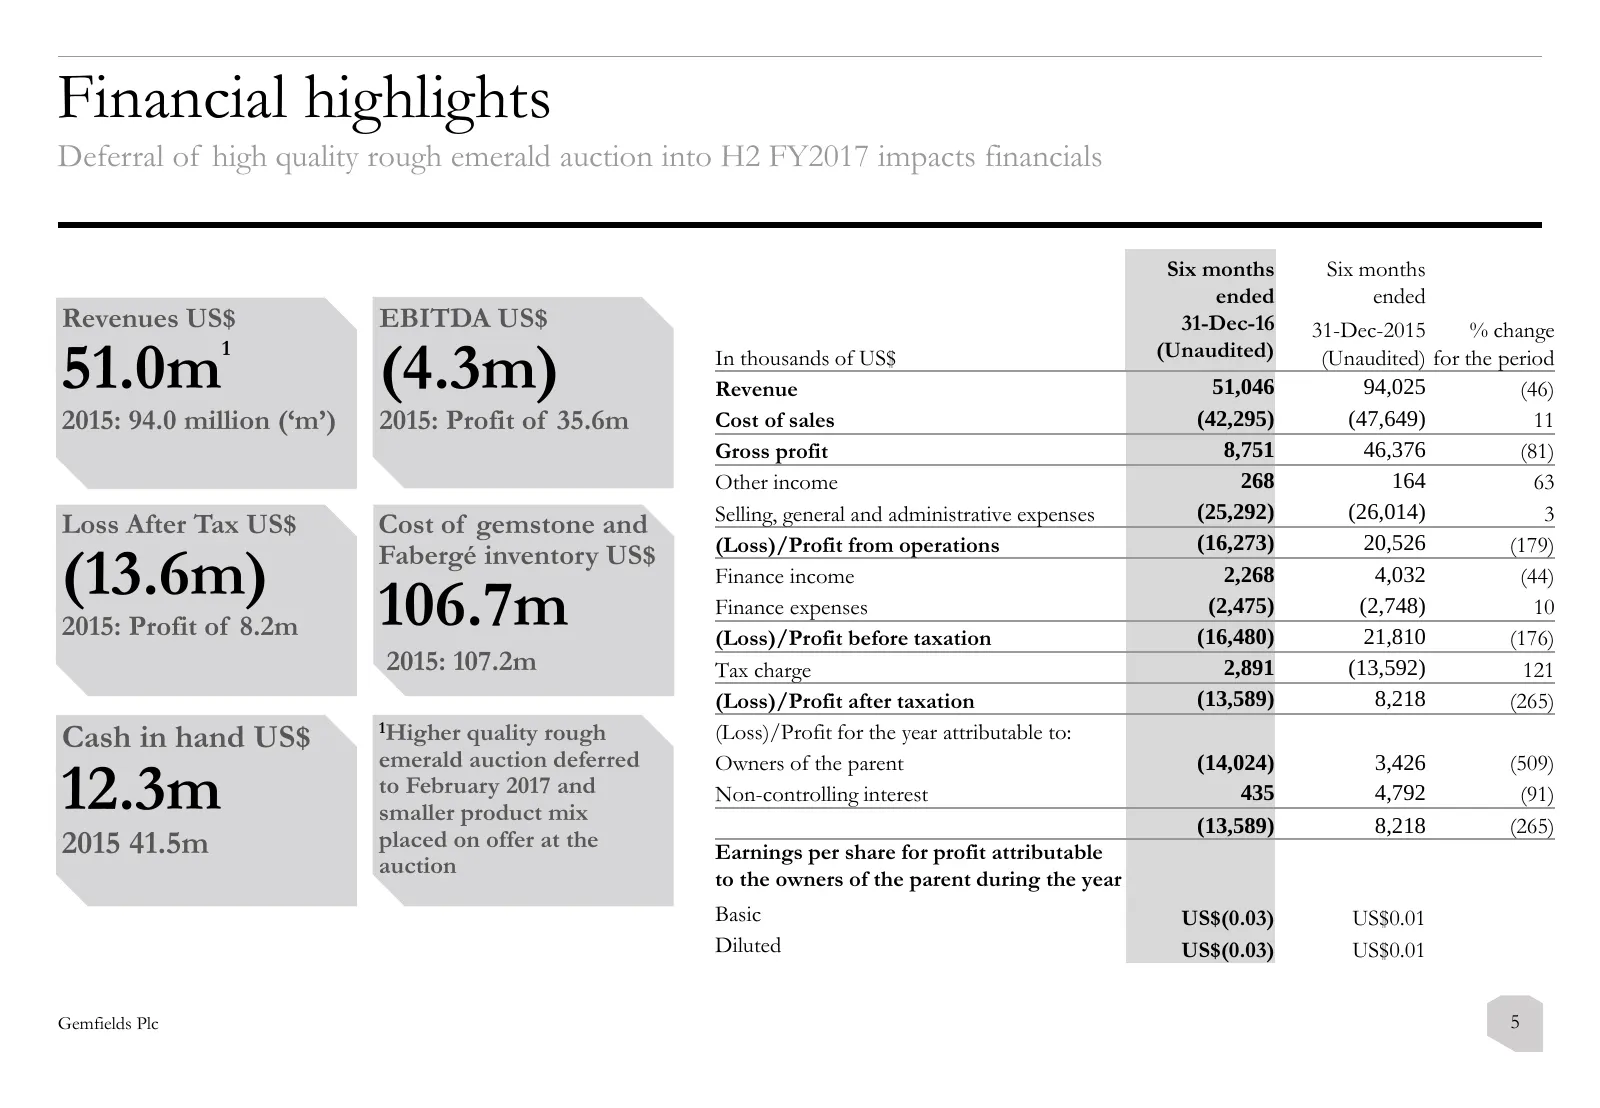
Financial highlights Deferral of high quality rough emerald auction into H2 FY2017 impacts financials Six months Six months ended ended Revenues US$ EBITDA US$ 31-Dec-16 31-Dec-2015 % change 51.0m 1 (4.3m) In thousands of US$ Revenue (Unaudited) 51,046 (Unaudited) for the period 94,025 (46) 2015: 94
Slide 6: Auction analysis – two auctions held during the period
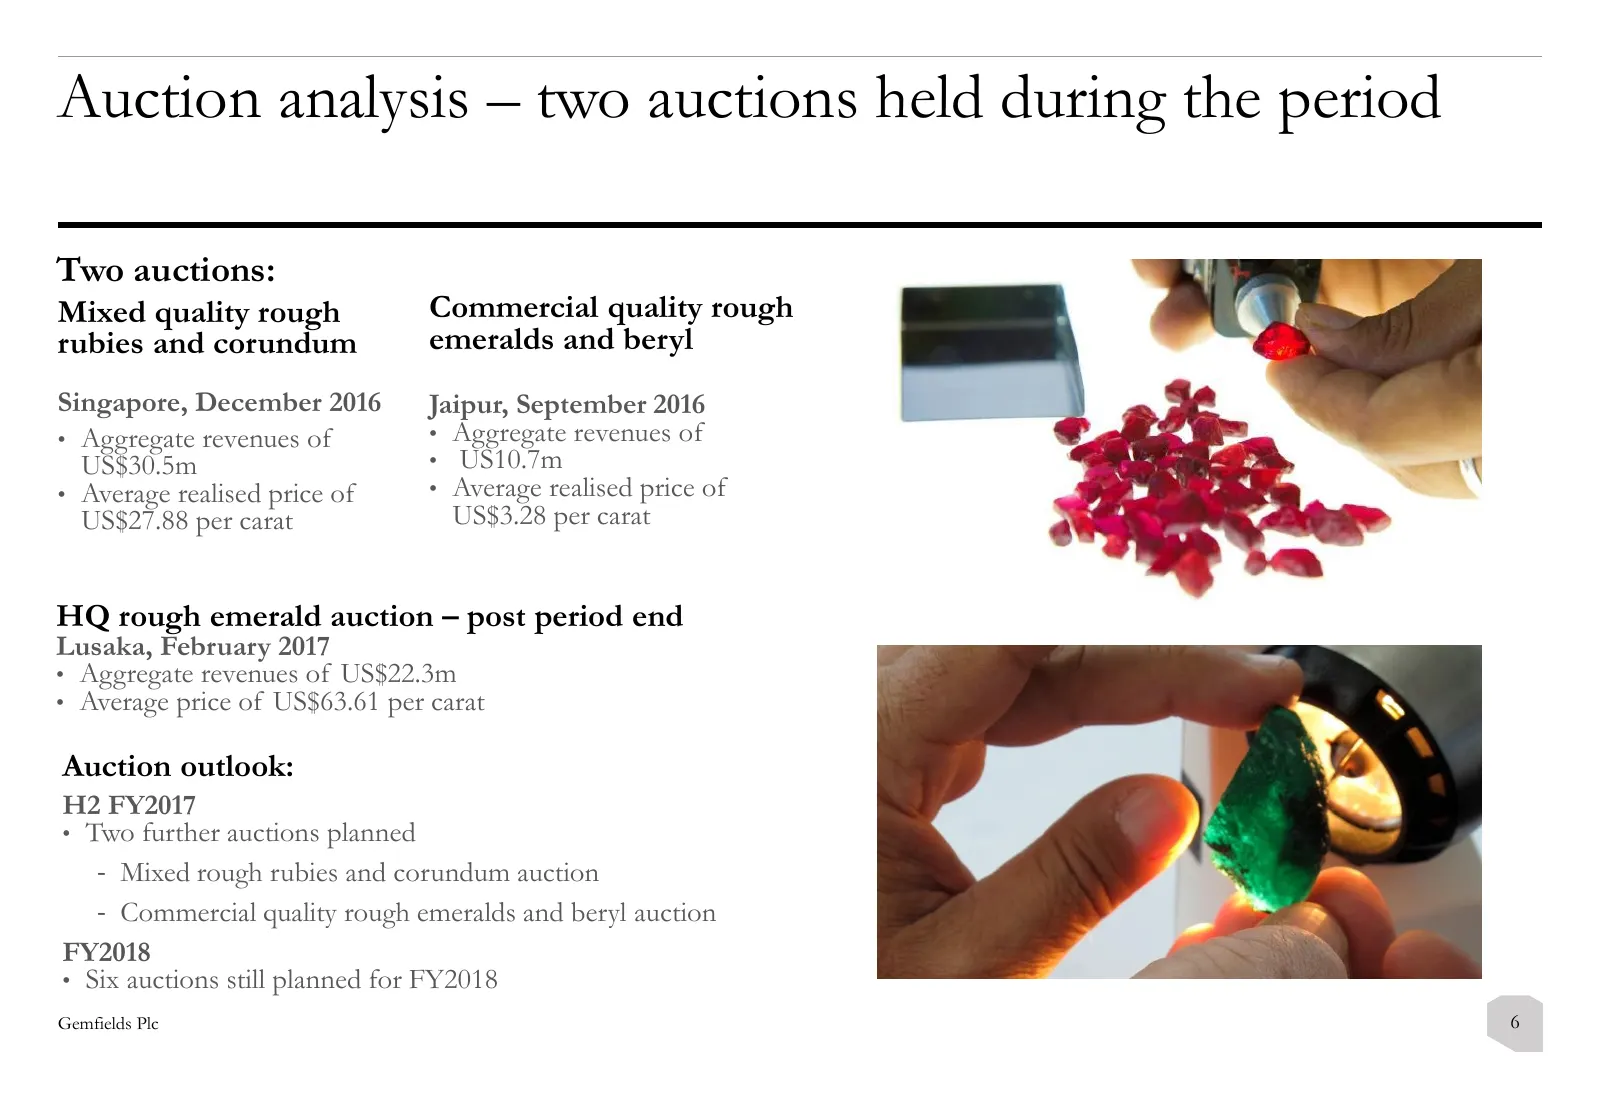
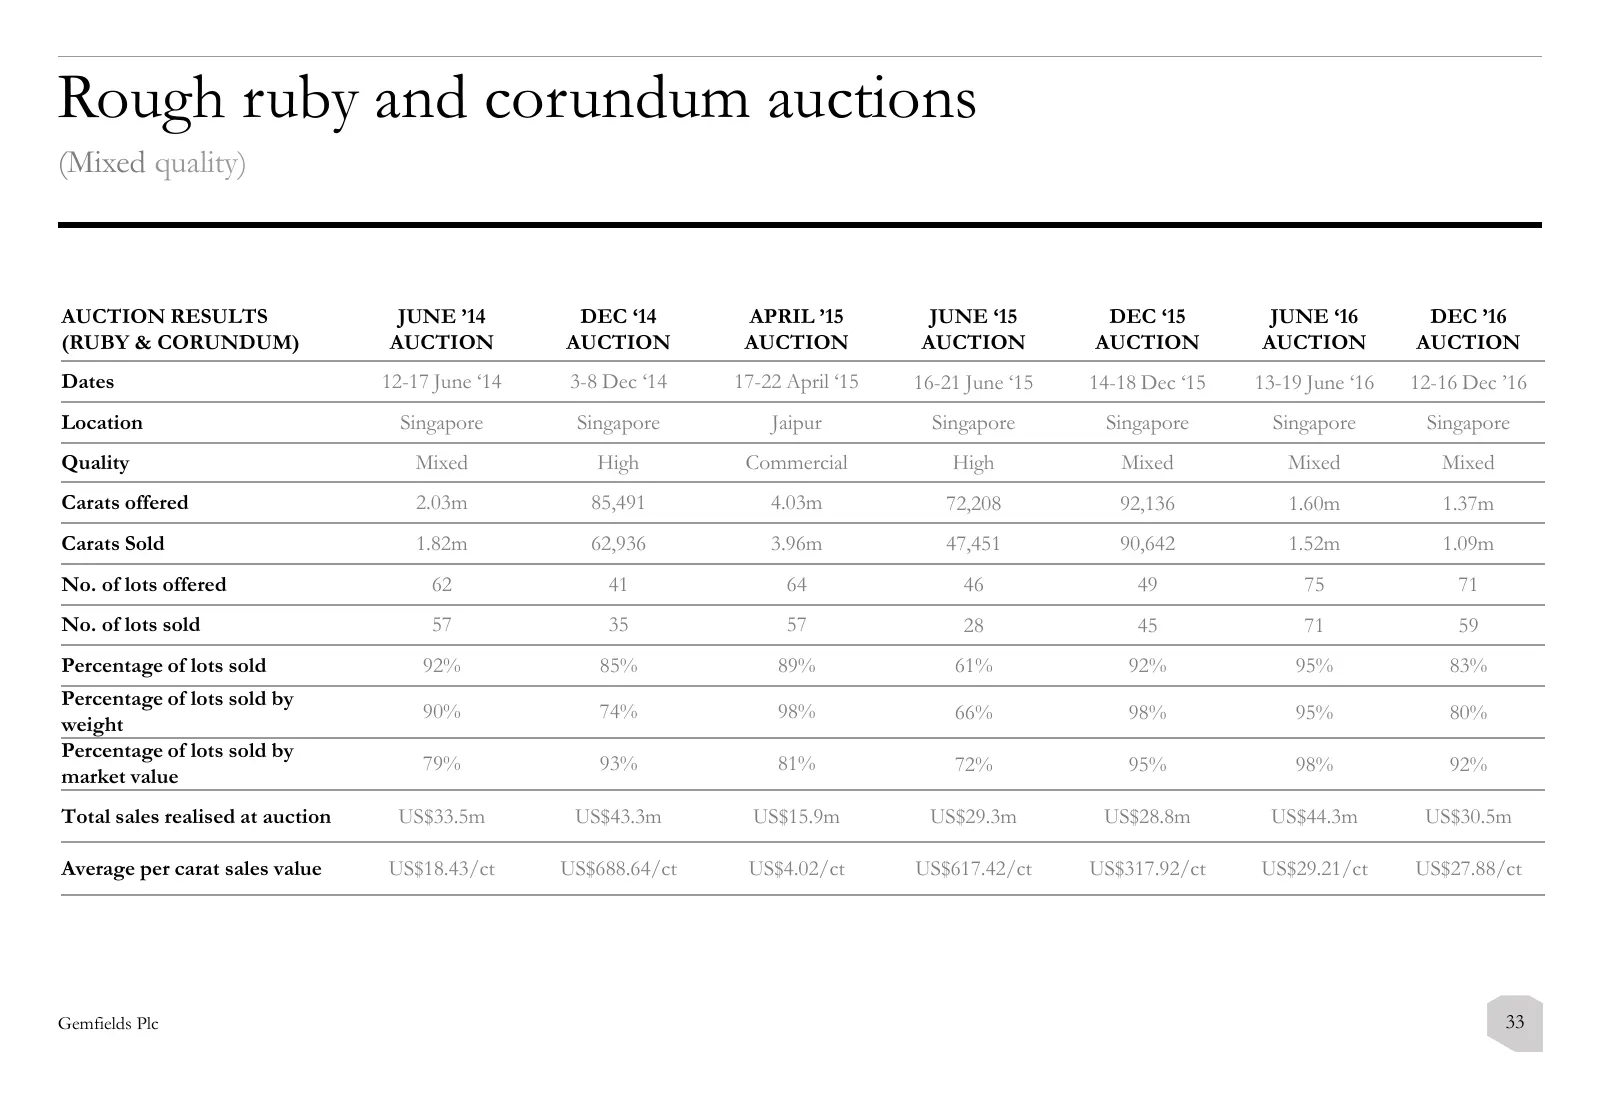
Auction analysis – two auctions held during the period Two auctions: Mixed quality rough Commercial quality rough rubies and corundum emeralds and beryl Singapore, December 2016 Jaipur, September 2016 • Aggregate revenues of • Aggregate revenues of US$30.5m • US10.7m • Average realised price of • Av
Slide 7: Cost of sales and inventory breakdown
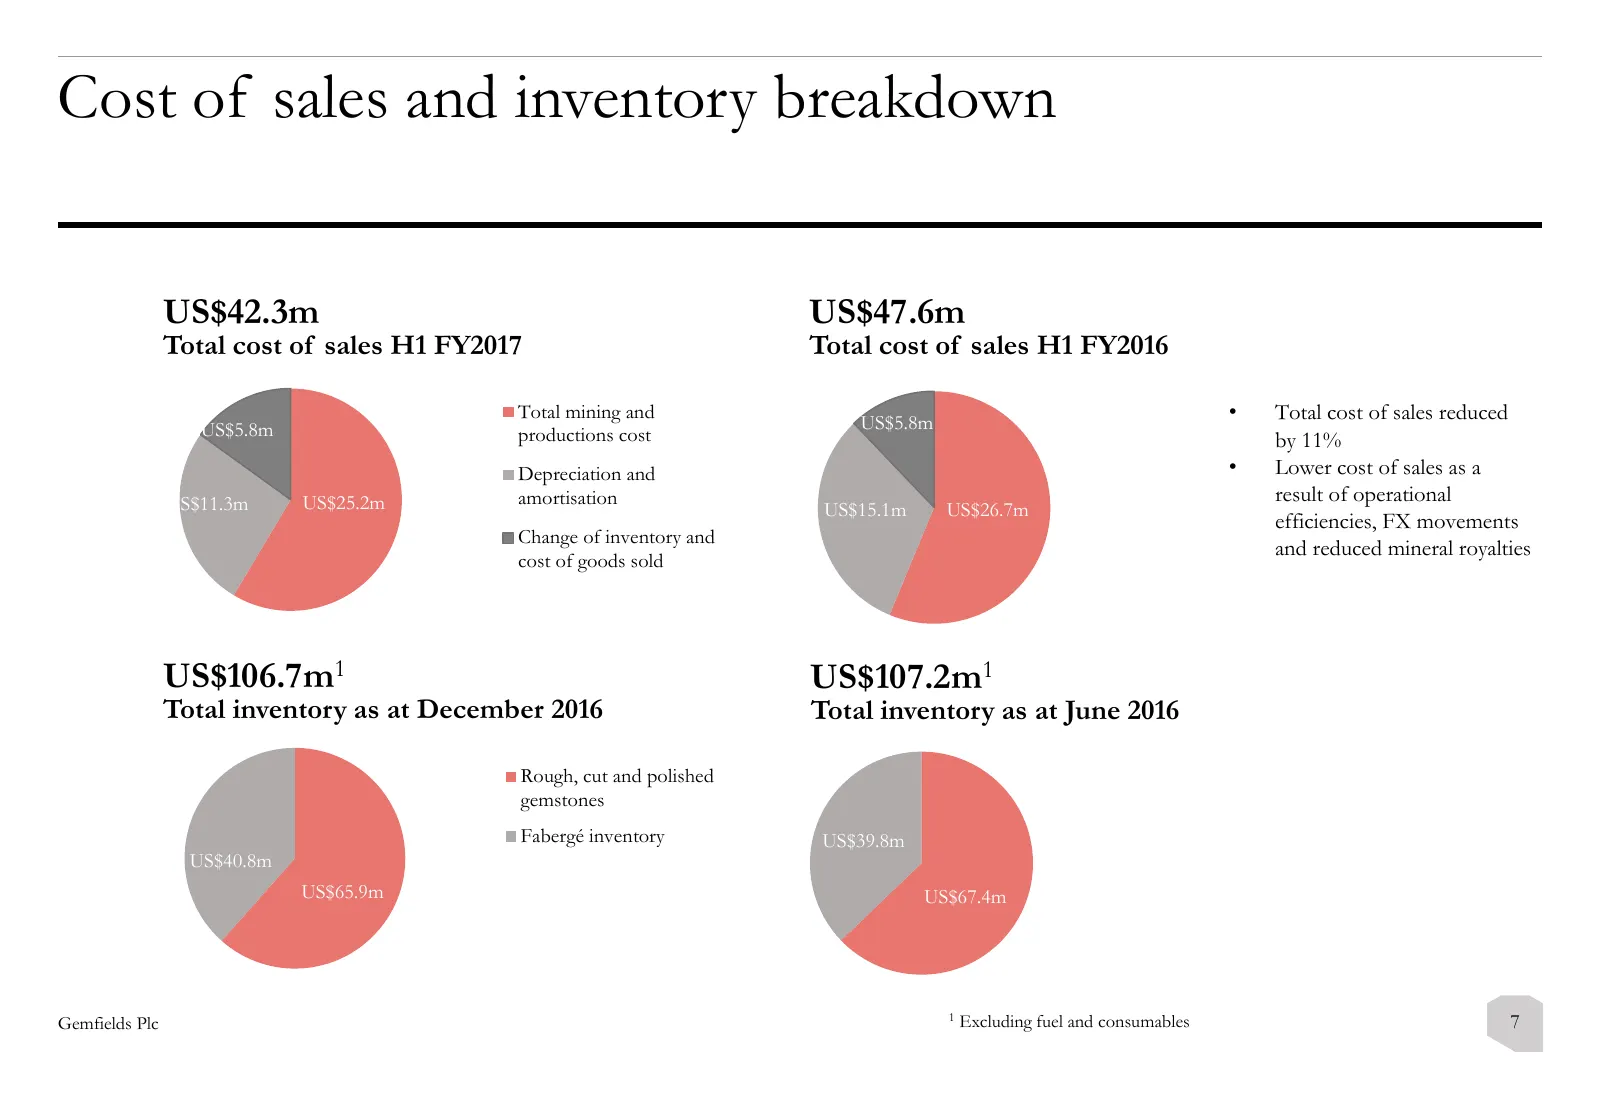
Cost of sales and inventory breakdown US$42.3m US$47.6m Total cost of sales H1 FY2017 Total cost of sales H1 FY2016 Total mining and US$5.8m • Total cost of sales reduced US$5.8m productions cost by 11% Depreciation and • Lower cost of sales as a US$11.3m US$25.2m amortisation result of operational
Slide 8: Mine cost analysis for Kagem, Zambia (75% owned)
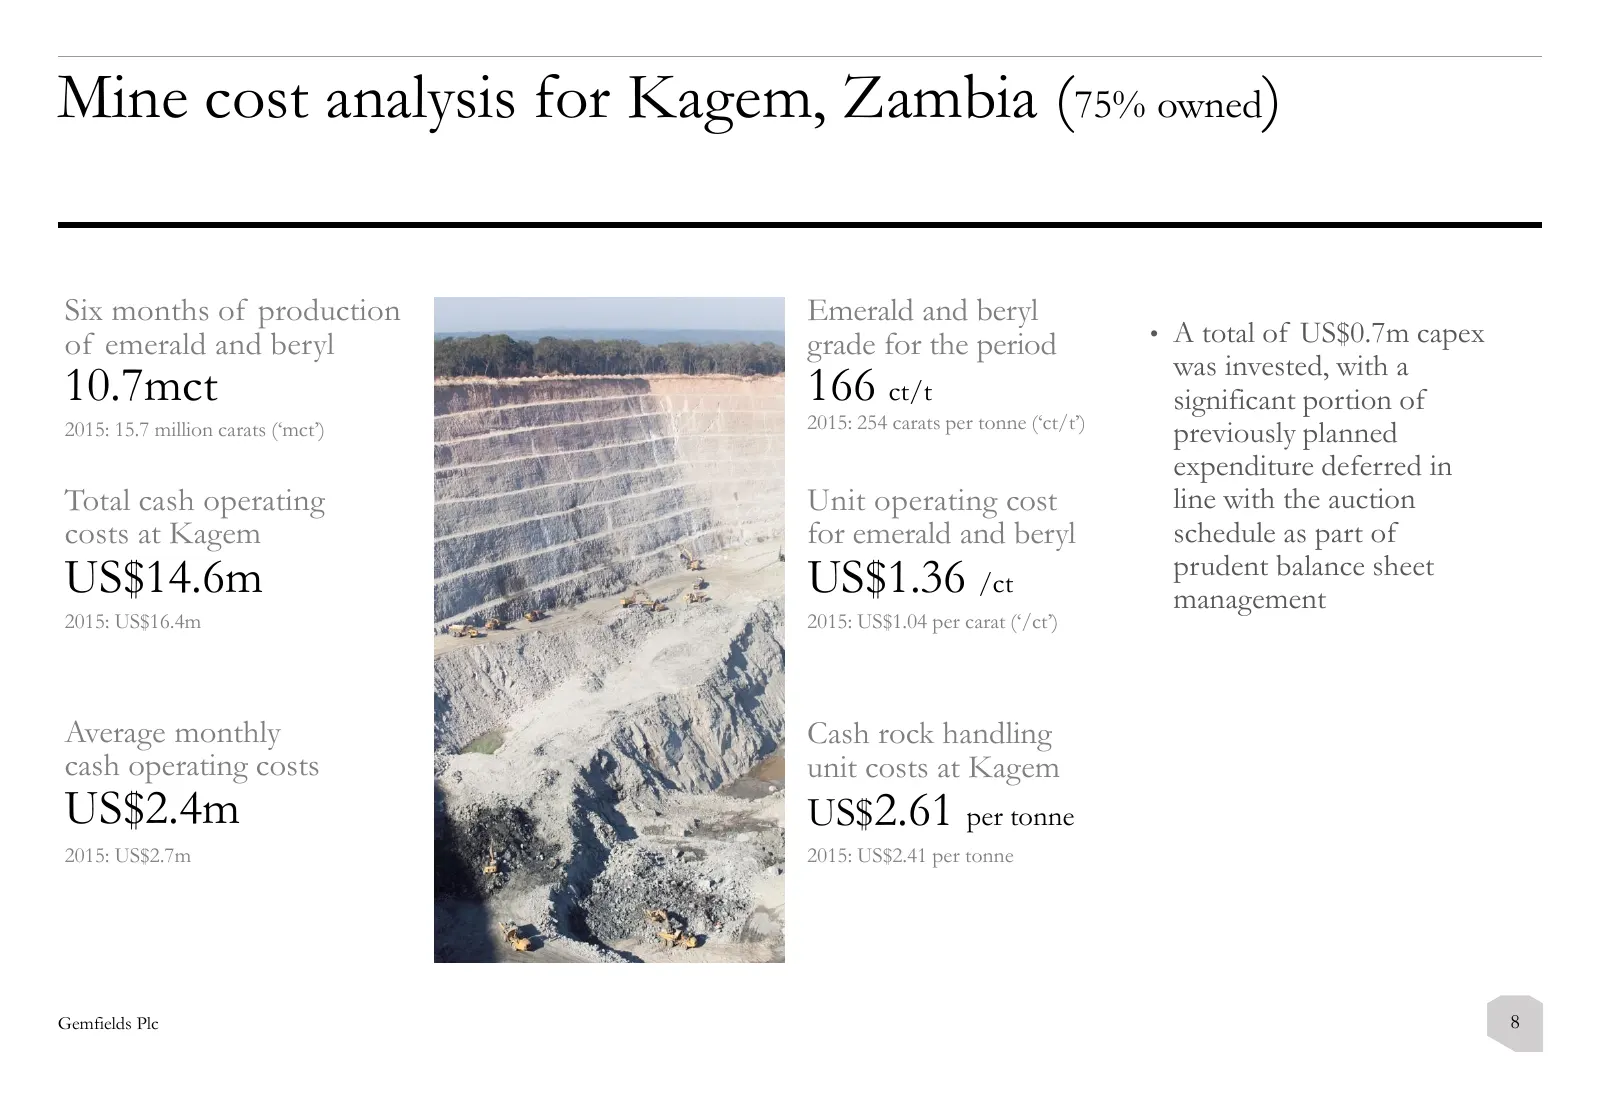
Mine cost analysis for Kagem, Zambia (75% owned) Six months of production Emerald and beryl of emerald and beryl grade for the period • A total of US$0.7m capex was invested, with a 10.7mct 166 ct/t significant portion of 2015: 254 carats per tonne (‘ct/t’) 2015: 15.7 million carats (‘mct’) previous
Slide 9: Mine cost analysis for Montepuez, Mozambique (75% owned)
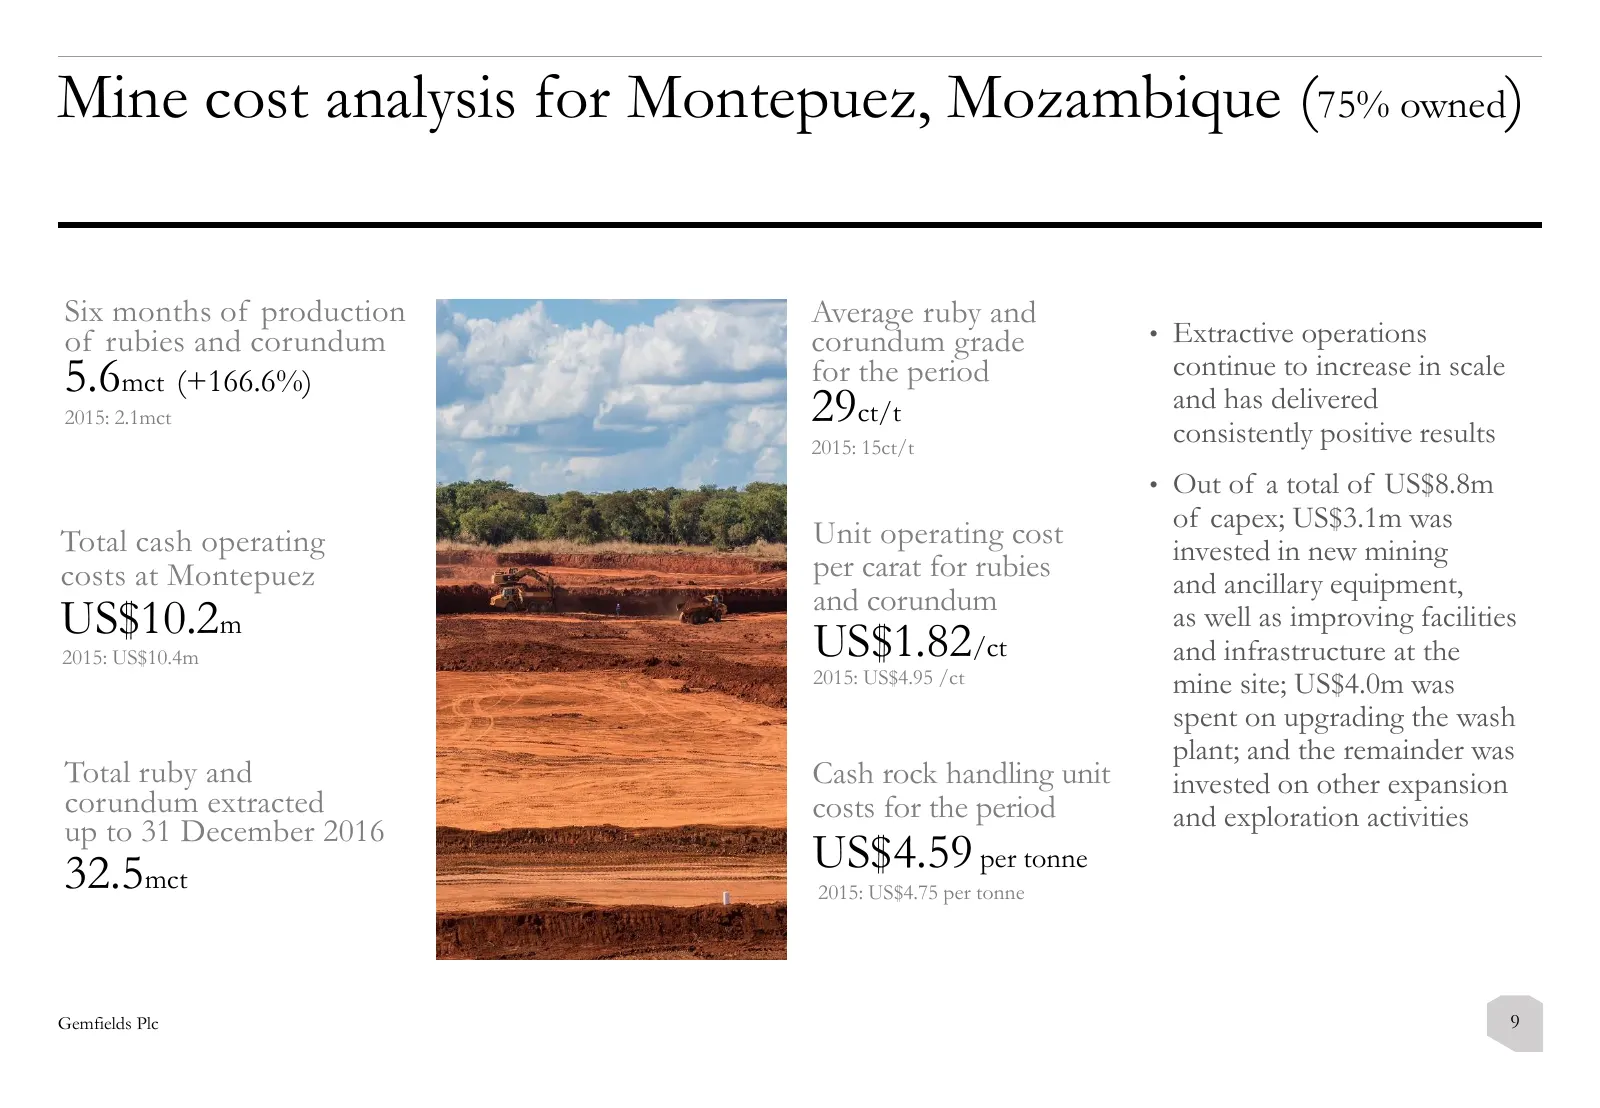
Mine cost analysis for Montepuez, Mozambique (75% owned) Six months of production Average ruby and of rubies and corundum corundum grade • Extractive operations continue to increase in scale 5.6mct (+166.6%) for the period 2015: 2.1mct 29ct/t and has delivered consistently positive results 2015: 15c
Slide 10: Operations
Operations Gemfields Plc 10
Slide 11: Kagem mine
Kagem mine Believed to be the world’s single largest producing emerald mine (75% ownership) Six months ended 31 December 2016 highlights Outlook • Safety performance continues to improve with no reportable injuries • Revised guidance target of 25-30mct of emerald and beryl during the period producti
Slide 12: Kagem production
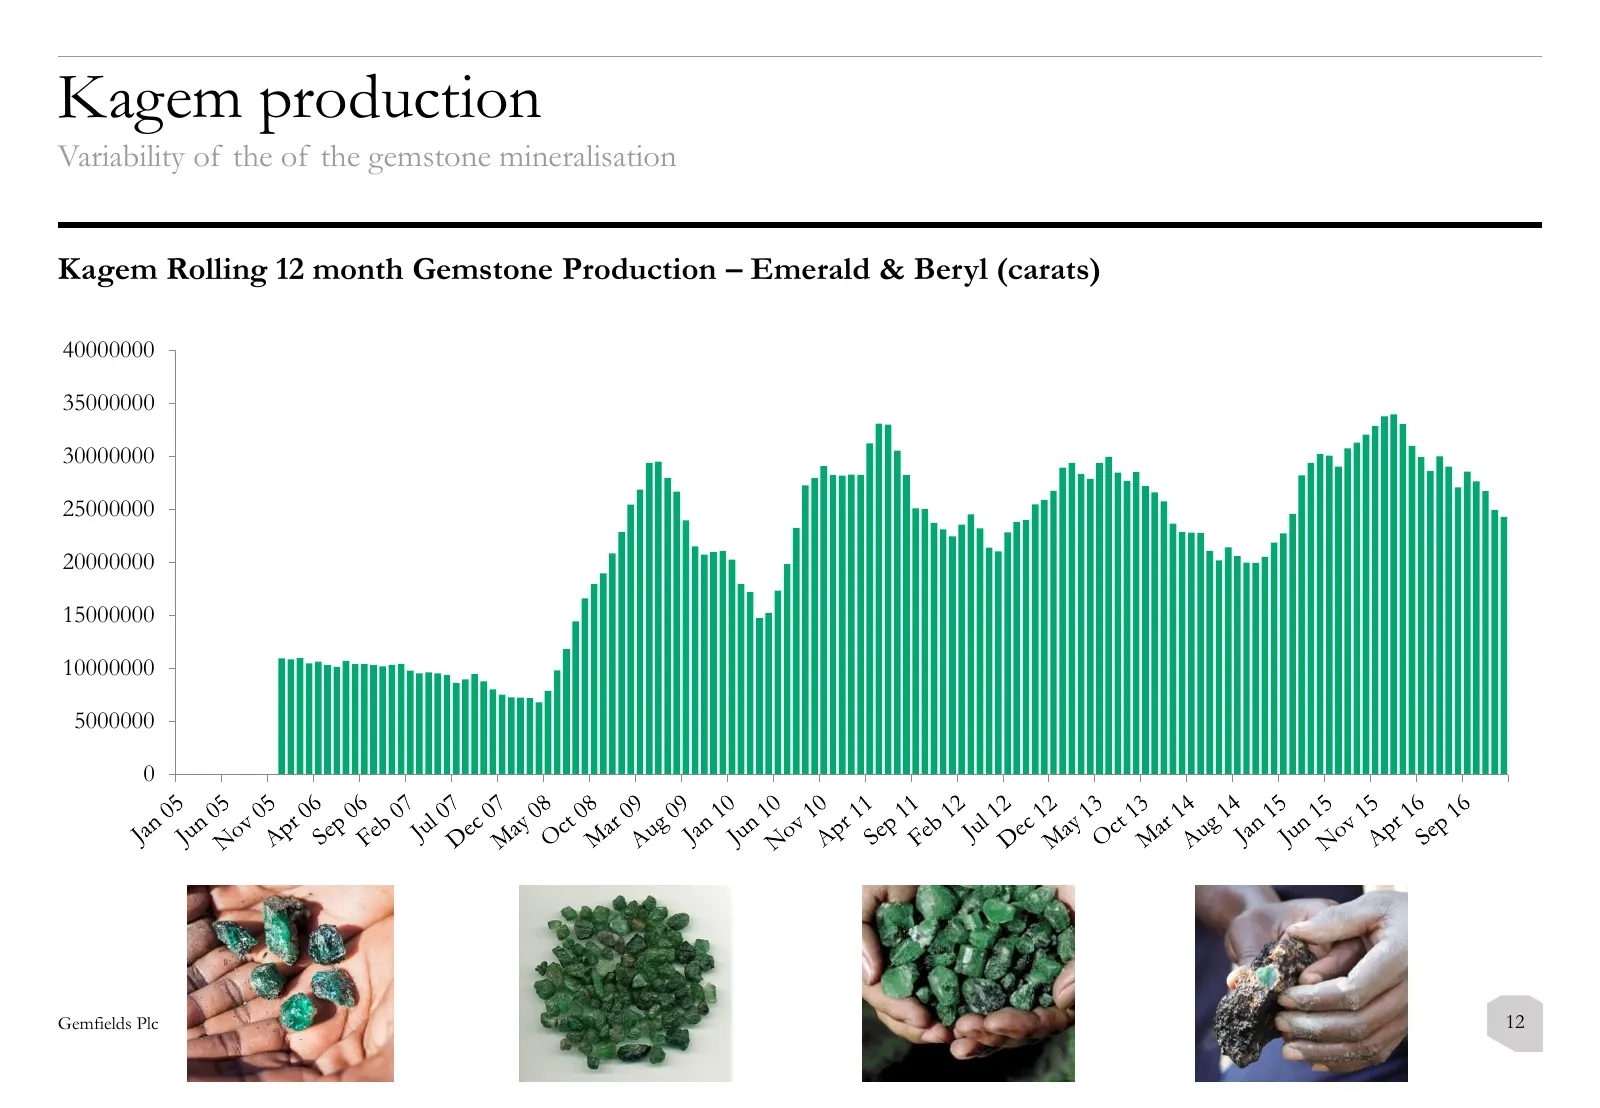
Kagem production Variability of the of the gemstone mineralisation Kagem Rolling 12 month Gemstone Production – Emerald & Beryl (carats) 40000000 35000000 30000000 25000000 20000000 15000000 10000000 5000000 0 Gemfields Plc 12
Slide 13: Montepuez mine
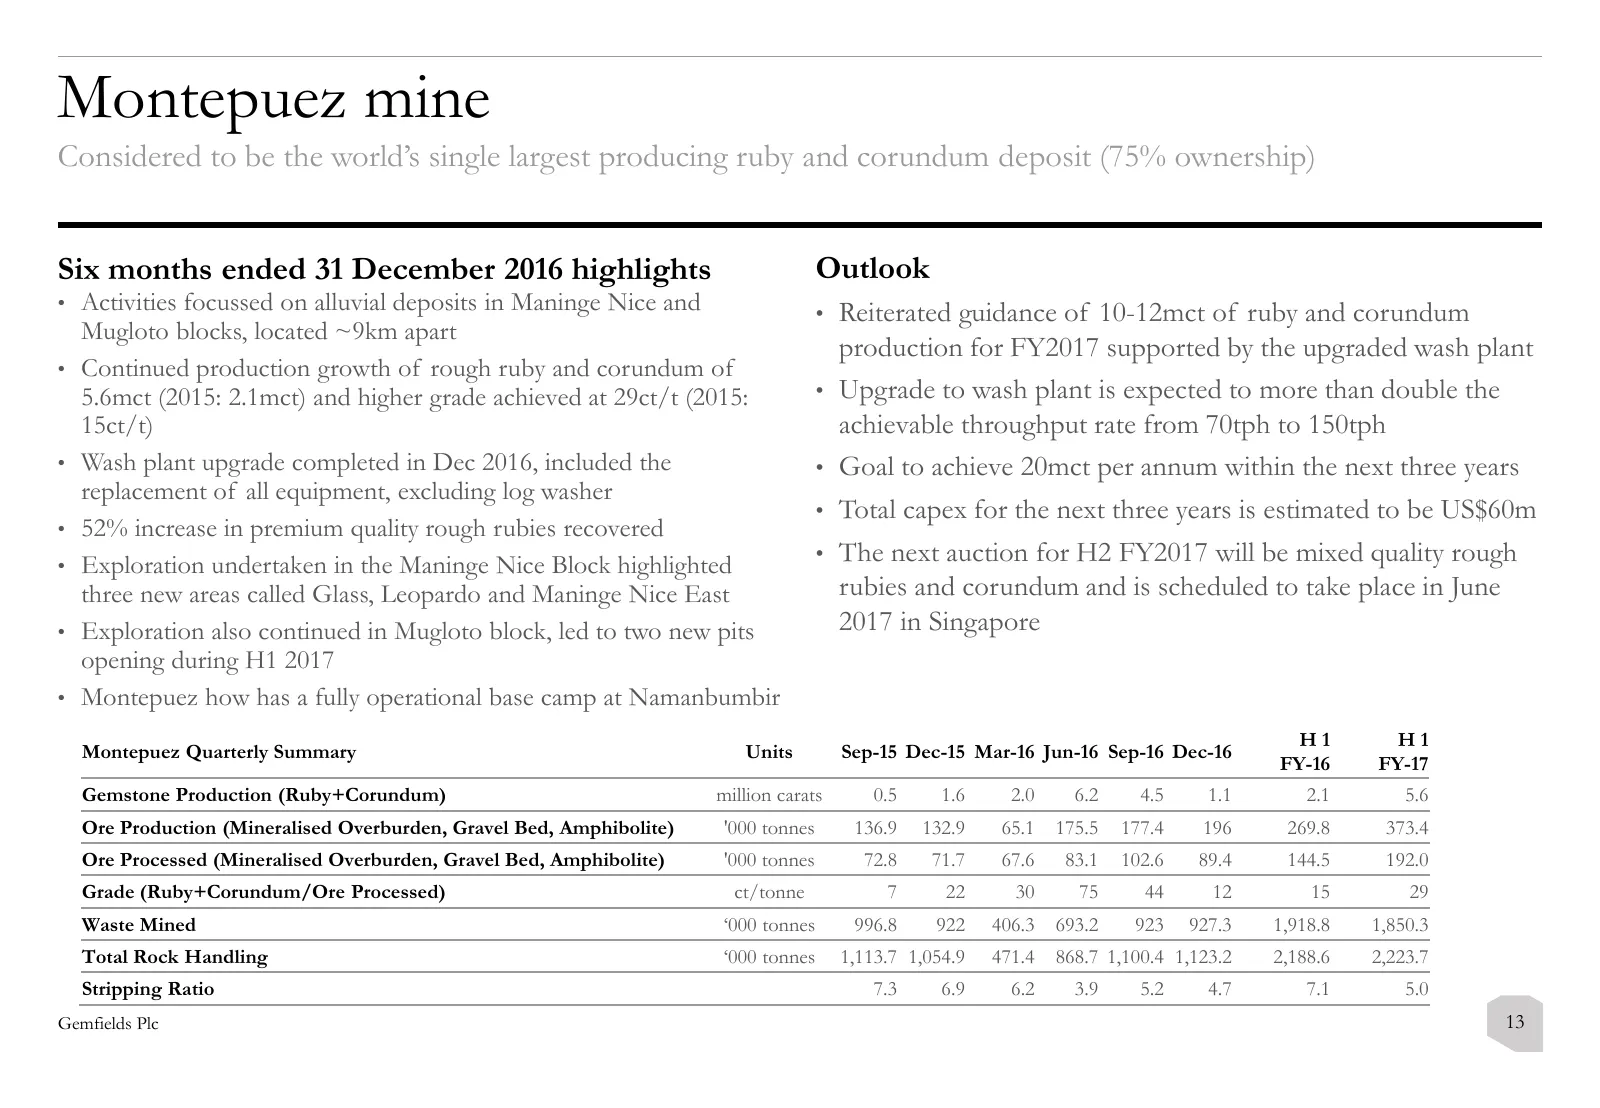
Montepuez mine Considered to be the world’s single largest producing ruby and corundum deposit (75% ownership) Six months ended 31 December 2016 highlights Outlook • Activities focussed on alluvial deposits in Maninge Nice and • Reiterated guidance of 10-12mct of ruby and corundum Mugloto blocks, lo
Slide 14: Fabergé
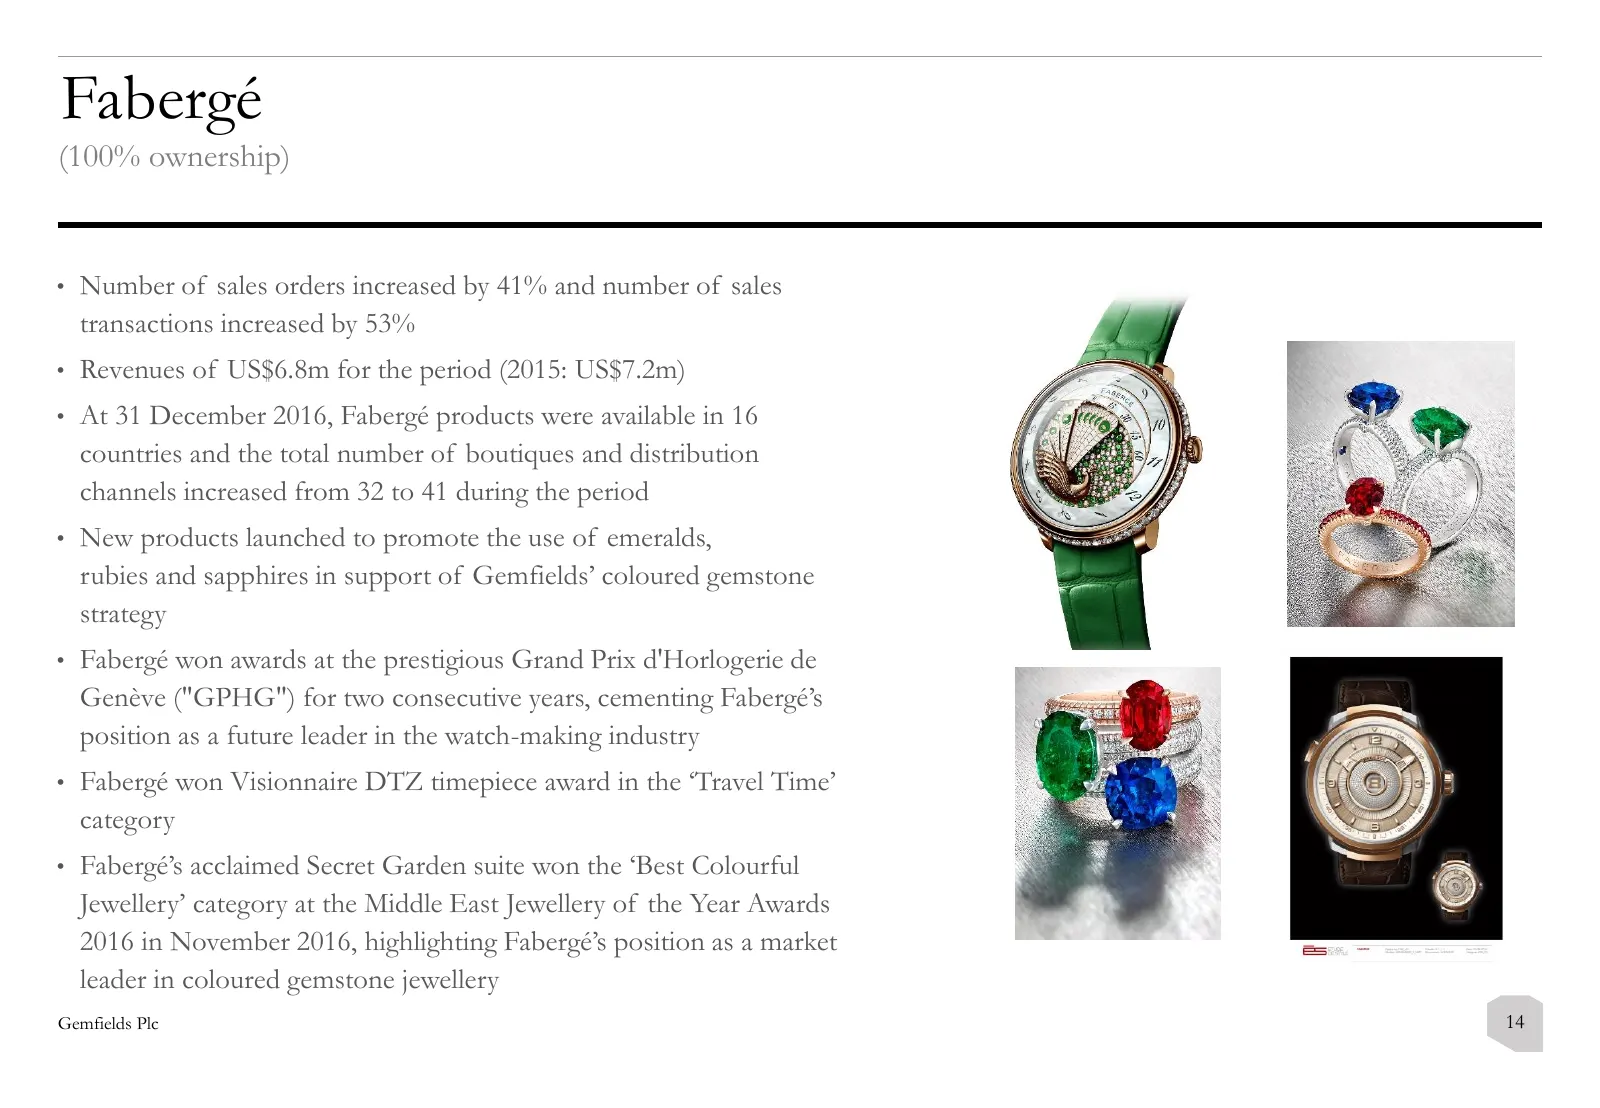
Fabergé (100% ownership) • Number of sales orders increased by 41% and number of sales transactions increased by 53% • Revenues of US$6.8m for the period (2015: US$7.2m) • At 31 December 2016, Fabergé products were available in 16 countries and the total number of boutiques and distribution channels
Slide 15: Leading the way and growing the business
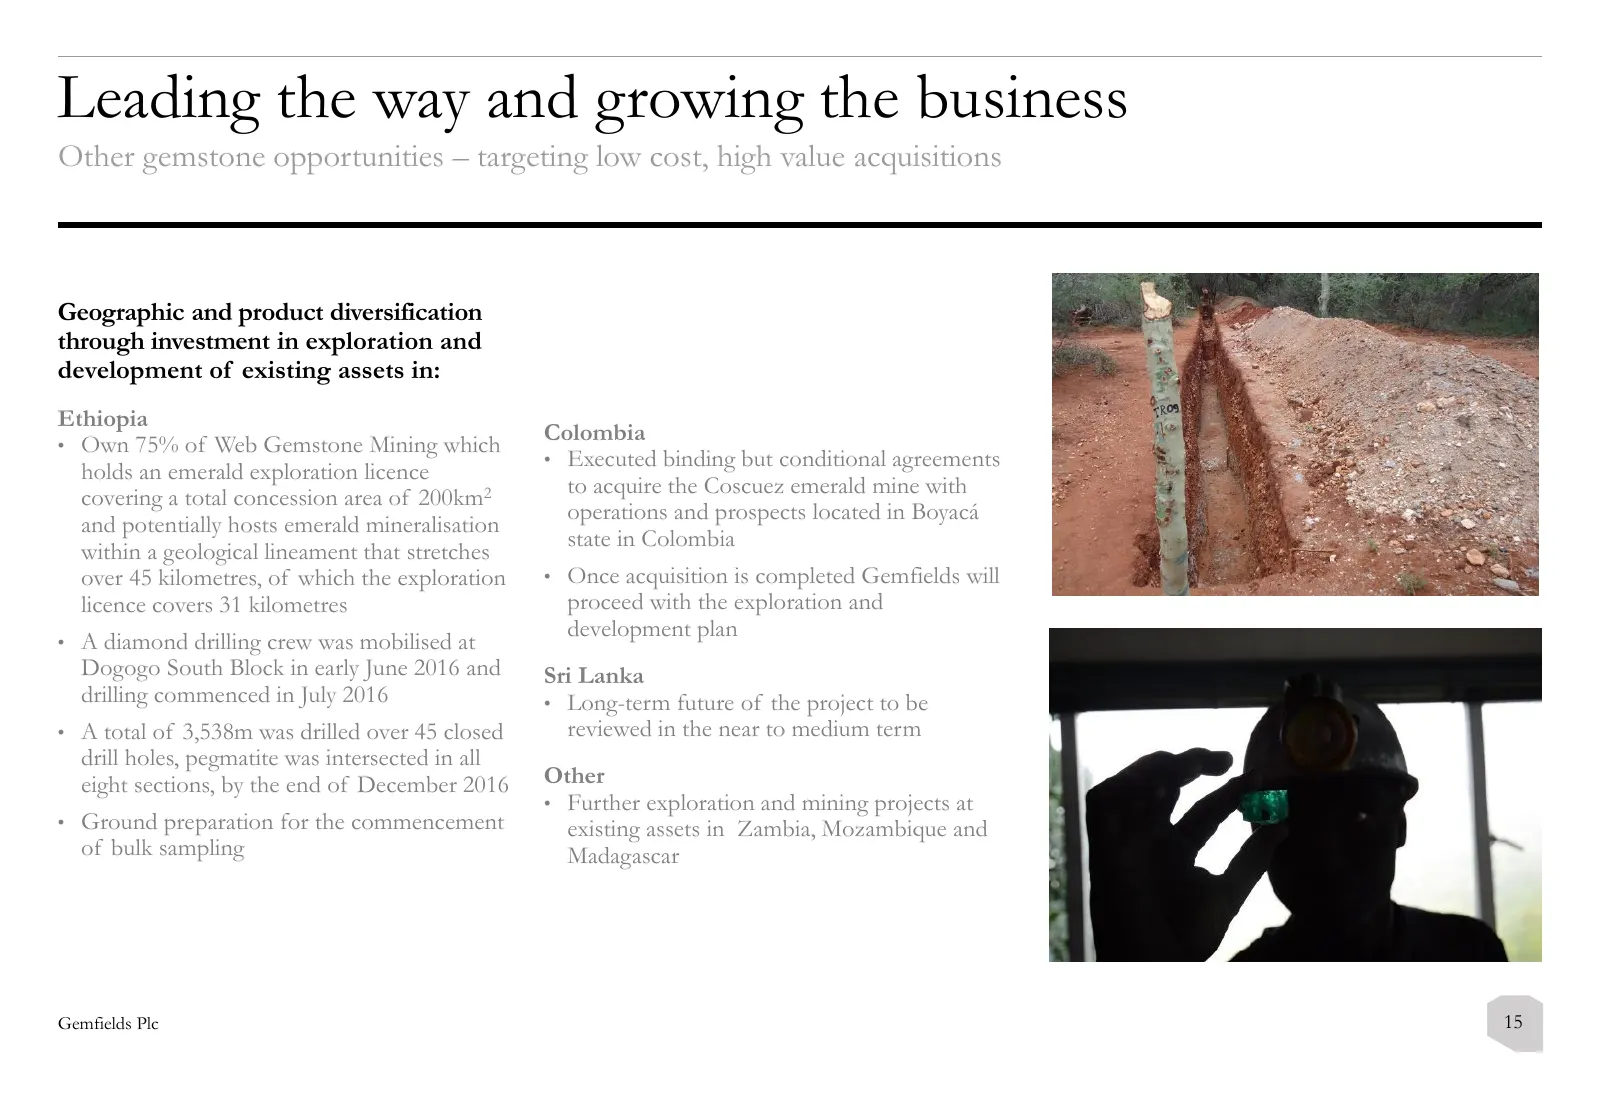
Leading the way and growing the business Other gemstone opportunities – targeting low cost, high value acquisitions Geographic and product diversification through investment in exploration and development of existing assets in: Ethiopia Colombia • Own 75% of Web Gemstone Mining which • Executed bind
Slide 16: Outlook
Outlook Gemfields Plc 16
Slide 17: Driving further value – upcoming milestones
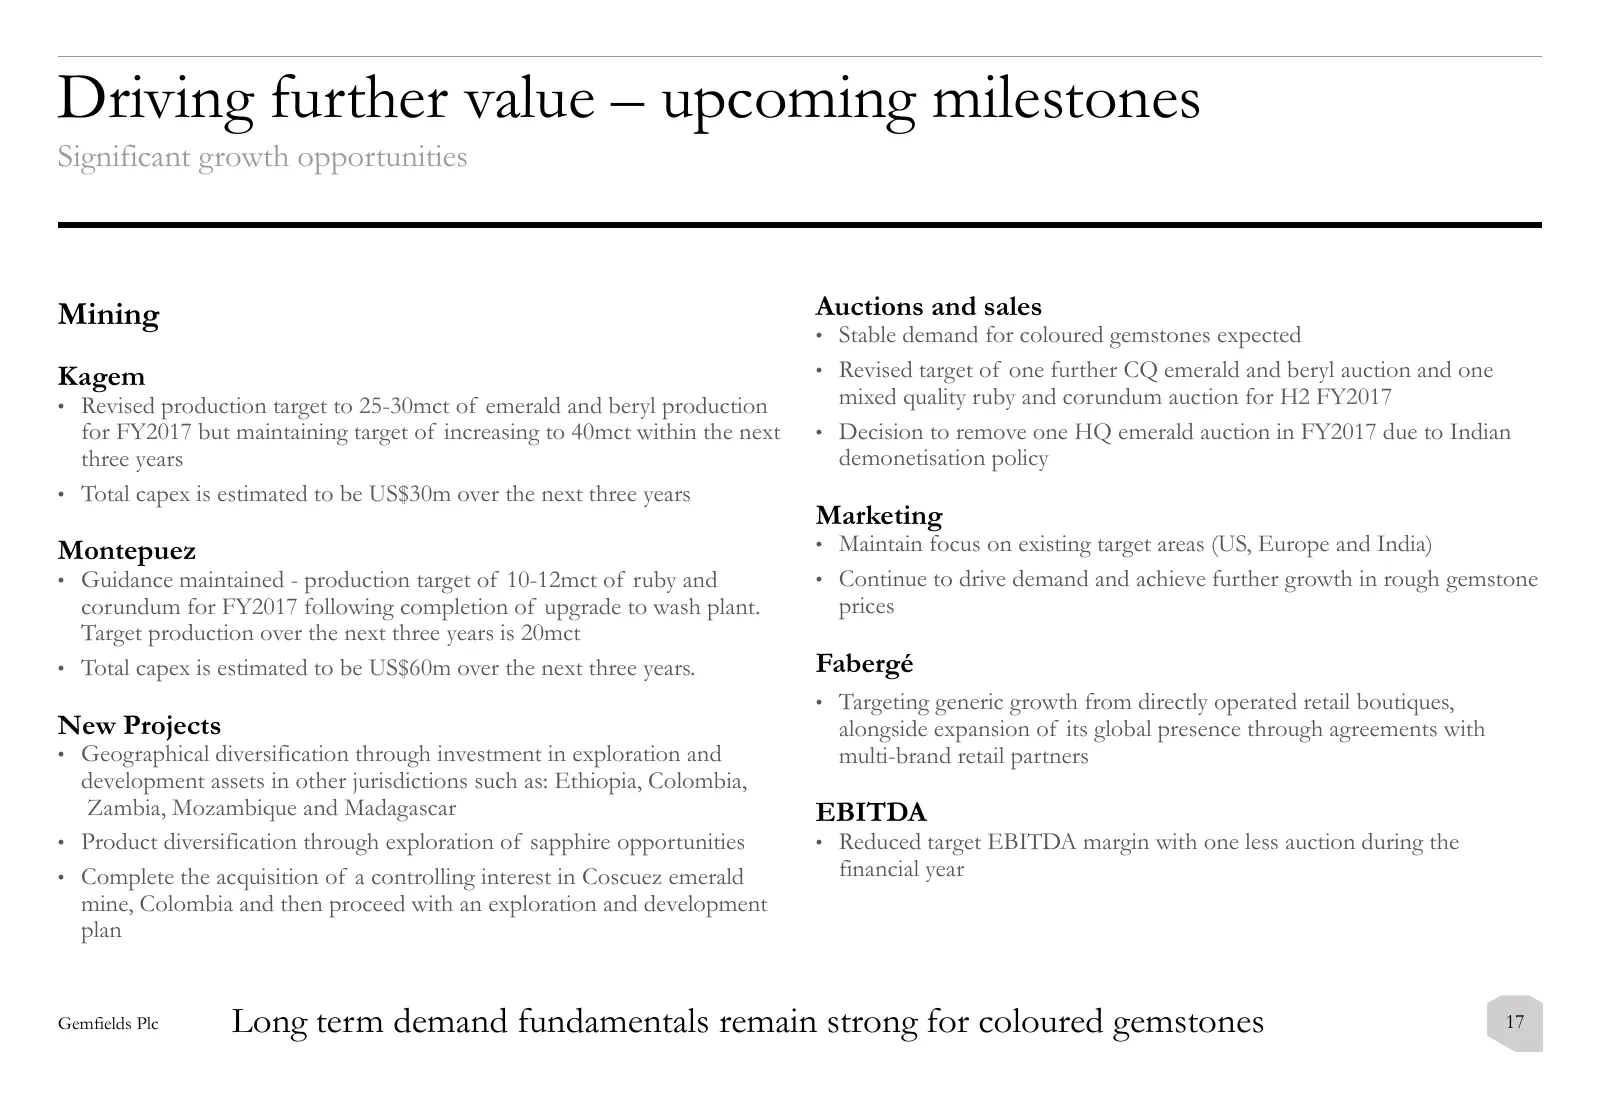
Driving further value – upcoming milestones Significant growth opportunities Mining Auctions and sales • Stable demand for coloured gemstones expected Kagem • Revised target of one further CQ emerald and beryl auction and one • Revised production target to 25-30mct of emerald and beryl production mi
Slide 18: Sales & Marketing
Sales & Marketing Gemfields Plc 18
Slide 19: Auction results
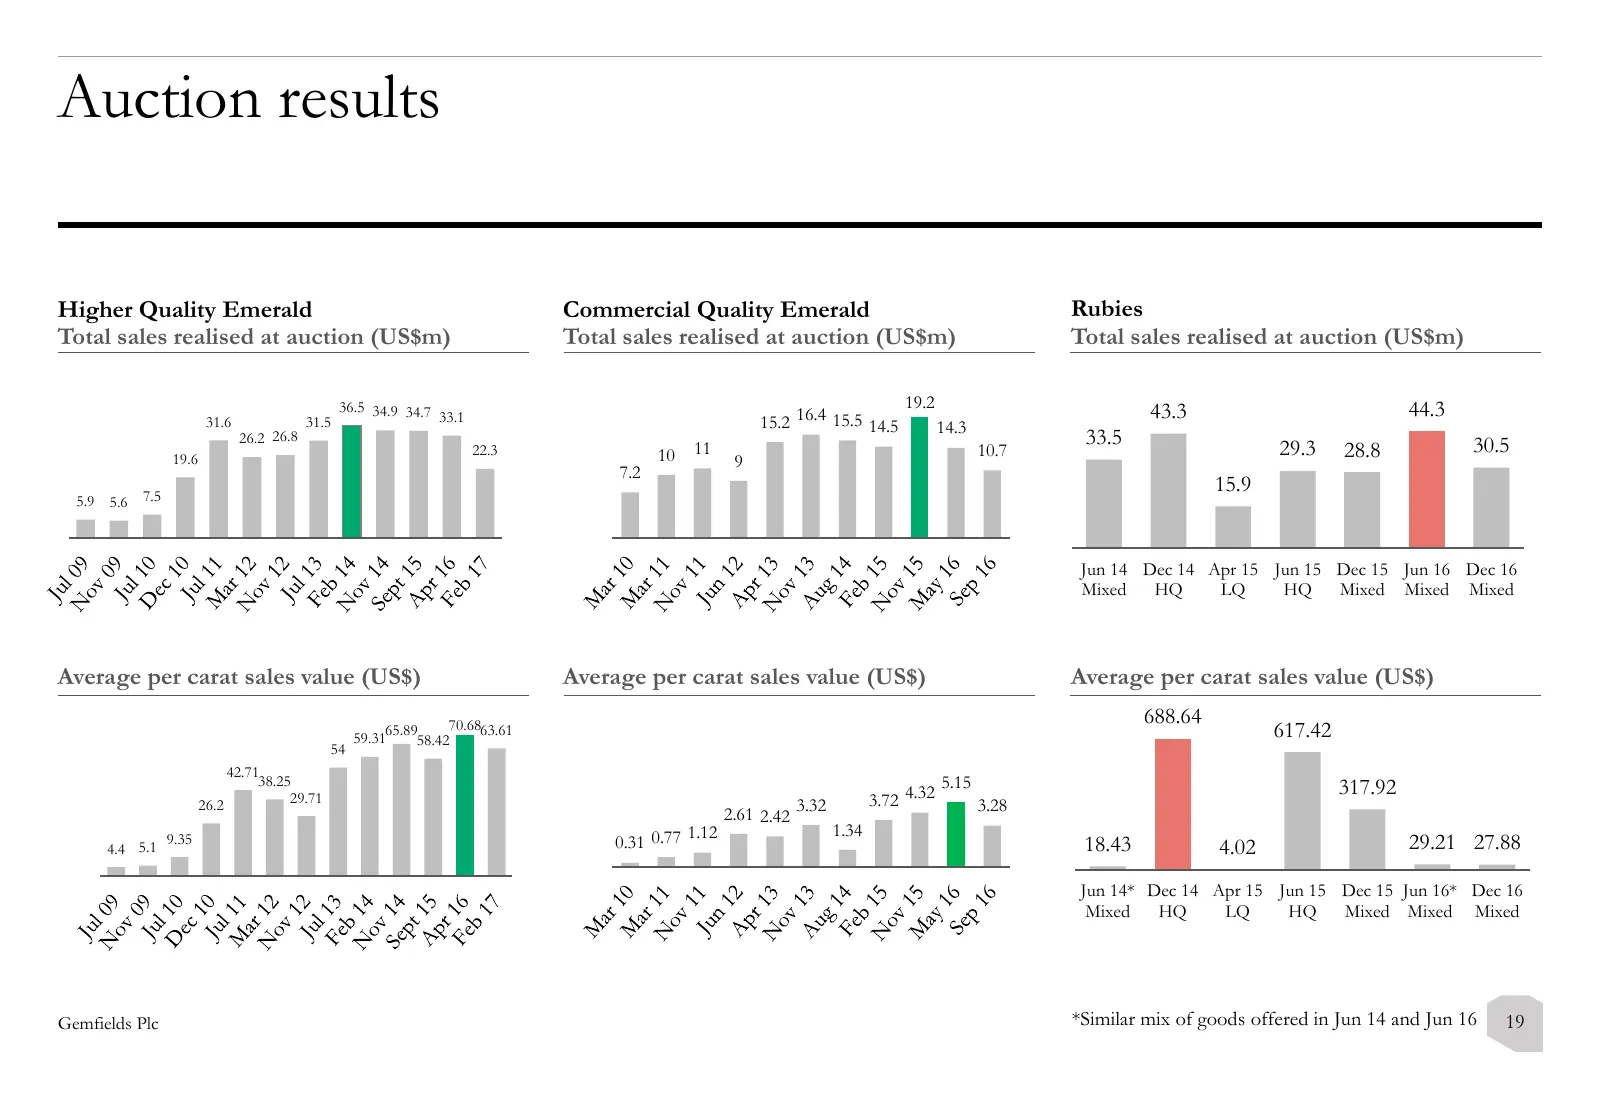
Auction results Higher Quality Emerald Commercial Quality Emerald Rubies Total sales realised at auction (US$m) Total sales realised at auction (US$m) Total sales realised at auction (US$m) 36.5 34.9 34.7 19.2 44.3 31.6 31.5 33.1 15.2 16.4 15.5 14.5 43.3 14.3 26.2 26.8 33.5 29.3 30.5 19.6 22.3 10 11
Slide 20: Marketing Highlights
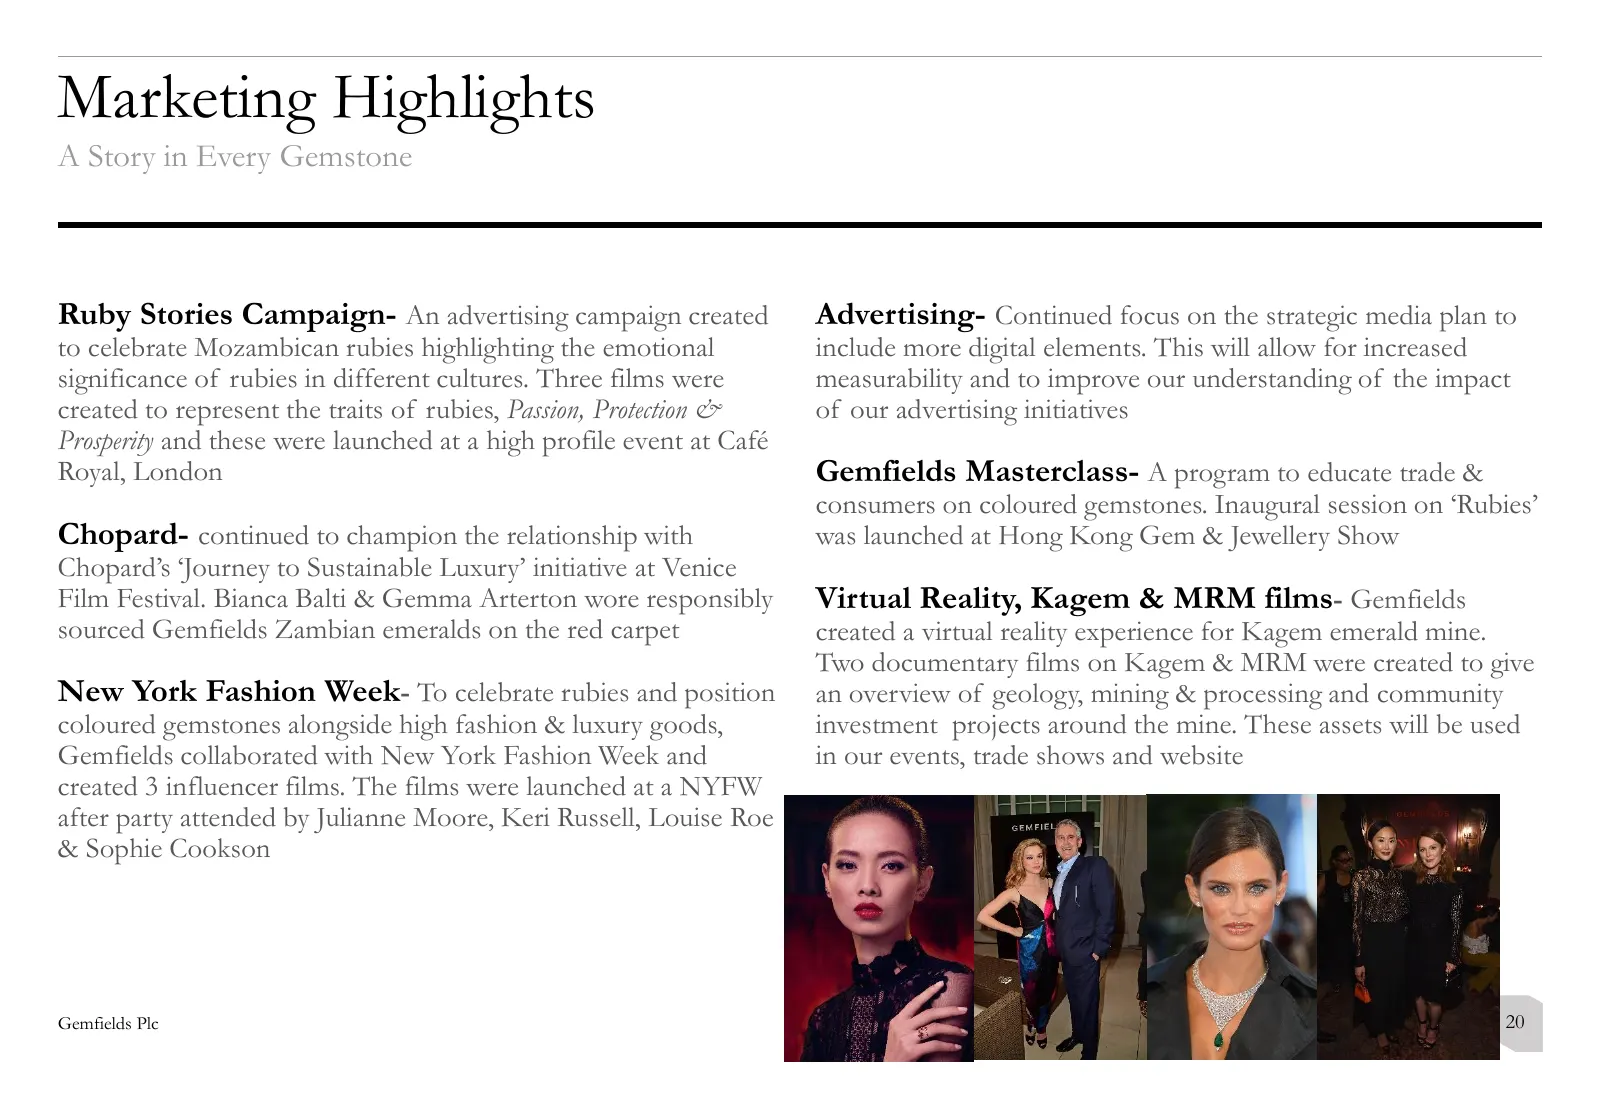
Marketing Highlights A Story in Every Gemstone Ruby Stories Campaign- An advertising campaign created Advertising- Continued focus on the strategic media plan to to celebrate Mozambican rubies highlighting the emotional include more digital elements. This will allow for increased significance of rub
Slide 21: Marketing Campaign Reach
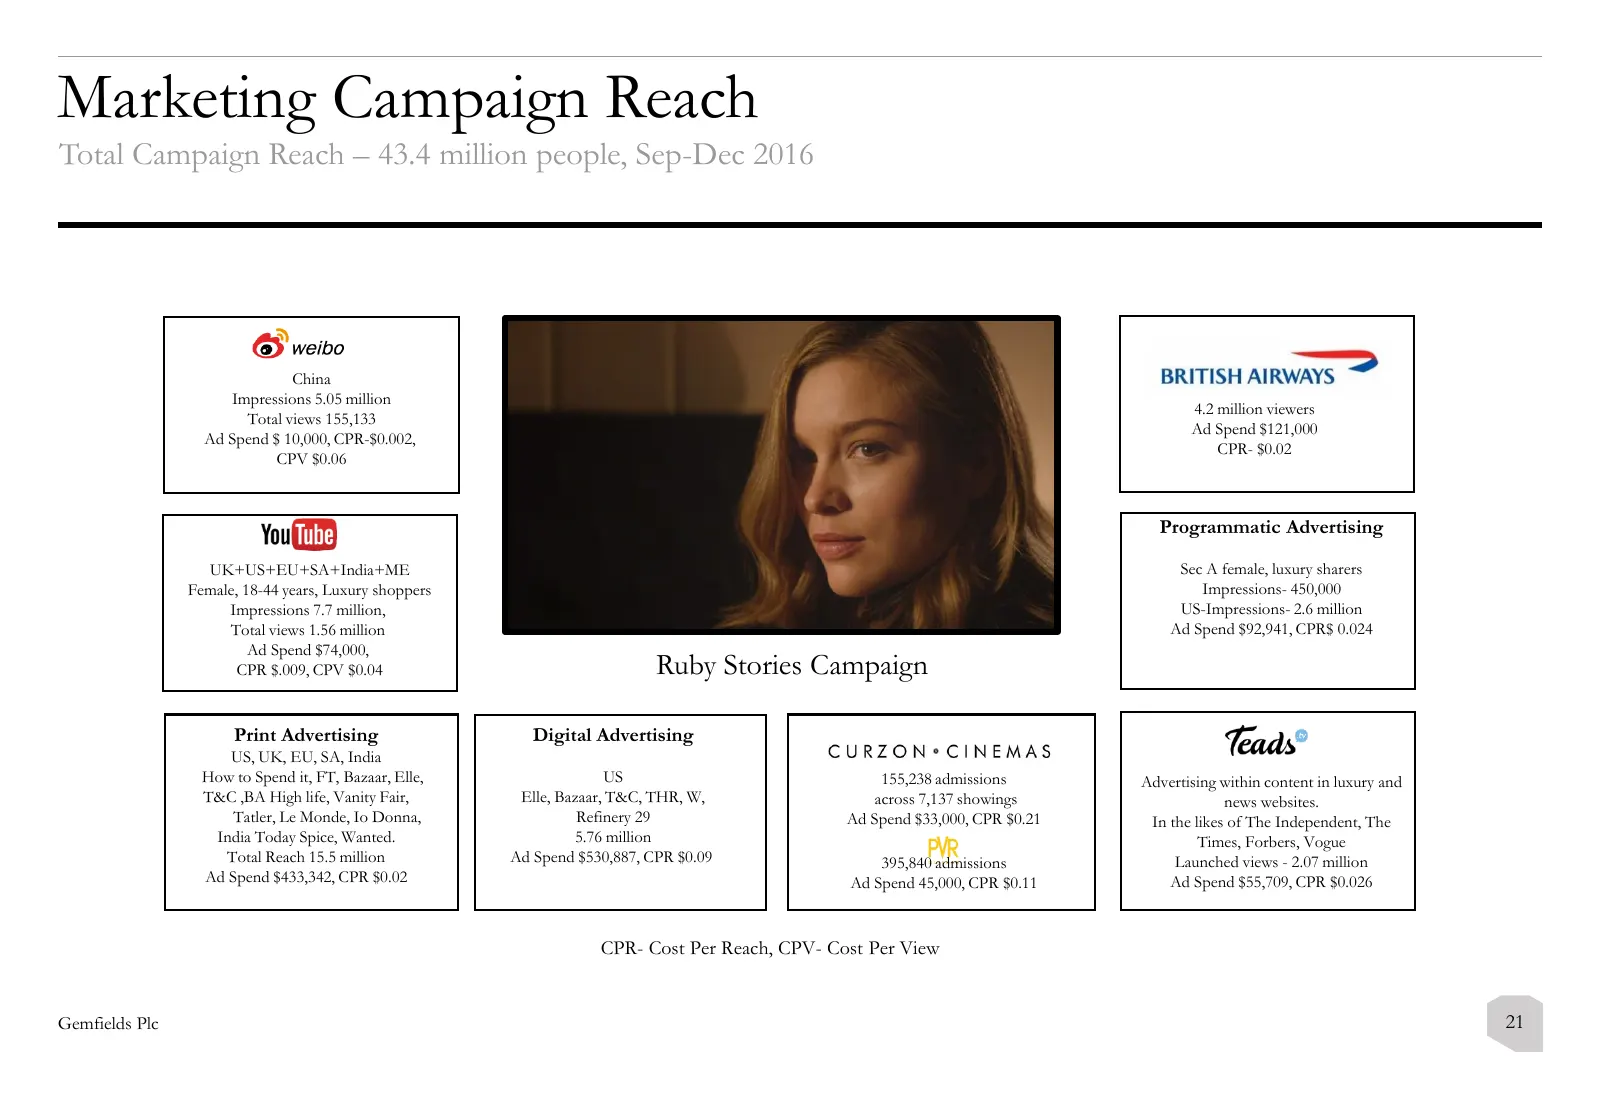
Marketing Campaign Reach Total Campaign Reach – 43.4 million people, Sep-Dec 2016 China Impressions 5.05 million 4.2 million viewers Total views 155,133 Ad Spend $121,000 Ad Spend $ 10,000, CPR-$0.002, CPR- $0.02 CPV $0.06 Programmatic Advertising UK+US+EU+SA+India+ME Sec A female, luxury sharers Fe
Slide 22: Responsibility & sustainability
Responsibility & sustainability Gemfields Plc 22
Slide 23: Responsibility & sustainability
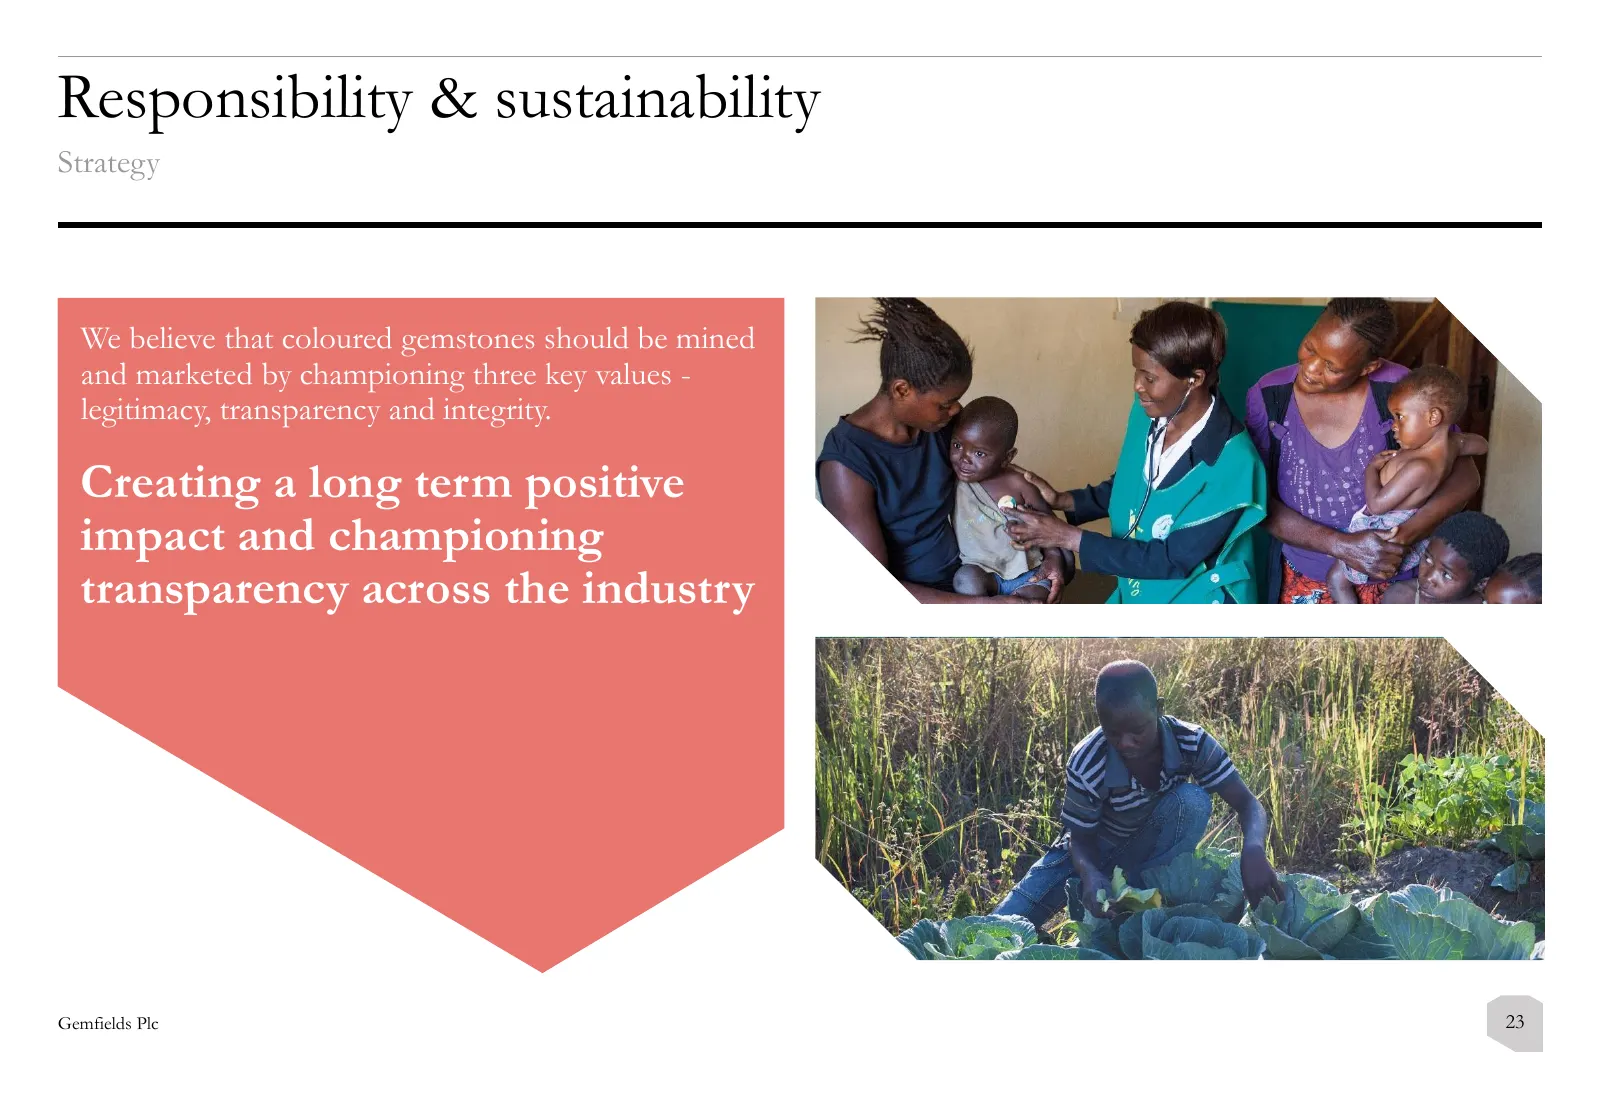
Responsibility & sustainability Strategy We believe that coloured gemstones should be mined and marketed by championing three key values - legitimacy, transparency and integrity. Creating a long term positive impact and championing transparency across the industry Gemfields Plc 23
Slide 24: Responsibility & sustainability - five key pillars
Responsibility & sustainability - five key pillars Operational implementation It’s our goal to operate in a way that contributes positively to national economies, takes a leading role in modernising the coloured gemstone sector and that builds lasting, sustainable livelihoods for the communities aro
Slide 25: Appendix
Appendix Gemfields Plc 25
Slide 26: Gemfields Locations
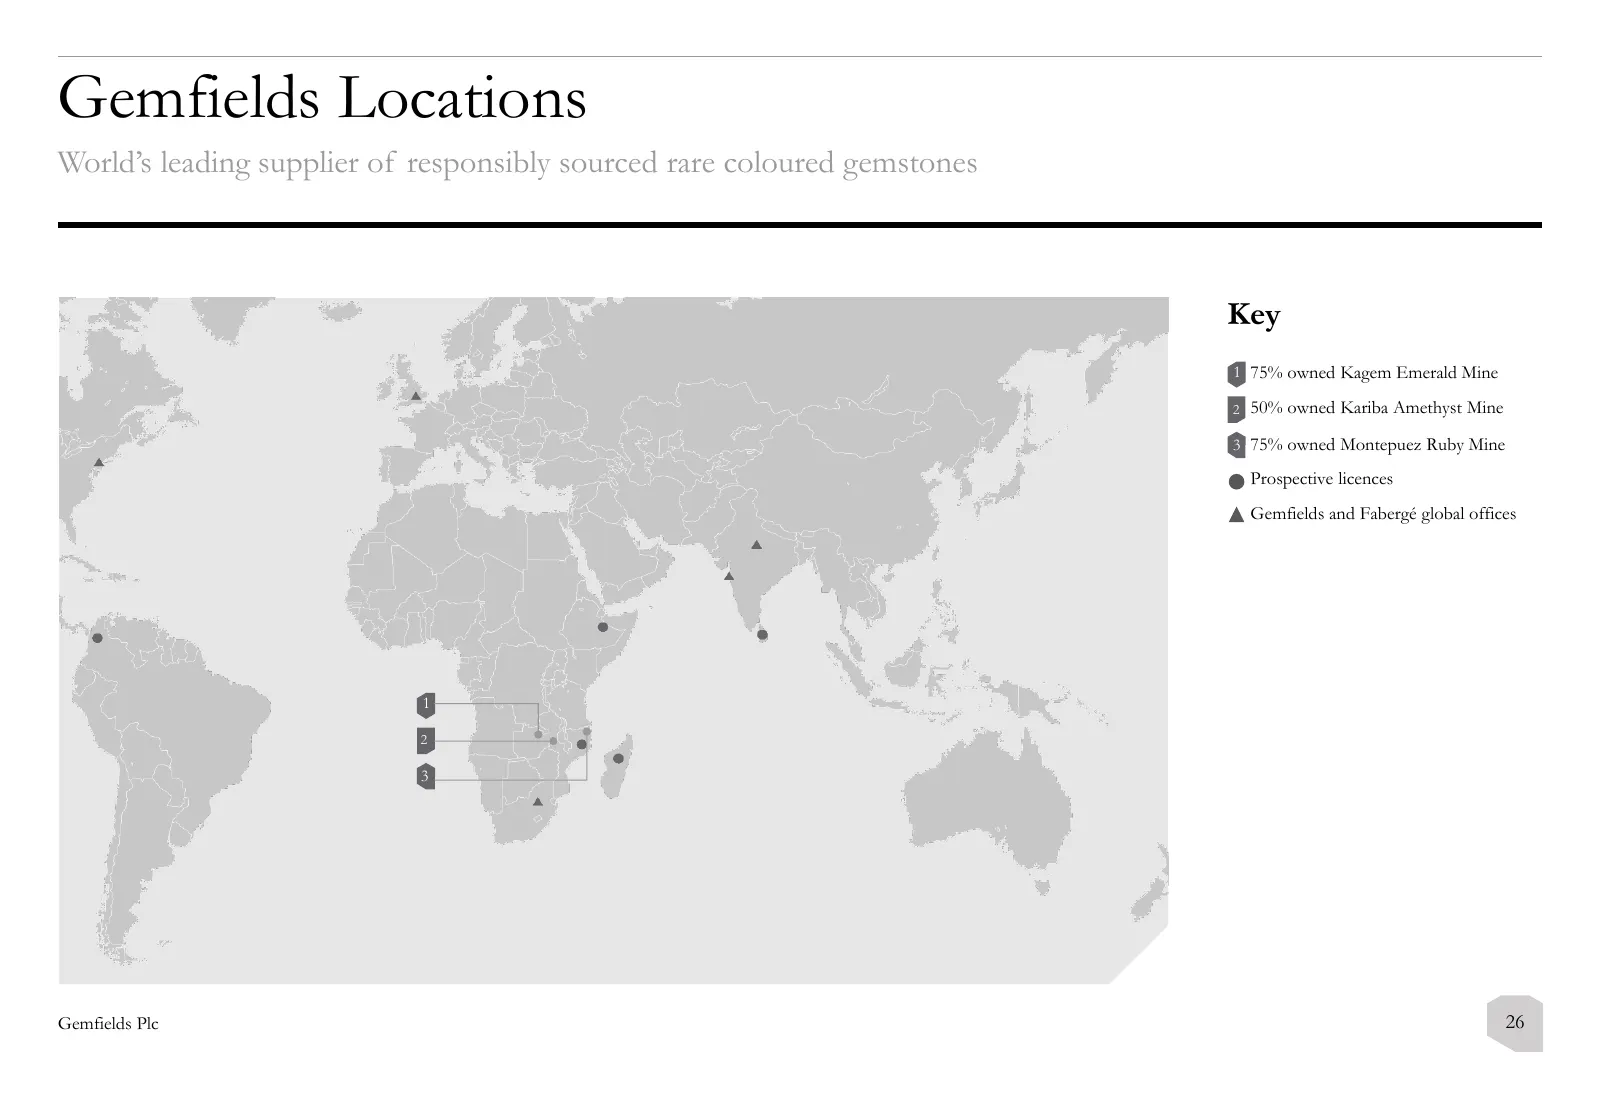
Gemfields Locations World’s leading supplier of responsibly sourced rare coloured gemstones Key 1 75% owned Kagem Emerald Mine 2 50% owned Kariba Amethyst Mine 3 75% owned Montepuez Ruby Mine Prospective licences Gemfields and Fabergé global offices 1 2 3 Gemfields Plc 26
Slide 27: Kagem JORC Resource and Reserves update
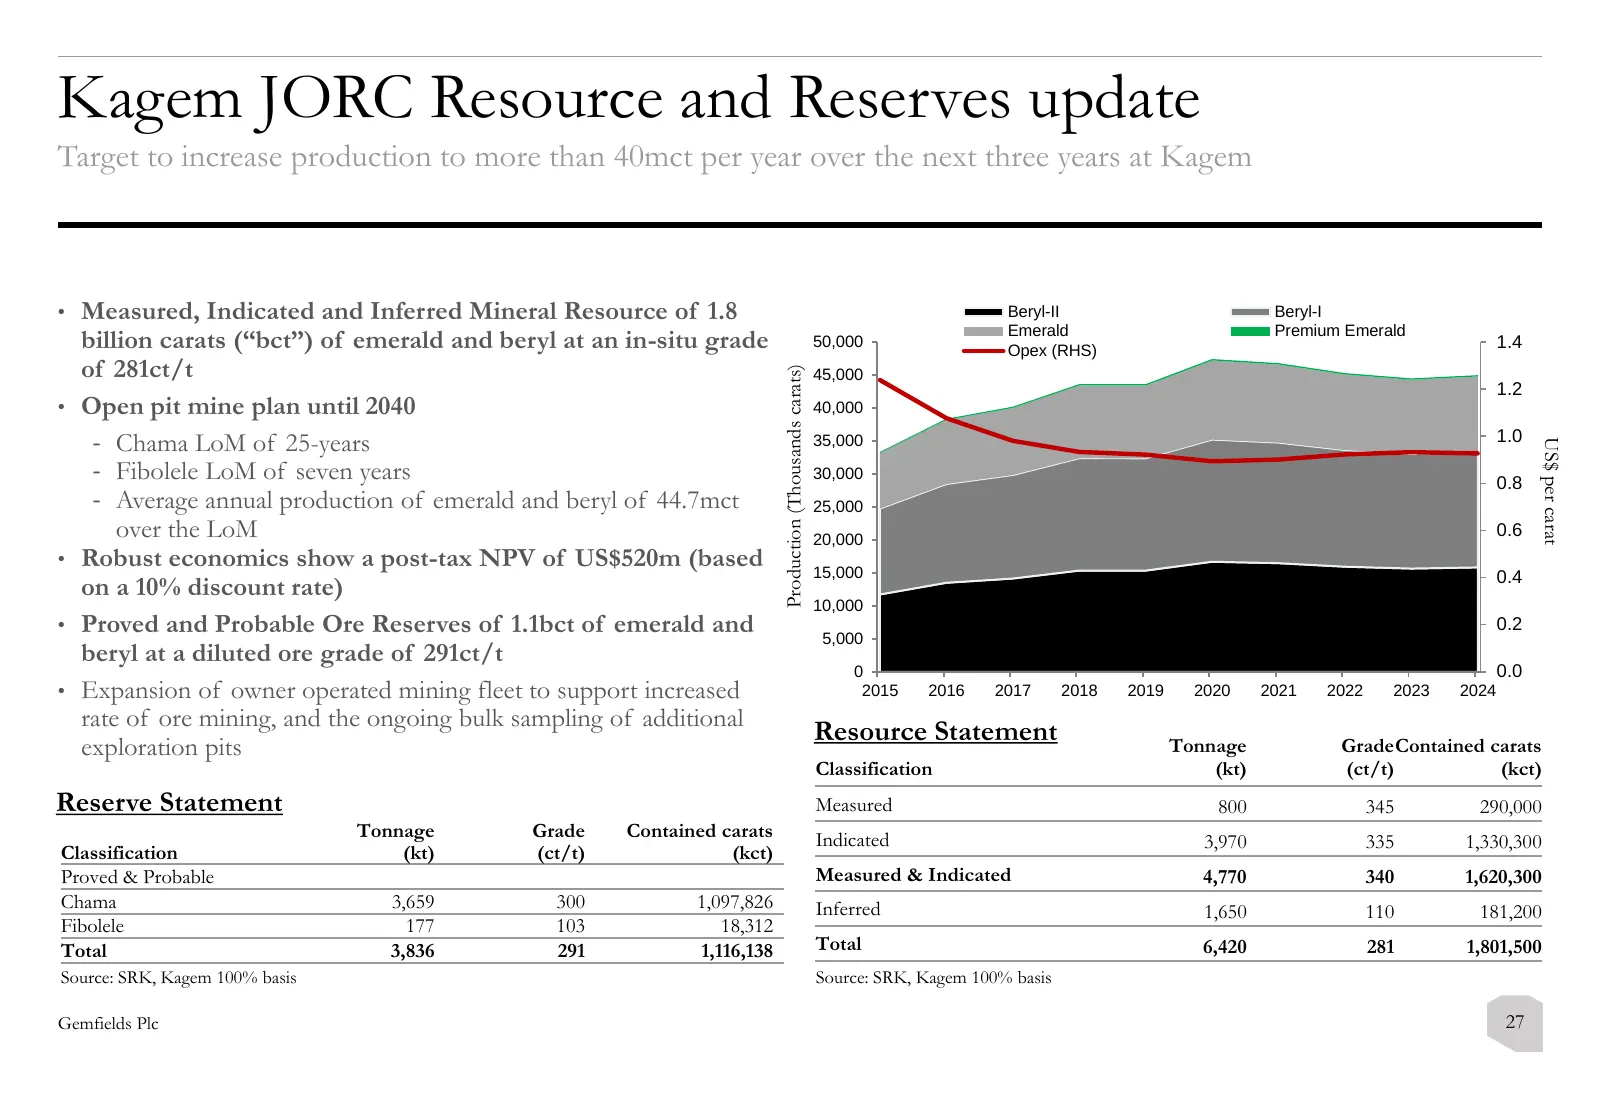
Kagem JORC Resource and Reserves update Target to increase production to more than 40mct per year over the next three years at Kagem • Measured, Indicated and Inferred Mineral Resource of 1.8 Beryl-II Beryl-I Emerald Premium Emerald billion carats (“bct”) of emerald and beryl at an in-situ grade 50,
Slide 28: Montepuez JORC Maiden Resource and Reserves
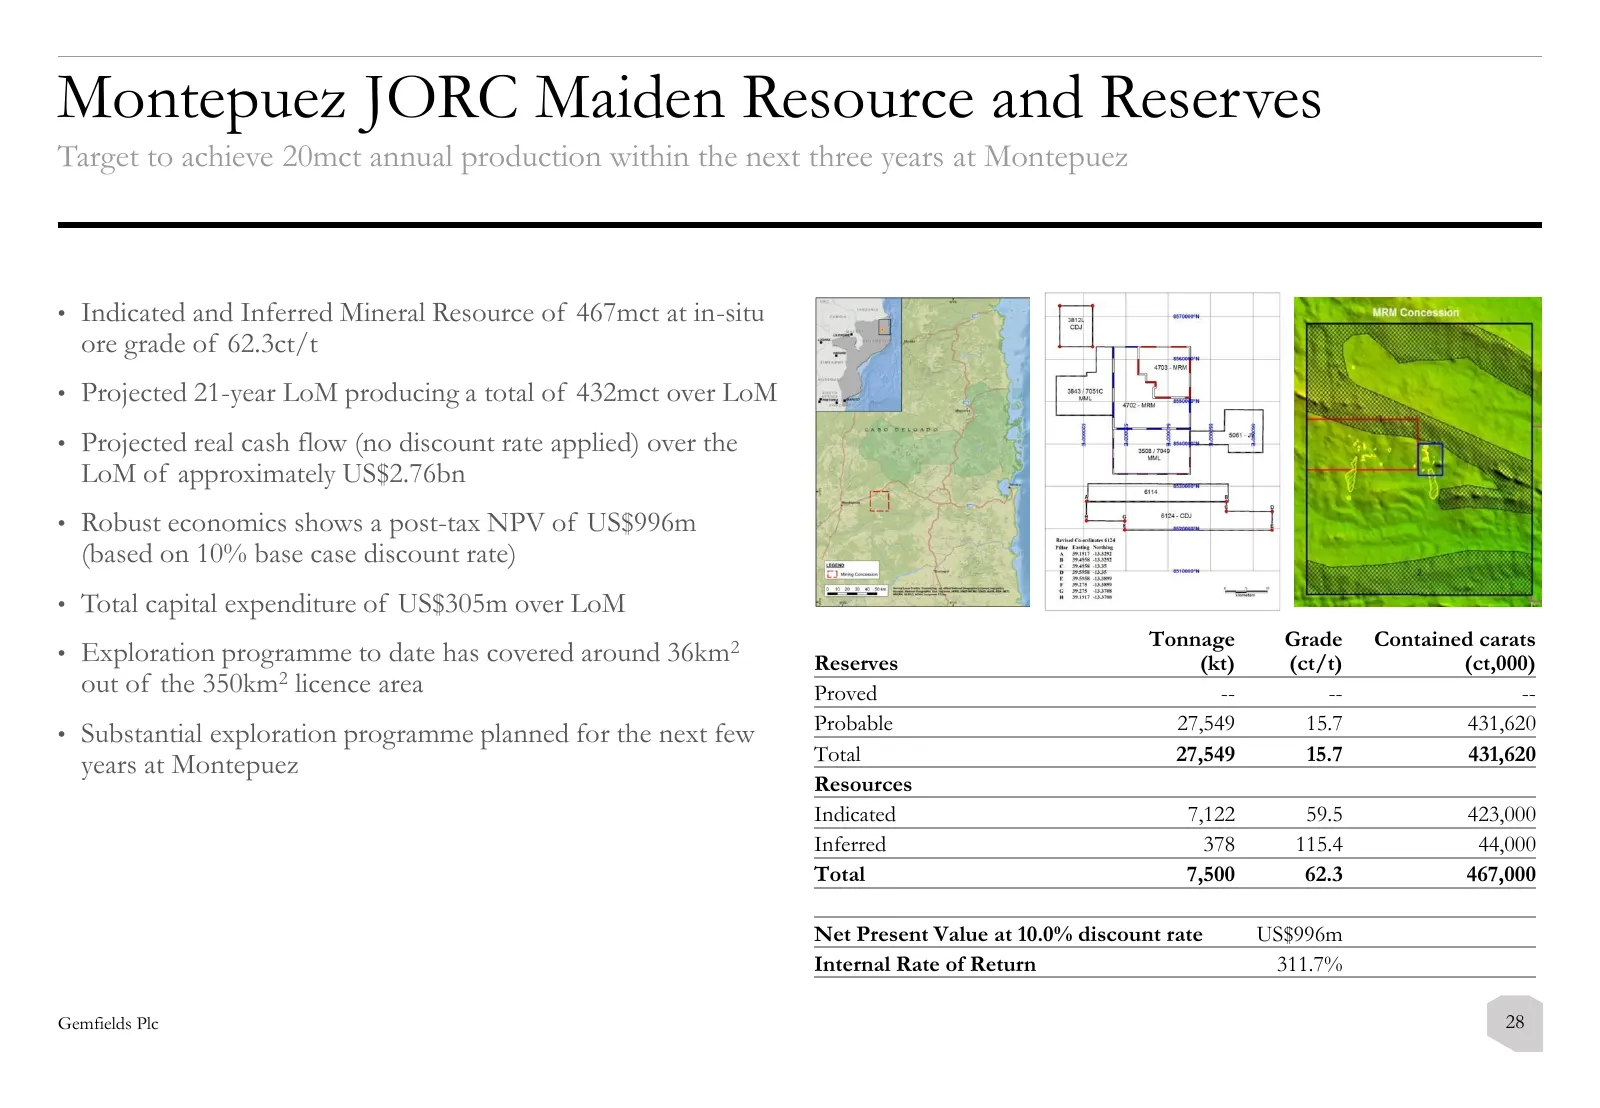
Montepuez JORC Maiden Resource and Reserves Target to achieve 20mct annual production within the next three years at Montepuez • Indicated and Inferred Mineral Resource of 467mct at in-situ ore grade of 62.3ct/t • Projected 21-year LoM producing a total of 432mct over LoM • Projected real cash flow
Slide 29: Company overview
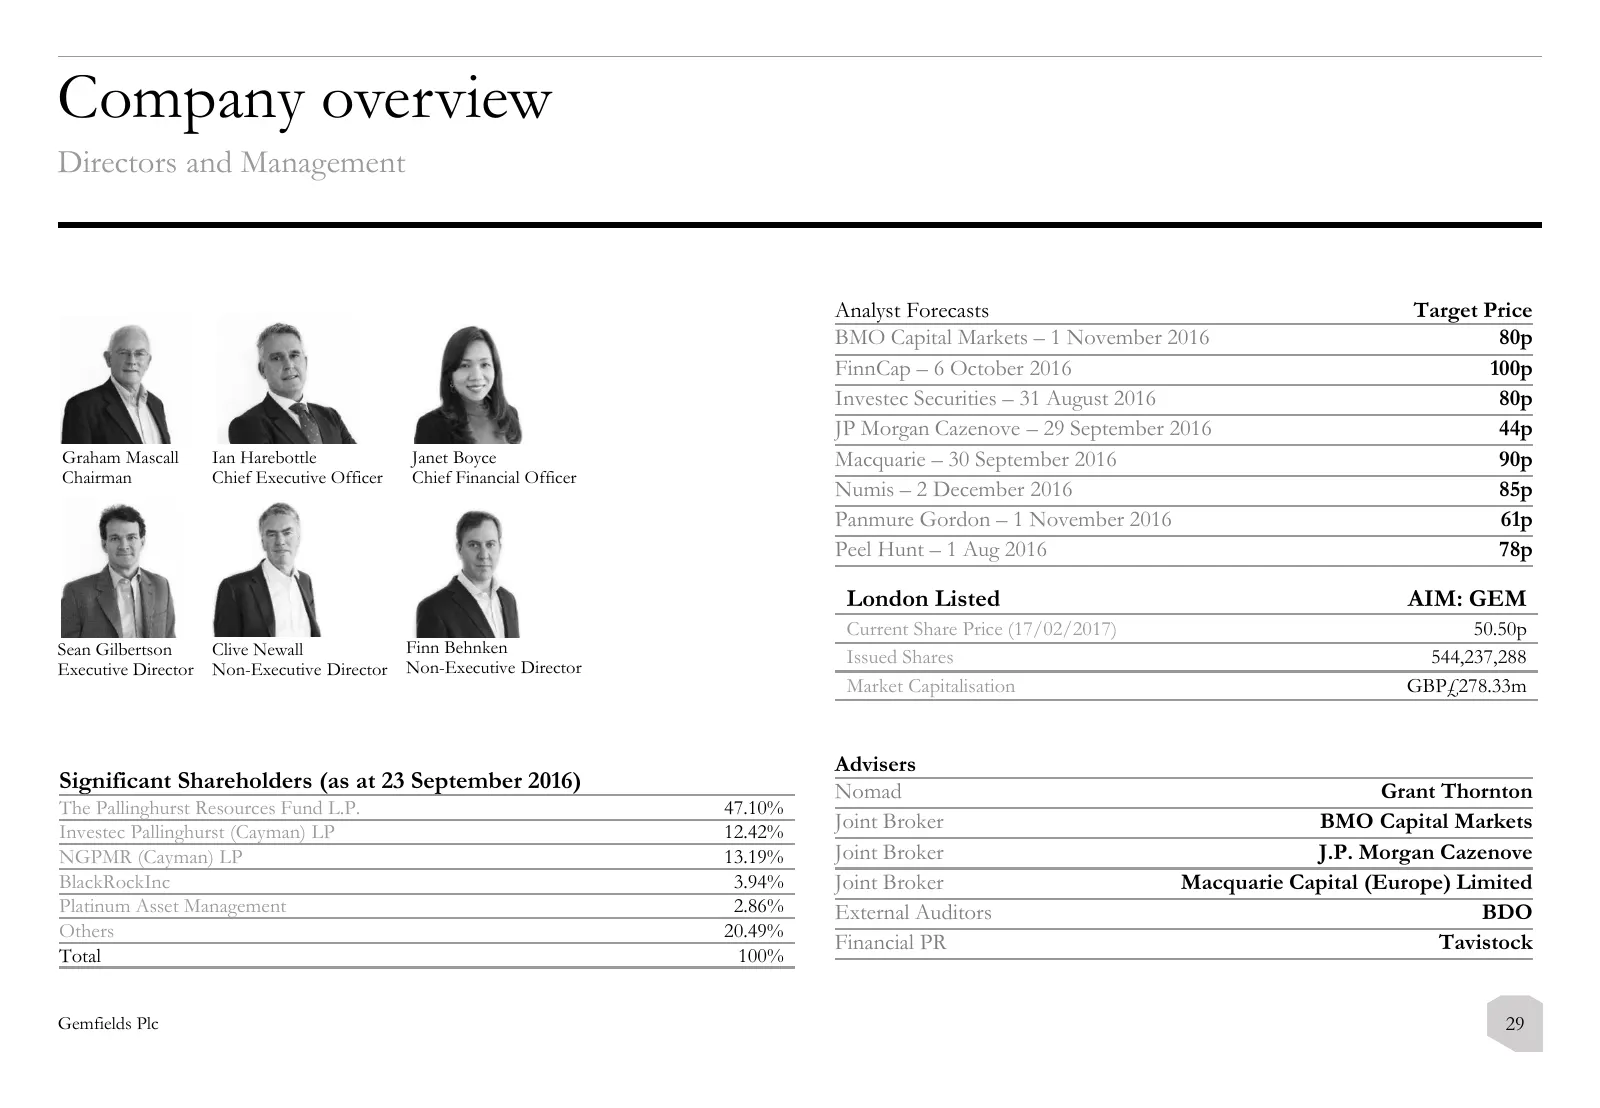
Company overview Directors and Management Analyst Forecasts Target Price BMO Capital Markets – 1 November 2016 80p FinnCap – 6 October 2016 100p Investec Securities – 31 August 2016 80p JP Morgan Cazenove – 29 September 2016 44p Graham Mascall Ian Harebottle Janet Boyce Macquarie – 30 September 2016
Slide 30: Gemstone Price Index
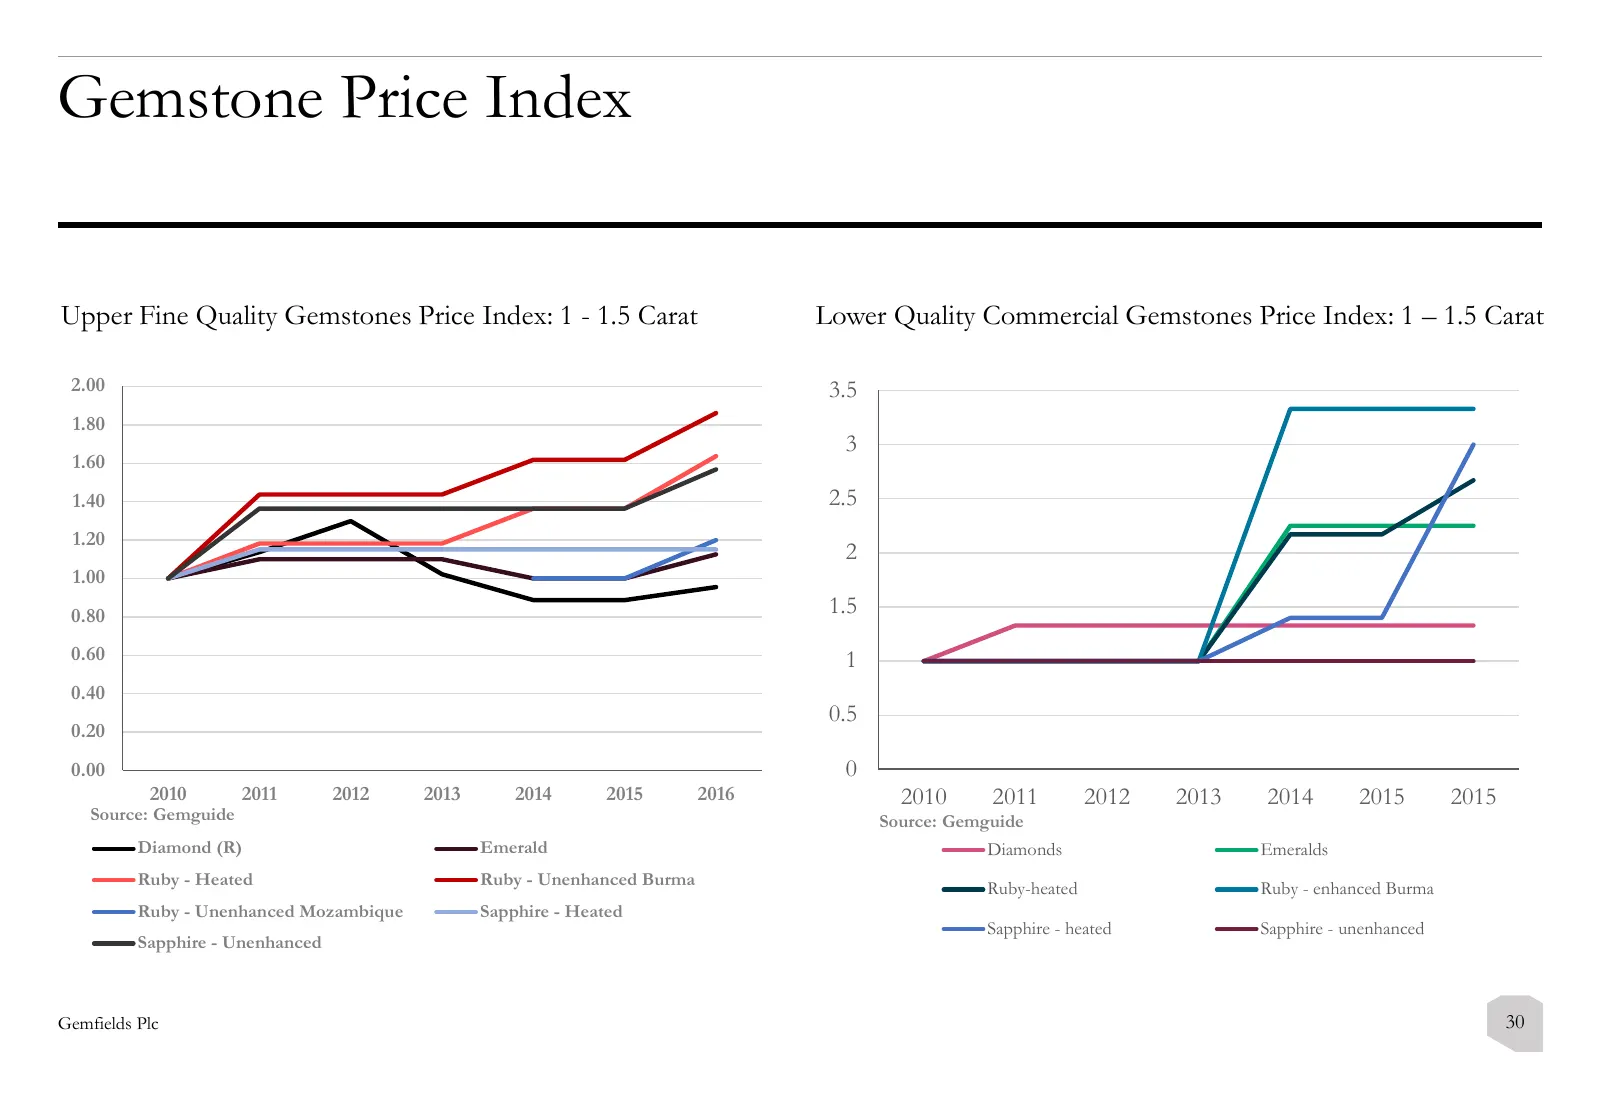
Gemstone Price Index Upper Fine Quality Gemstones Price Index: 1 - 1.5 Carat Lower Quality Commercial Gemstones Price Index: 1 – 1.5 Carat 2.00 3.5 1.80 3 1.60 1.40 2.5 1.20 2 1.00 0.80 1.5 0.60 1 0.40 0.5 0.20 0.00 0 2010 2011 2012 2013 2014 2015 2016 2010 2011 2012 2013 2014 2015 2015 Source: Gemg
Slide 31: Rough emerald and beryl sales (Commercial quality)
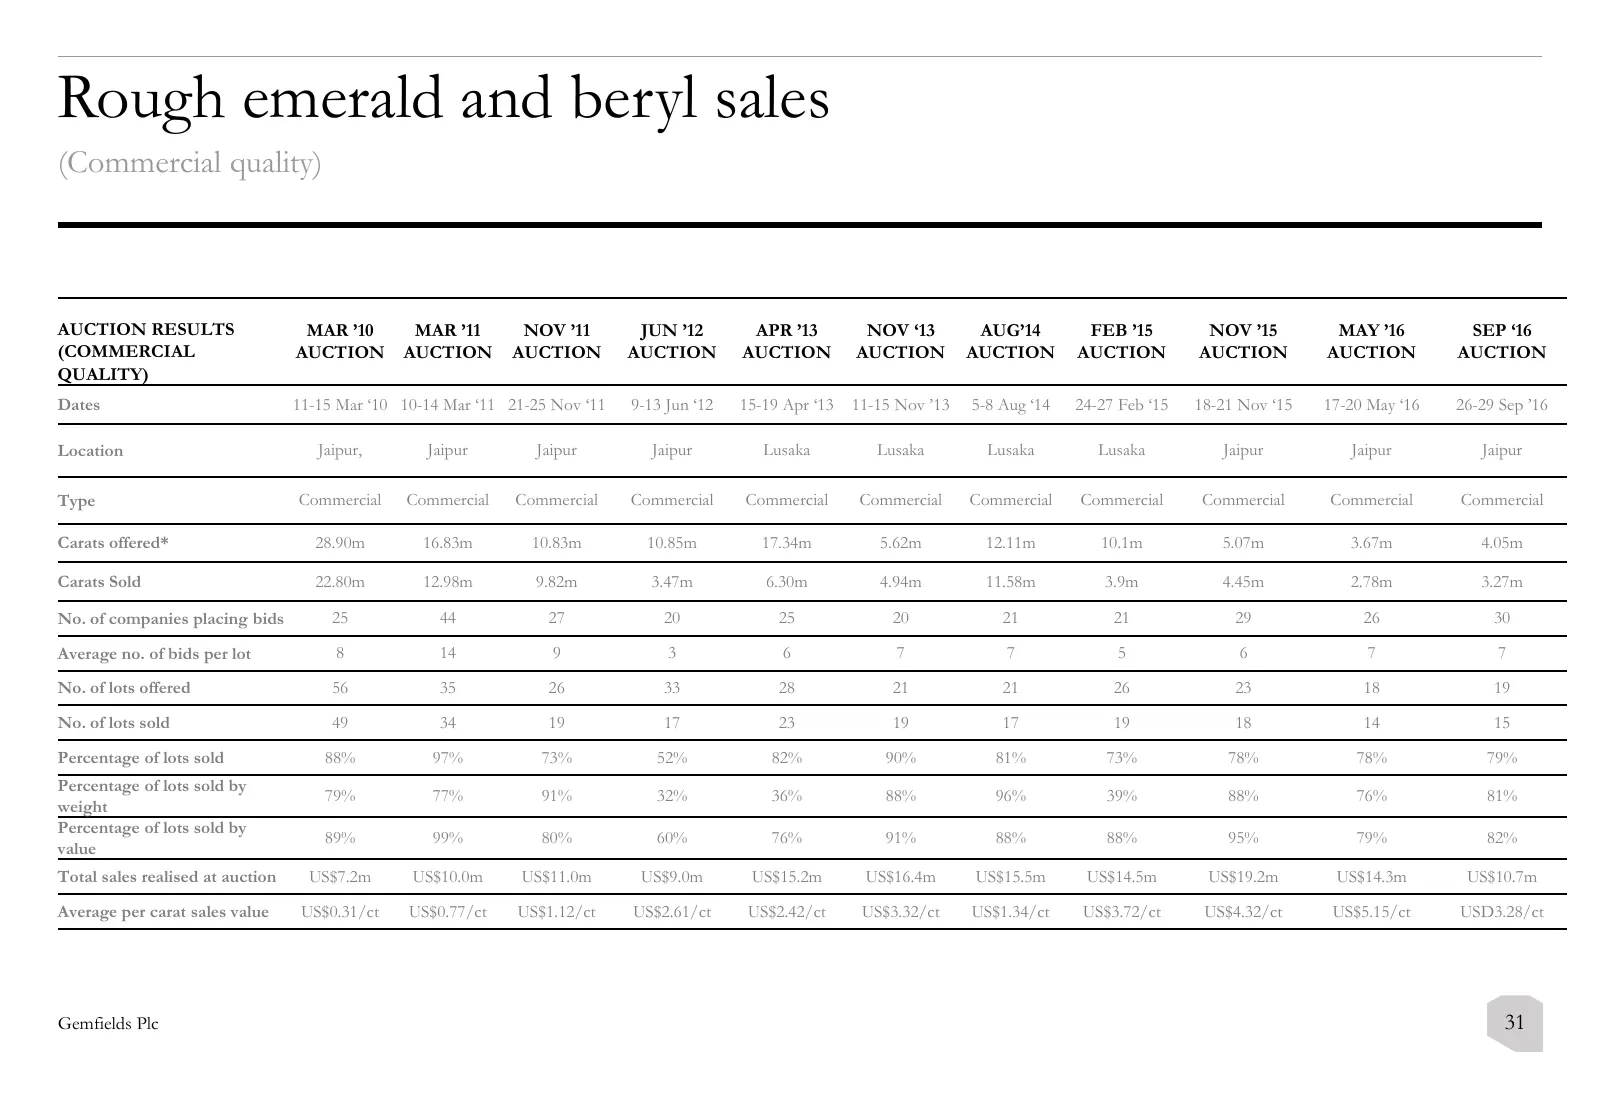
Rough emerald and beryl sales (Commercial quality) AUCTION RESULTS MAR ’10 MAR ’11 NOV ’11 JUN ’12 APR ’13 NOV ‘13 AUG’14 FEB ’15 NOV ’15 MAY ’16 SEP ‘16 (COMMERCIAL AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION QUALITY) Dates 11-15 Mar ‘10 10-14 Mar ‘11 21-
Slide 32: Rough emerald and beryl sales (Higher quality)
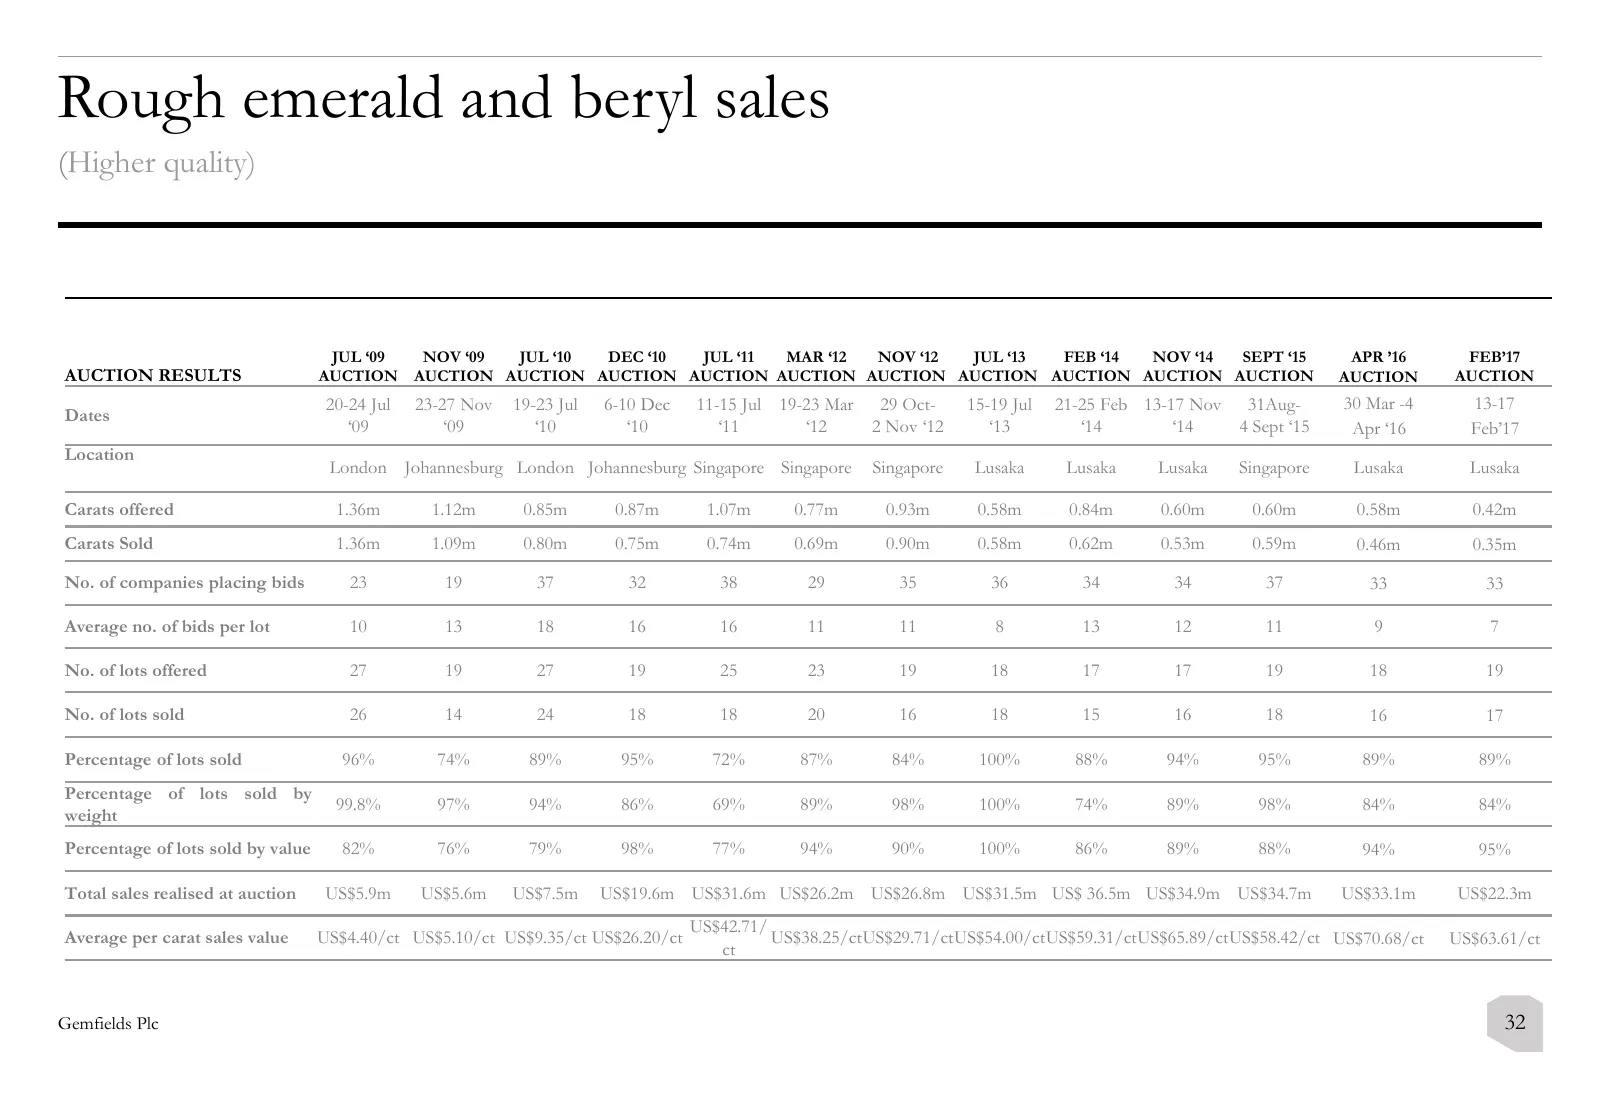
Rough emerald and beryl sales (Higher quality) JUL ‘09 NOV ‘09 JUL ‘10 DEC ‘10 JUL ‘11 MAR ‘12 NOV ‘12 JUL ‘13 FEB ‘14 NOV ‘14 SEPT ‘15 APR ’16 FEB’17 AUCTION RESULTS AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION 20-24 Jul 23-27 Nov 19-23 Jul
Slide 33: Rough ruby and corundum auctions
Rough ruby and corundum auctions (Mixed quality) AUCTION RESULTS JUNE ’14 DEC ‘14 APRIL ’15 JUNE ‘15 DEC ‘15 JUNE ‘16 DEC ’16 (RUBY & CORUNDUM) AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION Dates 12-17 June ‘14 3-8 Dec ‘14 17-22 April ‘15 16-21 June ‘15 14-18 Dec ‘15 13-19 June ‘16 12-16 D
Slide 34: Contact us
Contact us Gemfields Plc 4th Floor 1 New Burlington Place London W1S 2HR United Kingdom Tel: +44 (0)20 7518 3400 Fax: +44 (0) 20 7197 8193 Gemfields Plc
Source: Internet Archive copy of gemfieldsgroup.com
More decks from Gemfields Group Limited
 FY2025 Earnings Presentation26 slides · Mar 26, 2026
 H1 2025 Earnings Presentation74 slides · Sep 26, 2025
 FY2024 Earnings Presentation30 slides · Apr 11, 2025
 Investor Presentation (November 2024)39 slides · November 2024
 FY2023 Earnings Presentation37 slides · Mar 25, 2024
 FY2022 Earnings Presentation71 slides · Mar 24, 2023