Xero Limited · ASX:XRO
Xero — H1 FY27 Earnings Presentation
50 slides from Xero's earnings presentation, Nov 12, 2026
Slide 1: FY27 Interim Results Investor Presentation Market Release
FY27 Interim Results Investor Presentation MARKET RELEASE For personal use only WELLINGTON, 12 November 2026 — Xero Limited (ASX: XRO), in accordance with the ASX Listing Rules, attaches its FY27 Interim Results Investor Presentation. Xero’s H1 FY27 earnings webcast at 10:00am AEDT on 12 November
Slide 2: H1 FY27 Investor briefing
H1 FY27 al use only Investor briefing Results for the six months ended 30 September 2026 Sukhinder Singh Cassidy Chief Executive Officer Claire Bramley Chief Financial Officer 12 NOVEMBER 2026 1
Slide 3: Important notice
Important notice This presentation is given on behalf of Xero Limited (Xero) (ASX:XRO) (Company number NZ 183 0488, ARBN 160 661 183) Information in this presentation: ● is for general information purposes only, and is not an offer or invitation for subscription, or also include: general economic co
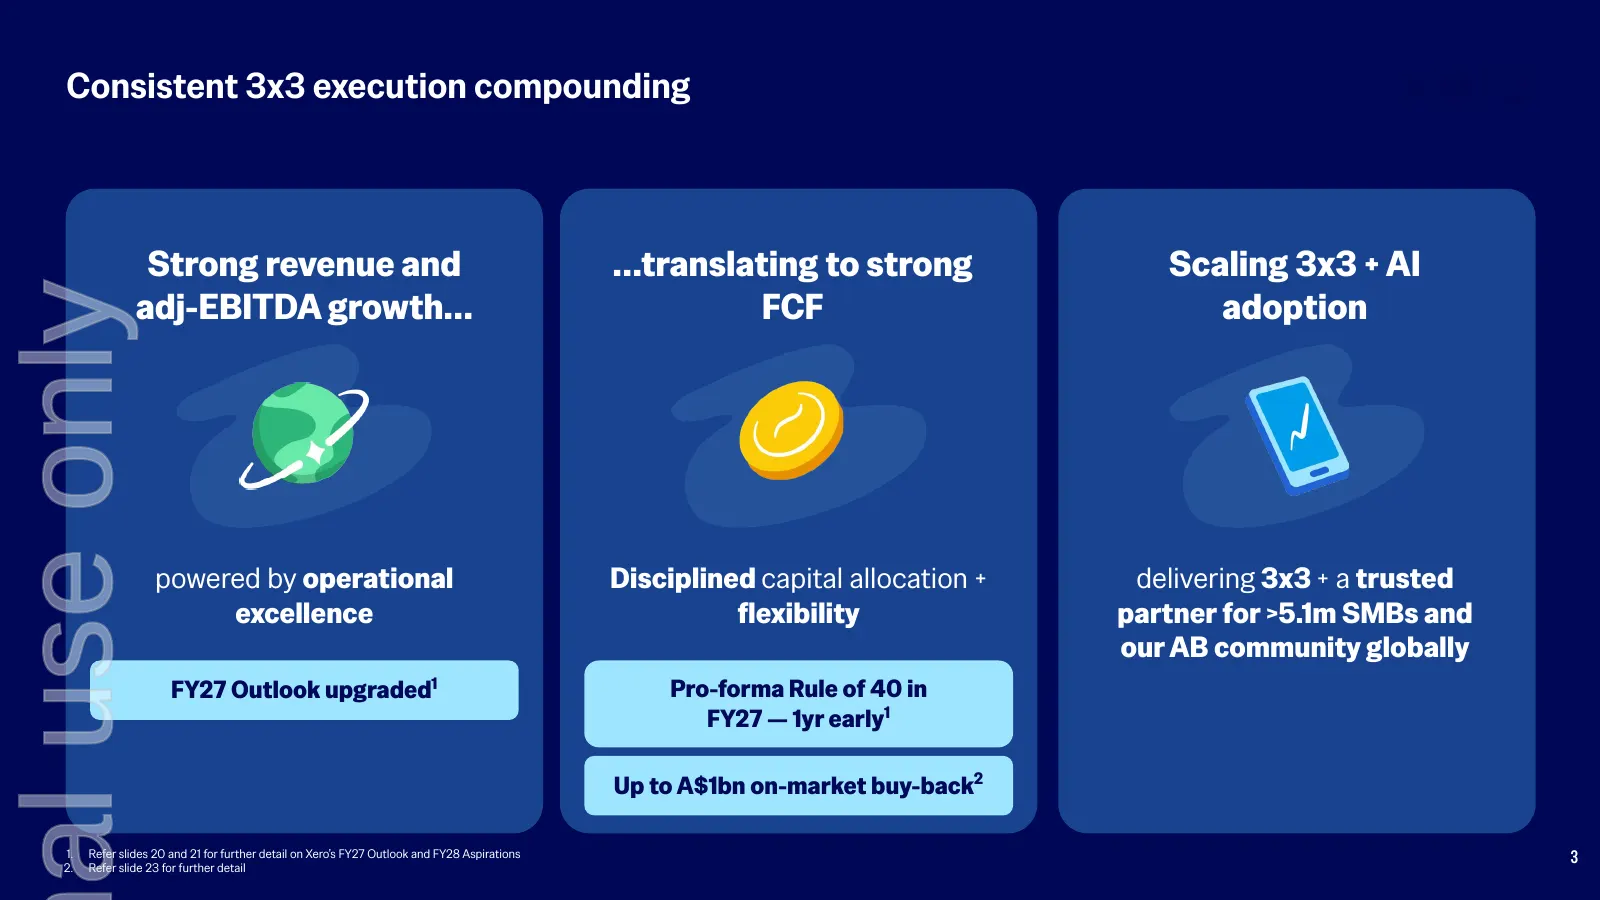
Slide 4: Consistent 3x3 execution compounding
Consistent 3x3 execution compounding Strong revenue and …translating to strong Scaling 3x3 + AI al use only adj-EBITDA growth… FCF adoption powered by operational Disciplined capital allocation + delivering 3x3 + a trusted excellence flexibility partner for >5.1m SMBs and our AB community globally F
Slide 5: Strong pro-forma revenue, adjusted EBITDA and FCF growth
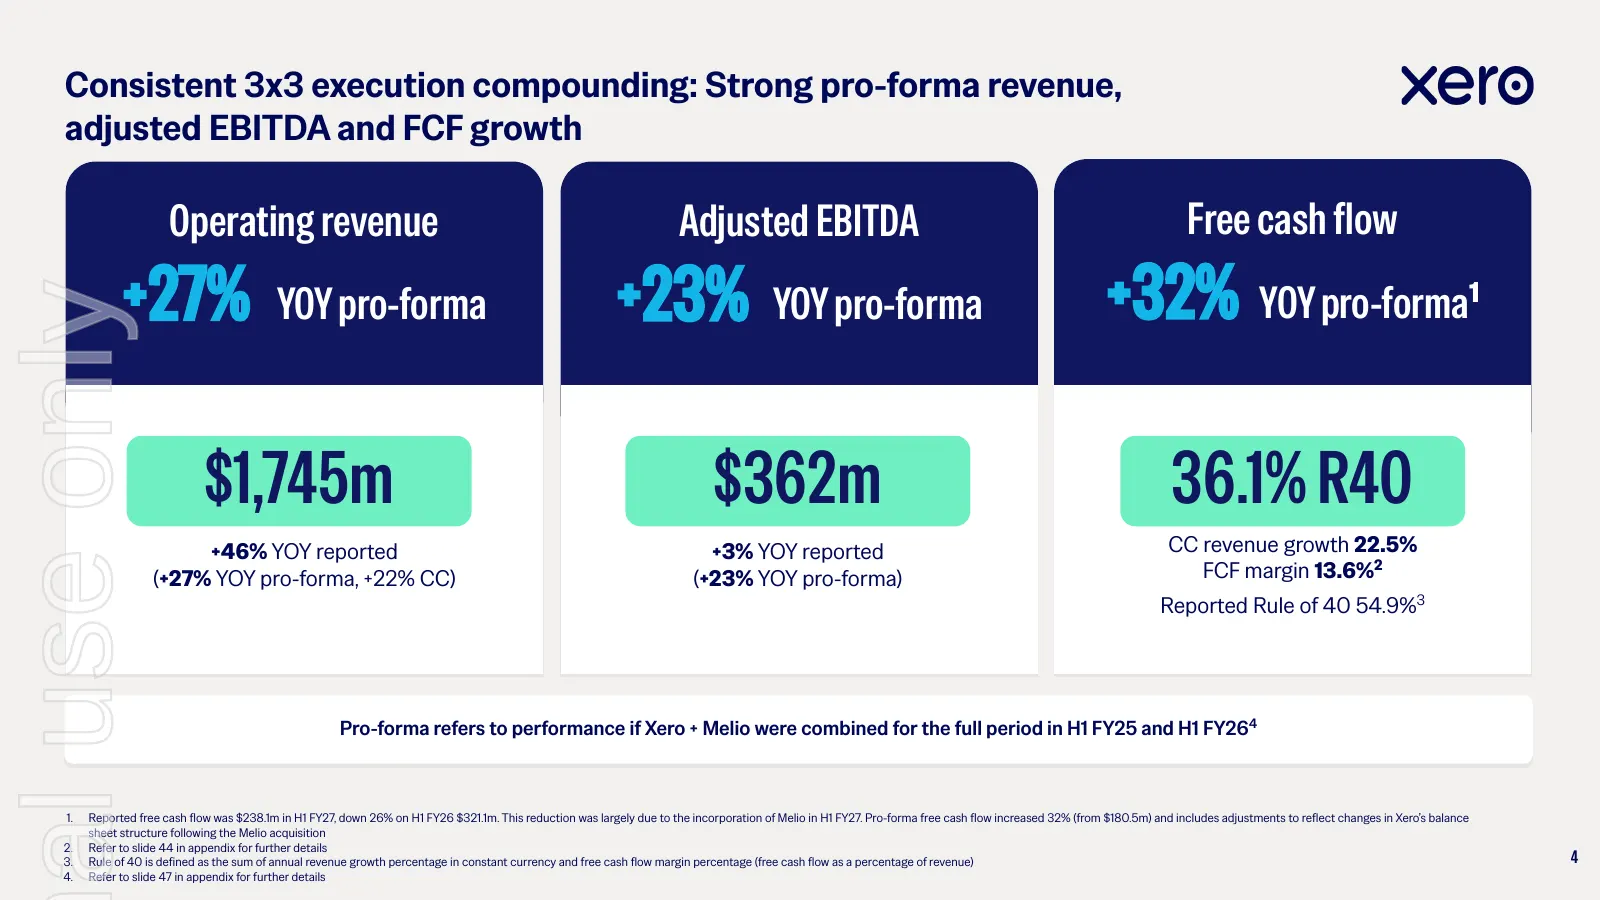
Consistent 3x3 execution compounding: Strong pro-forma revenue, adjusted EBITDA and FCF growth Operating revenue Adjusted EBITDA Free cash flow +27% YOY pro-forma +23% YOY pro-forma +32% YOY pro-forma 1 al use only $1,745m $362m 36.1% R40 +46% YOY reported +3% YOY reported CC revenue growth 22.5% (+
Slide 6: Strong revenue and adjusted EBITDA growth
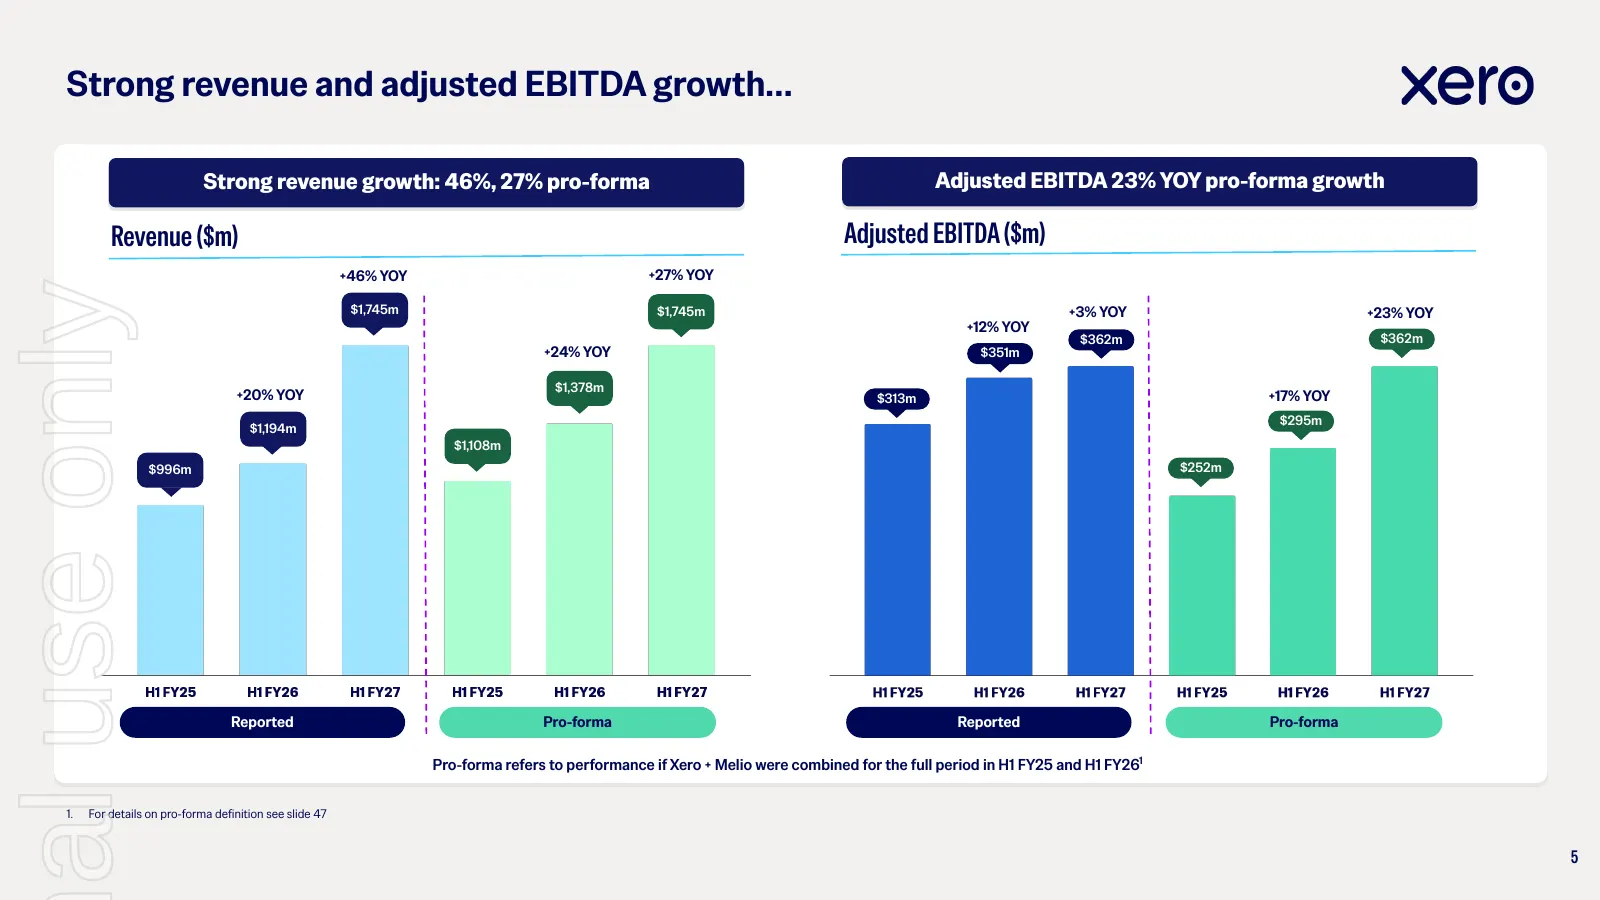
Strong revenue and adjusted EBITDA growth… Strong revenue growth: 46%, 27% pro-forma Adjusted EBITDA 23% YOY pro-forma growth Revenue ($m) Adjusted EBITDA ($m) +46% YOY +27% YOY al use only $1,745m $1,745m +3% YOY +23% YOY +12% YOY $362m $362m +24% YOY $351m $1,378m +20% YOY $313m +17% YOY $295m $1,
Slide 7: Translates to FCF growth and improving Rule of 40
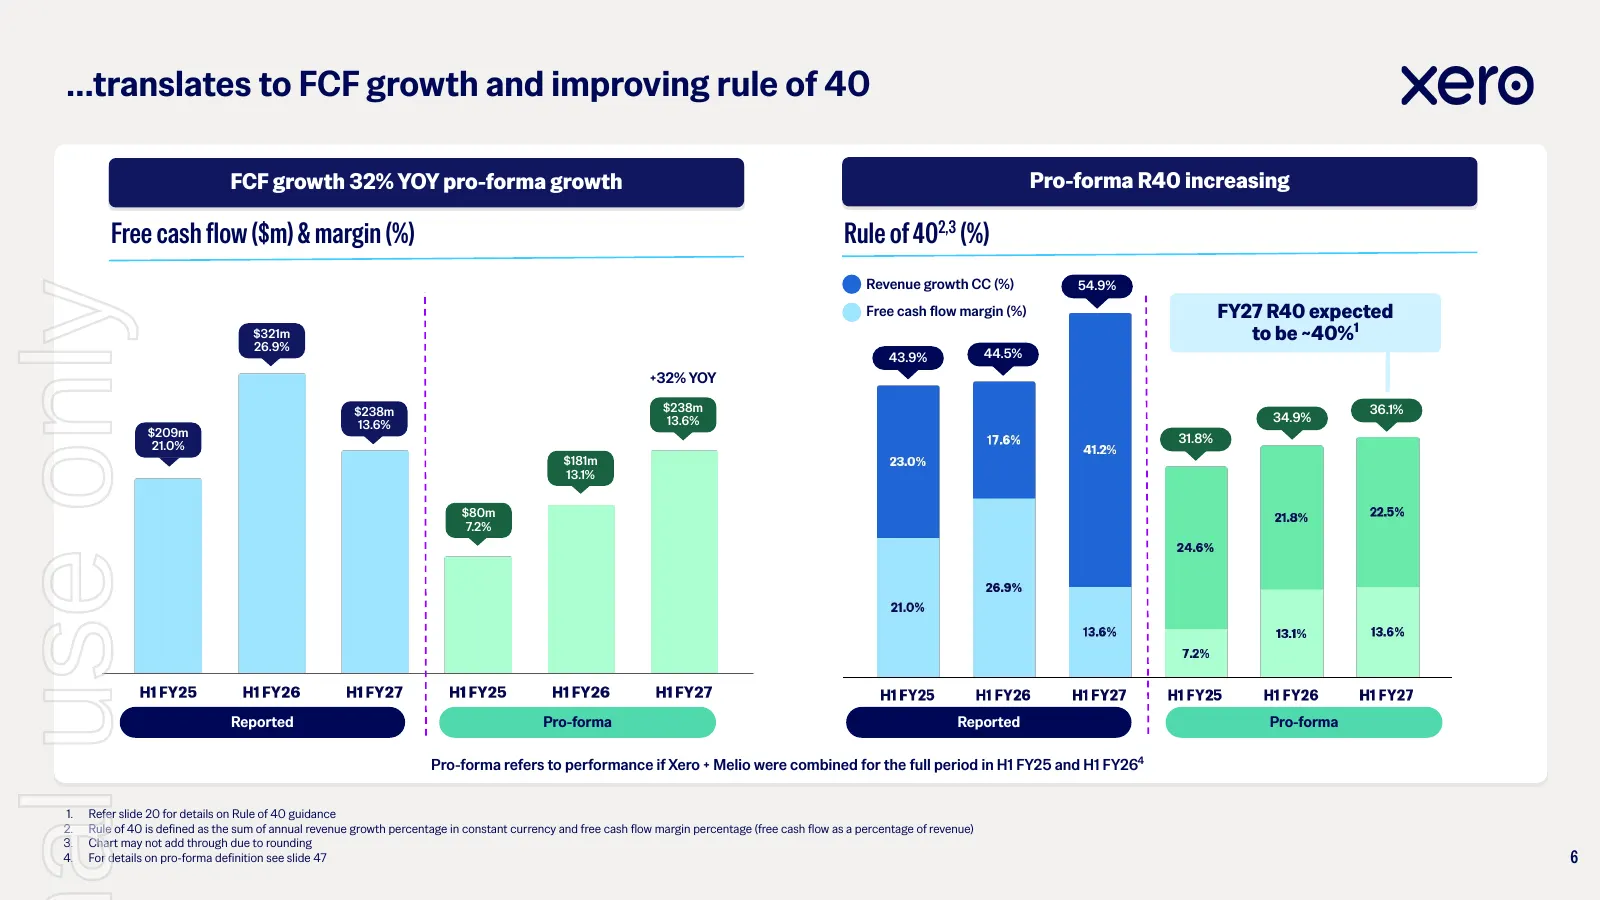
…translates to FCF growth and improving rule of 40 FCF growth 32% YOY pro-forma growth Pro-forma R40 increasing Pro-forma Rule of 40 increasing Free cash flow ($m) & margin (%) Rule of 402,3 (%) Revenue growth CC (%) 54.9% al use only Free cash flow margin (%) FY27 R40 expected $321m to be ~40%1 26.
Slide 8: Executing on our promises: broad based growth across our 3x3
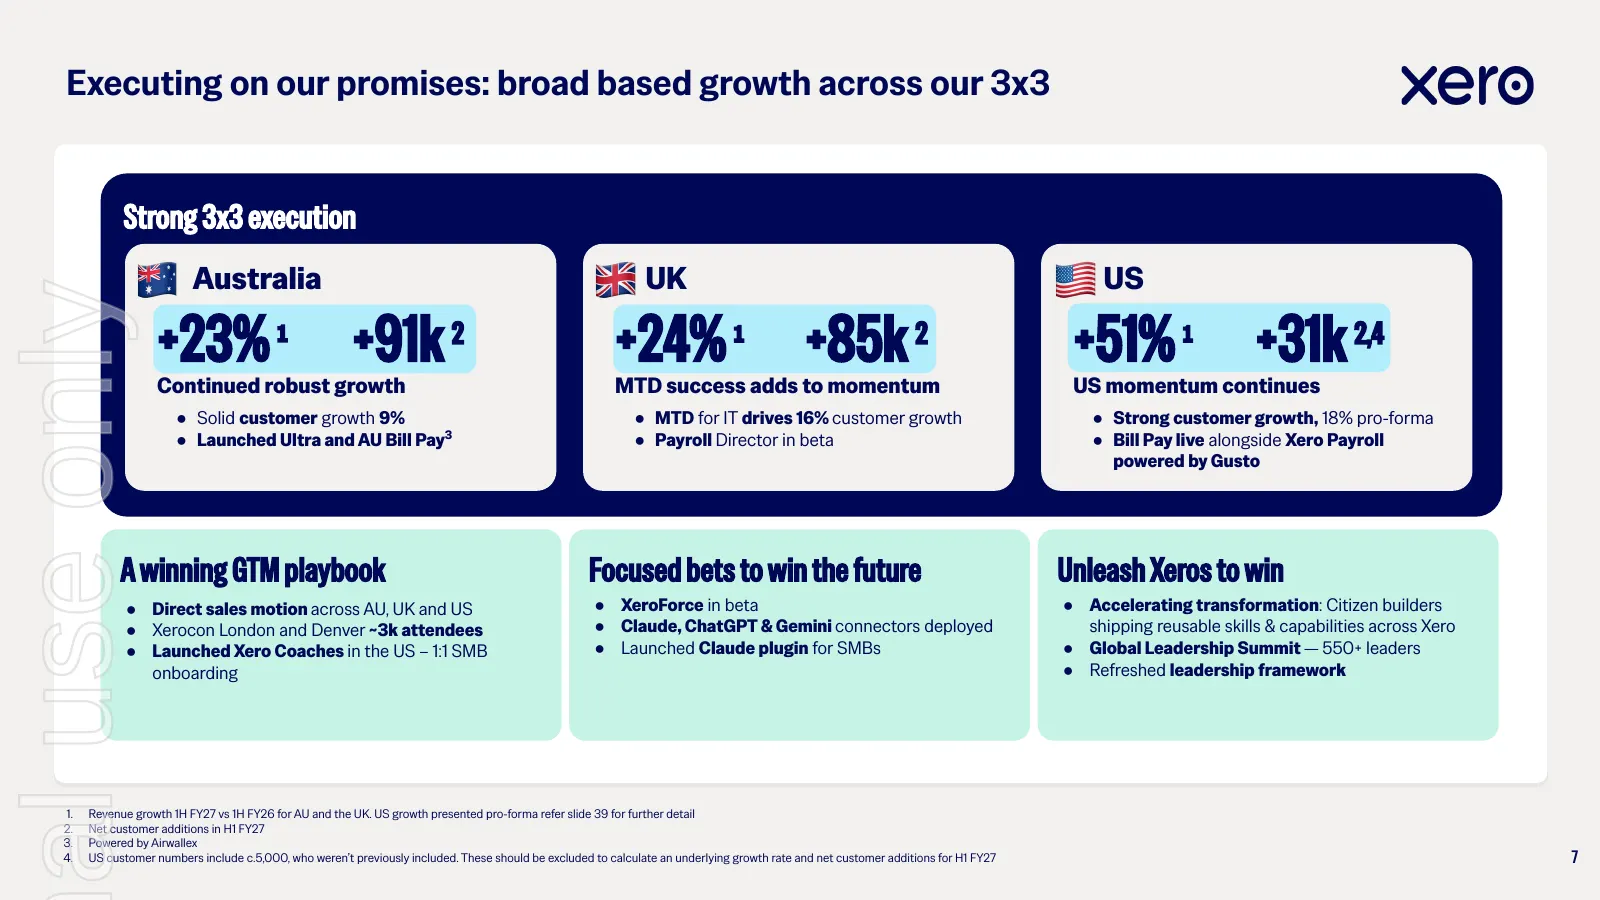
Executing on our promises: broad based growth across our 3x3 Strong 3x3 execution Australia UK US al use only +23% ¹ +91k 2 +24% ¹ +85k 2 +51% ¹ +31k 2,4 Continued robust growth MTD success adds to momentum US momentum continues ● Solid customer growth 9% ● MTD for IT drives 16% customer growth ● St
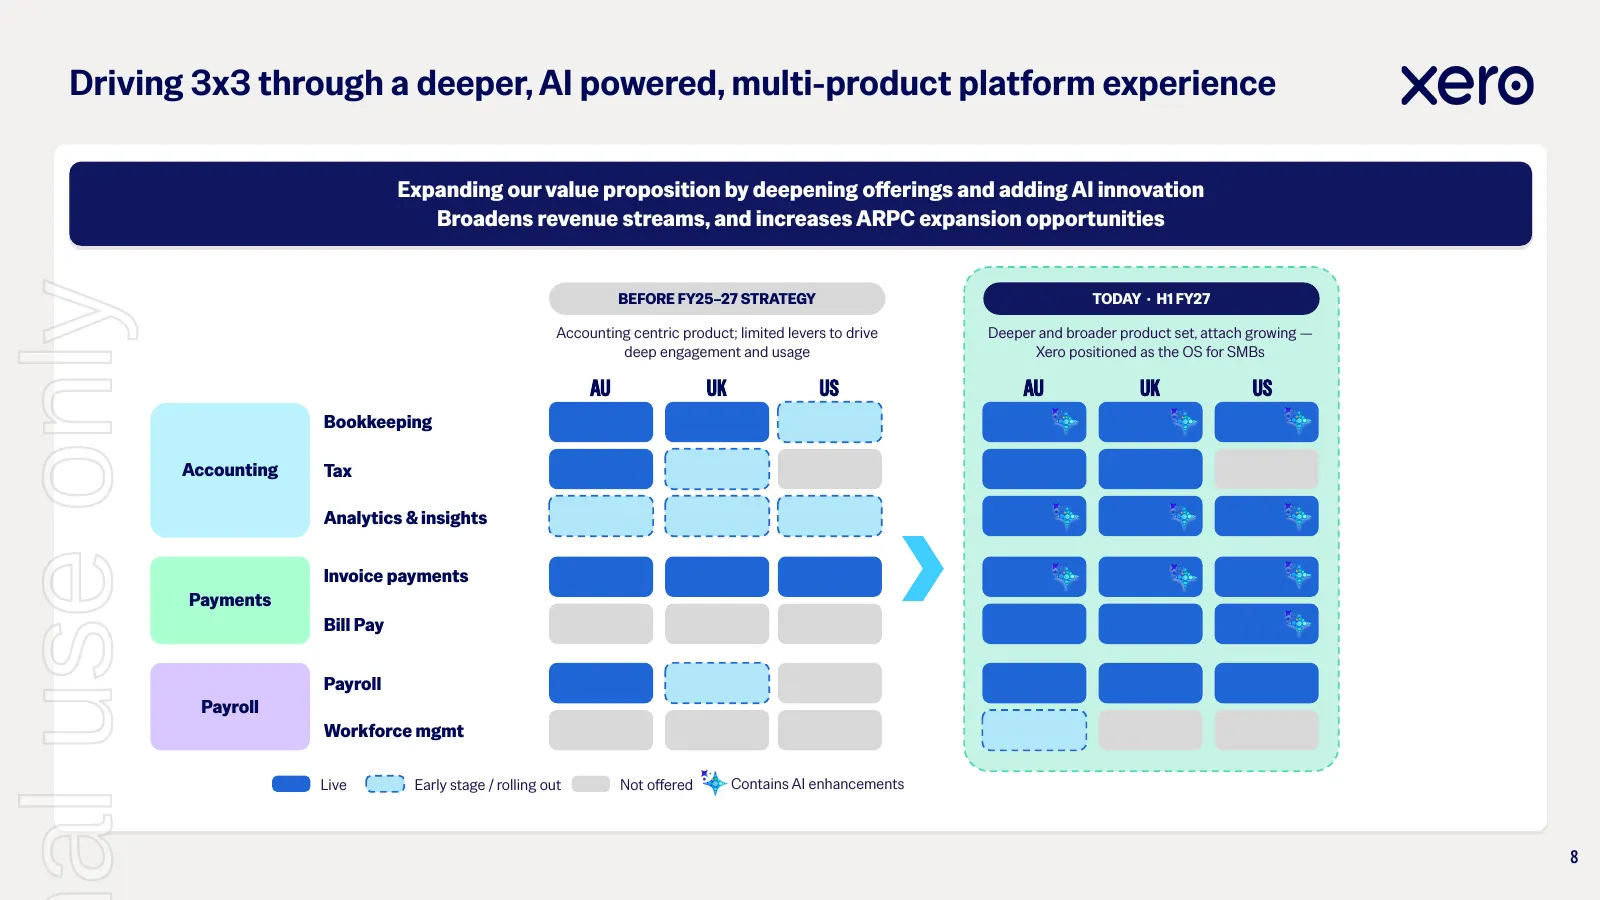
Slide 9: Driving 3x3 through a deeper, AI powered, multi-product platform
Driving 3x3 through a deeper, AI powered, multi-product platform experience Expanding our value proposition by deepening offerings and adding AI innovation Broadens revenue streams, and increases ARPC expansion opportunities al use only BEFORE FY25–27 STRATEGY TODAY · H1 FY27 Accounting centric prod
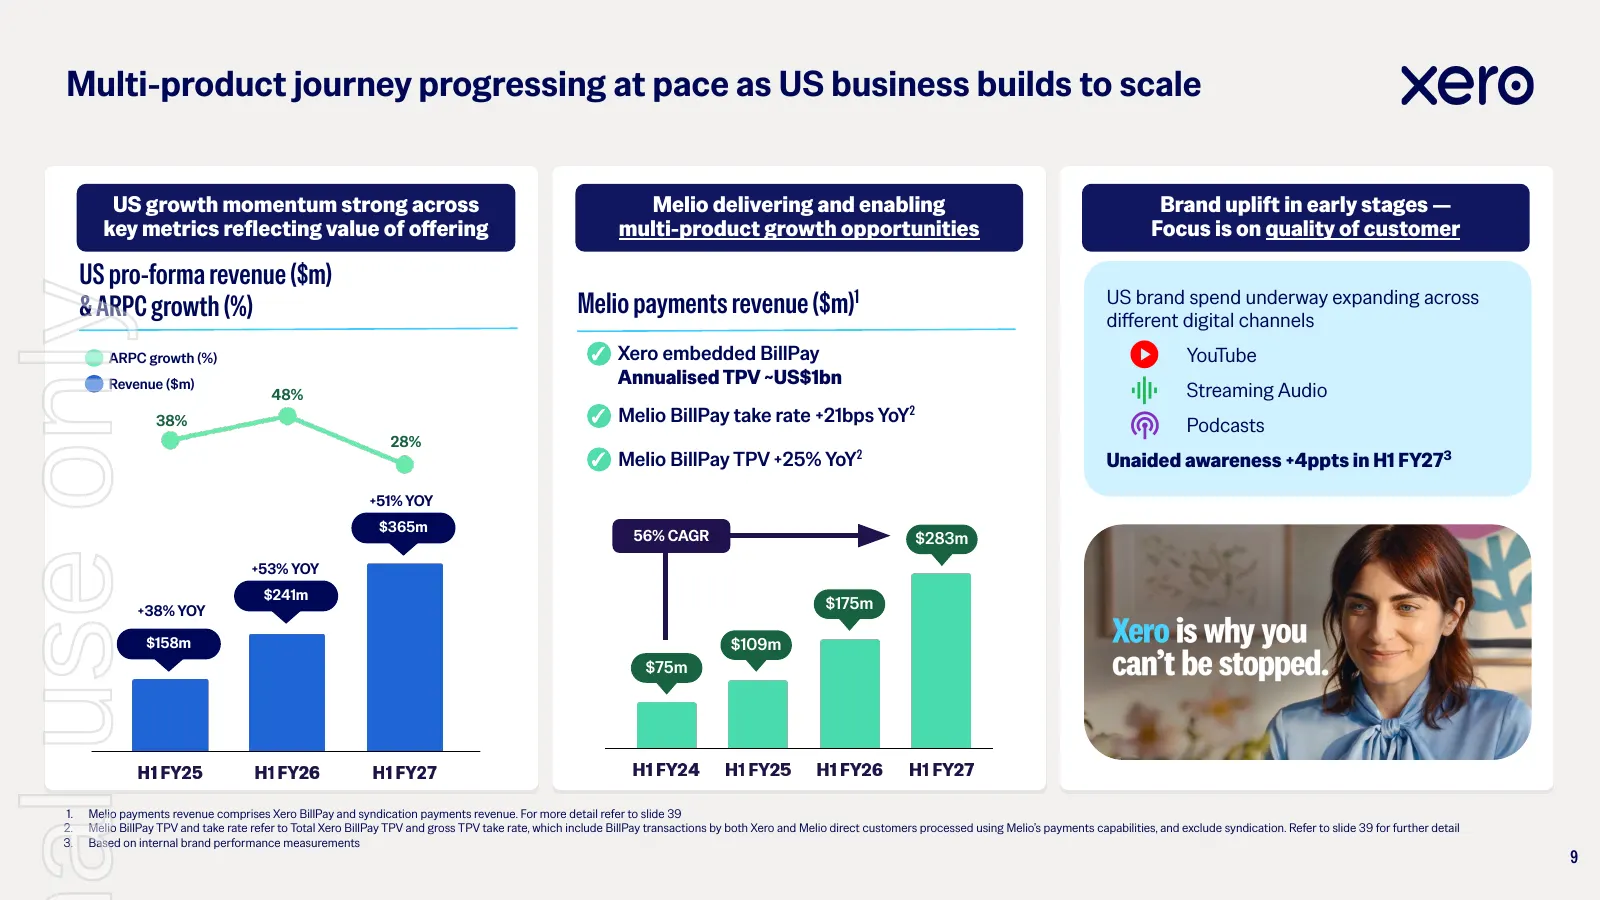
Slide 10: Multi-product journey progressing as US business builds to scale
Multi-product journey progressing at pace as US business builds to scale US growth momentum strong across Melio delivering and enabling Brand uplift in early stages — key metrics reflecting value of offering multi-product growth opportunities Focus is on quality of customer US pro-forma revenue ($m)
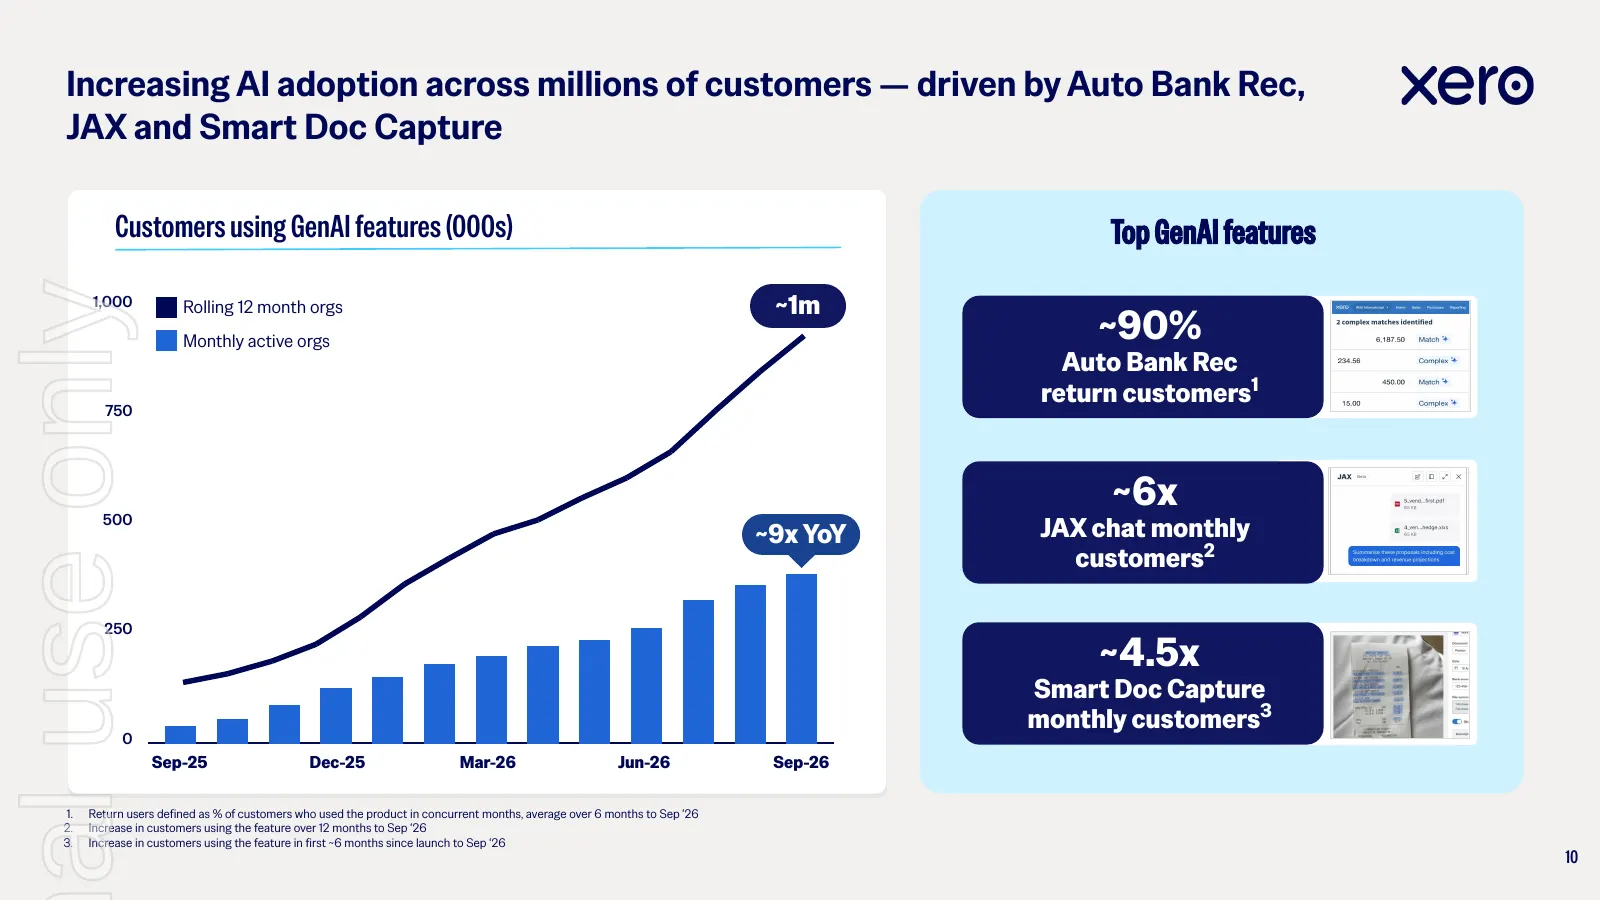
Slide 11: Increasing AI adoption across millions of customers
Increasing AI adoption across millions of customers — driven by Auto Bank Rec, JAX and Smart Doc Capture Customers using GenAI features (000s) Top GenAI features al use only 1,000 Rolling 12 month orgs ~1m Monthly active orgs ~90% Auto Bank Rec return customers1 750 ~6x 500 ~9x YoY JAX chat monthly
Slide 12: Financial results
Financial al use only results Claire Bramley Chief Financial Officer 11
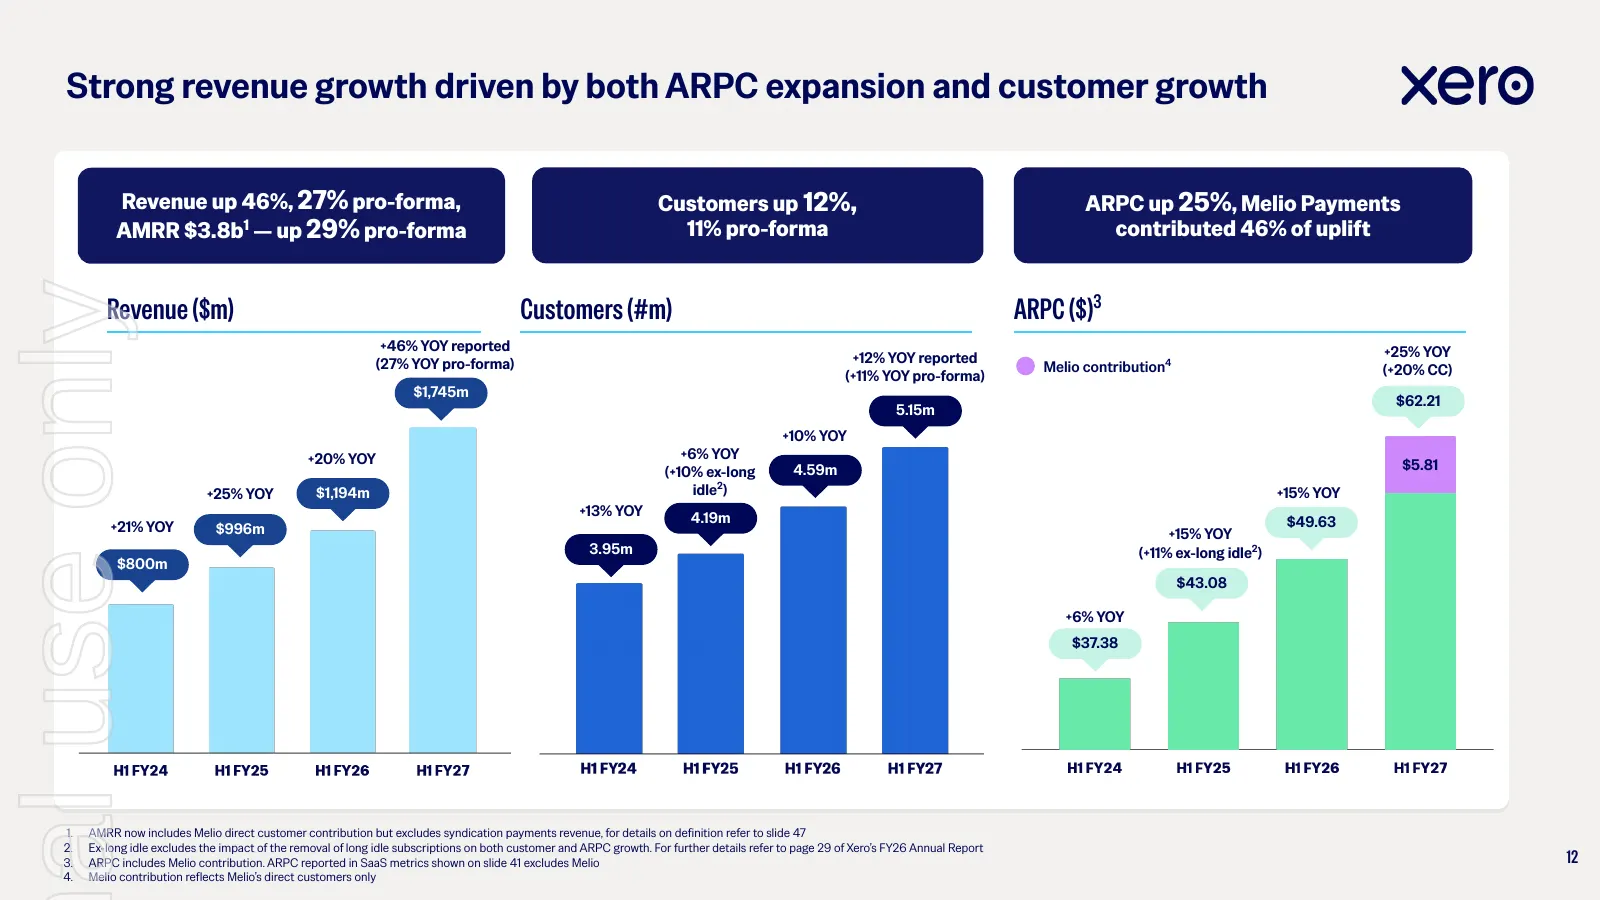
Slide 13: Strong revenue growth driven by ARPC expansion and customer growth
Strong revenue growth driven by both ARPC expansion and customer growth Revenue up 46%, 27% pro-forma, Customers up 12%, ARPC up 25%, Melio Payments AMRR $3.8b1 — up 29% pro-forma 11% pro-forma contributed 46% of uplift al use only Revenue ($m) Customers (#m) ARPC ($)3 +46% YOY reported +25% YOY (27
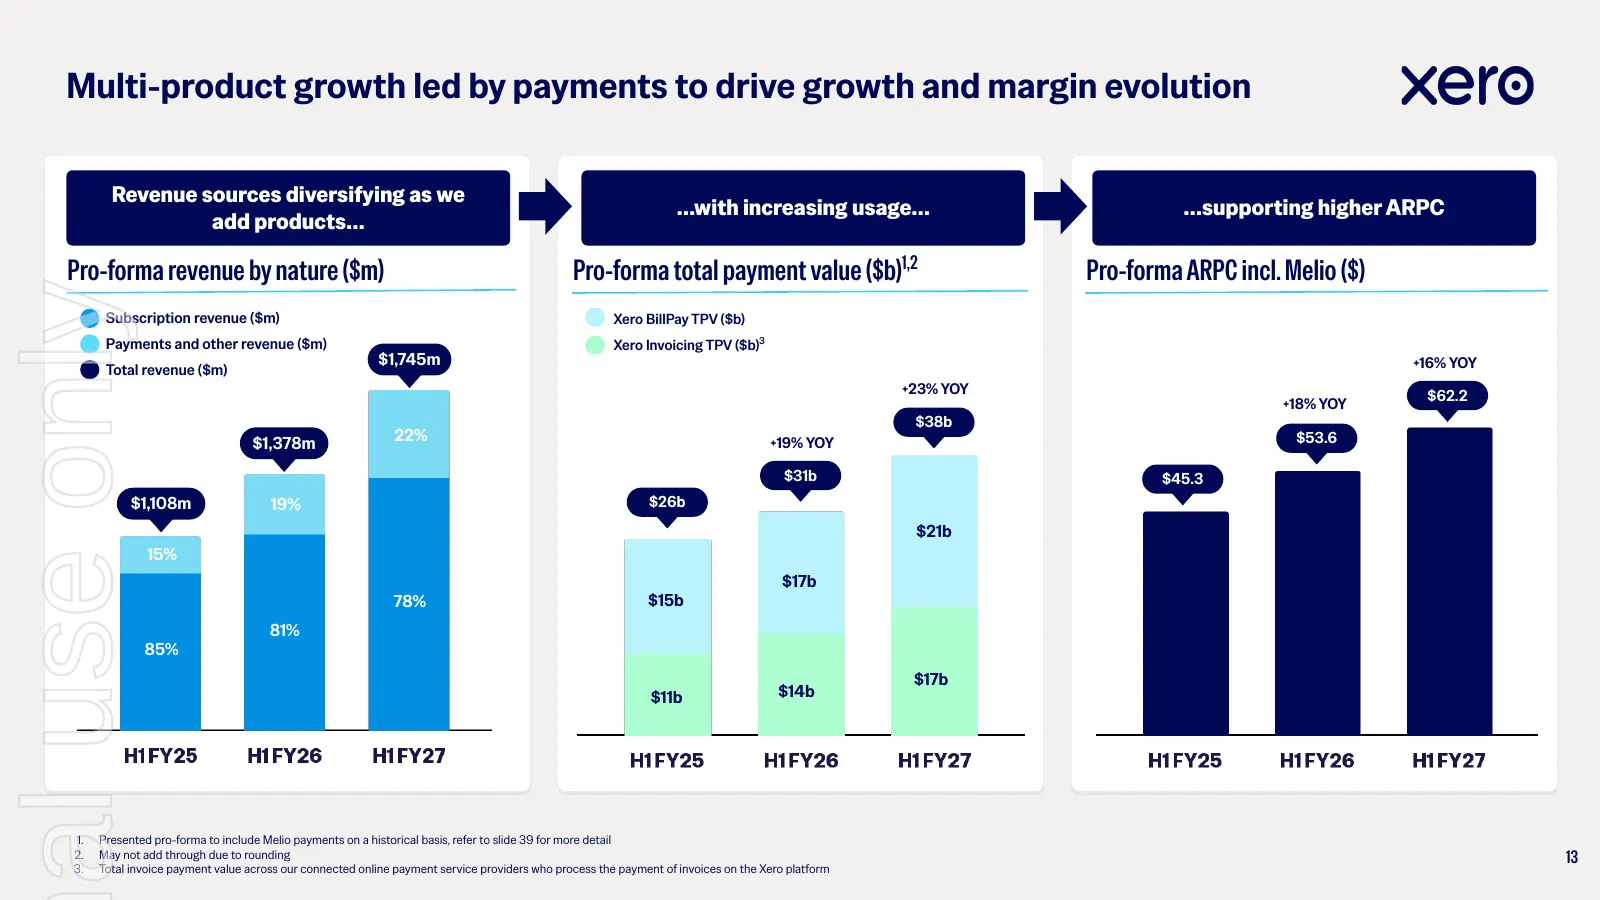
Slide 14: Multi-product growth led by payments
Multi-product growth led by payments to drive growth and margin evolution Revenue sources diversifying as we …with increasing usage… …supporting higher ARPC add products… Pro-forma revenue by nature ($m) Pro-forma total payment value ($b)1,2 Pro-forma ARPC incl. Melio ($) al use only Subscription re
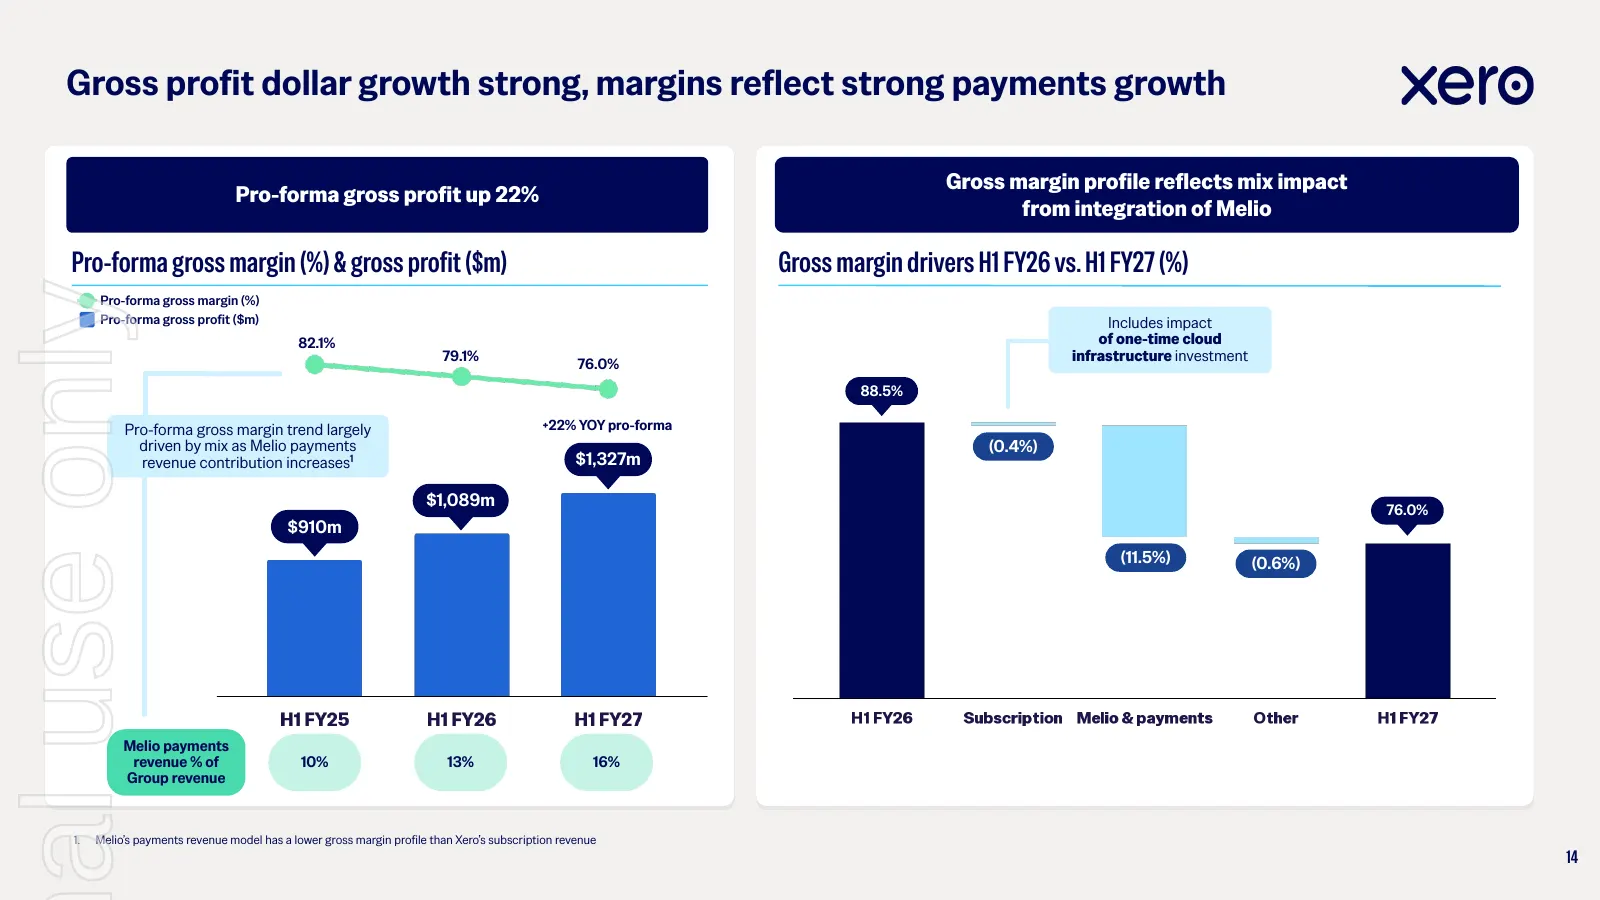
Slide 15: Gross profit dollar growth strong, margins reflect payments growth
Gross profit dollar growth strong, margins reflect strong payments growth Gross margin profile reflects mix impact Pro-forma gross profit up 22% from integration of Melio Pro-forma gross margin (%) & gross profit ($m) Gross margin drivers H1 FY26 vs. H1 FY27 (%) al use only Pro-forma gross margin (%
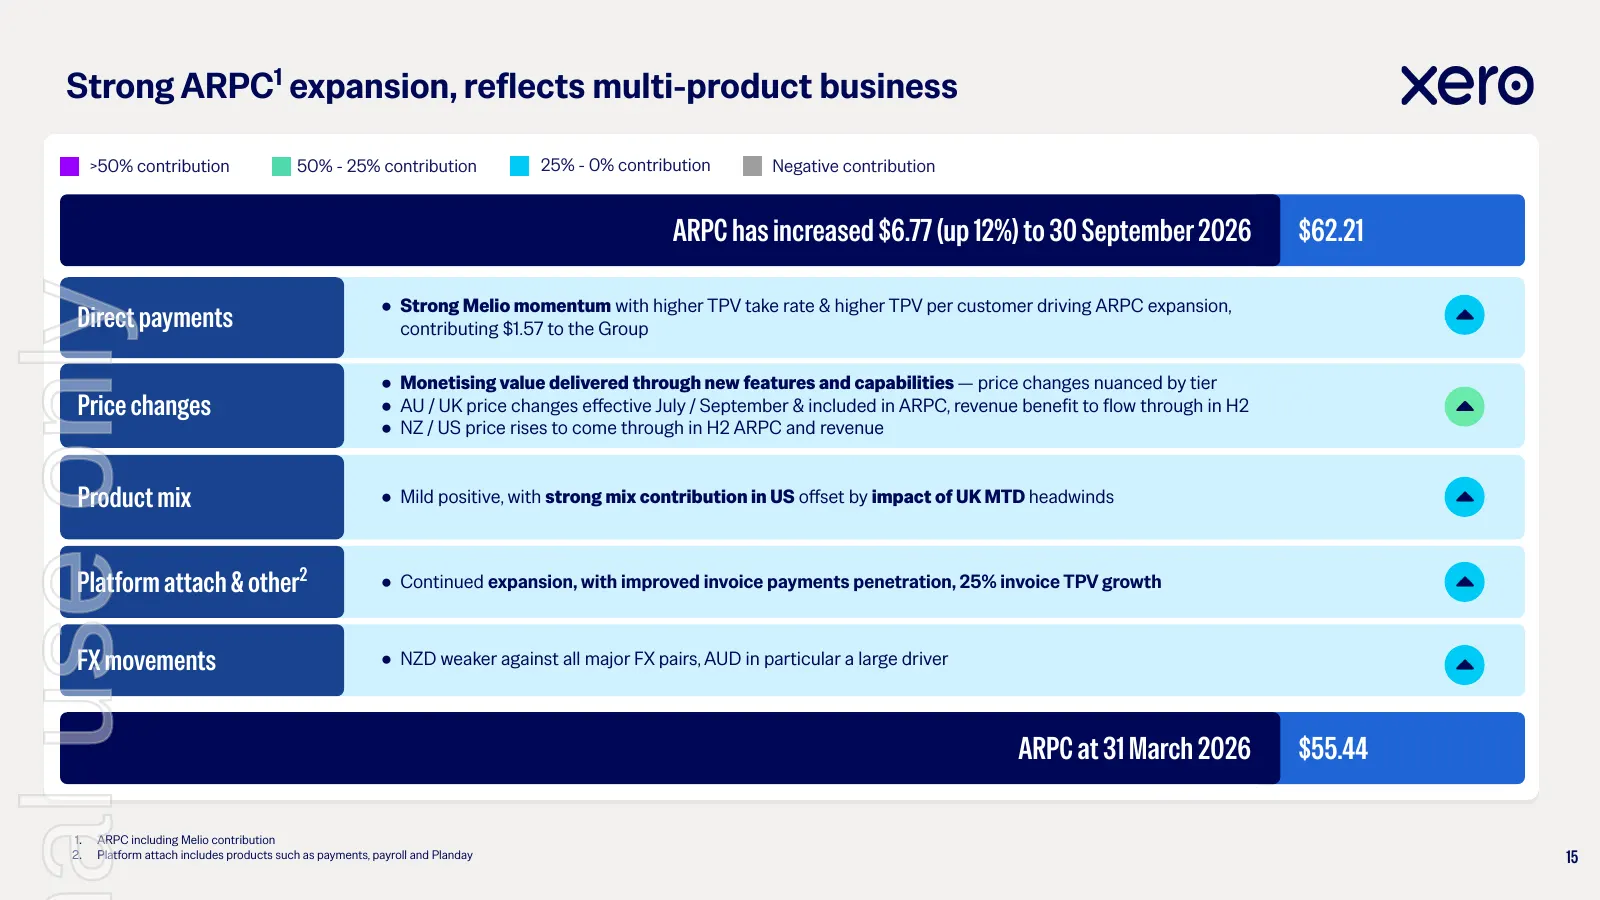
Slide 16: Strong ARPC expansion, reflects multi-product business
Strong ARPC1 expansion, reflects multi-product business >50% contribution 50% - 25% contribution 25% - 0% contribution Negative contribution ARPC has increased $6.77 (up 12%) to 30 September 2026 $62.21 al use only ● Strong Melio momentum with higher TPV take rate & higher TPV per customer driving A
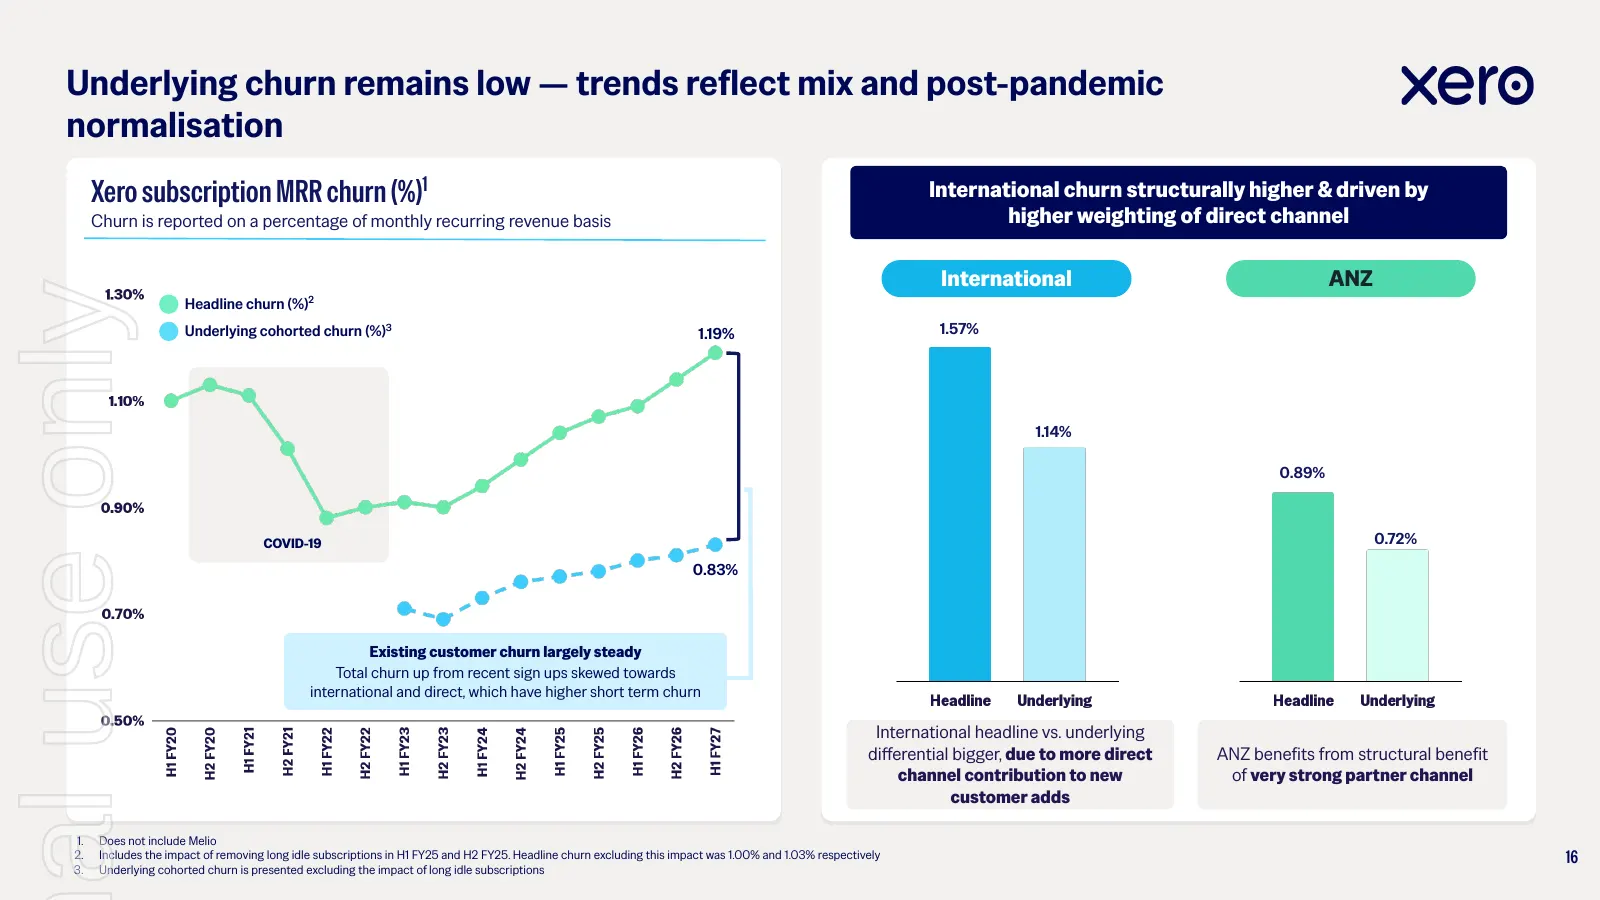
Slide 17: Underlying churn remains low
Underlying churn remains low — trends reflect mix and post-pandemic normalisation Xero subscription MRR churn (%)1 International churn structurally higher & driven by Churn is reported on a percentage of monthly recurring revenue basis higher weighting of direct channel International ANZ al use only
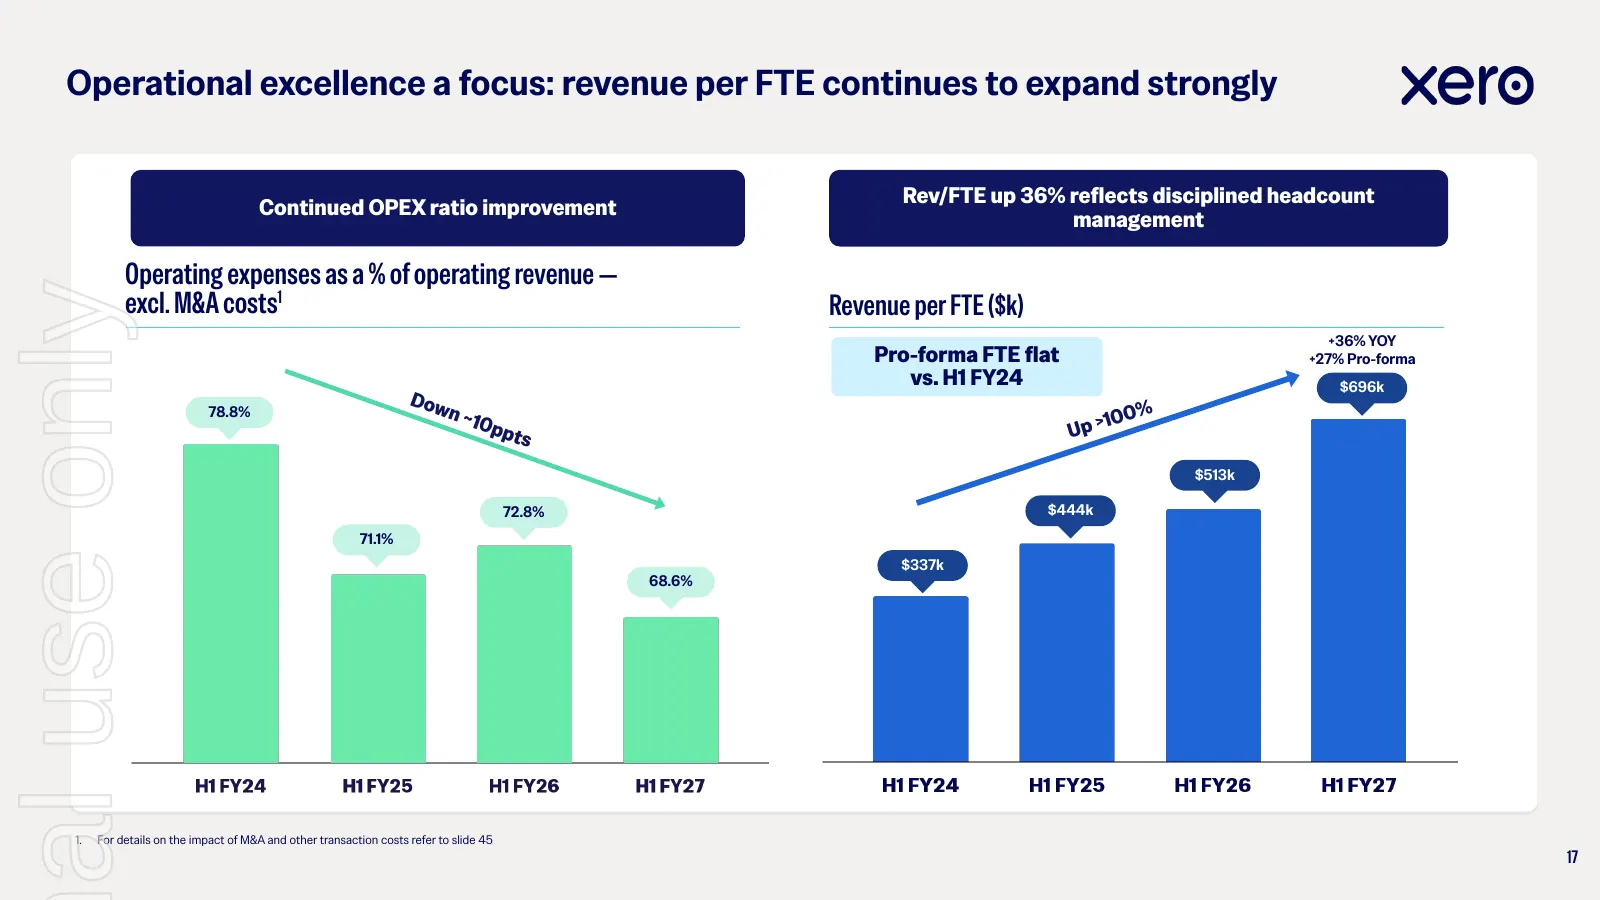
Slide 18: Operational excellence: revenue per FTE continues to expand
Operational excellence a focus: revenue per FTE continues to expand strongly Rev/FTE up 36% reflects disciplined headcount Continued OPEX ratio improvement management Operating expenses as a % of operating revenue — al use only excl. M&A costs1 Revenue per FTE ($k) +36% YOY Pro-forma FTE flat +27% P
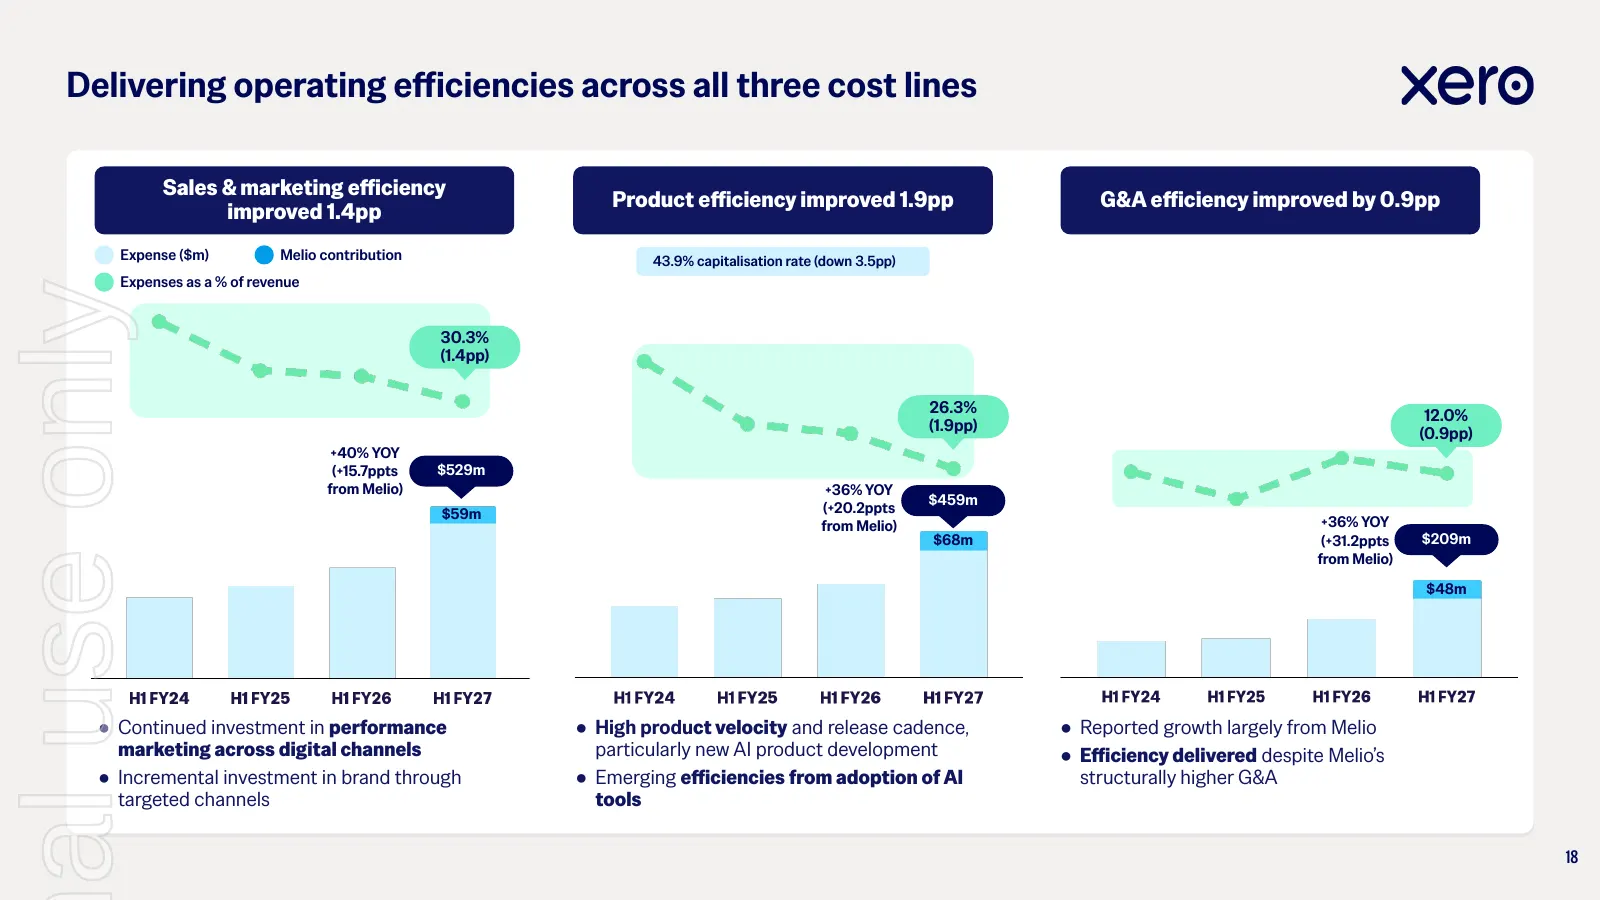
Slide 19: Delivering operating efficiencies across all three cost lines
Delivering operating efficiencies across all three cost lines Sales & marketing efficiency Product efficiency improved 1.9pp G&A efficiency improved by 0.9pp improved 1.4pp Expense ($m) Melio contribution 43.9% capitalisation rate (down 3.5pp) Expenses as a % of revenue al use only 30.3% (1.4pp) 26.
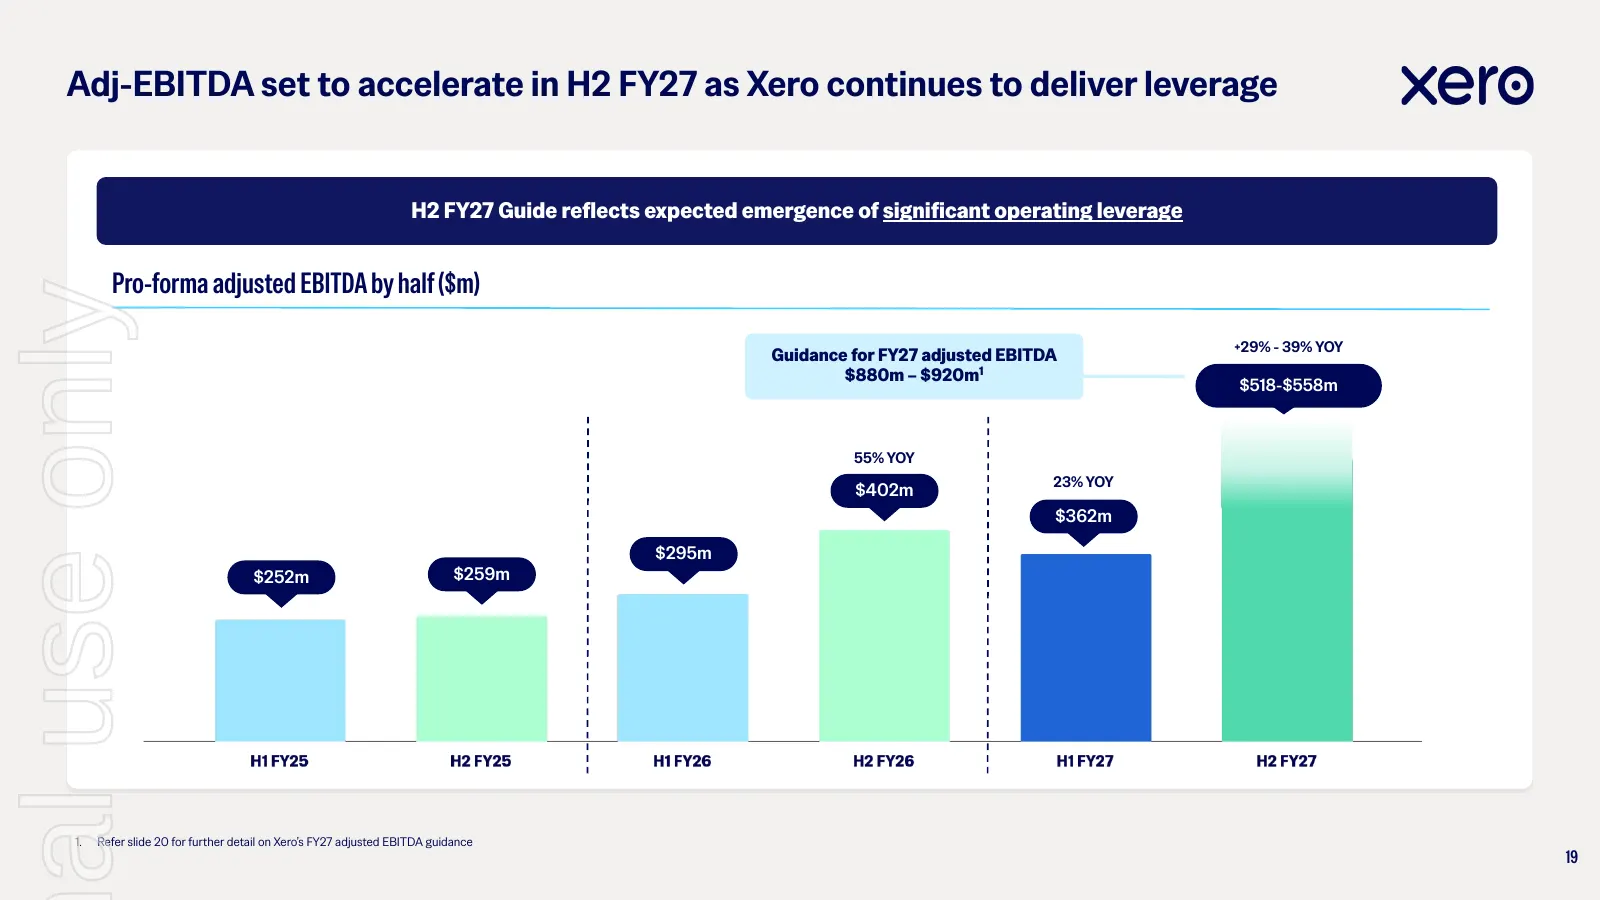
Slide 20: Adj-EBITDA set to accelerate in H2 FY27
Adj-EBITDA set to accelerate in H2 FY27 as Xero continues to deliver leverage H2 FY27 Guide reflects expected emergence of significant operating leverage Pro-forma adjusted EBITDA by half ($m) al use only +29% - 39% YOY Guidance for FY27 adjusted EBITDA $880m – $920m1 $518-$558m 55% YOY 23% YOY $402
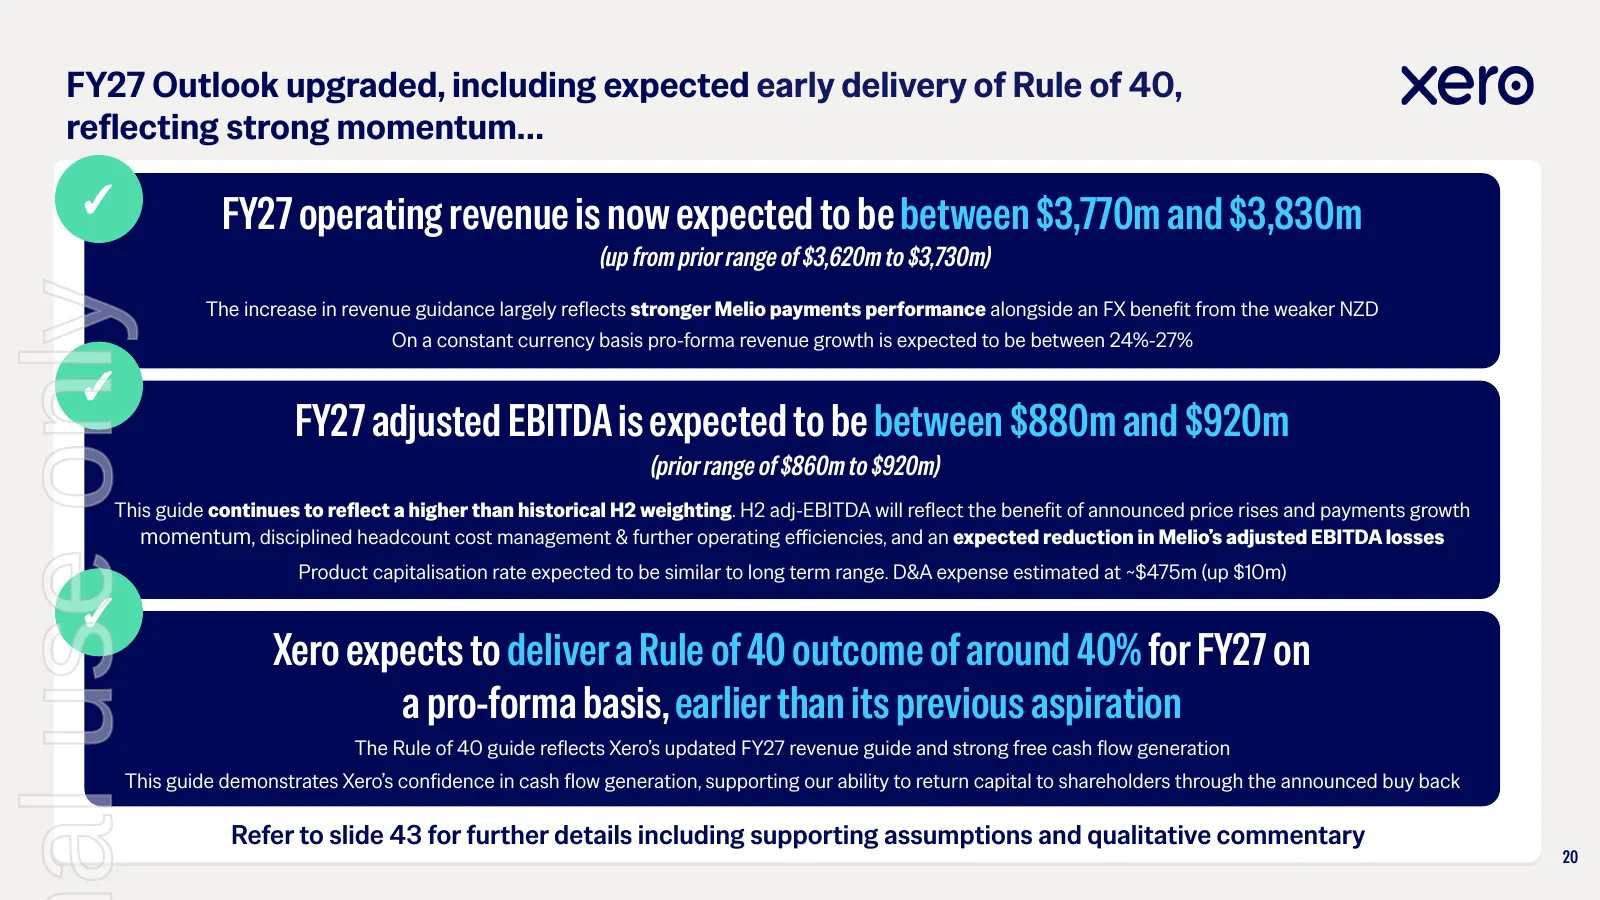
Slide 21: FY27 Outlook upgraded
FY27 Outlook upgraded, including expected early delivery of Rule of 40, reflecting strong momentum… ✓ FY27 operating revenue is now expected to be between $3,770m and $3,830m (up from prior range of $3,620m to $3,730m) al use only The increase in revenue guidance largely reflects stronger Melio paym
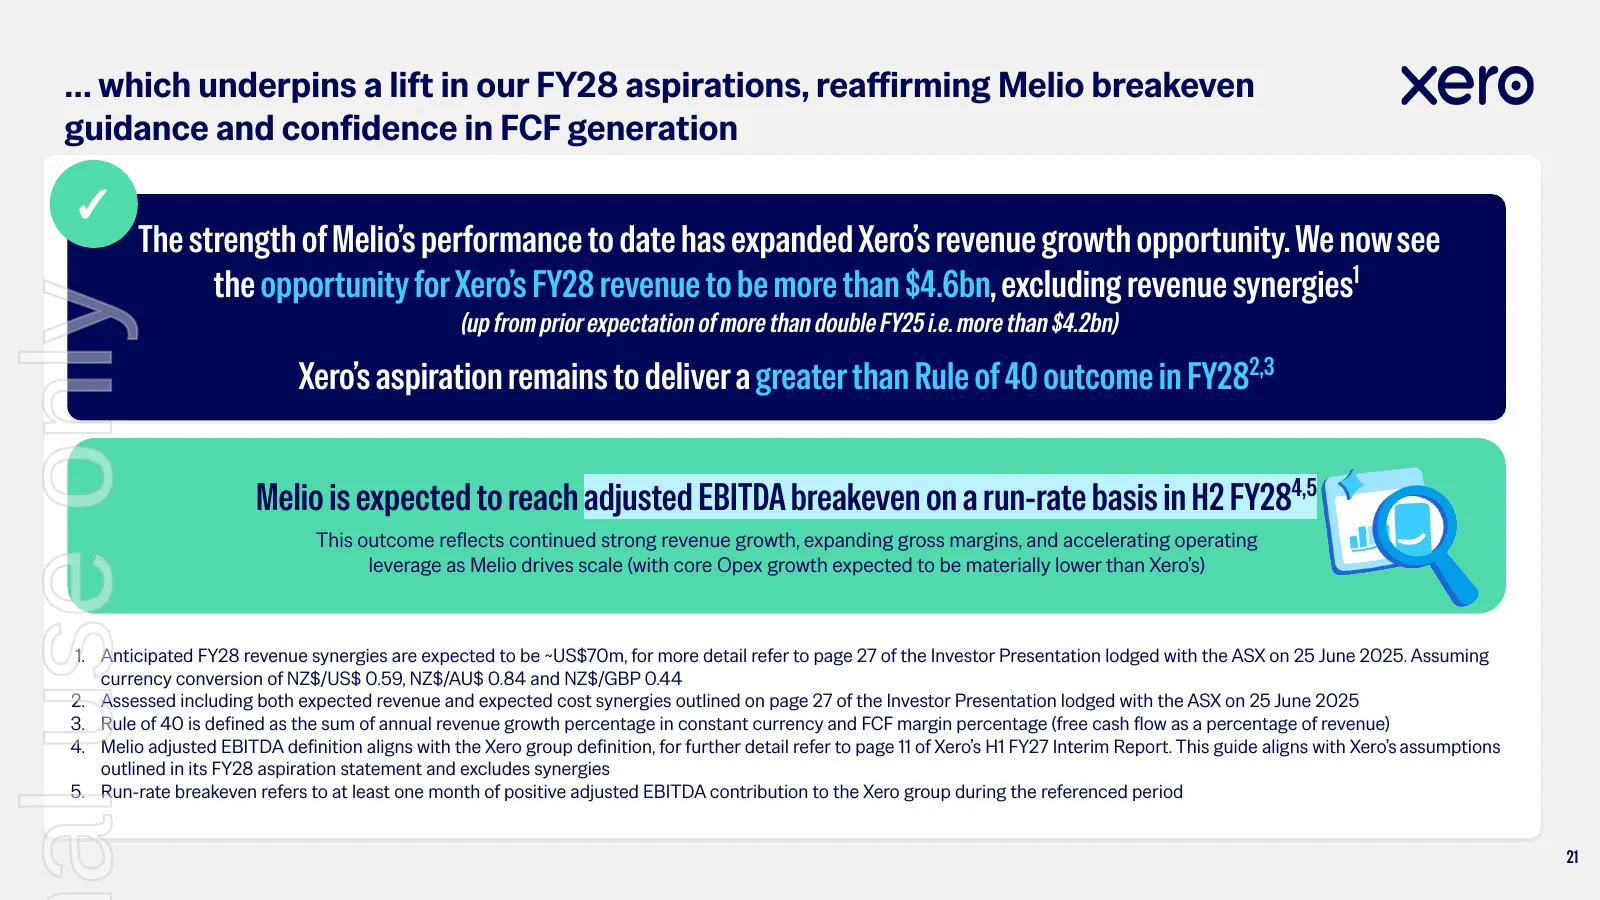
Slide 22: Lift in FY28 aspirations, reaffirming Melio breakeven guidance
… which underpins a lift in our FY28 aspirations, reaffirming Melio breakeven guidance and confidence in FCF generation ✓ The strength of Melio’s performance to date has expanded Xero’s revenue growth opportunity. We now see the opportunity for Xero’s FY28 revenue to be more than $4.6bn, excluding r
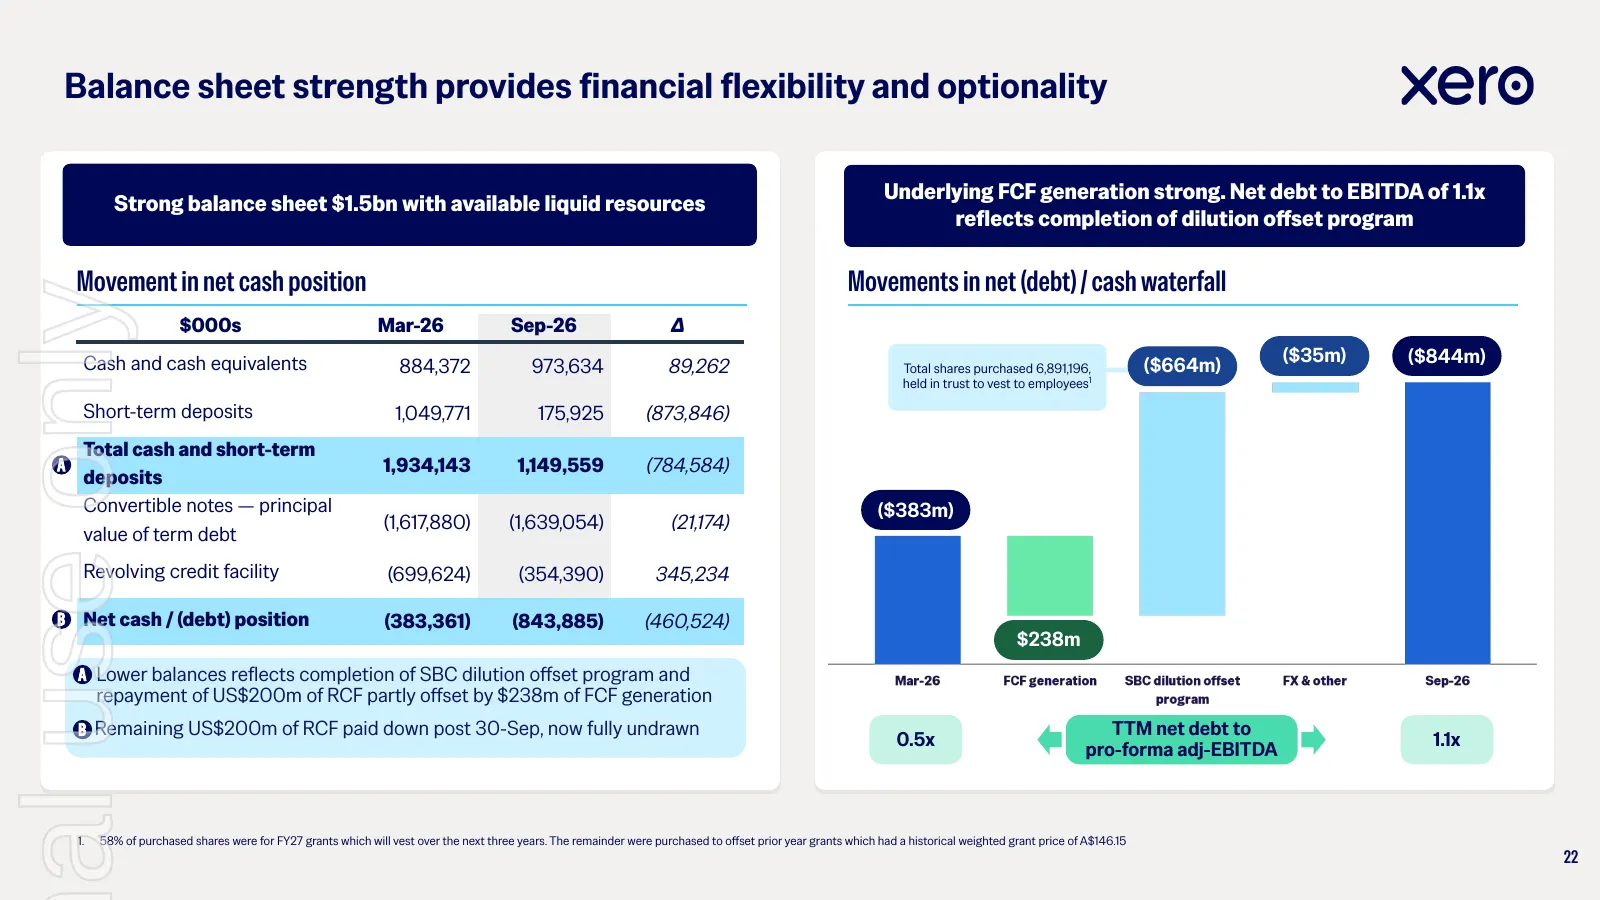
Slide 23: Balance sheet strength provides financial flexibility
Balance sheet strength provides financial flexibility and optionality Underlying FCF generation strong. Net debt to EBITDA of 1.1x Strong balance sheet $1.5bn with available liquid resources reflects completion of dilution offset program Movement in net cash position Movements in net (debt) / cash w
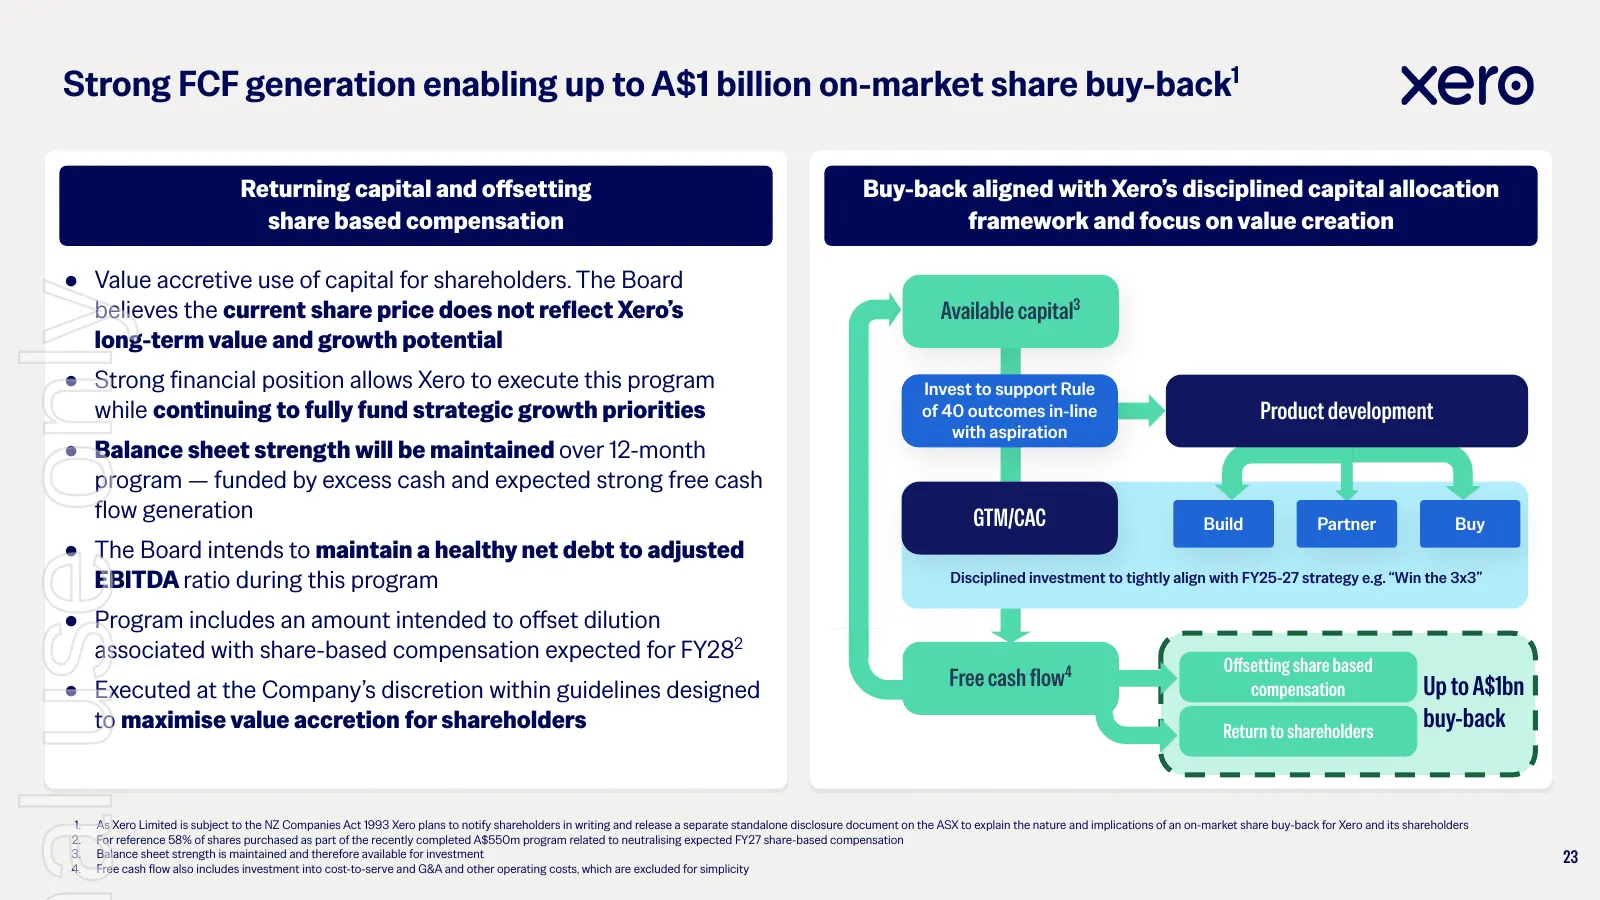
Slide 24: Up to A$1 billion on-market share buy-back
Strong FCF generation enabling up to A$1 billion on-market share buy-back1 Returning capital and offsetting Buy-back aligned with Xero’s disciplined capital allocation share based compensation framework and focus on value creation ● Value accretive use of capital for shareholders. The Board al use o
Slide 25: AI themes and wrap up
AI themes al use only and wrap up Sukhinder Singh Cassidy Chief Executive Officer 24
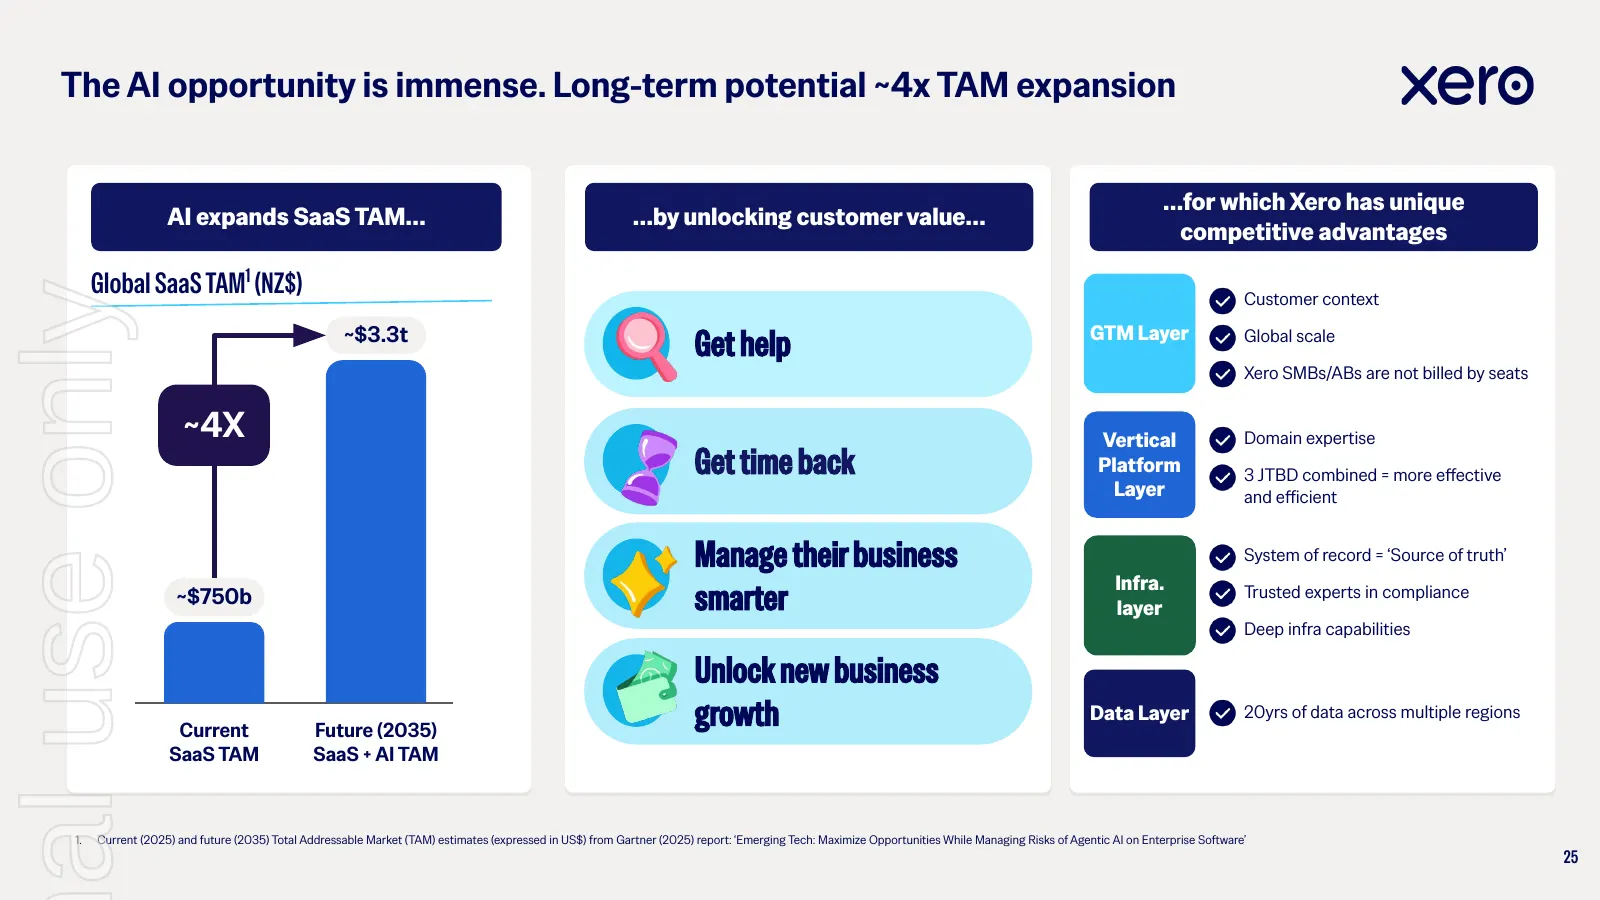
Slide 26: The AI opportunity is immense: ~4x TAM expansion
The AI opportunity is immense. Long-term potential ~4x TAM expansion …for which Xero has unique AI expands SaaS TAM… …by unlocking customer value… competitive advantages Global SaaS TAM1 (NZ$) al use only Customer context ~$3.3t Get help GTM Layer Global scale Xero SMBs/ABs are not billed by seats ~
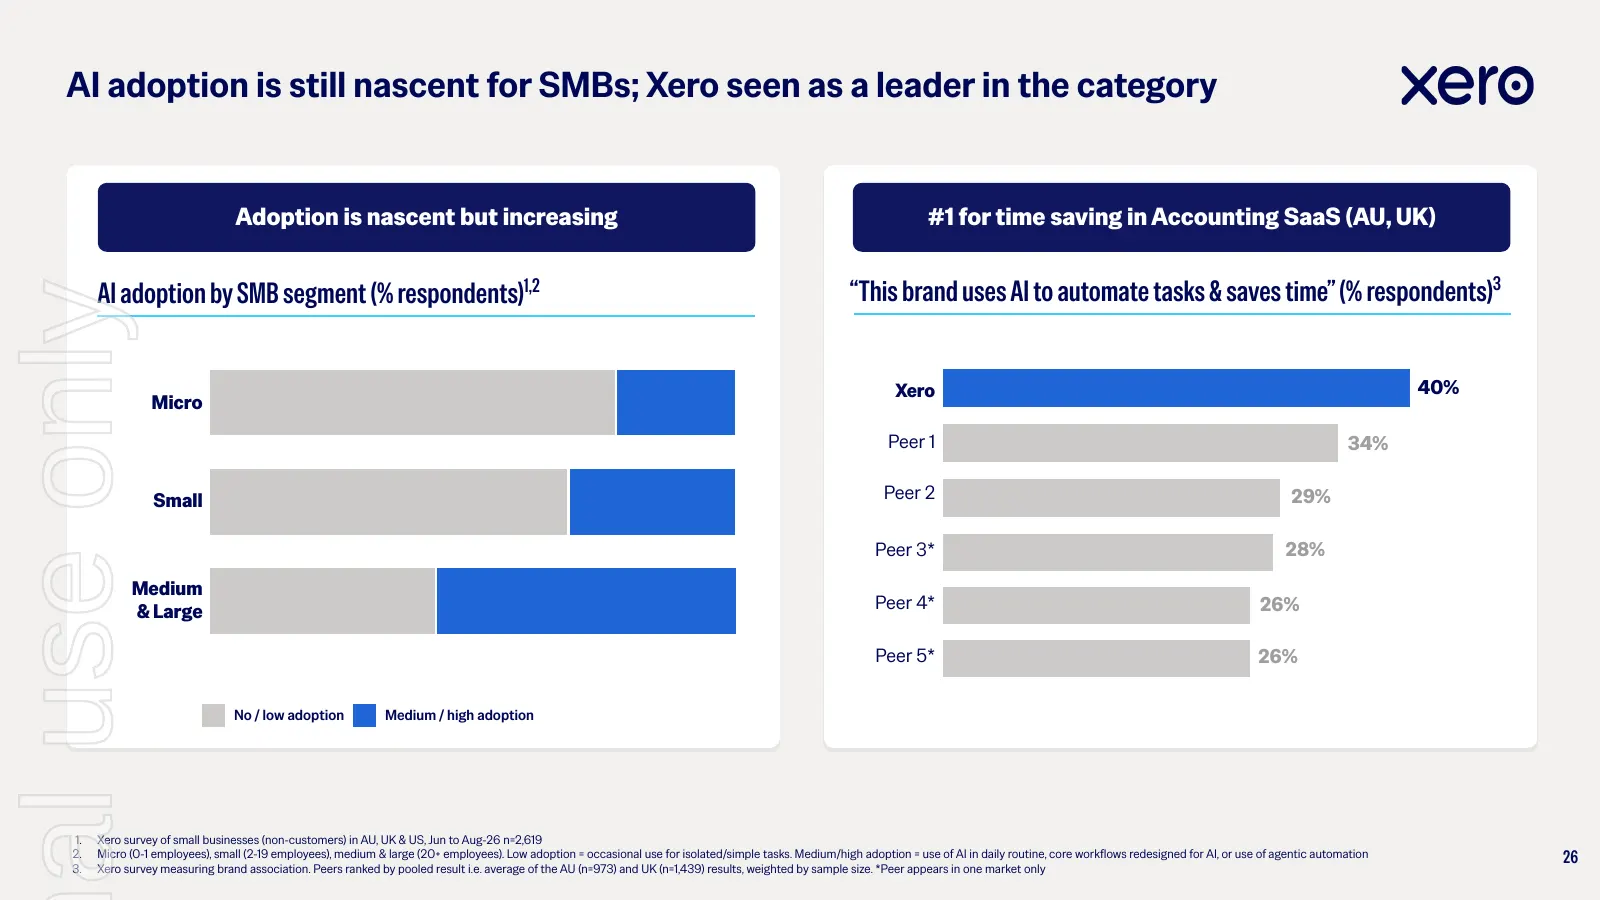
Slide 27: AI adoption still nascent for SMBs; Xero seen as a leader
AI adoption is still nascent for SMBs; Xero seen as a leader in the category Adoption is nascent but increasing #1 for time saving in Accounting SaaS (AU, UK) AI adoption by SMB segment (% respondents)1,2 “This brand uses AI to automate tasks & saves time” (% respondents)3 al use only Xero 40% Micro
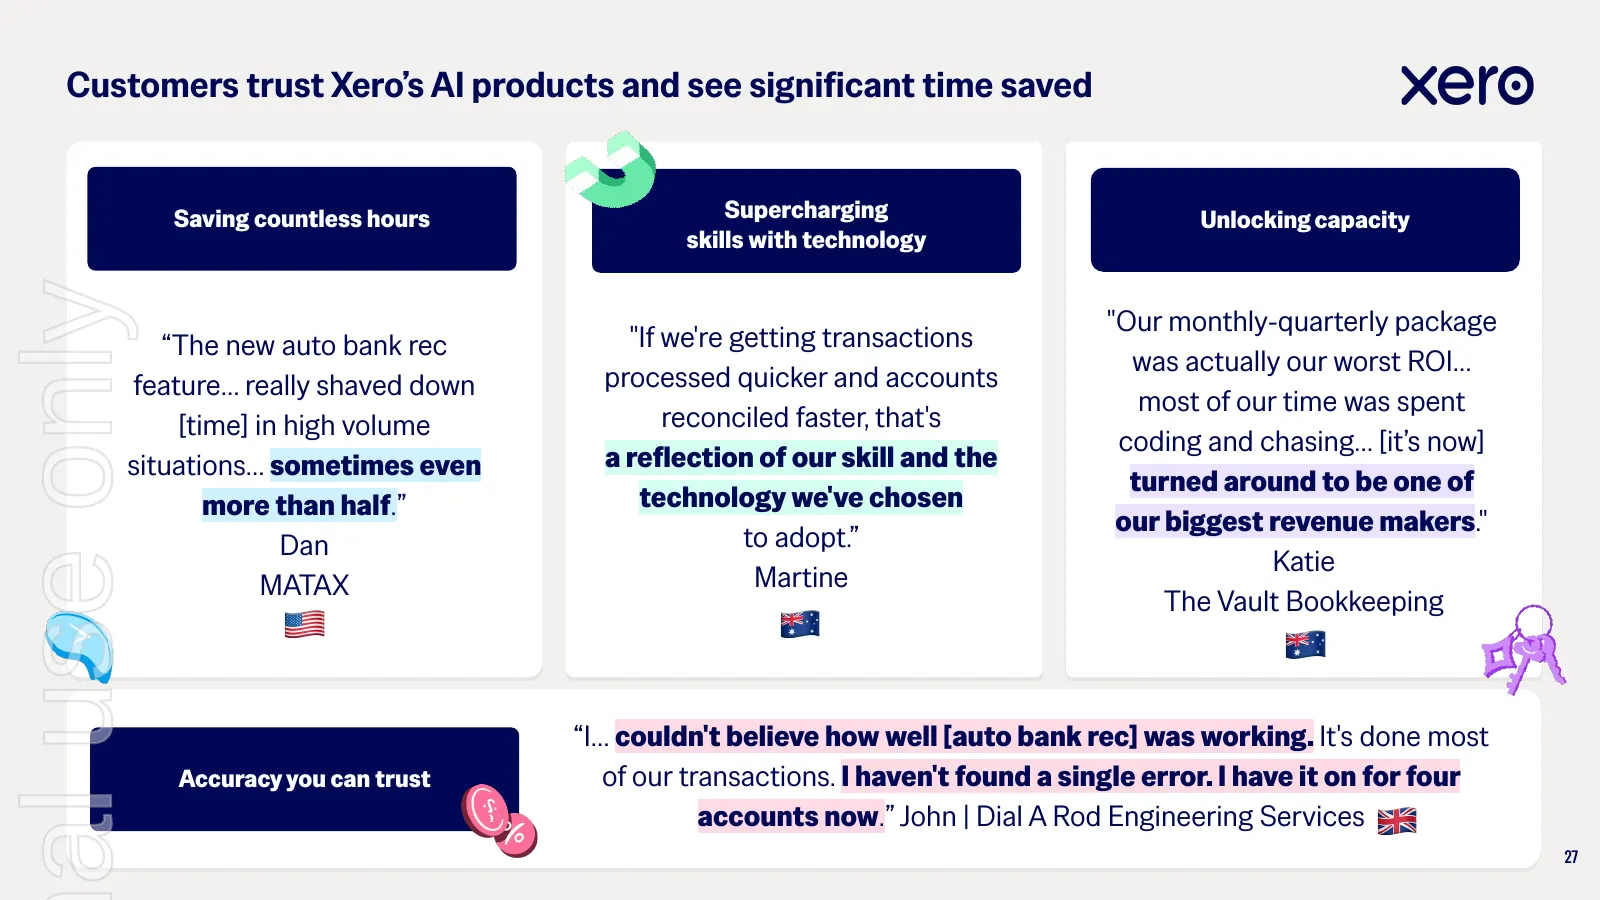
Slide 28: Customers trust Xero's AI products and see significant time saved
Customers trust Xero’s AI products and see significant time saved Saving countless hours Supercharging Unlocking capacity skills with technology al use only "Our monthly-quarterly package “The new auto bank rec "If we're getting transactions was actually our worst ROI… feature… really shaved down pr
Slide 29: Within the 1m customers using AI, power users also emerging
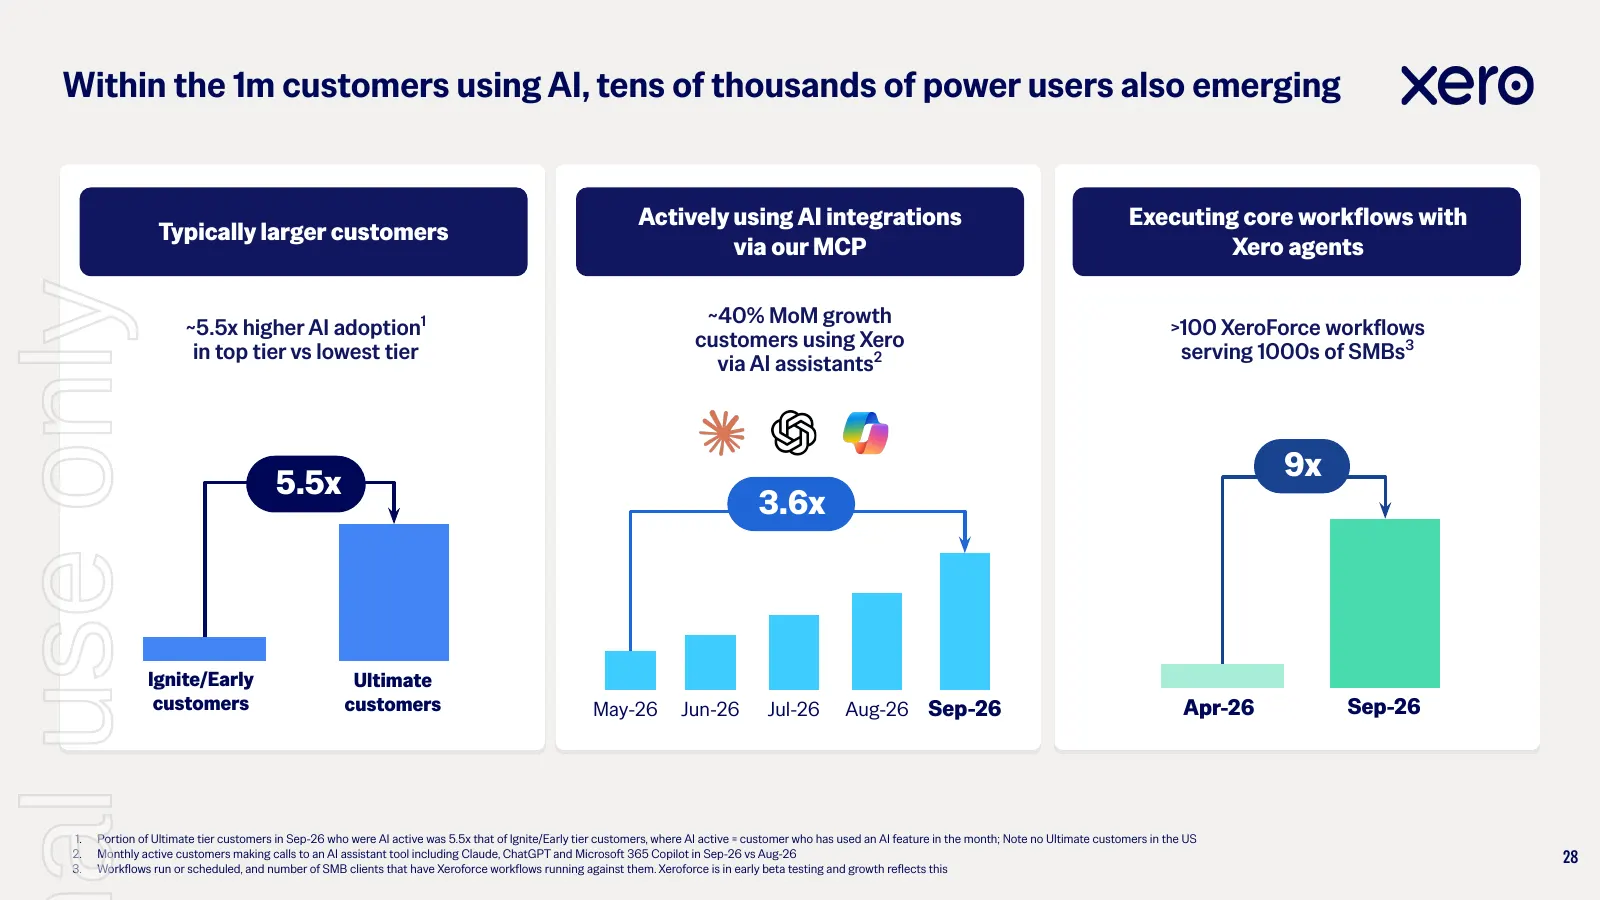
Within the 1m customers using AI, tens of thousands of power users also emerging Actively using AI integrations Executing core workflows with Typically larger customers via our MCP Xero agents al use only ~40% MoM growth ~5.5x higher AI adoption1 >100 XeroForce workflows customers using Xero in top
Slide 30: How we deliver AI for SMBs and accountants and bookkeepers
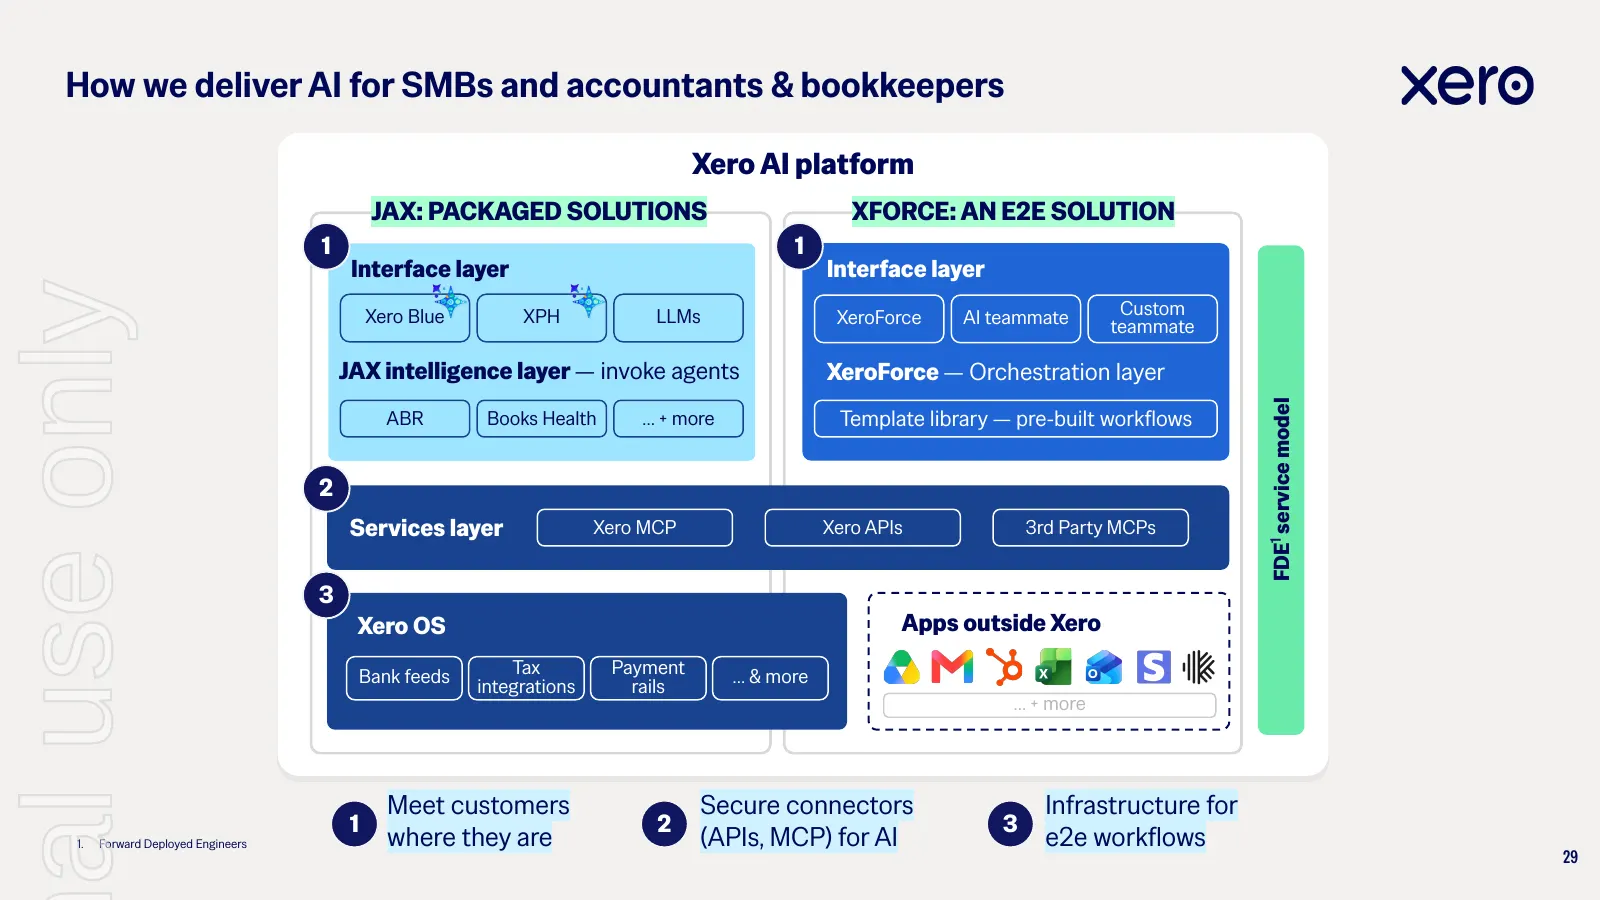
How we deliver AI for SMBs and accountants & bookkeepers Xero AI platform JAX: PACKAGED SOLUTIONS XFORCE: AN E2E SOLUTION 1 1 Interface layer Interface layer al use only Xero Blue XPH LLMs XeroForce AI teammate Custom teammate JAX intelligence layer — invoke agents XeroForce — Orchestration layer FD
Slide 31: Launching Xforce today
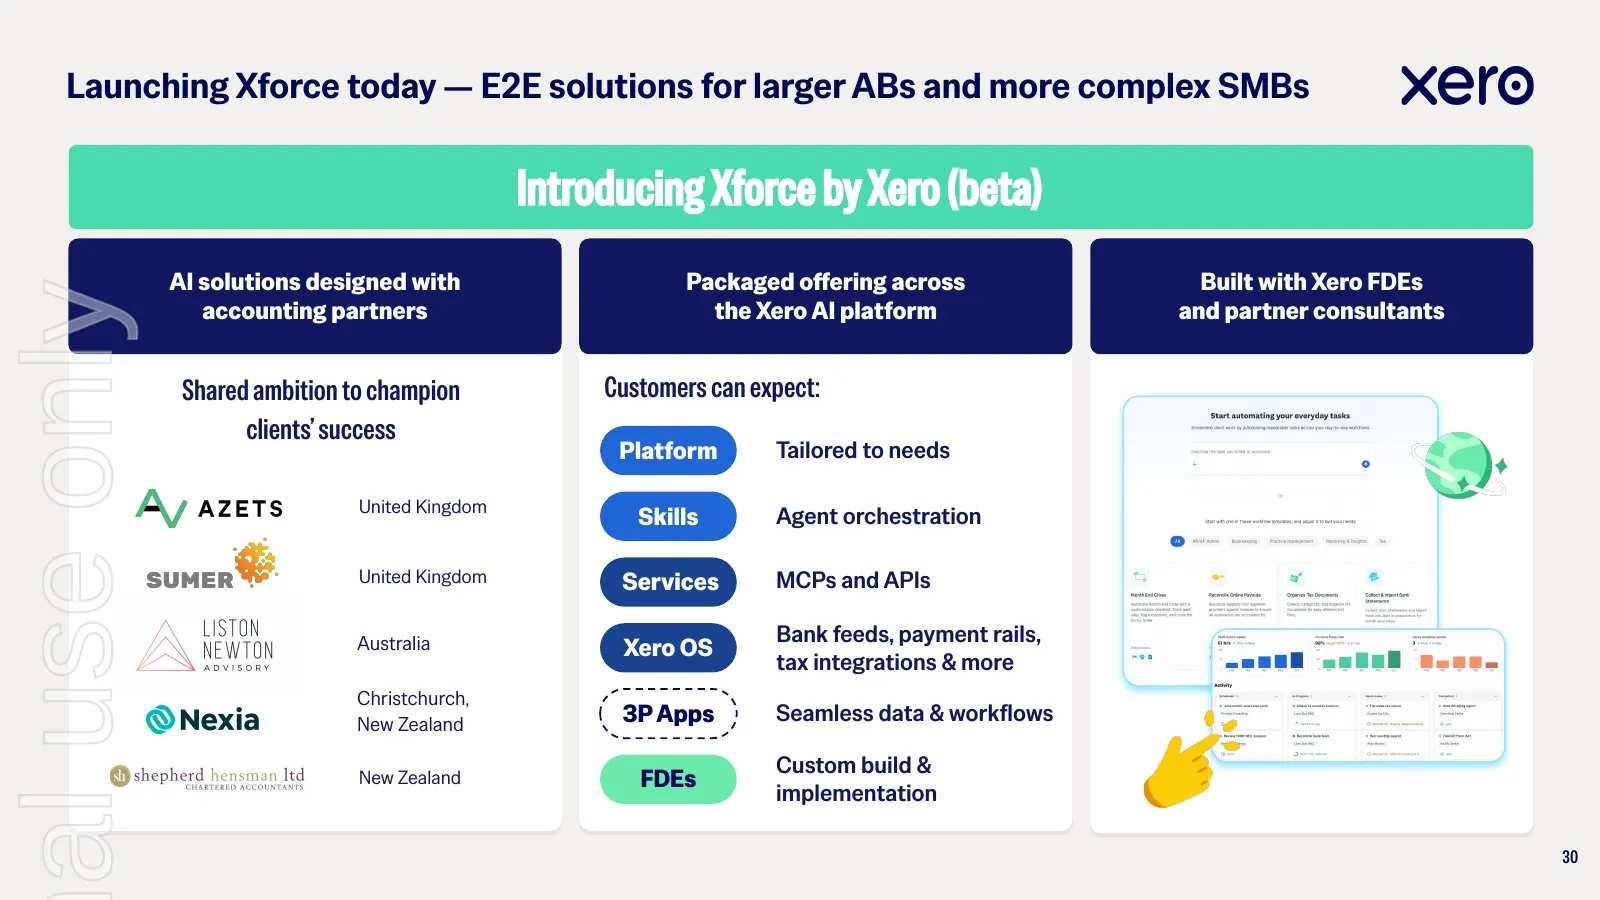
Launching Xforce today — E2E solutions for larger ABs and more complex SMBs Introducing Xforce by Xero (beta) AI solutions designed with Packaged offering across Built with Xero FDEs al use only accounting partners the Xero AI platform and partner consultants Shared ambition to champion Customers ca
Slide 32: AI monetisation opportunities in every layer
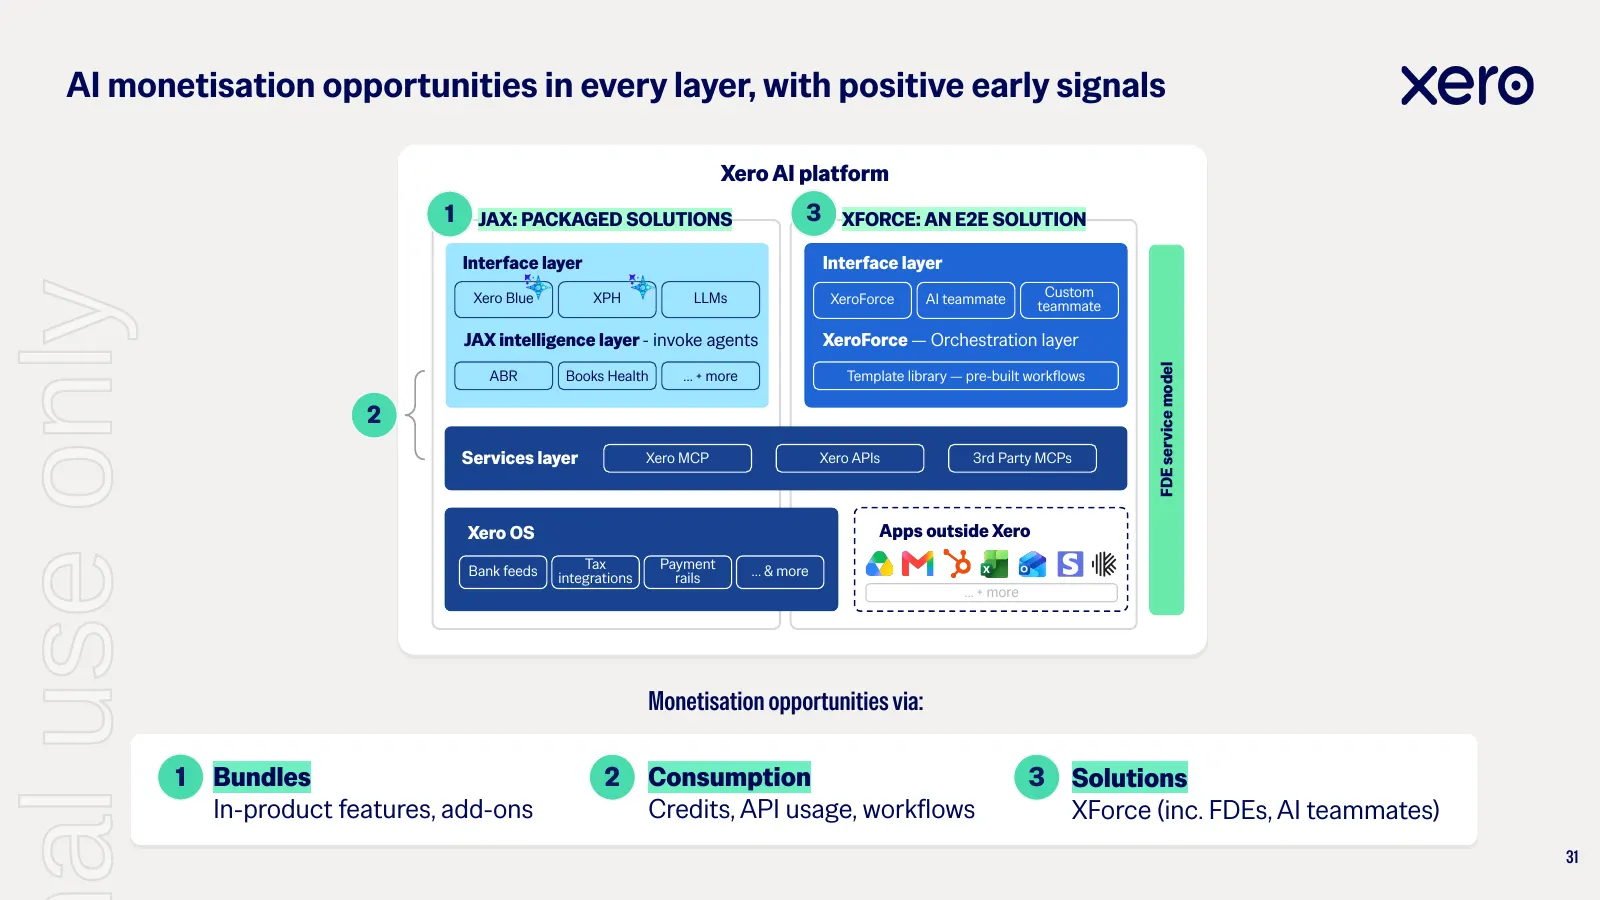
AI monetisation opportunities in every layer, with positive early signals Xero AI platform 1 JAX: PACKAGED SOLUTIONS 3 XFORCE: AN E2E SOLUTION Interface layer Interface layer al use only Xero Blue XPH LLMs XeroForce AI teammate Custom teammate JAX intelligence layer - invoke agents XeroForce — Orche
Slide 33: Wrap up: Strong H1 sets the stage for H2 FY27
Wrap up: Strong H1 sets the stage for an exciting H2 FY27 and beyond al use only 1 2 3 4 5 Strong revenue Consistent FCF generation Trusted partner Strong growth execution provides capital for ABs & SBs in momentum across all drives durable flexibility the AI journey entering next regions EBITDA gro
Slide 34: Appendix
al use only Appendix 33
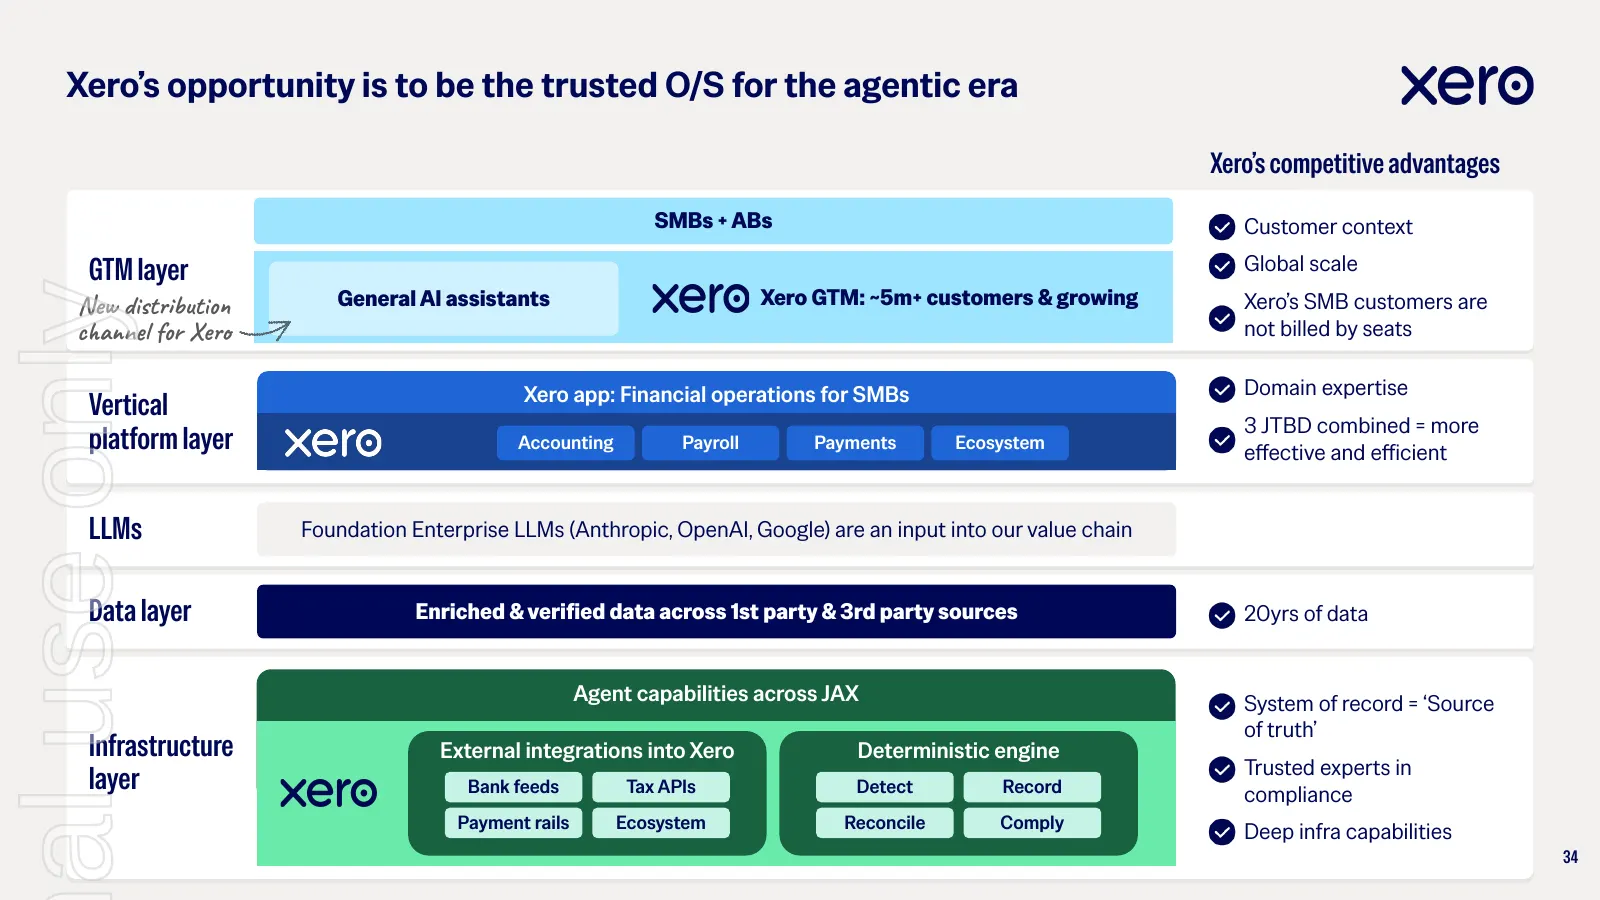
Slide 35: Xero's opportunity is to be the trusted O/S for the agentic era
Xero’s opportunity is to be the trusted O/S for the agentic era Xero’s competitive advantages SMBs + ABs Customer context GTM layer Global scale al use only New distribution General AI assistants Xero GTM: ~5m+ customers & growing Xero’s SMB customers are channel for Xero not billed by seats Xero ap
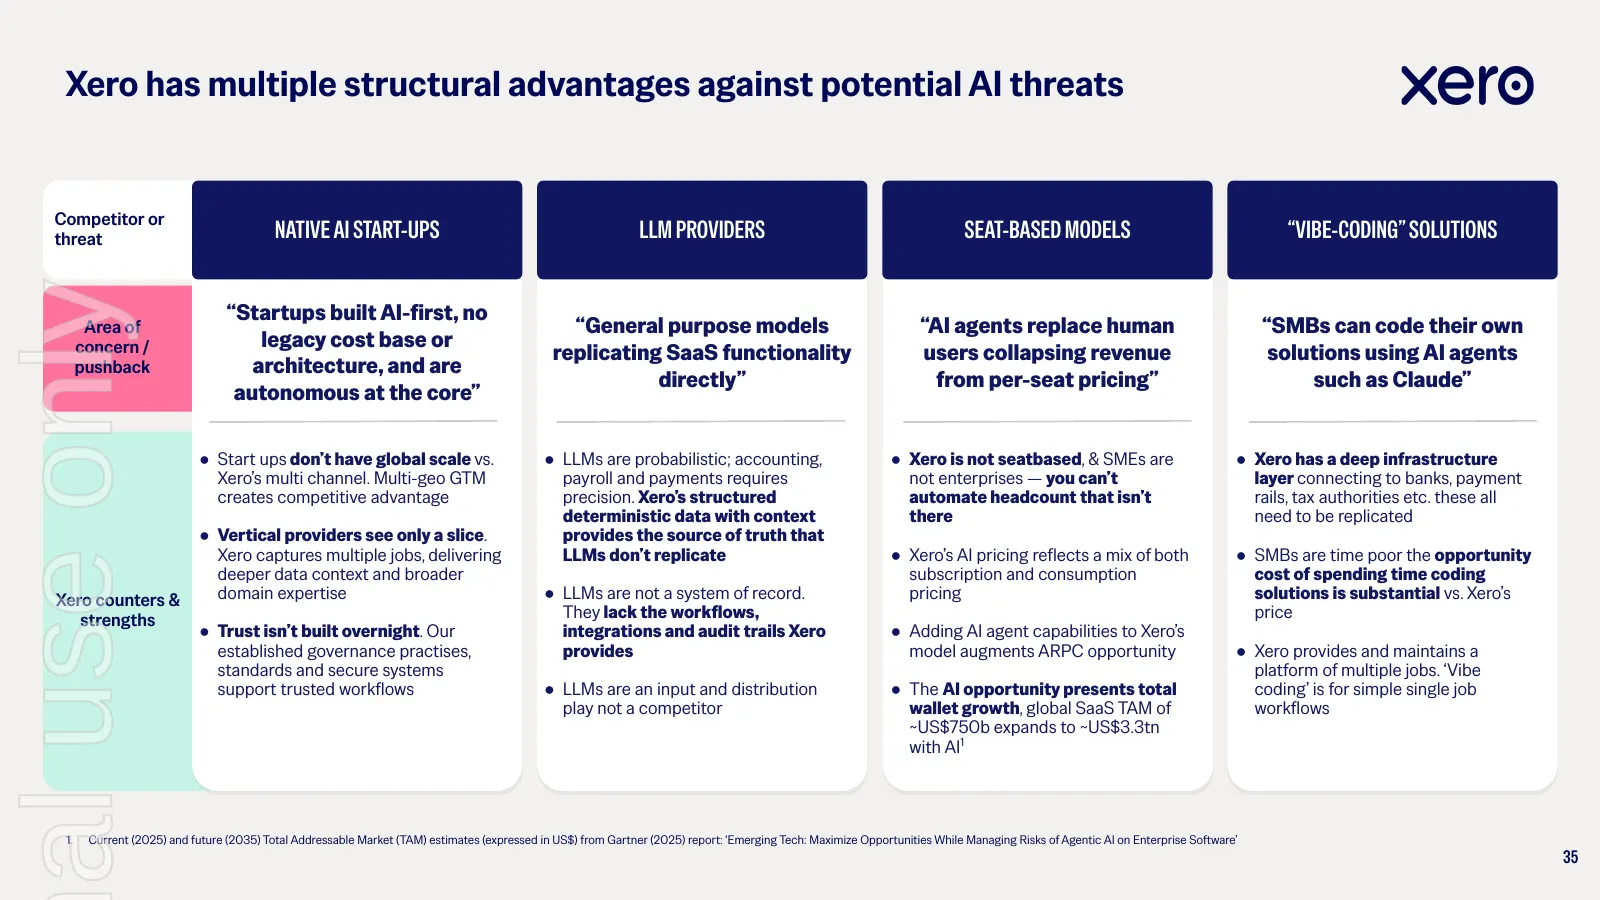
Slide 36: Xero has multiple structural advantages against AI threats
Xero has multiple structural advantages against potential AI threats Competitor or threat NATIVE AI START-UPS LLM PROVIDERS SEAT-BASED MODELS “VIBE-CODING” SOLUTIONS al use only “Startups built AI-first, no Area of “General purpose models “AI agents replace human “SMBs can code their own concern / l
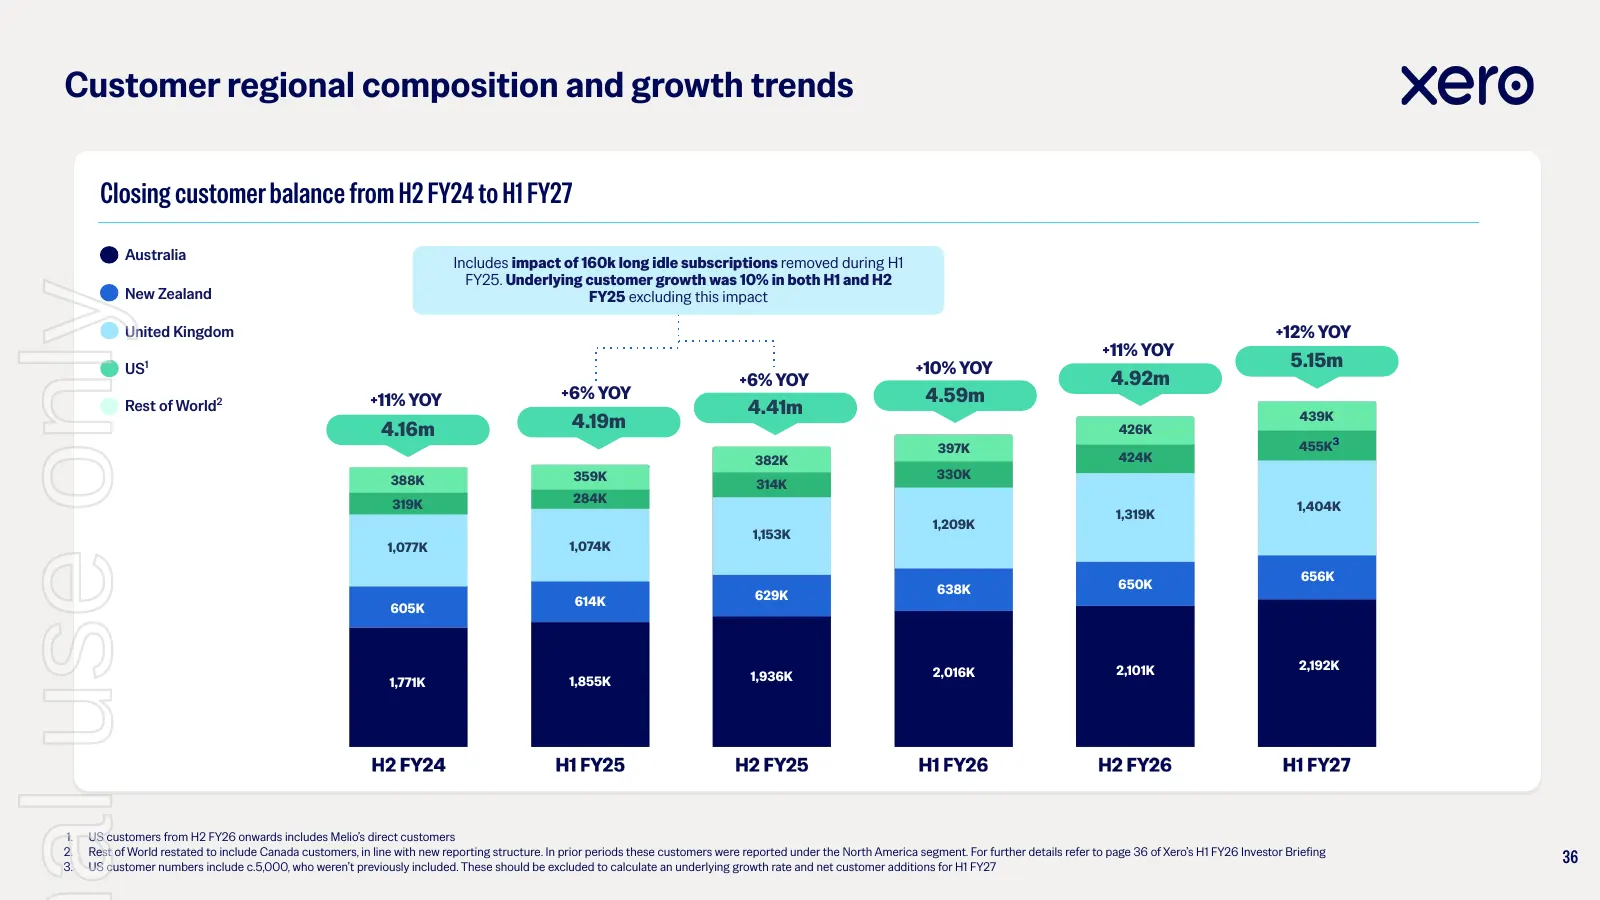
Slide 37: Customer regional composition and growth trends
Customer regional composition and growth trends Closing customer balance from H2 FY24 to H1 FY27 Australia Includes impact of 160k long idle subscriptions removed during H1 FY25. Underlying customer growth was 10% in both H1 and H2 al use only New Zealand FY25 excluding this impact United Kingdom +1
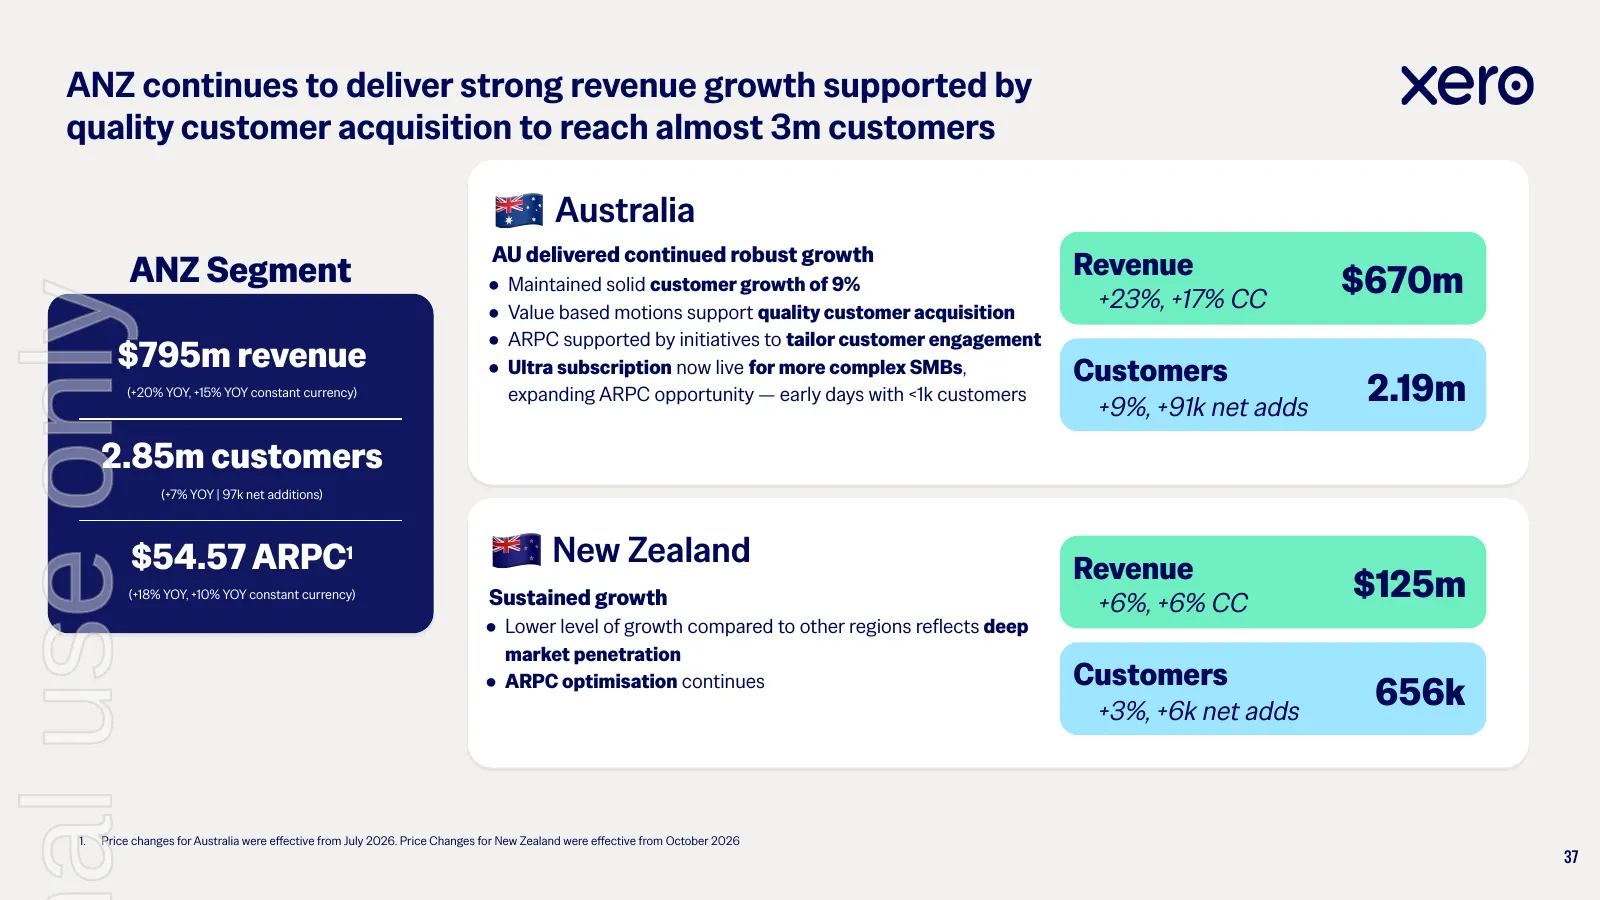
Slide 38: ANZ continues to deliver strong revenue growth
ANZ continues to deliver strong revenue growth supported by quality customer acquisition to reach almost 3m customers Australia AU delivered continued robust growth ANZ Segment Revenue ● Maintained solid customer growth of 9% $670m al use only ● Value based motions support quality customer acquisiti
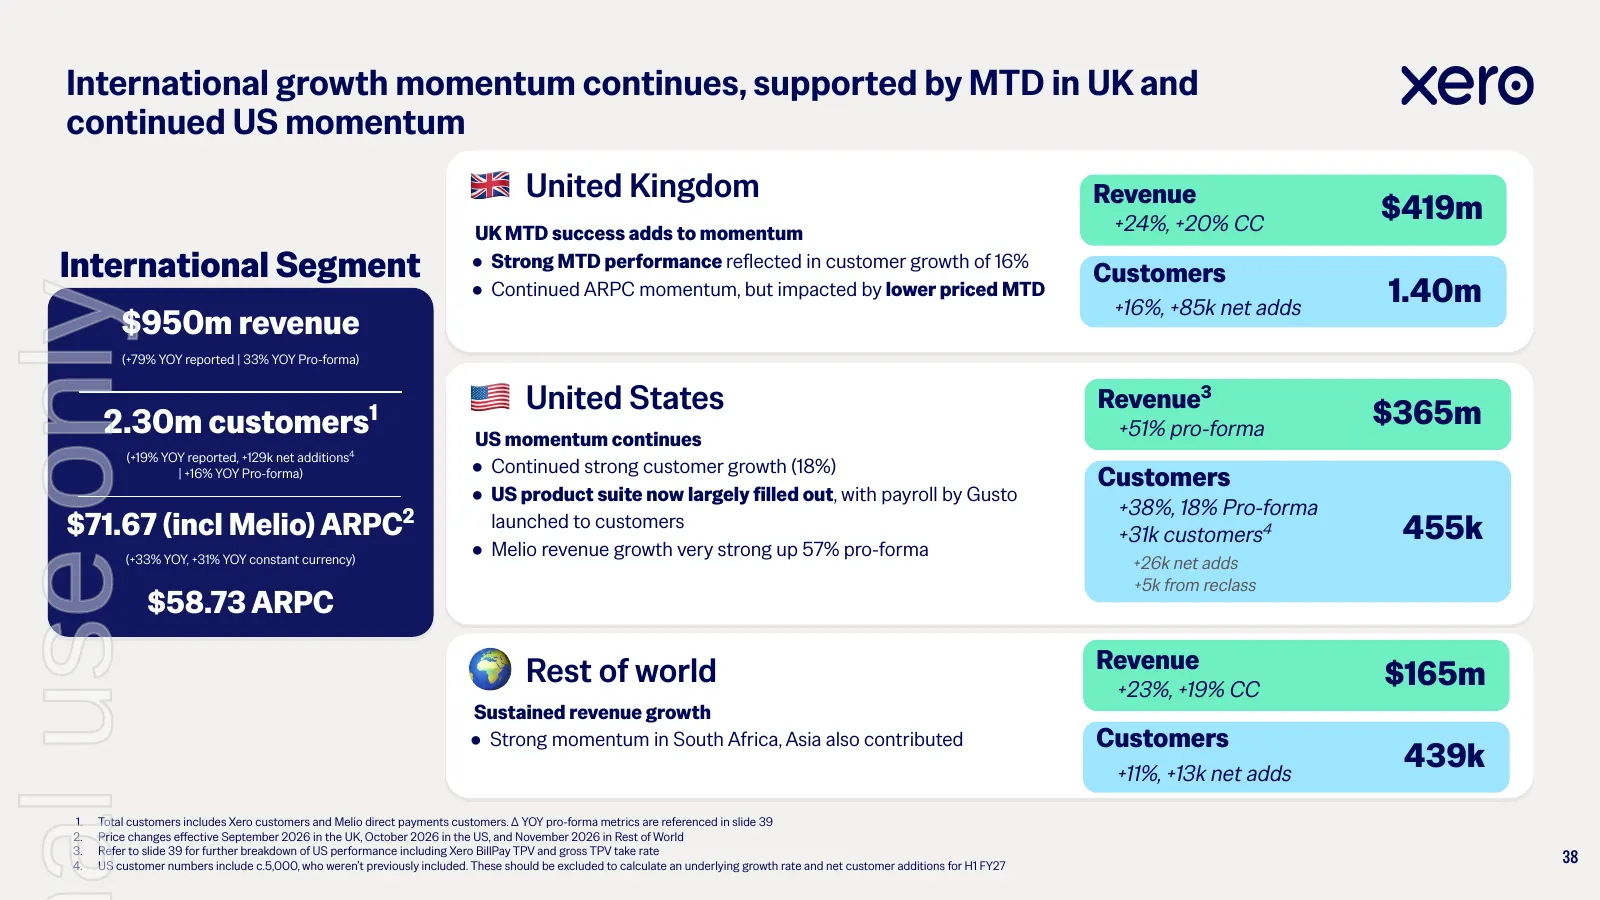
Slide 39: International growth momentum continues
International growth momentum continues, supported by MTD in UK and continued US momentum United Kingdom Revenue +24%, +20% CC $419m UK MTD success adds to momentum International Segment ● Strong MTD performance reflected in customer growth of 16% Customers ● Continued ARPC momentum, but impacted by
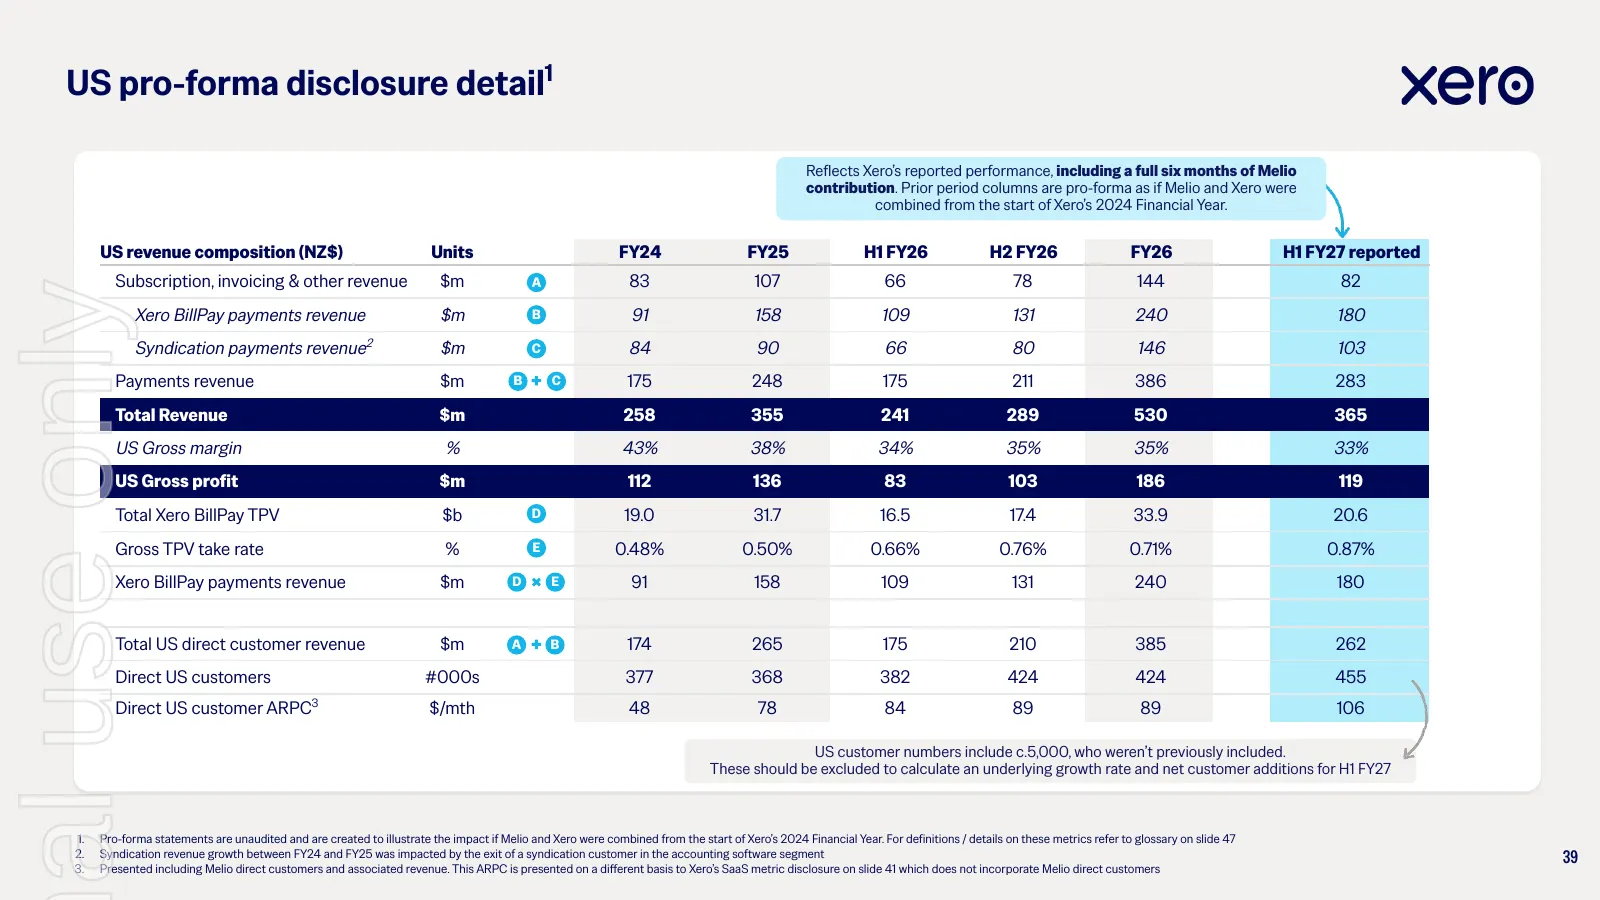
Slide 40: US pro-forma disclosure detail
US pro-forma disclosure detail1 Reflects Xero’s reported performance, including a full six months of Melio contribution. Prior period columns are pro-forma as if Melio and Xero were combined from the start of Xero’s 2024 Financial Year. US revenue composition (NZ$) Units FY24 FY25 H1 FY26 H2 FY26 FY
Slide 41: Organic unit economics: strong LTV expansion
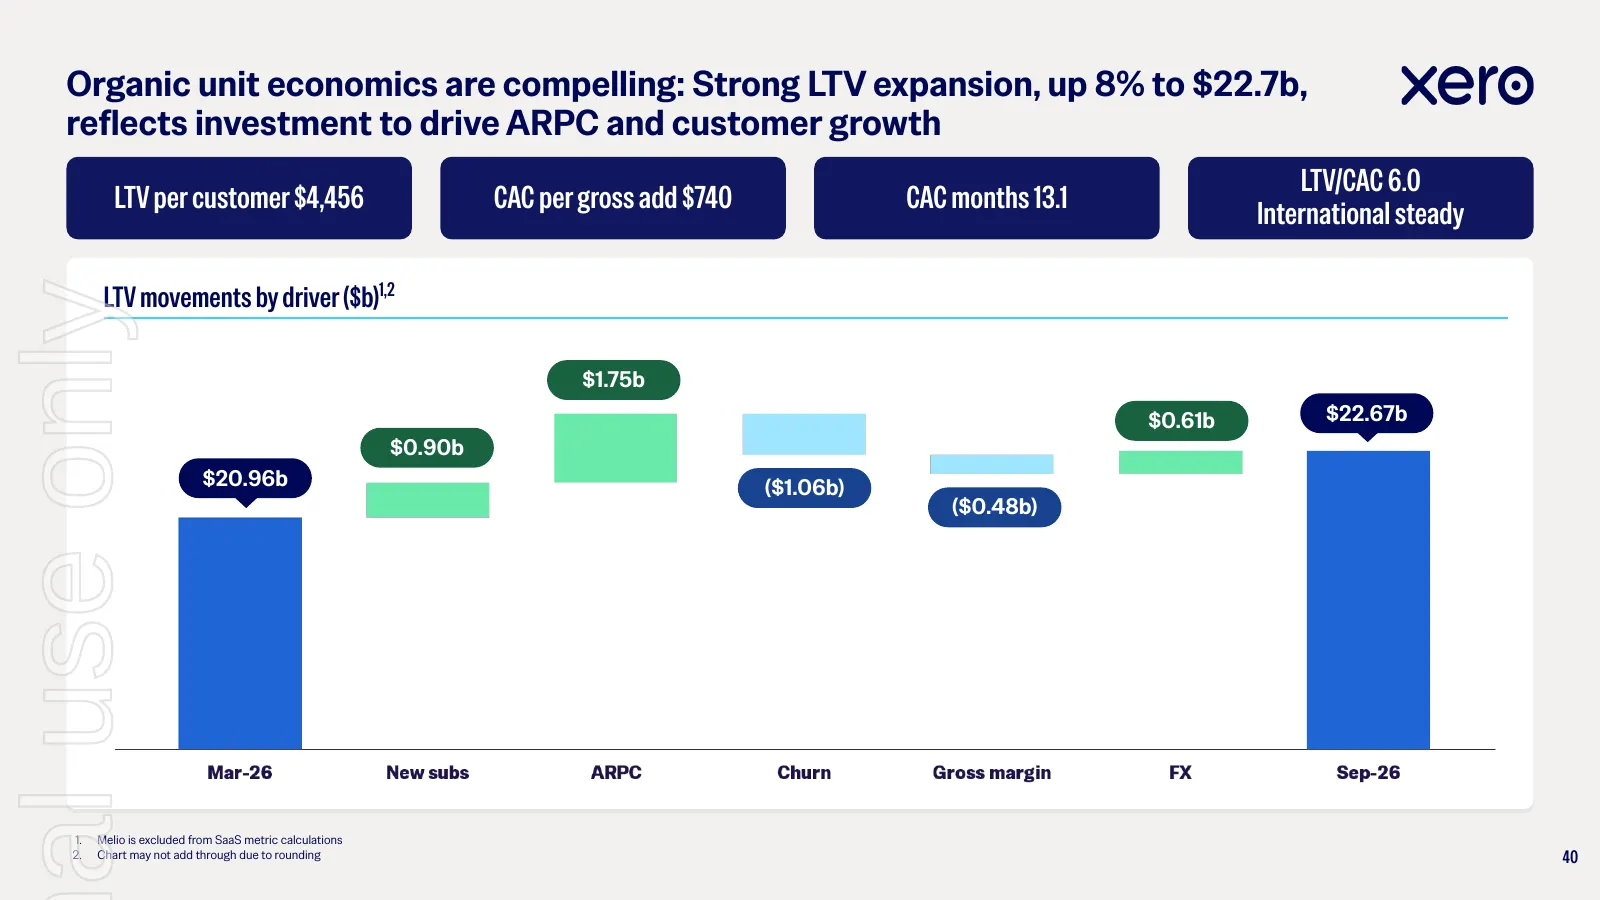
Organic unit economics are compelling: Strong LTV expansion, up 8% to $22.7b, reflects investment to drive ARPC and customer growth LTV/CAC 6.0 LTV per customer $4,456 CAC per gross add $740 CAC months 13.1 International steady LTV movements by driver ($b)1,2 al use only $1.75b $0.61b $22.67b $0.90b
Slide 42: SaaS metrics summary
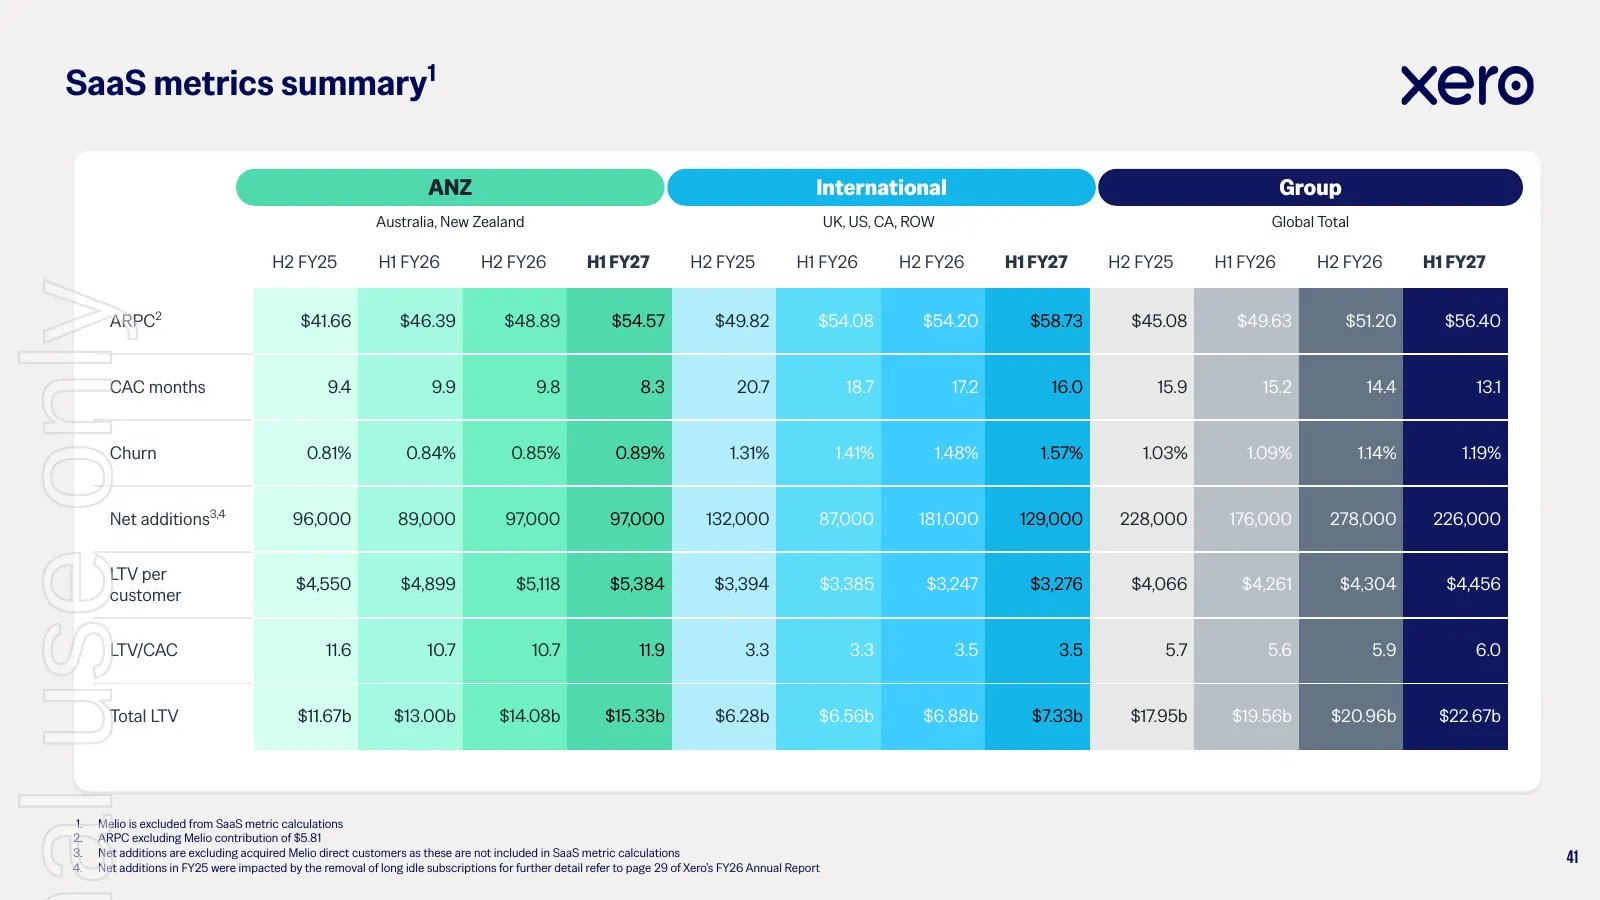
SaaS metrics summary1 ANZ International Group Australia, New Zealand UK, US, CA, ROW Global Total H2 FY25 H1 FY26 H2 FY26 H1 FY27 H2 FY25 H1 FY26 H2 FY26 H1 FY27 H2 FY25 H1 FY26 H2 FY26 H1 FY27 al use only ARPC2 $41.66 $46.39 $48.89 $54.57 $49.82 $54.08 $54.20 $58.73 $45.08 $49.63 $51.20 $56.40 CAC
Slide 43: Reported NPAT to adjusted NPATA reconciliation
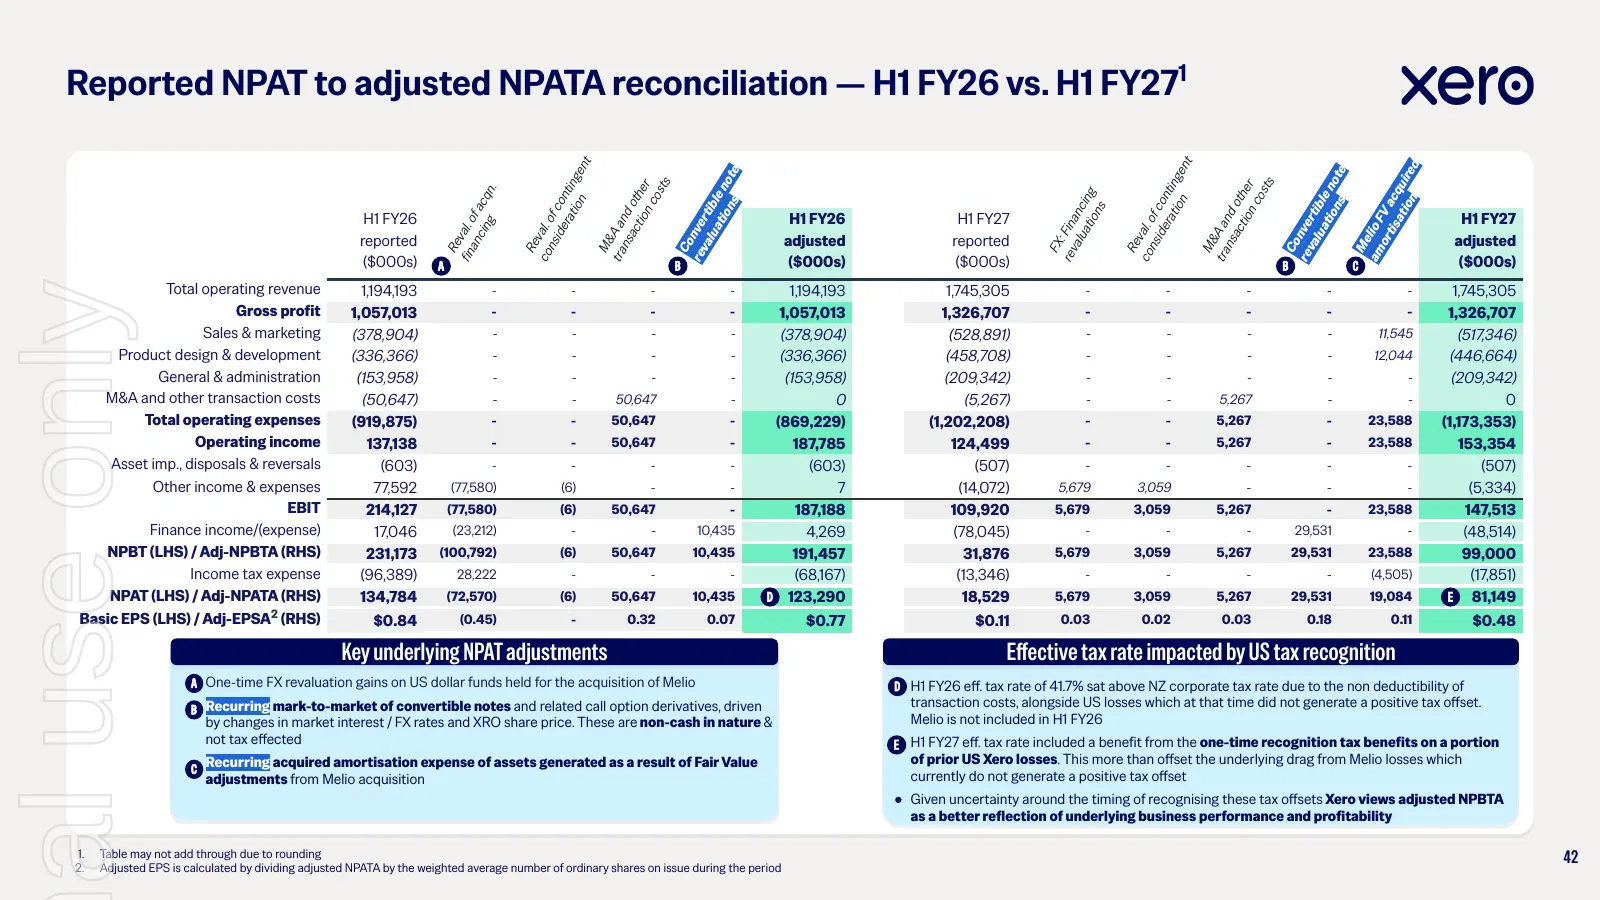
Reported NPAT to adjusted NPATA reconciliation — H1 FY26 vs. H1 FY271 nt nt on red e e ion ge ion ge on ot on ot ati cqui ts ts rat tin rat tin n c er n c er ati le n ati le n n. os os ati ing ac d oth ac d oth ide f con ide f con cin f acq s s or V a alu rtib alu rtib s alu nc H1 FY26 H1 FY26 H1 FY
Slide 44: FY27 Outlook: supporting assumptions and commentary
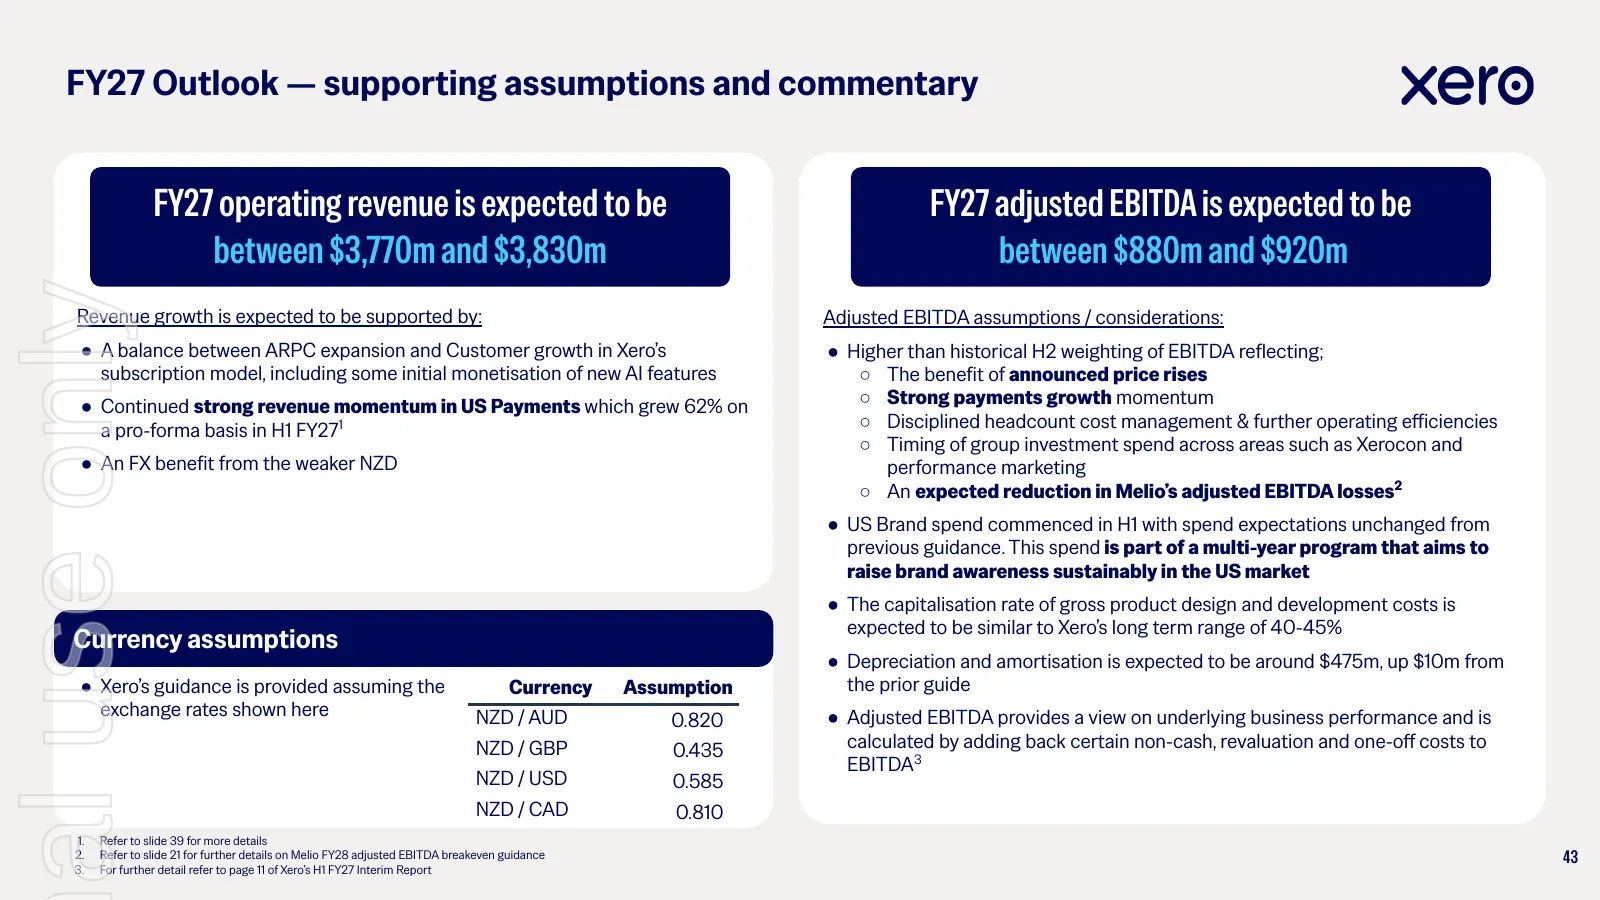
FY27 Outlook — supporting assumptions and commentary FY27 operating revenue is expected to be FY27 adjusted EBITDA is expected to be between $3,770m and $3,830m between $880m and $920m al use only Revenue growth is expected to be supported by: Adjusted EBITDA assumptions / considerations: ● A balanc
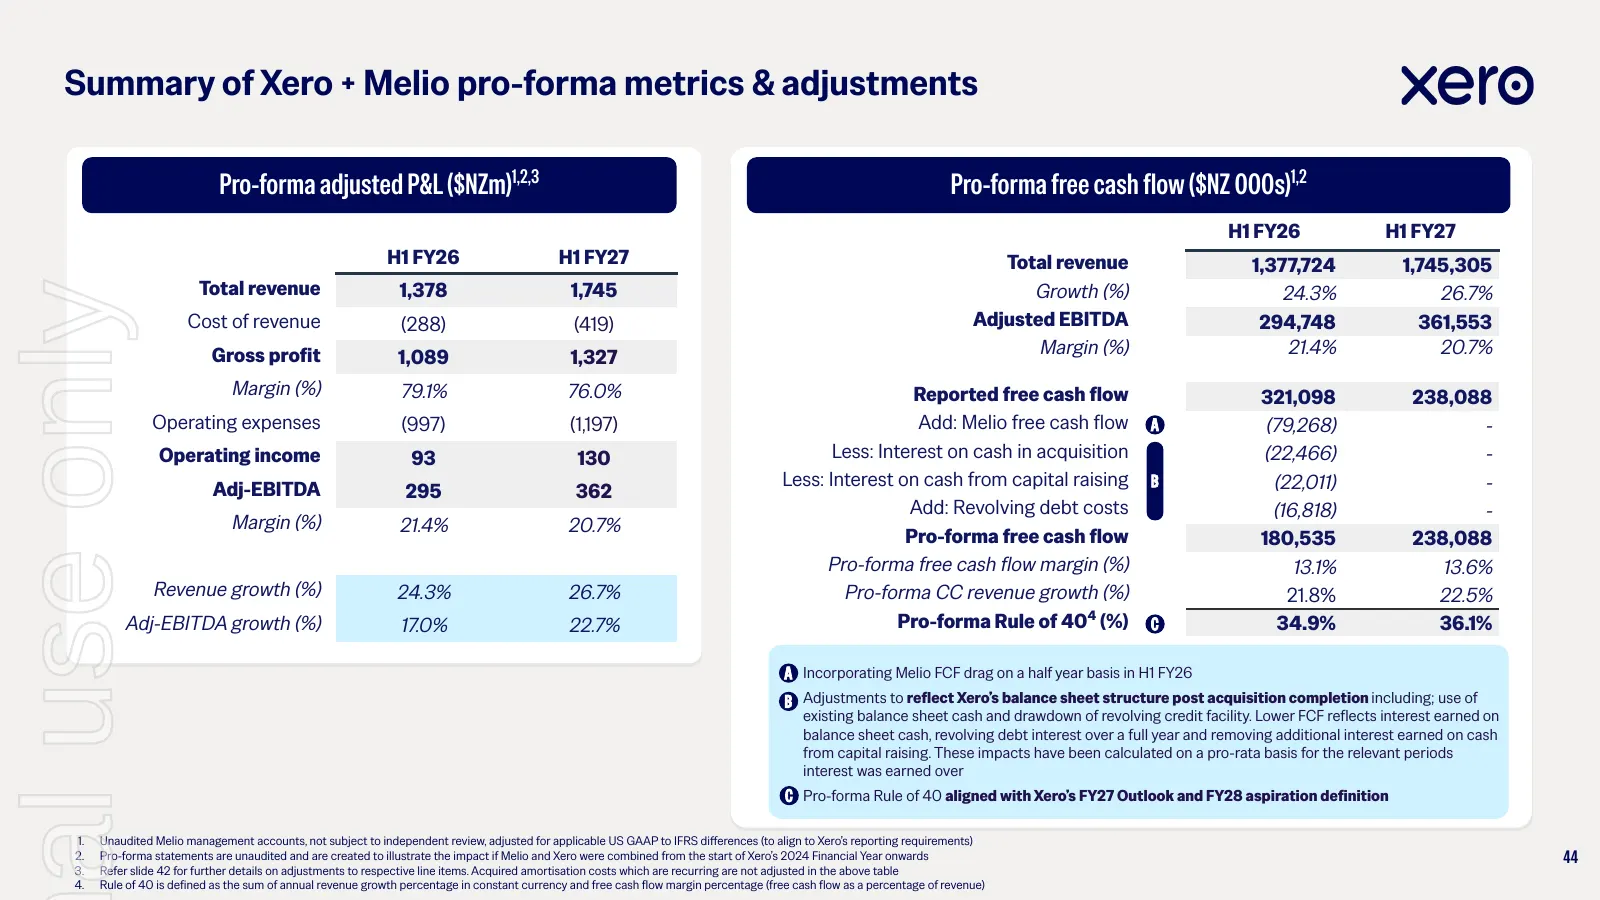
Slide 45: Summary of Xero + Melio pro-forma metrics and adjustments
Summary of Xero + Melio pro-forma metrics & adjustments Pro-forma adjusted P&L ($NZm)1,2,3 Pro-forma free cash flow ($NZ 000s)1,2 H1 FY26 H1 FY27 H1 FY26 H1 FY27 Total revenue 1,377,724 1,745,305 Total revenue 1,378 1,745 Growth (%) al use only 24.3% 26.7% Cost of revenue (288) (419) Adjusted EBITDA
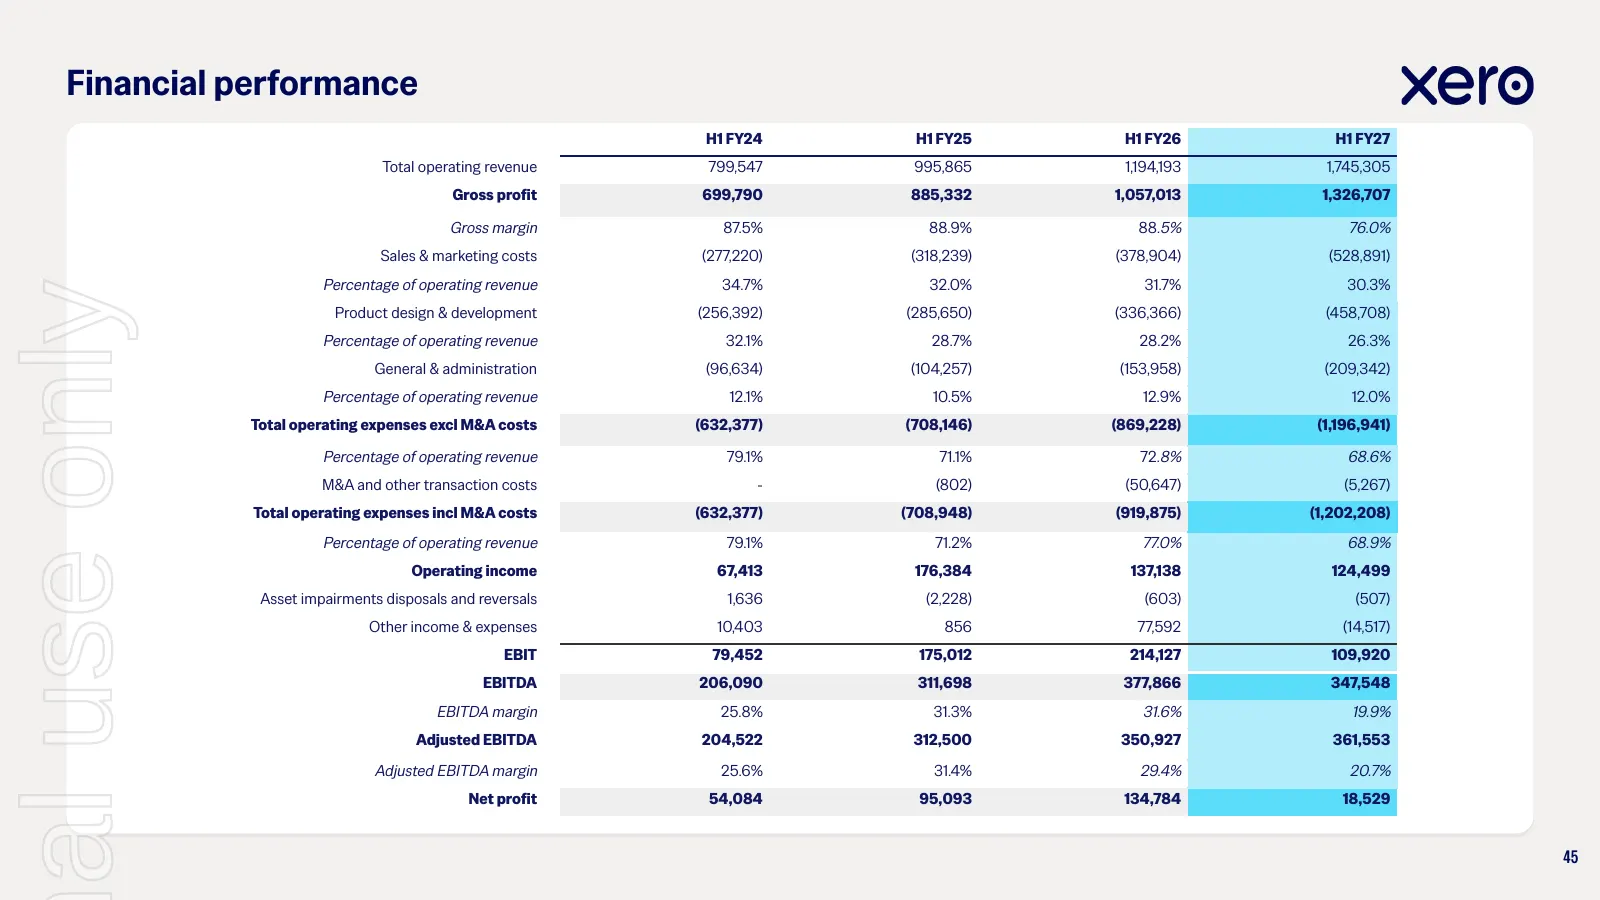
Slide 46: Financial performance
Financial performance H1 FY24 H1 FY25 H1 FY26 H1 FY27 Total operating revenue 799,547 995,865 1,194,193 1,745,305 Gross profit 699,790 885,332 1,057,013 1,326,707 Gross margin 87.5% 88.9% 88.5% 76.0% Sales & marketing costs (277,220) (318,239) (378,904) (528,891) Percentage of operating revenue 34.7
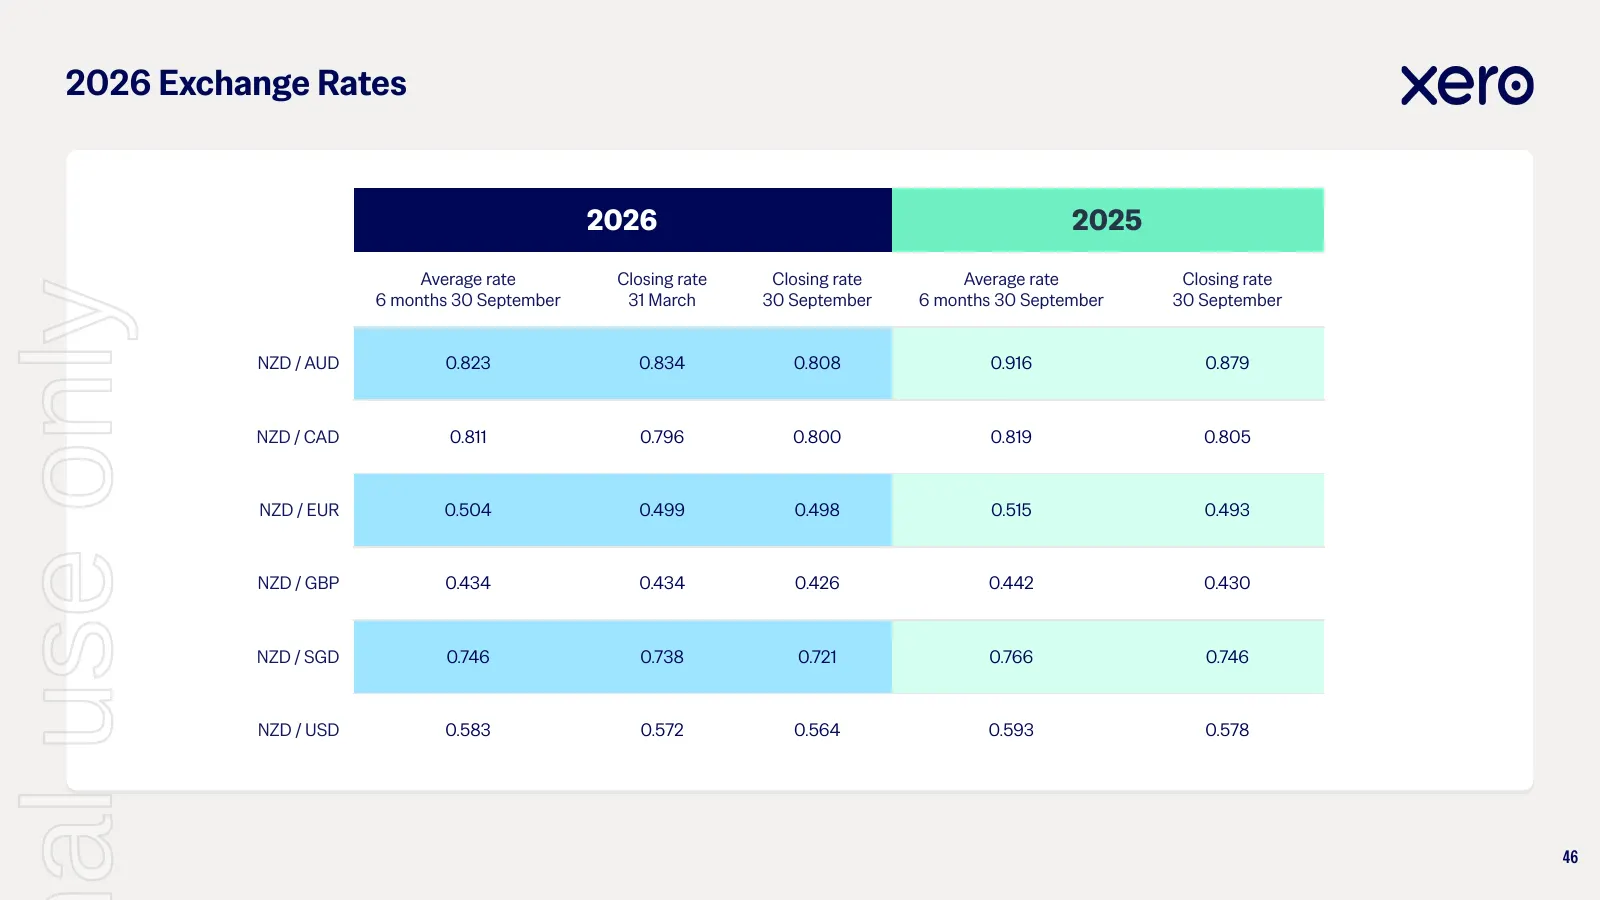
Slide 47: 2026 Exchange Rates
2026 Exchange Rates 2026 2025 Average rate Closing rate Closing rate Average rate Closing rate al use only 6 months 30 September 31 March 30 September 6 months 30 September 30 September NZD / AUD 0.823 0.834 0.808 0.916 0.879 NZD / CAD 0.811 0.796 0.800 0.819 0.805 NZD / EUR 0.504 0.499 0.498 0.515
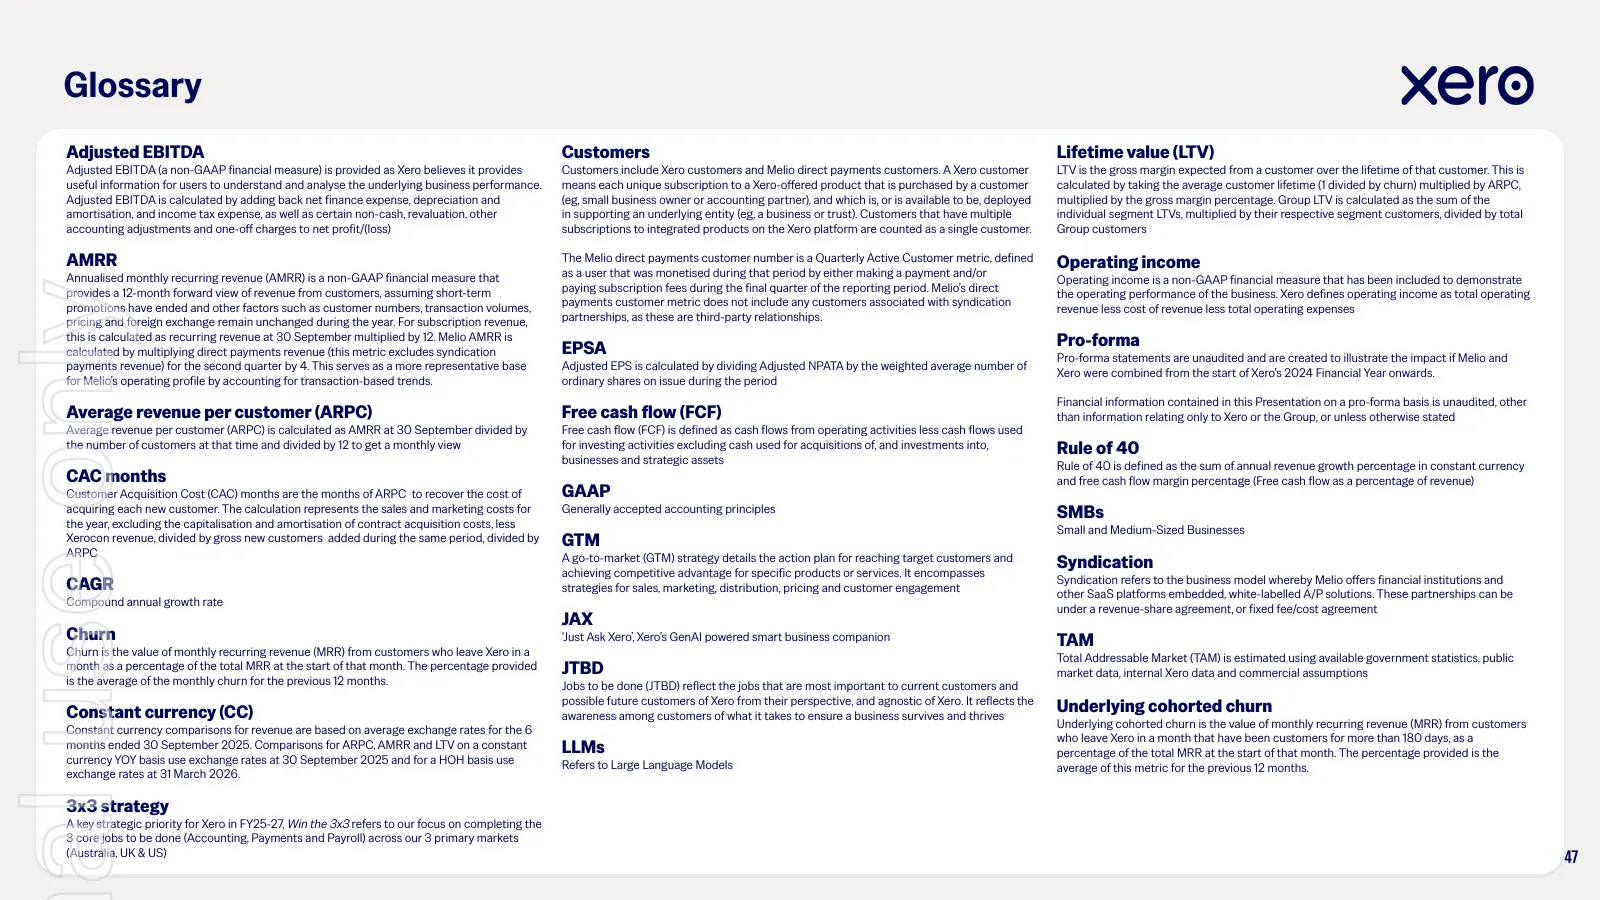
Slide 48: Glossary
Glossary Adjusted EBITDA Customers Lifetime value (LTV) Adjusted EBITDA (a non-GAAP financial measure) is provided as Xero believes it provides Customers include Xero customers and Melio direct payments customers. A Xero customer LTV is the gross margin expected from a customer over the lifetime of
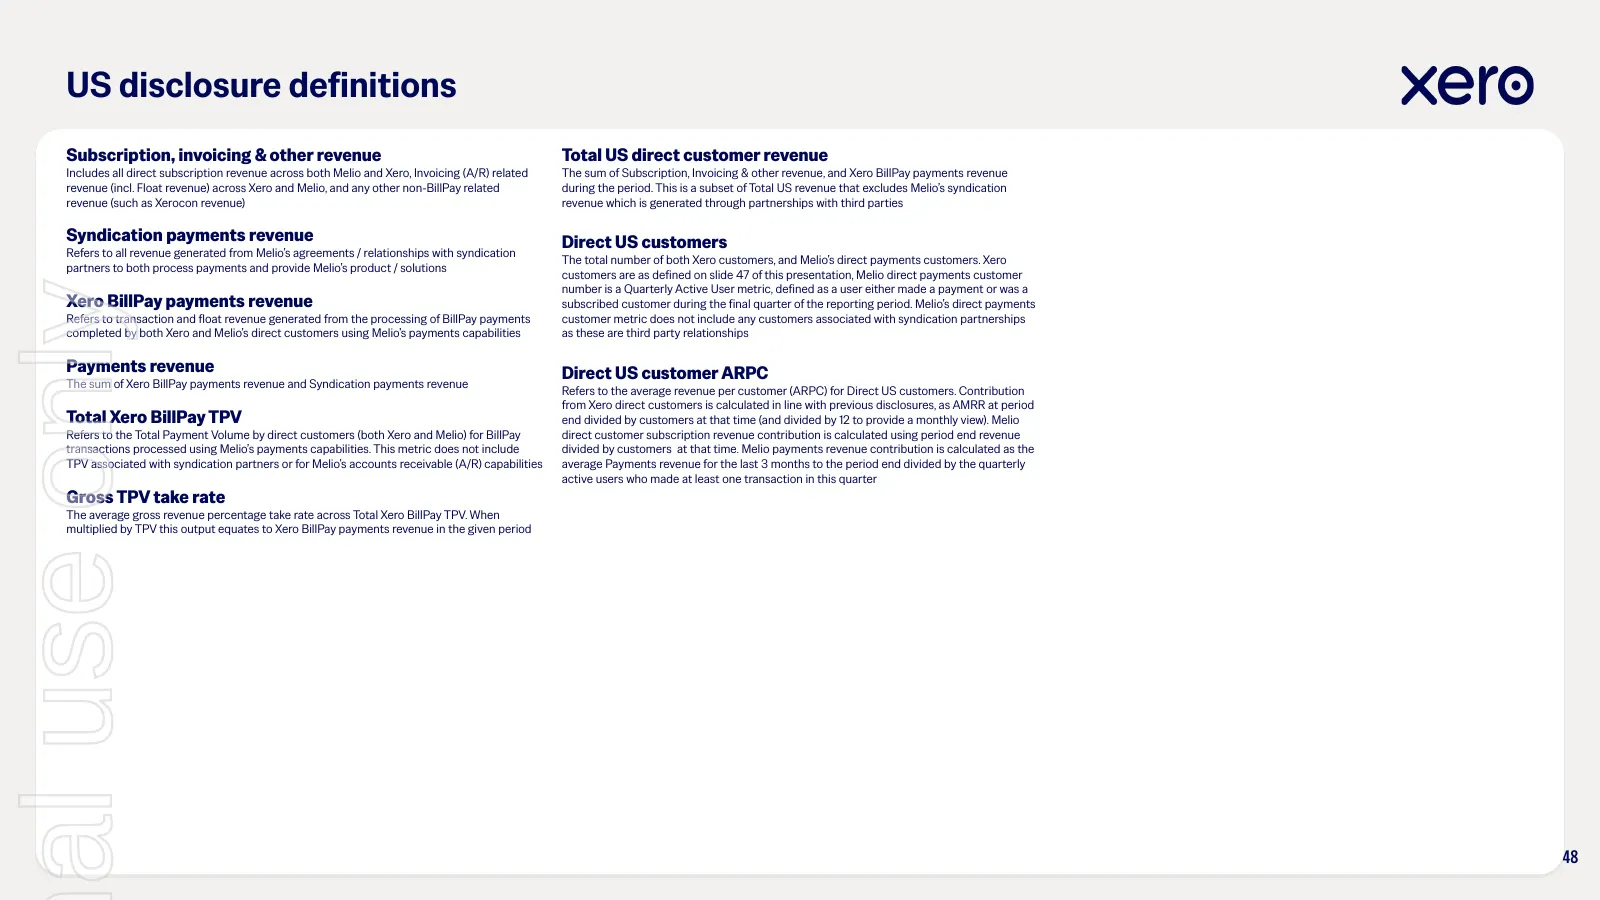
Slide 49: US disclosure definitions
US disclosure definitions Subscription, invoicing & other revenue Total US direct customer revenue Includes all direct subscription revenue across both Melio and Xero, Invoicing (A/R) related The sum of Subscription, Invoicing & other revenue, and Xero BillPay payments revenue revenue (incl. Float r
Slide 50: Contact
al use only Contact Nicole Mehalski Simon Fitzgerald Investor Relations Communications nicole.mehalski@xero.com simon.fitzgerald@xero.com +61 400 947 145 +61 460 294 680 49
Source: ASX announcement, Nov 12, 2026
More decks from Xero Limited
 H1 FY27 Earnings Presentation49 slides · Nov 12, 2026
 Shareholder Meeting (August 2026)33 slides · Aug 27, 2026
 FY2026 Earnings Presentation46 slides · May 14, 2026
 FY2026 Earnings Presentation47 slides · May 14, 2026
 Investor Day (February 2026)41 slides · Feb 3, 2026
 H1 FY26 Earnings Presentation43 slides · Nov 13, 2025