Center Financial — 11th Annual Financial Services Conference (May 2009)
33 slides from Center Financial's conference presentation, May 7, 2009
Slide 1: Center Financial Corporation – 11th Annual Financial Services Conference
CENTER FINANCIAL CORPORATION 11th Annual Financial Services Conference May 7, 2009
Slide 2: Safe Harbor
Safe Harbor During the course of this presentation, the Company may make or present forward-looking statements. These forward-looking statements may be subject to the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995. Such statements, including statements related to the
Slide 3: Corporate Profile
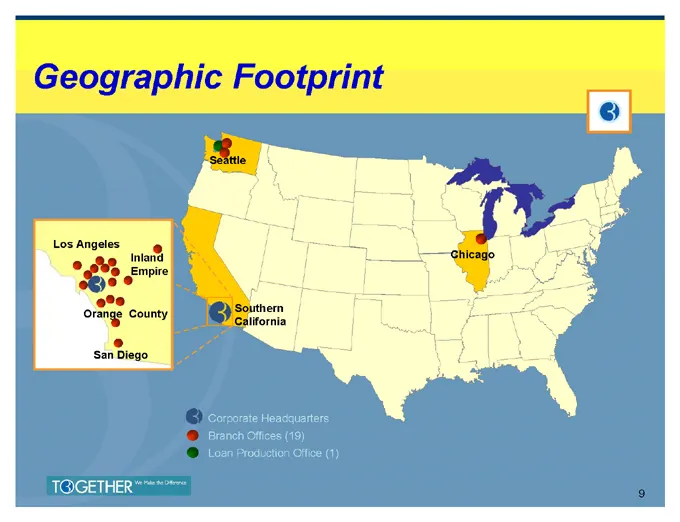
Corporate Profile 23 years of service as strong commercial franchise Leading provider of business-oriented products & services Recipient of the SBA’s 2006 Excellence in Lending Award 20 offices across the nation 19 full-service branches in Southern California, Seattle, Chicago One loan production of
Slide 4: Community Business Bank
Community Business Bank Core customer base Small to middle-market closely held businesses Professional associations Korean-American and other ethnic niche groups Centered around relationship banking philosophy Areas of expertise International trade finance SBA lending Cash management services
Slide 5: Resilient Koreatown
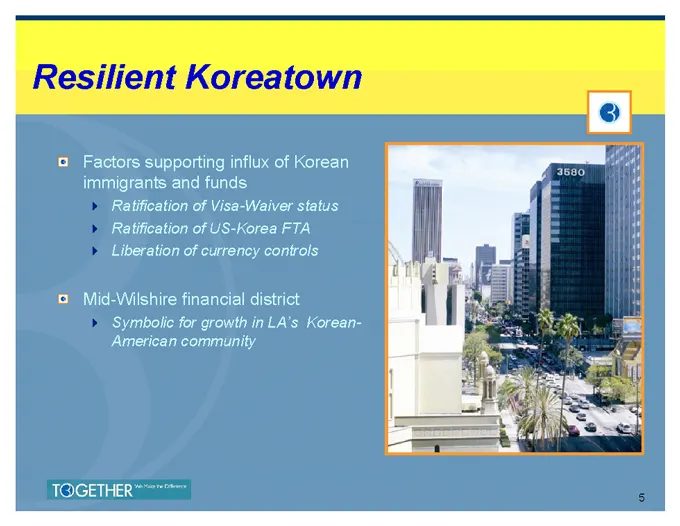
Resilient Koreatown Factors supporting influx of Korean immigrants and funds Ratification of Visa-Waiver status Ratification of US-Korea FTA Liberation of currency controls Mid-Wilshire financial district Symbolic for growth in LA’s Korean-American community
Slide 6: Supporting Our Customers
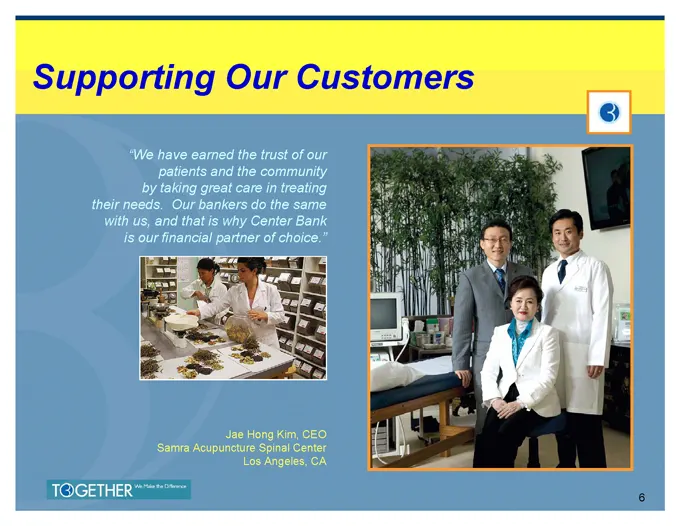
Supporting Our Customers “We have earned the trust of our patients and the community by taking great care in treating their needs. Our bankers do the same with us, and that is why Center Bank is our financial partner of choice.” Jae Hong Kim, CEO Samra Acupuncture Spinal Center Los Angeles, CA
Slide 7: Supporting Our Customers
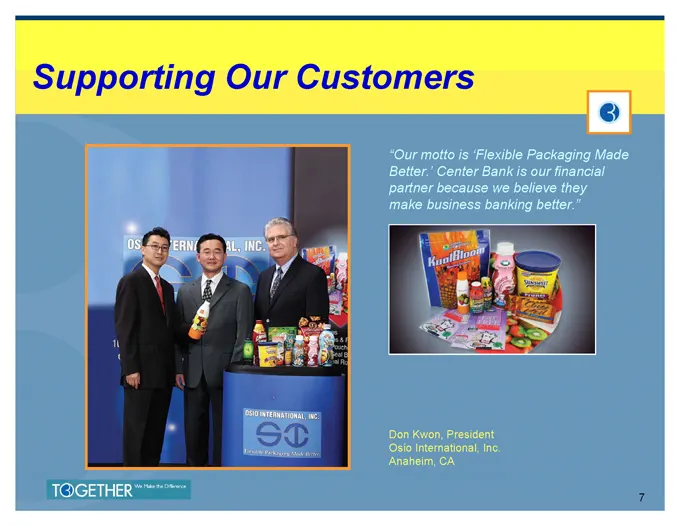
Supporting Our Customers “Our motto is ‘Flexible Packaging Made Better.’ Center Bank is our financial partner because we believe they make business banking better.” Don Kwon, President Osio International, Inc. Anaheim, CA
Slide 8: Supporting Our Customers
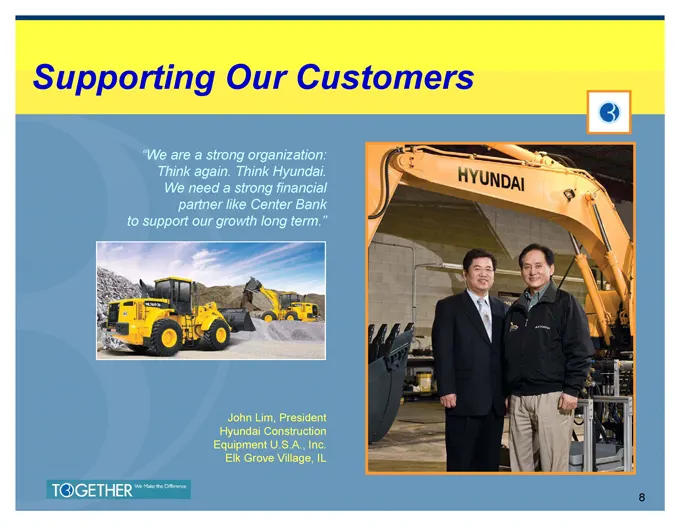
Supporting Our Customers “We are a strong organization: Think again. Think Hyundai. We need a strong financial partner like Center Bank to support our growth long term.” John Lim, President Hyundai Construction Equipment U.S.A., Inc. Elk Grove Village, IL
Slide 9: Geographic Footprint
Geographic Footprint Seattle Los Angeles Chicago Inland Empire Southern Orange County California San Diego Corporate Headquarters Branch Offices (19) Loan Production Office (1)
Slide 10: Seasoned, Conservative Leadership
Seasoned, Conservative Leadership Jae Whan (J.W.) Yoo, President & CEO Former HAFC CEO who executed the acquisition of PUBB Successfully resolved long-standing KEIC litigation Lonny Robinson, EVP & CFO Industry veteran as both executive management and consultant to community banks Jason Kim, SVP & C
Slide 11: Strategic Management Initiatives
Strategic Management Initiatives Enhance operational efficiencies Deleverage balance sheet Reduce potential credit risk Maintain solid capital position Increase liquidity
Slide 12: Reduced Cost Structure
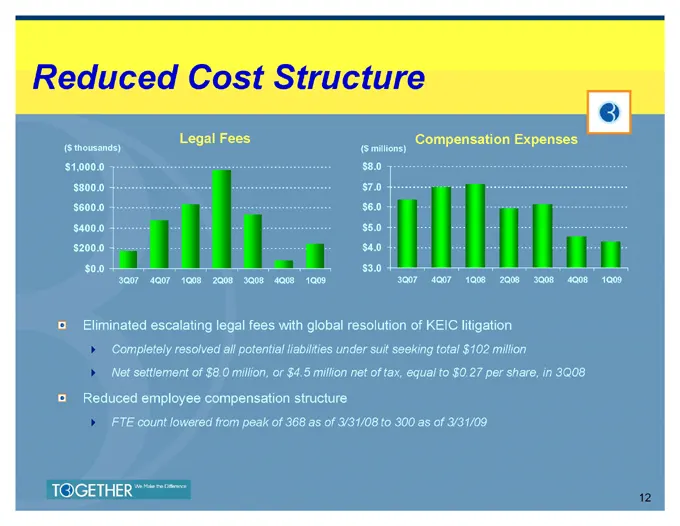
Reduced Cost Structure ($ thousands) Legal Fees Compensation Expenses ($ millions) $1,000.0 $8.0 $800.0 $7.0 $600.0 $6.0 $400.0 $5.0 $200.0 $4.0 $0.0 $3.0 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 Eliminated escalating legal fees with global resolution of KEIC litigation
Slide 13: Enhanced Efficiencies
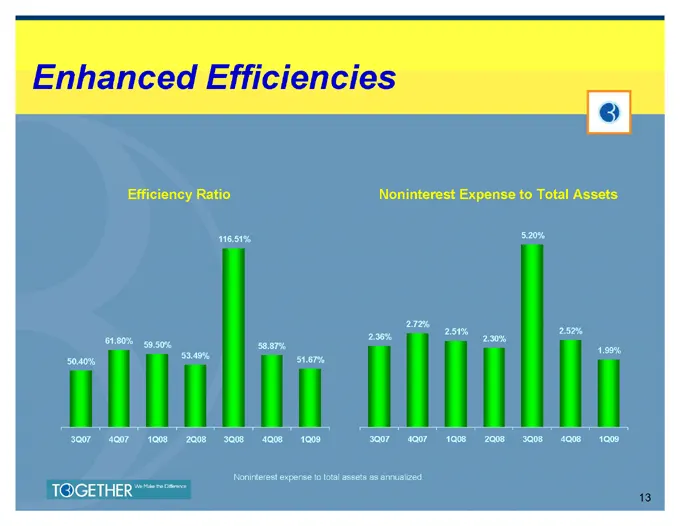
Enhanced Efficiencies Efficiency Ratio Noninterest Expense to Total Assets 5.20% 116.51% 2.72% 2.51% 2.52% 2.36% 2.30% 61.80% 59.50% 58.87% 1.99% 53.49% 50.40% 51.67% 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 Noninterest expense to total assets as annualized.
Slide 14: Deleveraged Balance Sheet
Deleveraged Balance Sheet Commenced deleveraging strategy at the close of 1Q08 Planned sales of approximately $100 million in loans Reduce CRE portfolio Mitigate growing fixed-rate concentration Forfeit unprofitable growth Focus on strengthening balance sheet in anticipation of weakening economy
Slide 15: Loan Portfolio
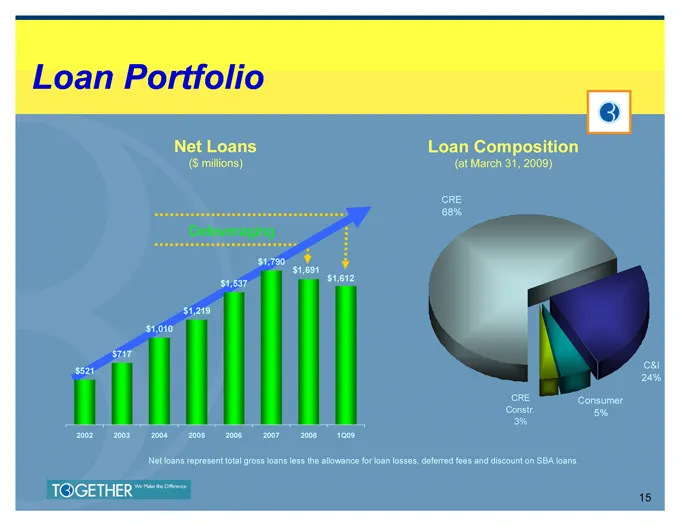
Loan Portfolio Net Loans Loan Composition ($ millions) (at March 31, 2009) CRE 68% Deleveraging $1,790 $1,691 $1,612 $1,537 $1,219 $1,010 $717 C&I $521 24% CRE Consumer Constr. 5% 3% 2002 2003 2004 2005 2006 2007 2008 1Q09 Net loans represent total gross loans less the allowance for loan losses, def
Slide 16: Conservative Credit Management
Conservative Credit Management Stringent underwriting guidelines Proactive loan portfolio management Semi-annual external loan review Annual internal stress testing
Slide 17: Vigilance to Credit Quality
Vigilance to Credit Quality Fully understanding the market Extensive management experience directly in marketplace Balancing marketing and credit quality Investing in resources Credit Administration Department Review and Monitoring Team Semi-annual external loan review Ongoing credit training String
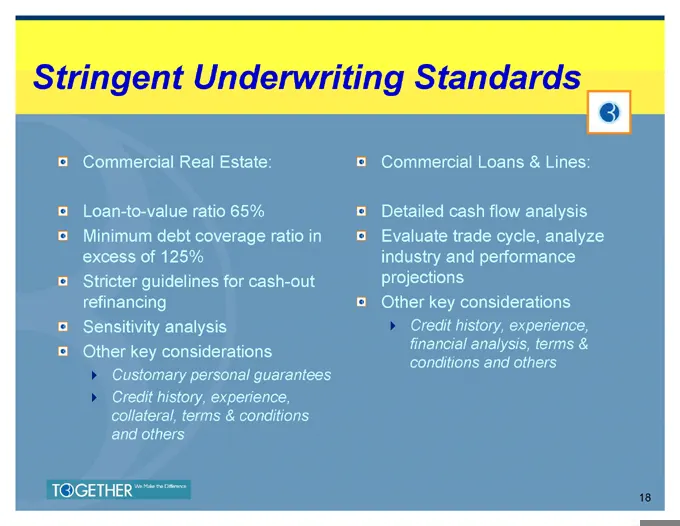
Slide 18: Stringent Underwriting Standards
Stringent Underwriting Standards Commercial Real Estate: Commercial Loans & Lines: Loan-to-value ratio 65% Detailed cash flow analysis Minimum debt coverage ratio in Evaluate trade cycle, analyze excess of 125% industry and performance Stricter guidelines for cash-out projections refinancing Other k
Slide 19: Mounting Headwinds
Mounting Headwinds Historical low interest rates Declining equity values Higher FDIC premiums Weakening economy – significant deterioration from 4Q08
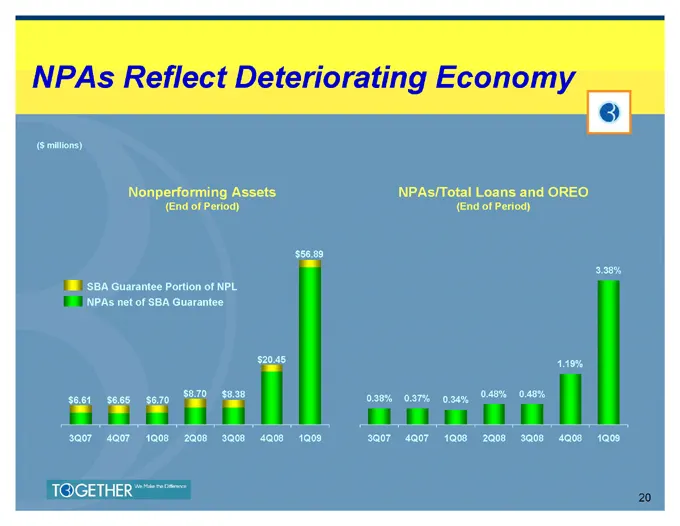
Slide 20: NPAs Reflect Deteriorating Economy
NPAs Reflect Deteriorating Economy ($ millions) Nonperforming Assets NPAs/Total Loans and OREO (End of Period) (End of Period) $56.89 3.38% SBA Guarantee Portion of NPL NPAs net of SBA Guarantee $20.45 1.19% $8.70 $8.38 0.48% 0.48% $6.61 $6.65 $6.70 0.38% 0.37% 0.34% 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q
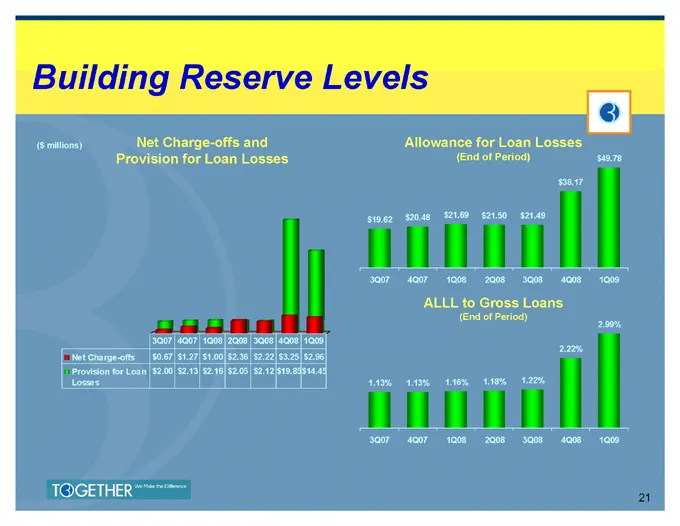
Slide 21: Building Reserve Levels
Building Reserve Levels ($ millions) Net Charge-offs and Allowance for Loan Losses Provision for Loan Losses (End of Period) $49.78 $38.17 $20.48 $21.69 $21.50 $21.49 $19.62 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 ALLL to Gross Loans (End of Period) 2.99% 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 2.22% Net Char
Slide 22: Tightened FAS Reserve Methodology
Tightened FAS 5 Reserve Methodology Heightened risk ratios for special mention and substandard credits Shortened loss experience evaluation period ` Better reflects current portfolio stresses and recent losses Designed to more adequately assess true directional consistency – given severity and swift
Slide 23: Heightened Credit Risk Management
Heightened Credit Risk Management Asset quality task force ` Proactive executive management involvement ` Bi-weekly review of delinquent loans greater than $500,000 ` Action plan initiated from day one of delinquency Internal stress testing mechanisms ` Deployment of new software enabling more regul
Slide 24: Shrinking Construction Portfolio
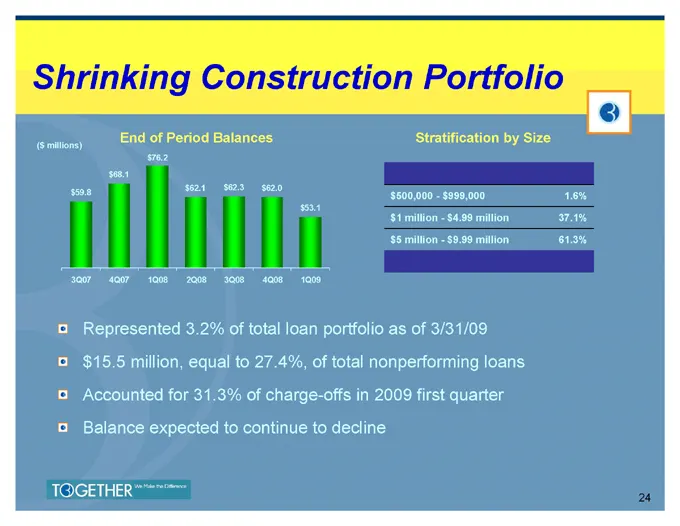
Shrinking Construction Portfolio End of Period Balances Stratification by Size ($ millions) $76.2 $68.1 $62.1 $62.3 $62.0 $59.8 $500,000—$999,000 1.6% $53.1 $1 million—$4.99 million 37.1% $5 million—$9.99 million 61.3% 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09 Represented 3.2% of total loan portfolio as of
Slide 25: Shrinking CRE Portfolio
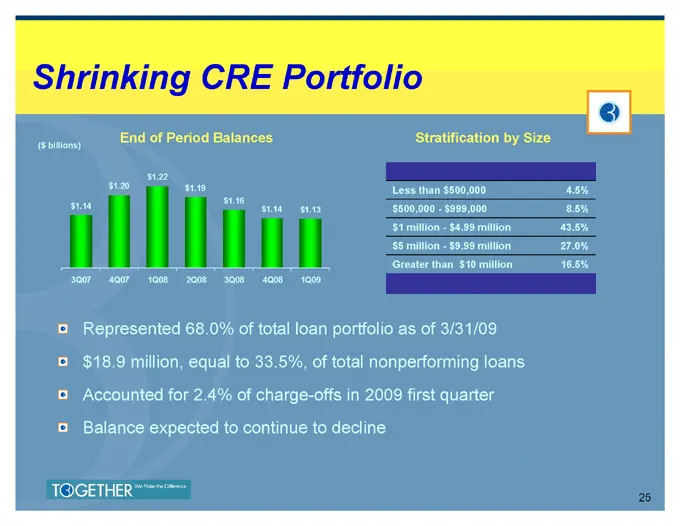
Shrinking CRE Portfolio End of Period Balances Stratification by Size ($ billions) $1.22 $1.20 $1.19 Less than $500,000 4.5% $1.16 $1.14 $1.14 $500,000—$999,000 8.5% $1.13 $1 million—$4.99 million 43.5% $5 million—$9.99 million 27.0% Greater than $10 million 16.5% 3Q07 4Q07 1Q08 2Q08 3Q08 4Q08 1Q09
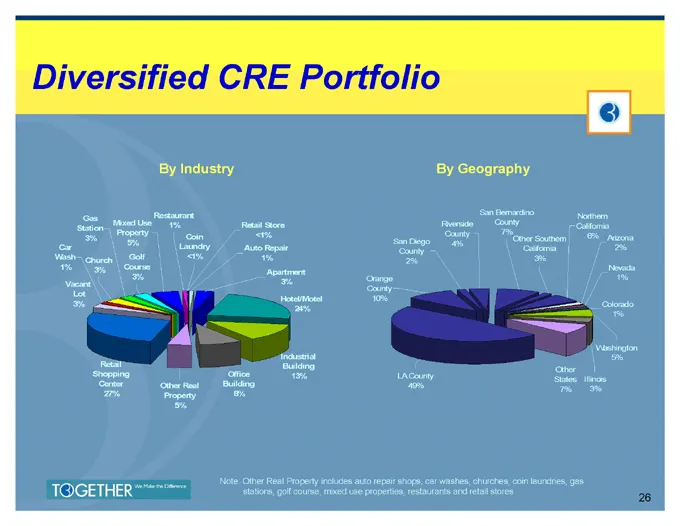
Slide 26: Diversified CRE Portfolio
Diversified CRE Portfolio By Industry By Geography Restaurant San Bernardino Gas Northern Mixed Use 1% Retail Store Riverside County Station California Property <1% County 7% 3% Coin Other Southern 6% Arizona 5% San Diego 4% Car Laundry Auto Repair California 2% County Wash Golf <1% 1% 3% Church 2%
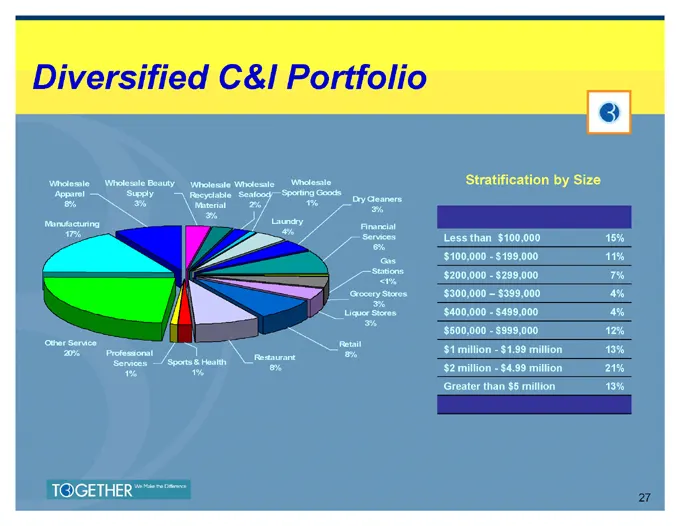
Slide 27: Diversified C&I Portfolio
Diversified C&I Portfolio Wholesale Wholesale Beauty Wholesale Wholesale Wholesale Stratification by Size Apparel Supply Recyclable Seafood Sporting Goods Dry Cleaners 8% 3% Material 2% 1% 3% 3% Manufacturing Laundry Financial 17% 4% Services Less than $100,000 15% 6% $100,000—$199,000 11% Gas Stati
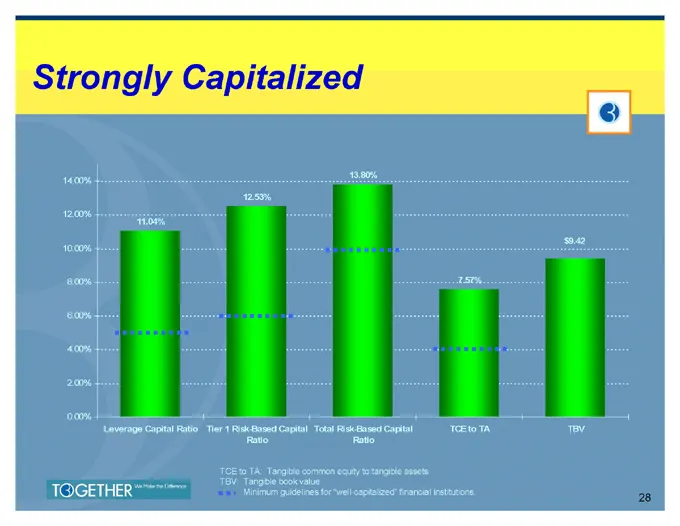
Slide 28: Strongly Capitalized
Strongly Capitalized 13.80% 14.00% 12.53% 12.00% 11.04% 10.00% $9.42 8.00% 7.57% 6.00% 4.00% 2.00% 0.00% Leverage Capital Ratio Tier 1 Risk-Based Capital Total Risk-Based Capital TCE to TA TBV Ratio Ratio TCE to TA: Tangible common equity to tangible assets TBV: Tangible book value Minimum guideline
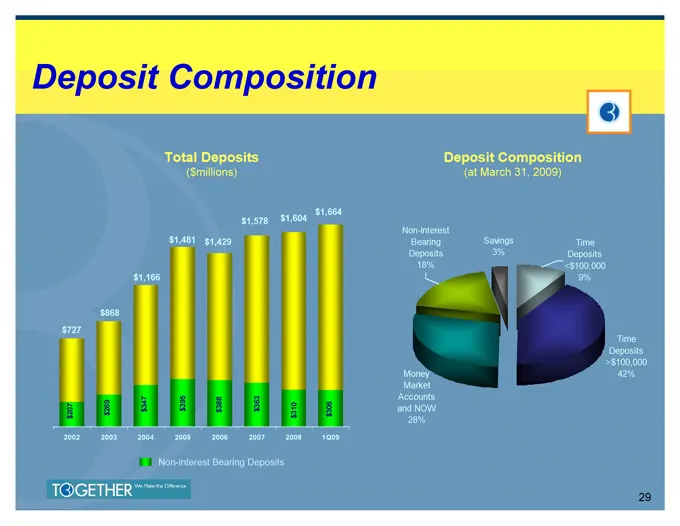
Slide 29: Deposit Composition
Deposit Composition Total Deposits Deposit Composition ($millions) (at March 31, 2009) $1,664 $1,578 $1,604 Non-Interest $1,481 $1,429 Bearing Savings Time Deposits 3% Deposits 18% <$100,000 $1,166 9% $868 $727 Time Deposits >$100,000 Money 42% Market 395 363 Accounts 347 388 and NOW 207 269 $ $ $ $
Slide 30: Increasing Liquidity Trends
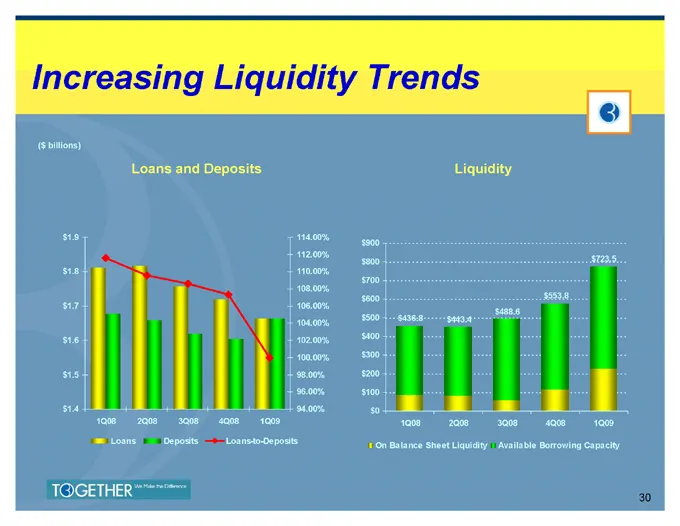
Increasing Liquidity Trends ($ billions) Loans and Deposits Liquidity $1.9 114.00% $900 112.00% $800 $723.5 $1.8 110.00% $700 108.00% $600 $553.8 $1.7 106.00% $488.6 $500 $436.8 $443.4 104.00% $400 $1.6 102.00% 100.00% $300 $1.5 98.00% $200 96.00% $100 $1.4 94.00% $0 1Q08 2Q08 3Q08 4Q08 1Q09 1Q08 2Q
Slide 31: Q1 2009 Summary
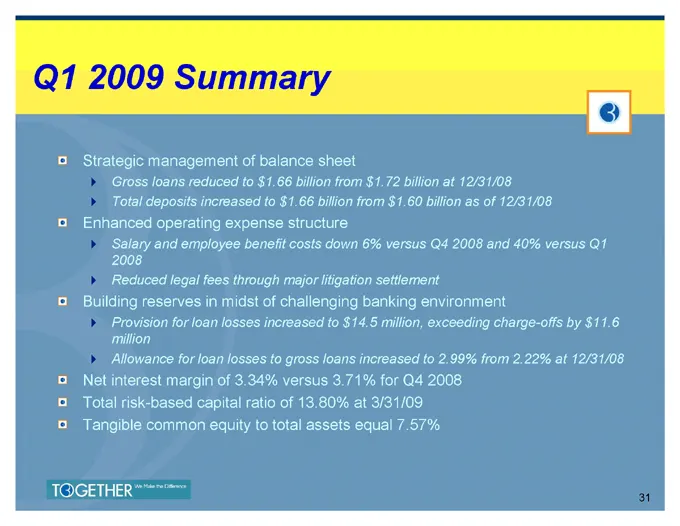
Q1 2009 Summary Strategic management of balance sheet ` Gross loans reduced to $1.66 billion from $1.72 billion at 12/31/08 ` Total deposits increased to $1.66 billion from $1.60 billion as of 12/31/08 Enhanced operating expense structure ` Salary and employee benefit costs down 6% versus Q4 2008 an
Slide 32: Investment Highlights
Investment Highlights Strong, cohesive executive team with extensive experience managing through financial crises Focused on balanced growth in recessionary environment Strong capital positioning Proactive risk recognition and management Building reserve levels against significant headwinds With the
Slide 33
Source: SEC EDGAR · 8-K filed May 7, 2009