BNC Bancorp — Gulf South Bank Conference May 2014
27 slides from BNC Bancorp's conference presentation, May 13, 2014
Slide 1: Gulf South Bank Conference May 2014
GULF SOUTH BANK CONFERENCE MAY 2014
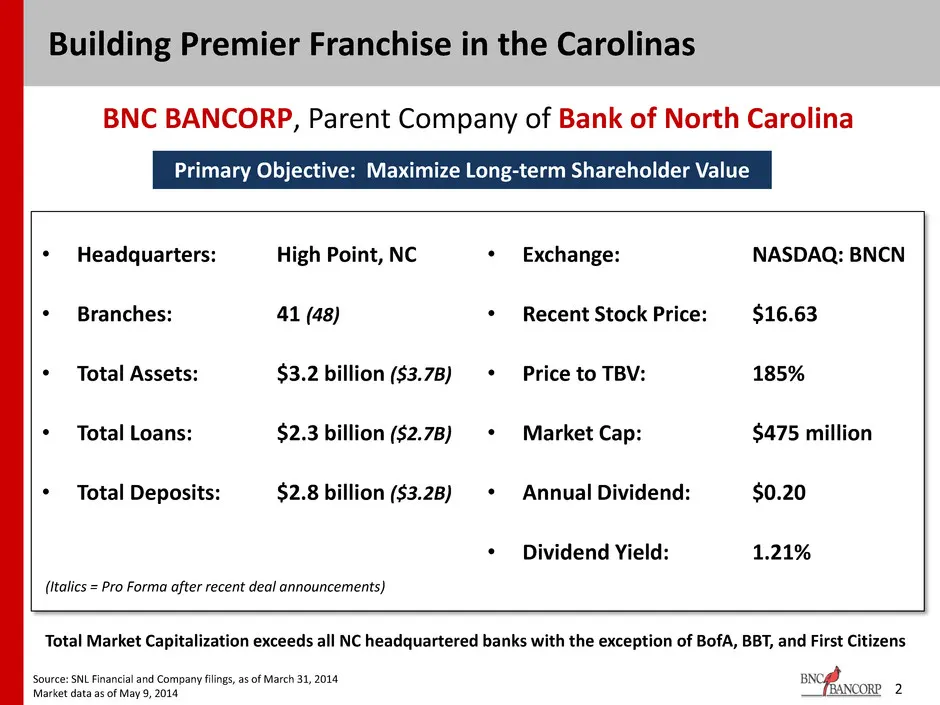
Slide 2: Building Premier Franchise in the Carolinas
• Headquarters: • Branches: • Total Assets: • Total Loans: • Total Deposits: High Point, NC 41 (48) $3.2 billion ($3.7B) $2.3 billion ($2.7B) $2.8 billion ($3.2B) Building Premier Franchise in the Carolinas • Exchange: • Recent Stock Price: • Price to TBV: • Market Cap: • Annual Dividend: • Dividend
Slide 3: Investment Thesis
• Attractive franchise concentrated in growth markets in the Carolinas – Pro forma, 4th largest bank headquartered in North Carolina • June 2013 addition to Russell Index ― Daily average trading volume: 55,000 shares, over $1 million daily float ― Pro forma, $500 million market cap • Proven acquirer
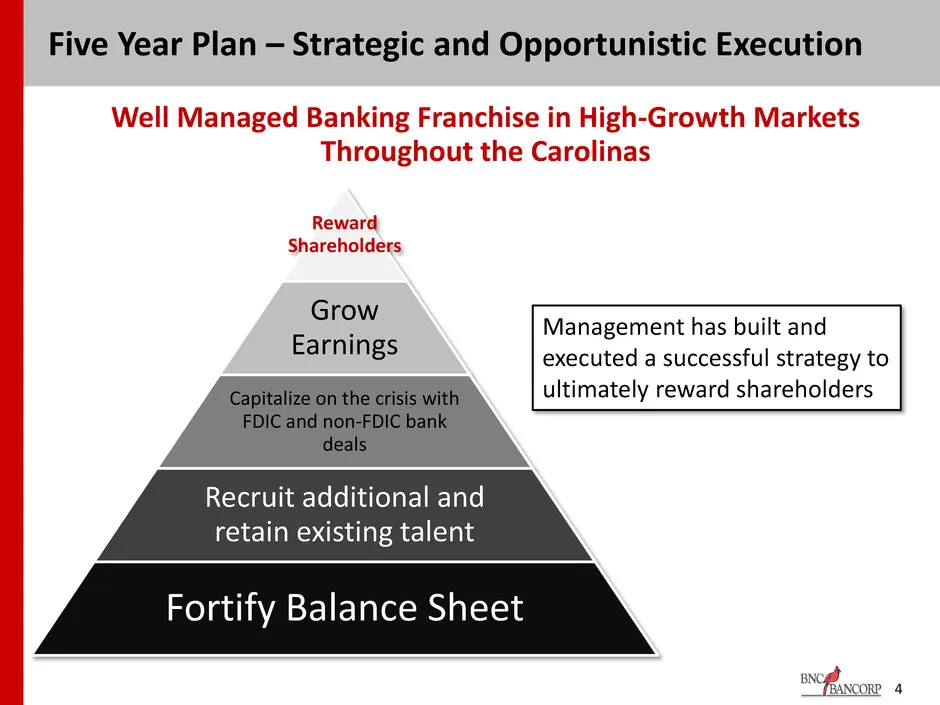
Slide 4: Five Year Plan – Strategic and Opportunistic Execution
Well Managed Banking Franchise in High-Growth Markets Throughout the Carolinas Five Year Plan – Strategic and Opportunistic Execution 4 Reward Shareholders Grow Earnings Capitalize on the crisis with FDIC and non-FDIC bank deals Recruit additional and retain existing talent Fortify Balance Sheet Man
Slide 5: The Results
BNCA ~__ {BANCORP The Results
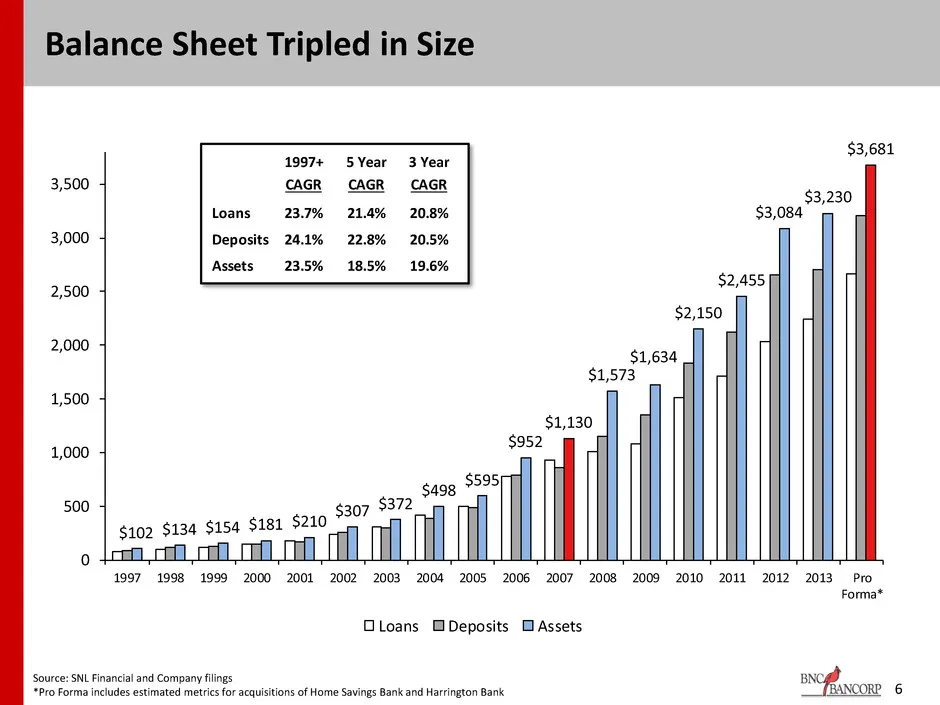
Slide 6: Balance Sheet Tripled in Size
$102 $134 $154 $181 $210 $307 $372 $498 $595 $952 $1,130 $1,573 $1,634 $2,150 $2,455 $3,084 $3,230 $3,681 0 500 1,000 1,500 2,000 2,500 3,000 3,500 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 Pro Forma* Loans Deposits Assets Source: SNL Financial and Company
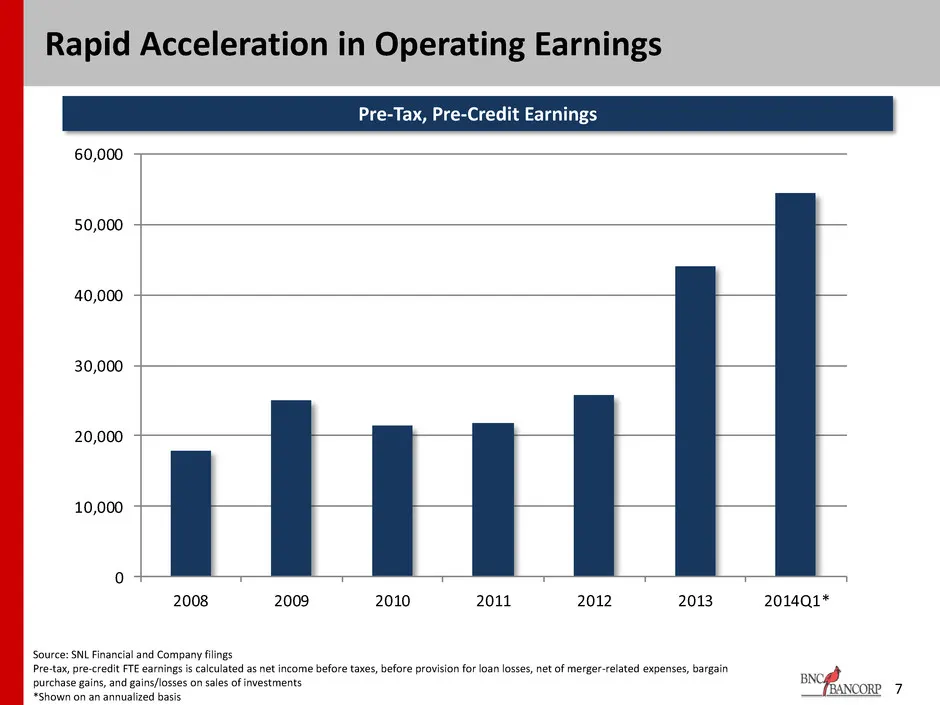
Slide 7: Rapid Acceleration in Operating Earnings
7 Rapid Acceleration in Operating Earnings Pre-Tax, Pre-Credit Earnings 0 10,000 20,000 30,000 40,000 50,000 60,000 2008 2009 2010 2011 2012 2013 2014Q1* Source: SNL Financial and Company filings Pre-tax, pre-credit FTE earnings is calculated as net income before taxes, before provision for loan los
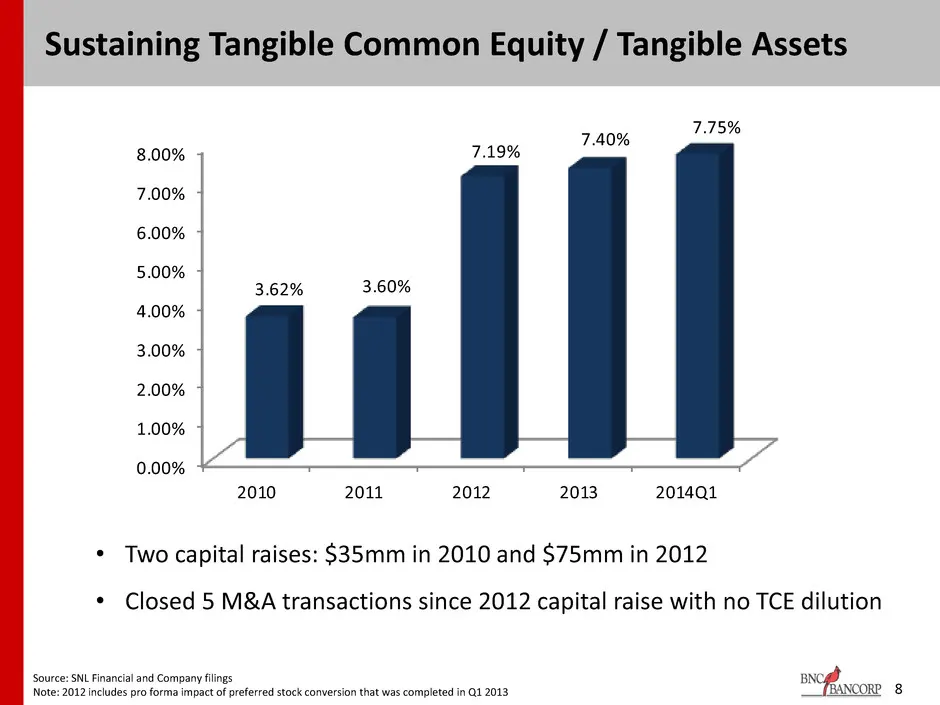
Slide 8: Sustaining Tangible Common Equity / Tangible Assets
8 Sustaining Tangible Common Equity / Tangible Assets • Two capital raises: $35mm in 2010 and $75mm in 2012 • Closed 5 M&A transactions since 2012 capital raise with no TCE dilution Source: SNL Financial and Company filings Note: 2012 includes pro forma impact of preferred stock conversion that was
Slide 9: Expansion through Disciplined Acquisition Strategy
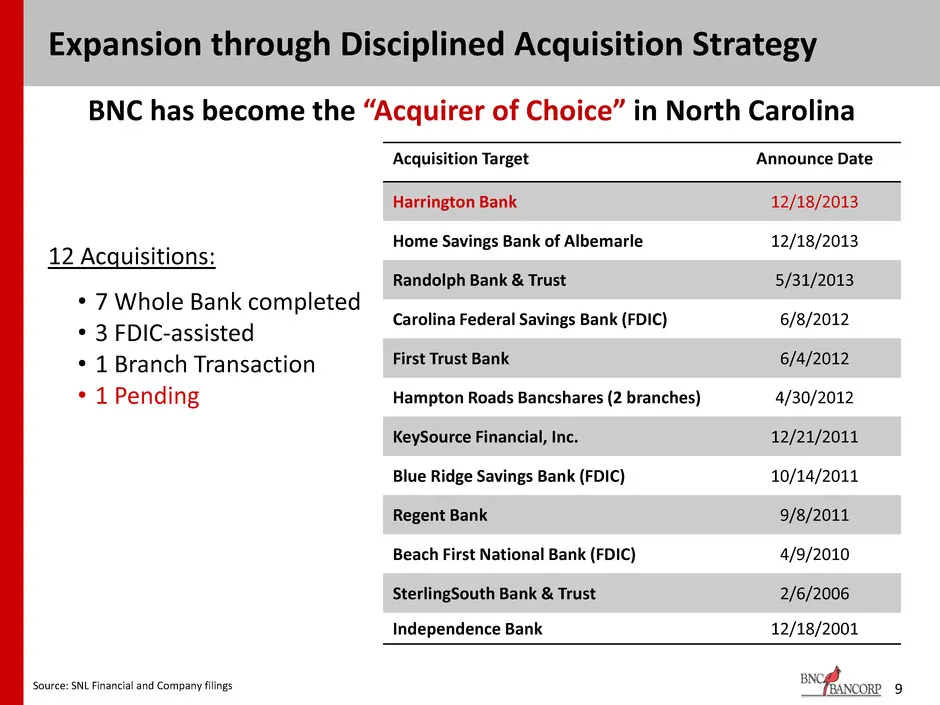
Expansion through Disciplined Acquisition Strategy Source: SNL Financial and Company filings 12 Acquisitions: • 7 Whole Bank completed • 3 FDIC-assisted • 1 Branch Transaction • 1 Pending Acquisition Target Announce Date Harrington Bank 12/18/2013 Home Savings Bank of Albemarle 12/18/2013 Randolph B
Slide 10: Franchise Expanded to All Key Markets in the Carolinas
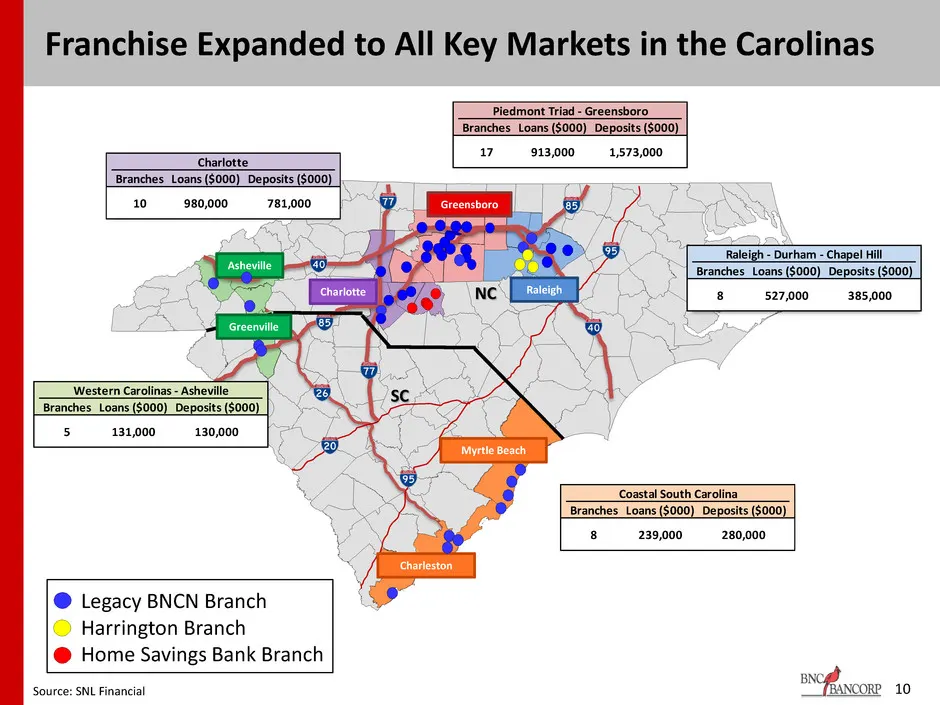
10 Franchise Expanded to All Key Markets in the Carolinas NC SC Charlotte Greensboro Raleigh Myrtle Beach Charleston Greenville Asheville Legacy BNCN Branch Harrington Branch Home Savings Bank Branch Source: SNL Financial Charlotte Branches Loans ($000) Deposits ($000) 10 980,000 781,000 Piedmont Tr
Slide 11: Attractive Markets
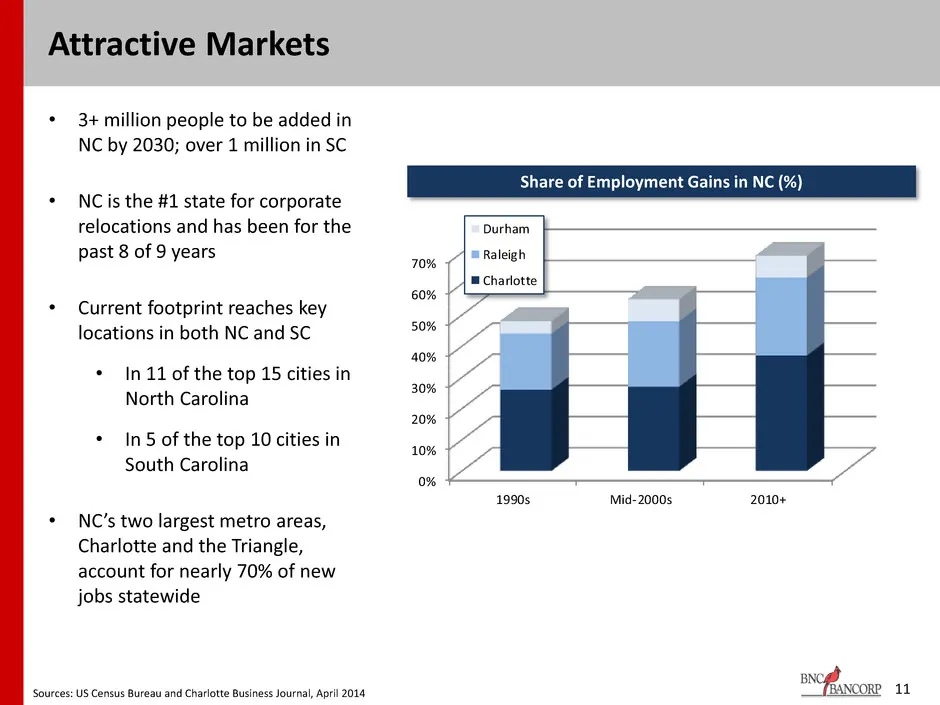
11 Attractive Markets • 3+ million people to be added in NC by 2030; over 1 million in SC • NC is the #1 state for corporate relocations and has been for the past 8 of 9 years • Current footprint reaches key locations in both NC and SC • In 11 of the top 15 cities in North Carolina • In 5 of the top
Slide 12: Earnings Per Share Ramping as Planned
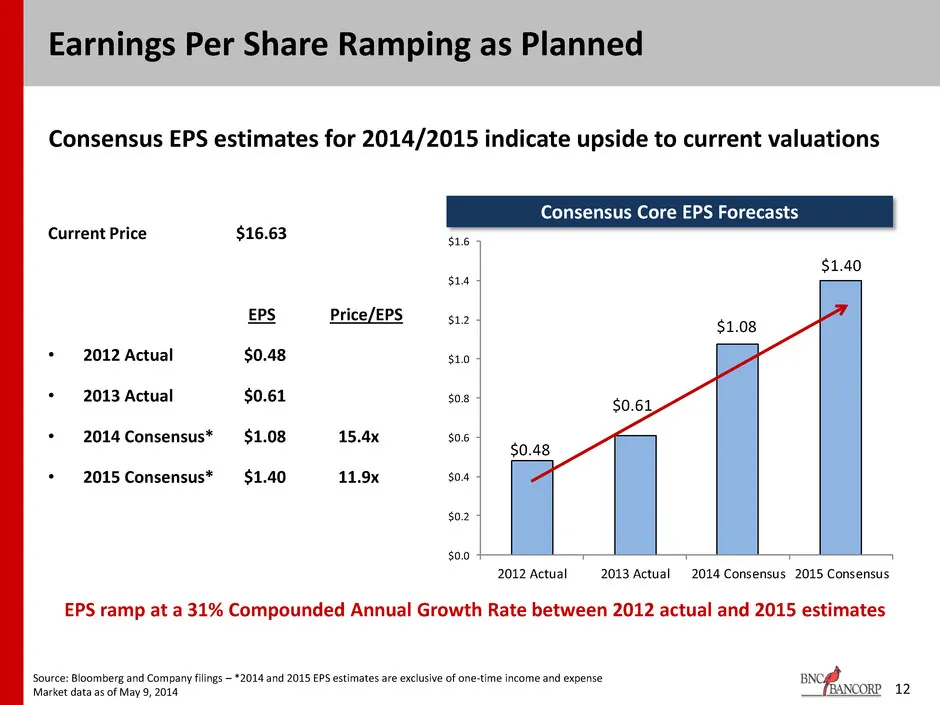
Earnings Per Share Ramping as Planned Current Price $16.63 EPS Price/EPS • 2012 Actual $0.48 • 2013 Actual $0.61 • 2014 Consensus* $1.08 15.4x • 2015 Consensus* $1.40 11.9x Consensus EPS estimates for 2014/2015 indicate upside to current valuations Source: Bloomberg and Company filings – *2014 and 2
Slide 13: Investment in Talent to Support Growth
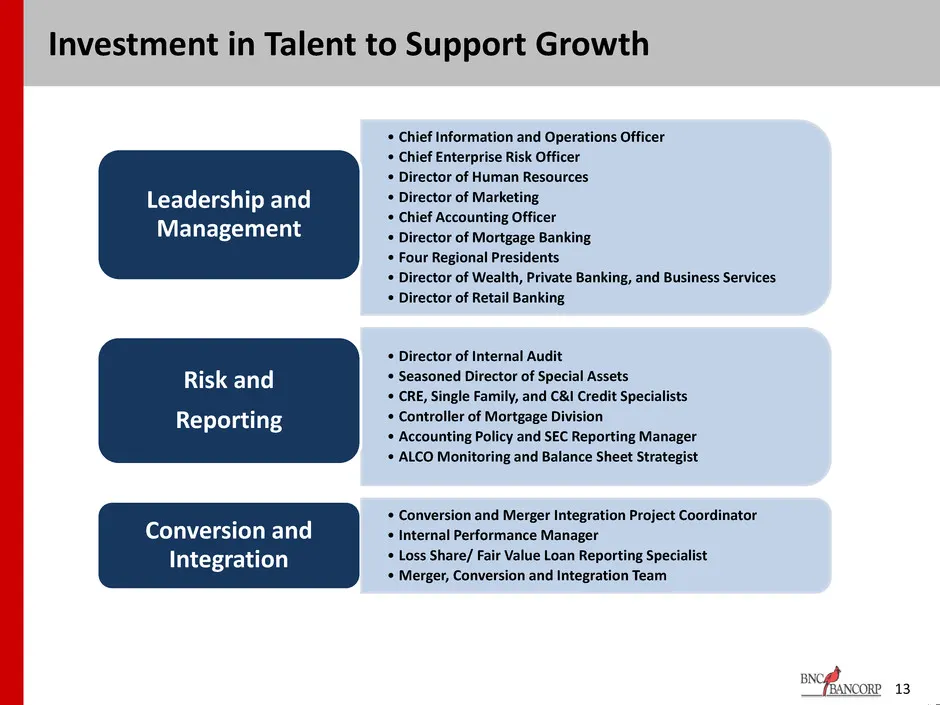
13 Investment in Talent to Support Growth • Chief Information and Operations Officer • Chief Enterprise Risk Officer • Director of Human Resources • Director of Marketing • Chief Accounting Officer • Director of Mortgage Banking • Four Regional Presidents • Director of Wealth, Private Banking, and B
Slide 14: Recent Acquisitions
BNC ___ {BANCORP Recent Acquisitions
Slide 15: Recently Announced Transaction Benefits
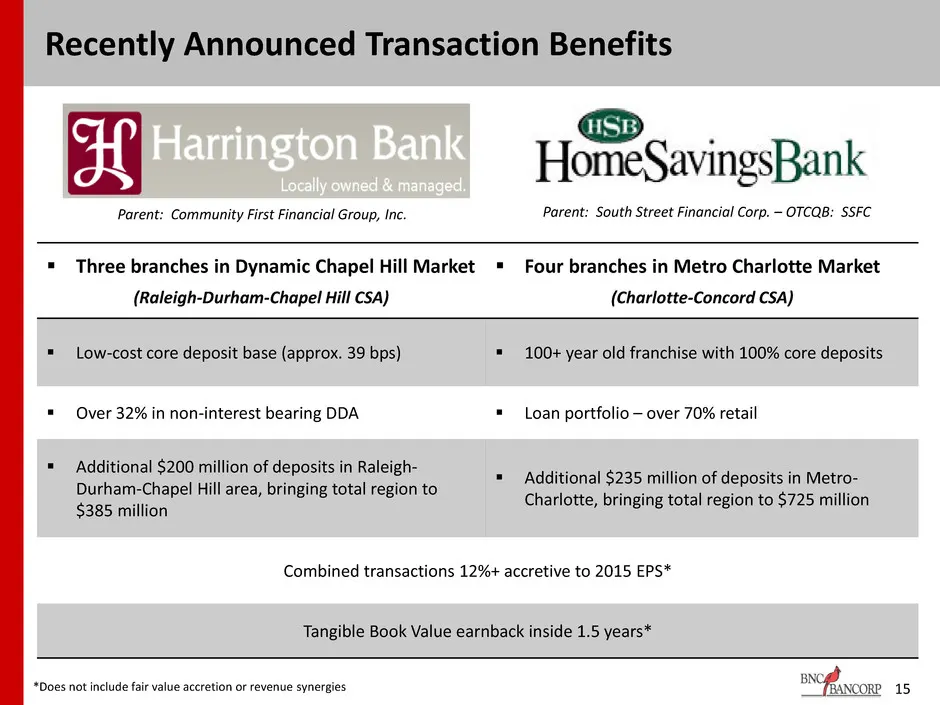
15 Recently Announced Transaction Benefits Three branches in Dynamic Chapel Hill Market (Raleigh-Durham-Chapel Hill CSA) Four branches in Metro Charlotte Market (Charlotte-Concord CSA) Low-cost core deposit base (approx. 39 bps) 100+ year old franchise with 100% core deposits Over 32% in n
Slide 16: Stock Price Performance
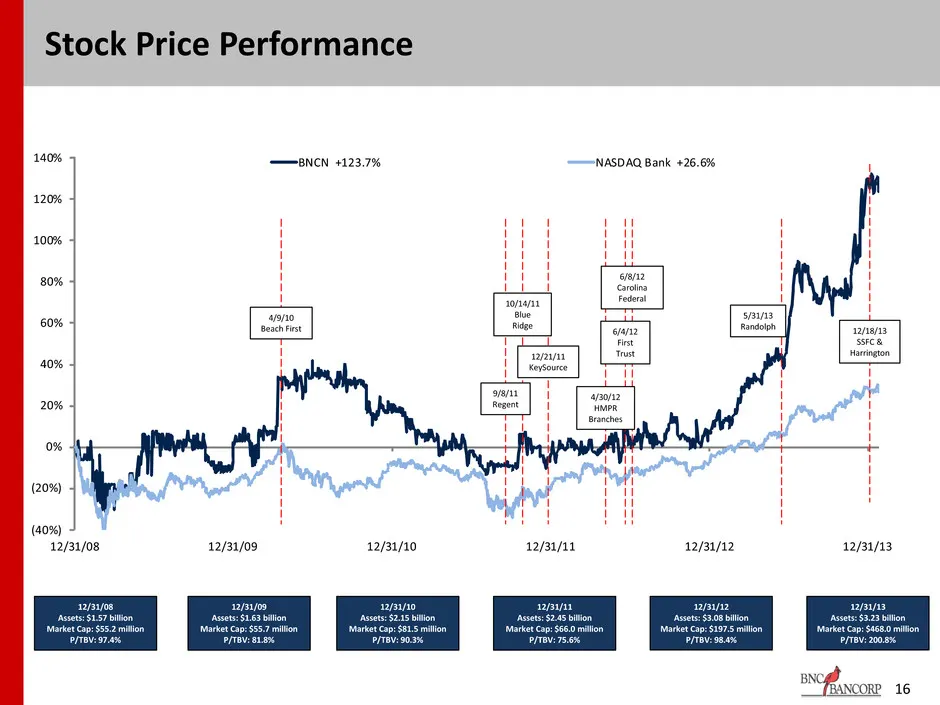
16 Stock Price Performance 12/31/08 Assets: $1.57 billion Market Cap: $55.2 million P/TBV: 97.4% 12/31/09 Assets: $1.63 billion Market Cap: $55.7 million P/TBV: 81.8% 12/31/10 Assets: $2.15 billion Market Cap: $81.5 million P/TBV: 90.3% 12/31/11 Assets: $2.45 billion Market Cap: $66.0 million P/TBV:
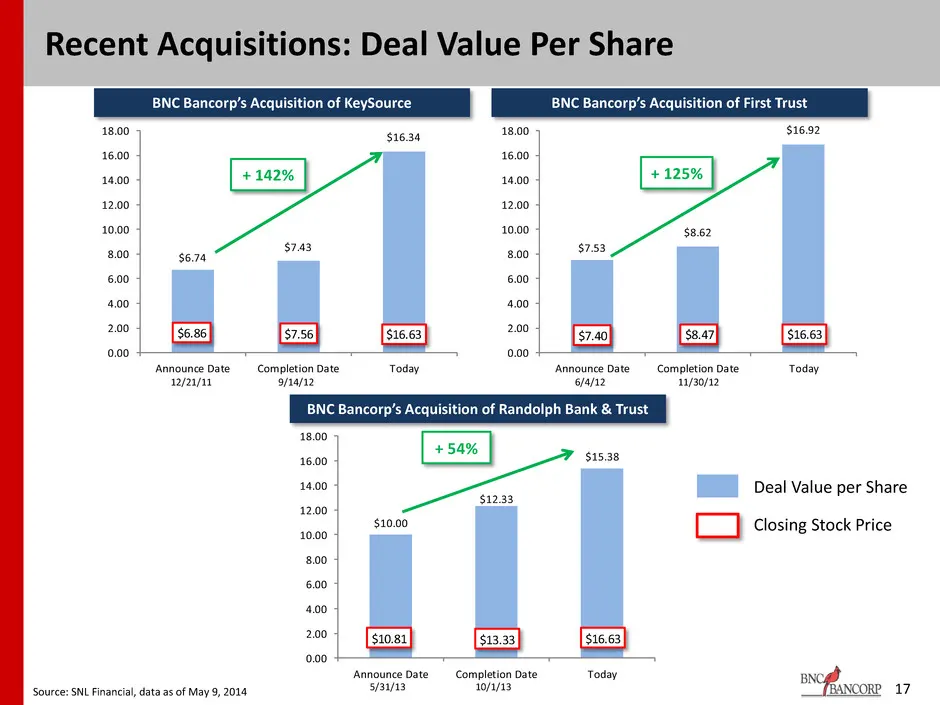
Slide 17: Recent Acquisitions: Deal Value Per Share
$6.74 $7.43 $16.34 $6.86 $7.56 $16.63 0.00 2.00 4.00 6.00 8.00 10.00 12.00 14.00 16.00 18.00 Announce Date Completion Date Today $7.53 $8.62 $16.92 $7.40 $8.47 $16.63 0.00 2.00 4.00 6.00 8.00 10.00 12.00 14.00 16.00 18.00 Announce Date Completion Date Today + 125% $10.00 $12.33 $15.38 $10.81 $13.33
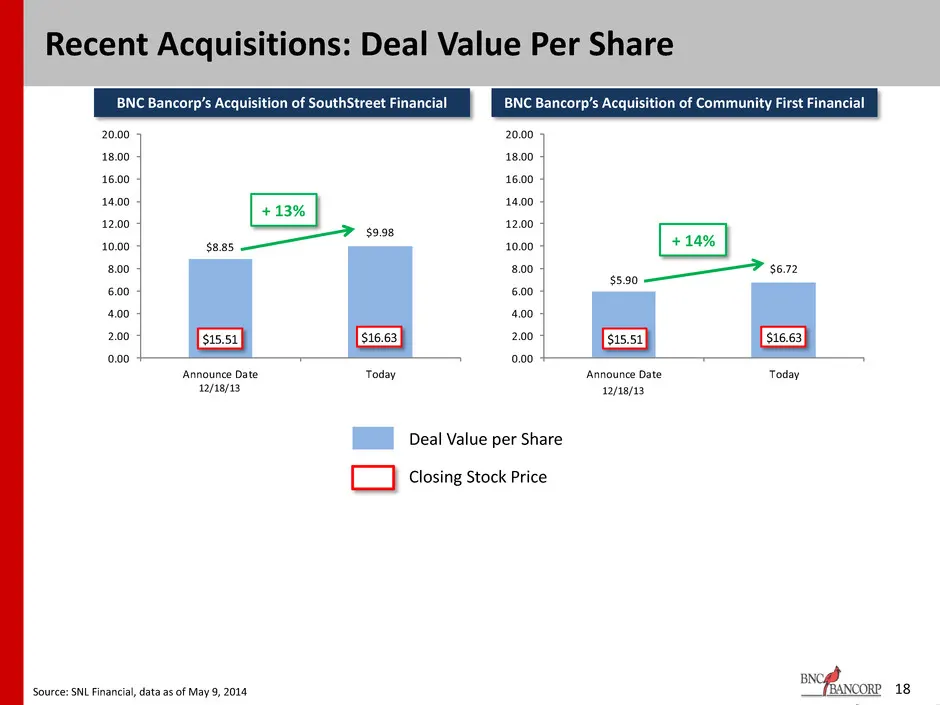
Slide 18: Recent Acquisitions: Deal Value Per Share
18 Recent Acquisitions: Deal Value Per Share BNC Bancorp’s Acquisition of SouthStreet Financial BNC Bancorp’s Acquisition of Community First Financial Source: SNL Financial, data as of May 9, 2014 Deal Value per Share Closing Stock Price $8.85 $9.98 $15.51 $16.63 0.00 2.00 4.00 6.00 8.00 10.00 12.00
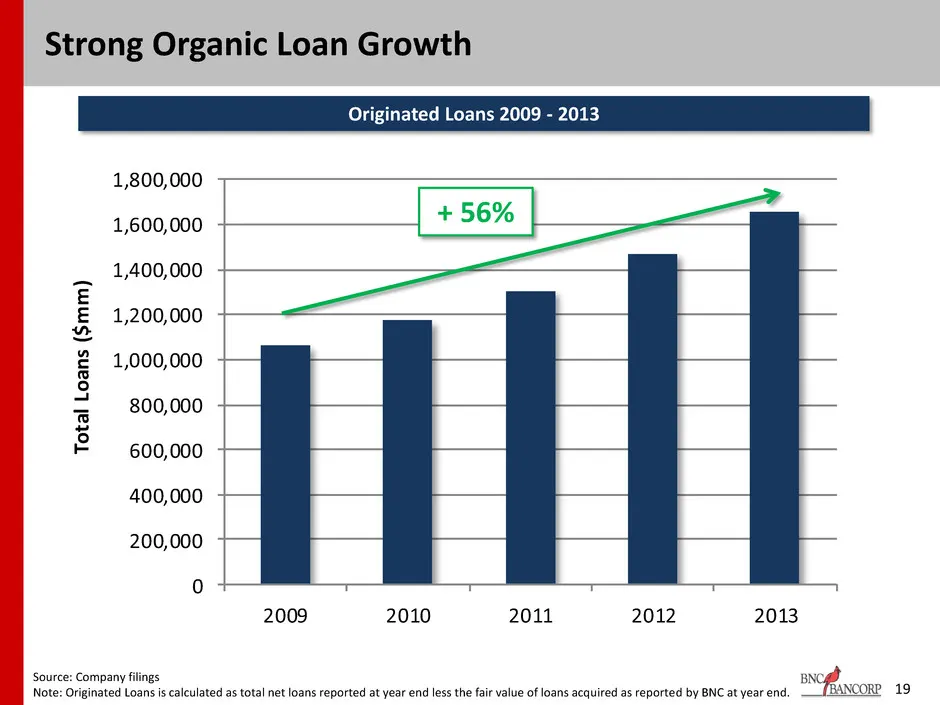
Slide 19: Strong Organic Loan Growth
0 200,000 400,000 600,000 800,000 1,000,000 1,200,000 1,400,000 1,600,000 1,800,000 2009 2010 2011 2012 2013 To tal Lo an s ( $m m) 19 Strong Organic Loan Growth Source: Company filings Note: Originated Loans is calculated as total net loans reported at year end less the fair value of loans acquired
Slide 20: Financial Appendix
BNCA ~__ {BANCORP Financial Appendix
Slide 21: Performance Metrics
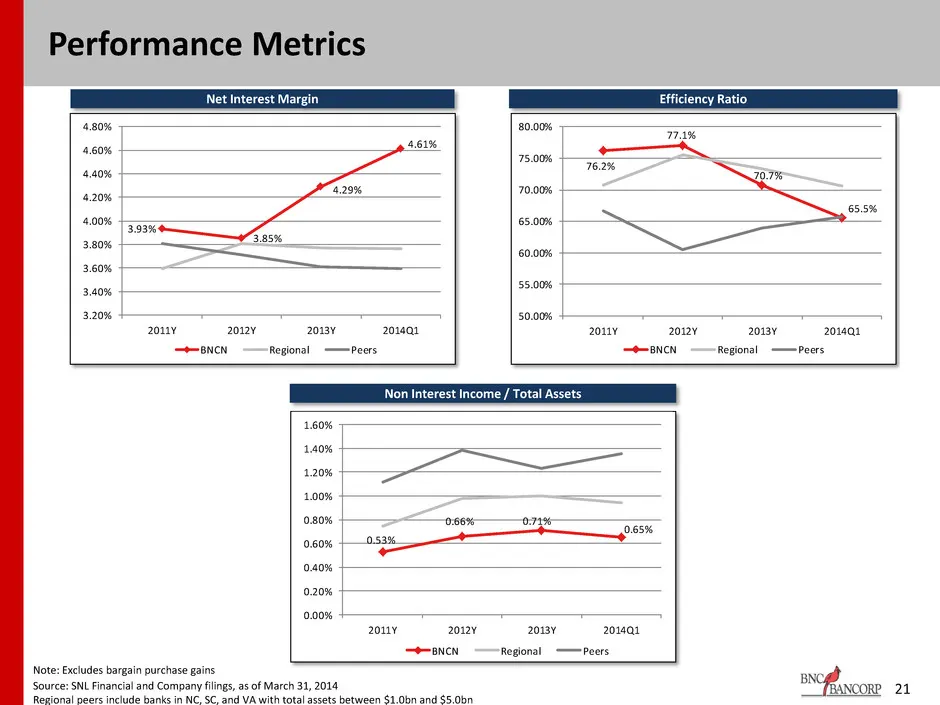
Note: Excludes bargain purchase gains 21 Source: SNL Financial and Company filings, as of March 31, 2014 Regional peers include banks in NC, SC, and VA with total assets between $1.0bn and $5.0bn Performance Metrics Net Interest Margin Efficiency Ratio Non Interest Income / Total Assets 3.93% 3.85%
Slide 22: Outstanding Net Interest Margin
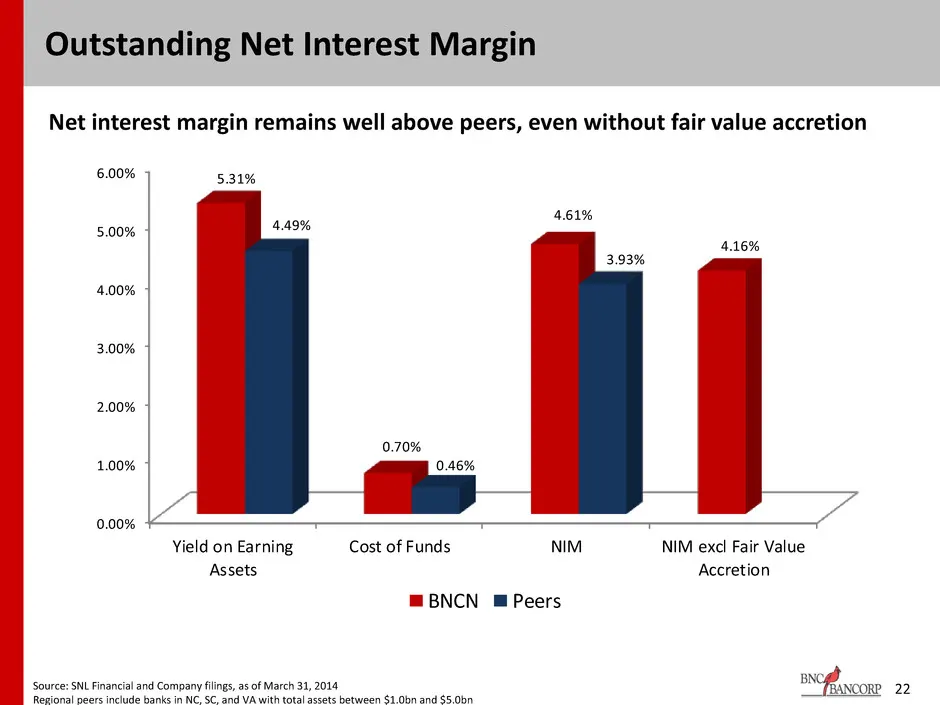
22 Outstanding Net Interest Margin 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% Yield on Earning Assets Cost of Funds NIM NIM excl Fair Value Accretion 5.31% 0.70% 4.61% 4.16% 4.49% 0.46% 3.93% BNCN Peers Net interest margin remains well above peers, even without fair value accretion Source: SNL Financ
Slide 23: Improving Funding Mix
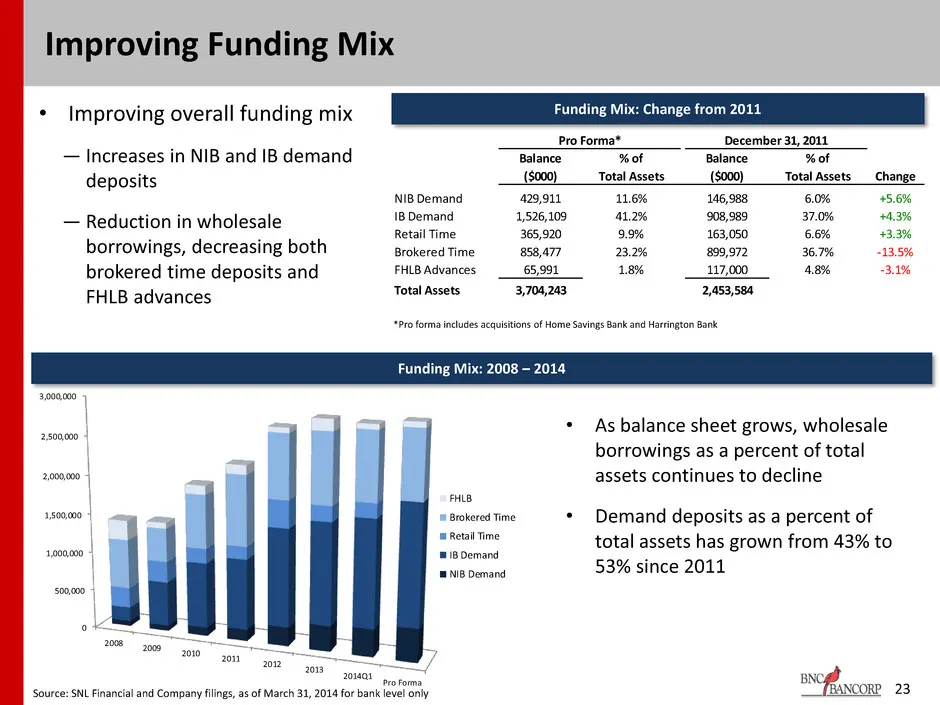
23 Improving Funding Mix Funding Mix: 2008 – 2014 Funding Mix: Change from 2011 • Improving overall funding mix ― Increases in NIB and IB demand deposits ― Reduction in wholesale borrowings, decreasing both brokered time deposits and FHLB advances • As balance sheet grows, wholesale borrowings as a
Slide 24: Loan Mix
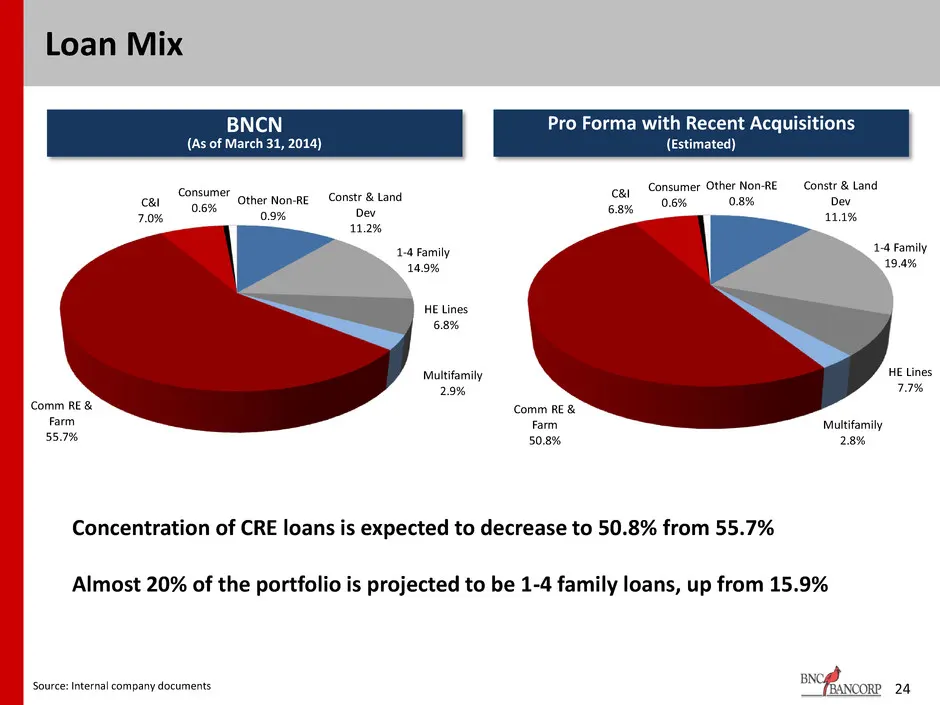
Constr & Land Dev 11.2% 1-4 Family 14.9% HE Lines 6.8% Multifamily 2.9% Comm RE & Farm 55.7% C&I 7.0% Consumer 0.6% Other Non-RE 0.9% Constr & Land Dev 11.1% 1-4 Family 19.4% HE Lines 7.7% Multifamily 2.8% Comm RE & Farm 50.8% C&I 6.8% Consumer 0.6% Other Non-RE 0.8% Loan Mix BNCN (As of March 31, 2
Slide 25: Deposit Mix
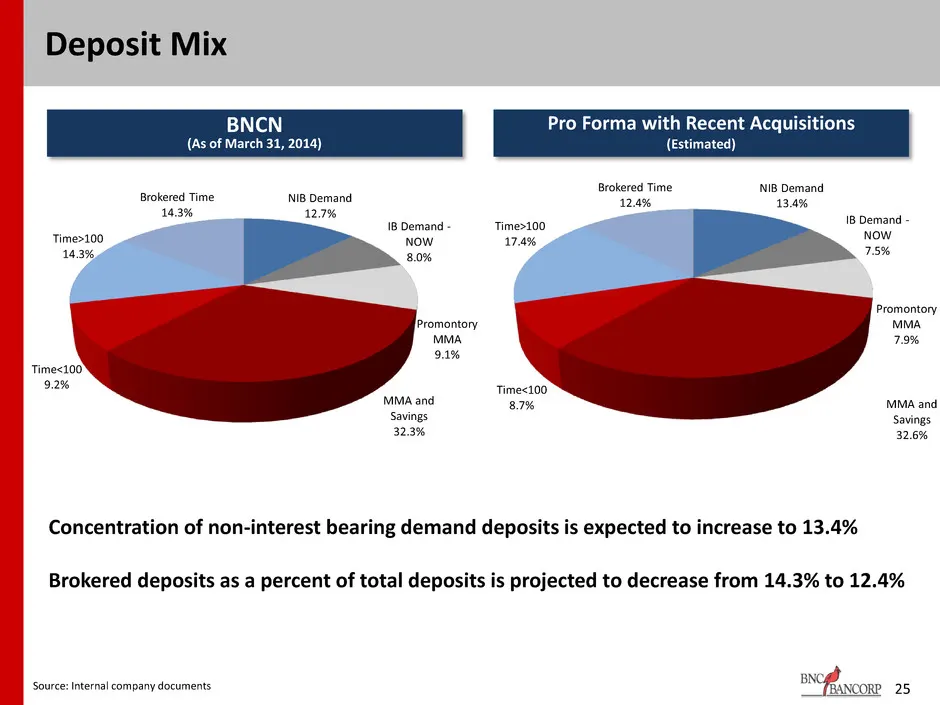
Deposit Mix BNCN (As of March 31, 2014) Pro Forma with Recent Acquisitions (Estimated) 25 Source: Internal company documents Concentration of non-interest bearing demand deposits is expected to increase to 13.4% Brokered deposits as a percent of total deposits is projected to decrease from 14.3% to
Slide 26: Forward Looking Statements
26 Forward Looking Statements This presentation contains certain forward-looking information about BNC Bancorp and subsidiaries (collectively, “BNCN”) that is intended to be covered by the safe harbor for “forward-looking statements” provided by the Private Securities Litigation Reform Act of 1995.
Slide 27: NC
NC
Source: SEC EDGAR · 8-K filed May 13, 2014
More decks from BNC Bancorp
 Merger or Acquisition (January 2017)37 slides · Jan 23, 2017
 Stephens Inc. Carolinas Roadshow - Charlotte November 201637 slides · Nov 8, 2016
 IPO Roadshow (July 2016)28 slides · Jul 20, 2016
 2016 Gulf South Bank Conference37 slides · May 2, 2016
 Merger or Acquisition (November 2015)32 slides · Nov 16, 2015
 Merger or Acquisition (August 2015)24 slides · Aug 14, 2015