Southern Community Financial Corp
Southern Community Financial — Southeast 2005
32 slides from Southern Community Financial's conference presentation, Aug 26, 2005
Slide 1: Southeast 2005 - Atlanta, GA August 25, 2005
Southeast 2005 - Atlanta, GA August 25, 2005
Slide 2: Forward-Looking Statements
This presentation may contain, in addition to historical information, various "forward-looking statements" that represent our judgment concerning the future and are subject to risks and uncertainties that could cause Southern Community's actual operating results and financial position to differ mate
Slide 3: Corporate Profile
Corporate Profile CORPORATE PROFILE Started - November 18, 1996 Established Holding Company (SCFC) - October 1, 2001 State Chartered, Fed Member and Report to the SEC SCFC Operates 18 Banking Offices in 7 Counties LPO in Iredell County - Mooresville, N.C. Subsidiaries: Southern Community Bank and Tr
Slide 4: Corporate & Financial Highlights
Corporate & Financial Highlights CORPORATE & FINANCIAL HIGHLIGHTS In our nine years of existence we have: Leveraged an experienced and entrepreneurial management team Achieved twenty-six consecutive quarters of profitability after becoming profitable in our seventh quarter of operation Acquired The
Slide 5: Corporate & Financial Highlights
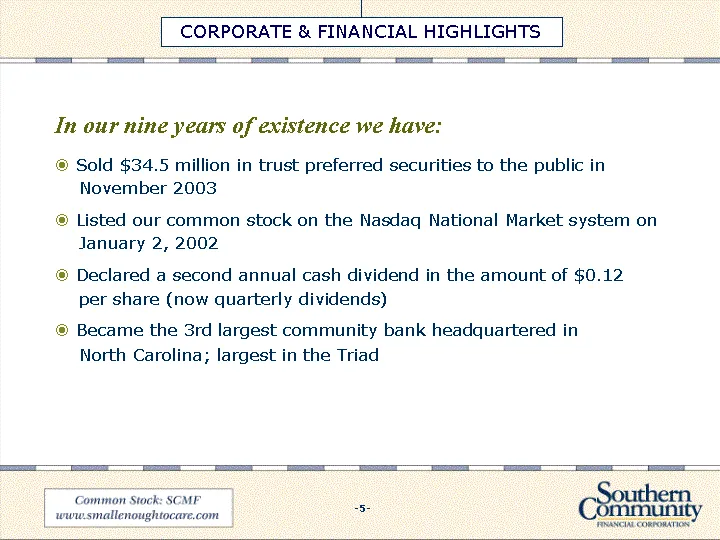
Corporate & Financial Highlights CORPORATE & FINANCIAL HIGHLIGHTS In our nine years of existence we have: Sold $34.5 million in trust preferred securities to the public in November 2003 Listed our common stock on the Nasdaq National Market system on January 2, 2002 Declared a second annual cash divi
Slide 6: Corporate & Financial Highlights
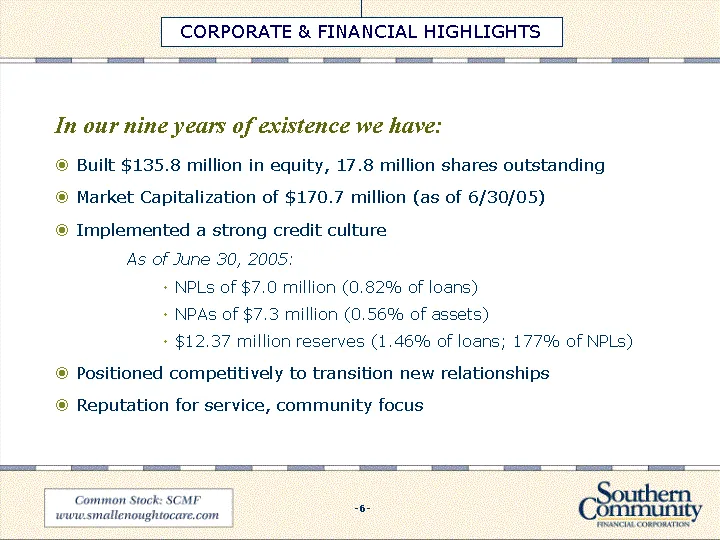
Corporate & Financial Highlights CORPORATE & FINANCIAL HIGHLIGHTS In our nine years of existence we have: Built $135.8 million in equity, 17.8 million shares outstanding Market Capitalization of $170.7 million (as of 6/30/05) Implemented a strong credit culture As of June 30, 2005: NPLs of $7.0 mill
Slide 7: Philosophy
Philosophy PHILOSOPHY PROFITABILITY G R O W T H Q U A L I T Y S E R V I C E - -13-
Slide 8: Management Team
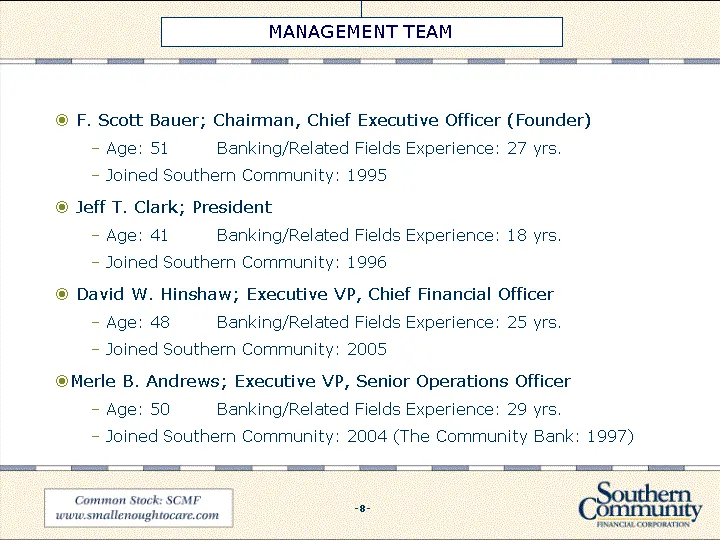
Target Market MANAGEMENT TEAM F. Scott Bauer; Chairman, Chief Executive Officer (Founder) Age: 51 Banking/Related Fields Experience: 27 yrs. Joined Southern Community: 1995 Jeff T. Clark; President Age: 41 Banking/Related Fields Experience: 18 yrs. Joined Southern Community: 1996 David W. Hinshaw; E
Slide 9: Management Team
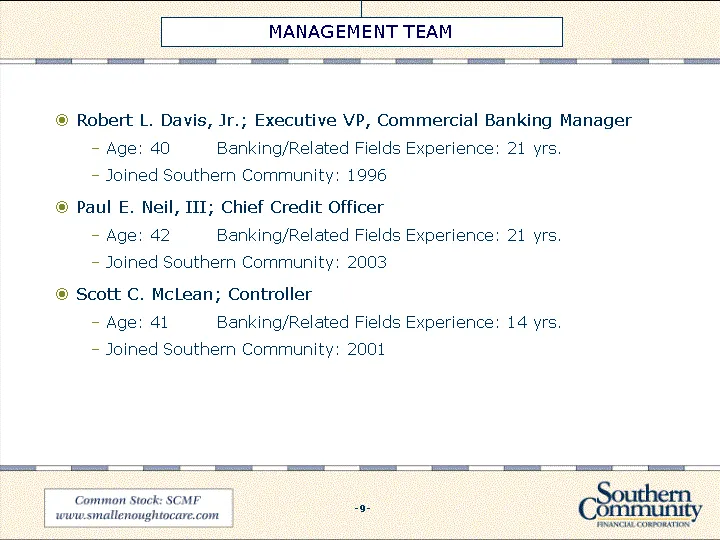
Target Market MANAGEMENT TEAM Robert L. Davis, Jr.; Executive VP, Commercial Banking Manager Age: 40 Banking/Related Fields Experience: 21 yrs. Joined Southern Community: 1996 Paul E. Neil, III; Chief Credit Officer Age: 42 Banking/Related Fields Experience: 21 yrs. Joined Southern Community: 2003 S
Slide 10: Target Markets
Target Market TARGET MARKETS Small & Medium Sized Businesses Owners Managers Professionals & Middle Managers of Locally Based Companies Residential Builders / Developers Retail Customers - -19-
Slide 11: Branch Network
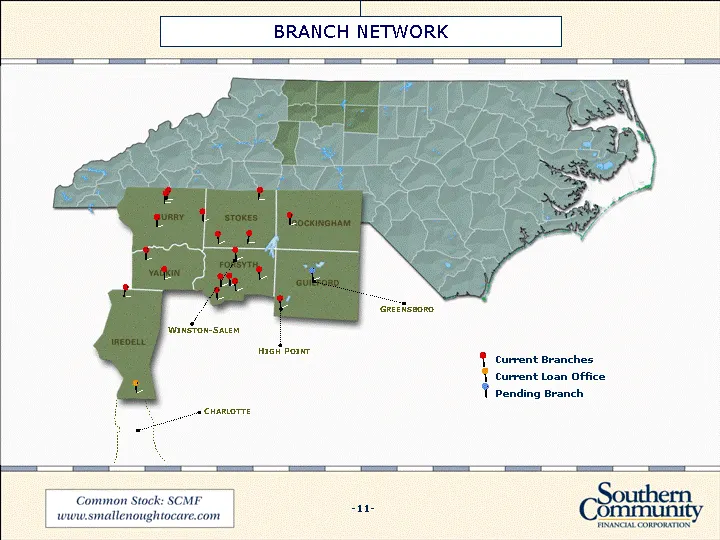
Branch Network BRANCH NETWORK Current Branches Current Loan Office Pending Branch CHARLOTTE WINSTON-SALEM GREENSBORO HIGH POINT - -21-
Slide 12: Our Market Area
Our Market Area OUR MARKET AREA The Piedmont Triad Named for the three largest cities in the region, Winston-Salem, Greensboro and High Point. Our market includes the Triad and surrounding counties. Part of the largest Metropolitan Statistical Area located entirely in North Carolina and in the top 5
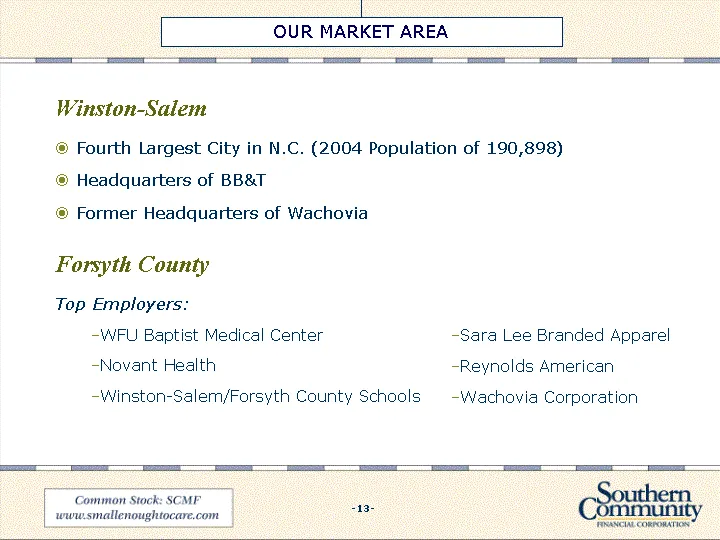
Slide 13: Our Market Area: Winston-Salem
Our Market Area Winston-Salem Fourth Largest City in N.C. (2004 Population of 190,898) Headquarters of BB&T Former Headquarters of Wachovia Forsyth County Top Employers: WFU Baptist Medical Center Novant Health Winston-Salem/Forsyth County Schools OUR MARKET AREA Sara Lee Branded Apparel Reynolds Am
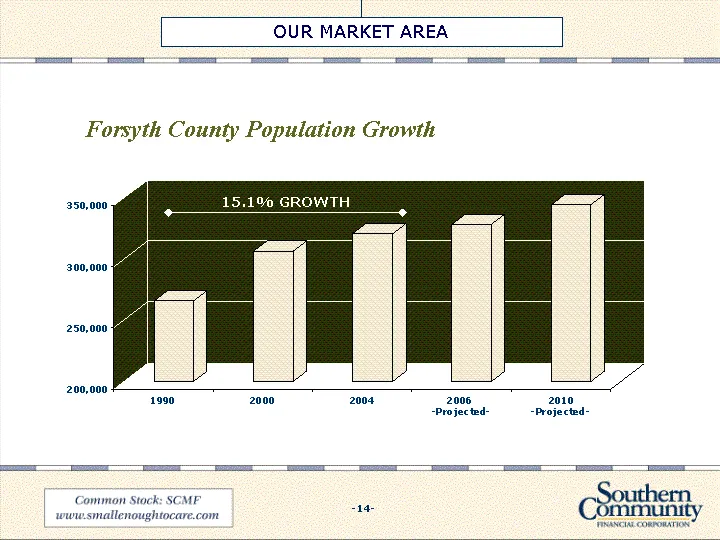
Slide 14: Our Market Area: Forsyth County Population Growth
OUR MARKET AREA Forsyth County Population Growth 15.1% GROWTH - -27-
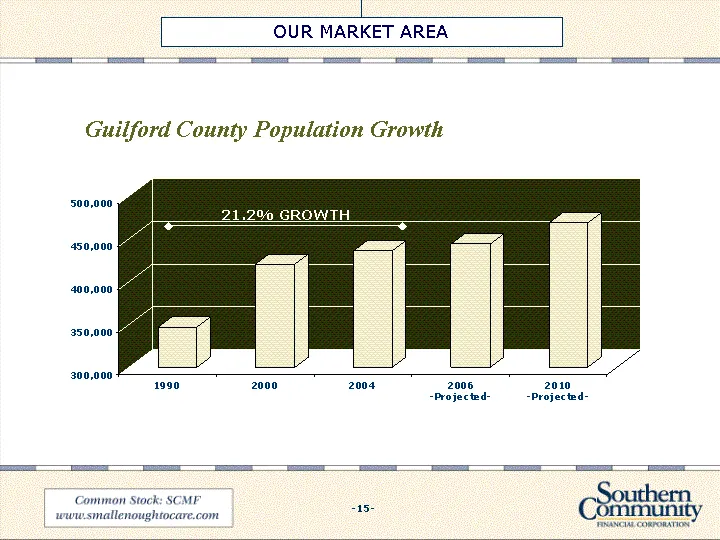
Slide 15: Our Market Area: Guilford County Population Growth
OUR MARKET AREA Guilford County Population Growth 21.2% GROWTH - -29-
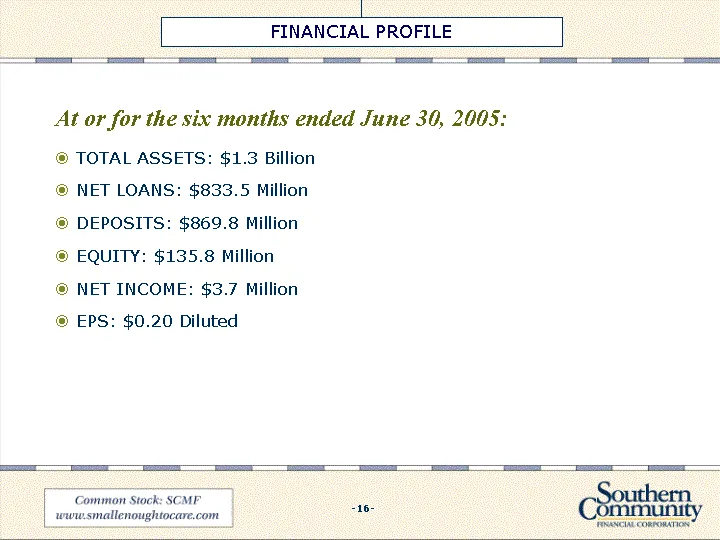
Slide 16: Financial Profile
FINANCIAL PROFILE At or for the six months ended June 30, 2005: TOTAL ASSETS: $1.3 Billion NET LOANS: $833.5 Million DEPOSITS: $869.8 Million EQUITY: $135.8 Million NET INCOME: $3.7 Million EPS: $0.20 Diluted - -31-
Slide 17: Key Financial Ratios
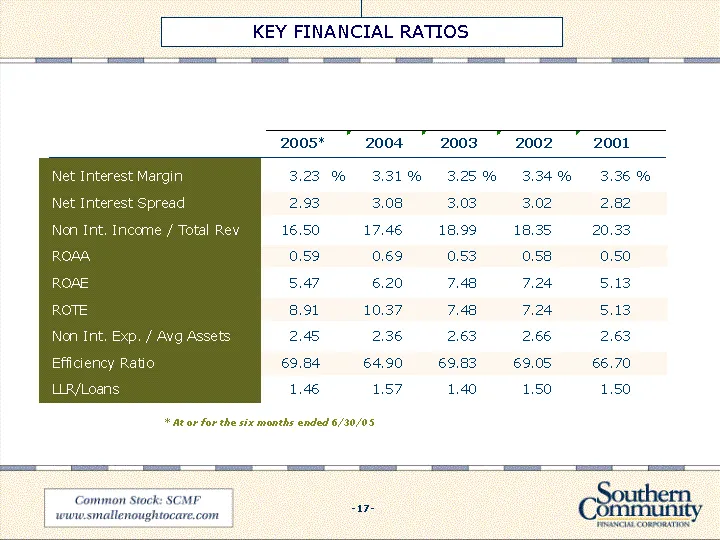
KEY FINANCIAL RATIOS * At or for the six months ended 6/30/05 - -33-
Slide 18: Revenue Growth
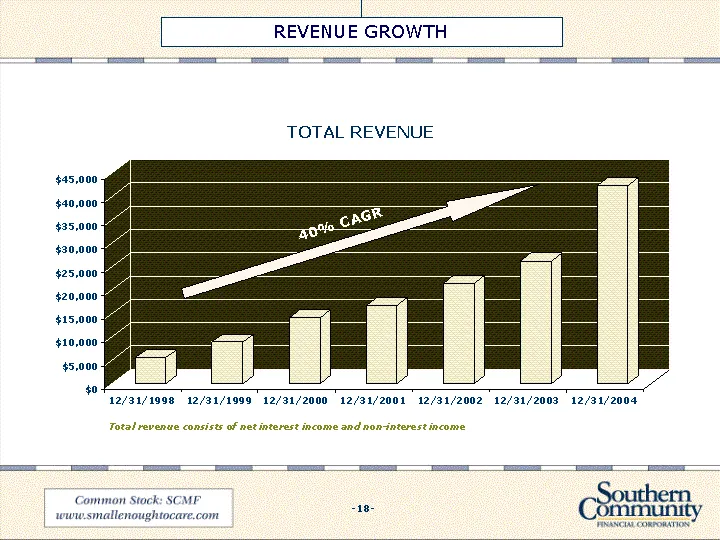
REVENUE GROWTH Total revenue consists of net interest income and non-interest income 40% CAGR TOTAL REVENUE - -35-
Slide 19: Non-Interest Income Growth
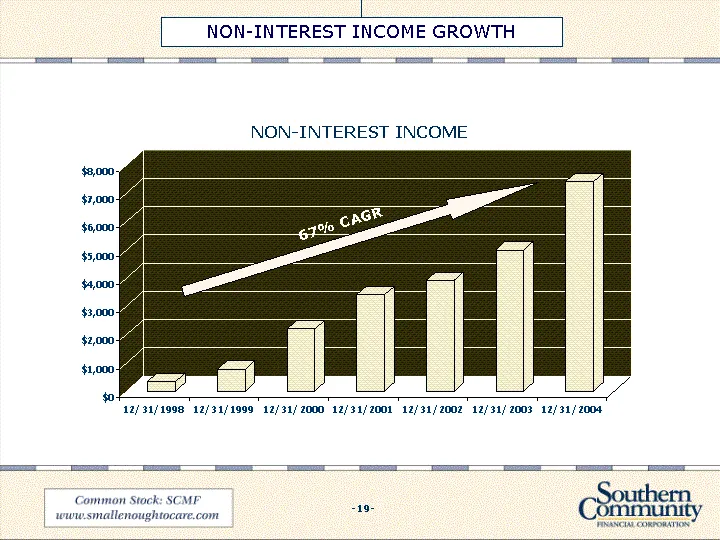
NON-INTEREST INCOME GROWTH 67% CAGR NON-INTEREST INCOME - -37-
Slide 20: Asset Growth
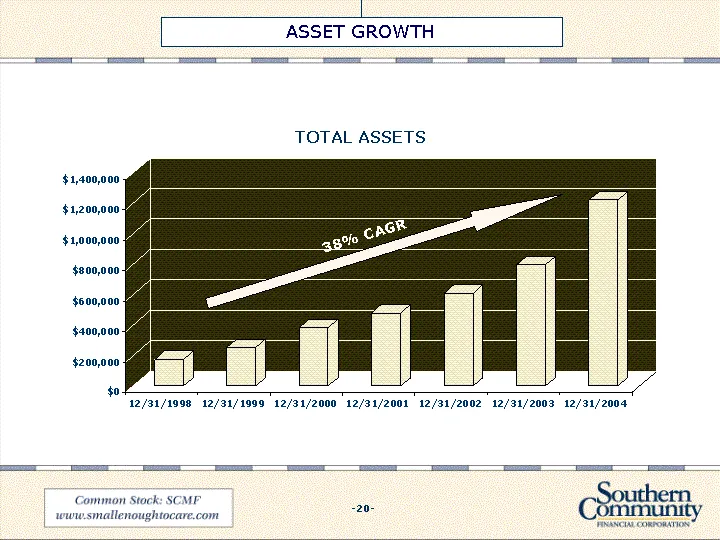
ASSET GROWTH 38% CAGR TOTAL ASSETS - -39-
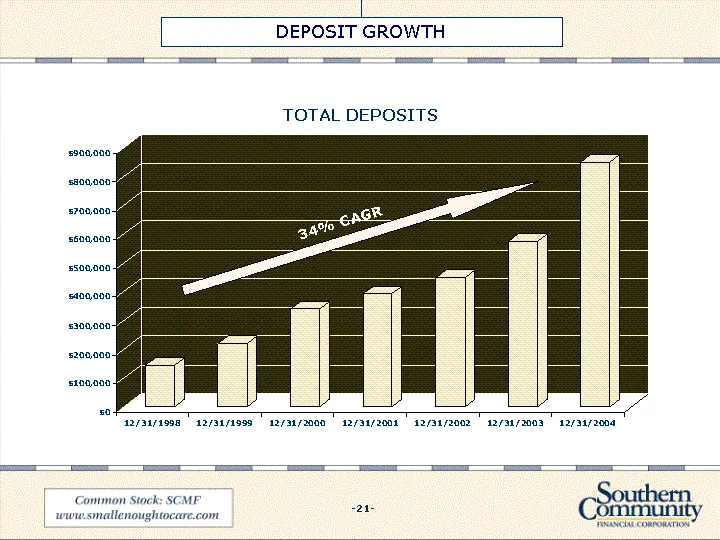
Slide 21: Deposit Growth
DEPOSIT GROWTH 34% CAGR TOTAL DEPOSITS - -41-
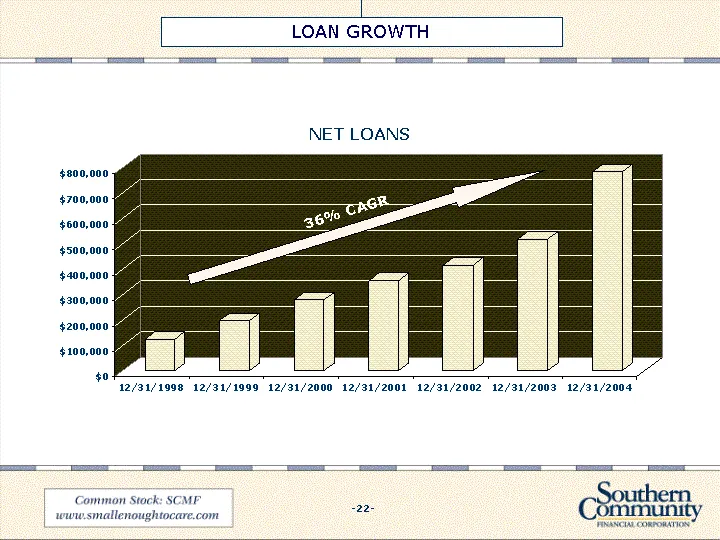
Slide 22: Loan Growth
LOAN GROWTH 36% CAGR NET LOANS - -43-
Slide 23: Asset Quality and Reserves
ASSET QUALITY AND RESERVES Lend to Established Businesses with Historical Cash Flow Do Not Participate in Large Syndications Independent Loan Review NPAs Are Low $12.4 Million in Reserves, 1.46% of Loans - -45-
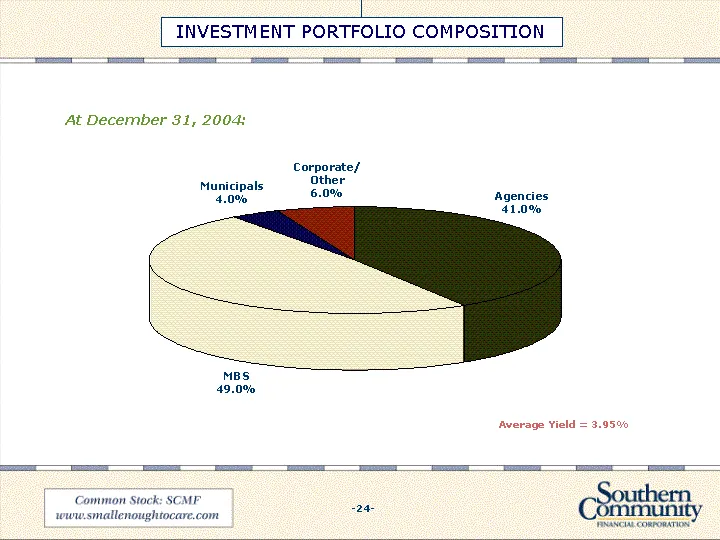
Slide 24: Investment Portfolio Composition
INVESTMENT PORTFOLIO COMPOSITION Agencies MBS Municipals Corporate/Other East 41 49 4 6 At December 31, 2004: Average Yield = 3.95% - -47-
Slide 25: Book Value Per Share Growth
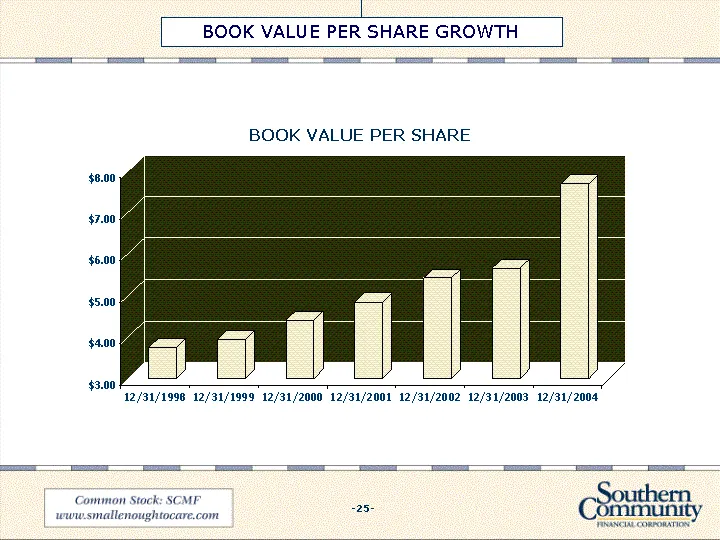
BOOK VALUE PER SHARE GROWTH BOOK VALUE PER SHARE - -49-
Slide 26: EPS Growth
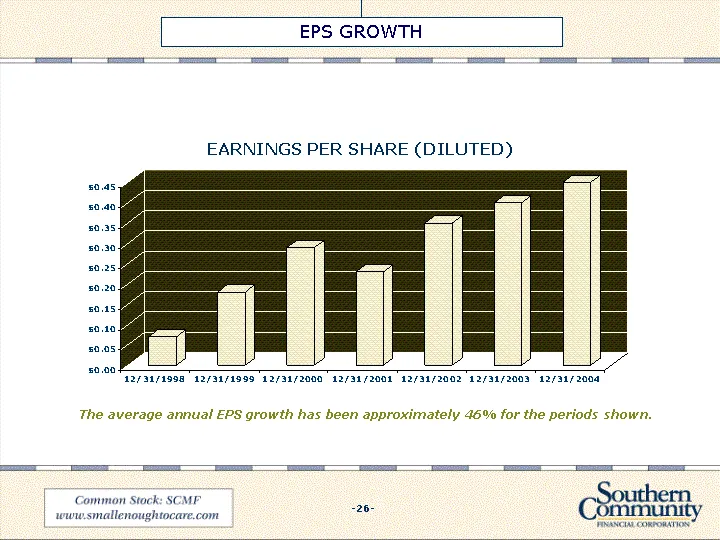
EPS GROWTH The average annual EPS growth has been approximately 46% for the periods shown. EARNINGS PER SHARE (DILUTED) - -51-
Slide 27: 2-Year Price-Volume Graph
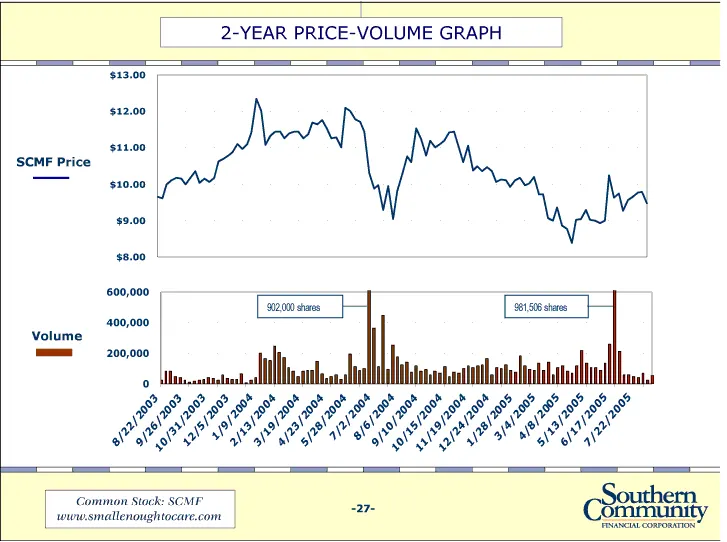
2-YEAR PRICE-VOLUME GRAPH Volume - -53- SCMF Price
Slide 28: Consolidation Creates Opportunity
CONSOLIDATION CREATES OPPORTUNITY First Union / Wachovia National Commerce Financial Corp. / CCB SunTrust / National Commerce Financial Corp. (Total of $1.2 billion in deposits in Forsyth and Guilford Counties) Royal Bank of Canada / Centura - -55-
Slide 29: Focus and Strategy
FOCUS AND STRATEGY Our Future Strategy: Expand Market Through de novo Locations or Accretive Acquisitions Diversify Our Revenue Expand Mortgage Operations Build Southern Community Advisors Build Core Deposit Base Leverage Commercial Bank Leverage Infrastructure and People - -57-
Slide 30: Focus and Strategy: Future Goals
FOCUS AND STRATEGY Future Goals: Continue to grow at a measured pace while maintaining an EPS growth rate of 10-15% or better Goals to be Achieved by end of 2006: Return on Tangible Equity: 11-12% (actual 2004: 10.37) Efficiency Ratio: Approximately 62% (actual 2004: 64.90) - -59-
Slide 31: Why Invest in Southern Community?
WHY INVEST IN SOUTHERN COMMUNITY? Service Focus Sound Credit Culture Strong Management Team, Committed Employees Consolidation Opportunities Inside Ownership (15.6% as of 1/31/04) - -61-
Slide 32: Closing Questions & Answers
CLOSING QUESTIONS & ANSWERS NASDAQ "SCMF" NASDAQ "SCMFO" - -63-
Source: SEC EDGAR · 8-K filed Aug 26, 2005
More decks from Southern Community Financial Corp
 KBW Investor Conference 201030 slides · Jul 27, 2010
 Investor Presentation (May 2009)26 slides · May 4, 2009
 Conference Presentation (February 2009)26 slides · Feb 6, 2009
 Southeast SuperCommunity Bank Conference (February 2008)28 slides · Feb 11, 2008
 America's Community Bankers Community Bank Investor Conference 200724 slides · Nov 2, 2007
 Emerging Growth Institutional Investor Forum 200727 slides · Mar 26, 2007