Sage Group plc · LSE:SGE
Sage — Merger or Acquisition (August 2006)
12 slides from Sage's merger presentation, August 2006
Slide 1: Acquisition of Emdeon Practice Services, Inc. (EPS)
Acquisition of Emdeon Practice Services, Inc. (EPS) August 2006
Slide 2: The Transaction
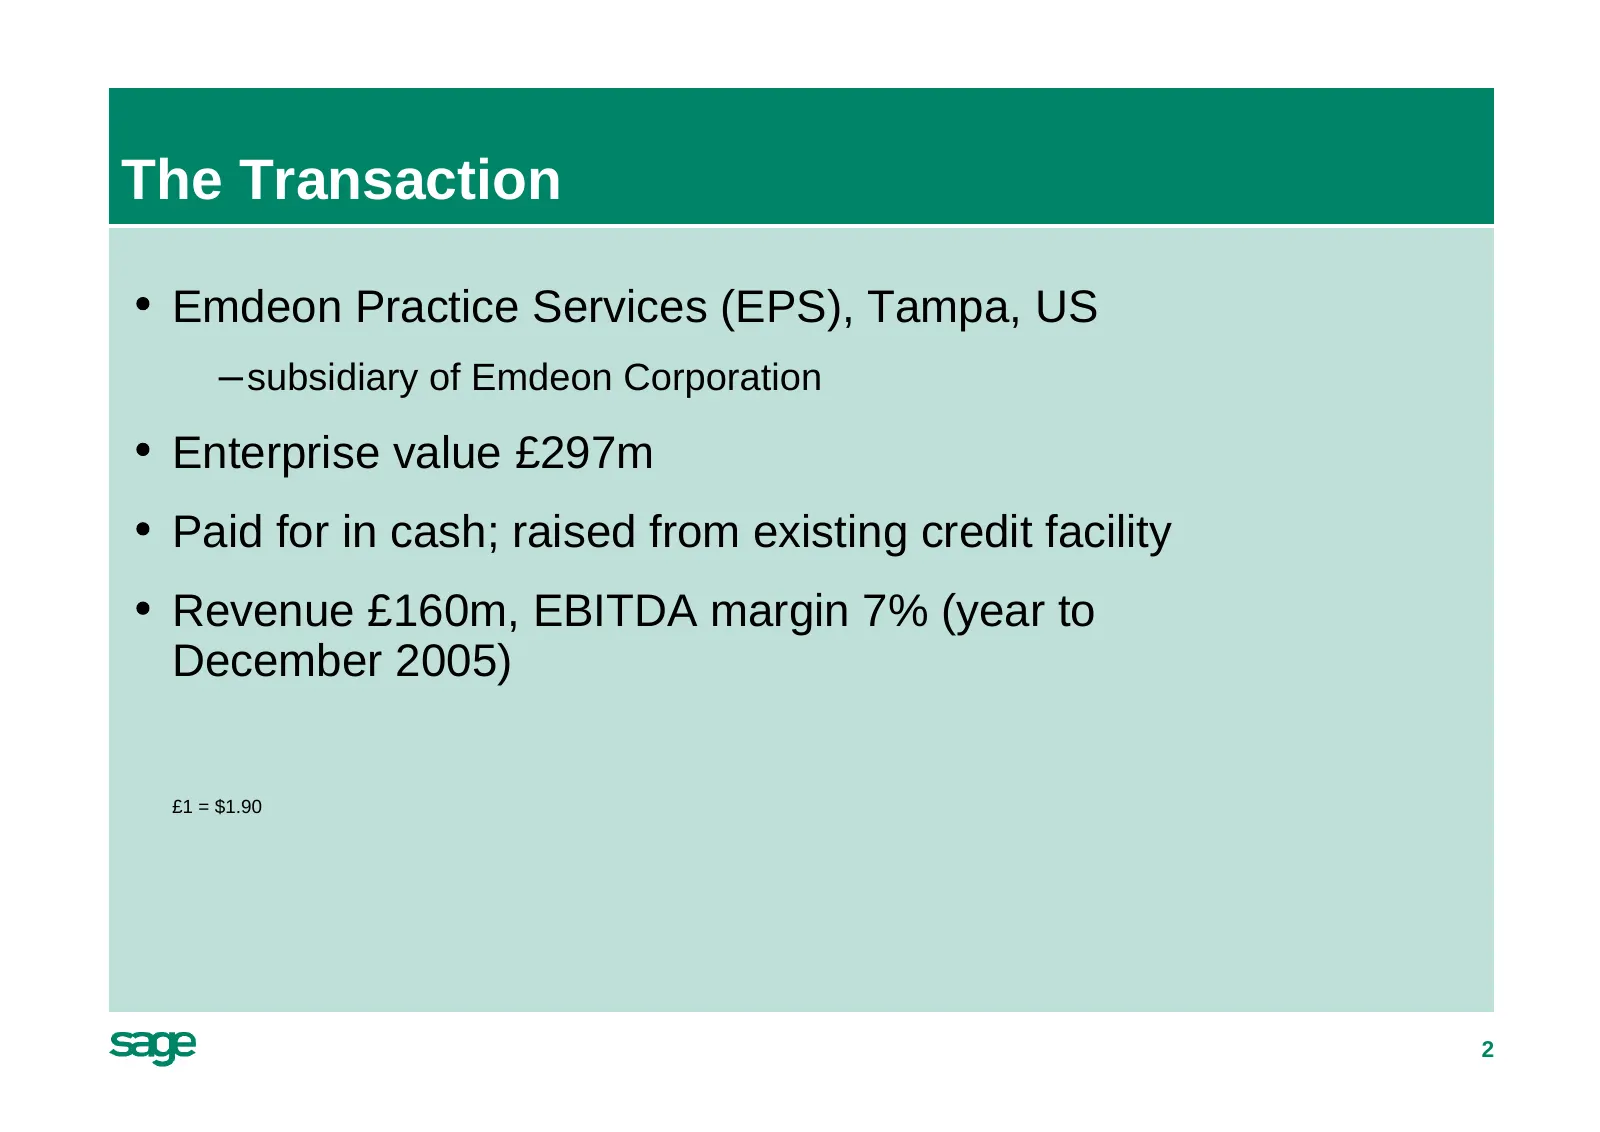
The Transaction Emdeon Practice Services (EPS), Tampa, US subsidiary of Emdeon Corporation Enterprise value £297m Paid for in cash; raised from existing credit facility Revenue £160m, EBITDA margin 7% (year to December 2005) £1 = $1.90 2
Slide 3: US Doctors Practices Market
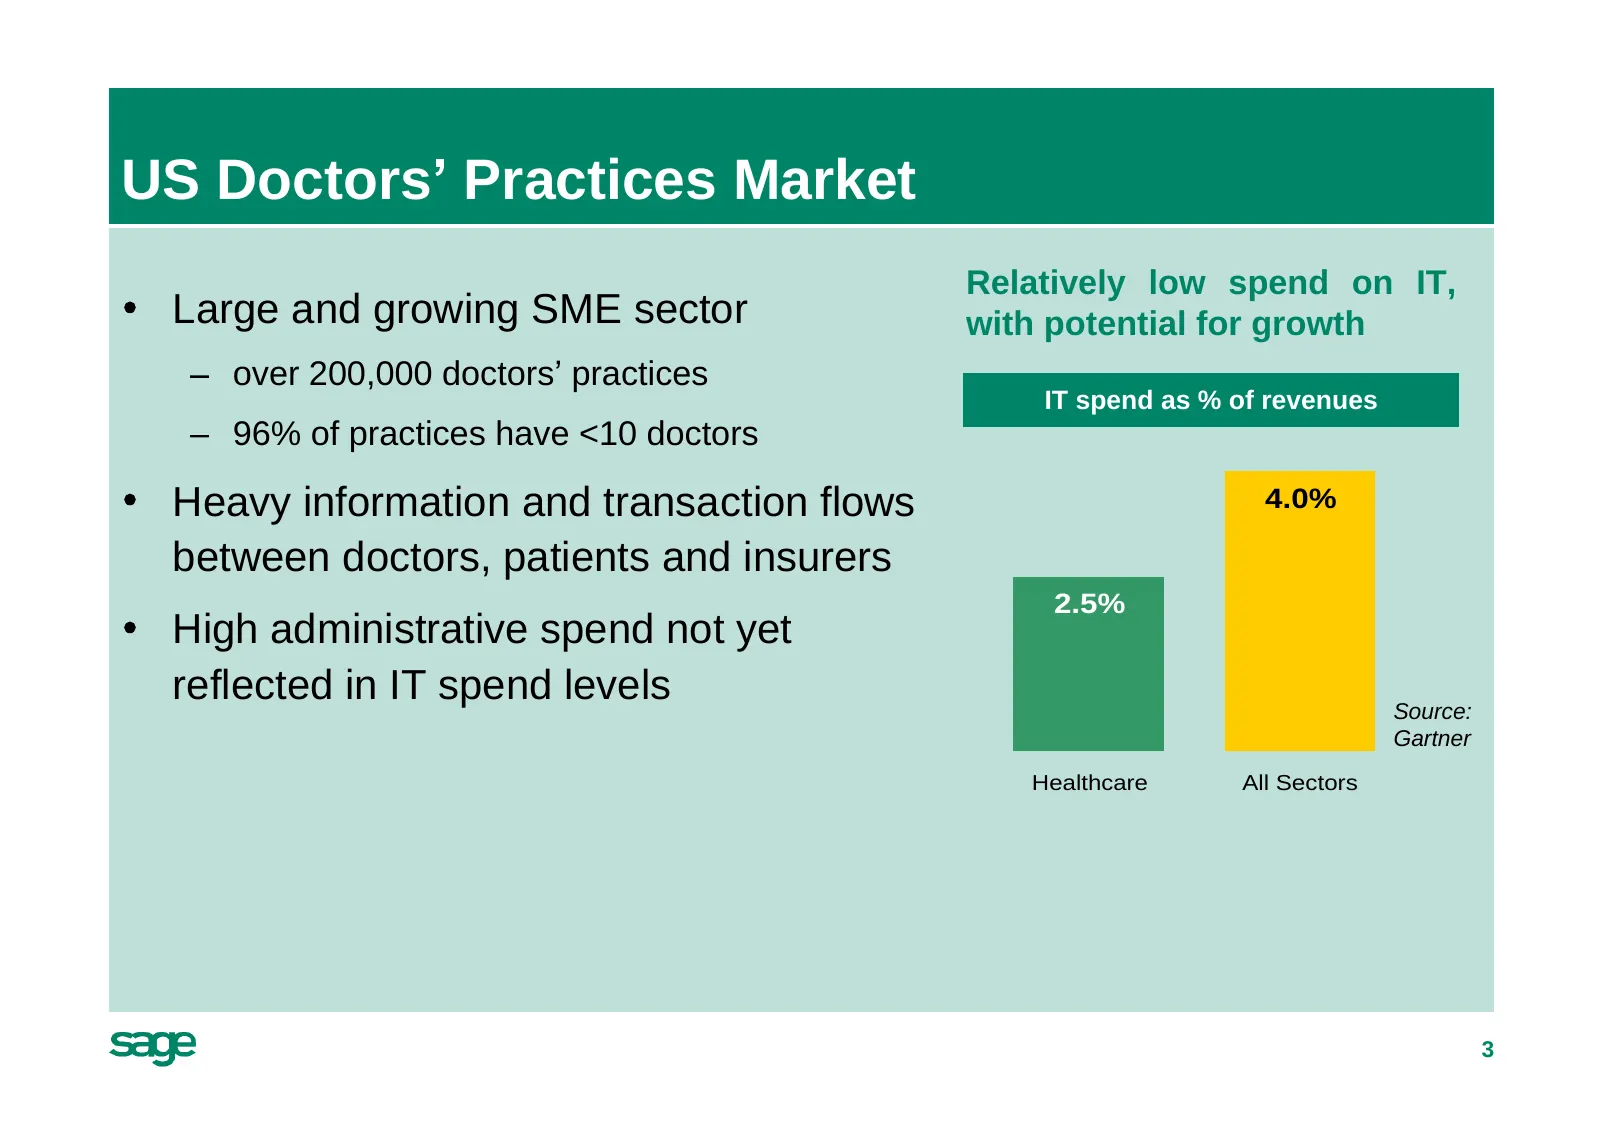
US Doctors Practices Market Relatively low spend on IT, Large and growing SME sector with potential for growth over 200,000 doctors practices IT spend as % of revenues 96% of practices have <10 doctors Heavy information and transaction flows 4.0% between doctors, patients and insurers 2.5% High admi
Slide 4: Growing IT investment
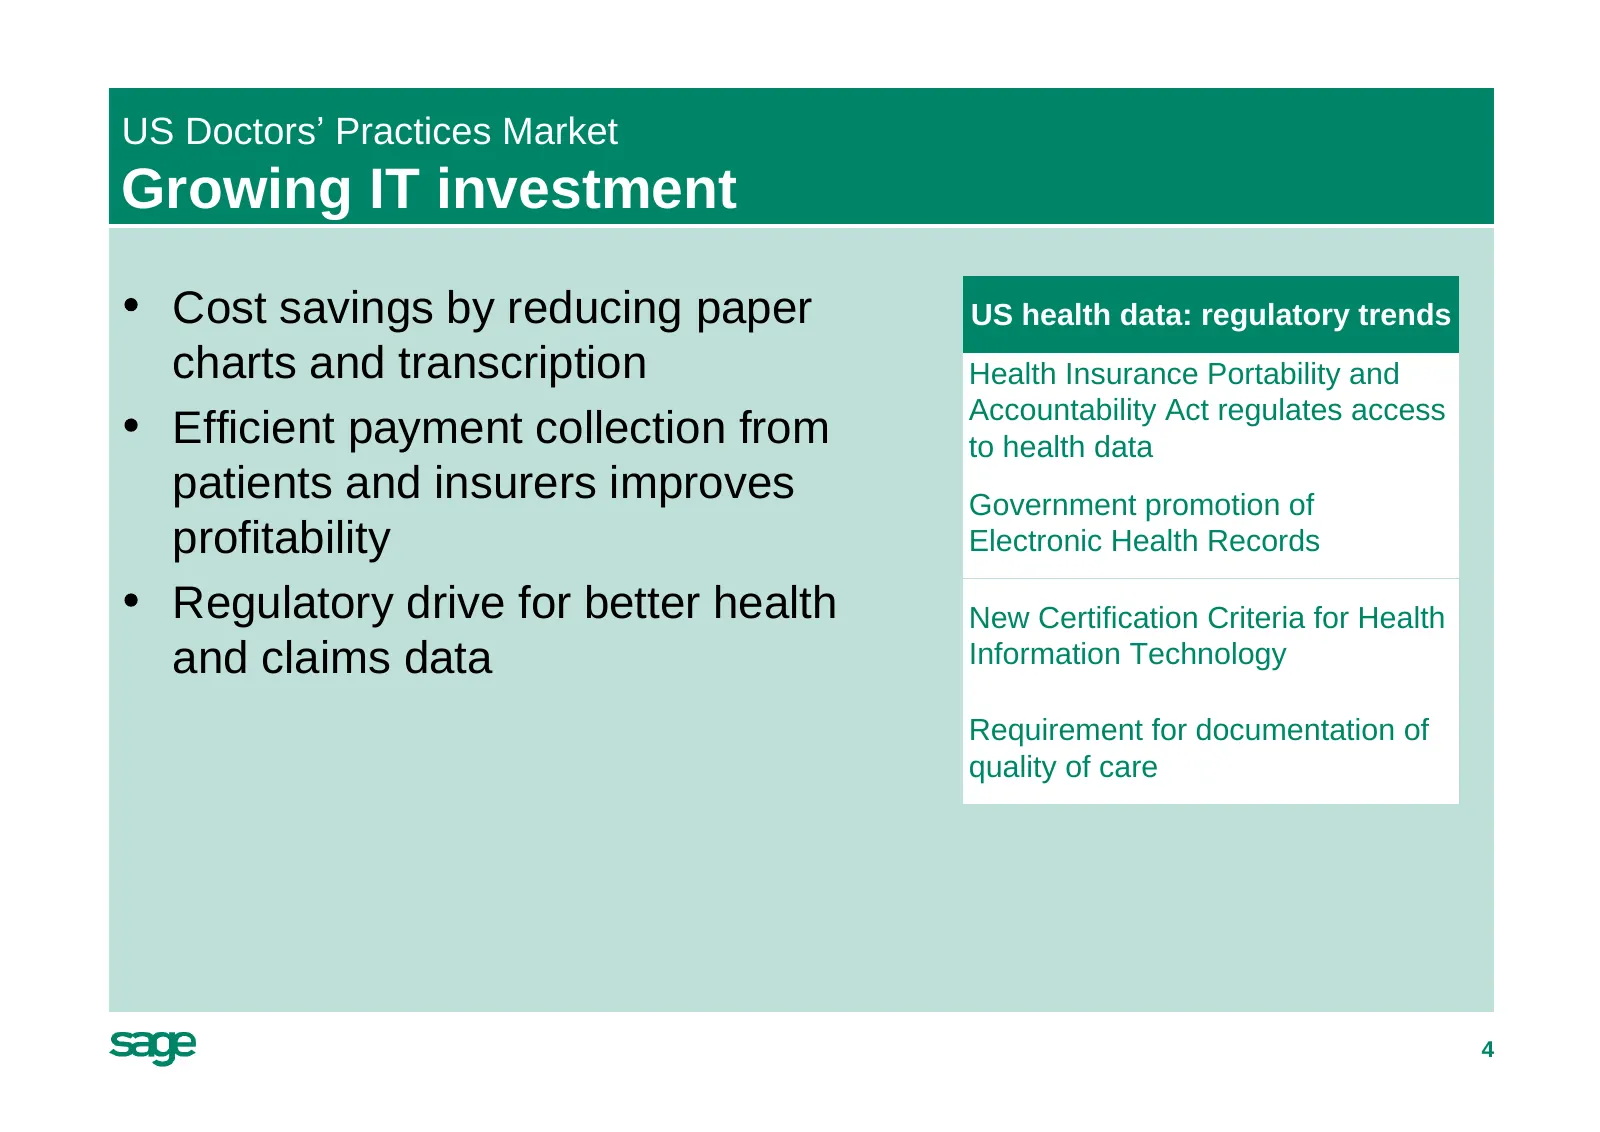
US Doctors Practices Market Growing IT investment Cost savings by reducing paper US health data: regulatory trends charts and transcription Health Insurance Portability and Accountability Act regulates access Efficient payment collection from to health data patients and insurers improves Government
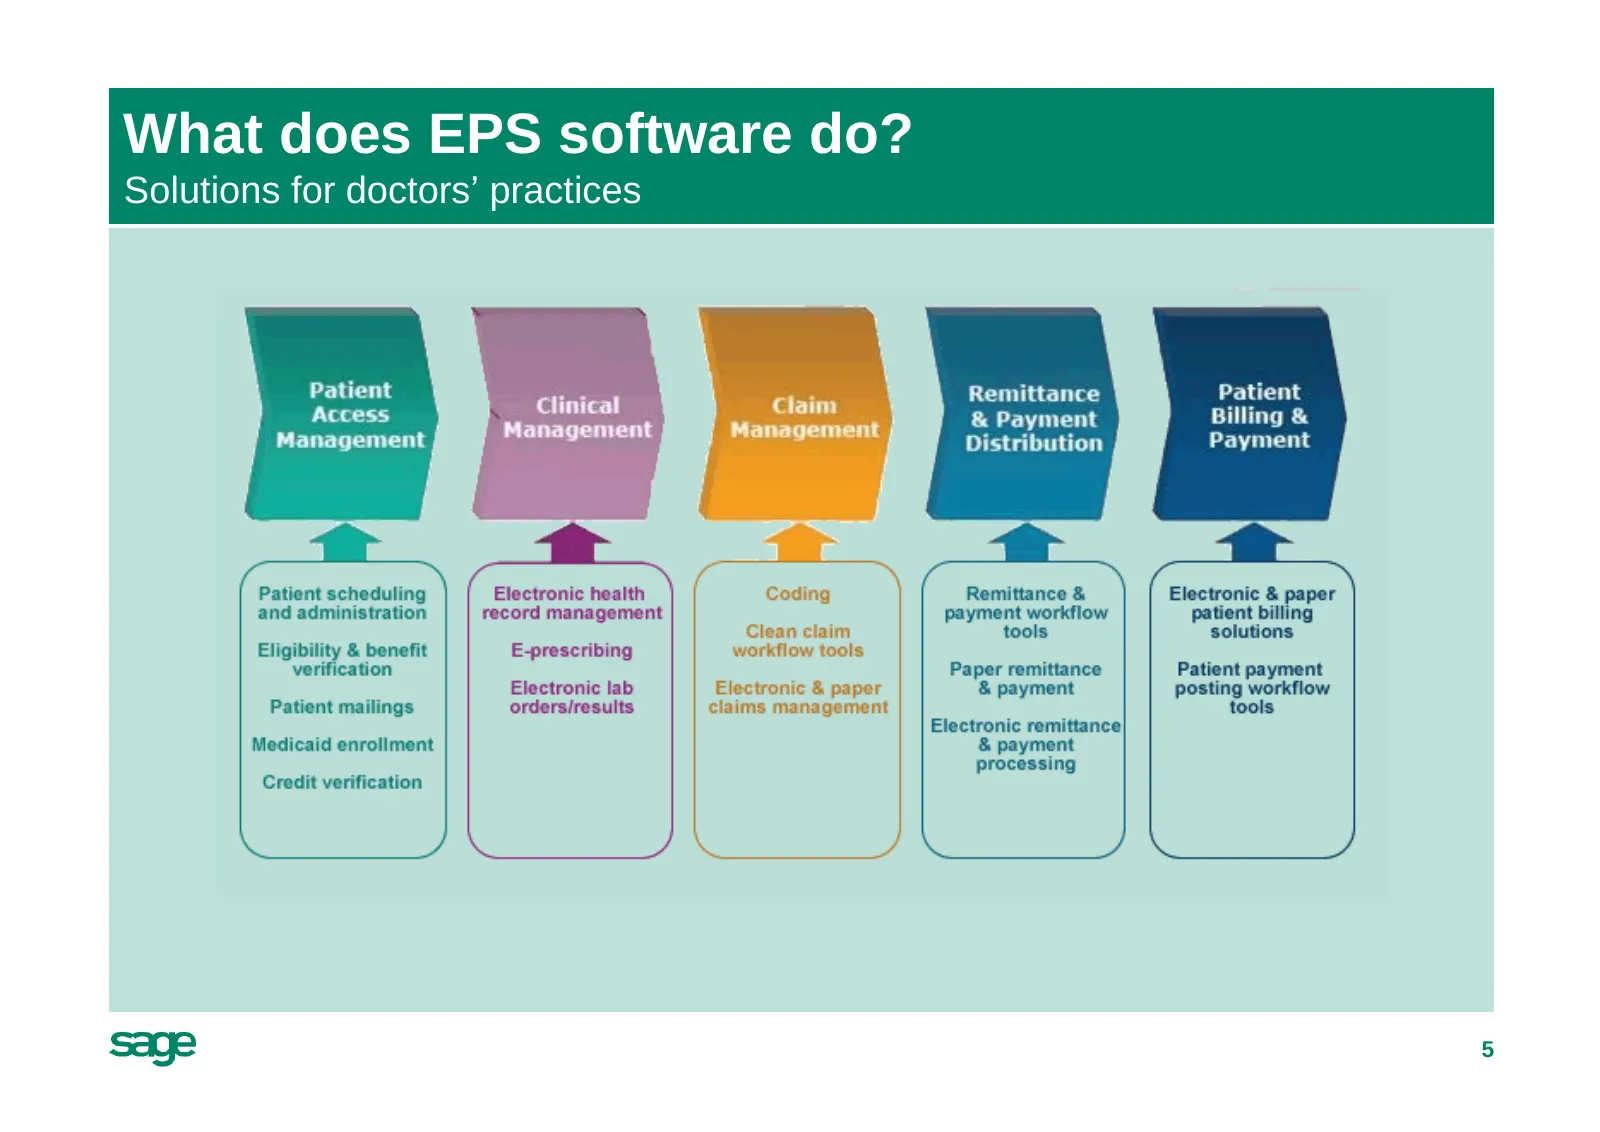
Slide 5: What does EPS software do?
What does EPS software do? Solutions for doctors practices 5
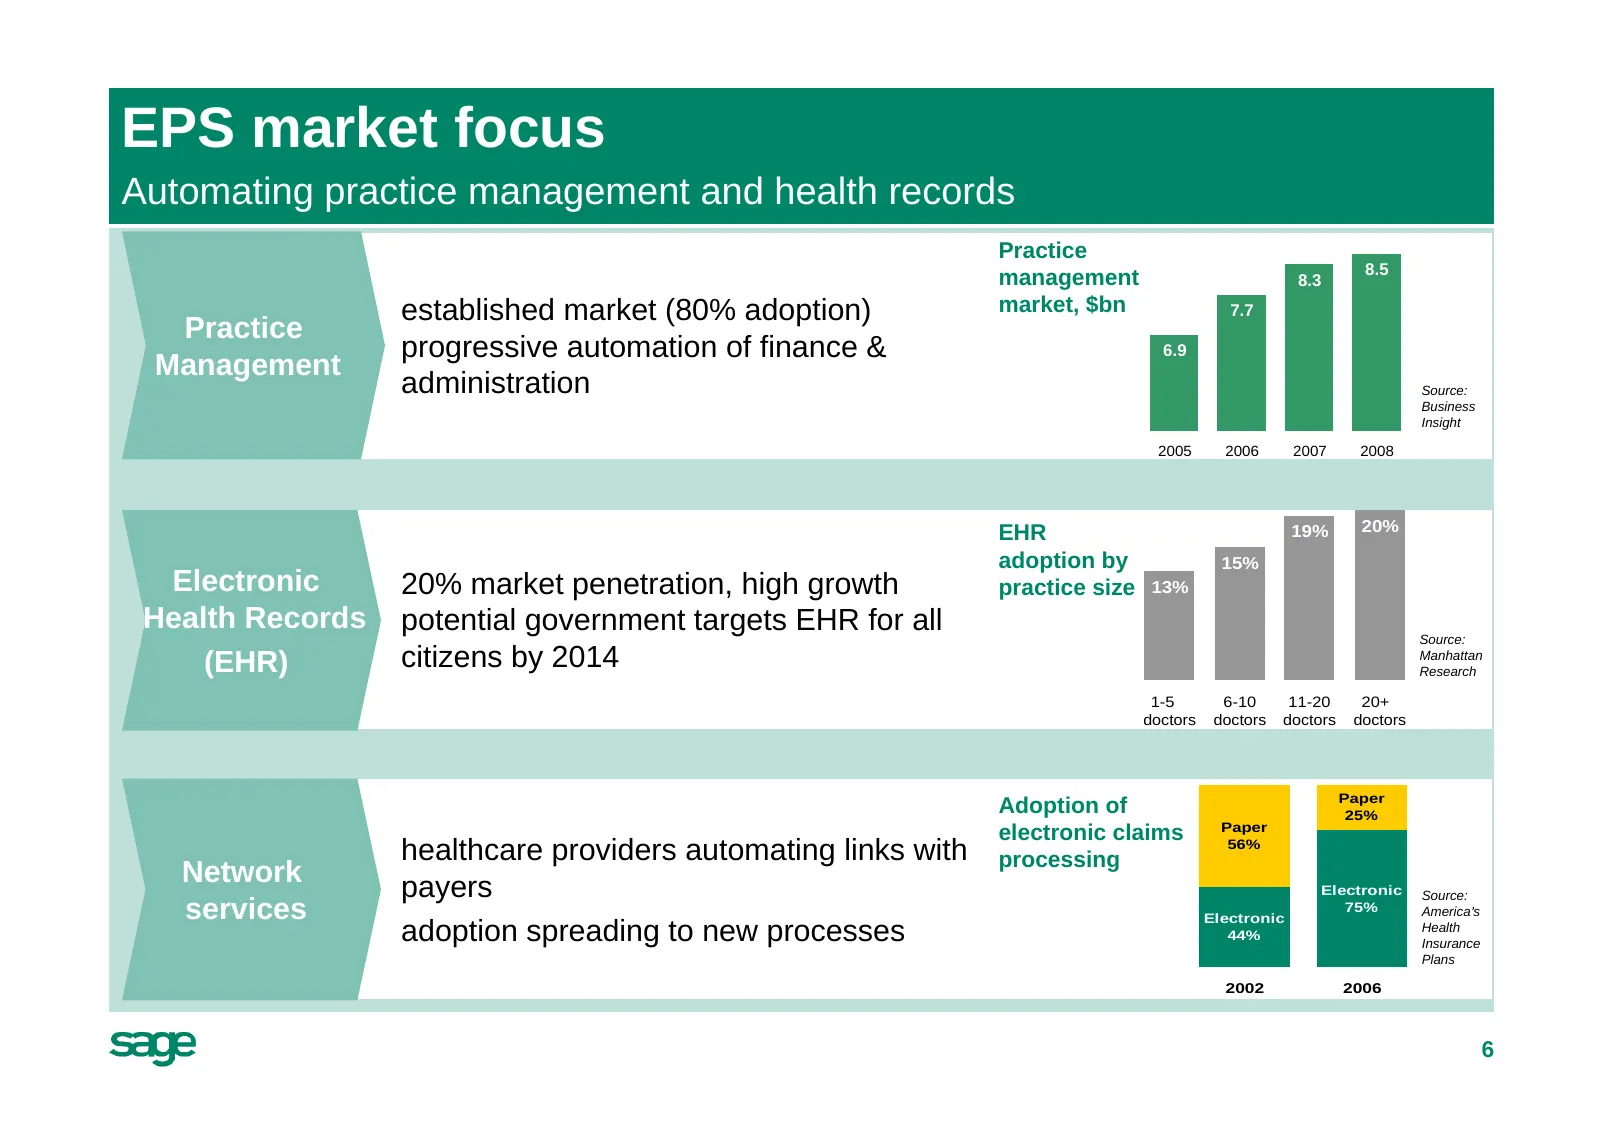
Slide 6: EPS market focus
EPS market focus Automating practice management and health records Practice 8.5 management 8.3 established market (80% adoption) market, $bn 7.7 Practice progressive automation of finance & 6.9 Management administration Source: Business Insight 2005 2006 2007 2008 EHR 19% 20% adoption by 15% Electro
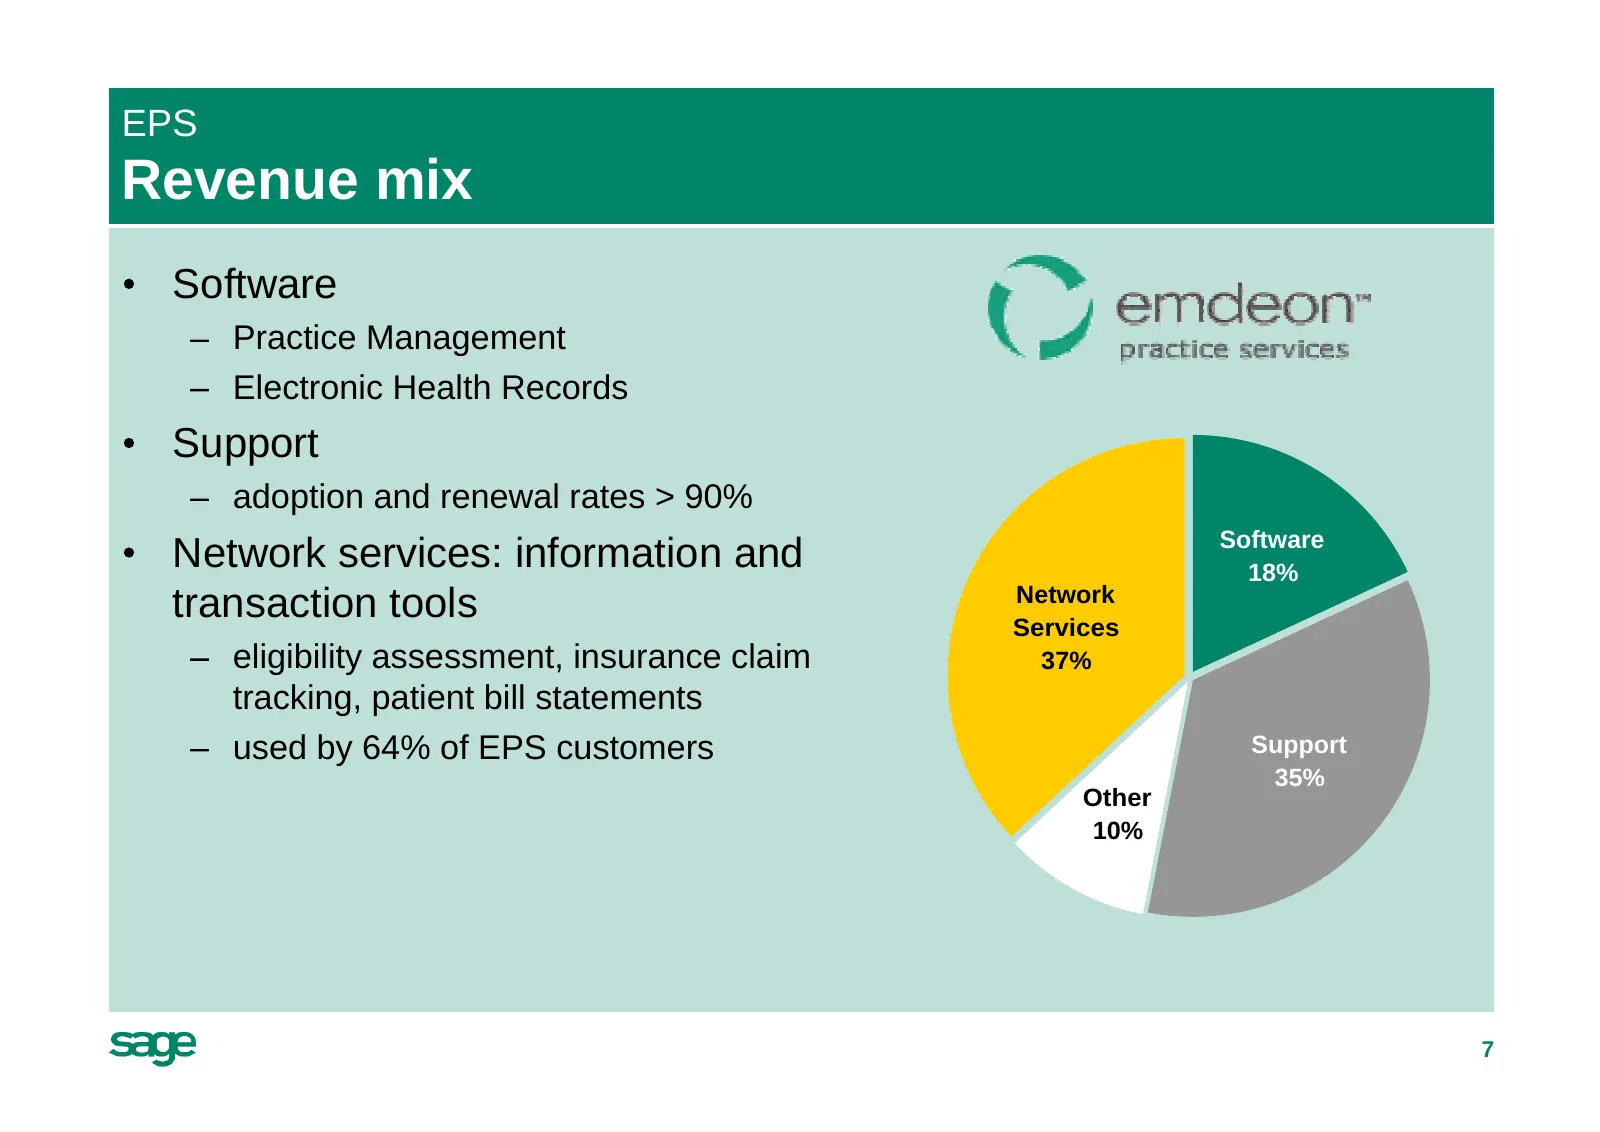
Slide 7: Revenue mix
EPS Revenue mix Software Practice Management Electronic Health Records Support adoption and renewal rates > 90% Software Network services: information and 18% Network transaction tools Services eligibility assessment, insurance claim 37% tracking, patient bill statements used by 64% of EPS customers
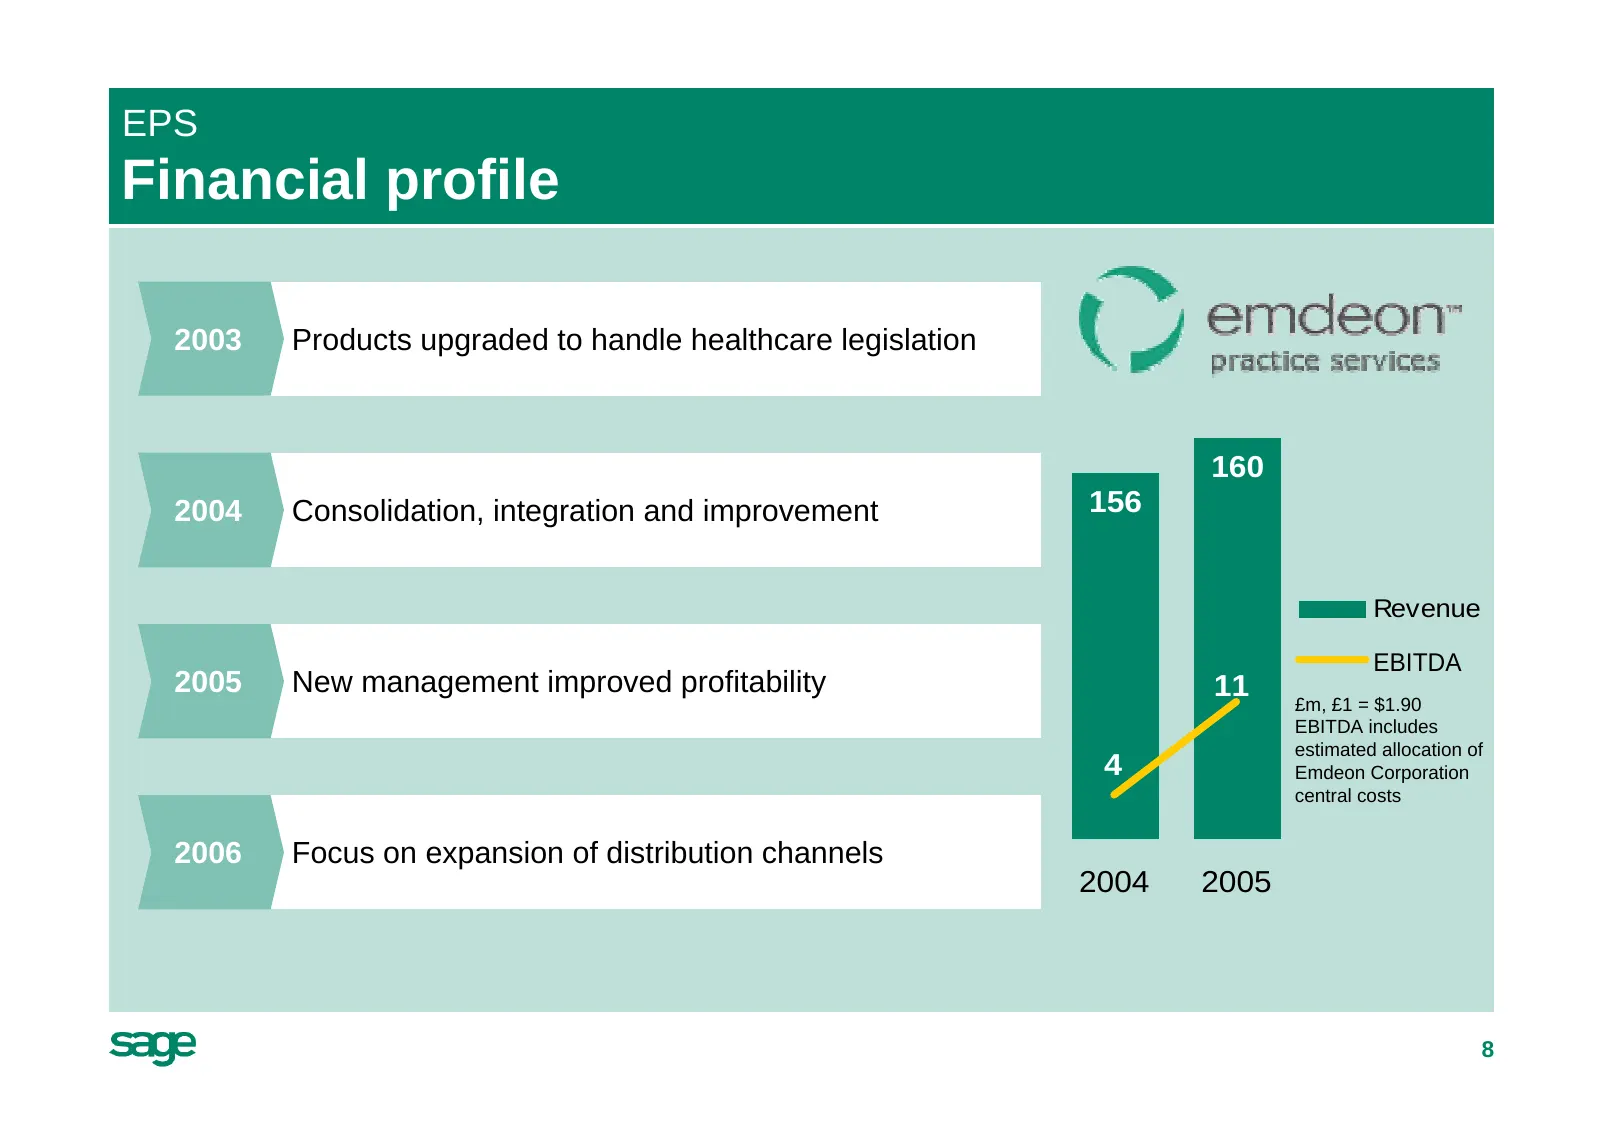
Slide 8: Financial profile
EPS Financial profile 2003 Products upgraded to handle healthcare legislation 160 2004 Consolidation, integration and improvement 156 Revenue EBITDA 2005 New management improved profitability 11 £m, £1 = $1.90 EBITDA includes estimated allocation of 4 Emdeon Corporation central costs 2006 Focus on e
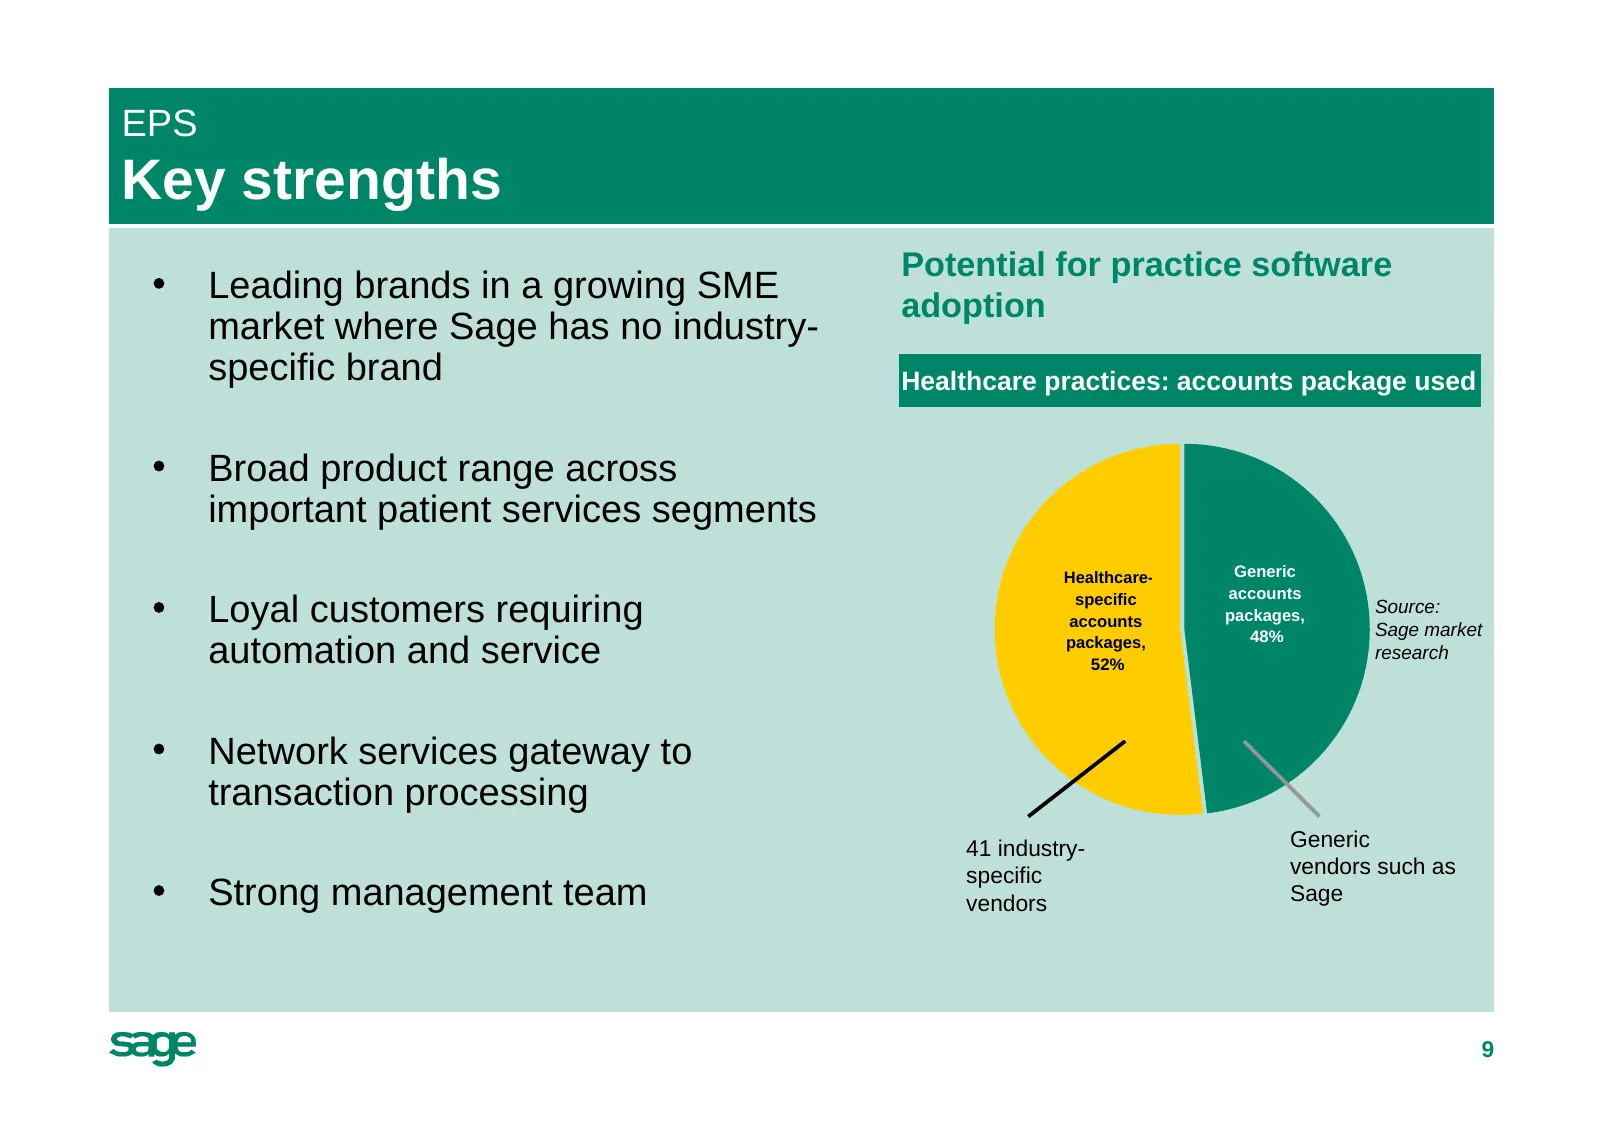
Slide 9: Key strengths
EPS Key strengths Potential for practice software Leading brands in a growing SME adoption market where Sage has no industry- specific brand Healthcare practices: accounts package used Broad product range across important patient services segments Healthcare- Generic specific accounts Loyal customer
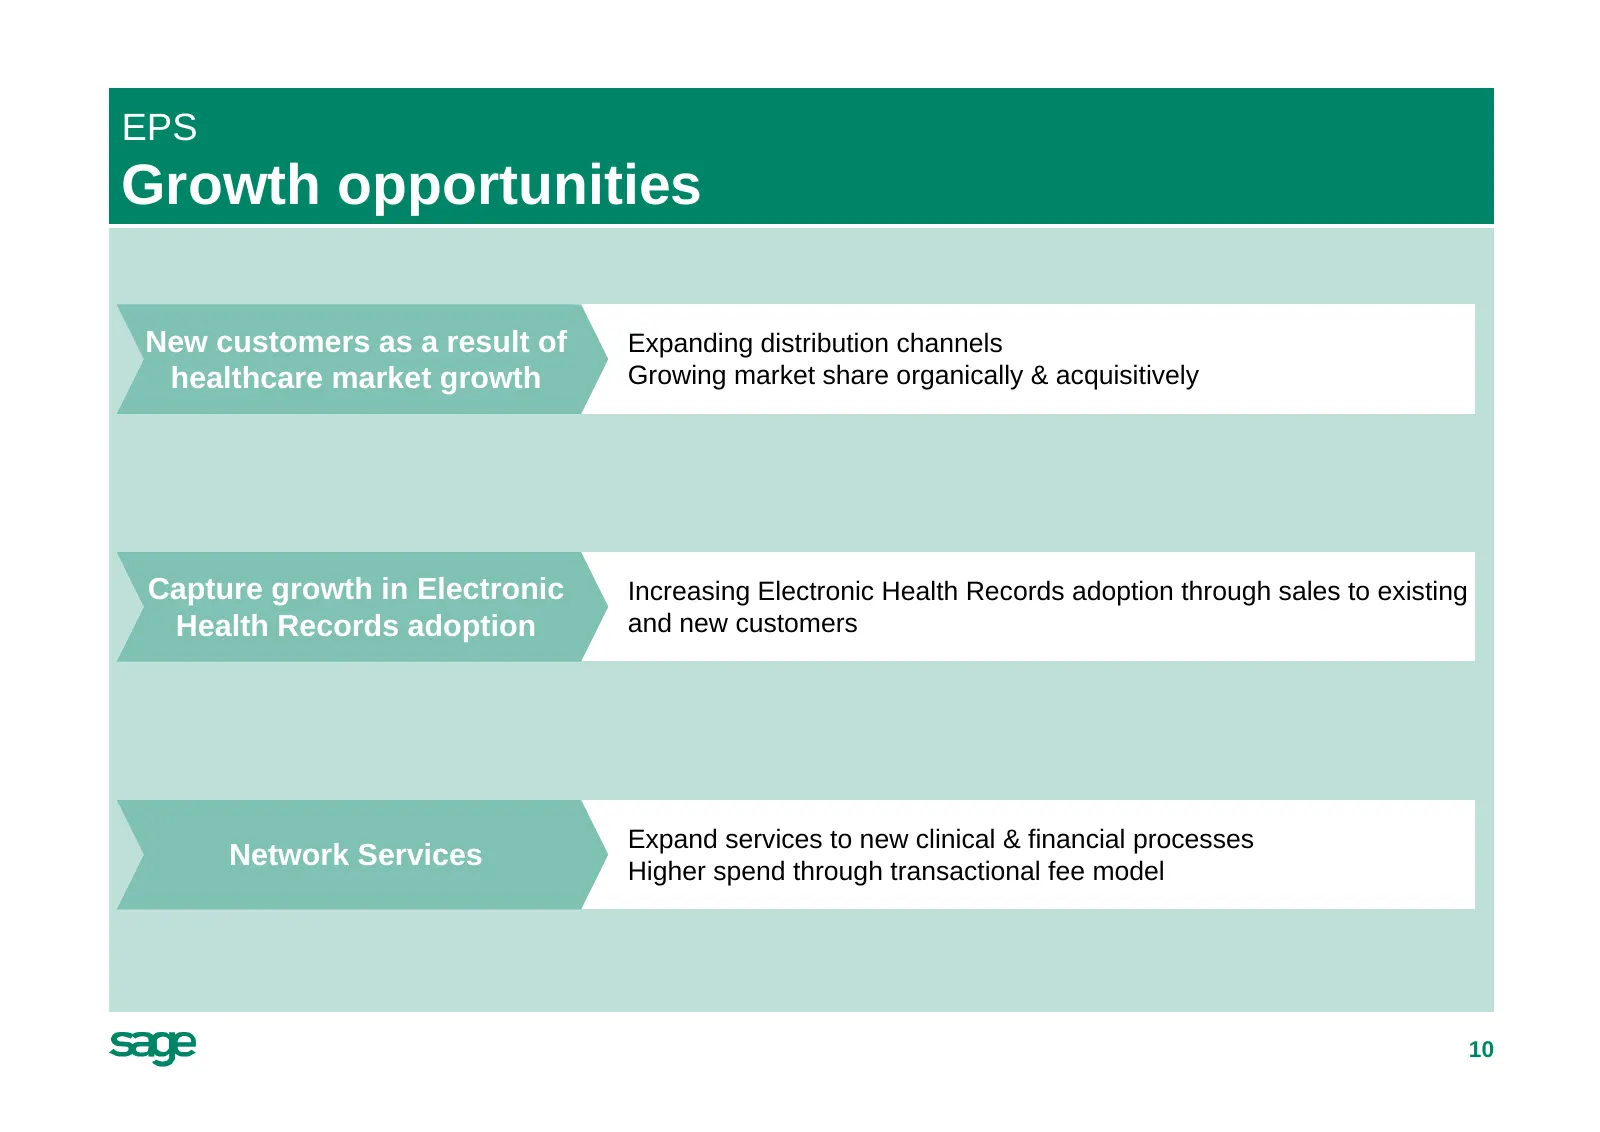
Slide 10: Growth opportunities
EPS Growth opportunities New customers as a result of Expanding distribution channels healthcare market growth Growing market share organically & acquisitively Capture growth in Electronic Increasing Electronic Health Records adoption through sales to existing Health Records adoption and new custome
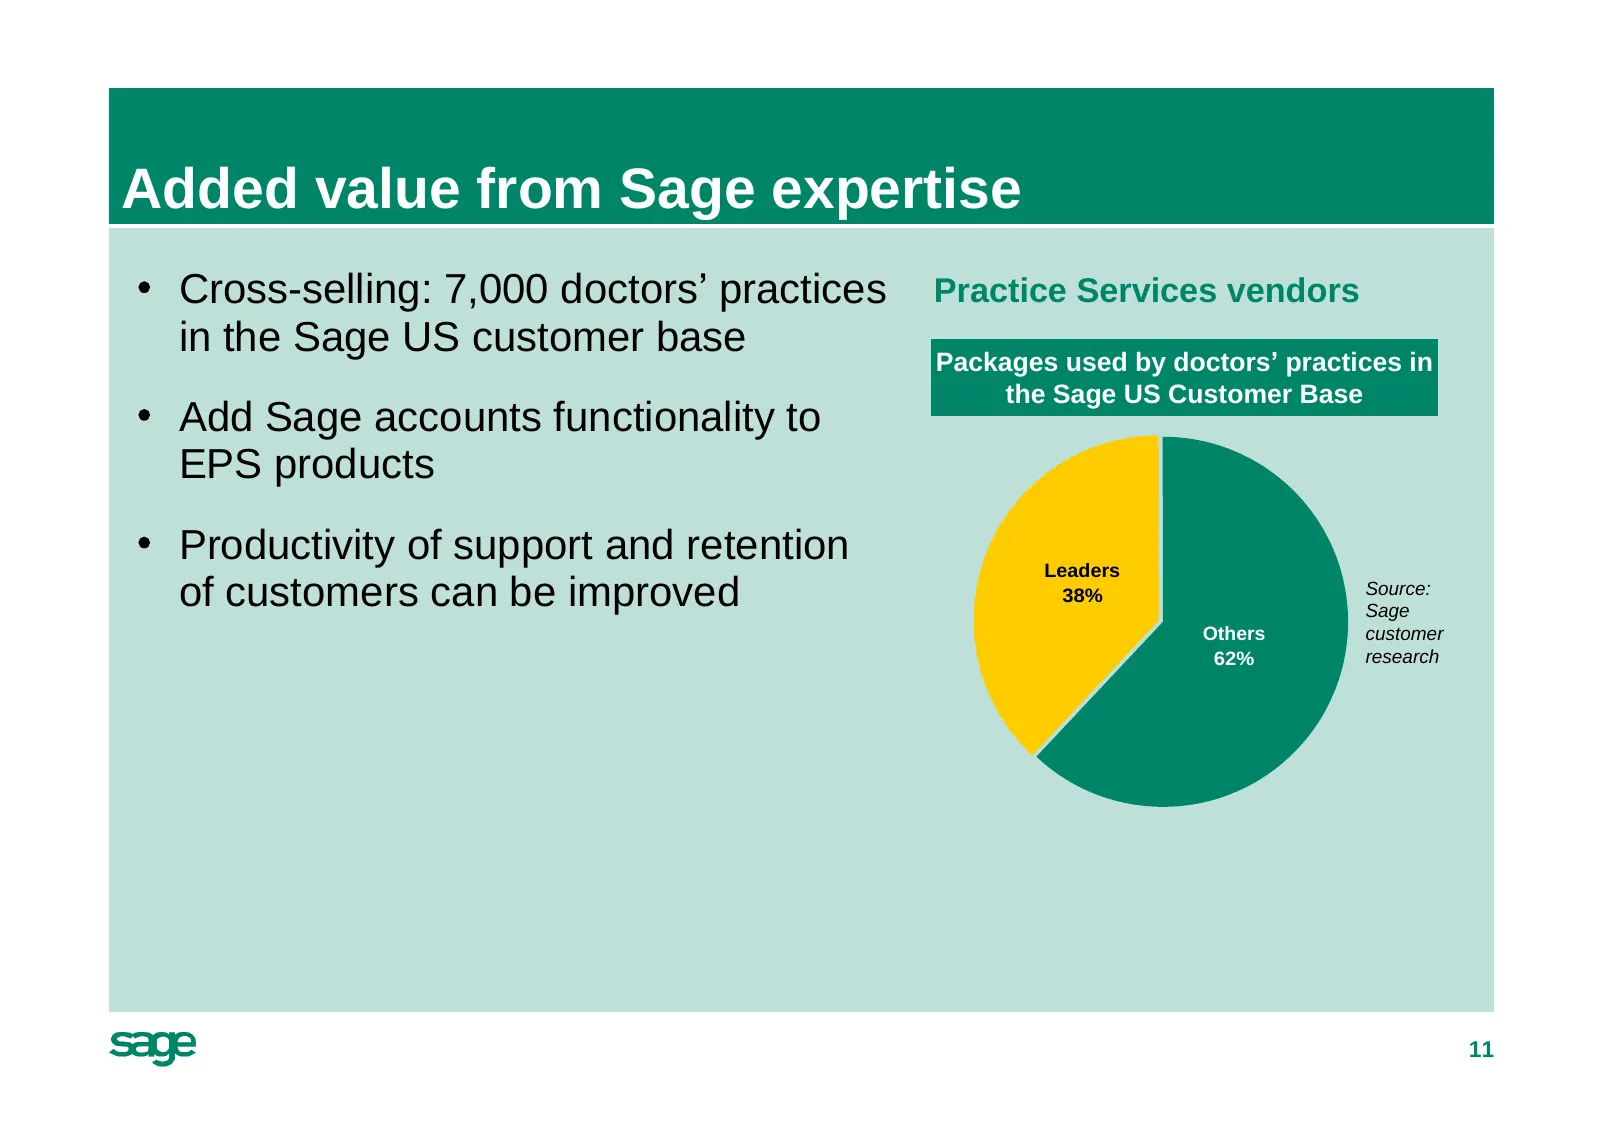
Slide 11: Added value from Sage expertise
Added value from Sage expertise Cross-selling: 7,000 doctors practices Practice Services vendors in the Sage US customer base Packages used by doctors practices in the Sage US Customer Base Add Sage accounts functionality to EPS products Productivity of support and retention Leaders of customers can
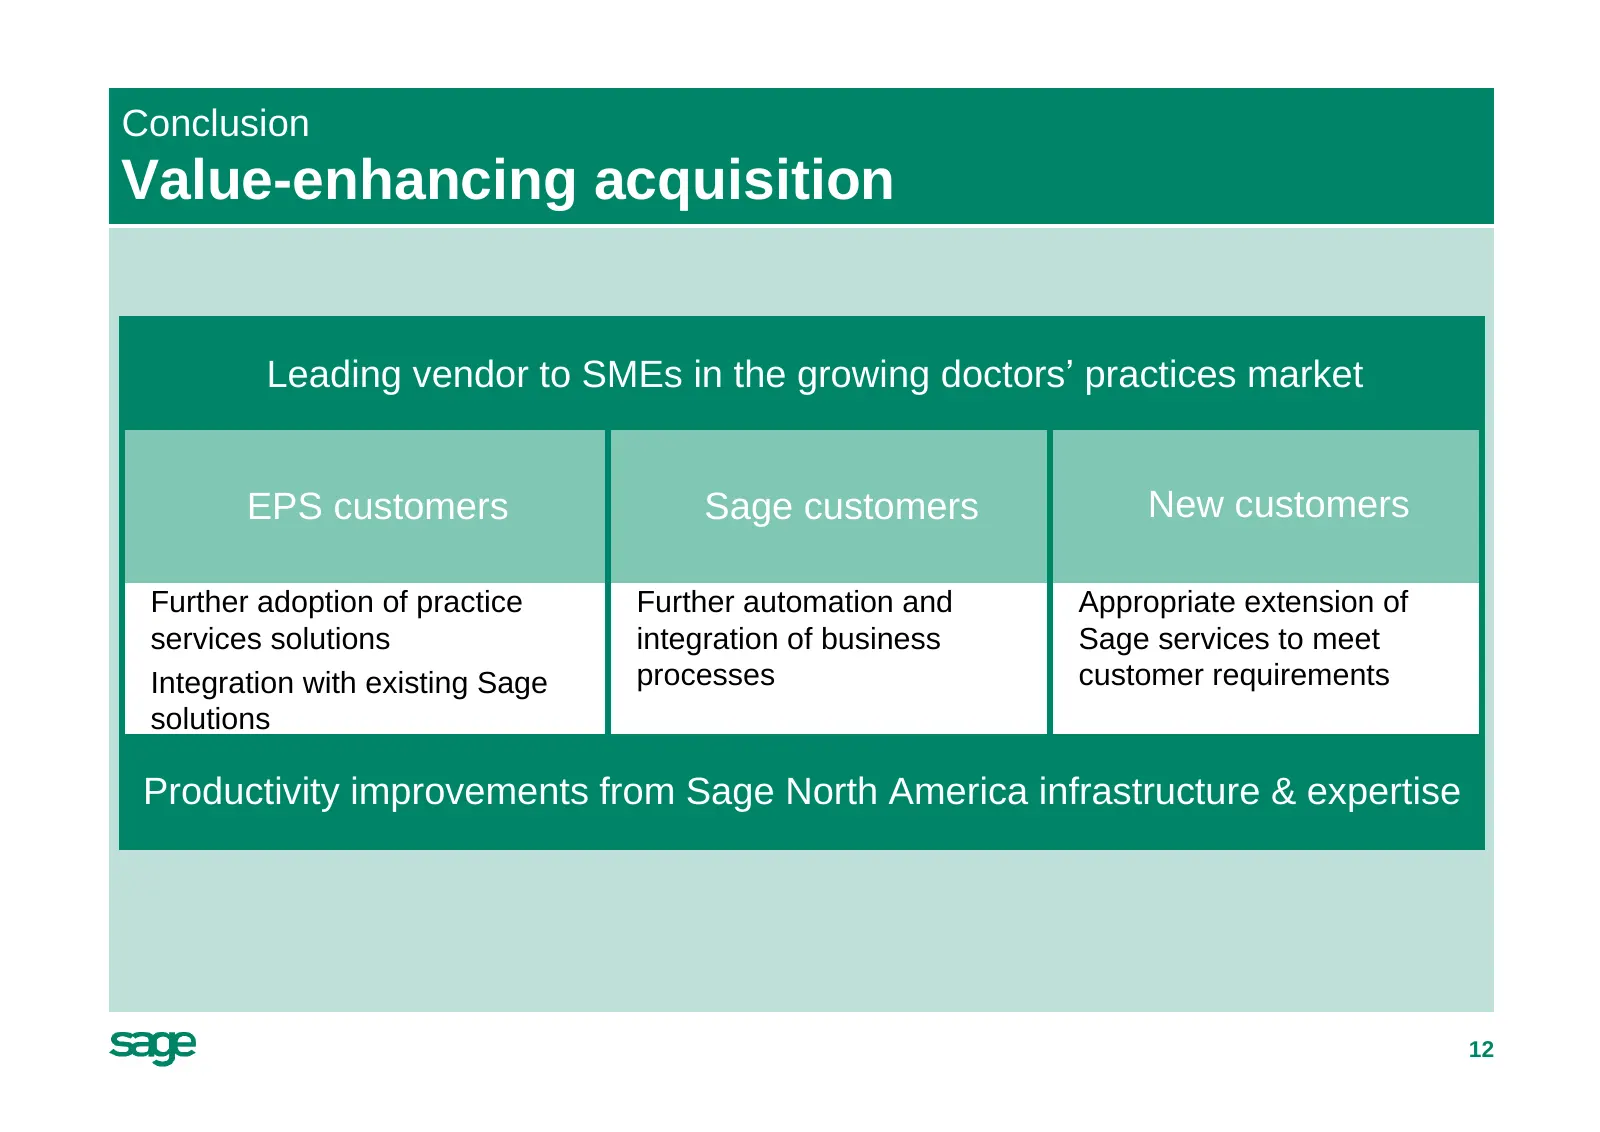
Slide 12: Value-enhancing acquisition
Conclusion Value-enhancing acquisition Leading vendor to SMEs in the growing doctors practices market EPS customers Sage customers New customers Further adoption of practice Further automation and Appropriate extension of services solutions integration of business Sage services to meet Integration w
Source: Internet Archive copy of sage.com
More decks from Sage Group plc
 H1 2026 Earnings Presentation44 slides · May 21, 2026
 FY2025 Earnings Presentation42 slides · Nov 19, 2025
 H1 2025 Earnings Presentation36 slides · May 15, 2025
 Investor Presentation (March 2025)47 slides · Mar 12, 2025
 FY2024 Earnings Presentation37 slides · Nov 20, 2024
 H1 2024 Earnings Presentation39 slides · May 16, 2024