Huron Consulting Group Inc. · NASDAQ:HURN
Huron Consulting — Conference Presentation (April 2010)
39 slides from Huron Consulting's conference presentation, Apr 16, 2010
Slide 1: Impact of the American Recovery and Reinvestment Act on A-133 Audits and Federal Agency Reviews
Webinar: Impact of the American Recovery and Reinvestment Act on A-133 Audits and Federal Agency Reviews April 16, 2010 © Huron Consulting Group Inc. All rights reserved. Huron is a management consulting firm and not a CPA firm, and does not provide attest services, audits, or other engagements in a
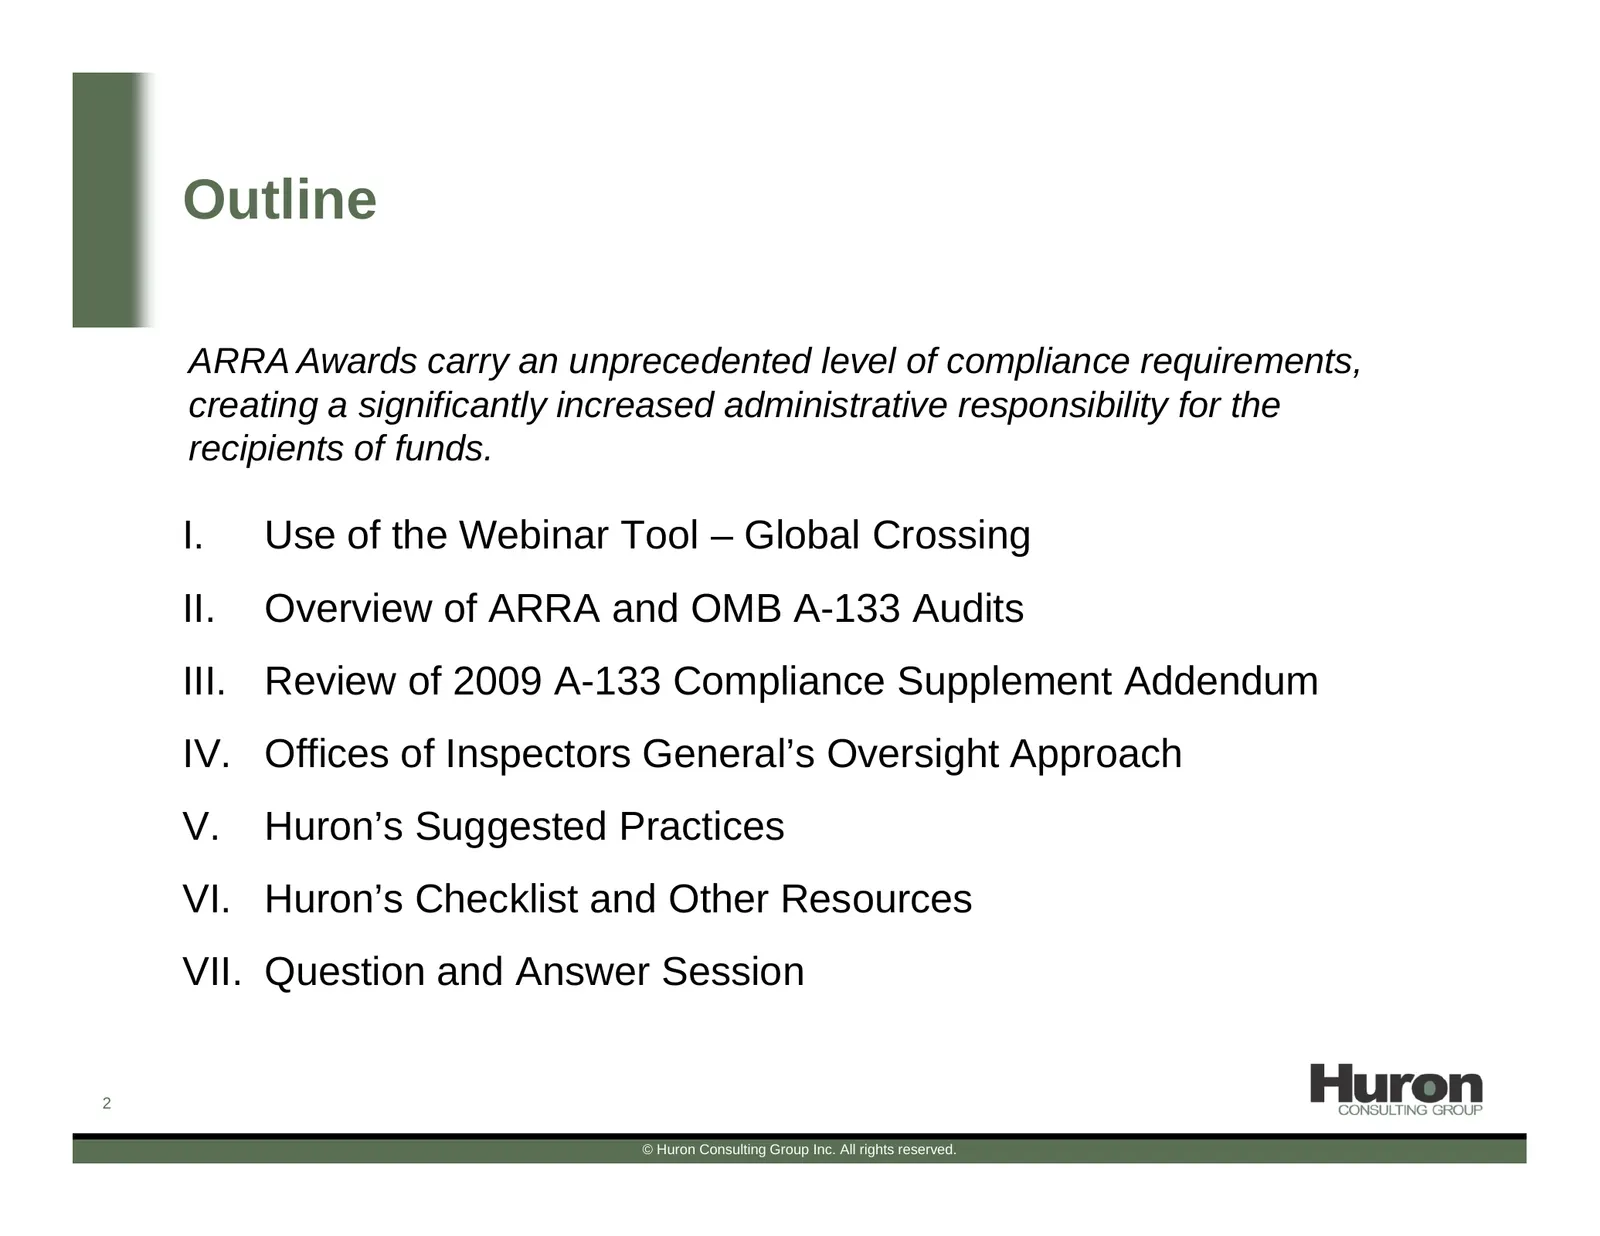
Slide 2: Outline
Outline ARRA Awards carry an unprecedented level of compliance requirements, creating a significantly increased administrative responsibility for the recipients of funds. I. Use of the Webinar Tool – Global Crossing II. Overview of ARRA and OMB A-133 Audits III. Review of 2009 A-133 Compliance Suppl
Slide 3: Use of the Webinar Tool
Use of the Webinar Tool 3
Slide 4: Webinar Tool – Global Crossing
Webinar Tool – Global Crossing • Please type your questions using the web tool during the presentation. • Huron professionals will group the questions with the intent to provide some order and to answer as many questions as possible. • Questions will be answered during the Question & Answer section
Slide 5: Overview of ARRA and A-133 Audits
Overview of ARRA and A-133 Audits 5
Slide 6: ARRA and A-133 Audits
ARRA and A-133 Audits • The American Recovery and Reinvestment Act (ARRA) of 2009 allocated an unprecedented $787 billion to help stimulate the nation’s economy, including $21.5 billion in federal research and development funding. • The ARRA includes extraordinary regulatory and other compliance req
Slide 7: ARRA and A-133 Audits (cont.)
ARRA and A-133 Audits (cont.) • President Obama recently reiterated the Government’s commitment to oversight of ARRA funds in a Memo dated April 6, 2010 [1]. – “Combating Noncompliance” was the objective of this Memo – Stated that his administration is “committed to transparency in tracking recovery
Slide 8: ARRA and A-133 Audits (cont.)
ARRA and A-133 Audits (cont.) • It is expected that federal agencies will use OMB Circular A-133: Audits of States, Local Governments, and Non-Profit Organizations as a key oversight tool to confirm the following accountability objectives of the ARRA: – The recipients and uses of all ARRA funds are
Slide 9: ARRA and A-133 Audits (cont.)
ARRA and A-133 Audits (cont.) • This Circular sets forth standards for obtaining consistency and uniformity among Federal agencies for the audit of States, local governments, and non-profit organizations expending Federal awards. • Each year, OMB will an A-133 Compliance Supplement to provide additi
Slide 10: Review of 2009 A-133 Compliance Supplement Addendum
Review of 2009 A-133 Compliance Supplement Addendum 10
Slide 11: 2009 A-133 Compliance Supplement Addendum
2009 A-133 Compliance Supplement Addendum • In June of 2009, OMB issued an Addendum[2] that supplements the 2009 Compliance Supplement to provide additional guidance for programs with ARRA expenditures. • The Addendum is effective for audits of fiscal years beginning after June 30, 2008. • Auditor a
Slide 12: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum modifies the following sections of the 2009 A-133 Compliance Supplement: Section Modification • The matrix was amended to show: 1. new ARRA-funded programs; 2. new clusters resulting from addition of ARRA programs; and Part 2 – Matrix of
Slide 13: 2009 A-133 Compliance Supplement Addendum (cont.)
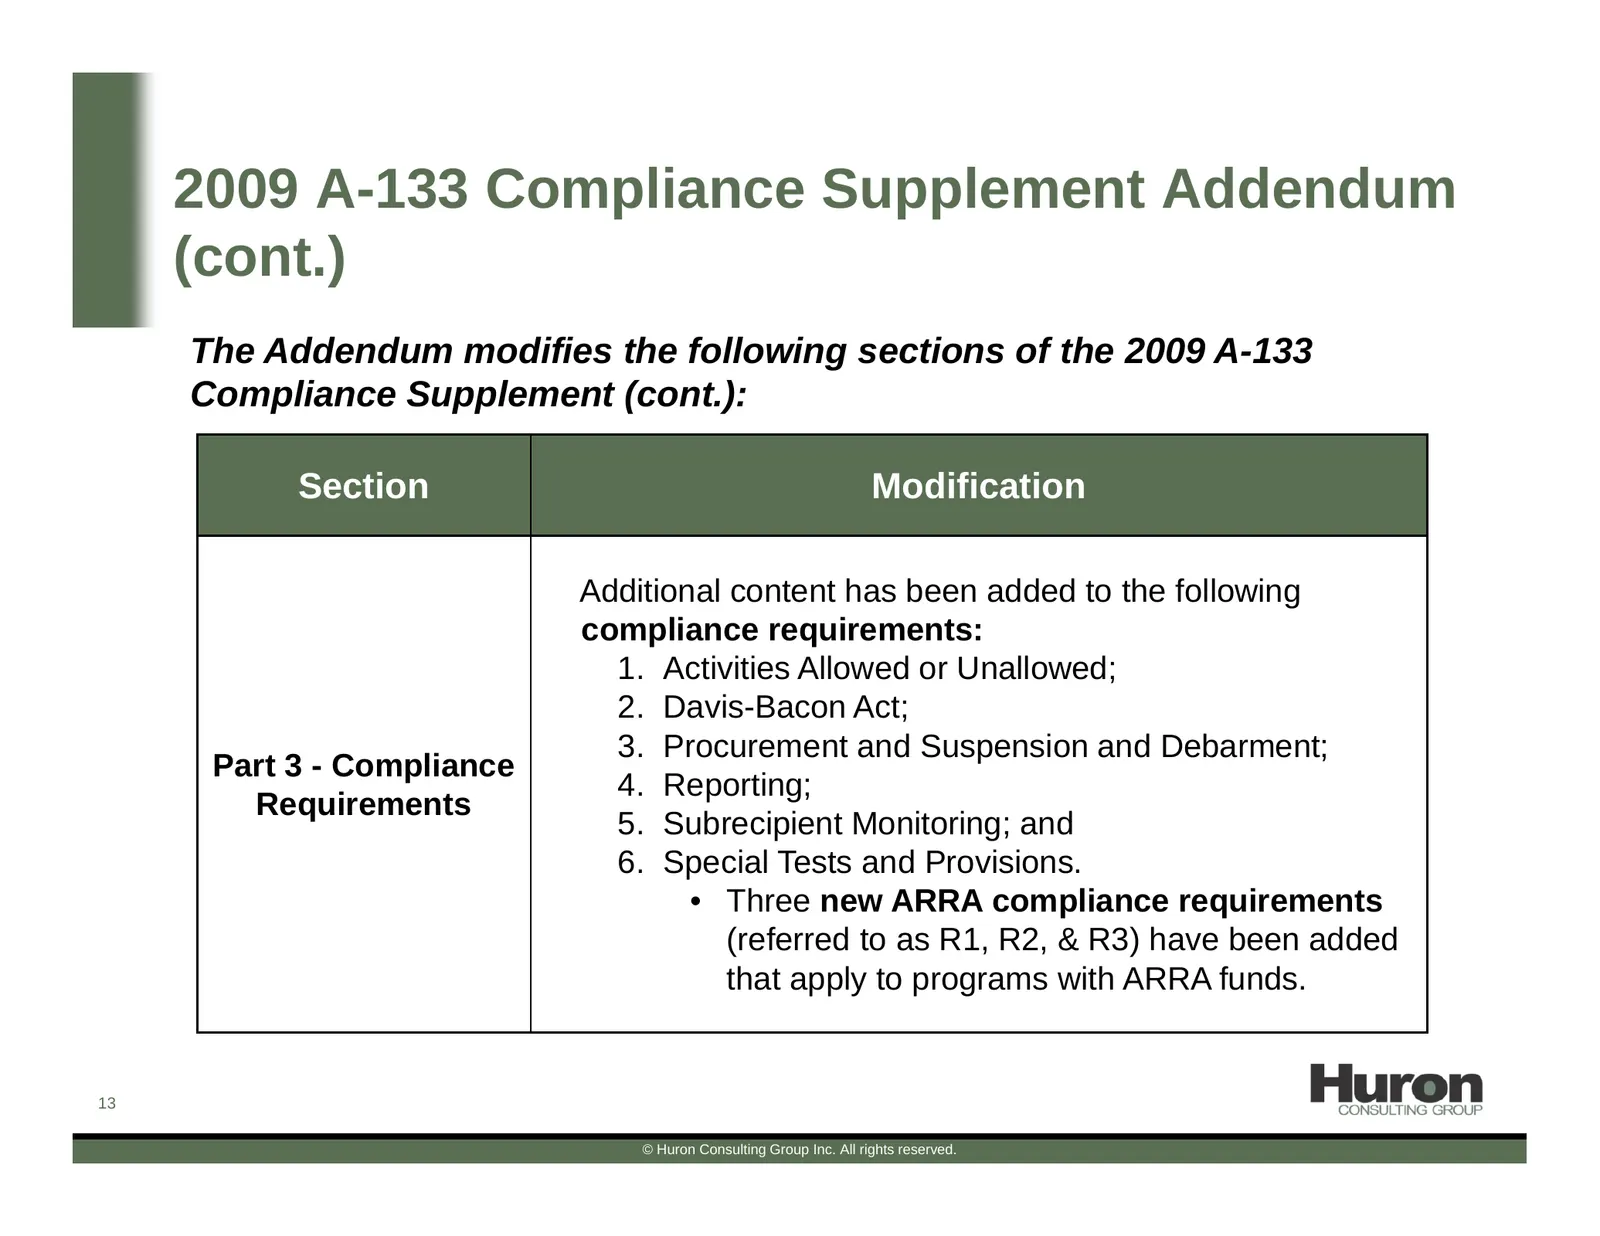
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum modifies the following sections of the 2009 A-133 Compliance Supplement (cont.): Section Modification Additional content has been added to the following compliance requirements: 1. Activities Allowed or Unallowed; 2. Davis-Bacon Act; 3.
Slide 14: 2009 A-133 Compliance Supplement Addendum (cont.)
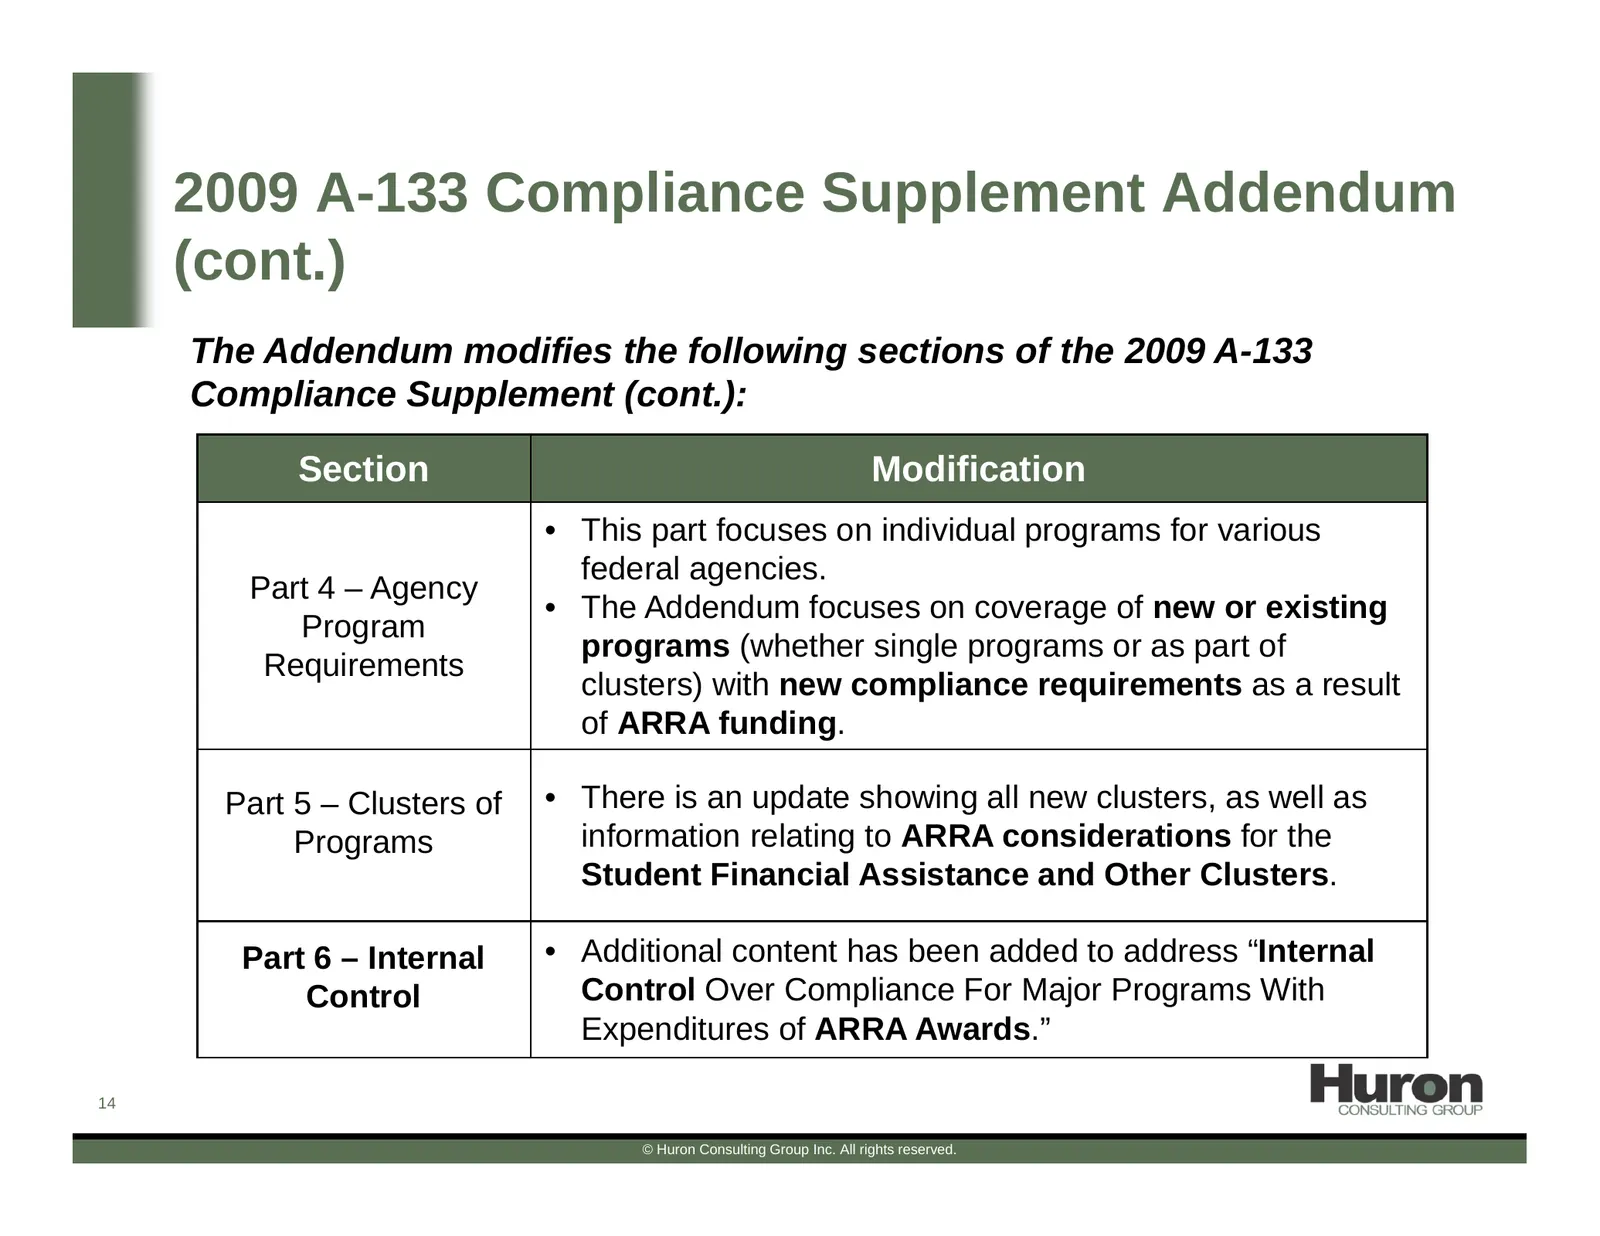
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum modifies the following sections of the 2009 A-133 Compliance Supplement (cont.): Section Modification • This part focuses on individual programs for various federal agencies. Part 4 – Agency • The Addendum focuses on coverage of new or e
Slide 15: 2009 A-133 Compliance Supplement Addendum (cont.)
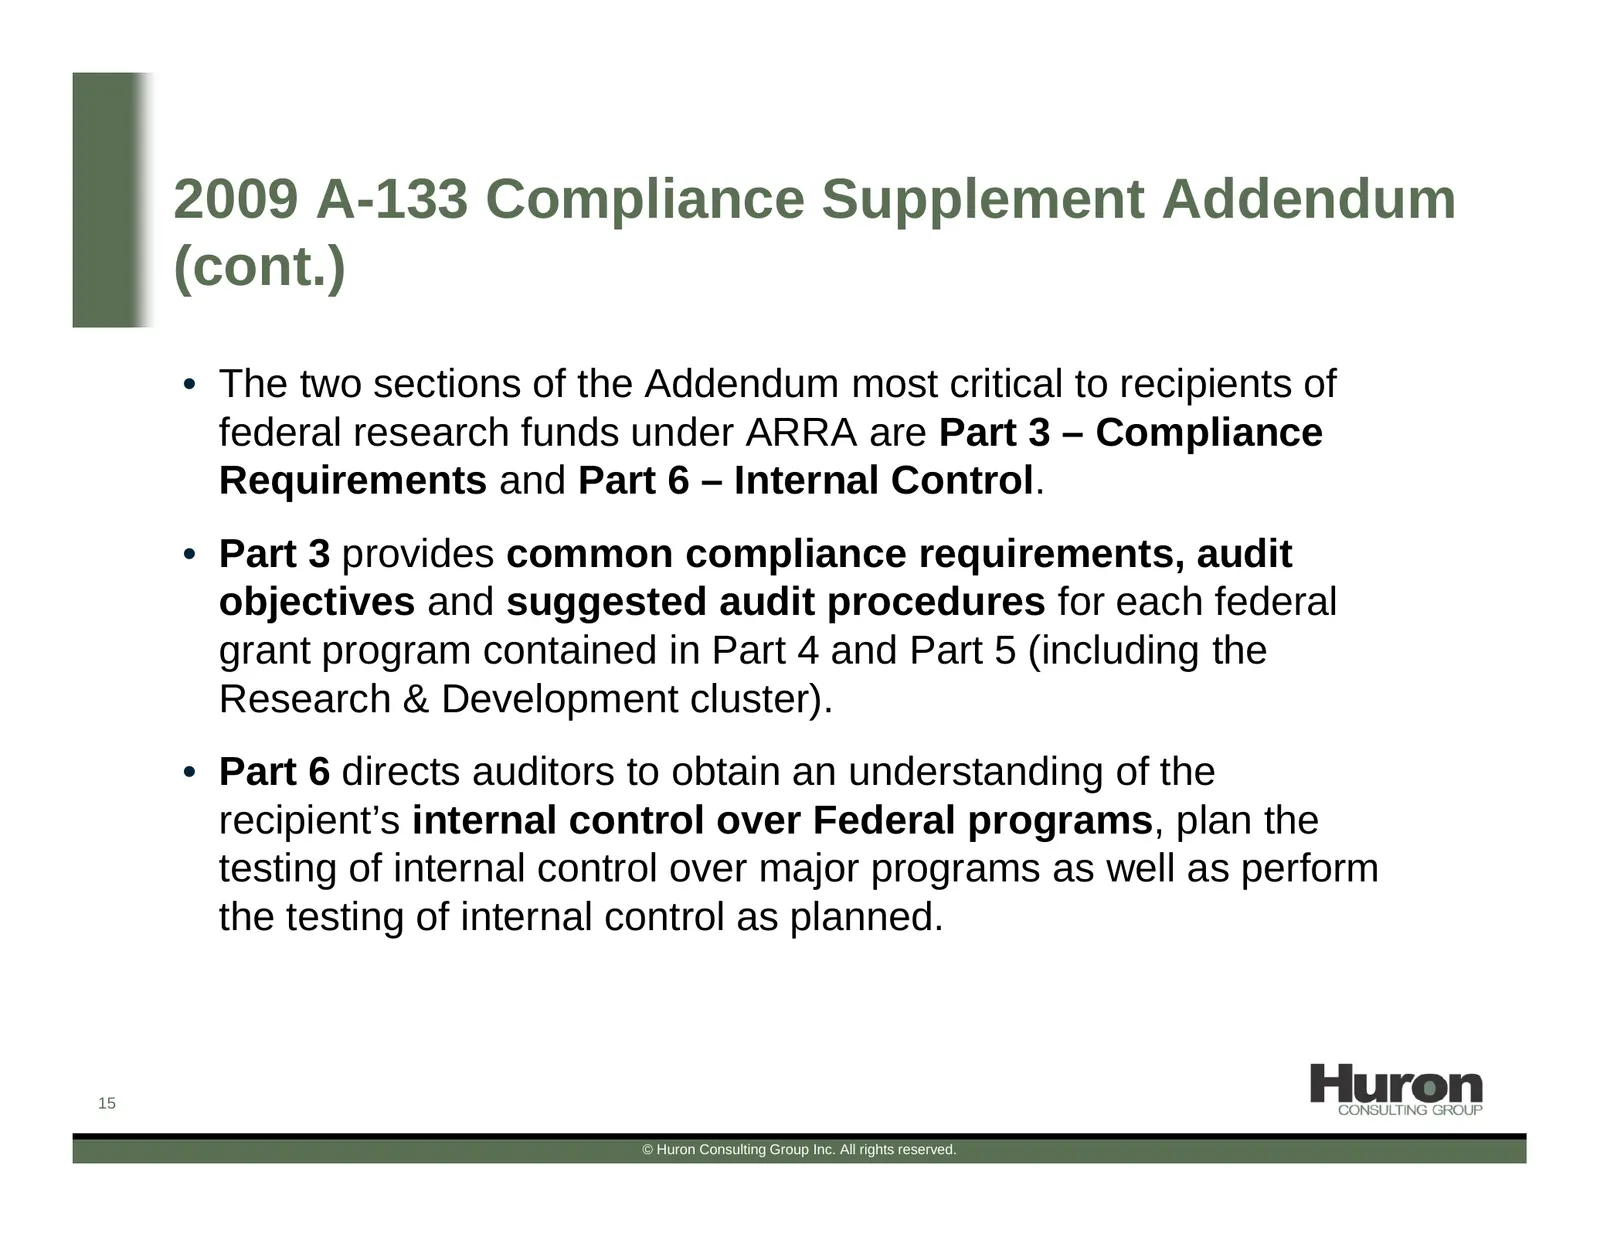
2009 A-133 Compliance Supplement Addendum (cont.) • The two sections of the Addendum most critical to recipients of federal research funds under ARRA are Part 3 – Compliance Requirements and Part 6 – Internal Control. • Part 3 provides common compliance requirements, audit objectives and suggested a
Slide 16: 2009 A-133 Compliance Supplement Addendum (cont.)
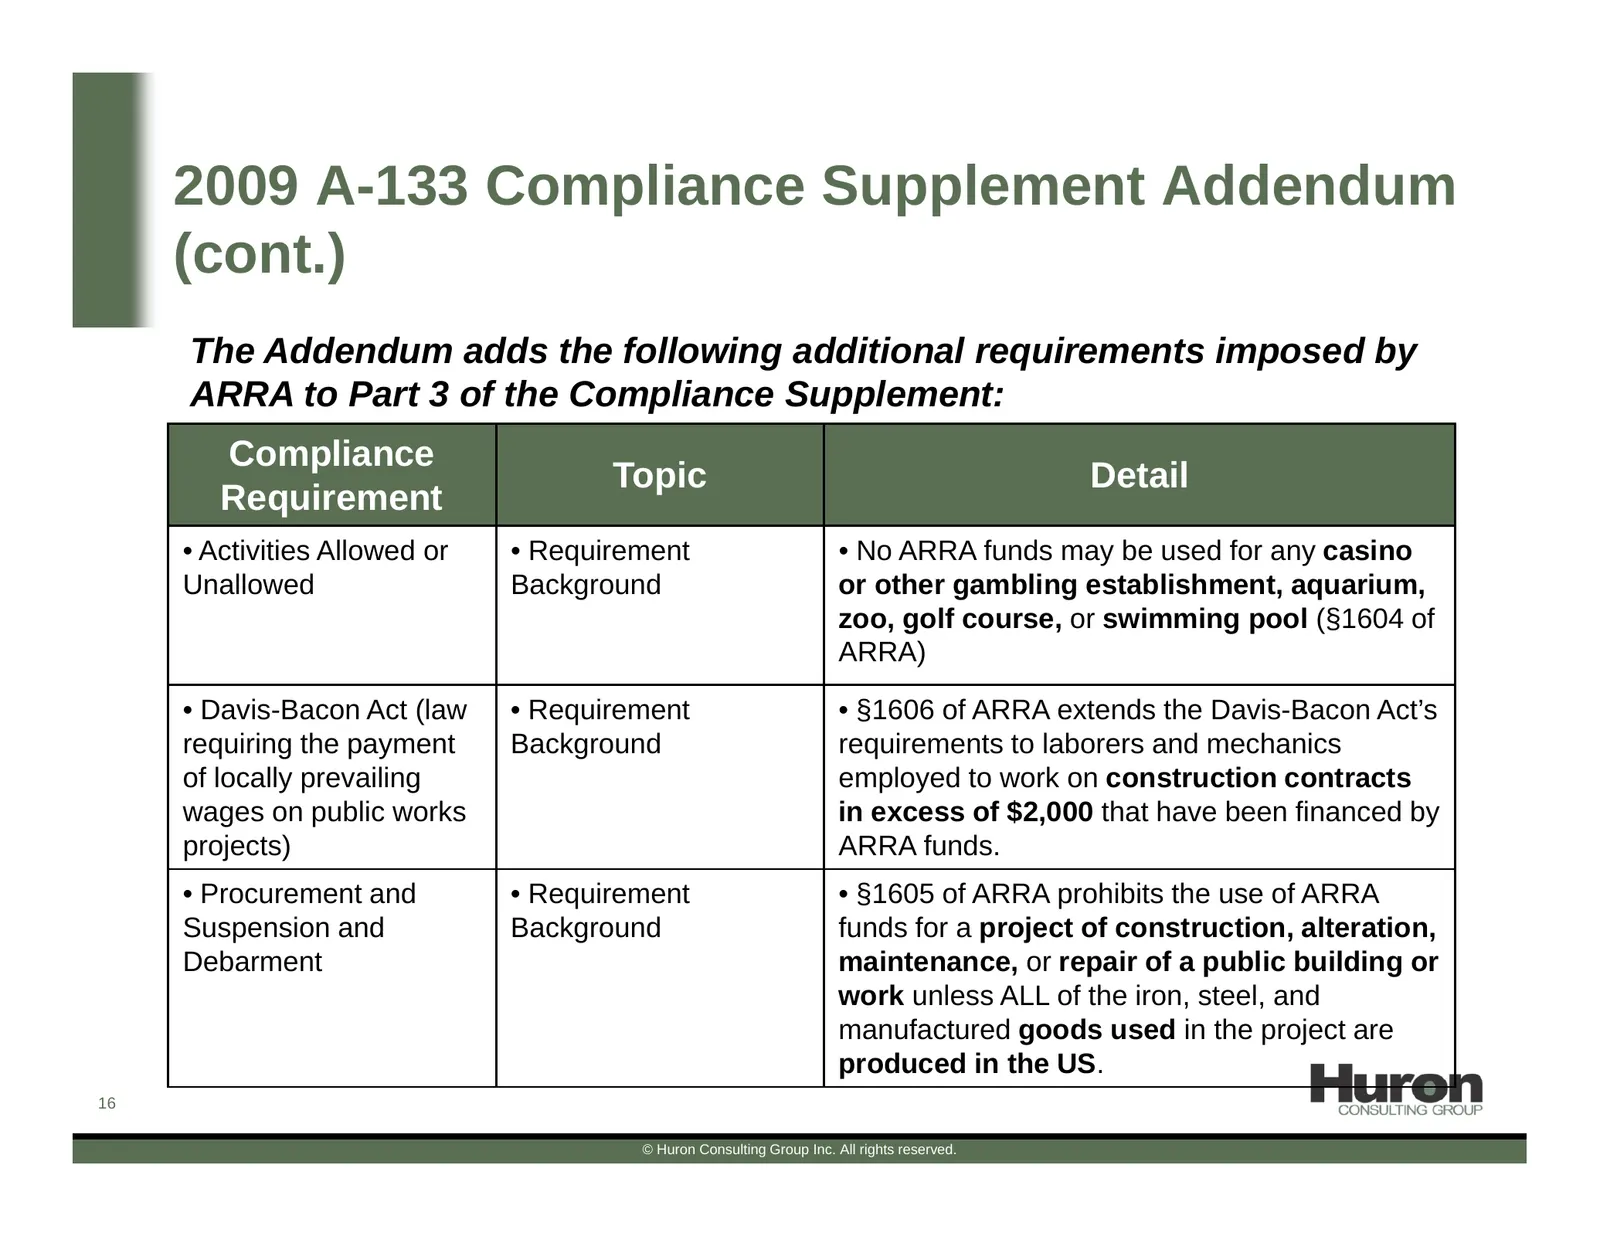
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement: Compliance Topic Detail Requirement • Activities Allowed or • Requirement • No ARRA funds may be used for any casino Unallowed Background
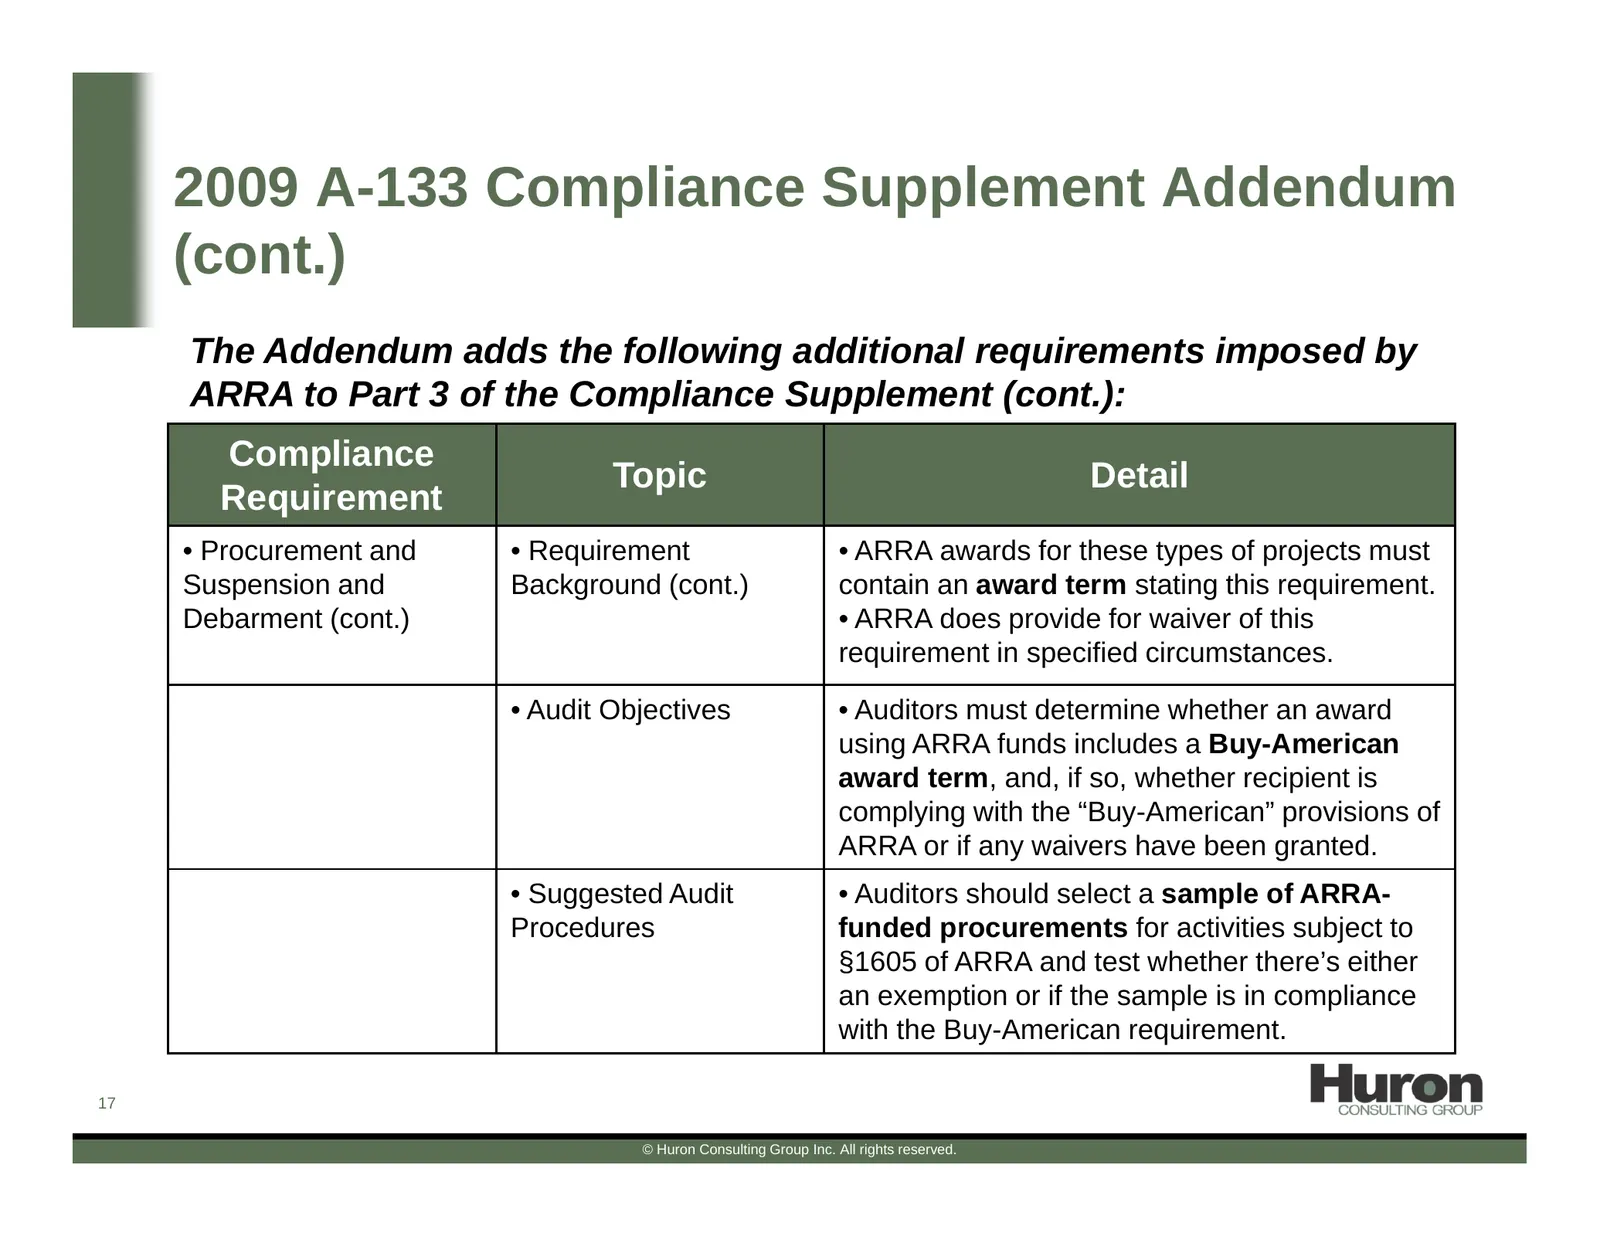
Slide 17: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Procurement and • Requirement • ARRA awards for these types of projects must Suspension and
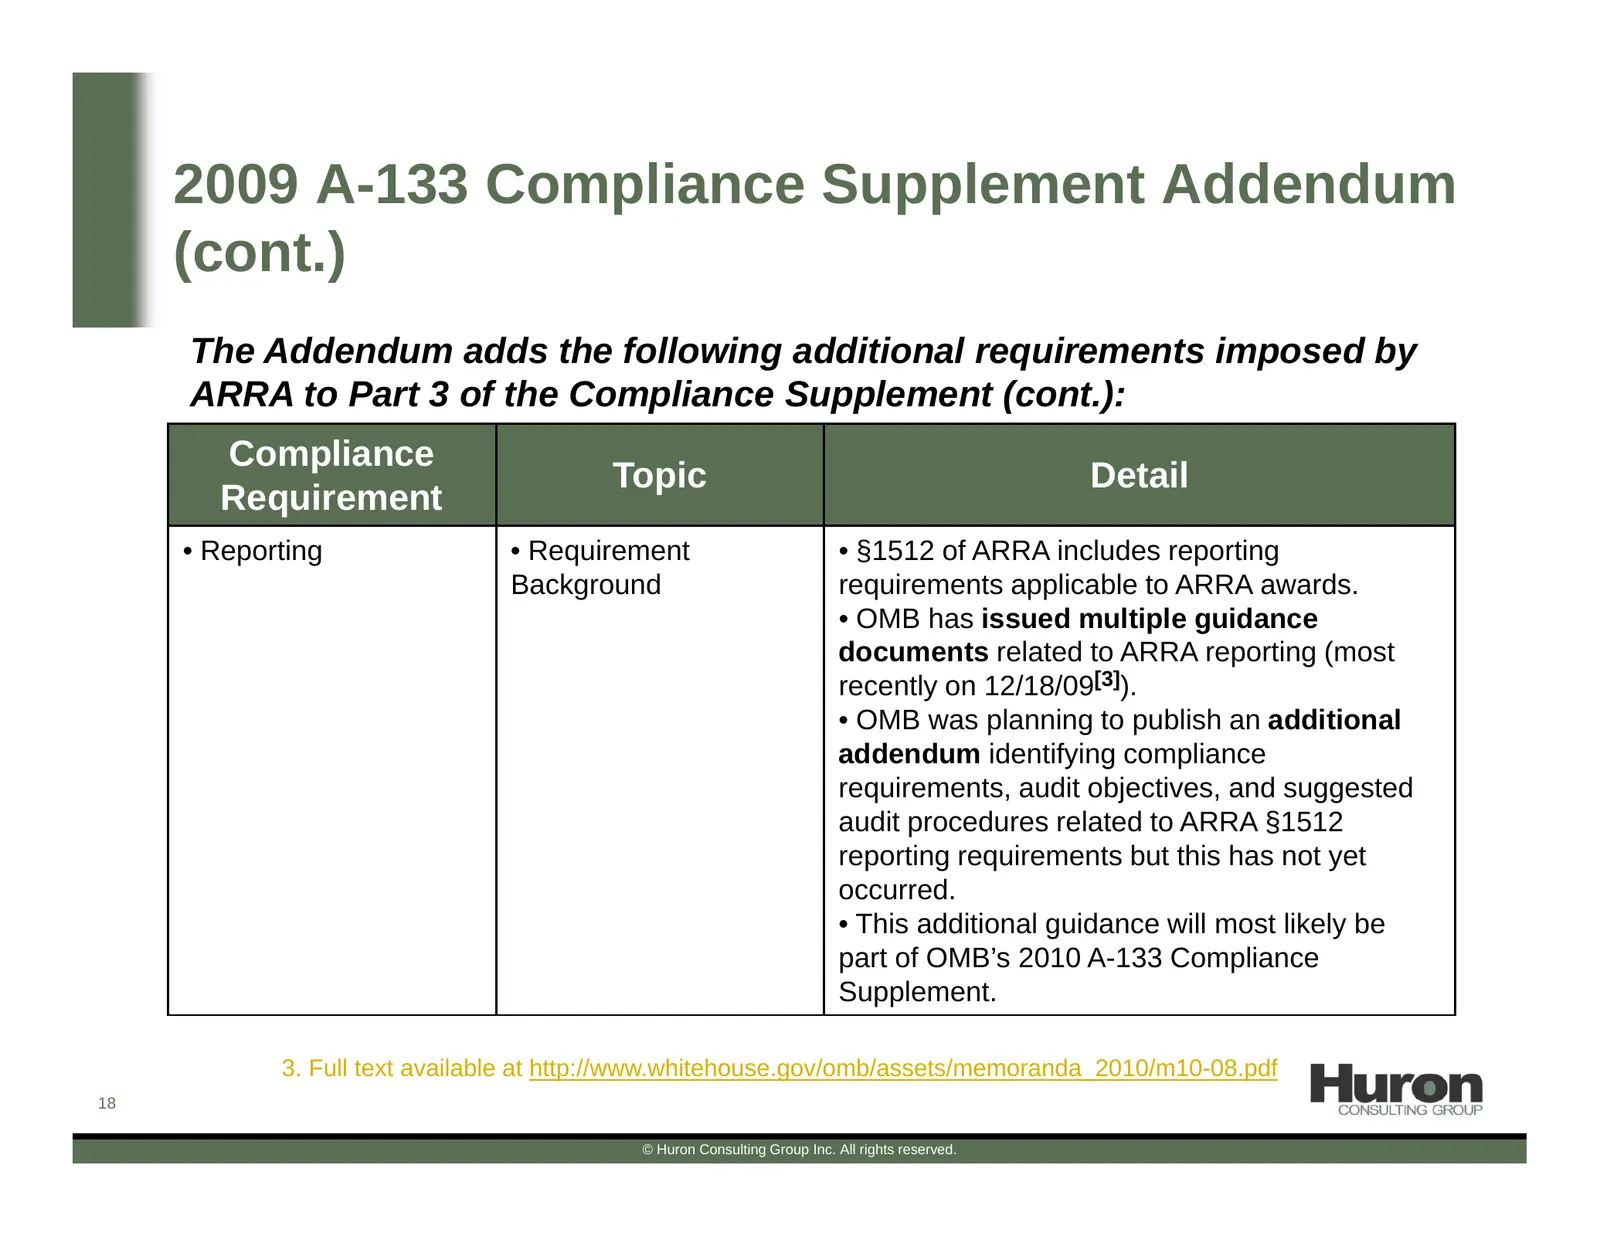
Slide 18: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Reporting • Requirement • §1512 of ARRA includes reporting Background requirements applicabl
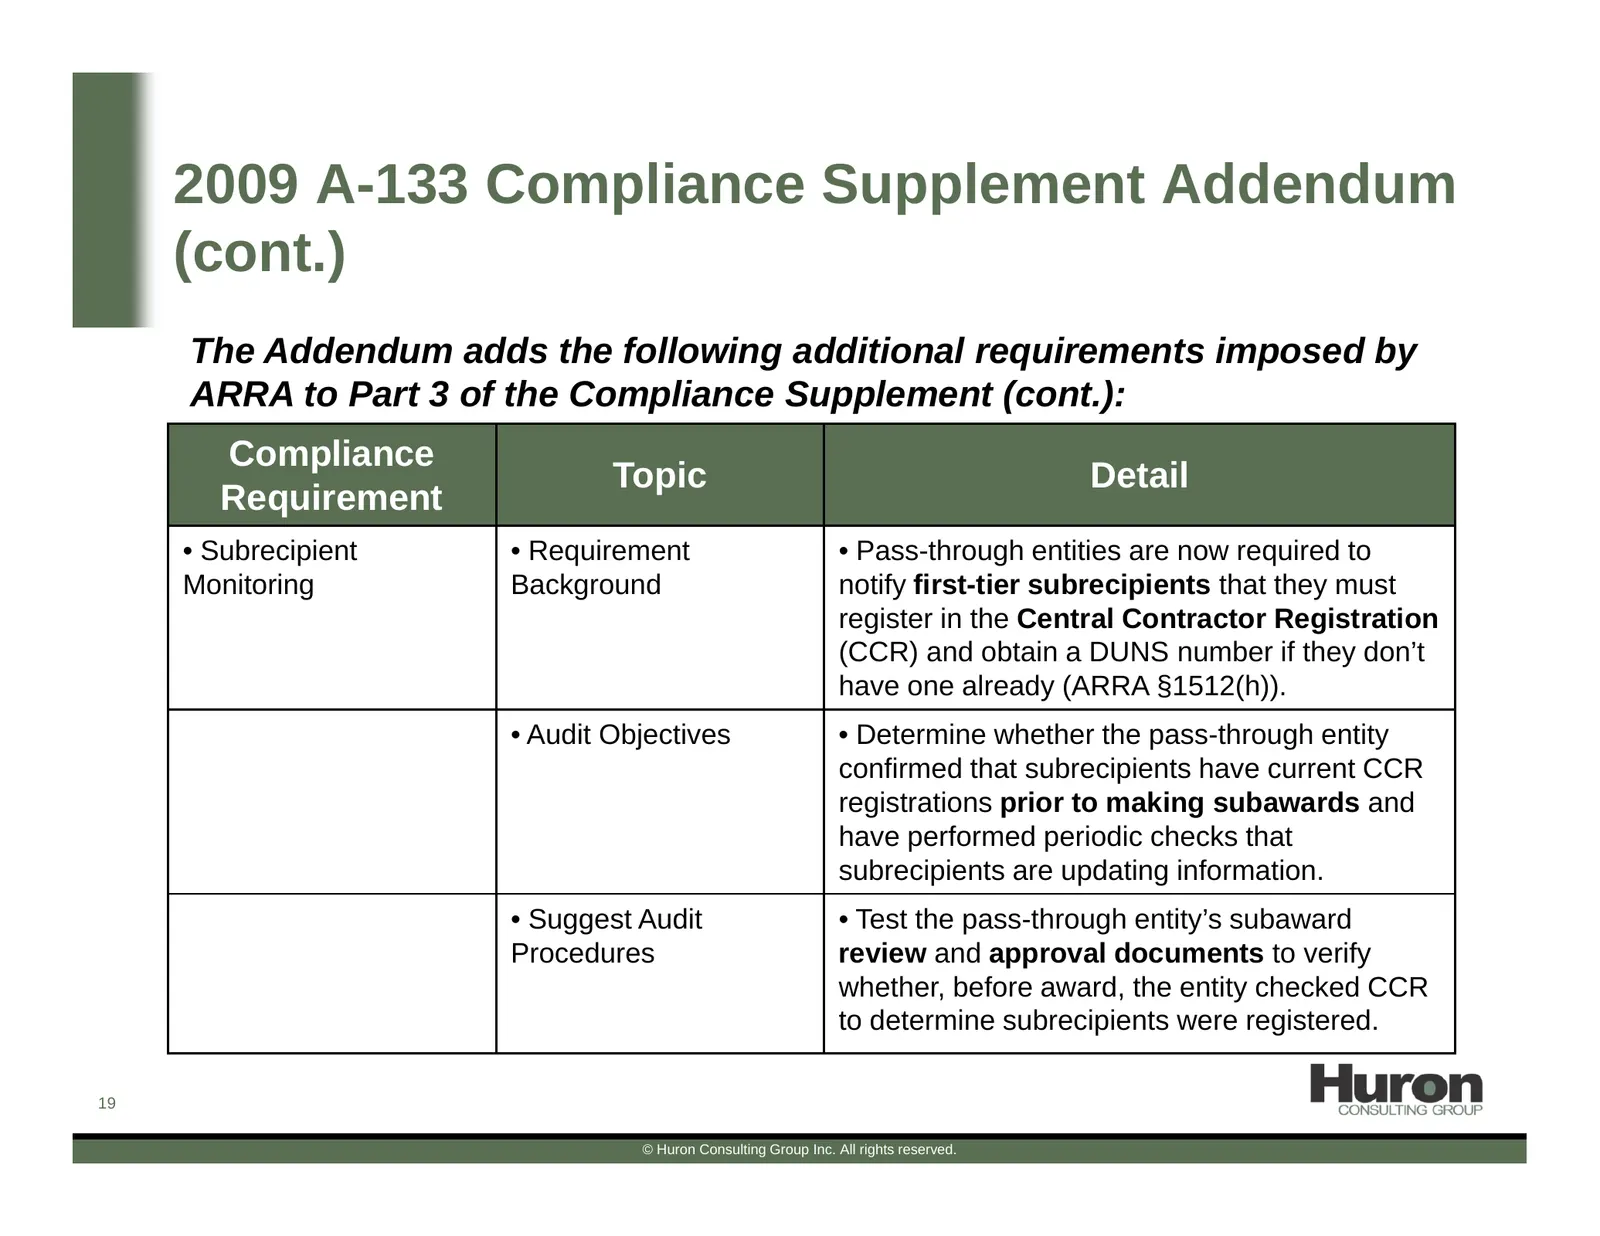
Slide 19: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Subrecipient • Requirement • Pass-through entities are now required to Monitoring Background
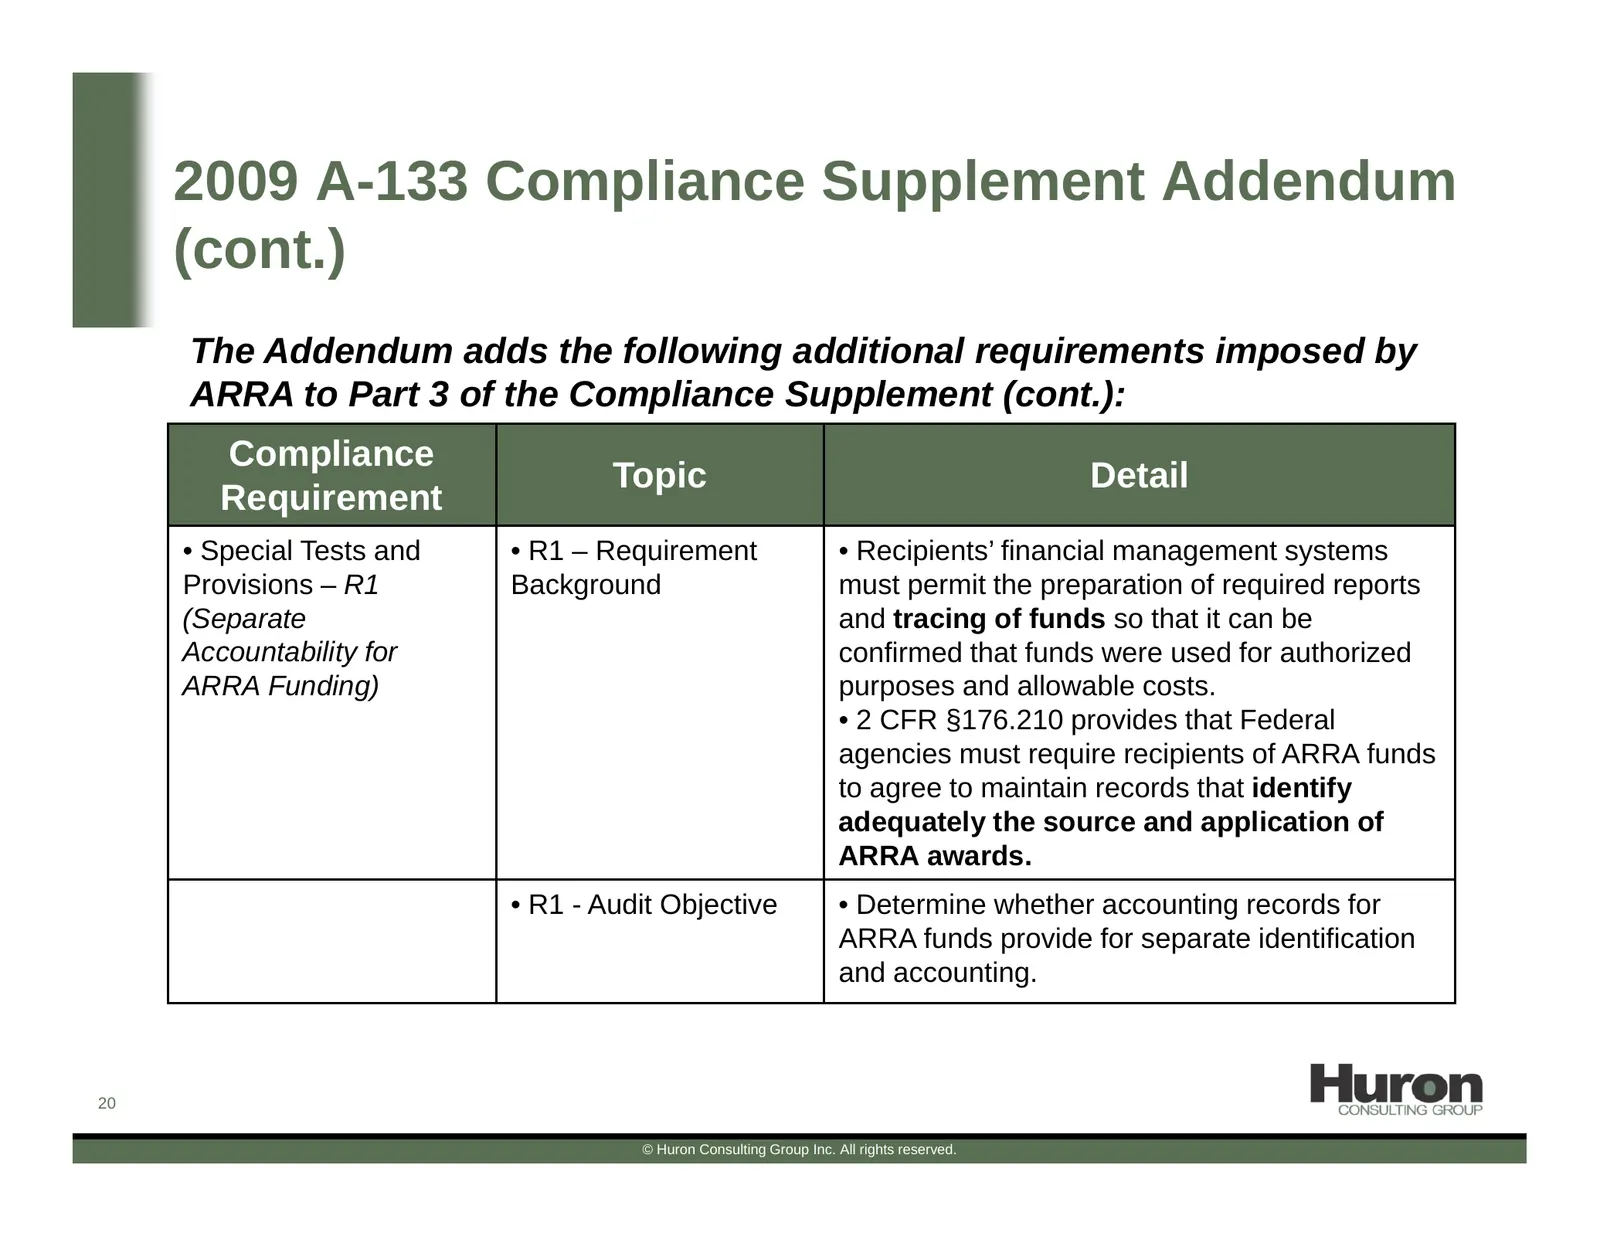
Slide 20: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Special Tests and • R1 – Requirement • Recipients’ financial management systems Provisions –
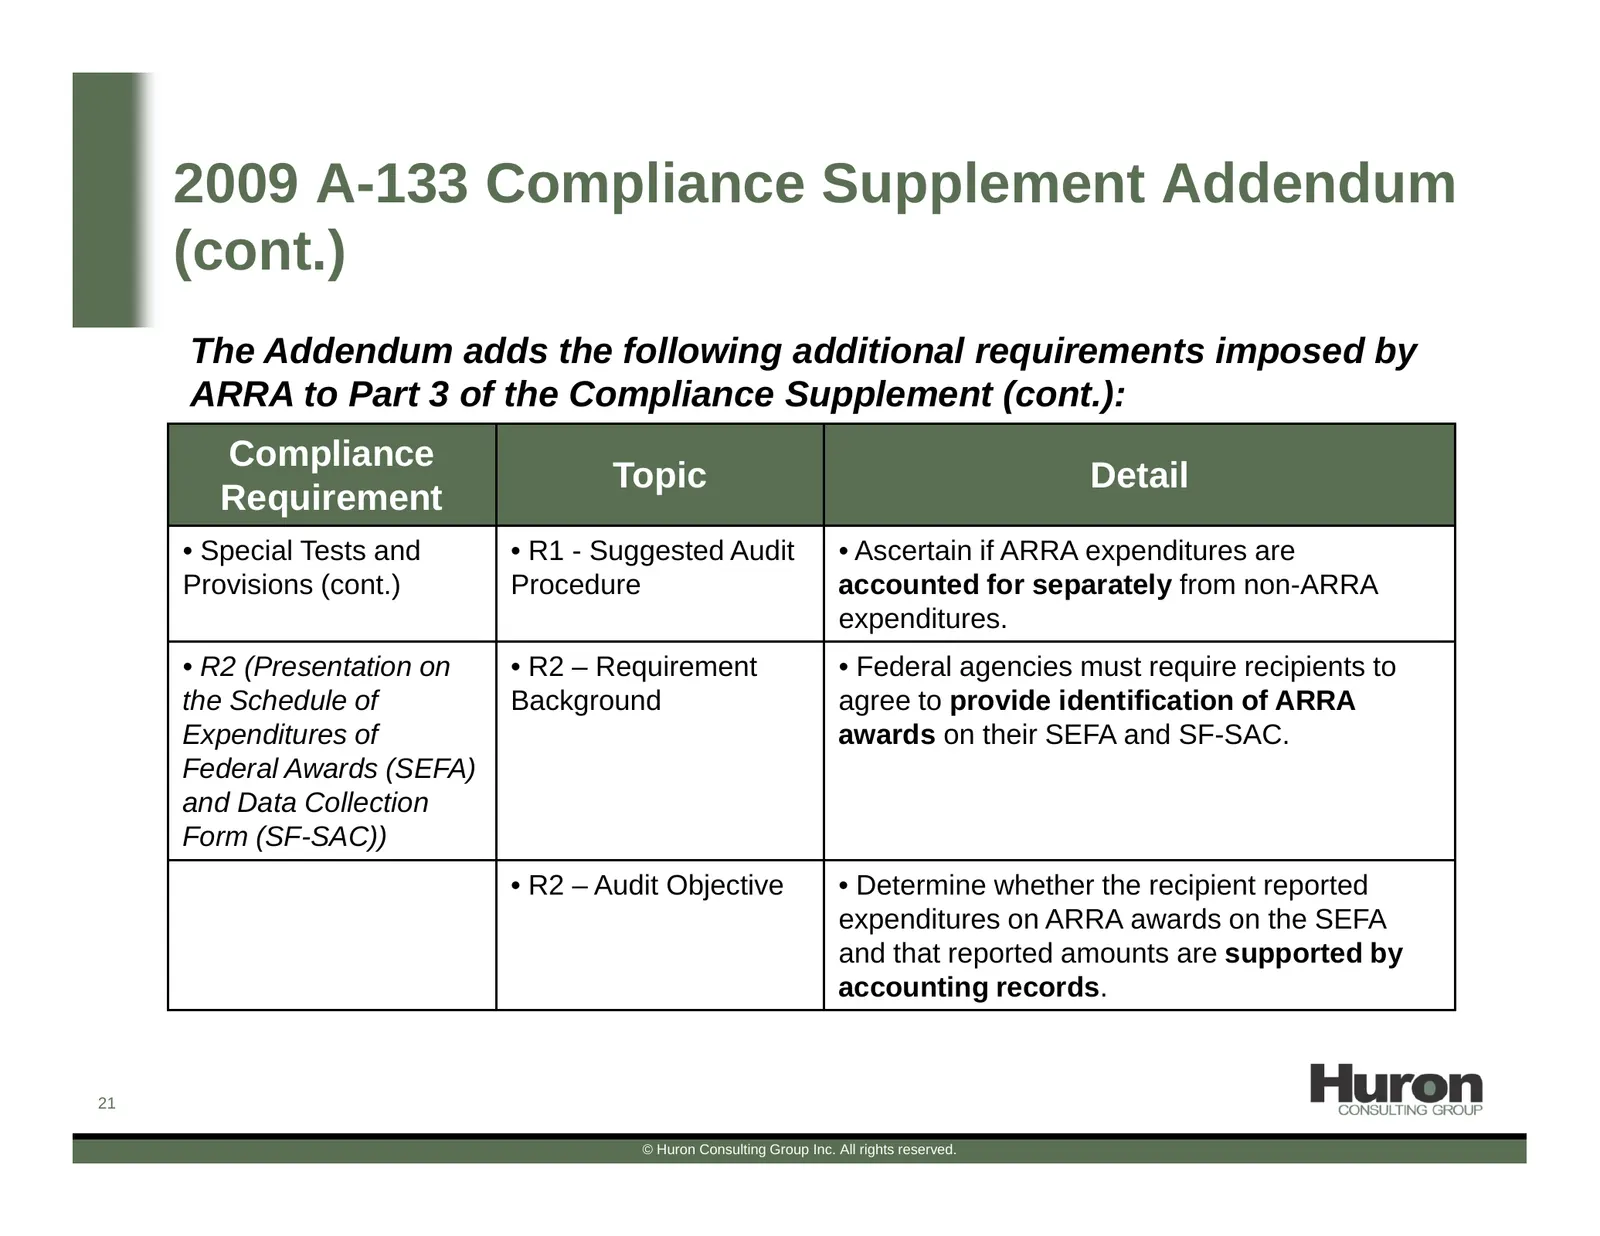
Slide 21: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Special Tests and • R1 - Suggested Audit • Ascertain if ARRA expenditures are Provisions (co
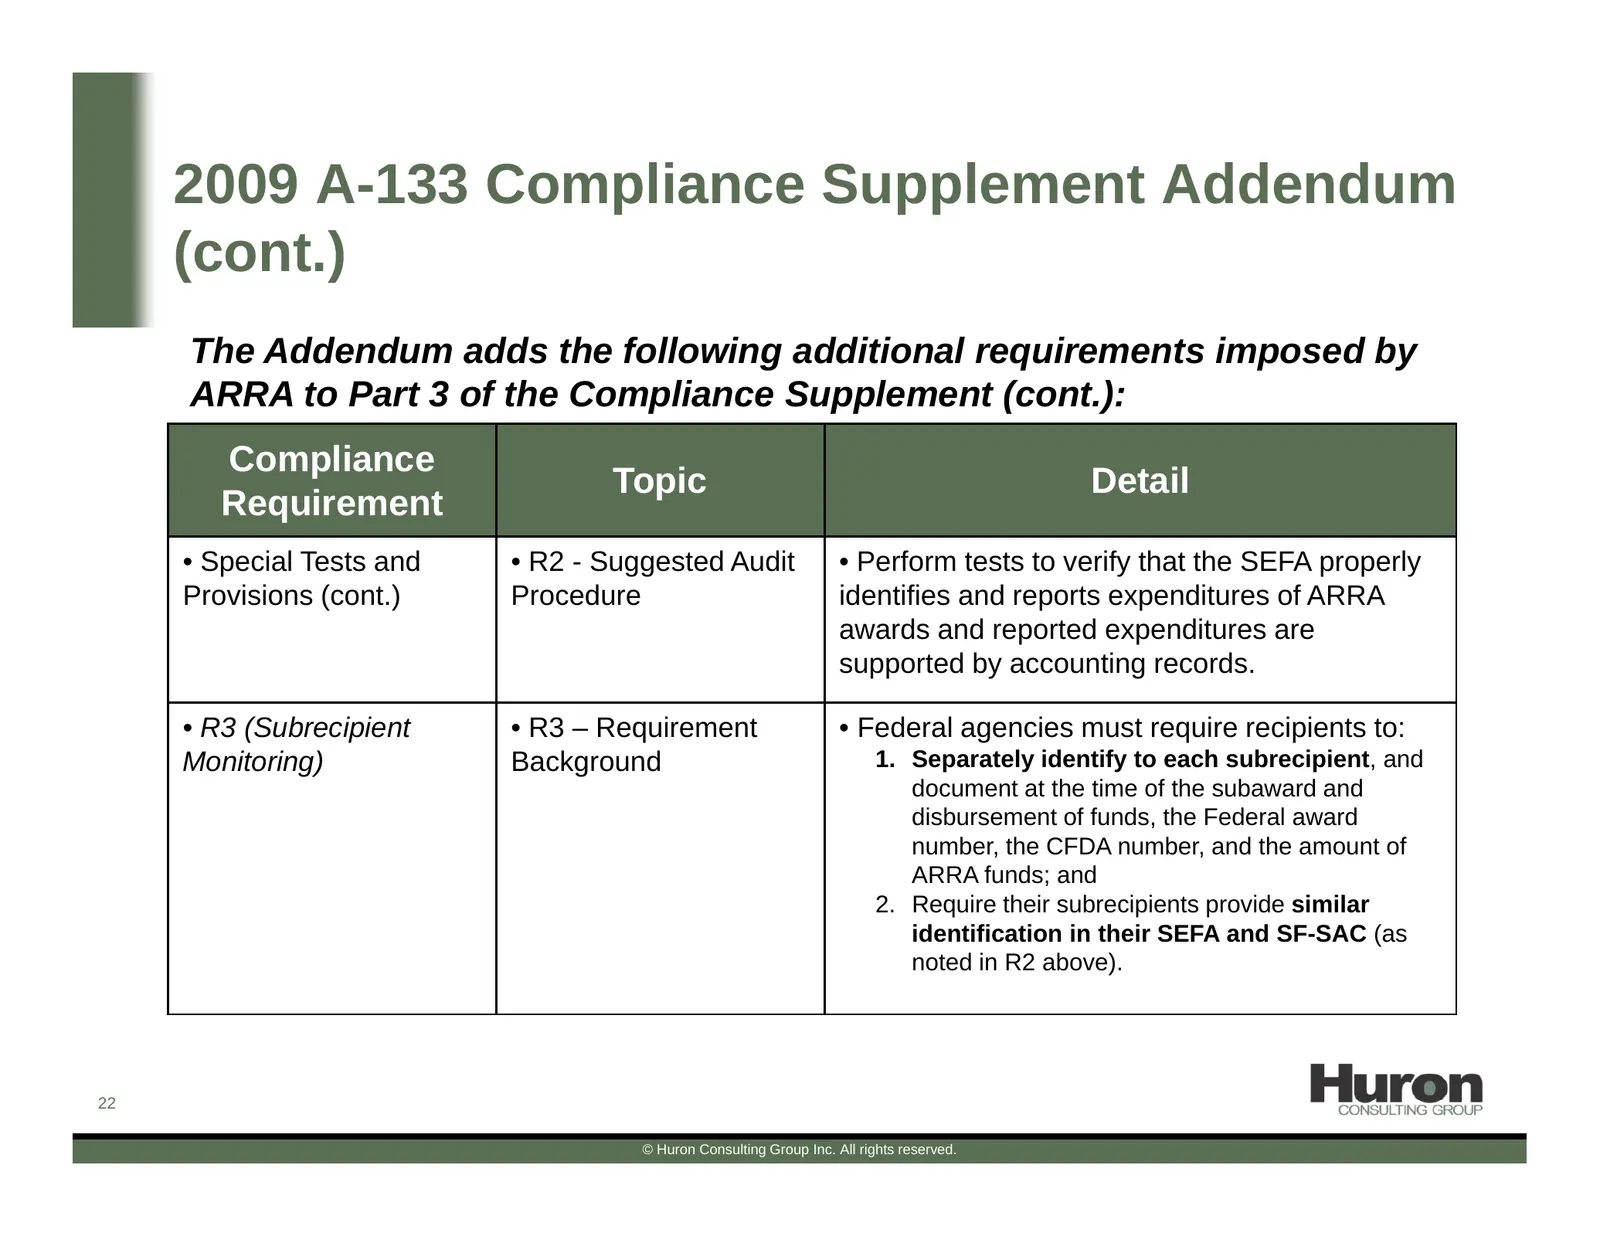
Slide 22: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Special Tests and • R2 - Suggested Audit • Perform tests to verify that the SEFA properly Pr
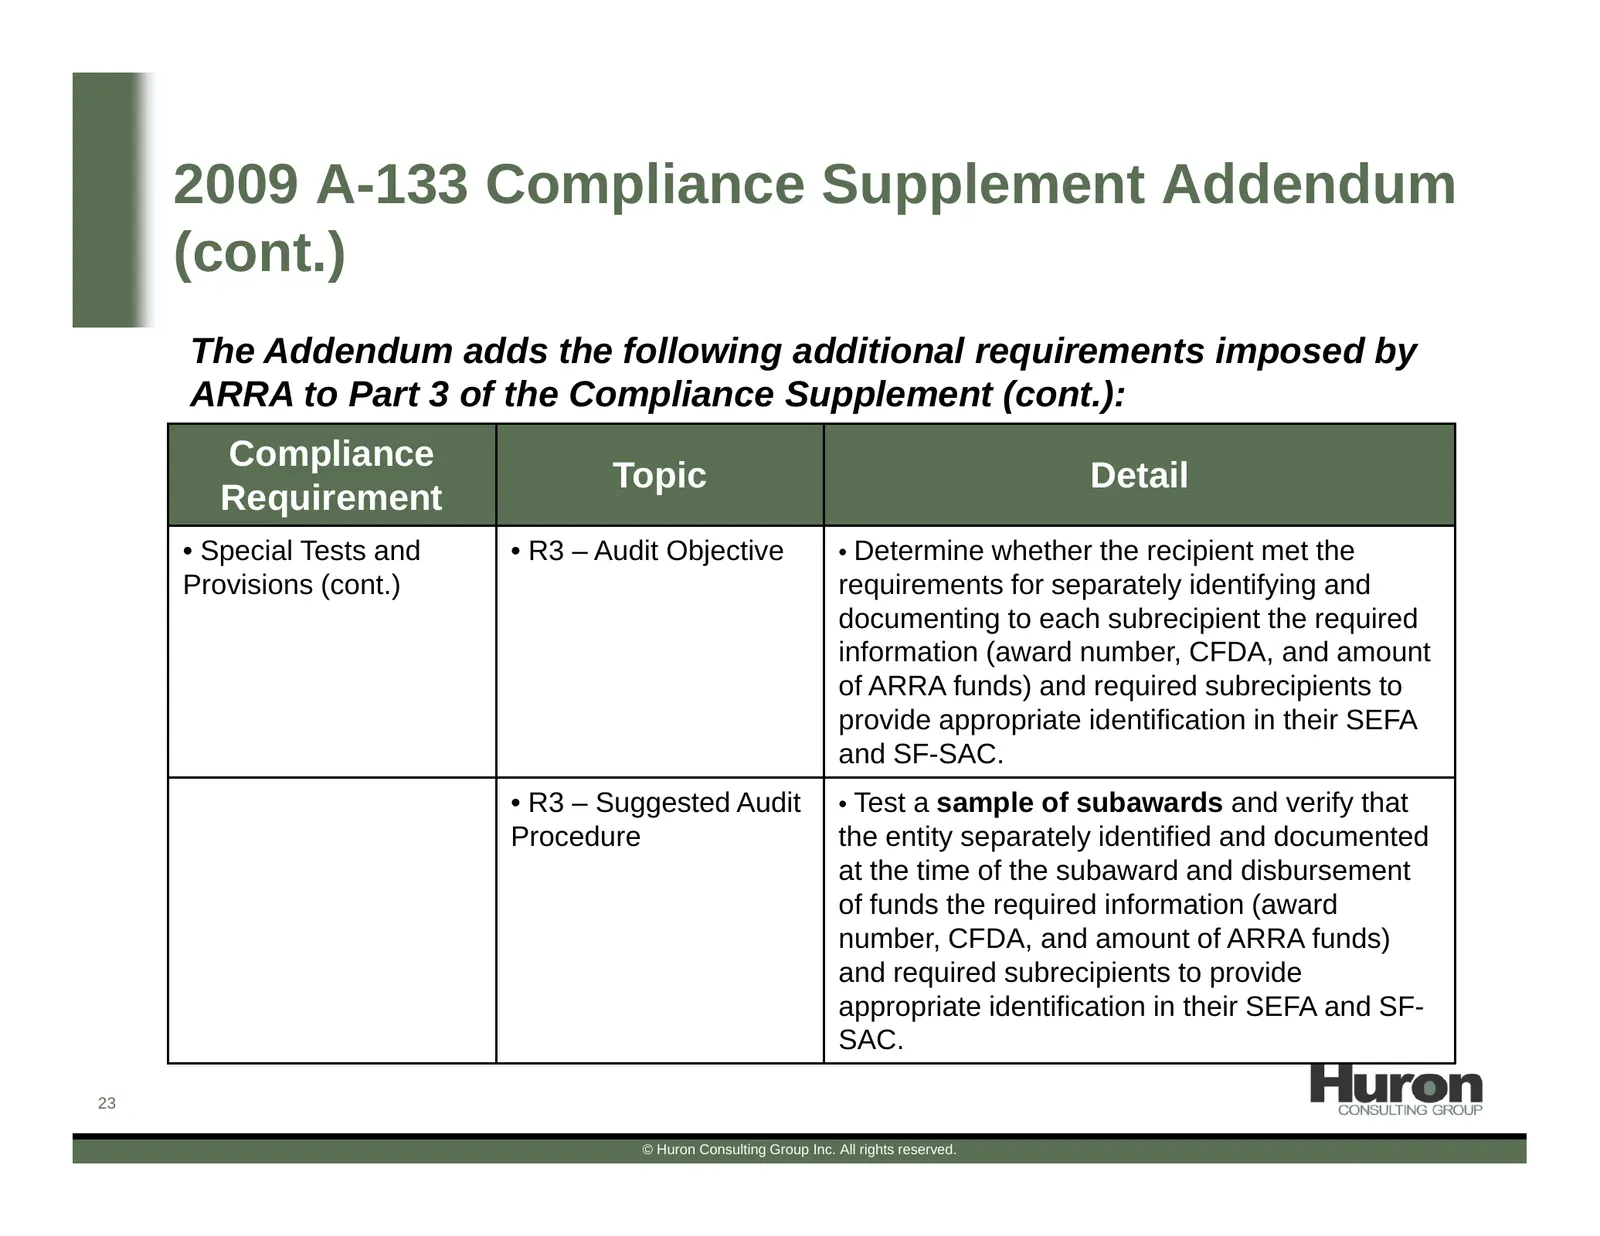
Slide 23: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) The Addendum adds the following additional requirements imposed by ARRA to Part 3 of the Compliance Supplement (cont.): Compliance Topic Detail Requirement • Special Tests and • R3 – Audit Objective • Determine whether the recipient met the Provision
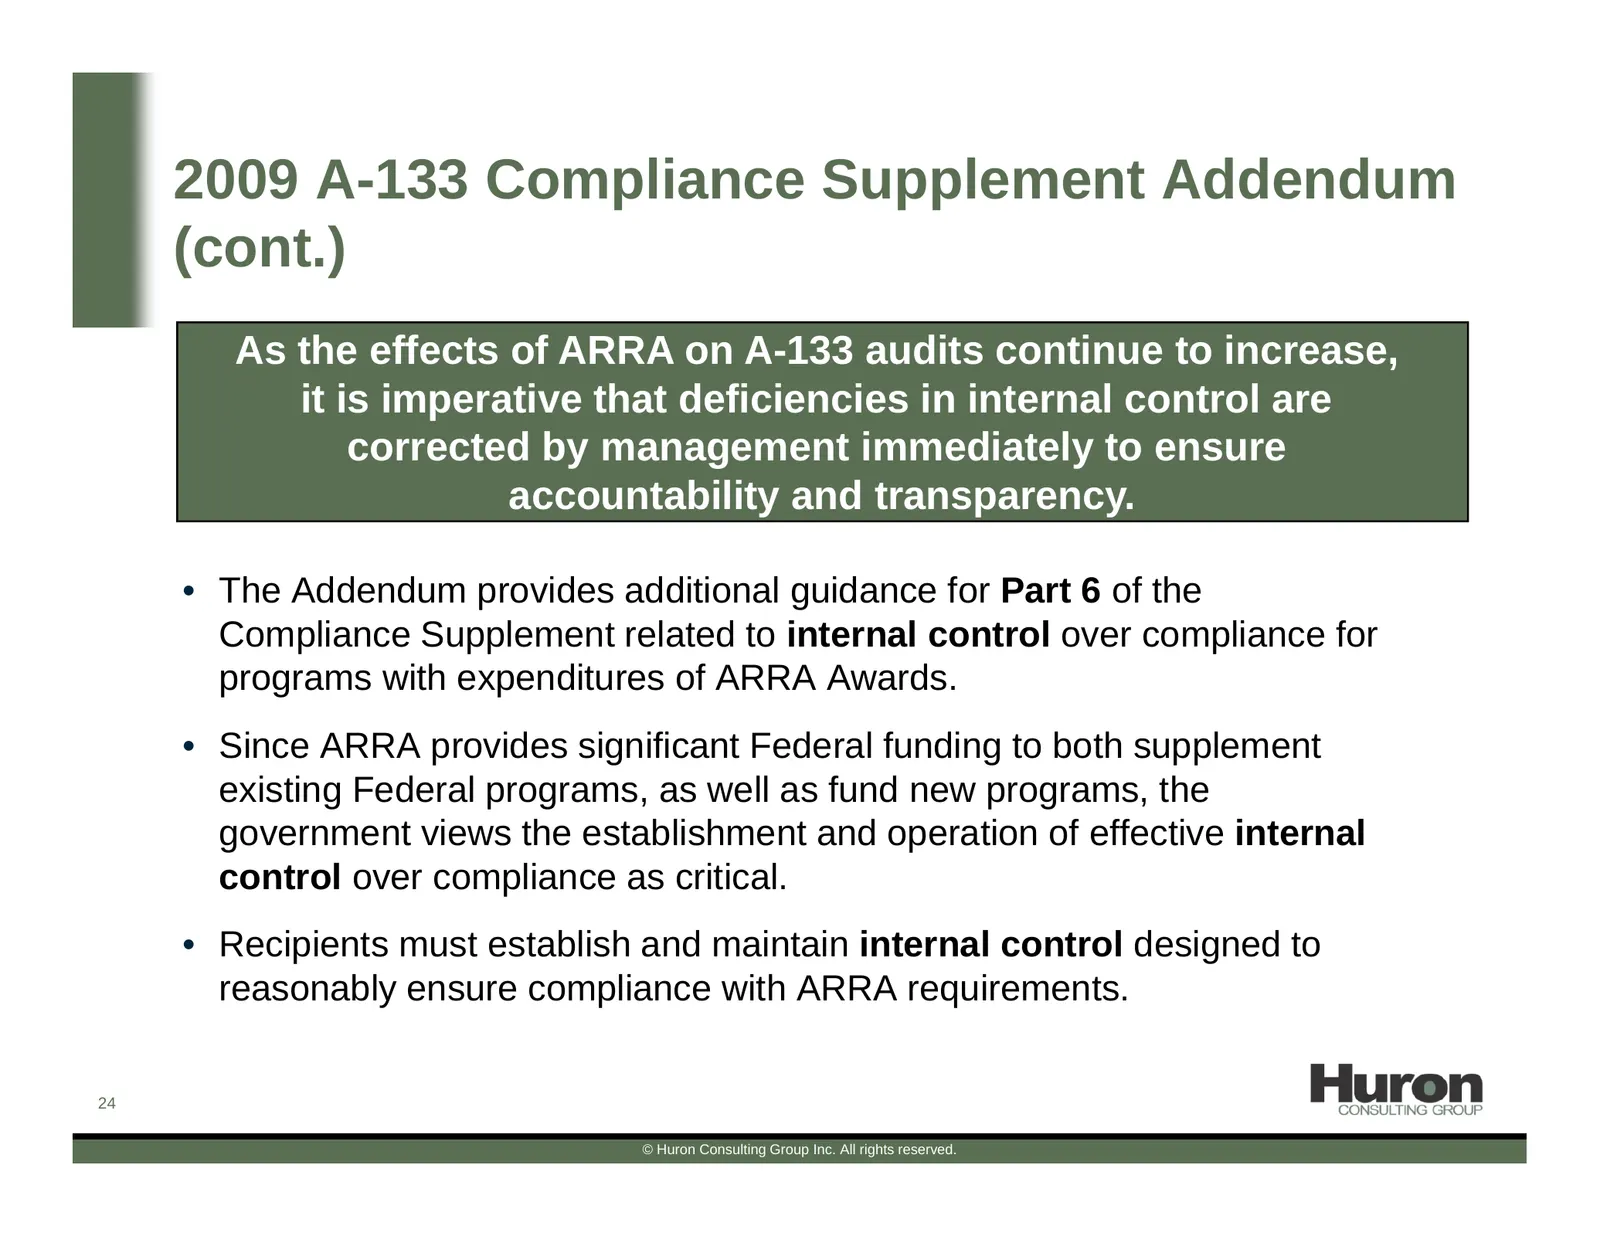
Slide 24: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) As the effects of ARRA on A-133 audits continue to increase, it is imperative that deficiencies in internal control are corrected by management immediately to ensure accountability and transparency. • The Addendum provides additional guidance for Par
Slide 25: 2009 A-133 Compliance Supplement Addendum (cont.)
2009 A-133 Compliance Supplement Addendum (cont.) • The Addendum instructs auditors to focus on the following aspects of internal control: – Early communication to management of material weaknesses and significant deficiencies with respect to ARRA funds that will allow prompt corrective action and m
Slide 26: Offices of Inspectors General (OIG) Oversight Approach
Offices of Inspectors General (OIG) Oversight Approach 26
Slide 27: OIG Oversight Approach: Current Activity
OIG Oversight Approach Current Activity • To ensure that accountability requirements are being met, the cognizant OIG’s of the 30 federal agencies distributing ARRA funds continually review their agencies' management of ARRA funds. • As of February 28, 2010, the OIG’s, along with the Recovery Accoun
Slide 28: OIG Oversight Approach: Objectives
OIG Oversight Approach Objectives • The RATB received approximately $84 million in funding and will oversee the audit activities of the OIG with respect to ARRA funds. • The goal of the OIG and the RATB with respect to oversight of ARRA funds is both: 1. Transparency; and 2. Prevention and detection
Slide 29: OIG Oversight Approach: NSF
OIG Oversight Approach NSF • NSF has indicated its approach will be proactive and carried out in three phases: – Phase I is an inward review of NSF’s monitoring and controls. – Phase II is both an inward and outward review. NSF is currently in this phase. NSF is conducting approximately 10 Capacity/
Slide 30: OIG Oversight Approach: DHHS
OIG Oversight Approach DHHS • DHHS is employing a risk-based approach to oversight of ARRA funds. – Like NSF it will be reviewing internal controls and assessing the likelihood and magnitude of identified vulnerabilities. – Unlike NSF it will not be doing “Capacity Reviews.” – Expect most ARRA audit
Slide 31: Suggested Practices
Suggested Practices 31
Slide 32: Suggested Practices
Suggested Practices • Start to prepare now (if you haven’t already done so) • Plan to assign additional resources to the audit since you may have more clusters classified as major programs • Understand the distinction between clusters and the addition of new clusters (e.g. State Fiscal Stabilization
Slide 33: Suggested Practices (cont.)
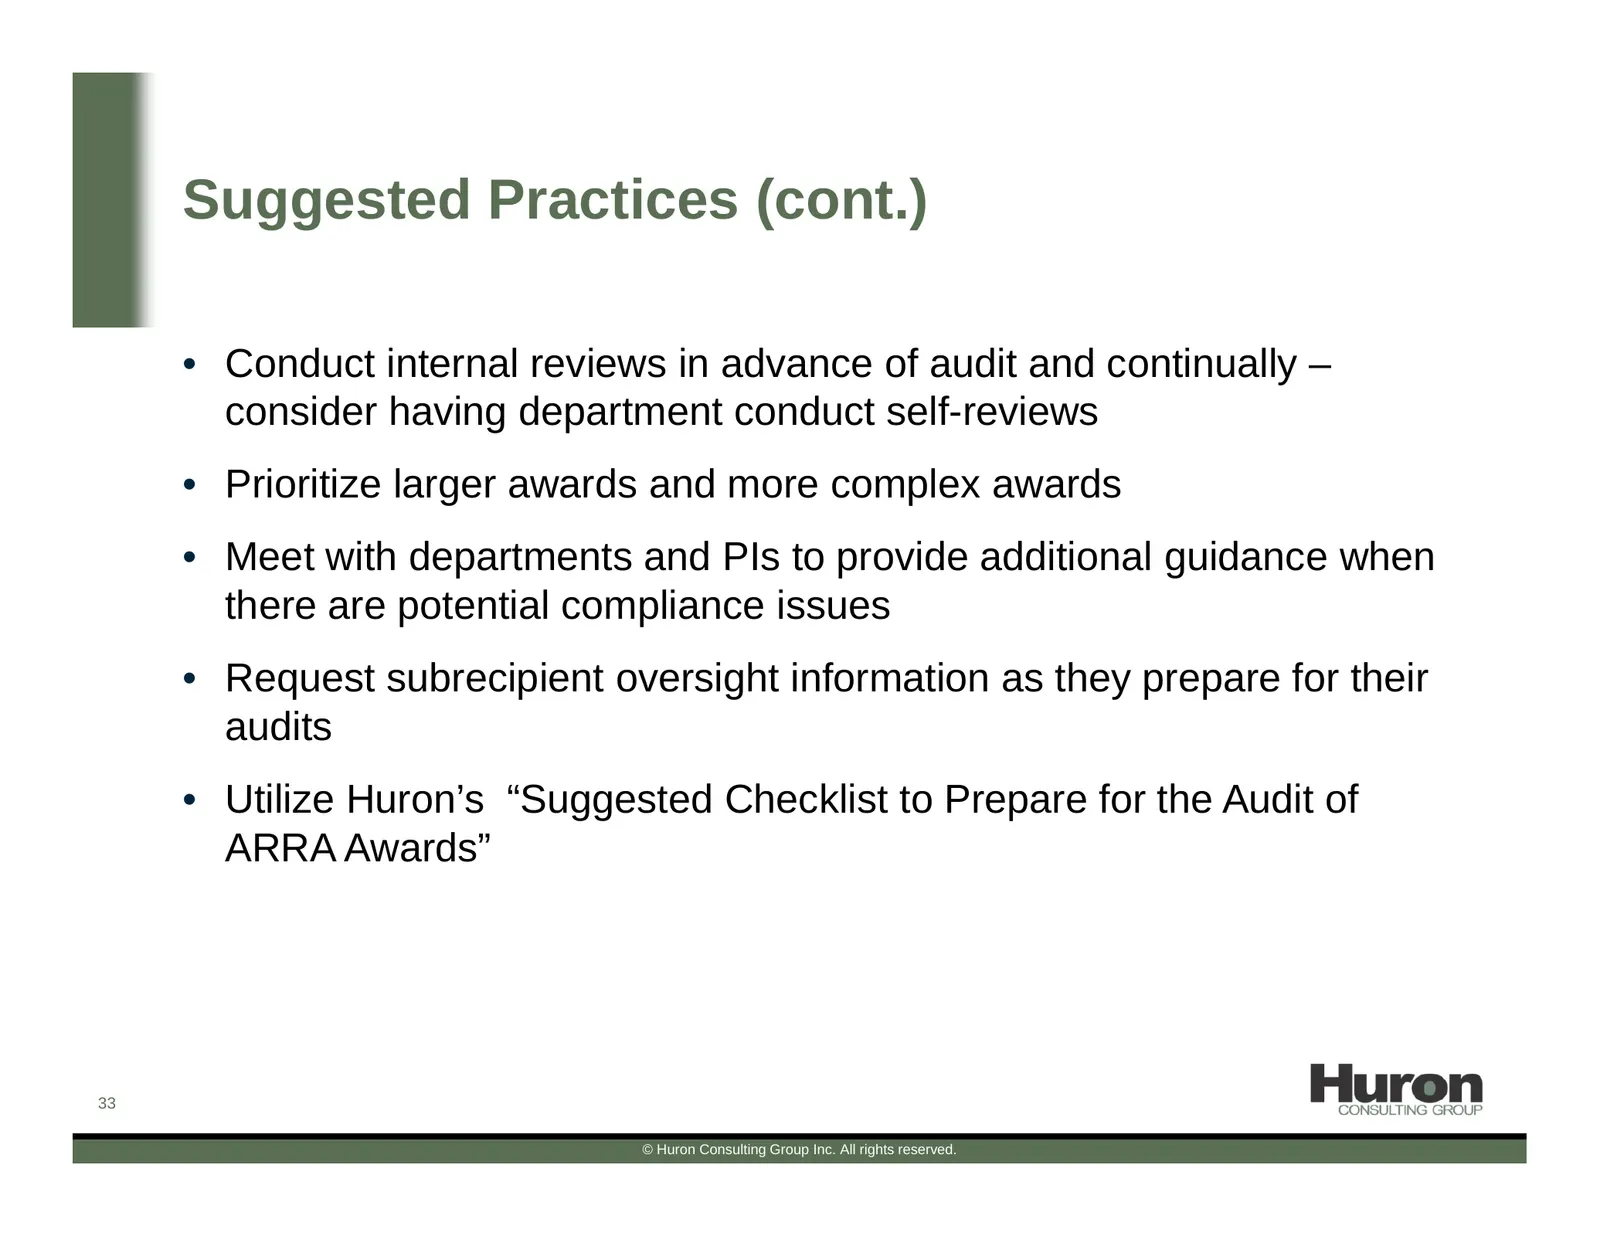
Suggested Practices (cont.) • Conduct internal reviews in advance of audit and continually – consider having department conduct self-reviews • Prioritize larger awards and more complex awards • Meet with departments and PIs to provide additional guidance when there are potential compliance issues •
Slide 34: Resources
Resources 34
Slide 35: Resources: Sample Checklist
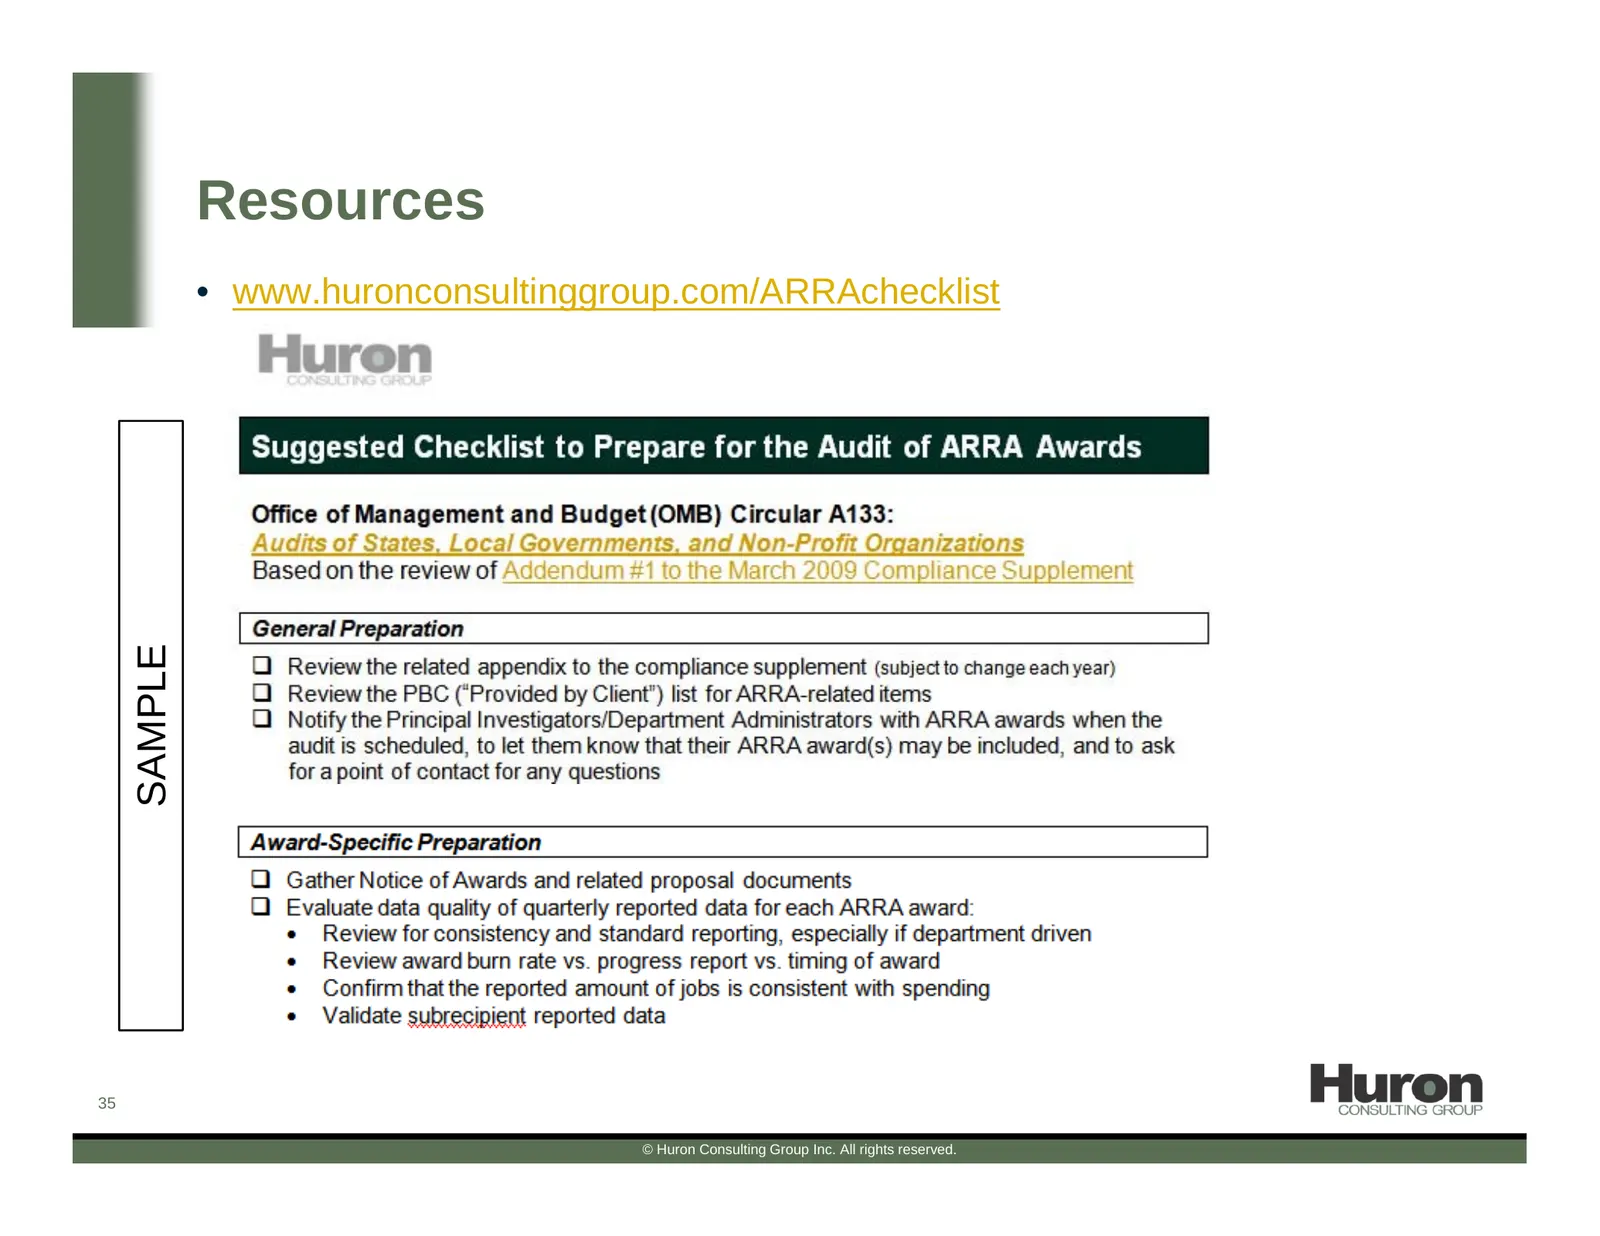
Resources • www.huronconsultinggroup.com/ARRAchecklist SAMPLE 35 © Huron Consulting Group Inc. All rights reserved.
Slide 36: Resources
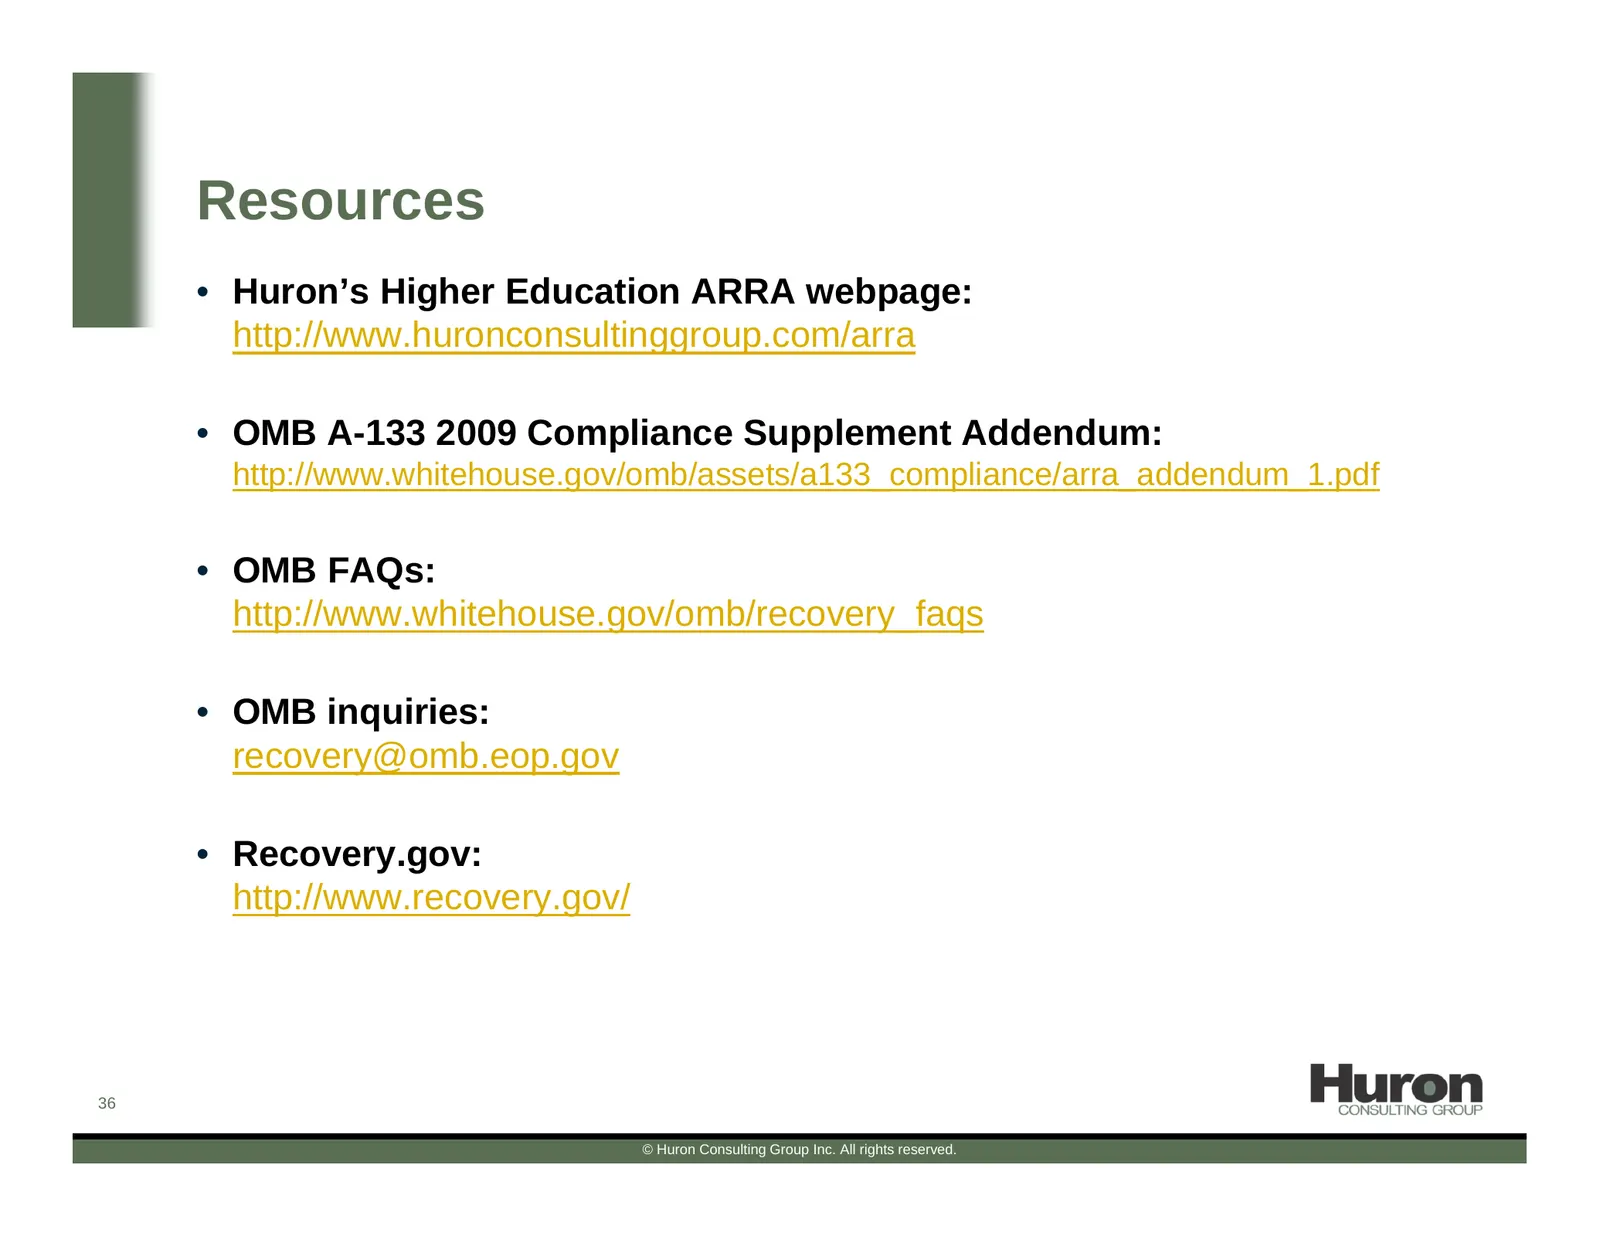
Resources • Huron’s Higher Education ARRA webpage: http://www.huronconsultinggroup.com/arra • OMB A-133 2009 Compliance Supplement Addendum: http://www.whitehouse.gov/omb/assets/a133_compliance/arra_addendum_1.pdf • OMB FAQs: http://www.whitehouse.gov/omb/recovery_faqs • OMB inquiries: recovery@omb.
Slide 37: Contact Info
Contact Info Mary Beth Rudofski Director, Higher Education Consulting 312-880-0534 mrudofski@huronconsultinggroup.com Anne Sullivan Director, Higher Education Consulting 312-880-3083 asullivan@huronconsultinggroup.com 37 © Huron Consulting Group Inc. All rights reserved.
Slide 38: Question & Answer Session
Question & Answer Session 38
Slide 39: © Huron Consulting Group Inc. All rights reserved.
© Huron Consulting Group Inc. All rights reserved.
Source: Internet Archive copy of huronconsultinggroup.com
More decks from Huron Consulting Group Inc.
 Investor Presentation (July 2026)49 slides · July 2026
 Investor Presentation (March 2026)49 slides · March 2026
 Q4 2025 Earnings Presentation12 slides · Feb 24, 2026
 Investor Presentation (July 2025)44 slides · July 2025
 Shareholder Meeting (March 2025)13 slides · Mar 28, 2025
 Investor Day (March 2025)77 slides · Mar 25, 2025