Washington Banking — Merger or Acquisition (October 2013)
20 slides from Washington Banking's merger presentation, Oct 24, 2013
Slide 1: Attractive Pacific Northwest Partnership
HERITAGE FINANCIAL CORPORATION NASDAQ: HFWA Washington Banking Company NASDAQ: WBCO Attractive Pacific Northwest Partnership October 23, 2013
Slide 2: Forward-Looking Statements
2 Forward?Looking Statements When used in this presentation and in other documents filed with or furnished to the Securities and Exchange Commission (the “SEC”), in press releases or other public shareholder communications, or in oral statements made with the approval of an authorized executive offi
Slide 3: Strategic Merger Rationale
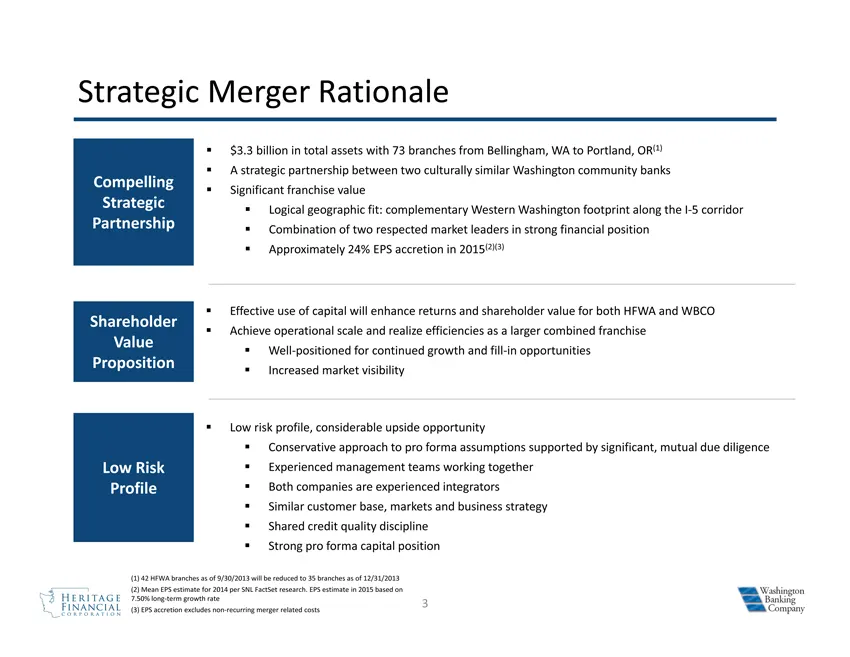
Strategic Merger Rationale Compelling Strategic Partnership Shareholder Value Proposition Low Risk Profile $3.3 billion in total assets with 73 branches from Bellingham, WA to Portland, OR(1) A strategic partnership between two culturally similar Washington community banks Significant franchise valu
Slide 4: Compelling Pro Forma Footprint
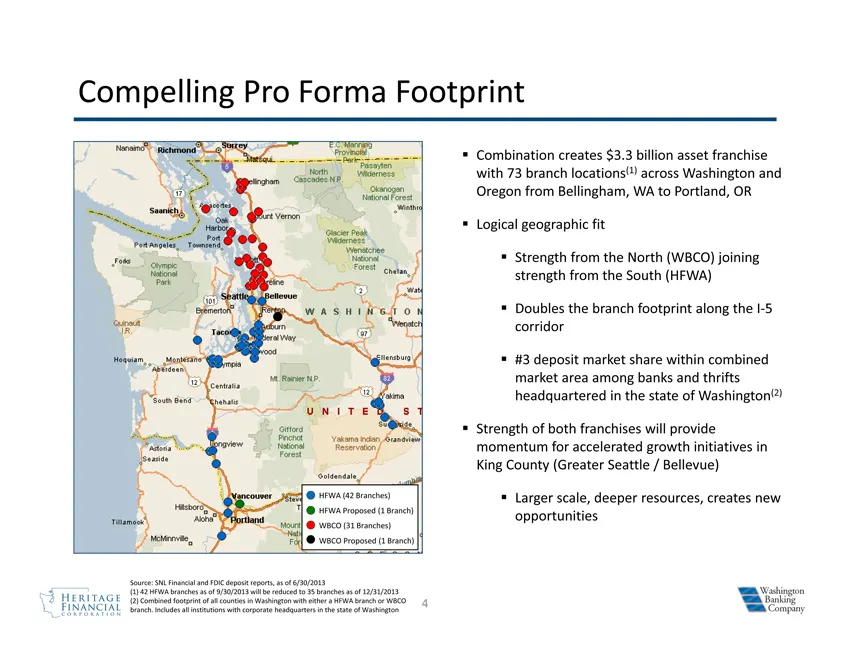
Compelling Pro Forma Footprint ¡ Combination creates $3.3 billion asset franchise with 73 branch locations(1) across Washington and Oregon from Bellingham, WA to Portland, OR Logical geographic fit Strength from the North (WBCO) joining strength from the South (HFWA) Doubles the branch footprint alo
Slide 5: Merger Summary
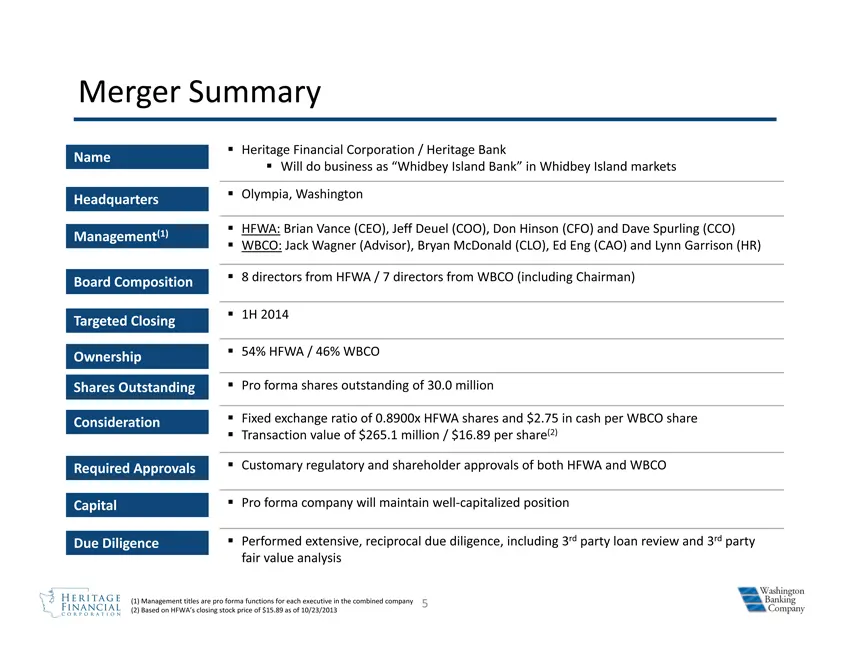
Merger Summary ¡ Heritage Financial Corporation / Heritage Bank Name ¡ Will do business as “Whidbey Island Bank” in Whidbey Island markets Headquarters ¡ Olympia, Washington (1) ¡ HFWA: Brian Vance (CEO), Jeff Deuel (COO), Don Hinson (CFO) and Dave Spurling (CCO) Management ¡ WBCO: Jack Wagner (Advi
Slide 6: Financial Impact
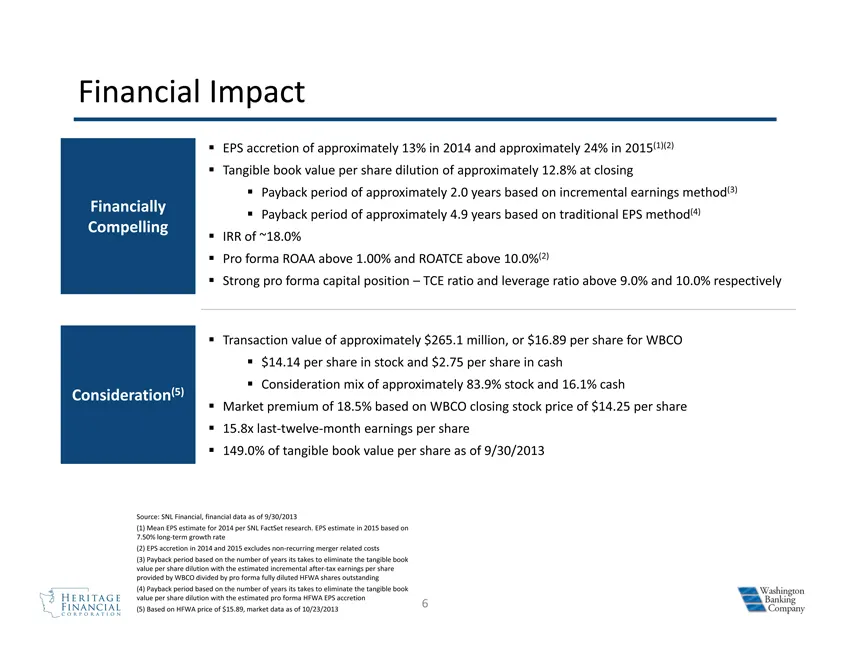
Financial Impact EPS accretion of approximately 13% in 2014 and approximately 24% in 2015(1)(2) Tangible book value per share dilution of approximately 12.8% at closing Payback period of approximately 2.0 years based on incremental earnings method(3) Financially (4) Payback period of approximately 4
Slide 7: Key Merger Assumptions / Diligence
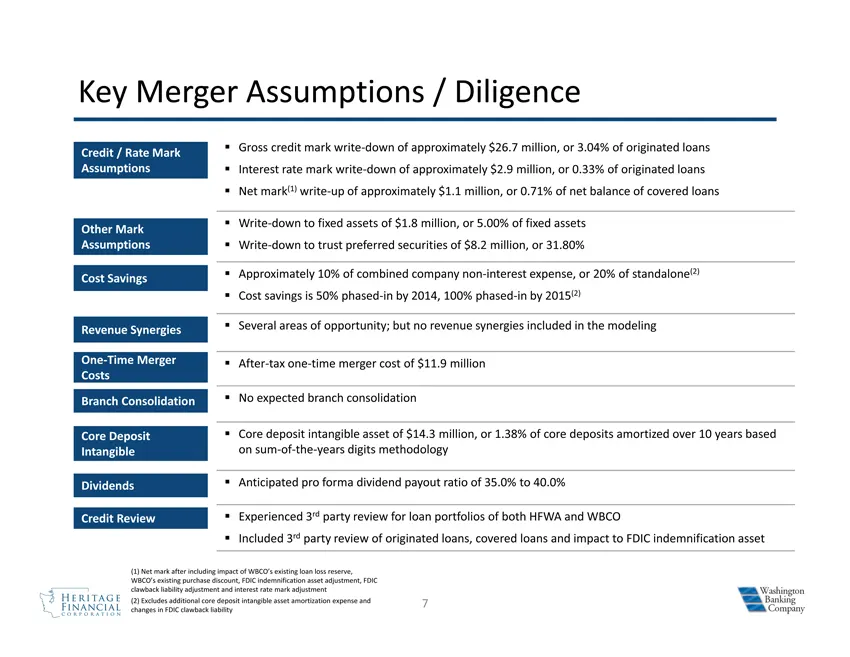
Key Merger Assumptions / Diligence ¡ Gross credit mark write down of approximately $26.7 million, or 3.04% of originated loans Credit / Rate Mark Assumptions ¡ Interest rate mark write down of approximately $2.9 million, or 0.33% of originated loans ¡ Net mark(1) write up of approximately $1.1 milli
Slide 8: Summary Pro Forma Financials
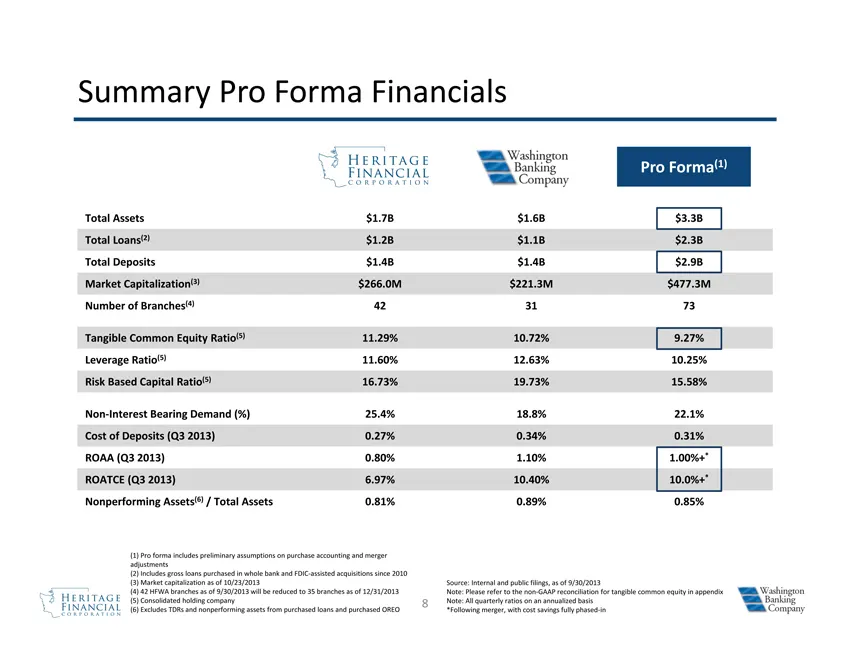
Summary Pro Forma Financials Total Assets $1.7B $1.6B $3.3B Total Loans(2) $1.2B $1.1B $2.3B Total Deposits $1.4B $1.4B $2.9B Market Capitalization(3) $266.0M $221.3M $477.3M Number of Branches(4) 42 31 73 Tangible Common Equity Ratio(5) 11.29% 10.72% 9.27% Leverage Ratio(5) 11.60% 12.63% 10.25% Ris
Slide 9: Pro Forma Loans & Deposits
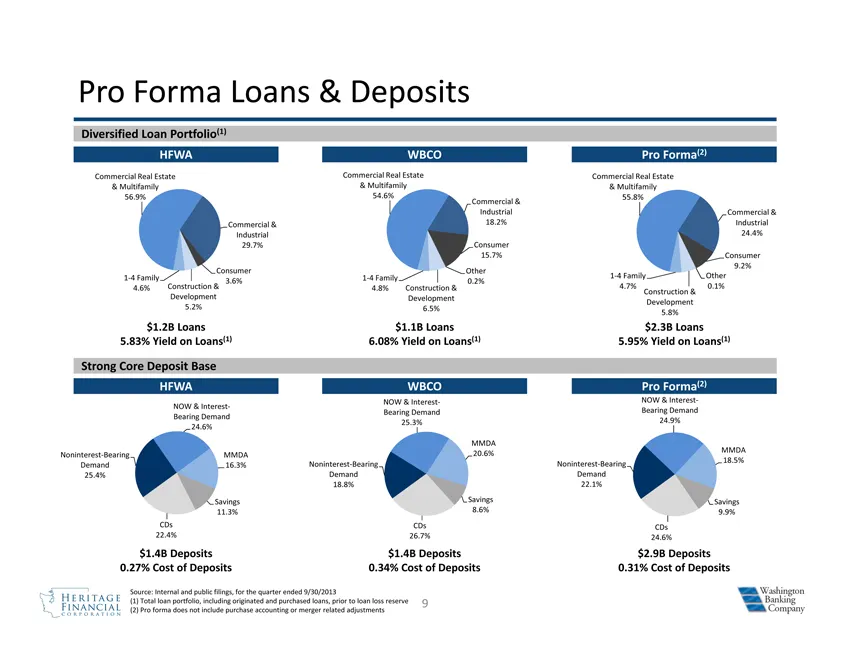
Pro Forma Loans & Deposits Diversified Loan Portfolio(1) HFWA WBCO Pro Forma(2) Commercial Real Estate Commercial Real Estate Commercial Real Estate & Multifamily & Multifamily & Multifamily 56.9% 54.6% Commercial & 55.8% Industrial Commercial & Commercial & 18.2% Industrial Industrial 24.4% 29.7% C
Slide 10: Strong Pro Forma Market Position in Washington
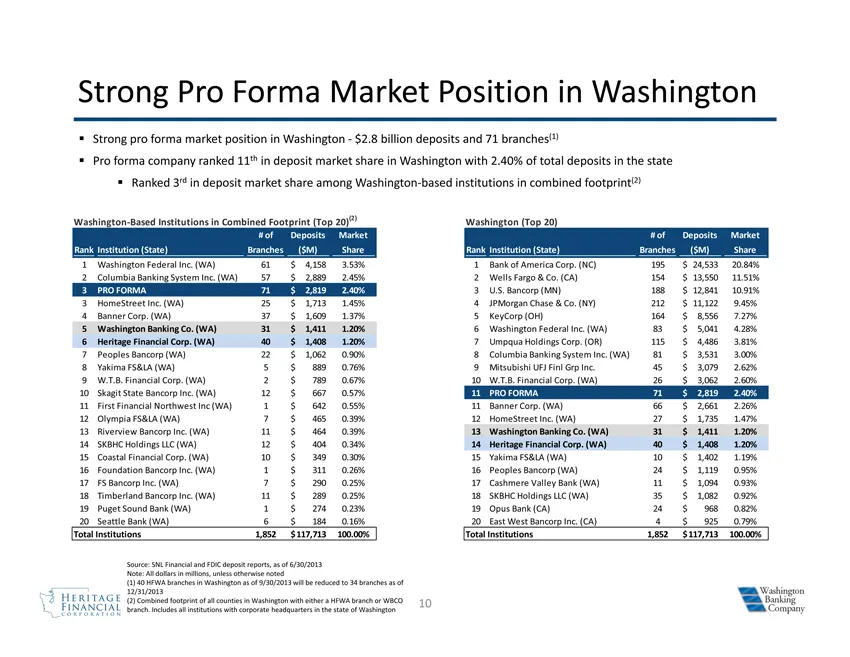
Strong Pro Forma Market Position in Washington ¡ Strong pro forma market position in Washington $2.8 billion deposits and 71 branches(1) ¡ Pro forma company ranked 11th in deposit market share in Washington with 2.40% of total deposits in the state ¡ Ranked 3rd in deposit market share among Washingt
Slide 11: Complementary Business Models
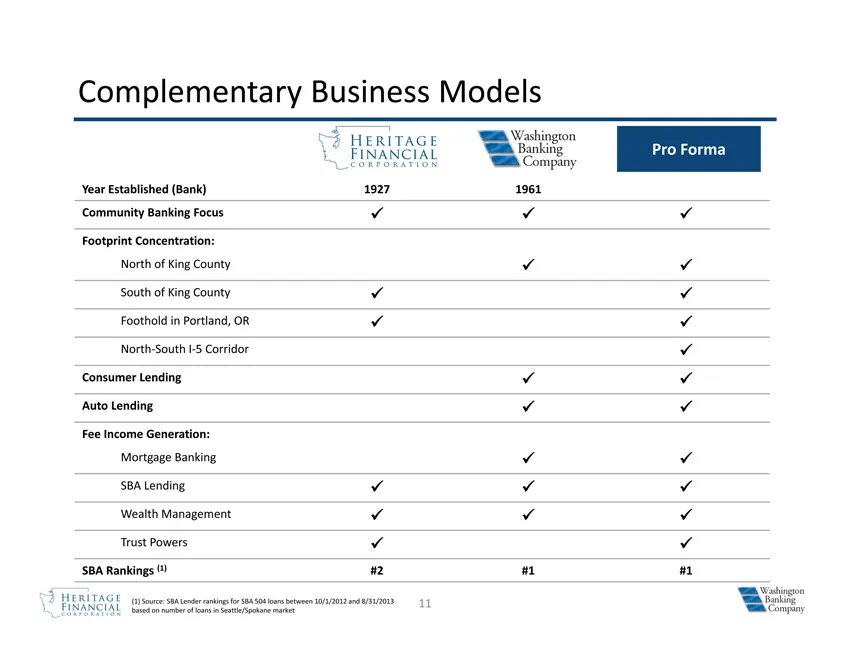
Complementary Business Models Pro Forma Year Established (Bank) 1927 1961 Community Banking Focus Footprint Concentration: North of King County South of King County Foothold in Portland, OR North South I 5 Corridor Consumer Lending Auto Lending Fee Income Generation: Mortgage Banking SBA Lending Wea
Slide 12: Benefits for All Stakeholders
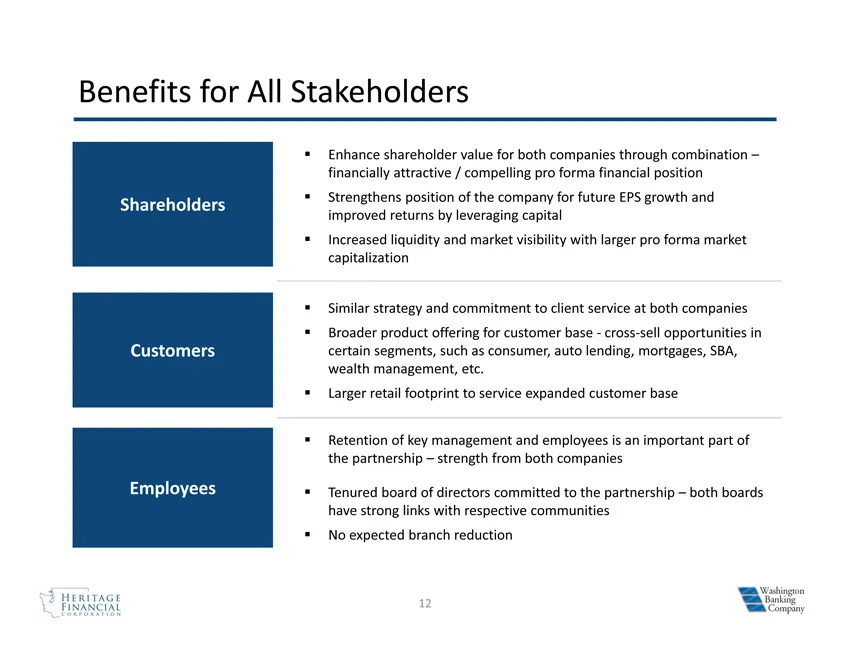
Benefits for All Stakeholders ¡ Enhance shareholder value for both companies through combination –financially attractive /compelling pro forma financial position ¡ Strengthens position of the company for future EPS growth and Shareholders improved returns by leveraging capital ¡ Increased liquidity
Slide 13: Summary
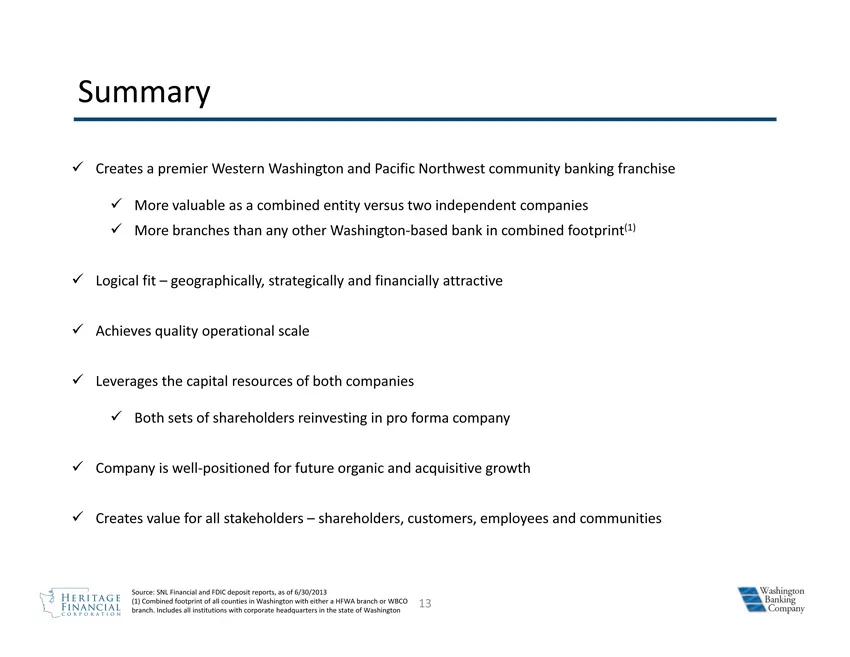
Summary Creates a premier Western Washington and Pacific Northwest community banking franchise More valuable as a combined entity versus two independent companies More branches than any other Washington based bank in combined footprint(1) Logical fit geographically, strategically and financially att
Slide 14: Questions & Answers
Questions & Answers Heritage Financial Corporation Washington Banking Company Brian Vance, President and CEO Jack Wagner, President and CEO Jeff Deuel, President and COO of Heritage Bank Bryan McDonald, President and CEO of Whidbey Island Bank Don Hinson, EVP and CFO Rick Shields, EVP and CFO 14
Slide 15: Appendix
Appendix 15
Slide 16: Strong Position in Primary Markets
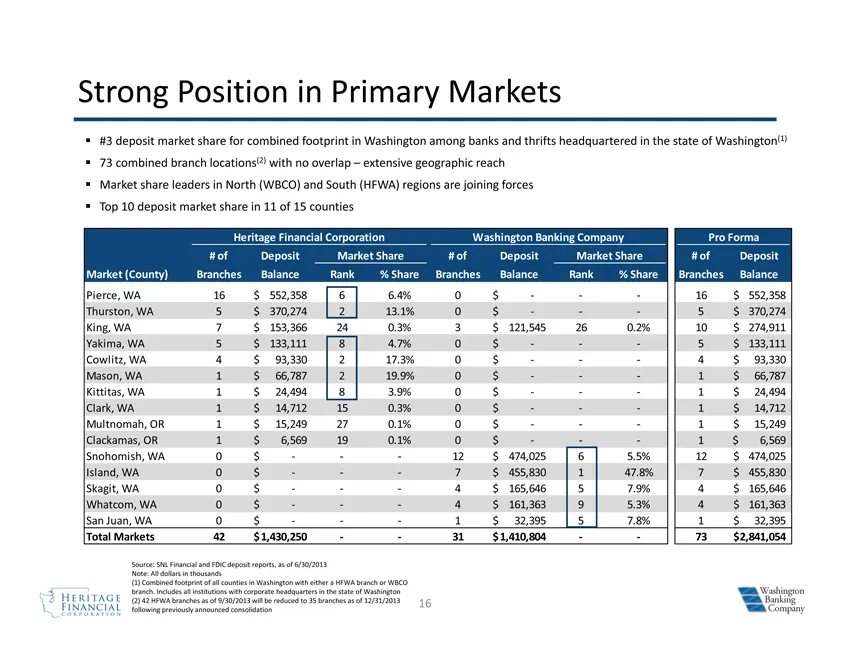
Strong Position in Primary Markets ¡ #3 deposit market share for combined footprint in Washington among banks and thrifts headquartered in the state of Washington(1) ¡ 73 combined branch locations(2) with no overlap – extensive geographic reach ¡ Market share leaders in North (WBCO) and South (HFWA)
Slide 17: HFWA Summary of 3rd Quarter Performance
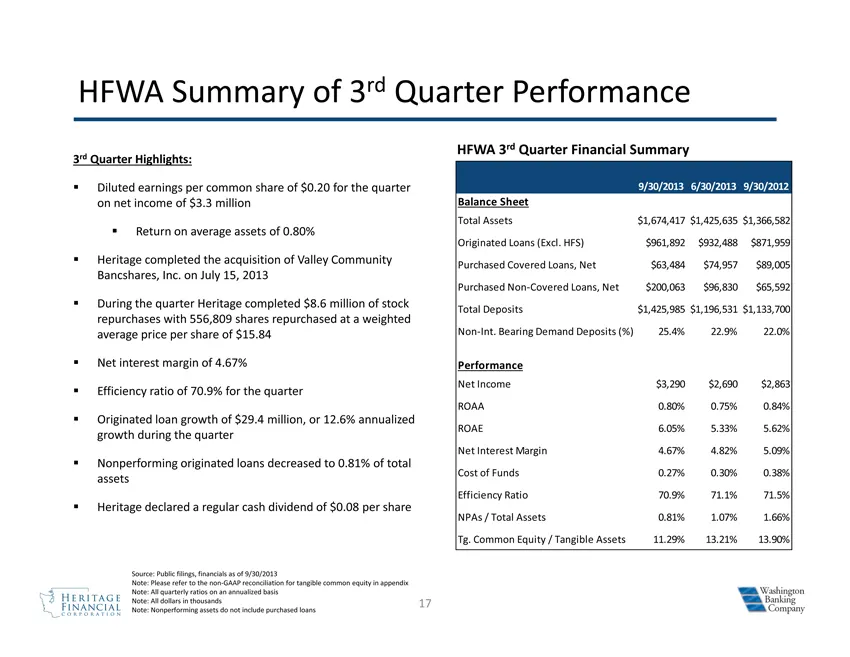
HFWA Summary of 3rd Quarter Performance HFWA 3rd Quarter Financial Summary 3rd Quarter Highlights: ¡ Diluted earnings per common share of $0.20 for the quarter 9/30/2013 6/30/2013 9/30/2012 on net income of $3.3 million Balance Sheet Total Assets $1,674,417 $1,425,635 $1,366,582 ¡ Return on average
Slide 18: WBCO Summary of 3rd Quarter Performance
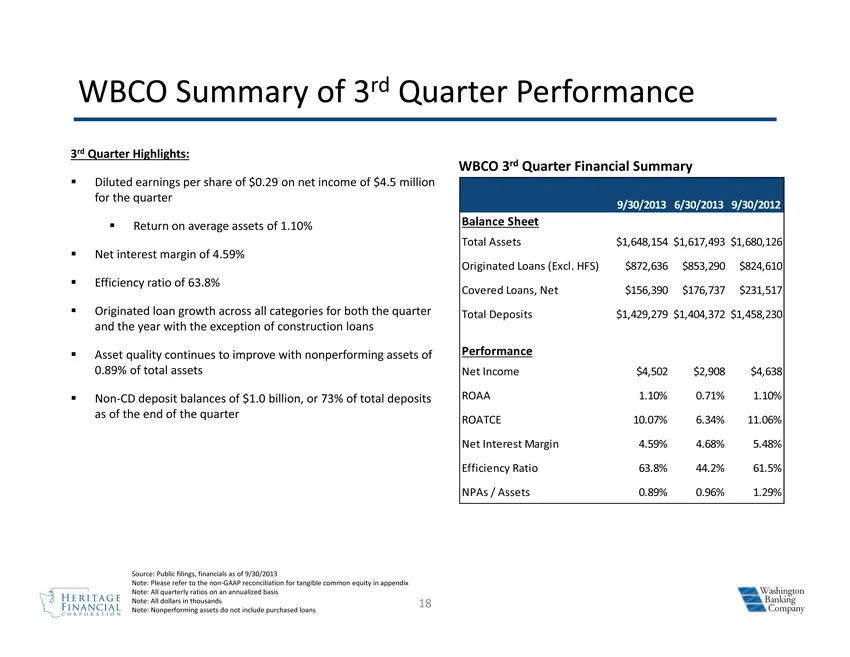
WBCO Summary of 3rd Quarter Performance 3rd Quarter Highlights: WBCO 3rd Quarter Financial Summary Diluted earnings per share of $0.29 on net income of $4.5 million for the quarter 9/30/2013 6/30/2013 9/30/2012 Return on average assets of 1.10% Balance Sheet Total Assets $1,648,154 $1,617,493 $1,680
Slide 19: Non GAAP Reconciliation
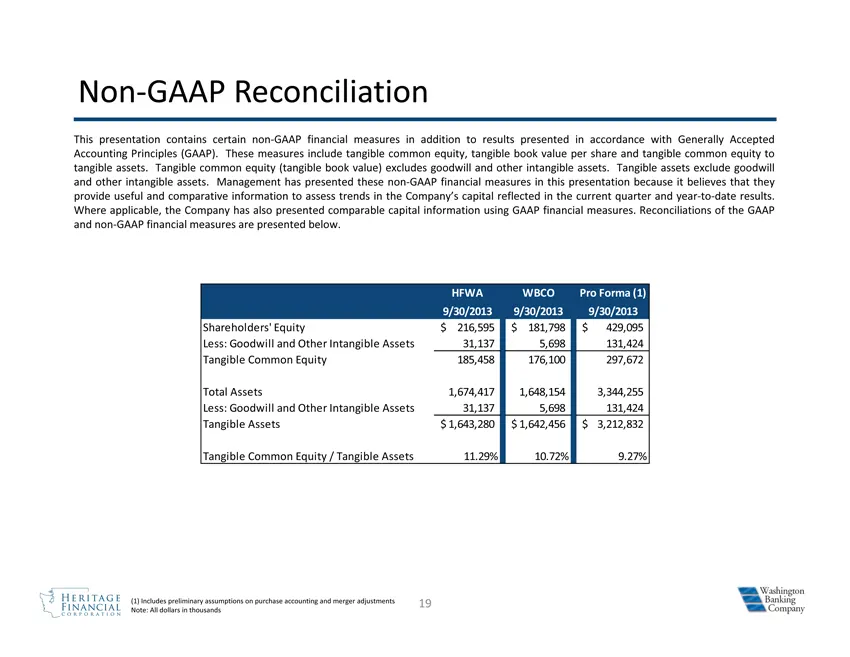
Non GAAP Reconciliation This presentation contains certain non GAAP financial measures in addition to results presented in accordance with Generally Accepted Accounting Principles (GAAP). These measures include tangible common equity, tangible book value per share and tangible common equity to tangi
Slide 20: Additional Information For Shareholders
Additional Information For Shareholders Heritage will file a registration statement on Form S 4 with the SEC in connection with the proposed transaction. The registration statement will include a joint proxy statement of Heritage and Washington Banking that also constitutes a prospectus of Heritage,
Source: SEC EDGAR · 425 filed Oct 24, 2013