Intercorp Financial Services Inc. · NYSE:IFS
Intercorp Financial Services — Investor Presentation (March 2023)
55 slides from Intercorp Financial Services's investor presentation, March 2023
Slide 1: Investor Presentation March 2023
Investor Presentation March 2023
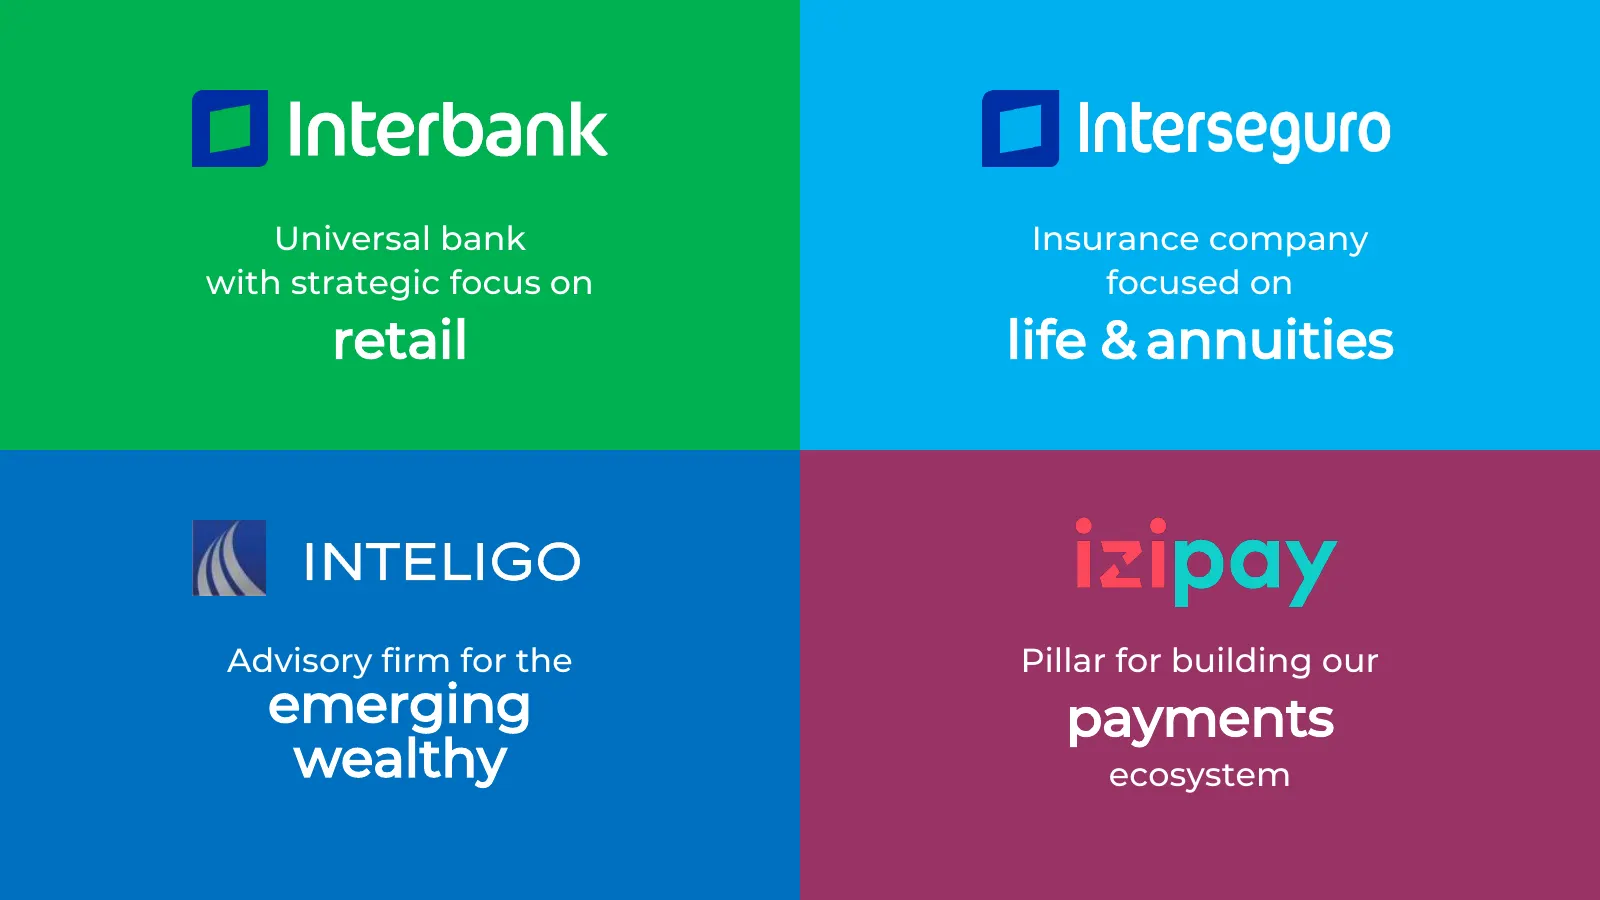
Slide 2: Four businesses: bank, insurance, wealth advisory, payments
Universal bank Insurance company with strategic focus on focused on retail life & annuities Advisory firm for the Pillar for building our emerging payments wealthy ecosystem
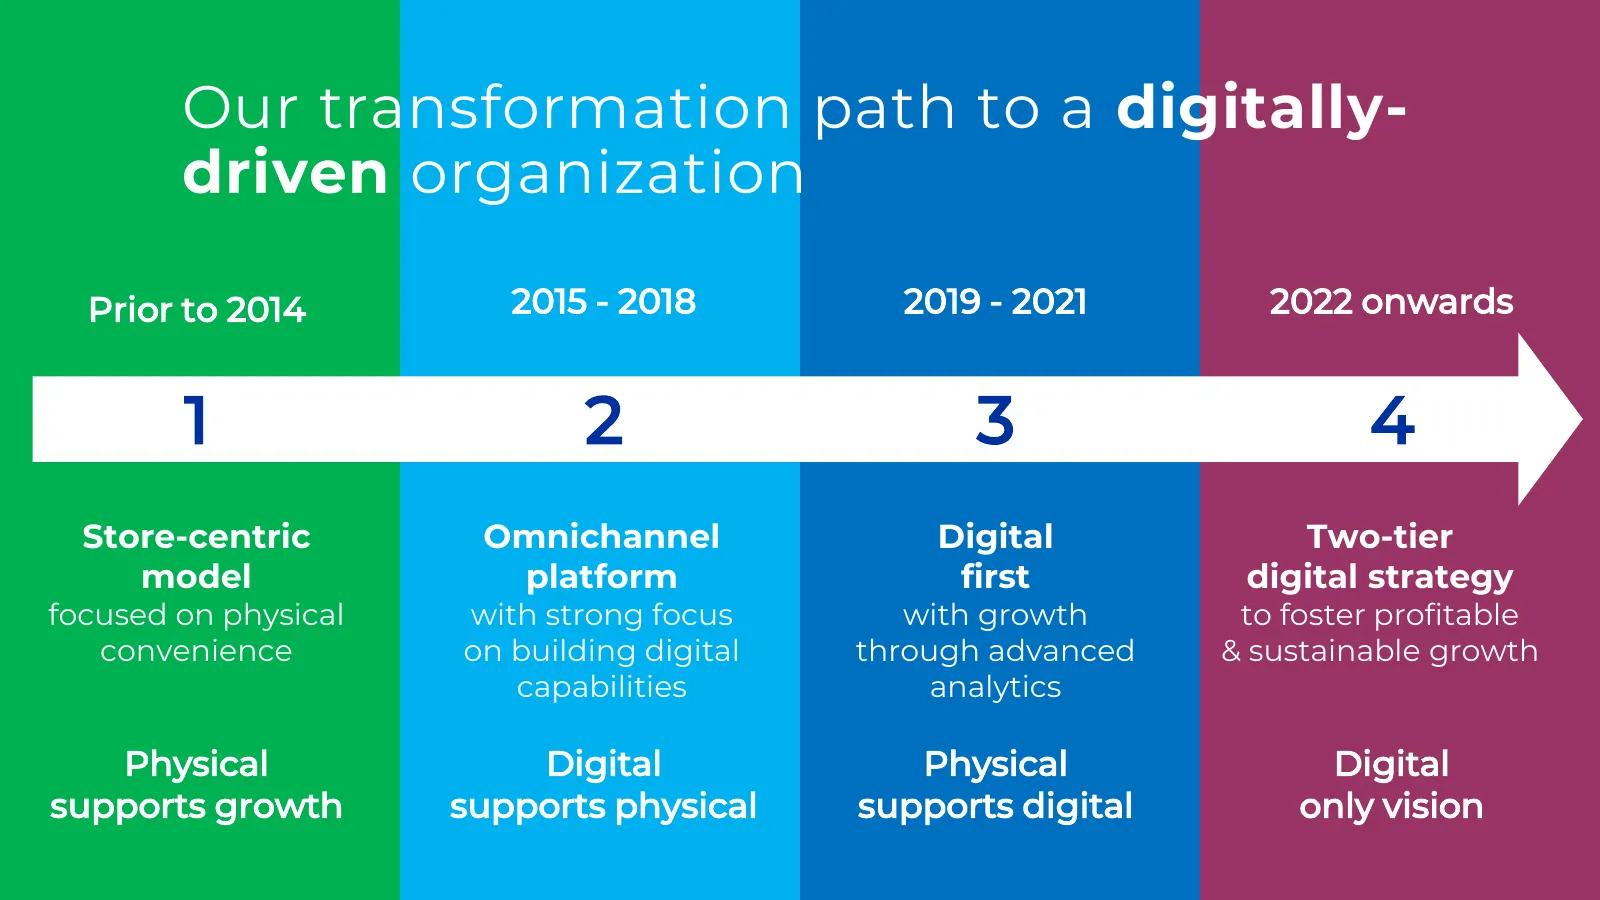
Slide 3: Our transformation path to a digitally-driven organization
Our transformation path to a digitally- driven organization Prior to 2014 2015 - 2018 2019 - 2021 2022 onwards 1 2 3 4 Store-centric Omnichannel Digital Two-tier model platform first digital strategy focused on physical with strong focus with growth to foster profitable convenience on building digit
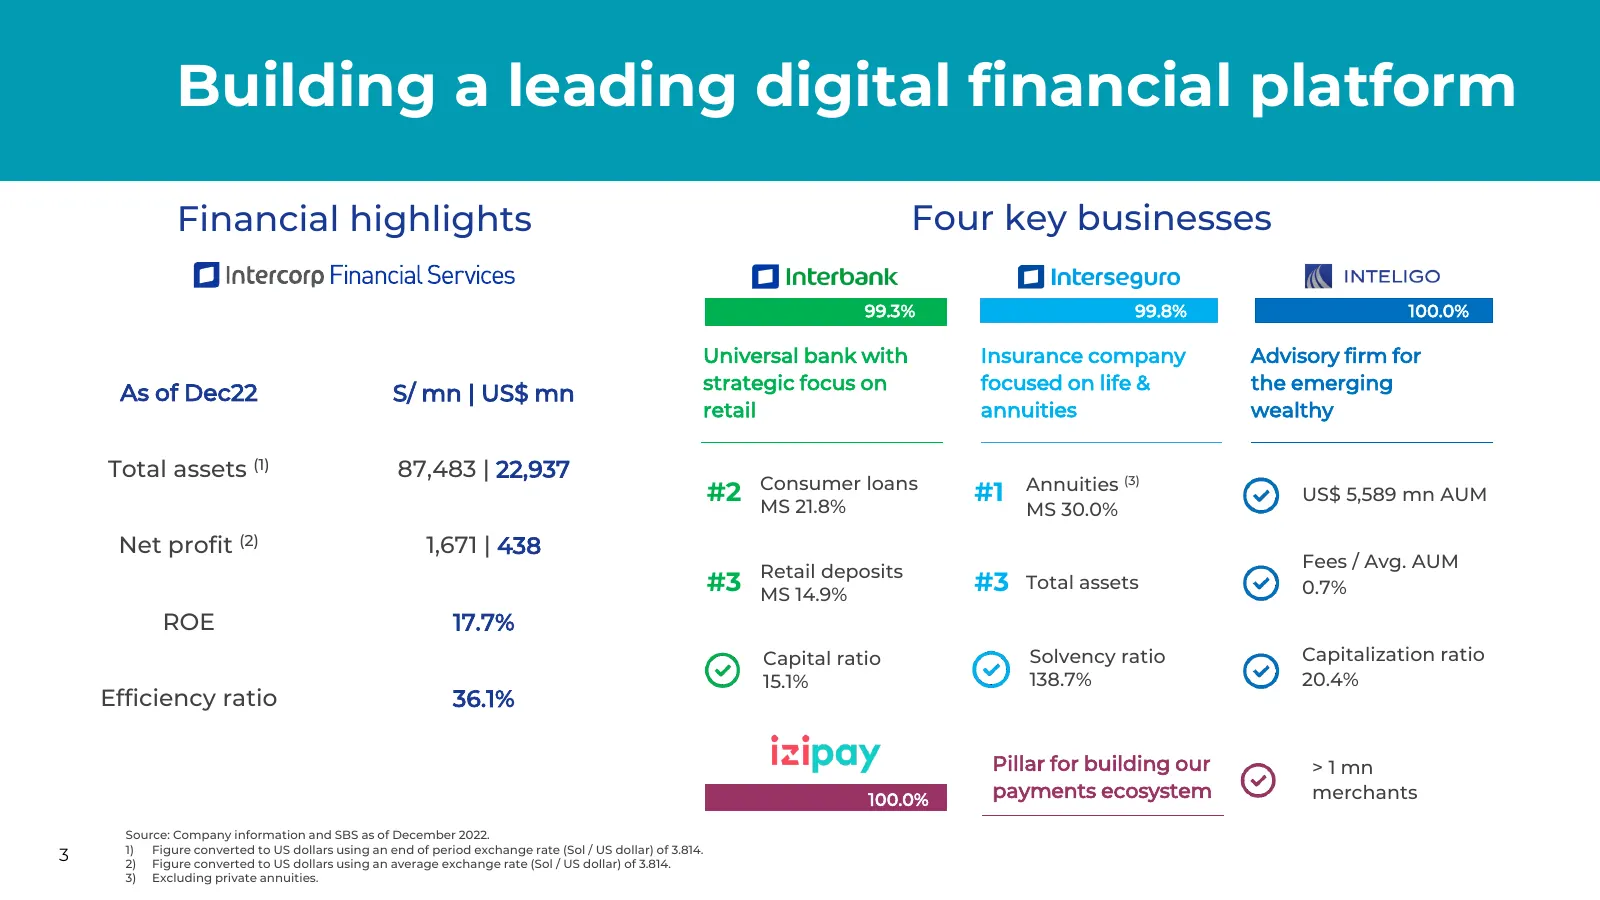
Slide 4: Building a leading digital financial platform
Building a leading digital financial platform Financial highlights Four key businesses 99.3% 99.8% 100.0% Universal bank with Insurance company Advisory firm for strategic focus on focused on life & the emerging As of Dec22 S/ mn | US$ mn retail annuities wealthy Total assets (1) 87,483 | 22,937 Con
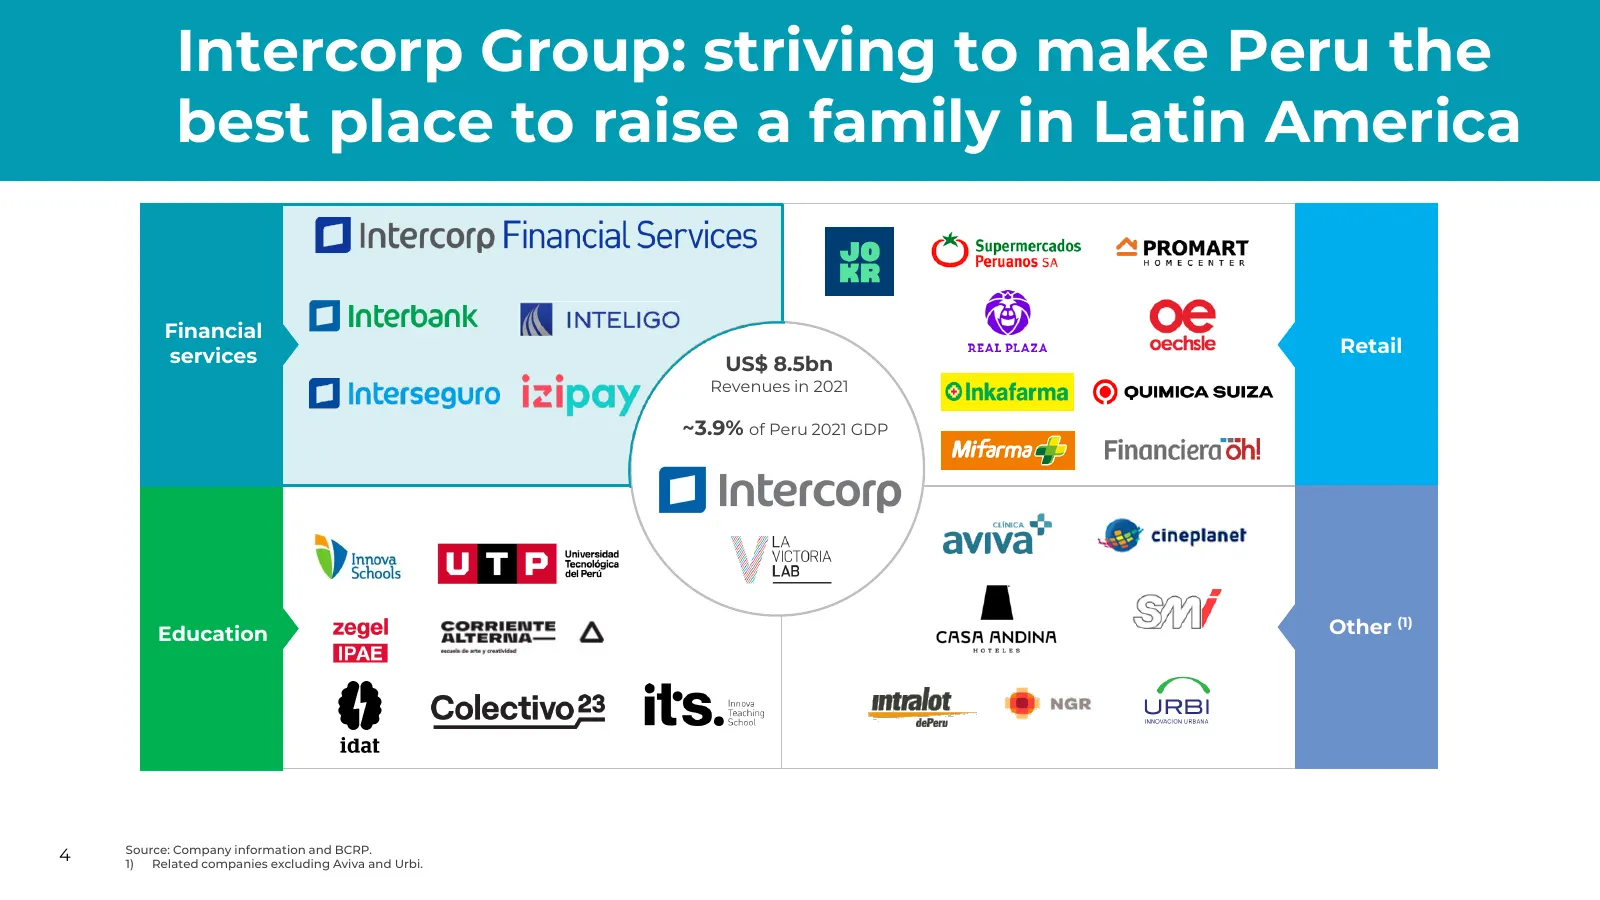
Slide 5: Intercorp Group: striving to make Peru the best place to raise a family
Intercorp Group: striving to make Peru the best place to raise a family in Latin America Financial services Retail US$ 8.5bn Revenues in 2021 ~3.9% of Peru 2021 GDP Education Other (1) Source: Company information and BCRP. 4 1) Related companies excluding Aviva and Urbi.
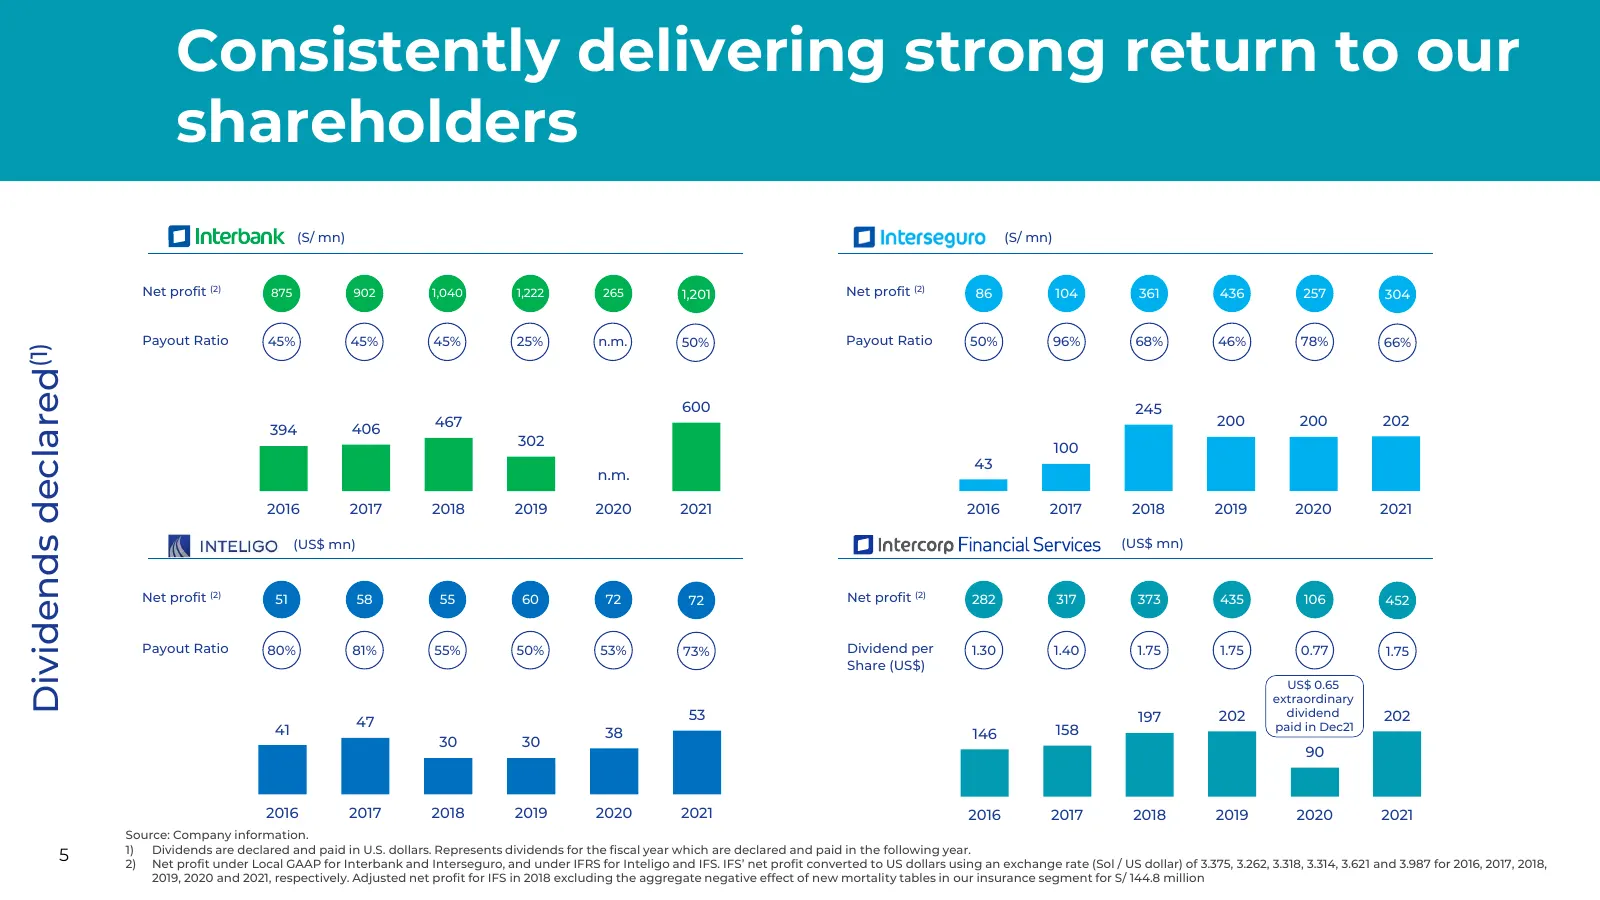
Slide 6: Consistently delivering strong return to our shareholders
Consistently delivering strong return to our shareholders (S/ mn) (S/ mn) Net profit (2) 875 902 1,040 1,222 265 1,201 Net profit (2) 86 104 361 436 257 304 Payout Ratio 45% 45% 45% 25% n.m. 50% Payout Ratio 50% 96% 68% 46% 78% 66% Dividends declared(1) 600 245 467 200 200 202 394 406 302 100 43 n.m
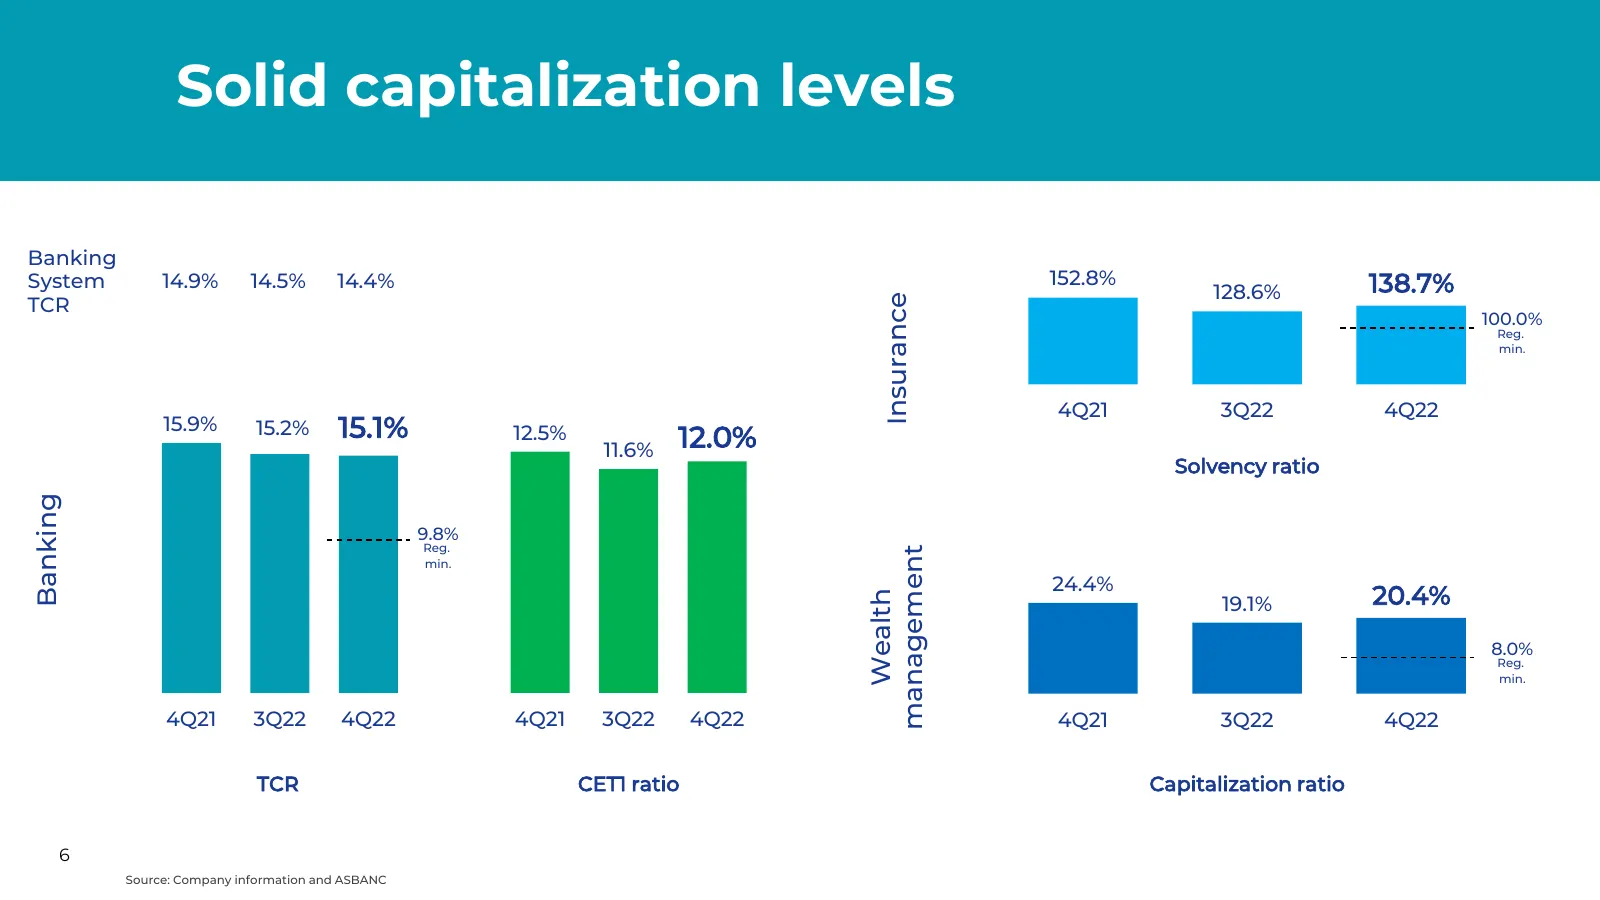
Slide 7: Solid capitalization levels
Solid capitalization levels Banking System 14.9% 14.5% 14.4% 152.8% 138.7% 128.6% TCR Insurance 100.0% Reg. min. 4Q21 3Q22 4Q22 15.9% 15.2% 15.1% 12.5% 12.0% 11.6% Solvency ratio Banking 9.8% Reg. management min. 24.4% 20.4% Wealth 19.1% 8.0% Reg. min. 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 TC
Slide 8: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
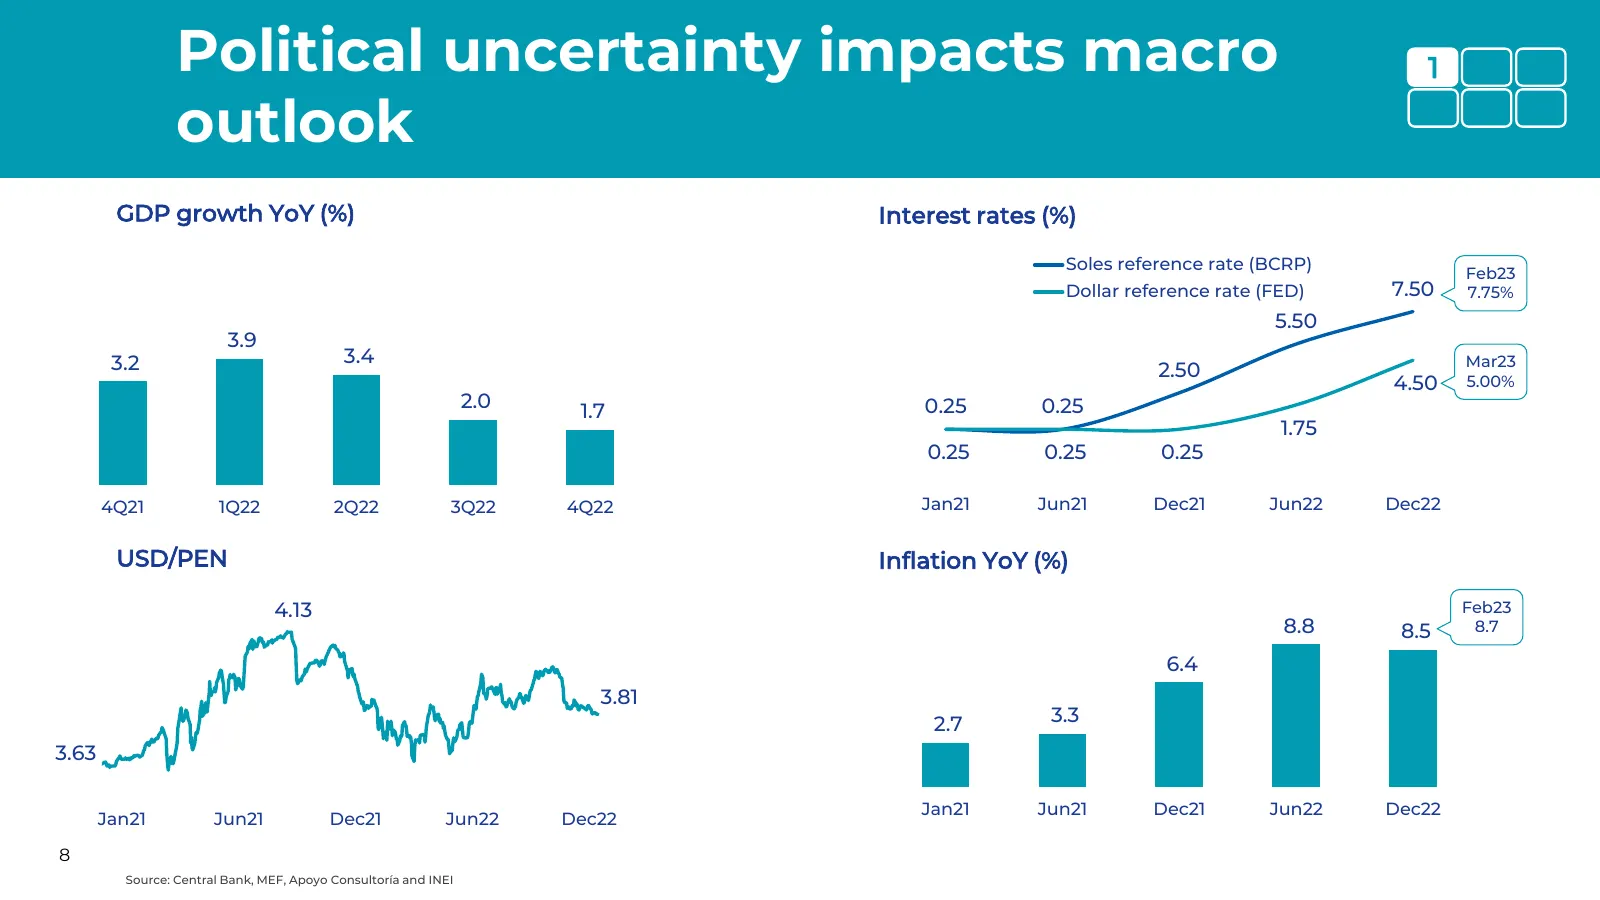
Slide 9: Political uncertainty impacts macro outlook
Political uncertainty impacts macro 1 outlook GDP growth YoY (%) Interest rates (%) Soles reference rate (BCRP) Feb23 Dollar reference rate (FED) 7.50 7.75% 5.50 3.9 3.2 3.4 Mar23 2.50 4.50 5.00% 2.0 1.7 0.25 0.25 1.75 0.25 0.25 0.25 4Q21 1Q22 2Q22 3Q22 4Q22 Jan21 Jun21 Dec21 Jun22 Dec22 USD/PEN Inf
Slide 10: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
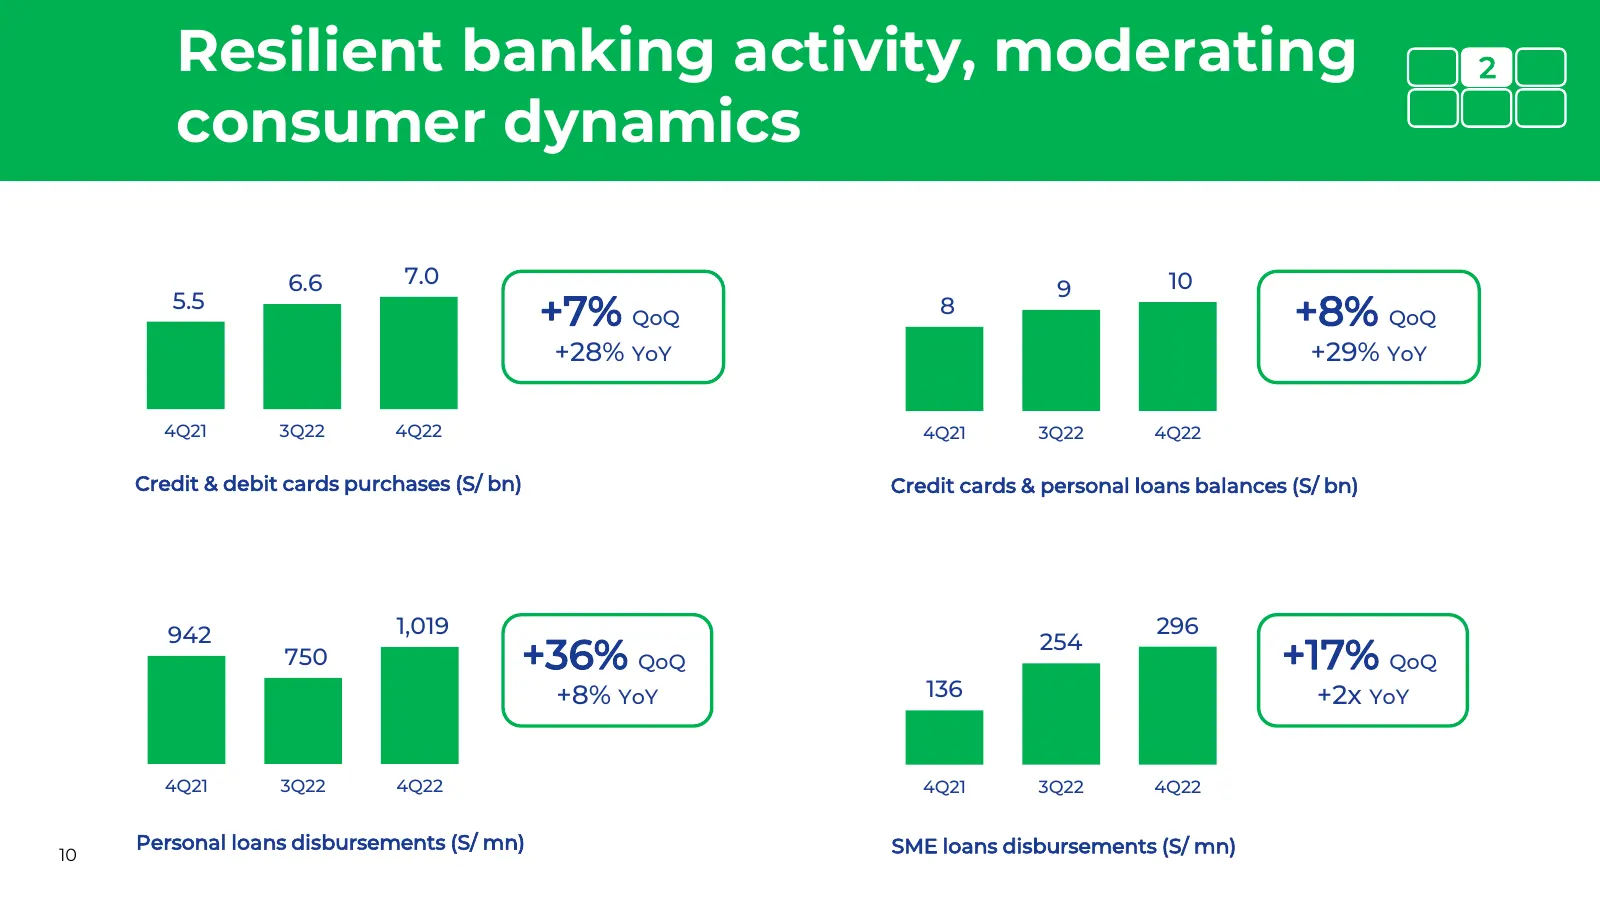
Slide 11: Resilient banking activity, moderating consumer dynamics
Resilient banking activity, moderating 2 consumer dynamics 6.6 7.0 10 9 5.5 +7% QoQ 8 +8% QoQ +28% YoY +29% YoY 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 Credit & debit cards purchases (S/ bn) Credit cards & personal loans balances (S/ bn) 942 1,019 296 254 750 +36% QoQ +17% QoQ +8% YoY 136 +2x YoY 4Q21 3Q22 4Q
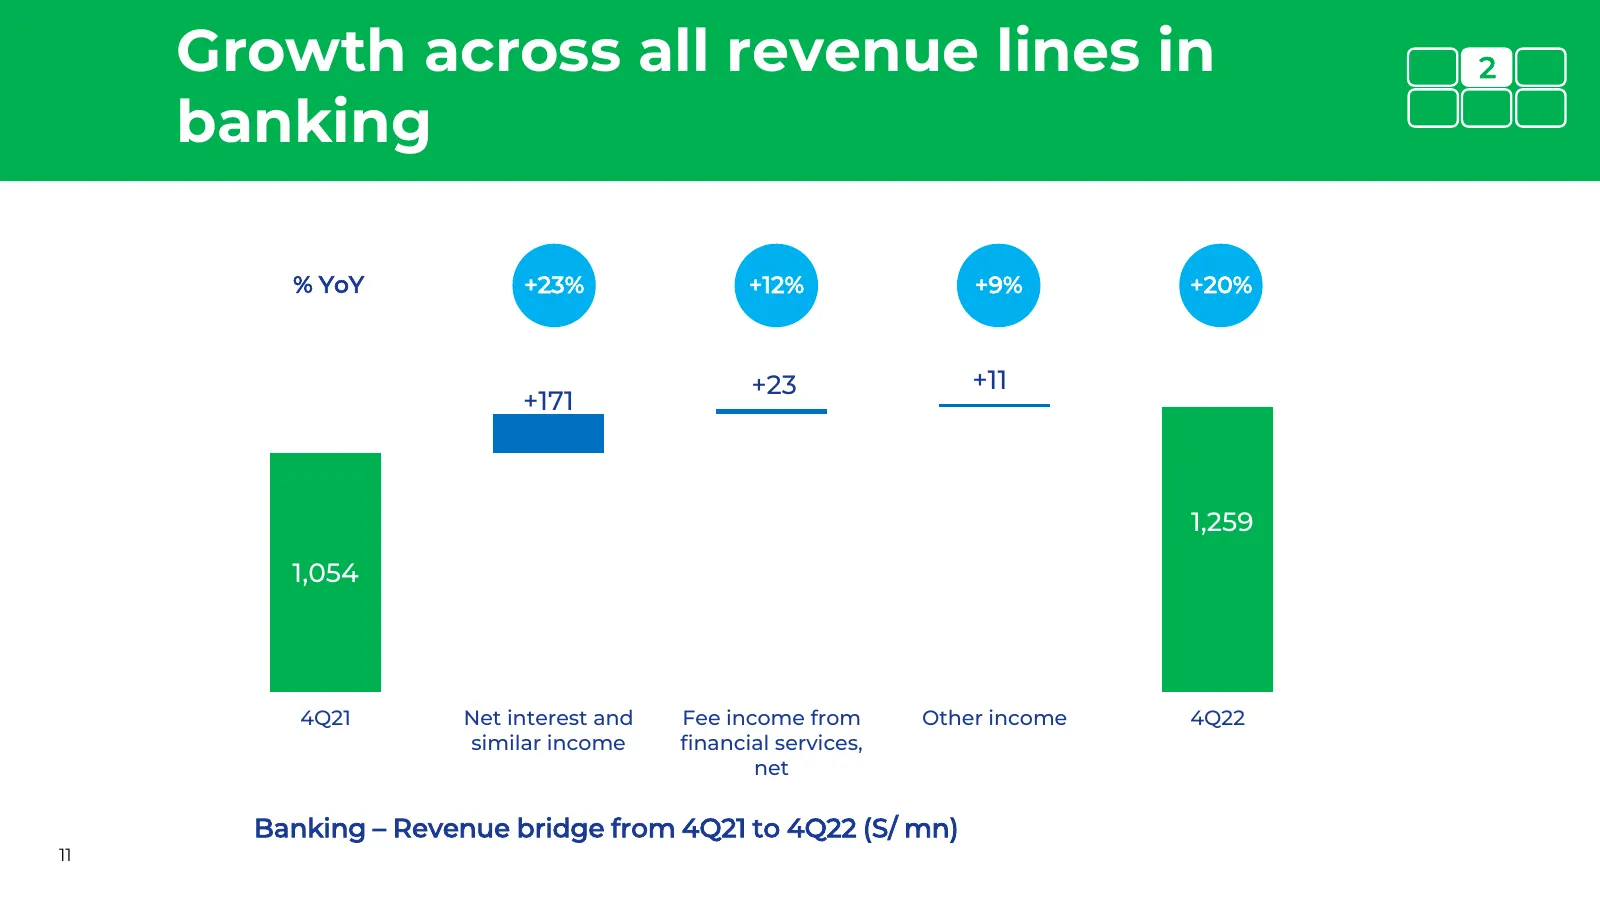
Slide 12: Growth across all revenue lines in banking
Growth across all revenue lines in 2 banking % YoY +23% +12% +9% +20% +23 +11 +171 1,259 1,054 4Q21 Net interest and Fee income from Other income 4Q22 similar income financial services, net Banking – Revenue bridge from 4Q21 to 4Q22 (S/ mn) 11
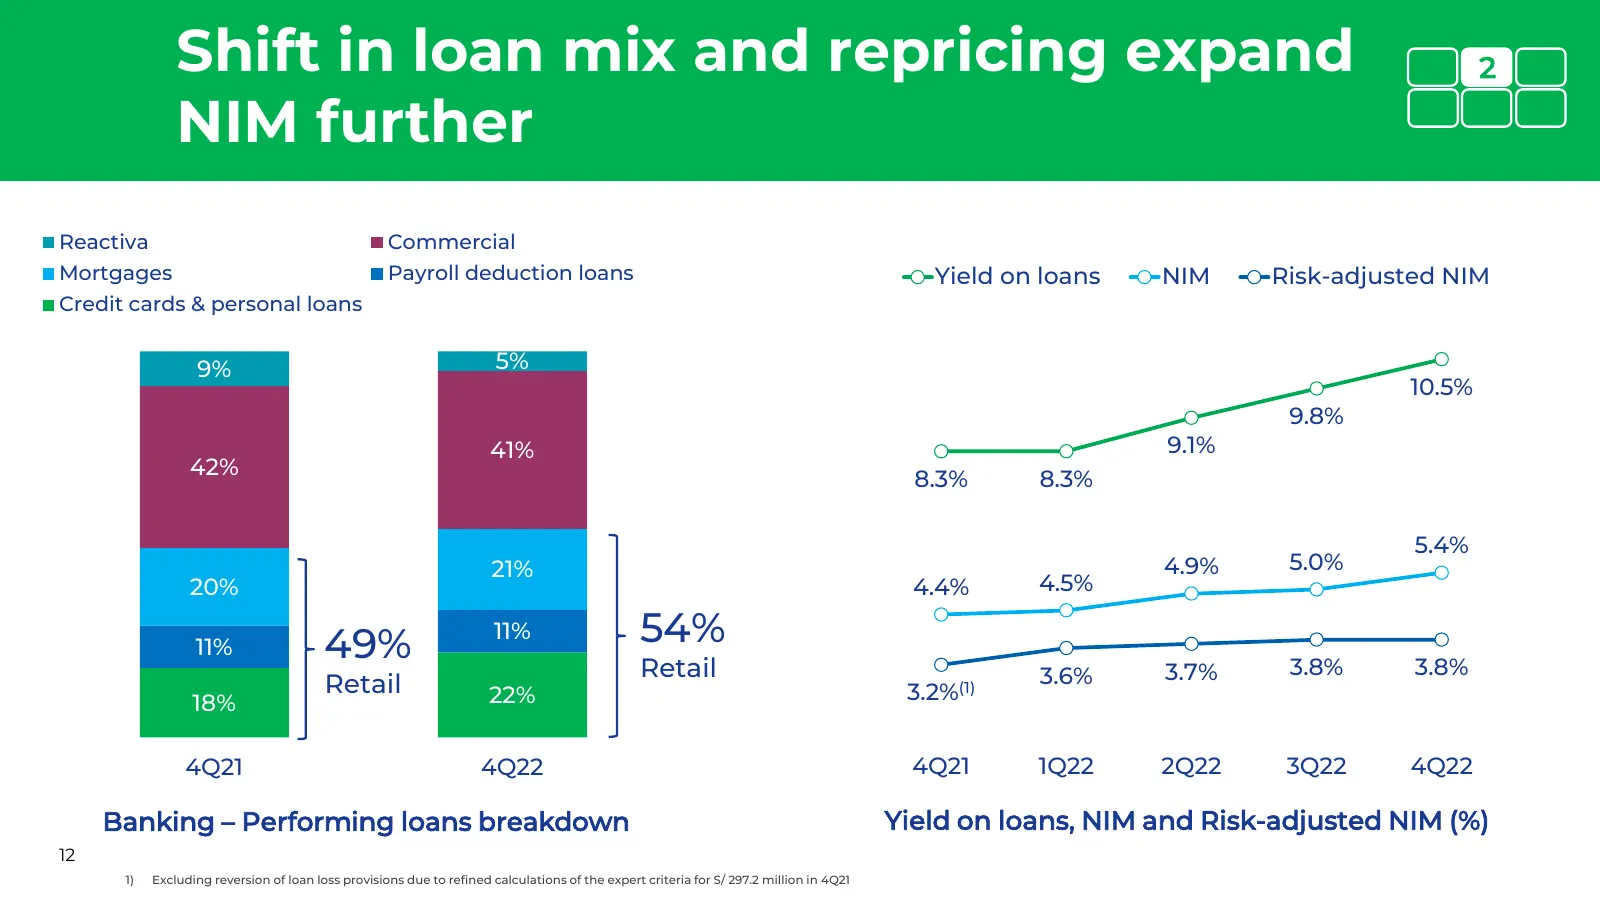
Slide 13: Shift in loan mix and repricing expand NIM further
Shift in loan mix and repricing expand 2 NIM further Reactiva Commercial Mortgages Payroll deduction loans Yield on loans NIM Risk-adjusted NIM Credit cards & personal loans 9% 5% 10.5% 9.8% 41% 9.1% 42% 8.3% 8.3% 5.4% 21% 4.9% 5.0% 20% 4.4% 4.5% 11% 49% 11% 54% Retail 3.6% 3.7% 3.8% 3.8% Retail 22%
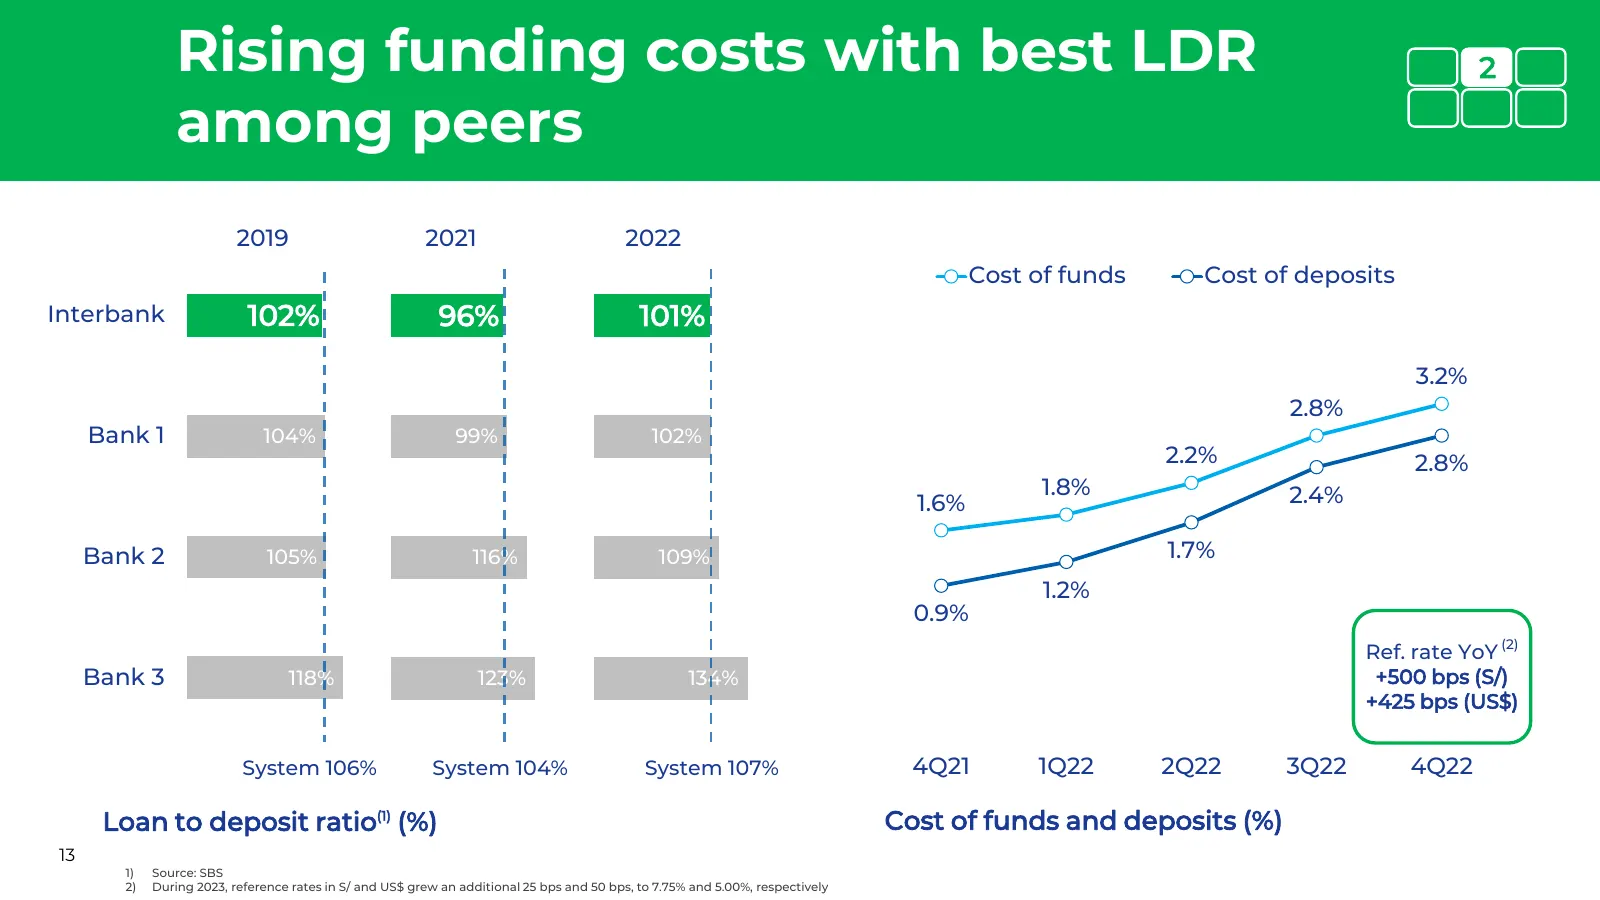
Slide 14: Rising funding costs with best LDR among peers
Rising funding costs with best LDR 2 among peers 2019 2021 2022 Cost of funds Cost of deposits Interbank 102% 96% 101% 3.2% 2.8% Bank 1 104% 99% 102% 2.2% 2.8% 1.8% 2.4% 1.6% Bank 2 105% 116% 109% 1.7% 1.2% 0.9% Ref. rate YoY (2) Bank 3 118% 123% 134% +500 bps (S/) +425 bps (US$) System 106% System
Slide 15: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
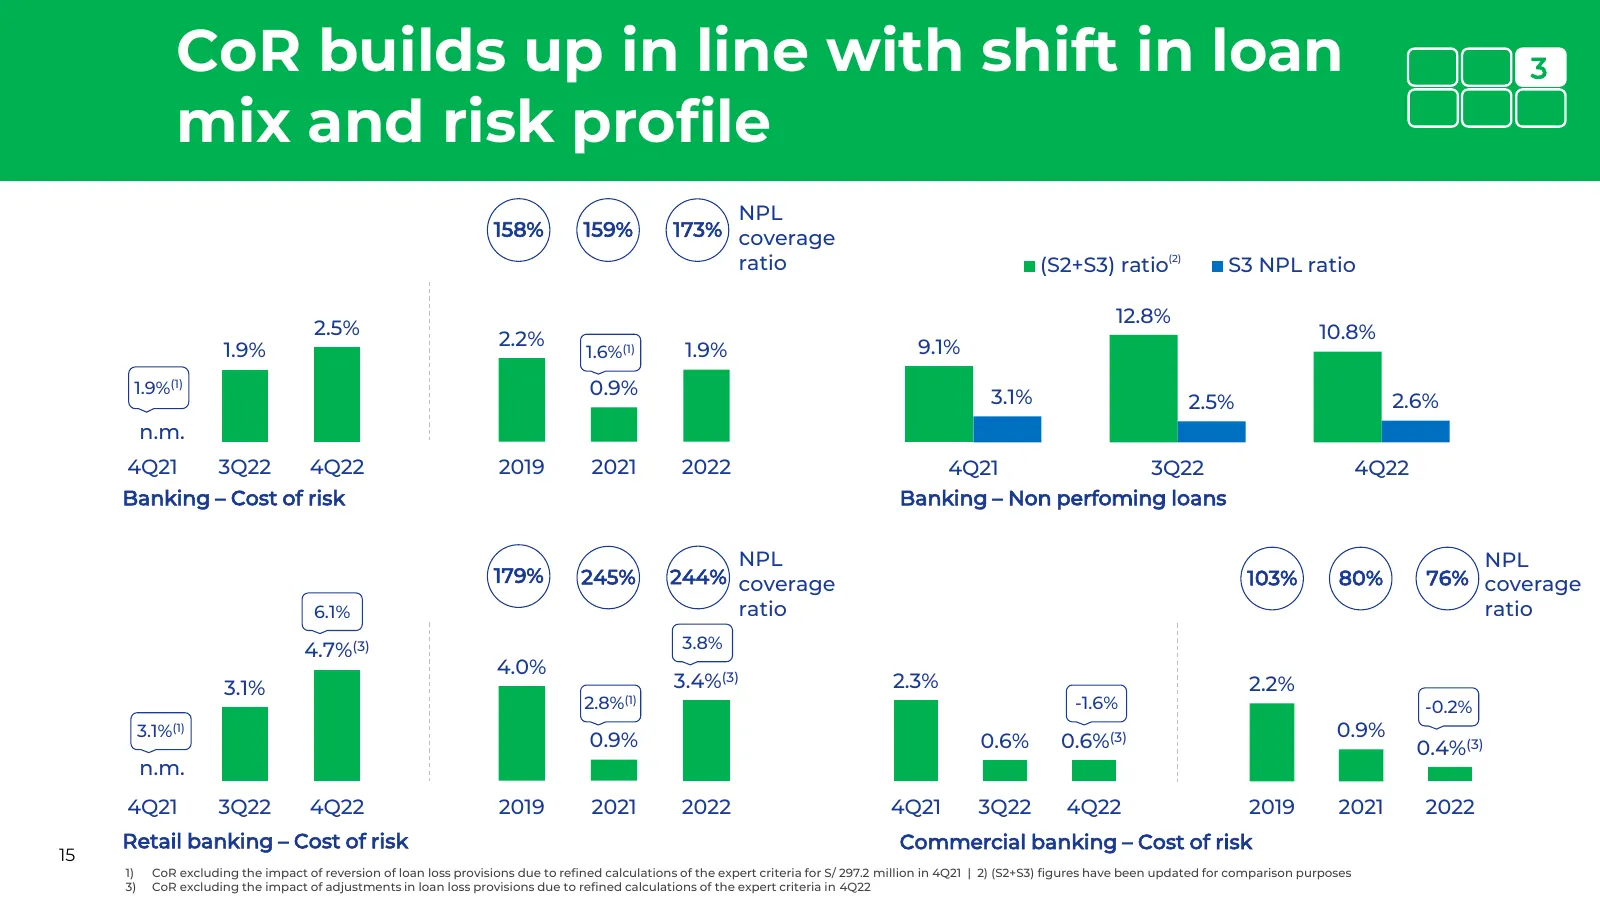
Slide 16: CoR builds up in line with shift in loan mix and risk profile
CoR builds up in line with shift in loan 3 mix and risk profile NPL 158% 159% 173% coverage ratio (S2+S3) ratio (2) S3 NPL ratio 12.8% 2.5% 10.8% 2.2% 9.1% 1.9% 1.6%(1) 1.9% 1.9%(1) 0.9% 3.1% 2.5% 2.6% n.m. 4Q21 3Q22 4Q22 2019 2021 2022 4Q21 3Q22 4Q22 Banking – Cost of risk Banking – Non perfoming l
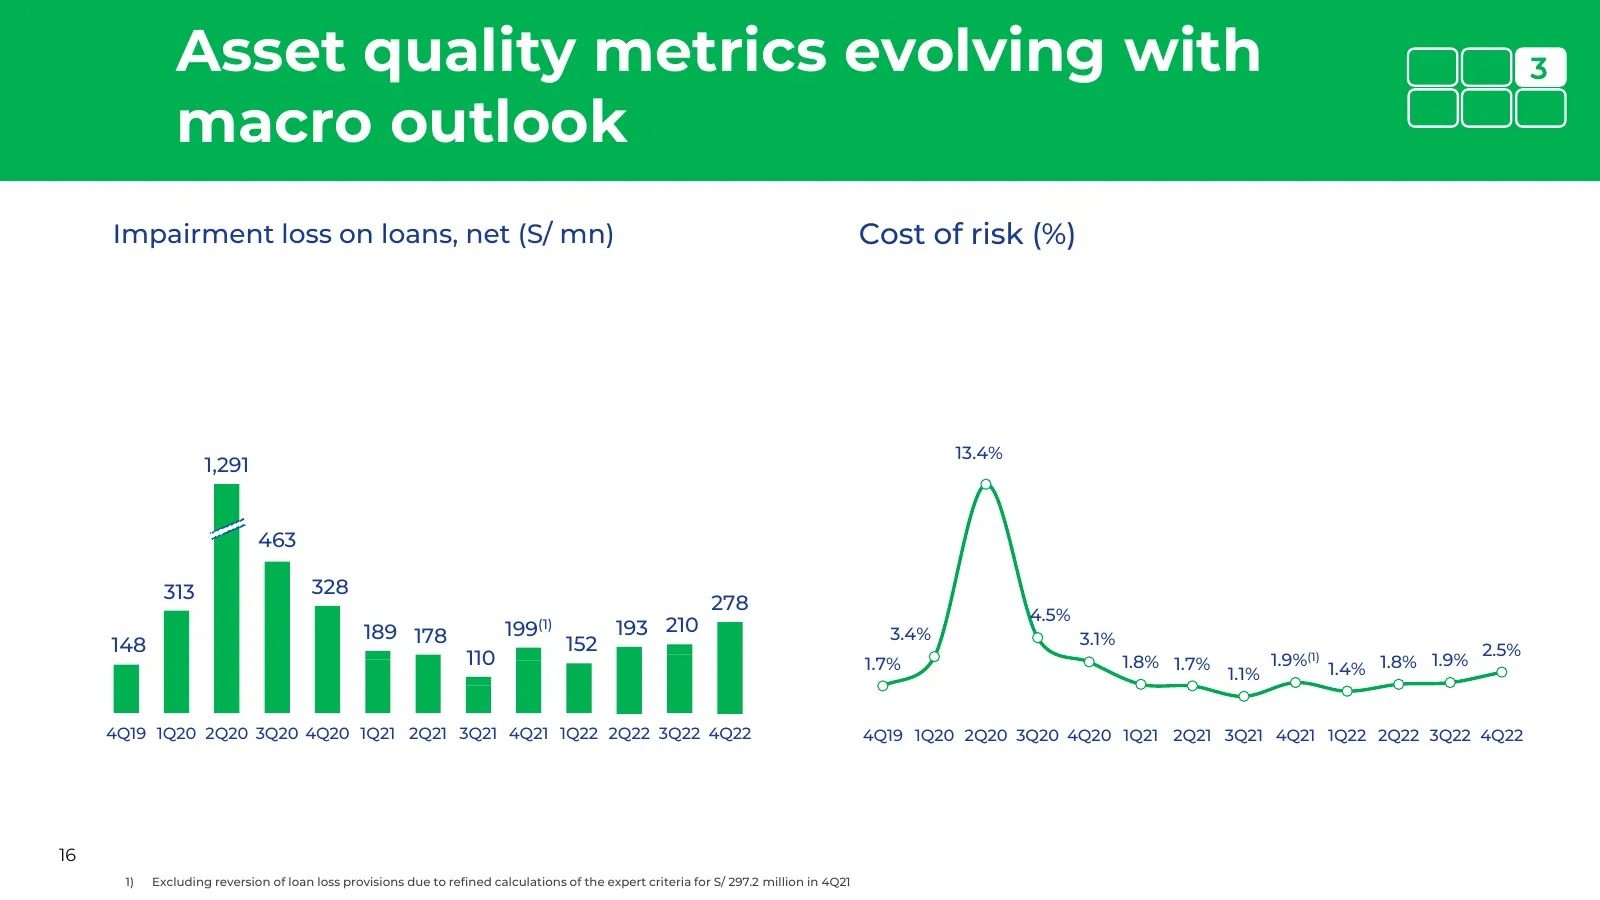
Slide 17: Asset quality metrics evolving with macro outlook
Asset quality metrics evolving with 3 macro outlook Impairment loss on loans, net (S/ mn) Cost of risk (%) 13.4% 1,291 463 313 328 278 4.5% 189 178 199(1) 193 210 3.4% 148 152 3.1% 2.5% 110 1.7% 1.8% 1.7% 1.9%(1) 1.4% 1.8% 1.9% 1.1% 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 2Q22 3Q22 4Q22 4Q
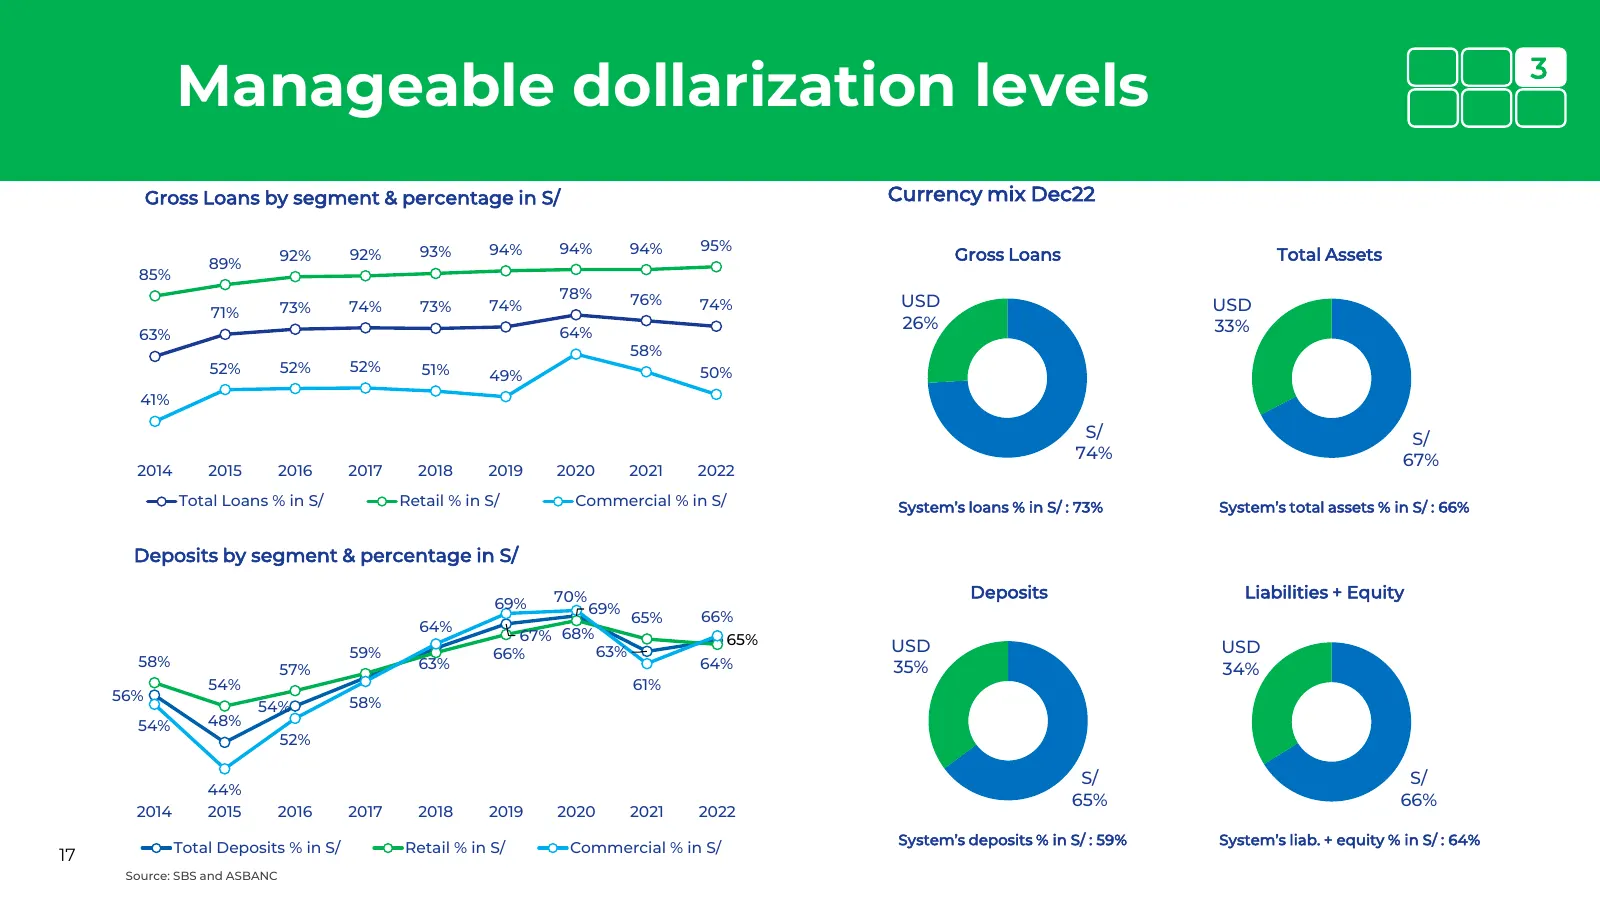
Slide 18: Manageable dollarization levels
Manageable dollarization levels 3 Gross Loans by segment & percentage in S/ Currency mix Dec22 93% 94% 94% 94% 95% 89% 92% 92% Gross Loans Total Assets 85% 78% 76% 73% 74% 73% 74% 74% USD USD 71% 26% 33% 63% 64% 58% 52% 52% 52% 51% 50% 49% 41% S/ S/ 74% 67% 2014 2015 2016 2017 2018 2019 2020 2021 20
Slide 19: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
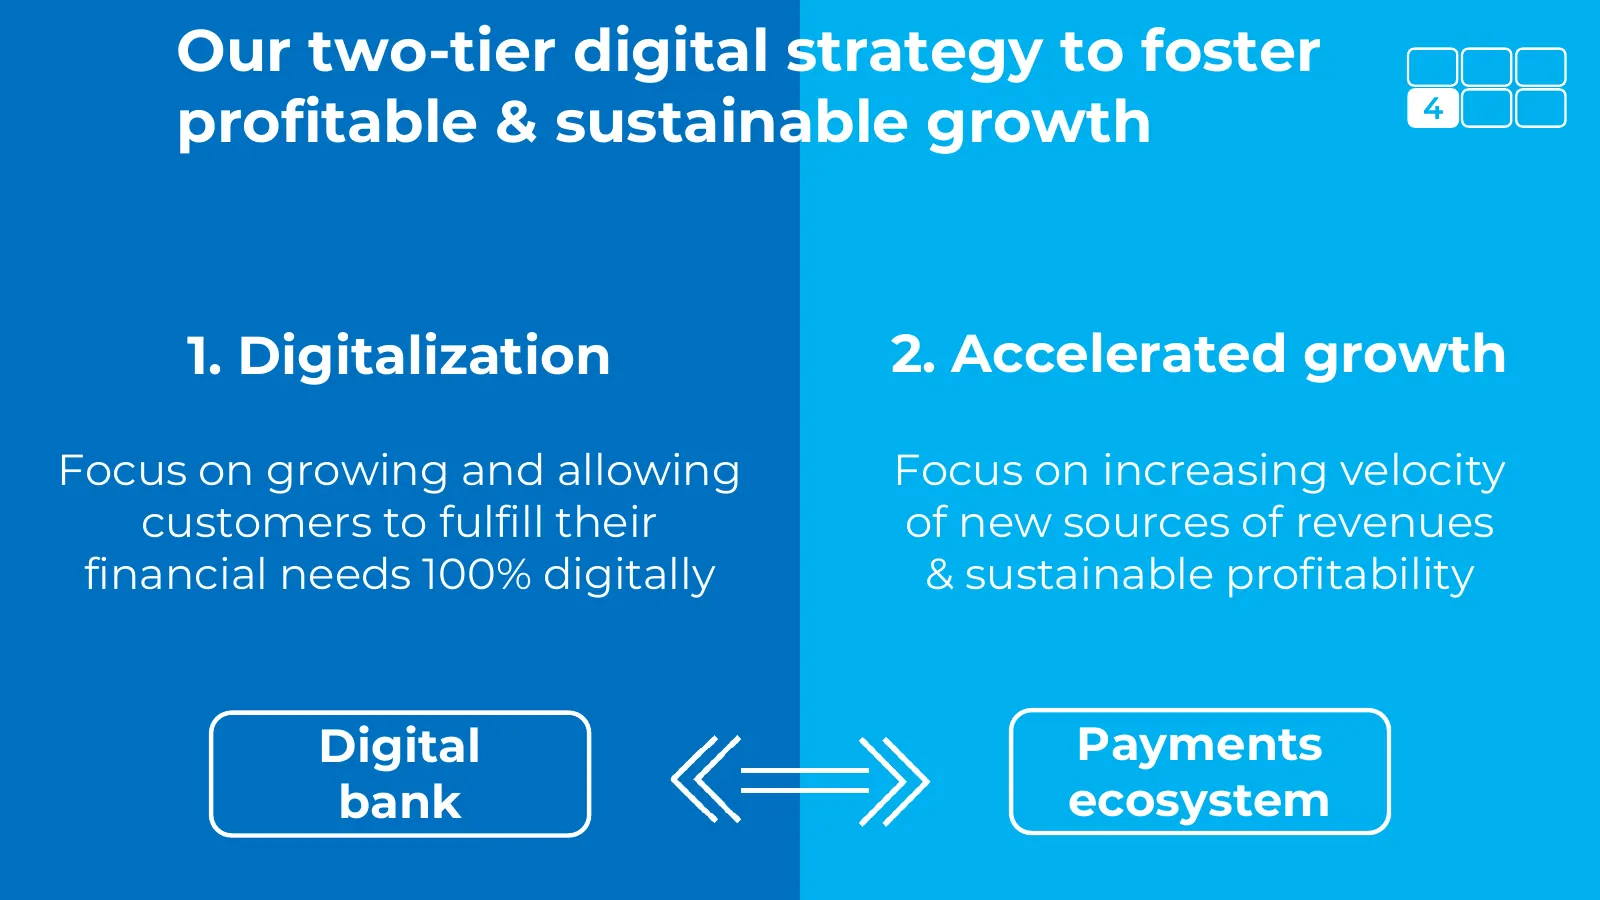
Slide 20: Our two-tier digital strategy to foster profitable & sustainable growth
Our two-tier digital strategy to foster profitable & sustainable growth 4 1. Digitalization 2. Accelerated growth Focus on growing and allowing Focus on increasing velocity customers to fulfill their of new sources of revenues financial needs 100% digitally & sustainable profitability Digital Paymen
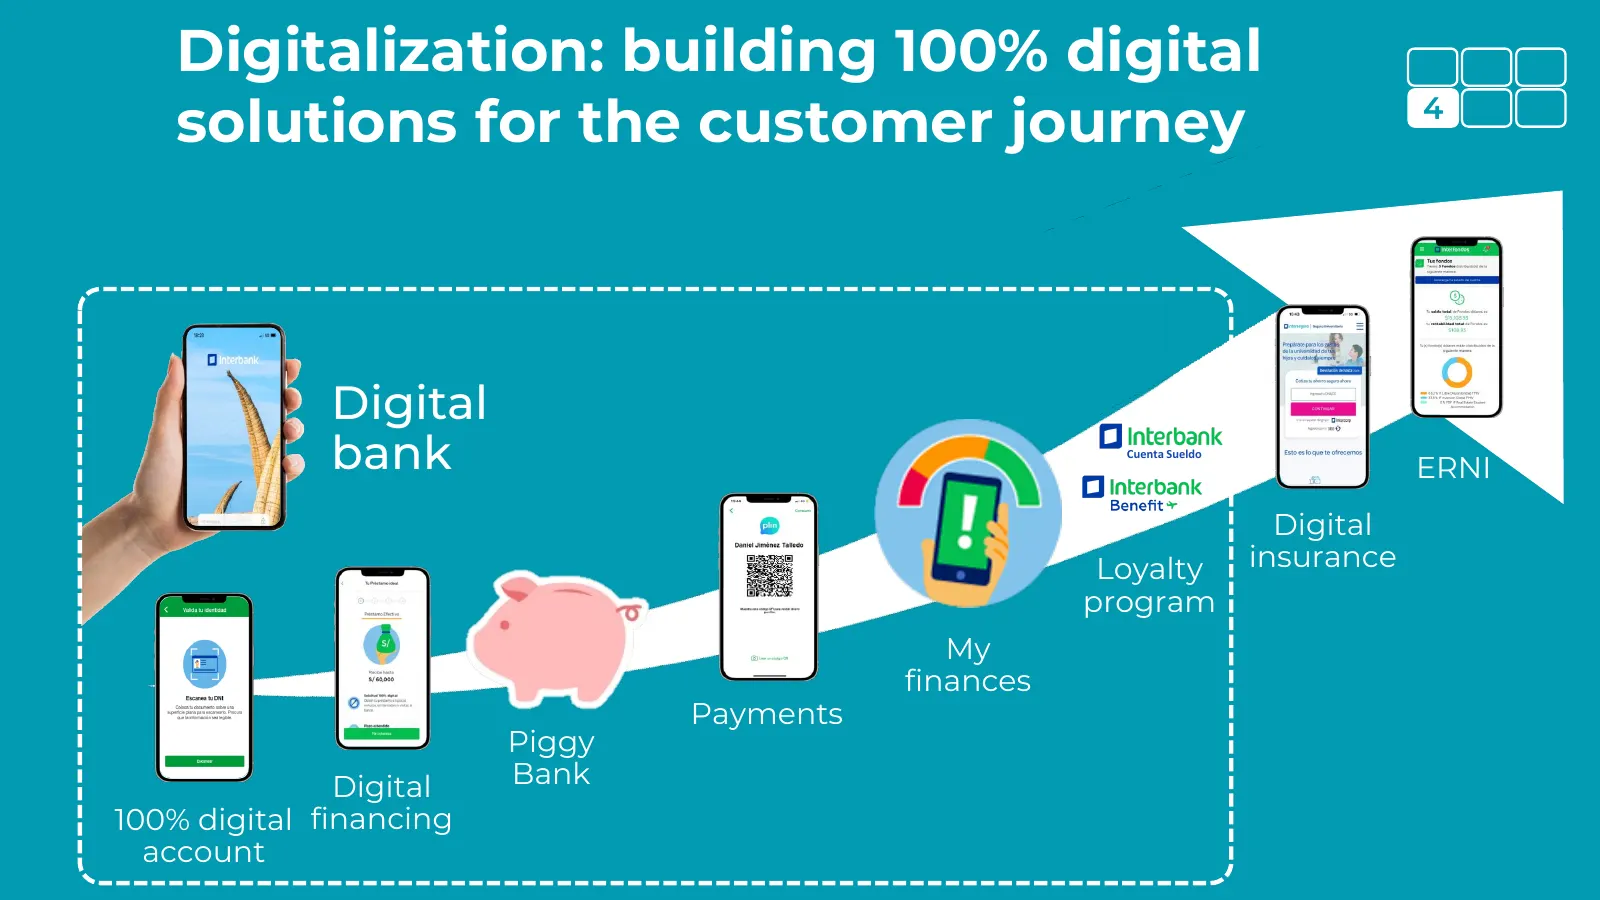
Slide 21: Digitalization: building 100% digital solutions for the customer journey
Digitalization: building 100% digital solutions for the customer journey 4 Digital bank Cuenta Sueldo ERNI Digital Loyalty insurance program My finances Payments Piggy Digital Bank 100% digital financing account
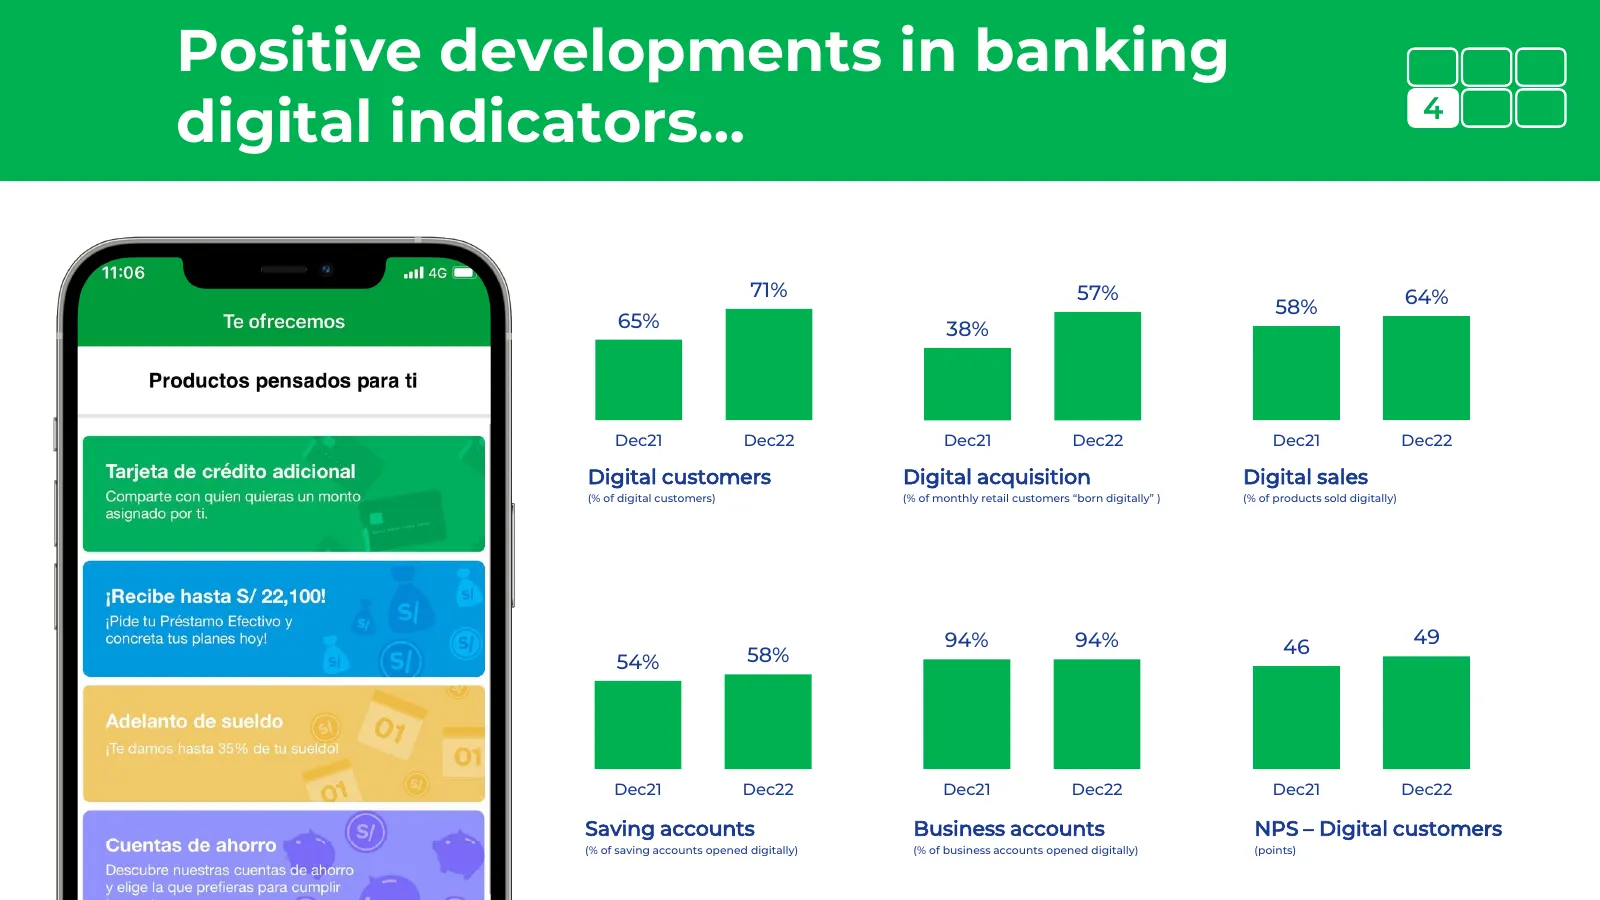
Slide 22: Positive developments in banking digital indicators
Positive developments in banking digital indicators… 4 71% 57% 64% 58% 65% 38% Dec21 Dec22 Dec21 Dec22 Dec21 Dec22 Digital customers Digital acquisition Digital sales (% of digital customers) (% of monthly retail customers “born digitally” ) (% of products sold digitally) 94% 94% 46 49 54% 58% Dec21
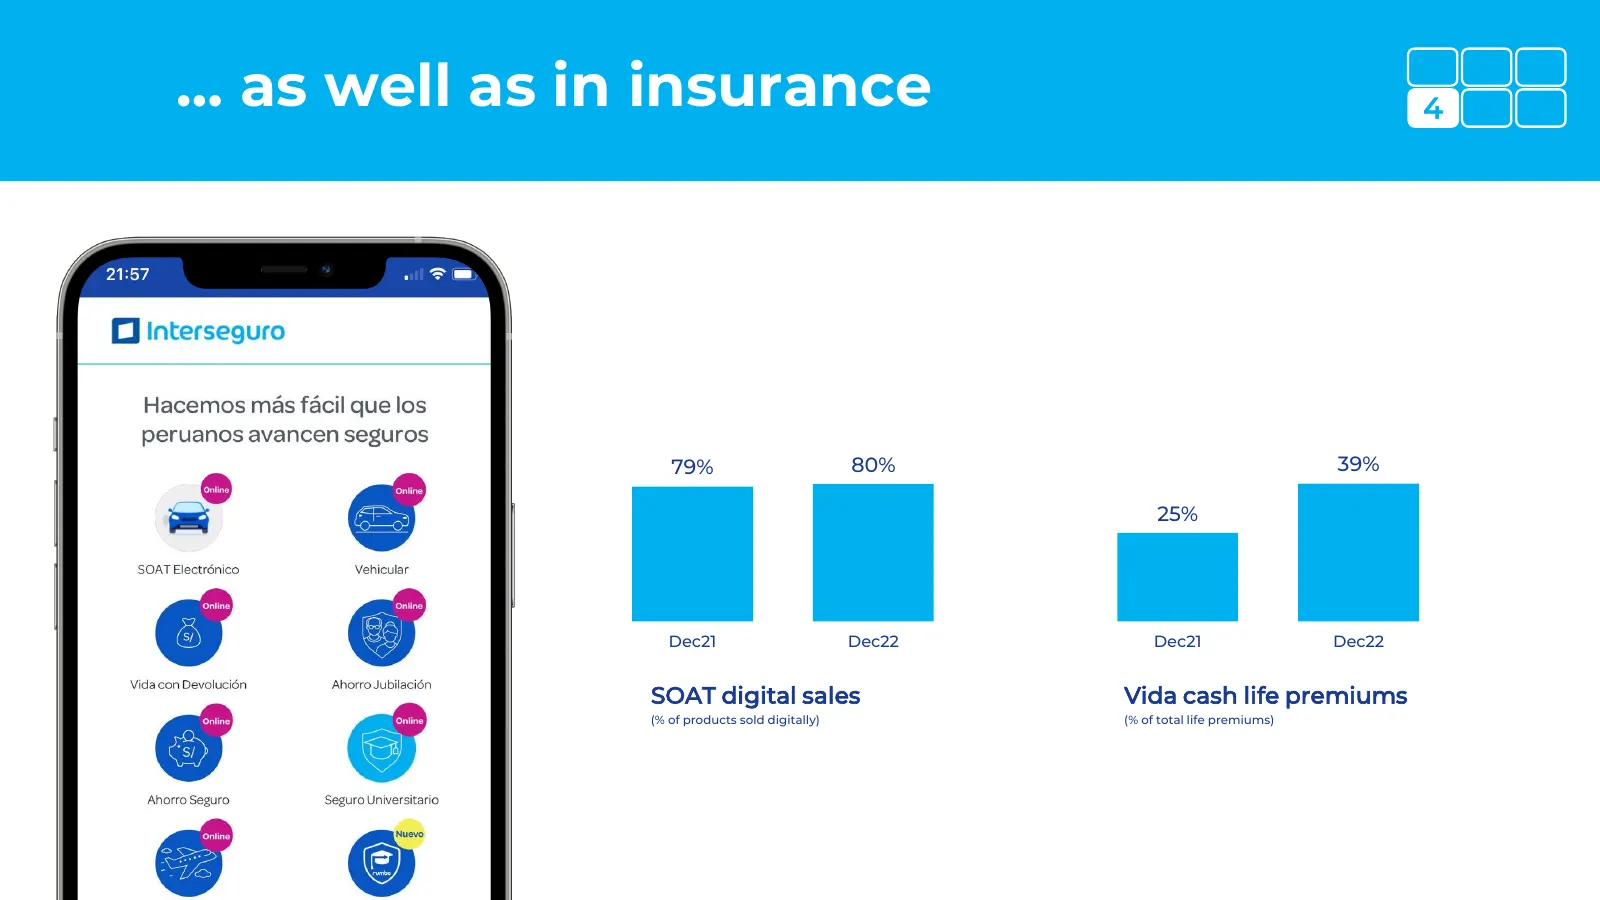
Slide 23: … as well as in insurance
… as well as in insurance 4 79% 80% 39% 25% Dec21 Dec22 Dec21 Dec22 SOAT digital sales Vida cash life premiums (% of products sold digitally) (% of total life premiums)
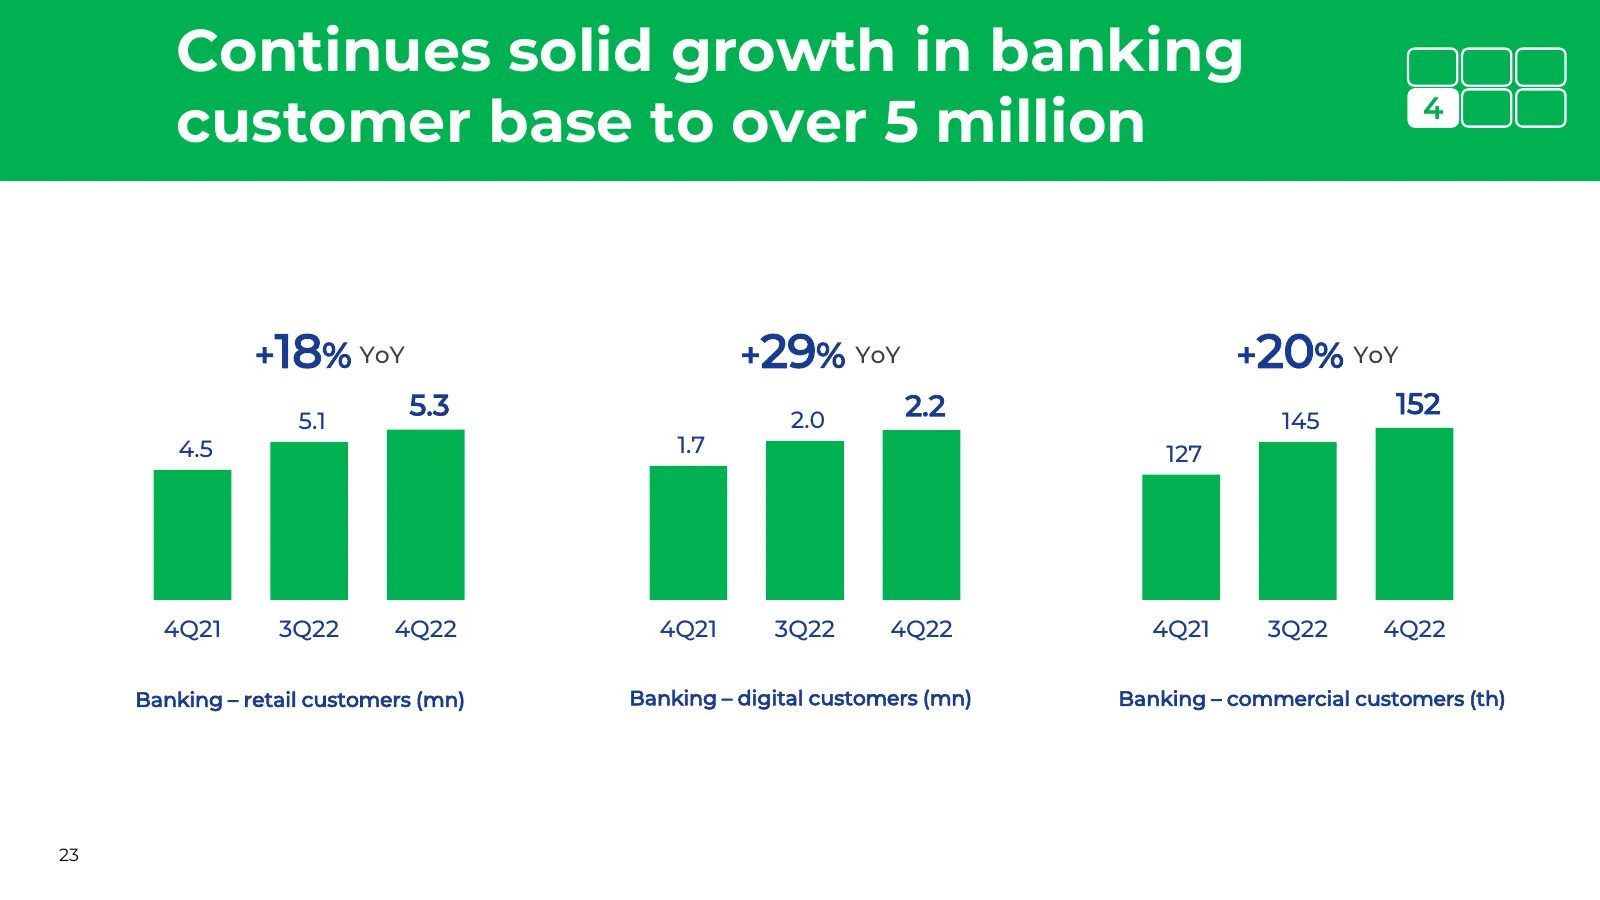
Slide 24: Continues solid growth in banking customer base to over 5 million
Continues solid growth in banking customer base to over 5 million 4 +18% YoY +29% YoY +20% YoY 5.3 2.0 2.2 152 5.1 145 4.5 1.7 127 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 Banking – retail customers (mn) Banking – digital customers (mn) Banking – commercial customers (th) 23
Slide 25: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
Slide 26: Izipay, pillar for building our payments ecosystem
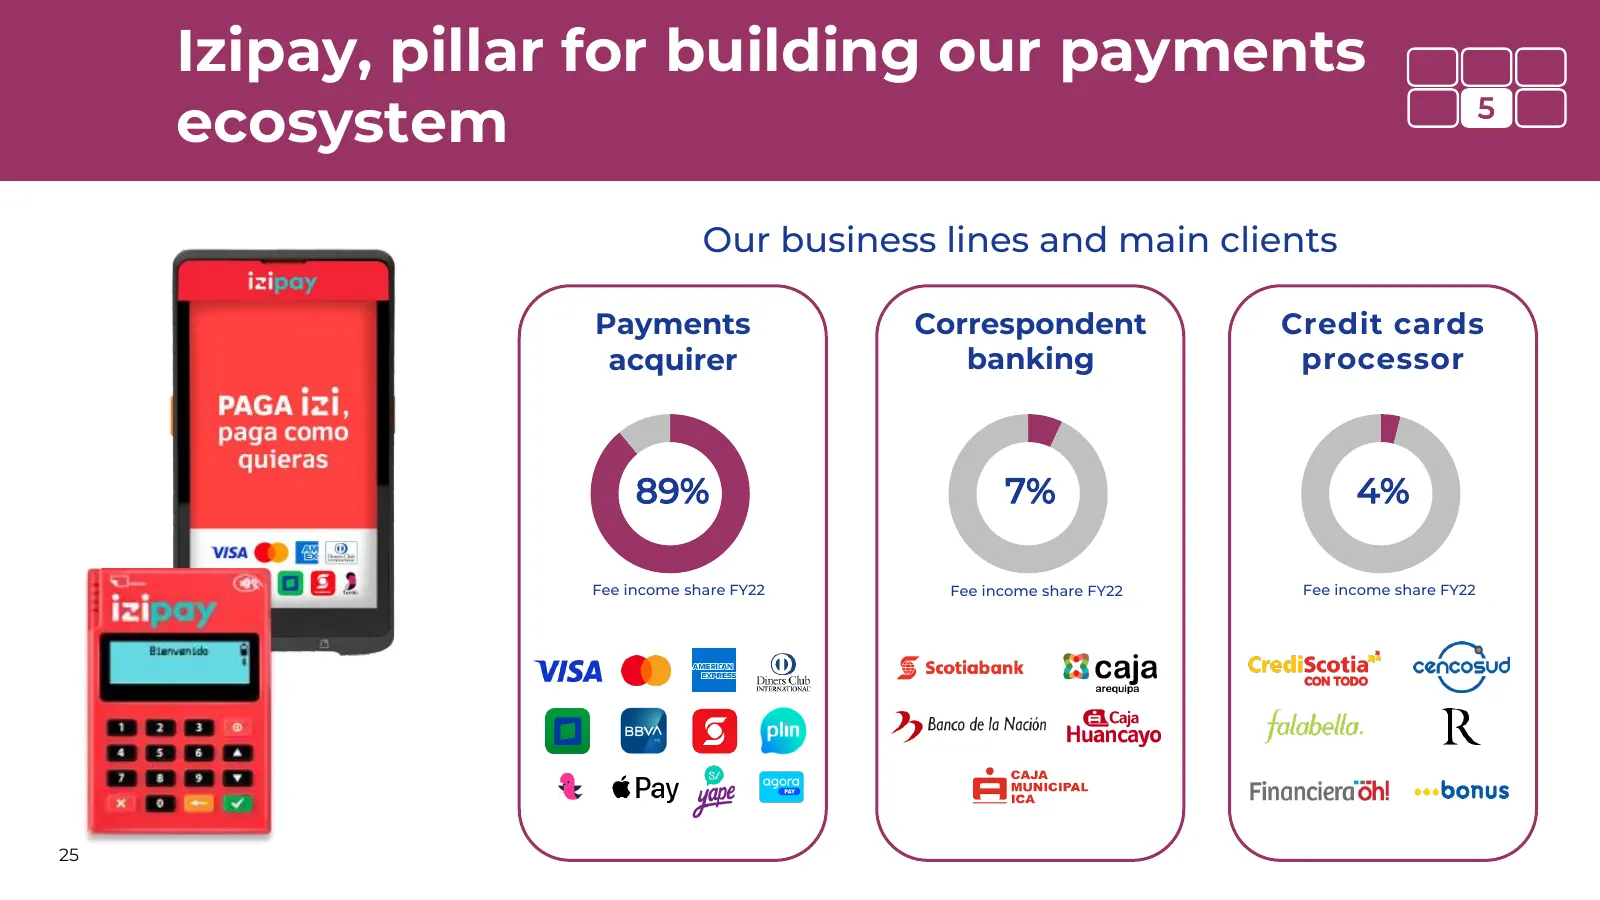
Izipay, pillar for building our payments ecosystem 5 Our business lines and main clients Payments Correspondent Credit cards acquirer banking processor 89% 7% 4% Fee income share FY22 Fee income share FY22 Fee income share FY22 25
Slide 27: Strong growth in all key indicators
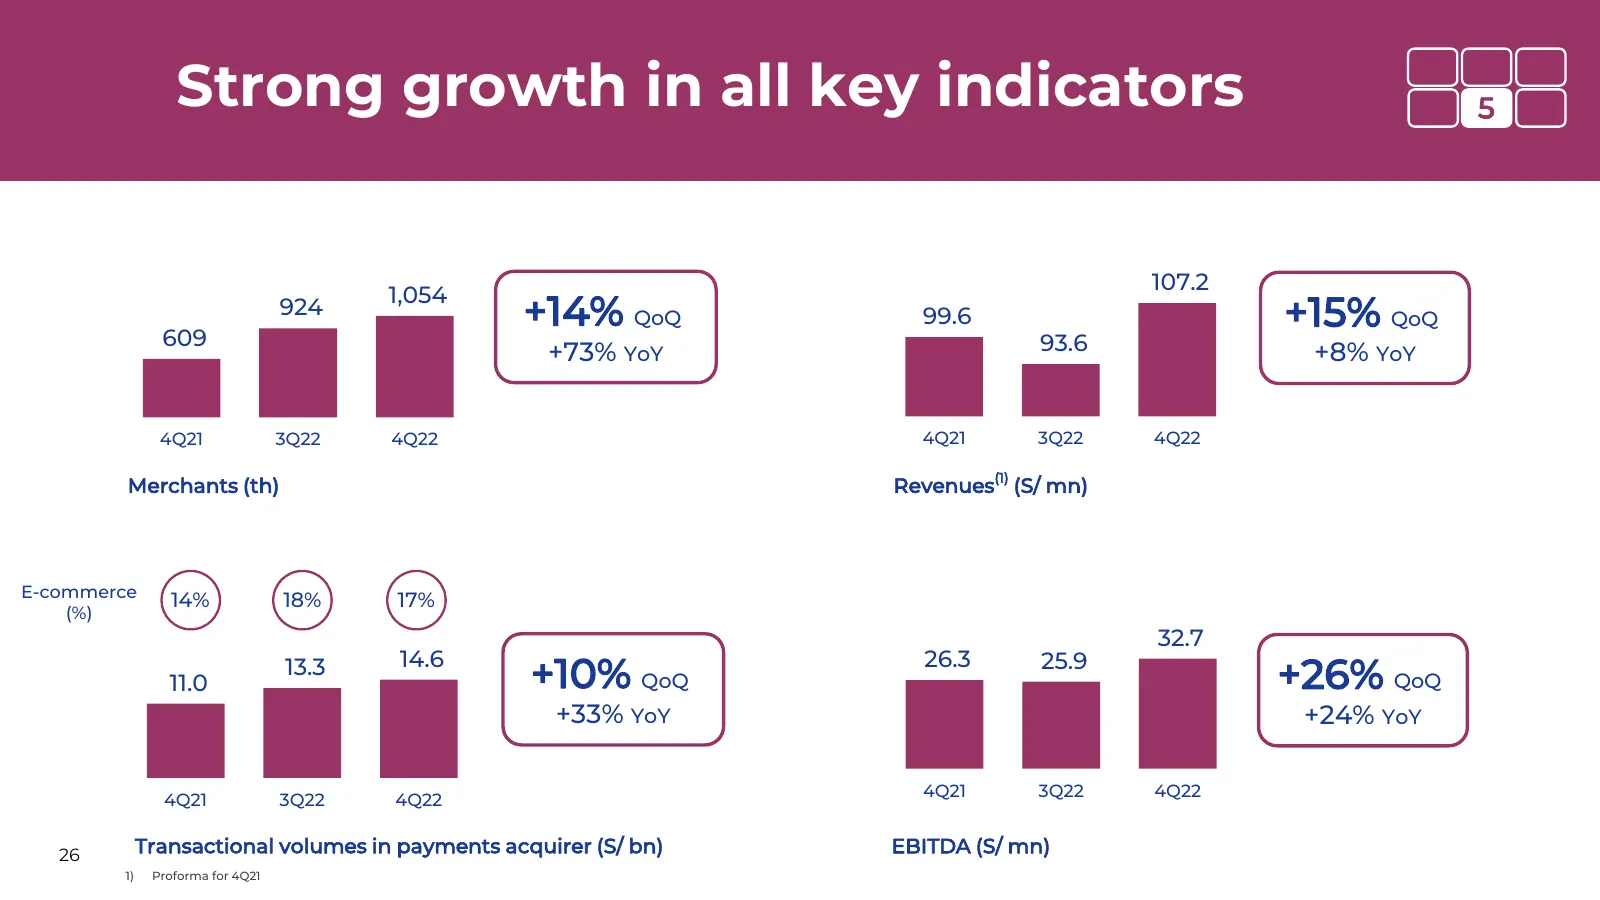
Strong growth in all key indicators 5 107.2 1,054 924 +14% QoQ 99.6 +15% QoQ 609 93.6 +73% YoY +8% YoY 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 Merchants (th) Revenues(1) (S/ mn) E-commerce 14% 18% 17% (%) 32.7 14.6 26.3 25.9 11.0 13.3 +10% QoQ +26% QoQ +33% YoY +24% YoY 4Q21 3Q22 4Q22 4Q21 3Q22 4Q22 26 Transa
Slide 28: 9.8 million users in Plin and 2.5 million in Tunki
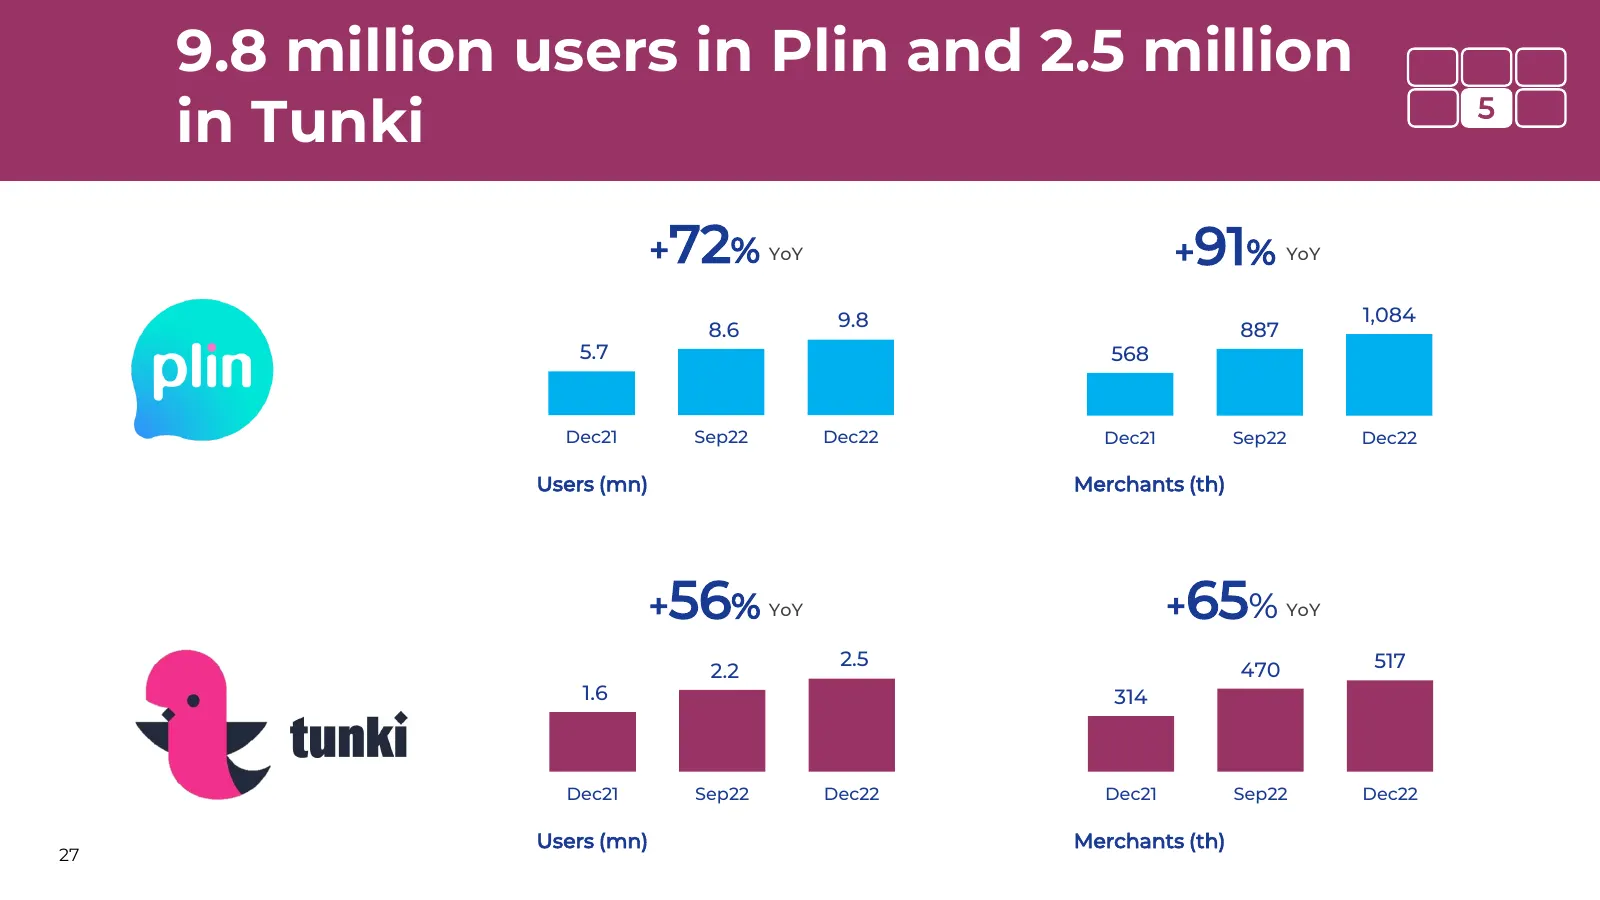
9.8 million users in Plin and 2.5 million in Tunki 5 +72% YoY +91% YoY 9.8 1,084 8.6 887 5.7 568 Dec21 Sep22 Dec22 Dec21 Sep22 Dec22 Users (mn) Merchants (th) +56% YoY +65% YoY 2.5 470 517 2.2 1.6 314 Dec21 Sep22 Dec22 Dec21 Sep22 Dec22 Users (mn) Merchants (th) 27
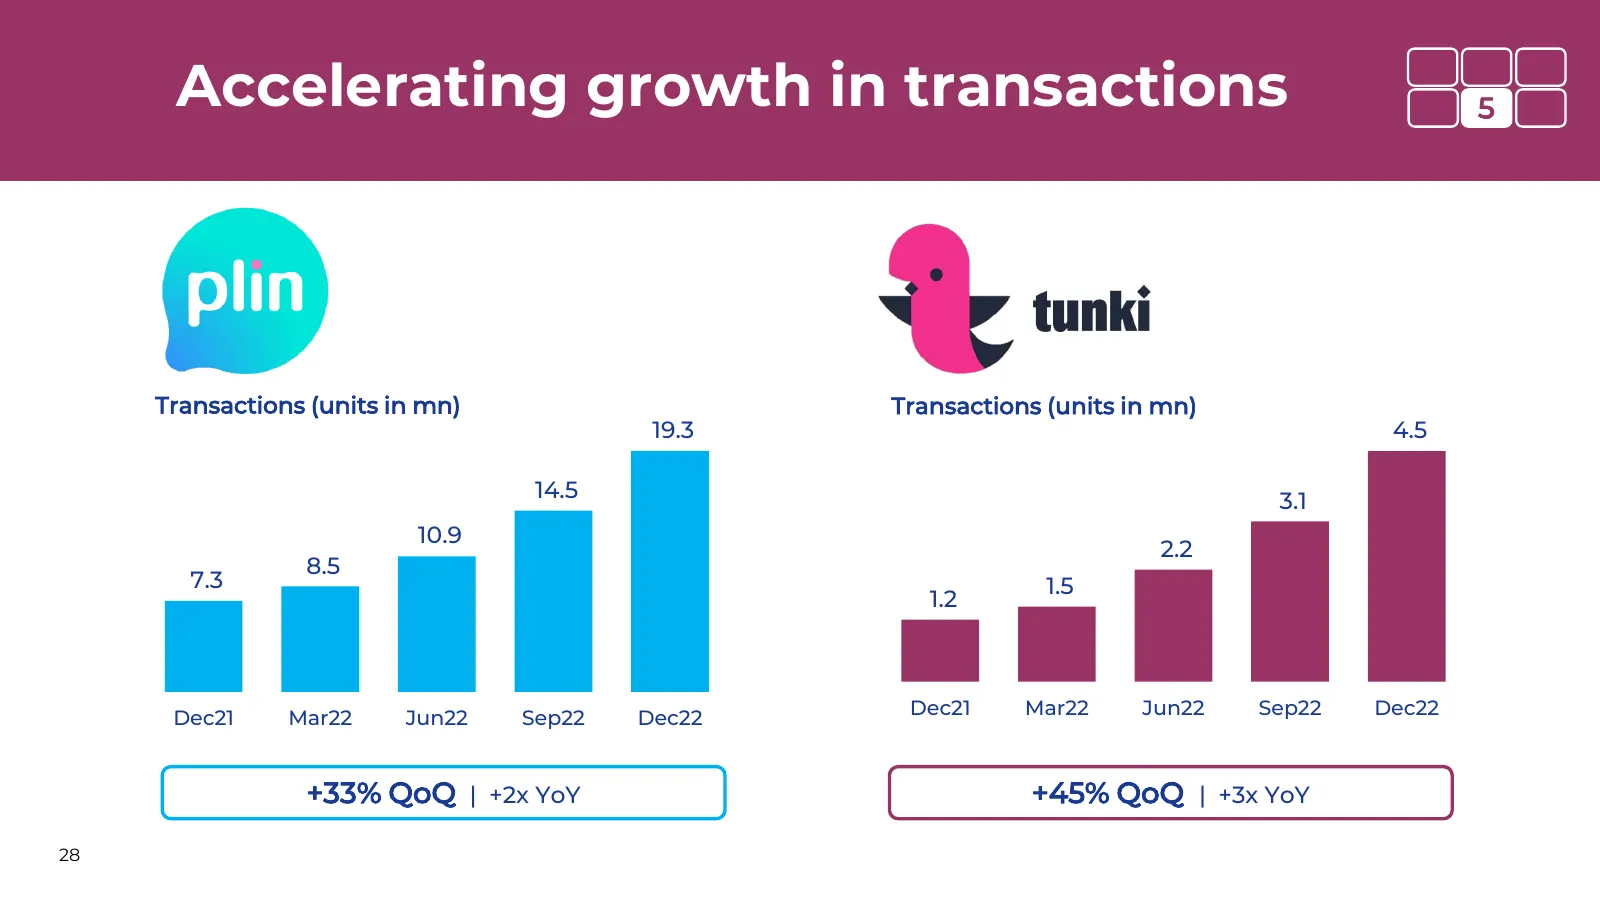
Slide 29: Accelerating growth in transactions
Accelerating growth in transactions 5 Transactions (units in mn) Transactions (units in mn) 19.3 4.5 14.5 3.1 10.9 2.2 8.5 7.3 1.5 1.2 Dec21 Mar22 Jun22 Sep22 Dec22 Dec21 Mar22 Jun22 Sep22 Dec22 +33% QoQ | +2x YoY +45% QoQ | +3x YoY 28
Slide 30: Key messages
Key messages 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
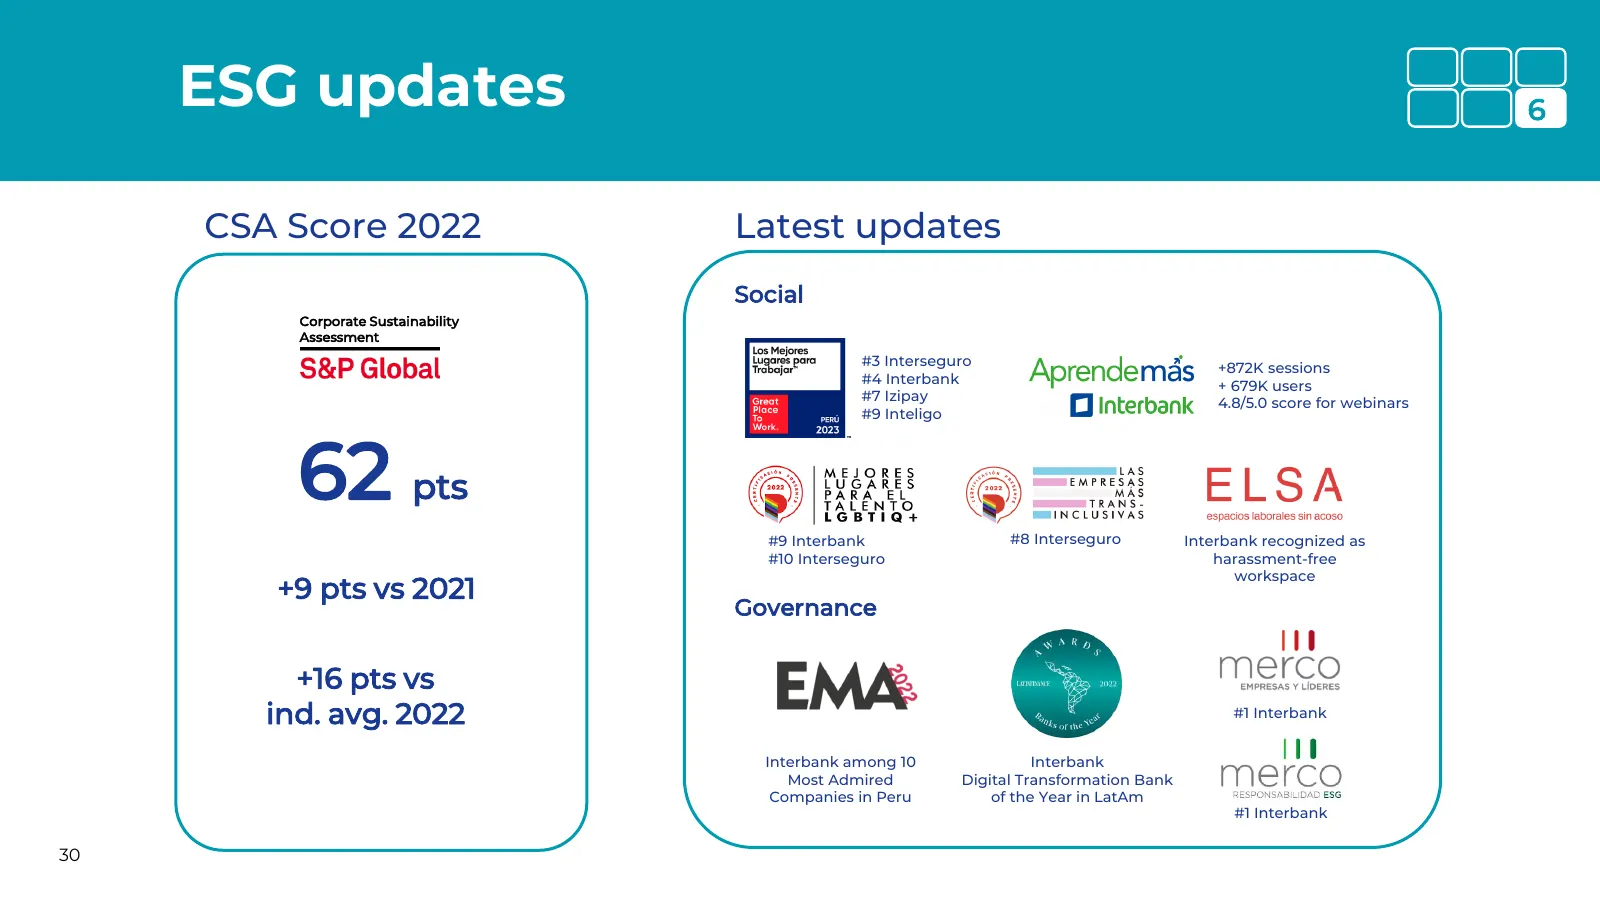
Slide 31: ESG updates
ESG updates 6 CSA Score 2022 Latest updates Social Corporate Sustainability Assessment #3 Interseguro +872K sessions #4 Interbank + 679K users #7 Izipay 4.8/5.0 score for webinars #9 Inteligo 62 pts #9 Interbank #8 Interseguro Interbank recognized as #10 Interseguro harassment-free workspace +9 pts
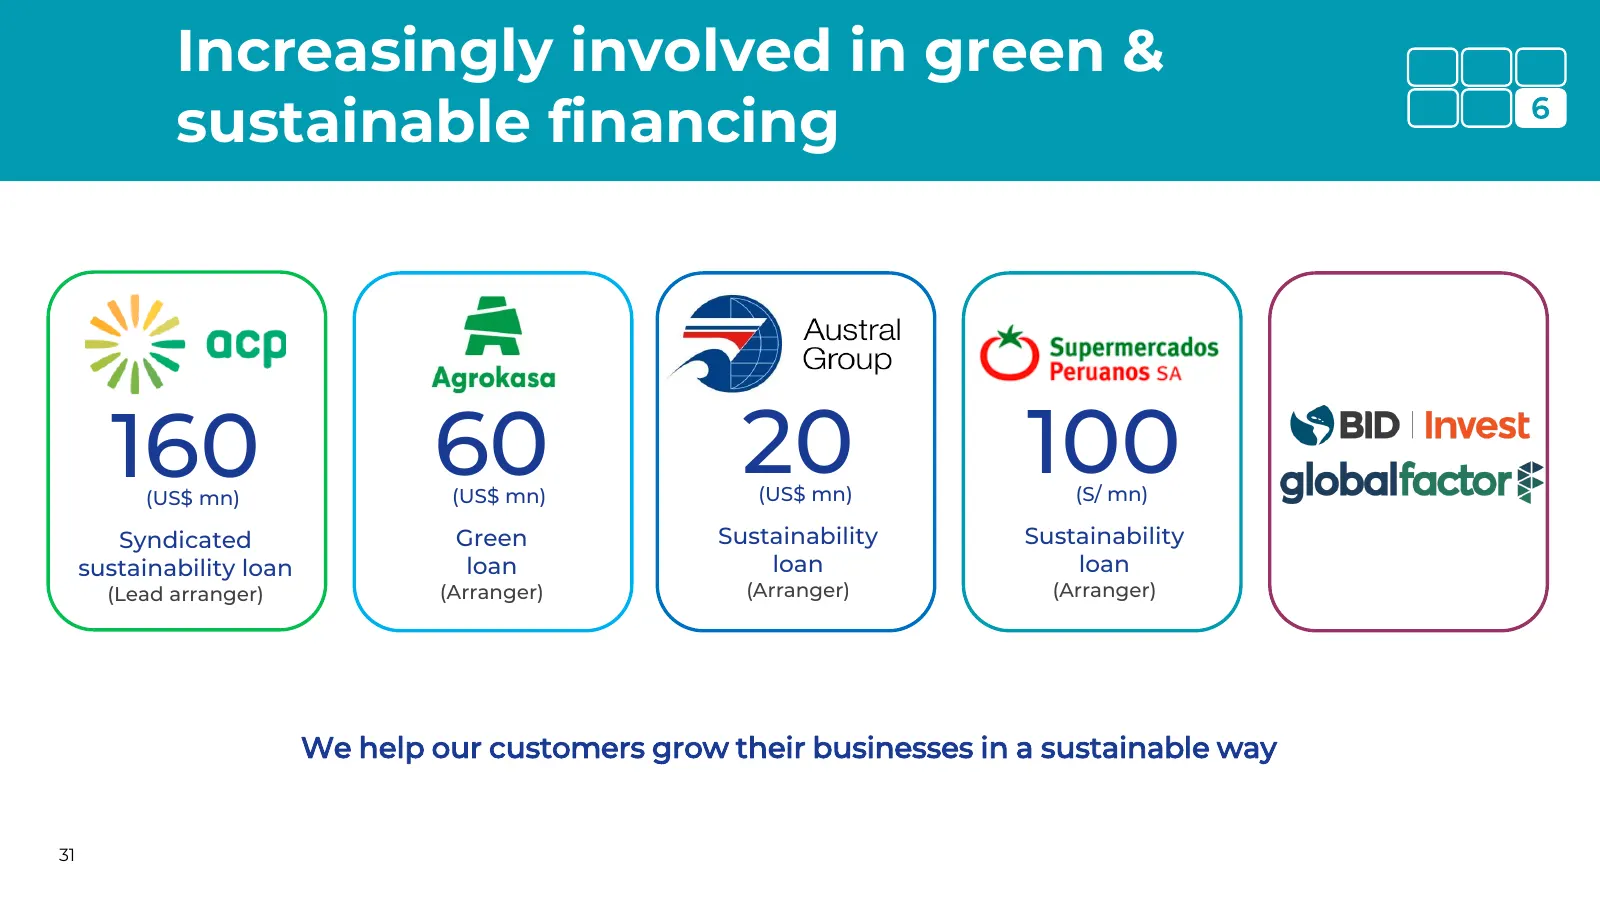
Slide 32: Increasingly involved in green & sustainable financing
Increasingly involved in green & sustainable financing 6 160(US$ mn) 60(US$ mn) 20 (US$ mn) 100 (S/ mn) Syndicated Green Sustainability Sustainability sustainability loan loan loan loan (Lead arranger) (Arranger) (Arranger) (Arranger) We help our customers grow their businesses in a sustainable way
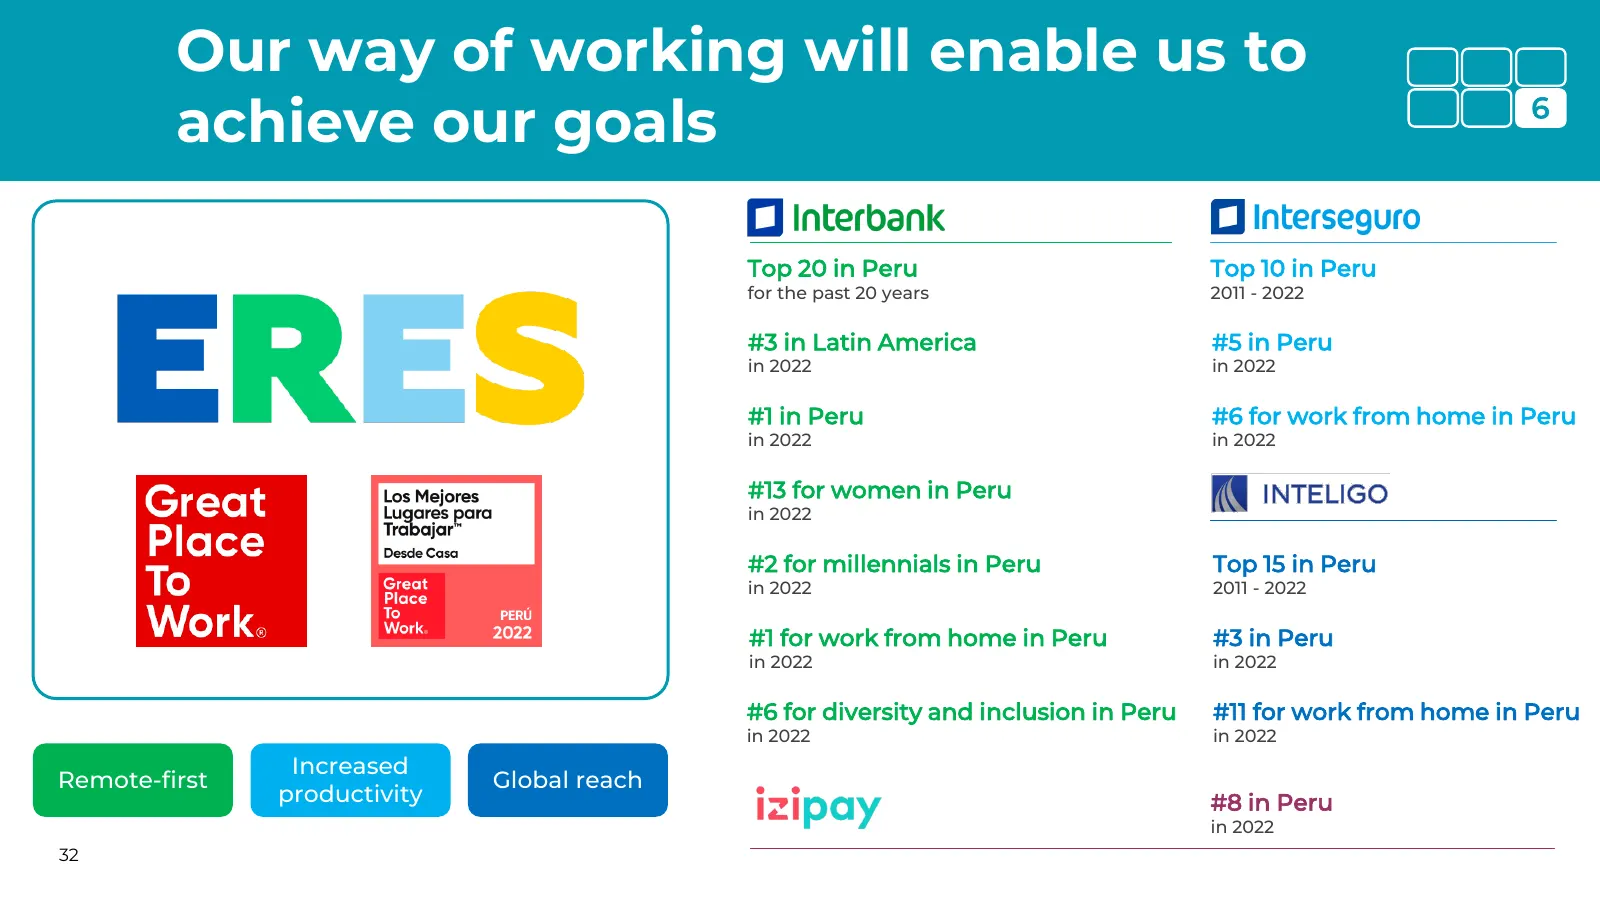
Slide 33: Our way of working will enable us to achieve our goals
Our way of working will enable us to achieve our goals 6 Top 20 in Peru Top 10 in Peru for the past 20 years 2011 - 2022 #3 in Latin America #5 in Peru in 2022 in 2022 #1 in Peru #6 for work from home in Peru in 2022 in 2022 #13 for women in Peru in 2022 #2 for millennials in Peru Top 15 in Peru in
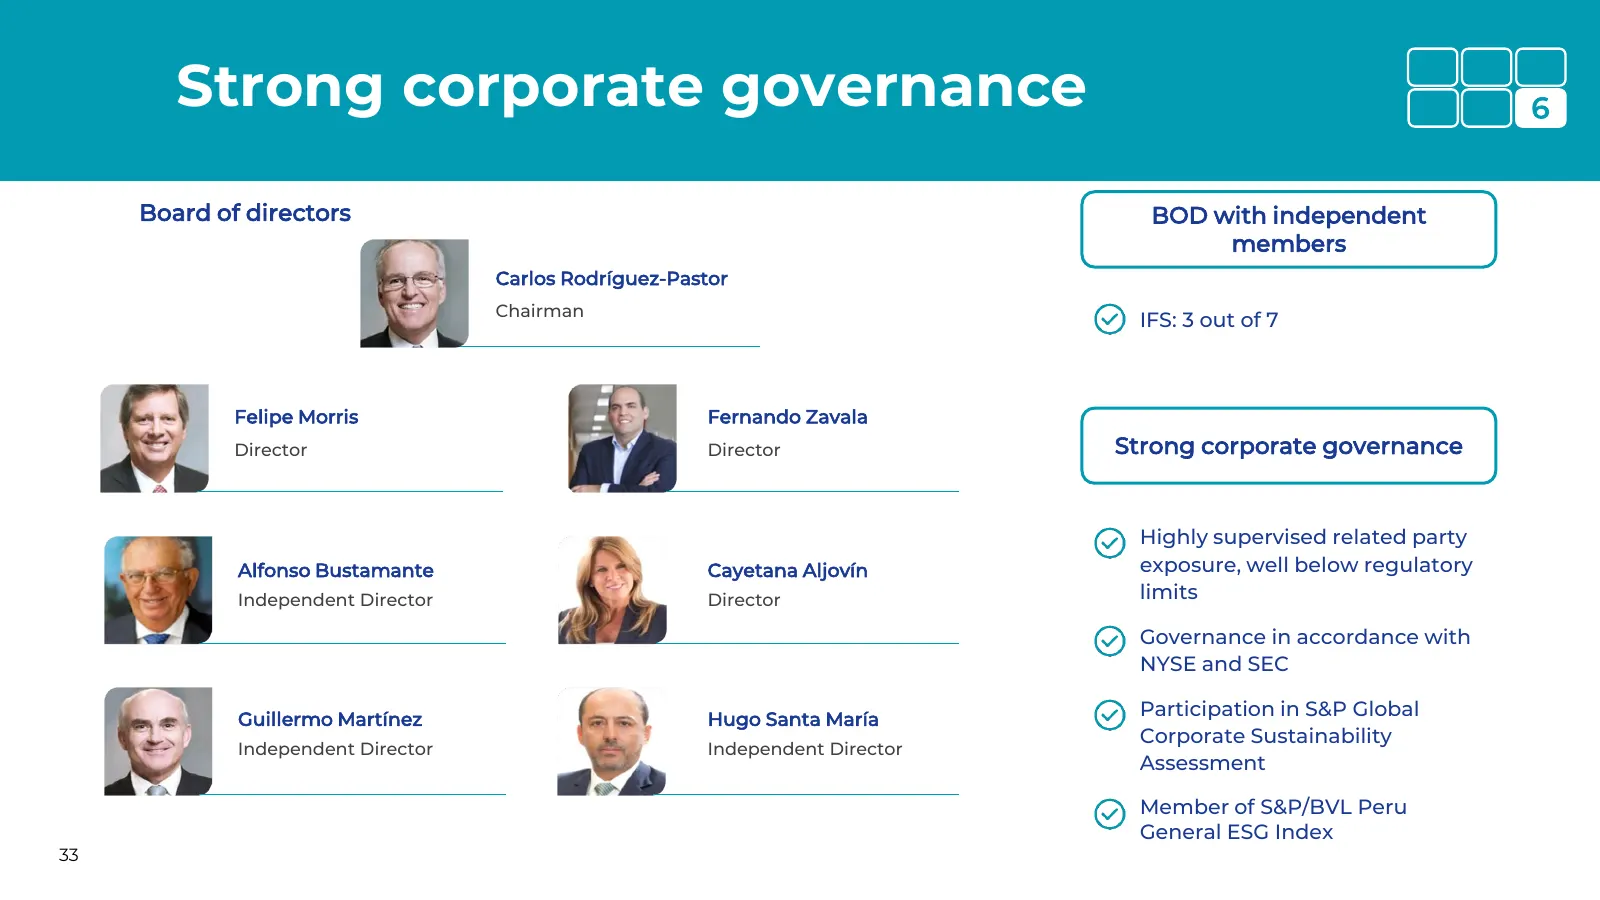
Slide 34: Strong corporate governance
Strong corporate governance 6 Board of directors BOD with independent members Carlos Rodríguez-Pastor Chairman IFS: 3 out of 7 Felipe Morris Fernando Zavala Director Director Strong corporate governance Highly supervised related party Alfonso Bustamante Cayetana Aljovín exposure, well below regulato
Slide 35: Takeaways
Takeaways 1 Political uncertainty impacts macro outlook 2 Strong year in banking activity 3 Solid risk management capabilities 4 Positive developments in digital indicators 5 Payments business in good shape to face further growth 6 ESG updates
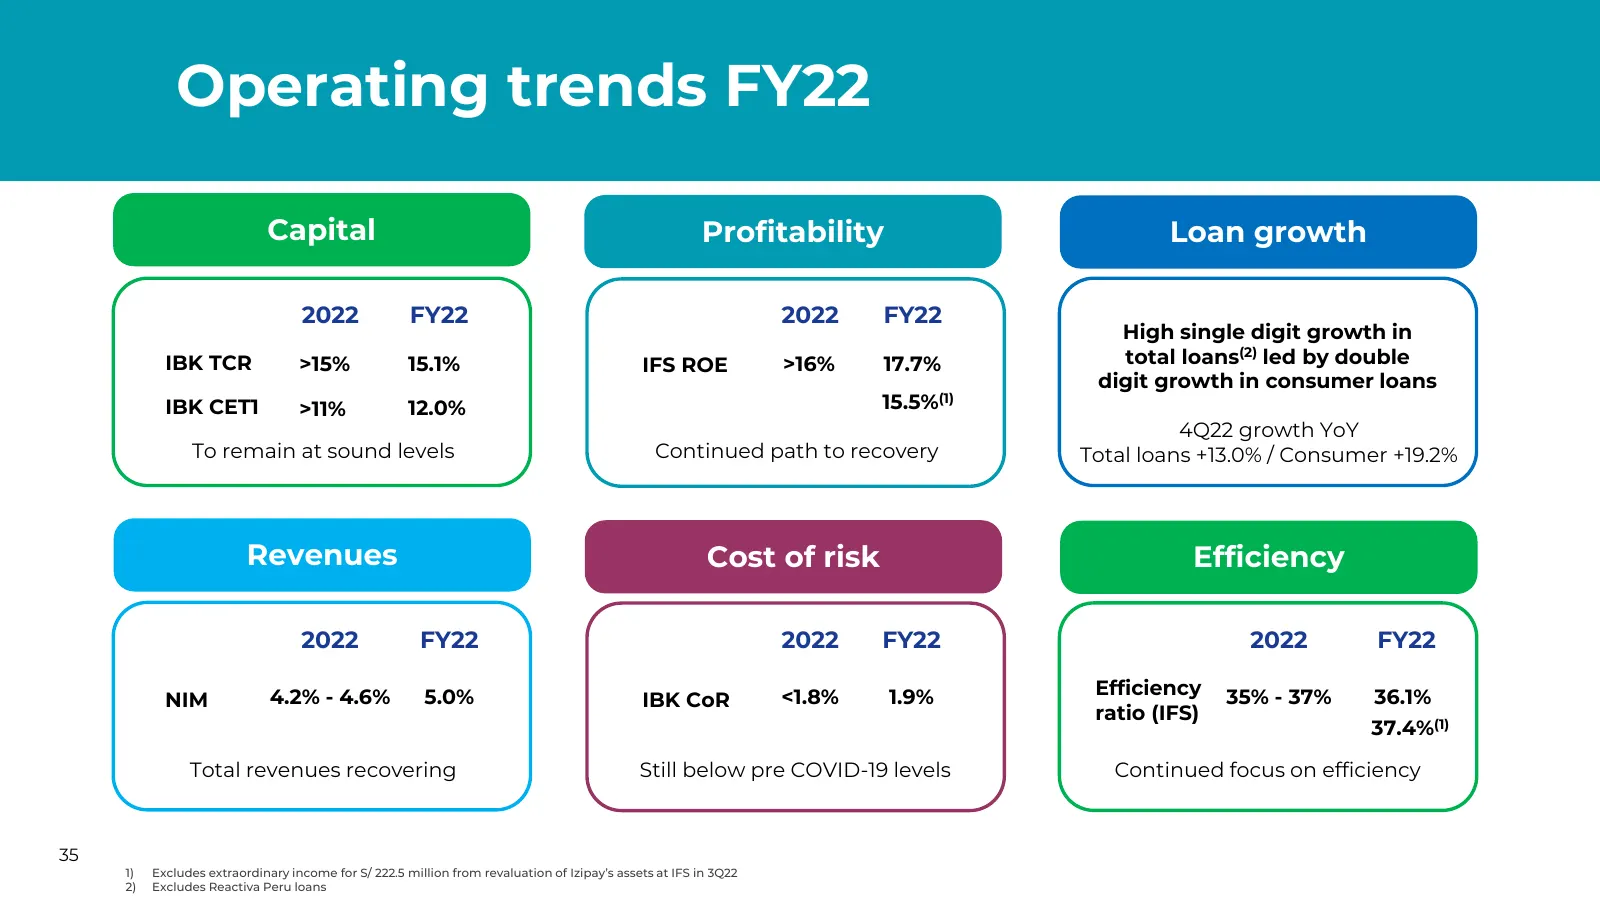
Slide 36: Operating trends FY22
Operating trends FY22 Capital Profitability Loan growth 2022 FY22 2022 FY22 High single digit growth in IBK TCR >15% 15.1% IFS ROE >16% 17.7% total loans(2) led by double digit growth in consumer loans IBK CET1 >11% 12.0% 15.5%(1) 4Q22 growth YoY To remain at sound levels Continued path to recovery
Slide 37: Operating trends 2023
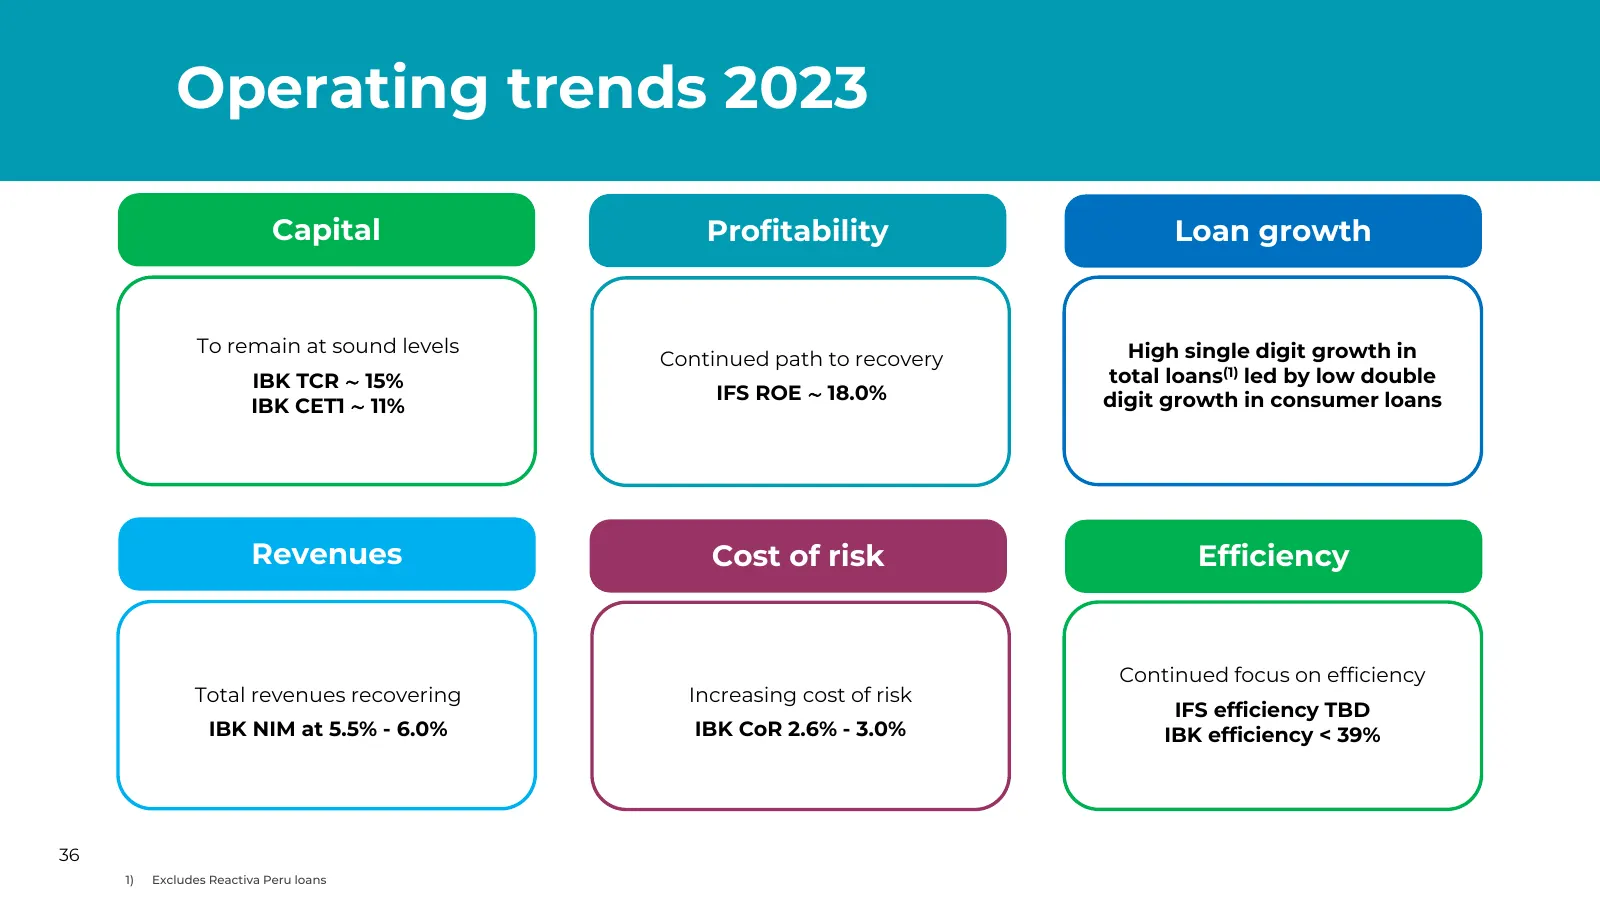
Operating trends 2023 Capital Profitability Loan growth To remain at sound levels High single digit growth in Continued path to recovery IBK TCR ∼ 15% total loans(1) led by low double IFS ROE ∼ 18.0% digit growth in consumer loans IBK CET1 ∼ 11% Revenues Cost of risk Efficiency Continued focus on ef
Slide 38: Appendix
Appendix
Slide 39: Continuous focus on efficiency
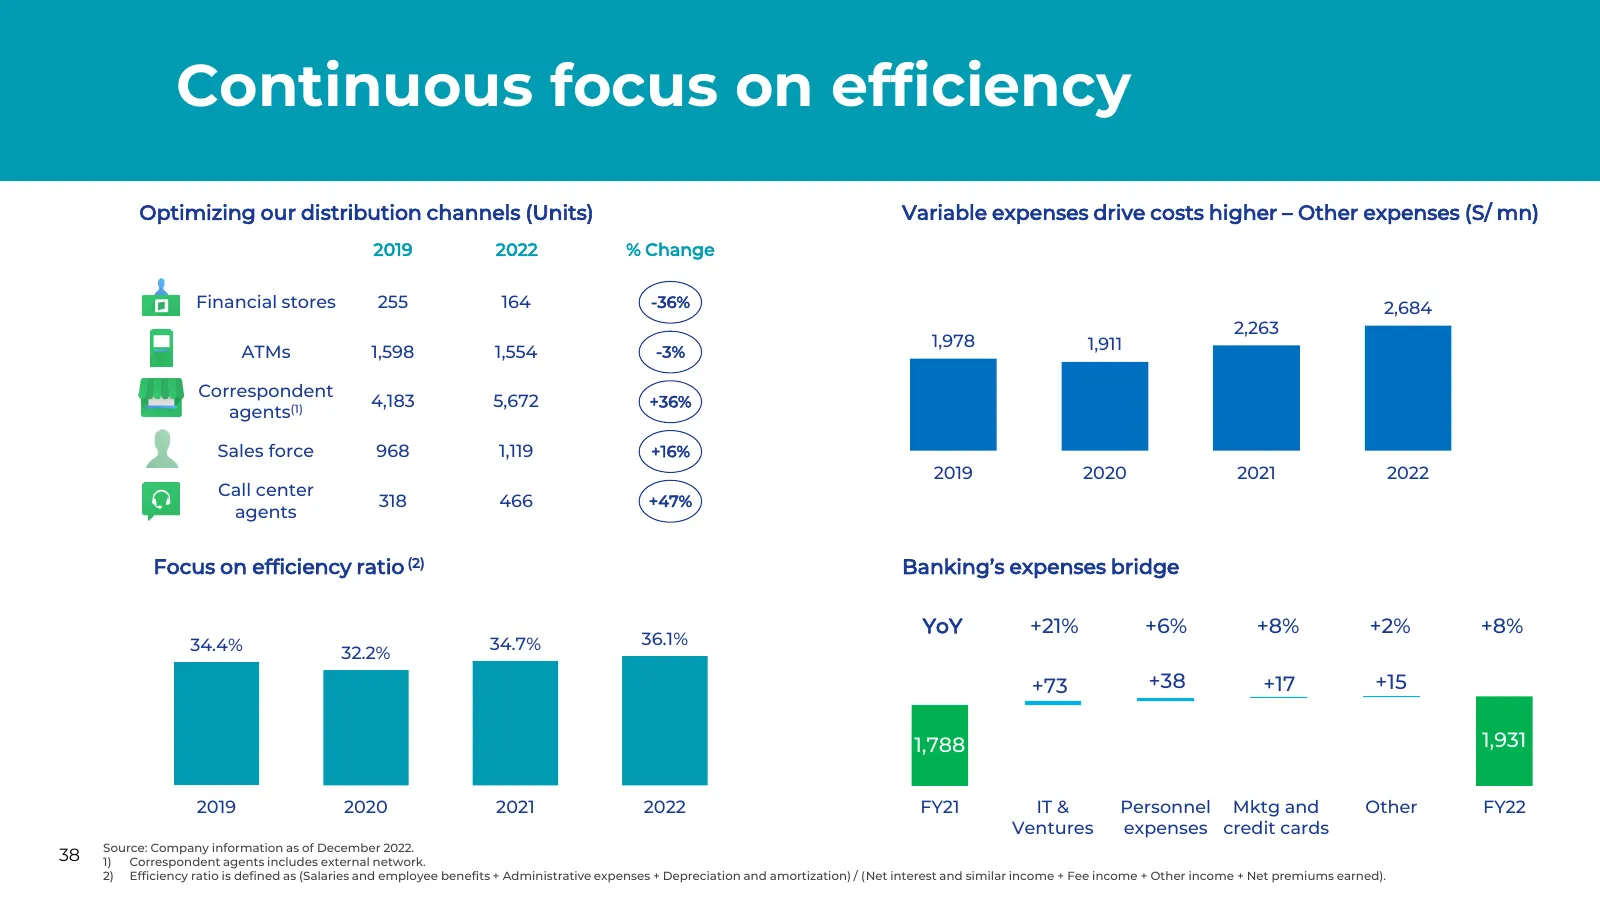
Continuous focus on efficiency Optimizing our distribution channels (Units) Variable expenses drive costs higher – Other expenses (S/ mn) 2019 2022 % Change Financial stores 255 164 -36% 2,684 2,263 1,978 1,911 ATMs 1,598 1,554 -3% Correspondent 4,183 5,672 +36% agents(1) Sales force 968 1,119 +16%
Slide 40: Sustained assets growth supported by appropriate funding
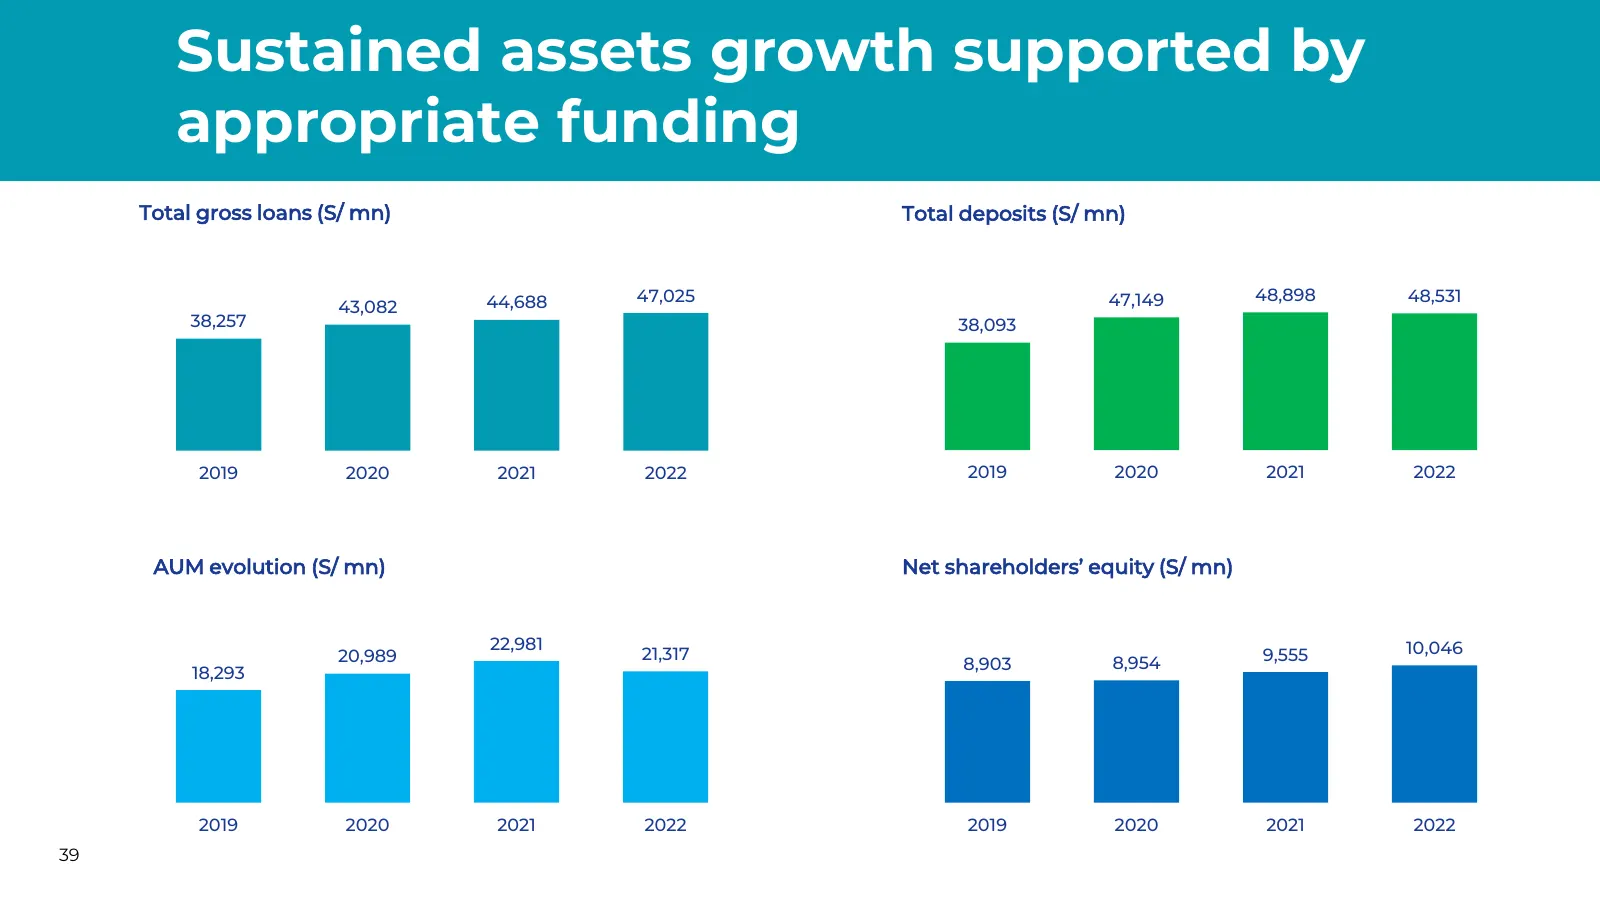
Sustained assets growth supported by appropriate funding Total gross loans (S/ mn) Total deposits (S/ mn) 44,688 47,025 47,149 48,898 48,531 43,082 38,257 38,093 2019 2020 2021 2022 2019 2020 2021 2022 AUM evolution (S/ mn) Net shareholders’ equity (S/ mn) 22,981 10,046 20,989 21,317 9,555 8,903 8,9
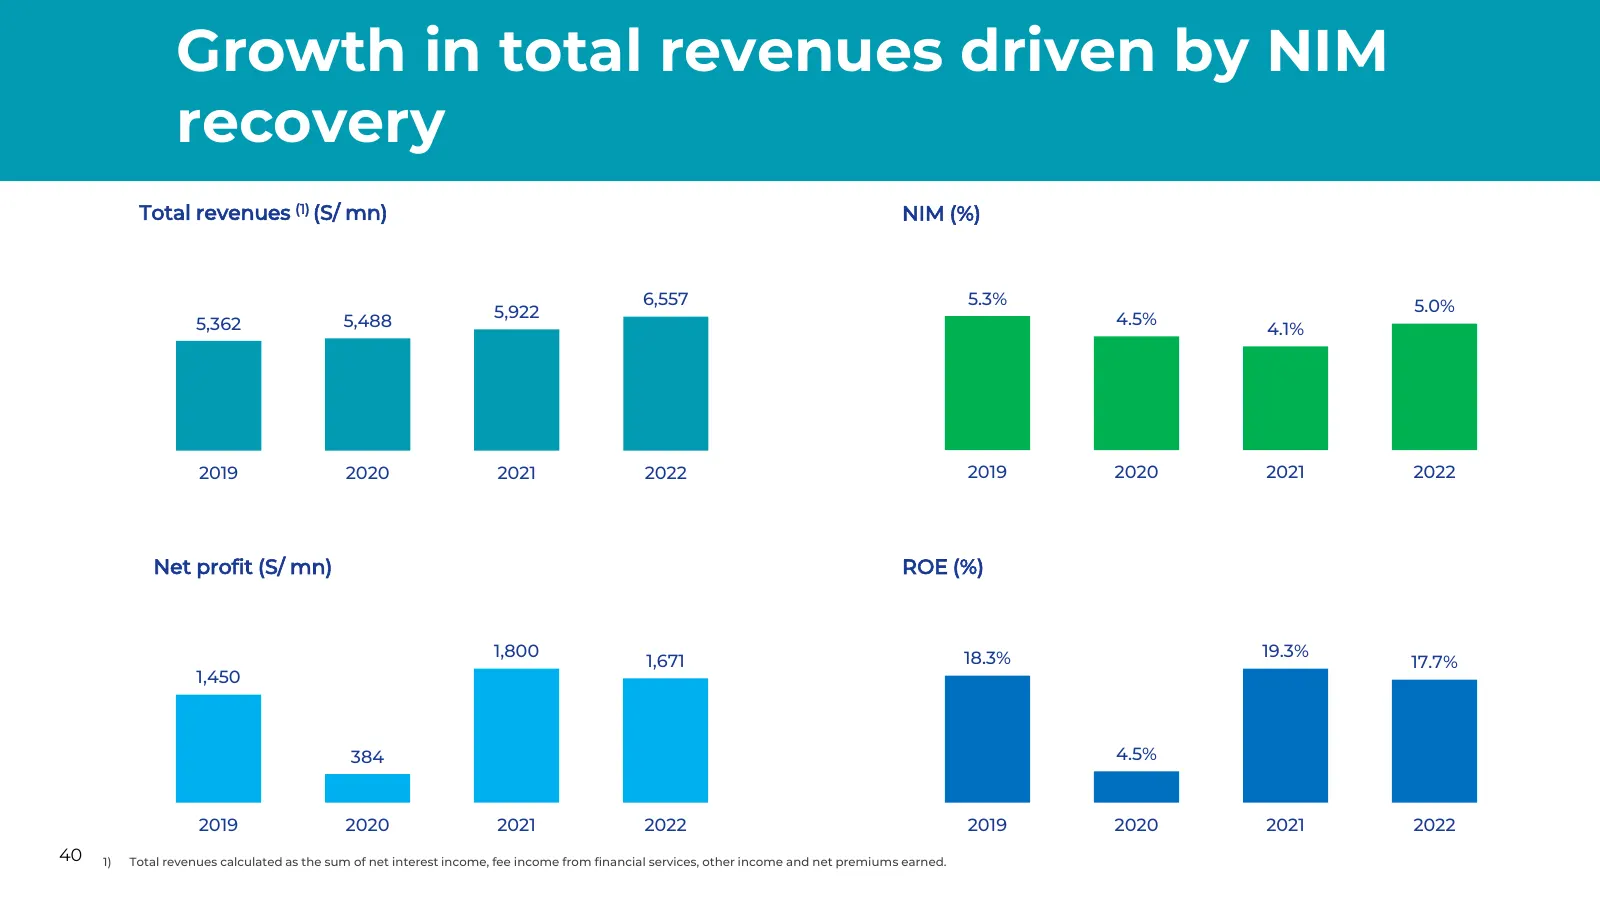
Slide 41: Growth in total revenues driven by NIM recovery
Growth in total revenues driven by NIM recovery Total revenues (1) (S/ mn) NIM (%) 6,557 5.3% 5.0% 5,922 4.5% 5,362 5,488 4.1% 2019 2020 2021 2022 2019 2020 2021 2022 Net profit (S/ mn) ROE (%) 1,800 18.3% 19.3% 1,671 17.7% 1,450 384 4.5% 2019 2020 2021 2022 2019 2020 2021 2022 40 1) Total revenues
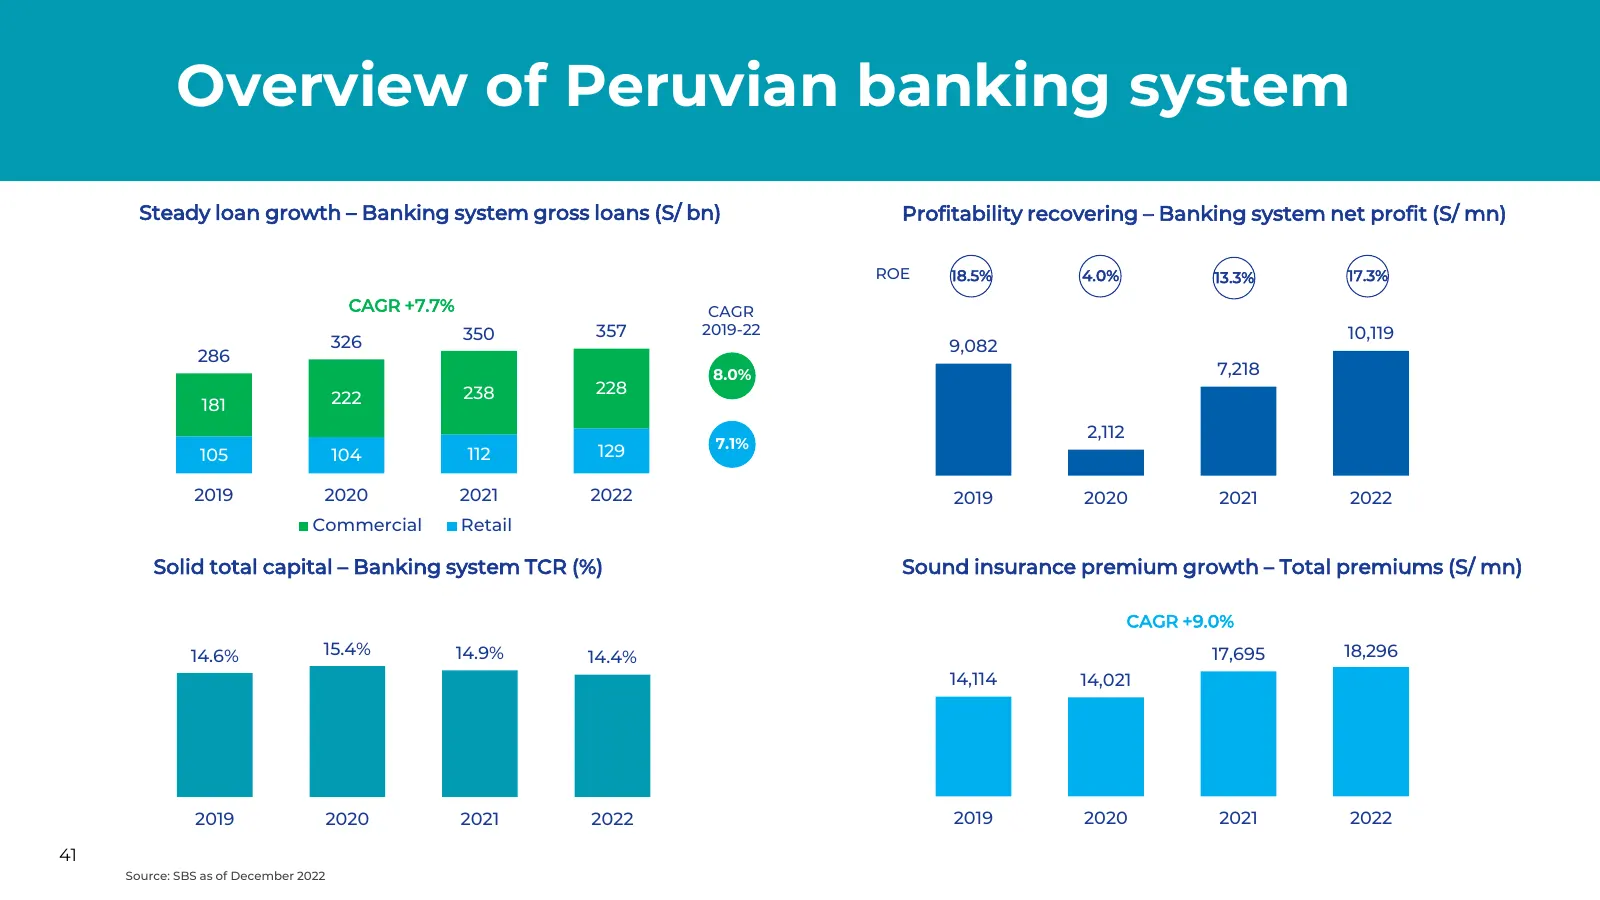
Slide 42: Overview of Peruvian banking system
Overview of Peruvian banking system Steady loan growth – Banking system gross loans (S/ bn) Profitability recovering – Banking system net profit (S/ mn) ROE 18.5% 4.0% 13.3% 17.3% CAGR +7.7% CAGR 350 357 2019-22 10,119 326 9,082 286 8.0% 7,218 238 228 181 222 2,112 129 7.1% 105 104 112 2019 2020 202
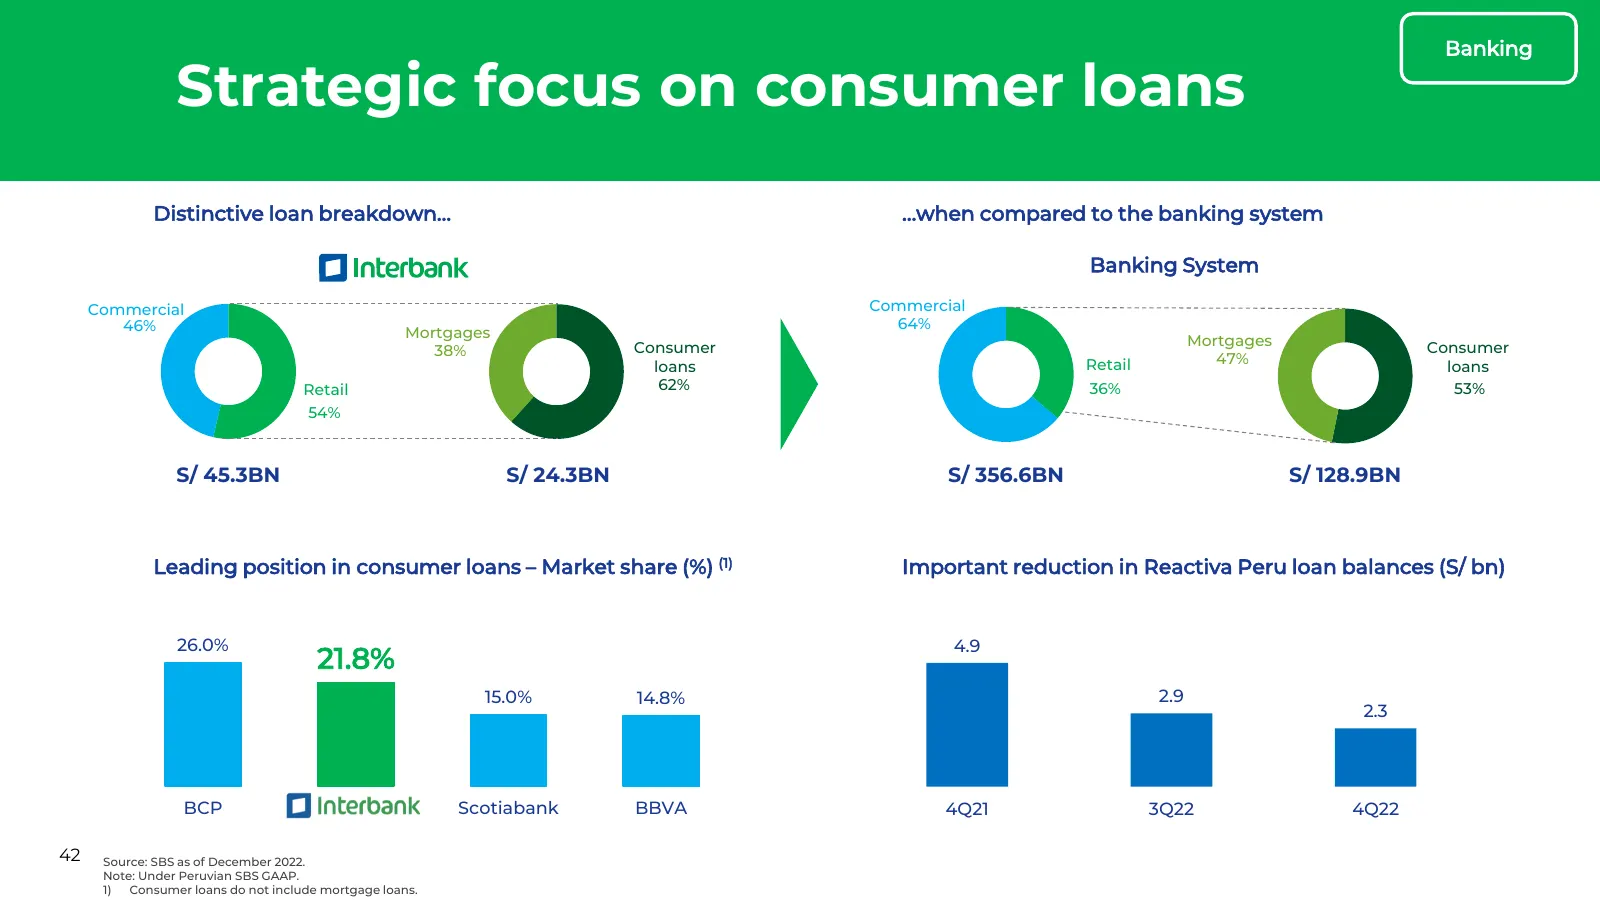
Slide 43: Strategic focus on consumer loans
Banking Strategic focus on consumer loans Distinctive loan breakdown… …when compared to the banking system Banking System Commercial Commercial 46% 64% Mortgages Consumer Mortgages Consumer 38% loans Retail 47% loans Retail 62% 36% 53% 54% S/ 45.3BN S/ 24.3BN S/ 356.6BN S/ 128.9BN Leading position i
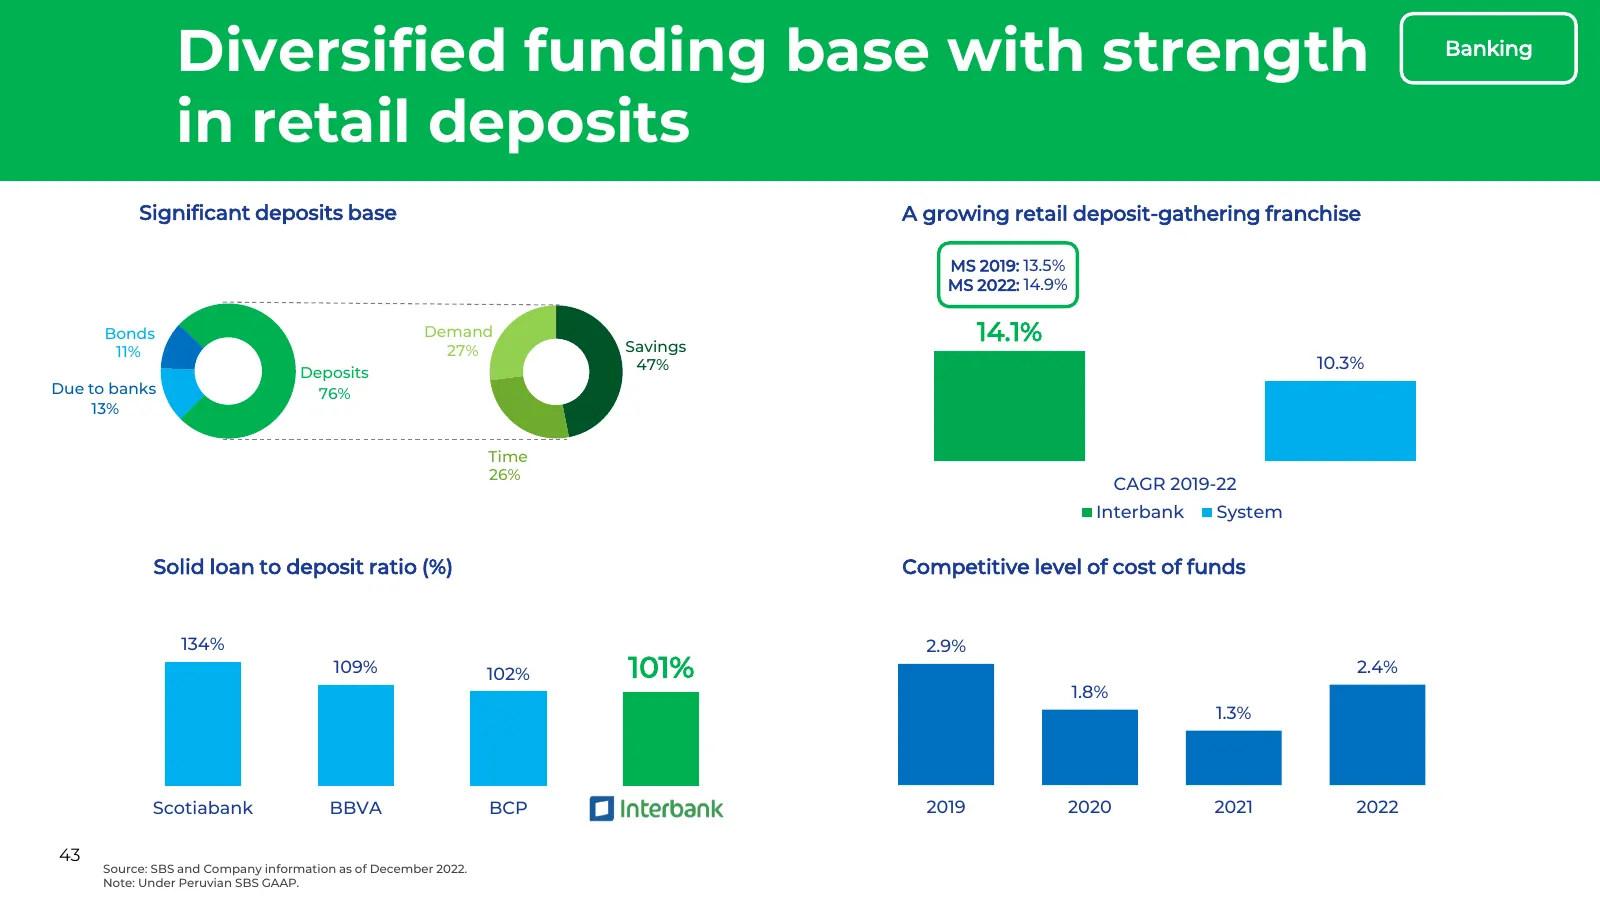
Slide 44: Diversified funding base with strength in retail deposits
Diversified funding base with strength Banking in retail deposits Significant deposits base A growing retail deposit-gathering franchise MS 2019: 13.5% MS 2022: 14.9% Bonds Demand Savings 14.1% 11% 27% 47% 10.3% Deposits Due to banks 76% 13% Time 26% CAGR 2019-22 Interbank System Solid loan to depos
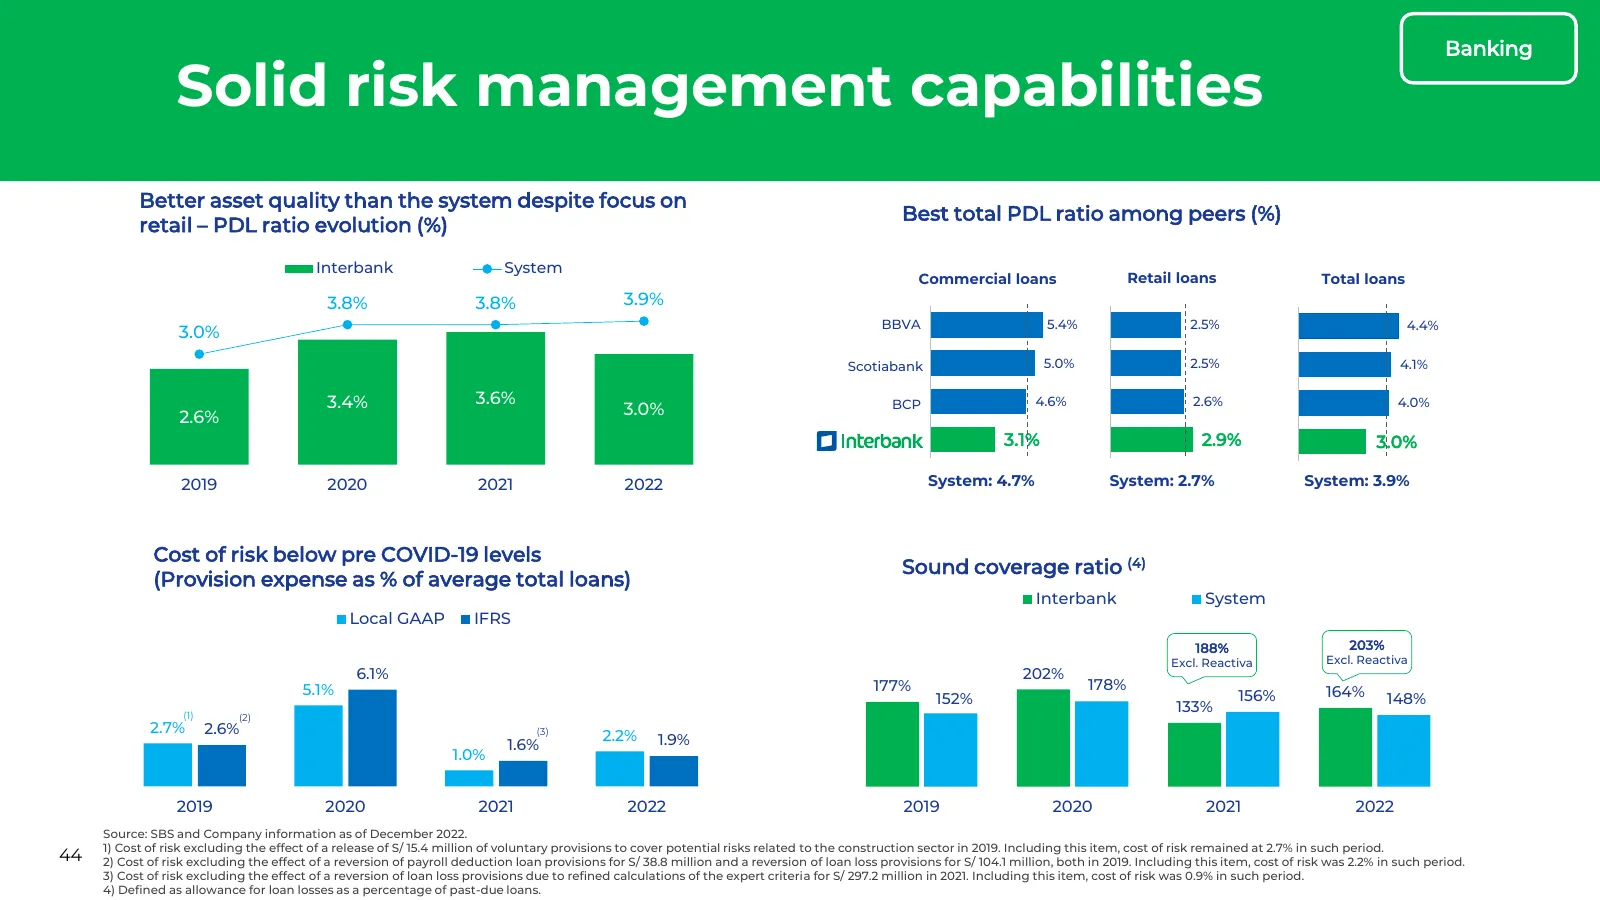
Slide 45: Solid risk management capabilities
Banking Solid risk management capabilities Better asset quality than the system despite focus on Best total PDL ratio among peers (%) retail – PDL ratio evolution (%) Interbank System Commercial loans Retail loans Total loans 3.8% 3.8% 3.9% BBVA BBVA 5.4% 2.5% BBVA 4.4% 3.0% Scotiabank Scotiabank 5.
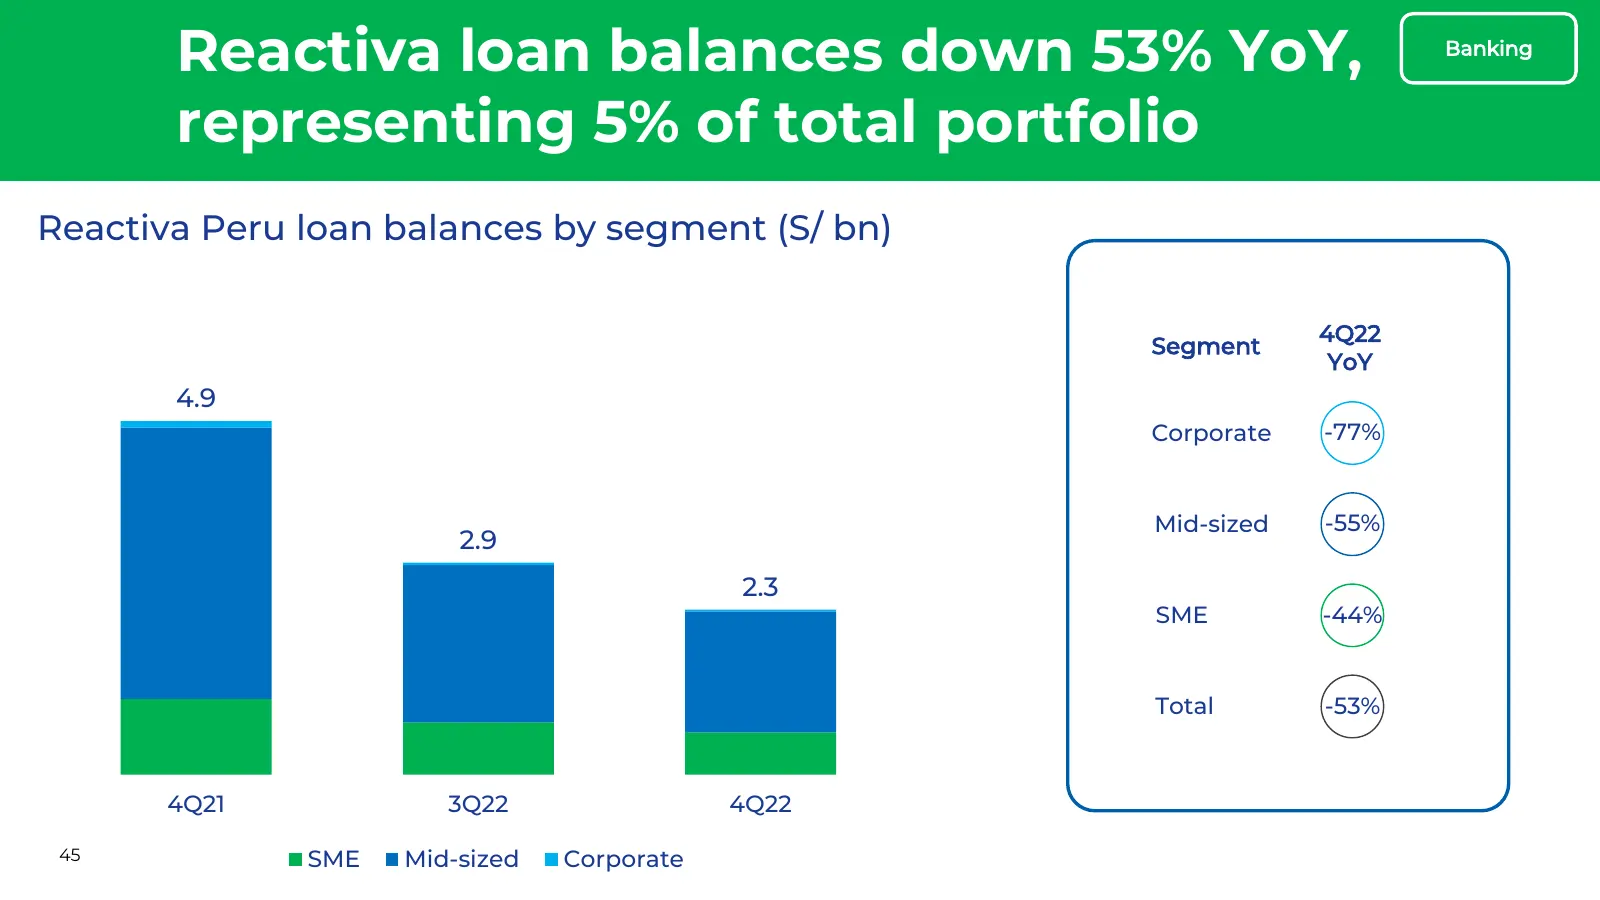
Slide 46: Reactiva loan balances down 53% YoY
Reactiva loan balances down 53% YoY, Banking representing 5% of total portfolio Reactiva Peru loan balances by segment (S/ bn) 4Q22 Segment YoY 4.9 Corporate -77% Mid-sized -55% 2.9 2.3 SME -44% Total -53% 4Q21 3Q22 4Q22 45 SME Mid-sized Corporate
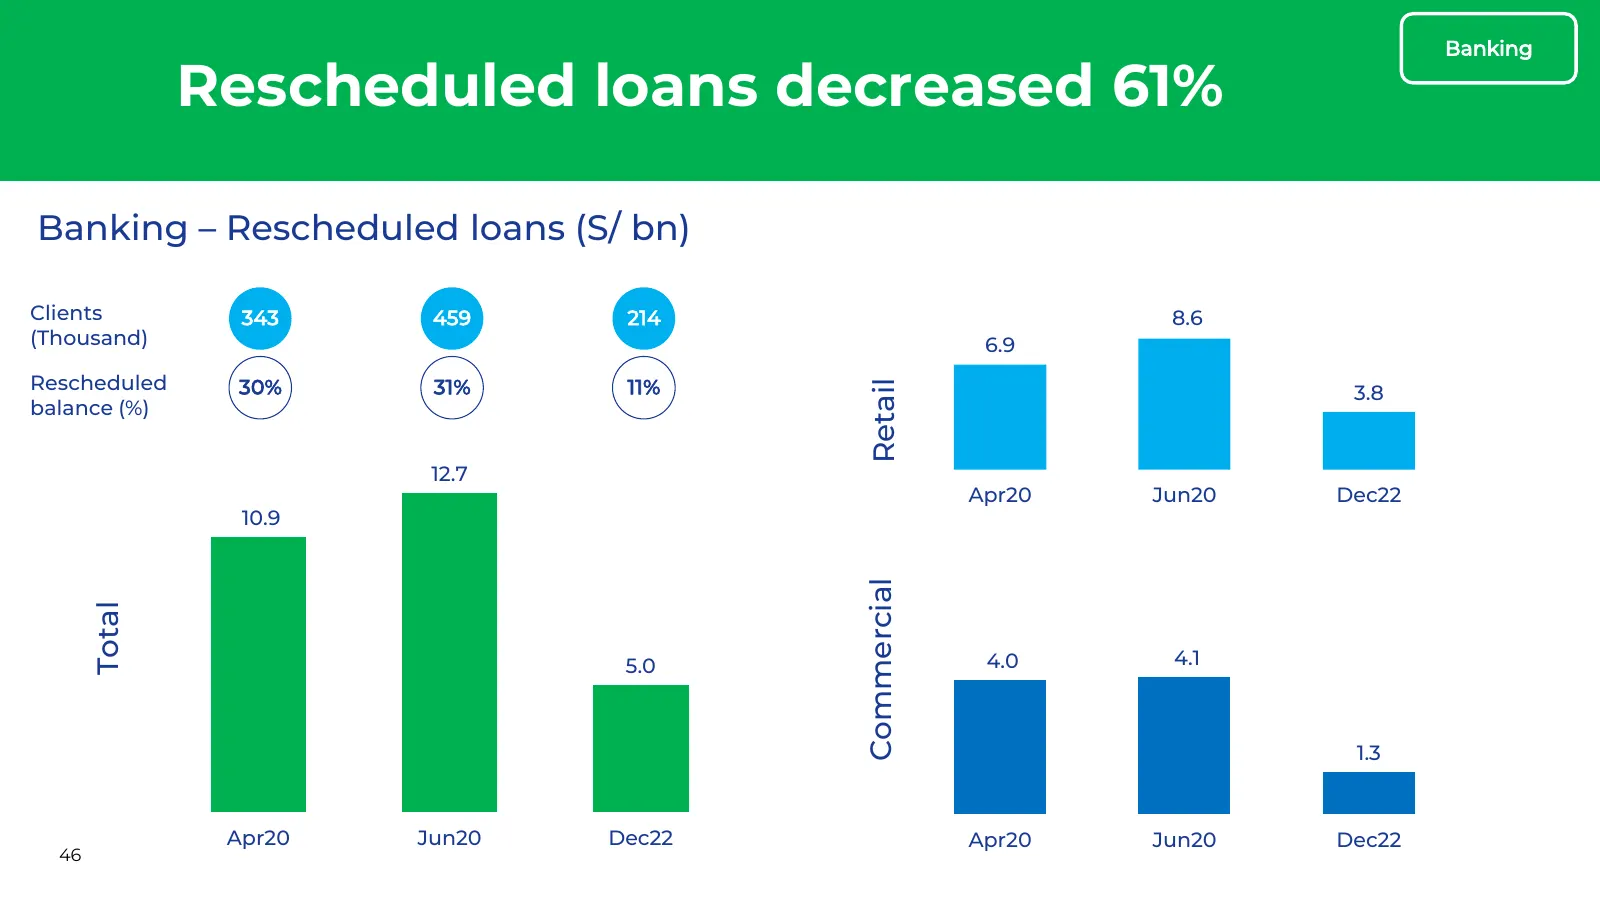
Slide 47: Commercial: rescheduled loans decreased 61%
Banking Rescheduled loans decreased 61% Banking – Rescheduled loans (S/ bn) Clients 343 459 214 8.6 (Thousand) 6.9 Rescheduled 30% 31% 11% Retail 3.8 balance (%) 12.7 Apr20 Jun20 Dec22 10.9 Commercial Total 5.0 4.0 4.1 1.3 Apr20 Jun20 Dec22 Apr20 Jun20 Dec22 46
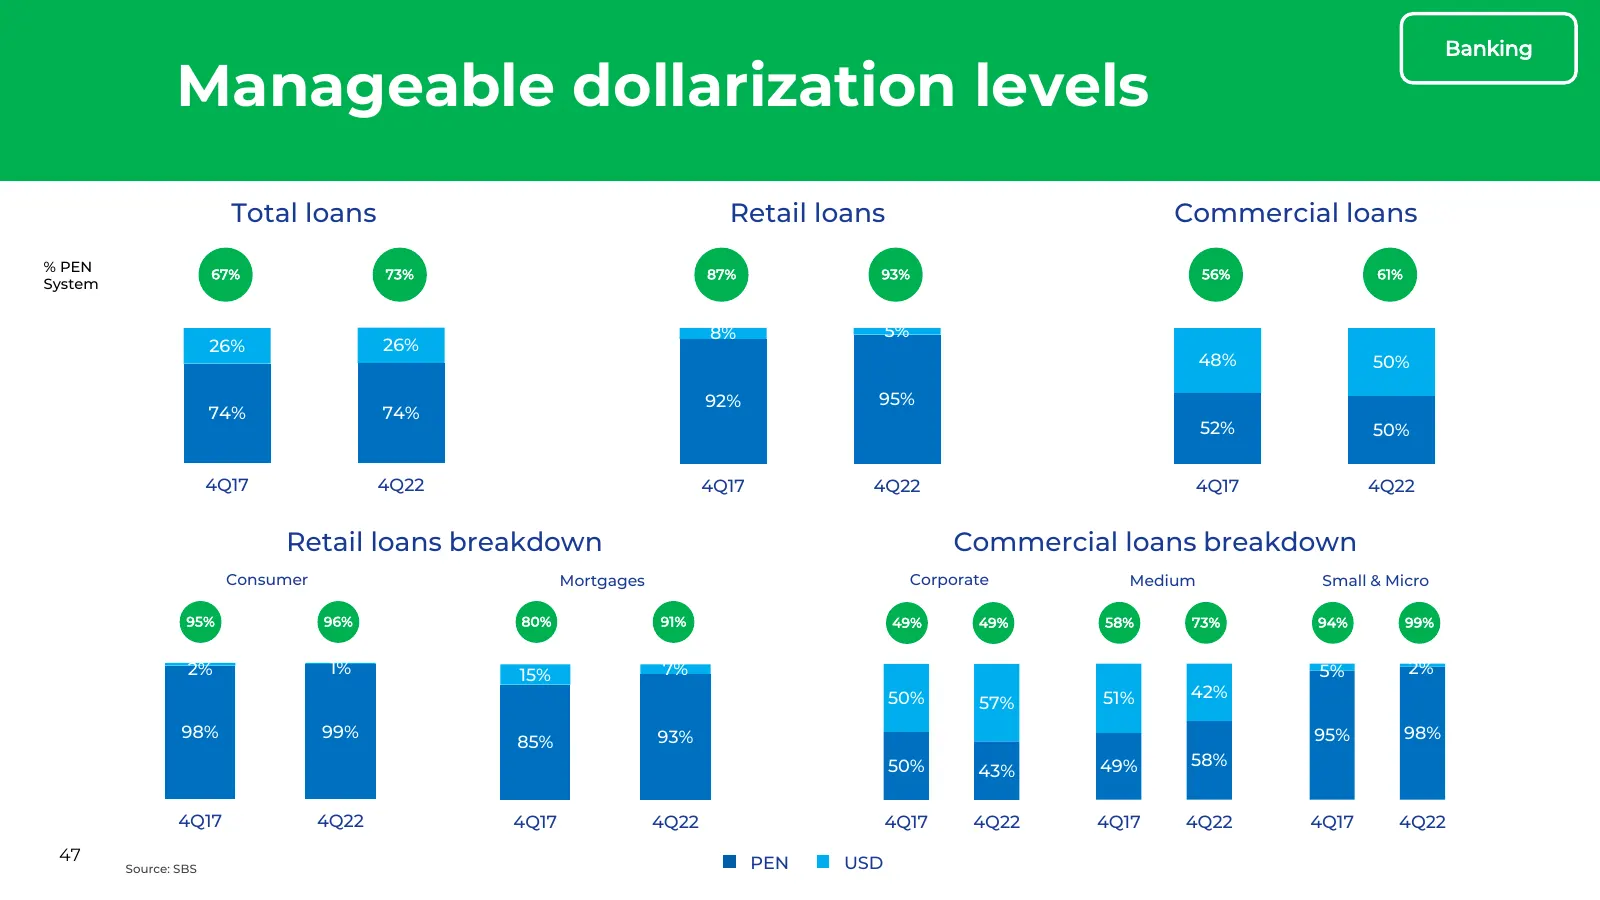
Slide 48: Manageable dollarization levels
Banking Manageable dollarization levels Total loans Retail loans Commercial loans % PEN 67% 73% 87% 93% 56% 61% System 8% 5% 26% 26% 48% 50% 92% 95% 74% 74% 52% 50% 4Q17 4Q22 4Q17 4Q22 4Q17 4Q22 Retail loans breakdown Commercial loans breakdown Consumer Mortgages Corporate Medium Small & Micro 95% 9
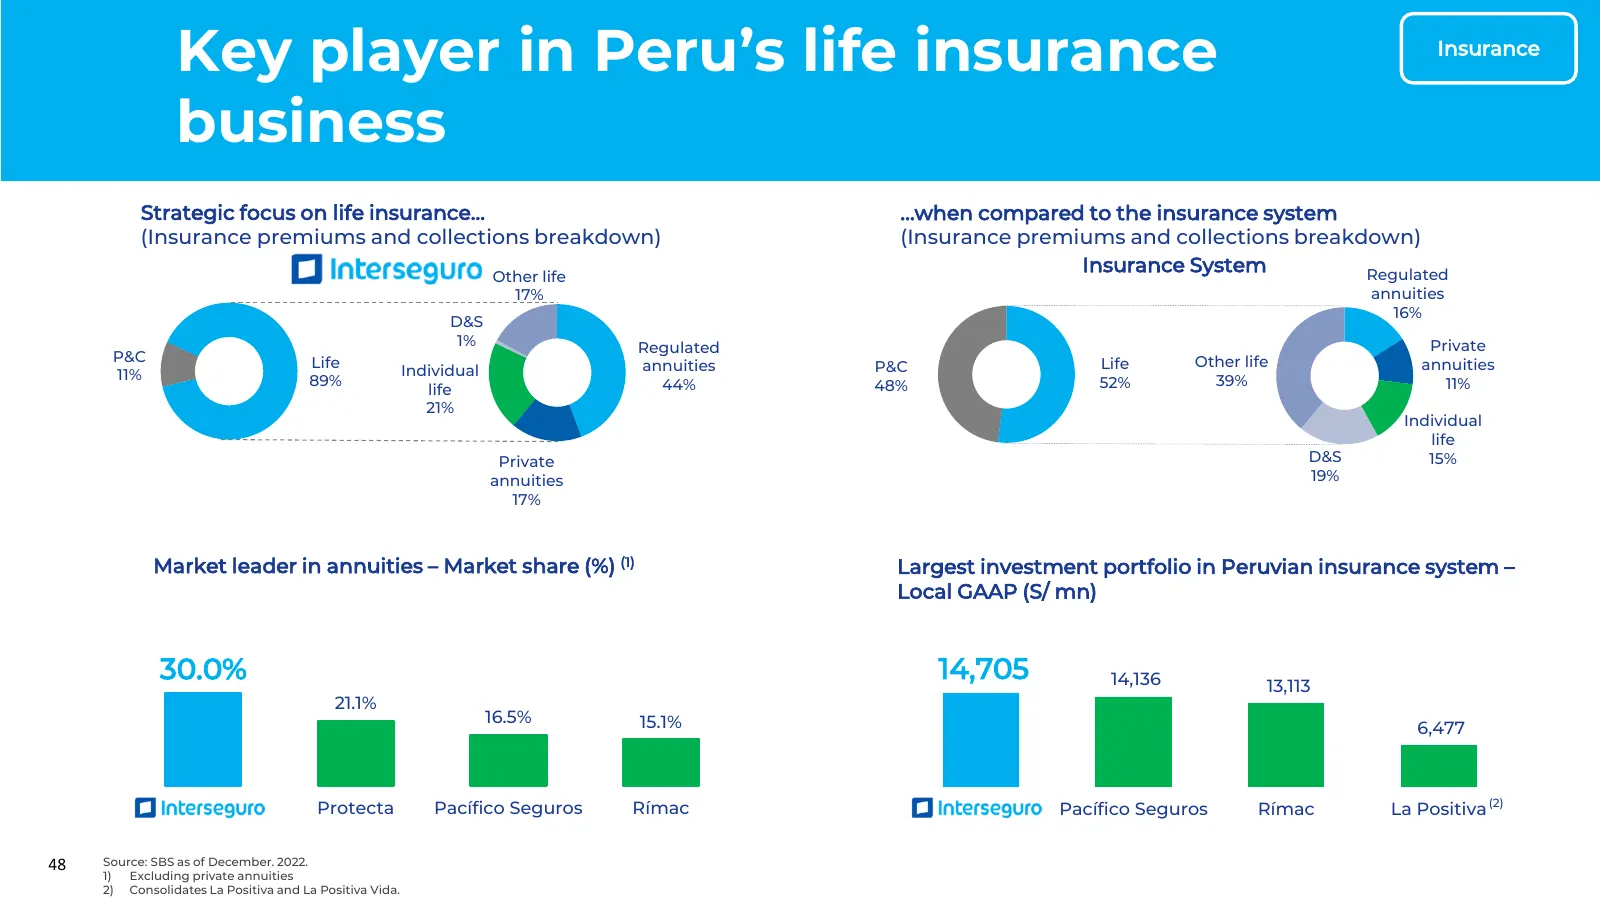
Slide 49: Key player in Peru's life insurance business
Key player in Peru’s life insurance Insurance business Strategic focus on life insurance… …when compared to the insurance system (Insurance premiums and collections breakdown) (Insurance premiums and collections breakdown) Other life Insurance System Regulated 17% annuities 16% D&S 1% Regulated Priv
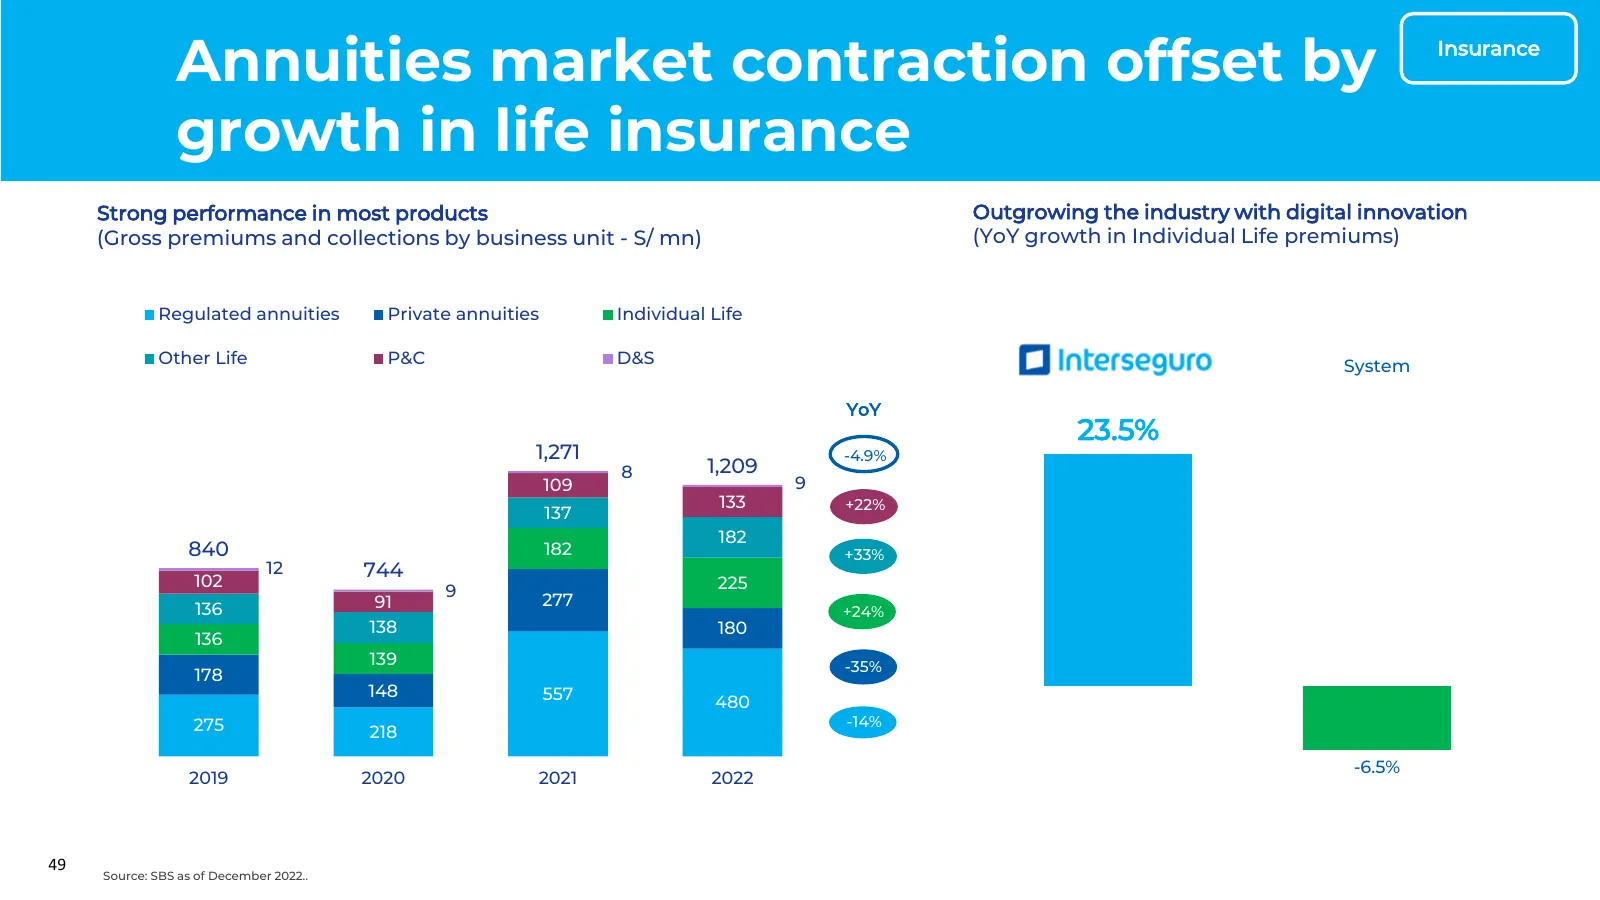
Slide 50: Annuities market contraction offset by growth in life insurance
Annuities market contraction offset by Insurance growth in life insurance Strong performance in most products Outgrowing the industry with digital innovation (Gross premiums and collections by business unit - S/ mn) (YoY growth in Individual Life premiums) Regulated annuities Private annuities Indiv
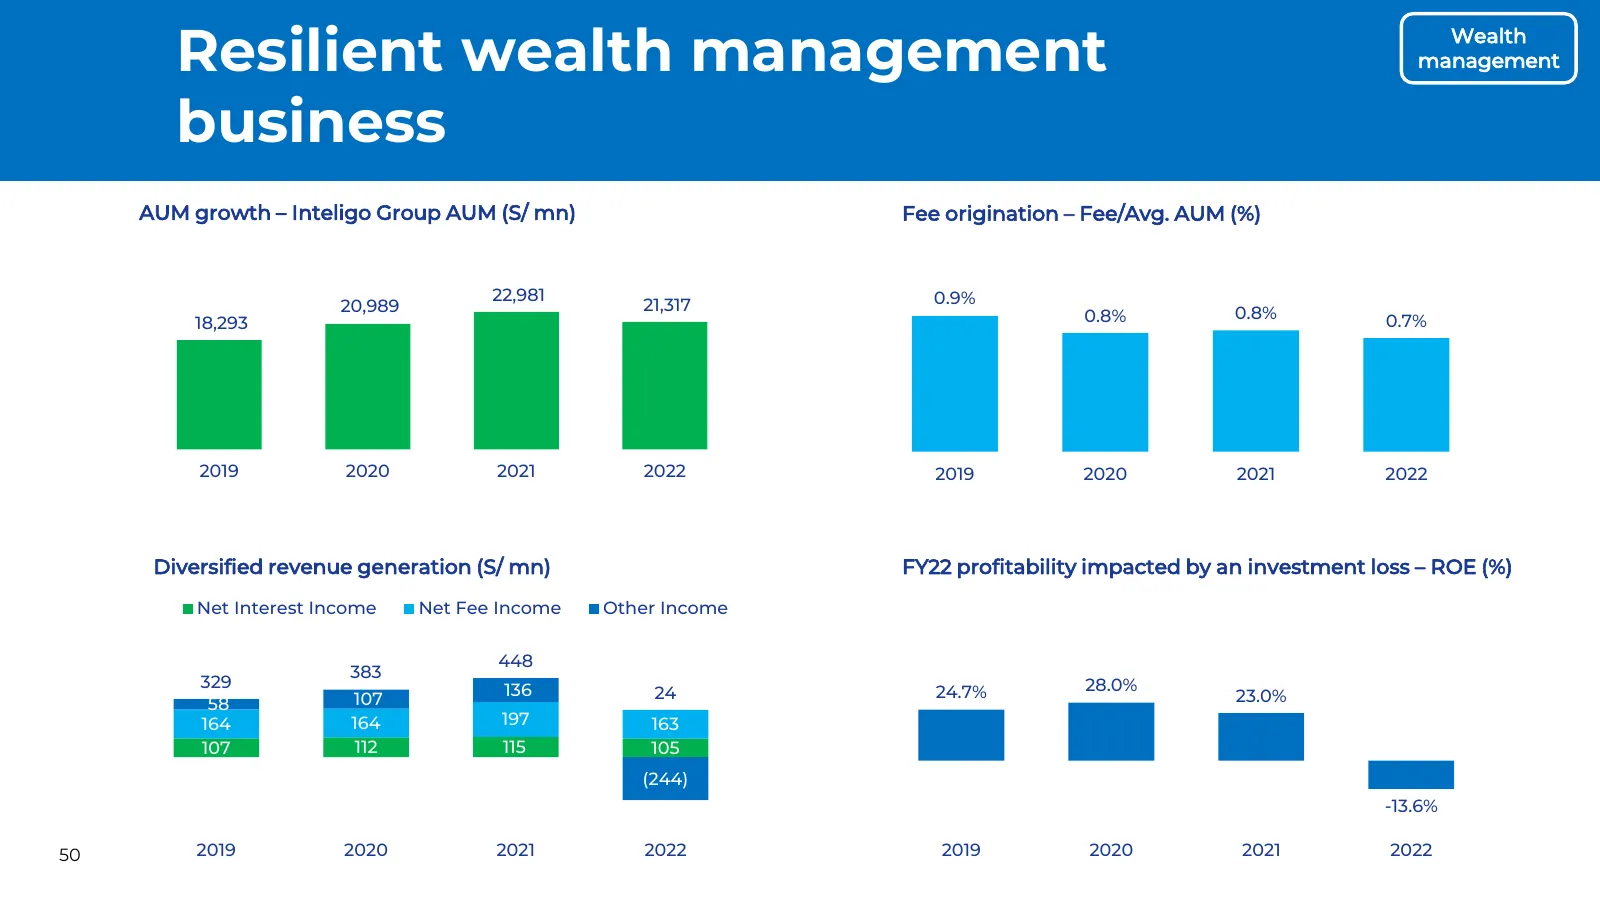
Slide 51: Resilient wealth management business
Resilient wealth management Wealth management business AUM growth – Inteligo Group AUM (S/ mn) Fee origination – Fee/Avg. AUM (%) 22,981 0.9% 20,989 21,317 0.8% 18,293 0.8% 0.7% 2019 2020 2021 2022 2019 2020 2021 2022 Diversified revenue generation (S/ mn) FY22 profitability impacted by an investmen
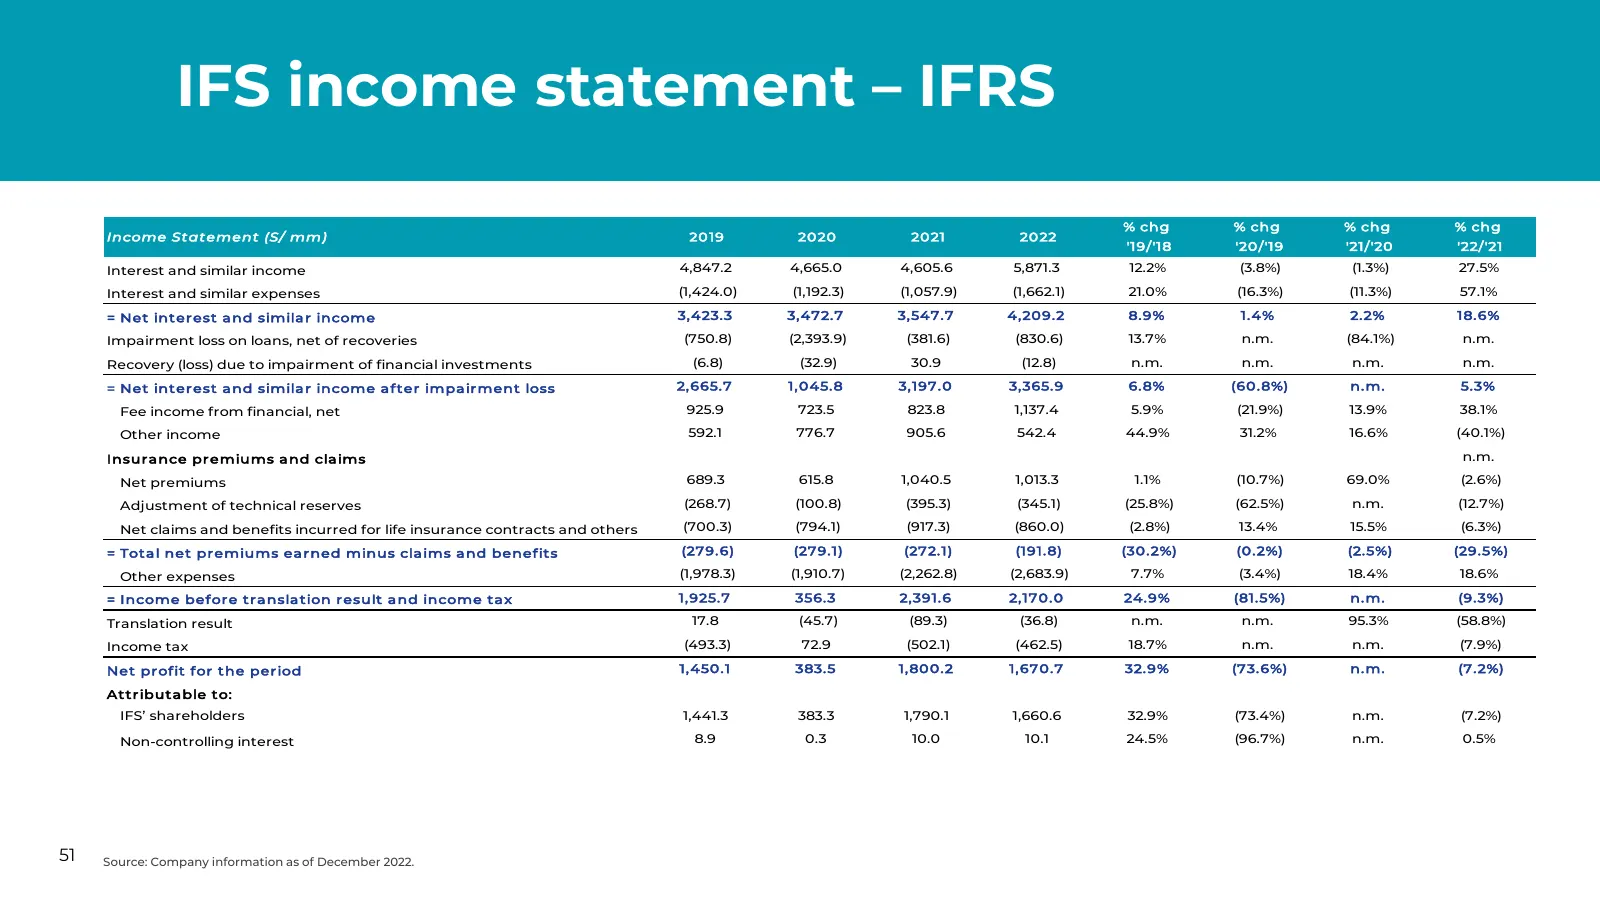
Slide 52: IFS income statement – IFRS
IFS income statement – IFRS % chg % chg % chg % chg Income Statement (S/ mm) 2019 2020 2021 2022 '19/'18 '20/'19 '21/'20 '22/'21 Interest and similar income 4,847.2 4,665.0 4,605.6 5,871.3 12.2% (3.8%) (1.3%) 27.5% Interest and similar expenses (1,424.0) (1,192.3) (1,057.9) (1,662.1) 21.0% (16.3%) (
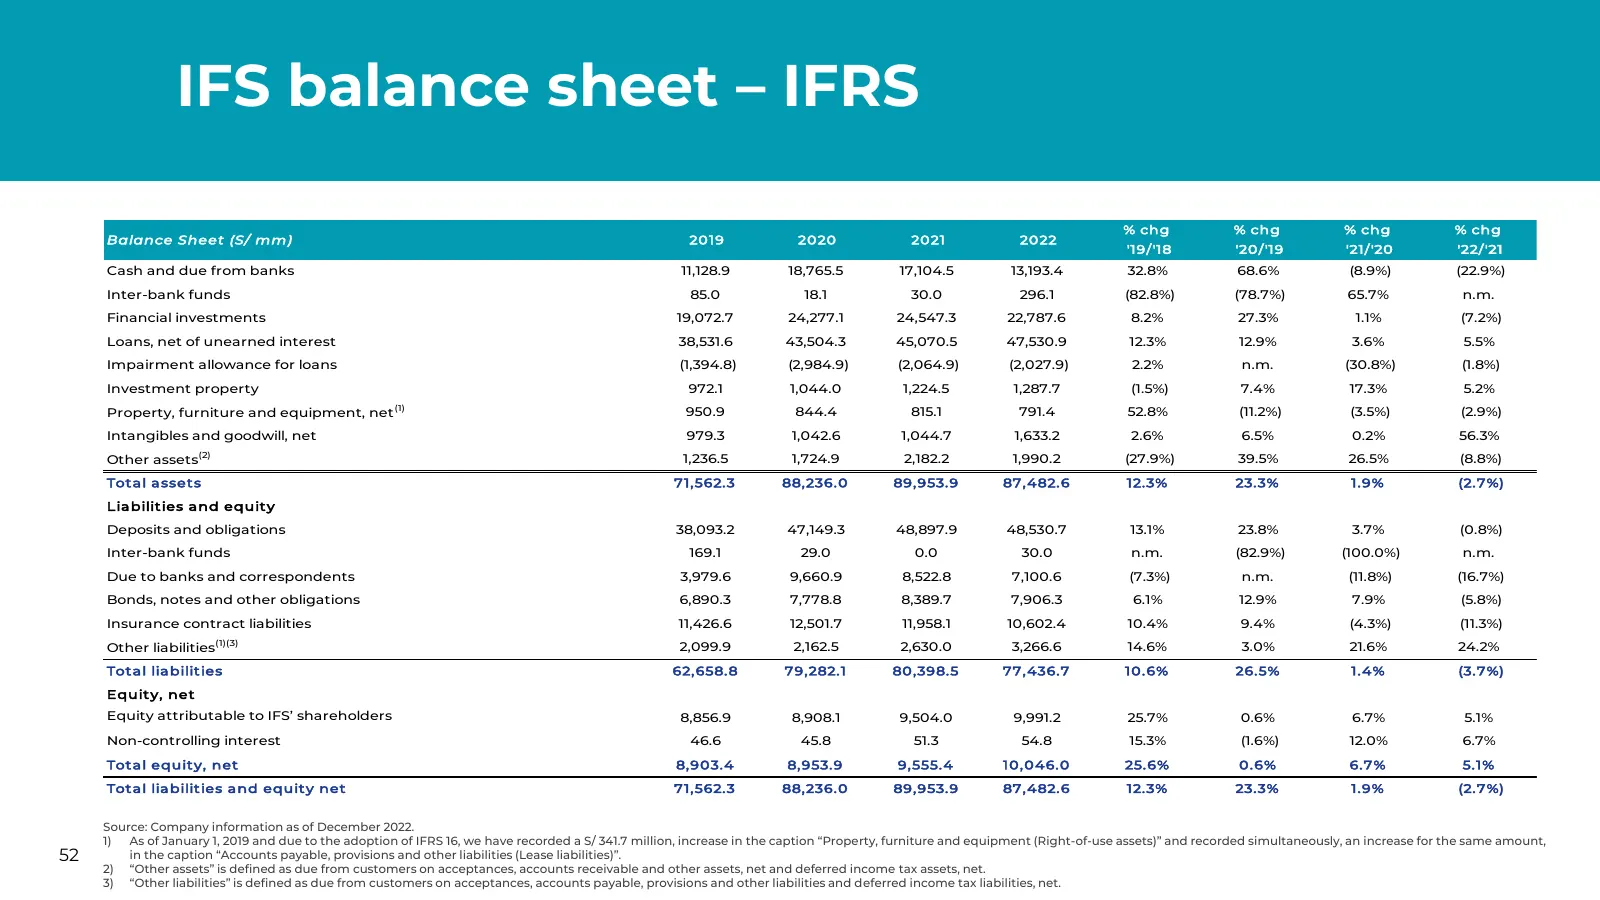
Slide 53: IFS balance sheet – IFRS
IFS balance sheet – IFRS % chg % chg % chg % chg Balance Sheet (S/ mm) 2019 2020 2021 2022 '19/'18 '20/'19 '21/'20 '22/'21 Cash and due from banks 11,128.9 18,765.5 17,104.5 13,193.4 32.8% 68.6% (8.9%) (22.9%) Inter-bank funds 85.0 18.1 30.0 296.1 (82.8%) (78.7%) 65.7% n.m. Financial investments 19,
Slide 54: Safe Harbor for Forward-Looking Statements
Safe Harbor for Forward-Looking Statements This corporate presentation contains “forward looking statements” within the meaning of Section 21E of the Securities Exchange Act of 1934. All statements other than statements of historical facts included in this corporate presentation regarding IFS’ busin
Slide 55: Intercorp Financial Services
[J Intercorp Financial rVviC
Source: company website
More decks from Intercorp Financial Services Inc.
 Q3 2026 Earnings Presentation54 slides · November 2026
 Q2 2026 Earnings Presentation54 slides · Aug 12, 2026
 Q2 2026 Earnings Presentation57 slides · August 2026
 Q2 2026 Earnings Presentation38 slides · August 2026
 Q1 2026 Earnings Presentation54 slides · May 12, 2026
 Q1 2026 Earnings Presentation51 slides · May 2026