PayPoint plc · LSE:PAY
PayPoint — FY2016 Earnings Presentation
48 slides from PayPoint's earnings presentation, May 26, 2016
Slide 1: Results for the year ended 31 March 2016
Keeping modern life moving Results for the year ended 31 March 2016
Slide 2: Agenda
Agenda 2 Introduction 3 Financial review 5 Capital allocation 11 Operational review 15 Strategy 21 Summary and future development 34 Appendices 36 1. Materials to support the consumer transaction - UK retail 2. Materials to support the consumer transaction - Collect+ Results for the year ended 31 Ma
Slide 3: Introduction - we said we would…
Introduction - we said we would… 3 Focus on multi-channel payments and services where we have retail networks Results for the year ended 31 March 2016
Slide 4: We said we would…continued
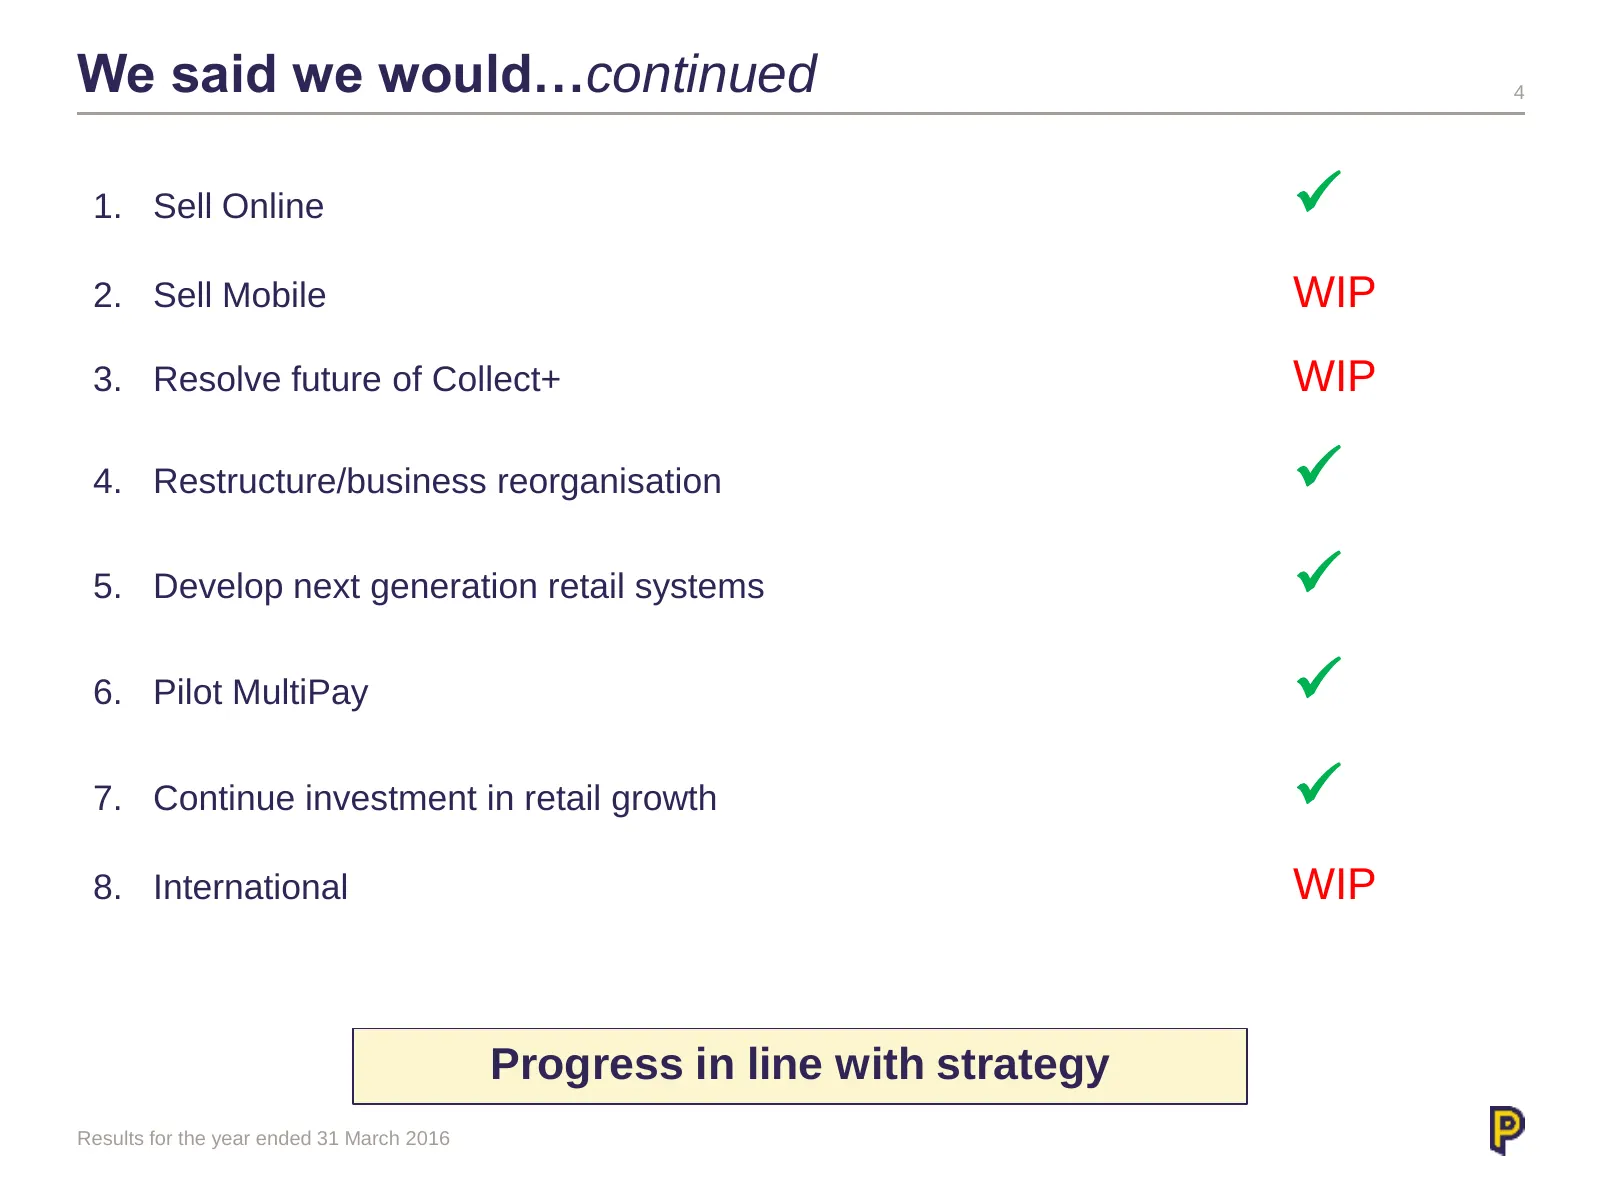
We said we would…continued 4 1. Sell Online 2. Sell Mobile WIP 3. Resolve future of Collect+ WIP 4. Restructure/business reorganisation 5. Develop next generation retail systems 6. Pilot MultiPay 7. Continue investment in retail growth 8. International WIP Progress in line with strategy Re
Slide 5: Financial review
Financial review
Slide 6: Results in line with expectations excluding impairment
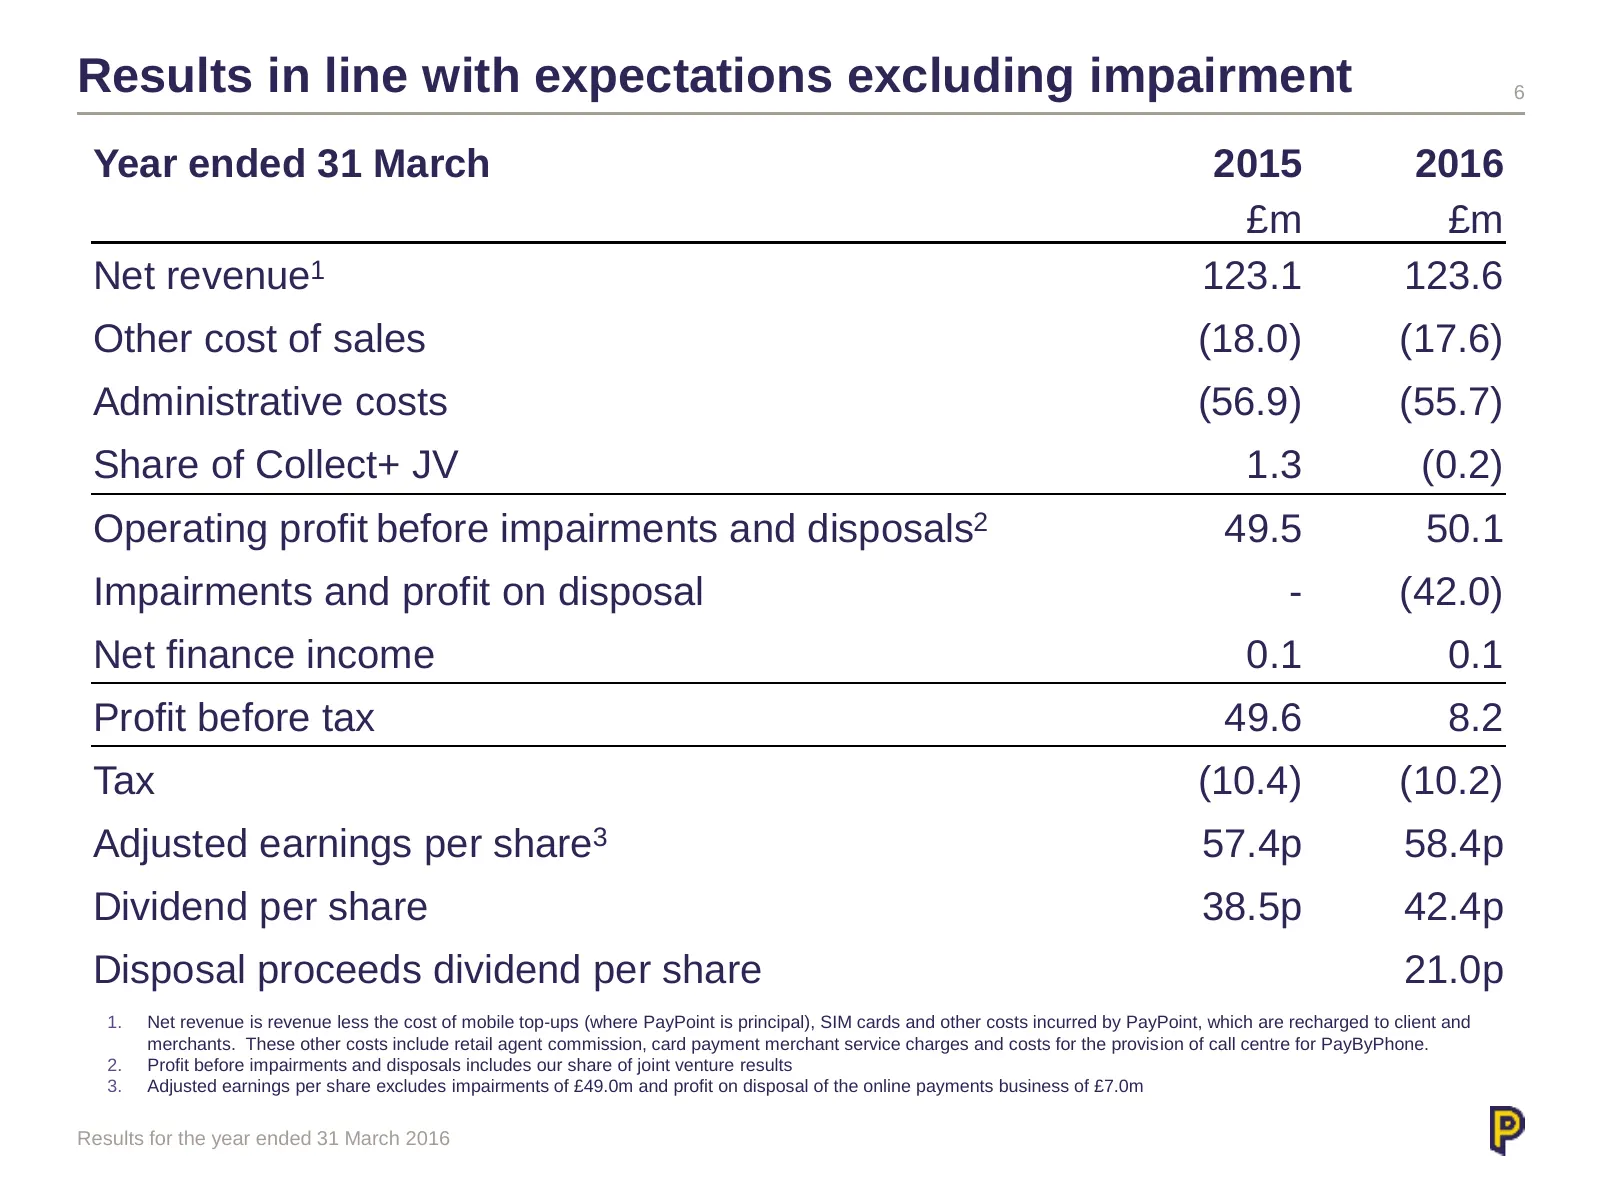
Results in line with expectations excluding impairment 6 Year ended 31 March 2015 2016 £m £m Net revenue1 123.1 123.6 Other cost of sales (18.0) (17.6) Administrative costs (56.9) (55.7) Share of Collect+ JV 1.3 (0.2) Operating profit before impairments and disposals2 49.5 50.1 Impairments and profi
Slide 7: Results excluding Mobile and Online
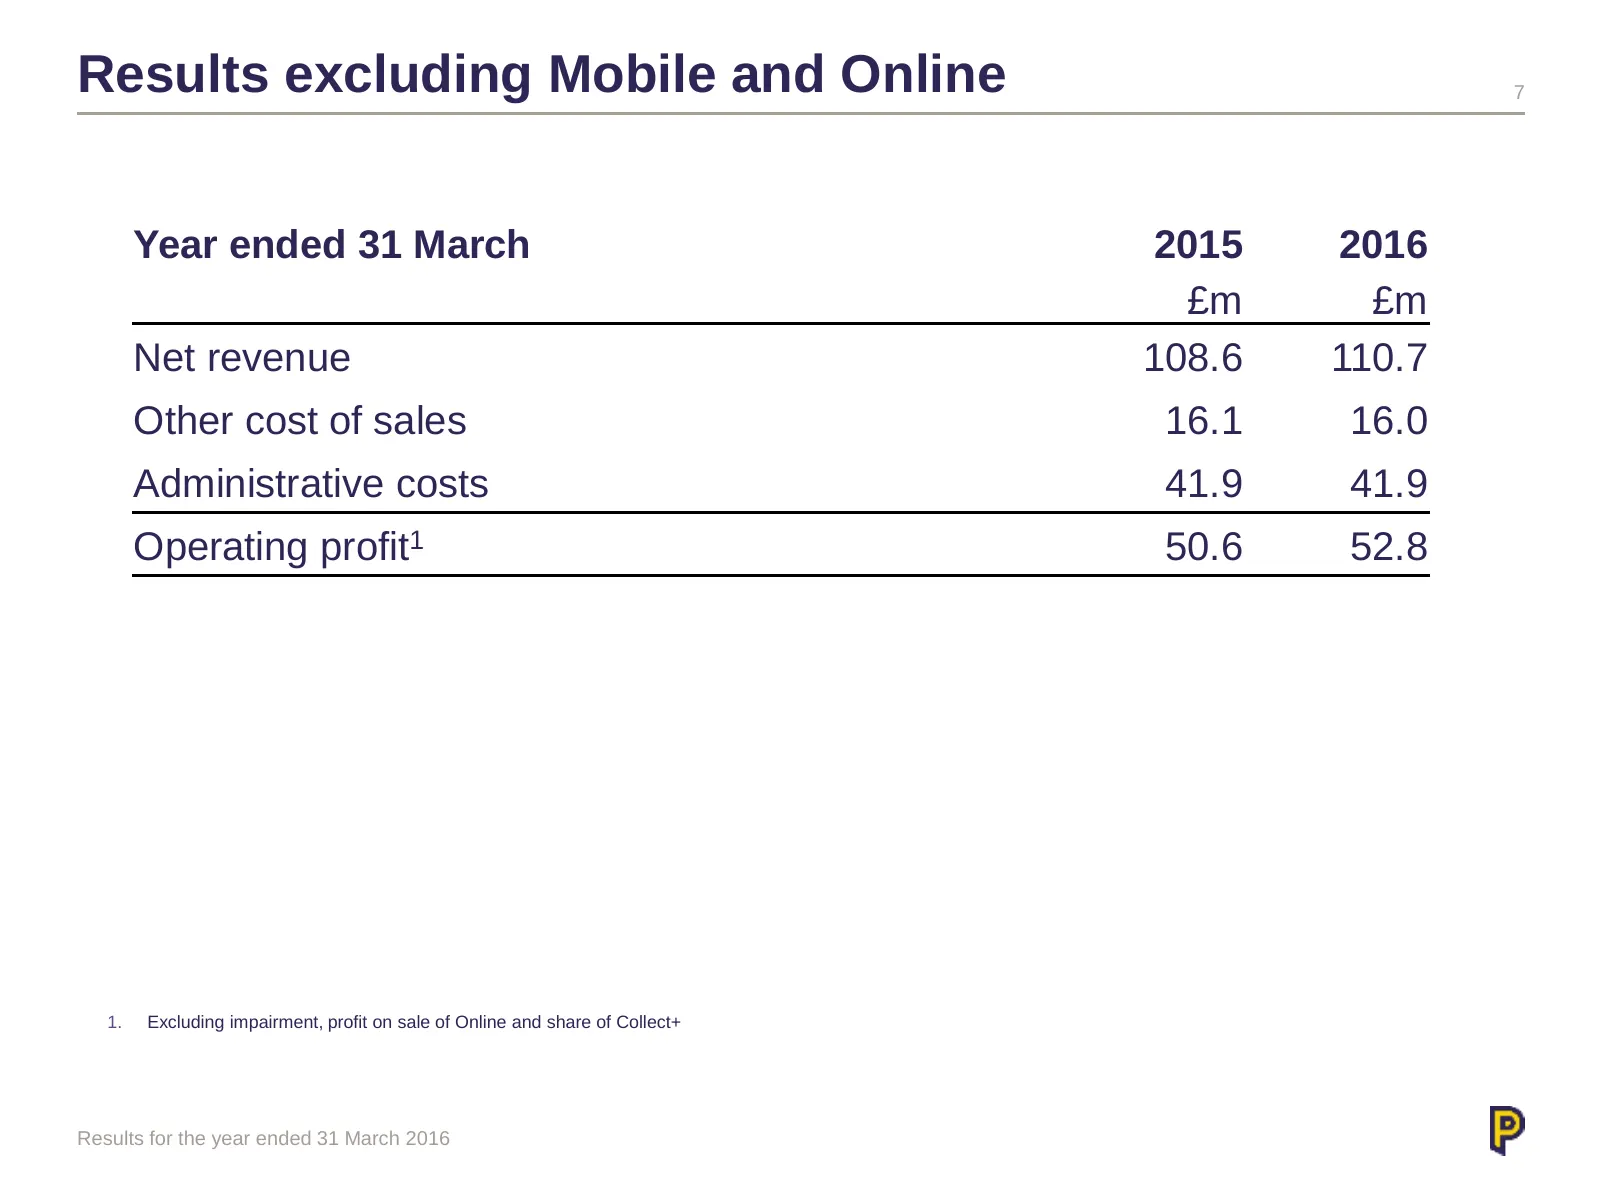
Results excluding Mobile and Online 7 Year ended 31 March 2015 2016 £m £m Net revenue 108.6 110.7 Other cost of sales 16.1 16.0 Administrative costs 41.9 41.9 Operating profit1 50.6 52.8 1. Excluding impairment, profit on sale of Online and share of Collect+ Results for the year ended 31 March 2016
Slide 8: Net revenue
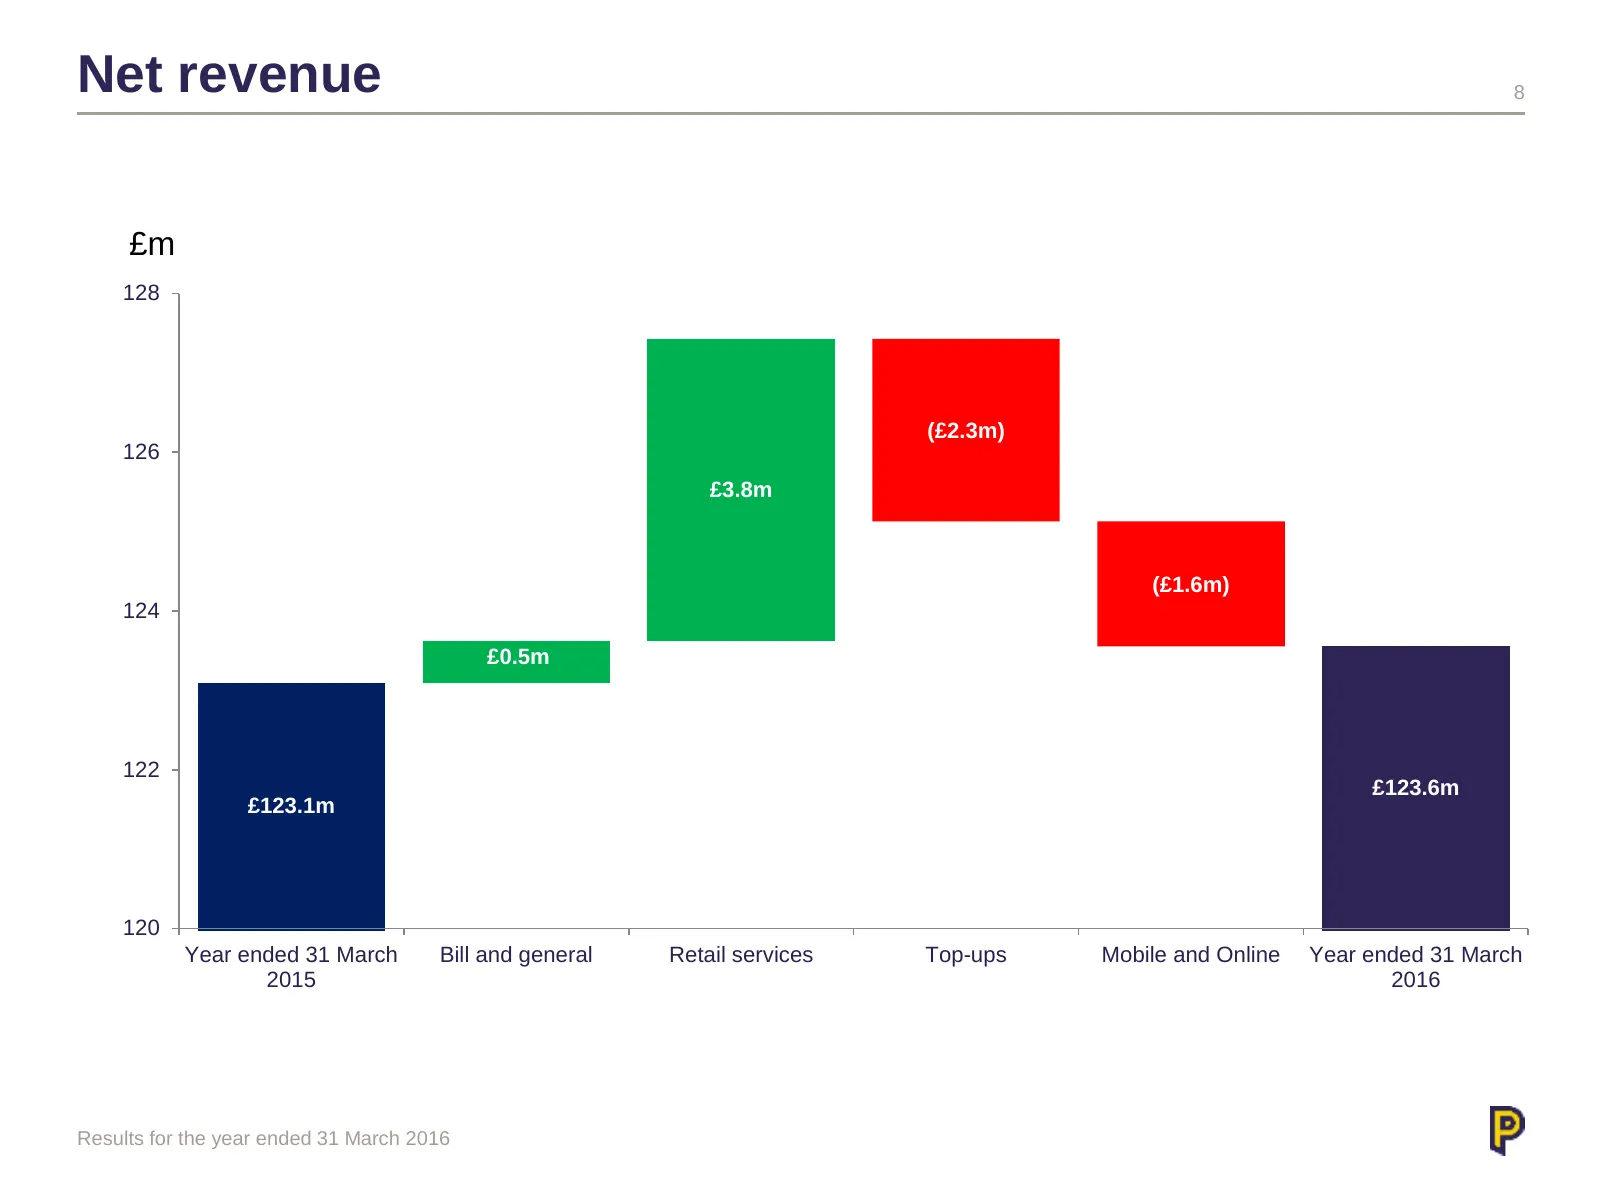
Net revenue 8 £m 128 (£2.3m) 126 £3.8m £123.1m (£1.6m) 124 £113.7m £0.5m 122 £123.6m £123.1m 120 Year ended 31 March Bill and general Retail services Top-ups Mobile and Online Year ended 31 March 2015 2016 Results for the year ended 31 March 2016
Slide 9: Impairment and sale of Online
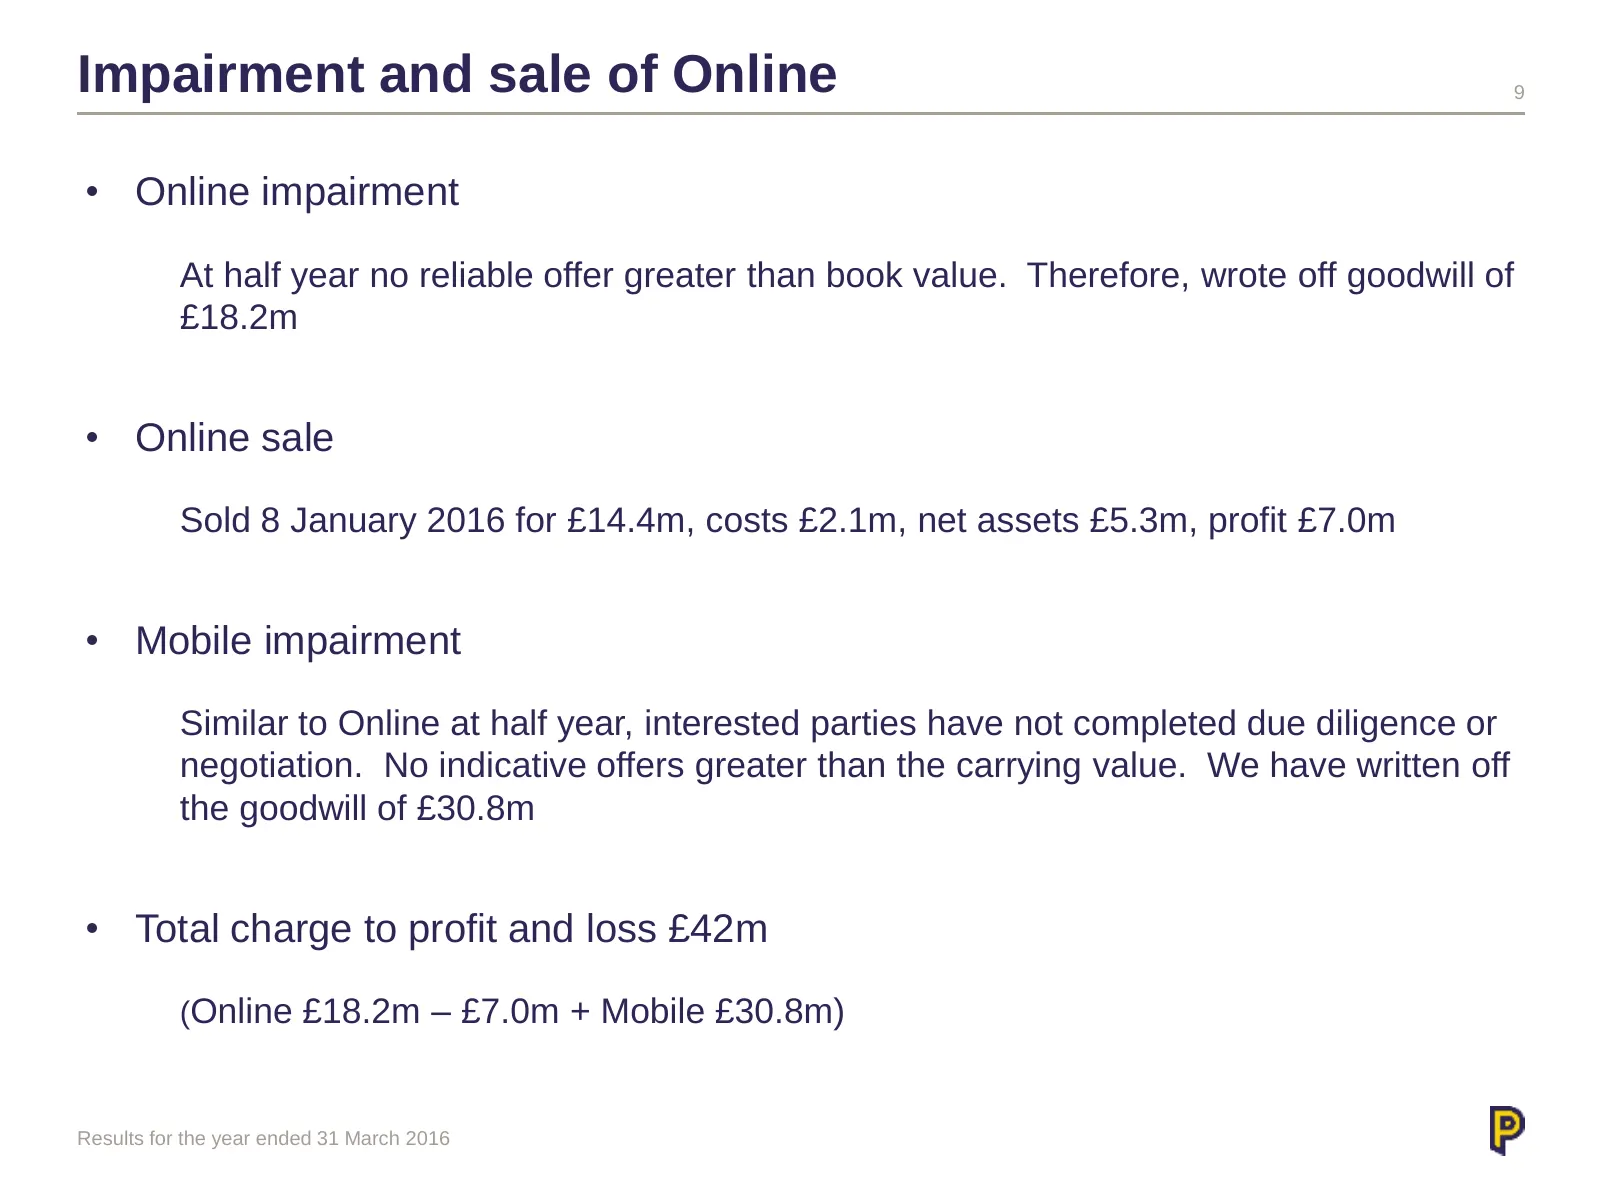
Impairment and sale of Online 9 • Online impairment At half year no reliable offer greater than book value. Therefore, wrote off goodwill of £18.2m • Online sale Sold 8 January 2016 for £14.4m, costs £2.1m, net assets £5.3m, profit £7.0m • Mobile impairment Similar to Online at half year, interested
Slide 10: Cash generation and use
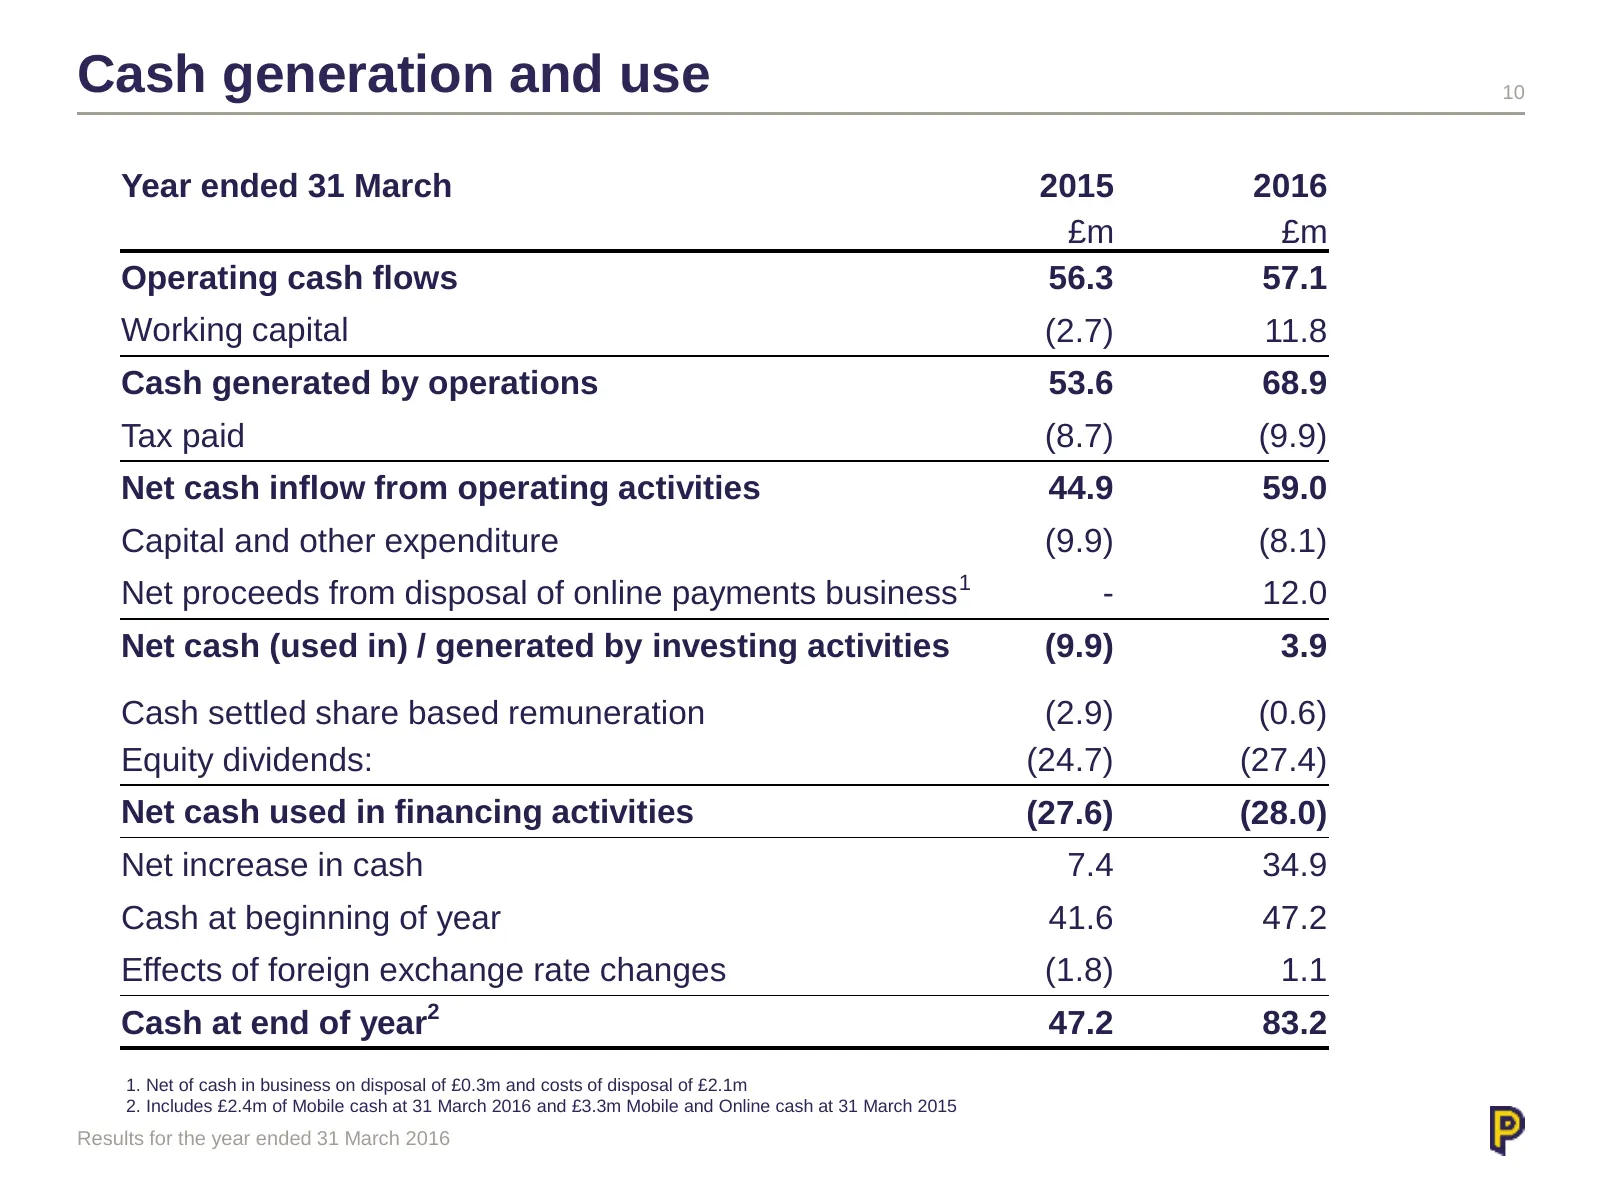
Cash generation and use 10 Year ended 31 March 2015 2016 £m £m Operating cash flows 56.3 57.1 Working capital (2.7) 11.8 Cash generated by operations 53.6 68.9 Tax paid (8.7) (9.9) Net cash inflow from operating activities 44.9 59.0 Capital and other expenditure (9.9) (8.1) Net proceeds from disposa
Slide 11: Capital allocation
Capital allocation
Slide 12: Capital allocation
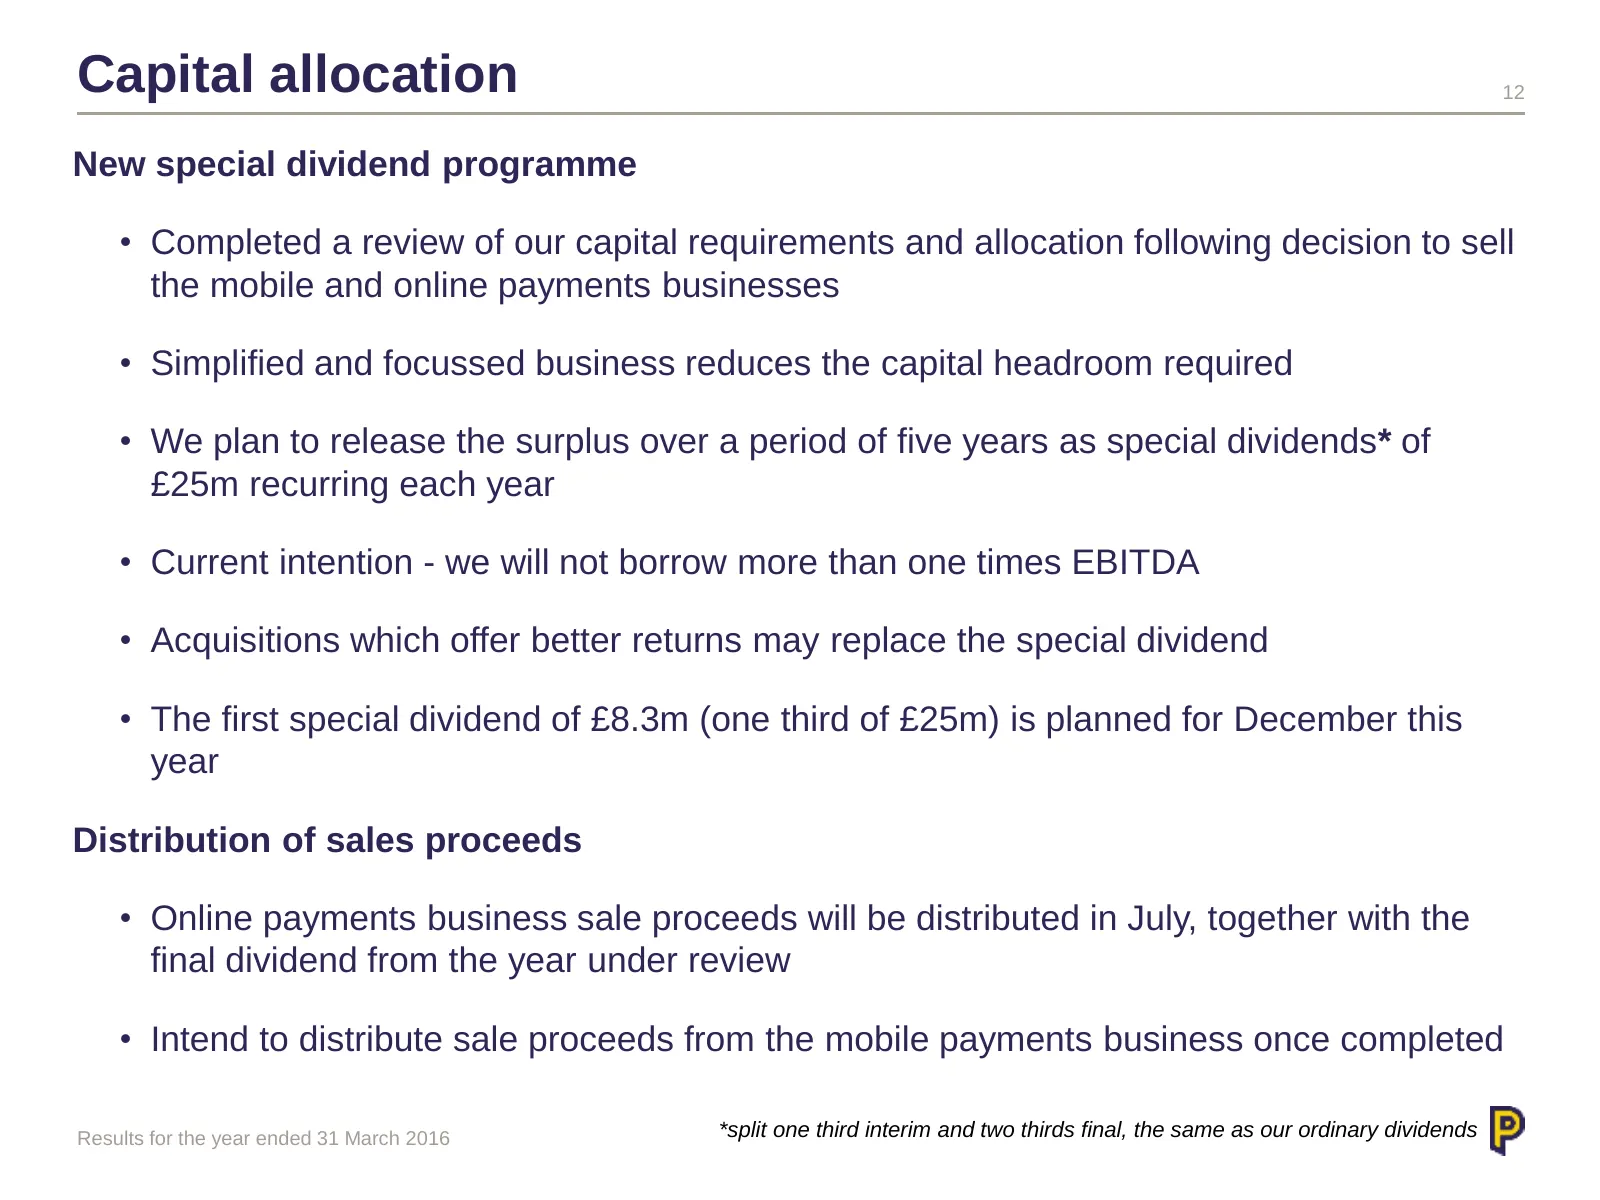
Capital allocation 12 New special dividend programme • Completed a review of our capital requirements and allocation following decision to sell the mobile and online payments businesses • Simplified and focussed business reduces the capital headroom required • We plan to release the surplus over a p
Slide 13: Dividends
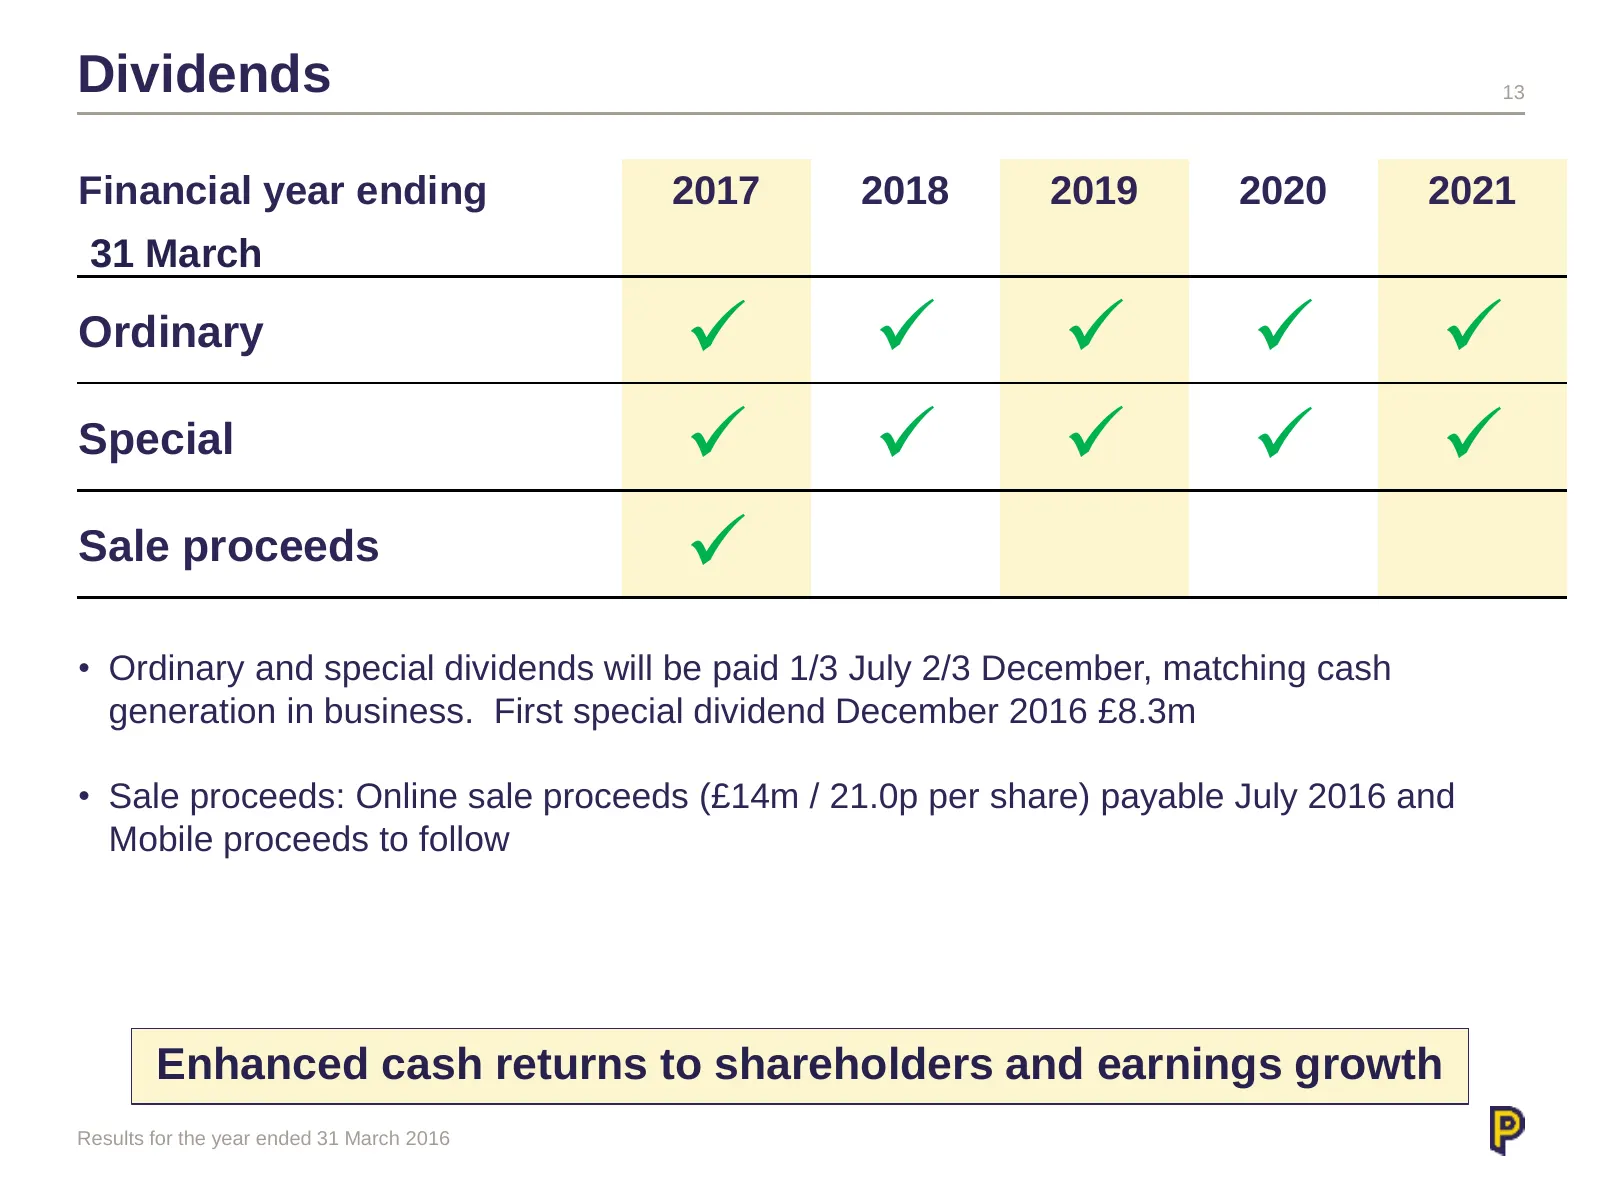
Dividends 13 Financial year ending 2017 2018 2019 2020 2021 31 March Ordinary Special Sale proceeds • Ordinary and special dividends will be paid 1/3 July 2/3 December, matching cash generation in business. First special dividend December 2016 £8.3m • Sale proceeds: Online sale
Slide 14: Financial review and capital allocation - conclusion
Financial review and capital allocation - conclusion 14 • Profits convert into cash • Low capital requirements • Multiple and substantial growth prospects • Prospects for growth in earnings and enhanced cash return to shareholders Results for the year ended 31 March 2016
Slide 15: Operational review
Operational review
Slide 16: Retail payments and services
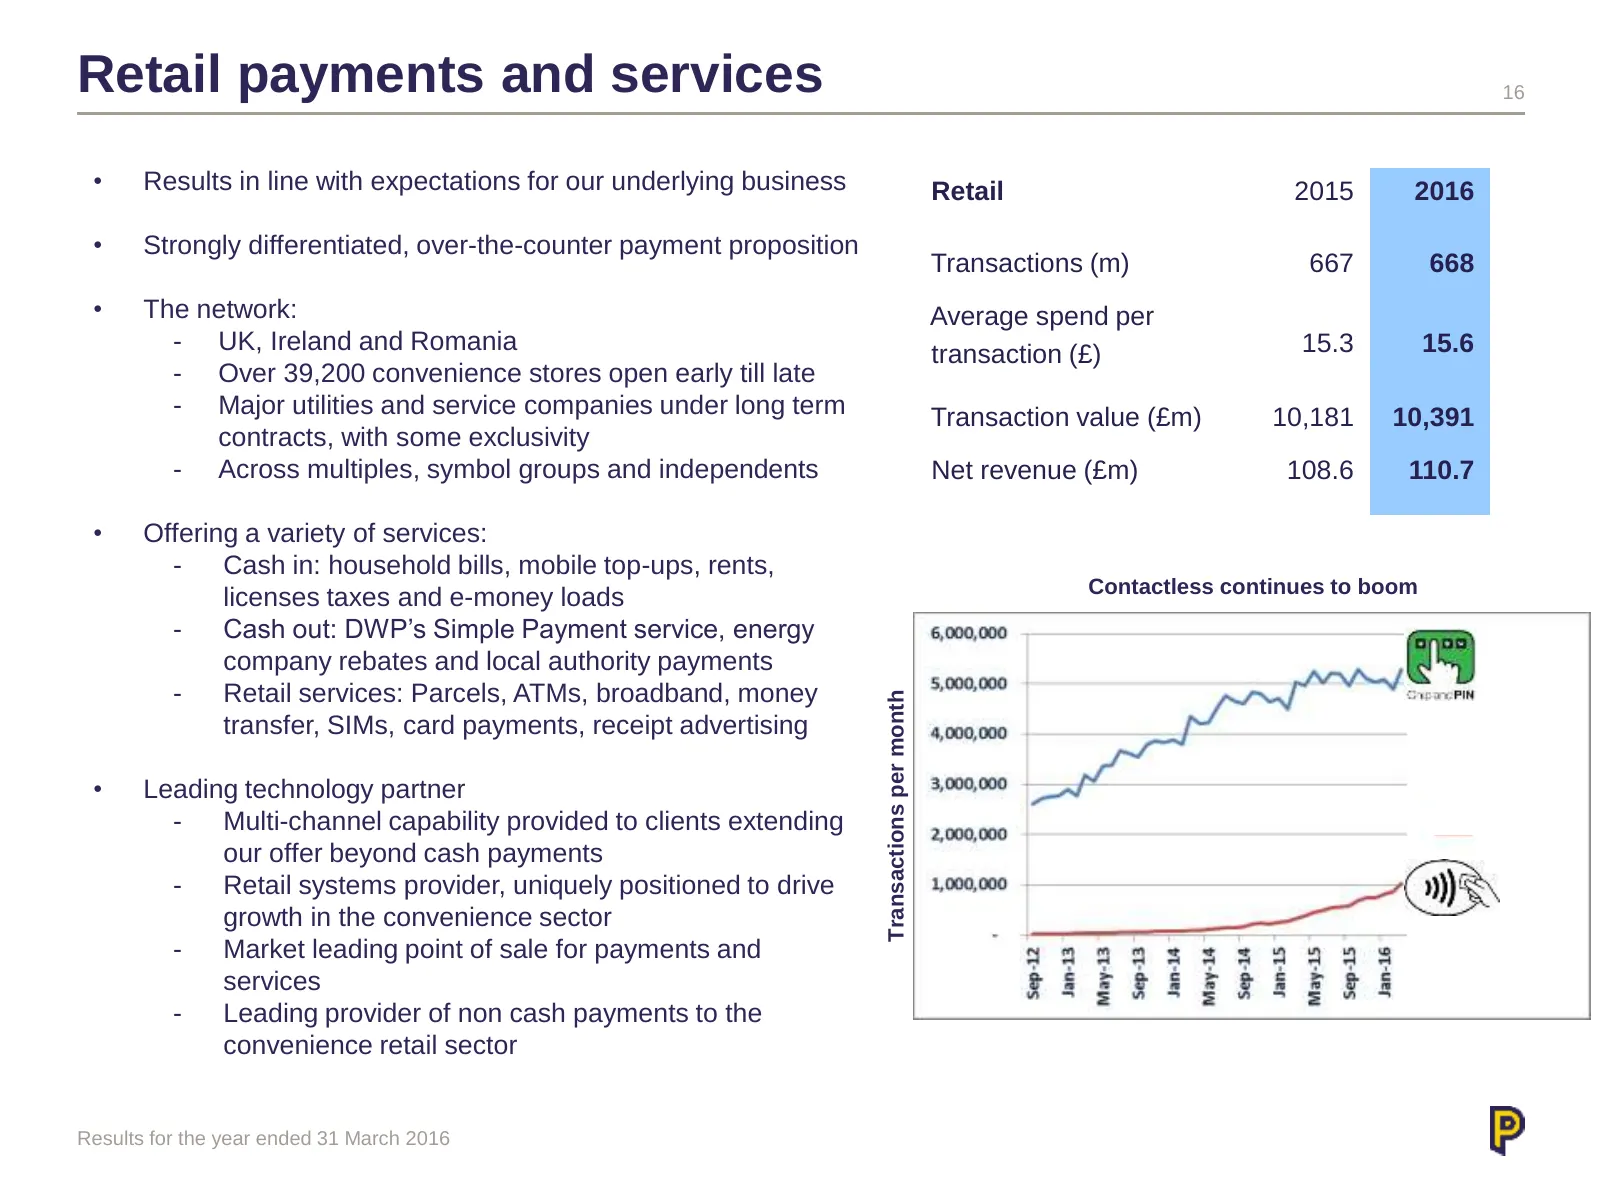
Retail payments and services 16 • Results in line with expectations for our underlying business Retail 2015 2016 • Strongly differentiated, over-the-counter payment proposition Transactions (m) 667 668 • The network: Average spend per - UK, Ireland and Romania 15.3 15.6 transaction (£) - Over 39,200
Slide 17: Retail payments and services – UK & Ireland
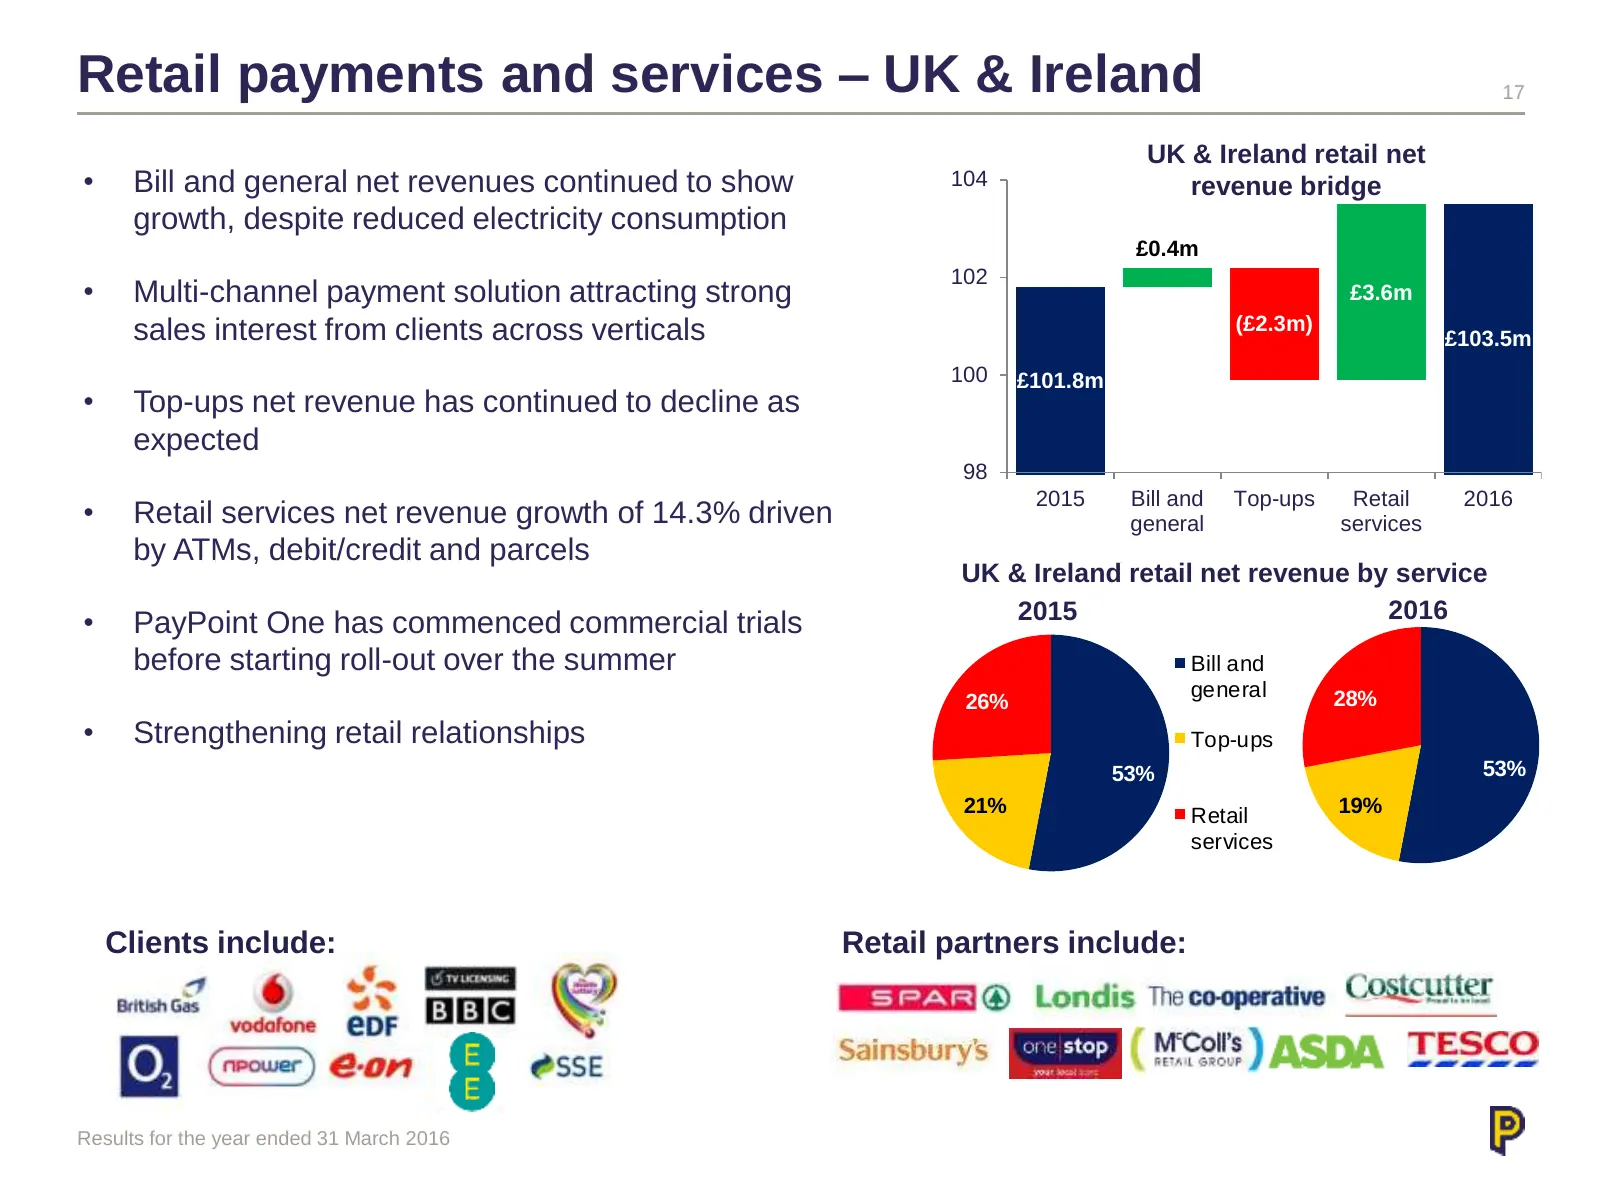
Retail payments and services – UK & Ireland 17 UK & Ireland retail net • Bill and general net revenues continued to show 104 revenue bridge growth, despite reduced electricity consumption £0.4m 102 • Multi-channel payment solution attracting strong £3.6m sales interest from clients across verticals
Slide 18: Retail payments and services - Romania
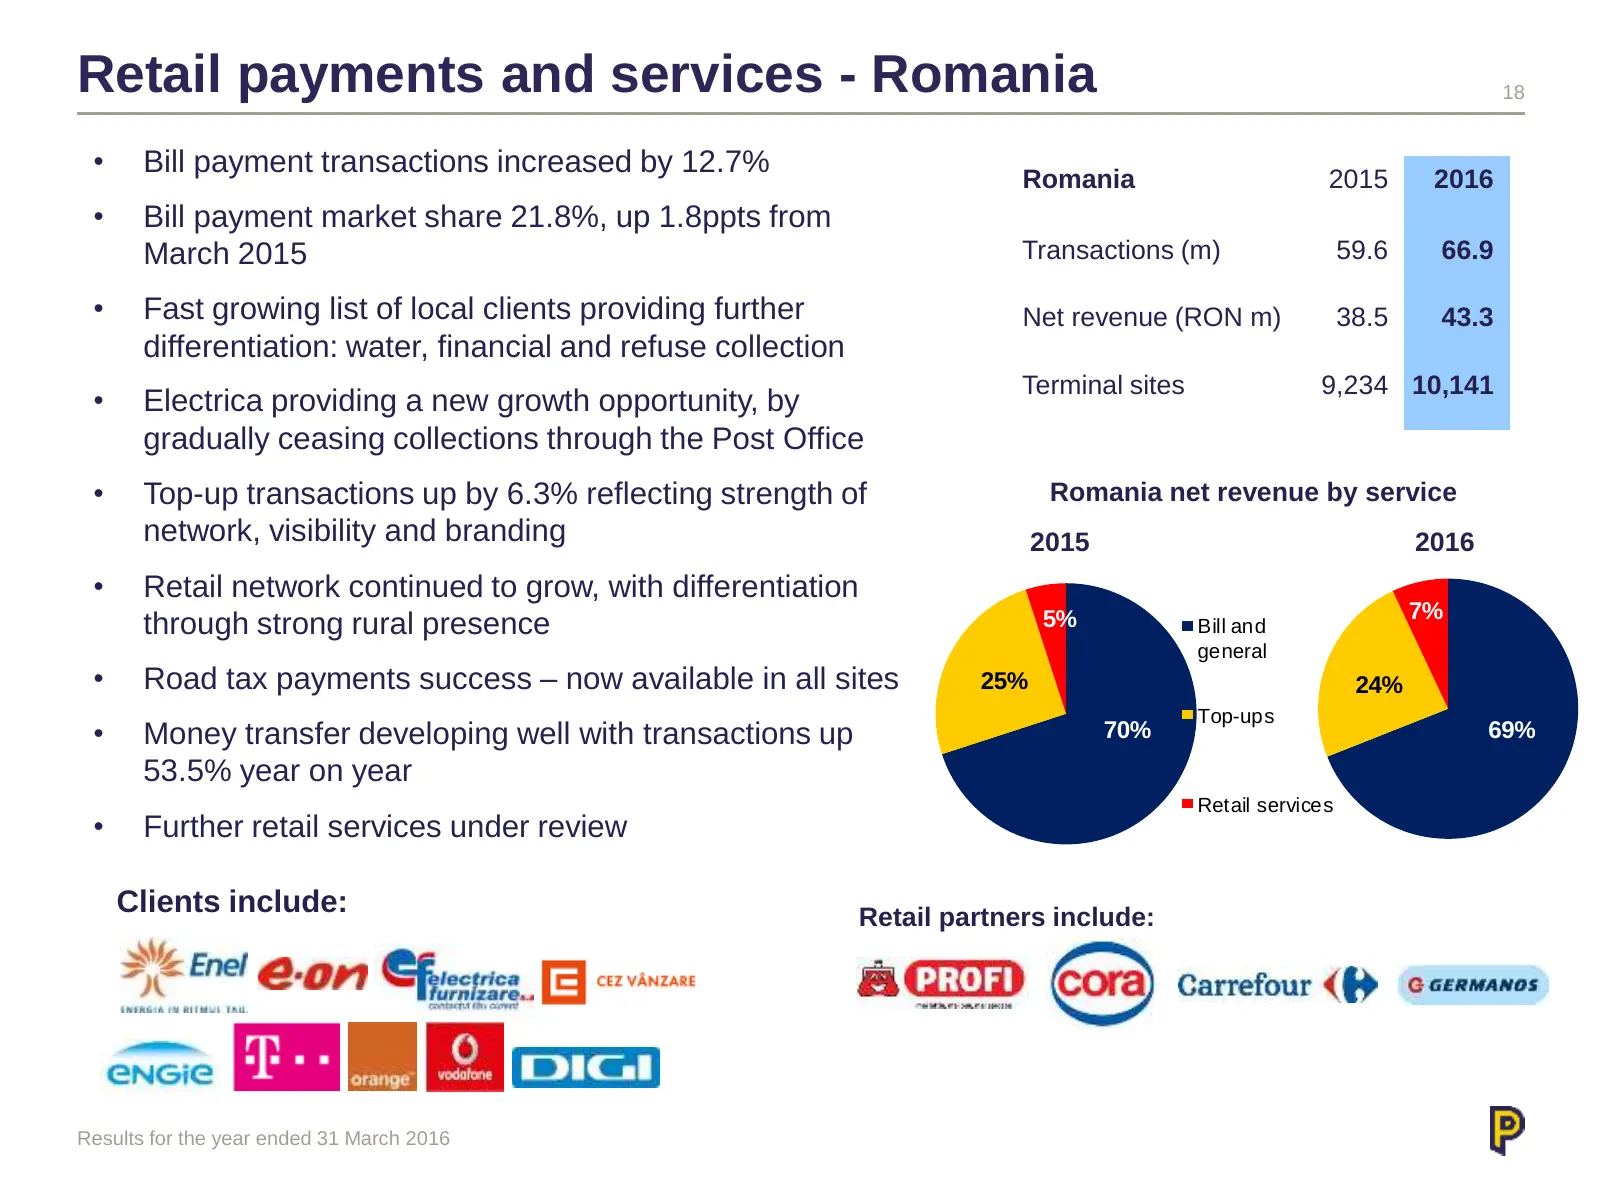
Retail payments and services - Romania 18 • Bill payment transactions increased by 12.7% Romania 2015 2016 • Bill payment market share 21.8%, up 1.8ppts from March 2015 Transactions (m) 59.6 66.9 • Fast growing list of local clients providing further Net revenue (RON m) 38.5 43.3 differentiation: wa
Slide 19: Collect+
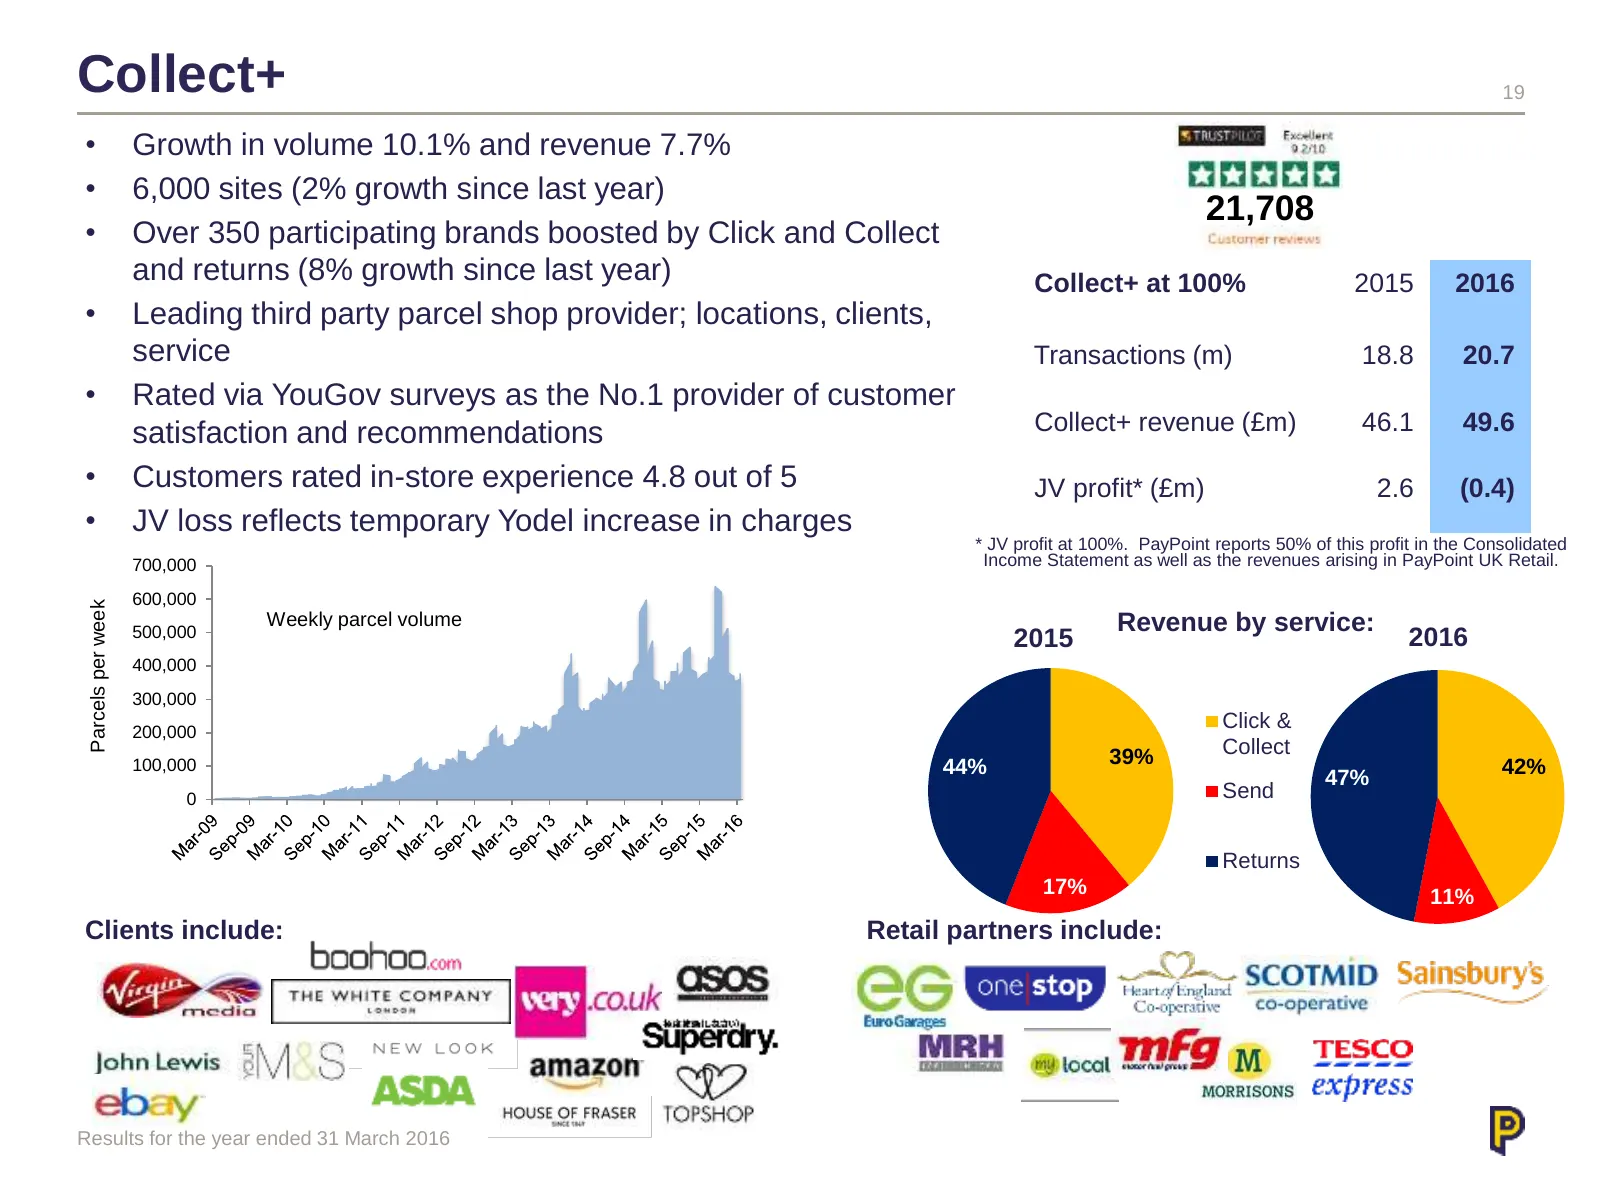
Collect+ 19 • Growth in volume 10.1% and revenue 7.7% • 6,000 sites (2% growth since last year) 21,708 • Over 350 participating brands boosted by Click and Collect and returns (8% growth since last year) Collect+ at 100% 2015 2016 • Leading third party parcel shop provider; locations, clients, servi
Slide 20: Mobile and Online
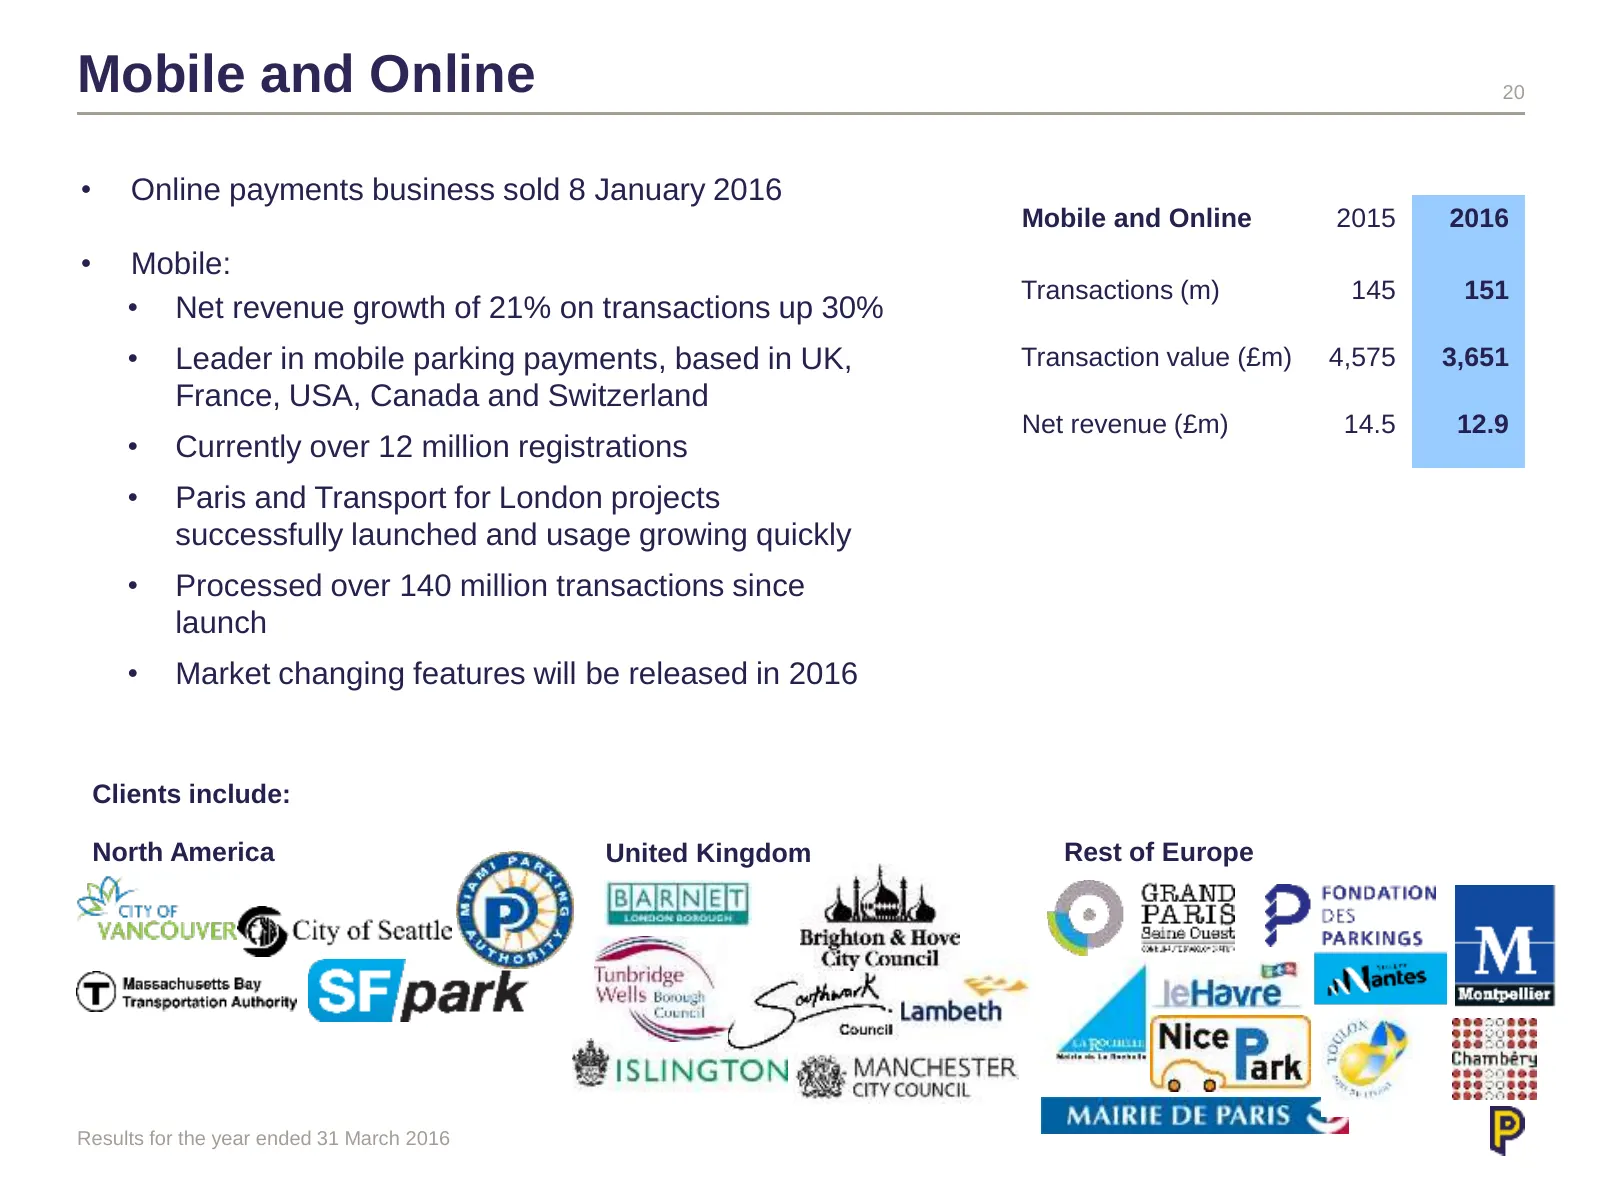
Mobile and Online 20 • Online payments business sold 8 January 2016 Mobile and Online 2015 2016 • Mobile: Transactions (m) 145 151 • Net revenue growth of 21% on transactions up 30% • Leader in mobile parking payments, based in UK, Transaction value (£m) 4,575 3,651 France, USA, Canada and Switzerla
Slide 21: Strategy
Strategy
Slide 22: Strategy - the world has changed and disruption is the norm
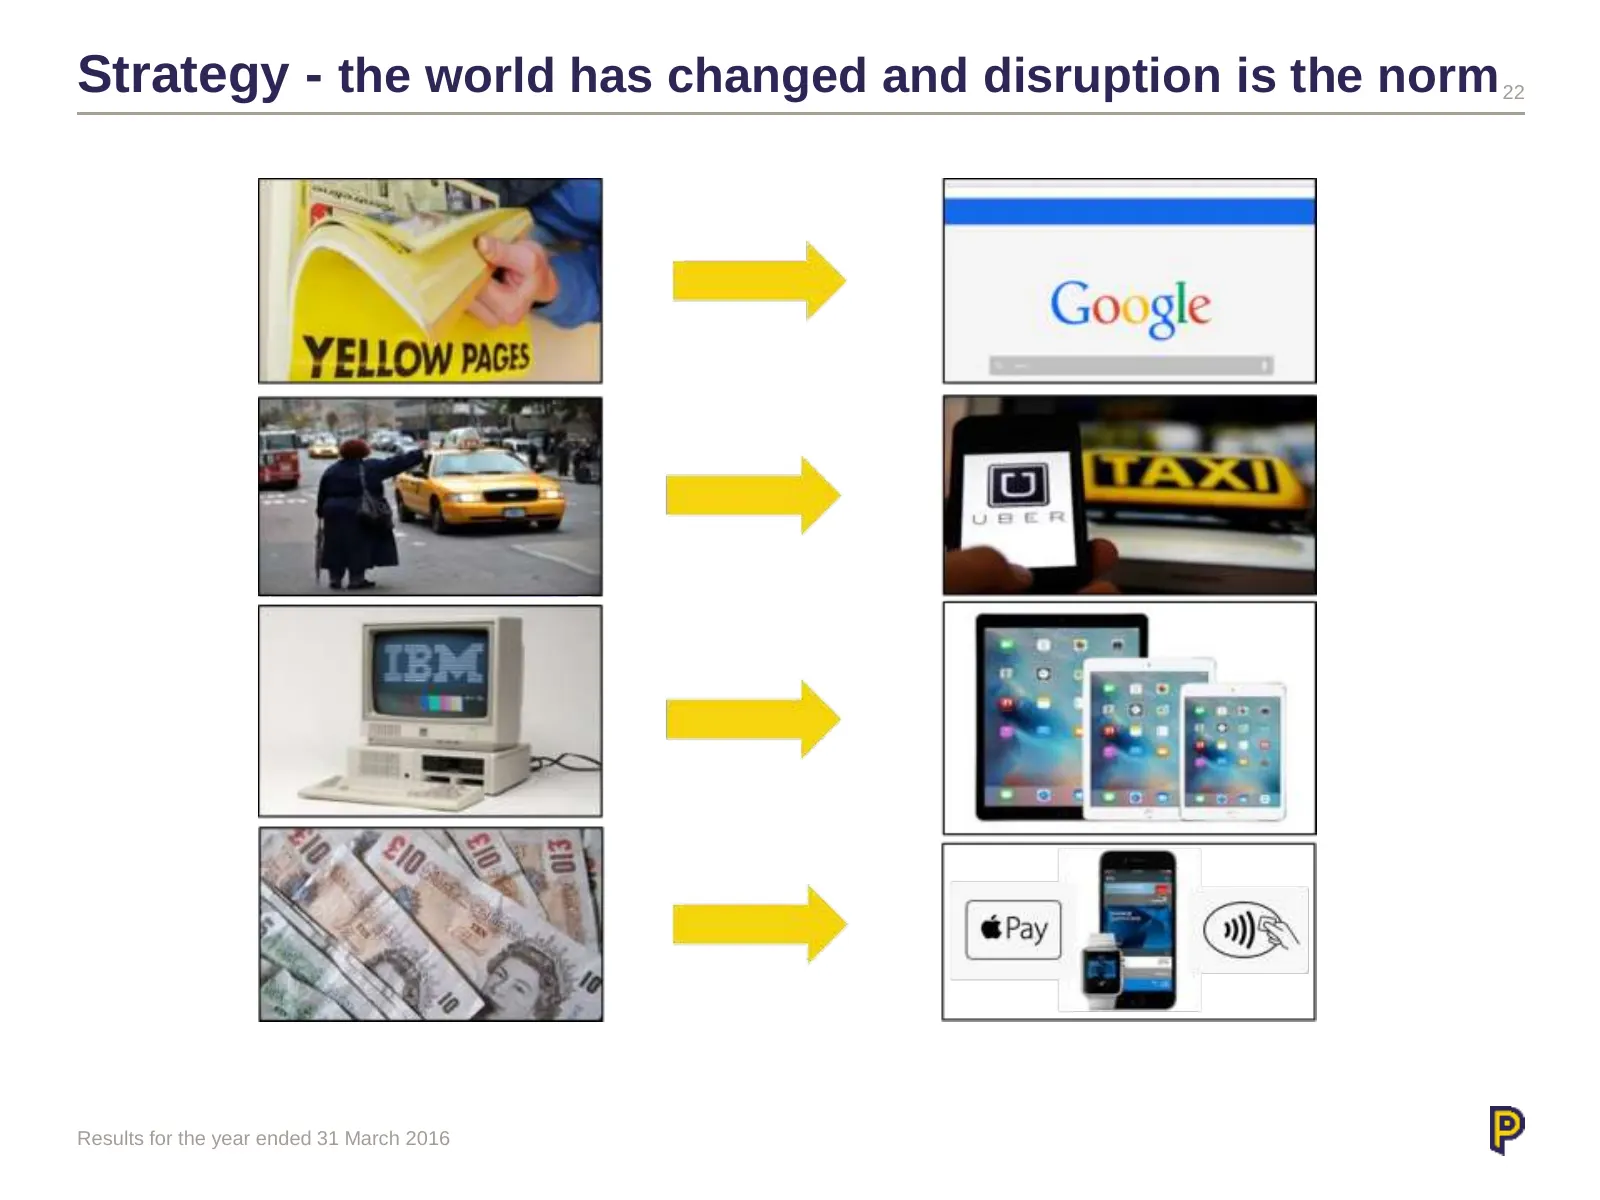
Strategy - the world has changed and disruption is the norm 22 Results for the year ended 31 March 2016
Slide 23: …and significant changes taking place on the high street
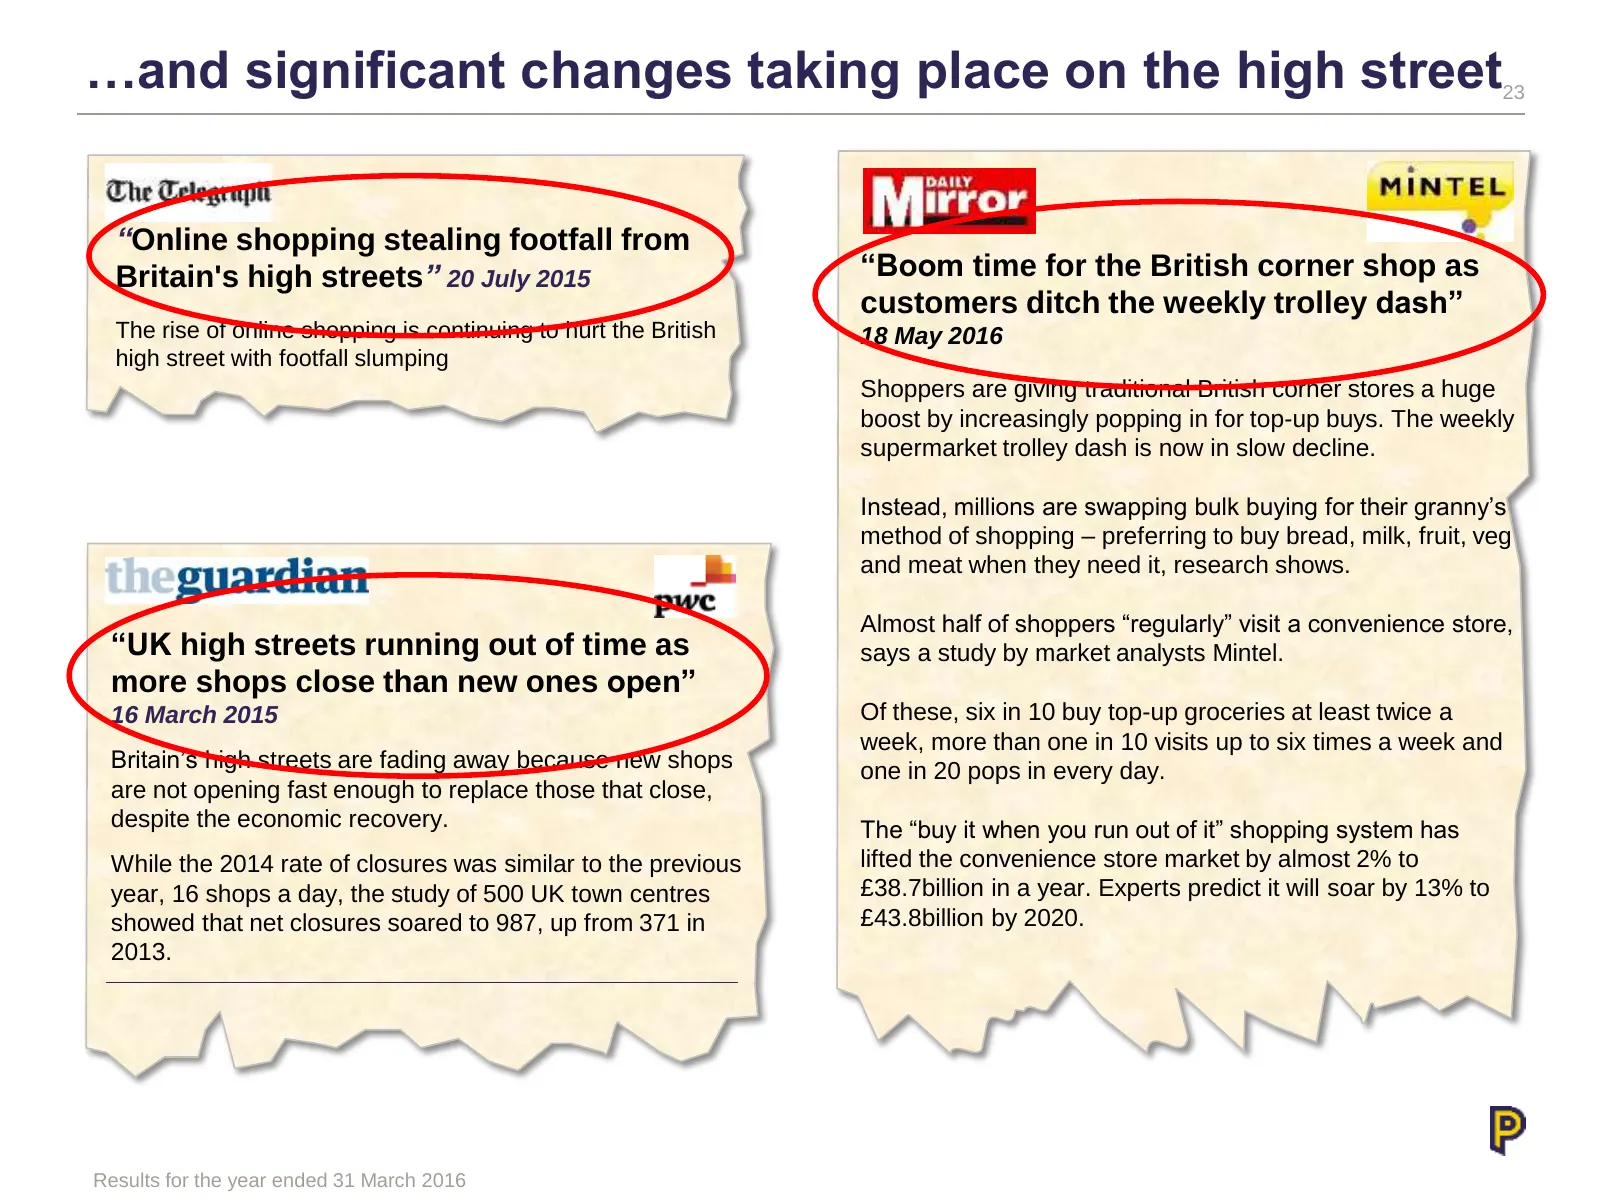
…and significant changes taking place on the high street 23 “Online shopping stealing footfall from Britain's high streets” 20 July 2015 “Boom time for the British corner shop as customers ditch the weekly trolley dash” The rise of online shopping is continuing to hurt the British 18 May 2016 high s
Slide 24: Our strategy has positioned us well
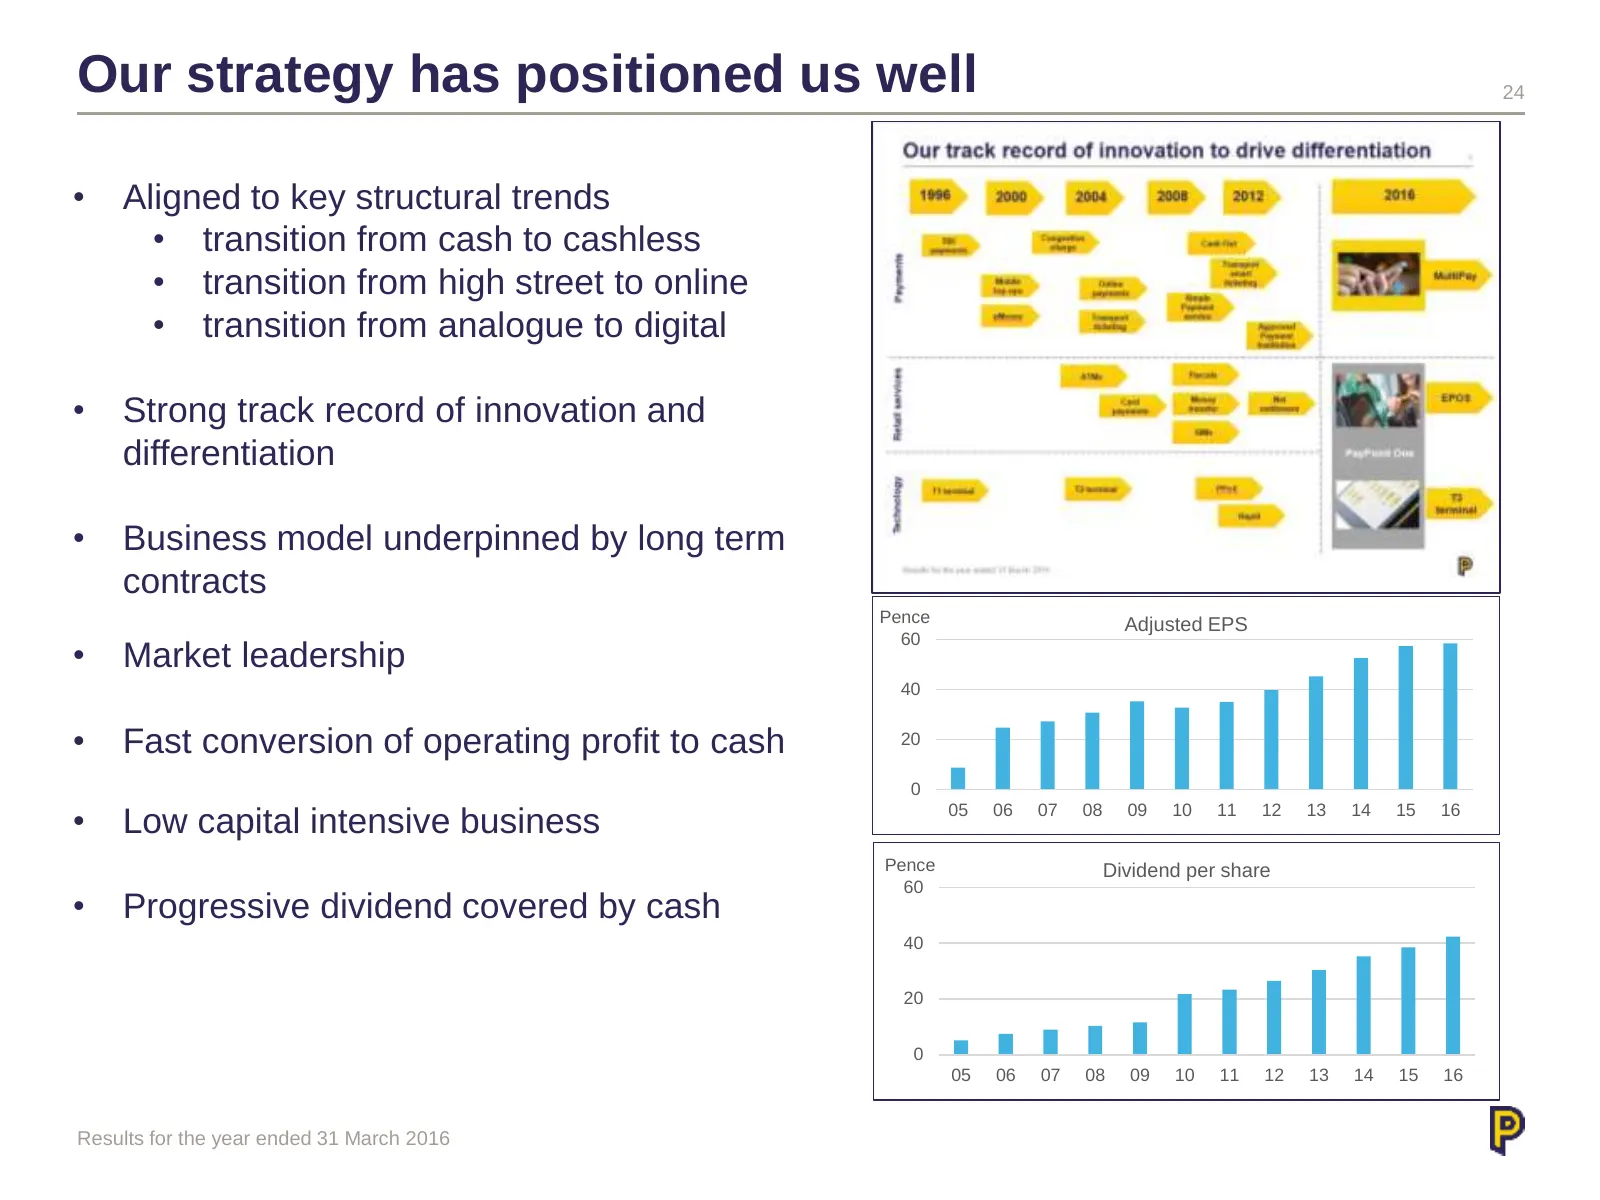
Our strategy has positioned us well 24 • Aligned to key structural trends • transition from cash to cashless • transition from high street to online • transition from analogue to digital • Strong track record of innovation and differentiation • Business model underpinned by long term contracts Pence
Slide 25: Strategic execution
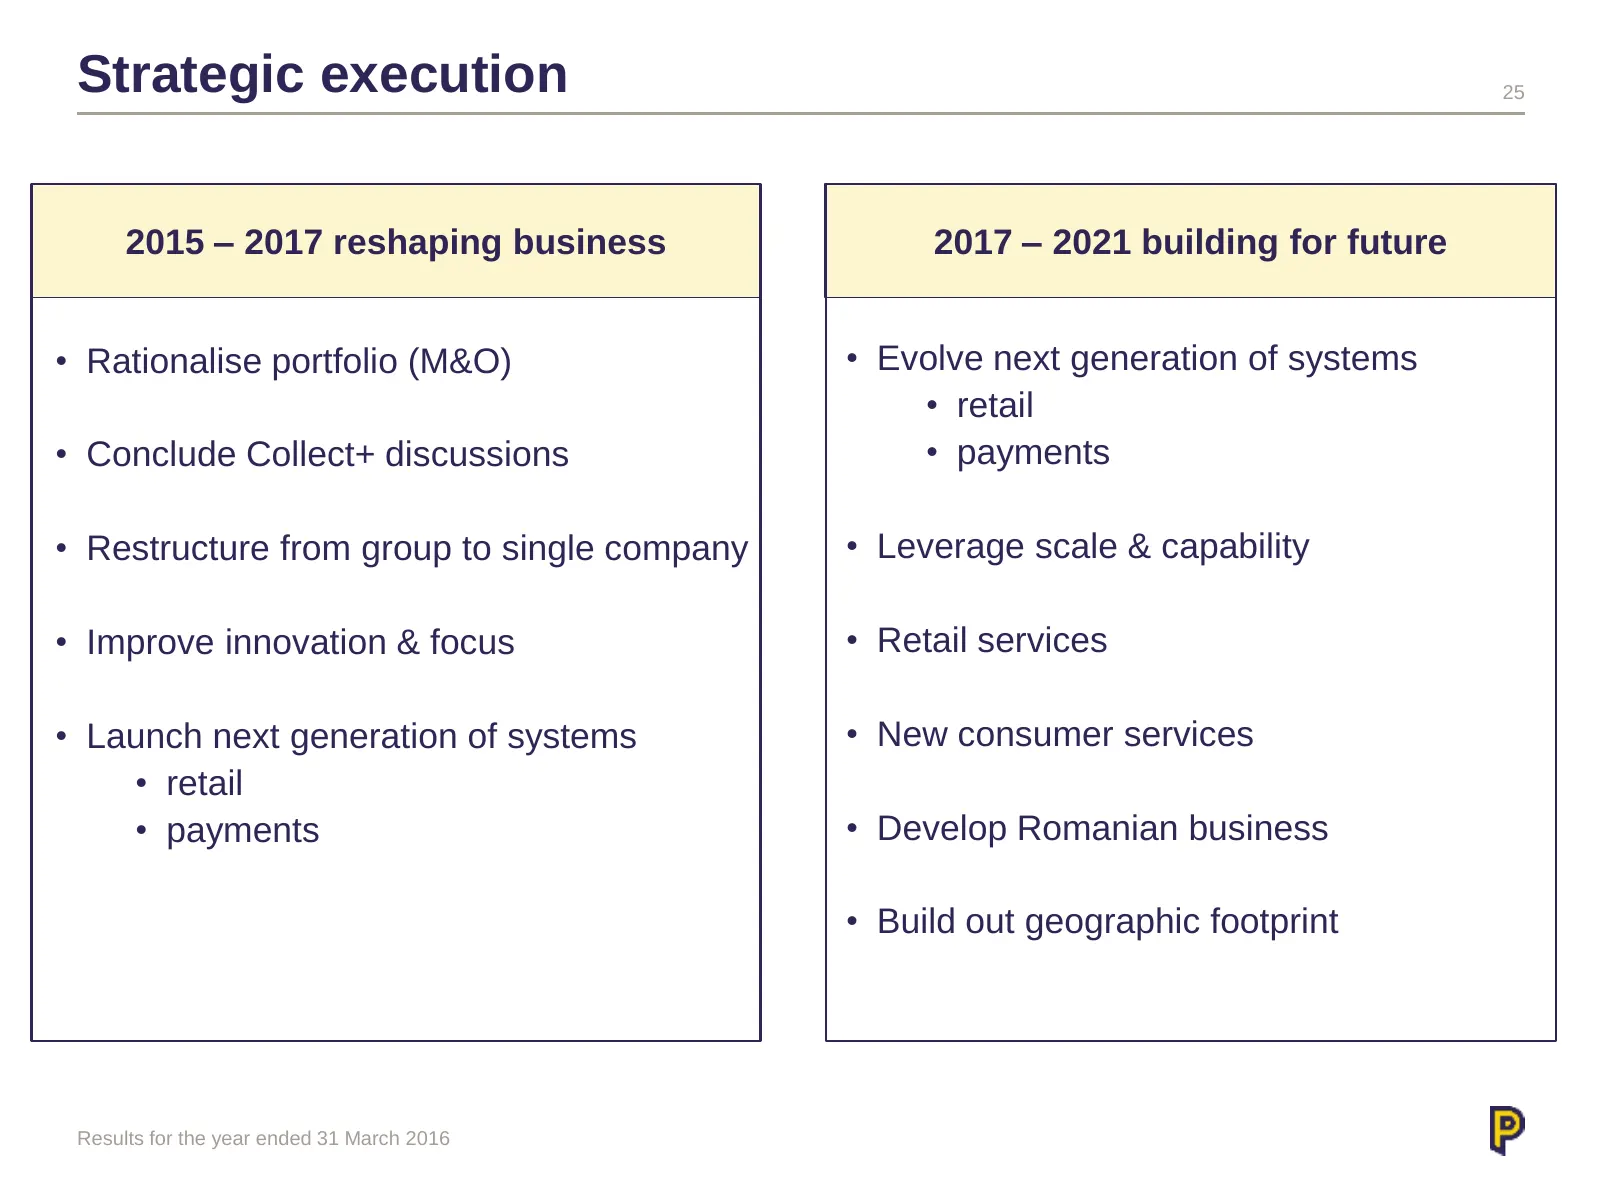
Strategic execution 25 2015 – 2017 reshaping business 2017 – 2021 building for future • Rationalise portfolio (M&O) • Evolve next generation of systems • retail • Conclude Collect+ discussions • payments • Restructure from group to single company • Leverage scale & capability • Improve innovation &
Slide 26: Reshaping business
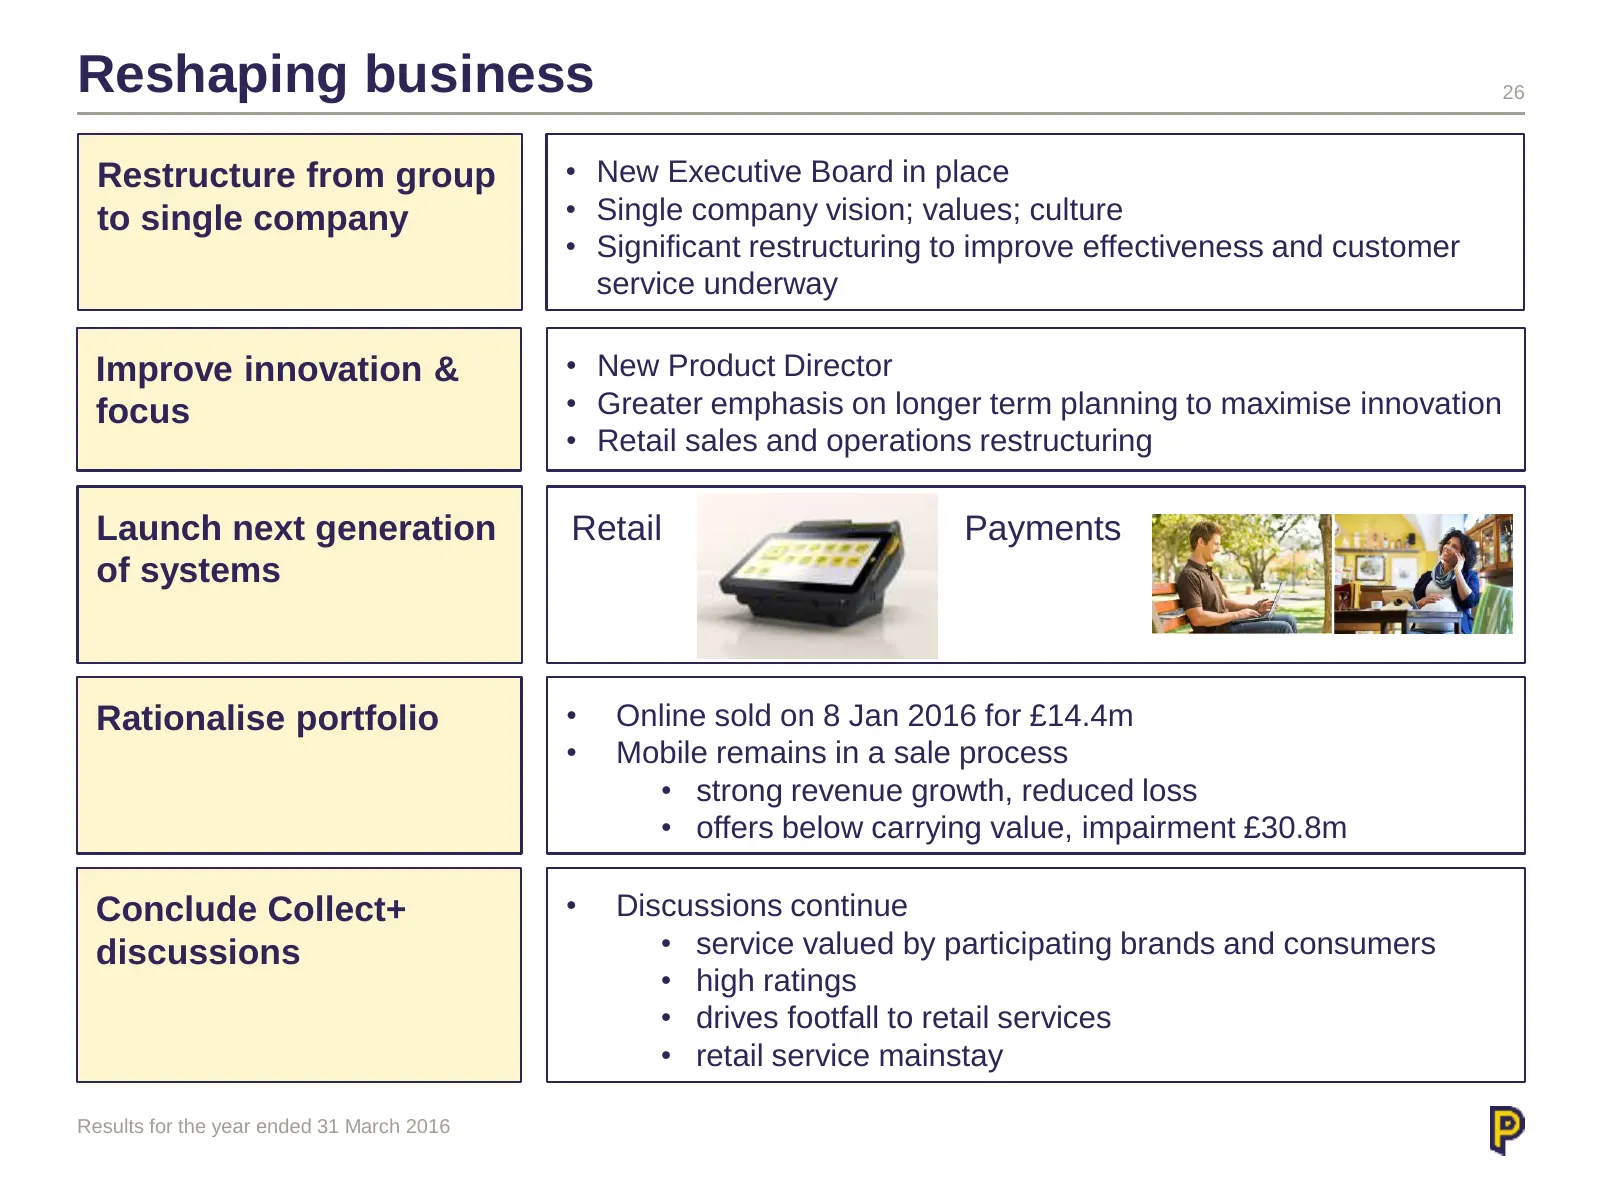
Reshaping business 26 Restructure from group • New Executive Board in place to single company • Single company vision; values; culture • Significant restructuring to improve effectiveness and customer service underway Improve innovation & • New Product Director focus • Greater emphasis on longer ter
Slide 27: Next generation of retail systems – PayPoint One
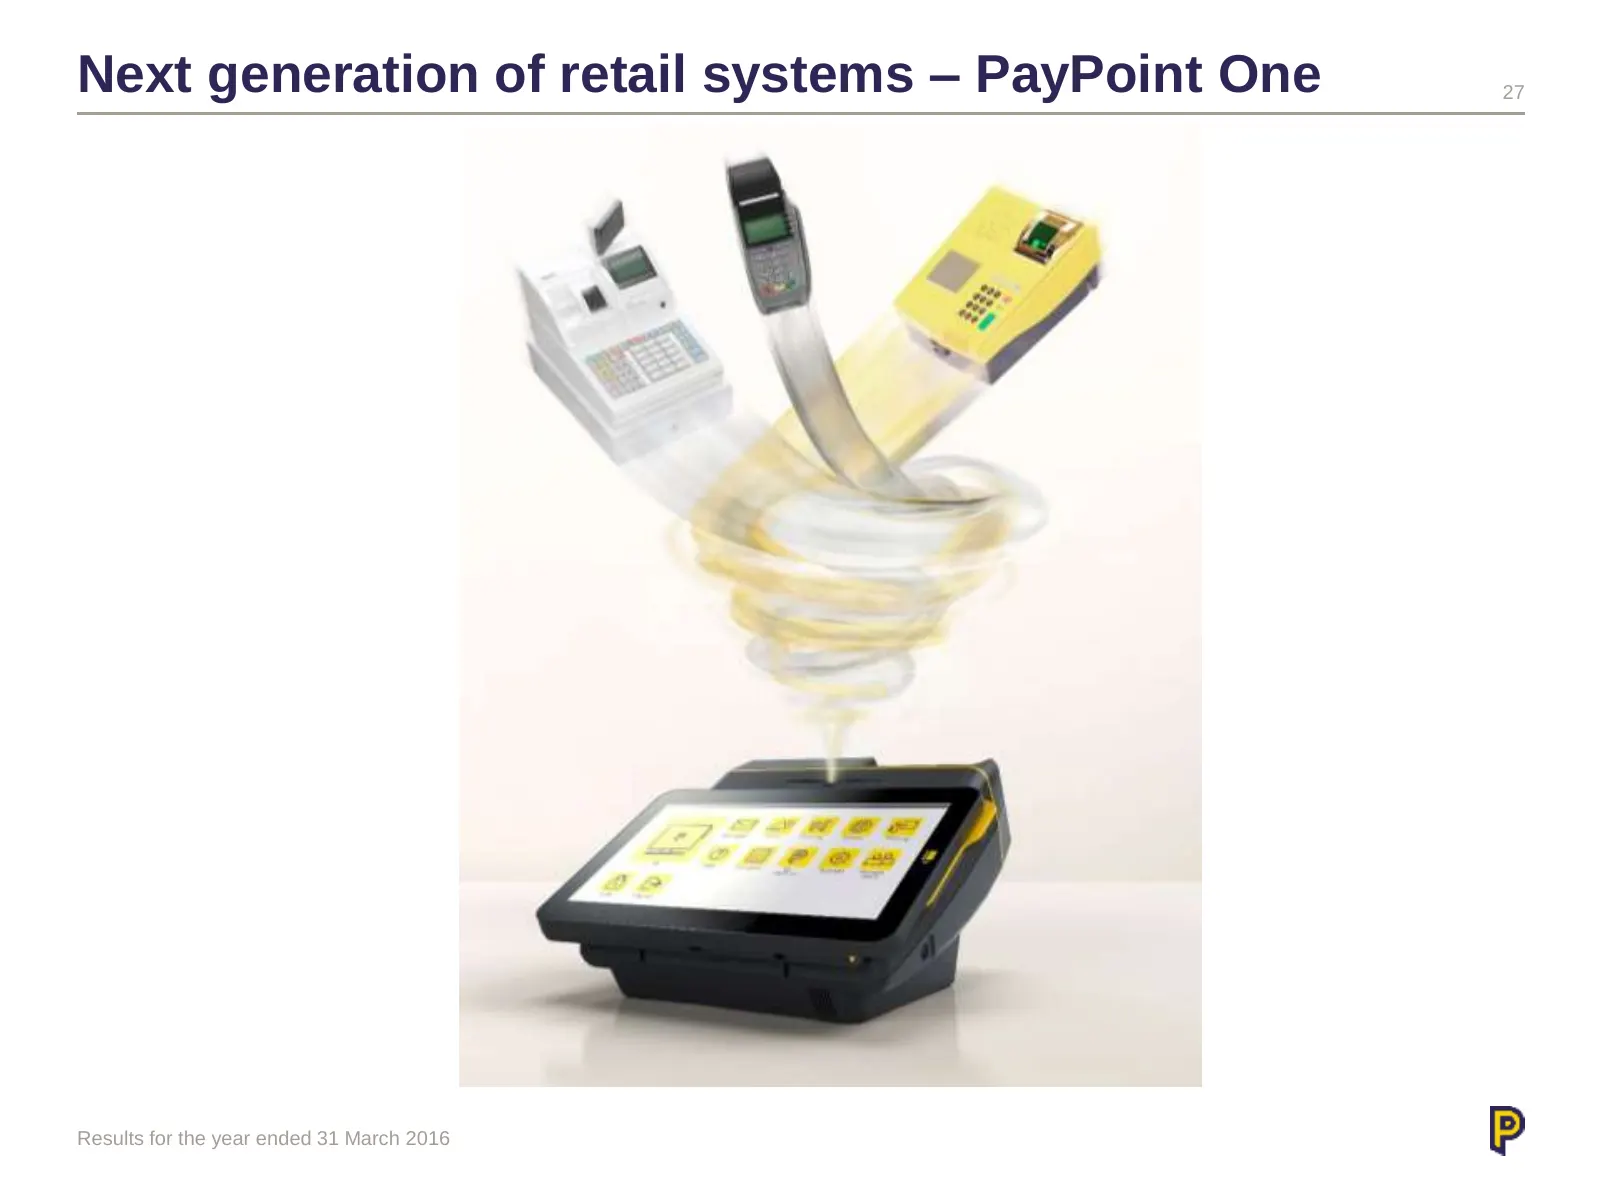
Next generation of retail systems – PayPoint One 27 Results for the year ended 31 March 2016
Slide 28: PayPoint One key attributes
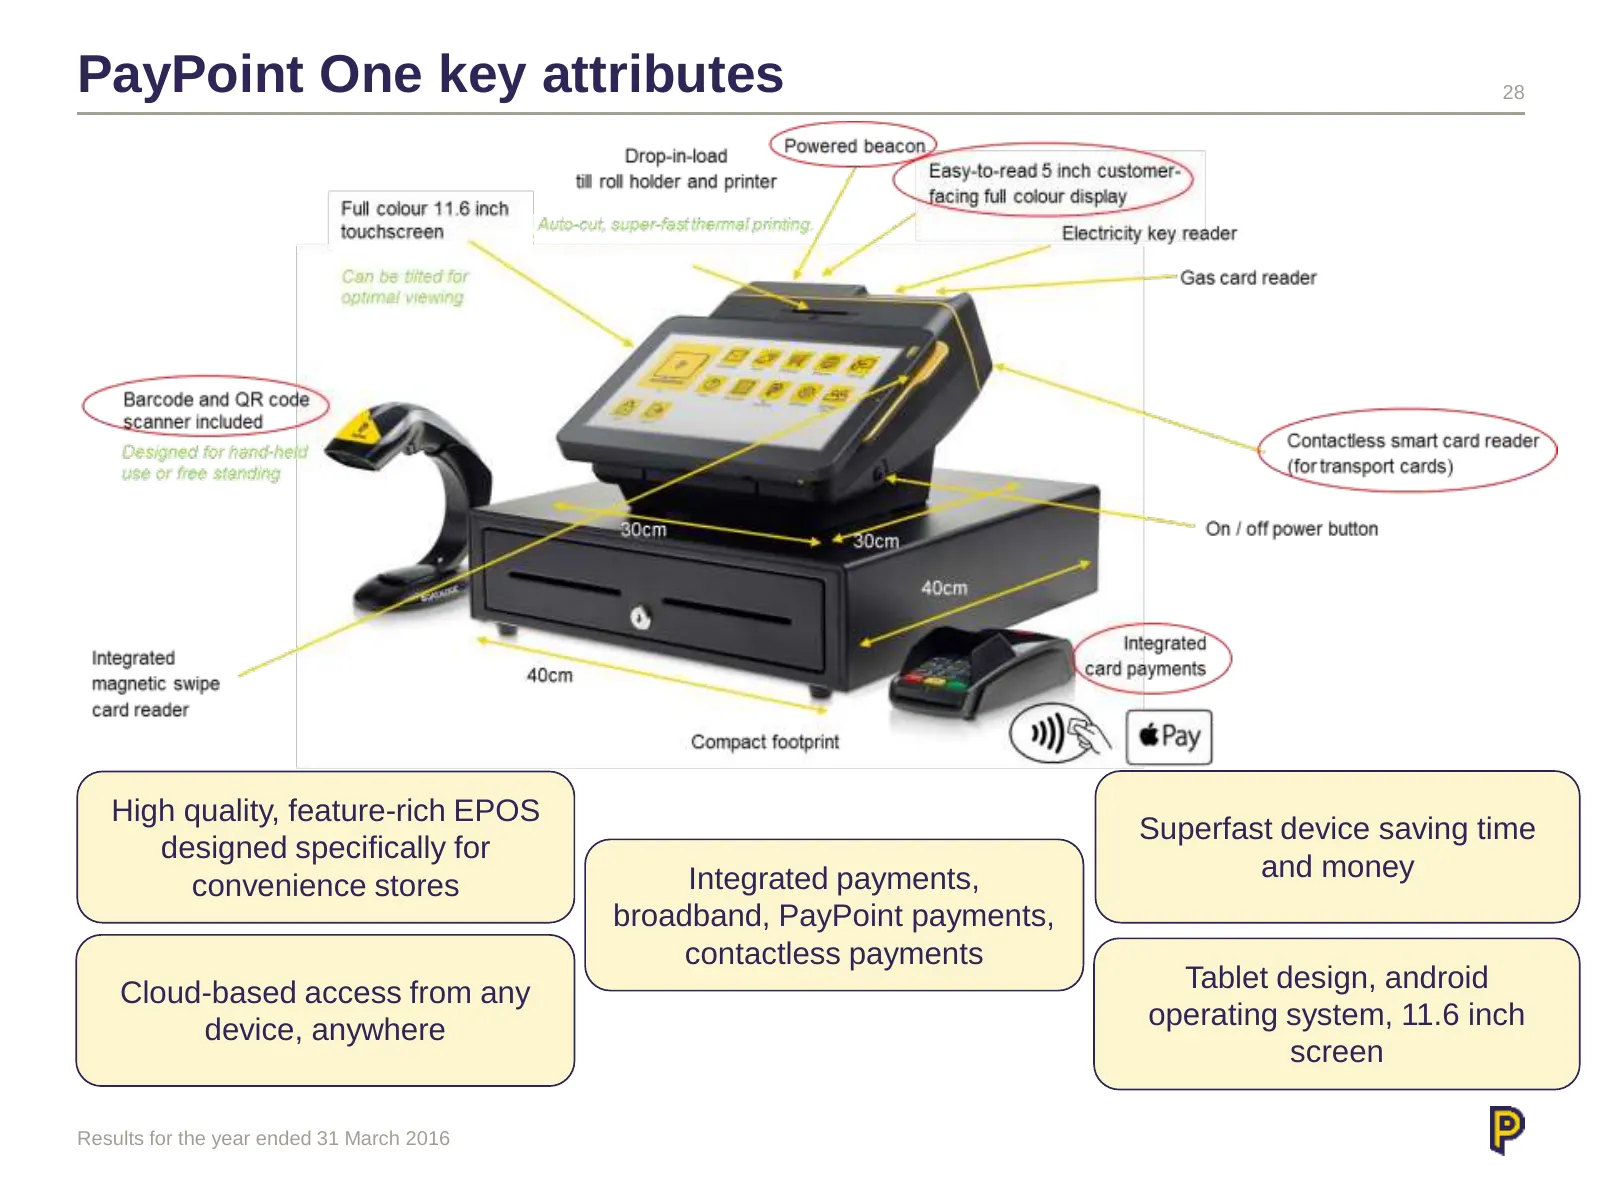
PayPoint One key attributes 28 High quality, feature-rich EPOS Superfast device saving time designed specifically for Integrated payments, and money convenience stores broadband, PayPoint payments, contactless payments Cloud-based access from any Tablet design, android device, anywhere operating sys
Slide 29: PayPoint One – positions PayPoint at the centre of the store
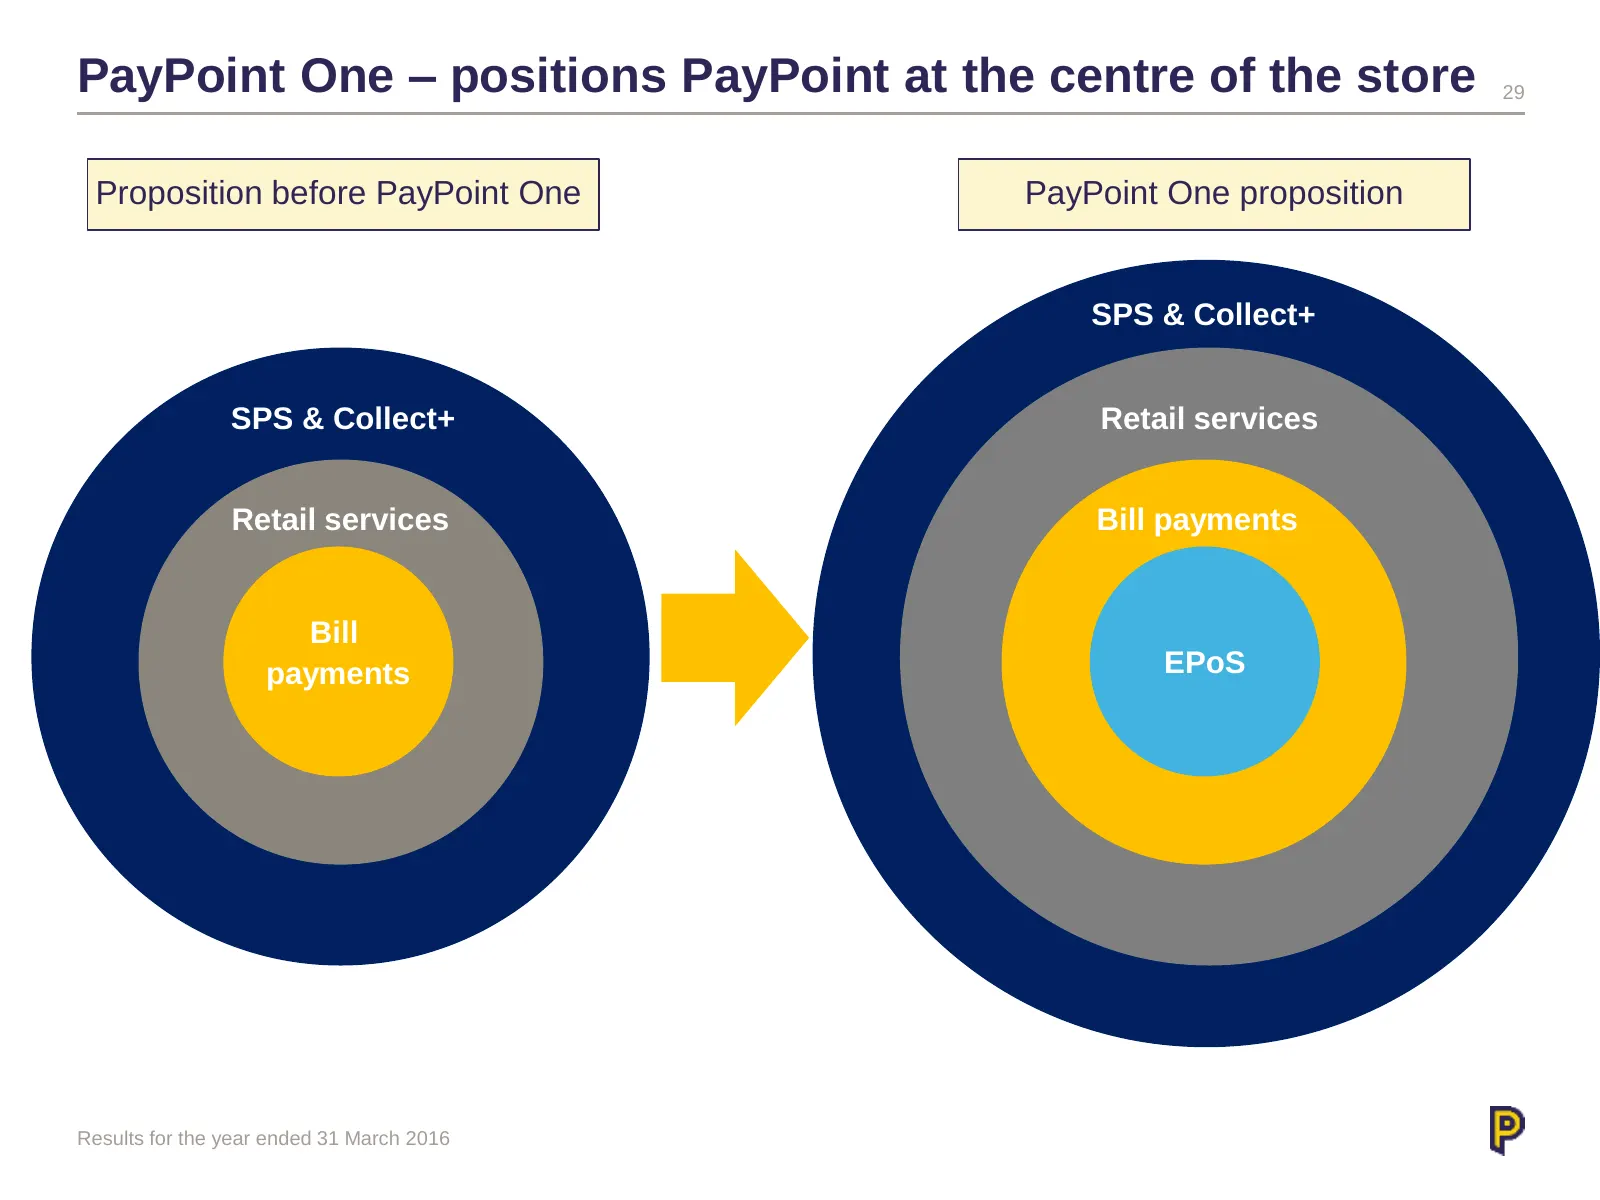
PayPoint One – positions PayPoint at the centre of the store 29 Proposition before PayPoint One PayPoint One proposition SPS & Collect+ SPS & Collect+ Retail services Retail services Bill payments Bill payments EPoS Results for the year ended 31 March 2016
Slide 30: PayPoint One – early feedback
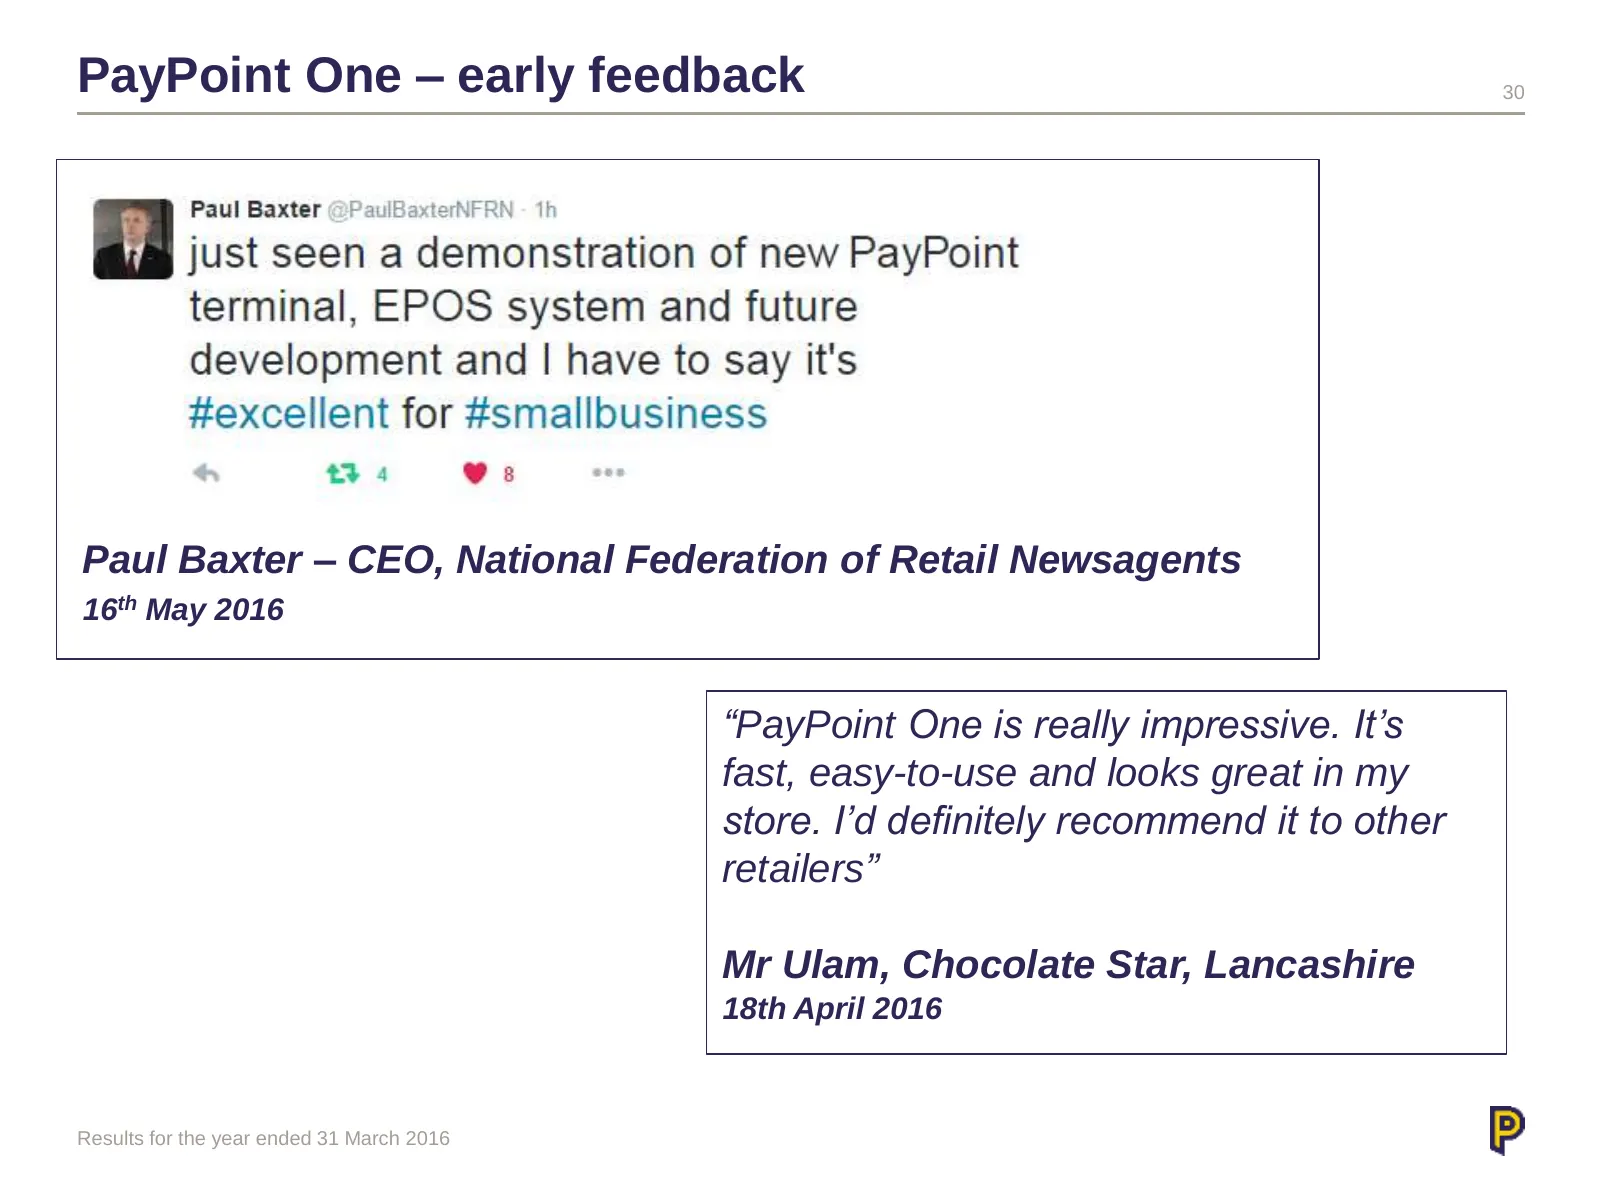
PayPoint One – early feedback 30 Paul Baxter – CEO, National Federation of Retail Newsagents 16th May 2016 “PayPoint One is really impressive. It’s fast, easy-to-use and looks great in my store. I’d definitely recommend it to other retailers” Mr Ulam, Chocolate Star, Lancashire 18th April 2016 Resul
Slide 31: Next generation of payment systems - MultiPay
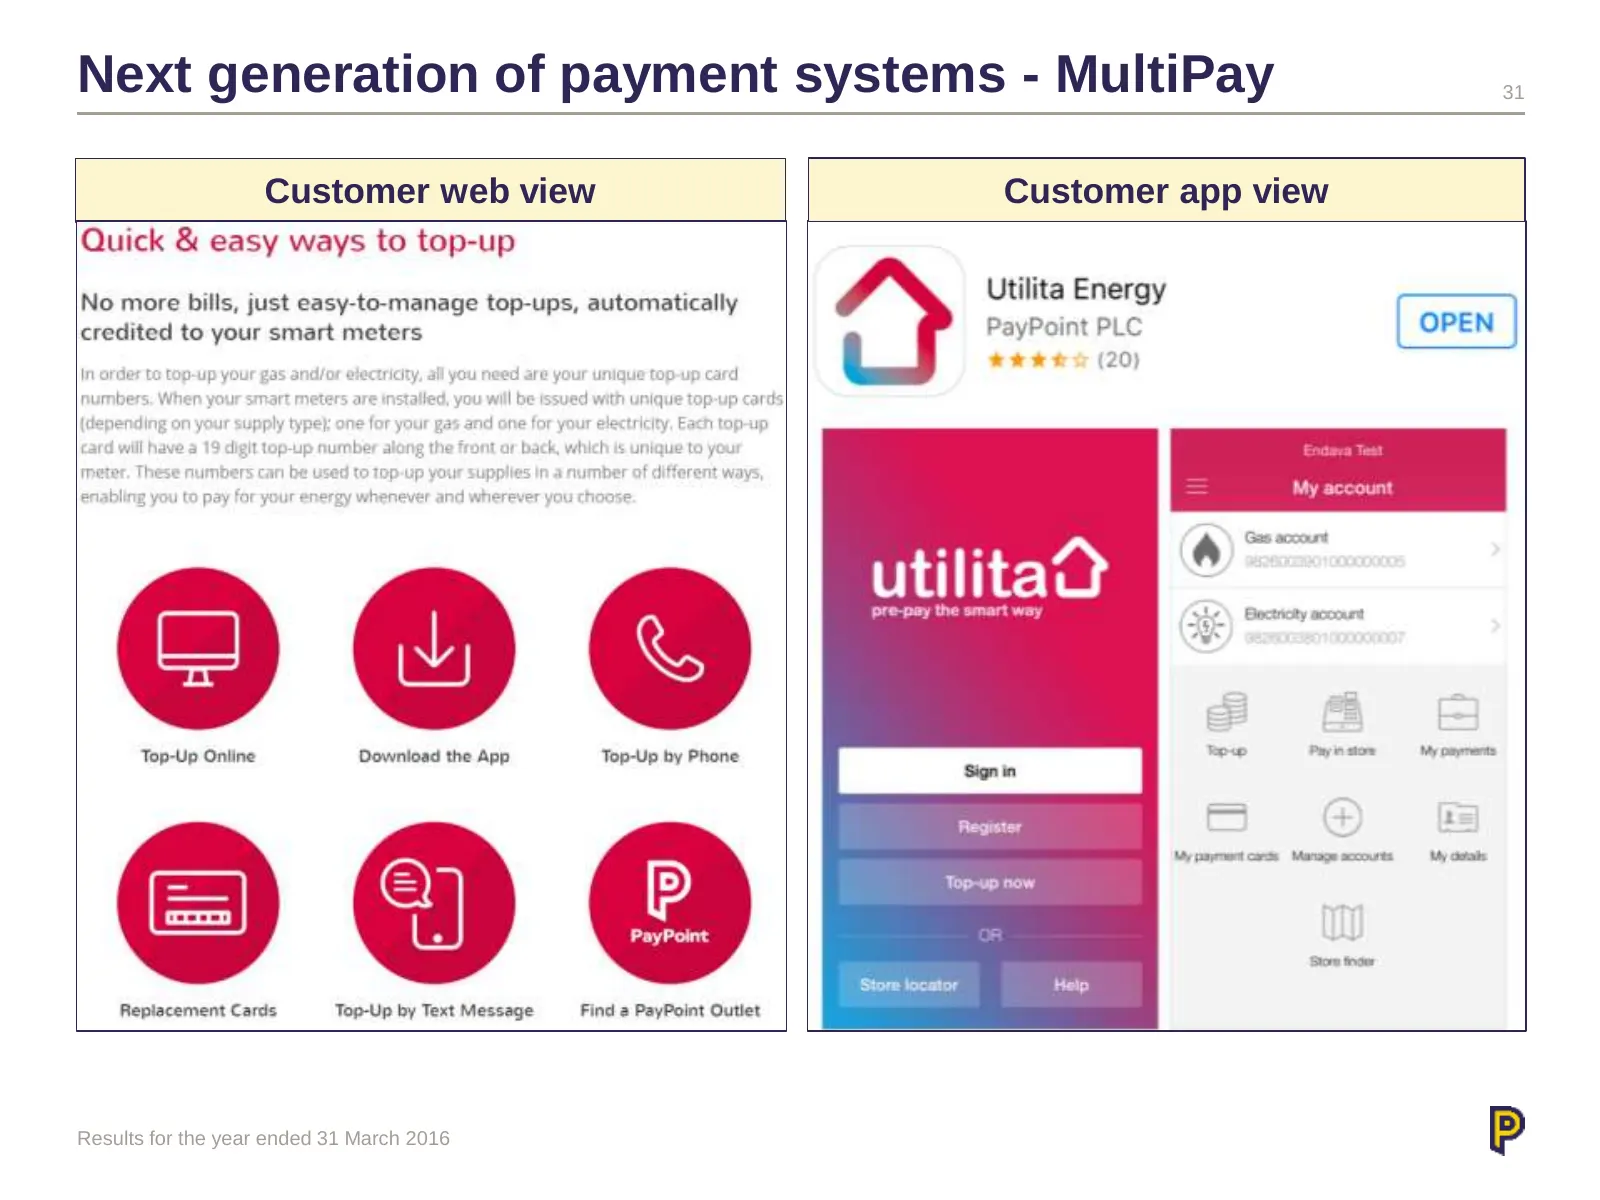
Next generation of payment systems - MultiPay 31 Customer web view Customer app view Results for the year ended 31 March 2016
Slide 32: MultiPay – payment cards complement cash
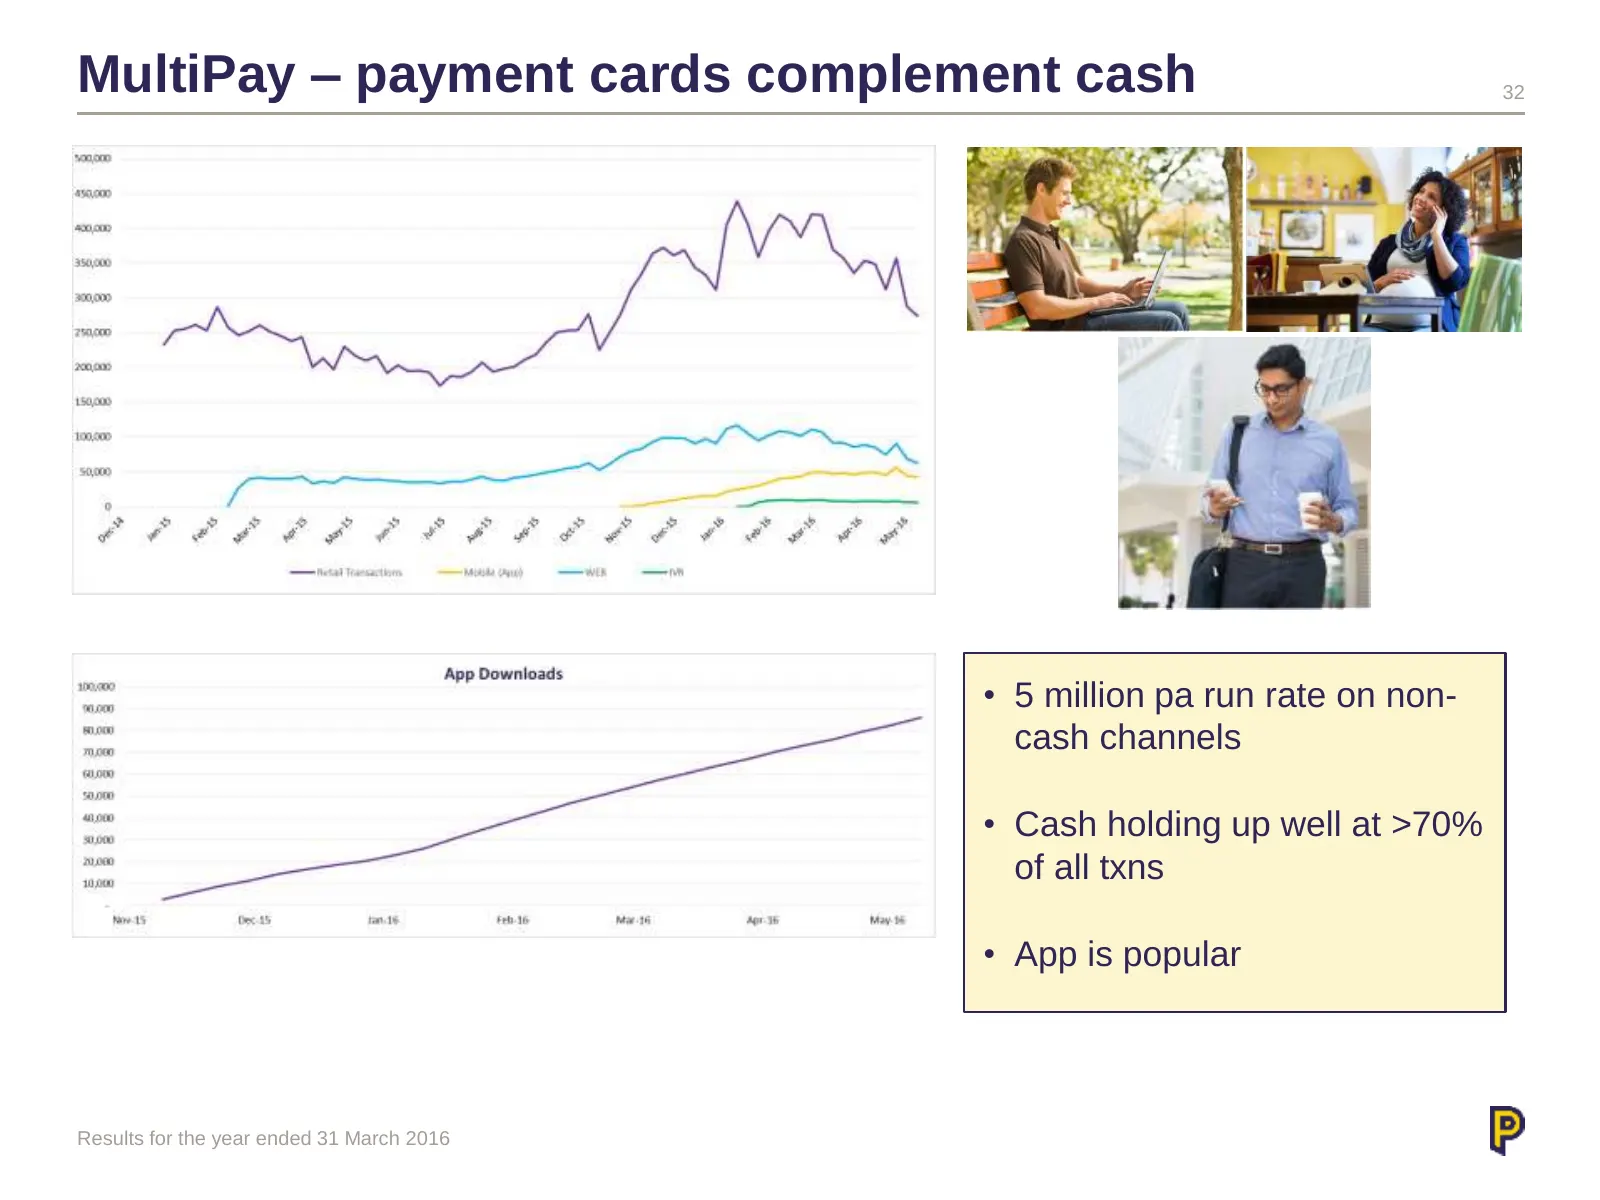
MultiPay – payment cards complement cash 32 • 5 million pa run rate on non- cash channels • Cash holding up well at >70% of all txns • App is popular Results for the year ended 31 March 2016
Slide 33: Long term strategic vision
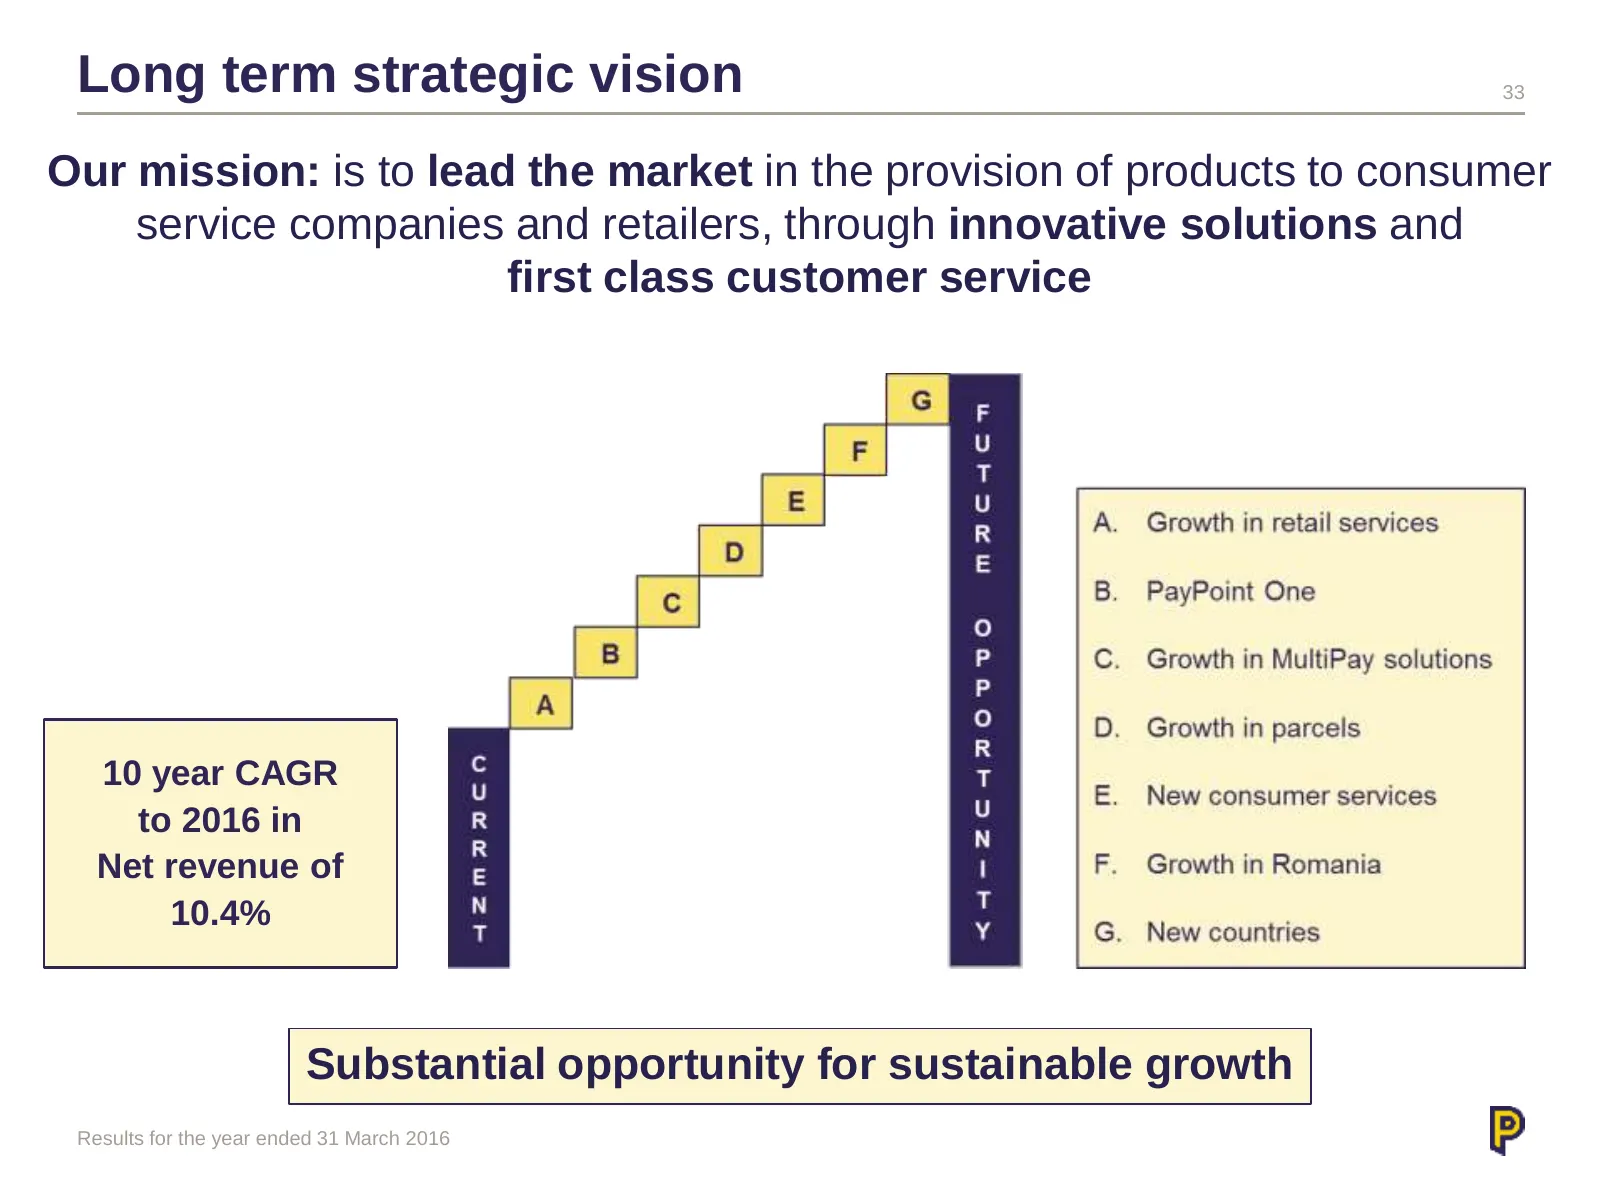
Long term strategic vision 33 Our mission: is to lead the market in the provision of products to consumer service companies and retailers, through innovative solutions and first class customer service 10 year CAGR to 2016 in Net revenue of 10.4% Substantial opportunity for sustainable growth Results
Slide 34: Summary and future development
Summary and future development
Slide 35: Future developments
Future developments 35 • Current financial year trading in line with the Company’s expectations • Retail networks should continue to deliver profitable growth, with further leverage from performance improvements • Investment in network expansion, PayPoint One and retail services, should increase ret
Slide 36: Appendices
Appendices
Slide 37: Appendix 1: UK retail
Appendix 1 Materials to support the consumer transaction UK retail
Slide 38: UK Retail: Client media payment
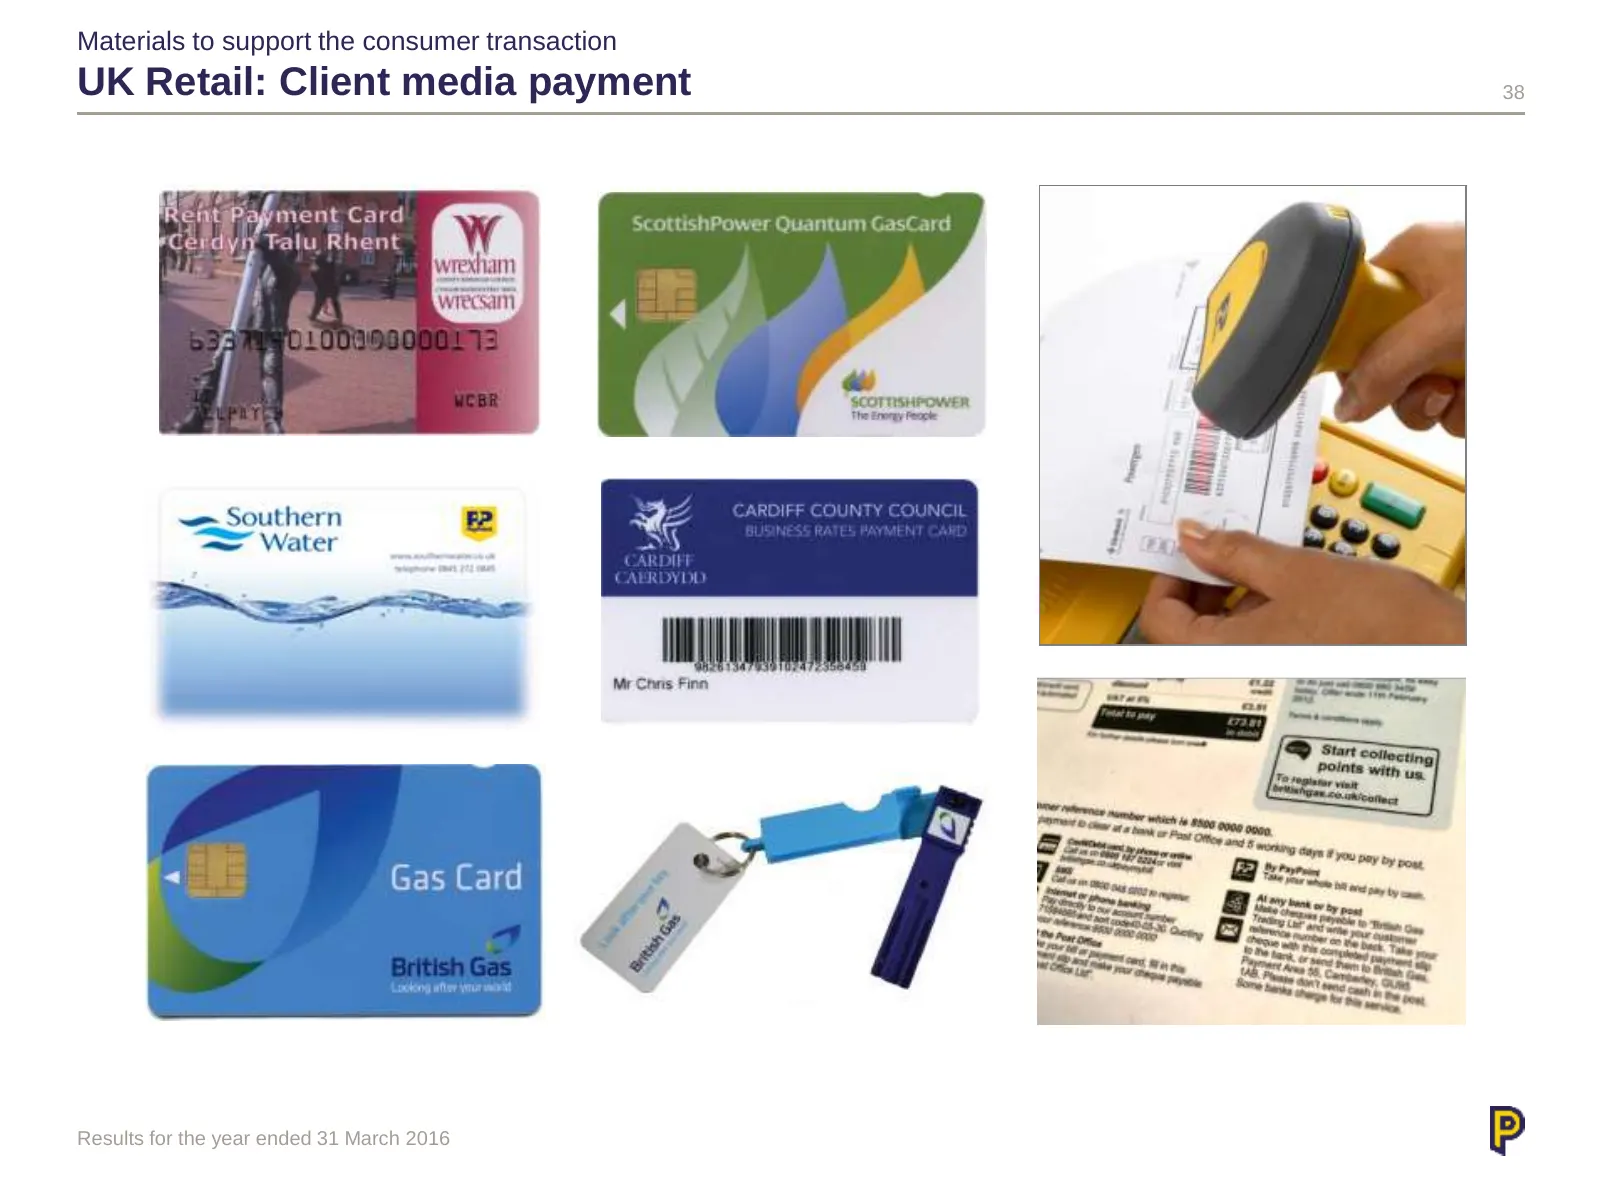
Materials to support the consumer transaction UK Retail: Client media payment 38 Results for the year ended 31 March 2016
Slide 39: UK Retail: Retail store
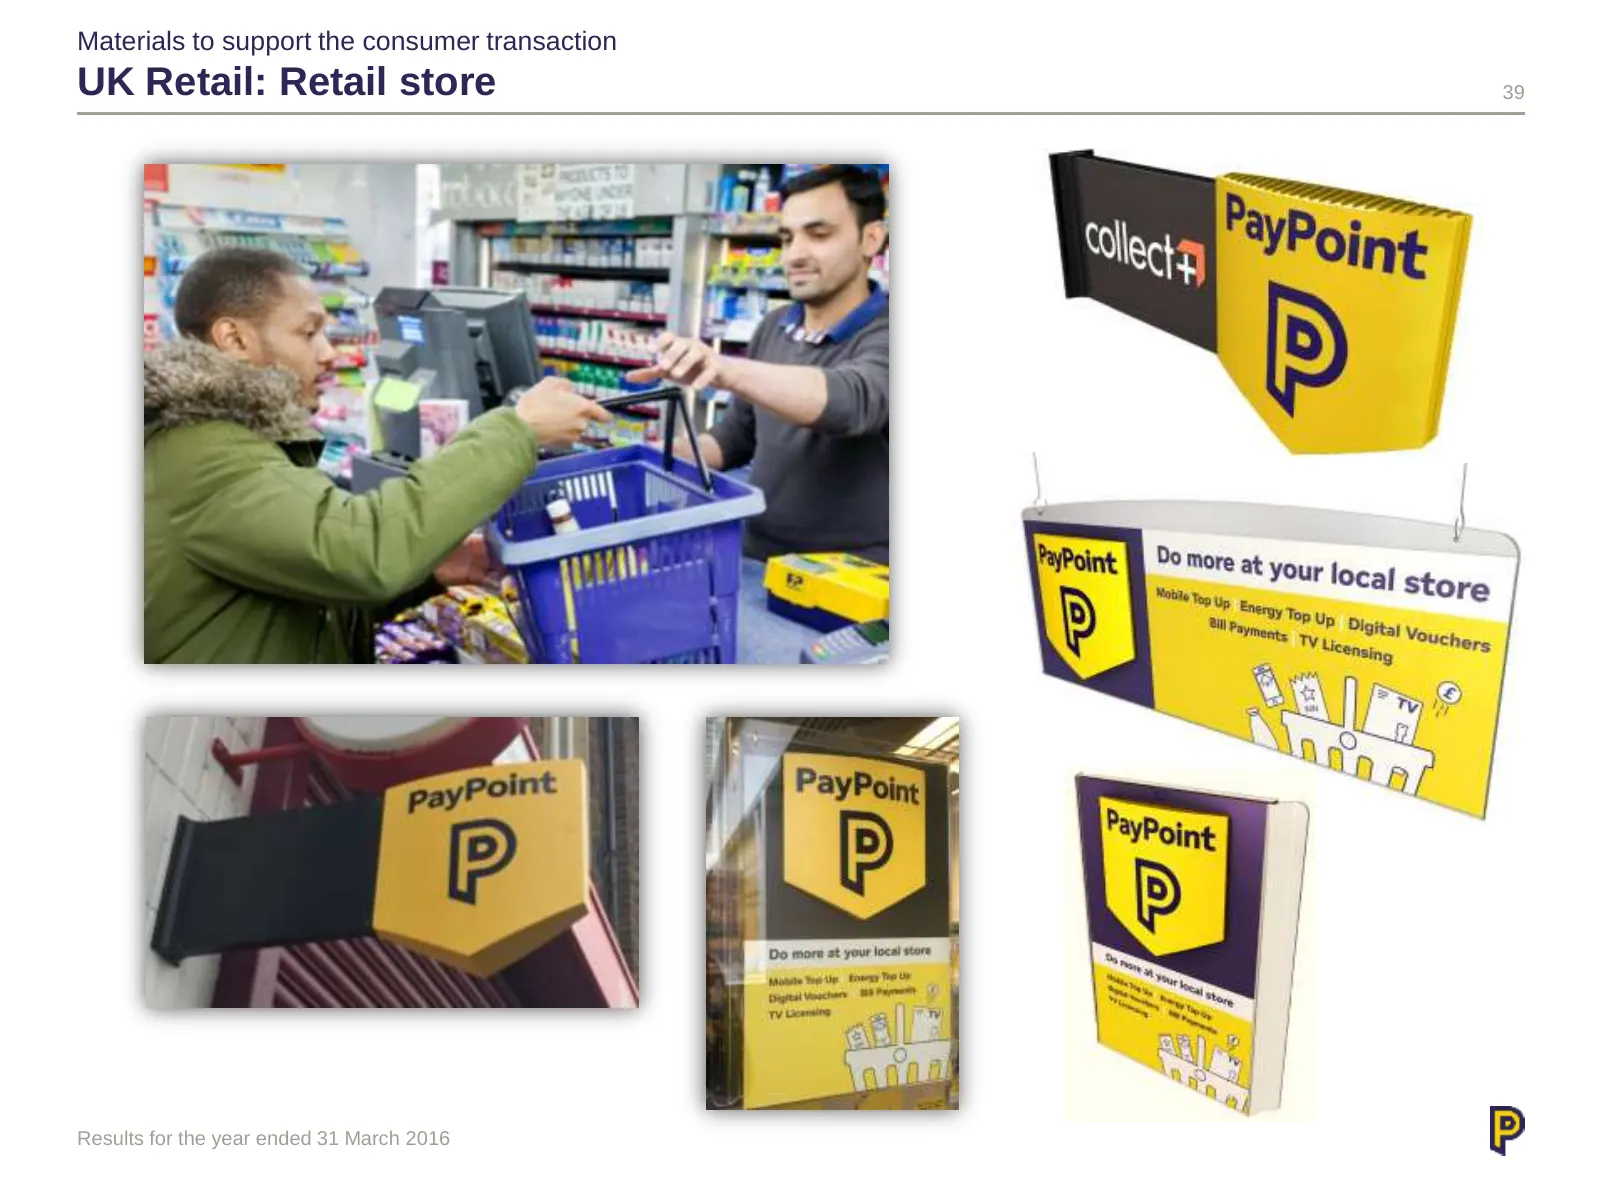
Materials to support the consumer transaction UK Retail: Retail store 39 Results for the year ended 31 March 2016
Slide 40: UK Retail: Terminals, Pin Pads and ATMs
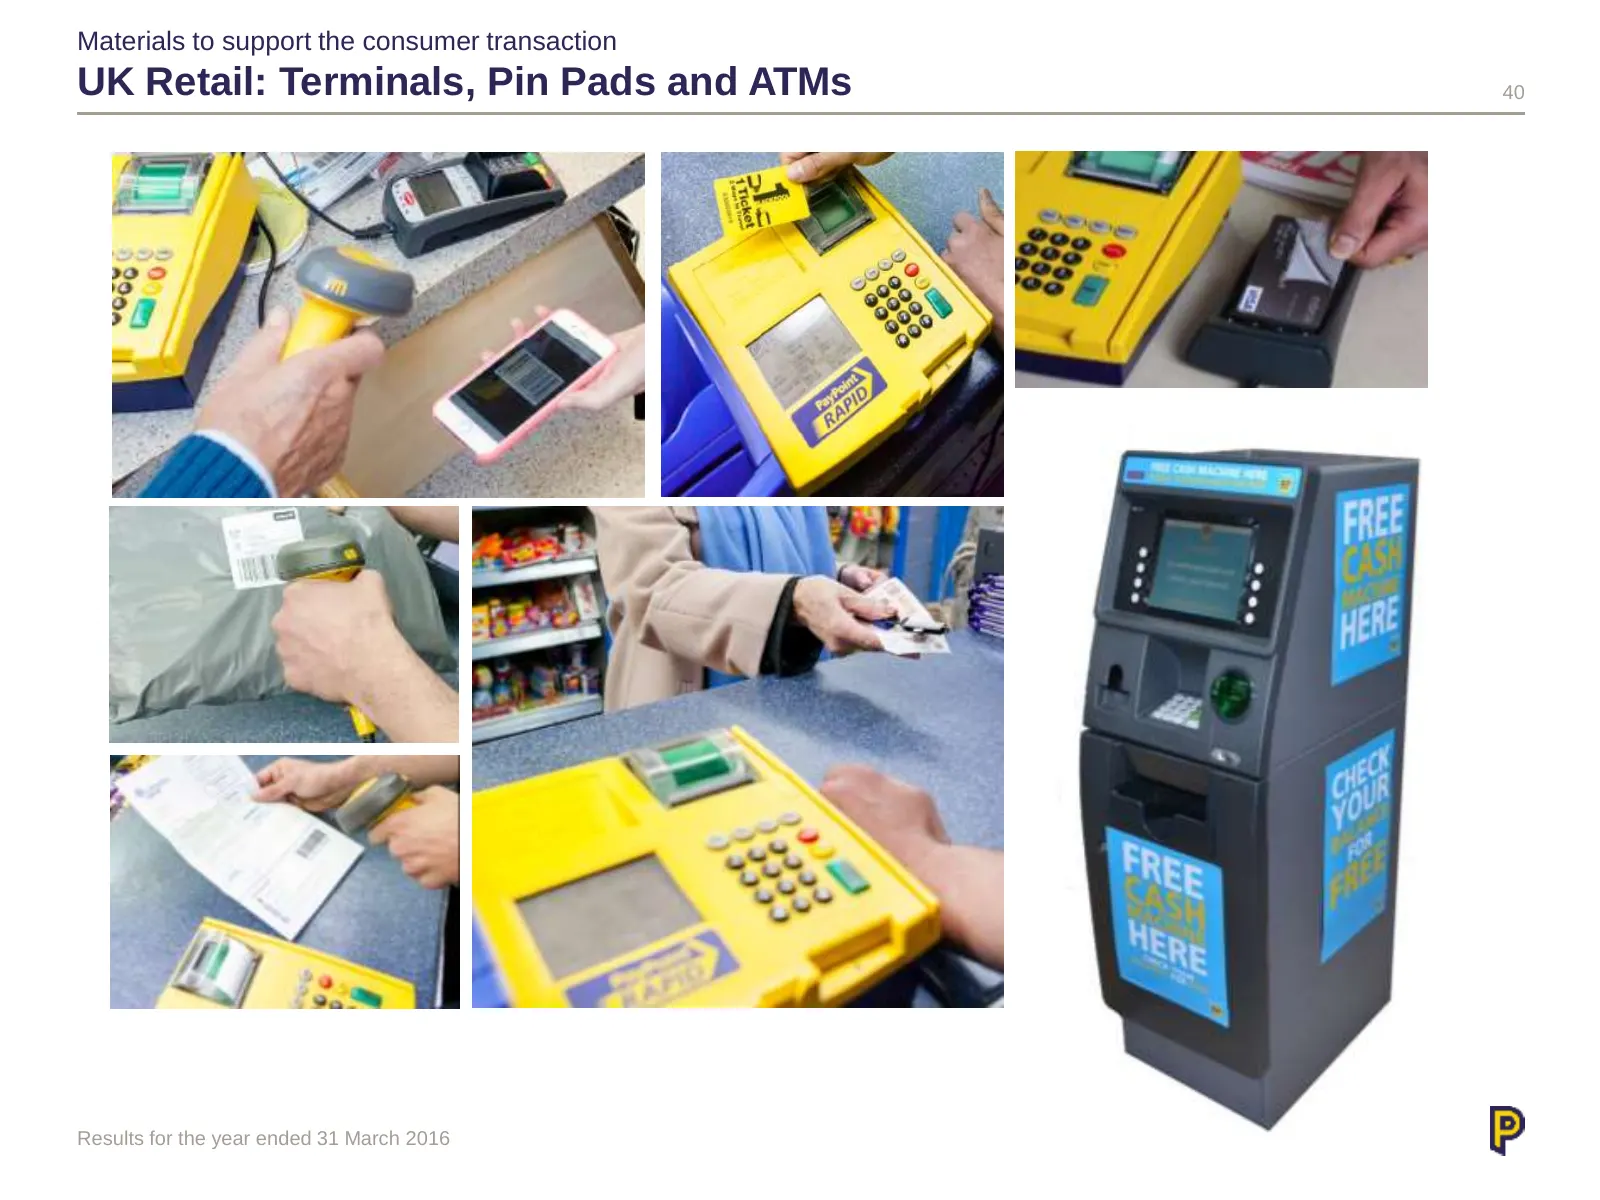
Materials to support the consumer transaction UK Retail: Terminals, Pin Pads and ATMs 40 Results for the year ended 31 March 2016
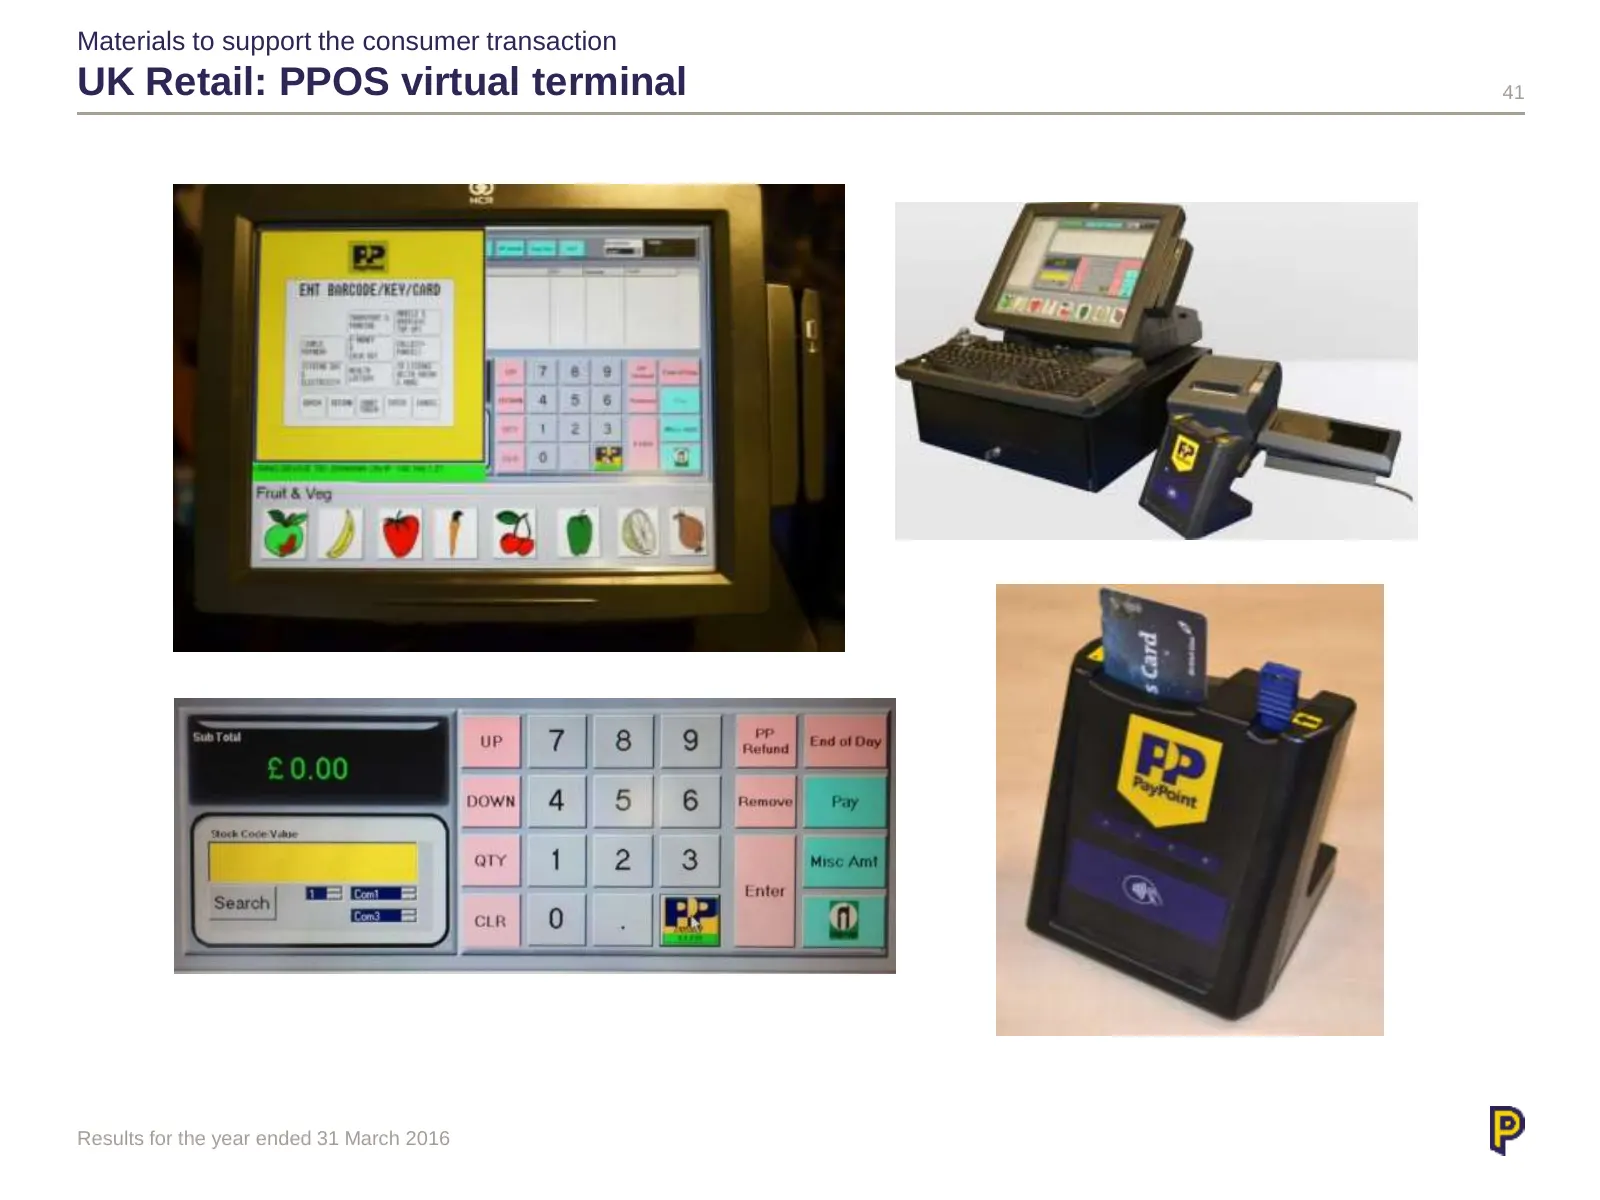
Slide 41: UK Retail: PPOS virtual terminal
Materials to support the consumer transaction UK Retail: PPOS virtual terminal 41 Results for the year ended 31 March 2016
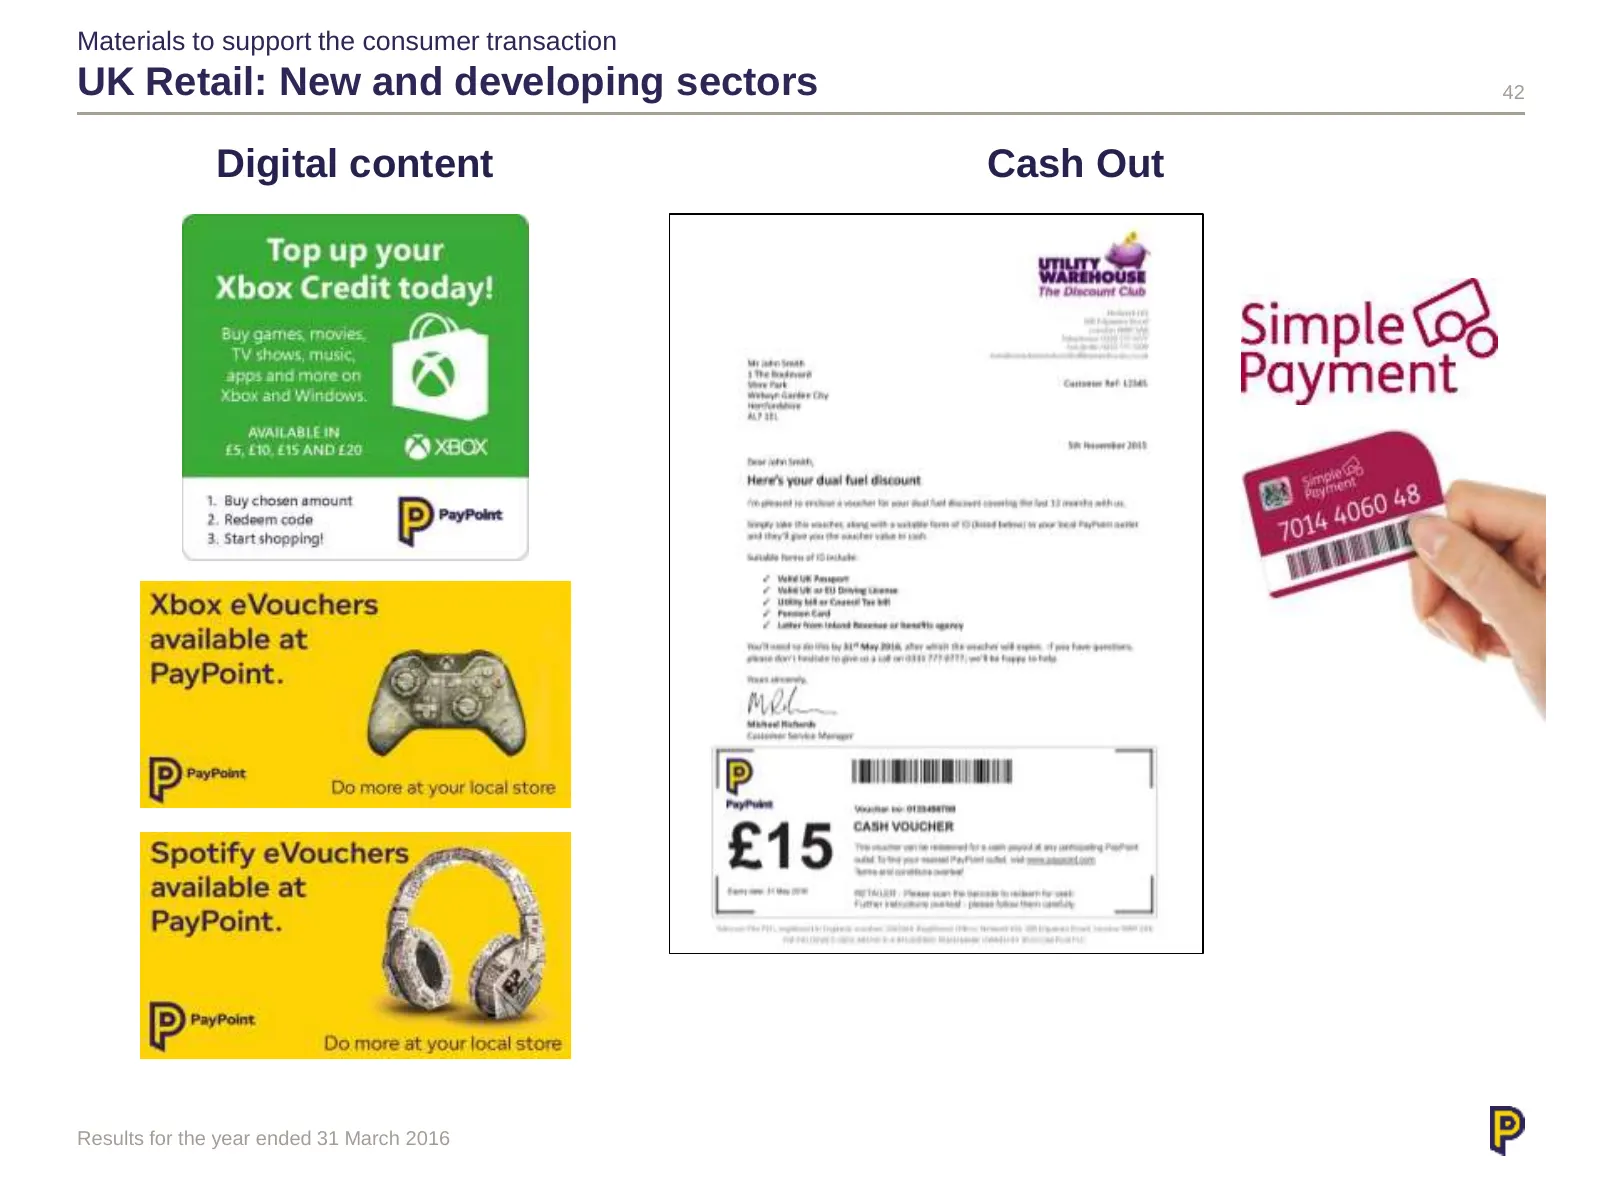
Slide 42: UK Retail: New and developing sectors
Materials to support the consumer transaction UK Retail: New and developing sectors 42 Digital content Cash Out Results for the year ended 31 March 2016
Slide 43: Appendix 2: Collect+
Appendix 2 Materials to support the consumer transaction Collect+
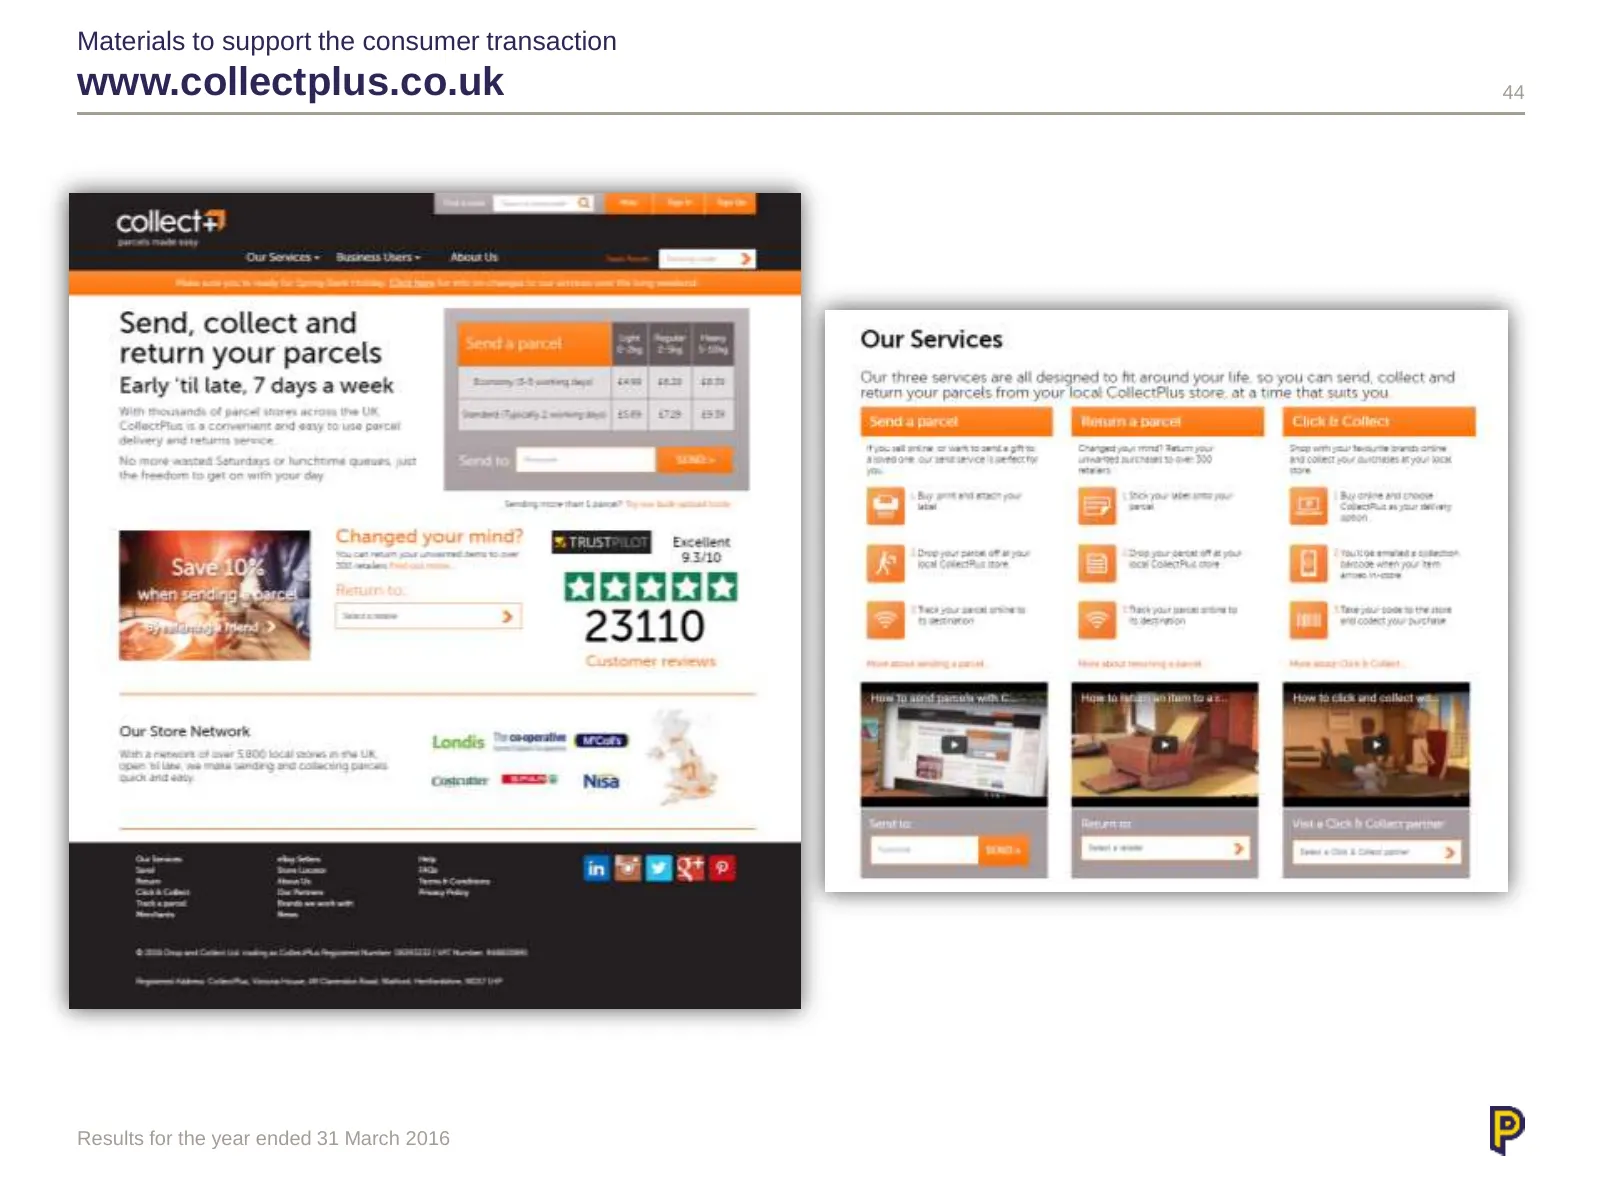
Slide 44: www.collectplus.co.uk
Materials to support the consumer transaction www.collectplus.co.uk 44 Results for the year ended 31 March 2016
Slide 45: www.collectplus.co.uk
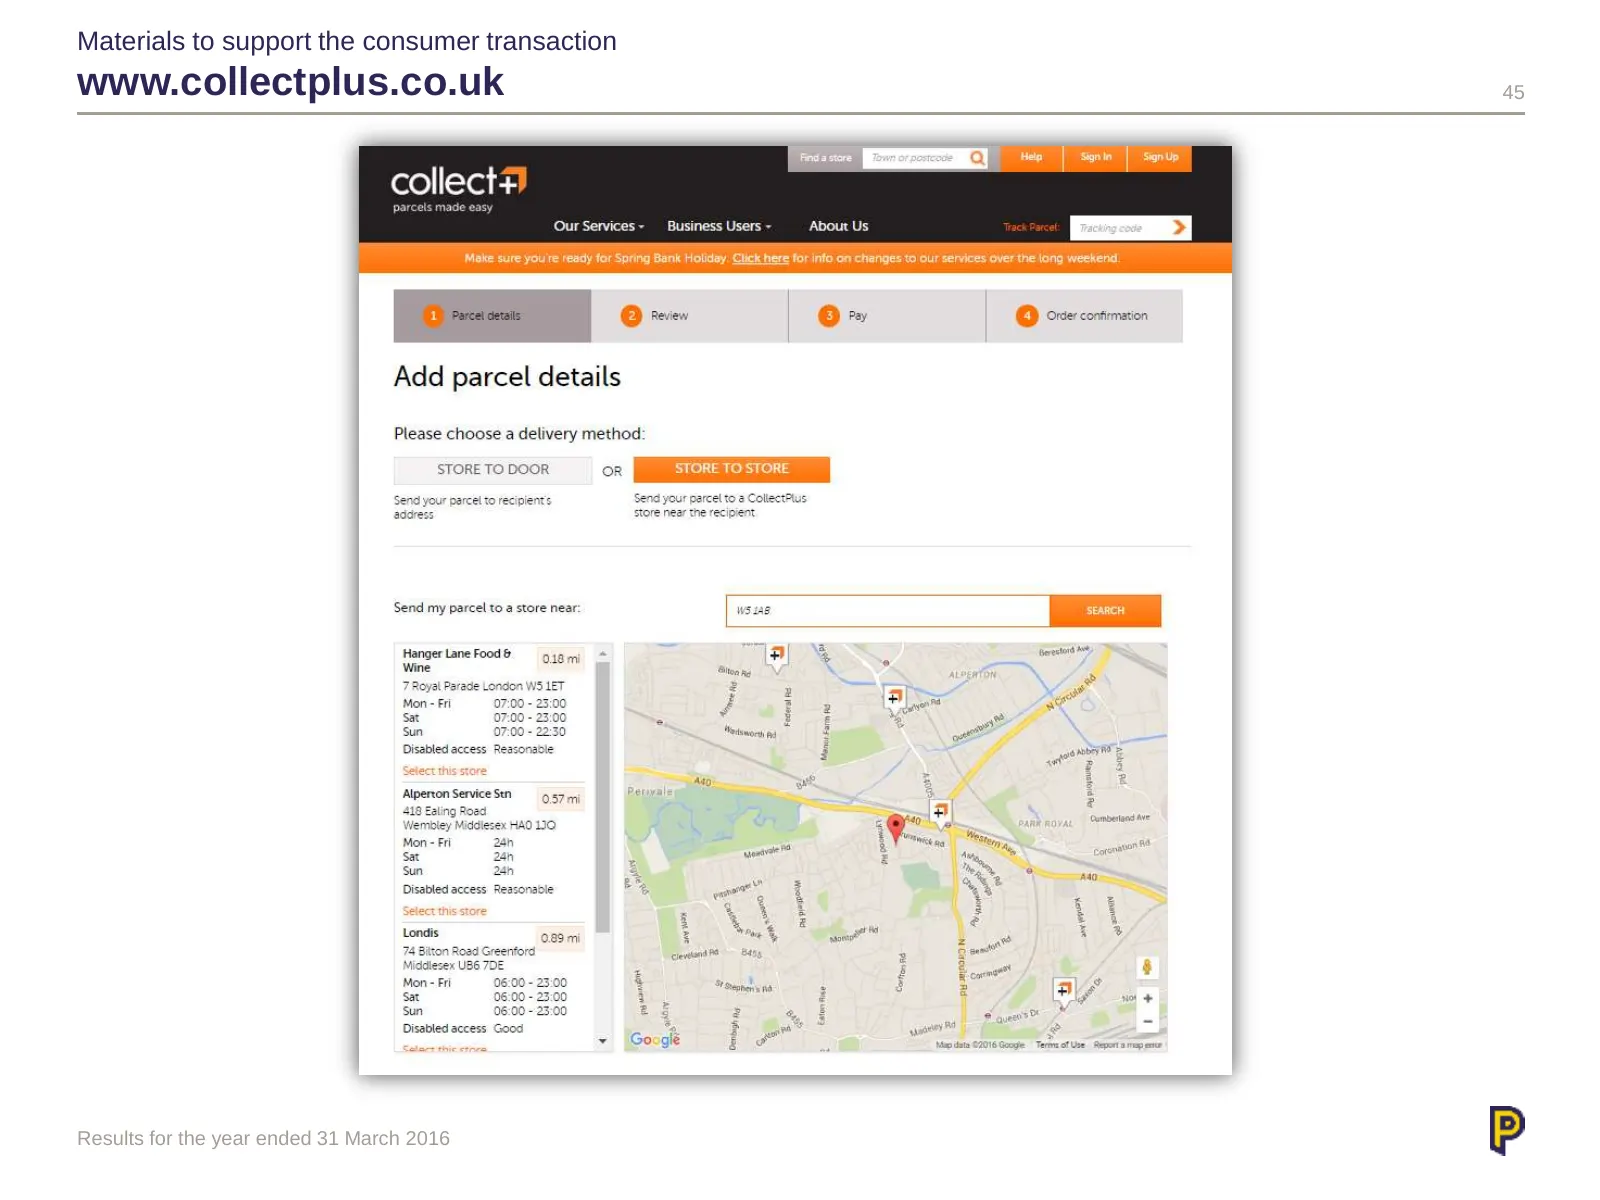
Materials to support the consumer transaction www.collectplus.co.uk 45 Results for the year ended 31 March 2016
Slide 46: www.collectplus.co.uk
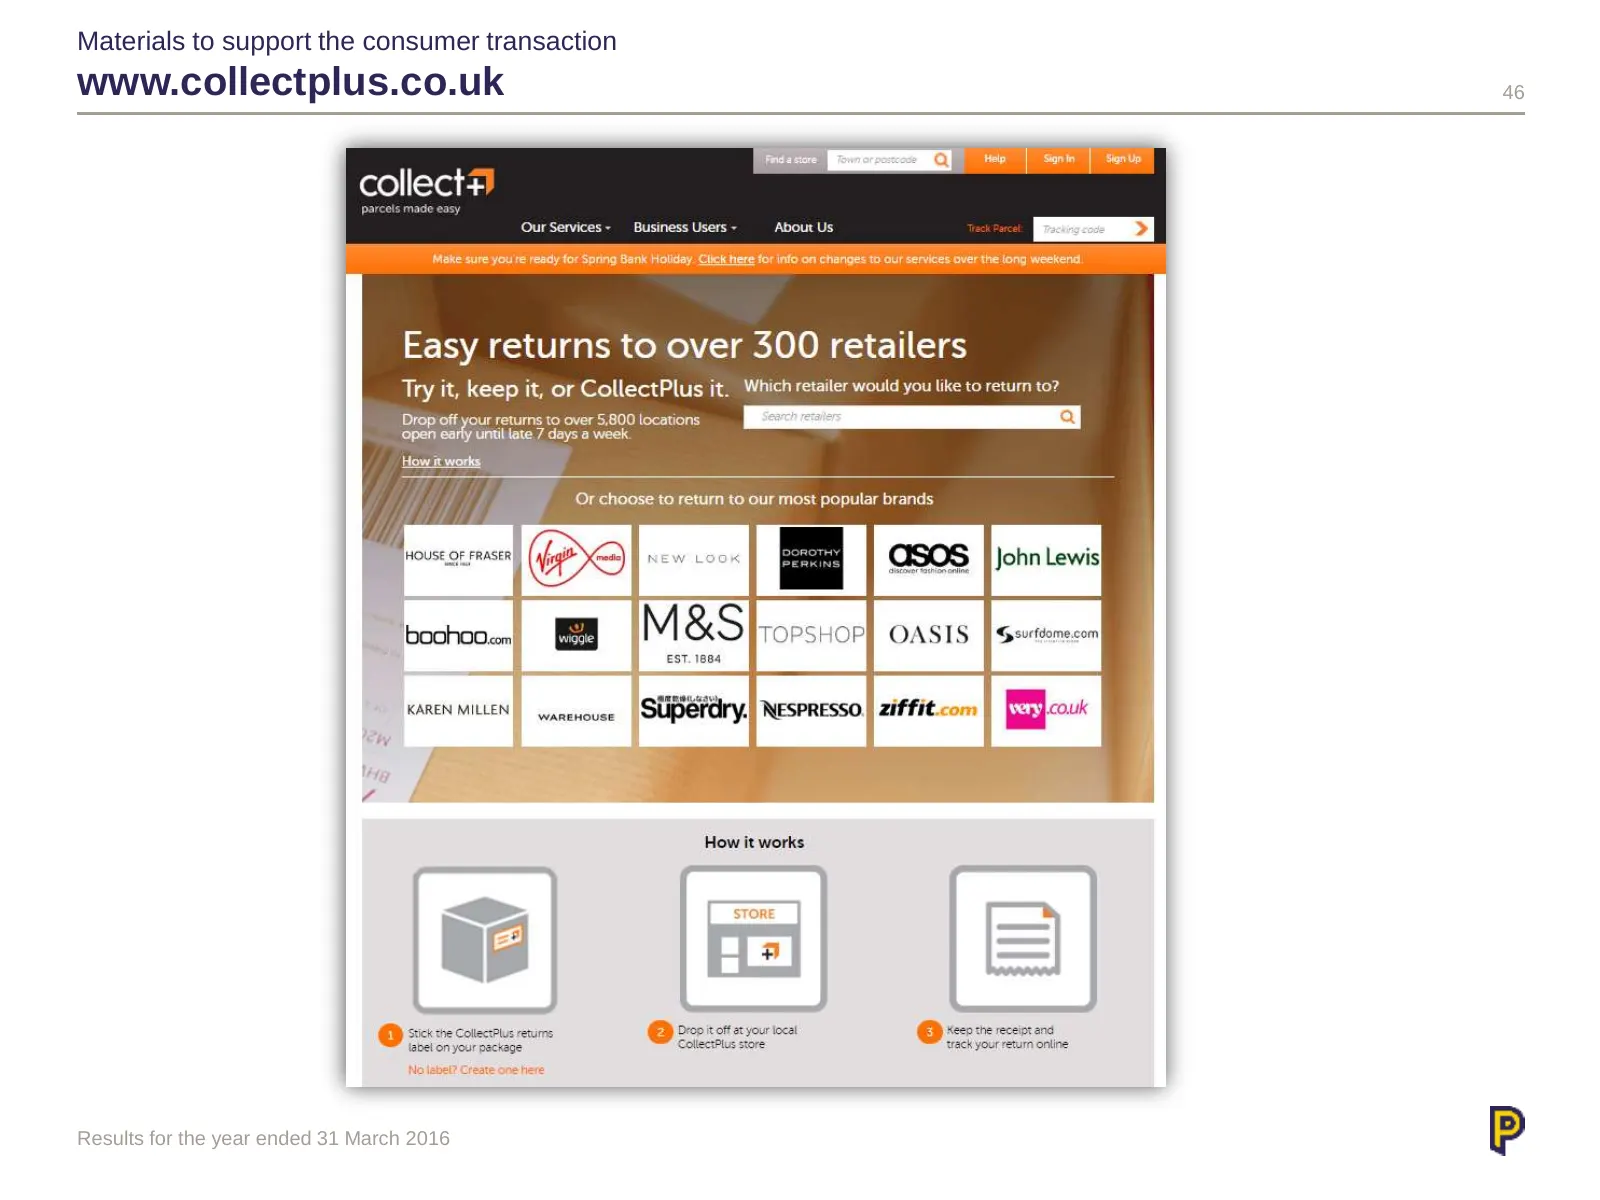
Materials to support the consumer transaction www.collectplus.co.uk 46 Results for the year ended 31 March 2016
Slide 47: Collect+: Phone pick up barcode
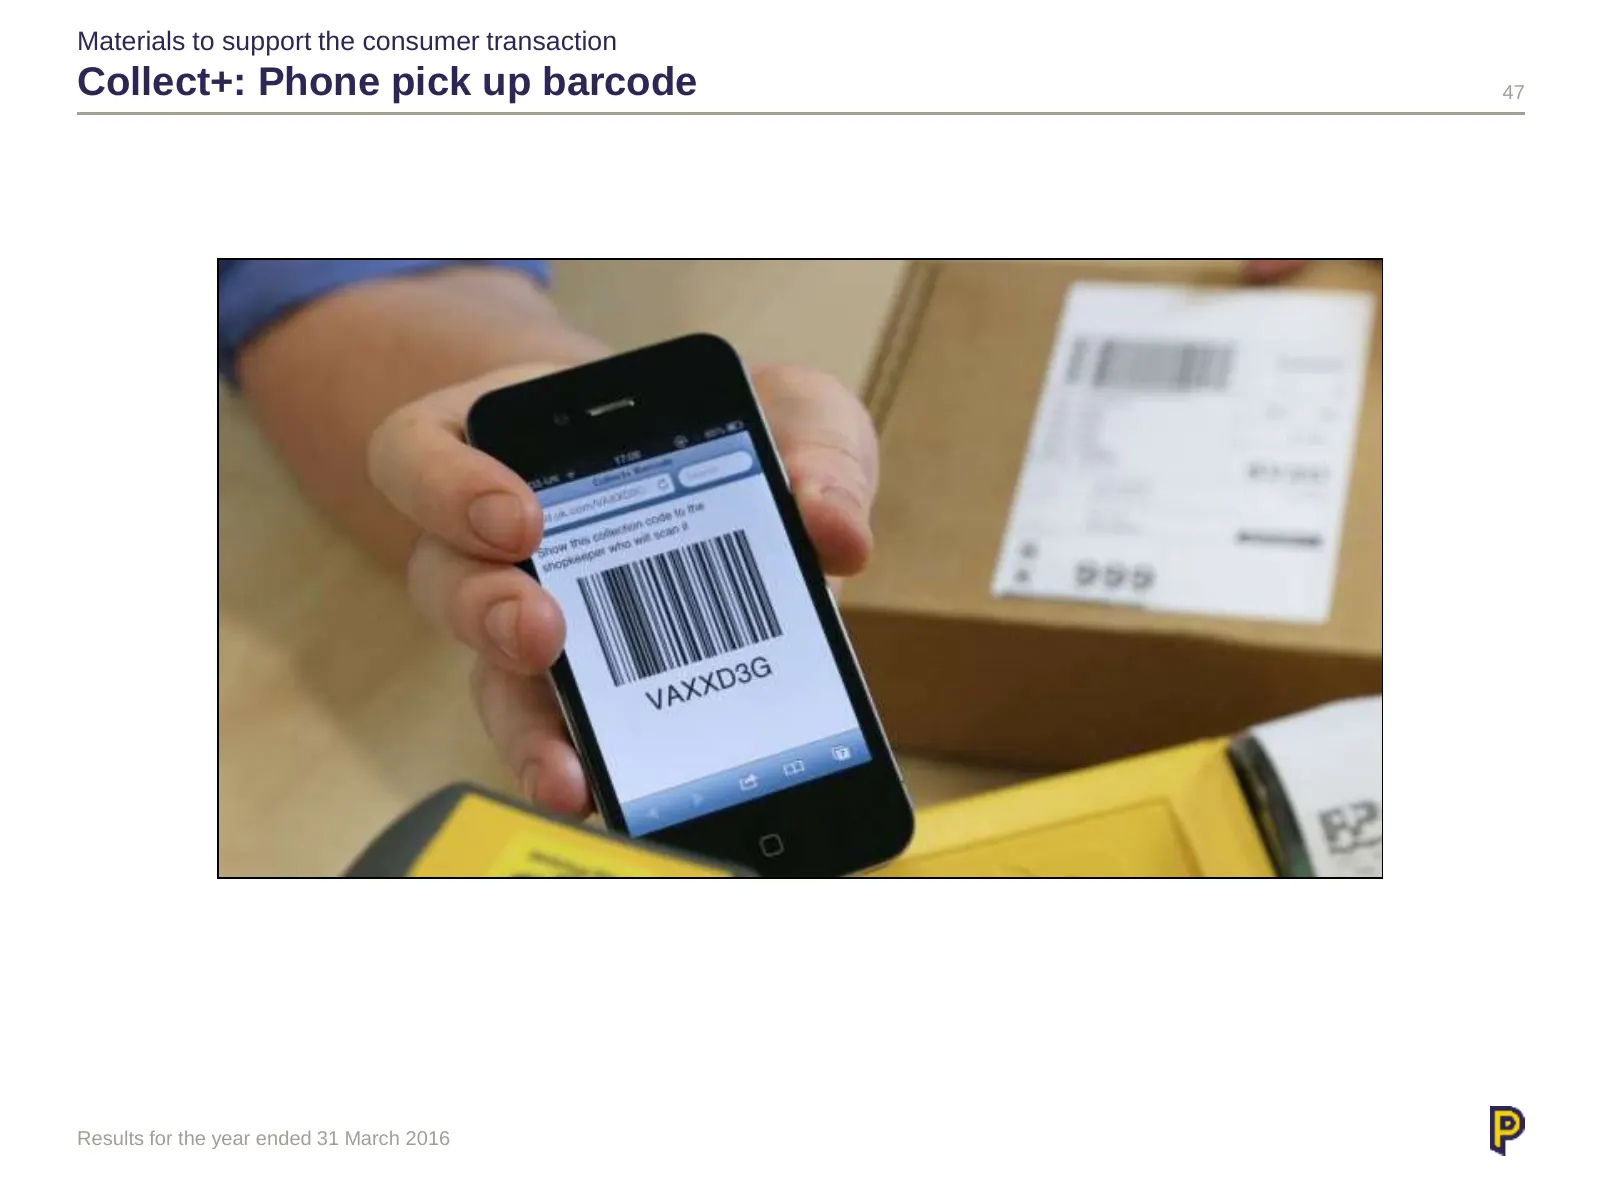
Materials to support the consumer transaction Collect+: Phone pick up barcode 47 Results for the year ended 31 March 2016
Slide 48: Collect+: UK network - over 6,000 locations live
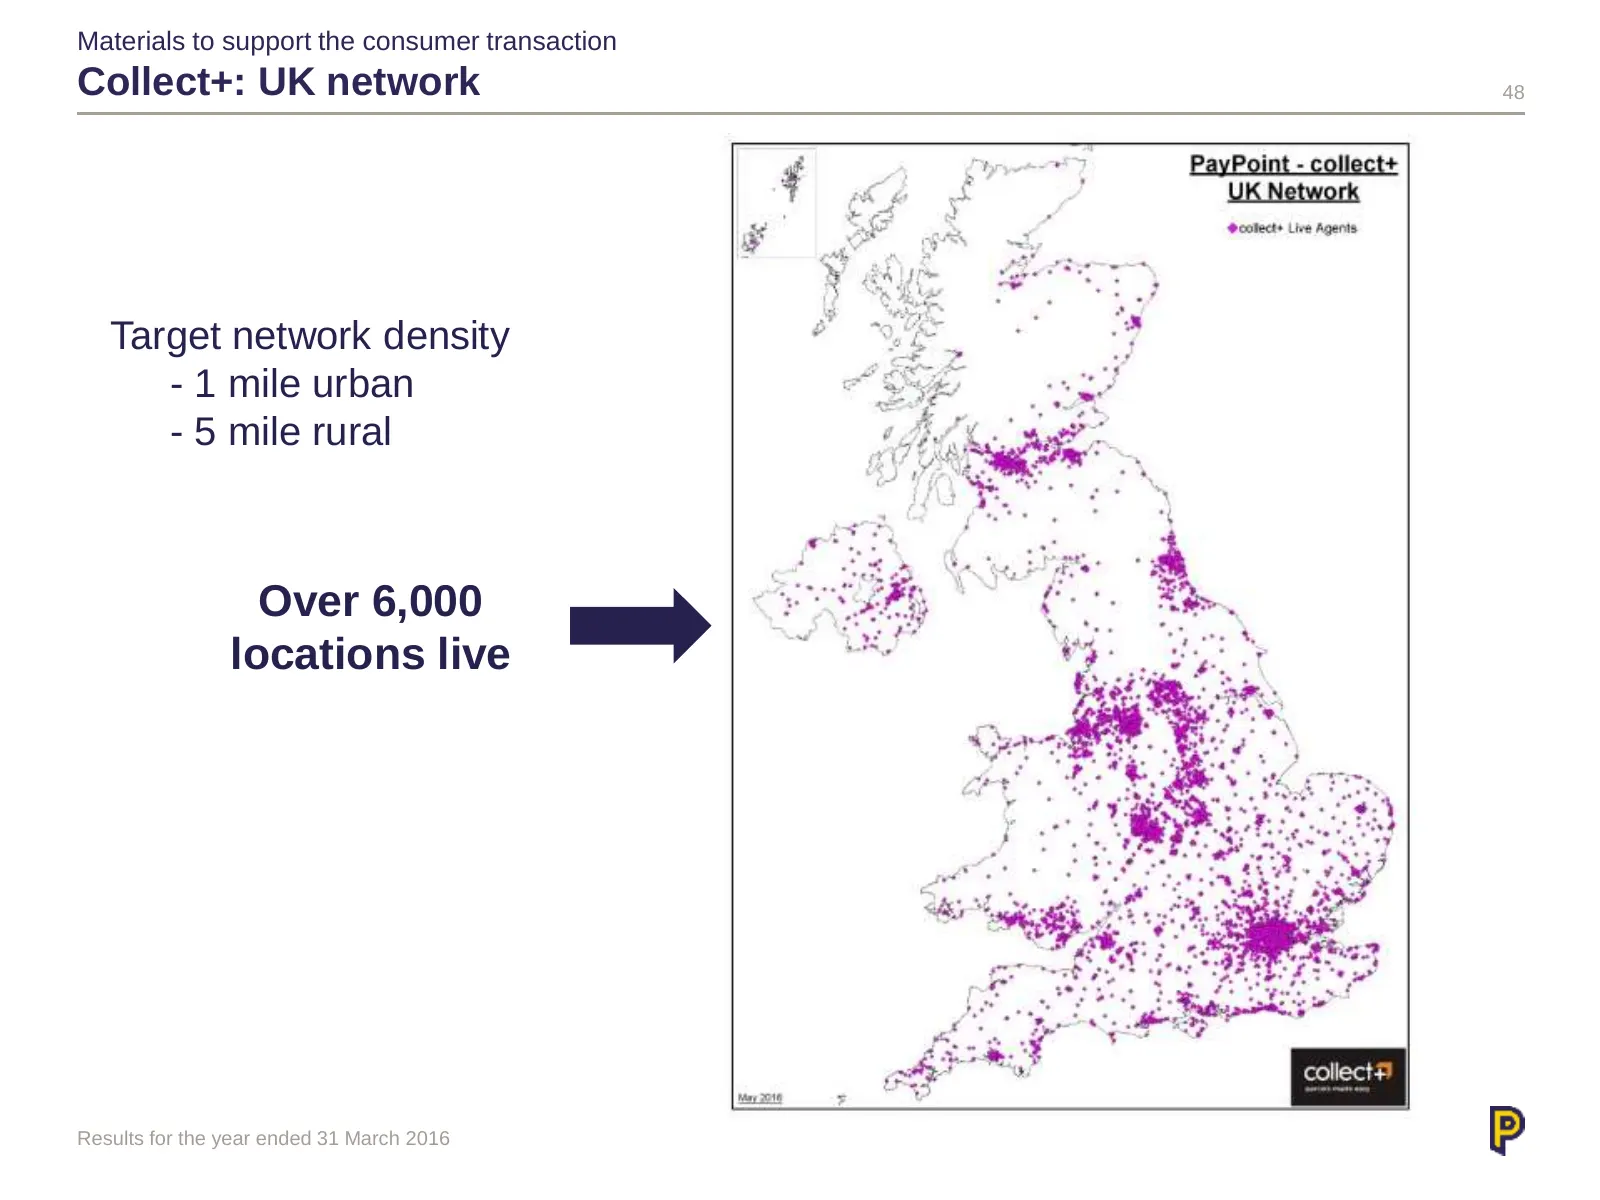
Materials to support the consumer transaction Collect+: UK network 48 Target network density - 1 mile urban - 5 mile rural Over 6,000 locations live Results for the year ended 31 March 2016
Source: Internet Archive copy of corporate.paypoint.com
More decks from PayPoint plc
 FY2026 Earnings Presentation28 slides · Jun 11, 2026
 Q2 2026 Earnings Presentation39 slides · Nov 20, 2025
 FY2025 Earnings Presentation34 slides · Jun 12, 2025
 H1 2025 Earnings Presentation34 slides · Nov 21, 2024
 FY2024 Earnings Presentation39 slides · Jun 25, 2024
 H1 FY24 Earnings Presentation41 slides · Nov 23, 2023