McBride plc · LSE:MCB
McBride — H1 2006-07 Earnings Presentation
24 slides from McBride's earnings presentation, February 2007
Slide 1: McBride plc 2006-07 Interim Results Presentation
McBride plc 2006-07 Interim Results Presentation February 2007 Overall best private label supplier in UK - Grocer Magazine “Senior buyers judged McBride the best, thanks to its D L excellent account management skills, reliability of N I BE H A BE E L deliveries, consistency of product quality, new p
Slide 2: Summary 2006-07 Half 1
Summary 2006-07 Half 1 » Results in line with expectations » Revenue and profit growth in both household and personal care » Operating margin improved to 5.9% » EPS up 9% » Major Italian Household cleaners acquisition » Small infill acquisition in Poland » Successful integration of recent UK acquisi
Slide 3: Business unit progress
Business unit progress » Western Continental Europe - Revenue growth in Italy, Spain and personal care - French household market weak but not declining - Continuing focus on innovation, service and costs » Eastern Continental Europe - Revenue growth - In fill acquisition of Schneider household and p
Slide 4: Bob Beveridge, Finance Director
Bob Beveridge Finance Director
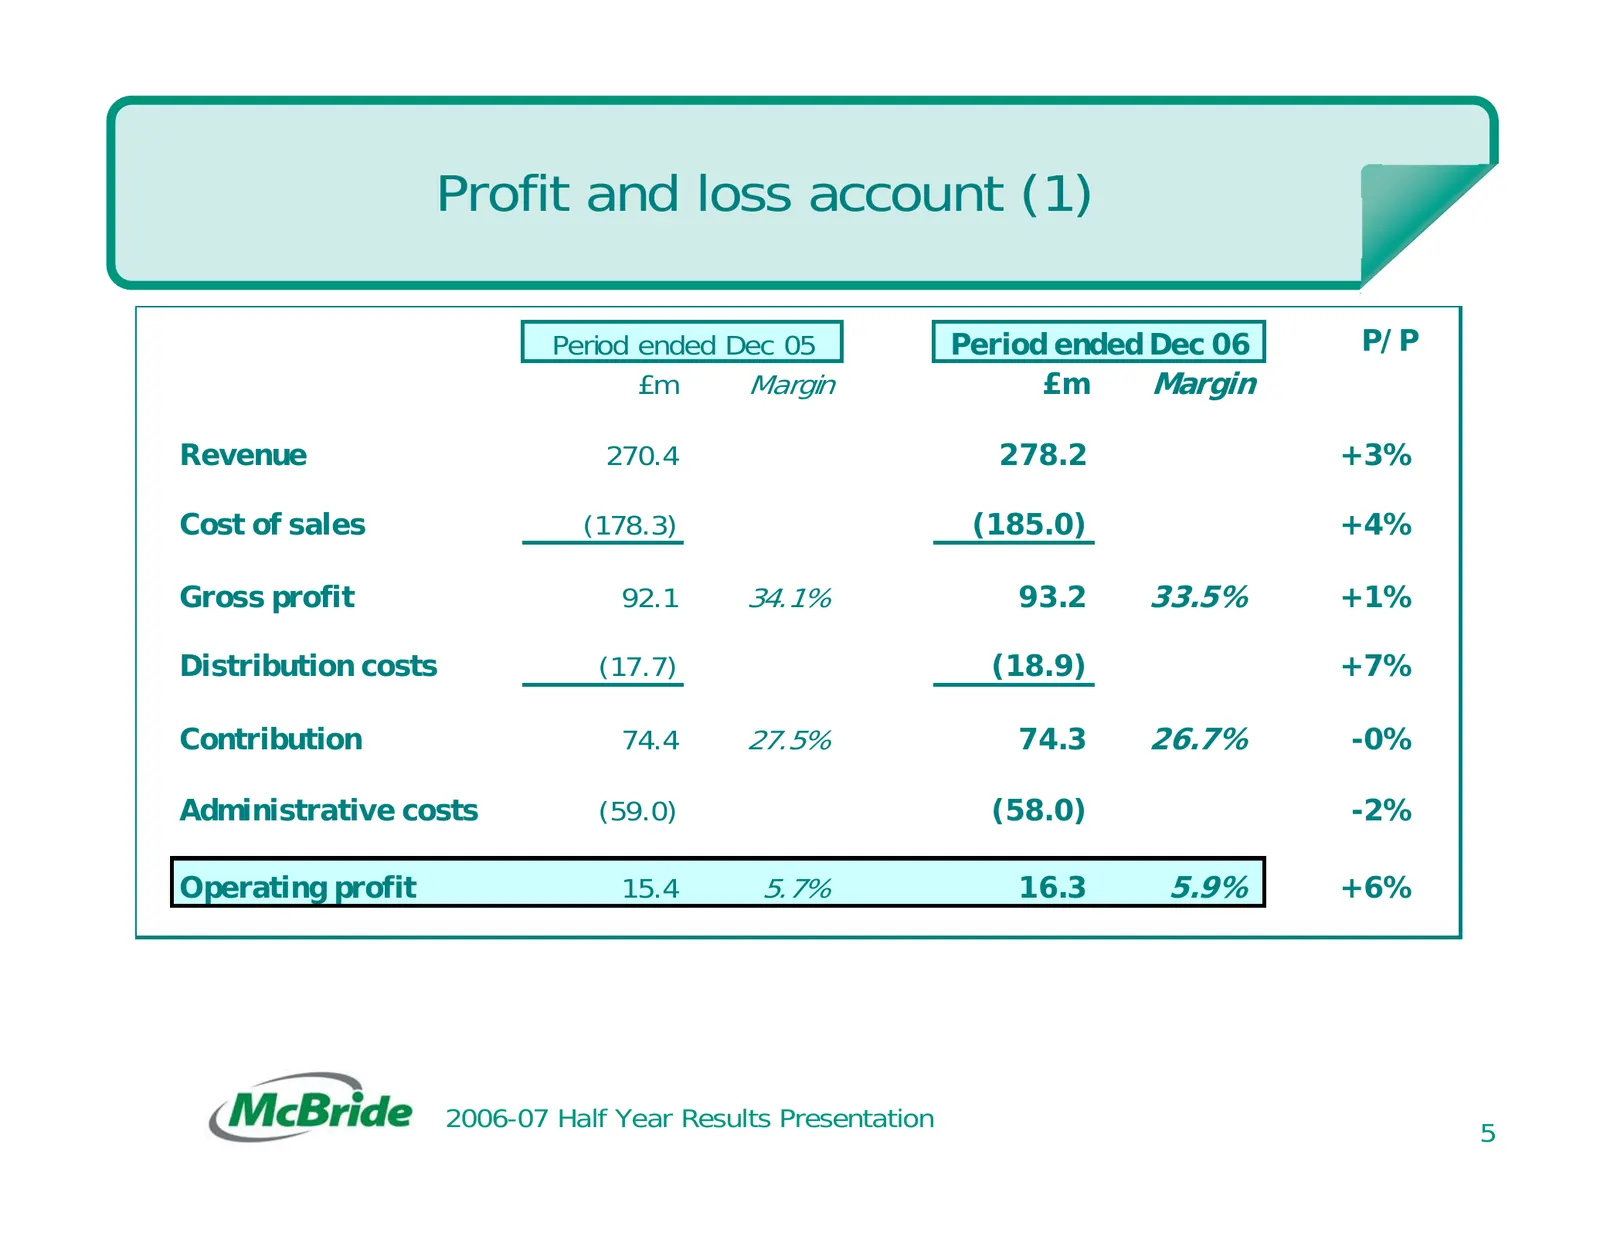
Slide 5: Profit and loss account (1)
Profit and loss account (1) Period ended Dec 05 Period ended Dec 06 P/P £m Margin £m Margin Revenue 270.4 278.2 +3% Cost of sales (178.3) (185.0) +4% Gross profit 92.1 34.1% 93.2 33.5% +1% Distribution costs (17.7) (18.9) +7% Contribution 74.4 27.5% 74.3 26.7% -0% Administrative costs (59.0) (58.0)
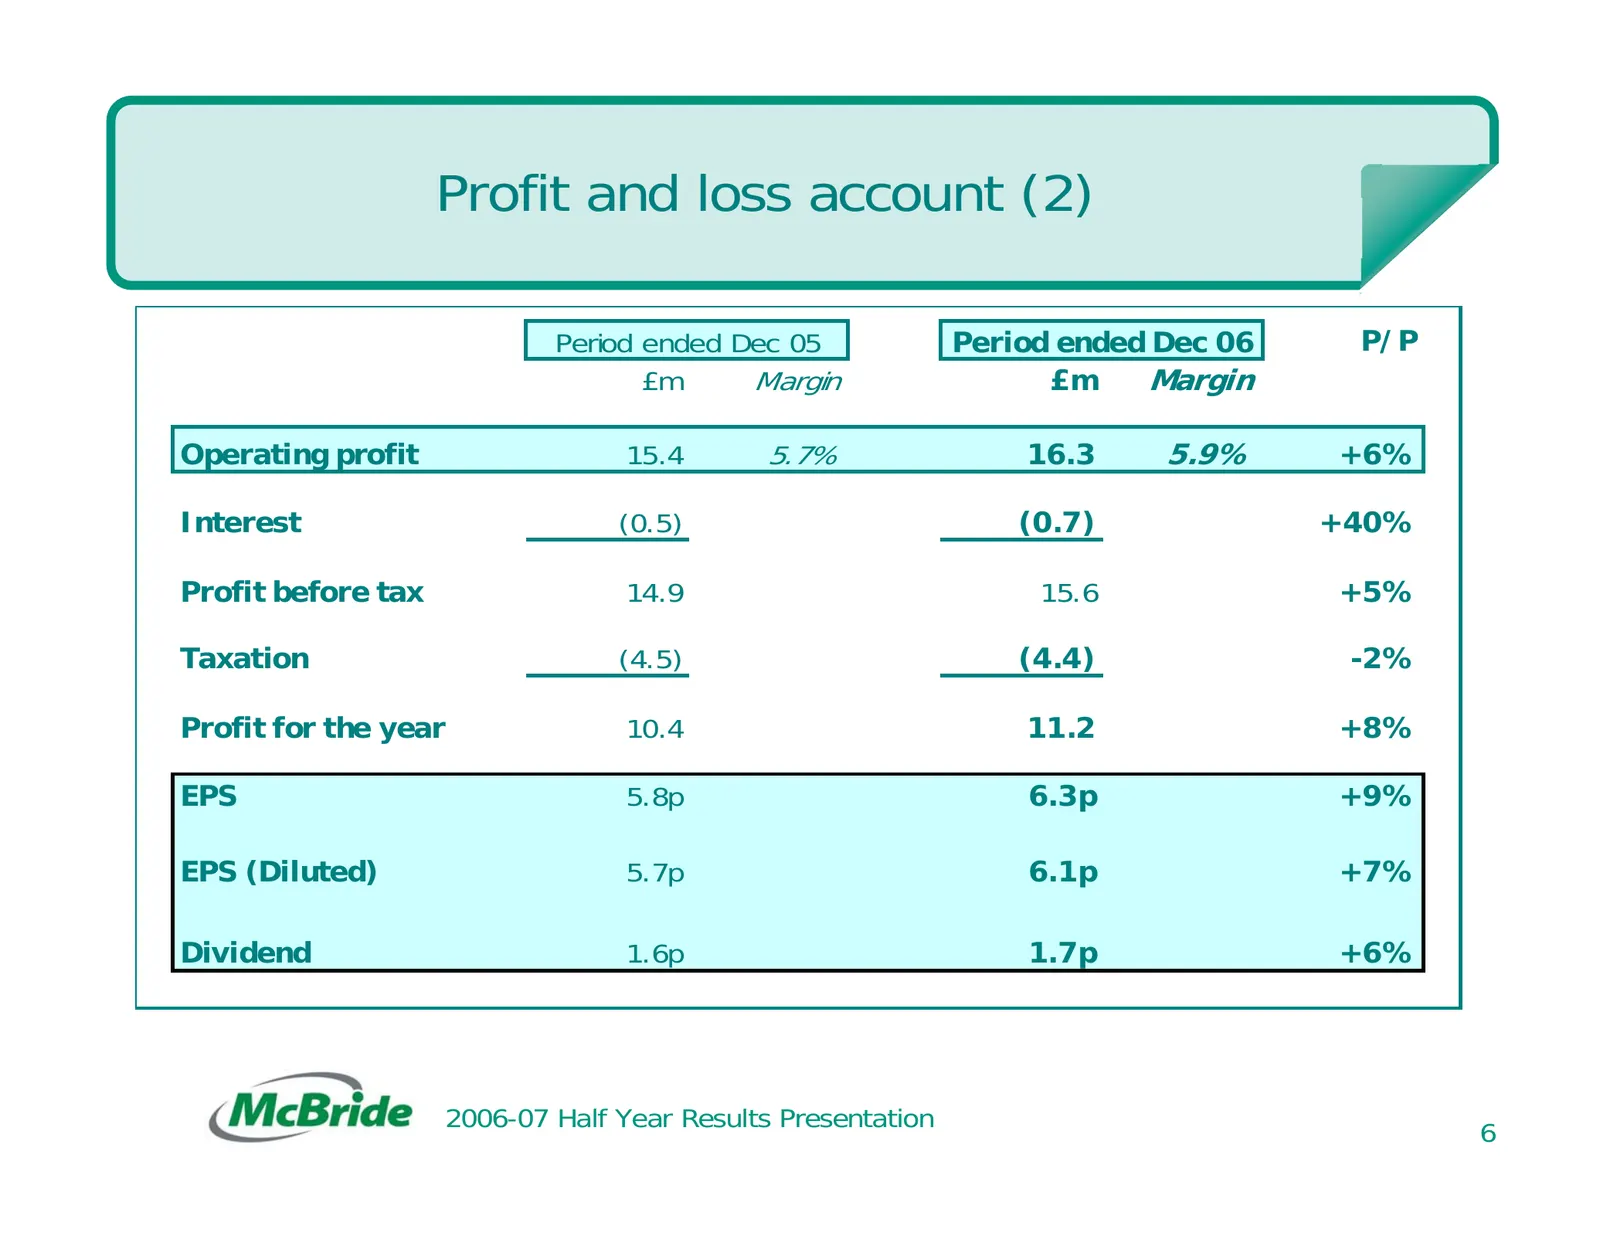
Slide 6: Profit and loss account (2)
Profit and loss account (2) Period ended Dec 05 Period ended Dec 06 P/P £m Margin £m Margin Operating profit 15.4 5.7% 16.3 5.9% +6% Interest (0.5) (0.7) +40% Profit before tax 14.9 15.6 +5% Taxation (4.5) (4.4) -2% Profit for the year 10.4 11.2 +8% EPS 5.8p 6.3p +9% EPS (Diluted) 5.7p 6.1p +7% Divi
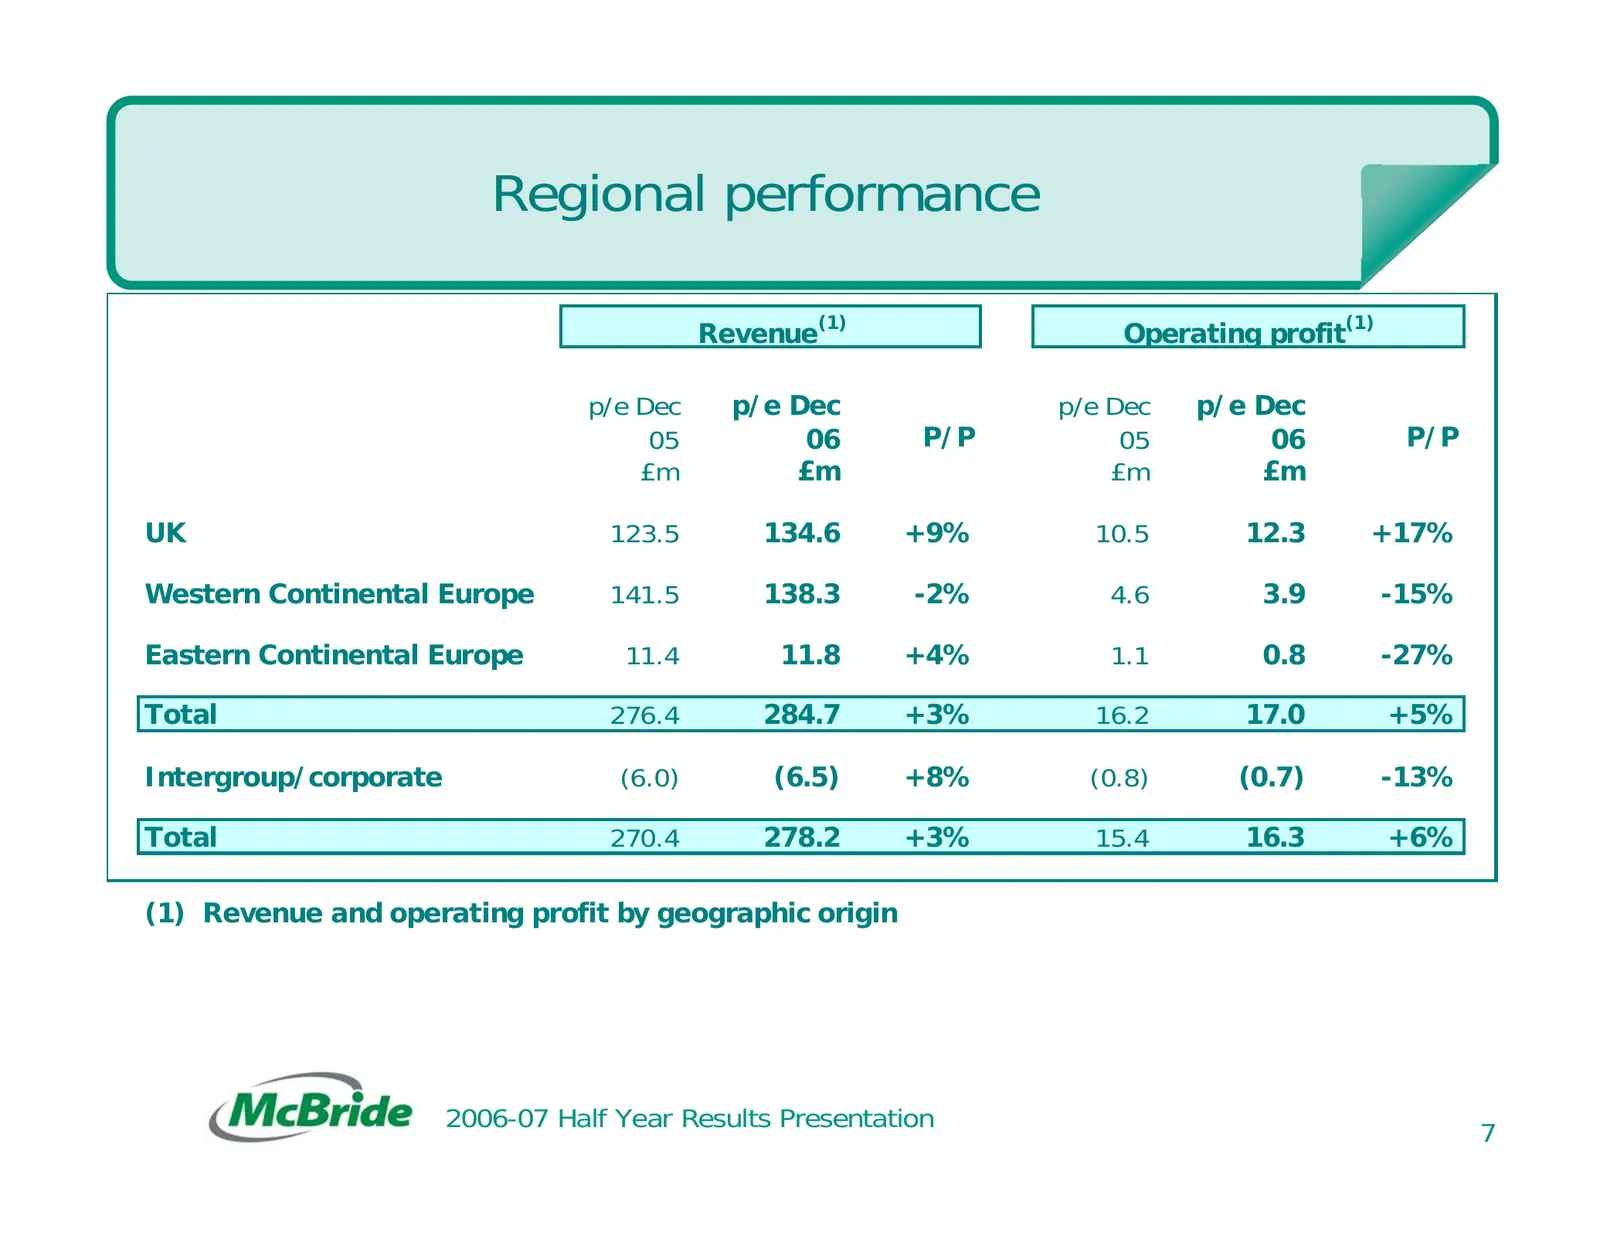
Slide 7: Regional performance
Regional performance (1) (1) Revenue Operating profit p/e Dec p/e Dec p/e Dec p/e Dec 05 06 P/P 05 06 P/P £m £m £m £m UK 123.5 134.6 +9% 10.5 12.3 +17% Western Continental Europe 141.5 138.3 -2% 4.6 3.9 -15% Eastern Continental Europe 11.4 11.8 +4% 1.1 0.8 -27% Total 276.4 284.7 +3% 16.2 17.0 +5% In
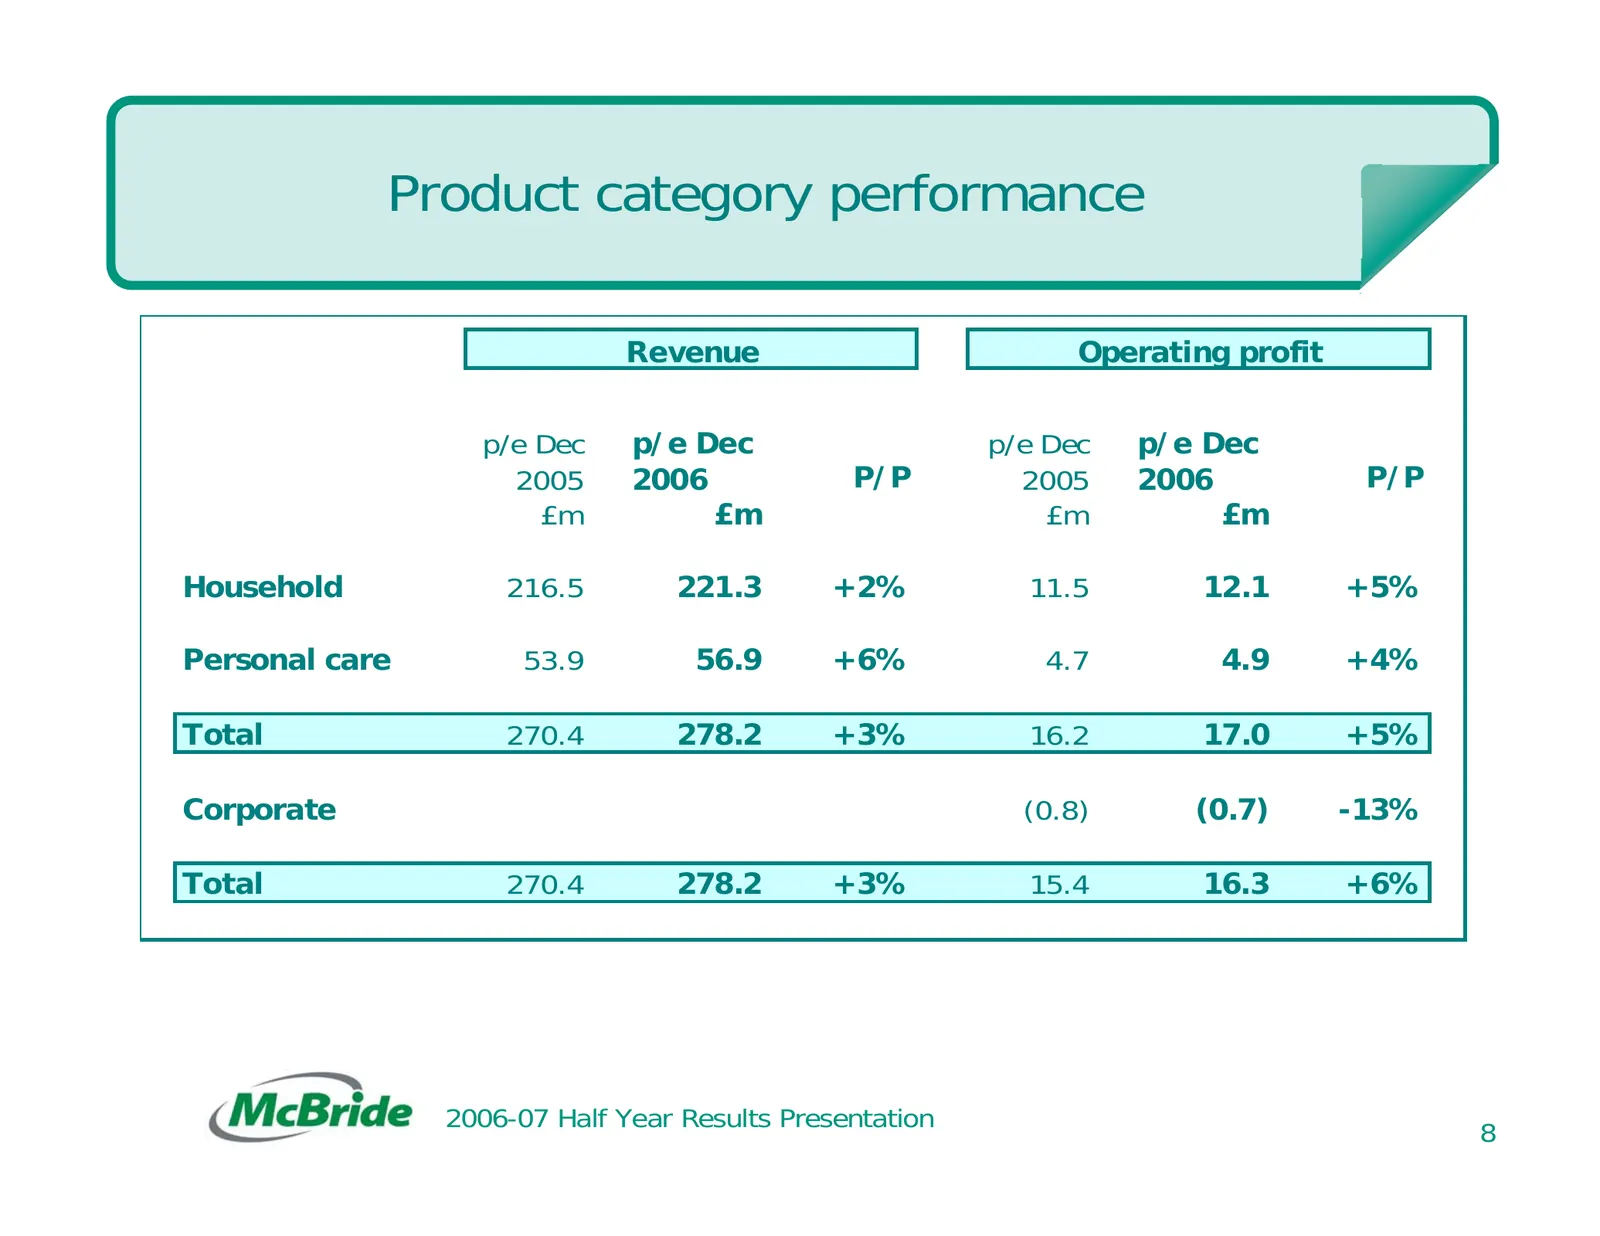
Slide 8: Product category performance
Product category performance Revenue Operating profit p/e Dec p/e Dec p/e Dec p/e Dec 2005 2006 P/P 2005 2006 P/P £m £m £m £m Household 216.5 221.3 +2% 11.5 12.1 +5% Personal care 53.9 56.9 +6% 4.7 4.9 +4% Total 270.4 278.2 +3% 16.2 17.0 +5% Corporate (0.8) (0.7) -13% Total 270.4 278.2 +3% 15.4 16.3
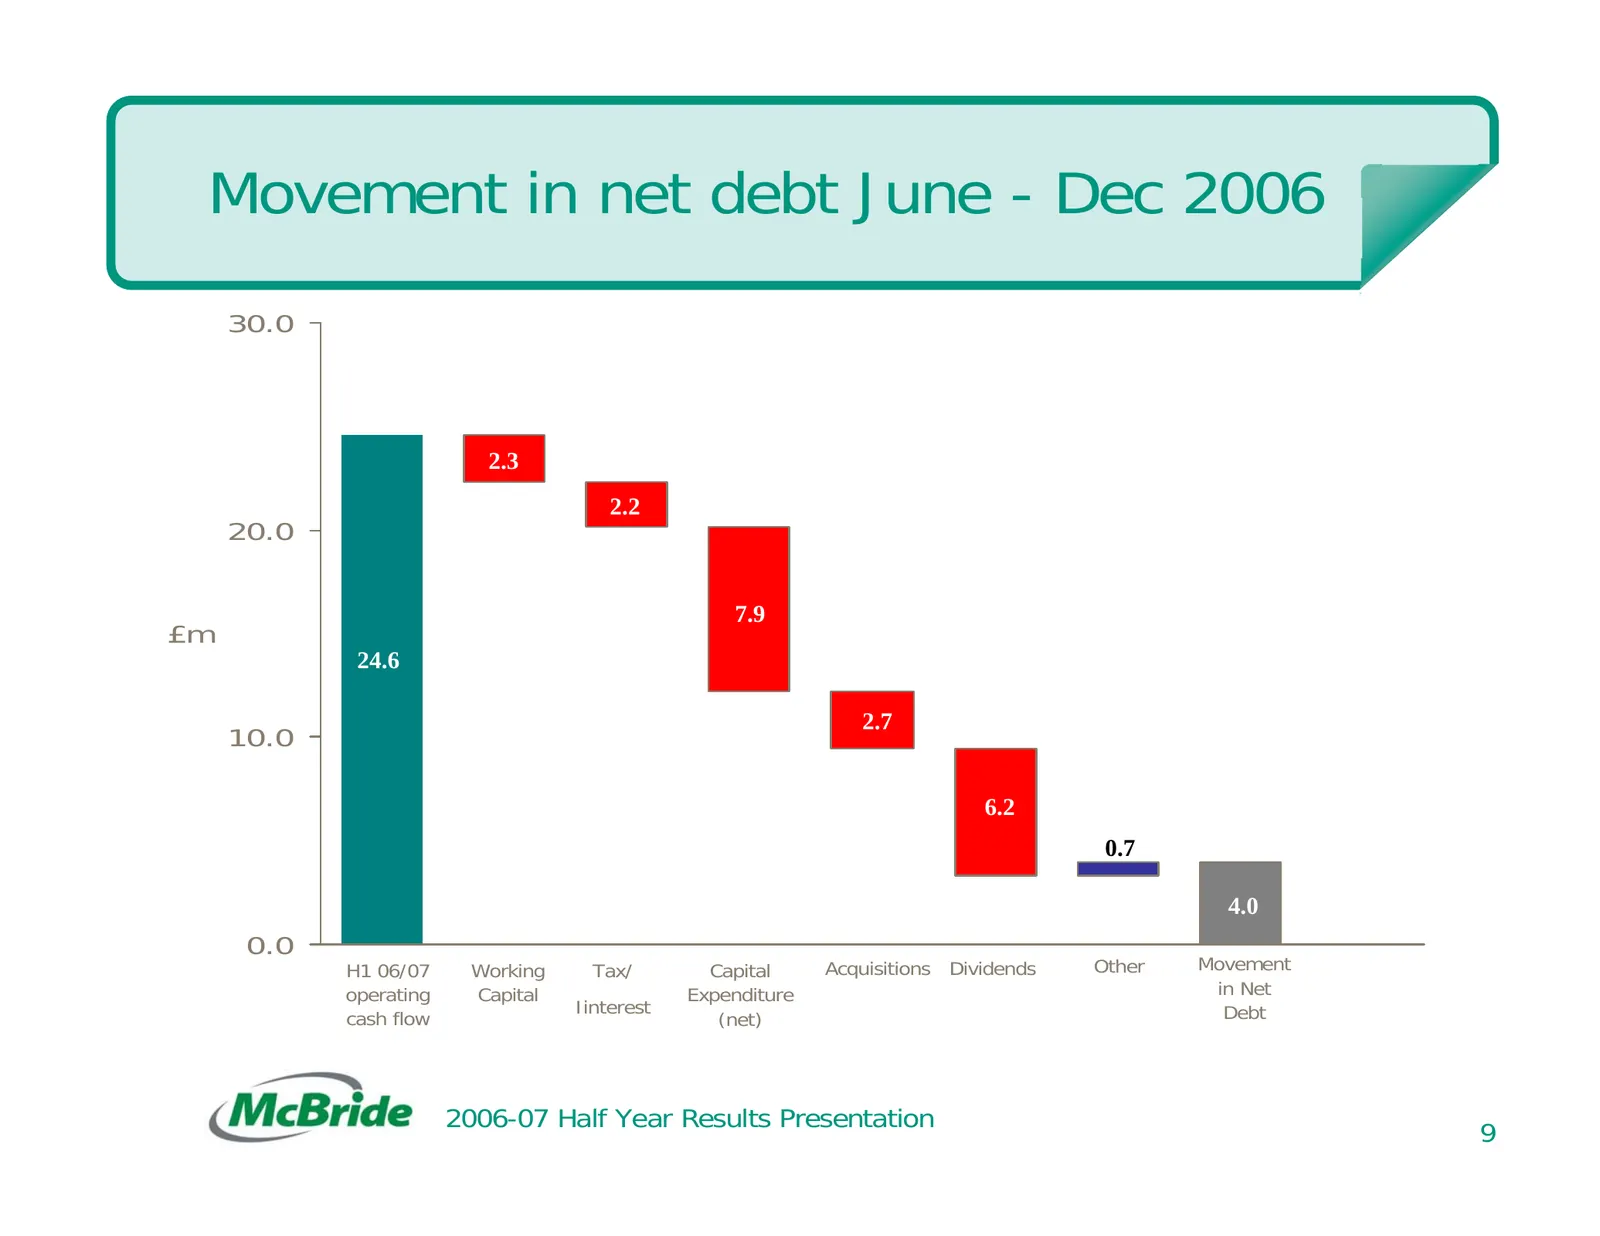
Slide 9: Movement in net debt June - Dec 2006
Movement in net debt June - Dec 2006 30.0 2.3 2.2 20.0 7.9 £m 24.6 2.7 10.0 6.2 0.7 4.0 0.0 H1 06/07 Working Tax/ Capital Acquisitions Dividends Other Movement operating Capital Expenditure in Net Iinterest Debt cash flow (net) 2006-07 Half Year Results Presentation 9
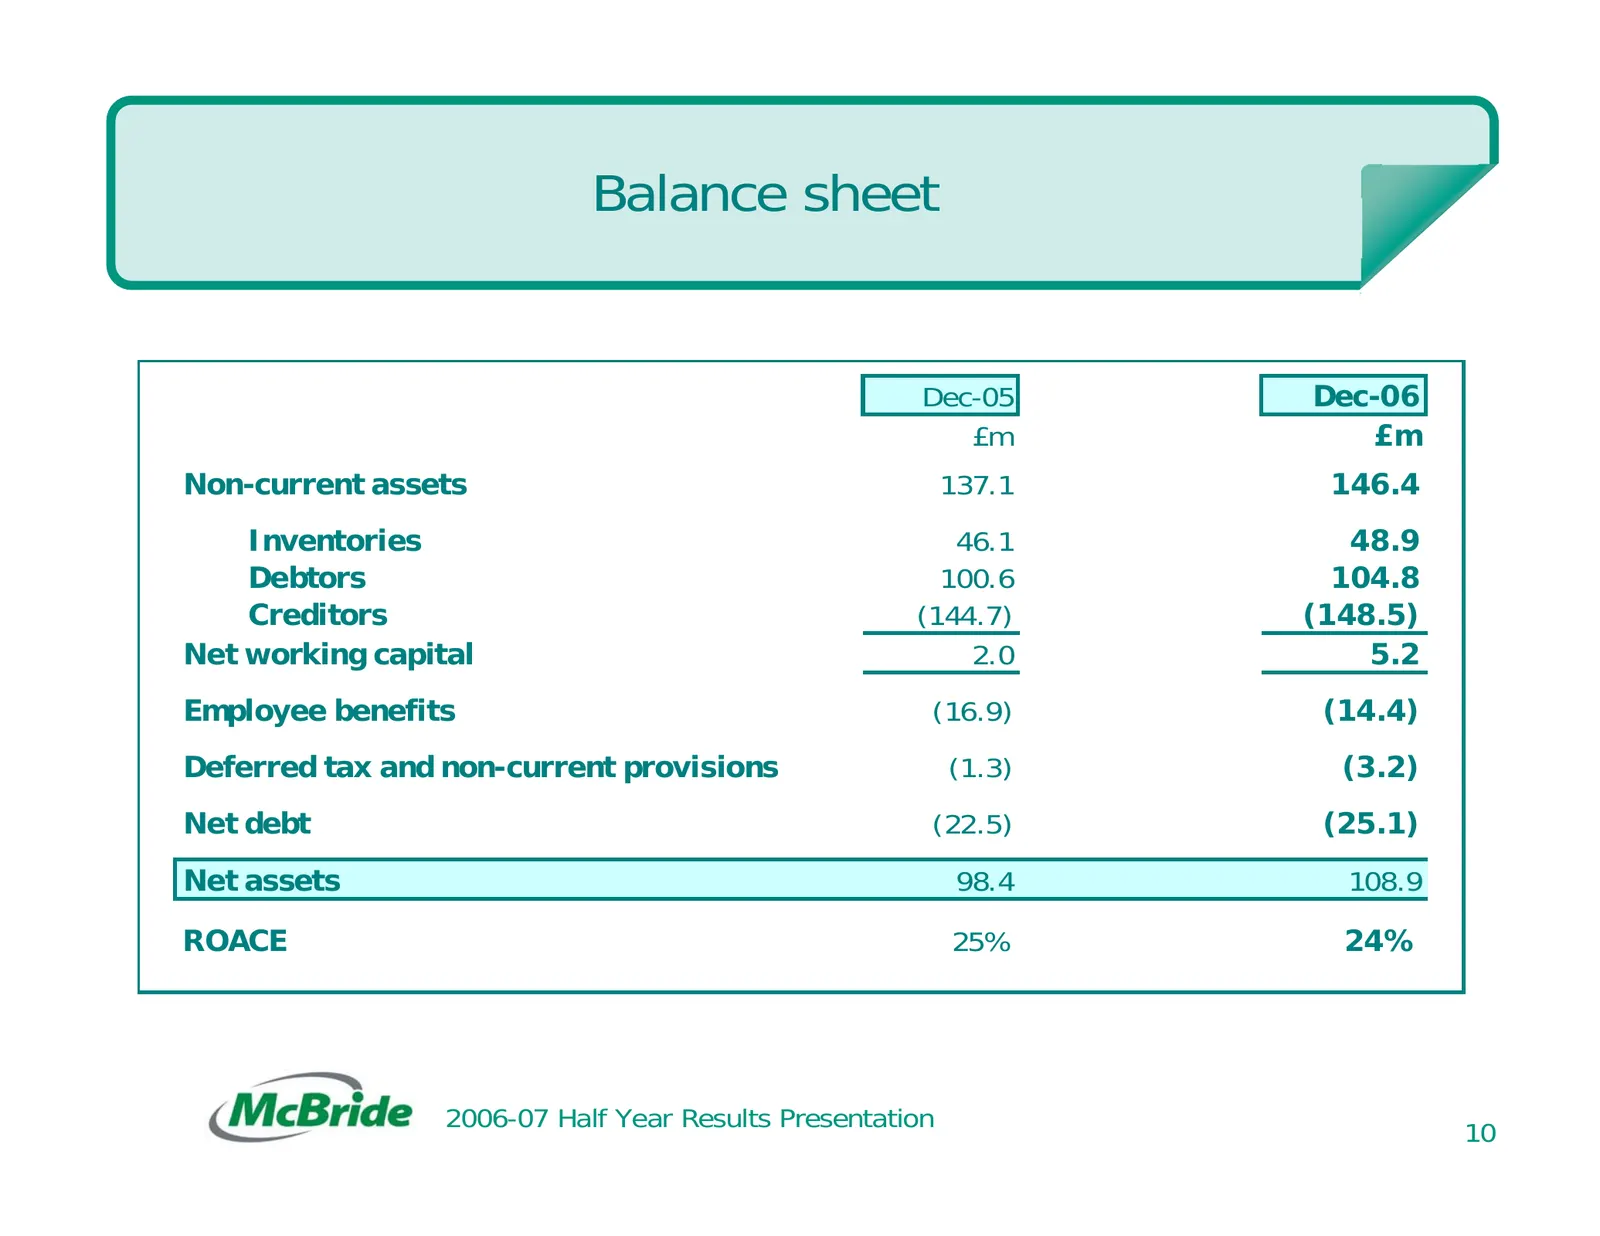
Slide 10: Balance sheet
Balance sheet Dec-05 Dec-06 £m £m Non-current assets 137.1 146.4 Inventories 46.1 48.9 Debtors 100.6 104.8 Creditors (144.7) (148.5) Net working capital 2.0 5.2 Employee benefits (16.9) (14.4) Deferred tax and non-current provisions (1.3) (3.2) Net debt (22.5) (25.1) Net assets 98.4 108.9 ROACE 25%
Slide 11: Focus on cost management
Focus on cost management » Overhead reductions in UK and WCE » Purchasing strategies to alleviate some input price pressures - Buy long » Value engineering benefits achieved in WCE » Labour efficiency improvements in WCE » China sourcing project delivery 2006-07 Half Year Results Presentation 11
Slide 12: Miles Roberts, Chief Executive
Miles Roberts Chief Executive
Slide 13: Strategy for growth
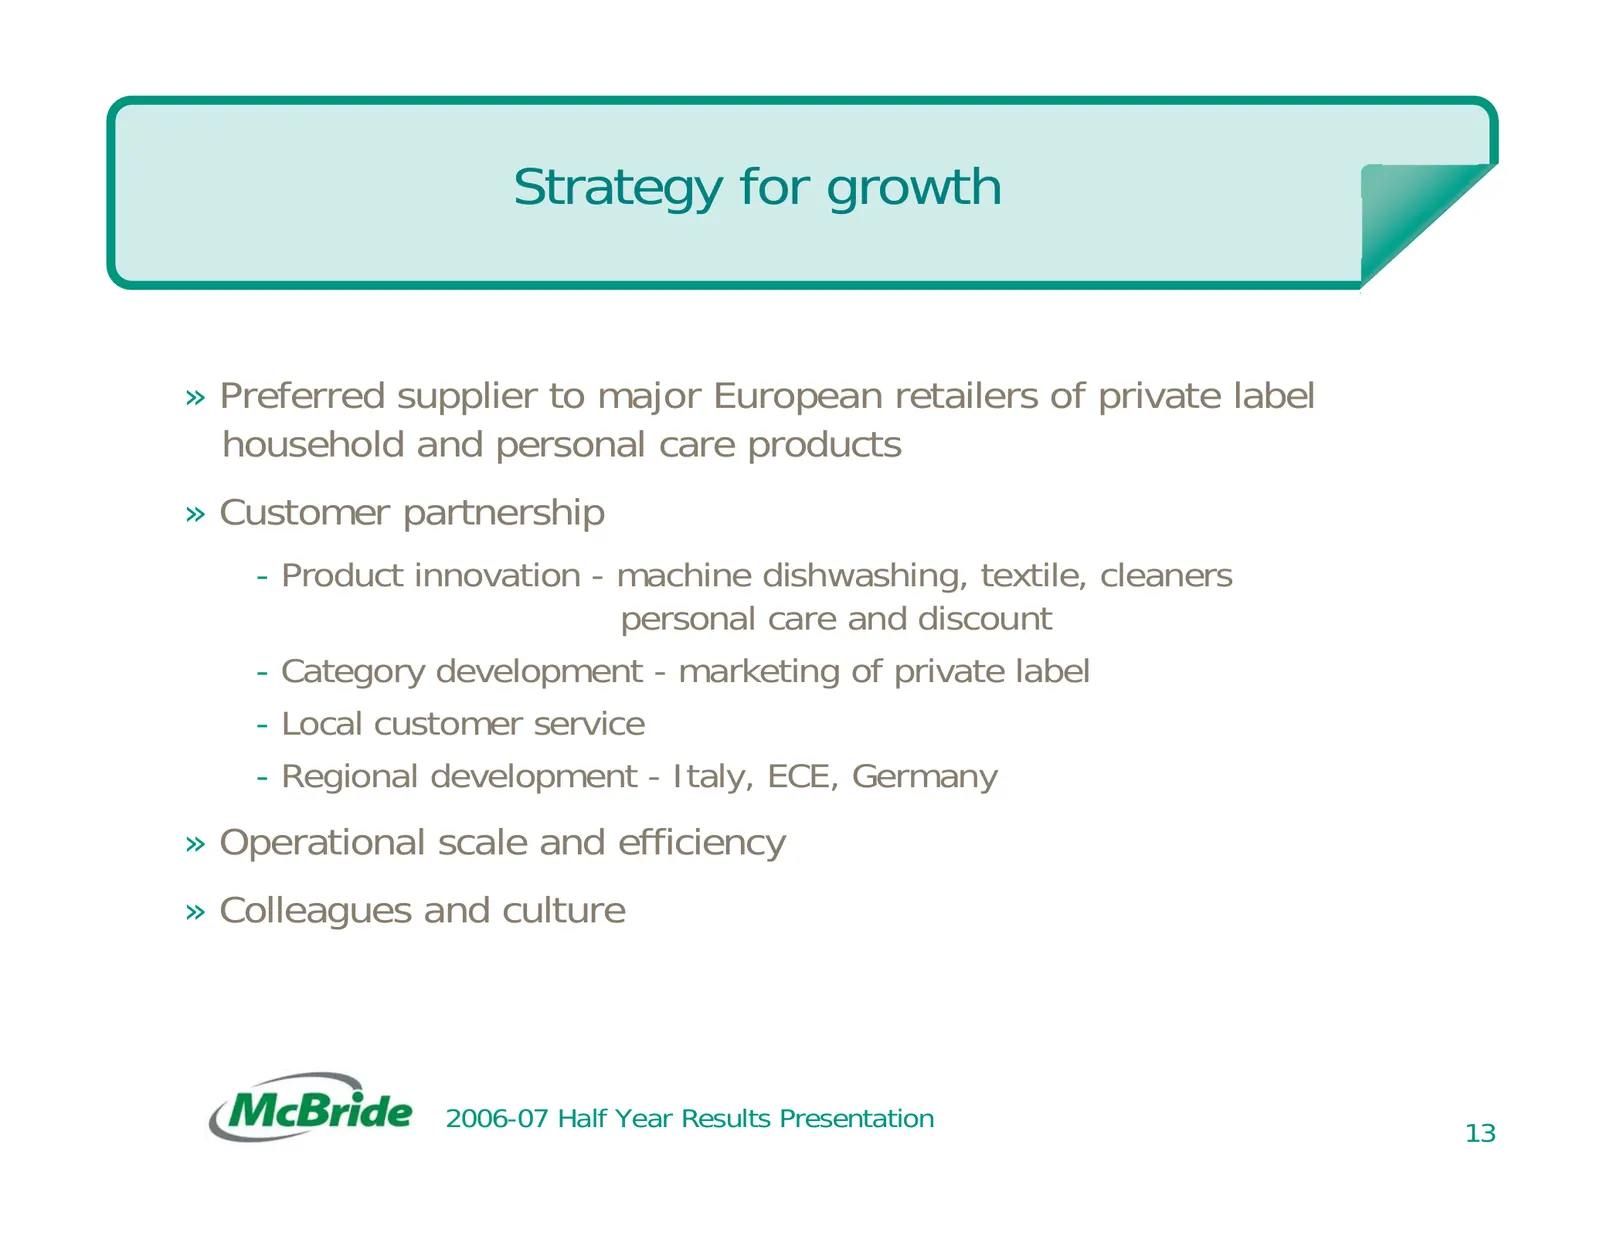
Strategy for growth » Preferred supplier to major European retailers of private label household and personal care products » Customer partnership - Product innovation - machine dishwashing, textile, cleaners personal care and discount - Category development - marketing of private label - Local custo
Slide 14: Acquisition of Dasty Italia SpA - background
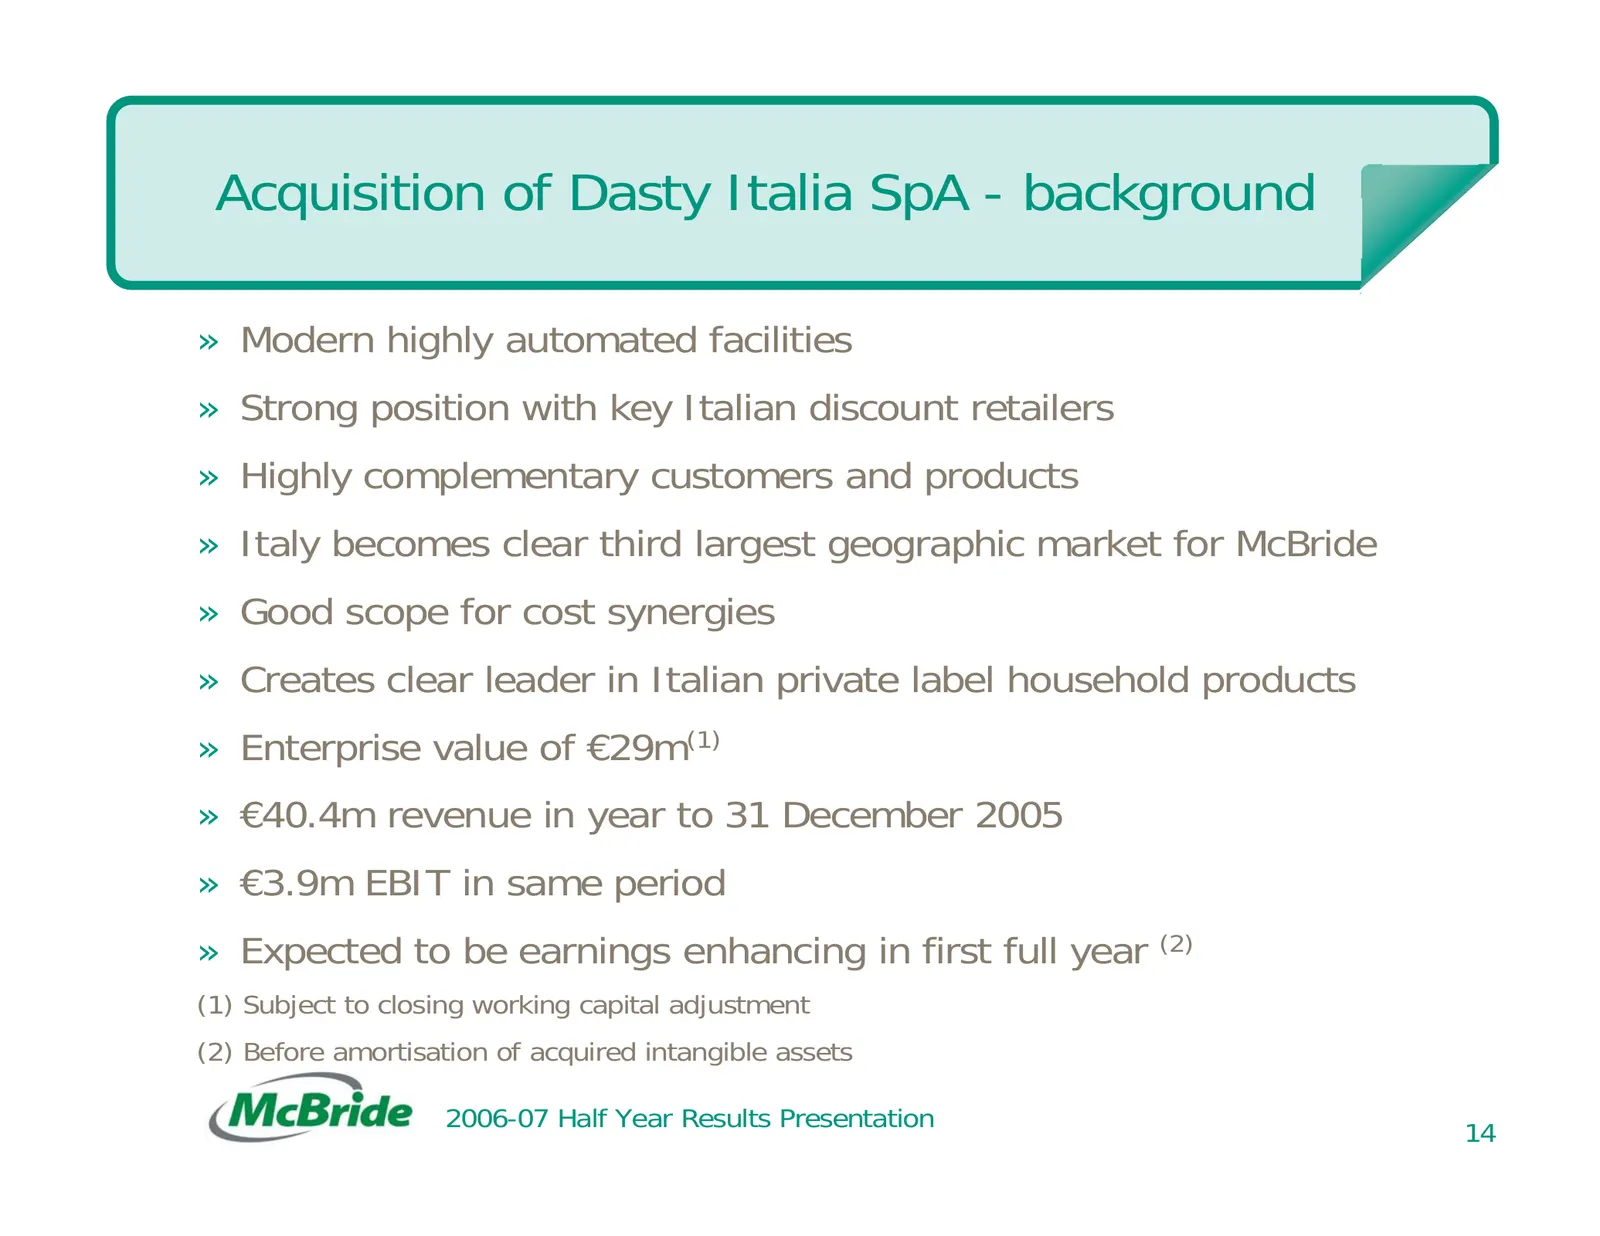
Acquisition of Dasty Italia SpA - background » Modern highly automated facilities » Strong position with key Italian discount retailers » Highly complementary customers and products » Italy becomes clear third largest geographic market for McBride » Good scope for cost synergies » Creates clear lead
Slide 15: Complementary customers
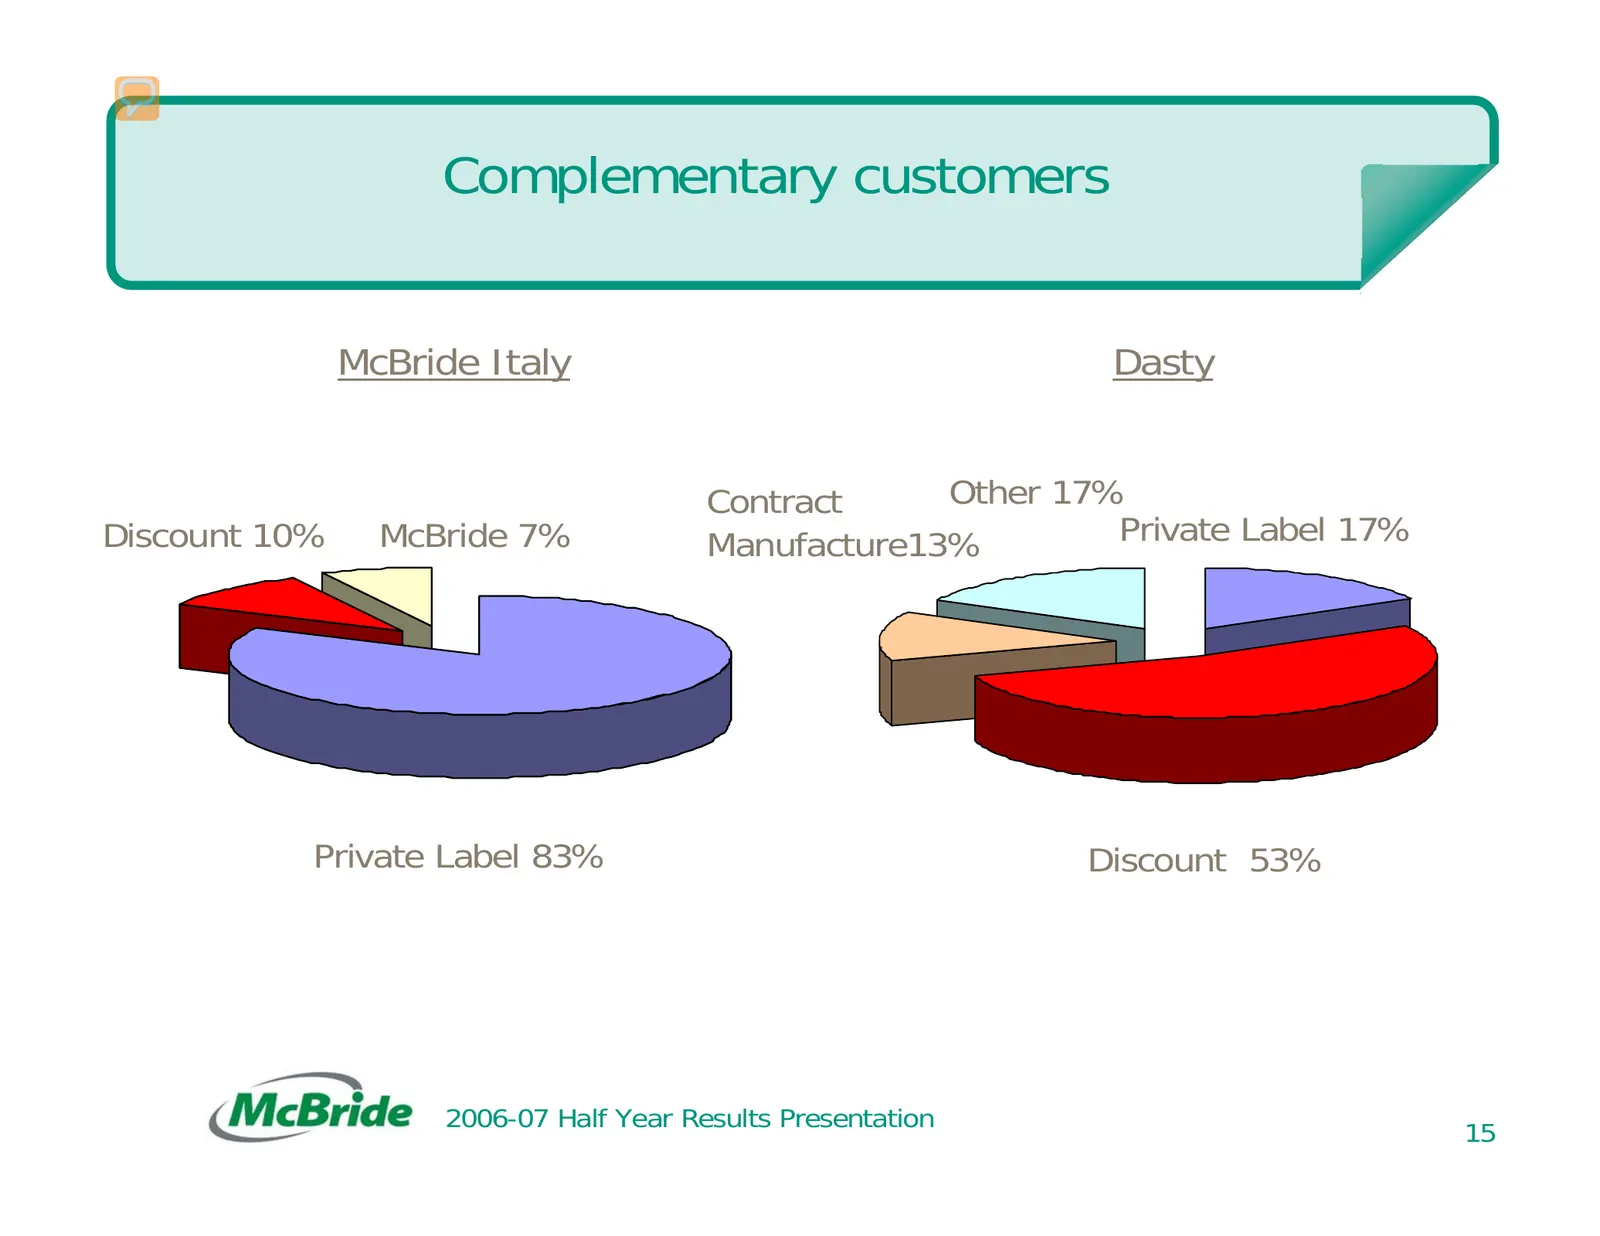
Complementary customers McBride Italy Dasty Contract Other 17% Discount 10% McBride 7% Manufacture13% Private Label 17% Private Label 83% Discount 53% 2006-07 Half Year Results Presentation 15
Slide 16: % Volume Share
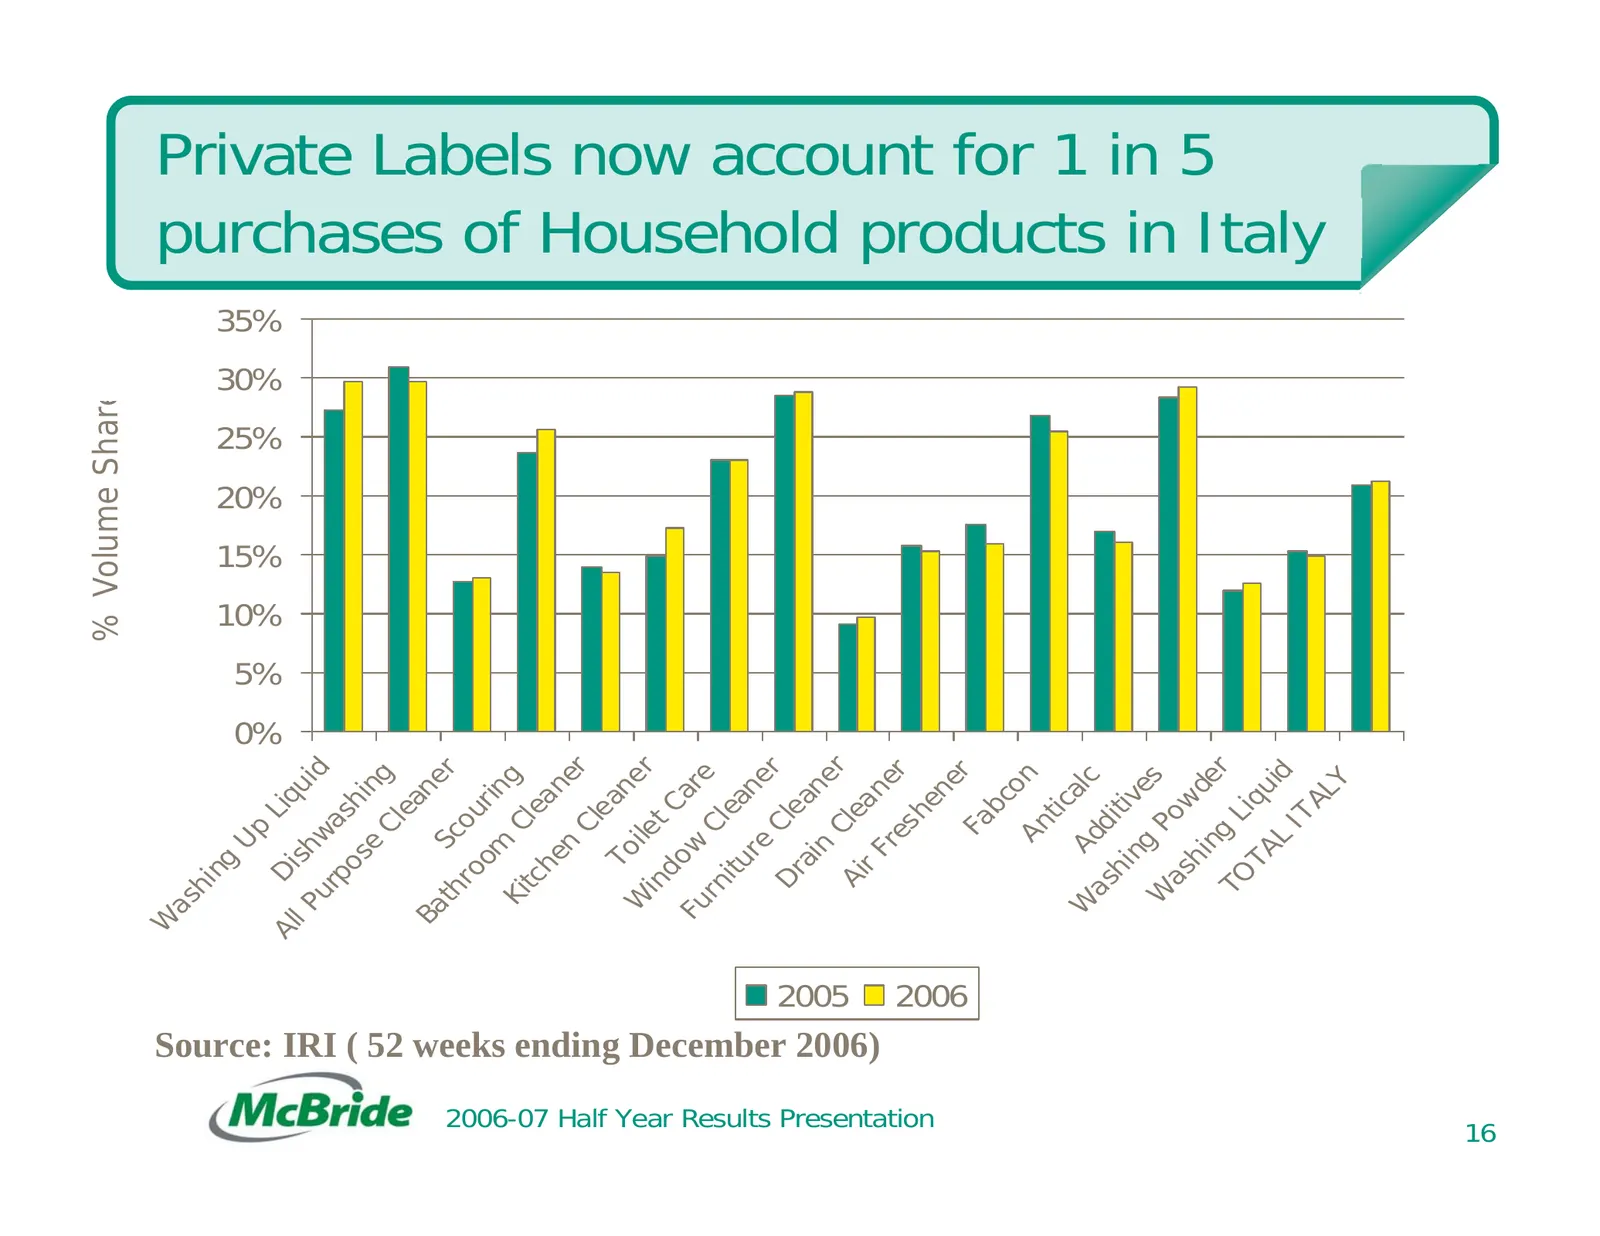
% Volume Share W as hi ng Up L 0% 5% 10% 15% 20% 25% 30% 35% A l Di l P sh iqui ur wa d po s se hin Cl g ea Ba ne th Sc r ro ou om rin Ki g tc Cle he an n er Cl e To an W er in ilet d C Fu ow are rn C itu lea r e ne Dr Cle r ai an n e 2005 Ai Cle r Source: IRI ( 52 weeks ending December 2006) r F an
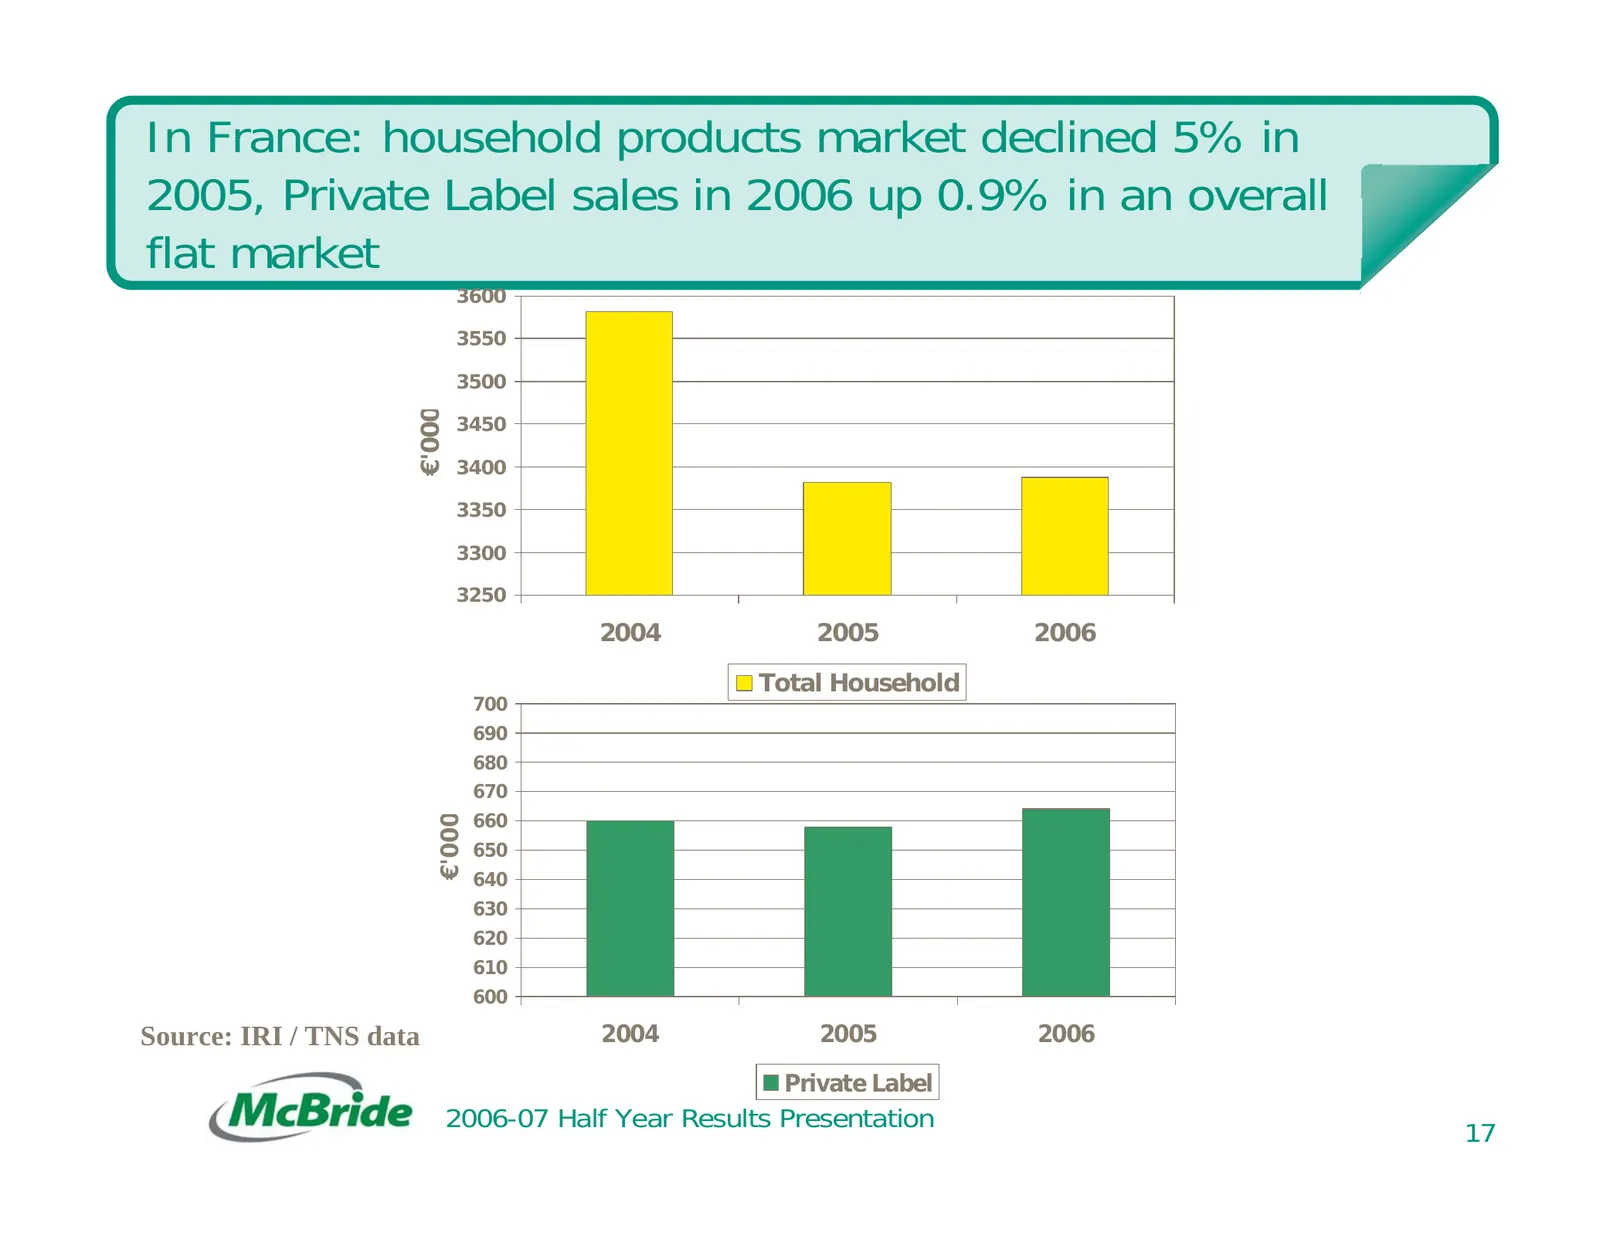
Slide 17: In France: household products market declined 5% in 2005
In France: household products market declined 5% in 2005, Private Label sales in 2006 up 0.9% in an overall flat market 3600 3550 3500 €'000 3450 3400 3350 3300 3250 2004 2005 2006 Total Household 700 690 680 670 660 €'000 650 640 630 620 610 600 Source: IRI / TNS data 2004 2005 2006 Private Label 2
Slide 18: France performance
France performance » Sales in Household declined; grew where focused » Performance good in parts » Completed price increases during H1, benefit H2 » Increase Category Development and NPD - Premium sectors - Personal care - Ecological trends - Focus on certain retailers » Continued focus on reducing
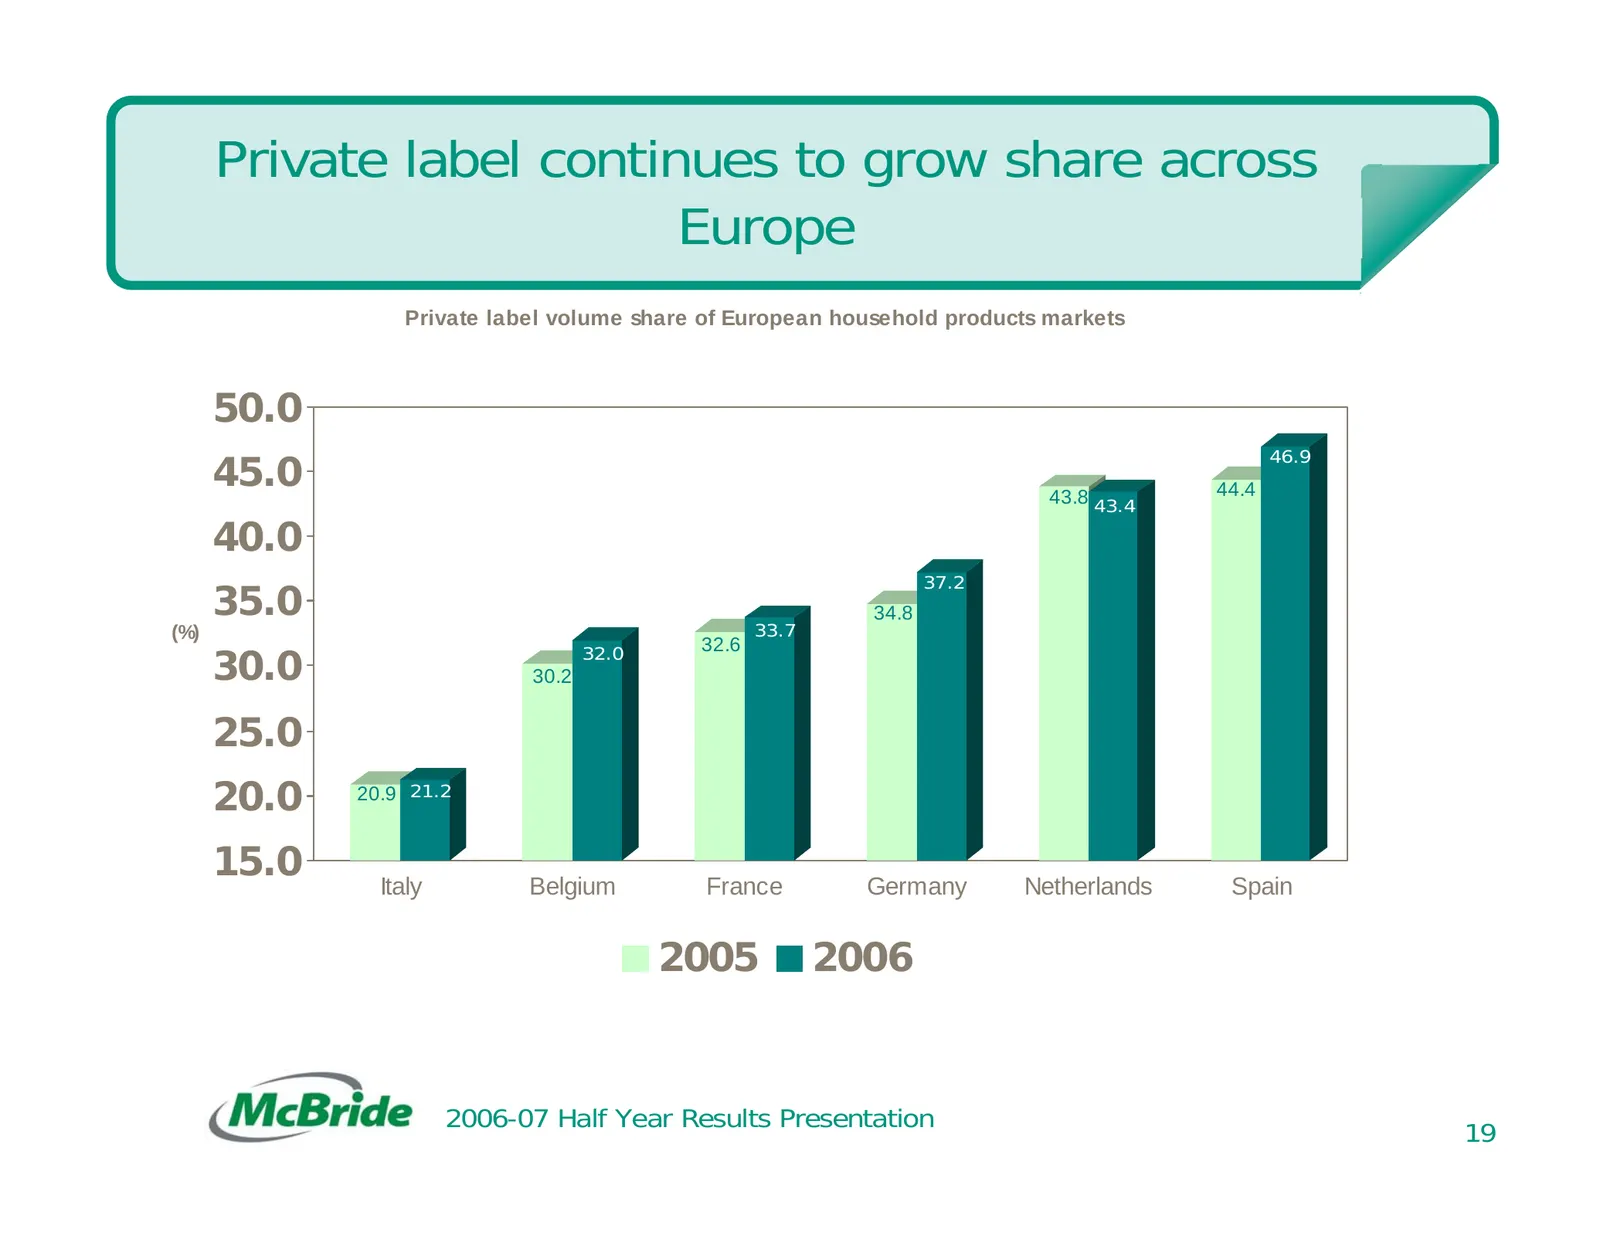
Slide 19: Private label continues to grow share across Europe
Private label continues to grow share across Europe Private label volume share of European household products markets 50.0 46.9 45.0 43.8 43.4 44.4 40.0 37.2 35.0 34.8 (%) 33.7 32.6 30.0 30.2 32.0 25.0 20.0 20.9 21.2 15.0 Italy Belgium France Germany Netherlands Spain 2005 2006 2006-07 Half Year Res
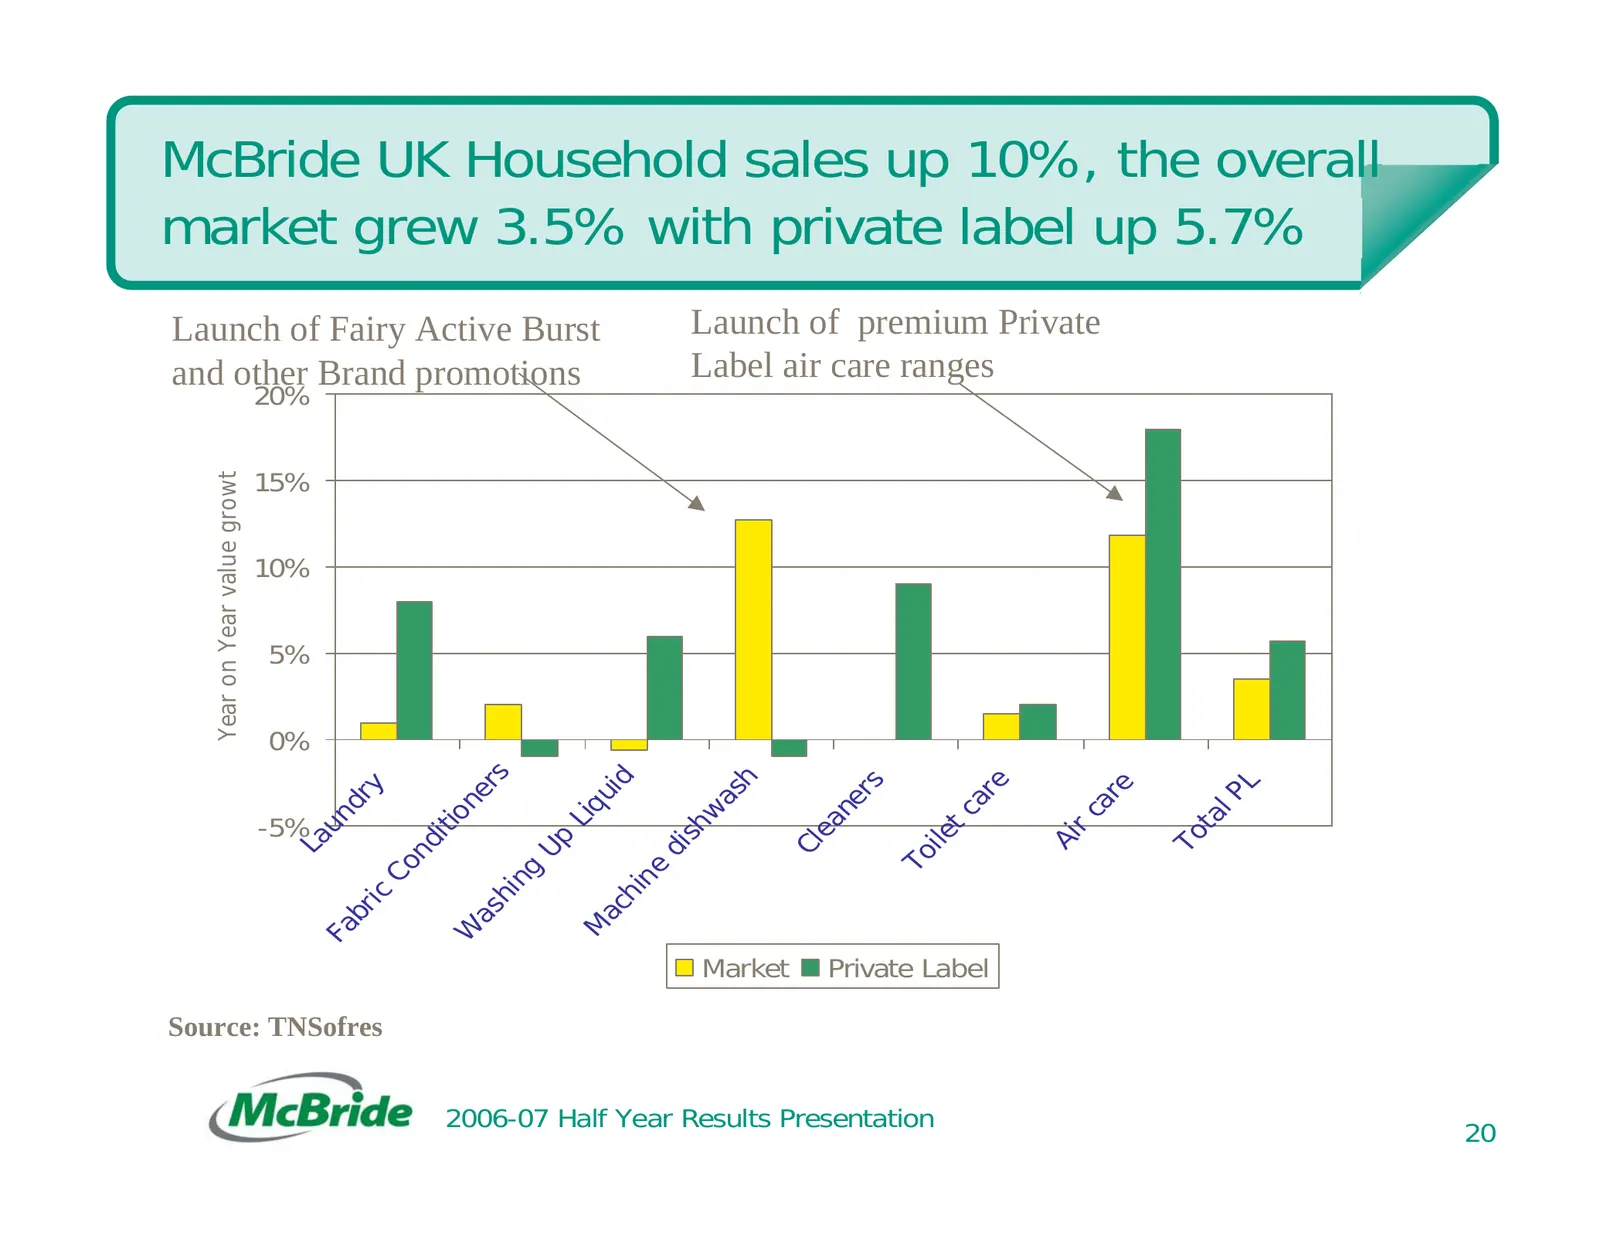
Slide 20: McBride UK Household sales up 10%
McBride UK Household sales up 10%, the overall market grew 3.5% with private label up 5.7% Launch of Fairy Active Burst Launch of premium Private and other Brand promotions Label air care ranges 20% 15% Year on Year value growt 10% 5% 0% s d h e s L er e ry as ui r ar lP r ne on nd ca Liq w -5% tc t
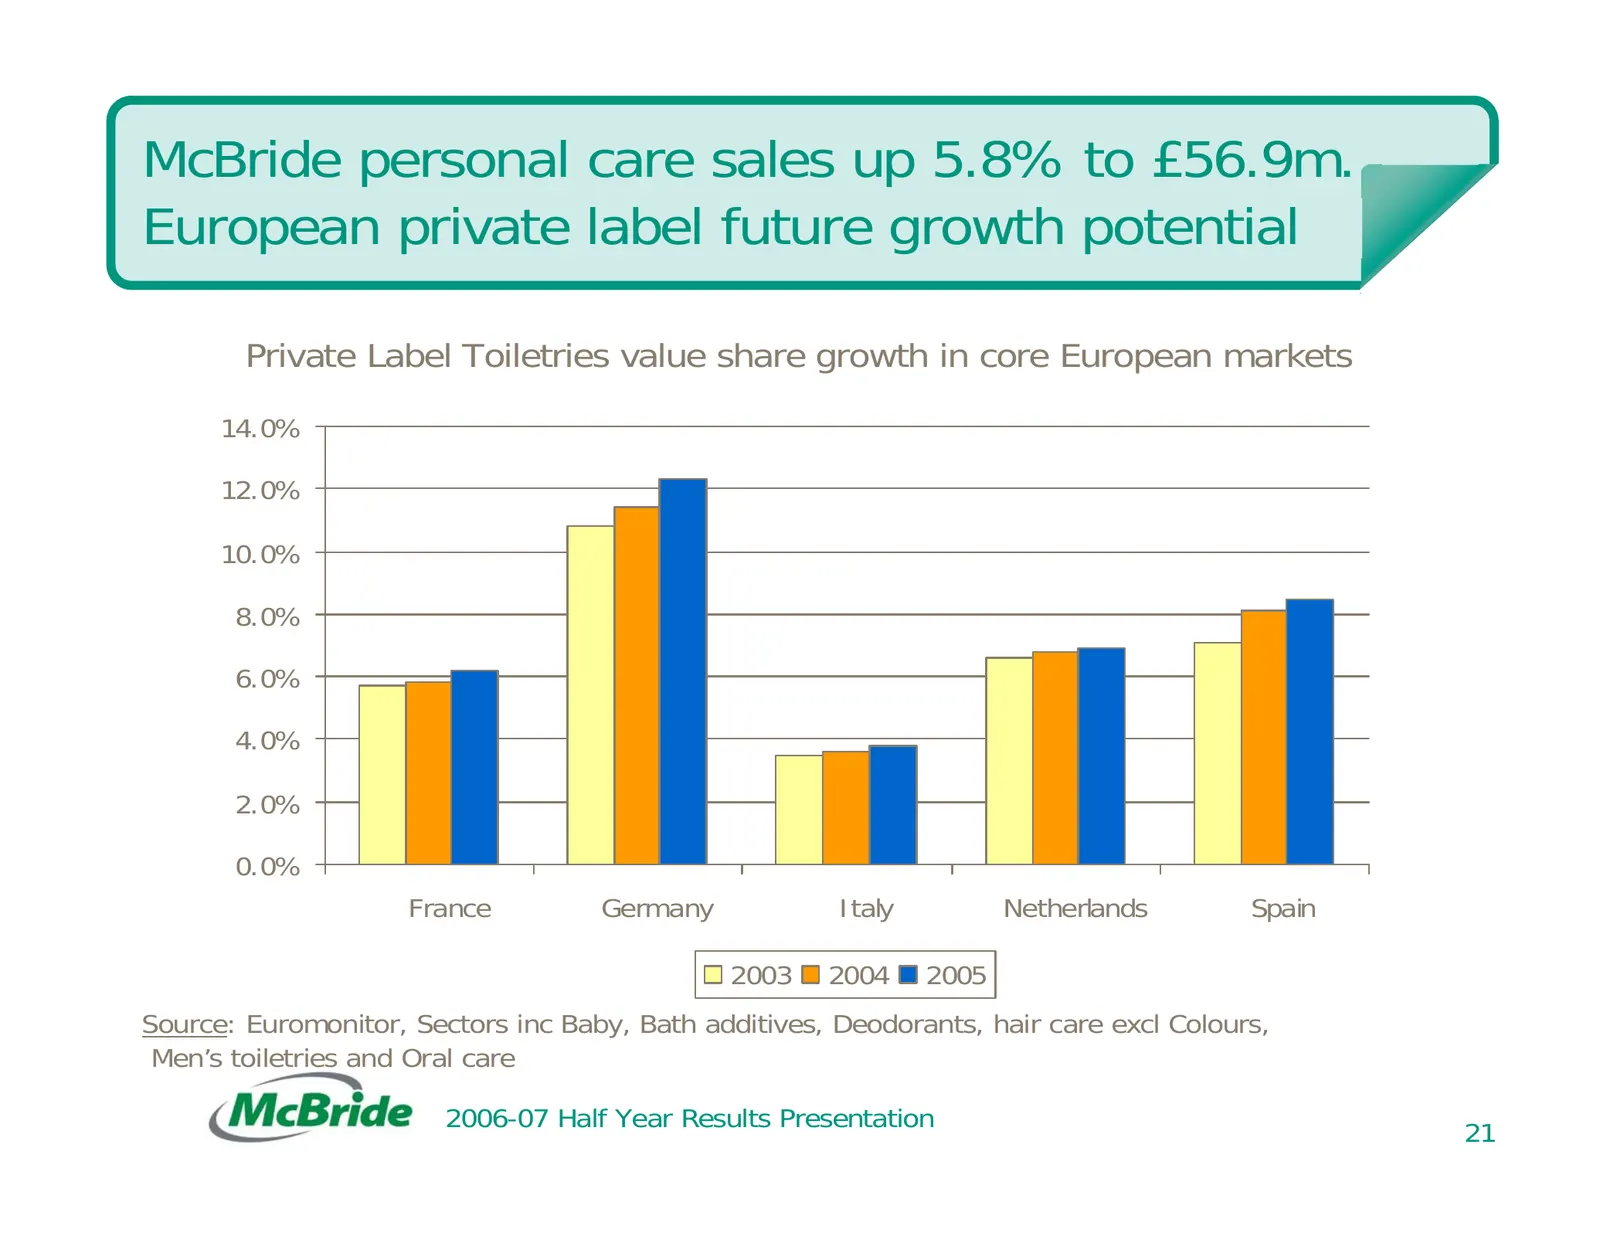
Slide 21: McBride personal care sales up 5.8% to £56.9m
McBride personal care sales up 5.8% to £56.9m. European private label future growth potential Private Label Toiletries value share growth in core European markets 14.0% 12.0% 10.0% 8.0% 6.0% 4.0% 2.0% 0.0% France Germany Italy Netherlands Spain 2003 2004 2005 Source: Euromonitor, Sectors inc Baby, B
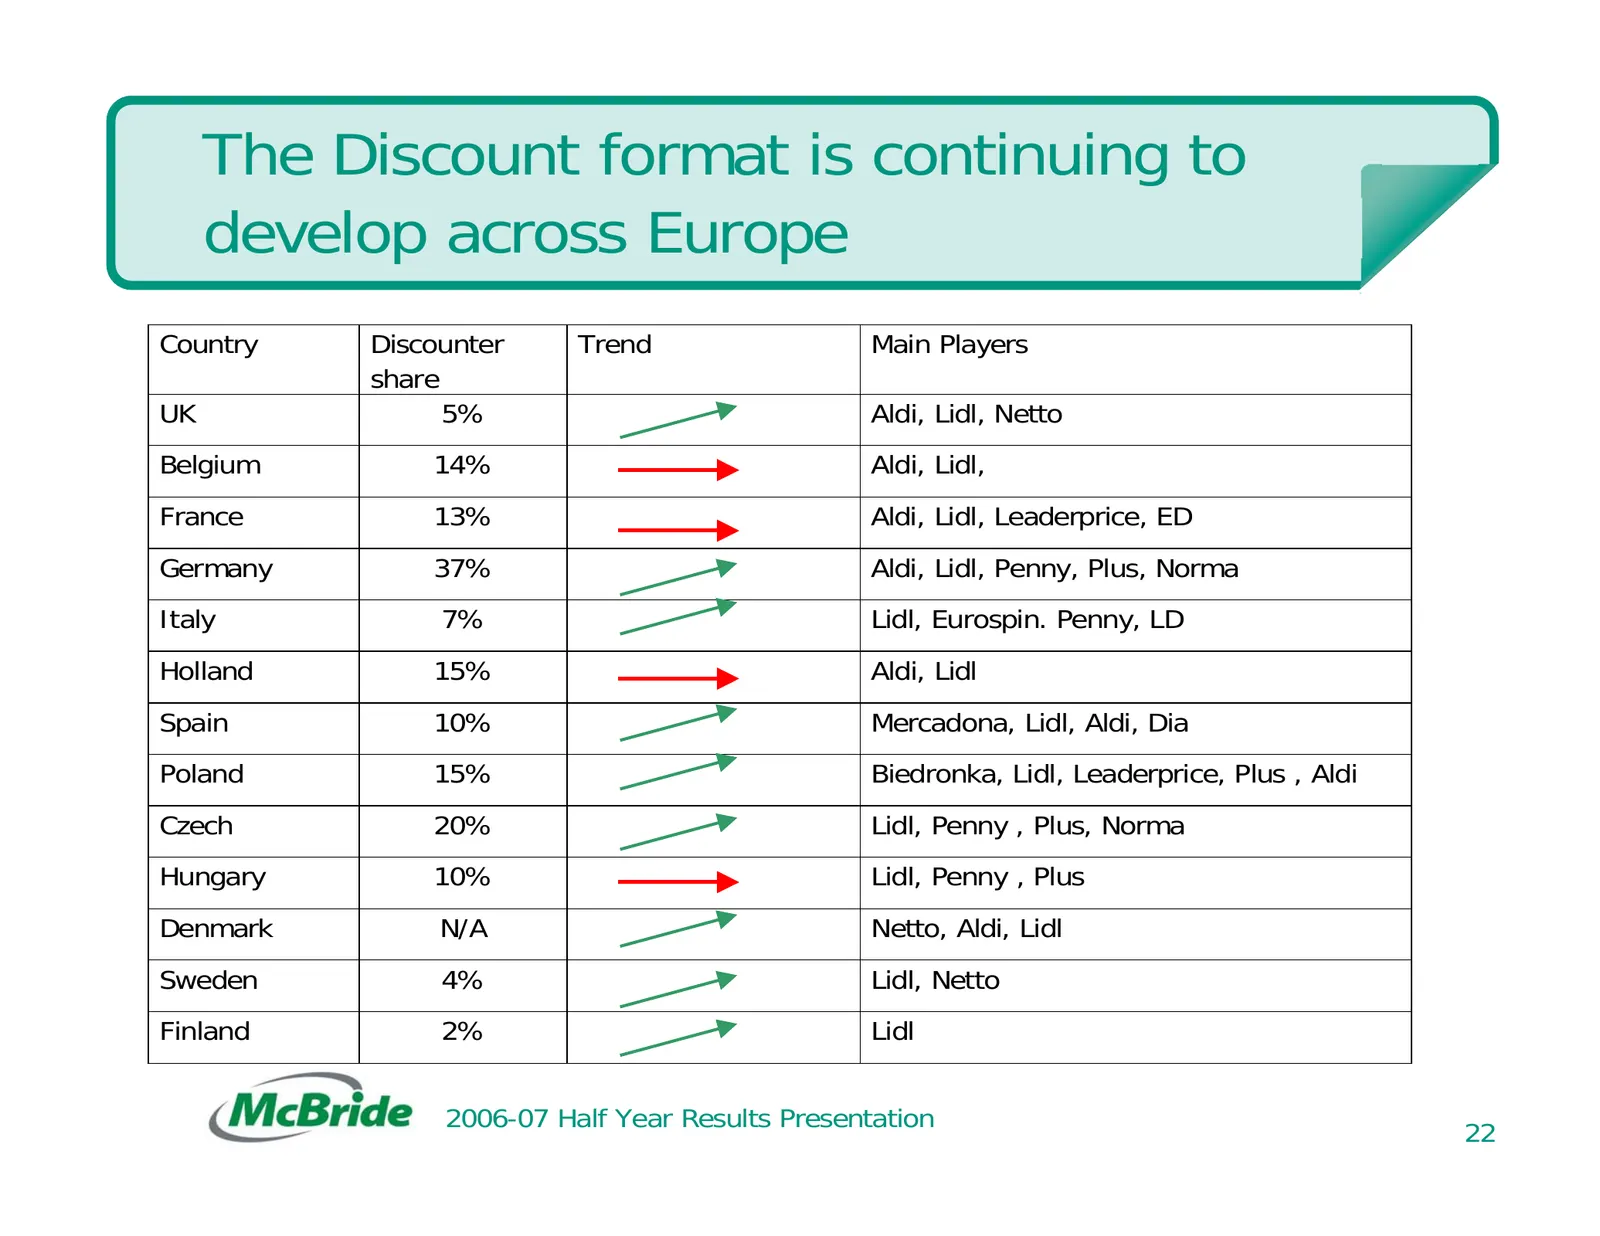
Slide 22: The Discount format is continuing to develop across Europe
The Discount format is continuing to develop across Europe Country Discounter Trend Main Players share UK 5% Aldi, Lidl, Netto Belgium 14% Aldi, Lidl, France 13% Aldi, Lidl, Leaderprice, ED Germany 37% Aldi, Lidl, Penny, Plus, Norma Italy 7% Lidl, Eurospin. Penny, LD Holland 15% Aldi, Lidl Spain 10%
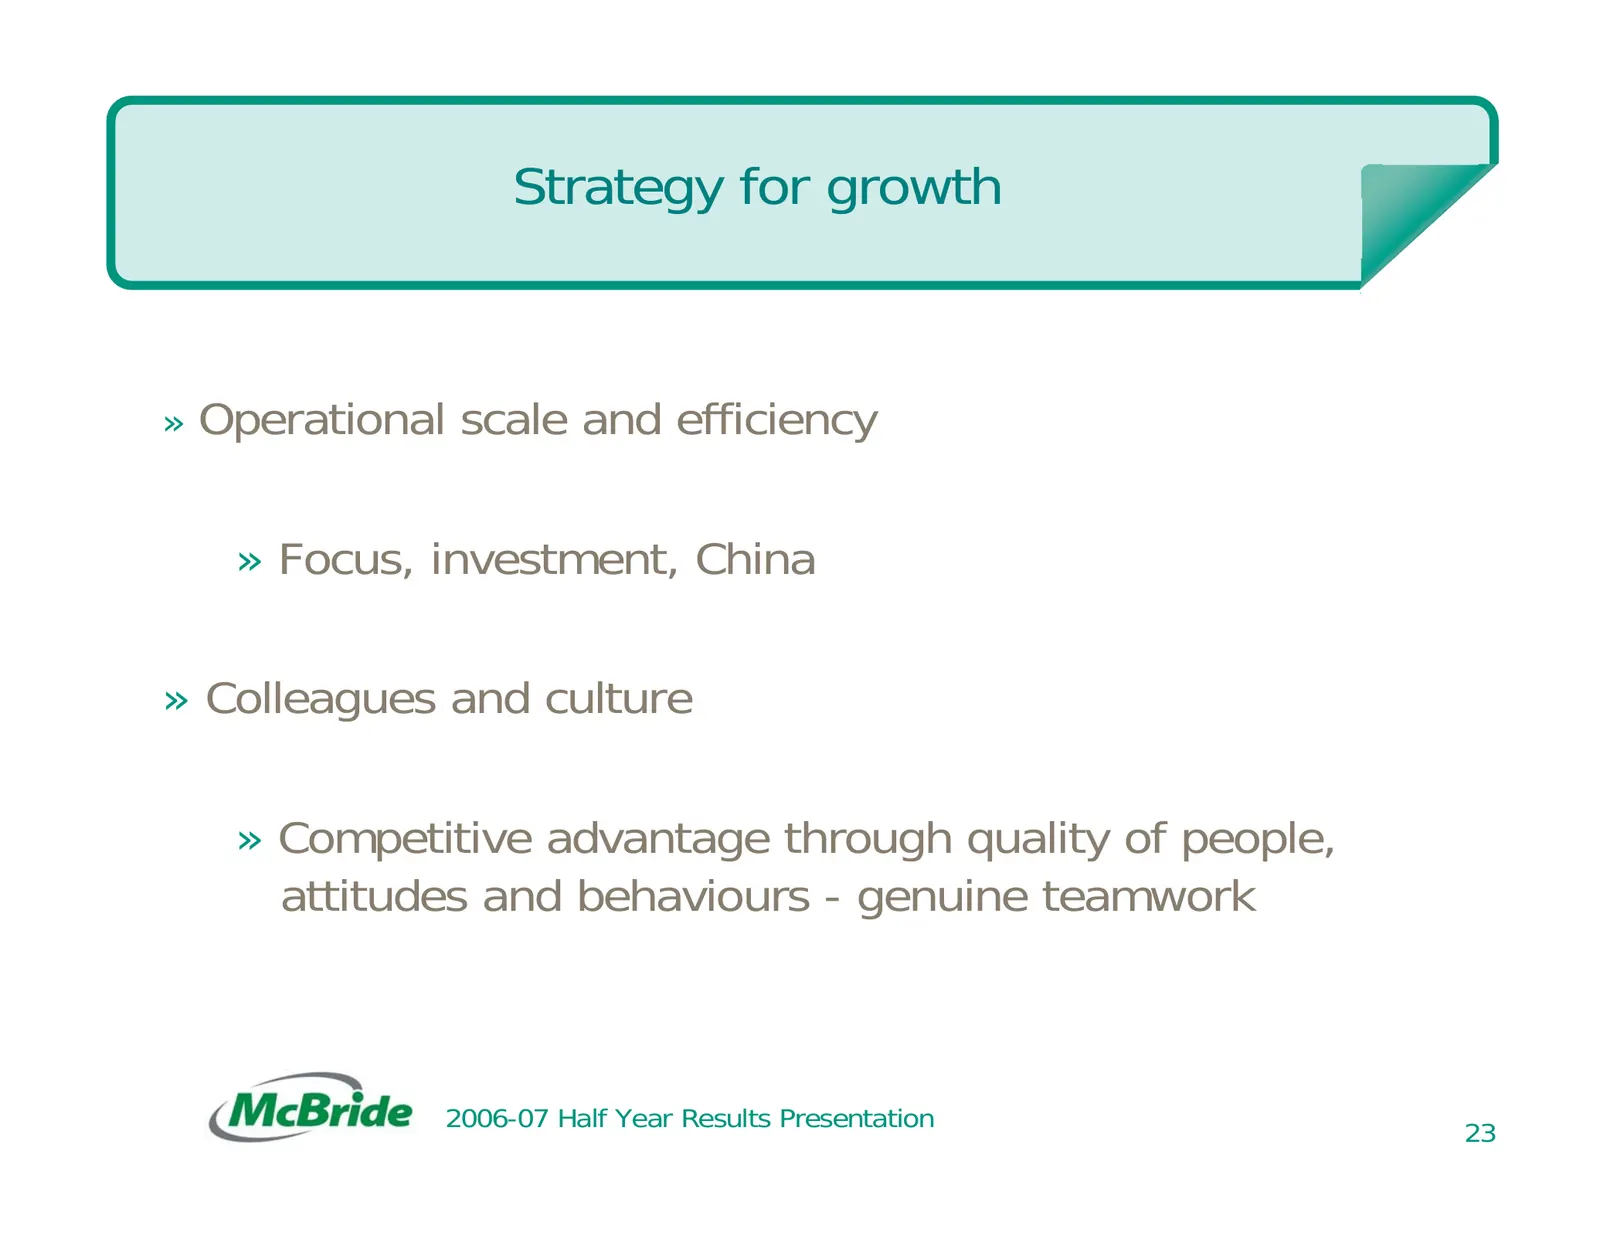
Slide 23: Strategy for growth
Strategy for growth » Operational scale and efficiency » Focus, investment, China » Colleagues and culture » Competitive advantage through quality of people, attitudes and behaviours - genuine teamwork 2006-07 Half Year Results Presentation 23
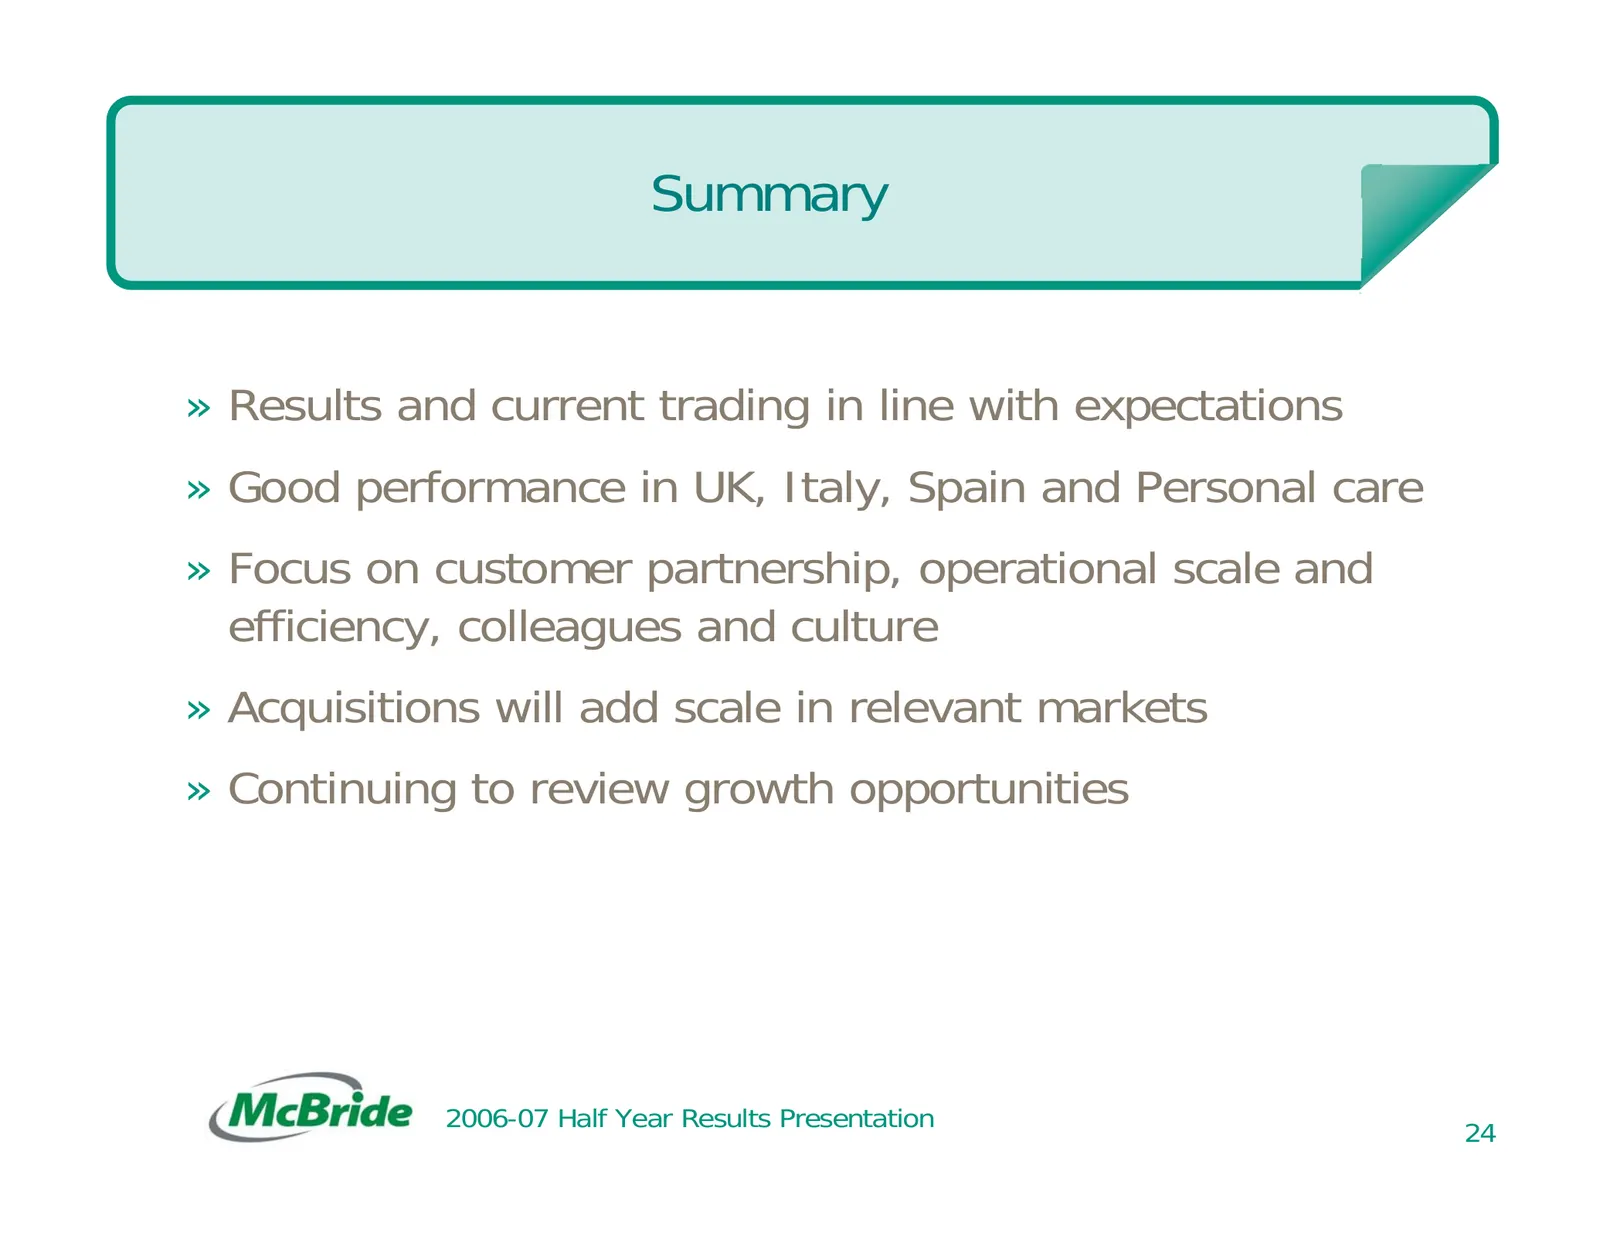
Slide 24: Summary
Summary » Results and current trading in line with expectations » Good performance in UK, Italy, Spain and Personal care » Focus on customer partnership, operational scale and efficiency, colleagues and culture » Acquisitions will add scale in relevant markets » Continuing to review growth opportuni
Source: Internet Archive copy of mcbride.co.uk
More decks from McBride plc
 FY2026 Earnings Presentation28 slides · Sep 15, 2026
 H1 FY26 Earnings Presentation22 slides · Feb 26, 2026
 FY2025 Earnings Presentation23 slides · Sep 18, 2025
 H1 FY2025 Earnings Presentation30 slides · Feb 25, 2025
 FY2024 Earnings Presentation30 slides · Sep 17, 2024
 Investor Day (March 2024)65 slides · Mar 13, 2024