easyJet plc · LSE:EZJ
easyJet — H1 2015 Earnings Presentation
46 slides from easyJet's earnings presentation, May 12, 2015
Slide 1: H1 2015 Results Analyst and Investor Presentation
H1 2015 Results Analyst and Investor Presentation Tuesday 12 May 2015
Slide 2: Introduction
Introduction Carolyn McCall Chief Executive Officer
Slide 3: Proven strategy, execution and returns
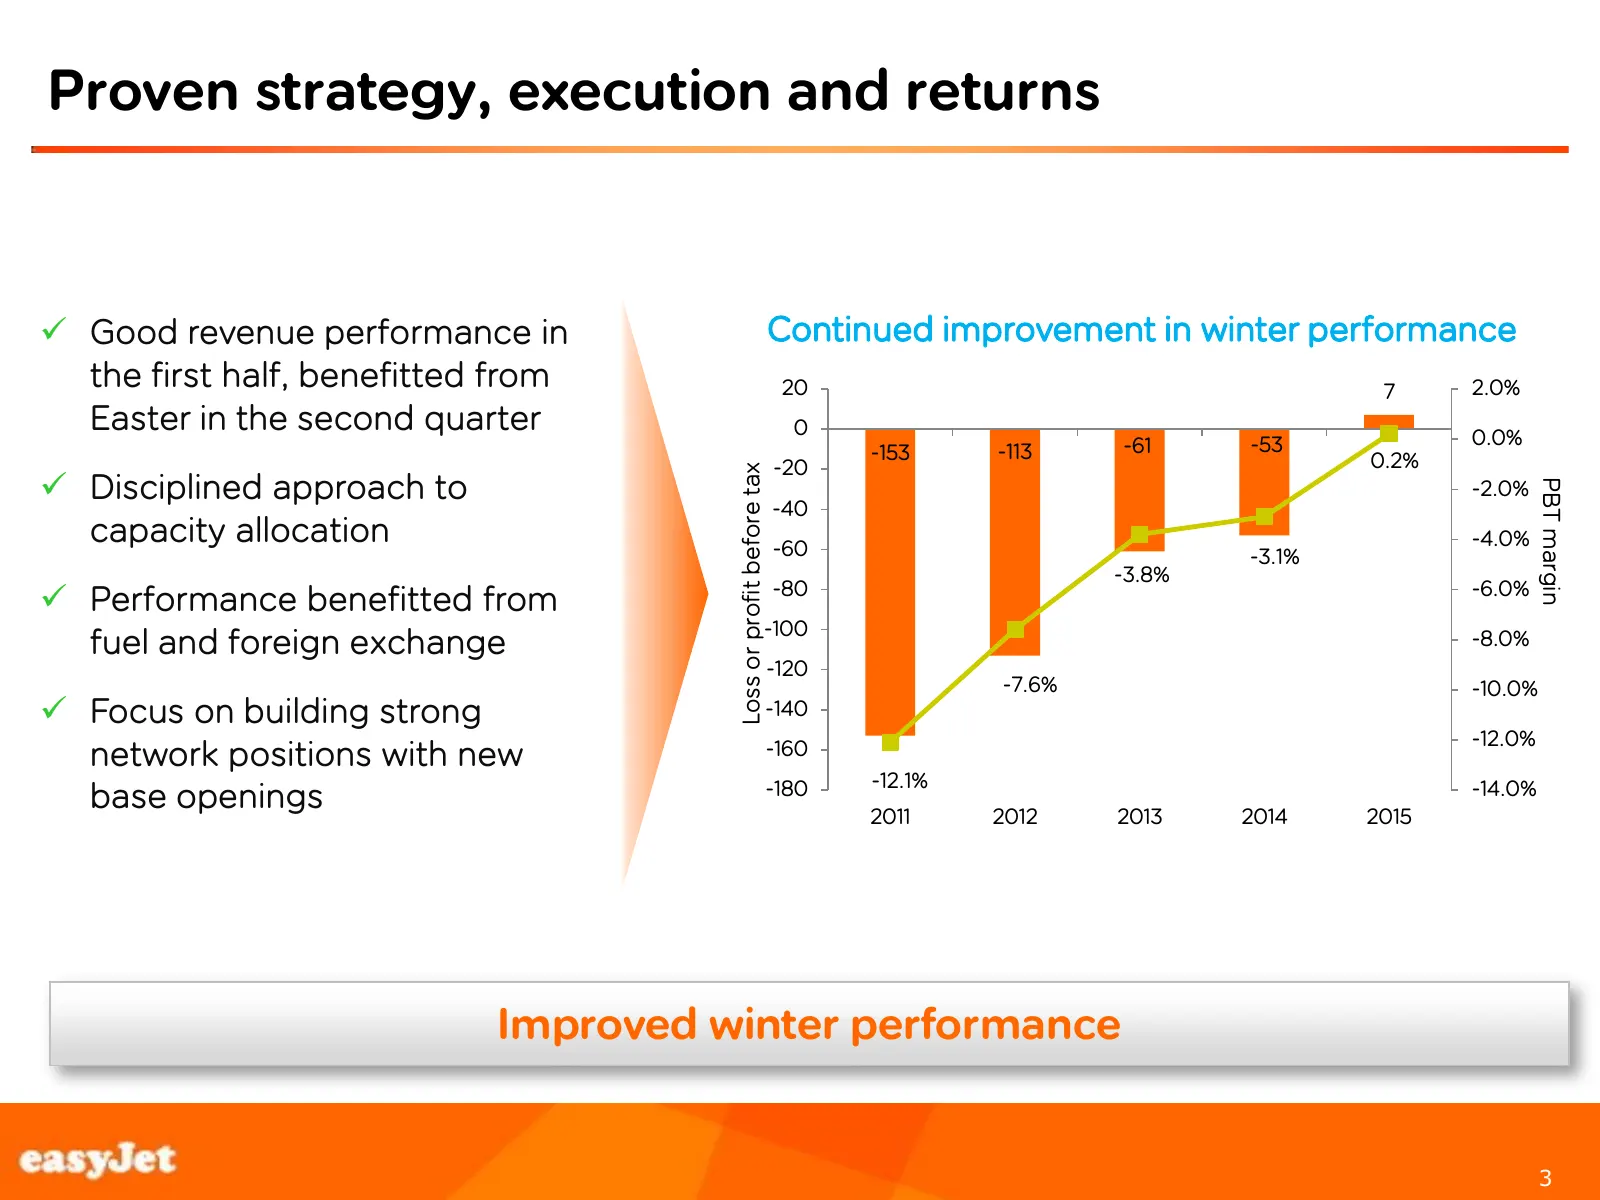
Proven strategy, execution and returns Good revenue performance in Continued improvement in winter performance the first half, benefitted from 20 7 2.0% Easter in the second quarter 0 0.0% -153 -113 -61 -53 -20 0.2% Loss or profit before tax Disciplined approach to PBT margin -2.0% -40 capacity
Slide 4: A business model which is hard to replicate
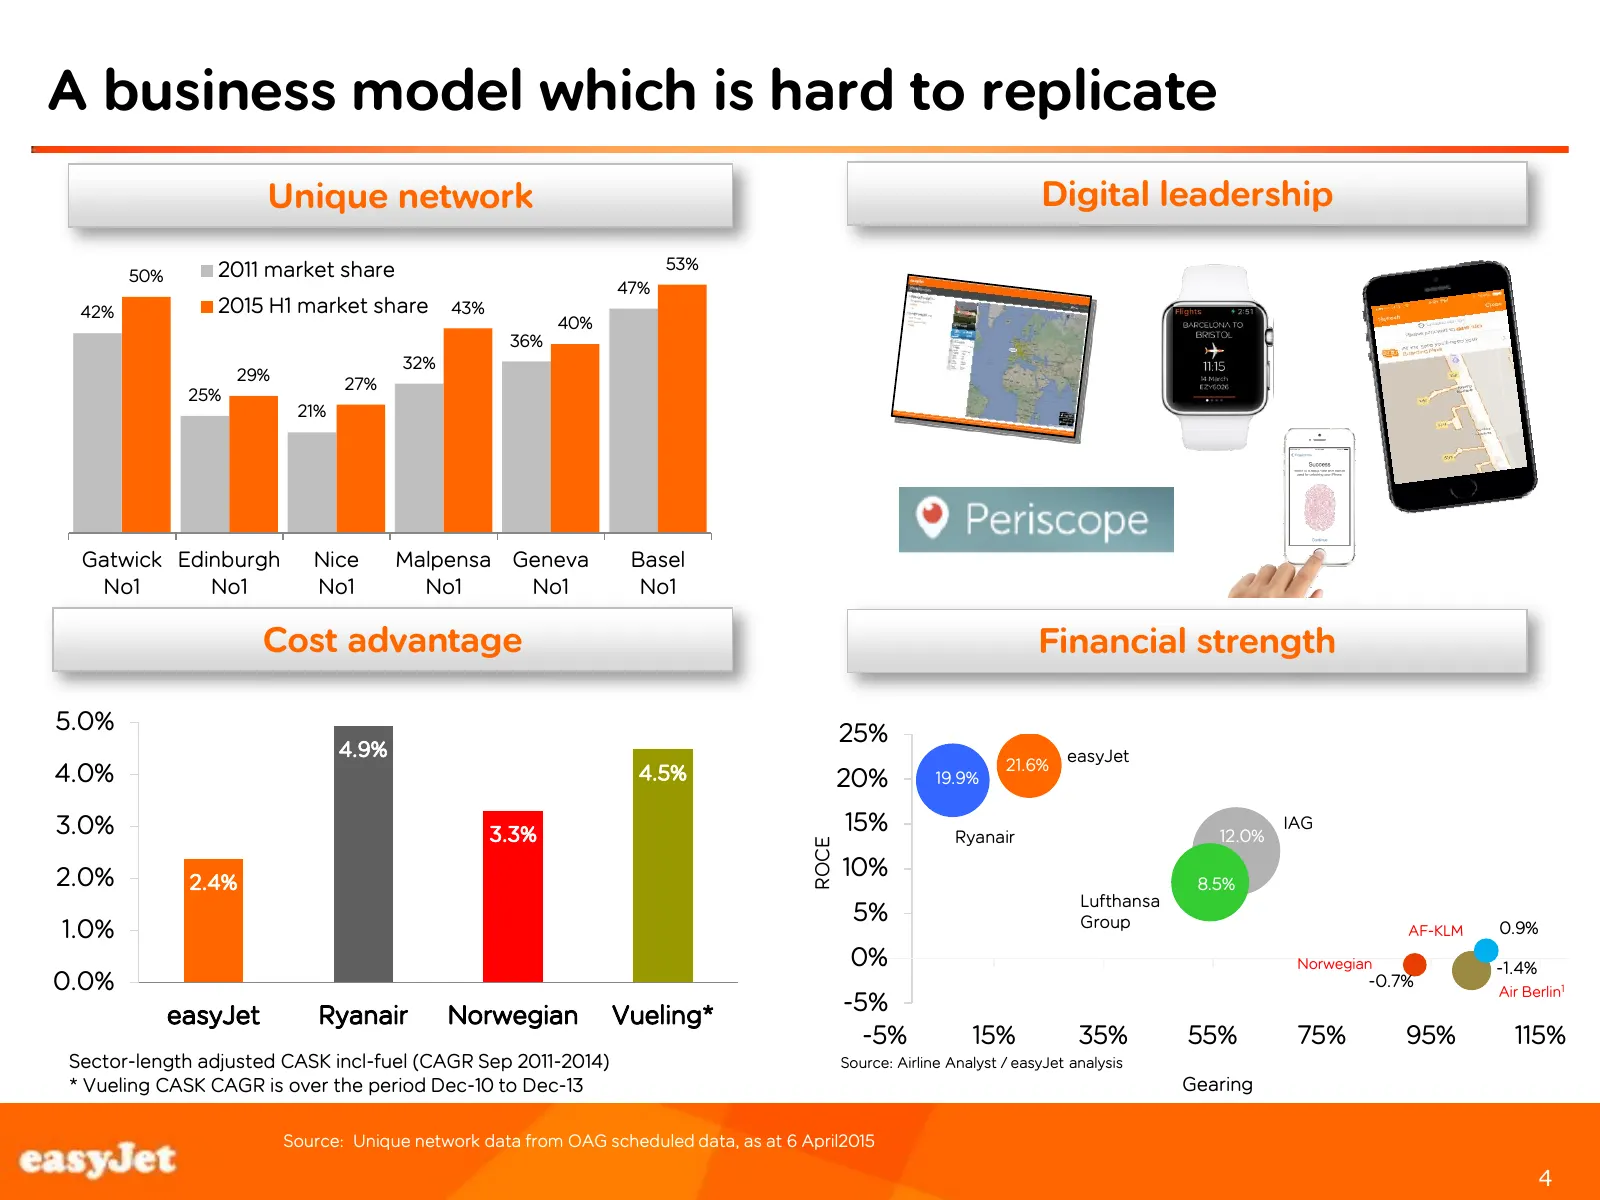
A business model which is hard to replicate Unique network Digital leadership 2011 market share 53% 50% 47% 42% 2015 H1 market share 43% 40% 36% 32% 29% 27% 25% 21% Gatwick Edinburgh Nice Malpensa Geneva Basel No1 No1 No1 No1 No1 No1 Cost advantage Financial strength 5.0% 25% 4.9% easyJet 21.6% 4.0%
Slide 5: Financial review
Financial review Chris Kennedy Chief Financial Officer
Slide 6: Result before tax increased
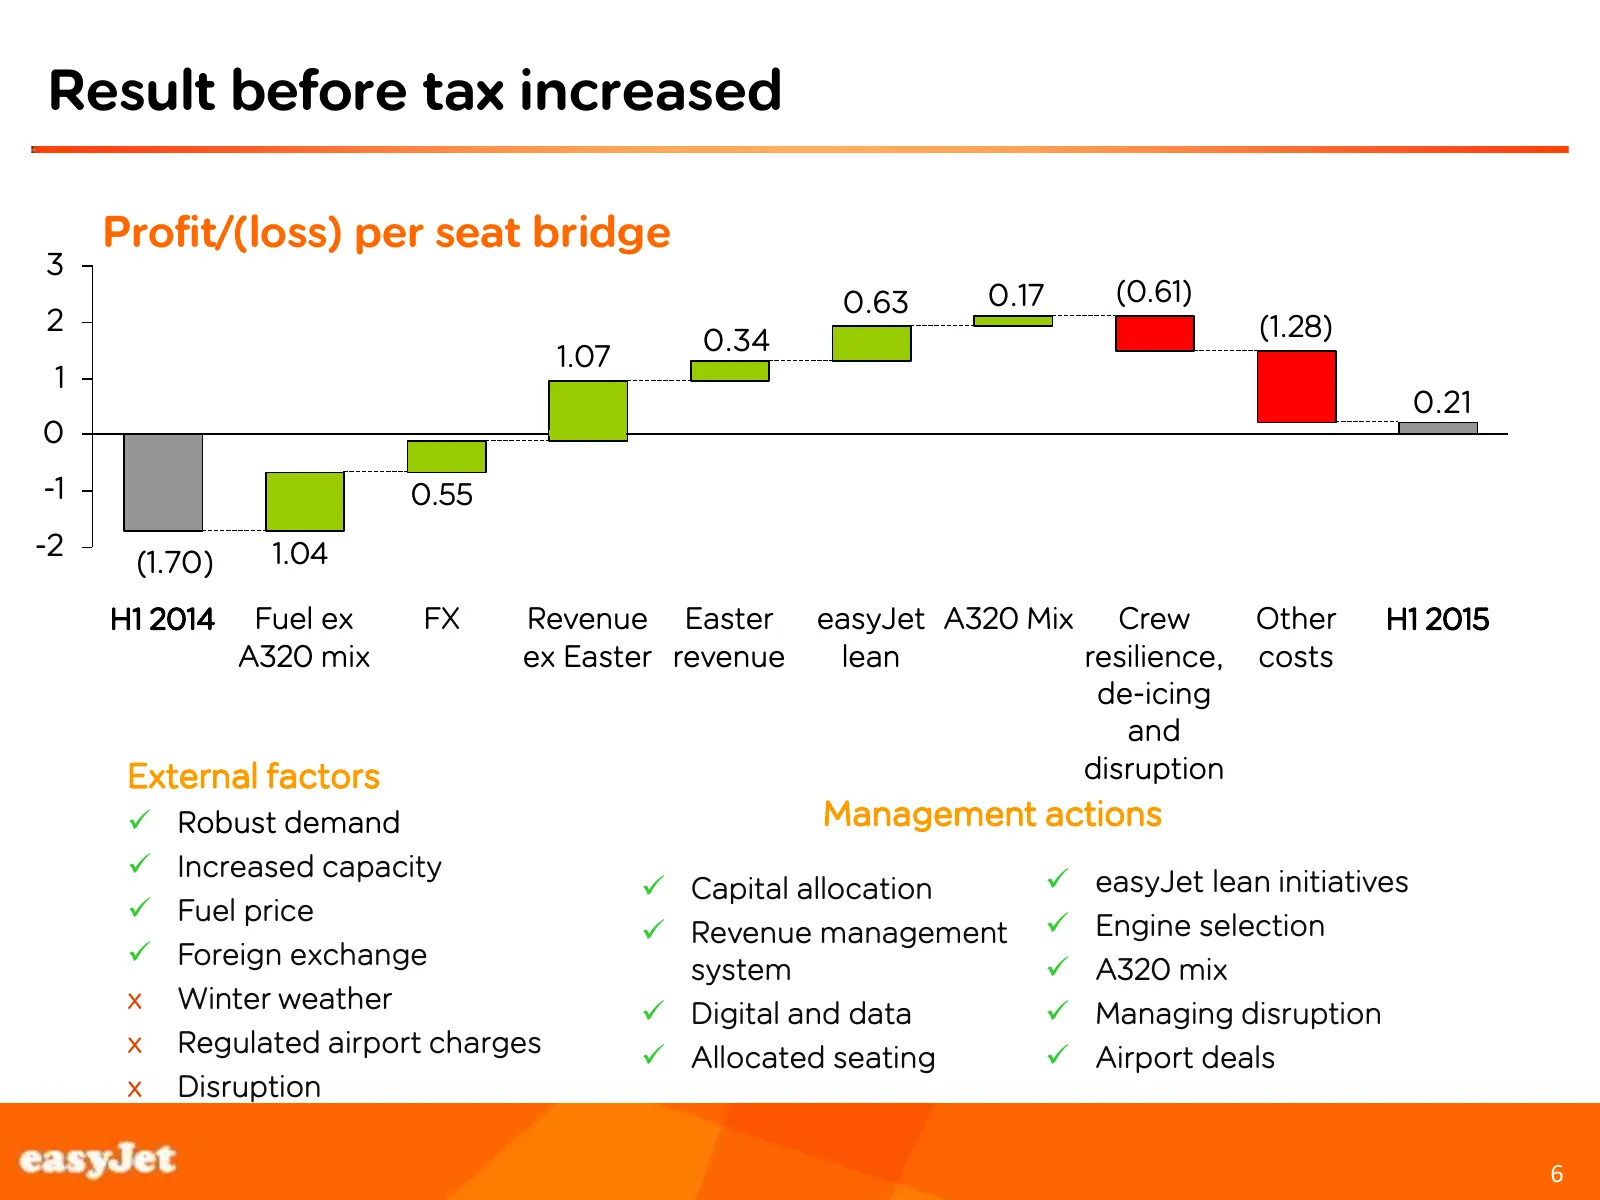
Result before tax increased Profit/(loss) per seat bridge 3 0.63 0.17 (0.61) 2 (1.28) 0.34 1.07 1 0.21 0 -1 0.55 -2 1.04 (1.70) H1 2014 Fuel ex FX Revenue Easter easyJet A320 Mix Crew Other H1 2015 A320 mix ex Easter revenue lean resilience, costs de-icing and External factors disruption Robust de
Slide 7: Financial results: Result before tax increased
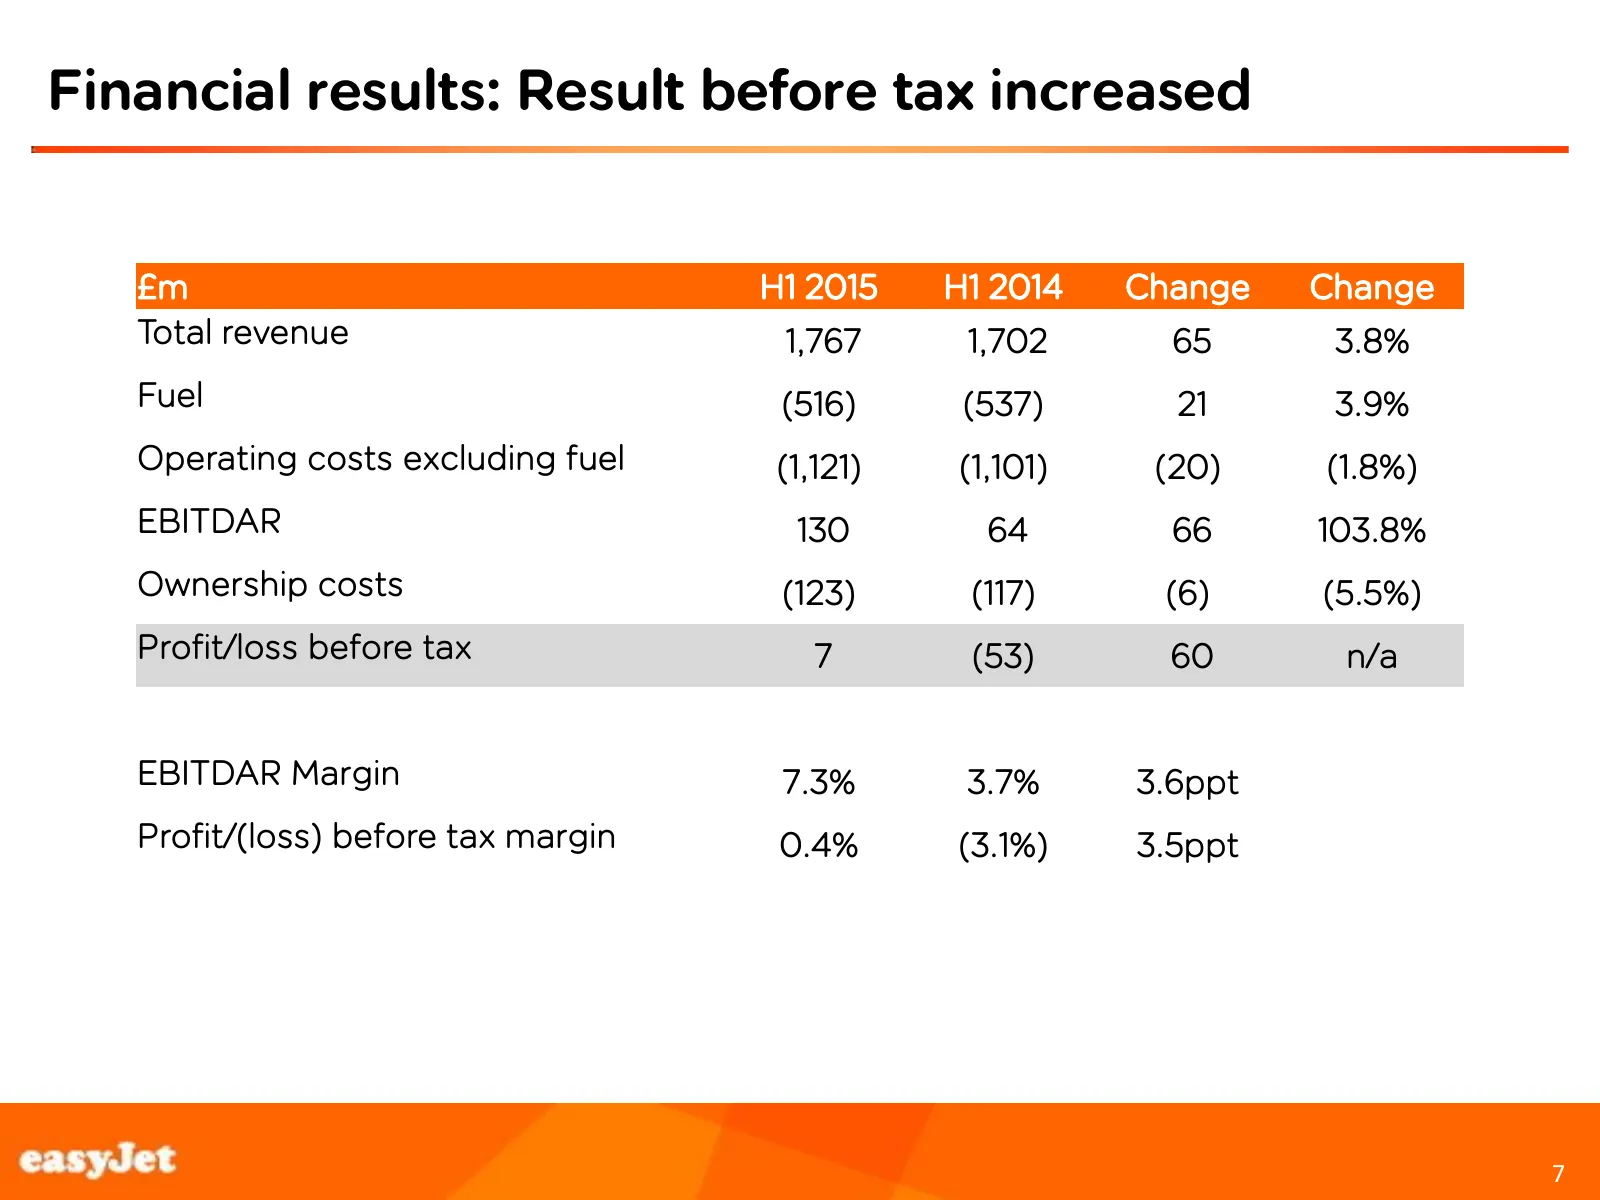
Financial results: Result before tax increased £m H1 2015 H1 2014 Change Change Total revenue 1,767 1,702 65 3.8% Fuel (516) (537) 21 3.9% Operating costs excluding fuel (1,121) (1,101) (20) (1.8%) EBITDAR 130 64 66 103.8% Ownership costs (123) (117) (6) (5.5%) Profit/loss before tax 7 (53) 60 n/a E
Slide 8: Financial results: Increase in EPS
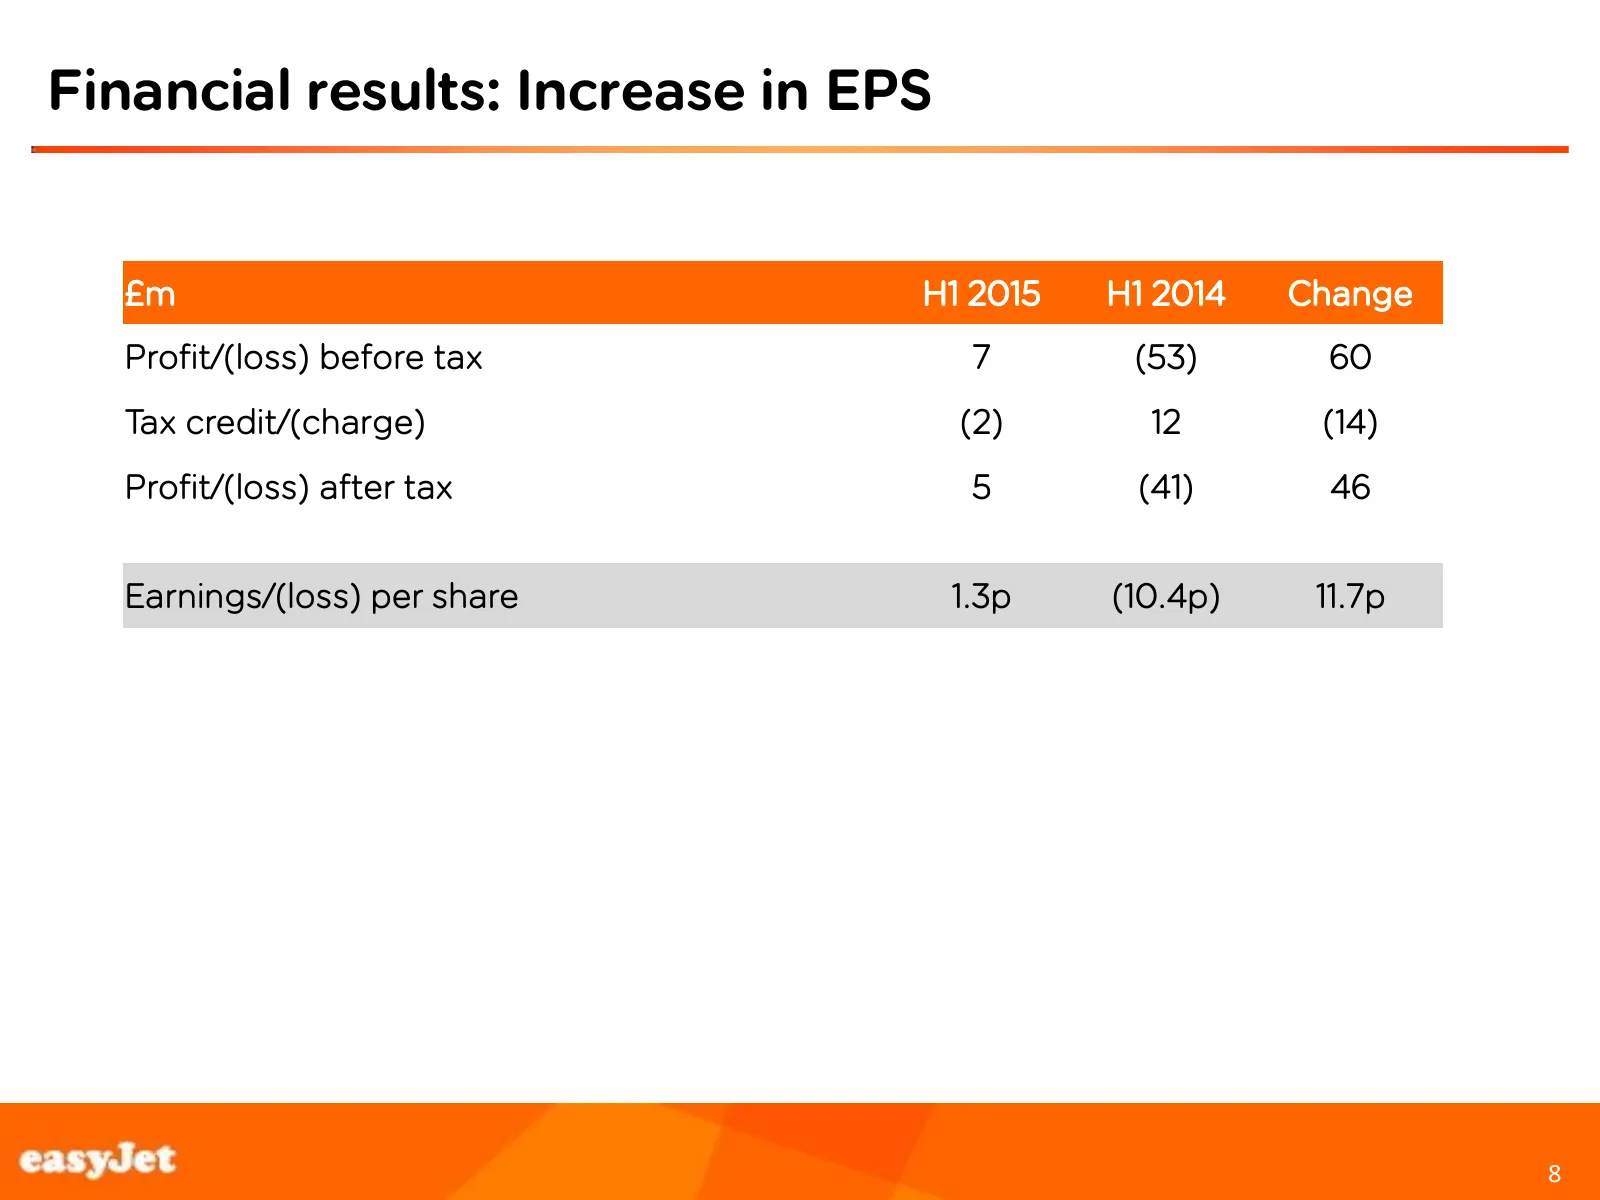
Financial results: Increase in EPS £m H1 2015 H1 2014 Change Profit/(loss) before tax 7 (53) 60 Tax credit/(charge) (2) 12 (14) Profit/(loss) after tax 5 (41) 46 Earnings/(loss) per share 1.3p (10.4p) 11.7p Footer box on intersect of lines line h=8.03 9 and v=8.75 with font 10pt Arial not bold 8 8
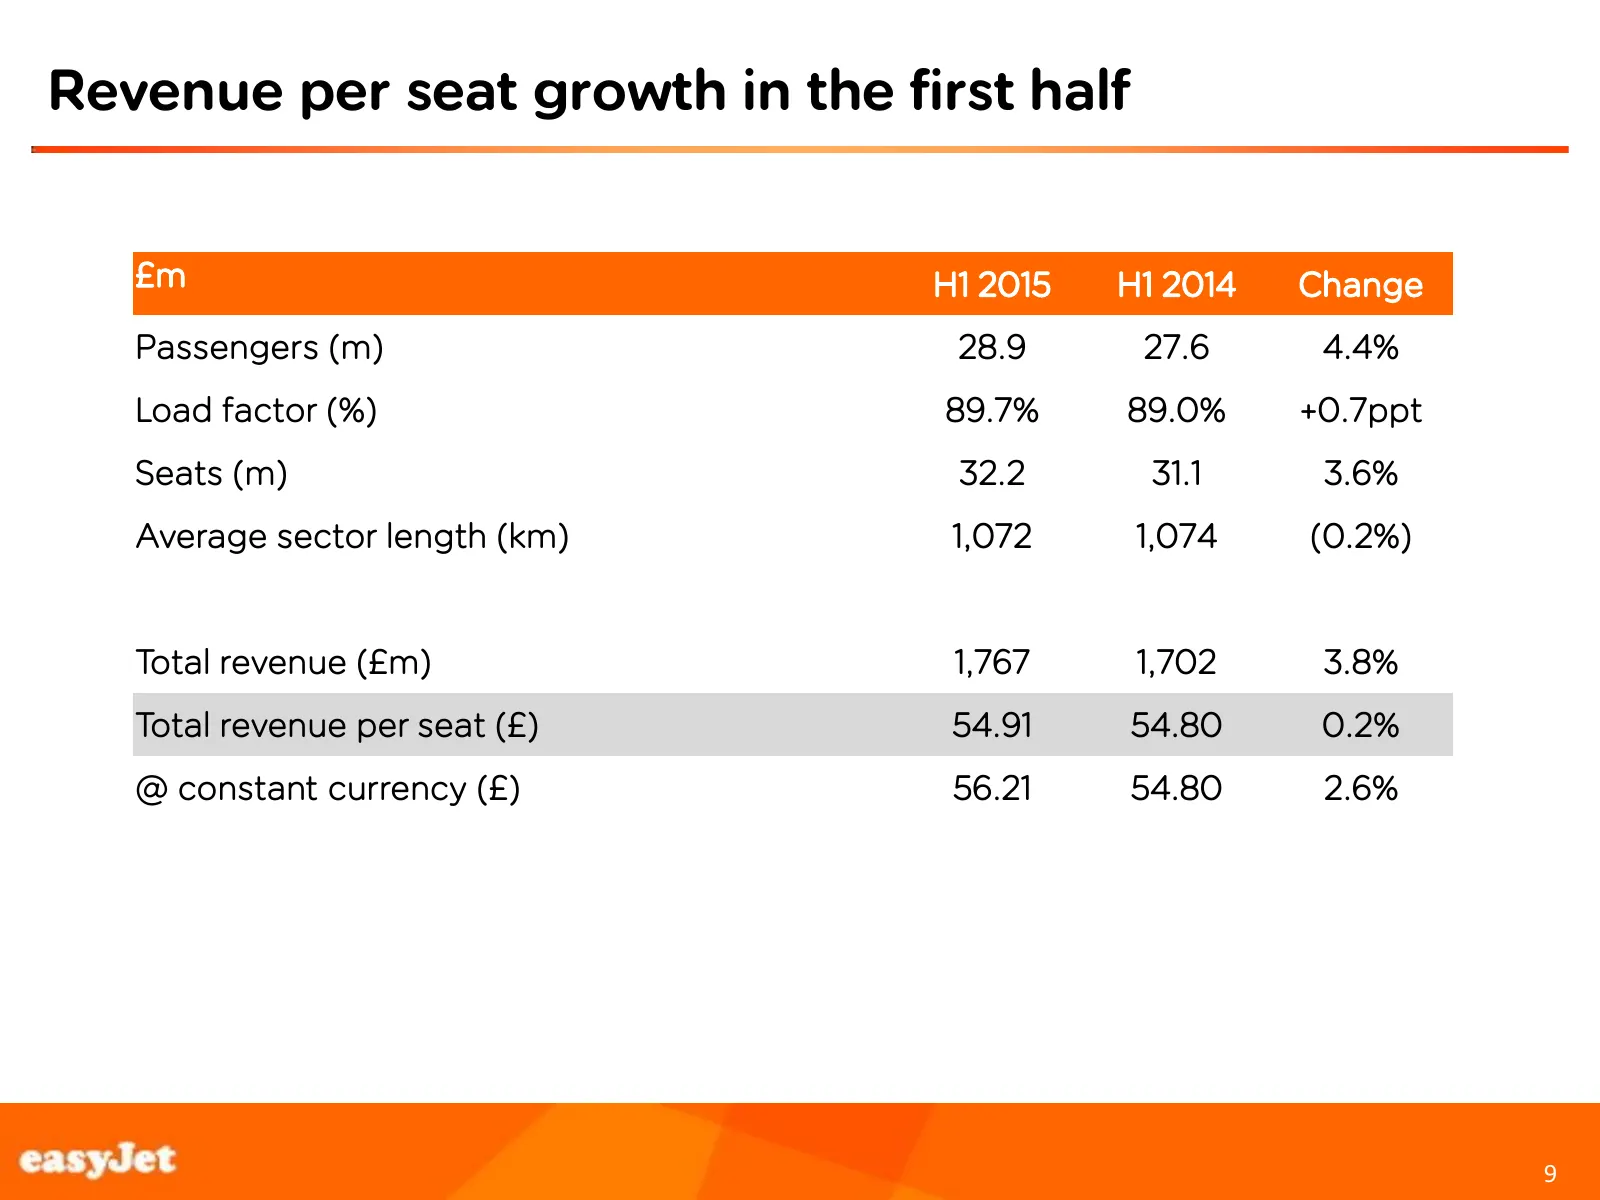
Slide 9: Revenue per seat growth in the first half
Revenue per seat growth in the first half £m H1 2015 H1 2014 Change Passengers (m) 28.9 27.6 4.4% Load factor (%) 89.7% 89.0% +0.7ppt Seats (m) 32.2 31.1 3.6% Average sector length (km) 1,072 1,074 (0.2%) Total revenue (£m) 1,767 1,702 3.8% Total revenue per seat (£) 54.91 54.80 0.2% @ constant curr
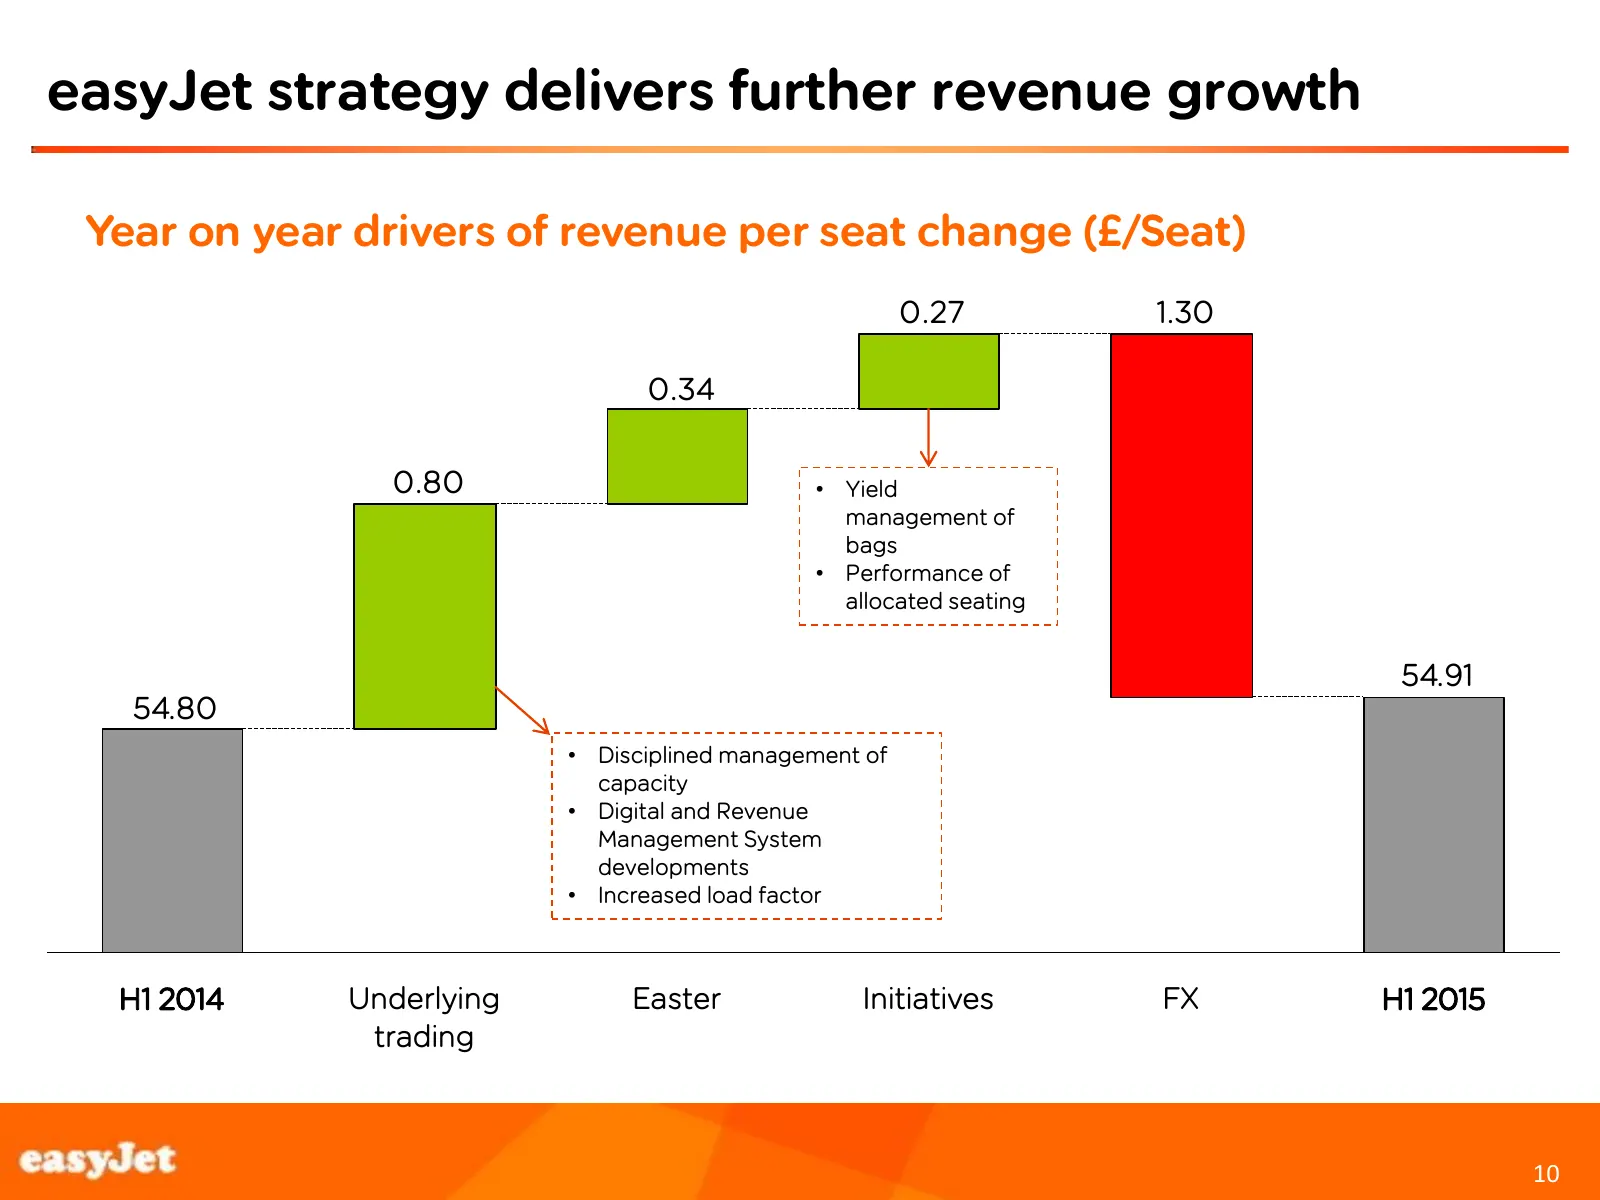
Slide 10: easyJet strategy delivers further revenue growth
easyJet strategy delivers further revenue growth Year on year drivers of revenue per seat change (£/Seat) 0.27 1.30 0.34 0.80 • Yield management of bags • Performance of allocated seating 54.91 54.80 • Disciplined management of capacity • Digital and Revenue Management System developments • Increase
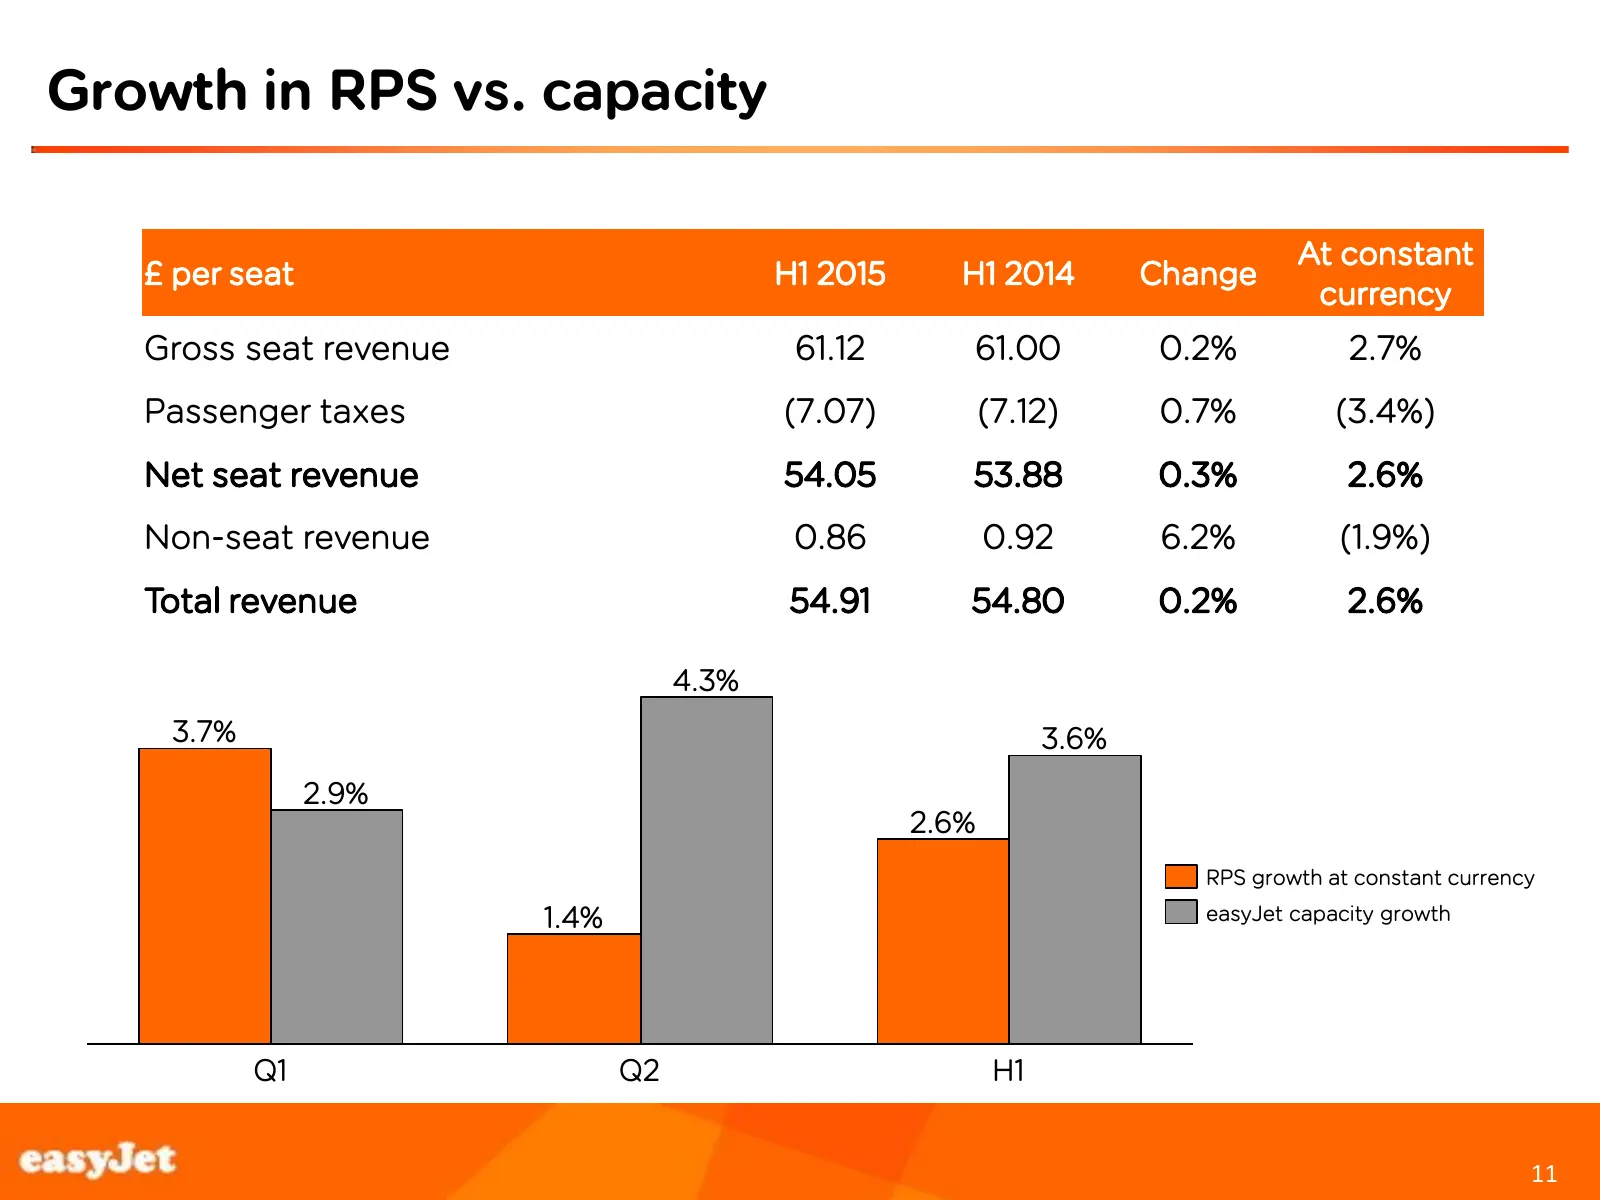
Slide 11: Growth in RPS vs. capacity
Growth in RPS vs. capacity At constant £ per seat H1 2015 H1 2014 Change currency Gross seat revenue 61.12 61.00 0.2% 2.7% Passenger taxes (7.07) (7.12) 0.7% (3.4%) Net seat revenue 54.05 53.88 0.3% 2.6% Non-seat revenue 0.86 0.92 6.2% (1.9%) Total revenue 54.91 54.80 0.2% 2.6% 4.3% 3.7% 3.6% 2.9% 2
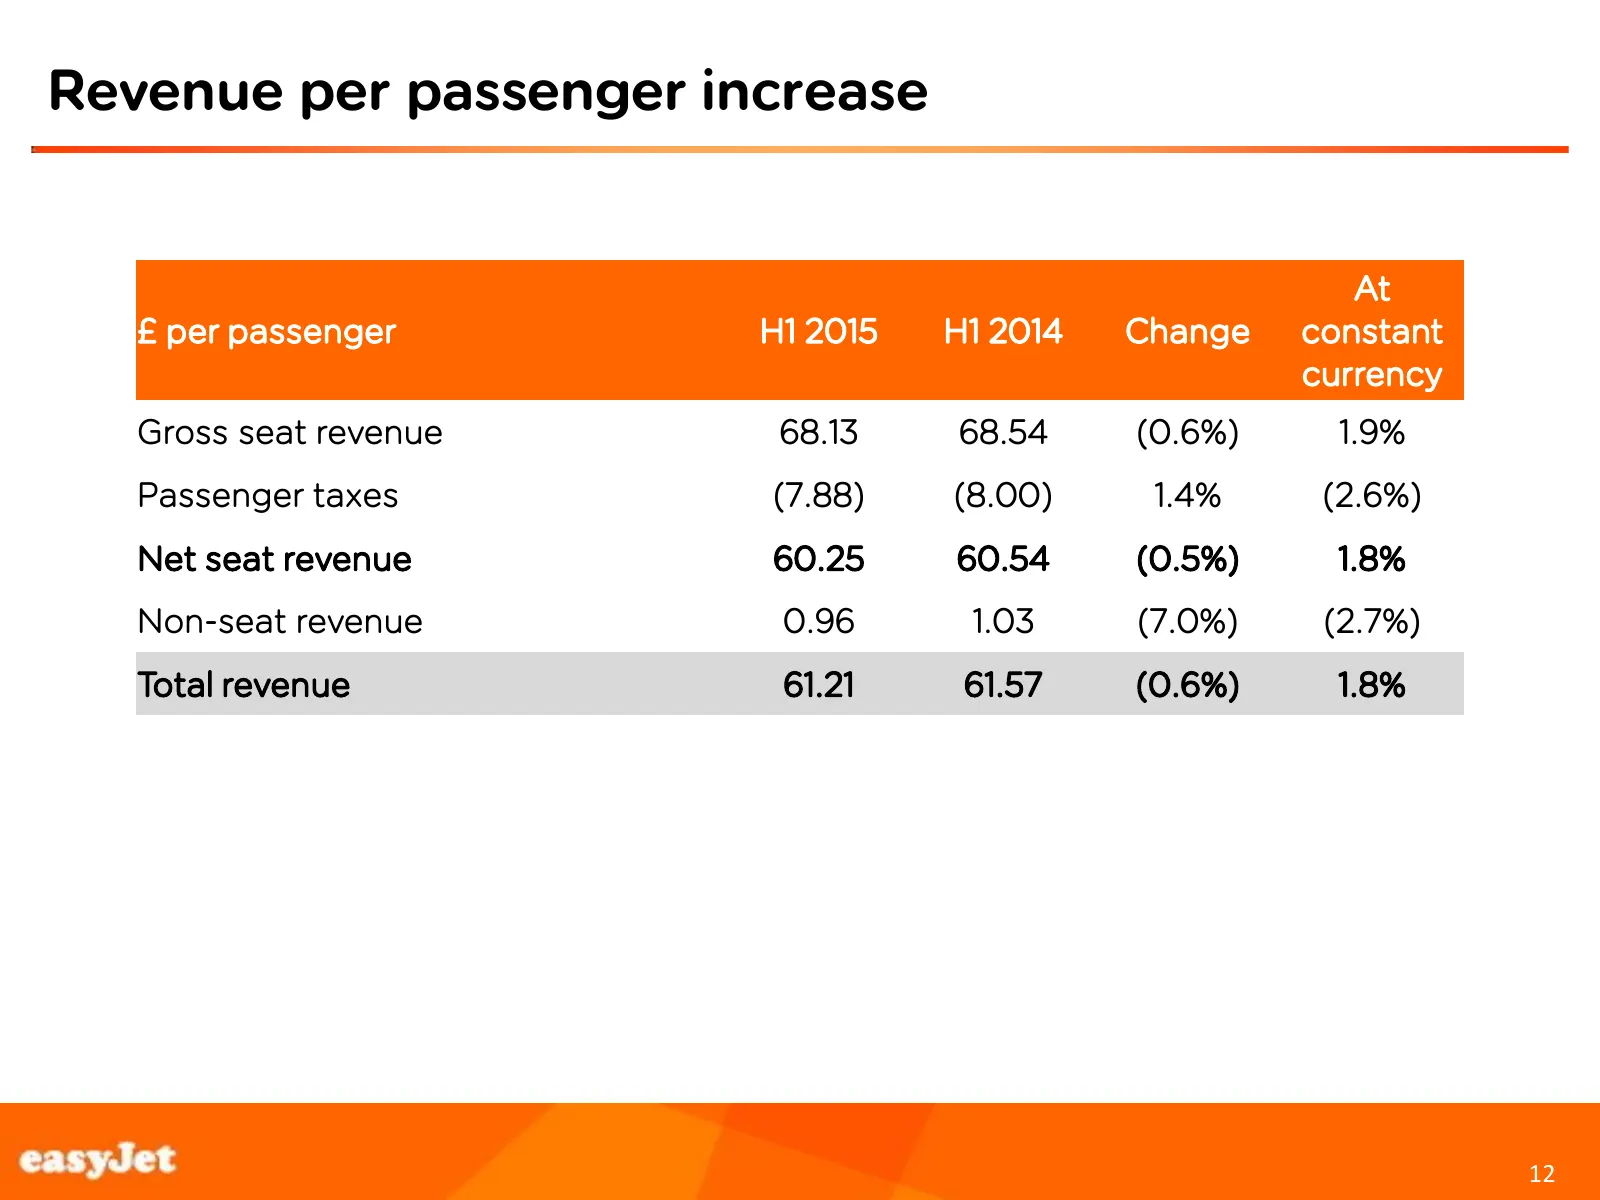
Slide 12: Revenue per passenger increase
Revenue per passenger increase At £ per passenger H1 2015 H1 2014 Change constant currency Gross seat revenue 68.13 68.54 (0.6%) 1.9% Passenger taxes (7.88) (8.00) 1.4% (2.6%) Net seat revenue 60.25 60.54 (0.5%) 1.8% Non-seat revenue 0.96 1.03 (7.0%) (2.7%) Total revenue 61.21 61.57 (0.6%) 1.8% Foot
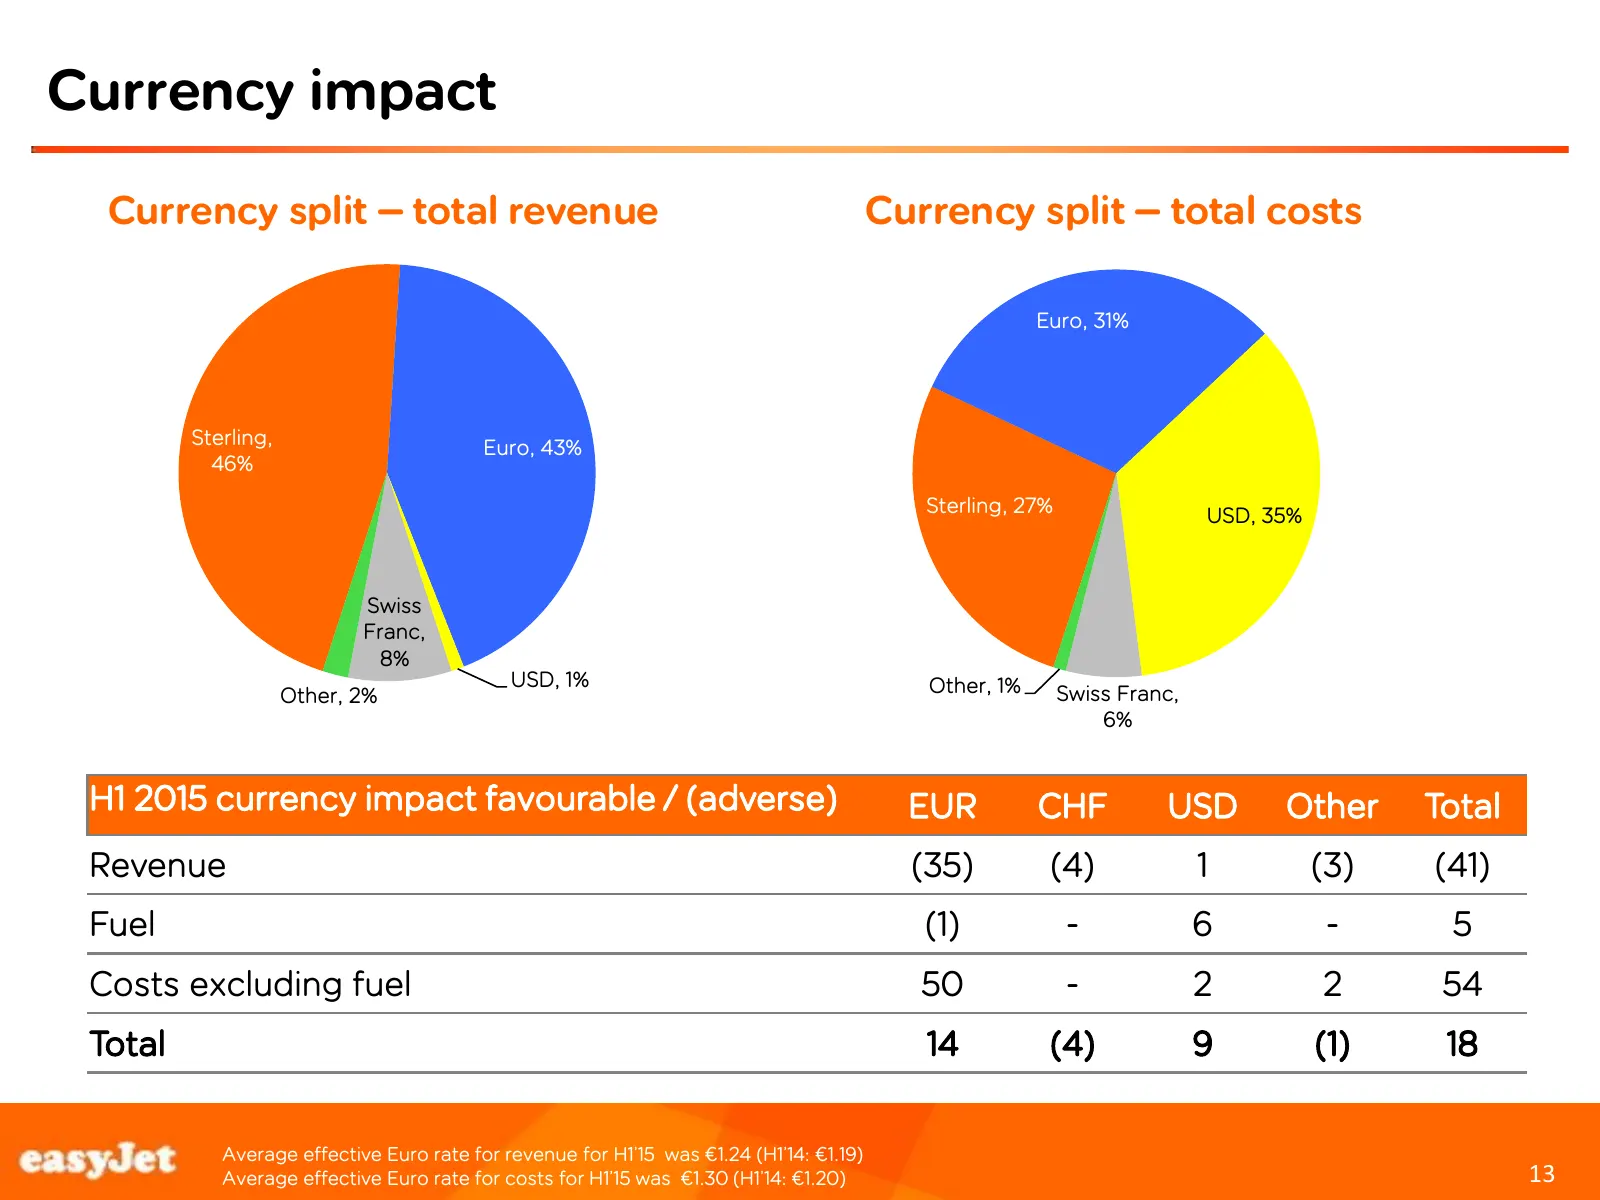
Slide 13: Currency impact
Currency impact Currency split – total revenue Currency split – total costs Euro, 31% Sterling, Euro, 43% 46% Sterling, 27% USD, 35% Swiss Franc, 8% USD, 1% Other, 1% Other, 2% Swiss Franc, 6% H1 2015 currency impact favourable / (adverse) EUR CHF USD Other Total Revenue (35) (4) 1 (3) (41) Fuel (1)
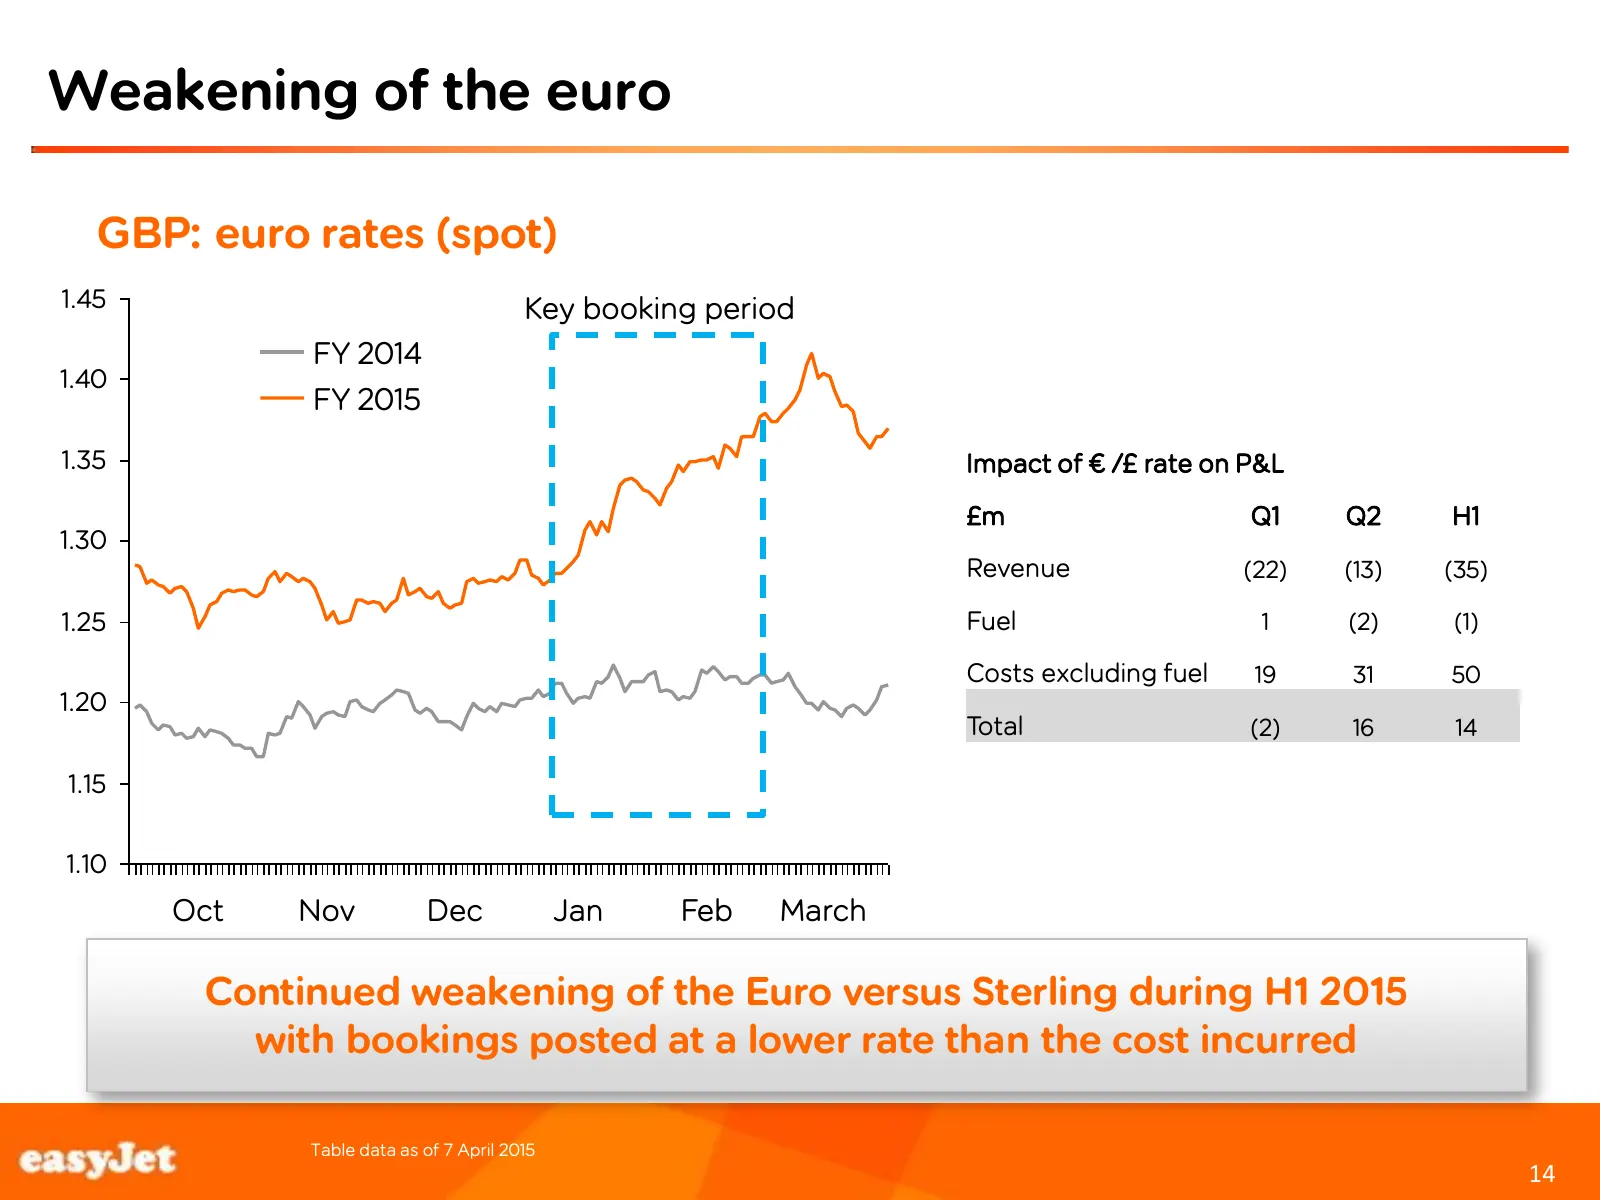
Slide 14: Weakening of the euro
Weakening of the euro GBP: euro rates (spot) 1.45 Key booking period FY 2014 1.40 FY 2015 1.35 Impact of € /£ rate on P&L £m Q1 Q2 H1 1.30 Revenue (22) (13) (35) 1.25 Fuel 1 (2) (1) Costs excluding fuel 19 31 50 1.20 Total (2) 16 14 1.15 1.10 Oct Nov Dec Jan Feb March Footer box on intersect of line
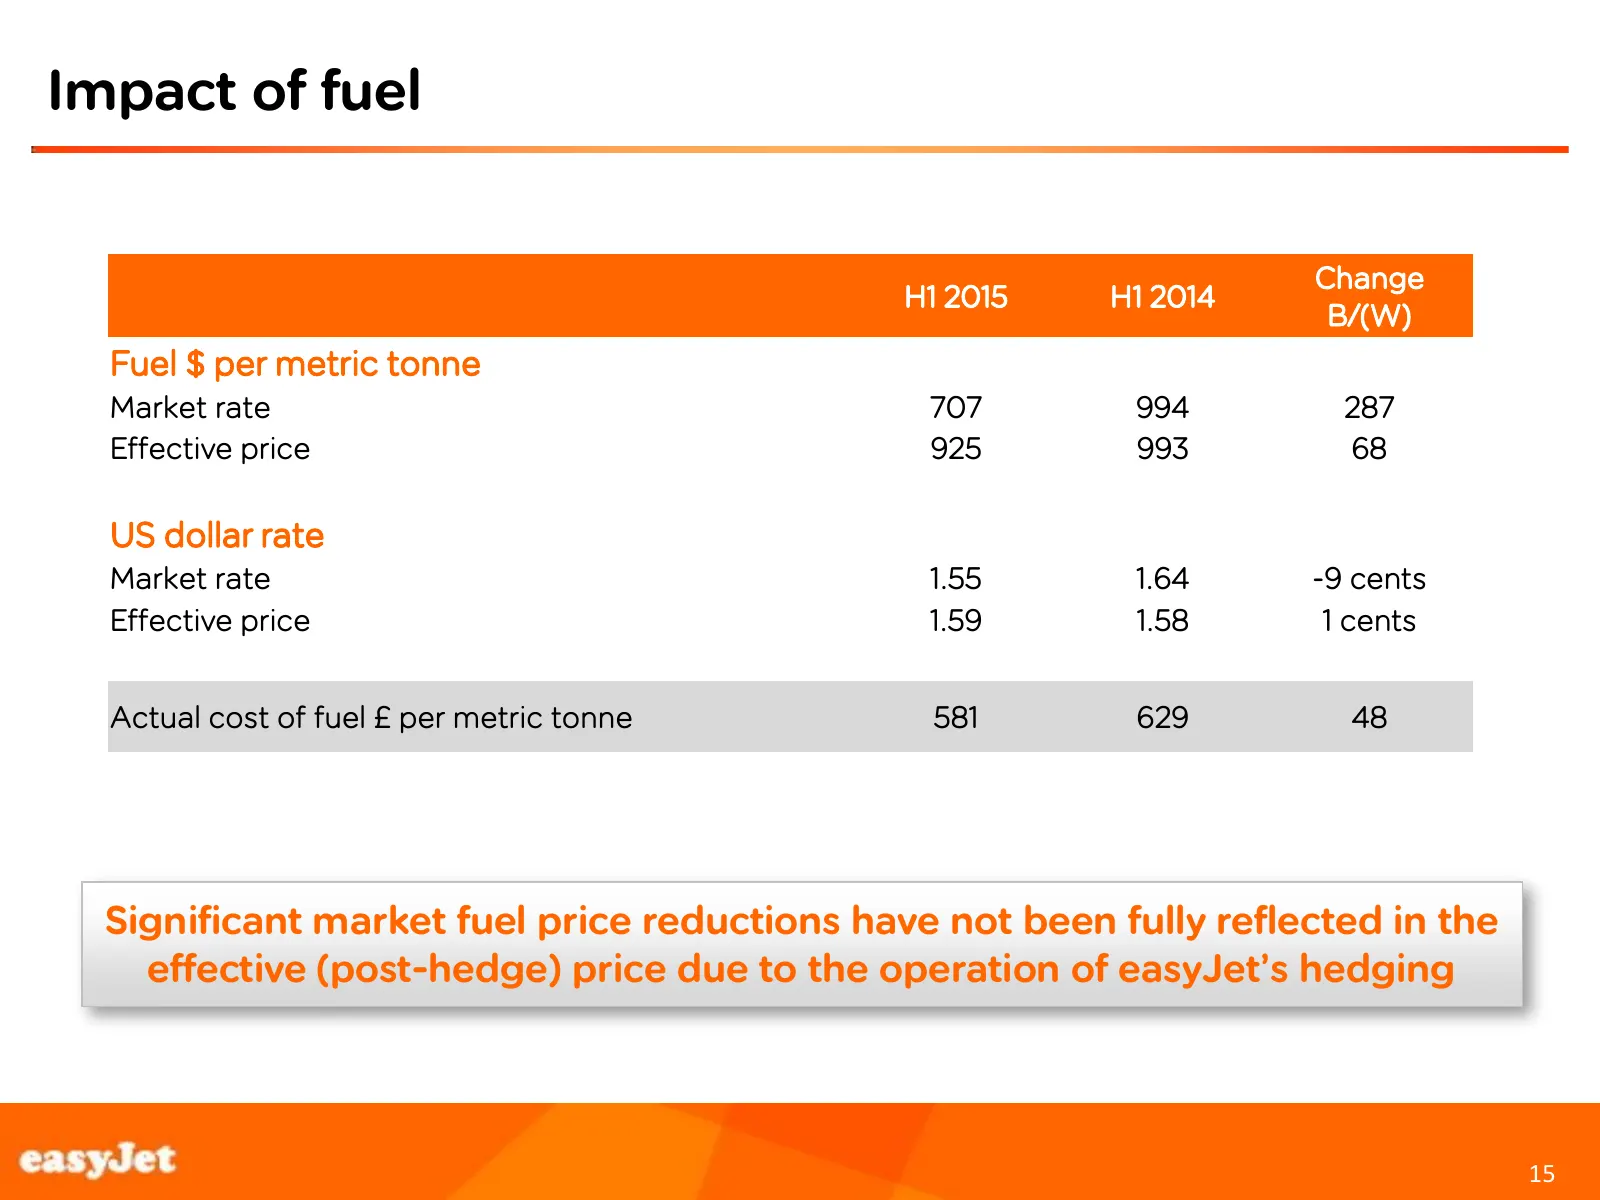
Slide 15: Impact of fuel
Impact of fuel Change H1 2015 H1 2014 B/(W) Fuel $ per metric tonne Market rate 707 994 287 Effective price 925 993 68 US dollar rate Market rate 1.55 1.64 -9 cents Effective price 1.59 1.58 1 cents Actual cost of fuel £ per metric tonne 581 629 48 Significant Footer market fuel price reductions hav
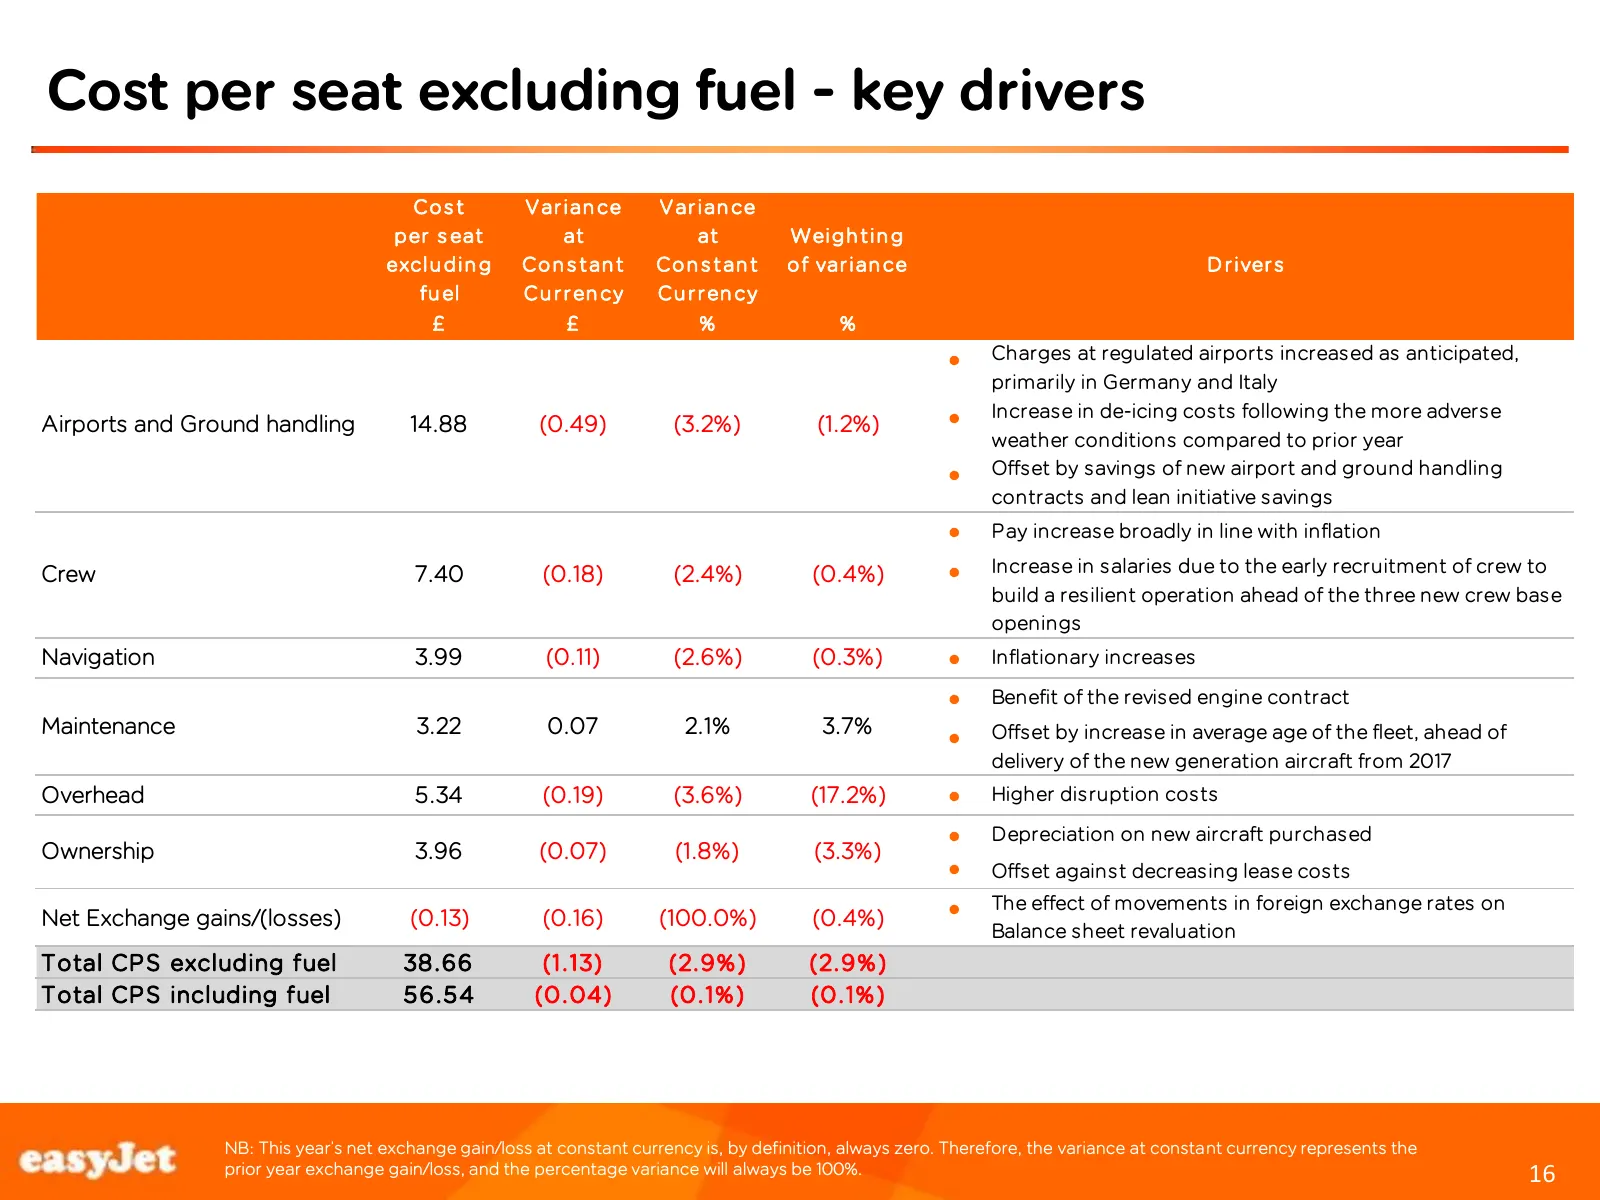
Slide 16: Cost per seat excluding fuel - key drivers
Cost per seat excluding fuel - key drivers Co s t Var ian ce Var ian ce per s eat at at Weigh t in g exclu din g Co n s t an t Co n s t an t o f var ian ce D r iver s fu el Cu r r en cy Cu r r en cy £ £ % % • Charges at regulated airports increased as anticipated, primarily in Germany and Italy • In
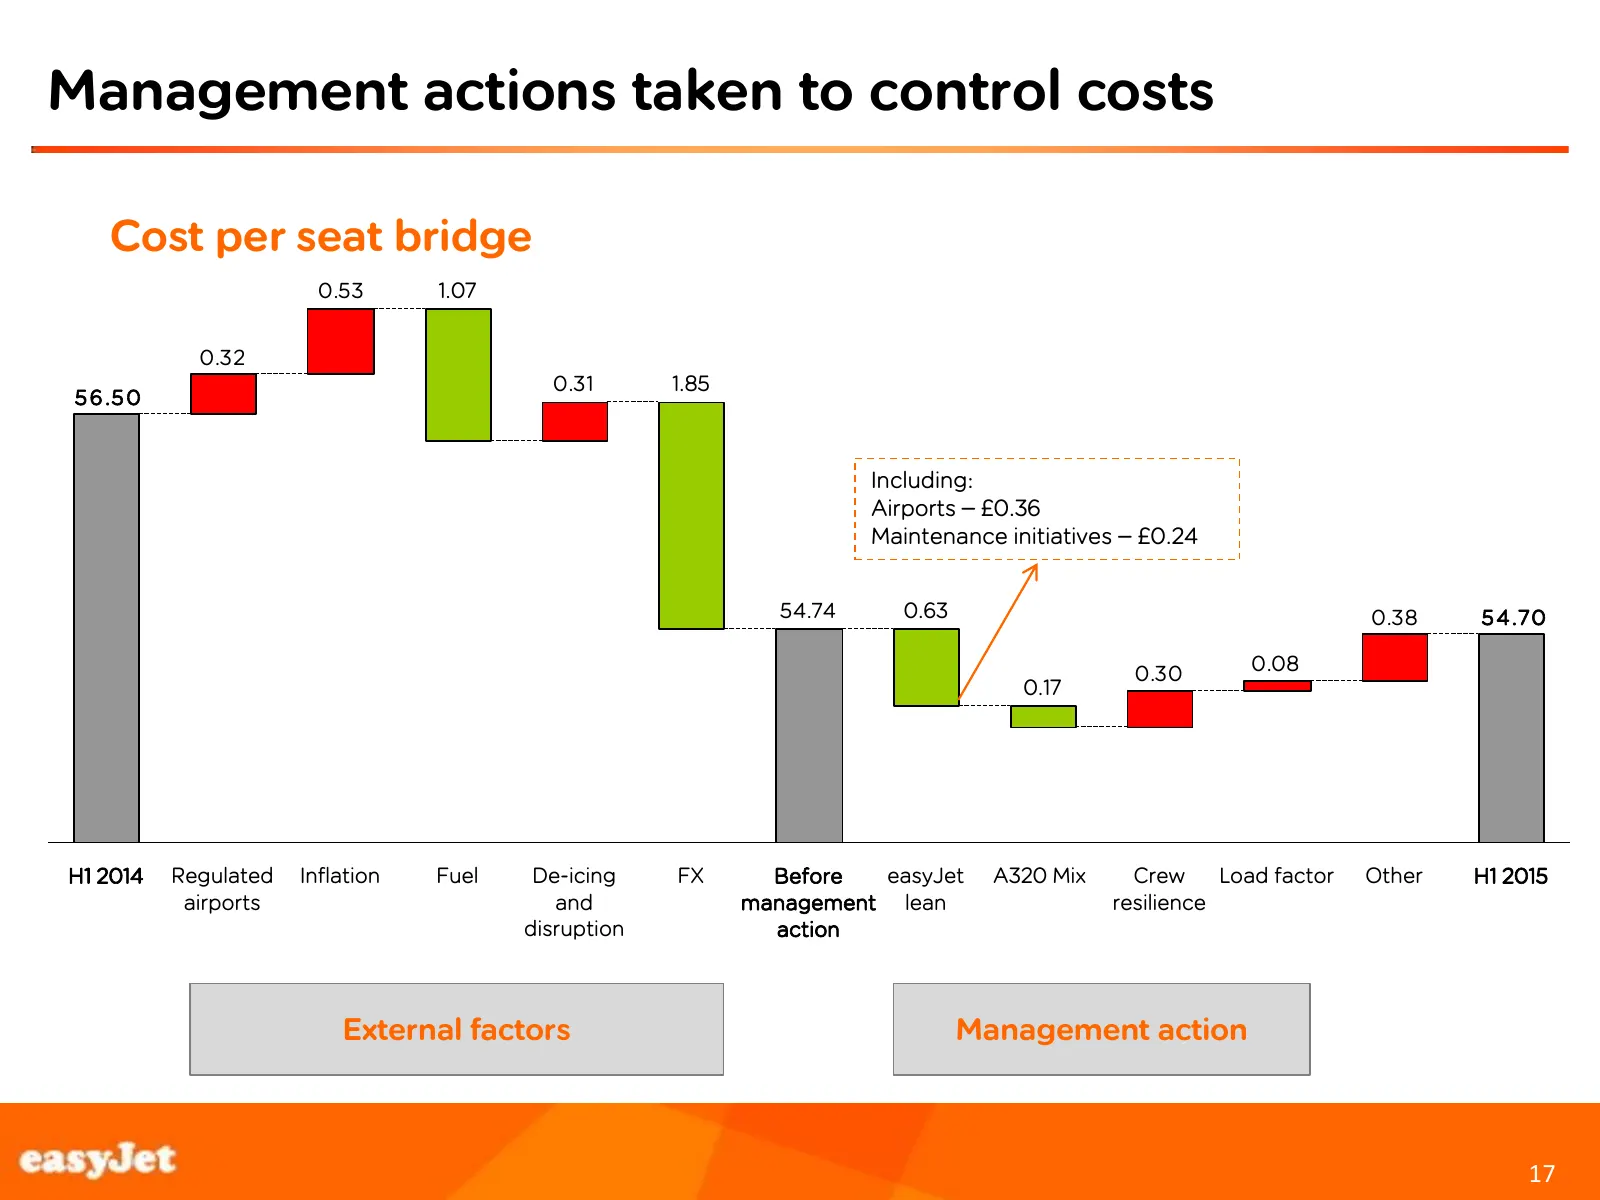
Slide 17: Management actions taken to control costs
Management actions taken to control costs Cost per seat bridge 0.53 1.07 0.32 0.31 1.85 5 6 .5 0 Including: Airports – £0.36 Maintenance initiatives – £0.24 54.74 0.63 0.38 5 4 .7 0 0.30 0.08 0.17 H1 2014 Regulated Inflation Fuel De-icing FX Before easyJet A320 Mix Crew Load factor Other H1 2015 air
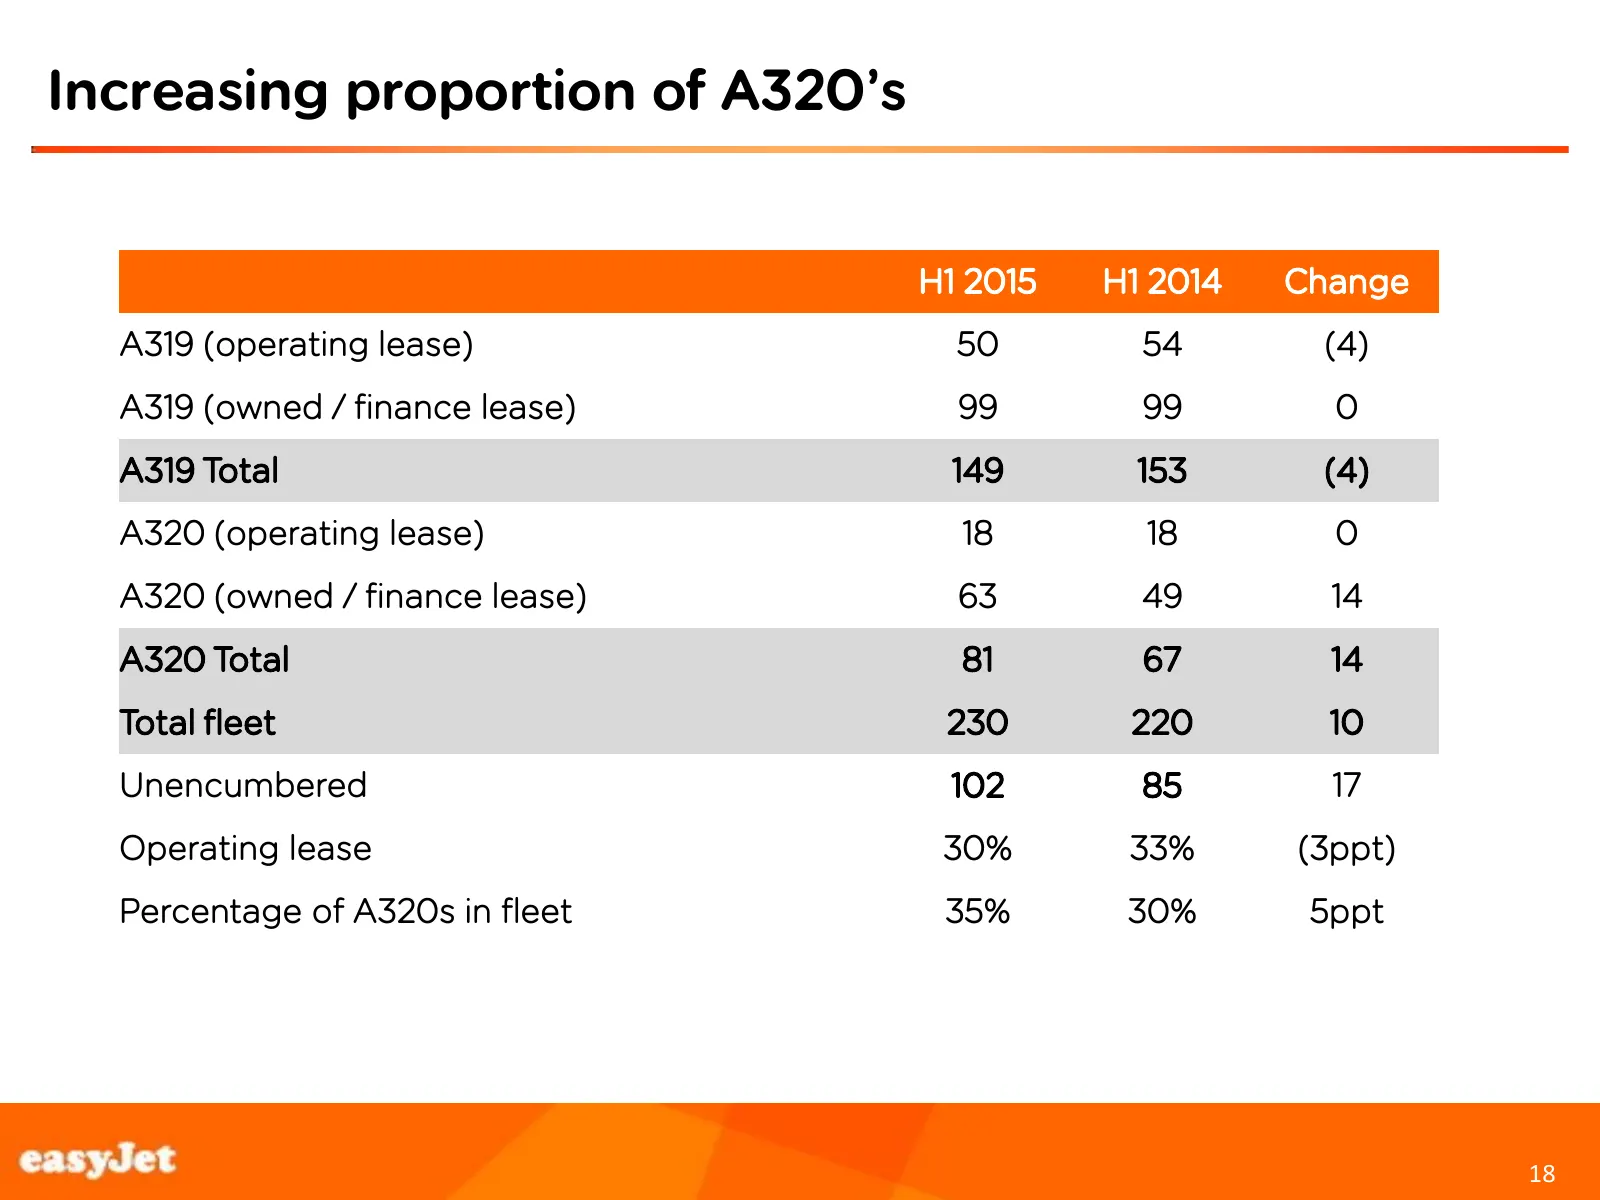
Slide 18: Increasing proportion of A320's
Increasing proportion of A320’s H1 2015 H1 2014 Change A319 (operating lease) 50 54 (4) A319 (owned / finance lease) 99 99 0 A319 Total 149 153 (4) A320 (operating lease) 18 18 0 A320 (owned / finance lease) 63 49 14 A320 Total 81 67 14 Total fleet 230 220 10 Unencumbered 102 85 17 Operating lease 3
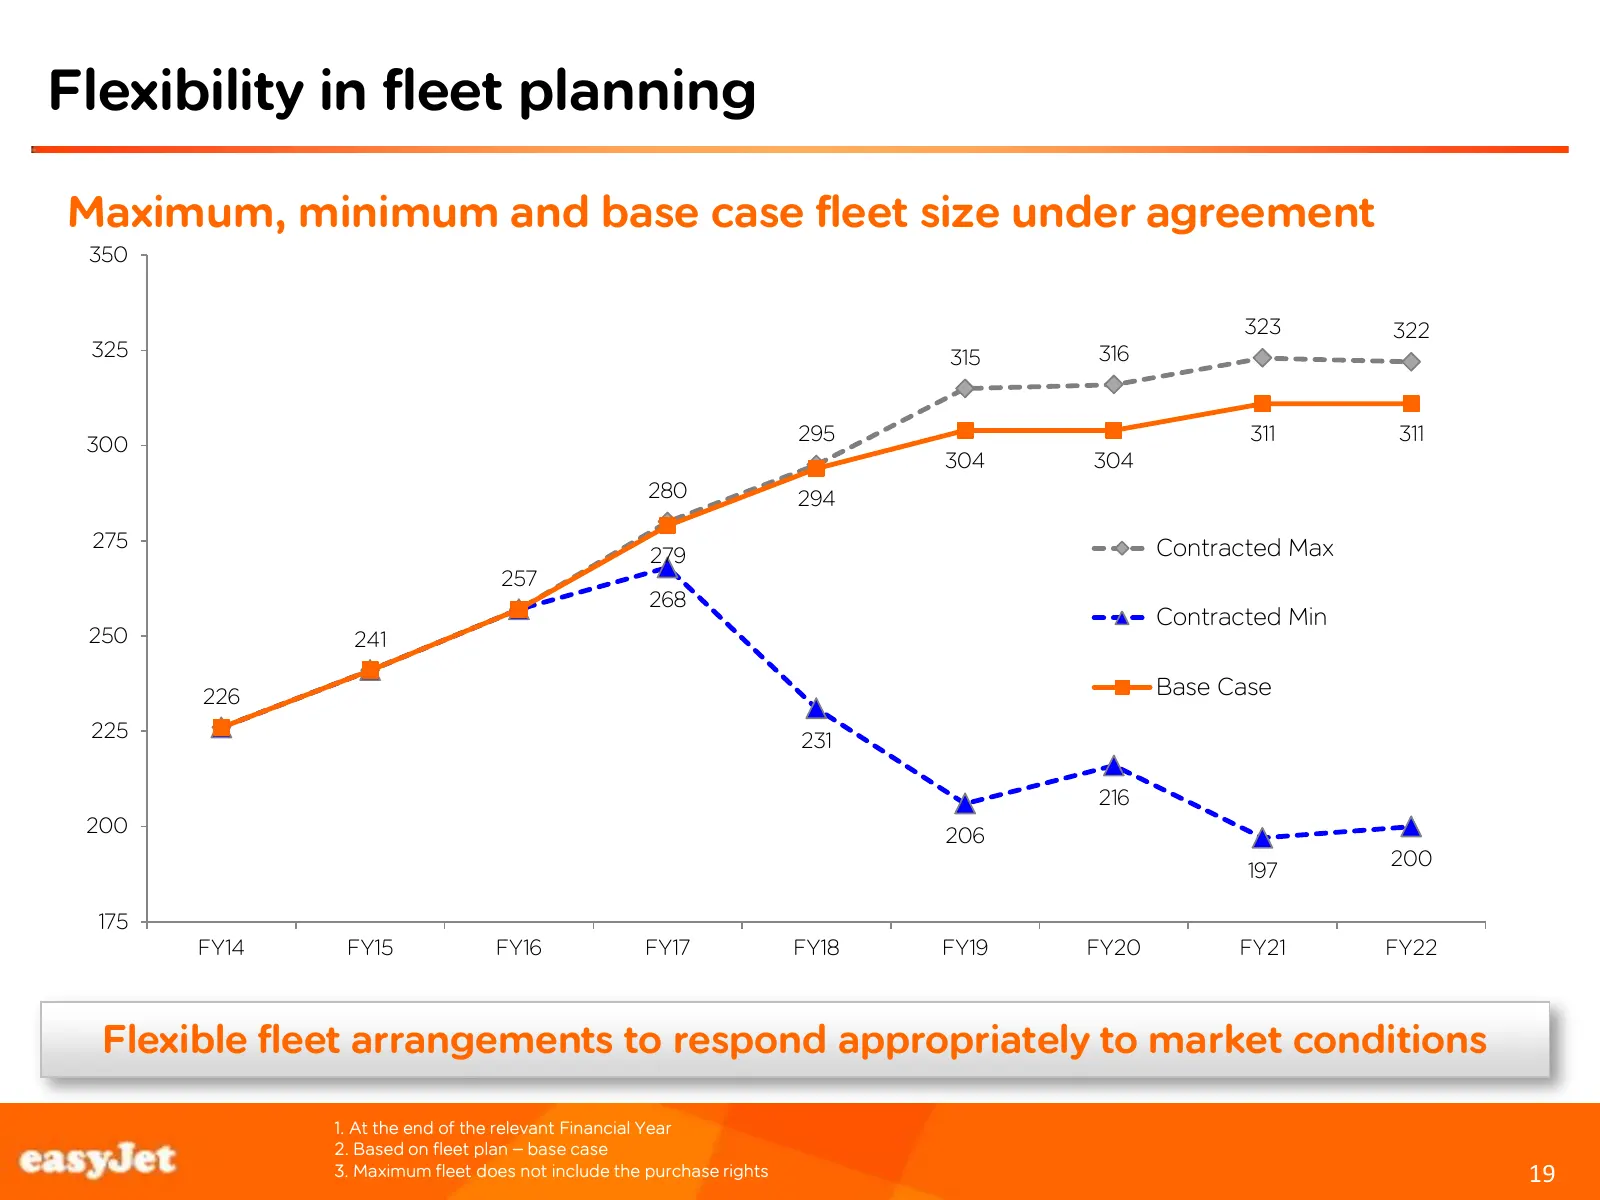
Slide 19: Flexibility in fleet planning
Flexibility in fleet planning Maximum, minimum and base case fleet size under agreement 350 323 322 325 315 316 295 311 311 300 304 304 280 294 275 Contracted Max 279 257 268 Contracted Min 250 241 226 Base Case 225 231 216 200 206 200 197 175 FY14 Footer FY15box on intersect FY16of lines lineFY17 h
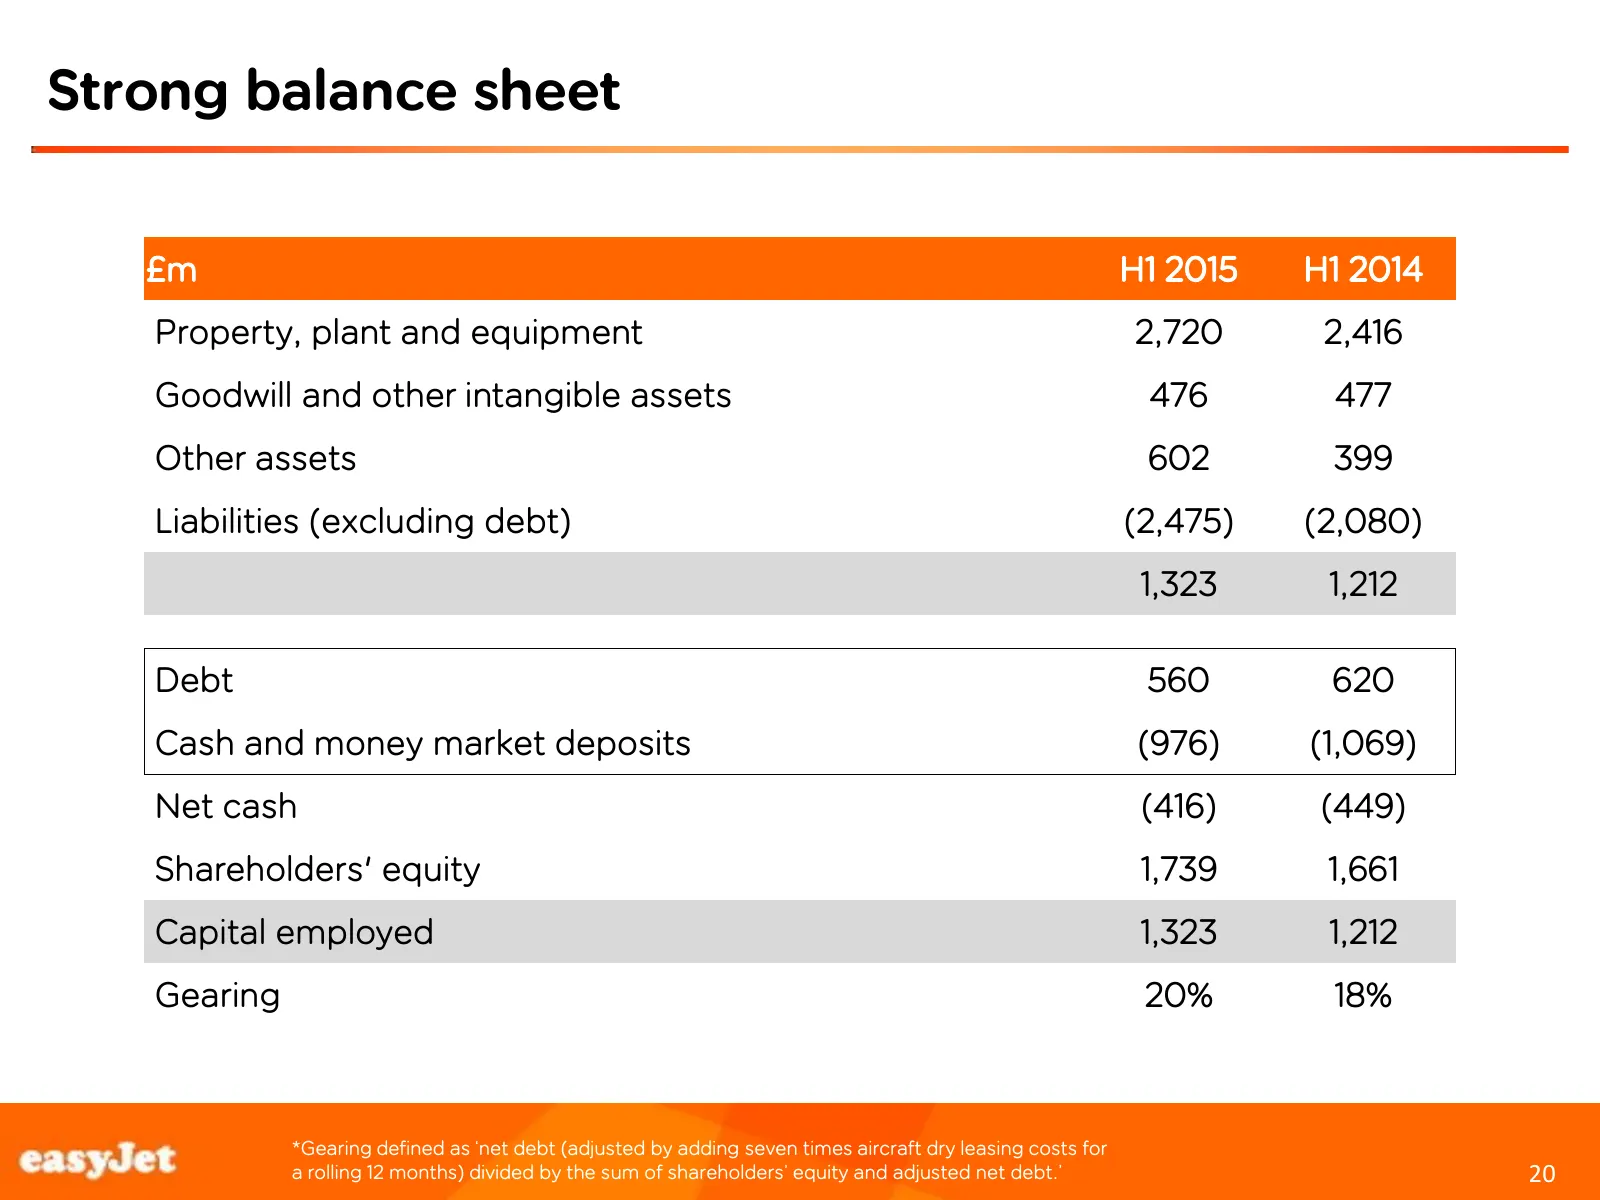
Slide 20: Strong balance sheet
Strong balance sheet £m H1 2015 H1 2014 Property, plant and equipment 2,720 2,416 Goodwill and other intangible assets 476 477 Other assets 602 399 Liabilities (excluding debt) (2,475) (2,080) 1,323 1,212 Debt 560 620 Cash and money market deposits (976) (1,069) Net cash (416) (449) Shareholders' eq
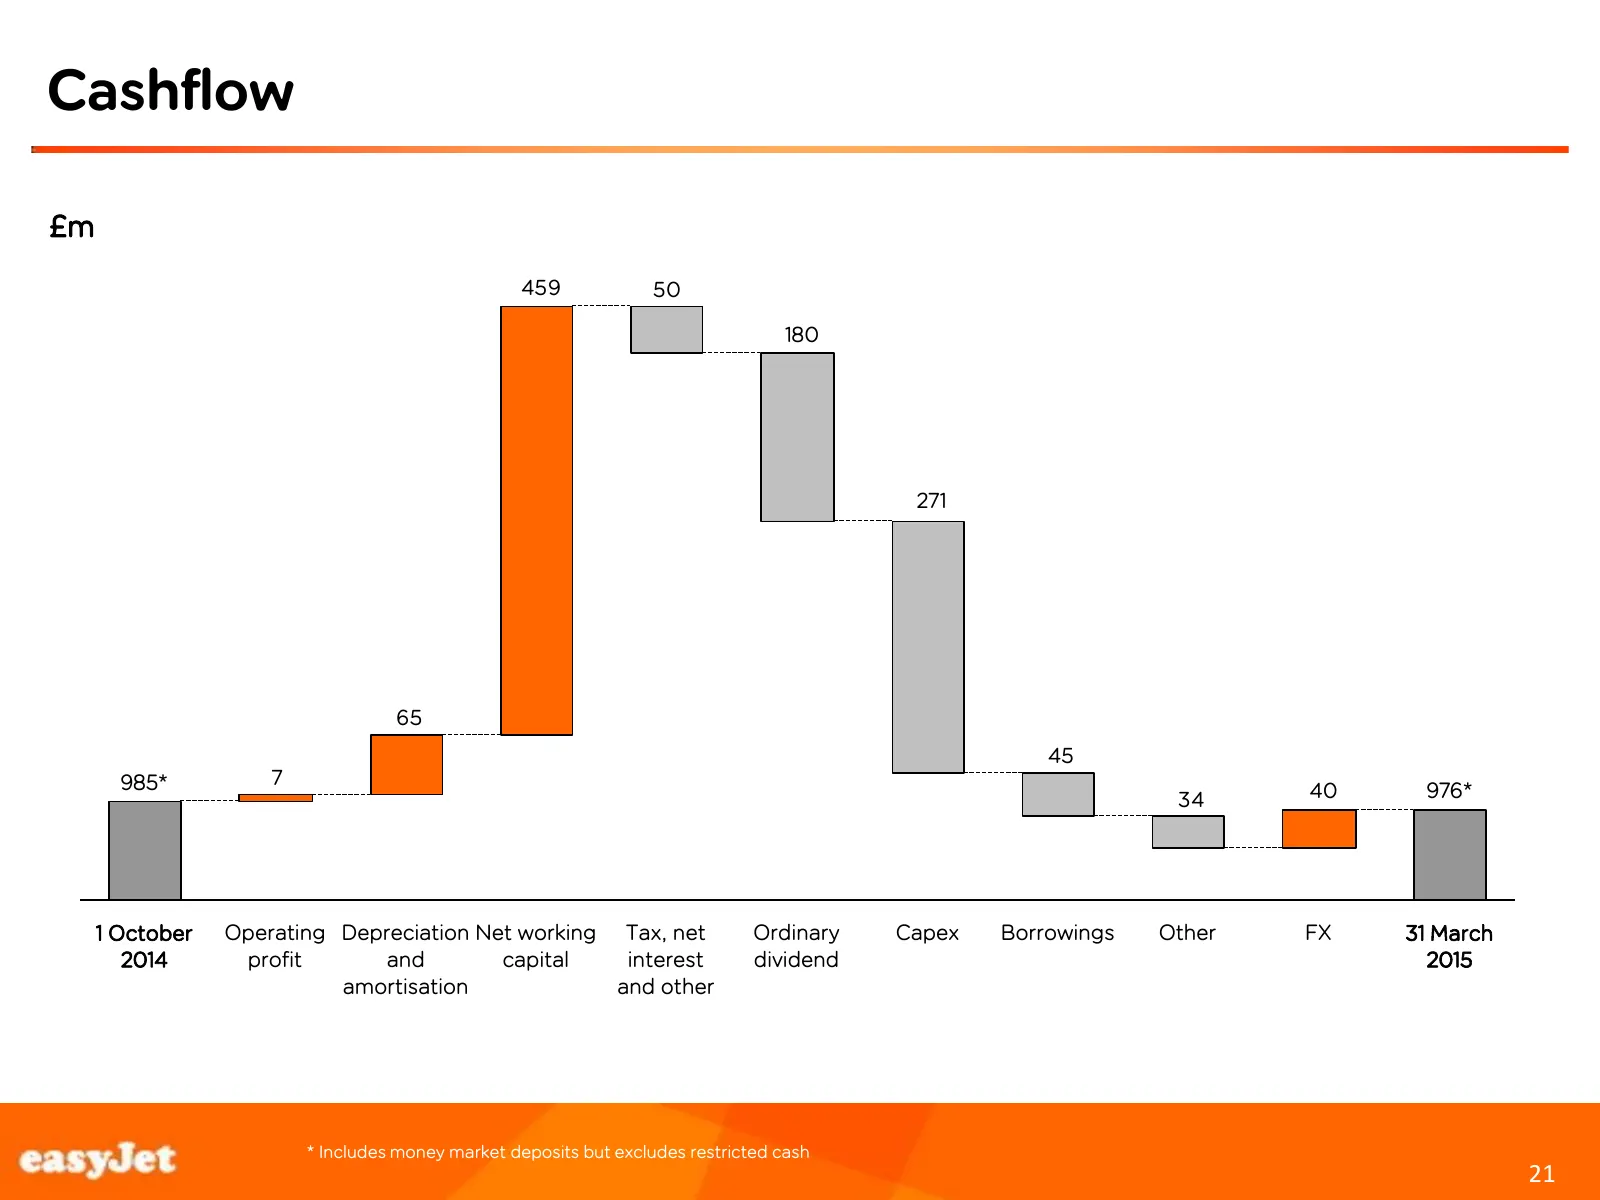
Slide 21: Cashflow
Cashflow £m 459 50 180 271 65 45 985* 7 34 40 976* 1 October Operating Depreciation Footer Net working box on intersect Tax,h=8.03 of lines line net 9 and Ordinary v=8.75 withCapex font 10pt Borrowings Arial not bold Other FX 31 March 2014 profit and capital interest dividend 2015 amortisation and o
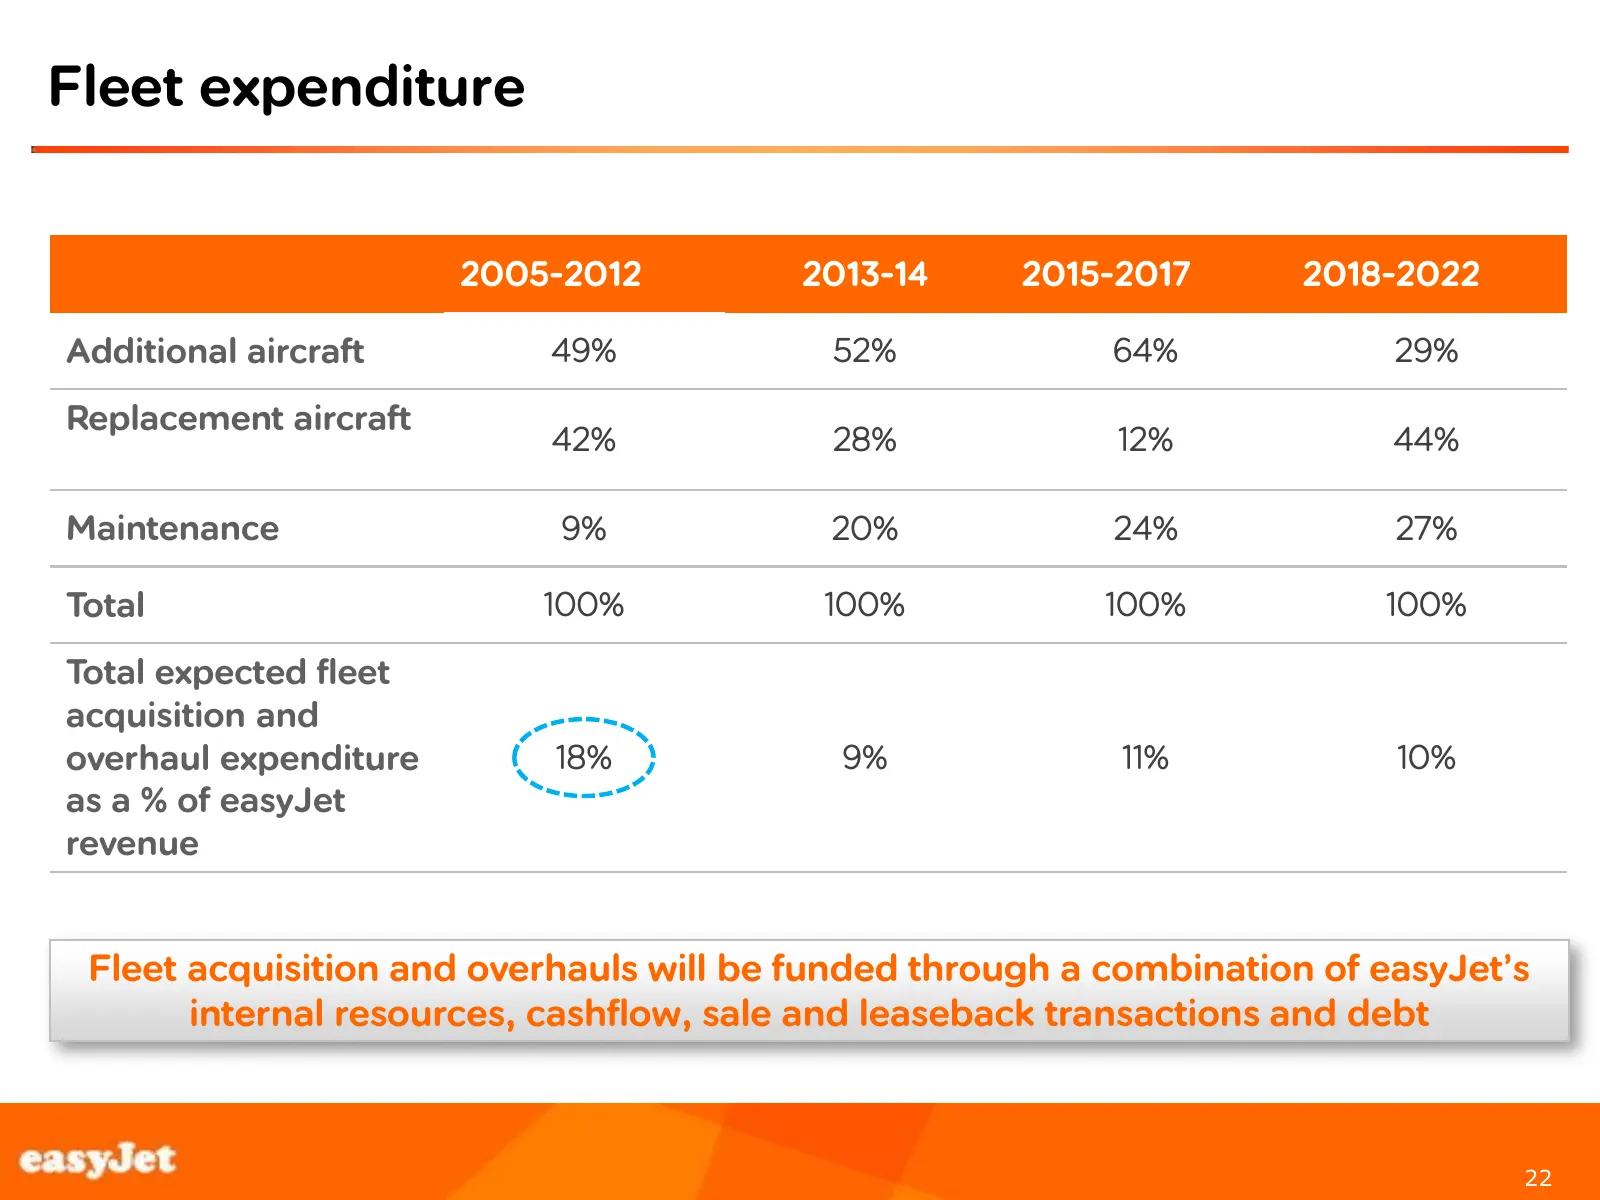
Slide 22: Fleet expenditure
Fleet expenditure 2005-2012 2013-14 2015-2017 2018-2022 Additional aircraft 49% 52% 64% 29% Replacement aircraft 42% 28% 12% 44% Maintenance 9% 20% 24% 27% Total 100% 100% 100% 100% Total expected fleet acquisition and overhaul expenditure 18% 9% 11% 10% as a % of easyJet revenue Footer box on inter
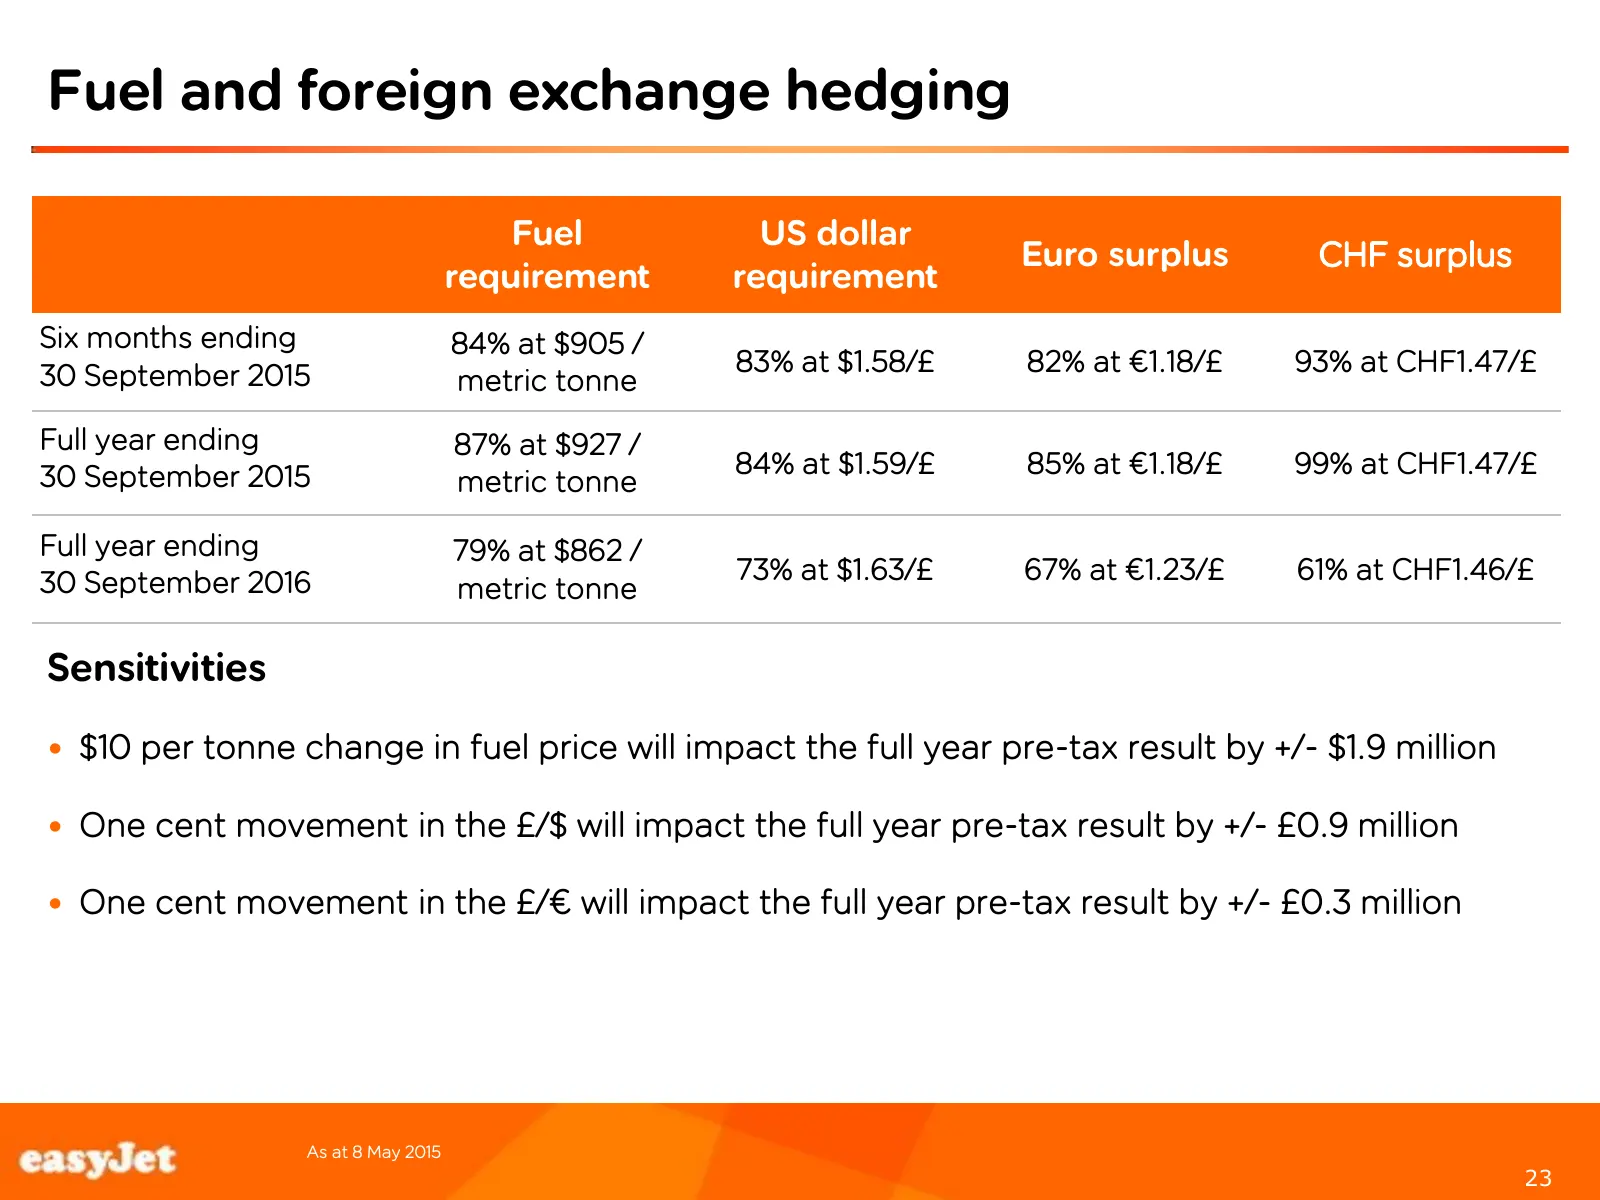
Slide 23: Fuel and foreign exchange hedging
Fuel and foreign exchange hedging Fuel US dollar Euro surplus CHF surplus requirement requirement Six months ending 84% at $905 / 30 September 2015 83% at $1.58/£ 82% at €1.18/£ 93% at CHF1.47/£ metric tonne Full year ending 87% at $927 / 30 September 2015 84% at $1.59/£ 85% at €1.18/£ 99% at CHF1.4
Slide 24: Business review
Business review Carolyn McCall Chief Executive Officer
Slide 25: easyJet well placed to win in competitive market
easyJet well placed to win in competitive market Compelling Affordable network fares Customer Cost Digital Strong advantage leadership balance sheet Footer box on intersect of lines line h=8.03 9 and v=8.75 with font 10pt Arial not bold Proven strategy, execution and returns 25 25
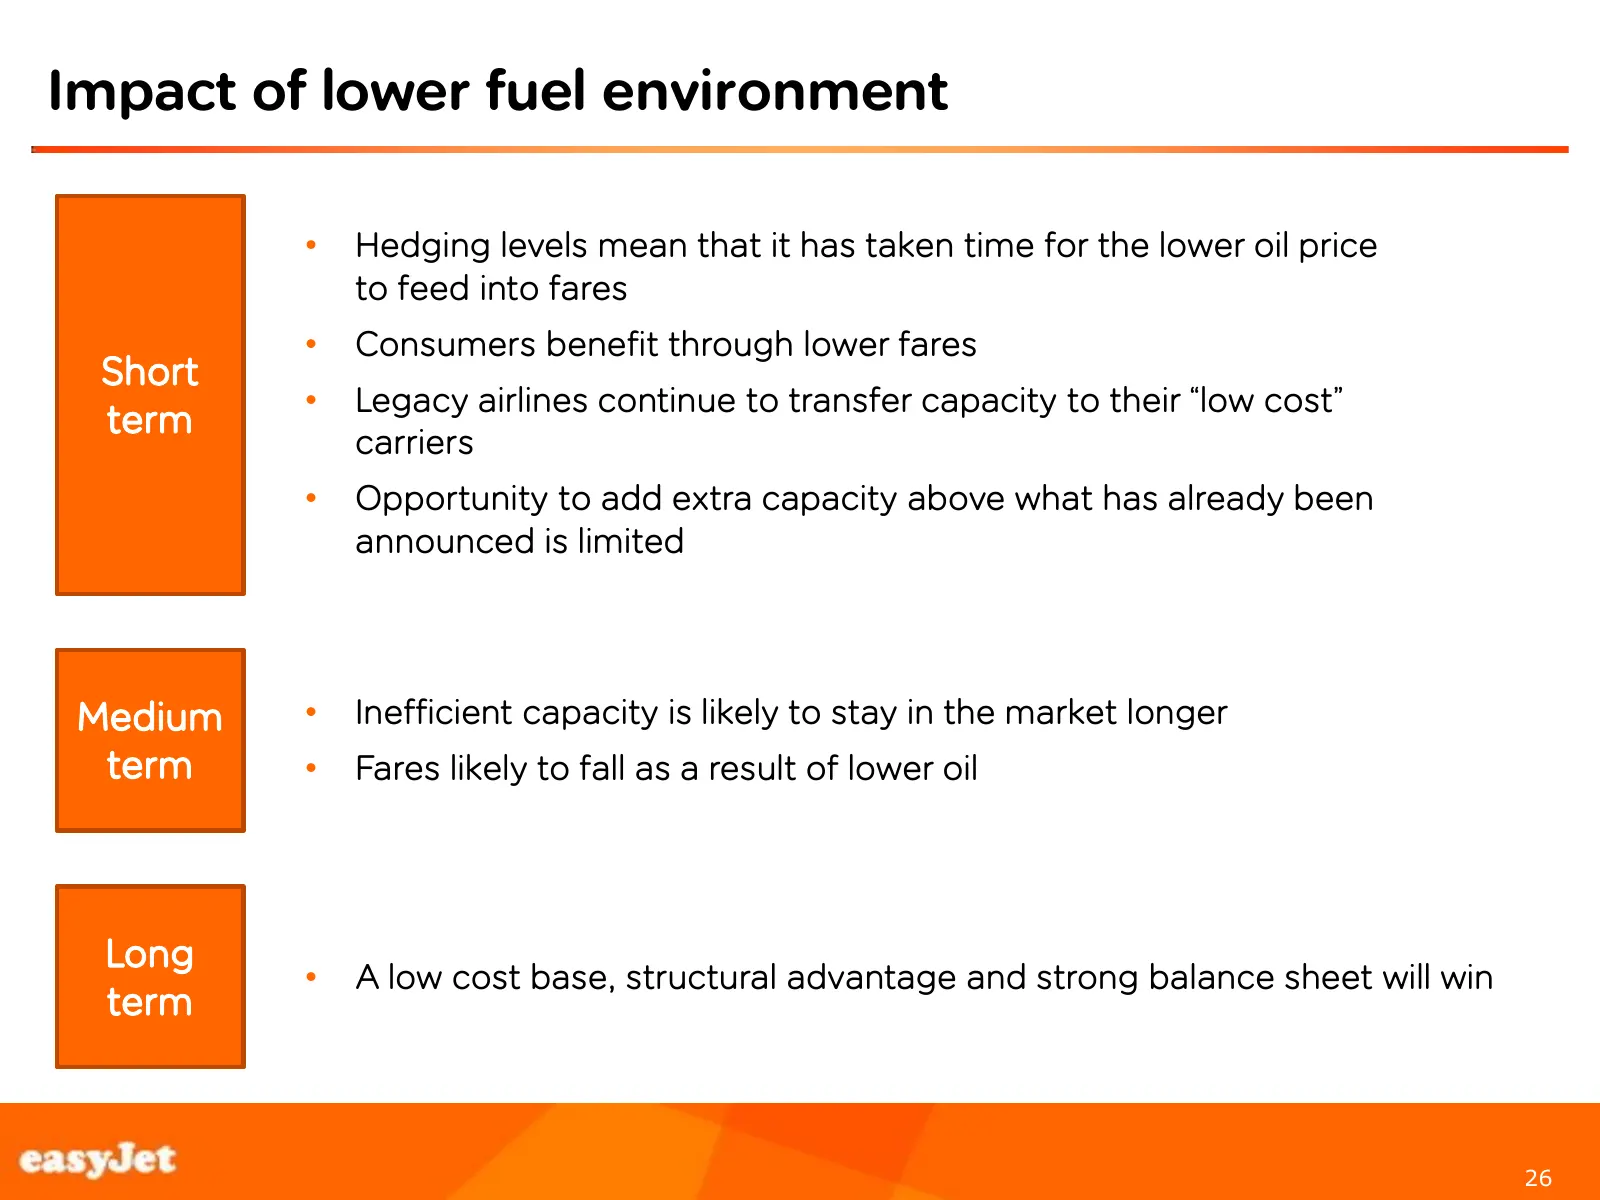
Slide 26: Impact of lower fuel environment
Impact of lower fuel environment • Hedging levels mean that it has taken time for the lower oil price to feed into fares • Consumers benefit through lower fares Short • Legacy airlines continue to transfer capacity to their “low cost” term carriers • Opportunity to add extra capacity above what has
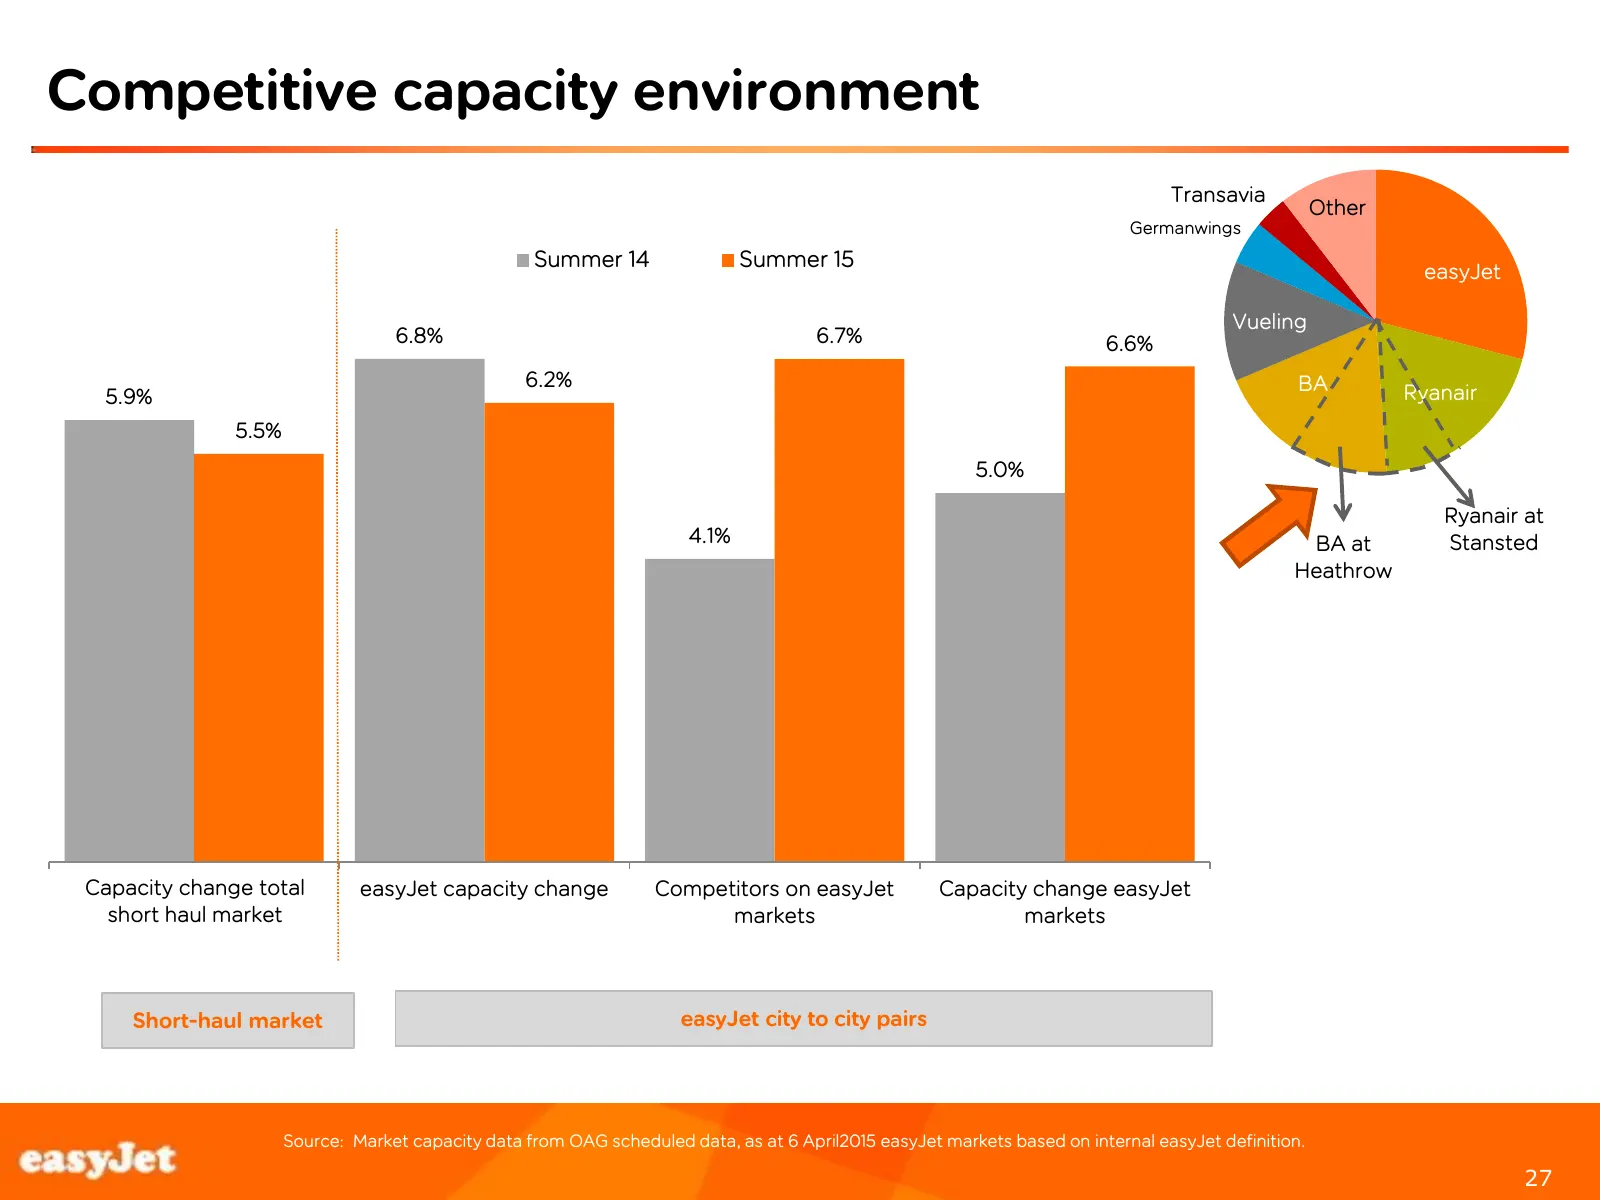
Slide 27: Competitive capacity environment
Competitive capacity environment Transavia Other Germanwings Summer 14 Summer 15 easyJet Vueling 6.8% 6.7% 6.6% 6.2% BA 5.9% Ryanair 5.5% 5.0% Ryanair at 4.1% BA at Stansted Heathrow Capacity Capacity change change total total SH easyJet capacity change Competitors on easyJet Capacity change easyJet
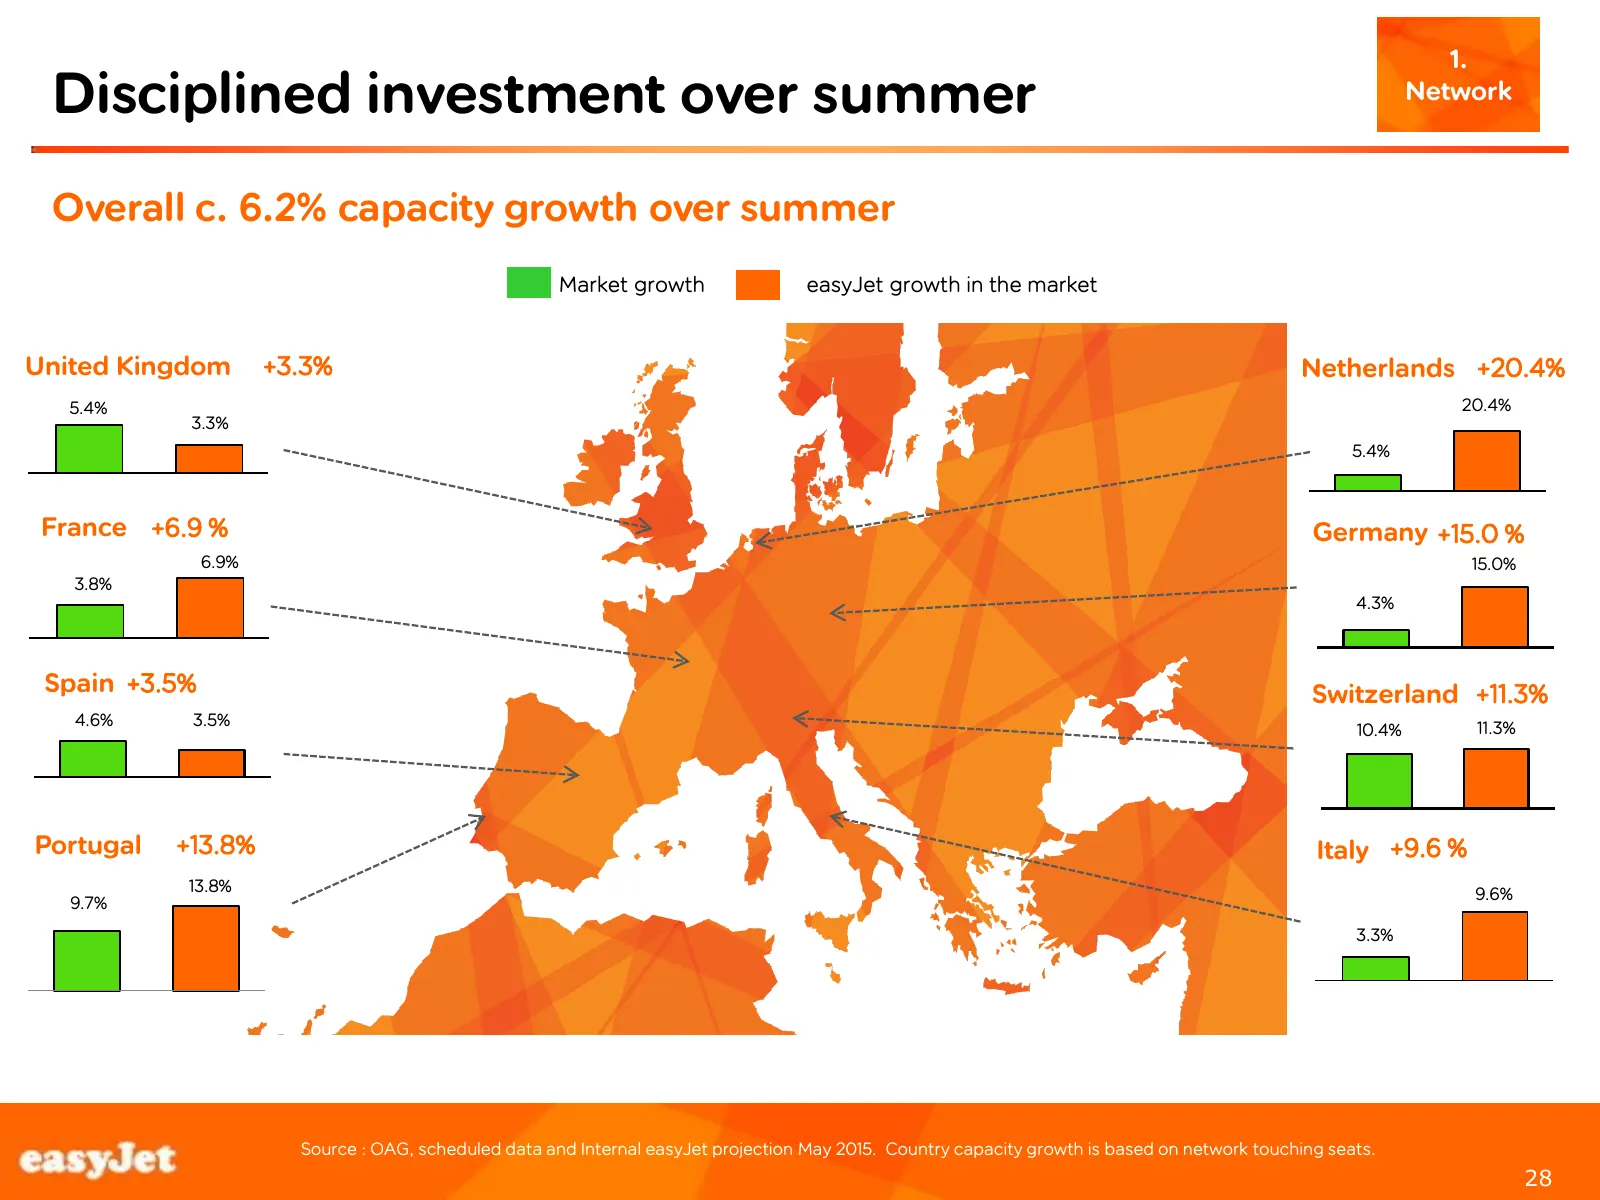
Slide 28: Disciplined investment over summer
1. Disciplined investment over summer Network Overall c. 6.2% capacity growth over summer Market growth easyJet growth in the market United Kingdom +3.3% Netherlands +20.4% 5.4% 20.4% 3.3% 5.4% France +6.9 % Germany +15.0 % 6.9% 15.0% 3.8% 4.3% Spain +3.5% Switzerland +11.3% 4.6% 3.5% 11.3% 10.4% Po
Slide 29: A unique network which is hard to replicate
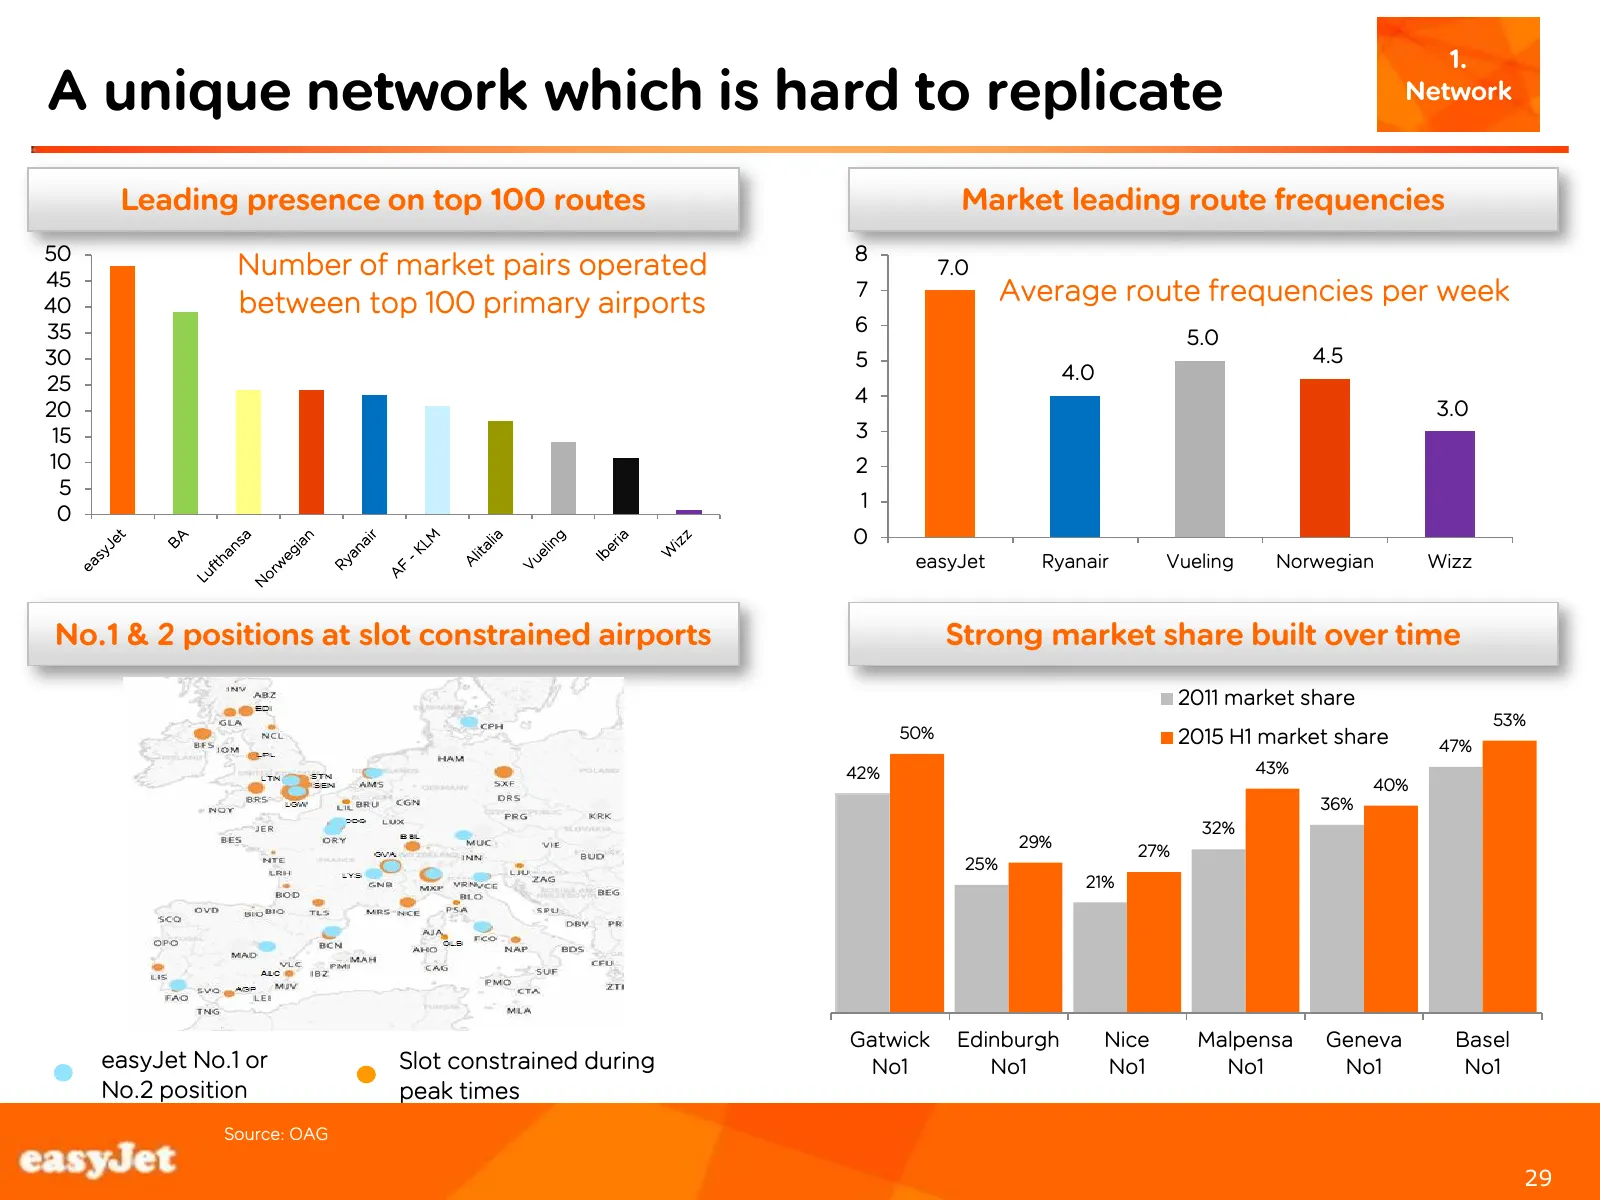
1. A unique network which is hard to replicate Network Leading presence on top 100 routes Market leading route frequencies 50 8 45 Number of market pairs operated 7.0 40 between top 100 primary airports 7 Average route frequencies per week 35 6 5.0 30 5 4.5 25 4.0 4 20 3.0 15 3 10 2 5 1 0 0 easyJet
Slide 30: Continuing to invest in the network
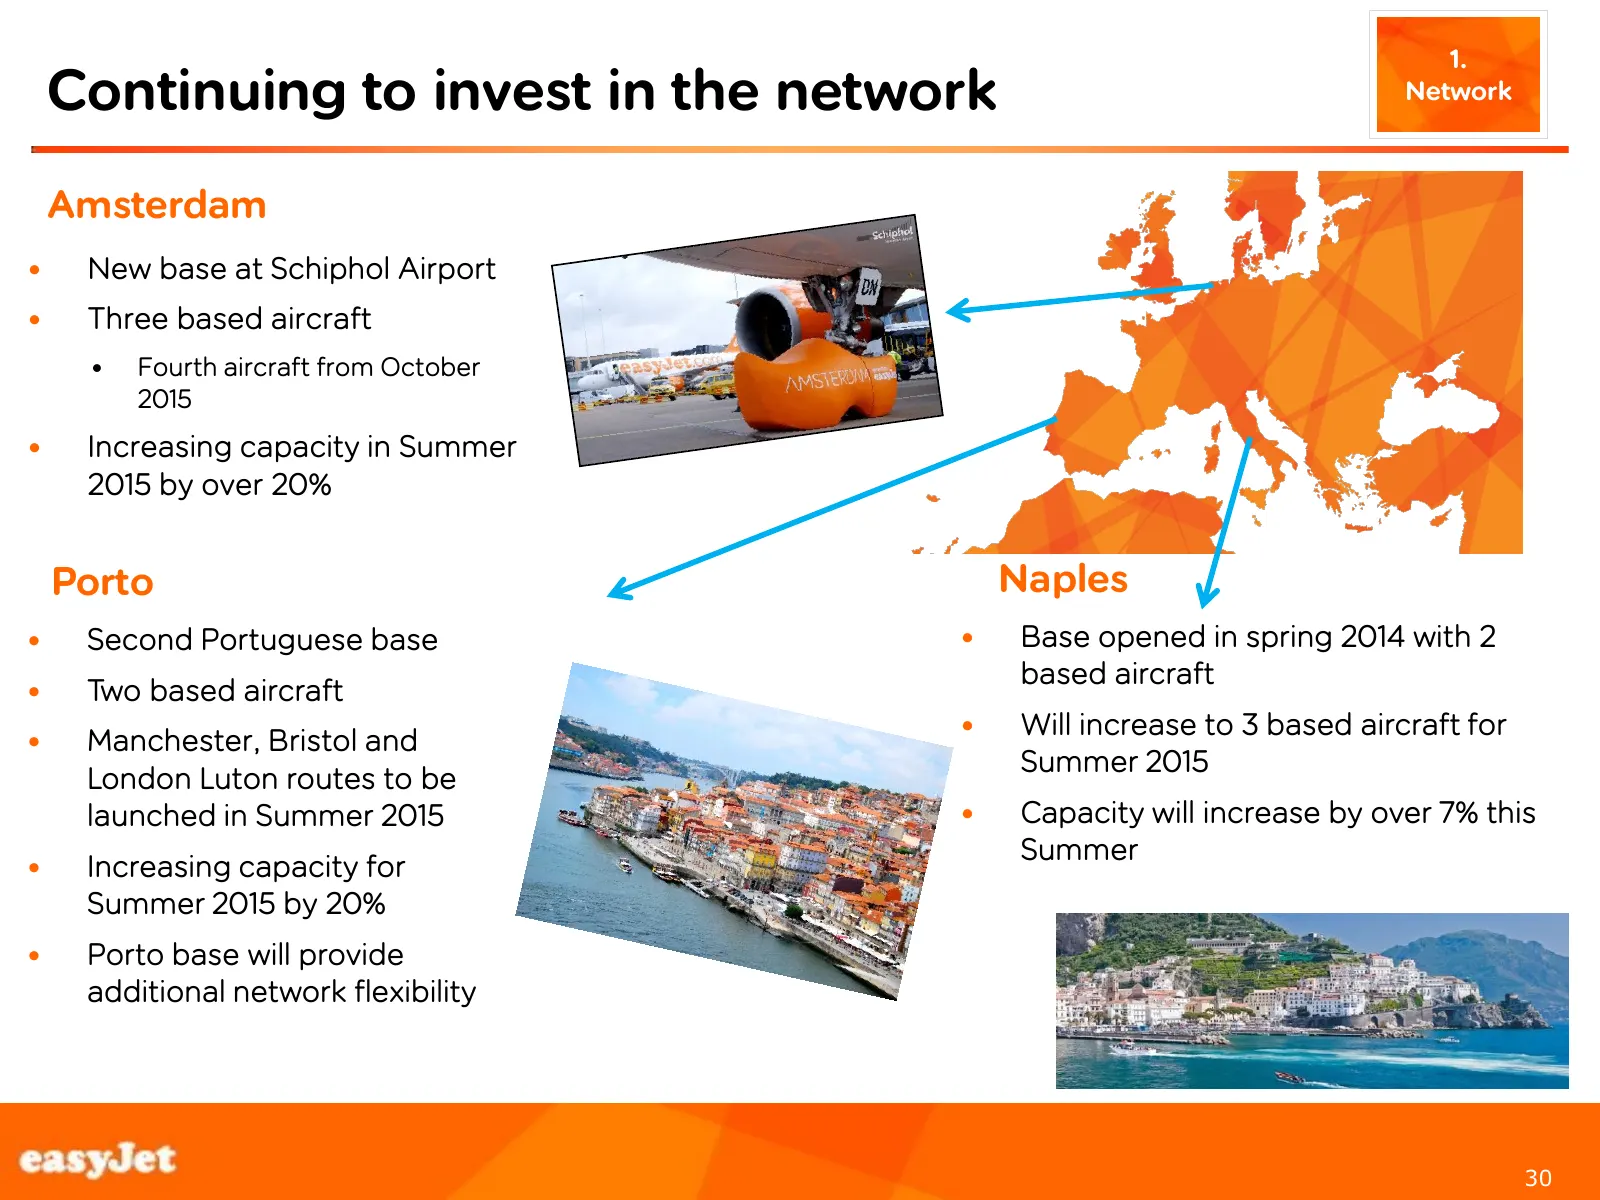
1. Continuing to invest in the network Network Amsterdam • New base at Schiphol Airport • Three based aircraft • Fourth aircraft from October 2015 • Increasing capacity in Summer 2015 by over 20% Porto Naples • Second Portuguese base • Base opened in spring 2014 with 2 based aircraft • Two based air
Slide 31: Proven yield model
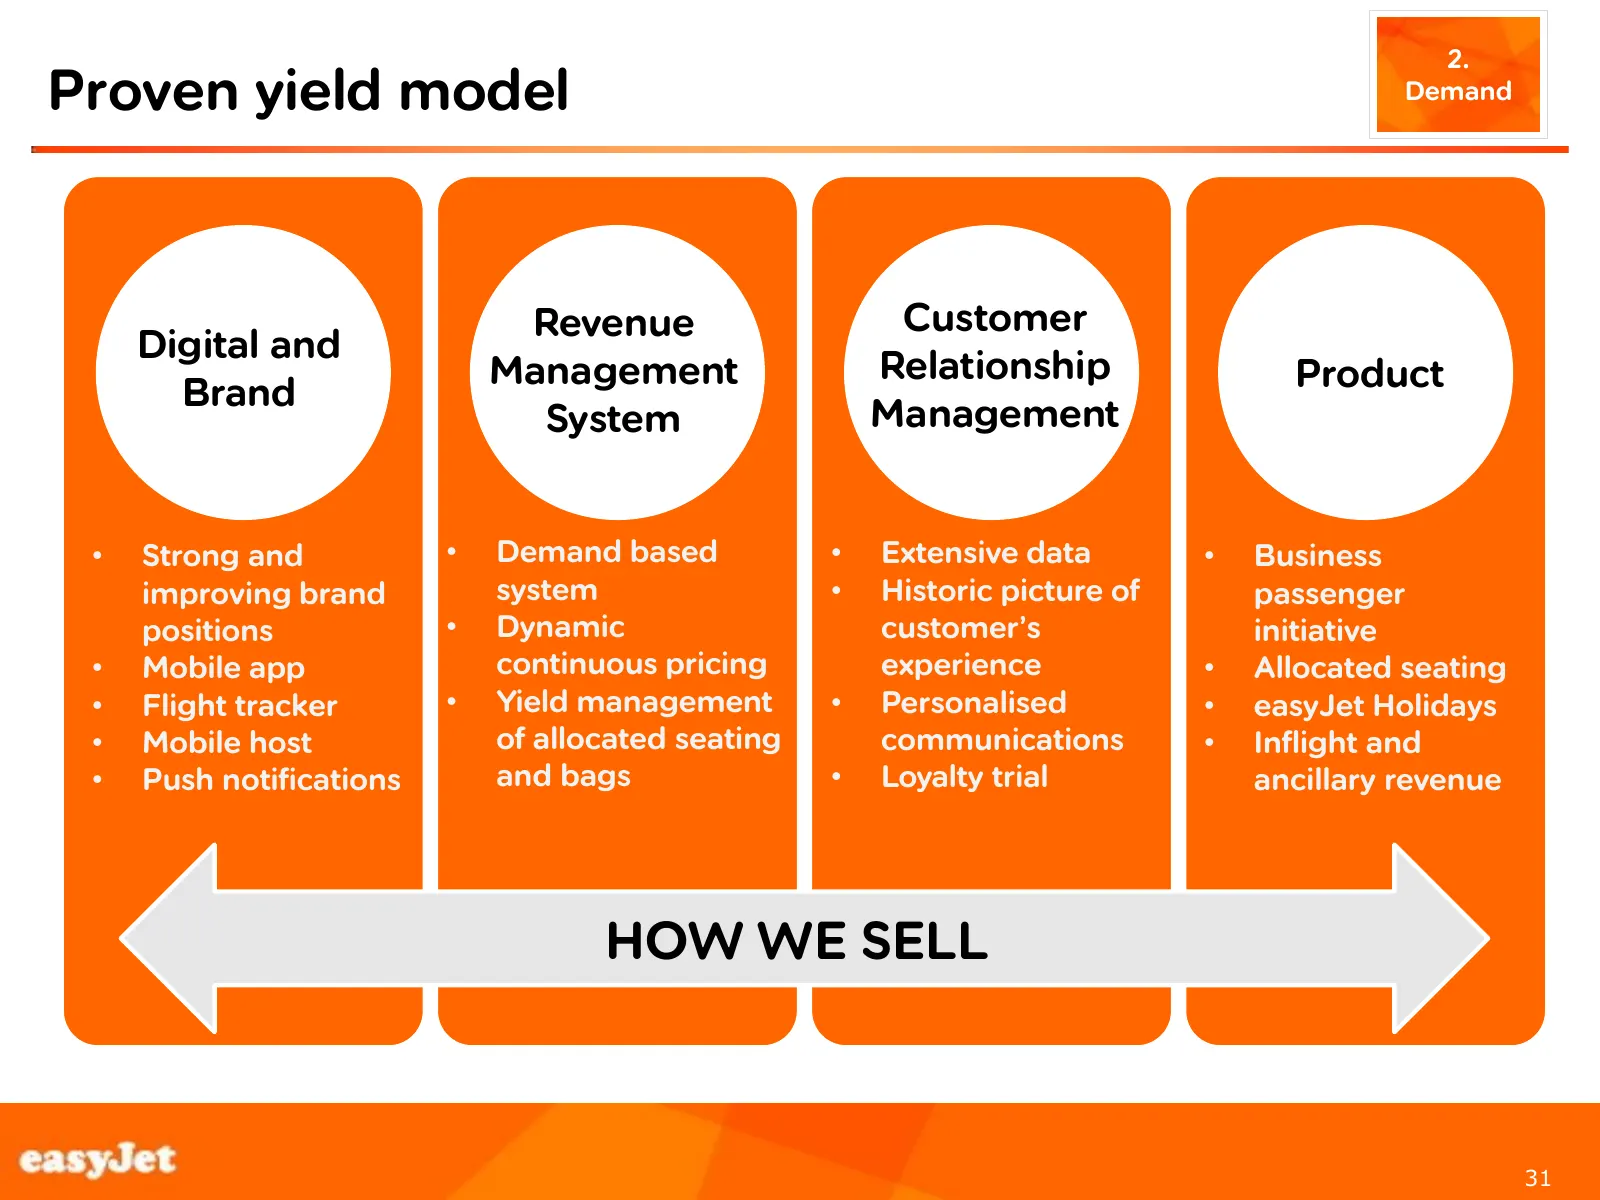
2. Proven yield model Demand Revenue Customer Digital and Management Relationship Product Brand System Management • Strong and • Demand based • Extensive data • Business improving brand system • Historic picture of passenger positions • Dynamic customer’s initiative • Mobile app continuous pricing e
Slide 32: Digital leadership
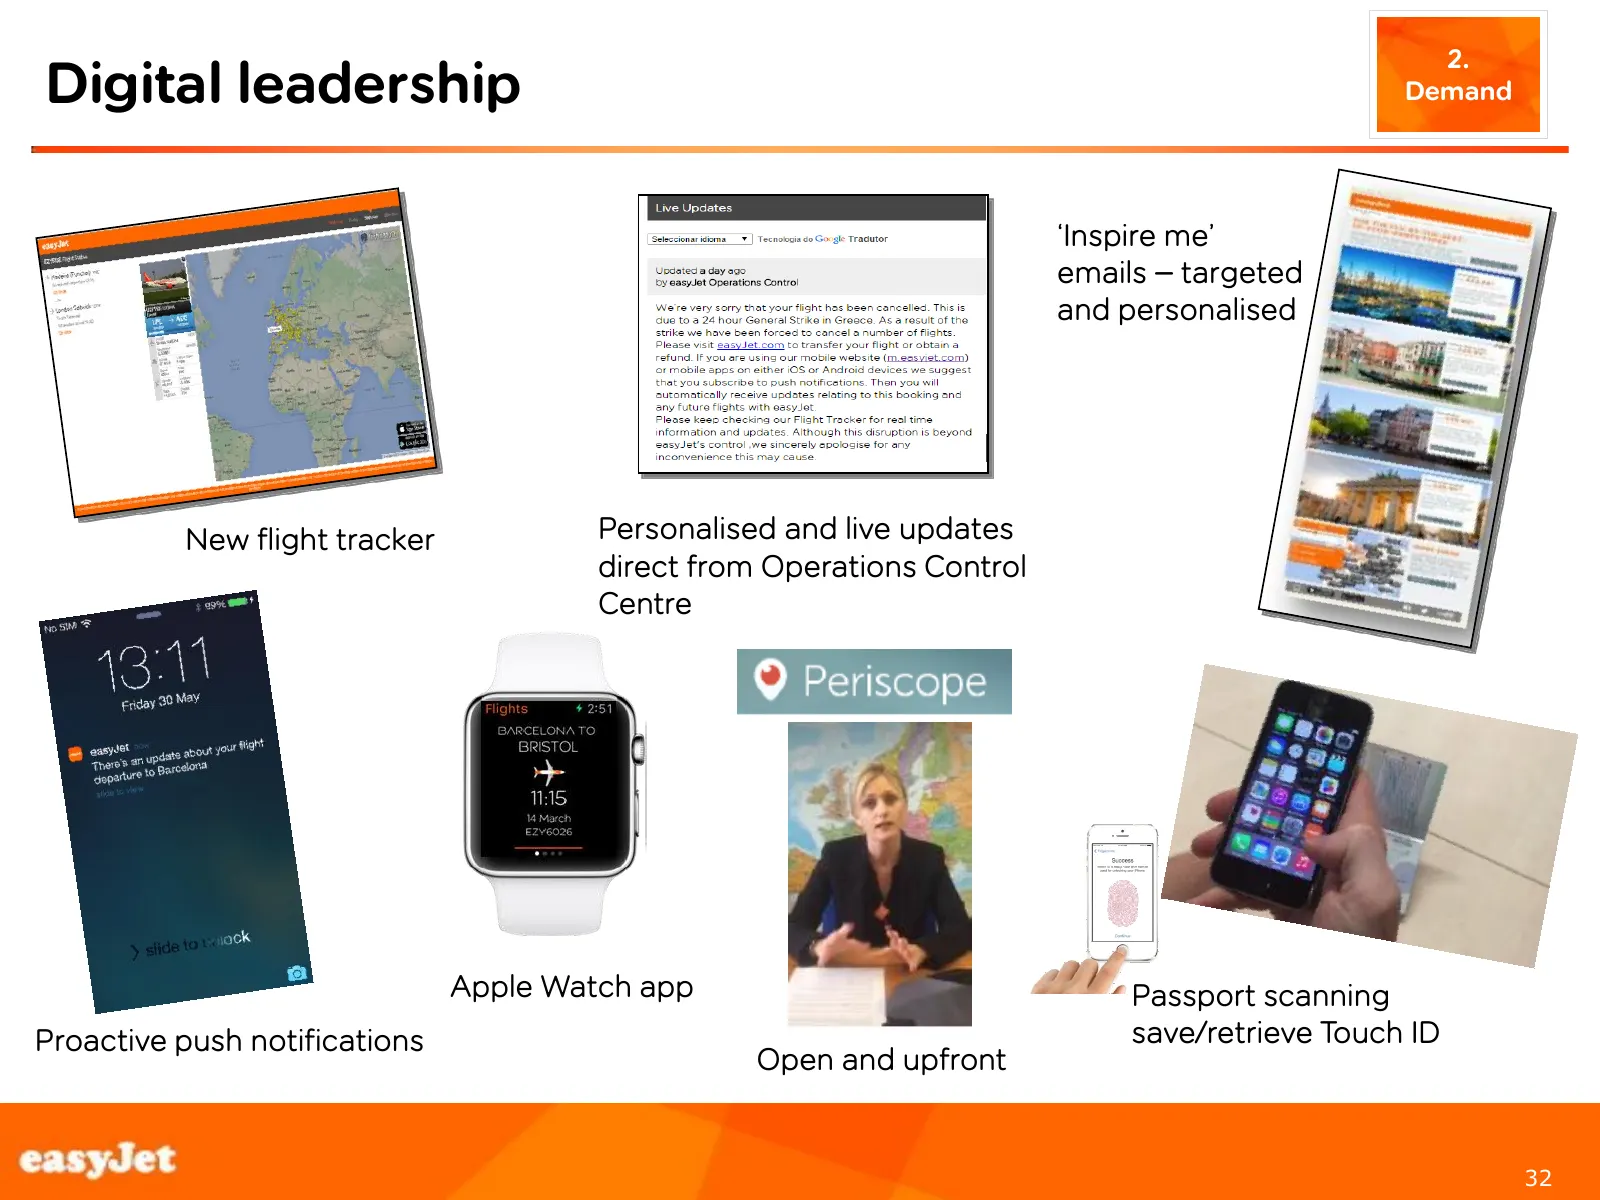
2. Digital leadership Demand ‘Inspire me’ emails – targeted and personalised New flight tracker Personalised and live updates direct from Operations Control Centre Footer box on intersect of lines line h=8.03 9 and v=8.75 with font 10pt Arial not bold Apple Watch app Passport scanning Proactive push
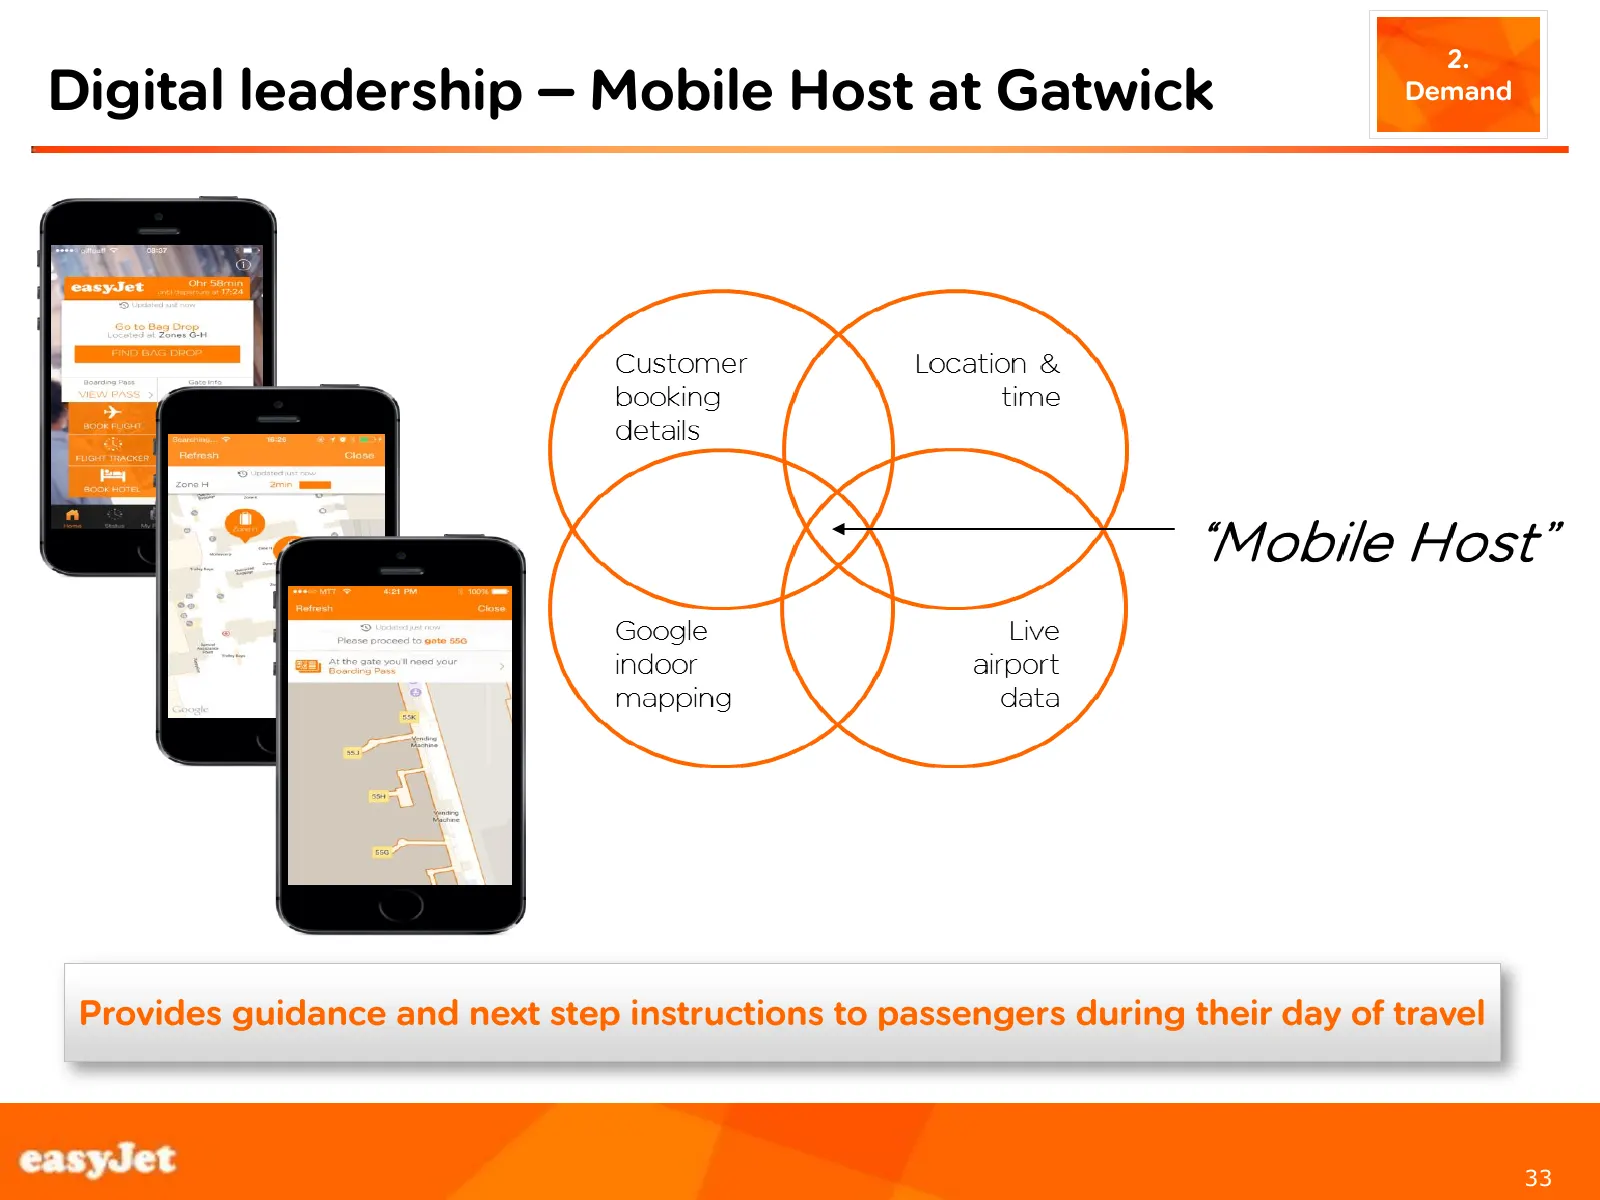
Slide 33: Digital leadership – Mobile Host at Gatwick
2. Digital leadership – Mobile Host at Gatwick Demand 3% Footer box on intersect of lines line h=8.03 9 and v=8.75 with font 10pt Arial not bold Provides guidance and next step instructions to passengers during their day of travel 33 33
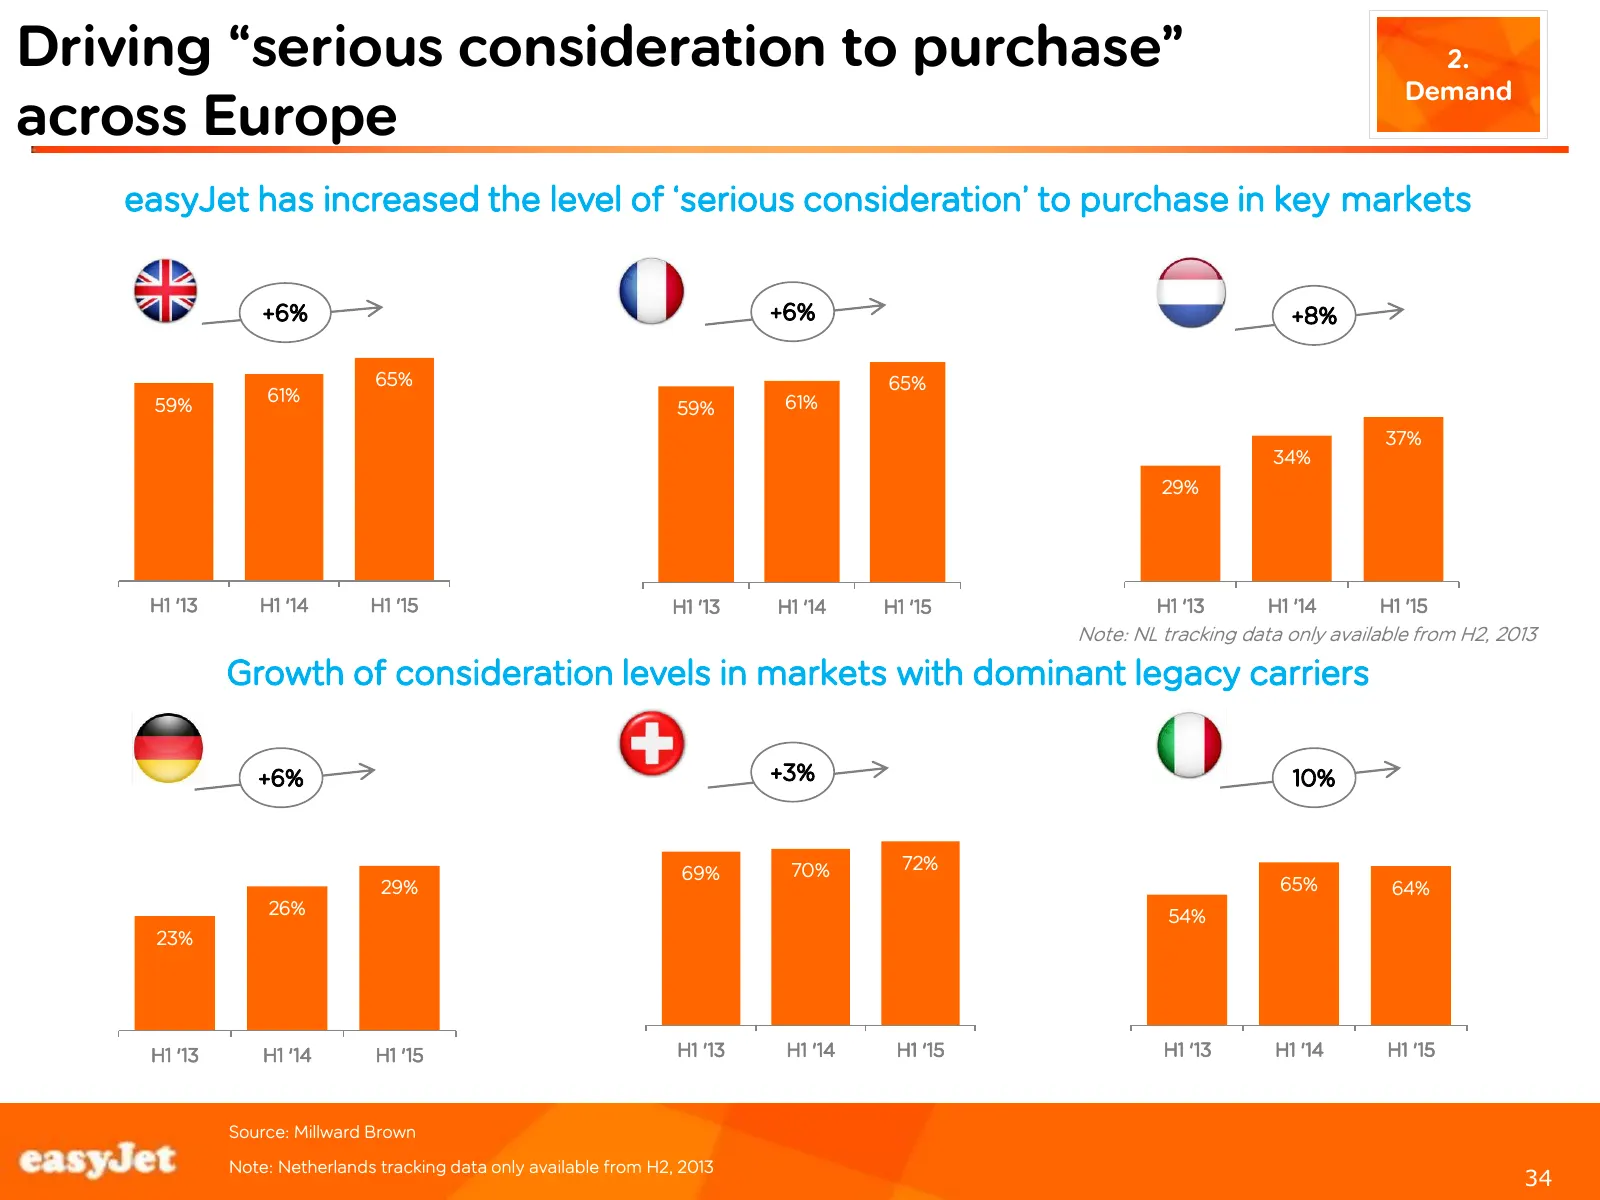
Slide 34: Driving serious consideration to purchase across Europe
Driving “serious consideration to purchase” 2. Demand across Europe easyJet has increased the level of ‘serious consideration’ to purchase in key markets +6% +6% +8% 65% 65% 59% 61% 61% 59% 37% 34% 29% H1 '13 H1 '14 H1 '15 H1 '13 H1 '14 H1 '15 H1 '13 H1 '14 H1 '15 Note: NL tracking data only availab
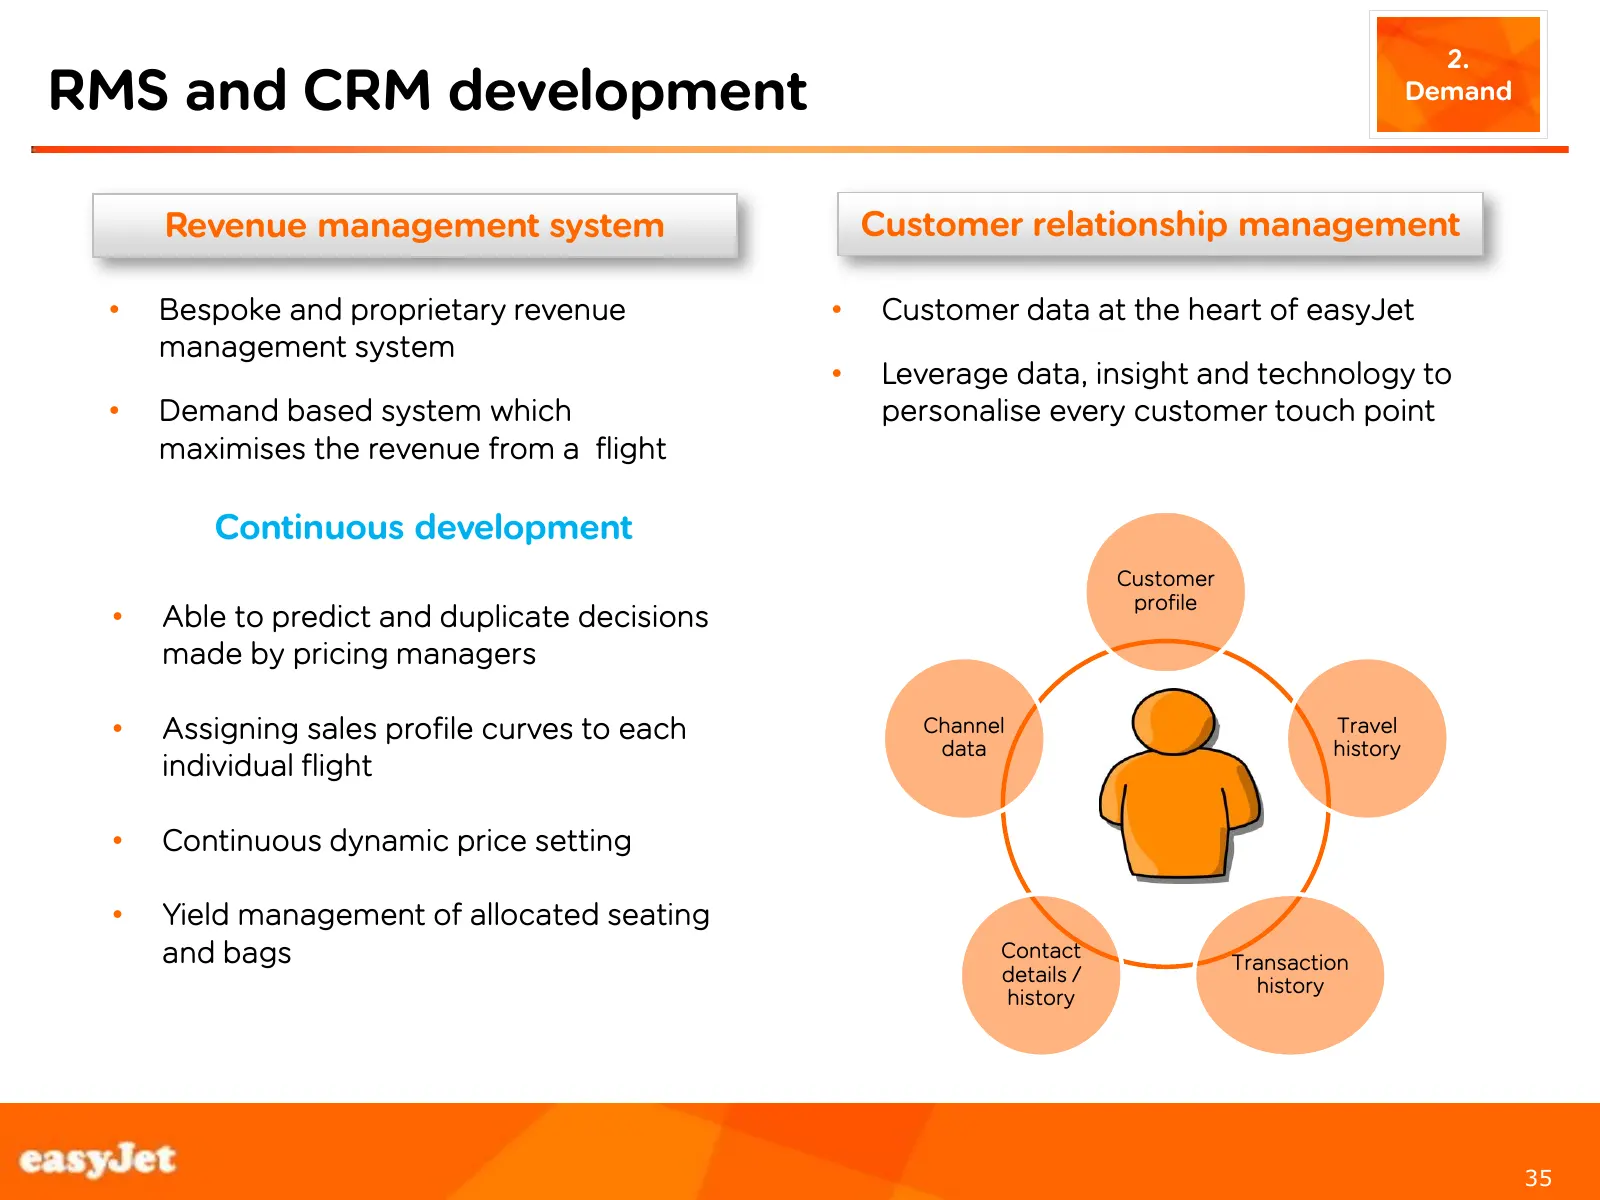
Slide 35: RMS and CRM development
2. RMS and CRM development Demand Revenue management system Customer relationship management • Bespoke and proprietary revenue • Customer data at the heart of easyJet management system • Leverage data, insight and technology to • Demand based system which personalise every customer touch point maxim
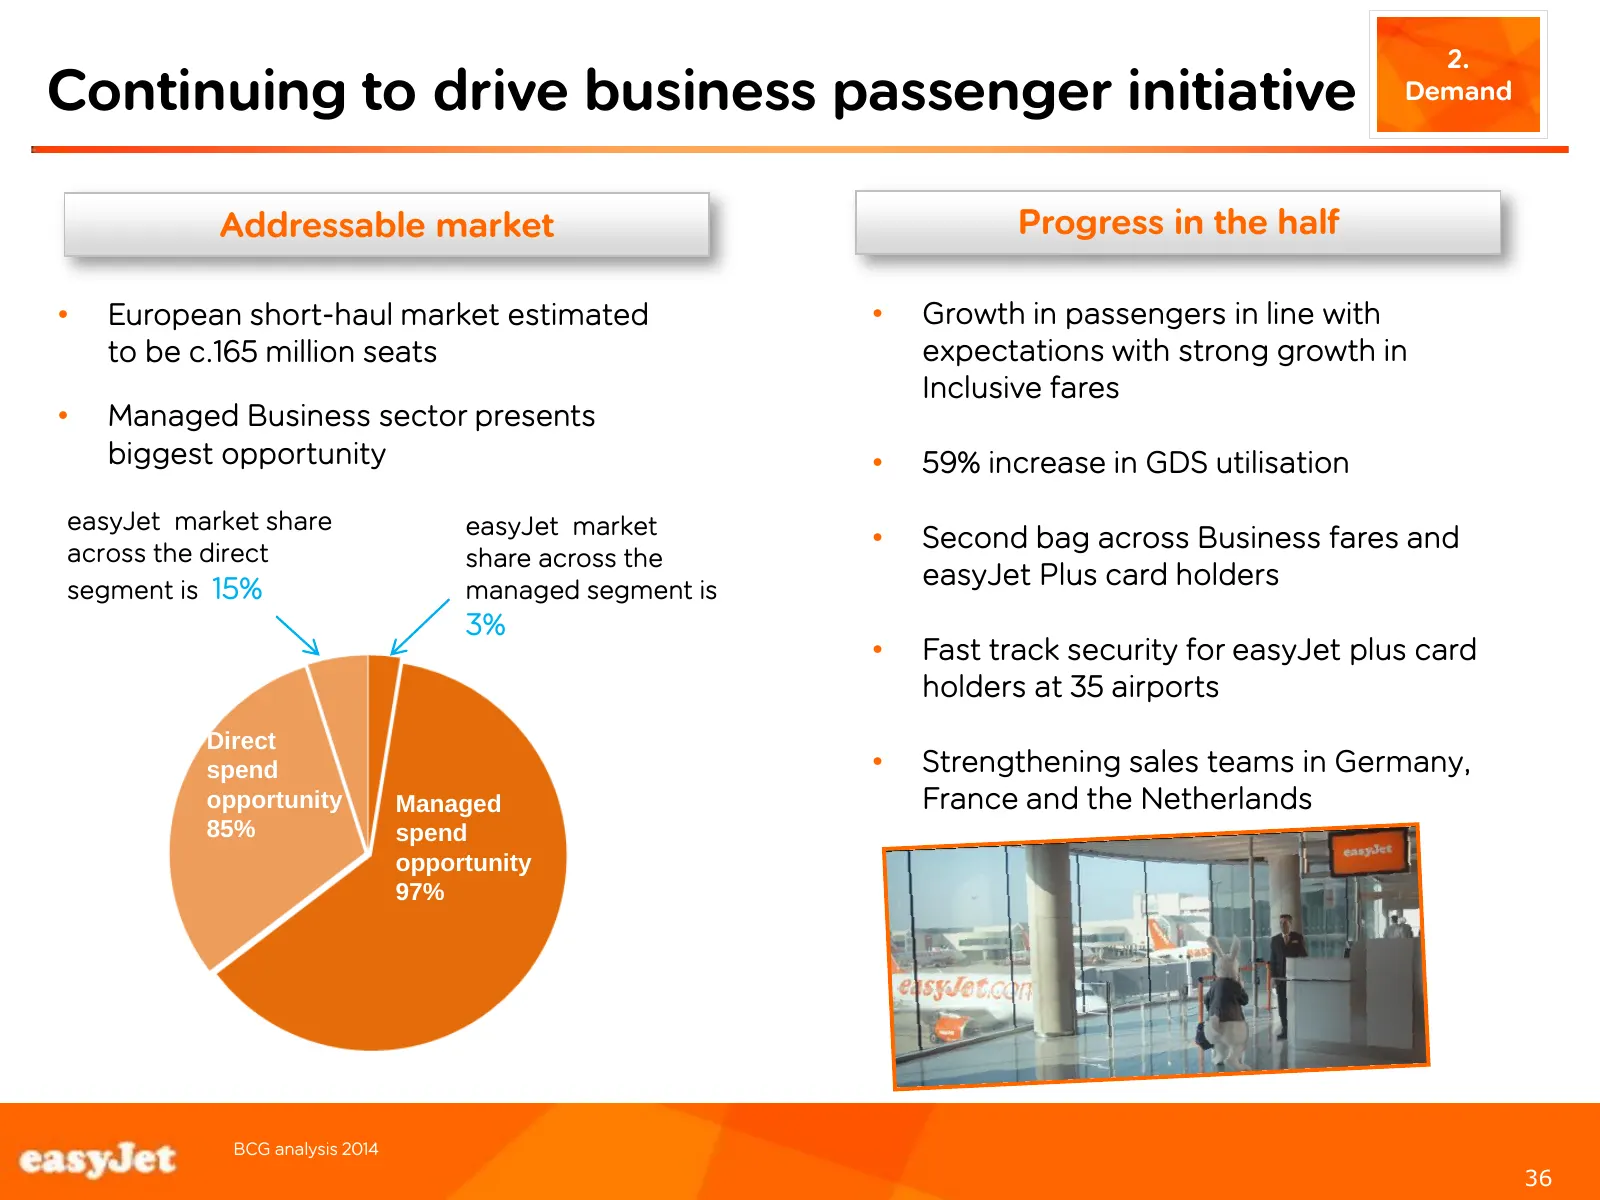
Slide 36: Continuing to drive business passenger initiative
2. Continuing to drive business passenger initiative Demand Addressable market Progress in the half • European short-haul market estimated • Growth in passengers in line with to be c.165 million seats expectations with strong growth in Inclusive fares • Managed Business sector presents biggest oppor
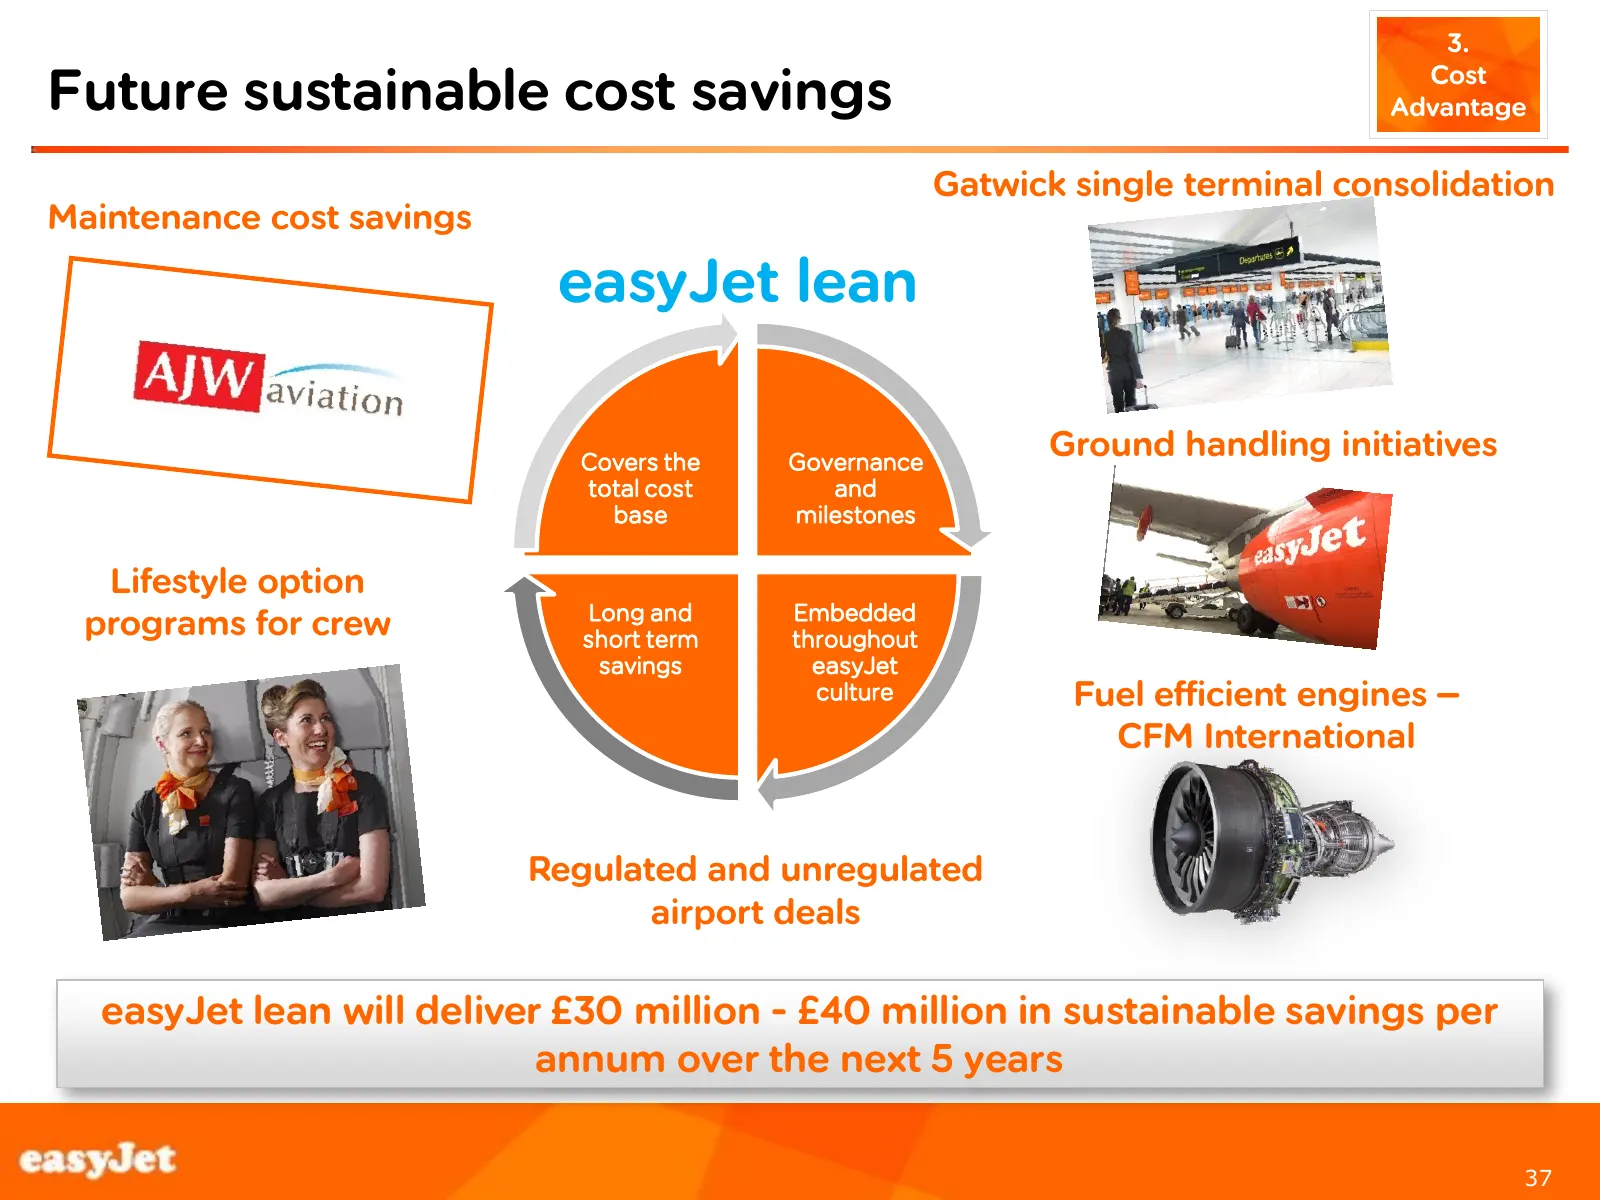
Slide 37: Future sustainable cost savings easyJet lean
3. Cost Future sustainable cost savings Advantage Gatwick single terminal consolidation Maintenance cost savings easyJet lean Covers the Governance Ground handling initiatives total cost and base milestones Lifestyle option Long and Embedded programs for crew short term throughout savings easyJet cu
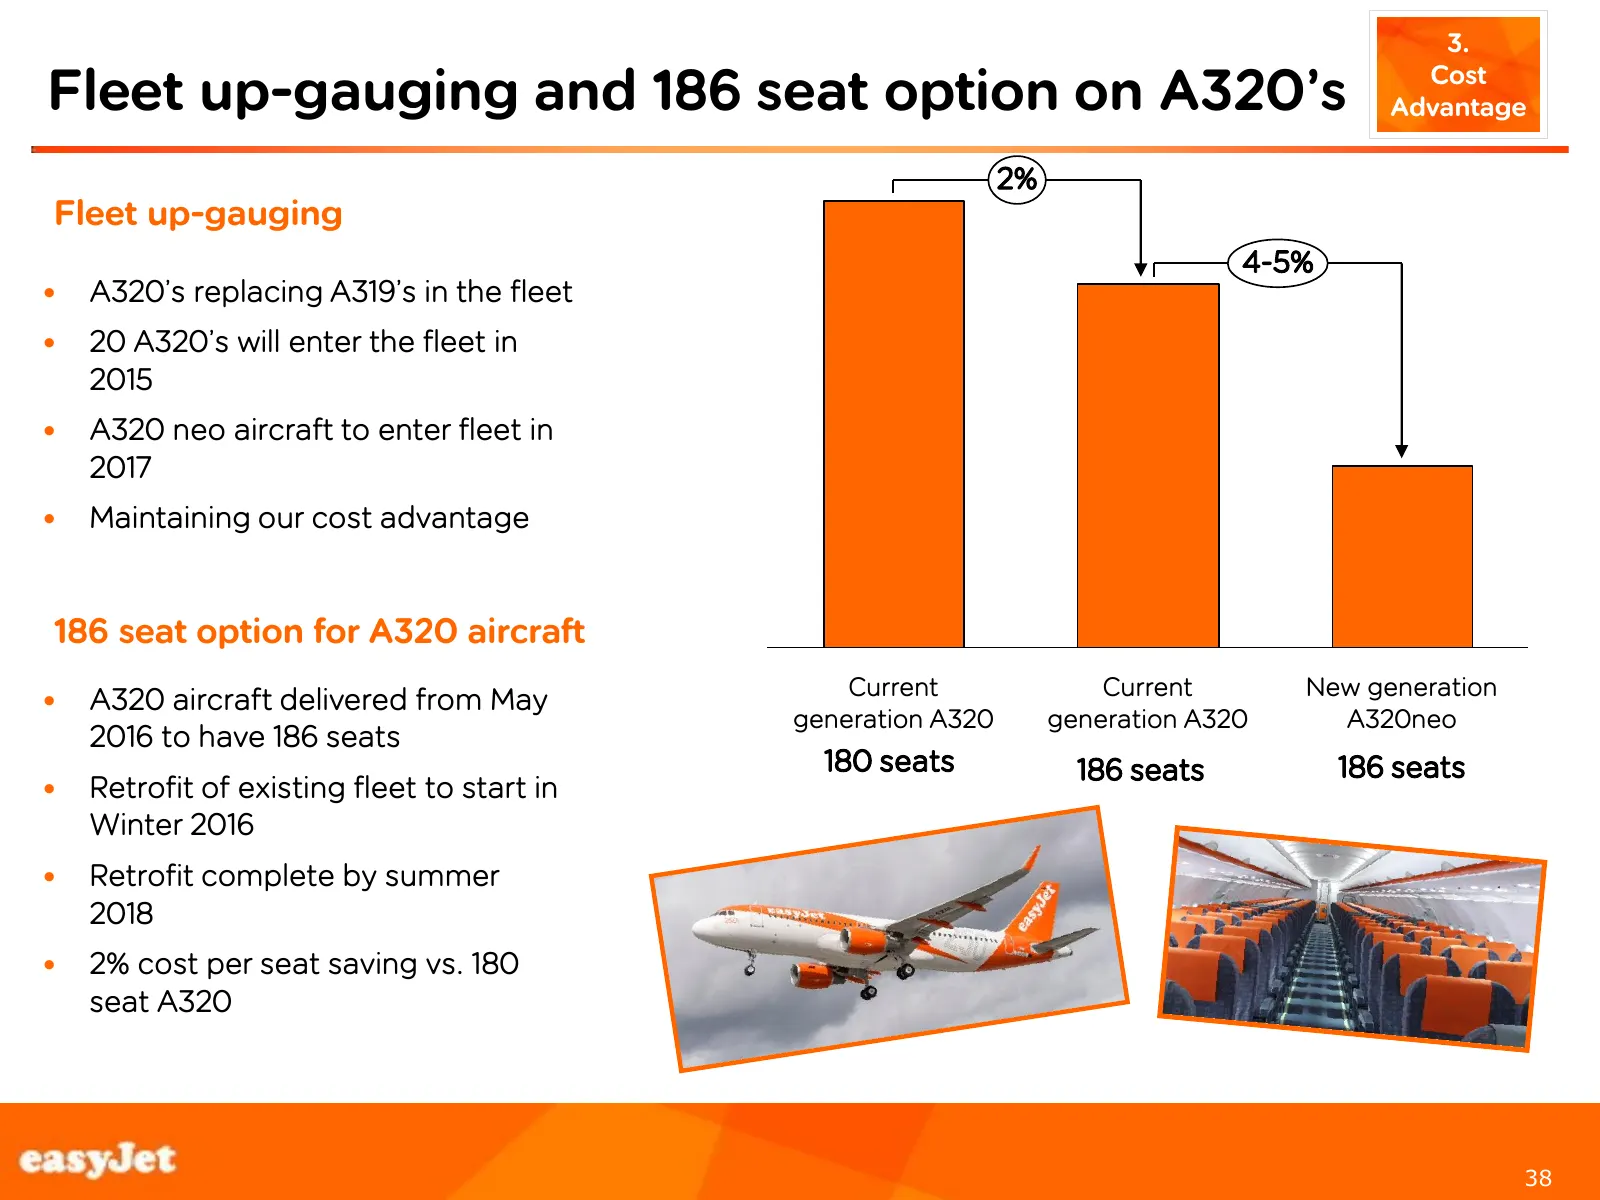
Slide 38: Fleet up-gauging and 186 seat option on A320's
3. Cost Fleet up-gauging and 186 seat option on A320’s Advantage 2% Fleet up-gauging 4-5% • A320’s replacing A319’s in the fleet • 20 A320’s will enter the fleet in 2015 • A320 neo aircraft to enter fleet in 2017 • Maintaining our cost advantage 186 seat option for A320 aircraft Current Current New
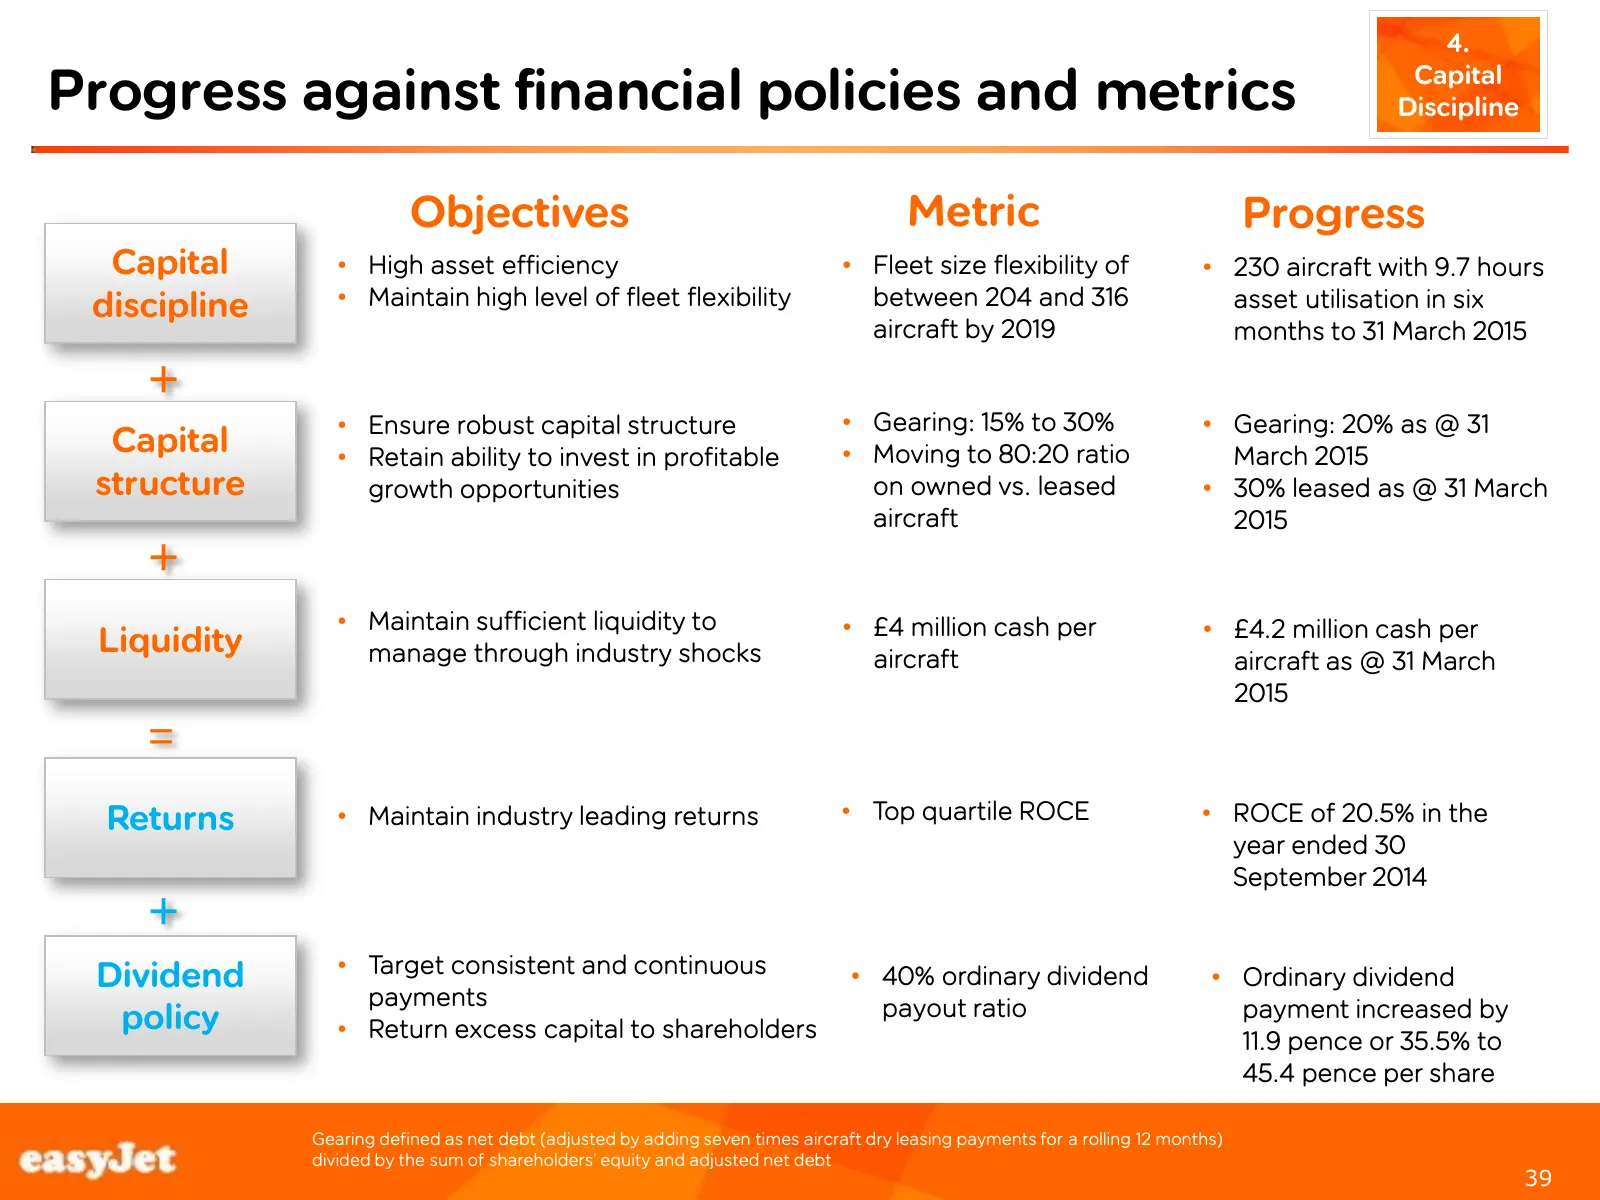
Slide 39: Progress against financial policies and metrics
4. Capital Progress against financial policies and metrics Discipline Objectives Metric Progress Capital • High asset efficiency • Fleet size flexibility of • 230 aircraft with 9.7 hours discipline • Maintain high level of fleet flexibility between 204 and 316 asset utilisation in six aircraft by 20
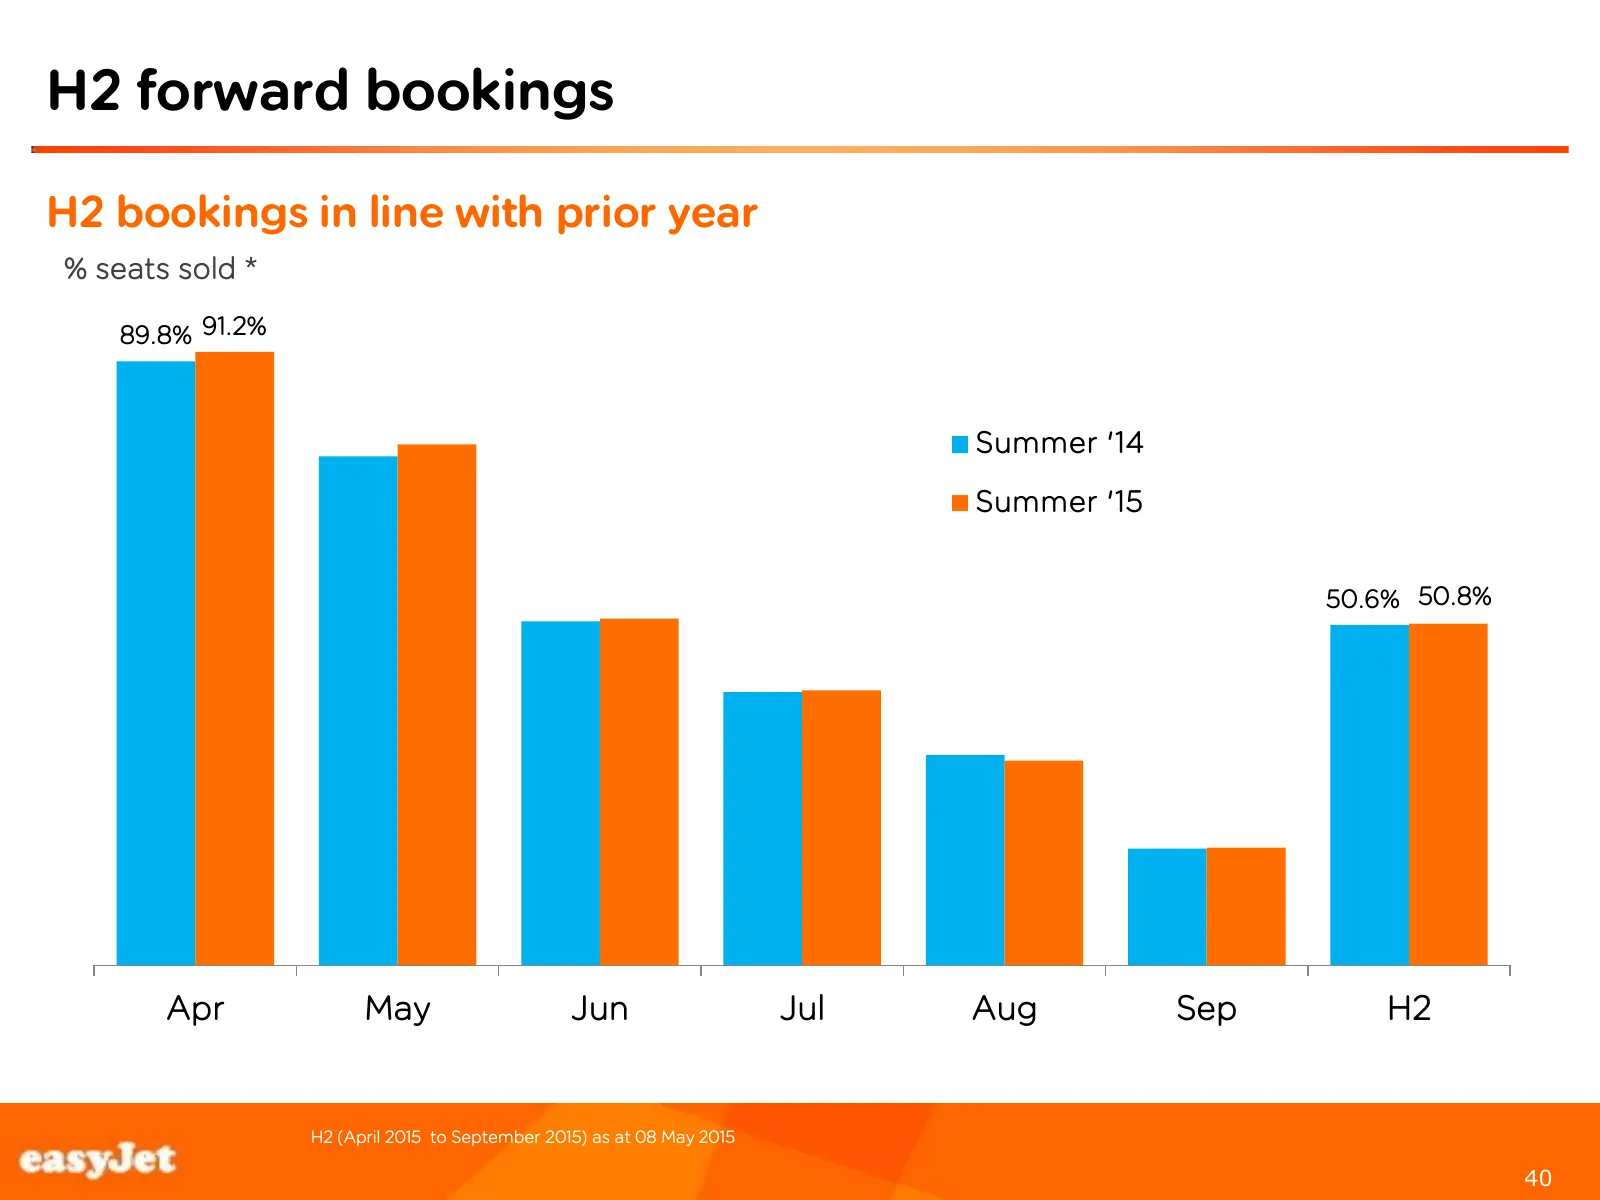
Slide 40: H2 forward bookings
H2 forward bookings H2 bookings in line with prior year % seats sold * 89.8% 91.2% Summer '14 Summer '15 50.6% 50.8% Footer box on intersect of lines line h=8.03 9 and v=8.75 with font 10pt Arial not bold Apr May Jun Jul Aug Sep H2 H2 (April 2015 to September 2015) as at 08 May 2015 40 40
Slide 41: Outlook
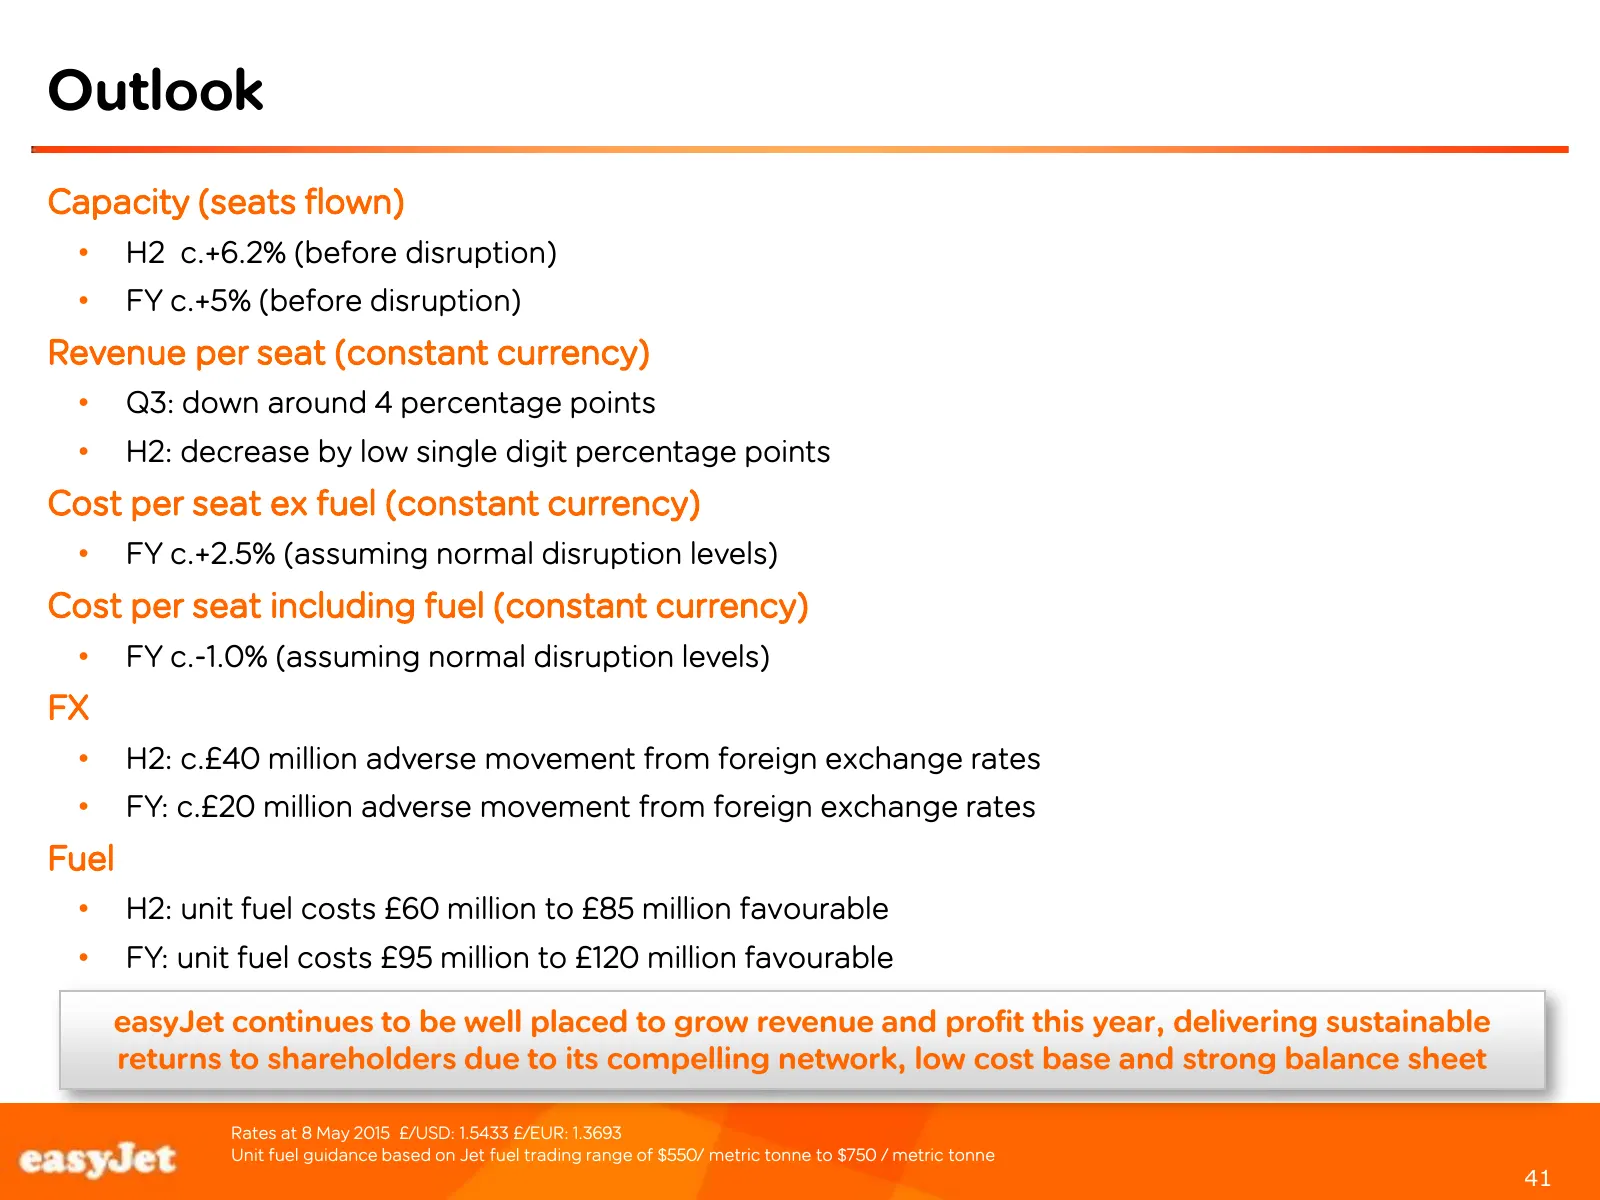
Outlook Capacity (seats flown) • H2 c.+6.2% (before disruption) • FY c.+5% (before disruption) Revenue per seat (constant currency) • Q3: down around 4 percentage points • H2: decrease by low single digit percentage points Cost per seat ex fuel (constant currency) • FY c.+2.5% (assuming normal disru
Slide 42: Summary
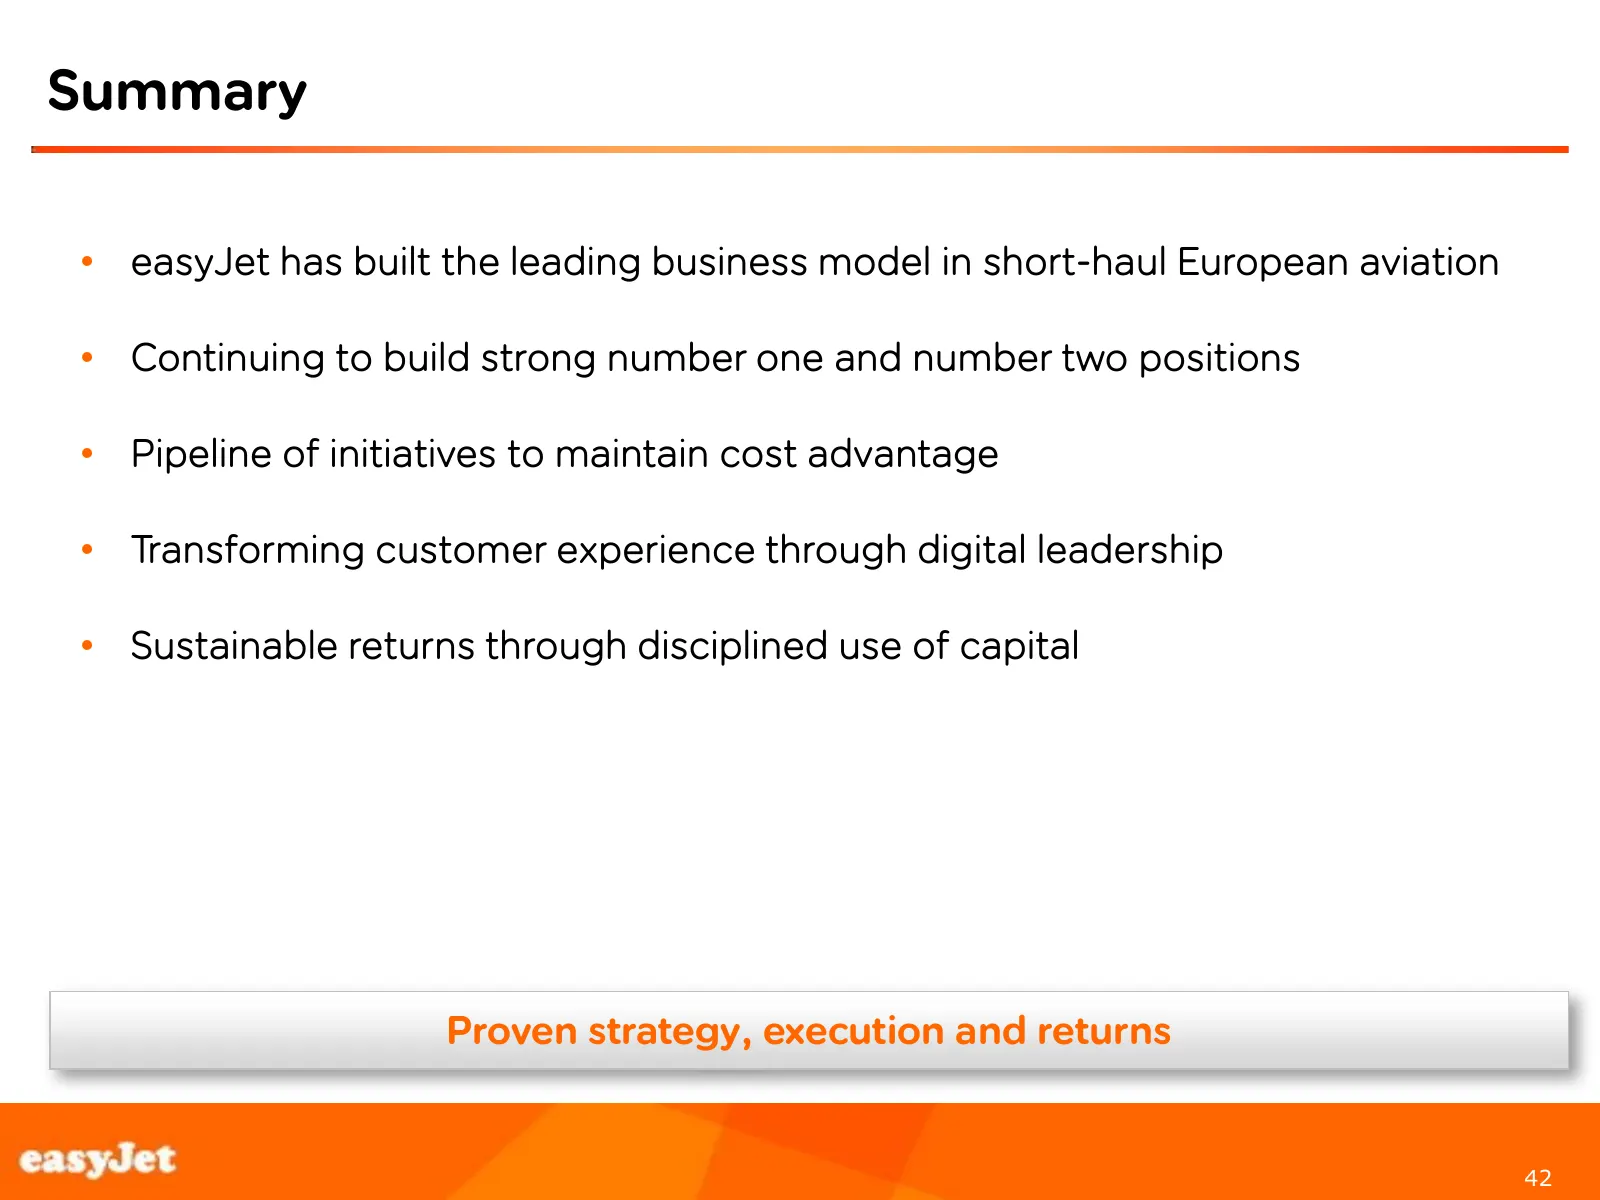
Summary • easyJet has built the leading business model in short-haul European aviation • Continuing to build strong number one and number two positions • Pipeline of initiatives to maintain cost advantage • Transforming customer experience through digital leadership • Sustainable returns through dis
Slide 43: Q&A
Q&A
Slide 44: Appendix
ro ~ APPENDIX ye
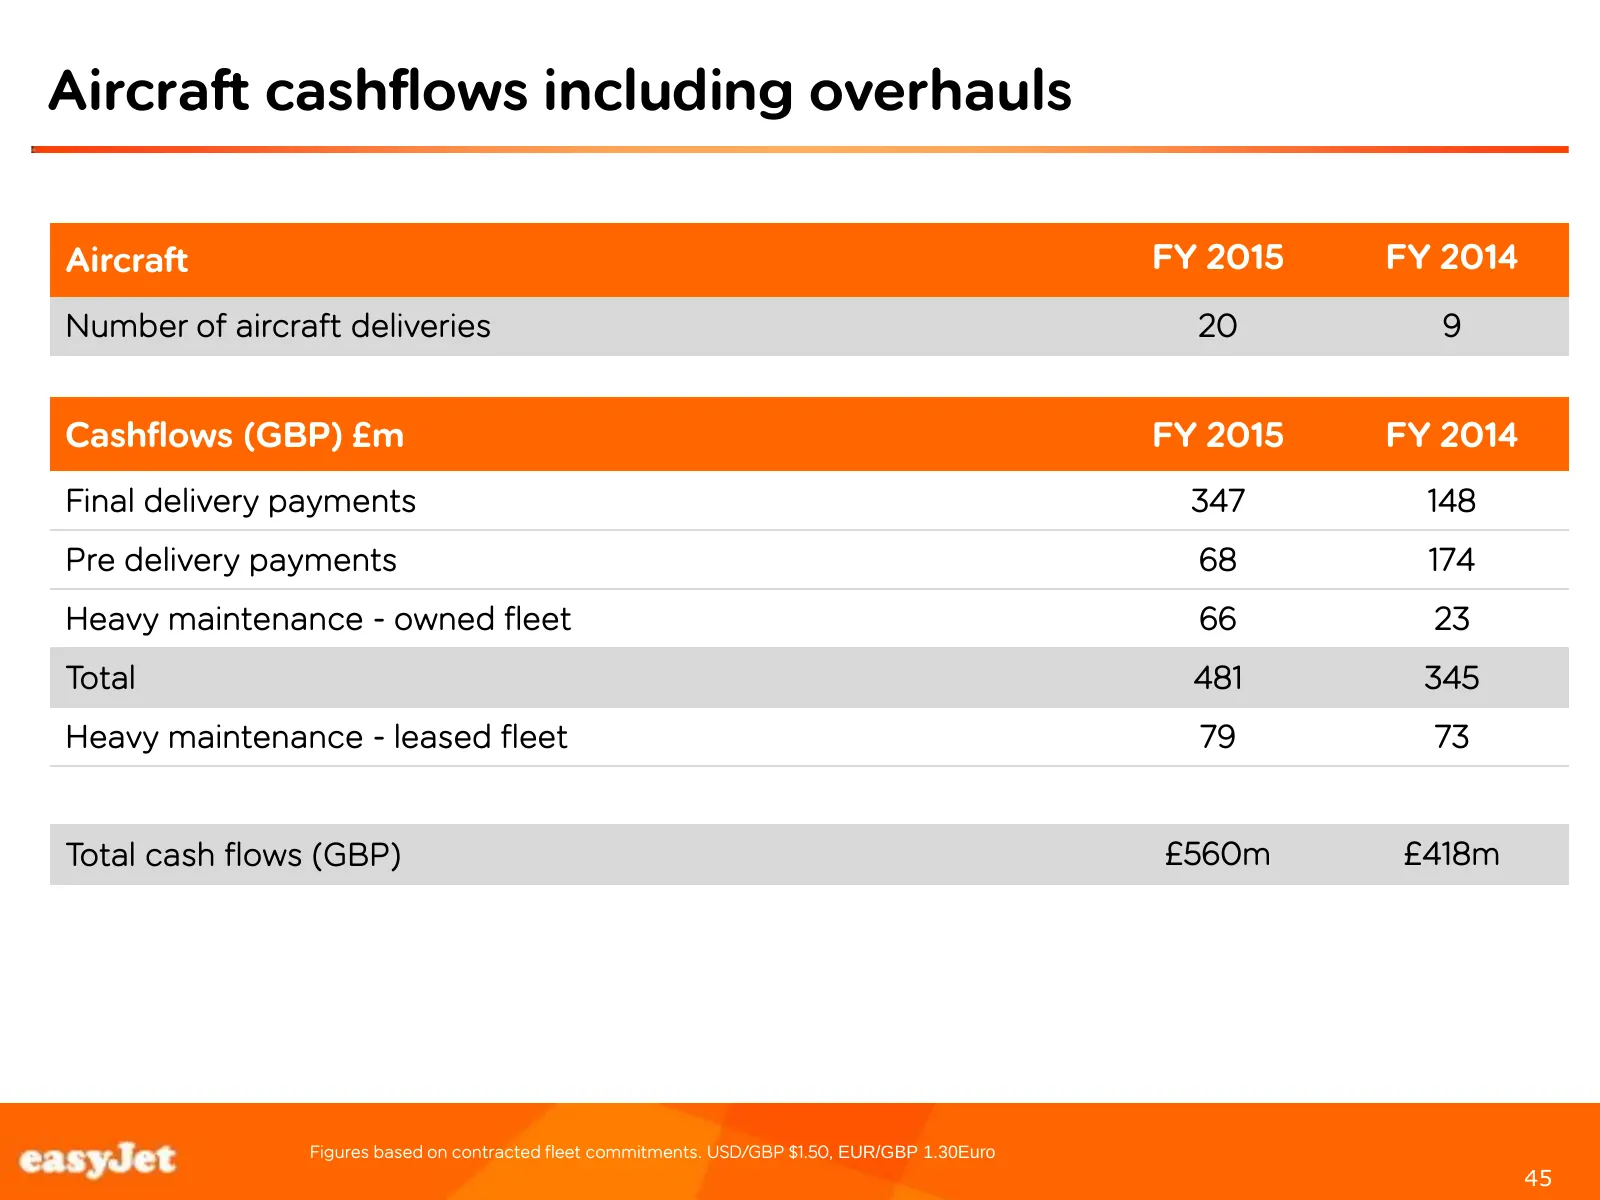
Slide 45: Aircraft cashflows including overhauls
Aircraft cashflows including overhauls Aircraft FY 2015 FY 2014 Number of aircraft deliveries 20 9 Cashflows (GBP) £m FY 2015 FY 2014 Final delivery payments 347 148 Pre delivery payments 68 174 Heavy maintenance - owned fleet 66 23 Total 481 345 Heavy maintenance - leased fleet 79 73 Total cash flo
Slide 46: Disclaimer
Disclaimer Certain statements in this presentation constitute or may constitute forward-looking statements. Any statement in this presentation that is not a statement of historical fact including, without limitation, those regarding the Company’s future expectations, operations, financial performanc
Source: company website
More decks from easyJet plc
 H1 2026 Earnings Presentation43 slides · May 21, 2026
 Investor Day (November 2025)24 slides · Nov 28, 2025
 FY2025 Earnings Presentation41 slides · Nov 25, 2025
 H1 2025 Earnings Presentation37 slides · May 22, 2025
 FY2024 Earnings Presentation34 slides · Nov 27, 2024
 Investor Day (June 2024)17 slides · Jun 20, 2024