Aleris International — Debt Investor Presentation (July 2006)
52 slides from Aleris International's debt investor presentation, Jul 11, 2006
Slide 1: Presentation to Public Lenders
Exhibit 99.2 Presentation to Public Lenders July 12, 2006
Slide 2: Safe Harbor
Safe Harbor Statements contained in this presentation that state the Company’s or its management’s expectations or predictions of the future are forward-looking statements intended to be covered by the safe harbor provisions of the Securities Act of 1933 and the Securities Exchange Act of 1934. The
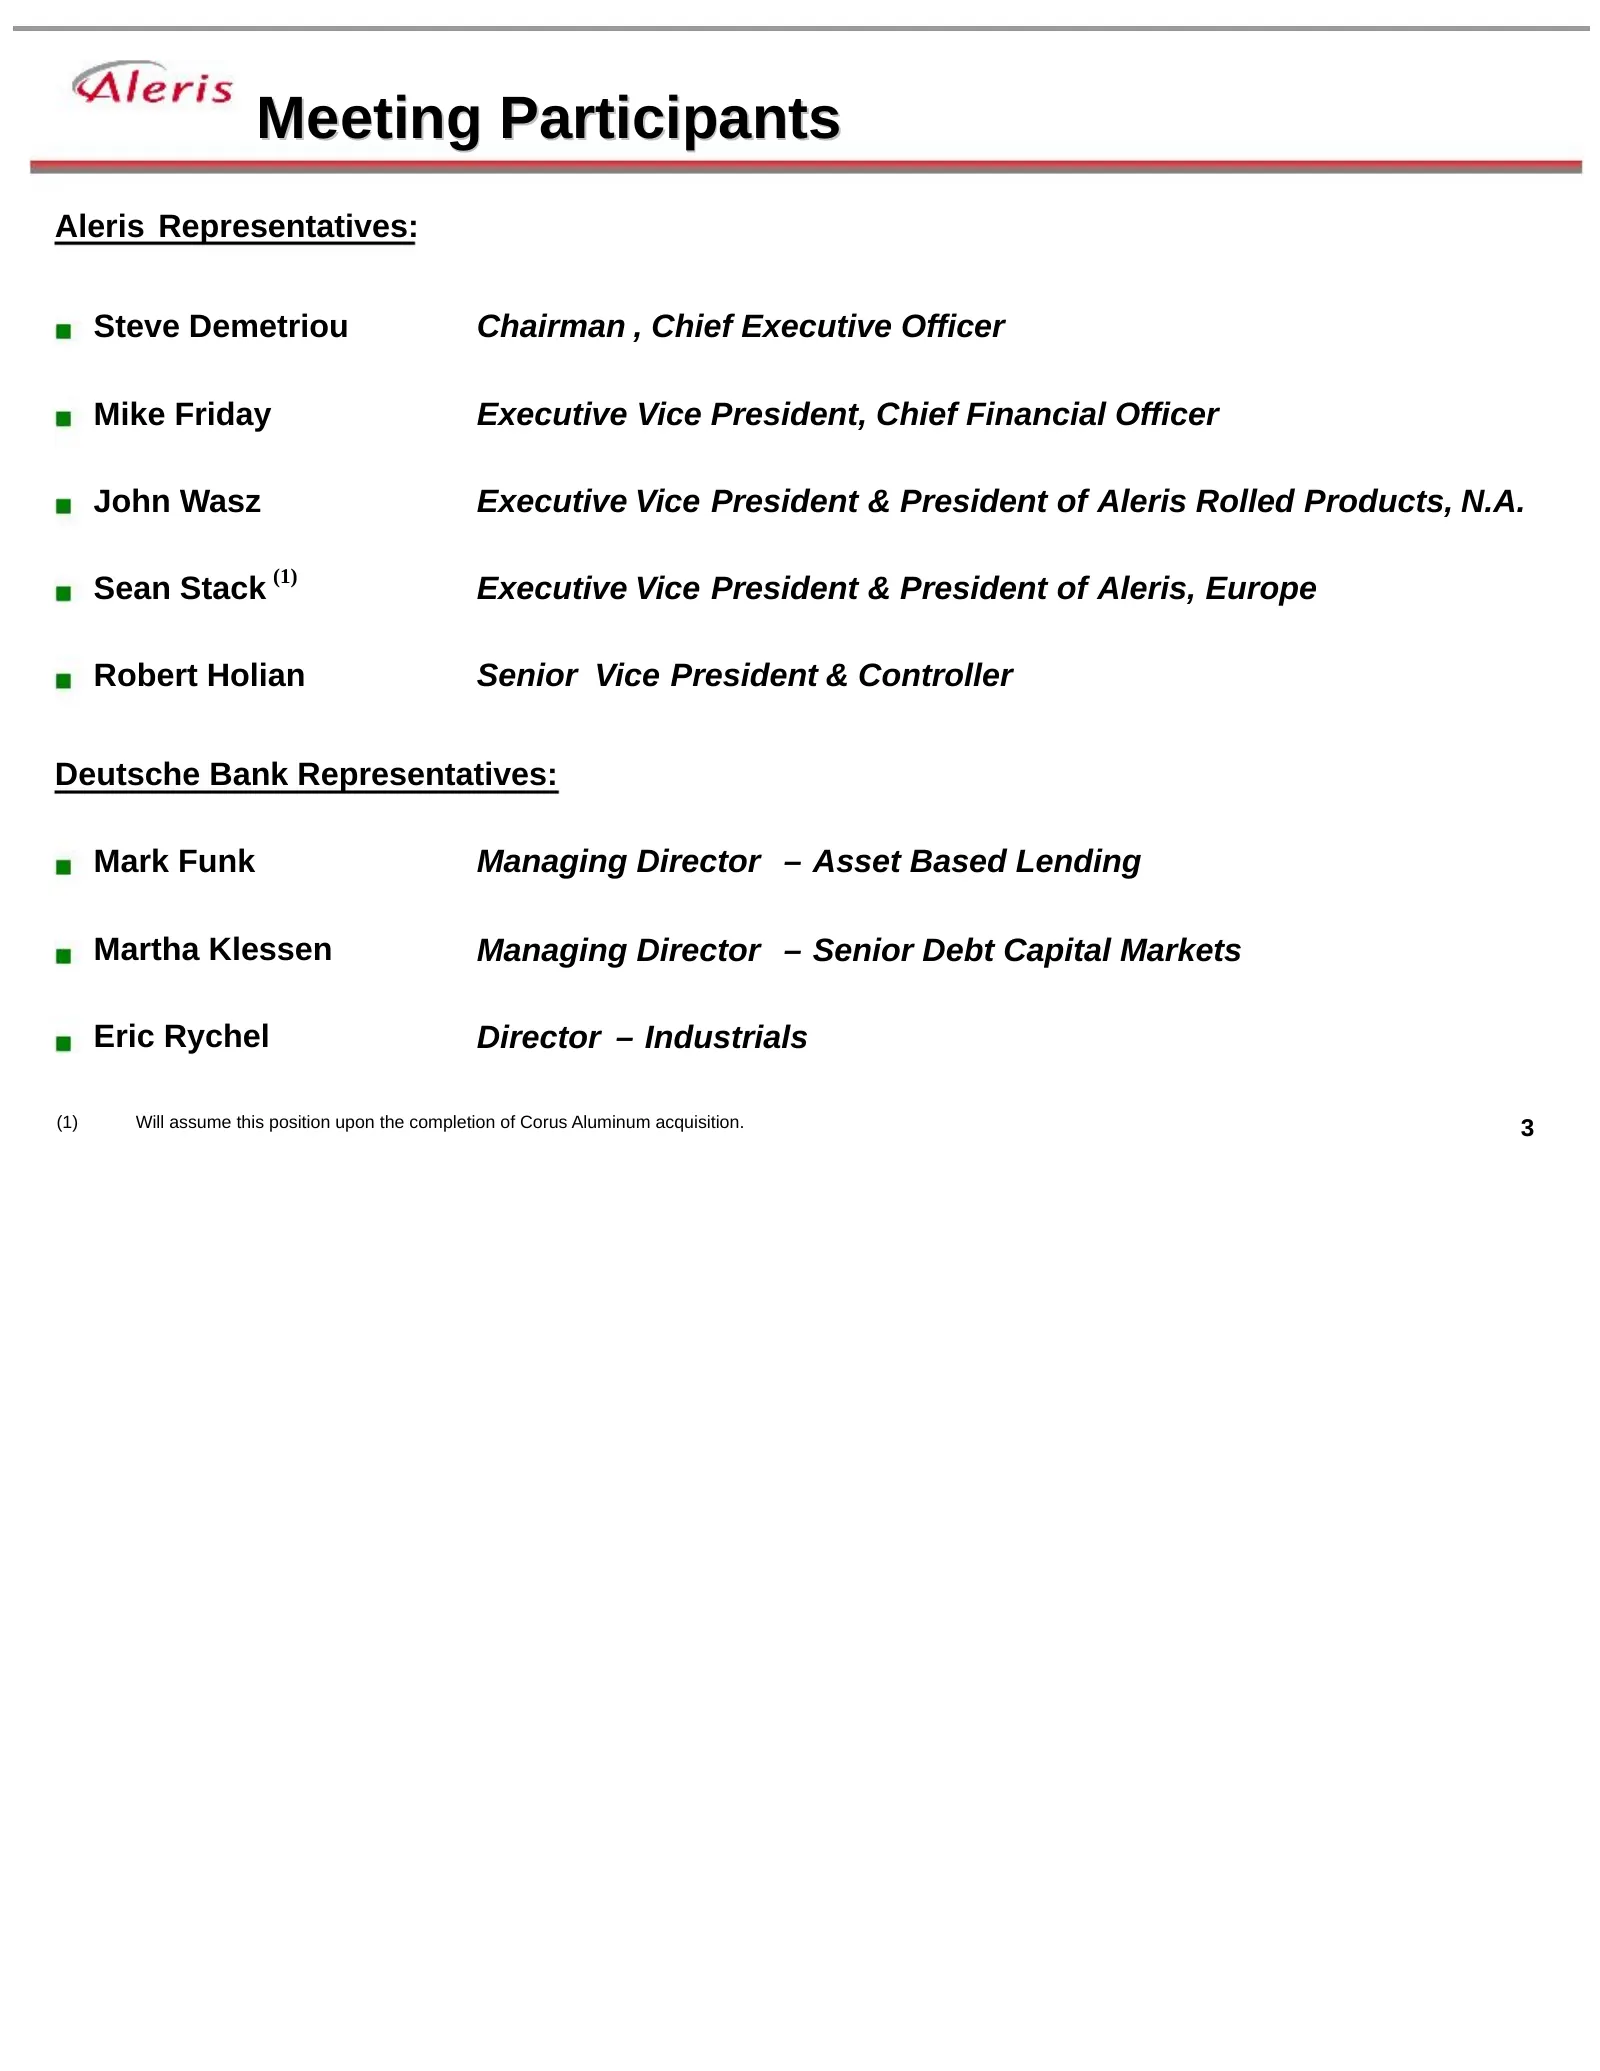
Slide 3: Meeting Participants
Meeting Participants Aleris Representatives: Steve Demetriou Chairman , Chief Executive Officer Mike Friday Executive Vice President, Chief Financial Officer John Wasz Executive Vice President & President of Aleris Rolled Products, N.A. Sean Stack (1) Executive Vice President & President of Aleris,
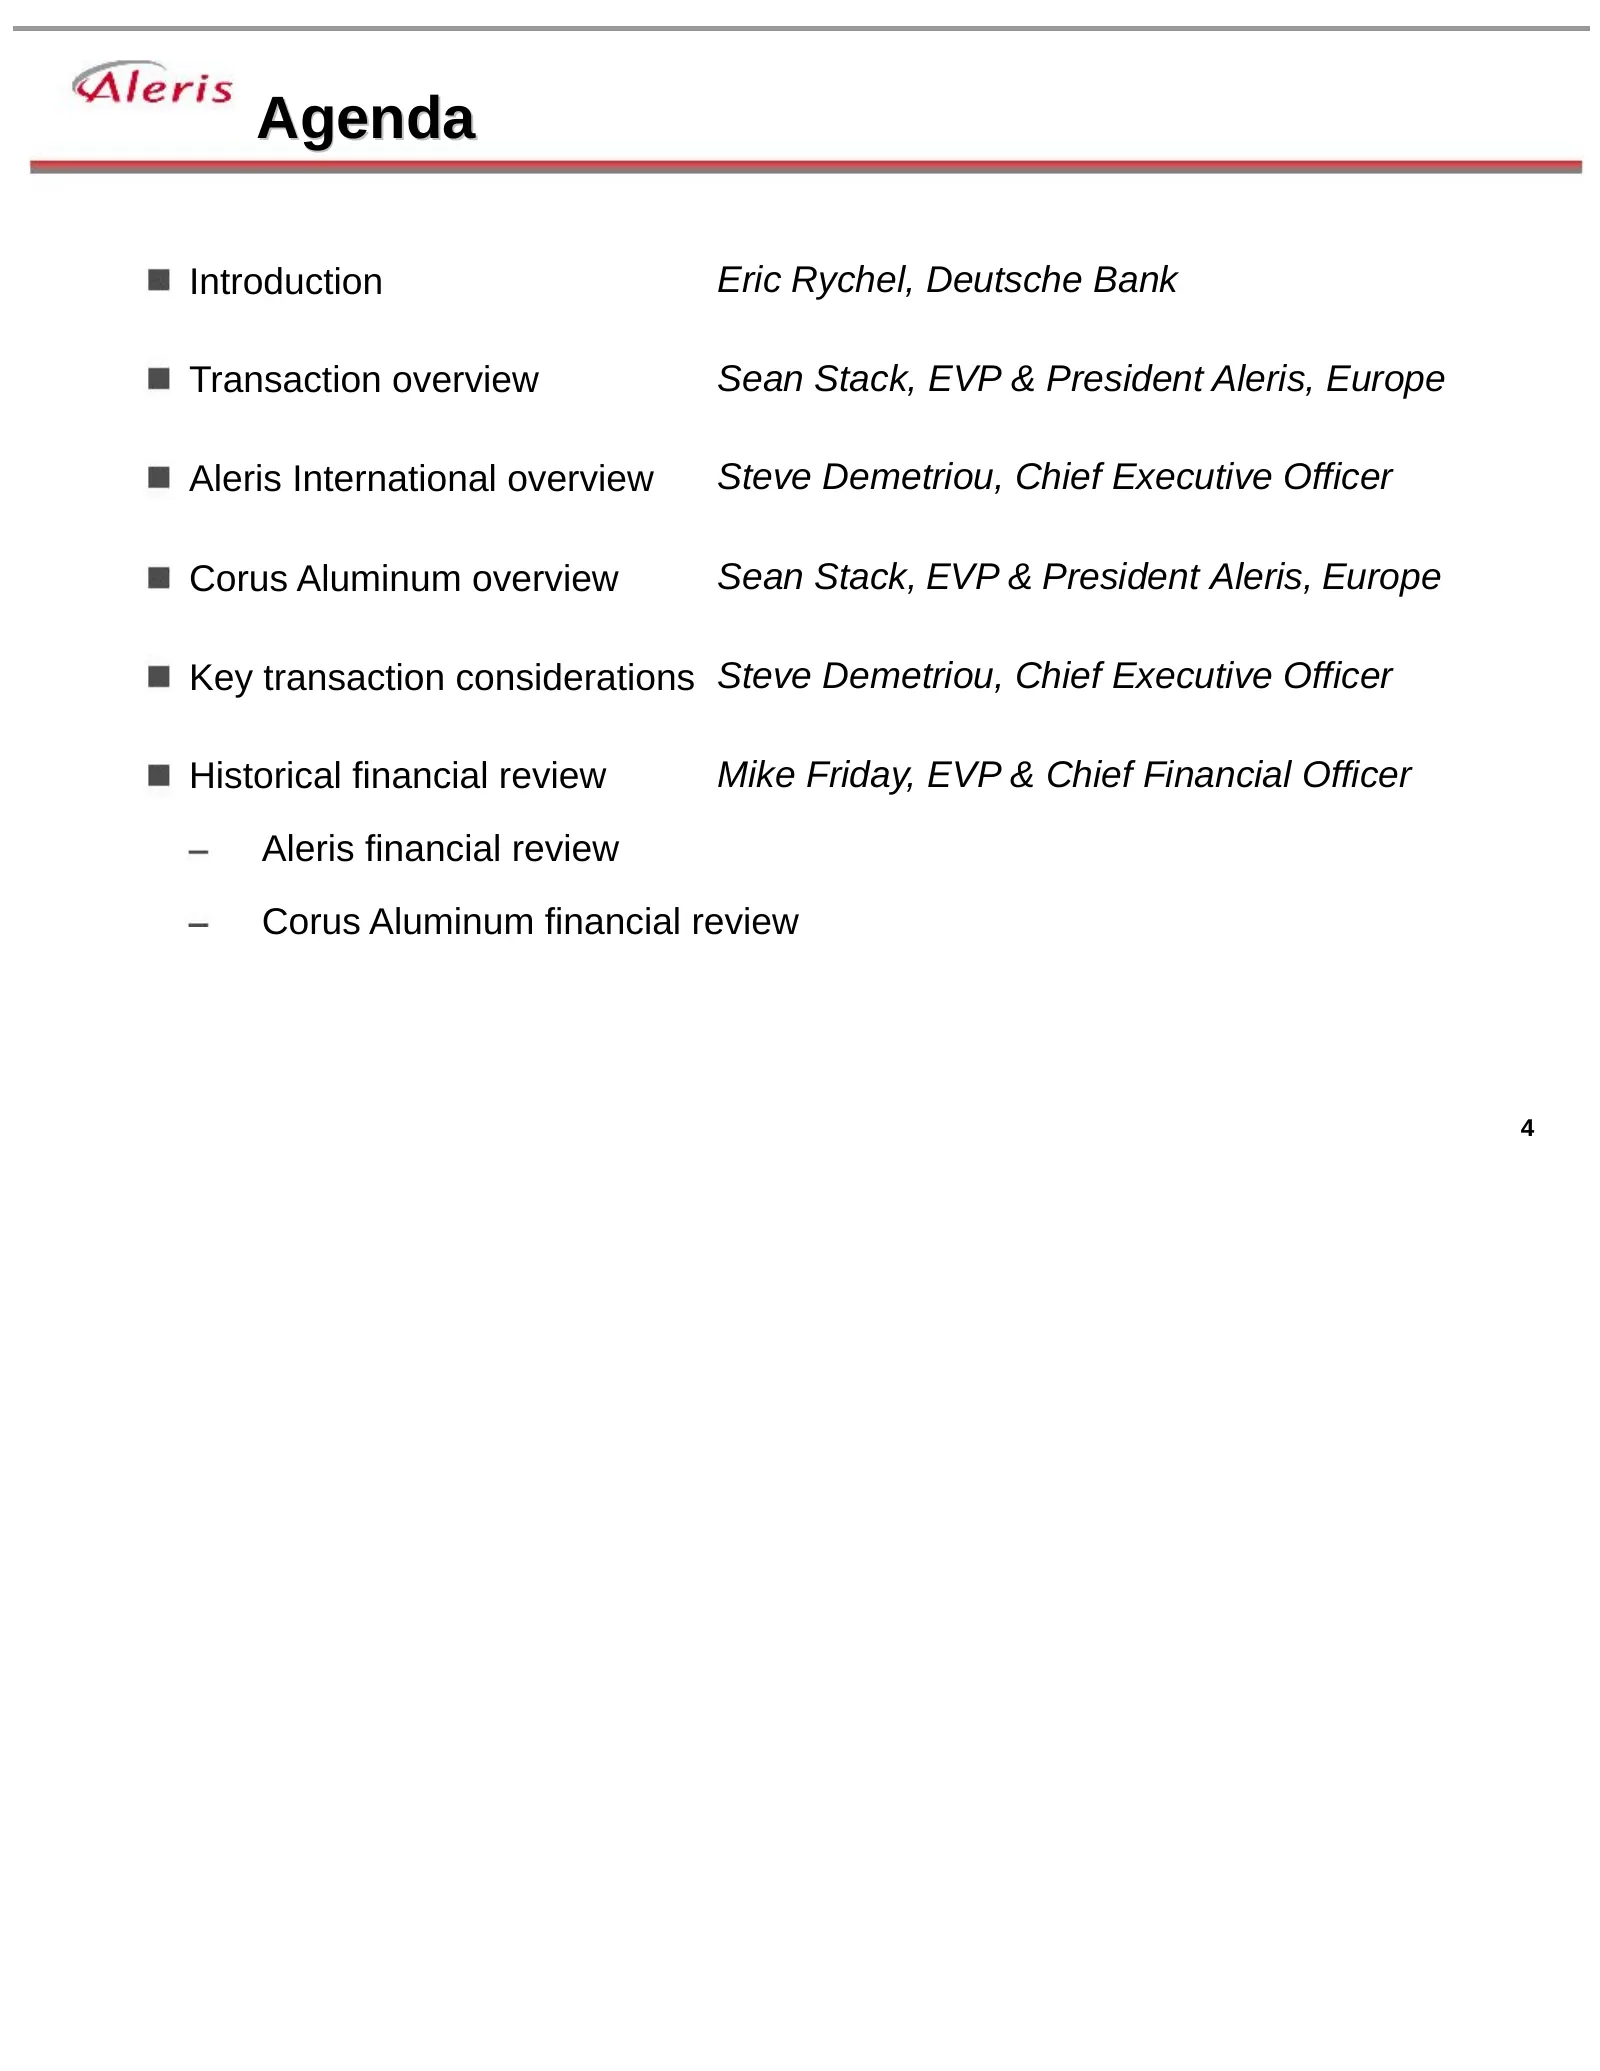
Slide 4: Agenda
Agenda Introduction Eric Rychel, Deutsche Bank Transaction overview Sean Stack, EVP & President Aleris, Europe Aleris International overview Steve Demetriou, Chief Executive Officer Corus Aluminum overview Sean Stack, EVP & President Aleris, Europe Key transaction considerations Steve Demetriou, Chi
Slide 5: Transaction Overview
Transaction Overview Sean Stack, Executive Vice President & President Aleris, Europe
Slide 6: Transaction Overview
Transaction Overview Aleris has entered into a definitive agreement to acquire Corus Group plc's downstream aluminum business (“Corus Aluminum”) for €691.0(1) million (the “Corus Acquisition”) 5.5x LTM 3/31/2006 Adjusted EBITDA with synergies of €126.6 million(2) The Corus Acquisition will continue
Slide 7: Creating a Global Rolled Products and Recycling Company
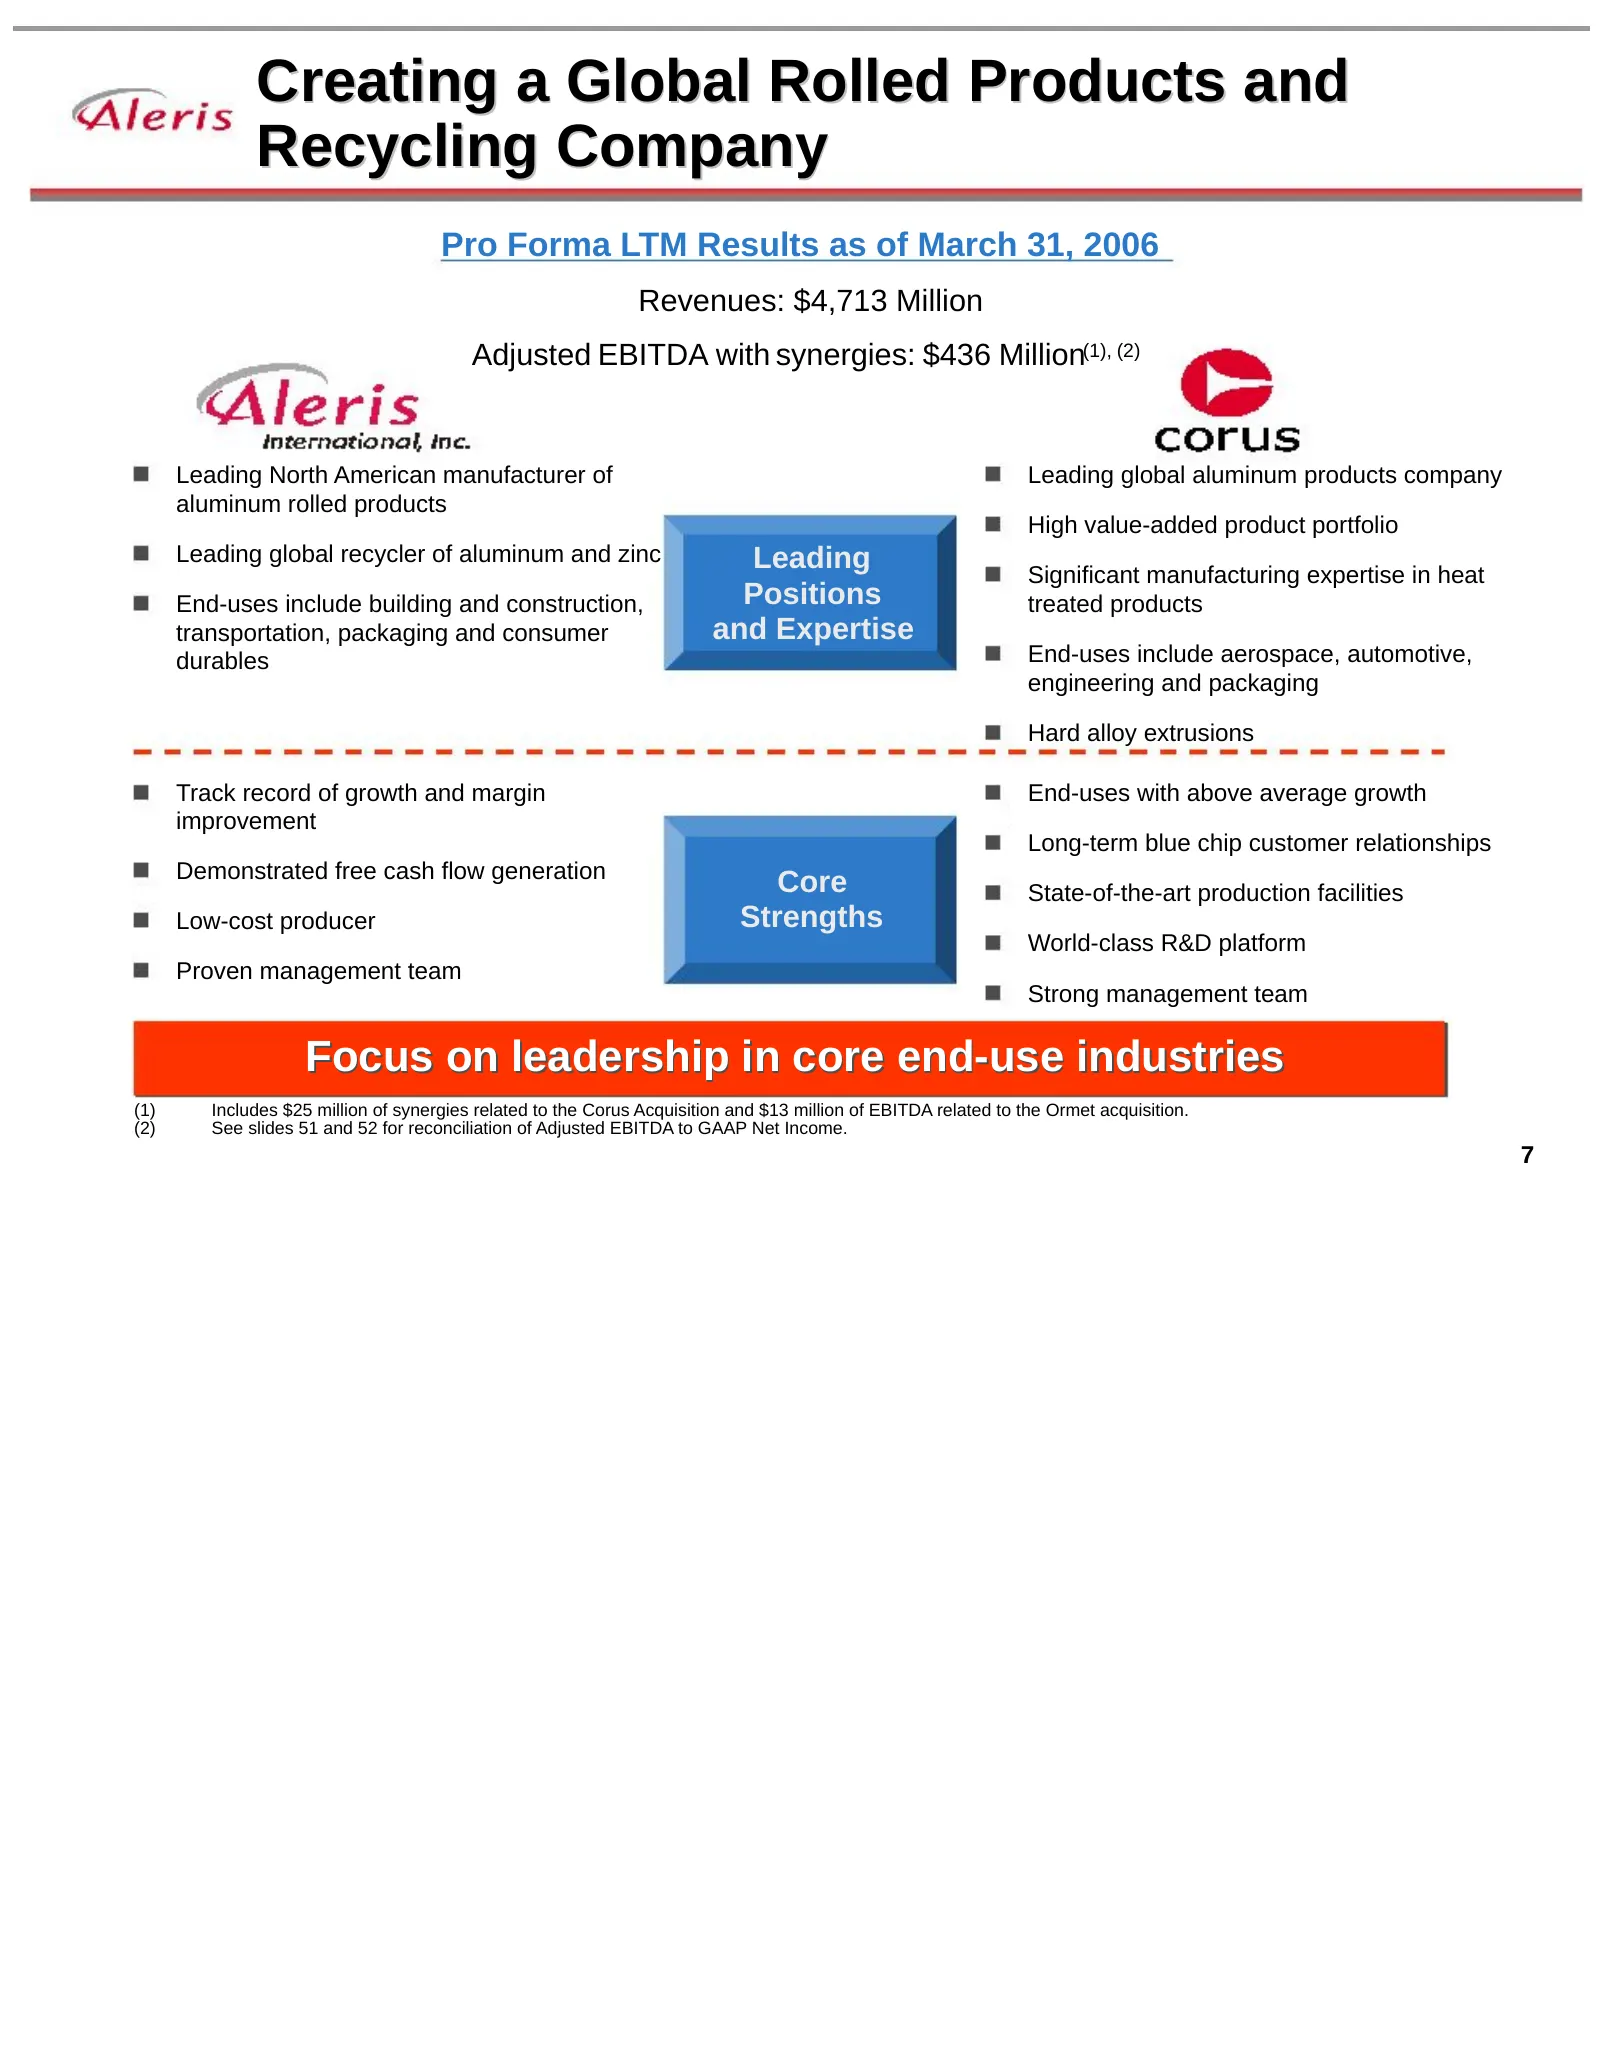
Creating a Global Rolled Products and Recycling Company Pro Forma LTM Results as of March 31, 2006 Revenues: $4,713 Million Adjusted EBITDA with synergies: $436 Million(1), (2) Leading North American manufacturer of Leading global aluminum products company aluminum rolled products High value-added p
Slide 8: Sources and Uses
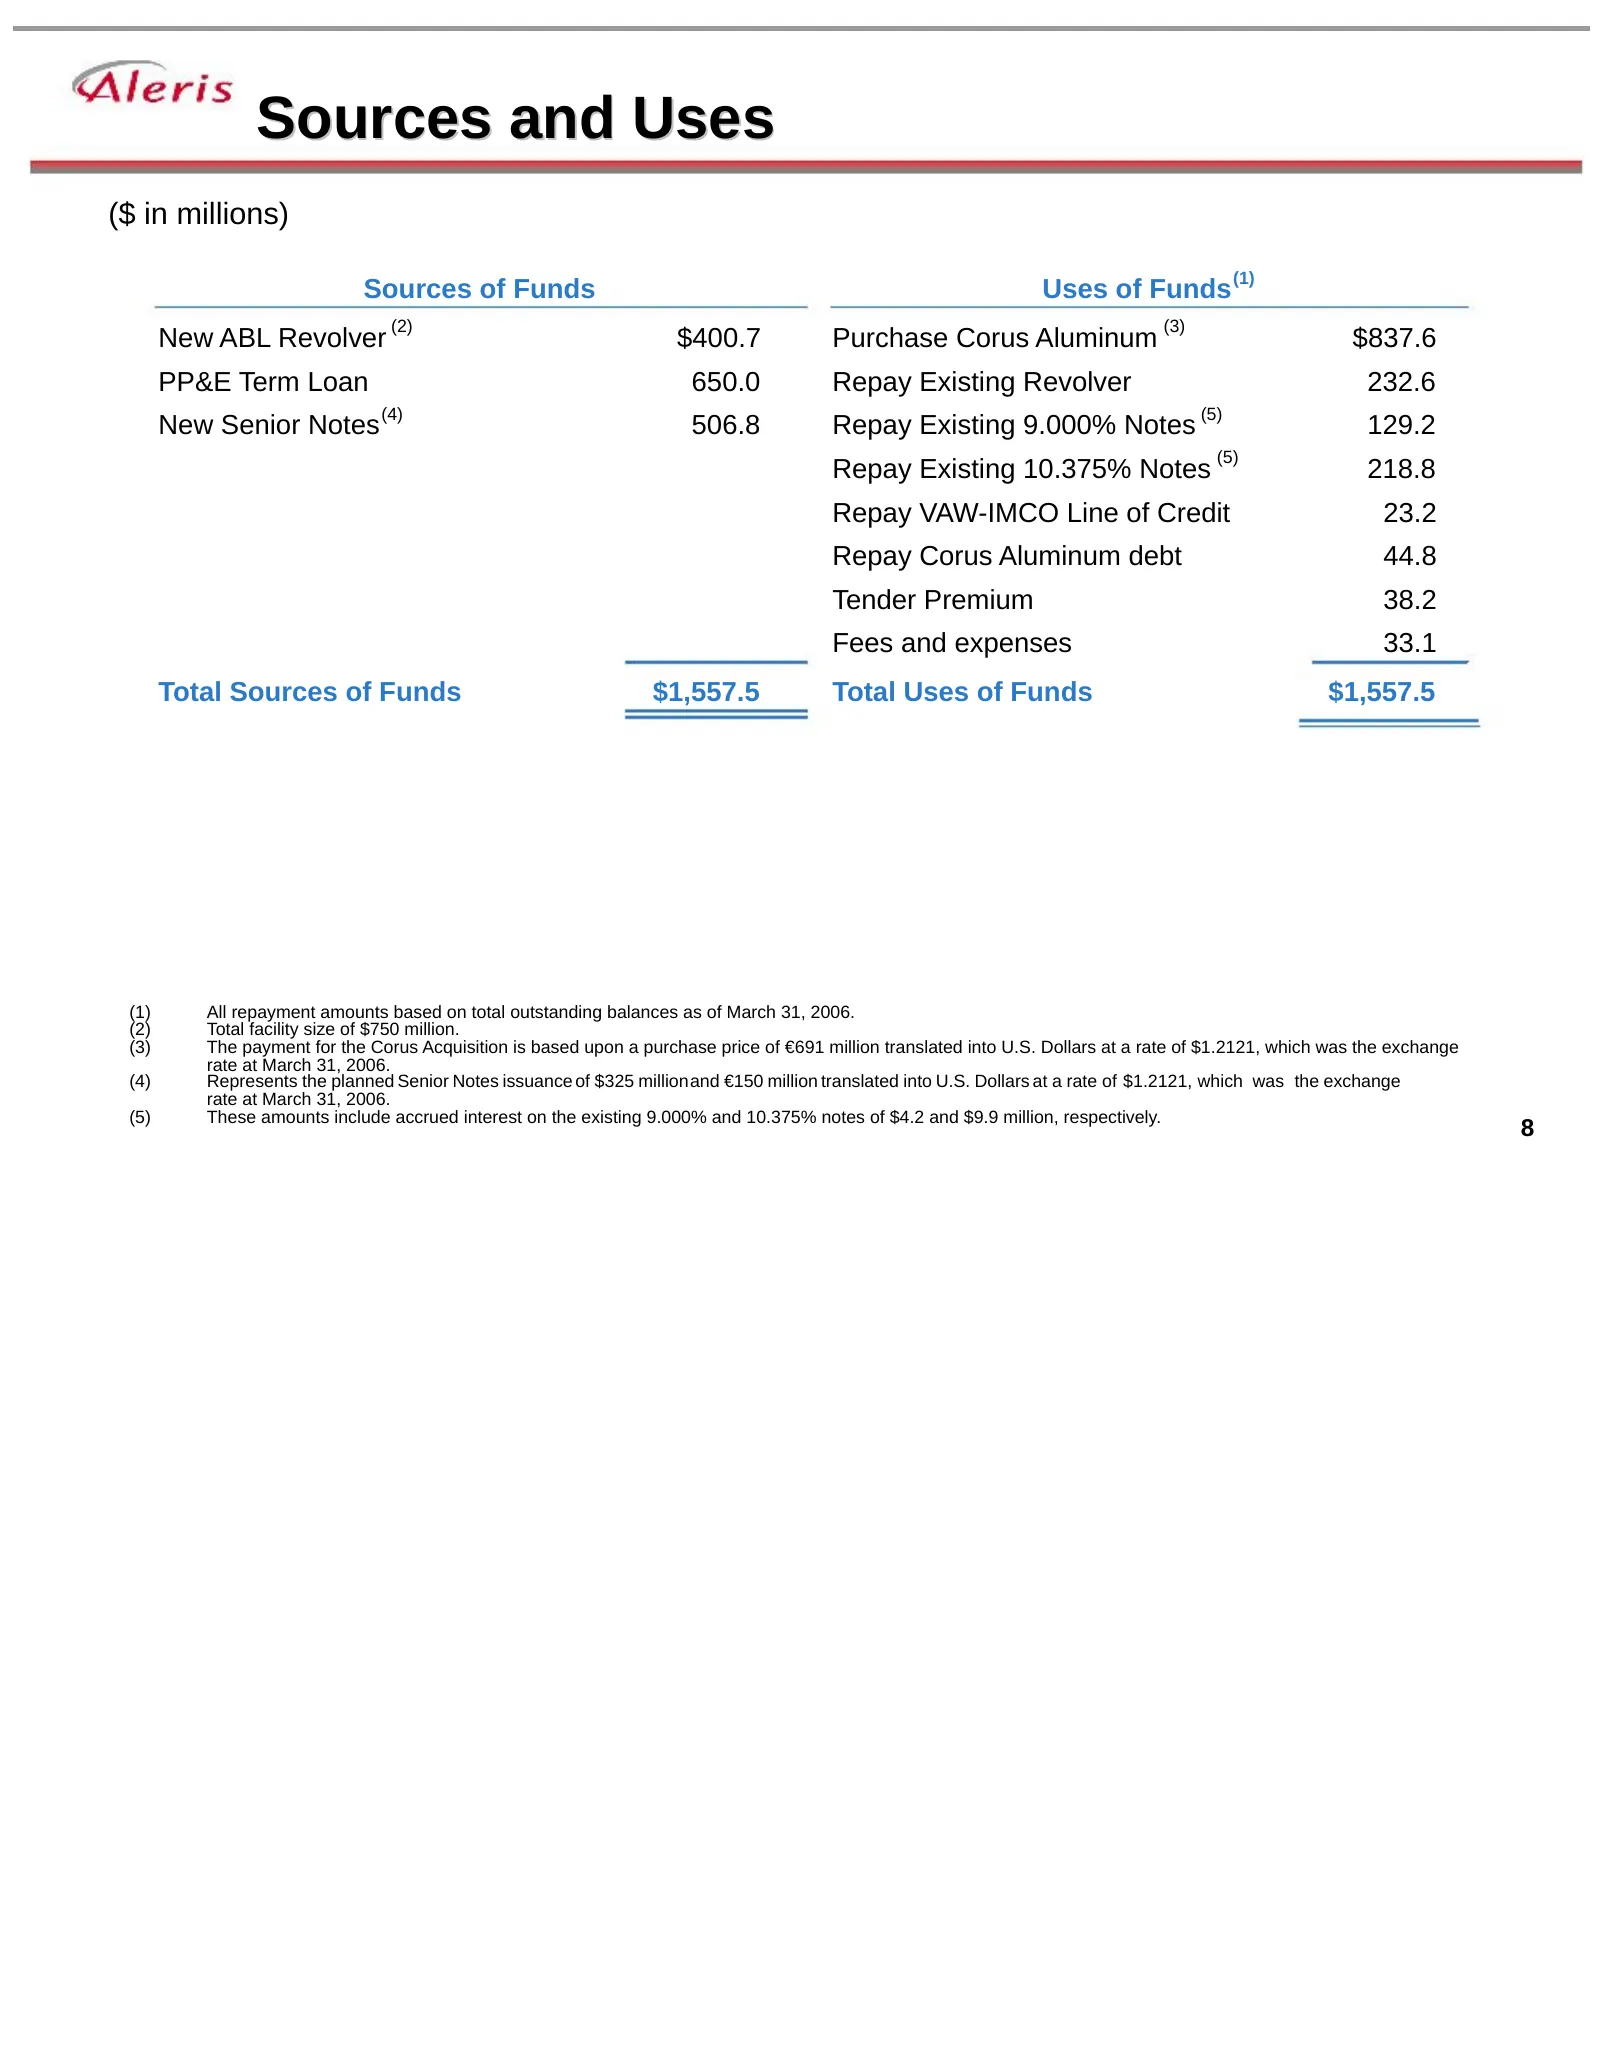
Sources and Uses ($ in millions) (1) Sources of Funds Uses of Funds (2) (3) New ABL Revolver $400.7 Purchase Corus Aluminum $837.6 PP&E Term Loan 650.0 Repay Existing Revolver 232.6 (4) (5) New Senior Notes 506.8 Repay Existing 9.000% Notes 129.2 (5) Repay Existing 10.375% Notes 218.8 Repay VAW-IMCO
Slide 9: Pro Forma Capitalization
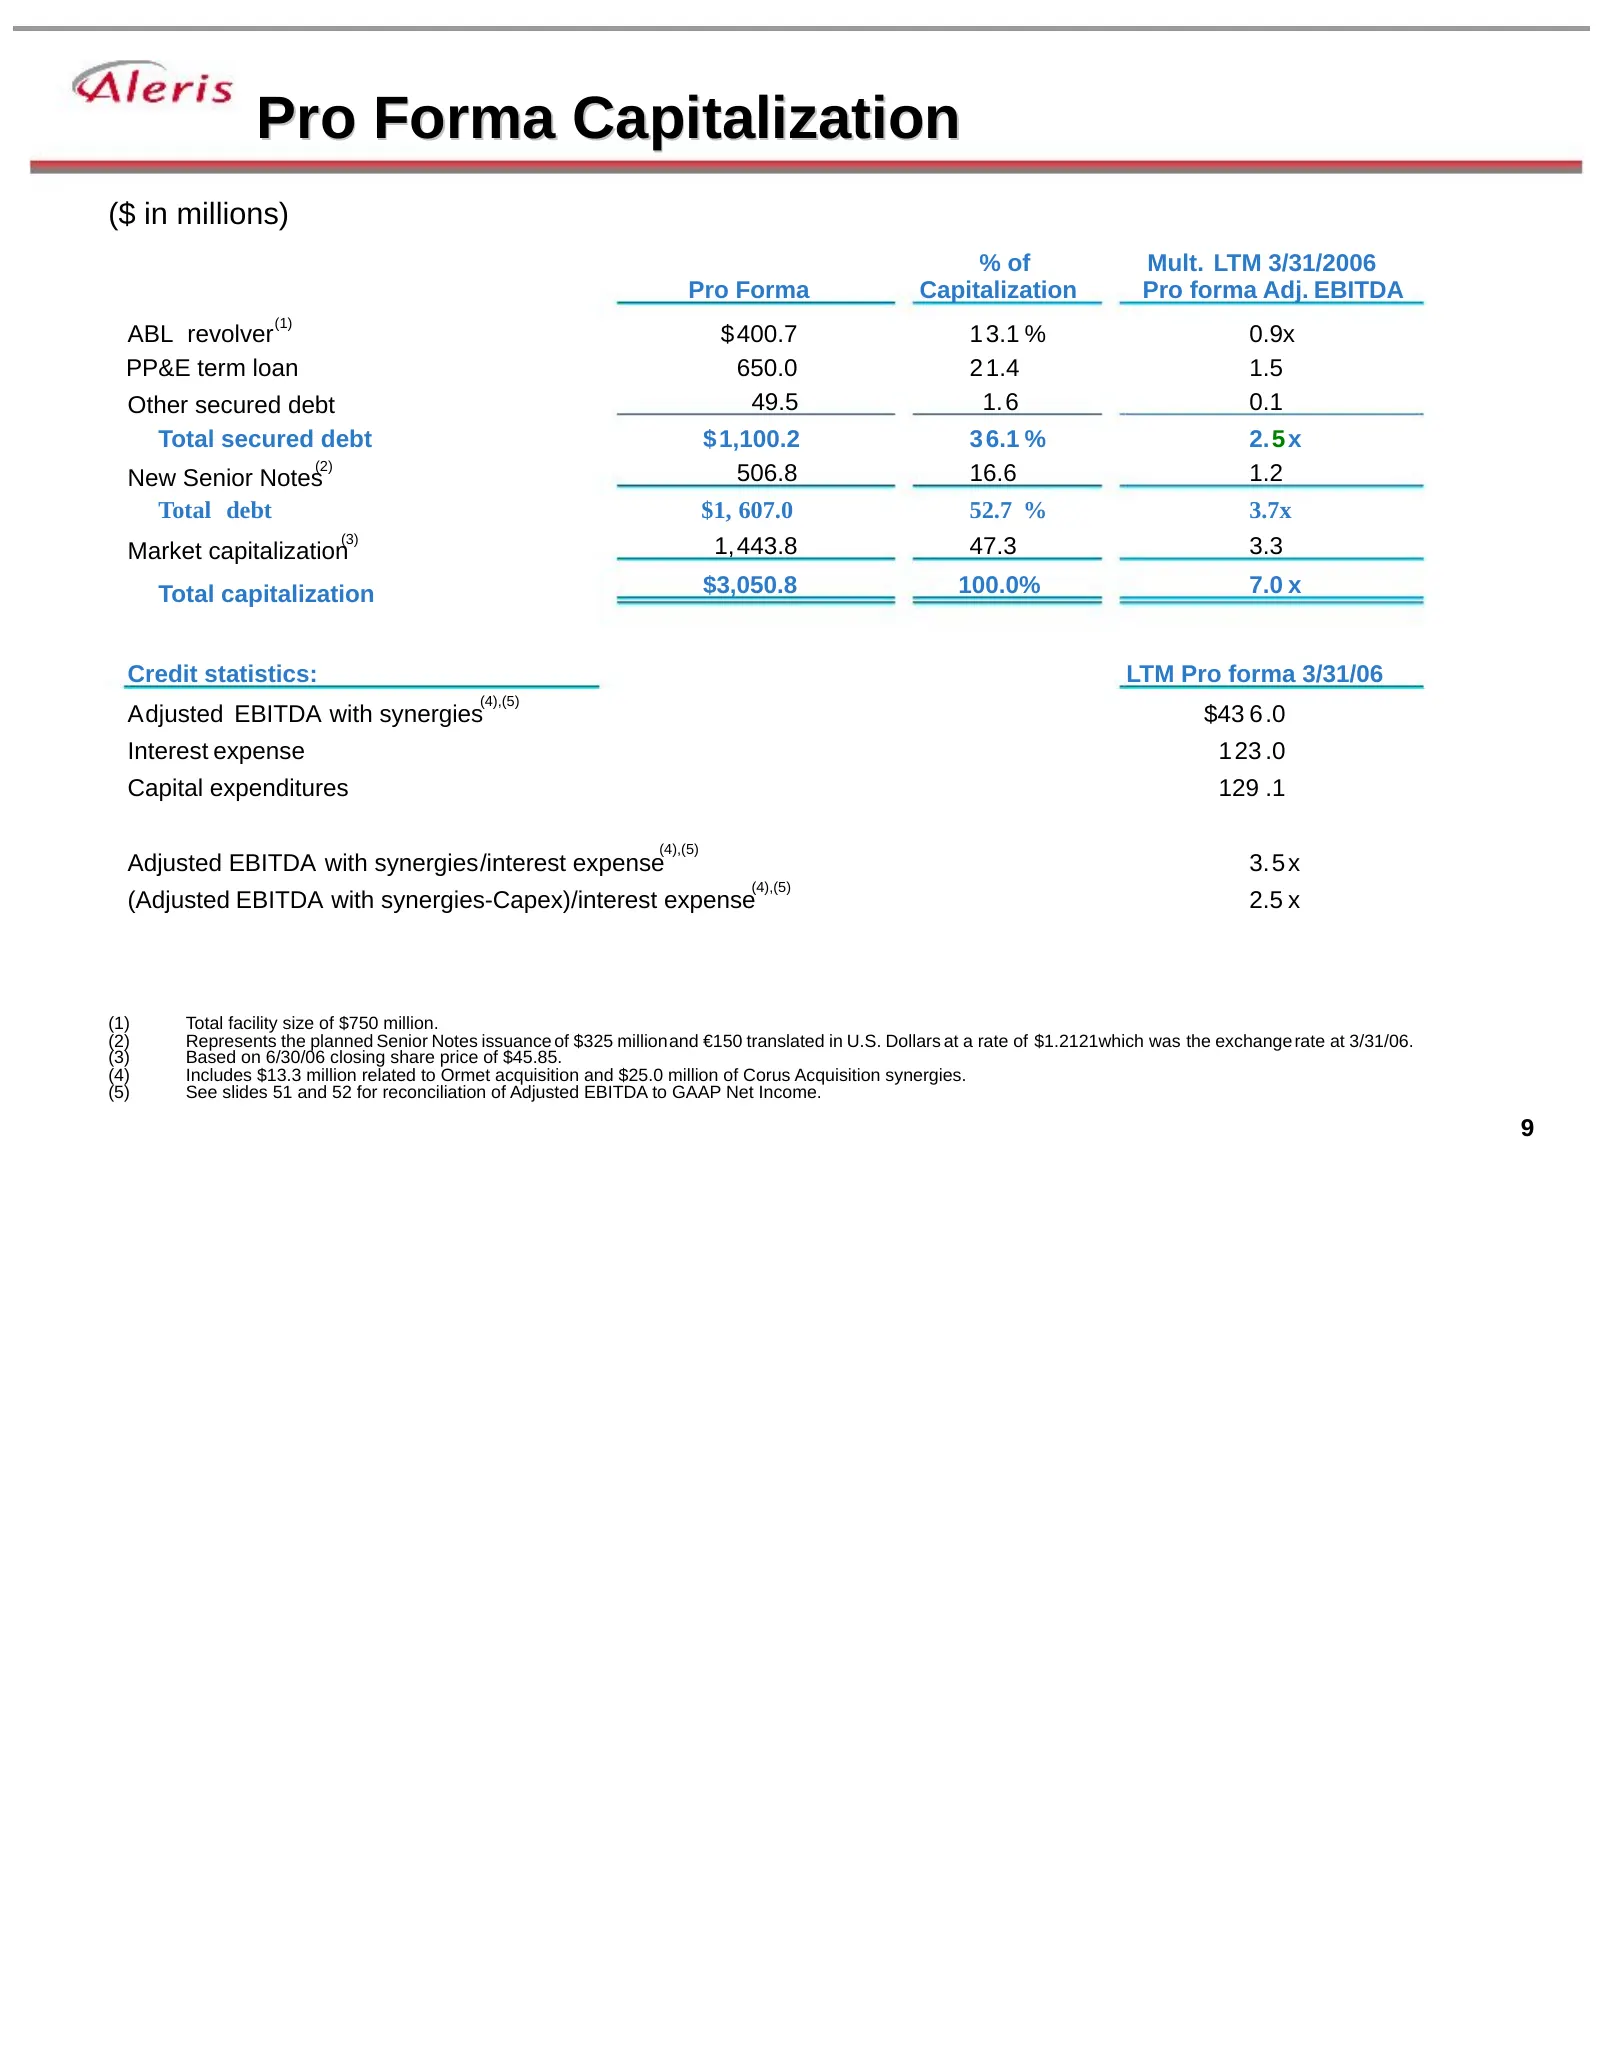
Pro Forma Capitalization ($ in millions) % of Mult. LTM 3/31/2006 Pro Forma Capitalization Pro forma Adj. EBITDA (1) ABL revolver $ 400.7 1 3.1 % 0.9x PP&E term loan 650.0 2 1.4 1.5 Other secured debt 49.5 1.6 0.1 Total secured debt $ 1,100.2 3 6.1 % 2.5 x (2) New Senior Notes 506.8 16.6 1.2 Total d
Slide 10: Aleris International Overview
Aleris International Overview Steve Demetriou, Chief Executive Officer
Slide 11: 2004 Pro Forma Merger Summary
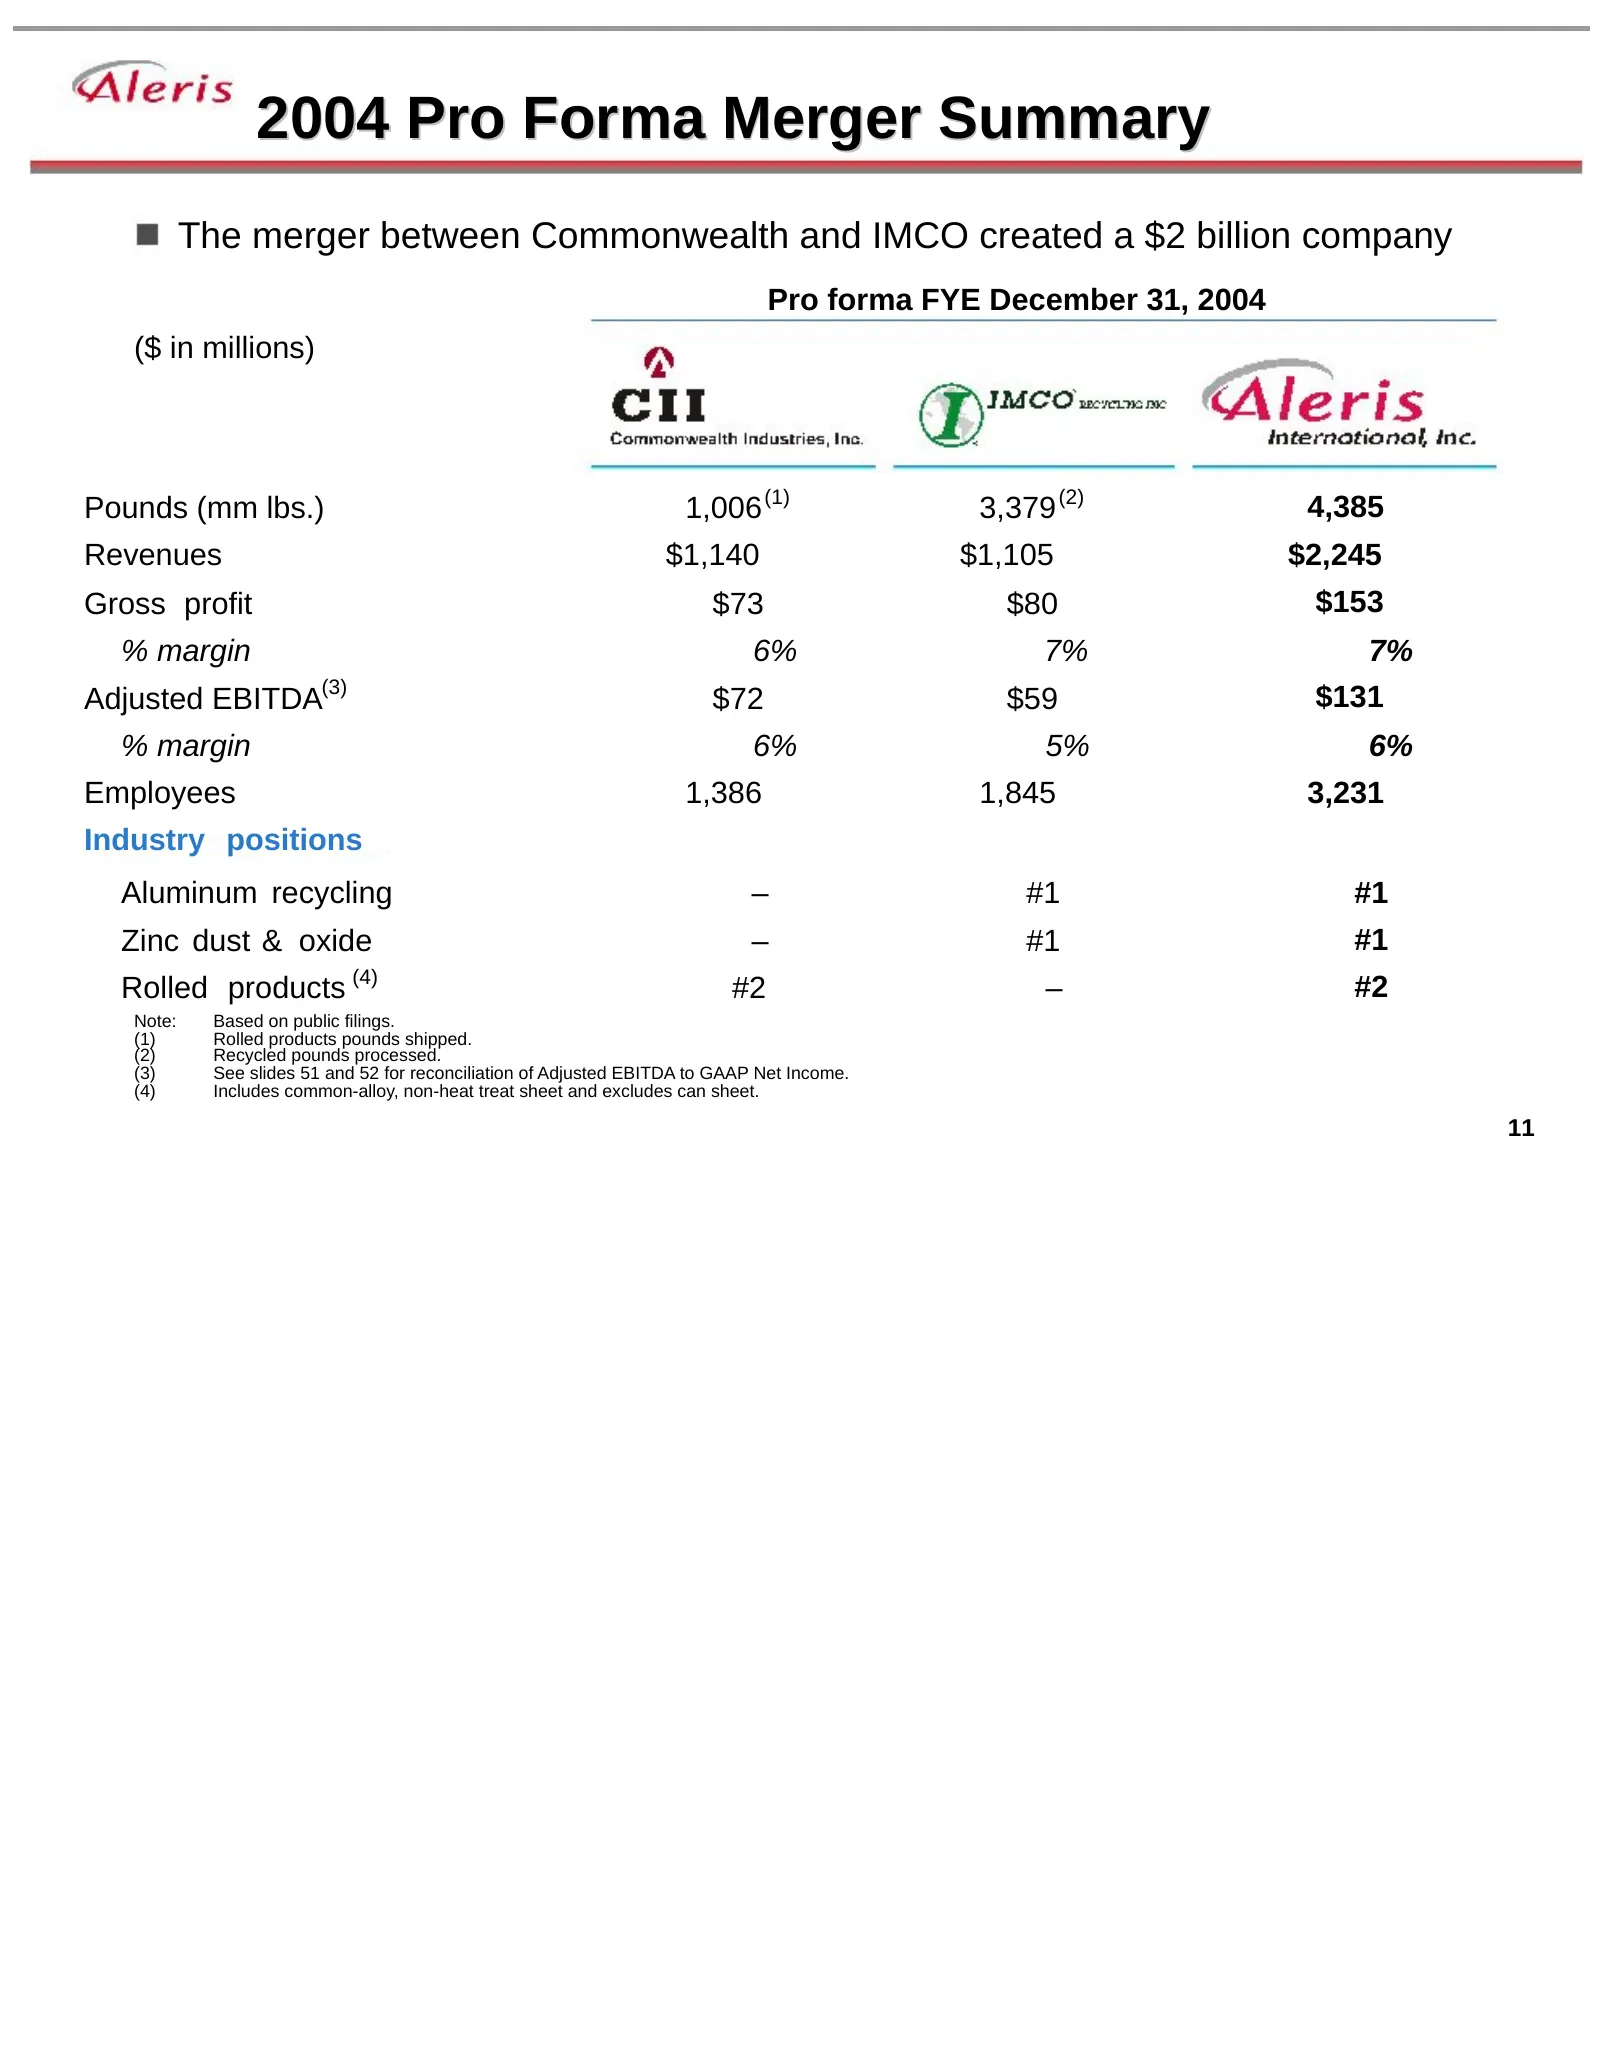
2004 Pro Forma Merger Summary The merger between Commonwealth and IMCO created a $2 billion company Pro forma FYE December 31, 2004 ($ in millions) Pounds (mm lbs.) 1,006 (1) 3,379 (2) 4,385 Revenues $1,140 $1,105 $2,245 Gross profit $73 $80 $153 % margin 6% 7% 7% (3) Adjusted EBITDA $72 $59 $131 %
Slide 12: Aleris Transformation
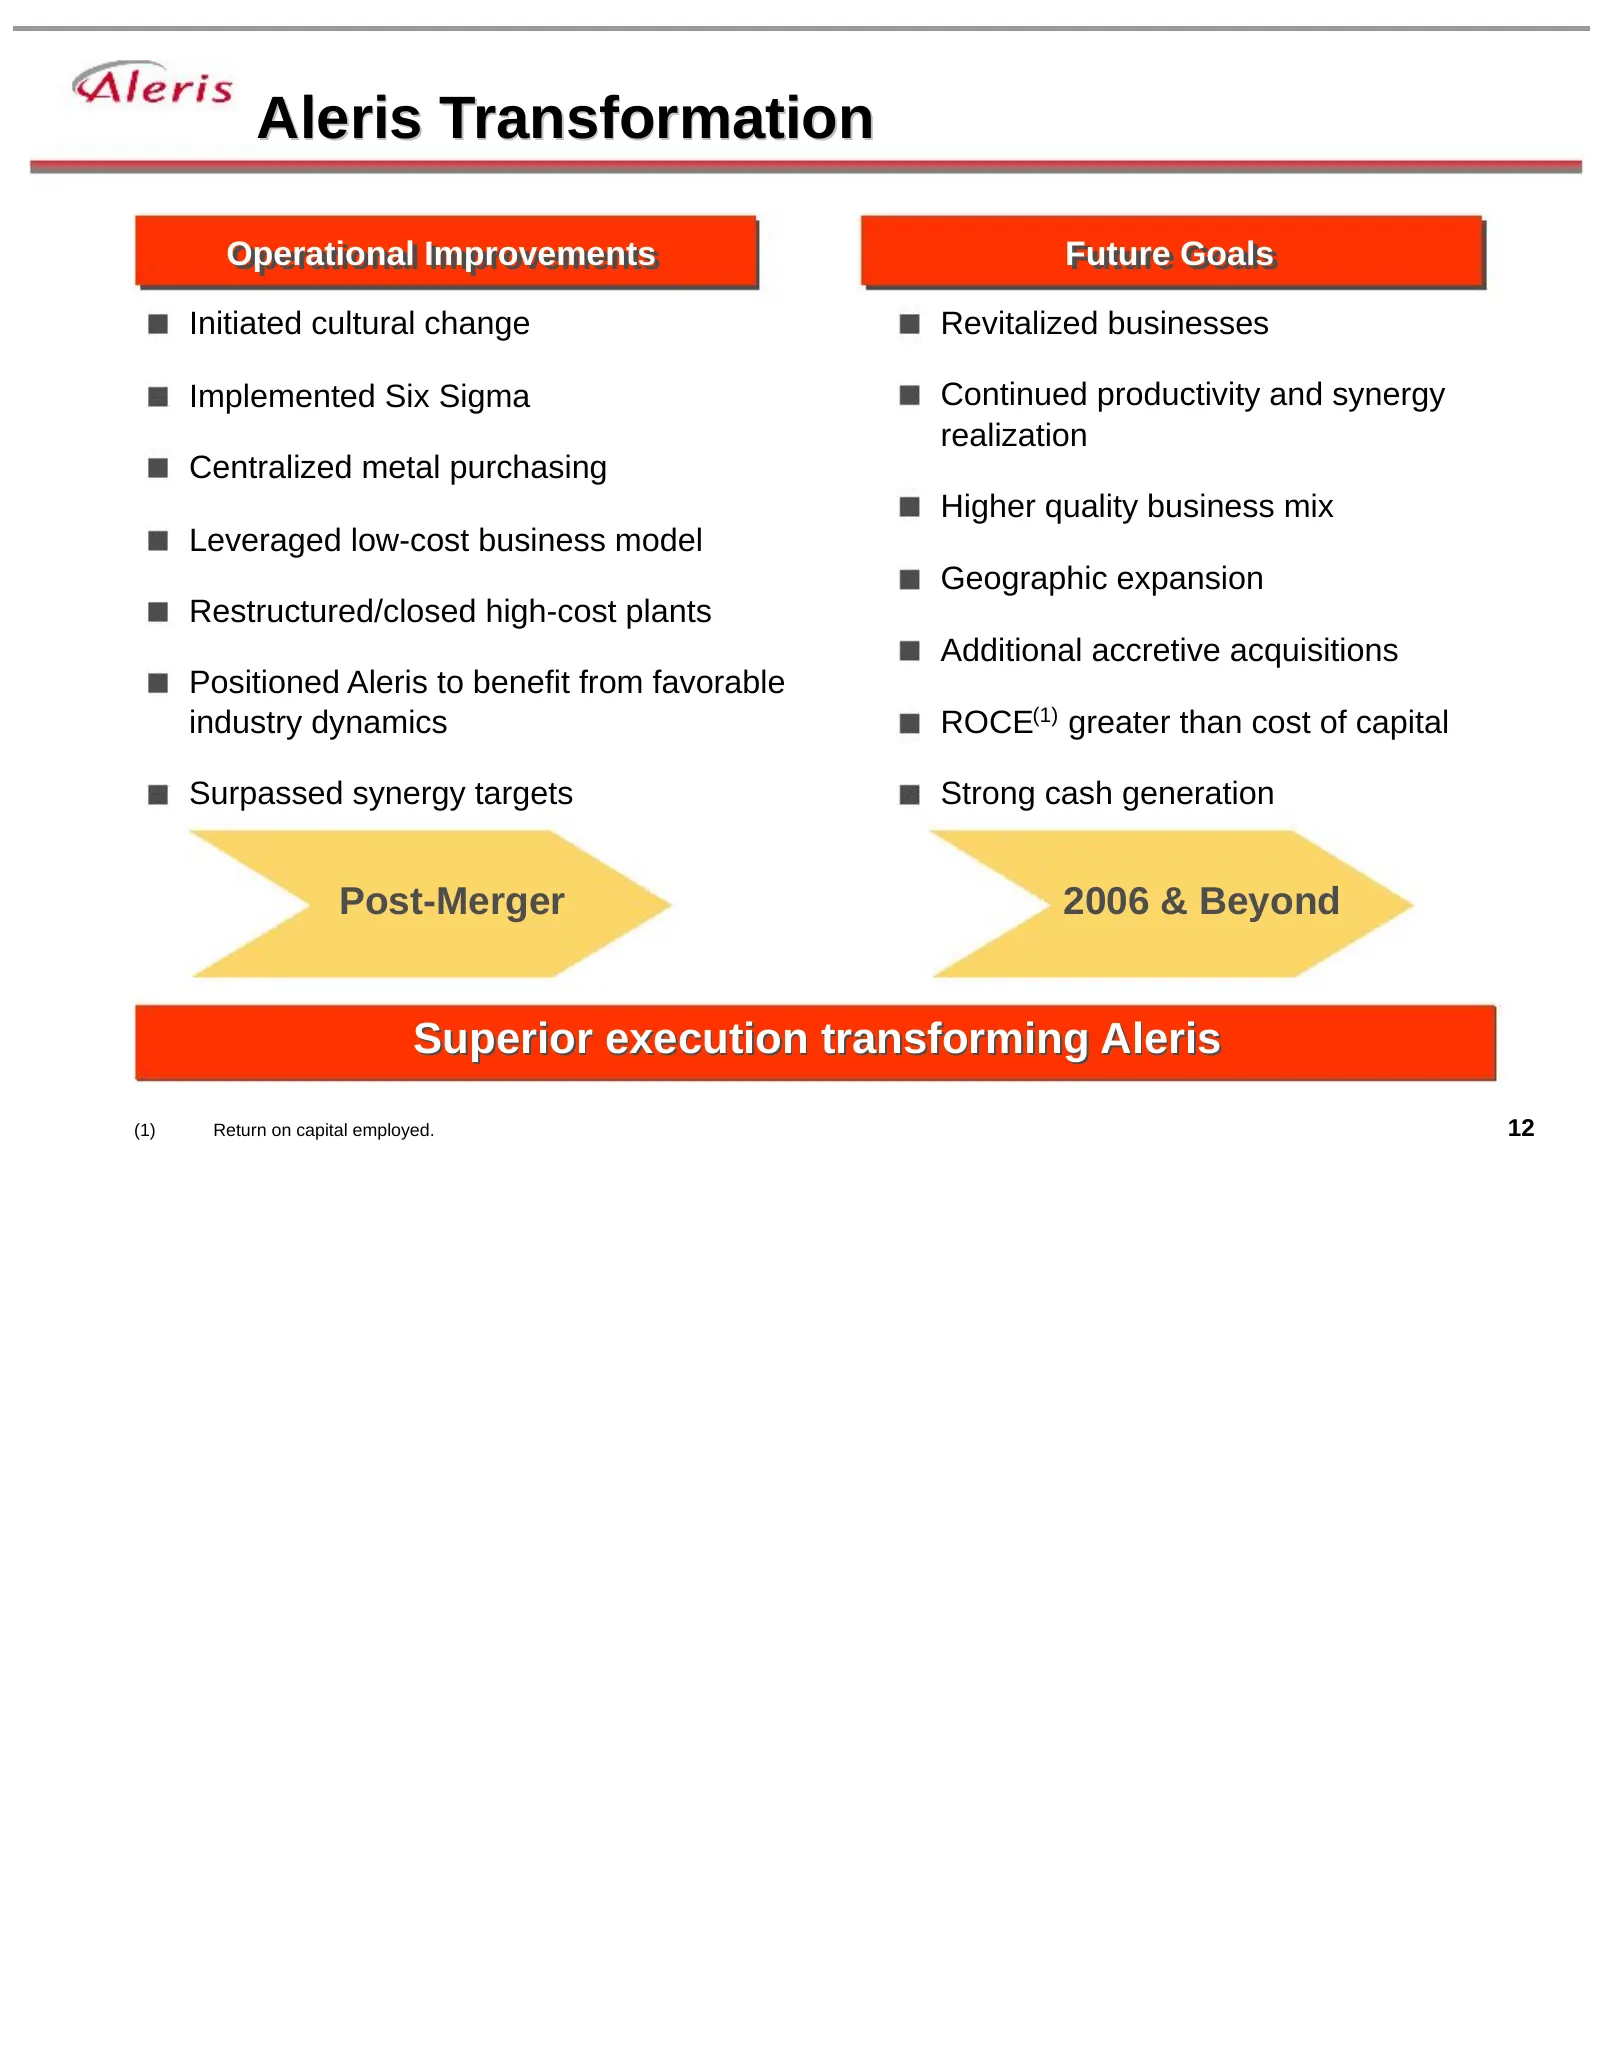
Aleris Transformation Operational Operational Improvements Improvements Future Future Goals Goals Initiated cultural change Revitalized businesses Implemented Six Sigma Continued productivity and synergy realization Centralized metal purchasing Higher quality business mix Leveraged low-cost business
Slide 13: Aleris Today
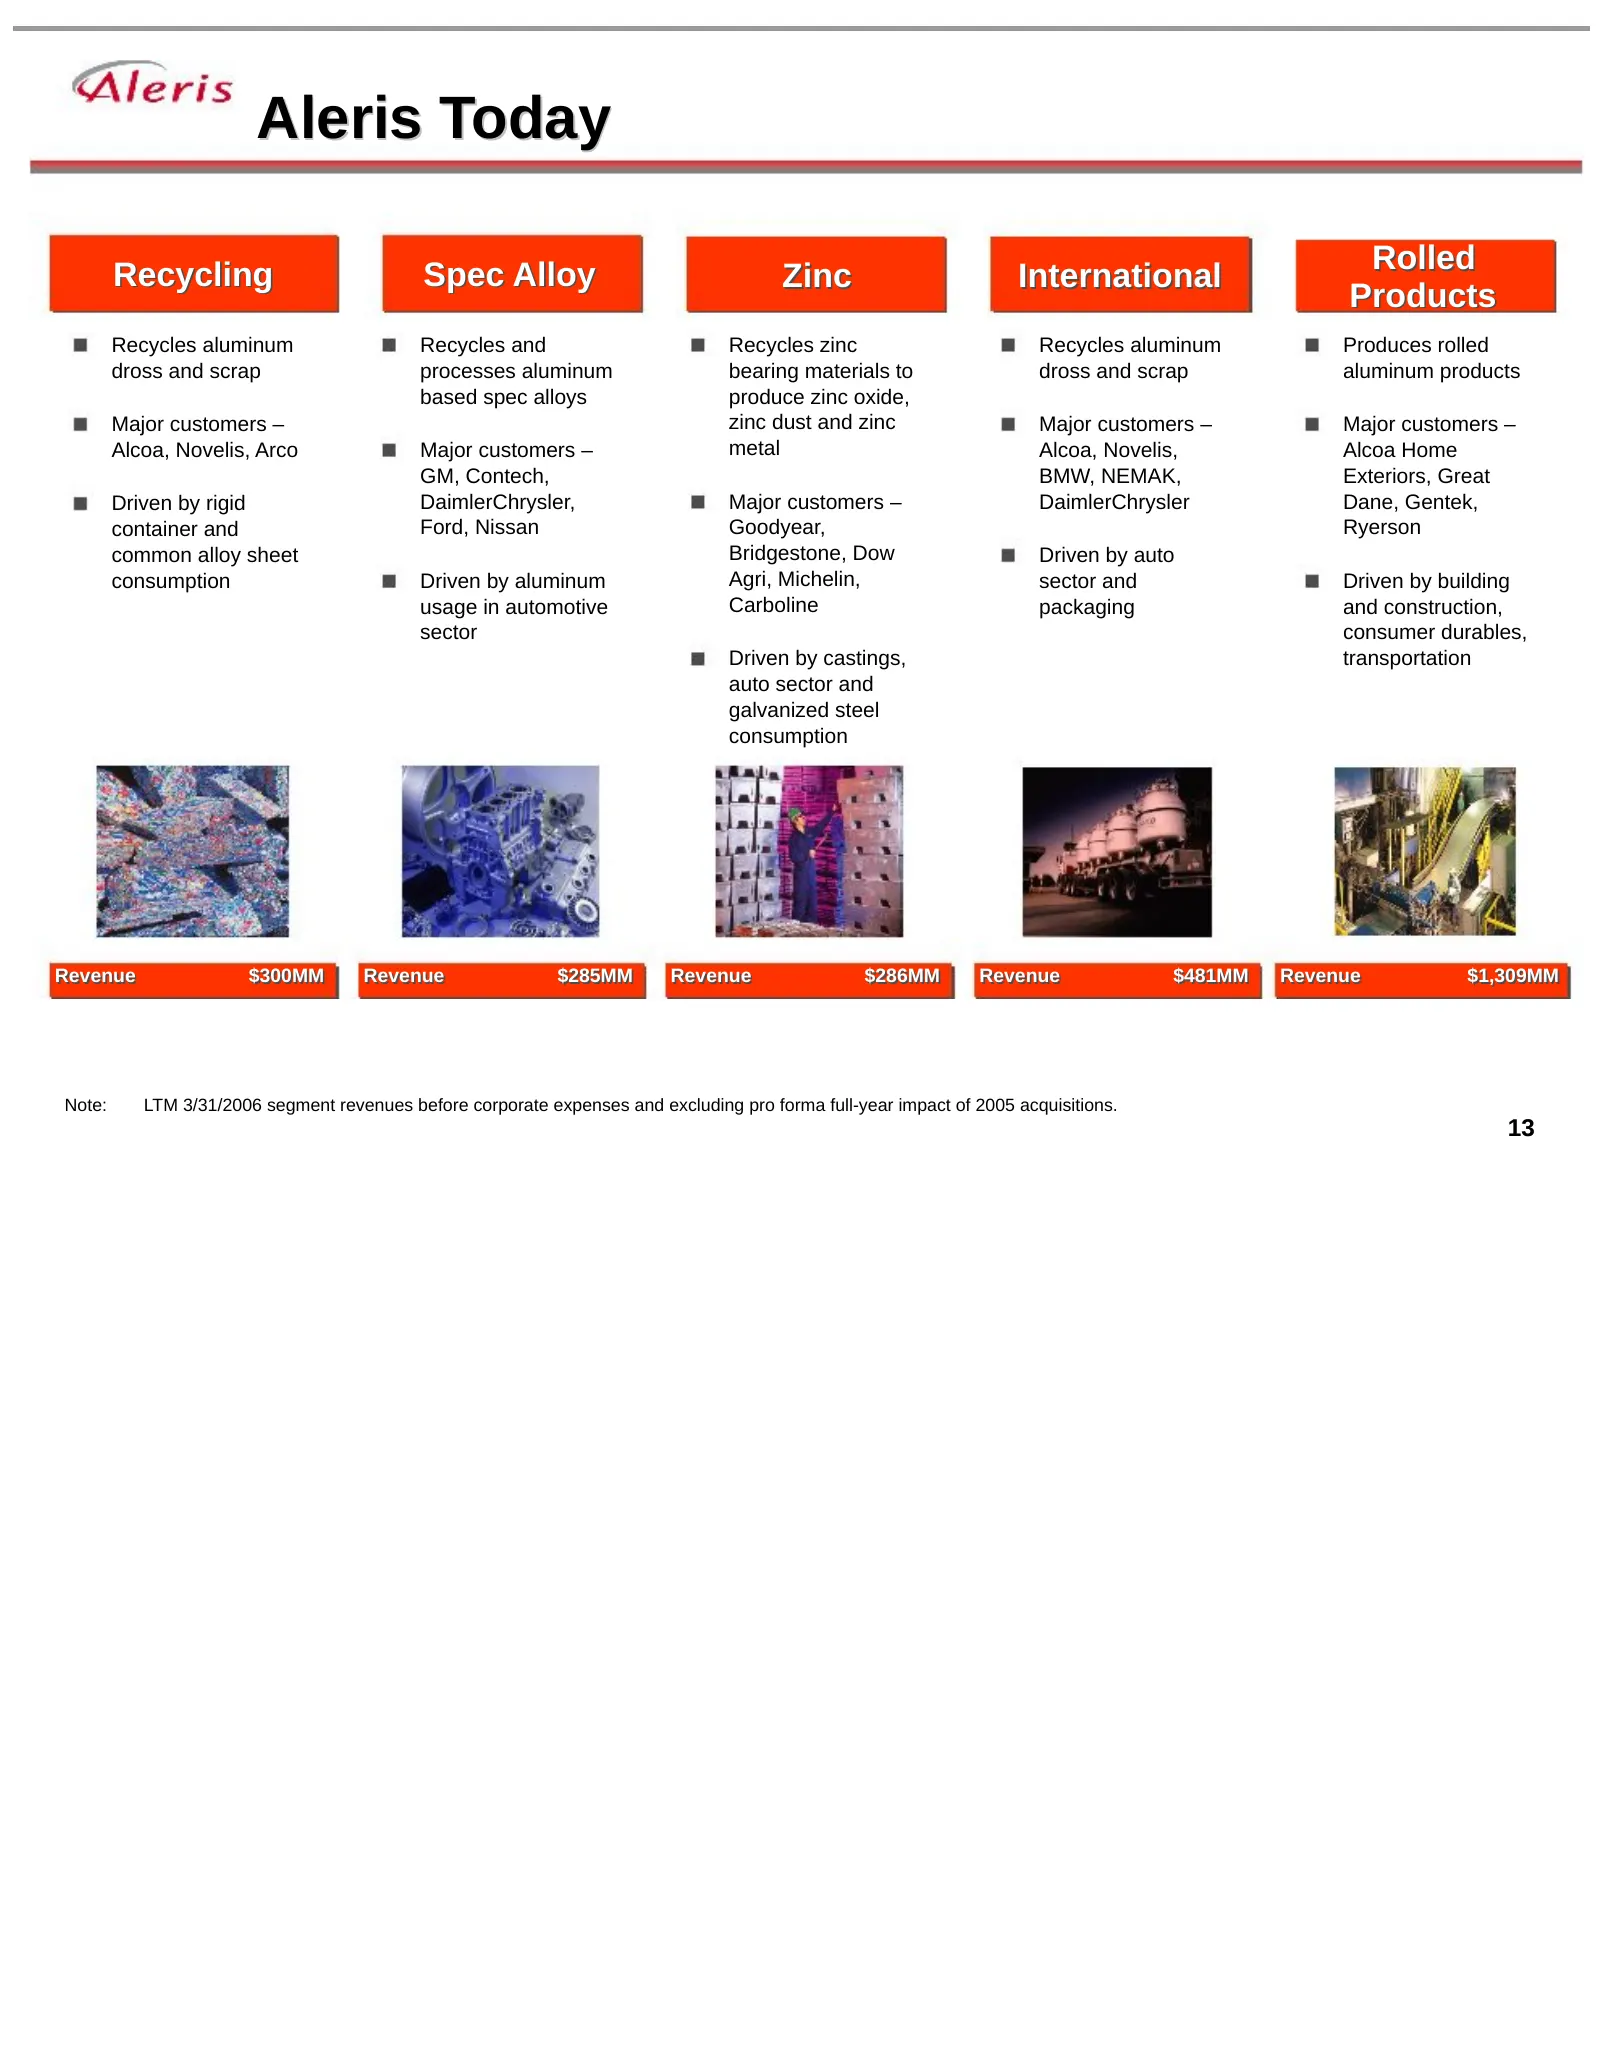
Aleris Today Recycling Spec Alloy Rolled Zinc International Products Recycles aluminum Recycles and Recycles zinc Recycles aluminum Produces rolled dross and scrap processes aluminum bearing materials to dross and scrap aluminum products based spec alloys produce zinc oxide, Major customers – zinc d
Slide 14: Aleris's Strategy
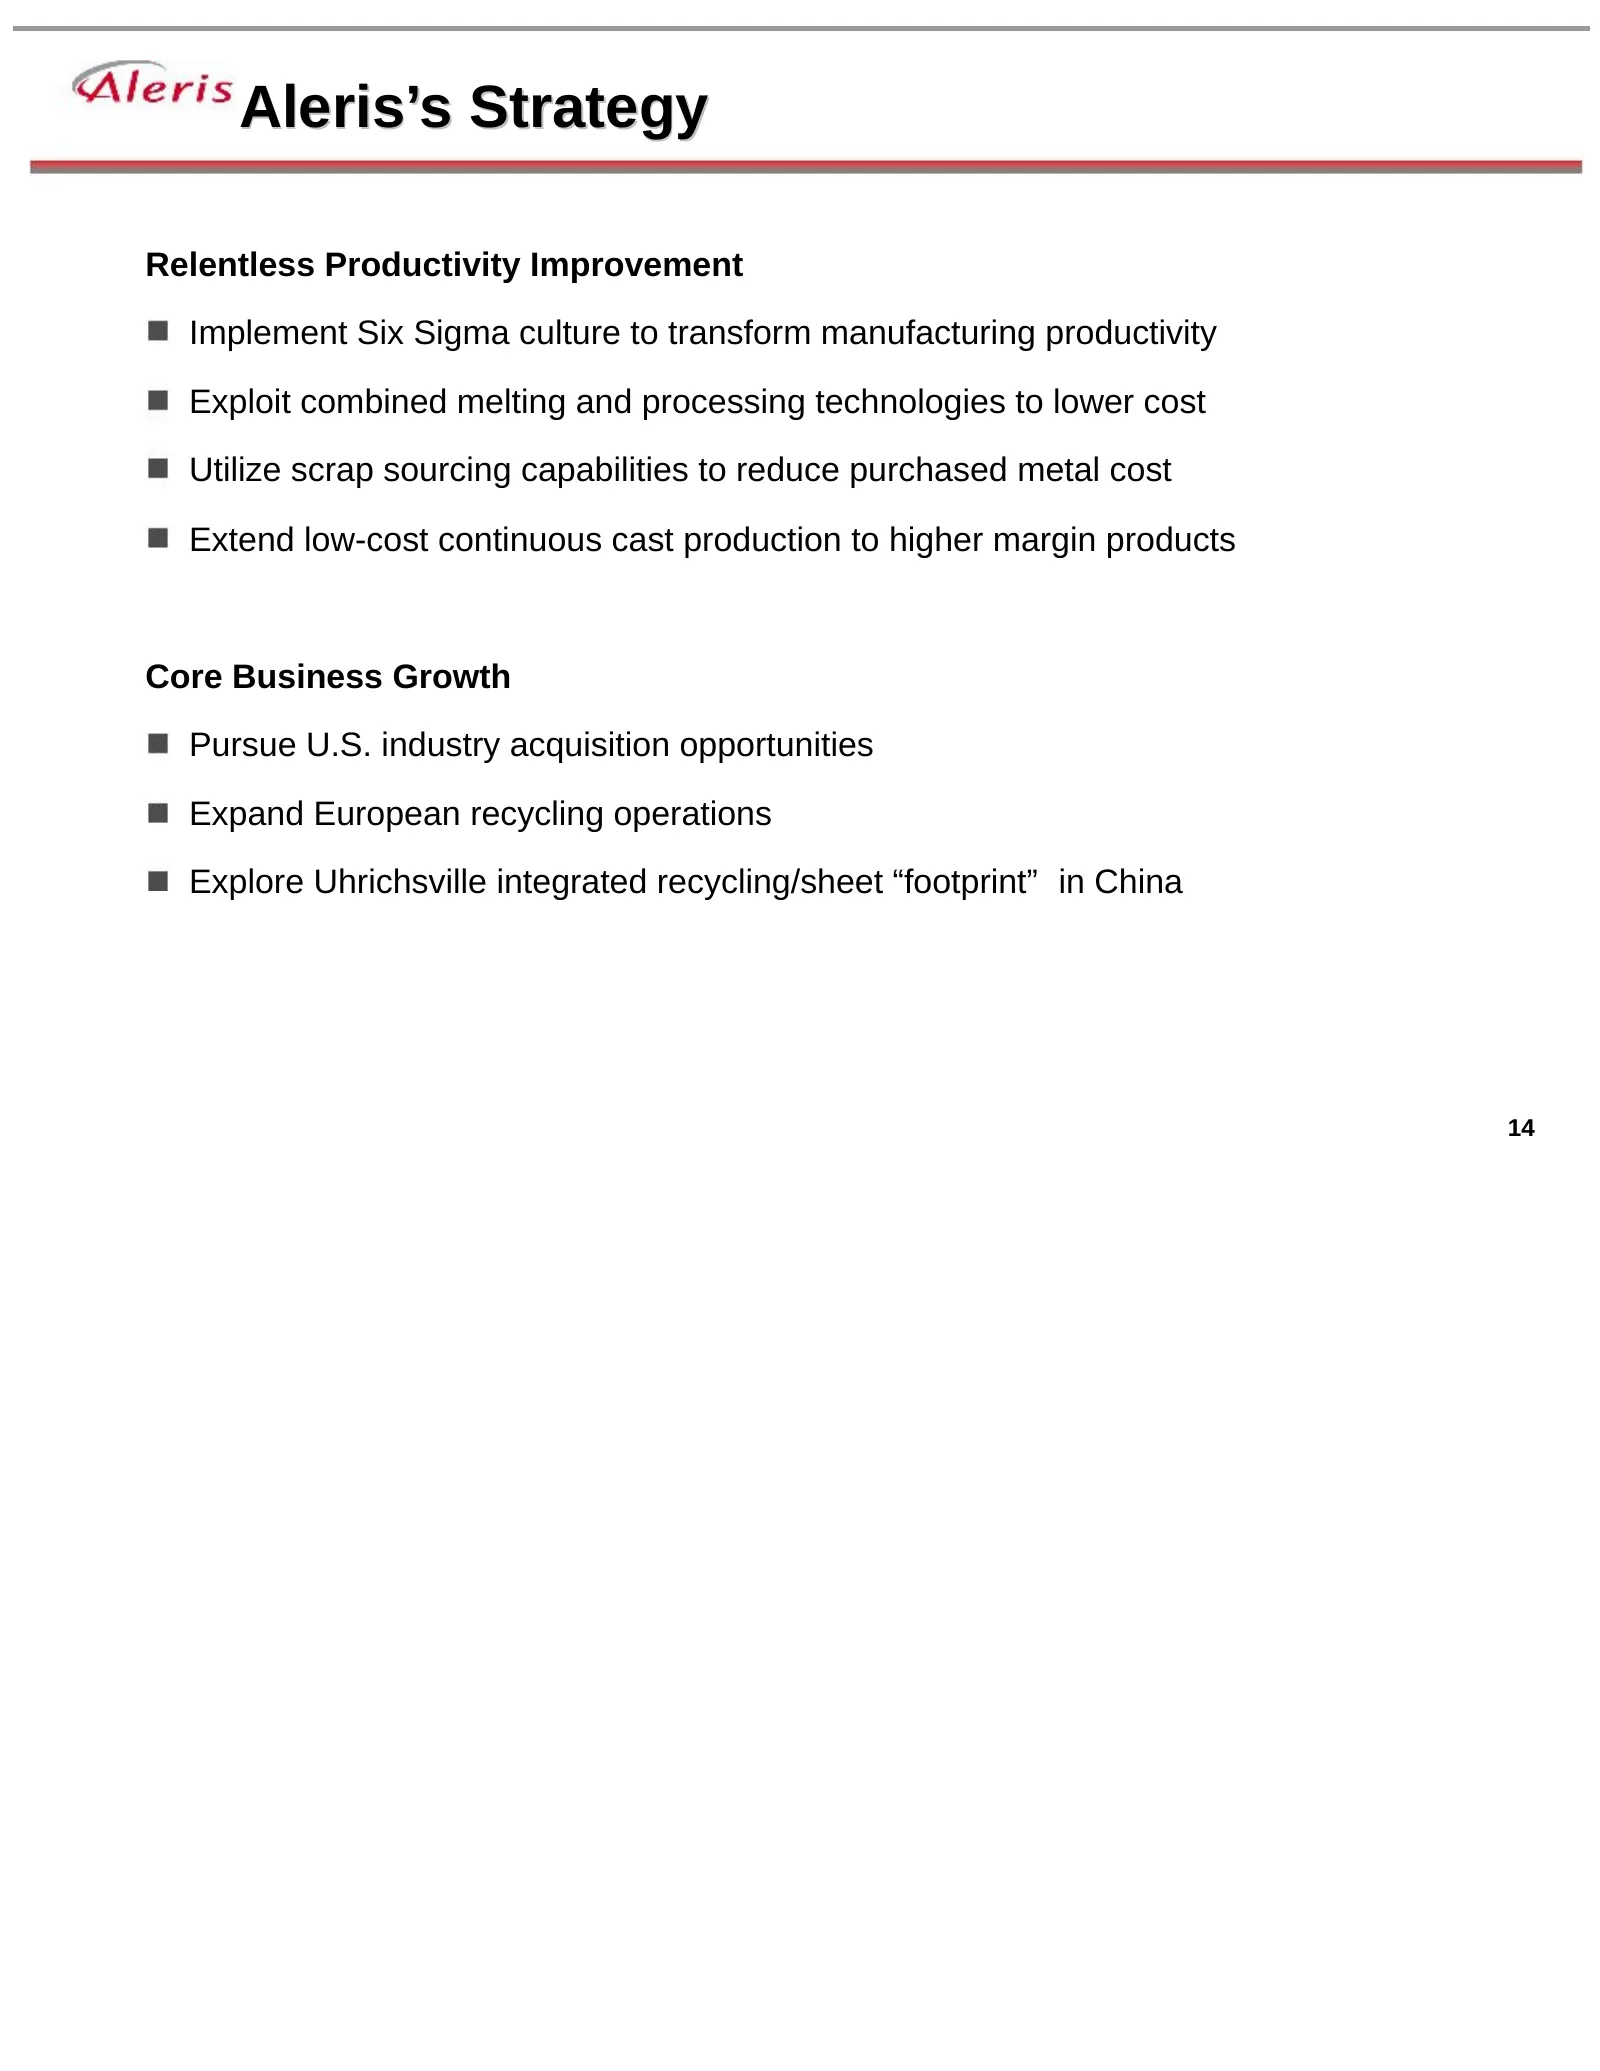
Aleris’s Strategy Relentless Productivity Improvement Implement Six Sigma culture to transform manufacturing productivity Exploit combined melting and processing technologies to lower cost Utilize scrap sourcing capabilities to reduce purchased metal cost Extend low-cost continuous cast production t
Slide 15: Merger Productivity & Synergy Realization
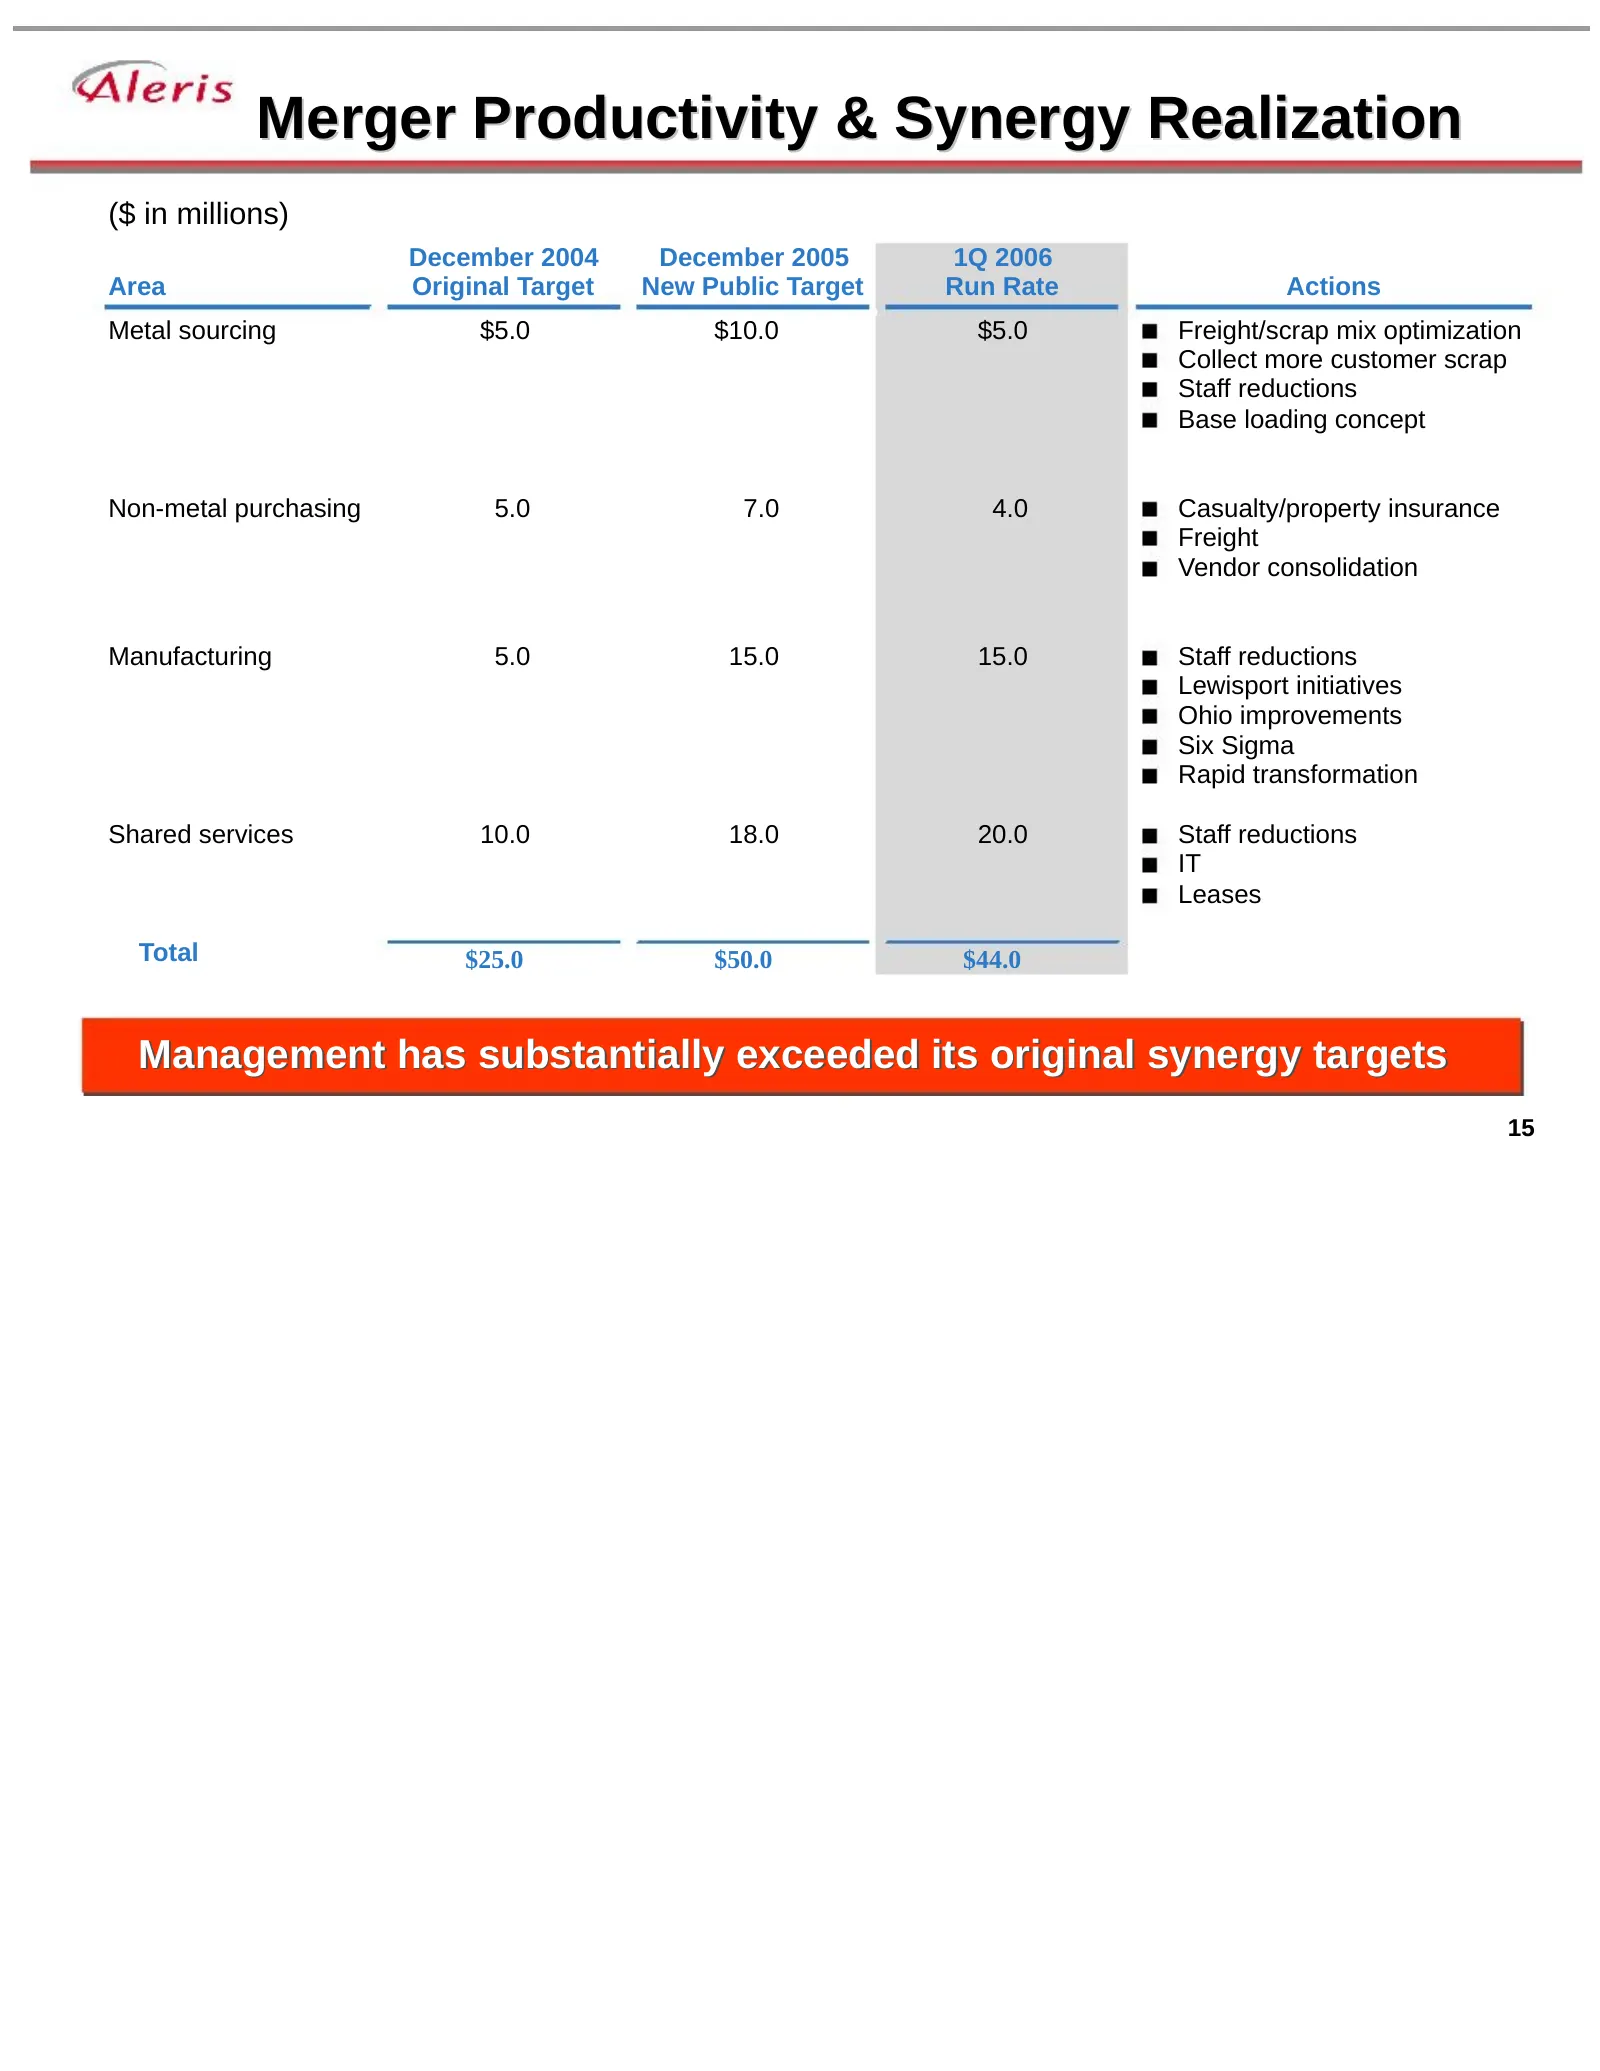
Merger Productivity & Synergy Realization ($ in millions) December 2004 December 2005 1Q 2006 Area Original Target New Public Target Run Rate Actions Metal sourcing $5.0 $10.0 $5.0 Freight/scrap mix optimization Collect more customer scrap Staff reductions Base loading concept Non-metal purchasing 5
Slide 16: Culture Change Driving Productivity
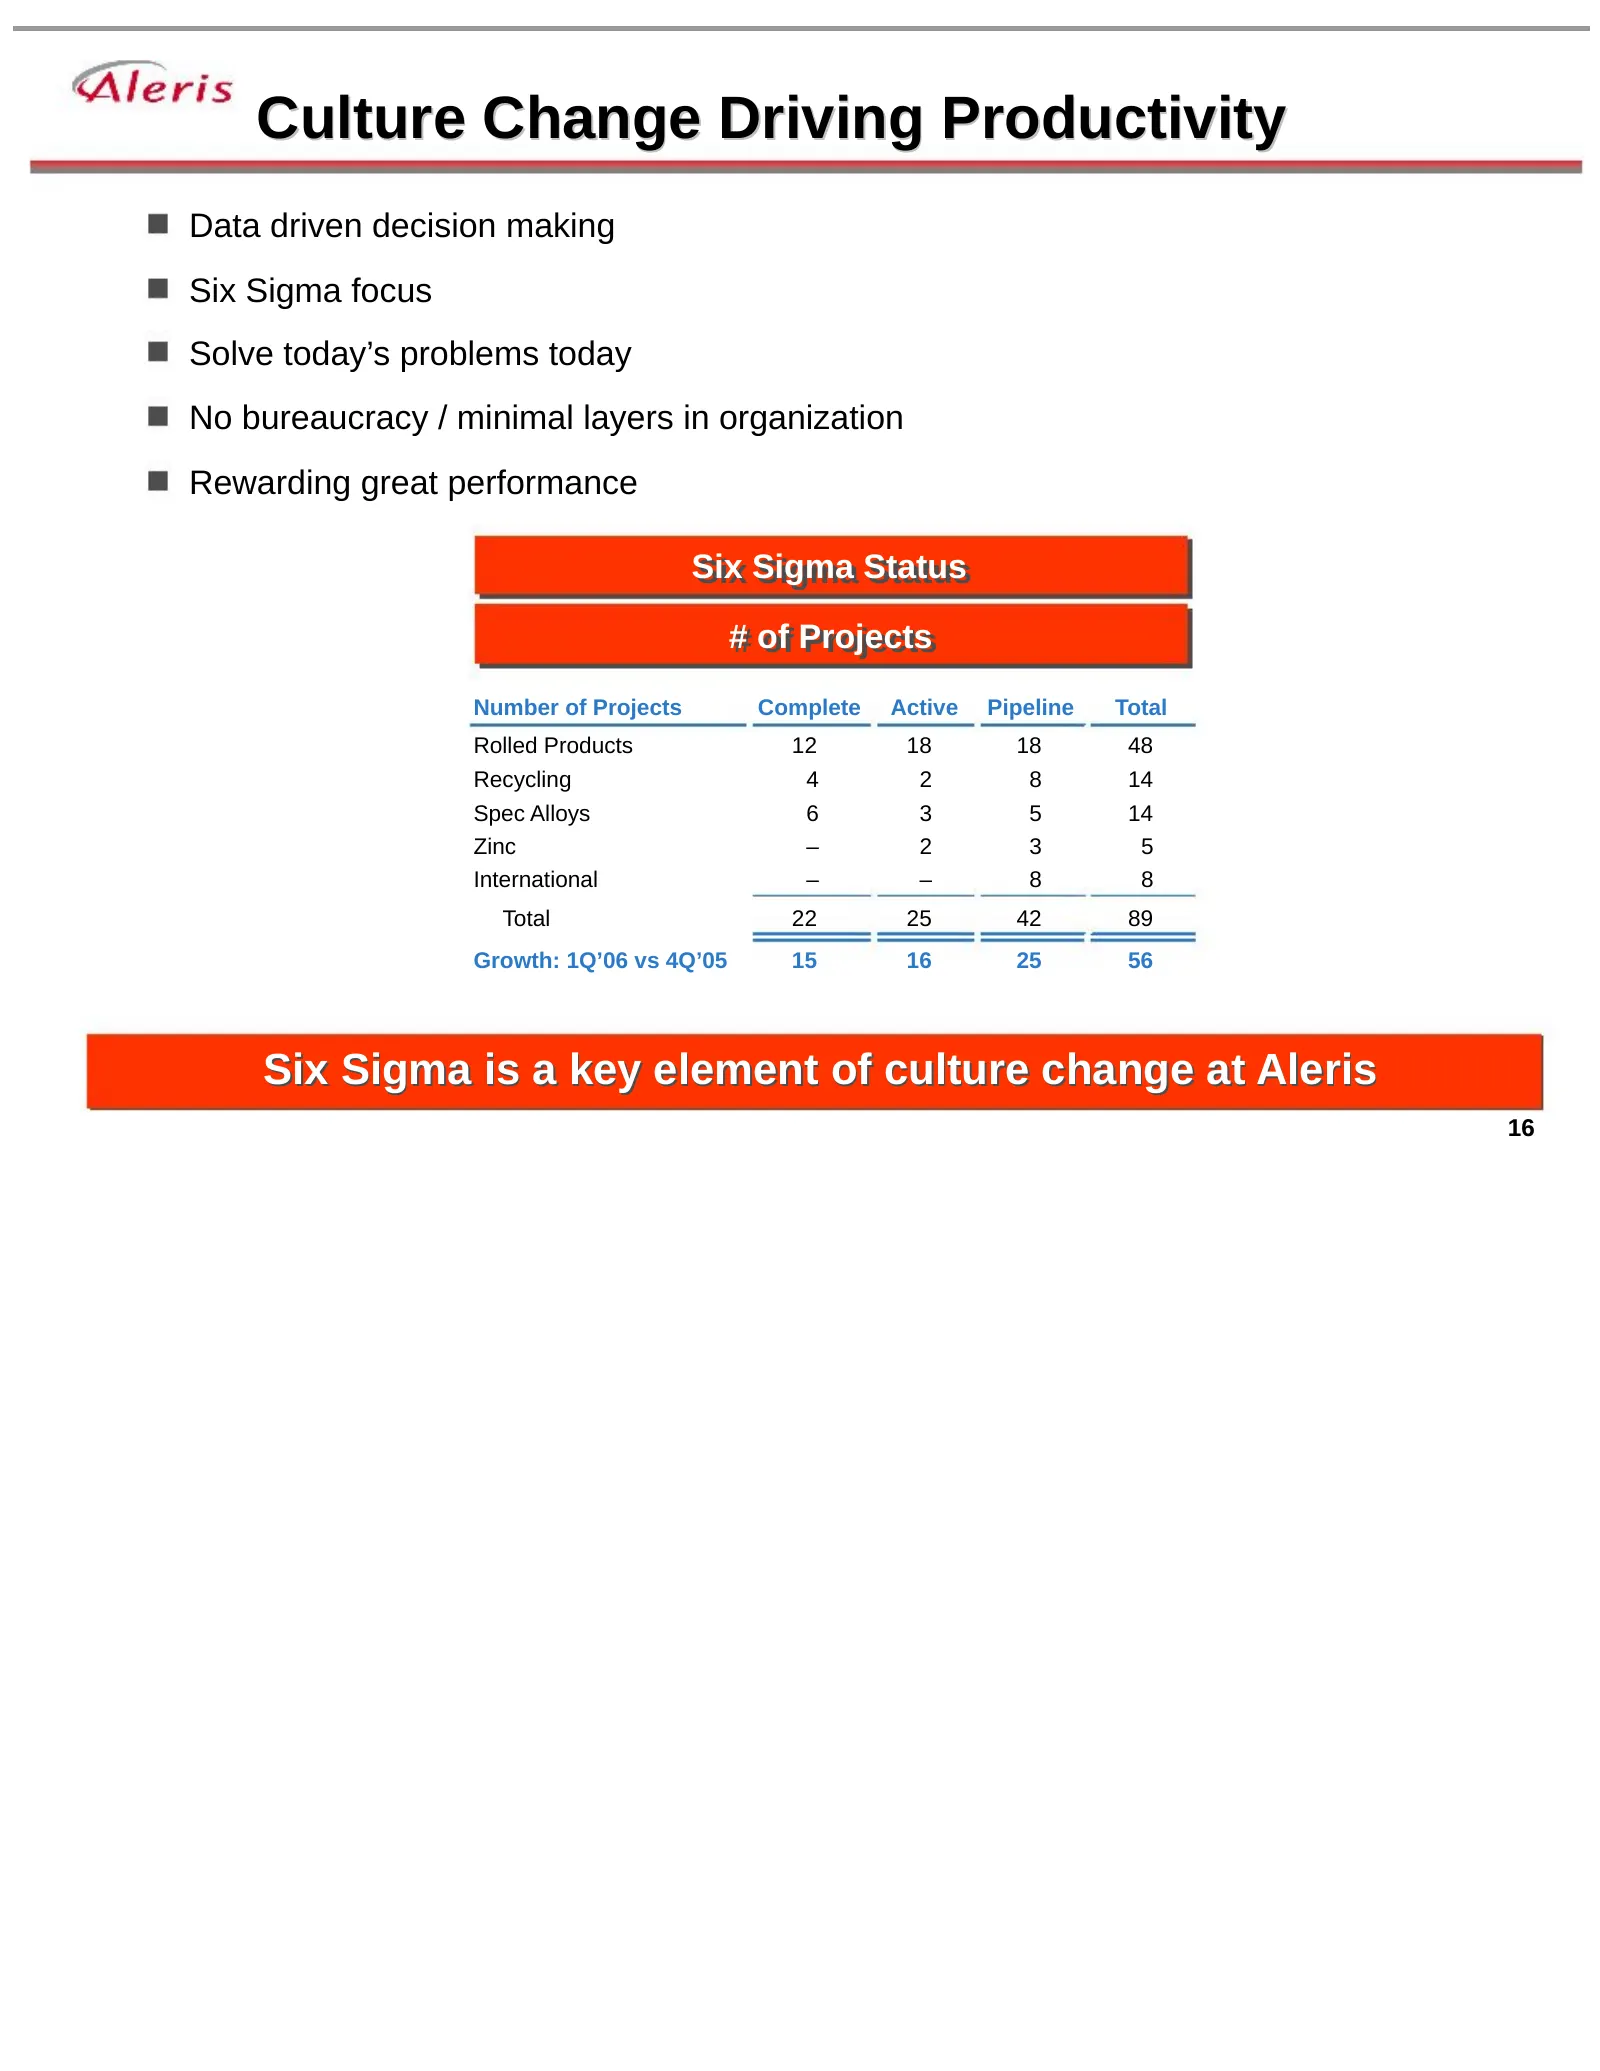
Culture Change Driving Productivity Data driven decision making Six Sigma focus Solve today’s problems today No bureaucracy / minimal layers in organization Rewarding great performance Six Six Sigma Sigma Status Status ## of of Projects Projects Number of Projects Complete Active Pipeline Total Roll
Slide 17: Improved Financial Results
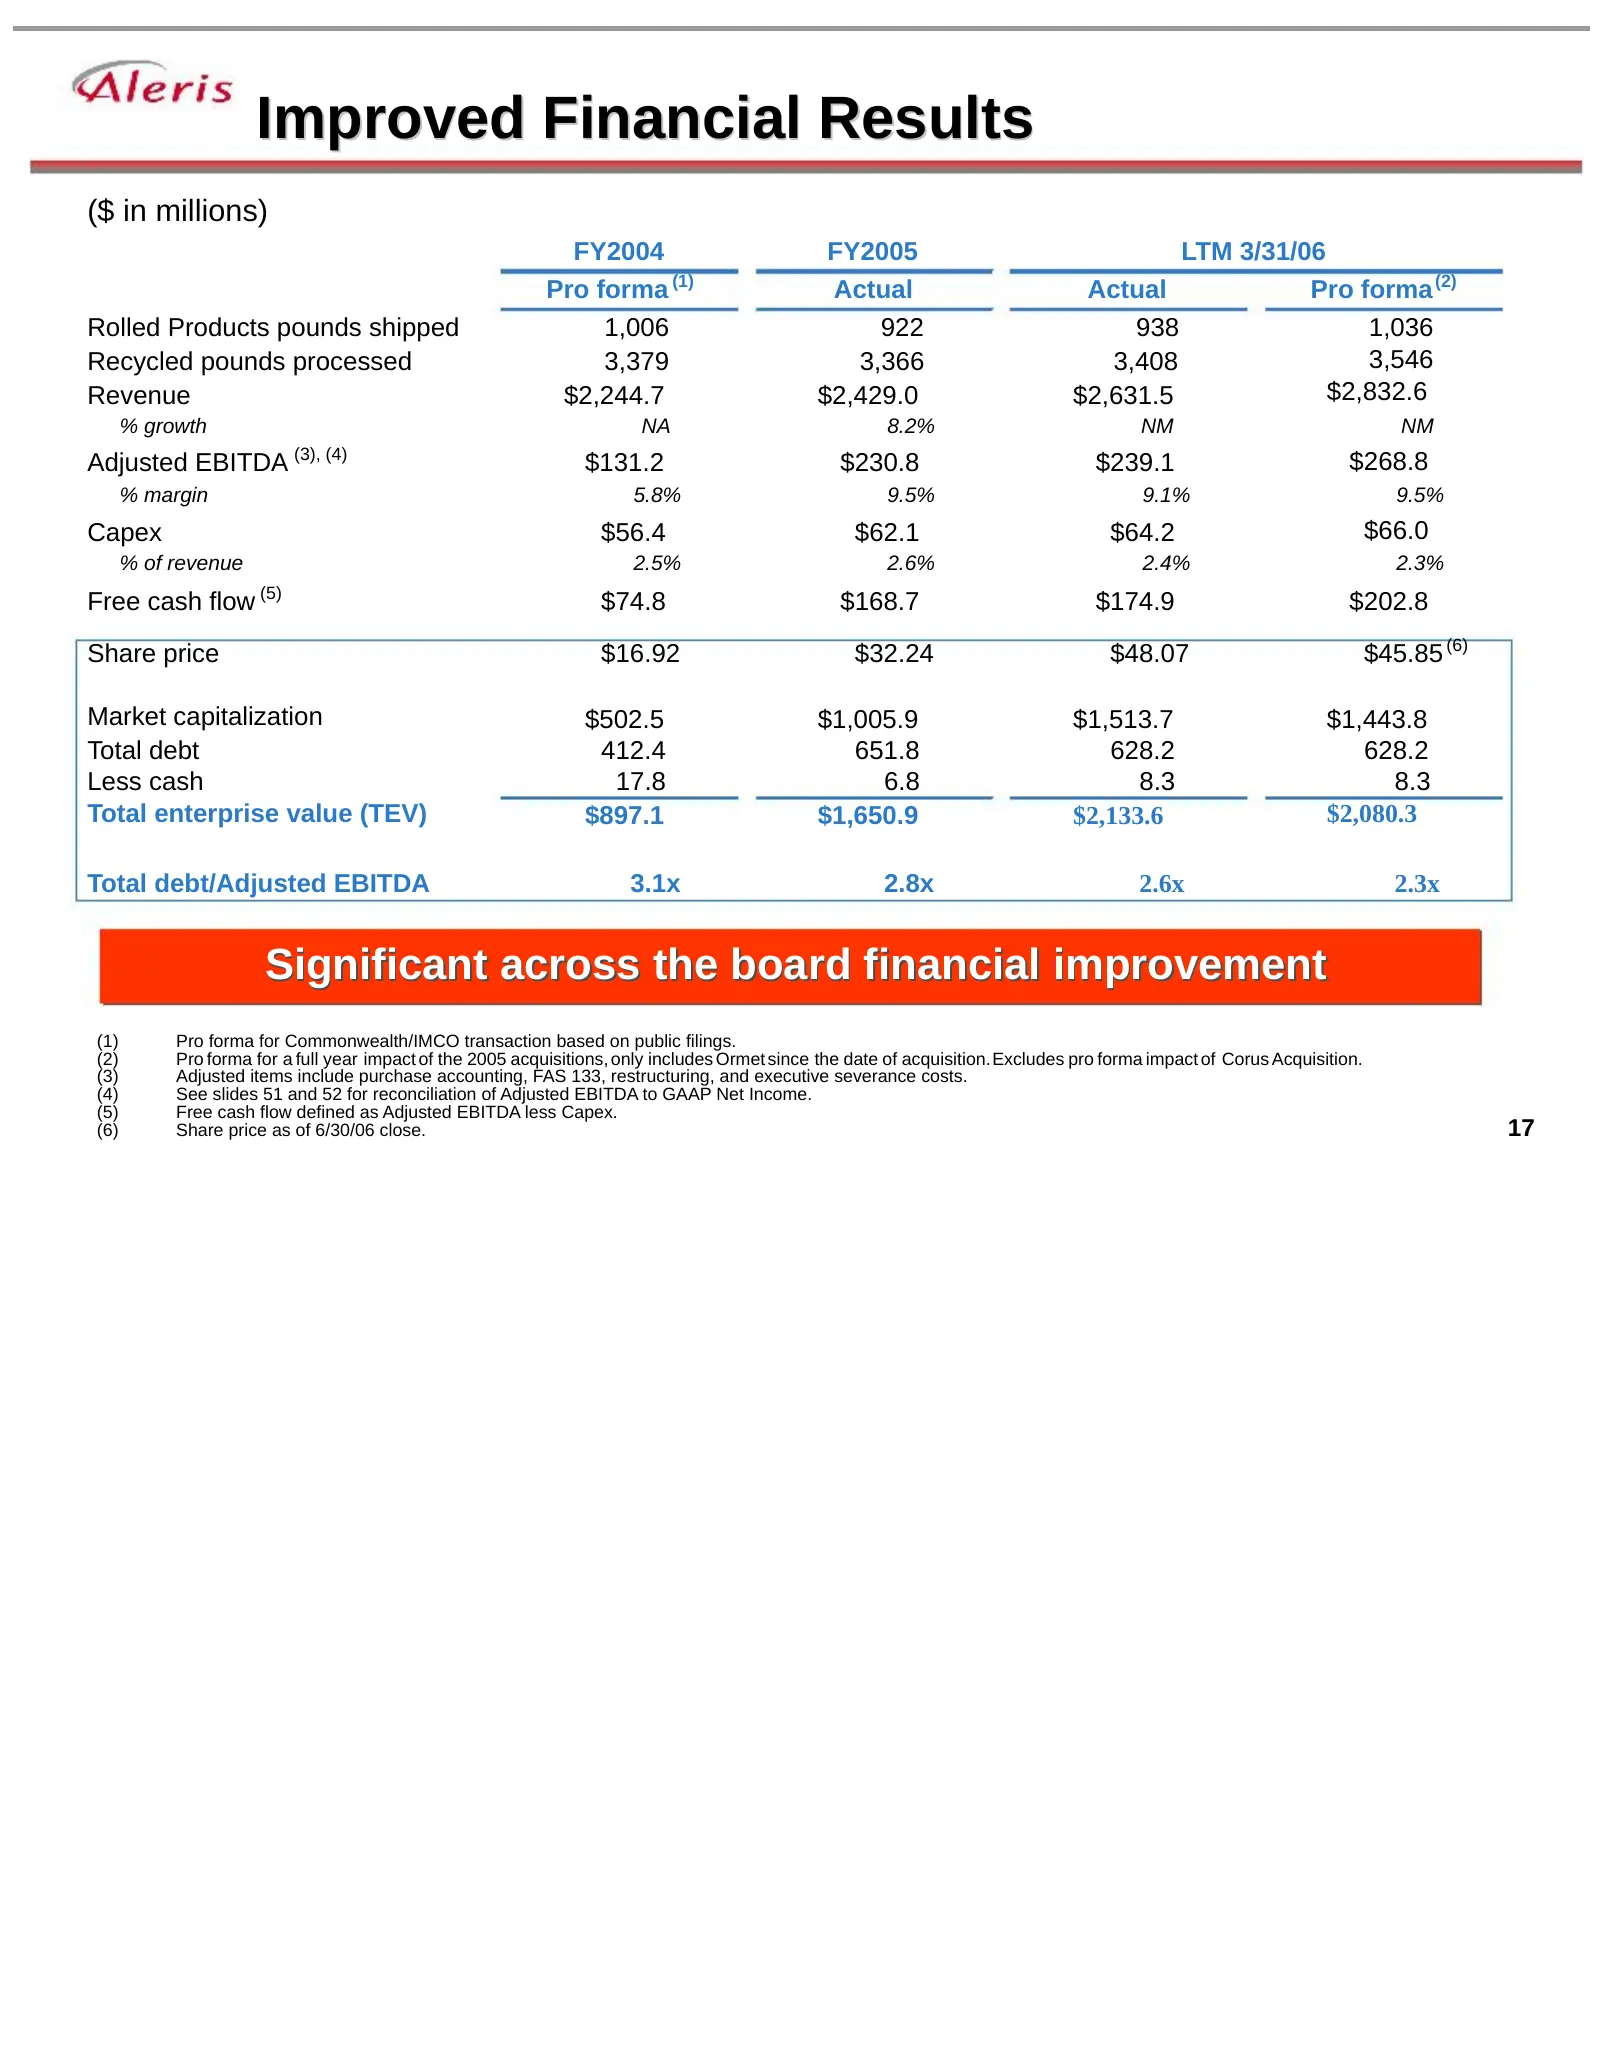
Improved Financial Results ($ in millions) FY2004 FY2005 LTM 3/31/06 (1) Pro forma Actual Actual Pro forma (2) Rolled Products pounds shipped 1,006 922 938 1,036 Recycled pounds processed 3,379 3,366 3,408 3,546 Revenue $2,244.7 $2,429.0 $2,631.5 $2,832.6 % growth NA 8.2% NM NM (3), (4) Adjusted EBI
Slide 18: 2005 Acquisition Overview
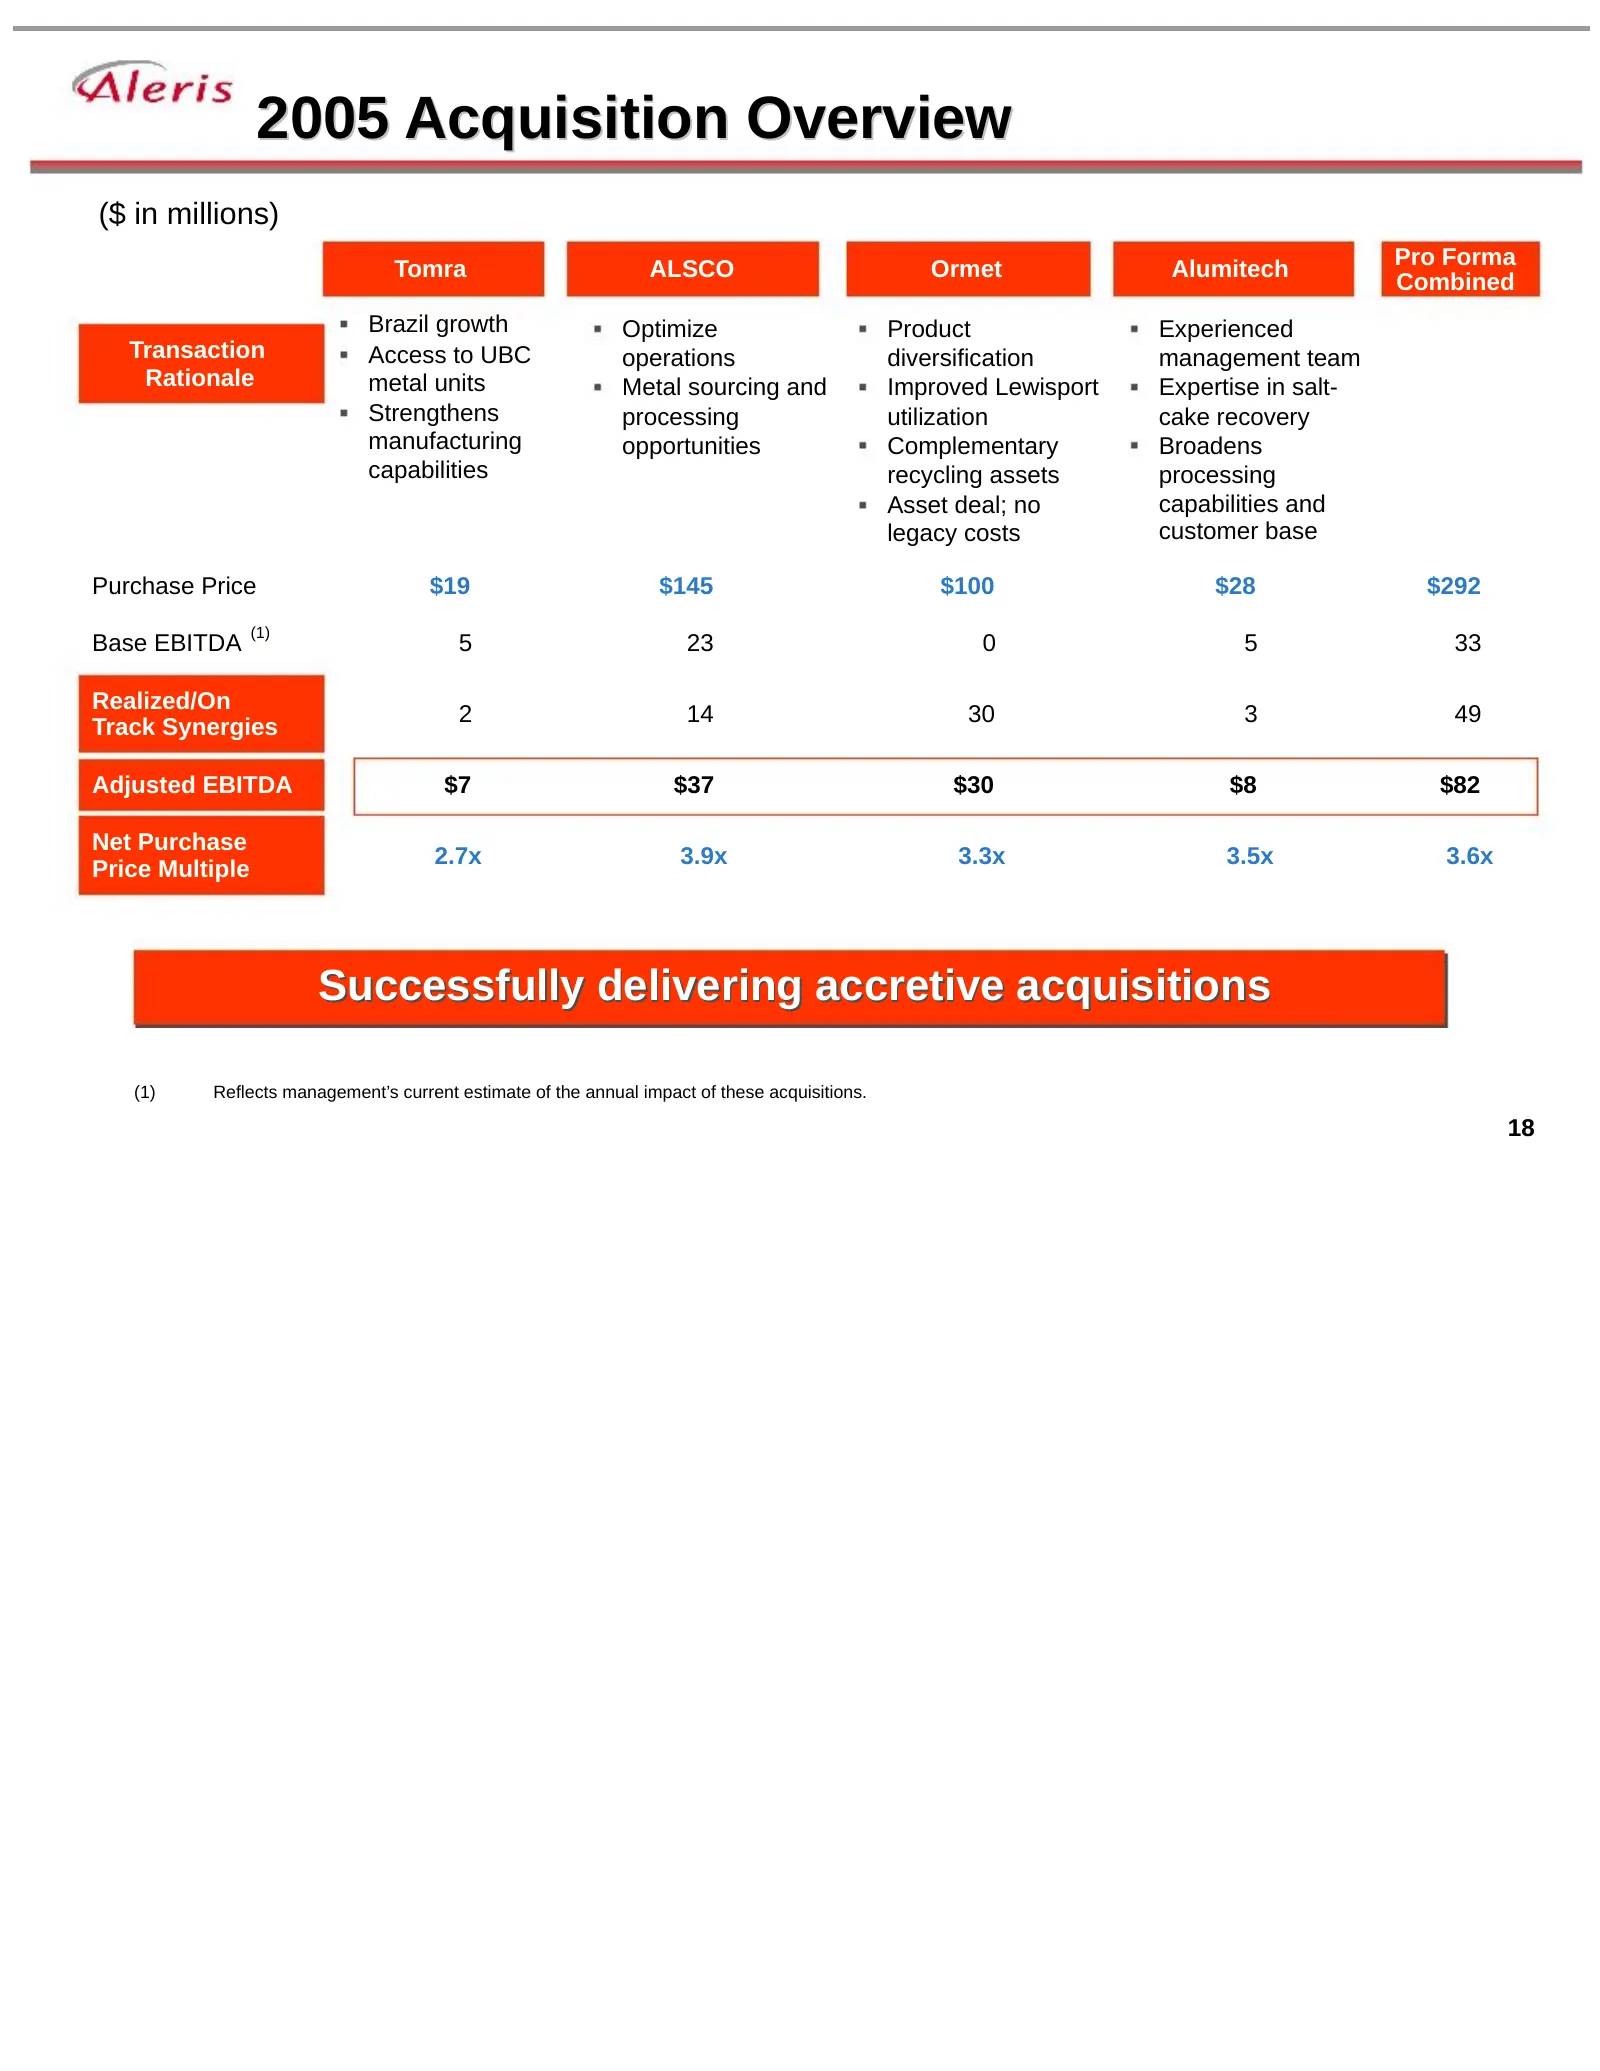
2005 Acquisition Overview ($ in millions) Pro Forma Tomra ALSCO Ormet Alumitech Combined Brazil growth Optimize Product Experienced Transaction Access to UBC operations diversification management team Rationale metal units Metal sourcing and Improved Lewisport Expertise in salt- Strengthens processi
Slide 19: 2005 Acquisitions Synergies
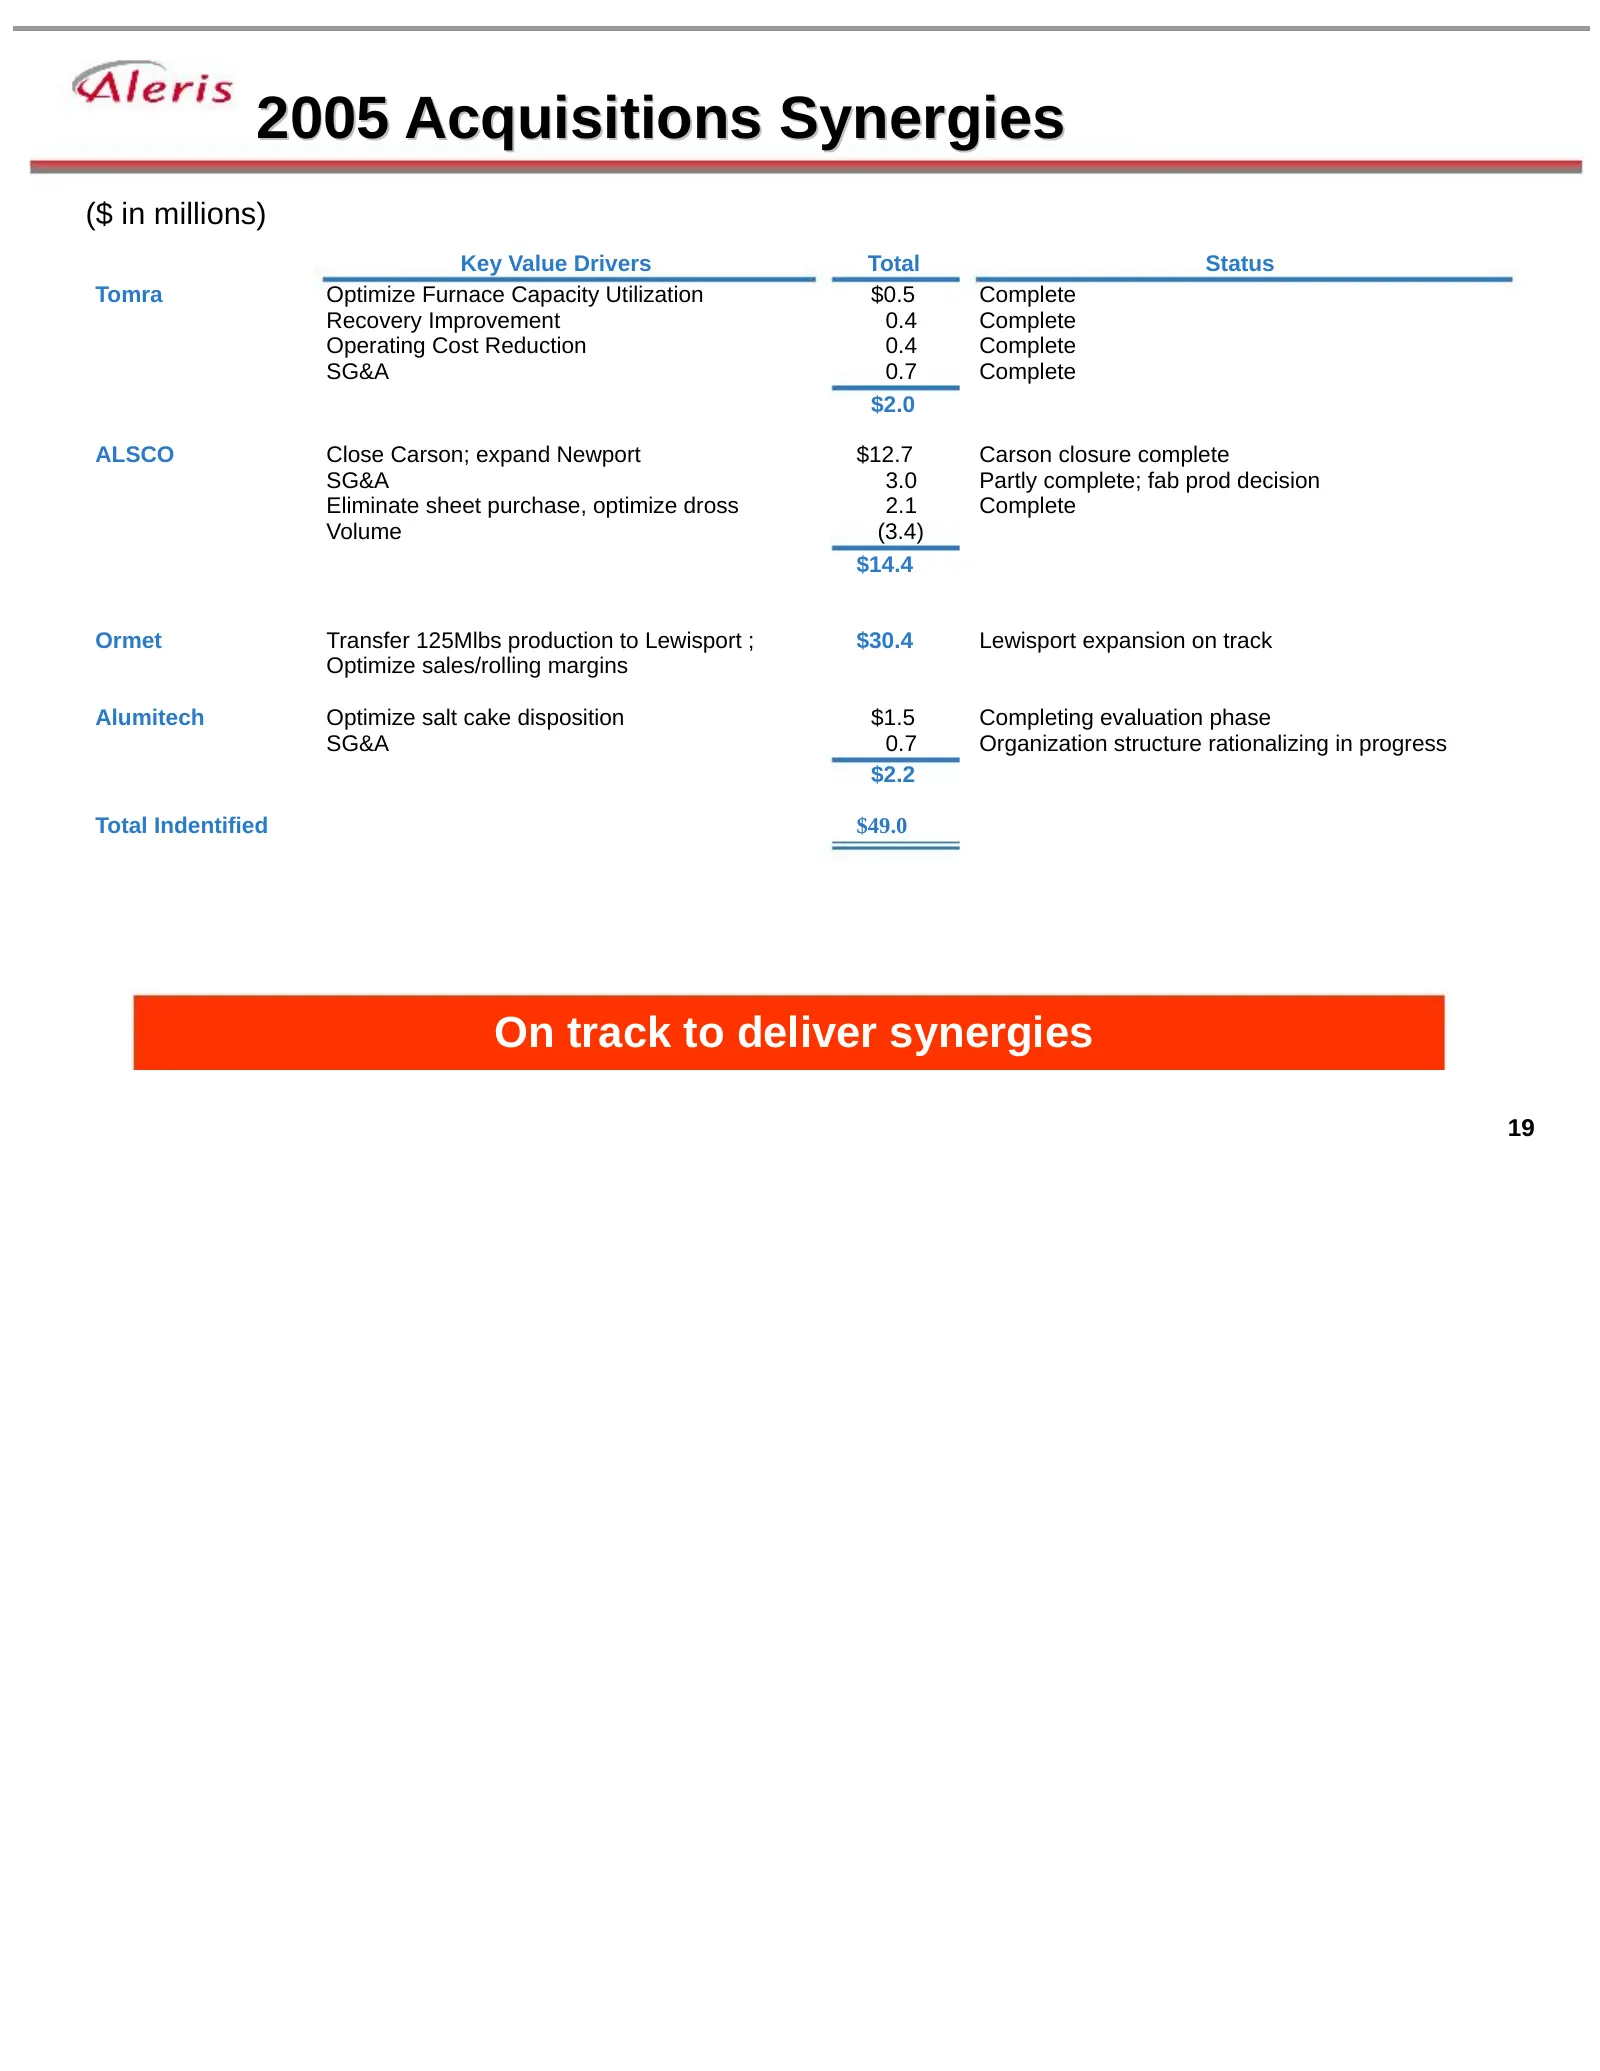
2005 Acquisitions Synergies ($ in millions) Key Value Drivers Total Status Tomra Optimize Furnace Capacity Utilization $0.5 Complete Recovery Improvement 0.4 Complete Operating Cost Reduction 0.4 Complete SG&A 0.7 Complete $2.0 ALSCO Close Carson; expand Newport $12.7 Carson closure complete SG&A 3.
Slide 20: Key Accomplishments
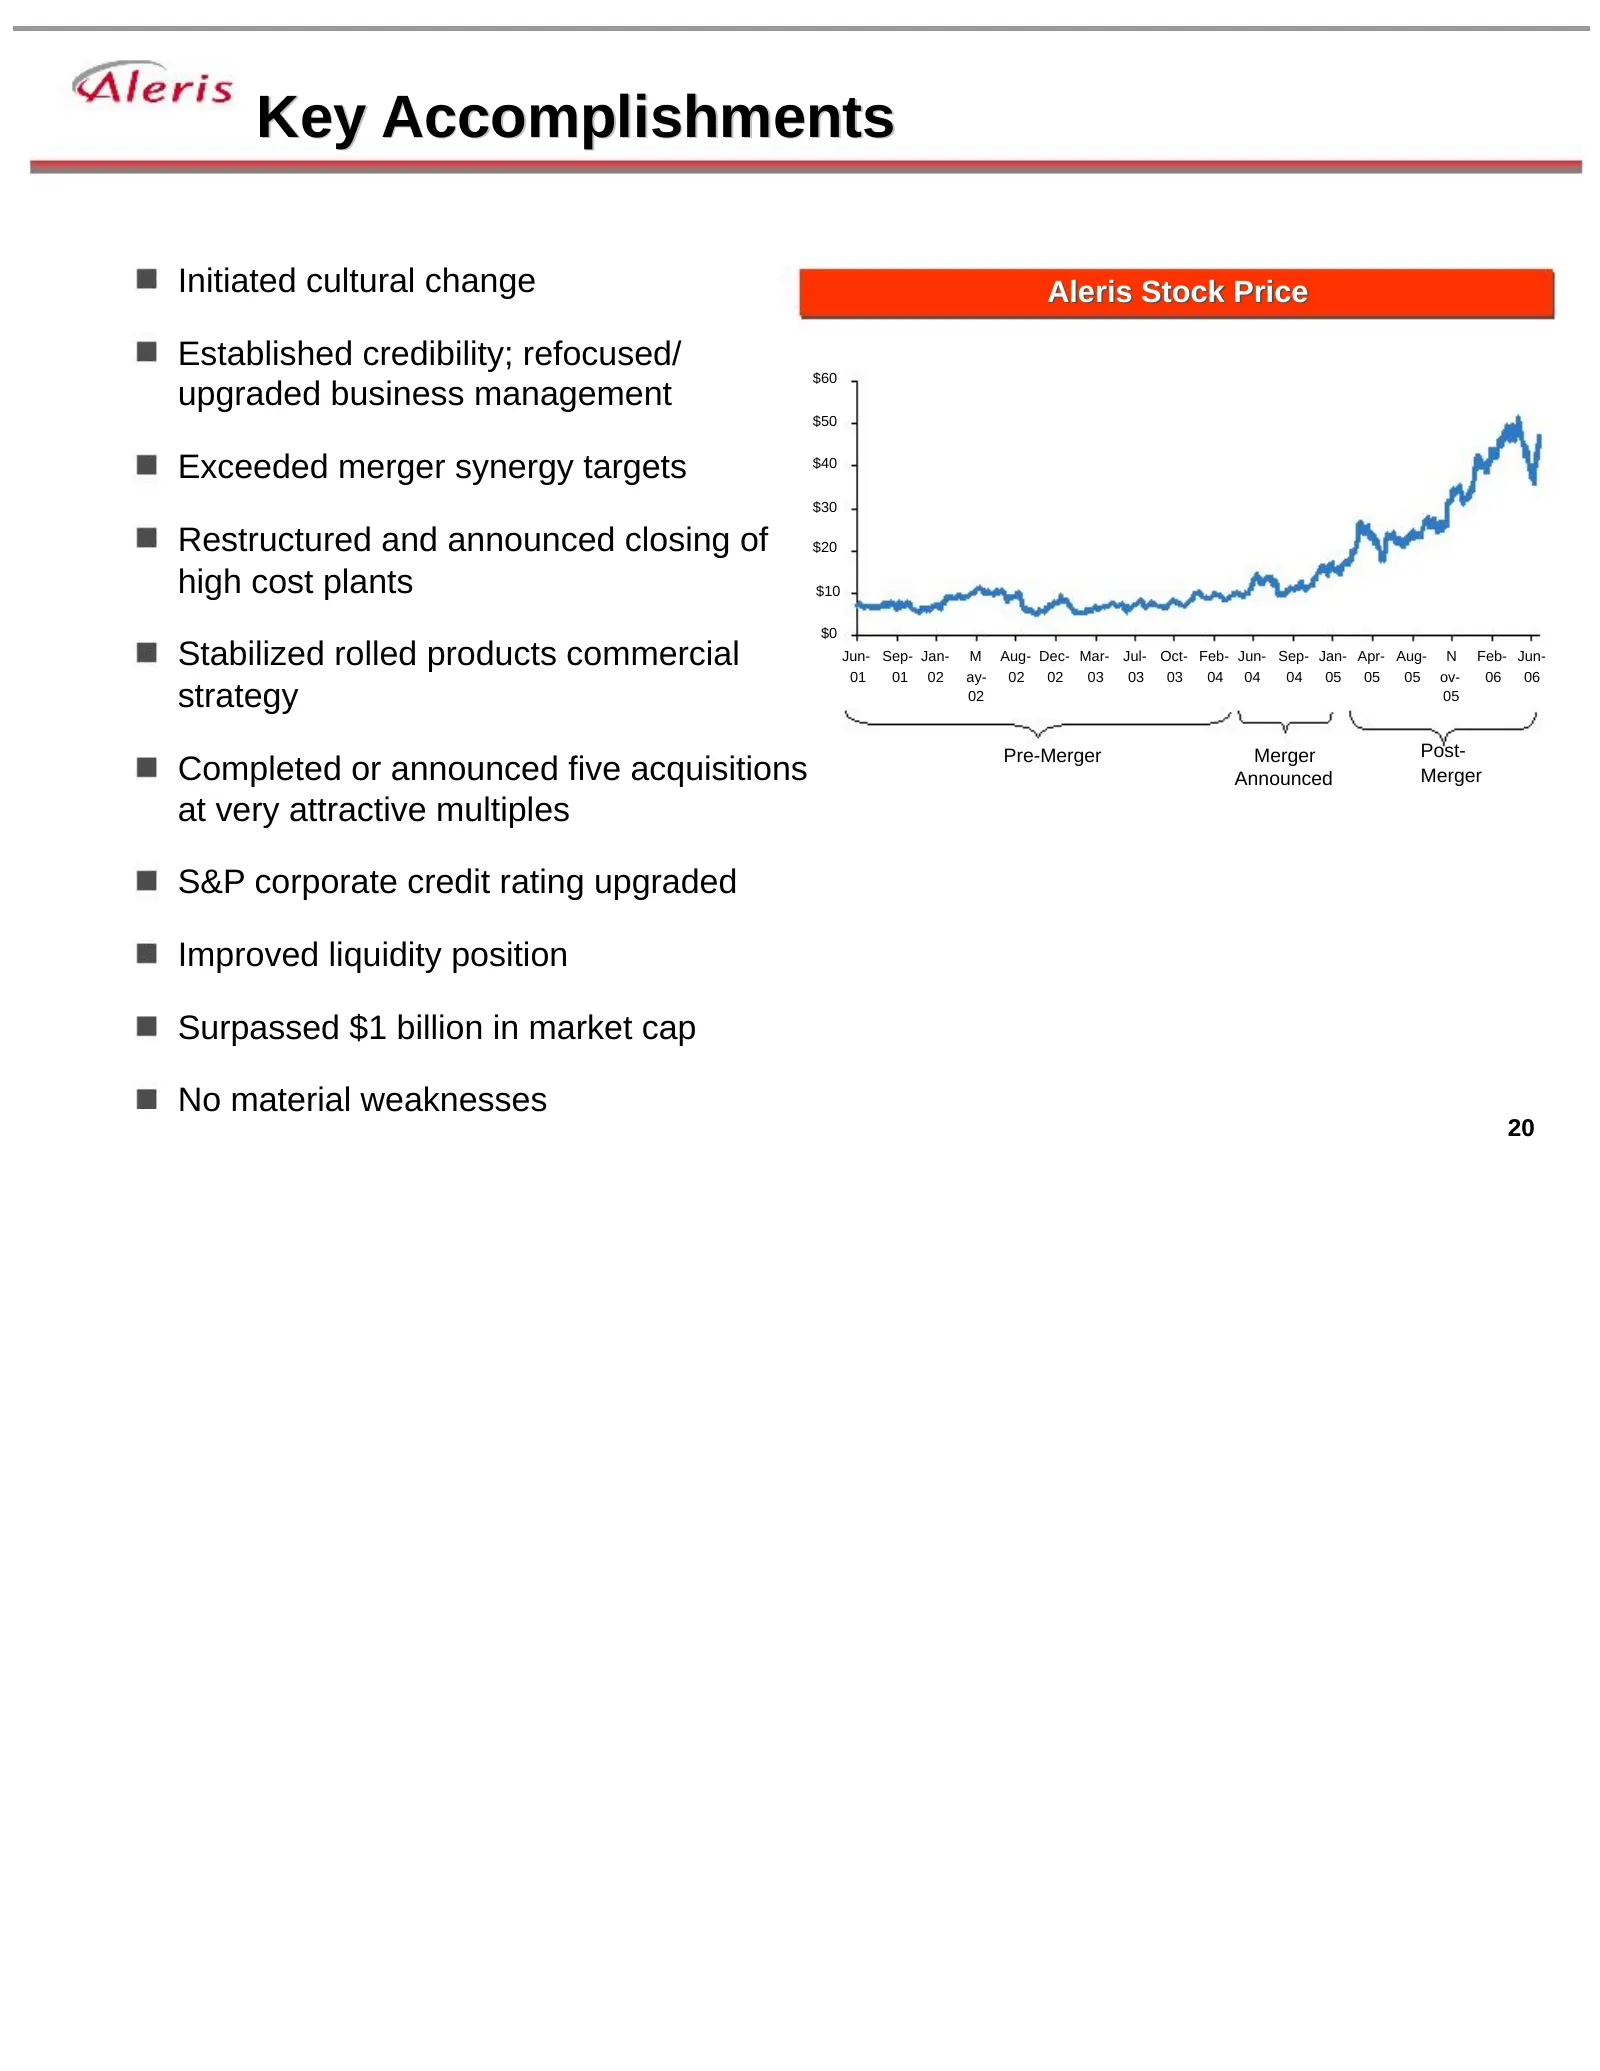
Key Accomplishments Initiated cultural change Aleris Stock Price Established credibility; refocused/ $60 upgraded business management $50 Exceeded merger synergy targets $40 $30 Restructured and announced closing of $20 high cost plants $10 $0 Stabilized rolled products commercial Jun- Sep- Jan- 01
Slide 21: Corus Aluminum Overview
Corus Aluminum Overview Sean Stack, Executive Vice President & President of Aleris, Europe
Slide 22: Corus Aluminum Acquisition Rationale
Corus Aluminum Acquisition Rationale High margin, value-added product lines Aerospace plate, heat treated commercial plate, heat exchanger sheet Hard alloy extrusions Best-in-class production capabilities Koblenz is one of the largest global specialized rolling mills Bonn recently installed one of t
Slide 23: Corus Aluminum Overview
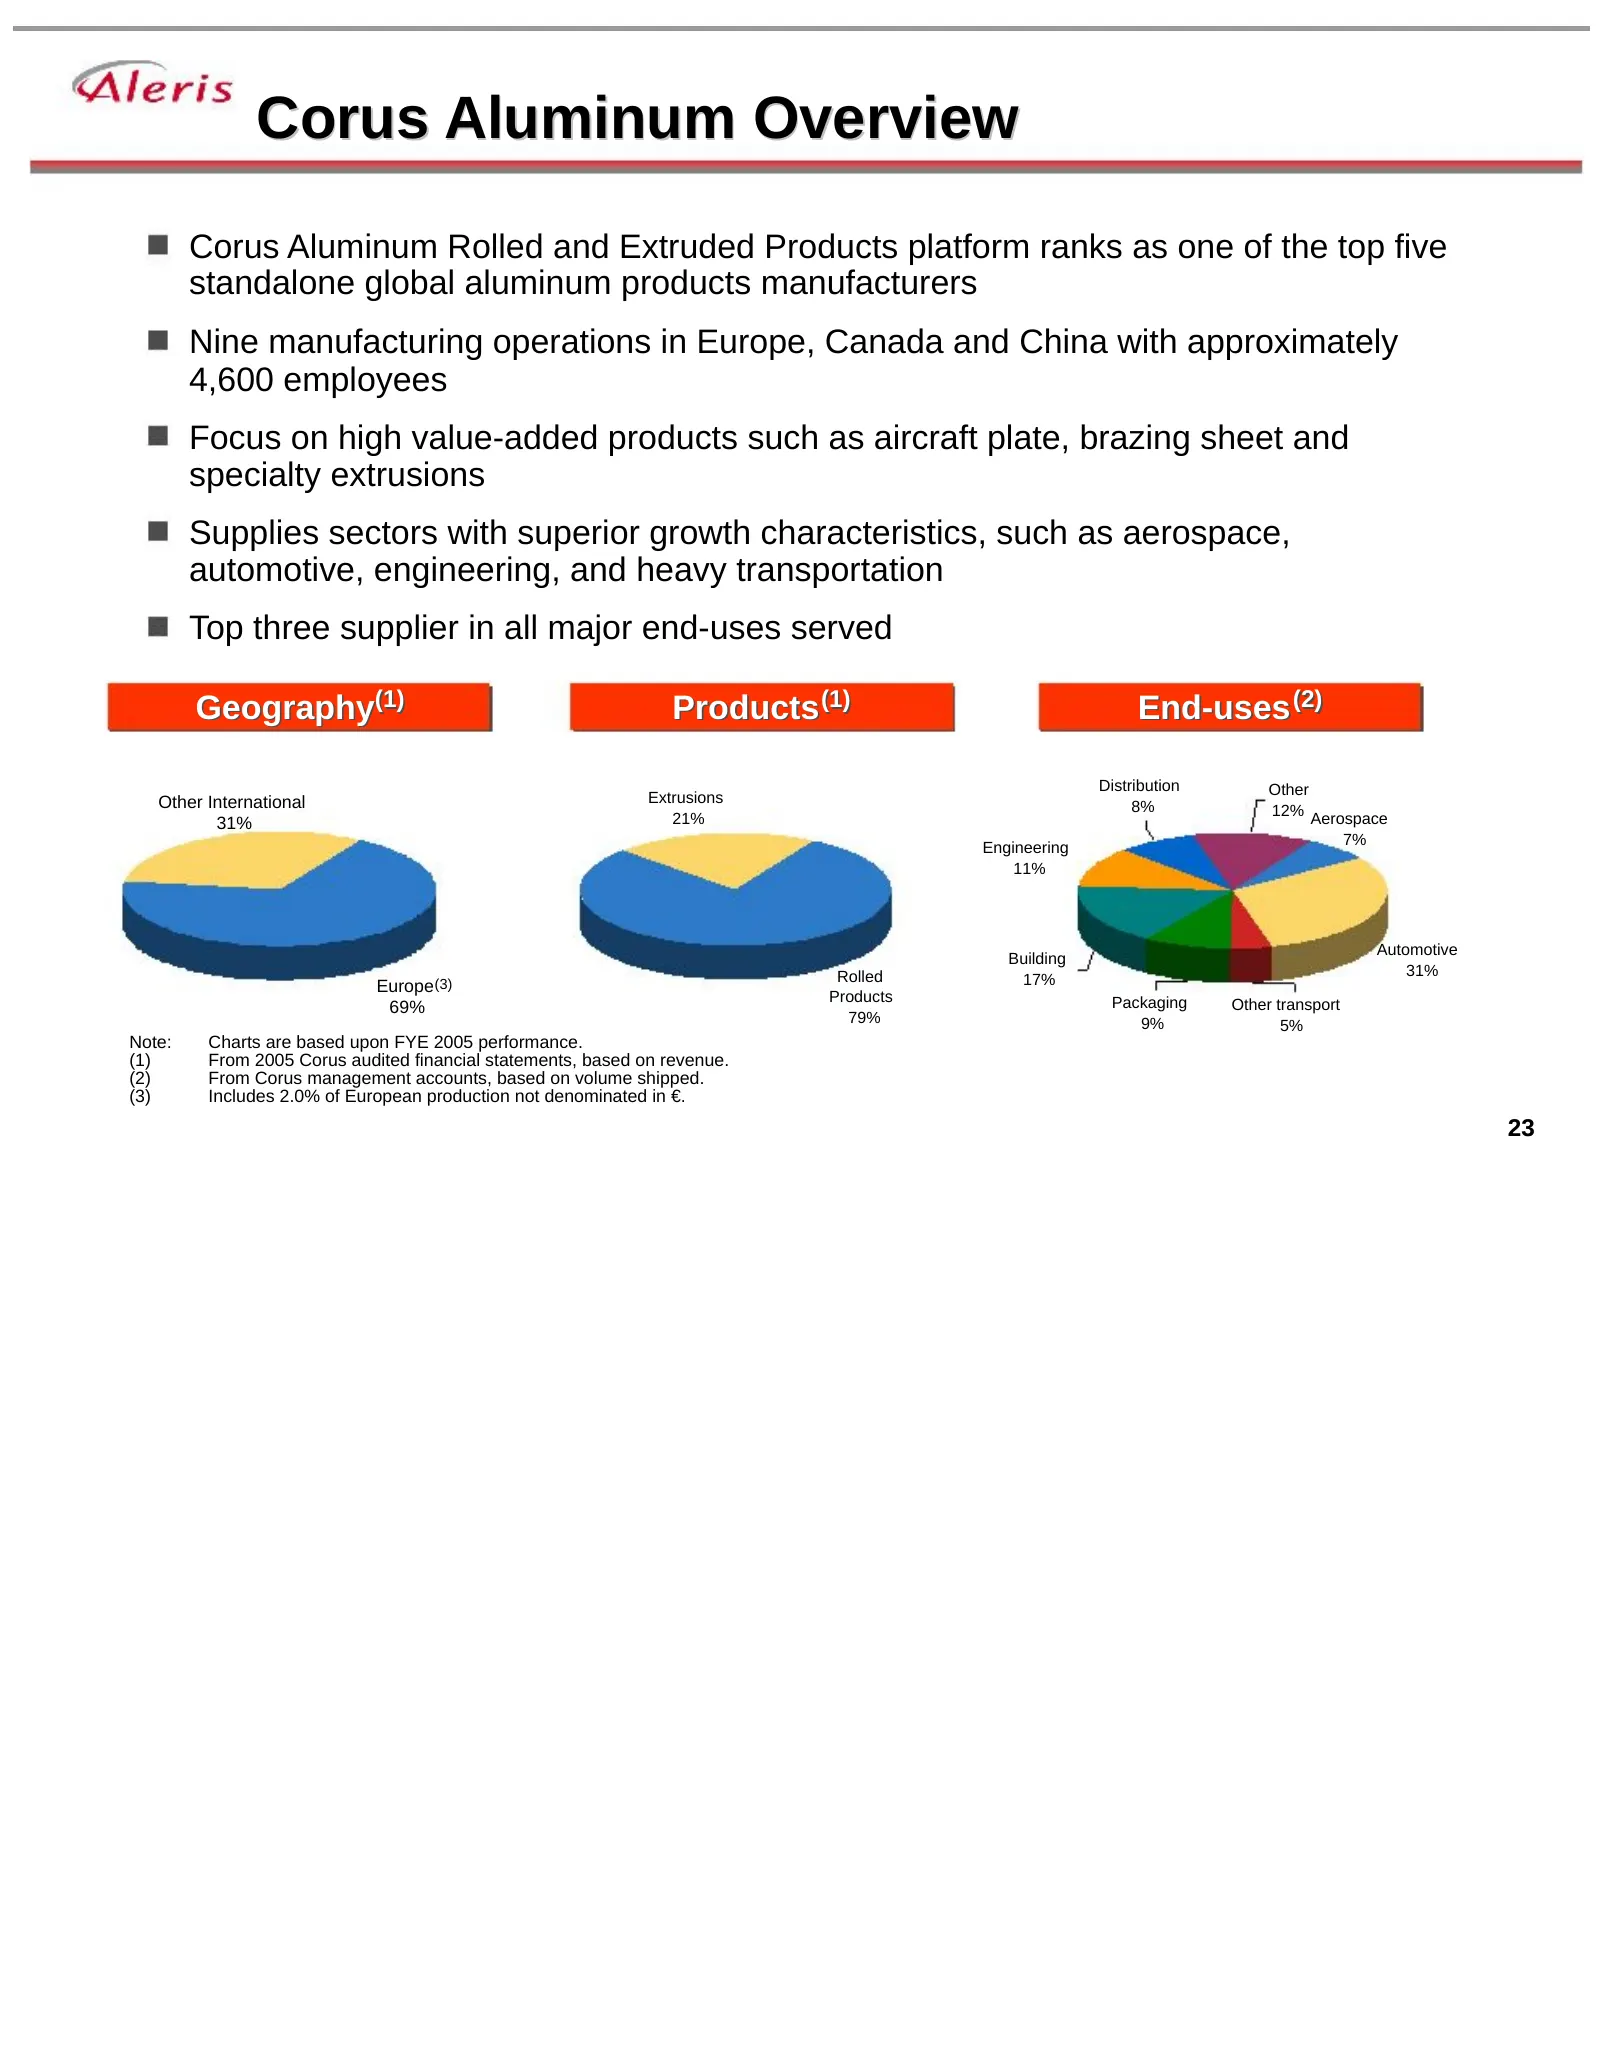
Corus Aluminum Overview Corus Aluminum Rolled and Extruded Products platform ranks as one of the top five standalone global aluminum products manufacturers Nine manufacturing operations in Europe, Canada and China with approximately 4,600 employees Focus on high value-added products such as aircraft
Slide 24: Corus Aluminum Geographic Footprint
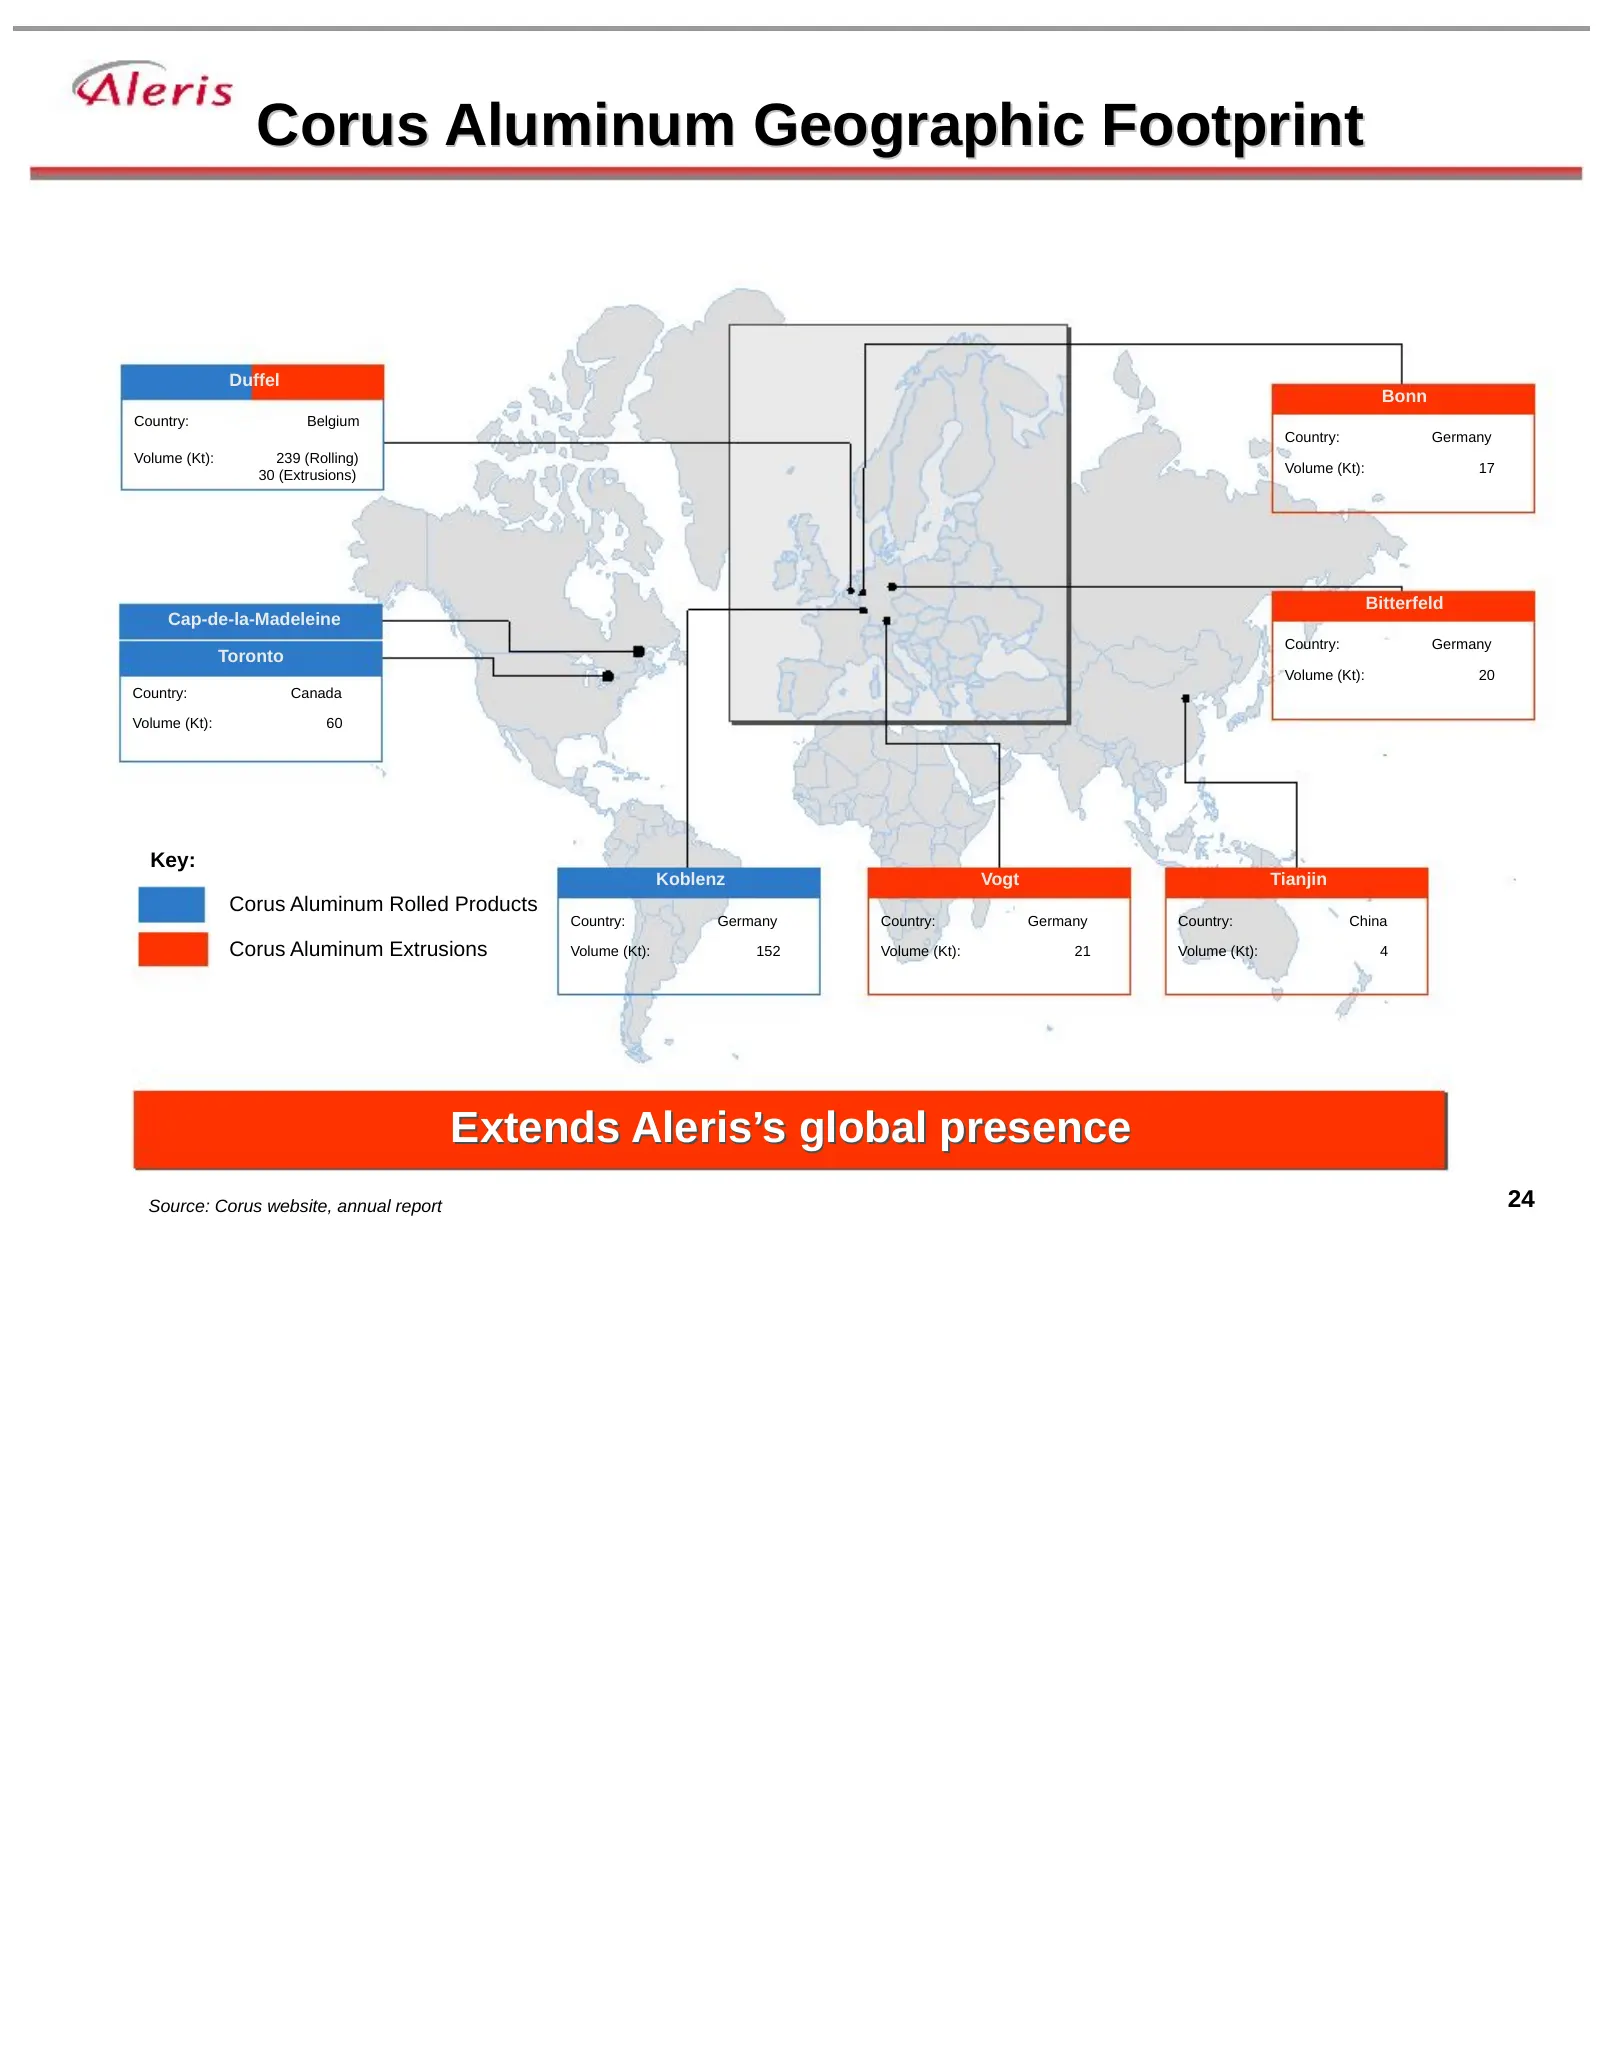
Corus Aluminum Geographic Footprint Duffel Bonn Country: Belgium Country: Germany Volume (Kt): 239 (Rolling) 30 (Extrusions) Volume (Kt): 17 Bitterfeld Cap-de-la-Madeleine Country: Germany Toronto Volume (Kt): 20 Country: Canada Volume (Kt): 60 Key: Koblenz Vogt Tianjin Corus Aluminum Rolled Product
Slide 25: Corus Aluminum Business Mix
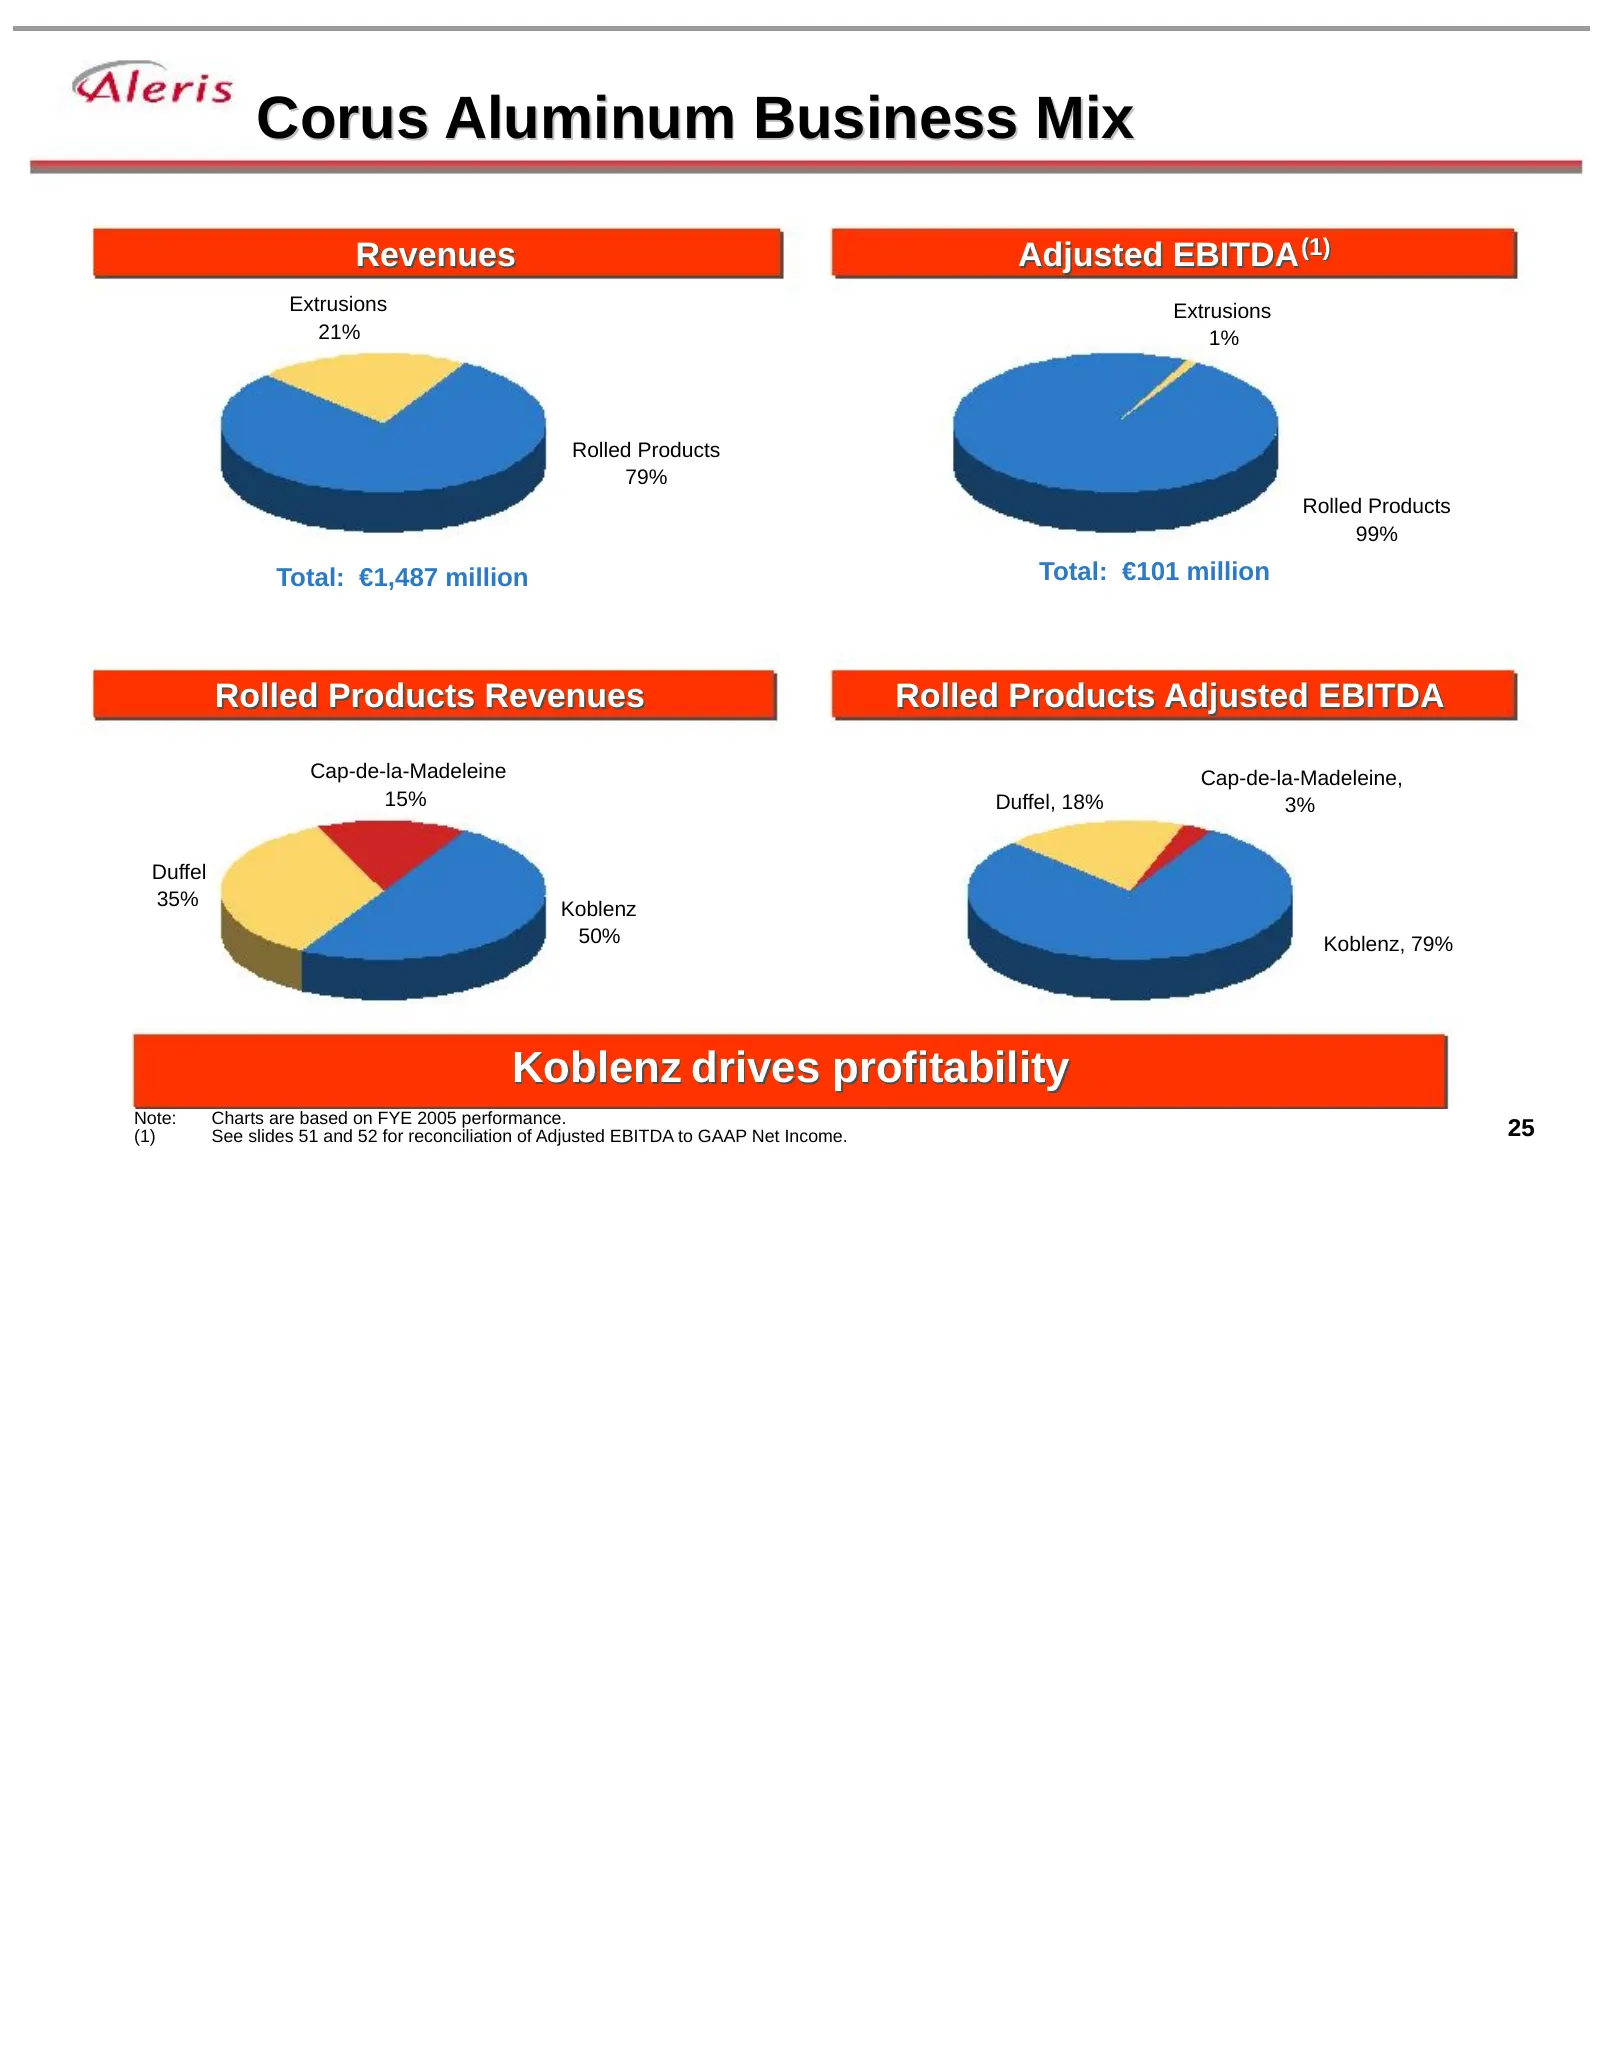
Corus Aluminum Business Mix Revenues Adjusted EBITDA (1) Extrusions Extrusions 21% 1% Rolled Products 79% Rolled Products 99% Total: €1,487 million Total: €101 million Rolled Products Revenues Rolled Products Adjusted EBITDA Cap-de-la-Madeleine Cap-de-la-Madeleine, 15% Duffel, 18% 3% Duffel 35% Kobl
Slide 26: Focus on High Value-Added Products
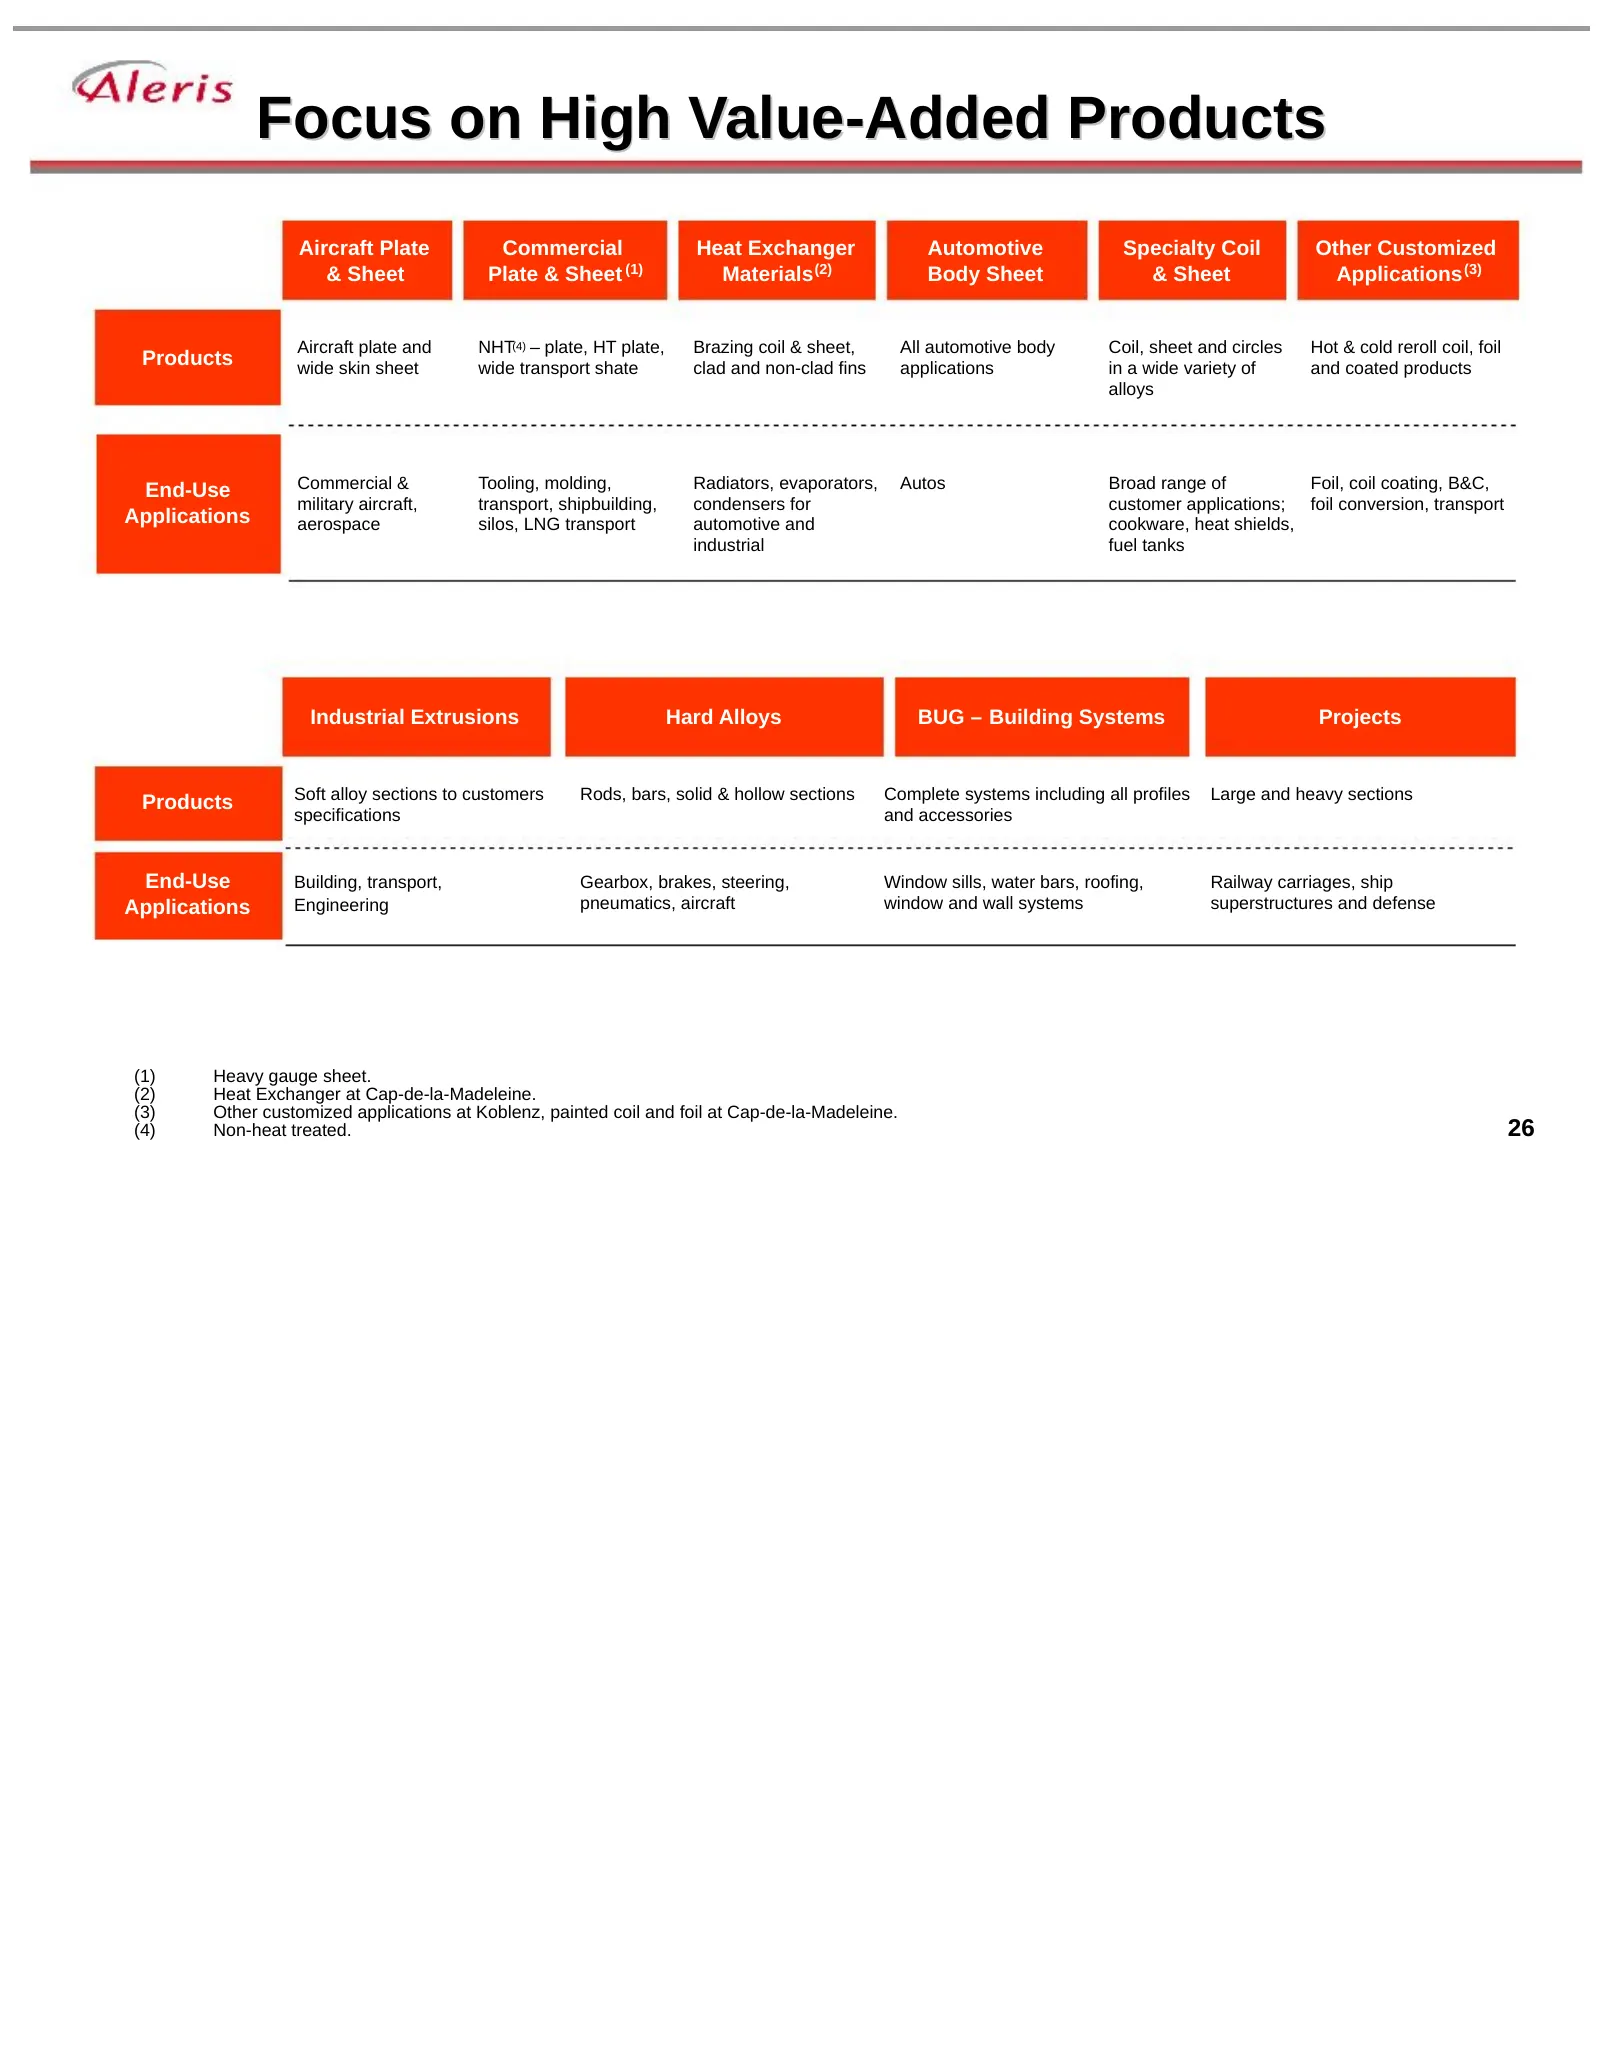
Focus on High Value-Added Products Aircraft Plate Commercial Heat Exchanger Automotive Specialty Coil Other Customized & Sheet Plate & Sheet (1) Materials (2) Body Sheet & Sheet Applications (3) Aircraft plate and NHT(4) – plate, HT plate, Brazing coil & sheet, All automotive body Coil, sheet and ci
Slide 27: Attractive Industry Positions
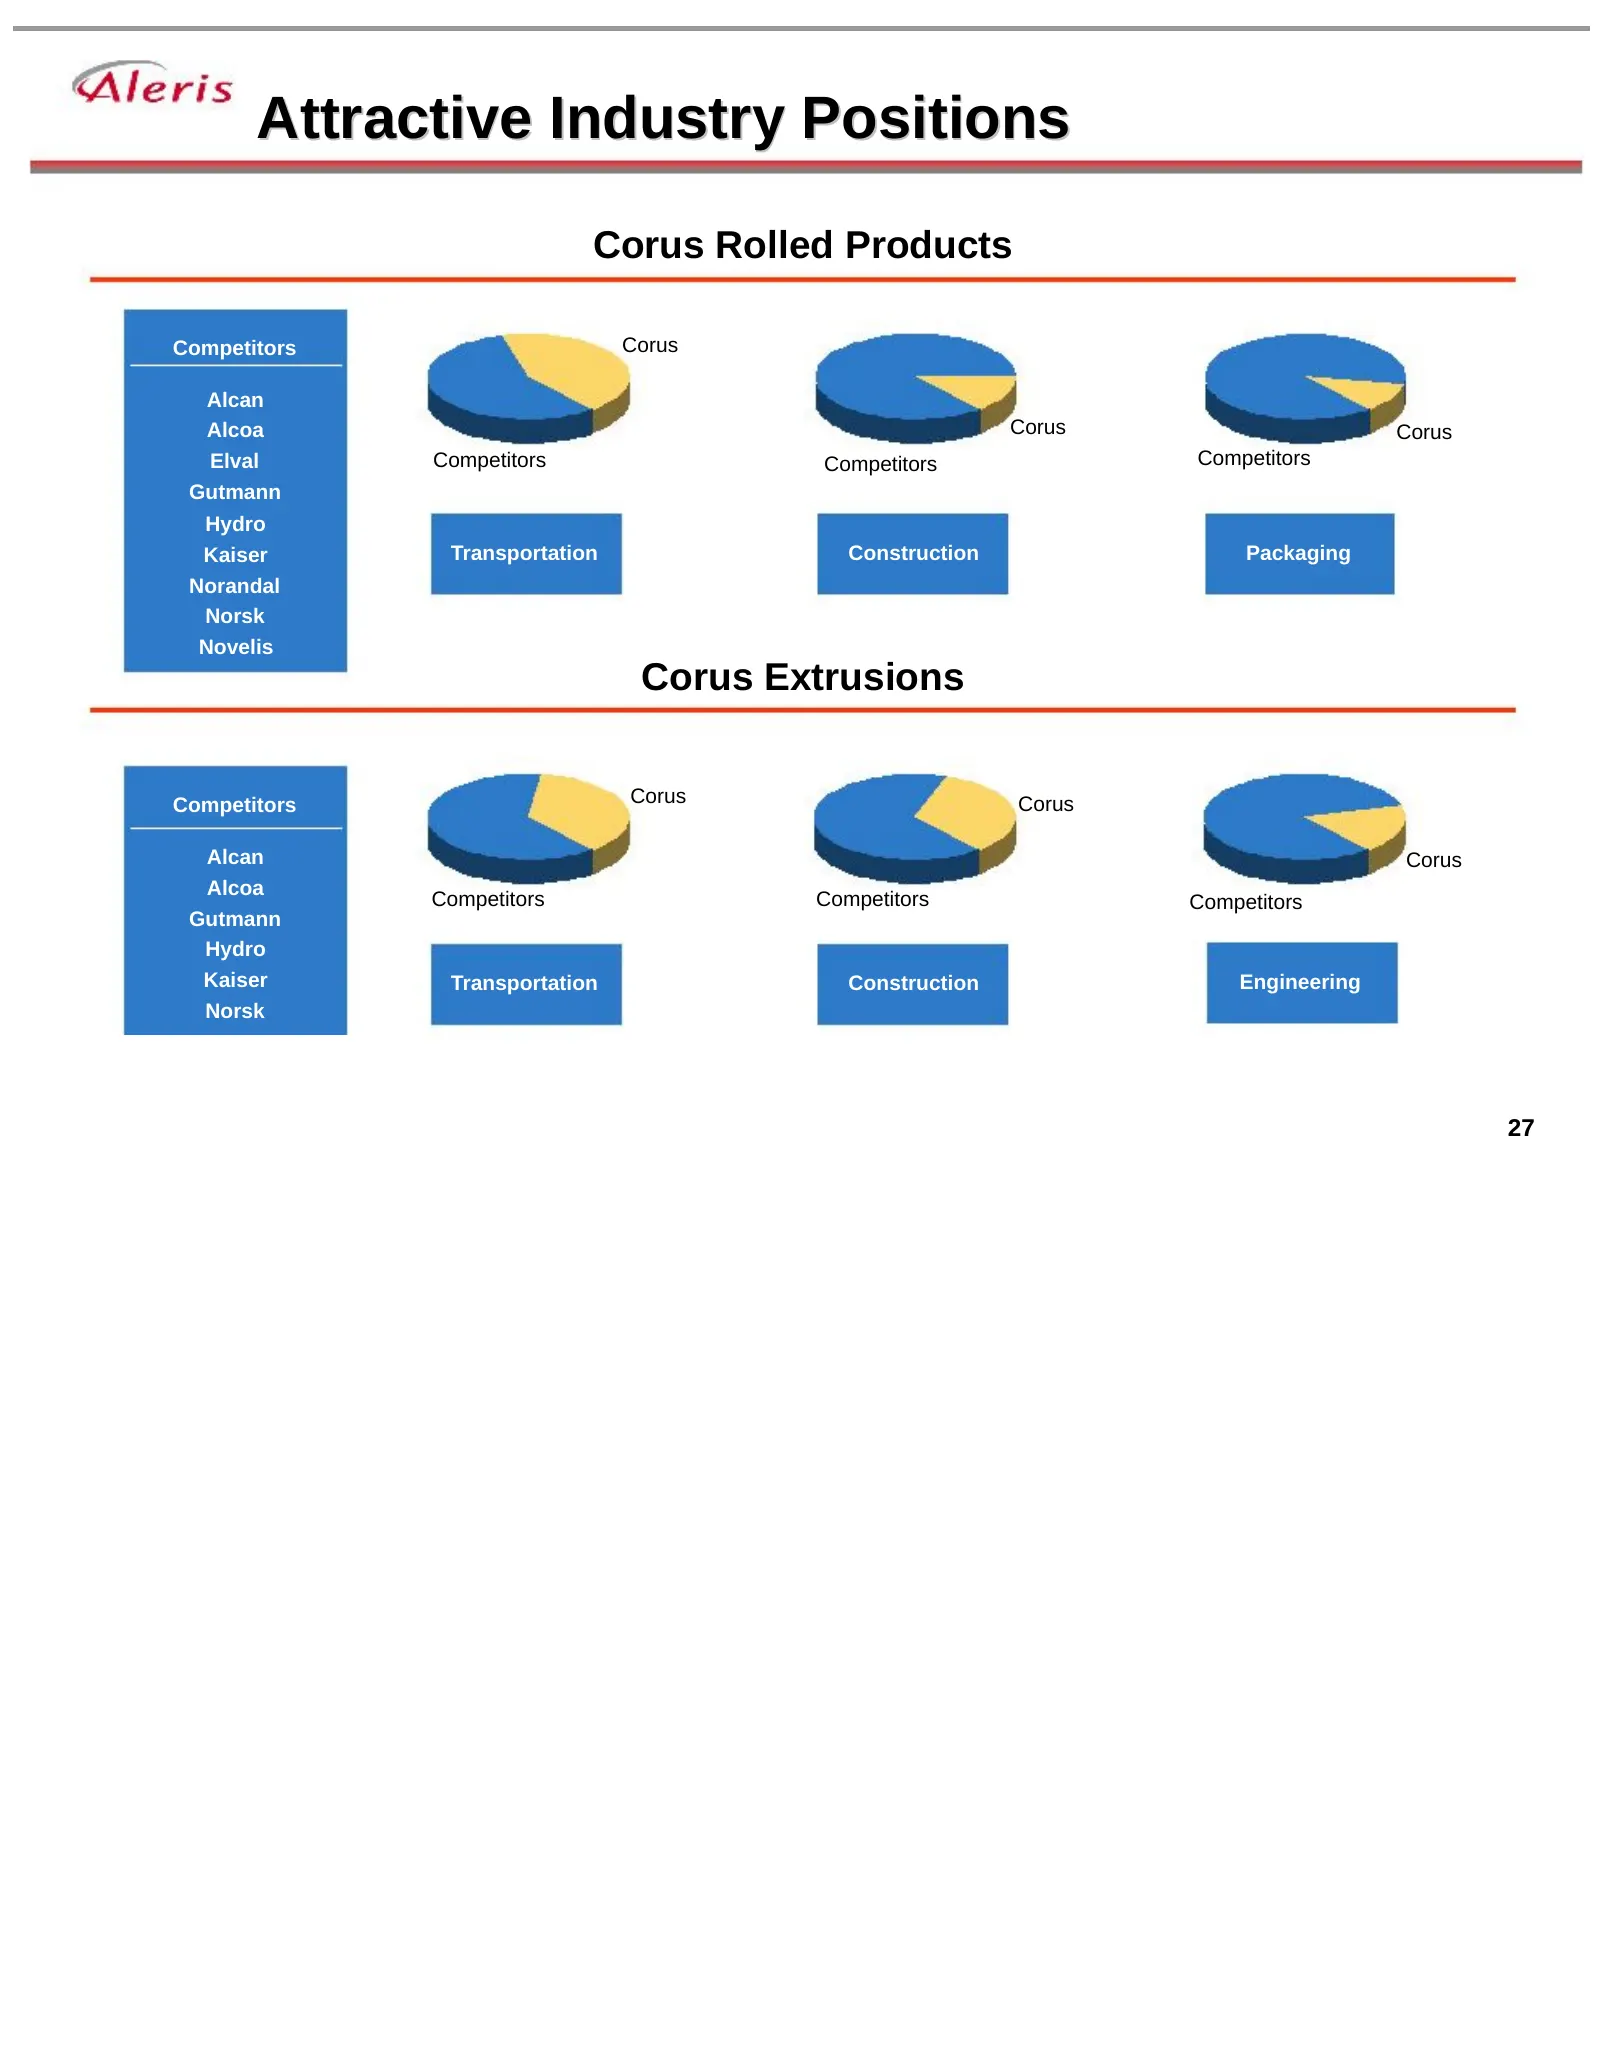
Attractive Industry Positions Corus Rolled Products Competitors Corus Alcan Alcoa Corus Corus Elval Competitors Competitors Competitors Gutmann Hydro Kaiser Transportation Construction Packaging Norandal Norsk Novelis Corus Extrusions Competitors Corus Corus Alcan Corus Alcoa Competitors Competitors
Slide 28: Strong Fundamentals in Aerospace Segment
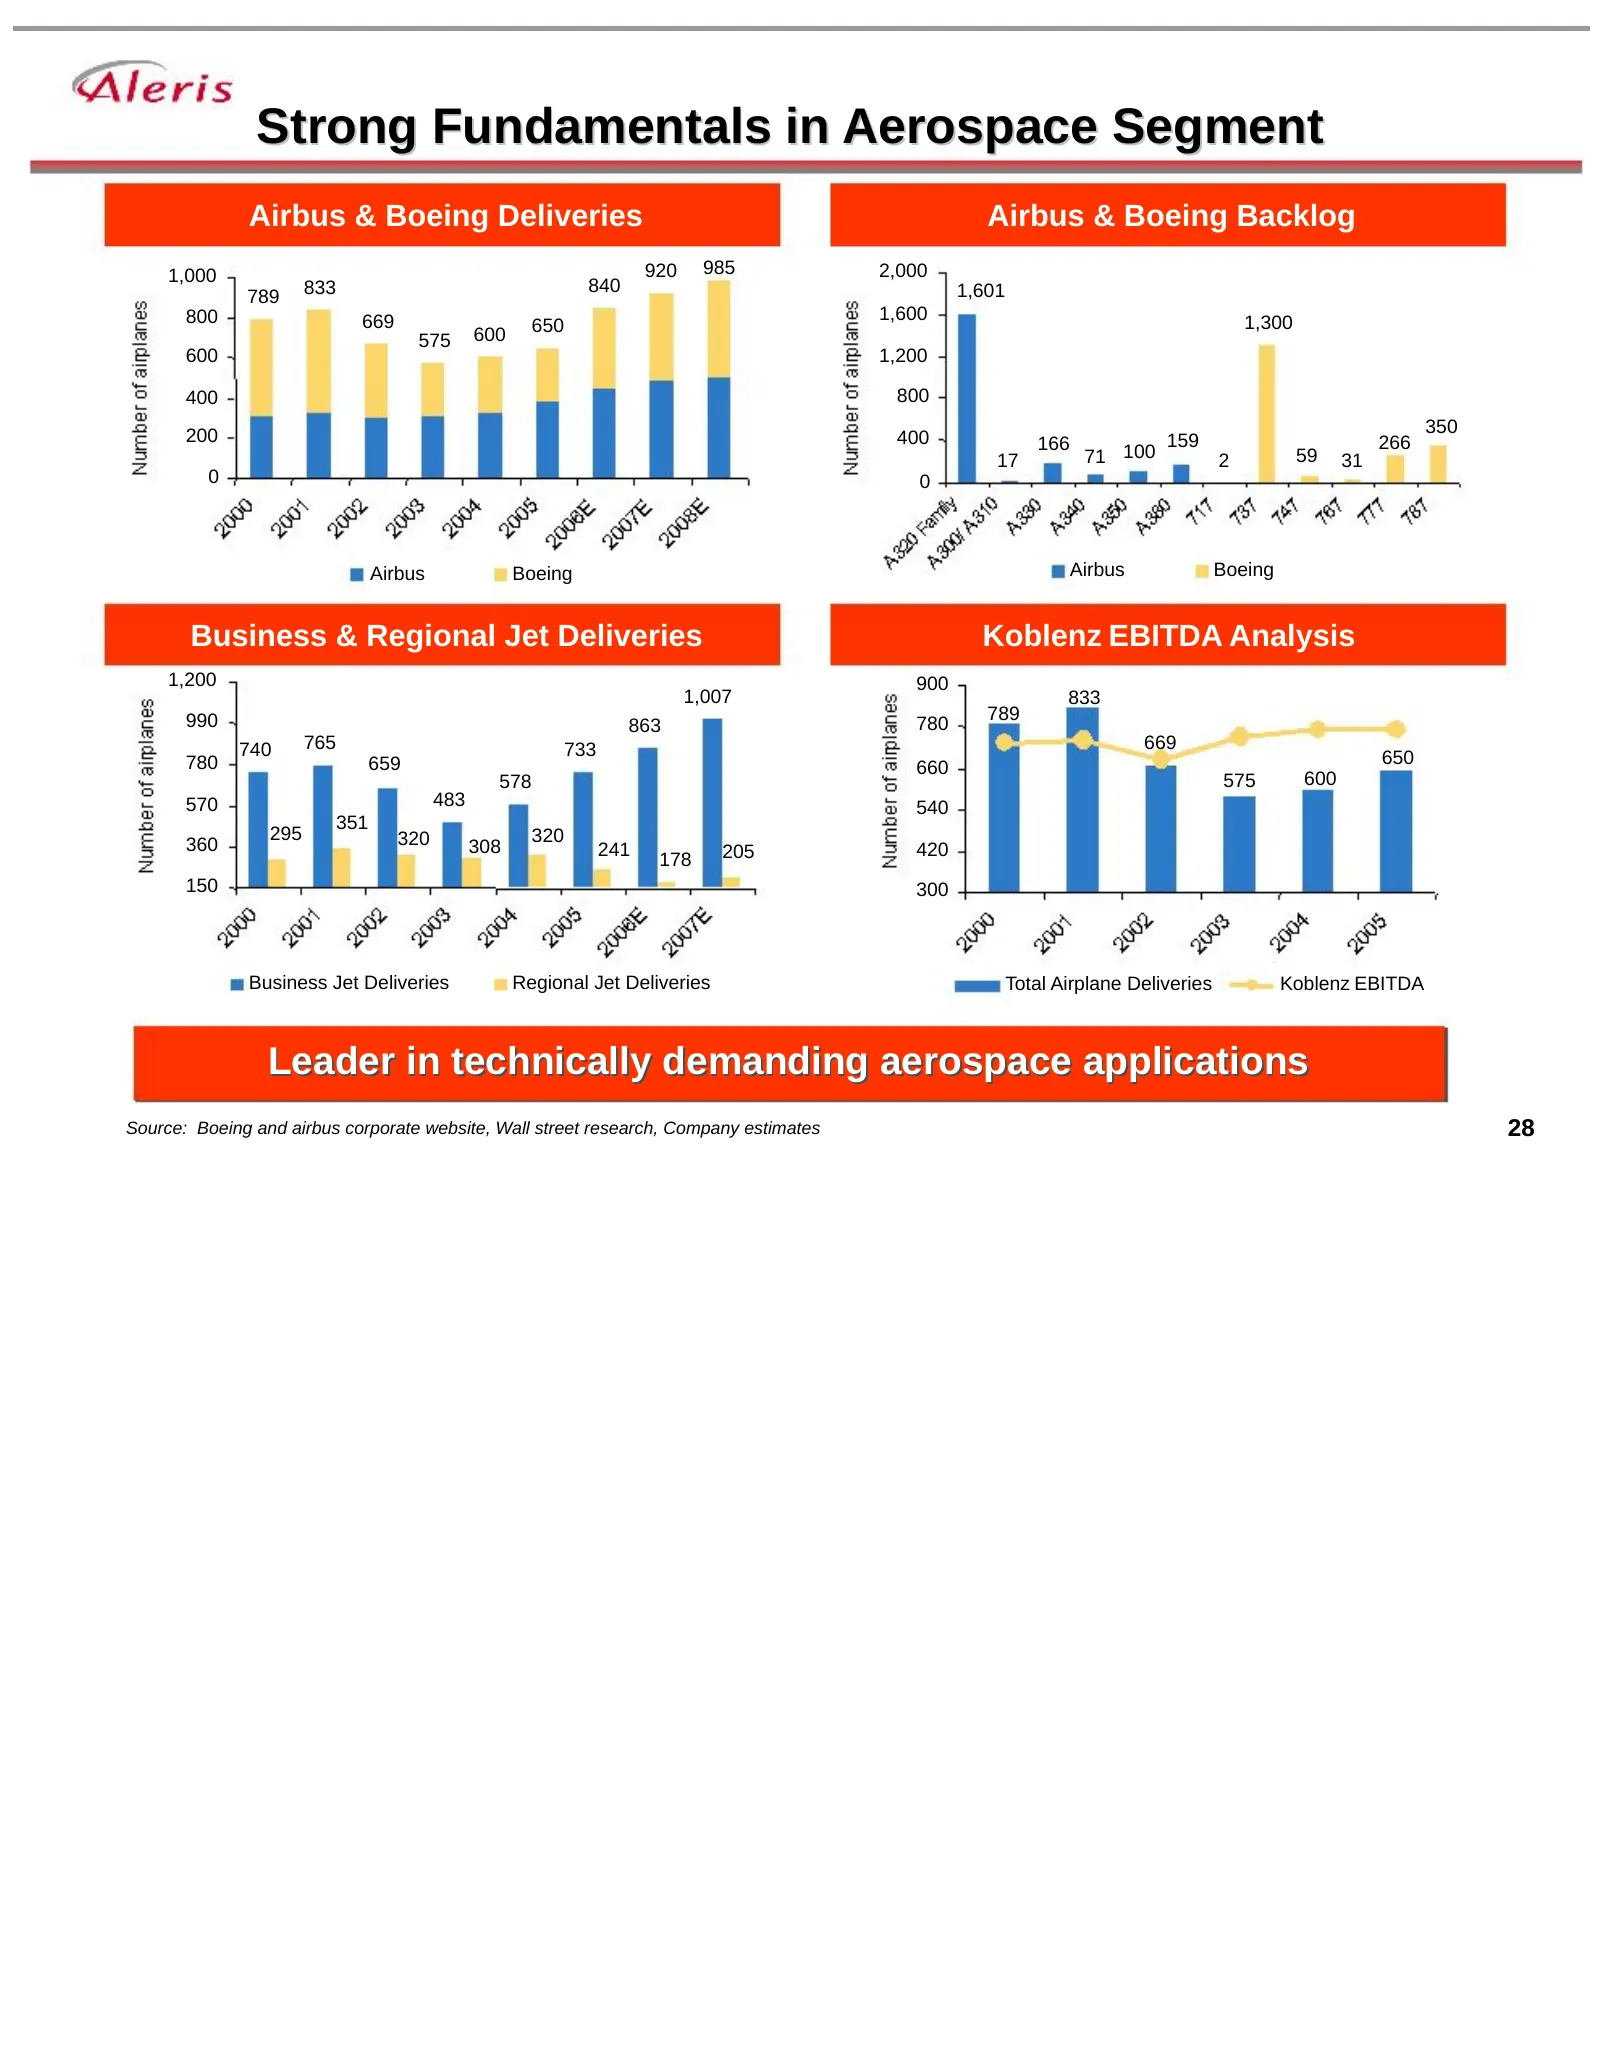
Strong Fundamentals in Aerospace Segment Airbus & Boeing Deliveries Airbus & Boeing Backlog 1,000 920 985 2,000 833 840 1,601 789 800 669 1,600 650 1,300 575 600 600 1,200 400 800 350 200 400 166 159 266 17 71 100 2 59 31 0 0 Airbus Boeing Airbus Boeing Business & Regional Jet Deliveries Koblenz EBI
Slide 29: Industry Leading Technology
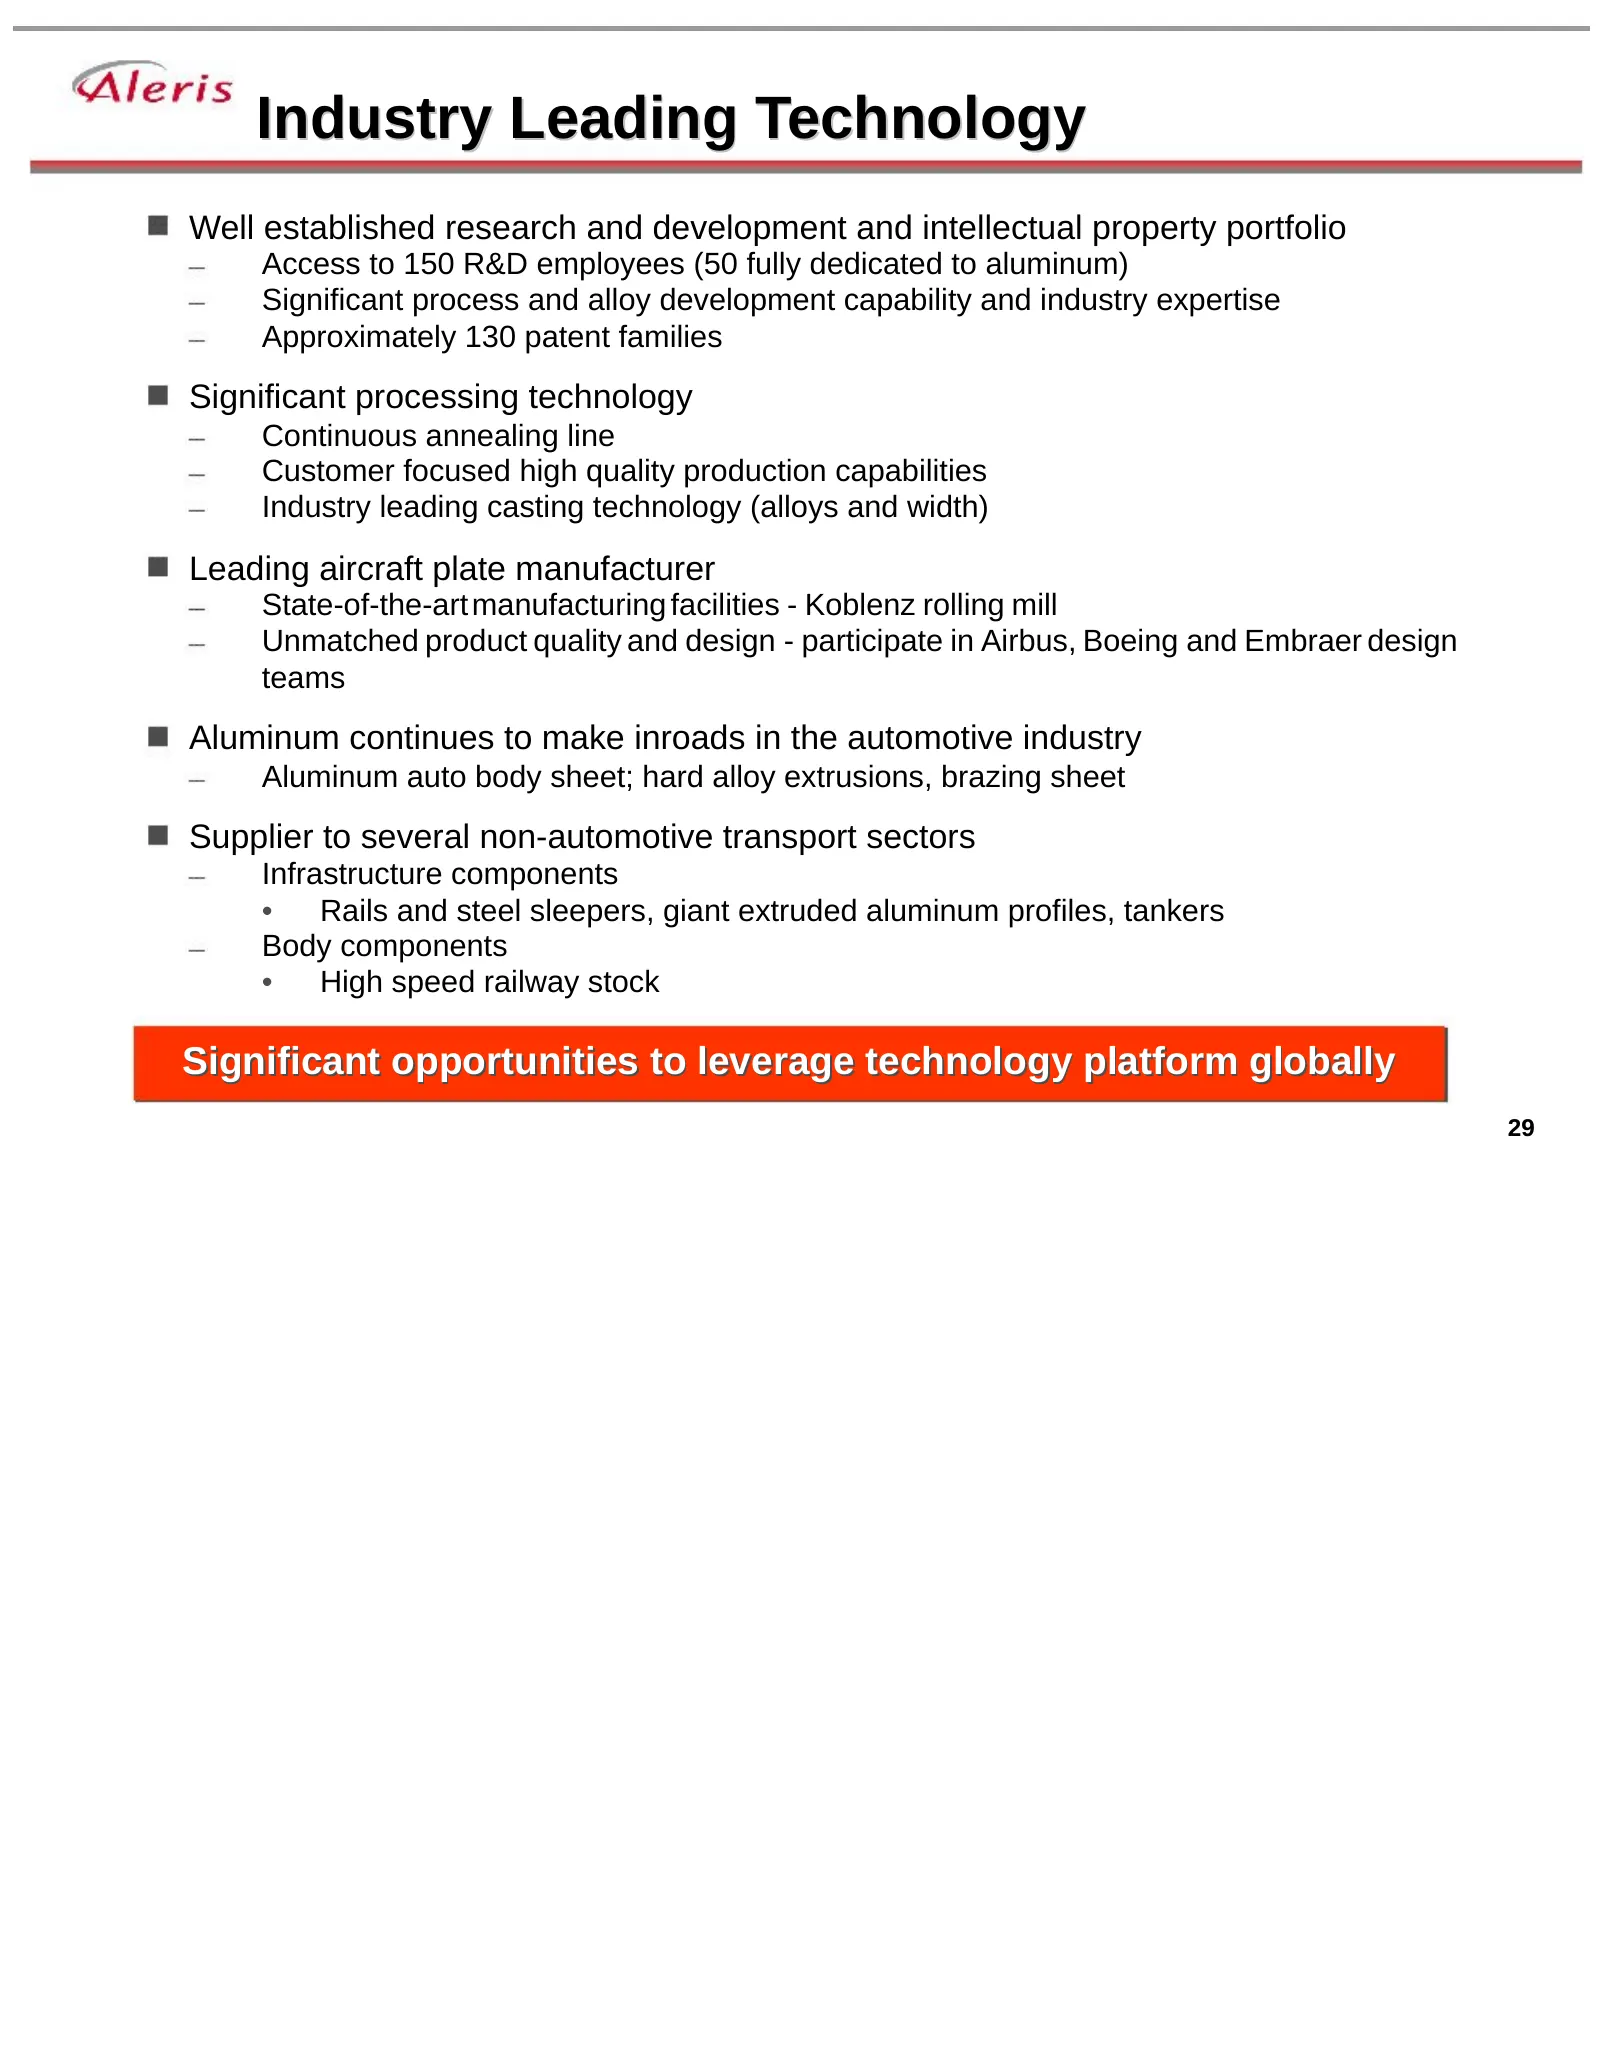
Industry Leading Technology Well established research and development and intellectual property portfolio Access to 150 R&D employees (50 fully dedicated to aluminum) Significant process and alloy development capability and industry expertise Approximately 130 patent families Significant processing
Slide 30: Corus Aluminum Synergy Opportunities
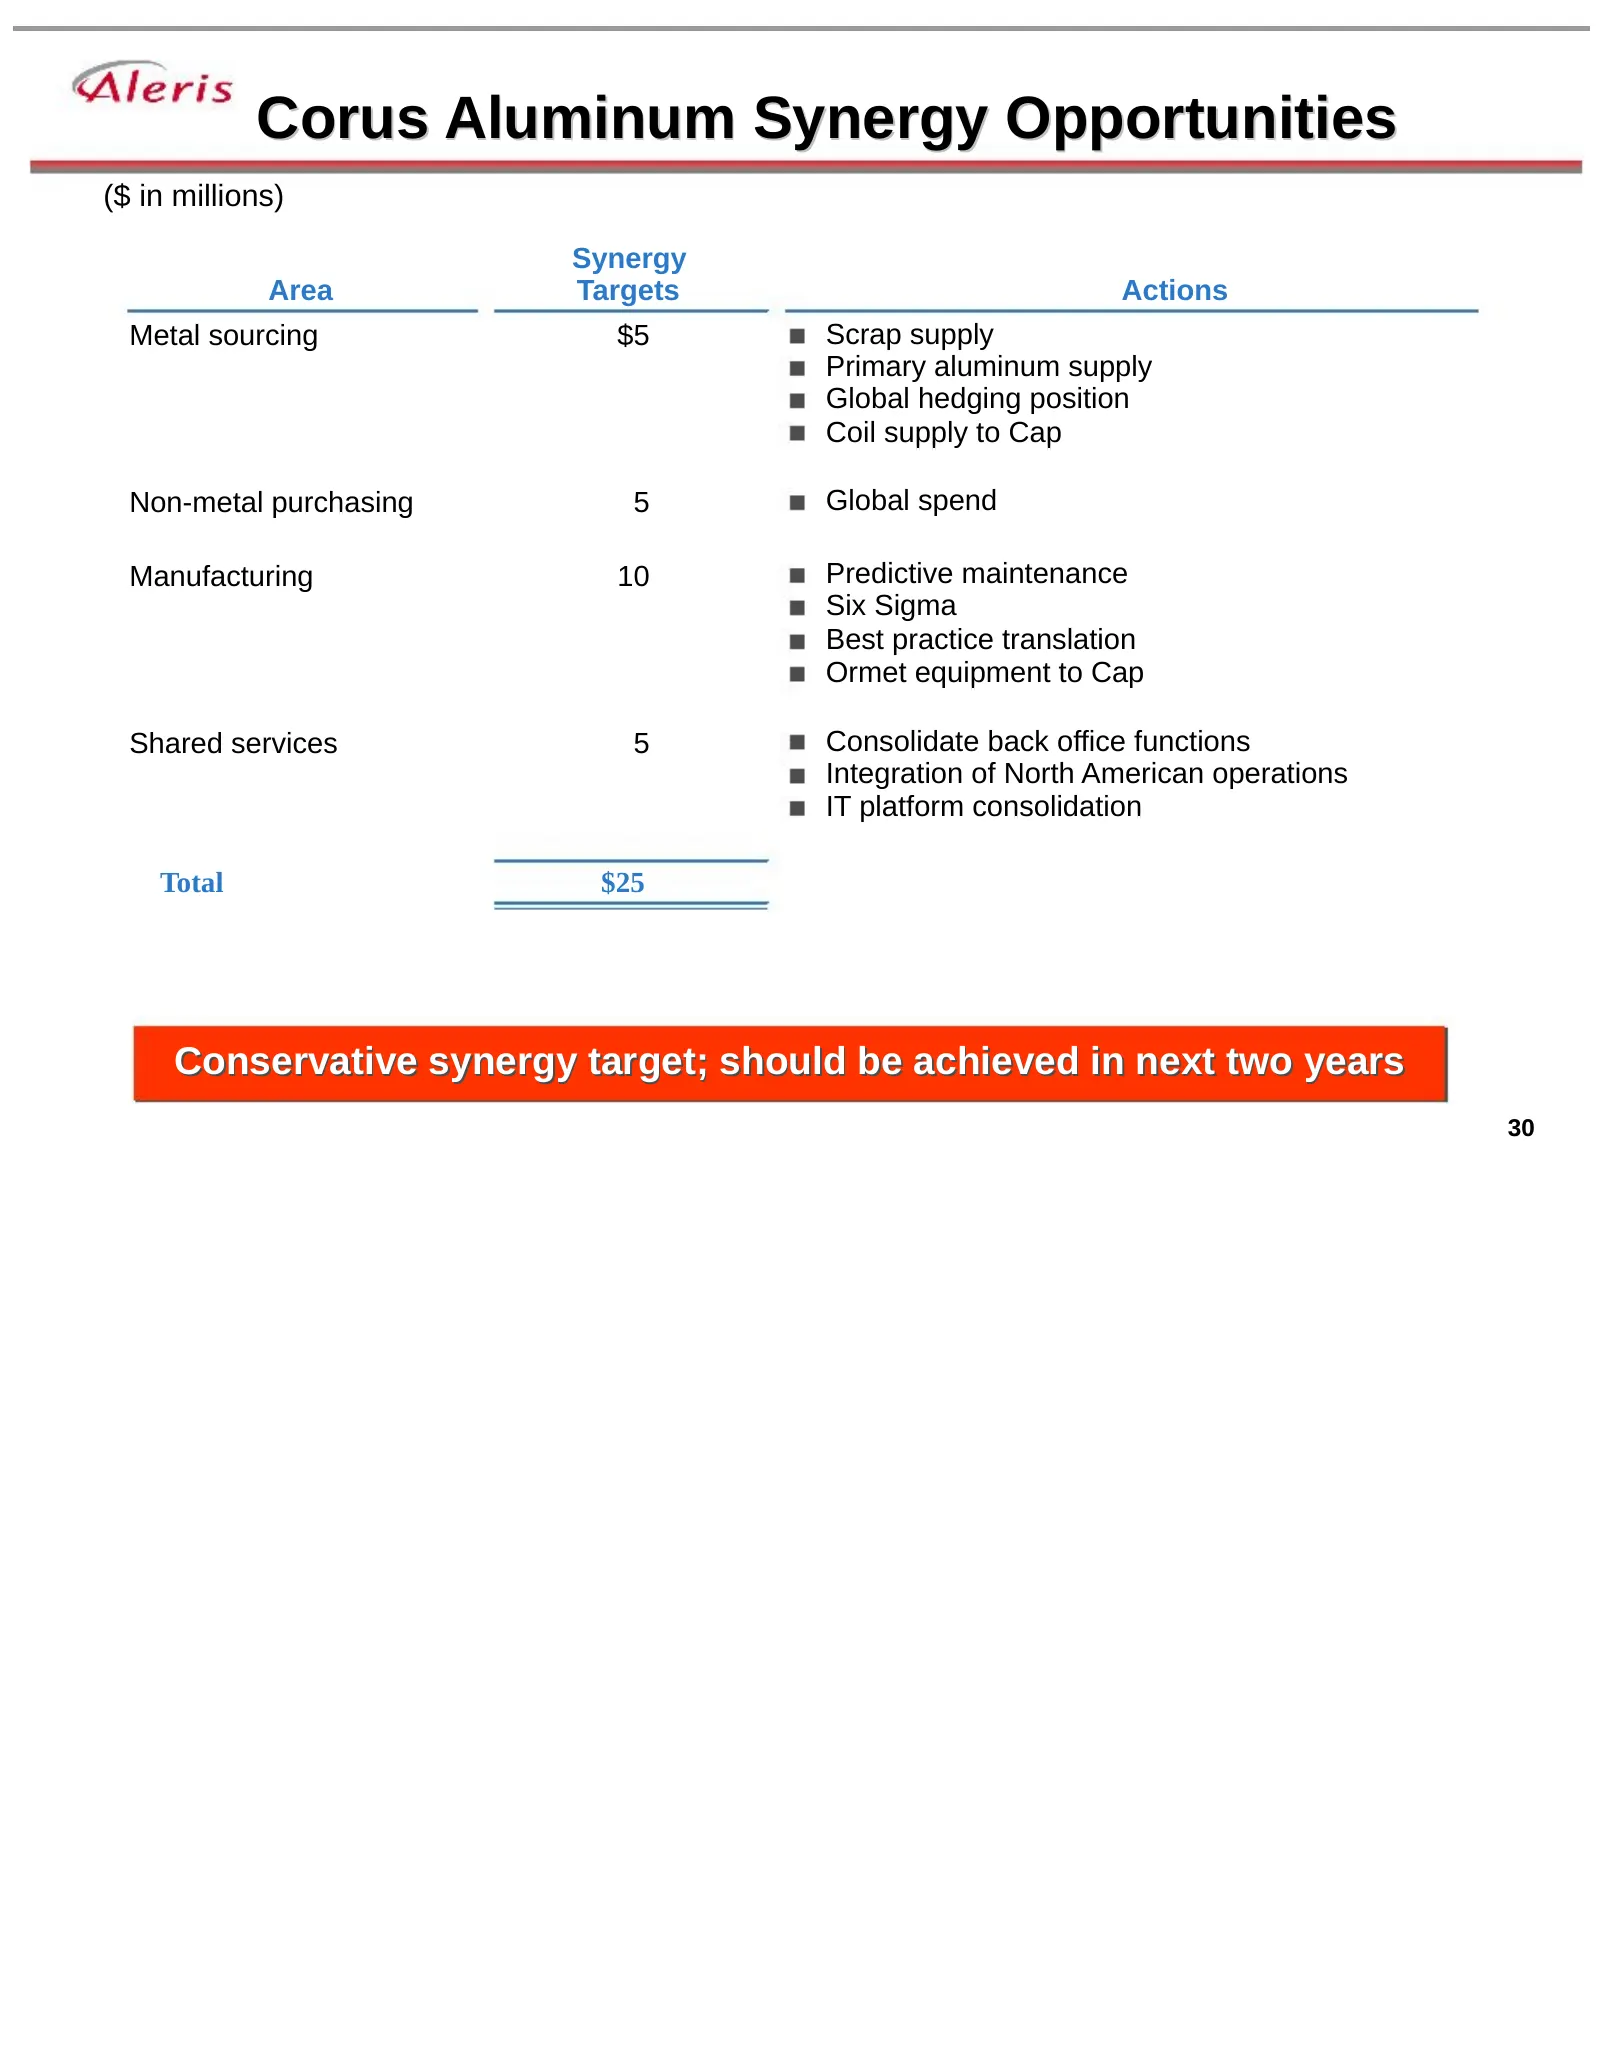
Corus Aluminum Synergy Opportunities ($ in millions) Synergy Area Targets Actions Metal sourcing $5 Scrap supply Primary aluminum supply Global hedging position Coil supply to Cap Non-metal purchasing 5 Global spend Manufacturing 10 Predictive maintenance Six Sigma Best practice translation Ormet eq
Slide 31: Focused Integration and Synergy Realization
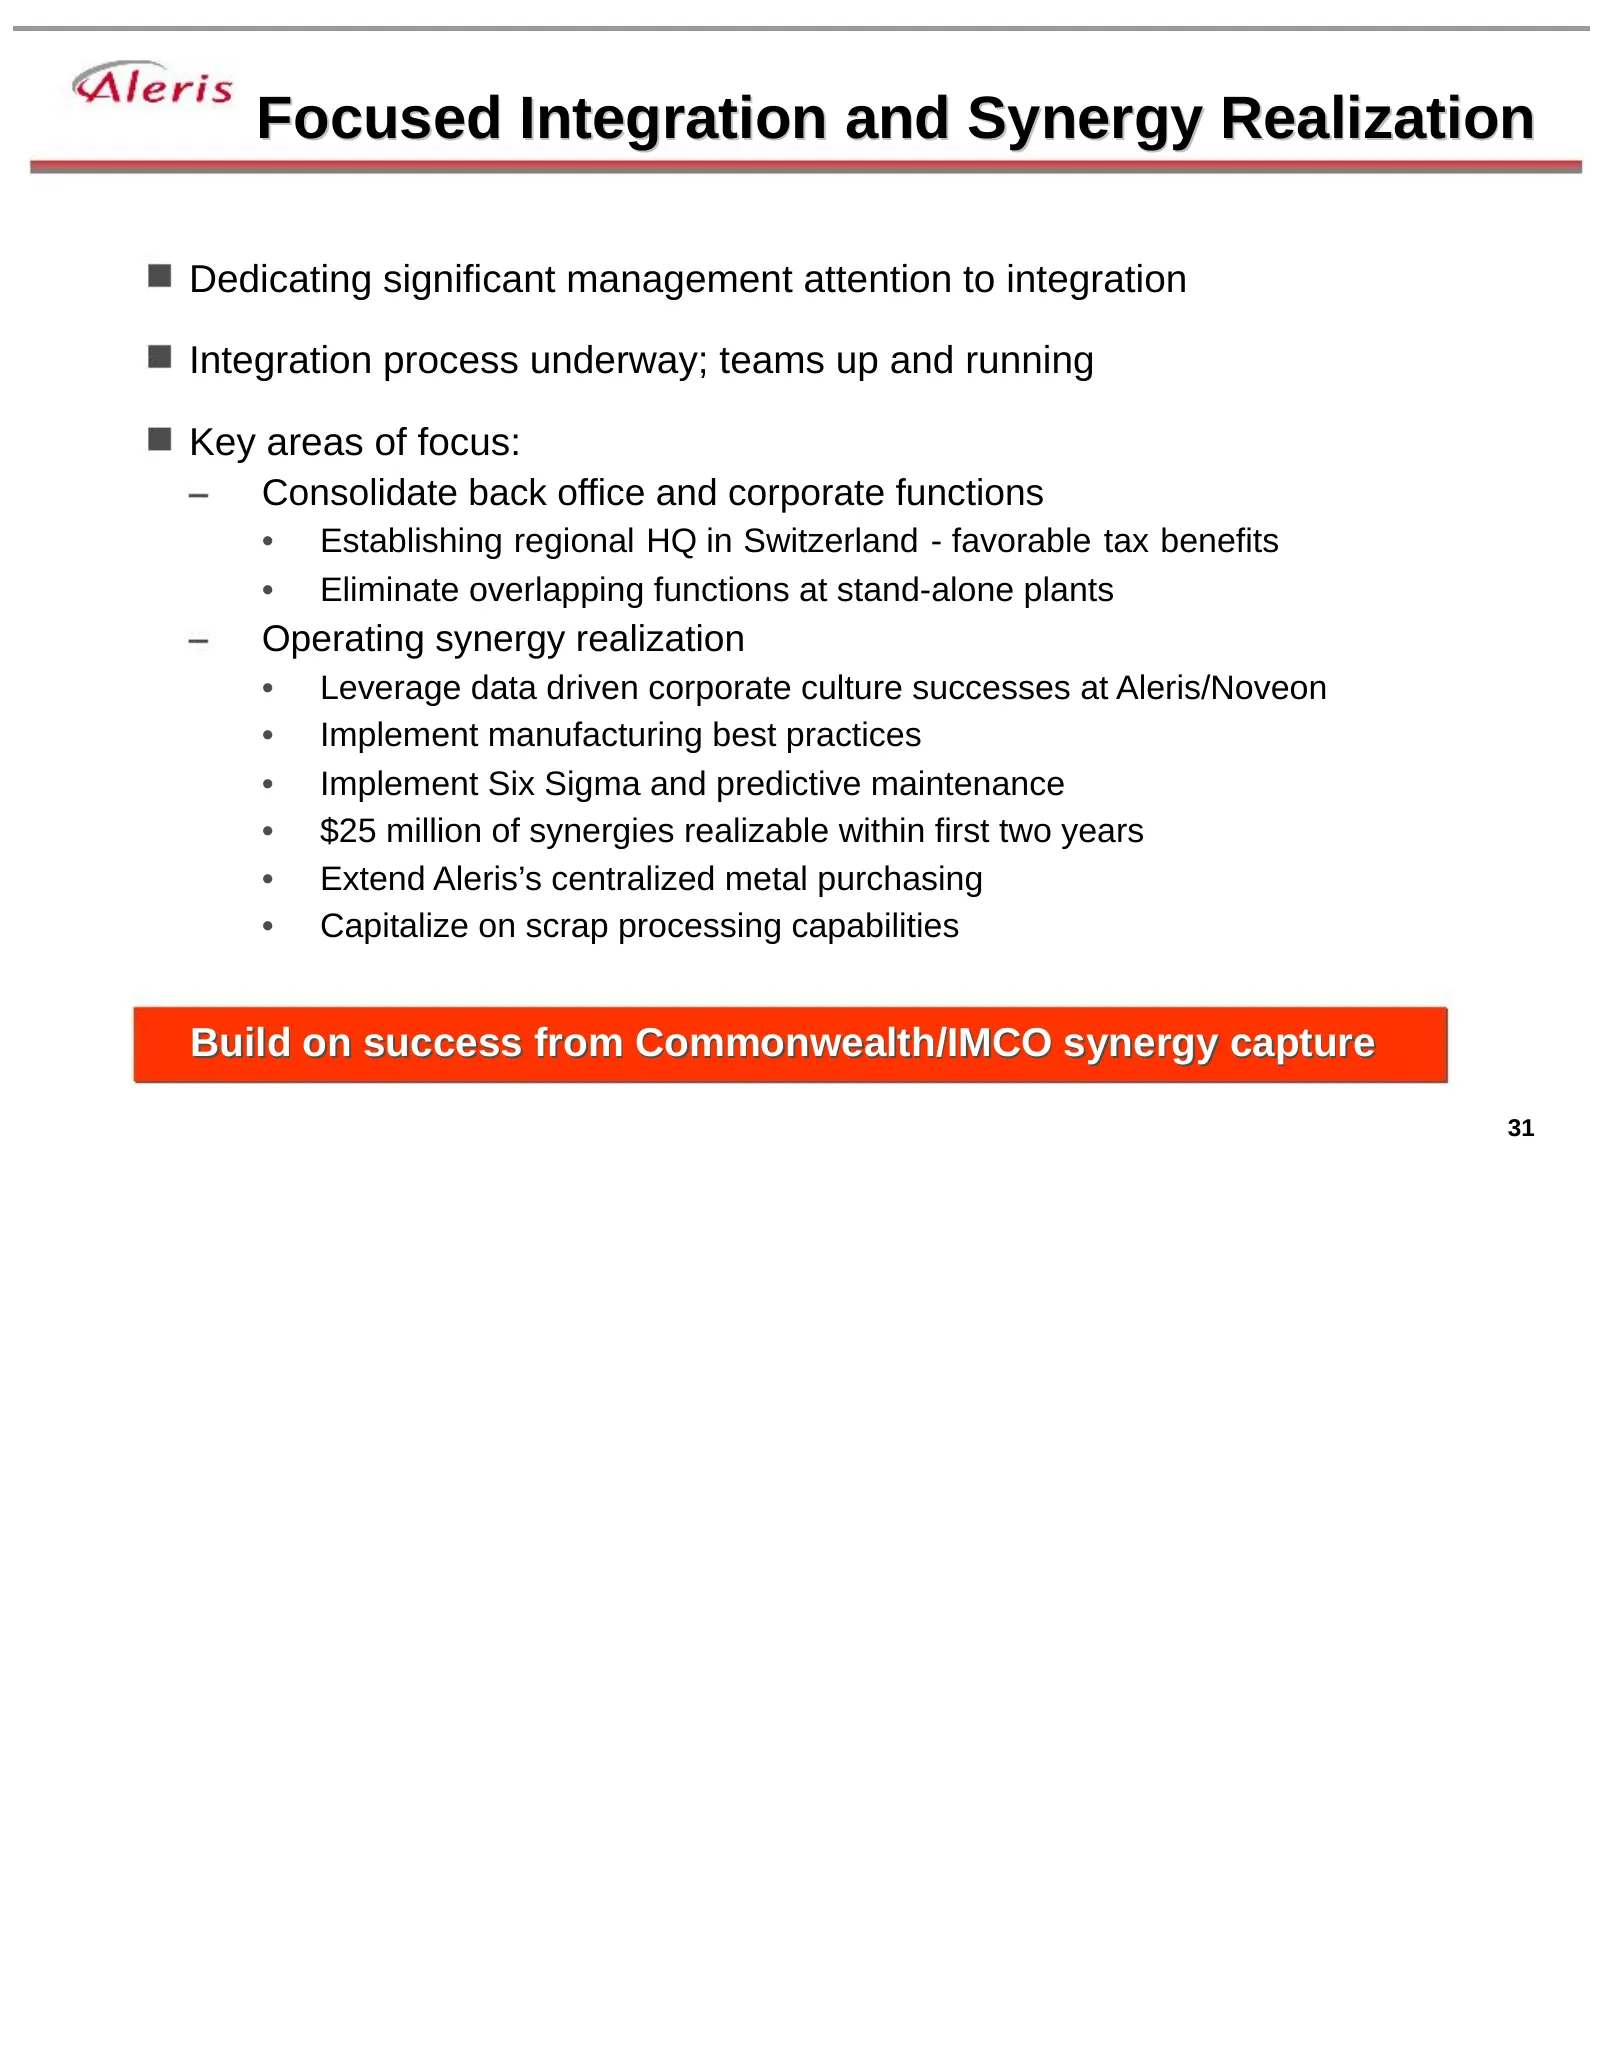
Focused Integration and Synergy Realization Dedicating significant management attention to integration Integration process underway; teams up and running Key areas of focus: Consolidate back office and corporate functions • Establishing regional HQ in Switzerland - favorable tax benefits • Eliminate
Slide 32: Key Transaction Considerations
Key Transaction Considerations Steve Demetriou, Chief Executive Officer
Slide 33: Key Transaction Considerations
Key Transaction Considerations Significant geographic and end-use diversification Leading global footprint Long-term customer relationships Leading industry positions Favorable long-term industry trends Restructured North American industry Reduced commodity exposure Credible senior management with e
Slide 34: Significant Geographic and End-Use Diversification
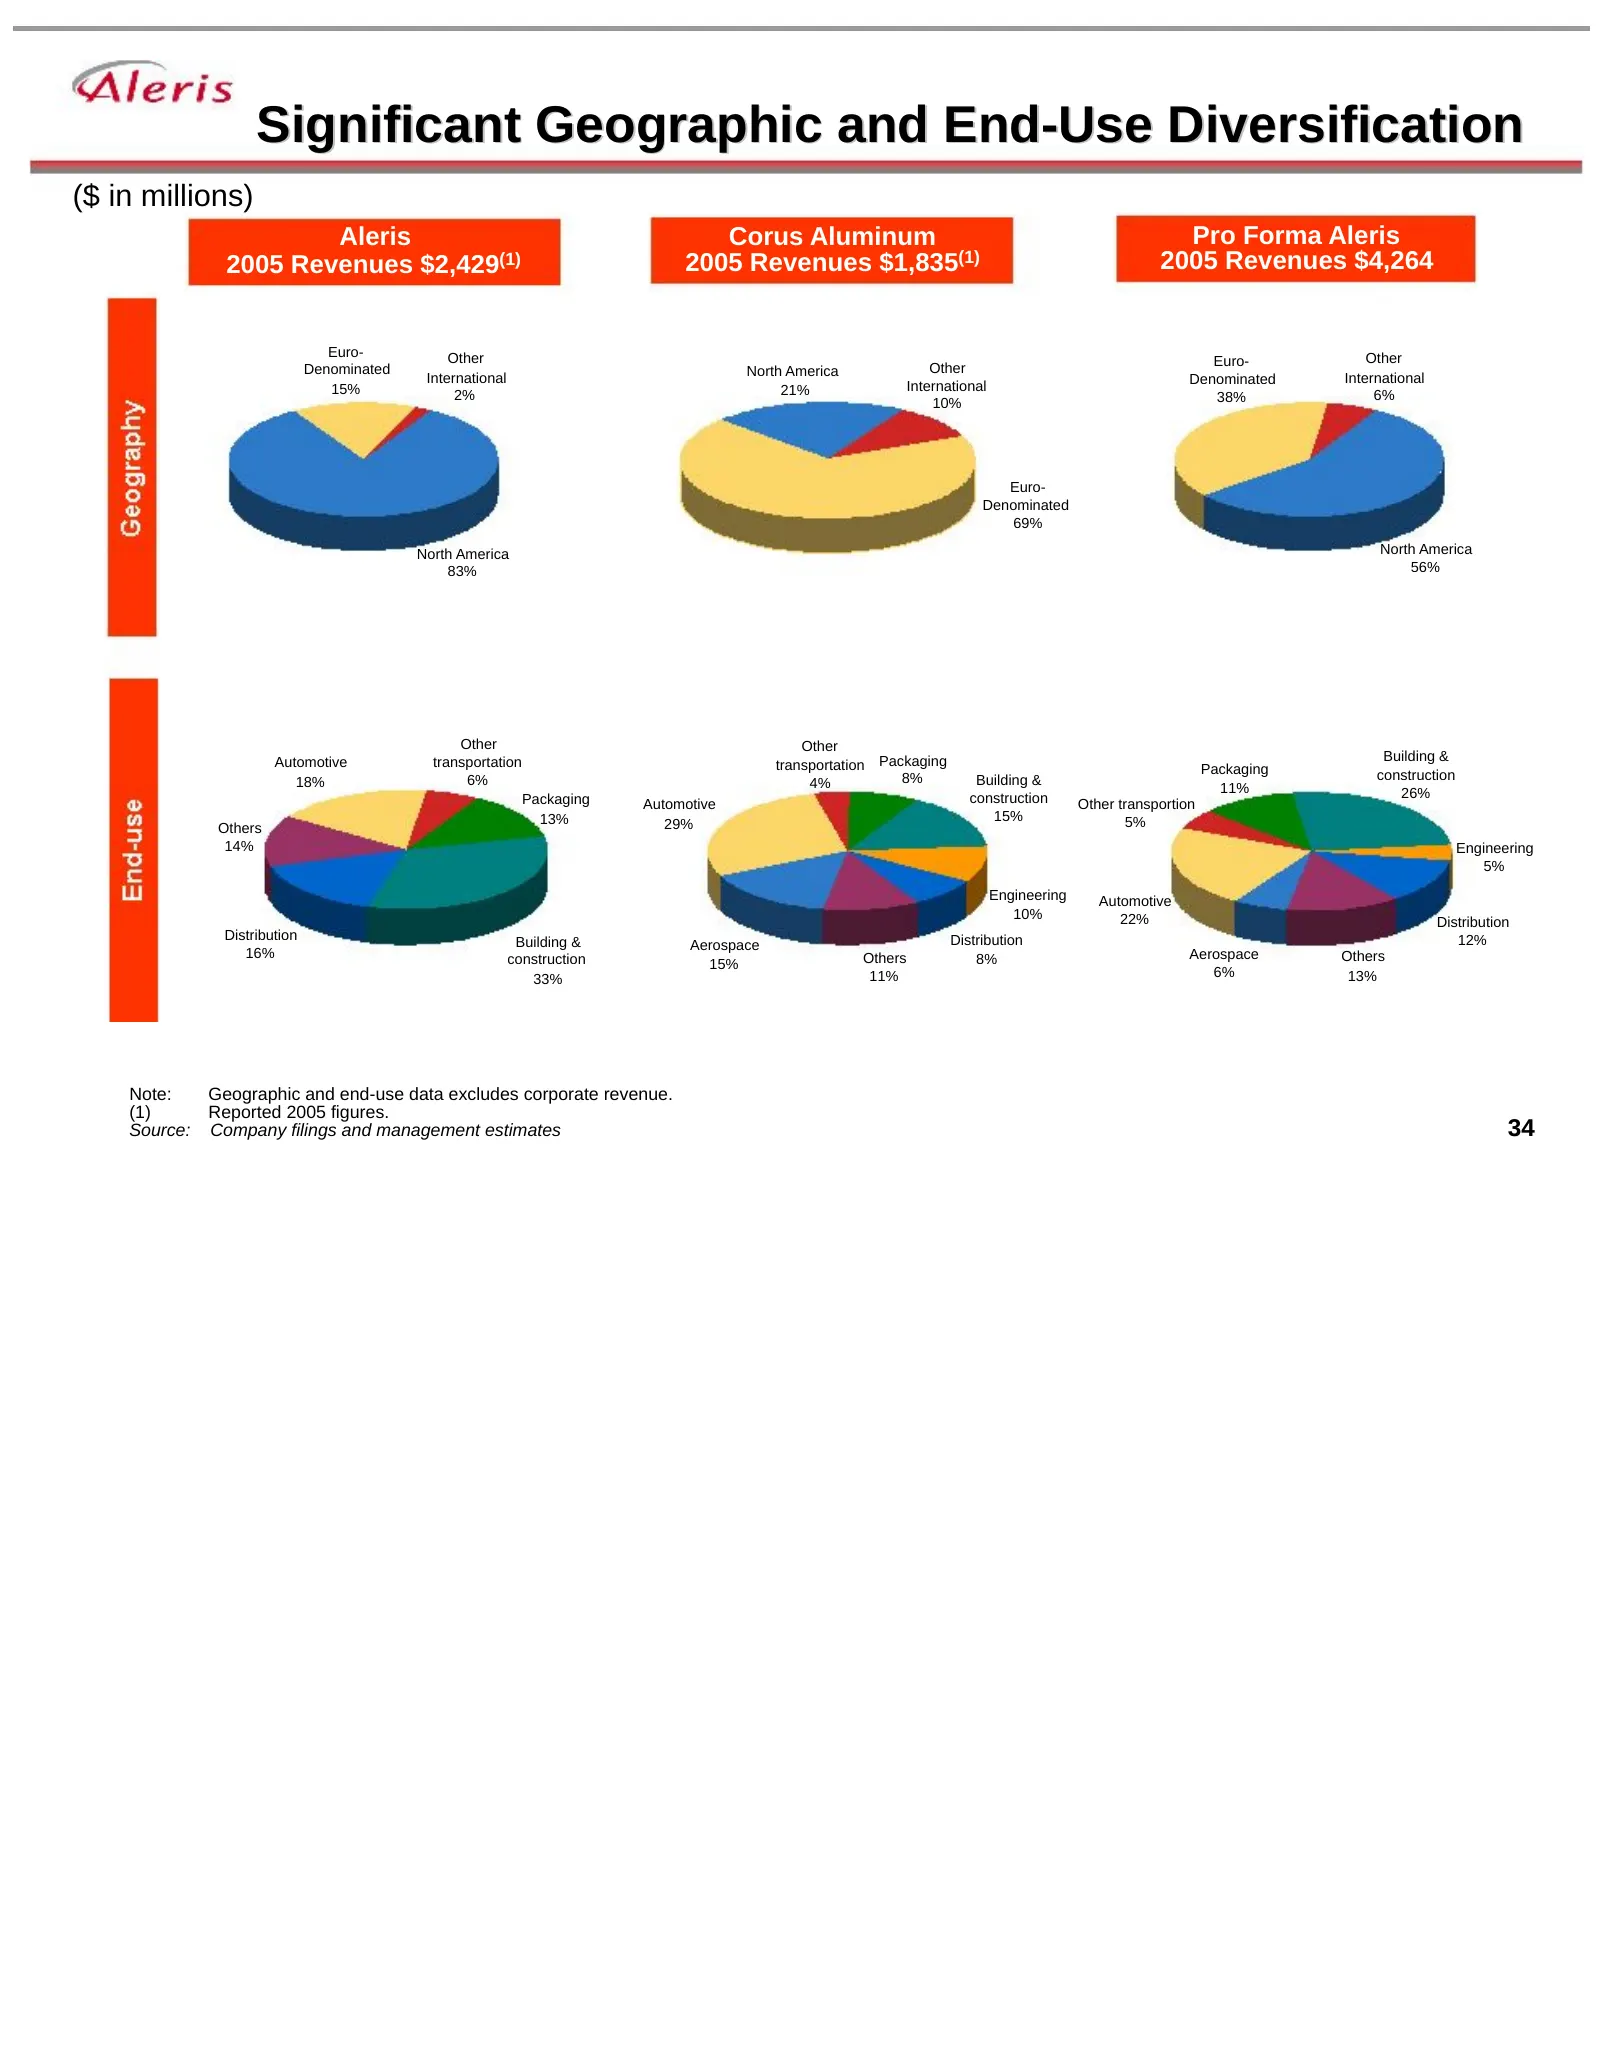
Significant Geographic and End-Use Diversification ($ in millions) Aleris Corus Aluminum Pro Forma Aleris 2005 Revenues $2,429(1) 2005 Revenues $1,835(1) 2005 Revenues $4,264 Euro- Other Other Other Euro- Denominated North America International Denominated International 15% 21% International 2% 38%
Slide 35: Leading Global Footprint
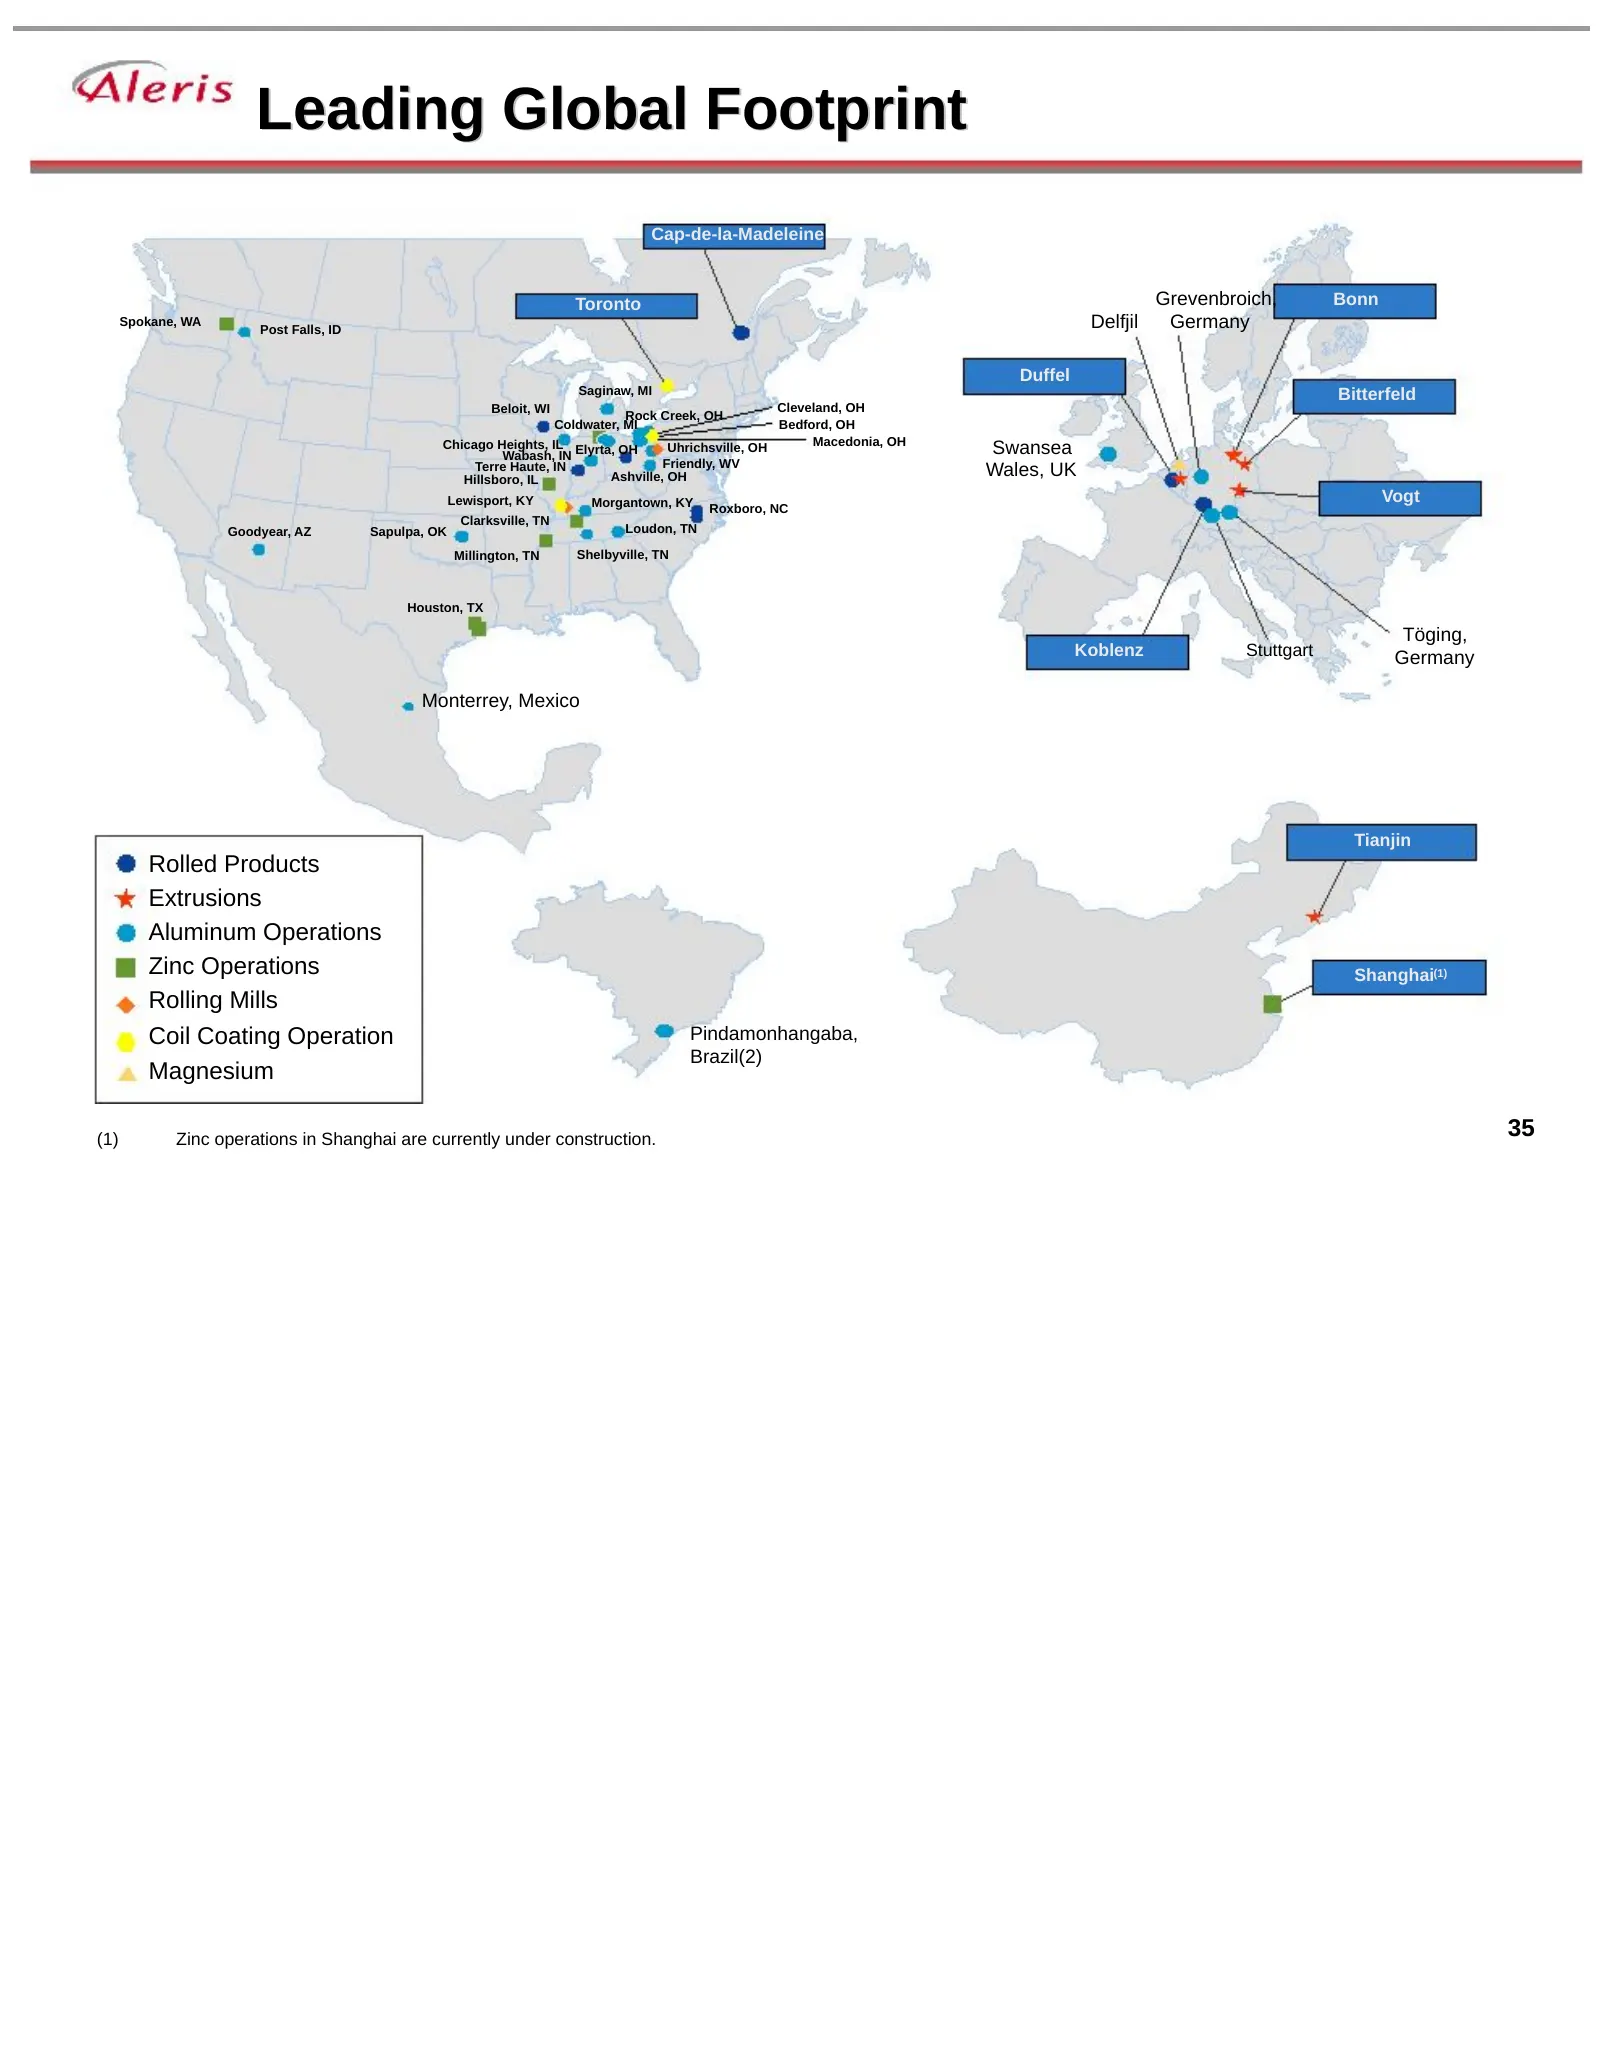
Leading Global Footprint Cap-de-la-Madeleine Toronto Grevenbroich, Bonn Spokane, WA Post Falls, ID Delfjil Germany Duffel Saginaw, MI Bitterfeld Beloit, WI Cleveland, OH Rock Creek, OH Coldwater, MI Bedford, OH Macedonia, OH Chicago Heights, IL Elyrta, OH Wabash, IN Uhrichsville, OH Swansea Friendly
Slide 36: Leading Industry Positions
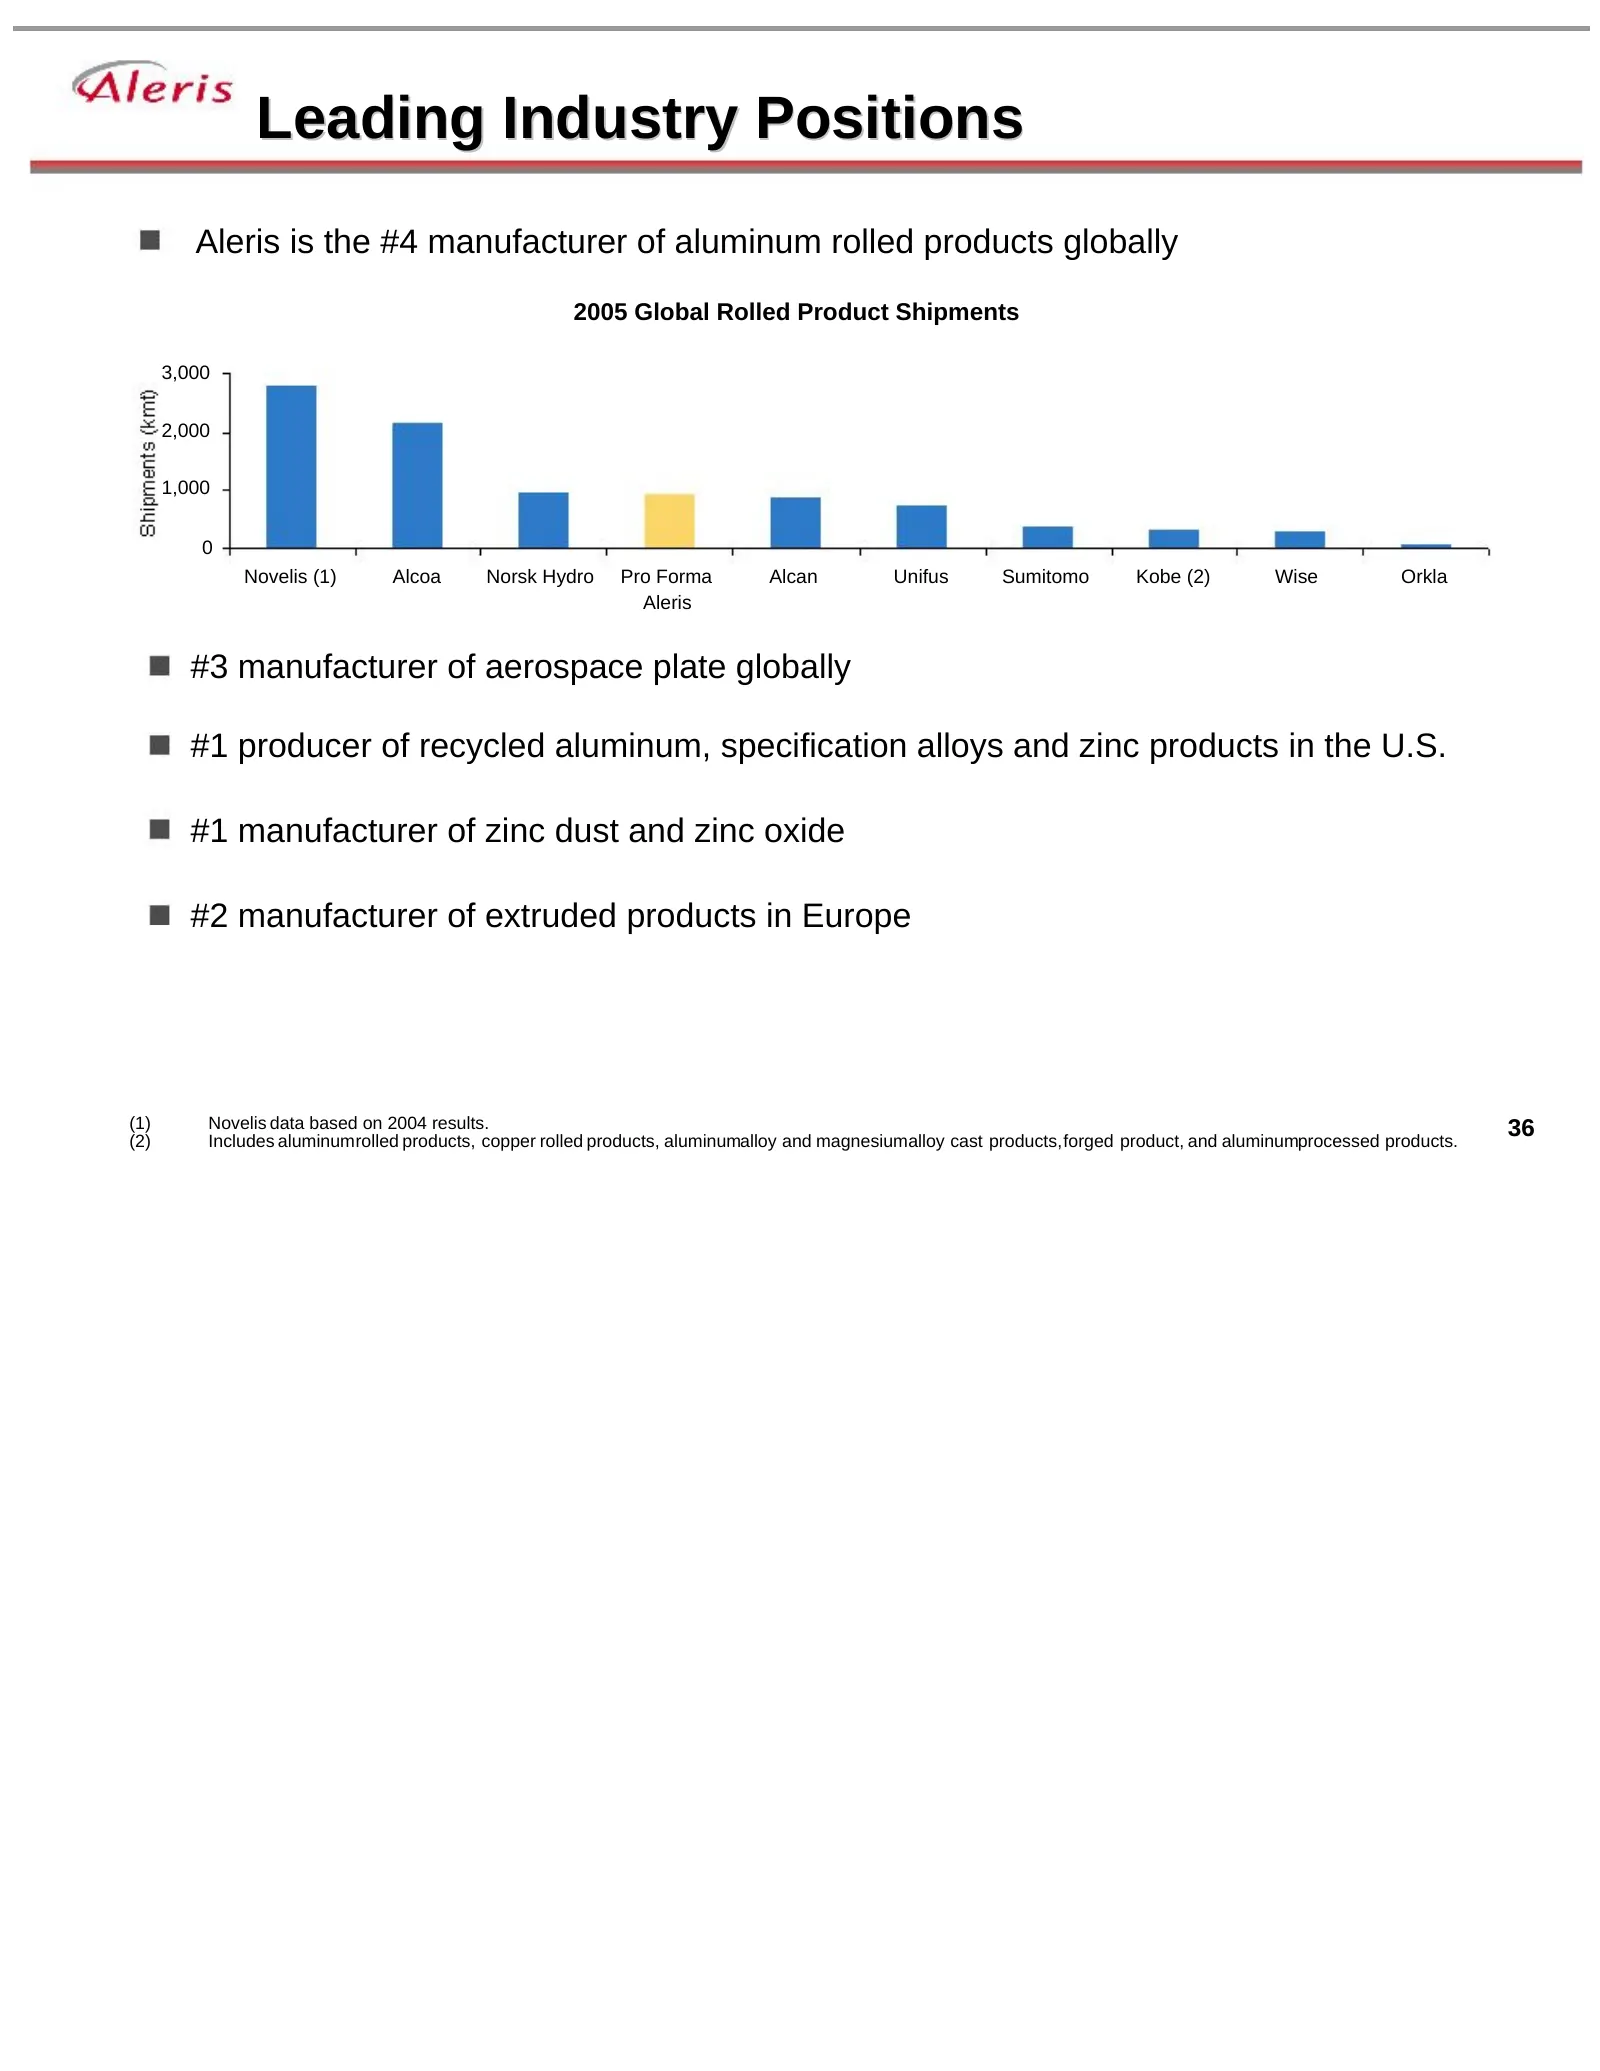
Leading Industry Positions Aleris is the #4 manufacturer of aluminum rolled products globally 2005 Global Rolled Product Shipments 3,000 2,000 1,000 0 Novelis (1) Alcoa Norsk Hydro Pro Forma Alcan Unifus Sumitomo Kobe (2) Wise Orkla Aleris #3 manufacturer of aerospace plate globally #1 producer of r
Slide 37: Favorable Long-Term Industry Trends
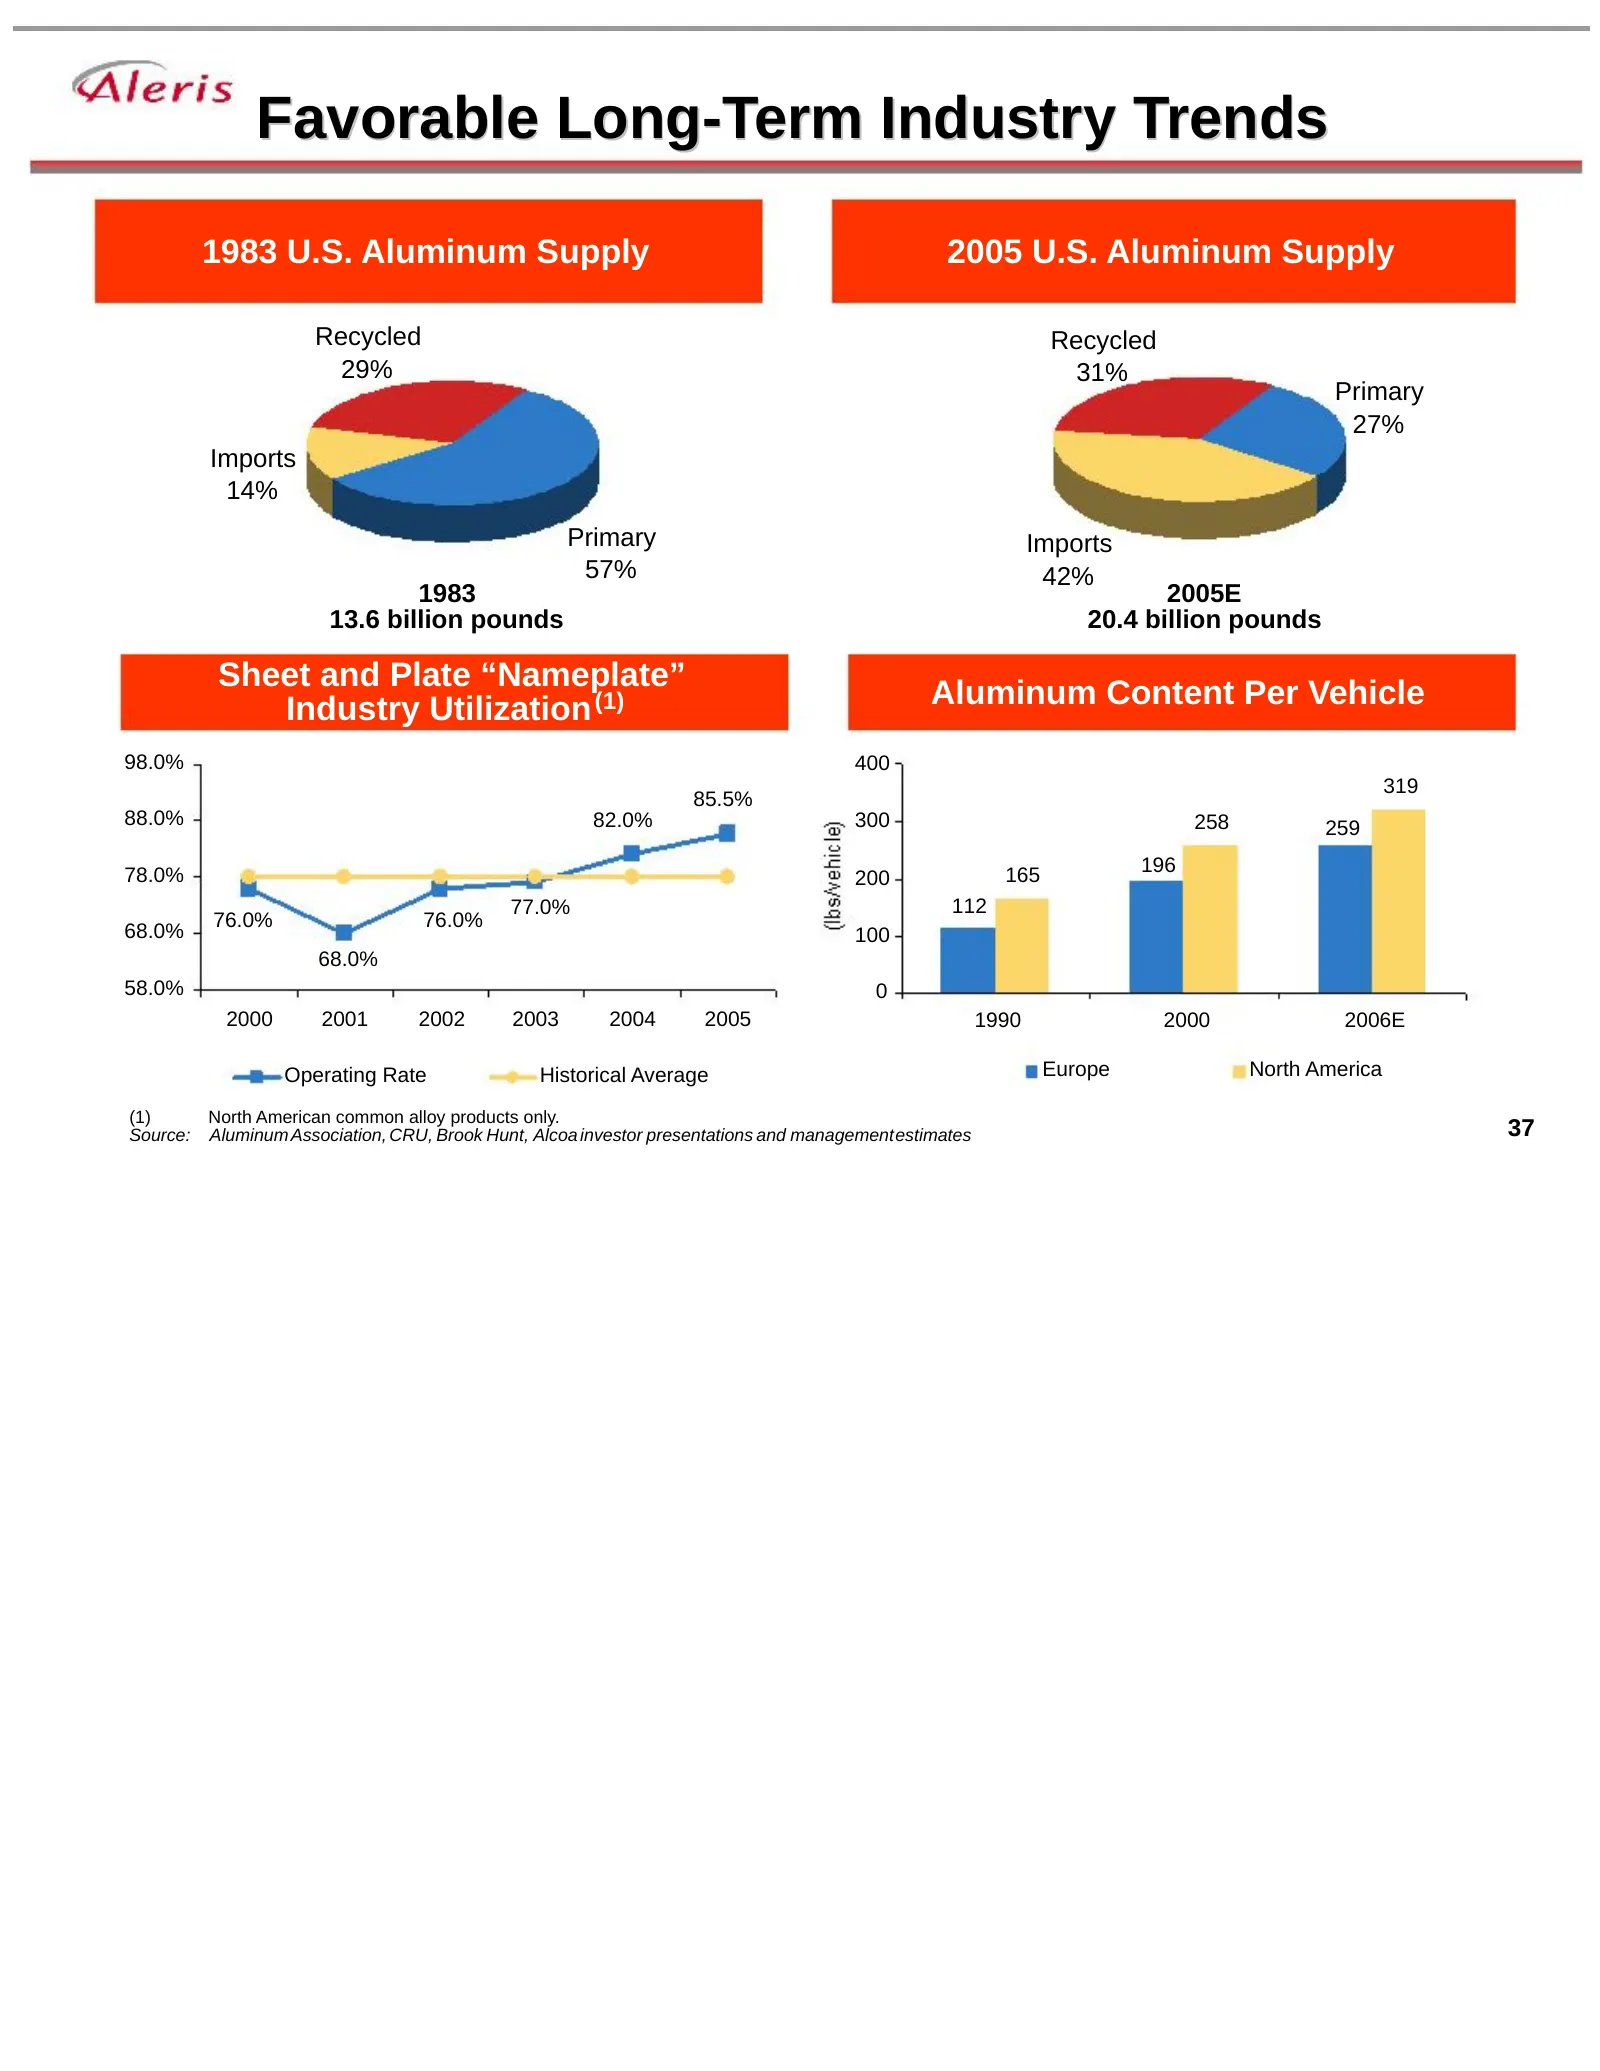
Favorable Long-Term Industry Trends 1983 U.S. Aluminum Supply 2005 U.S. Aluminum Supply Recycled Recycled 29% 31% Primary 27% Imports 14% Primary Imports 57% 42% 1983 2005E 13.6 billion pounds 20.4 billion pounds Sheet and Plate “Nameplate” Industry Utilization (1) Aluminum Content Per Vehicle 98.0%
Slide 38: North American Industry Landscape
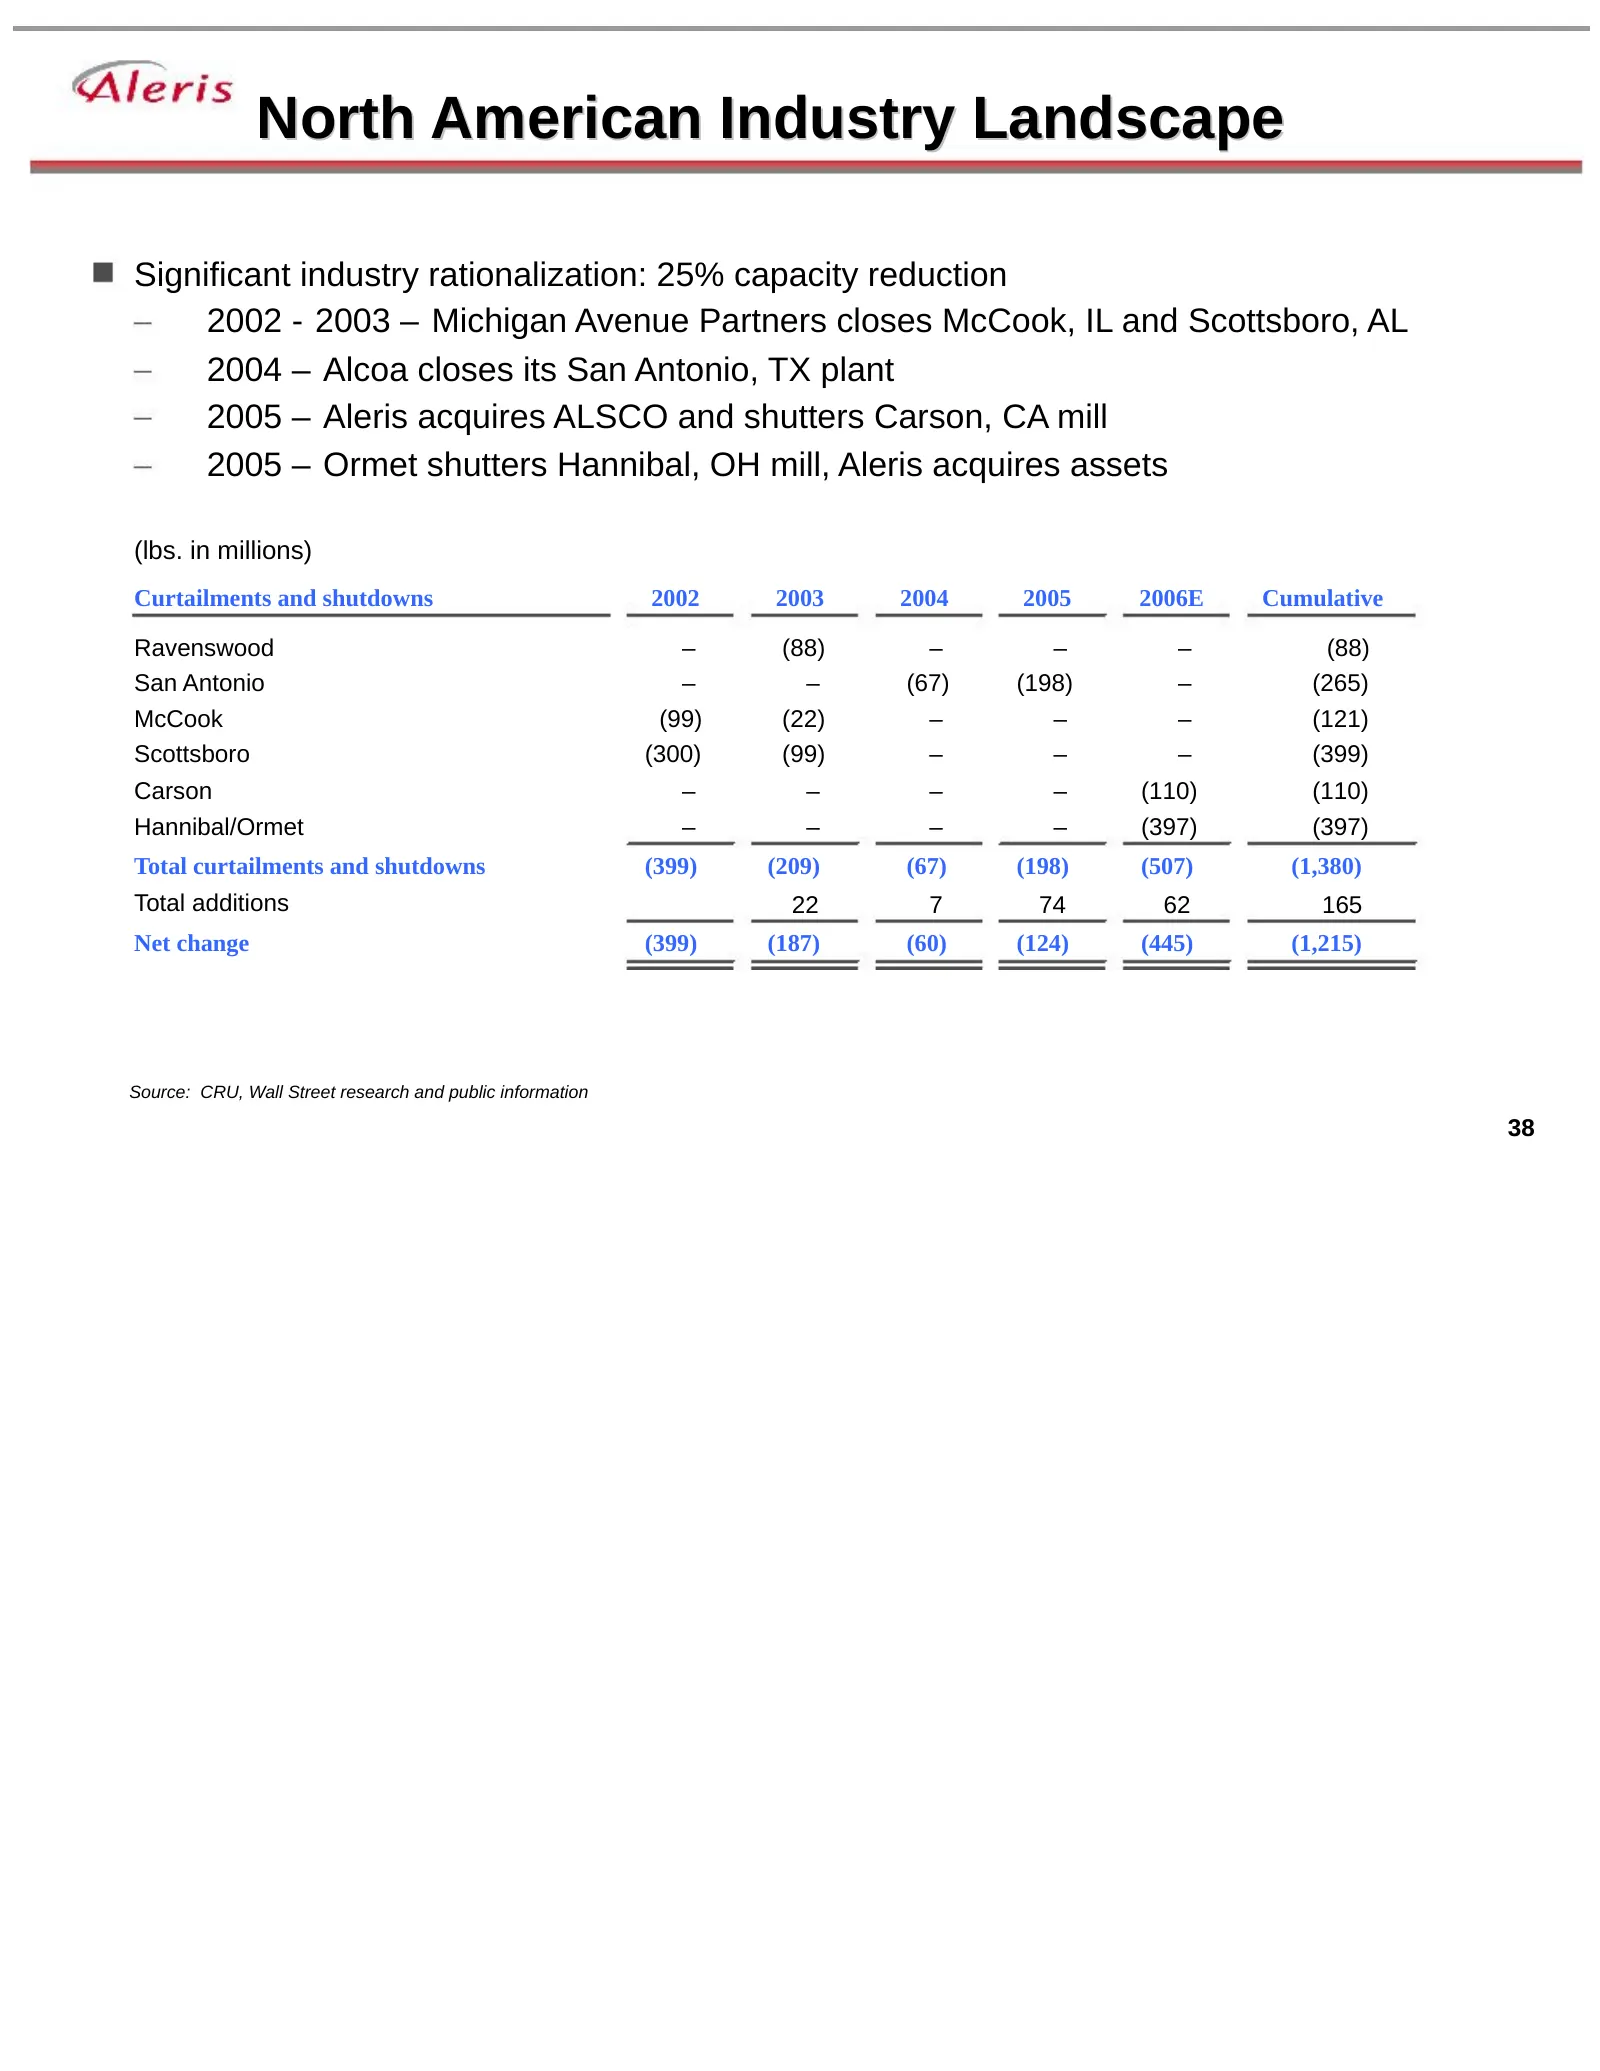
North American Industry Landscape Significant industry rationalization: 25% capacity reduction 2002 - 2003 – Michigan Avenue Partners closes McCook, IL and Scottsboro, AL 2004 – Alcoa closes its San Antonio, TX plant 2005 – Aleris acquires ALSCO and shutters Carson, CA mill 2005 – Ormet shutters Han
Slide 39: Reduced Commodity Exposure
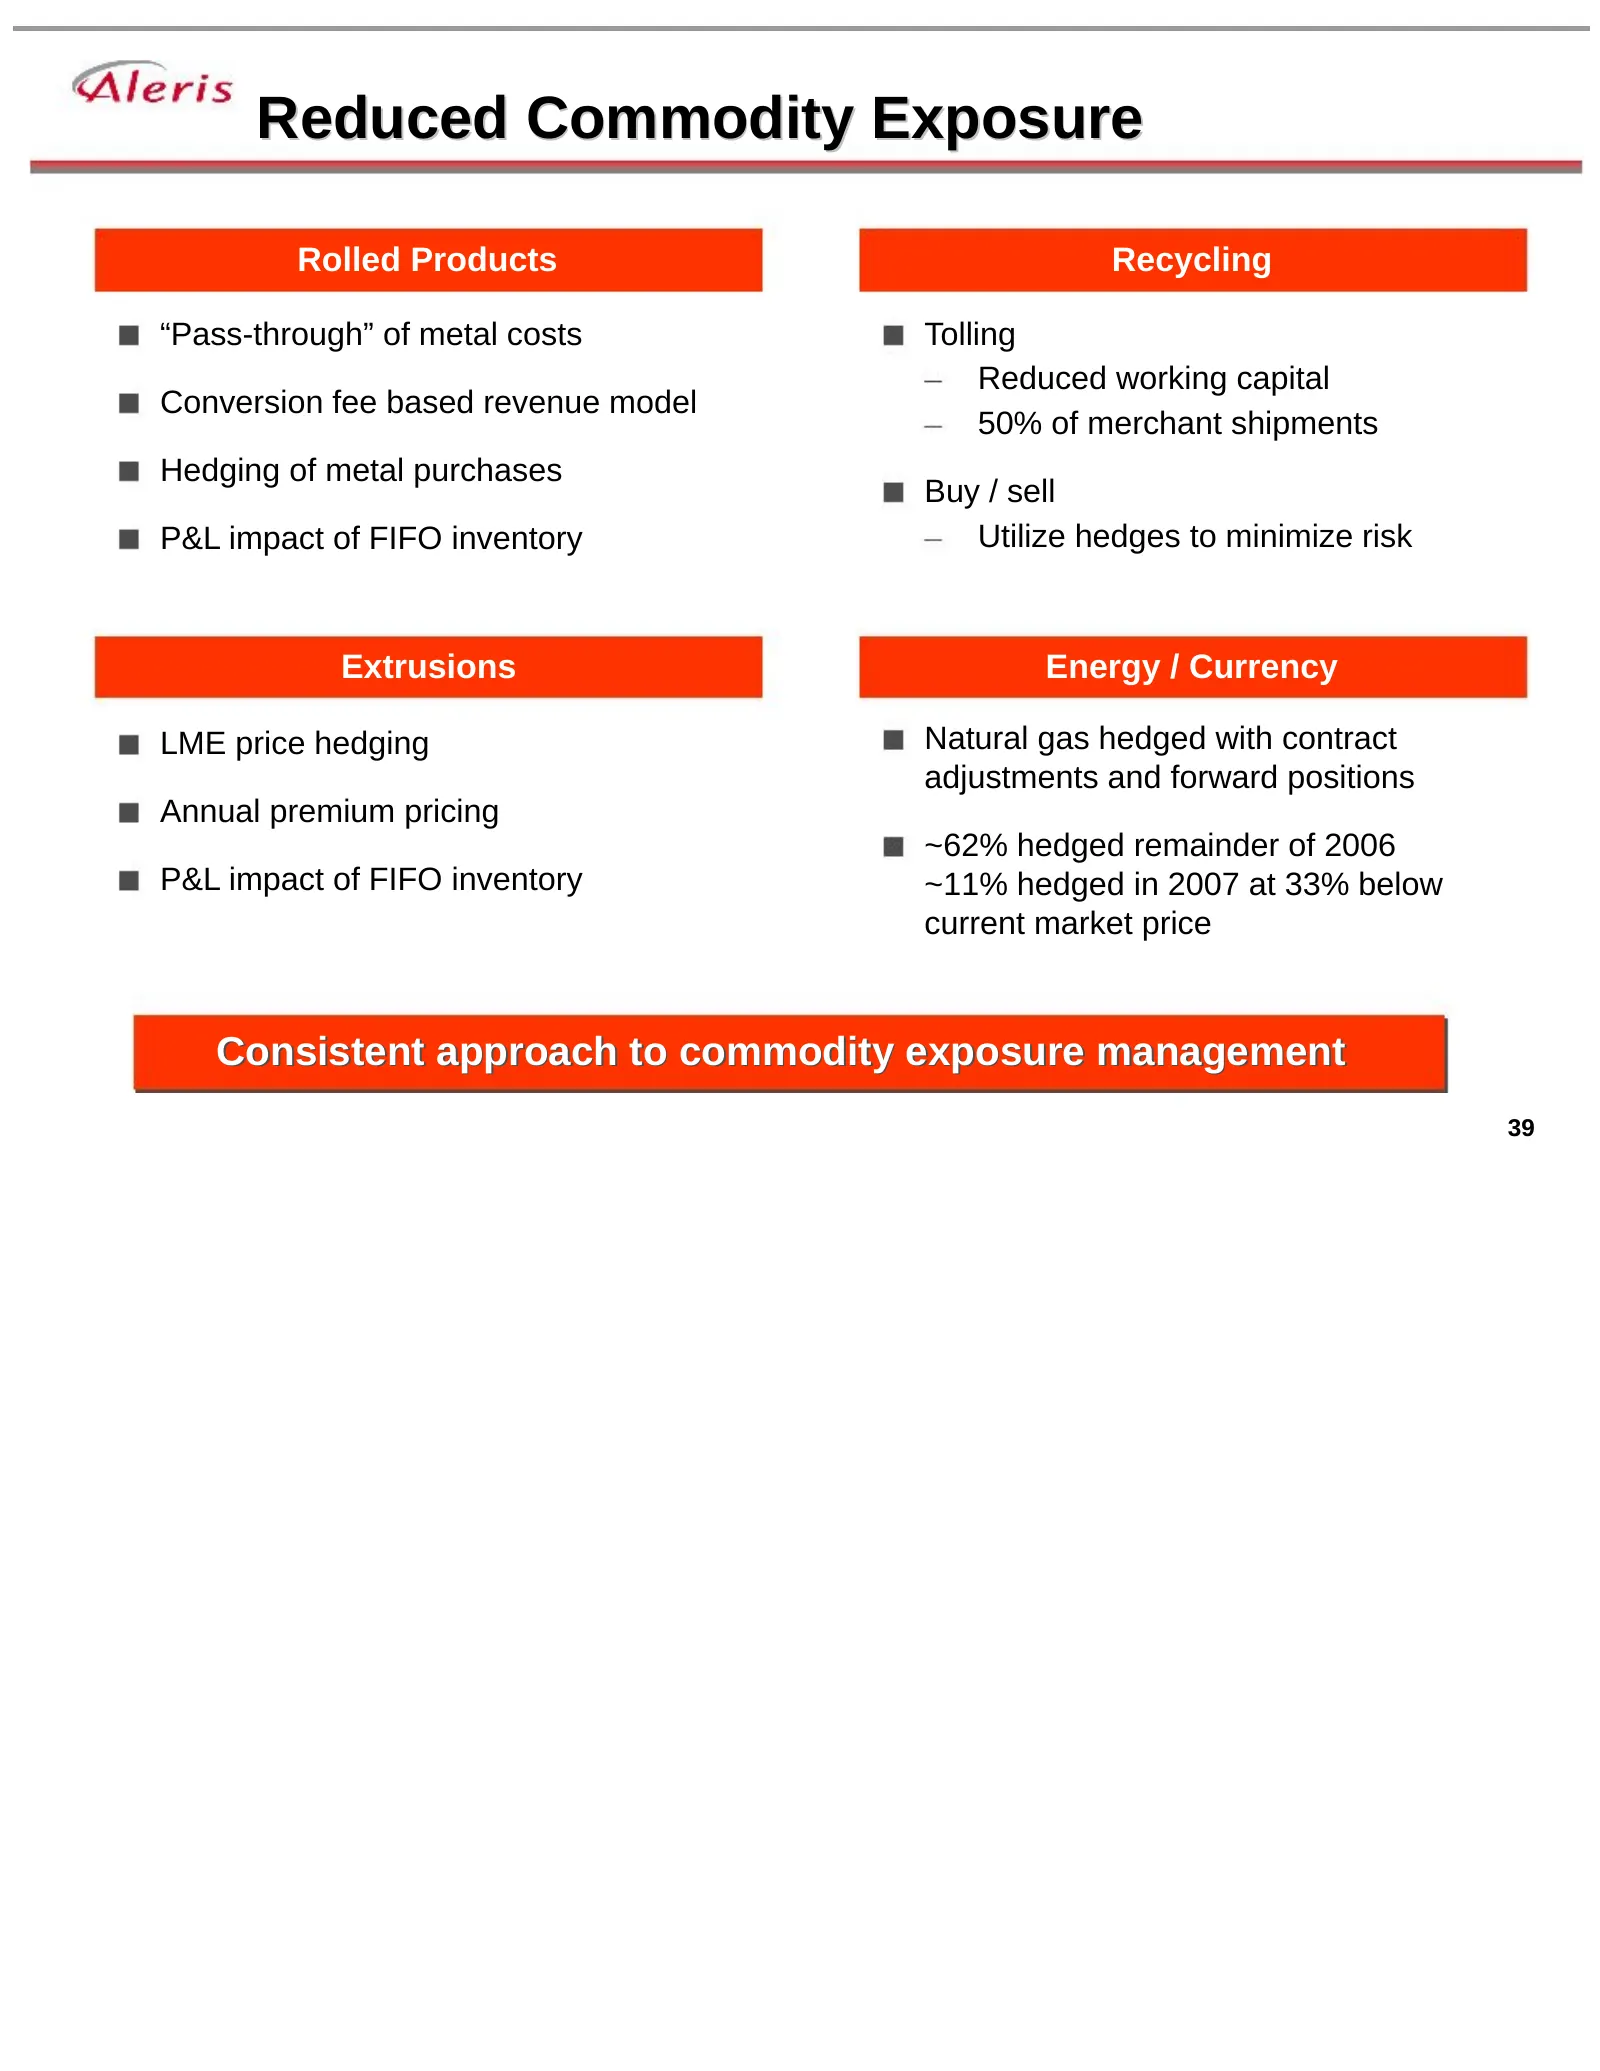
Reduced Commodity Exposure Rolled Products Recycling “Pass-through” of metal costs Tolling Reduced working capital Conversion fee based revenue model 50% of merchant shipments Hedging of metal purchases Buy / sell P&L impact of FIFO inventory Utilize hedges to minimize risk Extrusions Energy / Curre
Slide 40: Credible Senior Management Aligned with Experienced Business Unit Leaders
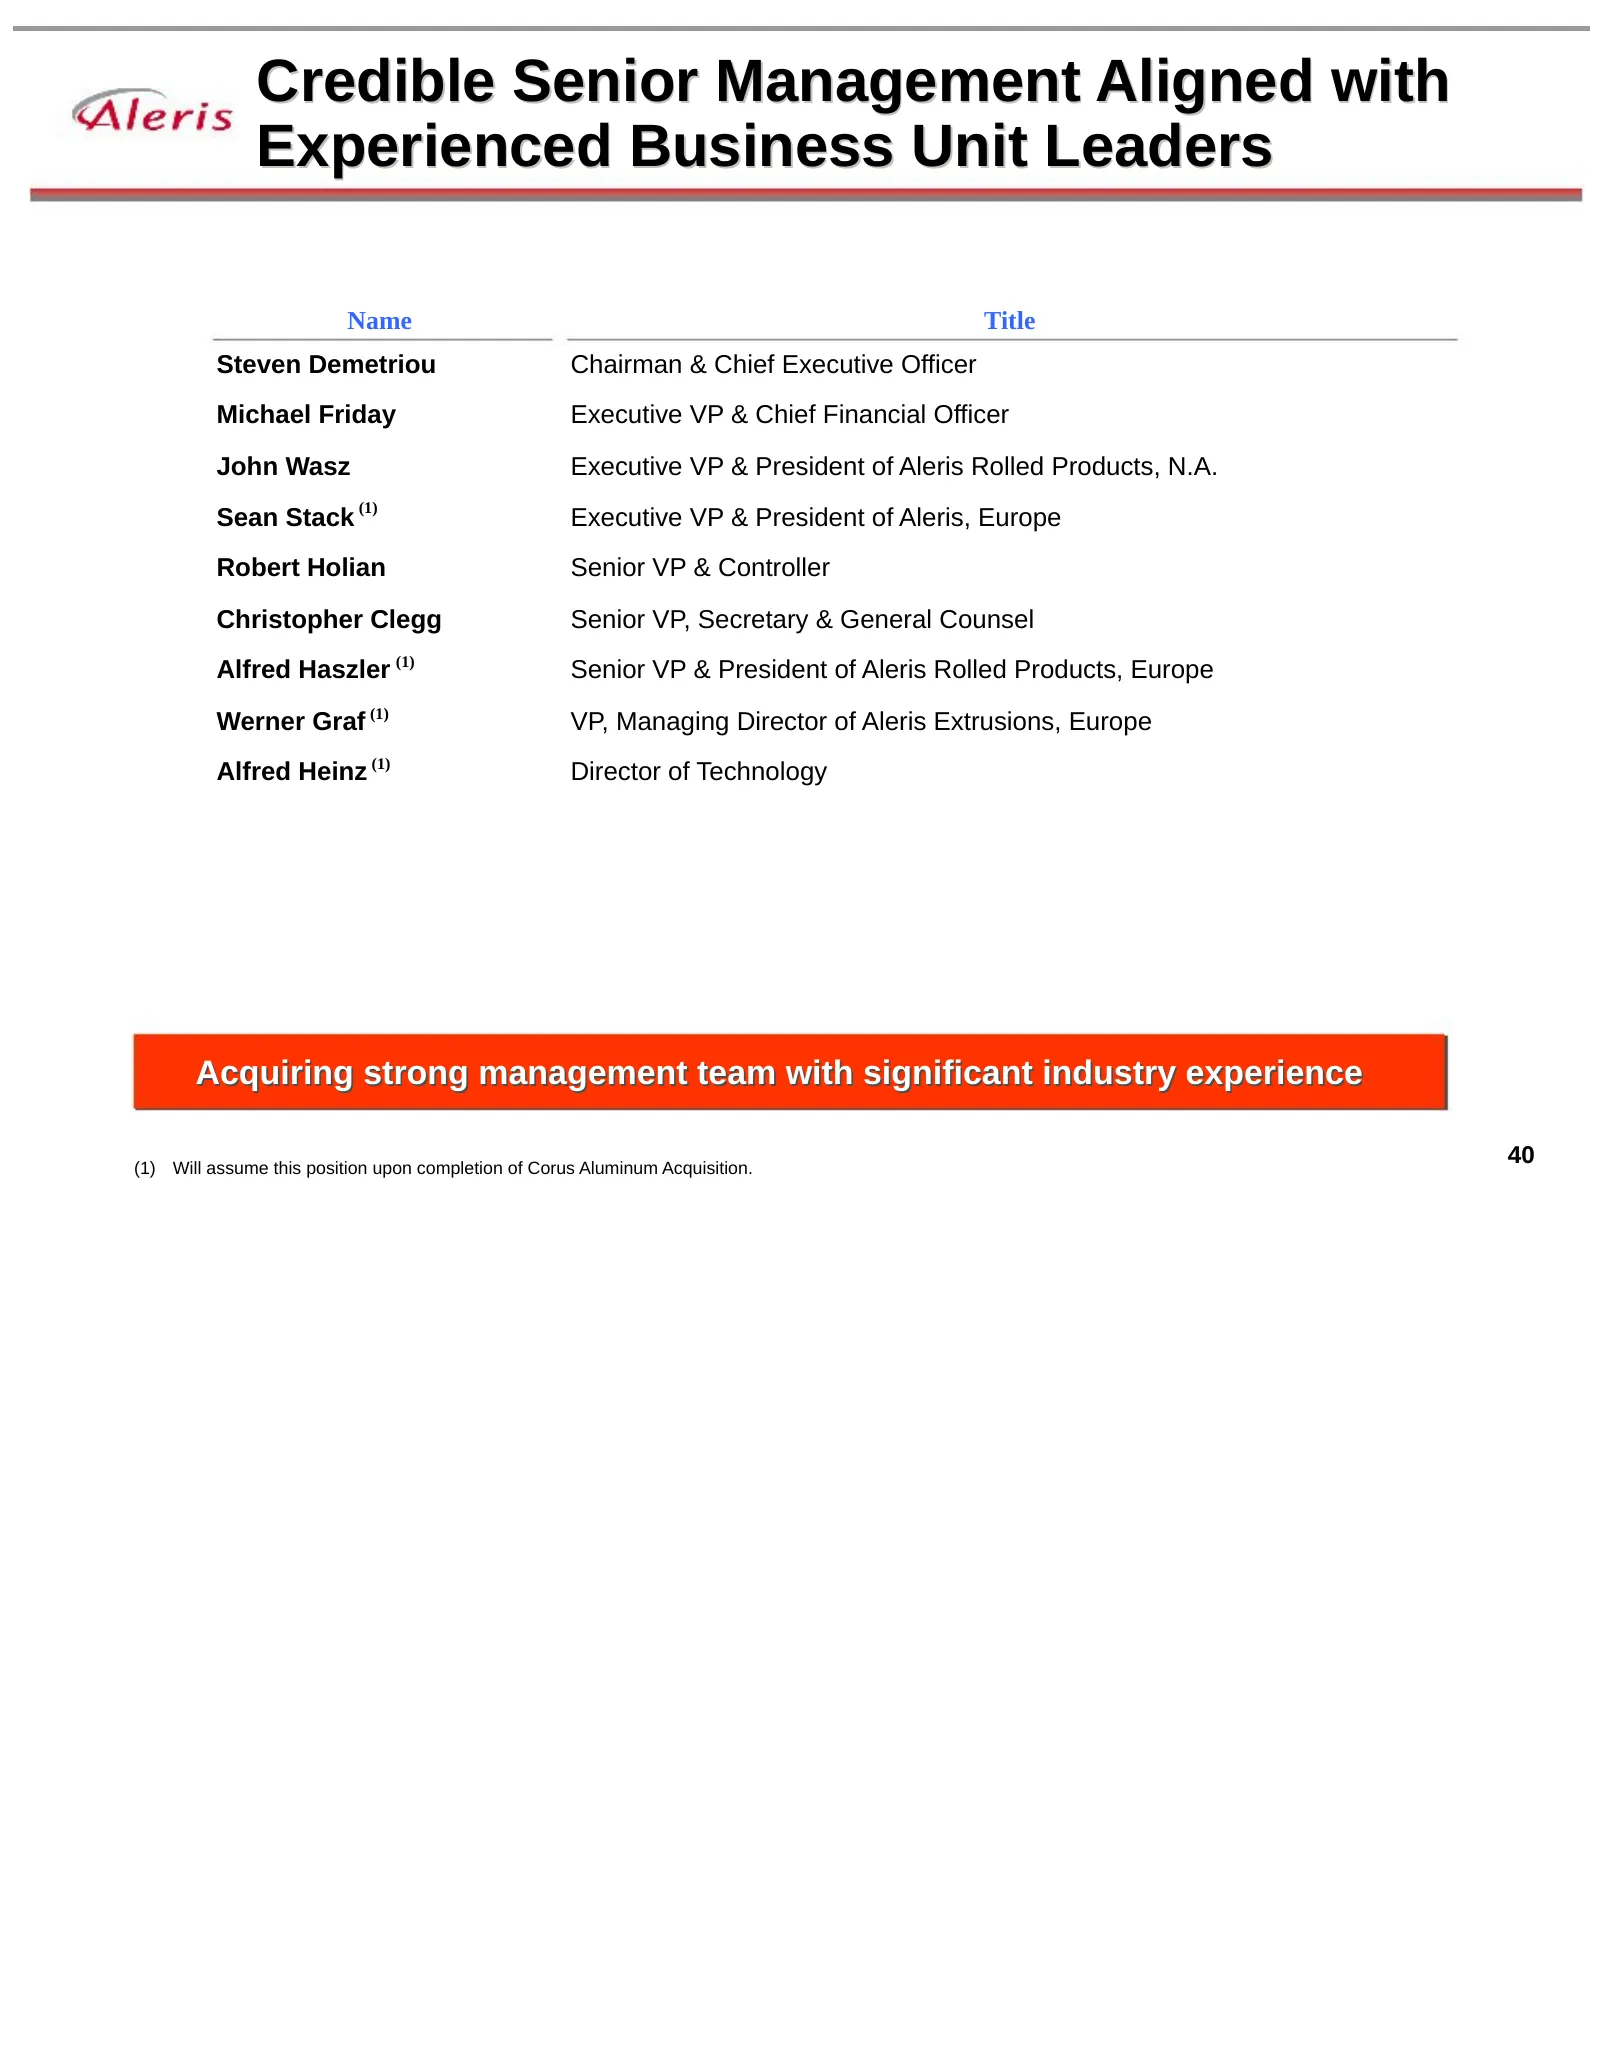
Credible Senior Management Aligned with Experienced Business Unit Leaders Name Title Steven Demetriou Chairman & Chief Executive Officer Michael Friday Executive VP & Chief Financial Officer John Wasz Executive VP & President of Aleris Rolled Products, N.A. (1) Sean Stack Executive VP & President of
Slide 41: Aleris Historical Financial Review
Aleris Historical Financial Review Mike Friday, Chief Financial Officer
Slide 42: Financial Summary
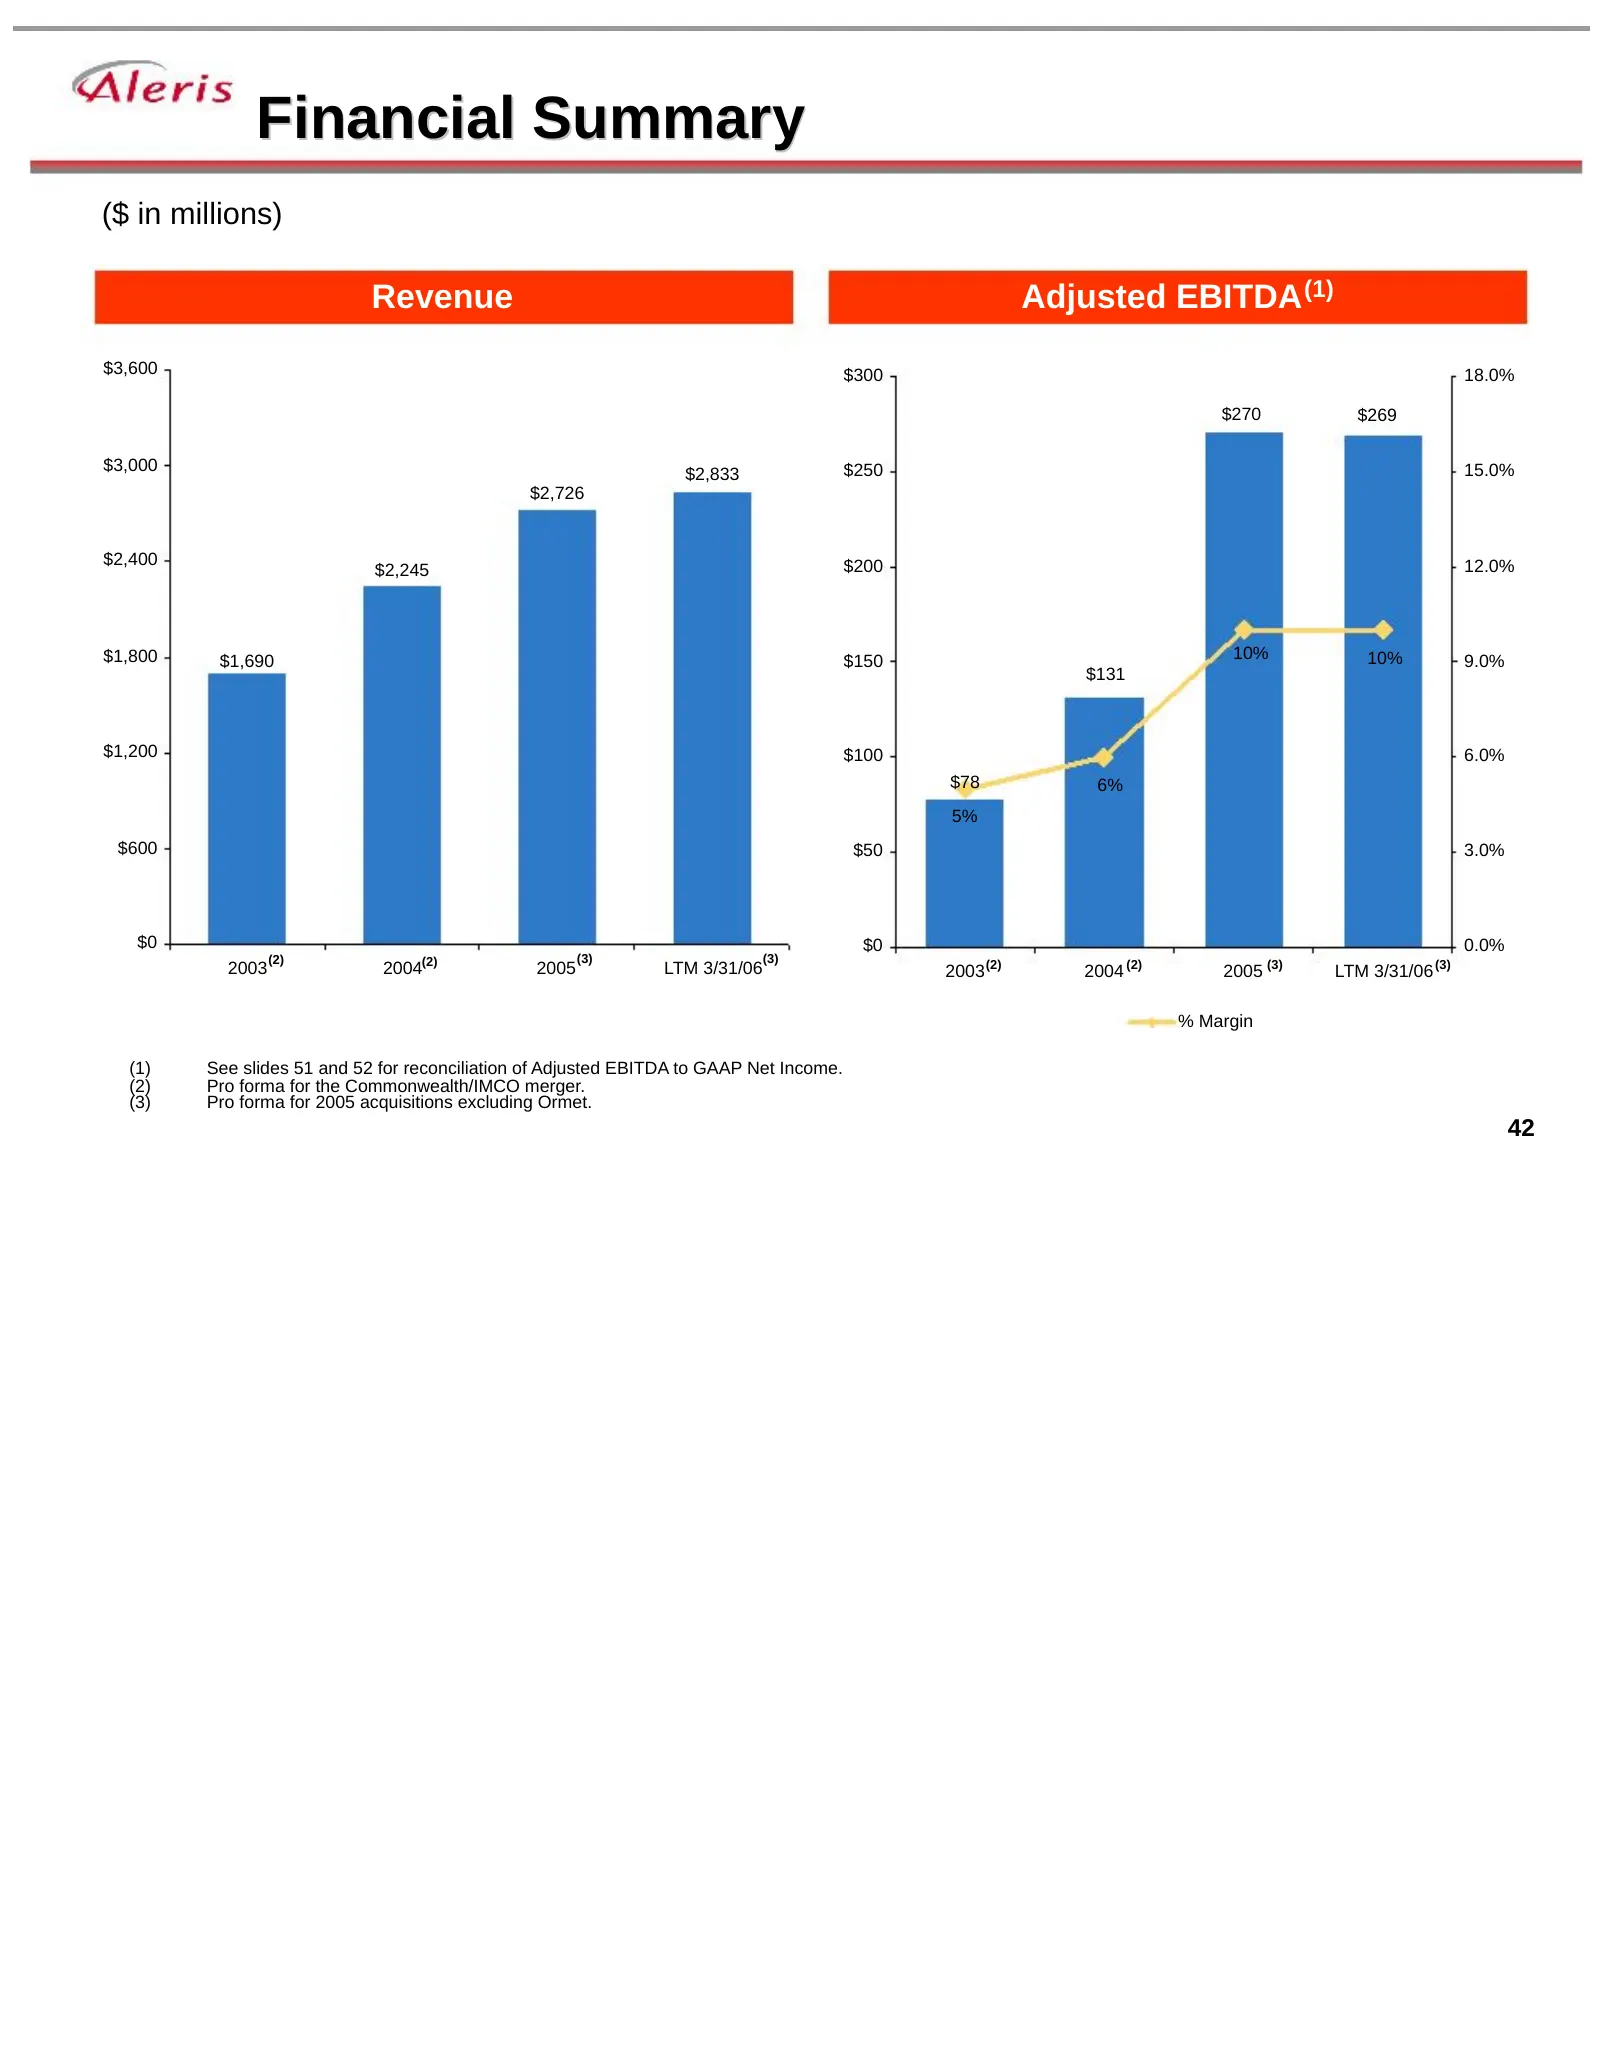
Financial Summary ($ in millions) Revenue Adjusted EBITDA (1) $3,600 $300 18.0% $270 $269 $3,000 $2,833 $250 15.0% $2,726 $2,400 $200 12.0% $2,245 $1,800 $1,690 $150 10% 10% 9.0% $131 $1,200 $100 6.0% $78 6% 5% $600 $50 3.0% $0 $0 0.0% (2) (3) (3) 2003 2004(2) 2005 LTM 3/31/06 2003 (2) 2004 (2) 2005
Slide 43: Rolled Products Margin Performance
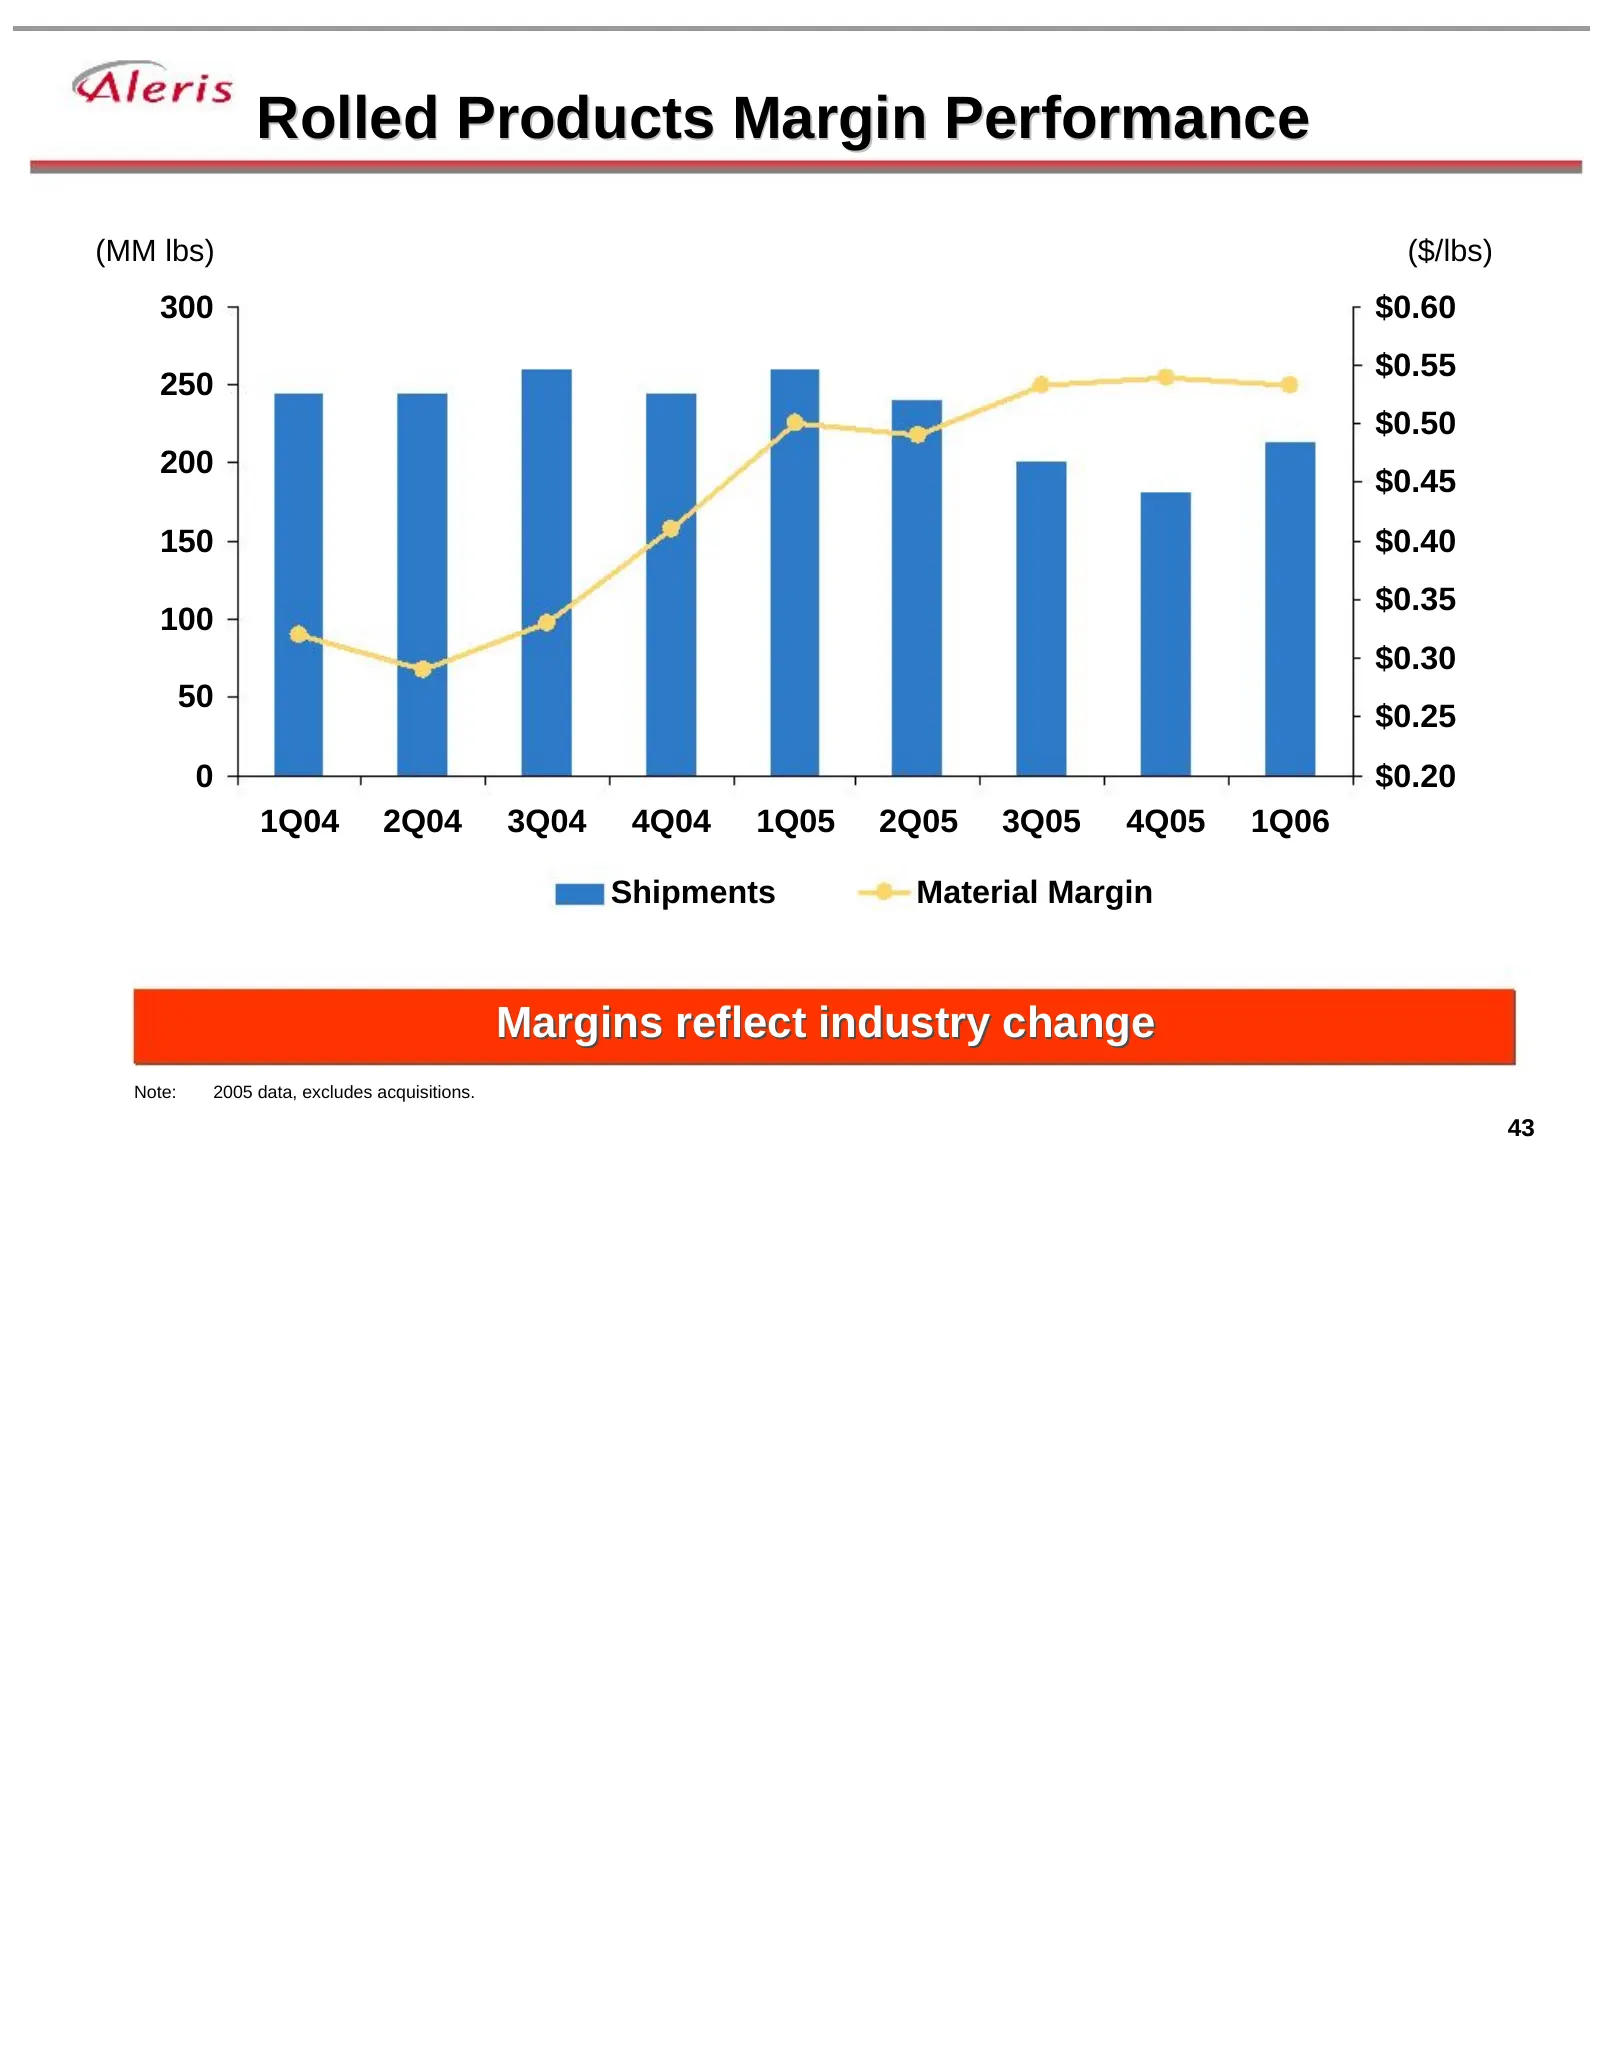
Rolled Products Margin Performance (MM lbs) ($/lbs) 300 $0.60 $0.55 250 $0.50 200 $0.45 150 $0.40 $0.35 100 $0.30 50 $0.25 0 $0.20 1Q04 2Q04 3Q04 4Q04 1Q05 2Q05 3Q05 4Q05 1Q06 Shipments Material Margin Margins reflect industry change Note: 2005 data, excludes acquisitions. 43
Slide 44: Capital Expenditures Overview
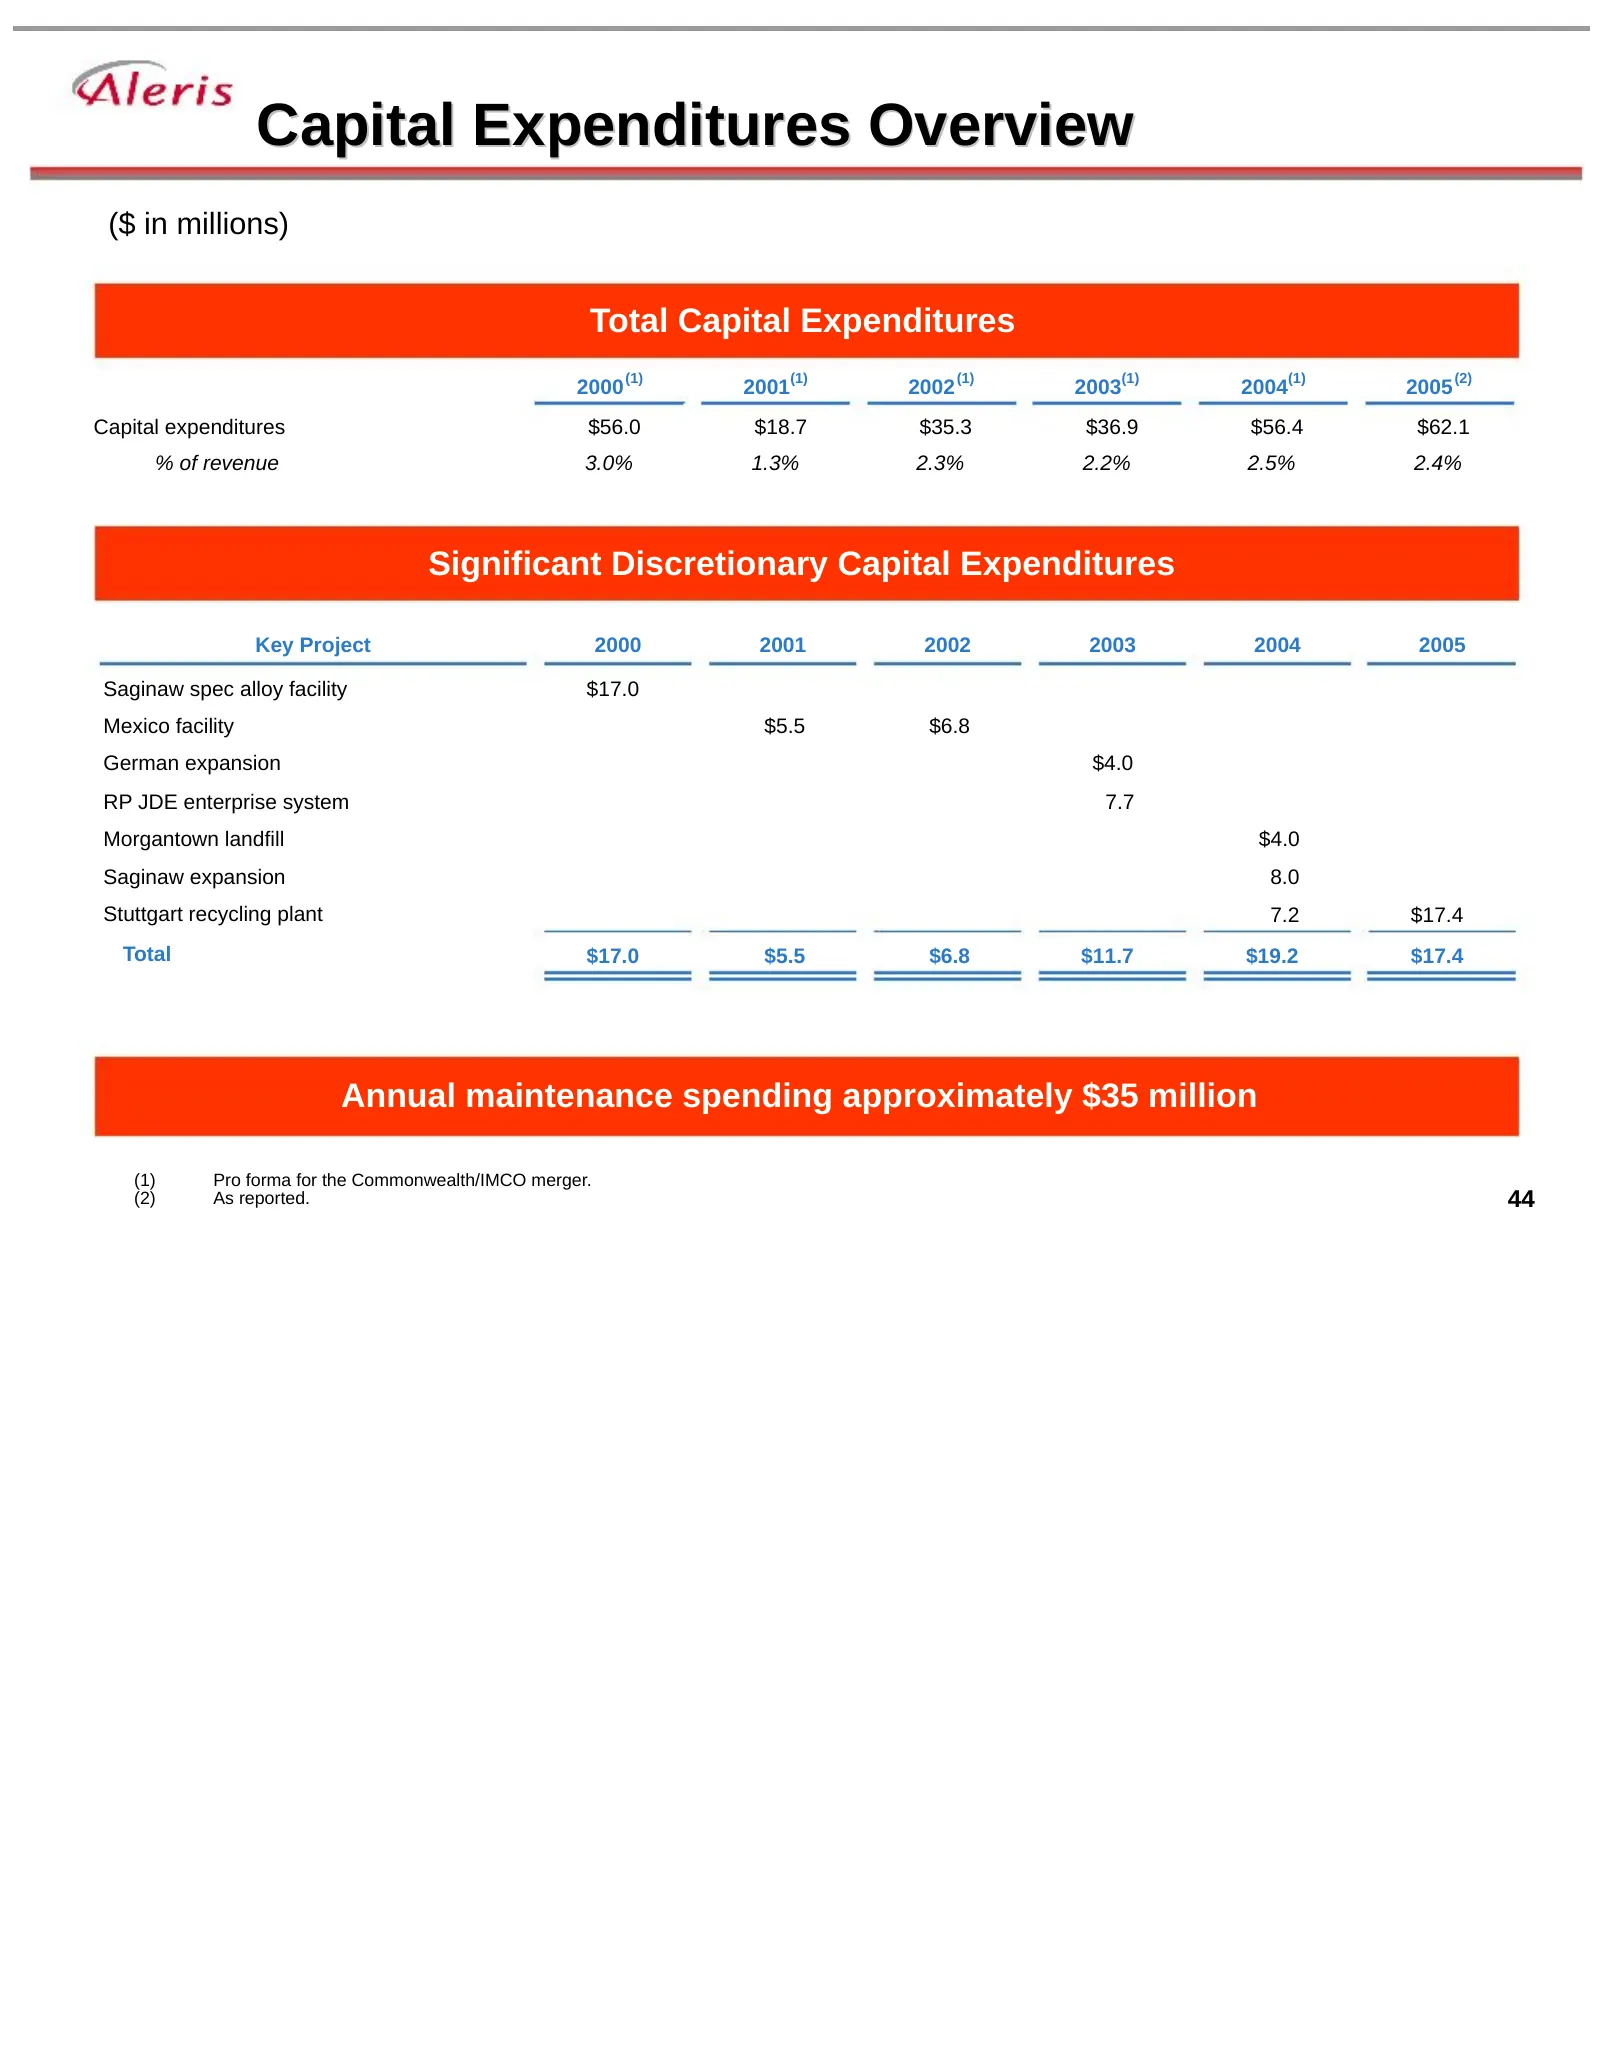
Capital Expenditures Overview ($ in millions) Total Capital Expenditures (1) (1) (1) (1) (1) (2) 2000 2001 2002 2003 2004 2005 Capital expenditures $56.0 $18.7 $35.3 $36.9 $56.4 $62.1 % of revenue 3.0% 1.3% 2.3% 2.2% 2.5% 2.4% Significant Discretionary Capital Expenditures Key Project 2000 2001 2002
Slide 45: Cash & Debt Summary
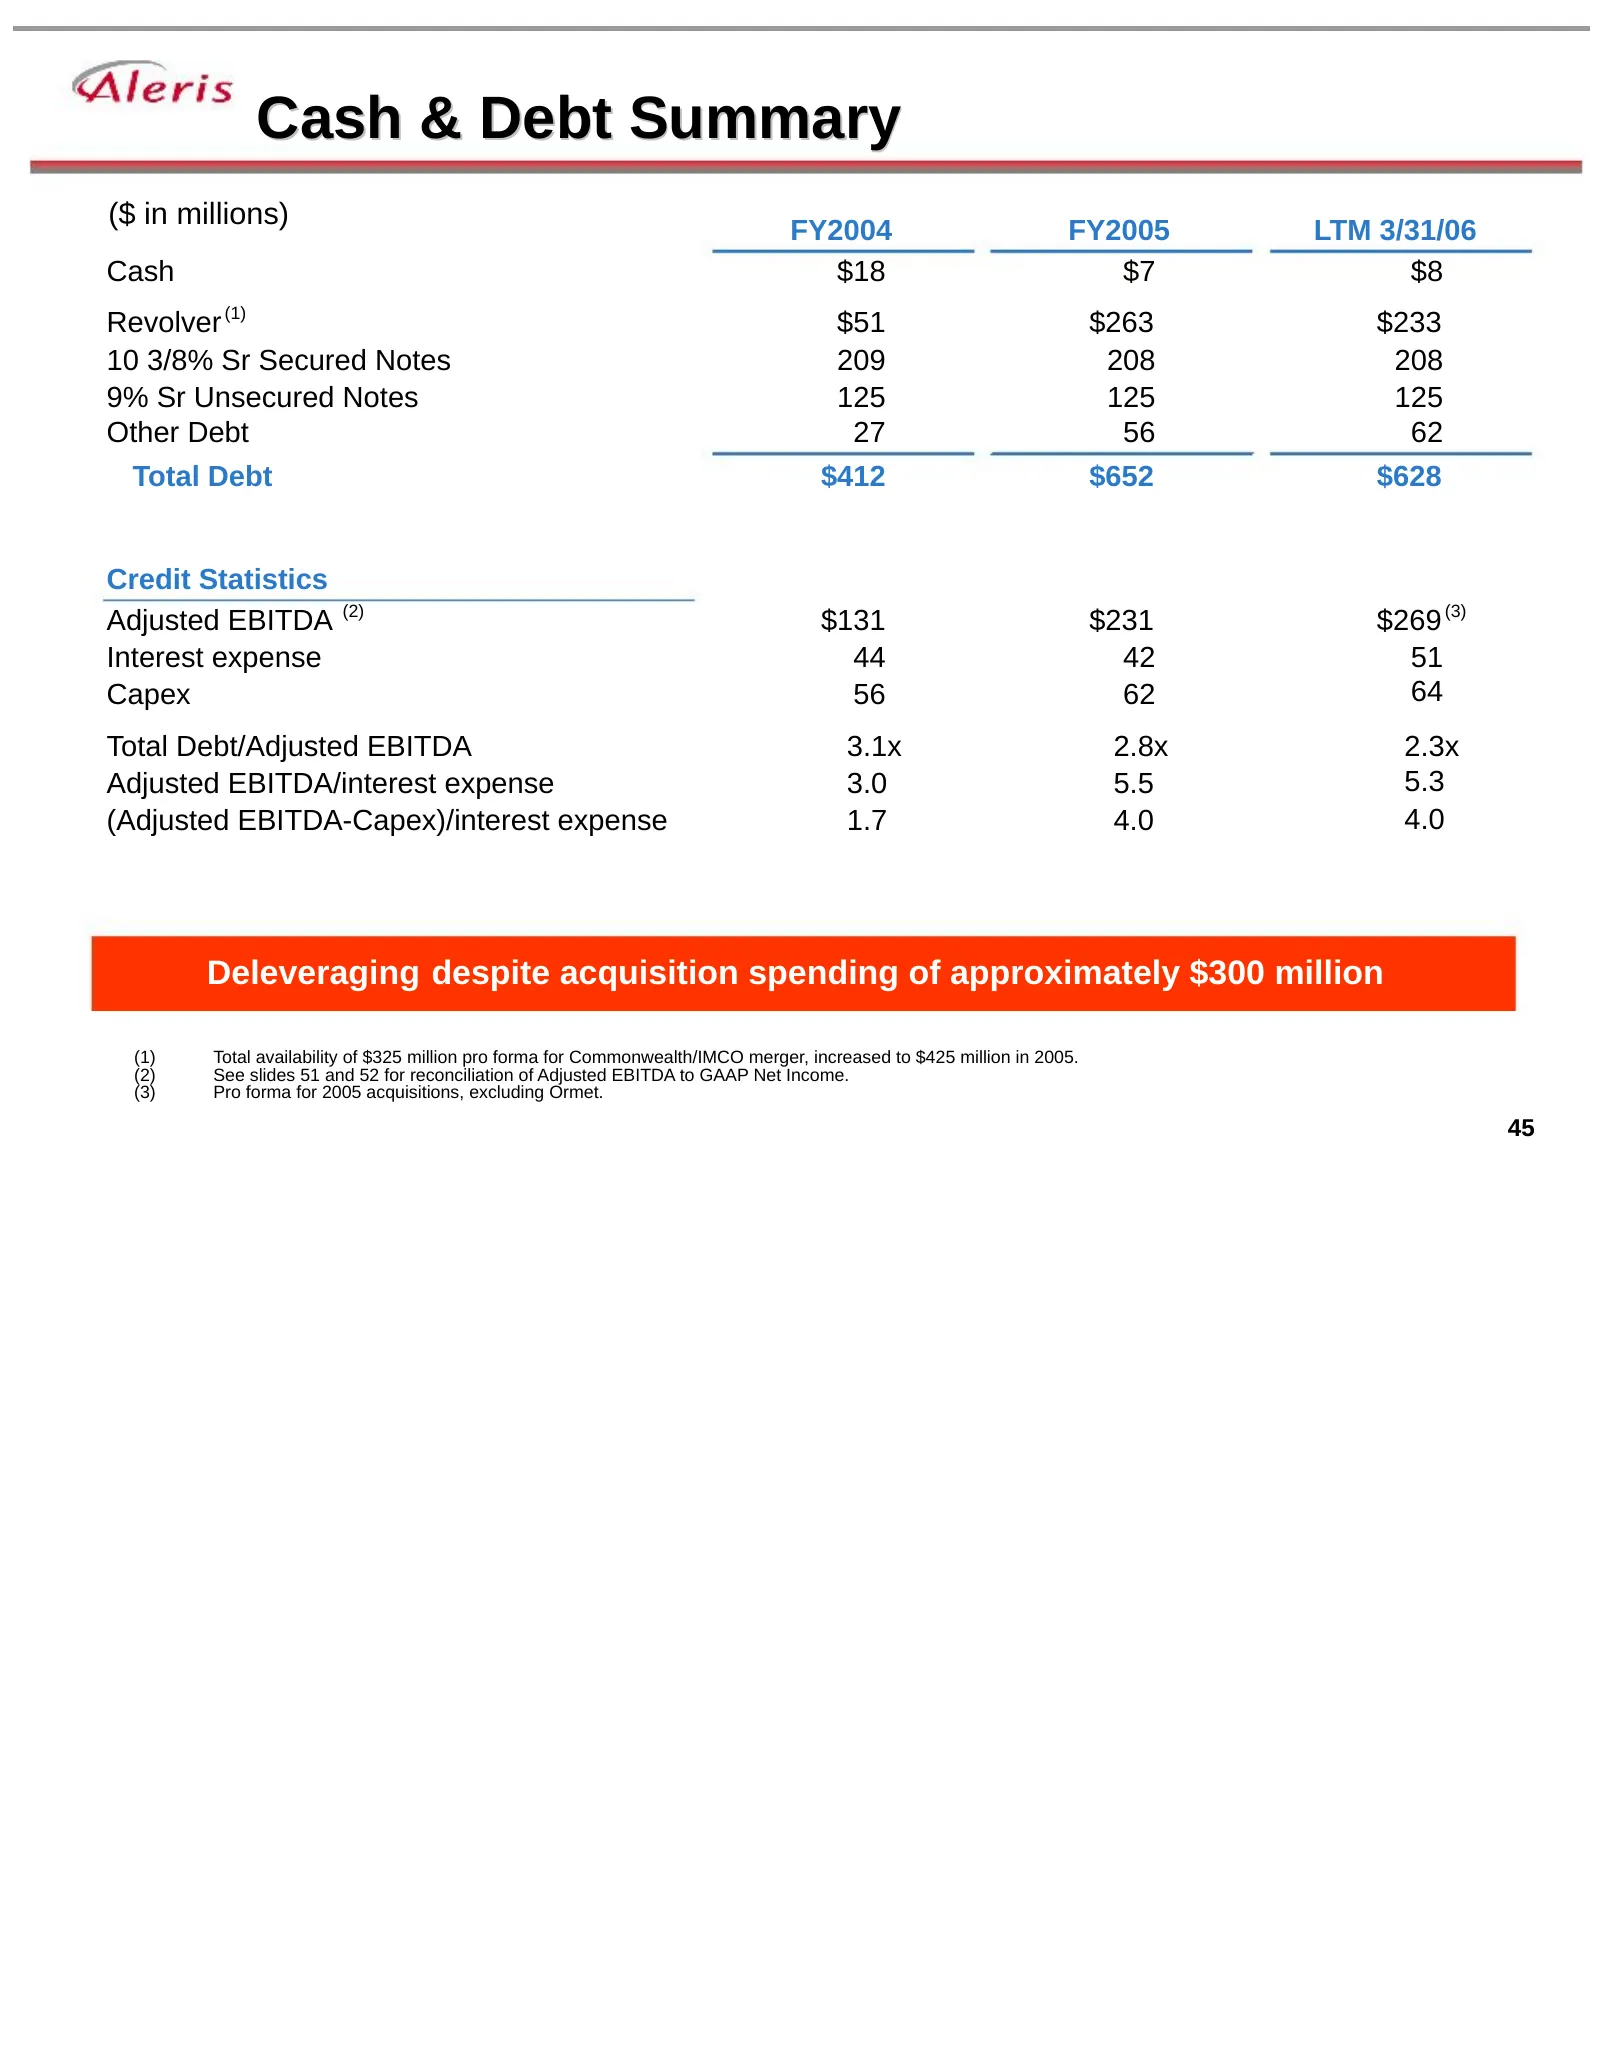
Cash & Debt Summary ($ in millions) FY2004 FY2005 LTM 3/31/06 Cash $18 $7 $8 Revolver (1) $51 $263 $233 10 3/8% Sr Secured Notes 209 208 208 9% Sr Unsecured Notes 125 125 125 Other Debt 27 56 62 Total Debt $412 $652 $628 Credit Statistics Adjusted EBITDA (2) $131 $231 $269 (3) Interest expense 44 42
Slide 46: Corus Aluminum Financial Review
Corus Aluminum Financial Review Mike Friday, Chief Financial Officer
Slide 47: Historical Financial Performance
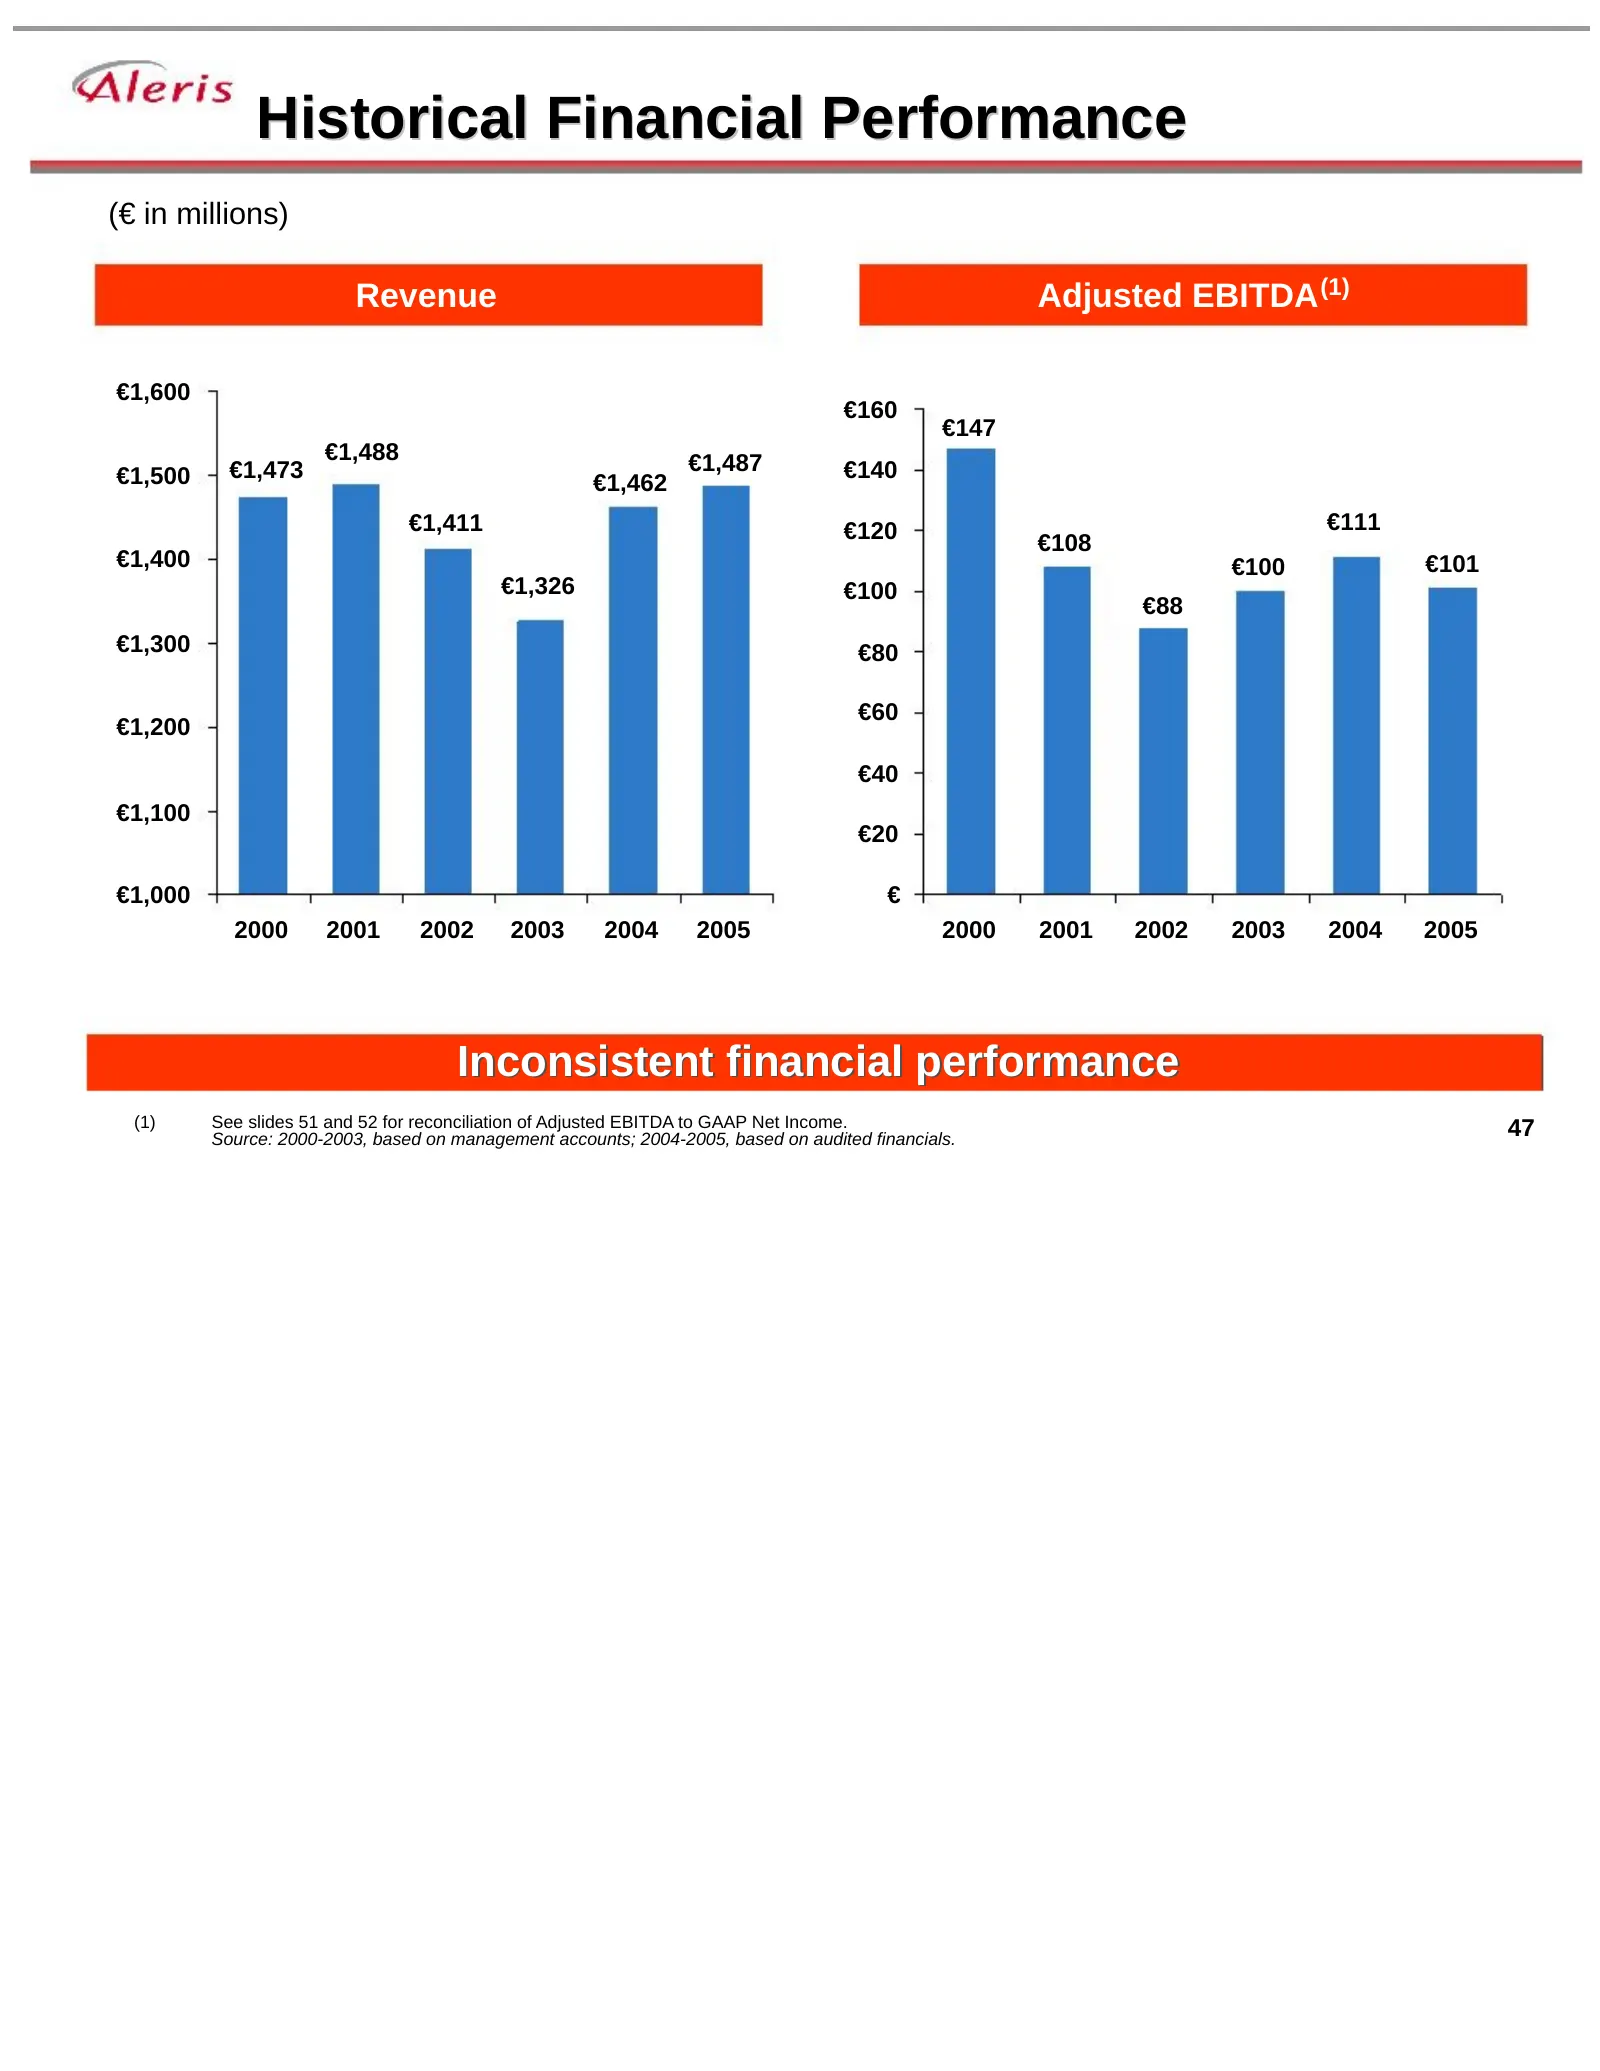
Historical Financial Performance (€ in millions) Revenue Adjusted EBITDA (1) €1,600 €160 €147 €1,488 €1,487 €1,500 €1,473 €140 €1,462 €1,411 €120 €111 €108 €1,400 €100 €101 €1,326 €100 €88 €1,300 €80 €60 €1,200 €40 €1,100 €20 €1,000 € 2000 2001 2002 2003 2004 2005 2000 2001 2002 2003 2004 2005 Incon
Slide 48: Financial Summary
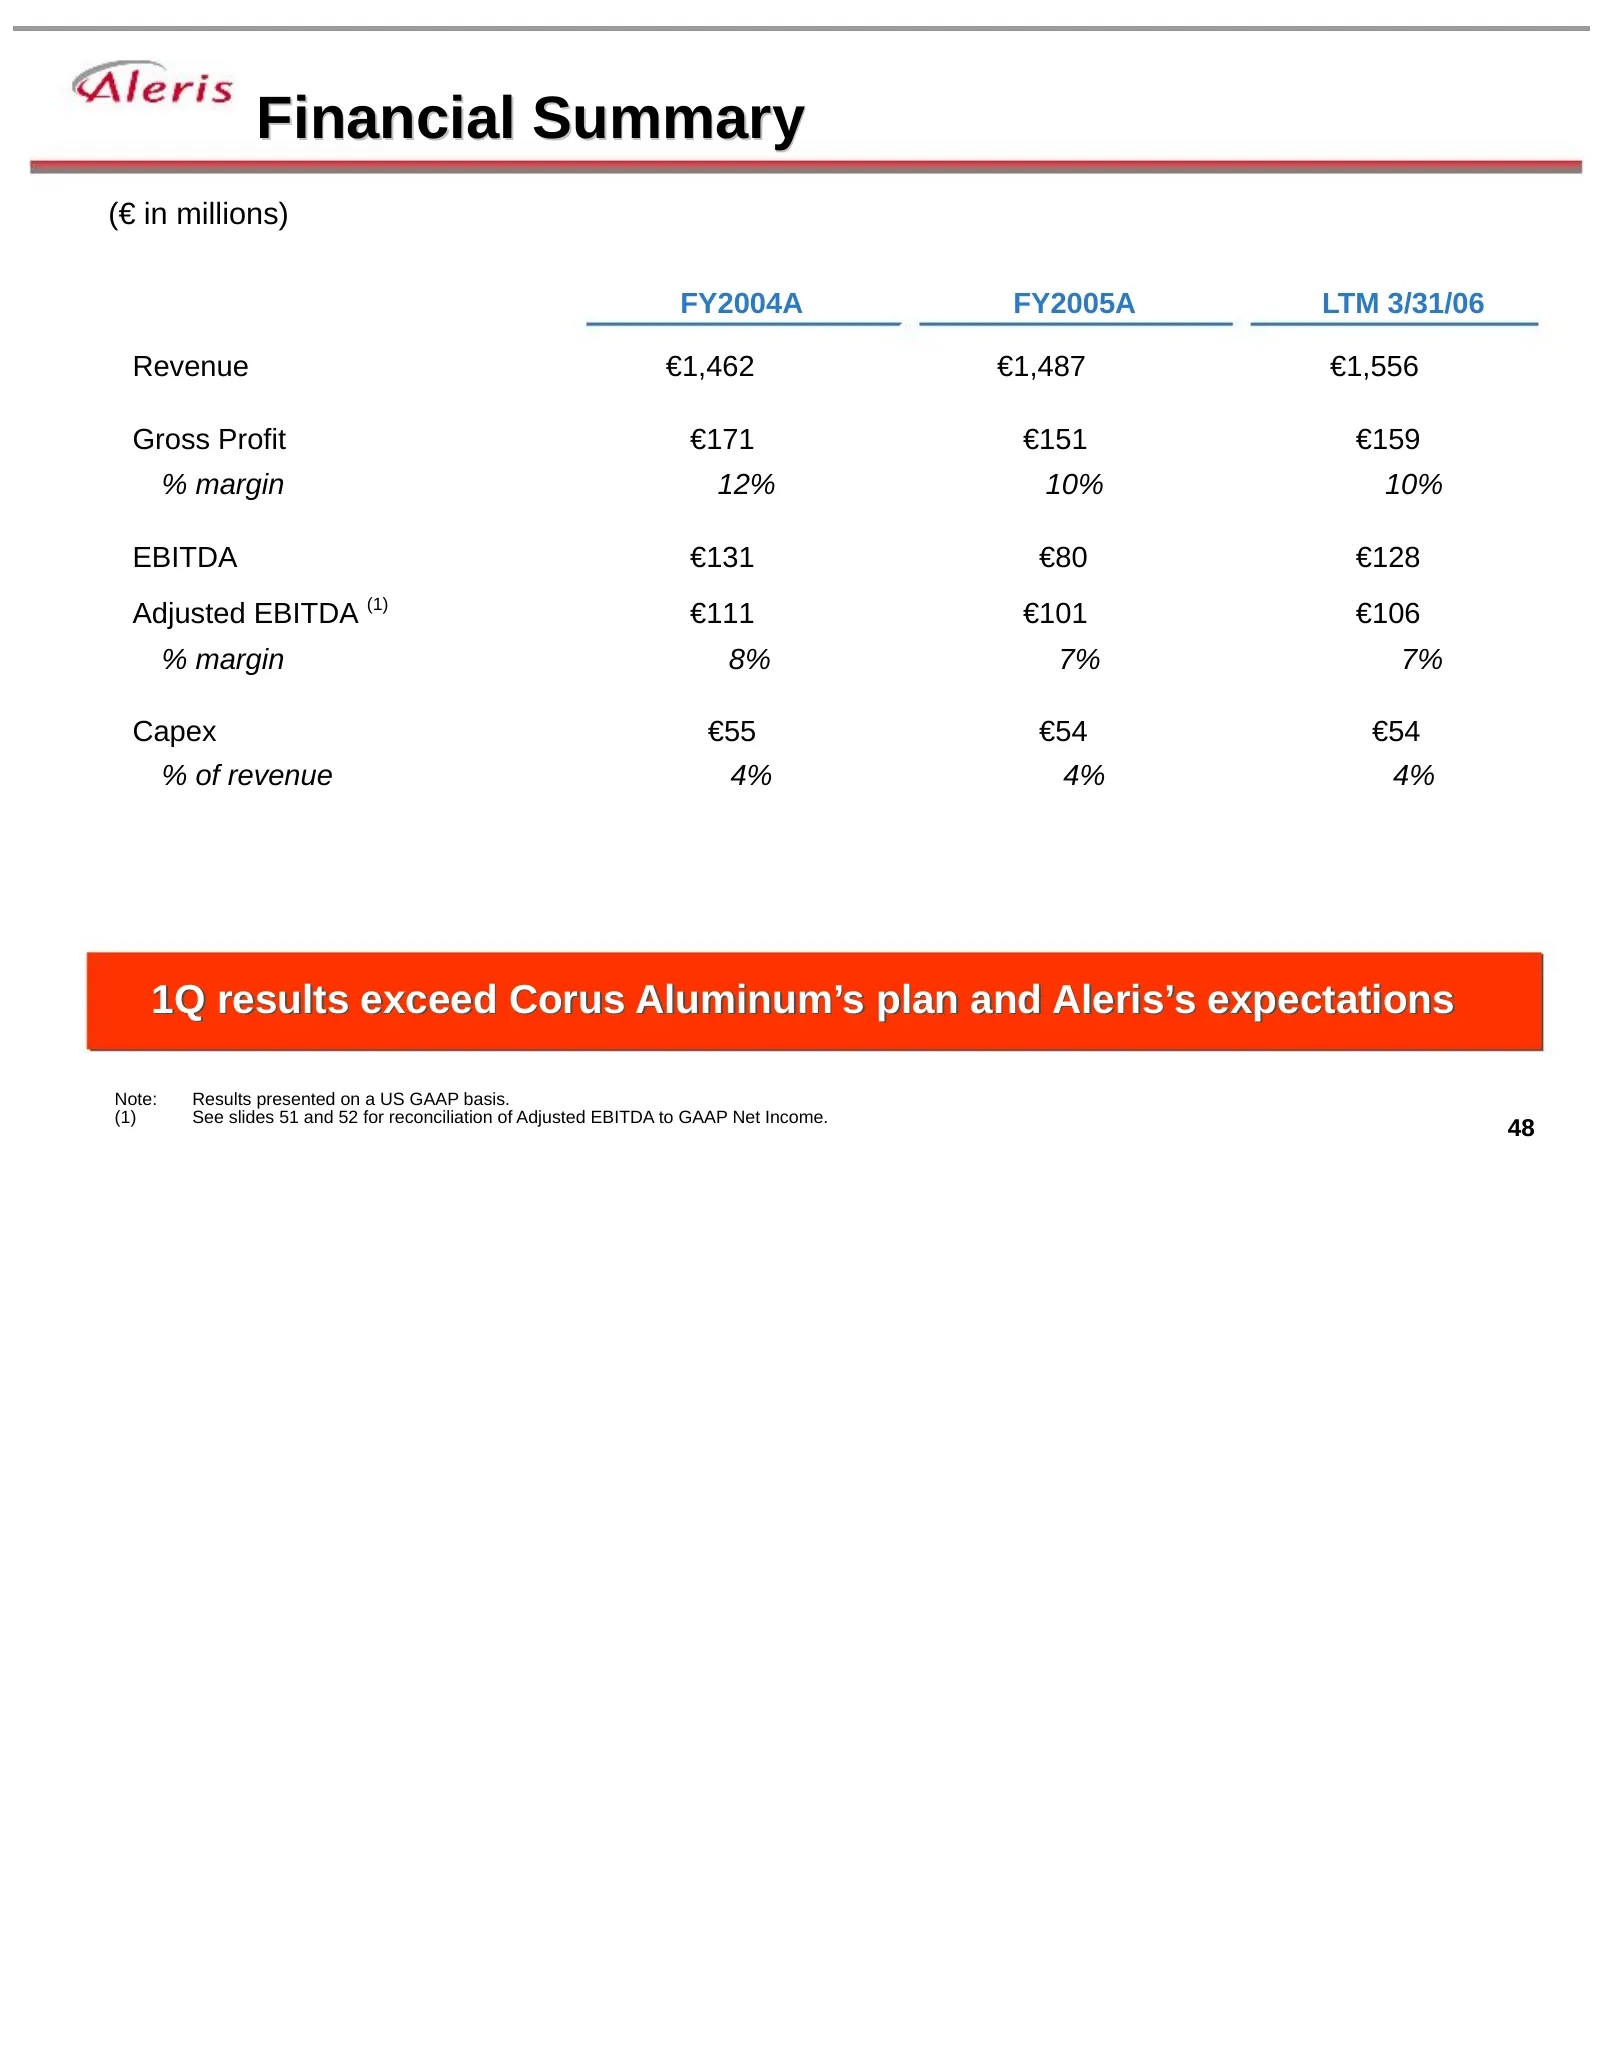
Financial Summary (€ in millions) FY2004A FY2005A LTM 3/31/06 Revenue €1,462 €1,487 €1,556 Gross Profit €171 €151 €159 % margin 12% 10% 10% EBITDA €131 €80 €128 Adjusted EBITDA (1) €111 €101 €106 % margin 8% 7% 7% Capex €55 €54 €54 % of revenue 4% 4% 4% 1Q results exceed Corus Aluminum’s plan and Al
Slide 49: 2005 Financial Performance
2005 Financial Performance Rolled products performance in 2005 negatively affected by unexpected operational upsets throughout the year Duffel transformer fire (January - March) Duffel casthouse shutdown (May - July) Koblenz gearbox failure (June - December) Rolled products operational problems offs
Slide 50: Conclusion
Conclusion Aleris has exceeded expectations since Commonwealth/IMCO merger Management continues to execute its strategy Acquisitions executed at attractive multiples and being successfully integrated Corus Acquisition provides diversification and additional synergies and business opportunities Asia-
Slide 51: EBITDA to Net Income Reconciliation
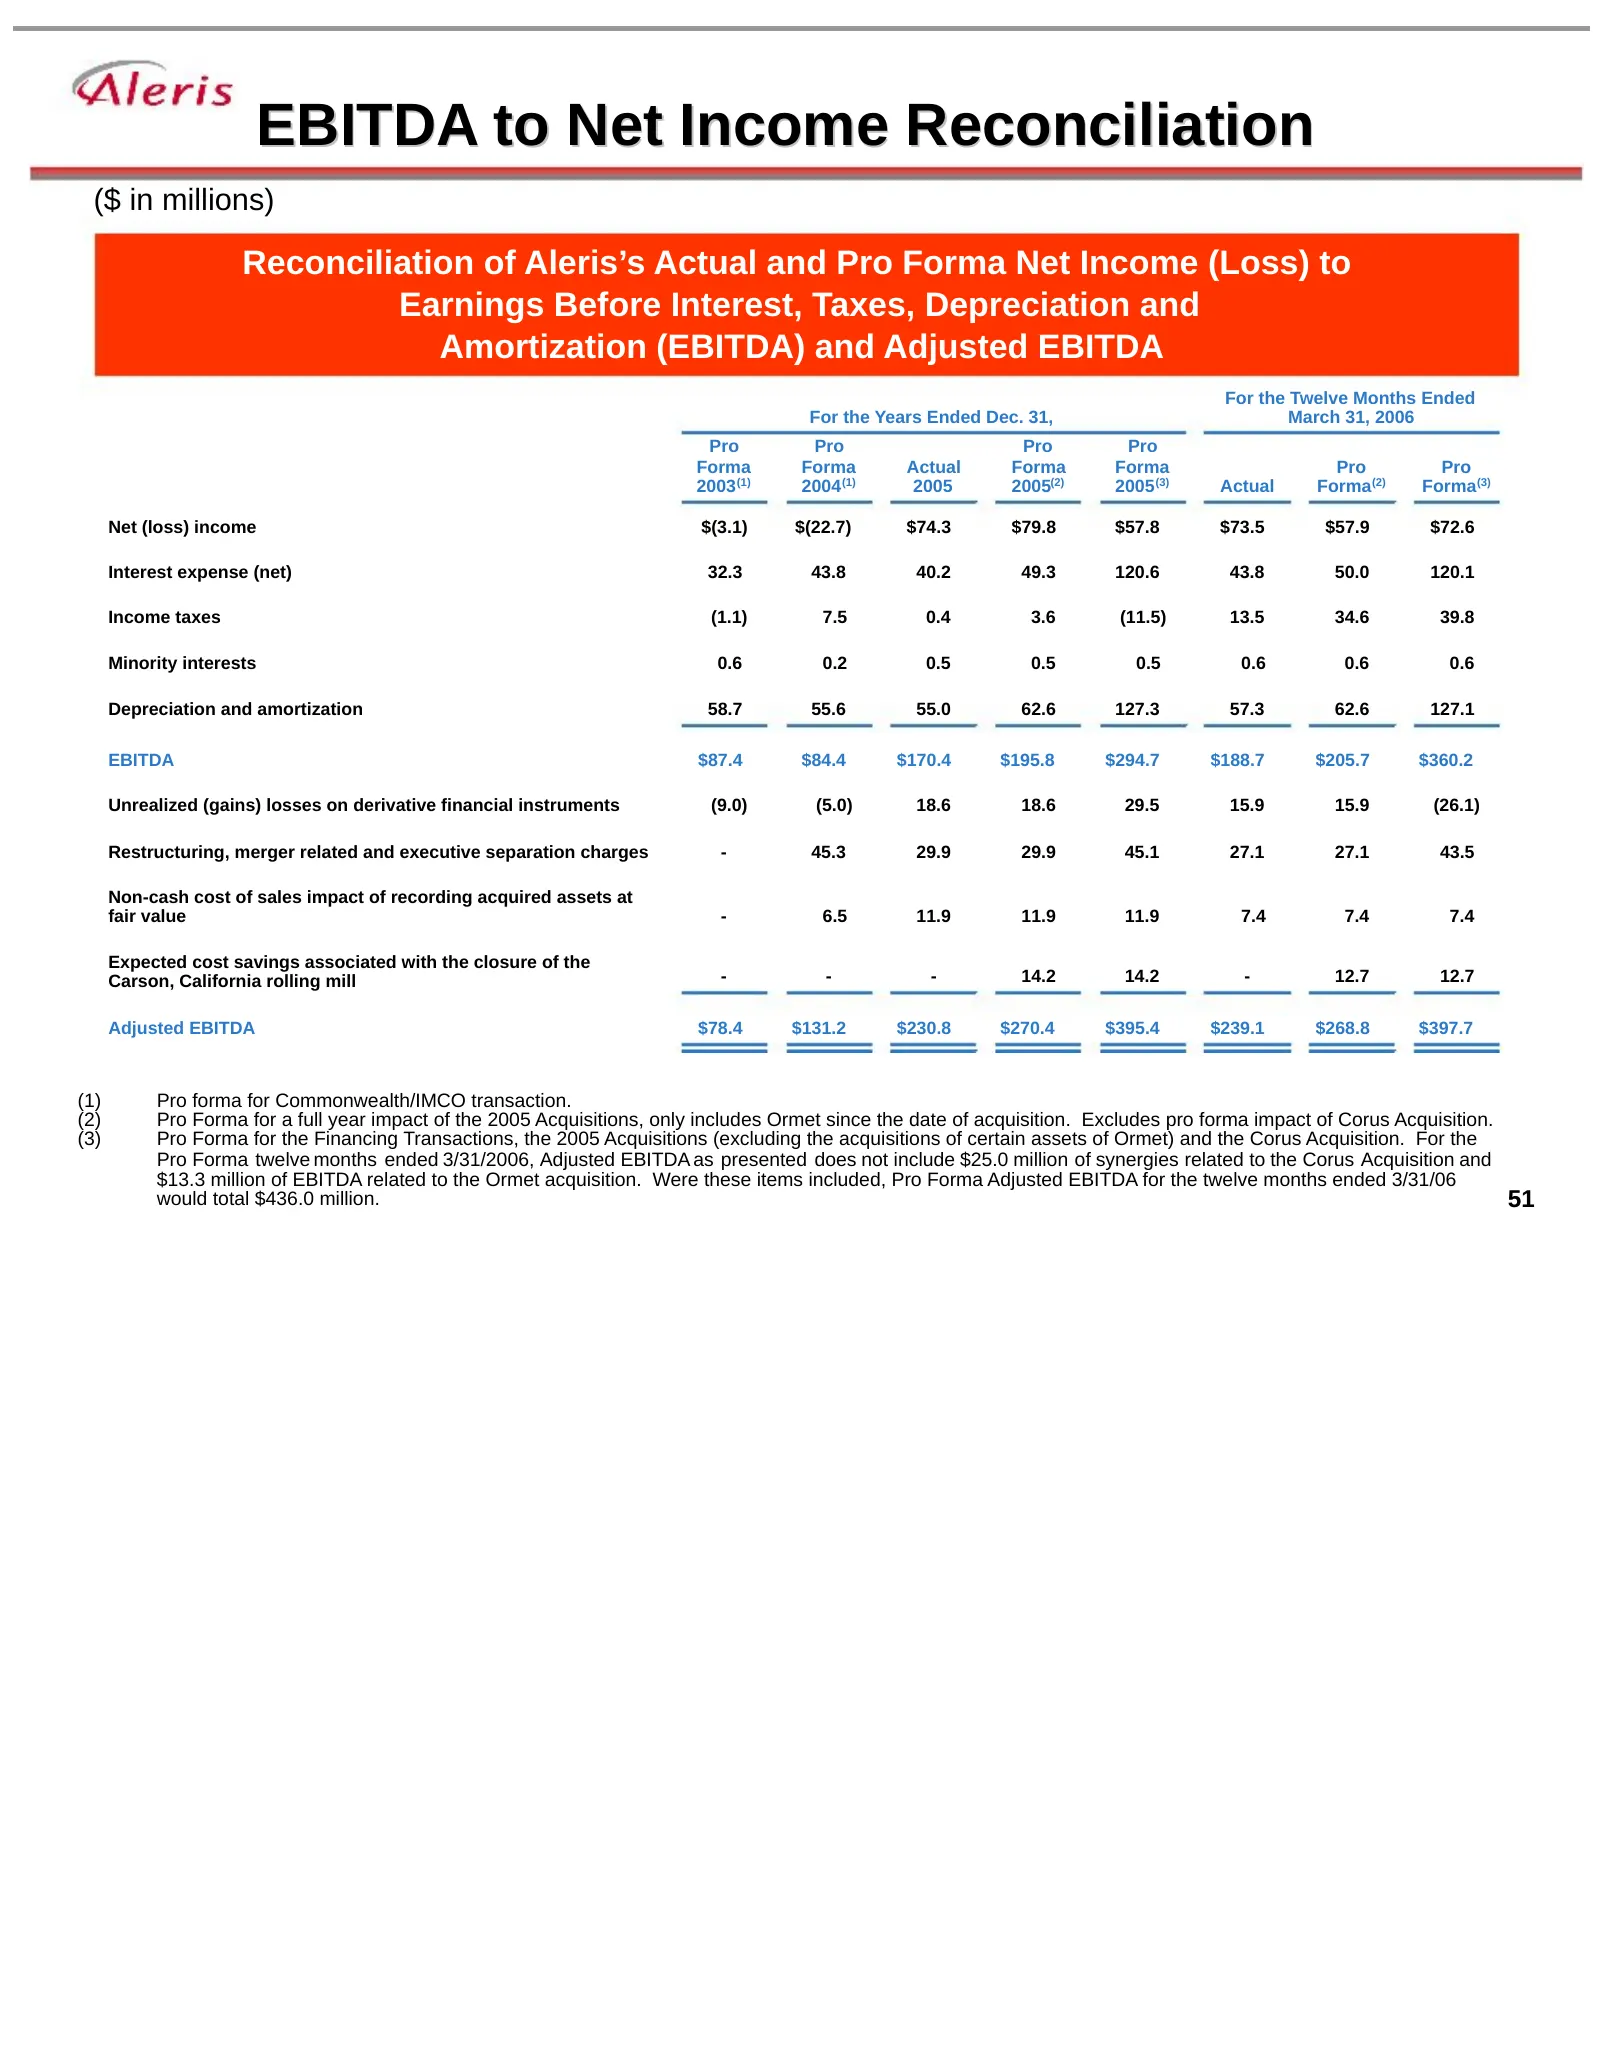
EBITDA to Net Income Reconciliation ($ in millions) Reconciliation of Aleris’s Actual and Pro Forma Net Income (Loss) to Earnings Before Interest, Taxes, Depreciation and Amortization (EBITDA) and Adjusted EBITDA For the Twelve Months Ended For the Years Ended Dec. 31, March 31, 2006 Pro Pro Pro Pro
Slide 52: EBITDA to Net Income Reconciliation
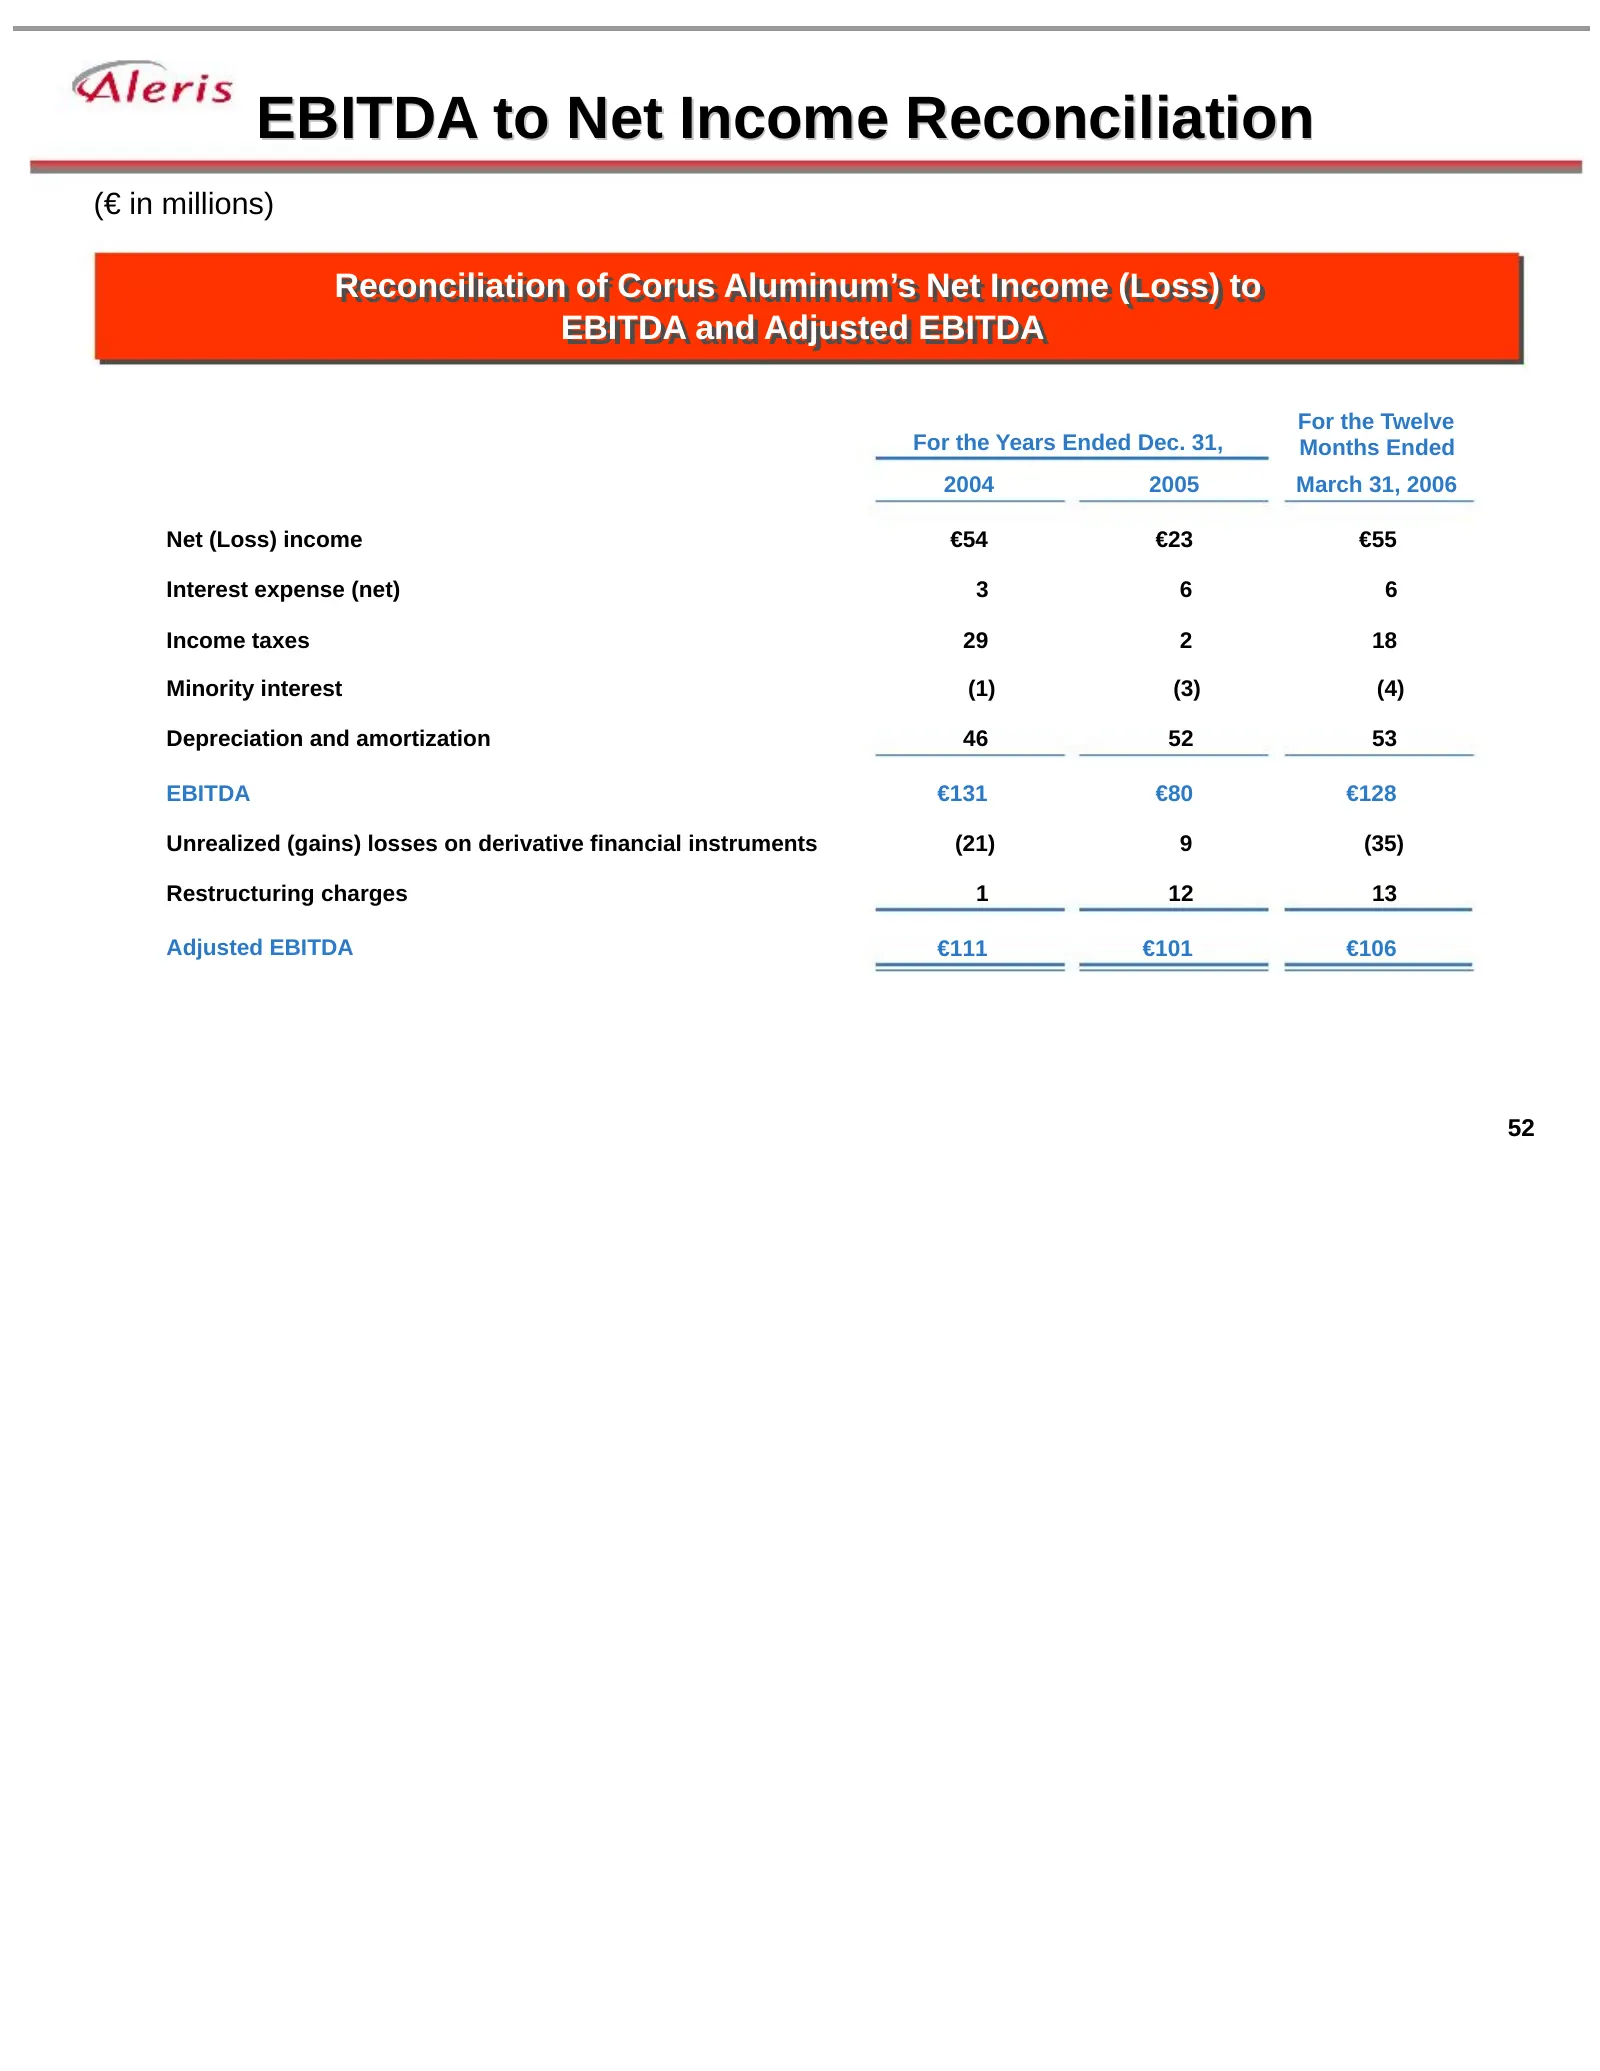
EBITDA to Net Income Reconciliation (€ in millions) Reconciliation Reconciliation of of Corus Corus Aluminum’s Aluminum’s Net Net Income Income (Loss) (Loss) to to EBITDA EBITDA and and Adjusted Adjusted EBITDA EBITDA For the Twelve For the Years Ended Dec. 31, Months Ended 2004 2005 March 31, 2006
Source: SEC EDGAR · 8-K filed Jul 11, 2006
More decks from Aleris International Inc
 2008 Bank of America Credit Conference26 slides · Nov 21, 2008
 Deutsche Bank Leverage Finance Conference 200828 slides · Sep 25, 2008
 FY2007 Earnings Presentation33 slides · Mar 31, 2008
 FY2007 Earnings Presentation33 slides · Mar 27, 2008
 Bear Stearns Commodity and Capital Goods Conference November 200723 slides · Nov 28, 2007
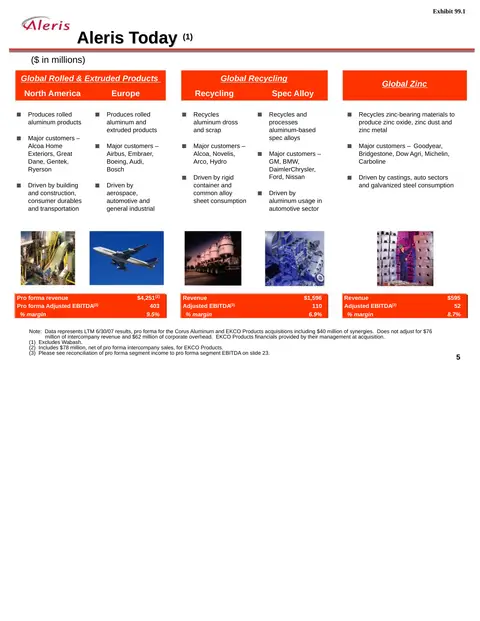 Investor Presentation (October 2007)14 slides · Oct 3, 2007