Chittenden — KBW Eastern Regional Bank Symposium (March 2003)
22 slides from Chittenden's conference presentation, Mar 7, 2003
Slide 1: KBW Eastern Regional Bank Symposium
‘CORPORATION ‘As of December 31, 2002 KBW Eastern Regional Bank Symposium Boston March 6, 2003
Slide 2: A Compelling Story
A Compelling Story Recognized competency in an attractive business mix Strategic acquisitions which provide strong earnings growth Low risk execution orientation provides an understandable opportunity Proven leadership provides aggressive focus to achieve superior financial results Well established
Slide 3: Strategic Direction
Strategic Direction « Continue to expand the existing franchise and our fee based businesses * Pursue acquisitions of banks and financial services companies
Slide 4: Acquisition Strategy
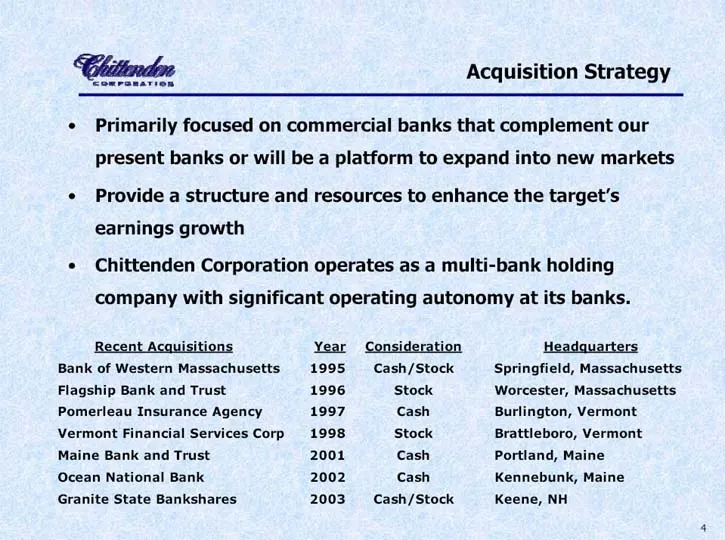
Acquisition Strategy ¢ Primarily focused on commercial banks that complement our present banks or will be a platform to expand into new markets ¢ Provide a structure and resources to enhance the target's earnings growth * Chittenden Corporation operates as a multi-bank holding company with significa
Slide 5: Our Markets
Our Markets Economies in which we operate are stable with limited excess real estate inventory The underlying economic drivers are well diversified and have minimal technology exposure Chittenden’s credit quality has remained very strong throughout the last ten years
Slide 6: Loans by State
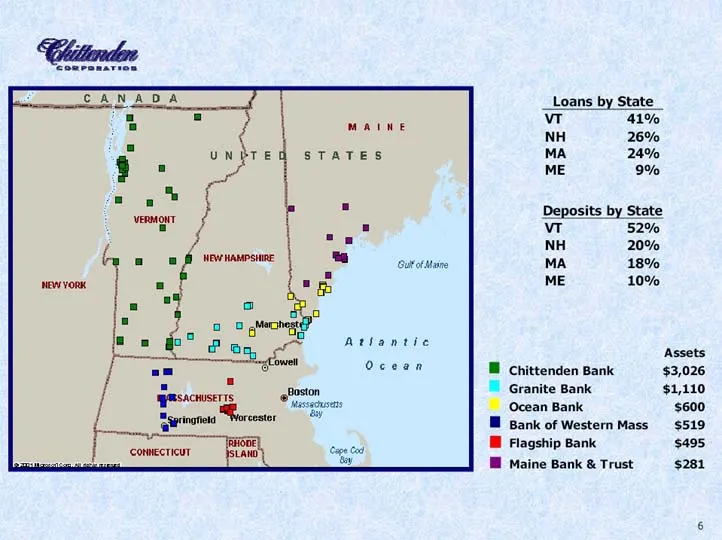
Loans by State Maine ve LS NH 26% STATES MA 24% ME 9% Deposits by State vt 52% NH 20% MA 18% ME 10% Assets B® Chittenden Bank $3,026 © Granite Bank $1,110 ‘Ocean Bank $600 MH Bank of Western Mass $519 I Flagship Bank $495 MH Maine Bank & Trust $281
Slide 7: Business Approach
Business Approach Deep relationships with worthwhile customers Focus on small and mid-sized businesses Maintain conservative underwriting standards and discipline Offer a complete range of banking products and services Geographically diverse branch franchise with both a consumer and small business f
Slide 8: Business Services
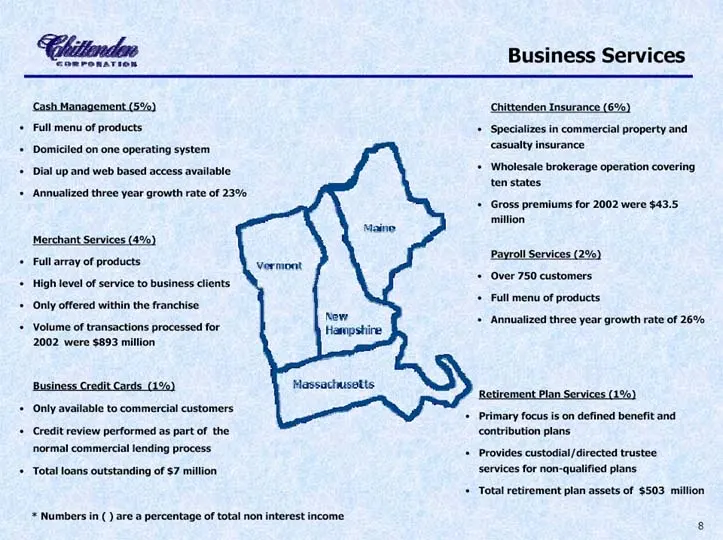
Business Services Chittenden Insurance (6%) Full menu of products + Specializes in commercial property and Domiciled on one operating system ‘casualty insurance Dial up and web based access available + Wholesale brokerage operation covering ten states ‘Annualized three year growth rate of 23% + Gros
Slide 9: Financial Management Services and Specialty Businesses
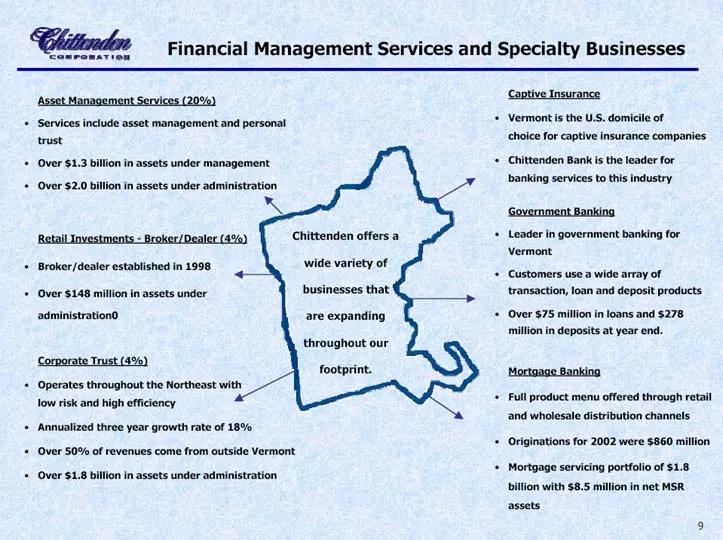
Financial Management Services and Specialty Businesses ‘Captive Insurance ‘Asset Management Services (20%) + Services include asset management and personal + Vermont is the U.S. domicile of trust ‘choice for captive insurance companies + Chittenden Bank is the leader for banking services to this ind
Slide 10: Earnings
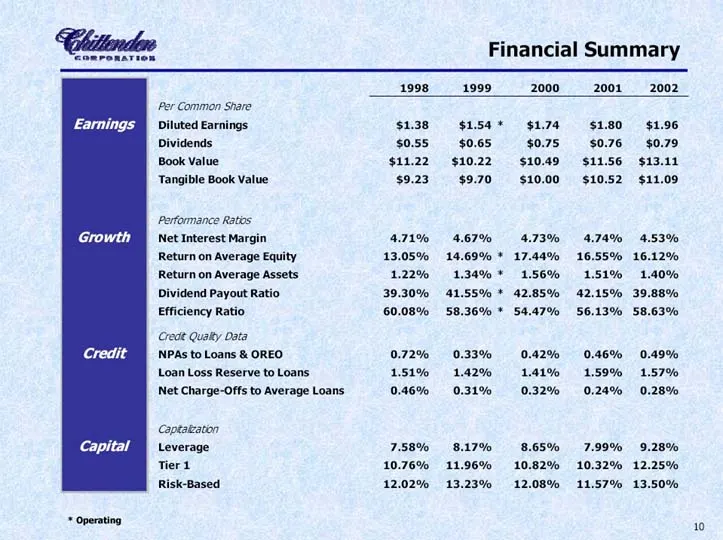
Earnings Tangible Book Value Performance Ratios Net Interest Margin Return on Average Equity Return on Average Assets Creat Quakty Osta NPAs to Loans & OREO Loan Loss Reserve to Loans Net Charge-Offs to Average Loans Coptakaton Leverage Tier. Financial Summary 1998 1999 2000 ~——-2001'_——-2002 $138 $
Slide 11: Consistent Superior Financial Performance
Consistent Superior Financial Performance Strong net interest margin Low cost stable sources of funding Strong fee based revenues in targeted businesses Efficient cost structure Strong capital Conservative reserves and excellent credit quality 1
Slide 12: A Diversified Loan Portfolio
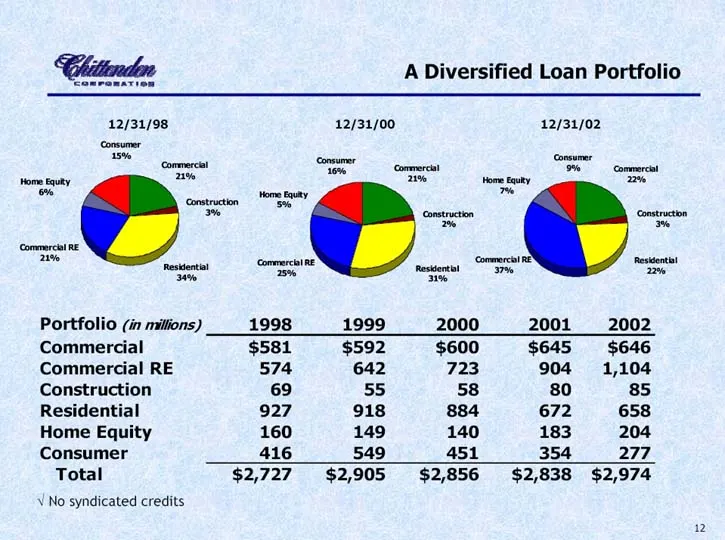
A Diversified Loan Portfolio 12/31/98 12/31/00 12/31/02 consumer 3% : aes ? cong ore katy nw Cie see oz cs oe Sty eS Spo ceee conetrction ‘constructon Comer RE ep Reset eae resent "Sym = “— ies er Portfolio (in mitions) 1998 1999 2000 2001 2002 Commercial $581 $592 $600 $645 $646 Commercial RE 574 6
Slide 13: Loan Composition Remains Well Diversified
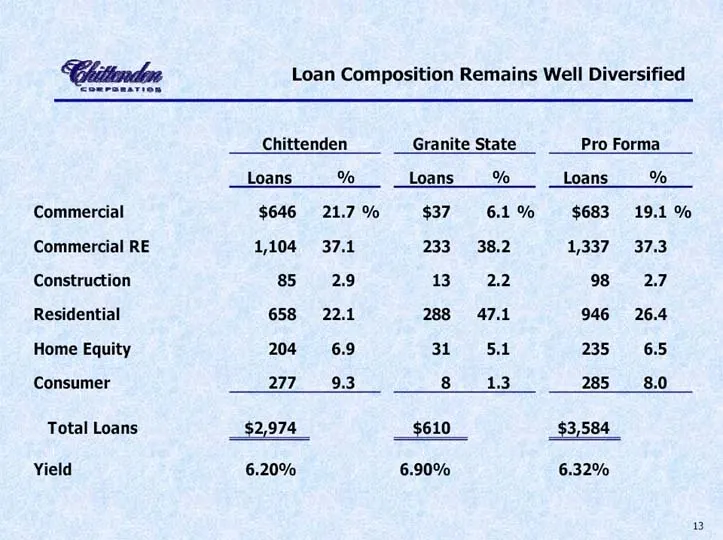
Commercial Commercial RE Construction Residential Home Equity Consumer Total Loans Yield Loan Compo: ion Remains Well Diversified Chittenden Granite State Pro Forma Loans % Loans %o Loans %o $646 21.7 % $37 6.1 % $683 19.1 % 1,104 37.1 233 38.2 1,337 37.3 85 2.9 13 2.2 98 27 658 22.1 288 «(47.1 946
Slide 14: Chittenden Has Maintained Excellent Asset Quality
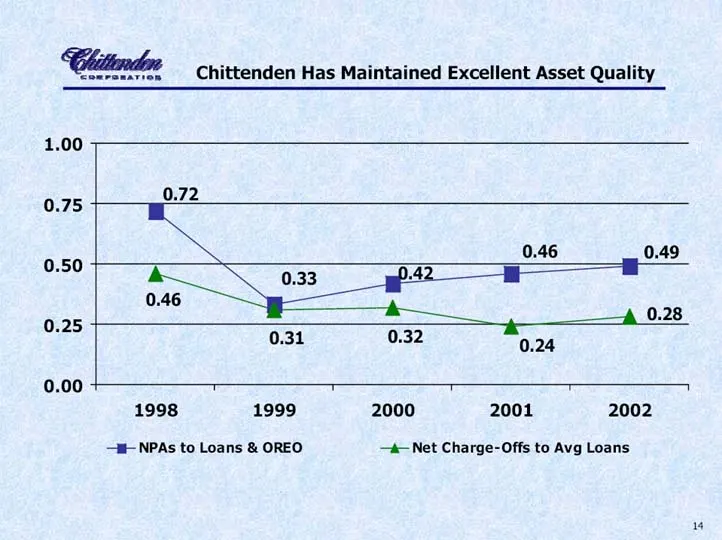
Chittenden Has Maintained Excellent Asset Quality 0.72 Ke 0.46 0.49 0.46 : 0.28 0.31 0.32 0.24 1998 1999 2000 2001 2002 —i- NPAs to Loans & OREO —4—Net Charge-Offs to Avg Loans “4
Slide 15: Granite Has Excellent Asset Quality
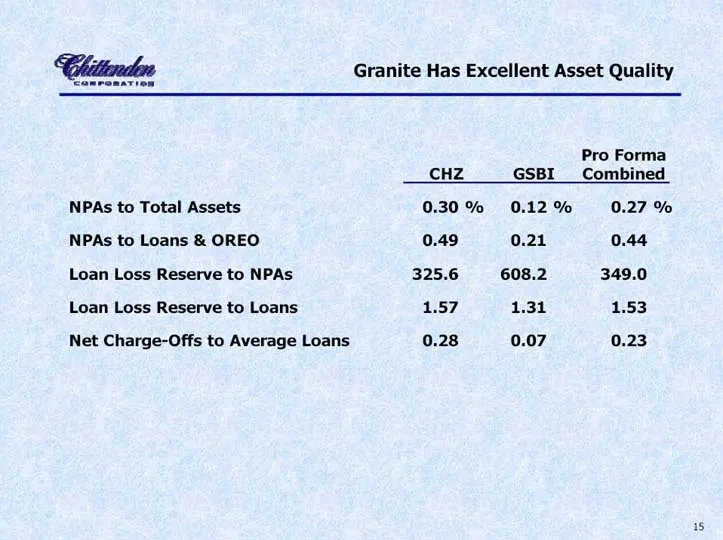
NPAs to Total Assets NPAs to Loans & OREO Loan Loss Reserve to NPAs Loan Loss Reserve to Loans Net Charge-Offs to Average Loans Granite Has Excellent Asset Quality Pro Forma CHZ GSBI__ Combined 0.30% 0.12 % 0.27 % 0.49 0.21 0.44 325.6 608.2 349.0 1.57 1.31 1.53 0.28 0.07 0.23
Slide 16: Strong Core Funding
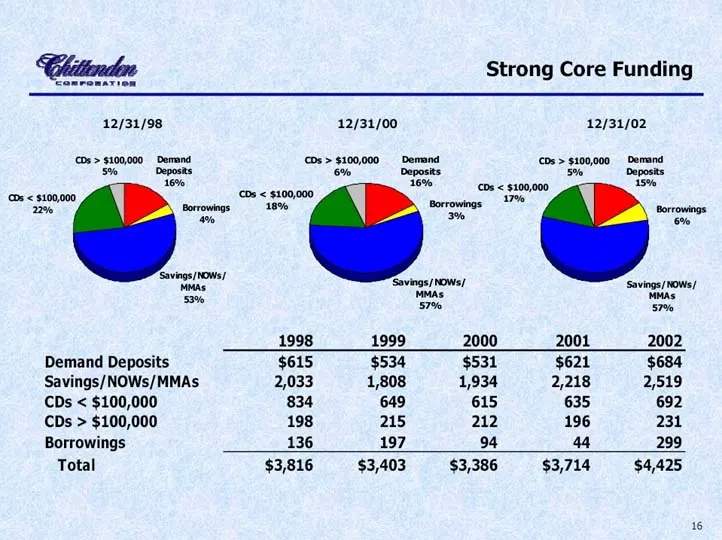
Strong Core Funding 12/31/98 12/31/00 12/31/02 eae toe Sab Sidiee oa cere ee oe = Sa 5 = rata fale i a <0800 ox < 09,000 erence et Bs aati af vogs/ NOW pe ee 1998 1999 2000 2001 2002 Demand Deposits $615 $534 $531 $621 $684 Savings/NOWs/MMAs 2,033 1,808 1,934 2,218 2,519 CDs < $100,000 834 649 615 6
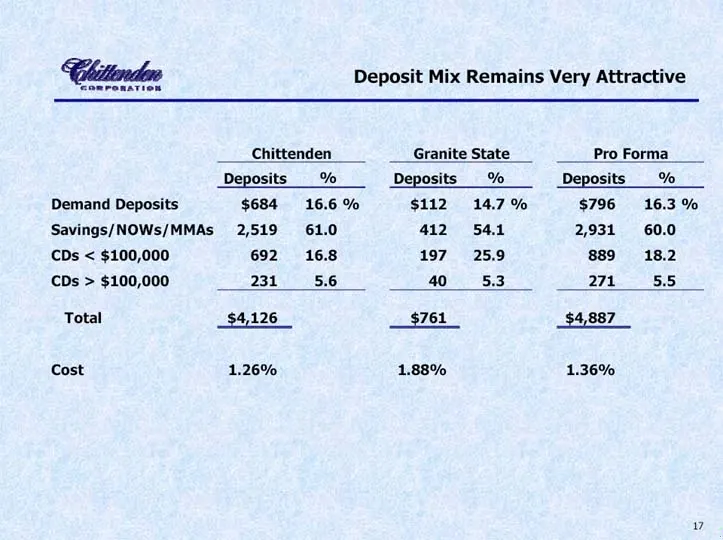
Slide 17: Deposit Mix Remains Very Attractive
Deposit Mix Remains Very Attractive Deposits _% Demand Deposits $112 14.7 % $796 16.3 % Savings/NOWs/MMAs 2,519 61.0 4120 54.1 2,931 60.0 CDs < $100,000 692 16.8 197 25.9 889 18.2 CDs > $100,000 231536! 40 5.3 274 55) Total $4,126 761 4,887 Cost 1.26% 1.88% 1.36% 7
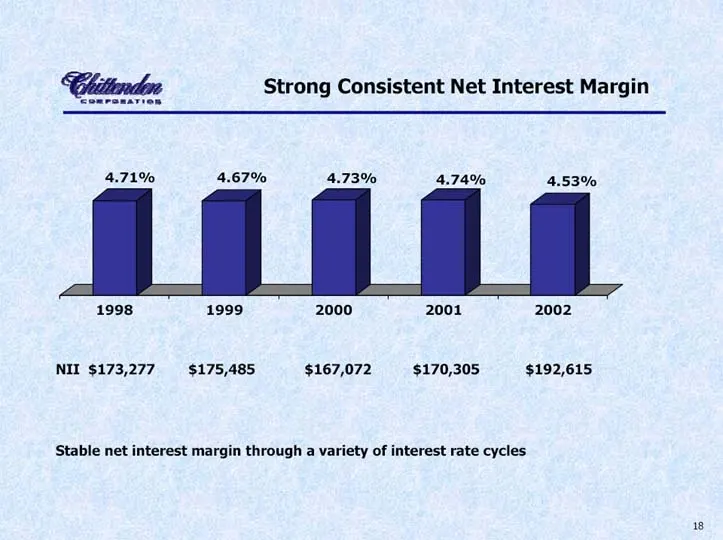
Slide 18: Strong Consistent Net Interest Margin
Strong Consistent Net Interest Margin 4.71% 4.67% 4.73% 4.74% 4.53% 1998 1999 2000 2001 2002 NII $173,277 $175,485 $167,072 $170,305 $192,615 Stable net interest margin through a variety of interest rate cycles 18
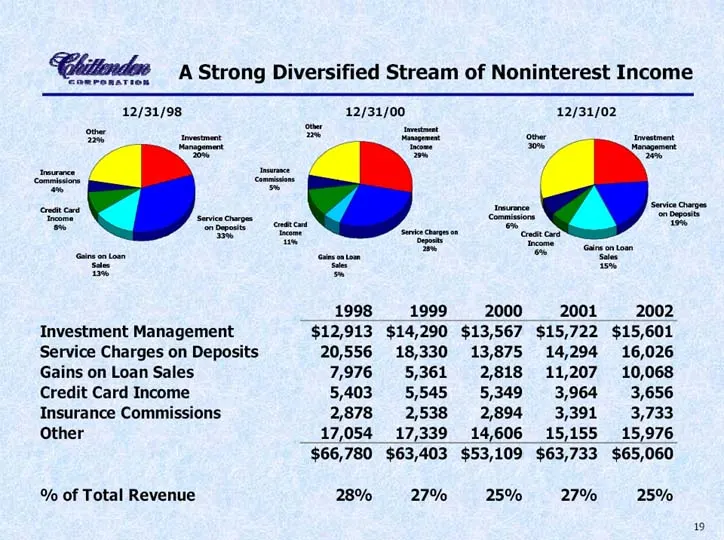
Slide 19: A Strong Diversified Stream of Noninterest Income
Chitindes A Strong Diversified Stream of Noninterest Income 12/31/98 12/31/00 12/31/02 1998 1999 2000 2001 2002 Investment Management $12,913 $14,290 $13,567 $15,722 $15,601 Service Charges on Deposits 20,556 18,330 13,875 14,294 16,026 Gains on Loan Sales 7,976 5,361 2,818 11,207 10,068 Credit Card
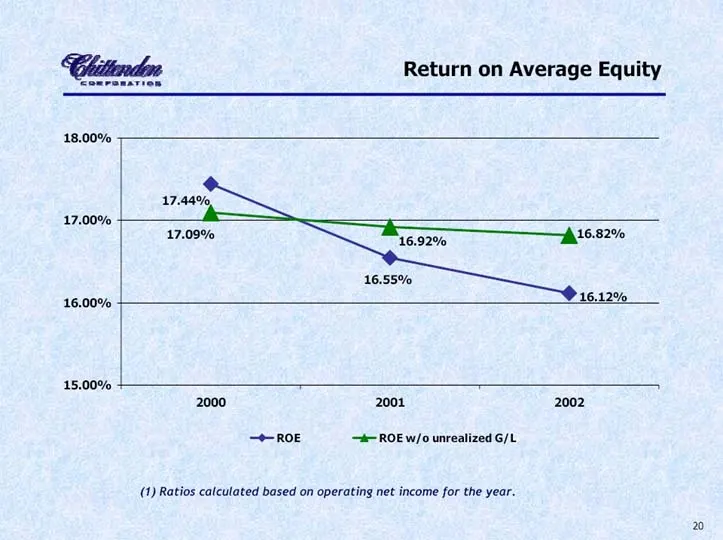
Slide 20: Return on Average Equity
Return on Average Equity 18.00% 17.00% 16.82% 16.00% 16.12% 15.00% 2000 2001 2002 + ROE ROE w/o unrealized G/L (1) Ratios calculated based on operating net income for the year.
Slide 21: A Compelling Story
A Compelling Story Strong market share and a proven acquisition acumen Low risk balance sheet with a prudent growth strategy Diversified banking services with a solid balance of net interest and fee revenues Low exposure to volatile sectors with a fortress balance sheet a
Slide 22: Website and forward-looking statements
CORPORATION Visit our website for a wide range of products, latest financial reports and many other interactive services: www.chittendencorp.com ‘This presentation contains “forward-looking statements” which may deseribe future plans and strategic initiatives. ‘These forward-looking statements are b
Source: SEC EDGAR · 8-K filed Mar 7, 2003
More decks from Chittenden Corp
 Investor Presentation (September 2007)38 slides · Sep 7, 2007
 Merger or Acquisition (June 2007)27 slides · Jun 27, 2007
 Chittenden — Merger or Acquisition (June 2007)25 slides · Jun 27, 2007
 Merger or Acquisition (June 2007)9 slides · Jun 5, 2007
 Investor Presentation (May 2007)36 slides · May 14, 2007
 Investor Presentation (February 2007)37 slides · Feb 16, 2007