Chittenden — Investor Presentation (February 2007)
37 slides from Chittenden's investor presentation, Feb 16, 2007
Slide 1: As of December 31, 2006
Exhibit 99.1 As of December 31, 2006
Slide 2: Who We Are
Who We Are • Multi-bank holding company with significant operating autonomy at the individual banks • Banking assets of $6.4 billion at December 31, 2006 • Listed on the NYSE (CHZ), market capitalization as of December 31, 2006 was $1.4 billion • 121 full service banking offices and 152 ATM location
Slide 3: A Tradition of Success
A Tradition of Success Recognized competency in an attractive business mix Deep relationships with worthwhile customers Conservative underwriting standards and disciplined lending Efficient generator of low cost stable deposits Proven leadership focus to achieve superior financial results Well-estab
Slide 4: Our Target Markets
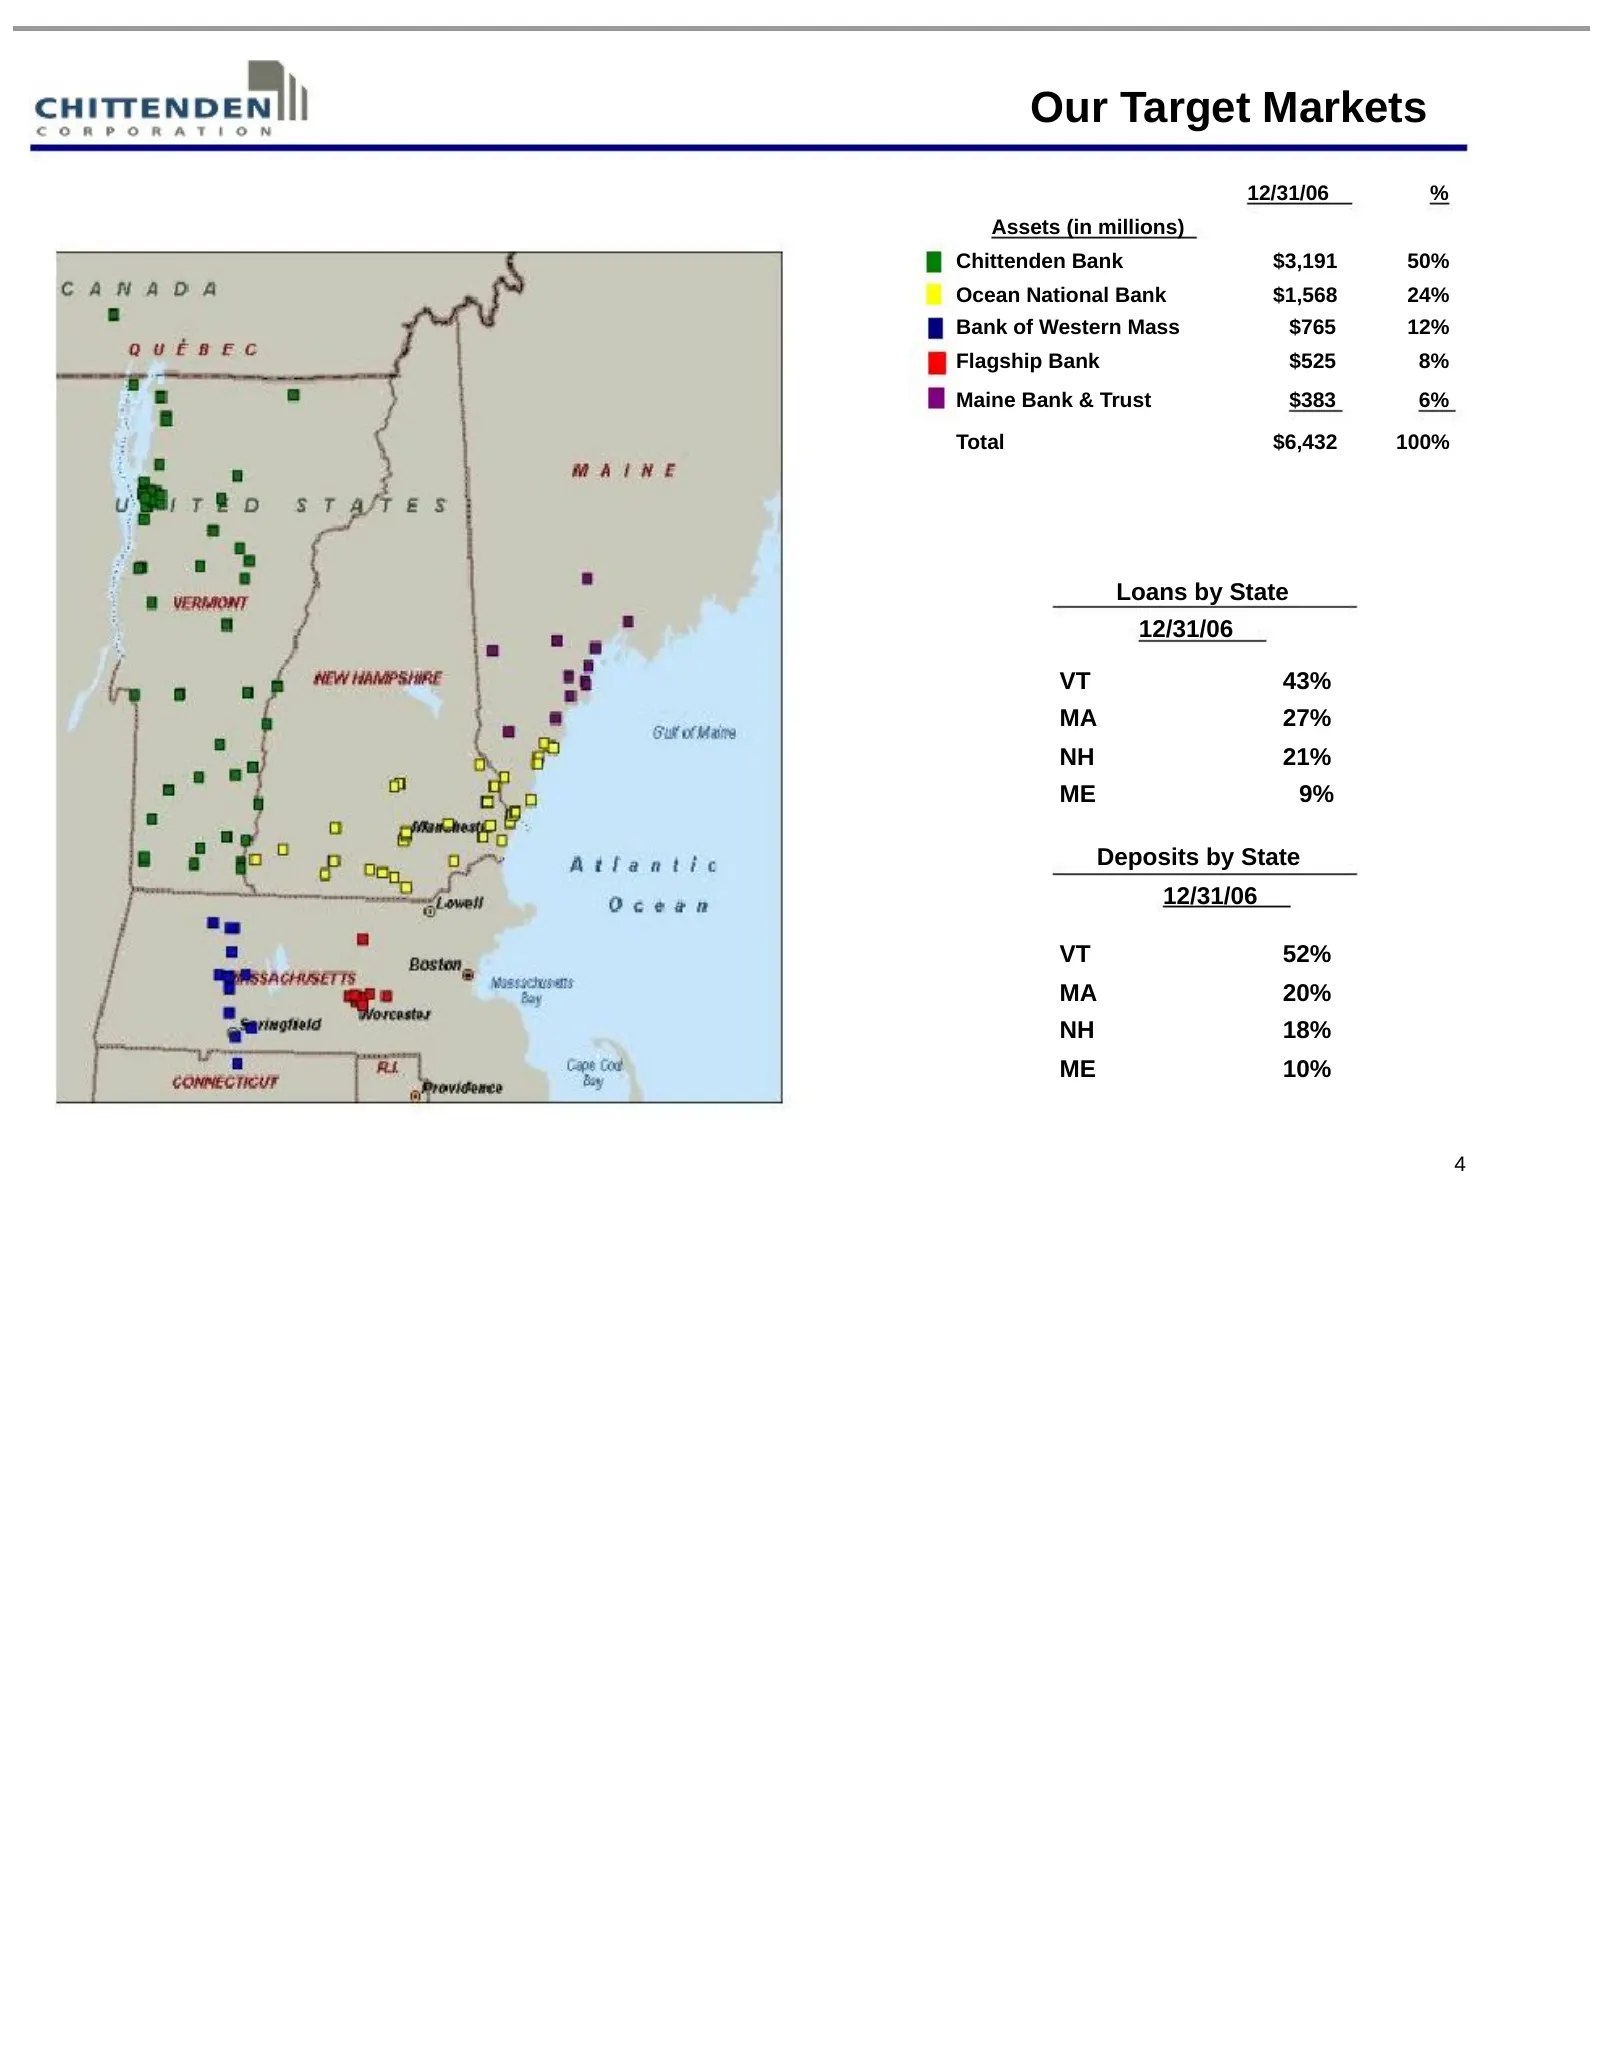
Our Target Markets 12/31/06 % Assets (in millions) Chittenden Bank $3,191 50% Ocean National Bank $1,568 24% Bank of Western Mass $765 12% Flagship Bank $525 8% Maine Bank & Trust $383 6% Total $6,432 100% Loans by State 12/31/06 VT 43% MA 27% NH 21% ME 9% Deposits by State 12/31/06 VT 52% MA 20% NH
Slide 5: Corporate Structure
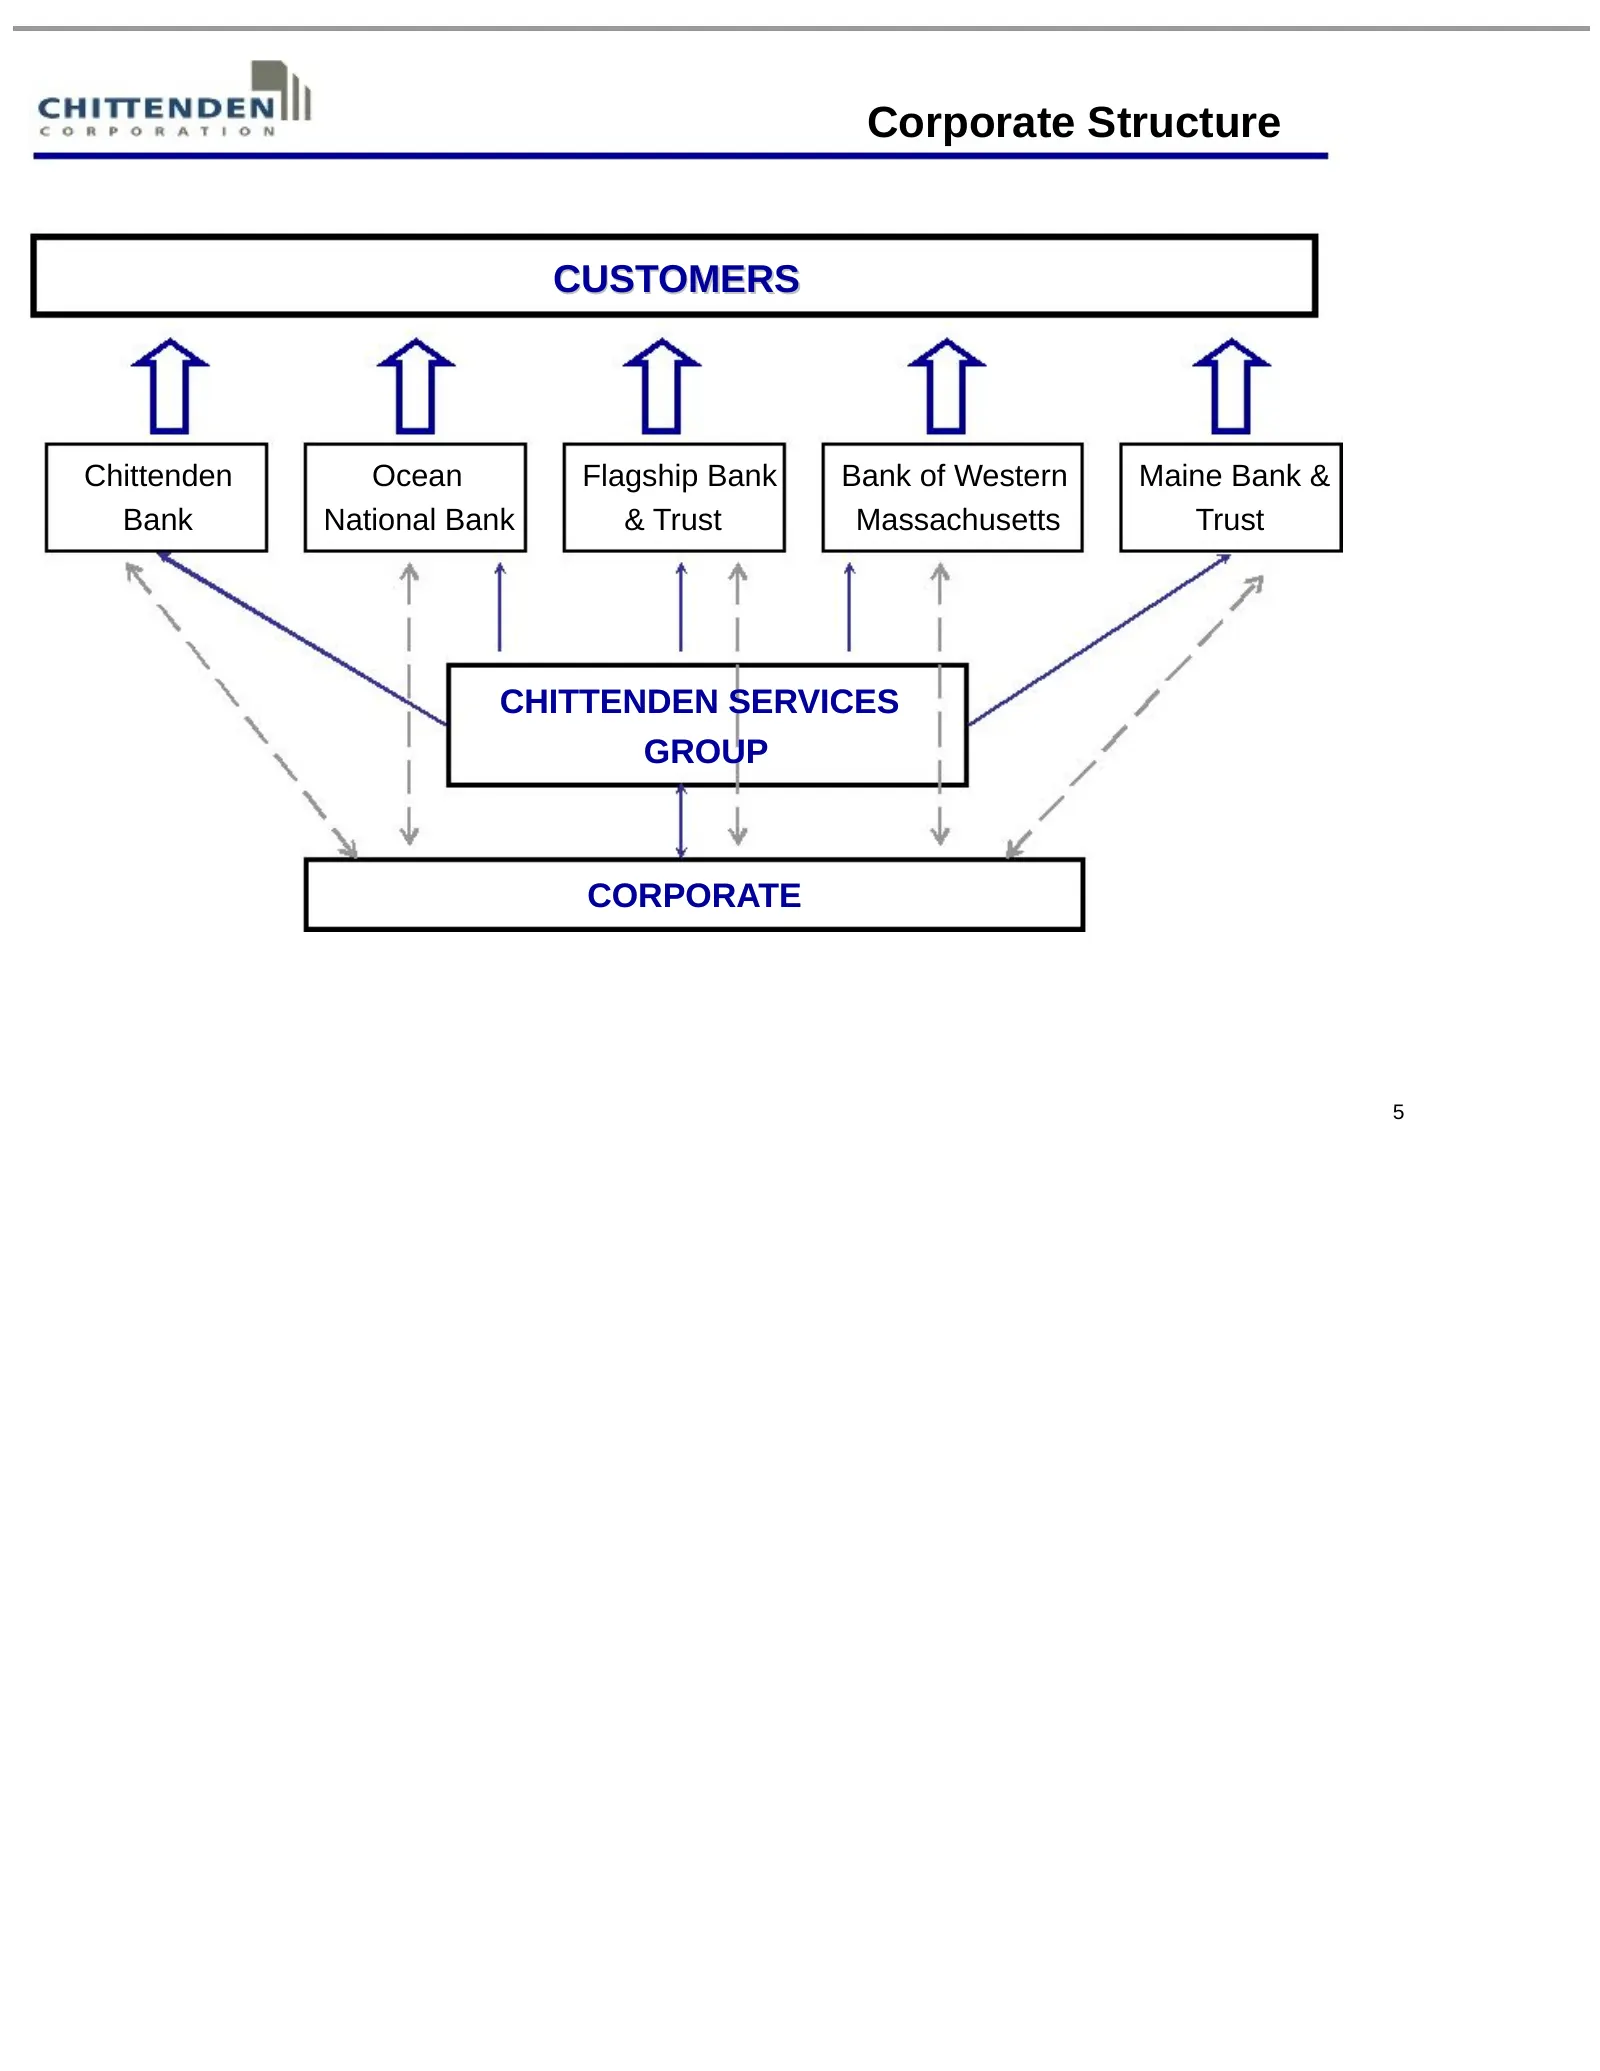
Corporate Structure CUSTOMERS Chittenden Ocean Flagship Bank Bank of Western Maine Bank & Bank National Bank & Trust Massachusetts Trust CHITTENDEN SERVICES GROUP CORPORATE 5
Slide 6: Our Target Markets: Vermont Market
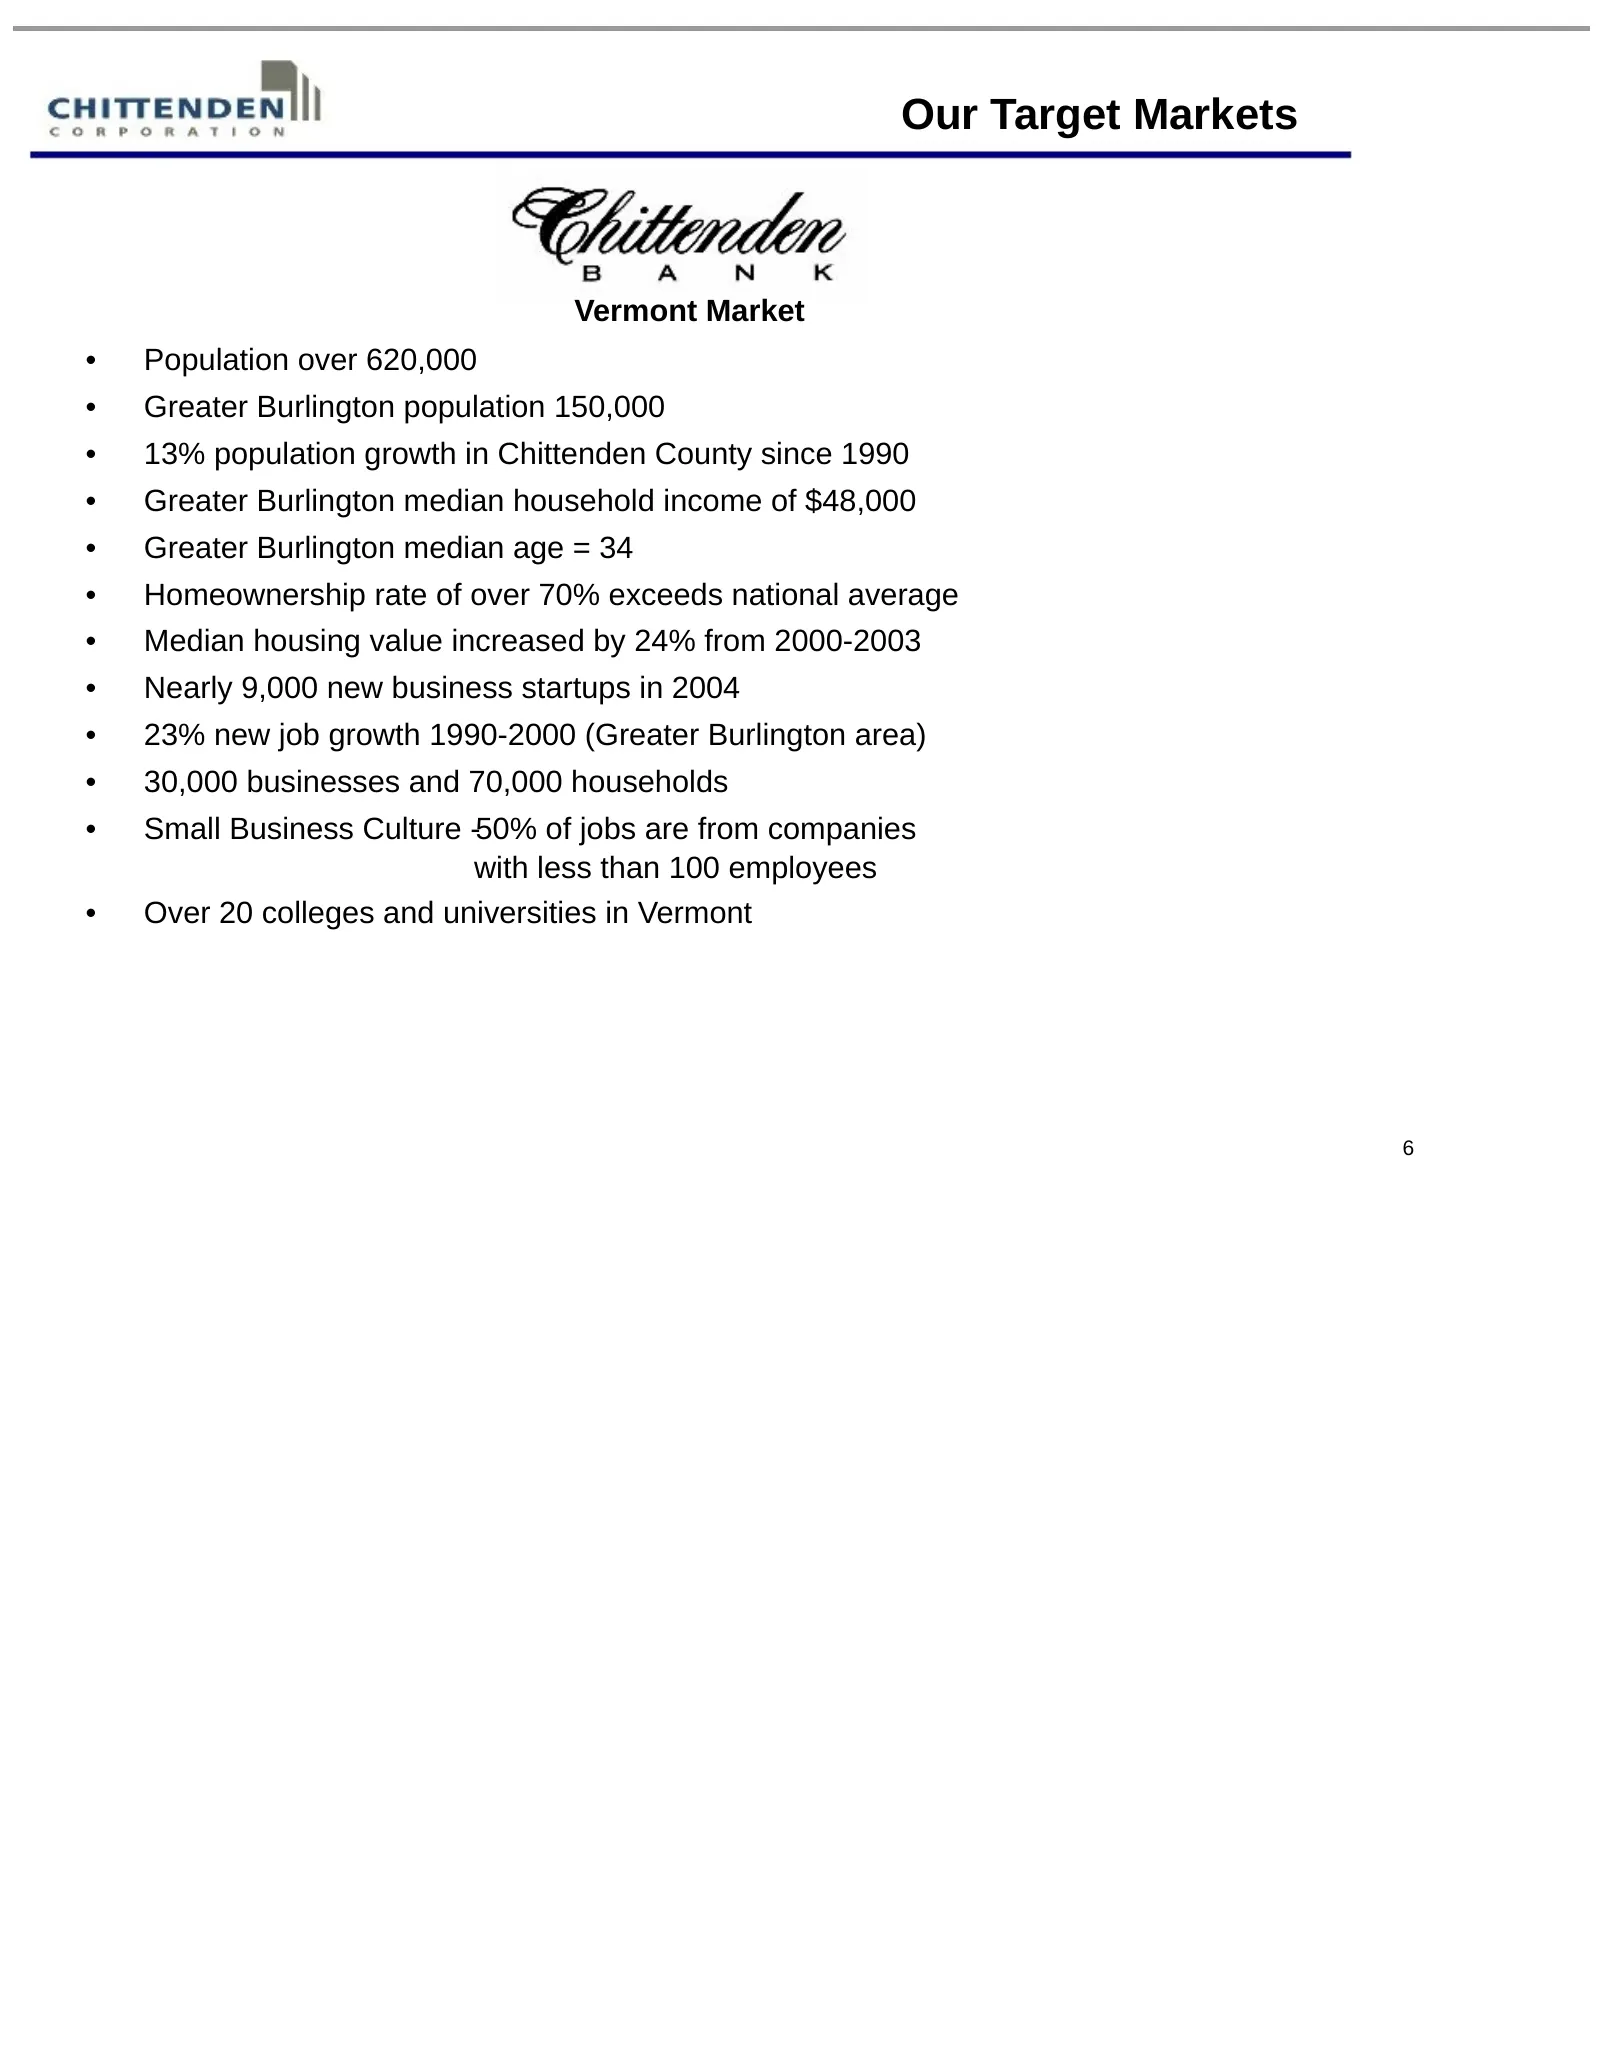
Our Target Markets Vermont Market • Population over 620,000 • Greater Burlington population 150,000 • 13% population growth in Chittenden County since 1990 • Greater Burlington median household income of $48,000 • Greater Burlington median age = 34 • Homeownership rate of over 70% exceeds national a
Slide 7: Our Target Markets: Springfield and Worcester
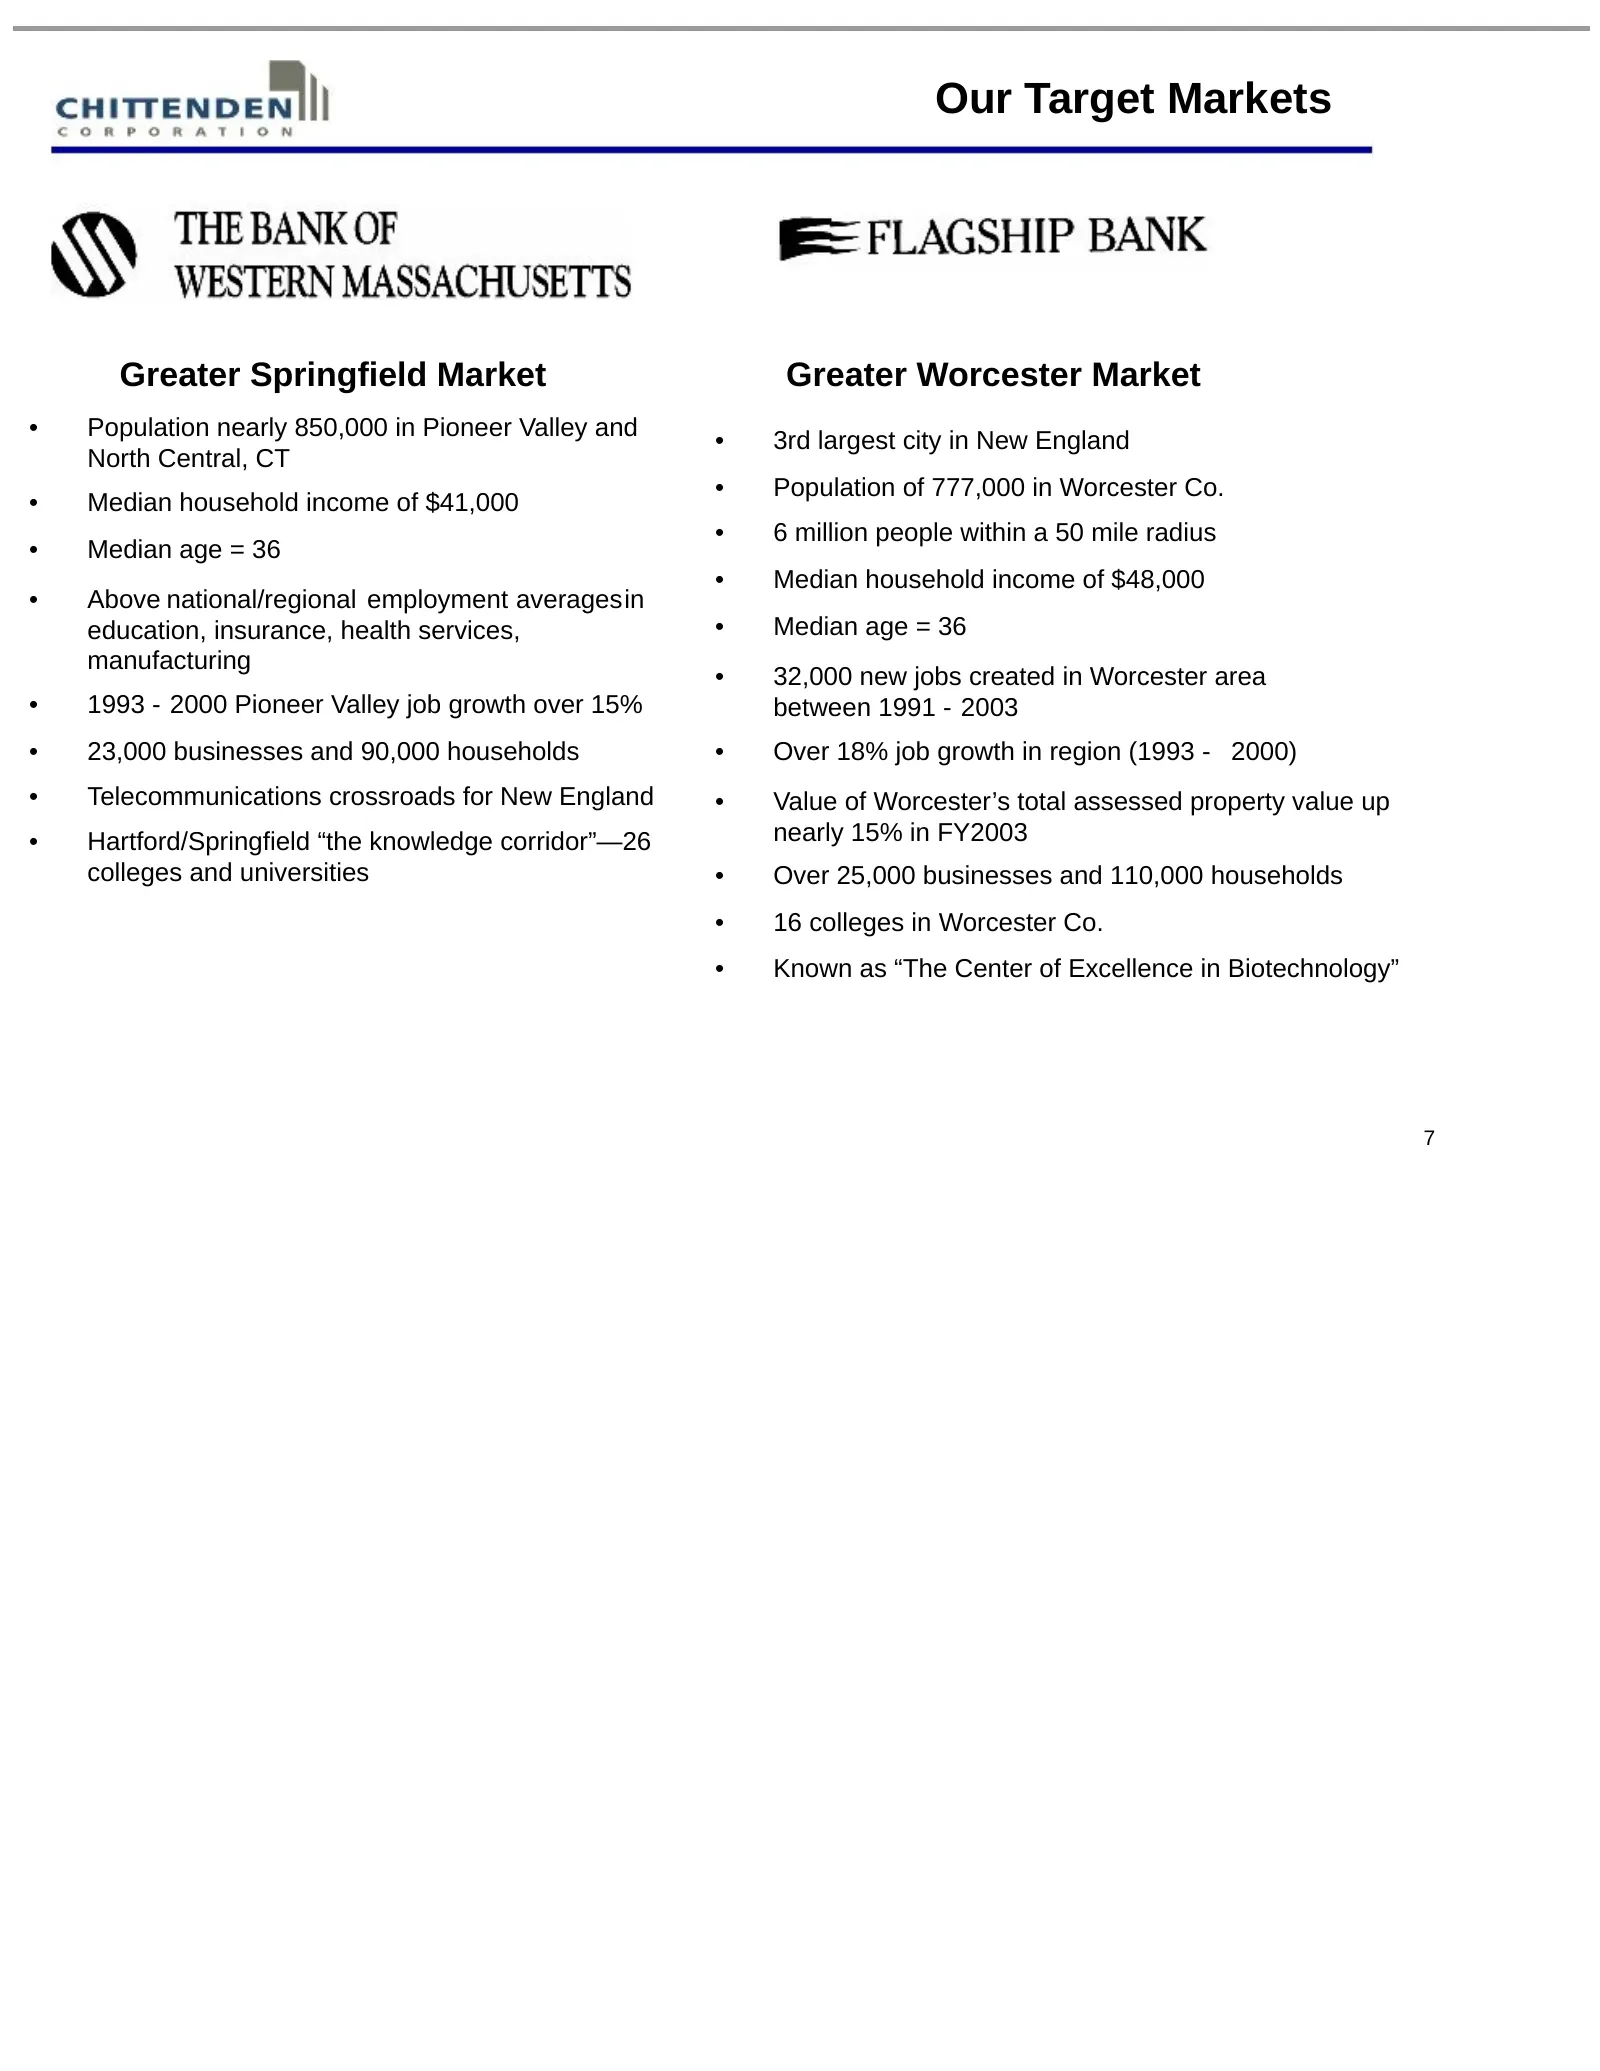
Our Target Markets Greater Springfield Market Greater Worcester Market • Population nearly 850,000 in Pioneer Valley and • 3rd largest city in New England North Central, CT • Population of 777,000 in Worcester Co. • Median household income of $41,000 • 6 million people within a 50 mile radius • Medi
Slide 8: Our Target Markets: Southern NH and Portland
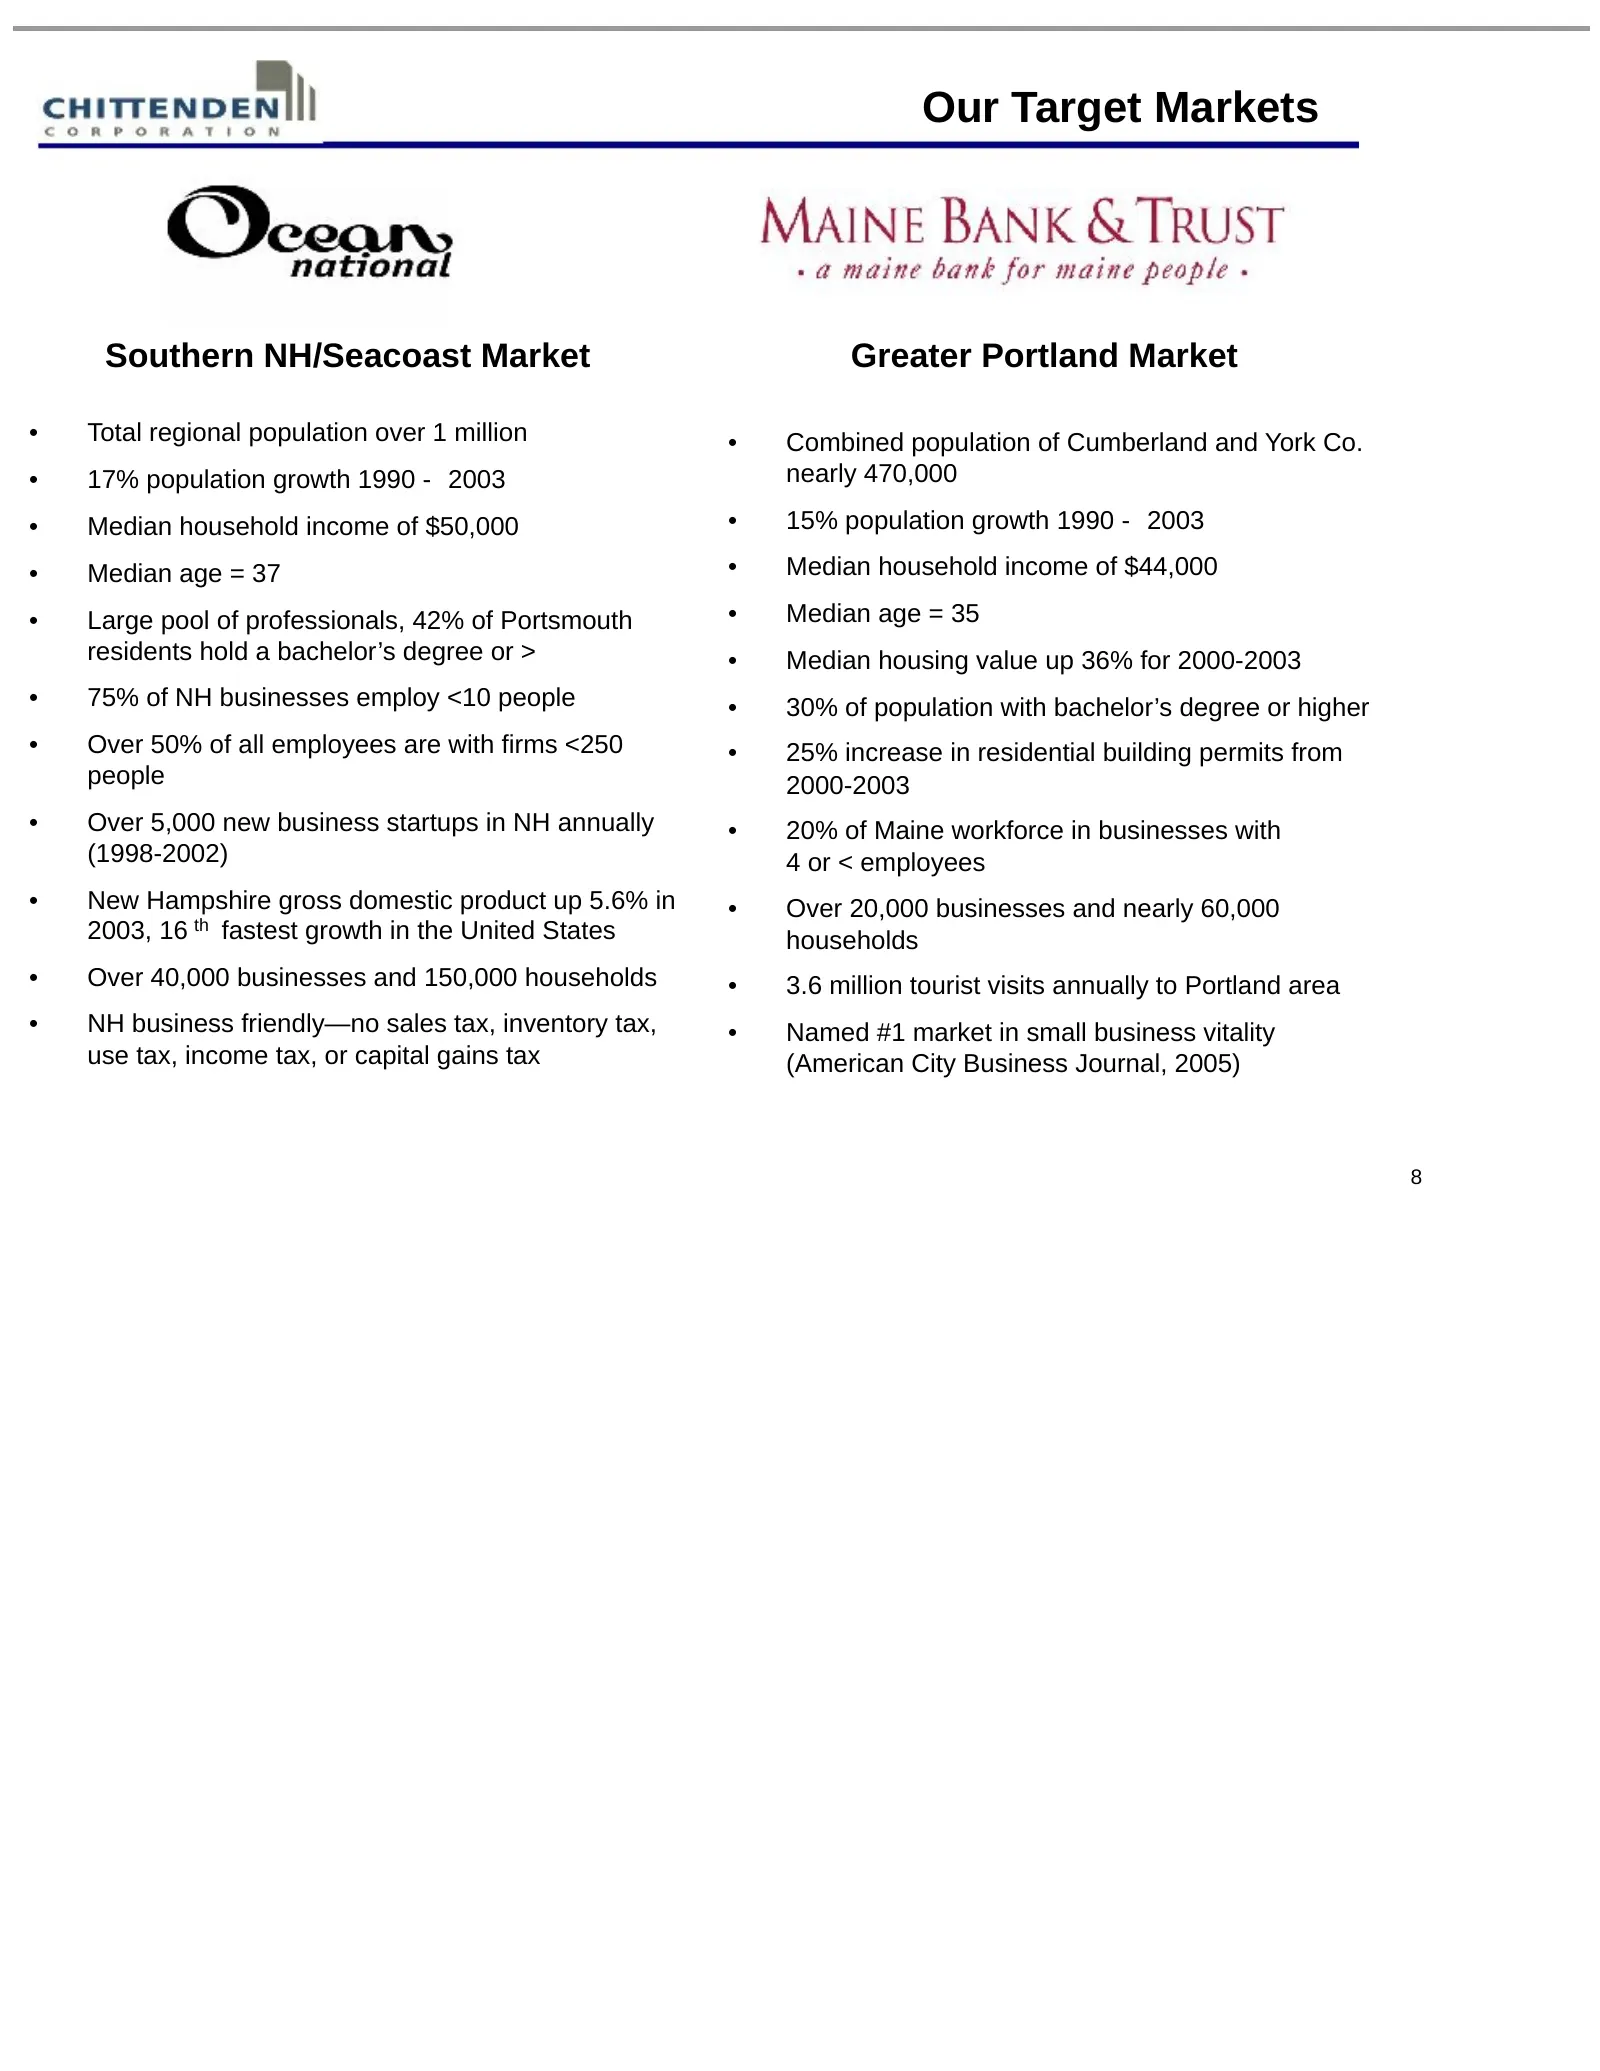
Our Target Markets Southern NH/Seacoast Market Greater Portland Market • Total regional population over 1 million • Combined population of Cumberland and York Co. • 17% population growth 1990 - 2003 nearly 470,000 • Median household income of $50,000 • 15% population growth 1990 - 2003 • Median age
Slide 9: Our Target Customers
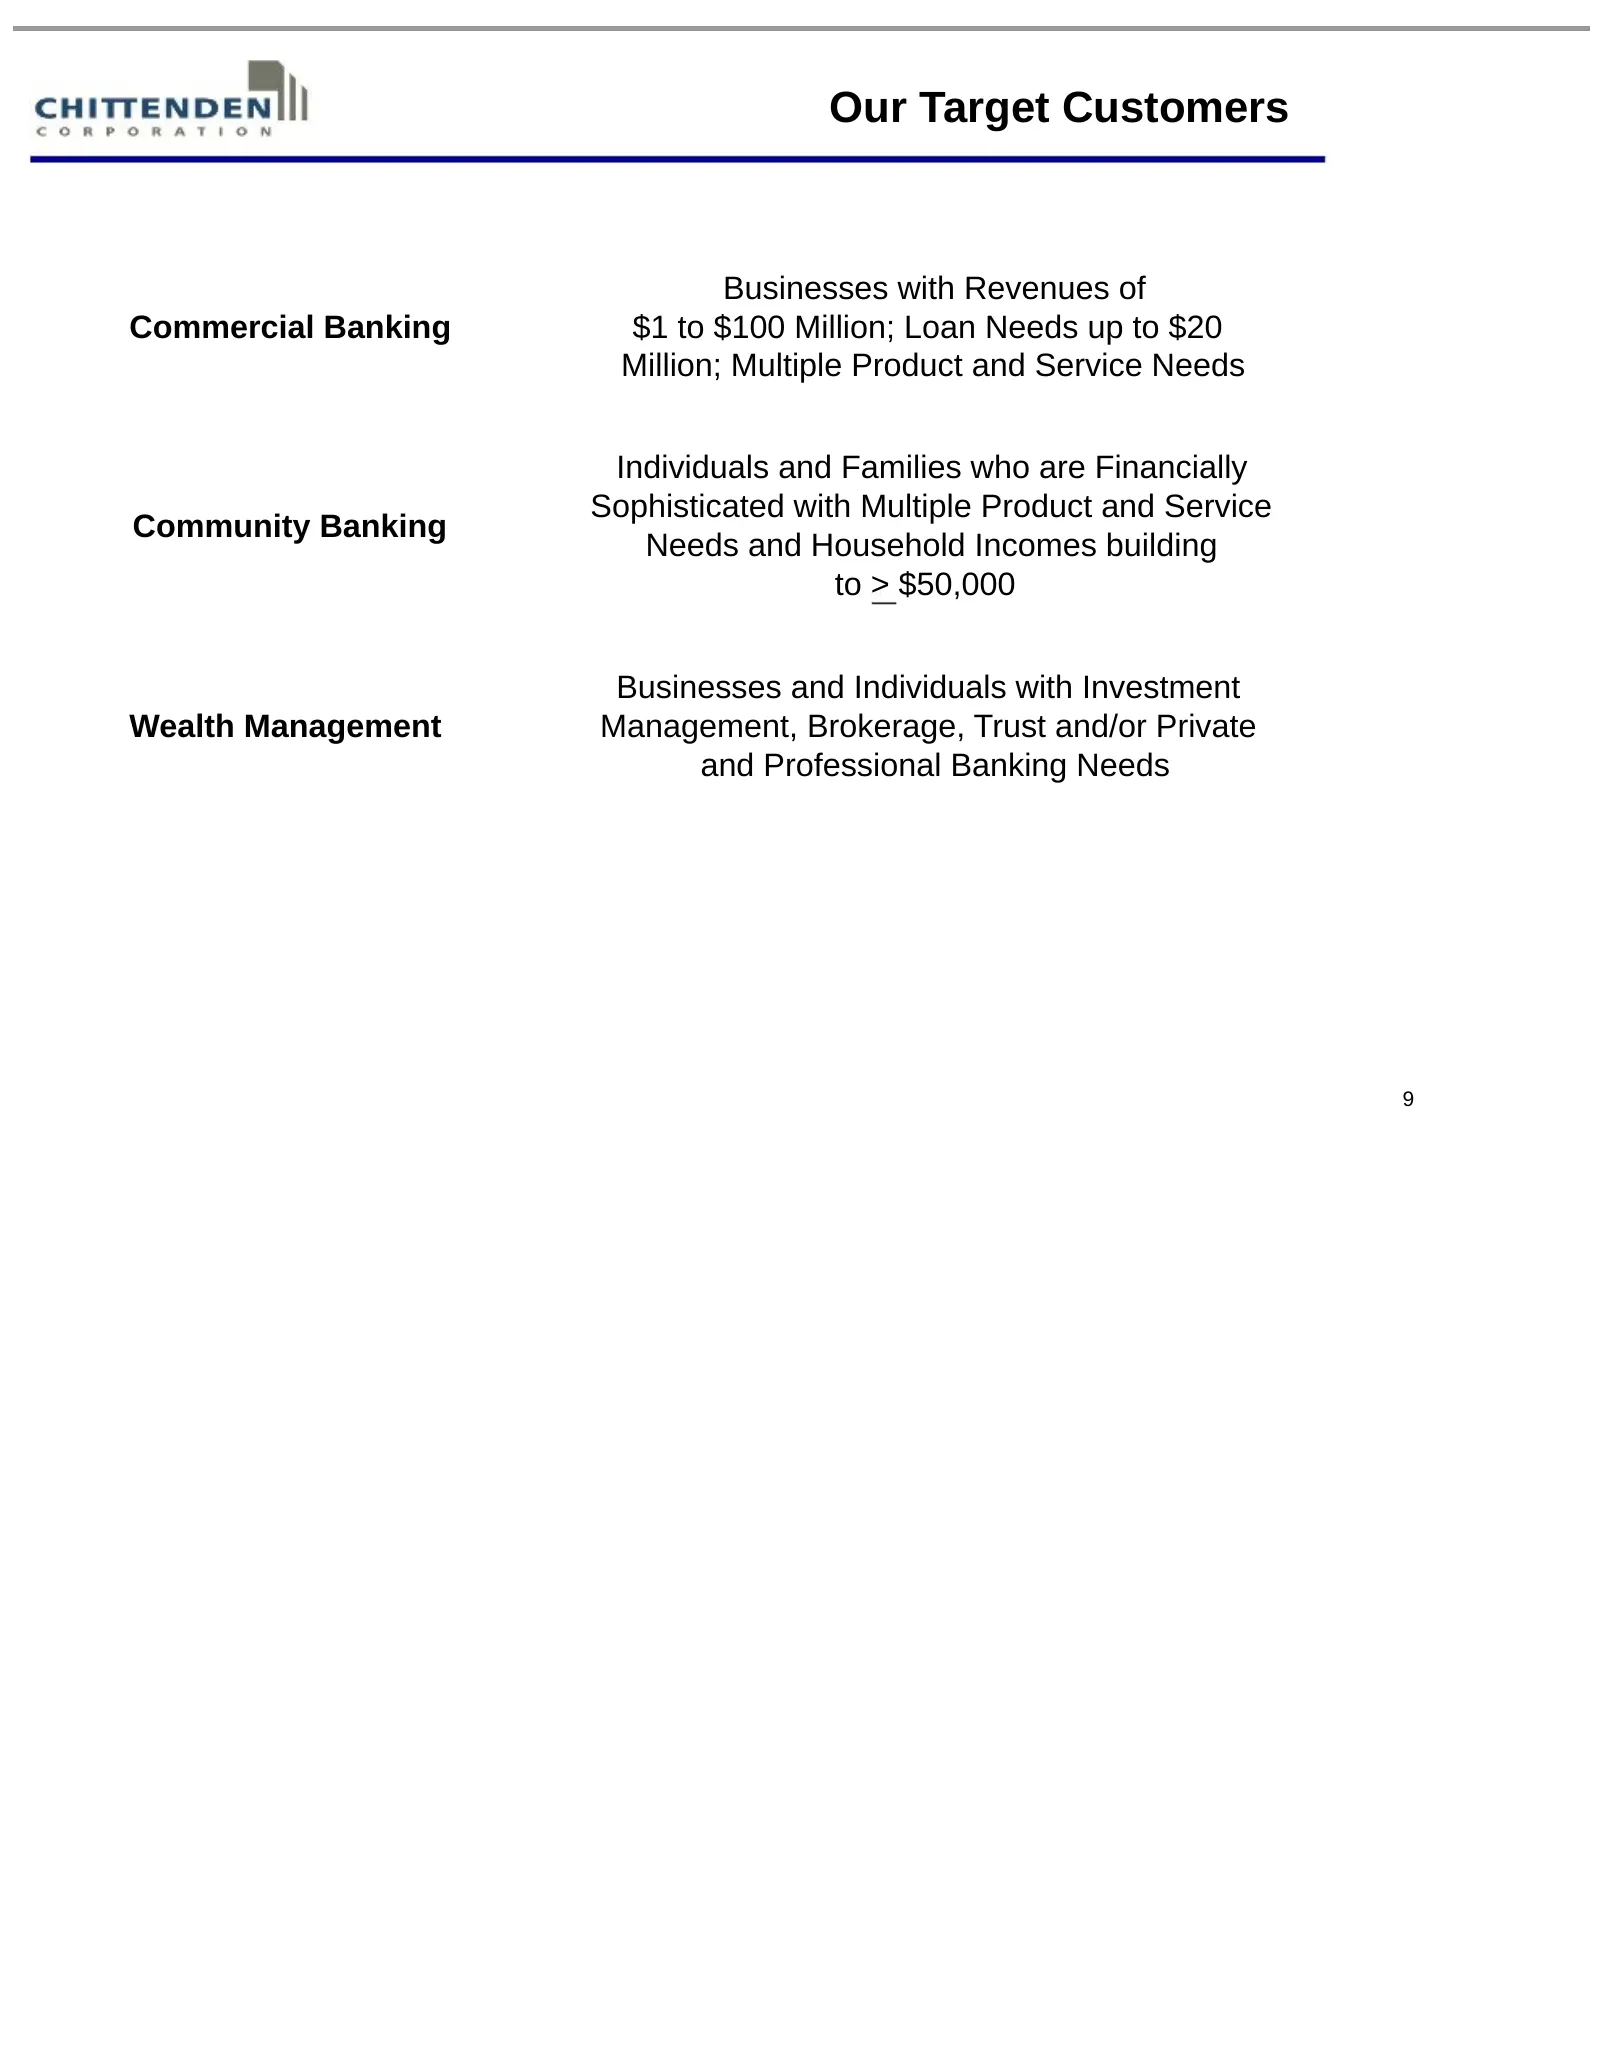
Our Target Customers Businesses with Revenues of Commercial Banking $1 to $100 Million; Loan Needs up to $20 Million; Multiple Product and Service Needs Individuals and Families who are Financially Sophisticated with Multiple Product and Service Community Banking Needs and Household Incomes building
Slide 10: Commercial & Community Banking
Commercial & Community Banking 10
Slide 11: A Diversified Loan Portfolio
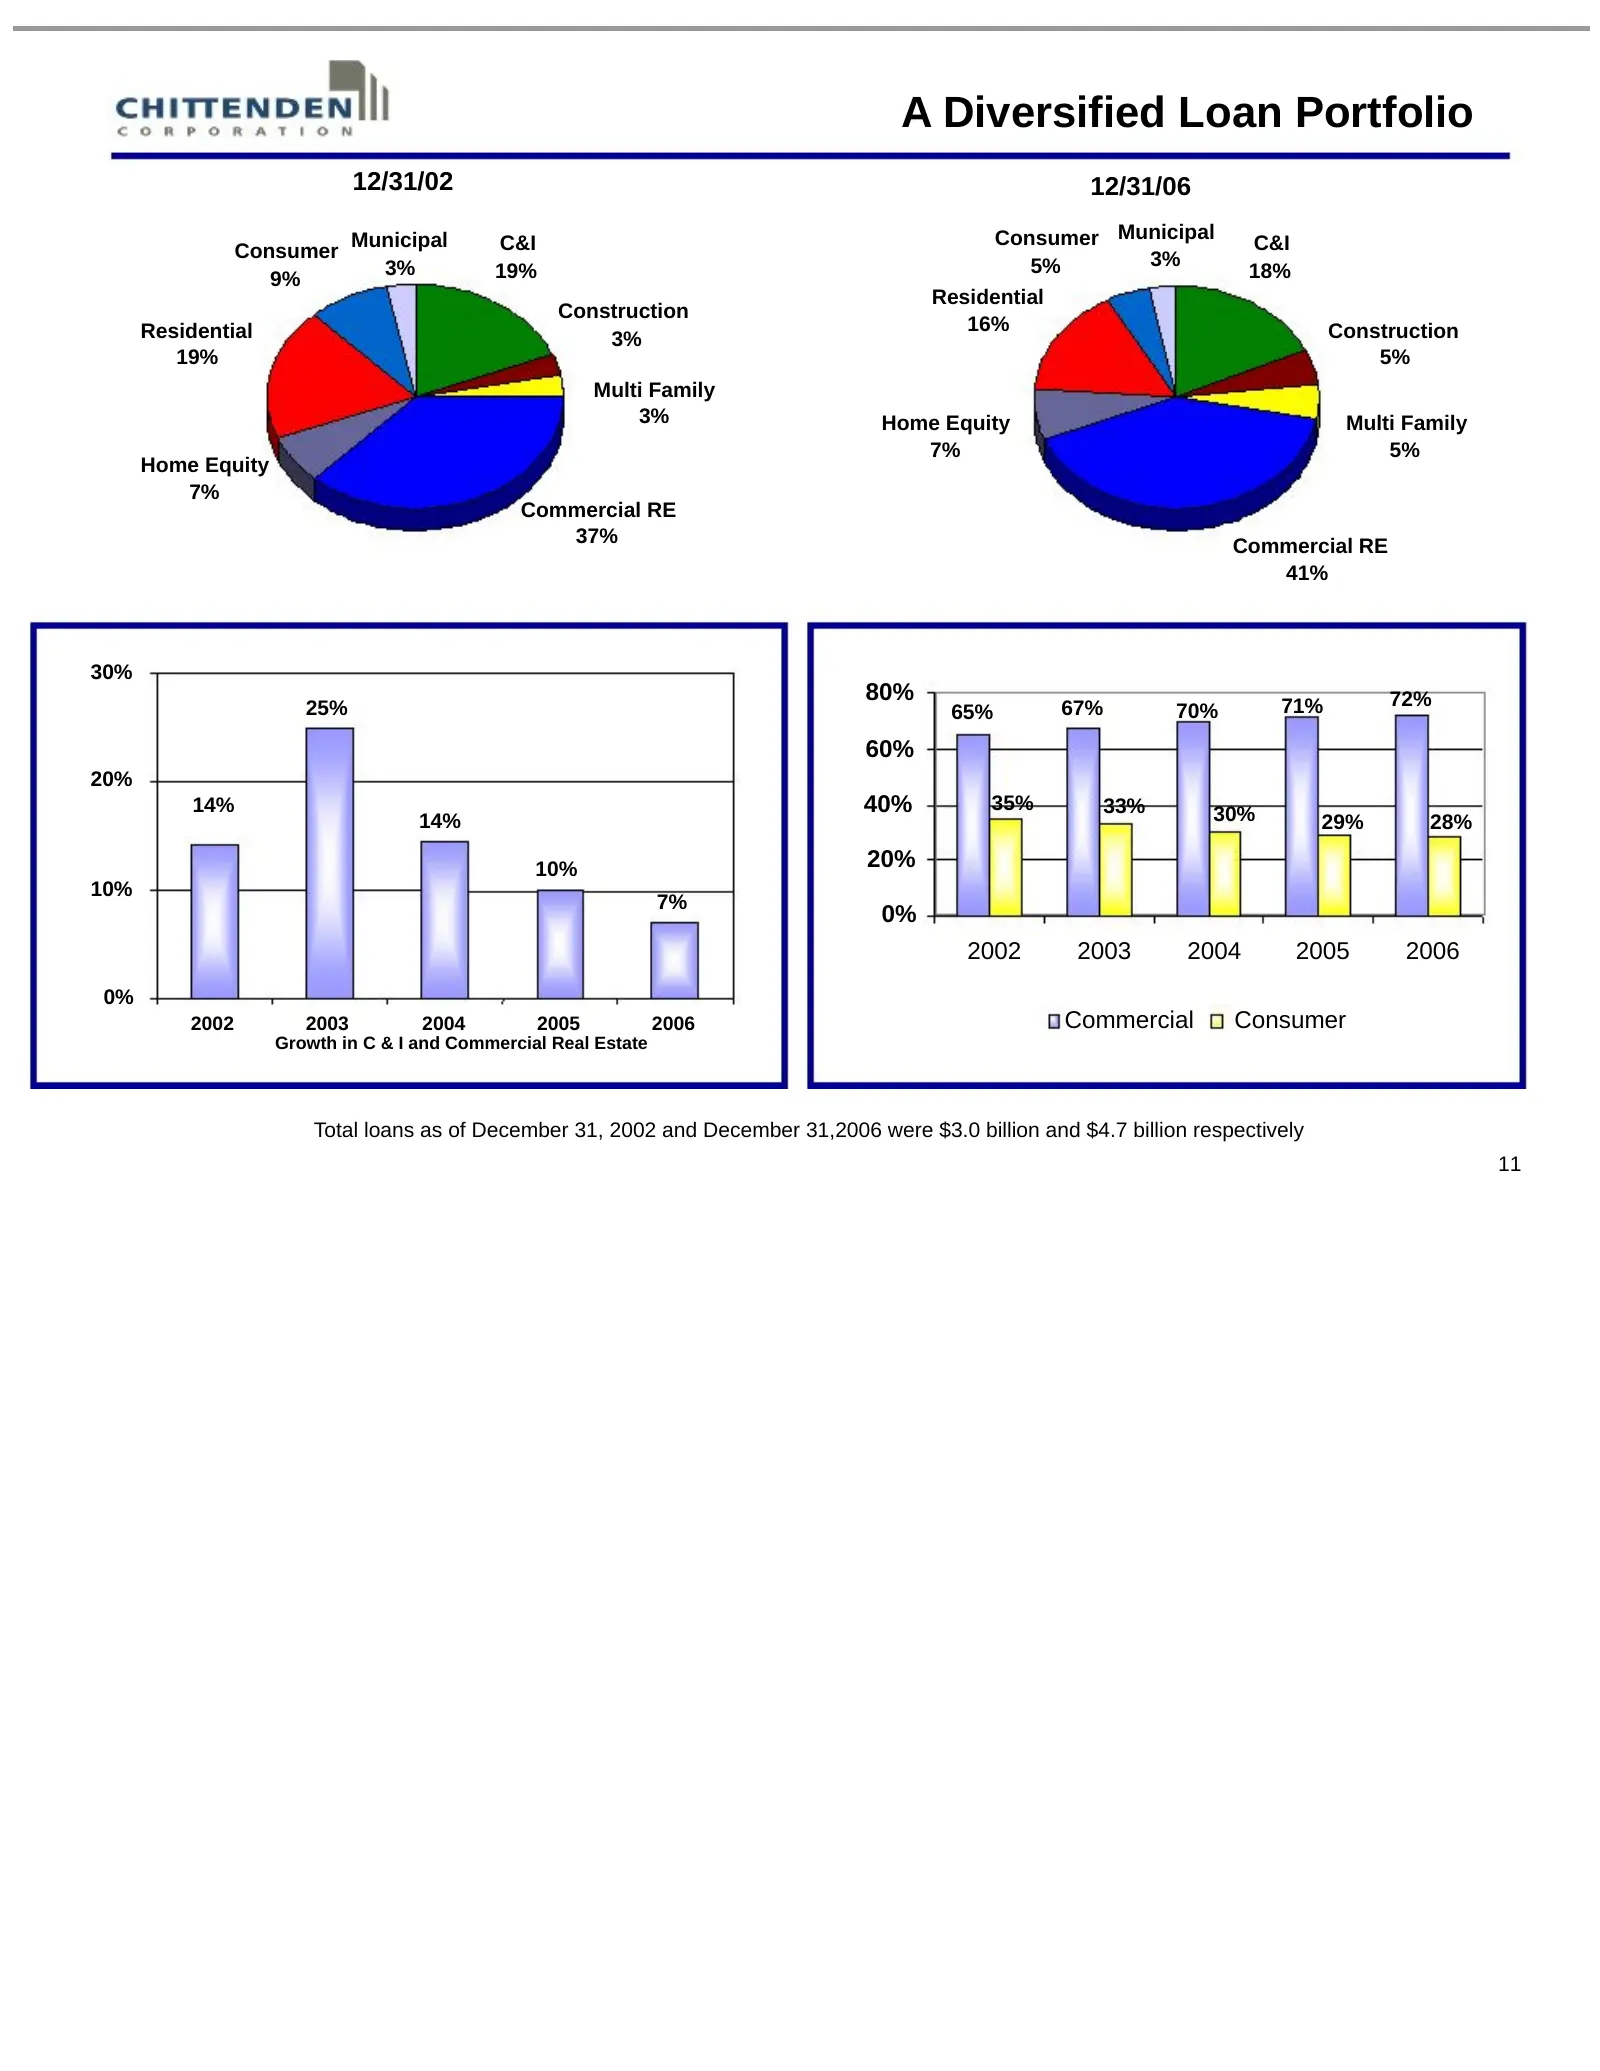
A Diversified Loan Portfolio 12/31/02 12/31/06 Municipal C&I Consumer Municipal C&I Consumer 3% 3% 19% 5% 18% 9% Residential Construction Residential 16% Construction 3% 19% 5% Multi Family 3% Home Equity Multi Family 7% 5% Home Equity 7% Commercial RE 37% Commercial RE 41% 30% 80% 72% 25% 65% 67% 7
Slide 12: Commercial Loan Diversification by Industry
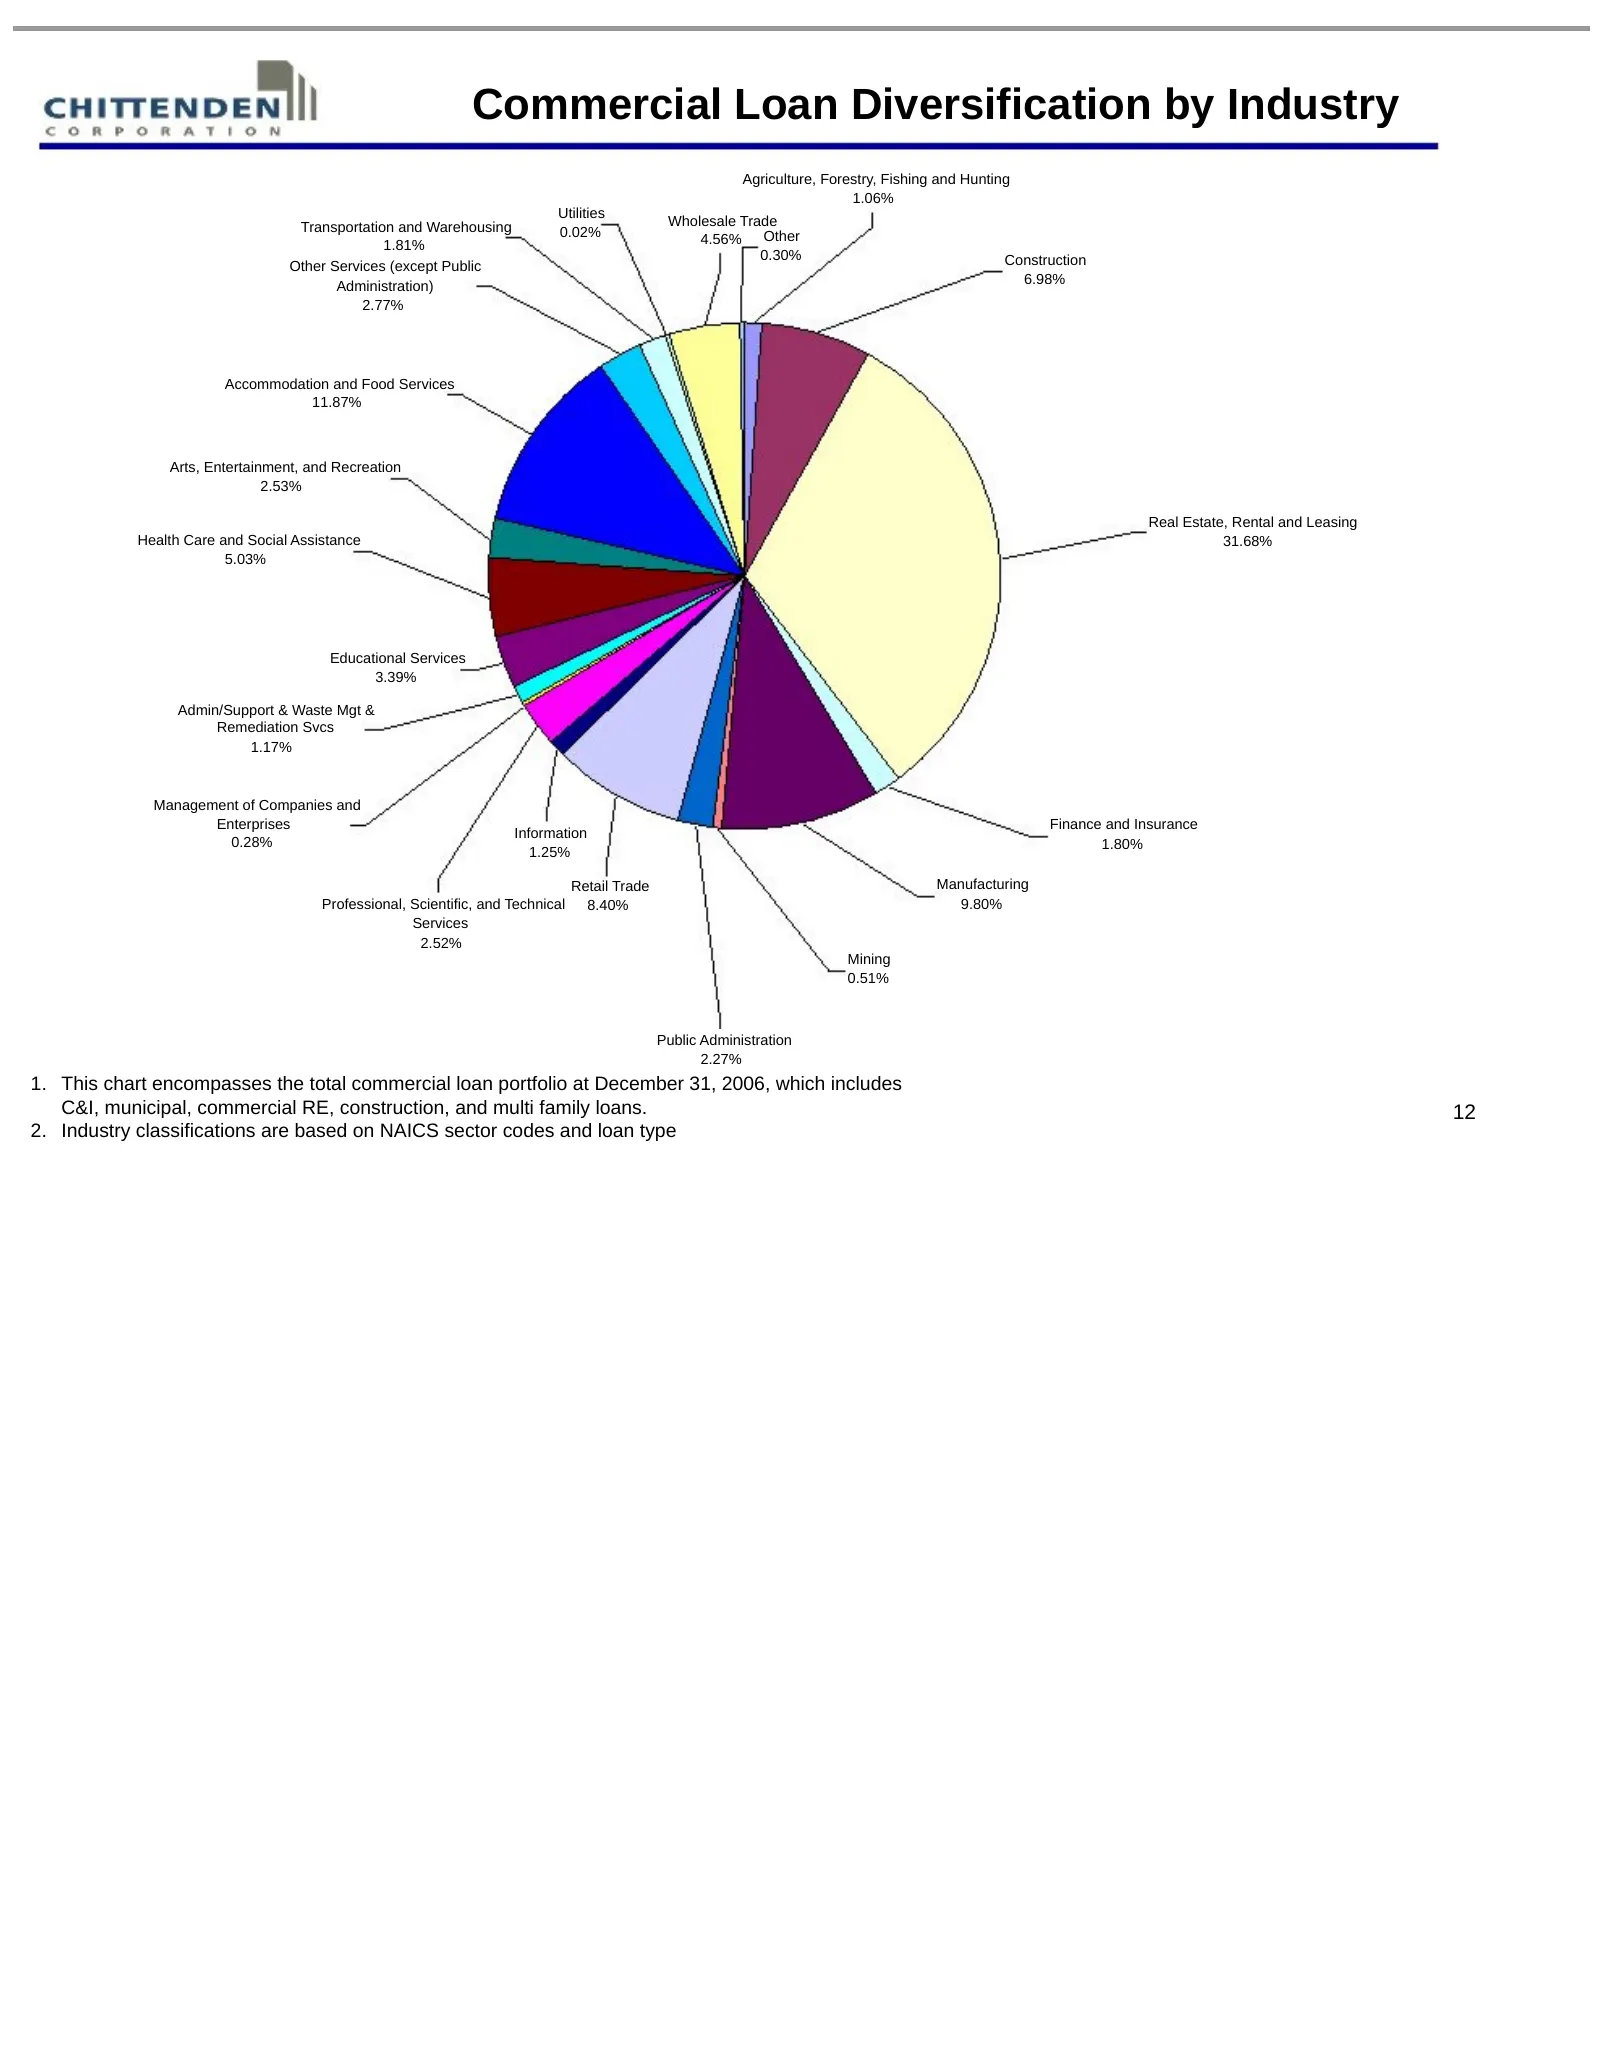
Commercial Loan Diversification by Industry Agriculture, Forestry, Fishing and Hunting 1.06% Utilities Transportation and Warehousing Wholesale Trade 0.02% 4.56% Other 1.81% 0.30% Construction Other Services (except Public Administration) 6.98% 2.77% Accommodation and Food Services 11.87% Arts, Ente
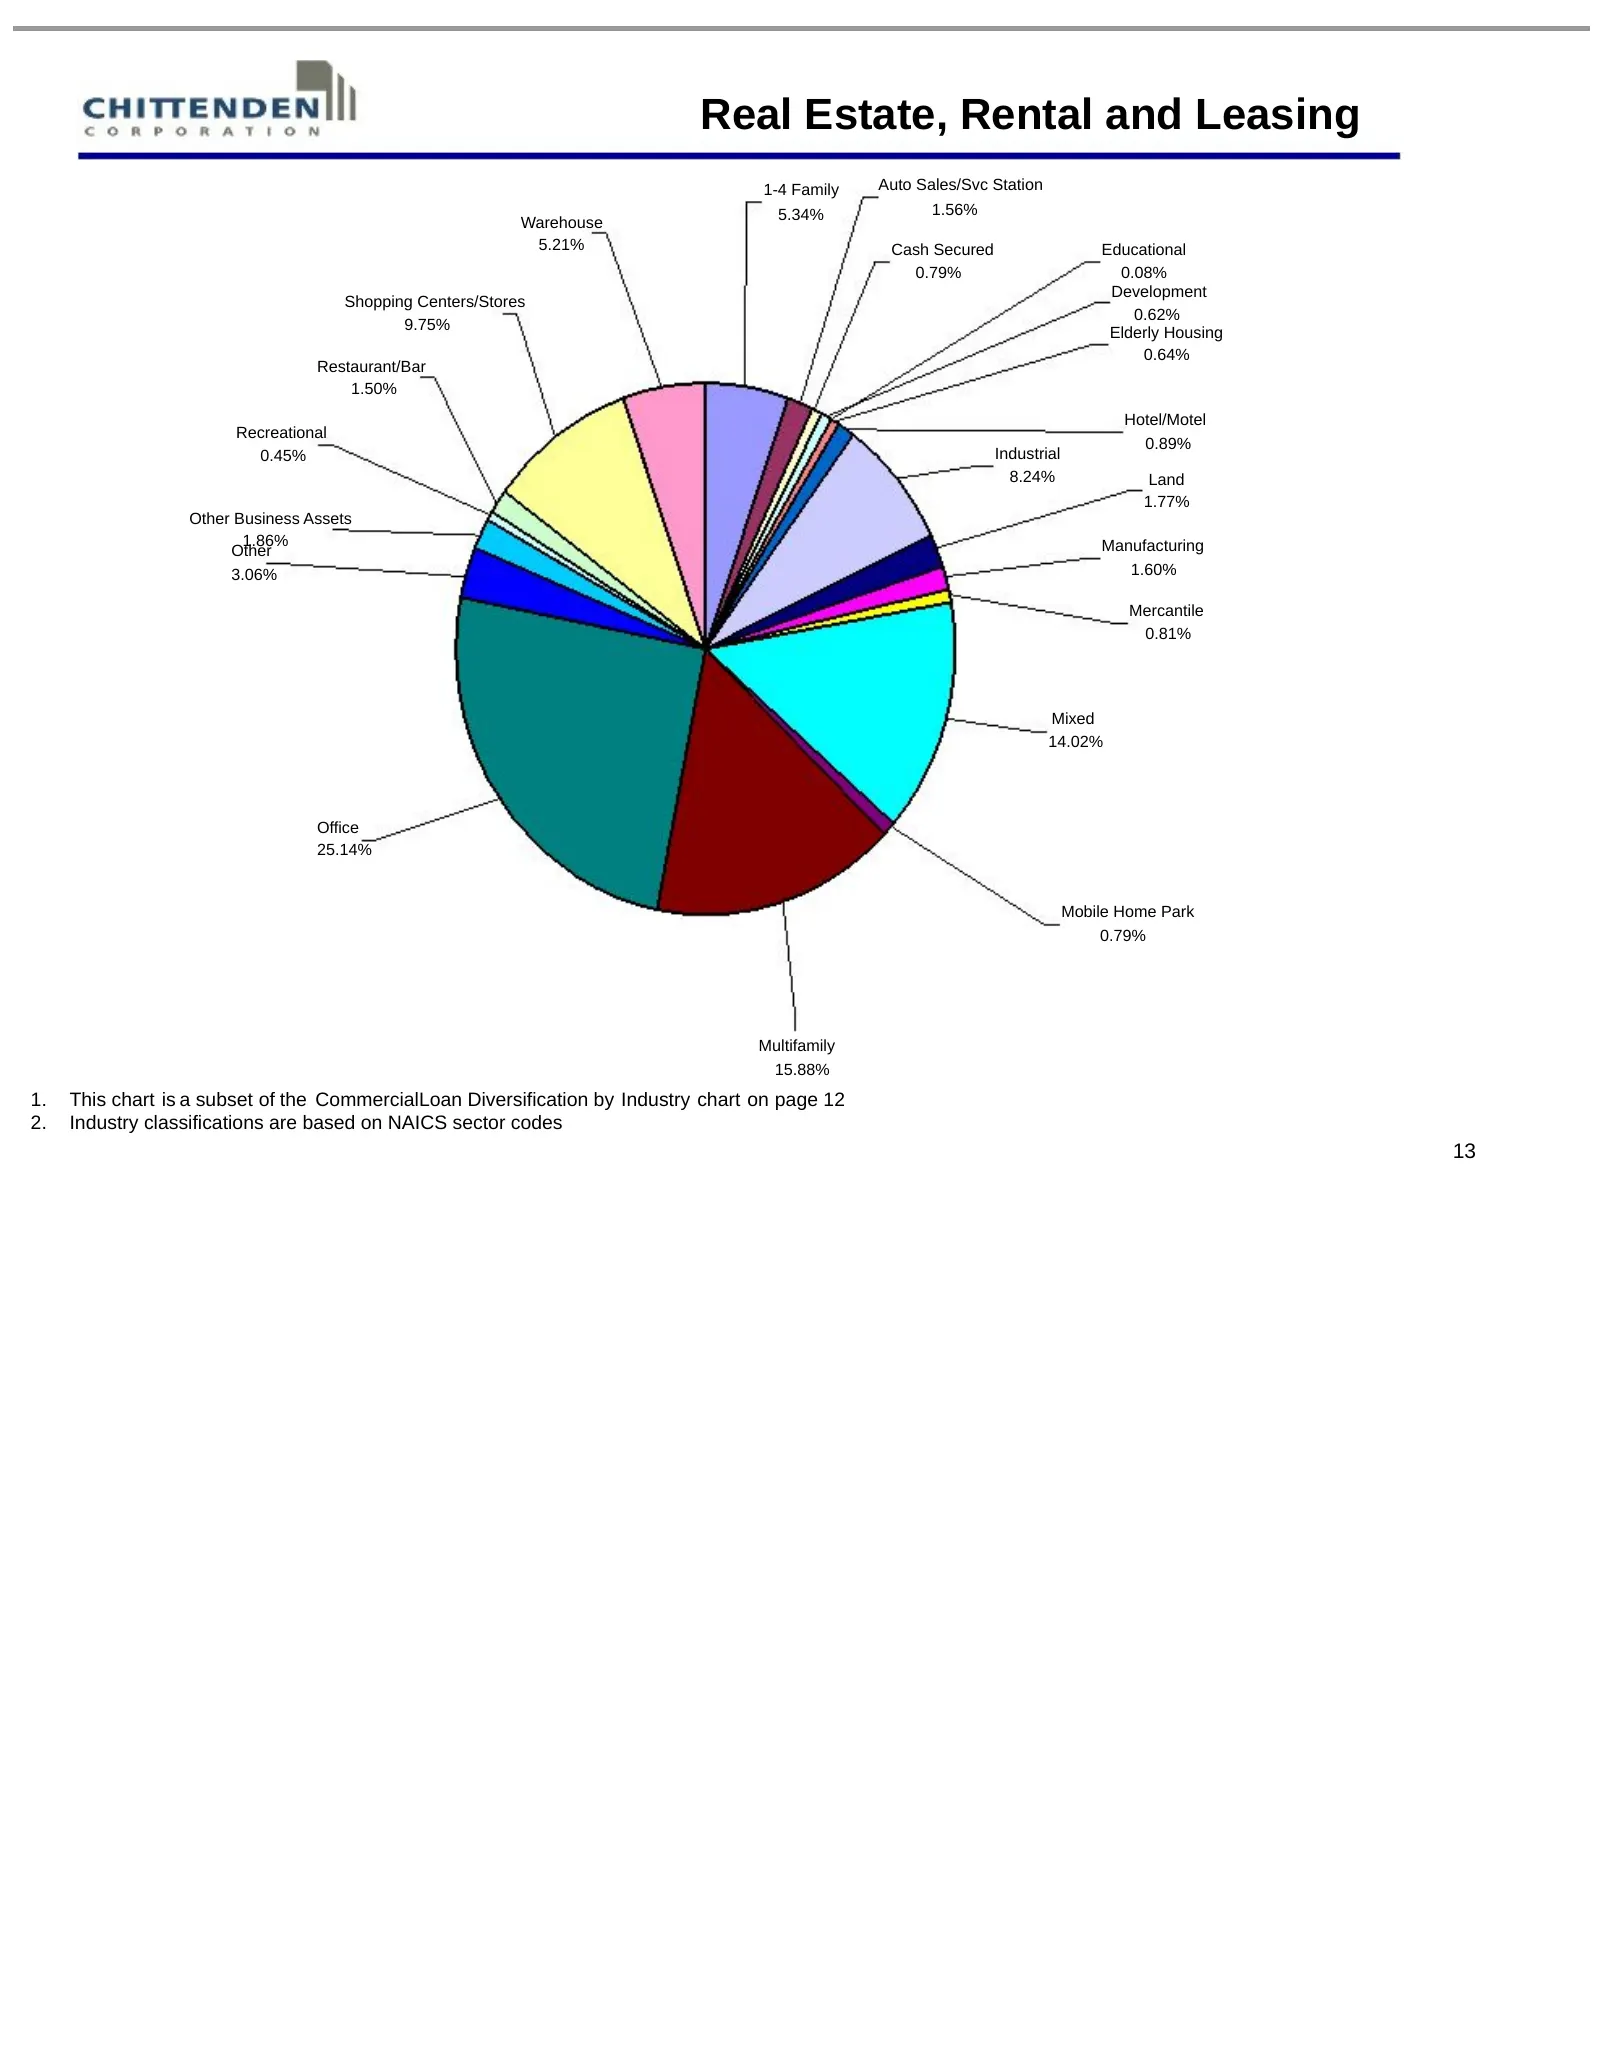
Slide 13: Real Estate, Rental and Leasing
Real Estate, Rental and Leasing 1-4 Family Auto Sales/Svc Station 5.34% 1.56% Warehouse 5.21% Cash Secured Educational 0.79% 0.08% Development Shopping Centers/Stores 0.62% 9.75% Elderly Housing 0.64% Restaurant/Bar 1.50% Hotel/Motel Recreational 0.89% 0.45% Industrial 8.24% Land 1.77% Other Busines
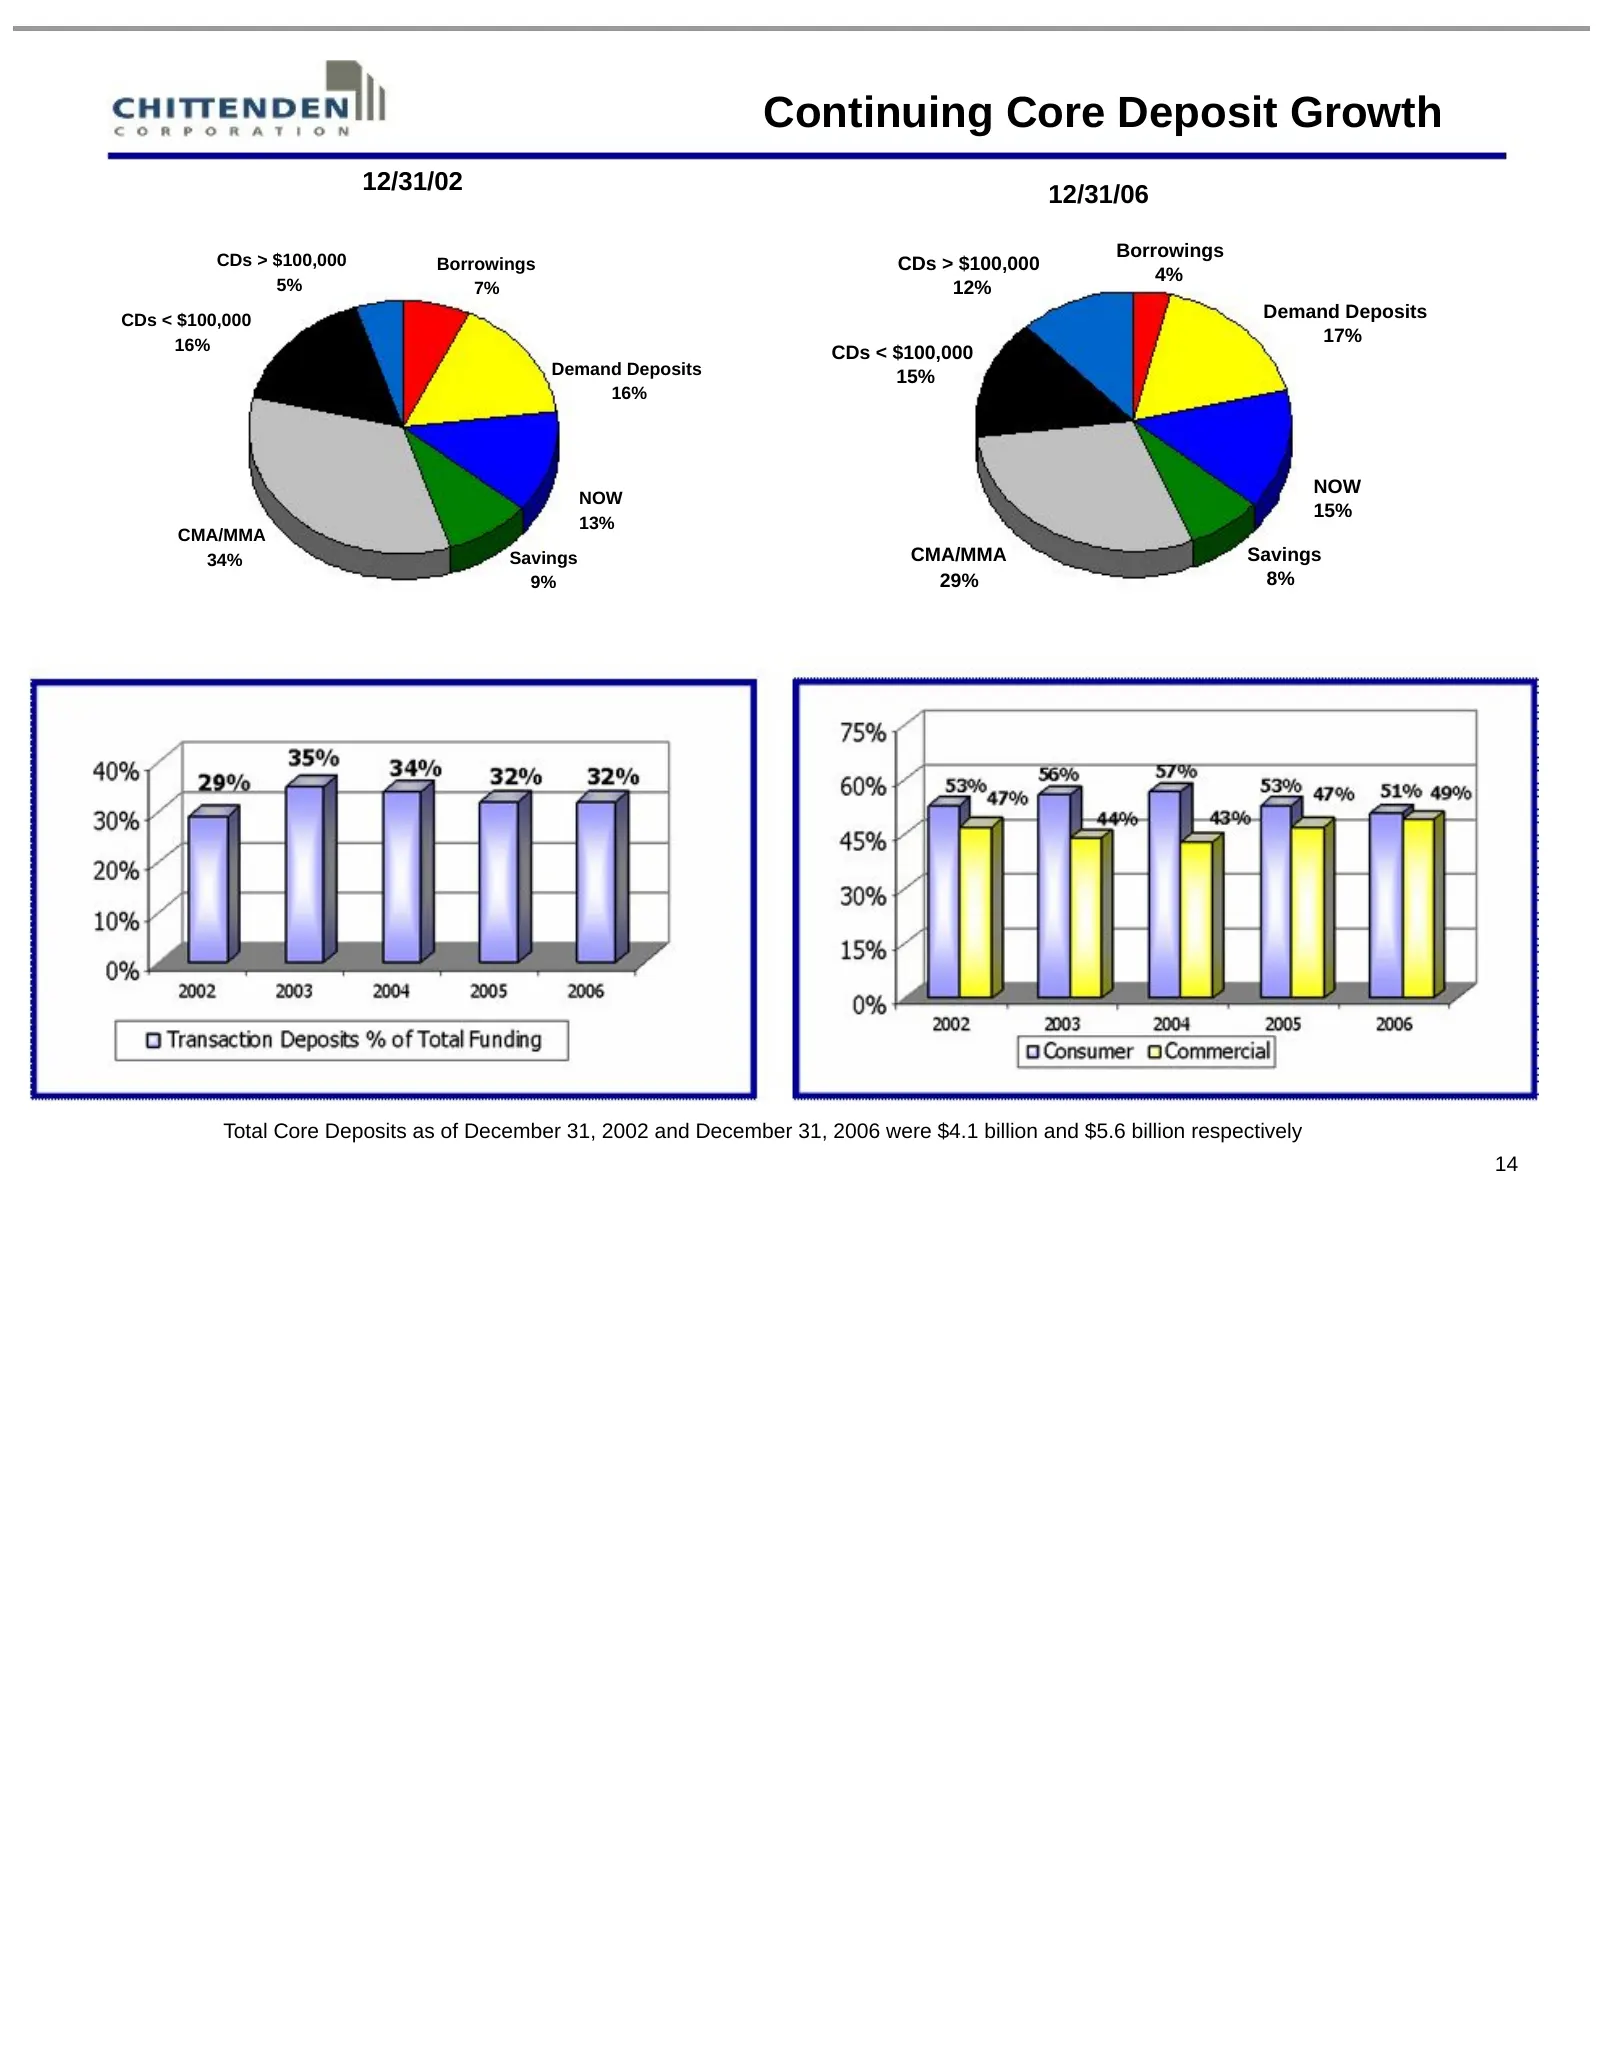
Slide 14: Continuing Core Deposit Growth
Continuing Core Deposit Growth 12/31/02 12/31/06 CDs > $100,000 Borrowings Borrowings CDs > $100,000 5% 4% 7% 12% CDs < $100,000 Demand Deposits 16% 17% CDs < $100,000 Demand Deposits 15% 16% NOW NOW 15% 13% CMA/MMA 34% Savings CMA/MMA Savings 9% 29% 8% Total Core Deposits as of December 31, 2002 an
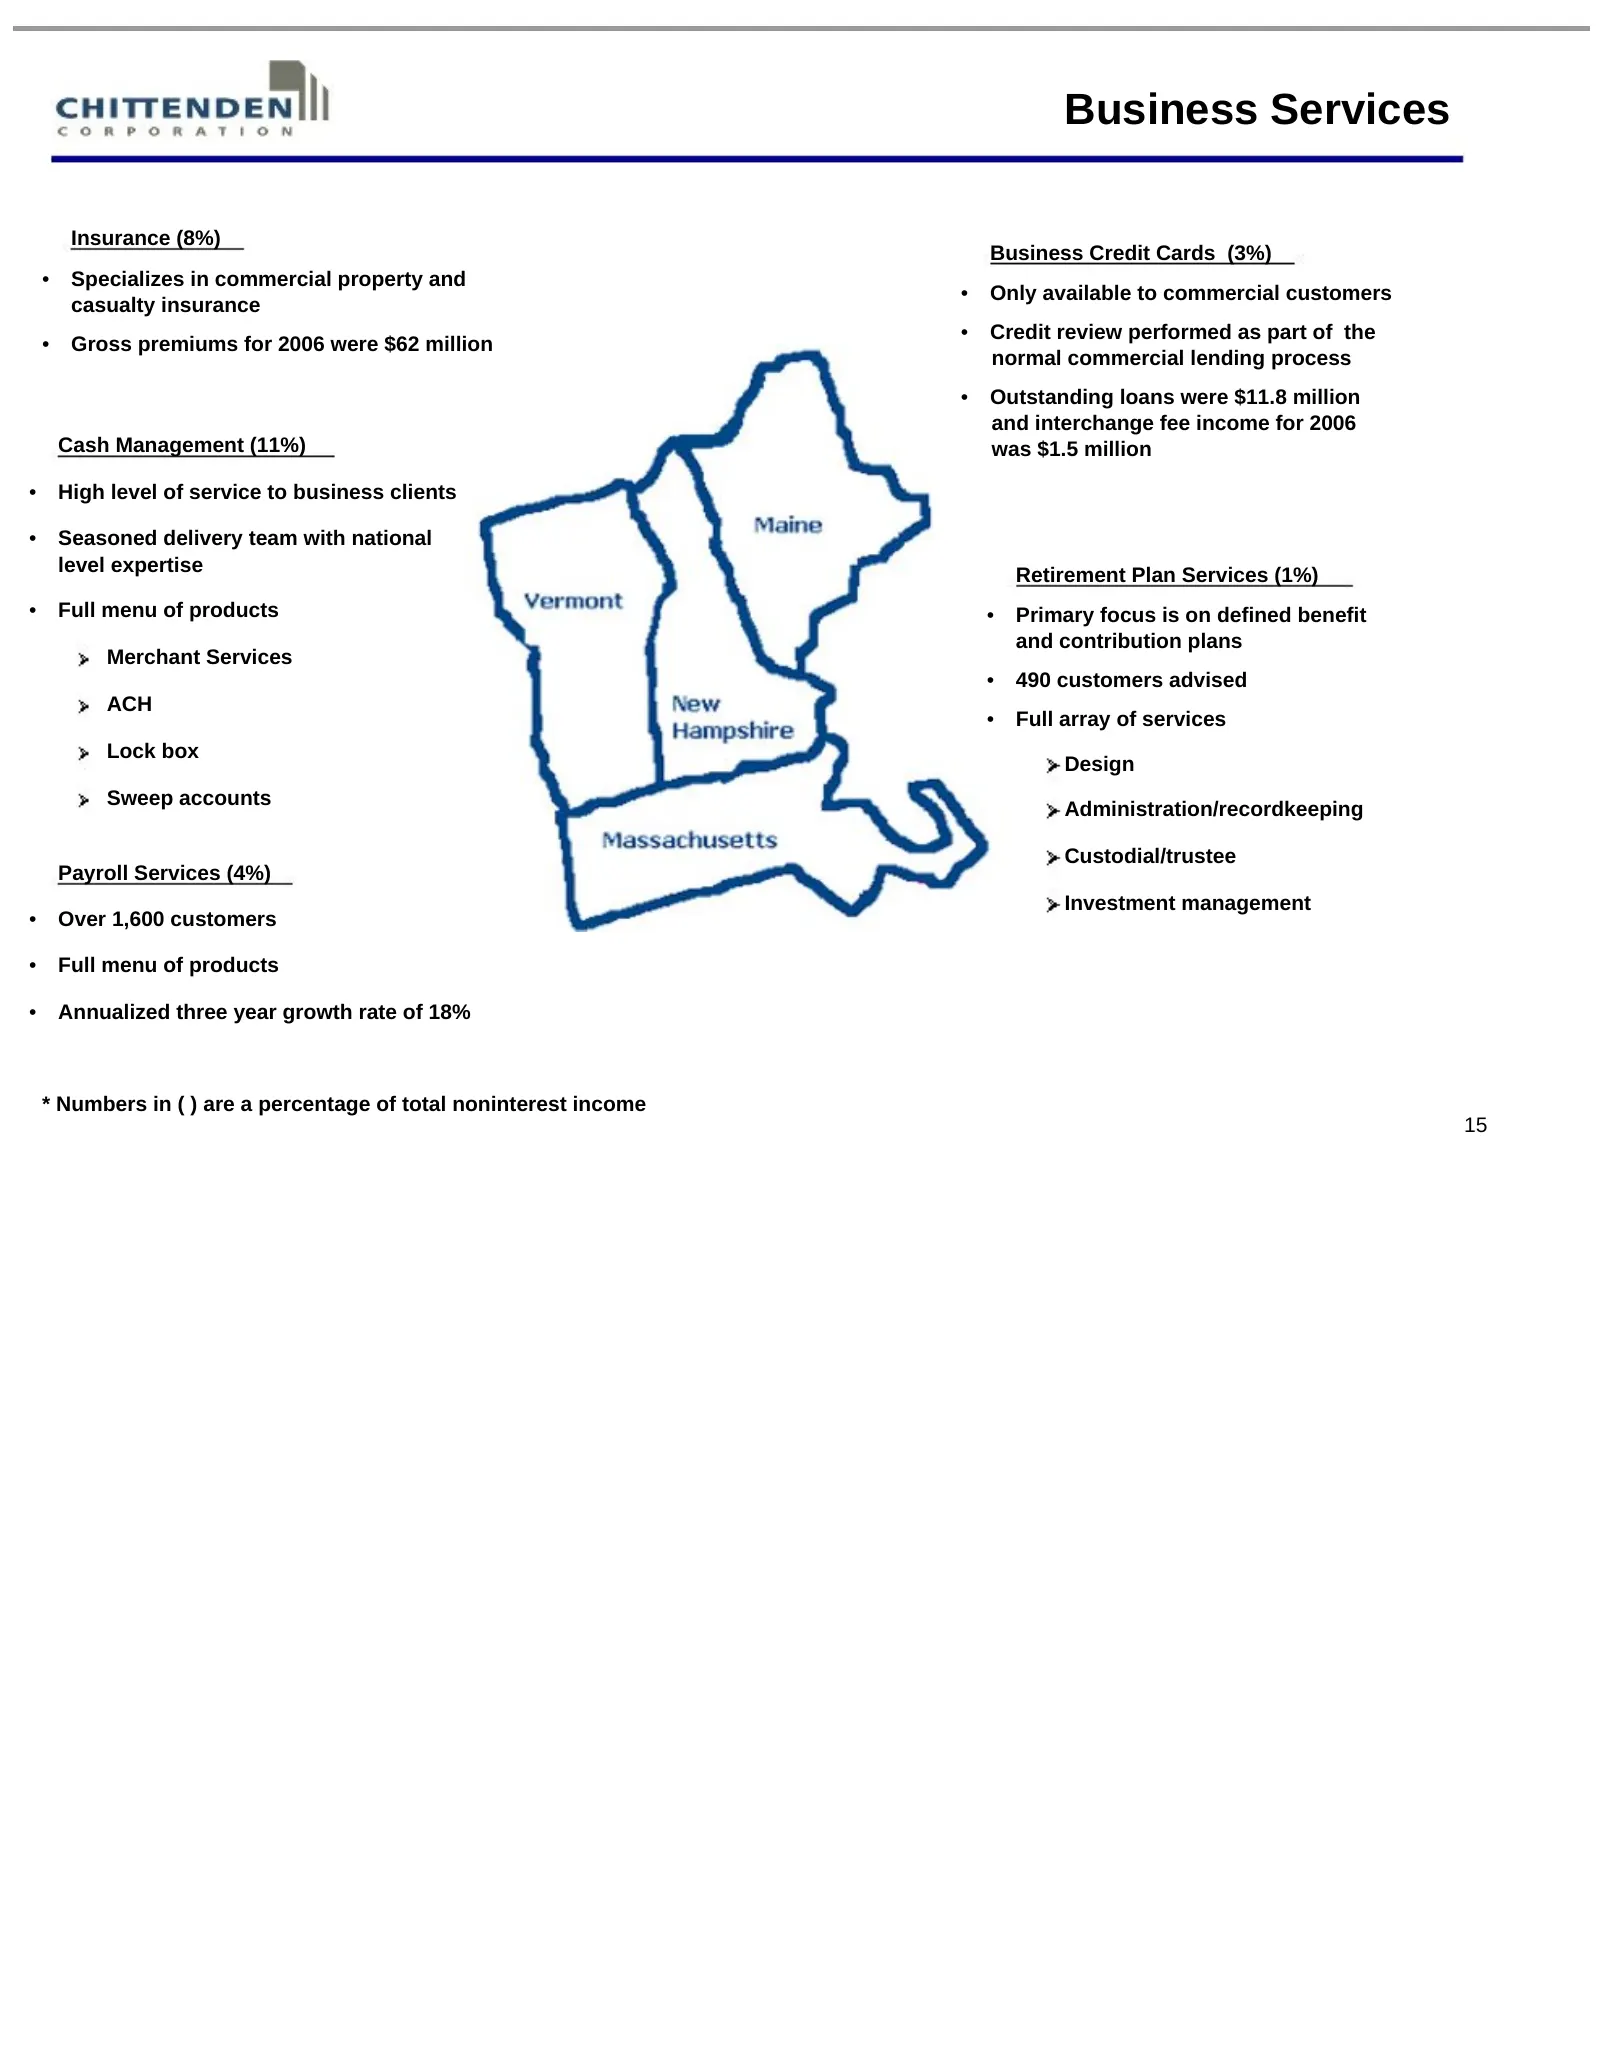
Slide 15: Business Services
Business Services Insurance (8%) Business Credit Cards (3%) • Specializes in commercial property and • Only available to commercial customers casualty insurance • Credit review performed as part of the • Gross premiums for 2006 were $62 million normal commercial lending process • Outstanding loans w
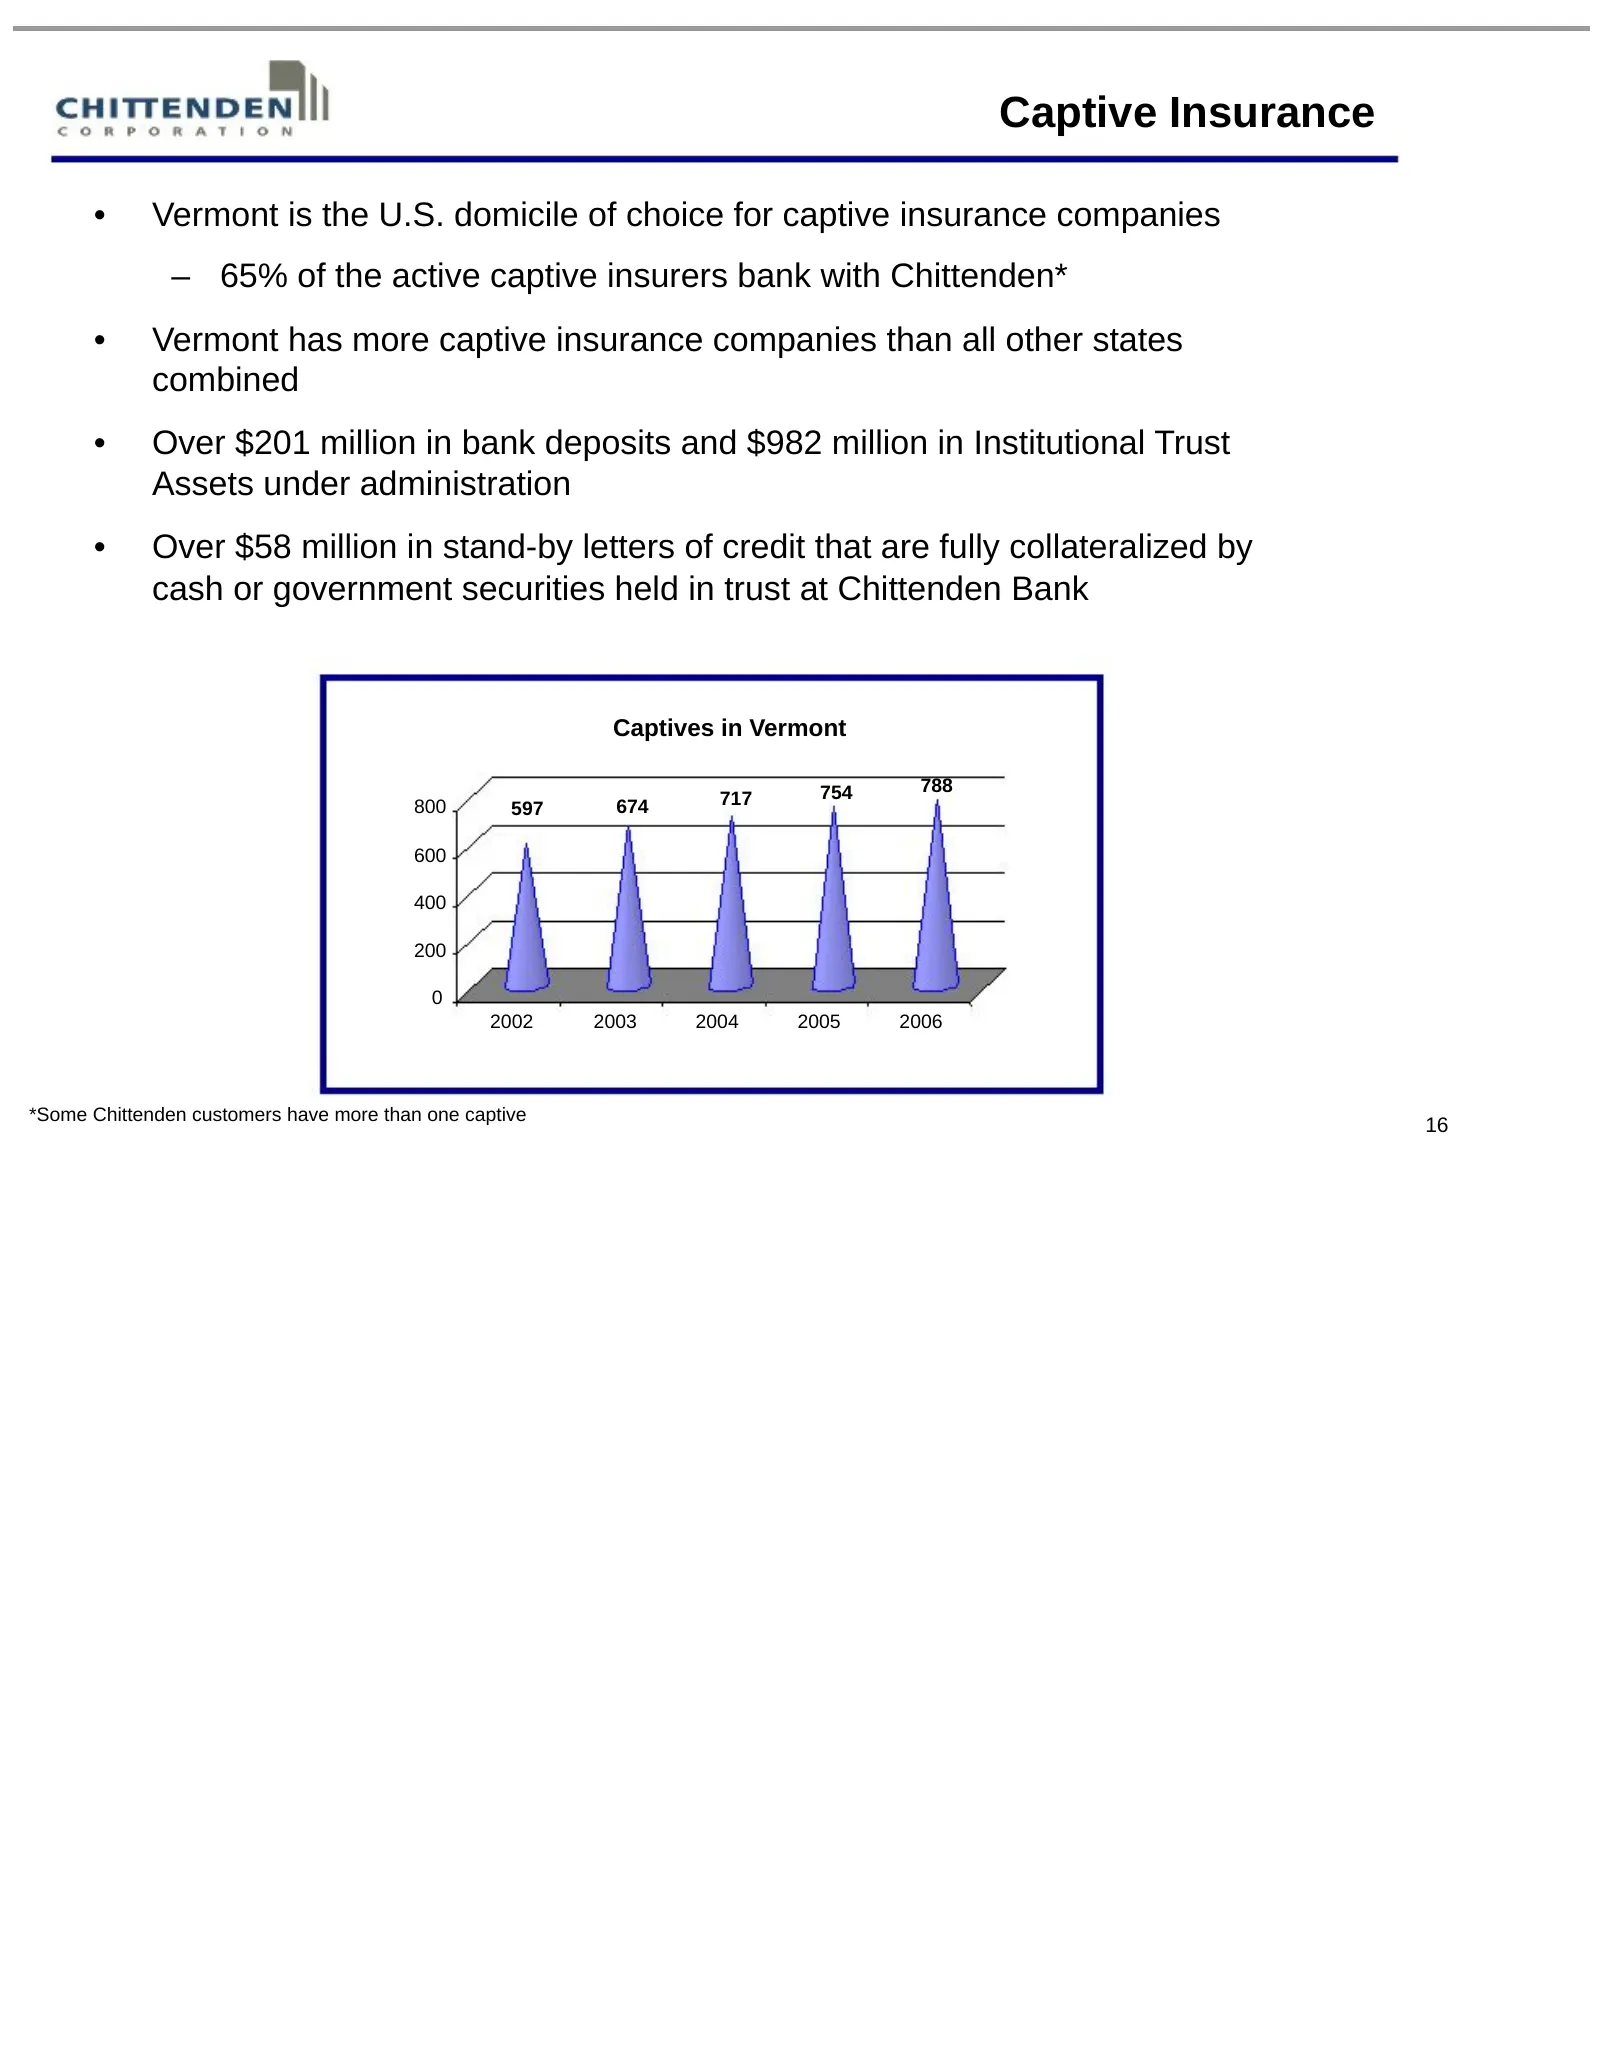
Slide 16: Captive Insurance
Captive Insurance • Vermont is the U.S. domicile of choice for captive insurance companies – 65% of the active captive insurers bank with Chittenden* • Vermont has more captive insurance companies than all other states combined • Over $201 million in bank deposits and $982 million in Institutional T
Slide 17: Government Banking
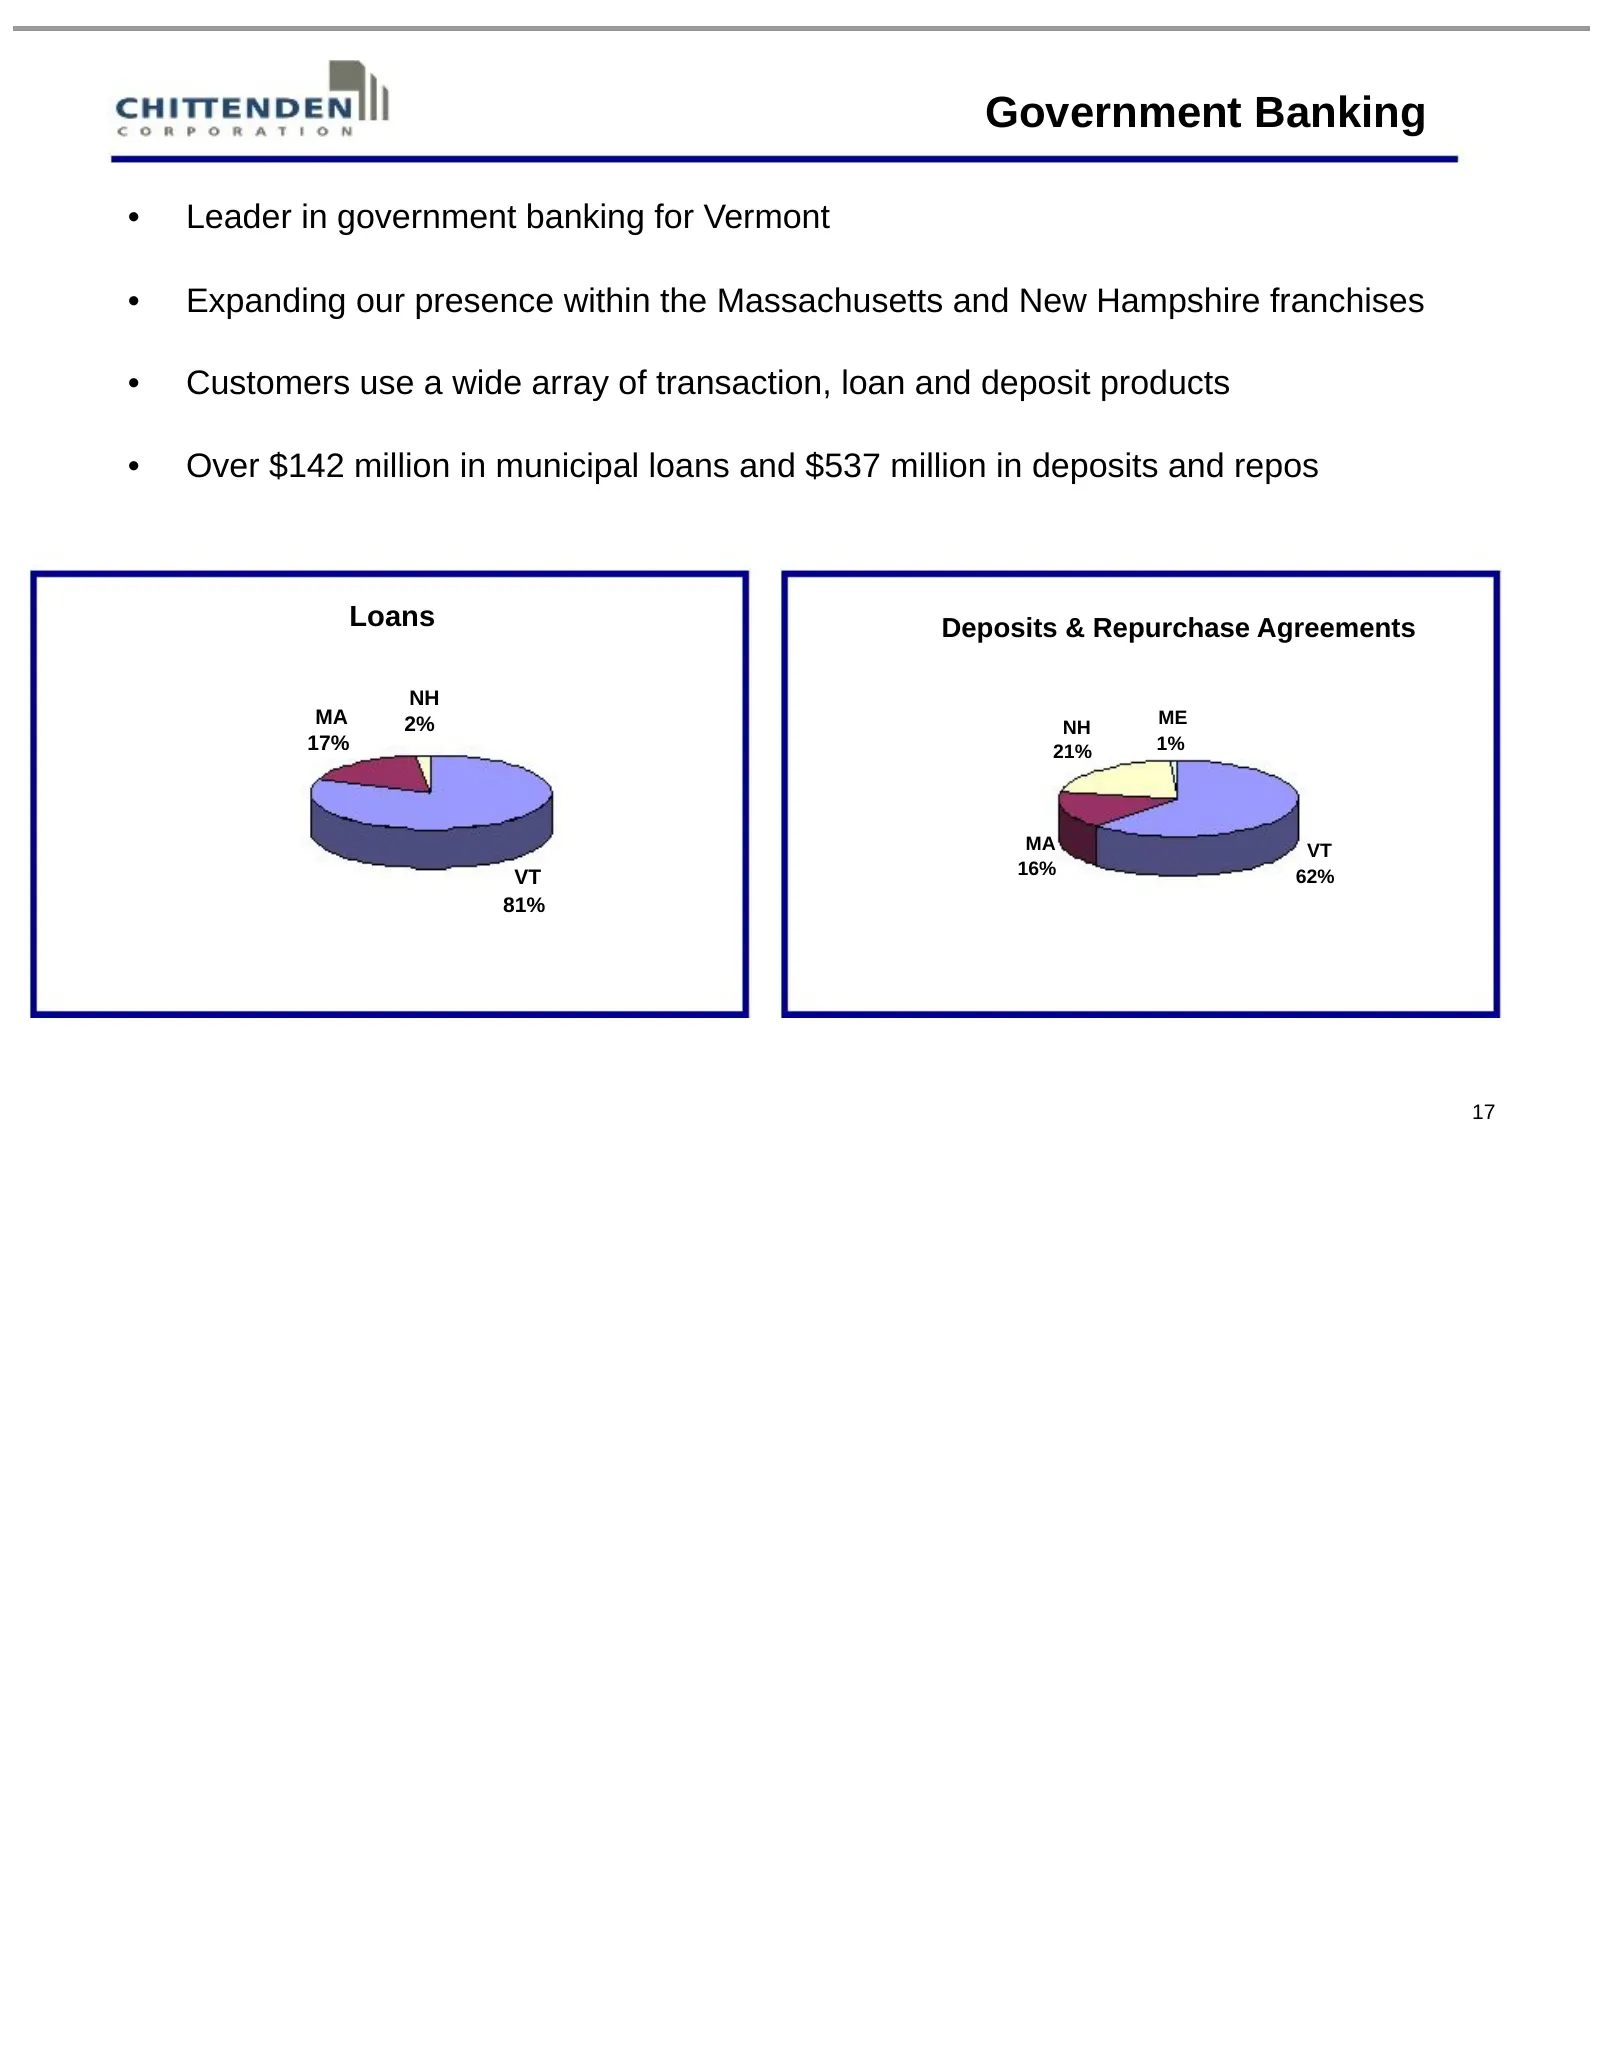
Government Banking • Leader in government banking for Vermont • Expanding our presence within the Massachusetts and New Hampshire franchises • Customers use a wide array of transaction, loan and deposit products • Over $142 million in municipal loans and $537 million in deposits and repos Loans Depo
Slide 18: Mortgage Banking
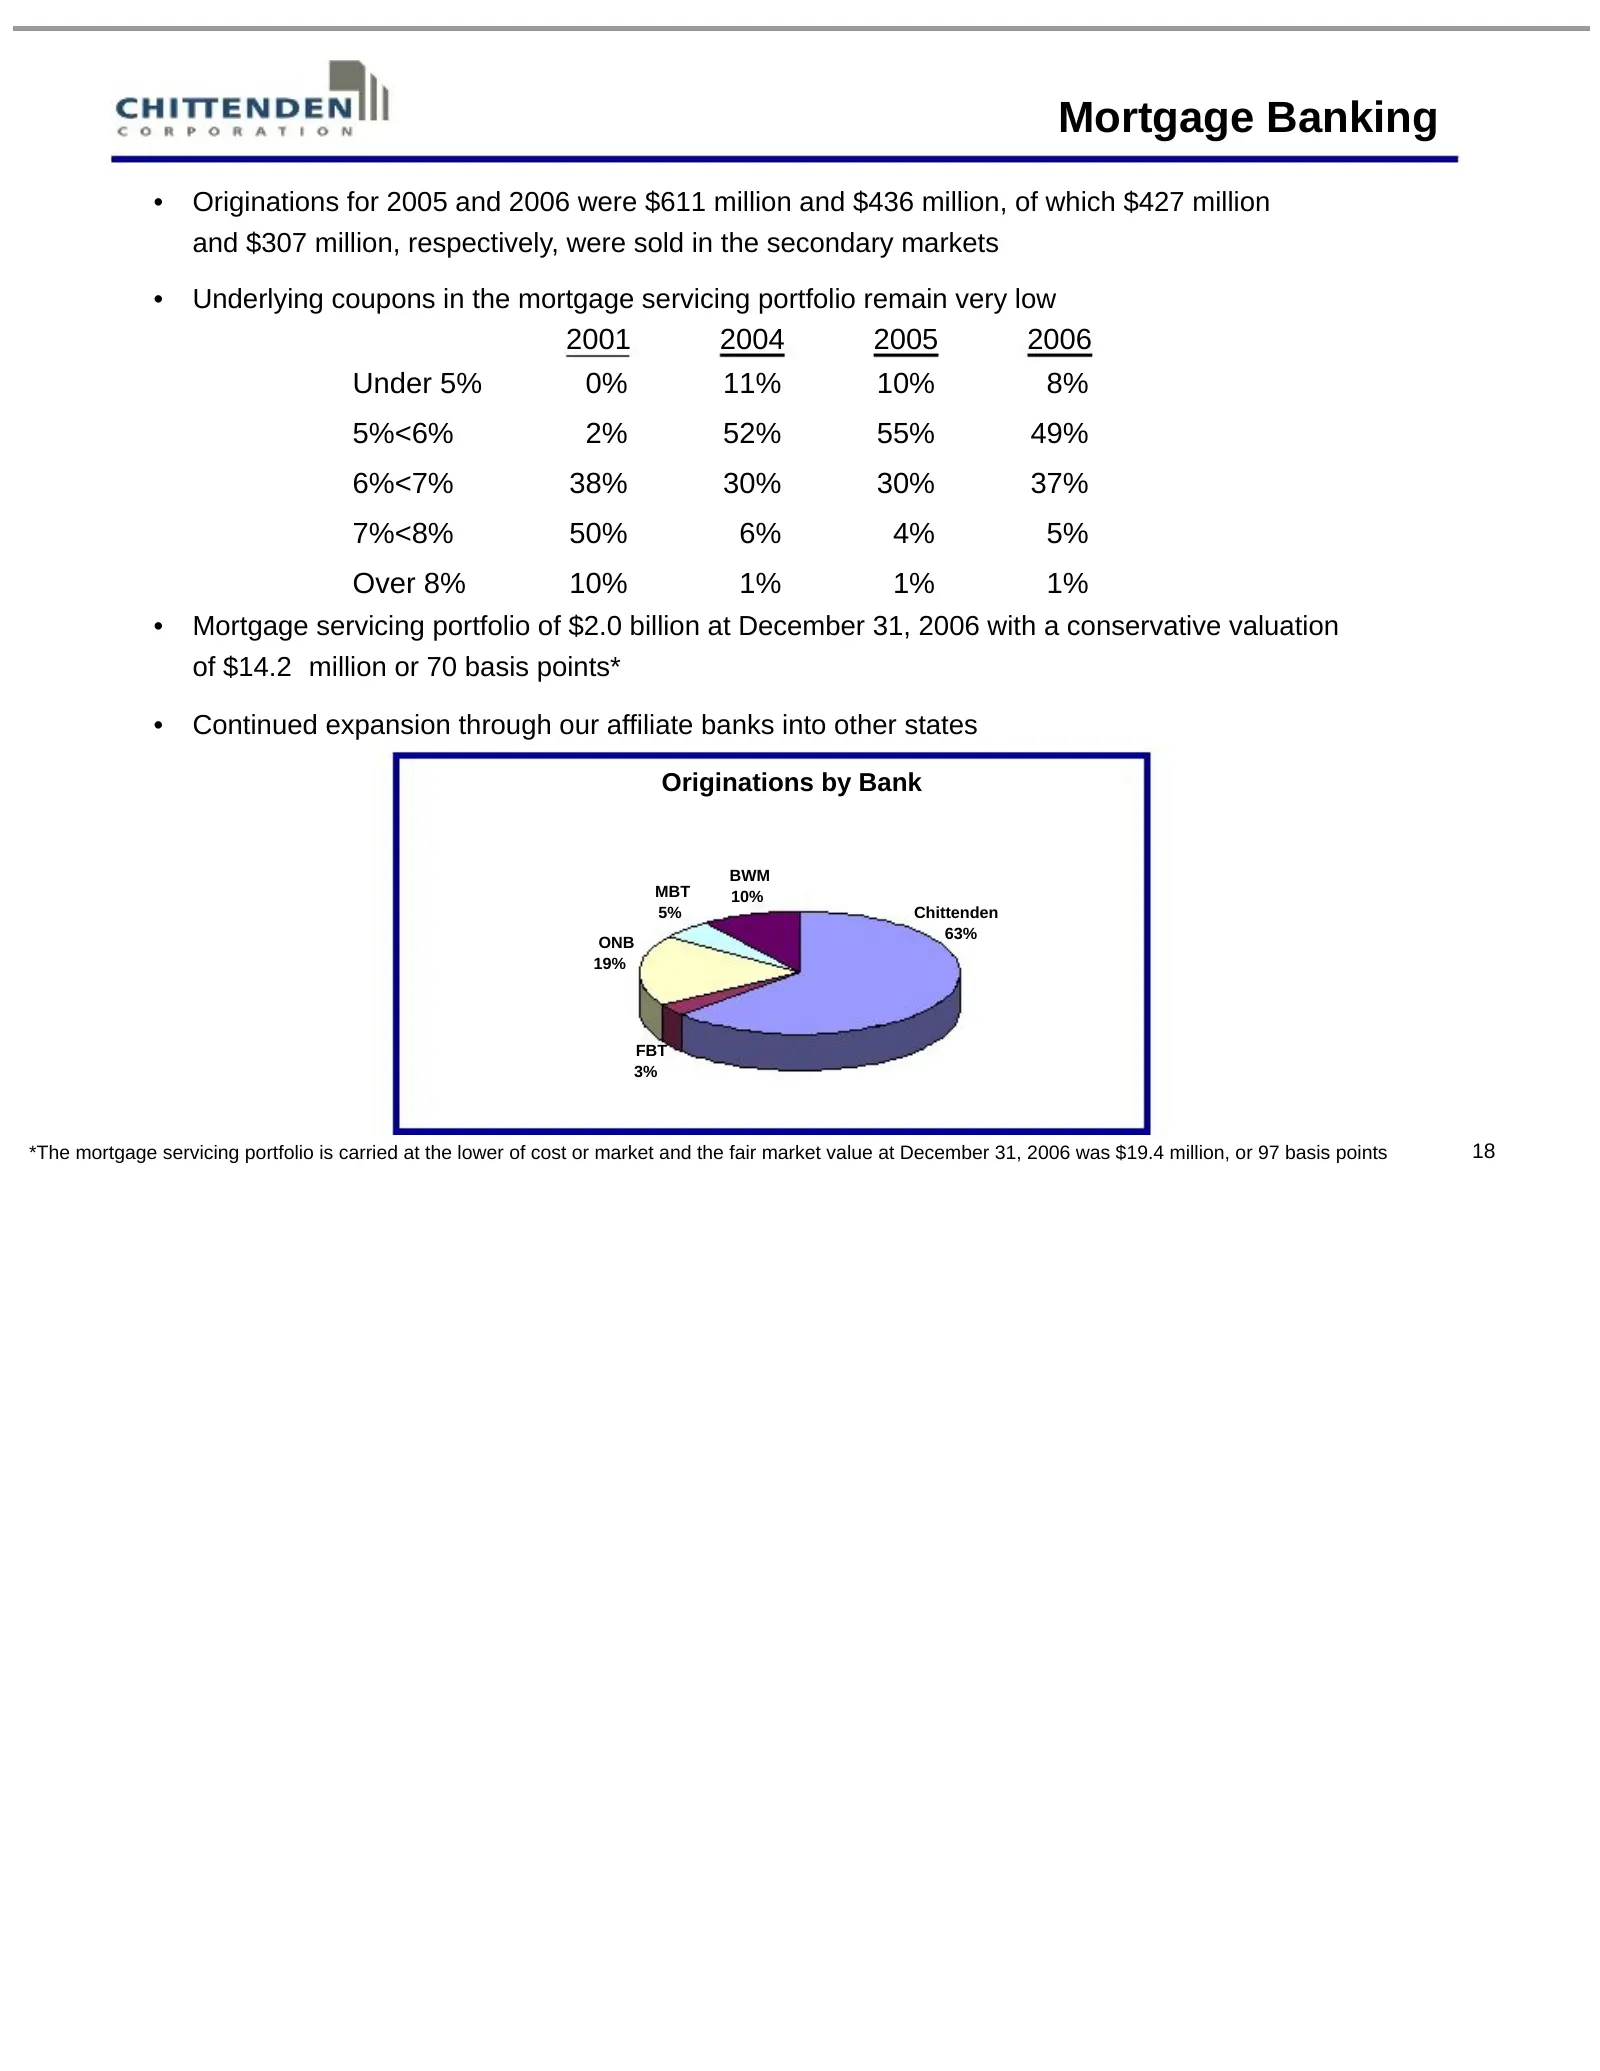
Mortgage Banking • Originations for 2005 and 2006 were $611 million and $436 million, of which $427 million and $307 million, respectively, were sold in the secondary markets • Underlying coupons in the mortgage servicing portfolio remain very low 2001 2004 2005 2006 Under 5% 0% 11% 10% 8% 5%<6% 2%
Slide 19: Wealth Management
Wealth Management 19
Slide 20: Asset Management Services
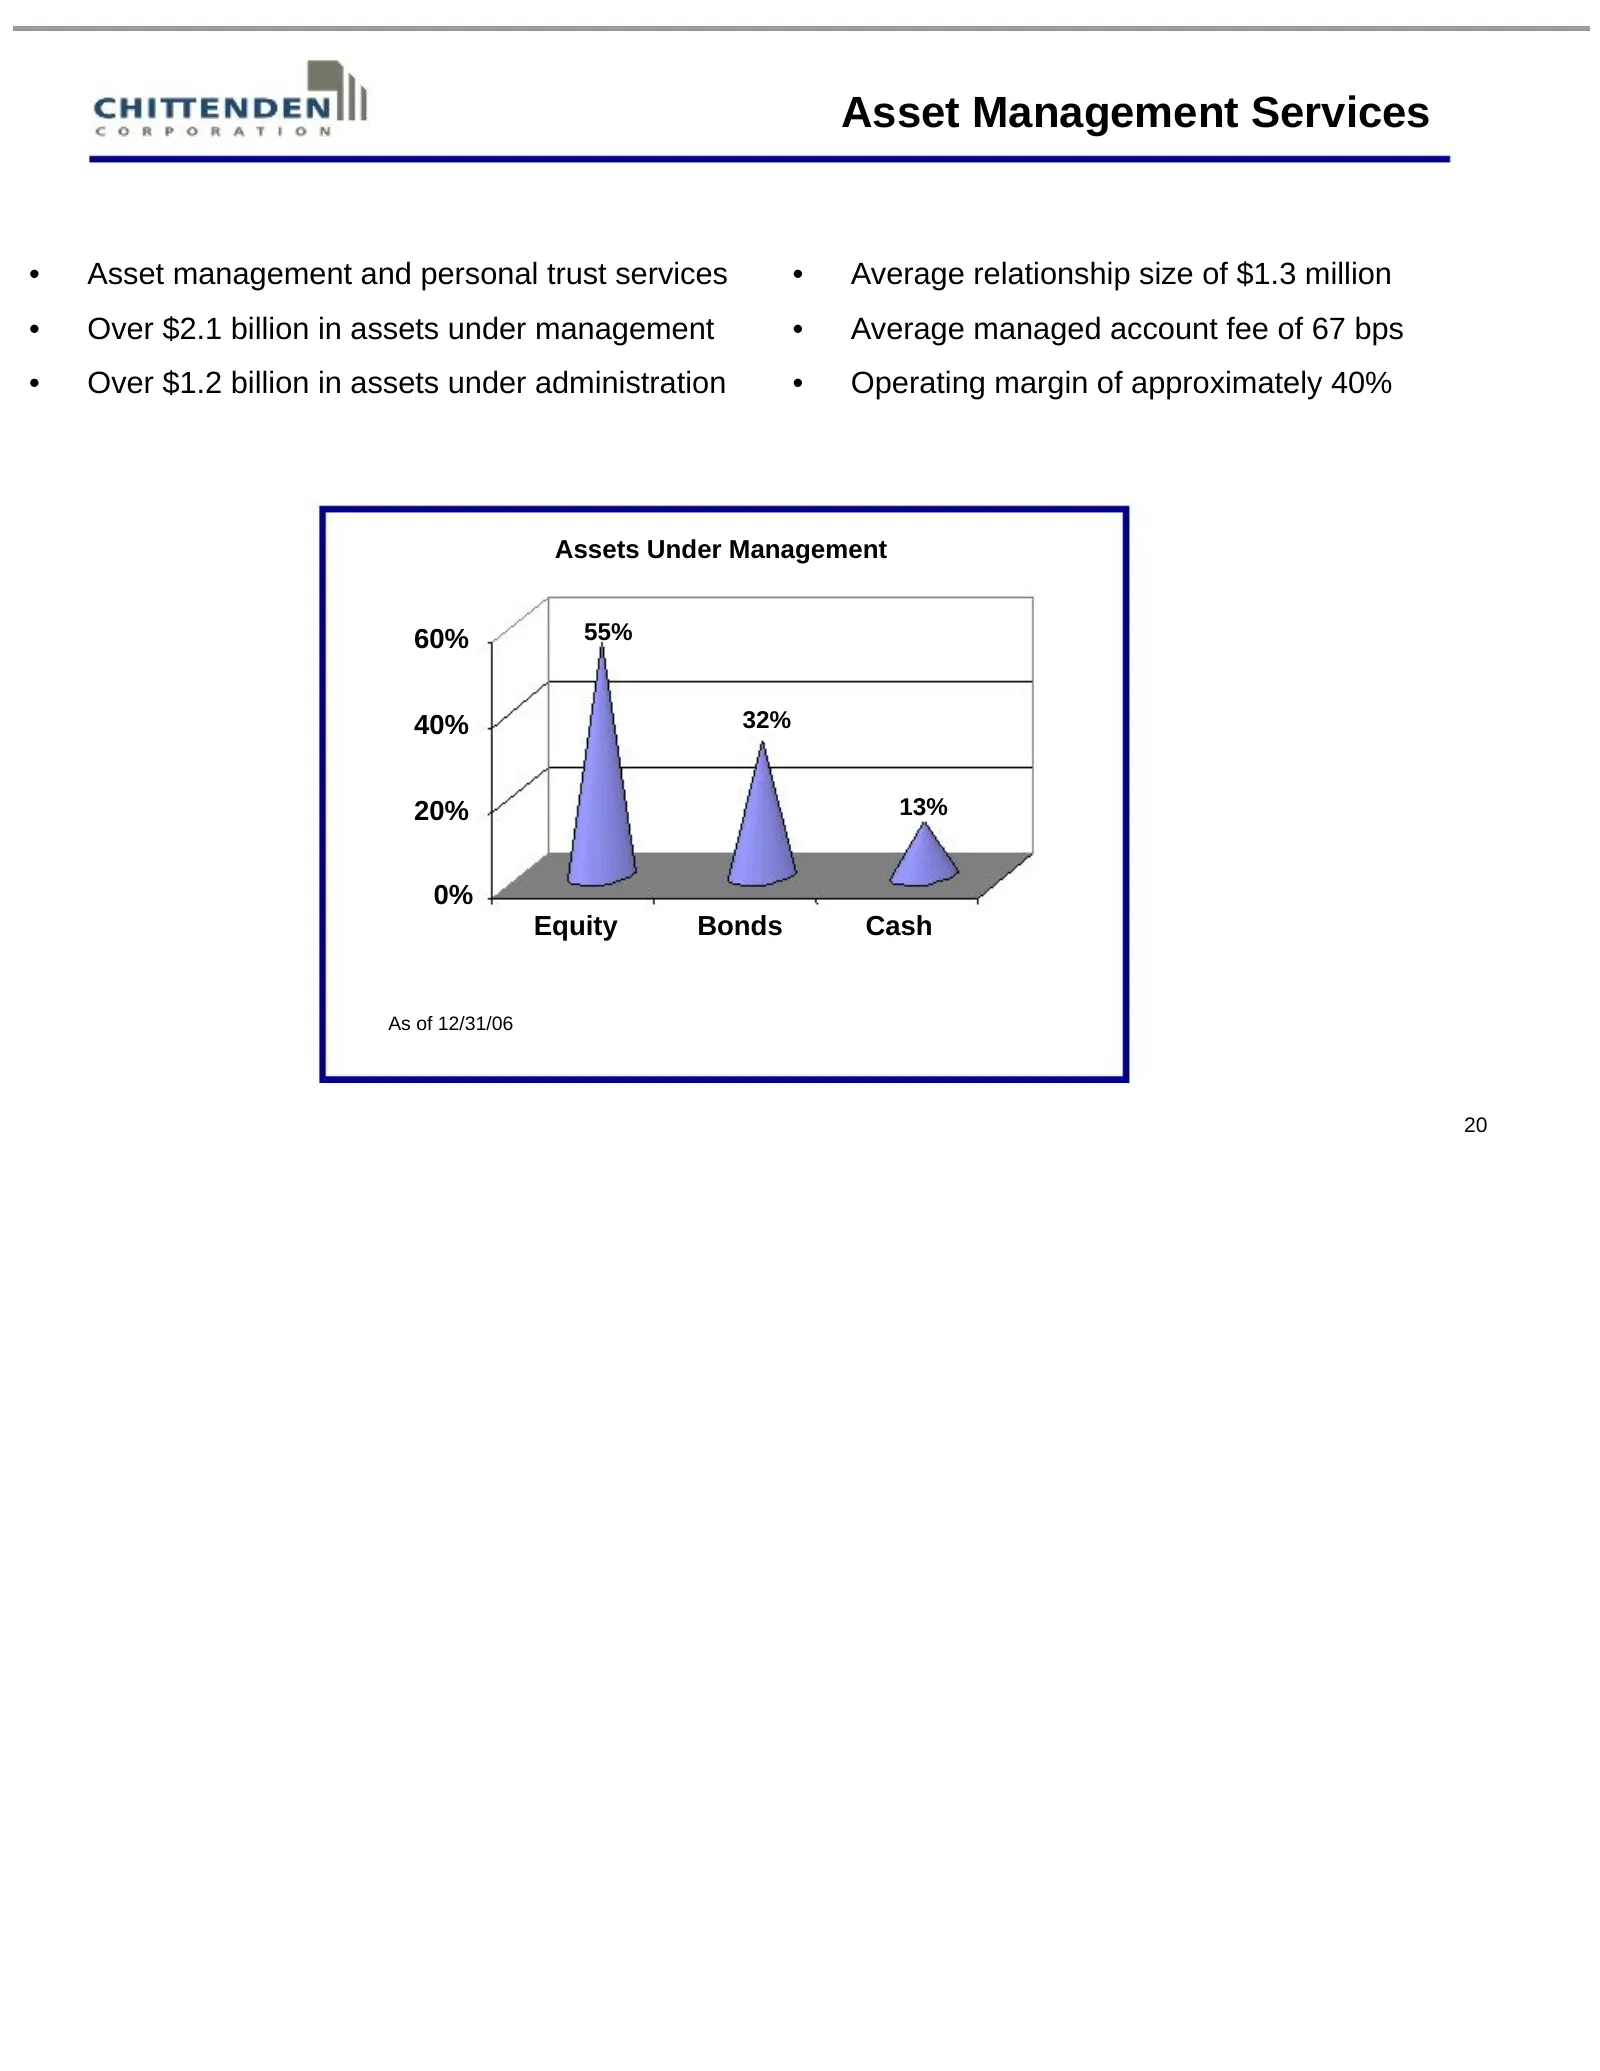
Asset Management Services • Asset management and personal trust services • Average relationship size of $1.3 million • Over $2.1 billion in assets under management • Average managed account fee of 67 bps • Over $1.2 billion in assets under administration • Operating margin of approximately 40% Asset
Slide 21: Wealth Management
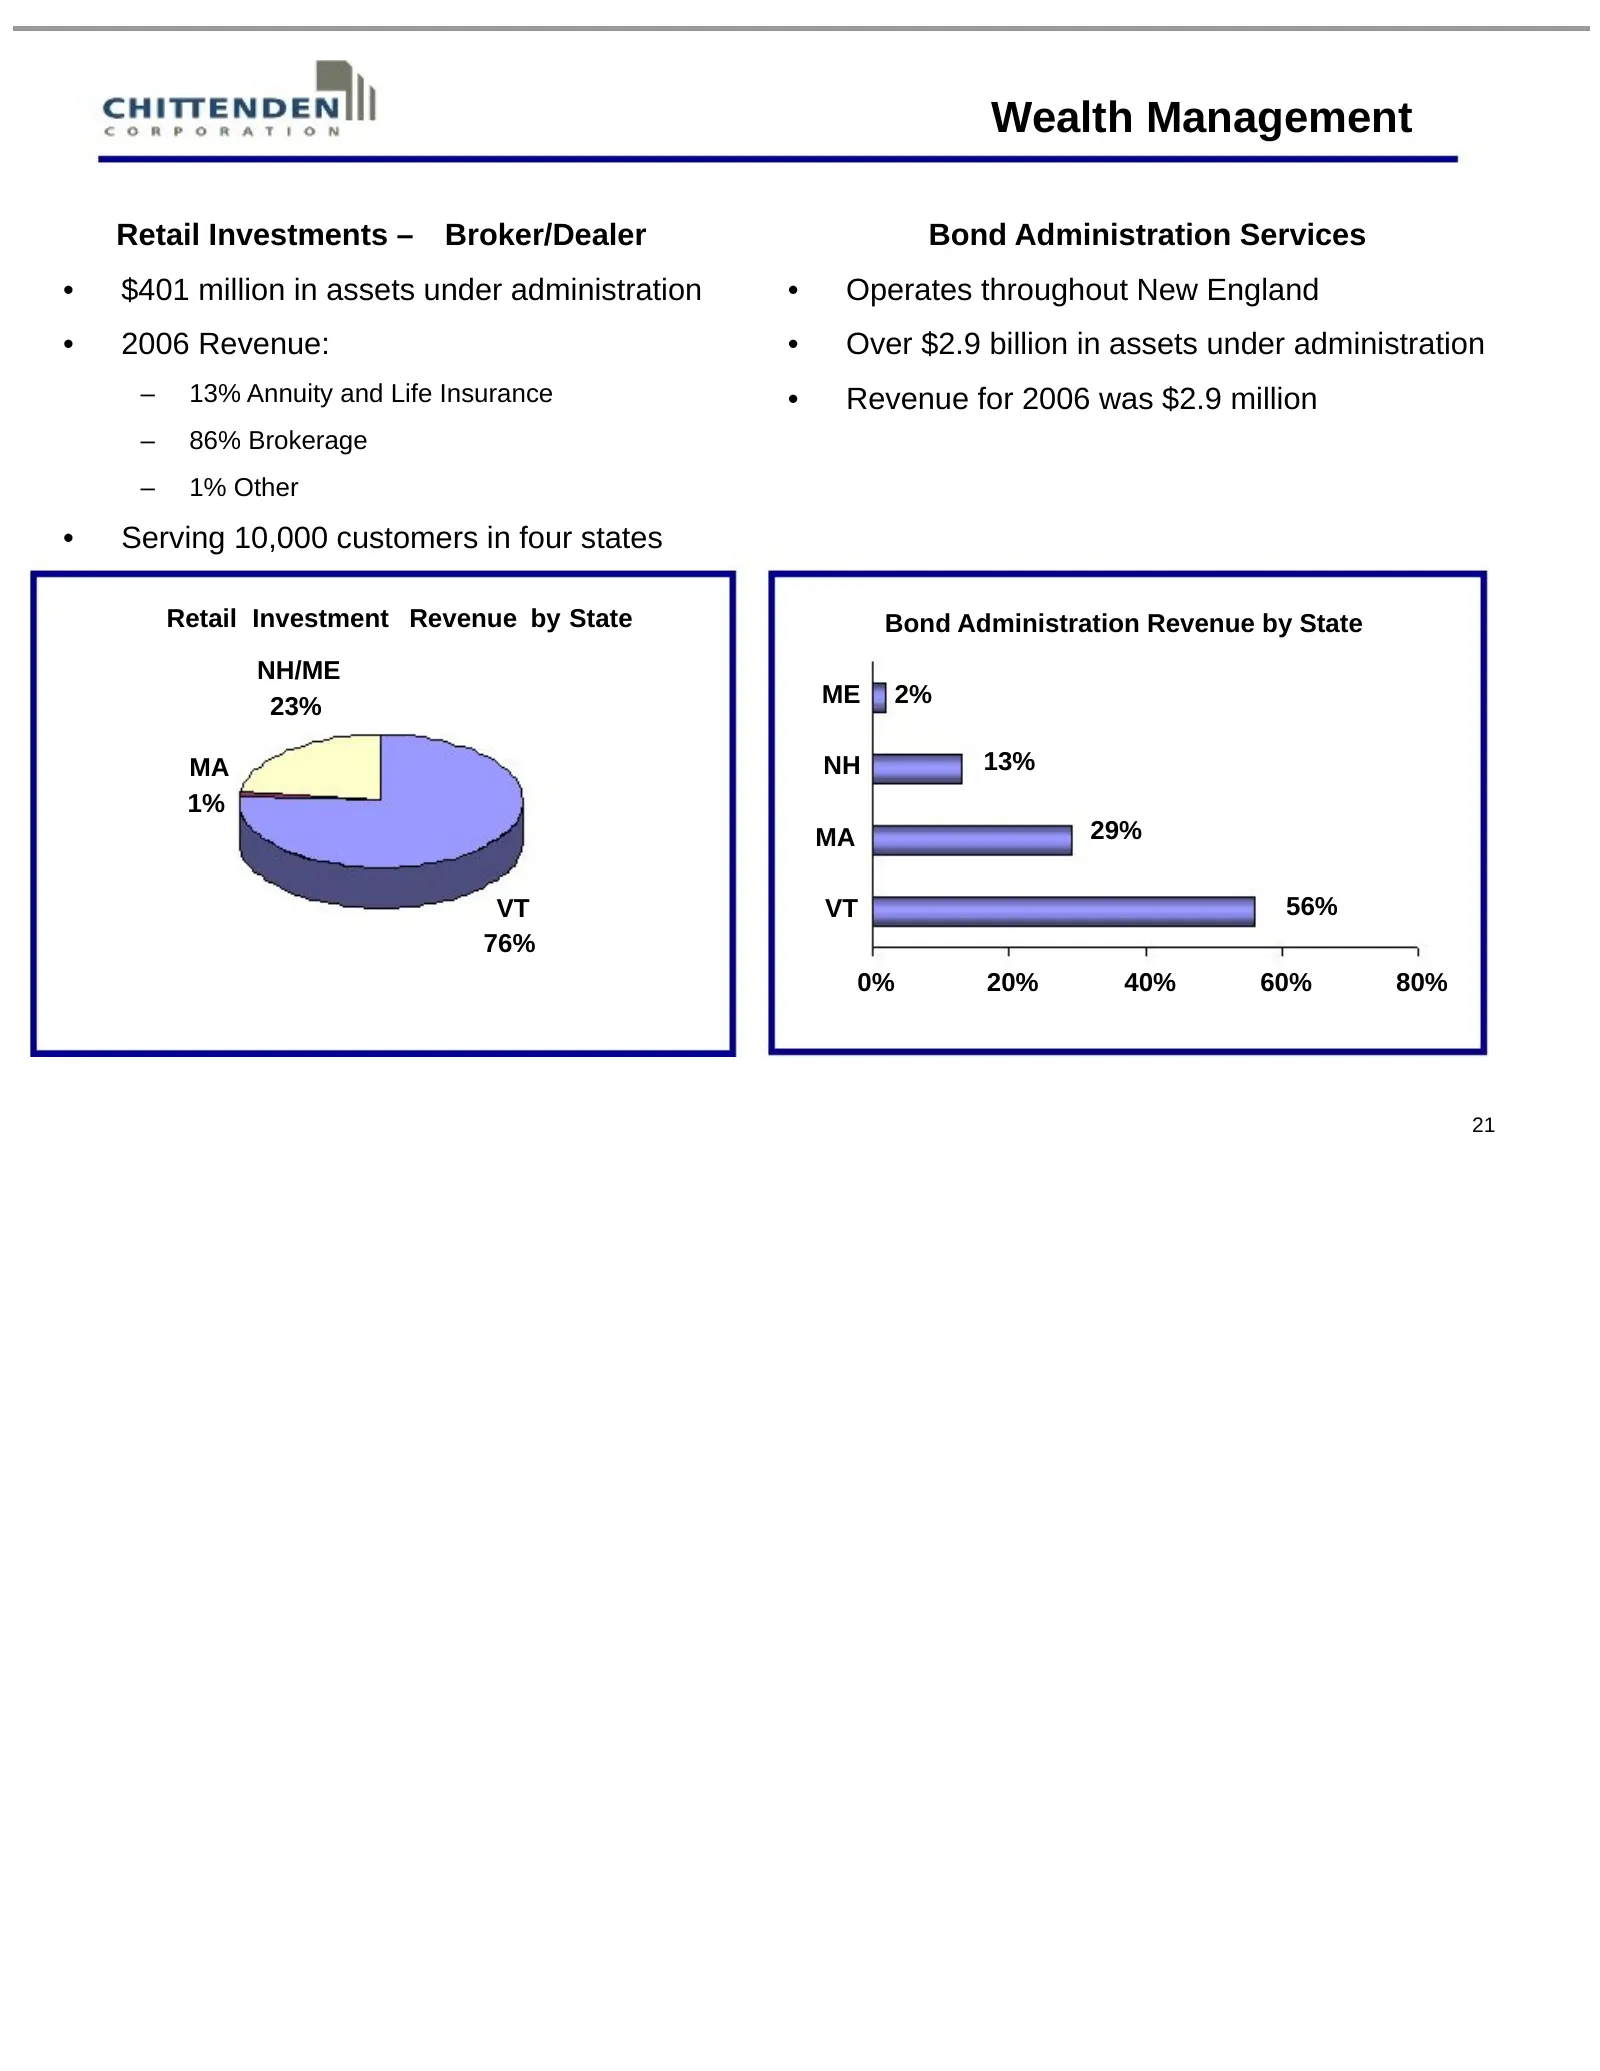
Wealth Management Retail Investments – Broker/Dealer Bond Administration Services • $401 million in assets under administration • Operates throughout New England • 2006 Revenue: • Over $2.9 billion in assets under administration – 13% Annuity and Life Insurance • Revenue for 2006 was $2.9 million –
Slide 22: Financial Performance
Financial Performance
Slide 23: Consistent Superior Financial Performance
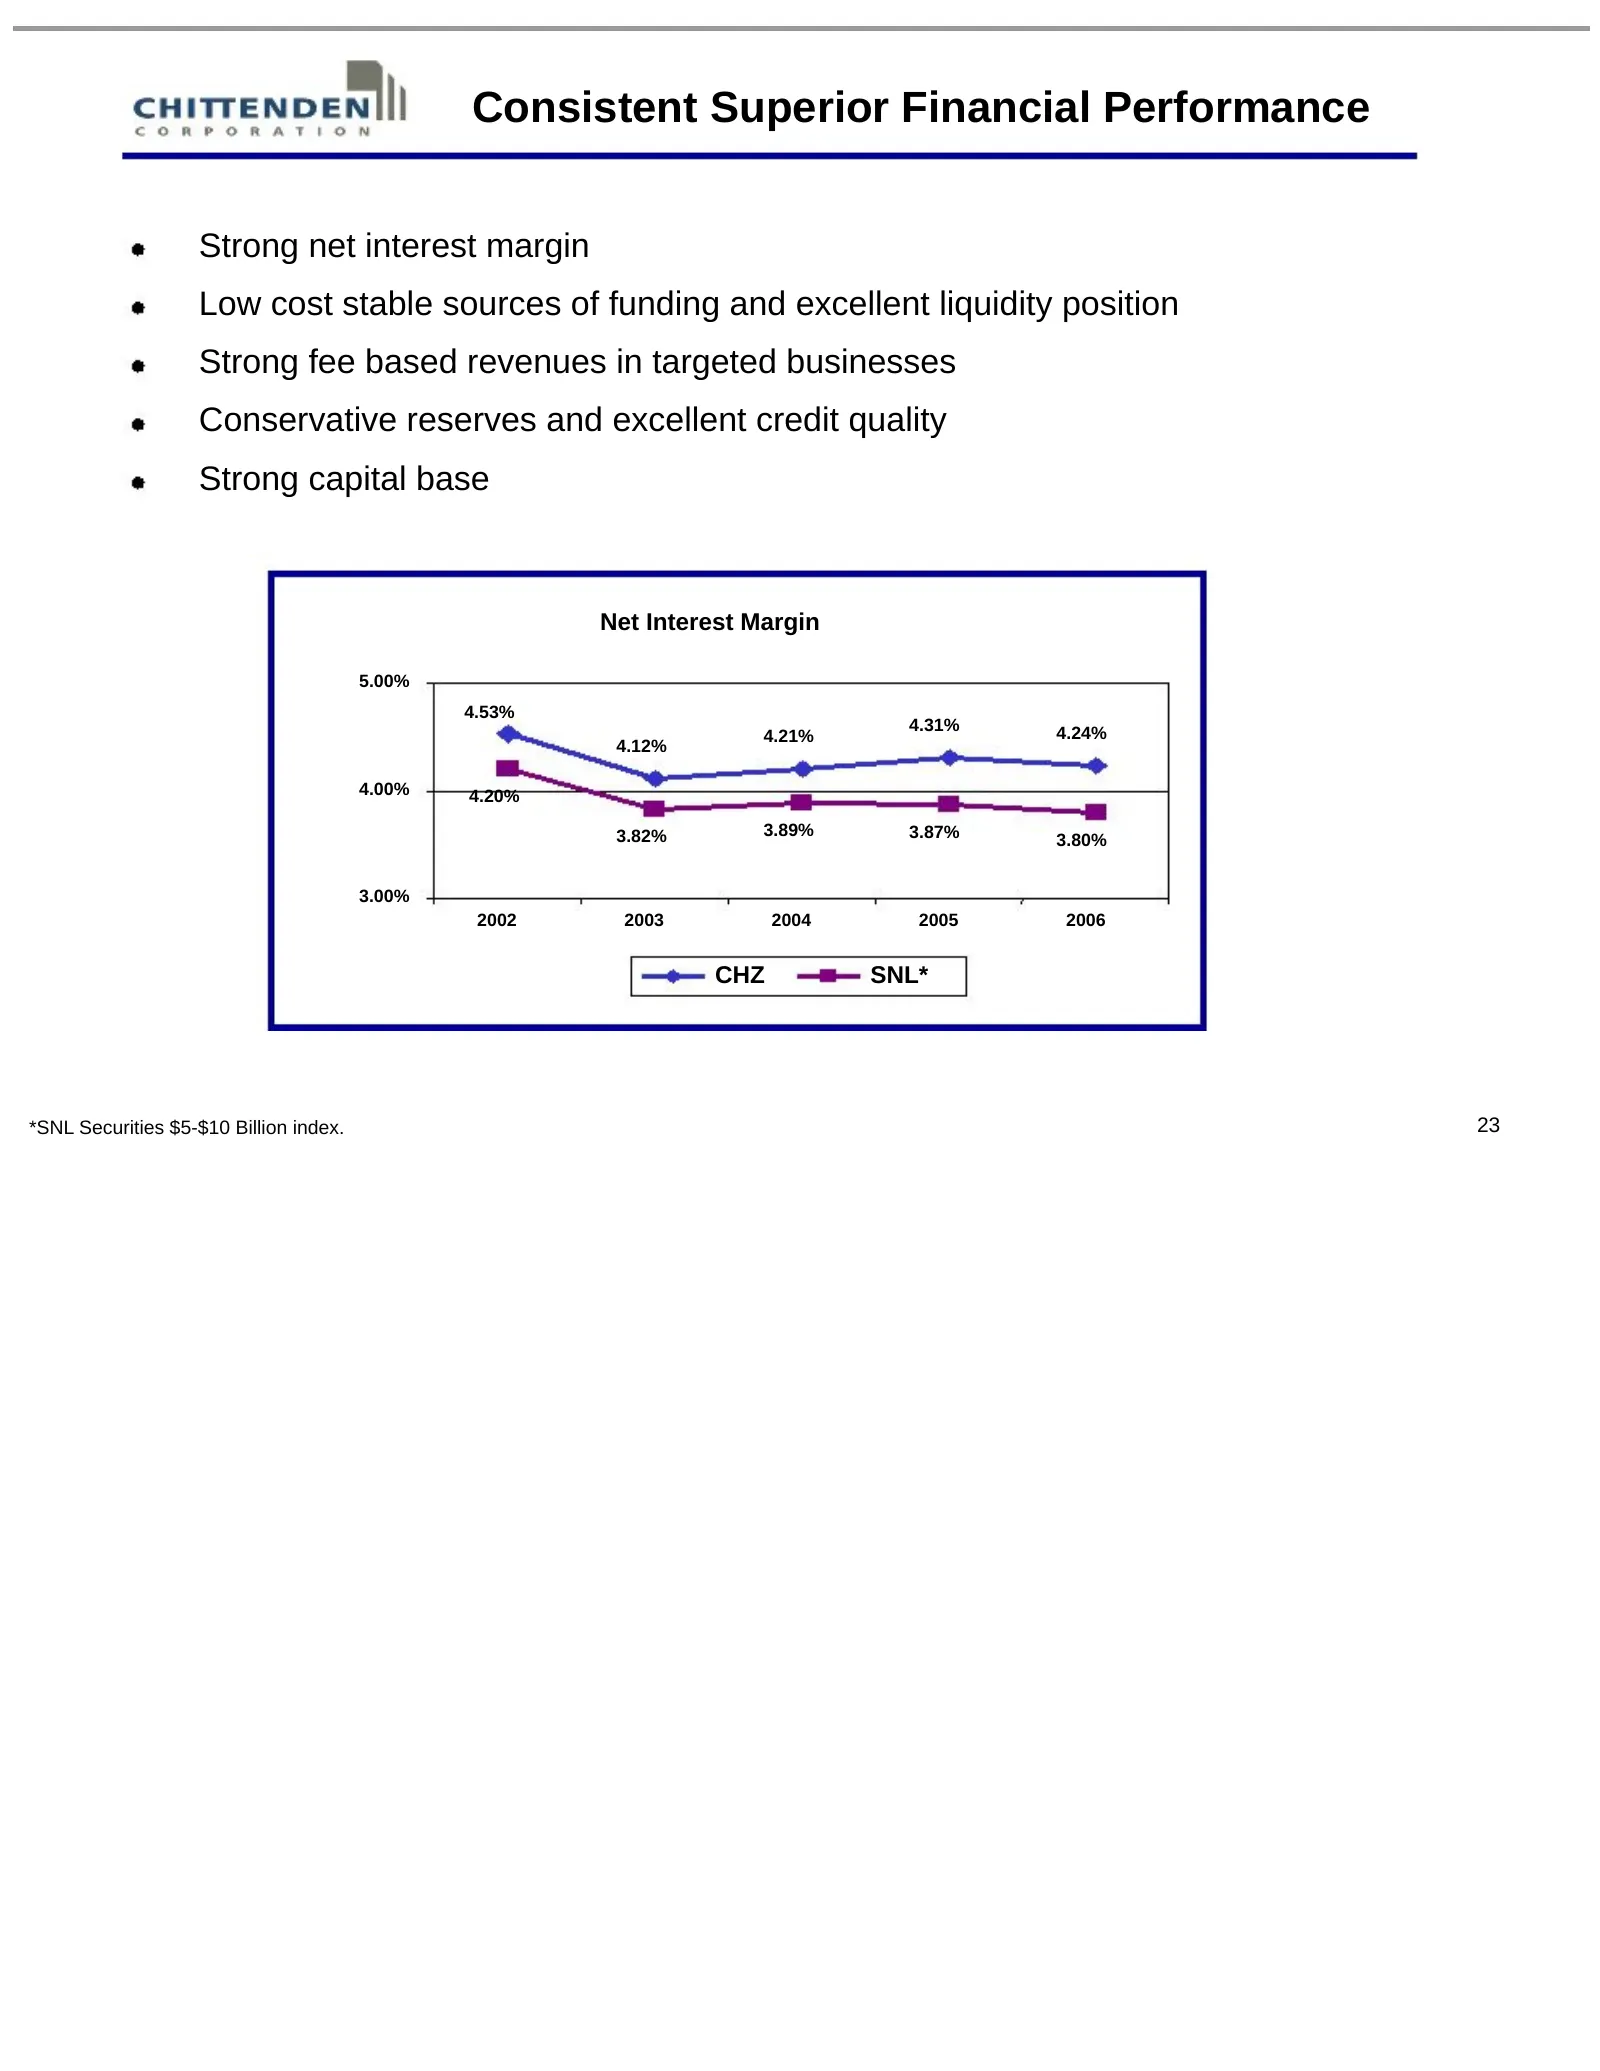
Consistent Superior Financial Performance Strong net interest margin Low cost stable sources of funding and excellent liquidity position Strong fee based revenues in targeted businesses Conservative reserves and excellent credit quality Strong capital base Net Interest Margin 5.00% 4.53% 4.31% 4.24%
Slide 24: Average Yields and Cost of Funds
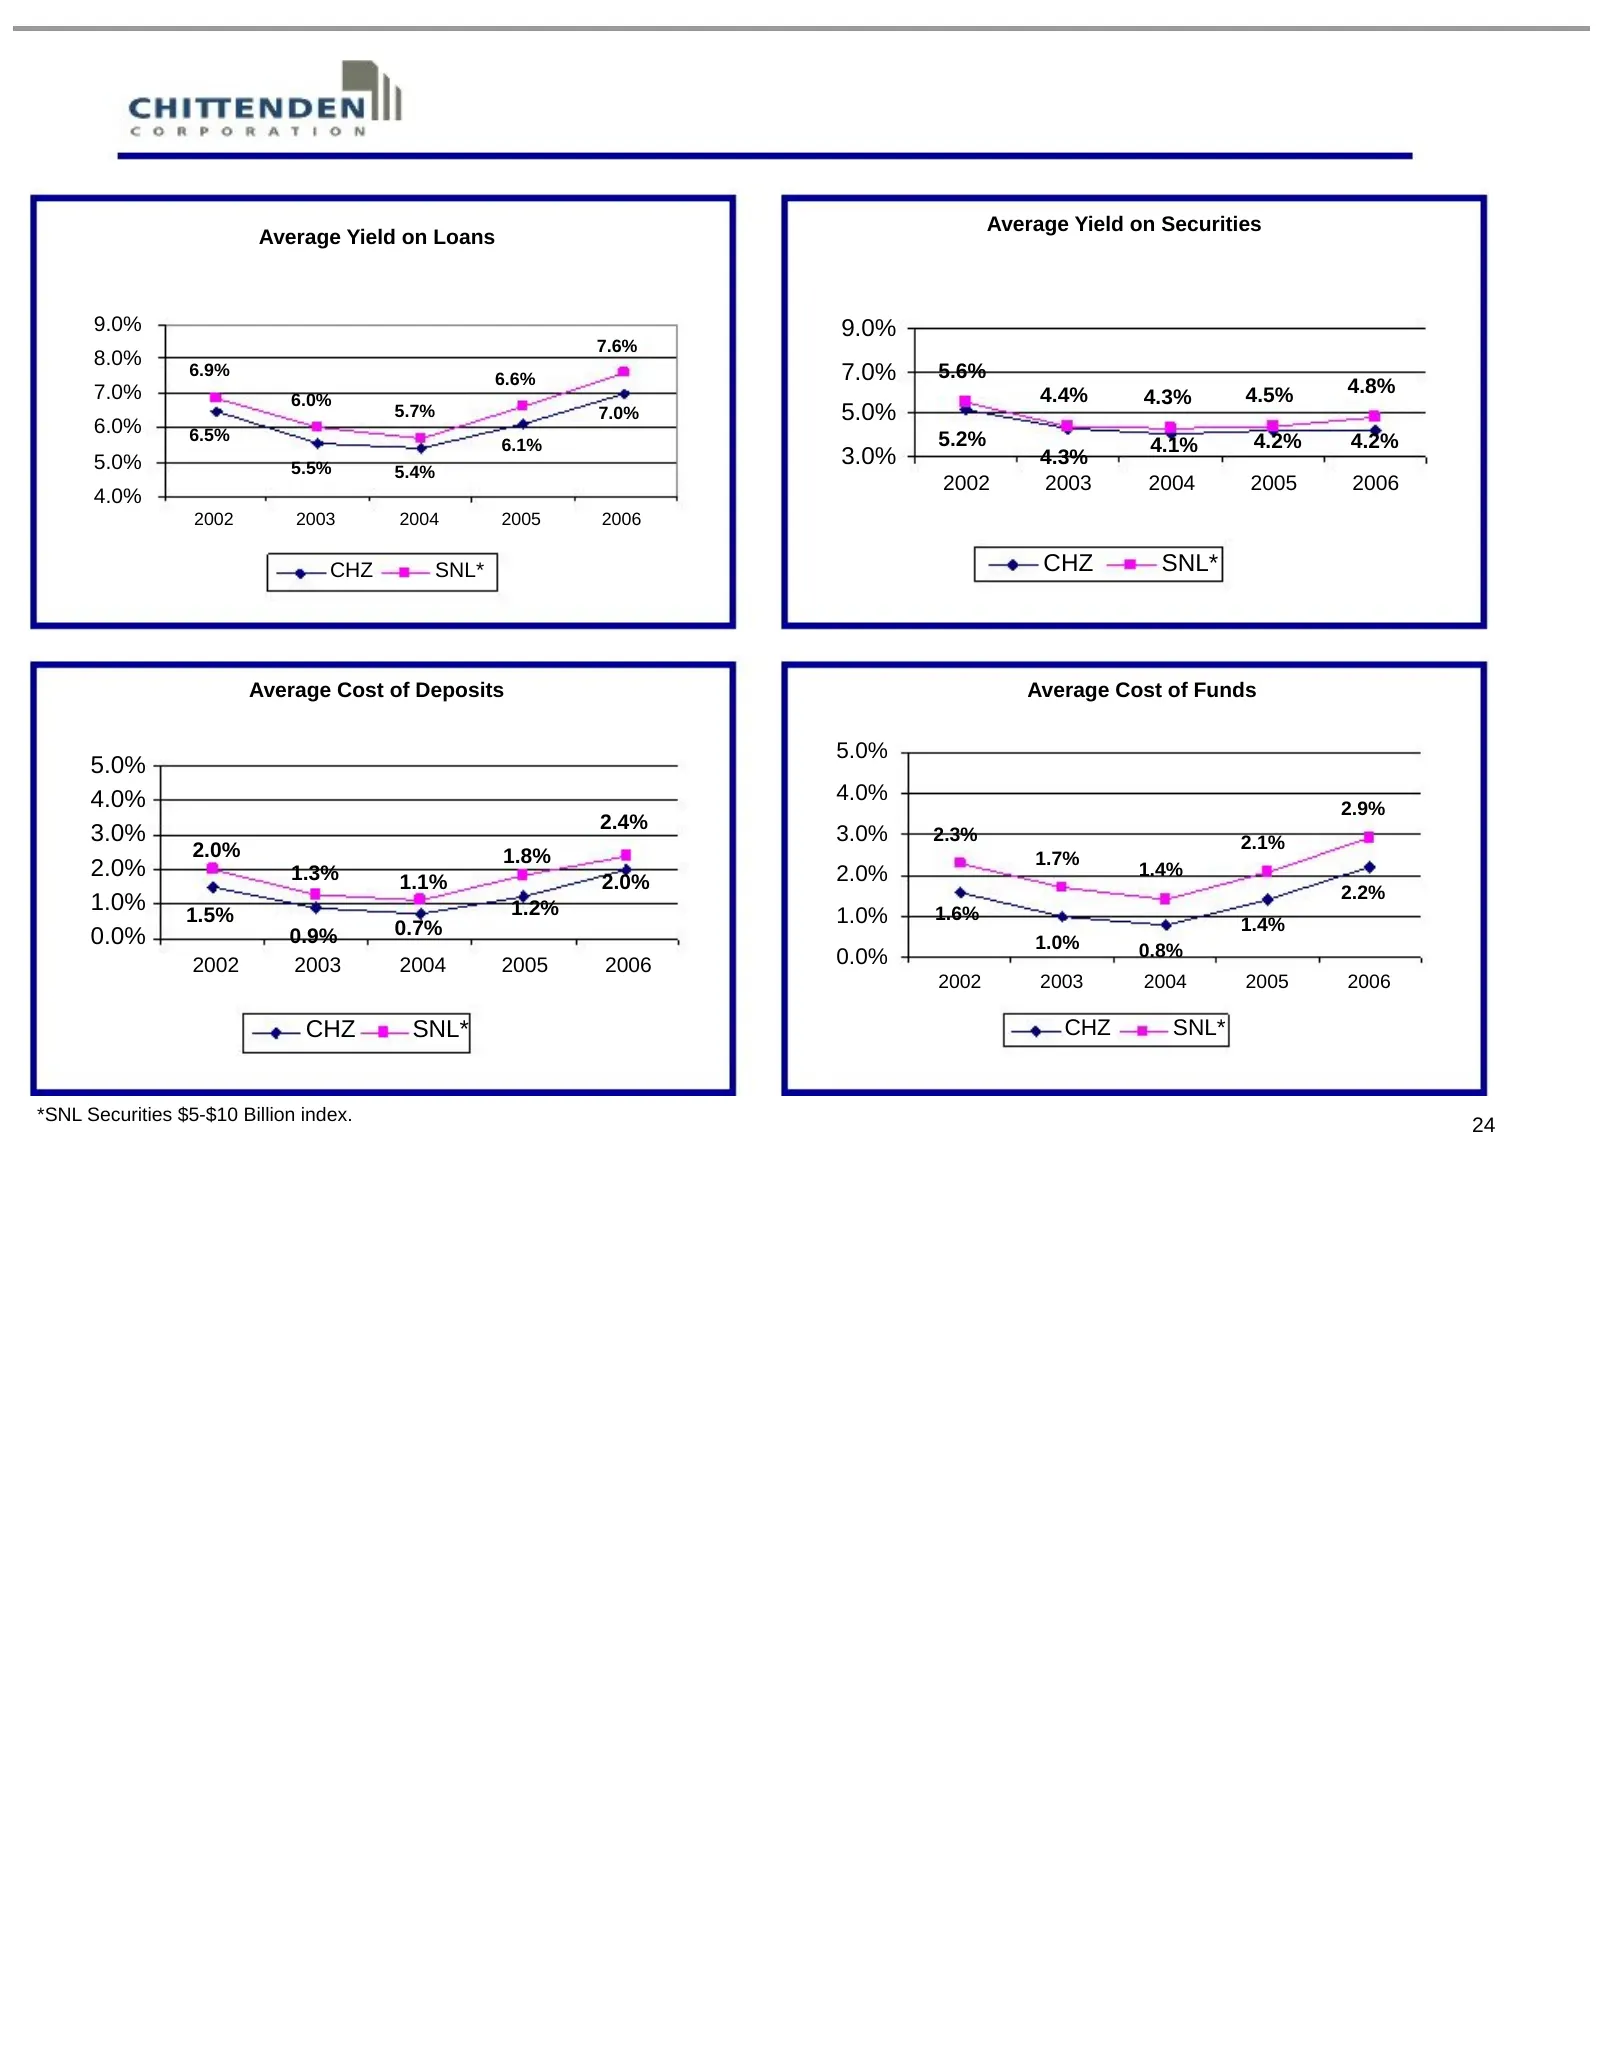
Average Yield on Securities Average Yield on Loans 9.0% 9.0% 7.6% 8.0% 6.9% 6.6% 7.0% 5.6% 7.0% 4.4% 4.5% 4.8% 6.0% 4.3% 5.7% 7.0% 5.0% 6.0% 6.5% 6.1% 5.2% 4.1% 4.2% 4.2% 5.0% 5.5% 3.0% 4.3% 5.4% 2002 2003 2004 2005 2006 4.0% 2002 2003 2004 2005 2006 CHZ SNL* CHZ SNL* Average Cost of Deposits Averag
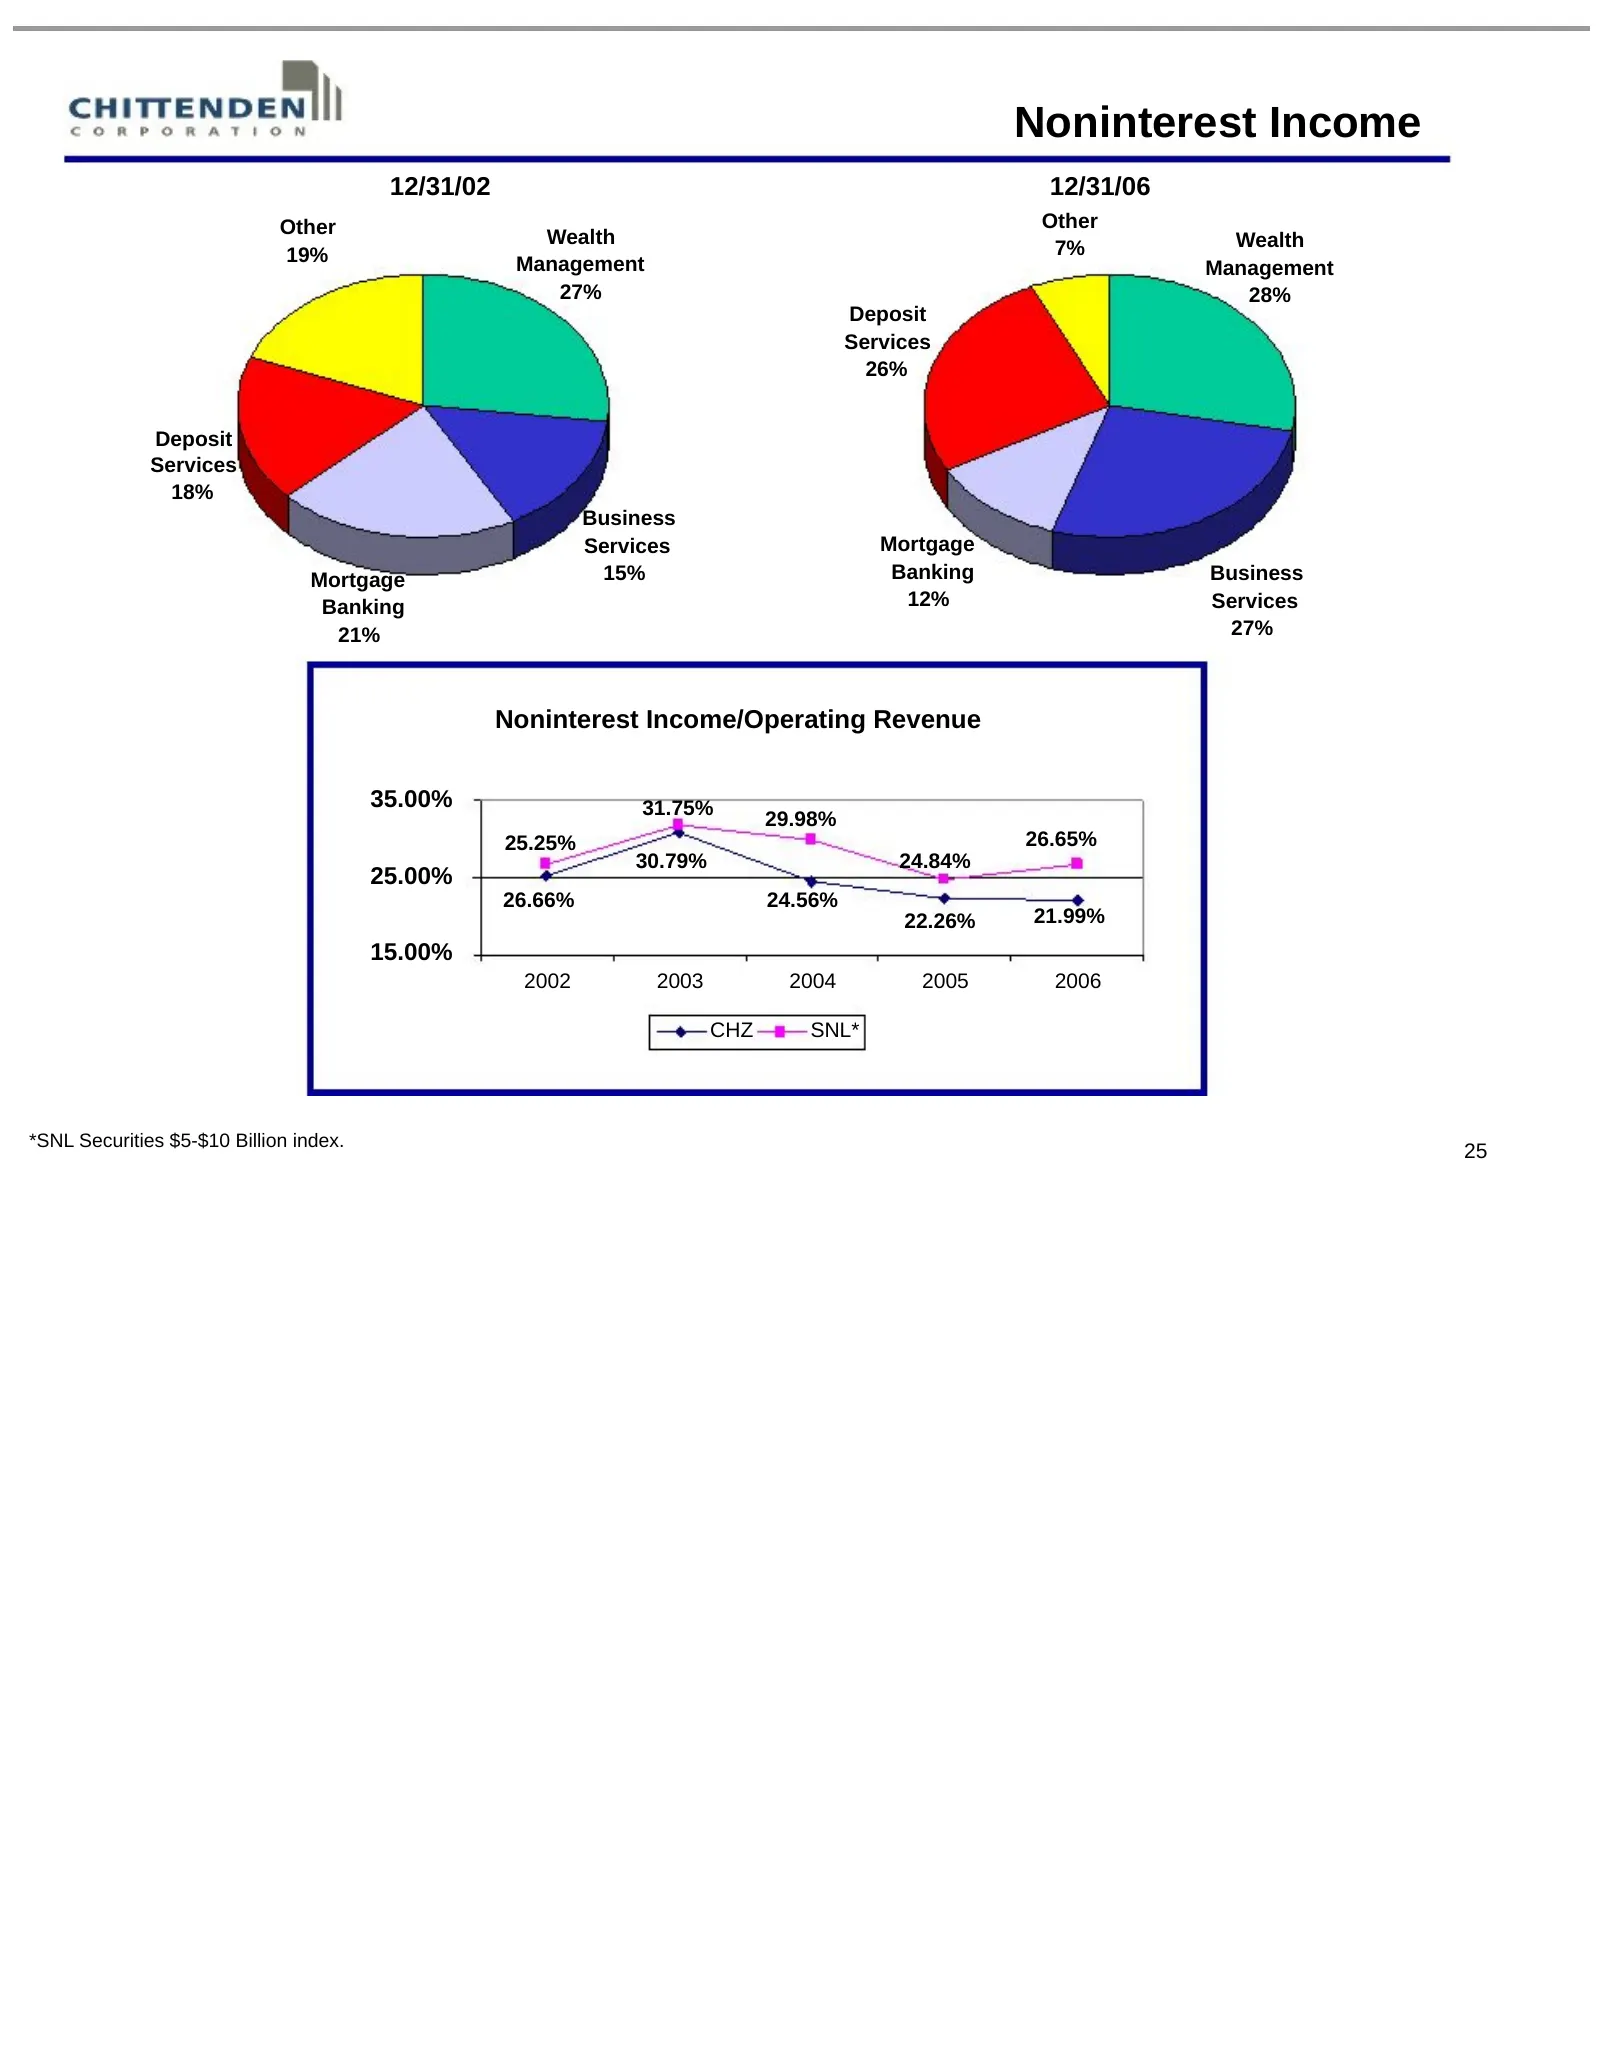
Slide 25: Noninterest Income
Noninterest Income 12/31/02 12/31/06 Other Other Wealth Wealth 19% 7% Management Management 27% 28% Deposit Services 26% Deposit Services 18% Business Services Mortgage Mortgage 15% Banking Business Banking 12% Services 21% 27% Noninterest Income/Operating Revenue 35.00% 31.75% 29.98% 25.25% 26.65%
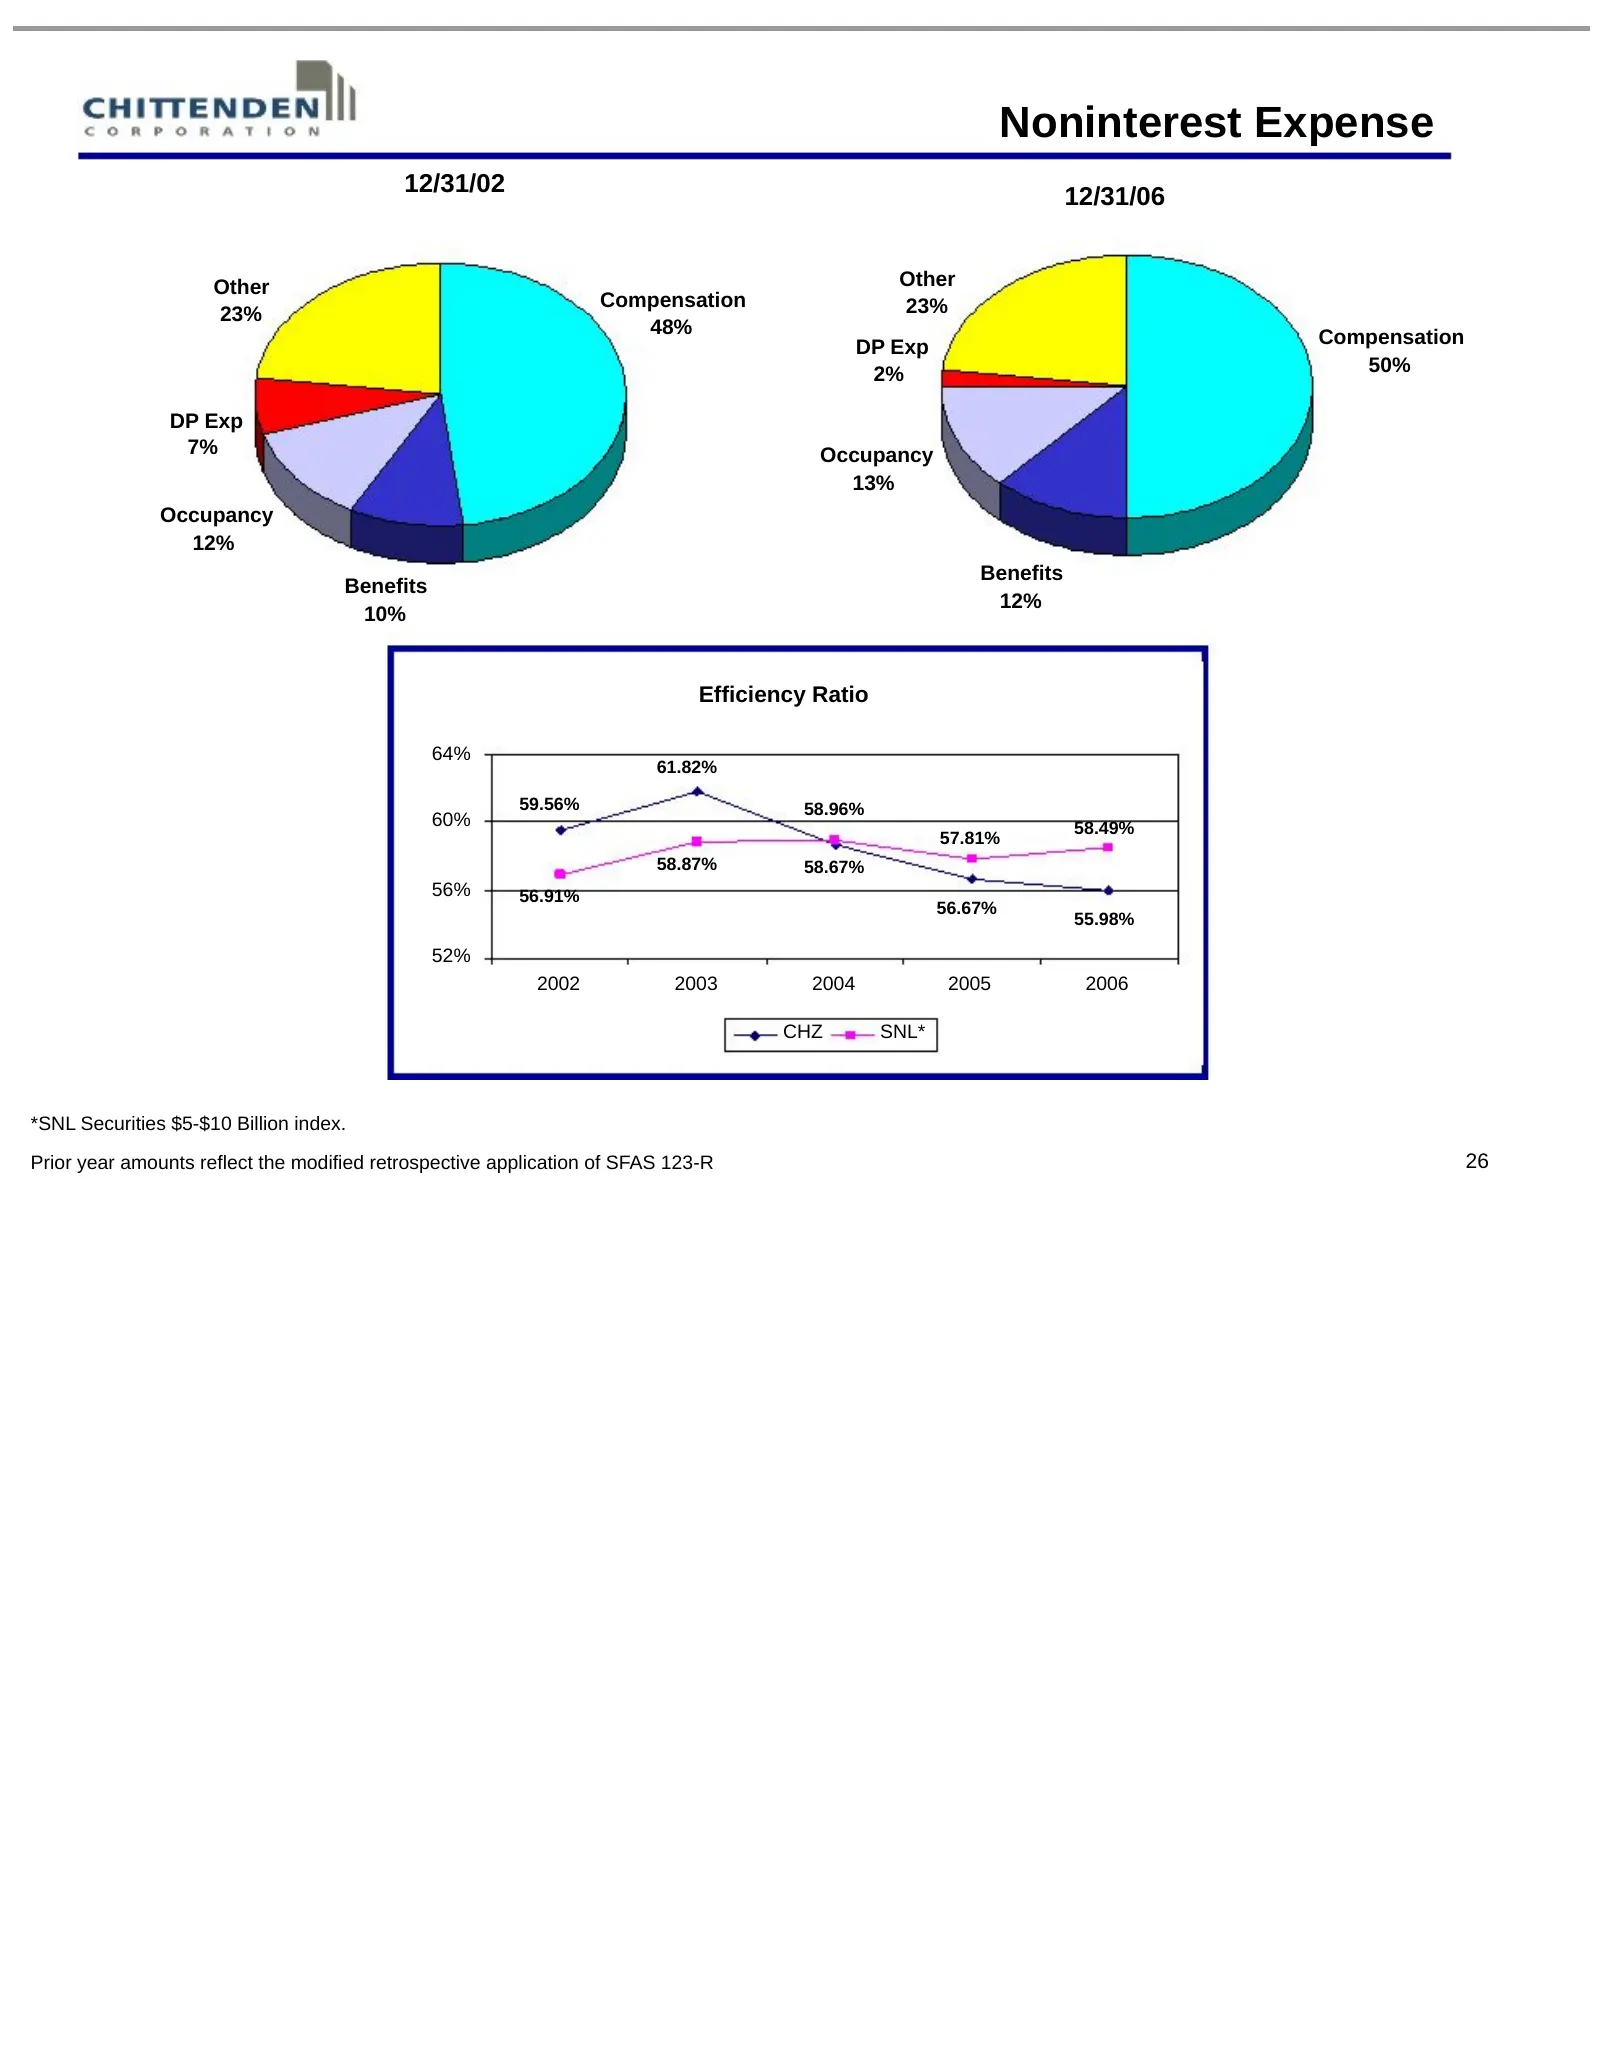
Slide 26: Noninterest Expense
Noninterest Expense 12/31/02 12/31/06 Other Other Compensation 23% 23% 48% Compensation DP Exp 2% 50% DP Exp 7% Occupancy 13% Occupancy 12% Benefits Benefits 12% 10% Efficiency Ratio 64% 61.82% 59.56% 58.96% 60% 58.49% 57.81% 58.87% 58.67% 56% 56.91% 56.67% 55.98% 52% 2002 2003 2004 2005 2006 CHZ SN
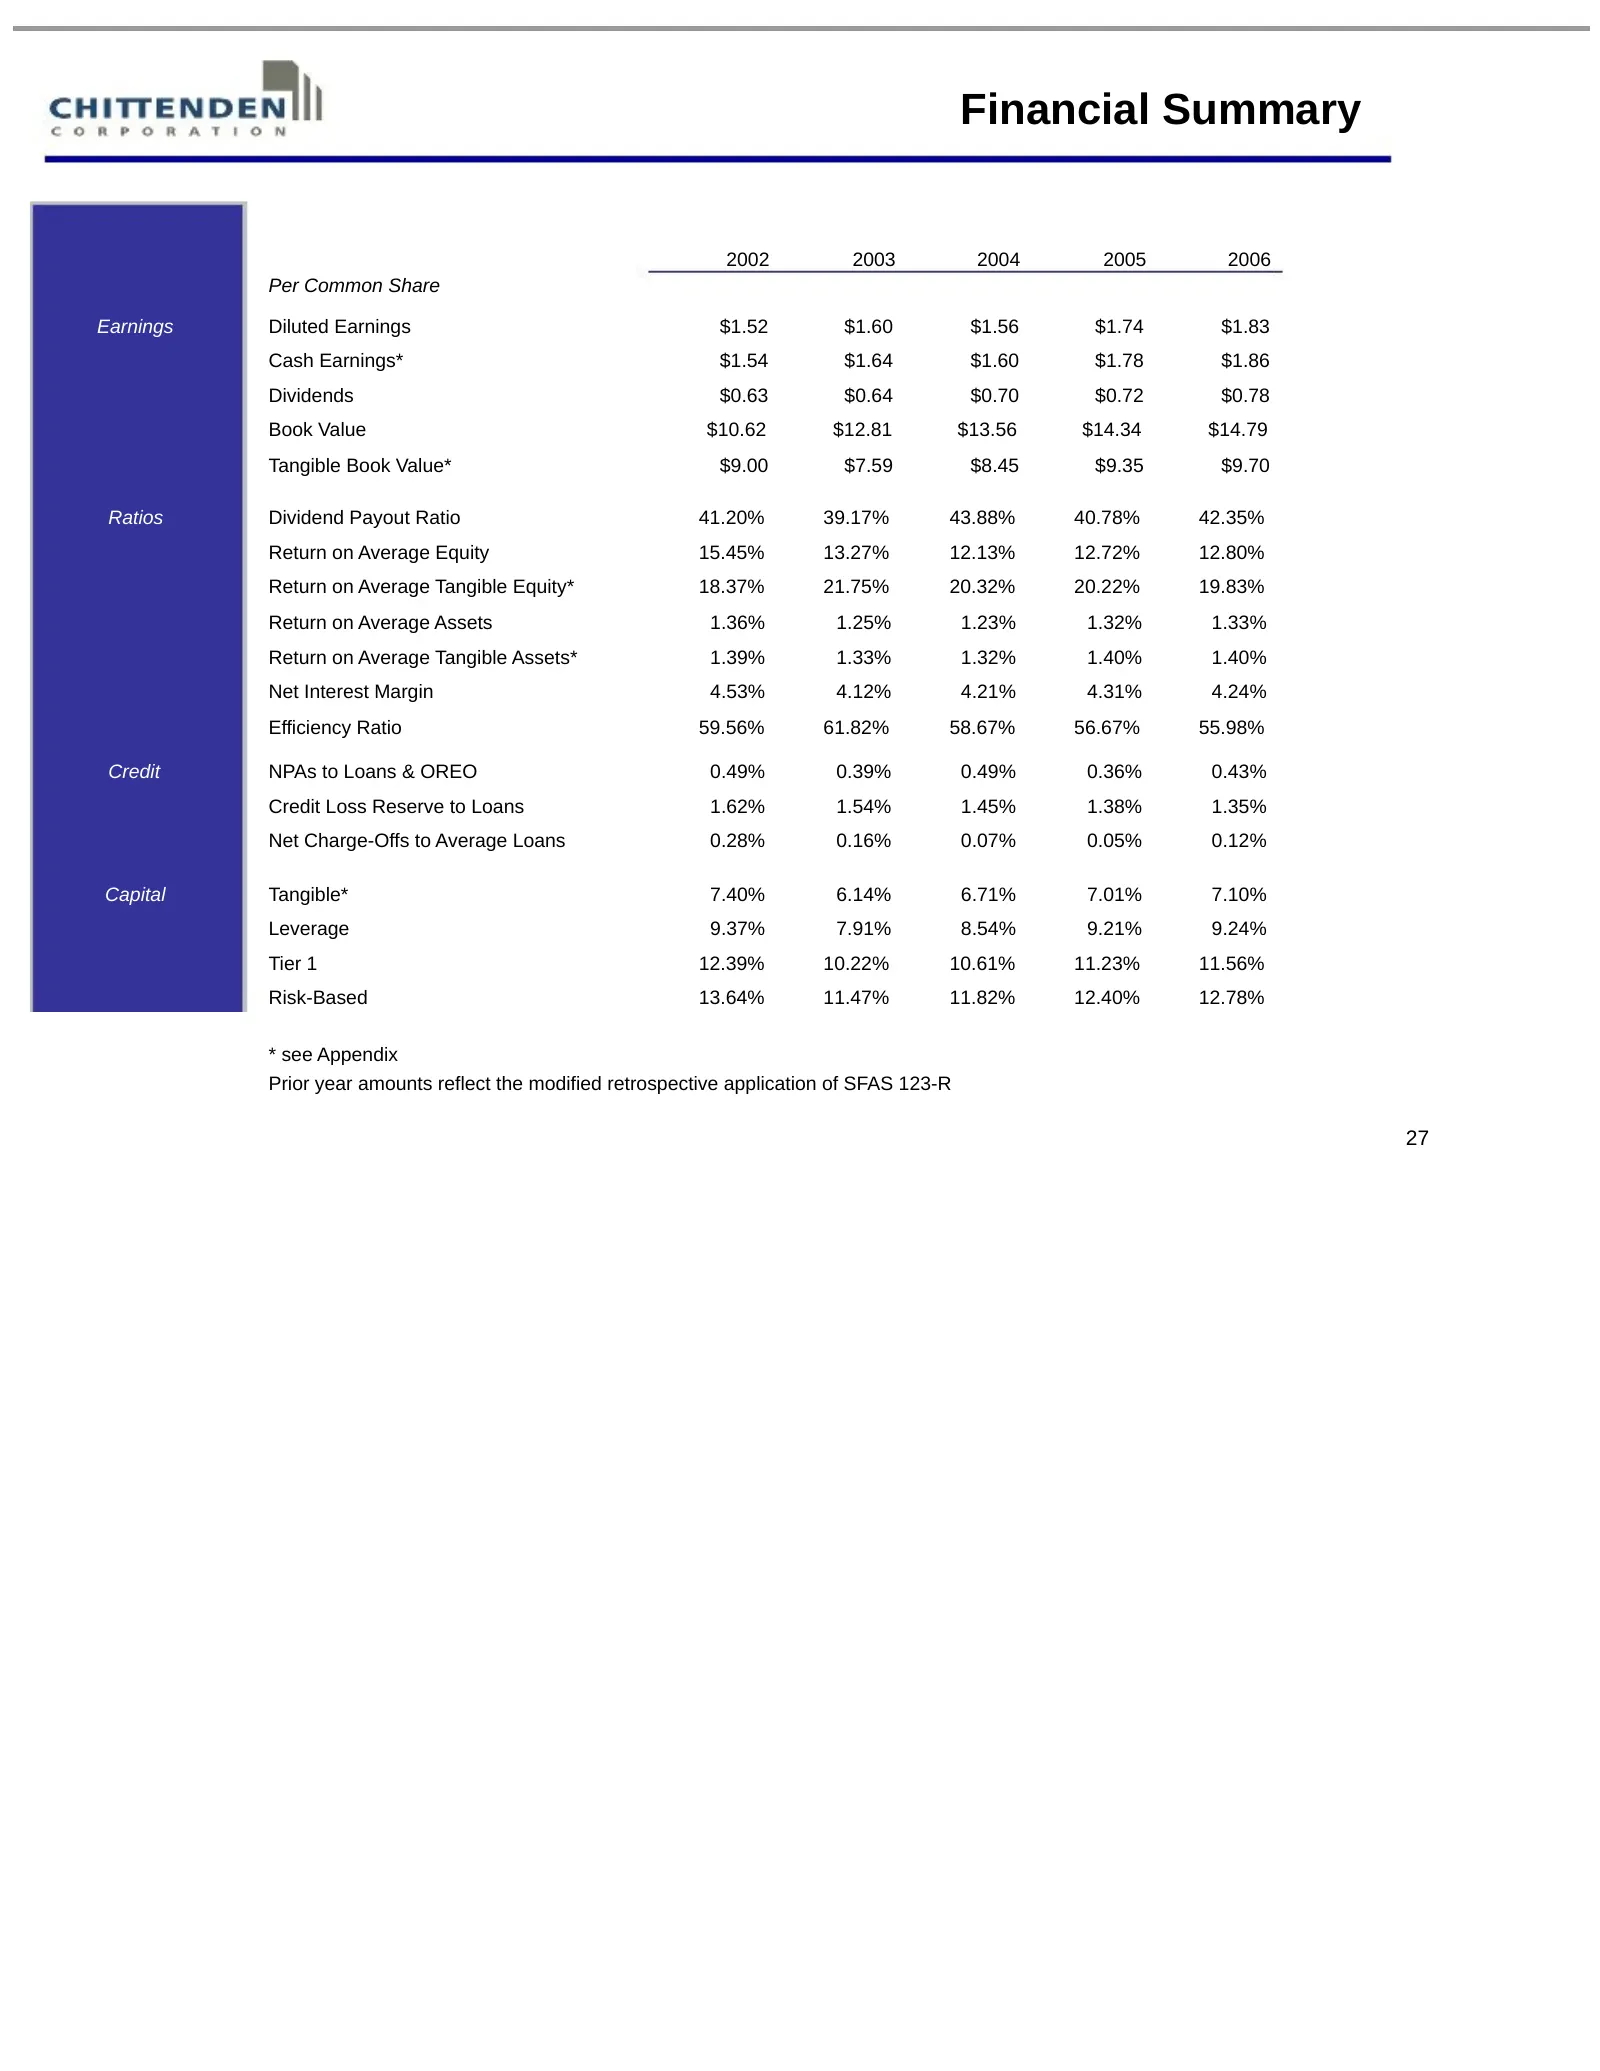
Slide 27: Financial Summary
Financial Summary 2002 2003 2004 2005 2006 Per Common Share Earnings Diluted Earnings $1.52 $1.60 $1.56 $1.74 $1.83 Cash Earnings* $1.54 $1.64 $1.60 $1.78 $1.86 Dividends $0.63 $0.64 $0.70 $0.72 $0.78 Book Value $10.62 $12.81 $13.56 $14.34 $14.79 Tangible Book Value* $9.00 $7.59 $8.45 $9.35 $9.70 Ra
Slide 28: Risk Management
Risk Management
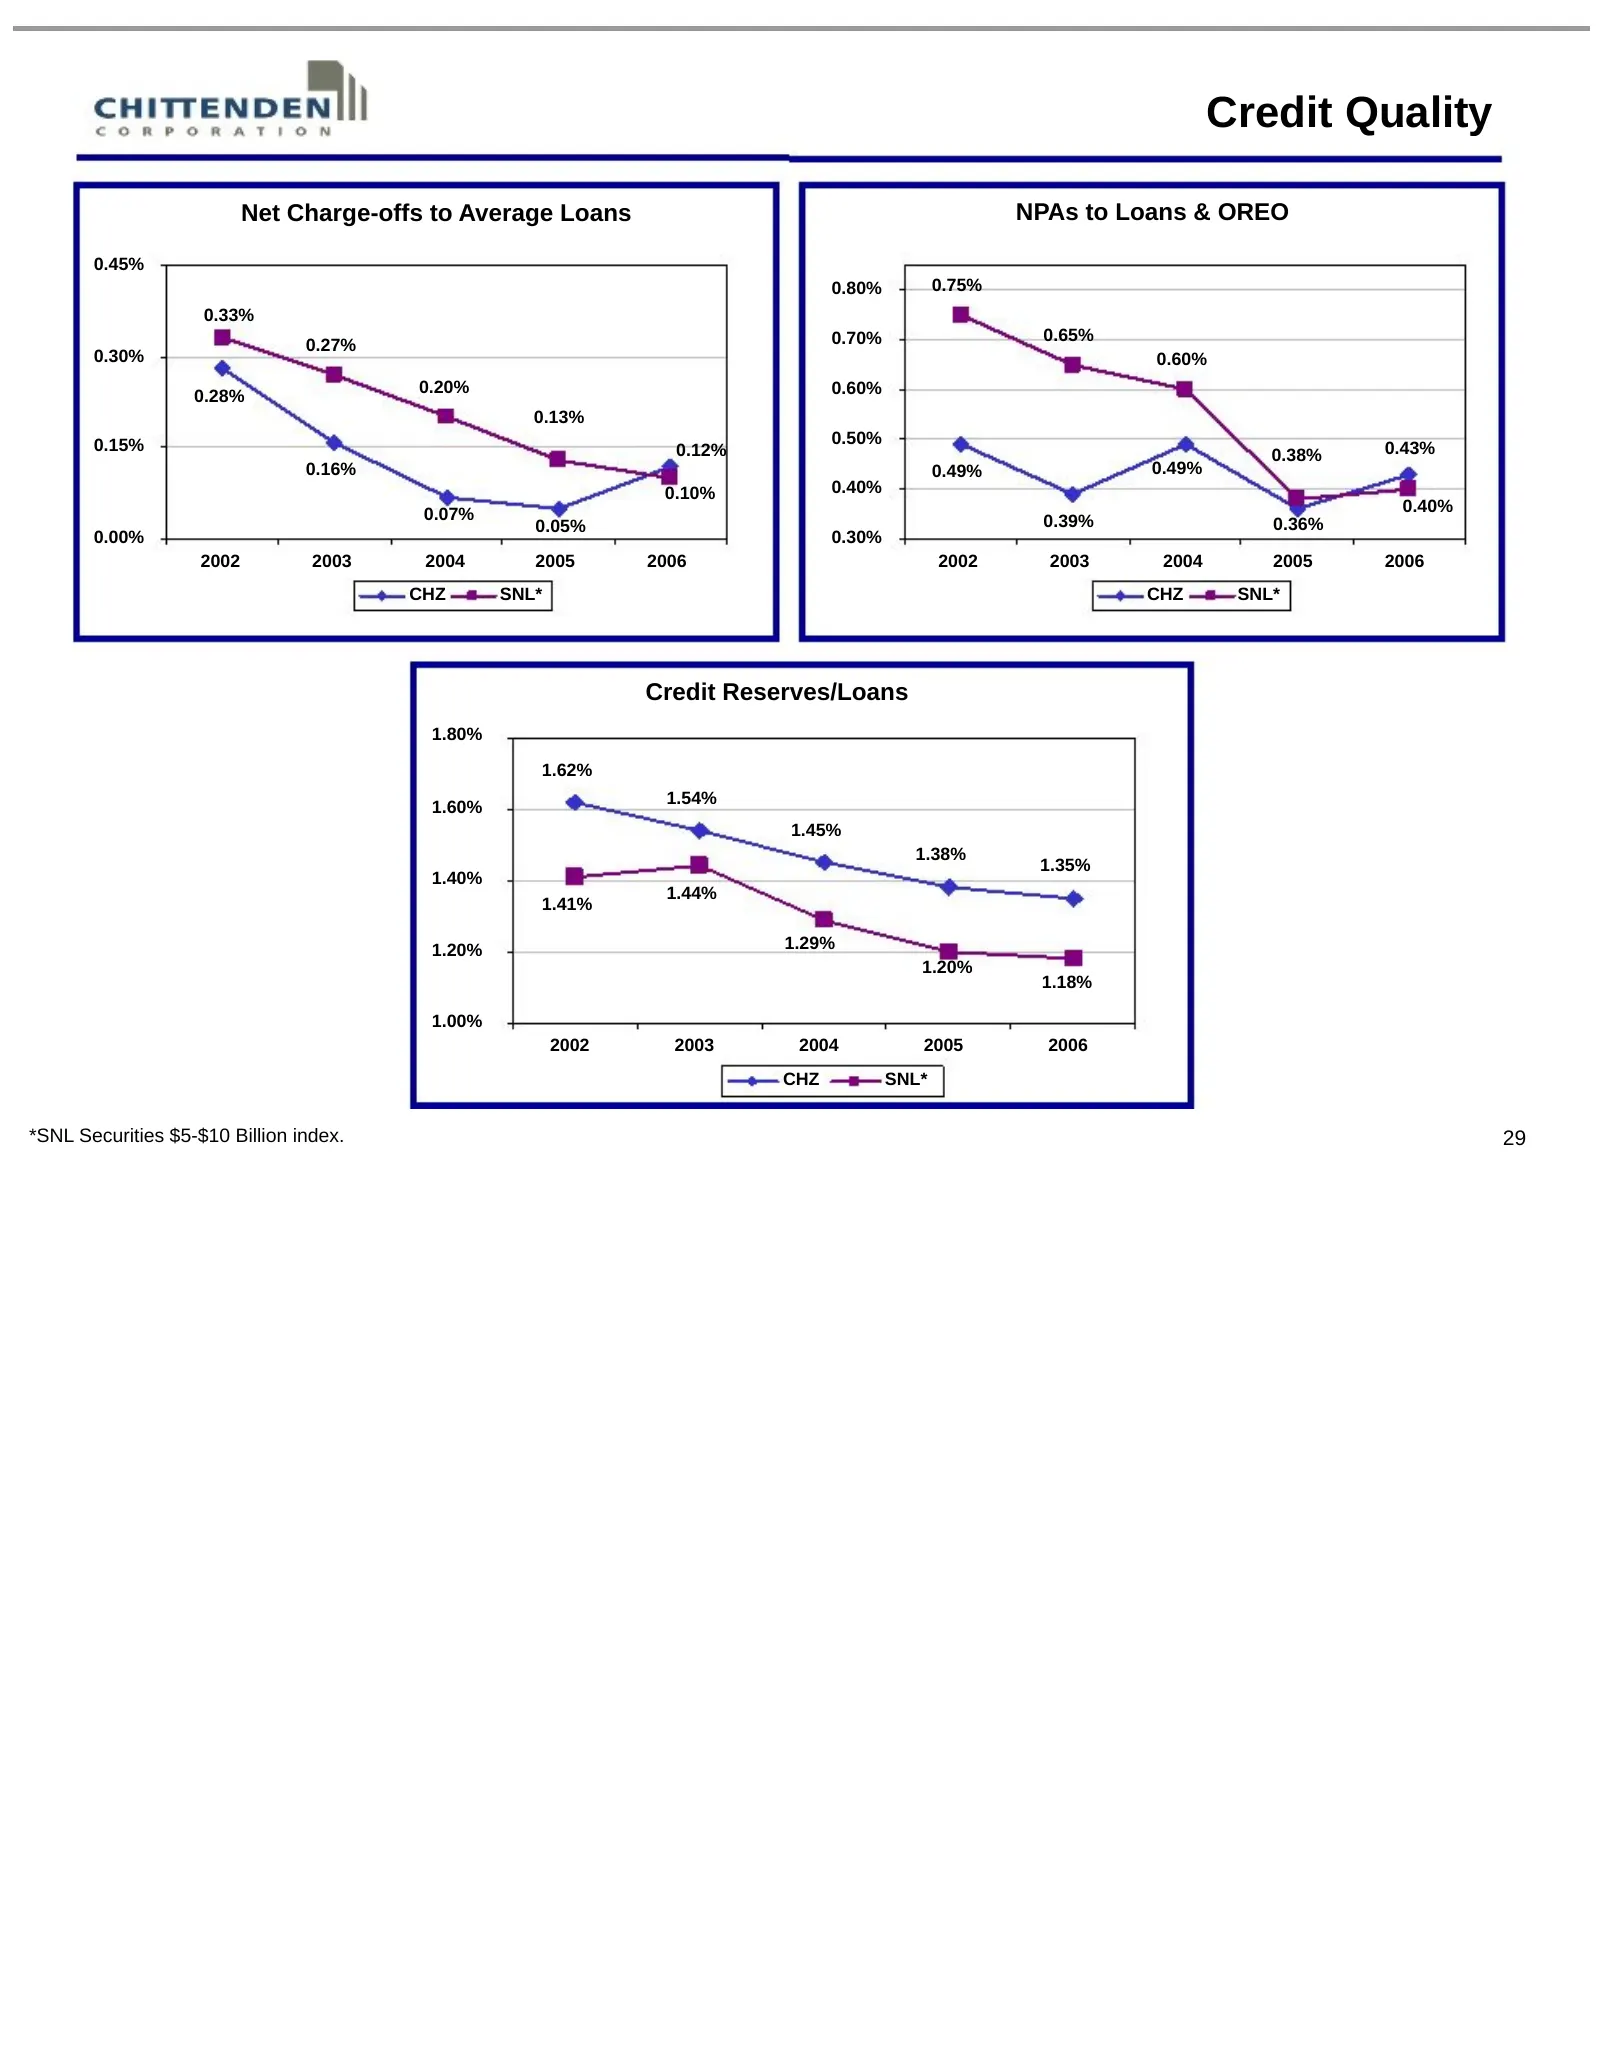
Slide 29: Credit Quality
Credit Quality Net Charge-offs to Average Loans NPAs to Loans & OREO 0.45% 0.80% 0.75% 0.33% 0.70% 0.65% 0.27% 0.30% 0.60% 0.20% 0.60% 0.28% 0.13% 0.15% 0.50% 0.12% 0.38% 0.43% 0.16% 0.49% 0.49% 0.10% 0.40% 0.07% 0.40% 0.05% 0.39% 0.36% 0.00% 0.30% 2002 2003 2004 2005 2006 2002 2003 2004 2005 2006 C
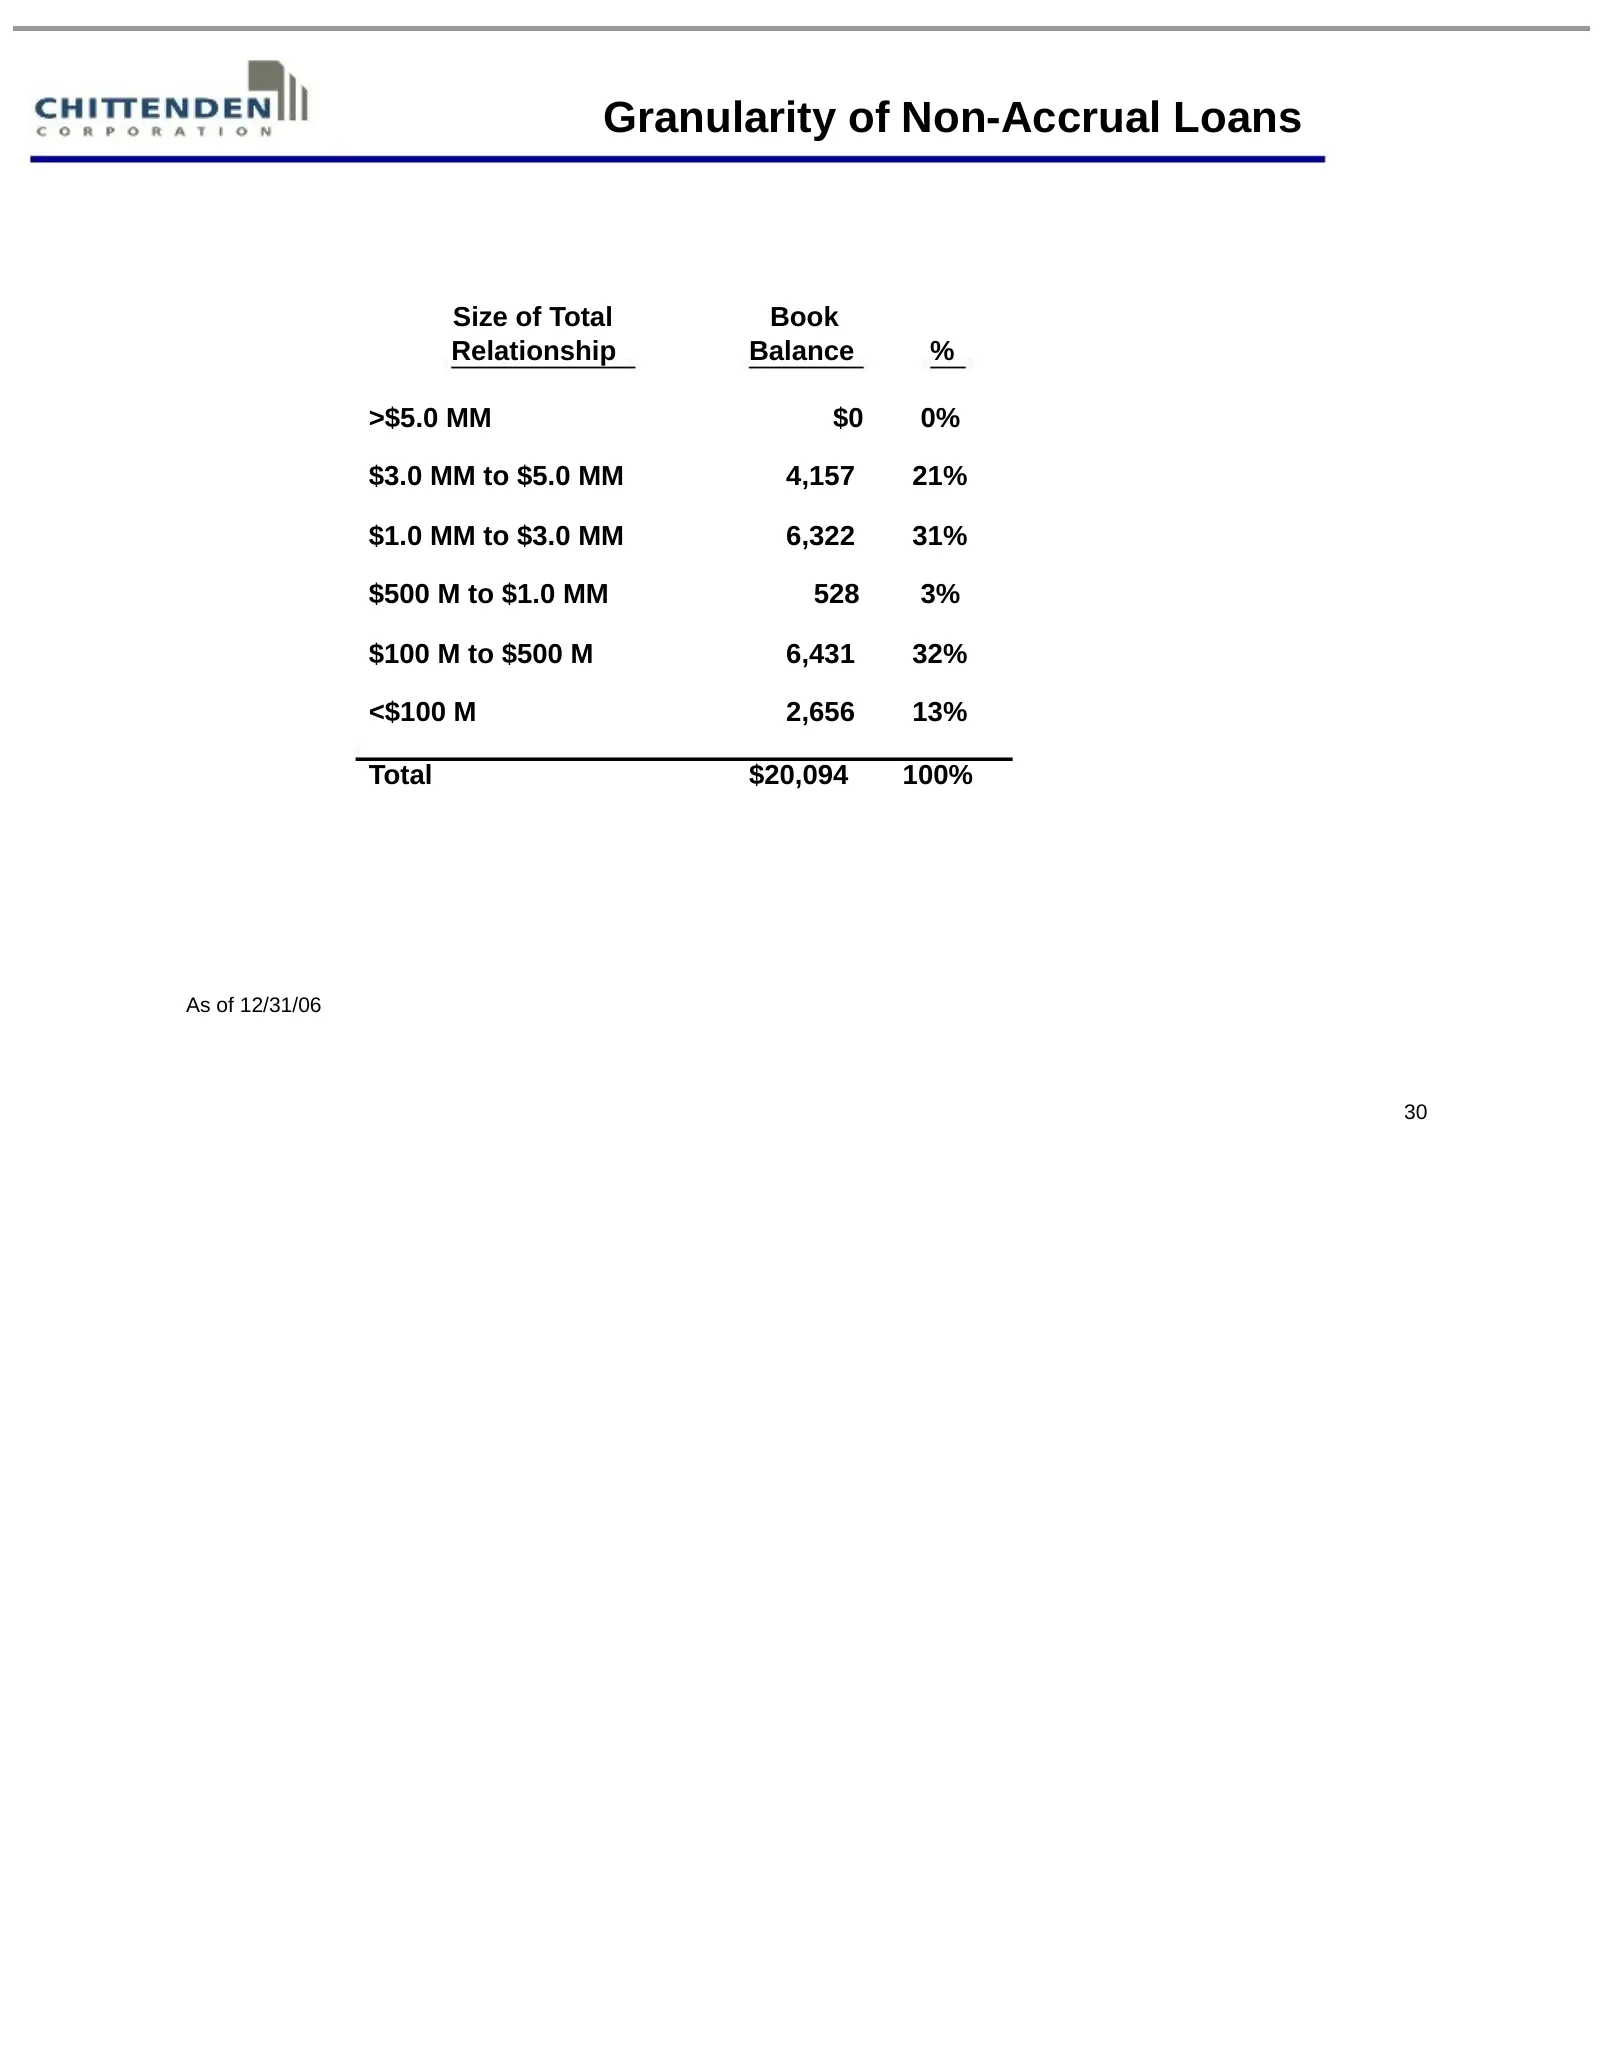
Slide 30: Granularity of Non-Accrual Loans
Granularity of Non-Accrual Loans Size of Total Book Relationship Balance % >$5.0 MM $0 0% $3.0 MM to $5.0 MM 4,157 21% $1.0 MM to $3.0 MM 6,322 31% $500 M to $1.0 MM 528 3% $100 M to $500 M 6,431 32% <$100 M 2,656 13% Total $20,094 100% As of 12/31/06 30
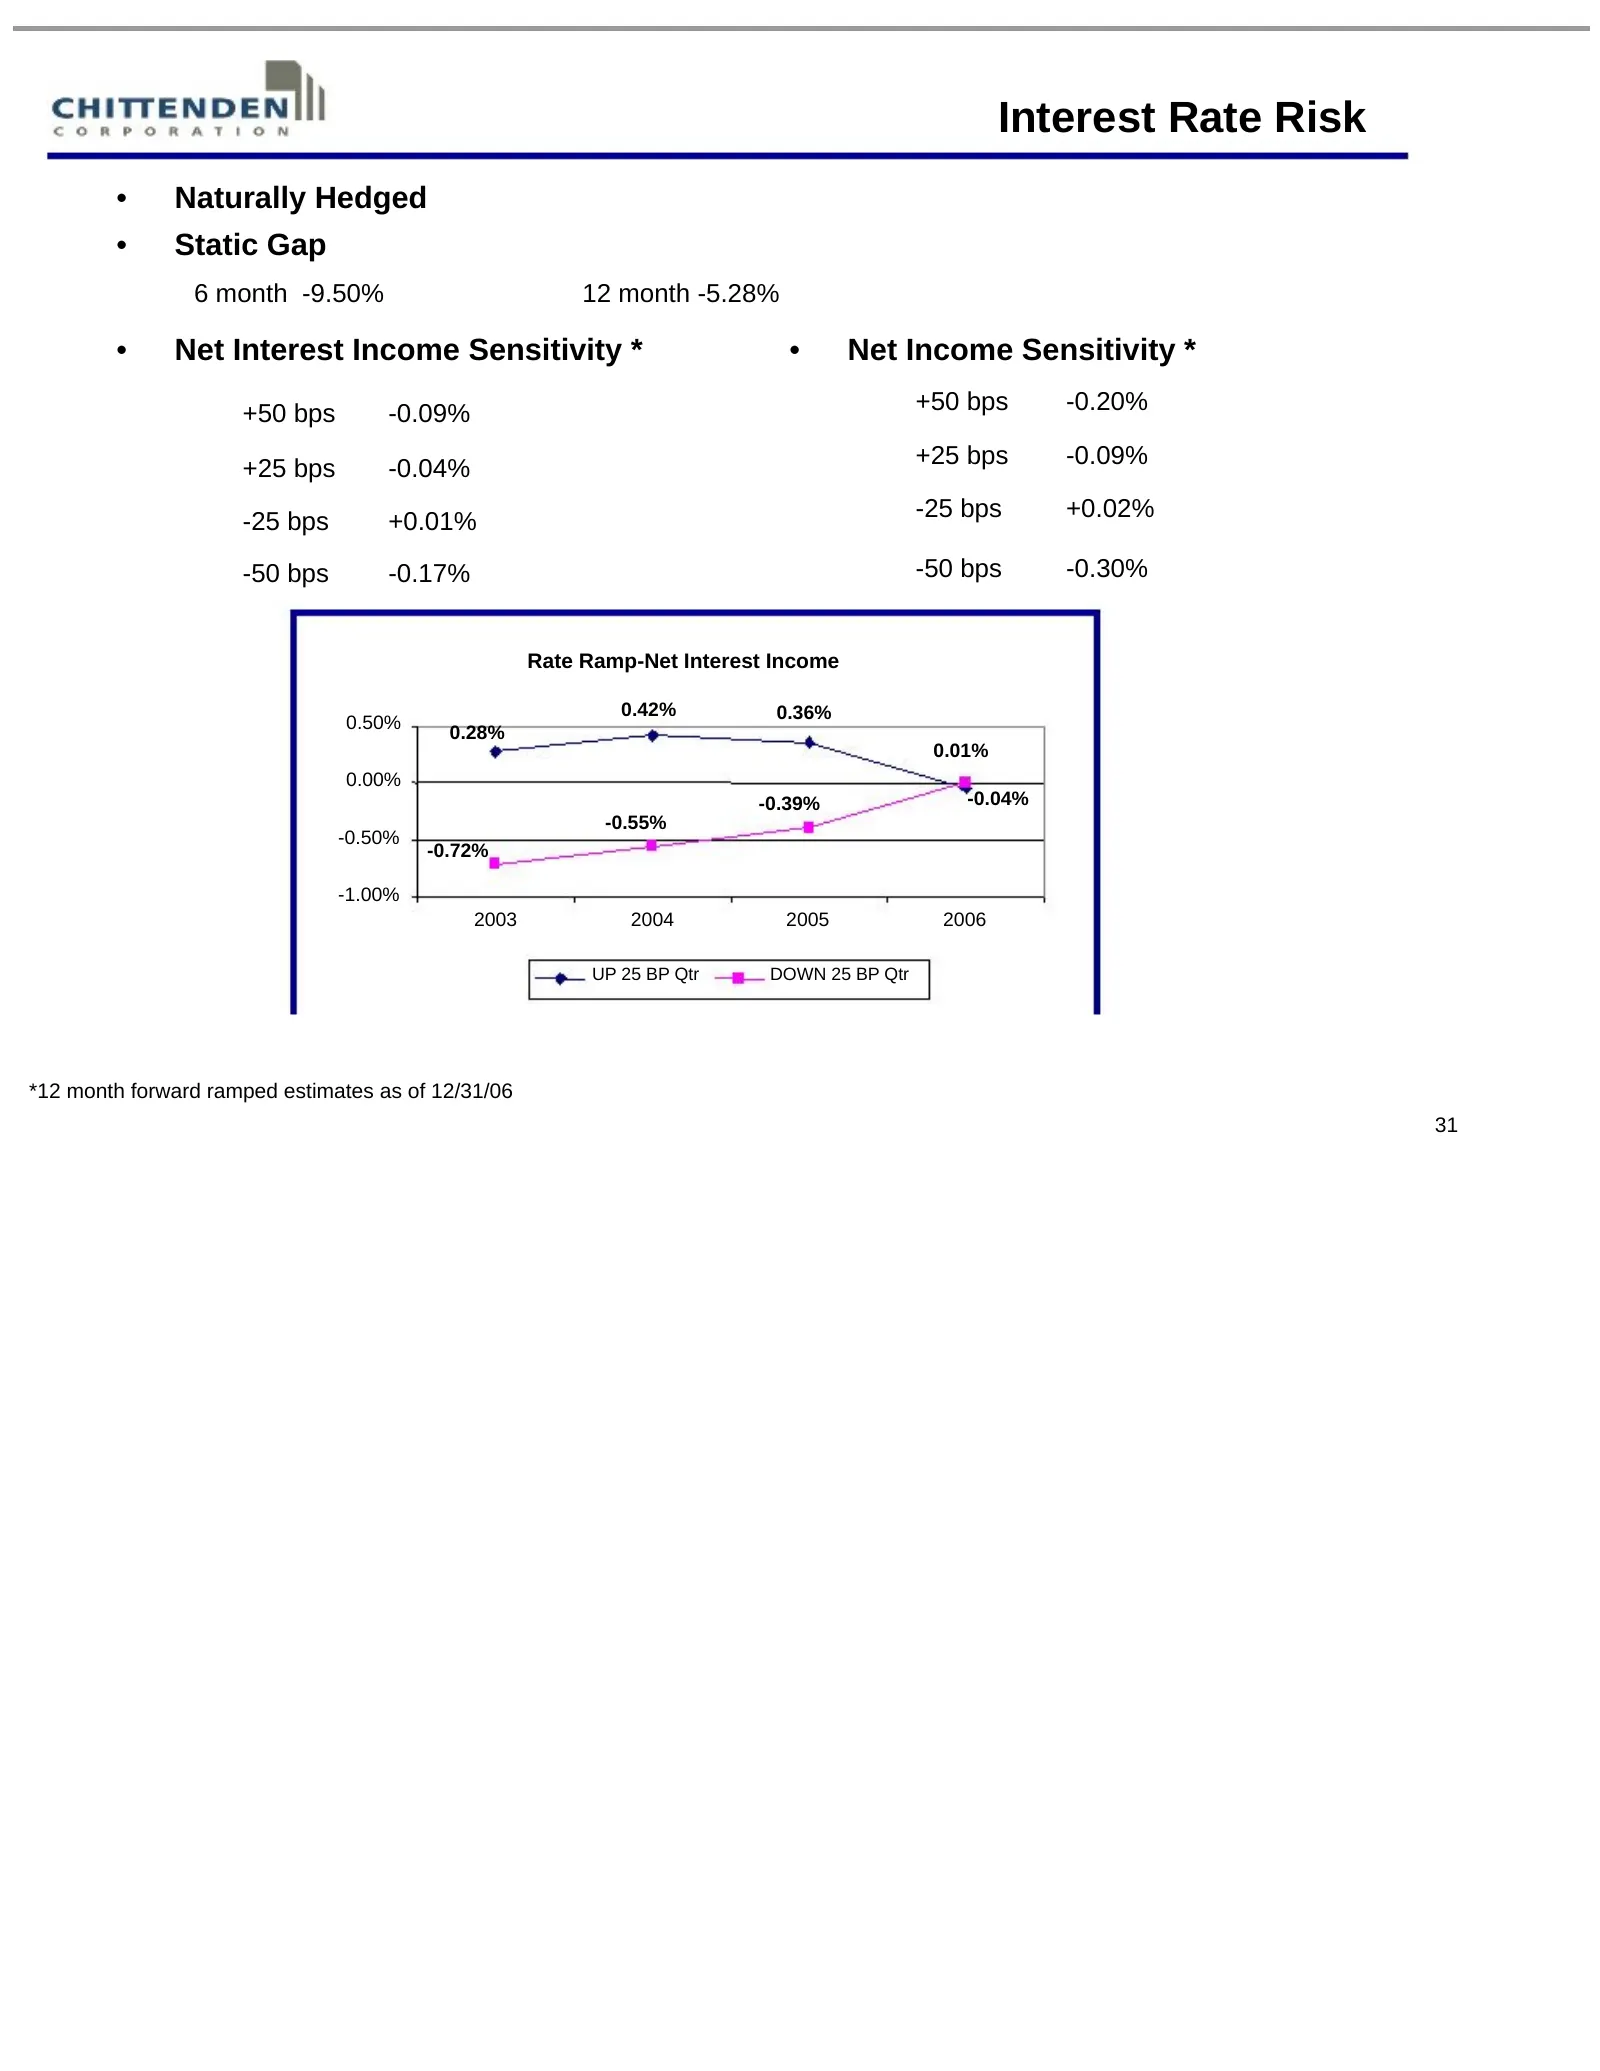
Slide 31: Interest Rate Risk
Interest Rate Risk • Naturally Hedged • Static Gap 6 month -9.50% 12 month -5.28% • Net Interest Income Sensitivity * • Net Income Sensitivity * +50 bps -0.09% +50 bps -0.20% +25 bps -0.09% +25 bps -0.04% -25 bps +0.02% -25 bps +0.01% -50 bps -0.17% -50 bps -0.30% Rate Ramp-Net Interest Income 0.42%
Slide 32: In Summary
In Summary
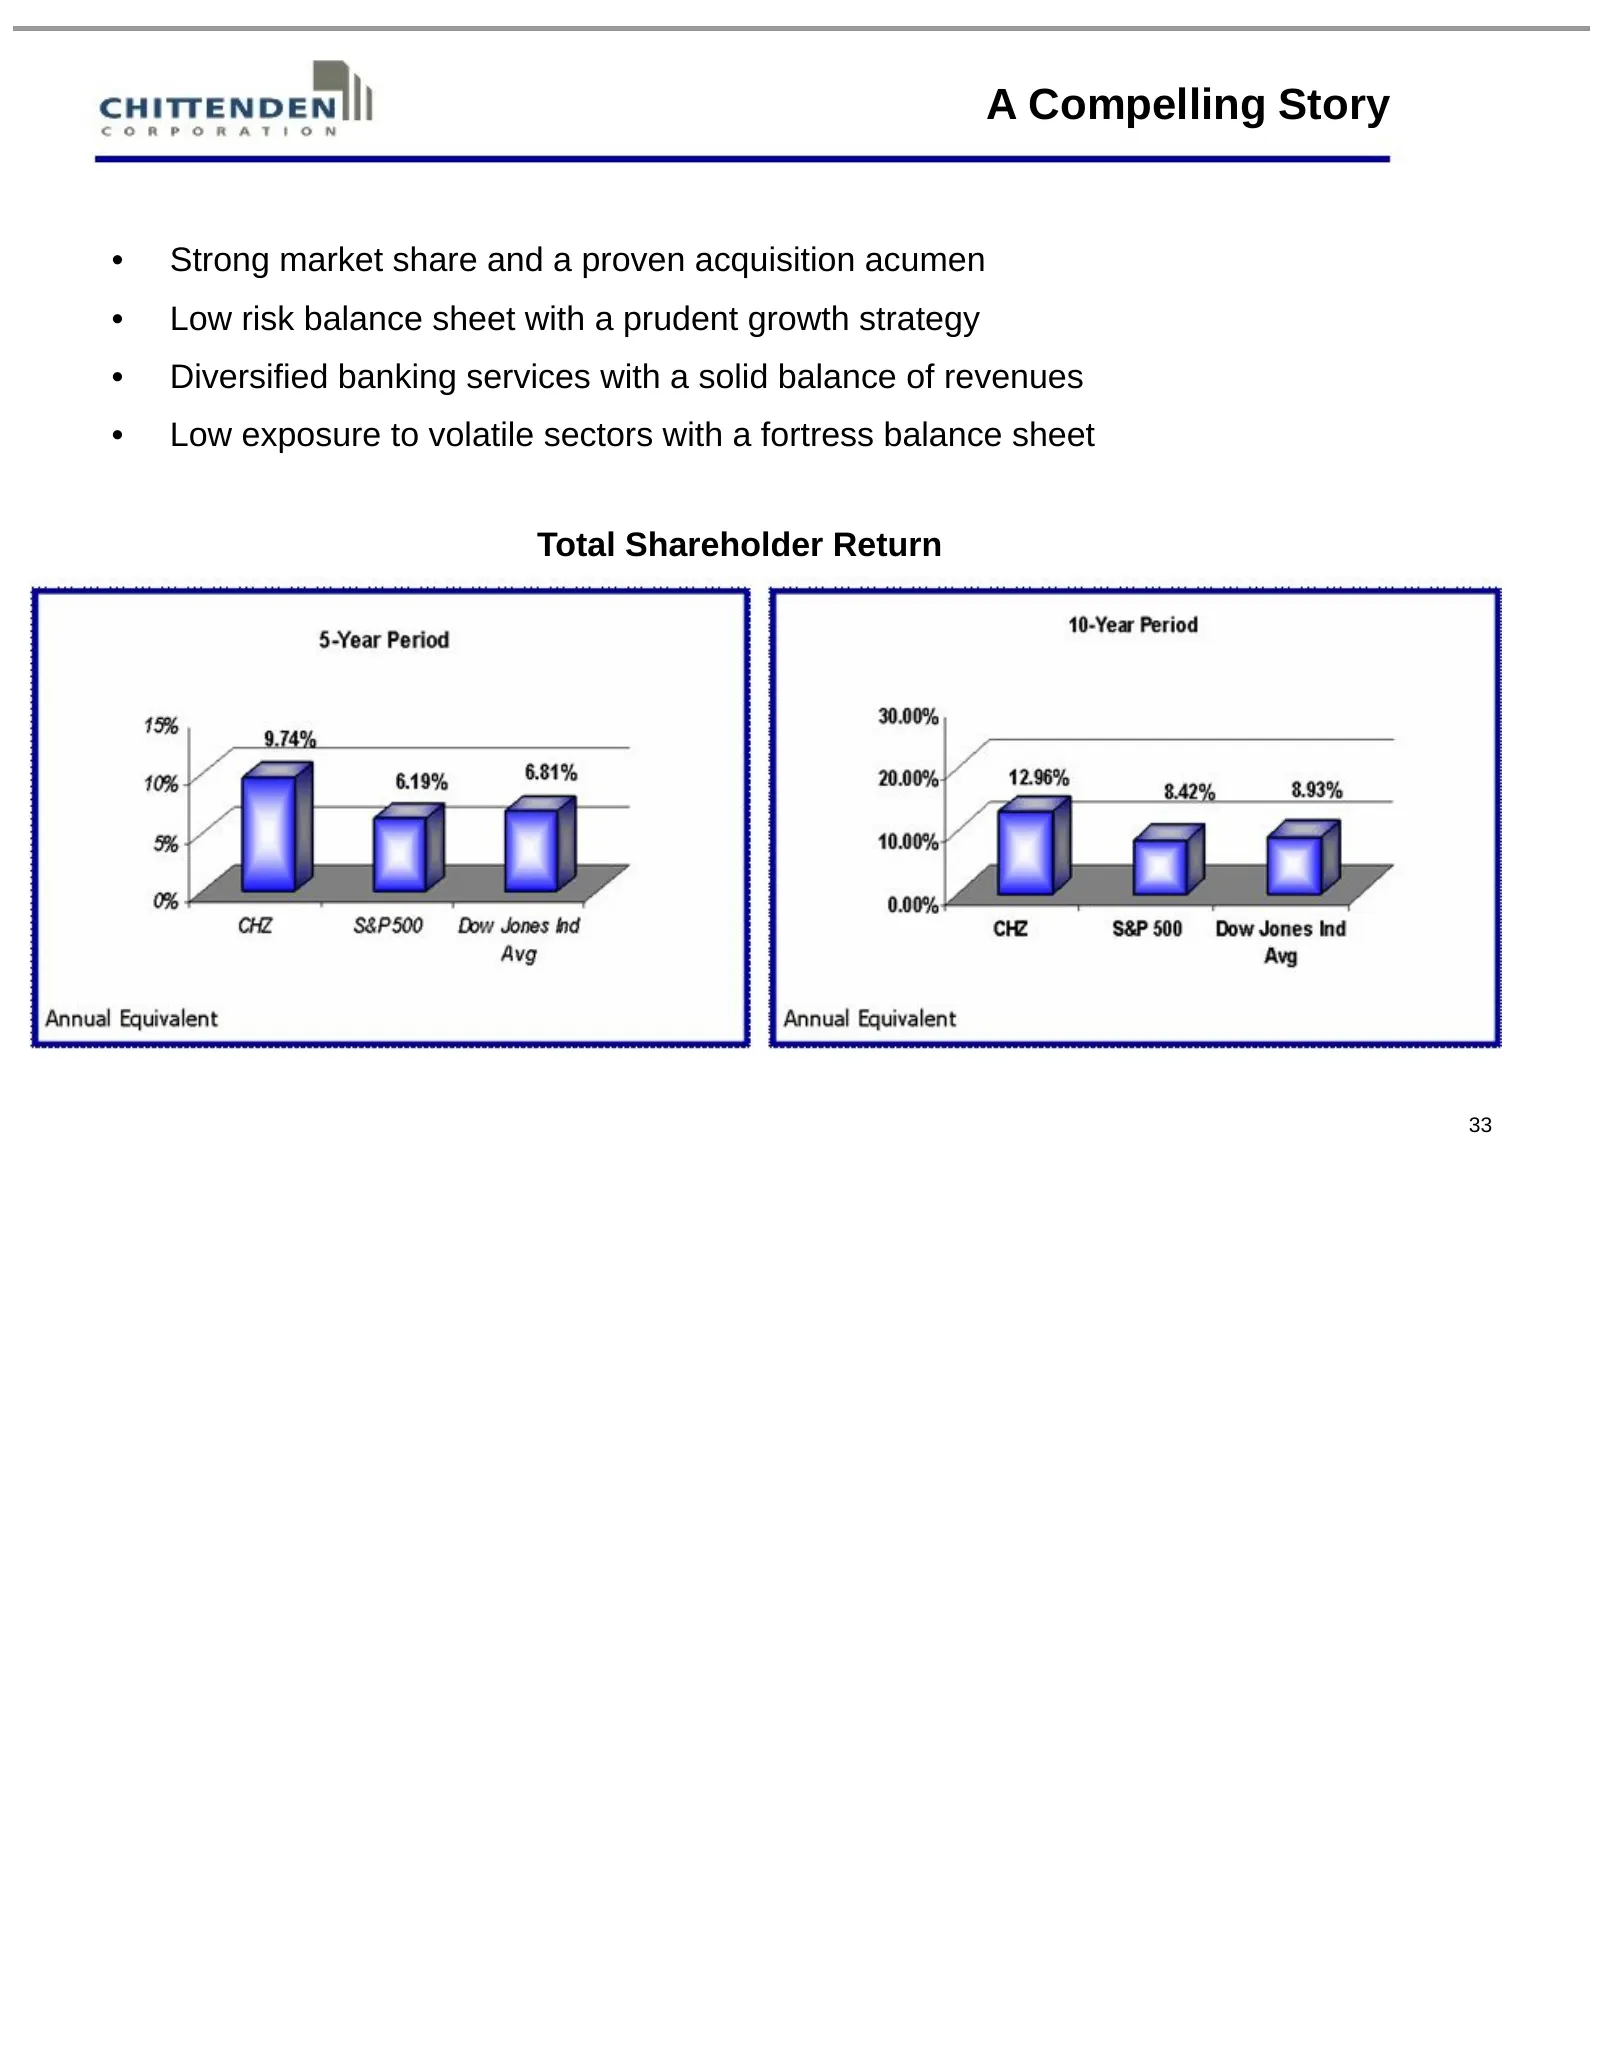
Slide 33: A Compelling Story
A Compelling Story • Strong market share and a proven acquisition acumen • Low risk balance sheet with a prudent growth strategy • Diversified banking services with a solid balance of revenues • Low exposure to volatile sectors with a fortress balance sheet Total Shareholder Return 33
Slide 34: Visit our website for products and financial reports
Visit our website for a wide range of products, latest financial reports and many other interactive services: www.chittendencorp.com This presentation contains “forward-looking statements” which may describe future plans and strategic initiatives. These forward- looking statements are based on curre
Slide 35: Appendix
Appendix
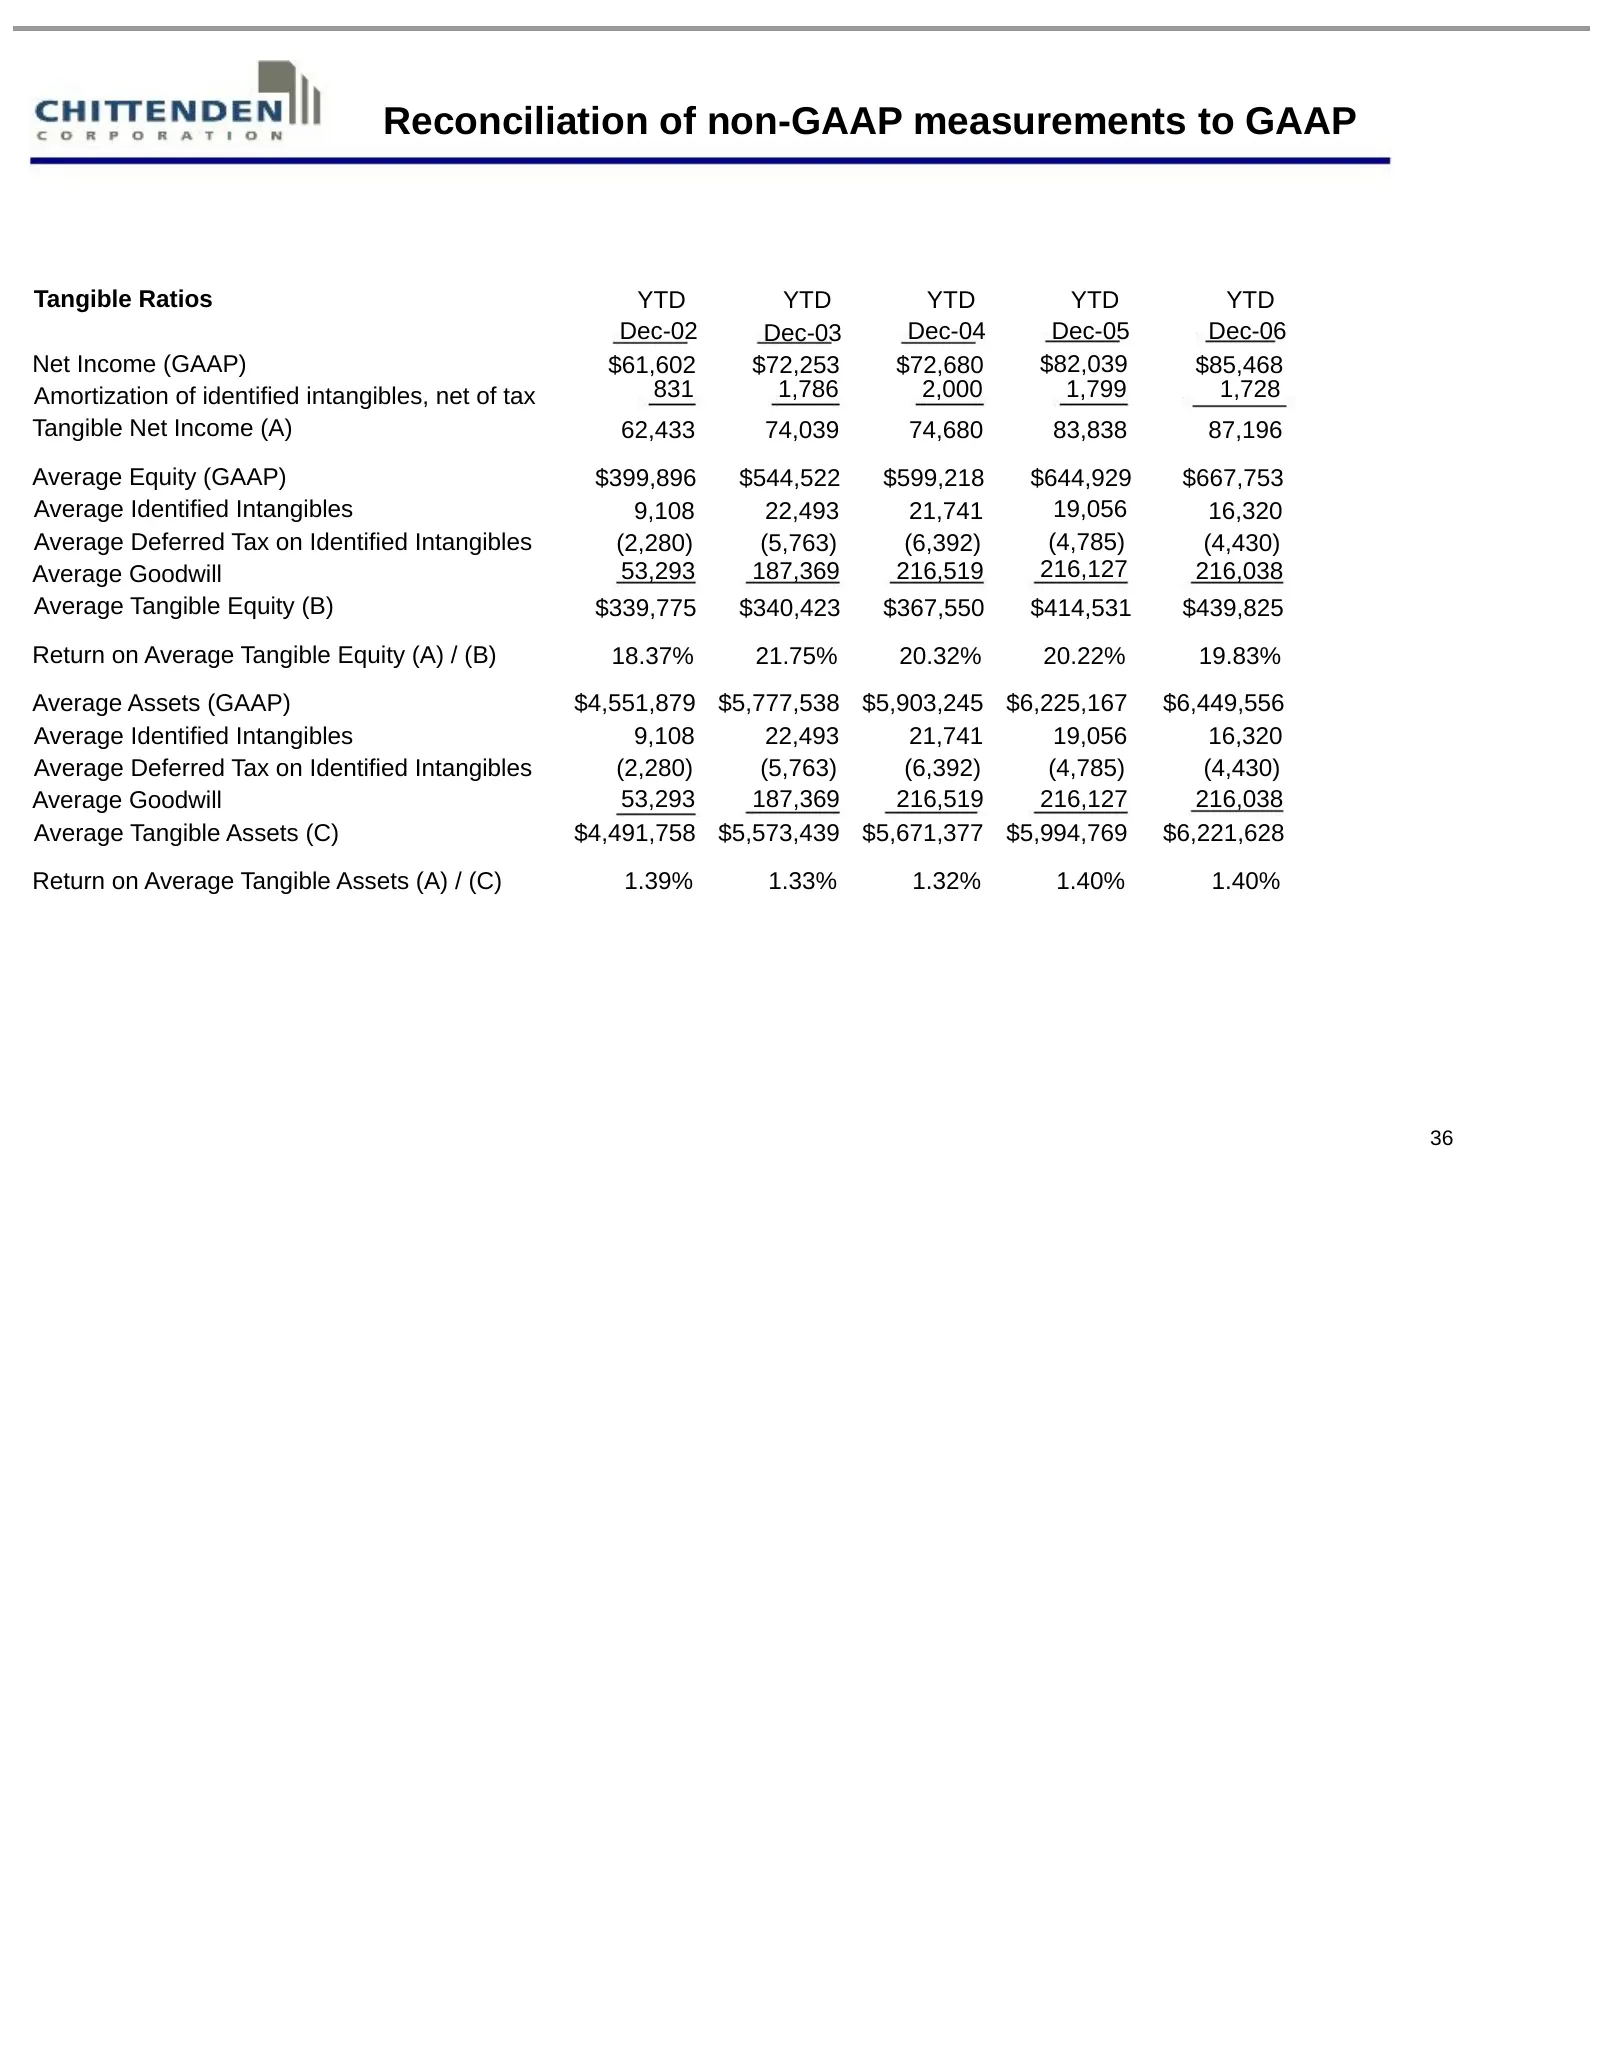
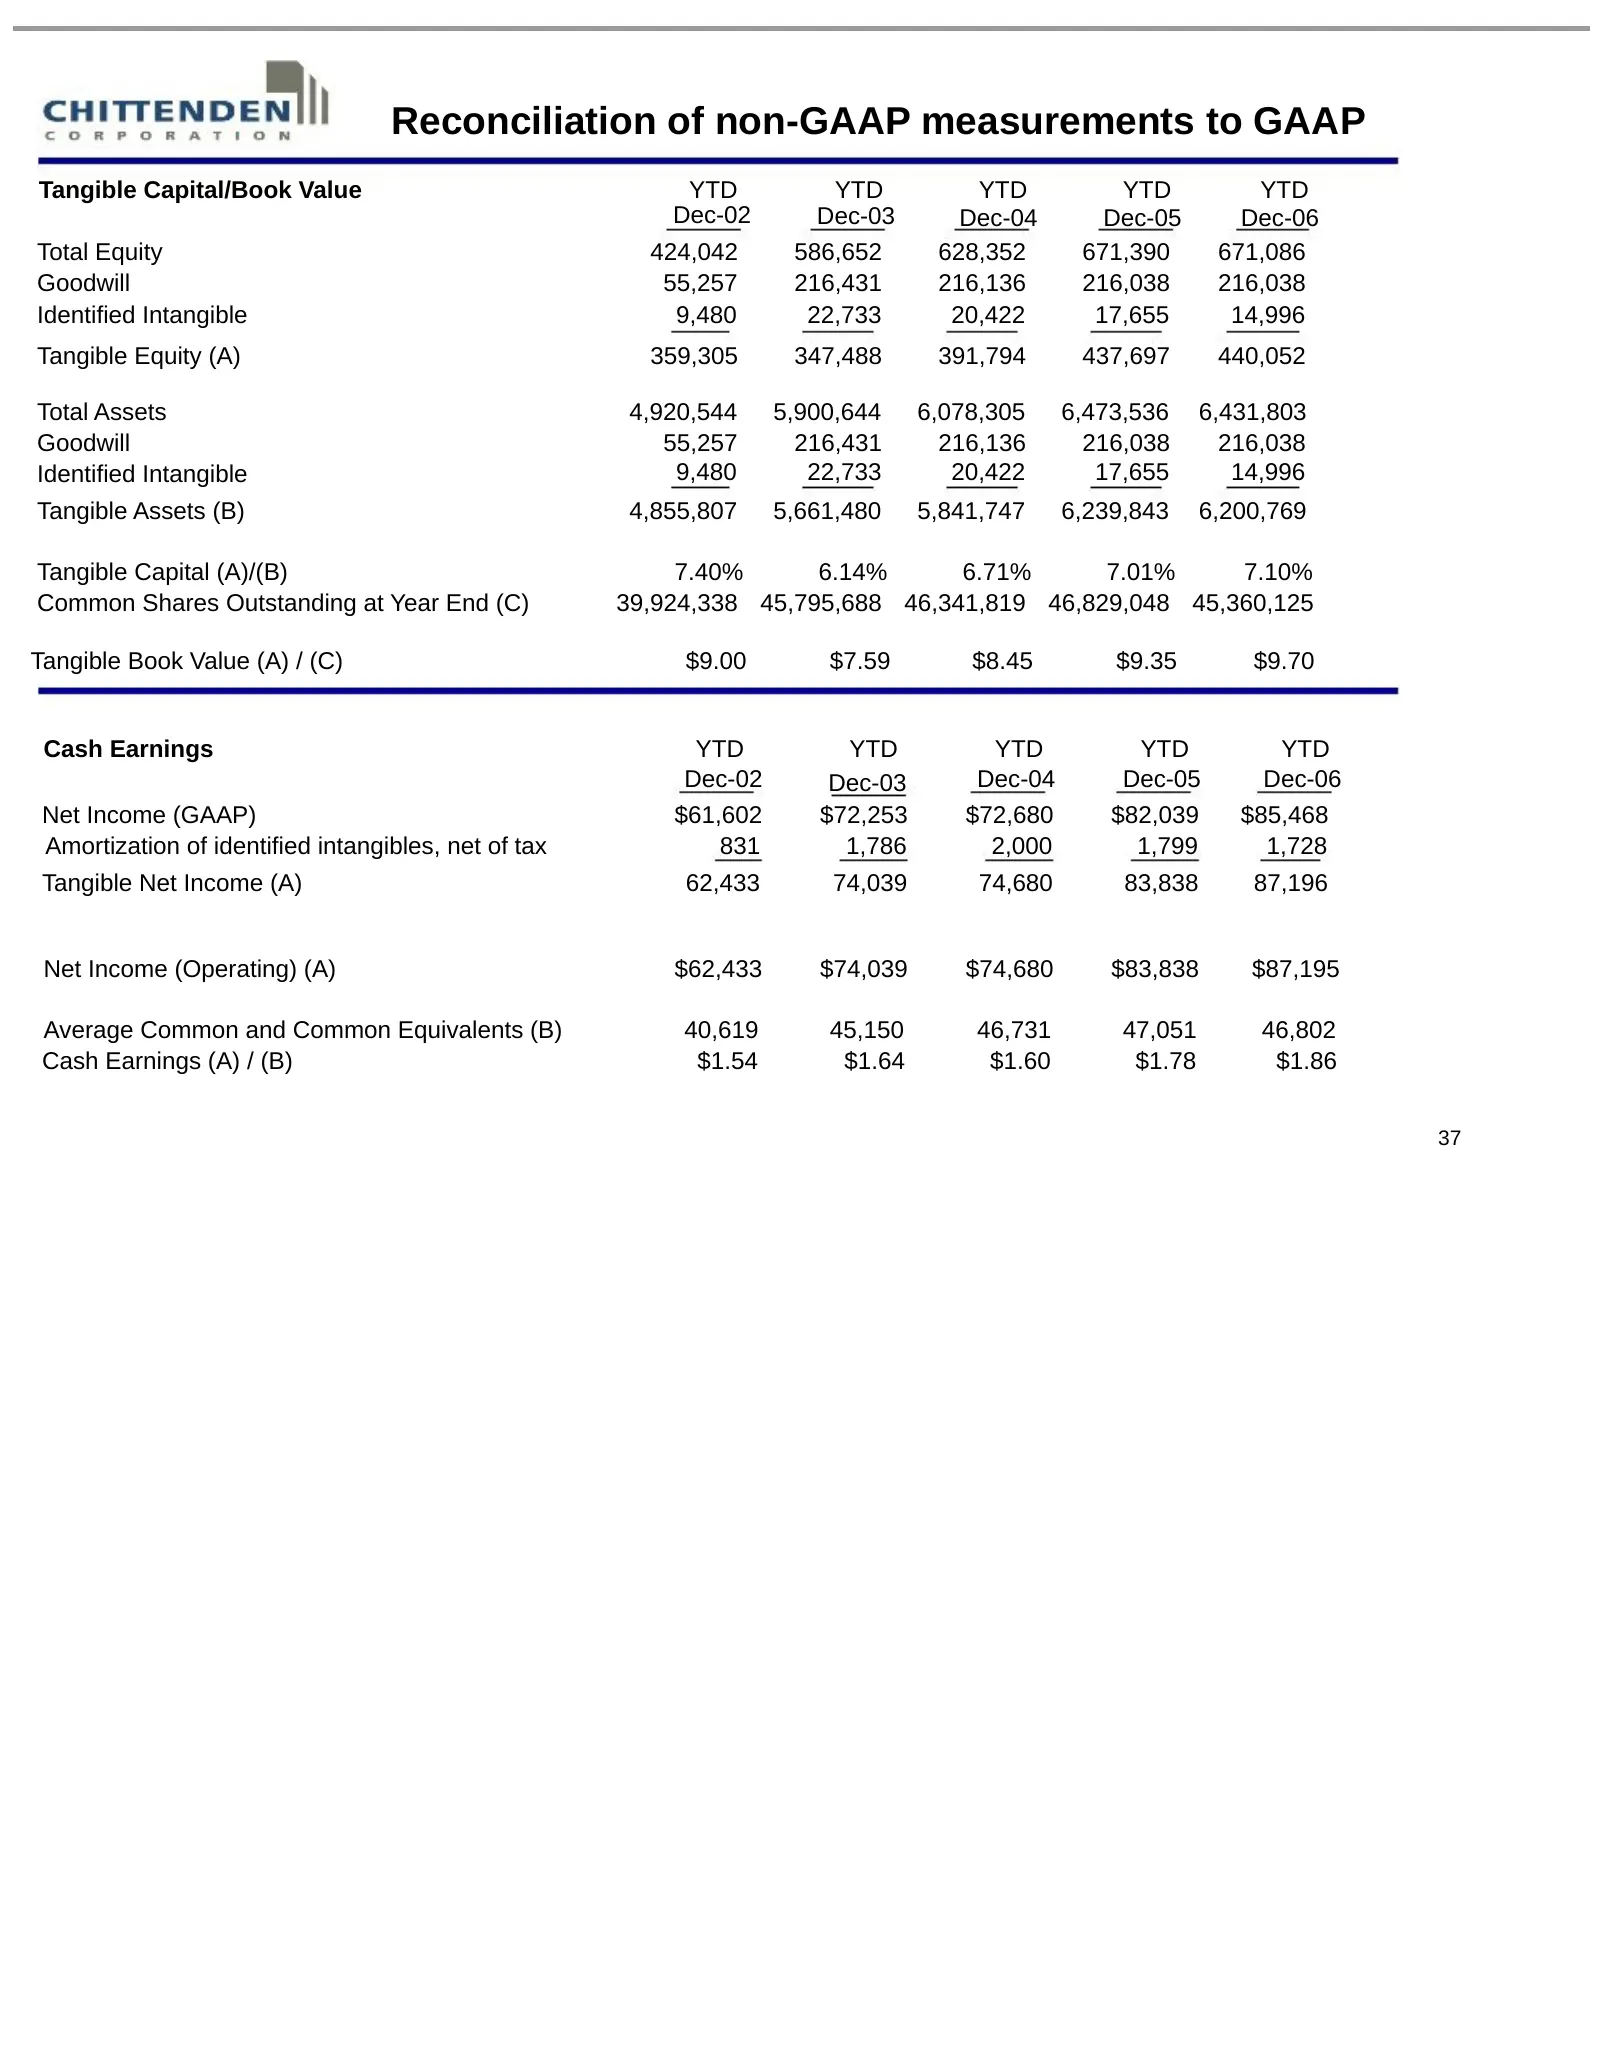
Slide 36: Reconciliation of non-GAAP measurements to GAAP
Reconciliation of non-GAAP measurements to GAAP Tangible Ratios YTD YTD YTD YTD YTD Dec-02 Dec-03 Dec-04 Dec-05 Dec-06 Net Income (GAAP) $61,602 $72,253 $72,680 $82,039 $85,468 Amortization of identified intangibles, net of tax 831 1,786 2,000 1,799 1,728 Tangible Net Income (A) 62,433 74,039 74,680
Slide 37: Reconciliation of non-GAAP measurements to GAAP
Reconciliation of non-GAAP measurements to GAAP Tangible Capital/Book Value YTD YTD YTD YTD YTD Dec-02 Dec-03 Dec-04 Dec-05 Dec-06 Total Equity 424,042 586,652 628,352 671,390 671,086 Goodwill 55,257 216,431 216,136 216,038 216,038 Identified Intangible 9,480 22,733 20,422 17,655 14,996 Tangible Equ
Source: SEC EDGAR · 8-K filed Feb 16, 2007
More decks from Chittenden Corp
 Investor Presentation (September 2007)38 slides · Sep 7, 2007
 Merger or Acquisition (June 2007)27 slides · Jun 27, 2007
 Chittenden — Merger or Acquisition (June 2007)25 slides · Jun 27, 2007
 Merger or Acquisition (June 2007)9 slides · Jun 5, 2007
 Investor Presentation (May 2007)36 slides · May 14, 2007
 Merrill Merchants Bancshares — Merger or Acquisition (January 2007)8 slides · Jan 19, 2007