OppFi Inc. · NYSE:OPFI
OppFi — SPAC Merger (April 2021)
43 slides from OppFi's SPAC merger presentation, Apr 7, 2021
Slide 1: A Leading FinTech Platform for the Everyday Consumer
A Leading FinTech Platform for the Everyday Consumer Analyst Day April 7, 2021
Slide 2: Disclaimer
Disclaimer This presentation (the “Presentation”) is for information purposes only. This Presentation has been prepared to assist parties in making their own evaluation with respect to a proposed transaction (the “Transaction”) as contemplated by a definitive business combination agreement between F
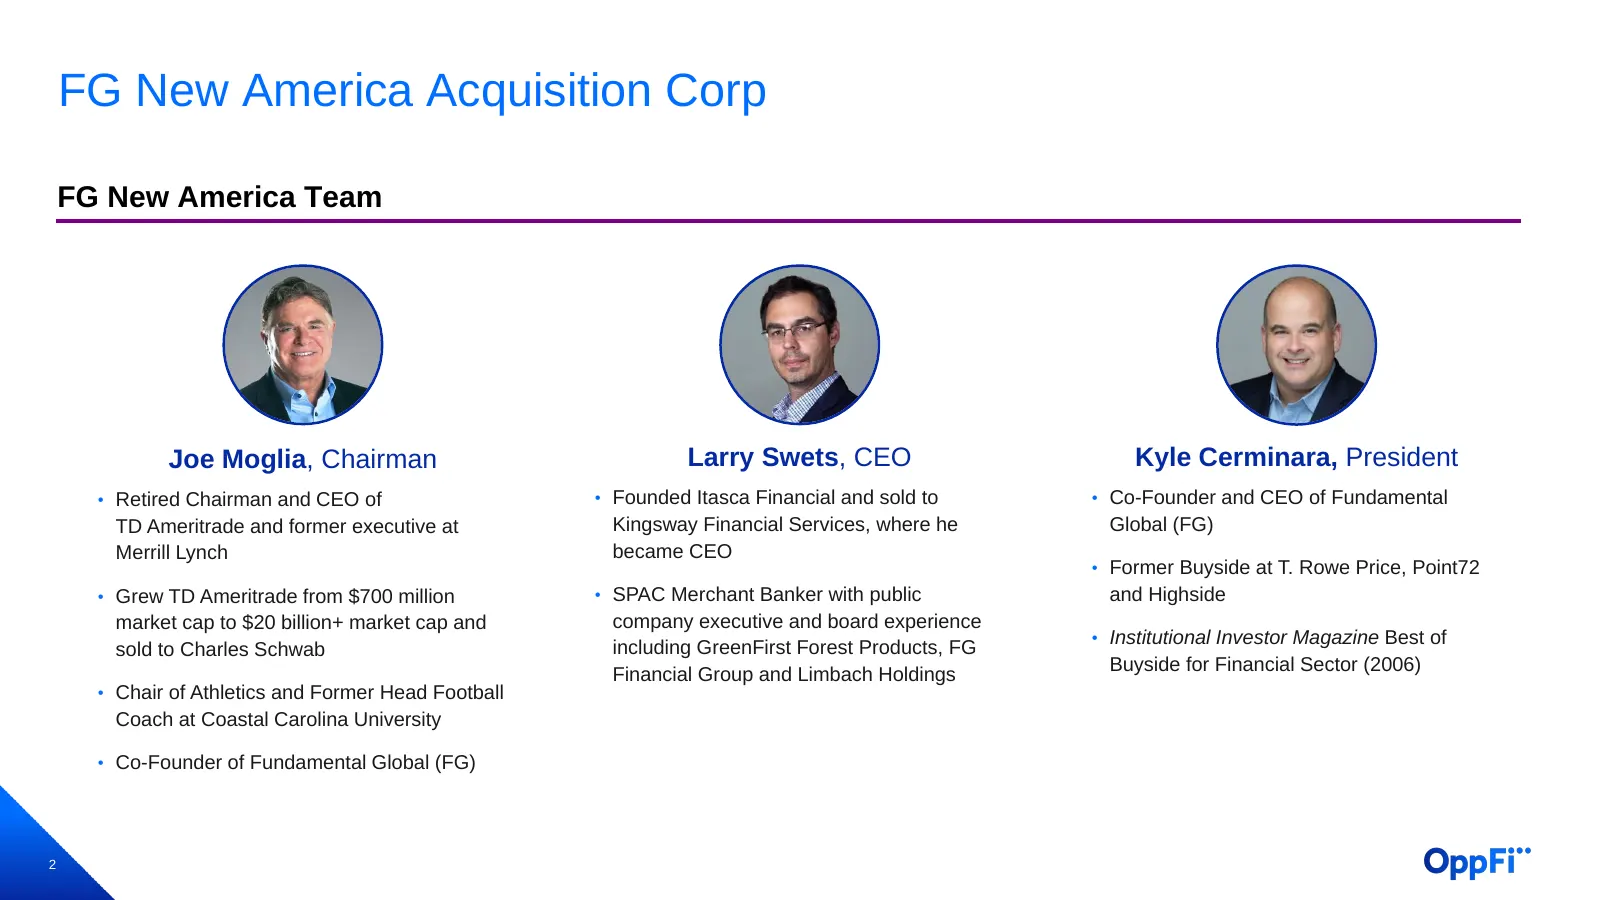
Slide 3: FG New America Team
FG New America Acquisition Corp FG New America Team Joe Moglia, Chairman Larry Swets, CEO Kyle Cerminara, President • Retired Chairman and CEO of • Founded Itasca Financial and sold to • Co-Founder and CEO of Fundamental TD Ameritrade and former executive at Kingsway Financial Services, where he Glo
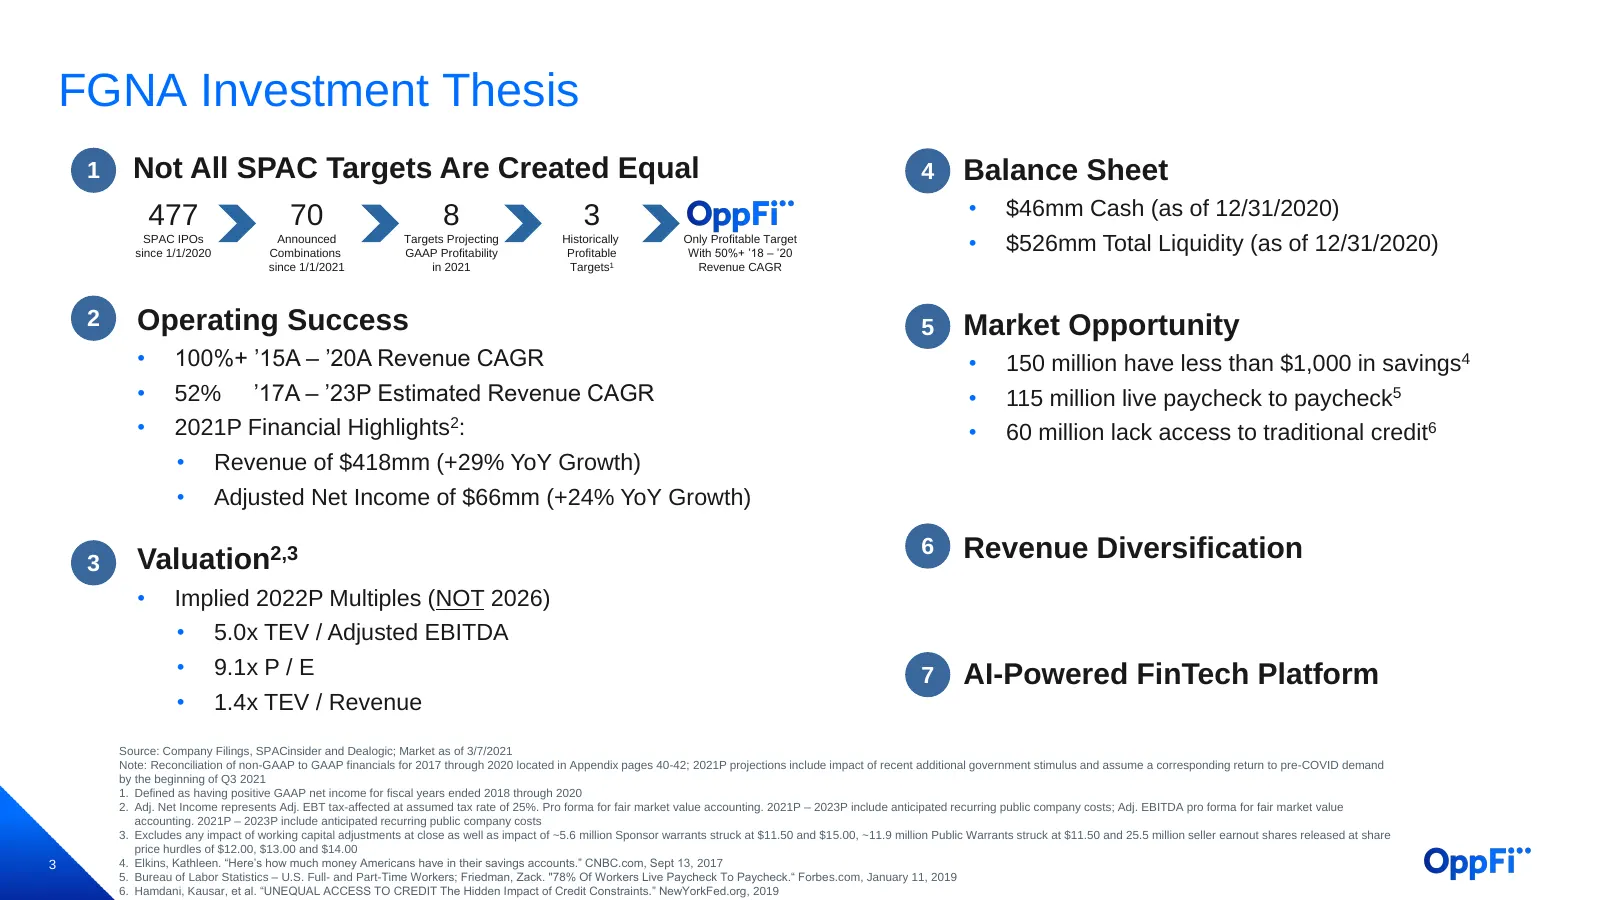
Slide 4: FGNA Investment Thesis
FGNA Investment Thesis 1 Not All SPAC Targets Are Created Equal 4 Balance Sheet 477 70 8 3 • $46mm Cash (as of 12/31/2020) SPAC IPOs since 1/1/2020 Announced Combinations Targets Projecting GAAP Profitability Historically Profitable Only Profitable Target With 50%+ ’18 – ’20 • $526mm Total Liquidity
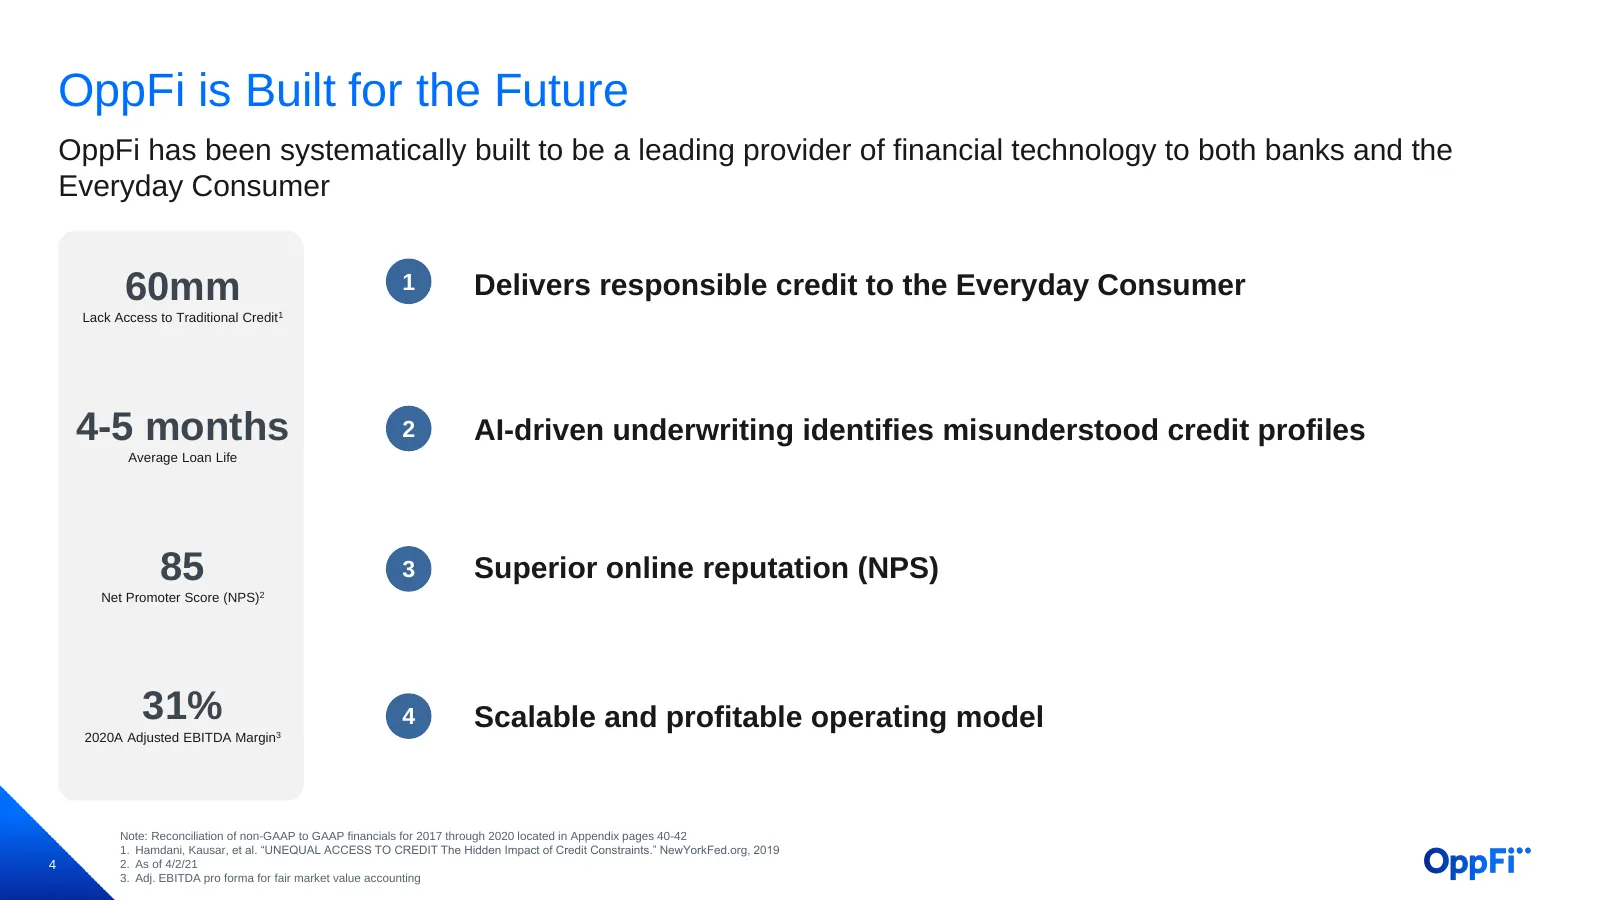
Slide 5: OppFi is Built for the Future
OppFi is Built for the Future OppFi has been systematically built to be a leading provider of financial technology to both banks and the Everyday Consumer 60mm 1 Delivers responsible credit to the Everyday Consumer Lack Access to Traditional Credit1 4-5 months 2 AI-driven underwriting identifies mis
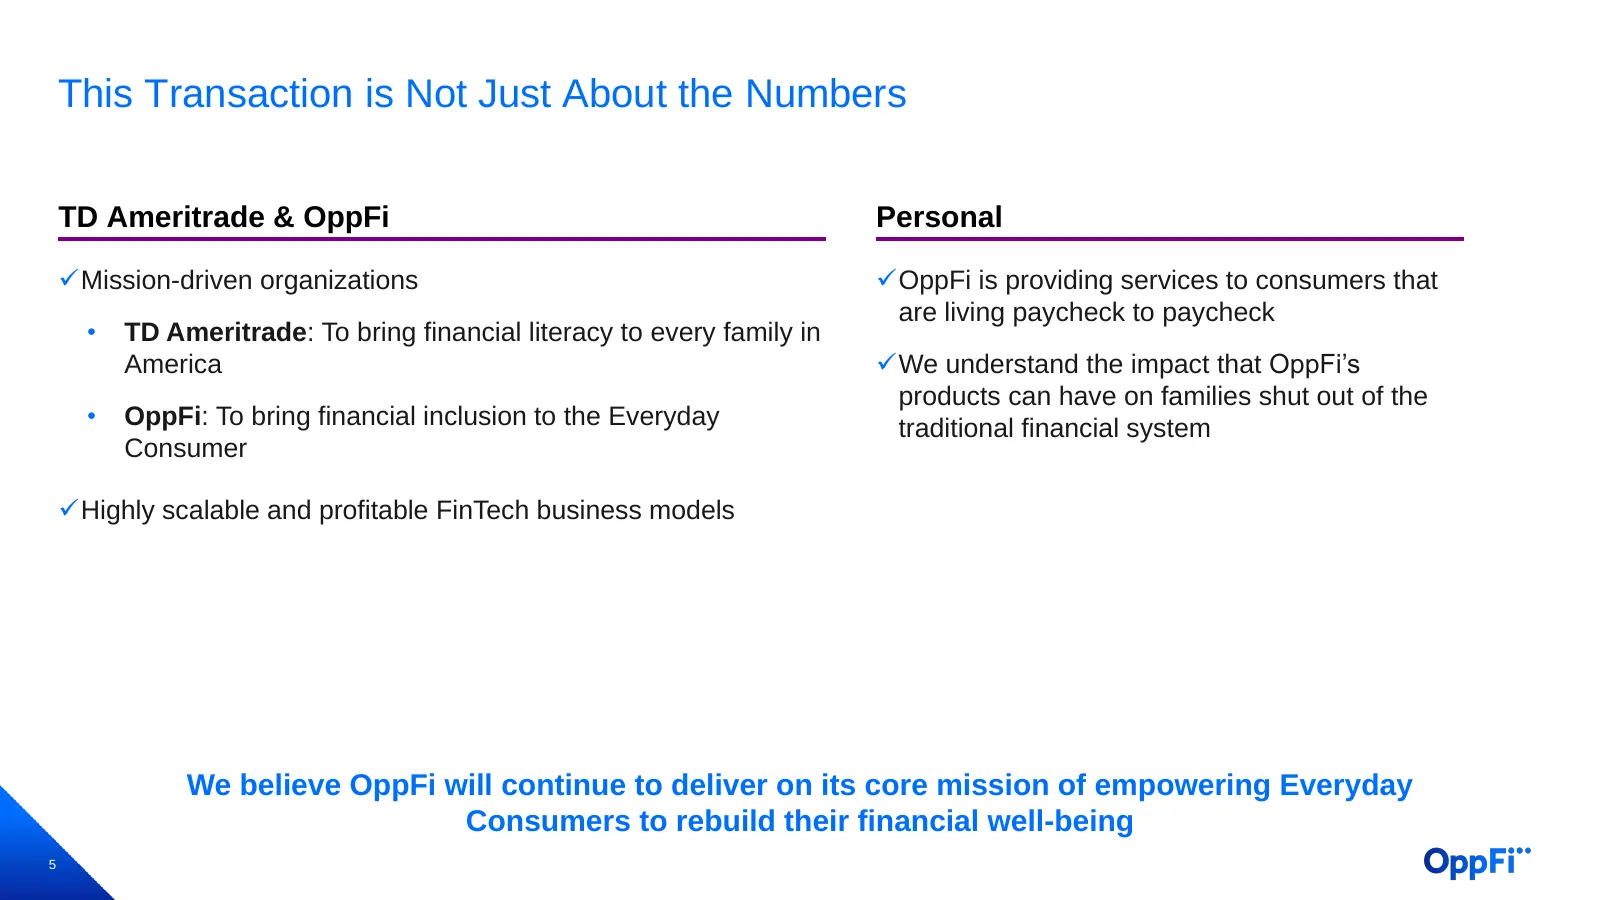
Slide 6: This Transaction is Not Just About the Numbers
This Transaction is Not Just About the Numbers TD Ameritrade & OppFi Personal Mission-driven organizations OppFi is providing services to consumers that are living paycheck to paycheck • TD Ameritrade: To bring financial literacy to every family in America We understand the impact that OppFi’s pr
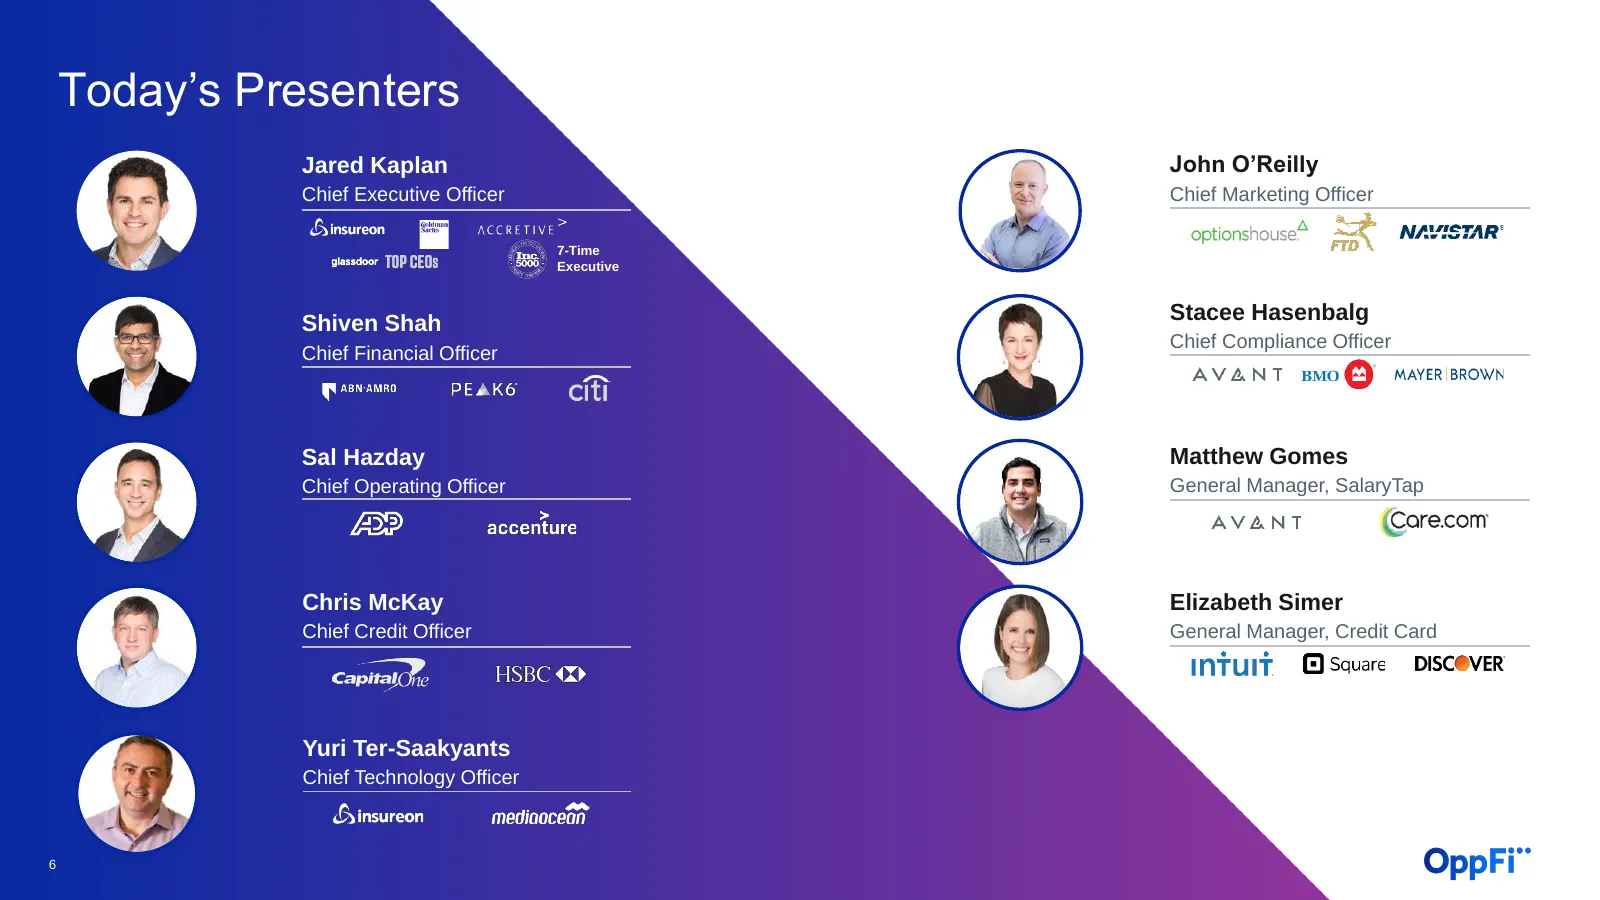
Slide 7: Today's Presenters
Today’s Presenters Jared Kaplan John O’Reilly Chief Executive Officer Chief Marketing Officer 7-Time Executive Stacee Hasenbalg Shiven Shah Chief Compliance Officer Chief Financial Officer Sal Hazday Matthew Gomes Chief Operating Officer General Manager, SalaryTap Chris McKay Elizabeth Simer Chief C
Slide 8: OppFi's Vision
OppFi’s Vision The Digital Financial Services Destination for the Everyday Consumer 7
Slide 9: OppFi's Mission
OppFi’s Mission Empower Everyday Consumers to Rebuild Financial Health Facilitate Enable Build credit access savings wealth 8
Slide 10: Most Americans Lack Savings and Credit Access
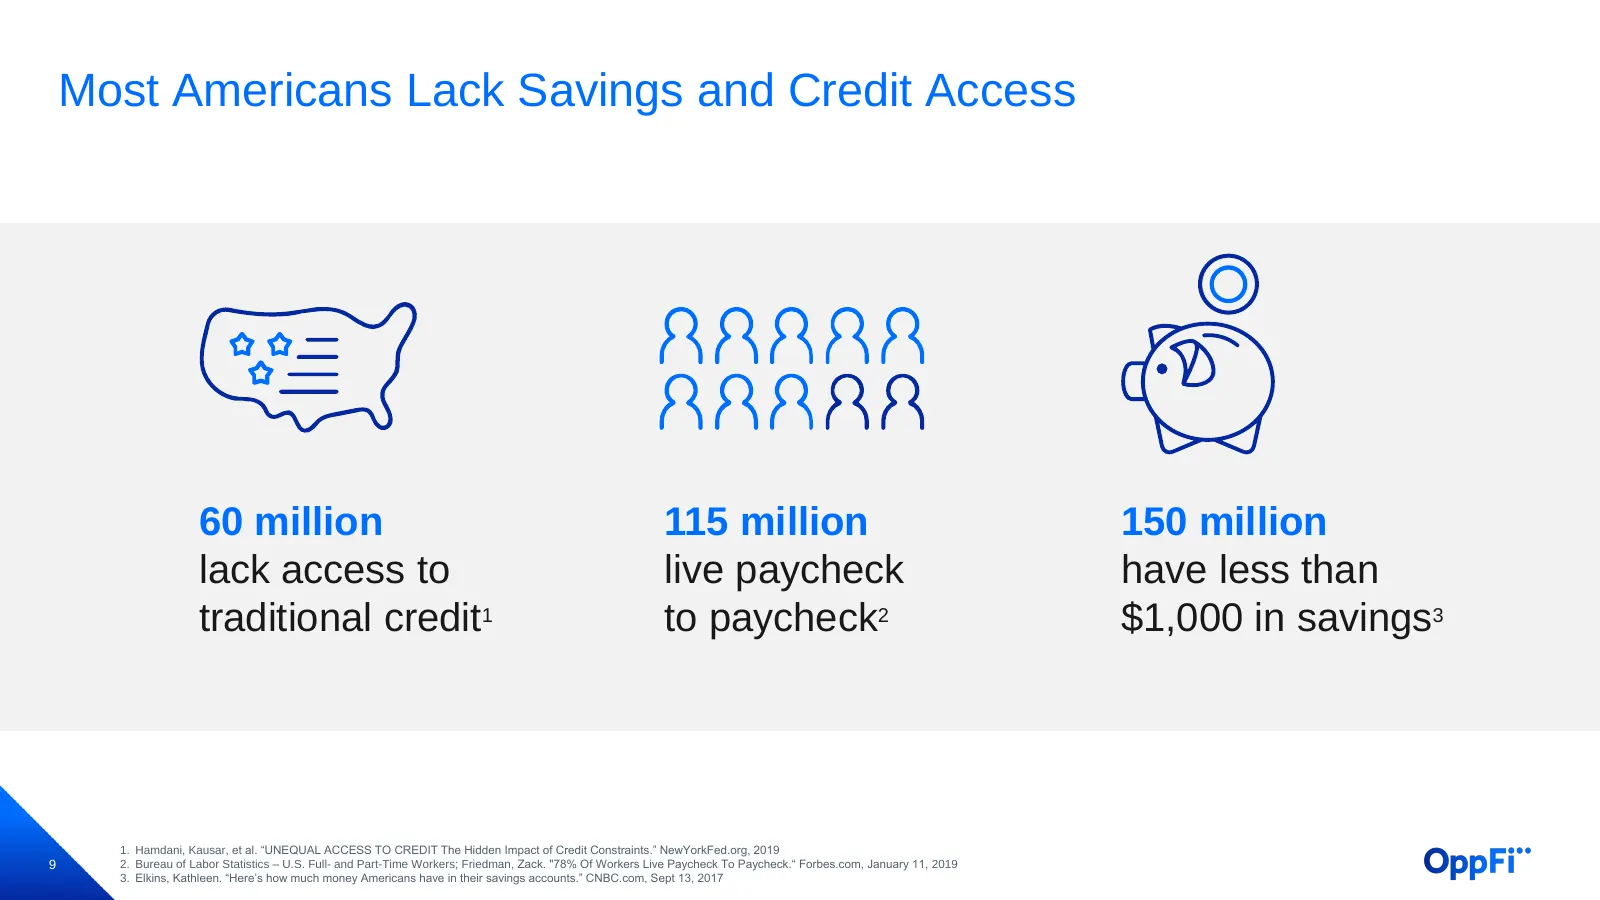
Most Americans Lack Savings and Credit Access 60 million 115 million 150 million lack access to live paycheck have less than traditional credit1 to paycheck2 $1,000 in savings3 1. Hamdani, Kausar, et al. “UNEQUAL ACCESS TO CREDIT The Hidden Impact of Credit Constraints.” NewYorkFed.org, 2019 9 2. Bu
Slide 11: We Help Everyday Consumers Solve Everyday Problems
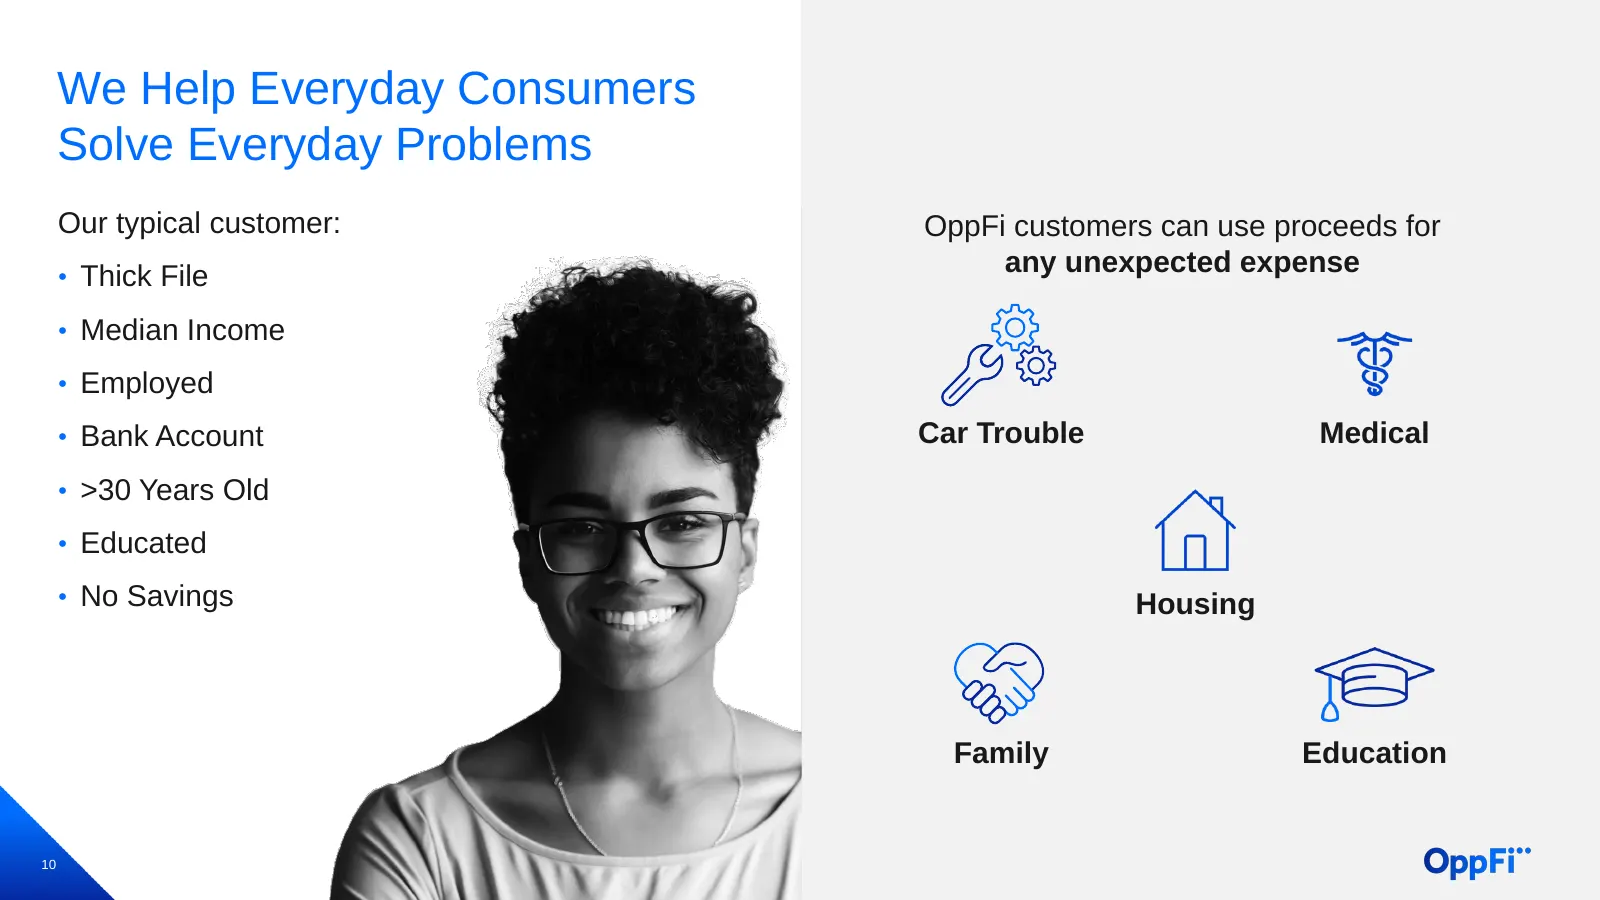
We Help Everyday Consumers Solve Everyday Problems Our typical customer: OppFi customers can use proceeds for • Thick File any unexpected expense • Median Income • Employed • Bank Account Car Trouble Medical • >30 Years Old • Educated • No Savings Housing Family Education 10
Slide 12: OppFi Powers Banks to Unlock Credit Access for the Everyday Consumer
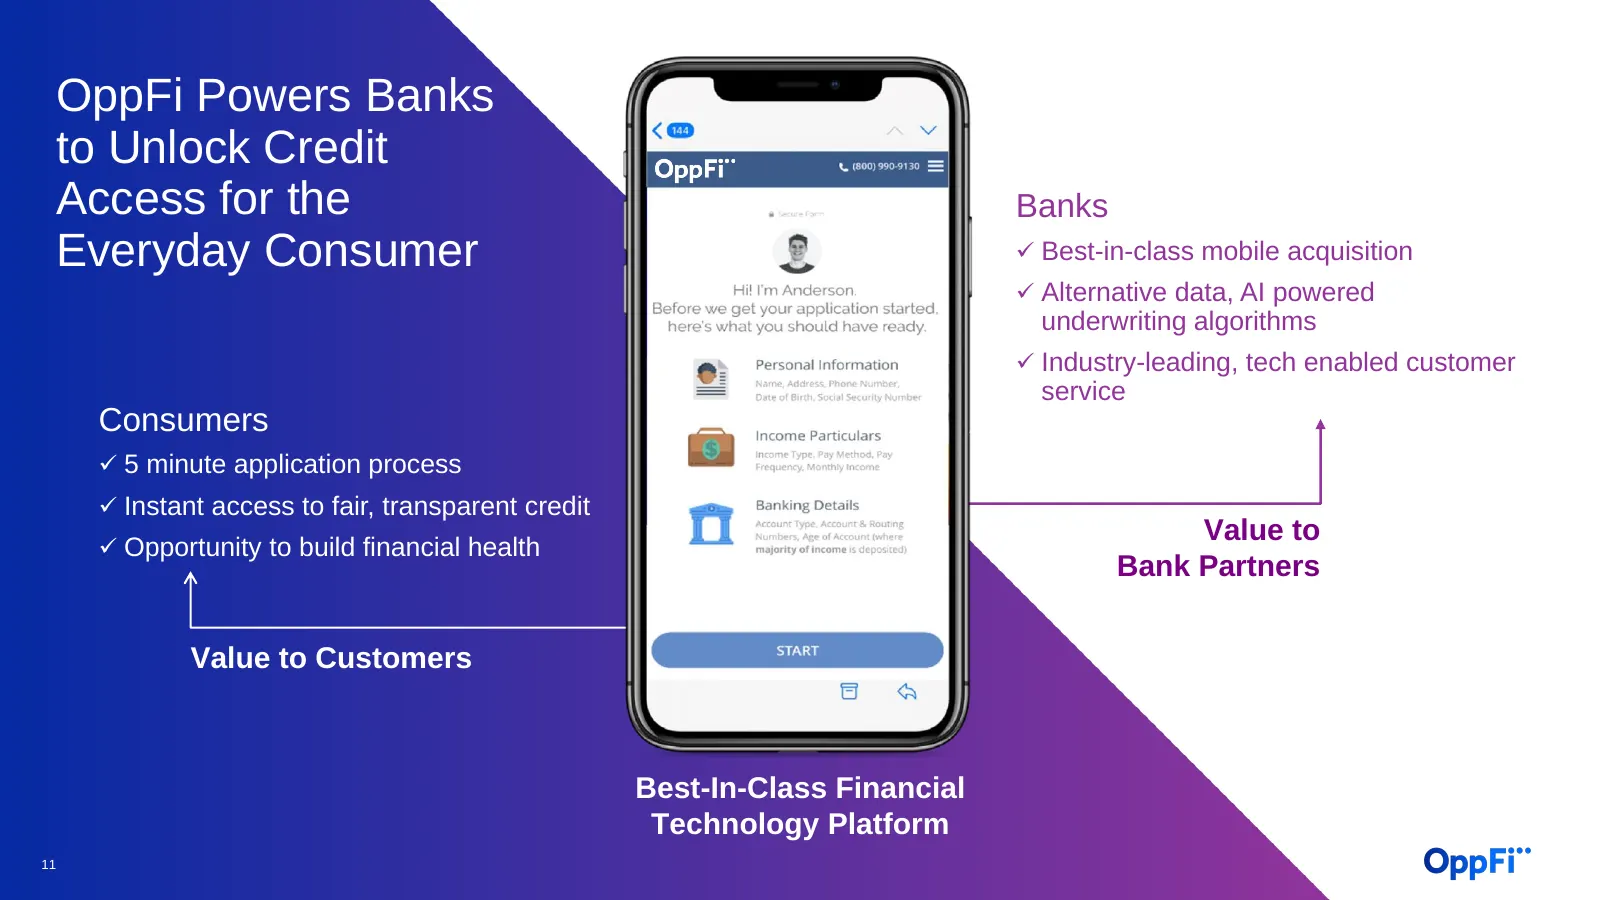
OppFi Powers Banks to Unlock Credit Access for the Banks Everyday Consumer Best-in-class mobile acquisition Alternative data, AI powered underwriting algorithms Industry-leading, tech enabled customer service Consumers 5 minute application process Instant access to fair, transparent credit
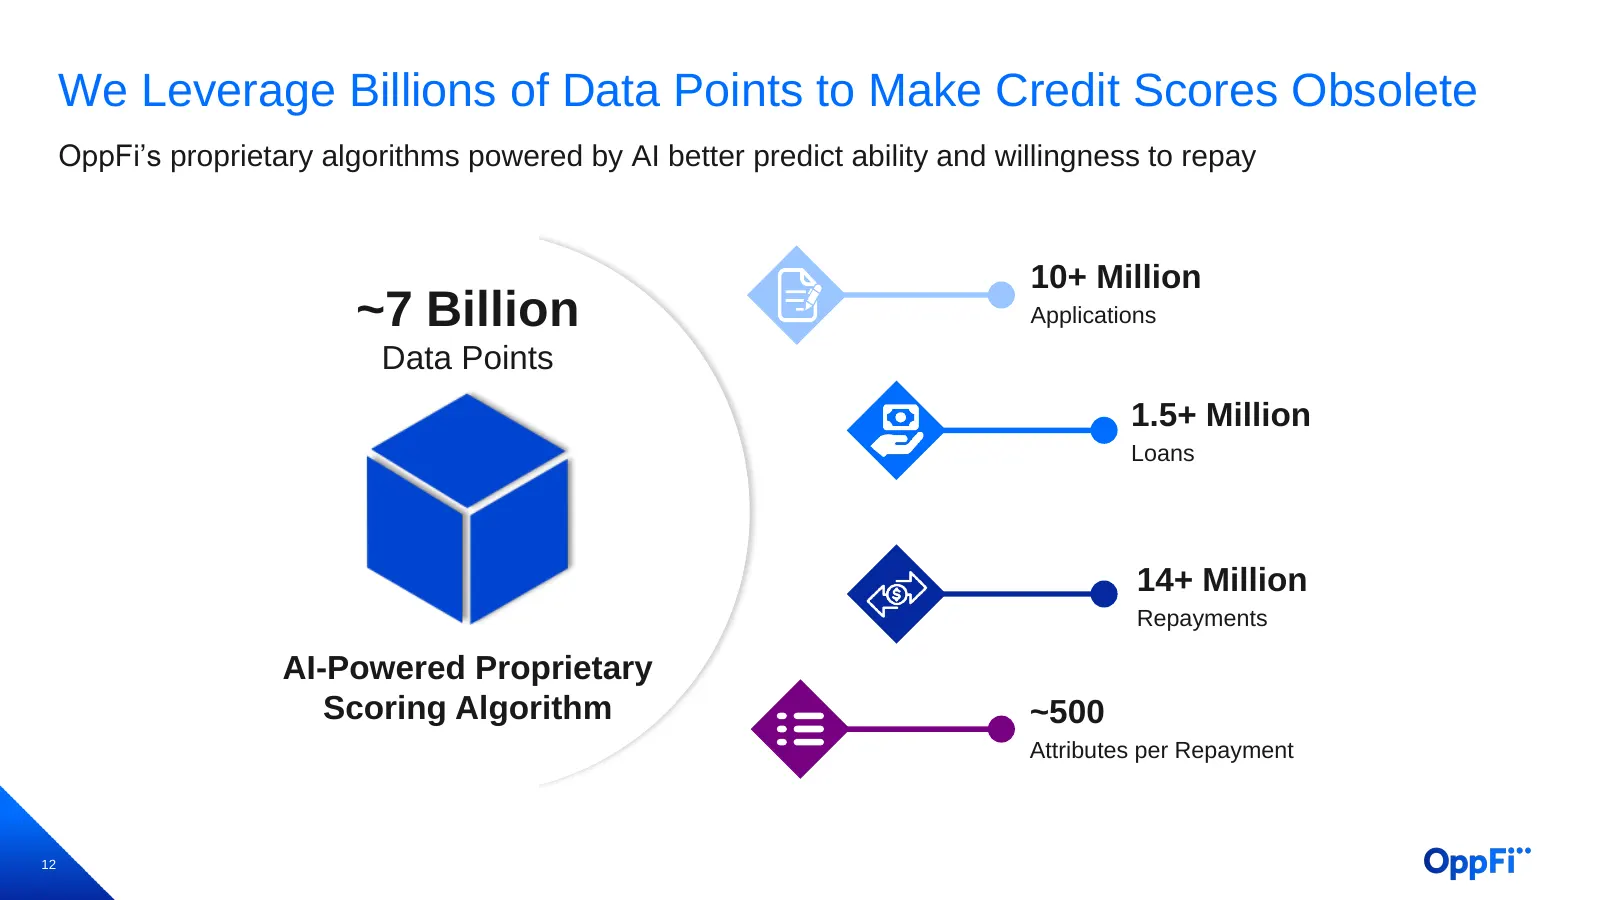
Slide 13: We Leverage Billions of Data Points to Make Credit Scores Obsolete
We Leverage Billions of Data Points to Make Credit Scores Obsolete OppFi’s proprietary algorithms powered by AI better predict ability and willingness to repay 10+ Million ~7 Billion Applications Data Points 1.5+ Million Loans 14+ Million Repayments AI-Powered Proprietary Scoring Algorithm ~500 Attr
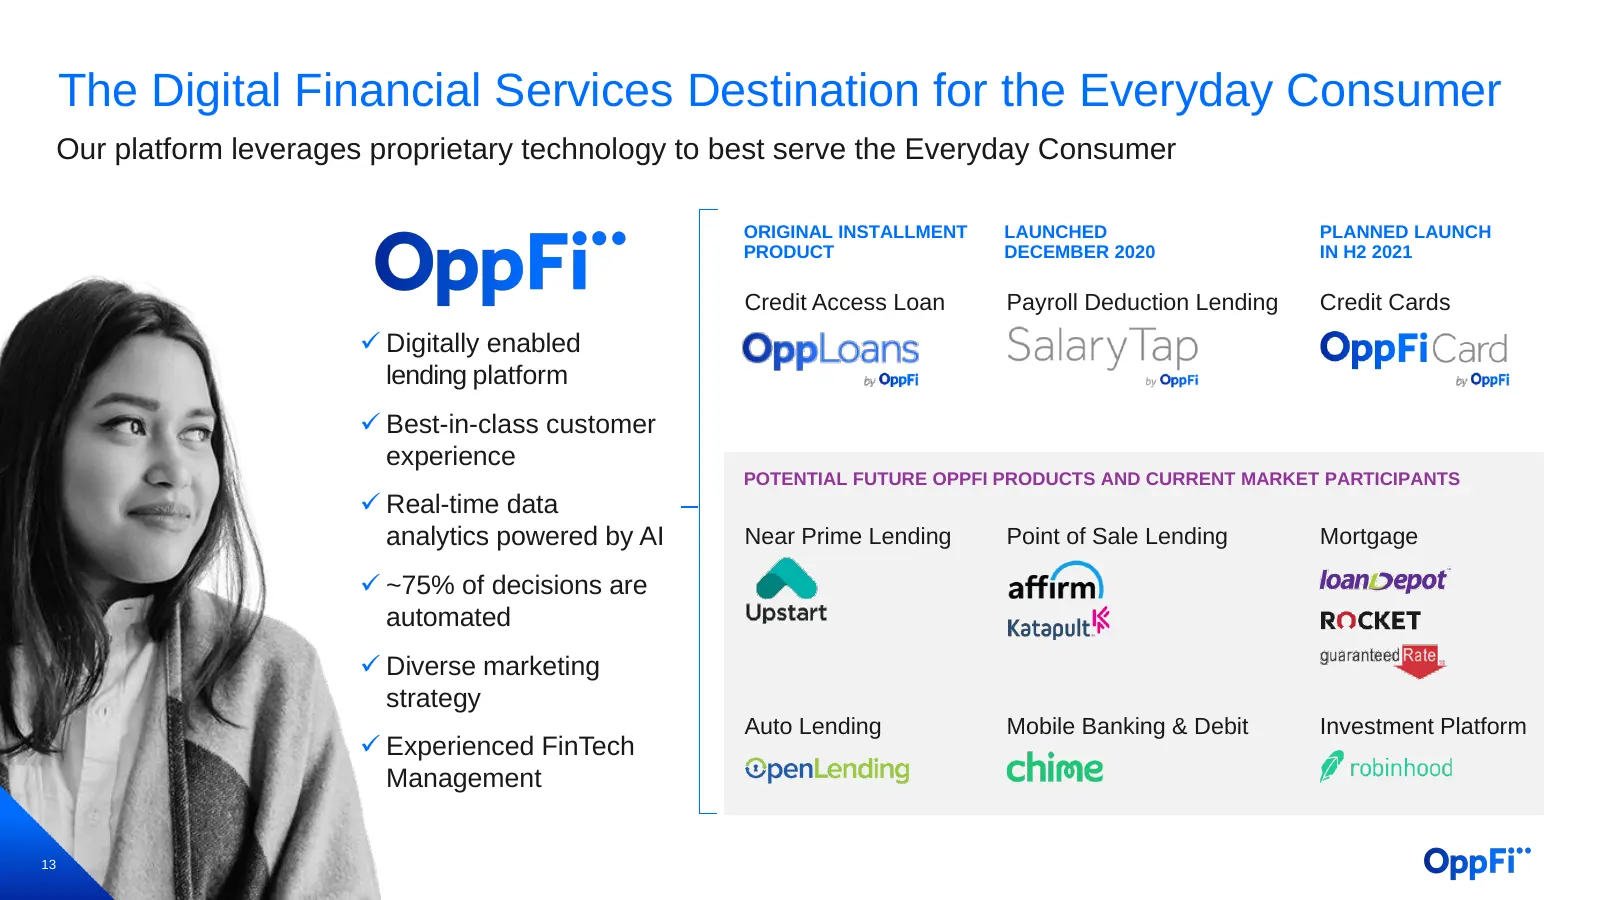
Slide 14: The Digital Financial Services Destination for the Everyday Consumer
The Digital Financial Services Destination for the Everyday Consumer Our platform leverages proprietary technology to best serve the Everyday Consumer ORIGINAL INSTALLMENT LAUNCHED PLANNED LAUNCH PRODUCT DECEMBER 2020 IN H2 2021 Credit Access Loan Payroll Deduction Lending Credit Cards Digitally e
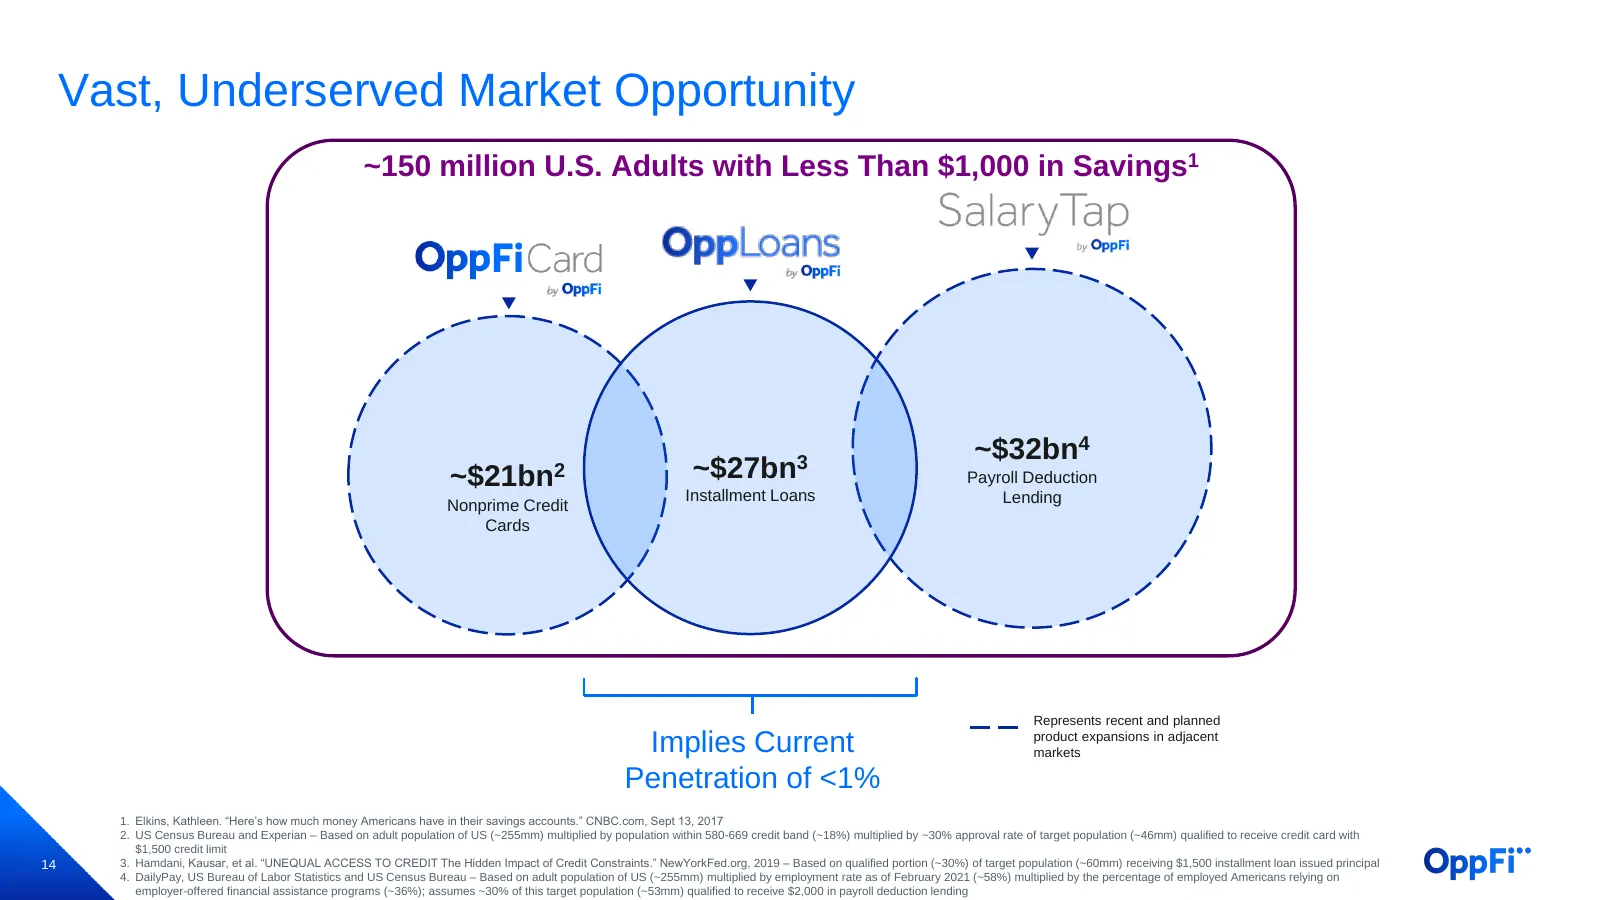
Slide 15: Vast, Underserved Market Opportunity
Vast, Underserved Market Opportunity ~150 million U.S. Adults with Less Than $1,000 in Savings1 ~$32bn4 ~$21bn2 ~$27bn3 Payroll Deduction Installment Loans Lending Nonprime Credit Cards Represents recent and planned Implies Current product expansions in adjacent markets Penetration of <1% 1. Elkins,
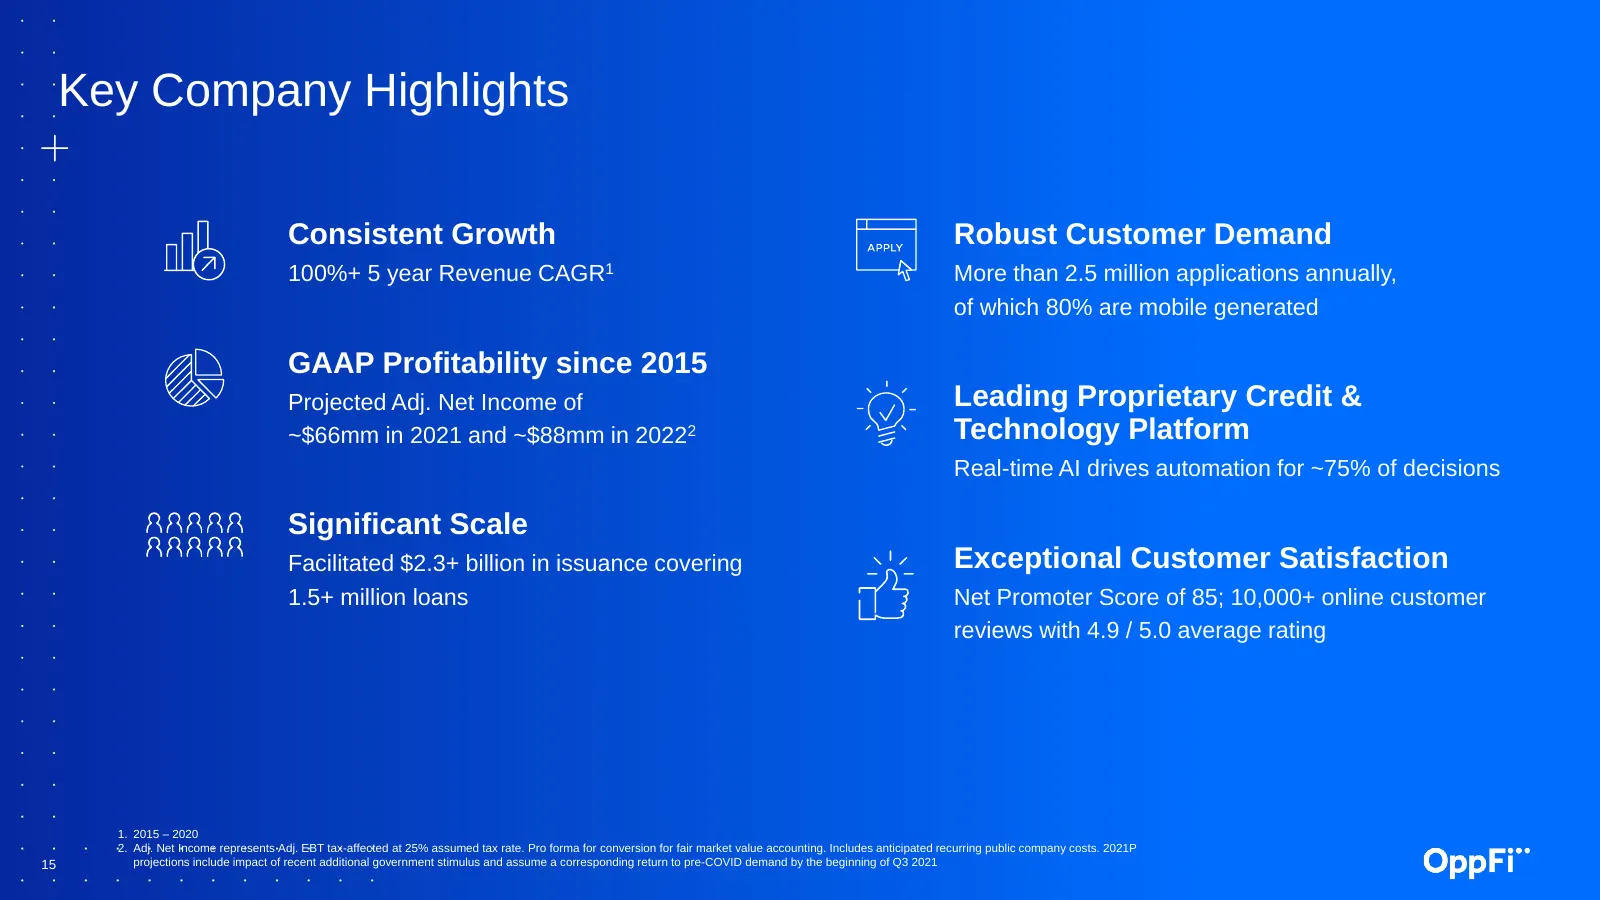
Slide 16: Key Company Highlights
Key Company Highlights Consistent Growth Robust Customer Demand 100%+ 5 year Revenue CAGR1 More than 2.5 million applications annually, of which 80% are mobile generated GAAP Profitability since 2015 Projected Adj. Net Income of Leading Proprietary Credit & ~$66mm in 2021 and ~$88mm in 20222 Technol
Slide 17: Customers Praise OppFi
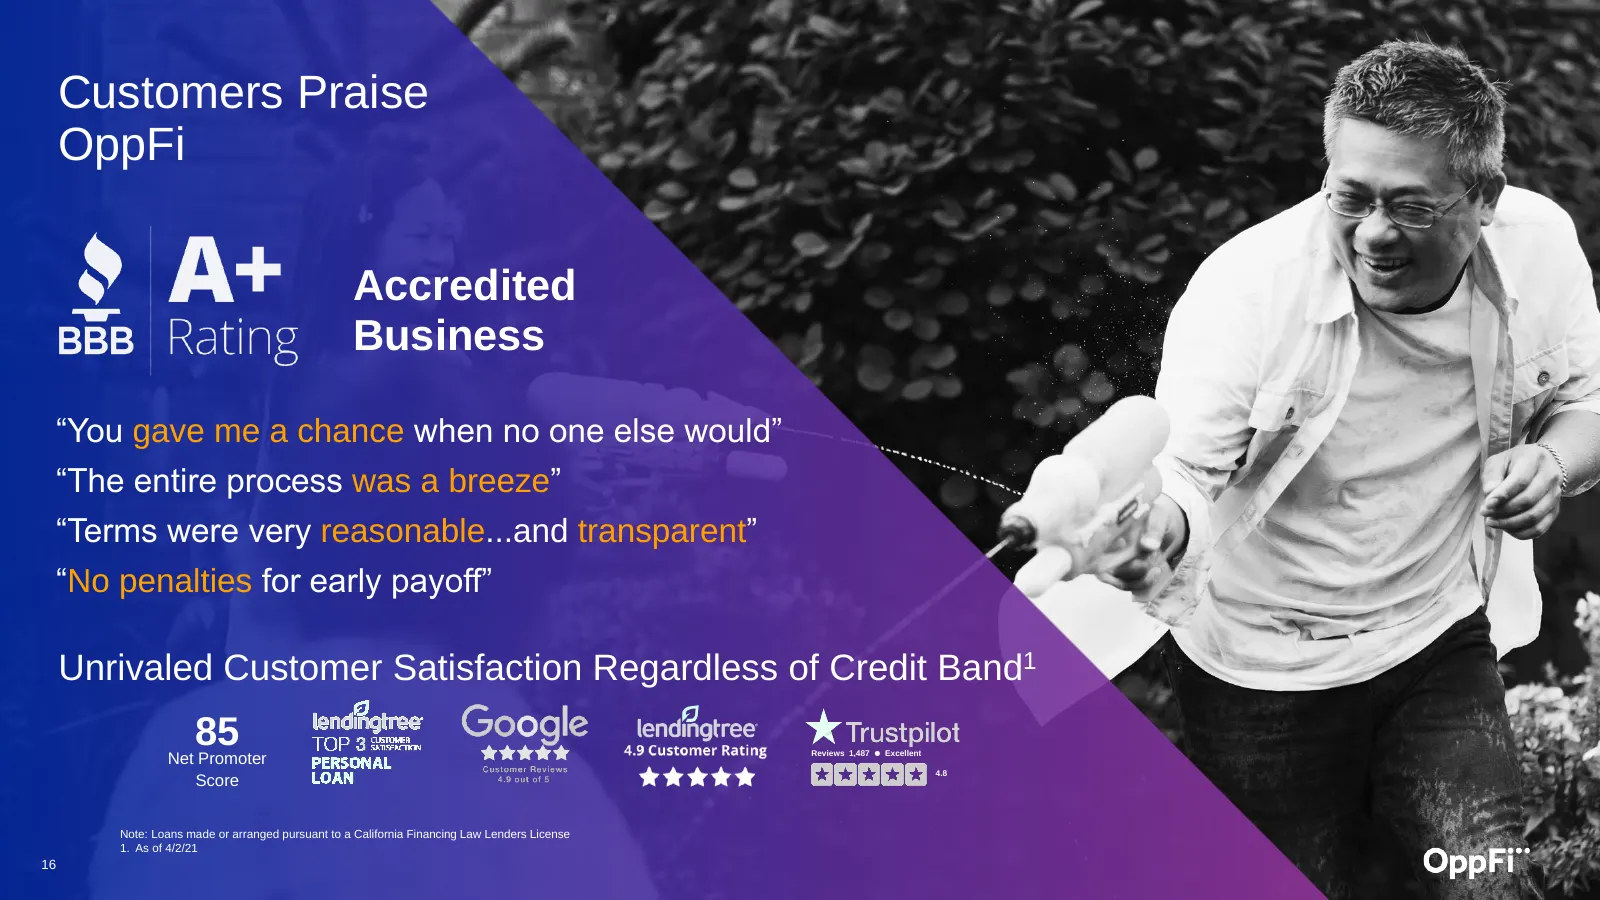
Customers Praise OppFi Accredited Business “You gave me a chance when no one else would” “The entire process was a breeze” “Terms were very reasonable...and transparent” “No penalties for early payoff” Unrivaled Customer Satisfaction Regardless of Credit Band1 85 Net Promoter Reviews 1,487 Excelle
Slide 18: Employees are Highly-Satisfied
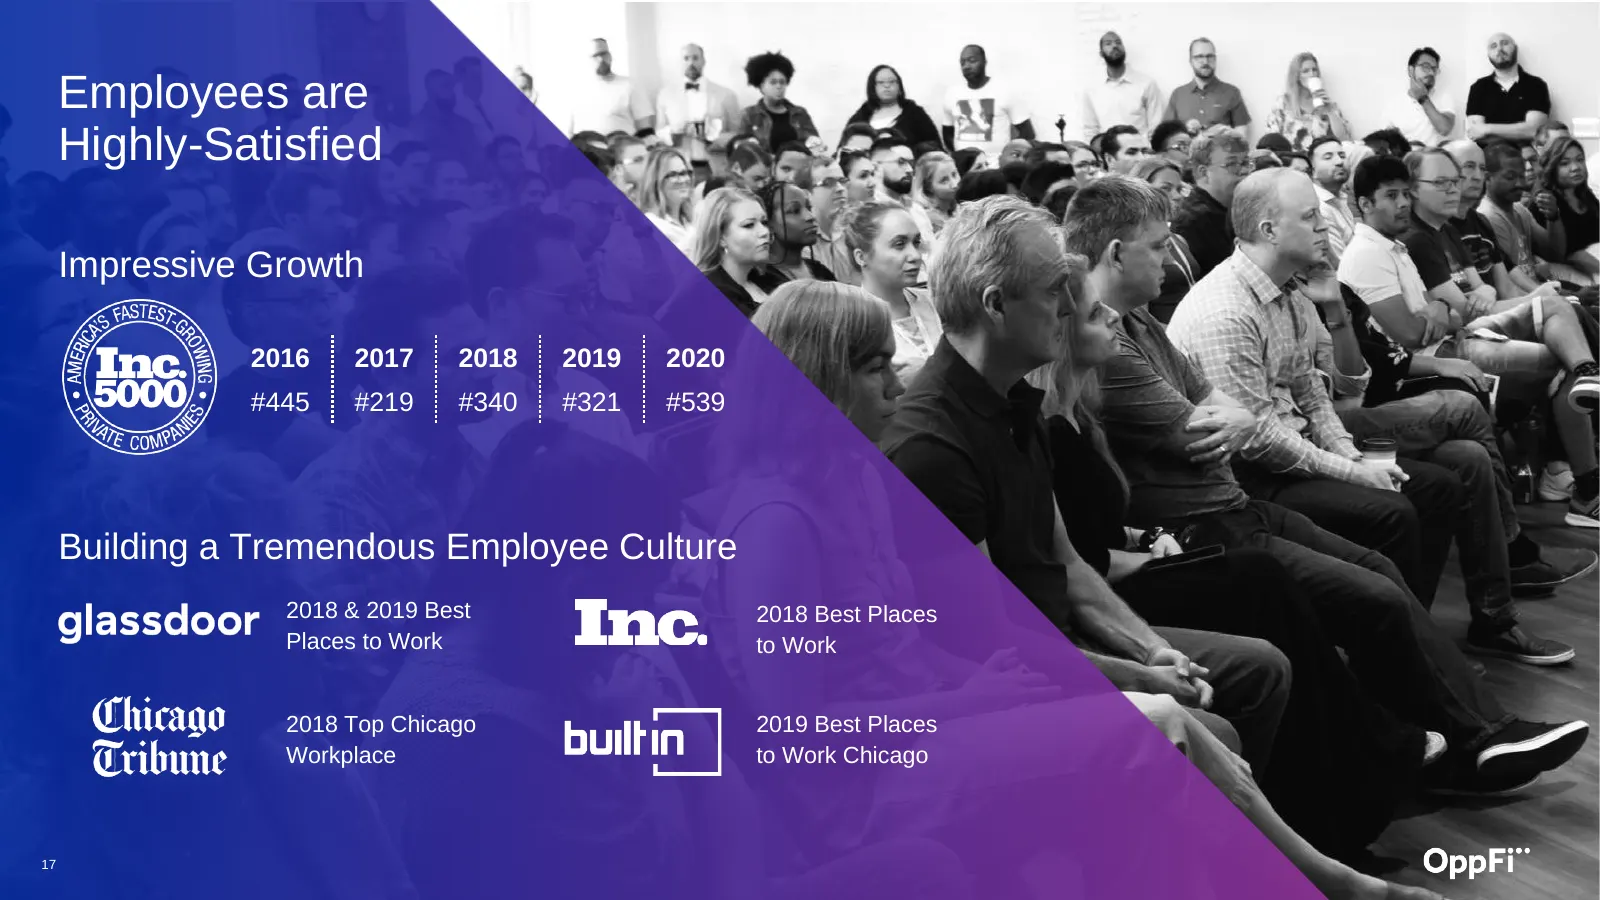
Employees are Highly-Satisfied Impressive Growth 2016 2017 2018 2019 2020 #445 #219 #340 #321 #539 Building a Tremendous Employee Culture 2018 & 2019 Best 2018 Best Places Places to Work to Work 2018 Top Chicago 2019 Best Places Workplace to Work Chicago 17
Slide 19: The OppFi Advantage
The OppFi Advantage A platform that puts you in control 18
Slide 20: Scalable, Diversified, Next Generation Marketing Platform
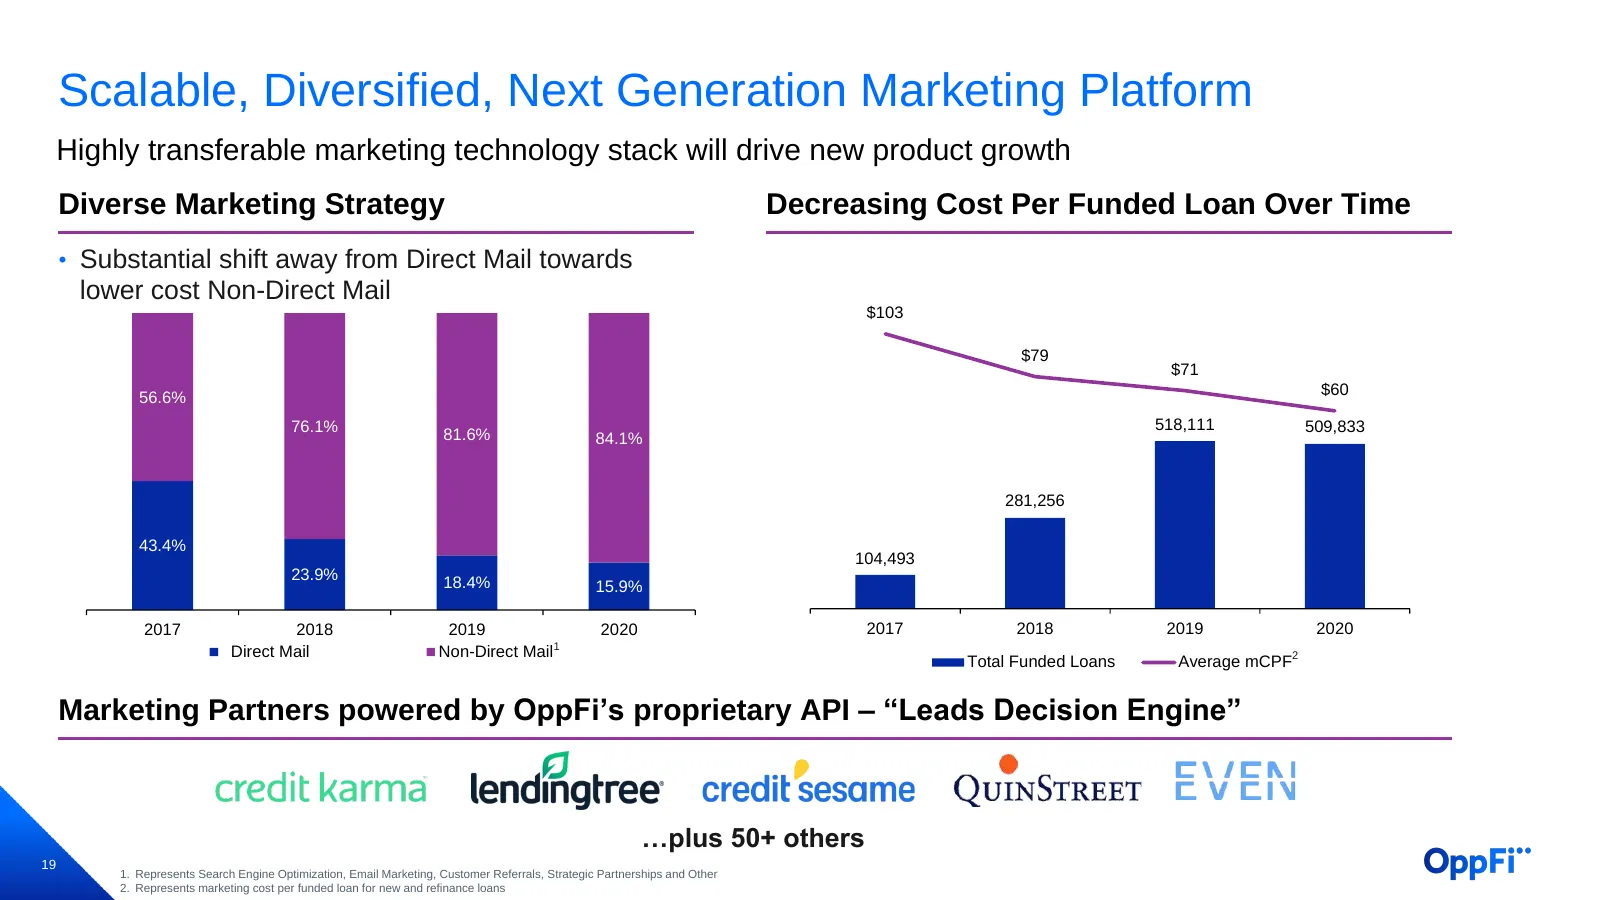
Scalable, Diversified, Next Generation Marketing Platform Highly transferable marketing technology stack will drive new product growth Diverse Marketing Strategy Decreasing Cost Per Funded Loan Over Time • Substantial shift away from Direct Mail towards lower cost Non-Direct Mail 110.0% 1,000,000 $1
Slide 21: Proprietary AI Powered, Credit Decisioning Algorithms
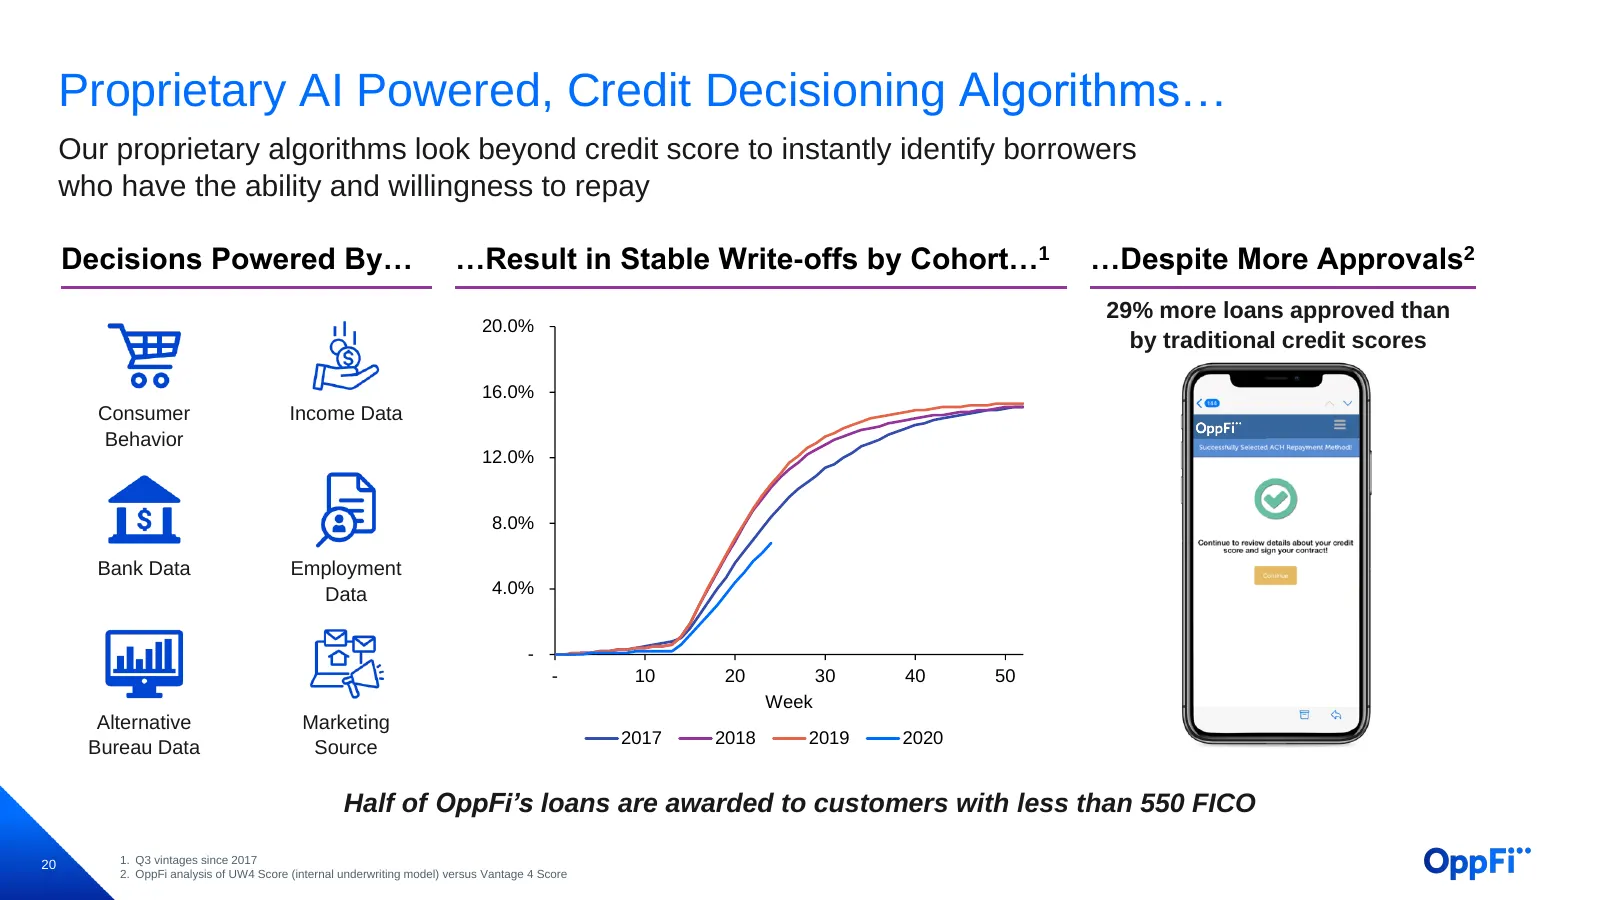
Proprietary AI Powered, Credit Decisioning Algorithms… Our proprietary algorithms look beyond credit score to instantly identify borrowers who have the ability and willingness to repay Decisions Powered By… …Result in Stable Write-offs by Cohort…1 …Despite More Approvals2 29% more loans approved tha
Slide 22: Powered by Modern and Leverageable Technology Stack
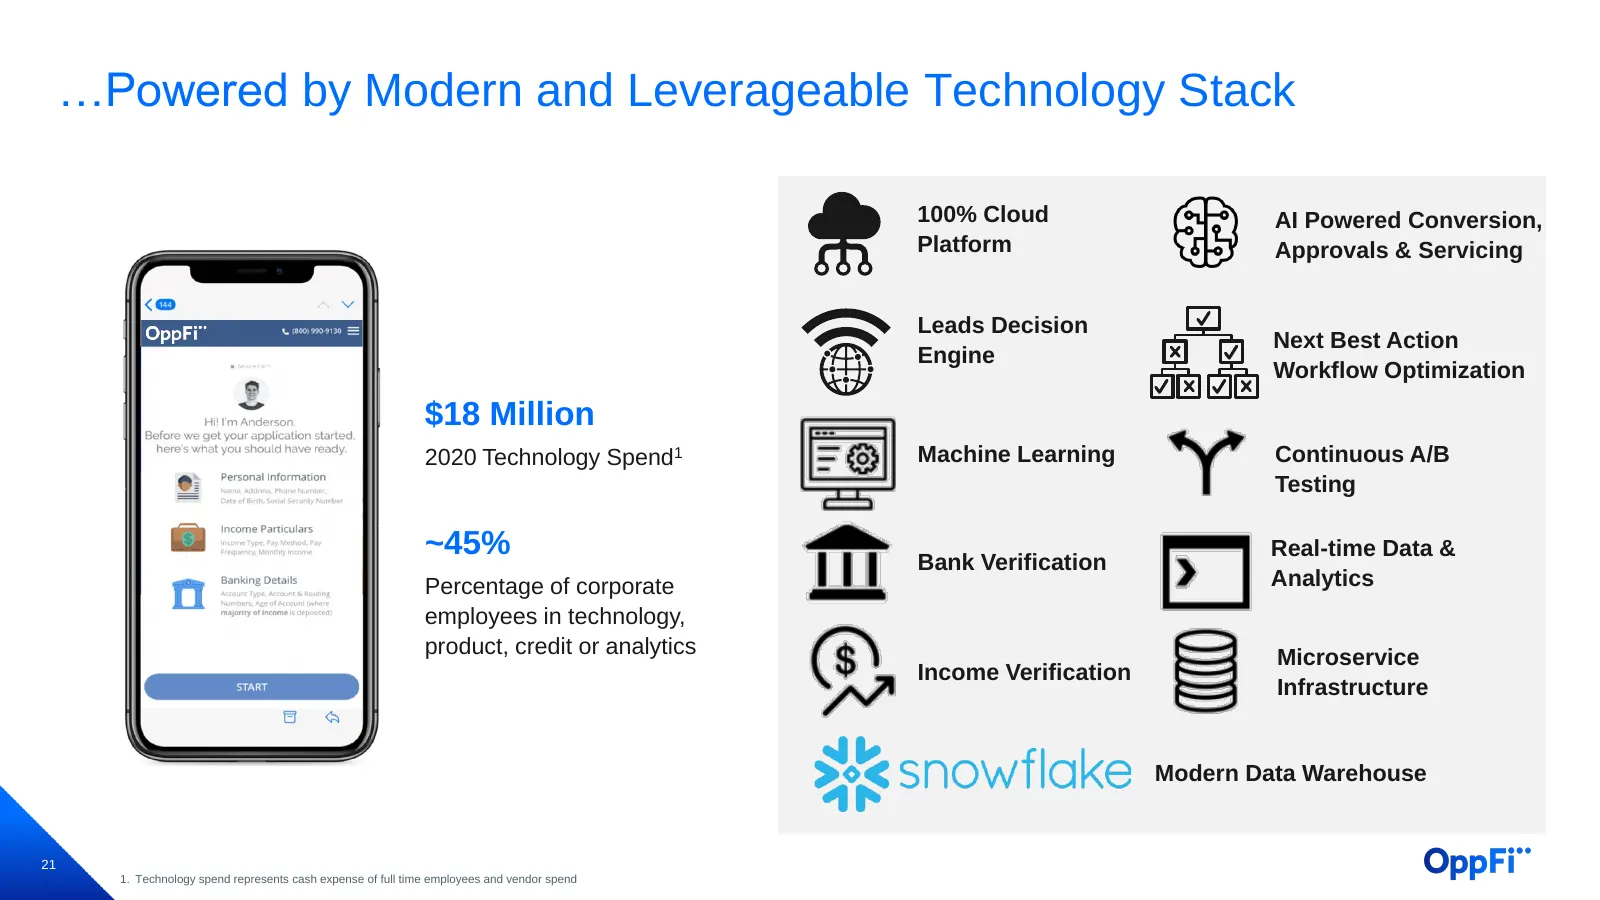
…Powered by Modern and Leverageable Technology Stack 100% Cloud AI Powered Conversion, Platform Approvals & Servicing Leads Decision Next Best Action Engine Workflow Optimization $18 Million 2020 Technology Spend1 Machine Learning Continuous A/B Testing ~45% Bank Verification Real-time Data & Percen
Slide 23: Driving Operational Leverage via Automation and Productivity Tools
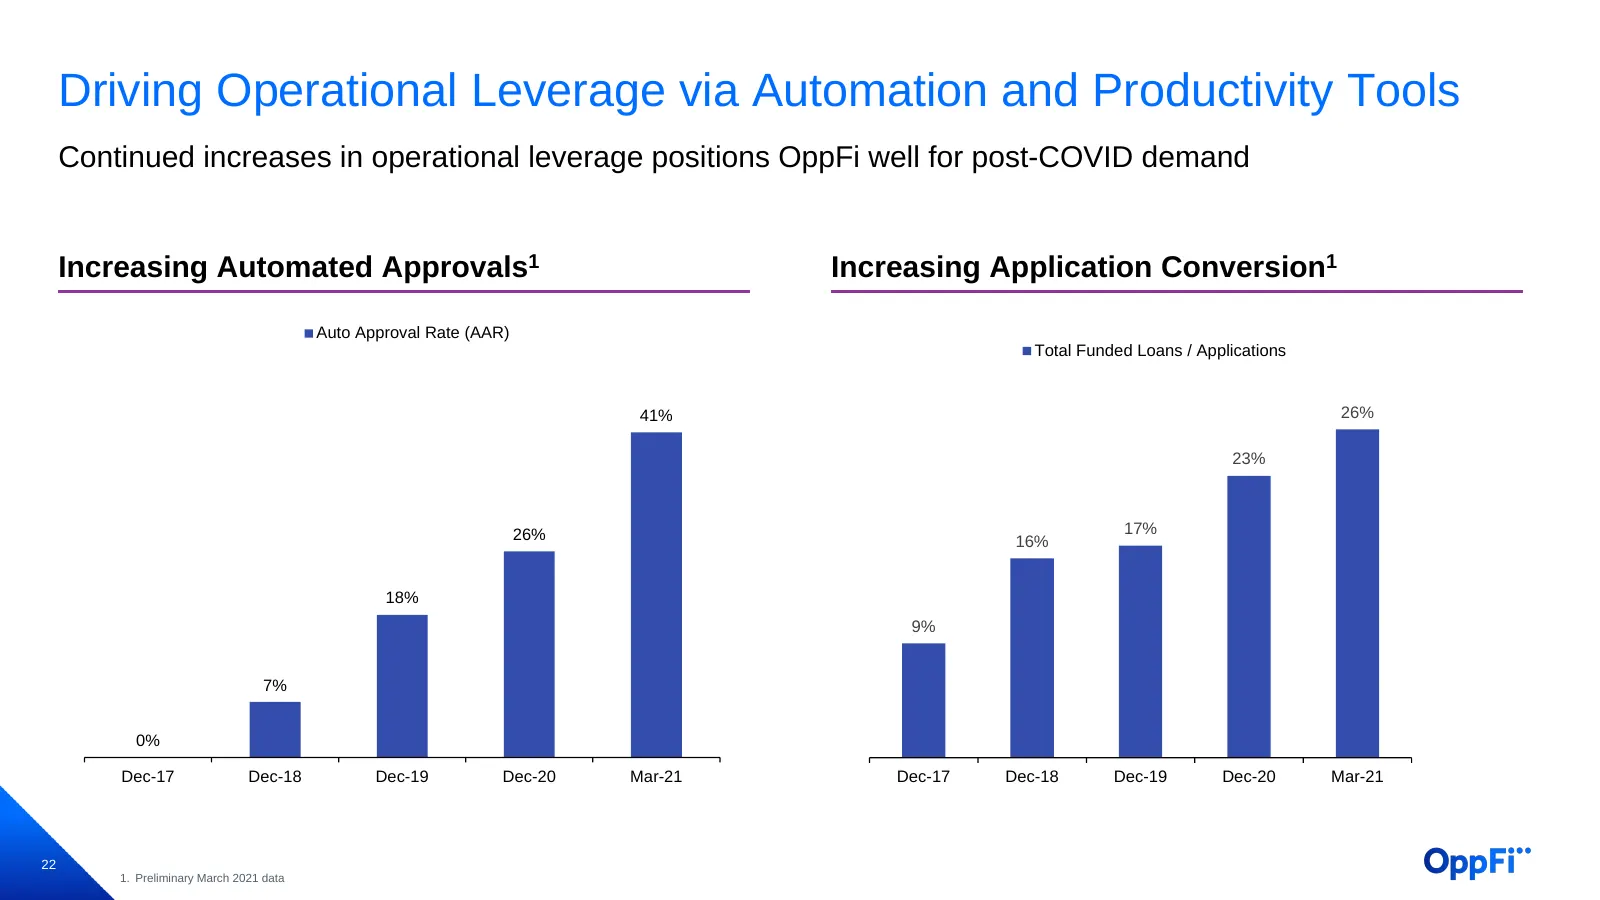
Driving Operational Leverage via Automation and Productivity Tools Continued increases in operational leverage positions OppFi well for post-COVID demand Increasing Automated Approvals1 Increasing Application Conversion1 Auto Approval Rate (AAR) Total Funded Loans / Applications 41% 26% 23% 26% 17%
Slide 24: Protected by Bank Level Compliance Infrastructure
Protected by Bank Level Compliance Infrastructure Integrated framework designed around three layers of defense Ownership All business units are responsible for identifying and managing risks Challenge Compliance Program Risk & Controls Governance • Complaint Handling • Risk Assessments • Change Mana
Slide 25: The OppFi Customer Journey
The OppFi Customer Journey 24
Slide 26: Product Demo - Typical Customer Journey
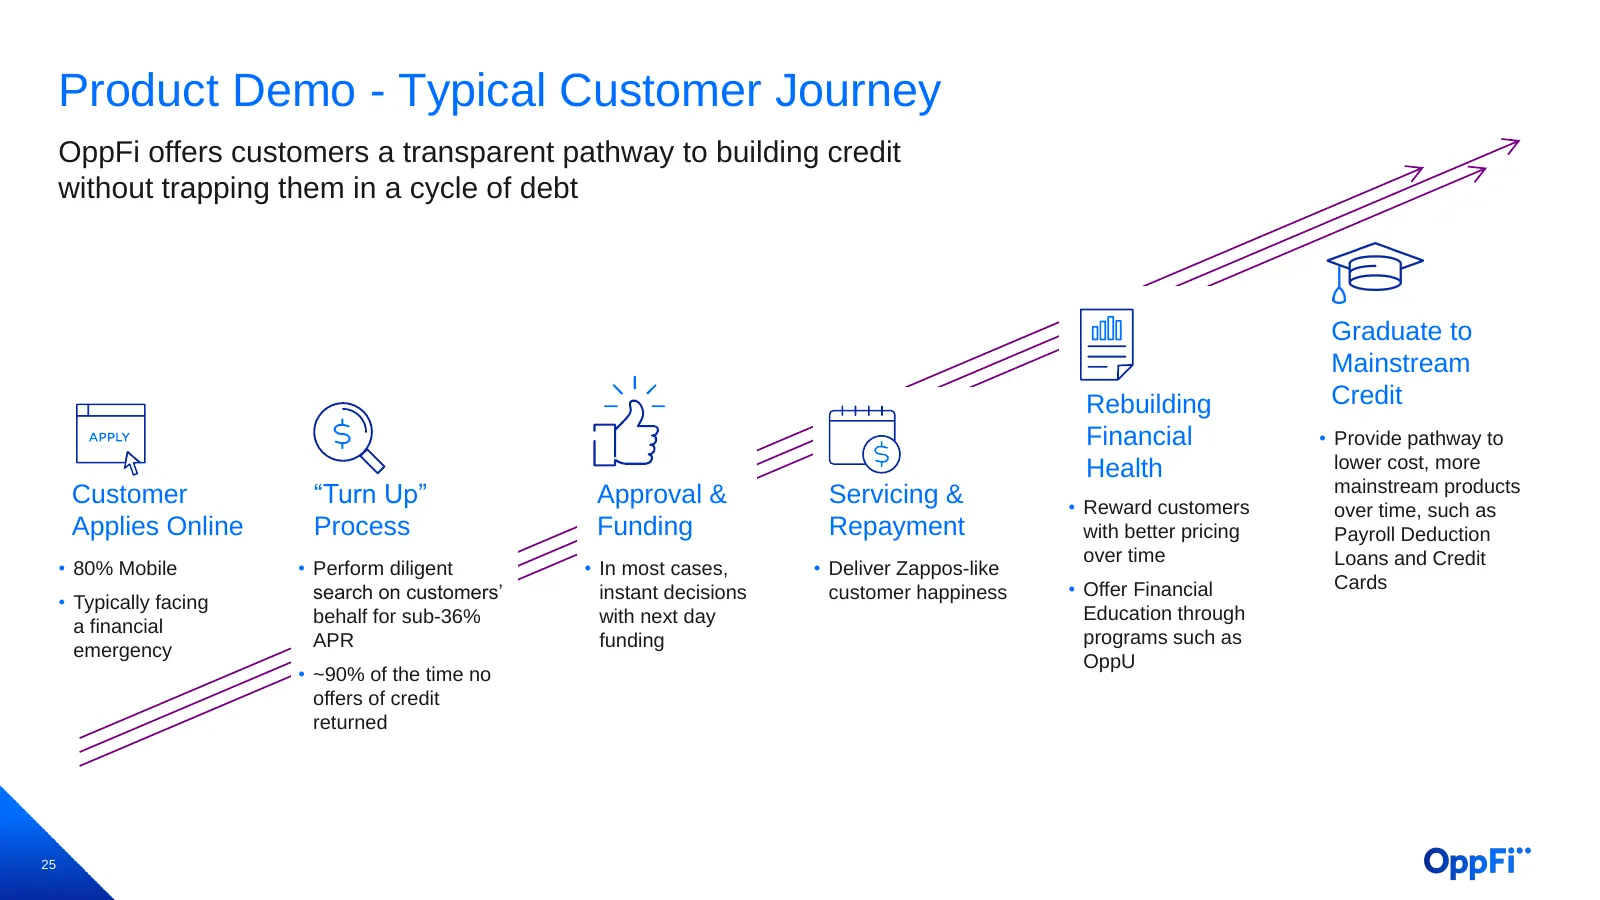
Product Demo - Typical Customer Journey OppFi offers customers a transparent pathway to building credit without trapping them in a cycle of debt Graduate to Mainstream Rebuilding Credit Financial • Provide pathway to Health lower cost, more mainstream products Customer “Turn Up” Approval & Servicing
Slide 27: Credit Access Product – the OppLoan
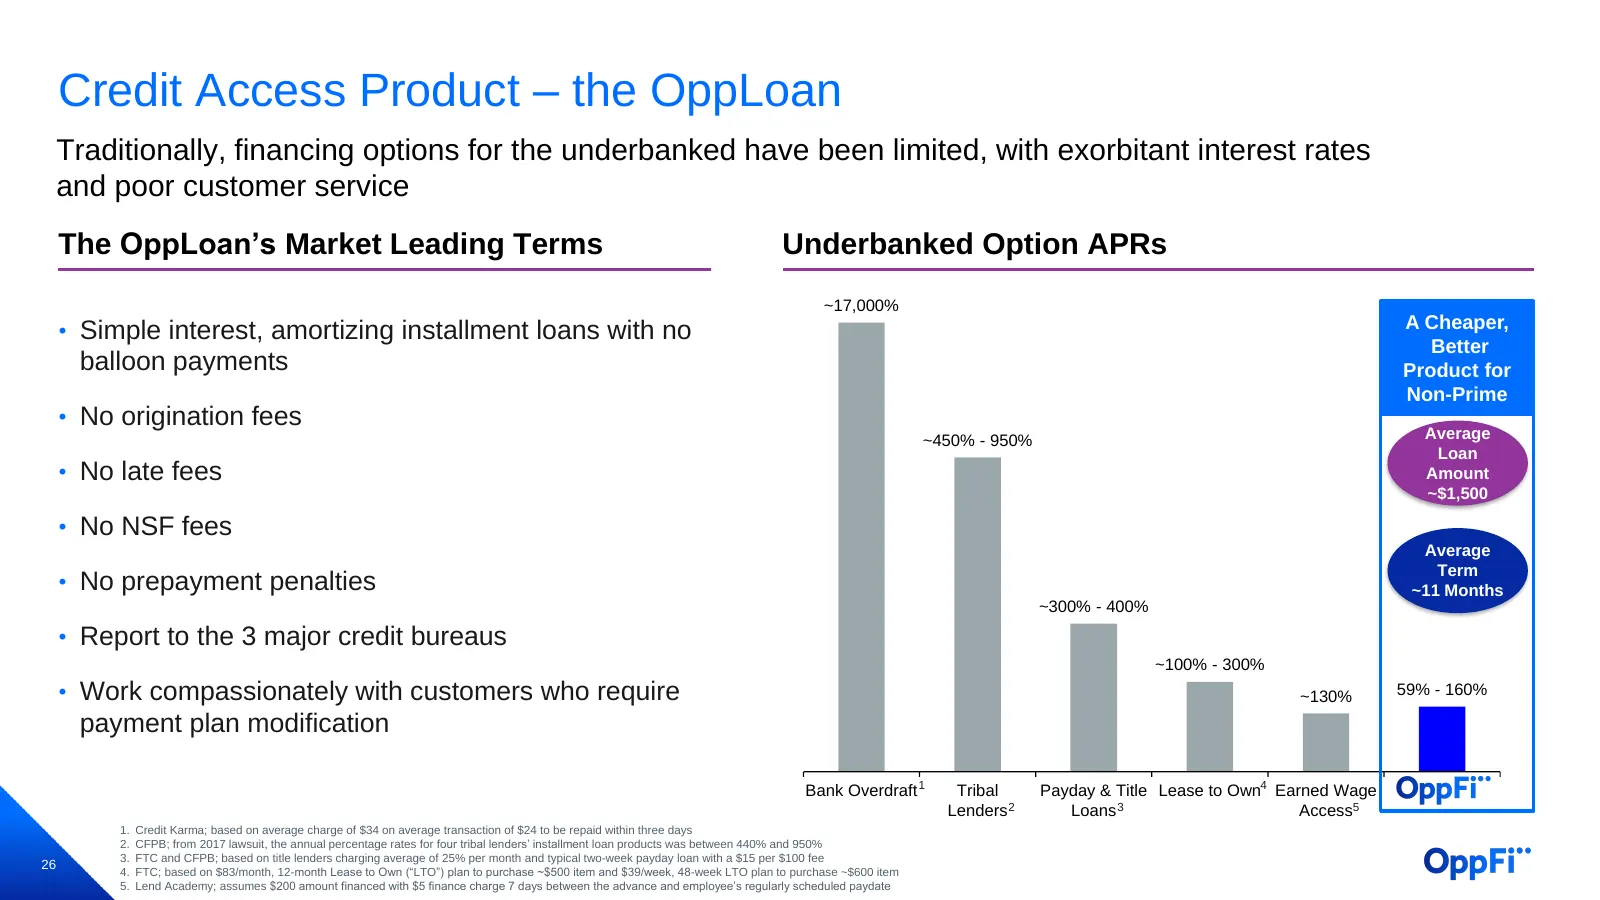
Credit Access Product – the OppLoan Traditionally, financing options for the underbanked have been limited, with exorbitant interest rates and poor customer service The OppLoan’s Market Leading Terms 1200% Underbanked Option APRs ~17,000% A Cheaper, • Simple interest, amortizing installment loans wi
Slide 28: SalaryTap Extends Prime Pricing to Non-Prime Consumers
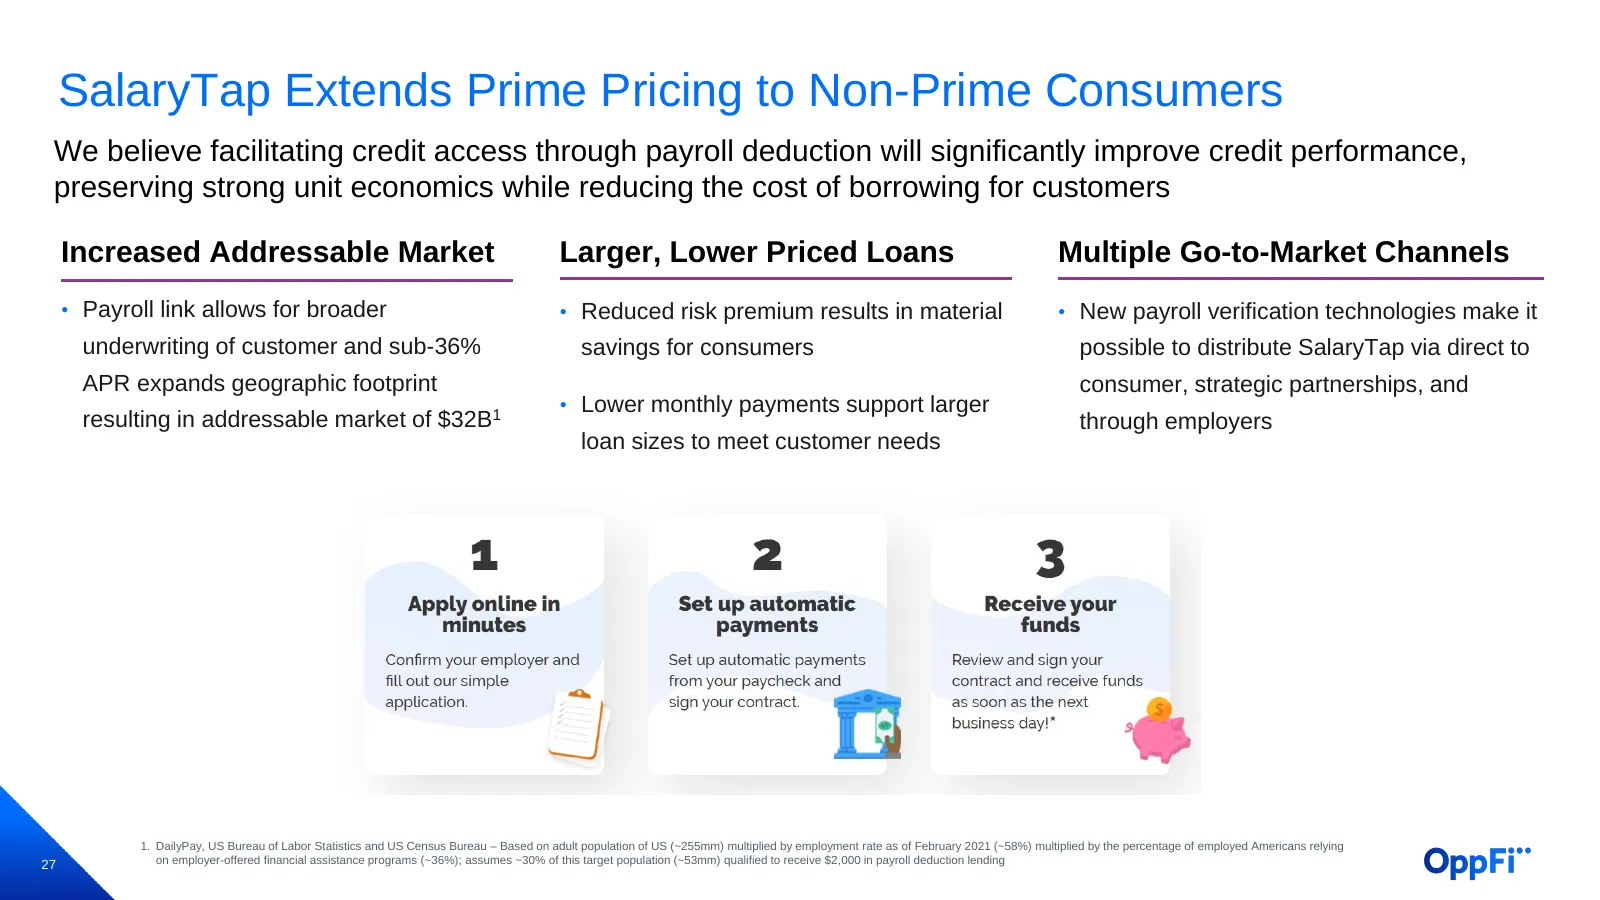
SalaryTap Extends Prime Pricing to Non-Prime Consumers We believe facilitating credit access through payroll deduction will significantly improve credit performance, preserving strong unit economics while reducing the cost of borrowing for customers Increased Addressable Market Larger, Lower Priced
Slide 29: OppFi Credit Card Serves as Graduation Pathway
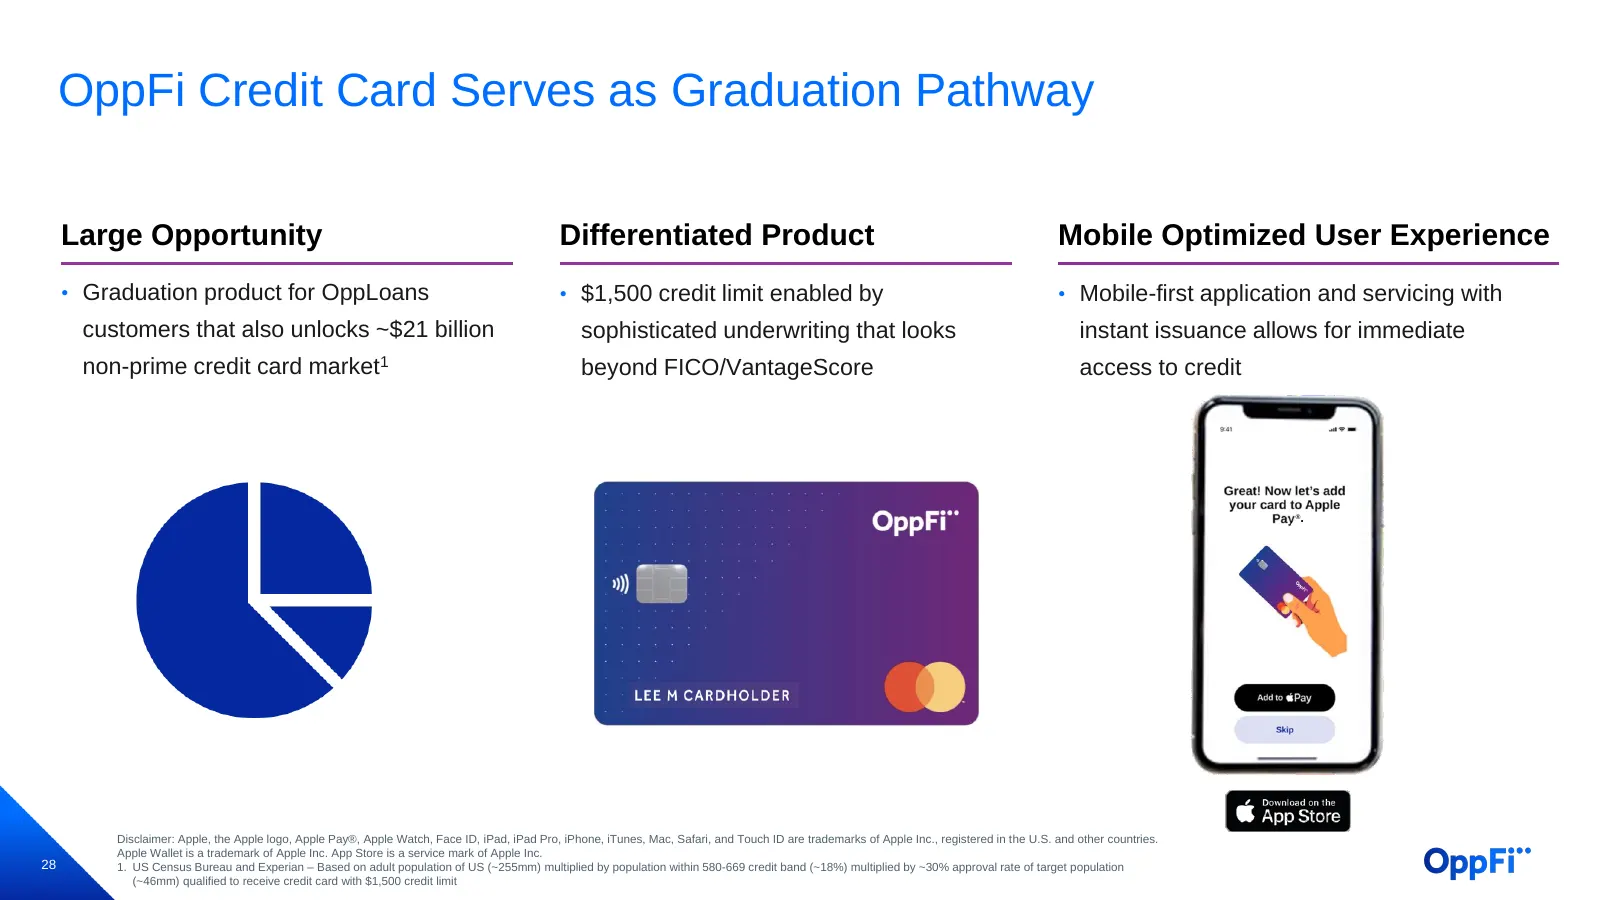
OppFi Credit Card Serves as Graduation Pathway Large Opportunity Differentiated Product Mobile Optimized User Experience • Graduation product for OppLoans • $1,500 credit limit enabled by • Mobile-first application and servicing with customers that also unlocks ~$21 billion sophisticated underwritin
Slide 30: Financial Performance
Financial Performance 29
Slide 31: Platform with Proven Ability to Scale Profitably
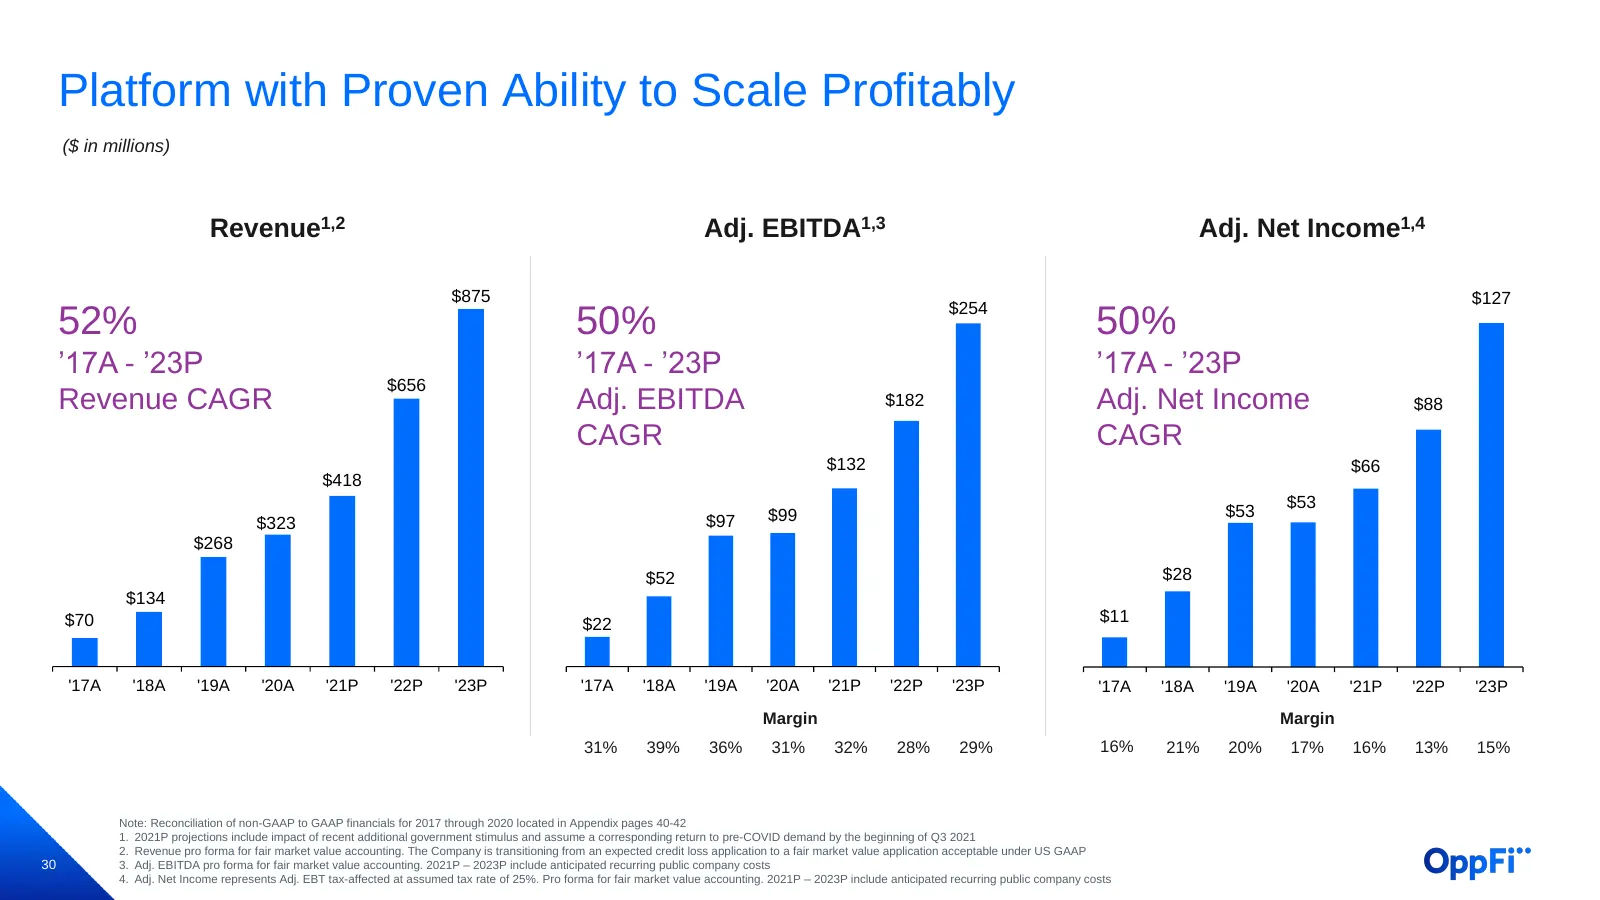
Platform with Proven Ability to Scale Profitably ($ in millions) Revenue1,2 Adj. EBITDA1,3 Adj. Net Income1,4 $1,000.0 $300 $150 $900.0 $875 $127 $254 $800.0 52% $250 50% $130 50% ’17A - ’23P ’17A - ’23P $110 ’17A - ’23P $656 $700.0 $600.0 Revenue CAGR $200 Adj. EBITDA $182 Adj. Net Income $88 $90 C
Slide 32: Growth Strategy and Drivers
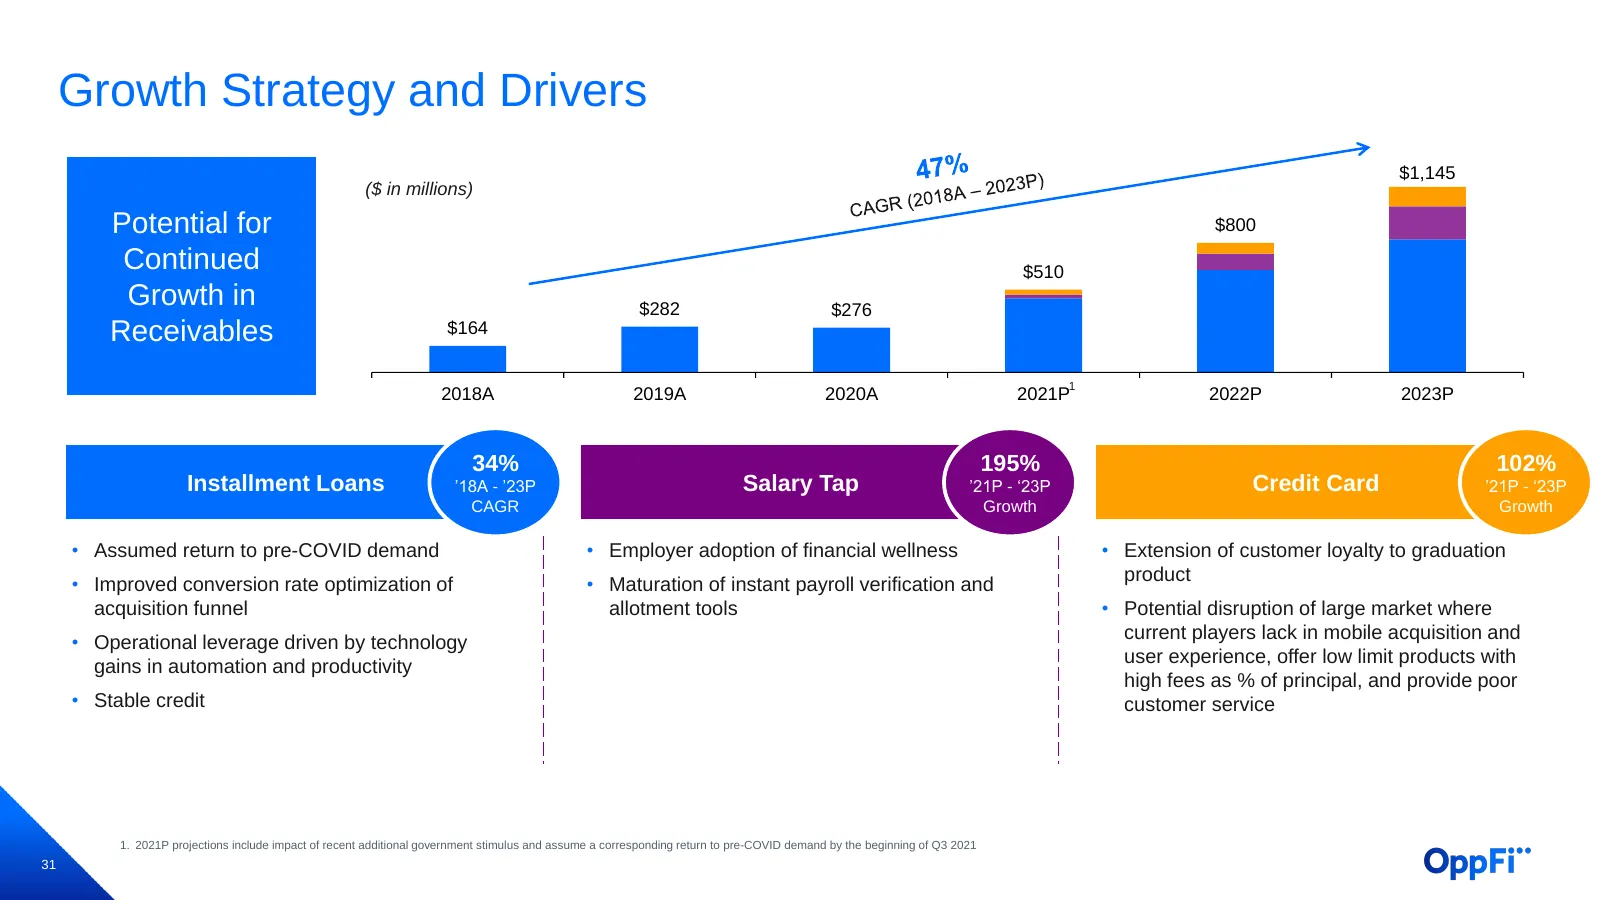
Growth Strategy and Drivers 1200 $1,145 ($ in millions) 1000 Potential for 800 $800 Continued 600 $510 Growth in 400 $282 $276 Receivables 200 $164 0 1 2018A 2019A 2020A 2021P 2022P 2023P 34% 195% 102% Installment Loans ’18A - ’23P Salary Tap ’21P - ‘23P Credit Card ’21P - ‘23P CAGR Growth Growth •
Slide 33: Exceptional Unit Economics – OppLoan Product
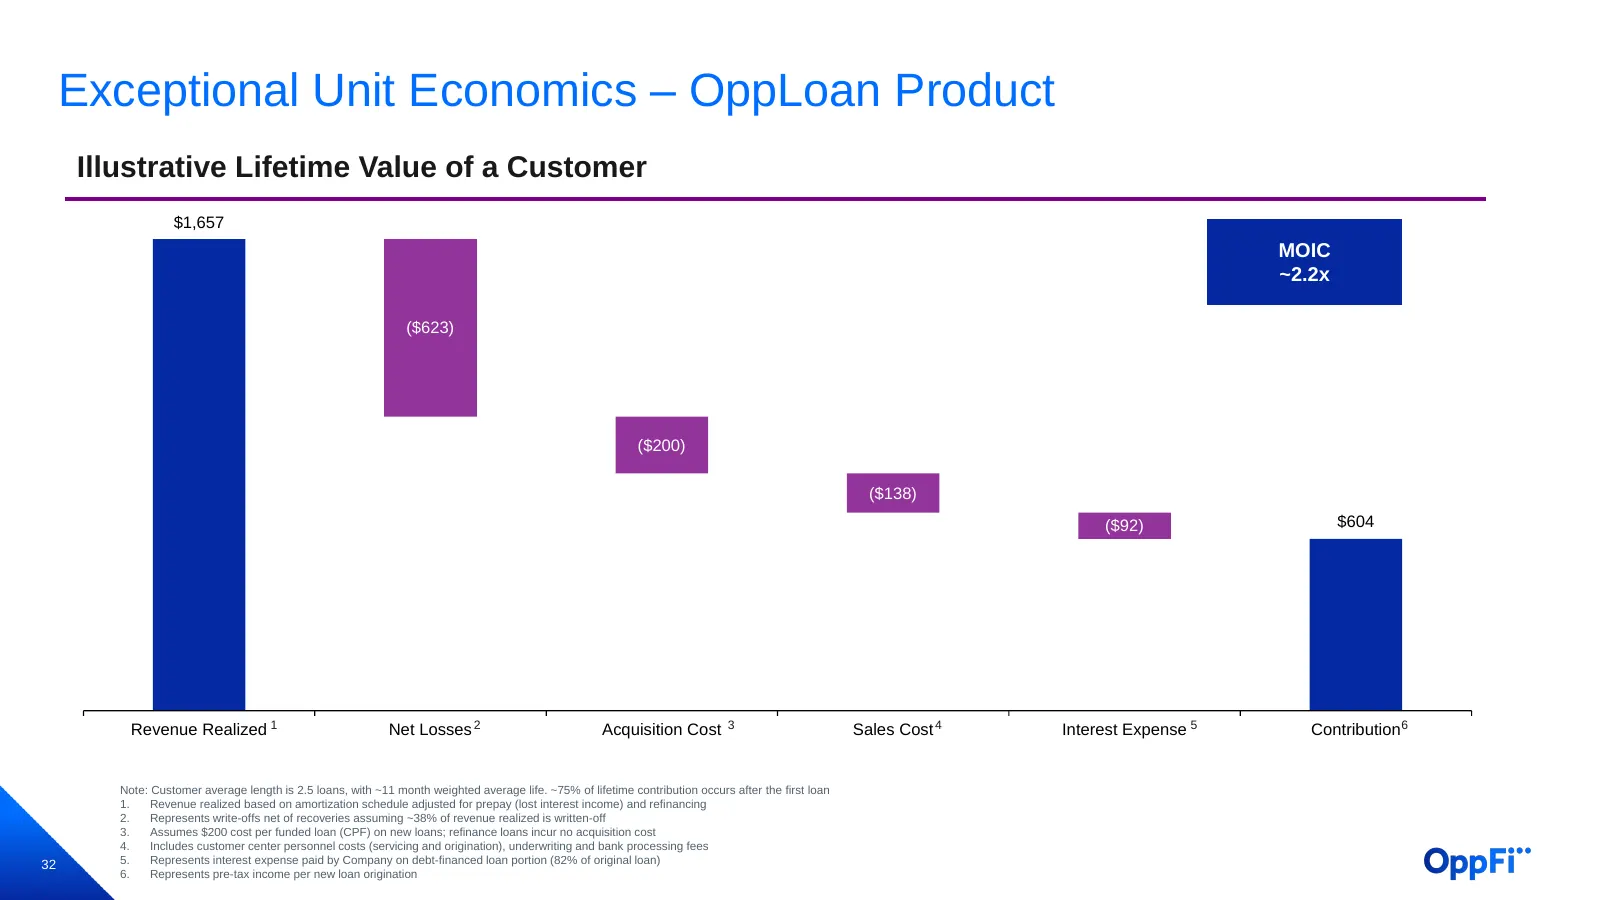
Exceptional Unit Economics – OppLoan Product Illustrative Lifetime Value of a Customer $1,700 $1,657 MOIC $1,500 ~2.2x $1,300 ($623) $1,100 $900 ($200) ($138) $700 ($92) $604 $500 $300 $100 ($100) Revenue Realized 1 Net Losses 2 Acquisition Cost 3 Sales Cost 4 Interest Expense 5 Contribution 6 Note:
Slide 34: Reduced Cost of Financing and Strong Balance Sheet Powers Growth
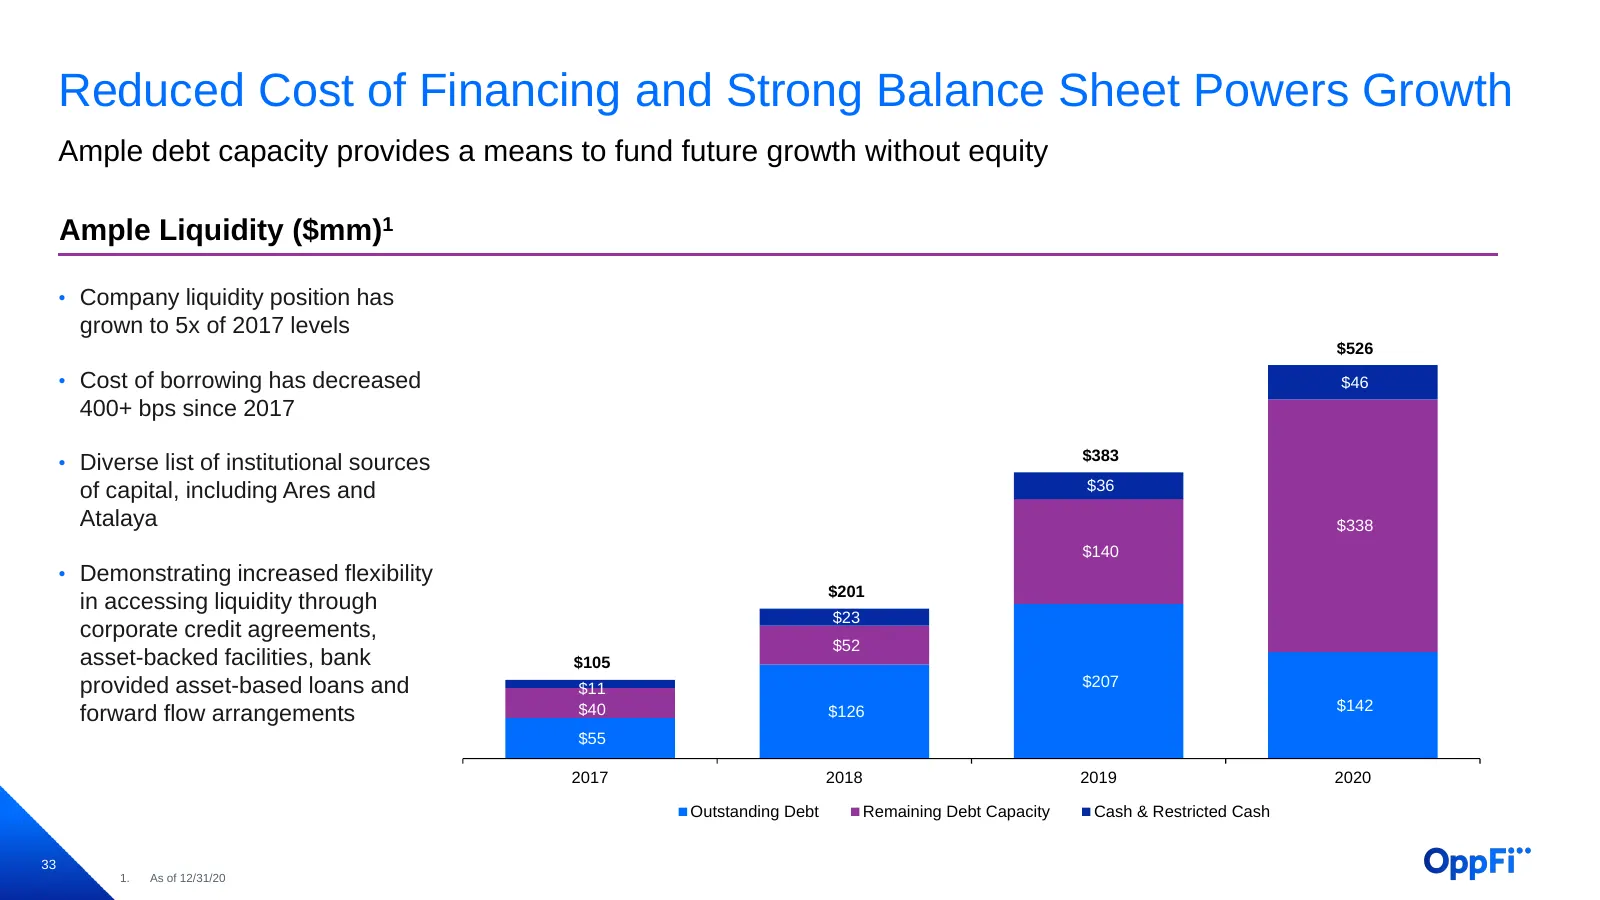
Reduced Cost of Financing and Strong Balance Sheet Powers Growth Ample debt capacity provides a means to fund future growth without equity Ample Liquidity ($mm)1 • Company liquidity position has grown to 5x of 2017 levels $526 • Cost of borrowing has decreased $46 400+ bps since 2017 $383 • Diverse
Slide 35: Benchmarking & Valuation
Benchmarking & Valuation 34
Slide 36: Upstart, Katapult and Affirm: Business Comparison
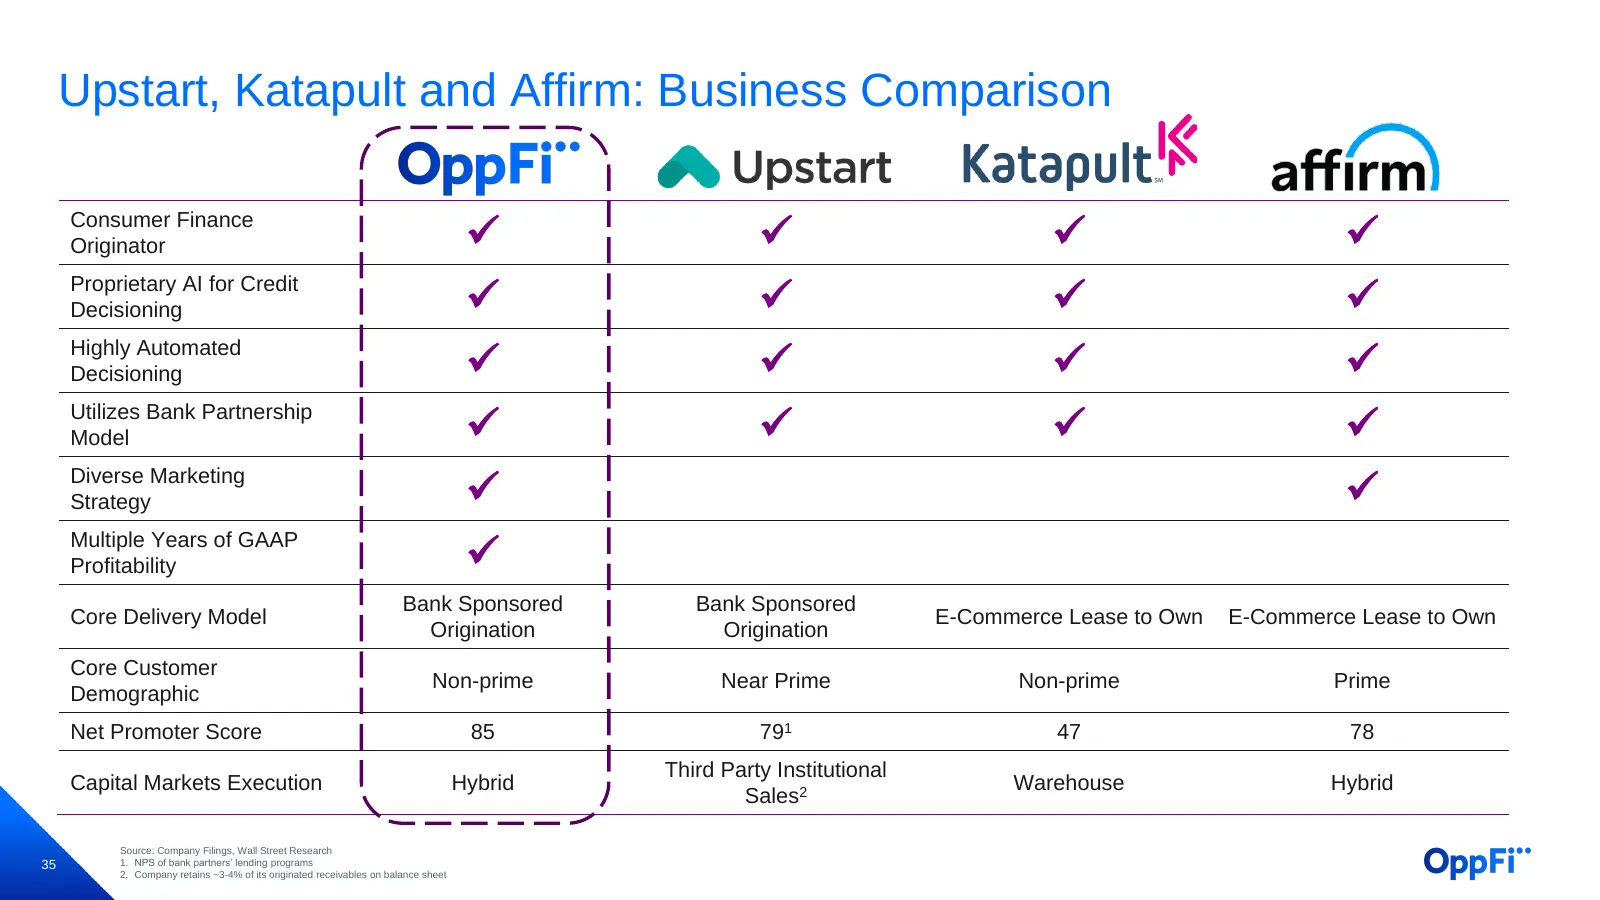
Upstart, Katapult and Affirm: Business Comparison Consumer Finance Originator Proprietary AI for Credit Decisioning Highly Automated Decisioning Utilizes Bank Partnership Model Diverse Marketing Strategy Multiple Years of GAAP Profitability Bank Sponsored Bank S
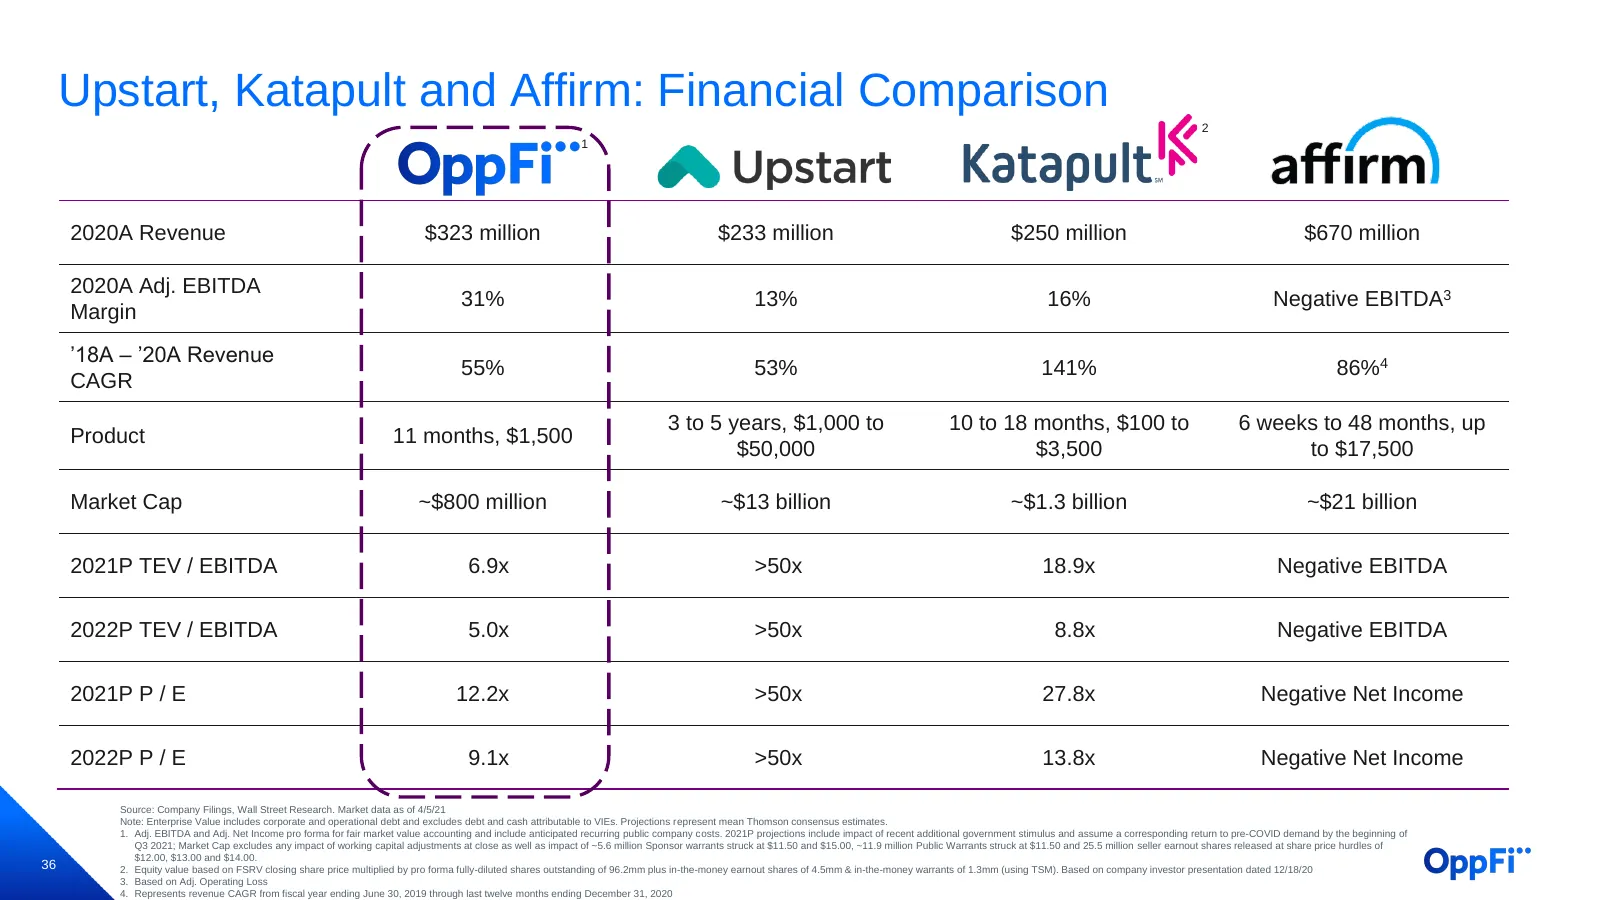
Slide 37: Upstart, Katapult and Affirm: Financial Comparison
Upstart, Katapult and Affirm: Financial Comparison 2 1 2020A Revenue $323 million $233 million $250 million $670 million 2020A Adj. EBITDA 31% 13% 16% Negative EBITDA3 Margin ’18A – ’20A Revenue 55% 53% 141% 86%4 CAGR 3 to 5 years, $1,000 to 10 to 18 months, $100 to 6 weeks to 48 months, up Product
Slide 38: Appendix
Appendix 37
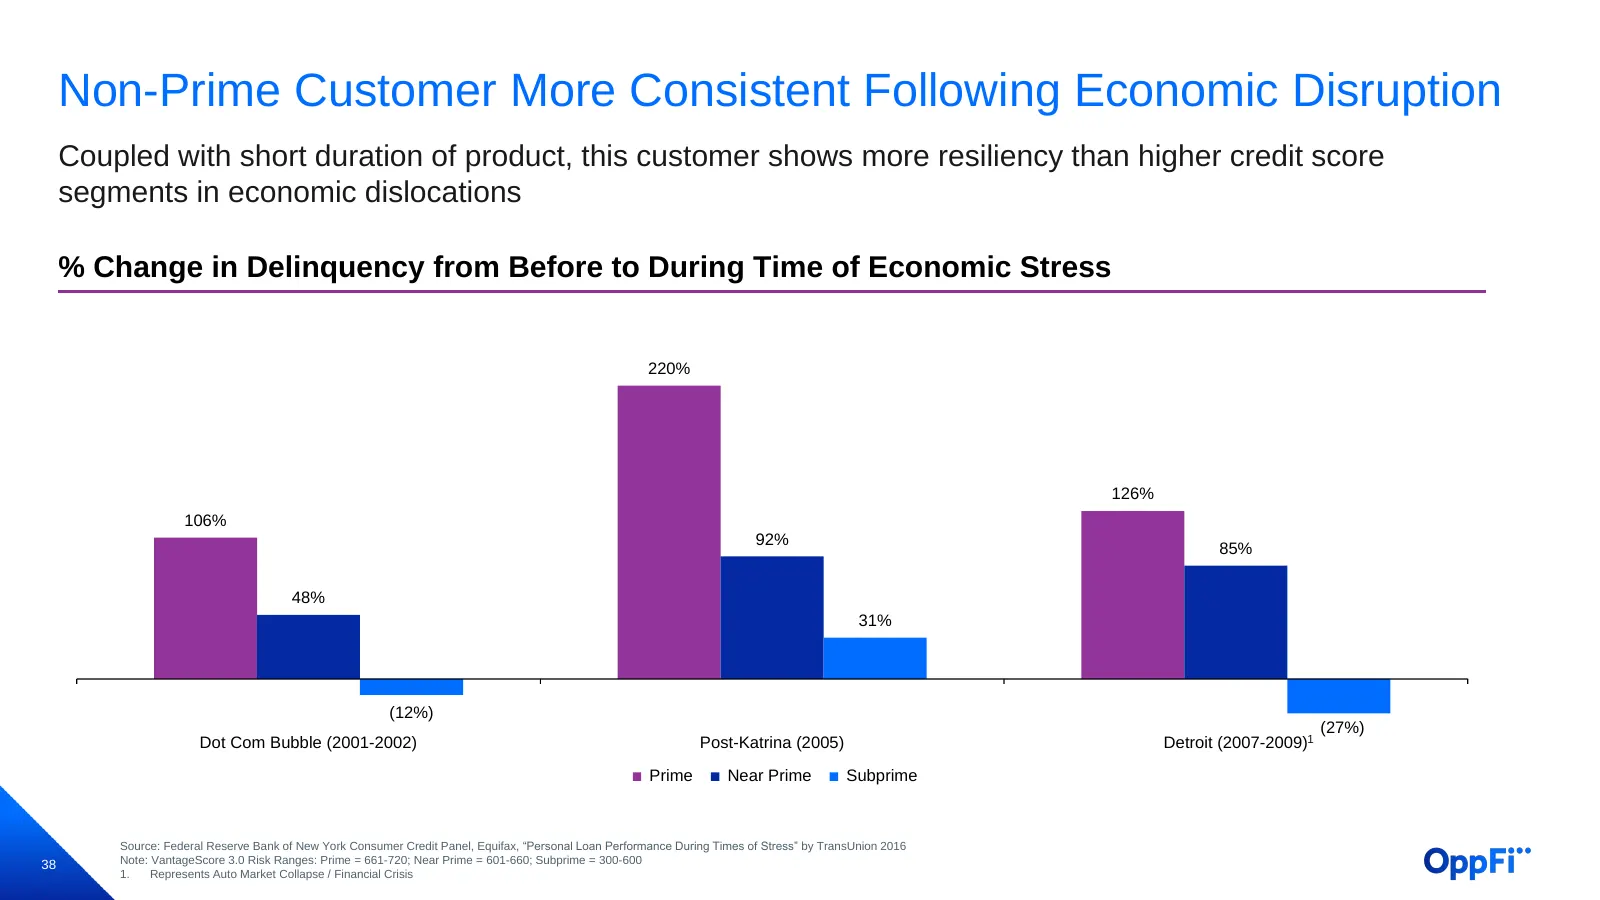
Slide 39: Non-Prime Customer More Consistent Following Economic Disruption
Non-Prime Customer More Consistent Following Economic Disruption Coupled with short duration of product, this customer shows more resiliency than higher credit score segments in economic dislocations % Change in Delinquency from Before to During Time of Economic Stress 220% 126% 106% 92% 85% 48% 31%
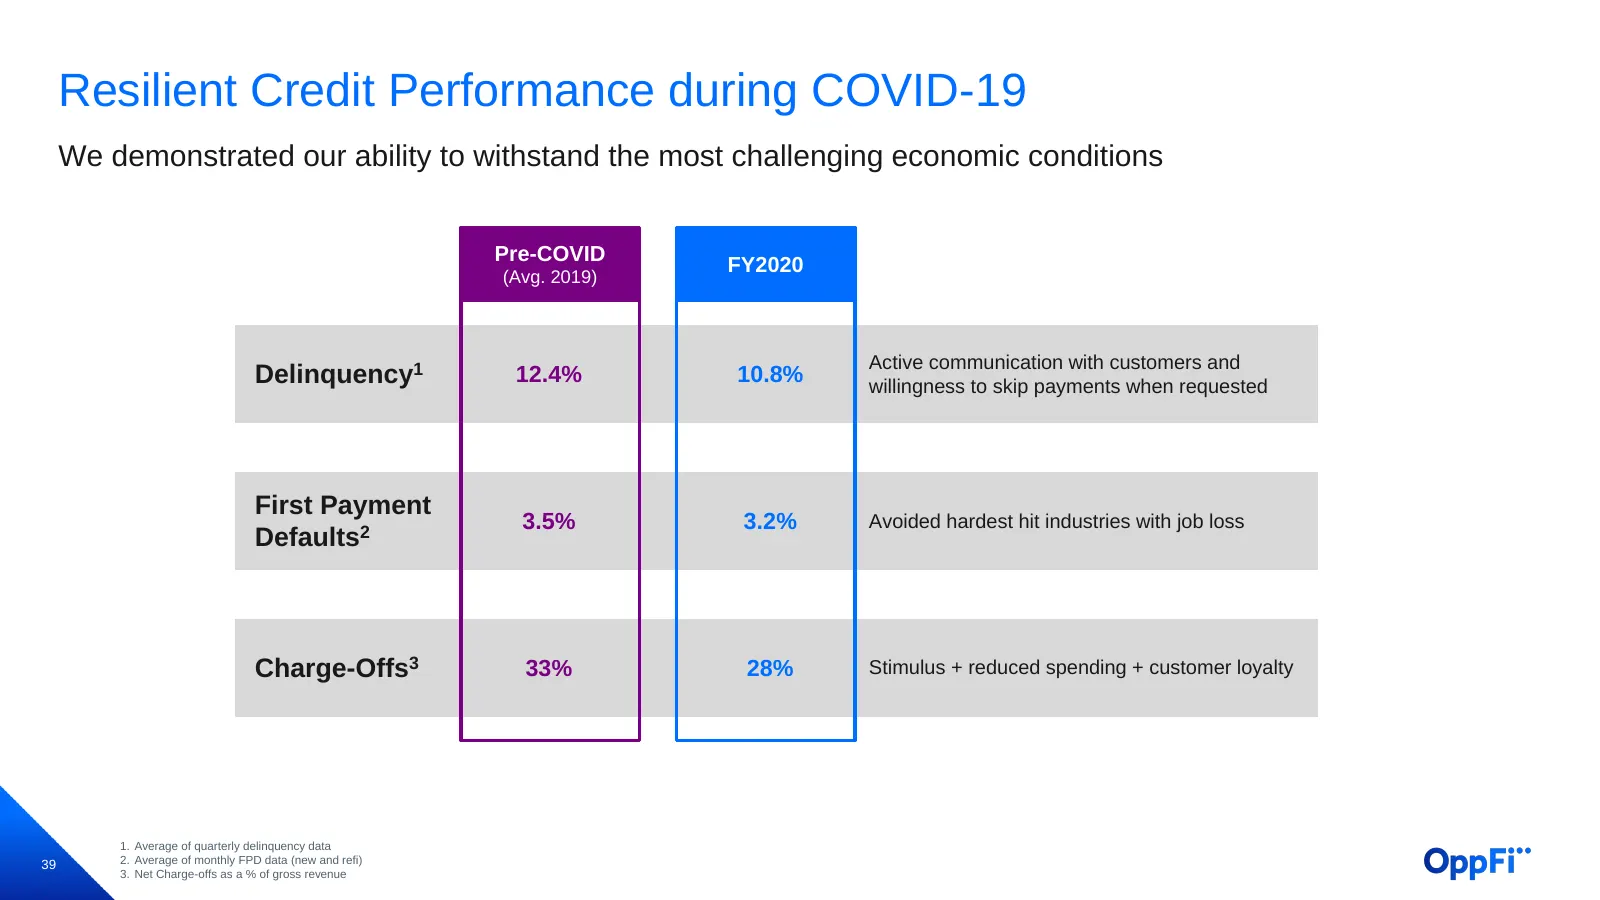
Slide 40: Resilient Credit Performance during COVID-19
Resilient Credit Performance during COVID-19 We demonstrated our ability to withstand the most challenging economic conditions Pre-COVID FY2020 (Avg. 2019) Active communication with customers and Delinquency1 12.4% 10.8% willingness to skip payments when requested First Payment 3.5% 3.2% Avoided har
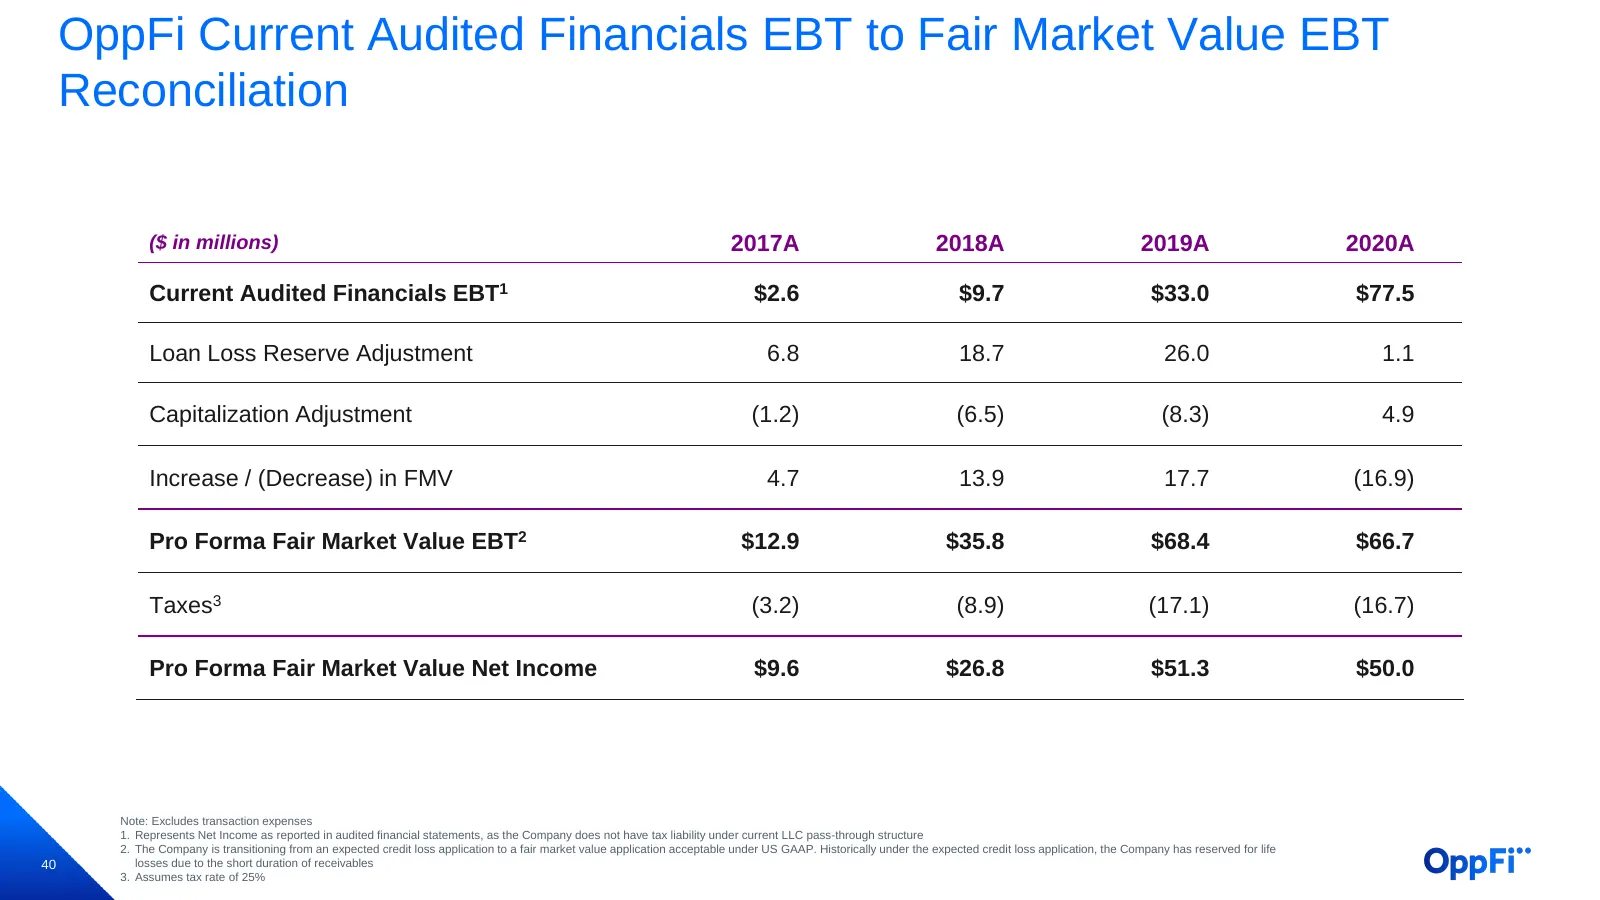
Slide 41: EBT to Fair Market Value EBT Reconciliation
OppFi Current Audited Financials EBT to Fair Market Value EBT Reconciliation ($ in millions) 2017A 2018A 2019A 2020A Current Audited Financials EBT1 $2.6 $9.7 $33.0 $77.5 Loan Loss Reserve Adjustment 6.8 18.7 26.0 1.1 Capitalization Adjustment (1.2) (6.5) (8.3) 4.9 Increase / (Decrease) in FMV 4.7 1
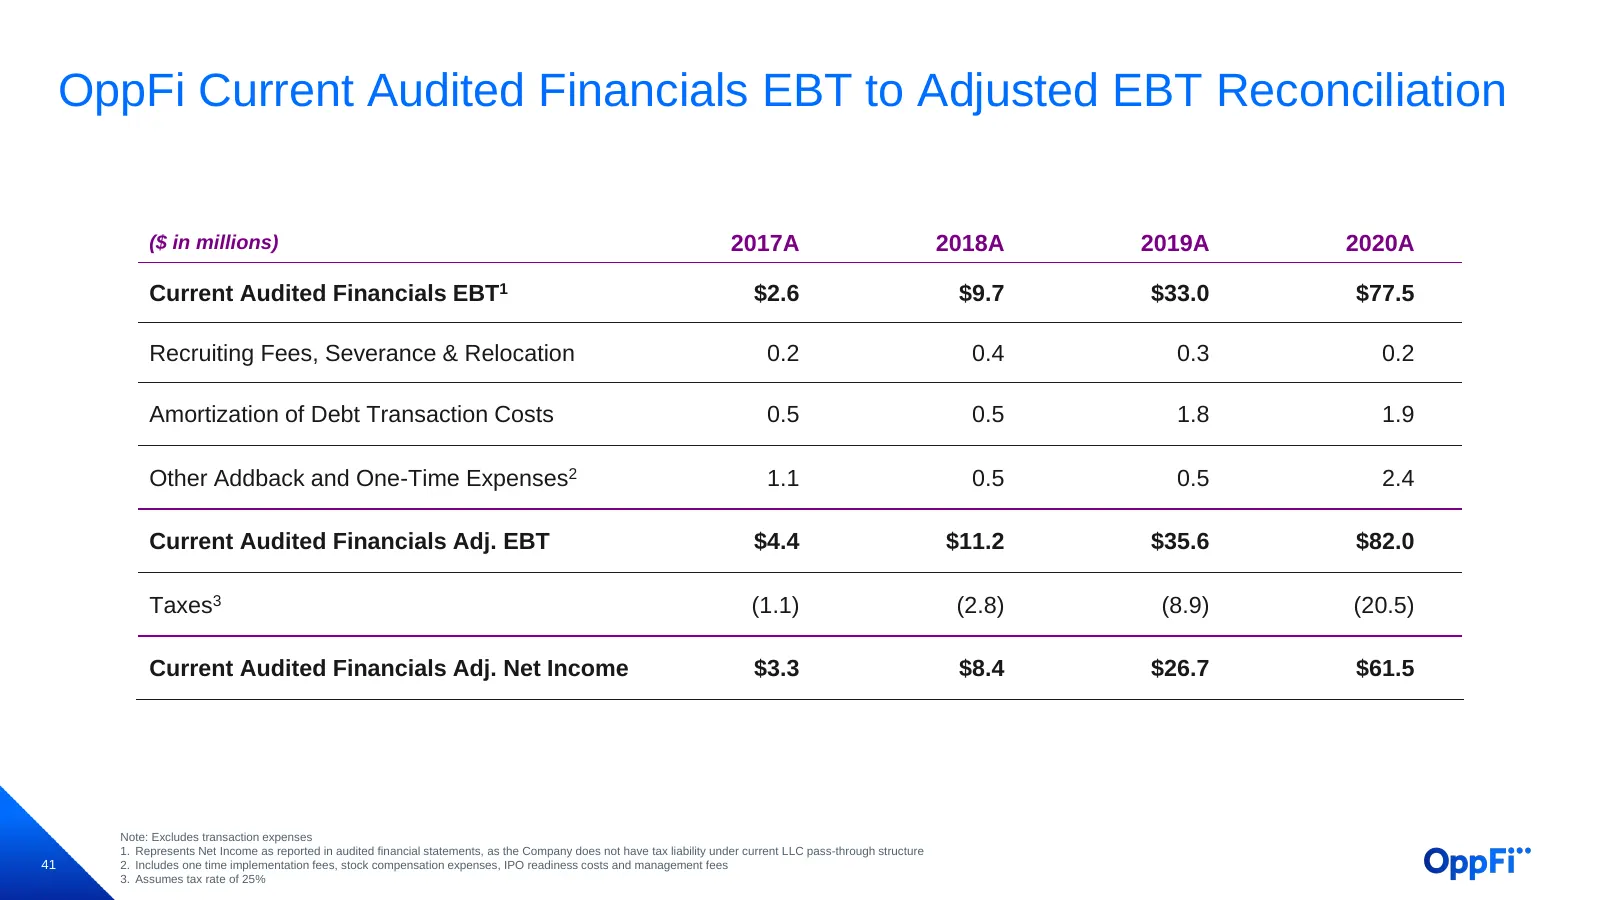
Slide 42: EBT to Adjusted EBT Reconciliation
OppFi Current Audited Financials EBT to Adjusted EBT Reconciliation ($ in millions) 2017A 2018A 2019A 2020A Current Audited Financials EBT1 $2.6 $9.7 $33.0 $77.5 Recruiting Fees, Severance & Relocation 0.2 0.4 0.3 0.2 Amortization of Debt Transaction Costs 0.5 0.5 1.8 1.9 Other Addback and One-Time
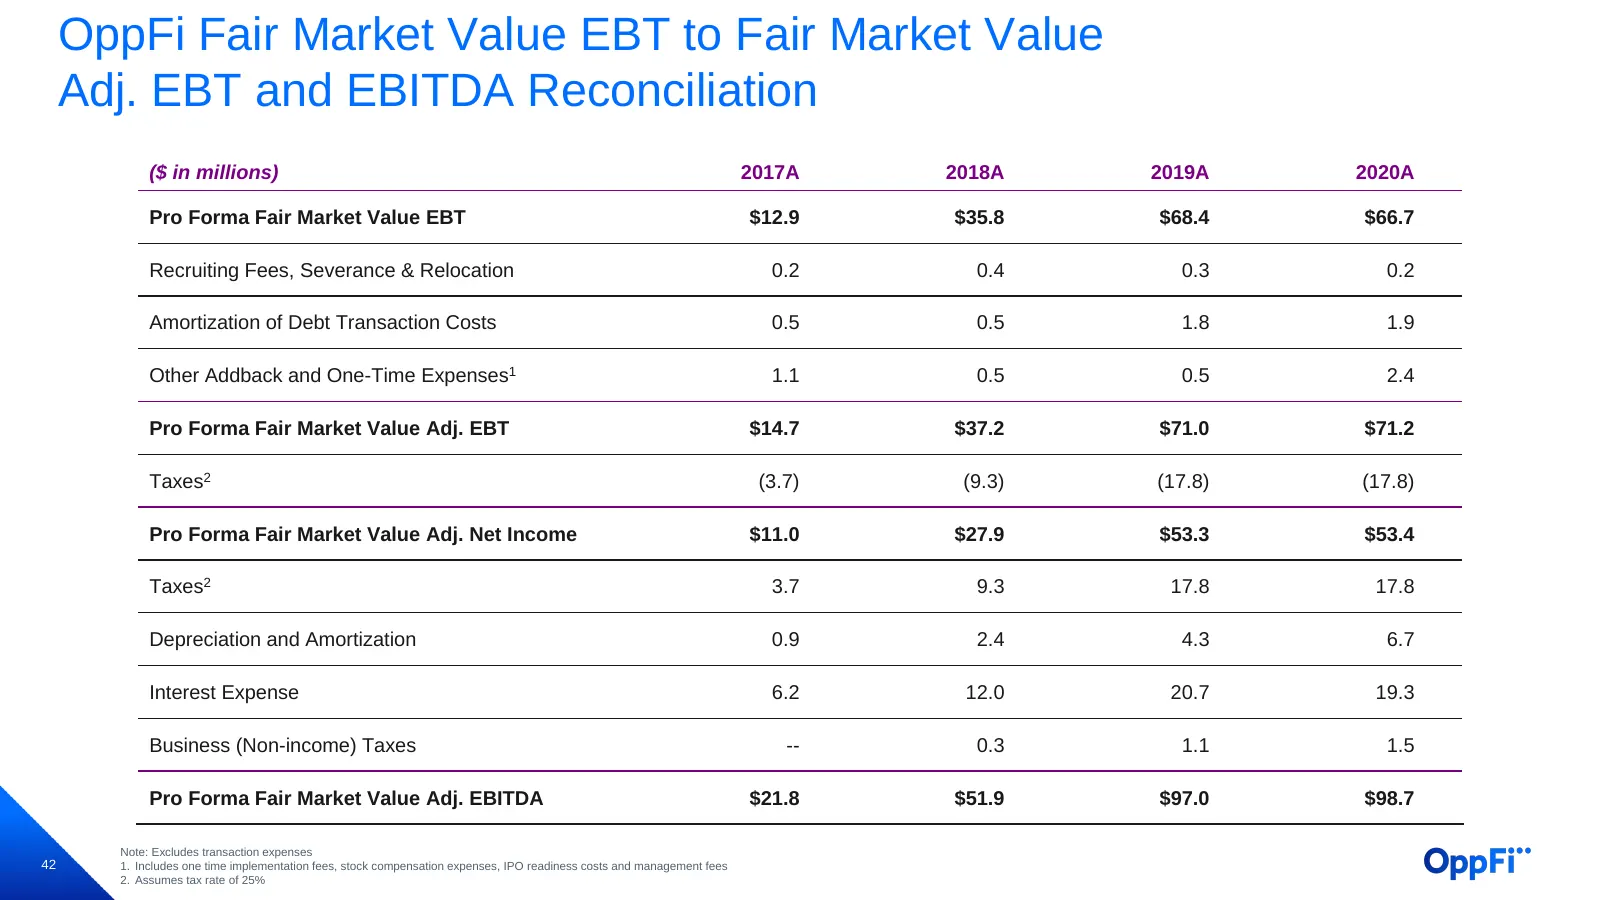
Slide 43: Fair Market Value EBT to Adj. EBT and EBITDA Reconciliation
OppFi Fair Market Value EBT to Fair Market Value Adj. EBT and EBITDA Reconciliation ($ in millions) 2017A 2018A 2019A 2020A Pro Forma Fair Market Value EBT $12.9 $35.8 $68.4 $66.7 Recruiting Fees, Severance & Relocation 0.2 0.4 0.3 0.2 Amortization of Debt Transaction Costs 0.5 0.5 1.8 1.9 Other Add
Source: Internet Archive copy of oppfi.com
More decks from OppFi Inc.
 Investor Presentation (November 2026)19 slides · Nov 10, 2026
 Q3 2026 Earnings Presentation22 slides · Oct 28, 2026
 Q2 2026 Earnings Presentation22 slides · Aug 10, 2026
 Investor Presentation (June 2026)25 slides · June 2026
 Q1 2026 Earnings Presentation19 slides · May 7, 2026
 Merger or Acquisition (April 2026)13 slides · Apr 29, 2026