OppFi Inc. · NYSE:OPFI
OppFi — FG New America Acquisition — SPAC Merger (February 2021)
46 slides from OppFi's SPAC merger presentation, Feb 10, 2021
Slide 1: A Leading FinTech Platform for the Everyday Consumer
Investor Presentation February 2021 A Leading FinTech Platform for the Everyday Consumer
Slide 2: Disclaimer
1 Disclaimer This presentation (the “Presentation ”) is for information purposes only . This Presentation has been prepared to assist parties in making their own evaluation with respect to a proposed transaction (the “Transaction”) as contemplated by a definitive business combination agreement betwe
Slide 3: Table of Contents
2 Table of Contents Intro To OppFi 5 Key Investment Highlights 16 Delivery Model & Product 26 Financial Performance 34 Benchmarking & Valuation 38 Appendix 41
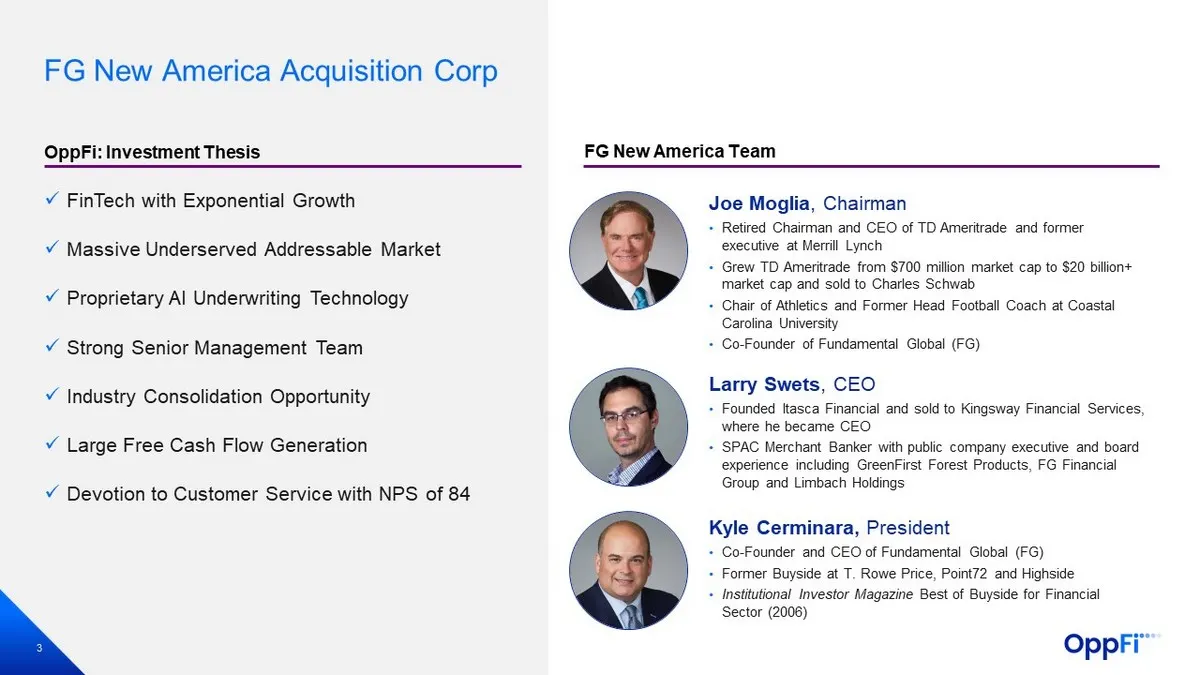
Slide 4: OppFi: Investment Thesis
3 FG New America Acquisition Corp x FinTech with Exponential Growth x Massive Underserved Addressable Market x Proprietary AI Underwriting Technology x Strong Senior Management Team x Industry Consolidation Opportunity x Large Free Cash Flow Generation x Devotion to Customer Service with NPS of 84 O
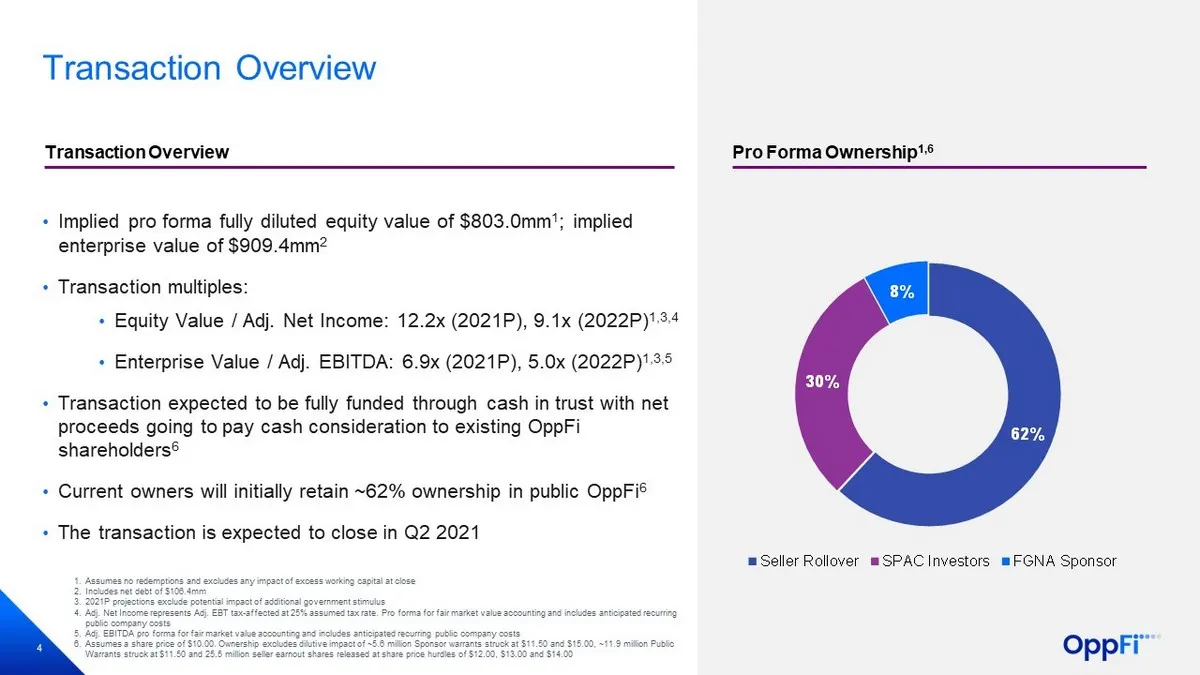
Slide 5: Transaction Overview
4 • Implied pro forma fully diluted equity value of $803.0mm 1 ; implied enterprise value of $ 909.4mm 2 • Transaction multiples: • Equity Value / Adj. Net Income: 12.2x (2021P), 9.1x (2022P) 1,3,4 • Enterprise Value / Adj. EBITDA: 6.9x (2021P), 5.0x (2022P) 1,3,5 • Transaction expected to be fully
Slide 6: Introduction to OppFi
5 Introduction to OppFi A platform that puts you in control
Slide 7: Management
6 6 Management Jared Kaplan OppFi, CEO Shiven Shah OppFi, CFO 7 - Time Executive
Slide 8: Meet OppFi
7 7 We facilitate financial inclusion and credit access to the 60 million Everyday Consumers who lack access to traditional credit through best available products and an unwavering commitment to our customers Meet OppFi
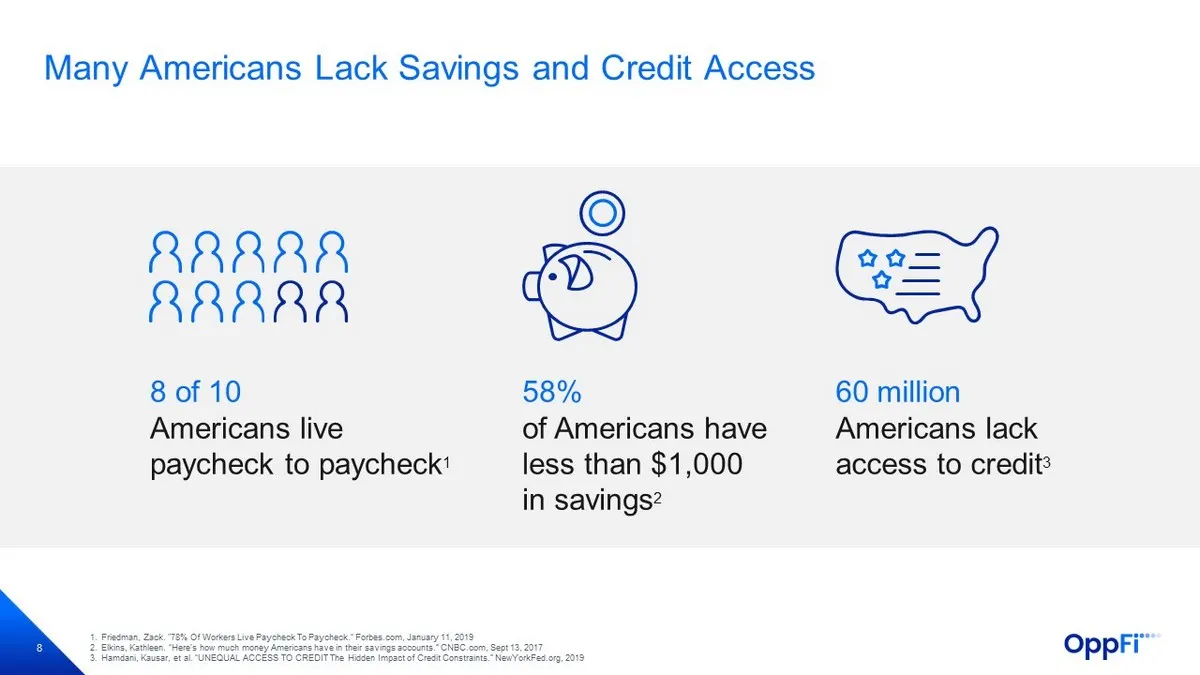
Slide 9: Many Americans Lack Savings and Credit Access
8 Many Americans Lack Savings and Credit Access 8 of 10 Americans live paycheck to paycheck 1 58% of Americans have less than $1,000 in savings 2 60 million Americans lack access to credit 3 1. Friedman, Zack. "78% Of Workers Live Paycheck To Paycheck.“ Forbes.com, January 11, 2019 2. Elkins, Kathle
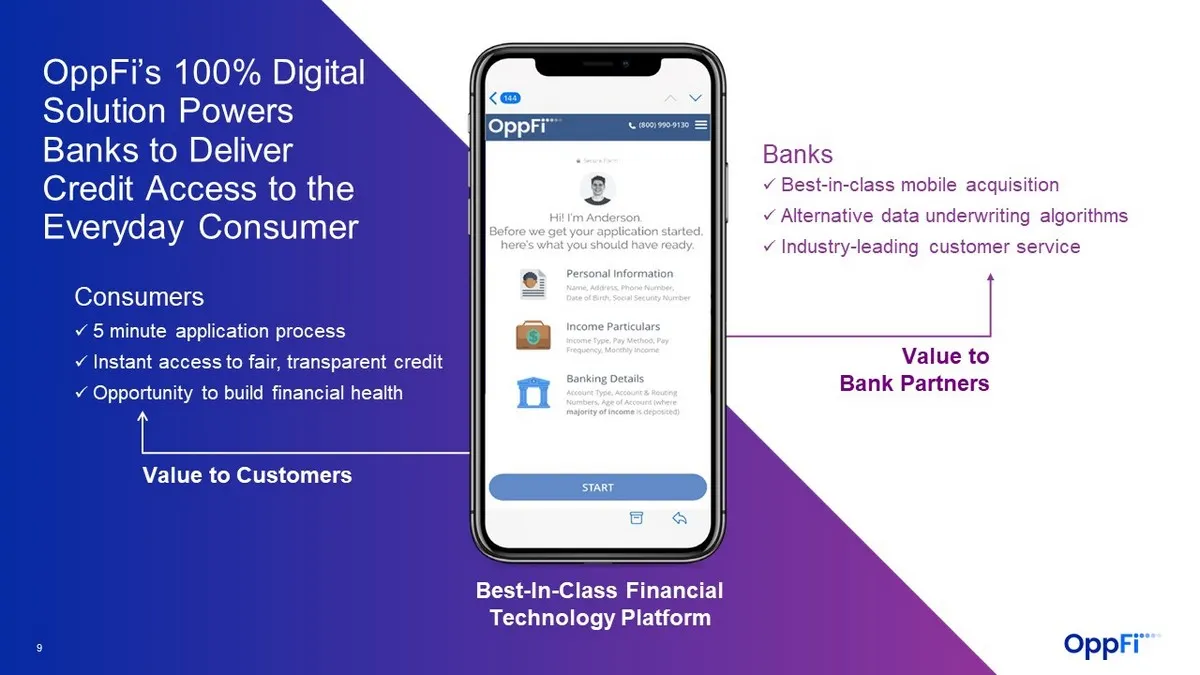
Slide 10: OppFi's 100% Digital Solution Powers Banks to Deliver Credit Access
9 9 Consumers x 5 minute application process x Instant access to fair, transparent credit x Opportunity to build financial health x Best - in - class mobile acquisition x Alternative data underwriting algorithms x Industry - leading customer service Banks Value to Bank Partners Value to Customers Op
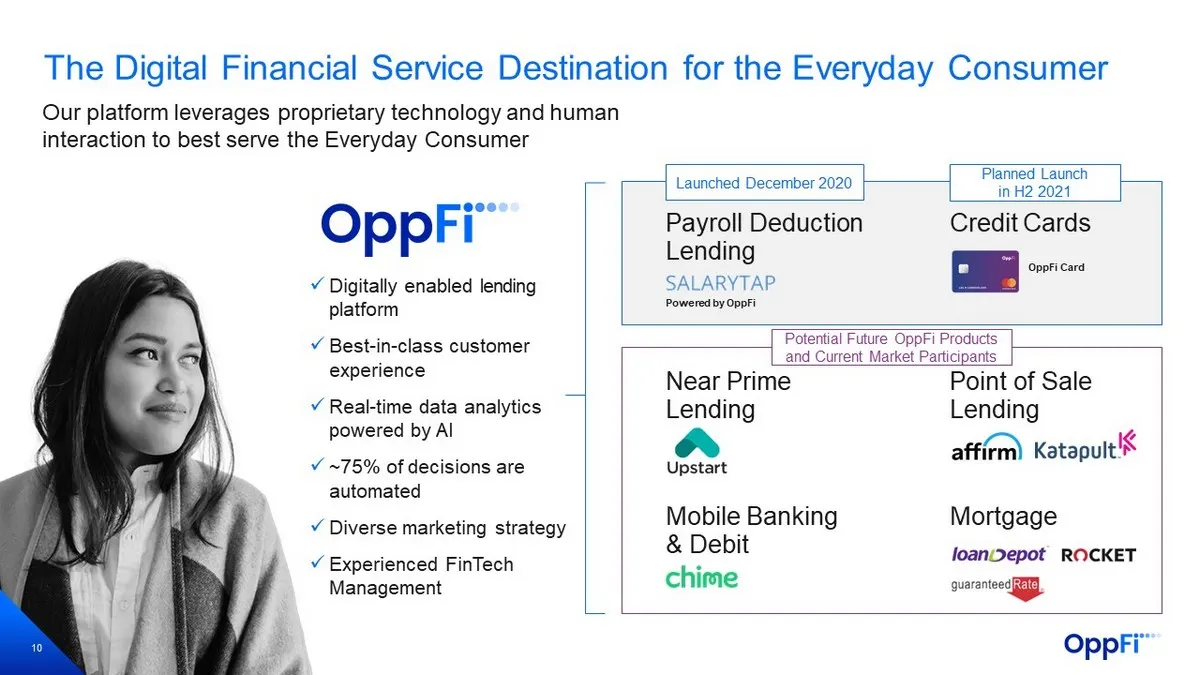
Slide 11: The Digital Financial Service Destination for the Everyday Consumer
10 The Digital Financial Service Destination for the Everyday Consumer Our platform leverages proprietary technology and human interaction to best serve the Everyday Consumer Near Prime Lending Payroll Deduction Lending Launched December 2020 Mobile Banking & Debit Point of Sale Lending Credit Cards
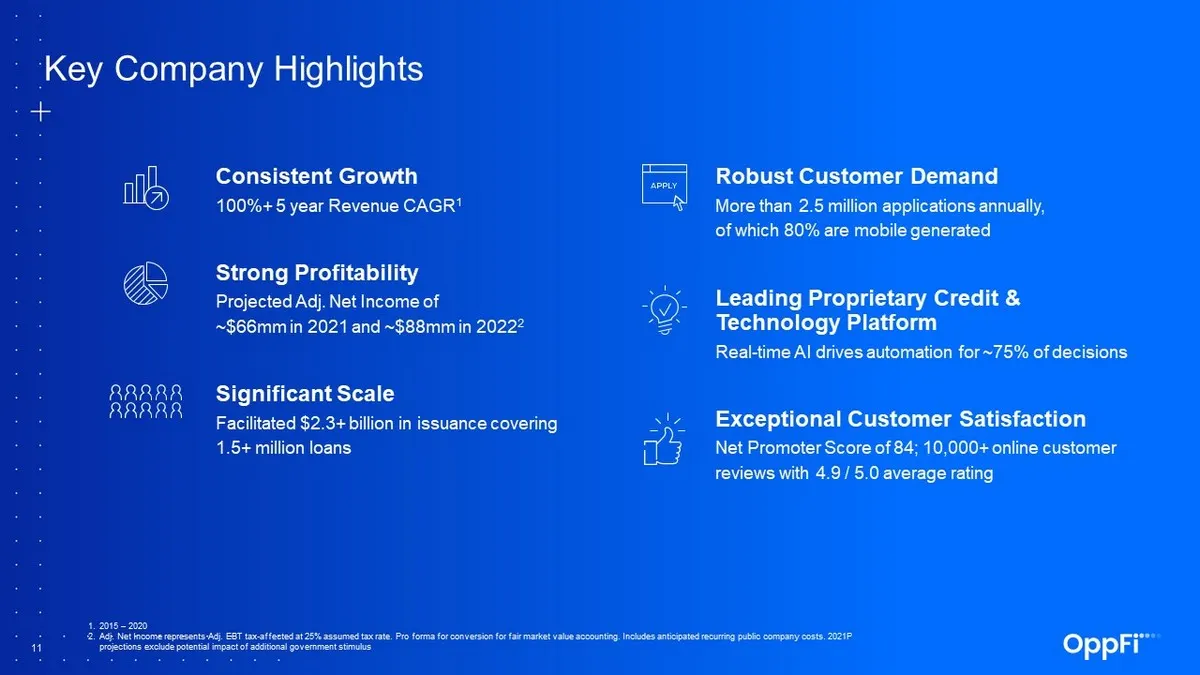
Slide 12: Key Company Highlights
11 11 Robust Customer Demand More than 2.5 million applications annually, of which 80% are mobile generated Leading Proprietary Credit & Technology Platform Real - time AI drives automation for ~75% of decisions Exceptional Customer Satisfaction Net Promoter Score of 84; 10,000+ online customer revi
Slide 13: Customers Praise OppFi
12 Customers Praise OppFi “You gave me a chance when no one else would” “The entire process was a breeze ” “Terms were very reasonable ...and transparent ” “ No penalties for early payoff” Accredited Business Unrivaled Customer Satisfaction Regardless of Credit Band 1 1 1 1. As of 1/11/21 12
Slide 14: Employees are Highly Satisfied
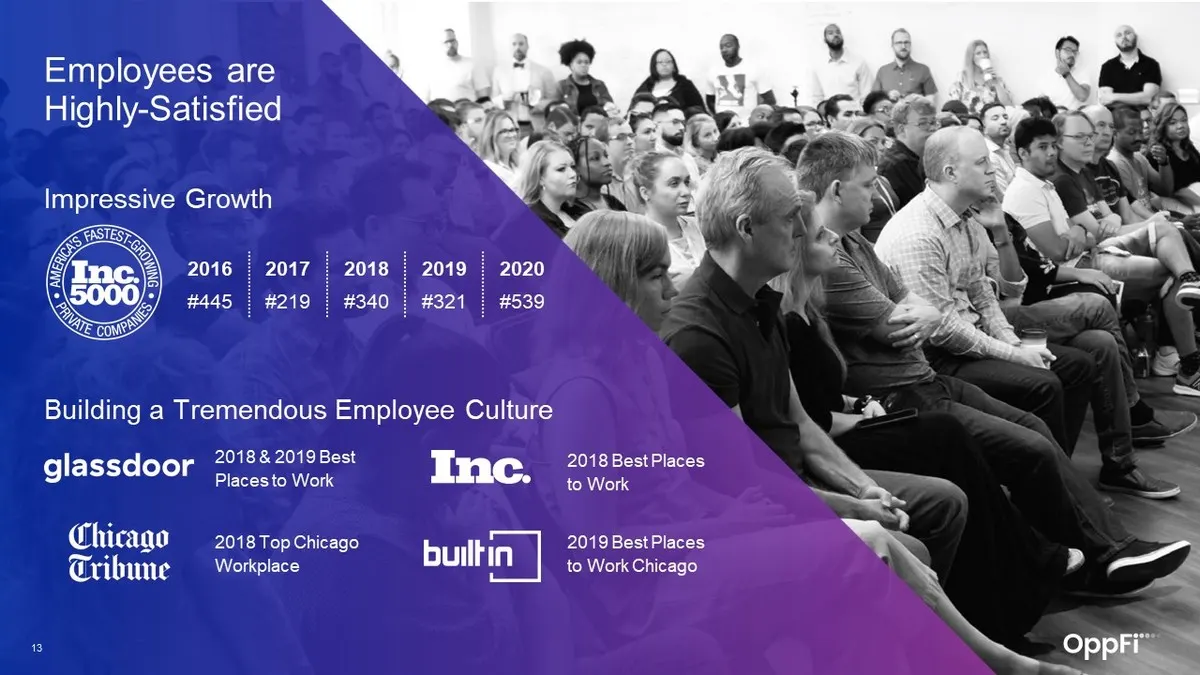
13 Employees are Highly - Satisfied Impressive Growth 2016 2017 2018 2019 2020 #445 #219 #340 #321 #539 Building a Tremendous Employee Culture 2018 & 2019 Best Places to Work 2019 Best Places to Work Chicago 2018 Best Places to Work 2018 Top Chicago Workplace 13
Slide 15: Platform with Proven Ability to Scale Profitably
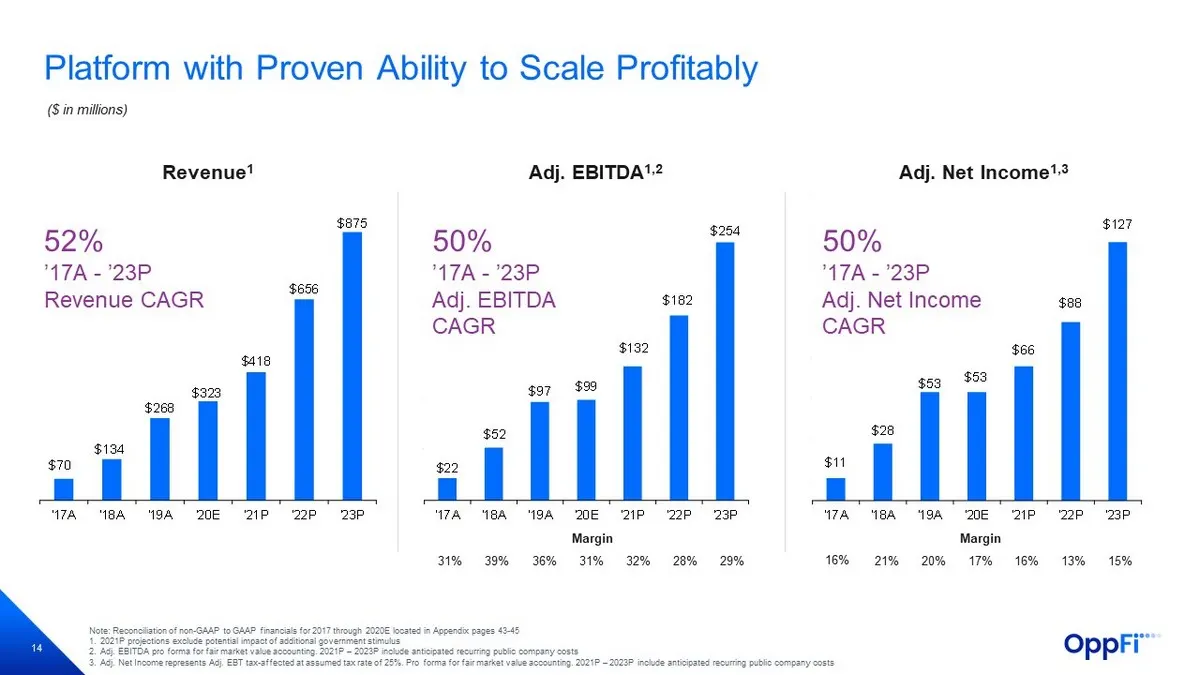
14 Platform with Proven Ability to Scale Profitably Revenue 1 Adj. EBITDA 1,2 Adj. Net Income 1,3 Note: Reconciliation of non - GAAP to GAAP financials for 2017 through 2020E located in Appendix pages 43 - 45 1. 2021P projections exclude potential impact of additional government stimulus 2. Adj. EBI
Slide 16: On Track to Become the Digital Financial Service Destination
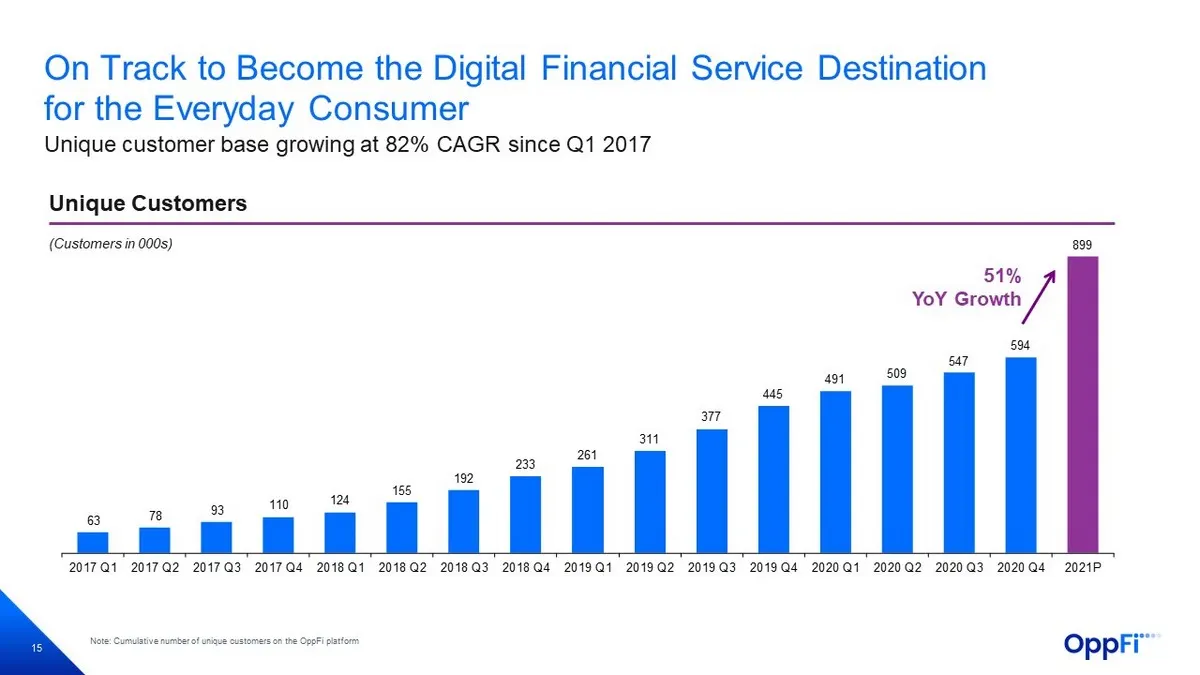
15 On Track to Become the Digital Financial Service Destination for the Everyday Consumer Unique Customers (Customers in 000s) Unique customer base growing at 82% CAGR since Q1 2017 51% YoY Growth Note: Cumulative number of unique customers on the OppFi platform 63 78 93 110 124 155 192 233 261 311
Slide 17: Key Investment Highlights
16 Key Investment Highlights
Slide 18: Key Investment Highlights
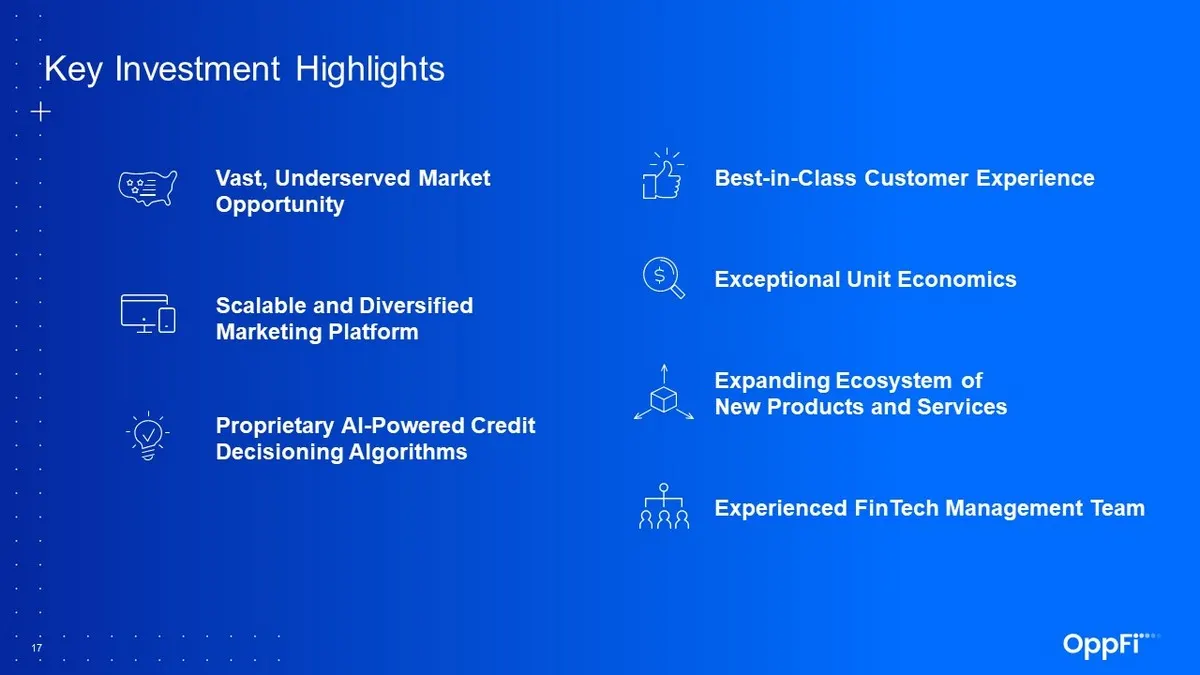
17 17 Key Investment Highlights Best - in - Class Customer Experience Exceptional Unit Economics Expanding Ecosystem of New Products and Services Experienced FinTech Management Team Vast, Underserved Market Opportunity Scalable and Diversified Marketing Platform Proprietary AI - Powered Credit Decis
Slide 19: Vast, Underserved Market Opportunity
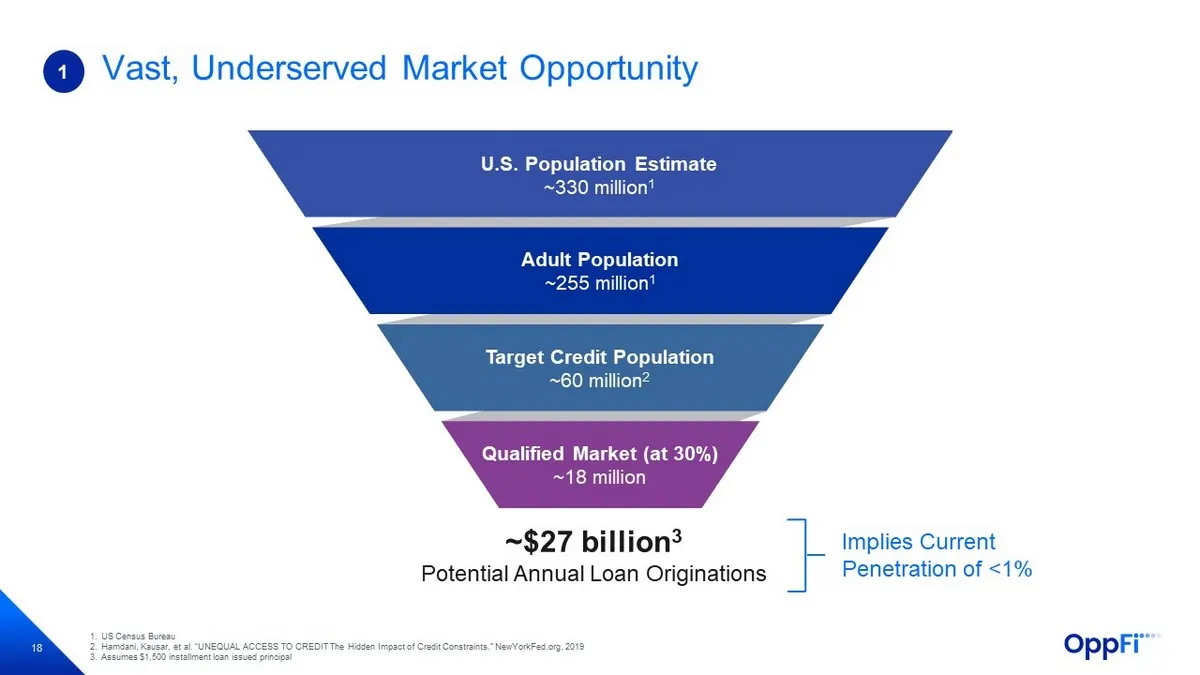
18 Vast, Underserved Market Opportunity 1 1. US Census Bureau 2. Hamdani, Kausar, et al. “UNEQUAL ACCESS TO CREDIT The Hidden Impact of Credit Constraints.” NewYorkFed.org, 2019 3. Assumes $1,500 installment loan issued principal ~$27 billion 3 Potential Annual Loan Originations U.S. Population Esti
Slide 20: Diversified Marketing Platform
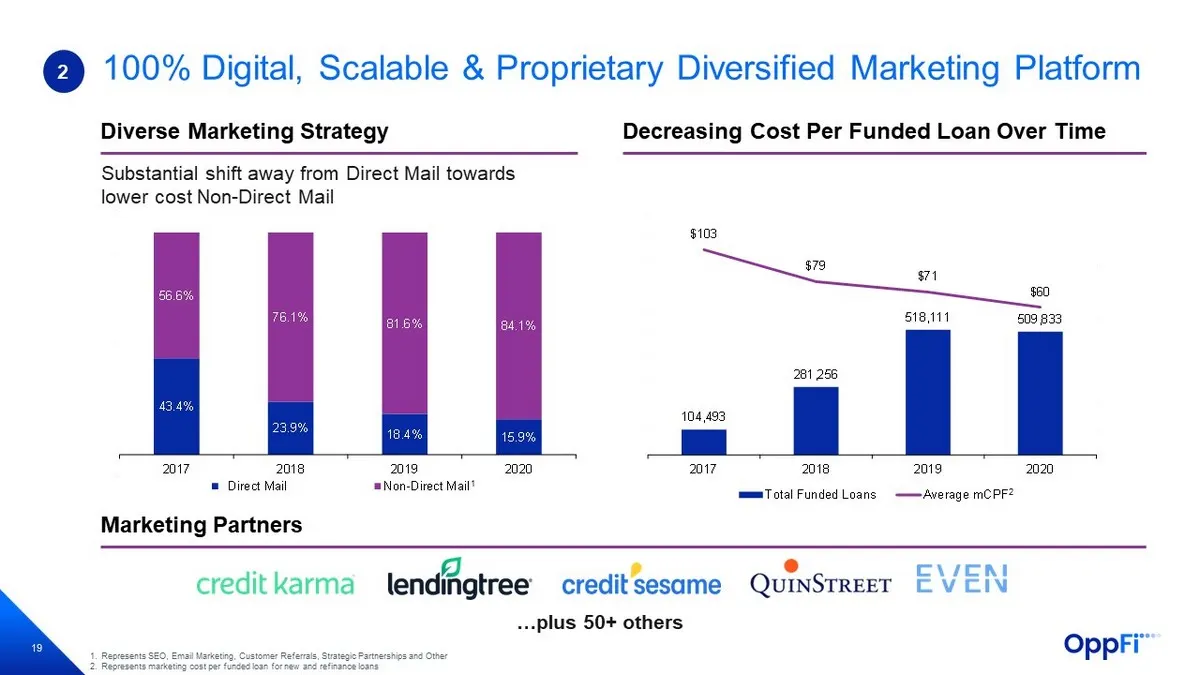
19 104,493 281,256 518,111 509,833 $103 $79 $71 $60 ($50) ($30) ($10) $10 $30 $50 $70 $90 $110 $130 0 100,000 200,000 300,000 400,000 500,000 600,000 700,000 800,000 900,000 1,000,000 2017 2018 2019 2020 Total Funded Loans Average mCPF 100% Digital, Scalable & Proprietary Diversified Marketing Platf
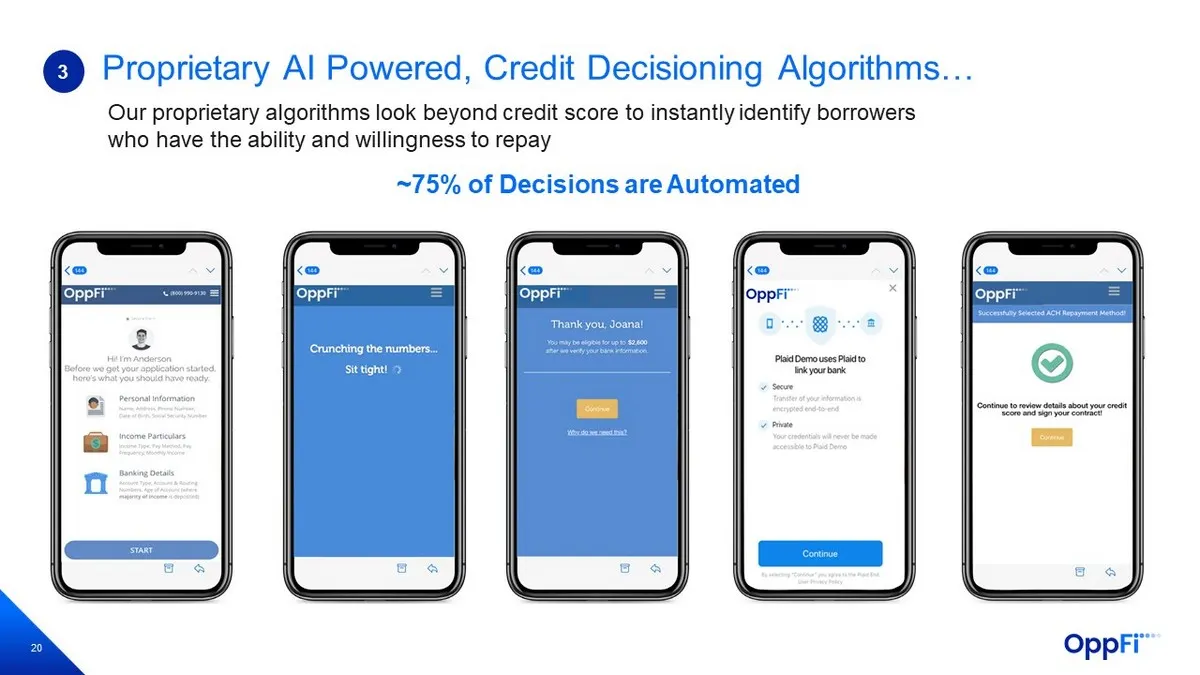
Slide 21: Proprietary AI Powered Credit Decisioning Algorithms
20 Proprietary AI Powered, Credit Decisioning Algorithms… 3 Our proprietary algorithms look beyond credit score to instantly identify borrowers who have the ability and willingness to repay ~75% of Decisions are Automated
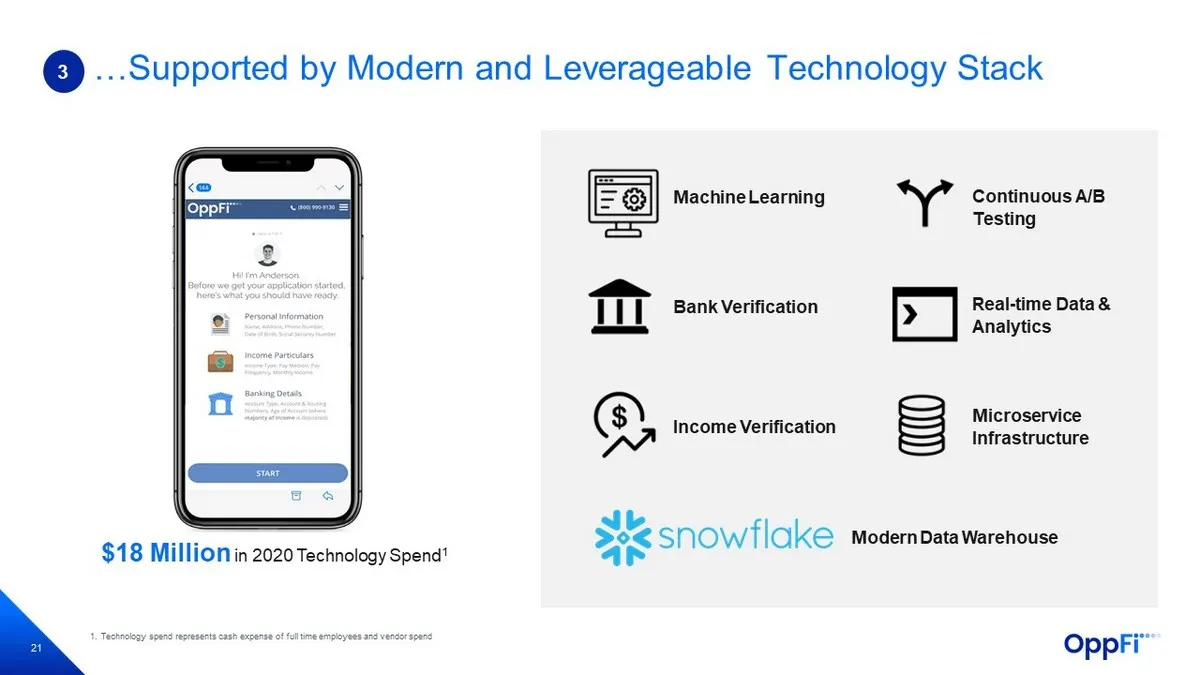
Slide 22: Supported by Modern and Leverageable Technology Stack
21 …Supported by Modern and Leverageable Technology Stack 3 Microservice Infrastructure Modern Data Warehouse Machine Learning Real - time Data & Analytics Continuous A/B Testing Bank Verification Income Verification $18 Million in 2020 Technology Spend 1 1. Technology spend represents cash expense
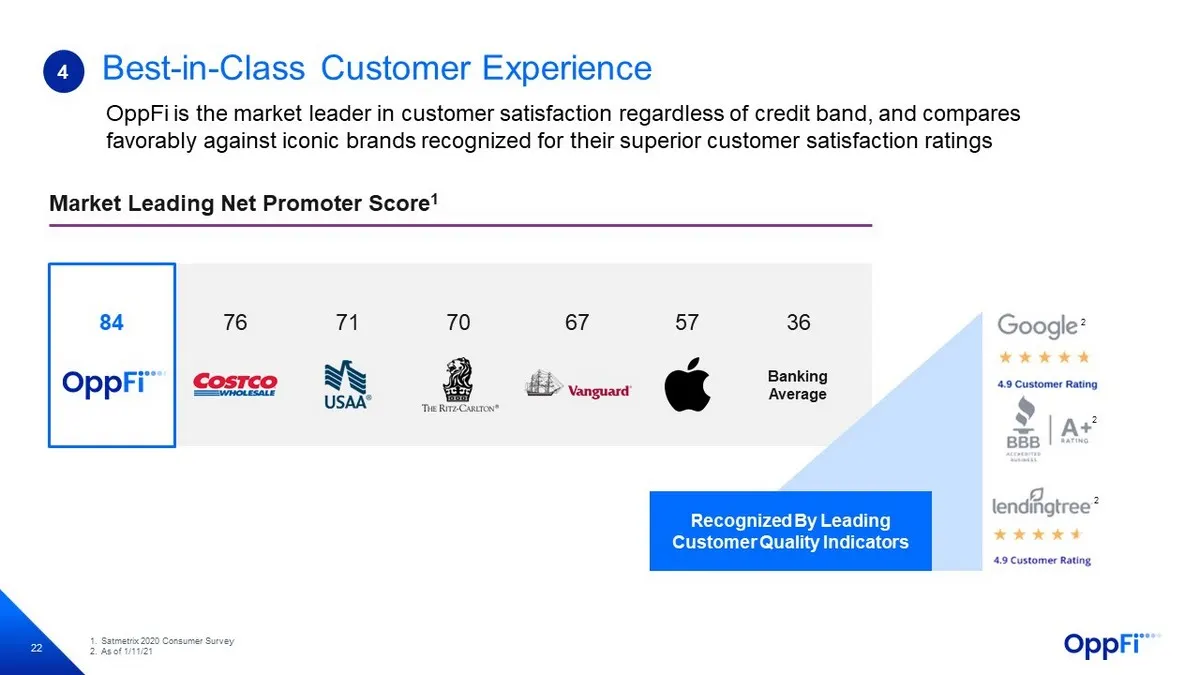
Slide 23: Best-in-Class Customer Experience
22 Best - in - Class Customer Experience 4 OppFi is the market leader in customer satisfaction regardless of credit band, and compares favorably against iconic brands recognized for their superior customer satisfaction ratings Market Leading Net Promoter Score 1 1. Satmetrix 2020 Consumer Survey 2.
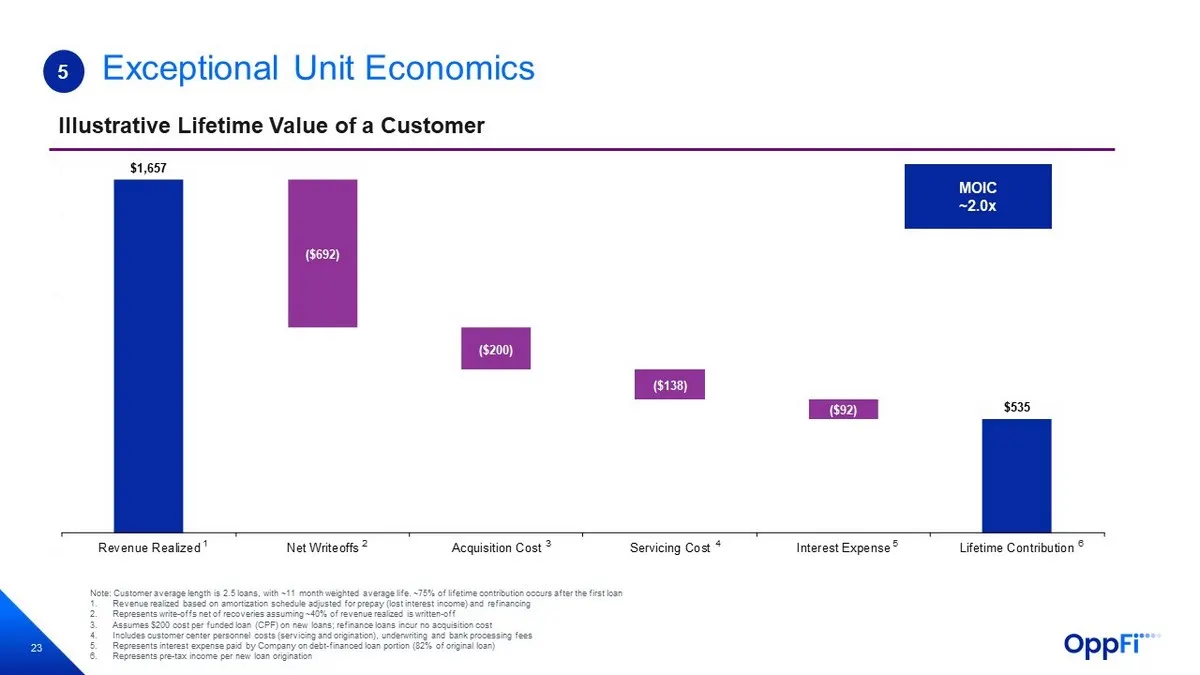
Slide 24: Exceptional Unit Economics
23 ($692) ($200) ($138) ($92) $1,657 $535 ($100) $100 $300 $500 $700 $900 $1,100 $1,300 $1,500 $1,700 Revenue Realized Net Writeoffs Acquisition Cost Servicing Cost Interest Expense Lifetime Contribution Exceptional Unit Economics 5 Illustrative Lifetime Value of a Customer MOIC ~2.0x Note: Customer
Slide 25: Expanding Ecosystem of New Products and Services
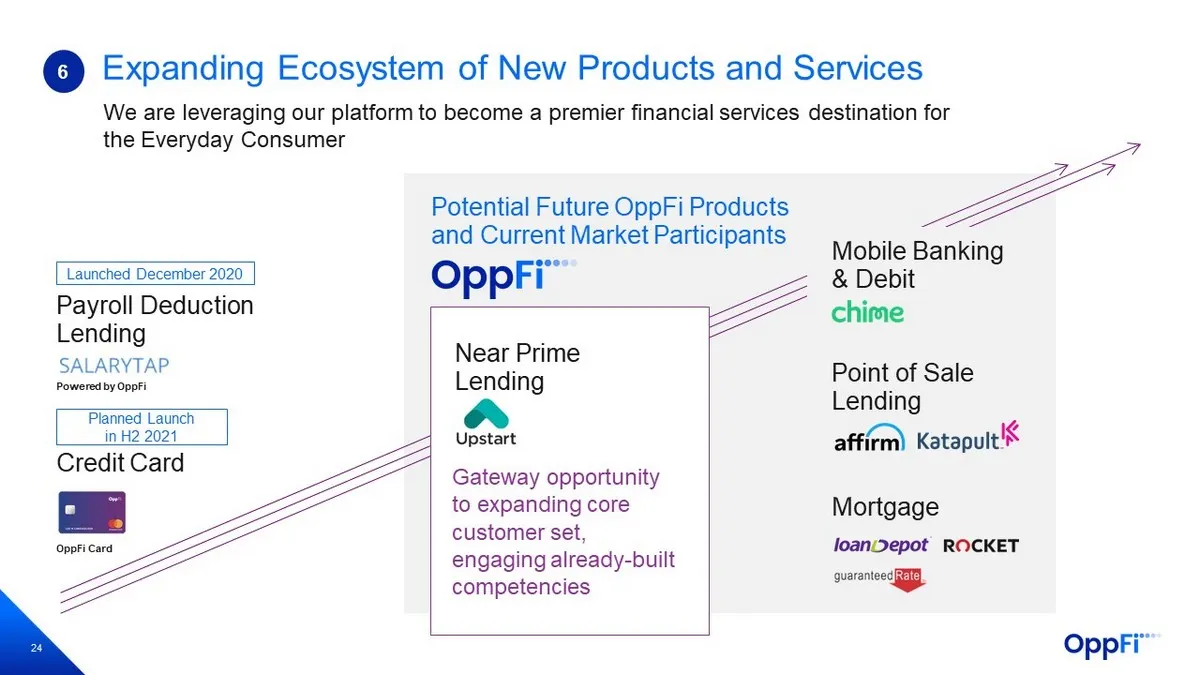
24 Expanding Ecosystem of New Products and Services 6 We are leveraging our platform to become a premier financial services destination for the Everyday Consumer Near Prime Lending Payroll Deduction Lending Powered by OppFi Launched December 2020 Credit Card Planned Launch in H2 2021 OppFi Card Gate
Slide 26: Experienced Management Team
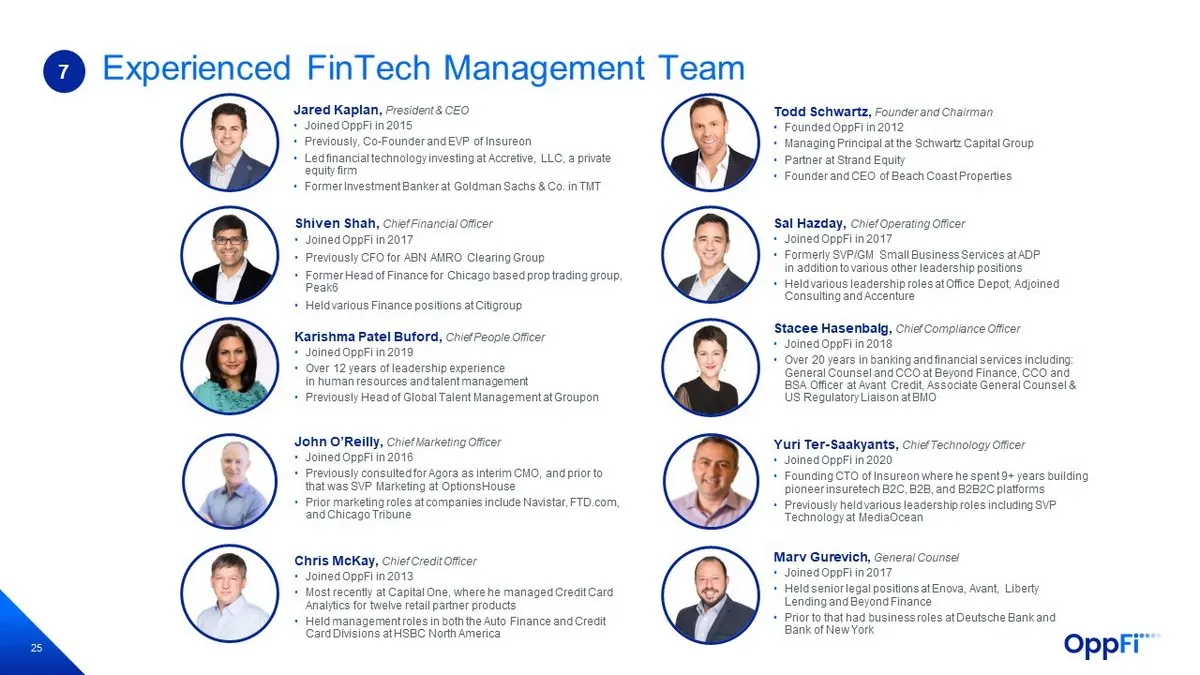
25 25 Sal Hazday, Chief Operating Officer • Joined OppFi in 2017 • Formerly SVP/GM Small Business Services at ADP in addition to various other leadership positions • Held various leadership roles at Office Depot, Adjoined Consulting and Accenture Chris McKay, Chief Credit Officer • Joined OppFi in 2
Slide 27: Delivery Model & Product
“+ _. Delivery Model & Product
Slide 28: We Serve the Median U.S. Consumer
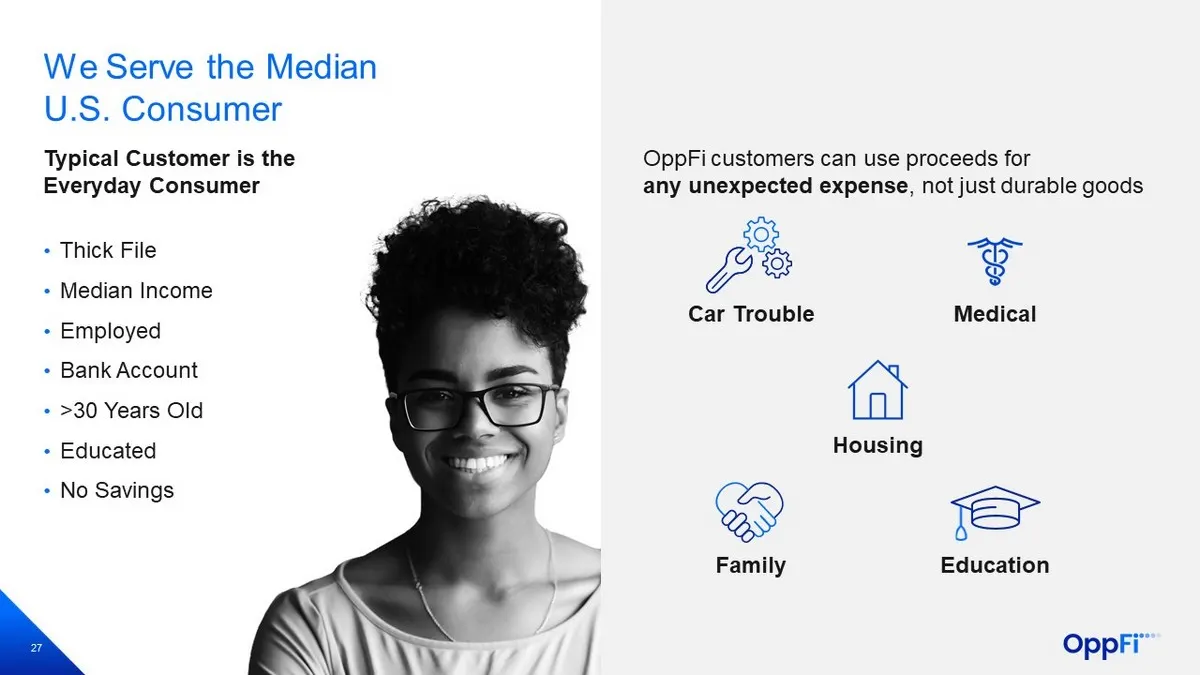
27 OppFi customers can use proceeds for any unexpected expense , not just durable goods We Serve the Median U.S. Consumer Typical Customer is the Everyday Consumer • Thick File • Median Income • Employed • Bank Account • >30 Years Old • Educated • No Savings Car Trouble Medical Housing Family Educat
Slide 29: Typical Customer Journey
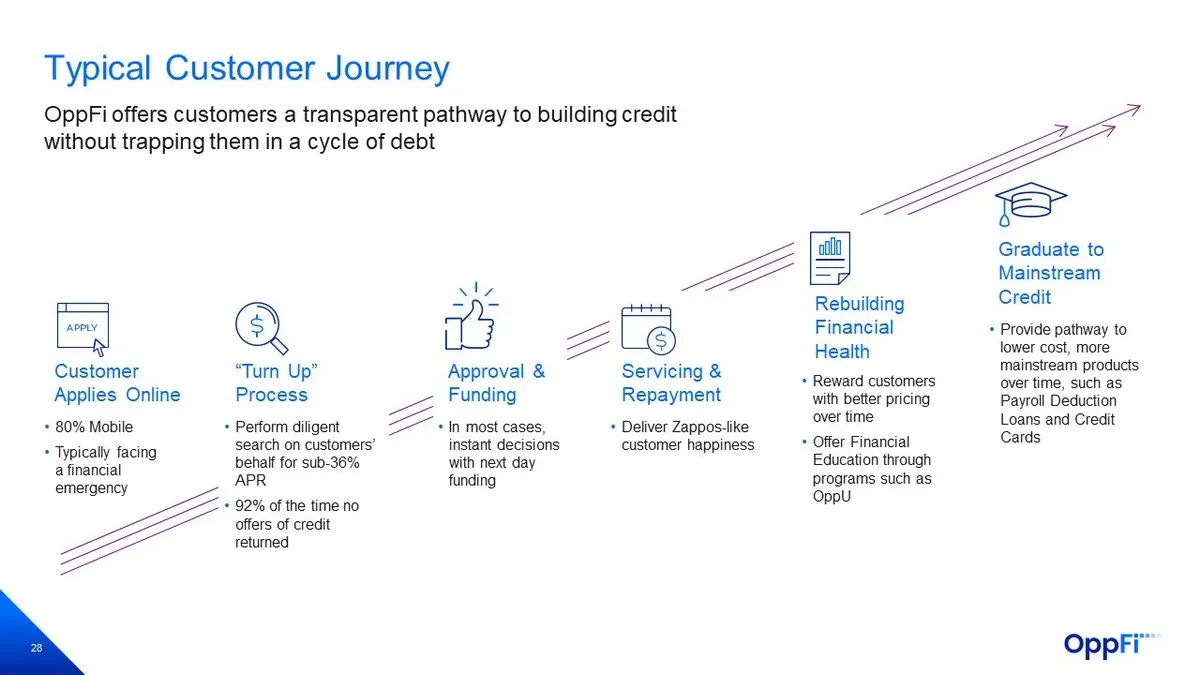
28 Typical Customer Journey Graduate to Mainstream Credit • Provide pathway to lower cost, more mainstream products over time, such as Payroll Deduction Loans and Credit Cards “Turn Up” Process • Perform diligent search on customers’ behalf for sub - 36% APR • 92% of the time no offers of credit ret
Slide 30: A Cheaper, Better Product for Non-Prime
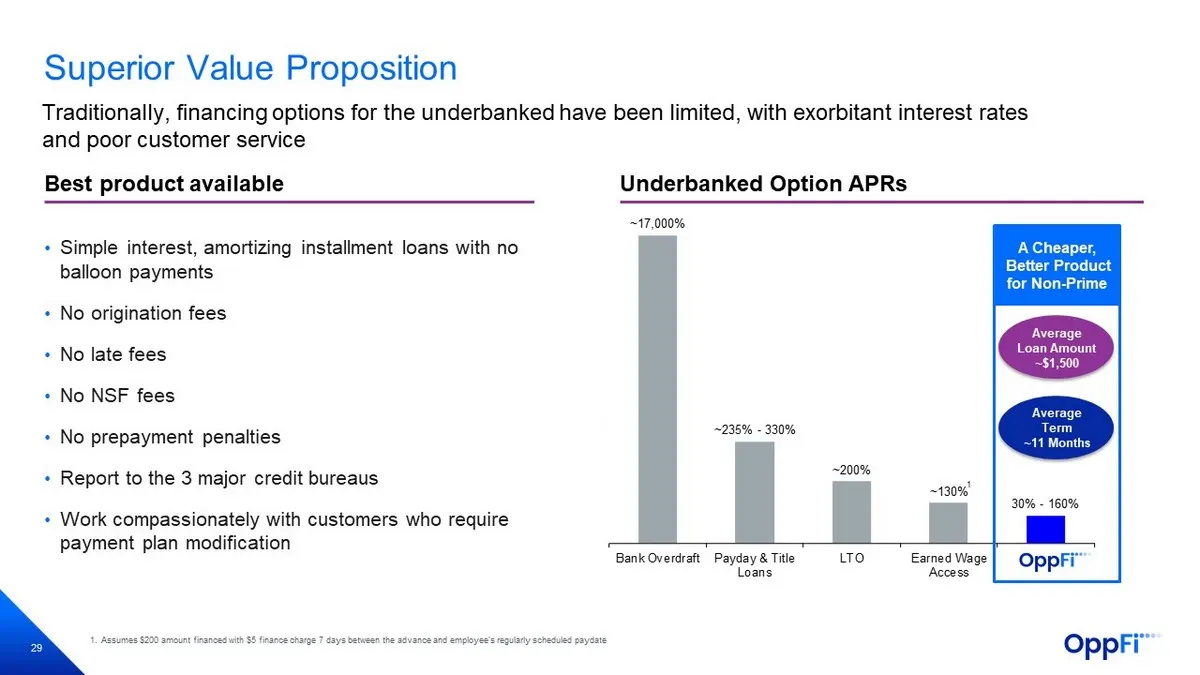
29 ~17,000% ~235% - 330% ~200% ~130% 30% - 160% 0% 200% 400% 600% 800% 1000% 1200% Bank Overdraft Payday & Title Loans LTO Earned Wage Access • Simple interest, amortizing installment loans with no balloon payments • No origination fees • No late fees • No NSF fees • No prepayment penalties • Report
Slide 31: Our Installment Product: Attractive Alternative to LTO
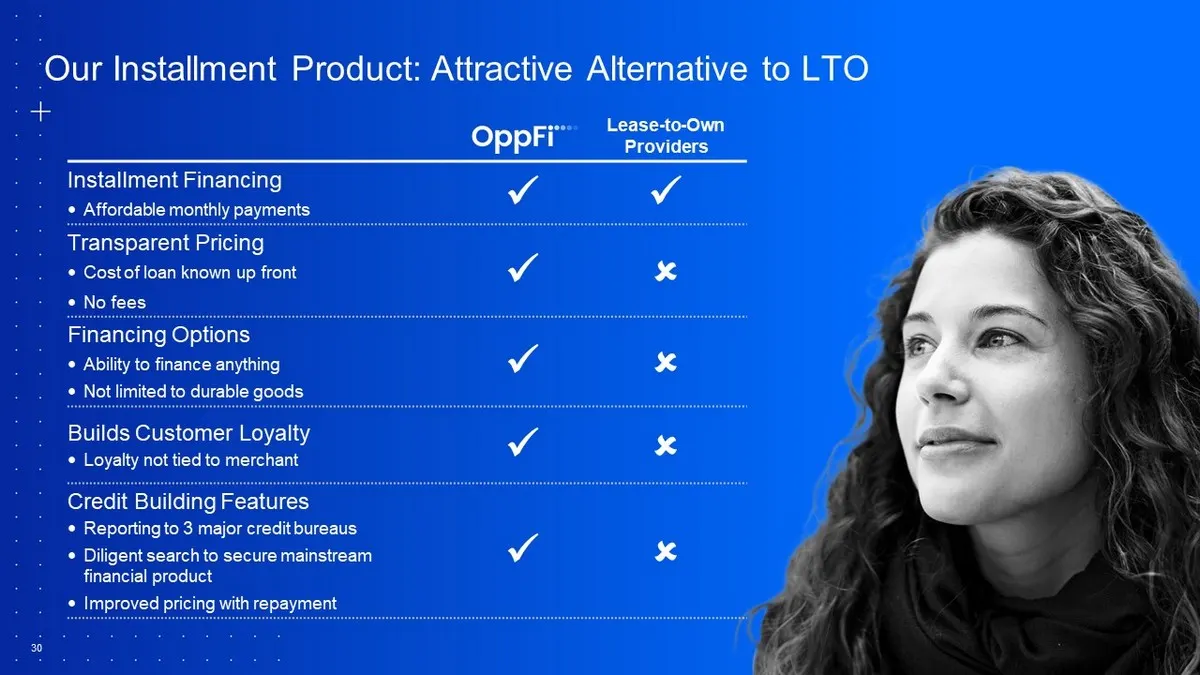
30 30 Our Installment Product: Attractive Alternative to LTO Lease - to - Own Providers Installment Financing Affordable monthly payments x x Transparent Pricing Cost of loan known up front No fees x Financing Options Ability to finance anything Not limited to durable goods x Builds Customer Loyalty
Slide 32: OppU, OppFi's Financial Education Platform
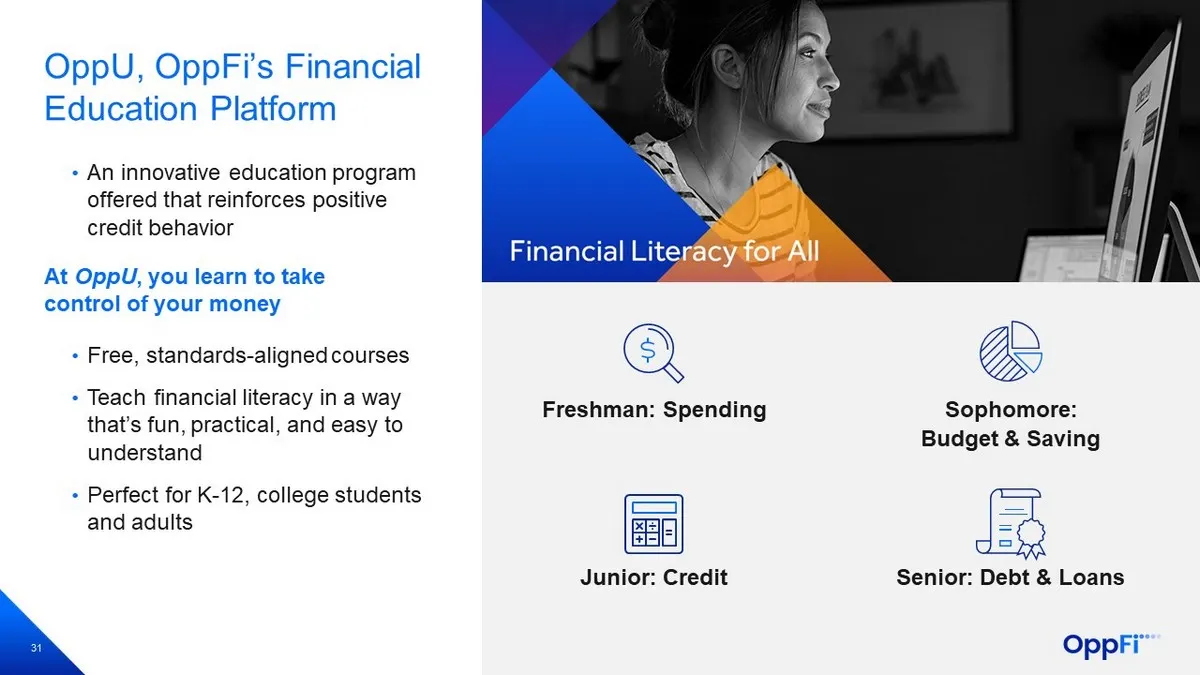
31 Freshman: Spending Junior: Credit Sophomore: Budget & Saving Senior: Debt & Loans OppU, OppFi’s Financial Education Platform • An innovative education program offered that reinforces positive credit behavior • Free, standards - aligned courses • Teach financial literacy in a way that’s fun, pract
Slide 33: Why Salary Tap?
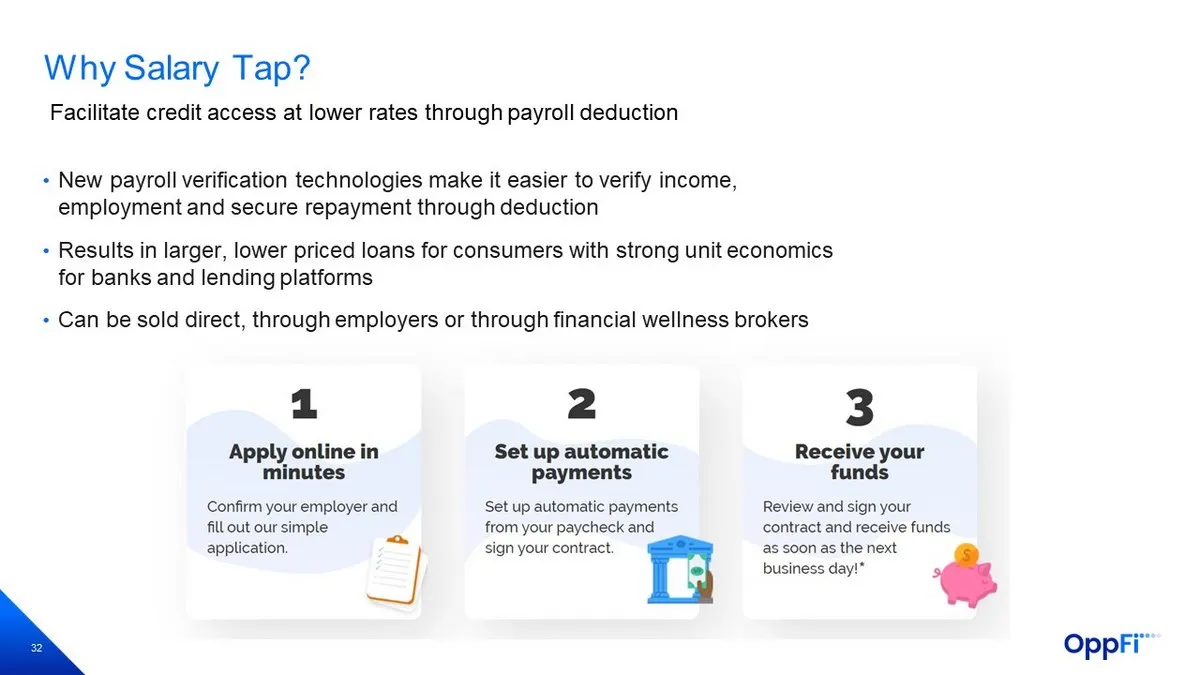
32 Why Salary Tap? Facilitate credit access at lower rates through payroll deduction • New payroll verification technologies make it easier to verify income, employment and secure repayment through deduction • Results in larger, lower priced loans for consumers with strong unit economics for banks a
Slide 34: Why the OppFi Credit Card?
33 Our understanding of the Everyday Consumer makes OppFi a natural entrant to the credit card market Why the OppFi Credit Card? • Graduation product for OppFi customers • Ability to move up market nationally • Can grab market share with higher limits, lower fees, mobile optimized user experience, o
Slide 35: Financial Performance
34 Financial Performance
Slide 36: Summary Financial Projections: Income Statement
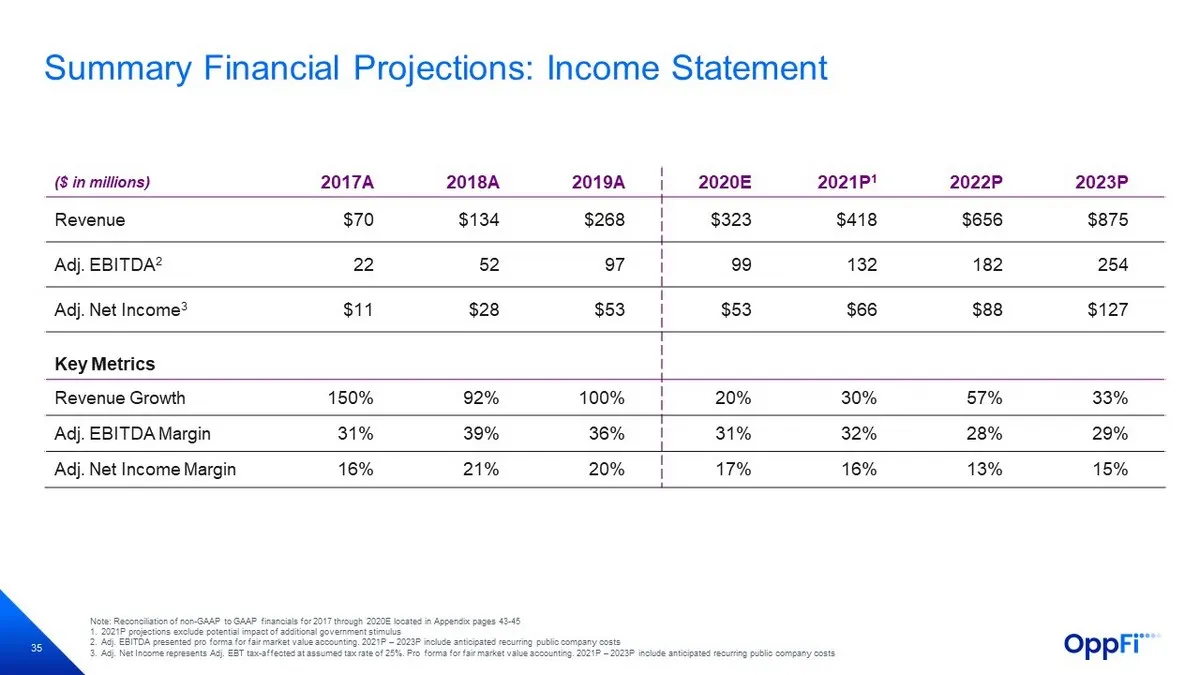
35 Summary Financial Projections: Income Statement ($ in millions) 2017A 2018A 2019A 2020E 2021P 1 2022P 2023P Revenue $70 $134 $268 $323 $418 $656 $875 Adj. EBITDA 2 22 52 97 99 132 182 254 Adj. Net Income 3 $11 $28 $53 $53 $66 $88 $127 Key Metrics Revenue Growth 150% 92% 100% 20% 30% 57% 33% Adj.
Slide 37: Potential for Continued Growth in Receivables
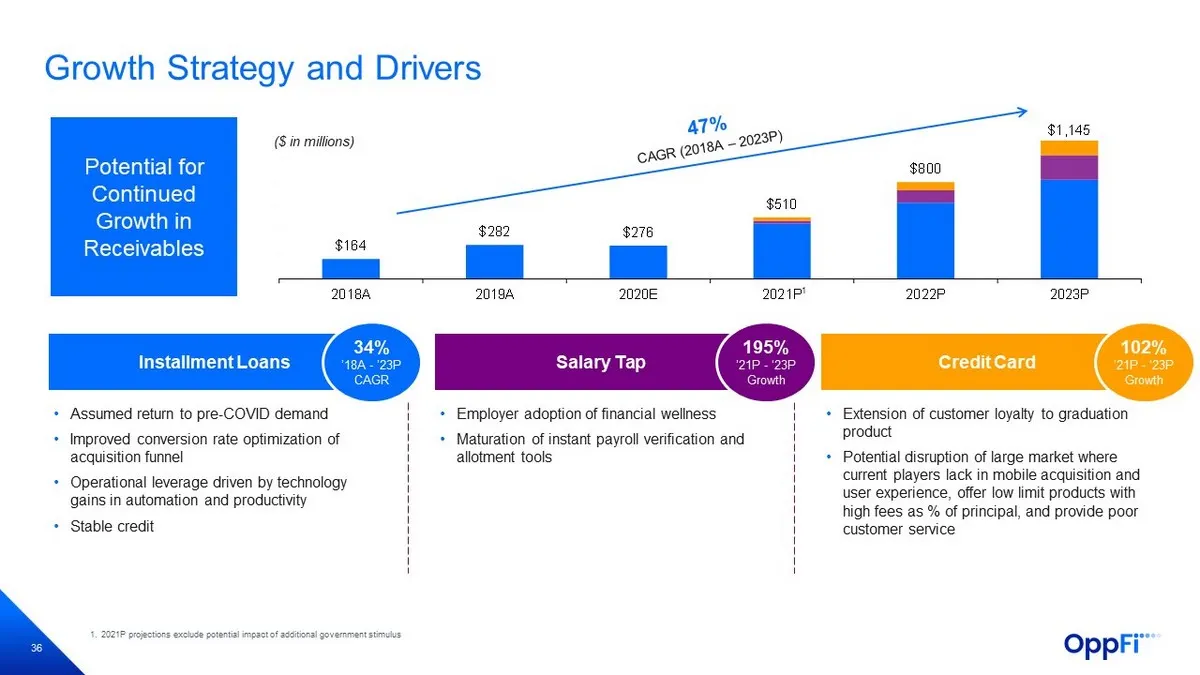
36 $164 $282 $276 $510 $800 $1,145 0 200 400 600 800 1000 1200 2018A 2019A 2020E 2021P 2022P 2023P Credit Card Salary Tap Installment Loans Growth Strategy and Drivers • Assumed return to pre - COVID demand • Improved conversion rate optimization of acquisition funnel • Operational leverage driven b
Slide 38: Capital Management
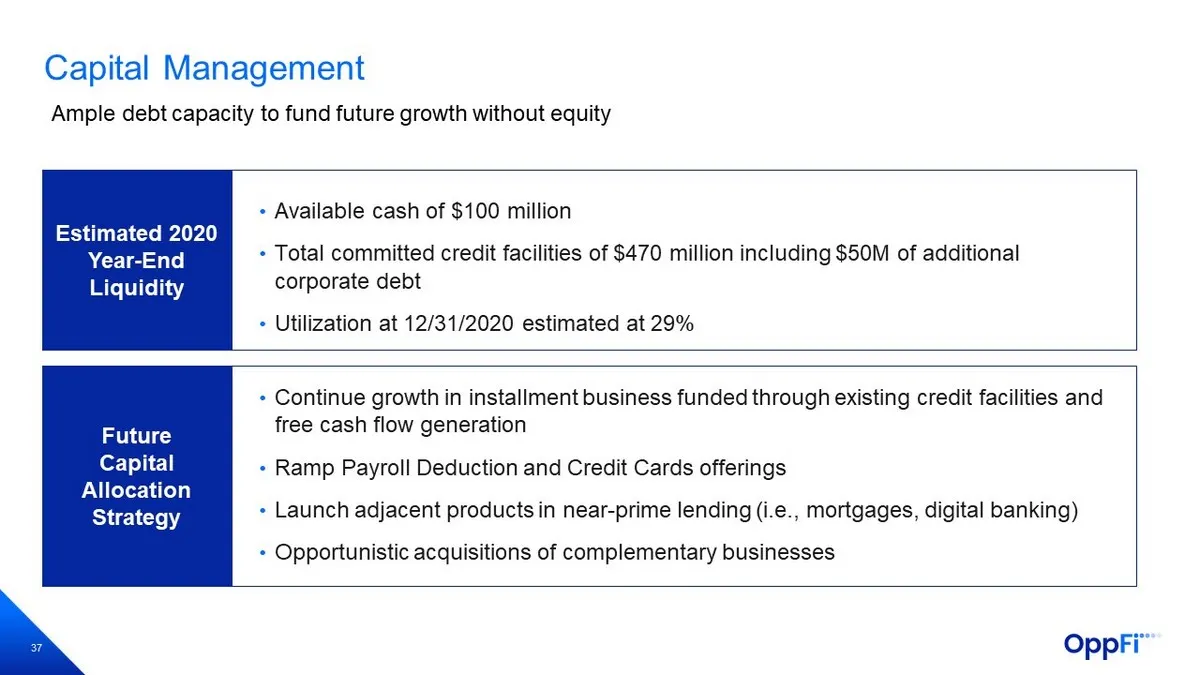
37 Capital Management • Available cash of $100 million • Total committed credit facilities of $470 million including $50M of additional corporate debt • Utilization at 12/31/2020 estimated at 29% Ample debt capacity to fund future growth without equity • Continue growth in installment business funde
Slide 39: Benchmarking & Valuation
38 Benchmarking & Valuation
Slide 40: Trading Comparables – Attractive Financial Profile
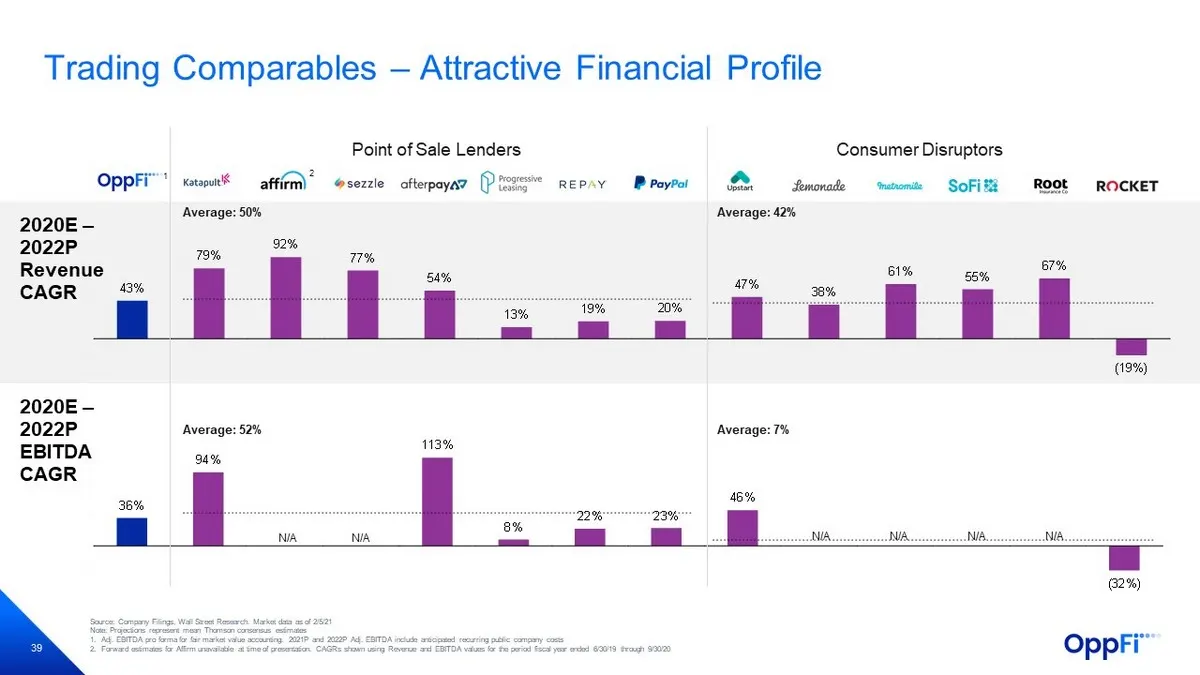
39 36% 94% 113% 8% 22% 23% 46% (32%) (40%) (20%) 0% 20% 40% 60% 80% 100% 120% 140% 43% 79% 92% 77% 54% 13% 19% 20% 47% 38% 61% 55% 67% (19%) (40%) (20%) 0% 20% 40% 60% 80% 100% 120% Trading Comparables – Attractive Financial Profile Source: Company Filings, Wall Street Research. Market data as of 2/
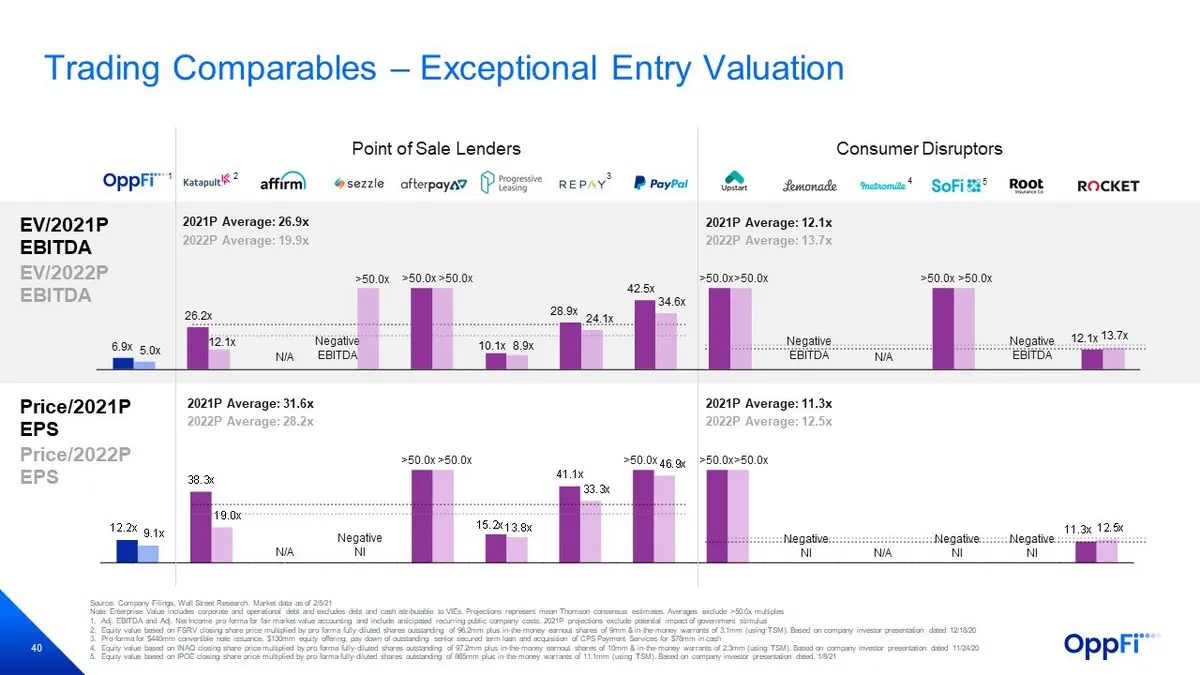
Slide 41: Trading Comparables – Exceptional Entry Valuation
40 12.2x 38.3x 15.2x 41.1x 11.3x 9.1x 19.0x 13.8x 33.3x 46.9x 12.5x 0.0x 10.0x 20.0x 30.0x 40.0x 50.0x 60.0x OppLoans Katapult Affirm Sezzle Afterpay Progressive Leasing Repay Paypal Upstart Lemonade Metromile Sofi Root Rocket Trading Comparables – Exceptional Entry Valuation Source: Company Filings
Slide 42: Appendix
41 Appendix
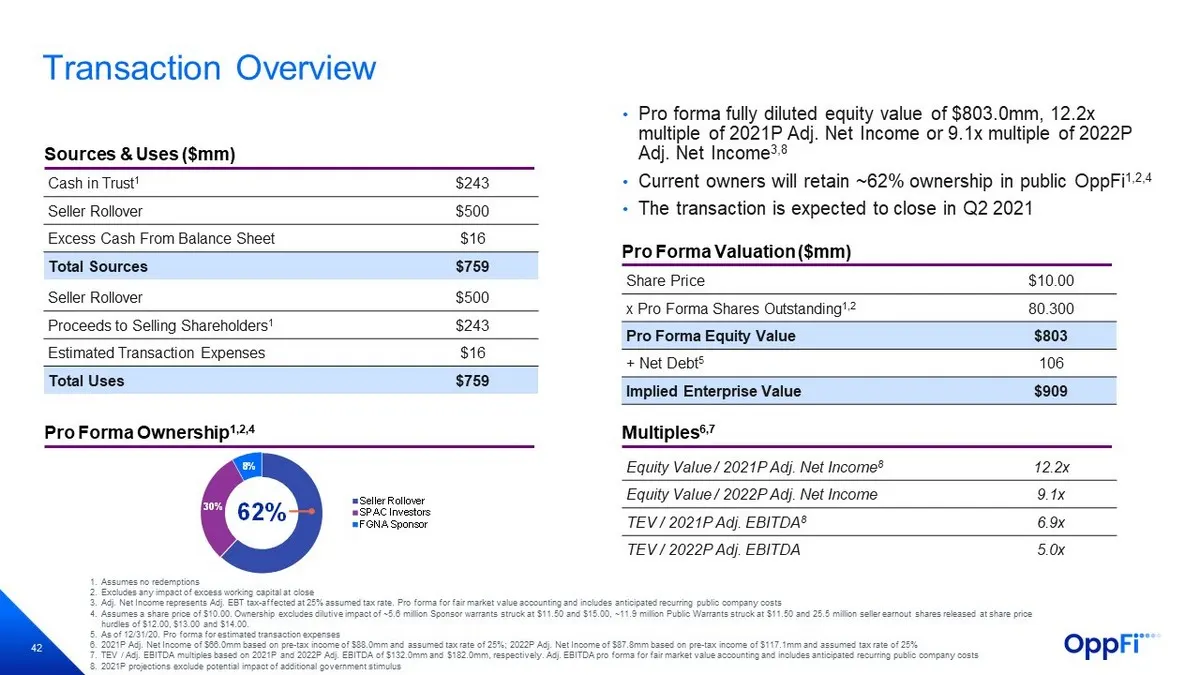
Slide 43: Transaction Overview: Sources & Uses and Pro Forma Valuation
42 • Pro forma fully diluted equity value of $803.0mm, 12.2x multiple of 2021P Adj. Net Income or 9.1x multiple of 2022P Adj. Net Income 3,8 • Current owners will retain ~62% ownership in public OppFi 1,2,4 • The transaction is expected to close in Q2 2021 Transaction Overview Cash in Trust 1 $243 S
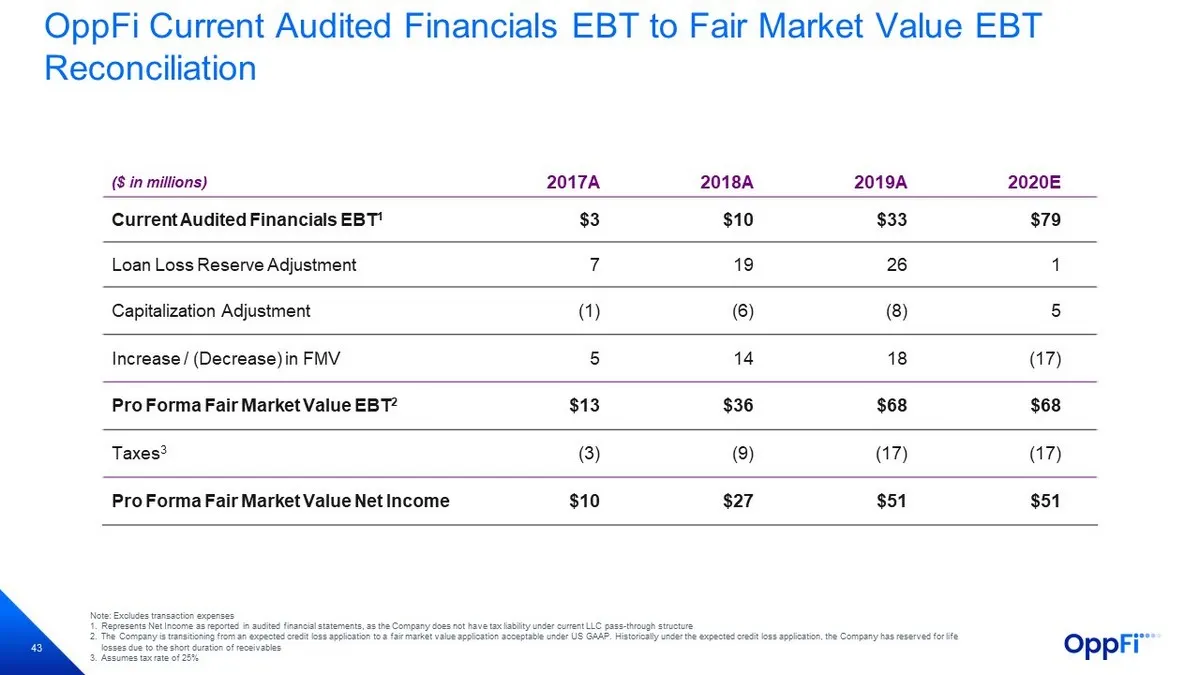
Slide 44: EBT to Fair Market Value EBT Reconciliation
43 OppFi Current Audited Financials EBT to Fair Market Value EBT Reconciliation ($ in millions) 2017A 2018A 2019A 2020E Current Audited Financials EBT 1 $3 $10 $33 $79 Loan Loss Reserve Adjustment 7 19 26 1 Capitalization Adjustment (1) (6) (8) 5 Increase / (Decrease) in FMV 5 14 18 (17) Pro Forma F
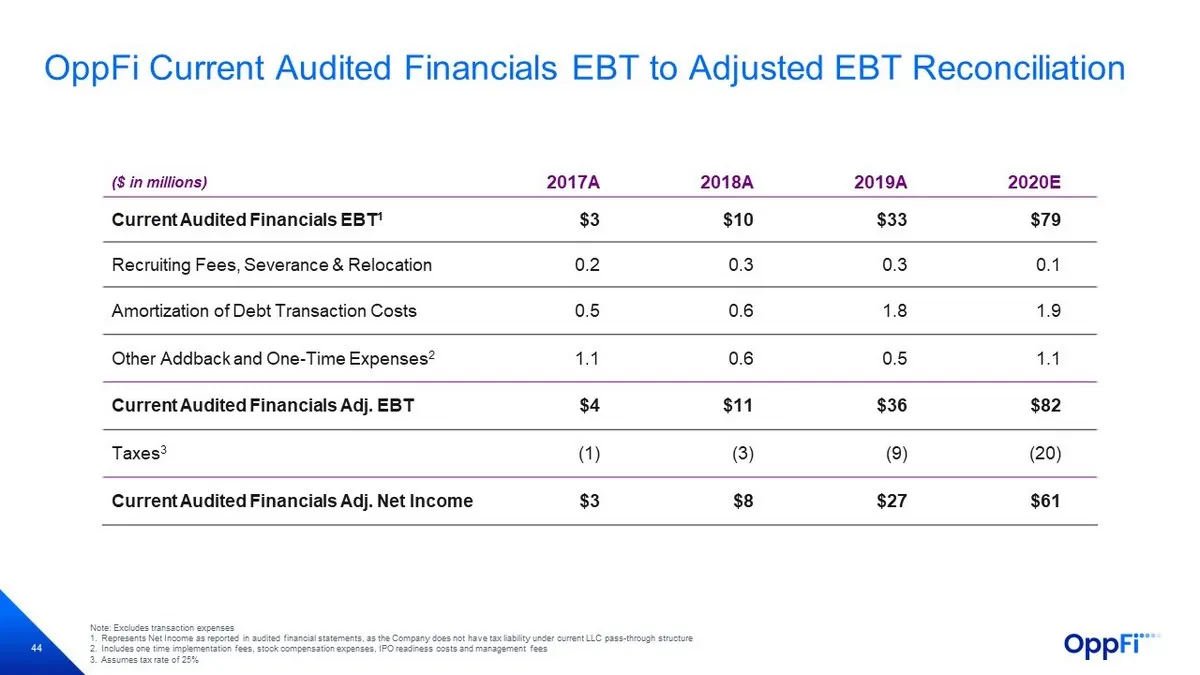
Slide 45: EBT to Adjusted EBT Reconciliation
44 OppFi Current Audited Financials EBT to Adjusted EBT Reconciliation ($ in millions) 2017A 2018A 2019A 2020E Current Audited Financials EBT 1 $3 $10 $33 $79 Recruiting Fees, Severance & Relocation 0.2 0.3 0.3 0.1 Amortization of Debt Transaction Costs 0.5 0.6 1.8 1.9 Other Addback and One - Time E
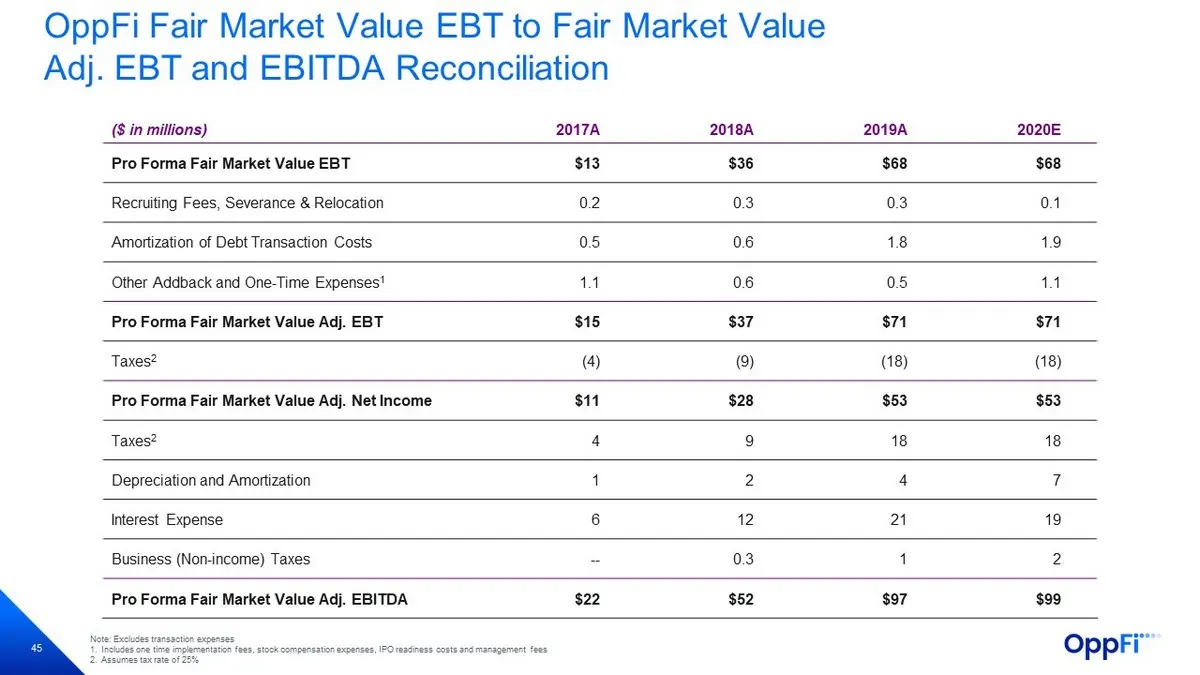
Slide 46: Fair Market Value EBT to Adj. EBT and EBITDA Reconciliation
45 OppFi Fair Market Value EBT to Fair Market Value Adj. EBT and EBITDA Reconciliation ($ in millions) 2017A 2018A 2019A 2020E Pro Forma Fair Market Value EBT $13 $36 $68 $68 Recruiting Fees, Severance & Relocation 0.2 0.3 0.3 0.1 Amortization of Debt Transaction Costs 0.5 0.6 1.8 1.9 Other Addback
Source: SEC EDGAR · 8-K filed Feb 10, 2021
More decks from OppFi Inc.
 Investor Presentation (November 2026)19 slides · Nov 10, 2026
 Q3 2026 Earnings Presentation22 slides · Oct 28, 2026
 Q2 2026 Earnings Presentation22 slides · Aug 10, 2026
 Investor Presentation (June 2026)25 slides · June 2026
 Q1 2026 Earnings Presentation19 slides · May 7, 2026
 Merger or Acquisition (April 2026)13 slides · Apr 29, 2026