Gemfields Group Limited · JSE:GML
Gemfields — FY2016 Earnings Presentation
37 slides from Gemfields's earnings presentation, Sep 26, 2016
Slide 1: Full year results to 30 June 2016
A leading supplier of responsibly sourced coloured gemstones Full year results to 30 June 2016 26 September 2016 Gemfields Plc
Slide 2: Gemfields: Mine and market strategy
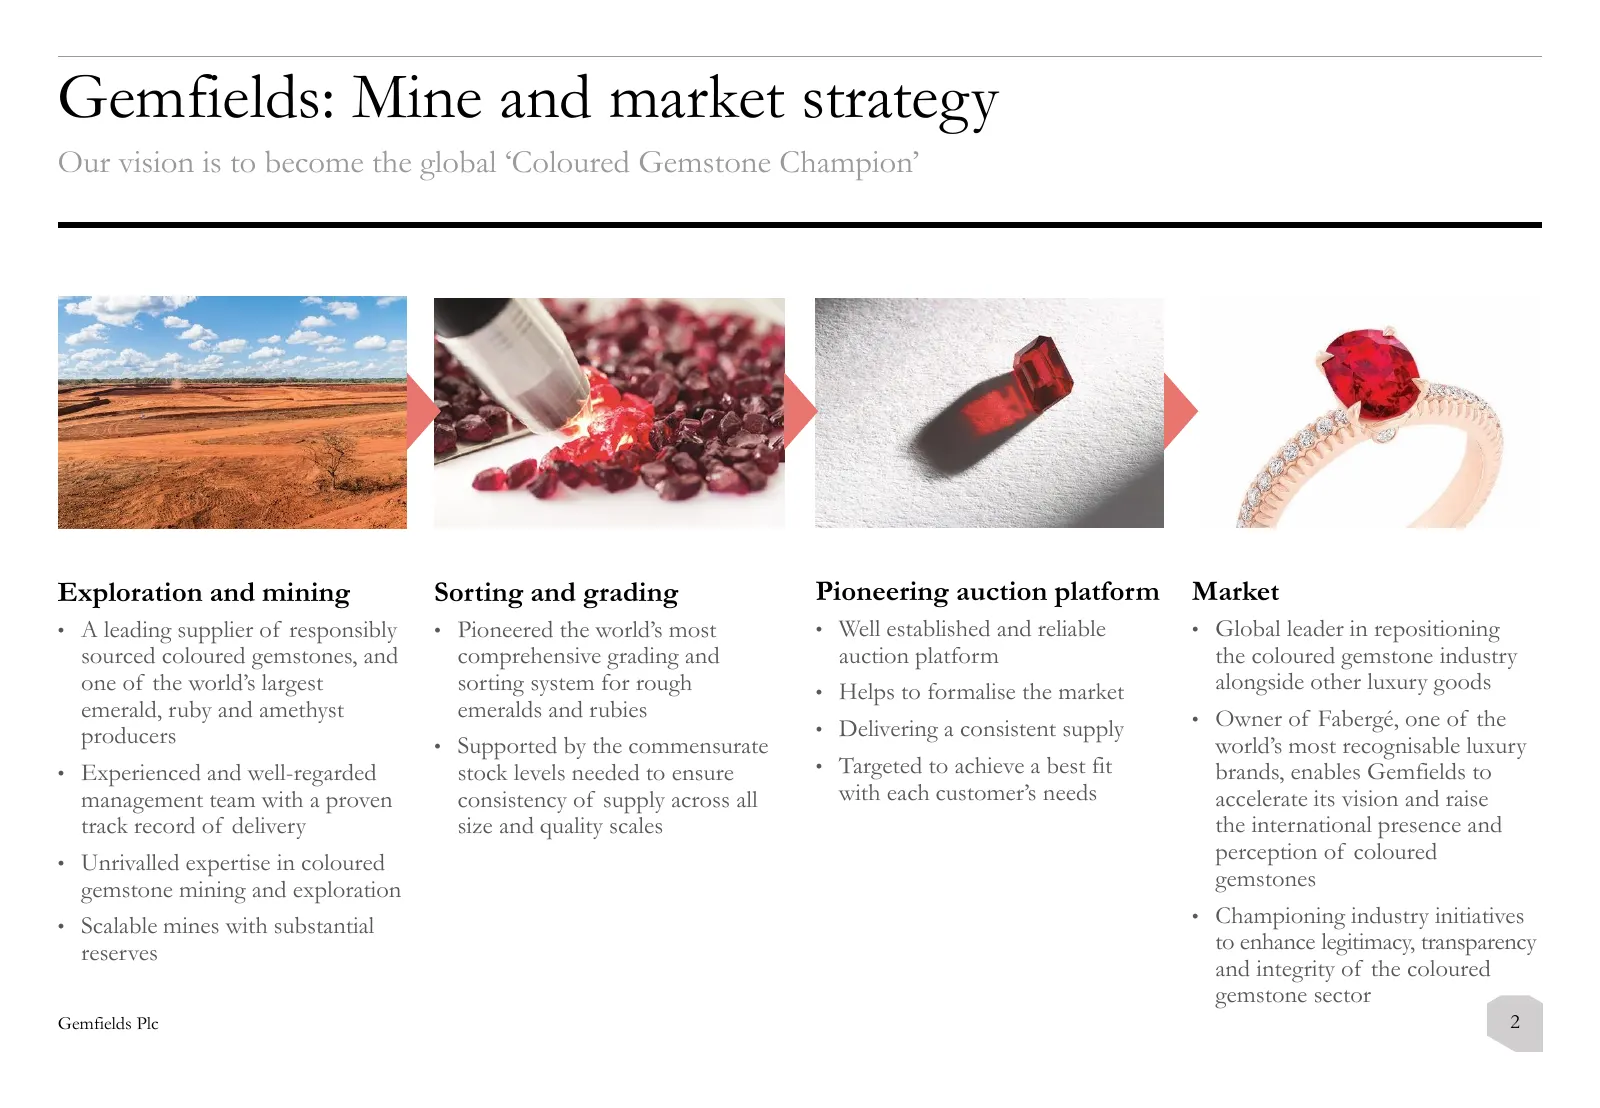
Gemfields: Mine and market strategy Our vision is to become the global ‘Coloured Gemstone Champion’ Exploration and mining Sorting and grading Pioneering auction platform Market • A leading supplier of responsibly • Pioneered the world’s most • Well established and reliable • Global leader in reposi
Slide 3: Gemfields: The opportunity
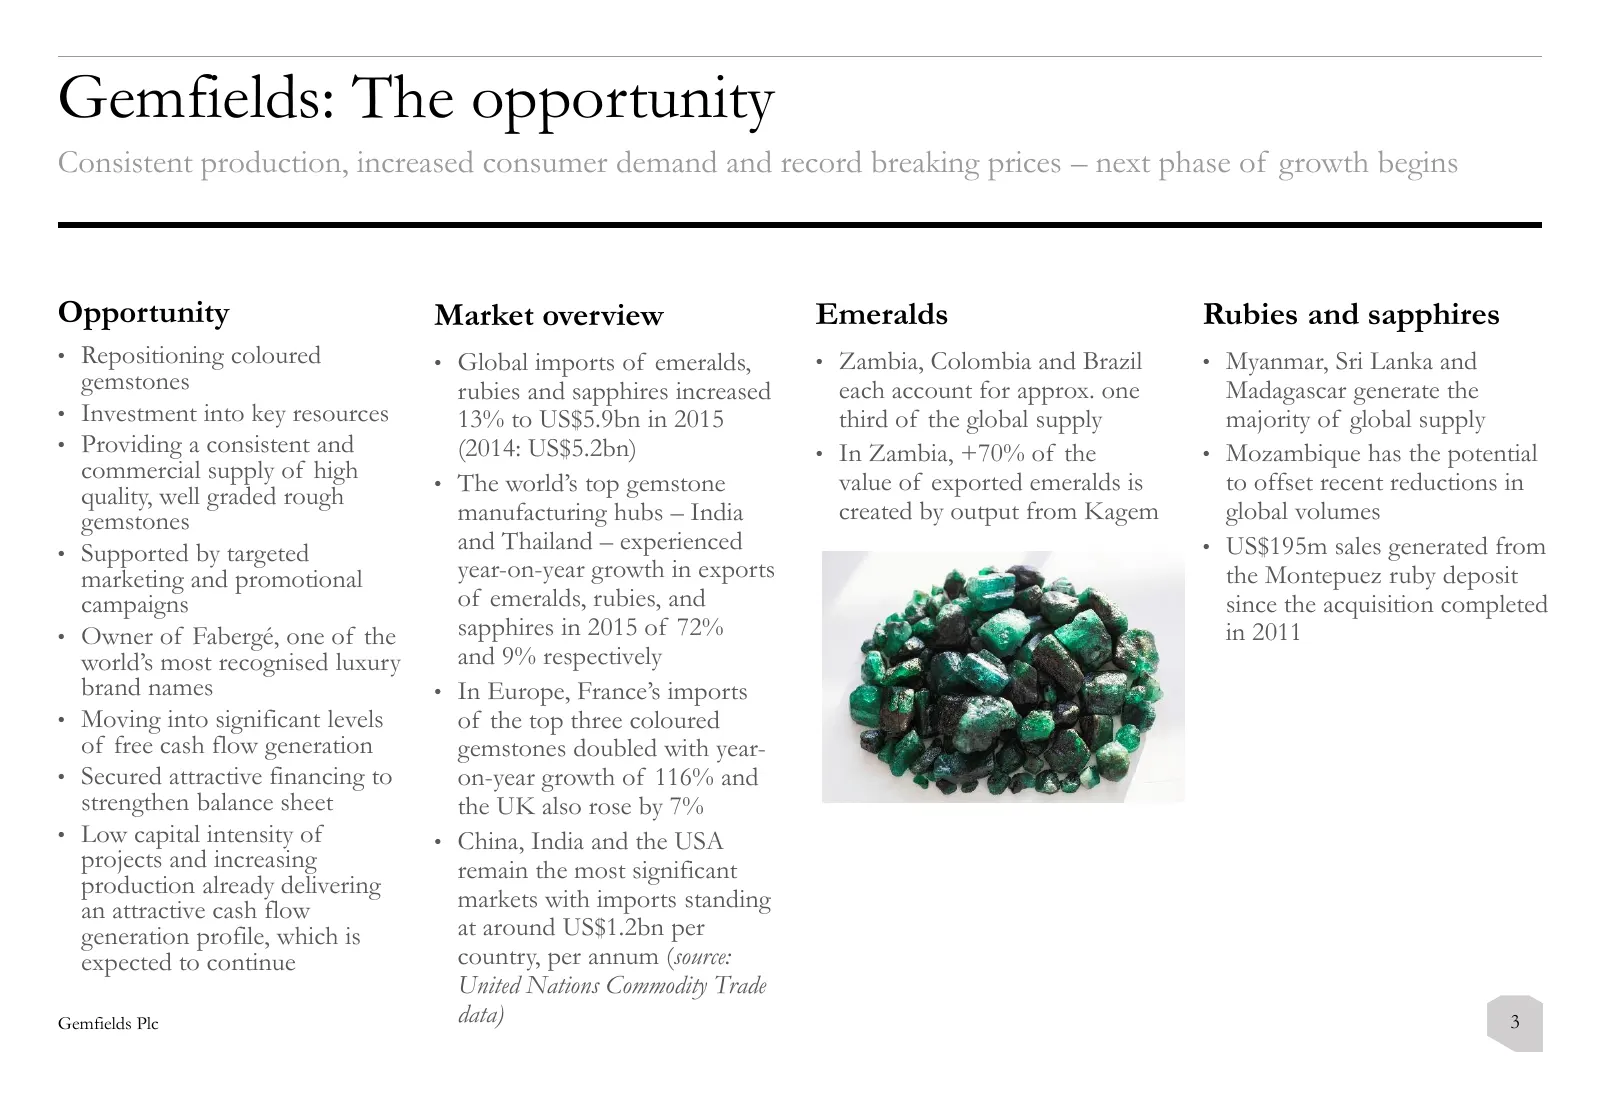
Gemfields: The opportunity Consistent production, increased consumer demand and record breaking prices – next phase of growth begins Opportunity Market overview Emeralds Rubies and sapphires • Repositioning coloured • Global imports of emeralds, • Zambia, Colombia and Brazil • Myanmar, Sri Lanka and
Slide 4: Financial Highlights
Financial Highlights Gemfields Plc 4
Slide 5: Financial highlights
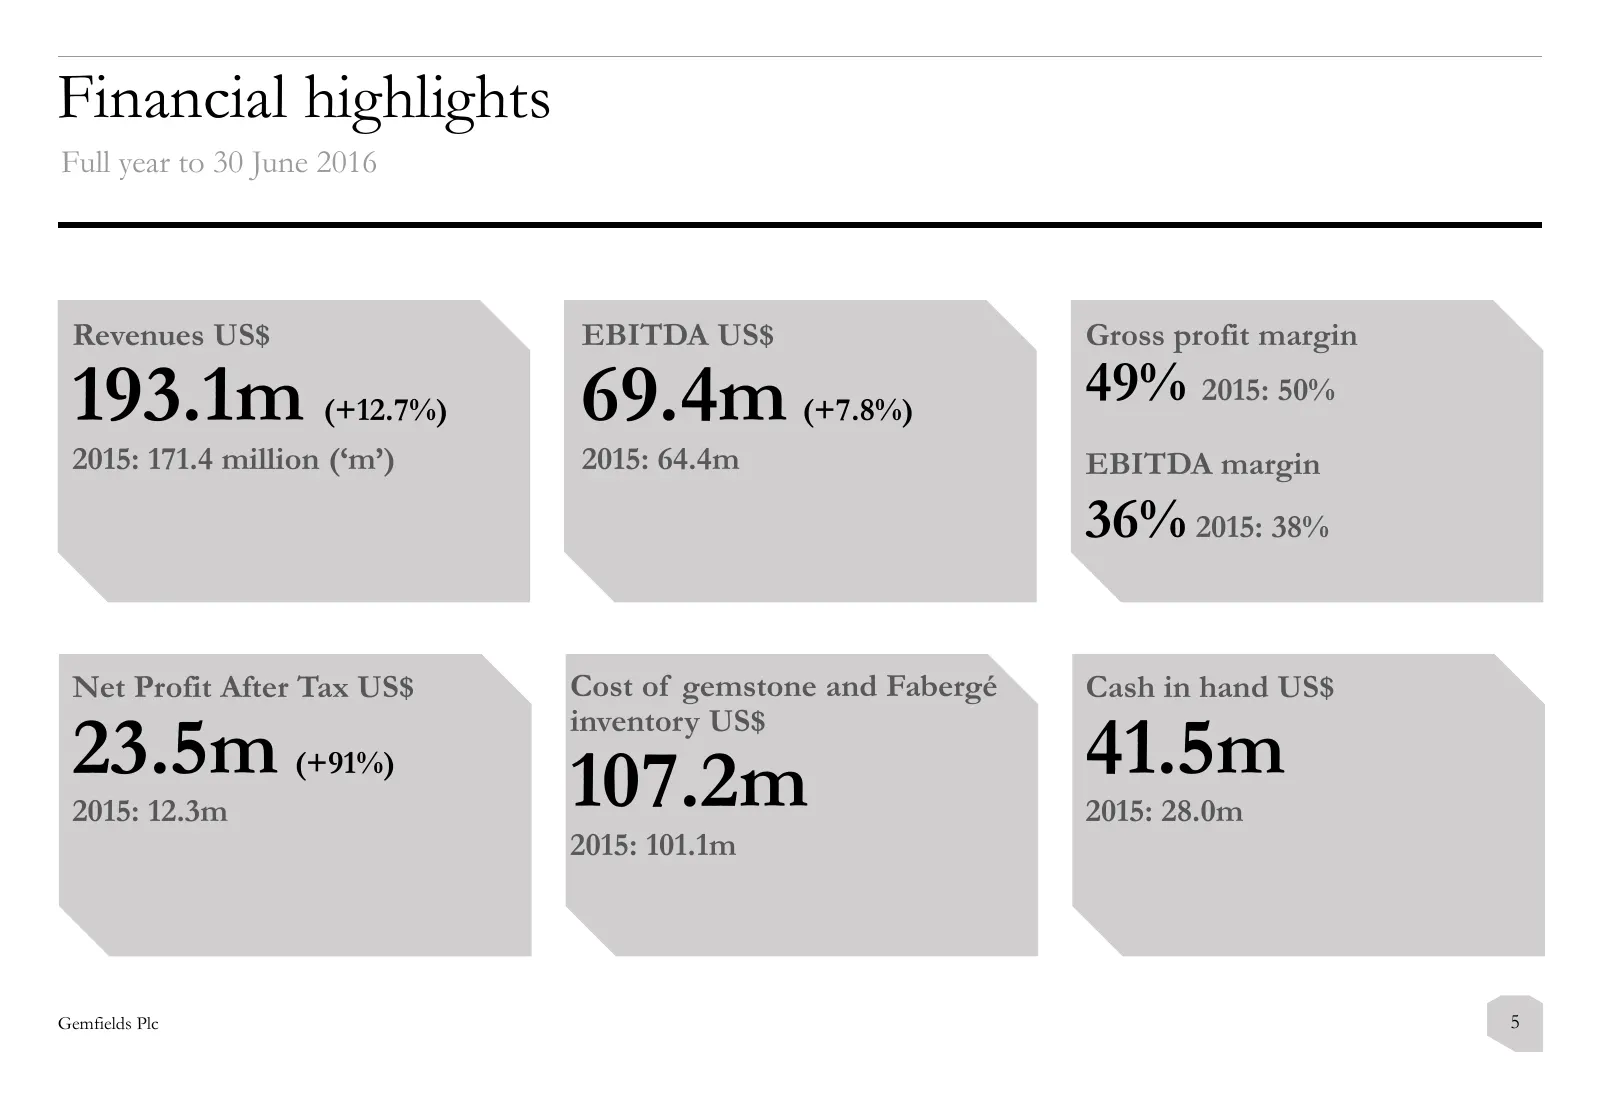
Financial highlights Full year to 30 June 2016 Revenues US$ EBITDA US$ Gross profit margin 193.1m (+12.7%) 69.4m (+7.8%) 49% 2015: 50% 2015: 171.4 million (‘m’) 2015: 64.4m EBITDA margin 36% 2015: 38% Net Profit After Tax US$ Cost of gemstone and Fabergé Cash in hand US$ 23.5m 41.5m inventory US$ 20
Slide 6: Consolidated income statement
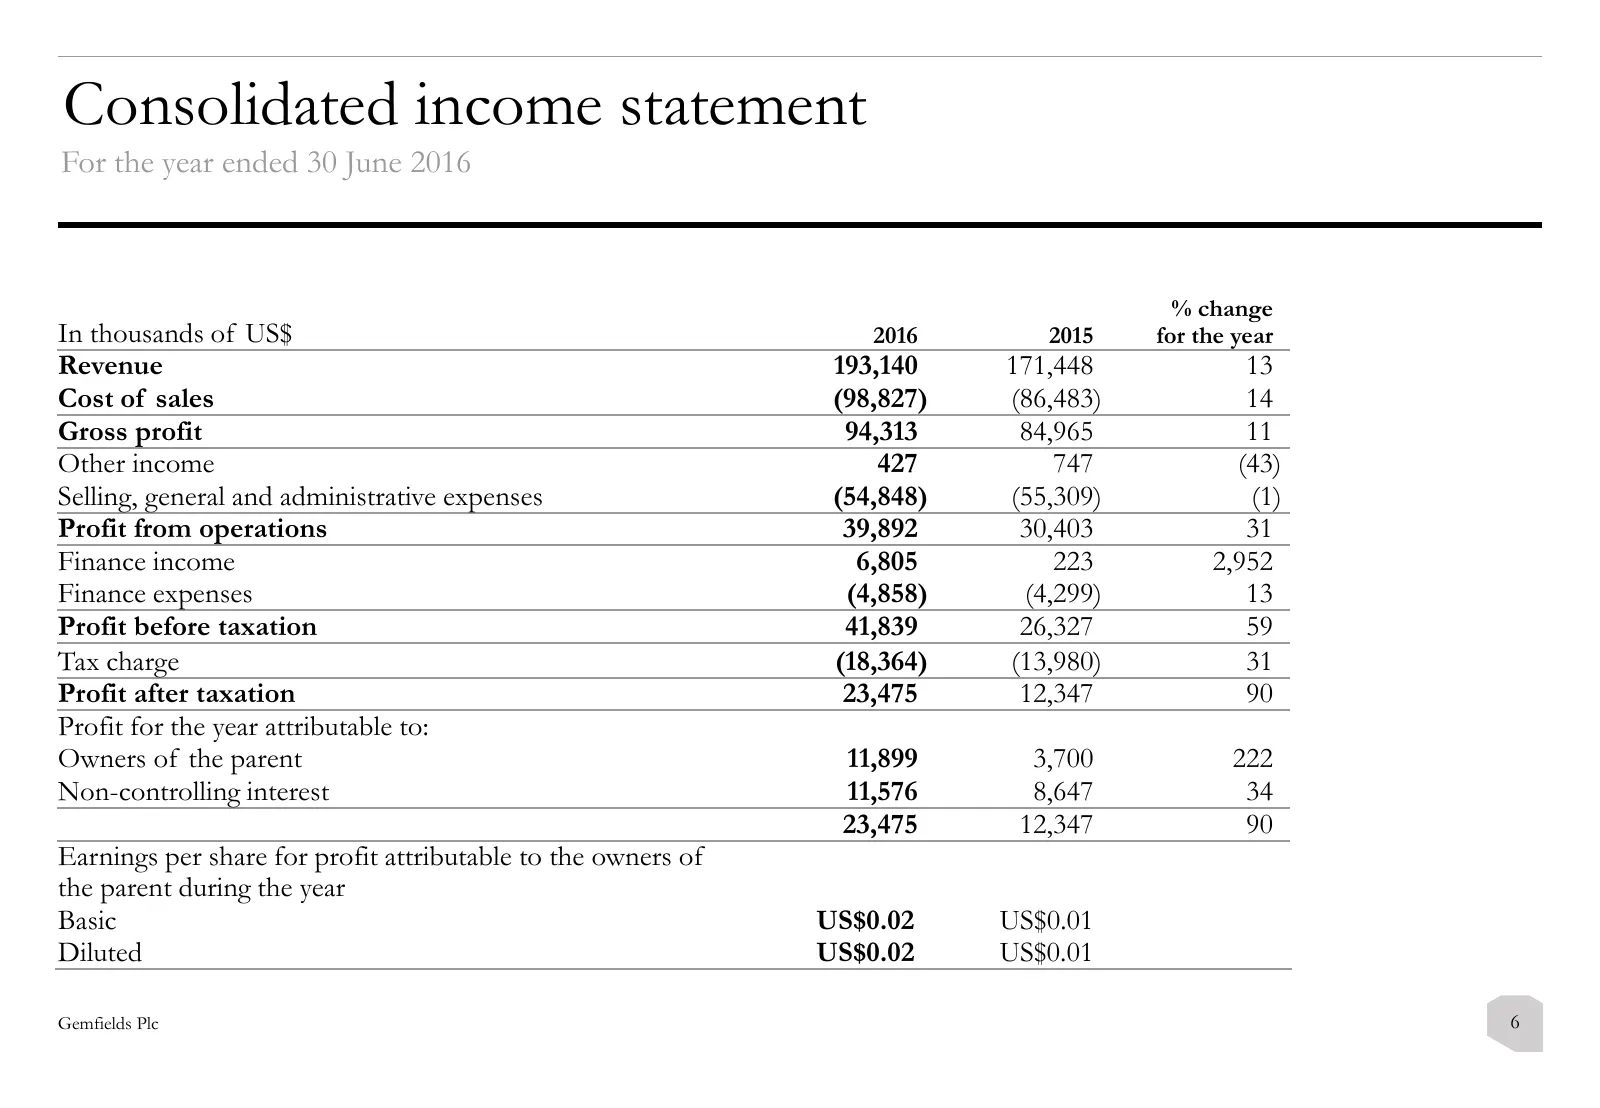
Consolidated income statement For the year ended 30 June 2016 % change In thousands of US$ 2016 2015 for the year Revenue 193,140 171,448 13 Cost of sales (98,827) (86,483) 14 Gross profit 94,313 84,965 11 Other income 427 747 (43) Selling, general and administrative expenses (54,848) (55,309) (1) P
Slide 7: Revenue analysis – six auctions held during the year
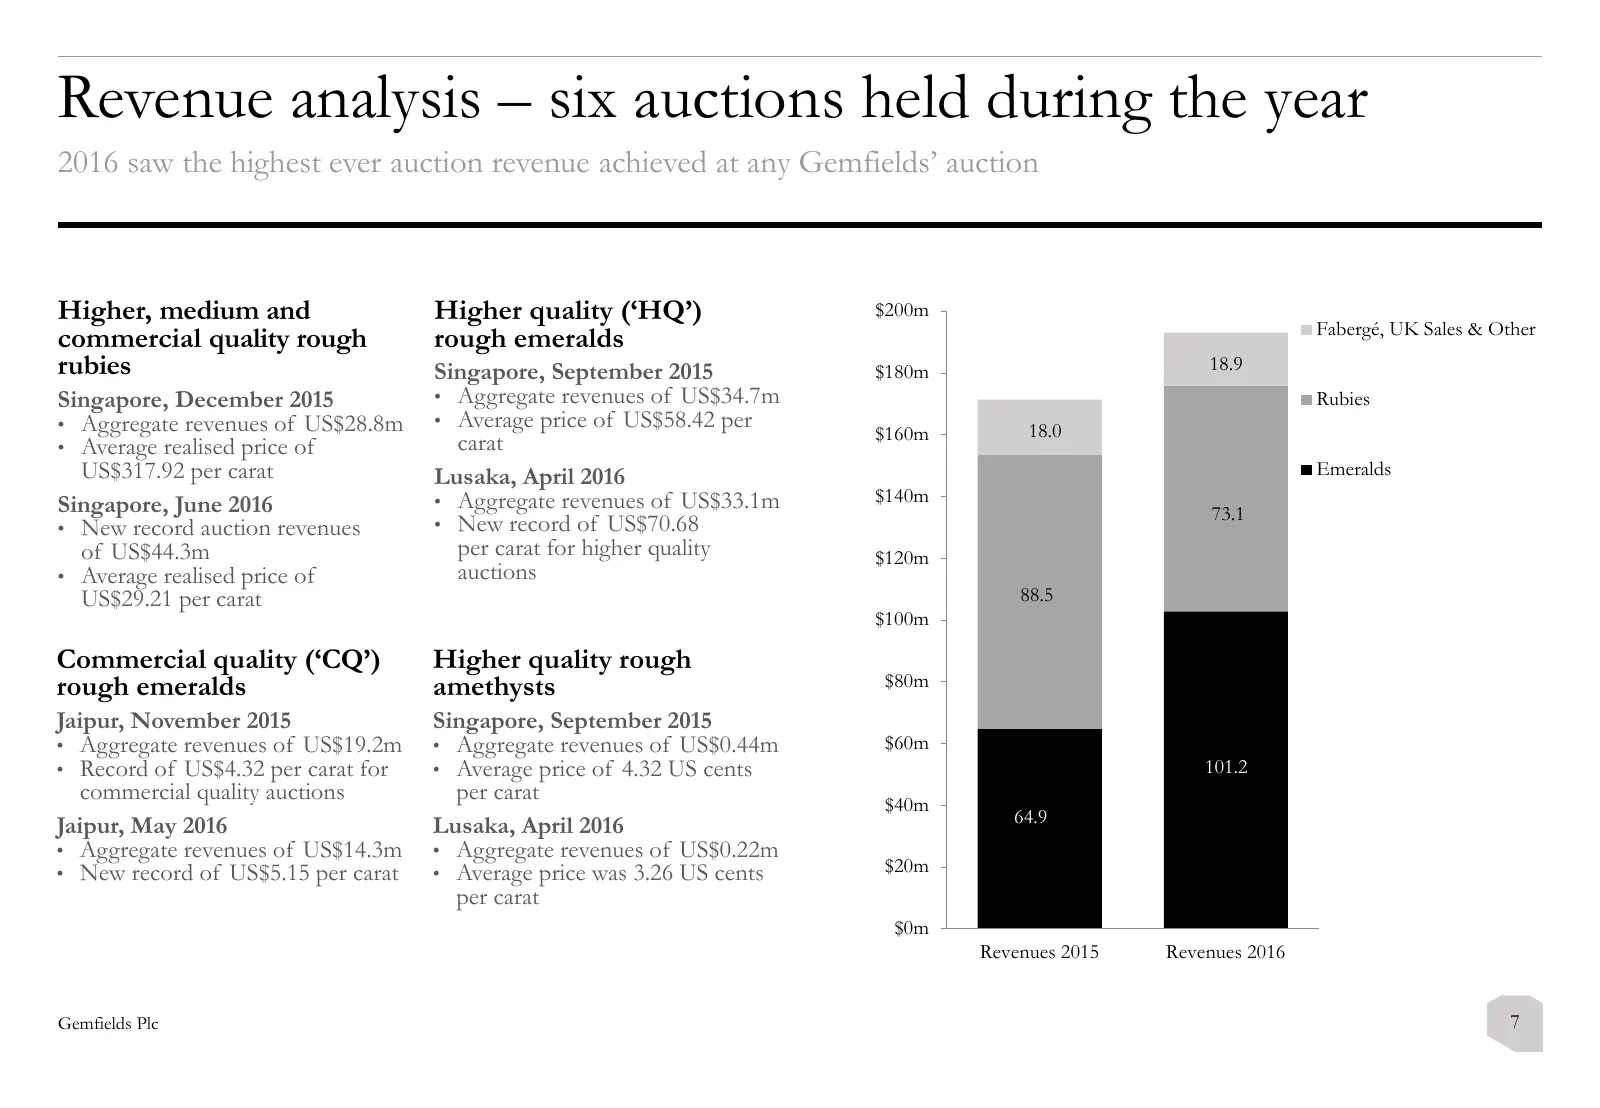
Revenue analysis – six auctions held during the year 2016 saw the highest ever auction revenue achieved at any Gemfields’ auction Higher, medium and Higher quality (‘HQ’) $200m Fabergé, UK Sales & Other commercial quality rough rough emeralds rubies Singapore, September 2015 $180m 18.9 Singapore, De
Slide 8: Cost of sales and inventory breakdown
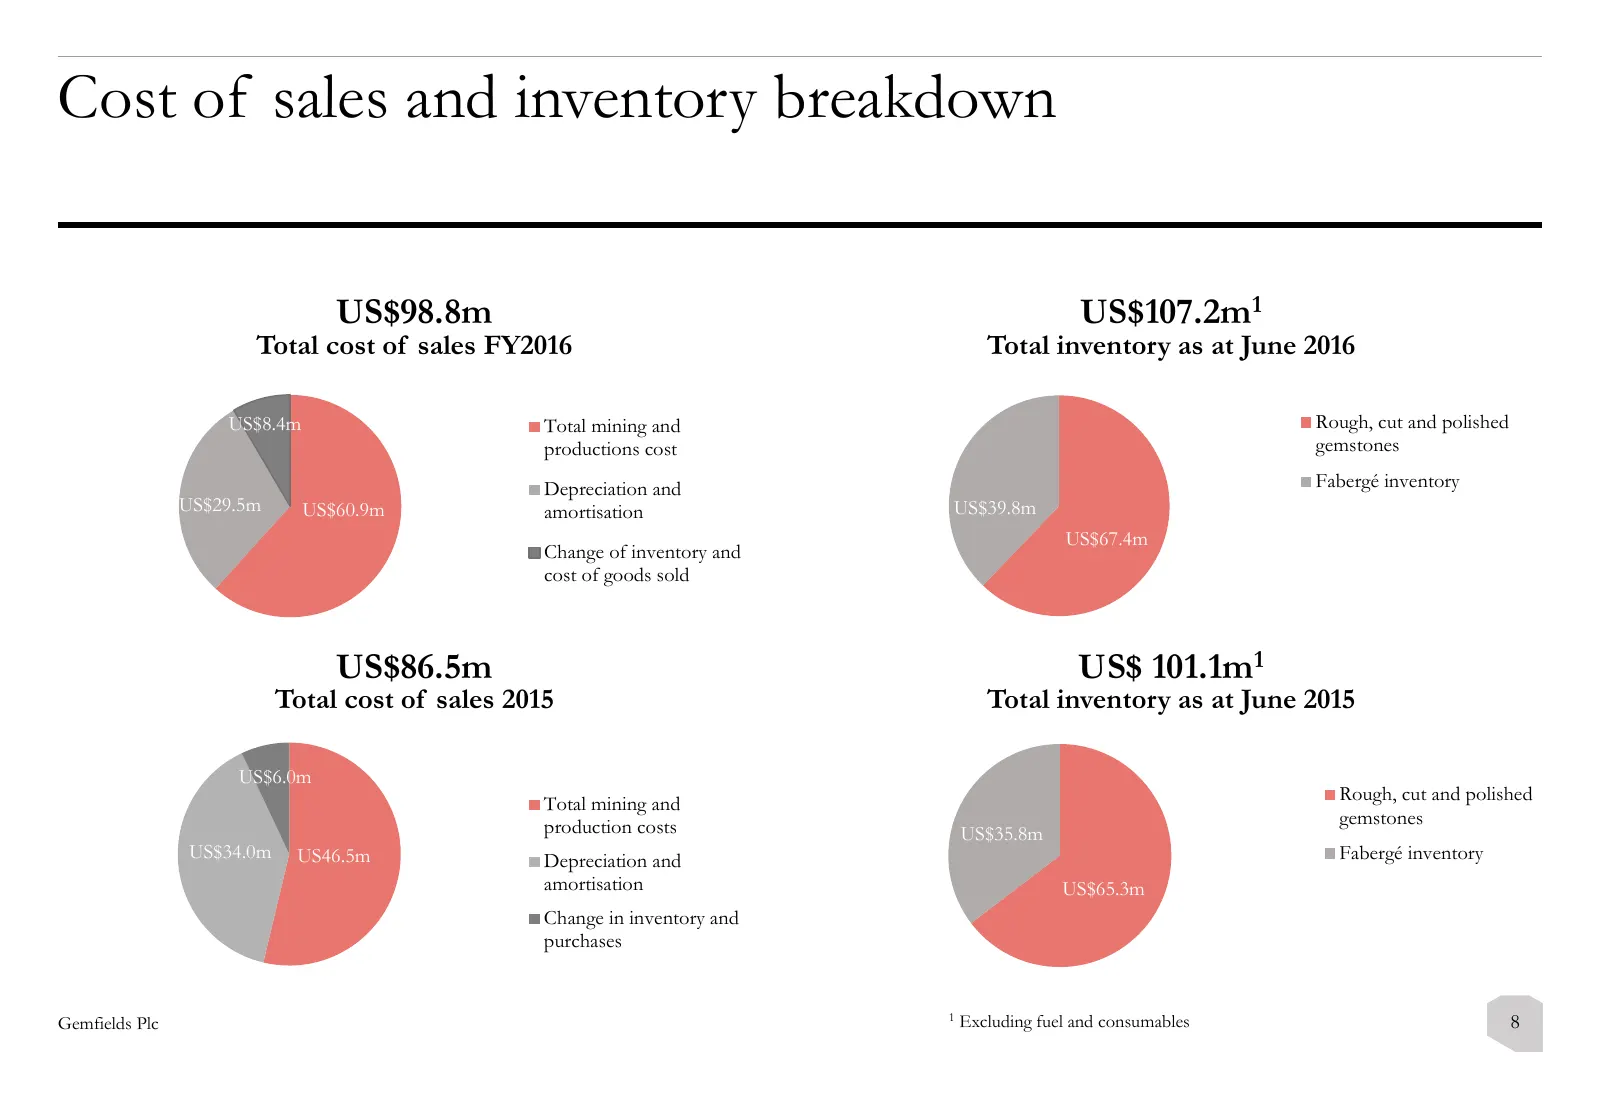
Cost of sales and inventory breakdown US$98.8m US$107.2m1 Total cost of sales FY2016 Total inventory as at June 2016 US$8.4m Total mining and Rough, cut and polished productions cost gemstones Depreciation and Fabergé inventory US$29.5m US$60.9m amortisation US$39.8m US$67.4m Change of inventory and
Slide 9: Mine cost analysis for Kagem, Zambia (75% owned)
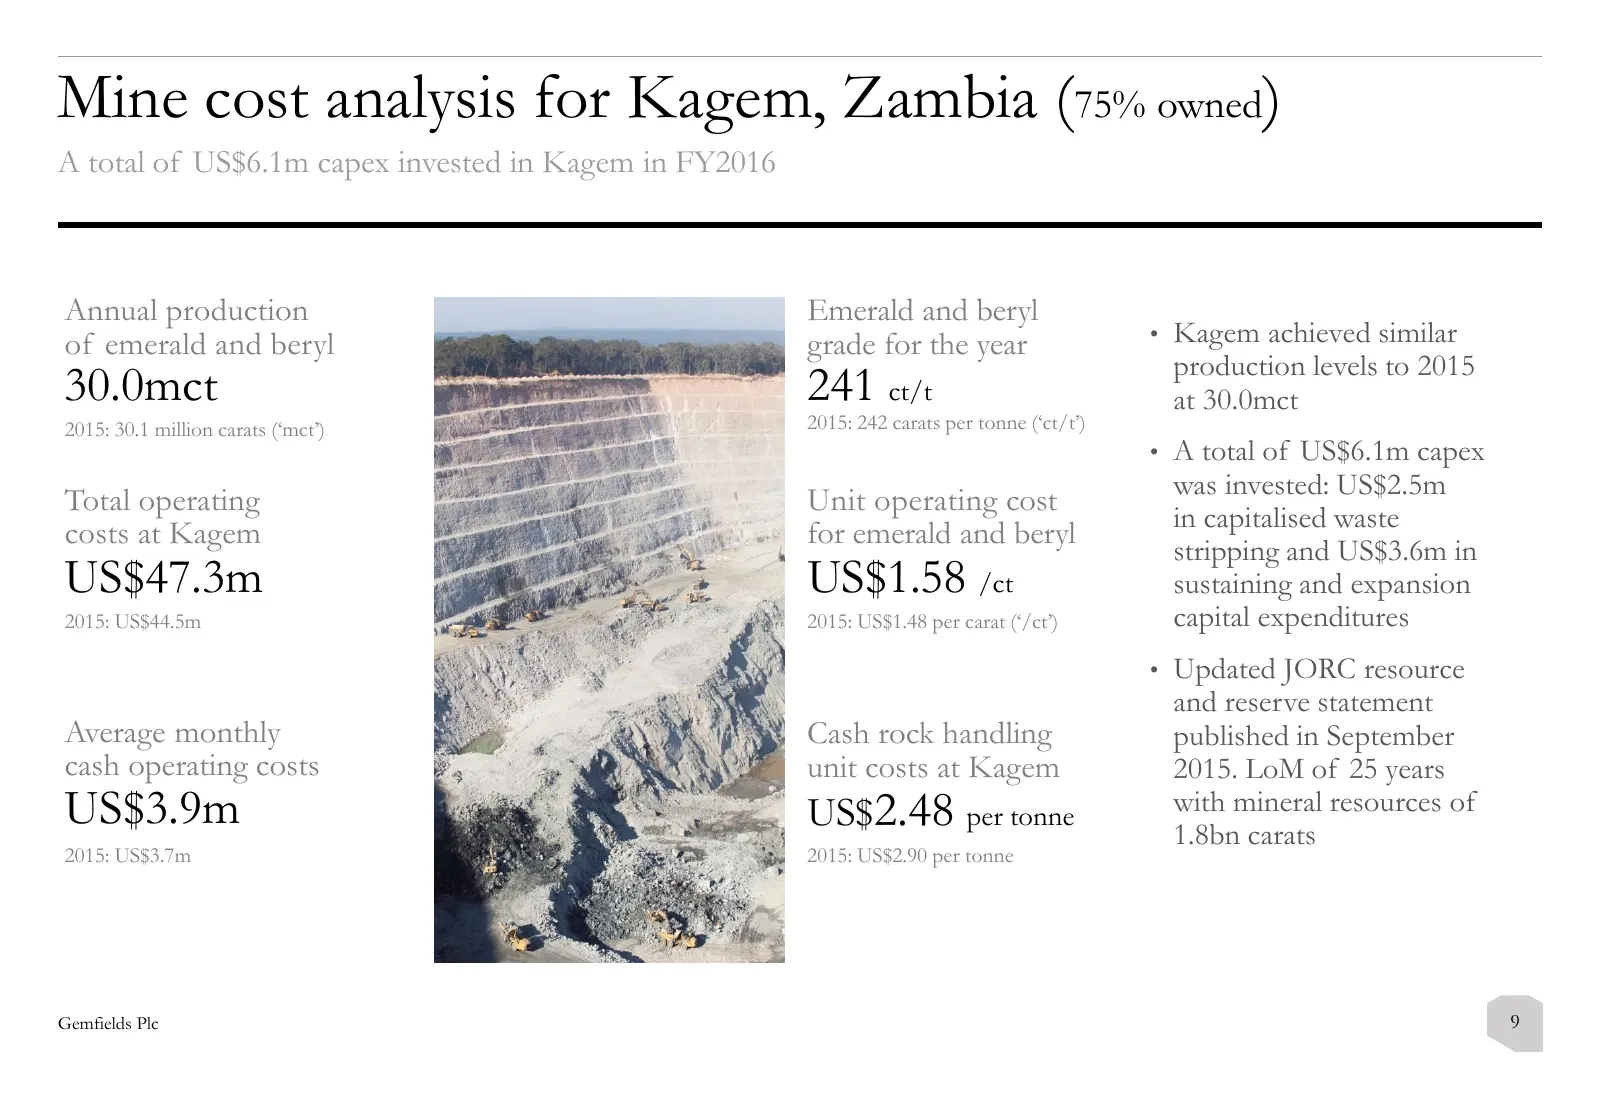
Mine cost analysis for Kagem, Zambia (75% owned) A total of US$6.1m capex invested in Kagem in FY2016 Annual production Emerald and beryl of emerald and beryl grade for the year • Kagem achieved similar production levels to 2015 30.0mct 241 ct/t at 30.0mct 2015: 30.1 million carats (‘mct’) 2015: 242
Slide 10: Mine cost analysis for Montepuez, Mozambique (75% owned)
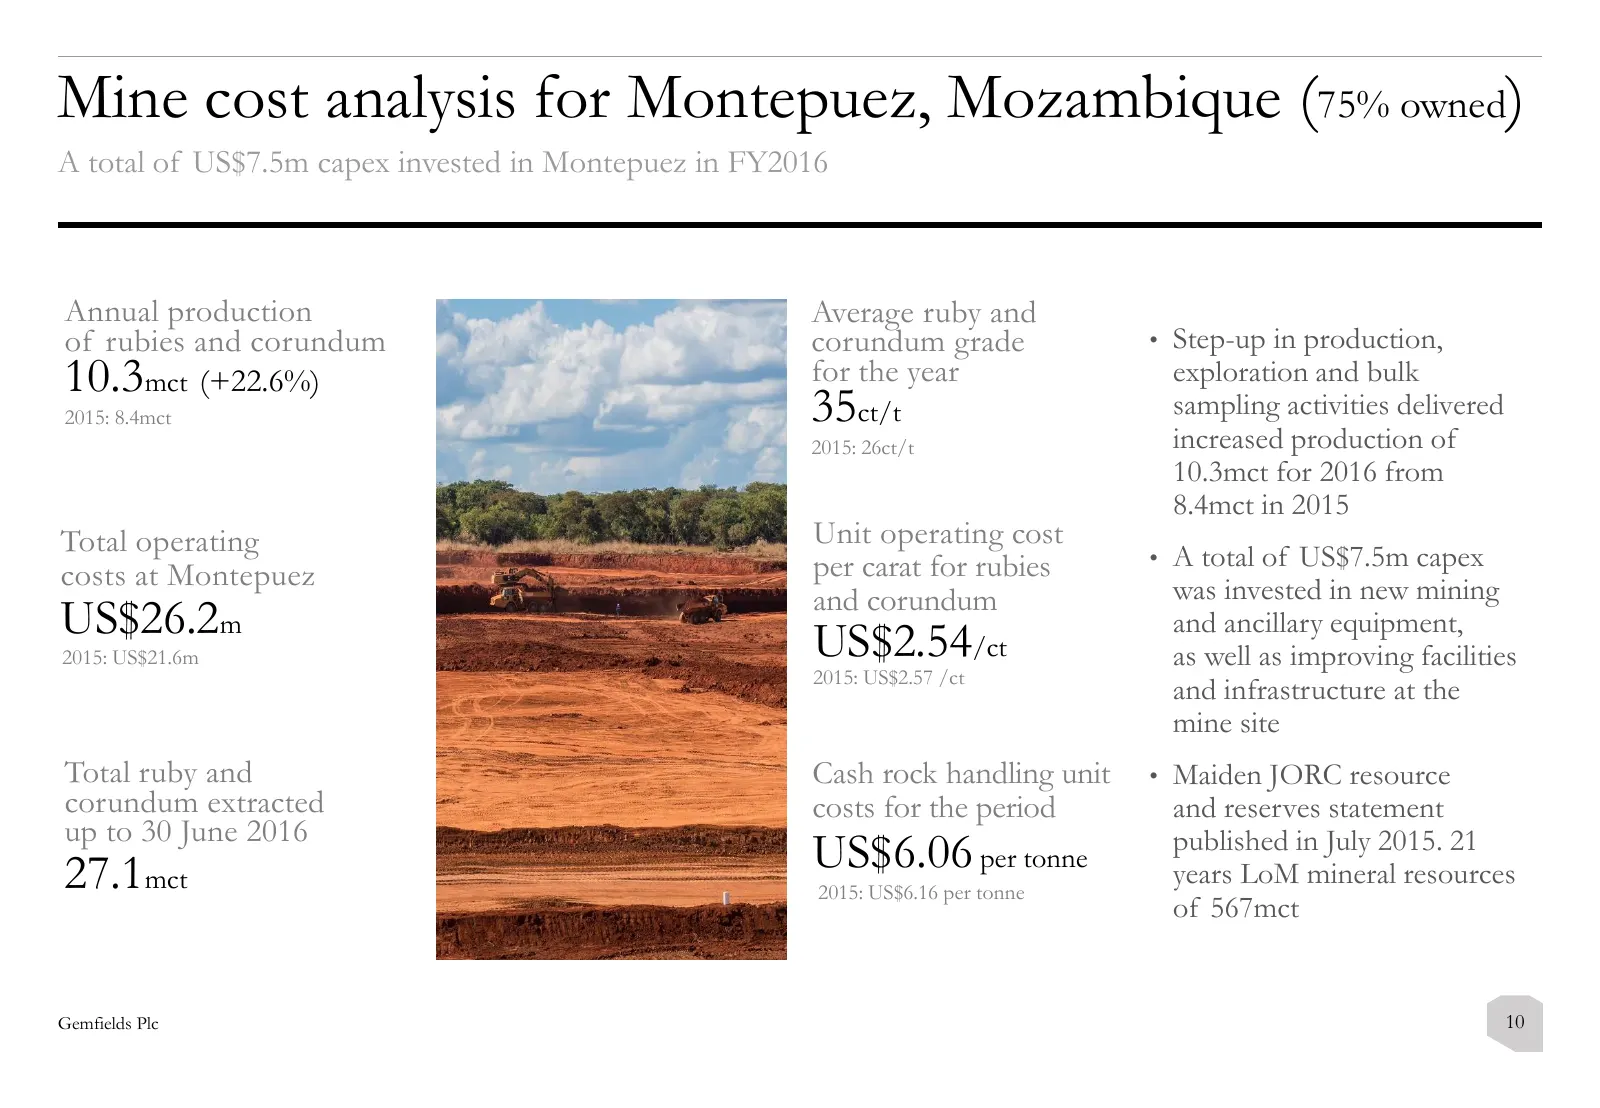
Mine cost analysis for Montepuez, Mozambique (75% owned) A total of US$7.5m capex invested in Montepuez in FY2016 Annual production Average ruby and of rubies and corundum corundum grade • Step-up in production, 10.3mct (+22.6%) for the year exploration and bulk 2015: 8.4mct 35ct/t sampling activiti
Slide 11: Cash flow and capex analysis
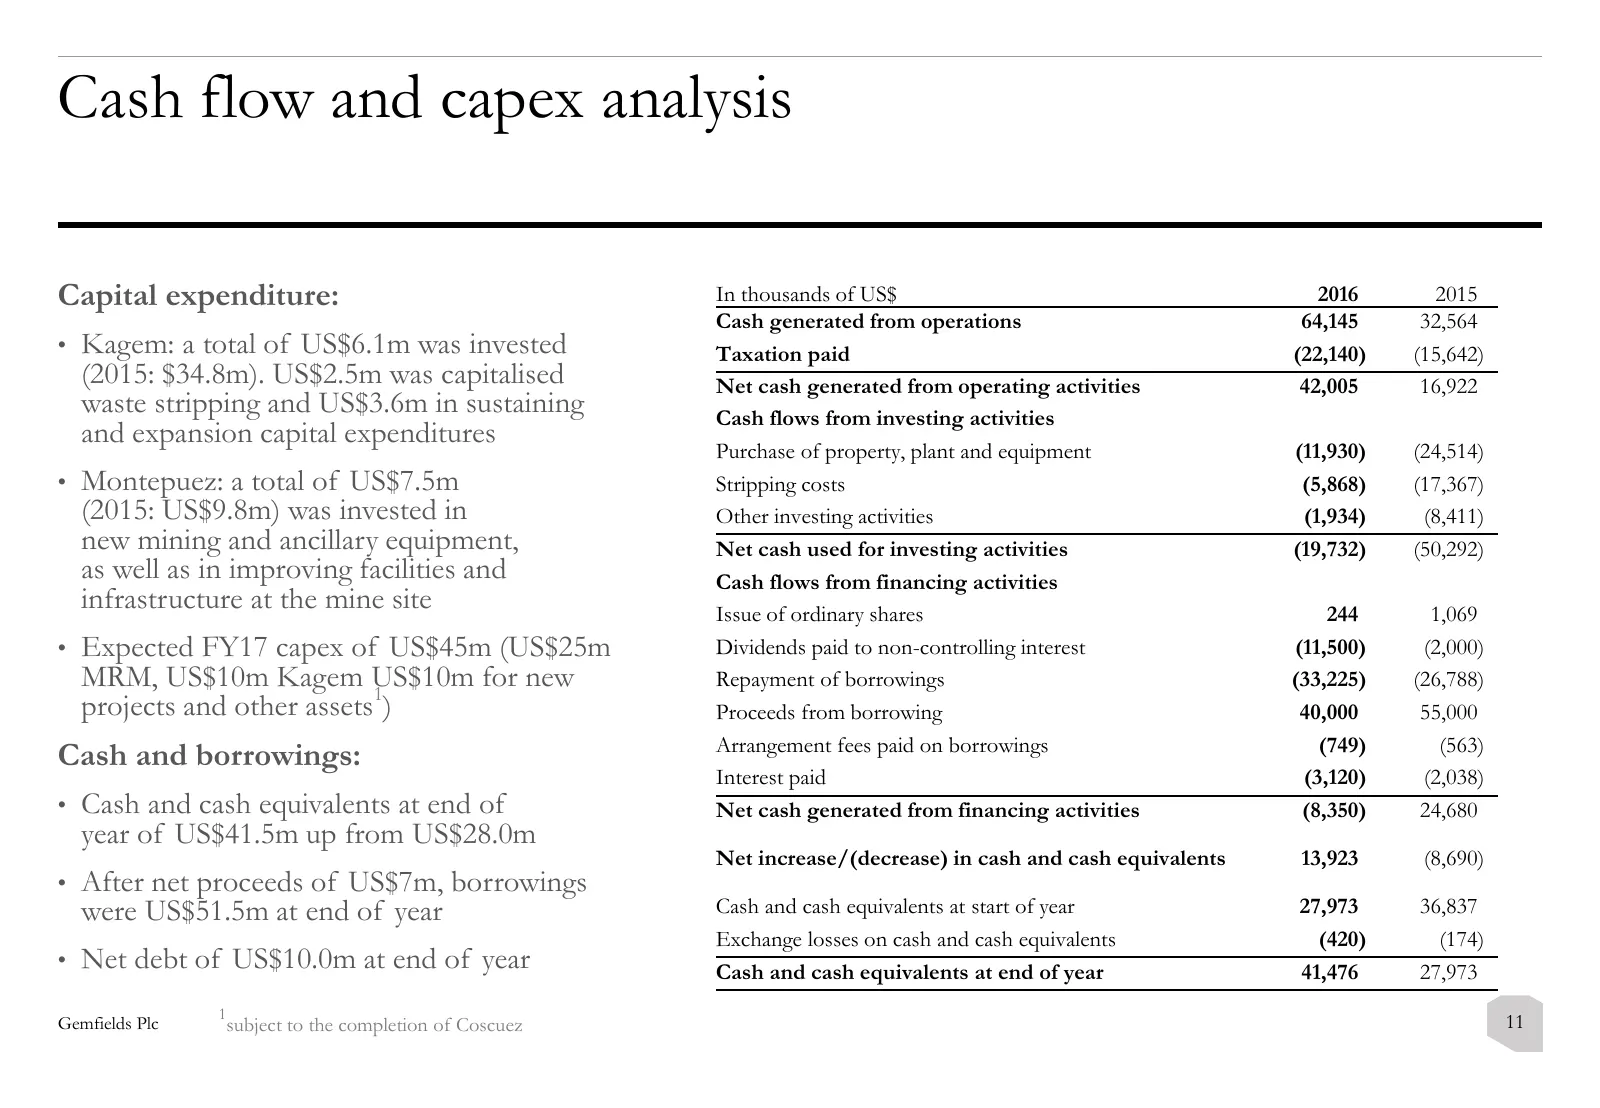
Cash flow and capex analysis Capital expenditure: In thousands of US$ 2016 2015 Cash generated from operations 64,145 32,564 • Kagem: a total of US$6.1m was invested Taxation paid (22,140) (15,642) (2015: $34.8m). US$2.5m was capitalised Net cash generated from operating activities 42,005 16,922 was
Slide 12: Operations
Operations Gemfields Plc 12
Slide 13: Gemfields Locations
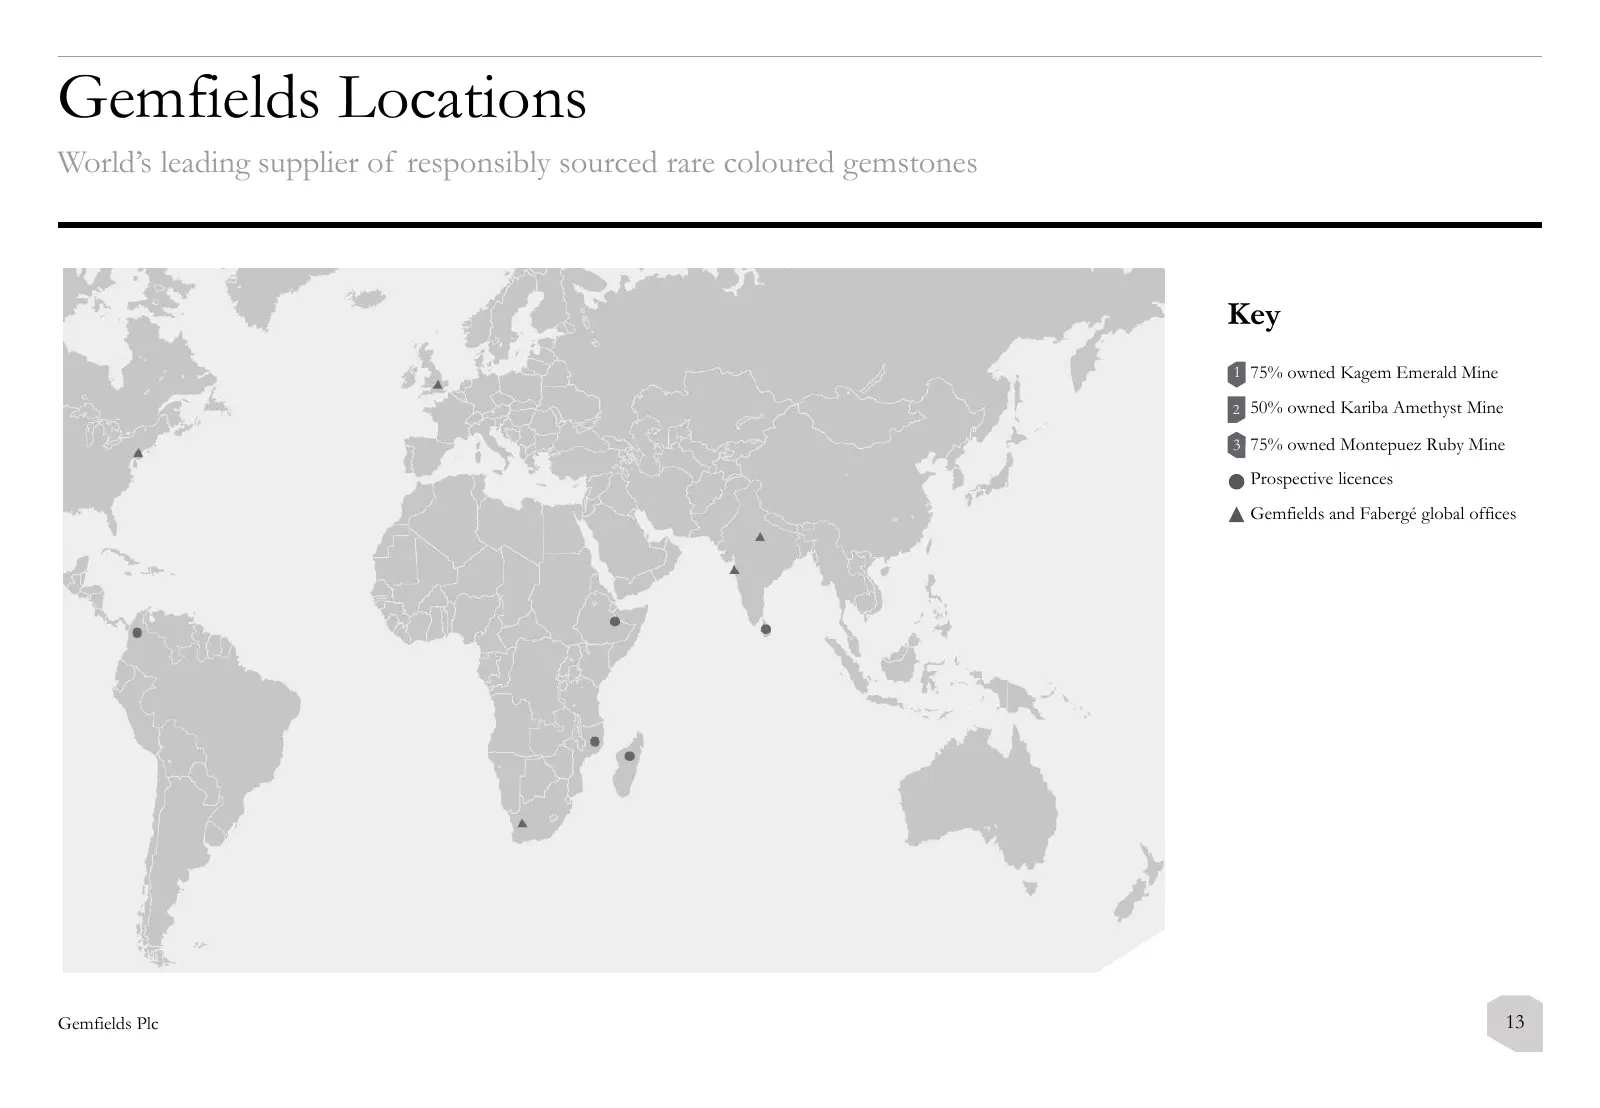
Gemfields Locations World’s leading supplier of responsibly sourced rare coloured gemstones Key 1 75% owned Kagem Emerald Mine 2 50% owned Kariba Amethyst Mine 3 75% owned Montepuez Ruby Mine Prospective licences Gemfields and Fabergé global offices 1 2 3 Gemfields Plc 13
Slide 14: Kagem mine
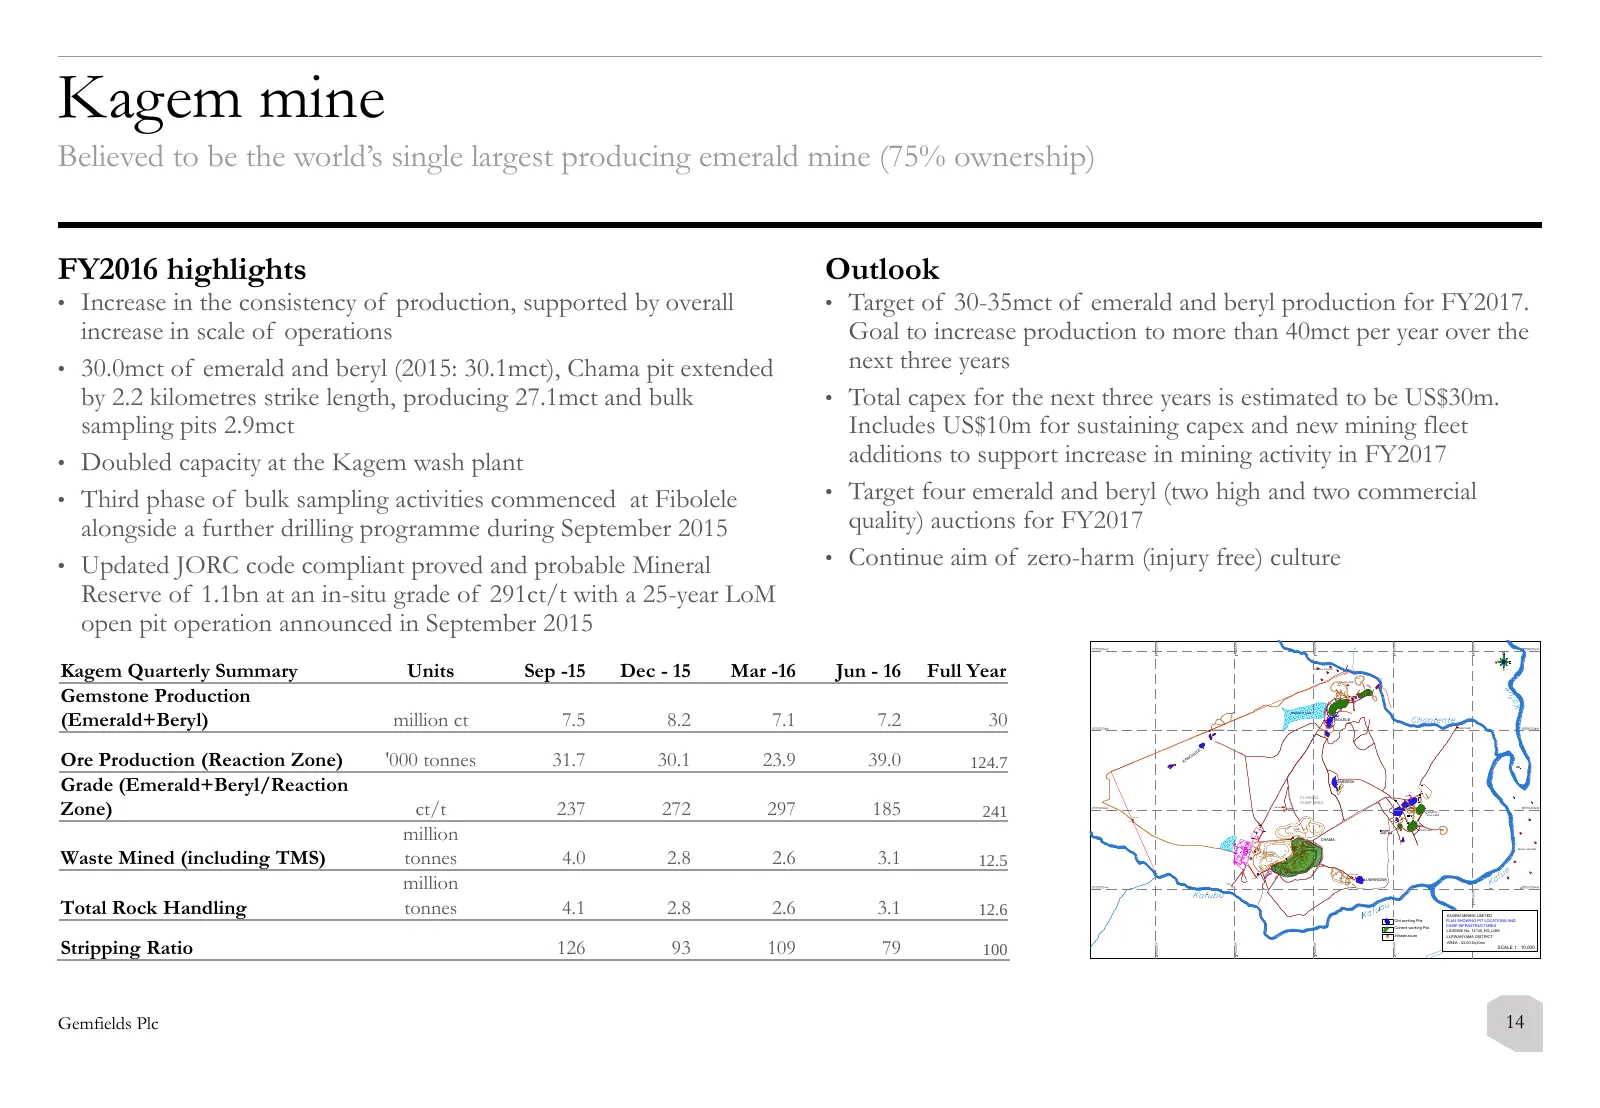
Kagem mine Believed to be the world’s single largest producing emerald mine (75% ownership) FY2016 highlights Outlook • Increase in the consistency of production, supported by overall • Target of 30-35mct of emerald and beryl production for FY2017. increase in scale of operations Goal to increase pr
Slide 15: Kagem JORC Resource and Reserves update
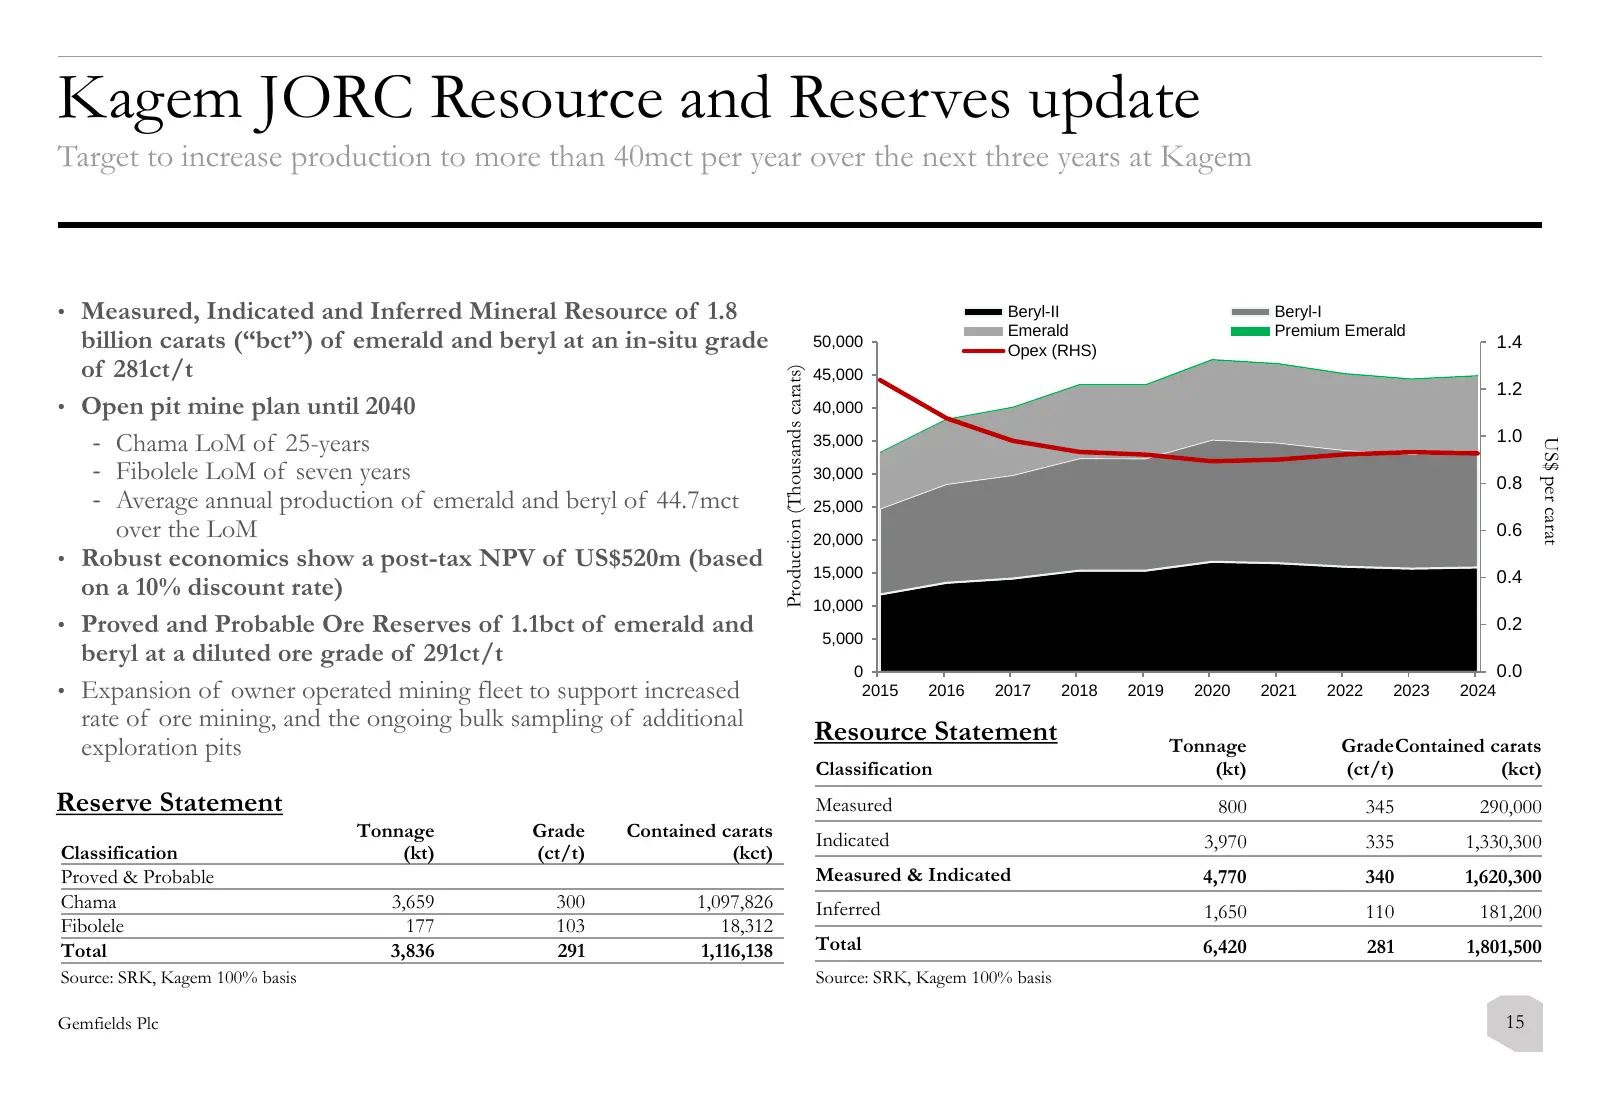
Kagem JORC Resource and Reserves update Target to increase production to more than 40mct per year over the next three years at Kagem • Measured, Indicated and Inferred Mineral Resource of 1.8 Beryl-II Beryl-I Emerald Premium Emerald billion carats (“bct”) of emerald and beryl at an in-situ grade 50,
Slide 16: Montepuez mine
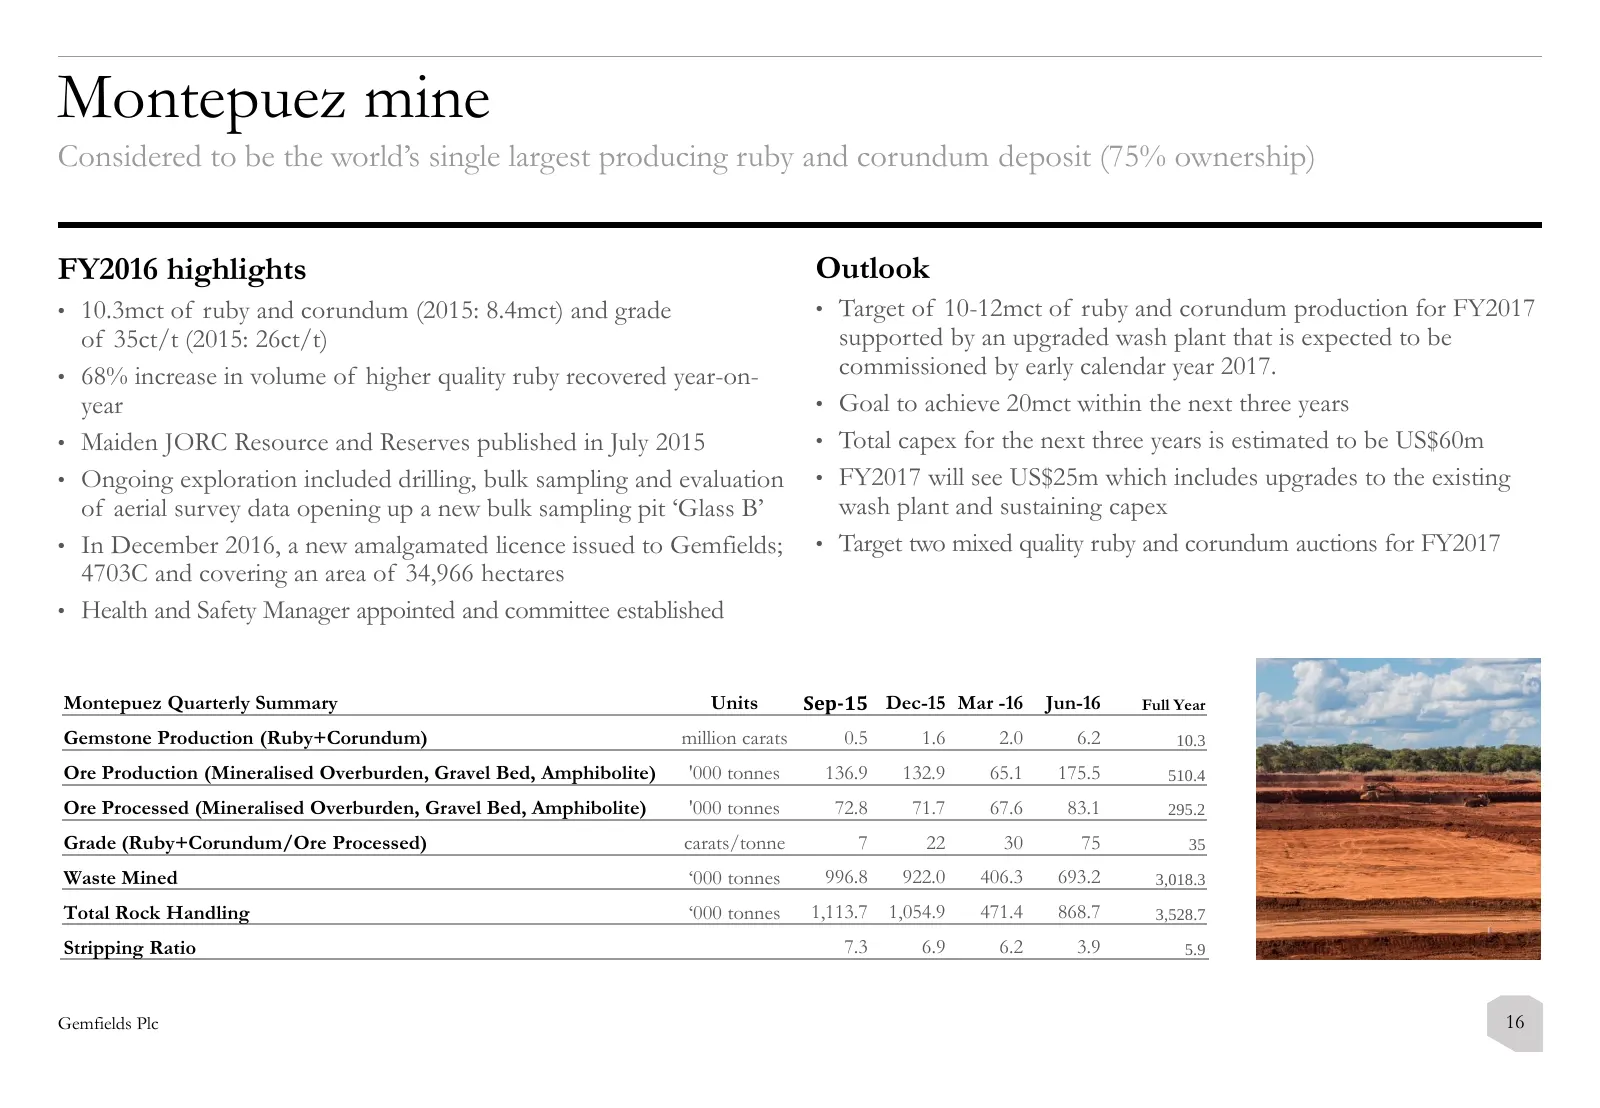
Montepuez mine Considered to be the world’s single largest producing ruby and corundum deposit (75% ownership) FY2016 highlights Outlook • 10.3mct of ruby and corundum (2015: 8.4mct) and grade • Target of 10-12mct of ruby and corundum production for FY2017 of 35ct/t (2015: 26ct/t) supported by an up
Slide 17: Montepuez JORC Maiden Resource and Reserves
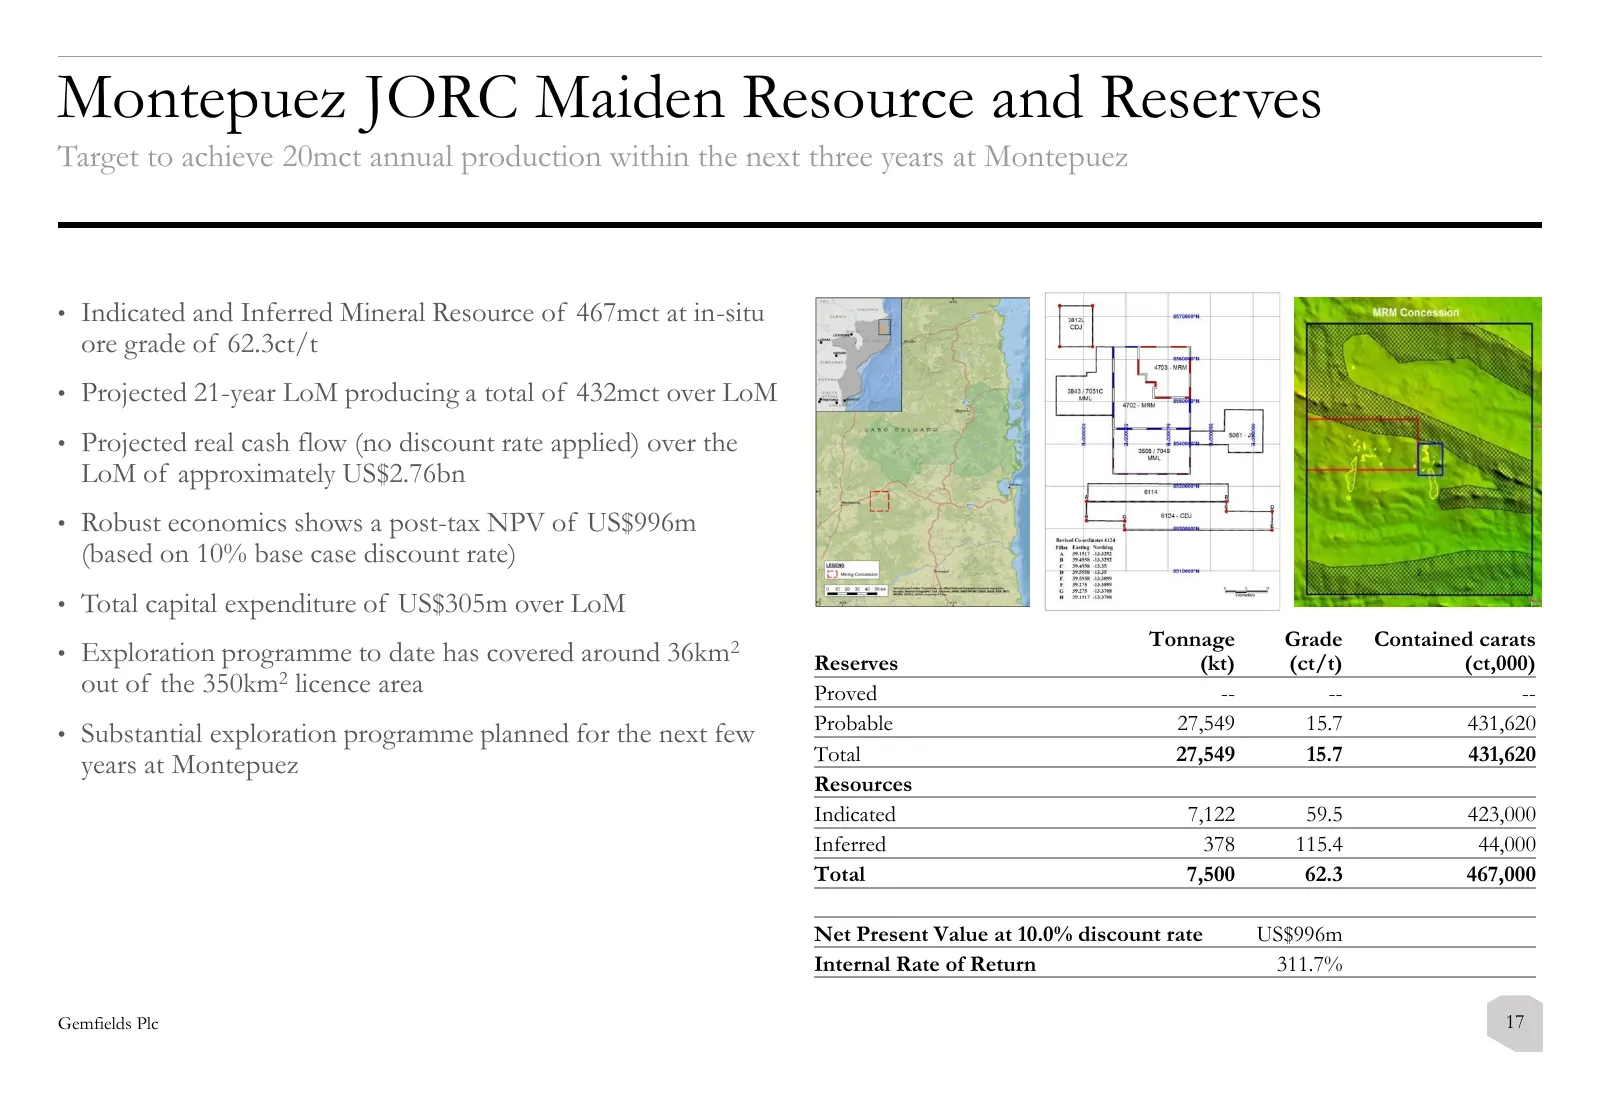
Montepuez JORC Maiden Resource and Reserves Target to achieve 20mct annual production within the next three years at Montepuez • Indicated and Inferred Mineral Resource of 467mct at in-situ ore grade of 62.3ct/t • Projected 21-year LoM producing a total of 432mct over LoM • Projected real cash flow
Slide 18: Leading the way and growing the business
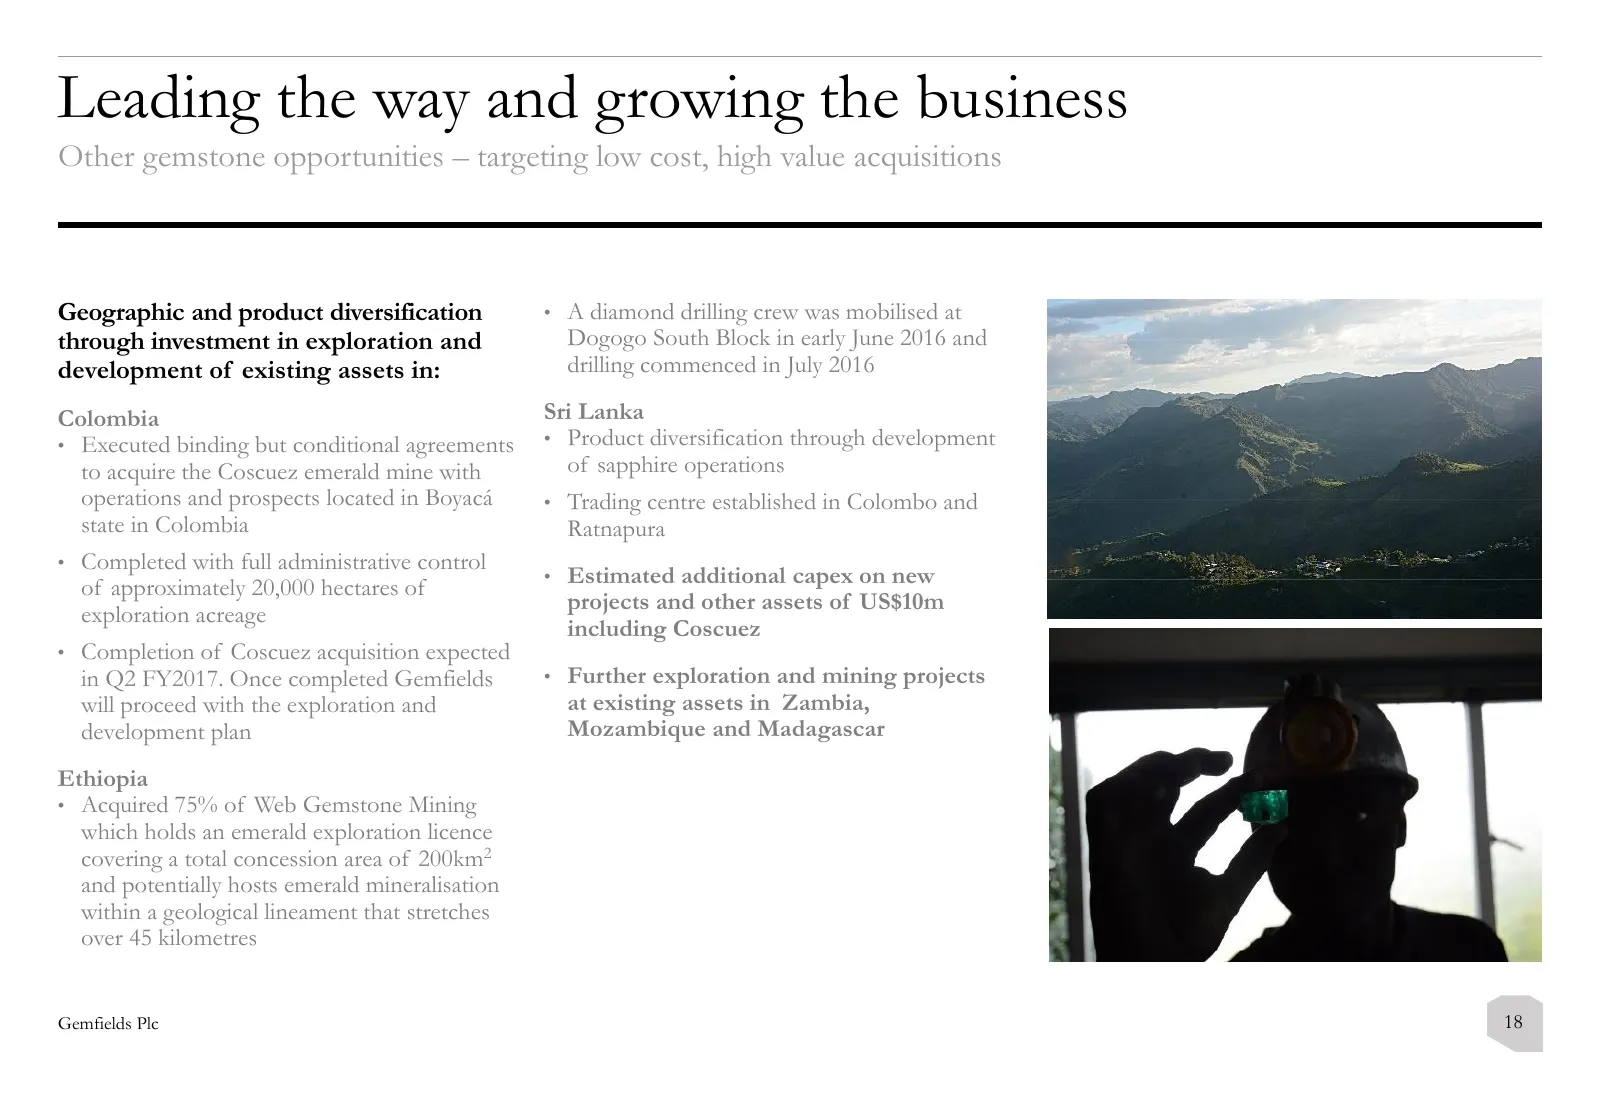
Leading the way and growing the business Other gemstone opportunities – targeting low cost, high value acquisitions Geographic and product diversification • A diamond drilling crew was mobilised at through investment in exploration and Dogogo South Block in early June 2016 and development of existin
Slide 19: Fabergé
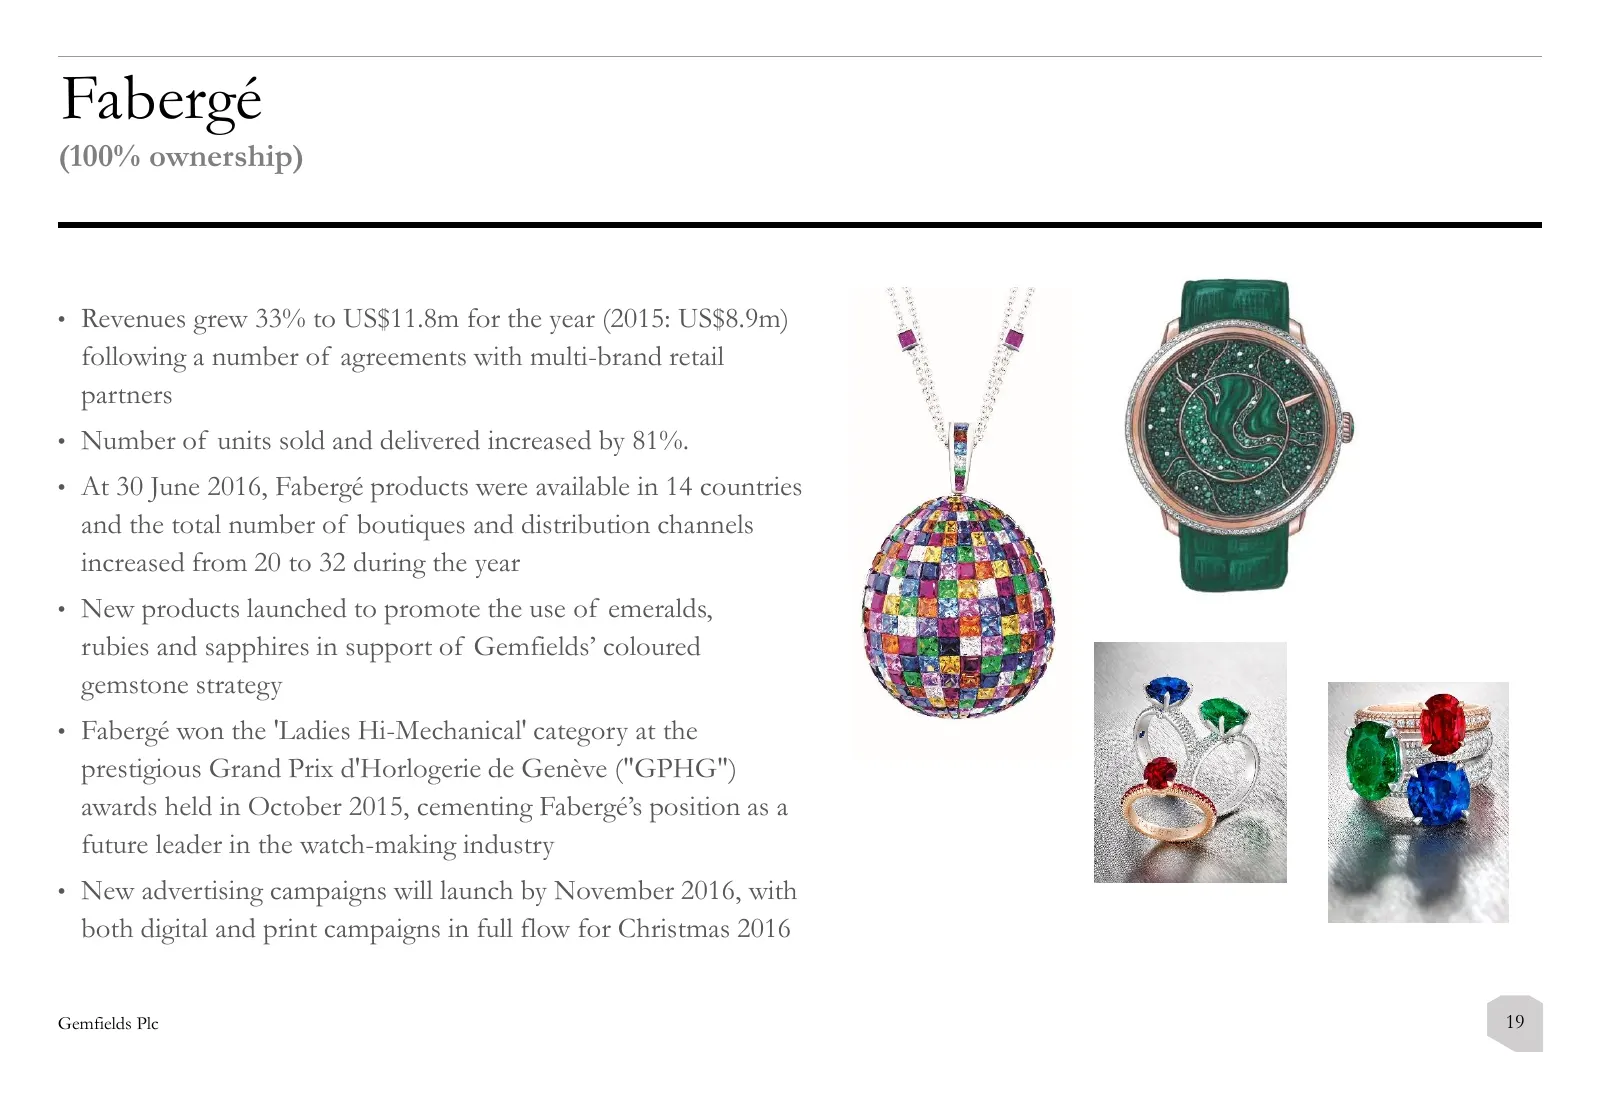
Fabergé (100% ownership) • Revenues grew 33% to US$11.8m for the year (2015: US$8.9m) following a number of agreements with multi-brand retail partners • Number of units sold and delivered increased by 81%. • At 30 June 2016, Fabergé products were available in 14 countries and the total number of bo
Slide 20: Outlook
Outlook Gemfields Plc 20
Slide 21: Driving further value – upcoming milestones
Driving further value – upcoming milestones Significant growth opportunities Mining Auctions and sales • Stable demand for coloured gemstones expected Kagem • Target of four emerald and beryl (two high and two commercial quality • Increasing production target to 30-35mct of emerald and beryl auction
Slide 22: Sales & Marketing
Sales & Marketing Gemfields Plc 22
Slide 23: Auction results
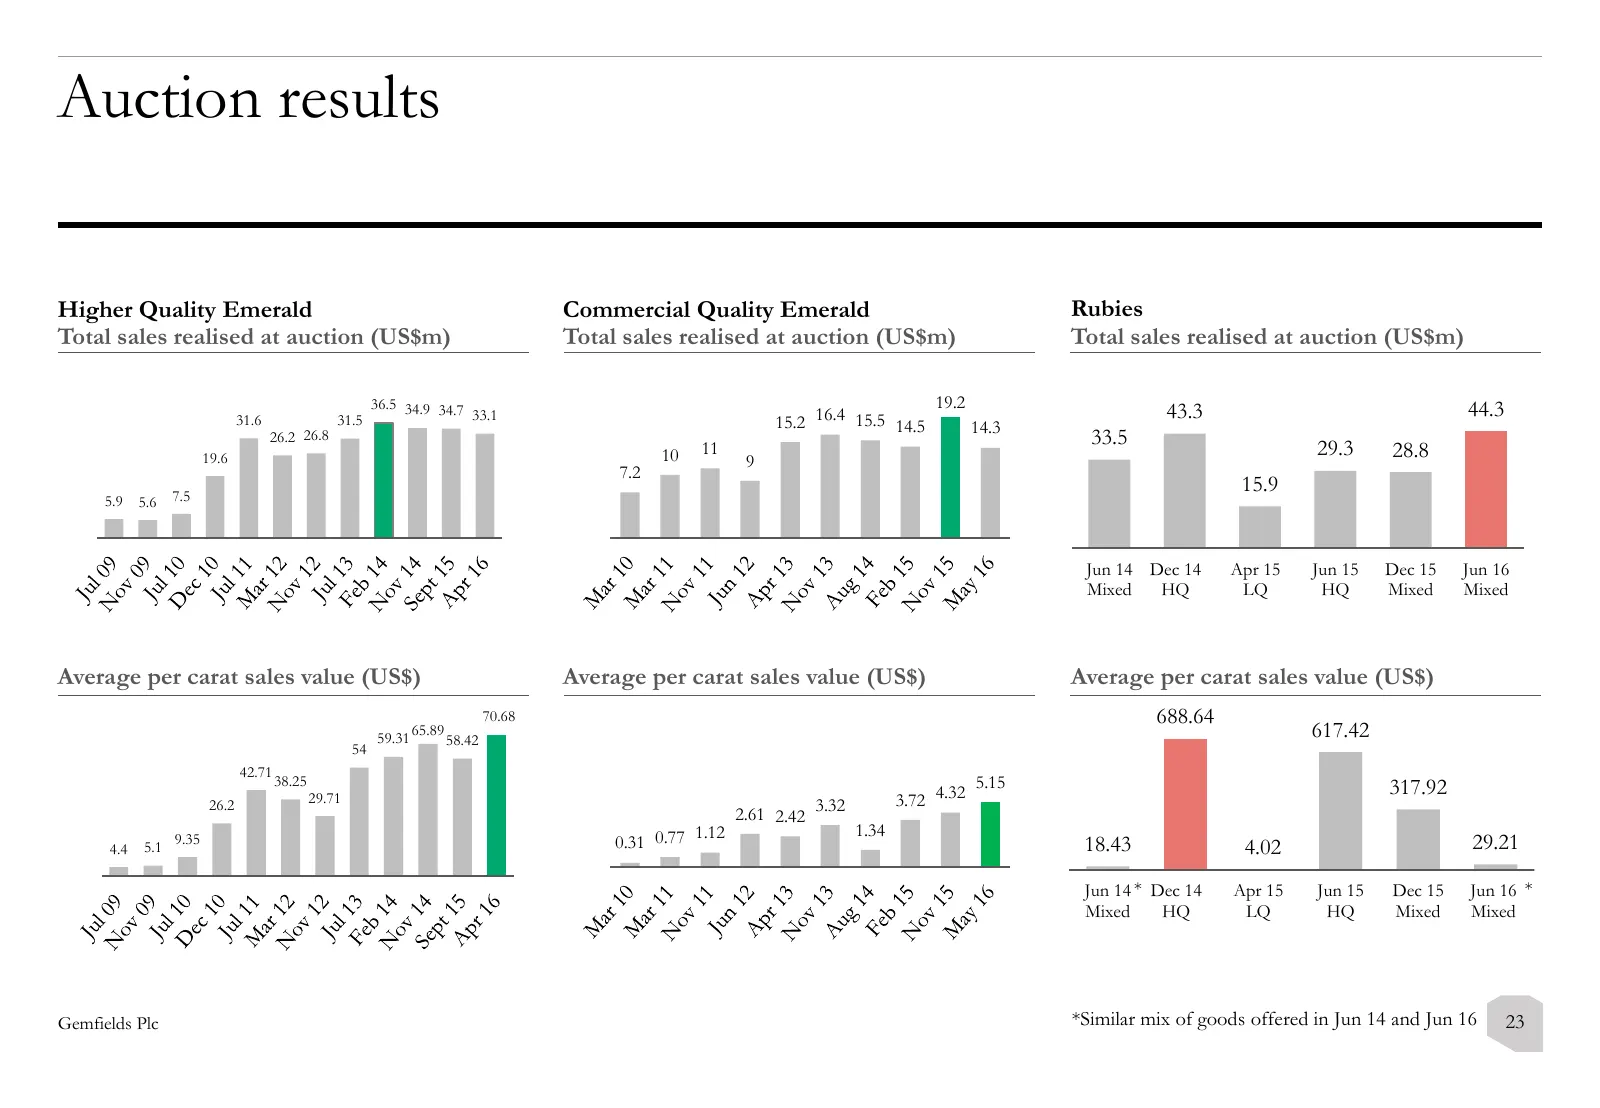
Auction results Higher Quality Emerald Commercial Quality Emerald Rubies Total sales realised at auction (US$m) Total sales realised at auction (US$m) Total sales realised at auction (US$m) 36.5 34.9 34.7 19.2 44.3 31.6 31.5 33.1 15.2 16.4 15.5 14.5 43.3 14.3 26.2 26.8 33.5 29.3 19.6 10 11 9 28.8 7.
Slide 24: Market overview
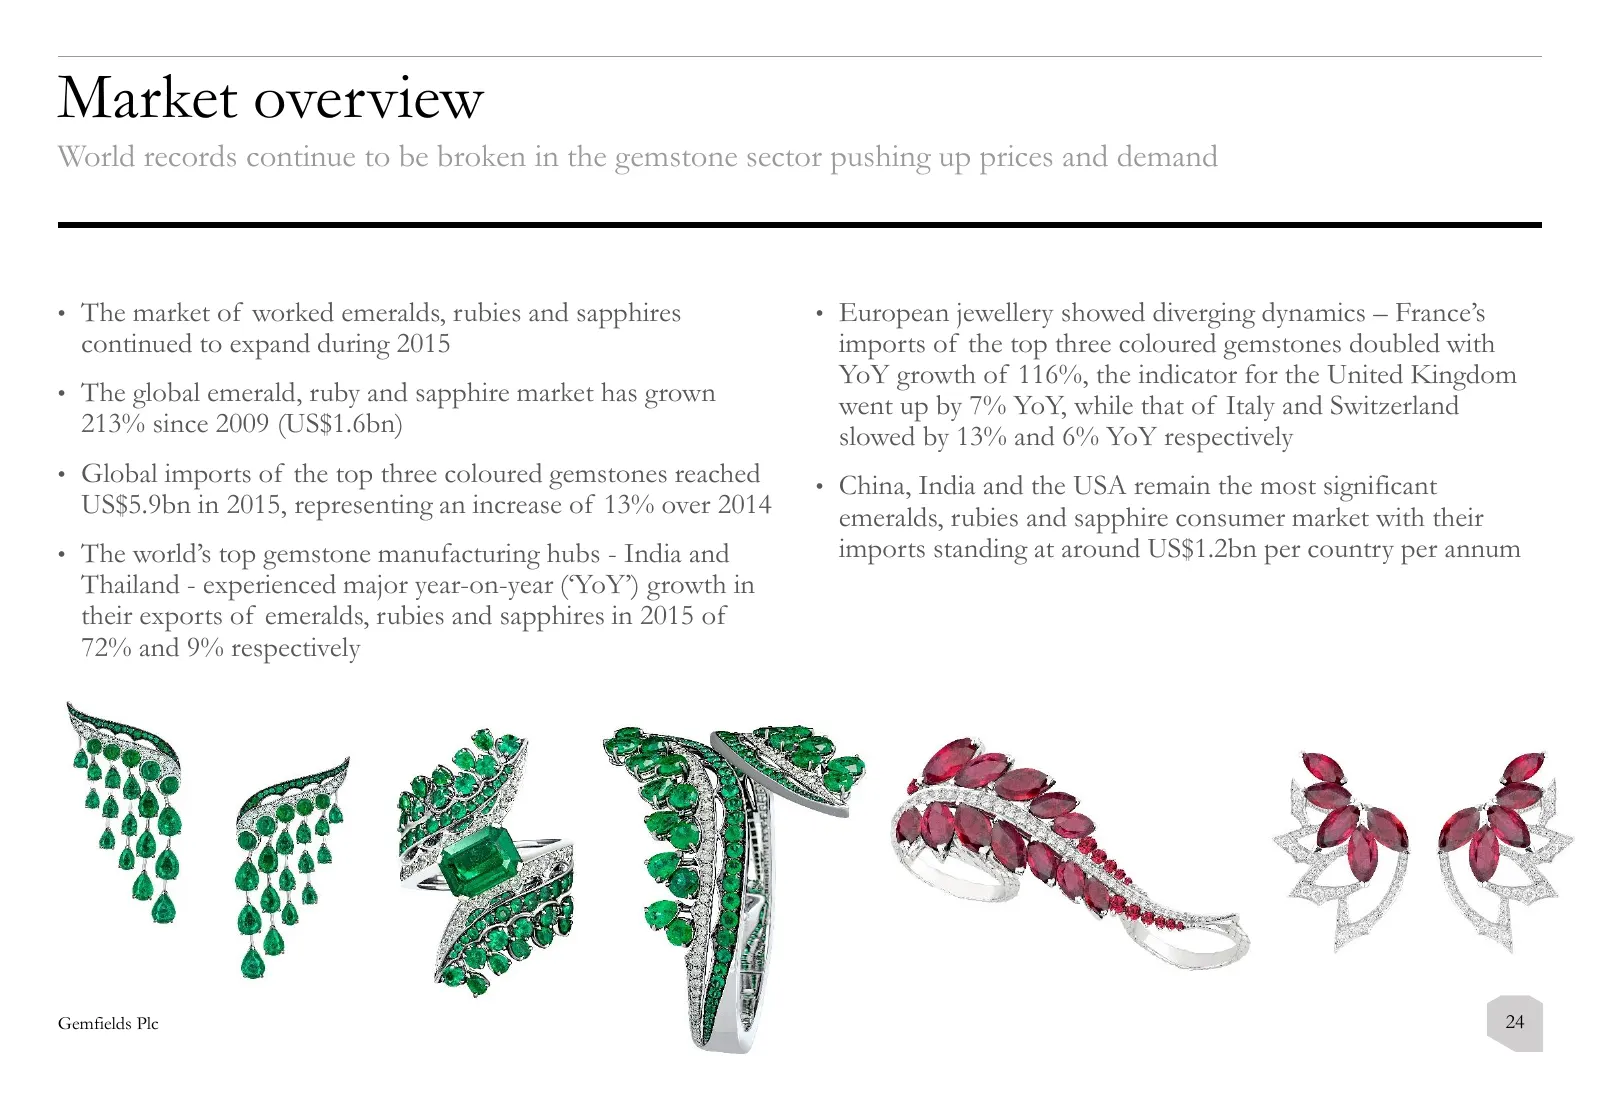
Market overview World records continue to be broken in the gemstone sector pushing up prices and demand • The market of worked emeralds, rubies and sapphires • European jewellery showed diverging dynamics – France’s continued to expand during 2015 imports of the top three coloured gemstones doubled
Slide 25: Chopard – Case Study, May 2016
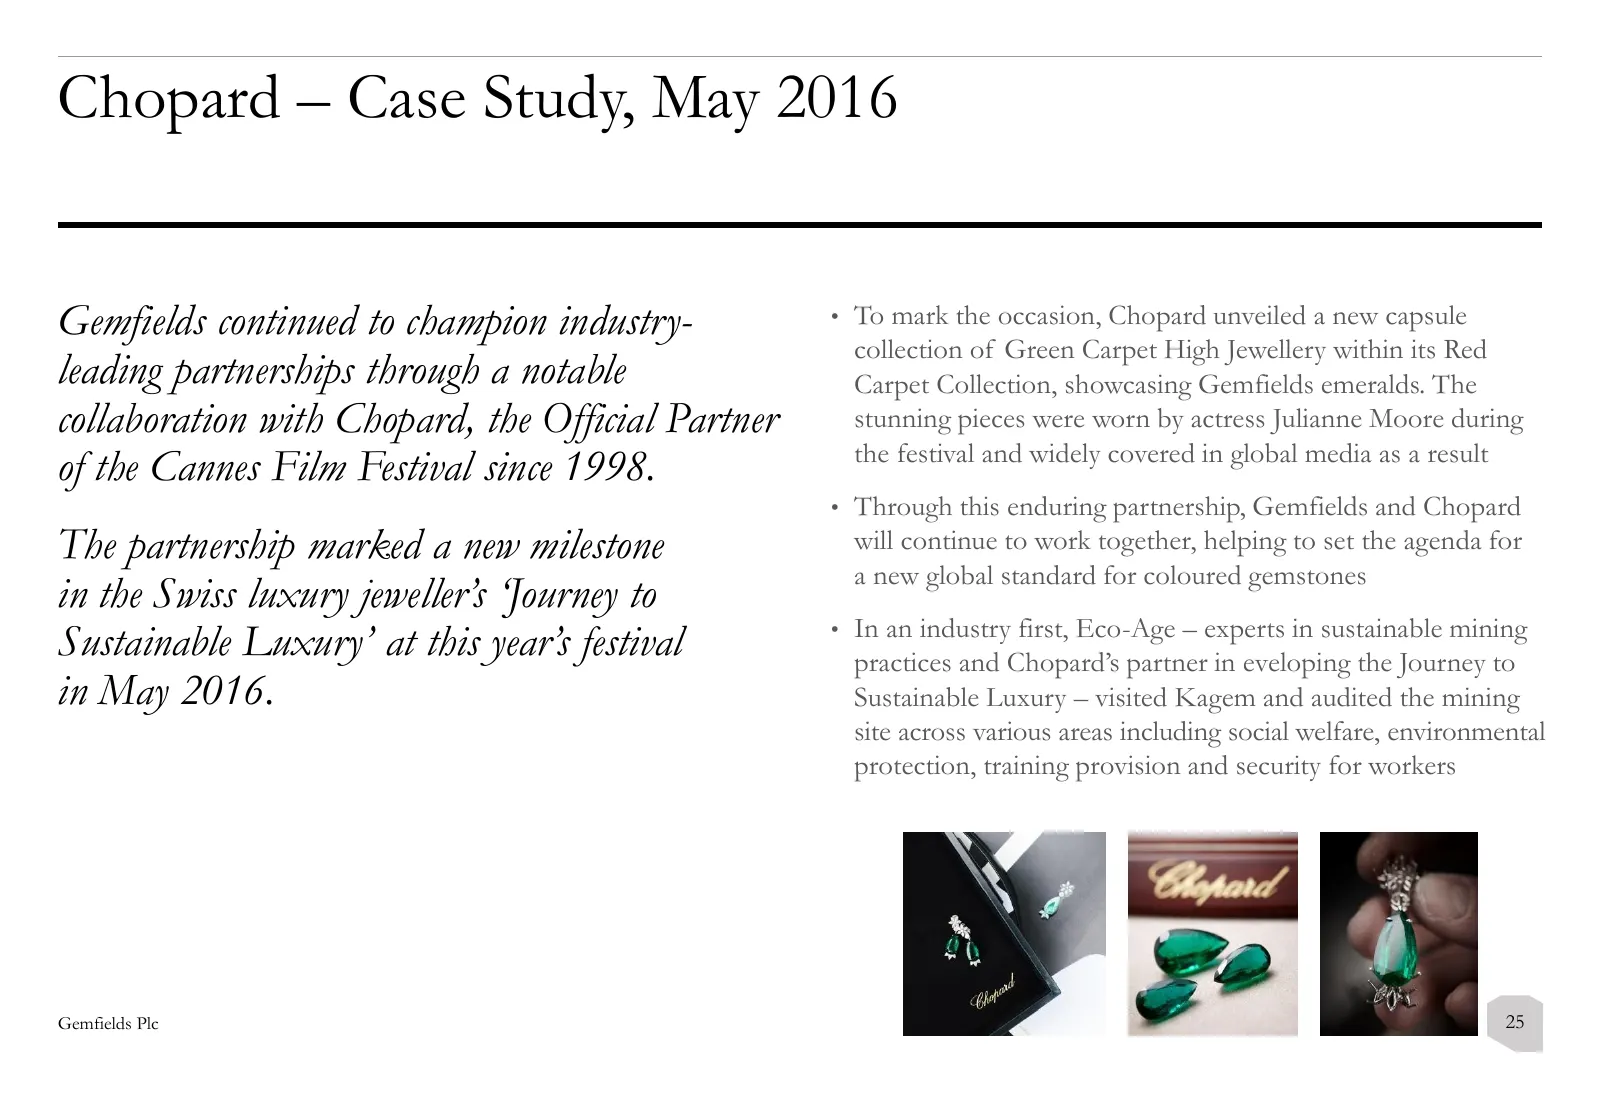
Chopard – Case Study, May 2016 Gemfields continued to champion industry- • To mark the occasion, Chopard unveiled a new capsule collection of Green Carpet High Jewellery within its Red leading partnerships through a notable Carpet Collection, showcasing Gemfields emeralds. The collaboration with Cho
Slide 26: Sustainability
Sustainability Gemfields Plc 26
Slide 27: Corporate social responsibility
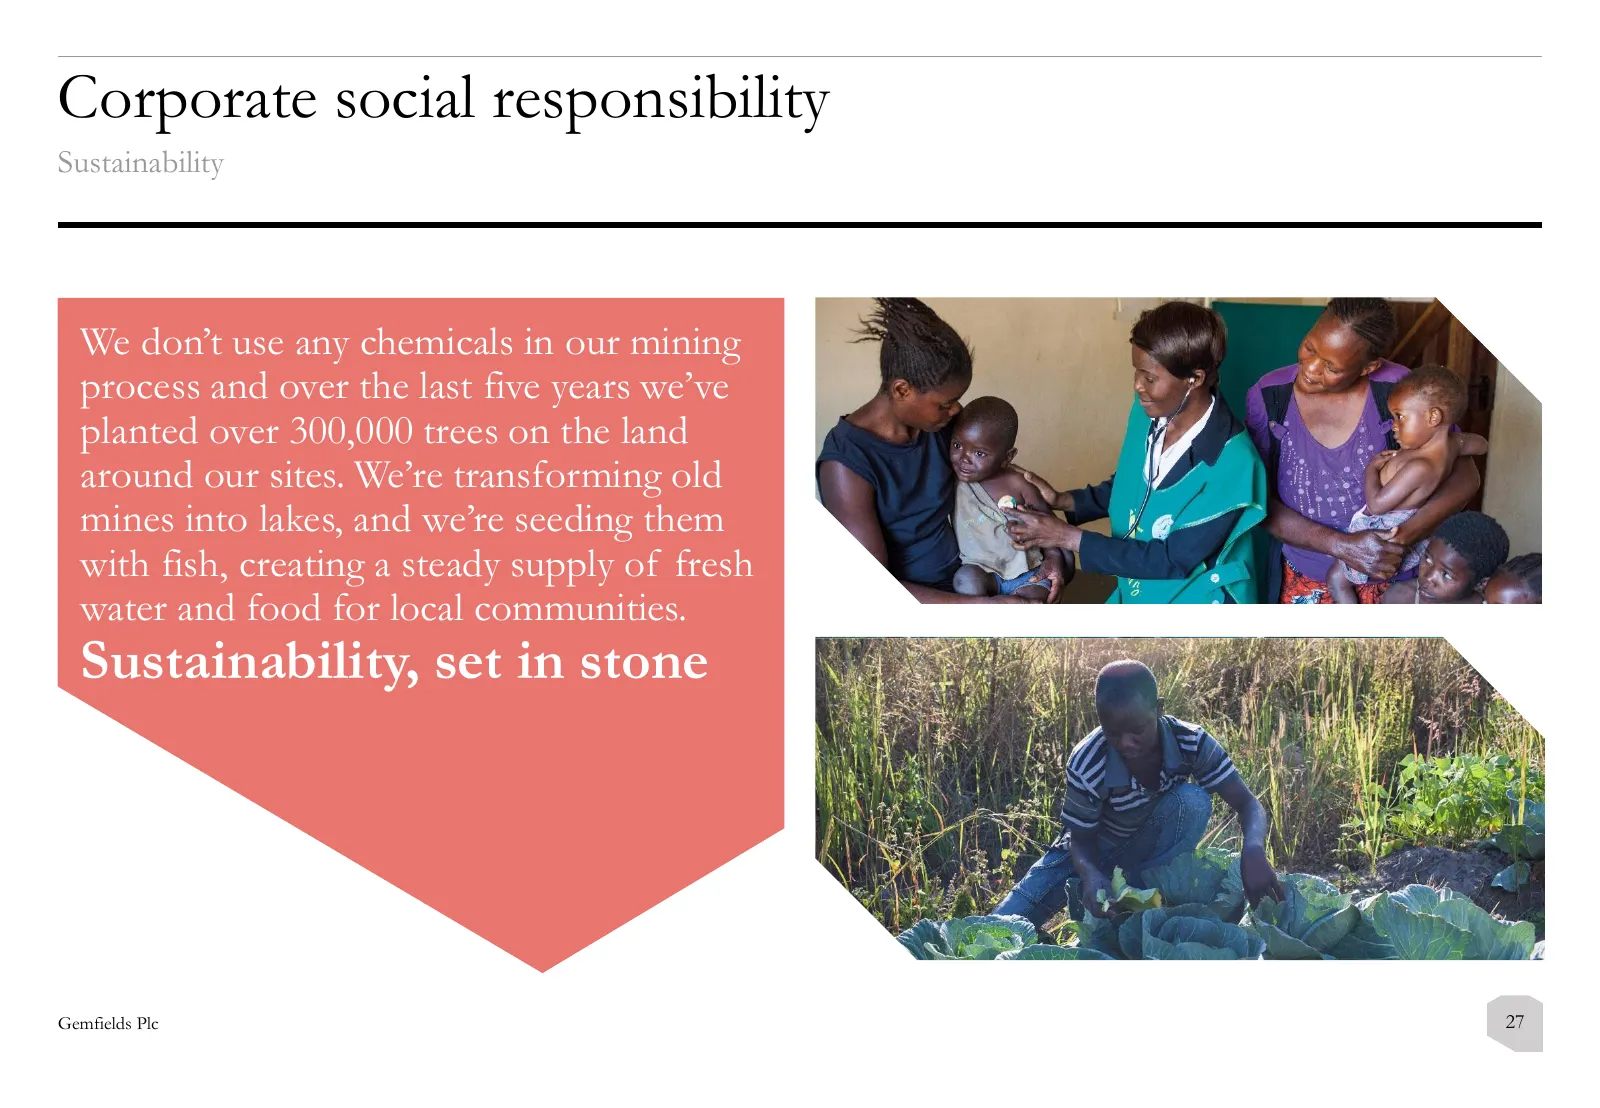
Corporate social responsibility Sustainability We don’t use any chemicals in our mining process and over the last five years we’ve planted over 300,000 trees on the land around our sites. We’re transforming old mines into lakes, and we’re seeding them with fish, creating a steady supply of fresh wat
Slide 28: Sustainability - five key pillars
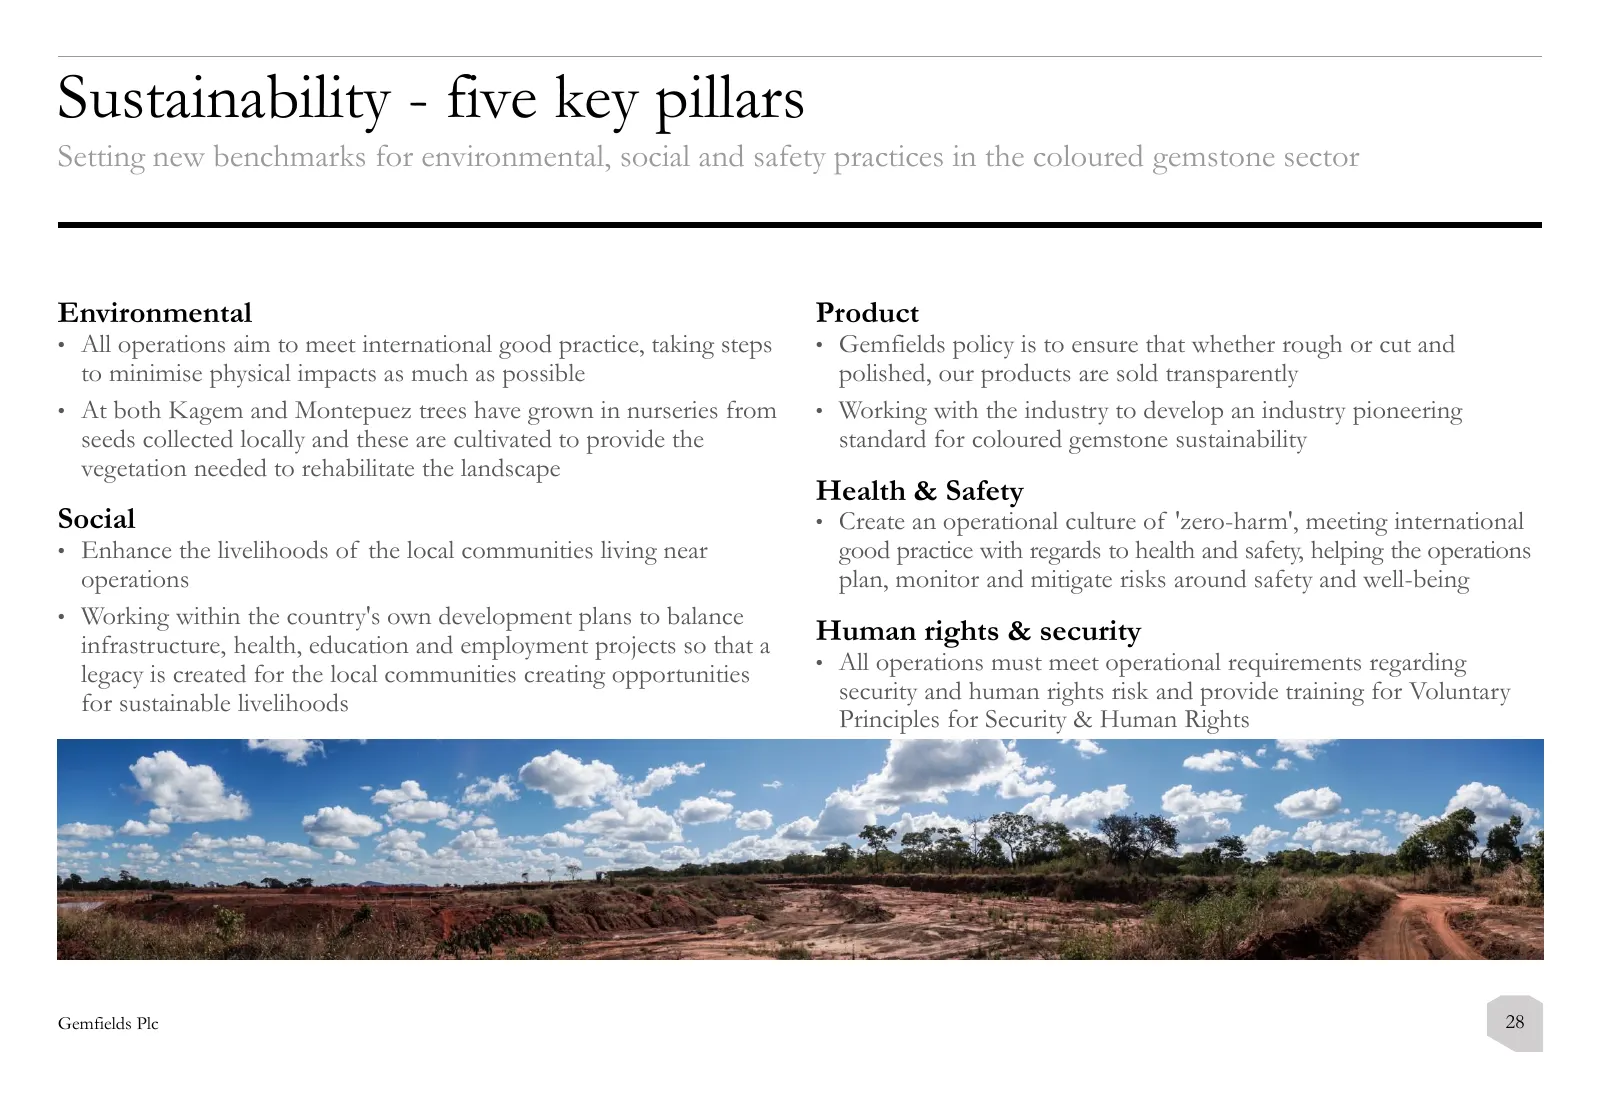
Sustainability - five key pillars Setting new benchmarks for environmental, social and safety practices in the coloured gemstone sector Environmental Product • All operations aim to meet international good practice, taking steps • Gemfields policy is to ensure that whether rough or cut and to minimi
Slide 29: Appendix
Appendix Gemfields Plc 29
Slide 30: Company overview
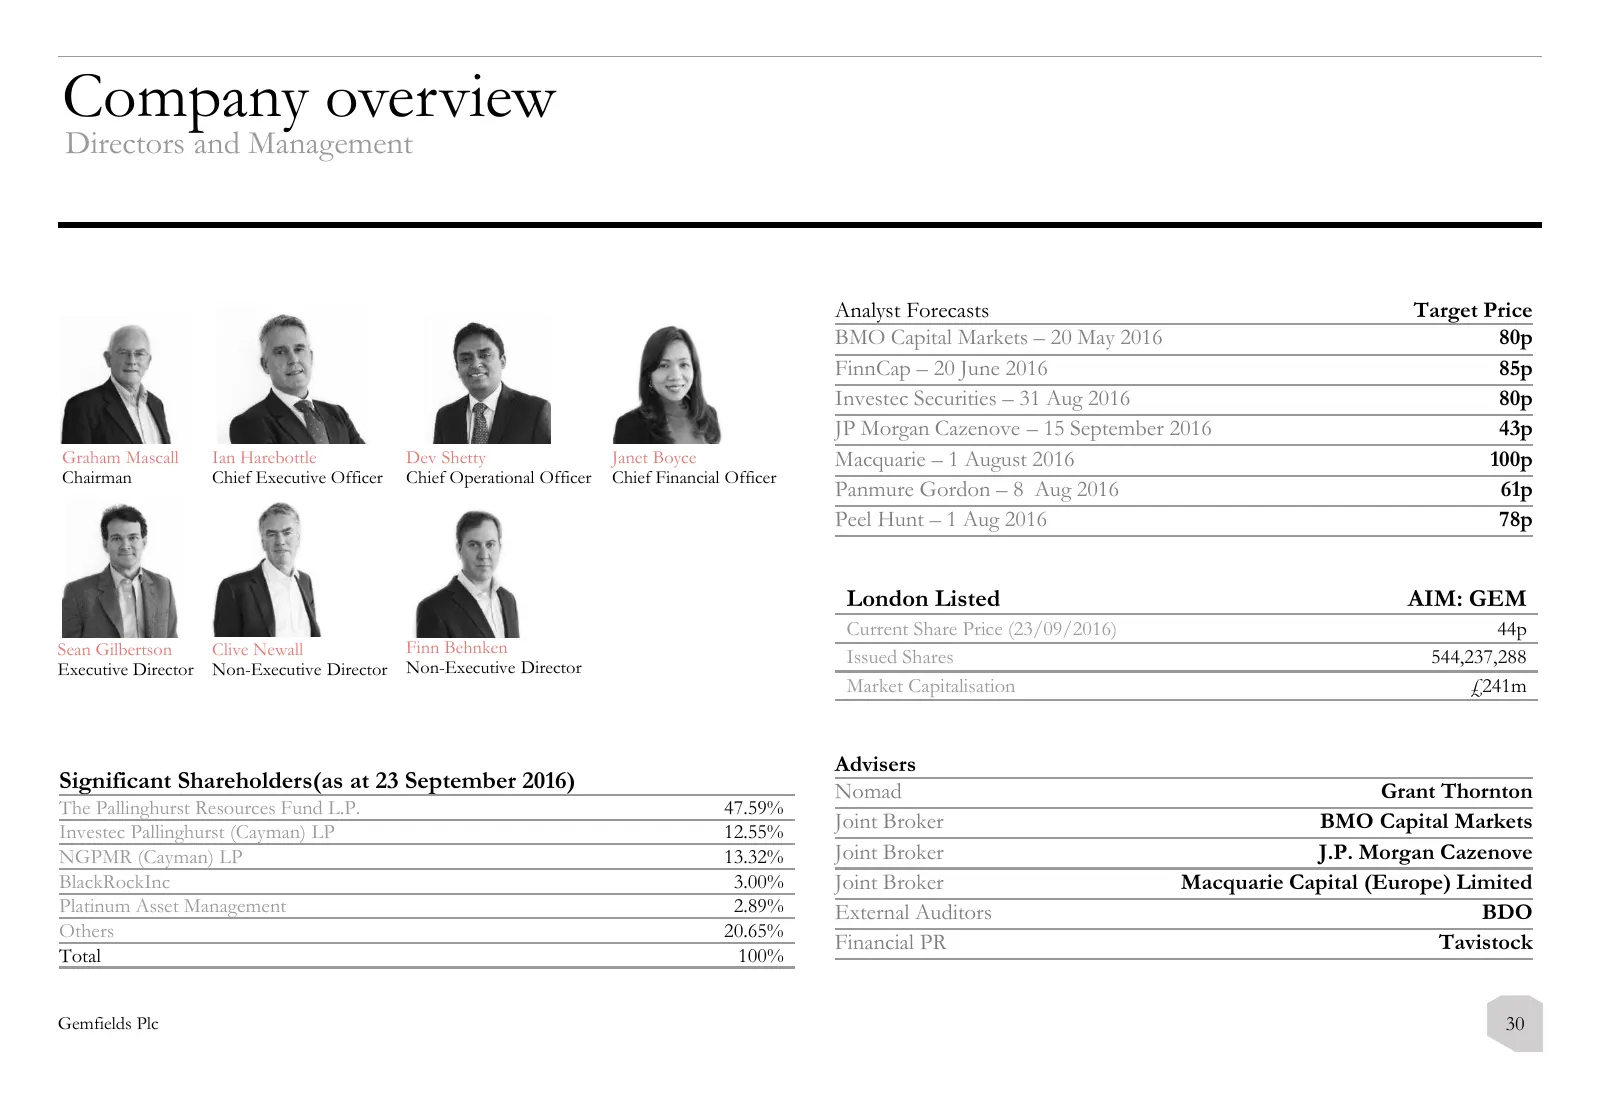
Company overview Directors and Management Analyst Forecasts Target Price BMO Capital Markets – 20 May 2016 80p FinnCap – 20 June 2016 85p Investec Securities – 31 Aug 2016 80p JP Morgan Cazenove – 15 September 2016 43p Graham Mascall Ian Harebottle Dev Shetty Janet Boyce Macquarie – 1 August 2016 10
Slide 31: Gemstone Price Index
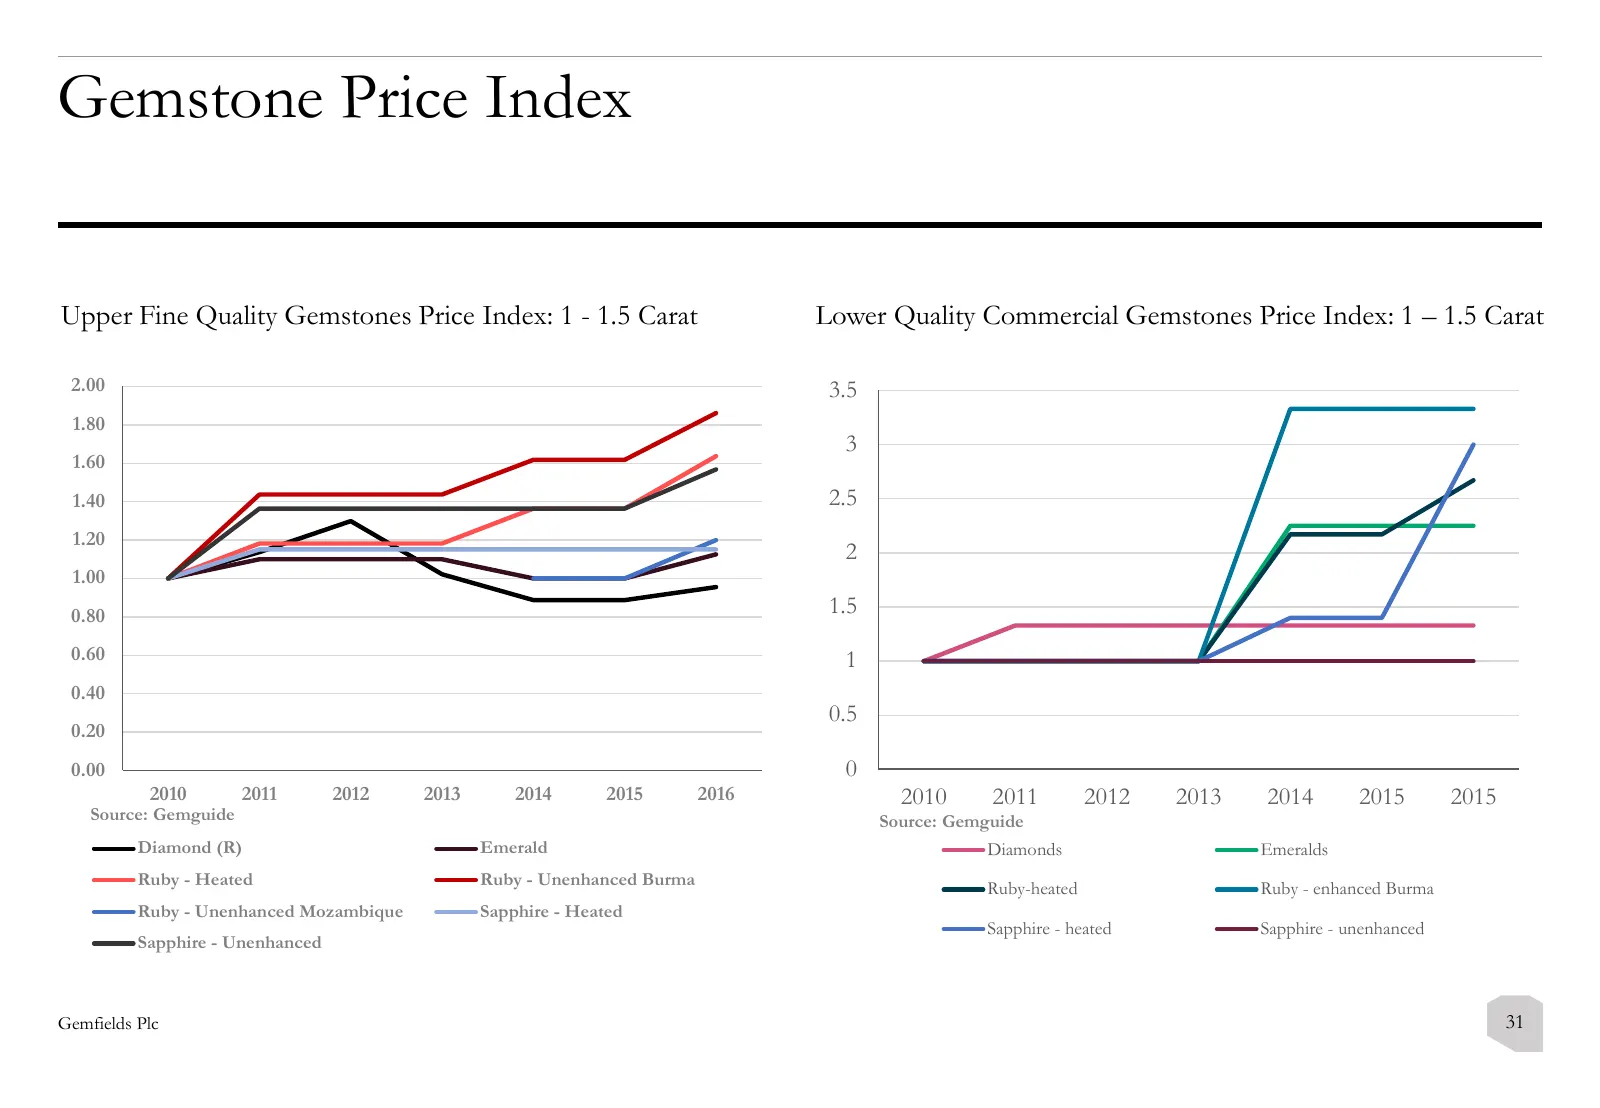
Gemstone Price Index Upper Fine Quality Gemstones Price Index: 1 - 1.5 Carat Lower Quality Commercial Gemstones Price Index: 1 – 1.5 Carat 2.00 3.5 1.80 3 1.60 1.40 2.5 1.20 2 1.00 0.80 1.5 0.60 1 0.40 0.5 0.20 0.00 0 2010 2011 2012 2013 2014 2015 2016 2010 2011 2012 2013 2014 2015 2015 Source: Gemg
Slide 32: Rough emerald and beryl sales (Commercial quality)
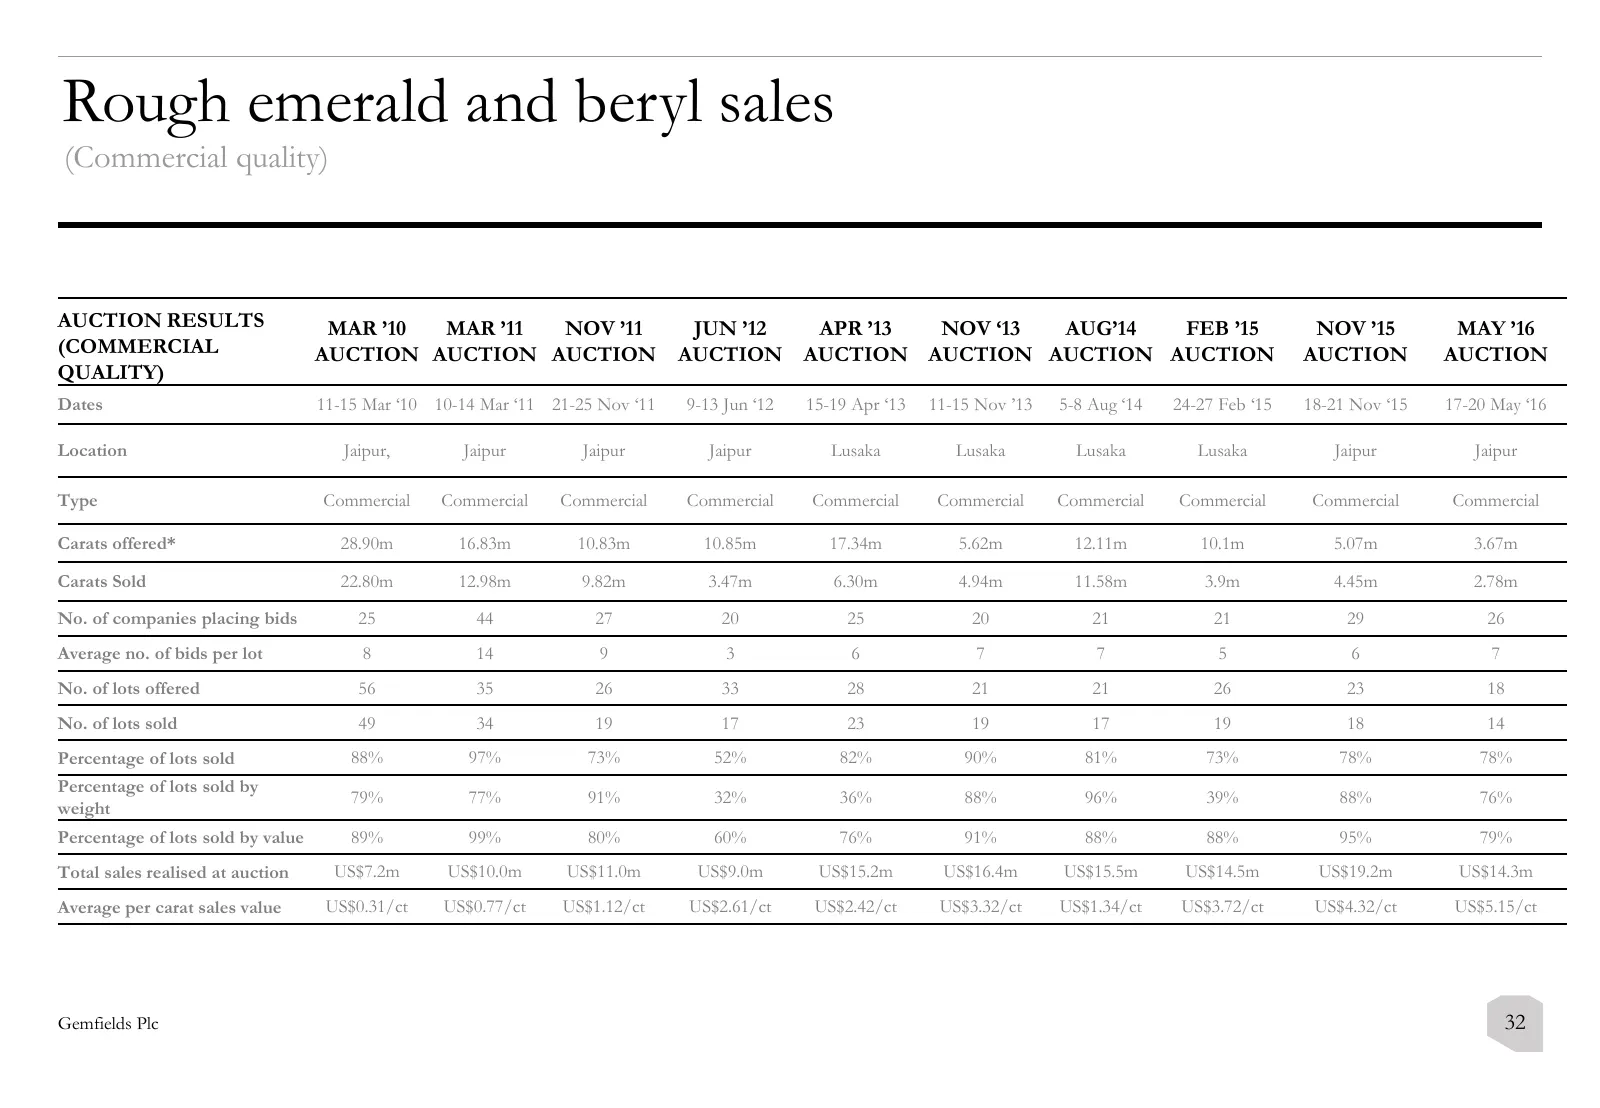
Rough emerald and beryl sales (Commercial quality) AUCTION RESULTS MAR ’10 MAR ’11 NOV ’11 JUN ’12 APR ’13 NOV ‘13 AUG’14 FEB ’15 NOV ’15 MAY ’16 (COMMERCIAL AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION QUALITY) Dates 11-15 Mar ‘10 10-14 Mar ‘11 21-25 Nov ‘11 9-13
Slide 33: Rough emerald and beryl sales (Higher quality)
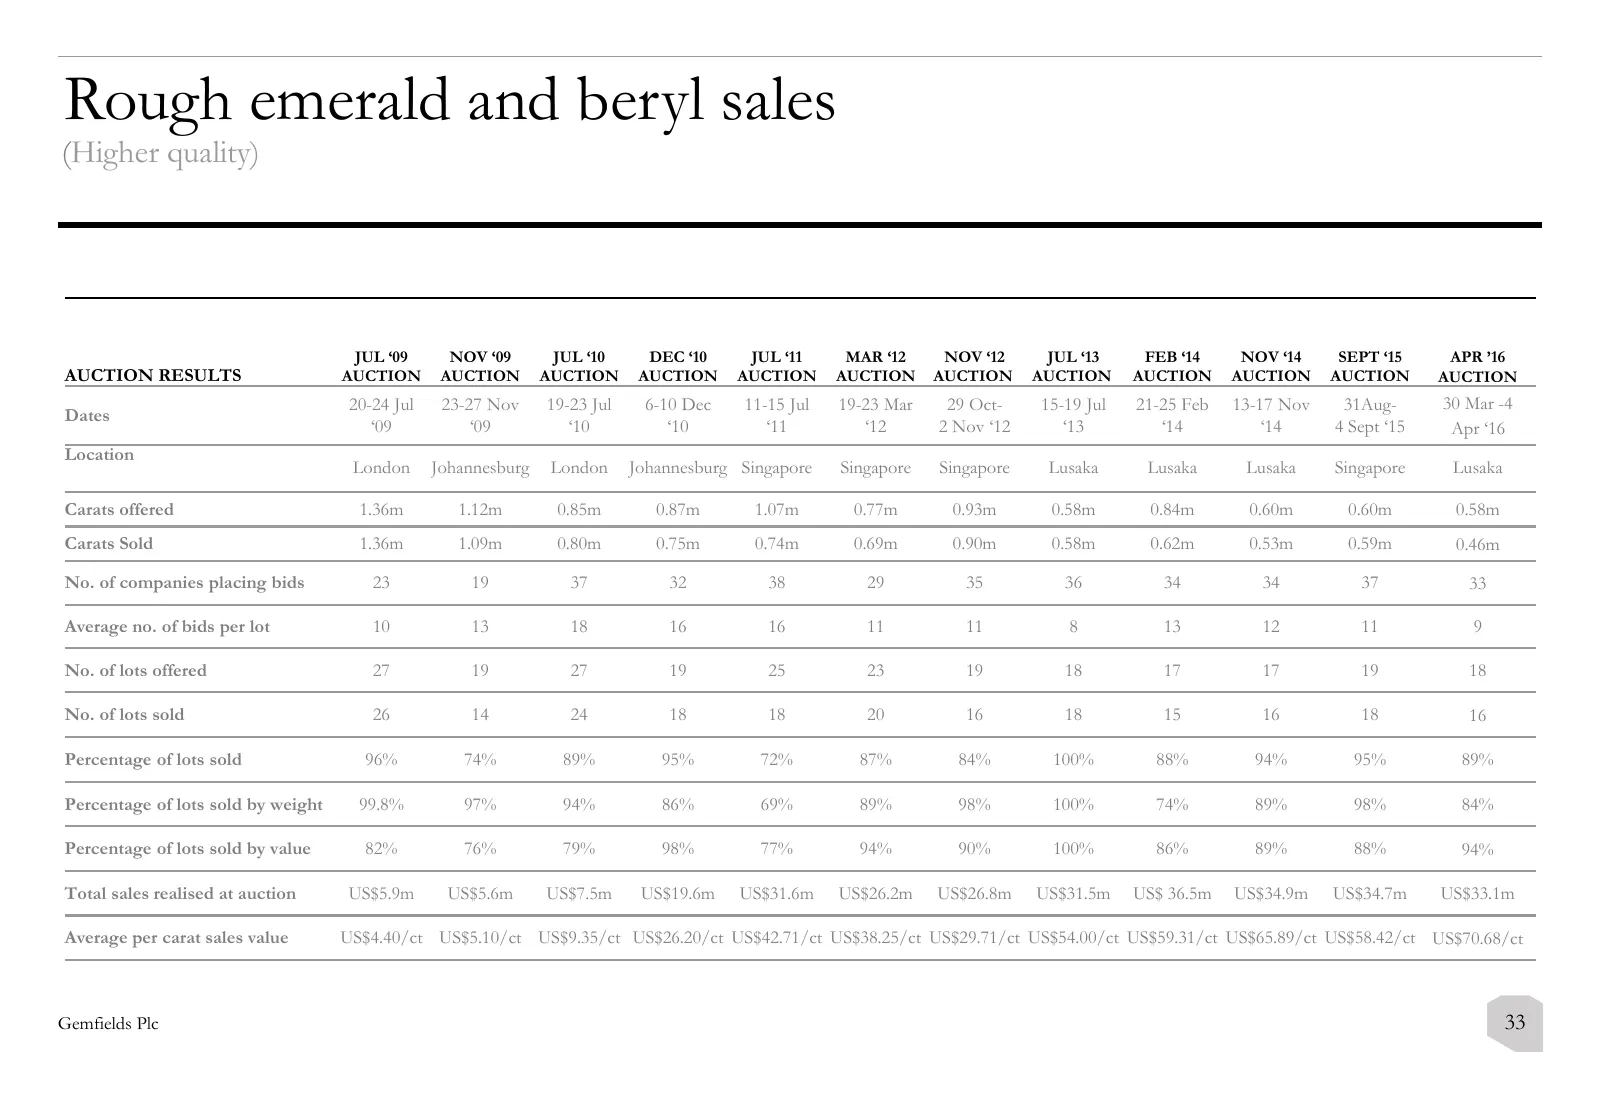
Rough emerald and beryl sales (Higher quality) JUL ‘09 NOV ‘09 JUL ‘10 DEC ‘10 JUL ‘11 MAR ‘12 NOV ‘12 JUL ‘13 FEB ‘14 NOV ‘14 SEPT ‘15 APR ’16 AUCTION RESULTS AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION 20-24 Jul 23-27 Nov 19-23 Jul 6-10 Dec 11-15
Slide 34: Rough ruby and corundum auctions
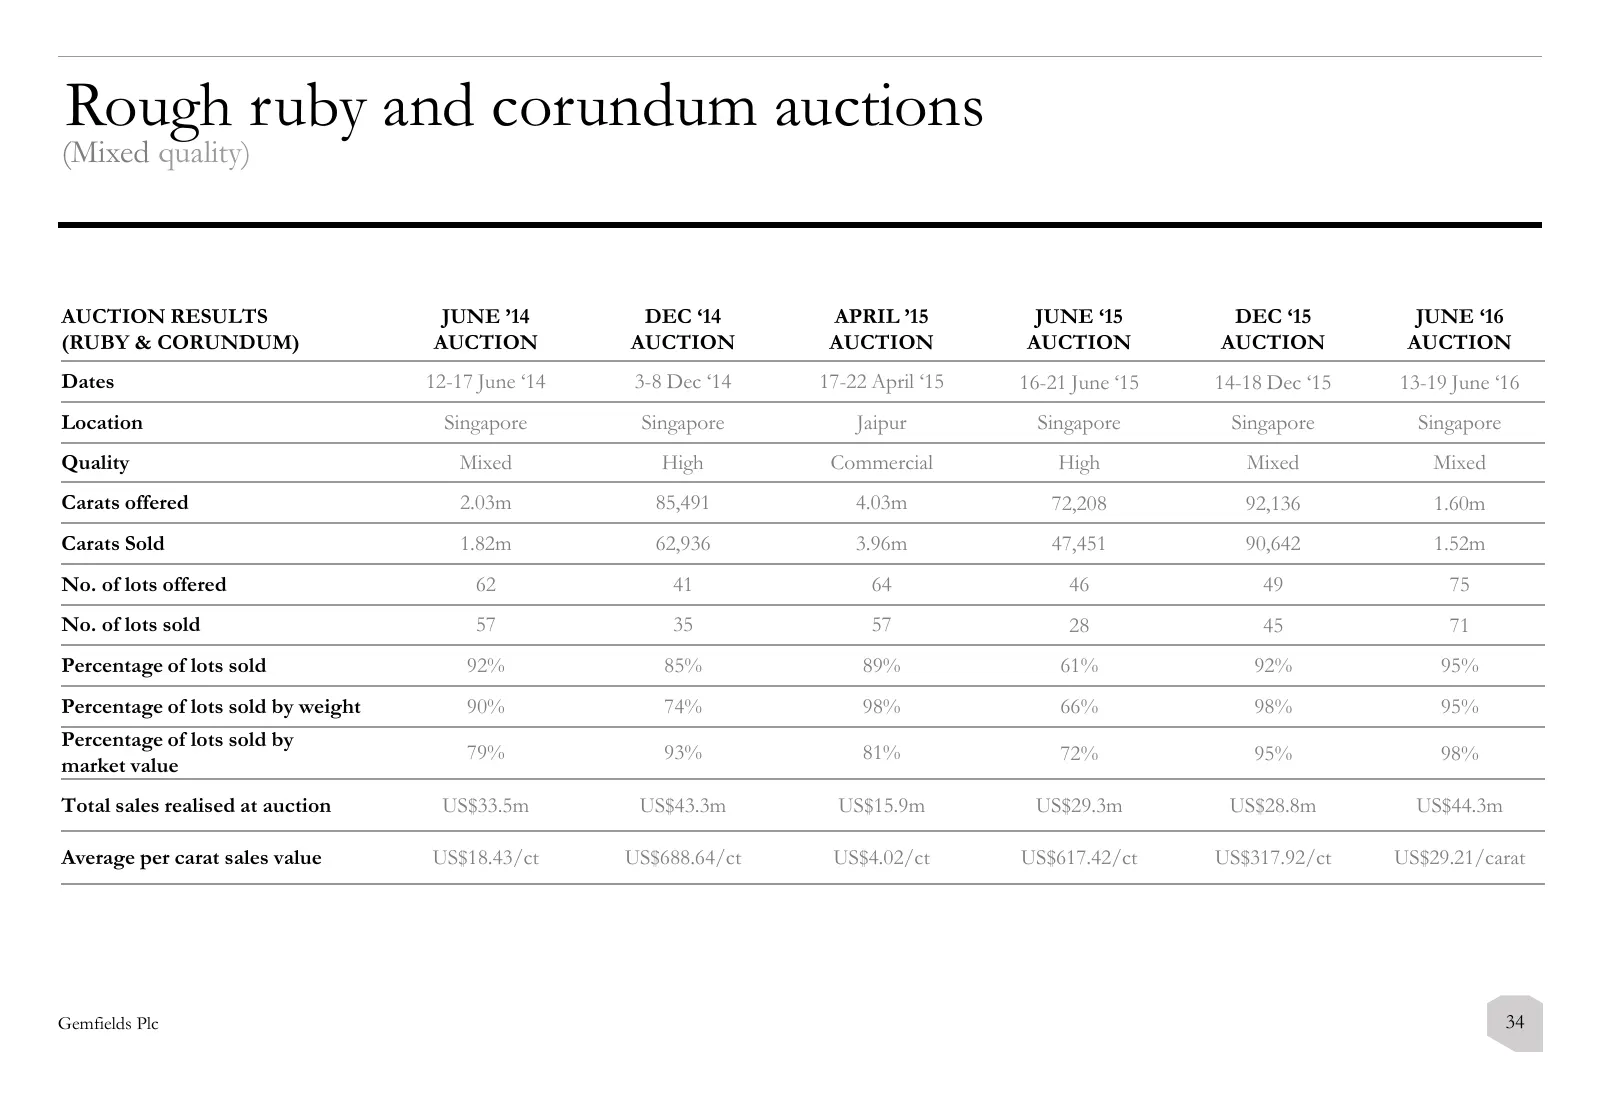
Rough ruby and corundum auctions (Mixed quality) AUCTION RESULTS JUNE ’14 DEC ‘14 APRIL ’15 JUNE ‘15 DEC ‘15 JUNE ‘16 (RUBY & CORUNDUM) AUCTION AUCTION AUCTION AUCTION AUCTION AUCTION Dates 12-17 June ‘14 3-8 Dec ‘14 17-22 April ‘15 16-21 June ‘15 14-18 Dec ‘15 13-19 June ‘16 Location Singapore Sing
Slide 35: Mining and production costs
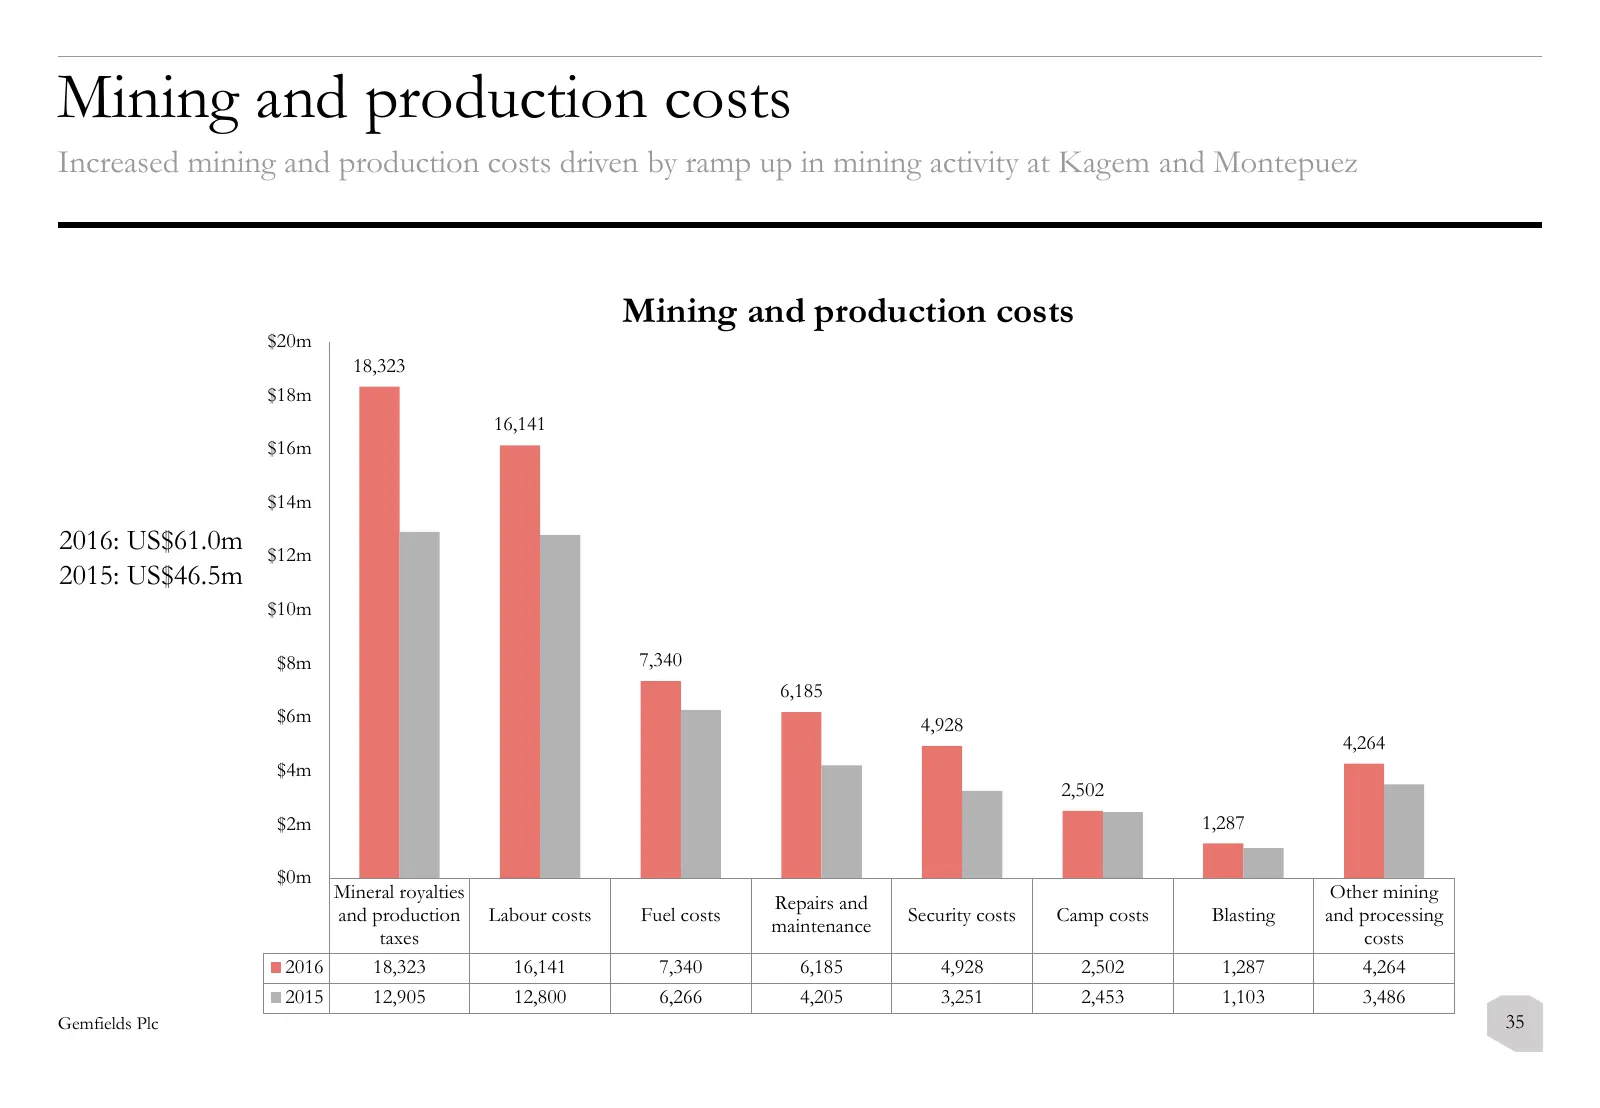
Mining and production costs Increased mining and production costs driven by ramp up in mining activity at Kagem and Montepuez Mining and production costs $20m 18,323 $18m 16,141 $16m $14m 2016: US$61.0m $12m 2015: US$46.5m $10m $8m 7,340 6,185 $6m 4,928 4,264 $4m 2,502 $2m 1,287 $0m Mineral royaltie
Slide 36: Selling, general and administrative expenses
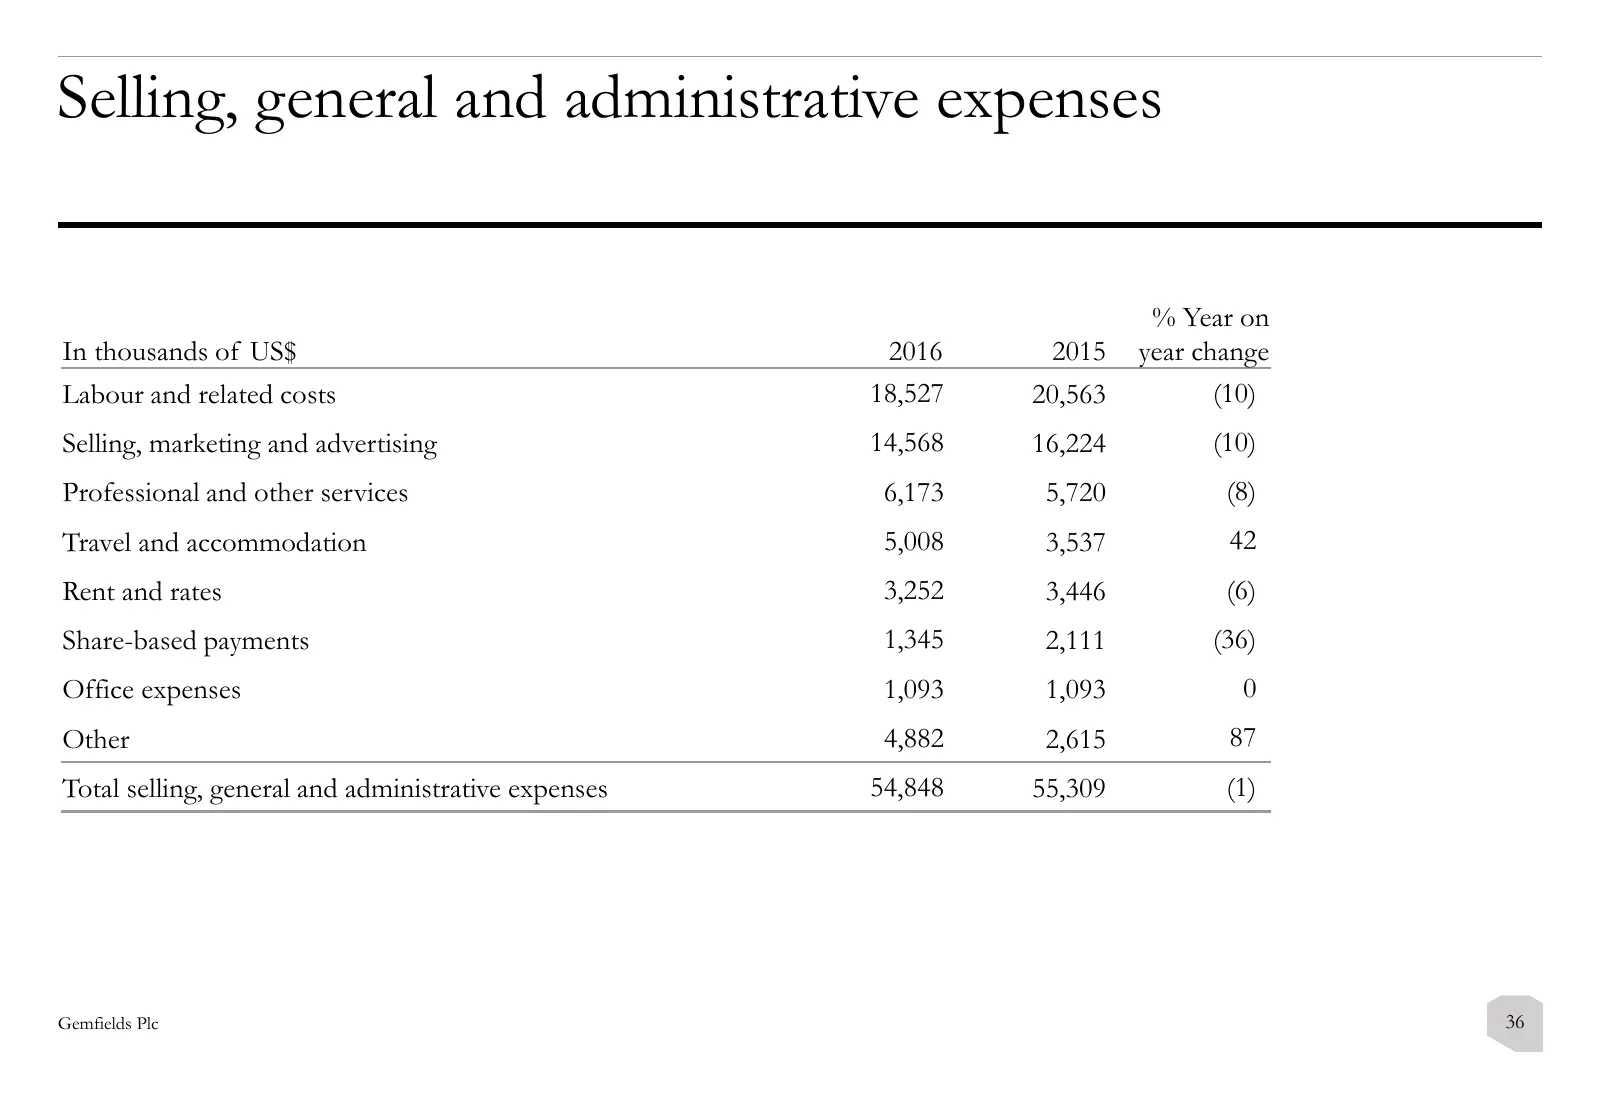
Selling, general and administrative expenses % Year on In thousands of US$ 2016 2015 year change Labour and related costs 18,527 20,563 (10) Selling, marketing and advertising 14,568 16,224 (10) Professional and other services 6,173 5,720 (8) Travel and accommodation 5,008 3,537 42 Rent and rates 3,
Slide 37: Contact us
Contact us Gemfields Plc 23 King Street London SW1Y 6QY United Kingdom Tel: +44 (0)20 7518 3400 Fax: +44 (0) 20 7197 8193 Gemfields Plc
Source: Internet Archive copy of gemfieldsgroup.com
More decks from Gemfields Group Limited
 FY2025 Earnings Presentation26 slides · Mar 26, 2026
 H1 2025 Earnings Presentation74 slides · Sep 26, 2025
 FY2024 Earnings Presentation30 slides · Apr 11, 2025
 Investor Presentation (November 2024)39 slides · November 2024
 FY2023 Earnings Presentation37 slides · Mar 25, 2024
 FY2022 Earnings Presentation71 slides · Mar 24, 2023