Atlas Pipeline Partners L.P — SPAC Merger (November 2014)
22 slides from Atlas Pipeline Partners L.P's SPAC merger presentation, Nov 12, 2014
Slide 1: Rule 425 filing legend
Filed by Targa Resources Partners LP Pursuant to Rule 425 of the Securities Act of 1933 and deemed filed pursuant to Rule 14a-12 of the Securities Exchange Act of 1934 Subject Company: Atlas Pipeline Partners, L.P. Commission File No.: 001-14998 This filing relates to a proposed business combination
Slide 2: Targa Resources – Jefferies 2014 Global Energy Conference
Targa Resources Jefferies 2014 Global Energy Conference November 11, 2014
Slide 3: Forward Looking Statements
Forward Looking Statements Certain statements in this presentation are "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. All statements, other than statements of historical fac
Slide 4: Additional Information
Additional Information Additional Information and Where to Find It In connection with the proposed transaction, Targa Resources Corp. (“TRC”) will file with the U.S. Securities and Exchange Commission (the “SEC”) a registration statement on Form S-4 that will include a joint proxy statement of Atlas
Slide 5: Targa Resources' Two Public Companies
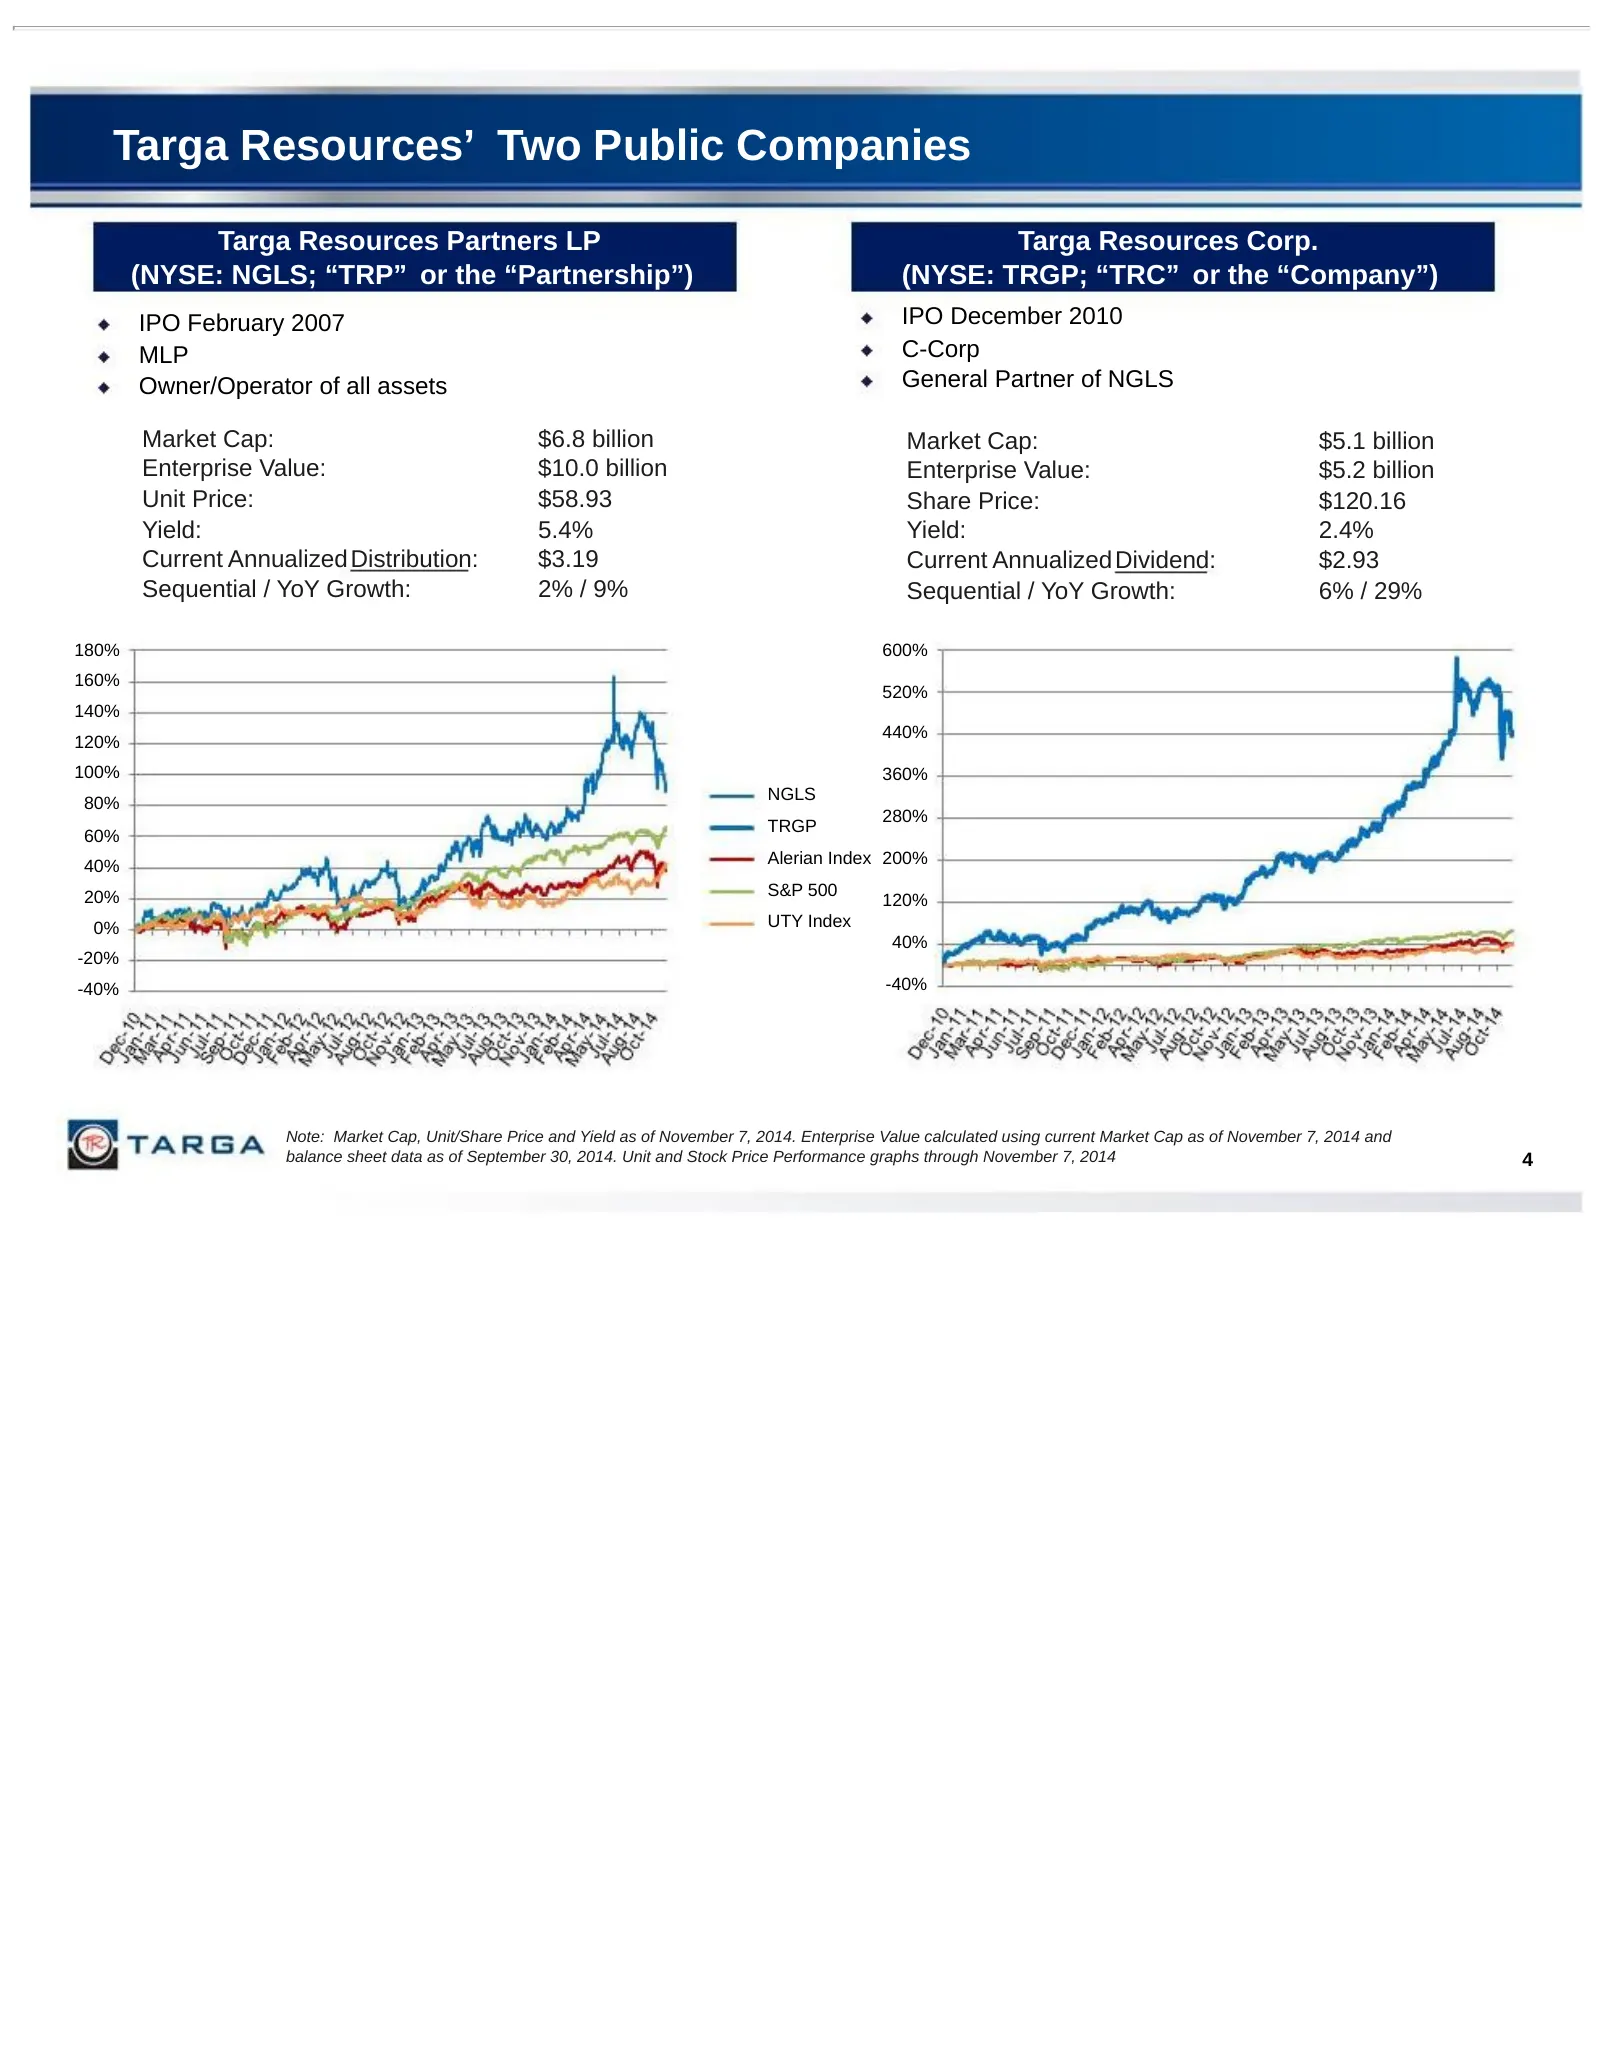
Targa Resources’ Two Public Companies Targa Resources Partners LP Targa Resources Corp. (NYSE: NGLS; “TRP” or the “Partnership”) (NYSE: TRGP; “TRC” or the “Company”) IPO February 2007 IPO December 2010 MLP C-Corp Owner/Operator of all assets General Partner of NGLS Market Cap: $6.8 billion Market Ca
Slide 6: TRP and TRC Performance
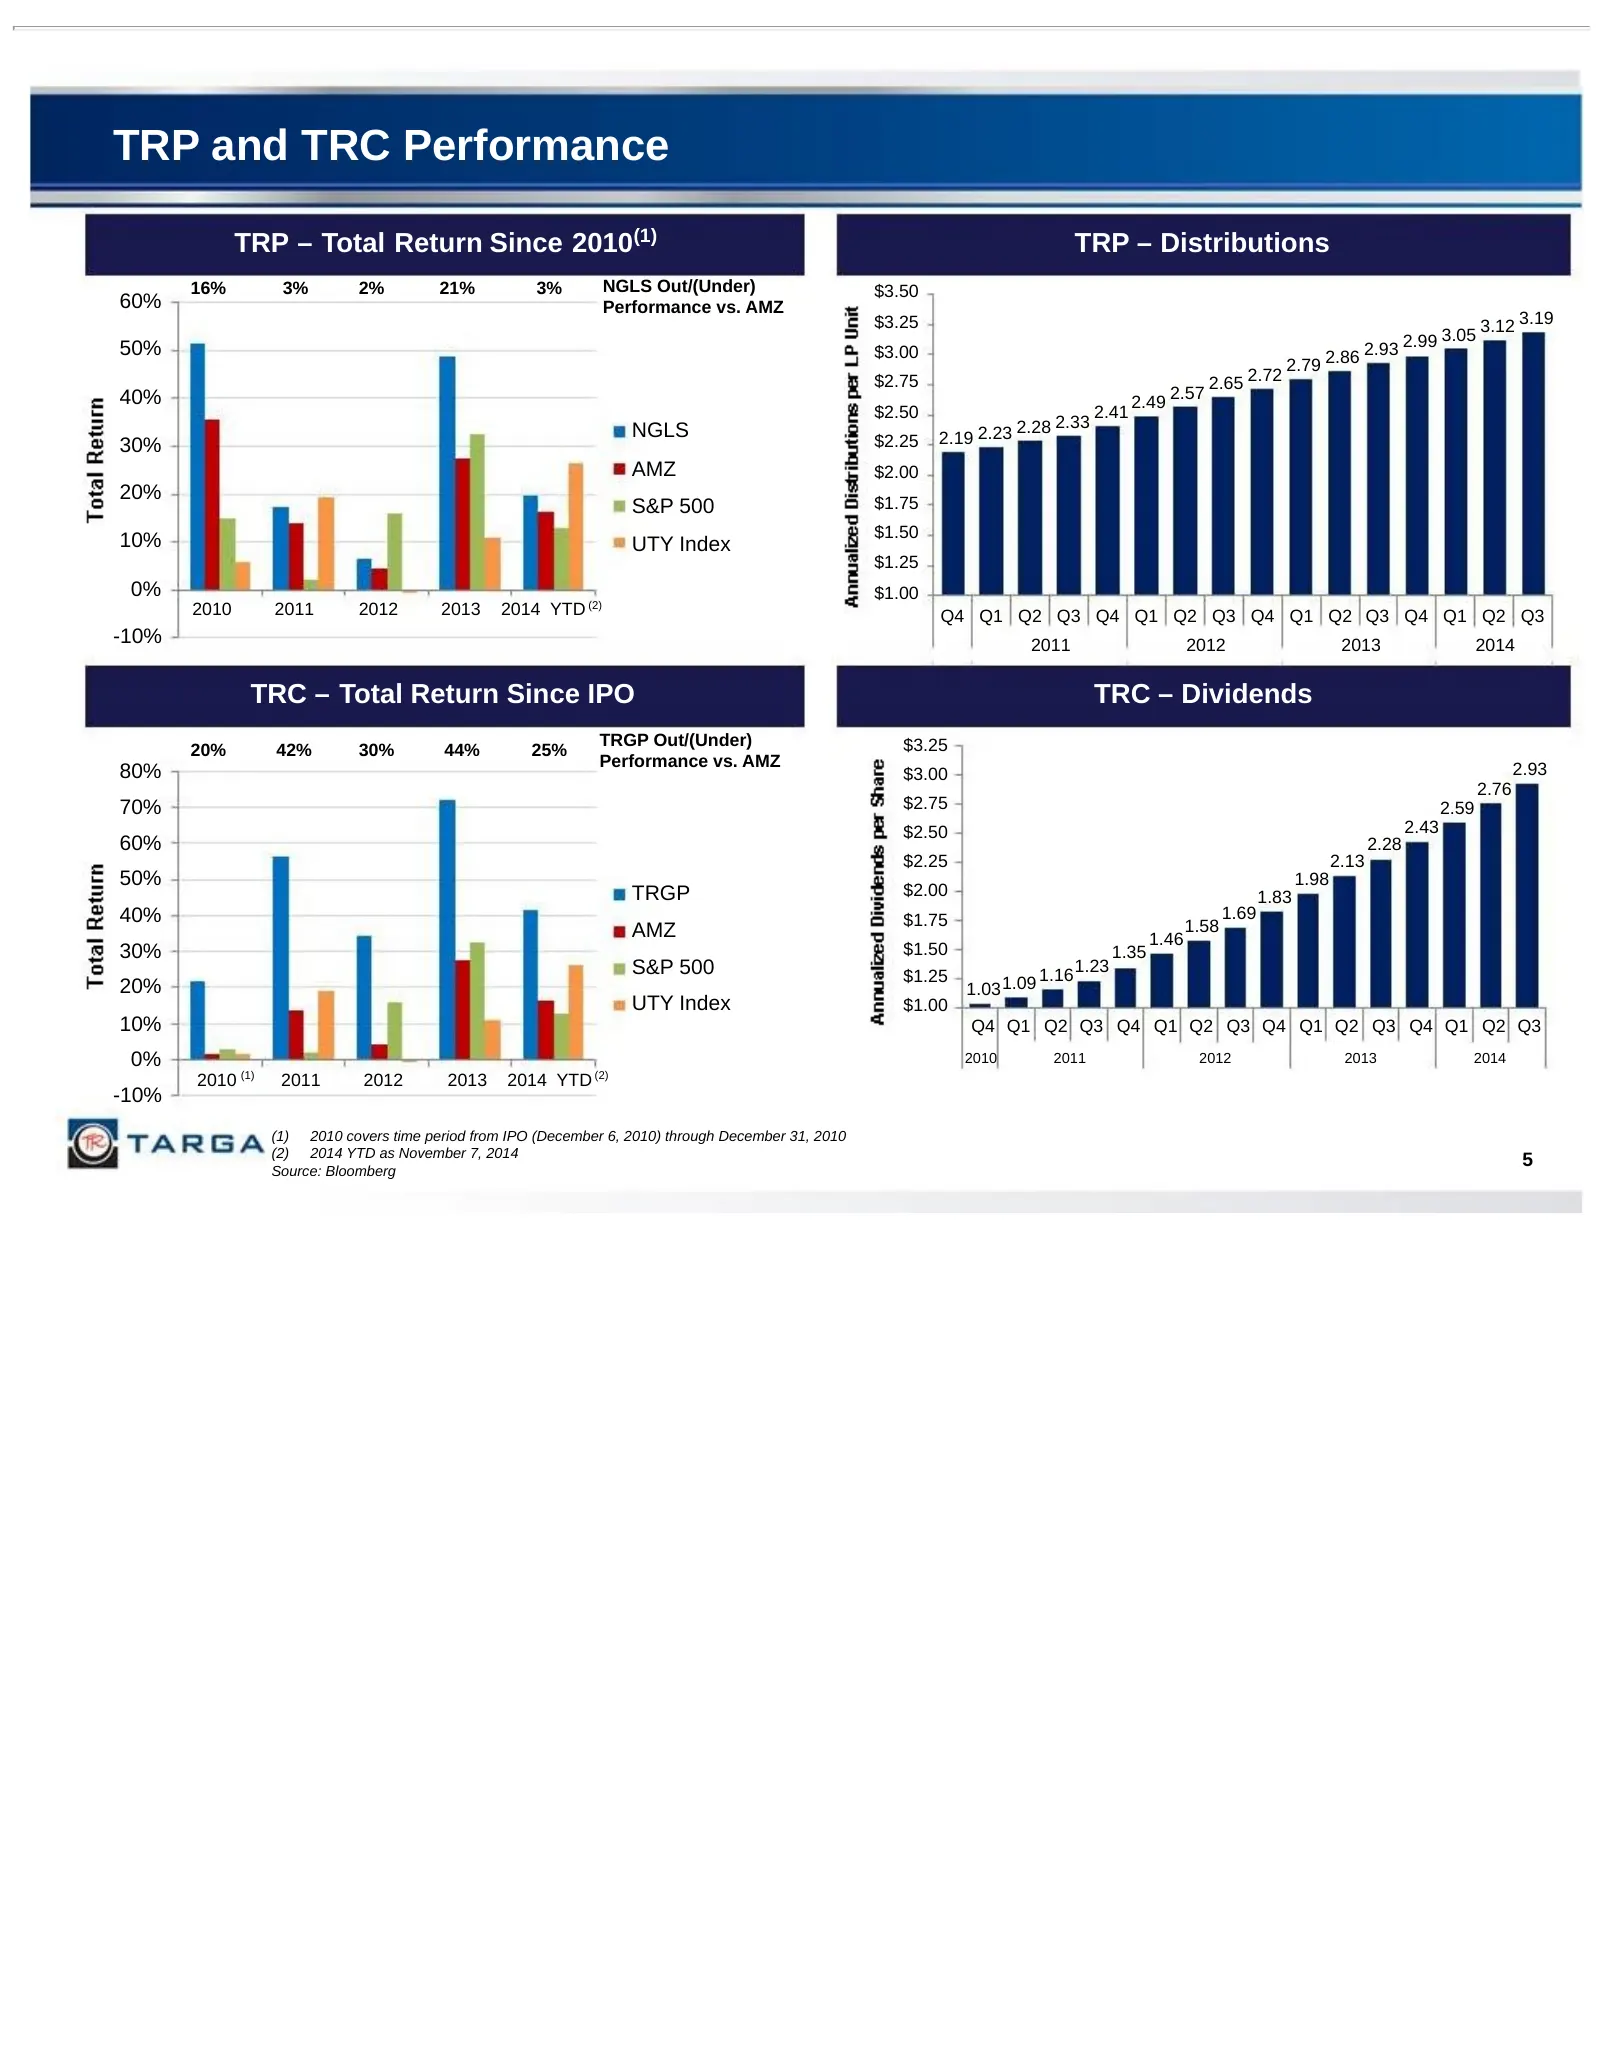
TRP and TRC Performance TRP – Total Return Since 2010(1) TRP – Distributions 16% 3% 2% 21% 3% NGLS Out/(Under) $3.50 60% Performance vs. AMZ $3.25 3.12 3.19 50% 2.93 2.99 3.05 $3.00 2.79 2.86 $2.75 2.65 2.72 40% 2.57 2.49 $2.50 2.41 NGLS 2.28 2.33 30% $2.25 2.19 2.23 AMZ $2.00 20% $1.75 S&P 500 $1.5
Slide 7: Targa's Diversified Midstream Platform
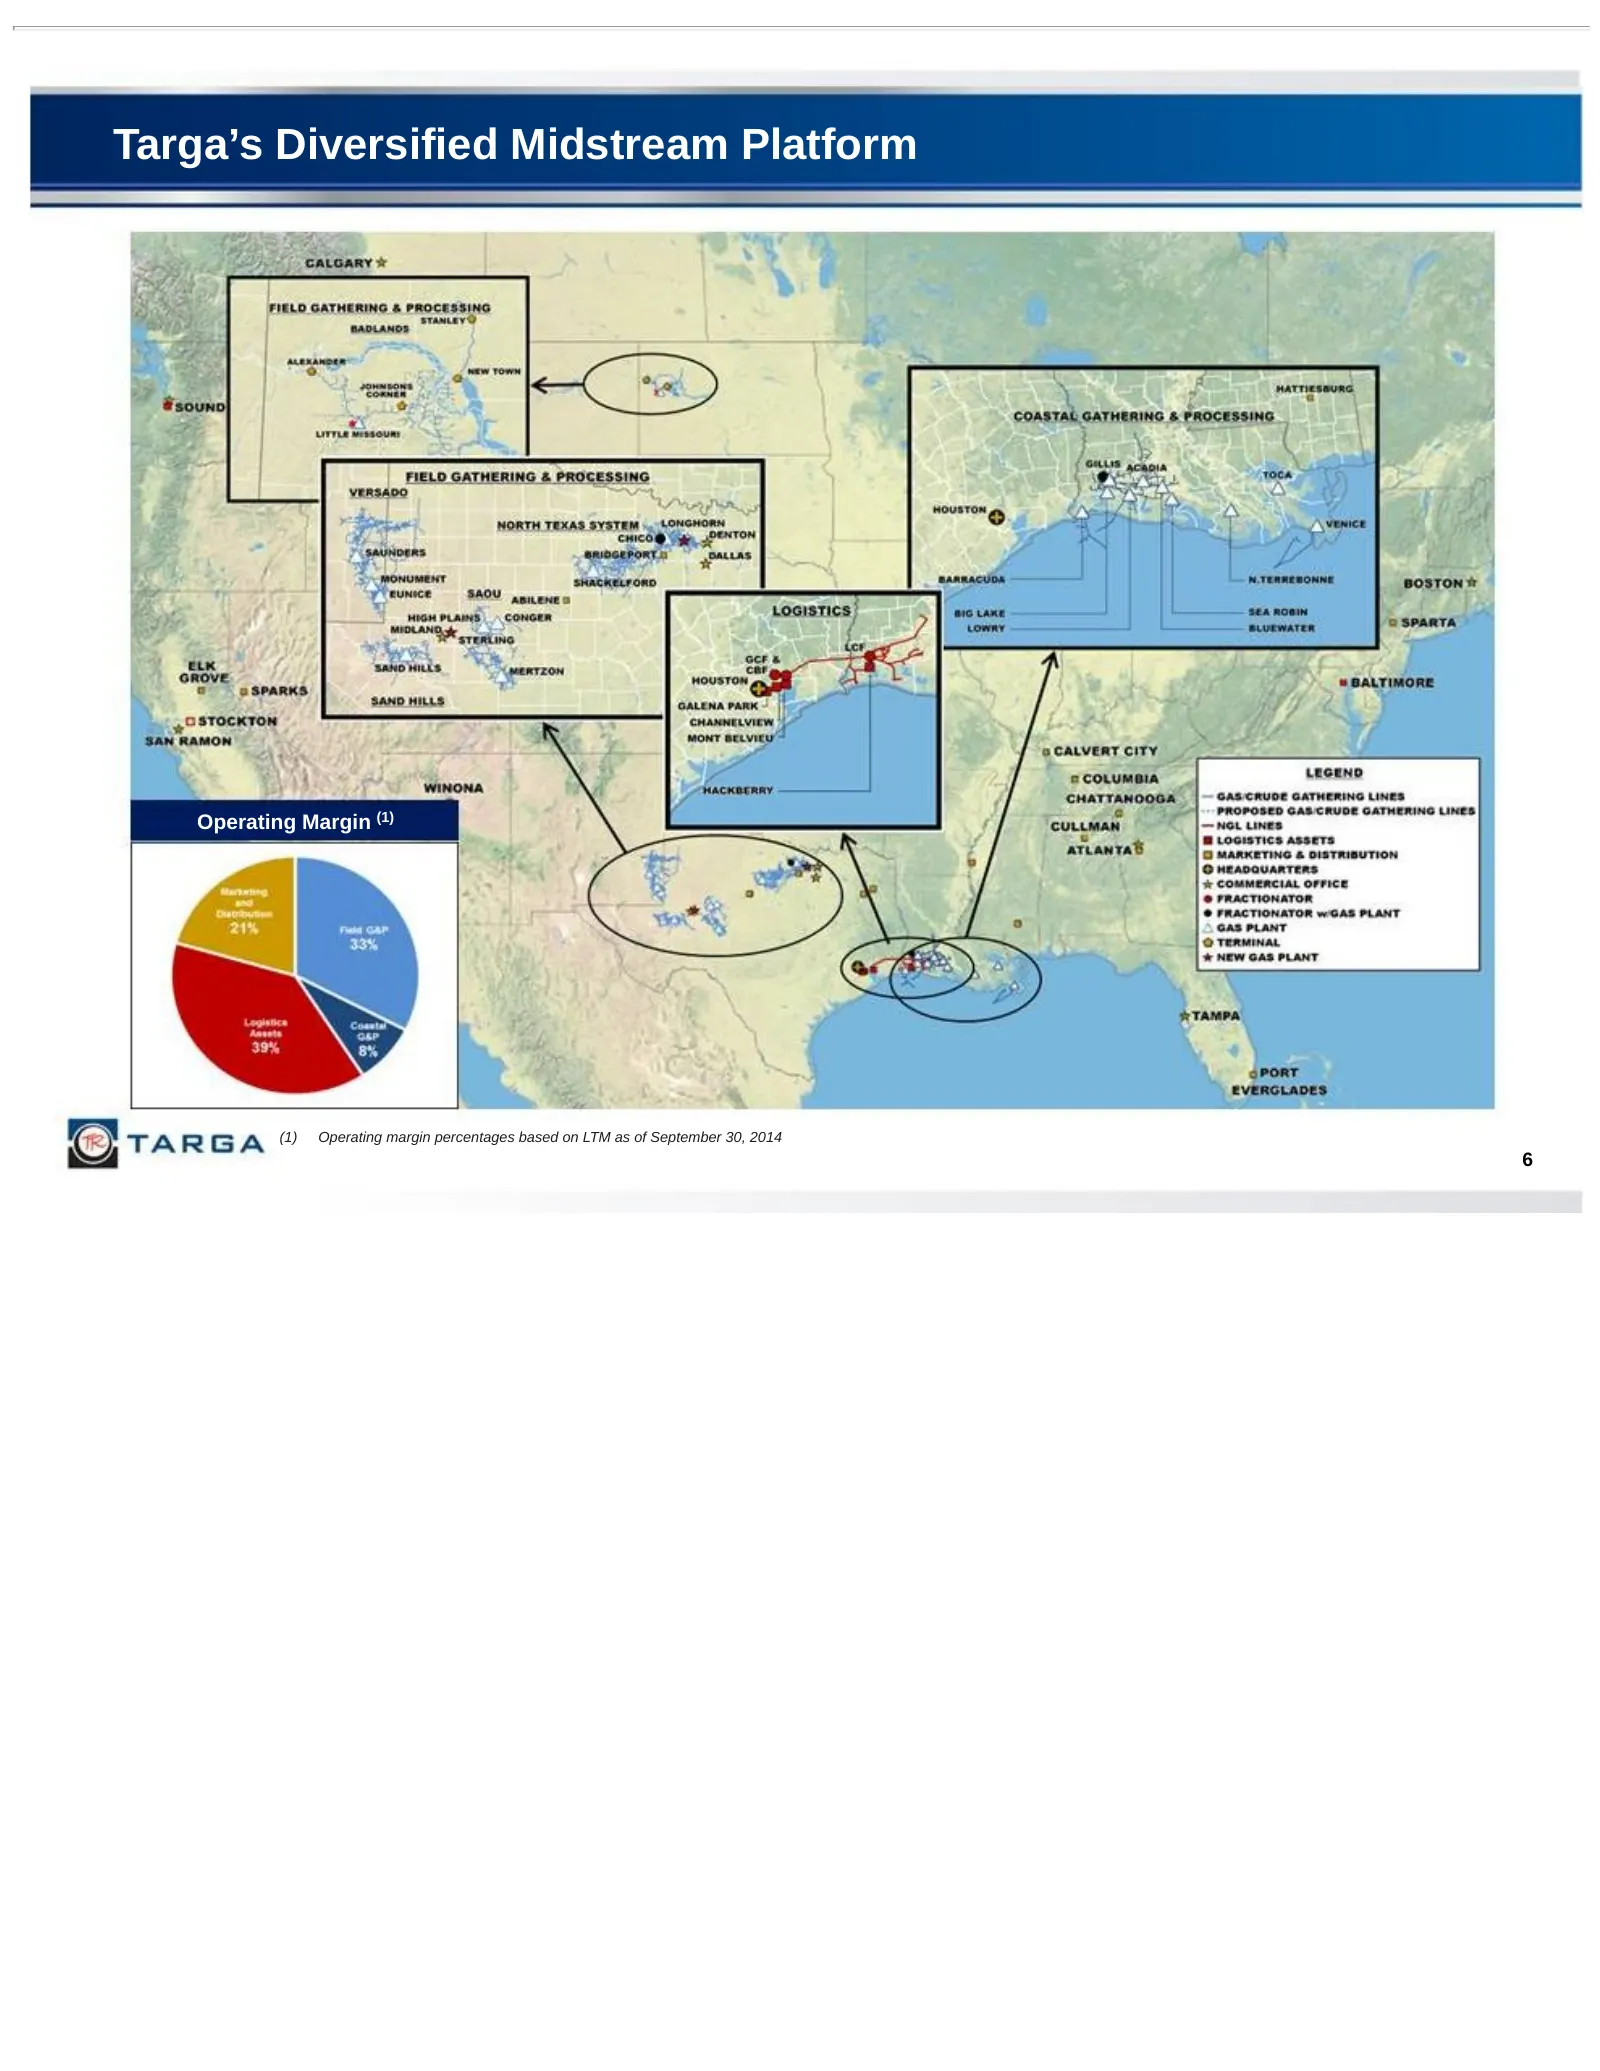
Targa’s Diversified Midstream Platform Operating Margin (1) (1) Operating margin percentages based on LTM as of September 30, 2014 6
Slide 8: Well Positioned for 2014 and Beyond
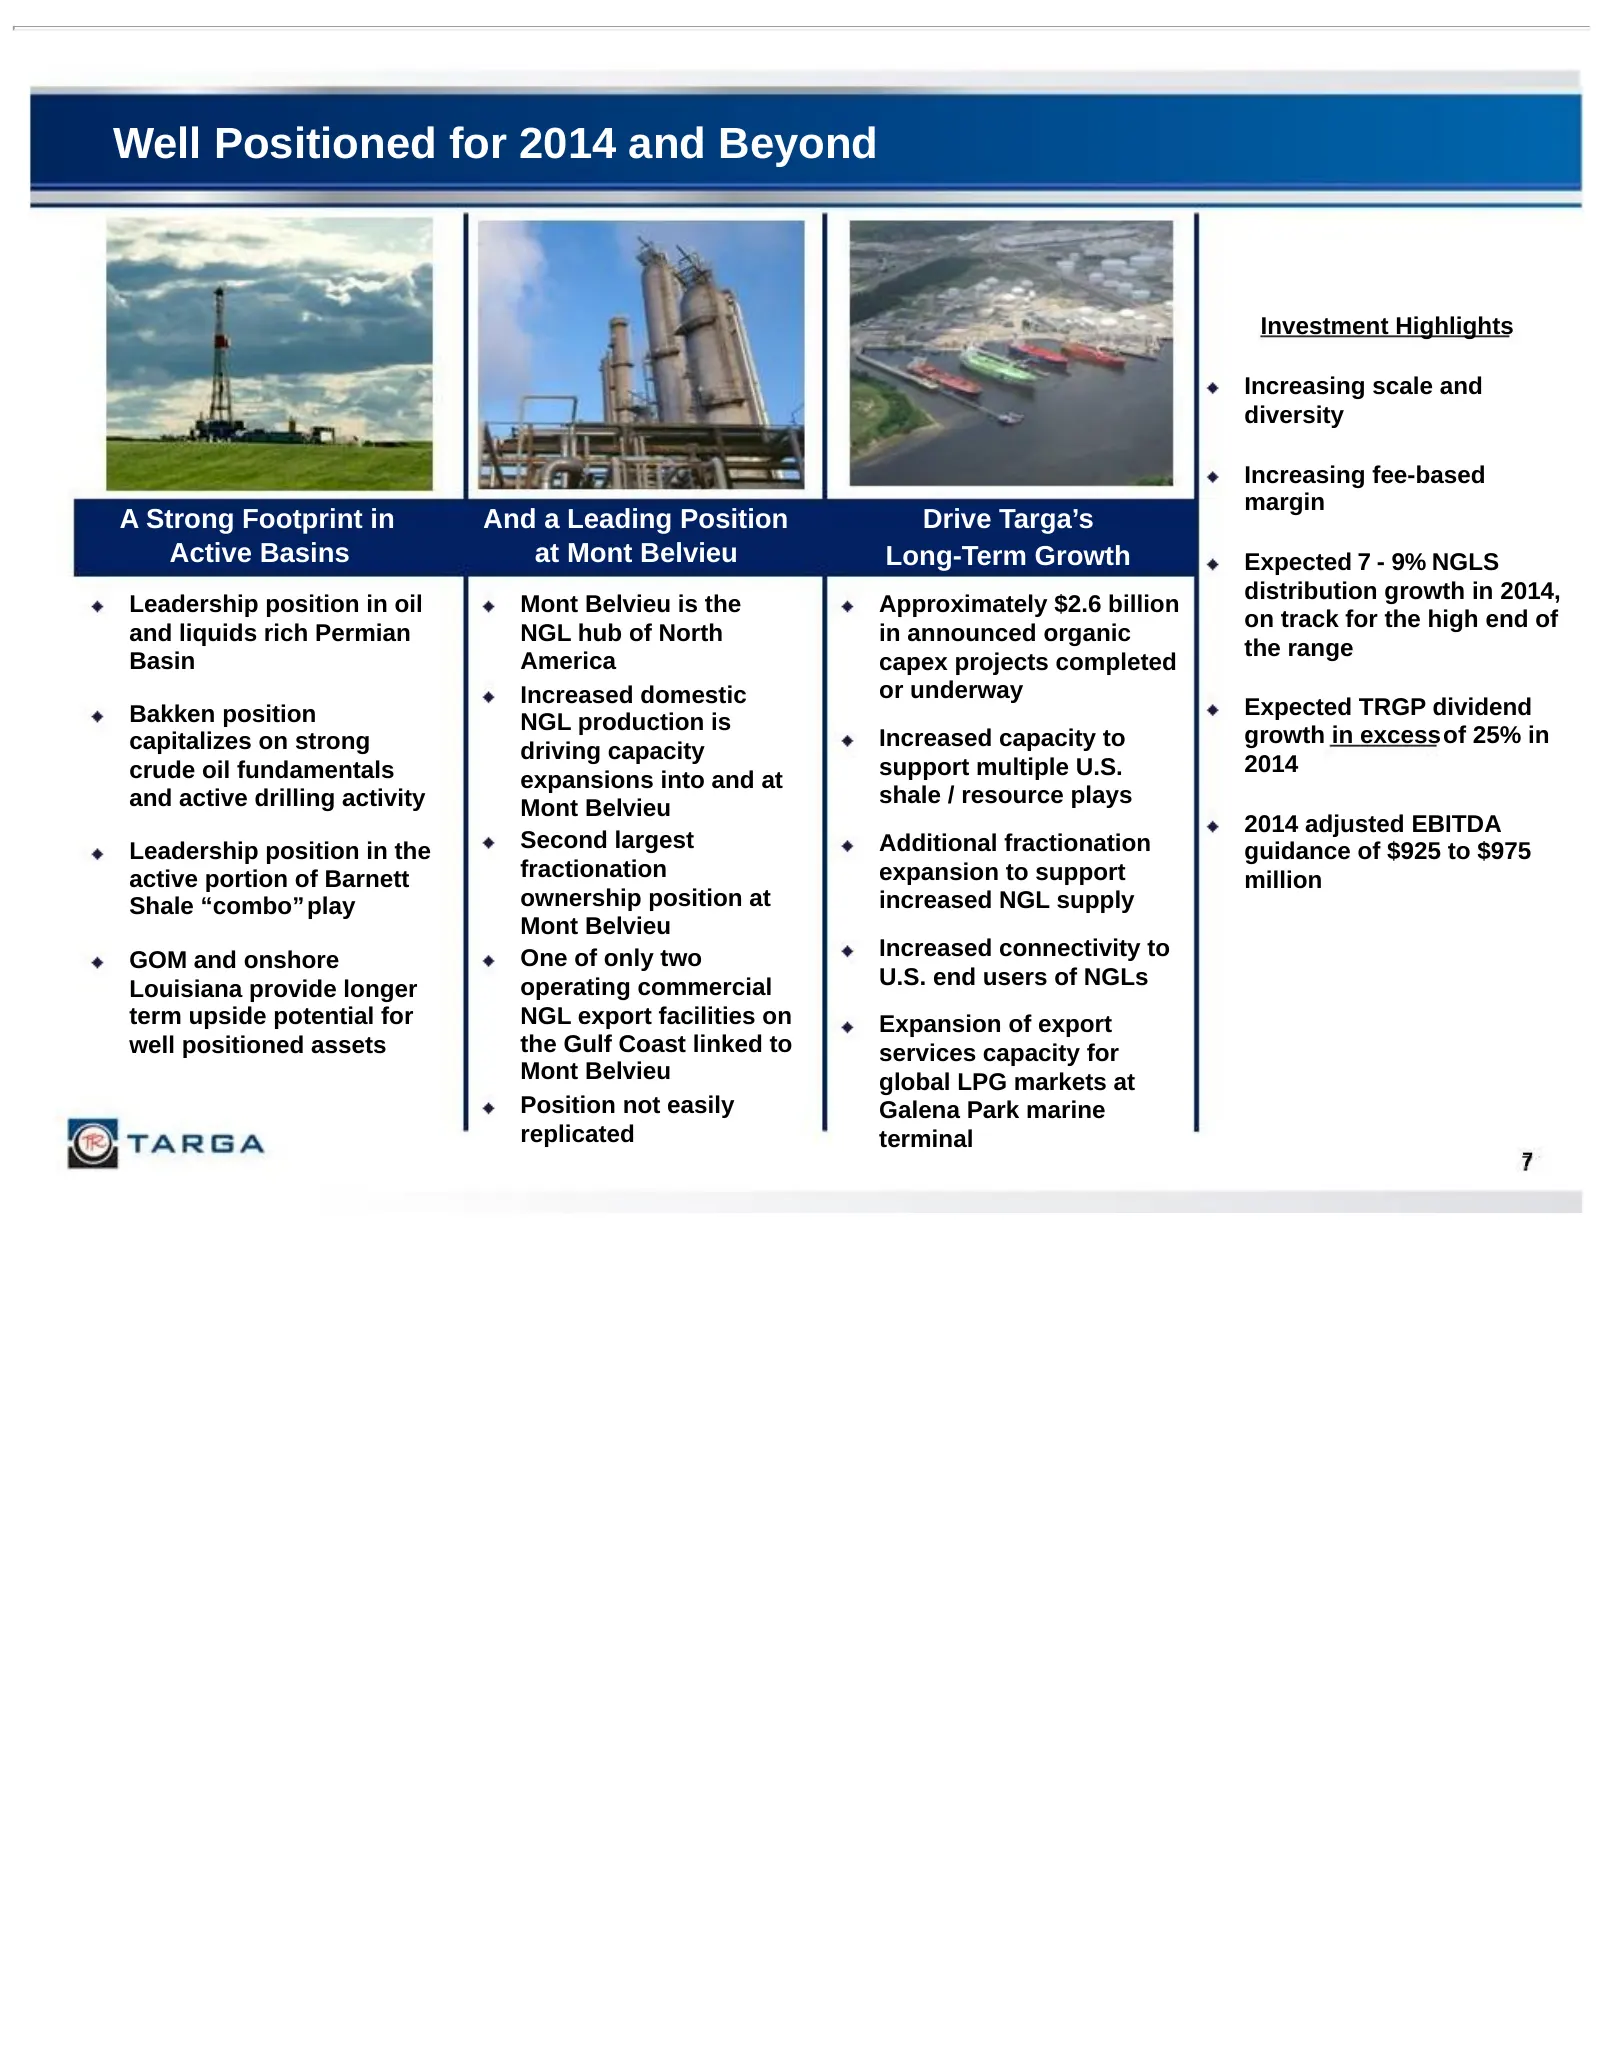
Well Positioned for 2014 and Beyond Investment Highlights Increasing scale and diversity Increasing fee-based margin A Strong Footprint in And a Leading Position Drive Targa’s Active Basins at Mont Belvieu Long-Term Growth Expected 7 - 9% NGLS distribution growth in 2014, Leadership position in oil
Slide 9: Major Announced Capital Projects
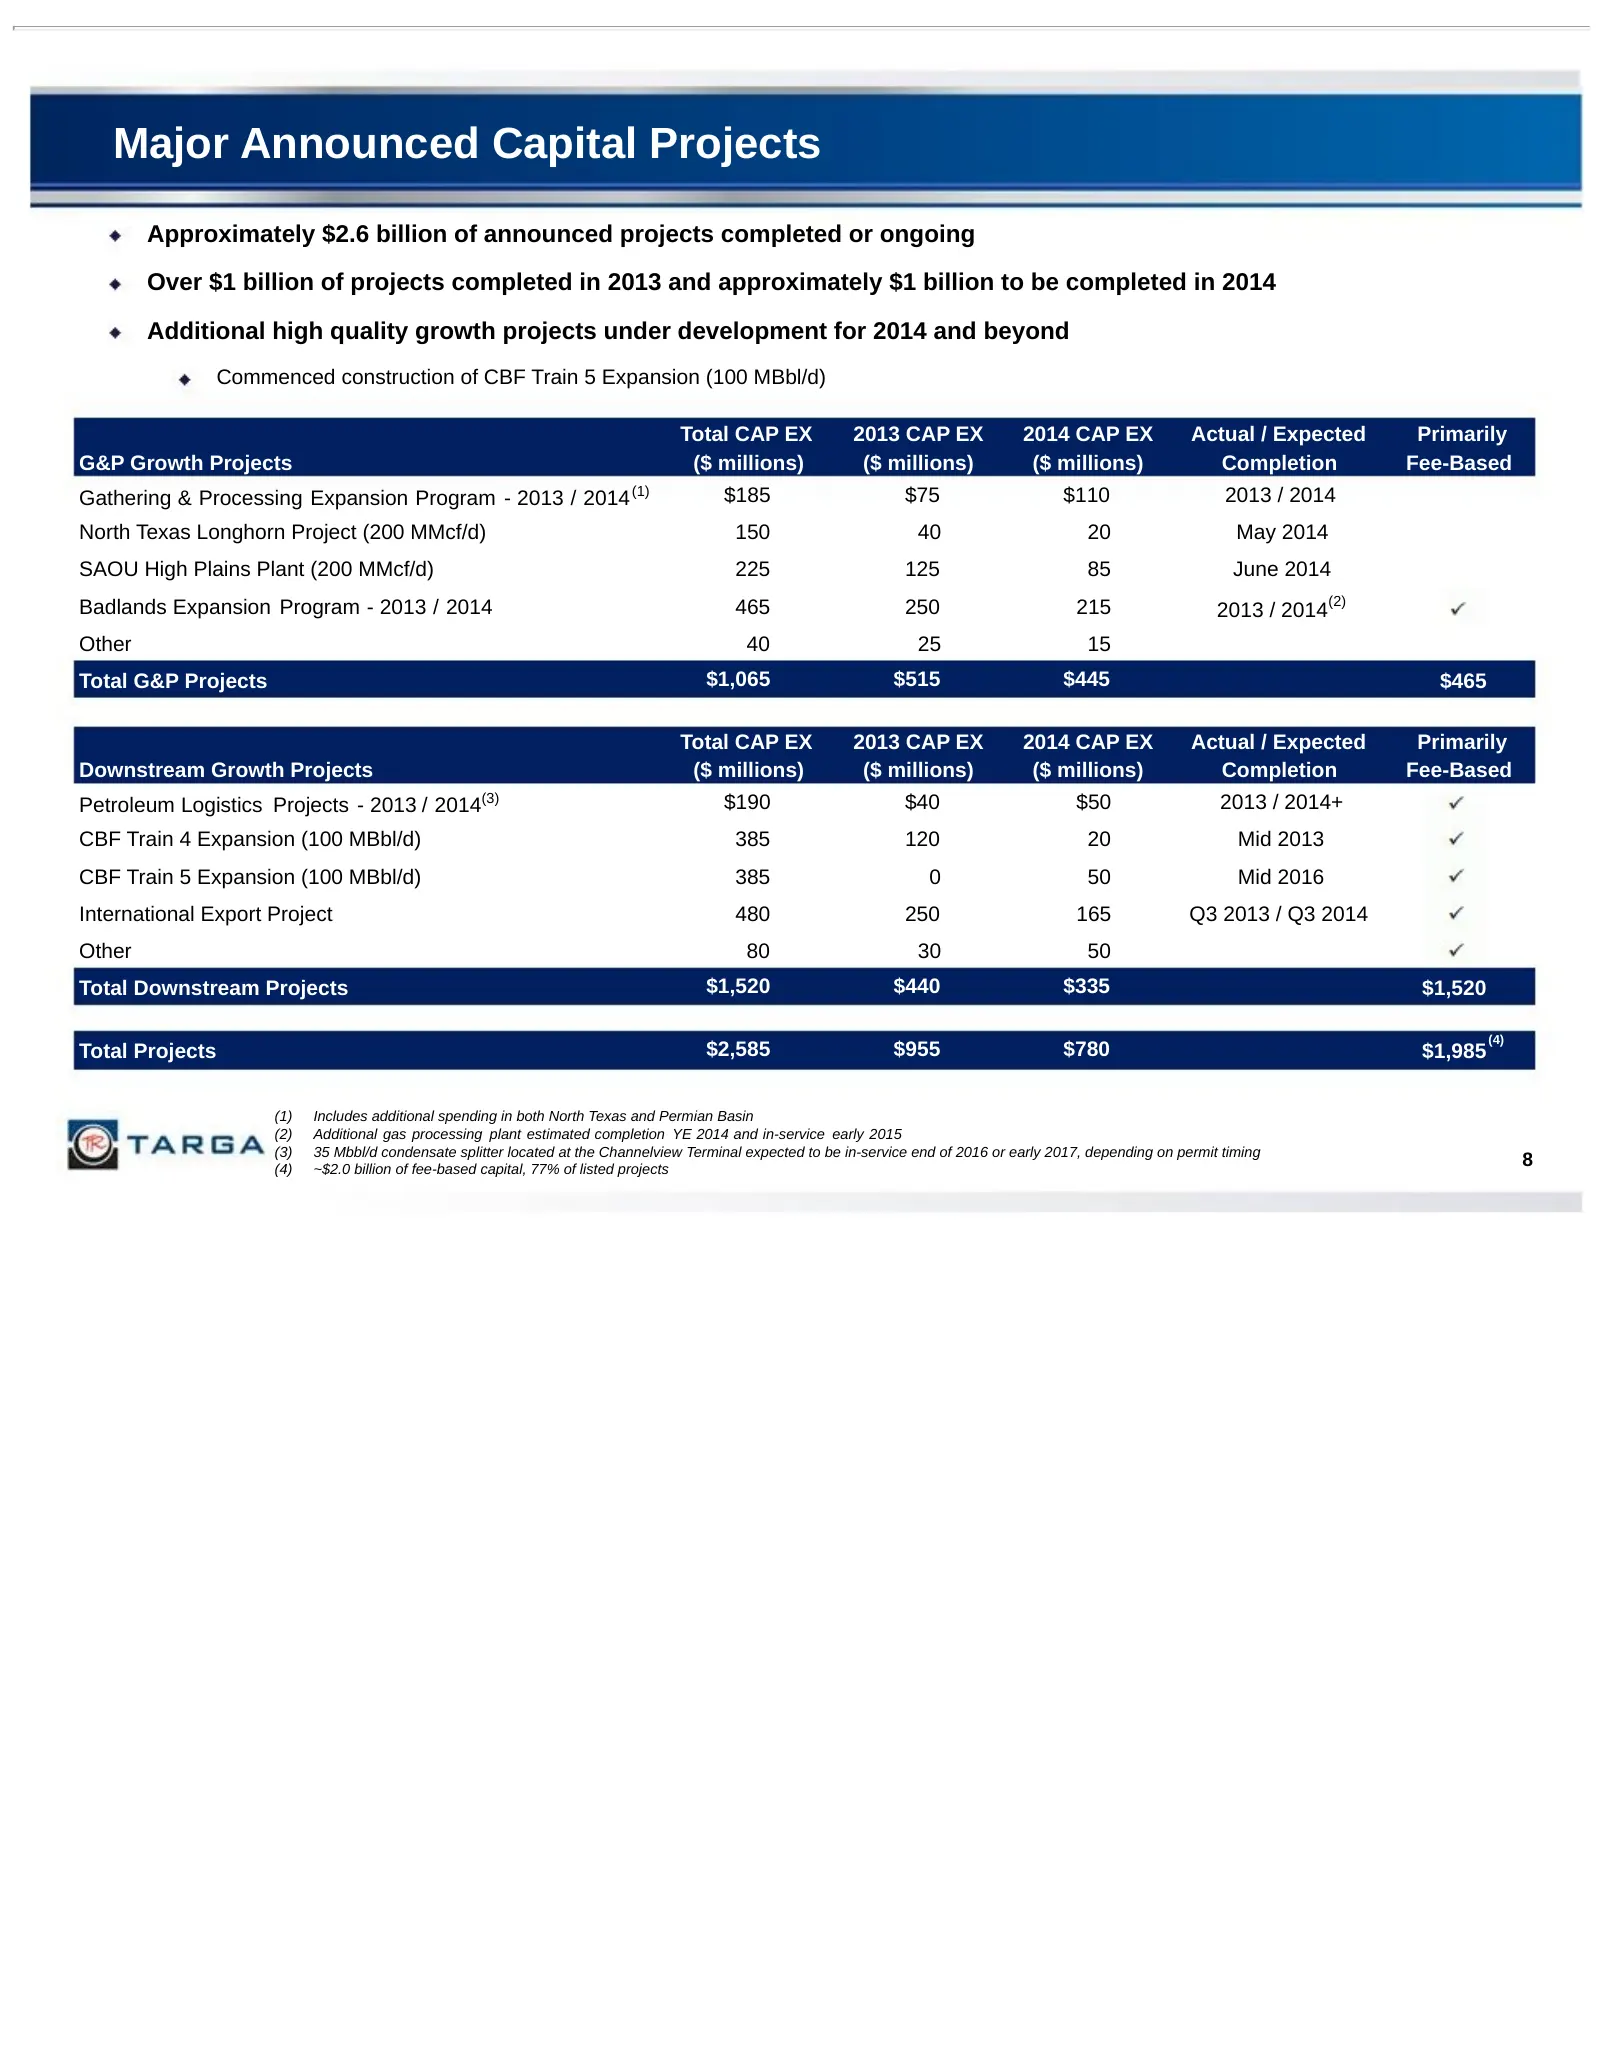
Major Announced Capital Projects Approximately $2.6 billion of announced projects completed or ongoing Over $1 billion of projects completed in 2013 and approximately $1 billion to be completed in 2014 Additional high quality growth projects under development for 2014 and beyond Commenced constructi
Slide 10: Major Capital Projects Under Development
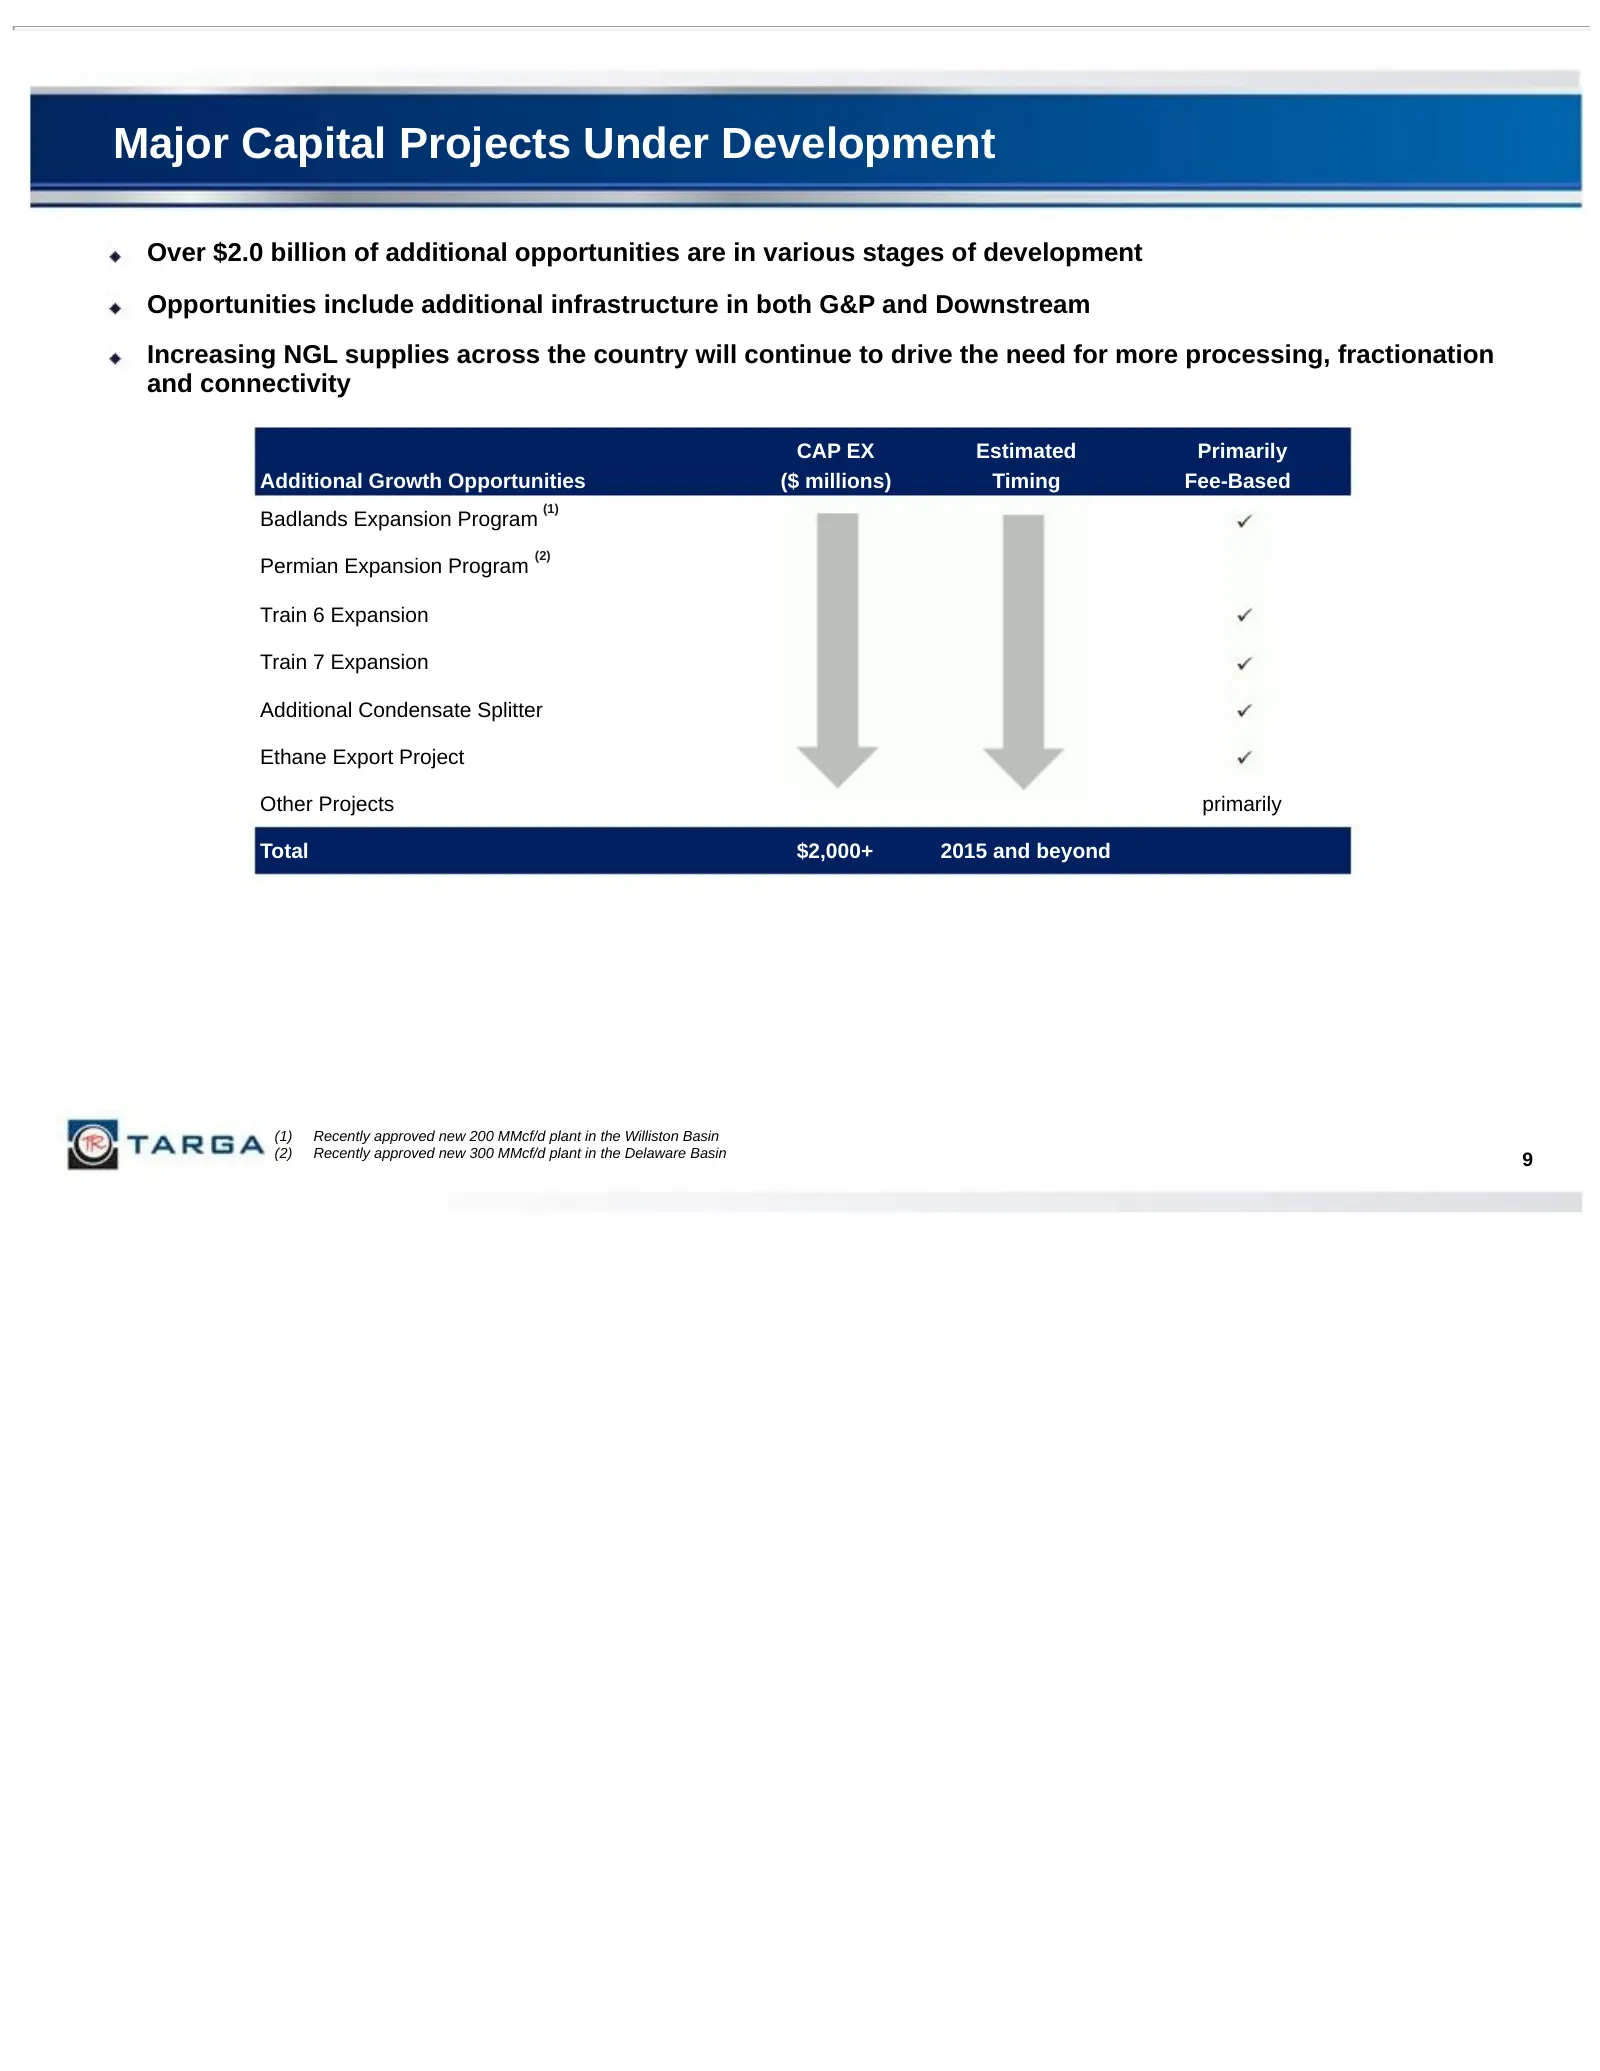
Major Capital Projects Under Development Over $2.0 billion of additional opportunities are in various stages of development Opportunities include additional infrastructure in both G&P and Downstream Increasing NGL supplies across the country will continue to drive the need for more processing, fract
Slide 11: Diversity and Scale Mitigate Commodity Price Changes
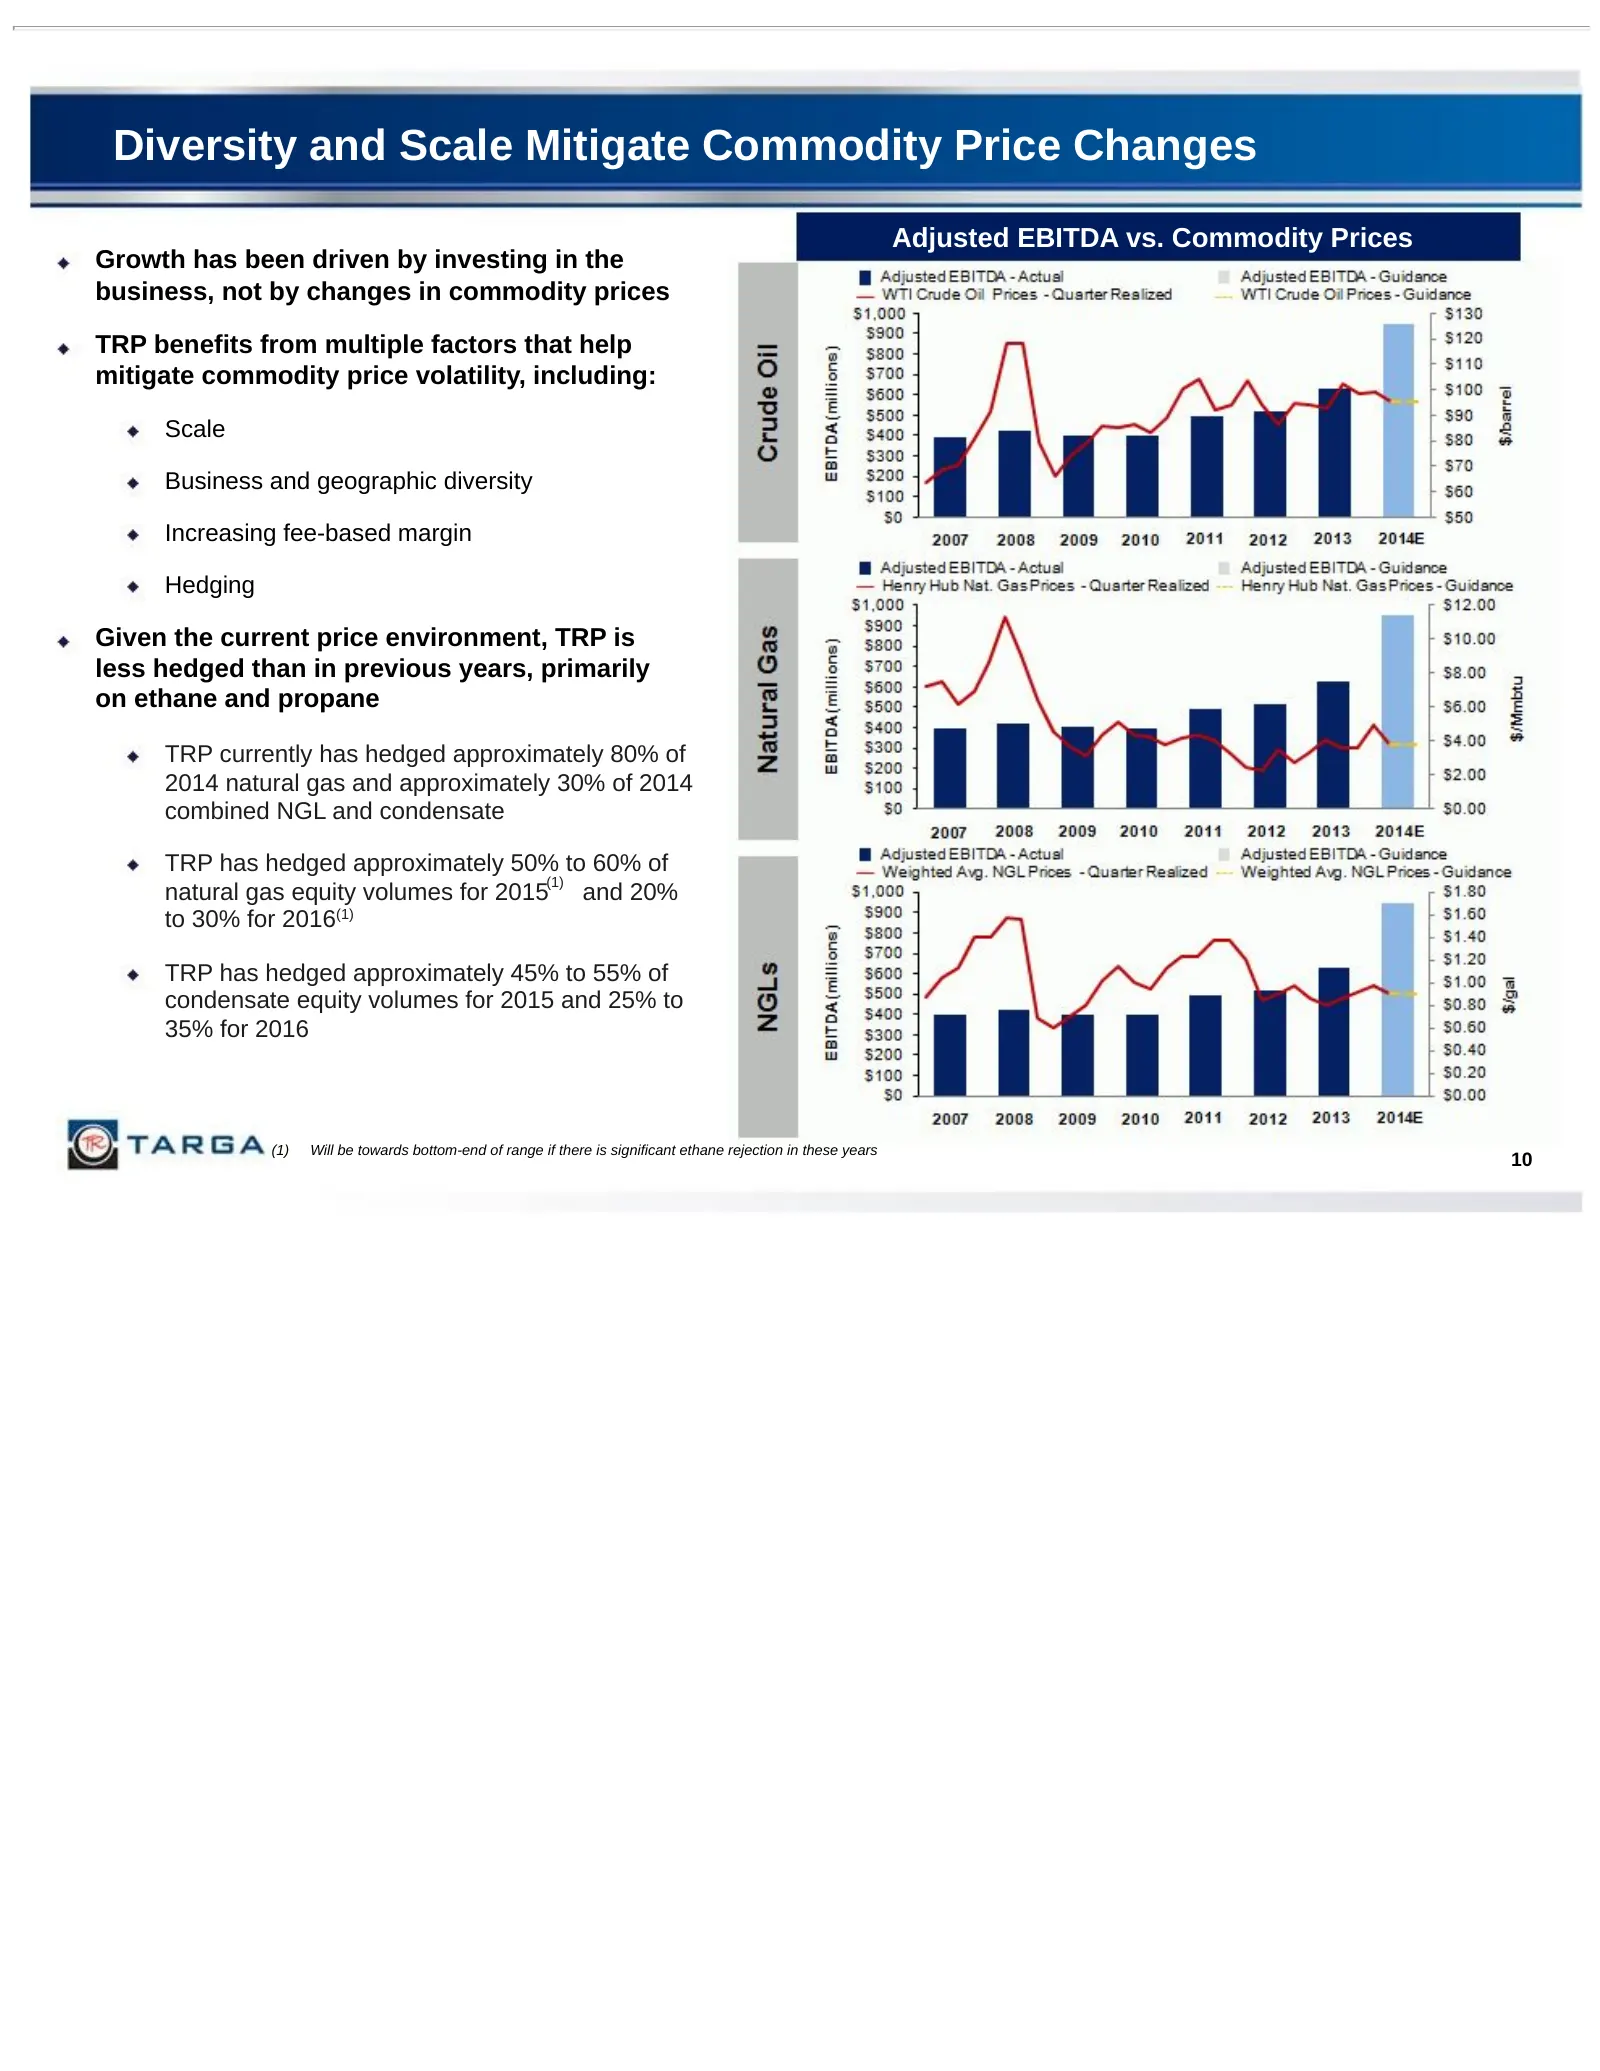
Diversity and Scale Mitigate Commodity Price Changes Adjusted EBITDA vs. Commodity Prices Growth has been driven by investing in the business, not by changes in commodity prices TRP benefits from multiple factors that help mitigate commodity price volatility, including: Scale Business and geographic
Slide 12: Targa Leverage and Liquidity
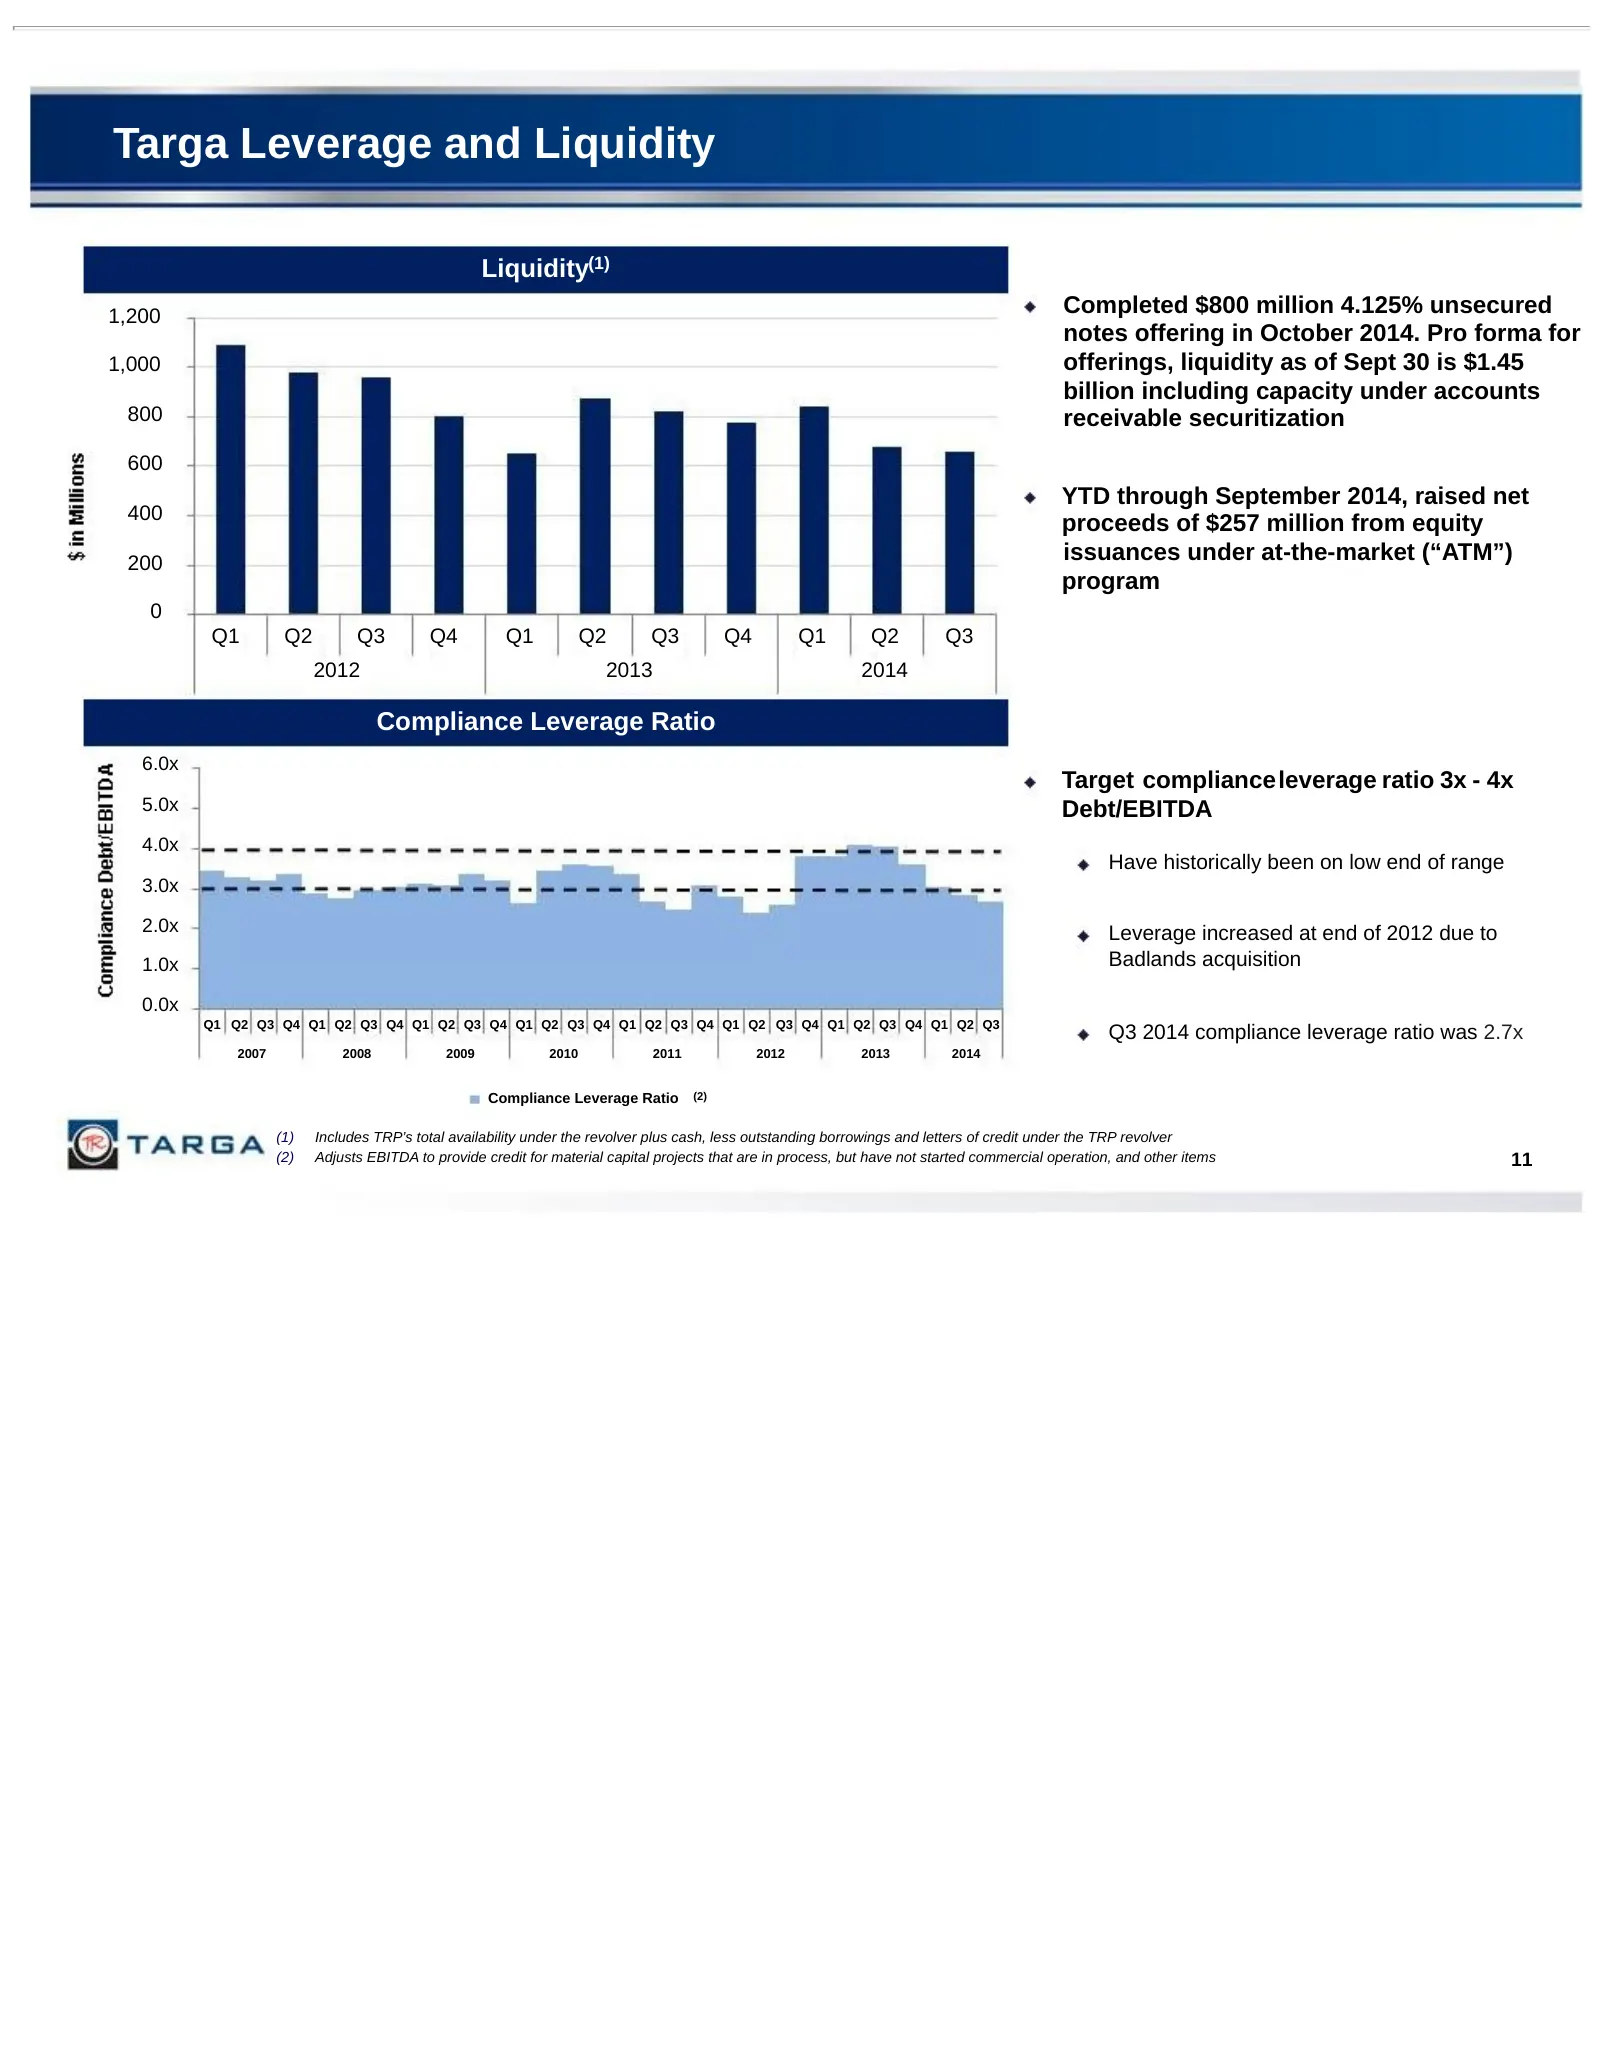
Targa Leverage and Liquidity Liquidity(1) 1,200 Completed $800 million 4.125% unsecured notes offering in October 2014. Pro forma for 1,000 offerings, liquidity as of Sept 30 is $1.45 billion including capacity under accounts 800 receivable securitization 600 YTD through September 2014, raised net 4
Slide 13: Targa + Atlas: Transaction Overview
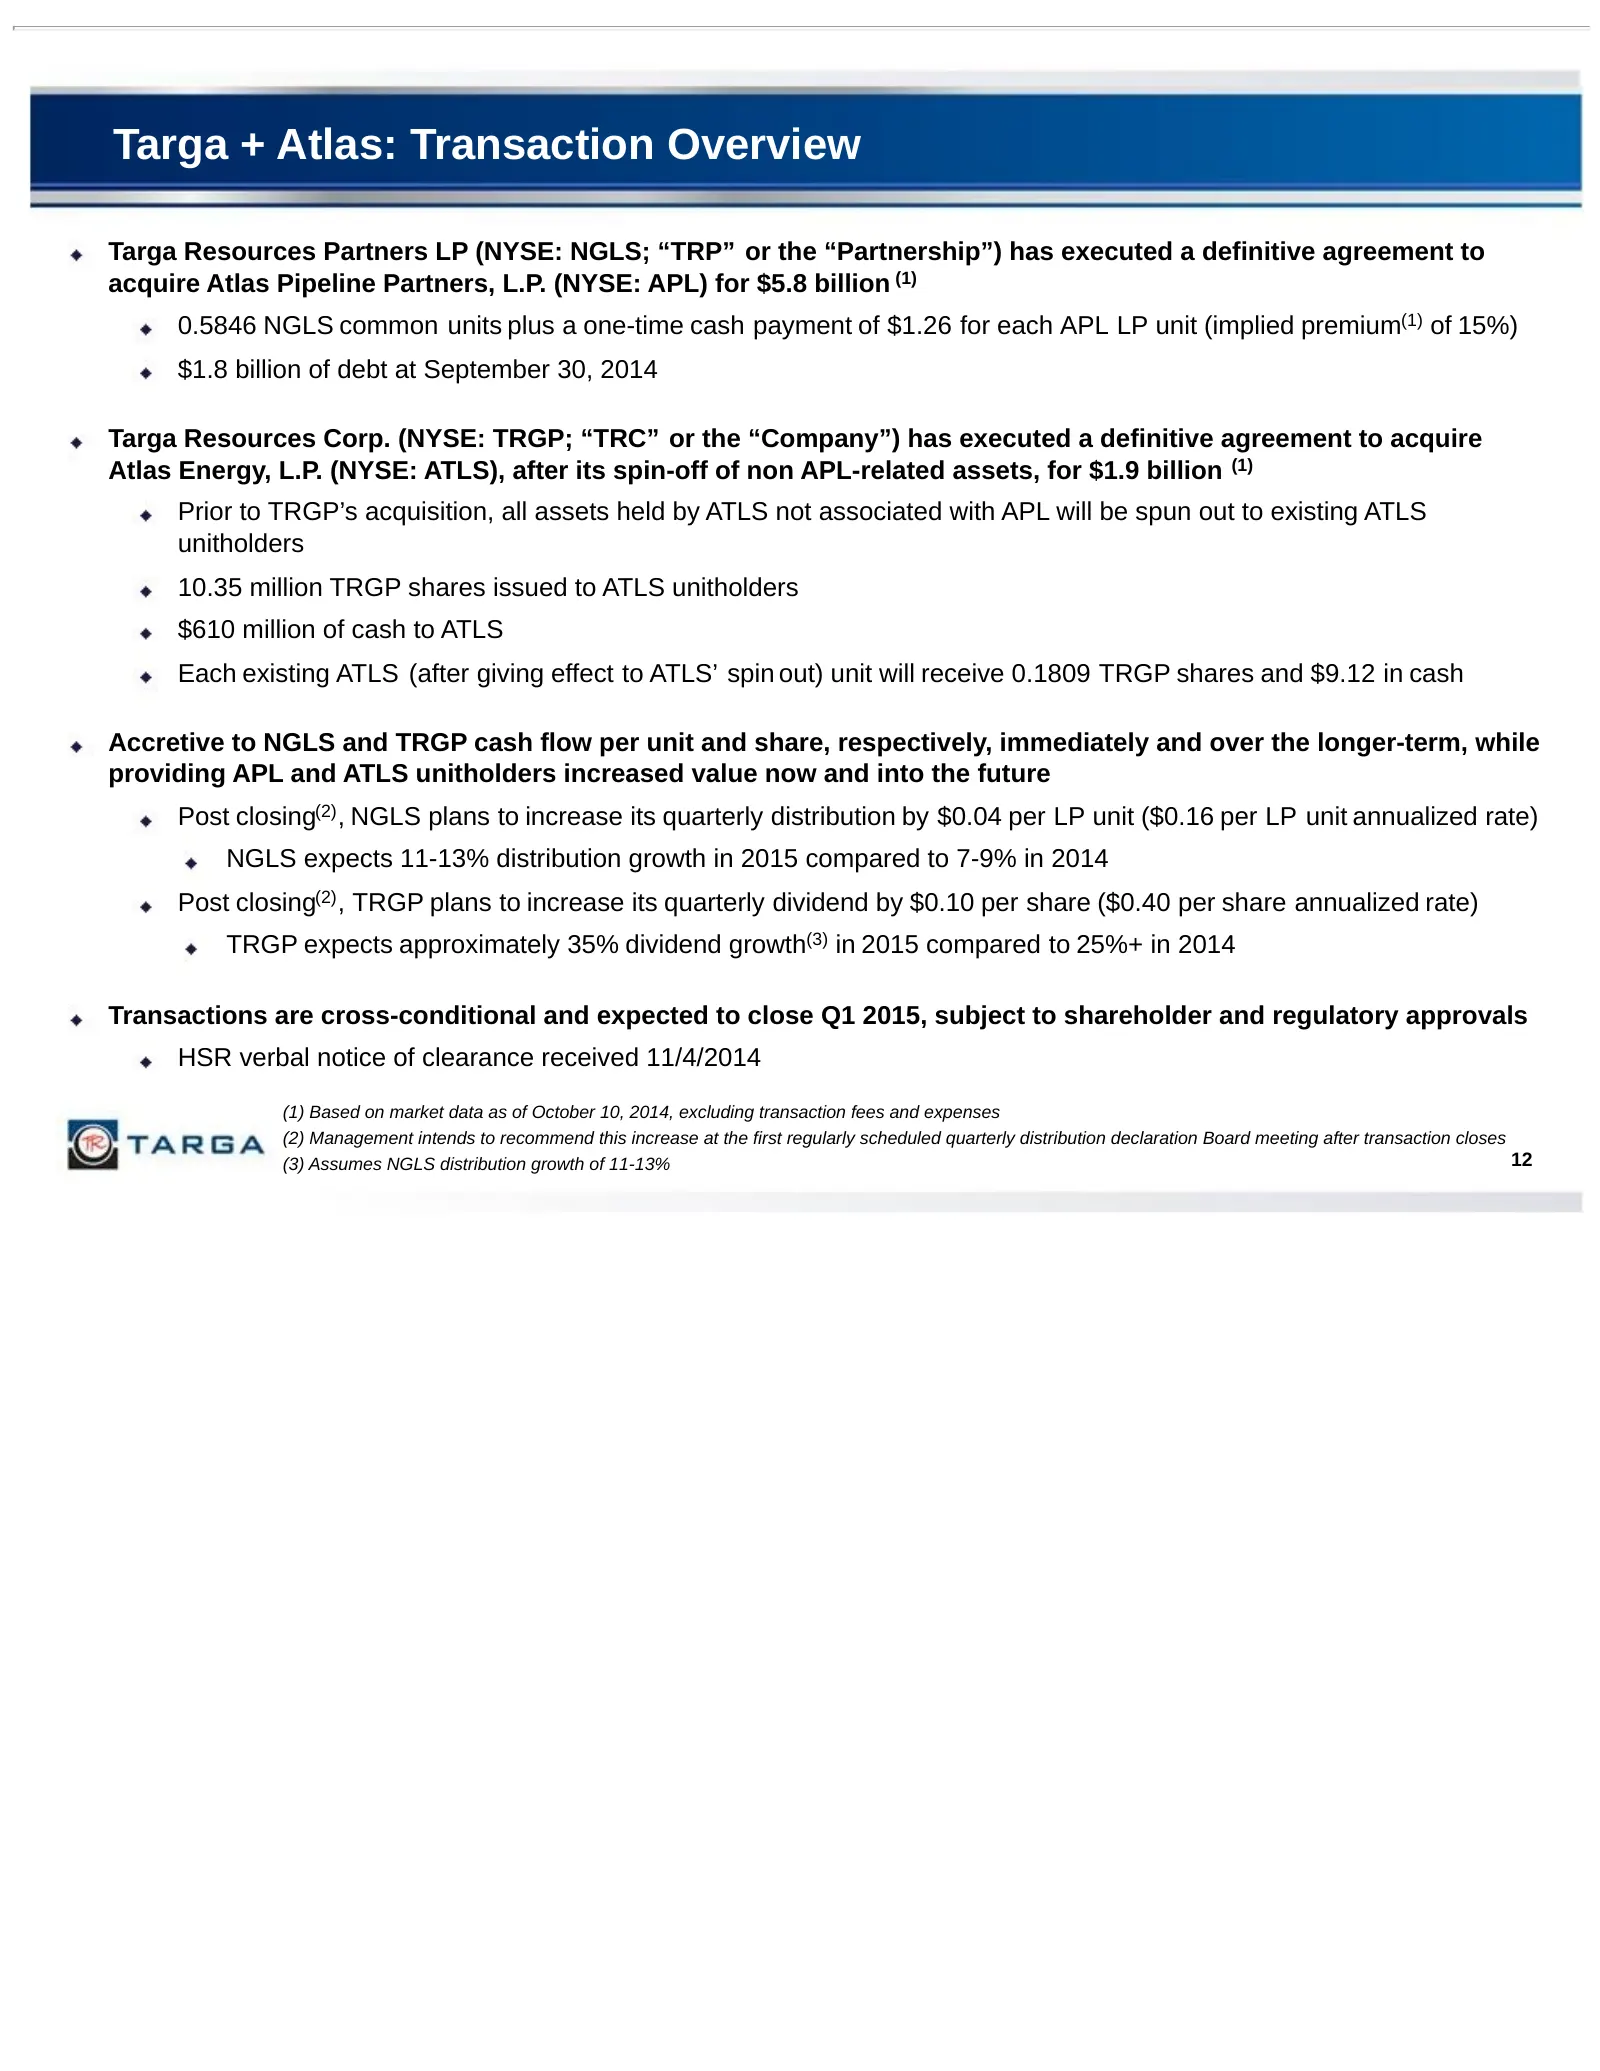
Targa + Atlas: Transaction Overview Targa Resources Partners LP (NYSE: NGLS; “TRP” or the “Partnership”) has executed a definitive agreement to acquire Atlas Pipeline Partners, L.P. (NYSE: APL) for $5.8 billion (1) 0.5846 NGLS common units plus a one-time cash payment of $1.26 for each APL LP unit (
Slide 14: Targa + Atlas: Attractive Positions in Active Basins
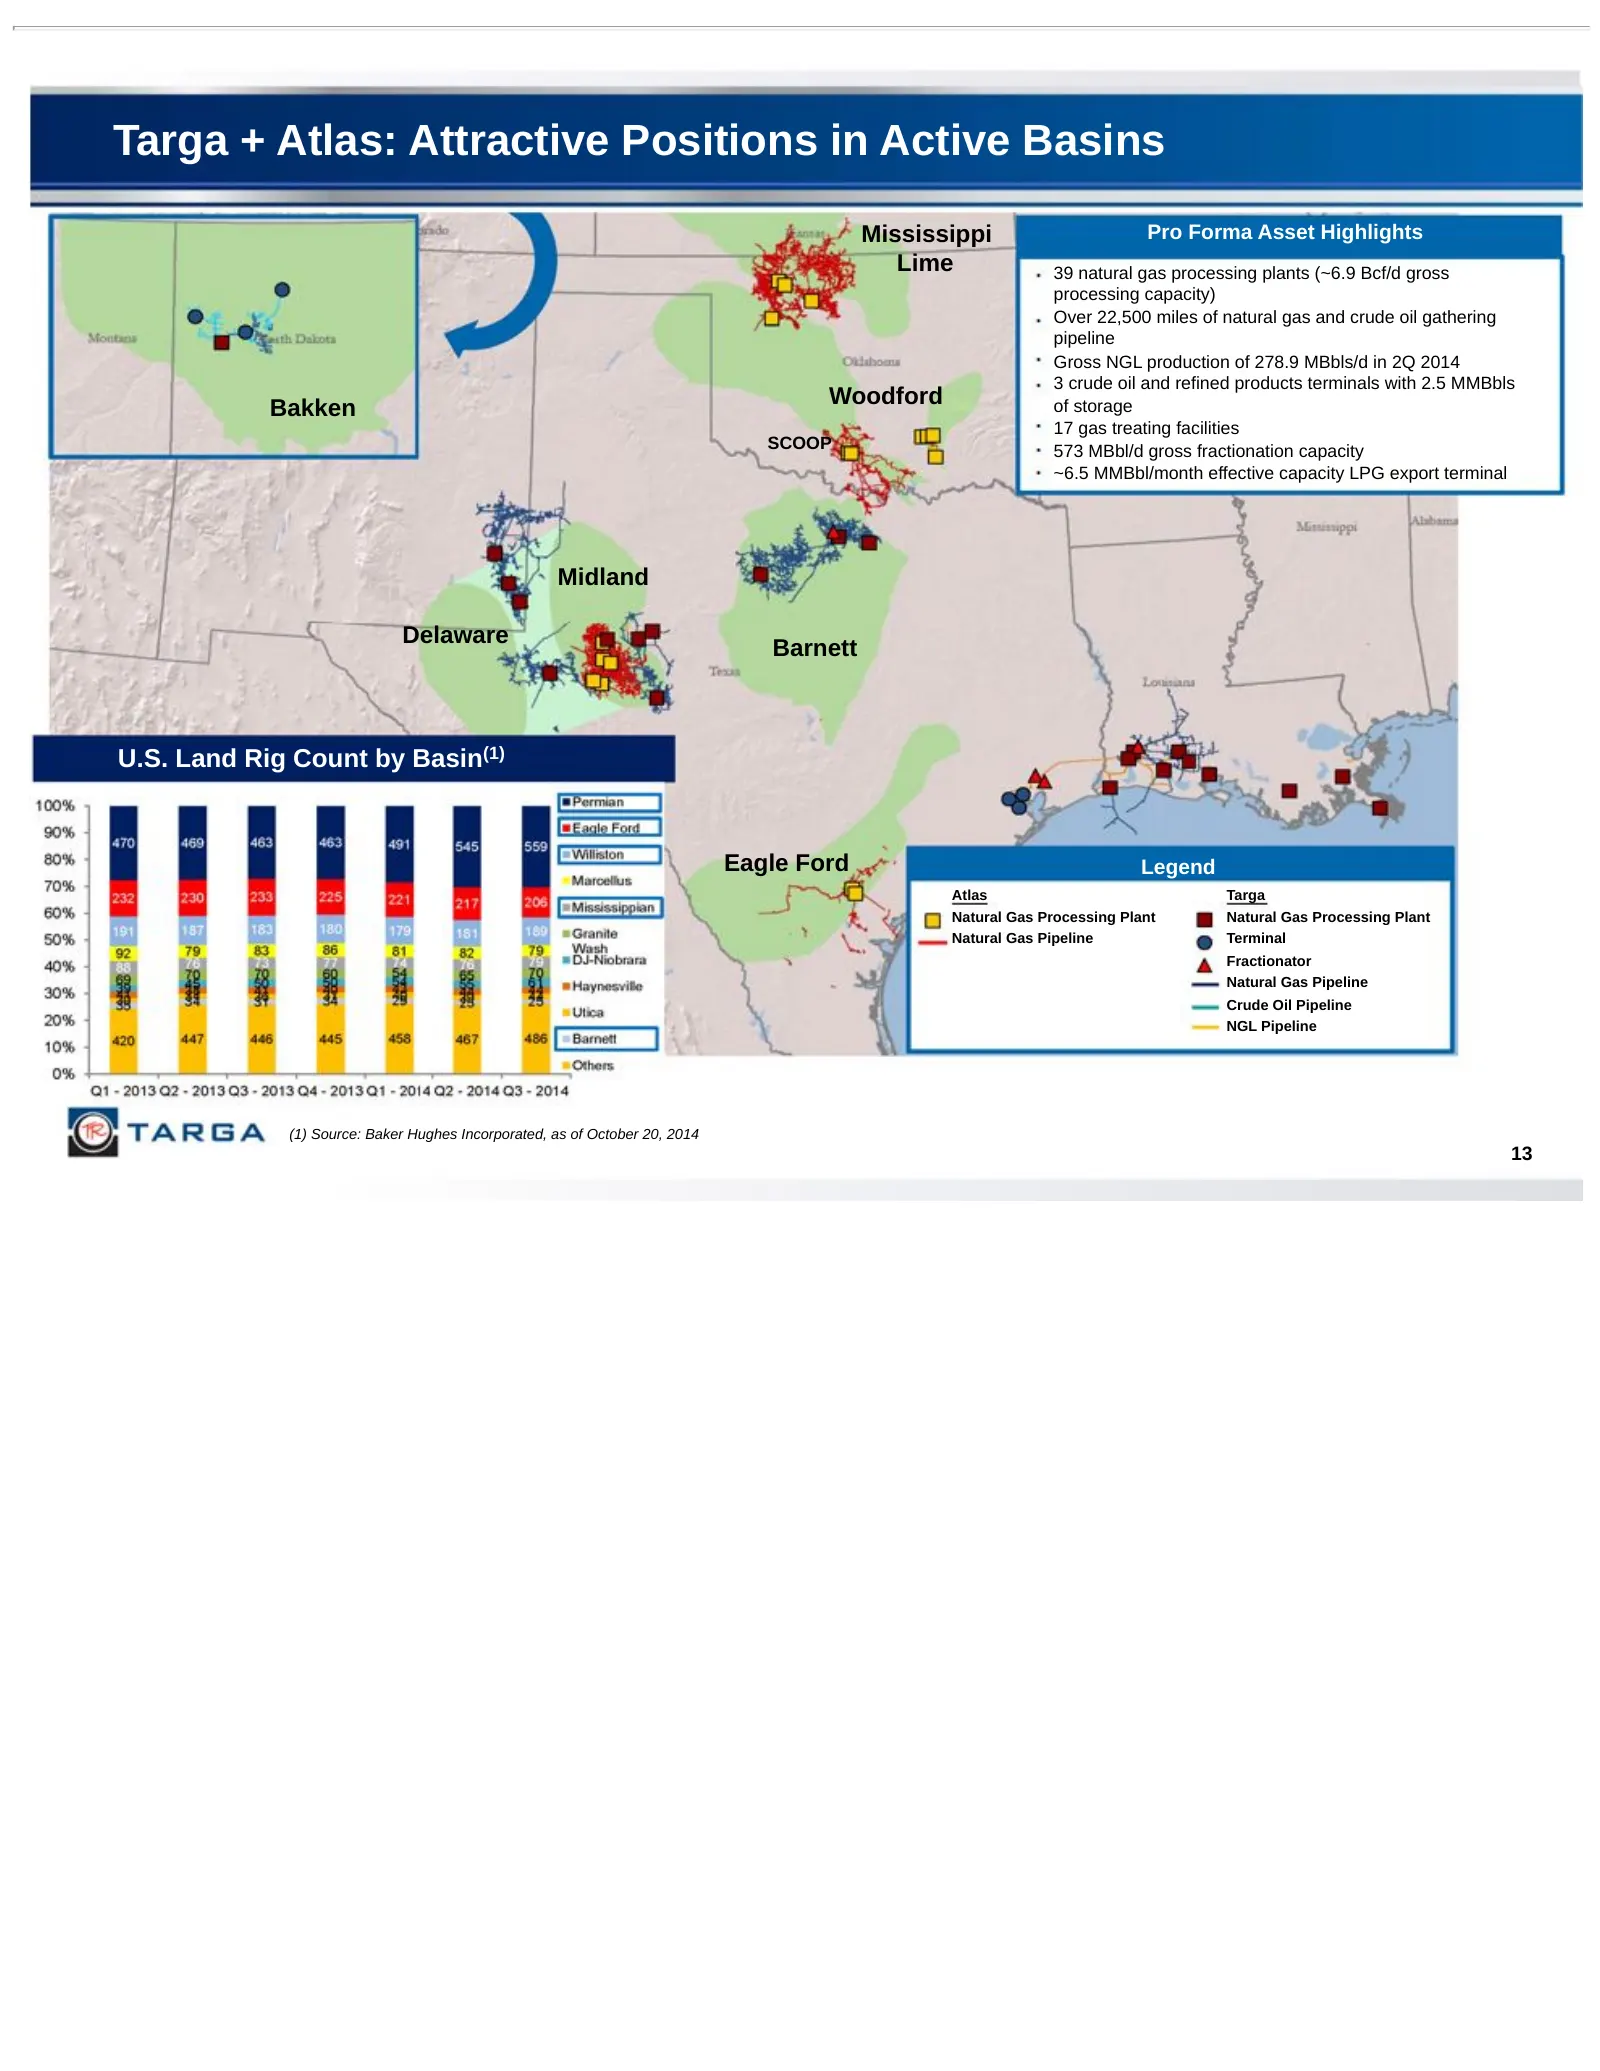
Targa + Atlas: Attractive Positions in Active Basins Mississippi Pro Forma Asset Highlights Lime 39 natural gas processing plants (~6.9 Bcf/d gross processing capacity) Over 22,500 miles of natural gas and crude oil gathering pipeline Gross NGL production of 278.9 MBbls/d in 2Q 2014 3 crude oil and
Slide 15: Producer Activity Drives NGL Flows to Mont Belvieu
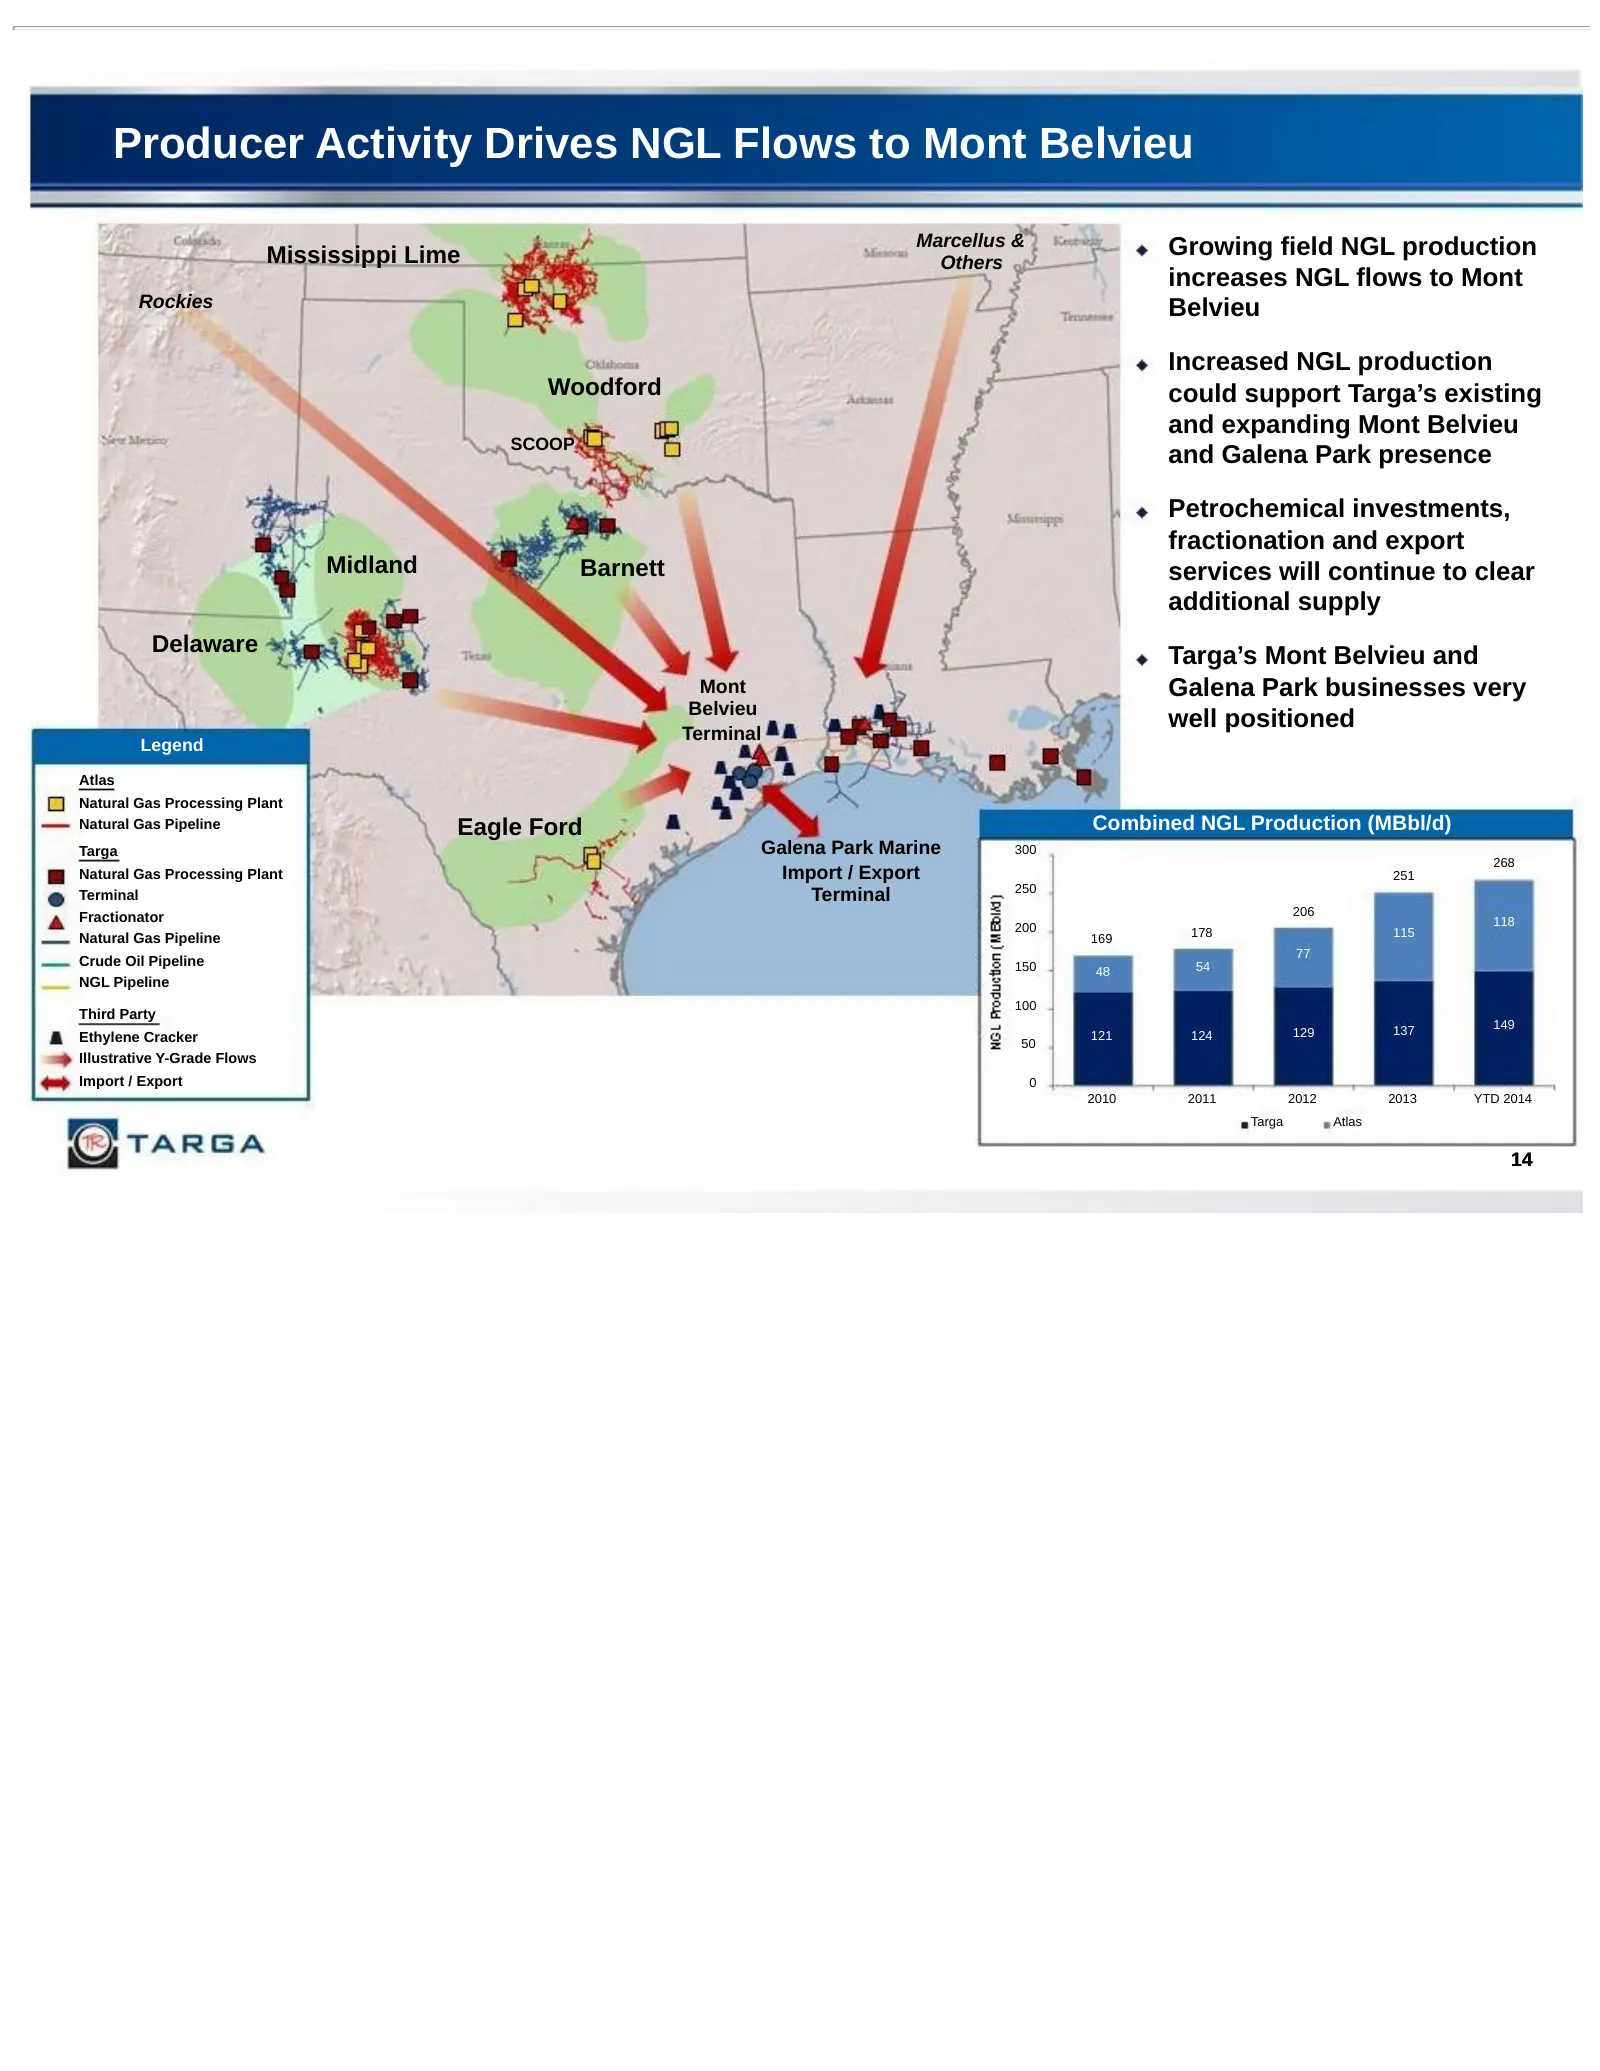
Producer Activity Drives NGL Flows to Mont Belvieu Marcellus & Growing field NGL production Mississippi Lime Others increases NGL flows to Mont Rockies Belvieu Increased NGL production Woodford could support Targa’s existing and expanding Mont Belvieu SCOOP and Galena Park presence Petrochemical inv
Slide 16: Targa + Atlas: Increased Size and Scale Enhance Credit Profile
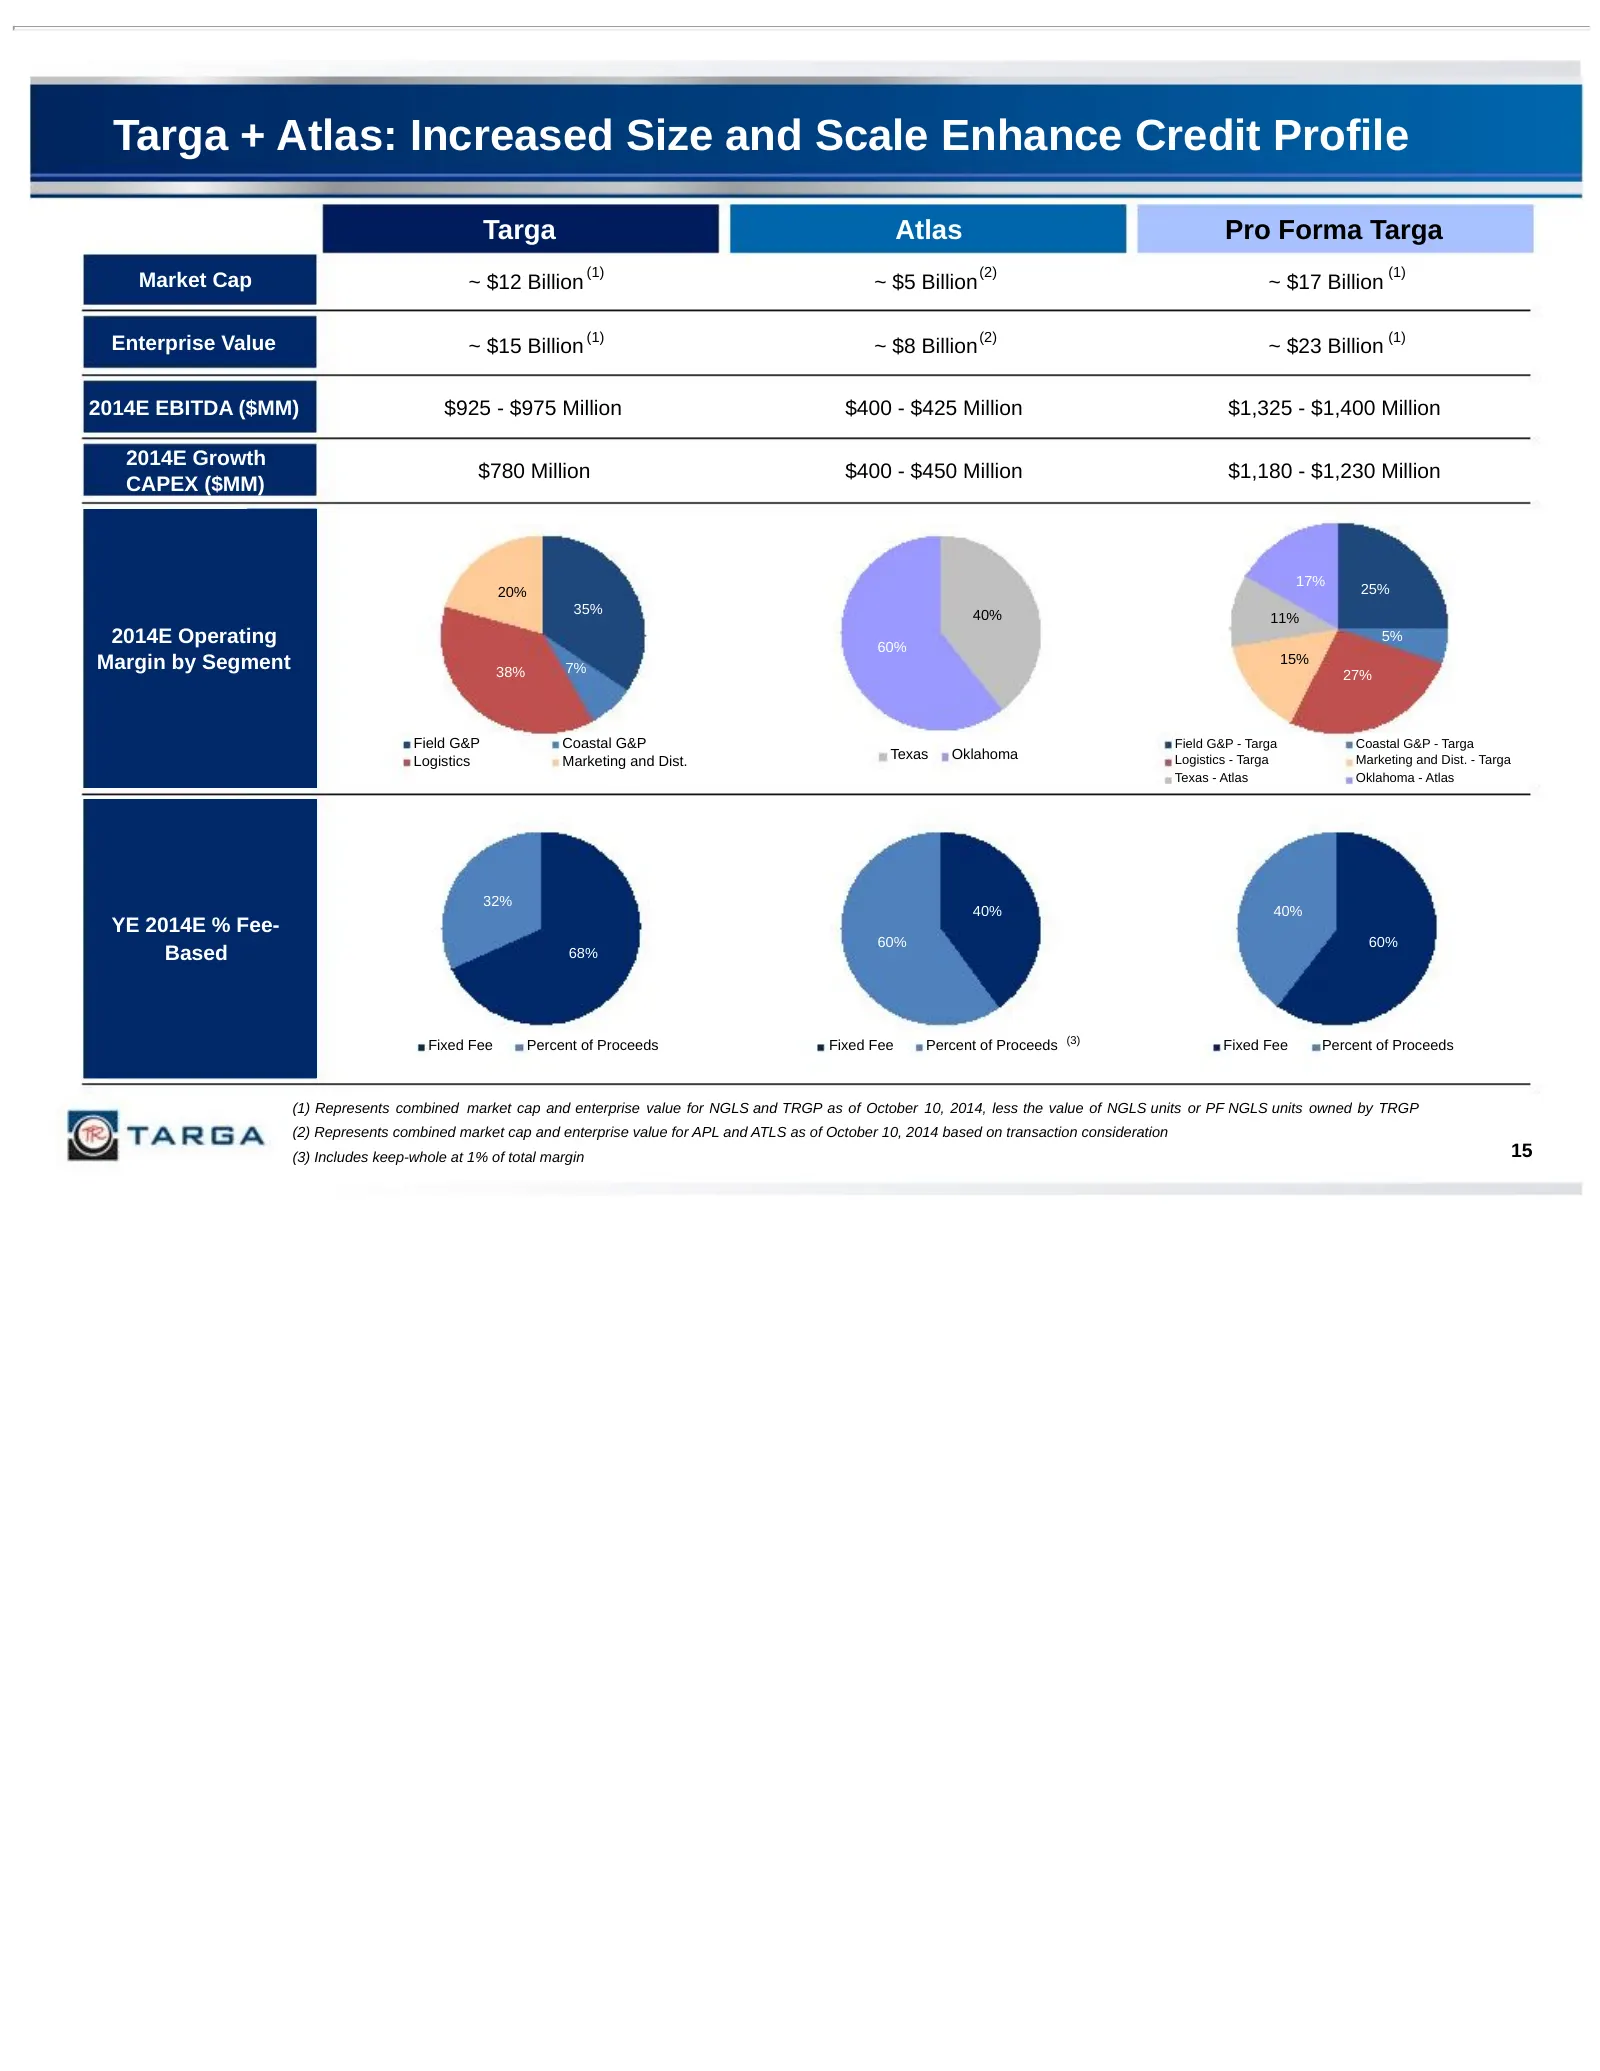
Targa + Atlas: Increased Size and Scale Enhance Credit Profile Targa Atlas Pro Forma Targa (1) (2) (1) Market Cap ~ $12 Billion ~ $5 Billion ~ $17 Billion (1) (2) (1) Enterprise Value ~ $15 Billion ~ $8 Billion ~ $23 Billion 2014E EBITDA ($MM) $925 - $975 Million $400 - $425 Million $1,325 - $1,400
Slide 17: Targa + Atlas: Strategic Highlights
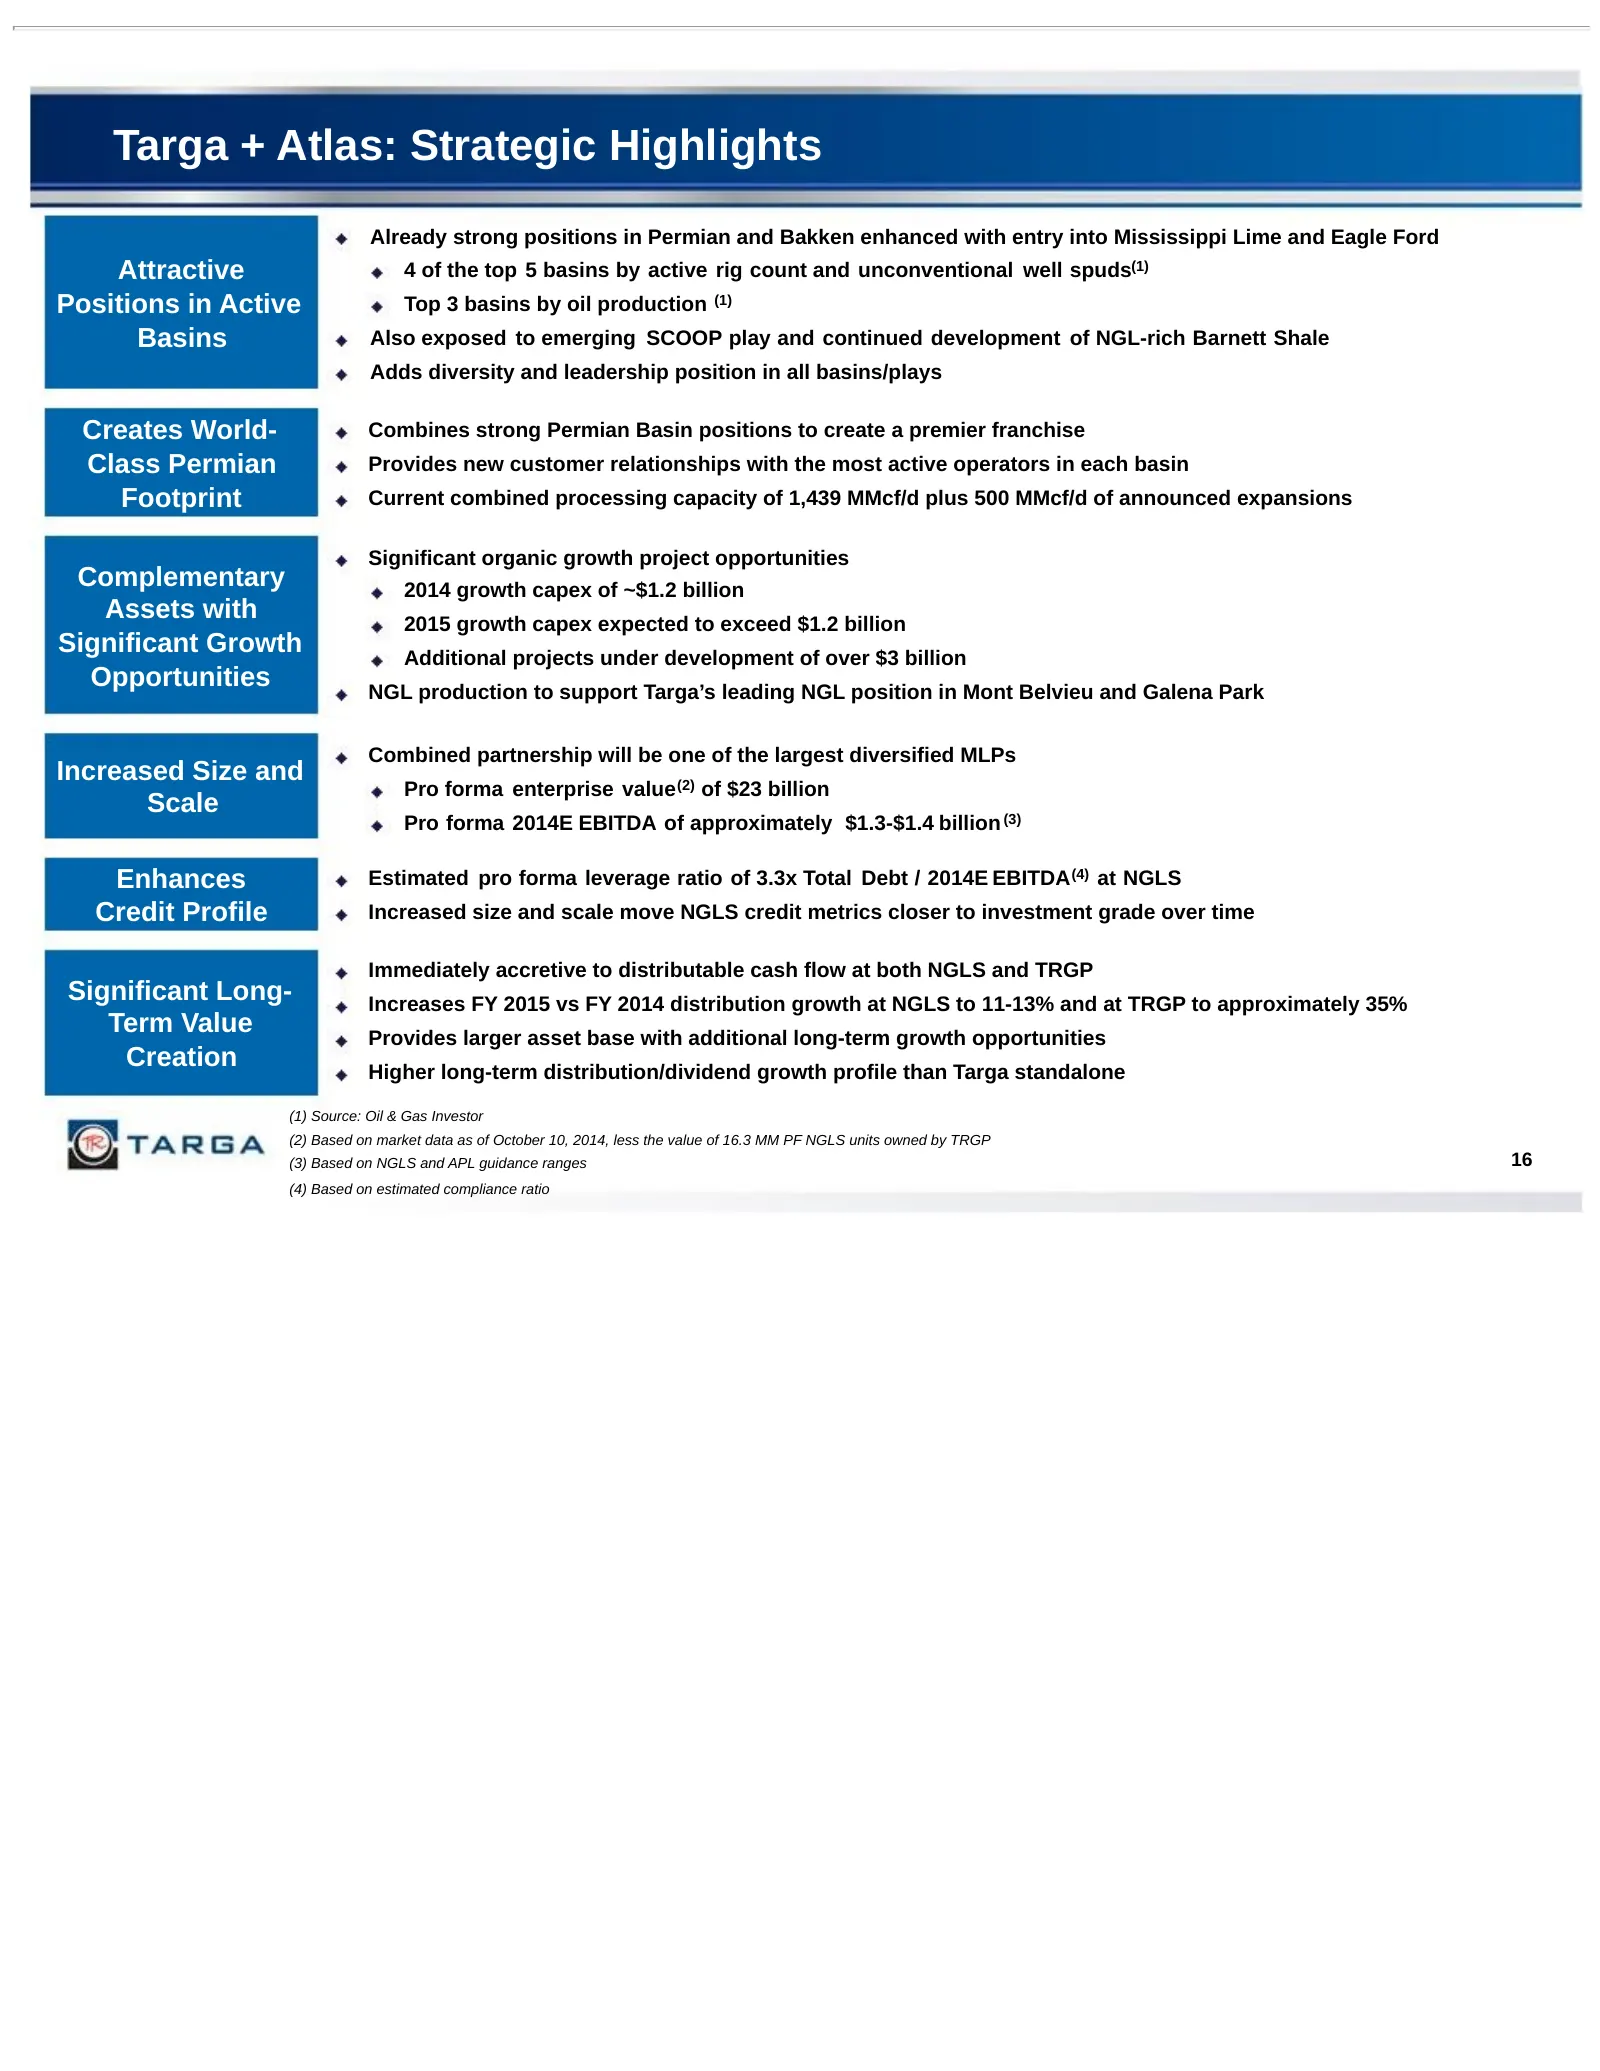
Targa + Atlas: Strategic Highlights Already strong positions in Permian and Bakken enhanced with entry into Mississippi Lime and Eagle Ford Attractive 4 of the top 5 basins by active rig count and unconventional well spuds(1) Positions in Active Top 3 basins by oil production (1) Basins Also exposed
Slide 18: Appendix
Appendix
Slide 19: Non-GAAP Measures Reconciliation
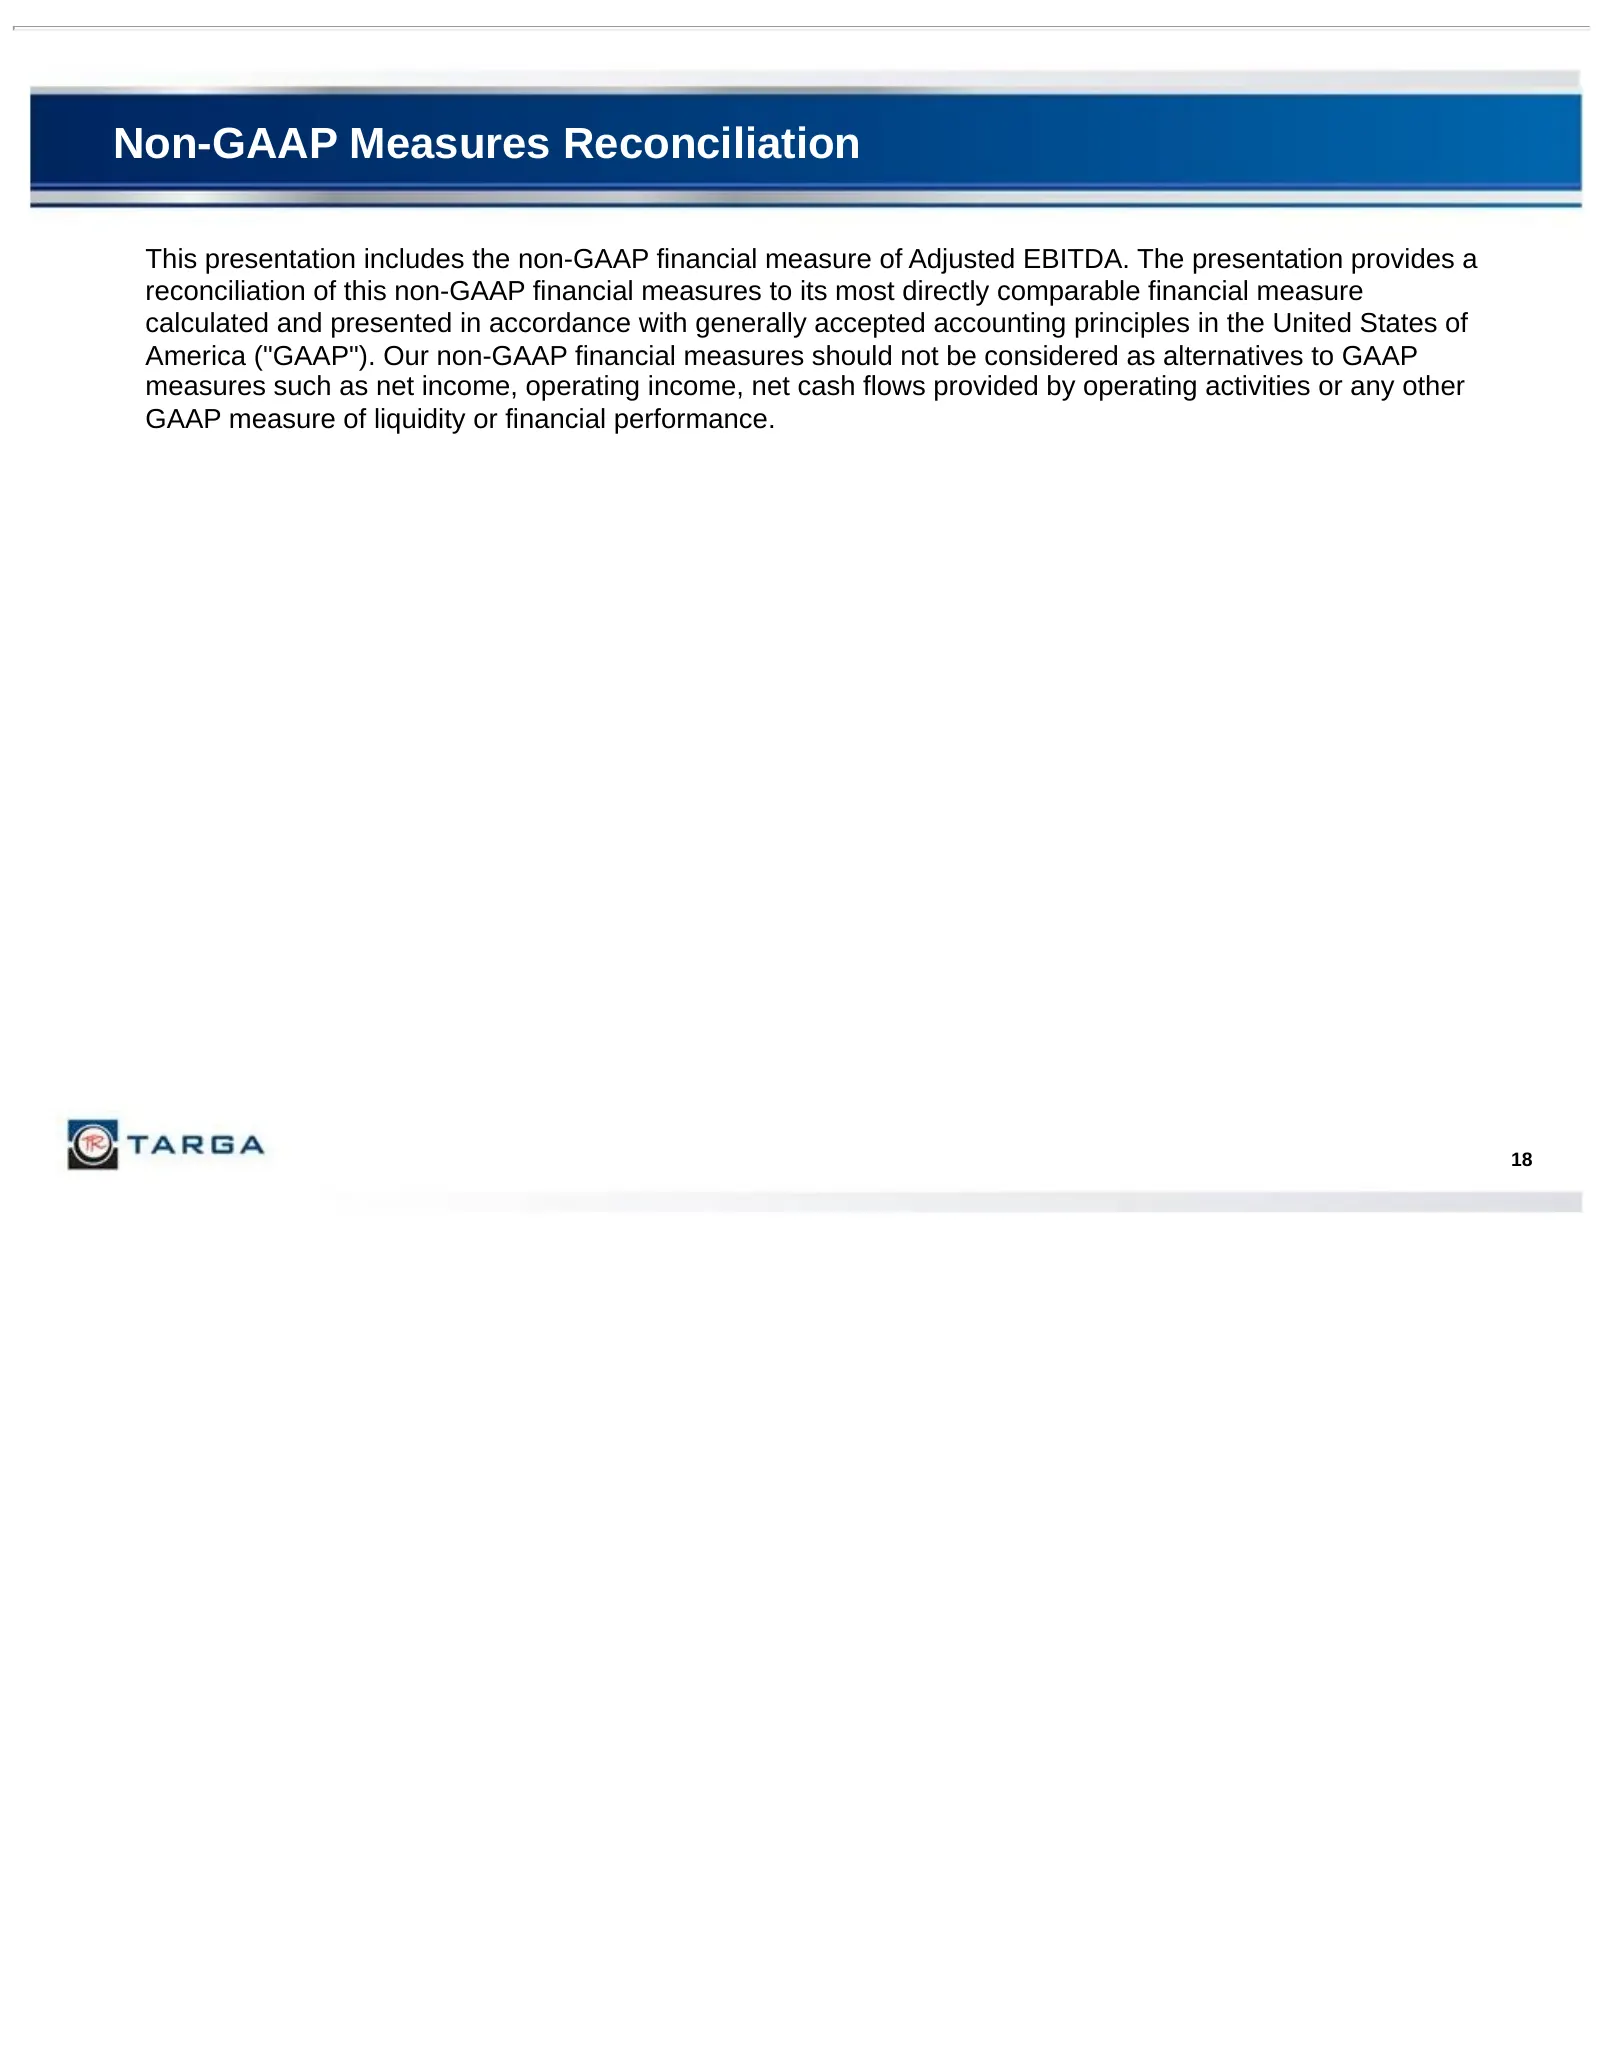
Non-GAAP Measures Reconciliation This presentation includes the non-GAAP financial measure of Adjusted EBITDA. The presentation provides a reconciliation of this non-GAAP financial measures to its most directly comparable financial measure calculated and presented in accordance with generally accept
Slide 20: Non-GAAP Measures Reconciliation
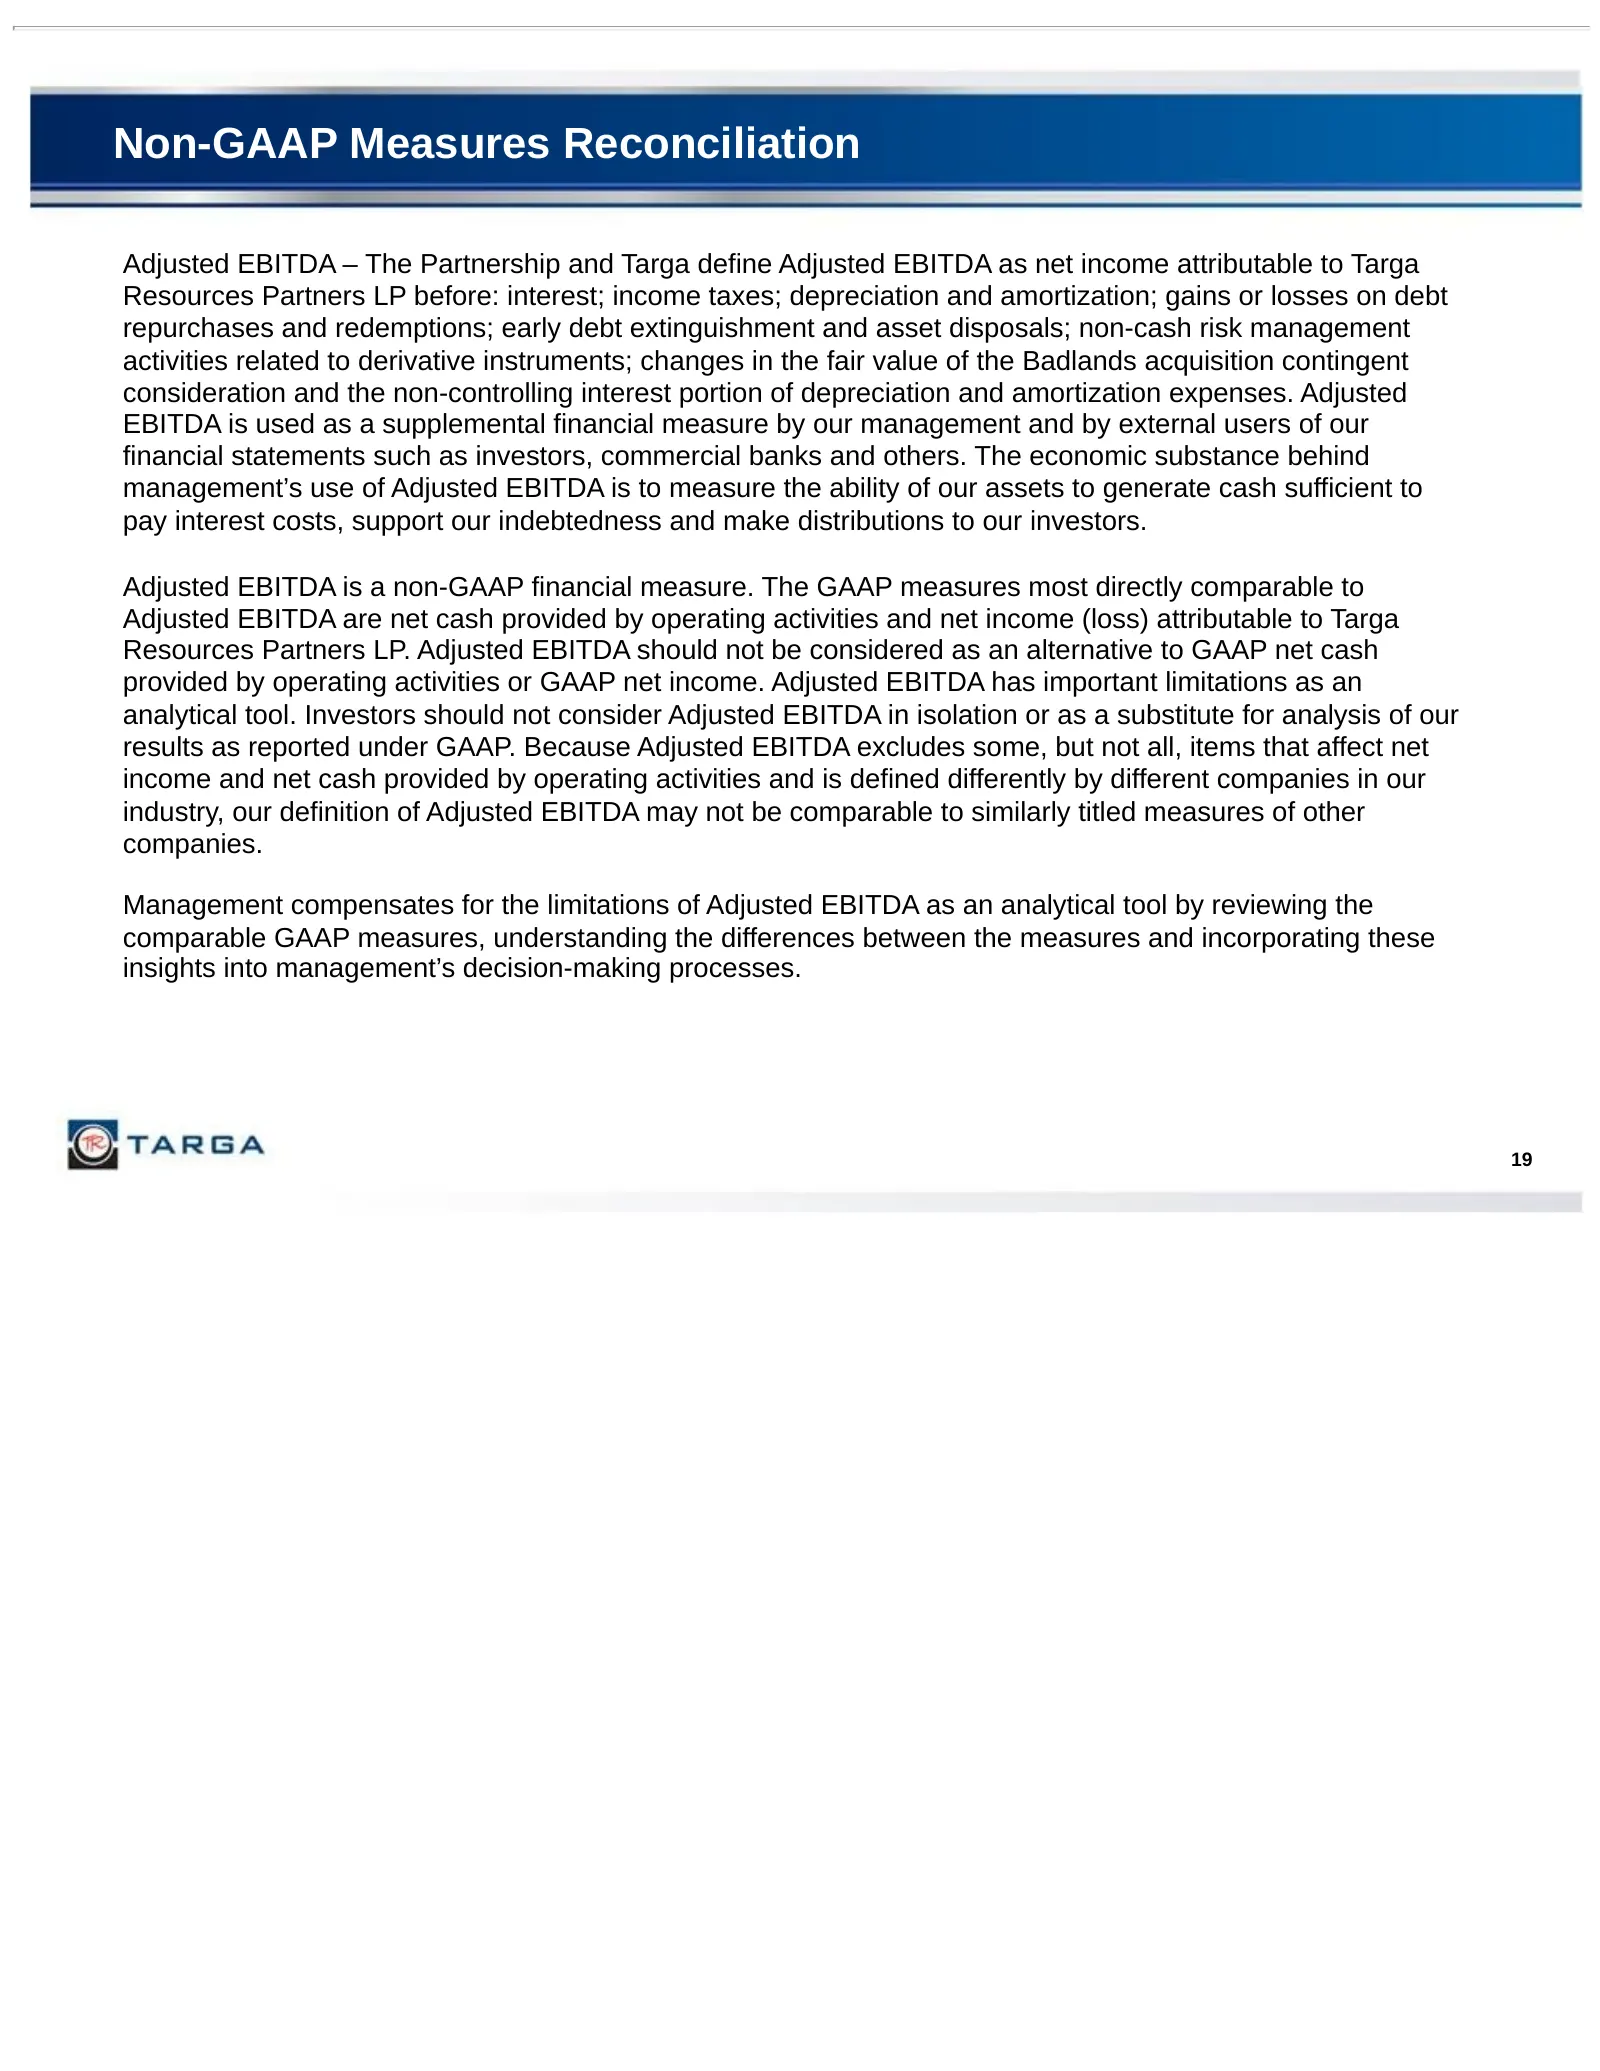
Non-GAAP Measures Reconciliation Adjusted EBITDA – The Partnership and Targa define Adjusted EBITDA as net income attributable to Targa Resources Partners LP before: interest; income taxes; depreciation and amortization; gains or losses on debt repurchases and redemptions; early debt extinguishment
Slide 21: Non-GAAP Reconciliation – 2014 EBITDA
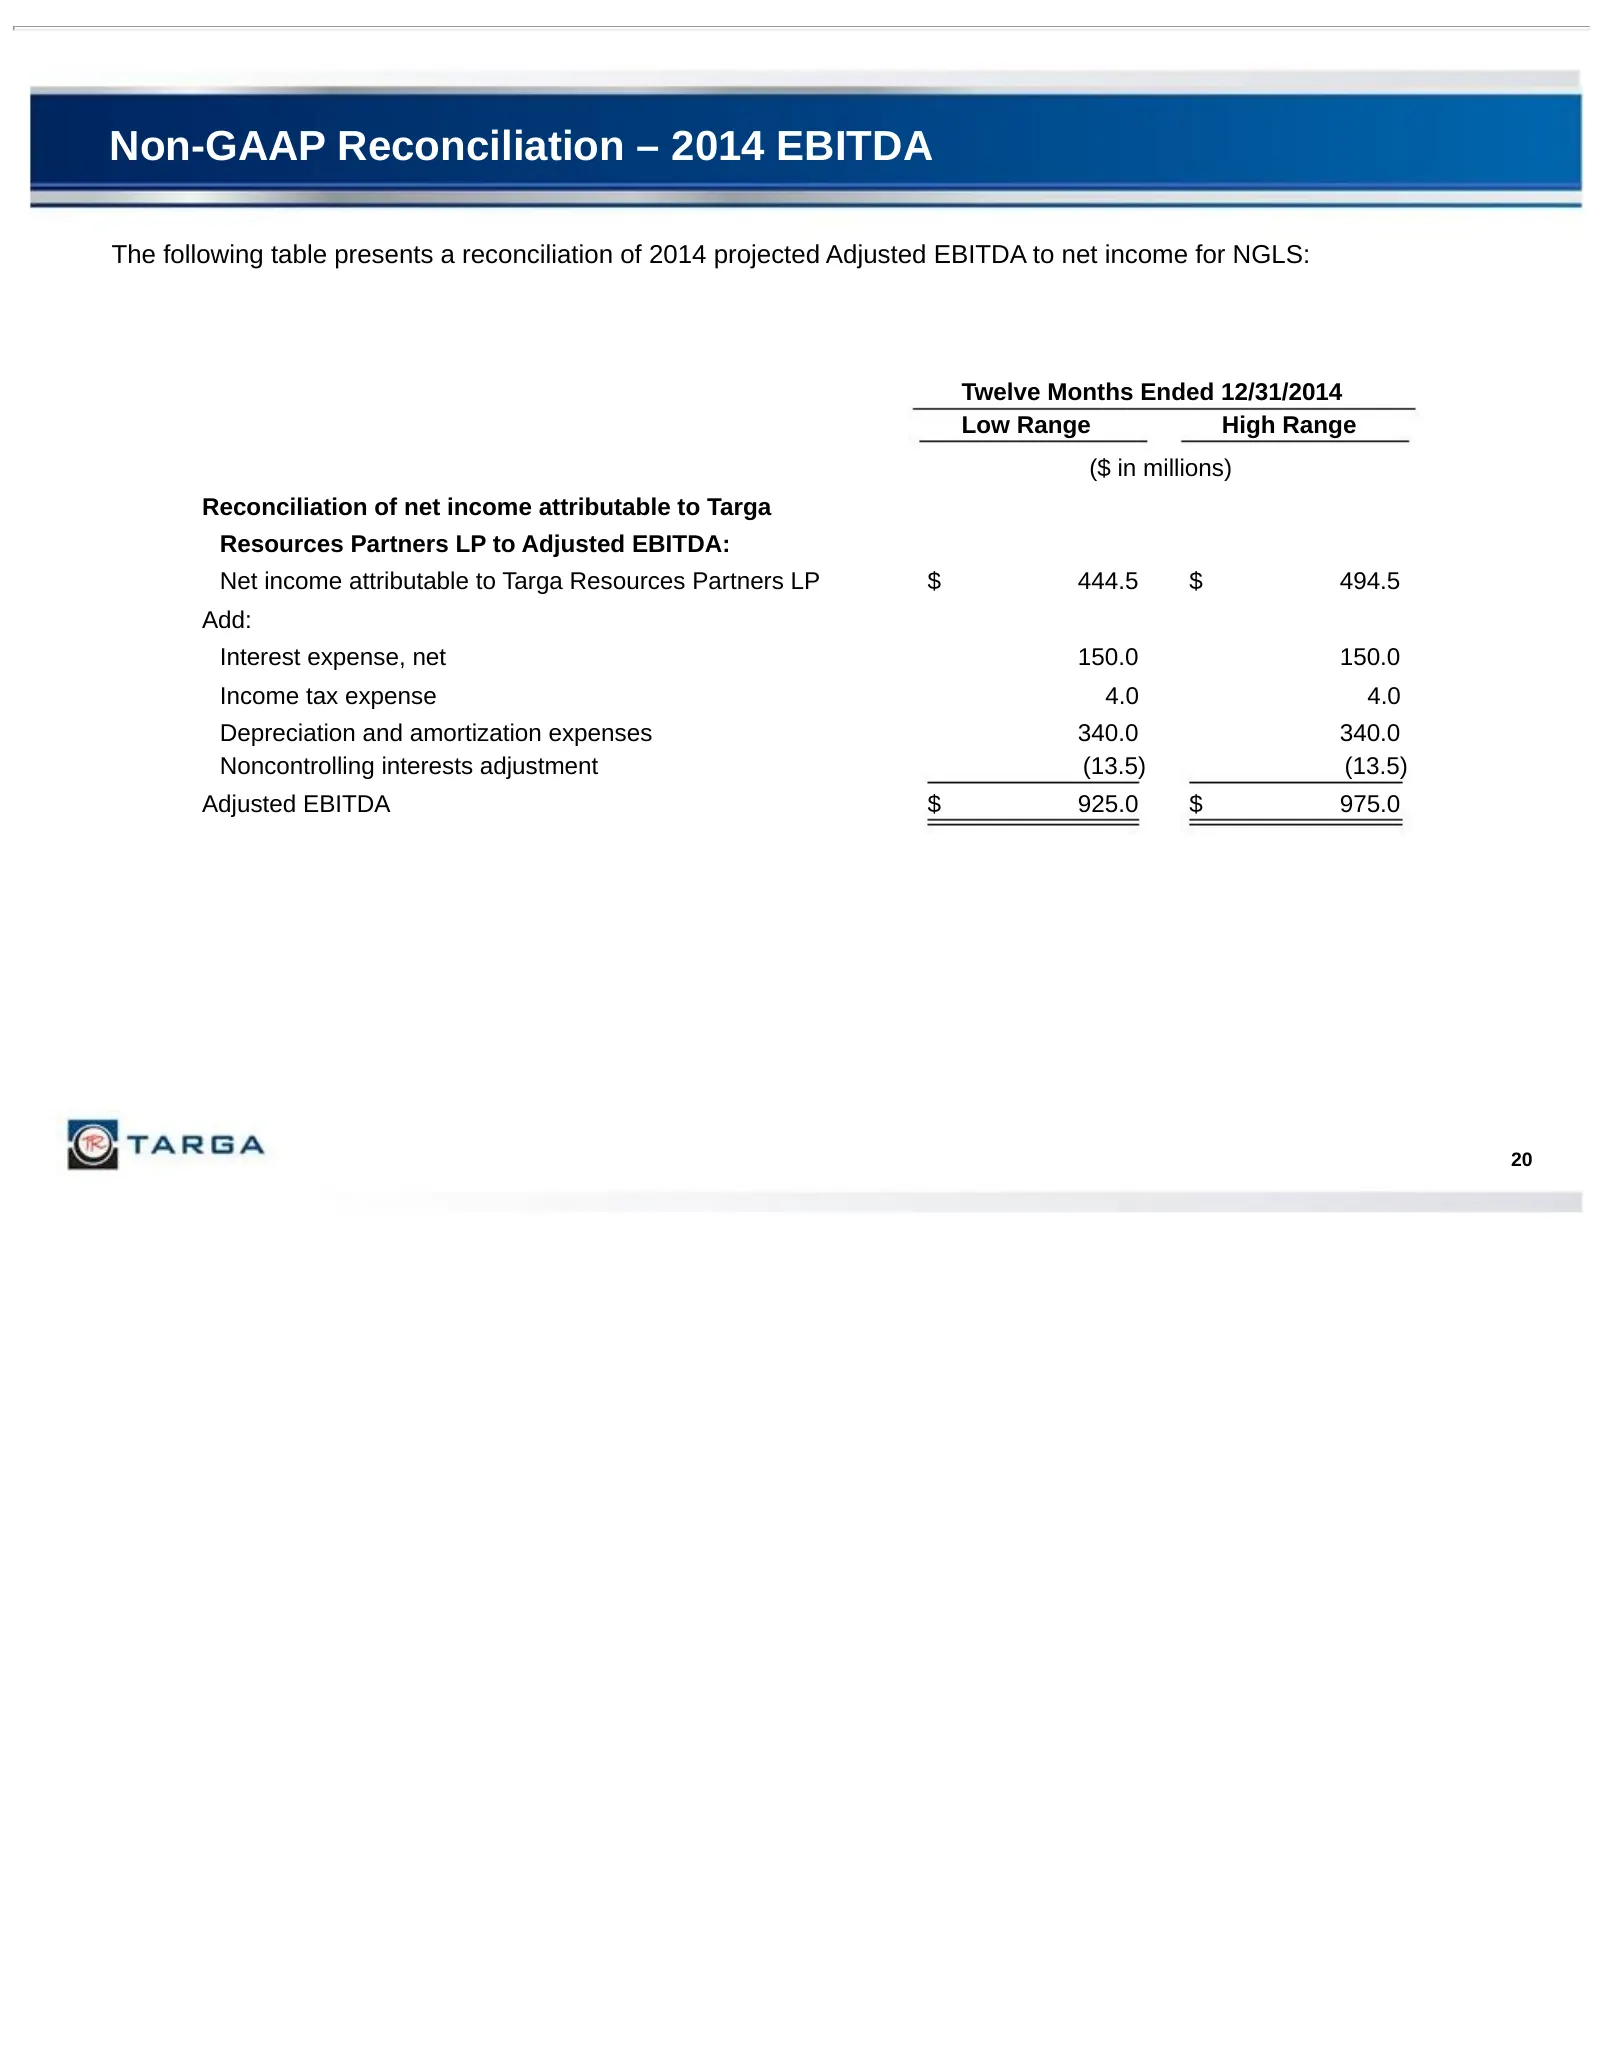
Non-GAAP Reconciliation – 2014 EBITDA The following table presents a reconciliation of 2014 projected Adjusted EBITDA to net income for NGLS: Twelve Months Ended 12/31/2014 Low Range High Range ($ in millions) Reconciliation of net income attributable to Targa Resources Partners LP to Adjusted EBITD
Slide 22: Targa Resources contact details
1000 Louisiana Suite 4300 Houston, TX 77002 Phone: (713) 584-1000 Email: InvestorRelations@targaresources.com Website: www.targaresources.com 21
Source: SEC EDGAR · 425 filed Nov 12, 2014
More decks from Atlas Pipeline Partners L.P.
 Goldman Sachs Global Energy Conference 201525 slides · Jan 7, 2015
 Stephens Fall Investment Conference 201430 slides · Nov 12, 2014
 SPAC Merger (November 2014)47 slides · Nov 5, 2014
 Investor Presentation (September 2008)35 slides · Sep 24, 2008
 Debt Investor Presentation (June 2007)49 slides · Jun 27, 2007