Rectifier Technologies Ltd · ASX:RFT
Rectifier Technologies — ICE — Investor Presentation (March 2004)
31 slides from Rectifier Technologies's investor presentation, March 2004
Slide 1: Company Presentation March 2004
Company Presentation March 2004
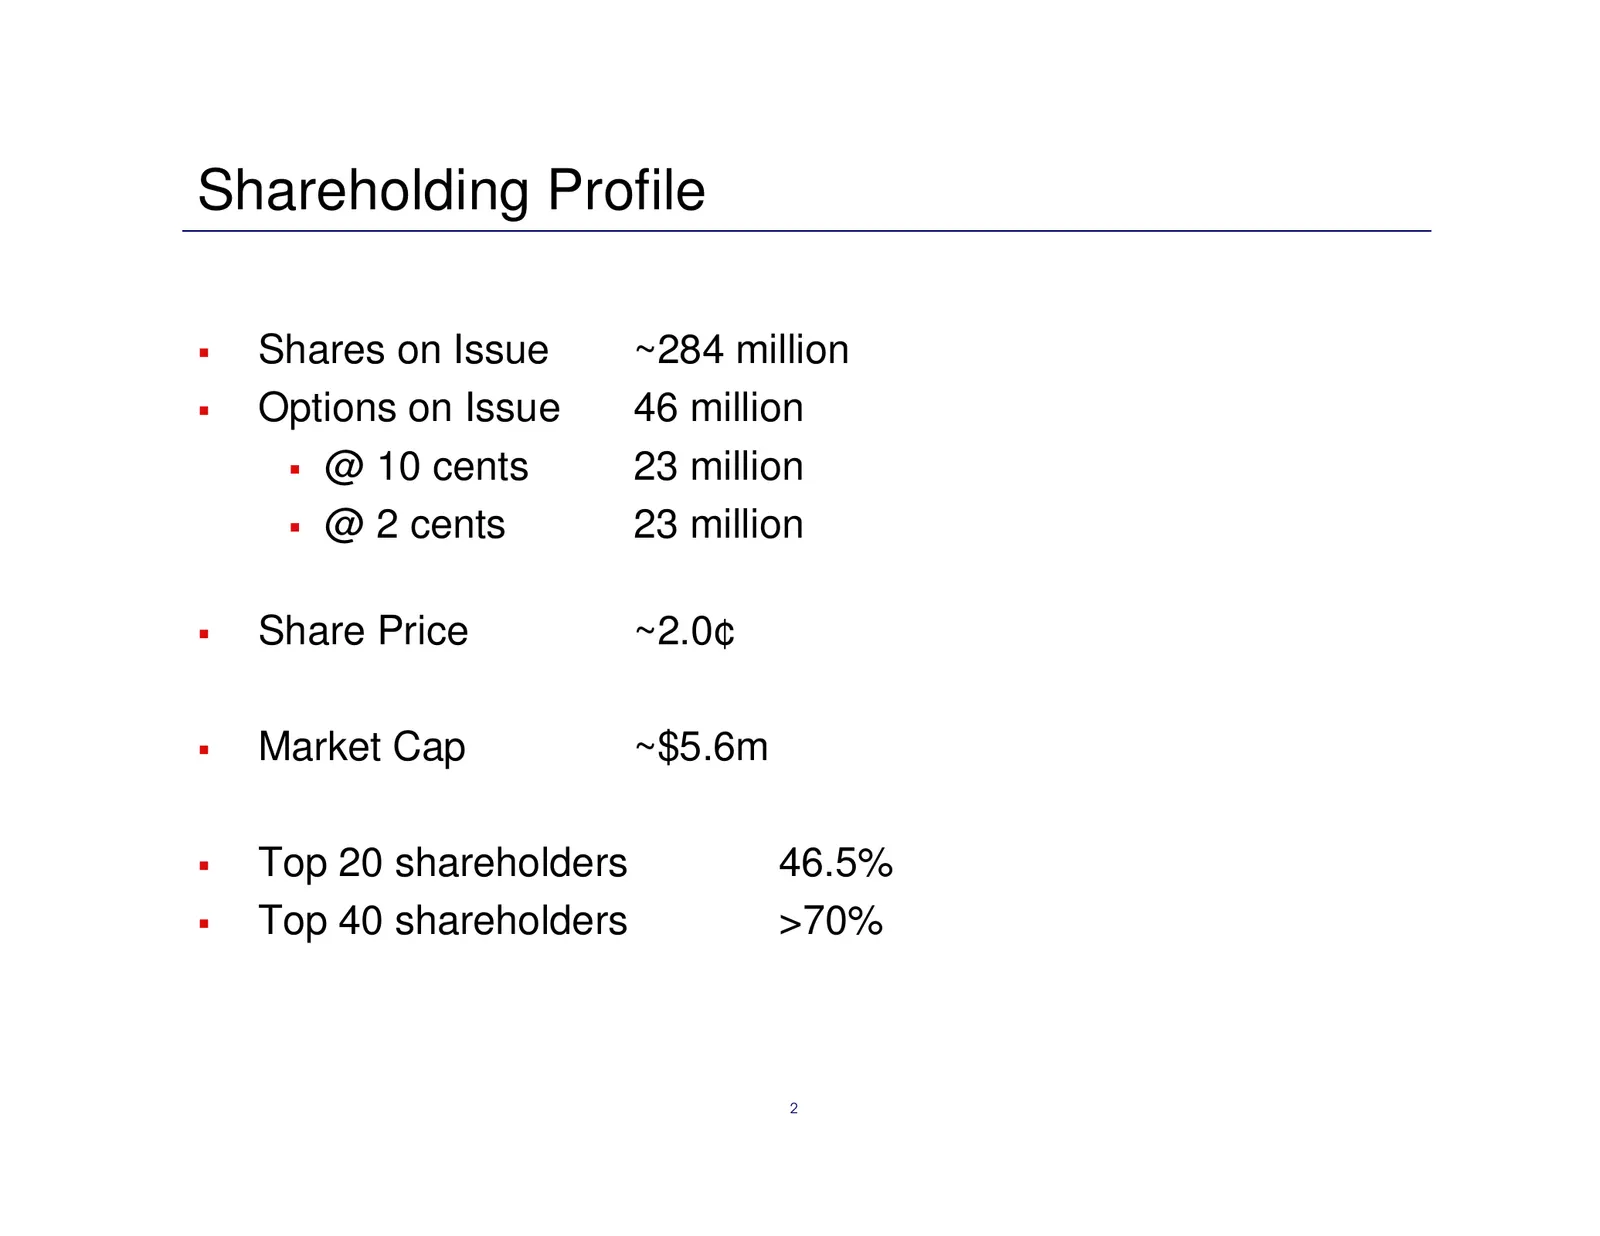
Slide 2: Shareholding Profile
Shareholding Profile Shares on Issue ~284 million Options on Issue 46 million @ 10 cents 23 million @ 2 cents 23 million Share Price ~2.0¢ Market Cap ~$5.6m Top 20 shareholders 46.5% Top 40 shareholders >70% 2
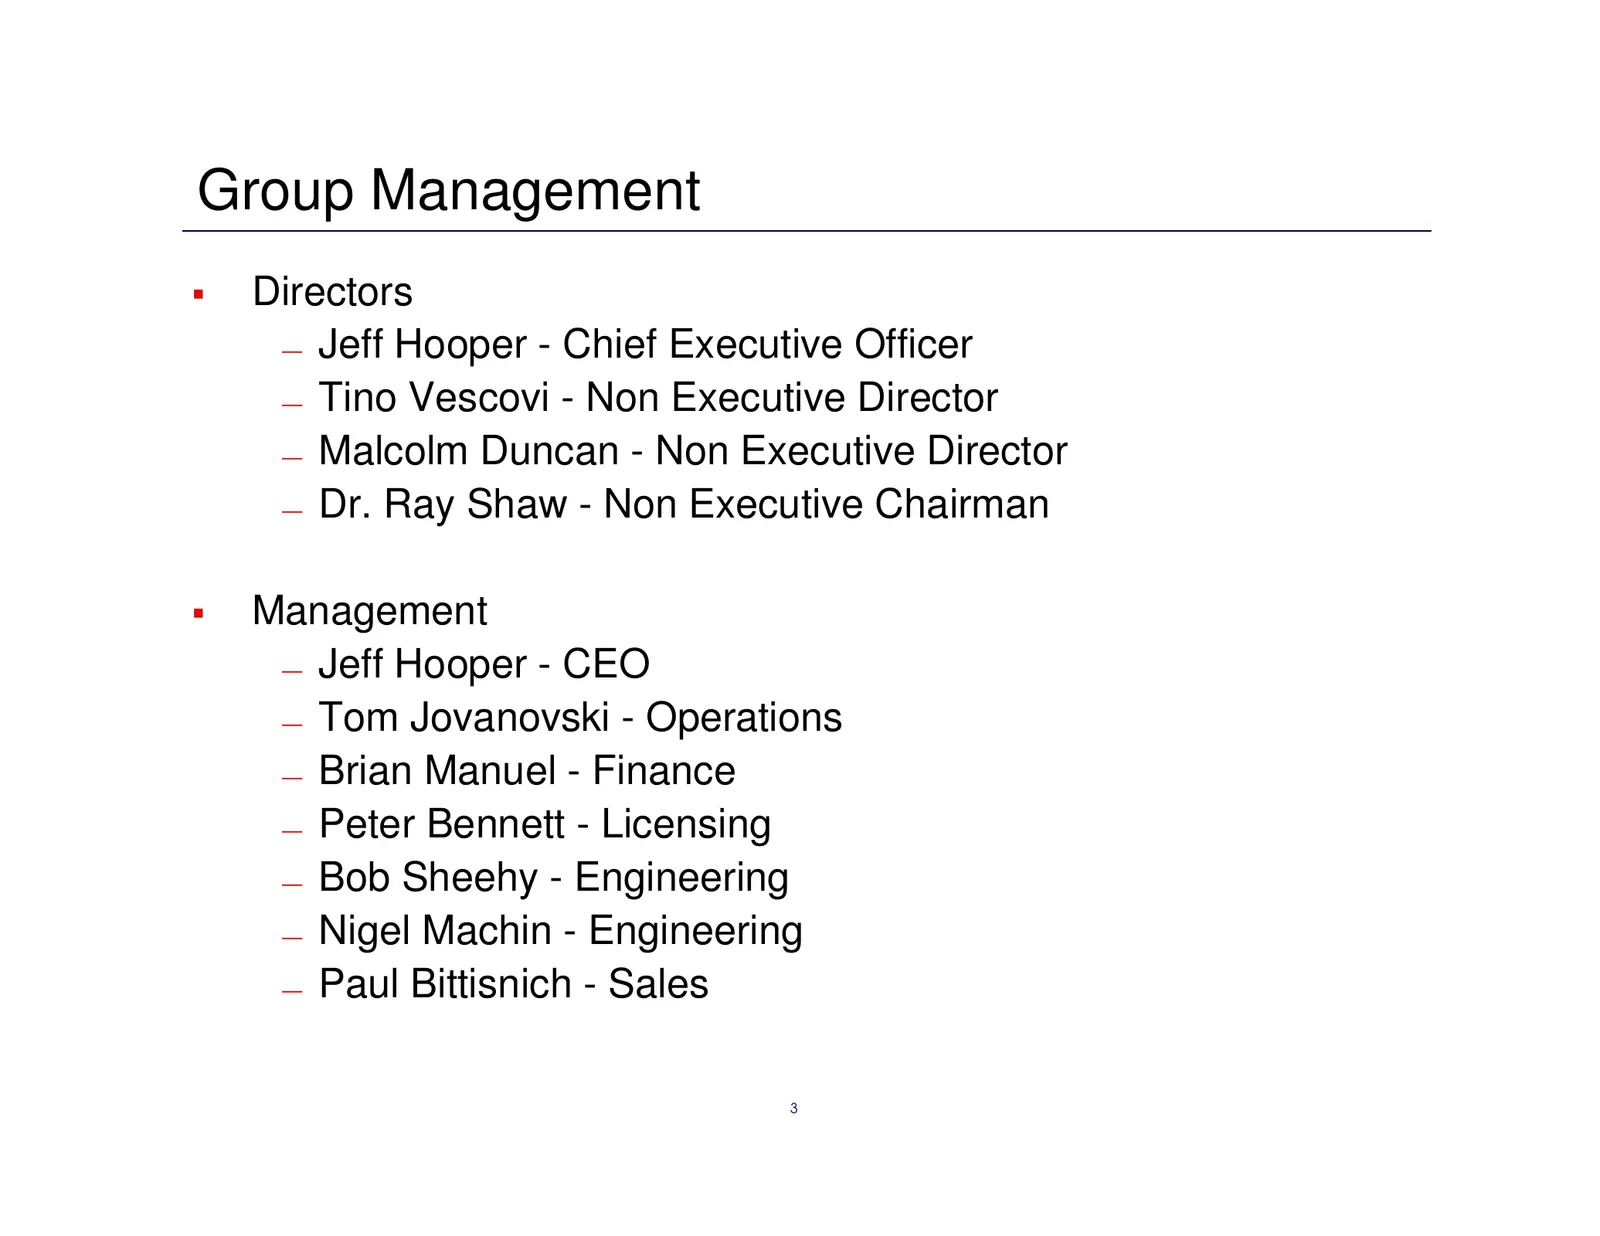
Slide 3: Group Management
Group Management Directors — Jeff Hooper - Chief Executive Officer — Tino Vescovi - Non Executive Director — Malcolm Duncan - Non Executive Director — Dr. Ray Shaw - Non Executive Chairman Management — Jeff Hooper - CEO — Tom Jovanovski - Operations — Brian Manuel - Finance — Peter Bennett - Lic
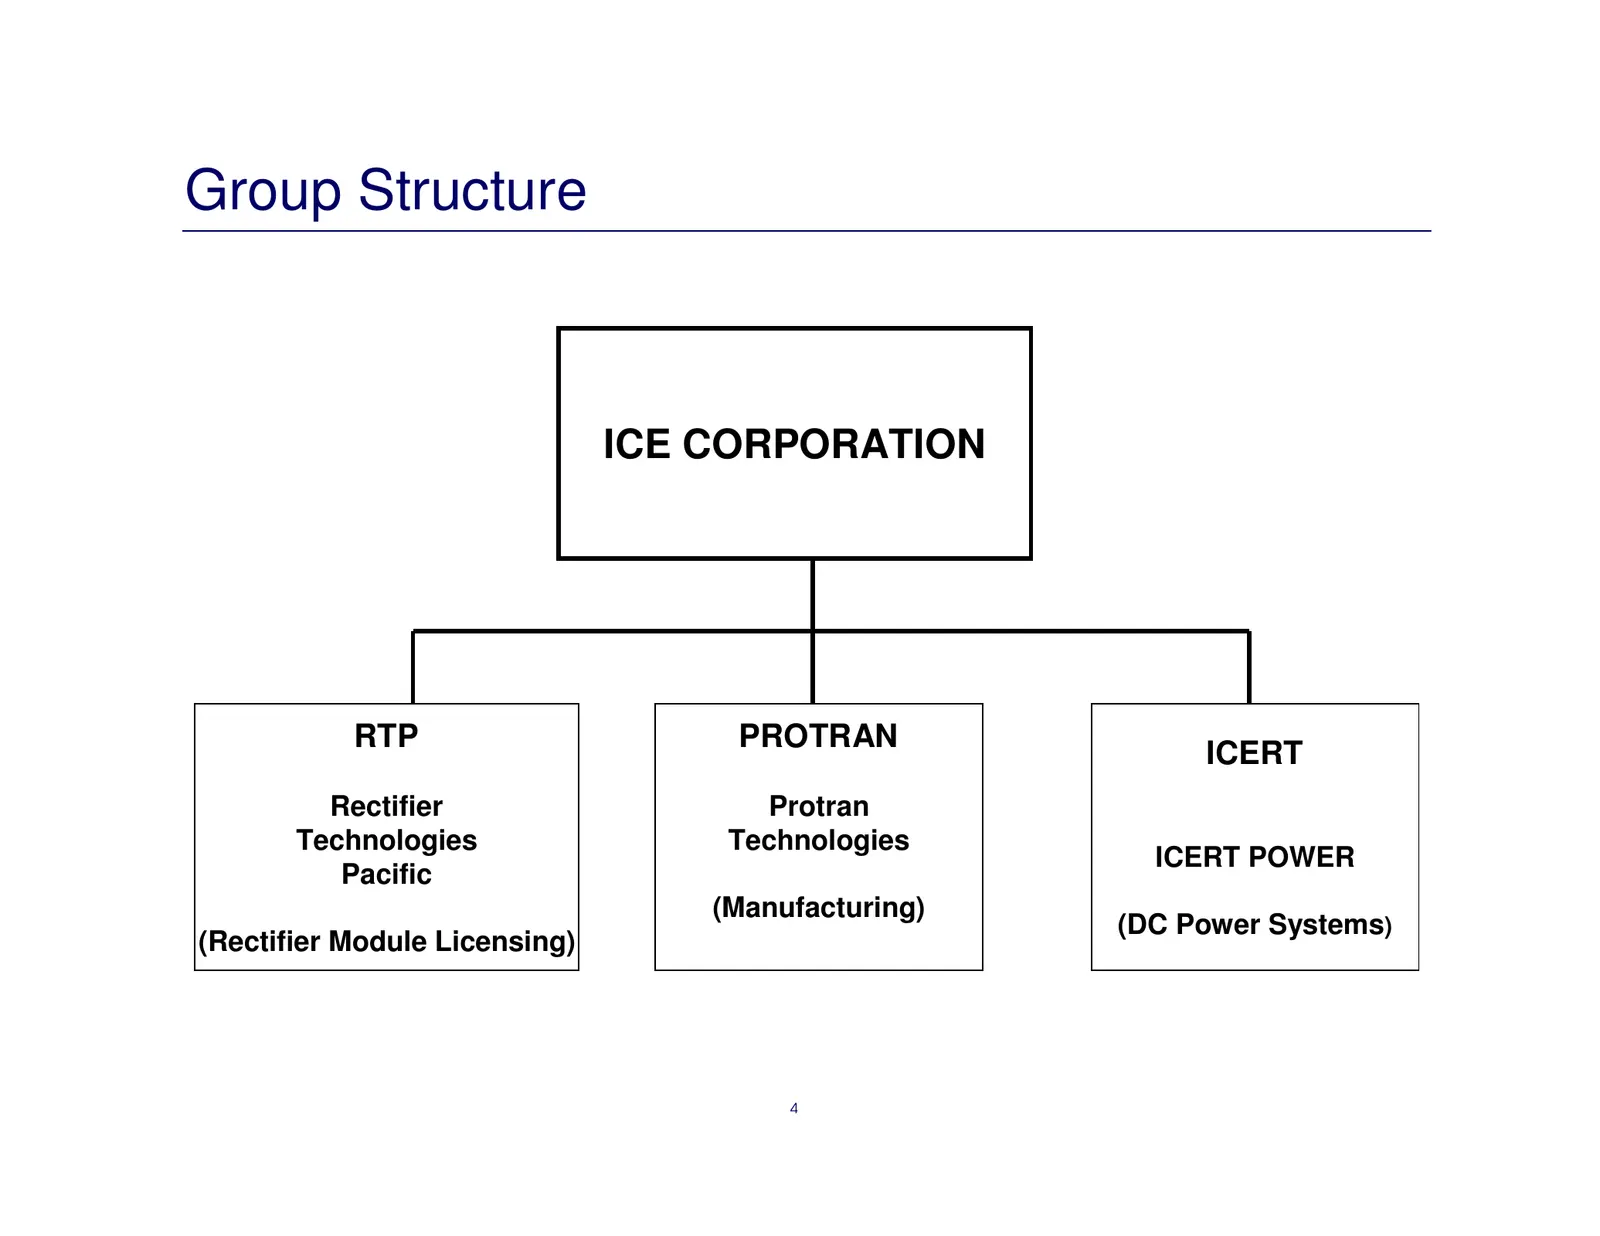
Slide 4: Group Structure
Group Structure ICE CORPORATION RTP PROTRAN ICERT Rectifier Protran Technologies Technologies ICERT POWER Pacific (Manufacturing) (DC Power Systems) (Rectifier Module Licensing) 4
Slide 5: What we do today: Design Modules & make Magnetics
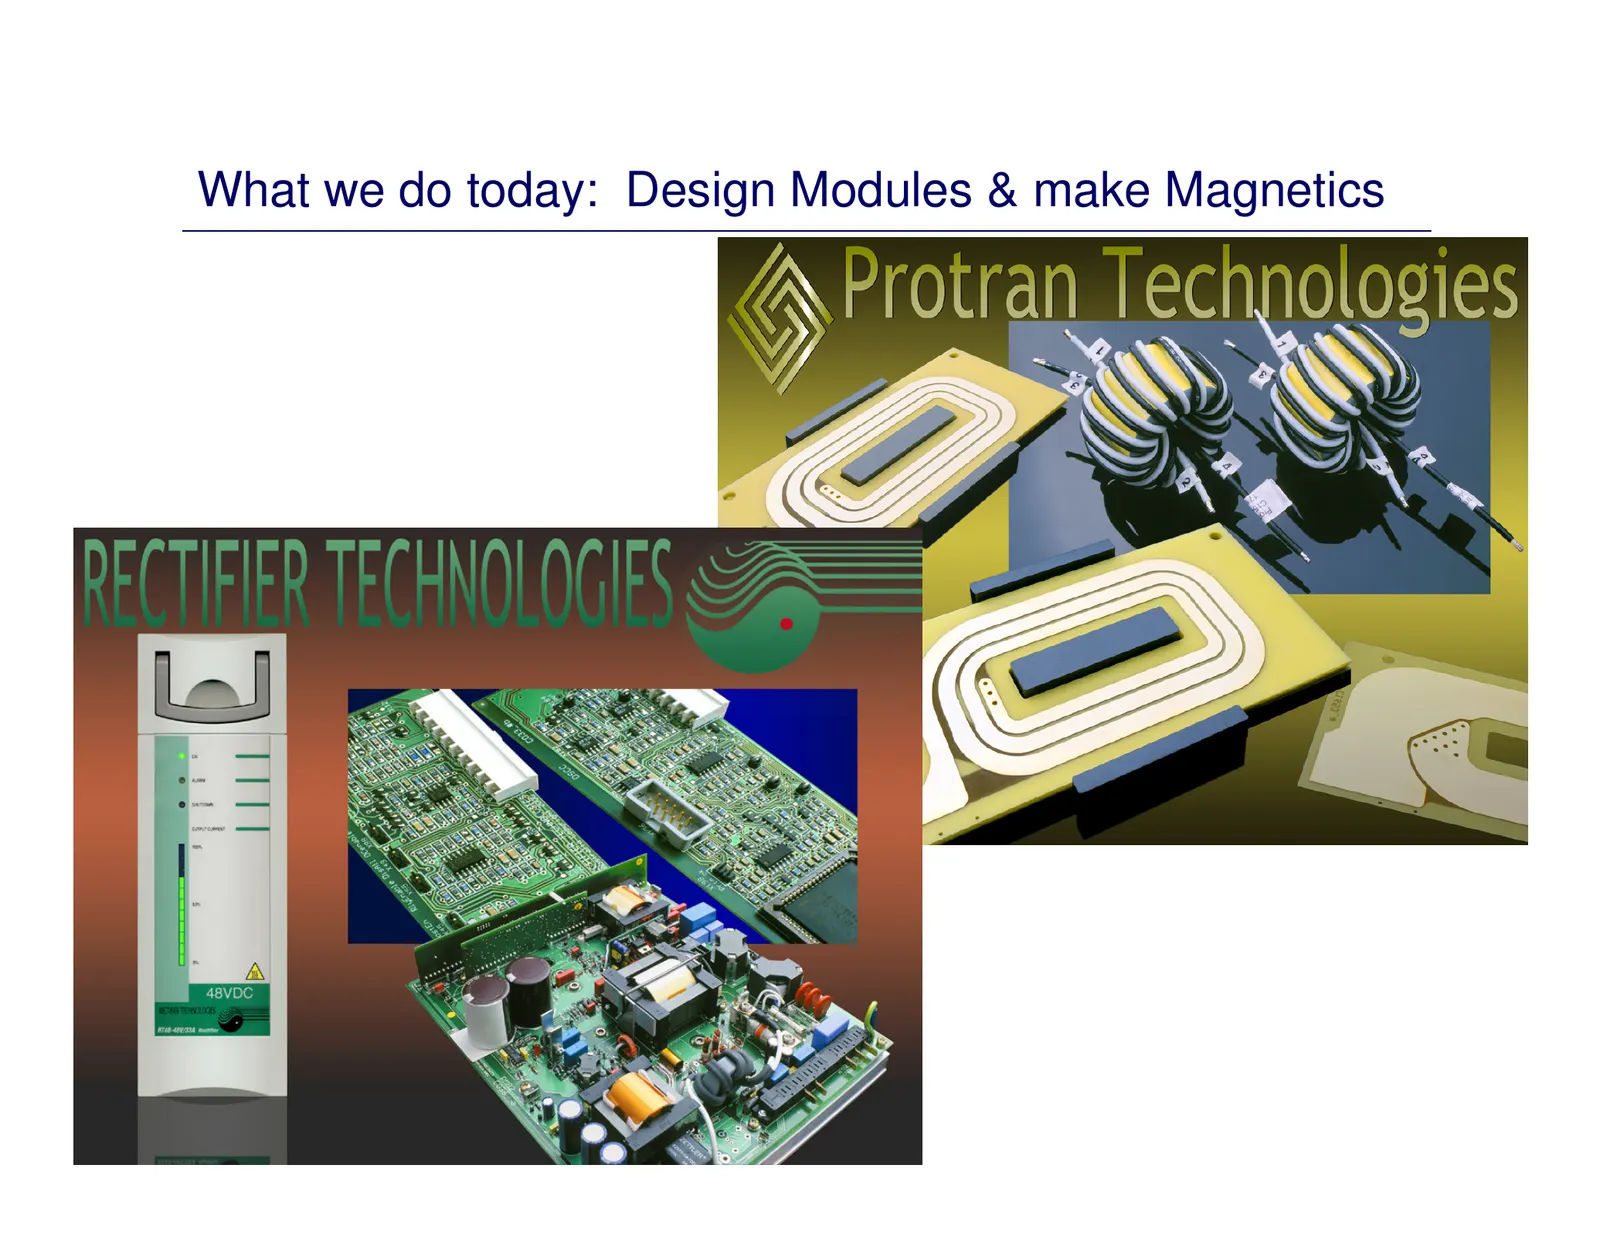
What we do today: Design Modules & make Magnetics 5
Slide 6: Performance Overview
Performance Overview Profitable in FY’04 and expanding in 2005 Telco market recovering R&D efforts increasing - Ausindustry Grant RTP and Protran one site – cost/efficiency savings More Licensees established 6
Slide 7: Key Financials
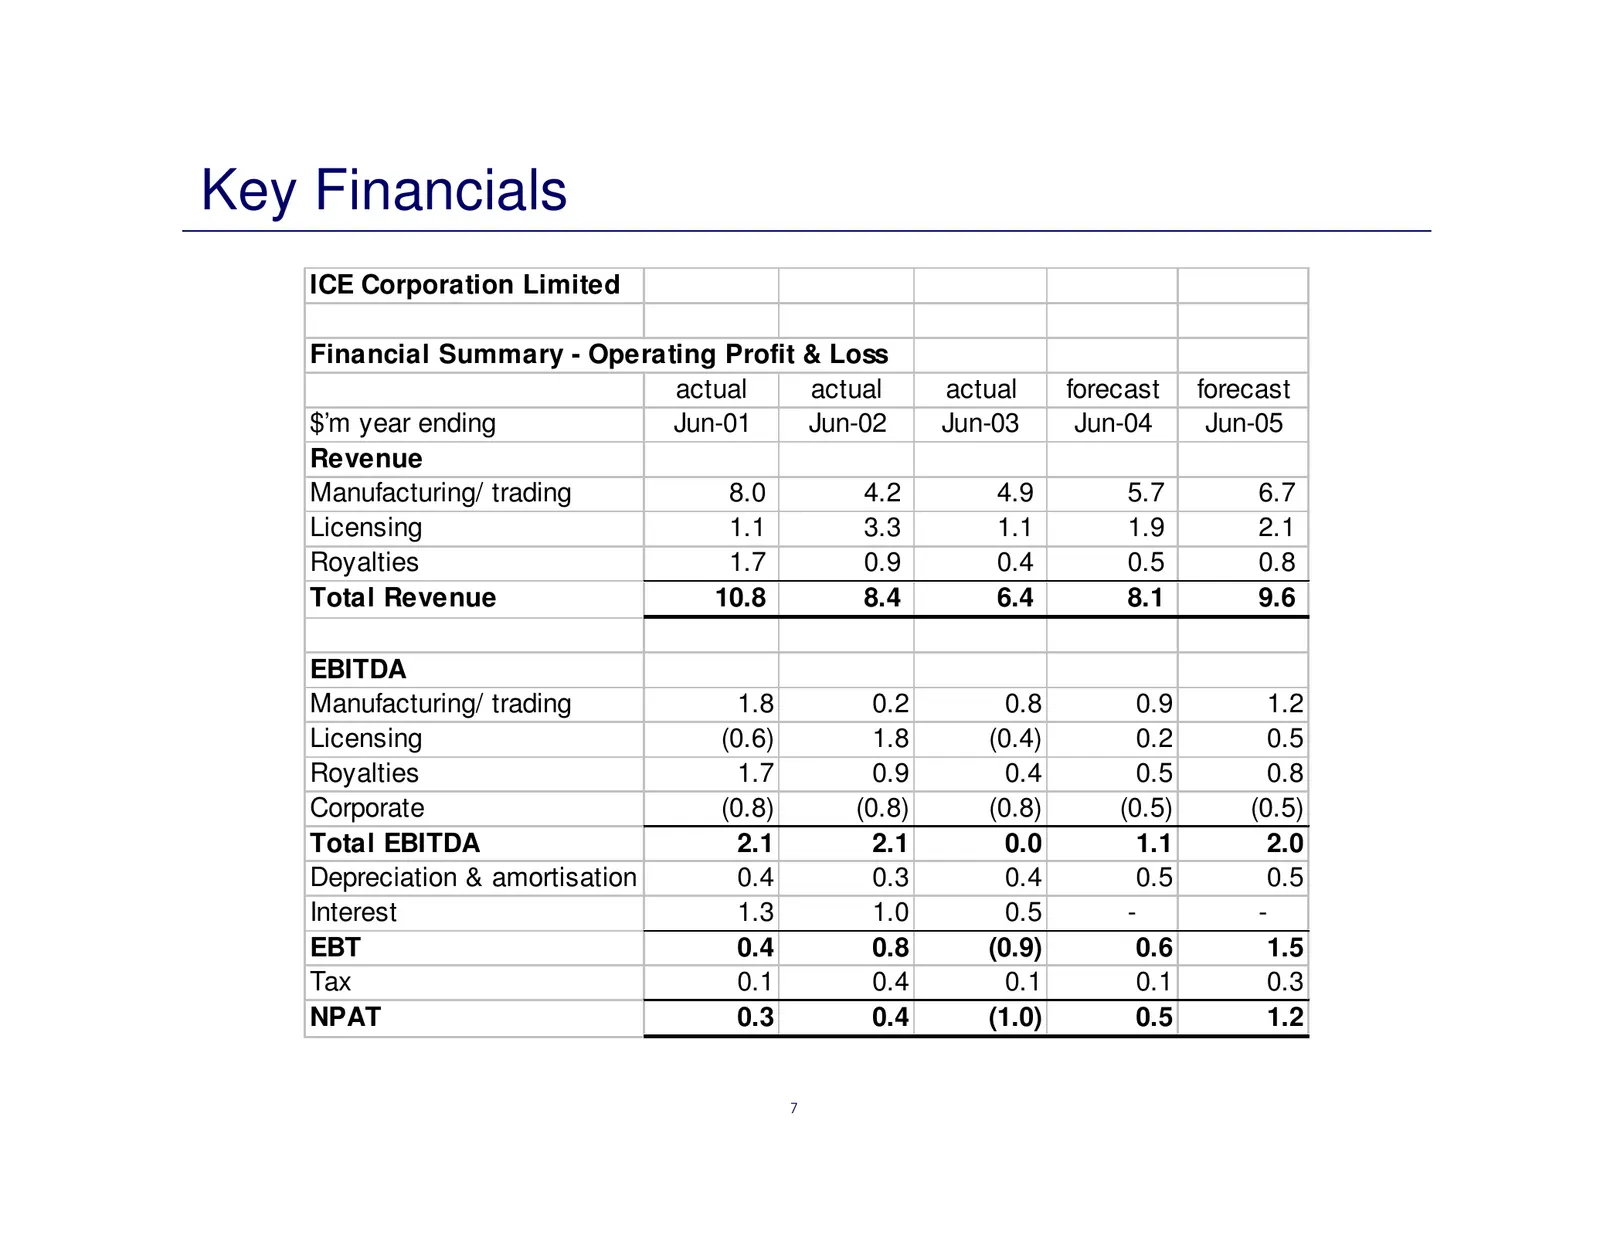
Key Financials ICE Corporation Limited Financial Summary - Operating Profit & Loss actual actual actual forecast forecast $’m year ending Jun-01 Jun-02 Jun-03 Jun-04 Jun-05 Revenue Manufacturing/ trading 8.0 4.2 4.9 5.7 6.7 Licensing 1.1 3.3 1.1 1.9 2.1 Royalties 1.7 0.9 0.4 0.5 0.8 Total Revenue 10
Slide 8: Key Financials
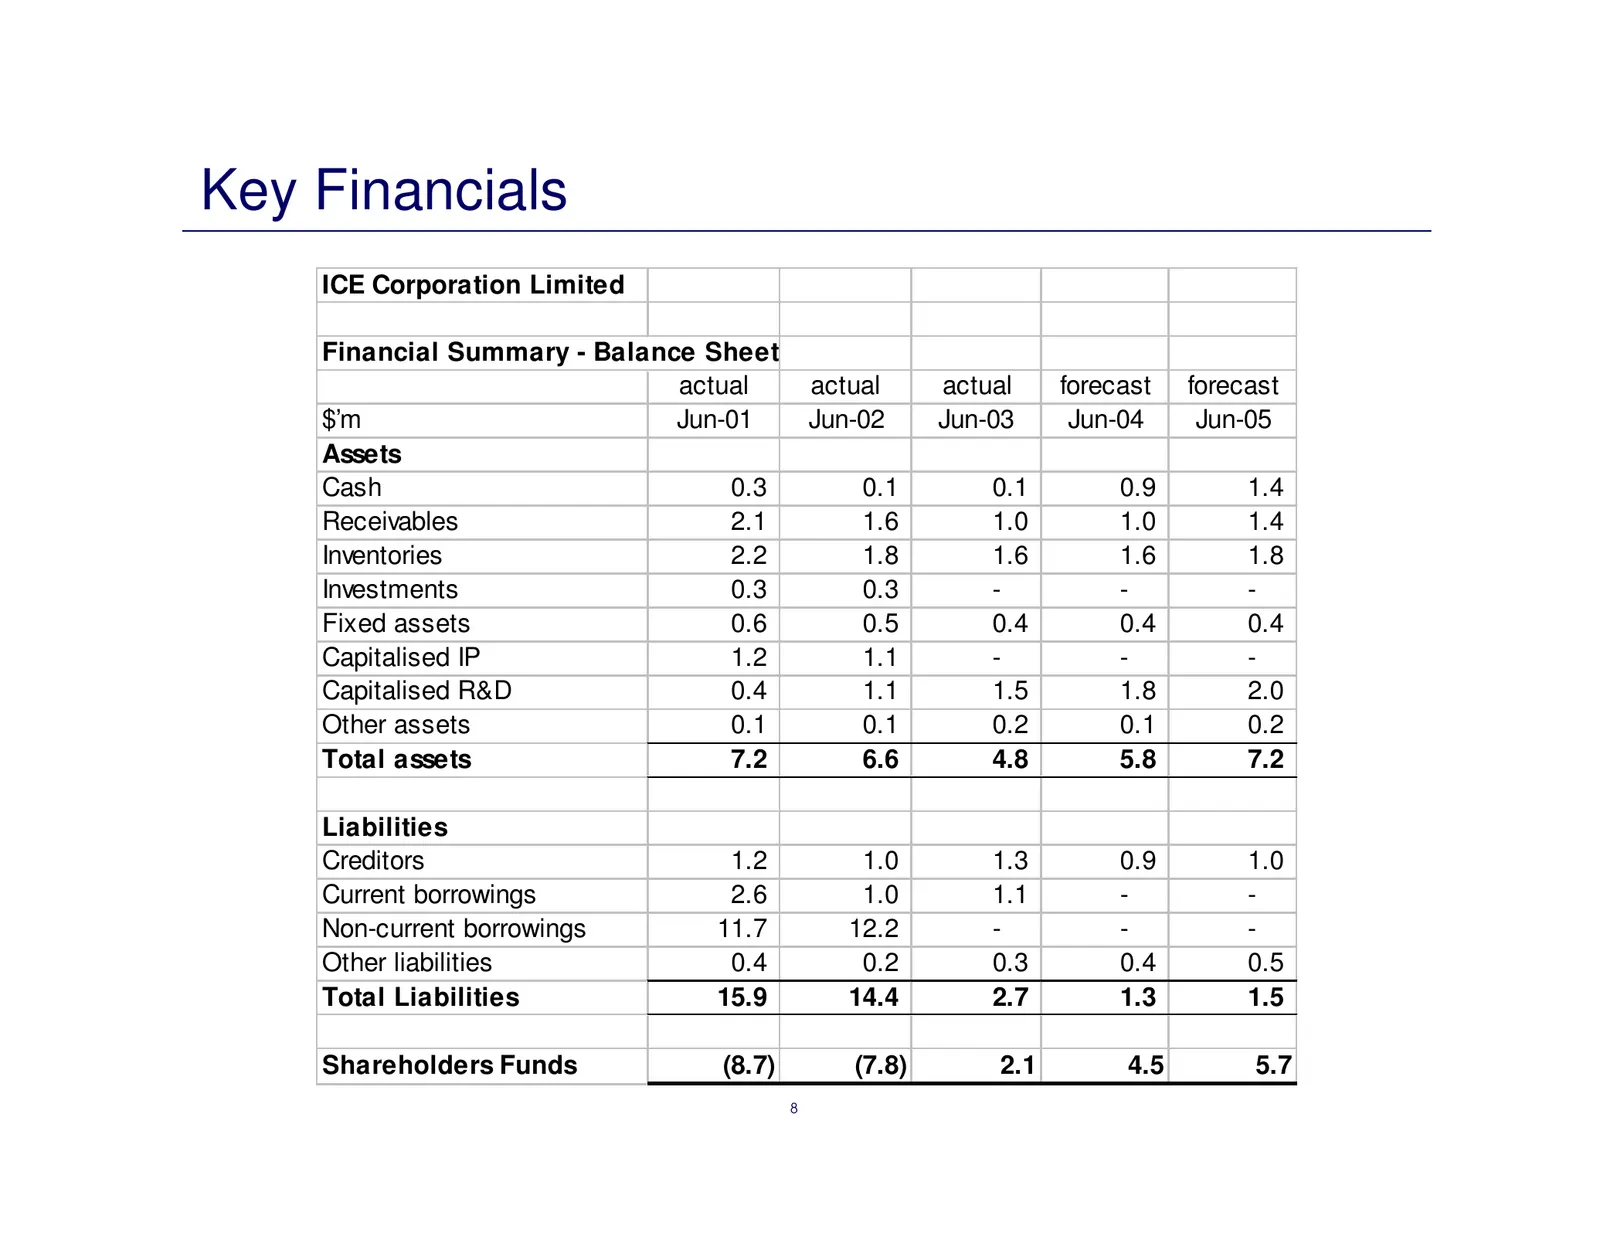
Key Financials ICE Corporation Limited Financial Summary - Balance Sheet actual actual actual forecast forecast $’m Jun-01 Jun-02 Jun-03 Jun-04 Jun-05 Assets Cash 0.3 0.1 0.1 0.9 1.4 Receivables 2.1 1.6 1.0 1.0 1.4 Inventories 2.2 1.8 1.6 1.6 1.8 Investments 0.3 0.3 - - - Fixed assets 0.6 0.5 0.4 0.
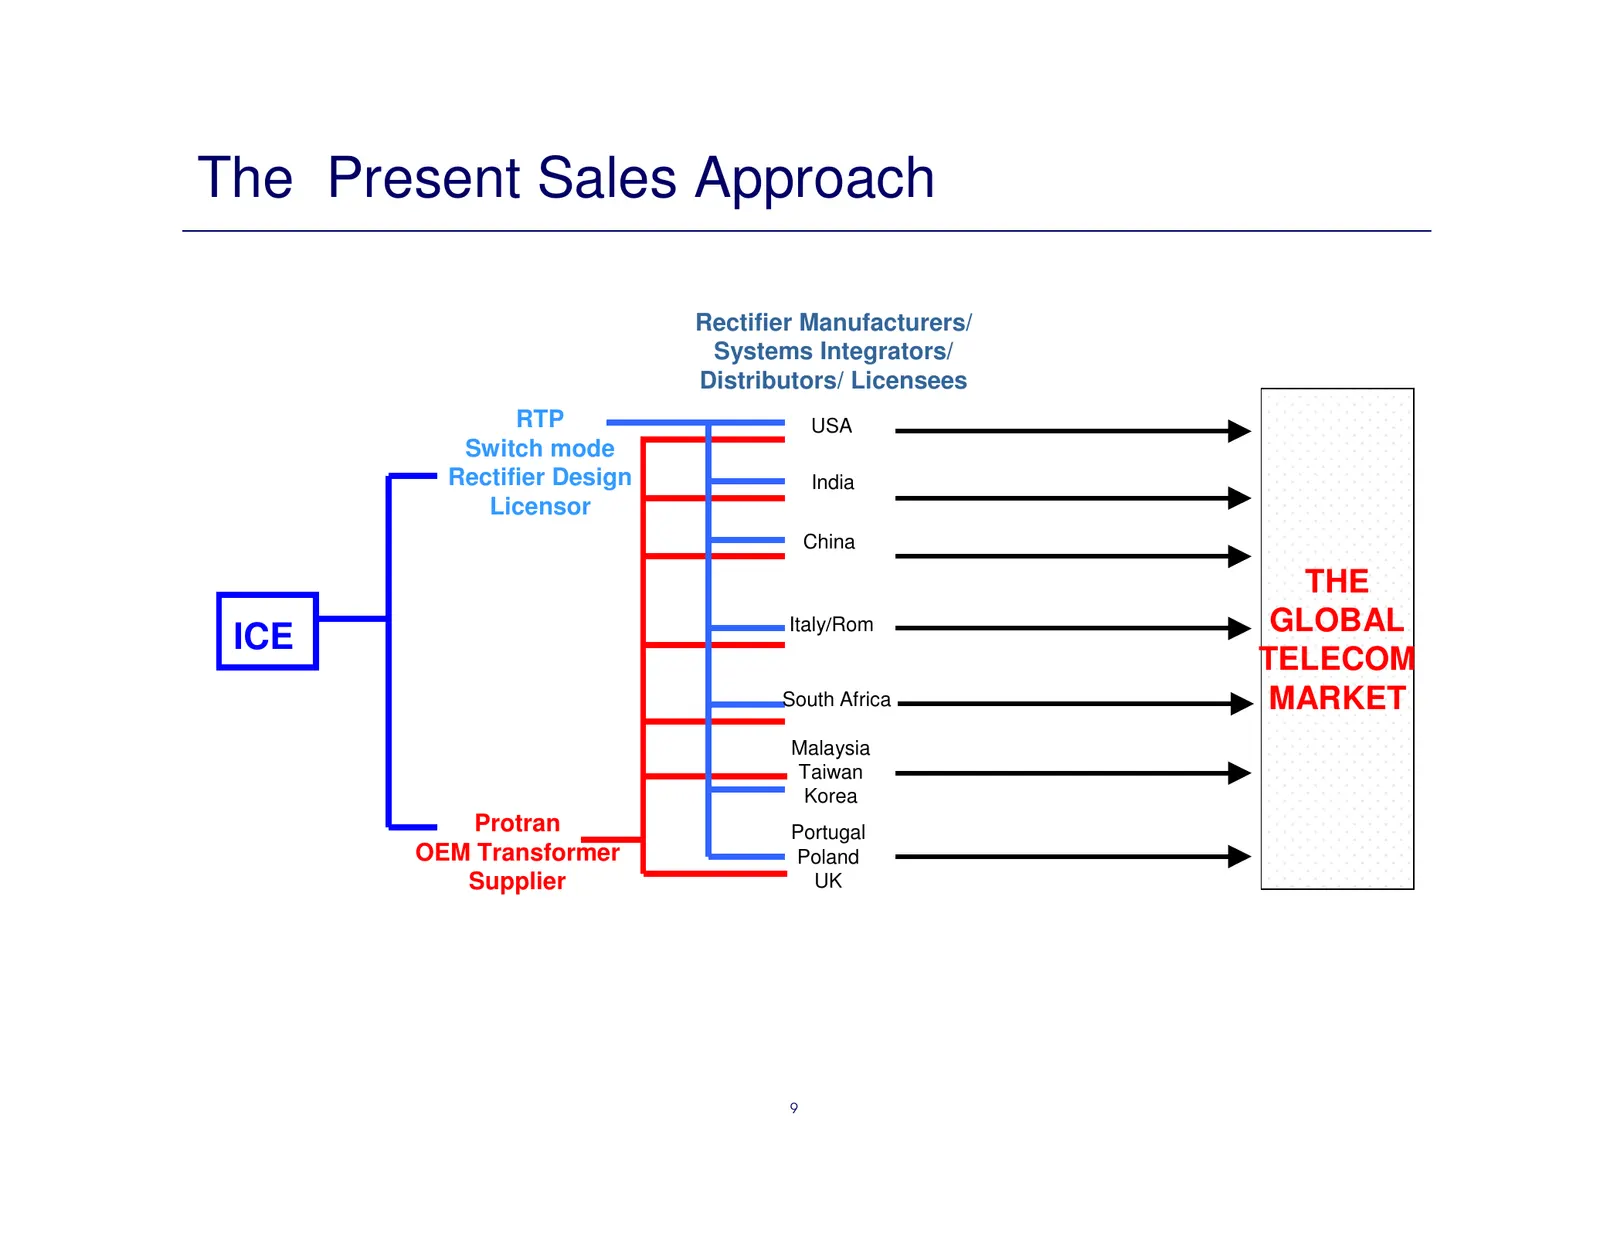
Slide 9: The Present Sales Approach
The Present Sales Approach Rectifier Manufacturers/ Systems Integrators/ Distributors/ Licensees RTP USA Switch mode Rectifier Design India Licensor China THE Italy/Rom GLOBAL ICE TELECOM South Africa MARKET Malaysia Taiwan Korea Protran Portugal OEM Transformer Poland Supplier UK 9
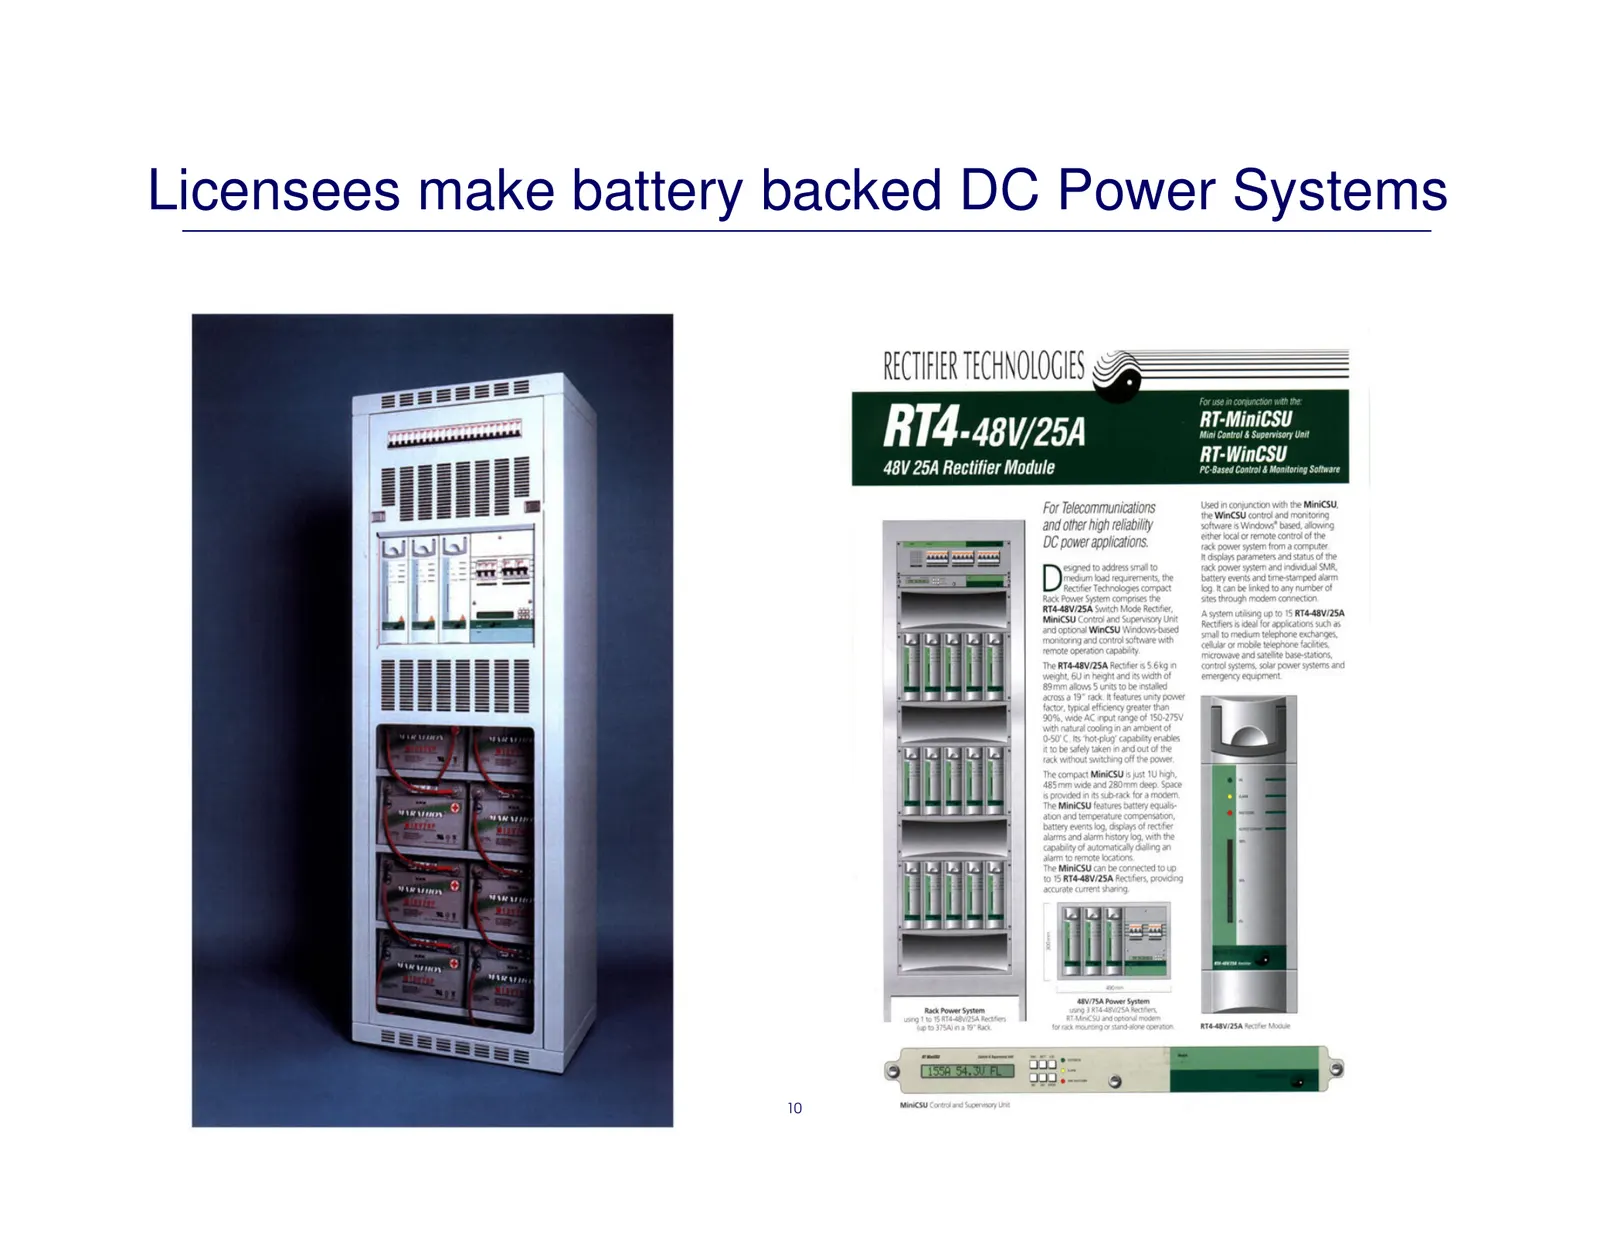
Slide 10: Licensees make battery backed DC Power Systems
Licensees make battery backed DC Power Systems 10
Slide 11: Markets: Backup/Emergency Power Supplies
Markets: Backup/Emergency Power Supplies Telecommunications — DIGITAL MOBILE — UNDERGROUND CABLE — MICROWAVE — SA T E L LI T E Power Utilities — SWI TCHING OF E L ECT RICAL CIRCUI T S — PROVIDING DC POWER — OPERATING INT E RNAL T E L ECOMS Large Private Power Users — MINING — OIL & GAS 11
Slide 12: End-users
End-users British Telecom China Telecom Korean Telecom China Unicom Vodacom South Africa China Mobile Telekom South Africa DOT/TEC India Cell C South Africa Portugal Telecom MTN Africa Taiwan Telecom (Chungwha) Cable and Wireless UK Mobilnet Venezuela Entel Chile Alls
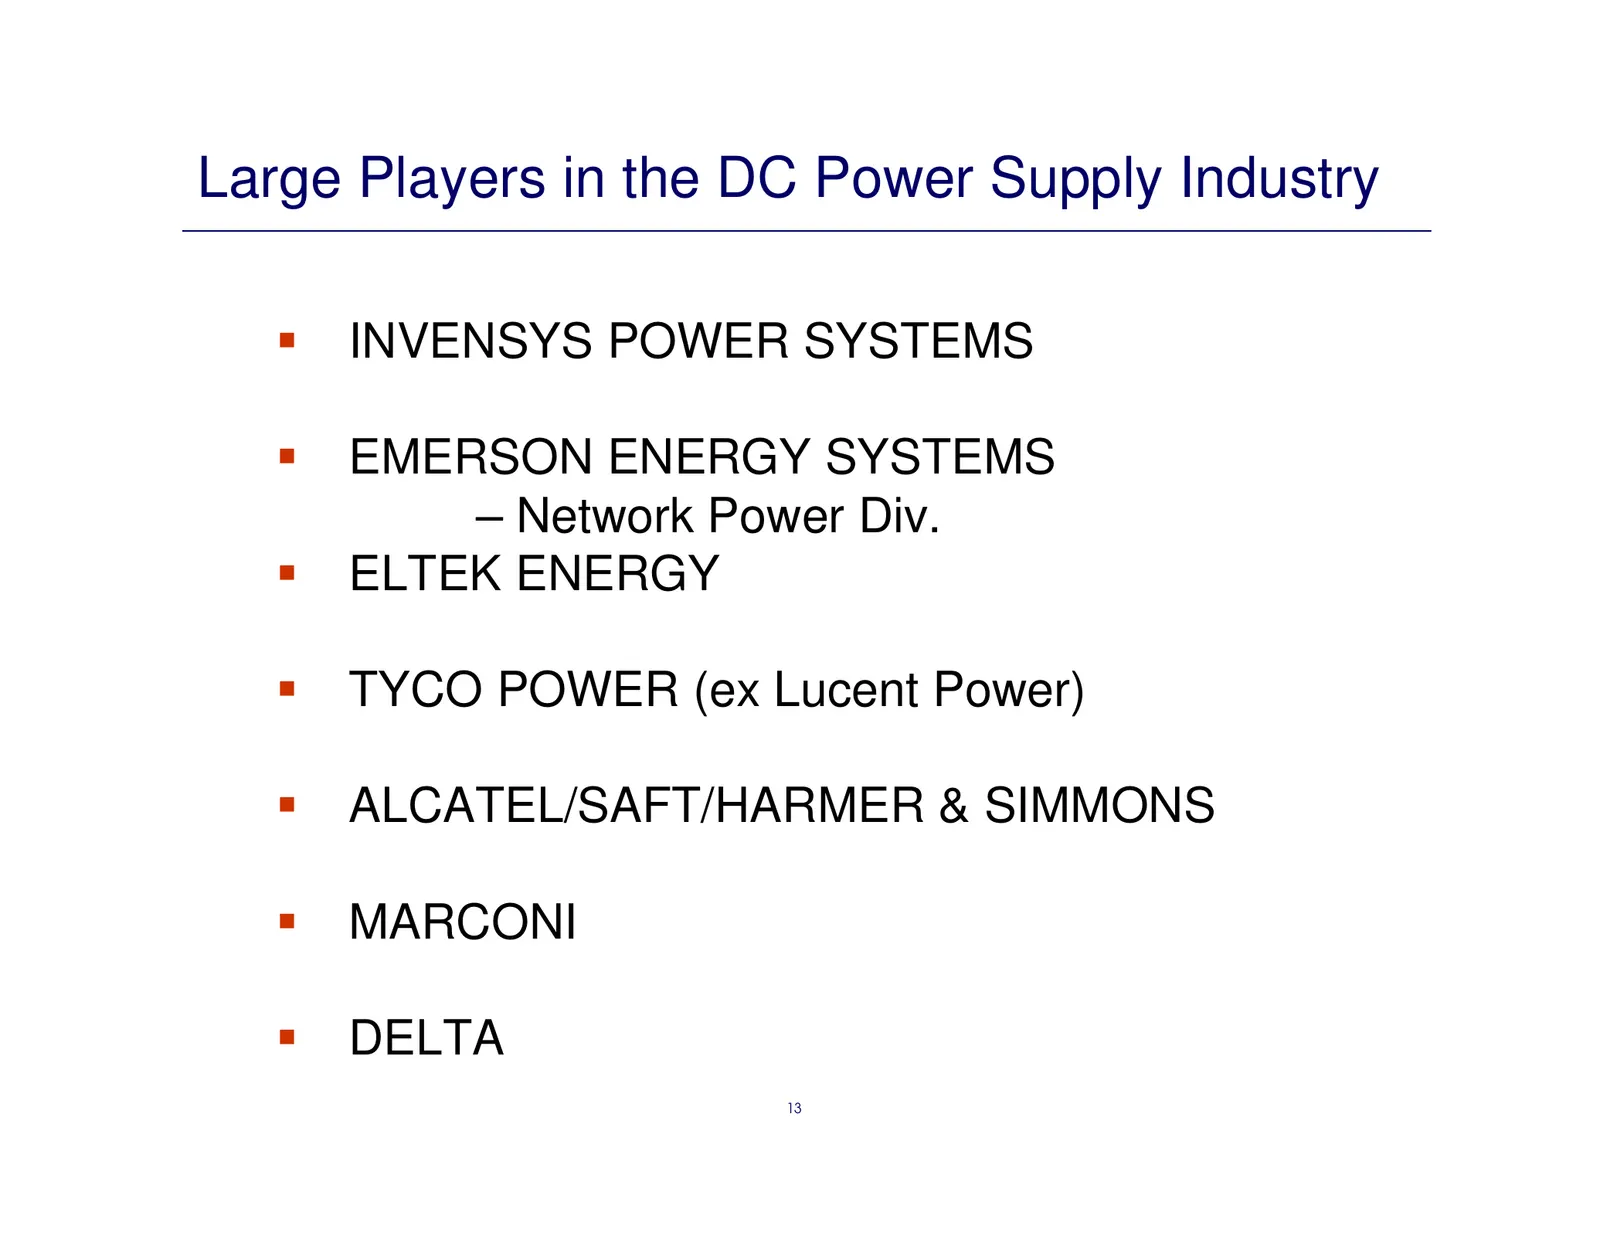
Slide 13: Large Players in the DC Power Supply Industry
Large Players in the DC Power Supply Industry INVENSYS POWER SYSTEMS EMERSON ENERGY SYSTEMS – Network Power Div. ELTEK ENERGY TYCO POWER (ex Lucent Power) ALCATEL/SAFT/HARMER & SIMMONS MARCONI DELTA 13
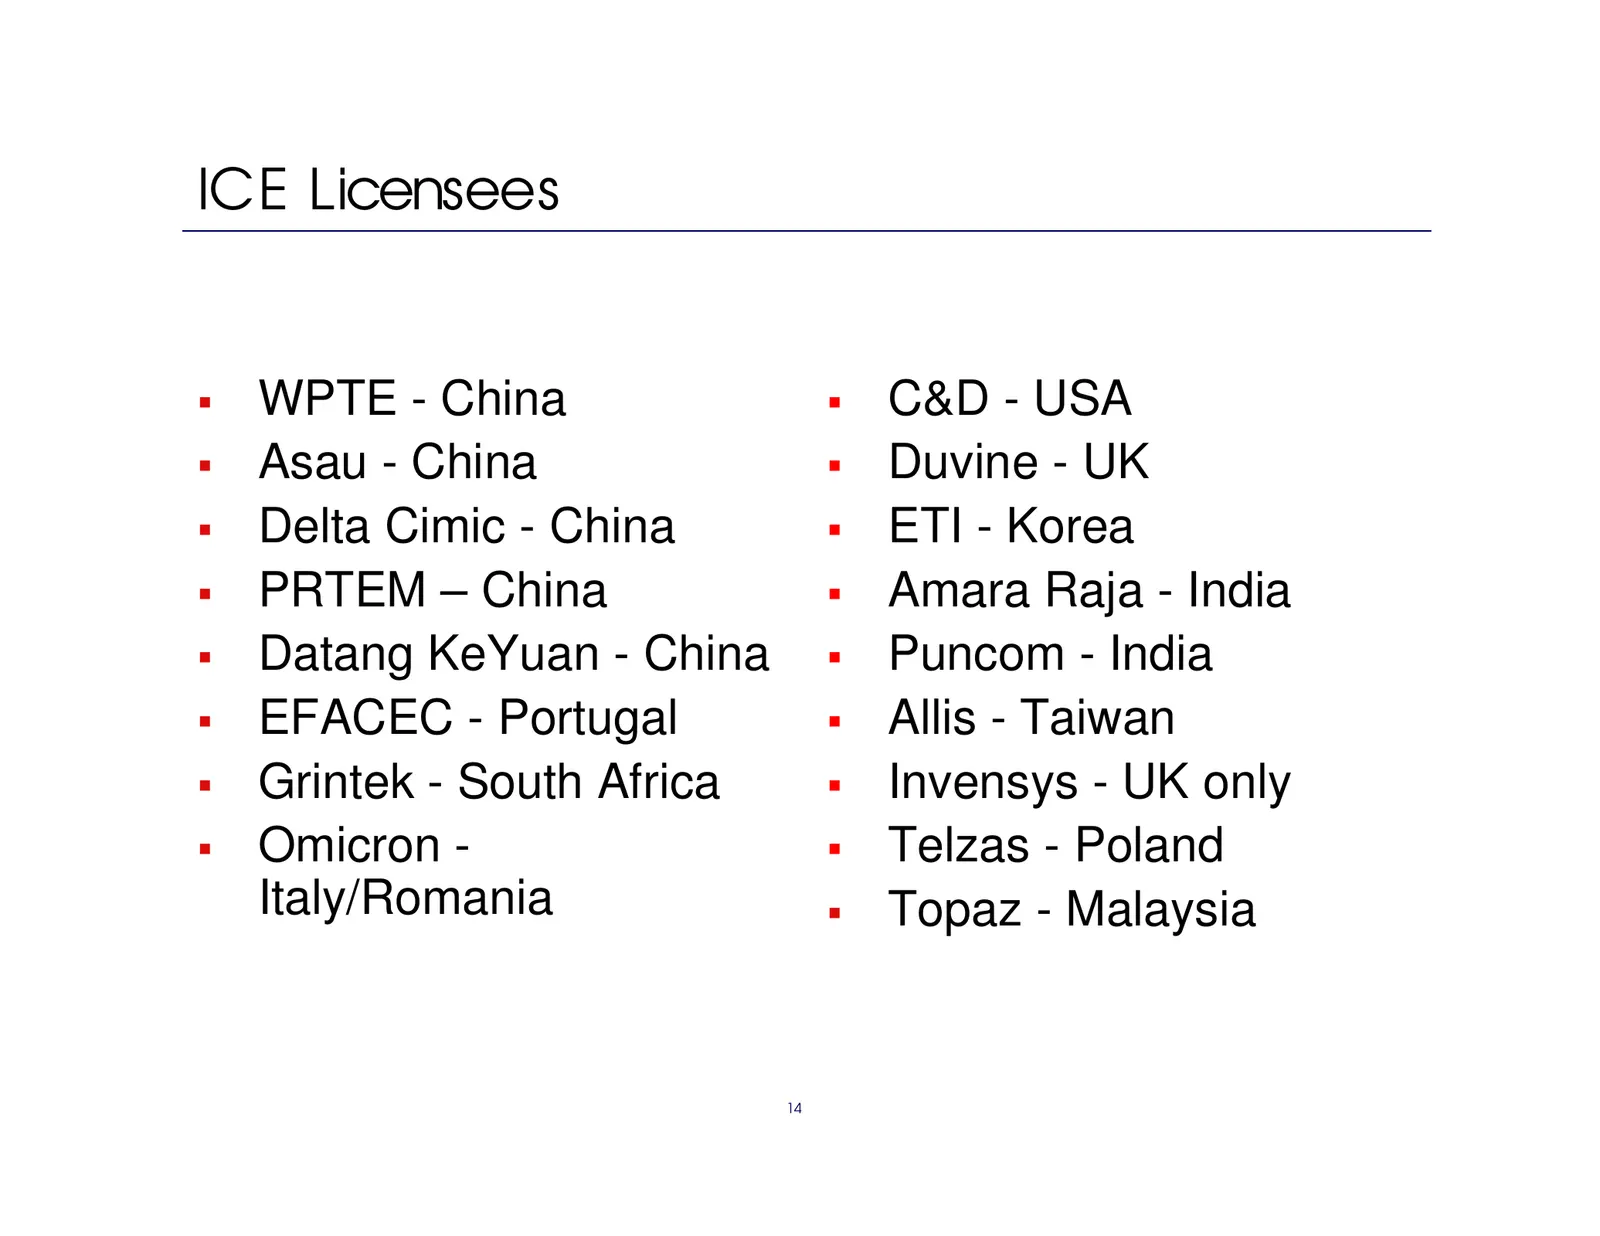
Slide 14: ICE Licensees
ICE Licensees WPTE - China C&D - USA Asau - China Duvine - UK Delta Cimic - China ETI - Korea PRTEM – China Amara Raja - India Datang KeYuan - China Puncom - India EFACEC - Portugal Allis - Taiwan Grintek - South Africa Invensys - UK only Omicron - Telzas - Poland Ita
Slide 15: ICE “Quo Vadis”?
ICE “Quo Vadis”? 15
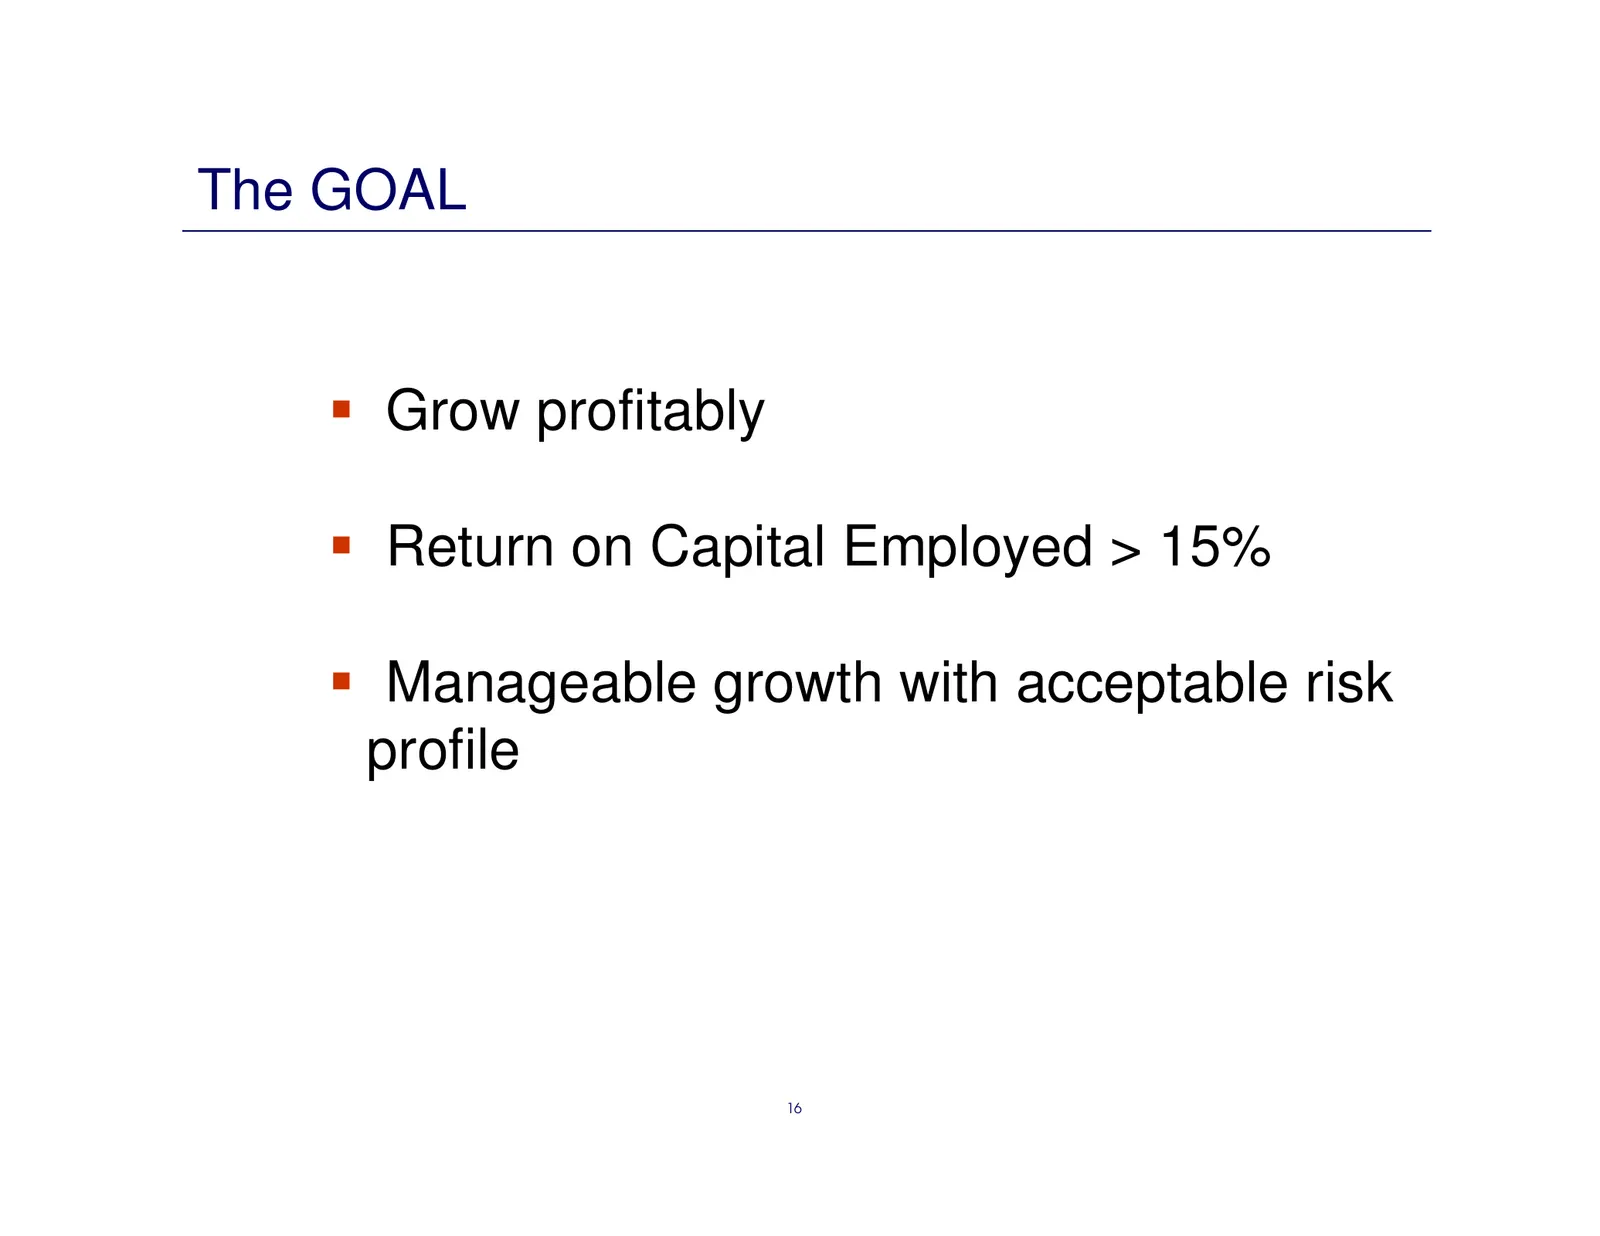
Slide 16: The Goal
The GOAL Grow profitably Return on Capital Employed > 15% Manageable growth with acceptable risk profile 16
Slide 17: Alternatives considered
3 Alternatives considered 1. Organic growth (no strategic change) 2. Diversified acquisitions to use public shell 3. Strategic mix of organic and acquisition growth within the present business activity 17
Slide 18: Organic Growth
Organic Growth Advantages — Familiar – capitalise on industry recovery — Can change approach in reaction to market pressures — Protran in good shape Concerns — Slow growth - ICE remains micro cap — Continues reliance on existing Licensing model for growth — Pressures Protran for manufacturing gr
Slide 19: Organic Growth - Conclusions
Organic Growth - Conclusions Poor option Continues business volatility cycles High risk/low reward Not preferred by the ICE Board 19
Slide 20: Diversified acquisitions
Diversified acquisitions Advantages Spreads public company costs May improve downside business risk Concerns Difficult for non-technical business partners to understand ICE Valuations of ICE invariably low – less than original business purchase prices May give away upside of global telecom
Slide 21: Diversified acquisitions - conclusions
Diversified acquisitions - conclusions Probably better than organic growth Ideal approach when bank debt was high. Deals with possible downside risk more than (greater) upside opportunities Ignores the positioning value of RTP in Telecom High risk with better returns than organic 21
Slide 22: The DC Power Supply Chain
THE DC POWER SUPPLY CHAIN RECTIFIER MODULES DESIGN MANUFACTURE SALES AND MARKETING INDUSTRIAL BATTERIES DESIGN AND MANUFACTURE SALES, MARKETING AND DISTRIBUTION METAL CASE MANUFACTURERS OEM PRODUCTION SYSTEMS INTEGRATORS DESIGN ASSEMBLY INSTALLATION BACKUP ELECTRICAL SERV
Slide 23: Some Western Licensees
Some Western Licensees: Core competence is sales/marketing Value add by systems integration and software development Can’t achieve manufacturing scale economies in making rectifier modules 23
Slide 24: Some Developing World Licensees Have
Some Developing World Licensees Have: ▲ Core competence is manufacturing ▲ Low manufacturing cost base ▲ Excess capacity for making rectifier modules ▲ Export and overseas expansion aims 24
Slide 25: Potential Future Alliances
Potential Future Alliances Establish different Strategic relationships ▲ Low cost module suppliers Value add sales licensees/franchisees Establish ICERT systems integration in Australia New products targeted to manufacturing licensees Partners to become ICE shareholders ? 25
Slide 26: ICE + MORE!
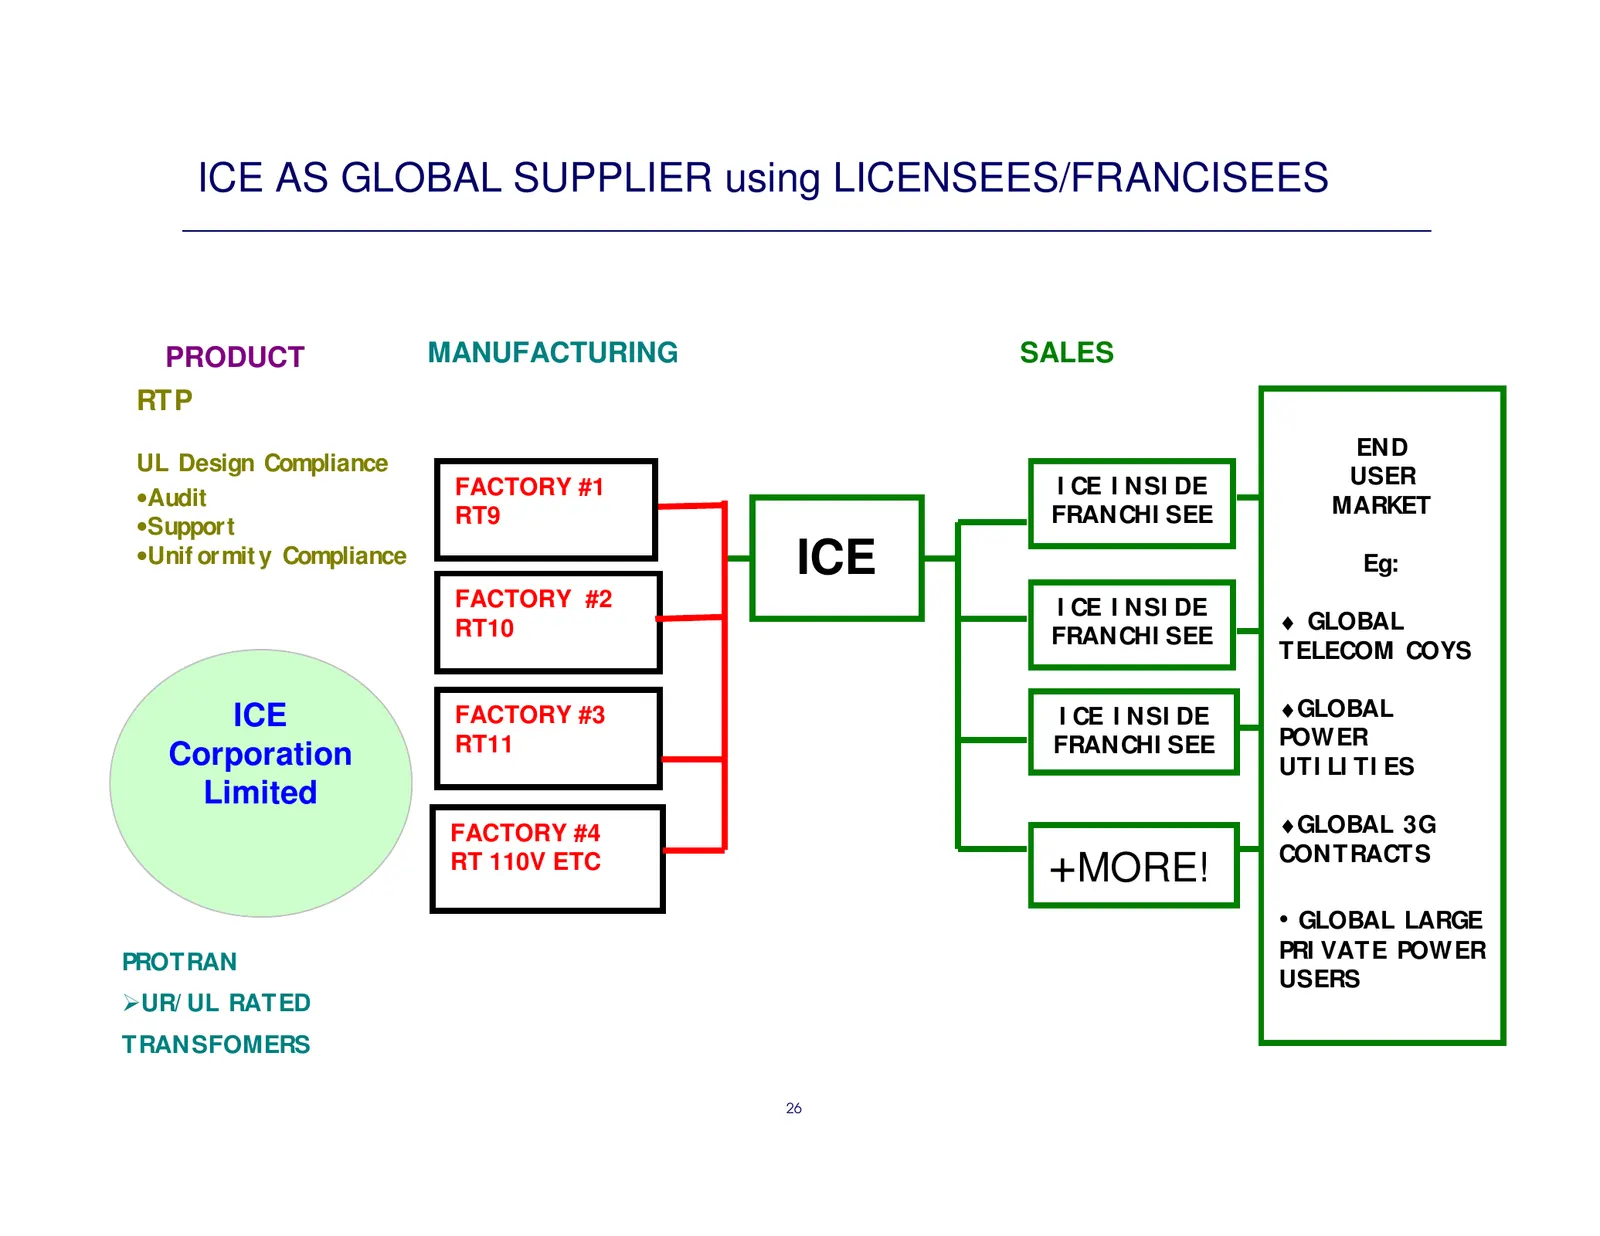
ICE AS GLOBAL SUPPLIER using LICENSEES/FRANCISEES PRODUCT MANUFACTURING SALES RTP END UL Design Compliance FACTORY #1 I CE I NSI DE USER •Audit MARKET •Support RT9 FRANCHI SEE •Unif ormit y Compliance ICE Eg: FACTORY #2 I CE I NSI DE RT10 ♦ GLOBAL FRANCHI SEE TELECOM COYS ICE FACTORY #3 I CE I NSI D
Slide 27: Strategic Mix: Acquisition/Organic Growth
Strategic Mix: Acquisition/Organic Growth Advantages Spreads public company costs Leverages off RTP positioning Leverages off Protran growth Provides upside by introducing a new business model in core businesses Fastest to implement – parties are interested Concerns Current Licensee stru
Slide 28: Strategic Mix: Acquisition/Organic Growth
Strategic Mix: Acquisition/Organic Growth Conclusions reached Manages downside risk Positions ICE as a visible player in the global industry Fastest to implement - global network is “ready” Overall conclusion Lowest Risk/Highest Return Preferred option 28
Slide 29: Aspects Of Implementation
Aspects Of Implementation: Modify organic approach to provide a new business model Target acquisitions to fast track the development of the organic approach and reduce market development risk Attract Key Investors to invest in ICE to underpin the business model 29
Slide 30: Summary
Summary Aim = to build a network with FOCUSSED TECHNOLOGY + LOW COST LARGE SCALE MANUF. + GLOBAL SALES NETWORK ■ Manufacturing Licensees = low cost ■ Sales Licensees = global customers ■ ICE = global contacts and global marketing presence ■ ICE = technology and R&D capability ■ ICE = ASX listed 30
Slide 31: Thank You Questions?
ICE CORPORATION Thank You Questions?
Source: Internet Archive copy of rectifiertechnologies.com
More decks from Rectifier Technologies Ltd
 Shareholder Meeting (November 2022)12 slides · Nov 25, 2022
 FY2022 Earnings Presentation16 slides · Nov 25, 2022
 Shareholder Meeting (November 2022)17 slides · November 2022
 Shareholder Meeting (January 2022)17 slides · Jan 25, 2022
 Shareholder Meeting (January 2022)14 slides · Jan 25, 2022
 Shareholder Meeting (January 2021)19 slides · Jan 29, 2021