Massey Energy — Bear Stearns Global Credit Conference 2006
32 slides from Massey Energy's conference presentation, May 17, 2006
Slide 1: Bear Stearns Global Credit Conference
1 Bear Stearns Global Credit Conference May 17, 2006 Katharine W. Kenny Vice President, Investor Relations Eric B. Tolbert Vice President & Chief Financial Officer Exhibit 99.1
Slide 2: Safe Harbor Statement
2 FORWARD-LOOKING STATEMENTS: Certain statements in this presentation are forward-looking as defined by the Private Securities Litigation Reform Act of 1995. Due to known and unknown risks, the Company’s actual results may differ materially from its expectations or projections. Factors potentially c
Slide 3: Coal is the Fuel of Choice
3 Coal is the Fuel of Choice
Slide 4: World Coal Demand Accelerating
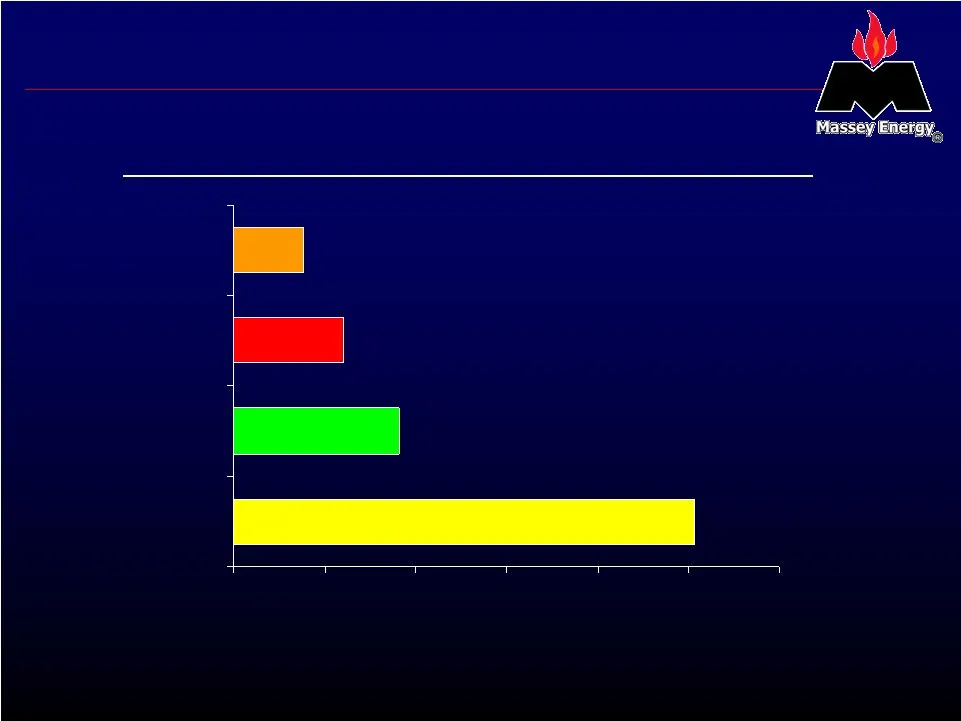
4 World Coal Demand Accelerating SOURCE: BP Statistical Review of World Energy 2005 World Energy Demand Growth from 2001 to 2004 25% 9% 6% 4% 0% 5% 10% 15% 20% 25% 30% Coal Natural Gas Oil Nuclear Growth in Btu Consumption
Slide 5: World Energy Demand
5 World Energy Demand SOURCE: U.S. Energy Information Administration Rest of World China U.S. 2020E 1990 375 237 98 27 125 85 Annual Energy Consumption (Quadrillion Btu) The modernization of the world’s most populous country imposes huge burdens on an increasingly tight global energy supply % Change
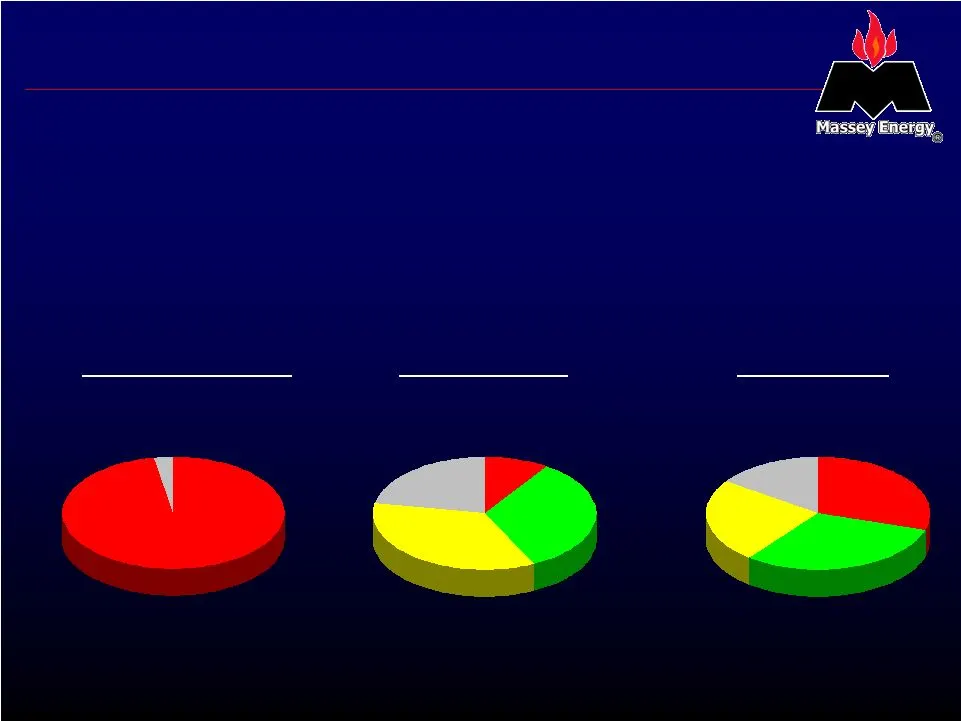
Slide 6: U.S. Energy Demand
6 U.S. Energy Demand The U.S. is increasingly competing for expensive and uncertain foreign supplies to power our cars, homes and factories Transportation Residential* Industrial* * Electricity consumption allocated to primary fuels based on U.S. utility average consumption SOURCE: U.S. Energy Infor
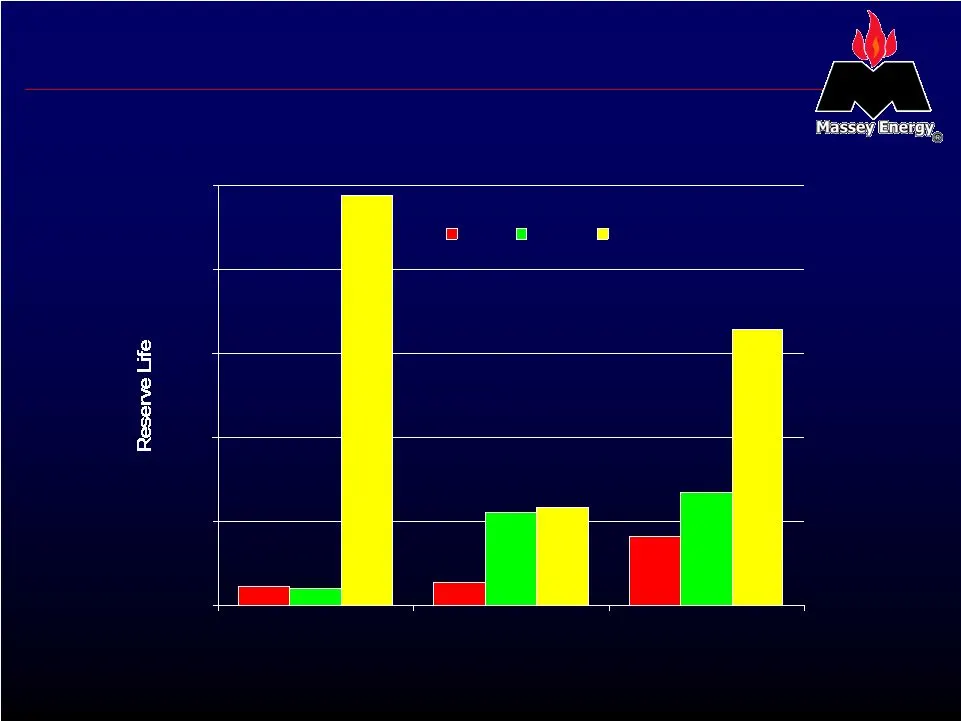
Slide 7: U.S. Coal - The Underutilized Energy Supply
7 U.S. Coal - The Underutilized Energy Supply SOURCE: BP Statistical Review of World Energy 2005 (2004 reserves and production) 11 years 10 years 245 years 0 50 100 150 200 250 U.S. China World Oil Gas Coal
Slide 8: U.S. Growth in Coal Demand
8 U.S. Growth in Coal Demand SOURCE: CSFB High prices of alternative energy sources 91 gigawatts of new coal-fired power plants in the U.S. have been proposed or are under development If only 50% actually are built, they would require approximately 135 million additional tons of coal annually • • »
Slide 9: Technology Driving Demand – Gasification/Liquefaction
9 Technology Driving Demand – Gasification/Liquefaction Coal gasification enables economic and environmentally responsible coal power generation Competitive with natural gas at $4.40/mmBtu Natural Gas prices averaged $7.89/mmBtu in 2005 Coal liquefaction provides a near-term solution to oil crisis C
Slide 10: Delivering Shareholder Value in Central Appalachia
10 Delivering Shareholder Value in Central Appalachia
Slide 11: Massey Production Growth
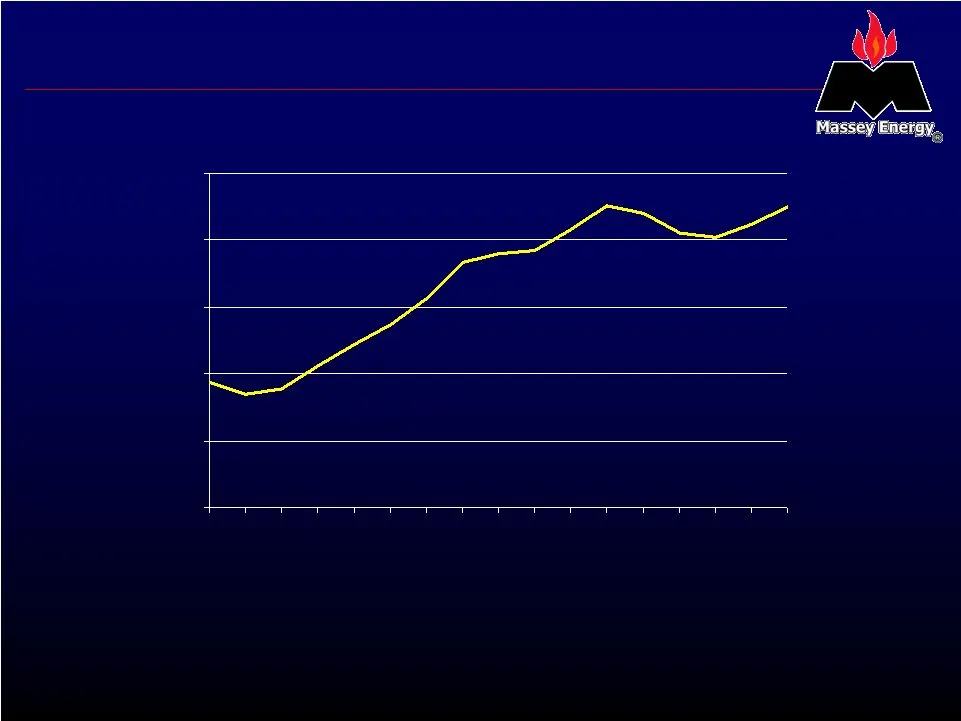
11 Massey Production Growth Massey has delivered long-term growth, via organic expansion and opportunistic acquisitions (million tons) 0 10 20 30 40 50 1990 1992 1994 1996 1998 2000 2002 2004 2006E
Slide 12: Other Central Appalachian Production Declines
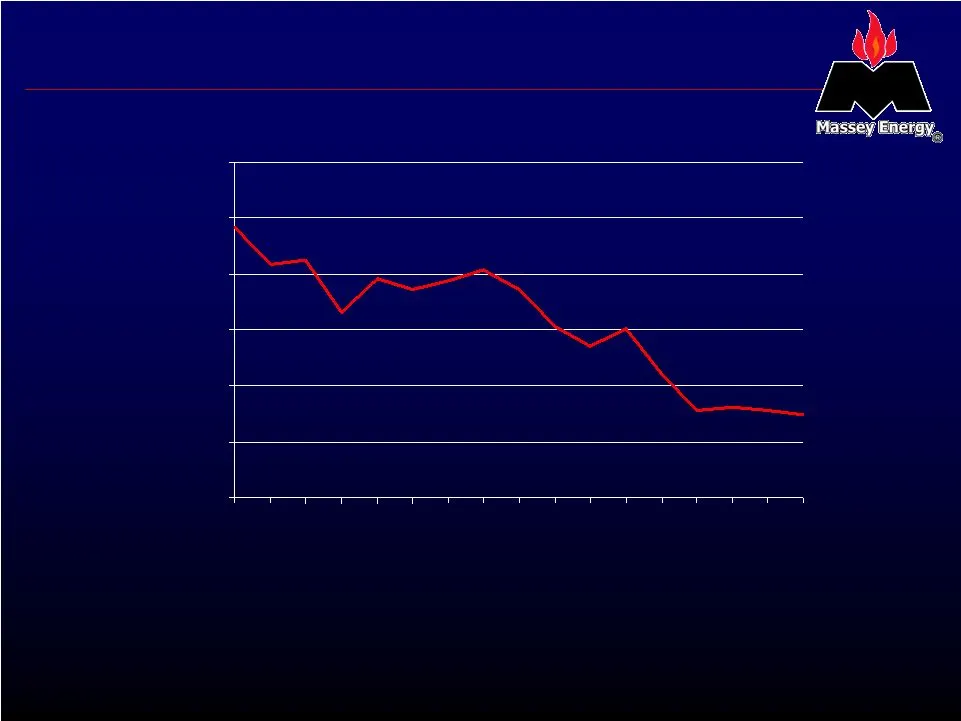
12 Other Central Appalachian Production Declines SOURCE: Energy Ventures Analysis, Inc. Central Appalachia competitors have had difficulty maintaining margins and growth (million tons) 150 175 200 225 250 275 300 1990 1992 1994 1996 1998 2000 2002 2004 2006E
Slide 13: Leading Regional Reserve Position
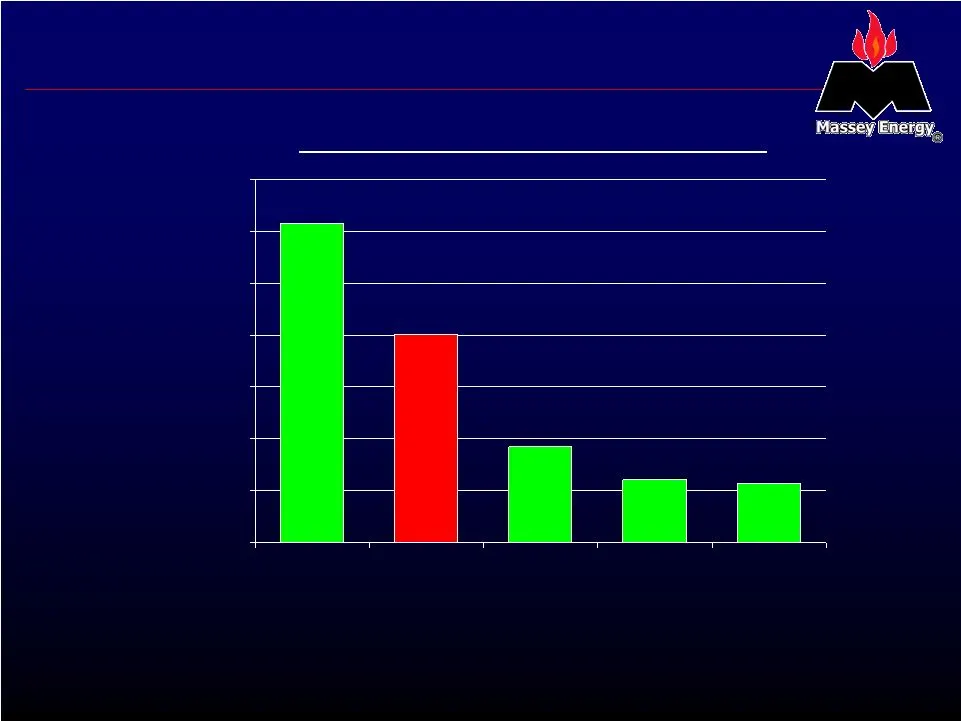
13 Leading Regional Reserve Position * 2005 Company reserves as % of estimated total 30 year forward regional production SOURCE: Energy Ventures Analysis, Inc., Company reports Reserve share in Primary Region* 62% 40% 12% 11% 18% 0% 10% 20% 30% 40% 50% 60% 70% CONSOL Massey Peabody Magnum Arch Prima
Slide 14: Geographically Advantaged
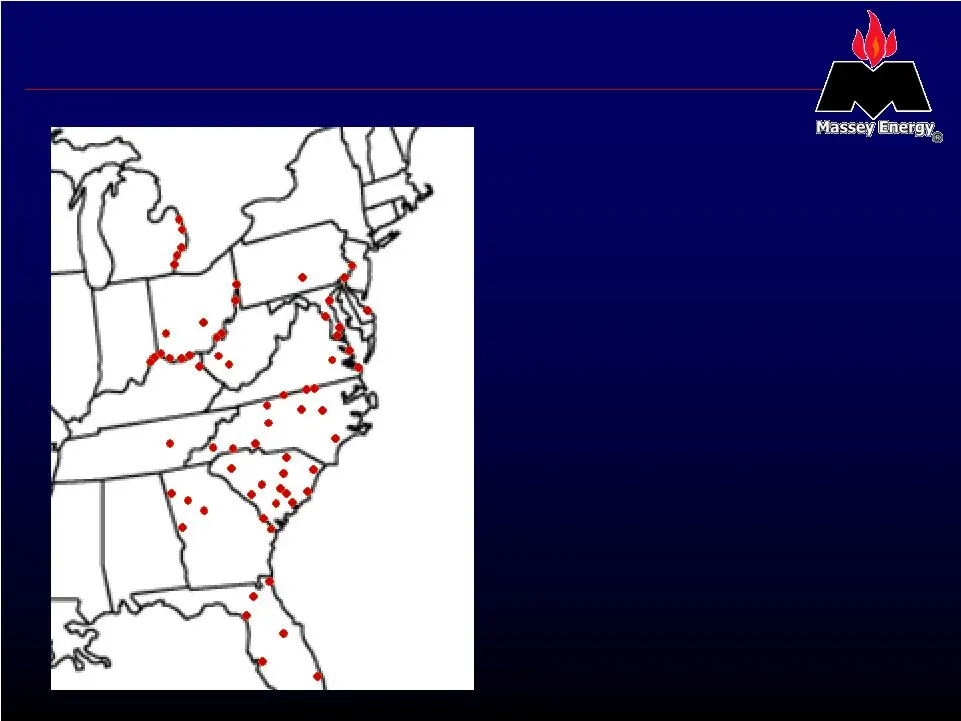
14 Geographically Advantaged In 2005, Massey’s steam coal customers were focused in the Southeastern and Mid- Atlantic states Central Appalachia enjoys tremendous transportation advantages in these markets, especially versus PRB low sulfur coals • •
Slide 15: Powder River Basin Challenges
15 Powder River Basin Challenges Greater exposure to rising freight rates and delivery interruptions Rail infrastructure capacity out of basin is constrained Rail system interchange bottlenecks Most advantaged markets have already switched Utility switching costs to reconfigure boilers is high Highe
Slide 16: Challenges Facing Imports
16 Challenges Facing Imports SOURCE: Energy Ventures Analysis, Inc. Port infrastructure constrained Source risk – not dependable for long-term secure supplies Weaker US dollar increases cost Imports remain a small fraction of overall U.S. coal consumption (2.7% in 2005) • • • •
Slide 17: Growing Revenue per Ton
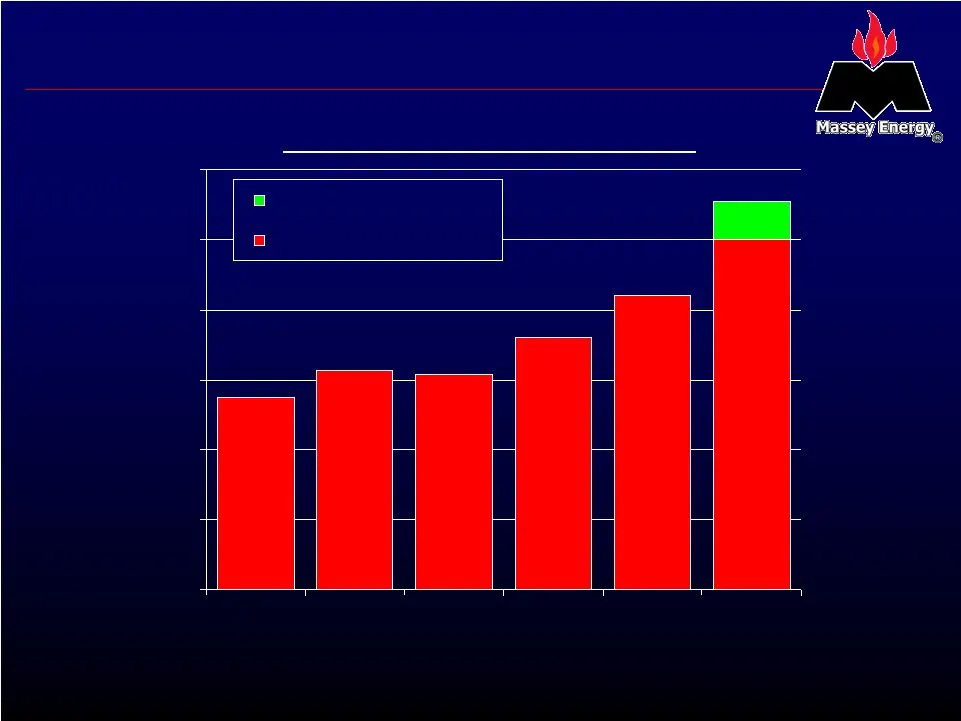
17 Growing Revenue per Ton 2001 – 2006E Revenue per ton $36.02 $30.79 $31.30 $27.51 $42.02 $50.00 $55.50 $0.00 $10.00 $20.00 $30.00 $40.00 $50.00 $60.00 2001* 2002 2003 2004 2005 2006E Estimated Market Value Revenue / Produced Ton * 2001 is for fiscal year ended October 31, 2001
Slide 18: Proven Ability to Maintain Margin
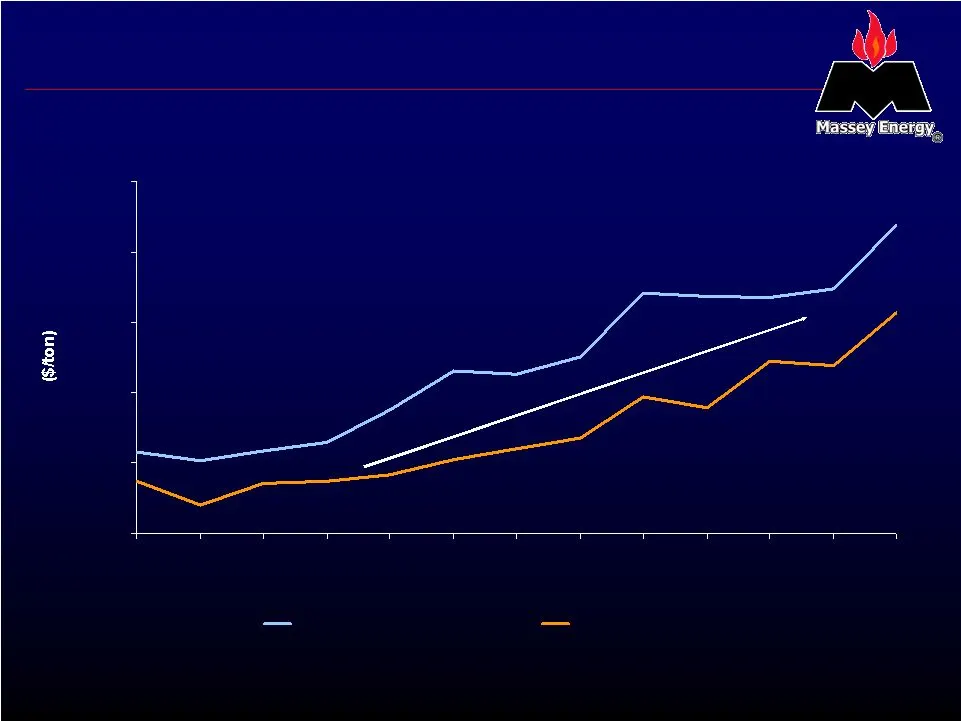
18 Proven Ability to Maintain Margin SOURCE: Company reports 30.85 31.44 33.74 36.52 36.33 37.57 42.07 41.88 41.75 42.39 46.90 30.14 30.74 40.69 37.20 33.95 34.73 31.76 30.99 30.20 29.14 28.66 28.56 26.97 28.66 36.90 $25.00 $30.00 $35.00 $40.00 $45.00 $50.00 Q1 2003 Q2 2003 Q3 2003 Q4 2003 Q1 2004 Q
Slide 19: Grow Surface Mine Capacity
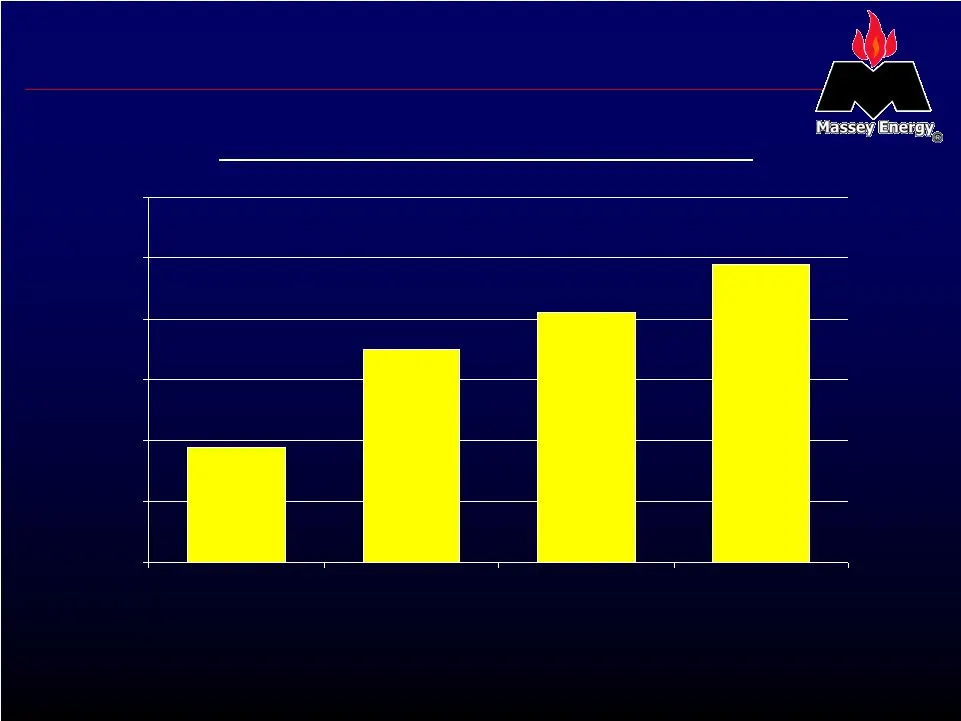
19 Grow Surface Mine Capacity 19% 35% 49% 41% 0% 10% 20% 30% 40% 50% 60% 1996 2003 2004 2005 Surface Tons as % of Total Production
Slide 20: Massey Energy: Strengths and Challenges
20 Massey Energy: Strengths and Challenges
Slide 21: Capital Discipline
21 Capital Discipline Opportunistic Central Appalachia consolidator Focus on asset purchases with minimal legacy liabilities Synergistic targets with clear strategic value Up to $270 million in capital investments projected for 2006 Capital restructuring in late 2005 Reduced fully diluted share coun
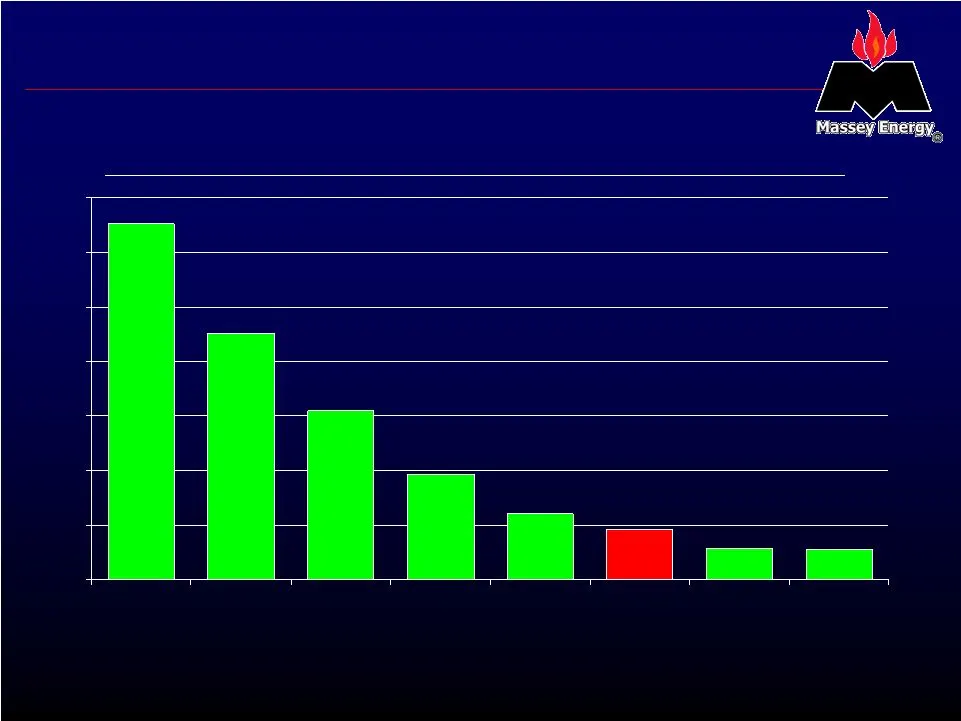
Slide 22: Low Legacy Liabilities
22 Low Legacy Liabilities 2005 Legacy Liabilities as a Percentage of Net Worth* * Net worth defined as shareholders equity less intangibles SOURCE: Company reports 326 226 97 60 46 29 28 155 0 50 100 150 200 250 300 350 CONSOL Foundation James River Peabody Alpha Massey ICG Arch
Slide 23: Labor Challenge
23 Labor Challenge Generation of miners lost during 1980s and 1990s Experienced labor key to past productivity Skilled labor critical to underground mining productivity Strong demand in current coal marketplace results in fierce competition for labor • • • •
Slide 24: Wage and Benefit Enhancements
24 Wage and Benefit Enhancements Measured wage increases Increased productivity and retention bonuses Enhanced medical program benefits Supplemental benefit programs to encourage longevity, such as auto and homeowners insurance New medical facility established in 2005 • • • • •
Slide 25: Comprehensive Training and Orientation
25 Comprehensive Training and Orientation Extensive training and member development Orientation and safety programs Mentor program • • •
Slide 26: Massey – Creating Long-term Value
26 Massey – Creating Long-term Value Foremost producer in Central Appalachia with increasing market share Leading Central Appalachian reserve base enables long- term organic growth Capital discipline to optimize leverage and liquidity requirements Safety, community and environmental stewardship prog
Slide 27: Financial Statistics
27 Financial Statistics
Slide 28: Recent Results
28 Recent Results $130 $42.07 11.3 10.6 $448 1 st Qtr. 2005 $81 $426 * EBITDA $46.90 $42.02 Average per ton realization 10.5 43.1 Tons produced 10.1 42.3 Produced tons sold $476 $1,778 Produced coal revenue 1 st Qtr. 2006 Full Year 2005 *Excluding charges of $212 related to the Company’s debt repurc
Slide 29: Outstanding Debt Securities
29 Outstanding Debt Securities As of March 31, 2006 B1/BB- $ 760.0 6.785% senior notes due 2013 0.8 9.6 335.0 B2/B 4.75% convertible senior notes due 2023 B1/BB- 2.25% convertible senior notes due 2024 B1/BB- 6.625% senior notes due 2010 In millions Ratings
Slide 30: Capitalization
30 Capitalization ($ in millions - except %) 48.0% 48.9% Total net debt-to-book capitalization ratio 59.8% 59.6% Total debt-to-book capitalization ratio $ 688.9 $ 721.8 Total net debt 105.0 105.0 Less: Restricted cash 319.4 282.0 Less: Cash $ 1,860.5 $ 1,861.8 Total capitalization 747.2 753.0 Shareh
Slide 31: Disclaimer
31 Disclaimer FORWARD-LOOKING STATEMENTS: Certain statements in this presentation are forward-looking as defined by the Private Securities Litigation Reform Act of 1995. Such forward-looking statements are based on facts and conditions as they exist at the time such statements are made as well as pr
Slide 32: with Energy
32 with Energy Doing the Right Thing...
Source: SEC EDGAR · 8-K filed May 17, 2006
More decks from Massey Energy Co
 Merger or Acquisition (March 2011)18 slides · Mar 9, 2011
 BMO Capital Markets 2011 Global Metals & Mining Conference27 slides · Mar 1, 2011
 Credit Suisse Energy Summit 201126 slides · Feb 10, 2011
 Merger or Acquisition (January 2011)19 slides · Jan 31, 2011
 Proxy Contest (May 2010)32 slides · May 5, 2010
 Proxy Contest (April 2010)26 slides · Apr 30, 2010