Tellurian — Scotia Howard Weil Conference 2017
27 slides from Tellurian's conference presentation, Mar 27, 2017
Slide 1: Investor presentation – Scotia Howard Weil Conference
Exhibit 99.1 NASDAQ: TELL Investor presentation Scotia Howard Weil Conference – March 27, 2017 Meg Gentle, President & CEO
Slide 2: Notice
Notice 1934, “may,” things, forward-looking we results filed this statements. statements, accordance similarly GAAPbelieve presentation with asor The financial our “plan,” amended. titled performance the business are information The we with Securities appropriate measures disclaim “potential,” forwa
Slide 3: Introducing Tellurian
Introducing Inception: Strategy: Project: Engineering Development Merger: shareholders Driftwood Tellurian Low-cost InTellurian and are February Funding: majority Construction: Investments LNG LNG Inc. 2016, $60 (DWLNG), provider owners (NASDAQ: million Charif and Bechtel, of capable Magellan contri
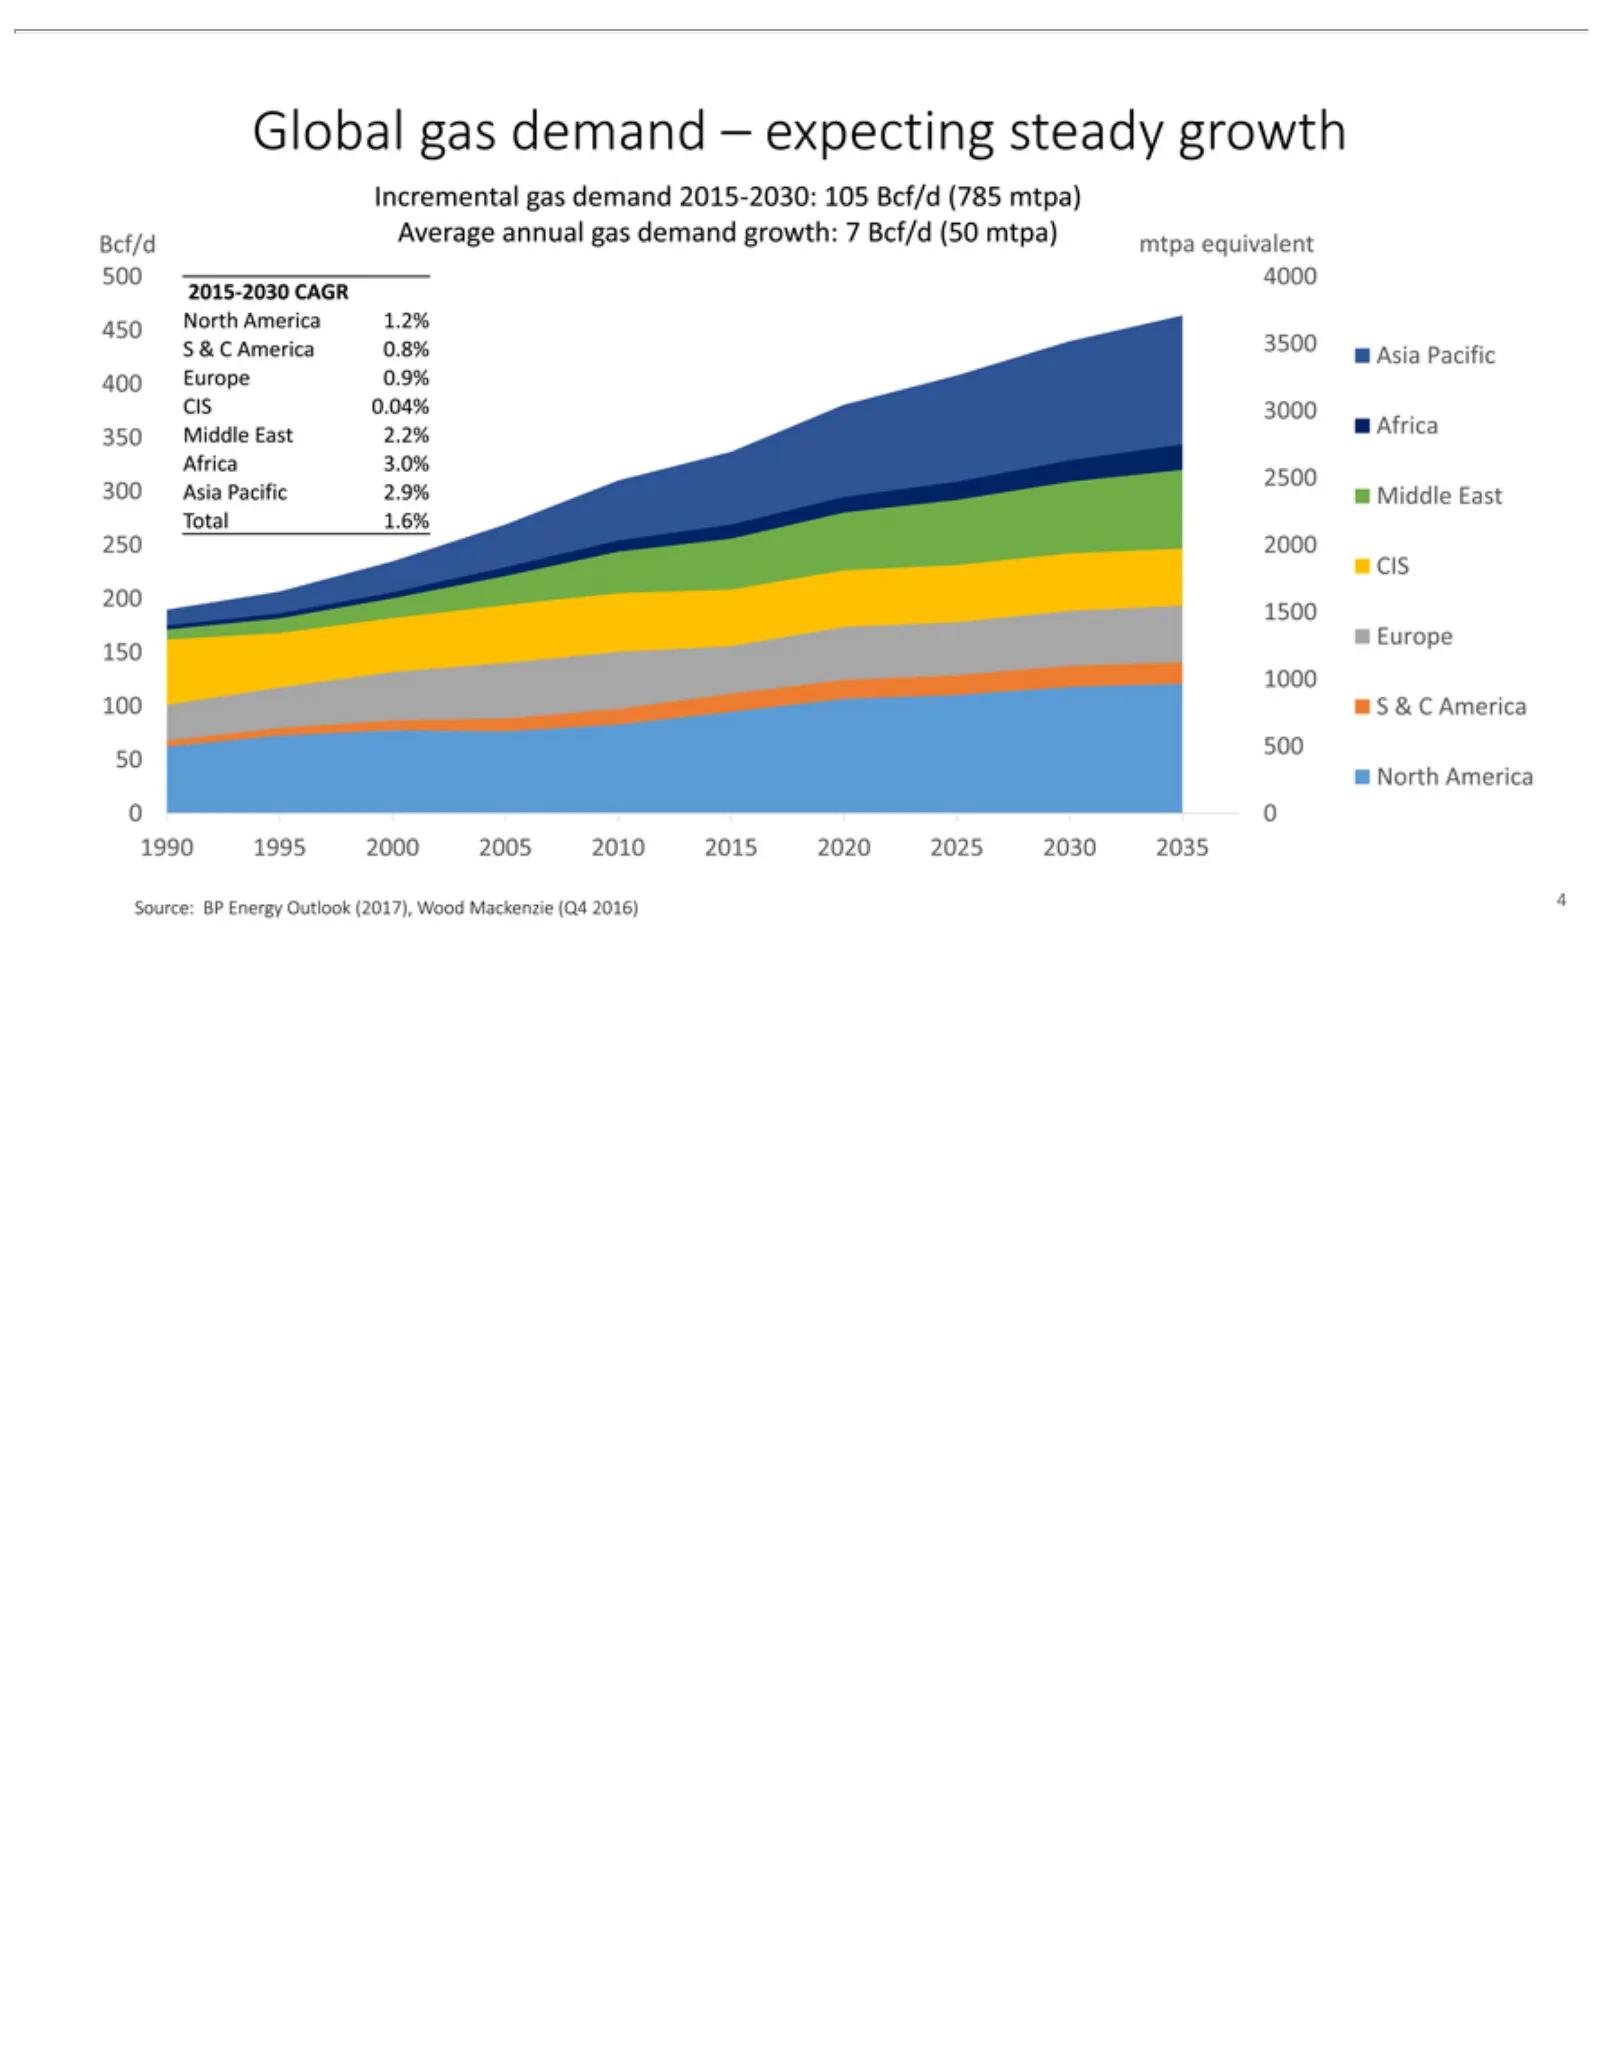
Slide 4: Global gas demand growth
GlobalAmerica North Europe gas 150demand 1000 1.2% 100 – Sexpecting S&&CCAmerica America steady0.8% 500 growth 50 3500 North Incremental AsiaAmerica Pacific gas 0400 0demand 1990 Europe 1995 2015-2030: 0.9% 2000 CIS 2005 0.04% 1052010 Bcf/d 3000 2015 (785 Africa 2020 mtpa) 350 2025 Average Middle 20
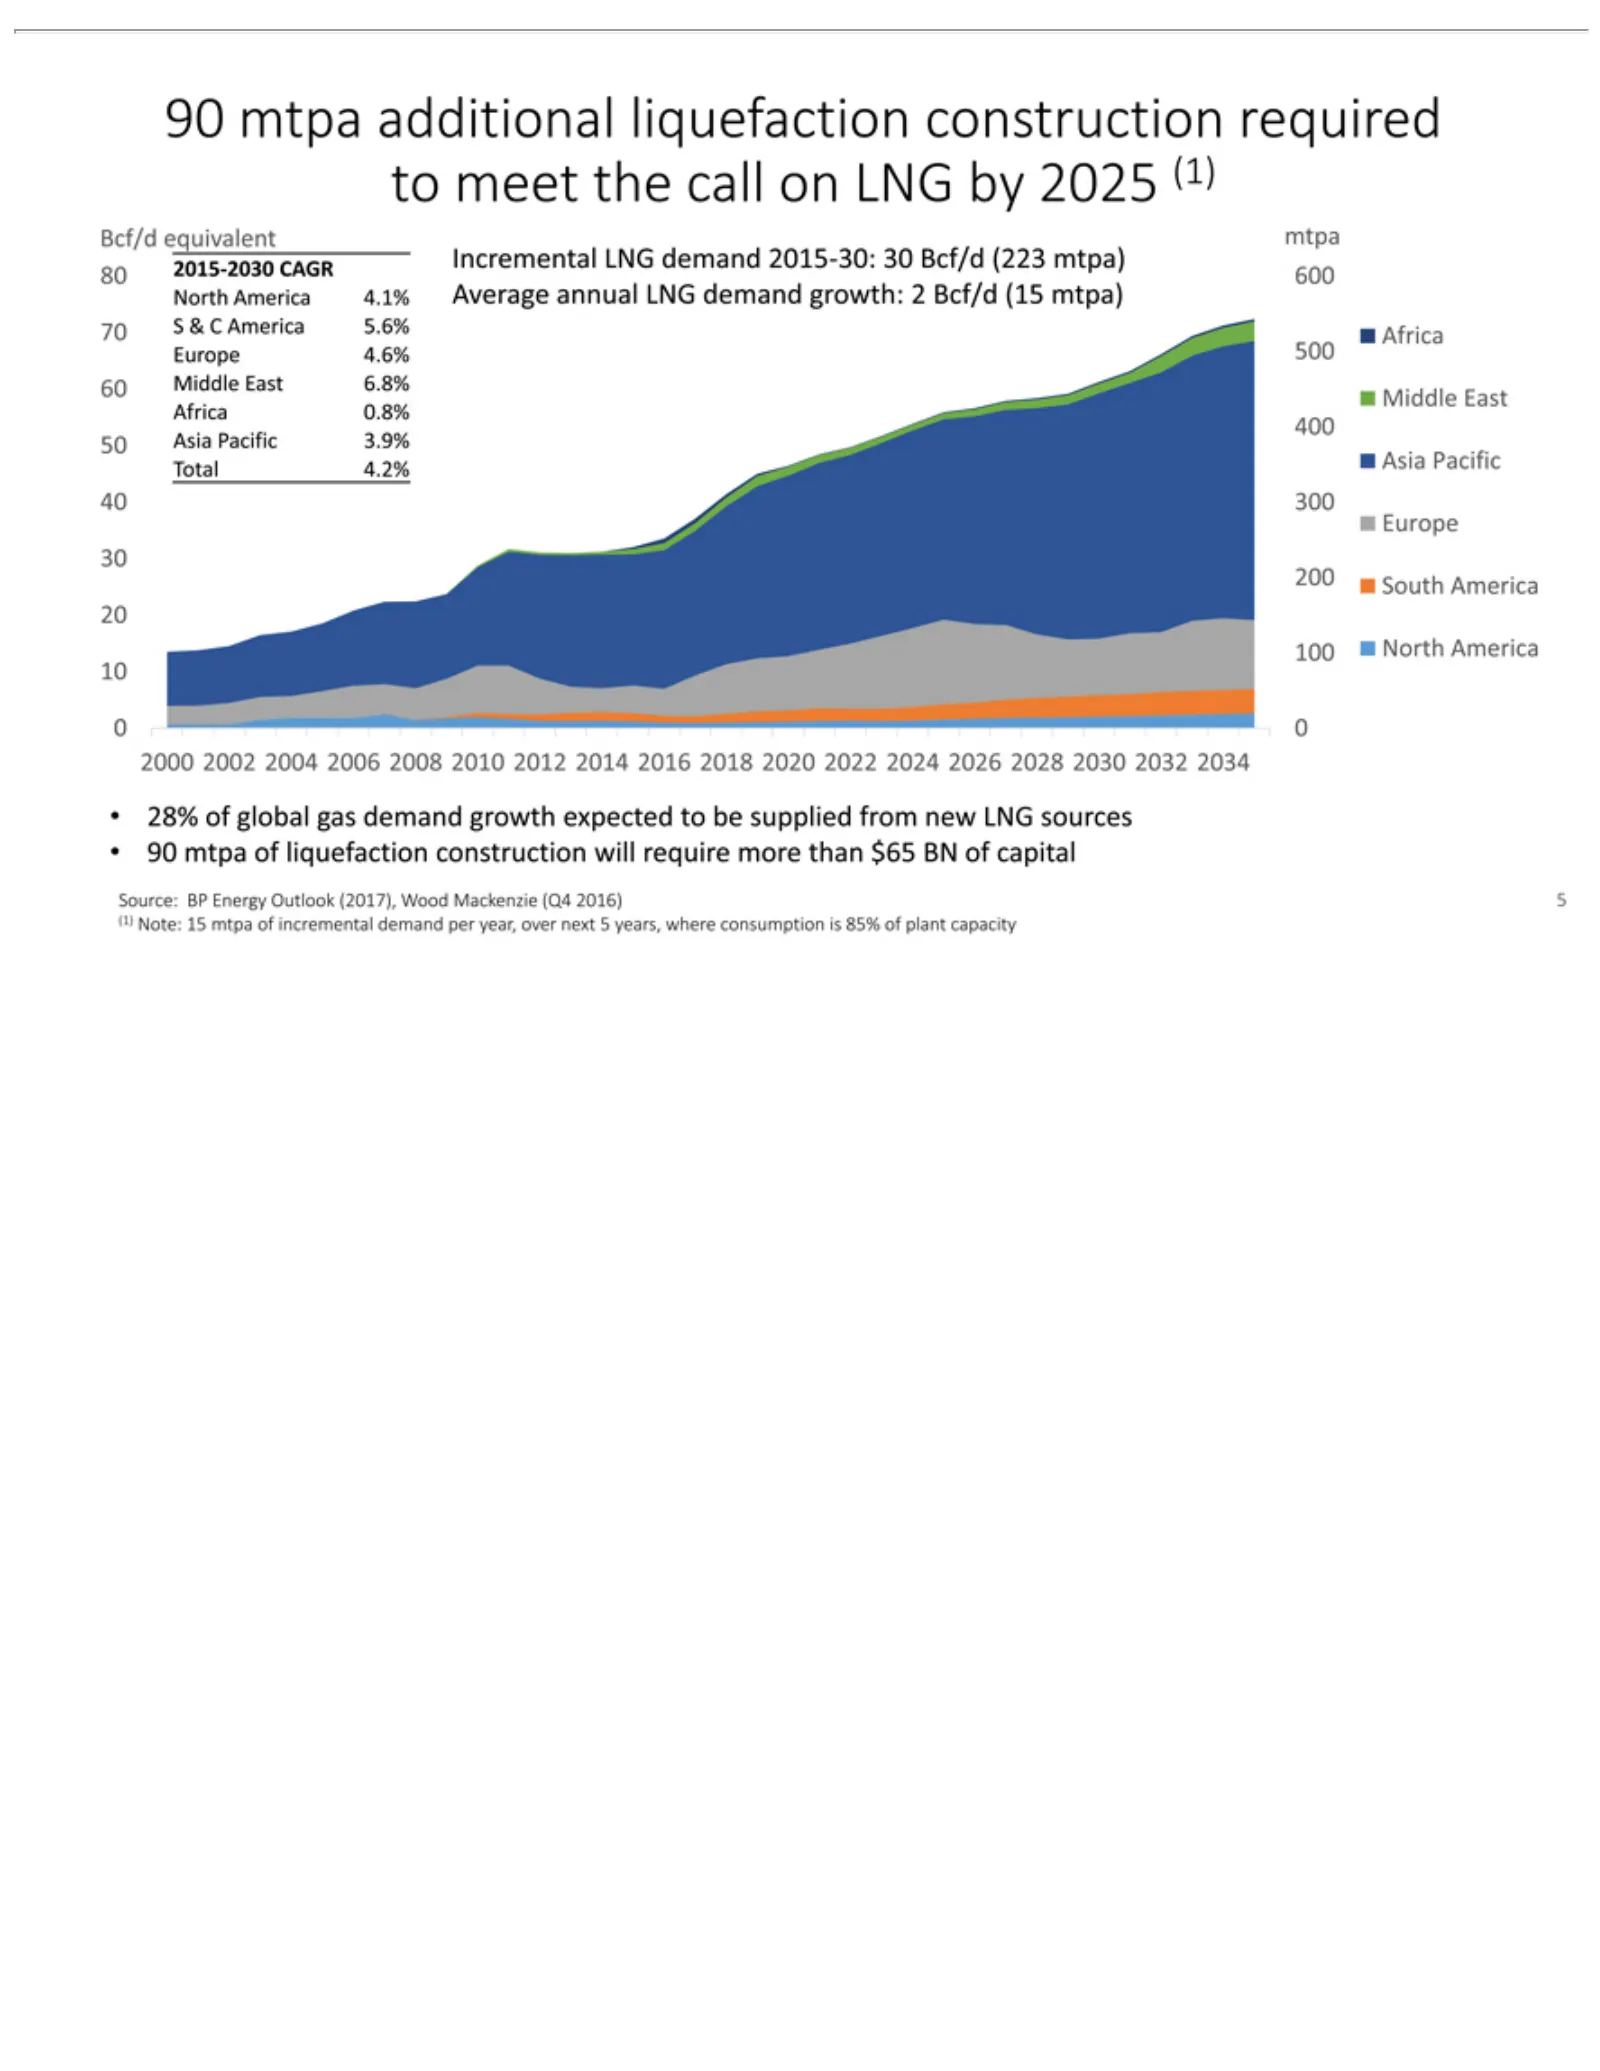
Slide 5: LNG demand and new liquefaction required
90 mtpa 4.1% Europe supplied demand Average 30per additional from 200 year, new annual South over liquefaction LNGAmerica LNG next sources demand 5 years, 20 construction •100 90growth: where mtpa Northconsumption of2America required liquefaction Bcf/d (15 to 10meet is mtpa) 0 85% construction 0 200
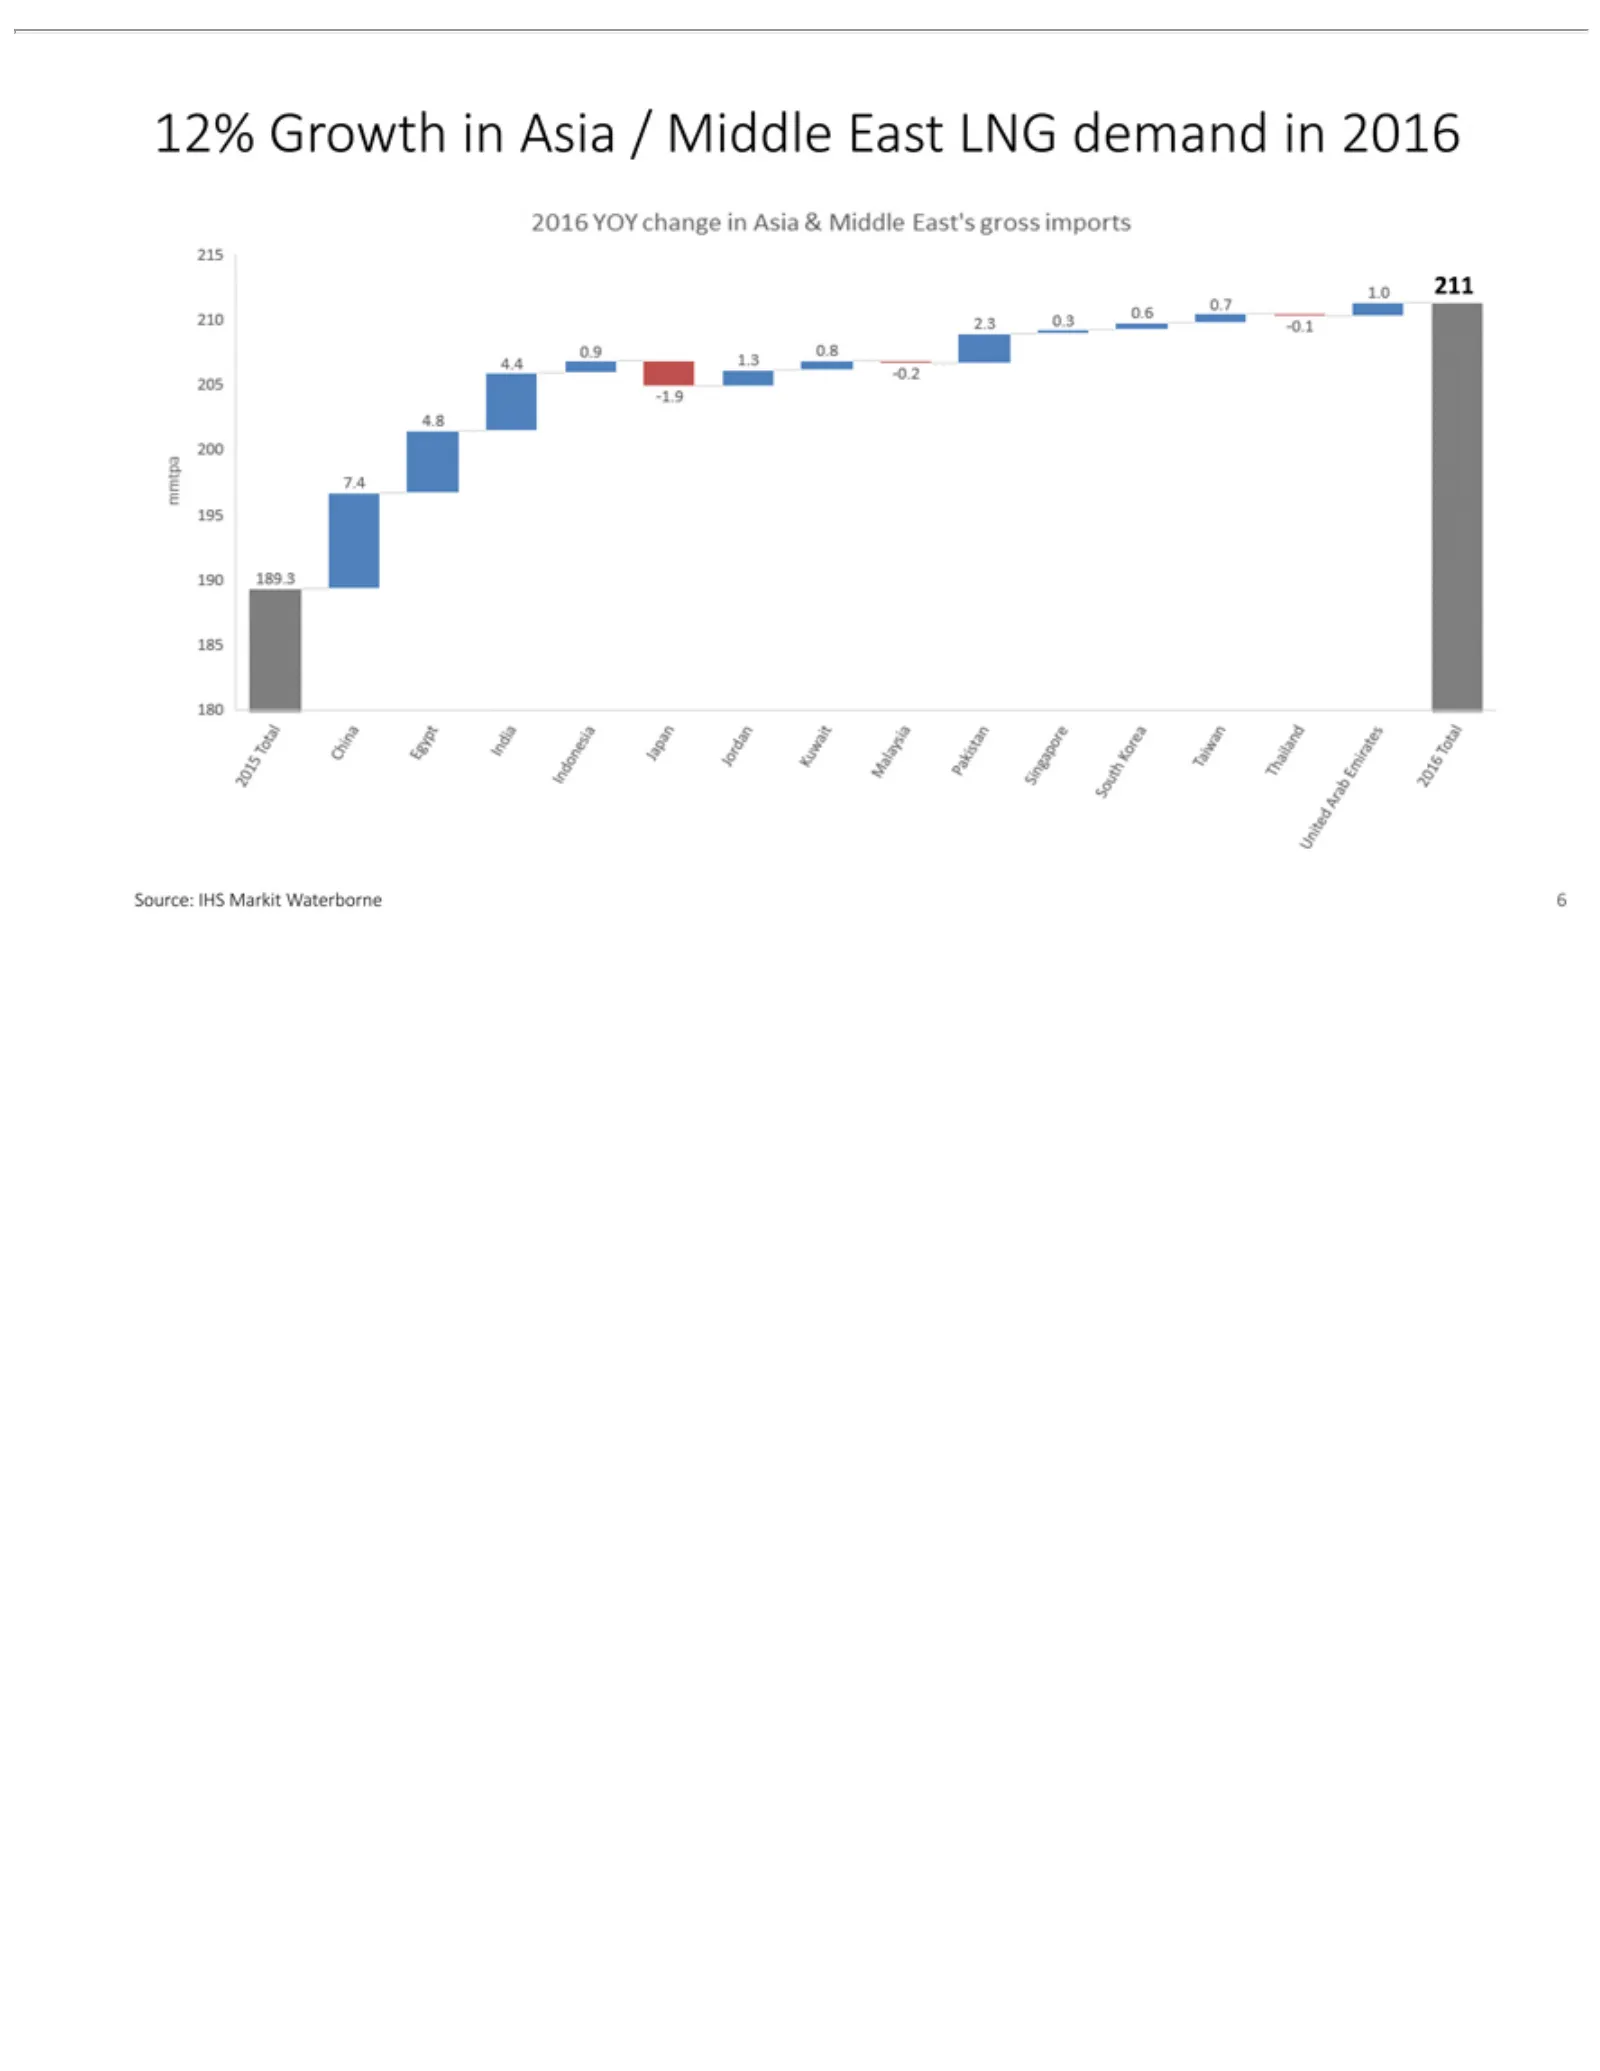
Slide 6: Growth in Asia / Middle East LNG demand in 2016
12% Growth in Asia / Middle East LNG demand in 2016 211 Source: IHS Markit Waterborne 6
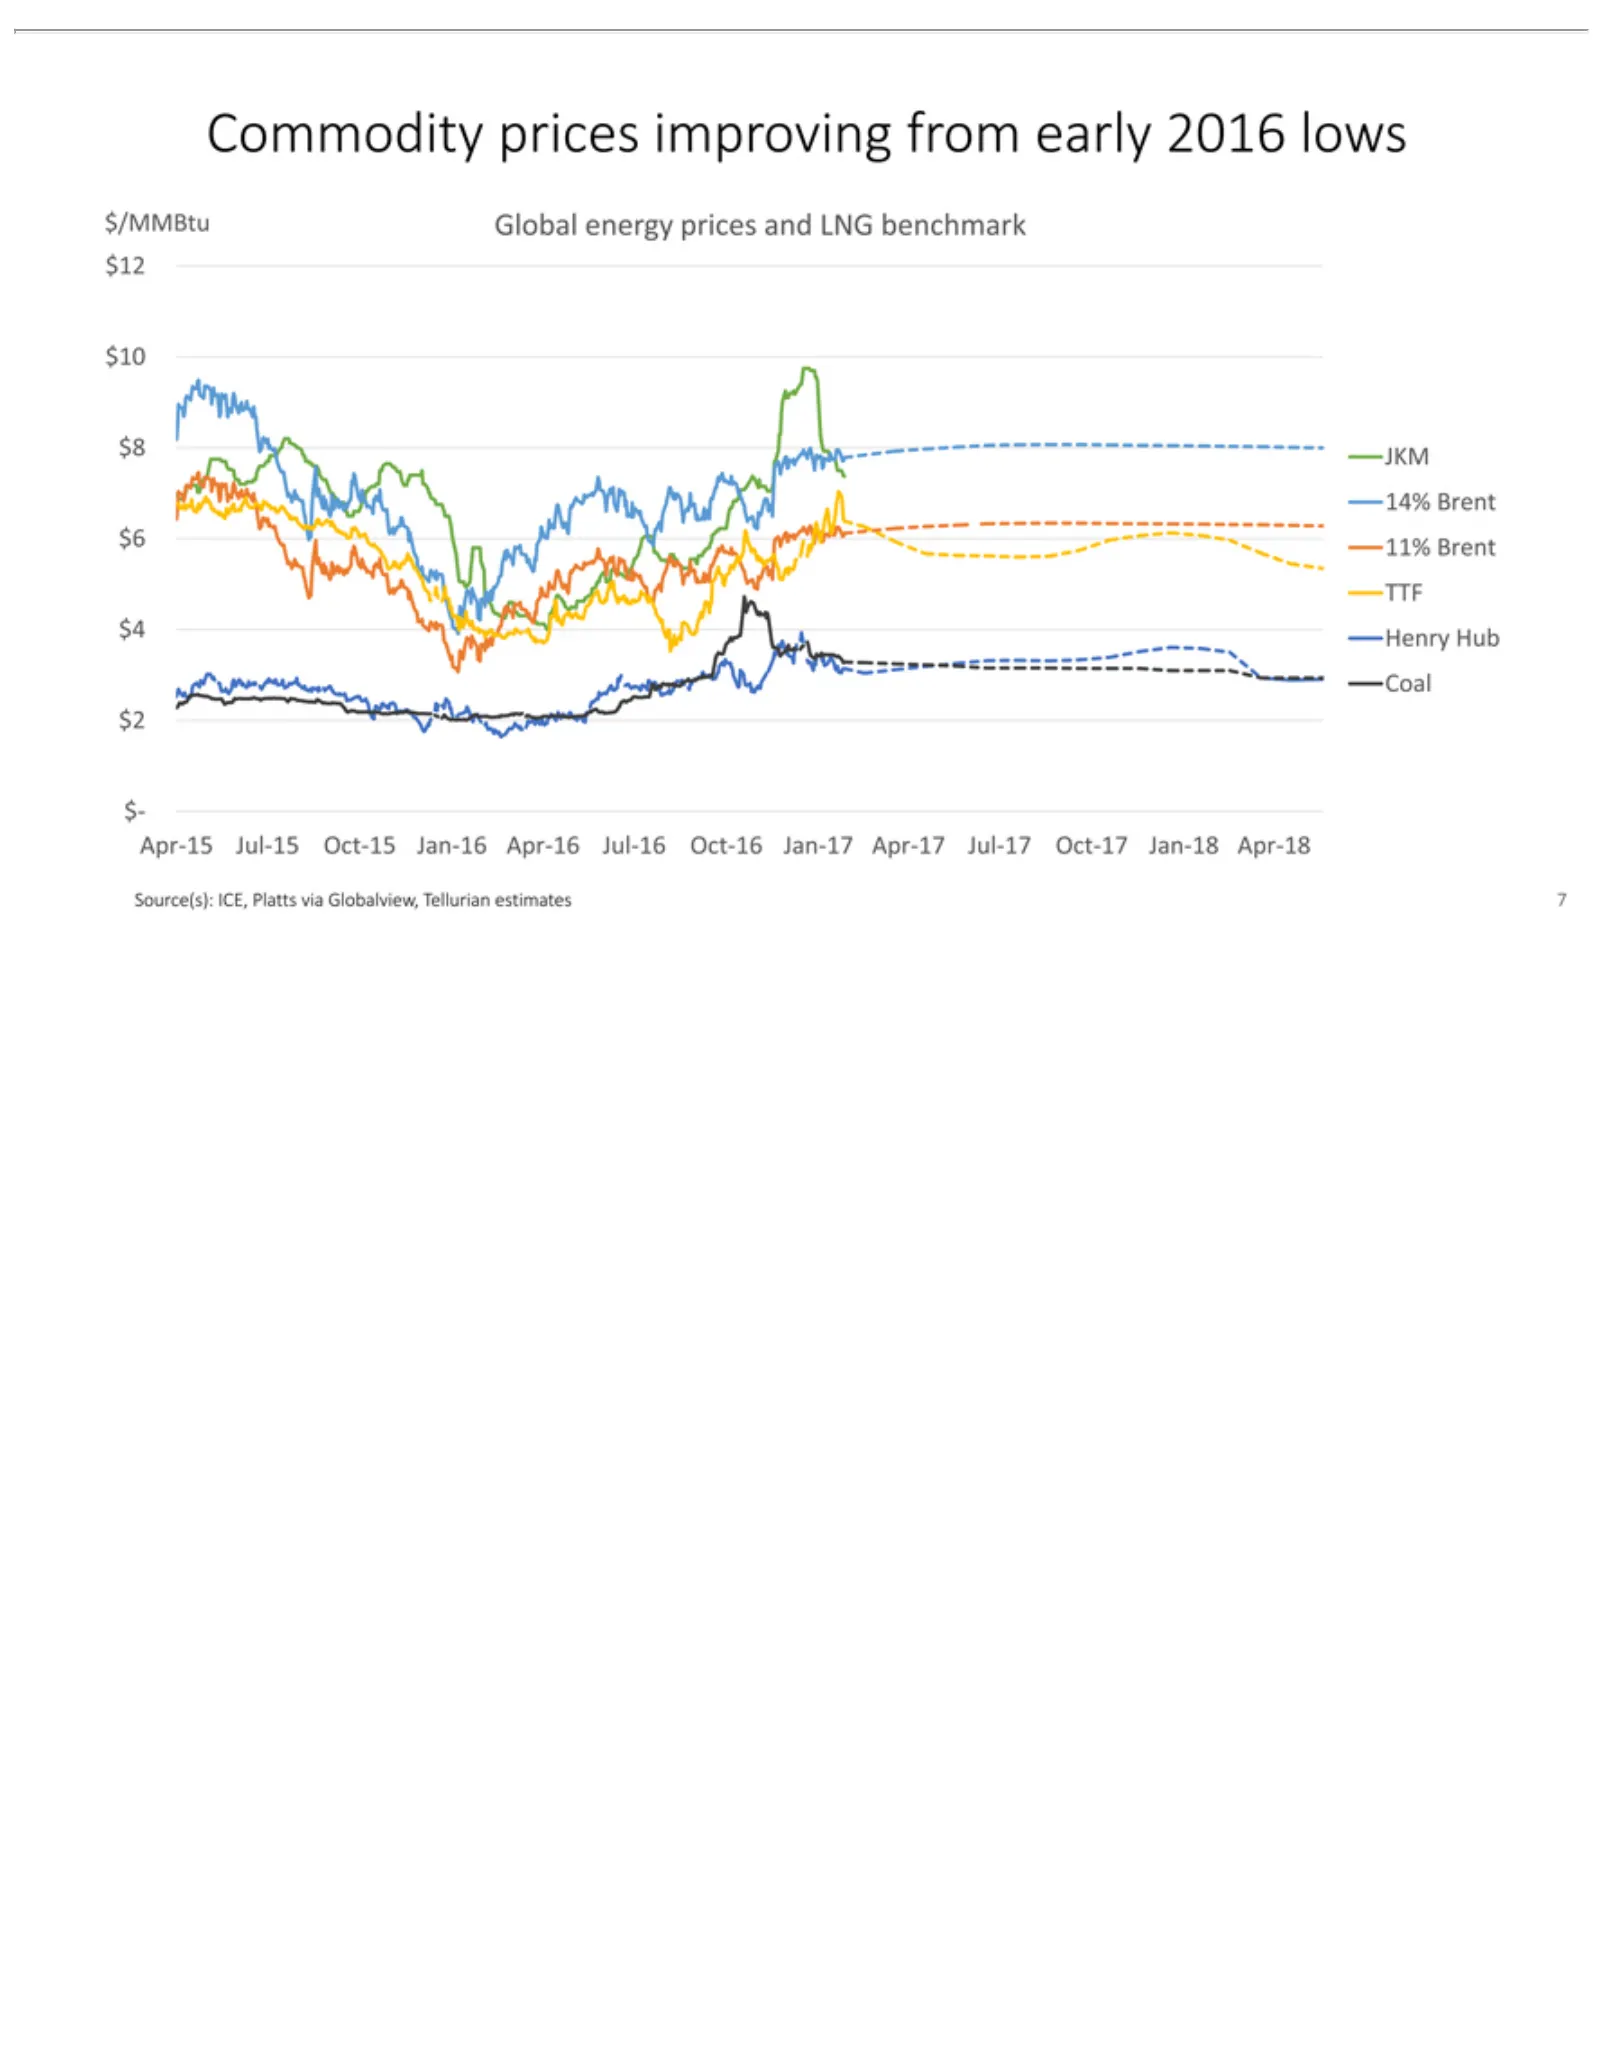
Slide 7: Commodity prices improving from early 2016 lows
Commodity $/MMBtu $8 $10 $12 $6 $4 Apr-15 $- Source(s): JKMJul-15 11% Henry Brent 14% Hub Global ICE, prices Brent TTF Oct-15 Coal Platts energy improving $2Jan-16 viaprices Globalview, Apr-16 from andearly LNG Jul-16 Tellurian 2016 benchmark Oct-16 lows estimates Jan-177Apr-17 Jul-17 Oct-17 Jan-18
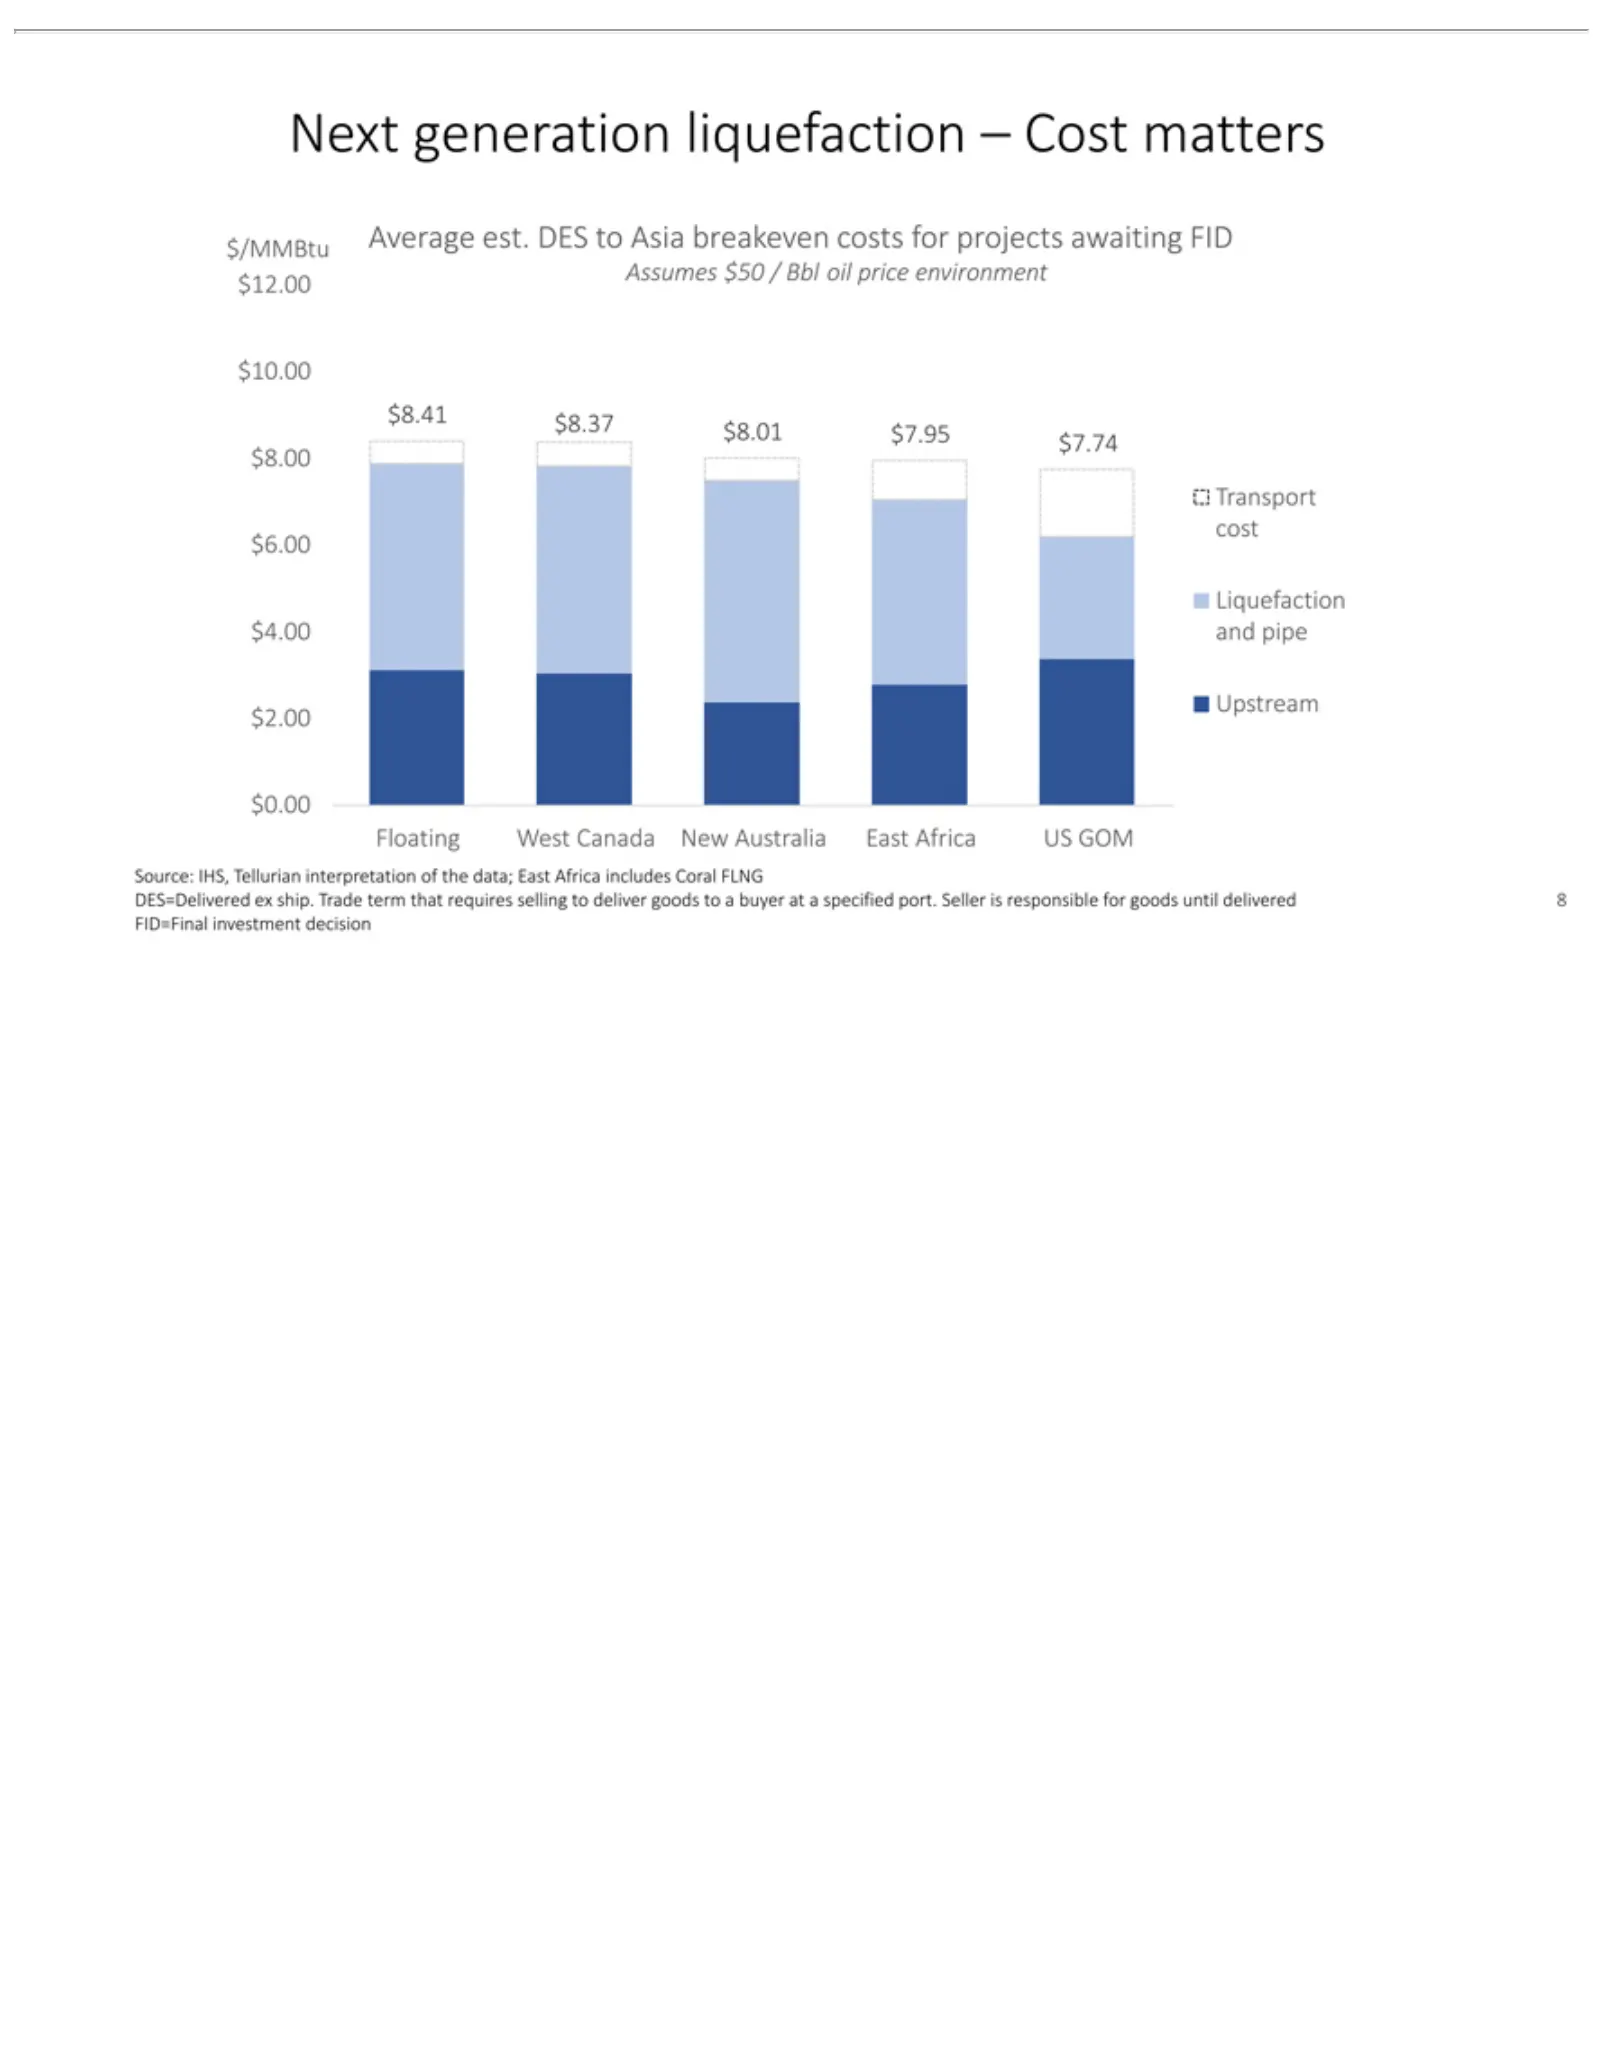
Slide 8: Next generation liquefaction – cost matters
Next generation Transport cost $6.00 liquefaction – Cost matters $/MMBtu Average est. DES to Asia breakeven costs for projects awaiting FID Assumes $50 / Bbl oil price environment $12.00 $10.00 $8.41 $8.37 $8.01 $7.95 $7.74 $8.00
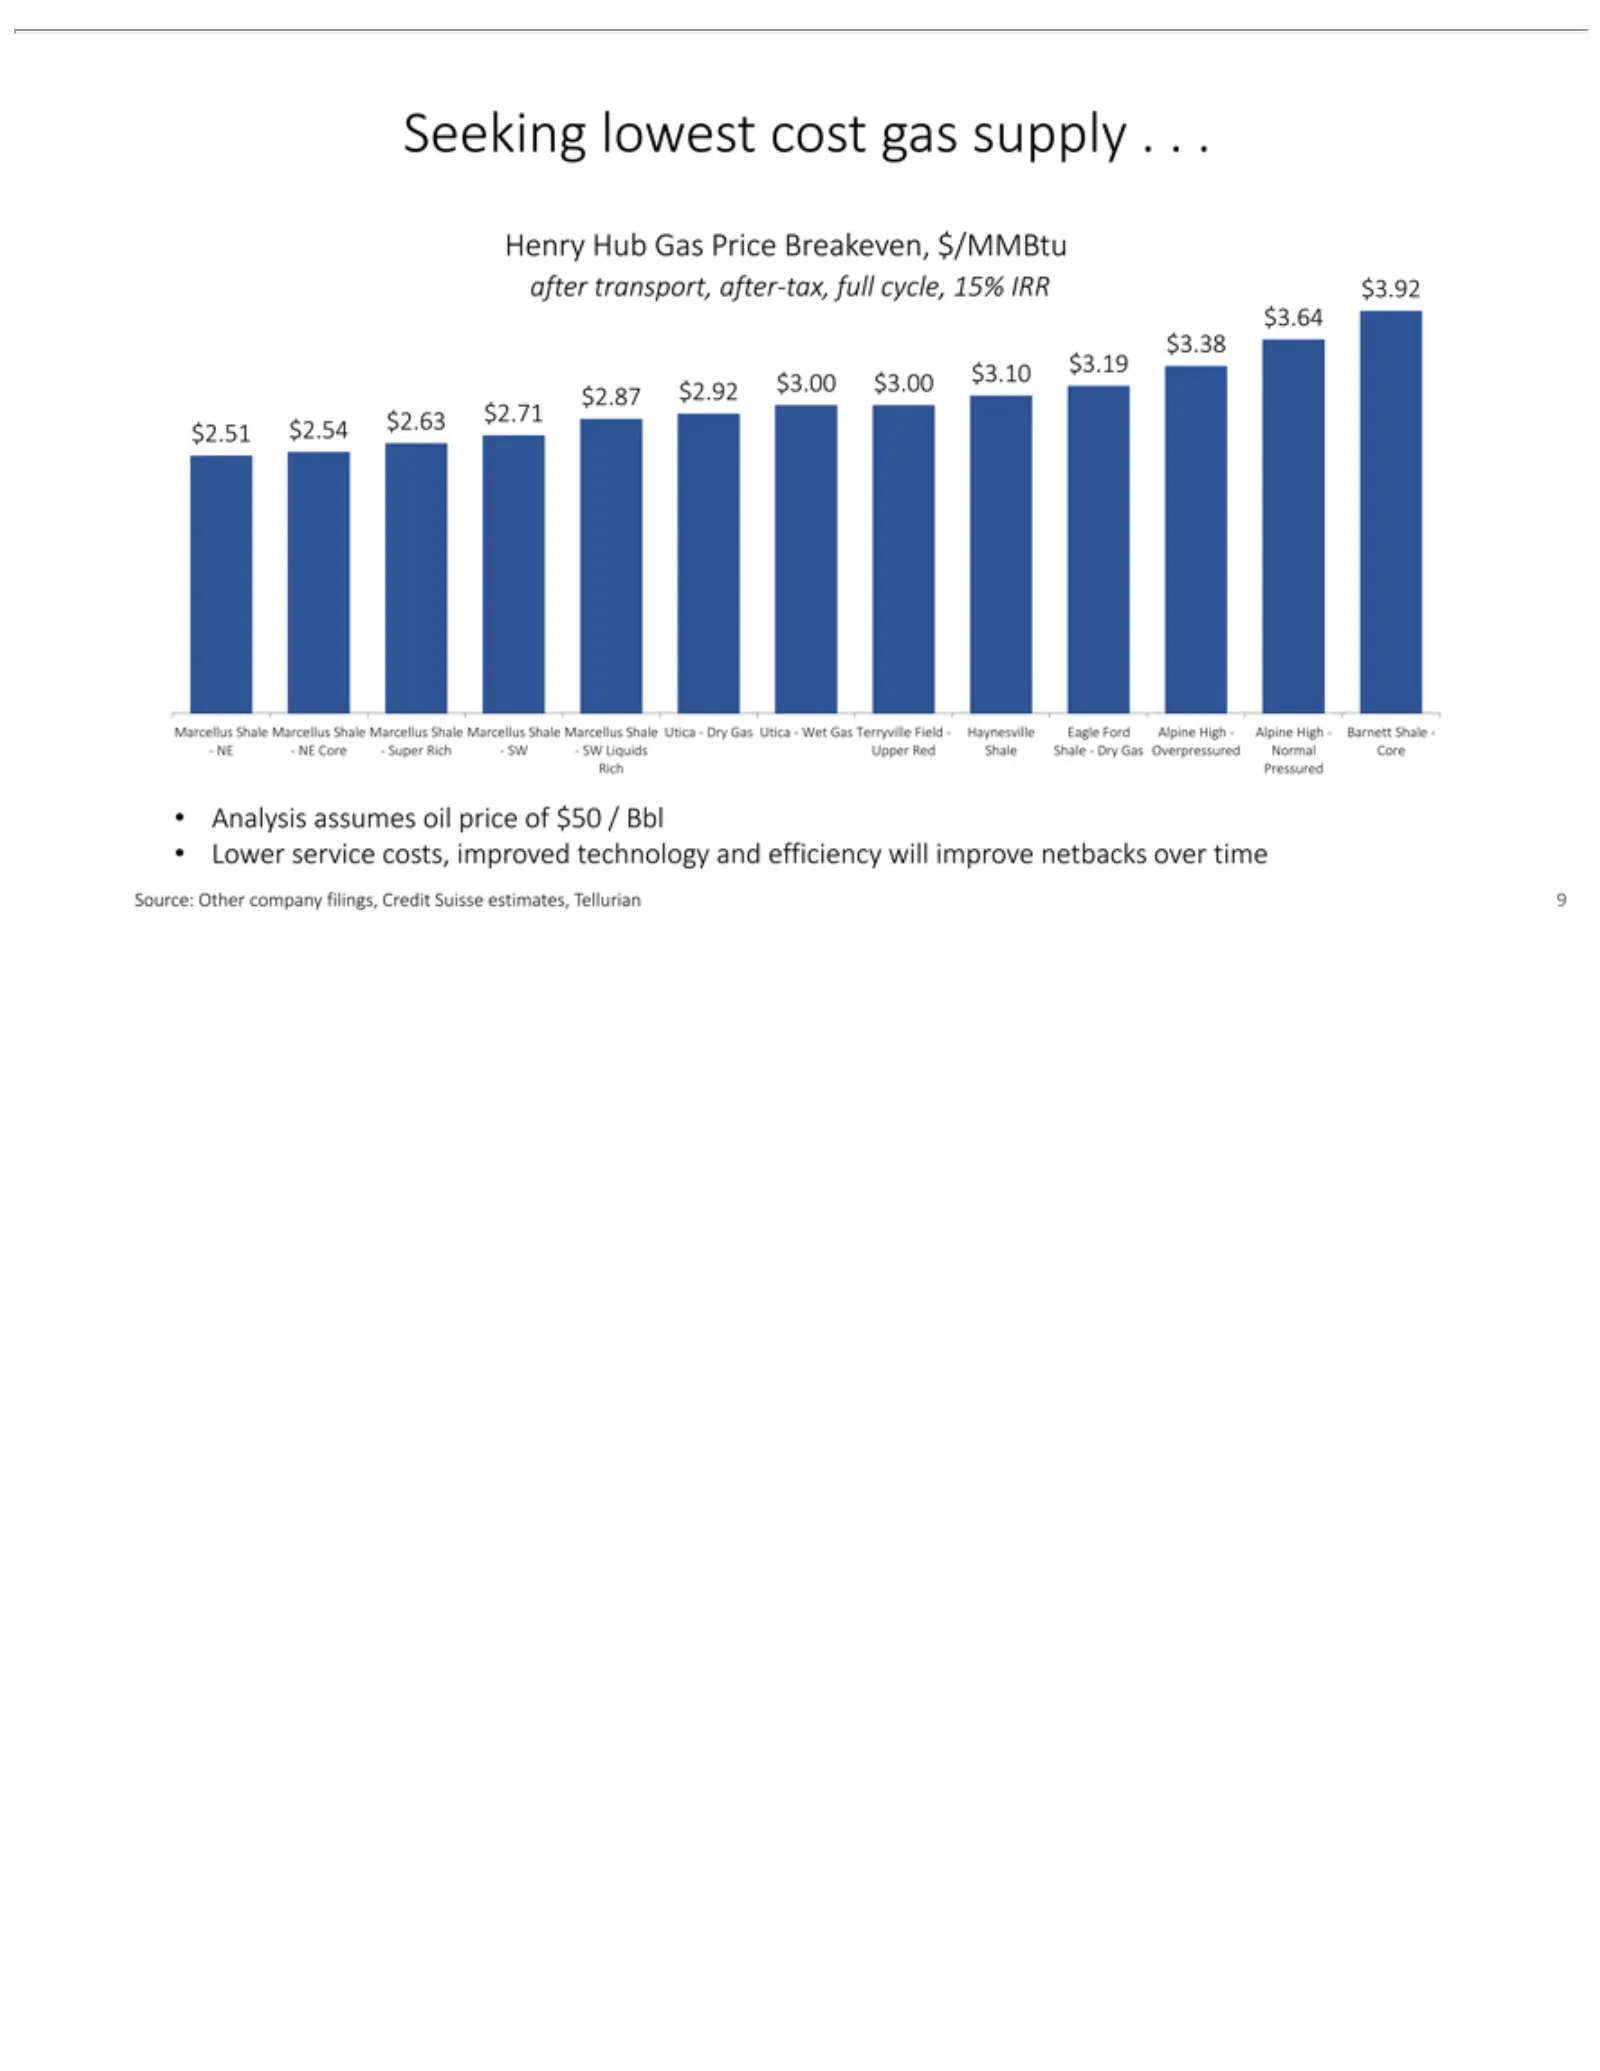
Slide 9: Seeking lowest cost gas supply
Seeking Henry after $3.64 Haynesville assumes transport, $3.19 Hub lowest oil Gas price $3.38 Eagle after-tax, cost Price of$3.00 Ford gas $50 Breakeven, Alpine supply /$3.00 full Bblcycle, •$3.10 High—Alpine .Lower . $/MMBtu . 15% $2.87 service IRR$2.92 $3.92 High—Barnett costs, $2.63 improved $2.7
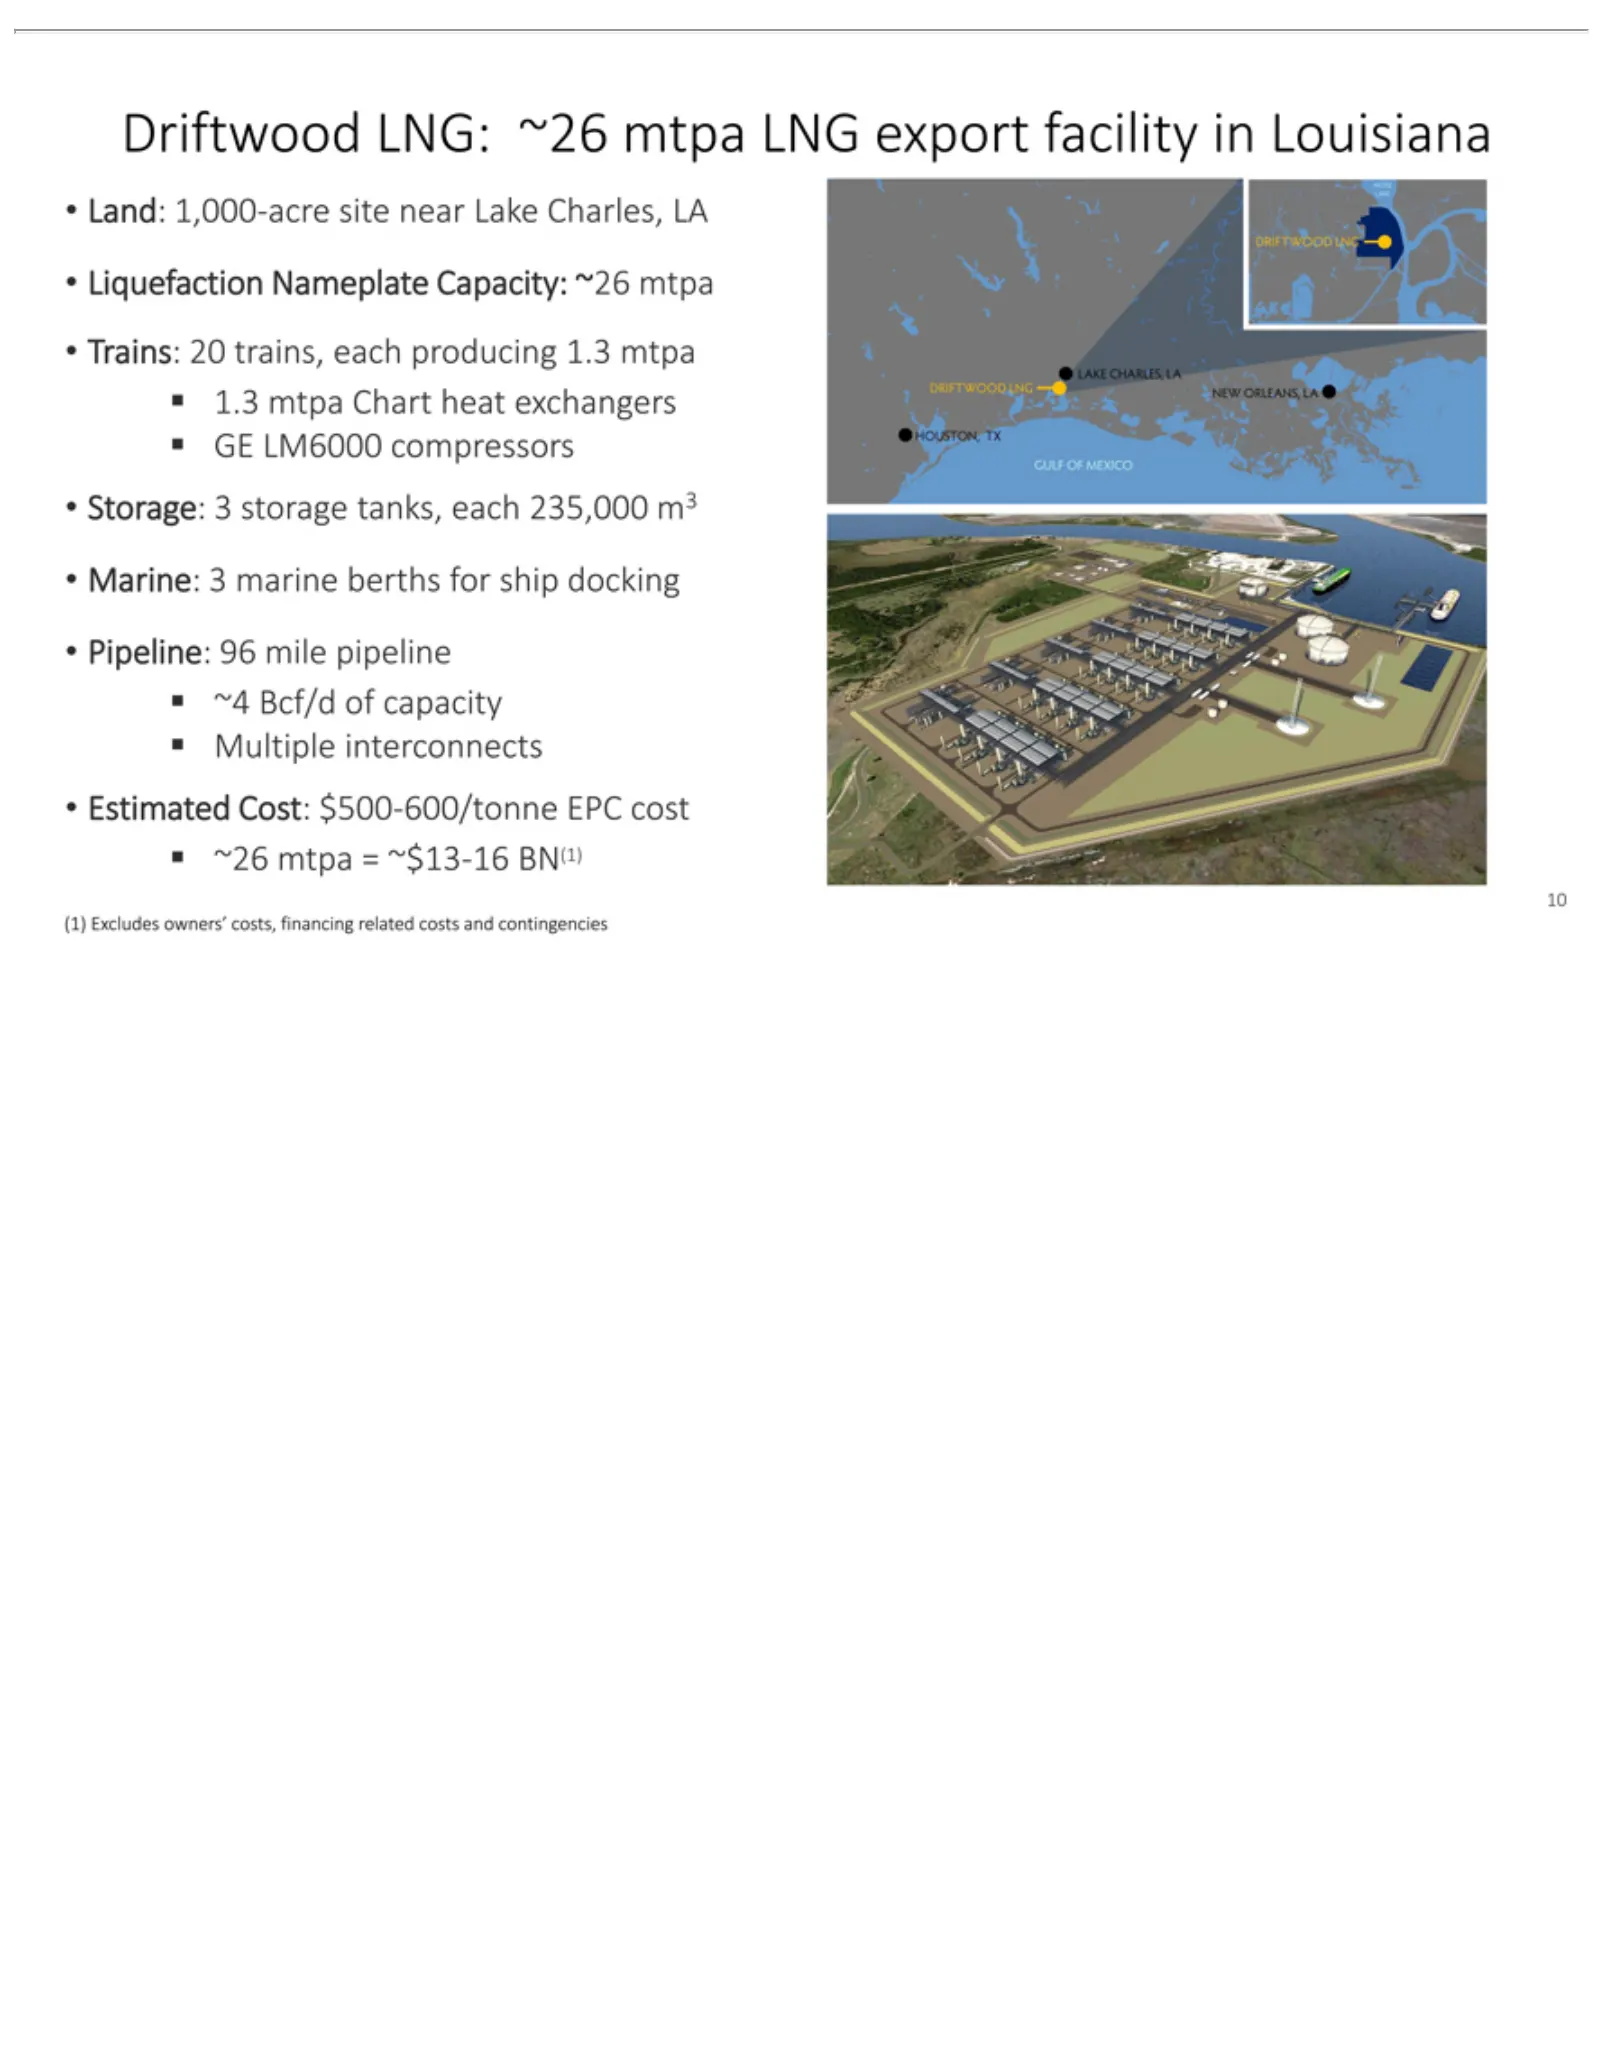
Slide 10: Driftwood LNG project overview
•Driftwood Trains: Land: 1,000-acre Liquefaction Storage: Marine: Pipeline: Estimated 20 3396 LNG: marine Cost: trains, storage mile Nameplate ~26 $500-600/tonne each site pipeline berths tanks, mtpa near producing for Capacity: each LNG ?Lake ~4 ship 235,000 Bcf/d export Charles, EPC docking 1.3 ~2
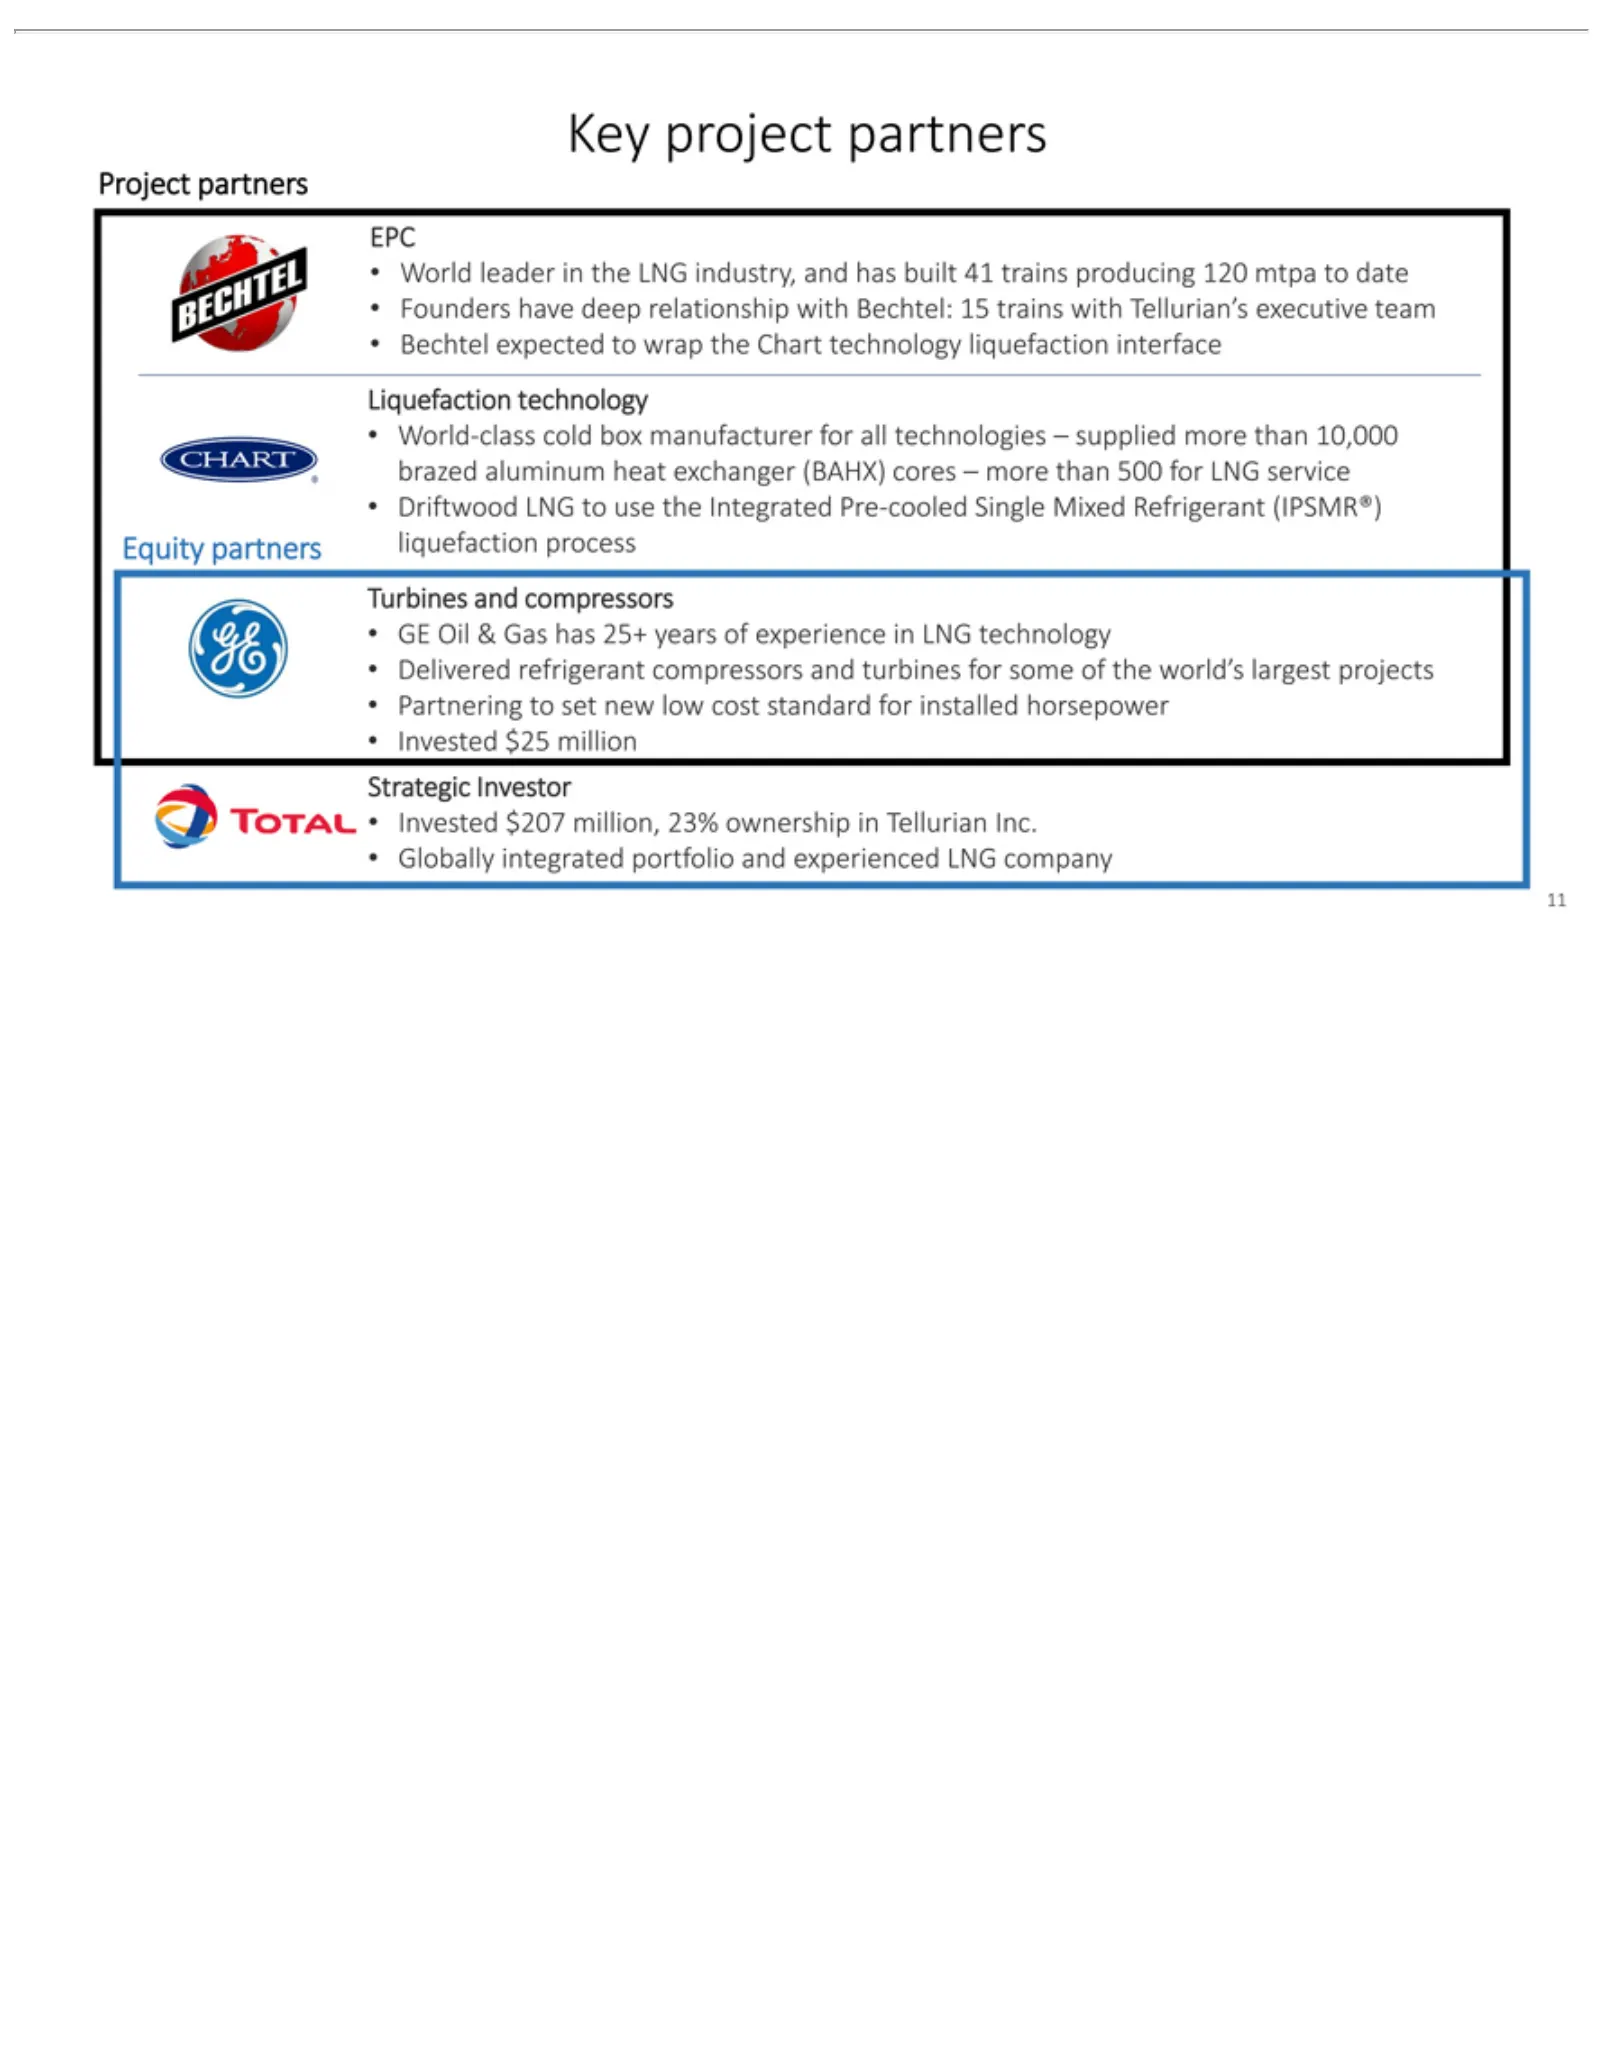
Slide 11: Key project partners
Key Project EPC Liquefaction •Strategic 11 World World-class Founders Bechtel Driftwood GE Delivered Partnering Invested Globally project Oilpartners leader & Investor expected $25 $207 integrated have Gas refrigerant partners to LNG technology cold million in set million, has deep the to new box to
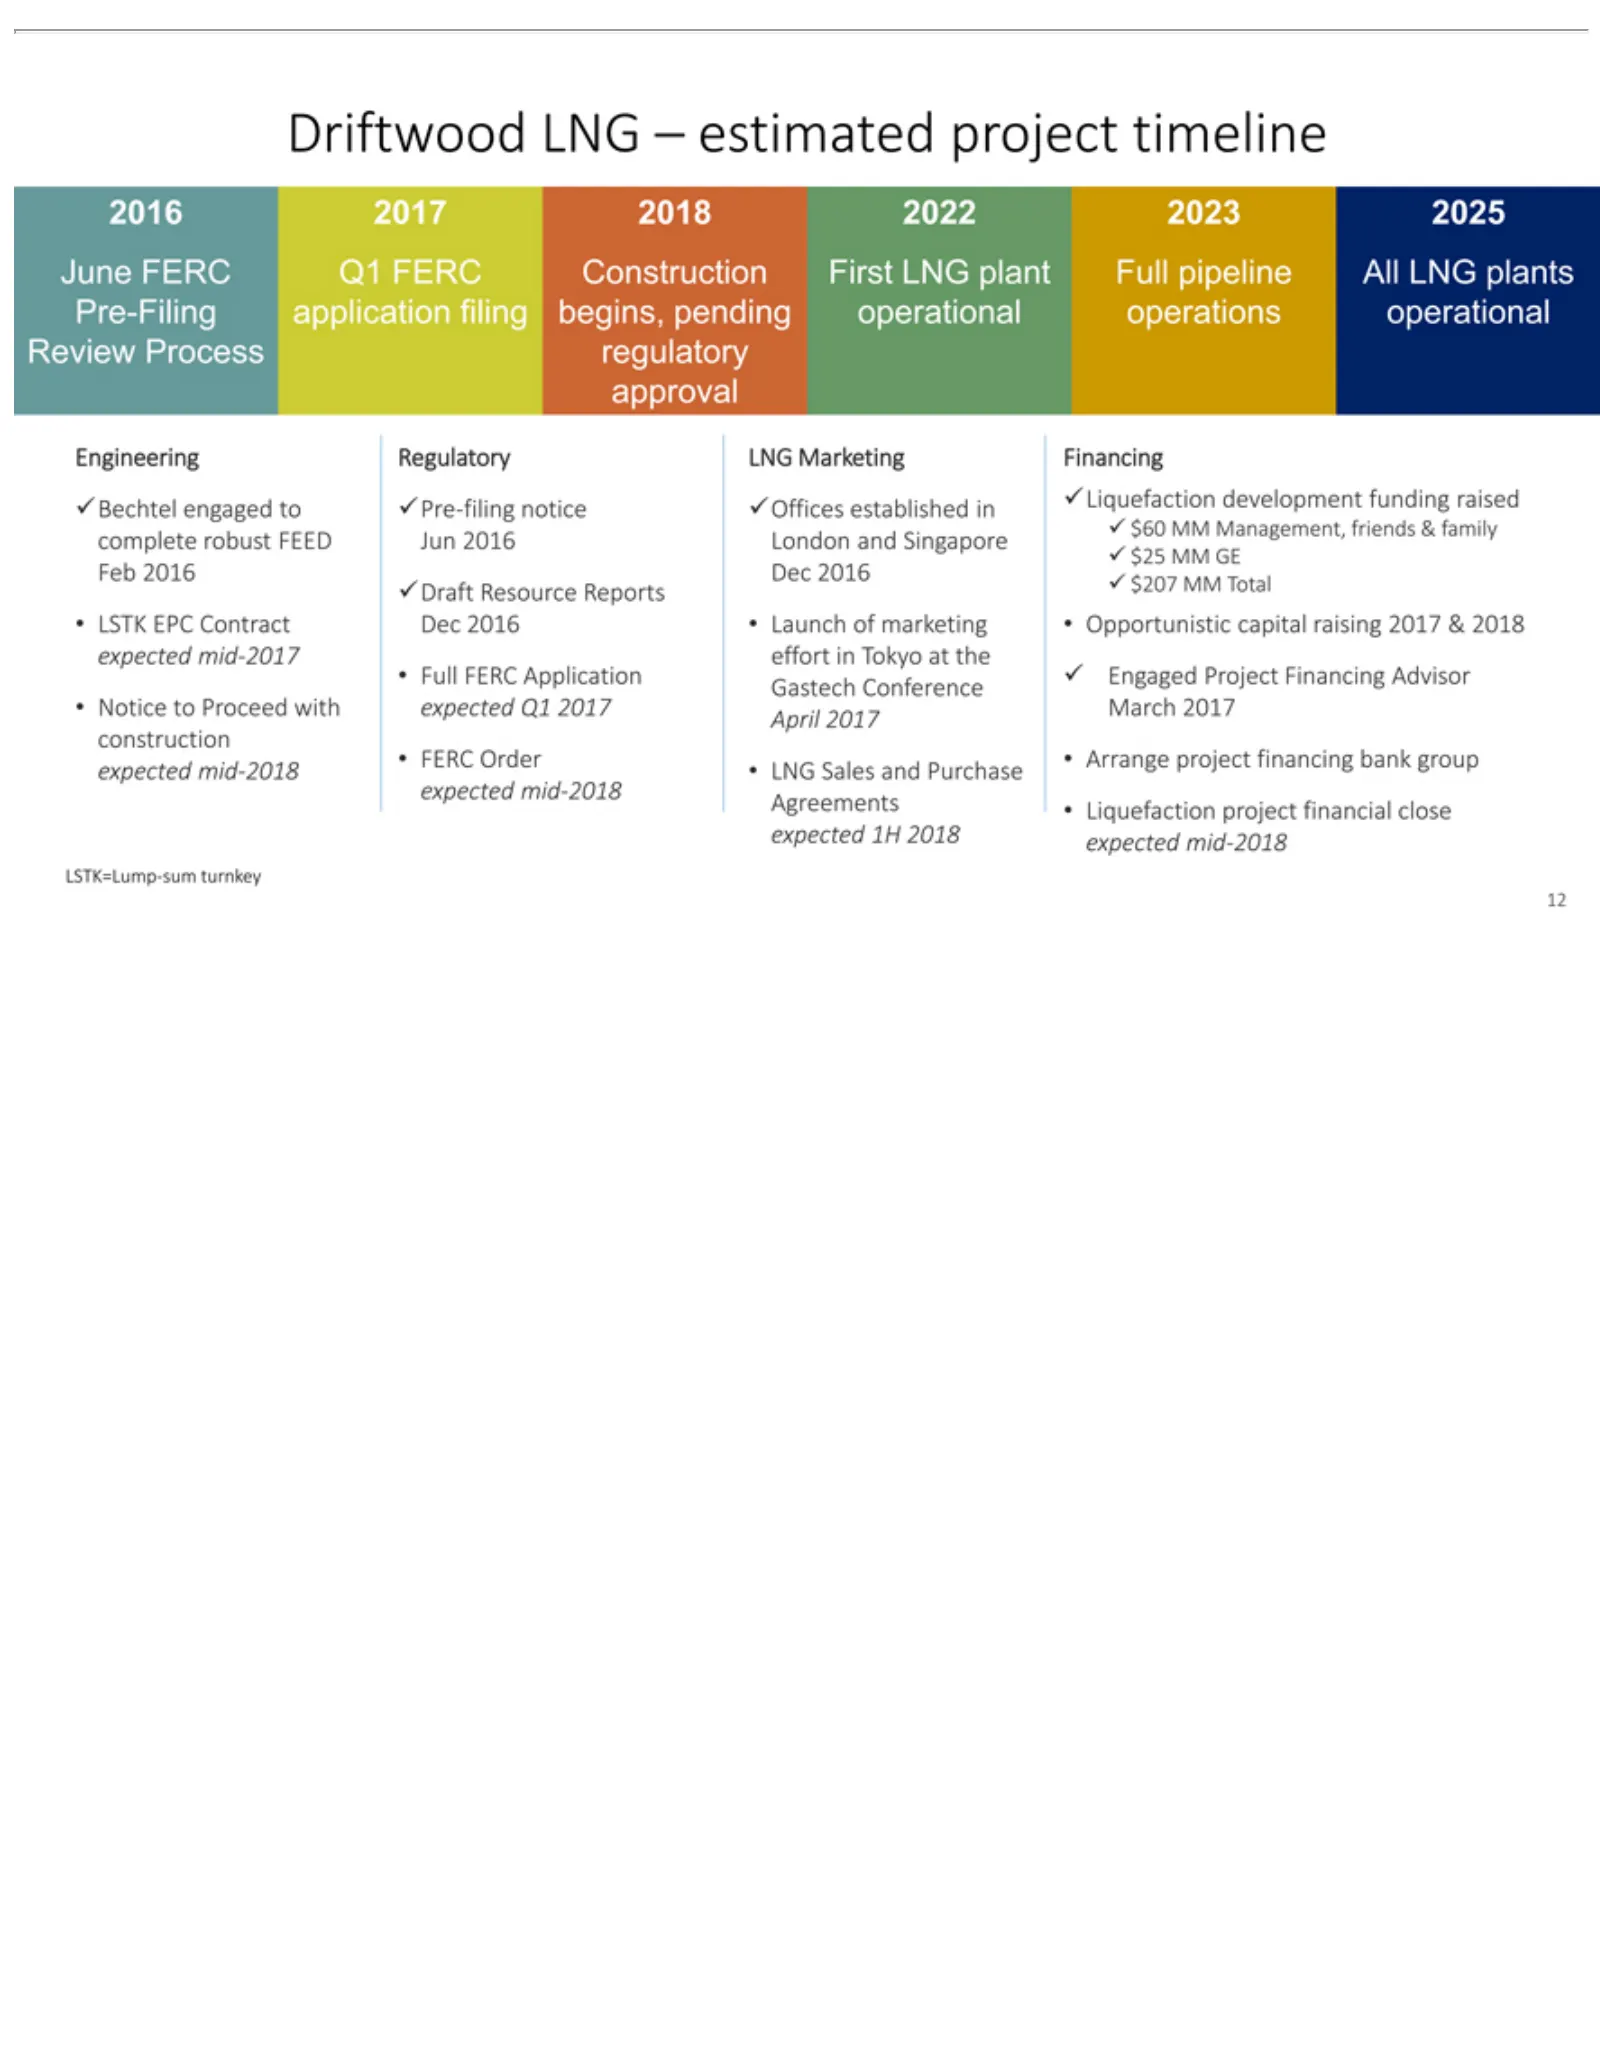
Slide 12: Driftwood timeline
Driftwood 2016 June Engineering $60 •marketing LNG Engaged MM FERC 2017 Sales Management, •Project LNG 2018 and Q1 Opportunistic Regulatory FERC Purchase –2022 estimated Proceed 2023 Construction friends LNG Agreements capital 2025 project with Marketing & family raising 2017 First timeline • Liquef
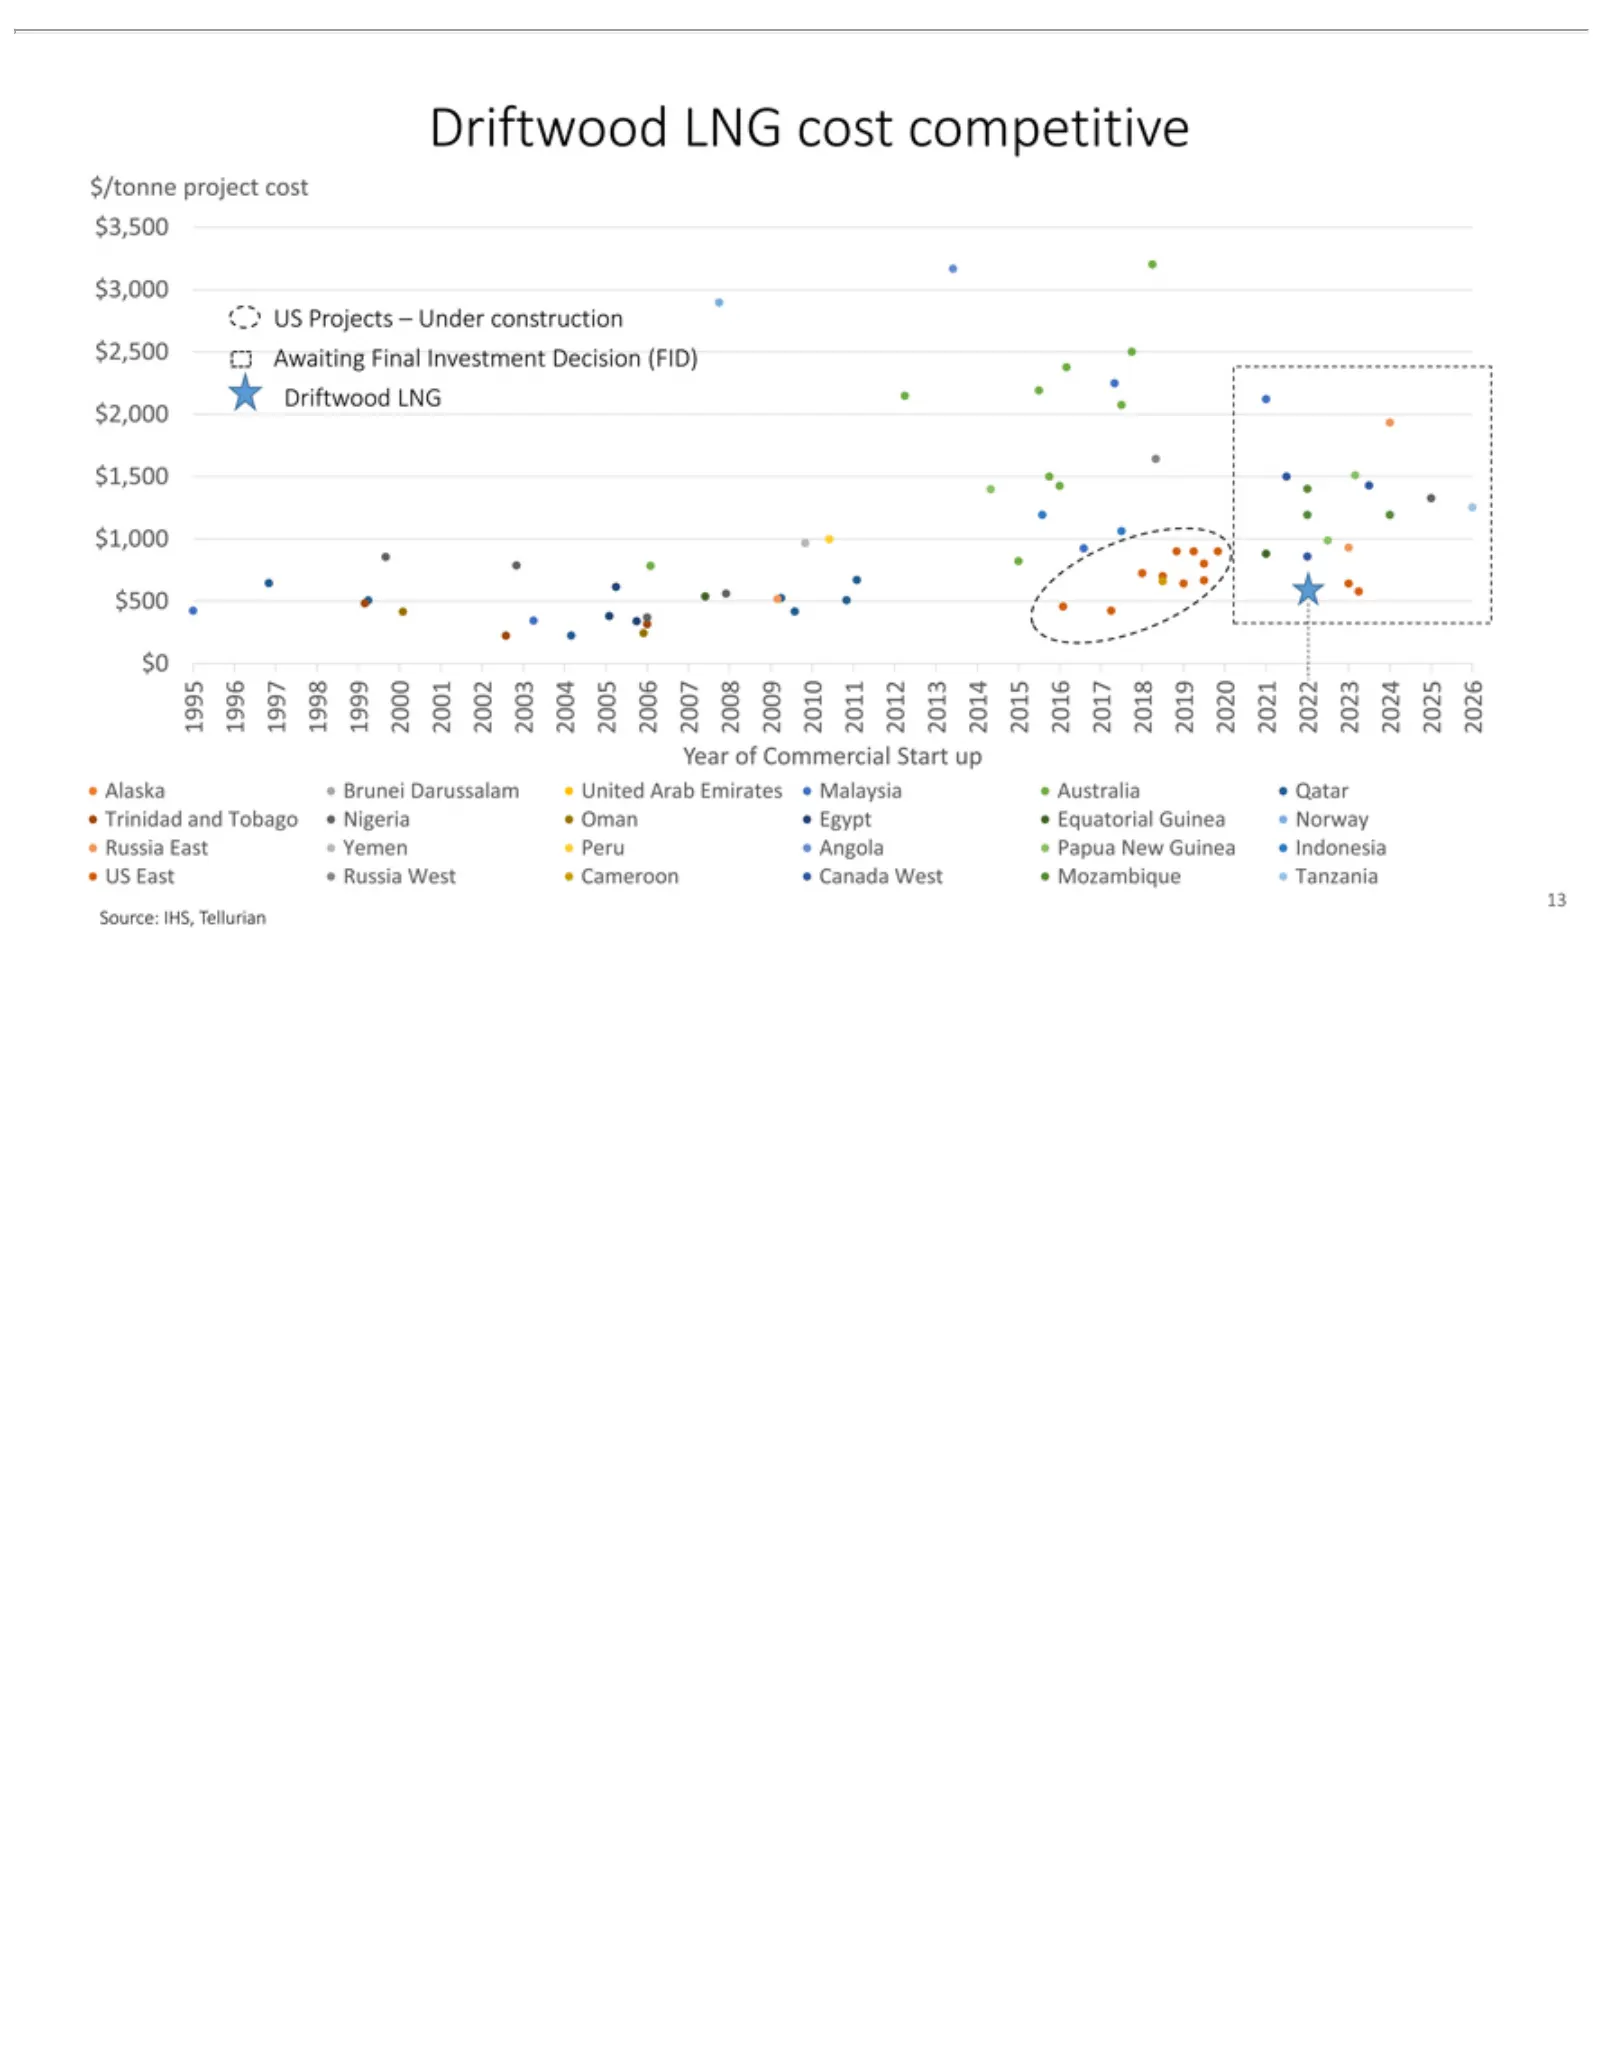
Slide 13: Driftwood project cost competitive
Driftwood $/tonne US $3,000 $1,500 1995 $0 Alaska Russia 13 Source: Projects 1996 West $1,000 Brunei project LNG 1997 IHS, –Cameroon Under Darussalam $500 cost Tellurian cost 1998$3,500 construction competitive 1999 Canada United 2000West 2001 $2,500 Arab Mozambique 2002 Emirates Awaiting 2003Malays
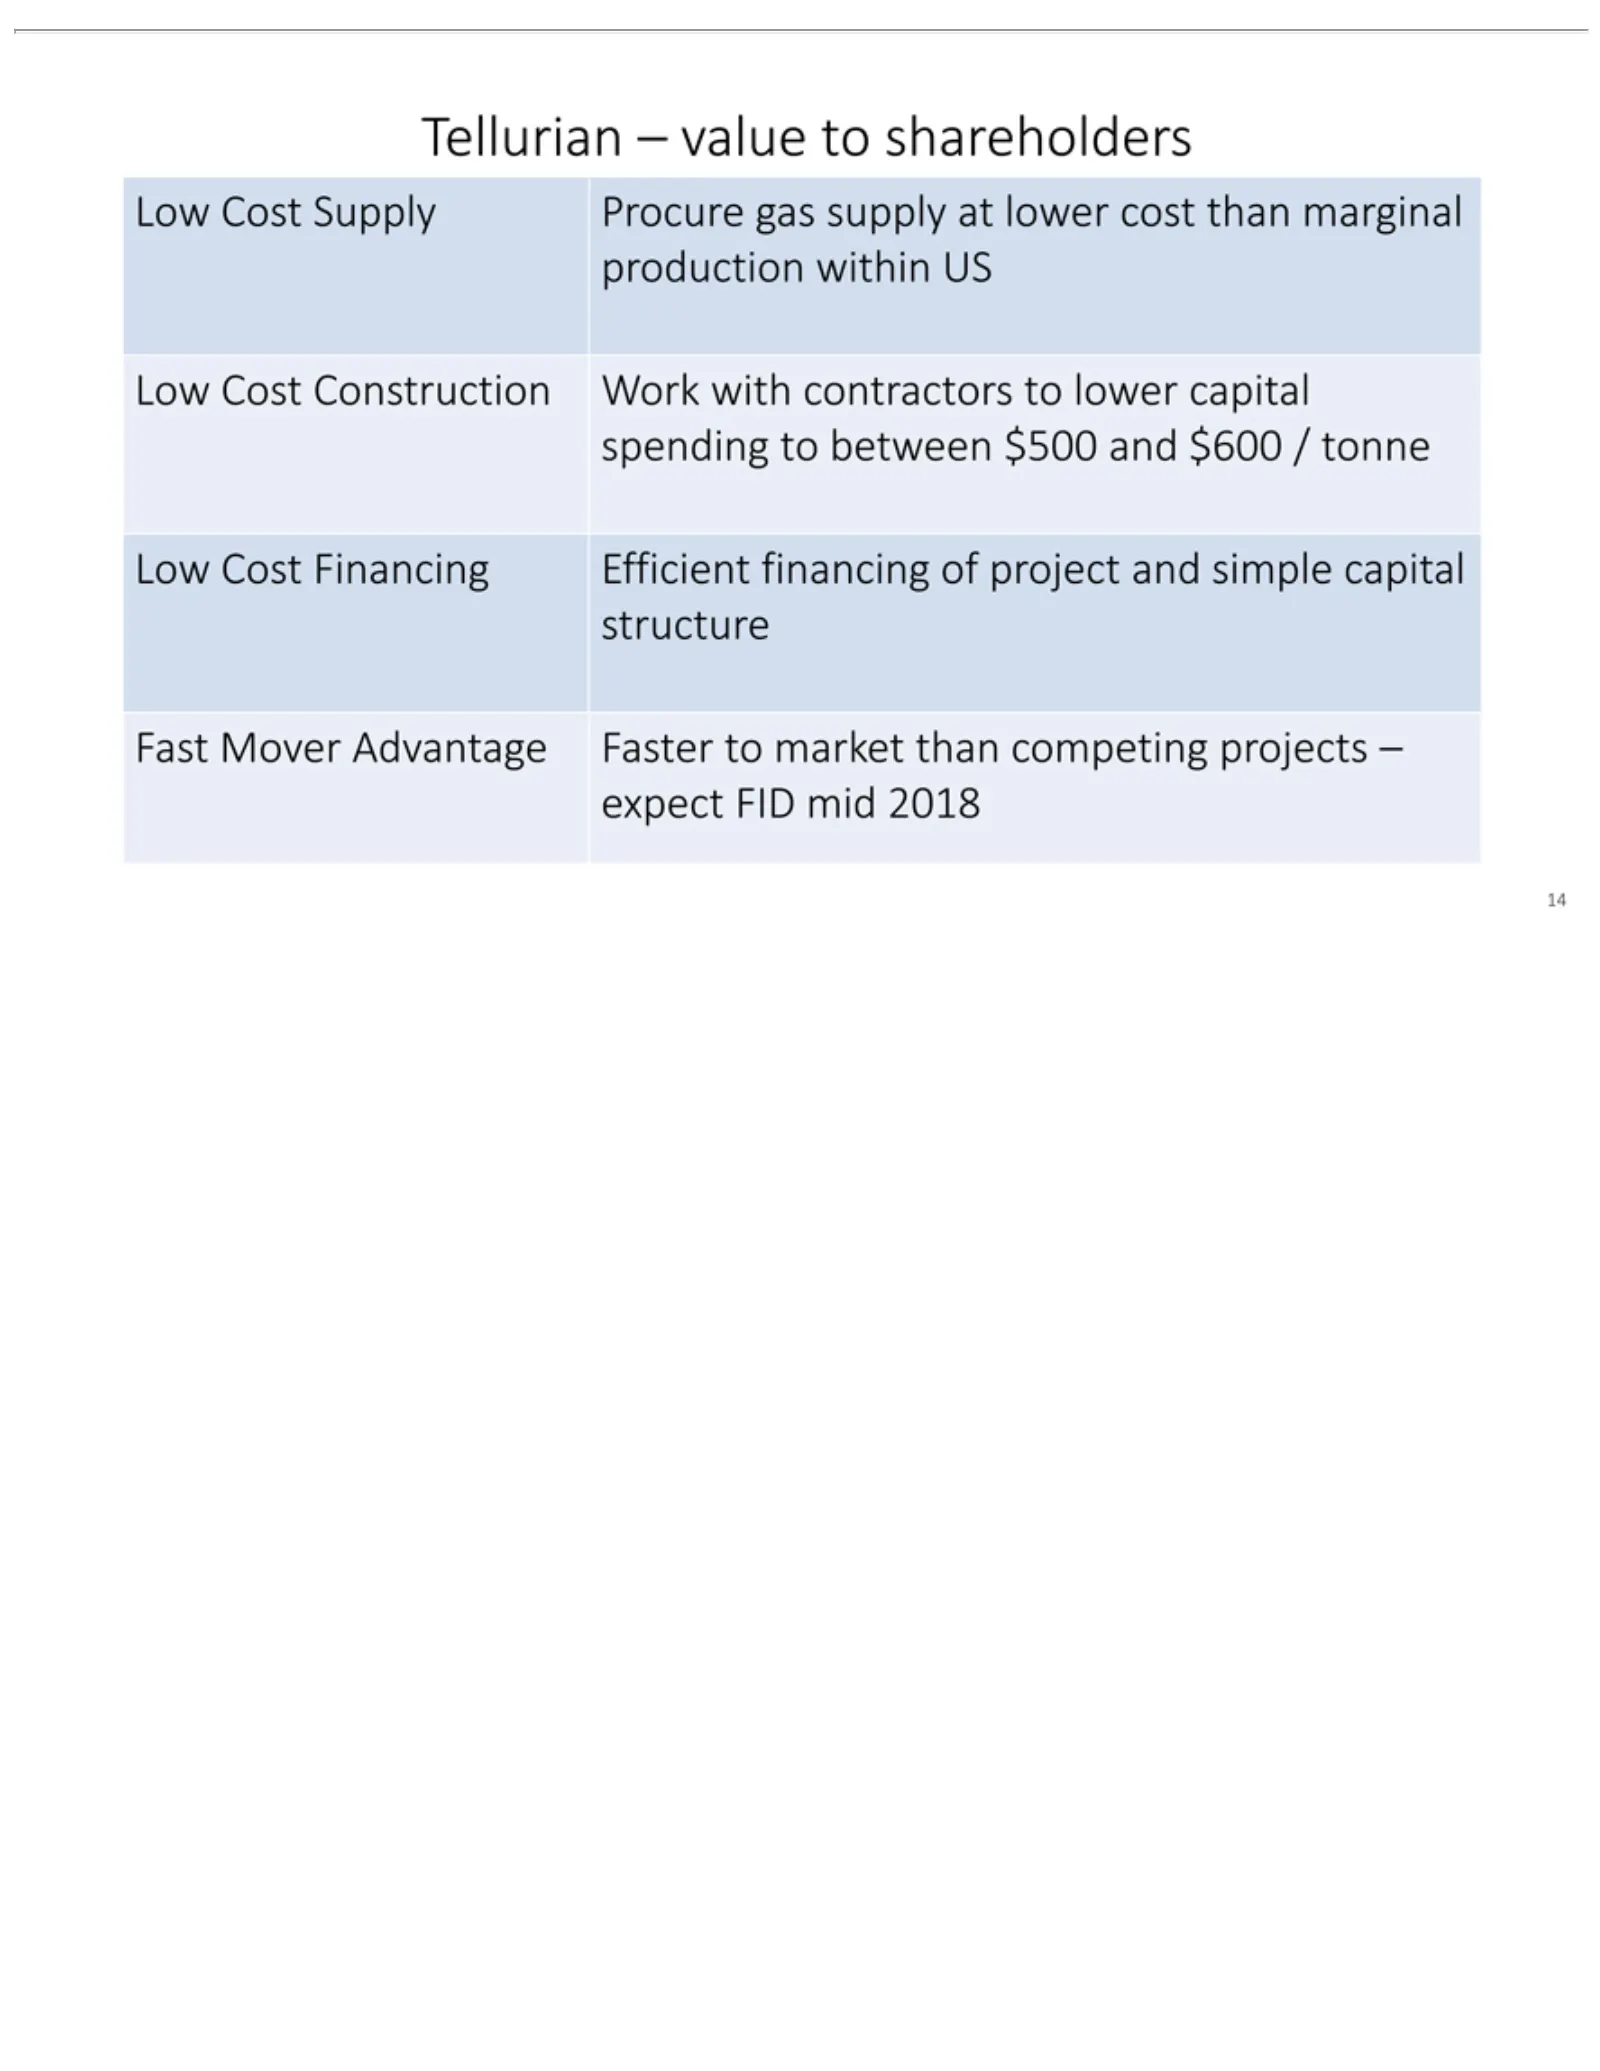
Slide 14: Tellurian value to shareholders
Tellurian Low Fast Mover Cost–Financing Supply Construction value Advantage to Procure shareholders Efficient Faster Work gas with to financing supply market contractors at lower than of project competing cost to lower and thansimple capital marginal projects capital spending –production expect stru
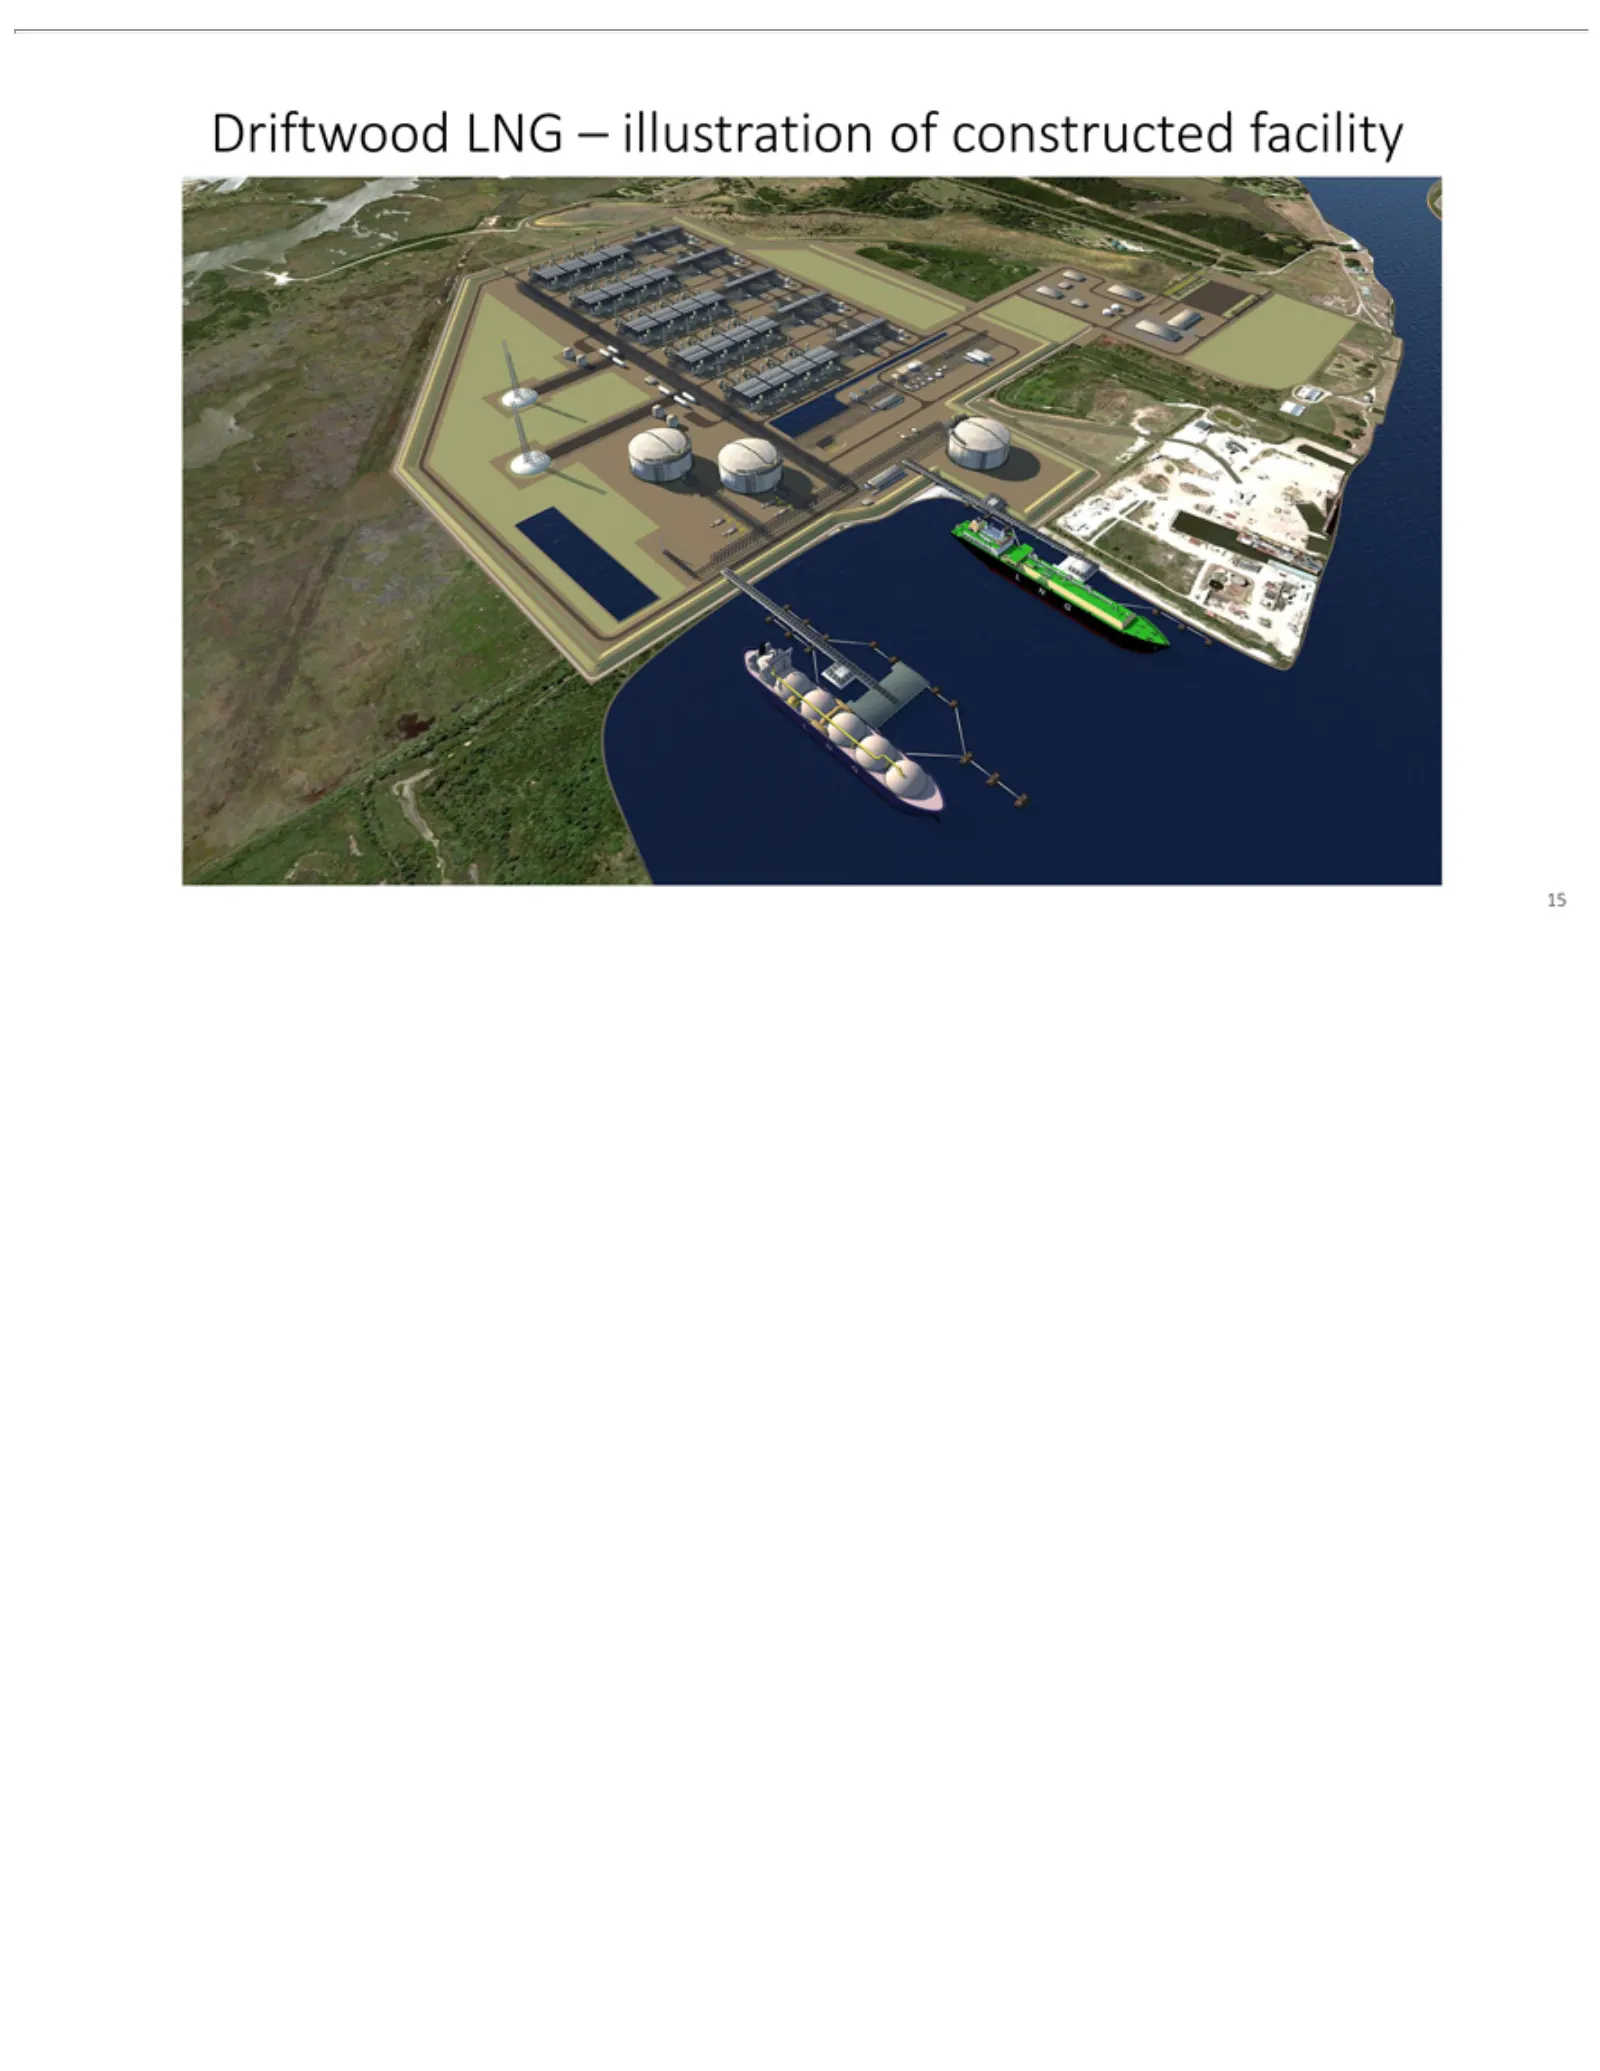
Slide 15: Driftwood LNG – illustration of constructed facility
Driftwood LNG – illustration of constructed facility 14 15
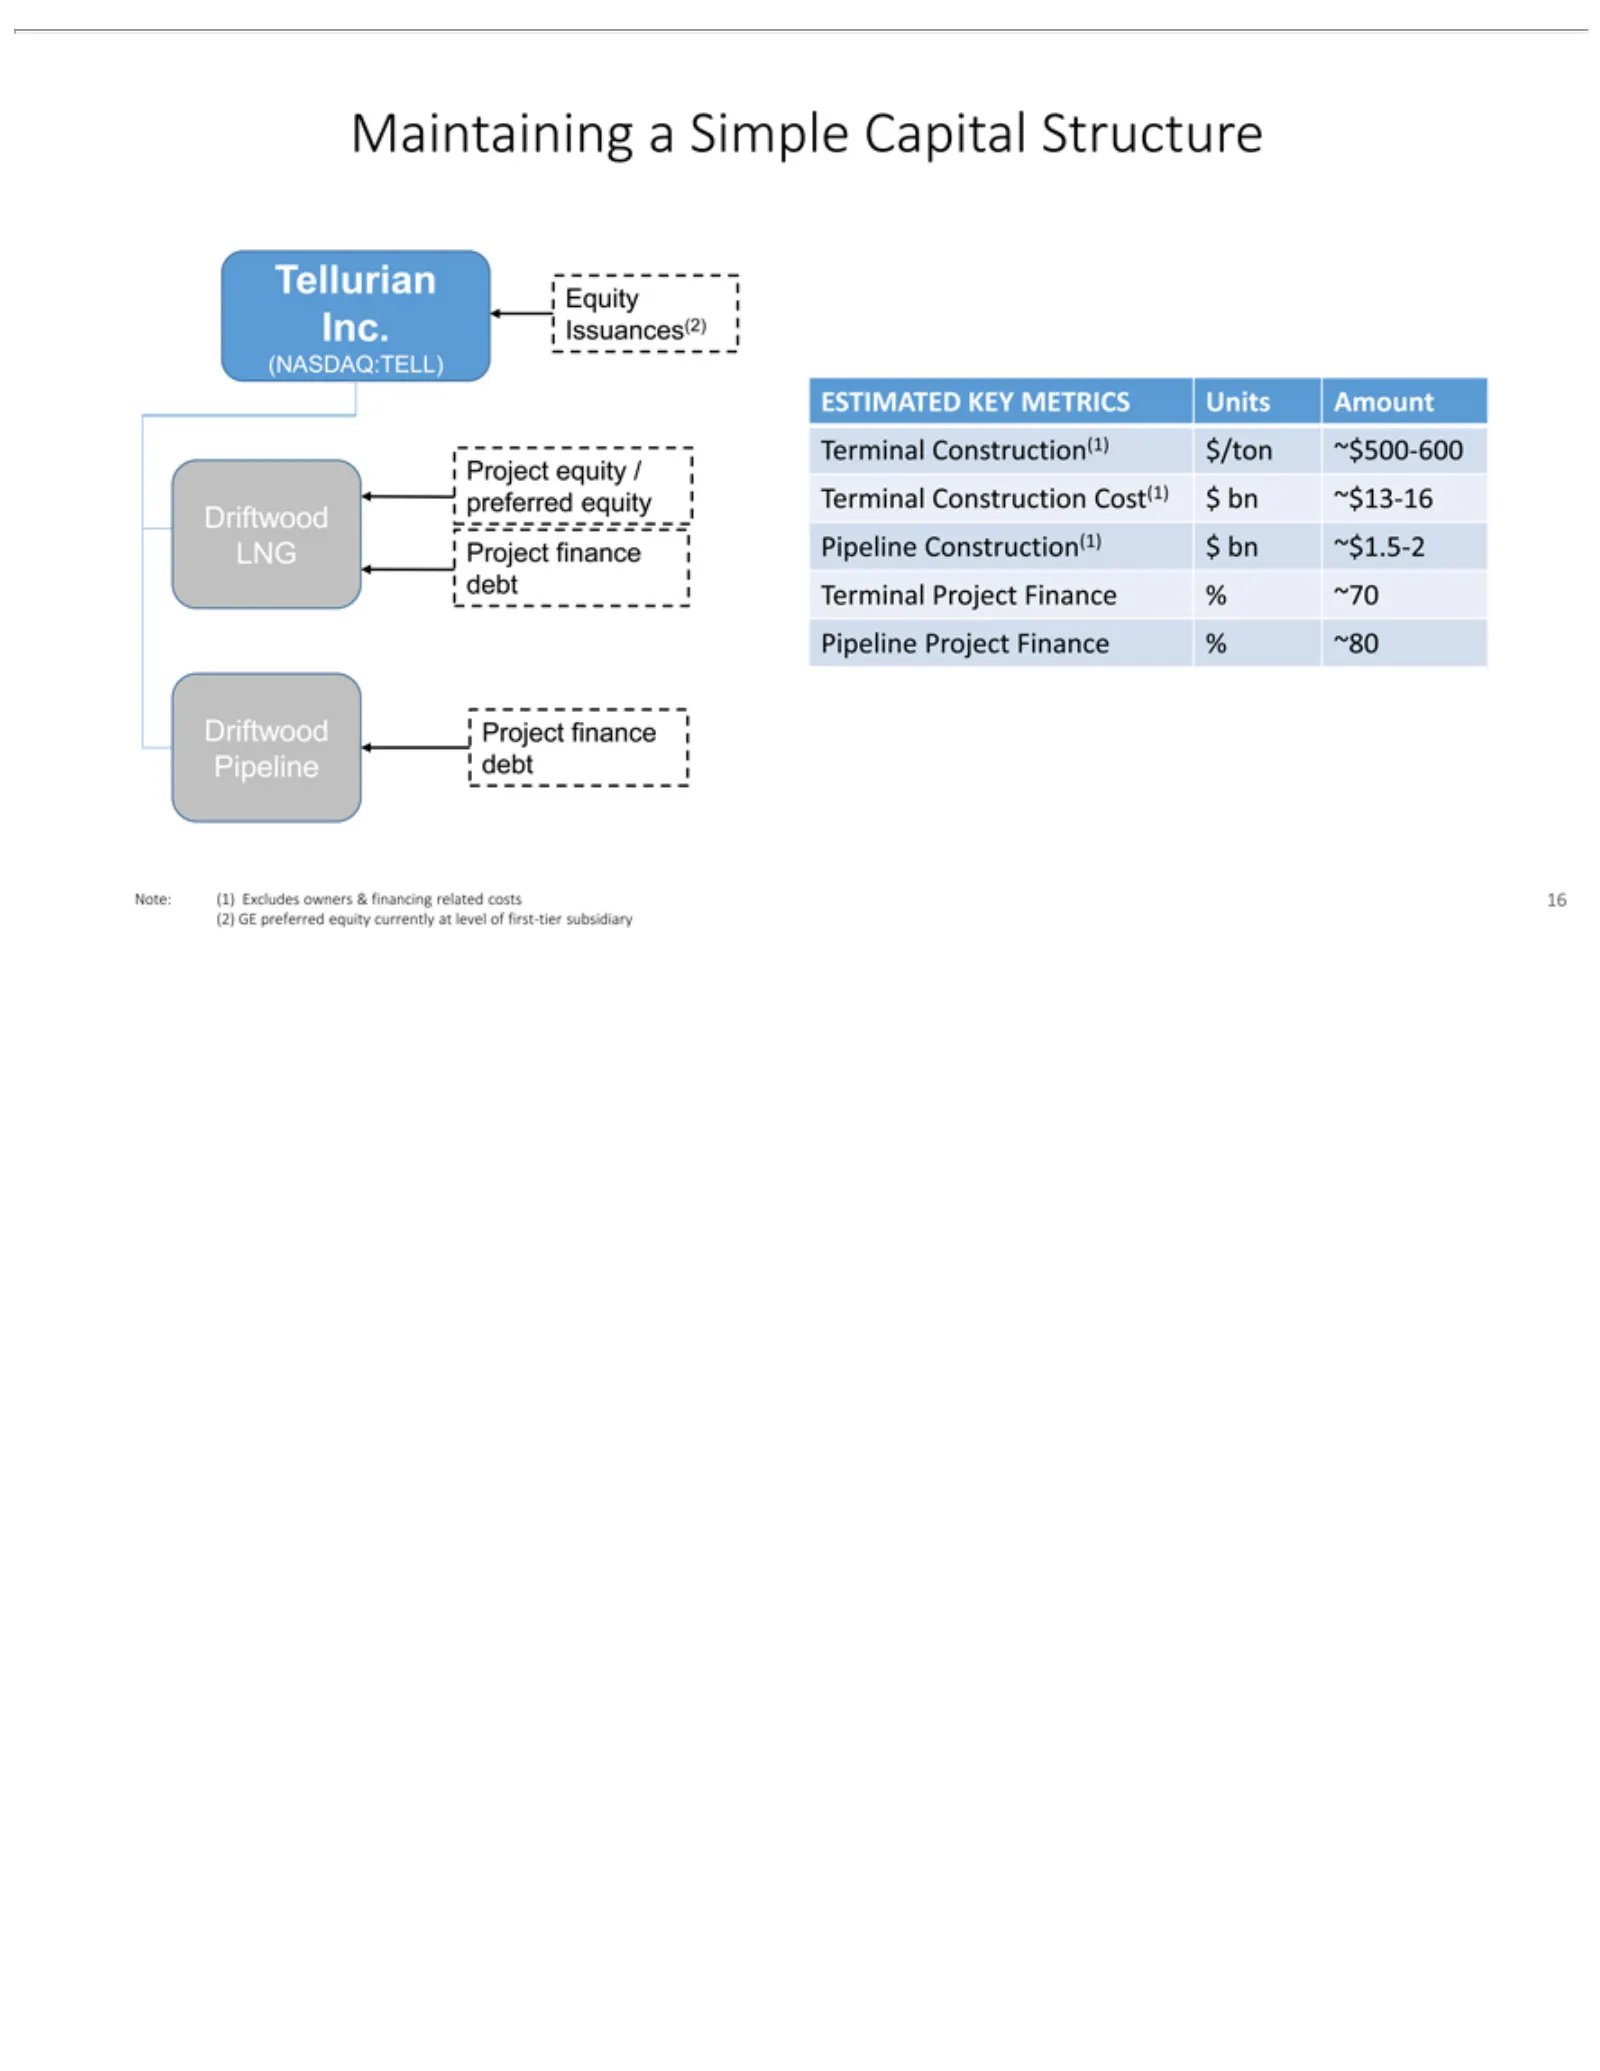
Slide 16: Simple capital structure and key metrics
Maintaining Equity Tellurian ESTIMATED (NASDAQ:TELL) Terminal Project preferred LNG Driftwood Pipeline Note: Project (1) Inc. equity debt Construction(1) Excludes equity Project Issuances(2) afinance KEY /Simple Terminal finance owners METRICS Pipeline Capital $/ton Construction & financing Structur
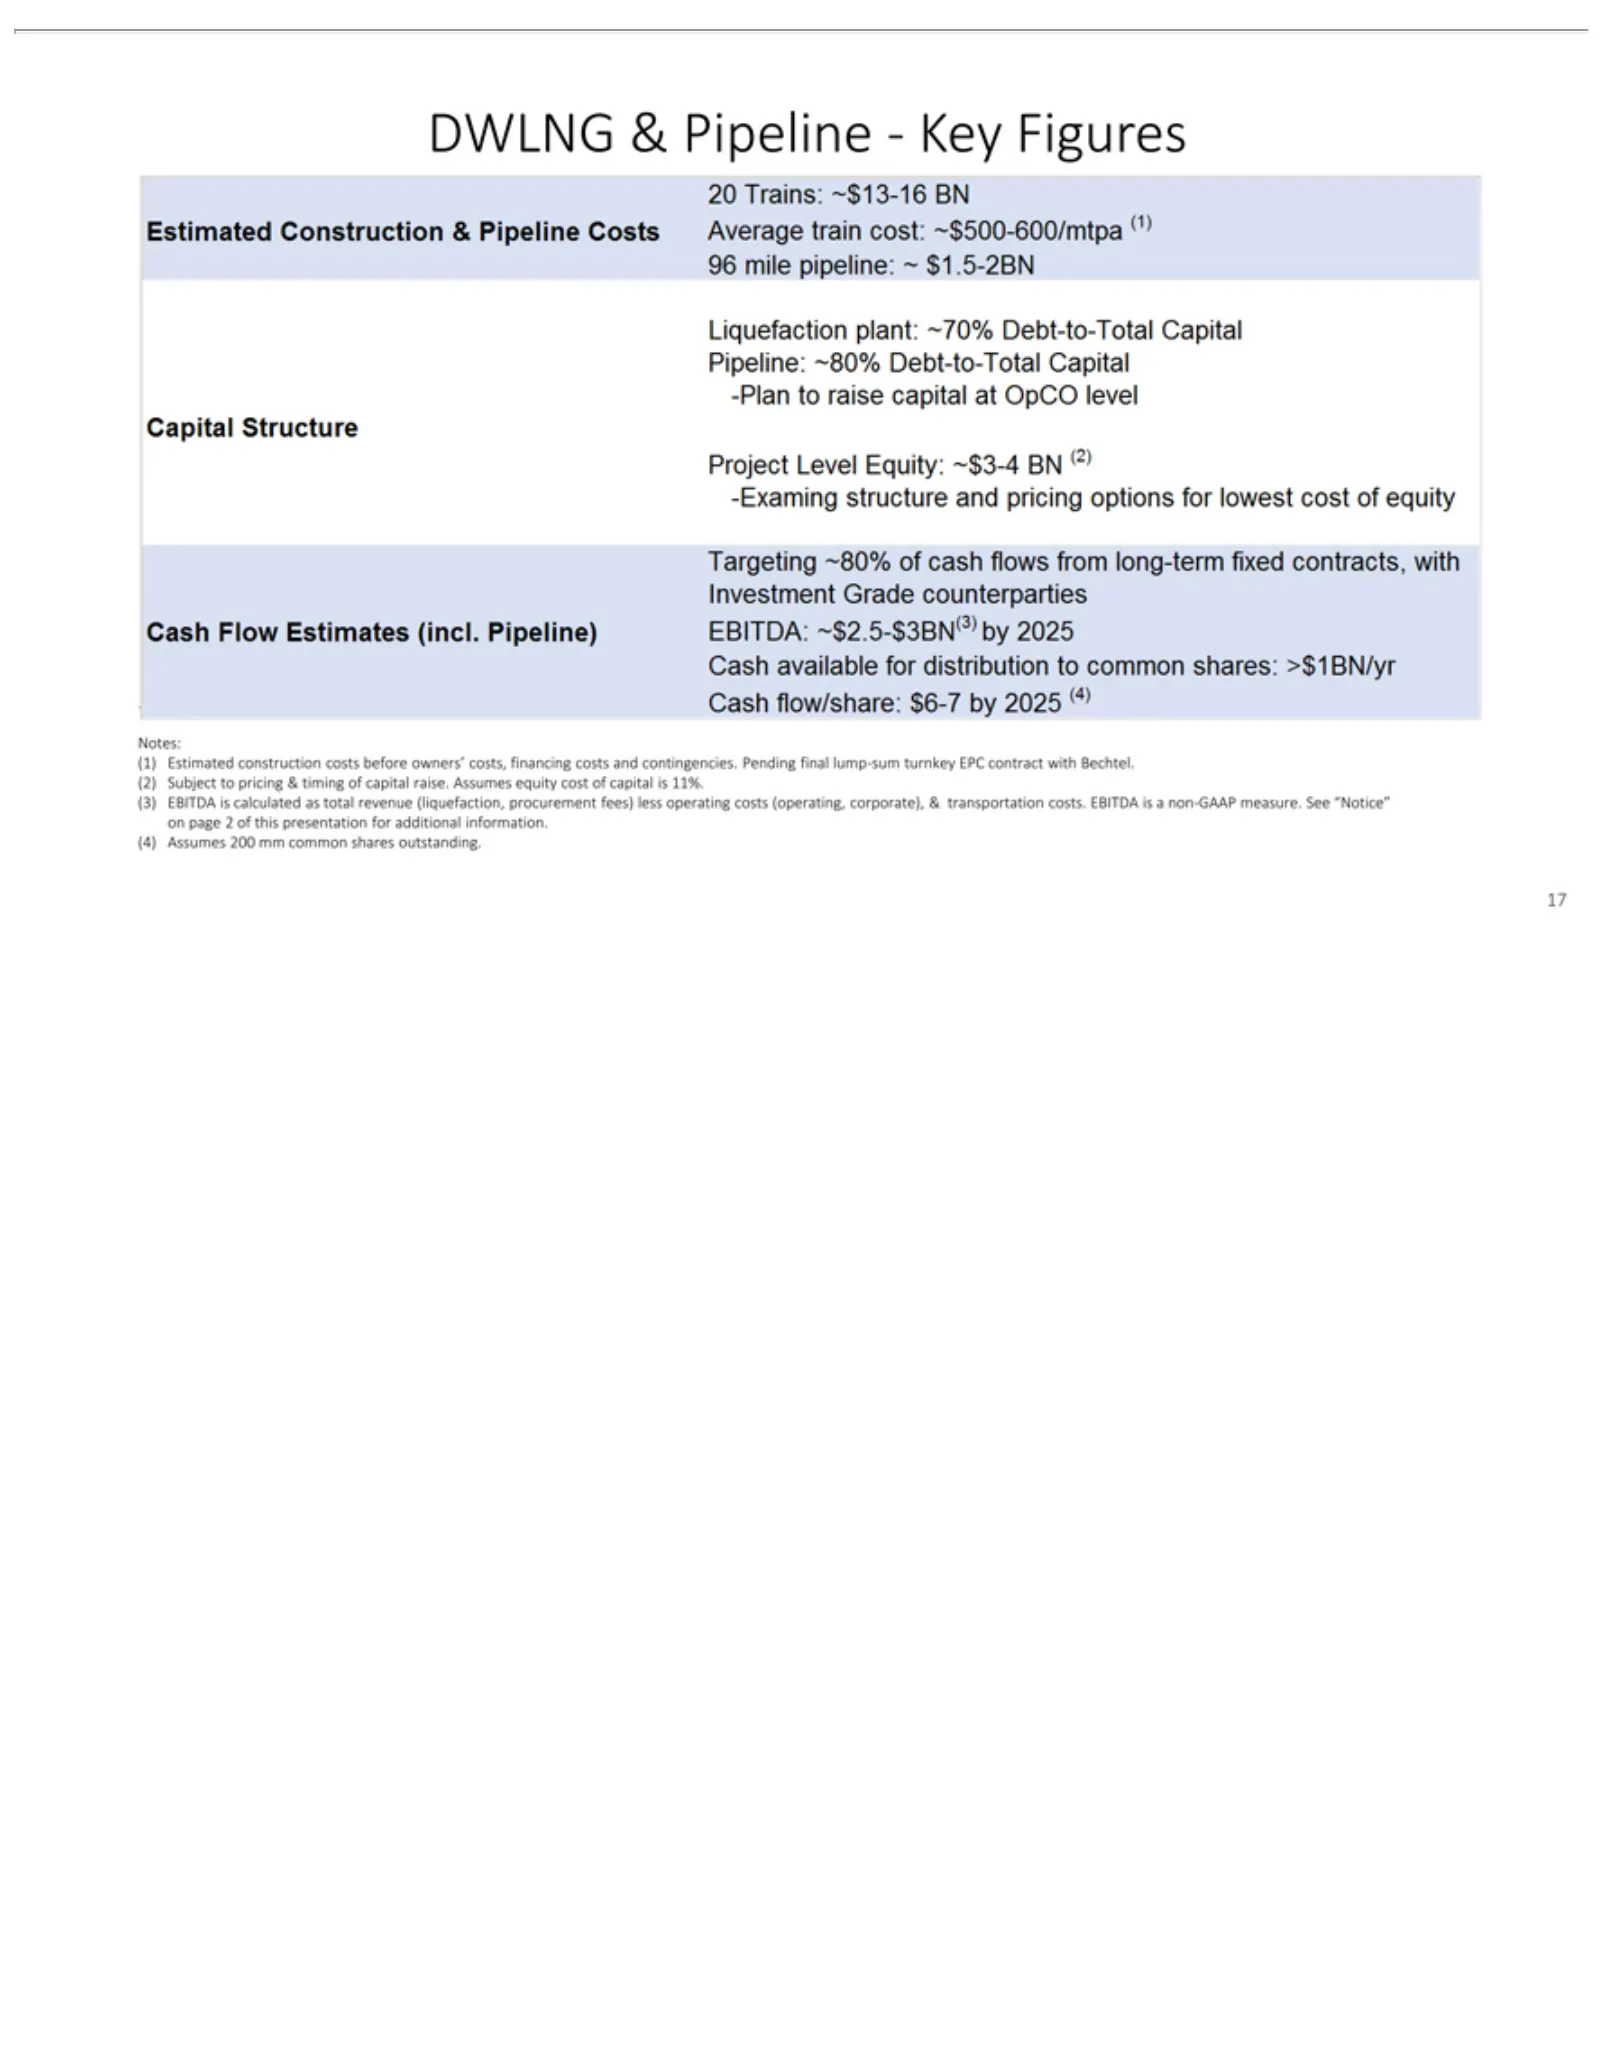
Slide 17: DWLNG and pipeline key metrics
DWLNG .N (1) (2) (3) presentation (4) 17otes: Assumes Estimated Subject EBITDA&toPipeline—Key for 200 isconstruction pricing calculated additional mm & common timing as information. costs Figures total shares ofbefore revenue capital outstanding. owners’ raise. (liquefaction, Assumes costs, financin
Slide 18: Thank you
Thank you
Slide 19: Investor Relations contacts
Investor Amit David amit.marwaha@tellurianinc.com Public dcastaneda@mdcgroup.com Joi joi.lecznar@tellurianinc.com Lecznar, Marwaha, Castaneda, Relations Contacts Relations 832-962-4044 832-485-2004 414-351-9758
Slide 20: Appendix
19 20 Appendix
Slide 21: Leadership
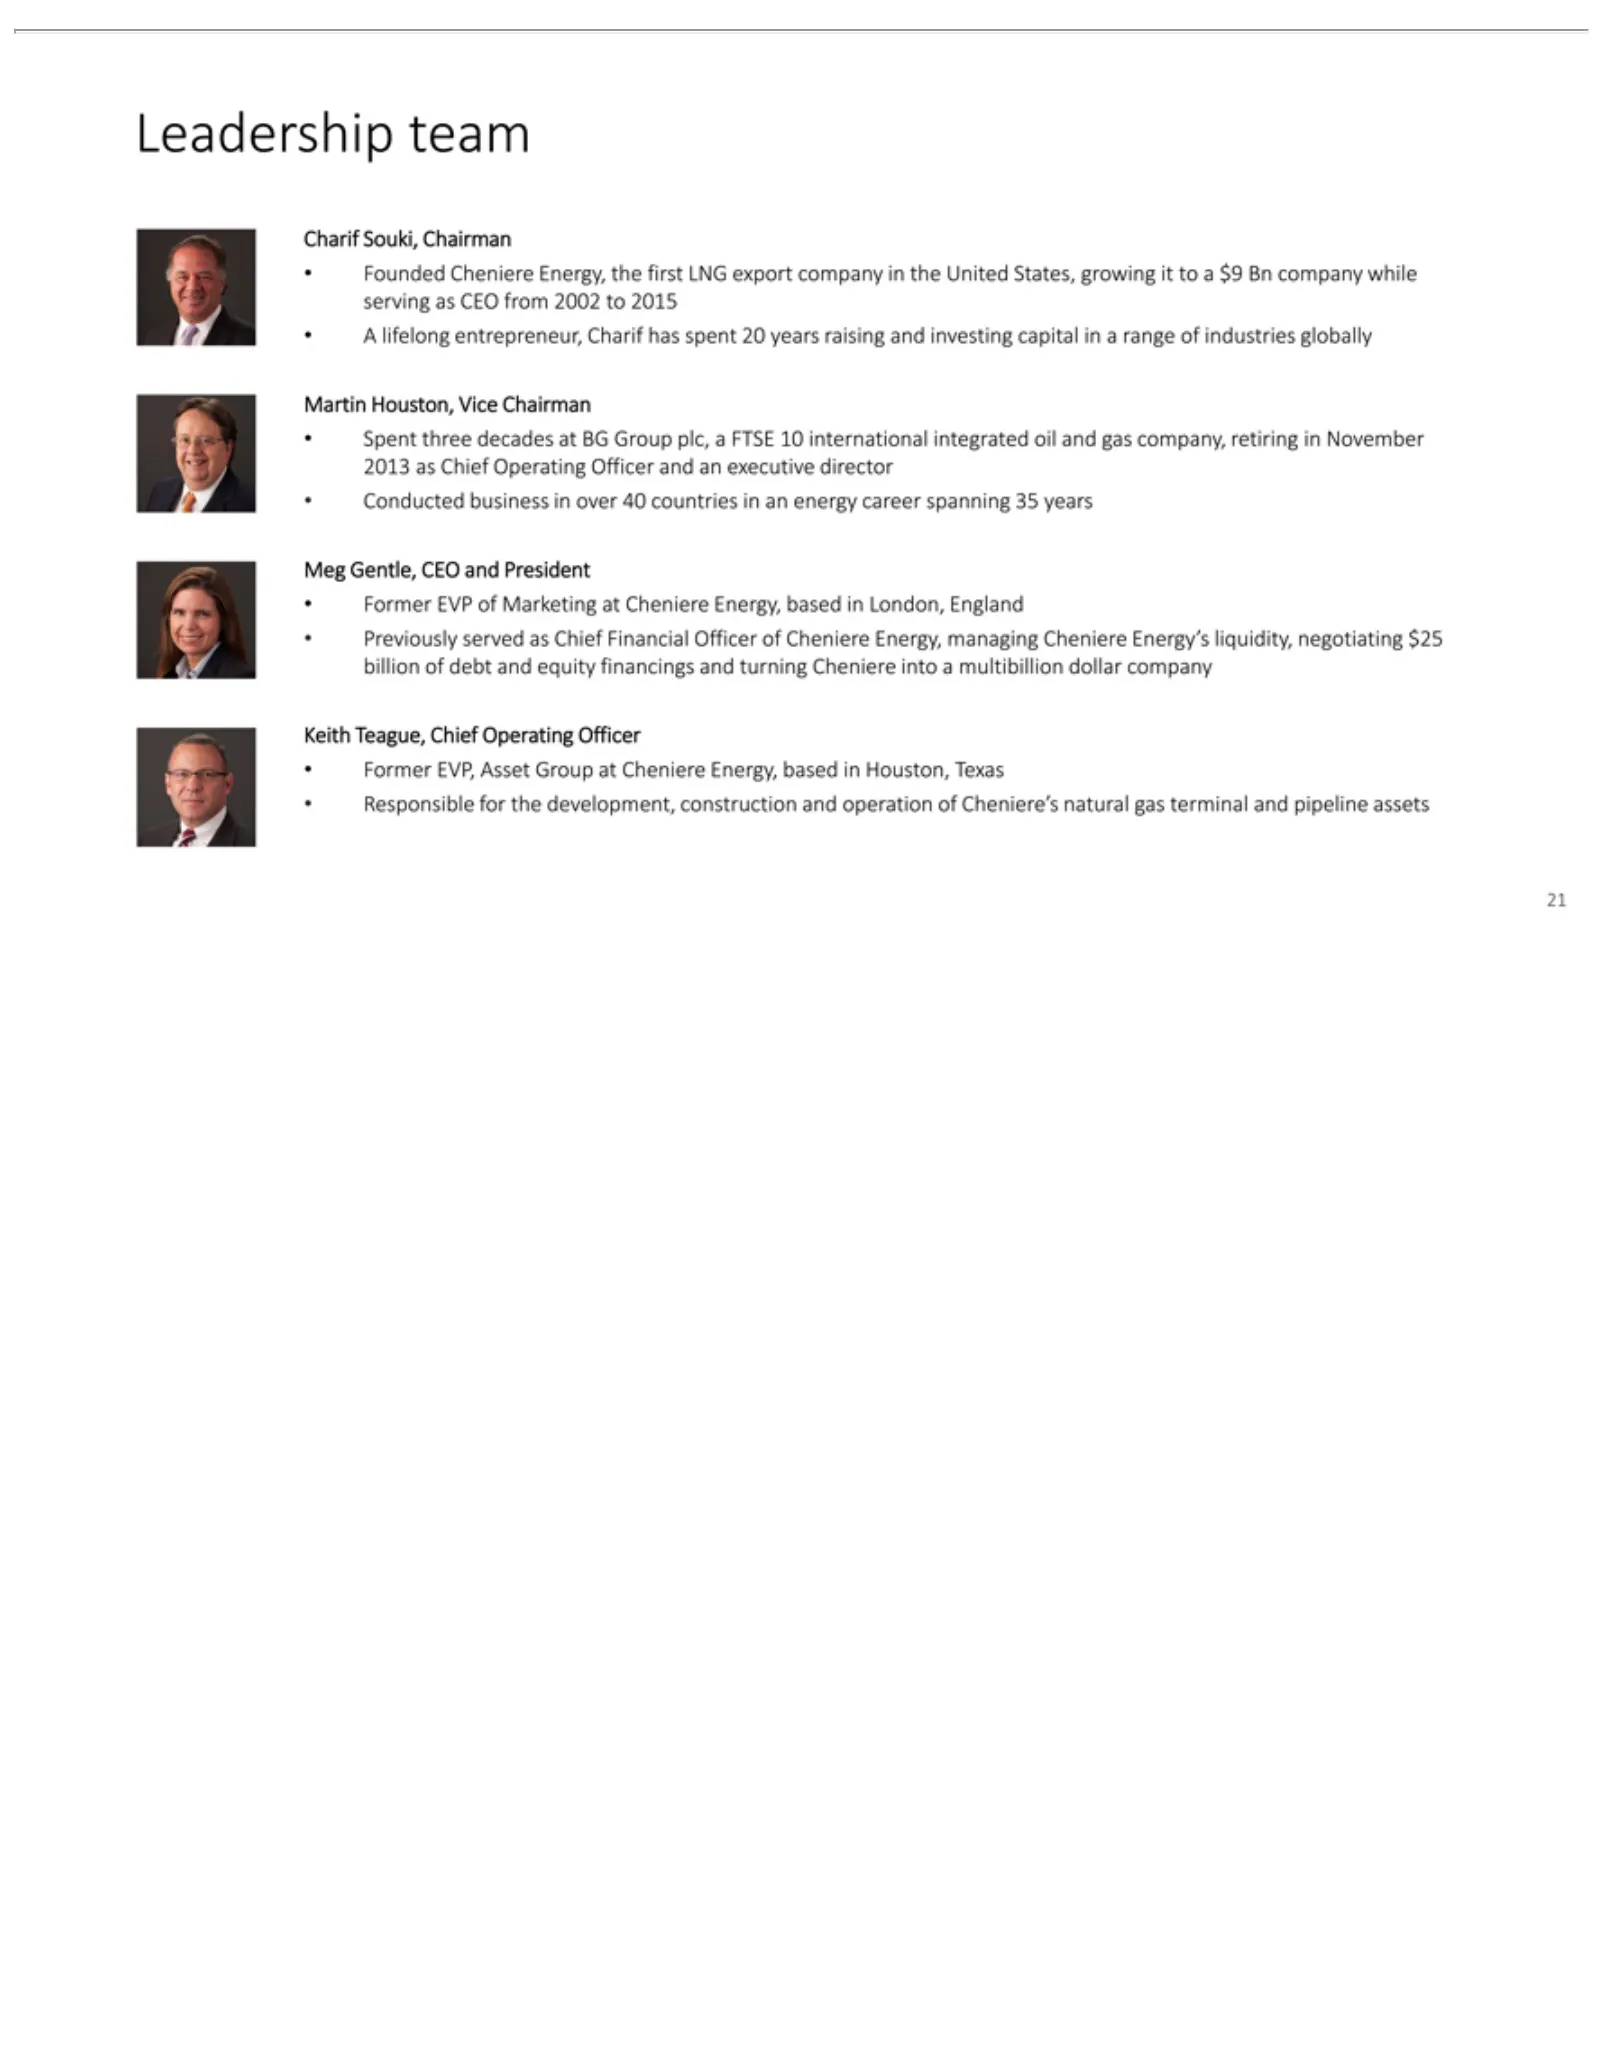
Leadership Charif Martin Meg •Keith 21 A Founded Spent Conducted Previously Former Responsible lifelong Gentle, Teague, Souki, Houston, three EVP EVP, Cheniere team entrepreneur, served business CEO decades Chairman for Chief of Asset Vice Marketing the and as Energy, Operating Group development, at
Slide 22: Leadership
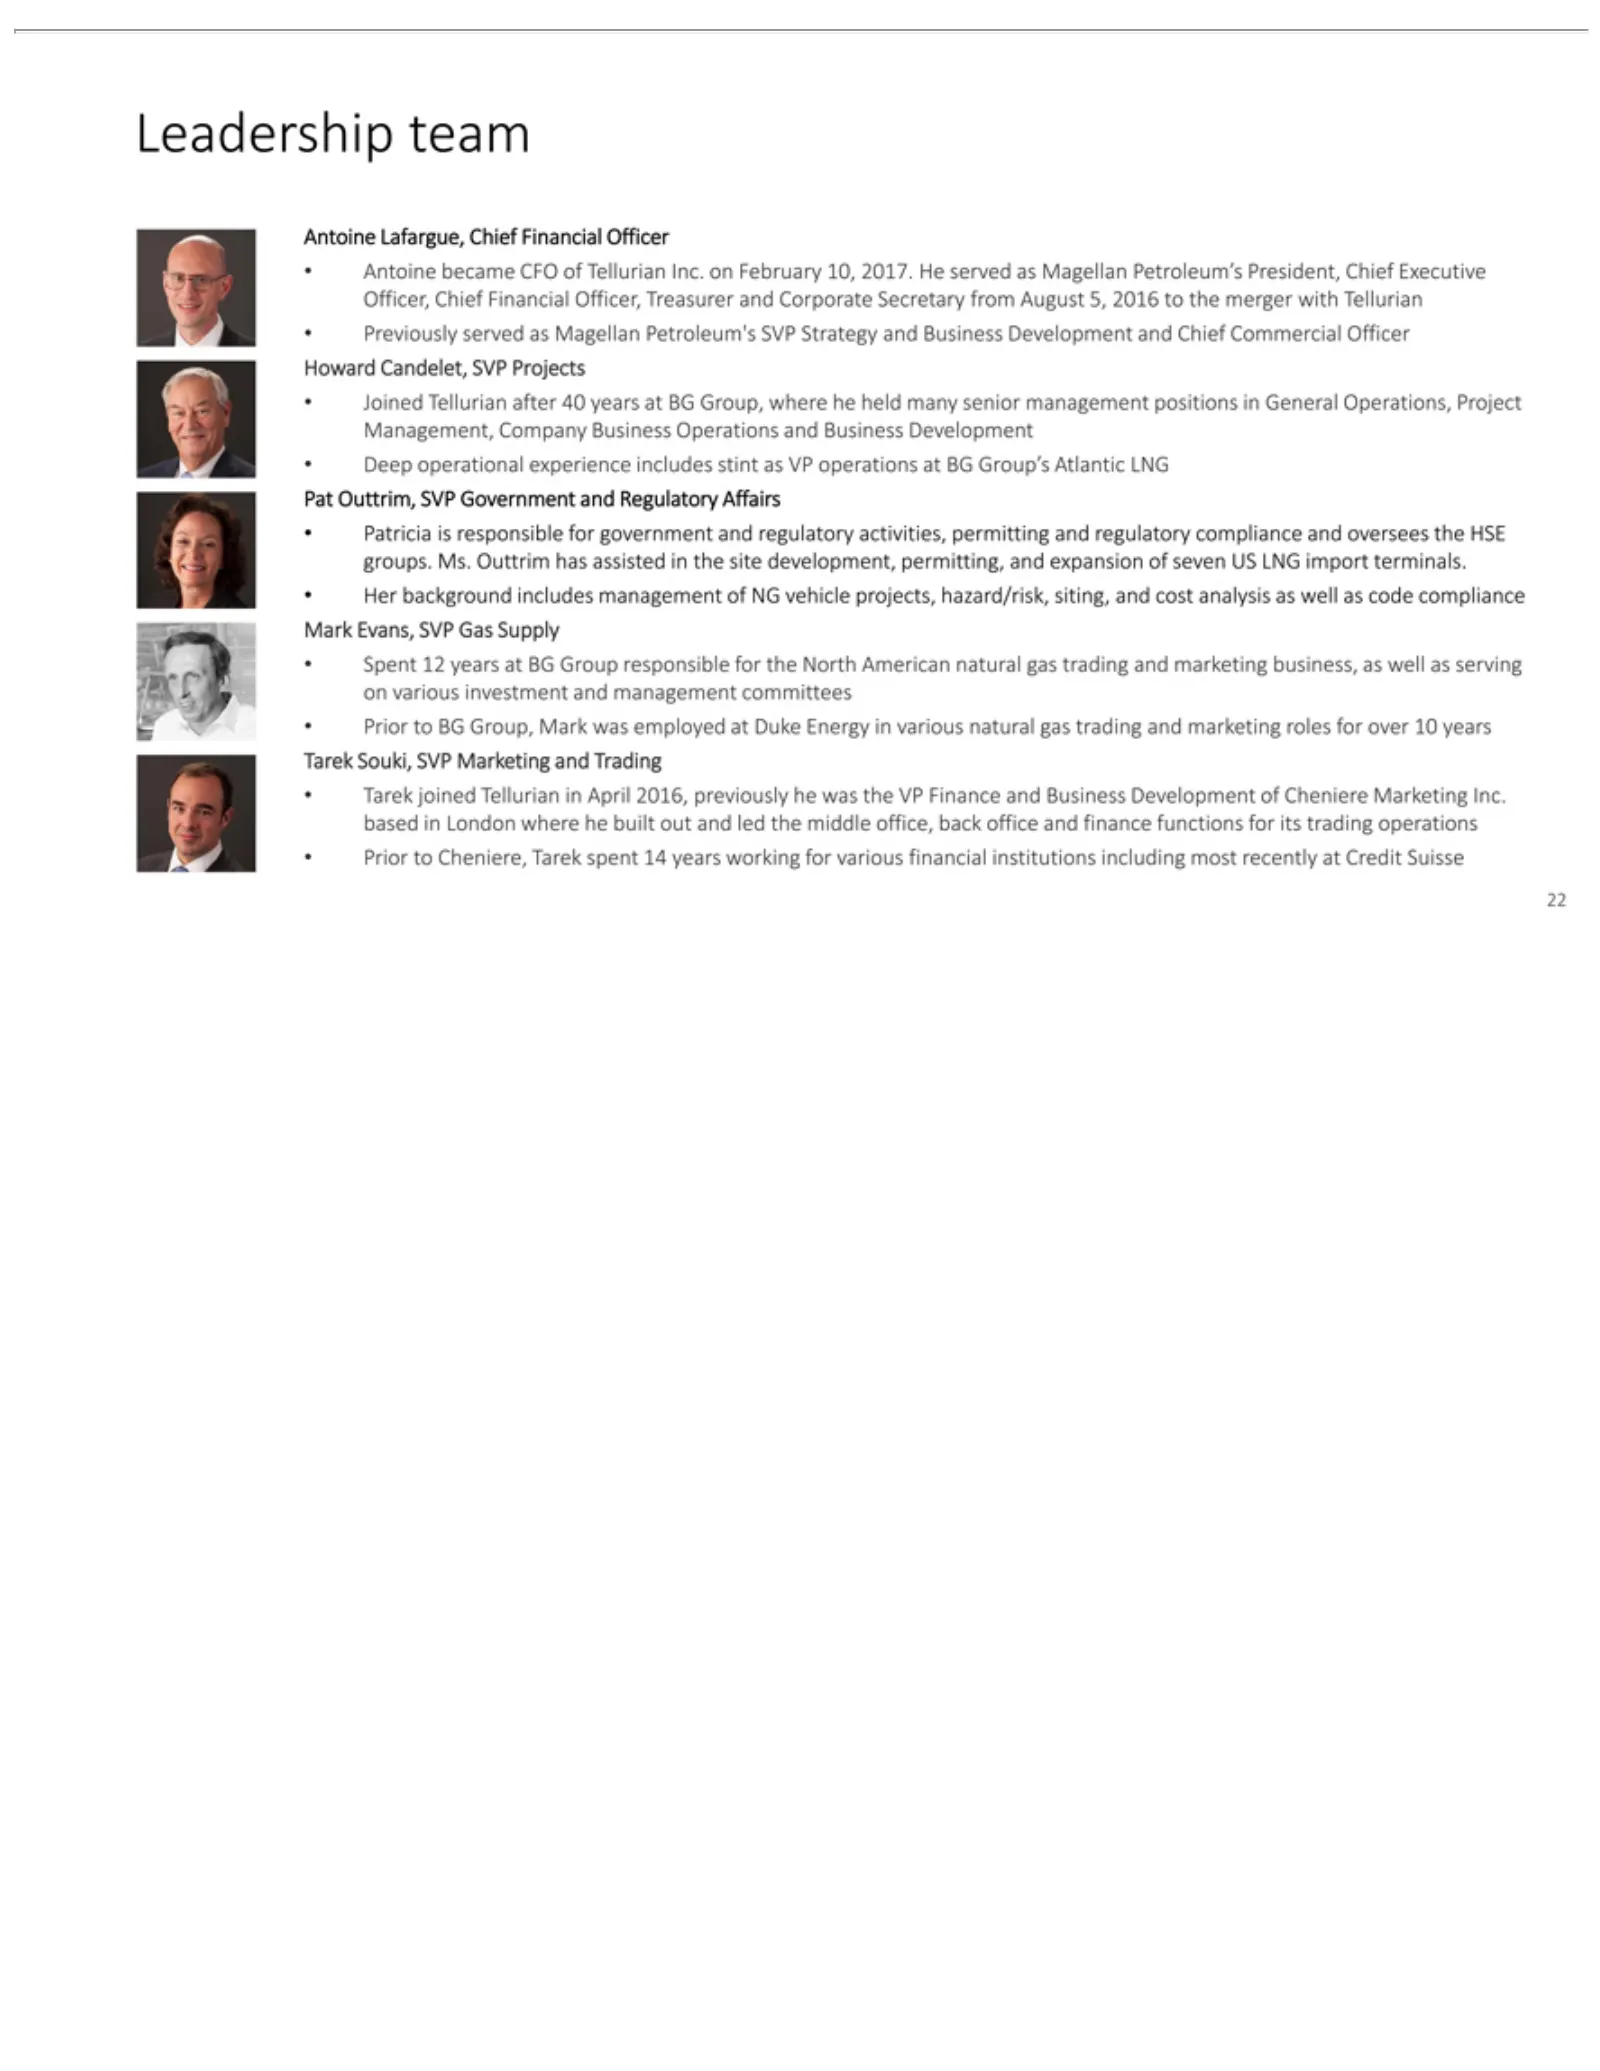
Leadership Antoine Officer, Pat seven •functions 22 Antoine Tarek Previously Joined Deep Patricia Her Spent Prior Outtrim, background US to operational joined 12 Chief Tellurian Lafargue, BG Cheniere, is for became LNG years team responsible served SVP its Group, Financial Tellurian import trading a
Slide 23: Key experience and management bench strength
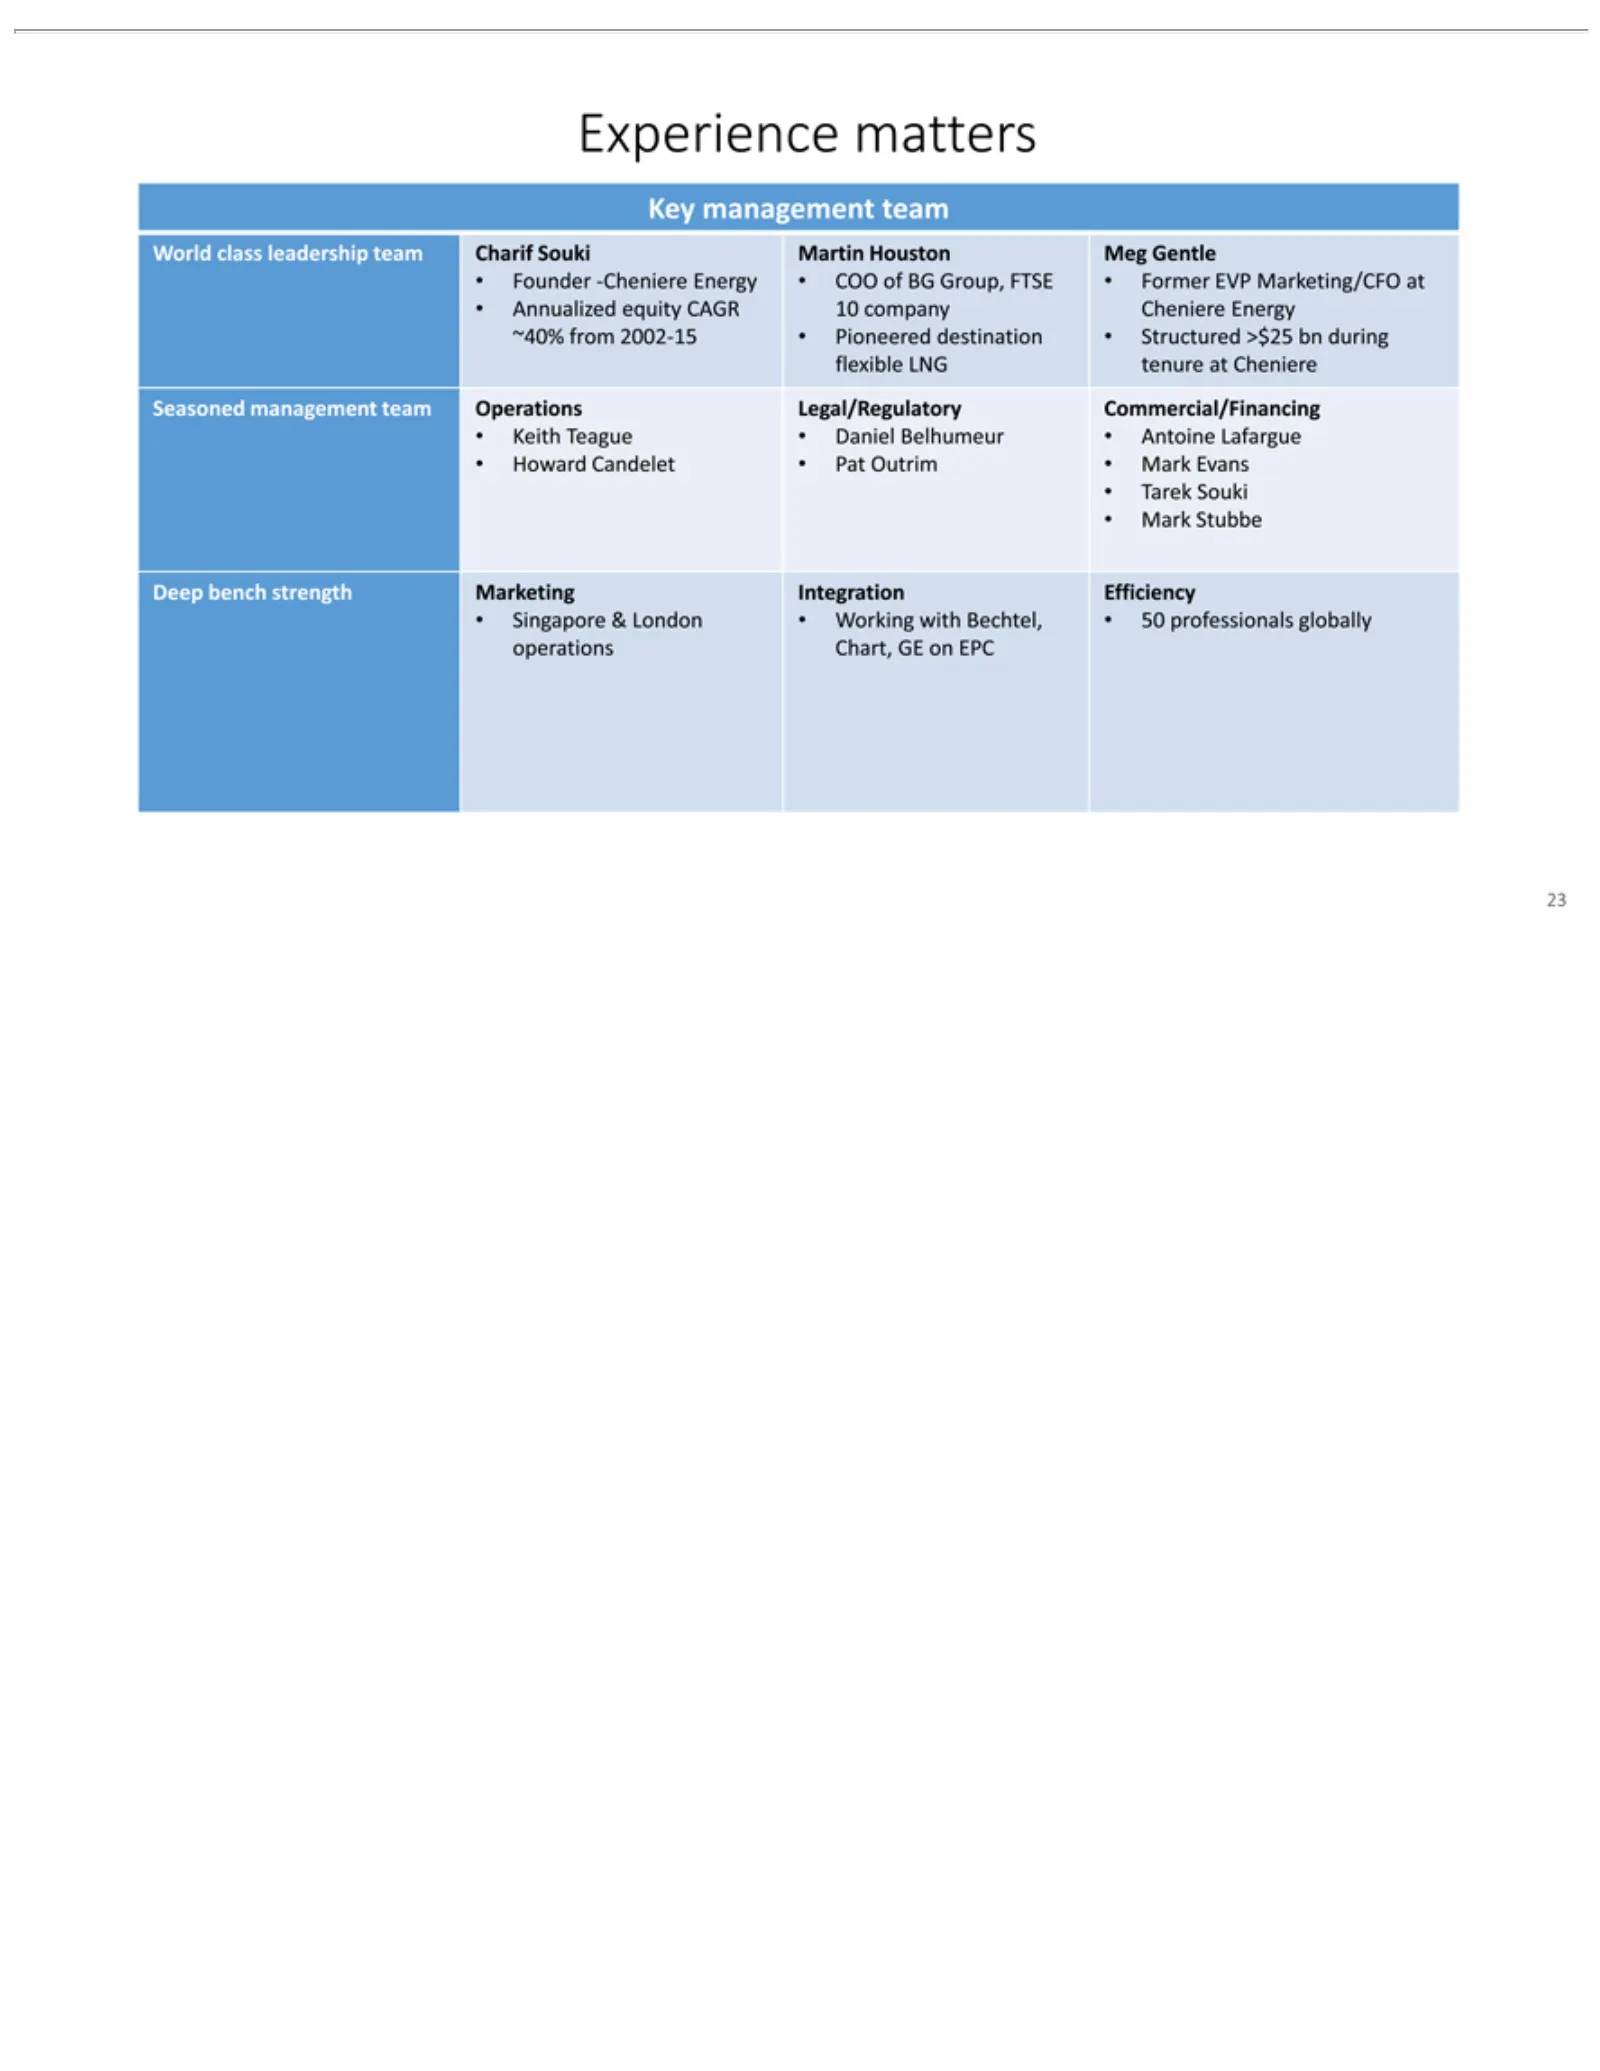
Experience Key World ~40% Seasoned •Deep 23 Annualized Tarek Founder Keith Howard Mark Singapore management bench from class Stubbe Teague Souki management Candelet -Cheniere matters 2002-15 & leadership strength equity London • Daniel team •CAGR Energy •Marketing Pat Pioneered team •team Belhumeur
Slide 24: DWLNG design advantages
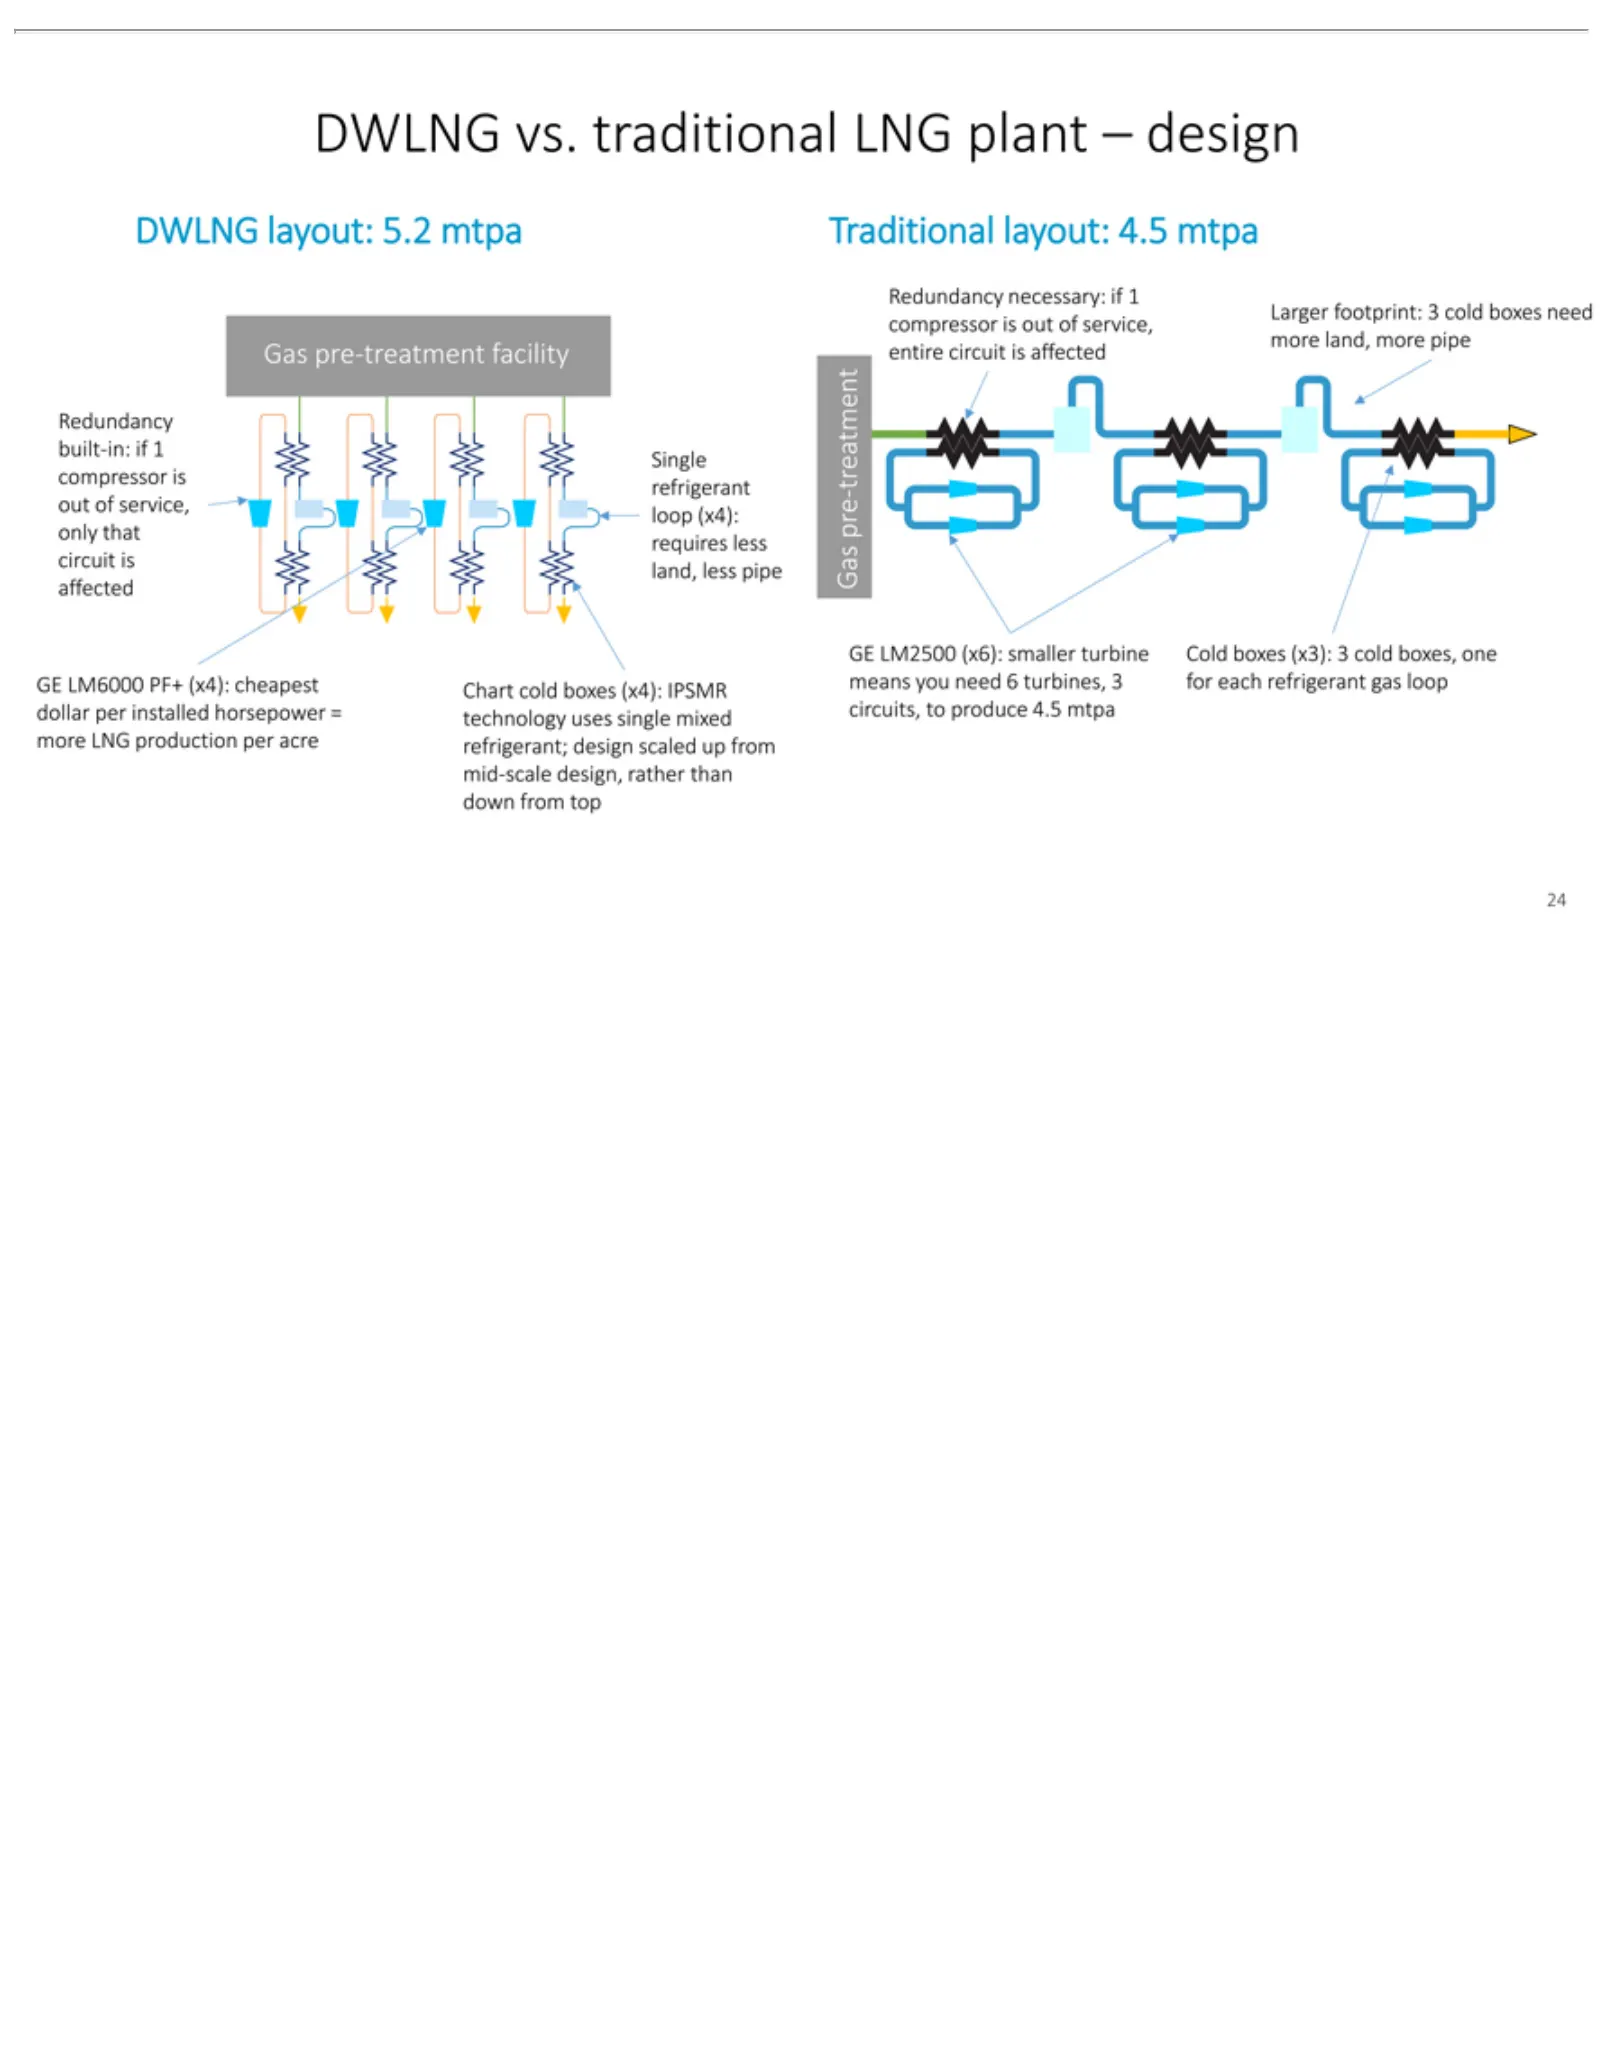
DWLNG Larger Gas Redundancy GE horsepower 24 LM2500 pre-treatment footprint: vs.=necessary: layout: built-in: (x6): traditional circuits, 35.2 facility smaller cold mtpa ifto1boxes if LNG produce compressor 1entire turbine Traditional plant need circuit 4.5 Cold –compressor design mtpa islayout: is
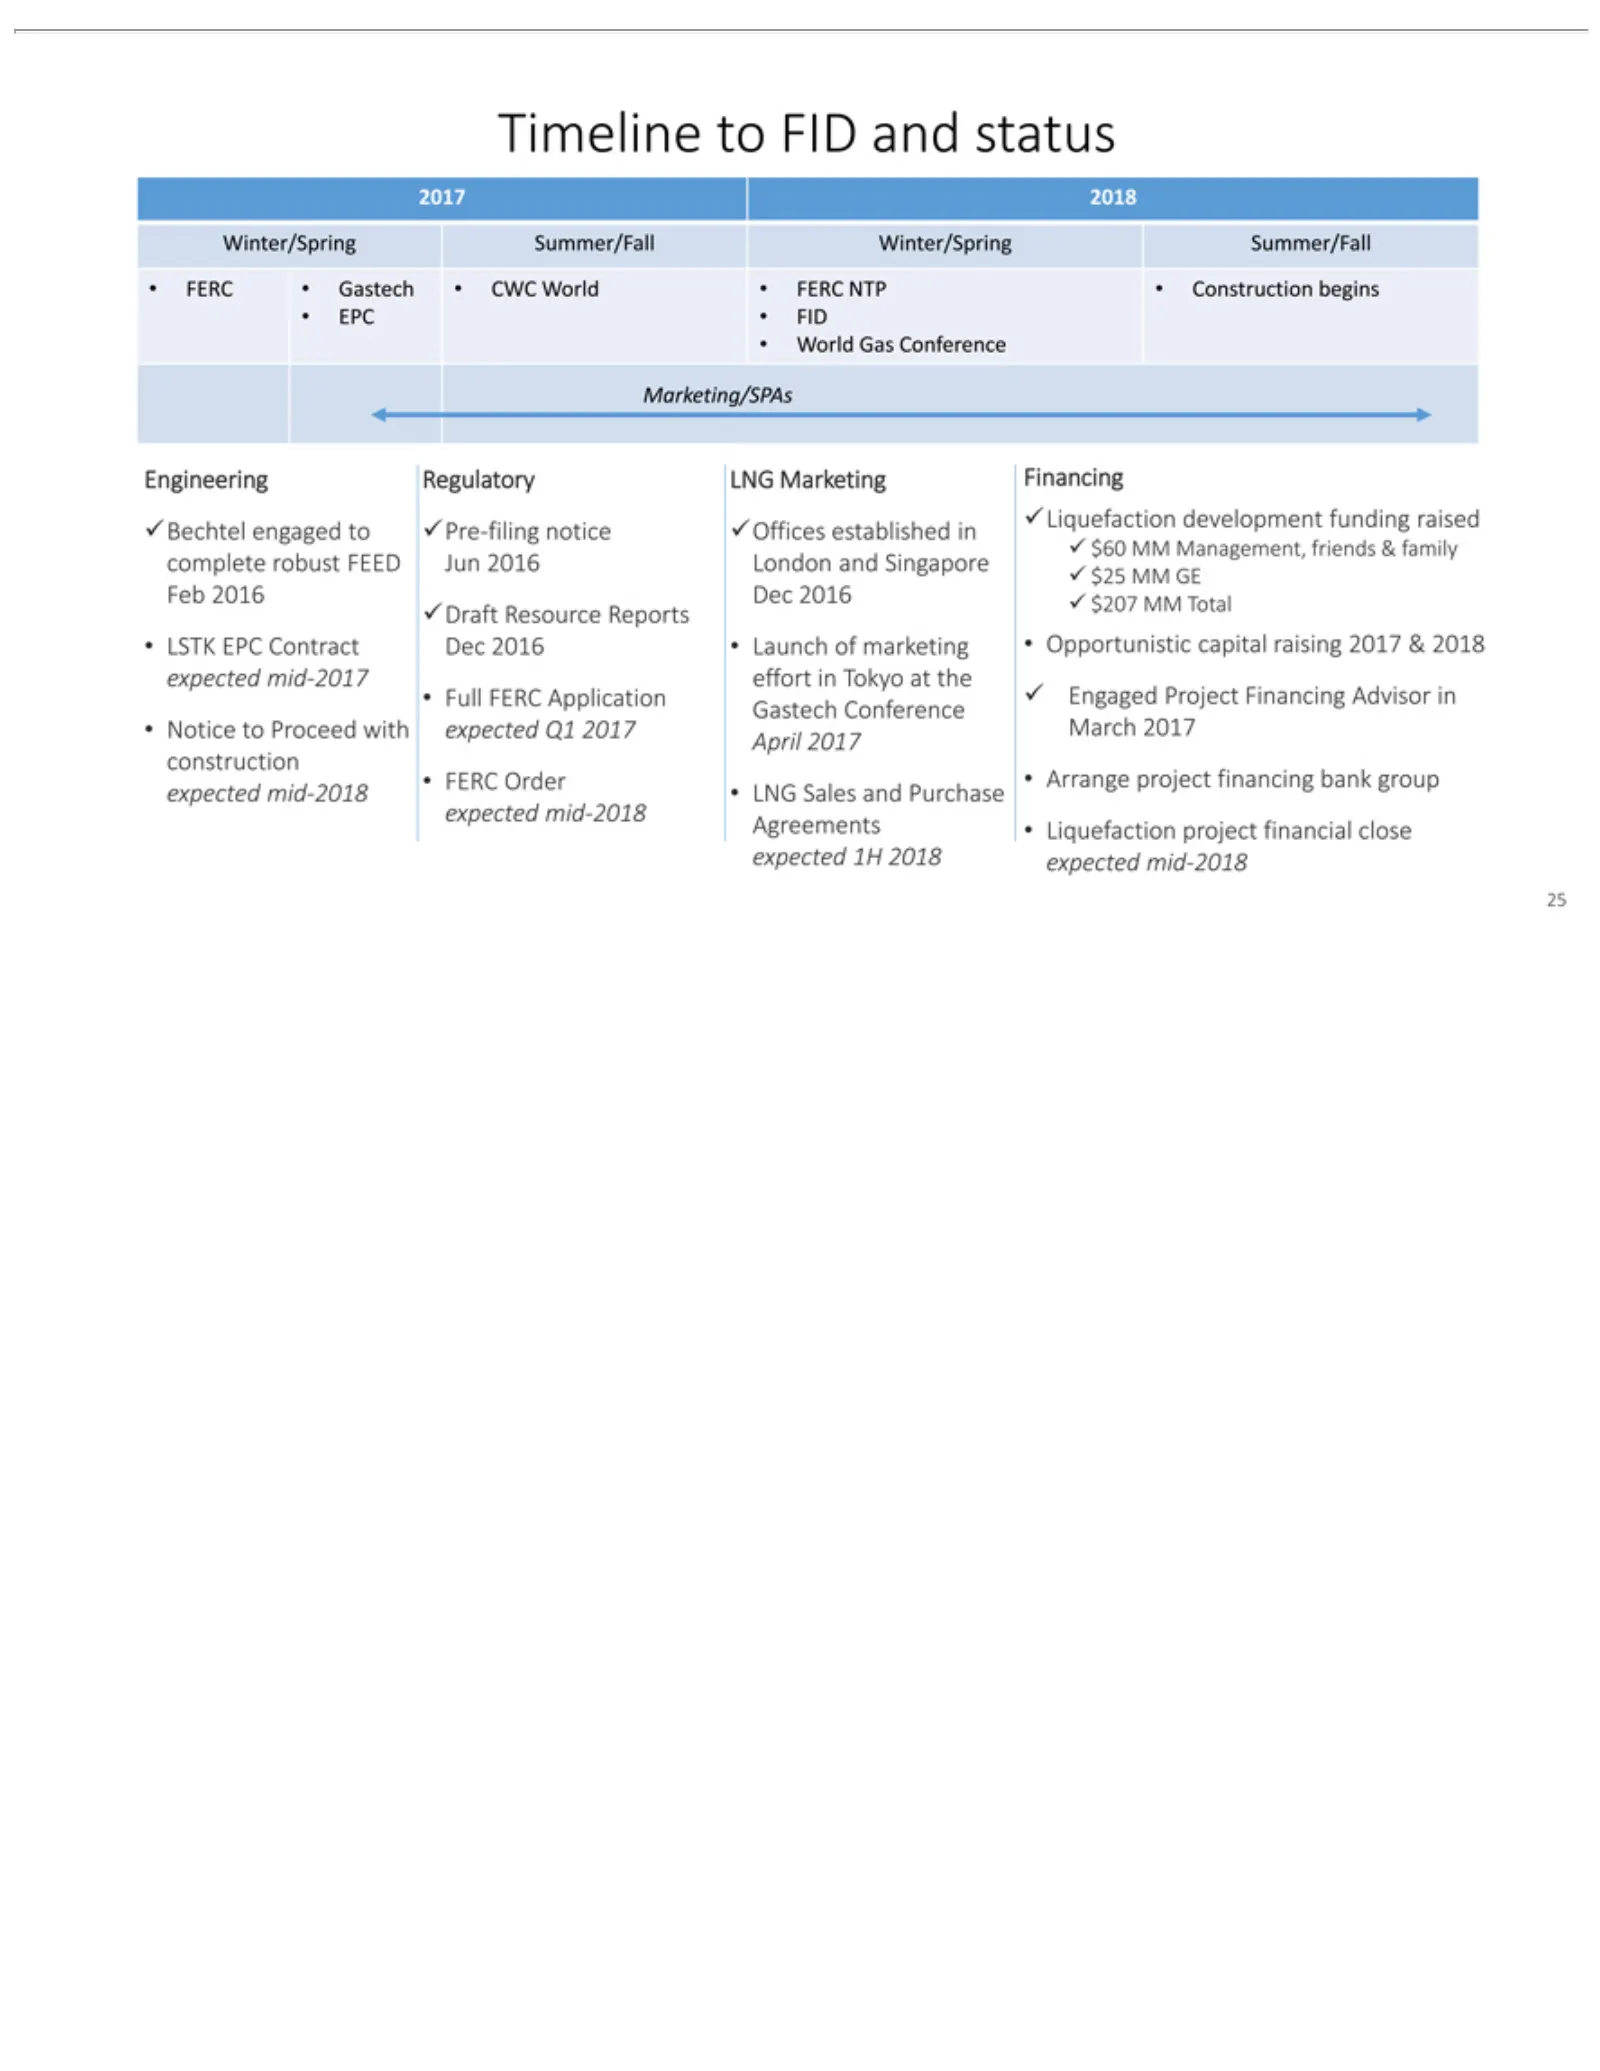
Slide 25: Timeline
Timeline 2017 Winter/Spring Engineering Marketing/SPAs Liquefaction $60 $207 •Draft 25 World EPC LSTK Full Notice FERC MM2018 MM Resource FERC • FID Gas EPC •to Order Management, to Gastech Total Proceed FID Conference Regulatory Application development Contract Summer/Fall • Reports Arrange and • w
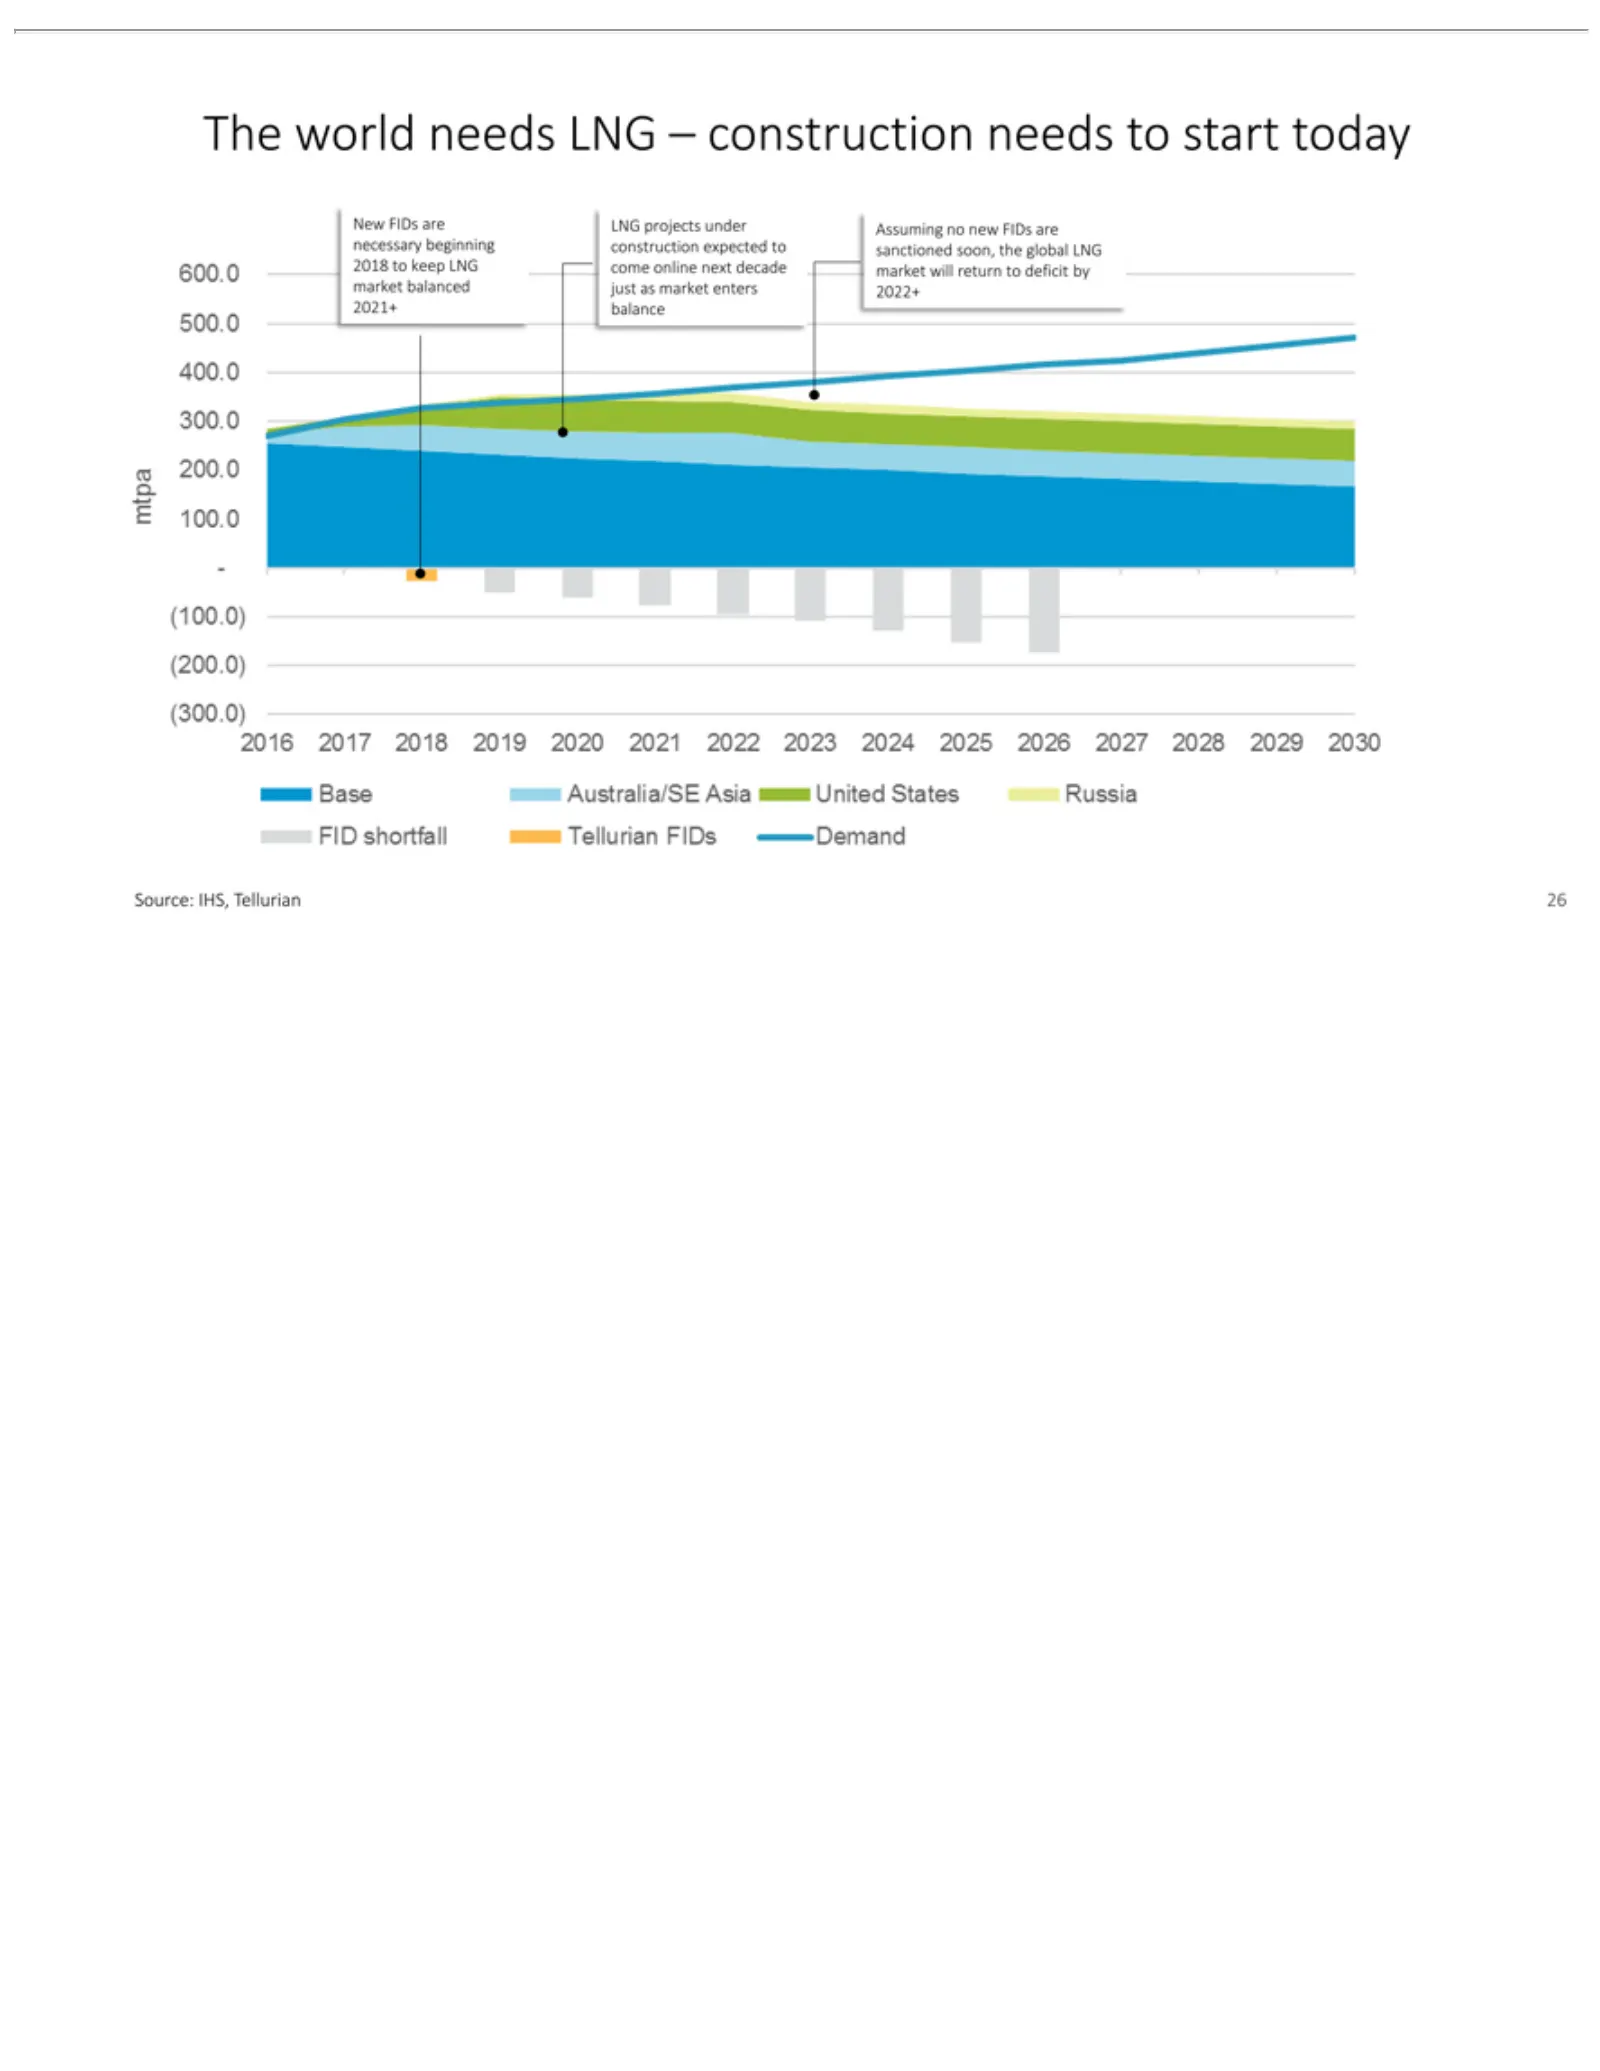
Slide 26: The market needs new LNG projects
Themarket New by Source: world FIDs IHS, balanced needs areTellurian LNGLNGjust projects –26as construction market underenters Assuming needs 2022+ tono start 2021+ newtoday FIDs balance are necessary beginning construction expected to sanctioned soon, the global LNG 2018 to keep LNG come online nex
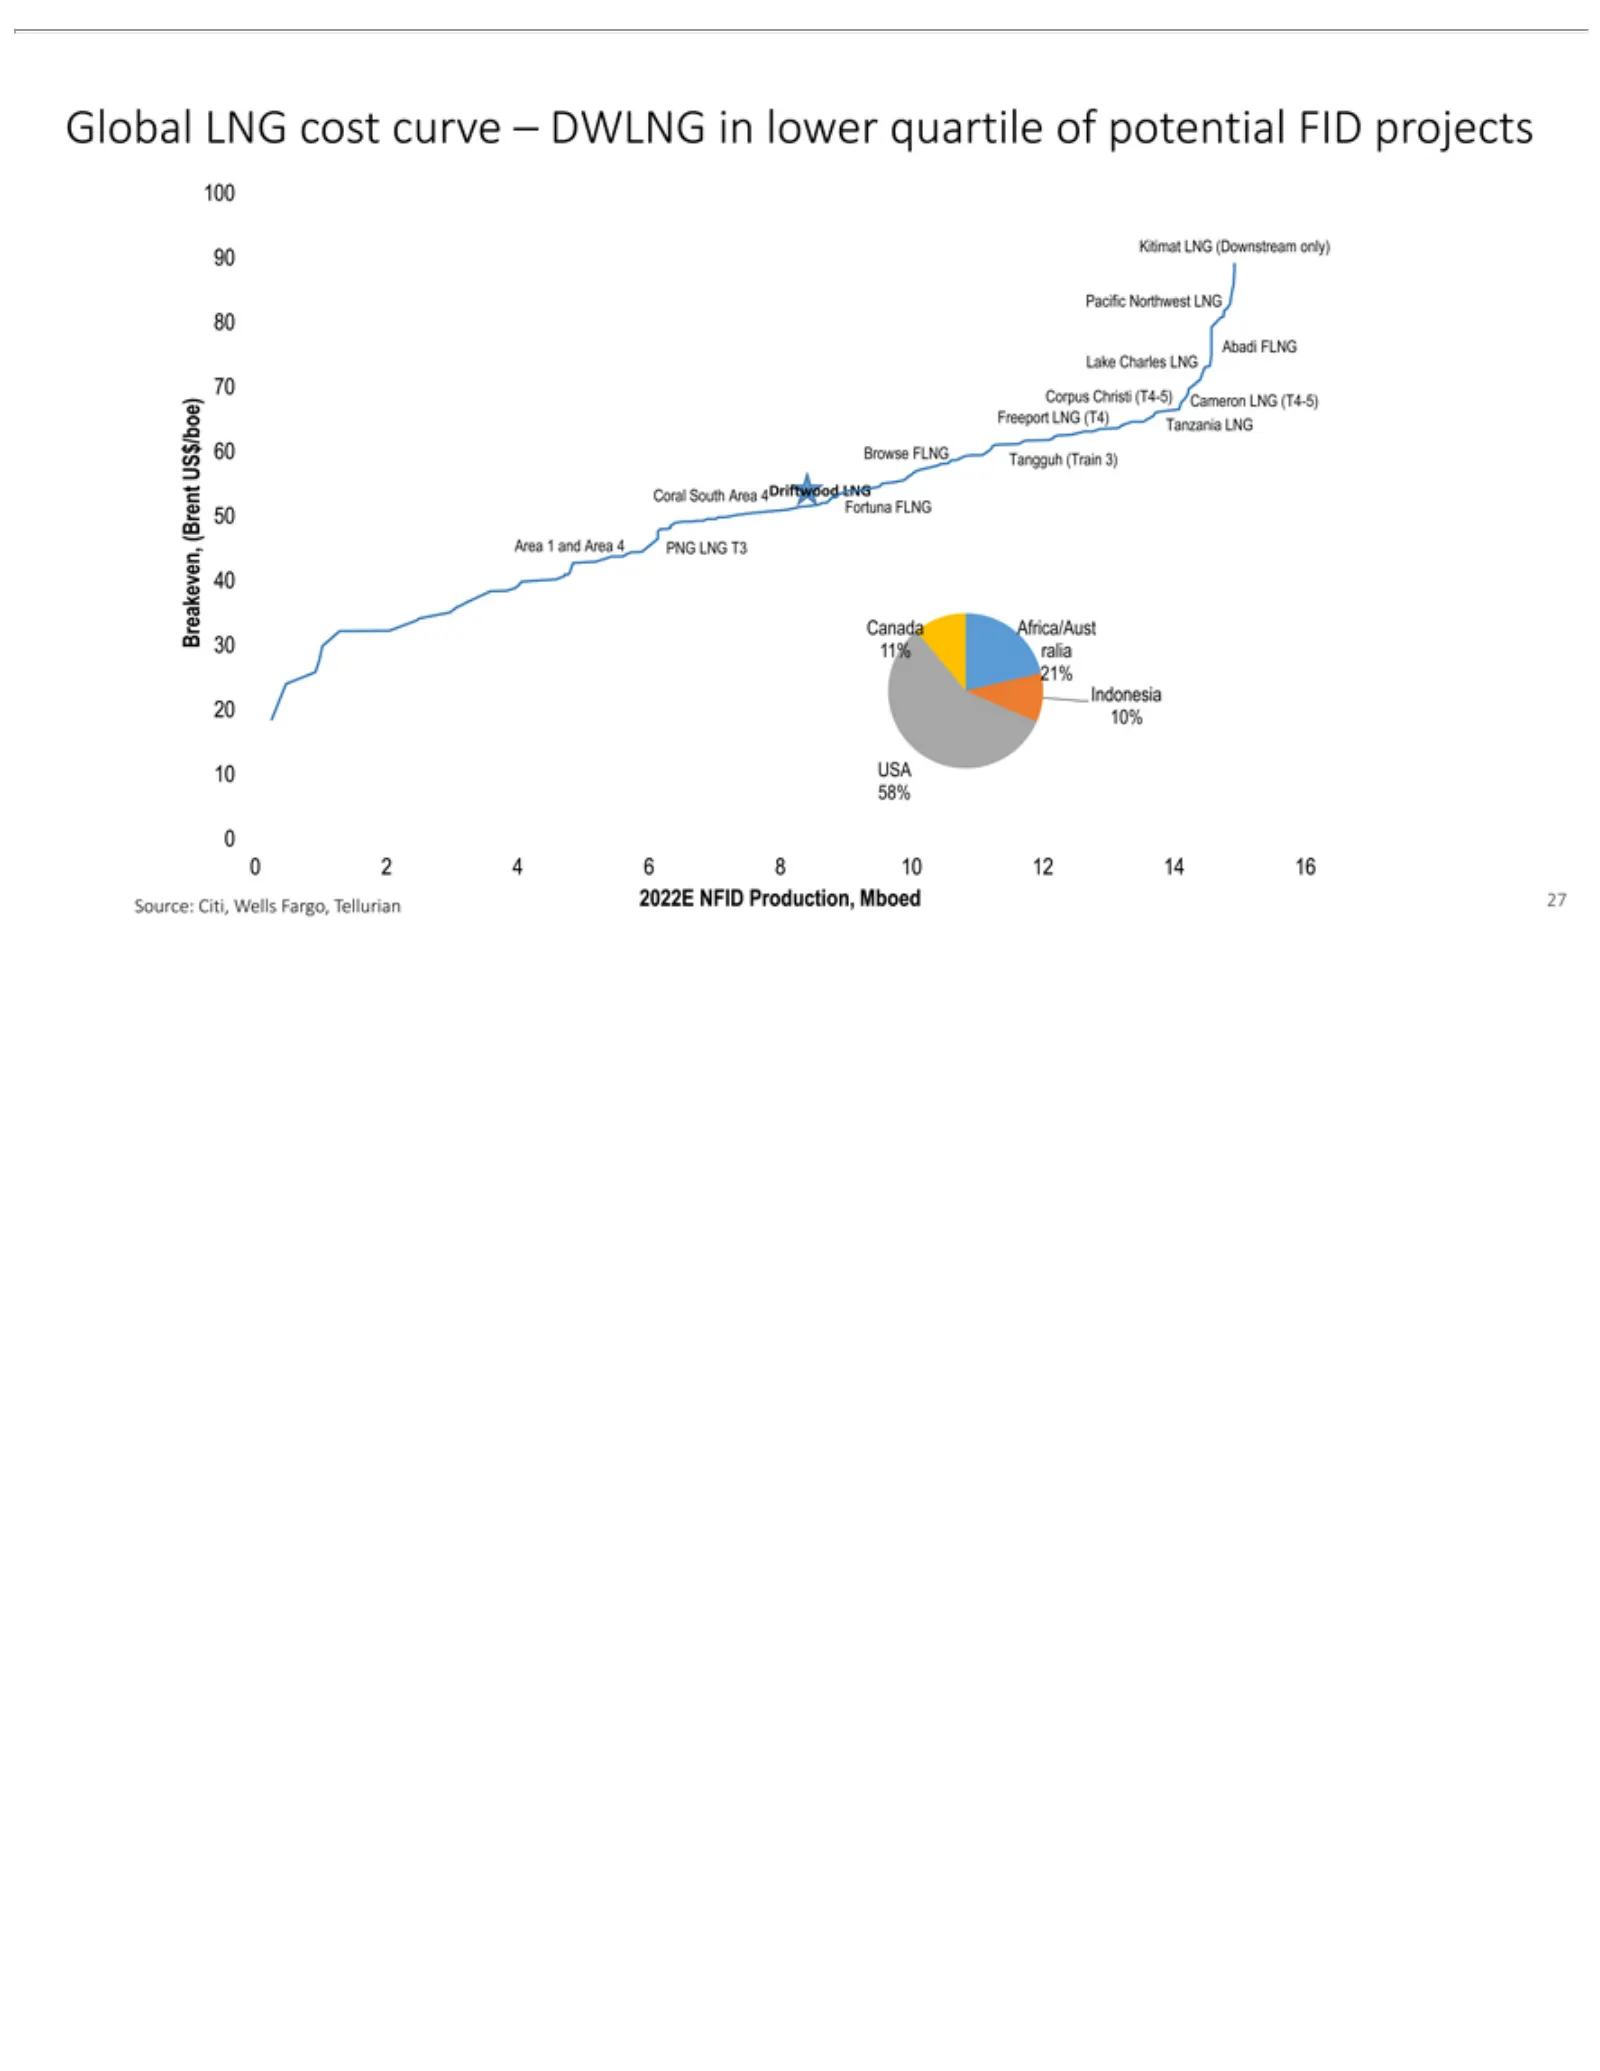
Slide 27: Global LNG cost curve
Global 90 100 Lake 80 Corpus $70 US Area (Br Breakeven, 40 30 20 Indonesia 010 Source: 260USA Kitimat 11% 10% 4Tangguh Browse 1Charles 6 and LNG 8Christi ralia Citi, 58% 10LNG Area Canada 12 (Train cost Wells FLNG 21% LNG (T4-5) 144(Downstream curve 16 PNG Fargo, Abadi 3) Africa/Aust Cameron Coral –
Source: SEC EDGAR · 8-K filed Mar 27, 2017
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (November 2022)19 slides · Nov 2, 2022