Tellurian — Investor Presentation (November 2022)
19 slides from Tellurian's investor presentation, Nov 2, 2022
Slide 1: Tellurian Inc. Corporate presentation November 2022
Tellurian Inc. Corporate presentation November 2022
Slide 2: Cautionary statements
Cautionary statements The information in this presentation includes “forward - looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. All statements other than statements of historical fact
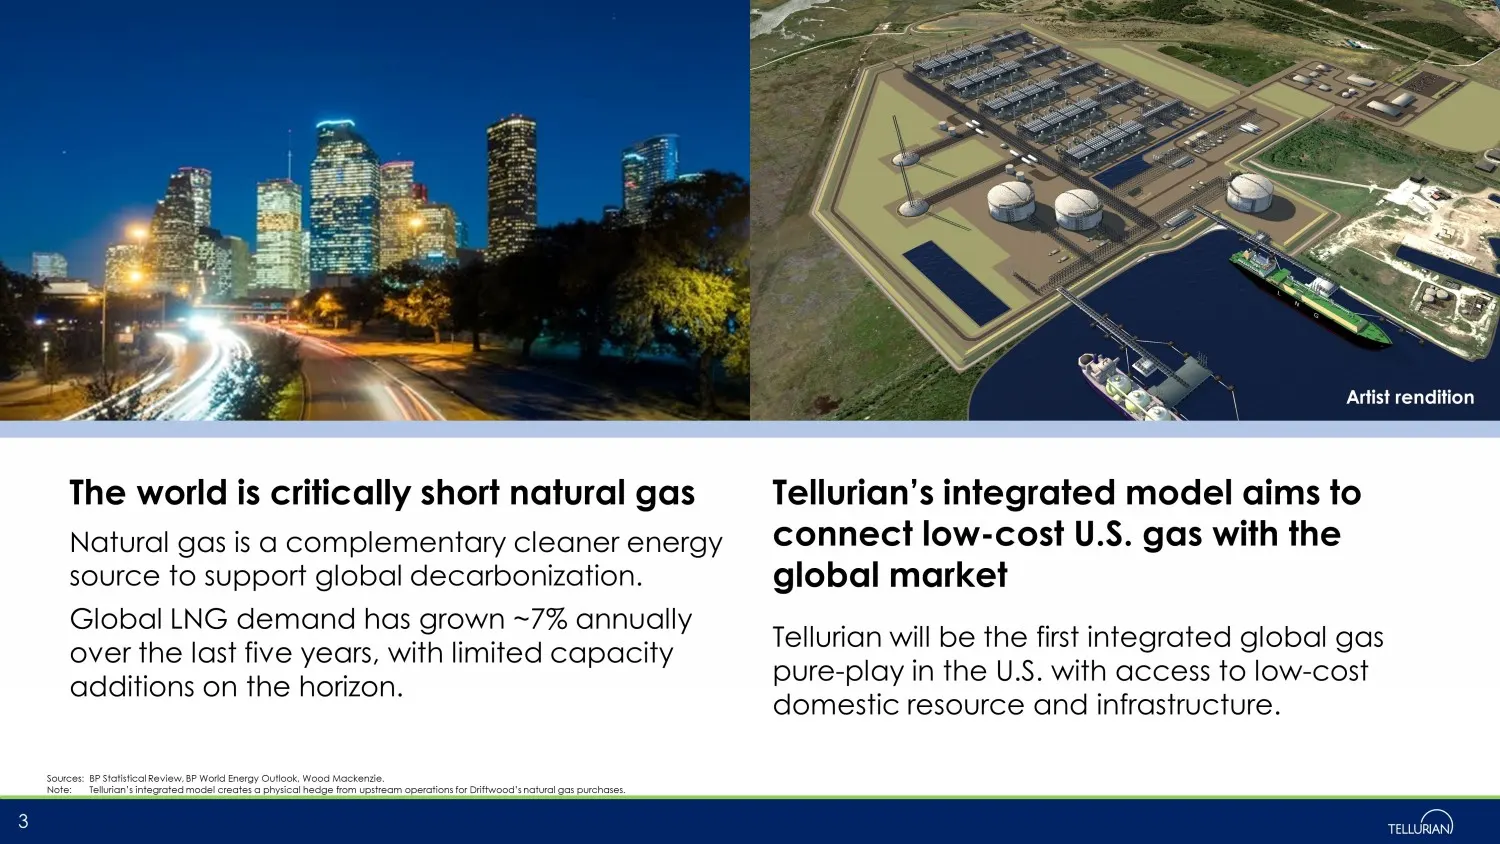
Slide 3: The world is critically short natural gas
The world is critically short natural gas Natural gas is a complementary cleaner energy source to support global decarbonization. Global LNG demand has grown ~7% annually over the last five years, with limited capacity additions on the horizon. Tellurian’s integrated model aims to connect low - cost
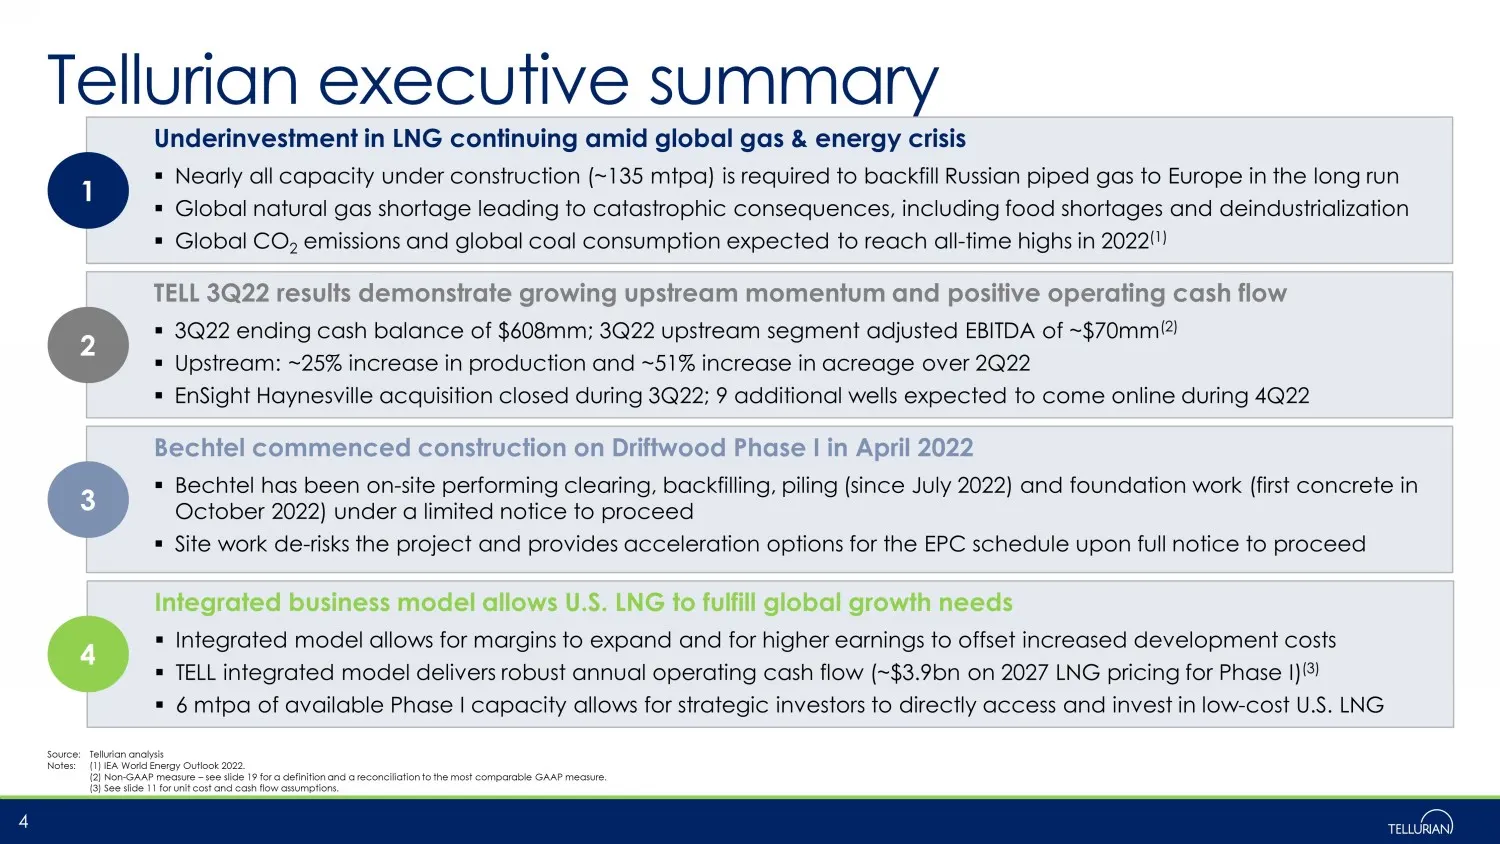
Slide 4: Tellurian executive summary
Tellurian executive summary 4 Bechtel commenced construction on Driftwood Phase I in April 2022 ▪ Bechtel has been on - site performing clearing, backfilling, piling (since July 2022) and foundation work (first concrete in October 2022) under a limited notice to proceed ▪ Site work de - risks the pr
Slide 5: Tellurian: fully integrated, pure-play LNG
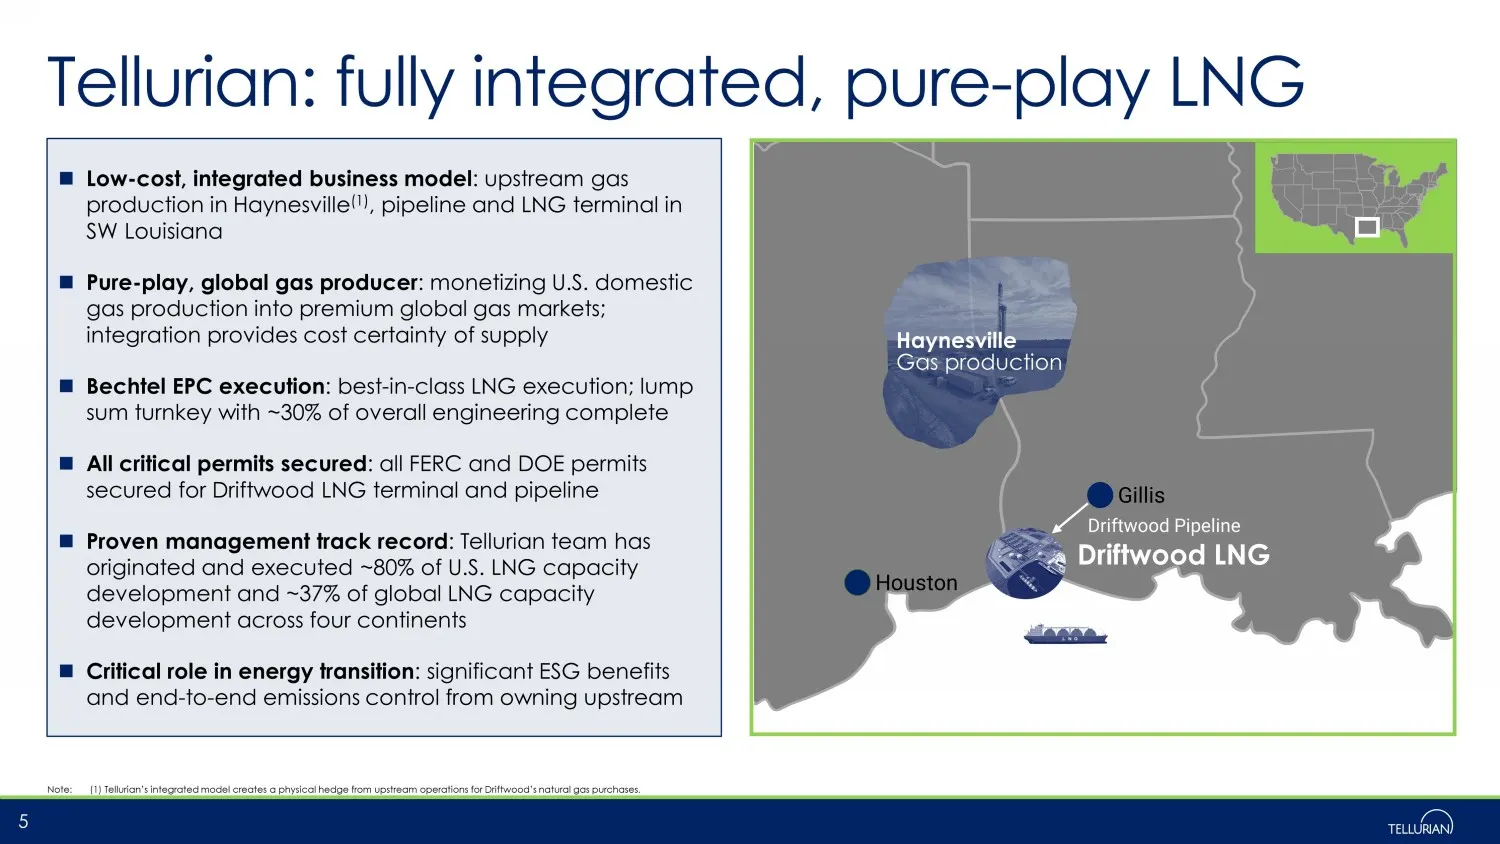
Houston Gillis Haynesville Gas production Driftwood LNG Driftwood Pipeline Tellurian: fully integrated, pure - play LNG 5 Low - cost, integrated business model : upstream gas production in Haynesville (1) , pipeline and LNG terminal in SW Louisiana Pure - play, global gas producer : monetizing U.S.
Slide 6: Upstream: building momentum into 2023
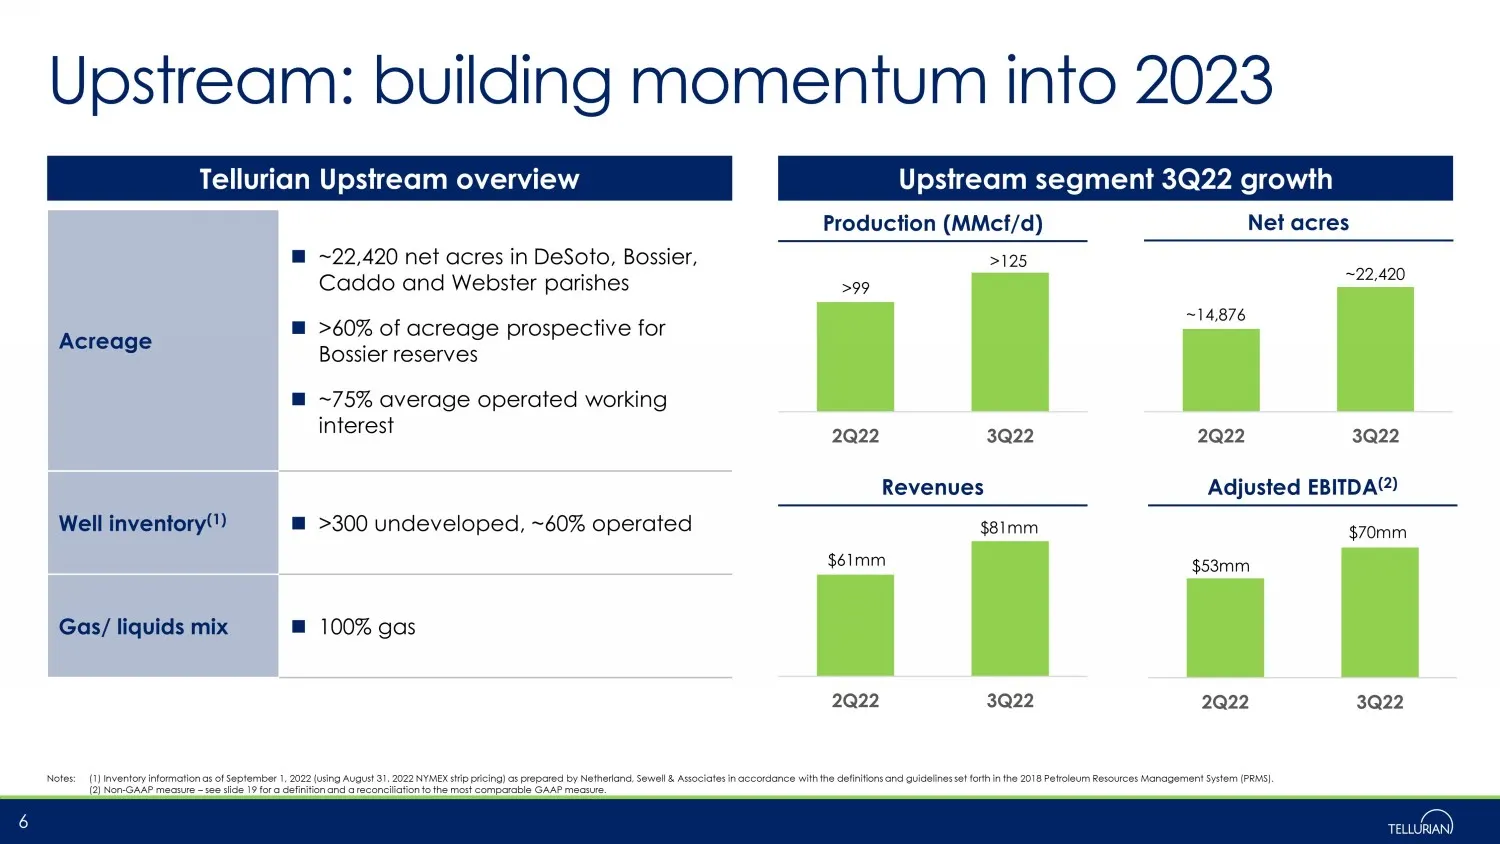
Upstream: building momentum into 2023 Notes: (1) Inventory information as of September 1, 2022 (using August 31, 2022 NYMEX strip pricing) as prepared by Netherland, Sewe ll & Associates in accordance with the definitions and guidelines set forth in the 2018 Petroleum Resources Management System (P
Slide 7: Driftwood LNG Phase I (2-plant, ~11 mtpa)
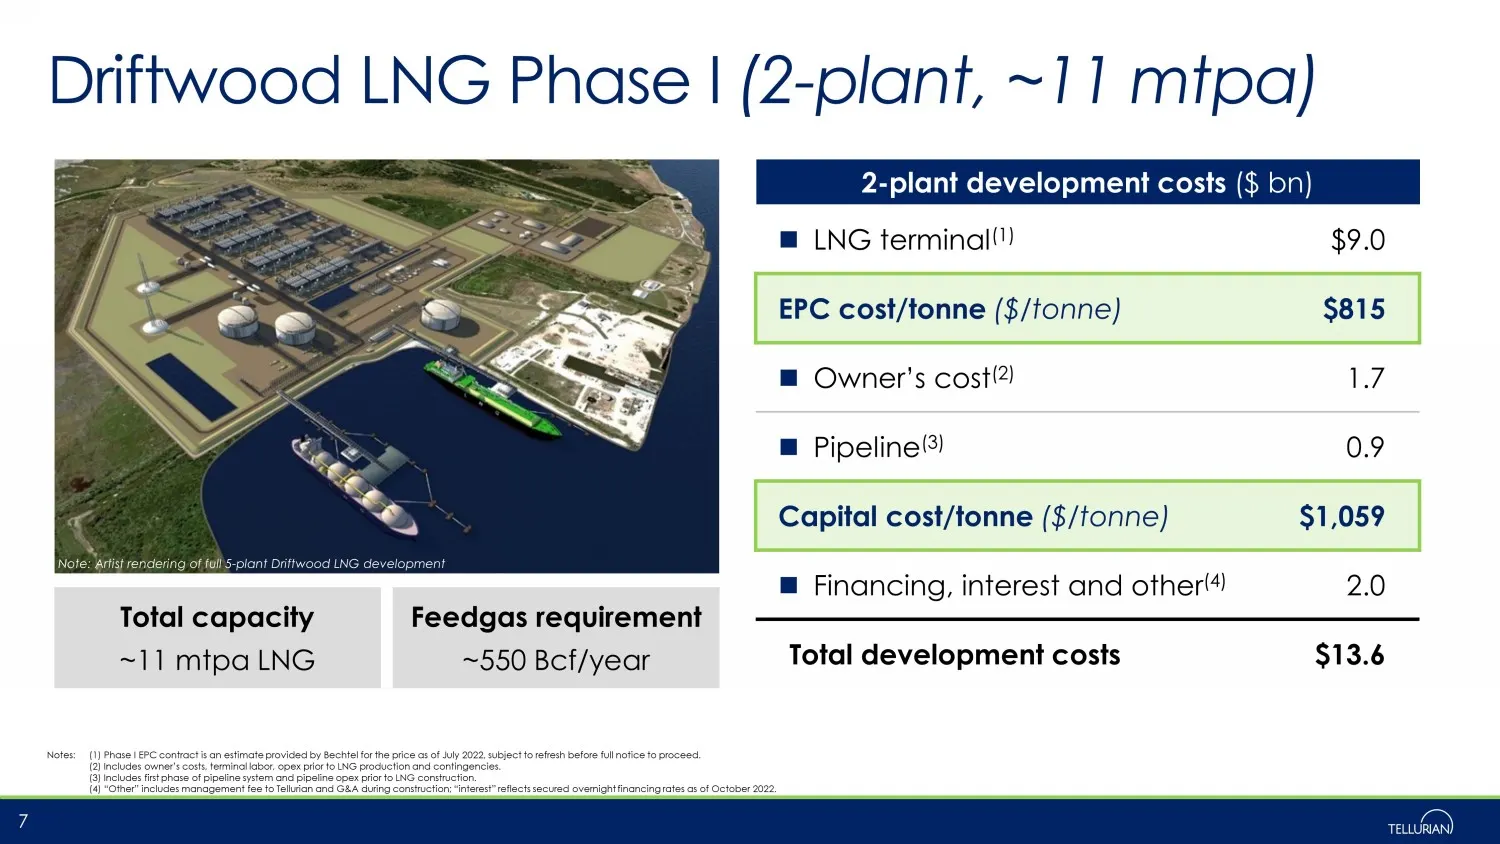
Driftwood LNG Phase I (2 - plant, ~11 mtpa) Notes: (1) Phase I EPC contract is an estimate provided by Bechtel for the price as of July 2022, subject to refresh before full notice to proce ed . (2) Includes owner’s costs, terminal labor, opex prior to LNG production and contingencies. (3) Includes f
Slide 8: Driftwood LNG: construction in progress
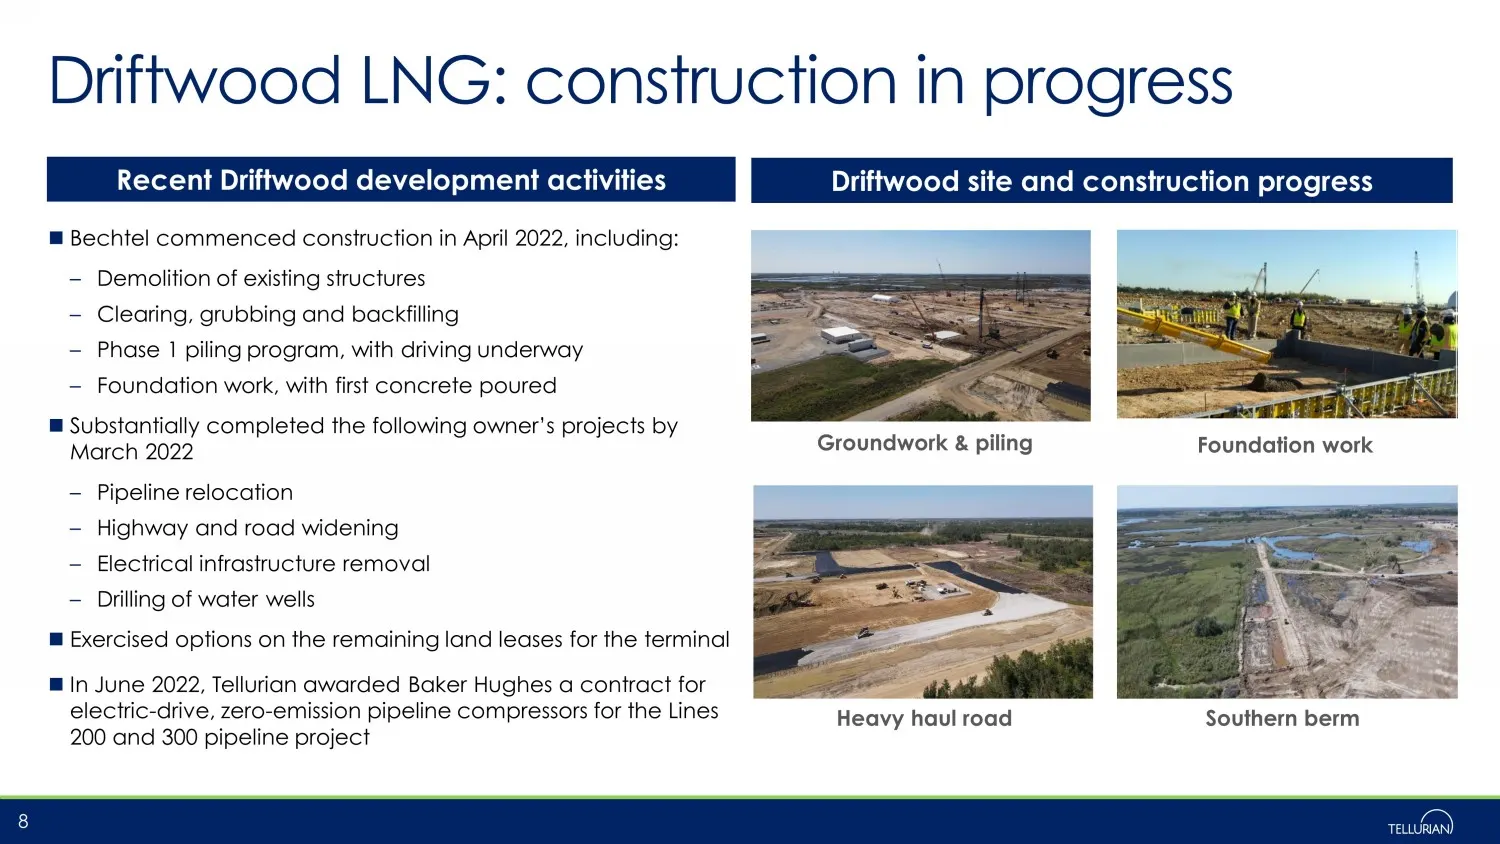
Driftwood LNG: construction in progress Bechtel commenced construction in April 2022, including: – Demolition of existing structures – Clearing, grubbing and backfilling – Phase 1 piling program, with driving underway – Foundation work, with first concrete poured Substantially completed the followin
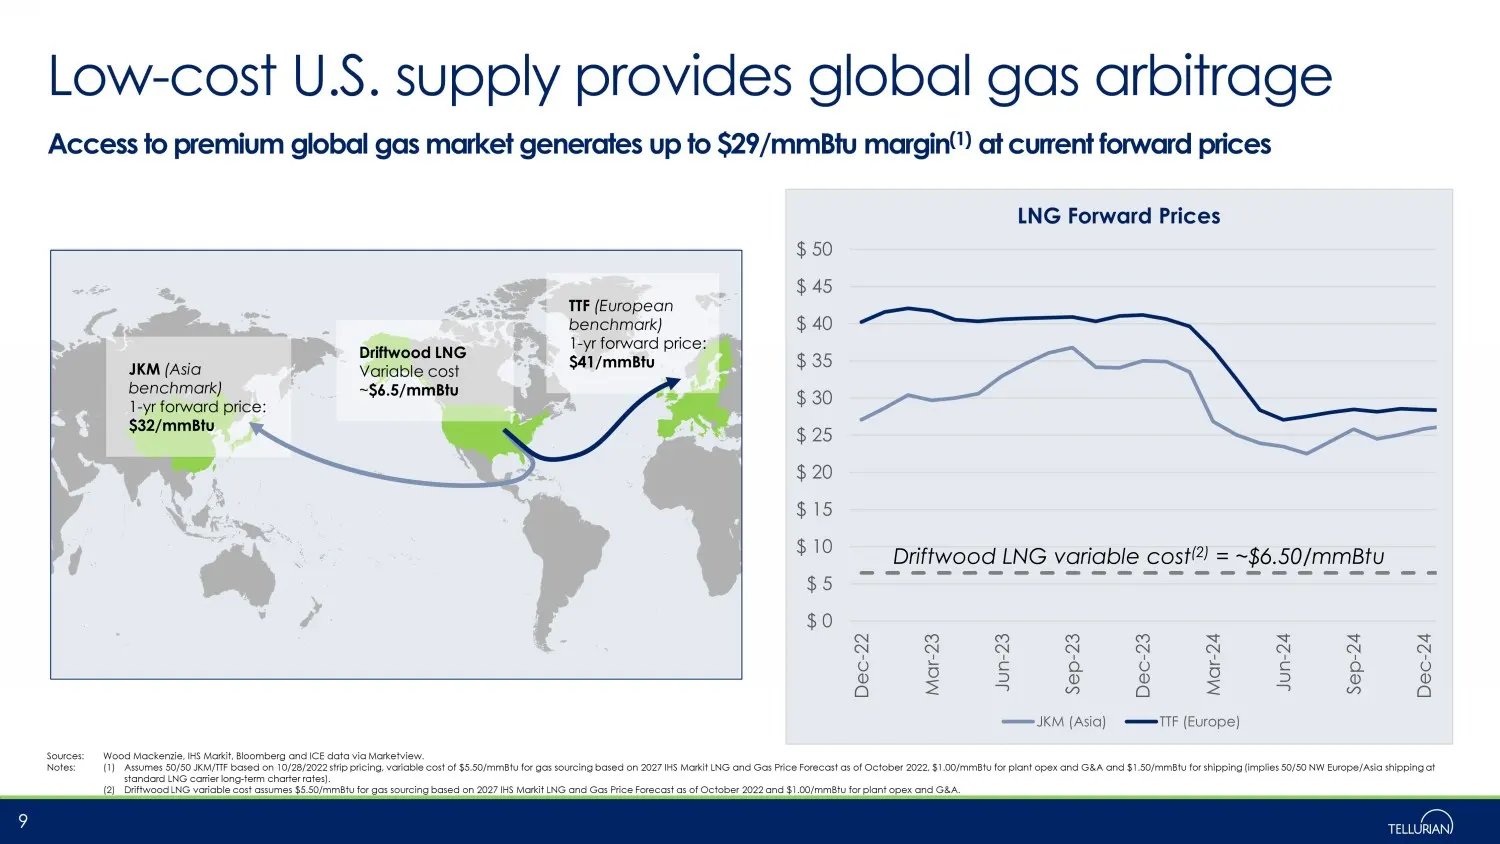
Slide 9: Low-cost U.S. supply provides global gas arbitrage
$ 0 $ 5 $ 10 $ 15 $ 20 $ 25 $ 30 $ 35 $ 40 $ 45 $ 50 Dec-22 Mar-23 Jun-23 Sep-23 Dec-23 Mar-24 Jun-24 Sep-24 Dec-24 LNG Forward Prices JKM (Asia) TTF (Europe) Low - cost U.S. supply provides global gas arbitrage 9 Access to premium global gas market generates up to $29/ mmBtu margin (1) at current f
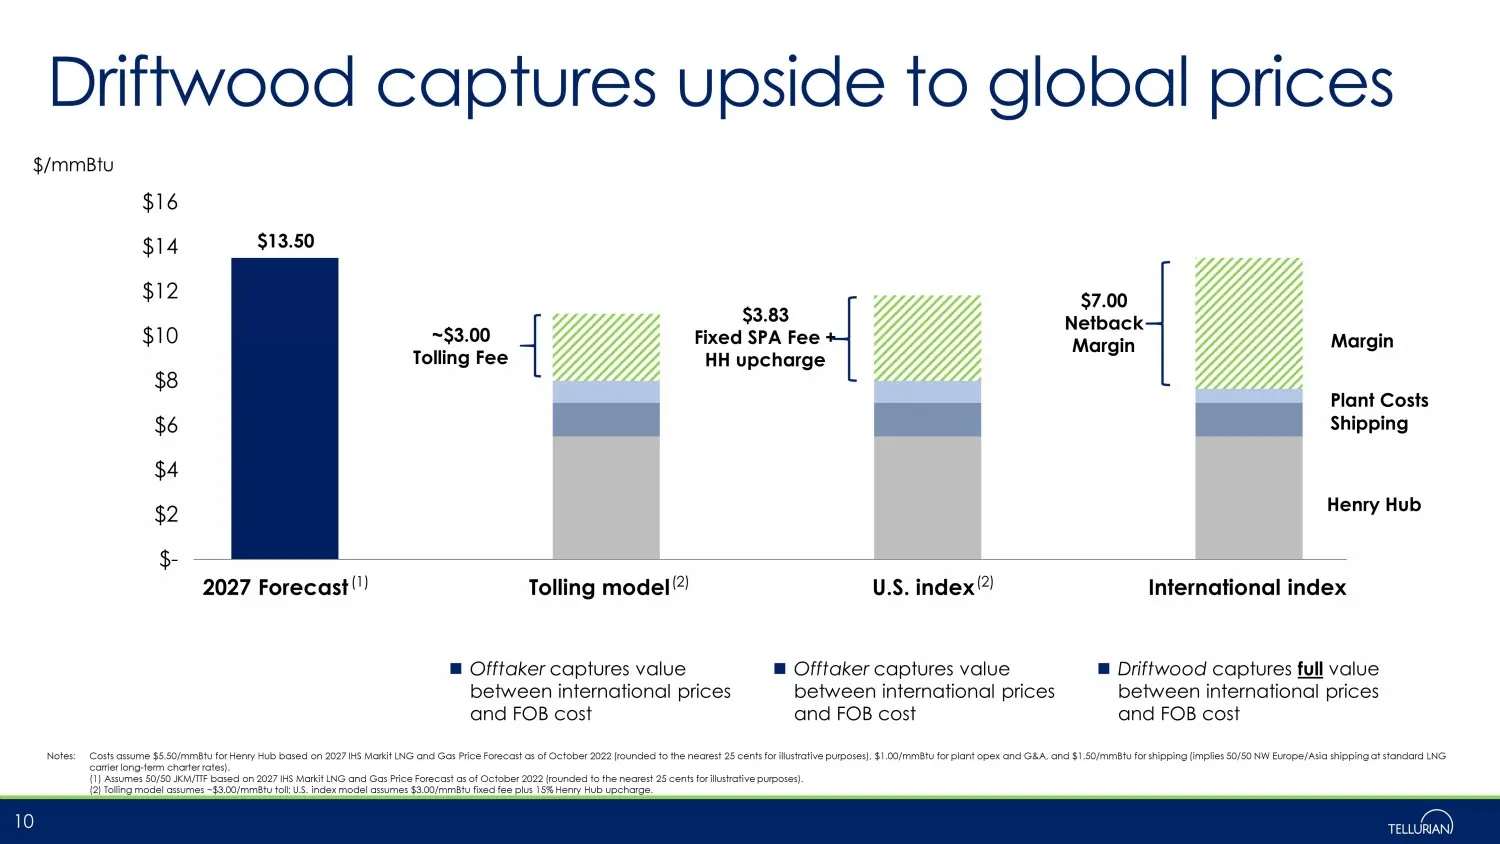
Slide 10: Driftwood captures full value between international prices and FOB cost
$- $2 $4 $6 $8 $10 $12 $14 $16 2027 Forecast Tolling model U.S. index International index Offtaker captures value between international prices and FOB cost Offtaker captures value between international prices and FOB cost Driftwood captures full value between international prices and FOB cost 10 Not
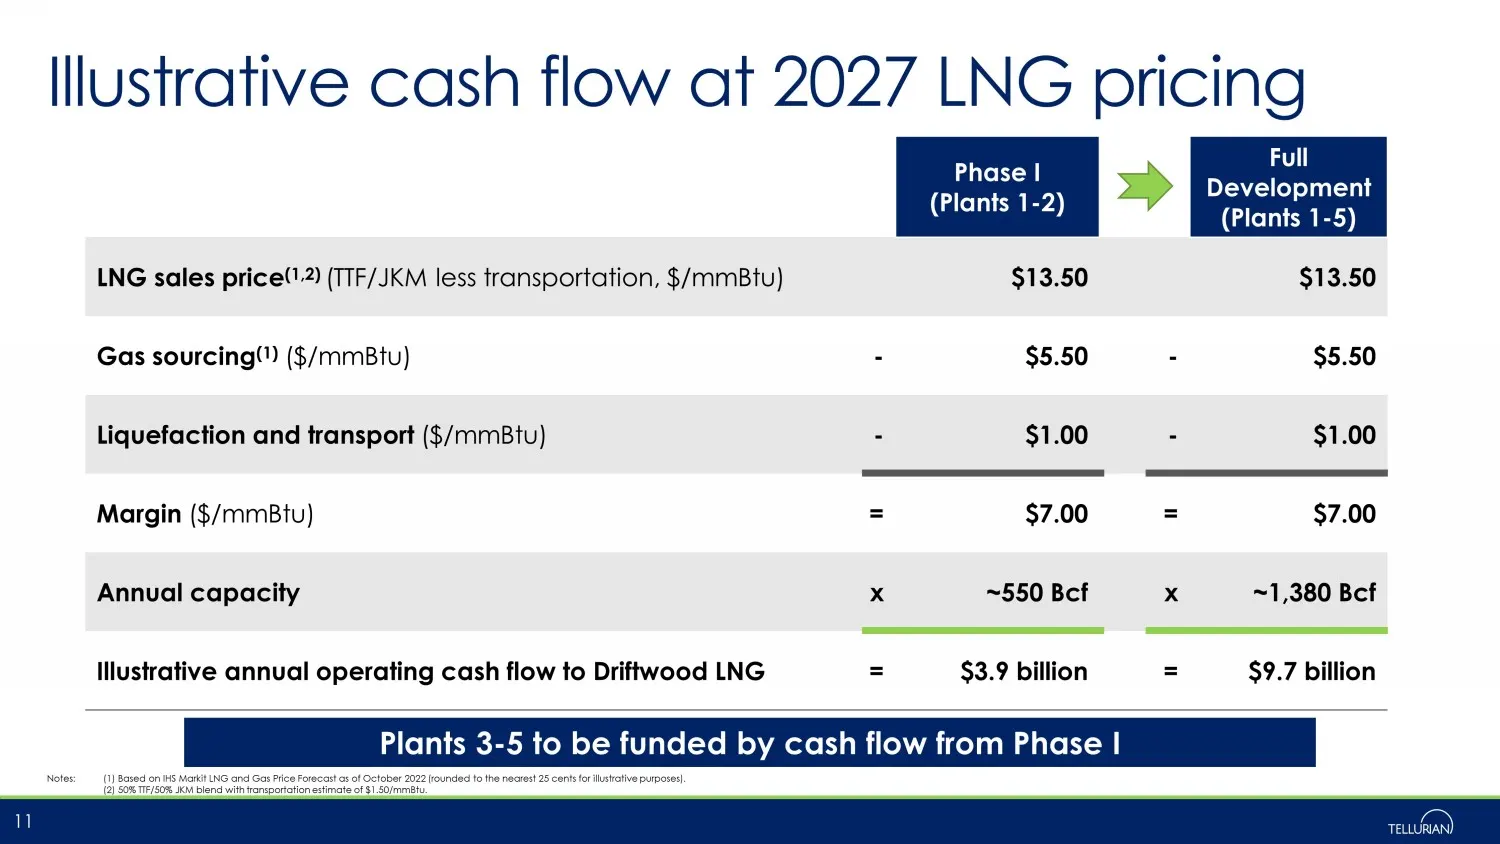
Slide 11: Illustrative cash flow at 2027 LNG pricing
Illustrative cash flow at 2027 LNG pricing Notes: (1) Based on IHS Markit LNG and Gas Price Forecast as of October 2022 (rounded to the nearest 25 cents for illustrative p urposes). (2) 50% TTF/50% JKM blend with transportation estimate of $1.50/ mmBtu . 11 Phase I (Plants 1 - 2) Full Development (P
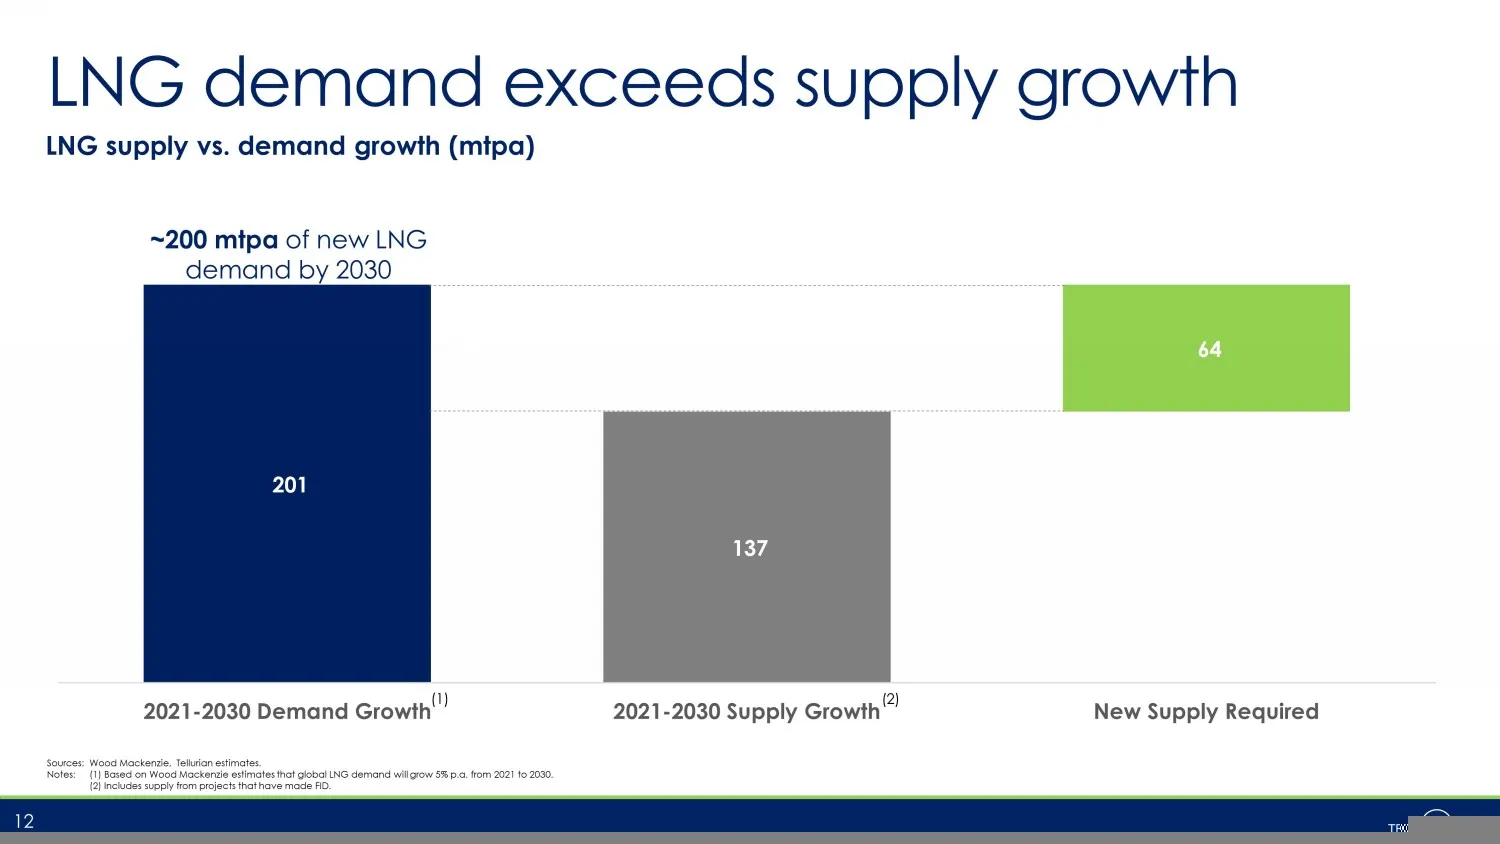
Slide 12: LNG supply vs. demand growth
201 137 64 2021-2030 Demand Growth 2021-2030 Supply Growth New Supply Required LNG supply vs. demand growth (mtpa) LNG demand exceeds supply growth 12 Sources: Wood Mackenzie, Tellurian estimates. Notes : ( 1) Based on Wood Mackenzie estimates that global LNG demand will grow 5% p.a. from 2021 to 20
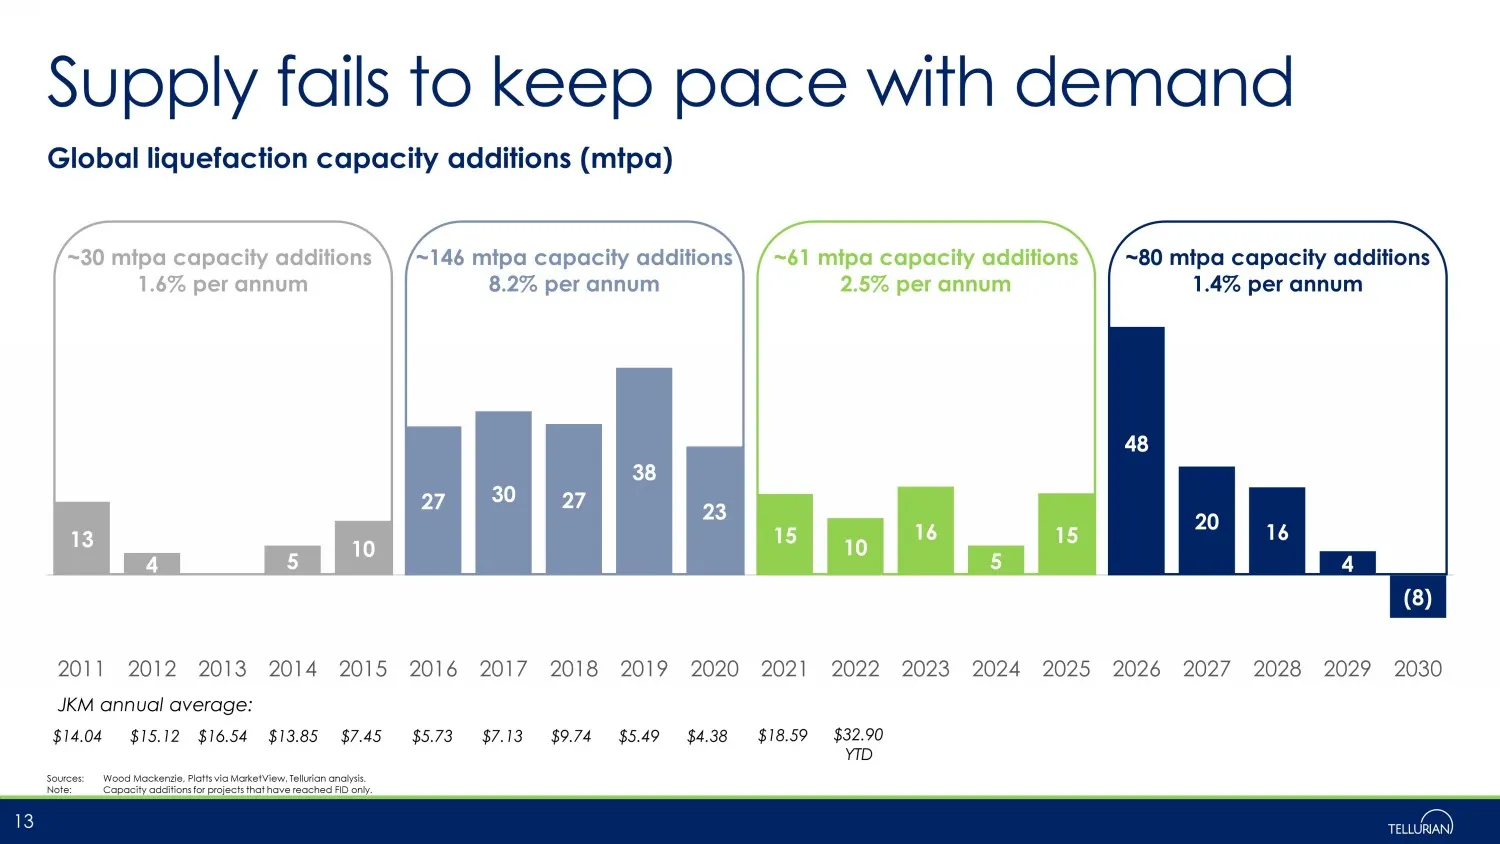
Slide 13: Supply fails to keep pace with demand
Supply fails to keep pace with demand Sources : Wood Mackenzie, Platts via MarketView , Tellurian analysis. Note: Capacity additions for projects that have reached FID only. 13 13 4 5 10 27 30 27 38 23 15 10 16 5 15 48 20 16 4 (8) 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024
Slide 14: Contact us
Contact us ▪ Matt Phillips VP, Investor Relations & Finance +1 832 320 9331 matthew.phillips@tellurianinc.com ▪ Joi Lecznar EVP, Public & Government Affairs +1 832 962 4044 joi.lecznar@tellurianinc.com 14 ▪ Johan Yokay Director , Investor Relations & Assistant Treasurer +1 832 320 9327 johan.yokay@t
Slide 15: Tellurian
TELLURIAN
Slide 16: Driftwood LNG's ideal site for exports
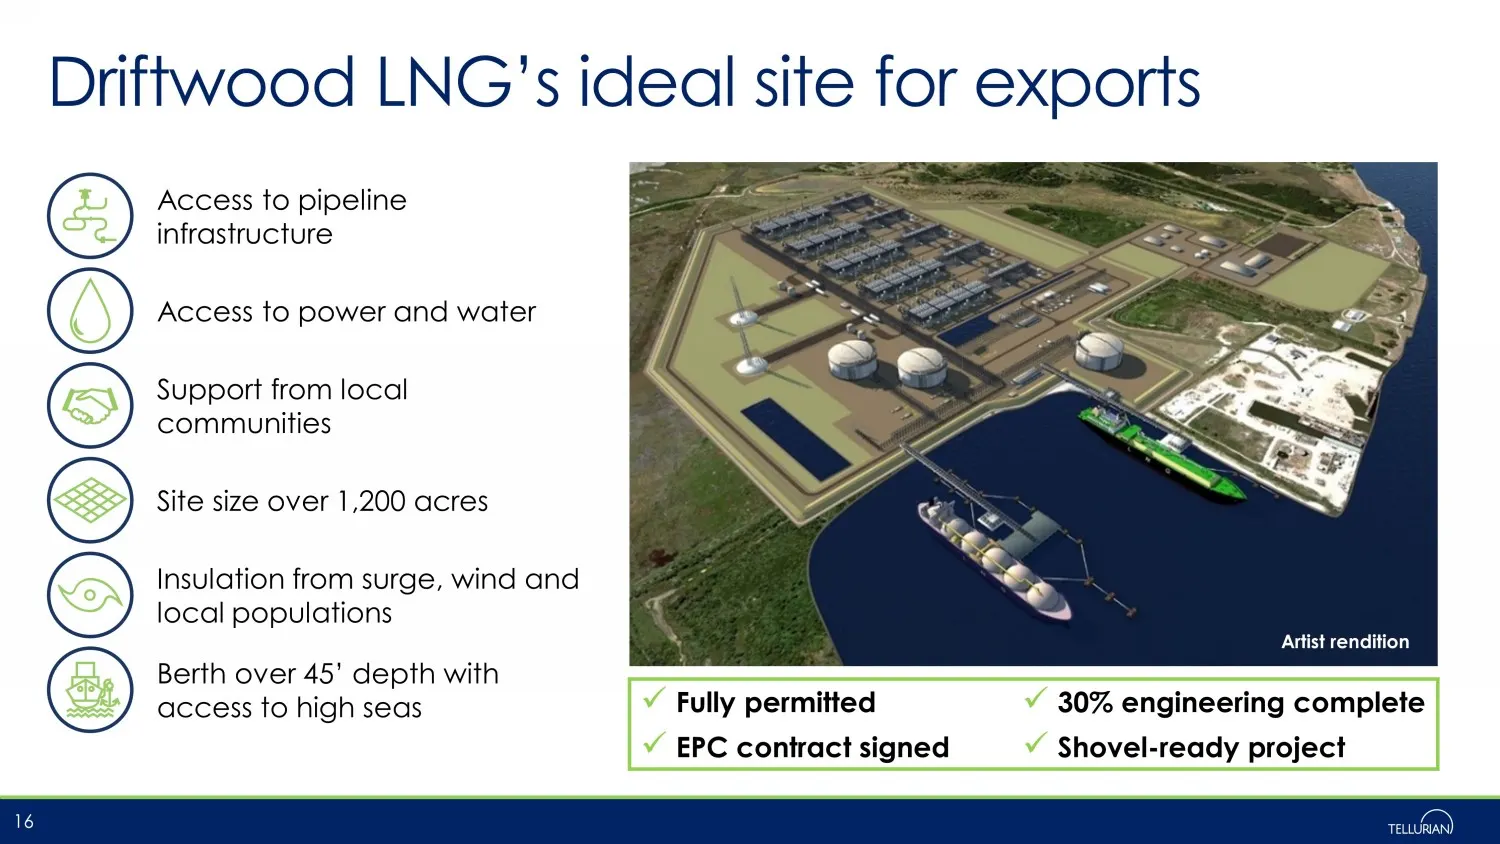
Driftwood LNG’s ideal site for exports 16 Access to power and water Berth over 45’ depth with access to high seas Support from local communities Access to pipeline infrastructure Site size over 1,200 acres Insulation from surge, wind and local populations Artist rendition x Fully permitted x 30% eng
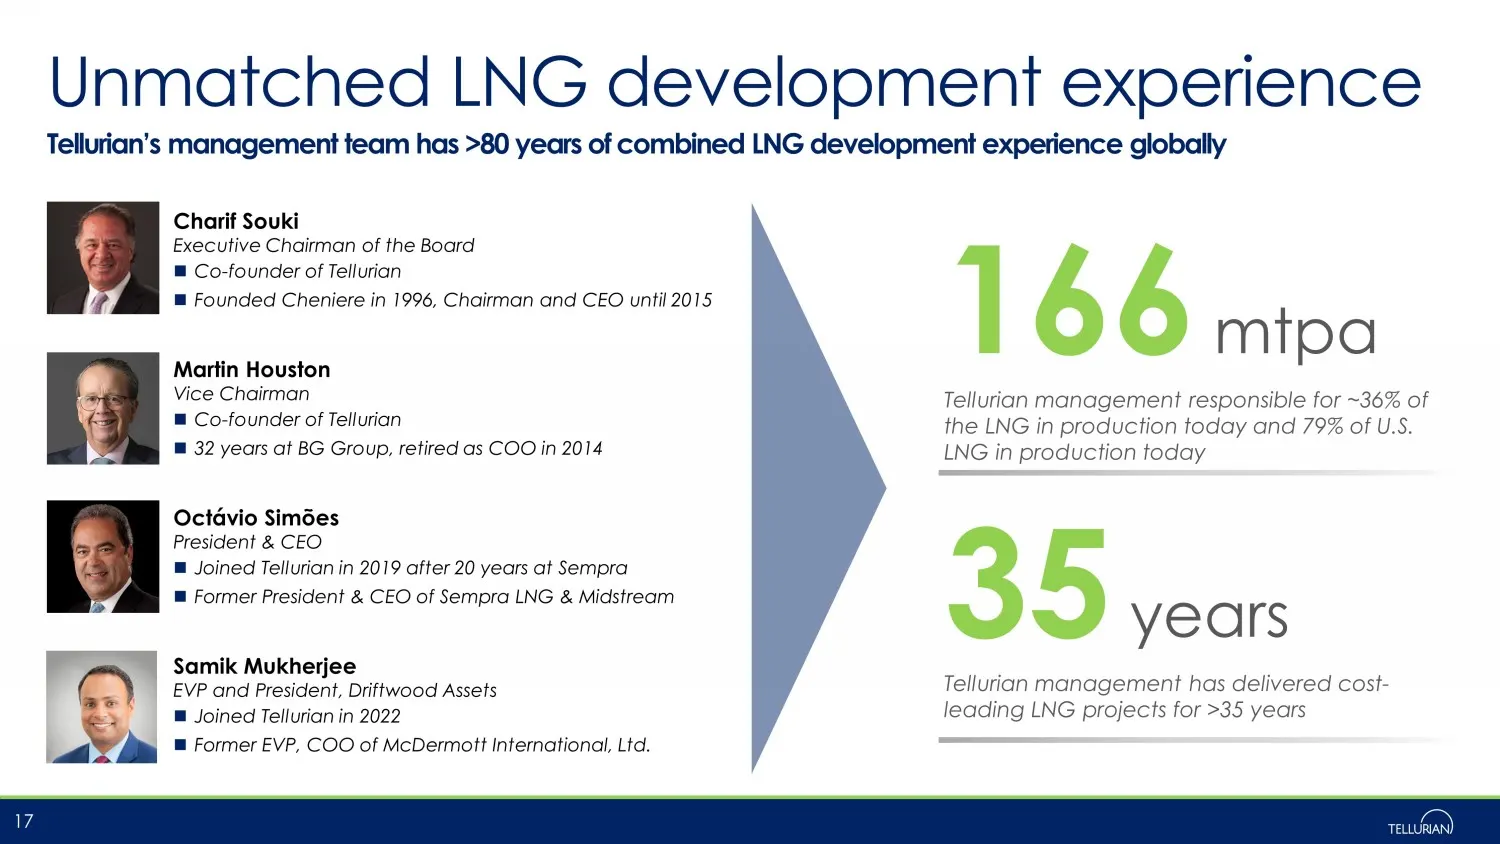
Slide 17: Unmatched LNG development experience
Unmatched LNG development experience Tellurian’s management team has >80 years of combined LNG development experience globally 17 Charif Souki Executive Chairman of the Board Co - founder of Tellurian Founded Cheniere in 1996, Chairman and CEO until 2015 Martin Houston Vice Chairman Co - founder of
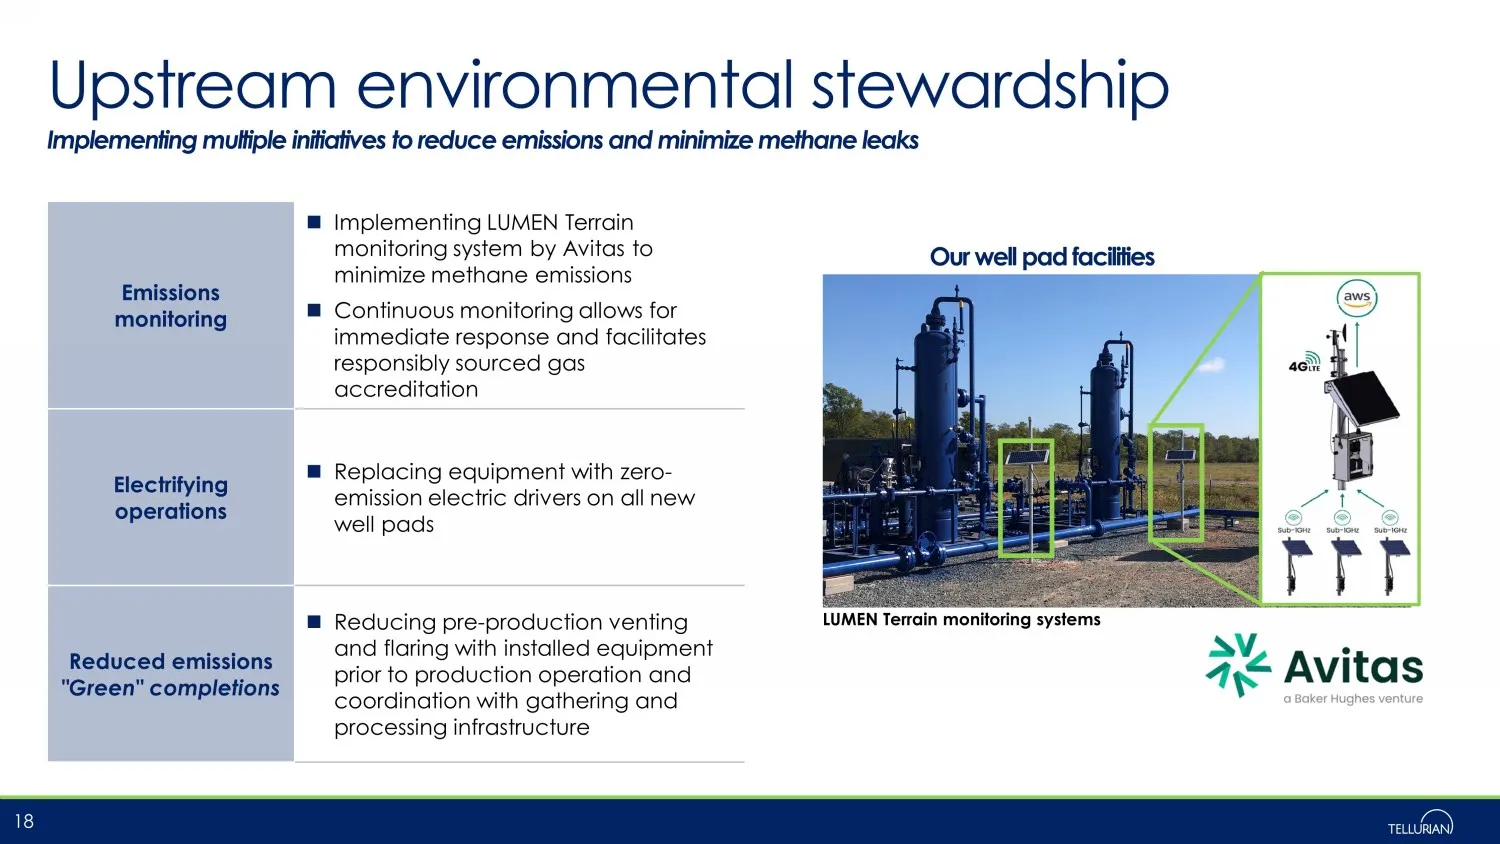
Slide 18: Upstream environmental stewardship
Upstream environmental stewardship Implementing multiple initiatives to reduce emissions and minimize methane leaks 18 Our well pad facilities LUMEN Terrain monitoring systems Emissions monitoring Implementing LUMEN Terrain monitoring system by Avitas to minimize methane emissions Continuous monitor
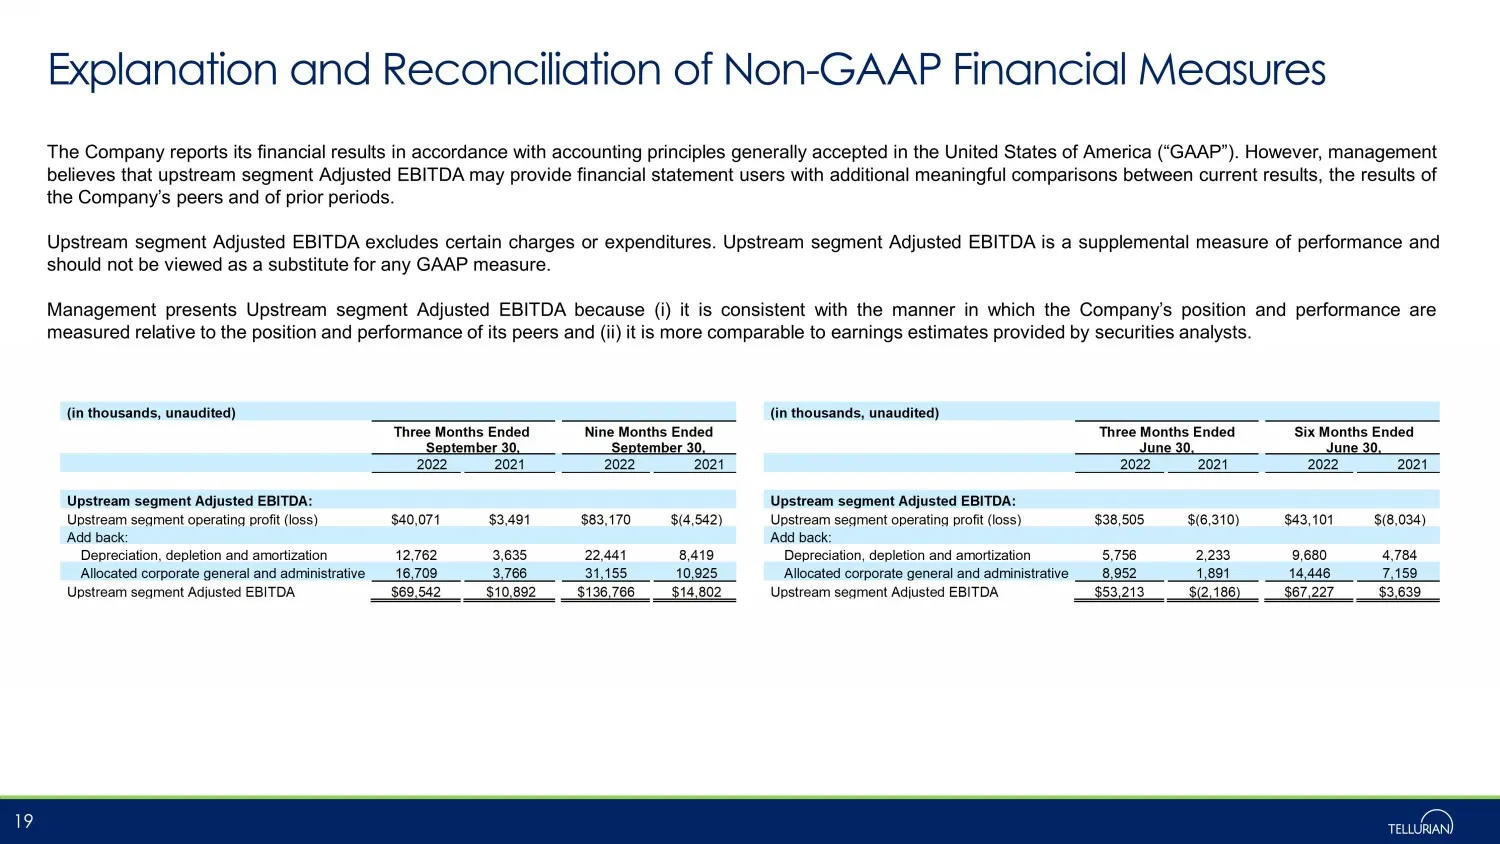
Slide 19: Upstream segment Adjusted EBITDA non-GAAP definition and reconciliation
The Company reports its financial results in accordance with accounting principles generally accepted in the United States of America (“GAAP”) . However, management believes that upstream segment Adjusted EBITDA may provide financial statement users with additional meaningful comparisons between cur
Source: SEC EDGAR · 8-K filed Nov 2, 2022
More decks from Tellurian Inc
 Merger or Acquisition (July 2024)27 slides · Jul 22, 2024
 Investor Presentation (March 2024)16 slides · Mar 4, 2024
 Investor Presentation (August 2023)20 slides · Aug 7, 2023
 Investor Presentation (May 2023)20 slides · May 3, 2023
 Investor Presentation (February 2023)21 slides · Feb 22, 2023
 Investor Presentation (July 2022)18 slides · Jul 13, 2022