Columbia Property Trust — Investor Day (February 2015)
57 slides from Columbia Property Trust's investor day presentation, Feb 23, 2015
Slide 1: Columbia Property Trust 2015 Investor Conference – New York City
1 Columbia Property Trust 2015 Investor Conference – New York City
Slide 2: Forward-Looking Statements
2 Forward-Looking Statements Certain statements contained in this presentation other than historical facts may be considered forward-looking statements. Such statements include, in particular, statements about our plans, strategies, and prospects, and are subject to certain risks and uncertainties,
Slide 3: Investor Conference Overview
3 Investor Conference Overview Executive Presentation: • Positioned to Compete • Portfolio Transformation • Proactive Operator • Strong and Flexible Balance Sheet Operations Presentation: • Leasing Successes and Opportunities Transactions Presentation: • Investment Underwriting and Execution
Slide 4: Positioned to Compete
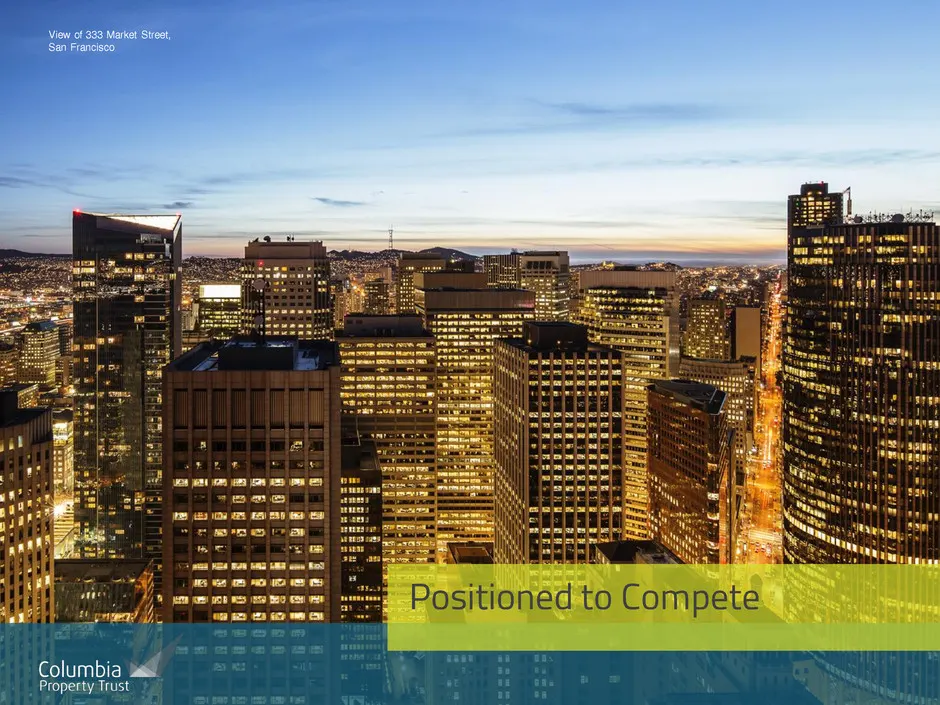
4 Positioned to Compete View of 333 Market Street, San Francisco
Slide 5: Executing Growth Strategy
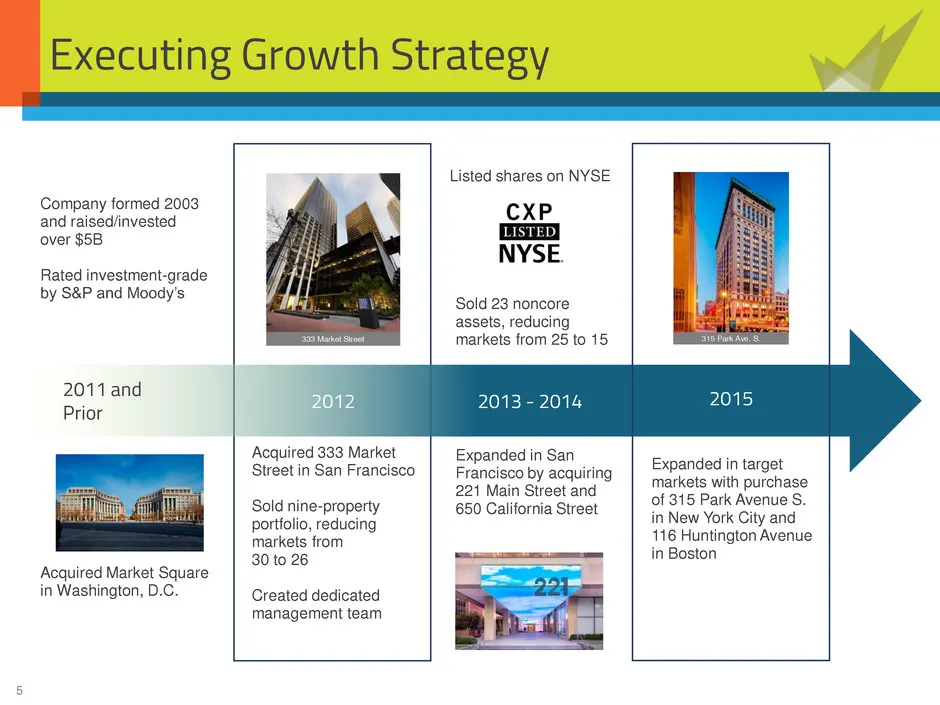
5 Executing Growth Strategy Company formed 2003 and raised/invested over $5B Rated investment-grade by S&P and Moody’s Acquired Market Square in Washington, D.C. Listed shares on NYSE Expanded in San Francisco by acquiring 221 Main Street and 650 California Street Acquired 333 Market Street in San F
Slide 6: Regional Management Platform
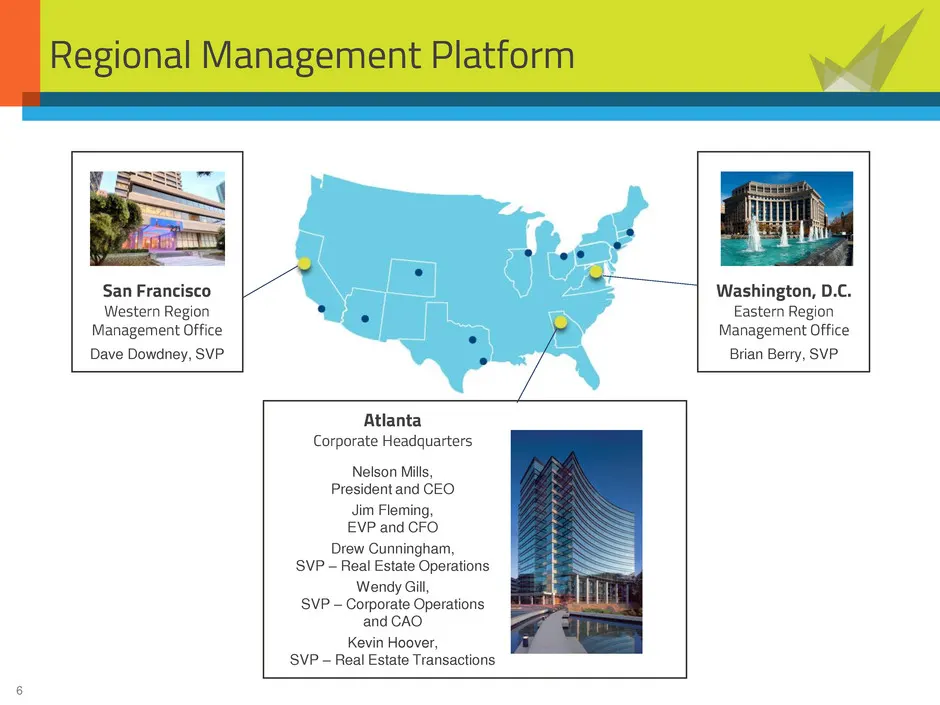
6 Regional Management Platform Atlanta Corporate Headquarters Nelson Mills, President and CEO Jim Fleming, EVP and CFO Drew Cunningham, SVP – Real Estate Operations Wendy Gill, SVP – Corporate Operations and CAO Kevin Hoover, SVP – Real Estate Transactions San Francisco Western Region Management Off
Slide 7: Competitive Positioning
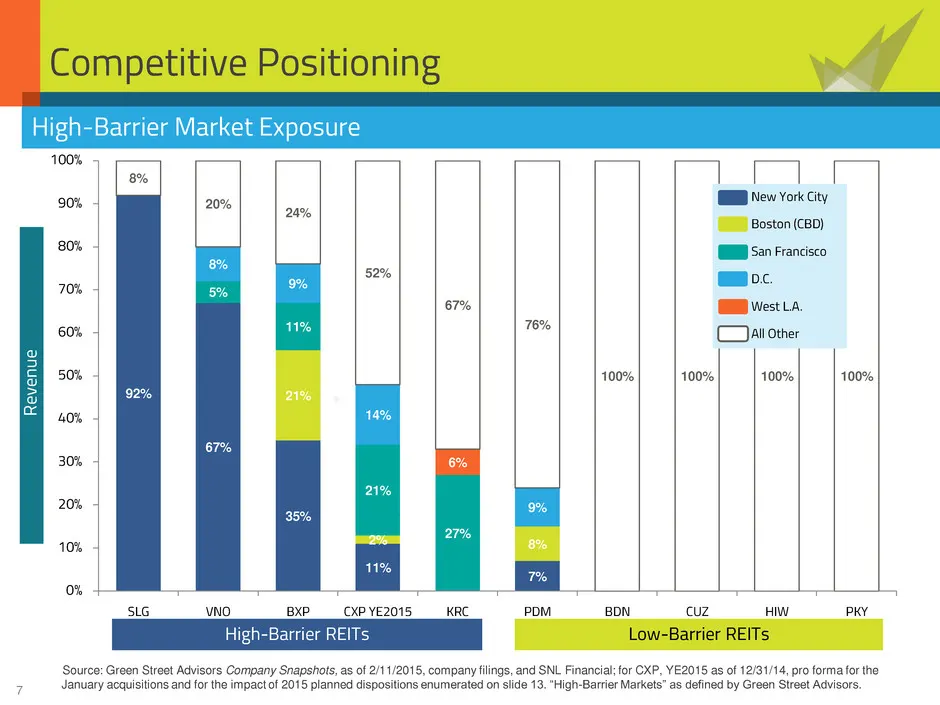
7 Competitive Positioning 92% 67% 35% 11% 7% 21% 2% 8% 5% 11% 21% 27% 8% 9% 14% 9% 6% 8% 20% 24% 52% 67% 76% 100% 100% 100% 100% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% SLG VNO BXP CXP YE2015 KRC PDM BDN CUZ HIW PKY New York City Boston (CBD) San Francisco D.C. West L.A. All Other Source: Green
Slide 8: Competitive Positioning: Net Rent Per Square Foot
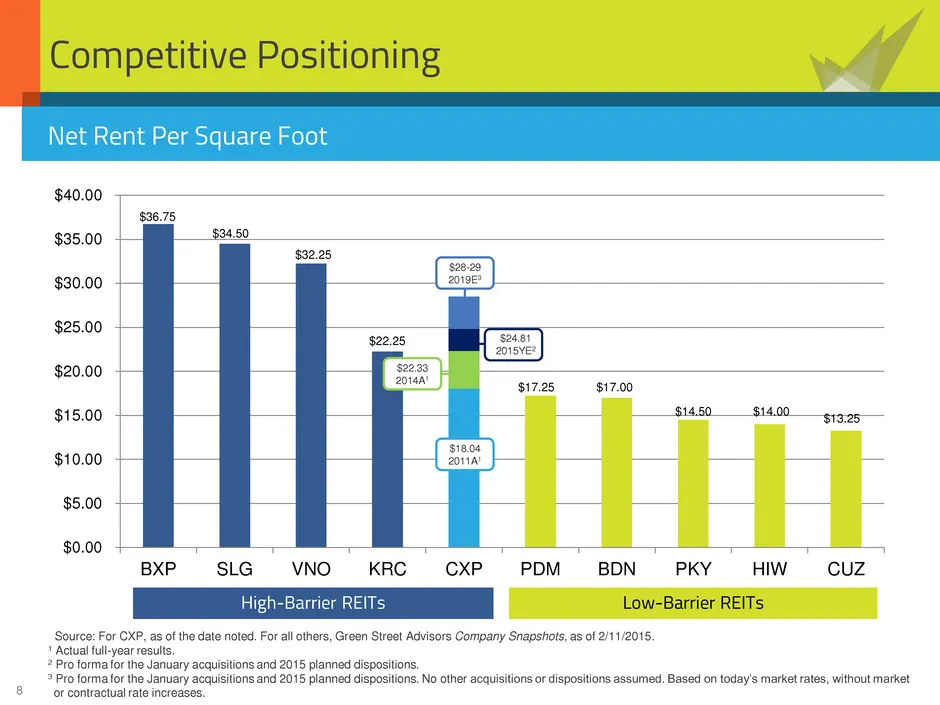
8 $0.00 $5.00 $10.00 $15.00 $20.00 $25.00 $30.00 $35.00 $40.00 BXP SLG VNO KRC CXP PDM BDN PKY HIW CUZ $32.25 $22.25 $34.50 $17.25 $17.00 $14.50 $14.00 $13.25 $28-29 2019E3 Competitive Positioning High-Barrier REITs Low-Barrier REITs Net Rent Per Square Foot Source: For CXP, as of the date noted. Fo
Slide 9: 2015 Objectives
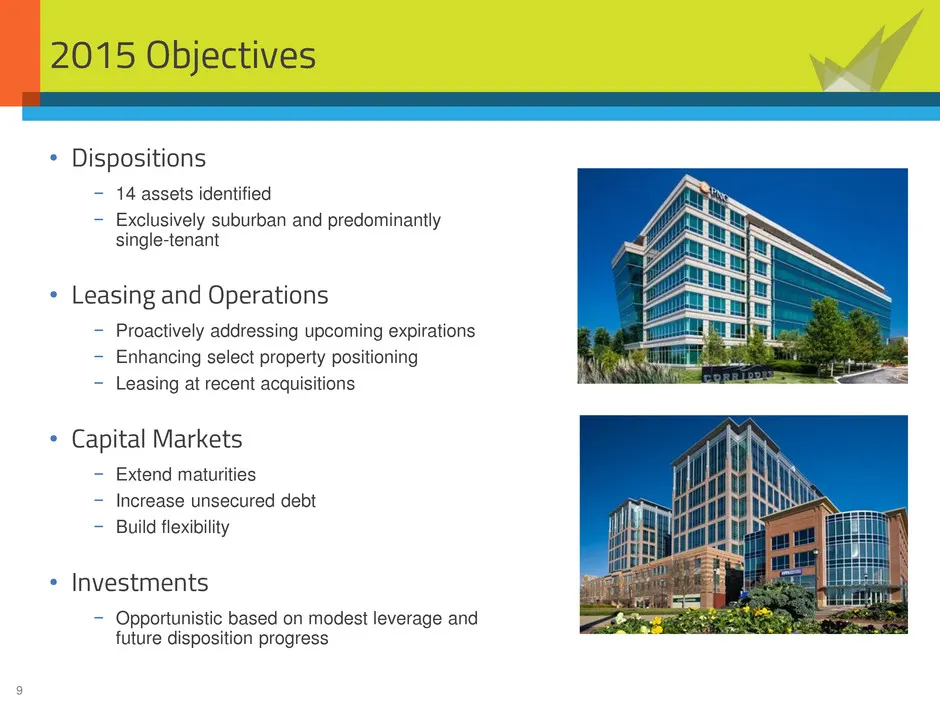
9 2015 Objectives • Dispositions − 14 assets identified − Exclusively suburban and predominantly single-tenant • Leasing and Operations − Proactively addressing upcoming expirations − Enhancing select property positioning − Leasing at recent acquisitions • Capital Markets − Extend maturities − Incre
Slide 10: 2015 Guidance
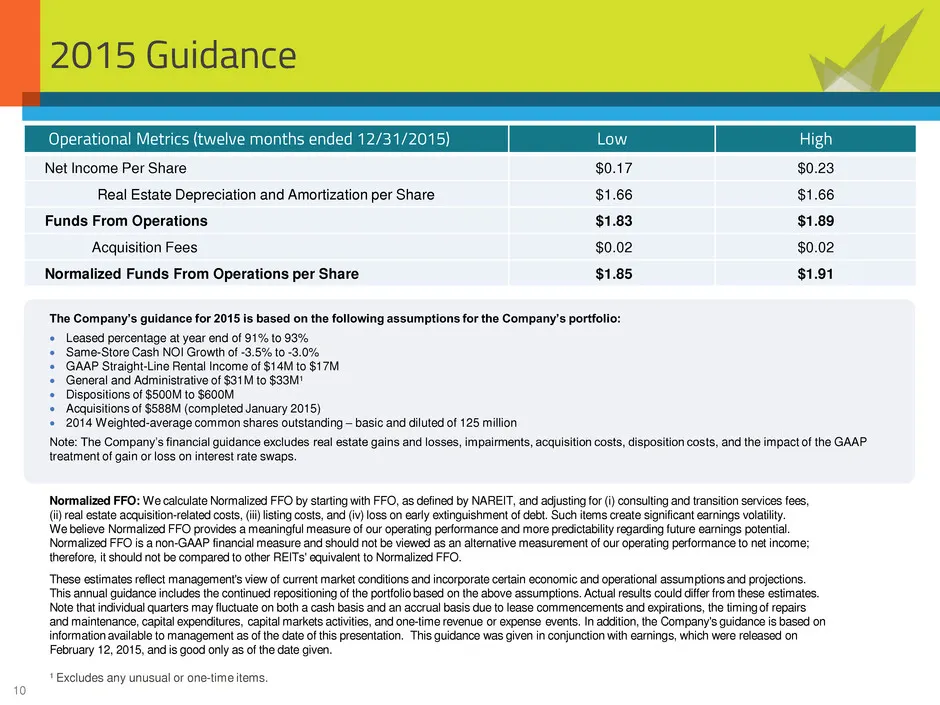
10 Operational Metrics (twelve months ended 12/31/2015) Low High Net Income Per Share $0.17 $0.23 Real Estate Depreciation and Amortization per Share $1.66 $1.66 Funds From Operations $1.83 $1.89 Acquisition Fees $0.02 $0.02 Normalized Funds From Operations per Share $1.85 $1.91 2015 Guidance 1 Excl
Slide 11: Portfolio Transformation
11 Portfolio Transformation 221 Main Street, San Francisco
Slide 12: Portfolio Transformation
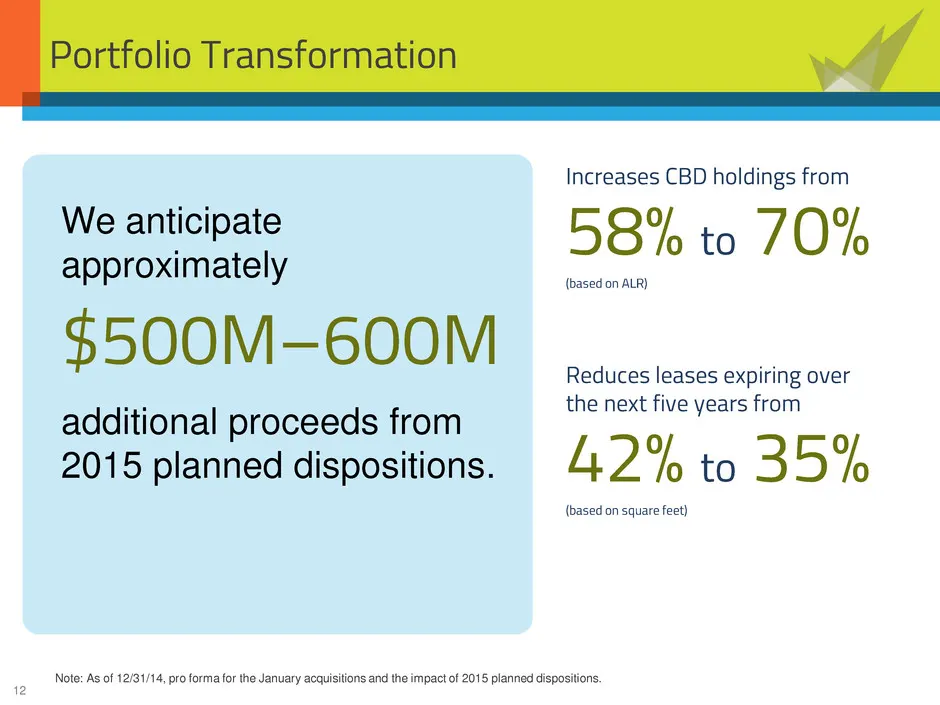
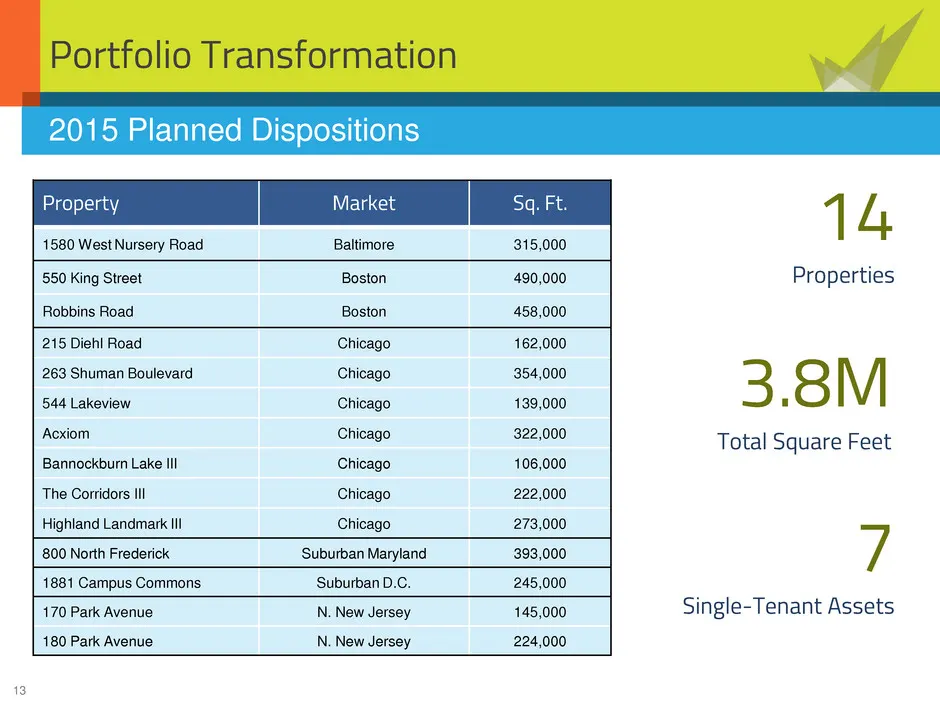
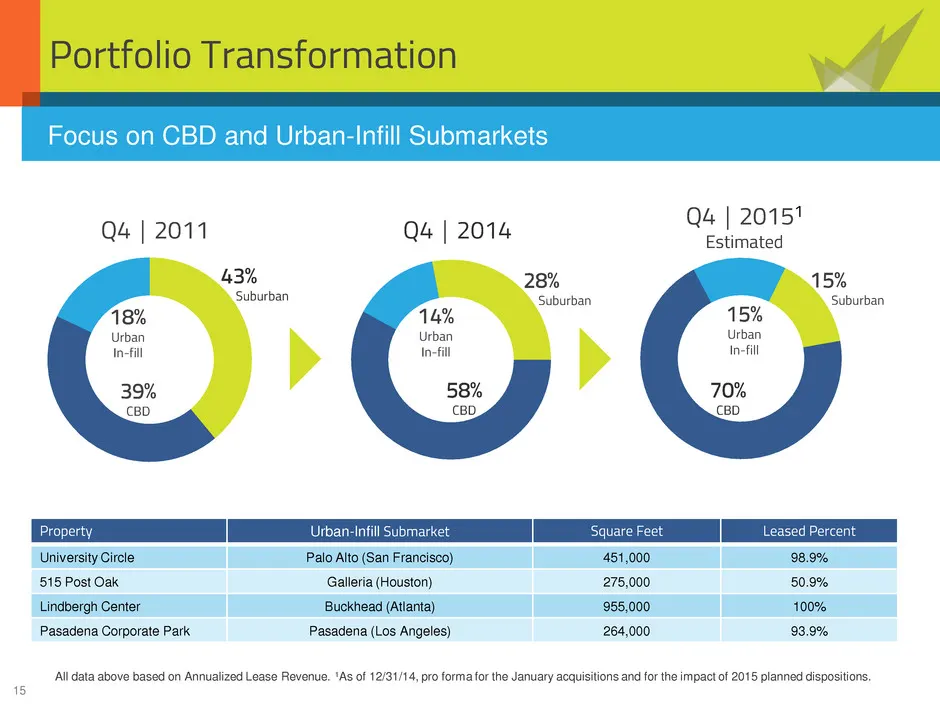
12 Reduces leases expiring over the next five years from 42% to 35% (based on square feet) Portfolio Transformation We anticipate approximately $500M–600M additional proceeds from 2015 planned dispositions. Increases CBD holdings from 58% to 70% (based on ALR) Note: As of 12/31/14, pro forma for the
Slide 13: 2015 Planned Dispositions
13 Portfolio Transformation Property Market Sq. Ft. 1580 West Nursery Road Baltimore 315,000 550 King Street Boston 490,000 Robbins Road Boston 458,000 215 Diehl Road Chicago 162,000 263 Shuman Boulevard Chicago 354,000 544 Lakeview Chicago 139,000 Acxiom Chicago 322,000 Bannockburn Lake III Chicago
Slide 14: Market Concentration
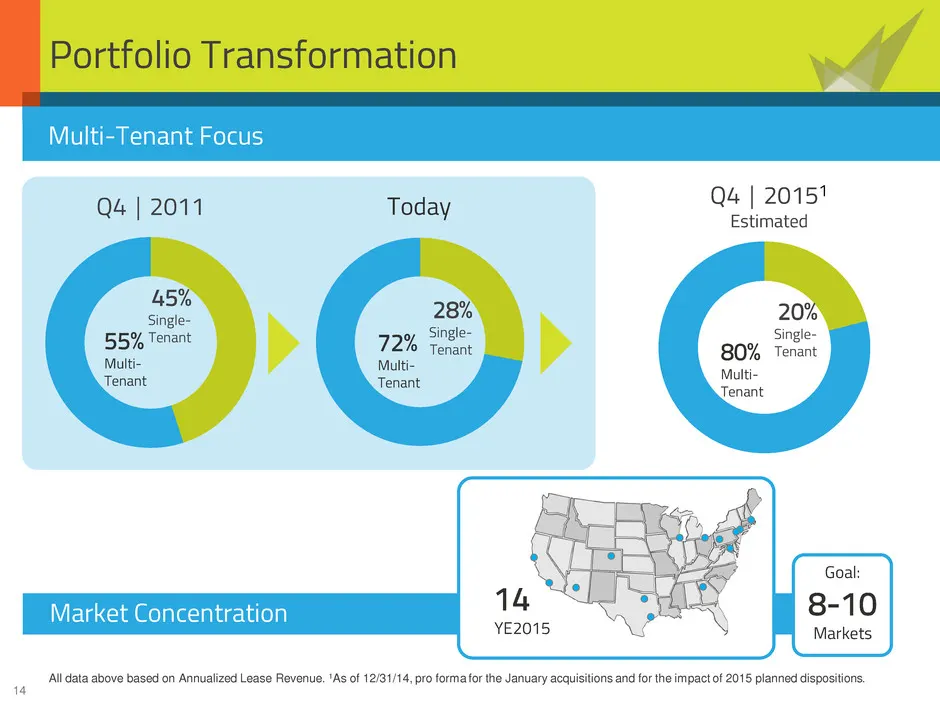
14 Market Concentration Portfolio Transformation Multi-Tenant Focus Single- Tenant Multi- Tenant Q4 │ 20151 Estimated Single- Tenant Multi- Tenant Today Single- Tenant Multi- Tenant Q4 │ 2011 YE2015 All data above based on Annualized Lease Revenue. 1As of 12/31/14, pro forma for the January acquisit
Slide 15: Focus on CBD and Urban-Infill Submarkets
15 Focus on CBD and Urban-Infill Submarkets Portfolio Transformation CBD Suburban Q4 │ 2014 Q4 │ 2011 Suburban CBD Suburban CBD Property Urban-Infill Submarket Square Feet Leased Percent University Circle Palo Alto (San Francisco) 451,000 98.9% 515 Post Oak Galleria (Houston) 275,000 50.9% Lindbergh
Slide 16: Target Portfolio – 2015 Year-End
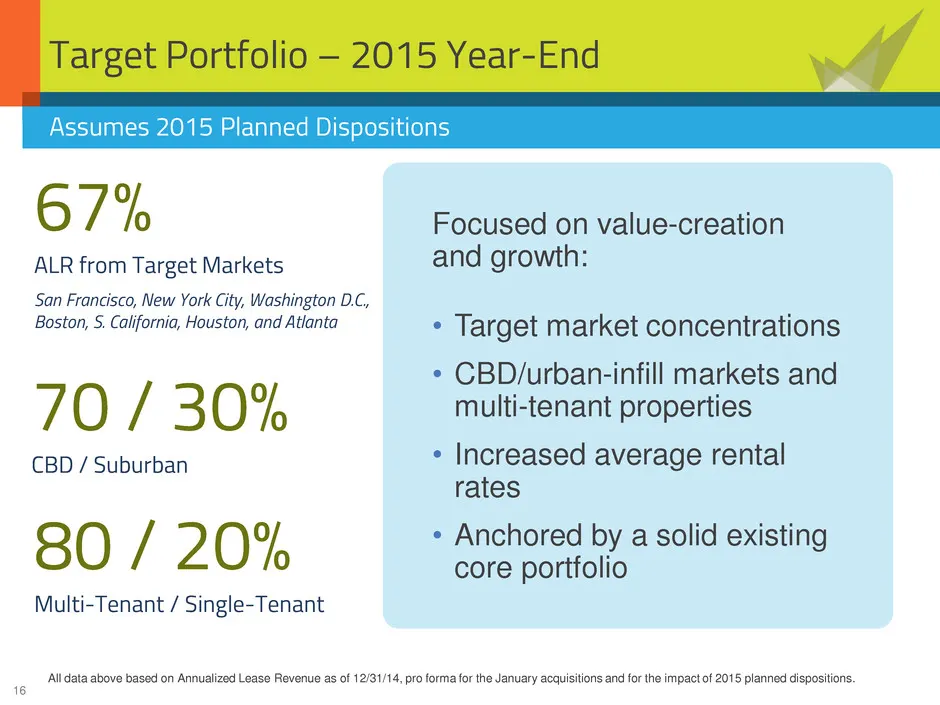
16 Target Portfolio – 2015 Year-End Focused on value-creation and growth: • Target market concentrations • CBD/urban-infill markets and multi-tenant properties • Increased average rental rates • Anchored by a solid existing core portfolio 67% ALR from Target Markets San Francisco, New York City, Was
Slide 17: Lease & Tenant Profiles
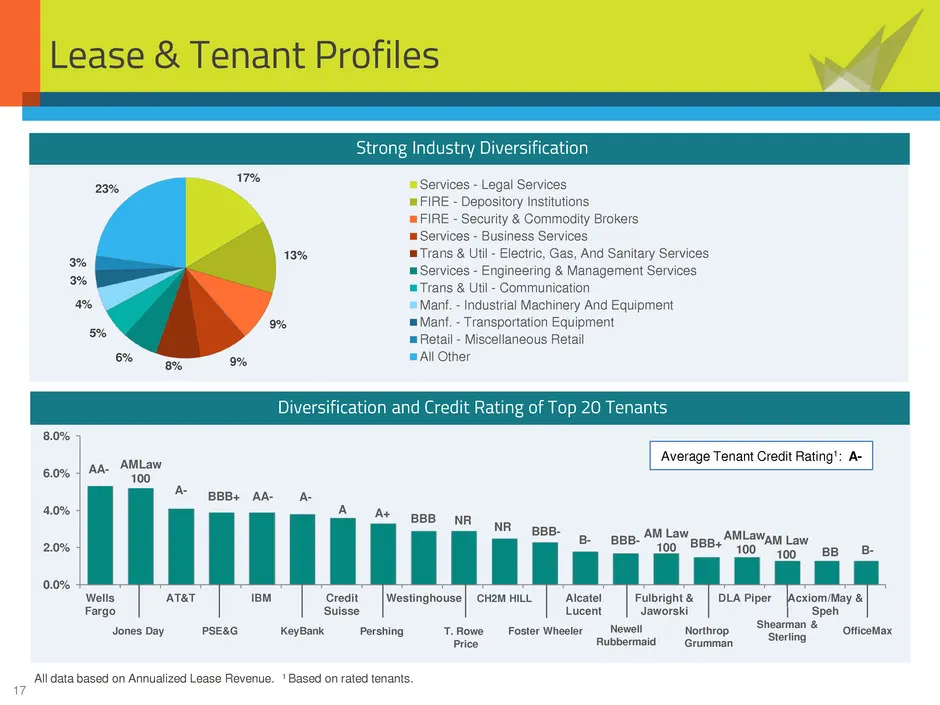
17 17% 13% 9% 9% 8% 6% 5% 4% 3% 3% 23% Services - Legal Services FIRE - Depository Institutions FIRE - Security & Commodity Brokers Services - Business Services Trans & Util - Electric, Gas, And Sanitary Services Services - Engineering & Management Services Trans & Util - Communication Manf. - Indus
Slide 18: Leasing Activity
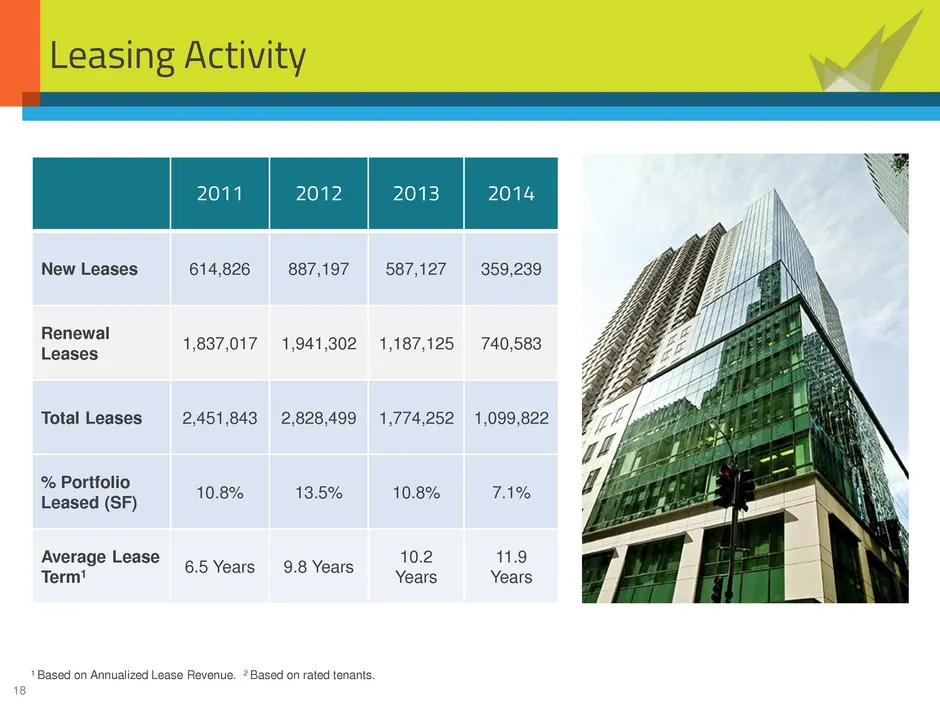
18 Leasing Activity 2011 2012 2013 2014 New Leases 614,826 887,197 587,127 359,239 Renewal Leases 1,837,017 1,941,302 1,187,125 740,583 Total Leases 2,451,843 2,828,499 1,774,252 1,099,822 % Portfolio Leased (SF) 10.8% 13.5% 10.8% 7.1% Average Lease Term1 6.5 Years 9.8 Years 10.2 Years 11.9 Years 1
Slide 19: Lease Expirations – Current Portfolio
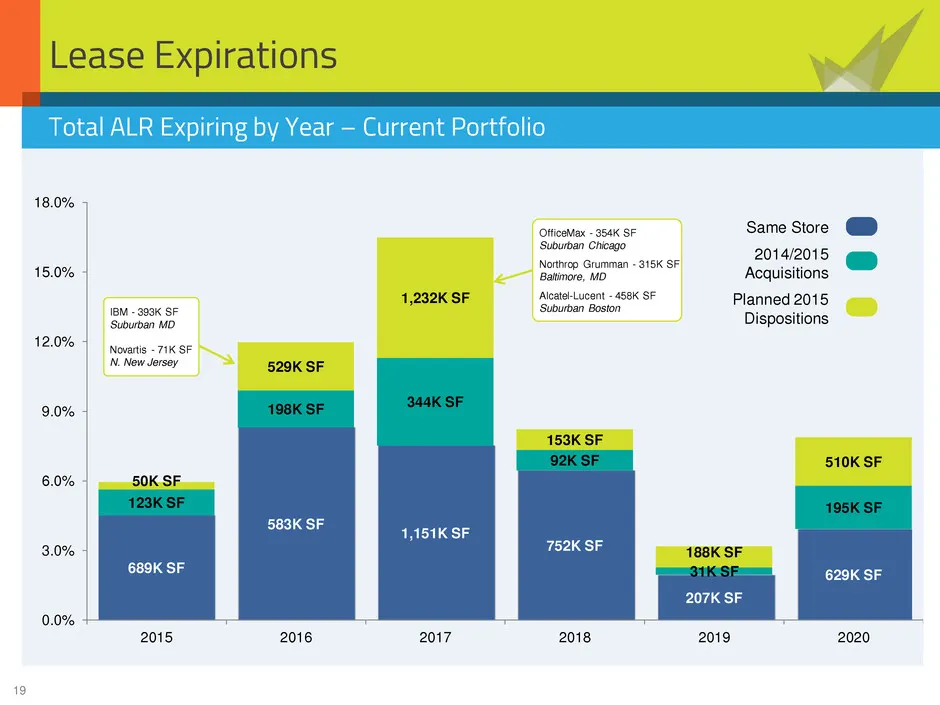
19 689K SF 583K SF 1,151K SF 752K SF 207K SF 629K SF 123K SF 198K SF 344K SF 92K SF 31K SF 195K SF 50K SF 529K SF 1,232K SF 153K SF 188K SF 510K SF 0.0% 3.0% 6.0% 9.0% 12.0% 15.0% 18.0% 2015 2016 2017 2018 2019 2020 Lease Expirations IBM - 393K SF Suburban MD Novartis - 71K SF N. New Jersey OfficeMa
Slide 20: Lease Expirations After Planned Dispositions
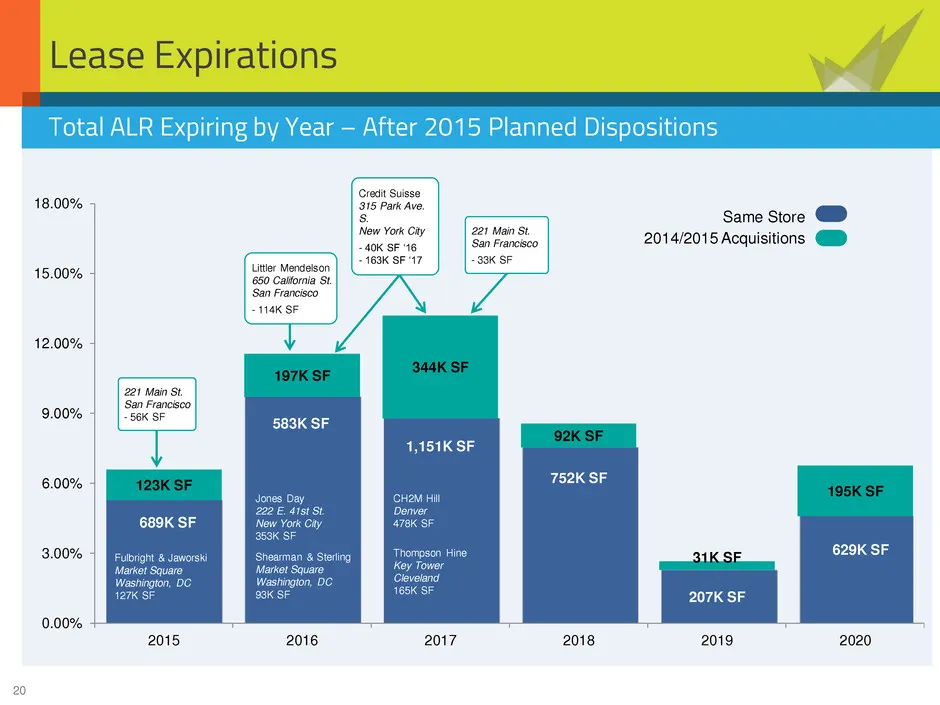
20 Lease Expirations 689K SF 583K SF 1,151K SF 752K SF 207K SF 629K SF 123K SF 197K SF 344K SF 92K SF 31K SF 195K SF 0.00% 3.00% 6.00% 9.00% 12.00% 15.00% 18.00% 2015 2016 2017 2018 2019 2020 Total ALR Expiring by Year – After 2015 Planned Dispositions Fulbright & Jaworski Market Square Washington,
Slide 21: Proactive Operator
21 Proactive Operator University Circle, Palo Alto, CA
Slide 22: Key Leasing Accomplishments: Proactive Lease Management
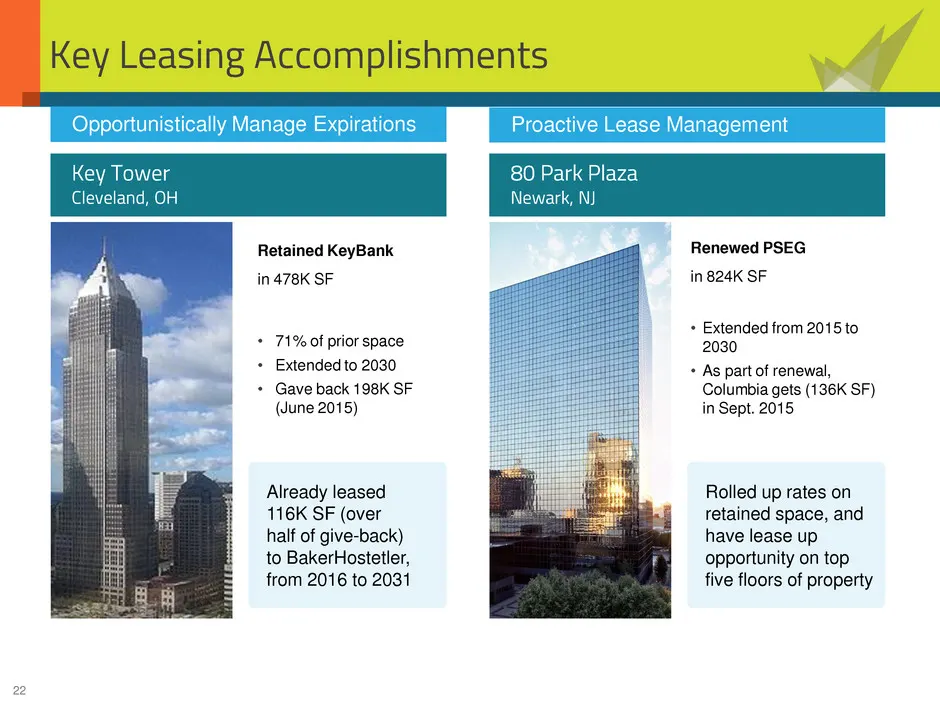
22 Key Leasing Accomplishments Retained KeyBank in 478K SF • 71% of prior space • Extended to 2030 • Gave back 198K SF (June 2015) Renewed PSEG in 824K SF • Extended from 2015 to 2030 • As part of renewal, Columbia gets (136K SF) in Sept. 2015 Proactive Lease Management Opportunistically Manage Expi
Slide 23: Key Leasing Accomplishments: Win/Win Opportunities
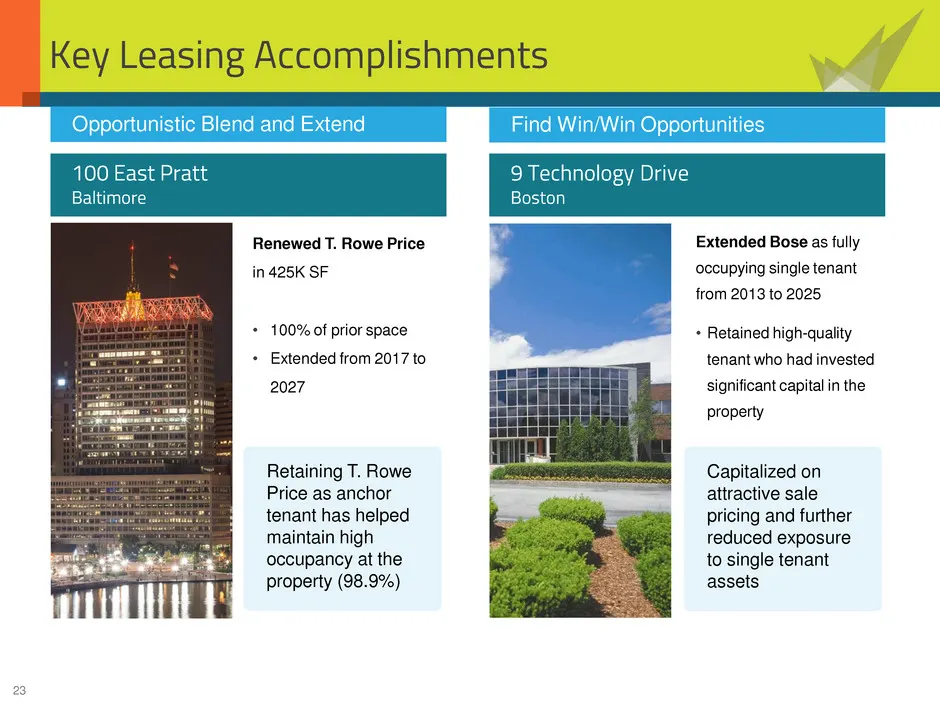
23 9 Technology Drive Boston 100 East Pratt Baltimore Key Leasing Accomplishments Renewed T. Rowe Price in 425K SF • 100% of prior space • Extended from 2017 to 2027 Find Win/Win Opportunities Opportunistic Blend and Extend Retaining T. Rowe Price as anchor tenant has helped maintain high occupancy
Slide 24: Key Leasing Accomplishments: University Circle
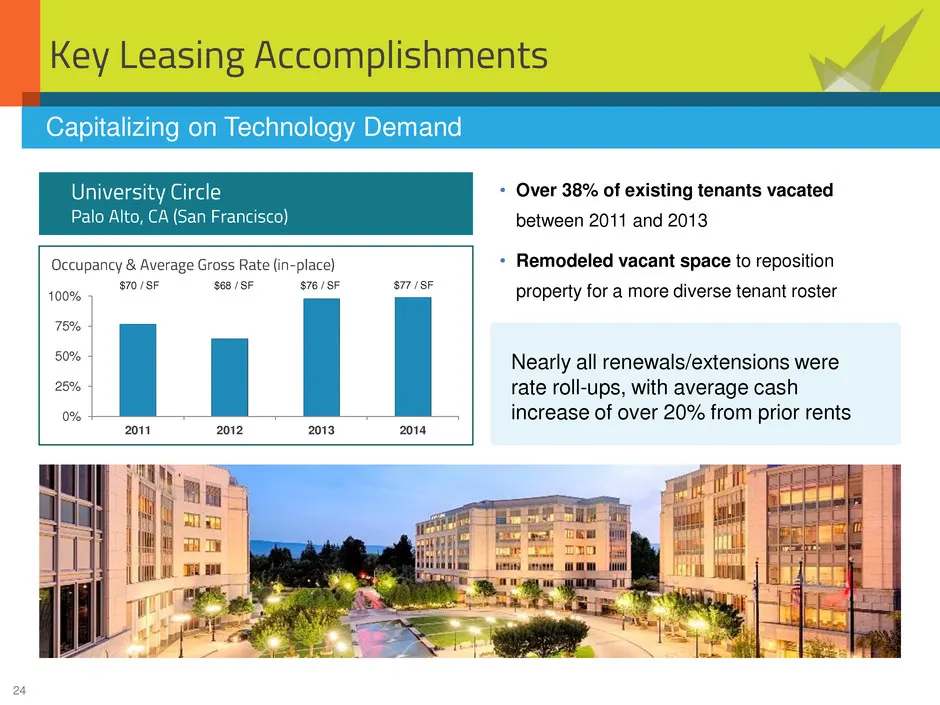
24 Key Leasing Accomplishments • Over 38% of existing tenants vacated between 2011 and 2013 • Remodeled vacant space to reposition property for a more diverse tenant roster 0% 25% 50% 75% 100% 2011 2012 2013 2014 Occupancy & Average Gross Rate (in-place) $70 / SF $68 / SF $76 / SF $77 / SF Capitaliz
Slide 25: Key Leasing Accomplishments: Main Street San Francisco
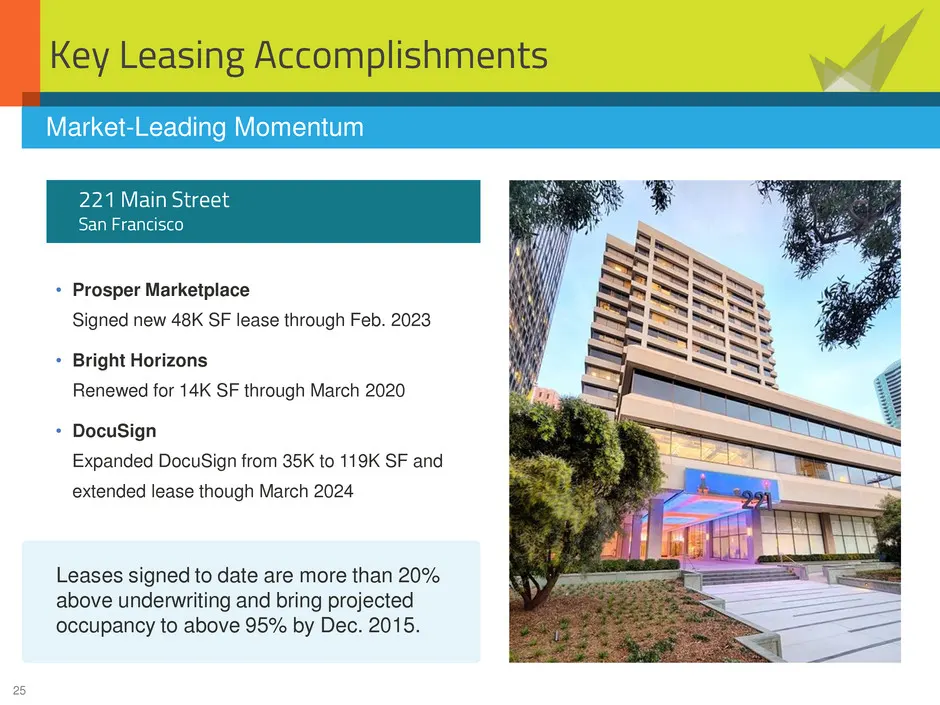
25 Key Leasing Accomplishments 221 Main Street San Francisco • Prosper Marketplace Signed new 48K SF lease through Feb. 2023 • Bright Horizons Renewed for 14K SF through March 2020 • DocuSign Expanded DocuSign from 35K to 119K SF and extended lease though March 2024 Market-Leading Momentum Leases si
Slide 26: Strong and Flexible Balance Sheet
26 Strong and Flexible Balance Sheet 222 East 41st Street, New York City
Slide 27: Capital Profile
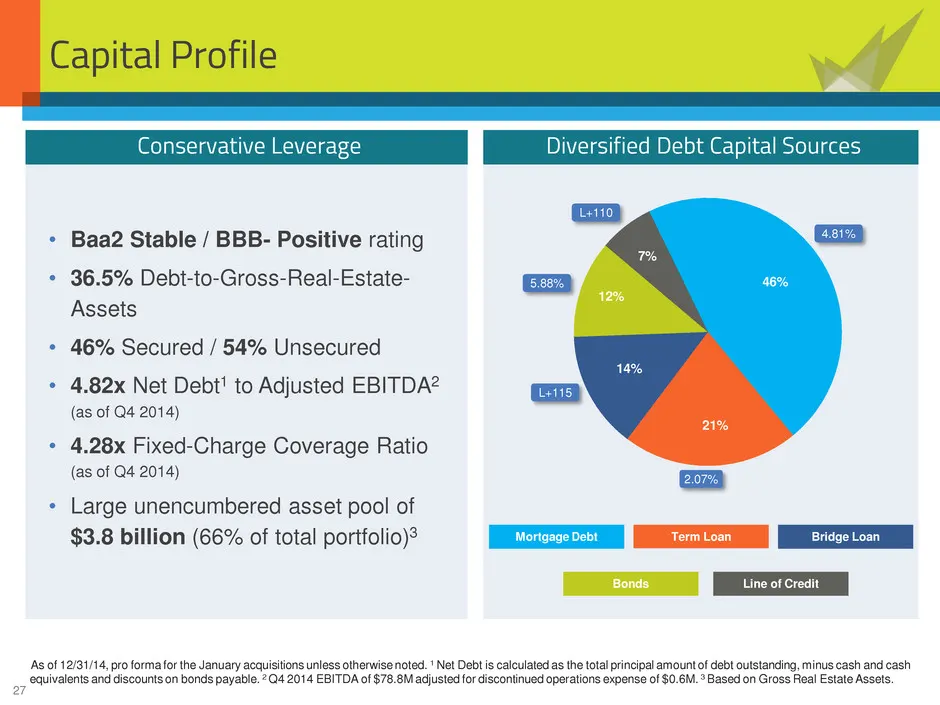
27 Capital Profile • Baa2 Stable / BBB- Positive rating • 36.5% Debt-to-Gross-Real-Estate- Assets • 46% Secured / 54% Unsecured • 4.82x Net Debt1 to Adjusted EBITDA2 (as of Q4 2014) • 4.28x Fixed-Charge Coverage Ratio (as of Q4 2014) • Large unencumbered asset pool of $3.8 billion (66% of total port
Slide 28: Current Debt Profile
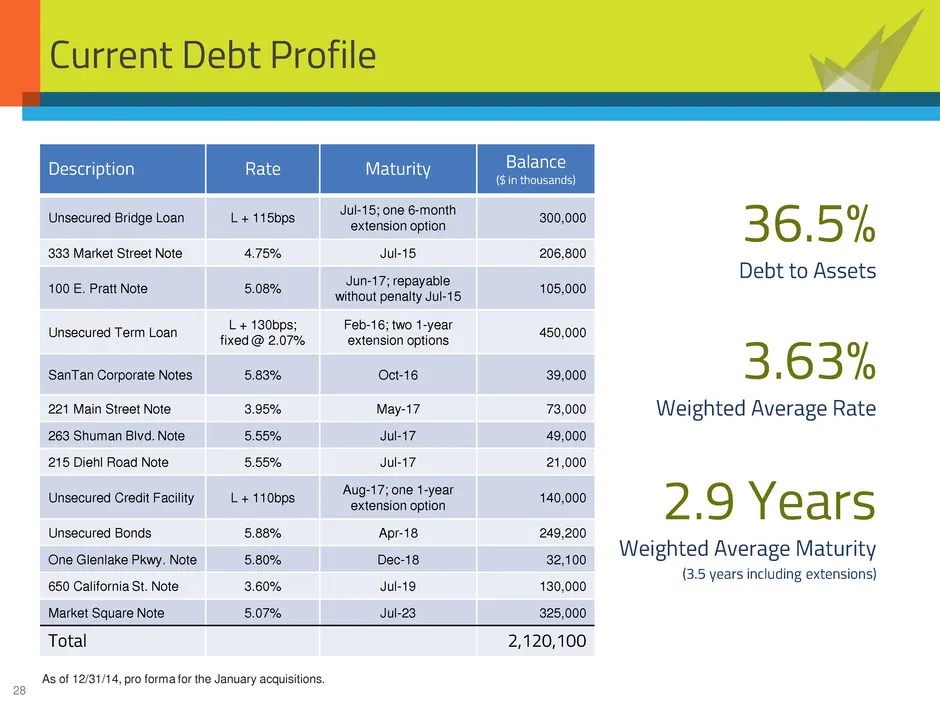
28 Current Debt Profile Description Rate Maturity Balance ($ in thousands) Unsecured Bridge Loan L + 115bps Jul-15; one 6-month extension option 300,000 333 Market Street Note 4.75% Jul-15 206,800 100 E. Pratt Note 5.08% Jun-17; repayable without penalty Jul-15 105,000 Unsecured Term Loan L + 130bps
Slide 29: 2015 Projected Debt Profile
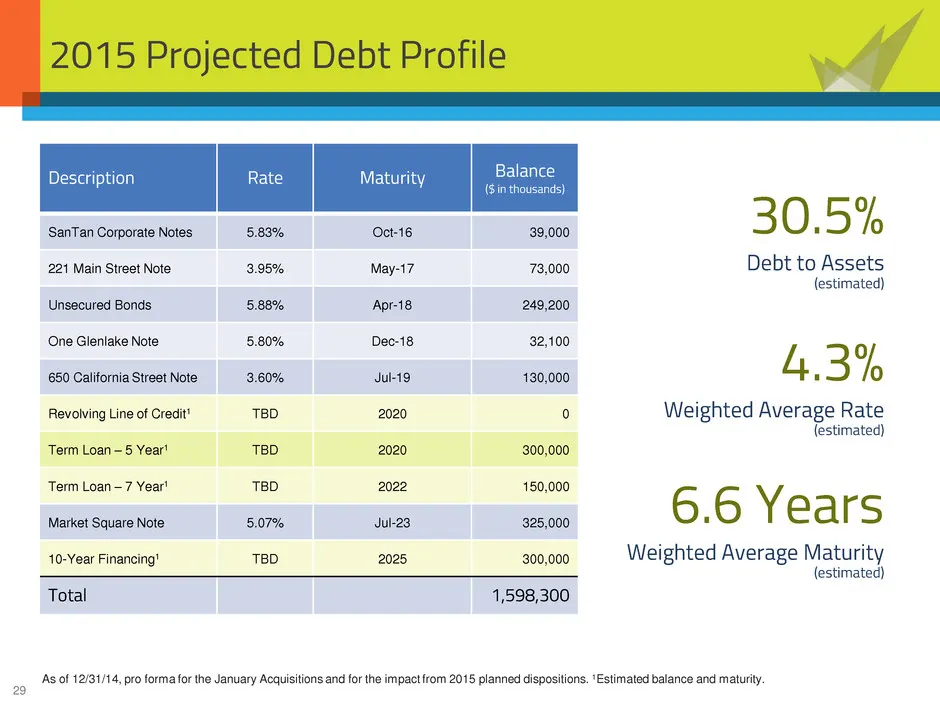
29 2015 Projected Debt Profile Description Rate Maturity Balance ($ in thousands) SanTan Corporate Notes 5.83% Oct-16 39,000 221 Main Street Note 3.95% May-17 73,000 Unsecured Bonds 5.88% Apr-18 249,200 One Glenlake Note 5.80% Dec-18 32,100 650 California Street Note 3.60% Jul-19 130,000 Revolving L
Slide 30: Debt Maturities
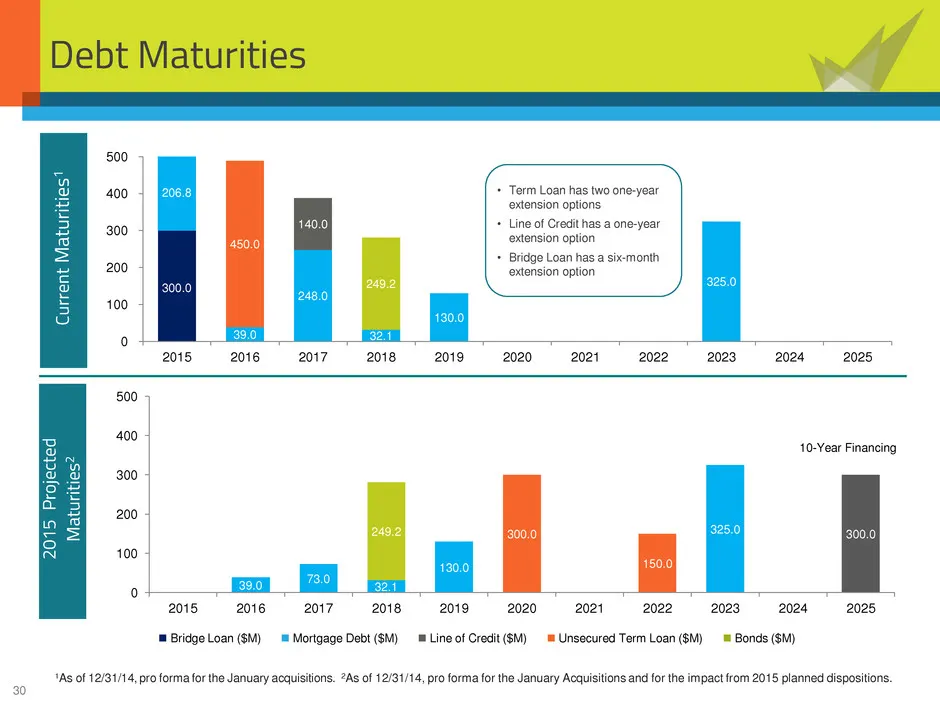
30 Debt Maturities 300.0 206.8 39.0 248.0 32.1 130.0 325.0 140.0 450.0 249.2 0 100 200 300 400 500 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 1As of 12/31/14, pro forma for the January acquisitions. 2As of 12/31/14, pro forma for the January Acquisitions and for the impact from 2015 plan
Slide 31: Q&A
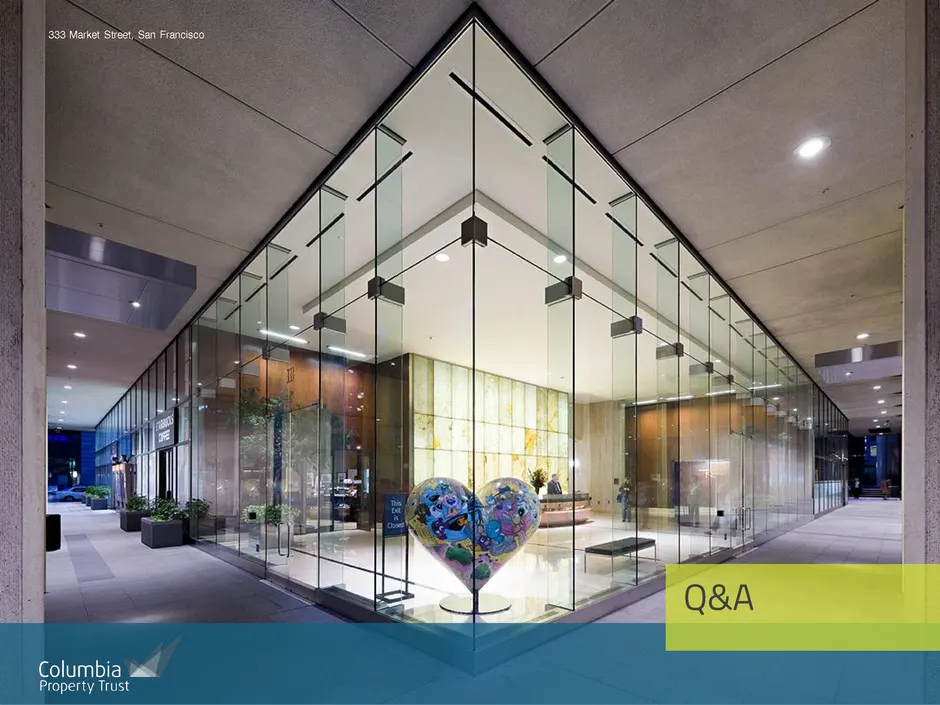
31 Q&A 333 Market Street, San Francisco
Slide 32: Leasing Successes and Opportunities
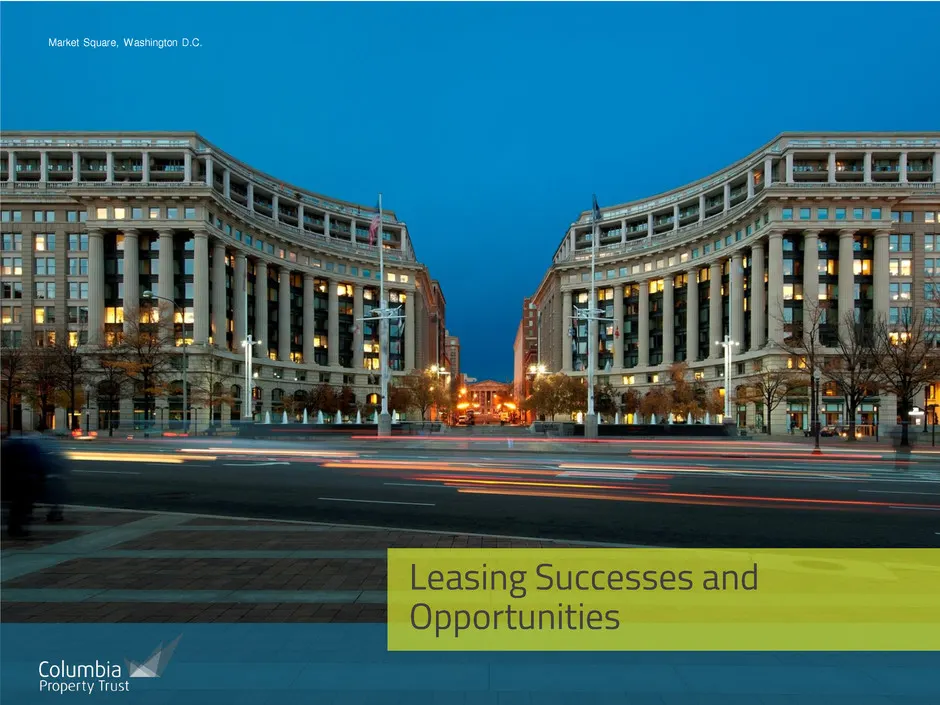
32 Leasing Successes and Opportunities Market Square, Washington D.C.
Slide 33: Leasing Overview
33 Proactive Operator • Leasing Accomplishments • Leasing Opportunities − Summary of 2015-2017 Major Expirations − 650 California Street, San Francisco − Market Square, Washington D.C. − 222 E. 41st Street, New York (Jones Day) − Other Major Expirations Leasing Overview
Slide 34: Summary of Key Leasing Accomplishments
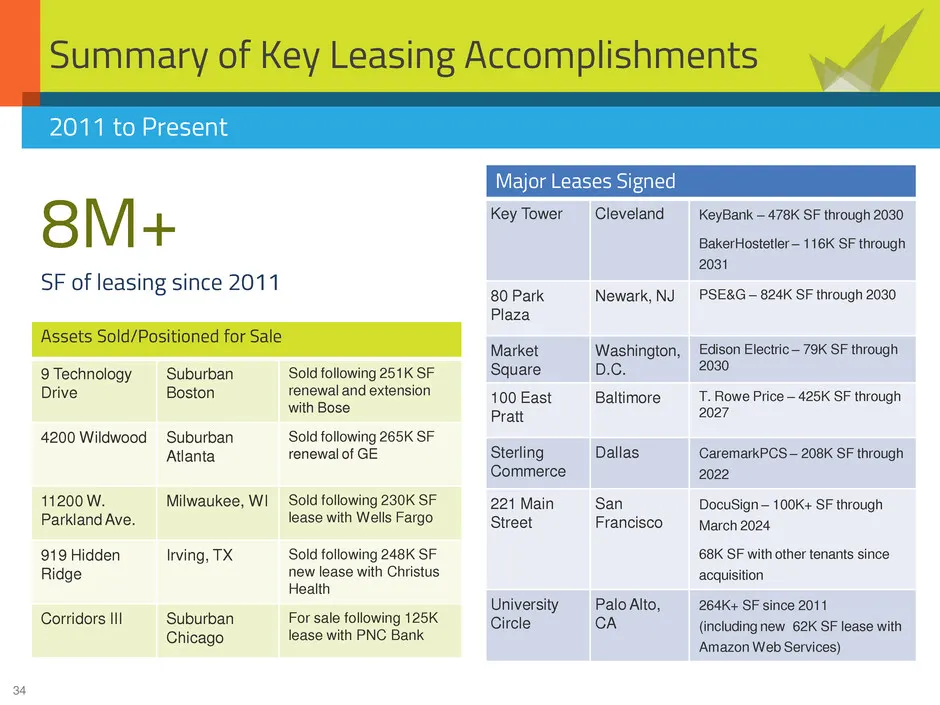
34 Summary of Key Leasing Accomplishments 2011 to Present 8M+ SF of leasing since 2011 Assets Sold/Positioned for Sale 9 Technology Drive Suburban Boston Sold following 251K SF renewal and extension with Bose 4200 Wildwood Suburban Atlanta Sold following 265K SF renewal of GE 11200 W. Parkland Ave.
Slide 35: Summary of Key Leasing Opportunities
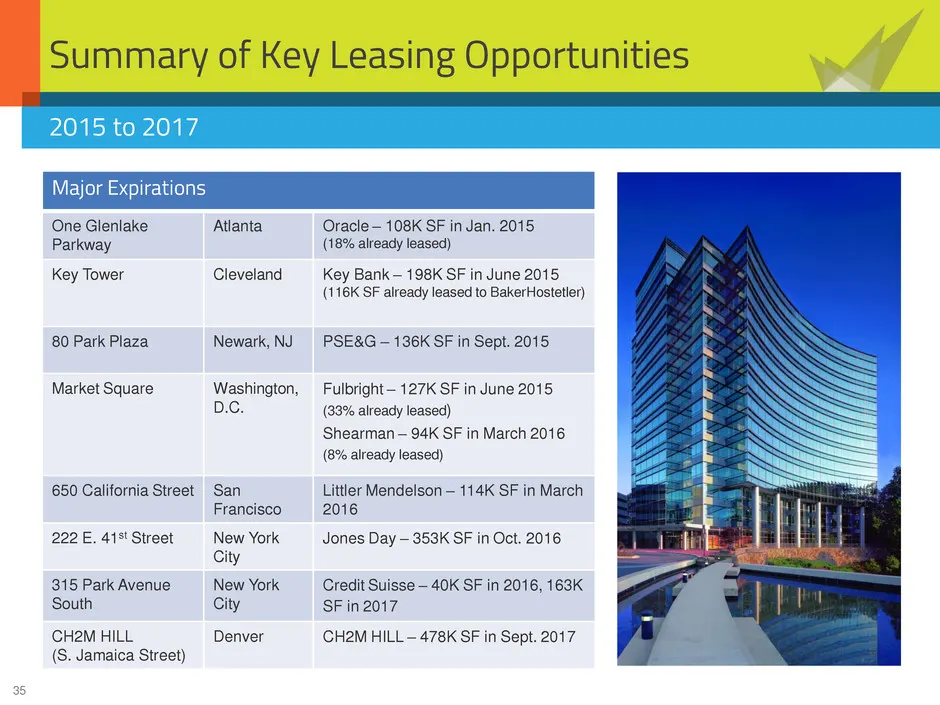
35 Summary of Key Leasing Opportunities Major Expirations One Glenlake Parkway Atlanta Oracle – 108K SF in Jan. 2015 (18% already leased) Key Tower Cleveland Key Bank – 198K SF in June 2015 (116K SF already leased to BakerHostetler) 80 Park Plaza Newark, NJ PSE&G – 136K SF in Sept. 2015 Market Squar
Slide 36: Key Leasing Opportunities: 650 California Street
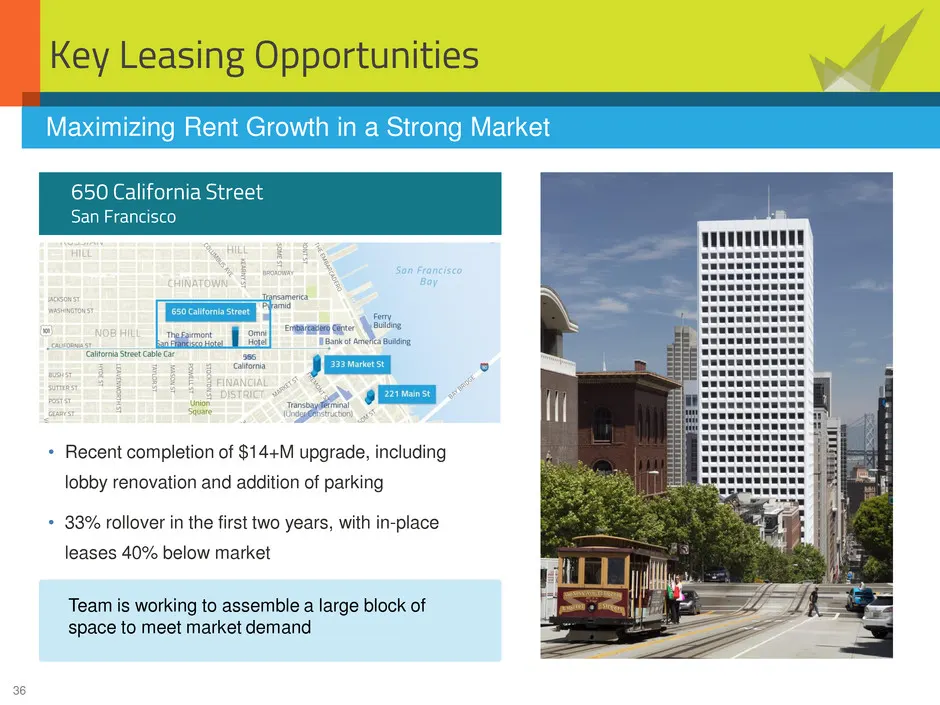
36 Key Leasing Opportunities • Recent completion of $14+M upgrade, including lobby renovation and addition of parking • 33% rollover in the first two years, with in-place leases 40% below market Maximizing Rent Growth in a Strong Market 650 California Street San Francisco Team is working to assemble
Slide 37: Key Leasing Opportunities: Market Square
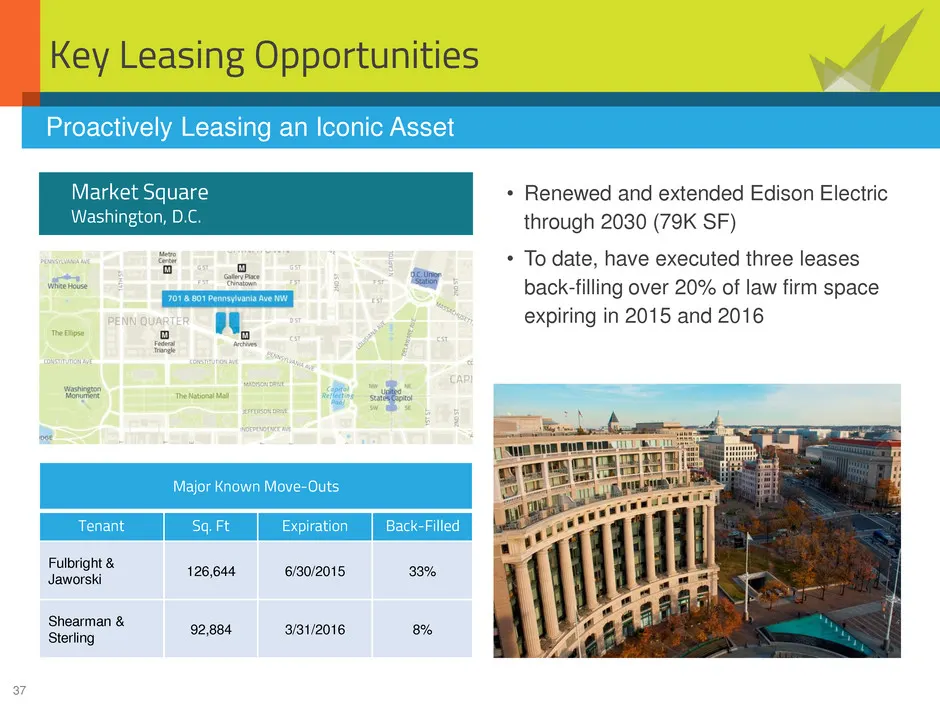
37 Key Leasing Opportunities • Renewed and extended Edison Electric through 2030 (79K SF) • To date, have executed three leases back-filling over 20% of law firm space expiring in 2015 and 2016 Major Known Move-Outs Tenant Sq. Ft Expiration Back-Filled Fulbright & Jaworski 126,644 6/30/2015 33% Shea
Slide 38: Market Square – Capital Plans
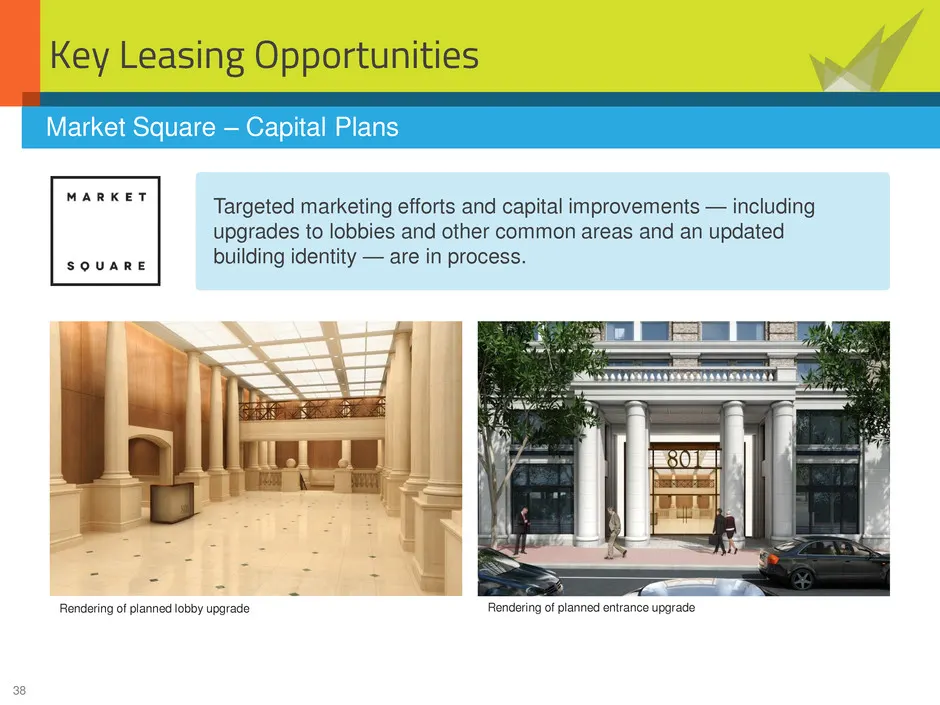
38 Key Leasing Opportunities Market Square – Capital Plans Targeted marketing efforts and capital improvements — including upgrades to lobbies and other common areas and an updated building identity — are in process. Rendering of planned lobby upgrade Rendering of planned entrance upgrade
Slide 39: Near-Term Leasing Opportunities
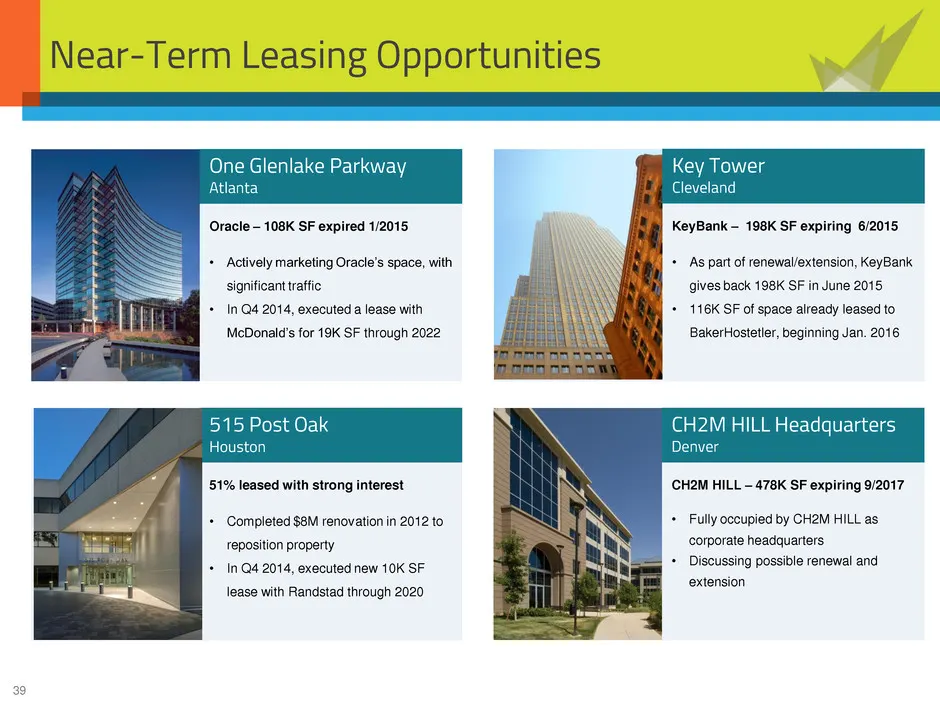
39 Near-Term Leasing Opportunities One Glenlake Parkway Atlanta Oracle – 108K SF expired 1/2015 • Actively marketing Oracle’s space, with significant traffic • In Q4 2014, executed a lease with McDonald’s for 19K SF through 2022 Key Tower Cleveland KeyBank – 198K SF expiring 6/2015 • As part of rene
Slide 40: Key Leasing Opportunities: 222 East 41st Street
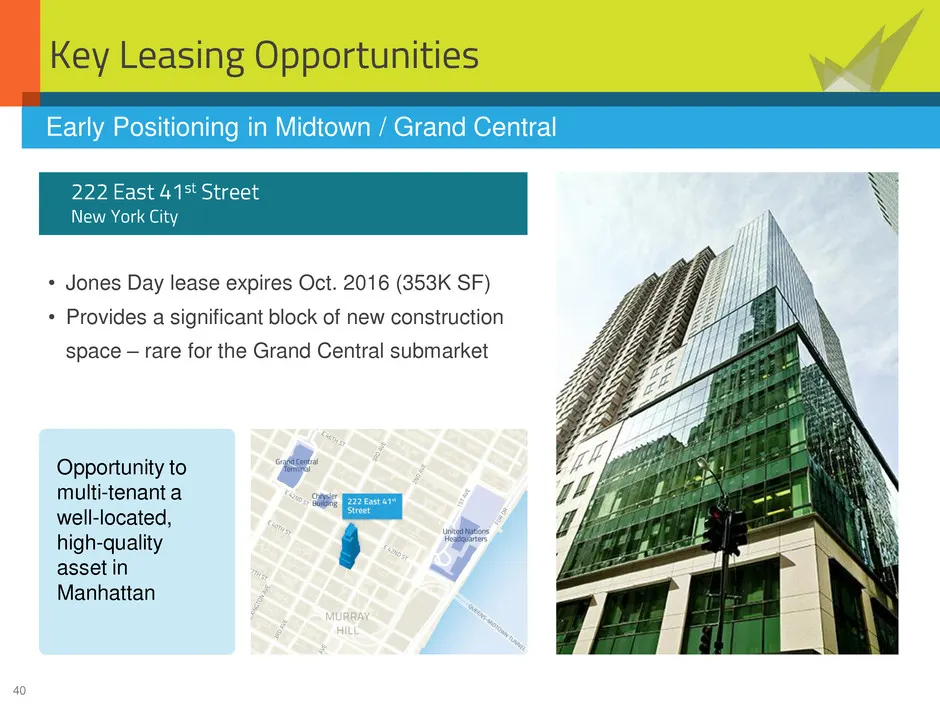
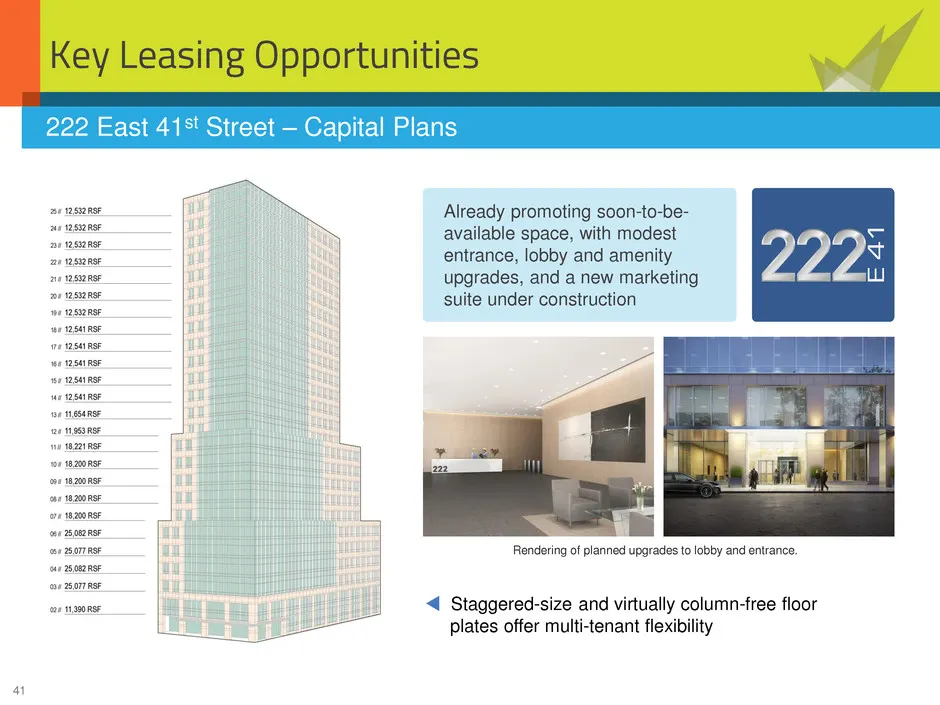
40 Key Leasing Opportunities • Jones Day lease expires Oct. 2016 (353K SF) • Provides a significant block of new construction space – rare for the Grand Central submarket Early Positioning in Midtown / Grand Central 222 East 41st Street New York City Opportunity to multi-tenant a well-located, high-
Slide 41: 222 East 41st Street – Capital Plans
41 Already promoting soon-to-be- available space, with modest entrance, lobby and amenity upgrades, and a new marketing suite under construction Key Leasing Opportunities 222 East 41st Street – Capital Plans Staggered-size and virtually column-free floor plates offer multi-tenant flexibility Rende
Slide 42: Leasing Takeaways
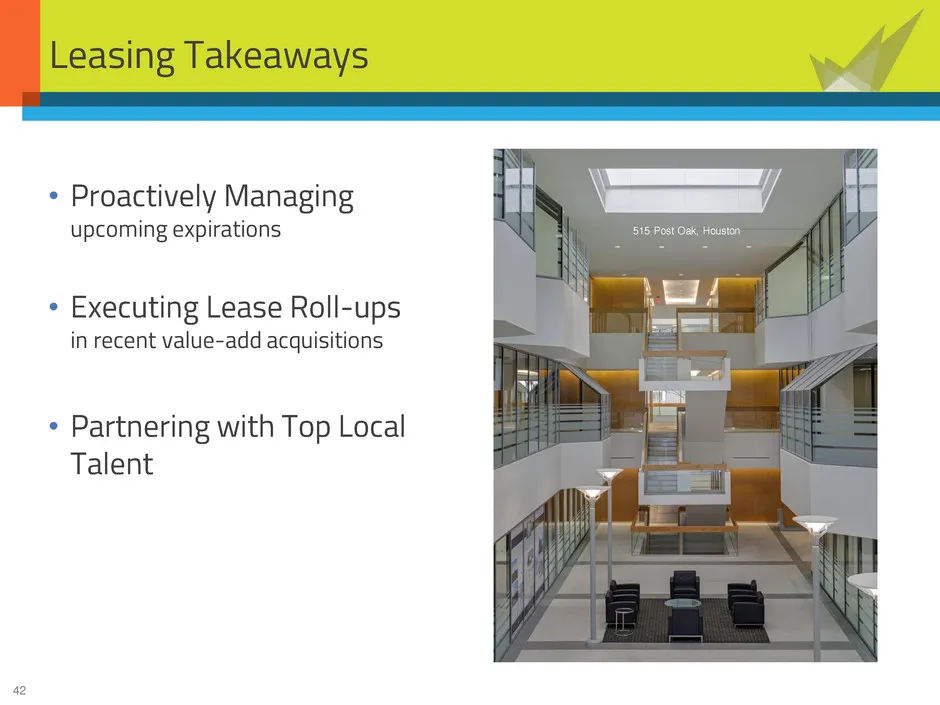
42 Leasing Takeaways • Proactively Managing upcoming expirations • Executing Lease Roll-ups in recent value-add acquisitions • Partnering with Top Local Talent 515 Post Oak, Houston
Slide 43: Q&A
43 Q&A International Financial Tower, N. New Jersey
Slide 44: Investment Underwriting and Execution
44 Investment Underwriting and Execution 315 Park Avenue South, New York City
Slide 45: Acquisition Strategy Overview: Target Investment Criteria
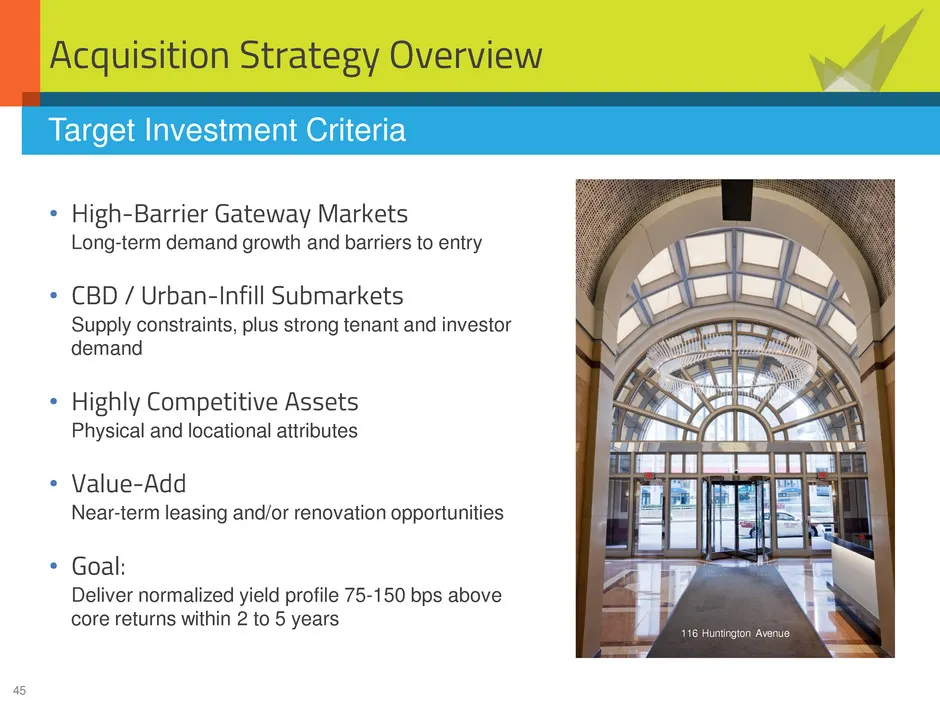
45 Acquisition Strategy Overview • High-Barrier Gateway Markets Long-term demand growth and barriers to entry • CBD / Urban-Infill Submarkets Supply constraints, plus strong tenant and investor demand • Highly Competitive Assets Physical and locational attributes • Value-Add Near-term leasing and/or
Slide 46: Acquisition Strategy Overview: Transaction Process
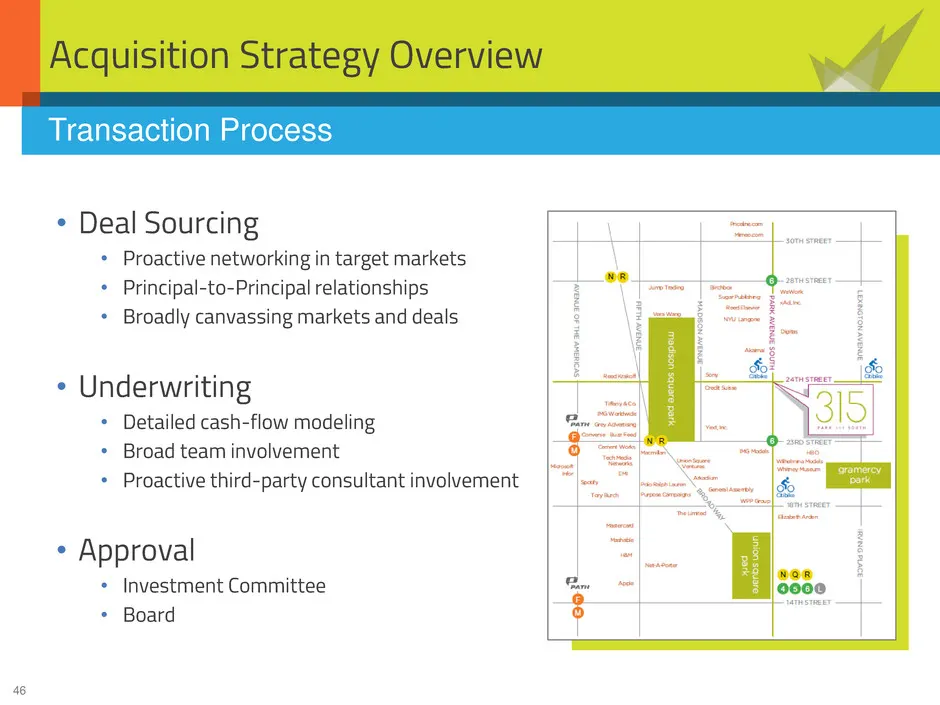
46 Acquisition Strategy Overview • Deal Sourcing • Proactive networking in target markets • Principal-to-Principal relationships • Broadly canvassing markets and deals • Underwriting • Detailed cash-flow modeling • Broad team involvement • Proactive third-party consultant involvement • Approval • In
Slide 47: Recent San Francisco Transactions
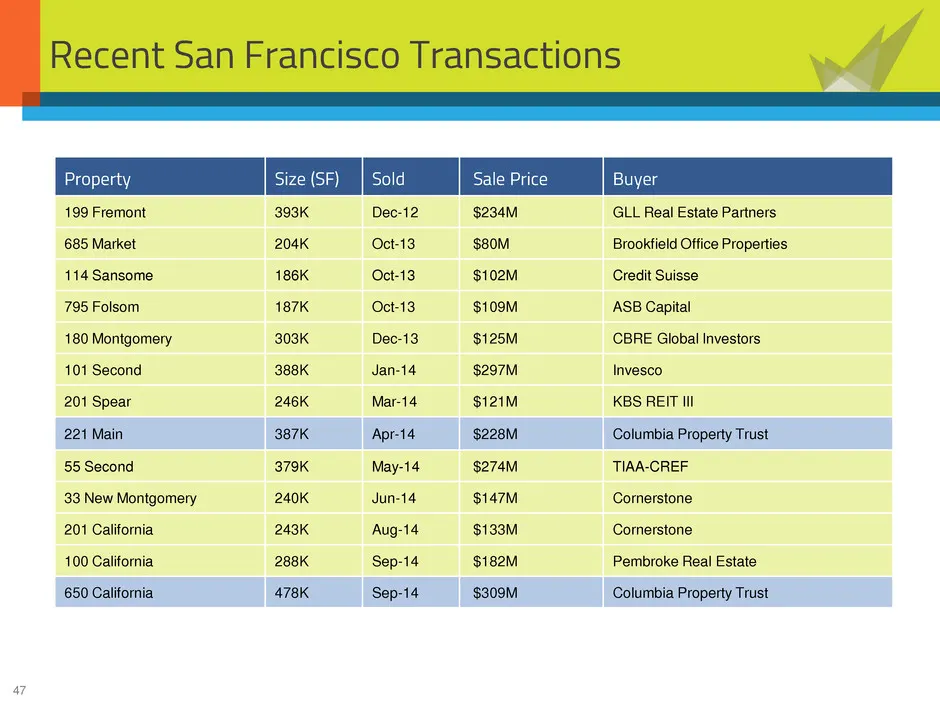
47 Recent San Francisco Transactions Property Size (SF) Sold Sale Price Buyer 199 Fremont 393K Dec-12 $234M GLL Real Estate Partners 685 Market 204K Oct-13 $80M Brookfield Office Properties 114 Sansome 186K Oct-13 $102M Credit Suisse 795 Folsom 187K Oct-13 $109M ASB Capital 180 Montgomery 303K Dec-1
Slide 48: San Francisco
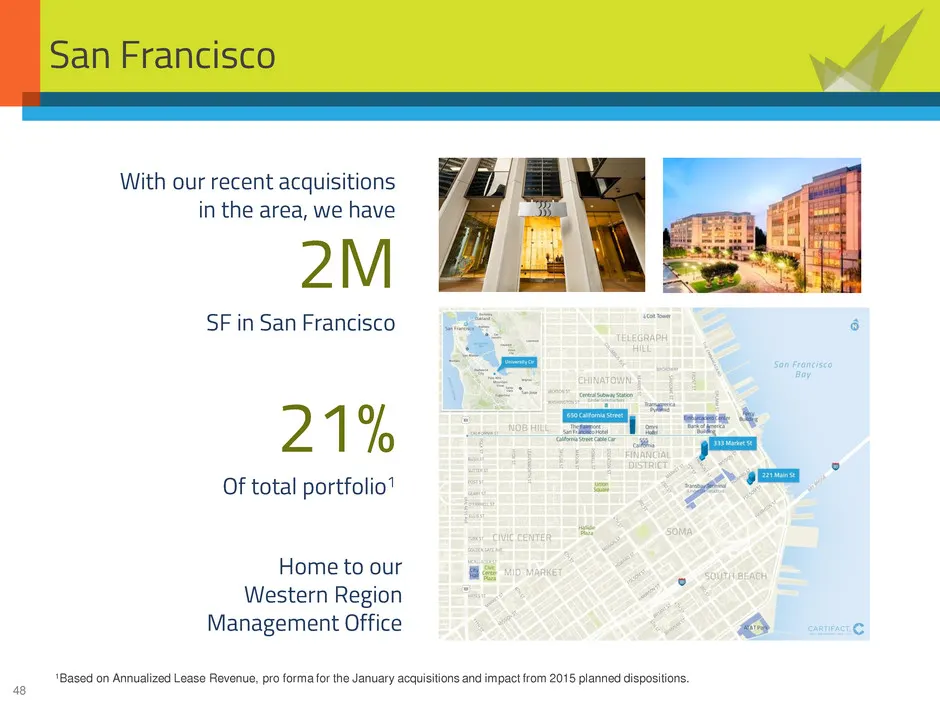
48 San Francisco 21% Of total portfolio1 With our recent acquisitions in the area, we have 2M SF in San Francisco Home to our Western Region Management Office 1Based on Annualized Lease Revenue, pro forma for the January acquisitions and impact from 2015 planned dispositions.
Slide 49: San Francisco – 2014 Acquisitions: 221 Main Street
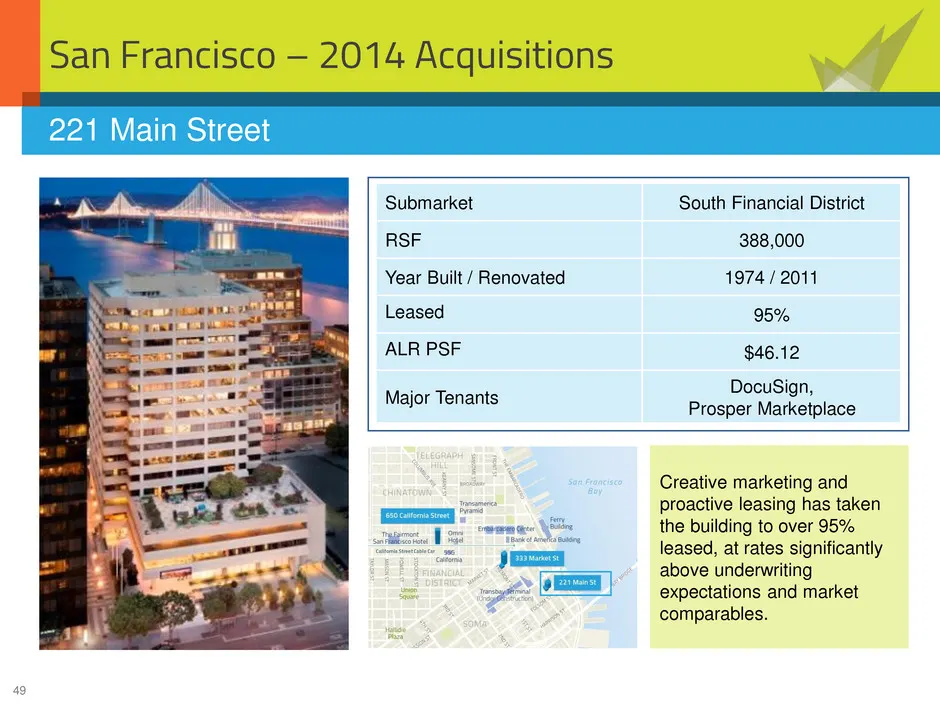
49 San Francisco – 2014 Acquisitions Submarket South Financial District RSF 388,000 Year Built / Renovated 1974 / 2011 Leased 95% ALR PSF $46.12 Major Tenants DocuSign, Prosper Marketplace 221 Main Street Creative marketing and proactive leasing has taken the building to over 95% leased, at rates si
Slide 50: San Francisco – 2014 Acquisitions: 650 California Street
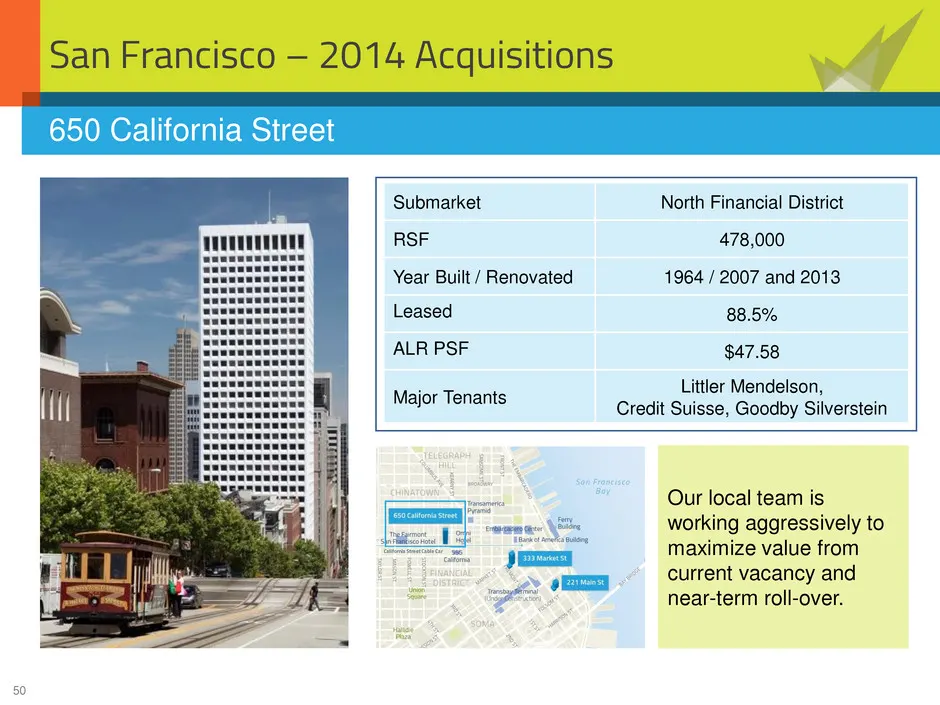
50 San Francisco – 2014 Acquisitions 650 California Street Submarket North Financial District RSF 478,000 Year Built / Renovated 1964 / 2007 and 2013 Leased 88.5% ALR PSF $47.58 Major Tenants Littler Mendelson, Credit Suisse, Goodby Silverstein Our local team is working aggressively to maximize valu
Slide 51: Expanding in Top Markets – Boston
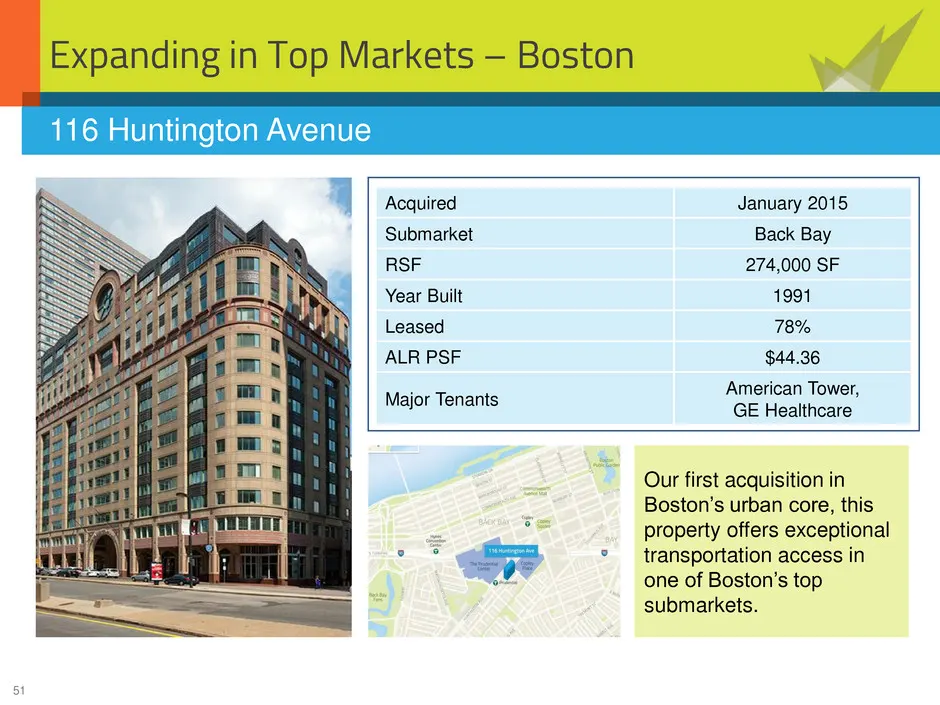
51 Expanding in Top Markets – Boston Acquired January 2015 Submarket Back Bay RSF 274,000 SF Year Built 1991 Leased 78% ALR PSF $44.36 Major Tenants American Tower, GE Healthcare 116 Huntington Avenue Our first acquisition in Boston’s urban core, this property offers exceptional transportation acces
Slide 52: Value-Add Opportunity – Boston
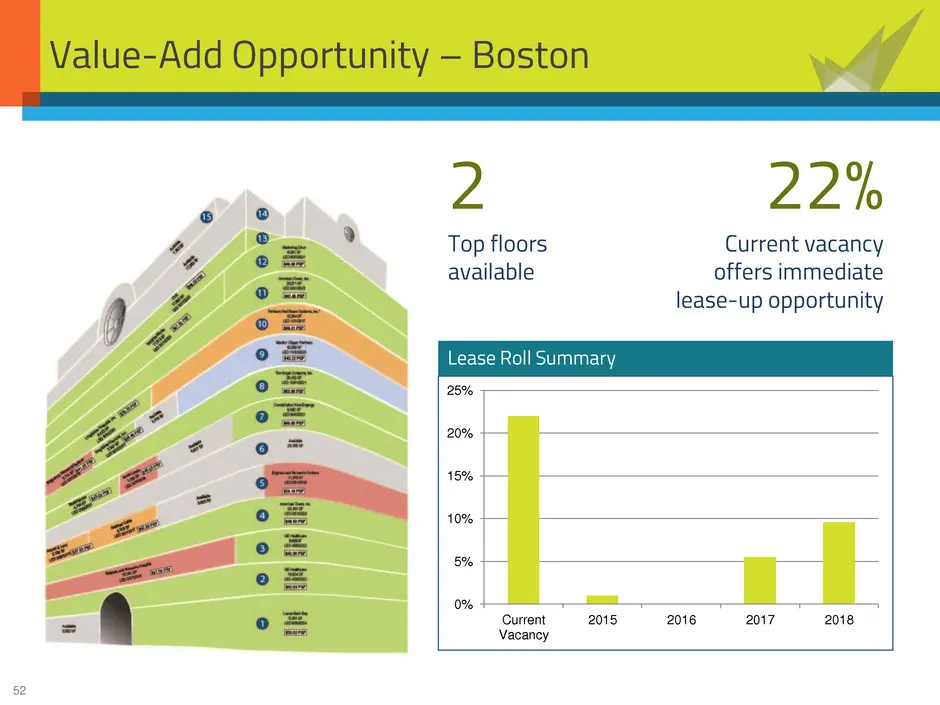
52 Value-Add Opportunity – Boston Lease Roll Summary 0% 5% 10% 15% 20% 25% Current Vacancy 2015 2016 2017 2018 22% Current vacancy offers immediate lease-up opportunity 2 Top floors available
Slide 53: Expanding in Top Markets – New York City
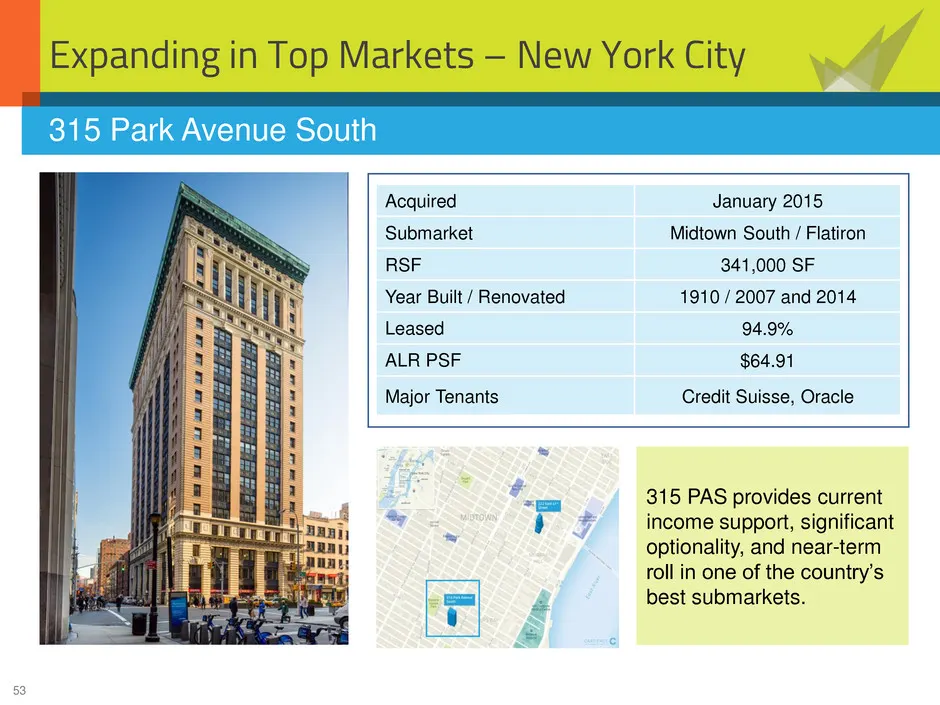
53 Expanding in Top Markets – New York City Acquired January 2015 Submarket Midtown South / Flatiron RSF 341,000 SF Year Built / Renovated 1910 / 2007 and 2014 Leased 94.9% ALR PSF $64.91 Major Tenants Credit Suisse, Oracle 315 Park Avenue South 315 PAS provides current income support, significant o
Slide 54: Value-Add Opportunity – New York City
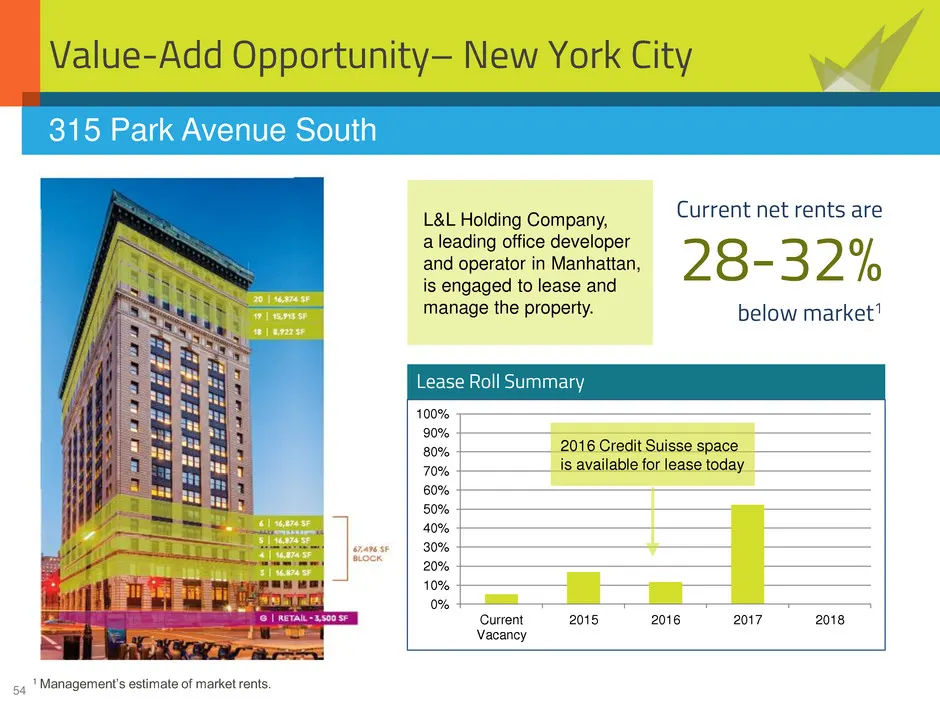
54 Value-Add Opportunity– New York City Lease Roll Summary 315 Park Avenue South 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% Current Vacancy 2015 2016 2017 2018 Current net rents are 28-32% below market1 1 Management’s estimate of market rents. 2016 Credit Suisse space is available for lease today L
Slide 55: Investment Summary
55 Investment Summary • Value-add • High-barrier markets • Regional platforms • Partnering with top local talent • Disciplined underwriting process
Slide 56: Q&A
56 Q&A 650 California Street, San Francisco
Slide 57: For more information
57 For more information: Columbia Property Trust Investor Relations t 800.899.8411 e IR @ columbiapropertytrust.com 0017-CXPPRES1501 IC 116 Huntington Avenue, Boston
Source: SEC EDGAR · 8-K filed Feb 23, 2015
More decks from Columbia Property Trust Inc
 Investor Presentation (November 2020)33 slides · Nov 17, 2020
 Investor Presentation (August 2020)34 slides · Aug 31, 2020
 Investor Presentation (June 2020)34 slides · Jun 1, 2020
 Investor Presentation (February 2020)29 slides · Feb 26, 2020
 Corporate Update (December 2019)12 slides · Dec 3, 2019
 Investor Presentation (November 2019)28 slides · Nov 12, 2019