Inchcape plc · LSE:INCH
Inchcape — Investor Presentation (February 2018)
30 slides from Inchcape's investor presentation, February 2018
Slide 1: Investor Presentation
INVESTOR SUNITA ENTWISLE PRESENTATION HEAD OF INVESTOR RELATIONS 020 7546 8225 SUNITA.ENTWISLE@INCHCAPE.COM FEBRUARY 2018
Slide 2: Summary
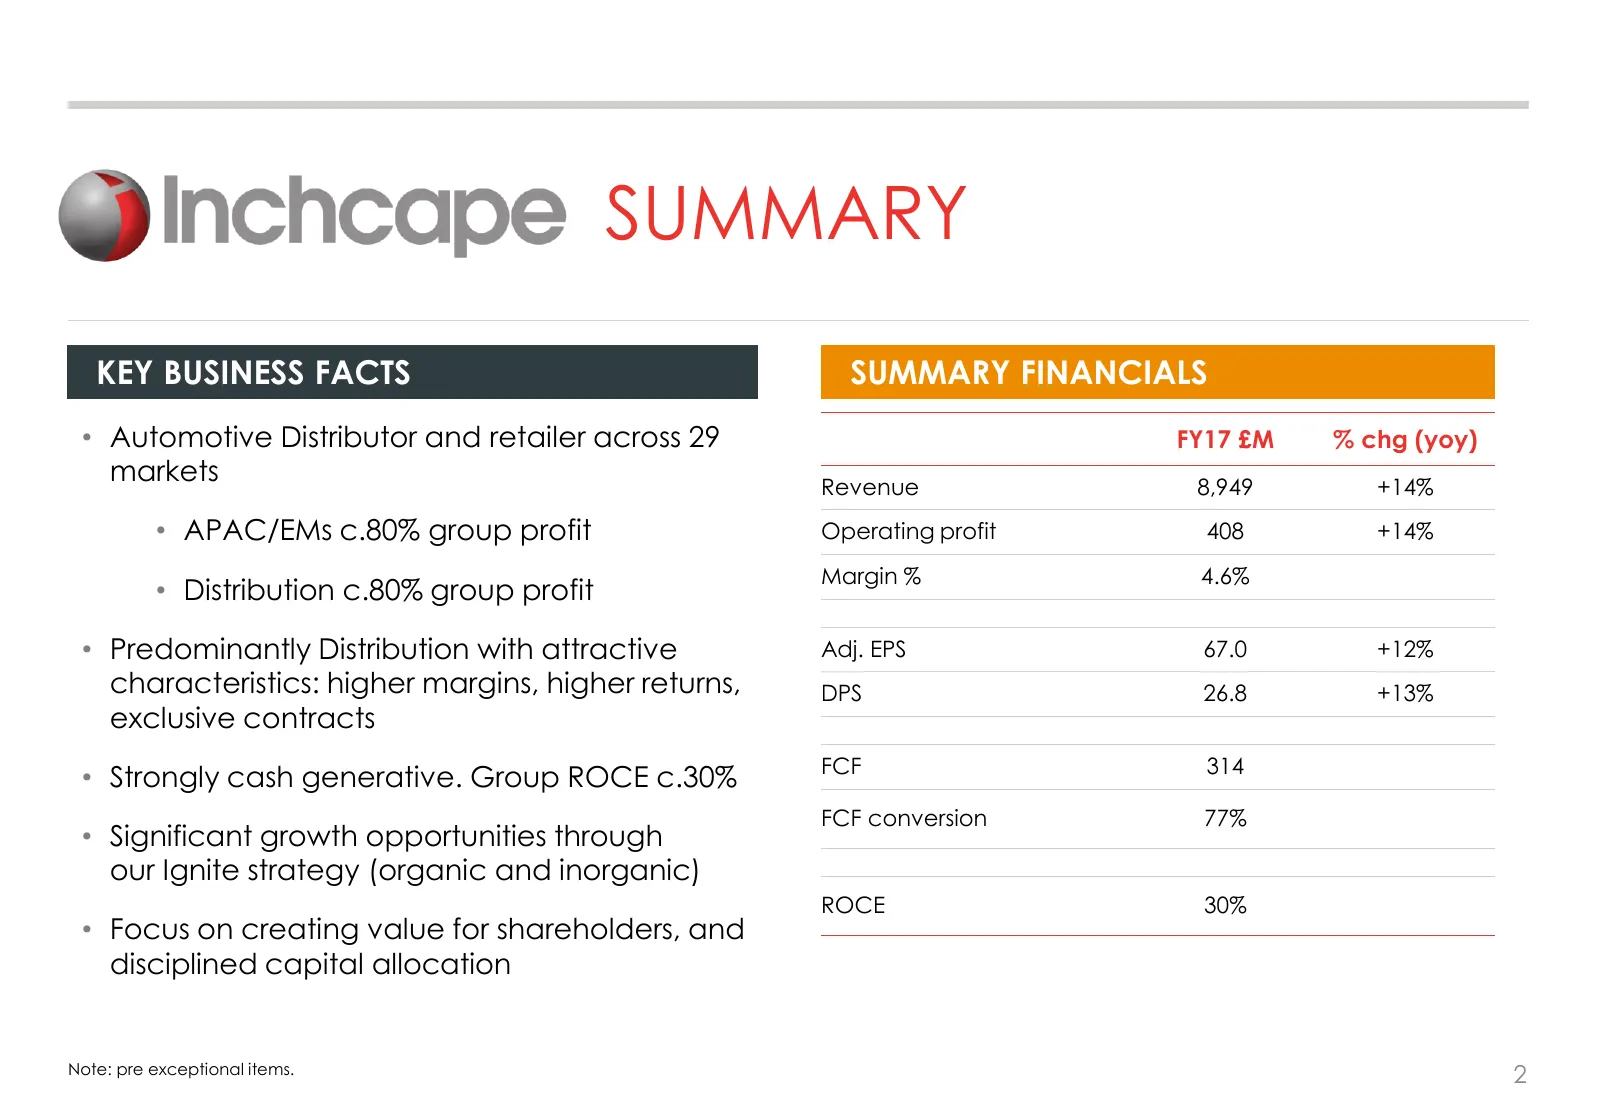
SUMMARY KEY BUSINESS FACTS SUMMARY FINANCIALS • Automotive Distributor and retailer across 29 FY17 £M % chg (yoy) markets Revenue 8,949 +14% • APAC/EMs c.80% group profit Operating profit 408 +14% Margin % 4.6% • Distribution c.80% group profit • Predominantly Distribution with attractive Adj. EPS 6
Slide 3: Business Model
BUSINESS MODEL
Slide 4: Business Mix & Geography
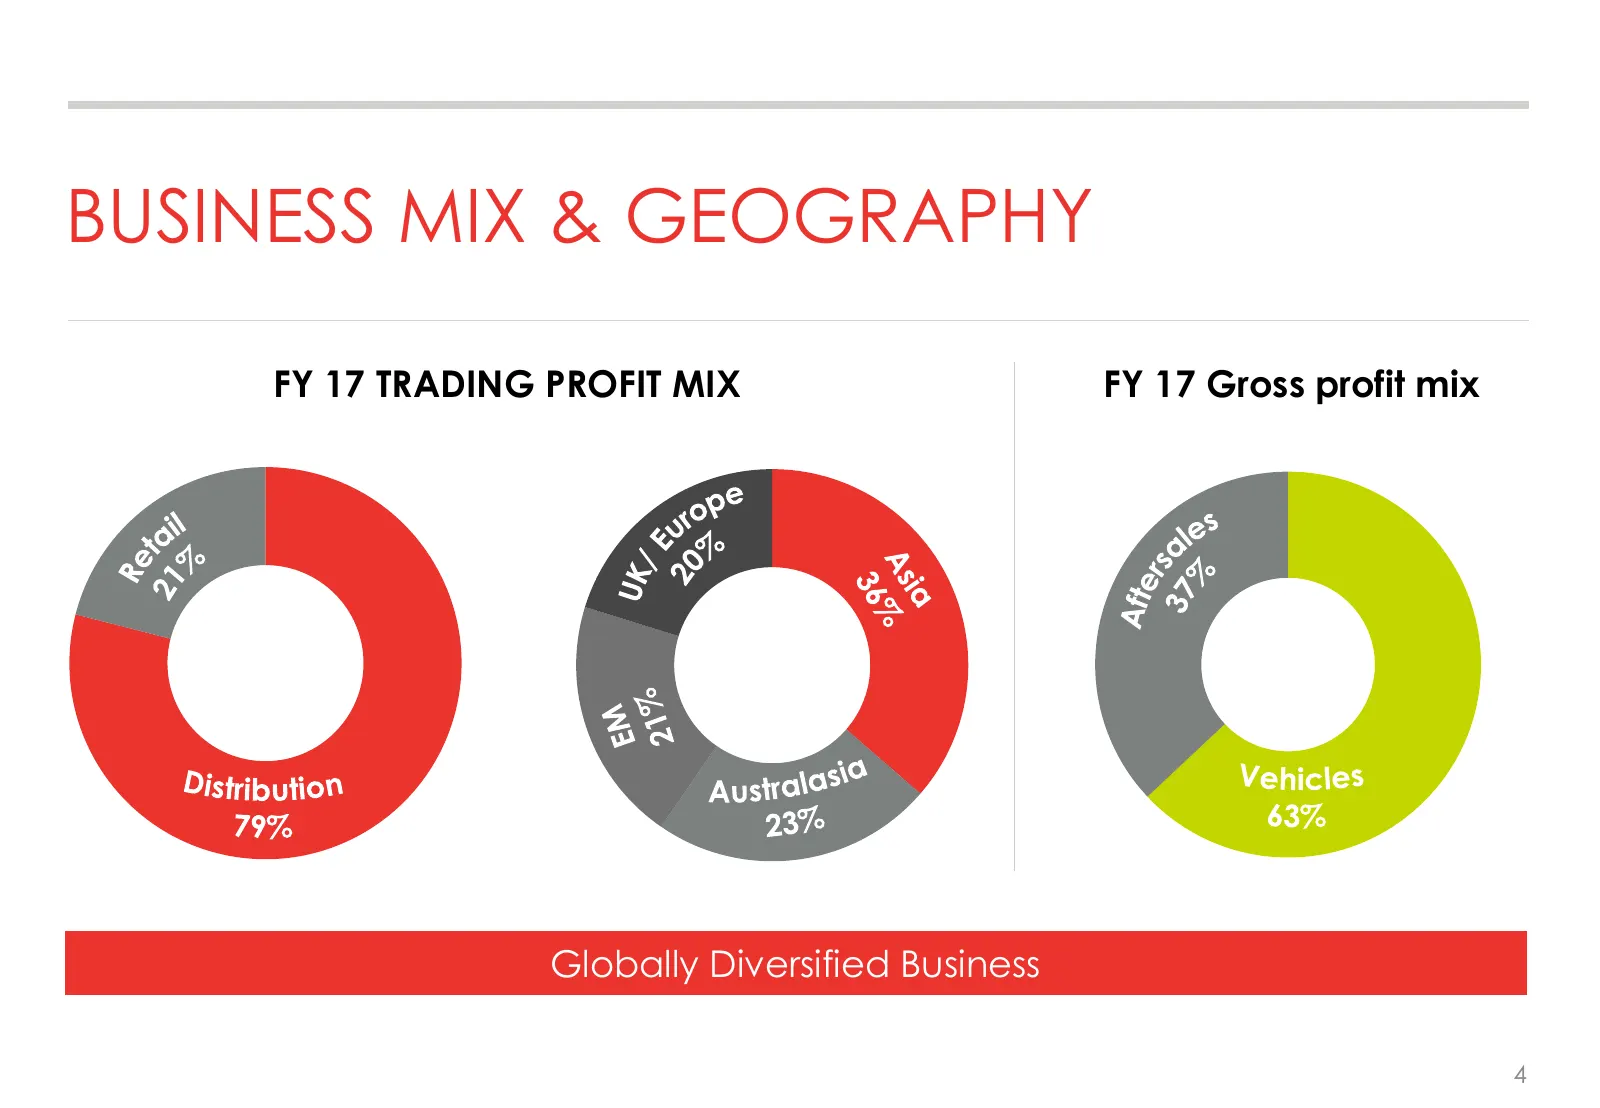
BUSINESS MIX & GEOGRAPHY FY 17 TRADING PROFIT MIX FY 17 Gross profit mix Globally Diversified Business 4
Slide 5: Automotive Value Chain
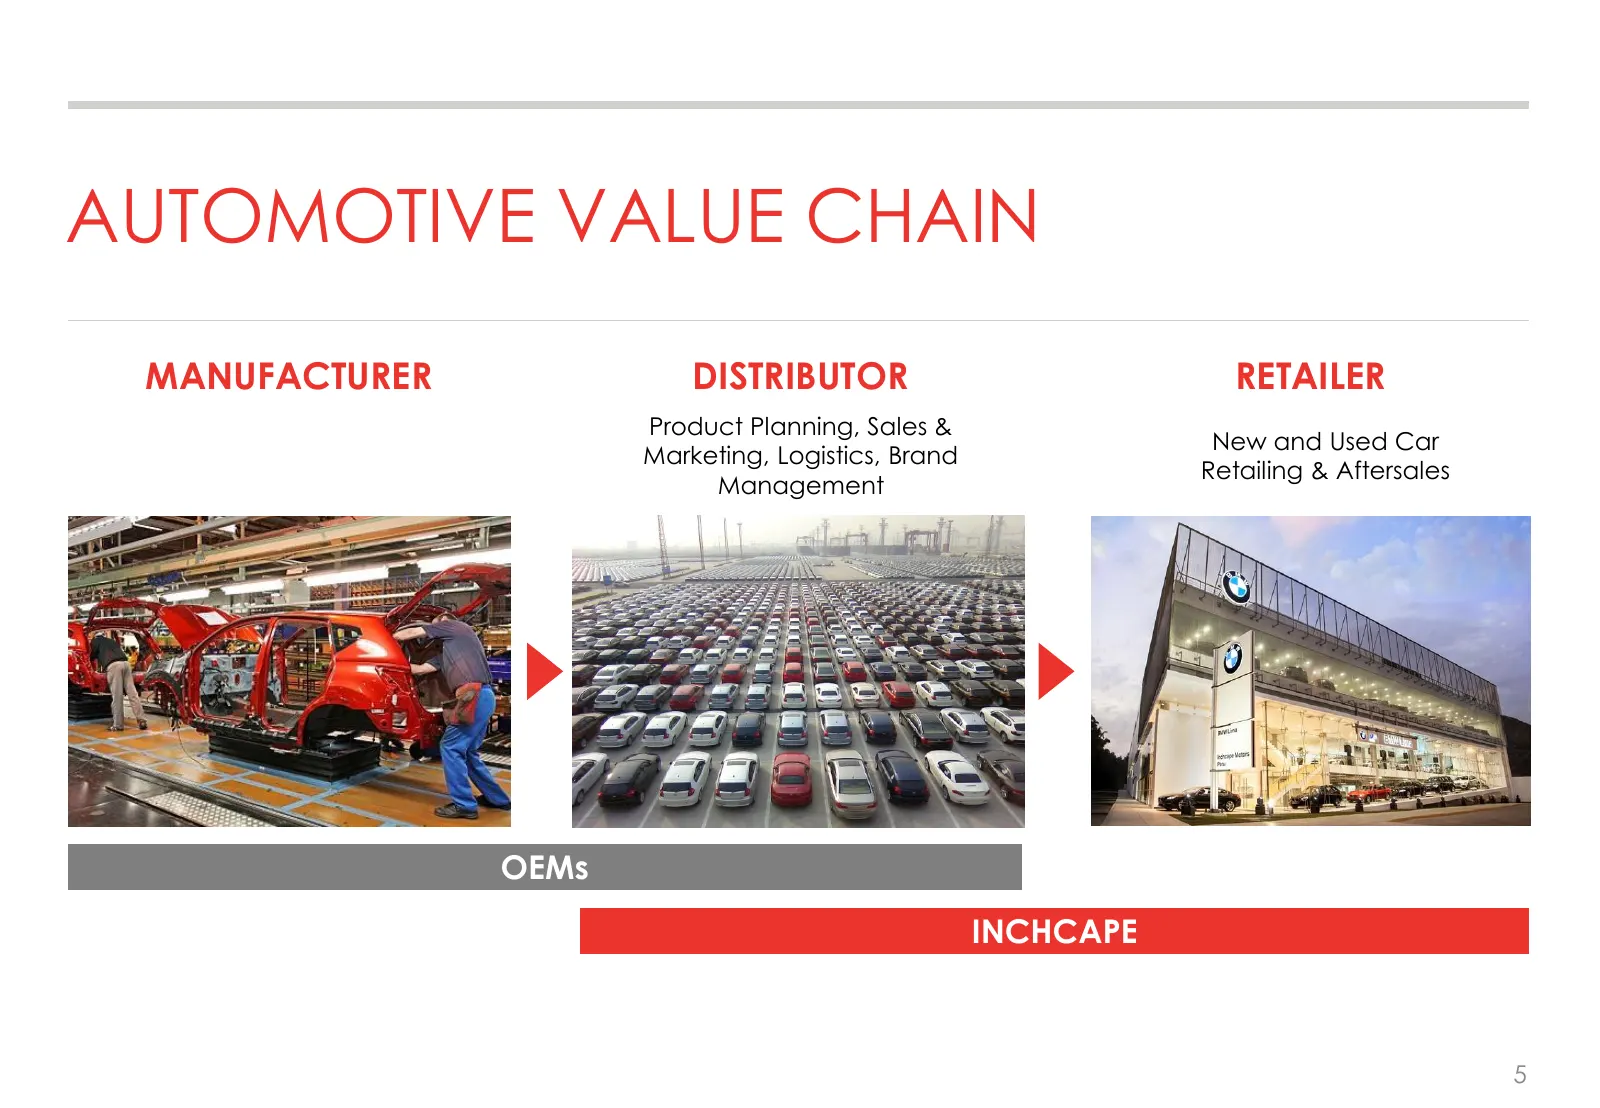
AUTOMOTIVE VALUE CHAIN MANUFACTURER DISTRIBUTOR RETAILER Product Planning, Sales & New and Used Car Marketing, Logistics, Brand Retailing & Aftersales Management OEMs INCHCAPE 5
Slide 6: Automotive Value Chain (Cont'd)
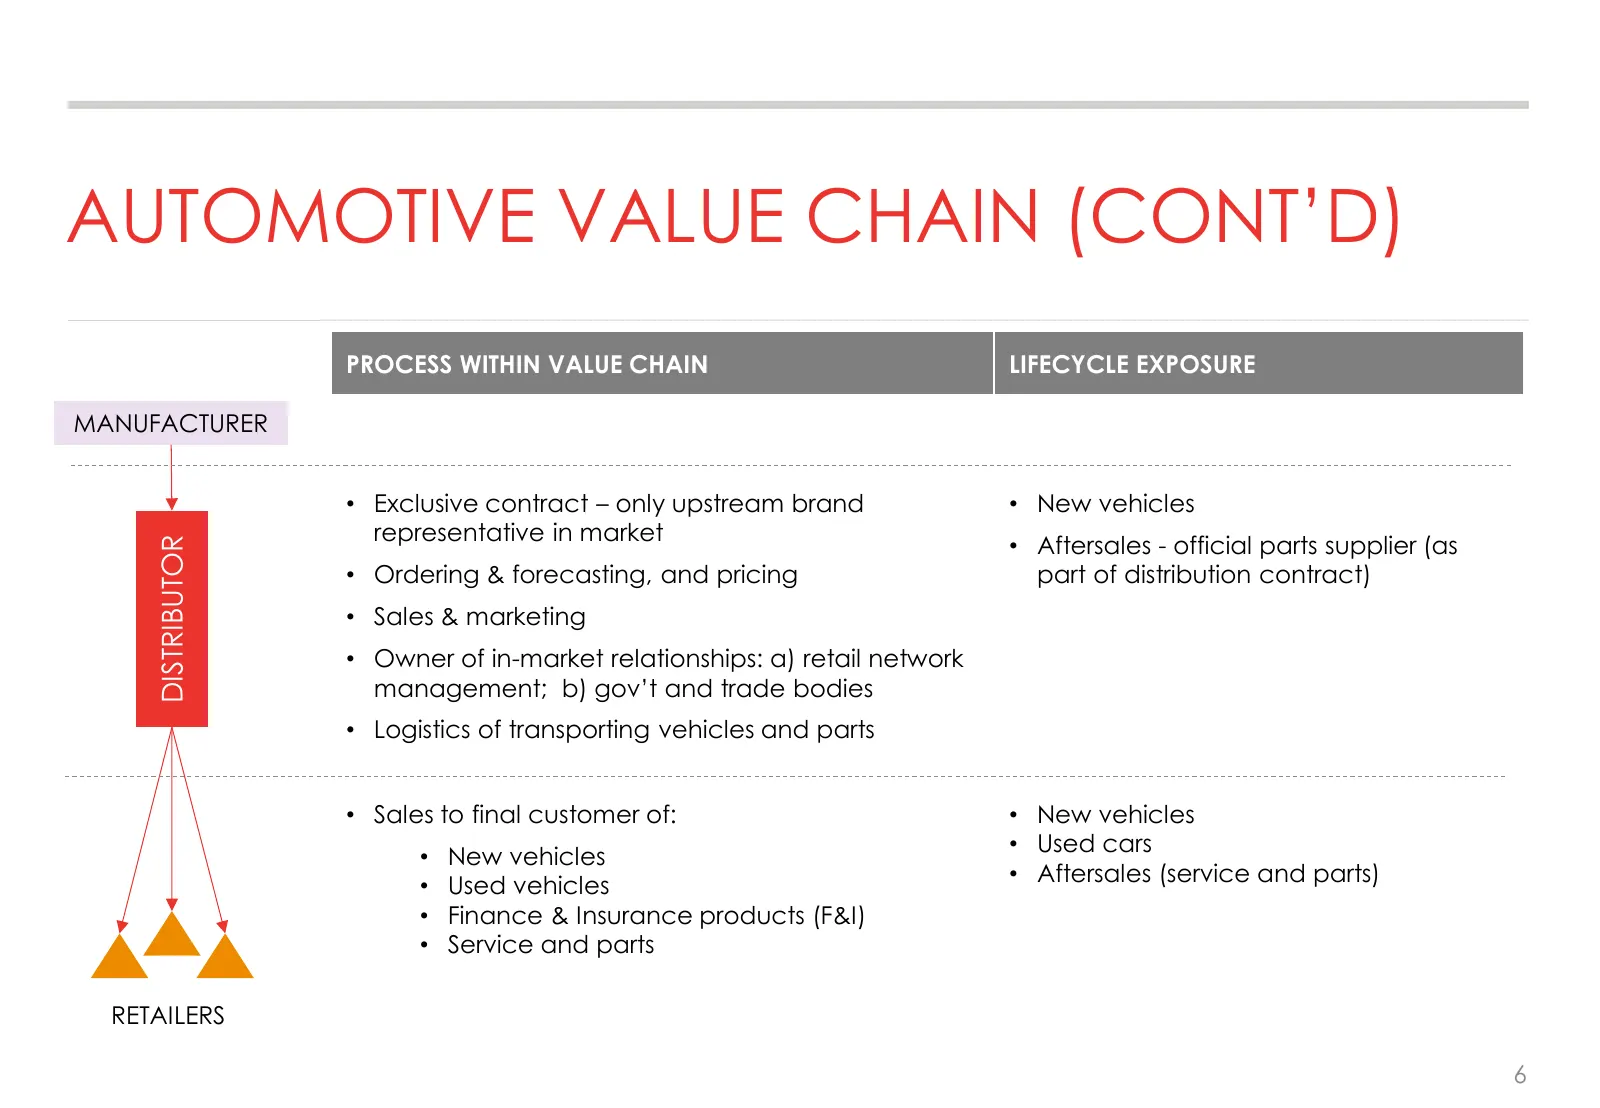
AUTOMOTIVE VALUE CHAIN (CONT’D) PROCESS WITHIN VALUE CHAIN LIFECYCLE EXPOSURE MANUFACTURER • Exclusive contract – only upstream brand • New vehicles representative in market • Aftersales - official parts supplier (as DISTRIBUTOR • Ordering & forecasting, and pricing part of distribution contract) •
Slide 7: Capturing More of the Value Chain
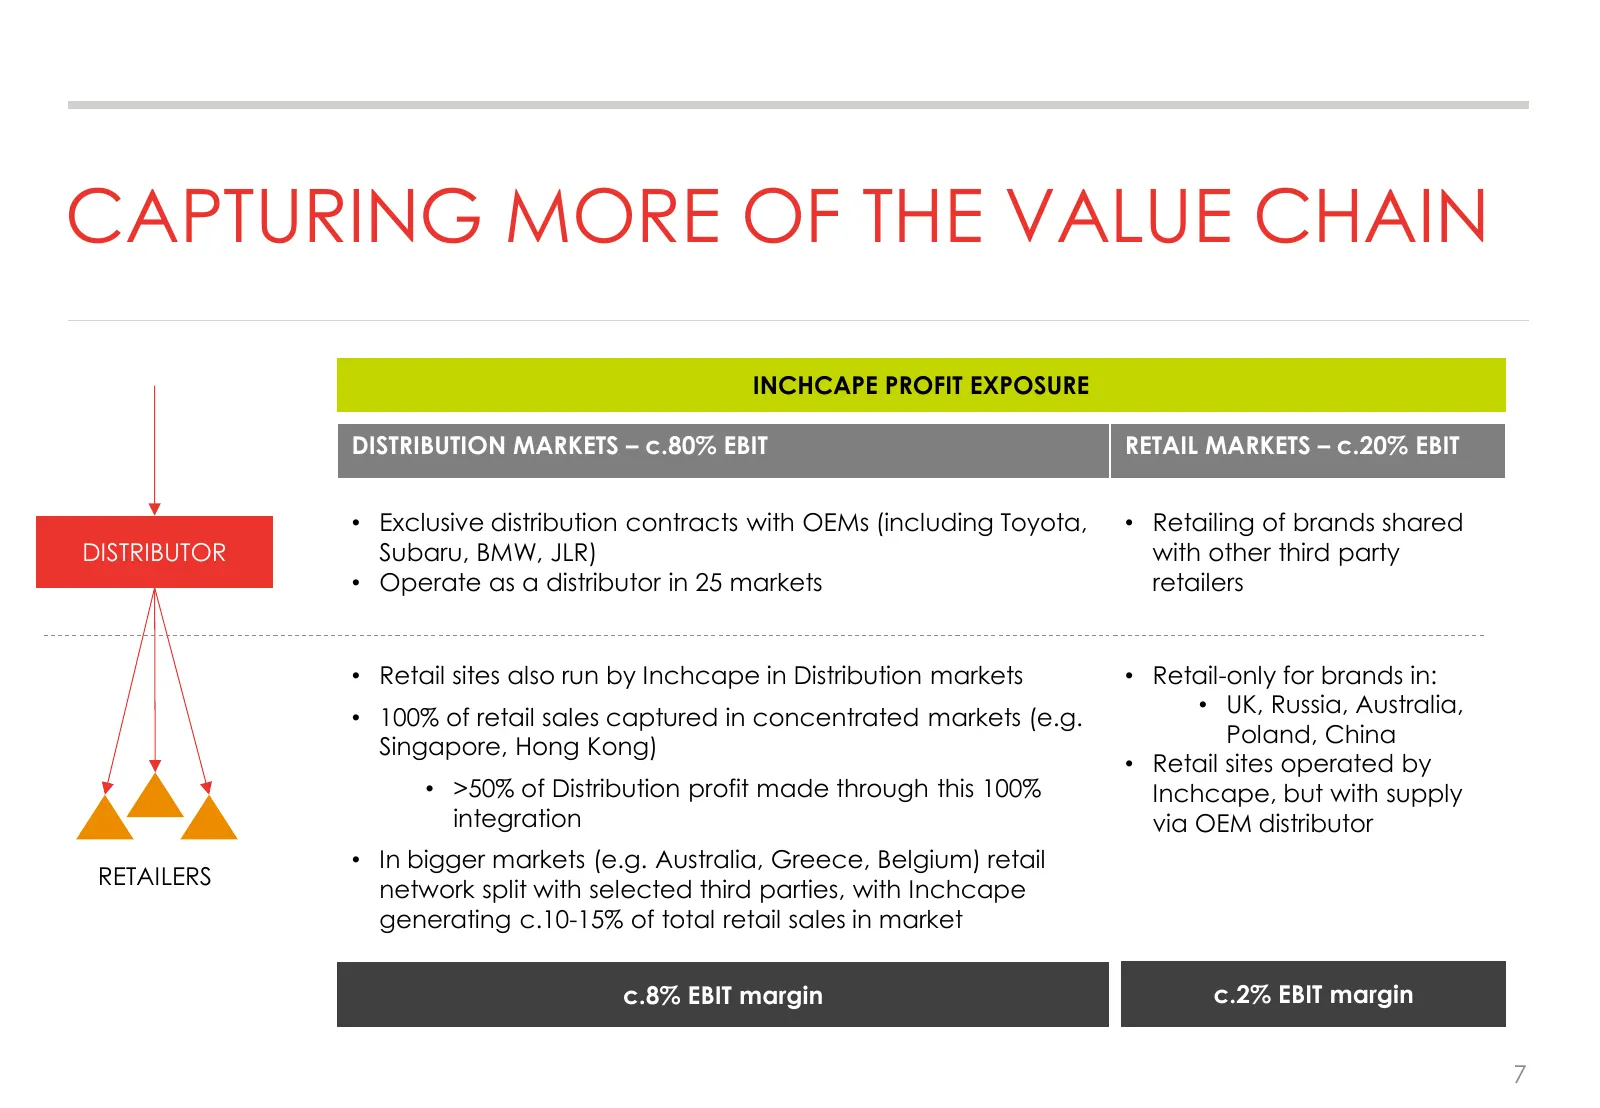
CAPTURING MORE OF THE VALUE CHAIN INCHCAPE PROFIT EXPOSURE DISTRIBUTION MARKETS – c.80% EBIT RETAIL MARKETS – c.20% EBIT • Exclusive distribution contracts with OEMs (including Toyota, • Retailing of brands shared DISTRIBUTOR Subaru, BMW, JLR) with other third party • Operate as a distributor in 25
Slide 8: Distribution
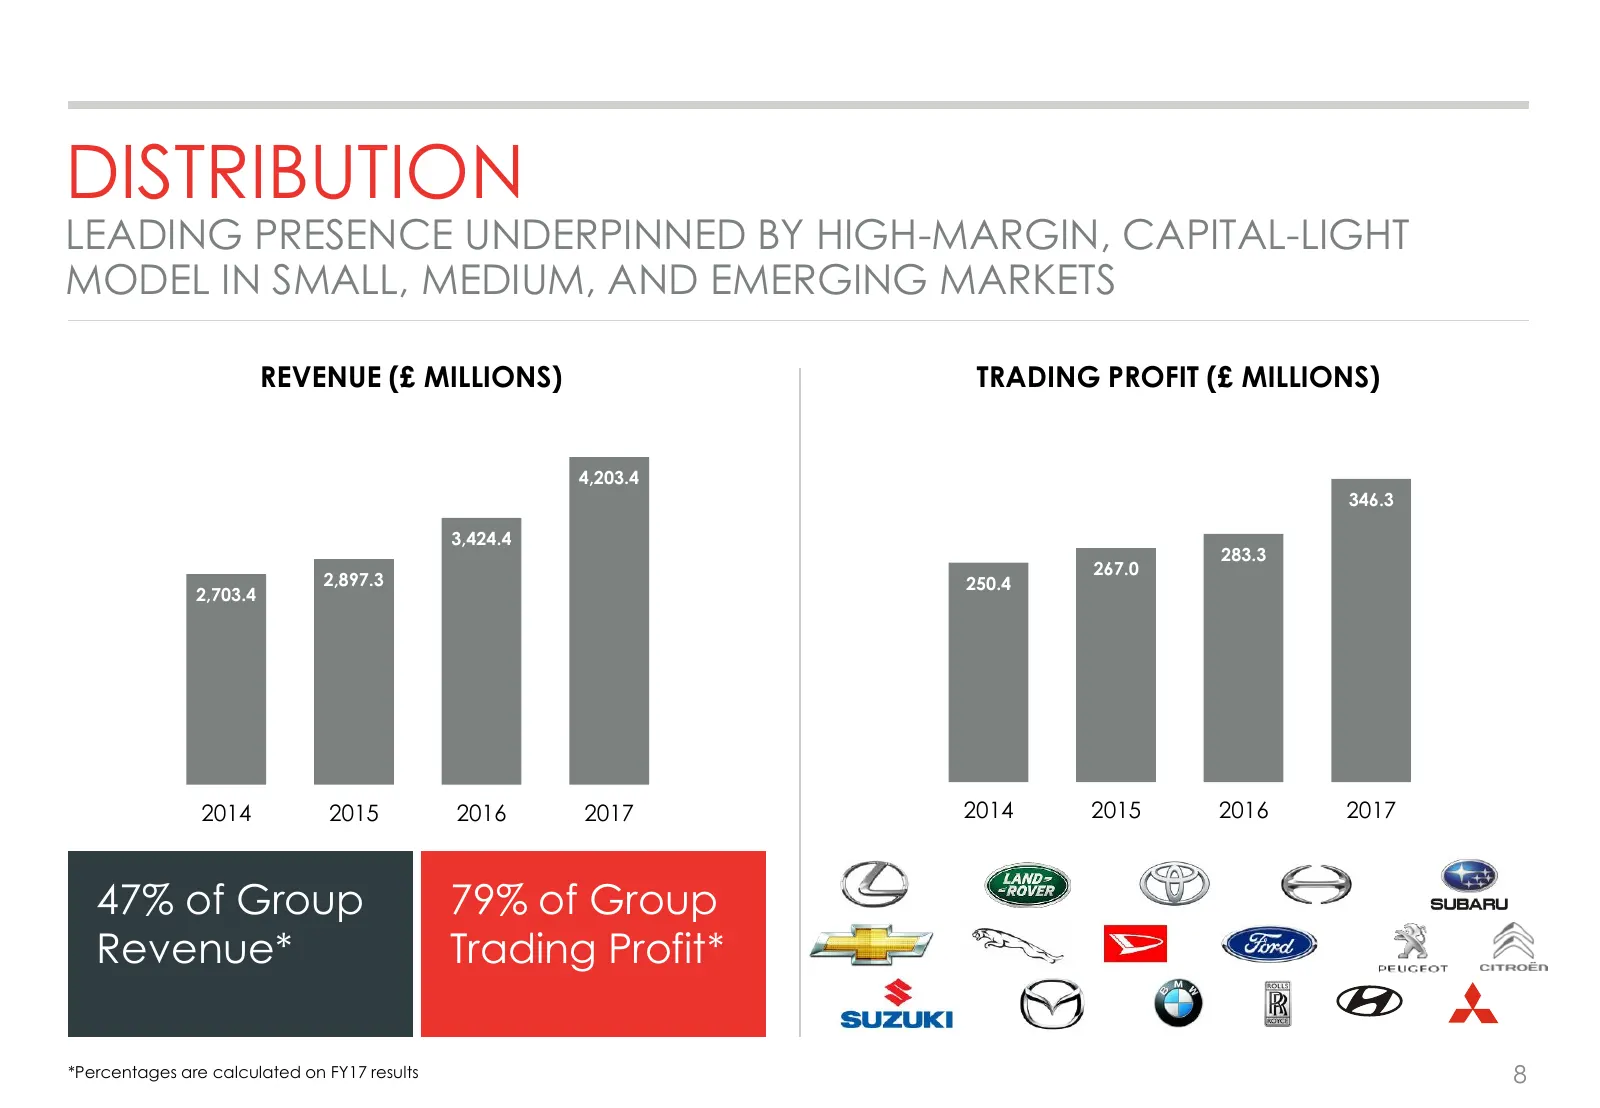
DISTRIBUTION LEADING PRESENCE UNDERPINNED BY HIGH-MARGIN, CAPITAL-LIGHT MODEL IN SMALL, MEDIUM, AND EMERGING MARKETS REVENUE (£ MILLIONS) TRADING PROFIT (£ MILLIONS) 4,203.4 346.3 3,424.4 283.3 267.0 2,897.3 250.4 2,703.4 2014 2015 2016 2017 2014 2015 2016 2017 47% of Group 79% of Group Revenue* Tra
Slide 9: Retail
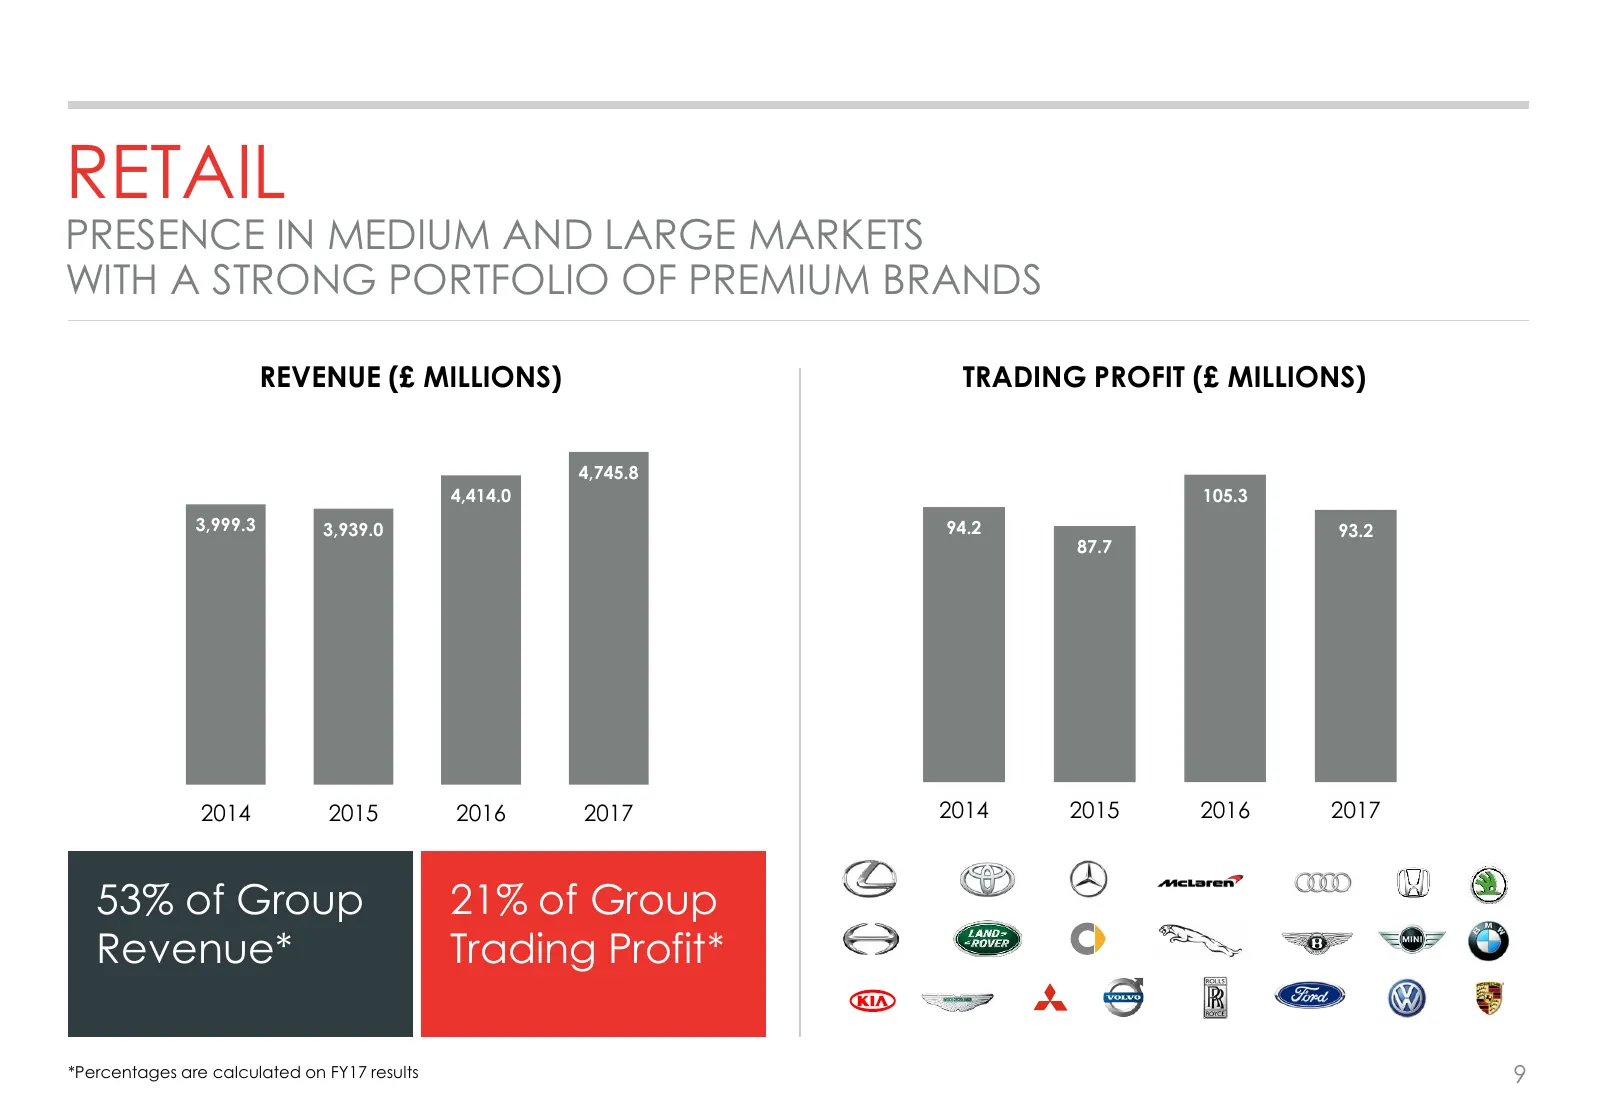
RETAIL PRESENCE IN MEDIUM AND LARGE MARKETS WITH A STRONG PORTFOLIO OF PREMIUM BRANDS REVENUE (£ MILLIONS) TRADING PROFIT (£ MILLIONS) 4,745.8 4,414.0 105.3 3,999.3 3,939.0 94.2 93.2 87.7 2014 2015 2016 2017 2014 2015 2016 2017 53% of Group 21% of Group Revenue* Trading Profit* *Percentages are calc
Slide 10: A Fragmented Industry…
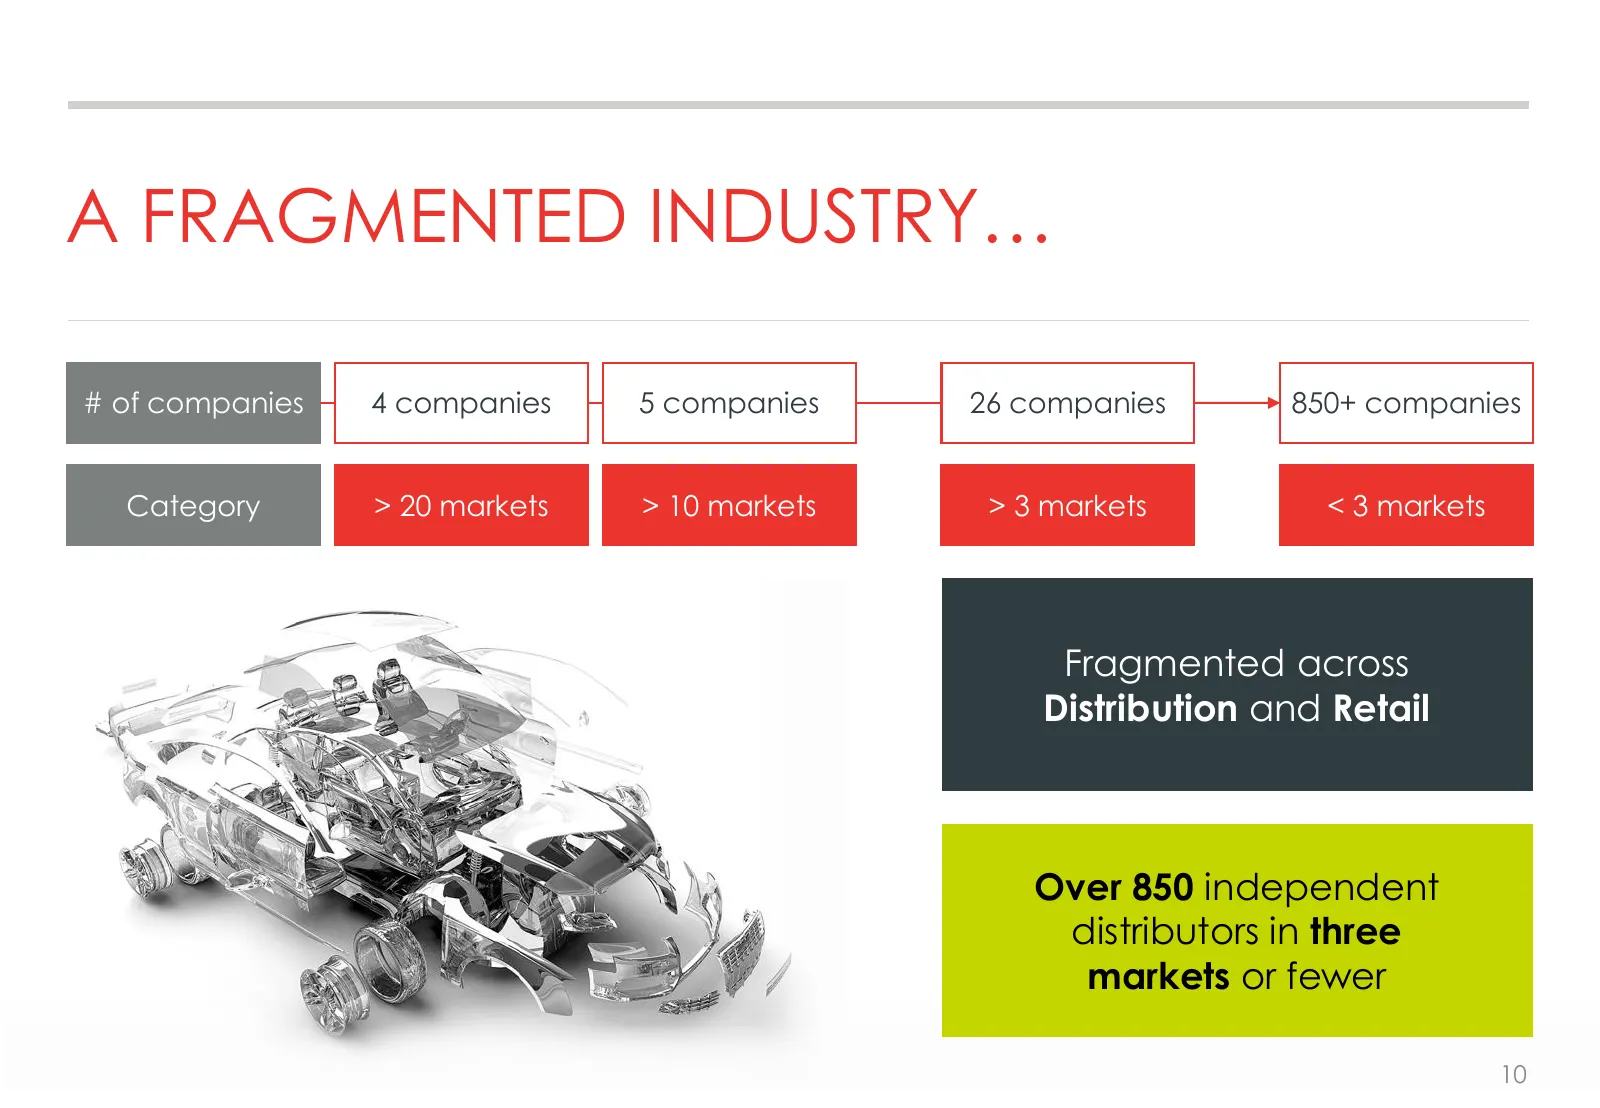
A FRAGMENTED INDUSTRY… # of companies 4 companies 5 companies 26 companies 850+ companies Category > 20 markets > 10 markets > 3 markets < 3 markets Fragmented across Distribution and Retail Over 850 independent distributors in three markets or fewer 10
Slide 11: …With Strong Barriers to Entry
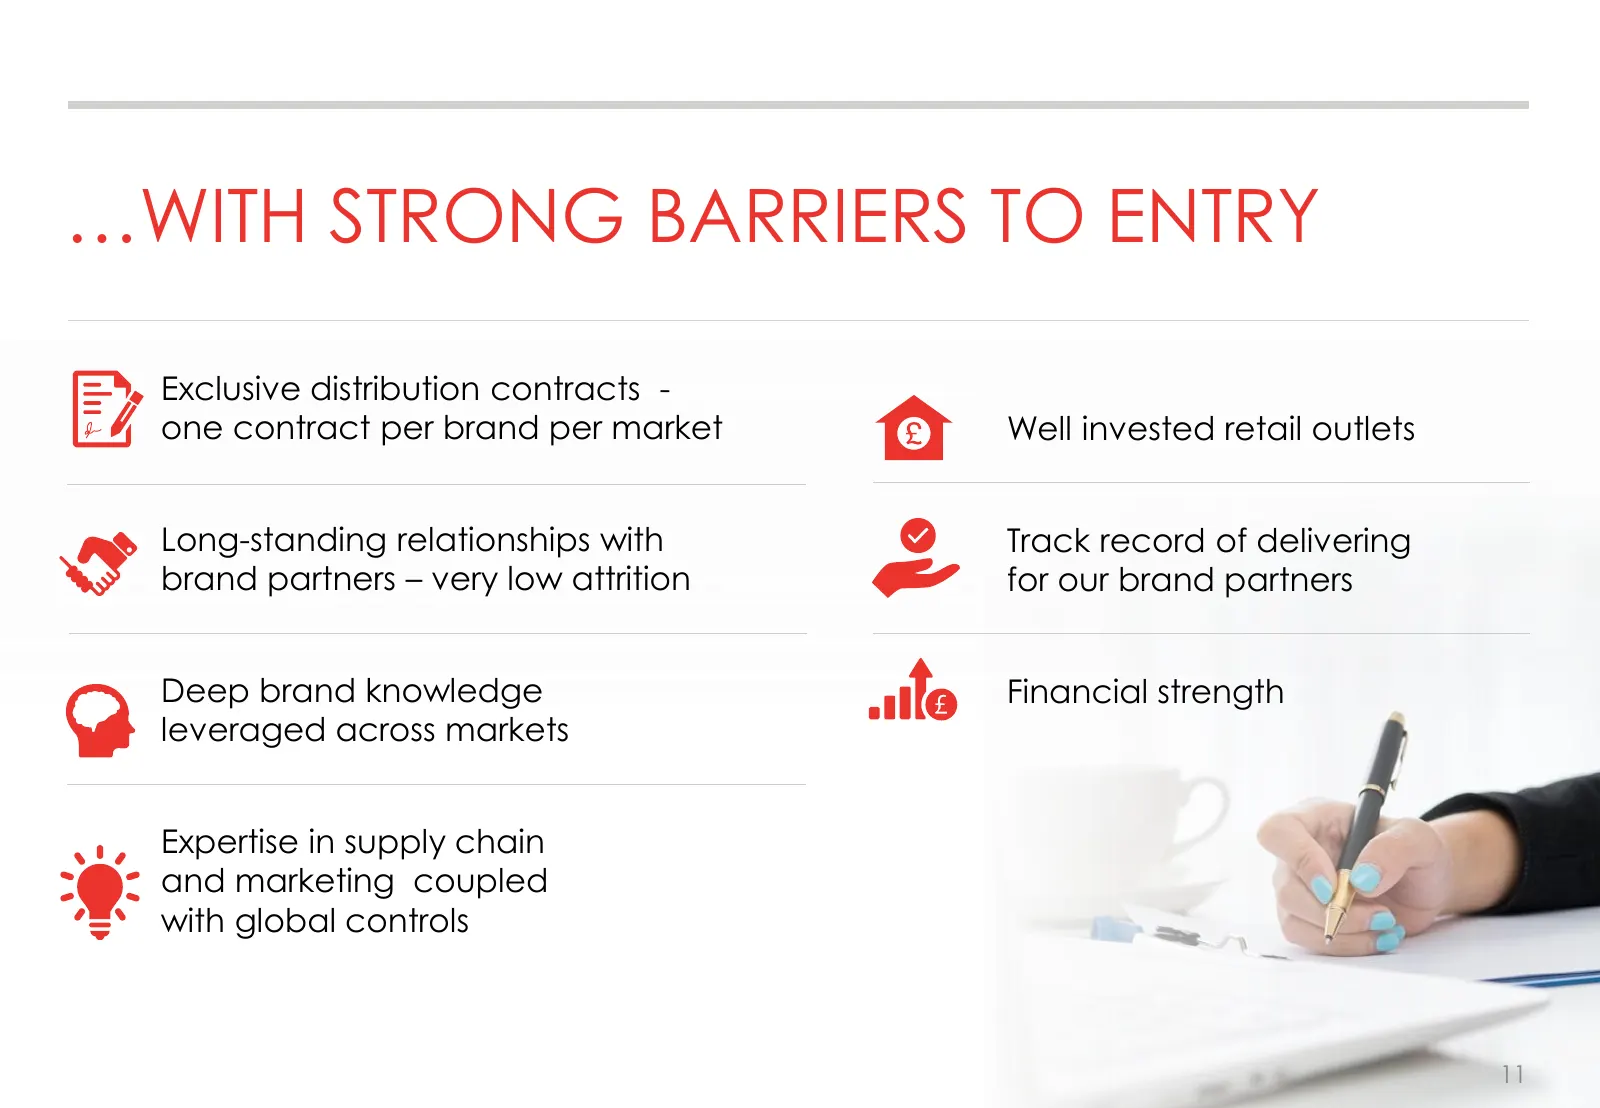
…WITH STRONG BARRIERS TO ENTRY Exclusive distribution contracts - one contract per brand per market Well invested retail outlets Long-standing relationships with Track record of delivering brand partners – very low attrition for our brand partners Deep brand knowledge Financial strength leveraged ac
Slide 12: Long Standing OEM Partnerships
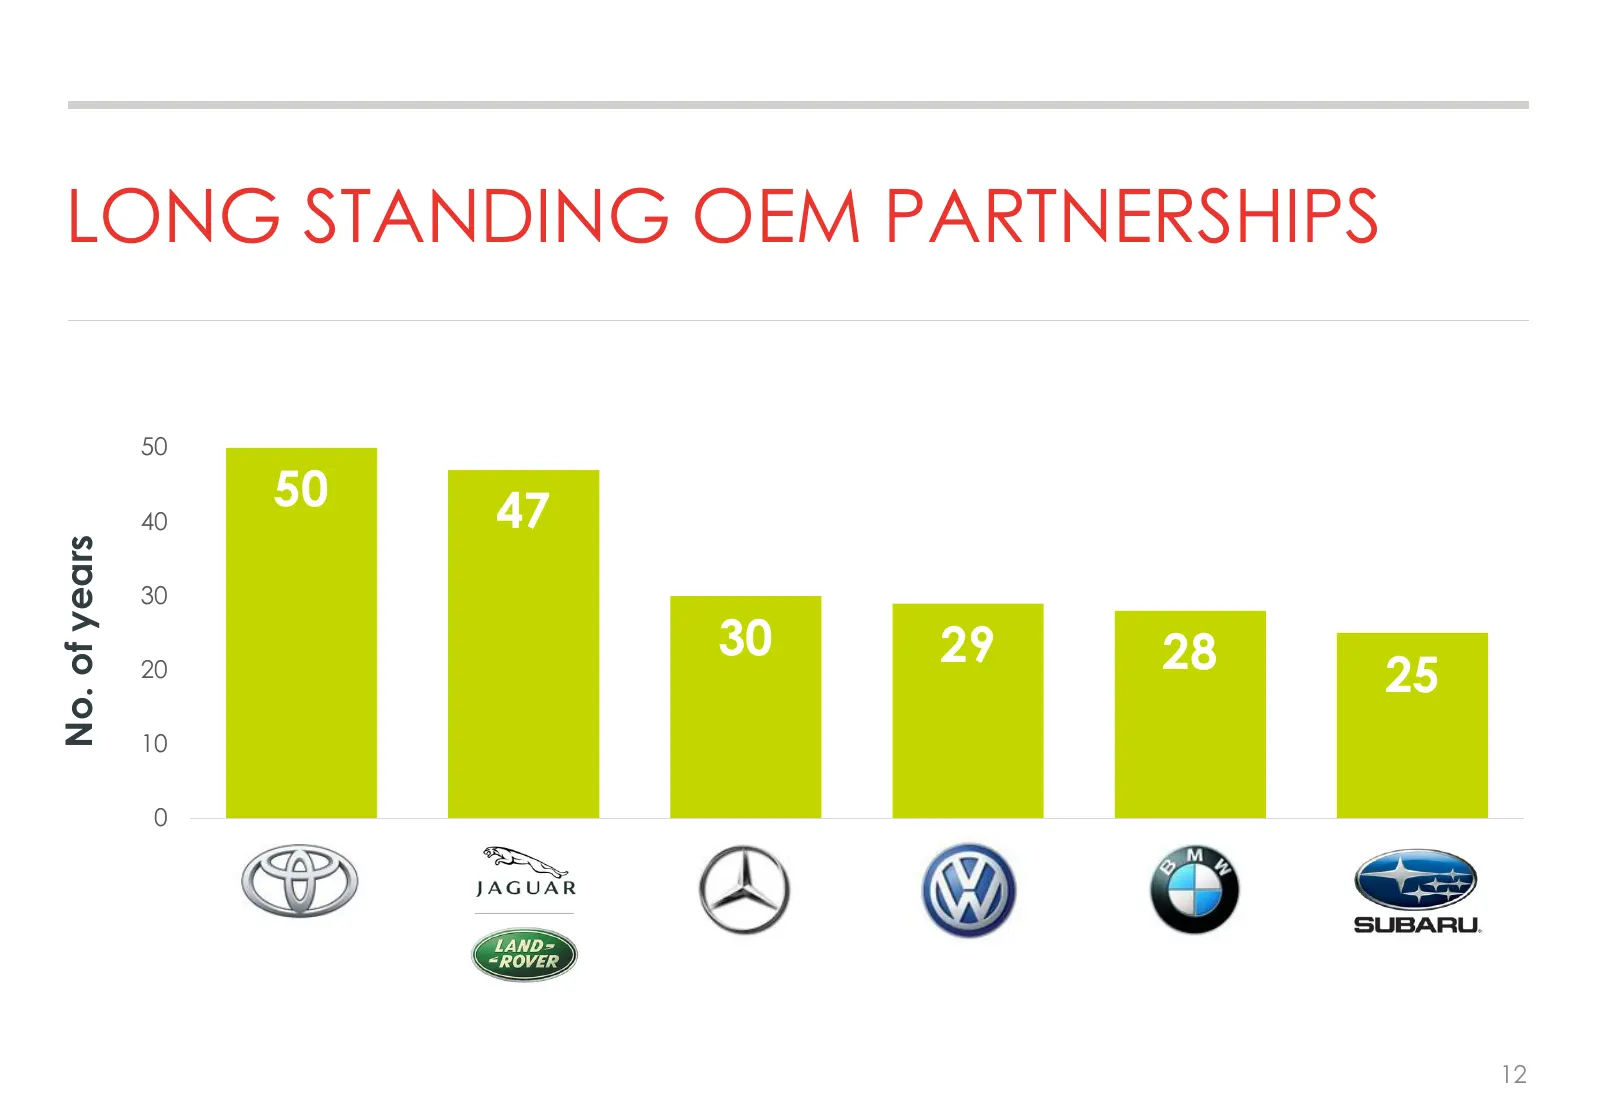
LONG STANDING OEM PARTNERSHIPS 50 40 50 47 No. of years 30 30 29 28 20 25 10 0 12
Slide 13: Performance Overview
PERFORMANCE OVERVIEW
Slide 14: Consistent Performance
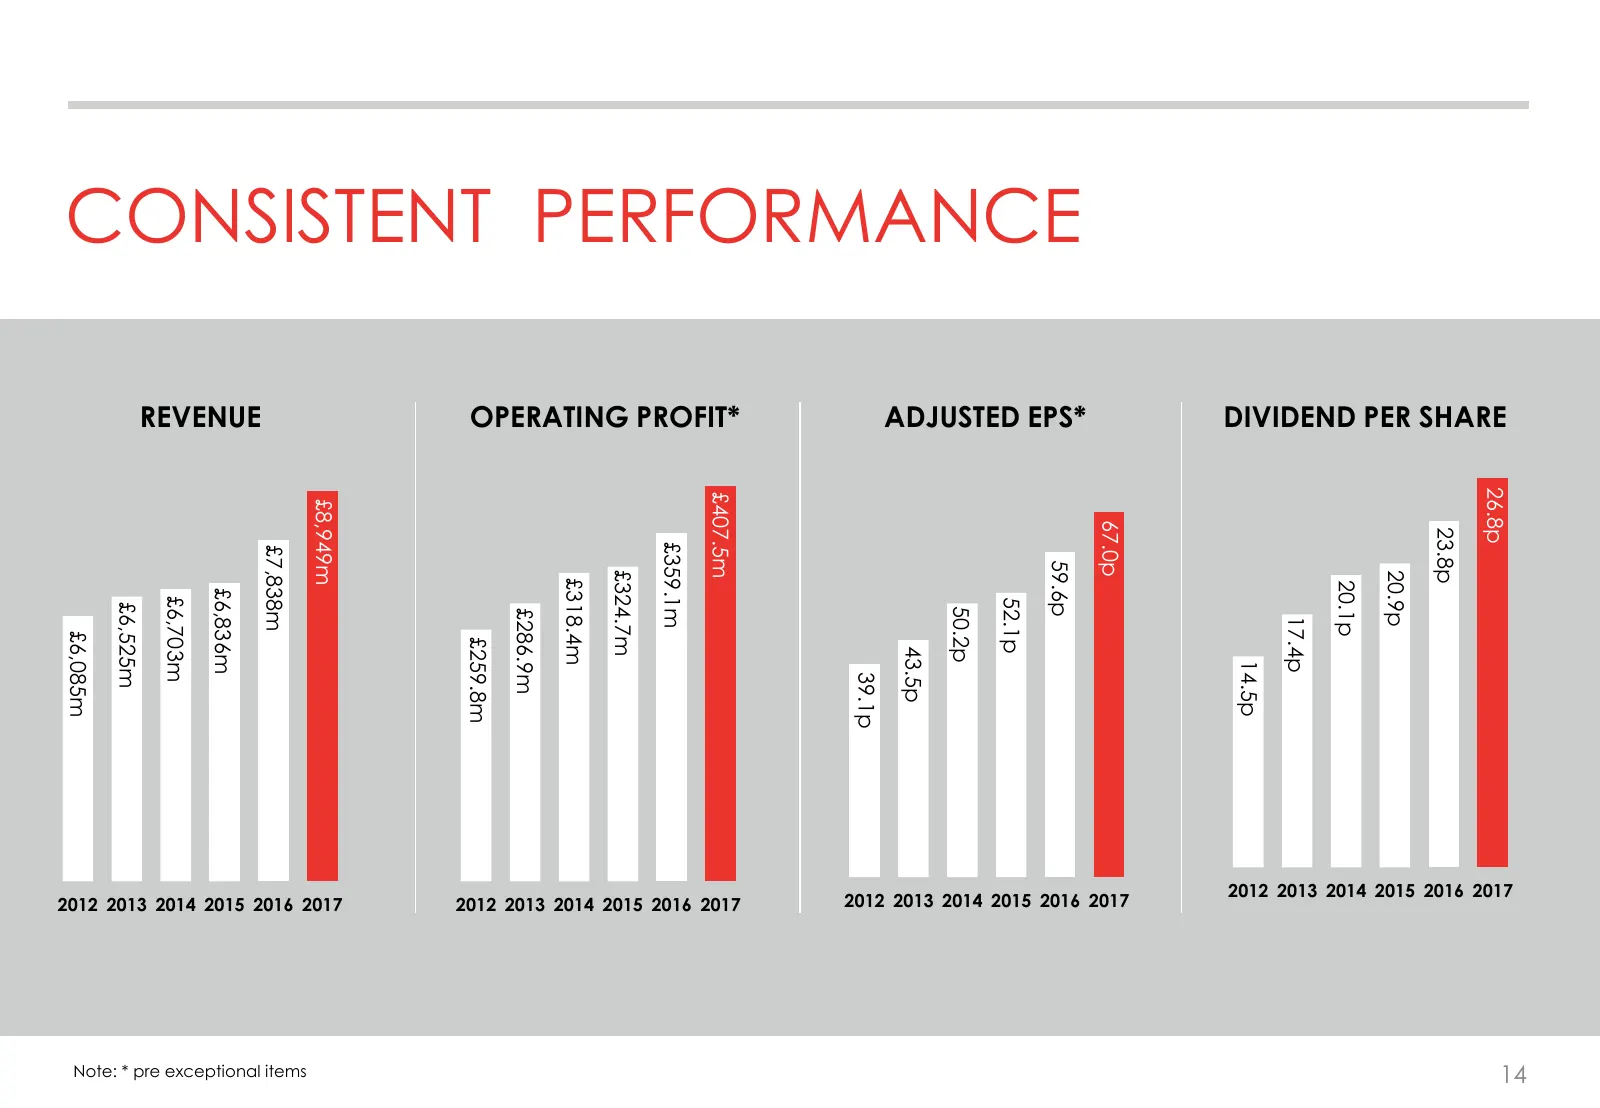
CONSISTENT PERFORMANCE REVENUE OPERATING PROFIT* ADJUSTED EPS* DIVIDEND PER SHARE 26.8p £407.5m £8,949m 67.0p 23.8p £359.1m £7,838m 59.6p £324.7m 20.9p £318.4m 20.1p £6,836m £6,703m 52.1p £6,525m 50.2p £286.9m 17.4p £6,085m £259.8m 43.5p 14.5p 39.1p 2012 2013 2014 2015 2016 2017 2012 2013 2014 2015
Slide 15: Solid Returns
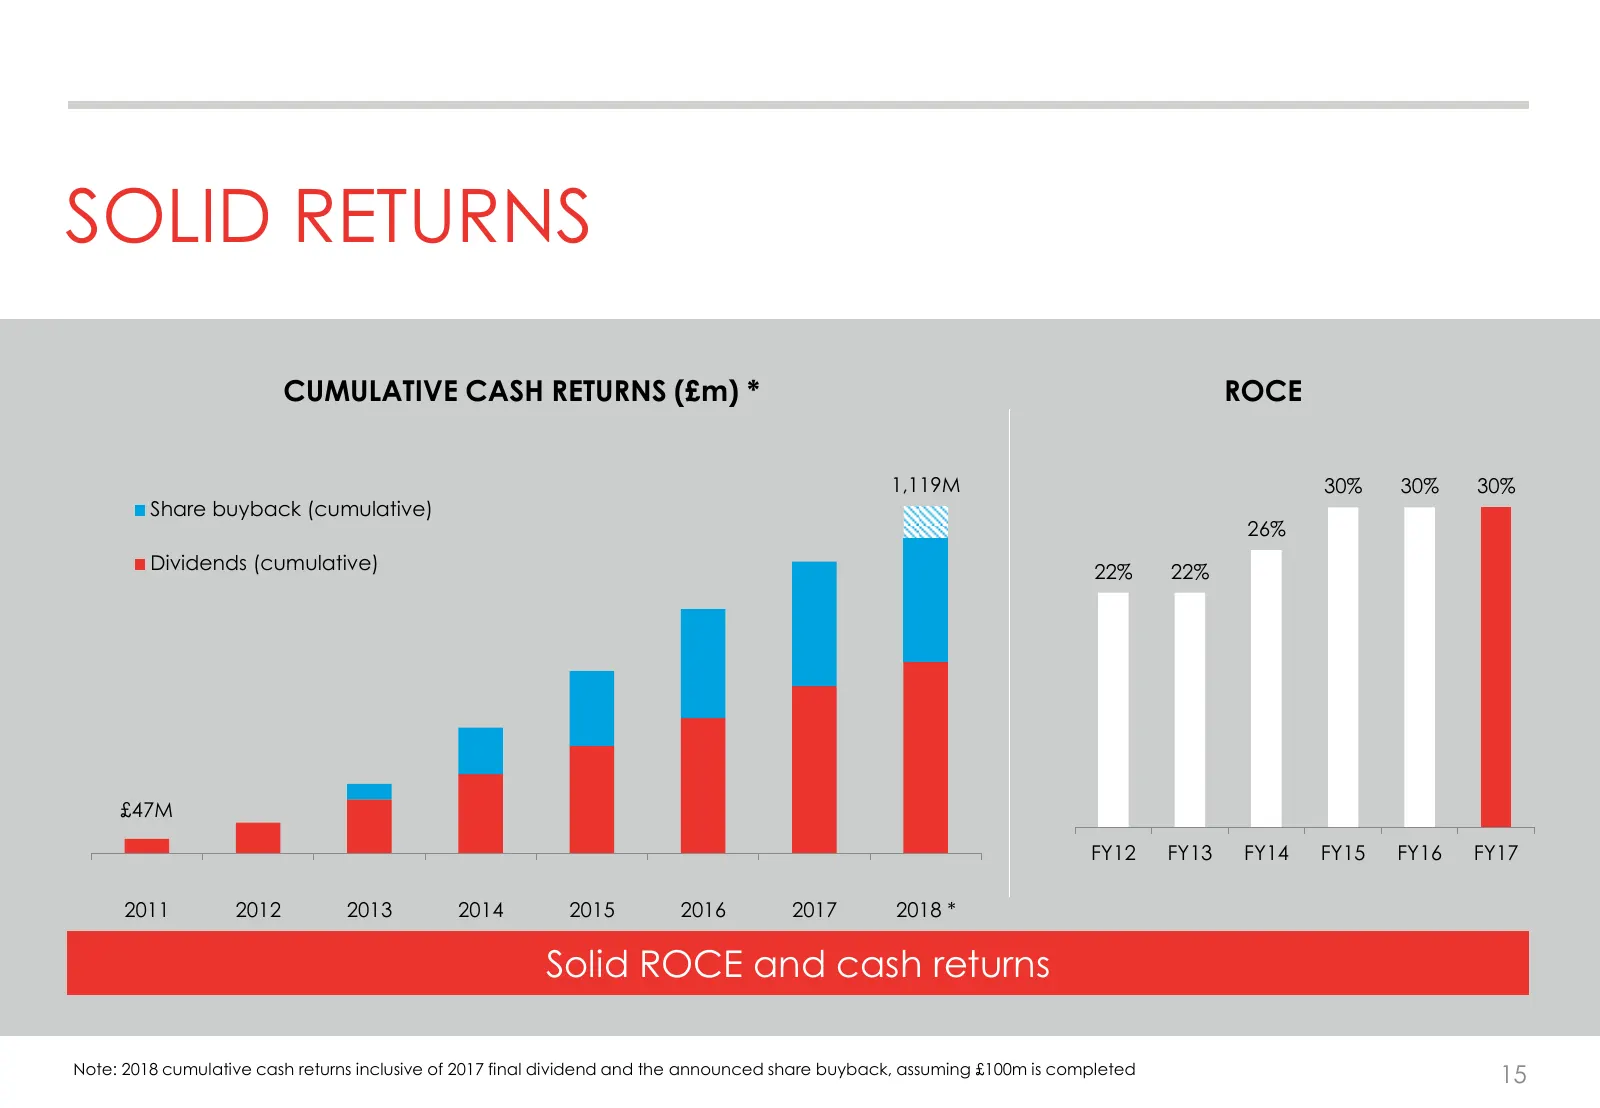
SOLID RETURNS CUMULATIVE CASH RETURNS (£m) * ROCE 1,119M 30% 30% 30% Share buyback (cumulative) 26% Dividends (cumulative) 22% 22% £47M FY12 FY13 FY14 FY15 FY16 FY17 2011 2012 2013 2014 2015 2016 2017 2018 * Solid ROCE and cash returns Note: 2018 cumulative cash returns inclusive of 2017 final divid
Slide 16: Resilient Performance
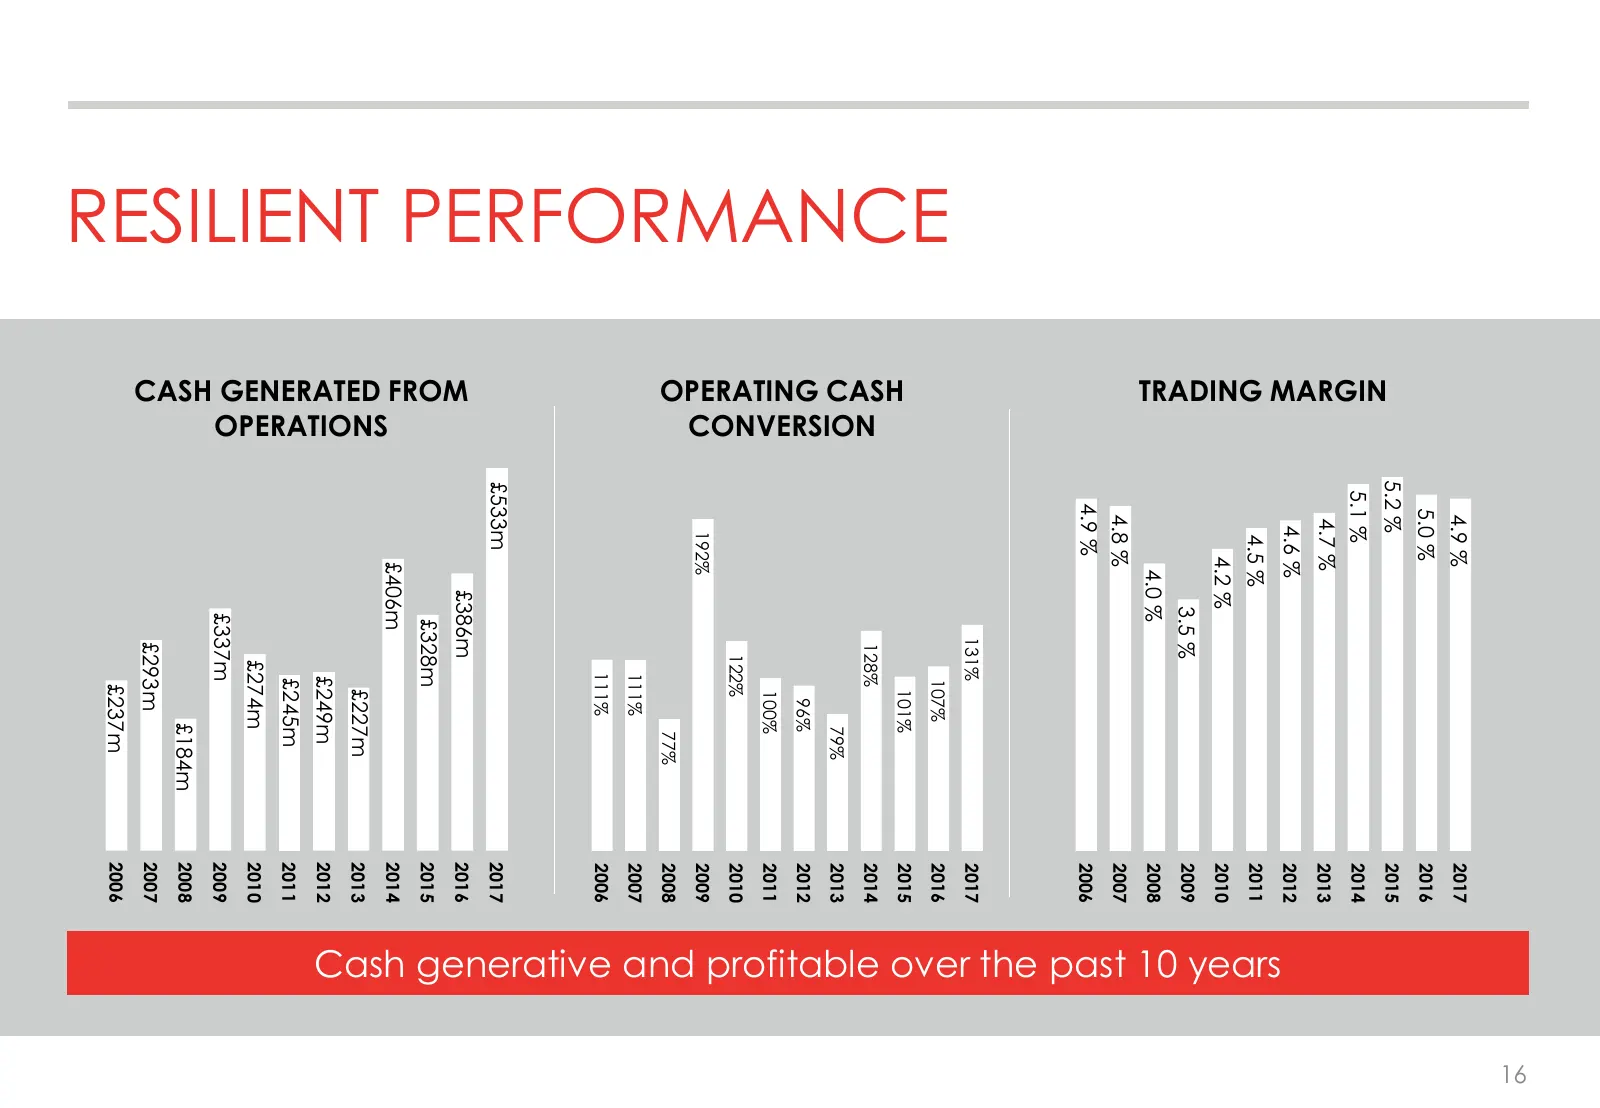
16 4.9 % 2017 5.0 % 2016 5.2 % 2015 TRADING MARGIN 5.1 % 2014 4.7 % 2013 4.6 % 2012 Cash generative and profitable over the past 10 years 4.5 % 2011 4.2 % 2010 3.5 % 2009 4.0 % 2008 4.8 % 2007 4.9 % 2006 131% 2017 RESILIENT PERFORMANCE 107% 2016 101% 2015 OPERATING CASH 128% 2014 CONVERSION 79% 2013
Slide 17: Ignite Strategy
IGNITE STRATEGY
Slide 18: Strategy
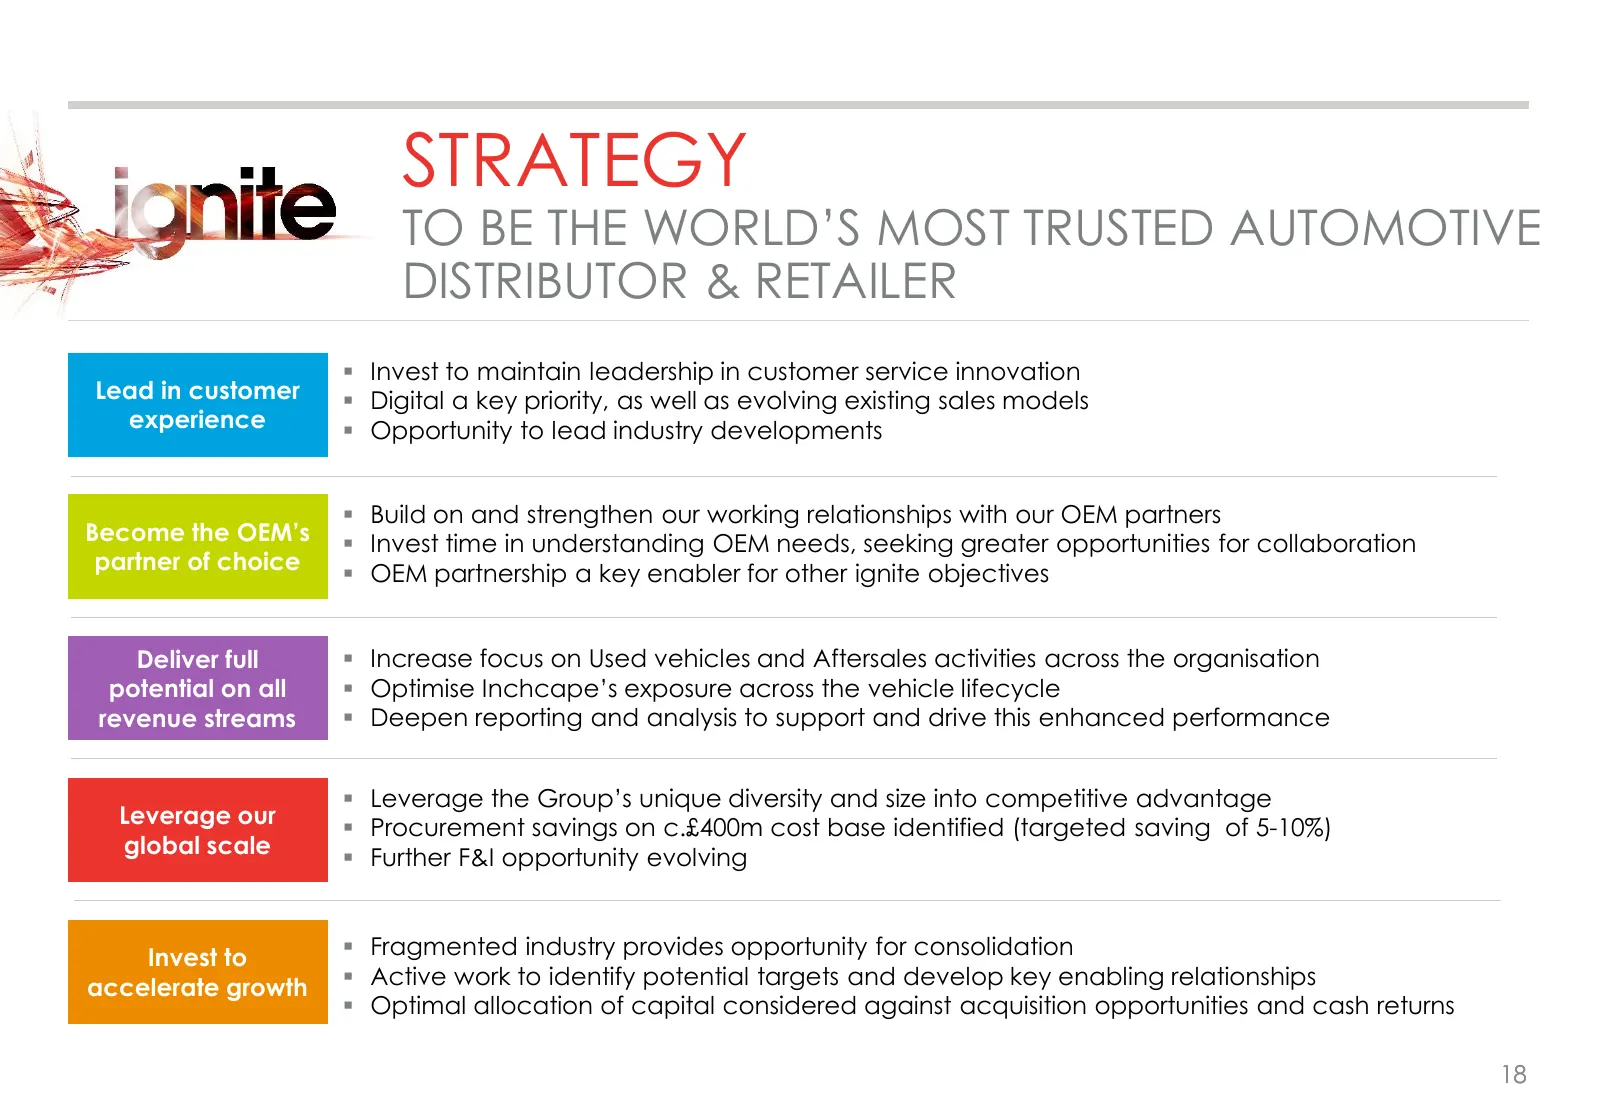
STRATEGY TO BE THE WORLD’S MOST TRUSTED AUTOMOTIVE DISTRIBUTOR & RETAILER Invest to maintain leadership in customer service innovation Lead in customer Digital a key priority, as well as evolving existing sales models experience Opportunity to lead industry developments Build on and strength
Slide 19: South America Acquisition
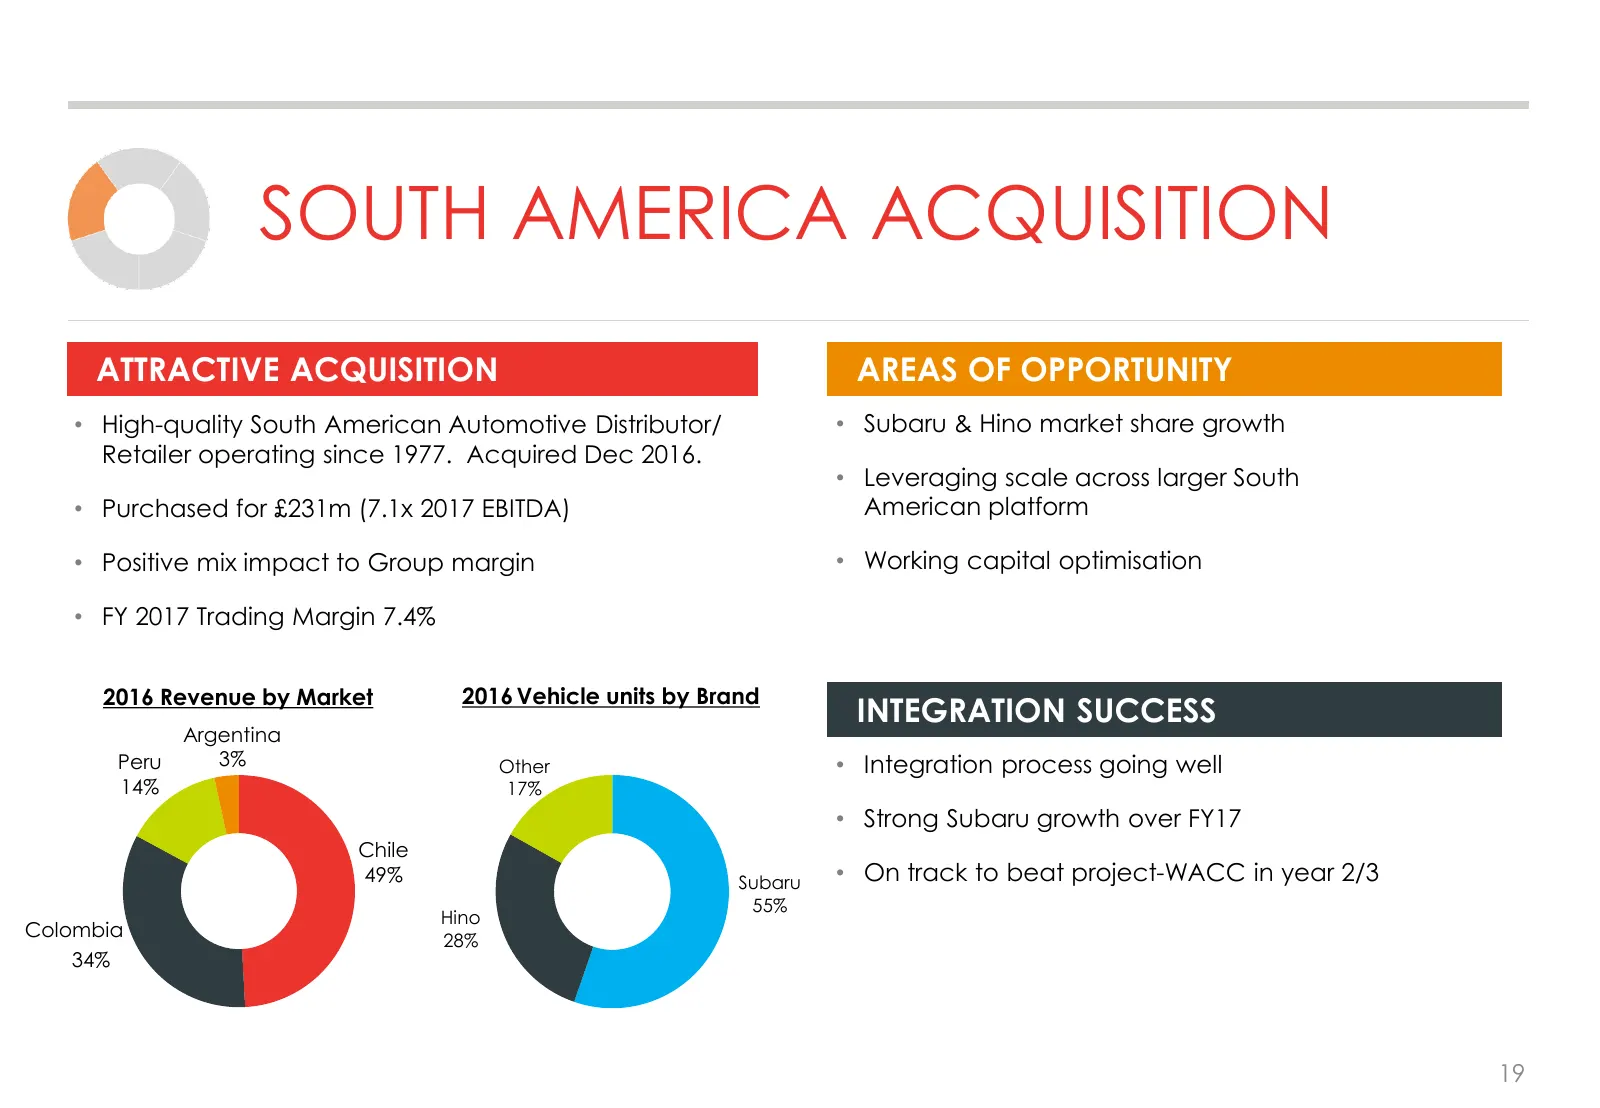
SOUTH AMERICA ACQUISITION ATTRACTIVE ACQUISITION AREAS OF OPPORTUNITY • High-quality South American Automotive Distributor/ • Subaru & Hino market share growth Retailer operating since 1977. Acquired Dec 2016. • Leveraging scale across larger South • Purchased for £231m (7.1x 2017 EBITDA) American p
Slide 20: Invest to Accelerate Growth
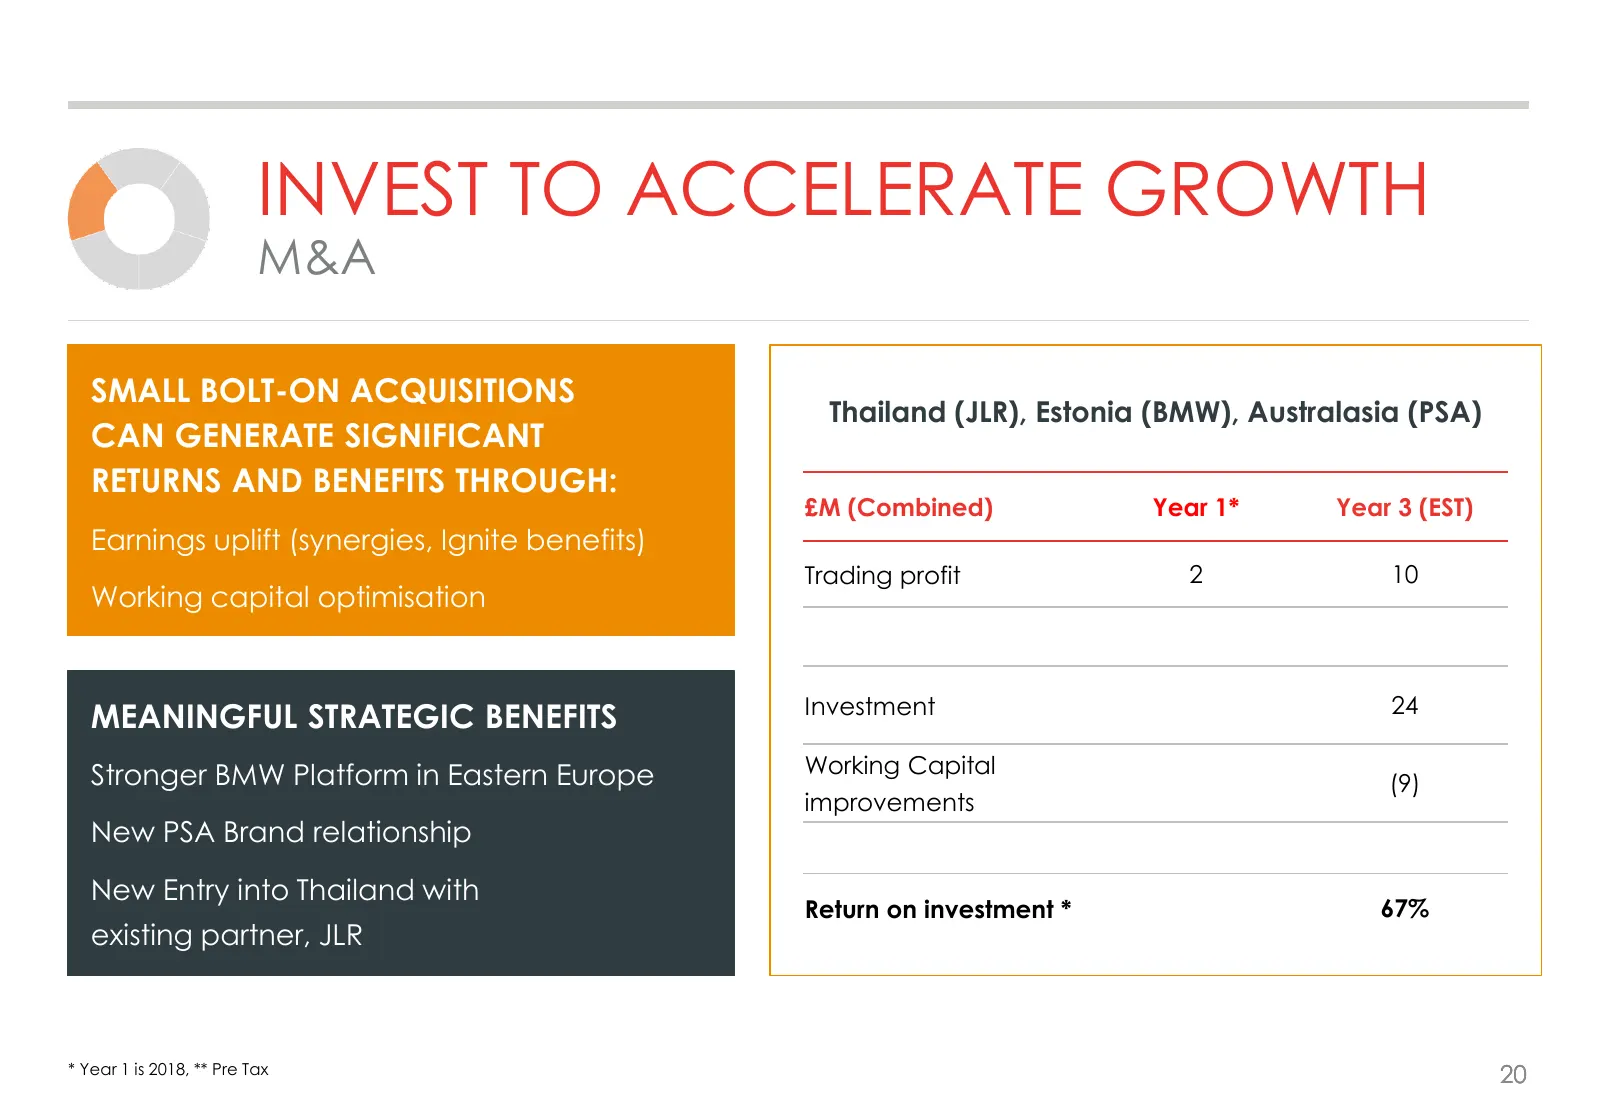
INVEST TO ACCELERATE GROWTH M&A SMALL BOLT-ON ACQUISITIONS Thailand (JLR), Estonia (BMW), Australasia (PSA) CAN GENERATE SIGNIFICANT RETURNS AND BENEFITS THROUGH: £M (Combined) Year 1* Year 3 (EST) Earnings uplift (synergies, Ignite benefits) Trading profit 2 10 Working capital optimisation Investme
Slide 21: Regions
REGIONS
Slide 22: Australasia
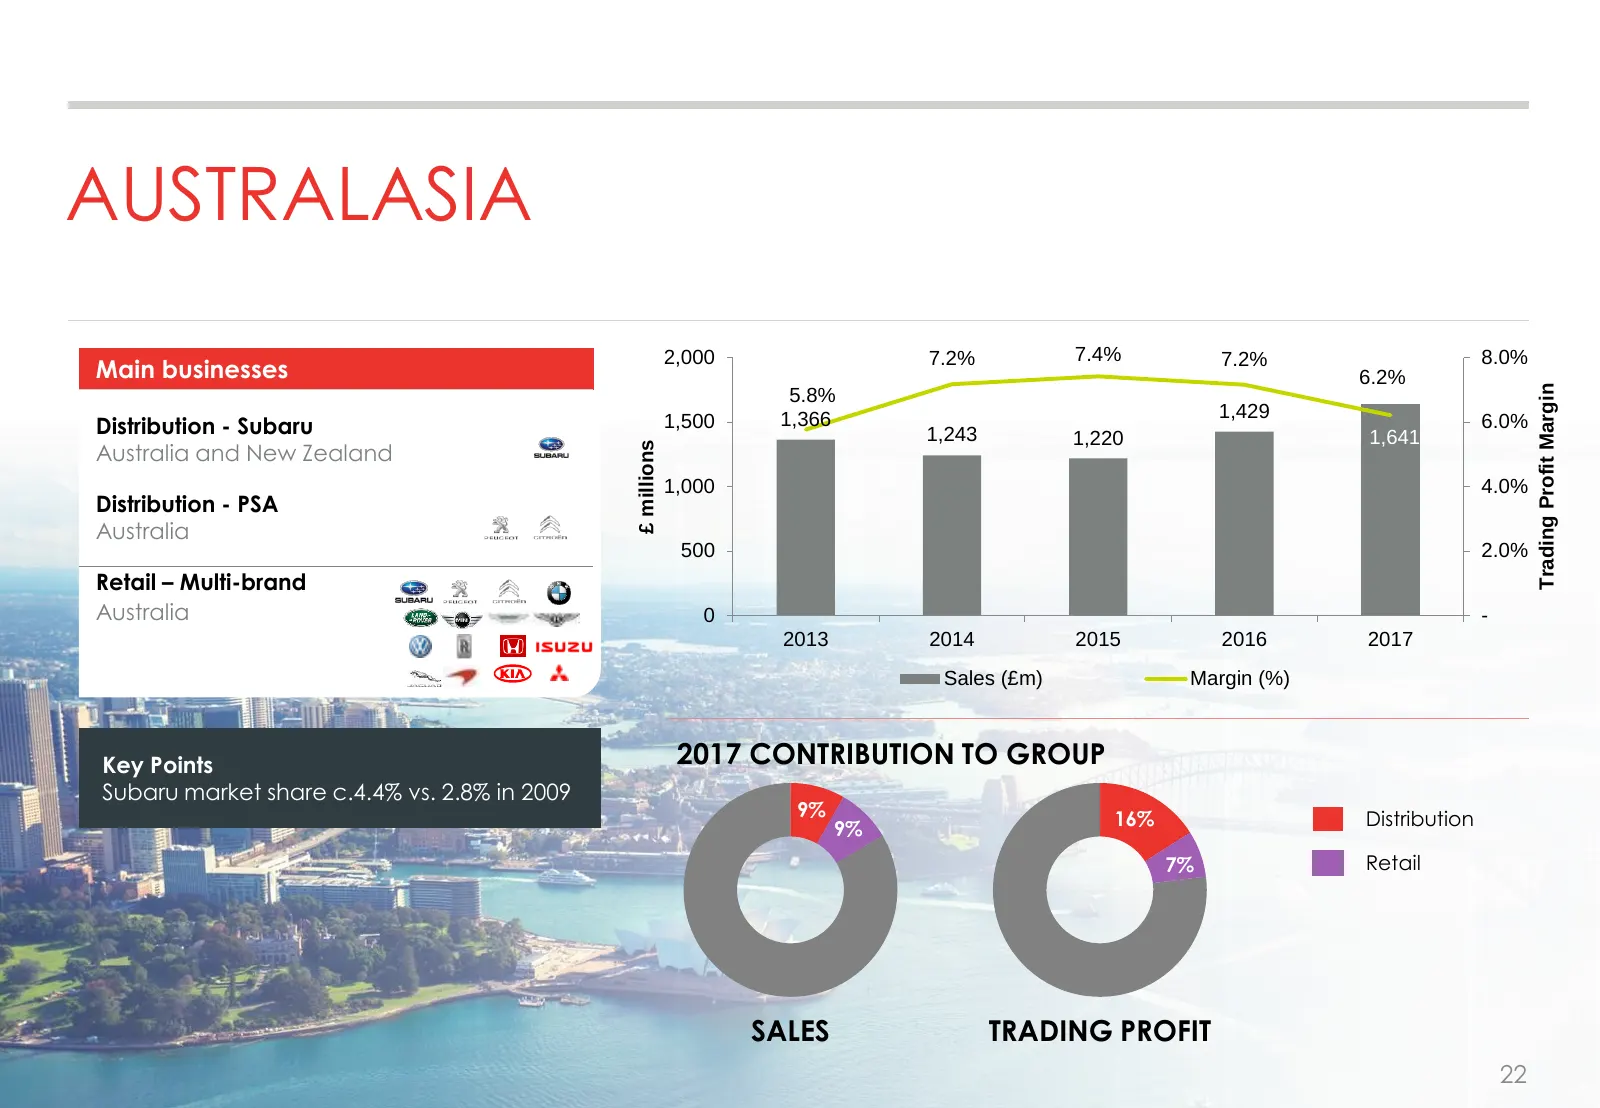
AUSTRALASIA 2,000 7.2% 7.4% 7.2% 8.0% Main businesses 6.2% Trading Profit Margin 5.8% 1,429 Distribution - Subaru 1,500 1,366 1,243 1,220 1,641 6.0% Australia and New Zealand £ millions 1,000 4.0% Distribution - PSA Australia 500 2.0% Retail – Multi-brand Australia 0 - 2013 2014 2015 2016 2017 Sales
Slide 23: Asia
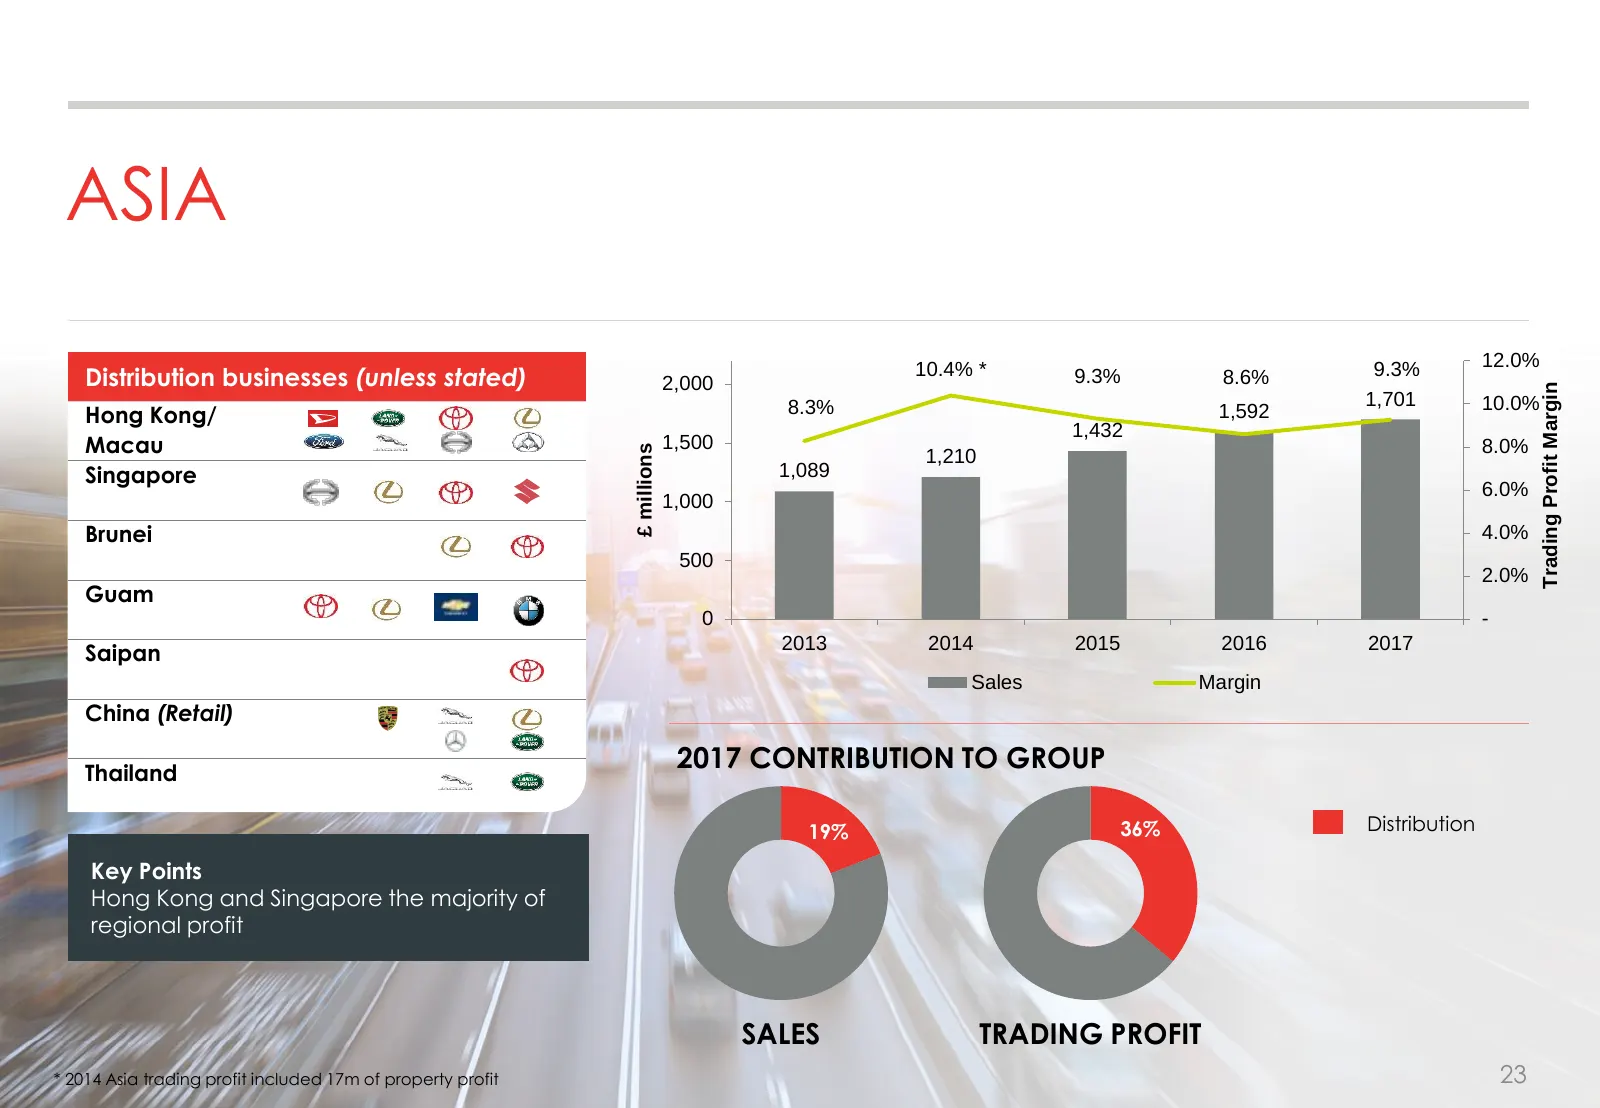
ASIA 12.0% Distribution businesses (unless stated) 2,000 10.4% * 9.3% 8.6% 9.3% Trading Profit Margin 8.3% 1,701 10.0% Hong Kong/ 1,592 1,432 Macau 1,500 8.0% £ millions 1,210 Singapore 1,089 6.0% 1,000 Brunei 4.0% 500 2.0% Guam 0 - 2013 2014 2015 2016 2017 Saipan Sales Margin China (Retail) Thailan
Slide 24: UK & Europe
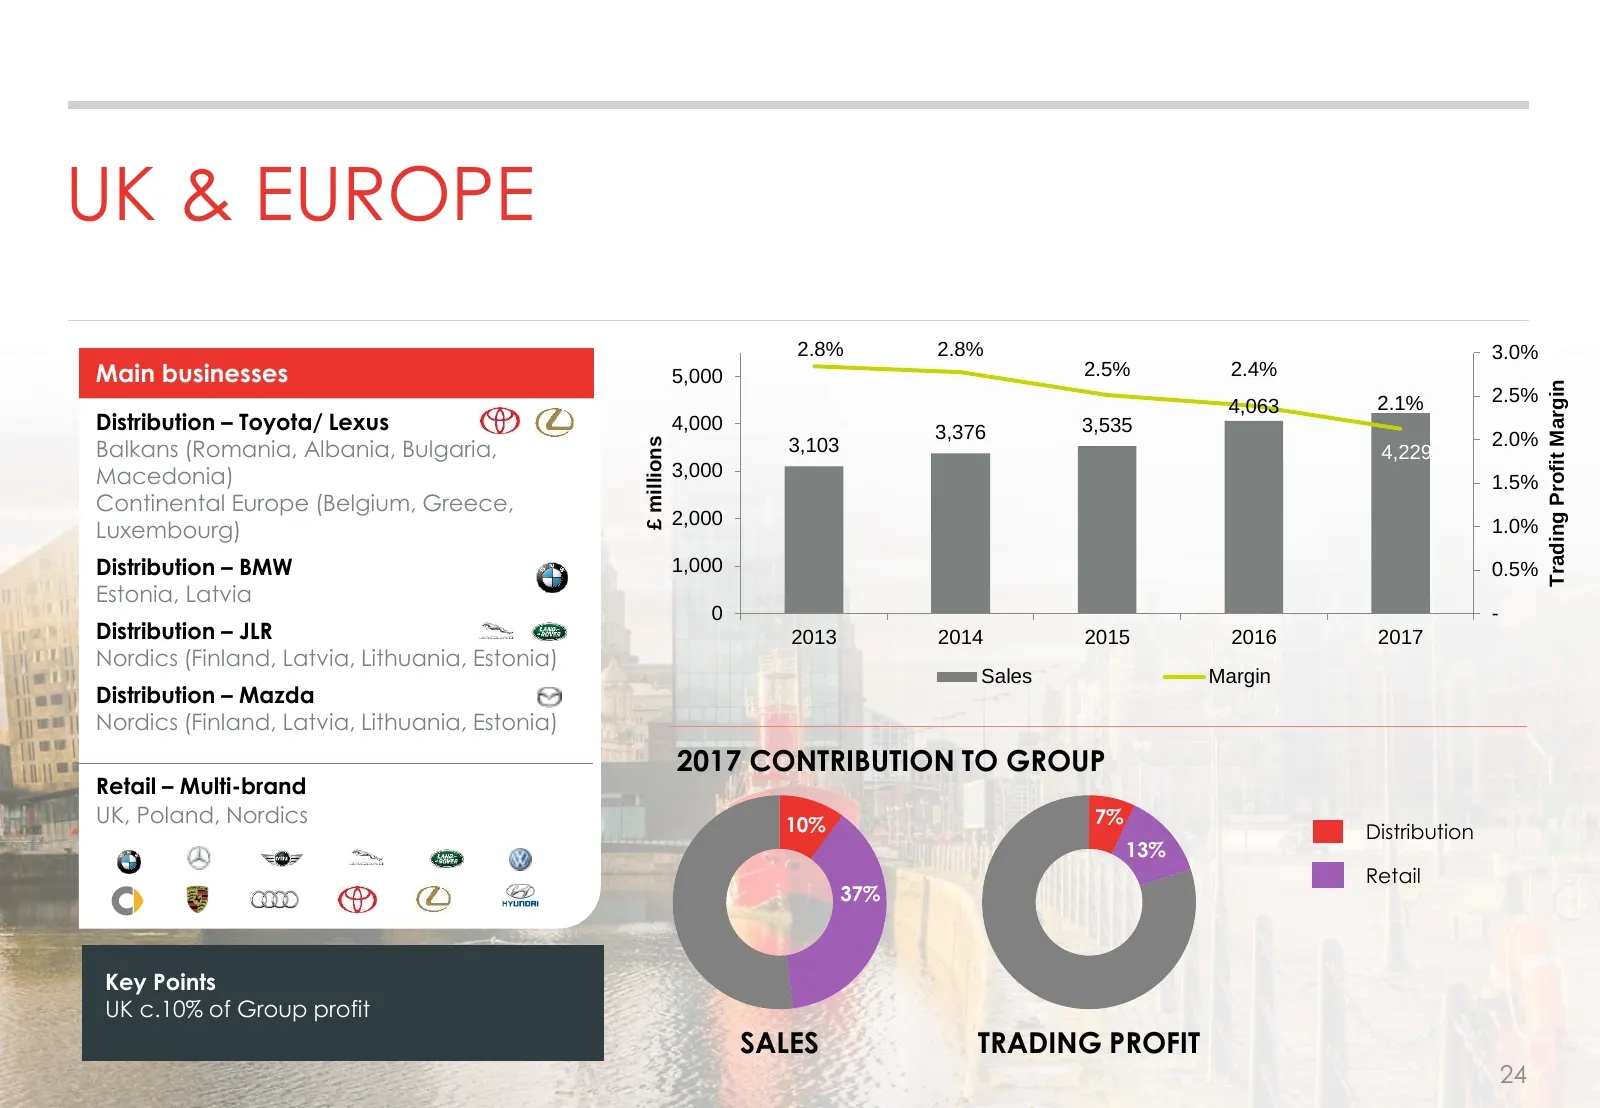
UK & EUROPE 2.8% 2.8% 3.0% Main businesses 5,000 2.5% 2.4% Trading Profit Margin 2.1% 2.5% 4,063 Distribution – Toyota/ Lexus 4,000 3,376 3,535 2.0% Balkans (Romania, Albania, Bulgaria, £ millions 3,103 4,229 Macedonia) 3,000 1.5% Continental Europe (Belgium, Greece, 2,000 Luxembourg) 1.0% Distribut
Slide 25: Emerging Markets
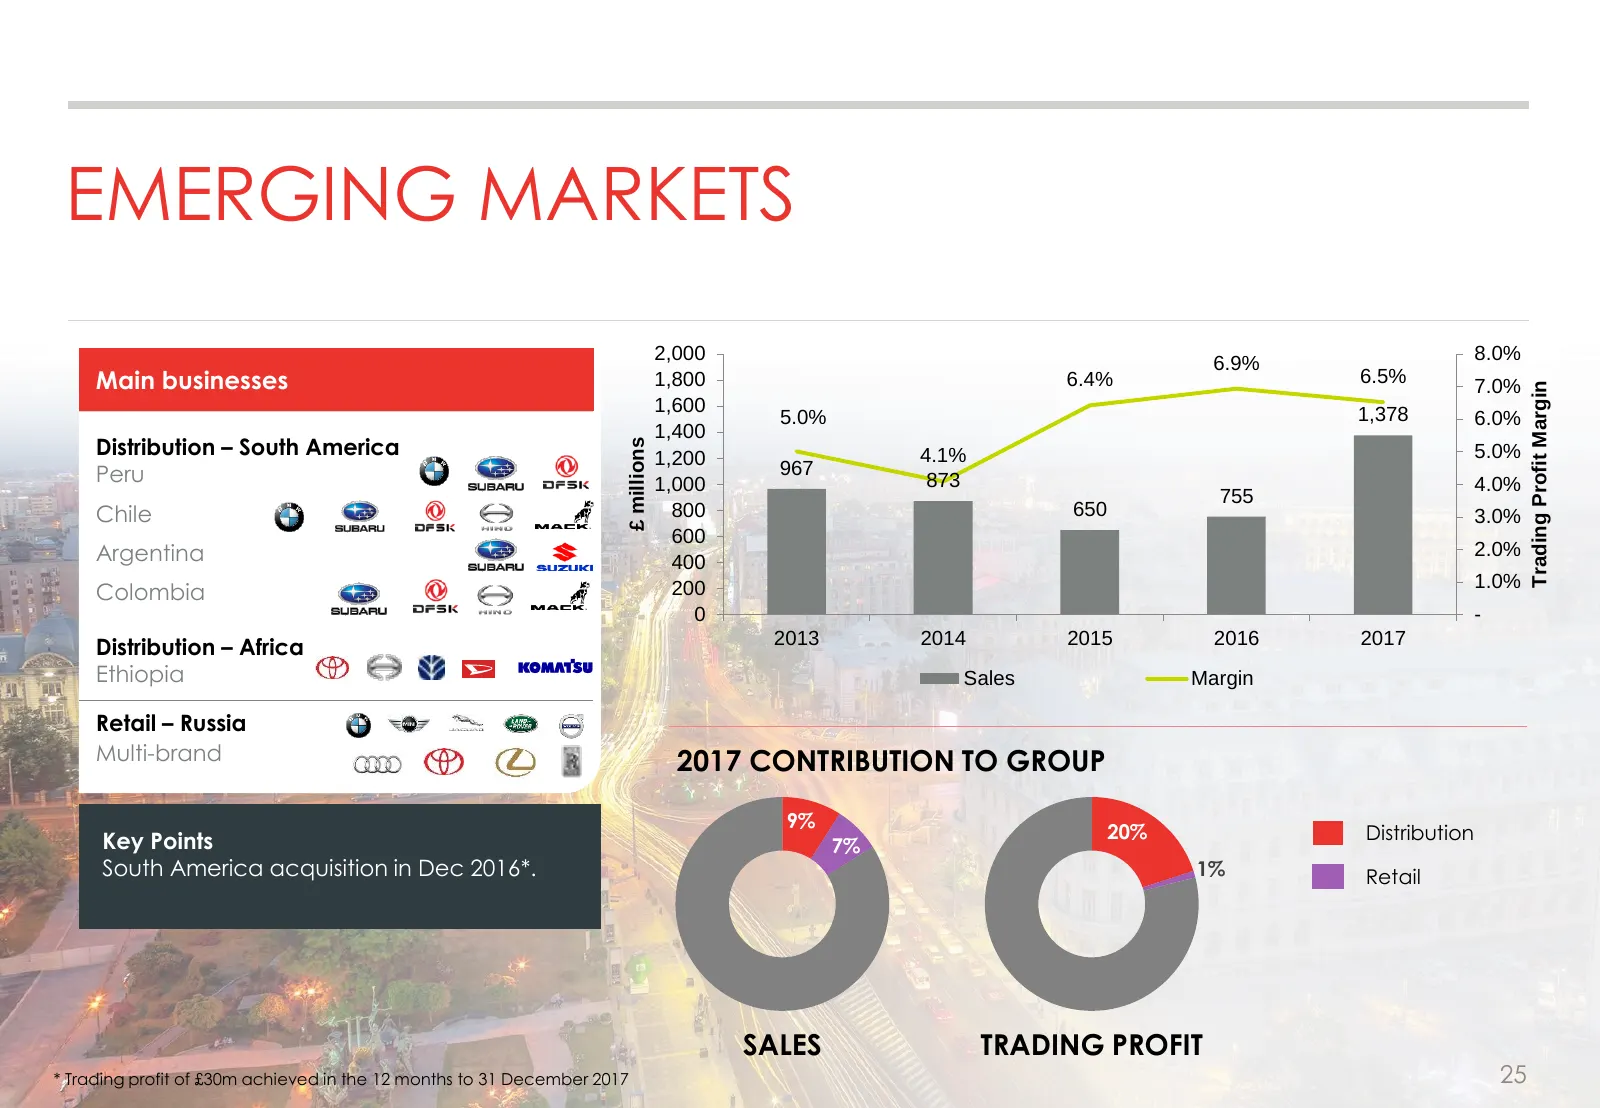
EMERGING MARKETS 2,000 6.9% 8.0% Main businesses 1,800 6.4% 6.5% 7.0% Trading Profit Margin 1,600 1,378 5.0% 6.0% 1,400 Distribution – South America £ millions 1,200 4.1% 5.0% Peru 1,000 967 873 4.0% 755 Chile 800 650 3.0% 600 Argentina 400 2.0% 1.0% Colombia 200 0 - Distribution – Africa 2013 2014
Slide 26: Appendix
APPENDIX
Slide 27: Leadership Team
LEADERSHIP TEAM Stefan Bomhard, CEO Stefan was appointed Inchcape Group Chief Executive in April 2015. Before joining Inchcape, Stefan was President of Bacardi Limited's European region and was also responsible for Bacardi's Global commercial organisation and Global Travel Retail Stefan has a PhD in
Slide 28: Inchcape History
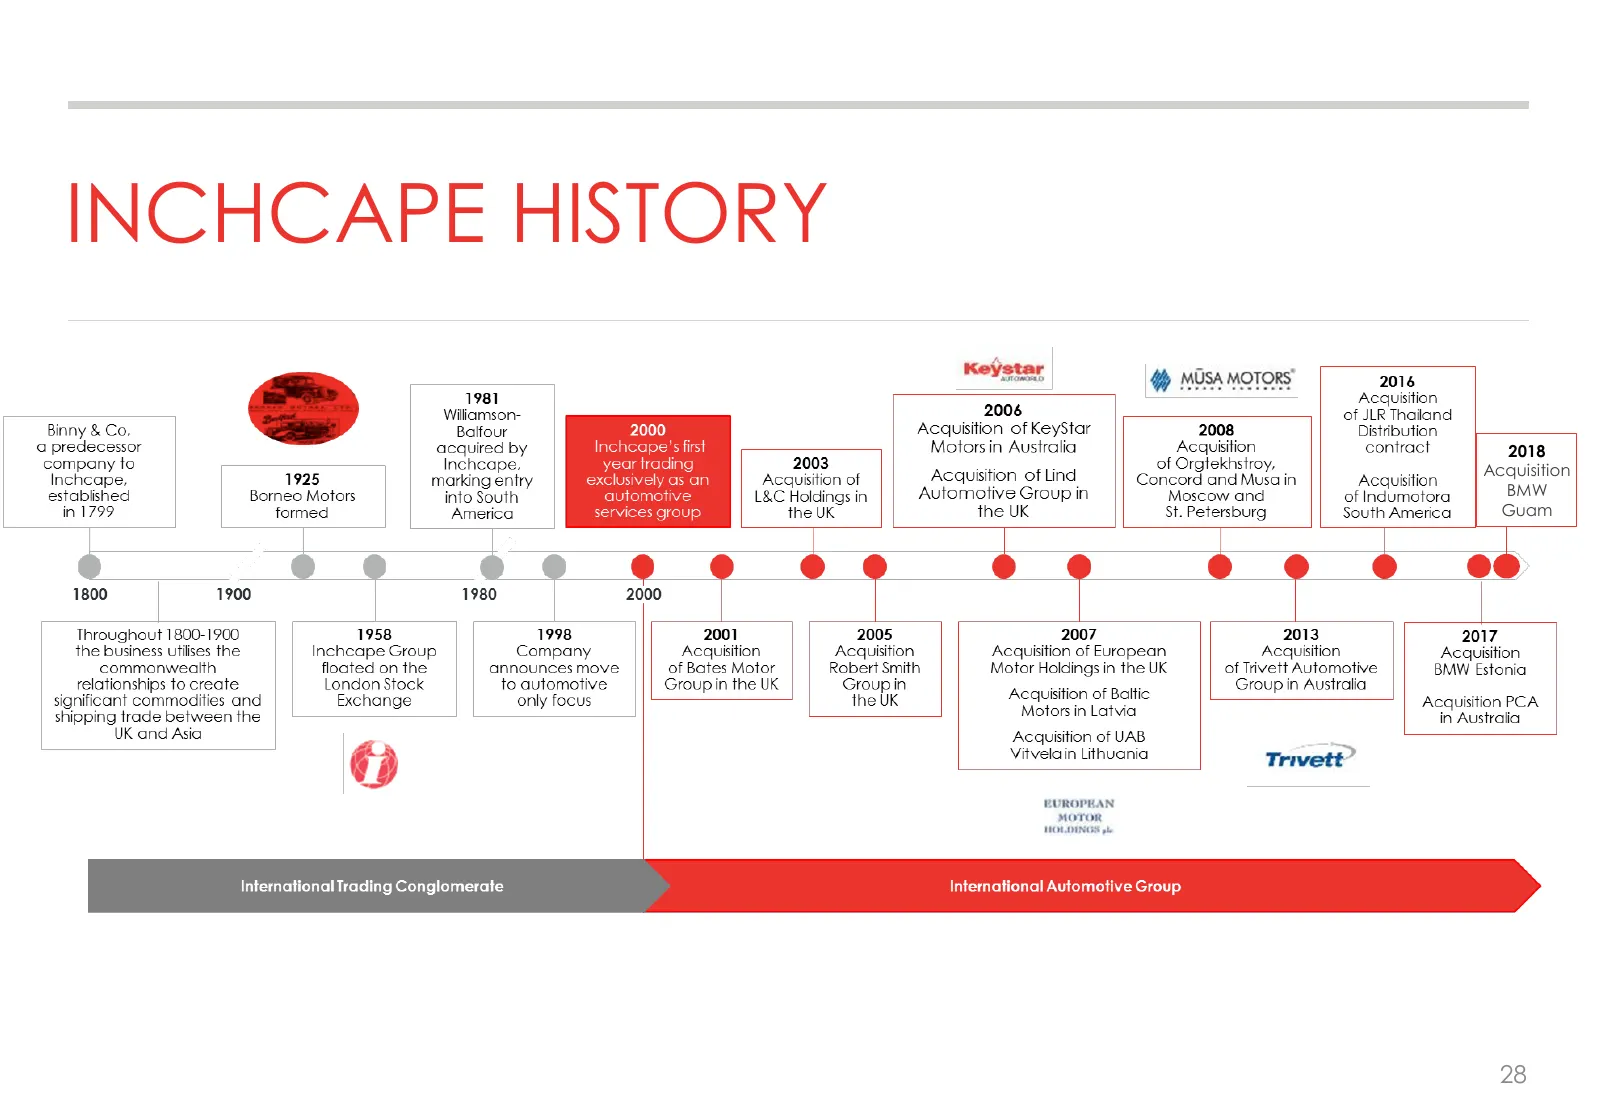
INCHCAPE HISTORY 2018 Acquisition BMW Guam 28
Slide 29: Inchcape ADR
INCHCAPE ADR Inchcape has established a sponsored Level 1 ADR program for which Deutsche Bank are the depositary bank. Inchcape ADRs trade on the U.S. OTC market. Ticker: INCPY ADR key benefits Exchange: OTC - Convenient means of trading/holding foreign shares CUSIP: 45326V202 - USD-denominated secu
Slide 30: Disclaimer
DISCLAIMER The information contained in this presentation in relation to Inchcape plc (“Inchcape”) and its subsidiaries (the "Inchcape Group") has been prepared solely for use at this presentation. It should not be used for whole or in part for any other purpose. The presentation is not directed to,
Source: company website
More decks from Inchcape plc
 H1 2026 Earnings Presentation27 slides · Jul 28, 2026
 FY 2025 Earnings Presentation26 slides · Mar 3, 2026
 Investor Day (January 2026)42 slides · Jan 15, 2026
 H1 2025 Earnings Presentation26 slides · Jul 29, 2025
 Investor Day (March 2025)5 slides · Mar 5, 2025
 FY 2024 Earnings Presentation32 slides · Mar 4, 2025