Perion Network Ltd · NASDAQ:PERI
Perion Network — Investor Day (December 2015)
65 slides from Perion Network's investor day presentation, Dec 31, 2015
Slide 1: Analyst Day
ANALYST DAY DECEMBER 31, 2015 1
Slide 2: Forward Looking Statements; Non-GAAP Measures
FORWARD LOOKING STATEMENTS This presentation contains historical information and forward-looking statements within the meaning of The Private Securities Litigation Reform Act of 1995 with respect to the business, financial condition and results of operations of Perion. The words “will”, “believe,” “
Slide 3: Executive Summary
EXECUTIVE SUMMARY 3
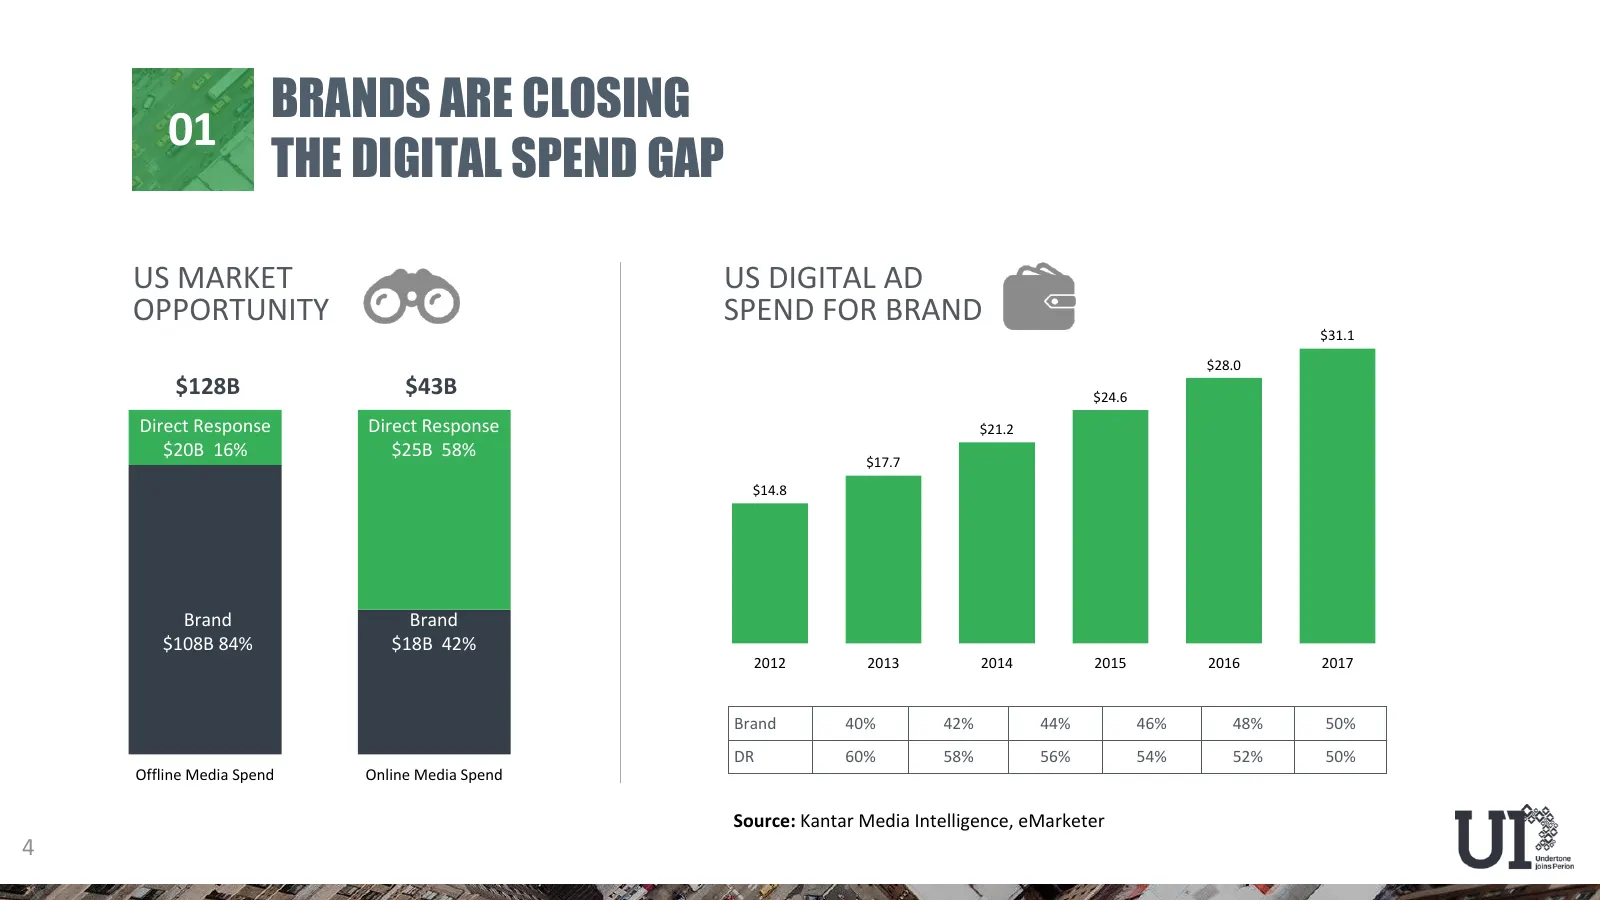
Slide 4: Brands are closing the digital spend gap
BRANDS ARE CLOSING 01 THE DIGITAL SPEND GAP US MARKET US DIGITAL AD OPPORTUNITY SPEND FOR BRAND $31.1 $28.0 $128B $43B $24.6 Direct Response Direct Response $21.2 $20B 16% $25B 58% $17.7 $14.8 Brand Brand $108B 84% $18B 42% 2012 2013 2014 2015 2016 2017 Brand 40% 42% 44% 46% 48% 50% DR 60% 58% 56% 5
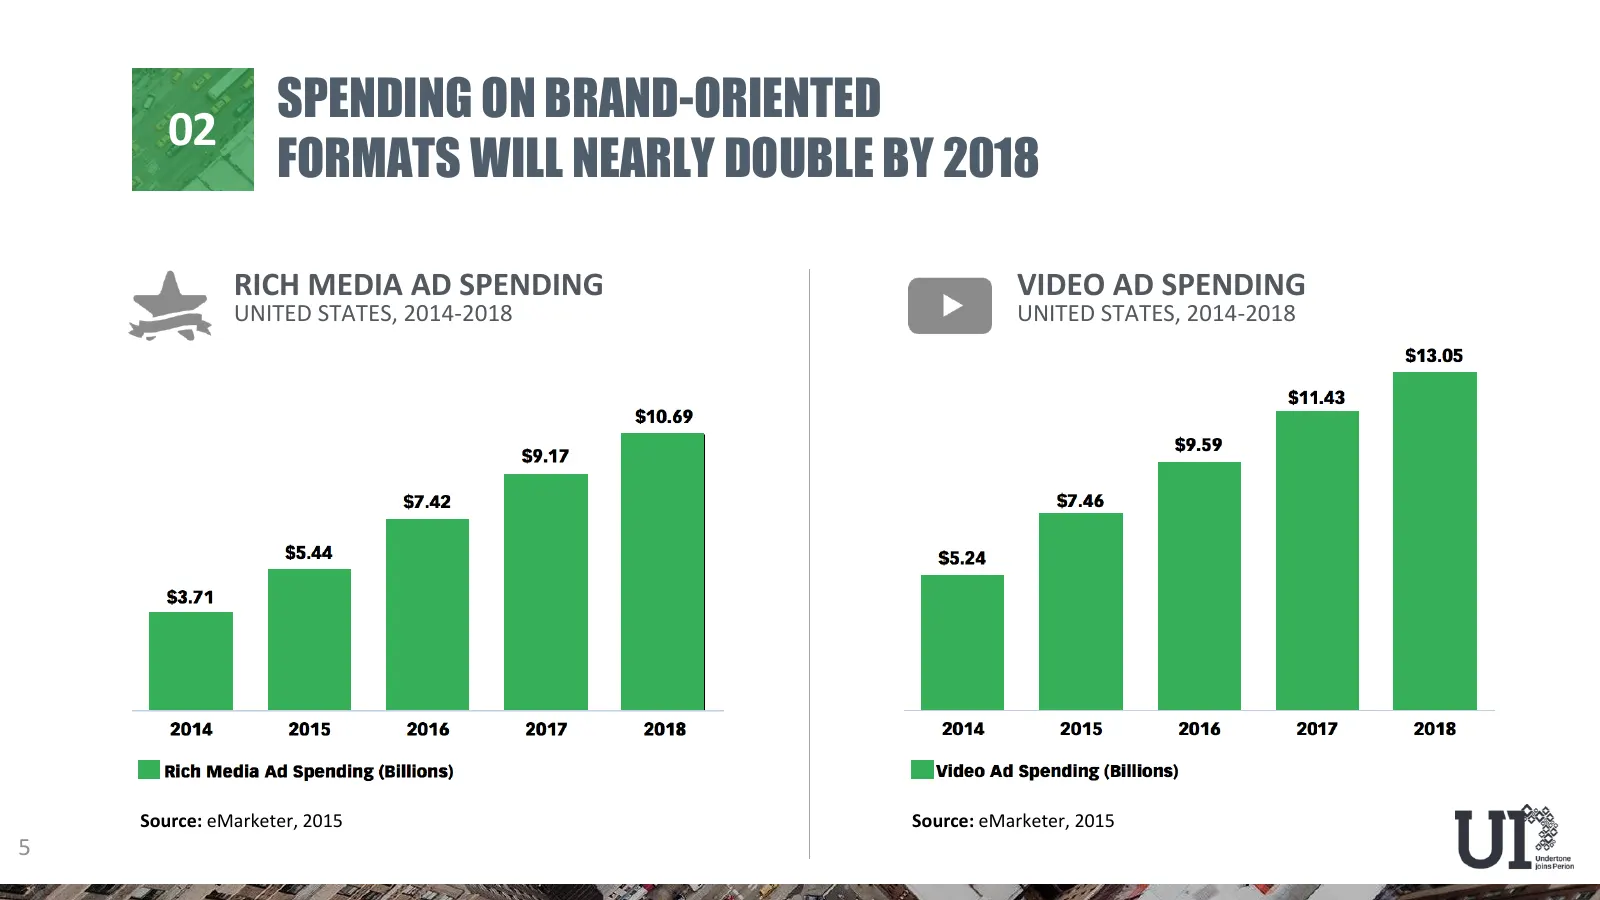
Slide 5: Spending on brand-oriented formats will nearly double by 2018
SPENDING ON BRAND-ORIENTED 02 FORMATS WILL NEARLY DOUBLE BY 2018 RICH MEDIA AD SPENDING VIDEO AD SPENDING UNITED STATES, 2014-2018 UNITED STATES, 2014-2018 Source: eMarketer, 2015 Source: eMarketer, 2015 5
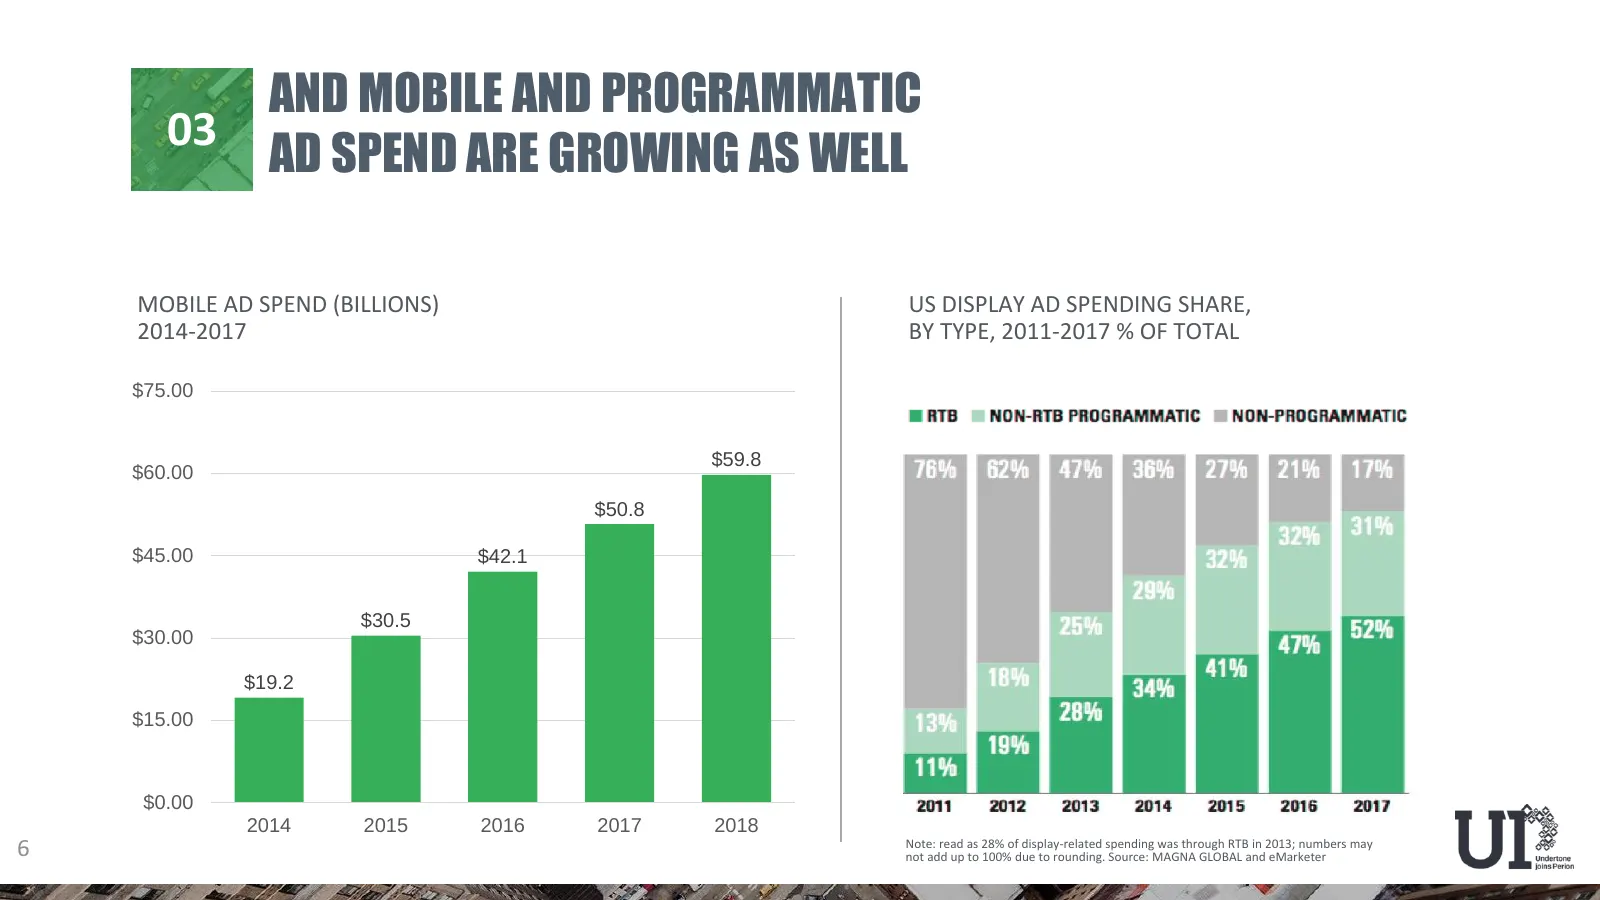
Slide 6: And mobile and programmatic ad spend are growing as well
AND MOBILE AND PROGRAMMATIC 03 AD SPEND ARE GROWING AS WELL MOBILE AD SPEND (BILLIONS) US DISPLAY AD SPENDING SHARE, 2014-2017 BY TYPE, 2011-2017 % OF TOTAL $75.00 $59.8 $60.00 $50.8 $45.00 $42.1 $30.5 $30.00 $19.2 $15.00 $0.00 2014 2015 2016 2017 2018 6 Note: read as 28% of display-related spending
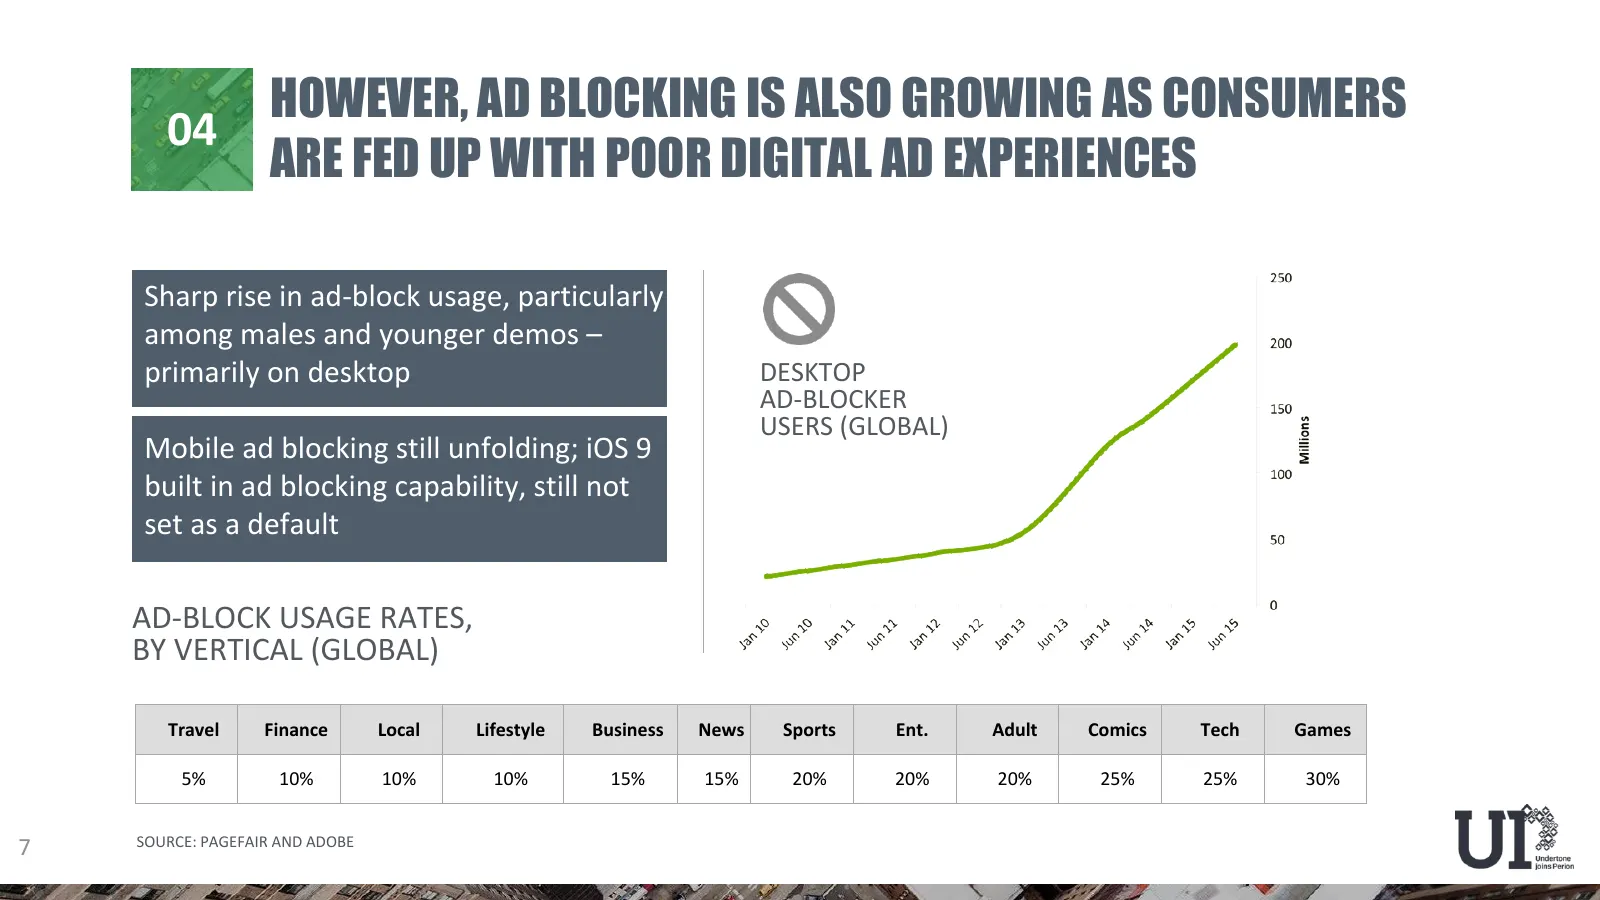
Slide 7: However, ad blocking is also growing
HOWEVER, AD BLOCKING IS ALSO GROWING AS CONSUMERS 04 ARE FED UP WITH POOR DIGITAL AD EXPERIENCES Sharp rise in ad-block usage, particularly among males and younger demos – primarily on desktop DESKTOP AD-BLOCKER USERS (GLOBAL) Mobile ad blocking still unfolding; iOS 9 built in ad blocking capability
Slide 8: Our strategy takes into account these trends
OUR STRATEGY TAKES INTO ACCOUNT THESE TRENDS… 8
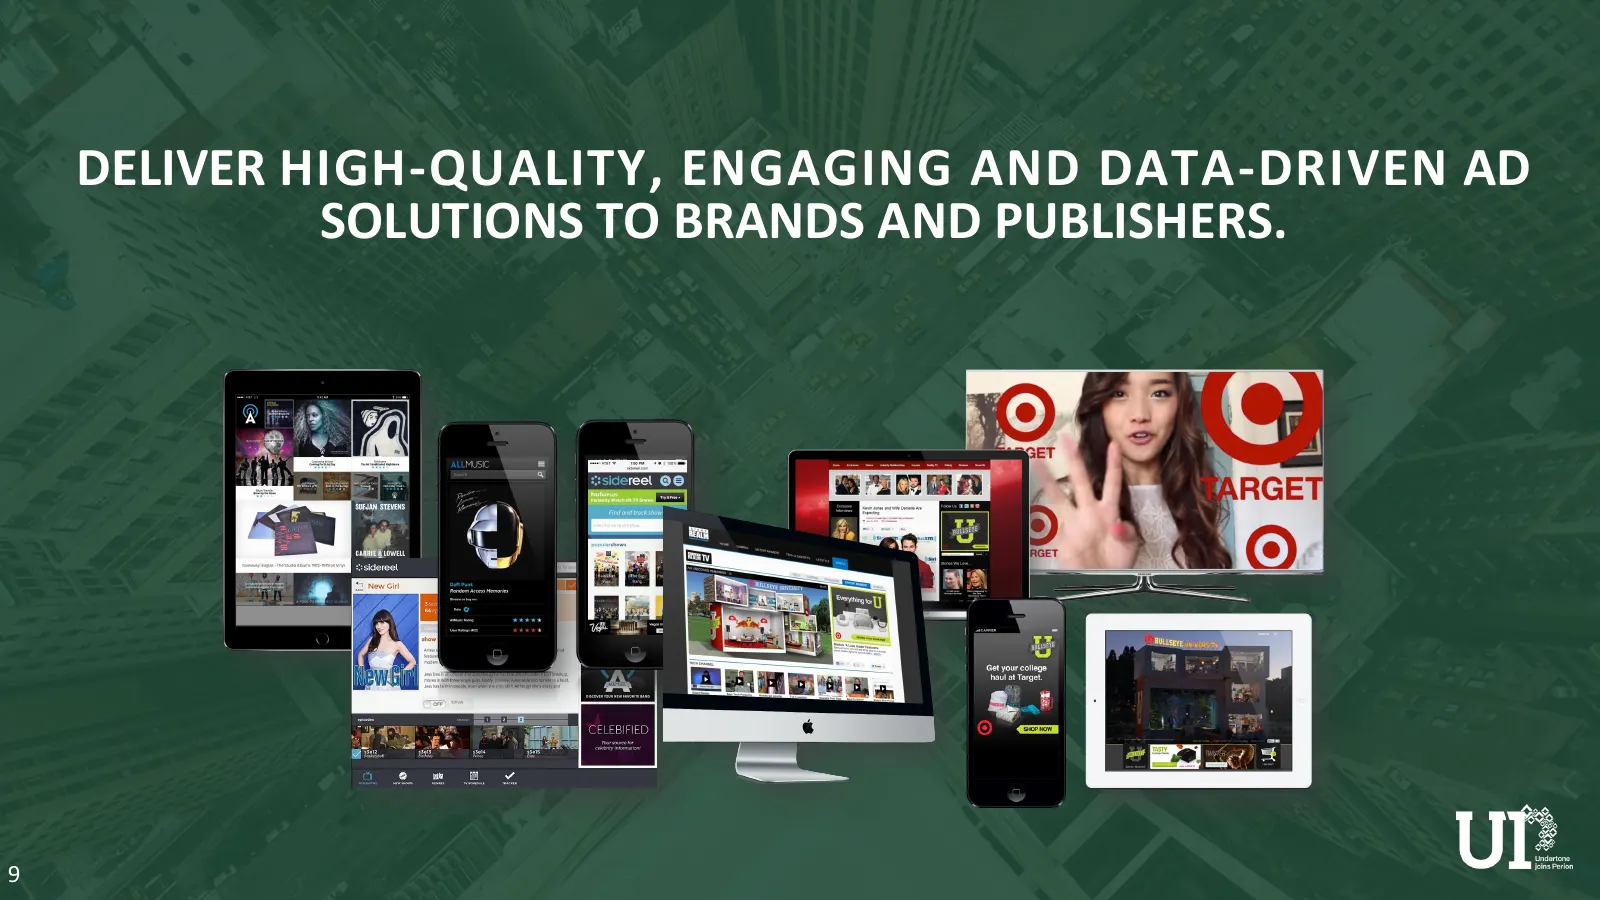
Slide 9: Deliver high-quality, engaging and data-driven ad solutions
DELIVER HIGH-QUALITY, ENGAGING AND DATA-DRIVEN AD SOLUTIONS TO BRANDS AND PUBLISHERS. 9
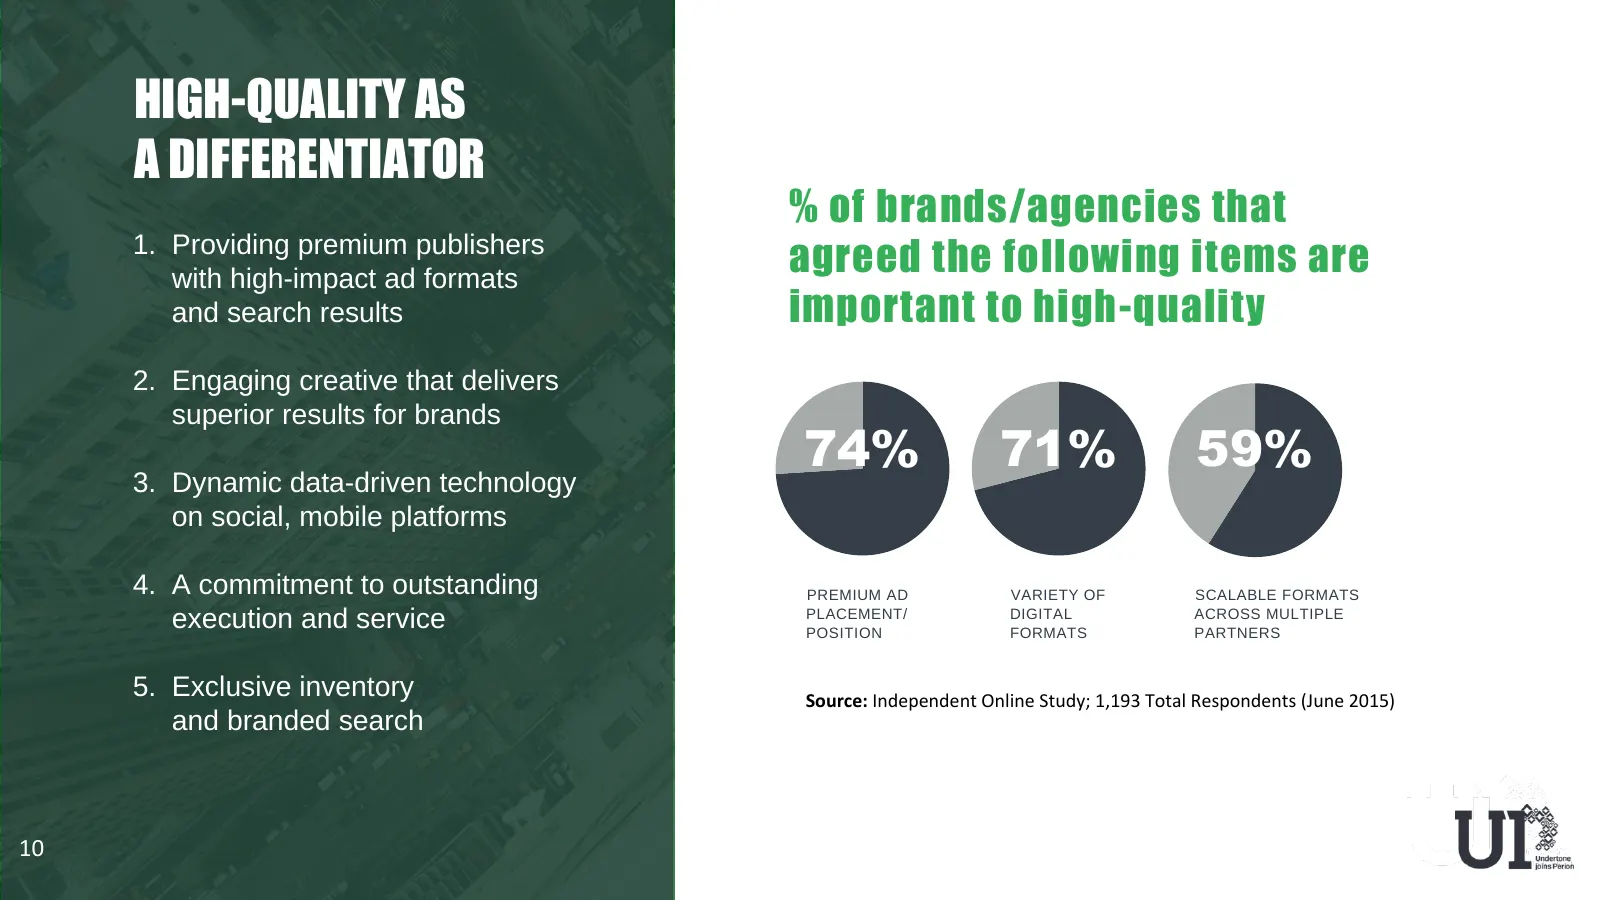
Slide 10: High-quality as a differentiator
HIGH-QUALITY AS A DIFFERENTIATOR % of brands/agencies that 1. Providing premium publishers with high-impact ad formats agreed the following items are and search results important to high-quality 2. Engaging creative that delivers superior results for brands 74% 71% 59% 3. Dynamic data-driven technol
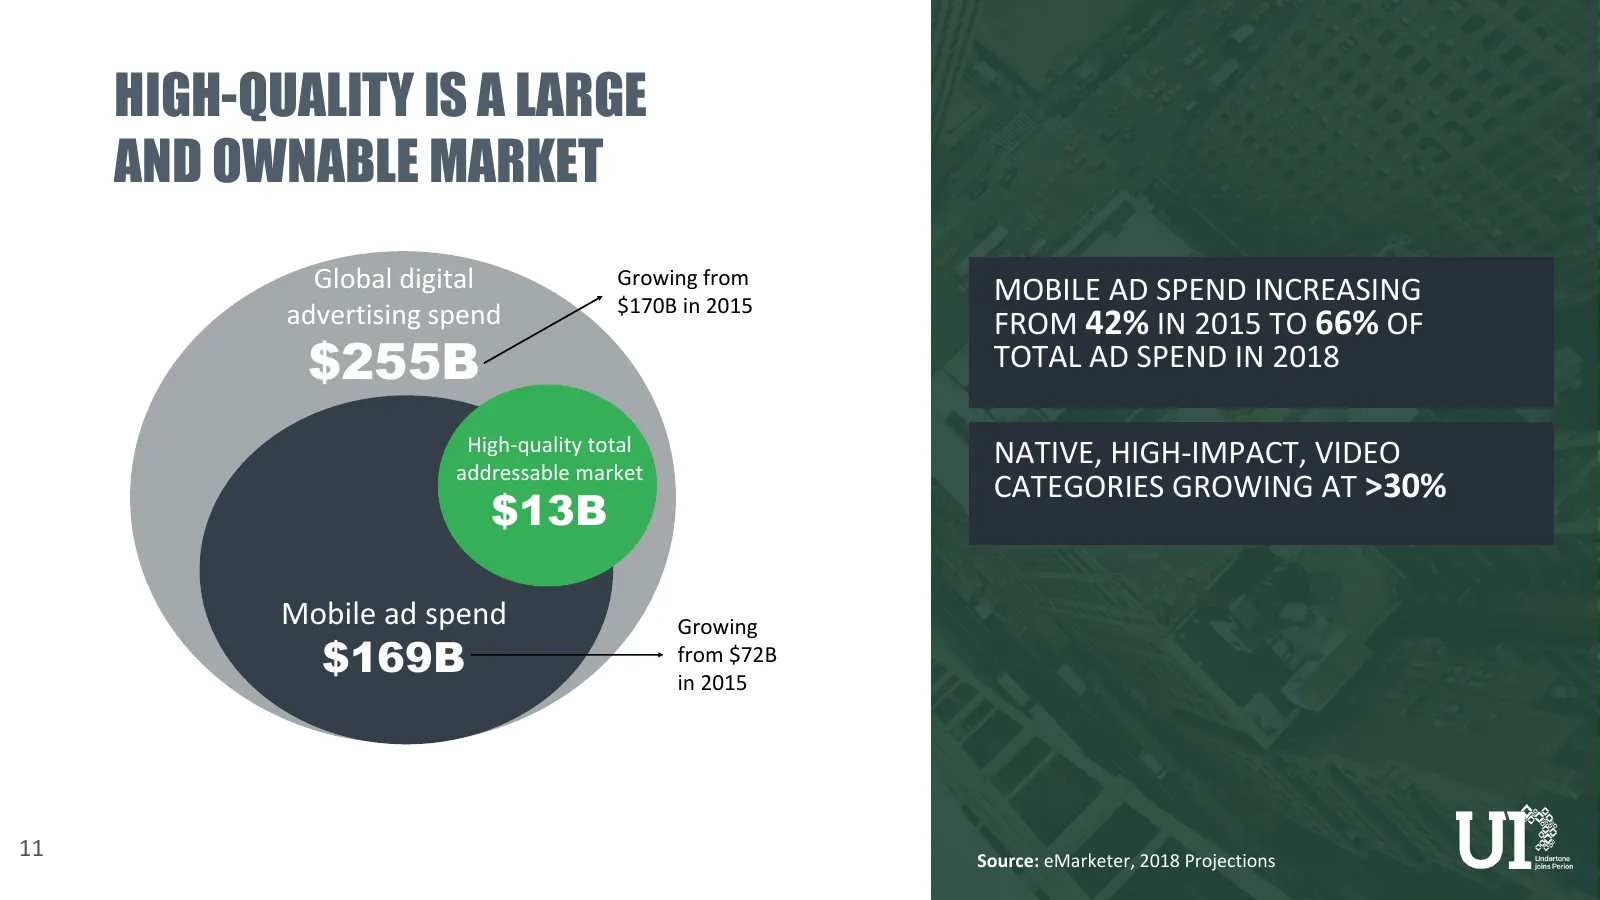
Slide 11: High-quality is a large and ownable market
HIGH-QUALITY IS A LARGE AND OWNABLE MARKET Global digital Growing from MOBILE AD SPEND INCREASING advertising spend $170B in 2015 FROM 42% IN 2015 TO 66% OF $255B TOTAL AD SPEND IN 2018 High-quality total NATIVE, HIGH-IMPACT, VIDEO addressable market CATEGORIES GROWING AT >30% $13B Mobile ad spend G
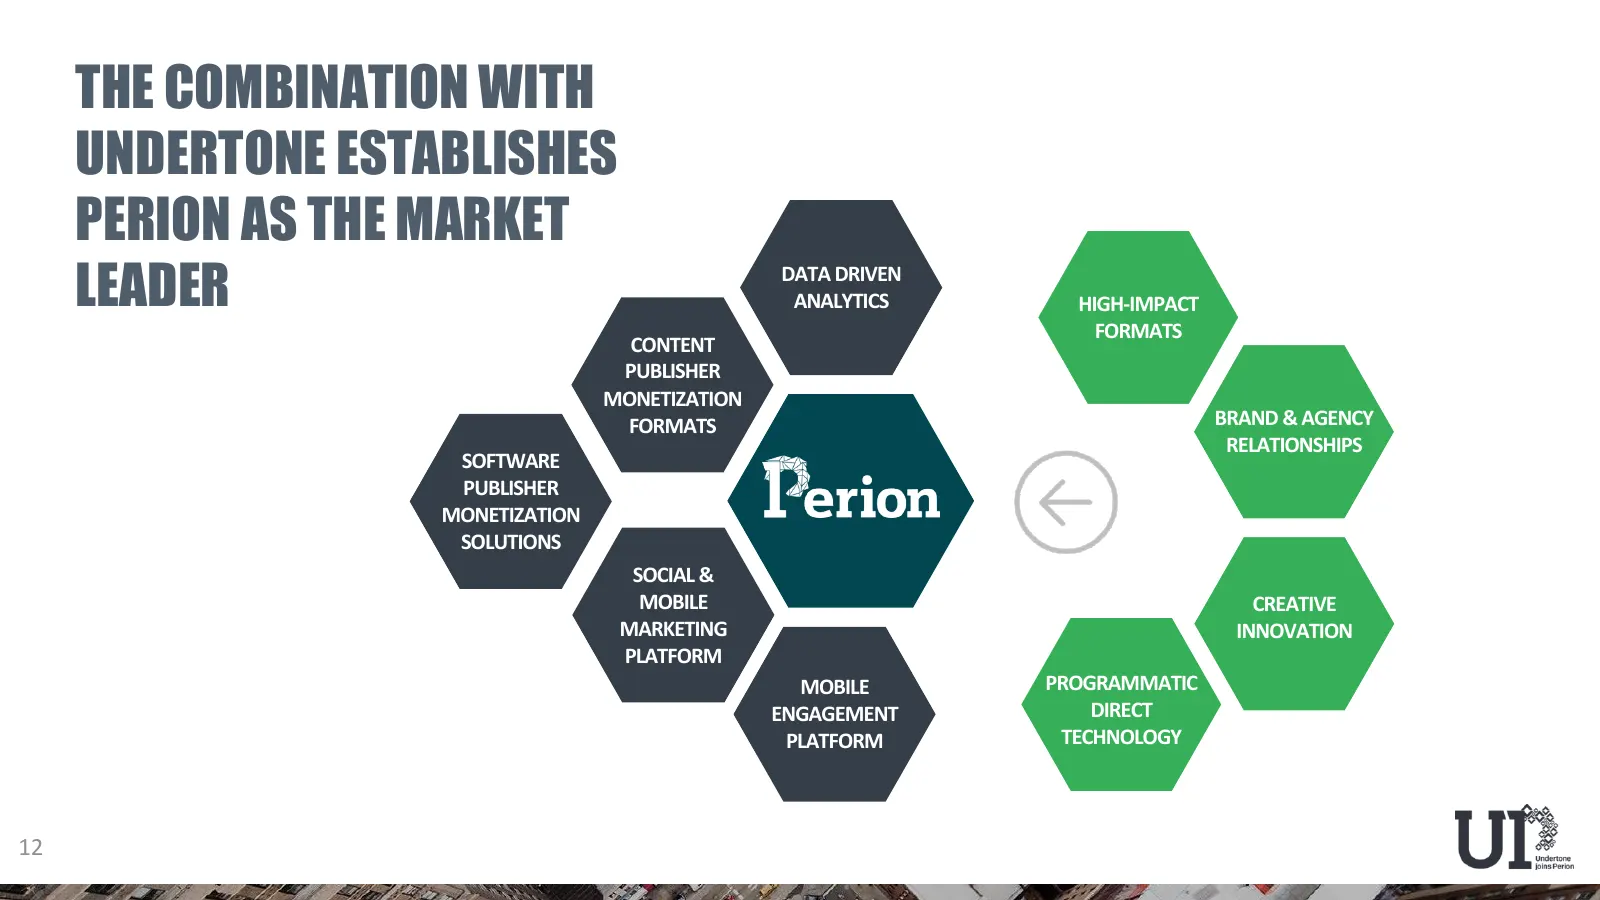
Slide 12: The combination with Undertone establishes Perion as the market leader
THE COMBINATION WITH UNDERTONE ESTABLISHES PERION AS THE MARKET LEADER DATA DRIVEN ANALYTICS HIGH-IMPACT FORMATS CONTENT PUBLISHER MONETIZATION FORMATS BRAND & AGENCY RELATIONSHIPS SOFTWARE PUBLISHER MONETIZATION SOLUTIONS SOCIAL & MOBILE CREATIVE MARKETING INNOVATION PLATFORM MOBILE PROGRAMMATIC EN
Slide 13: Our three main areas of focus for 2016
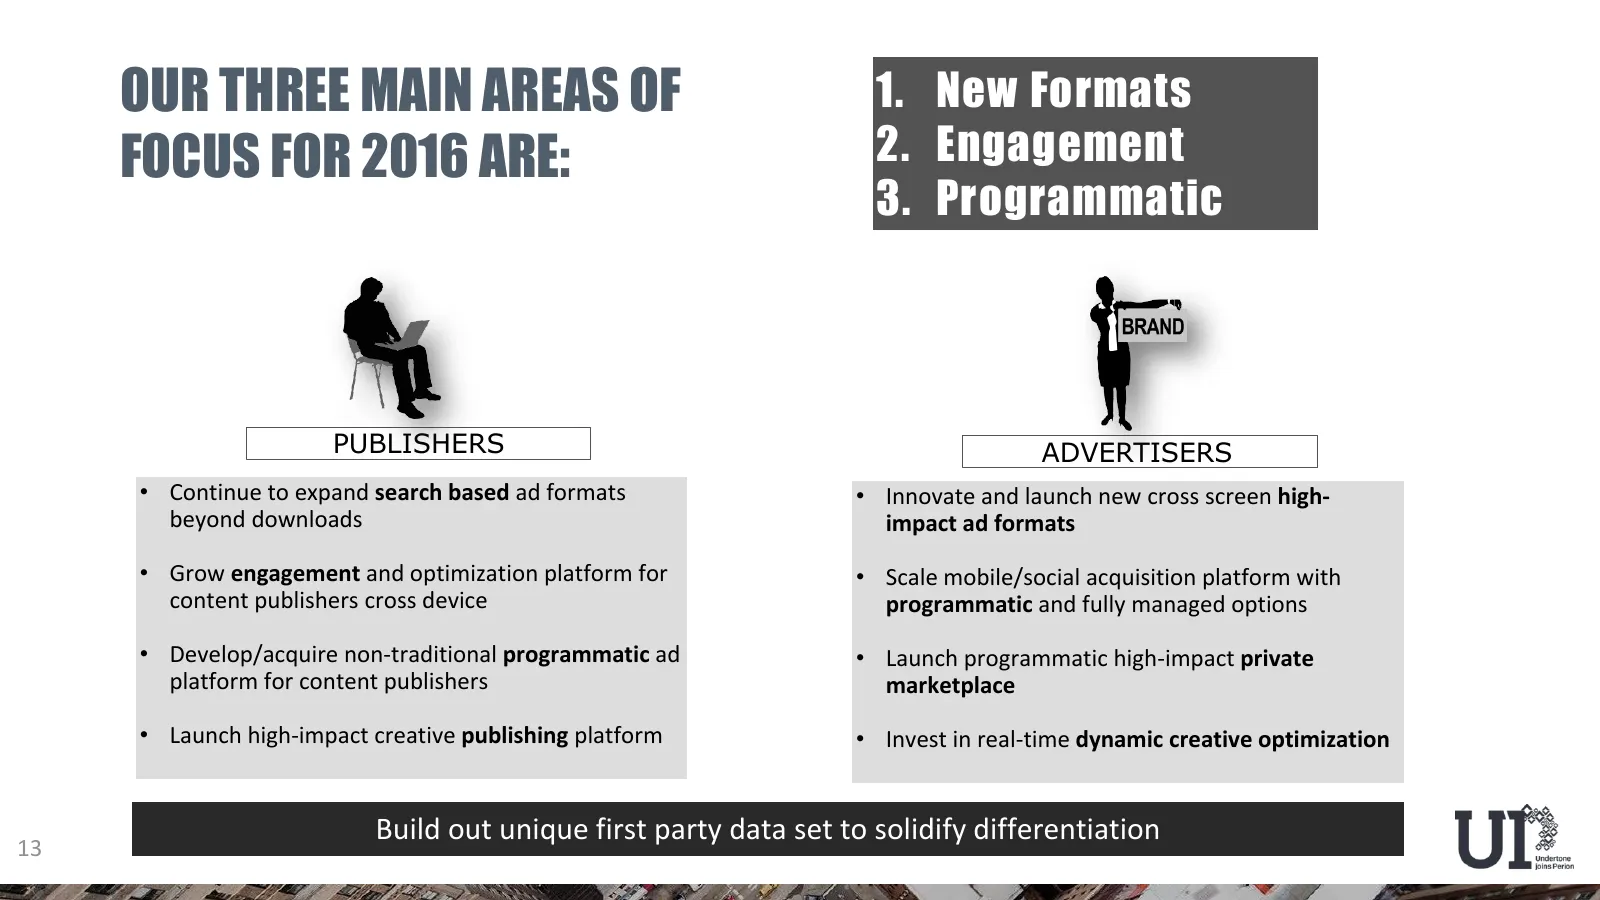
OUR THREE MAIN AREAS OF 1. New Formats FOCUS FOR 2016 ARE: 2. Engagement 3. Programmatic PUBLISHERS ADVERTISERS • Continue to expand search based ad formats • Innovate and launch new cross screen high- beyond downloads impact ad formats • Grow engagement and optimization platform for • Scale mobile/
Slide 14: CodeFuel
14 ce ee a la OT“ Oa CodeFuel Cte Oe he ~~ £4» oo Sf ZFS Ip
Slide 15: Search represents 50% of total digital ad spending
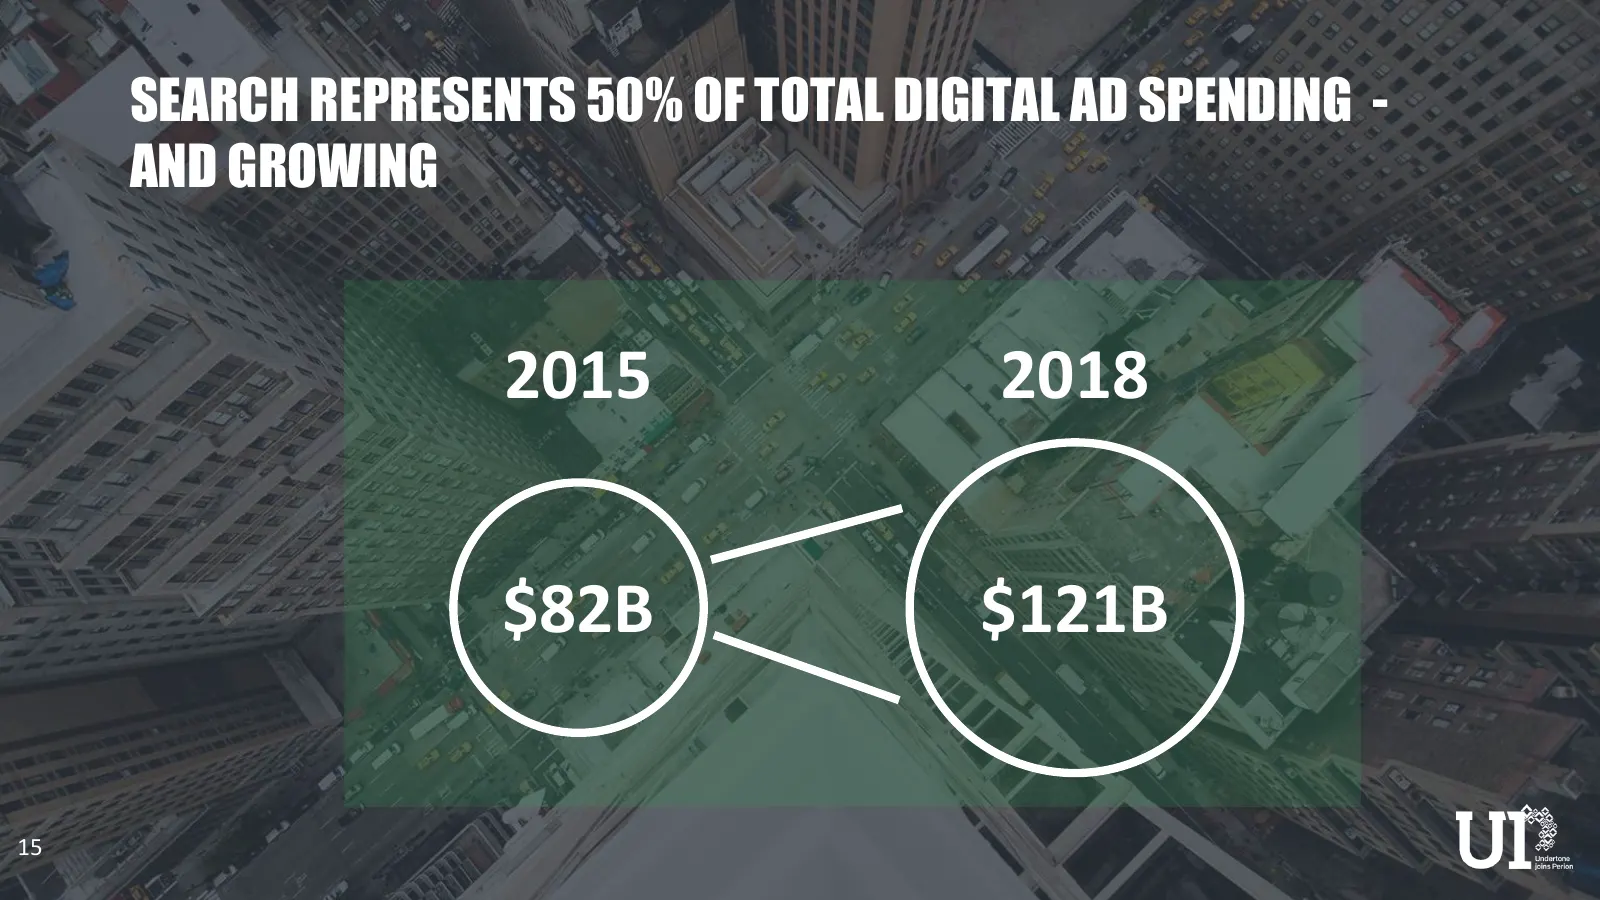
SEARCH REPRESENTS 50% OF TOTAL DIGITAL AD SPENDING - AND GROWING 2015 2018 $82B $121B 15
Slide 16: Our search business has stabilized
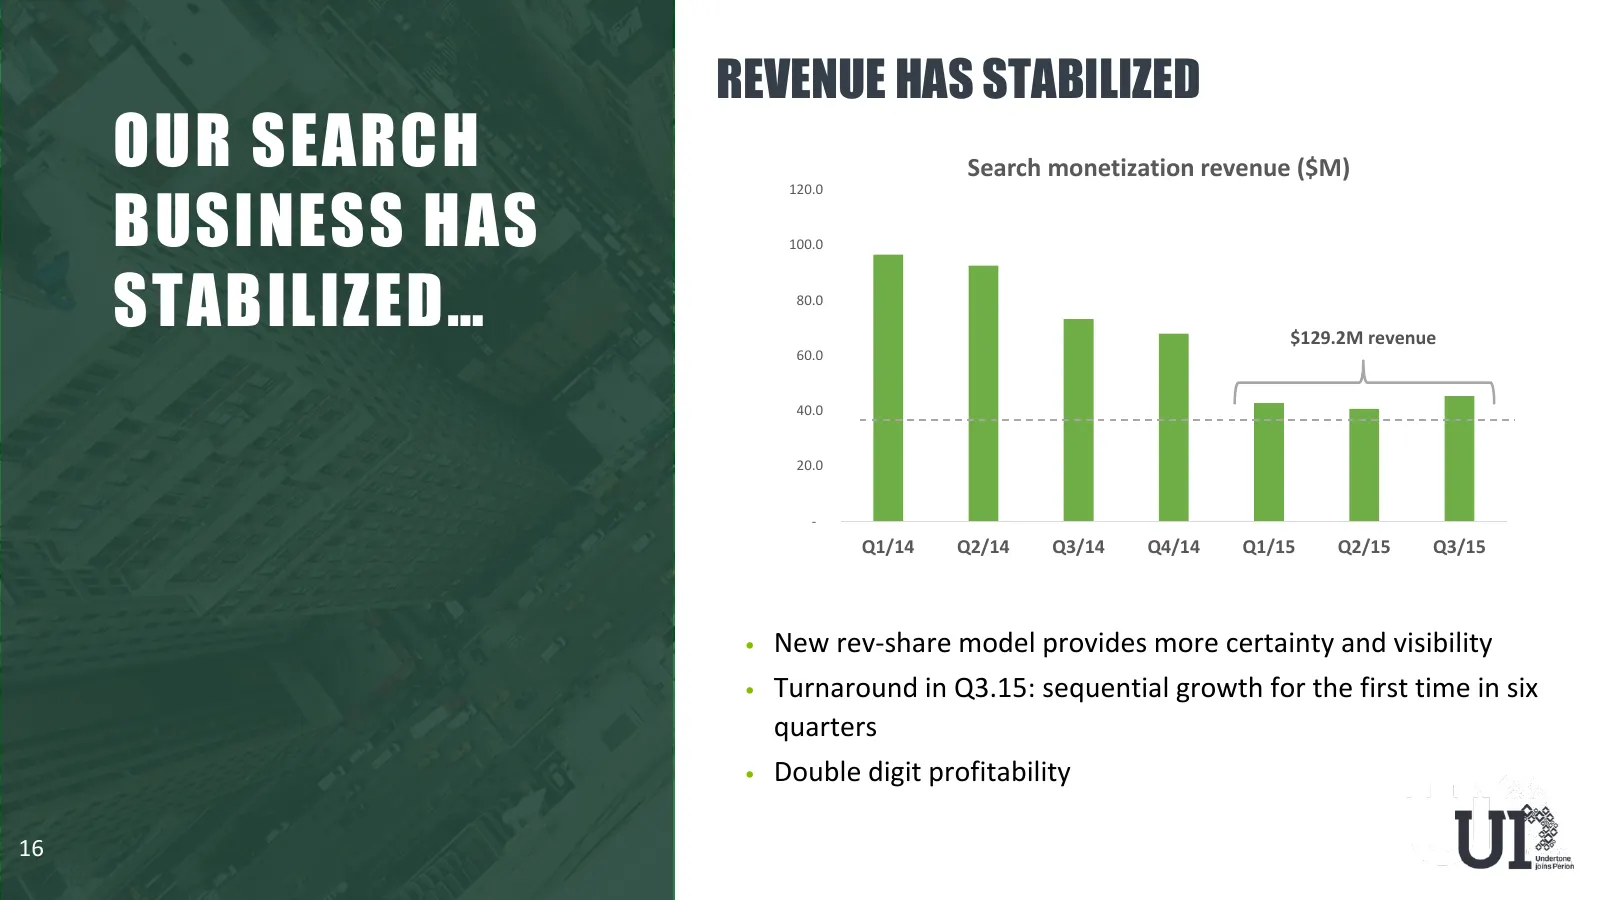
REVENUE HAS STABILIZED OUR SEARCH Search monetization revenue ($M) BUSINESS HAS 120.0 100.0 STABILIZED… 80.0 $129.2M revenue 60.0 40.0 20.0 - Q1/14 Q2/14 Q3/14 Q4/14 Q1/15 Q2/15 Q3/15 • New rev-share model provides more certainty and visibility • Turnaround in Q3.15: sequential growth for the first
Slide 17: However the industry is still volatile
NO PLACE FOR SMALL PLAYERS: … HOWEVER THE INDUSTRY IS • Downloadable software market is shrinking, STILL VOLATILE leaving room only for big players such as Perion • Perion has already proven its ability to execute in this changing environment • Additional policies and new changes in the ecosystem: •
Slide 18: Opportunities for 2016: leveraging our assets
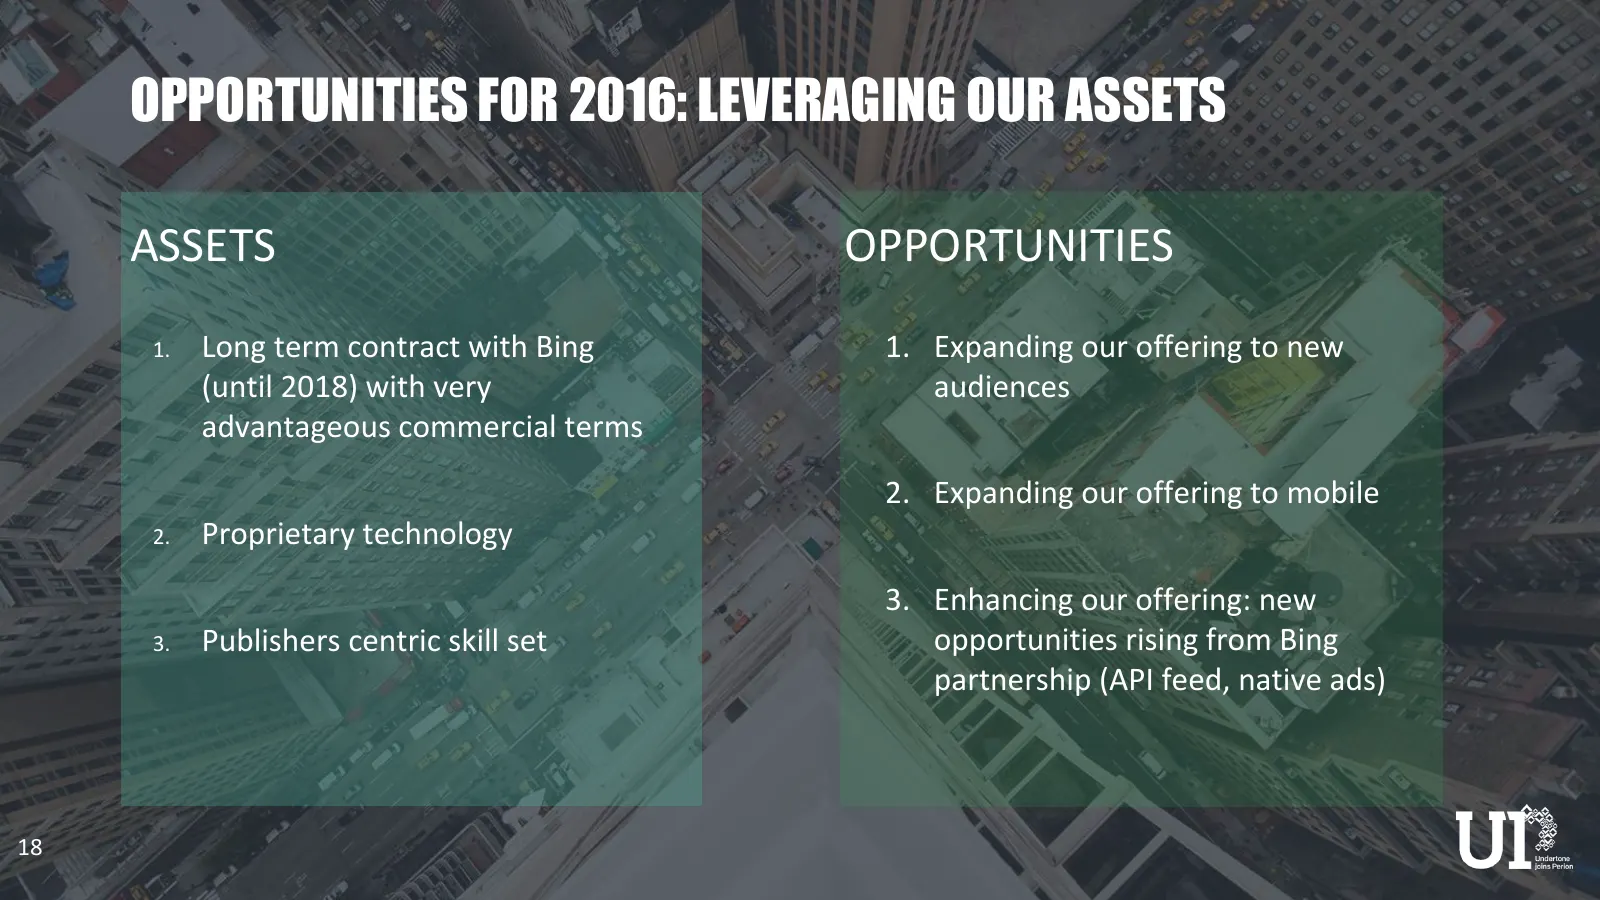
OPPORTUNITIES FOR 2016: LEVERAGING OUR ASSETS ASSETS OPPORTUNITIES 1. Long term contract with Bing 1. Expanding our offering to new (until 2018) with very audiences advantageous commercial terms 2. Expanding our offering to mobile 2. Proprietary technology 3. Enhancing our offering: new 3. Publisher
Slide 19: Our new target audience: content publishers
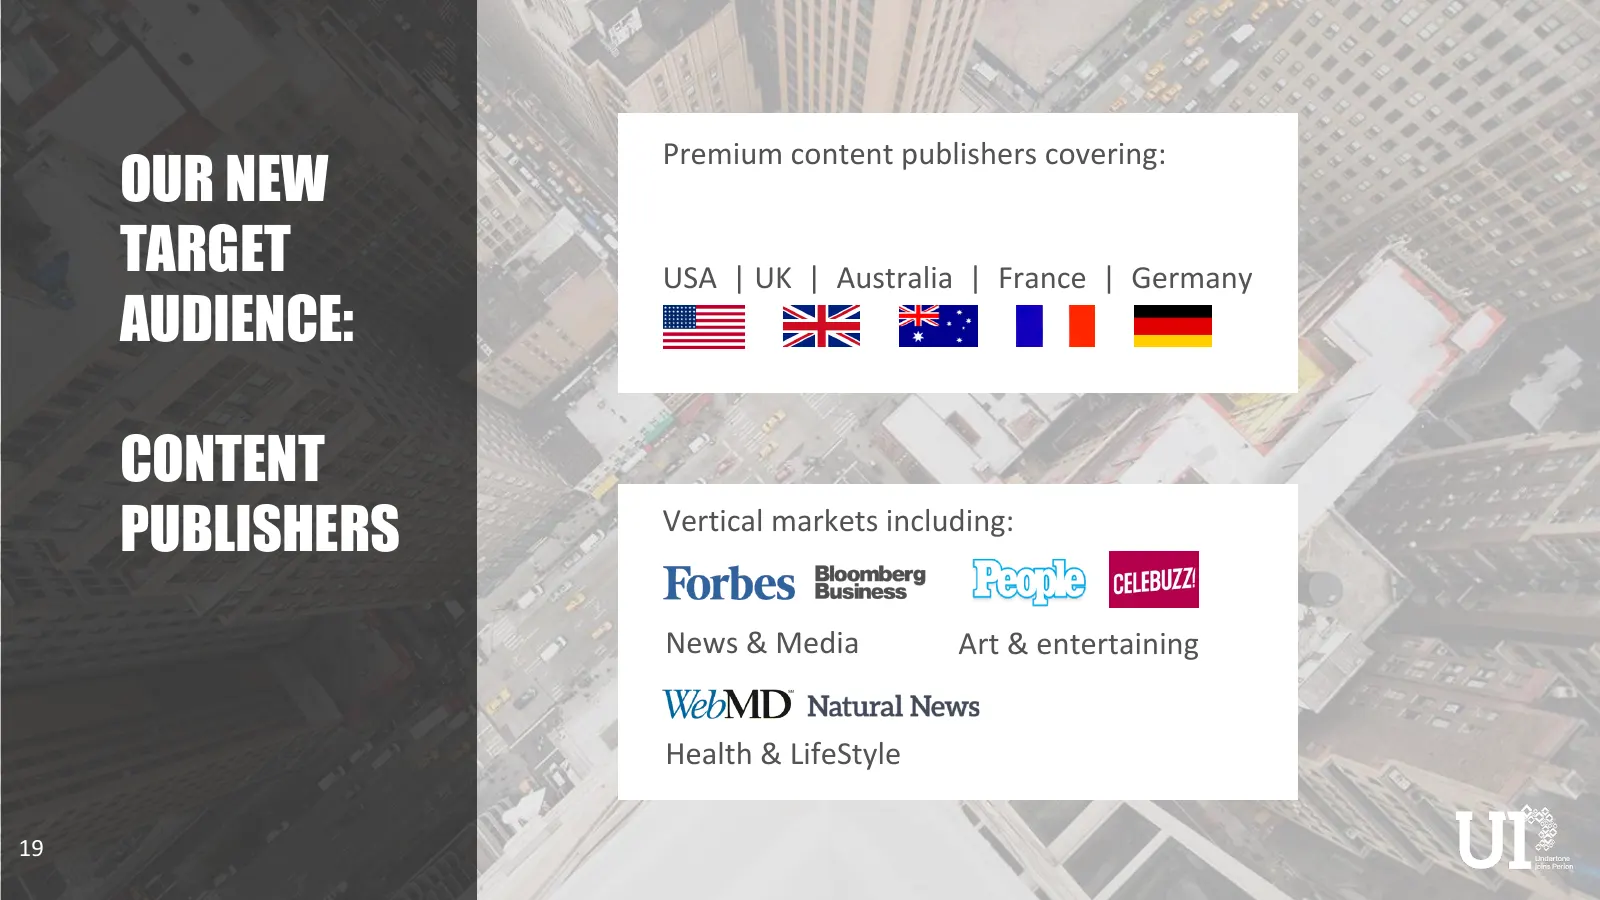
Premium content publishers covering: OUR NEW TARGET USA | UK | Australia | France | Germany AUDIENCE: CONTENT PUBLISHERS Vertical markets including: News & Media Art & entertaining Health & LifeStyle 19
Slide 20: None of them knows how to balance engagement and monetization
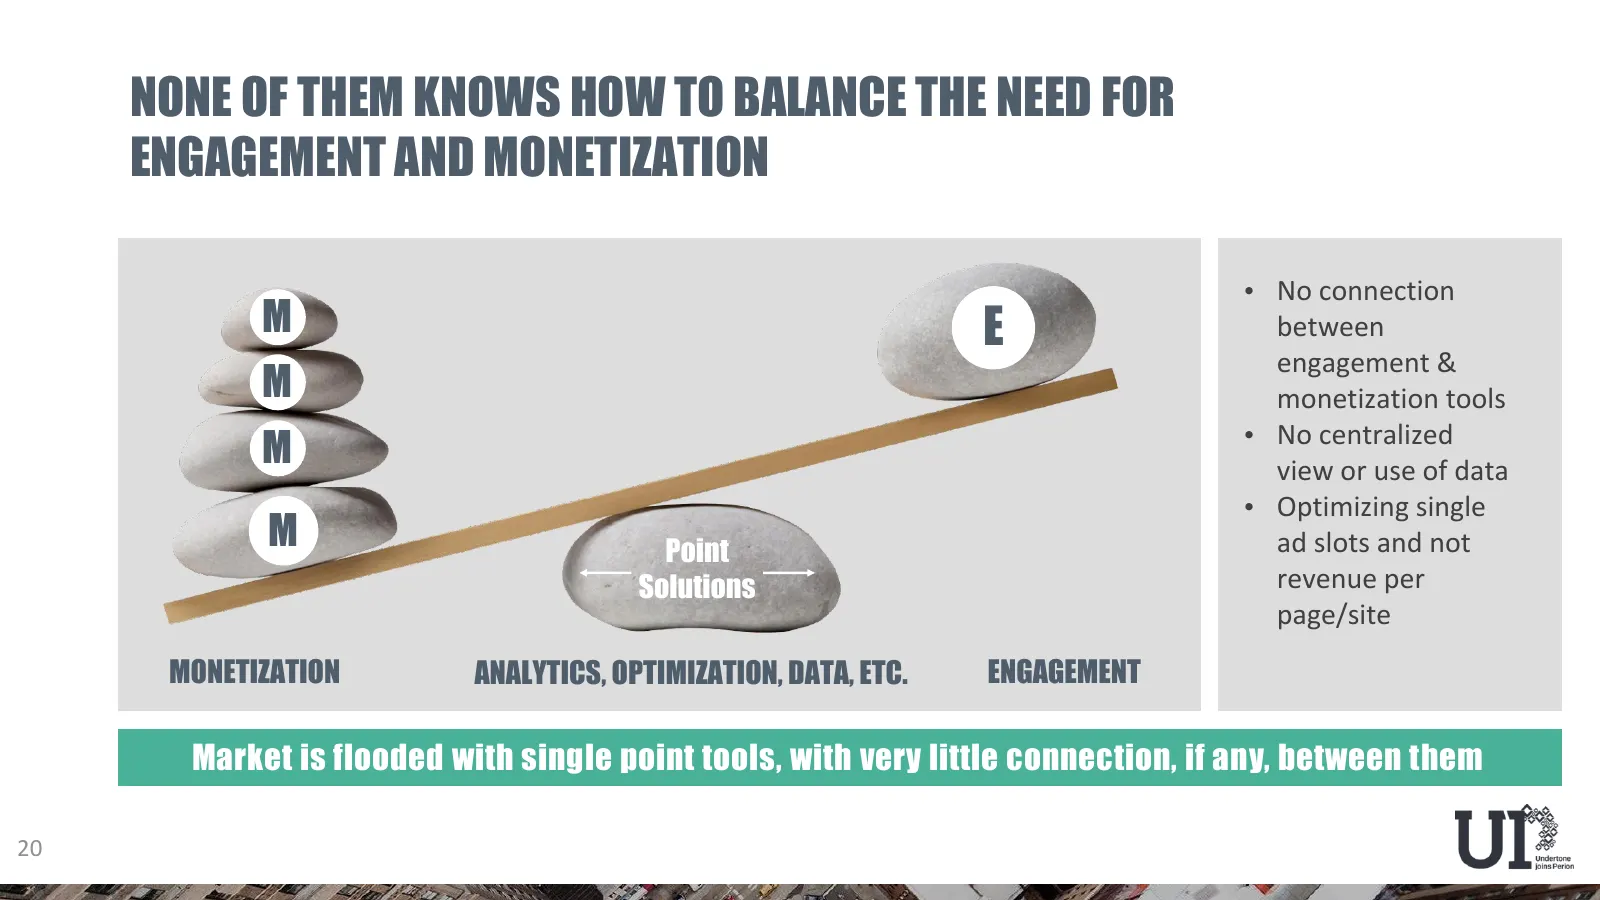
NONE OF THEM KNOWS HOW TO BALANCE THE NEED FOR ENGAGEMENT AND MONETIZATION • No connection M E between engagement & M monetization tools • No centralized M view or use of data • Optimizing single M Point ad slots and not Solutions revenue per page/site MONETIZATION ANALYTICS, OPTIMIZATION, DATA, ETC
Slide 21: Publishers don't have the capacity to look beyond immediate threats
AND PUBLISHERS DON'T HAVE THE CAPACITY TO LOOK BEYOND IMMEDIATE THREATS • Majority of Publishers are still Most trending topics are all focused on developing an adequate immediate threats… digital/mobile solution as they are in the war for survival Ad Blockers • Very few have been able to dedicate s
Slide 22: Addressed with too many single point solutions
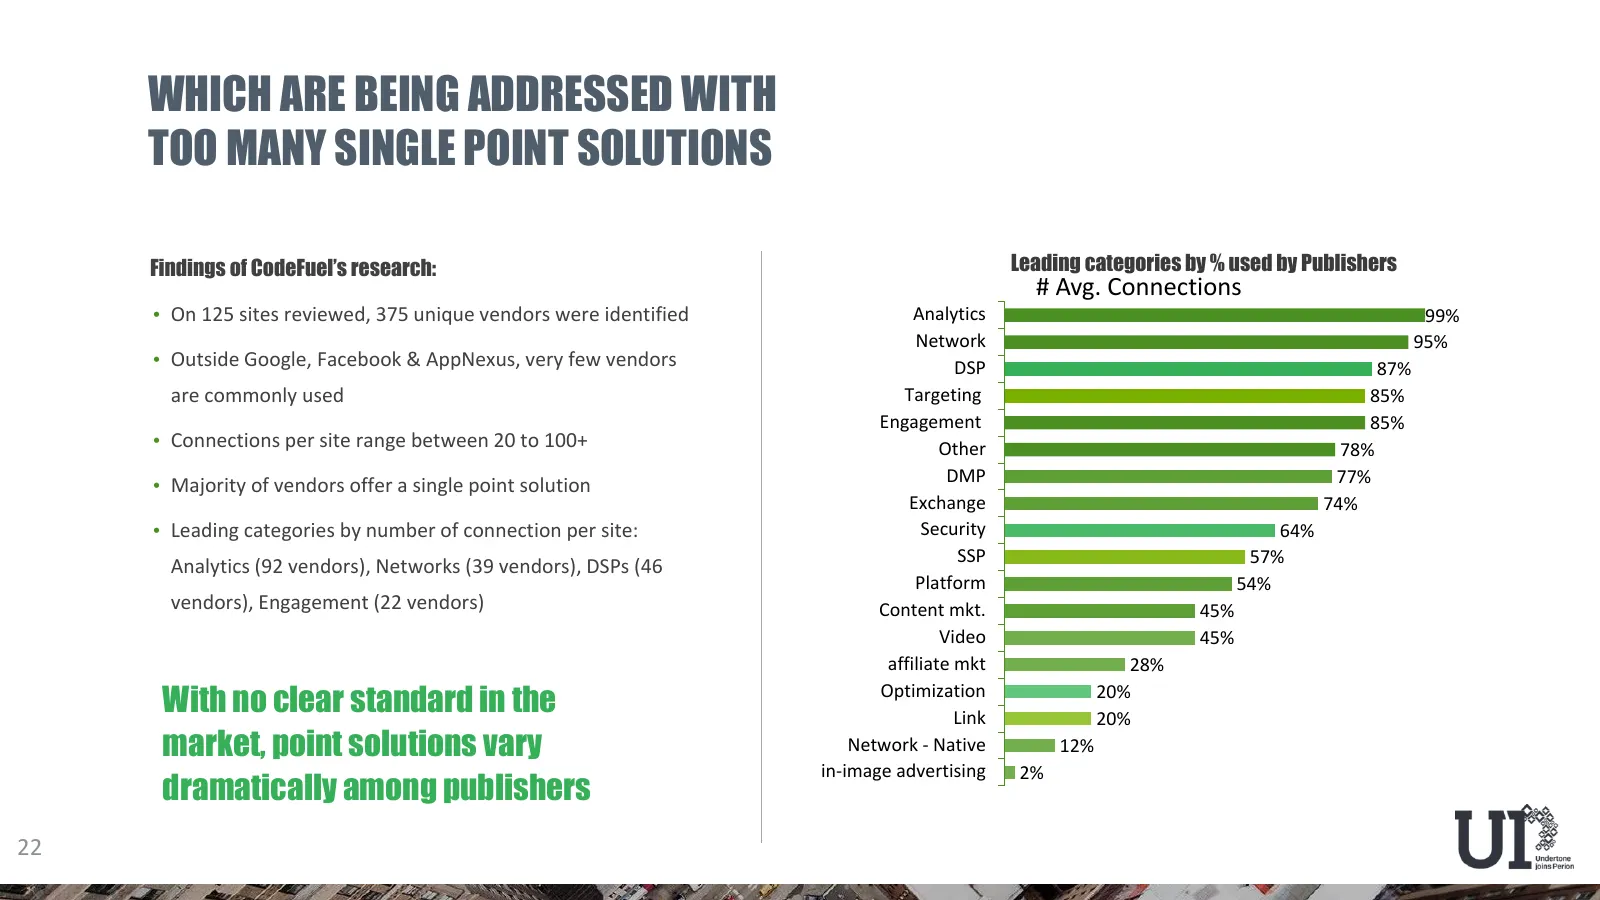
WHICH ARE BEING ADDRESSED WITH TOO MANY SINGLE POINT SOLUTIONS Findings of CodeFuel’s research: Leading categories by % used by Publishers # Avg. Connections • On 125 sites reviewed, 375 unique vendors were identified Analytics 99% Network 95% • Outside Google, Facebook & AppNexus, very few vendors
Slide 23: Our value proposition: make the publisher's life simpler
= OUR VALUE PROPOSITION: MAKE THE PUBLISHER'S LIFE SIMPLER Allow Publishers To Focus On What They Do Best By Building Engagement & Monetization Solutions Not Tools Tools = require extensive additional efforts by Publisher 23 Solution = require limited efforts by Publisher
Slide 24: Our solution
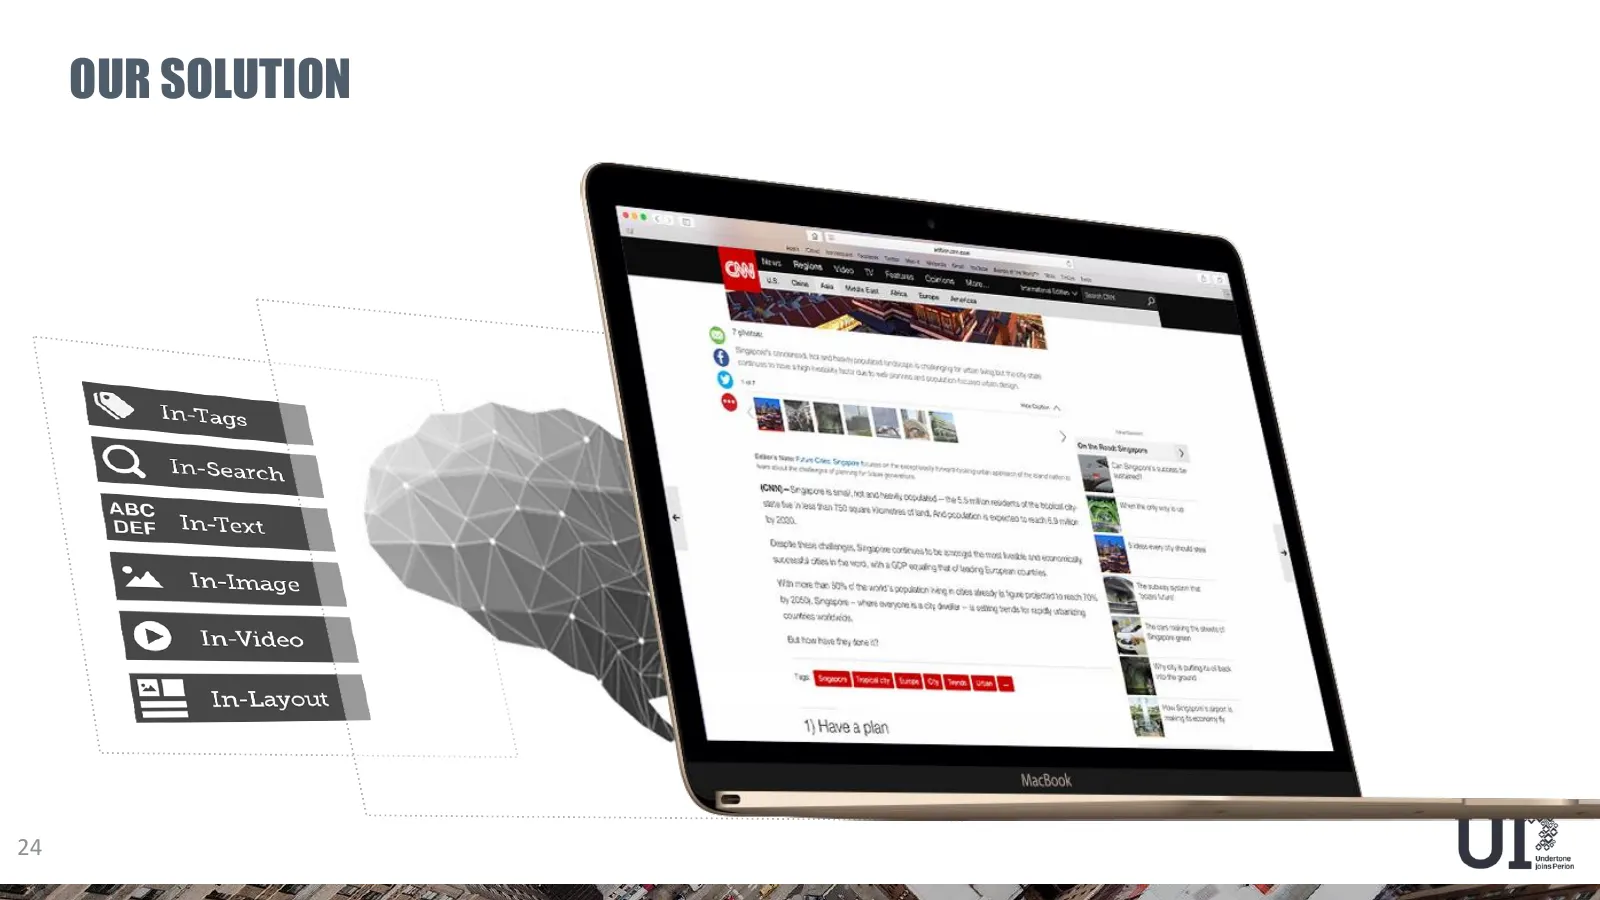
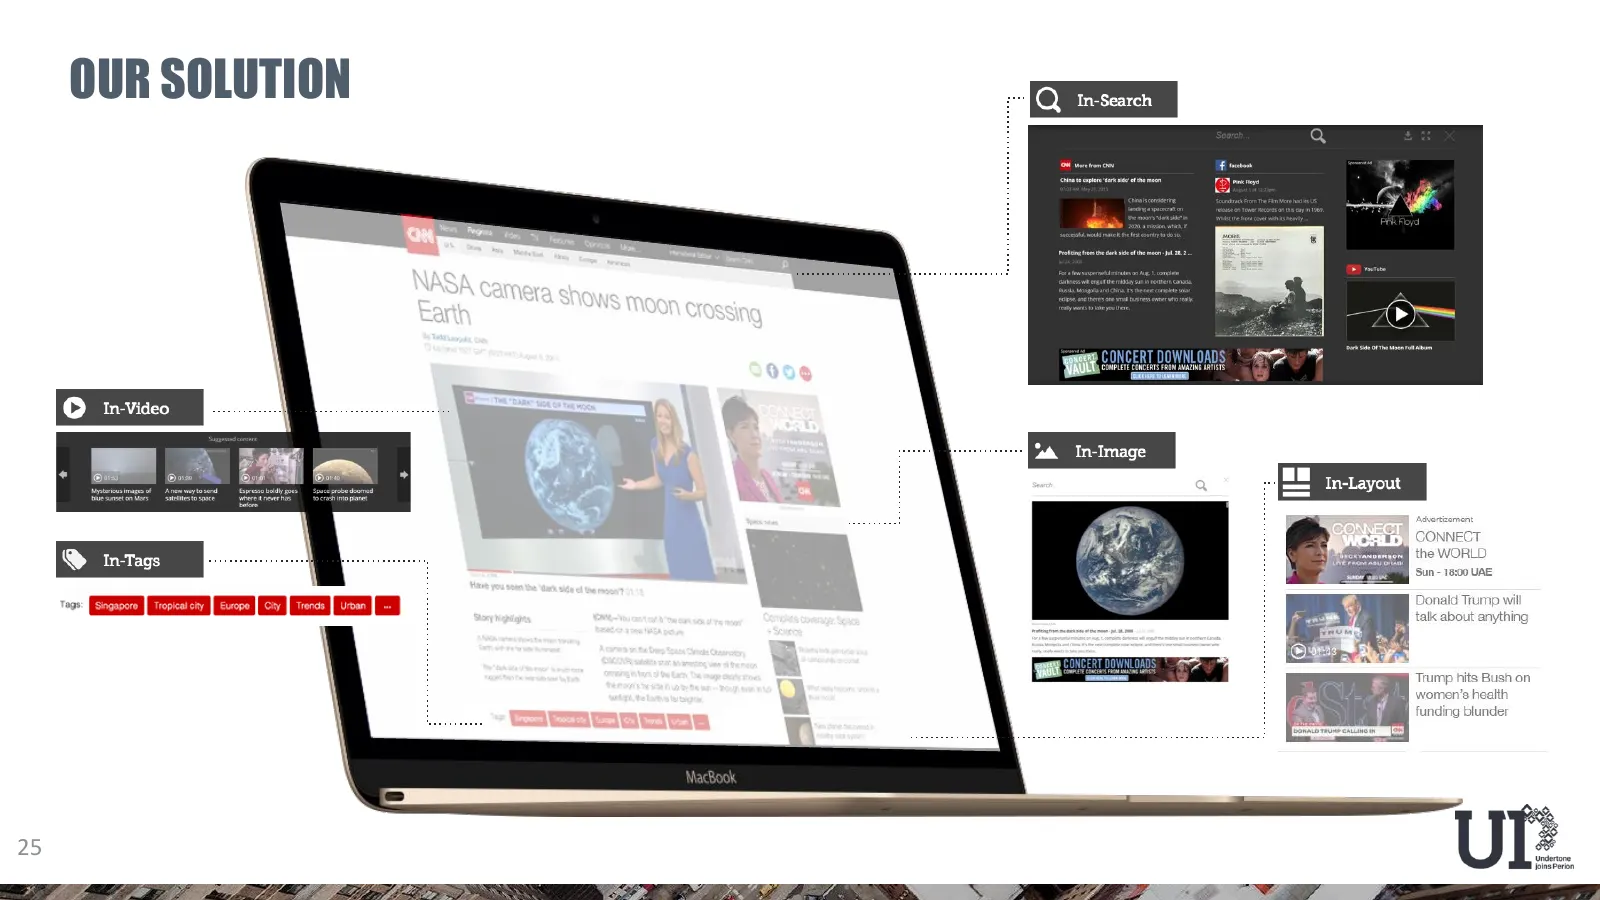
OUR SOLUTION ABC © inviaco Be in-Layout — 24 ——— 8 8 -<f ae
Slide 25: Our solution
OUR SOLUTION Trump hits Bush on n’s health ding blunder \ FEET = Cti(<‘é‘“;*‘<‘é ww Y''' «éFF2_™V OS
Slide 26: 26
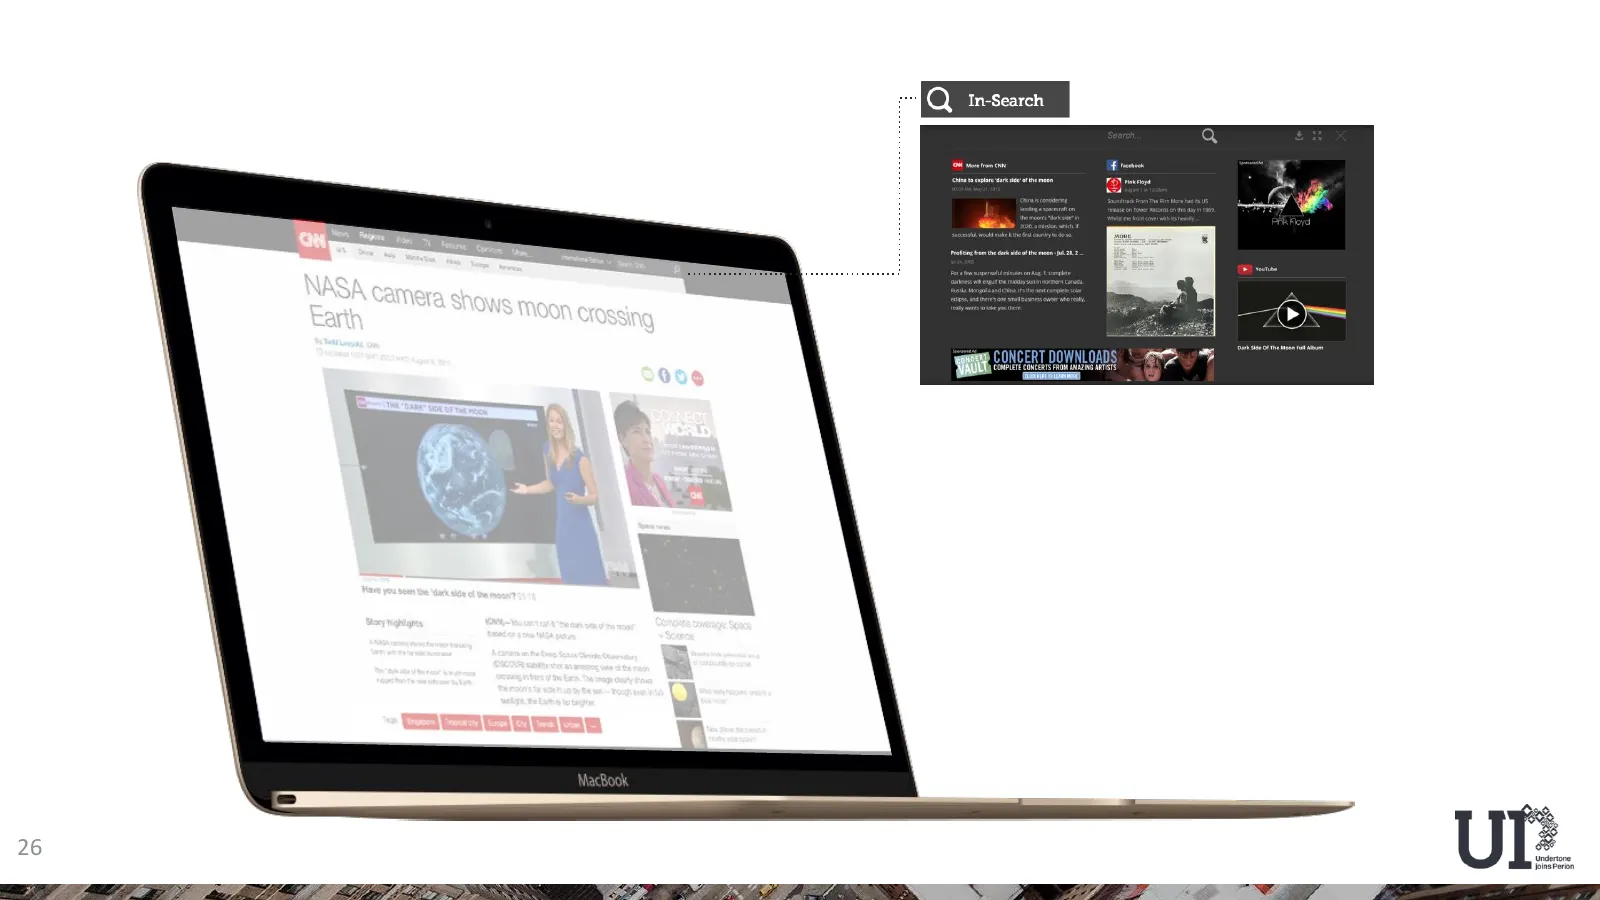
26
Slide 27: Desktop In-Tag
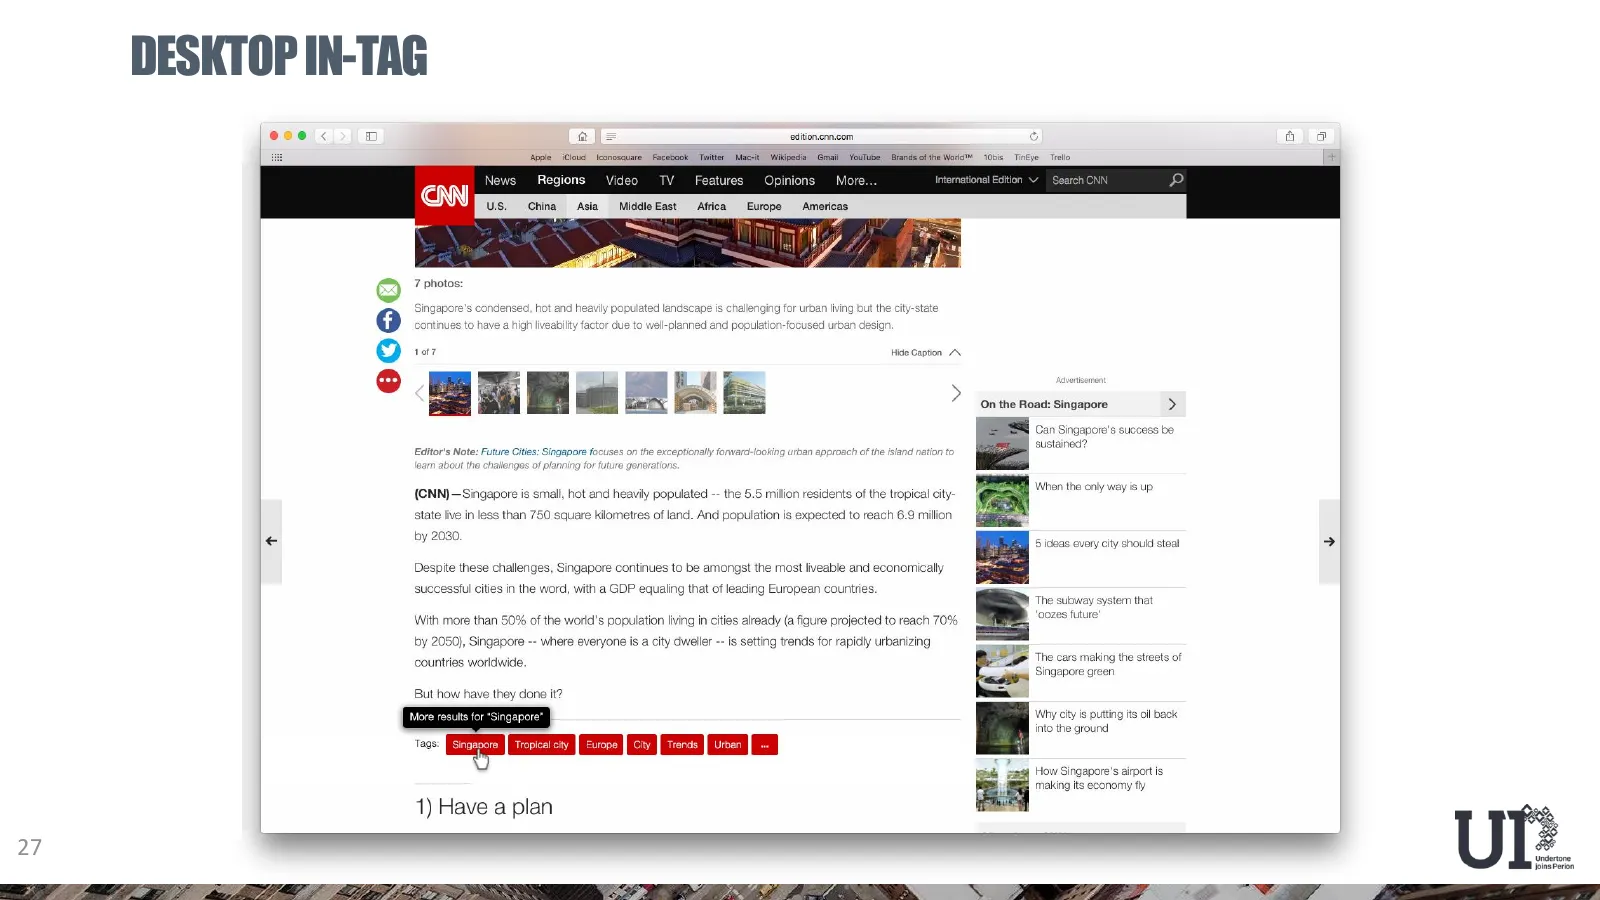
DESKTOP IN-TAG Ge Were™ ton Taye To Middle East Africa Qu y-state ide Caption A, 606 > ‘On the Road: Singapore > (Can Singanore's success be . sustained? Ealtor's Note: Future Cities: Singapore focuses on the except {CNN)—Singapore is small, hot and heavily populated -- the 5.5 milion residents of t
Slide 28: Expanding to mobile: mobile web solution
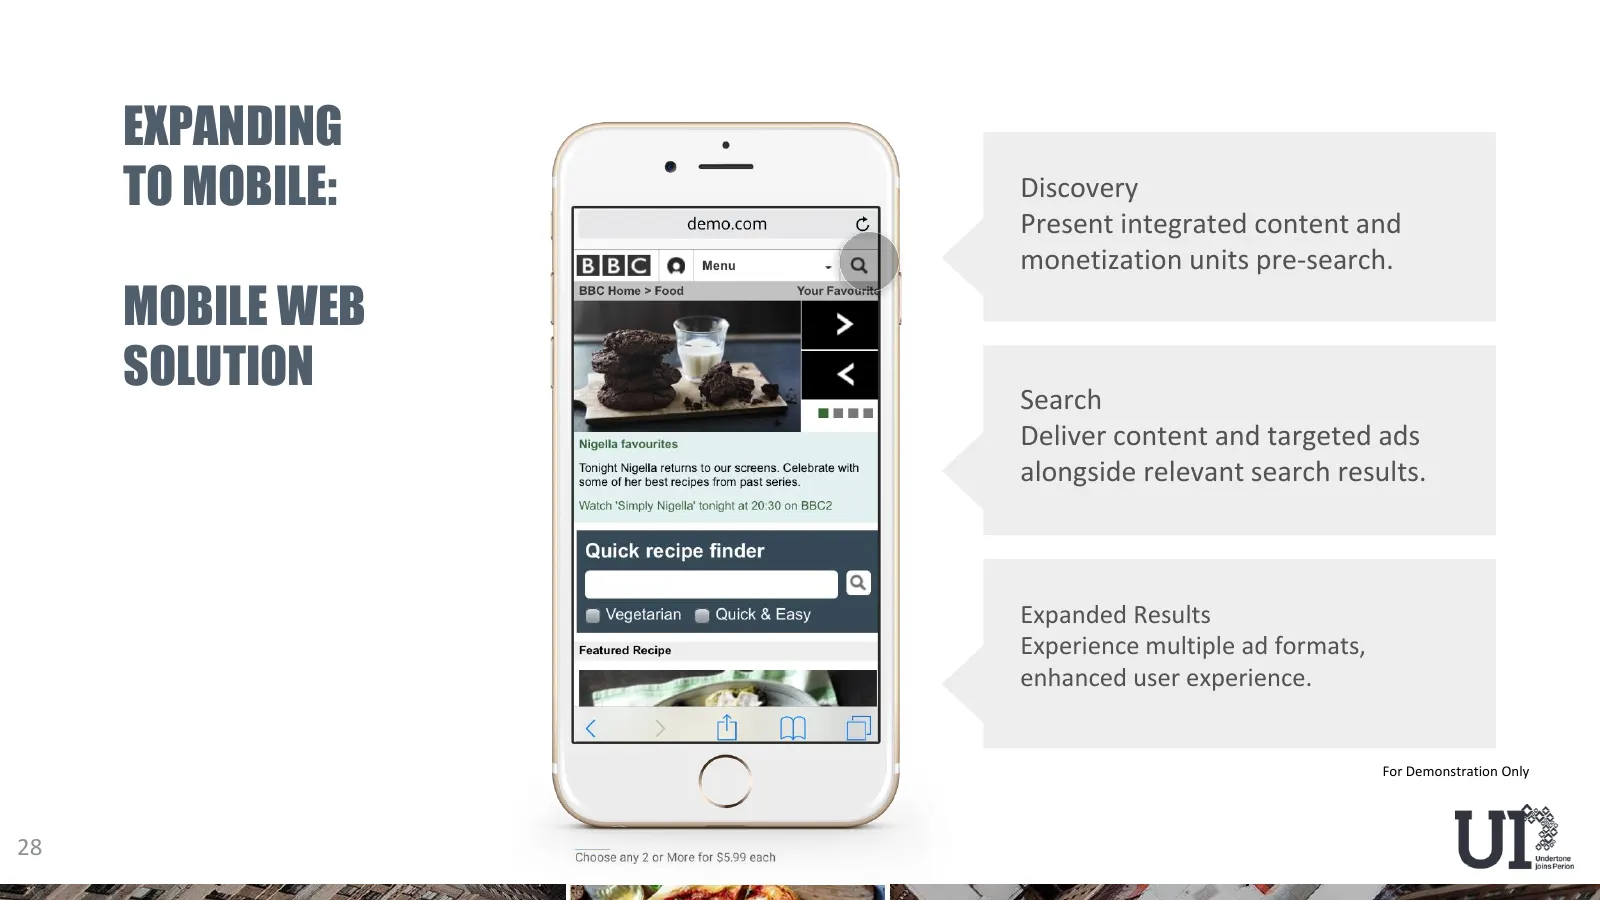
EXPANDING TO MOBILE: Discovery Present integrated content and monetization units pre-search. MOBILE WEB SOLUTION Search Deliver content and targeted ads alongside relevant search results. Expanded Results Experience multiple ad formats, enhanced user experience. For Demonstration Only 28
Slide 29: Summary
SUMMARY = 1. Stabilizing legacy business 2. New growth opportunities leveraging our existing assets 29
Slide 30: Undertone
30 ae OU Undertane. YS ZETA! py
Slide 31: Capturing consumer attention is difficult
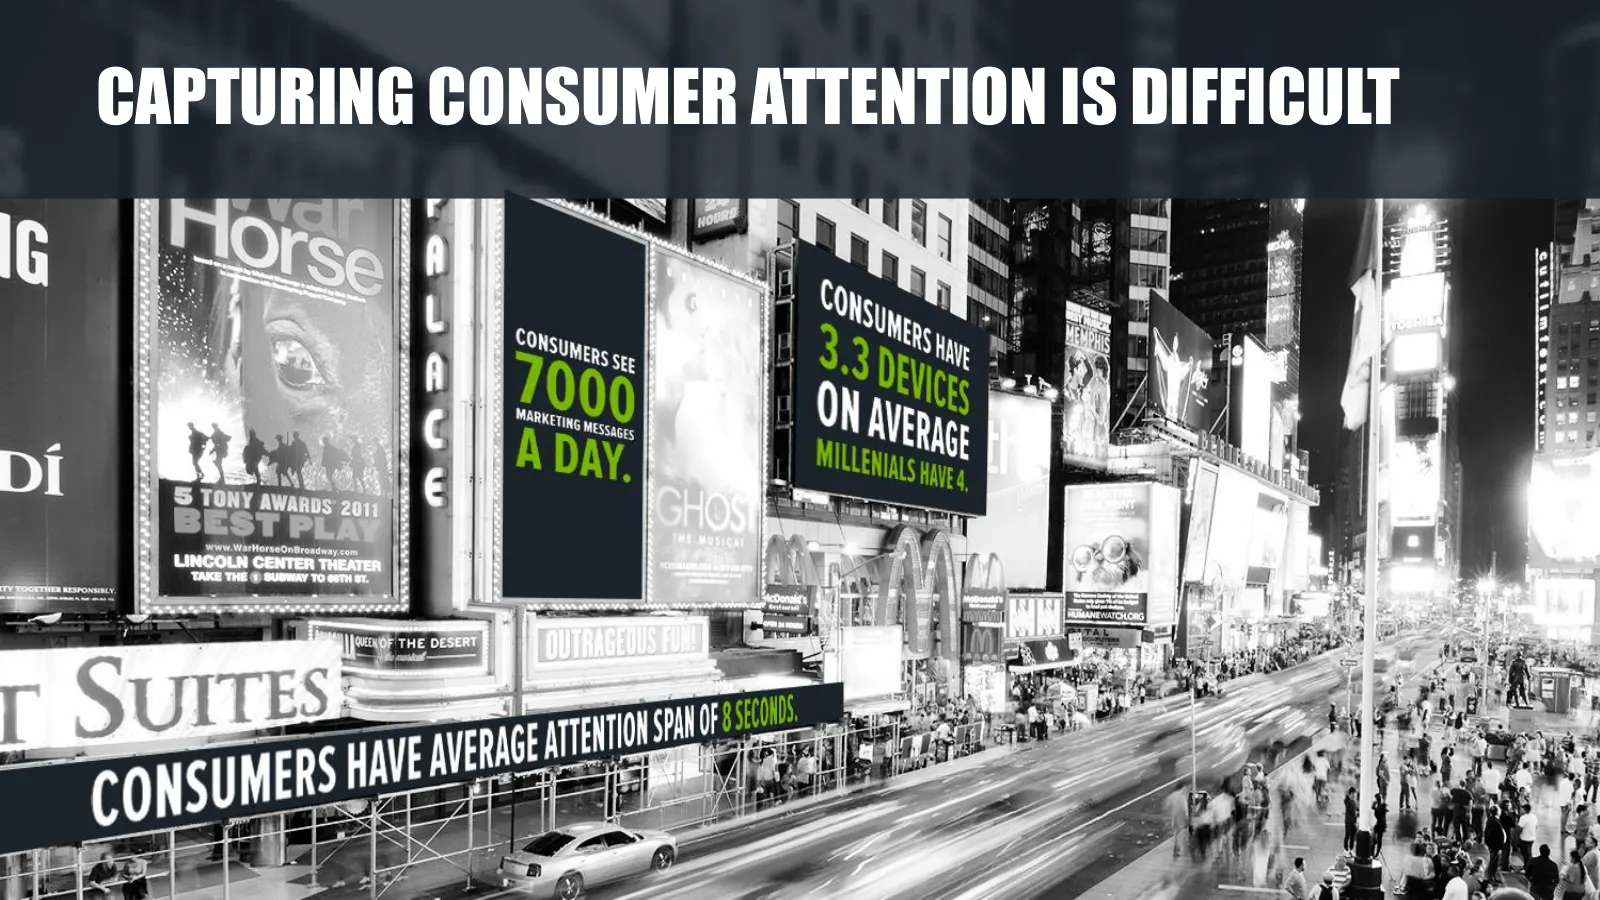
CAPTURING CONSUMER ATTENTION IS DIFFICULT Source: Forrester Research, "The State of Consumers and Technology Benchmark 2014 US" as cited in company blog, Jan 16, 2015 184904
Slide 32: How we do it
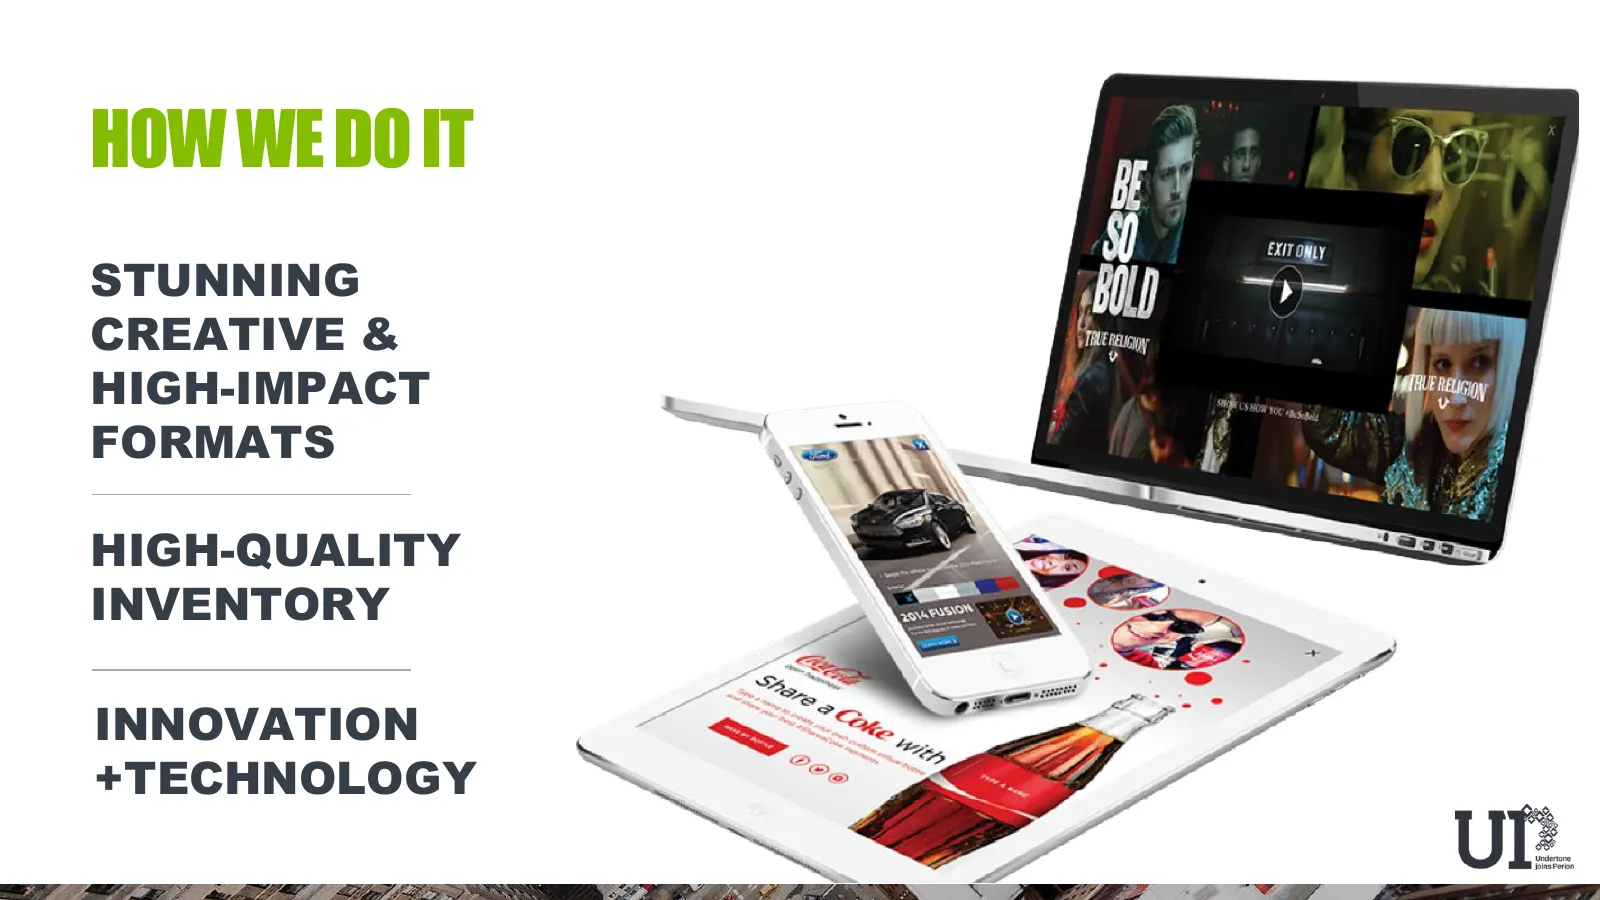
HOW WE DO IT STUNNING CREATIVE & HIGH-IMPACT FORMATS HIGH-QUALITY INVENTORY INNOVATION +TECHNOLOGY
Slide 33: Who we do it for
WHO WE DO IT FOR Auto CPG Fin Services Pharmaceutical Retail Tech/Telecom 33
Slide 34: What we do: full service delivery and support
WHAT WE DO: FULL SERVICE DELIVERY & SUPPORT MEDIA CLIENT INVENTORY PERFORMANCE CREATIVE Turns creative PLANNING SERVICES MANAGEMENT Performs deep Finds a solution Maintains quality analysis to vision into digital Works with client that works best for of our publishers strategically reality through f
Slide 35: Standout creative formats drive better results
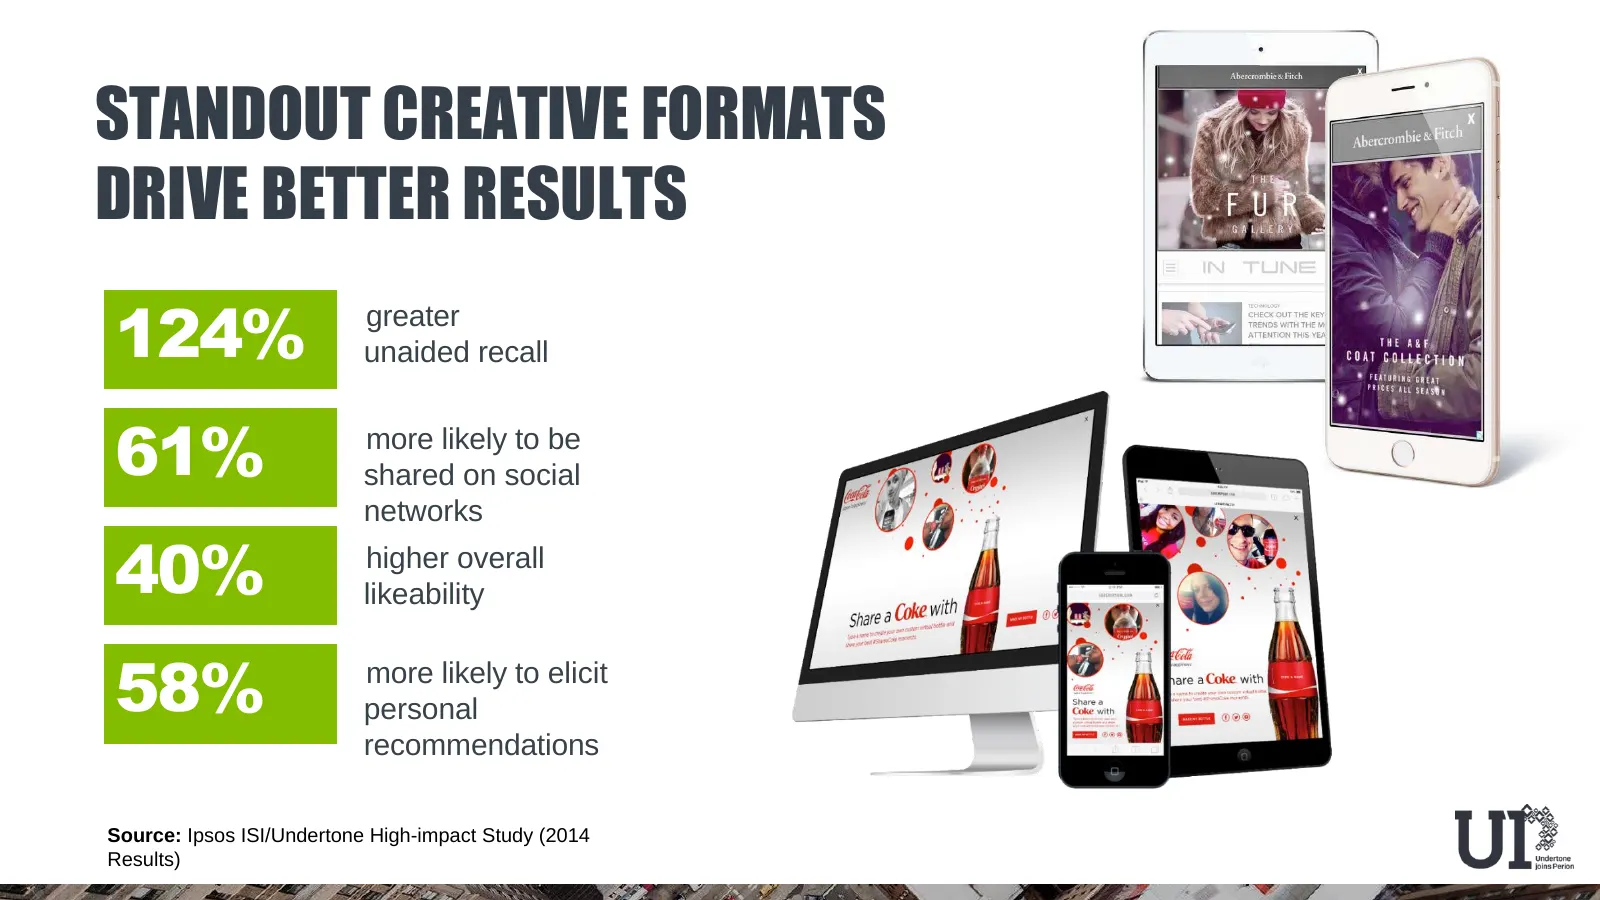
STANDOUT CREATIVE FORMATS DRIVE BETTER RESULTS 124% greater unaided recall 61% more likely to be shared on social networks 40% higher overall likeability 58% more likely to elicit personal recommendations Source: Ipsos ISI/Undertone High-impact Study (2014 Results)
Slide 36: PageGrabber X
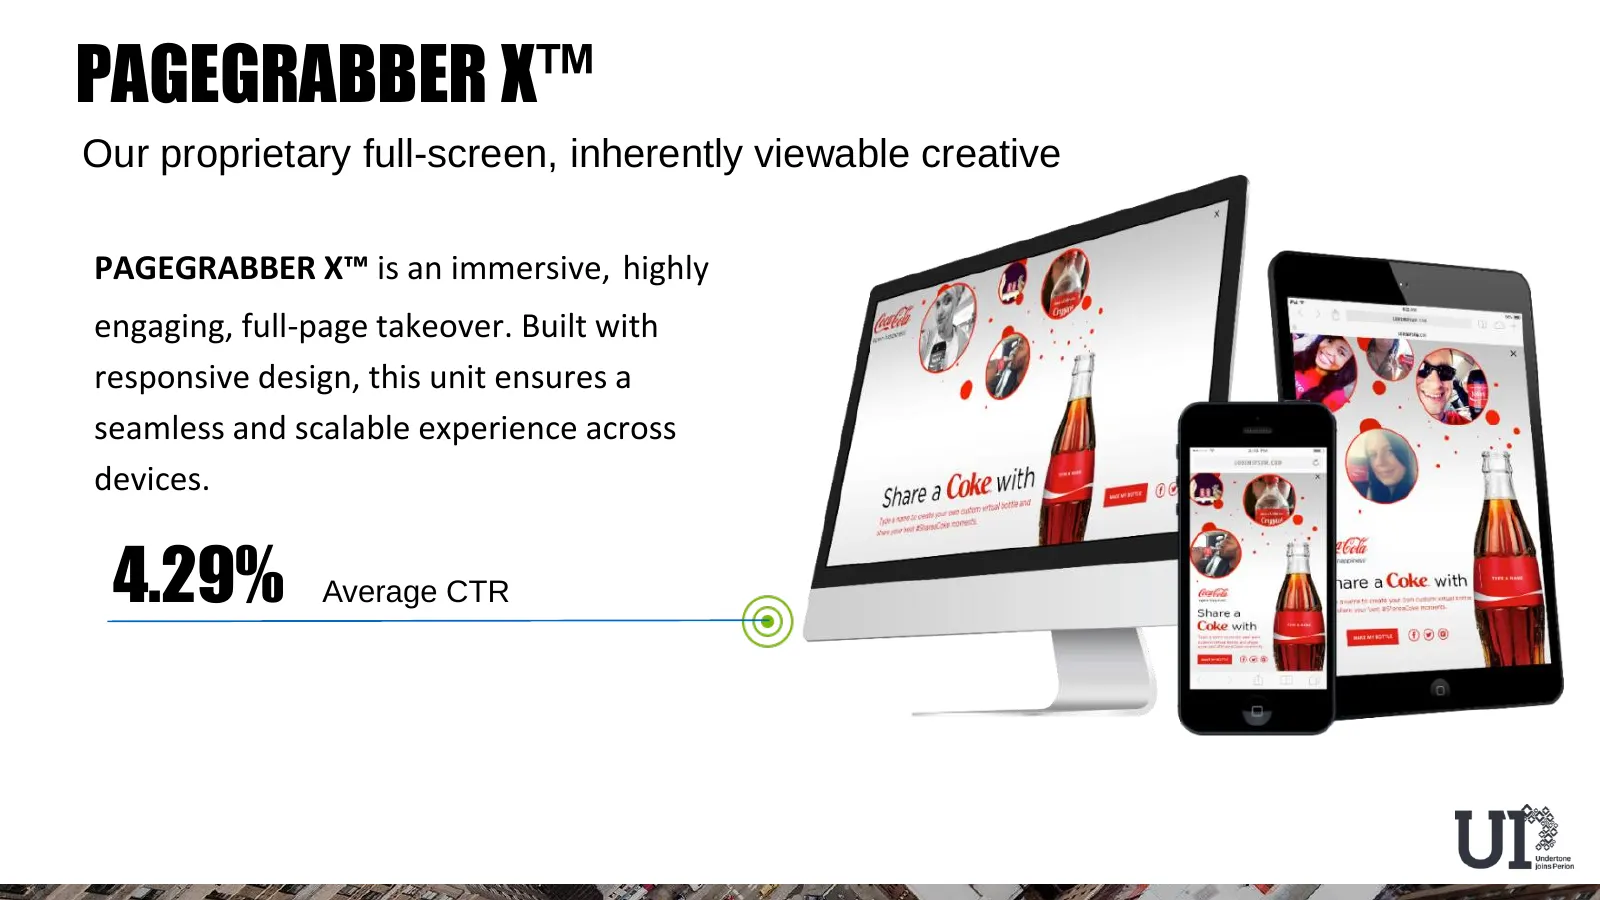
PAGEGRABBER X™ Our proprietary full-screen, inherently viewable creative PAGEGRABBER X™ is an immersive, highly engaging, full-page takeover. Built with responsive design, this unit ensures a seamless and scalable experience across devices. 4.29% Average CTR
Slide 37: ScreenShift
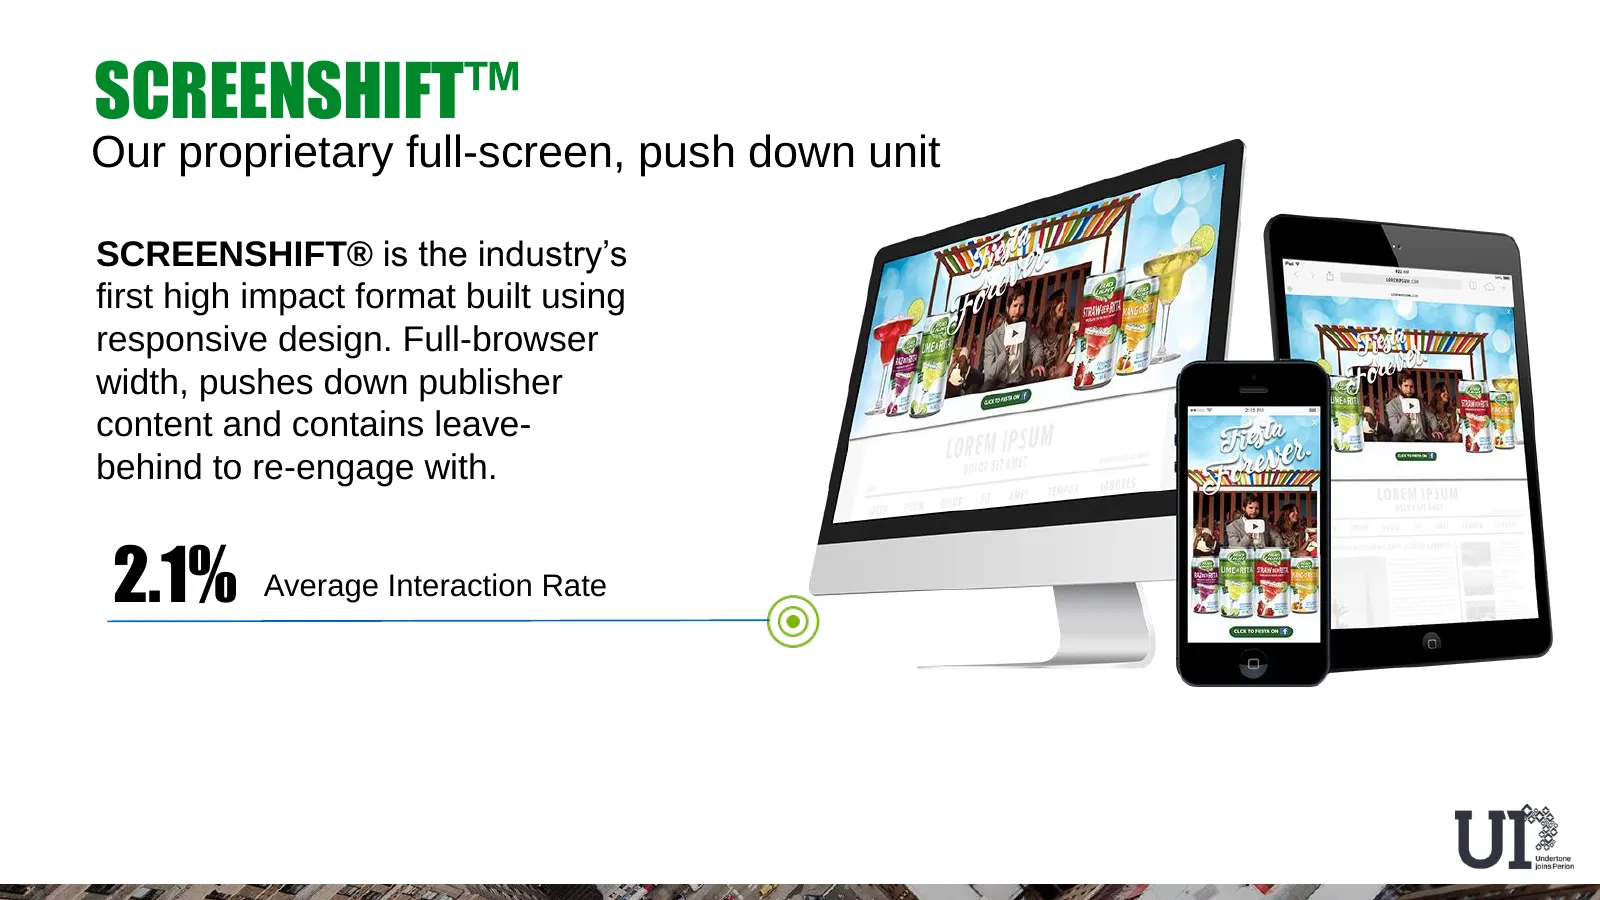
SCREENSHIFT™ Our proprietary full-screen, push down unit SCREENSHIFT® is the industry’s first high impact format built using responsive design. Full-browser width, pushes down publisher content and contains leave- behind to re-engage with. 2.1% Average Interaction Rate
Slide 38: UMotion Ads
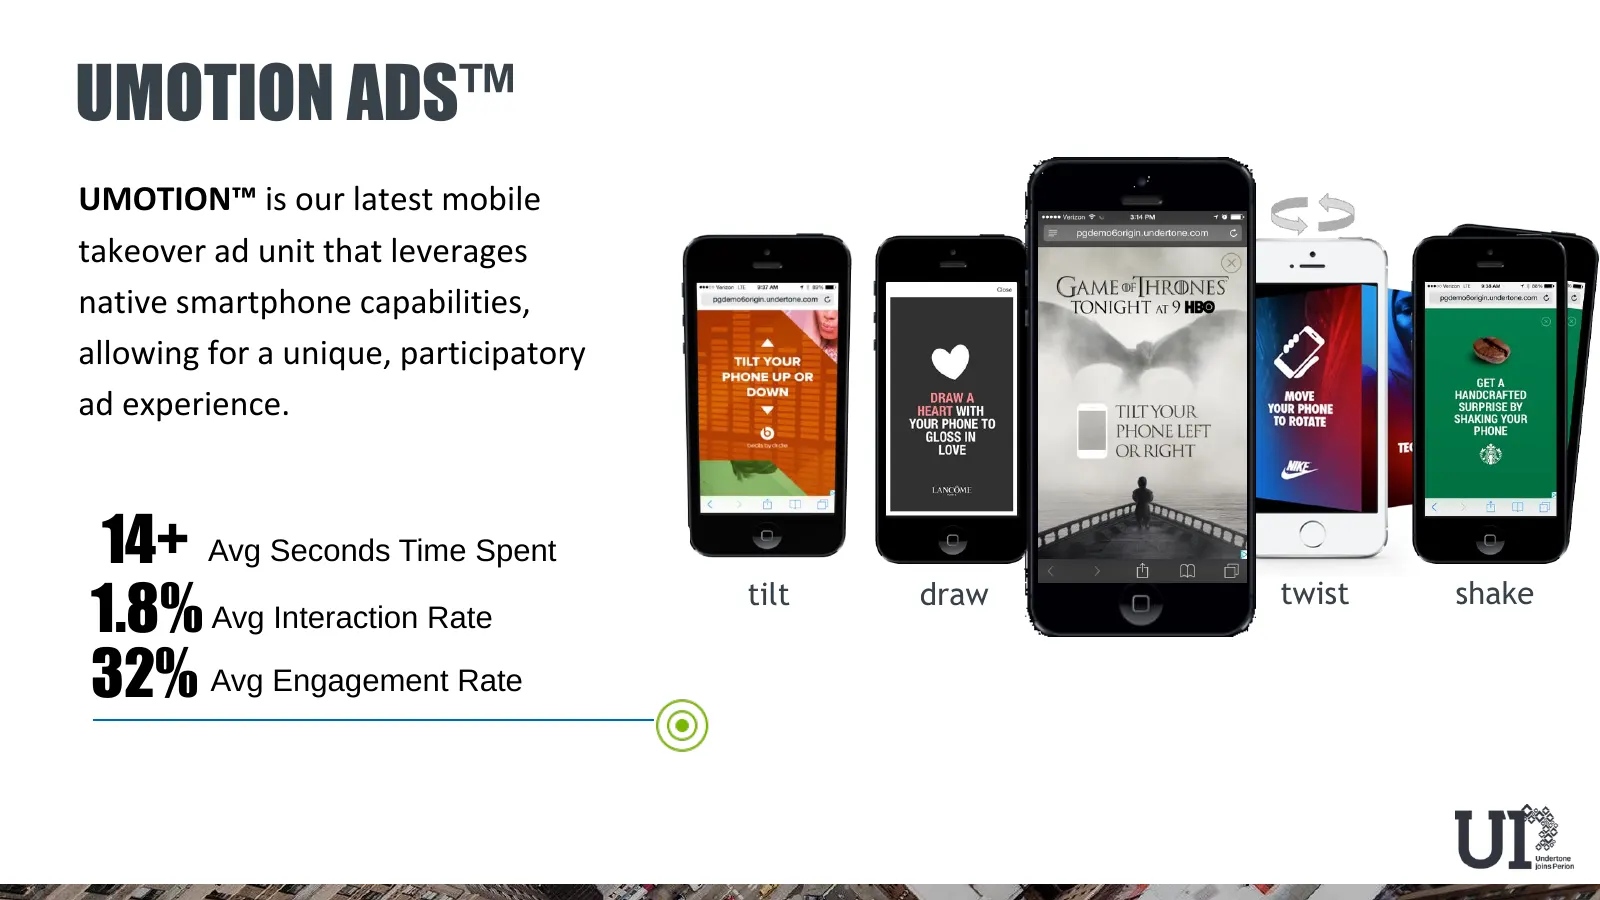
UMOTION ADS™ UMOTION™ is our latest mobile takeover ad unit that leverages native smartphone capabilities, allowing for a unique, participatory ad experience. 14+ Avg Seconds Time Spent 32% 1.8% Avg Interaction Rate tilt draw twist shake 32% Avg Engagement Rate
Slide 39: Tapestry
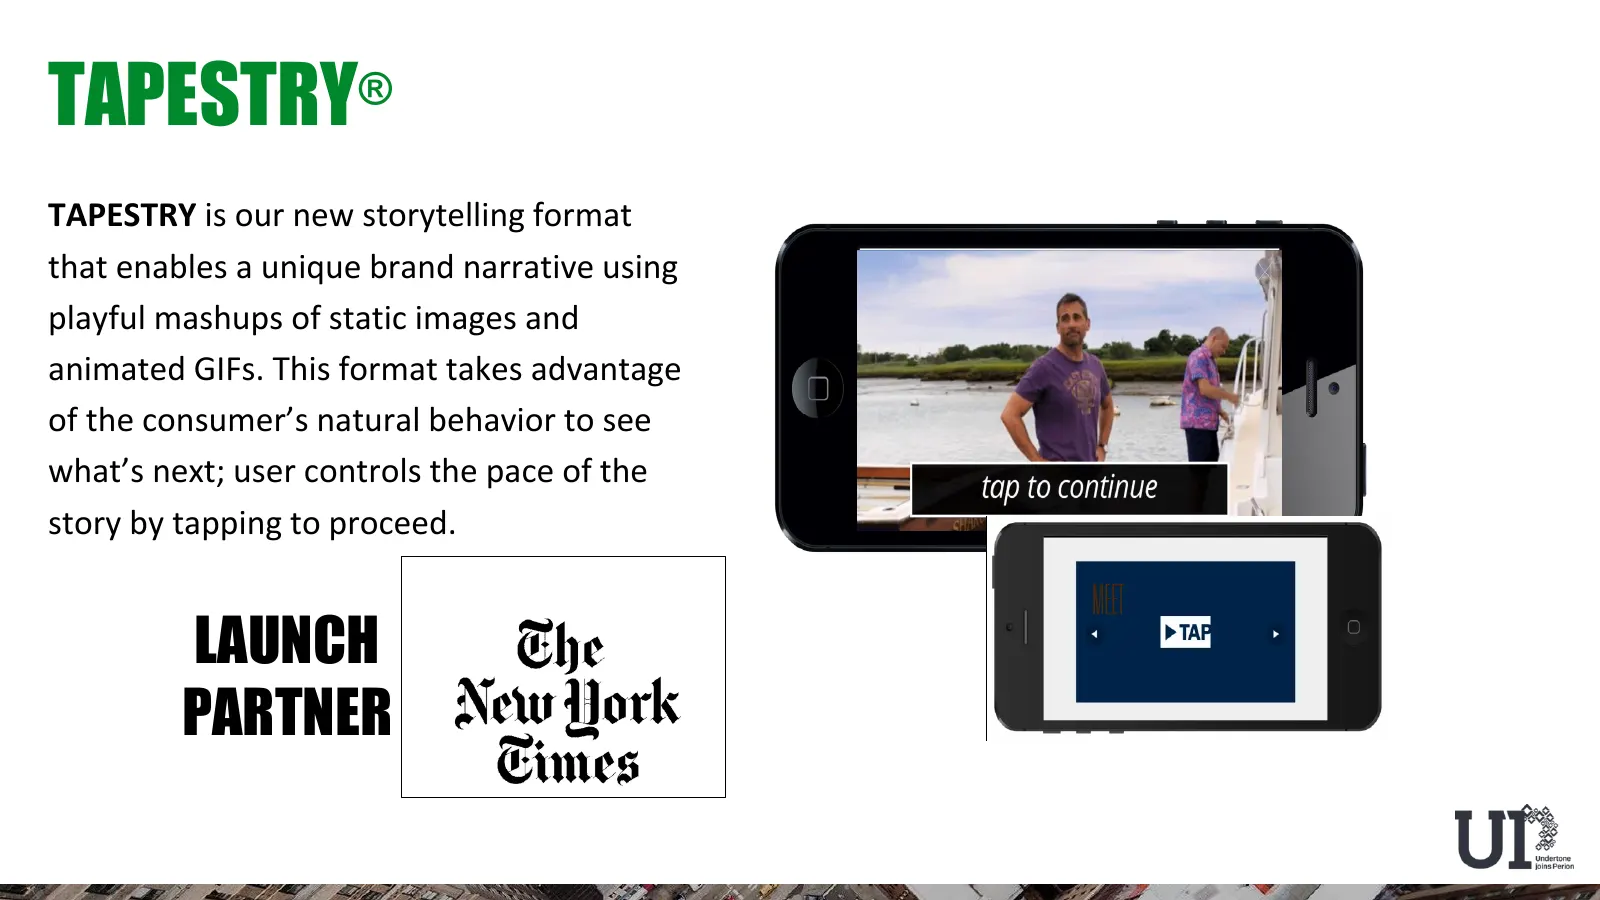
TAPESTRY ® TAPESTRY is our new storytelling format that enables a unique brand narrative using playful mashups of static images and animated GIFs. This format takes advantage of the consumer’s natural behavior to see what’s next; user controls the pace of the story by tapping to proceed. LAUNCH PART
Slide 40: The Green List
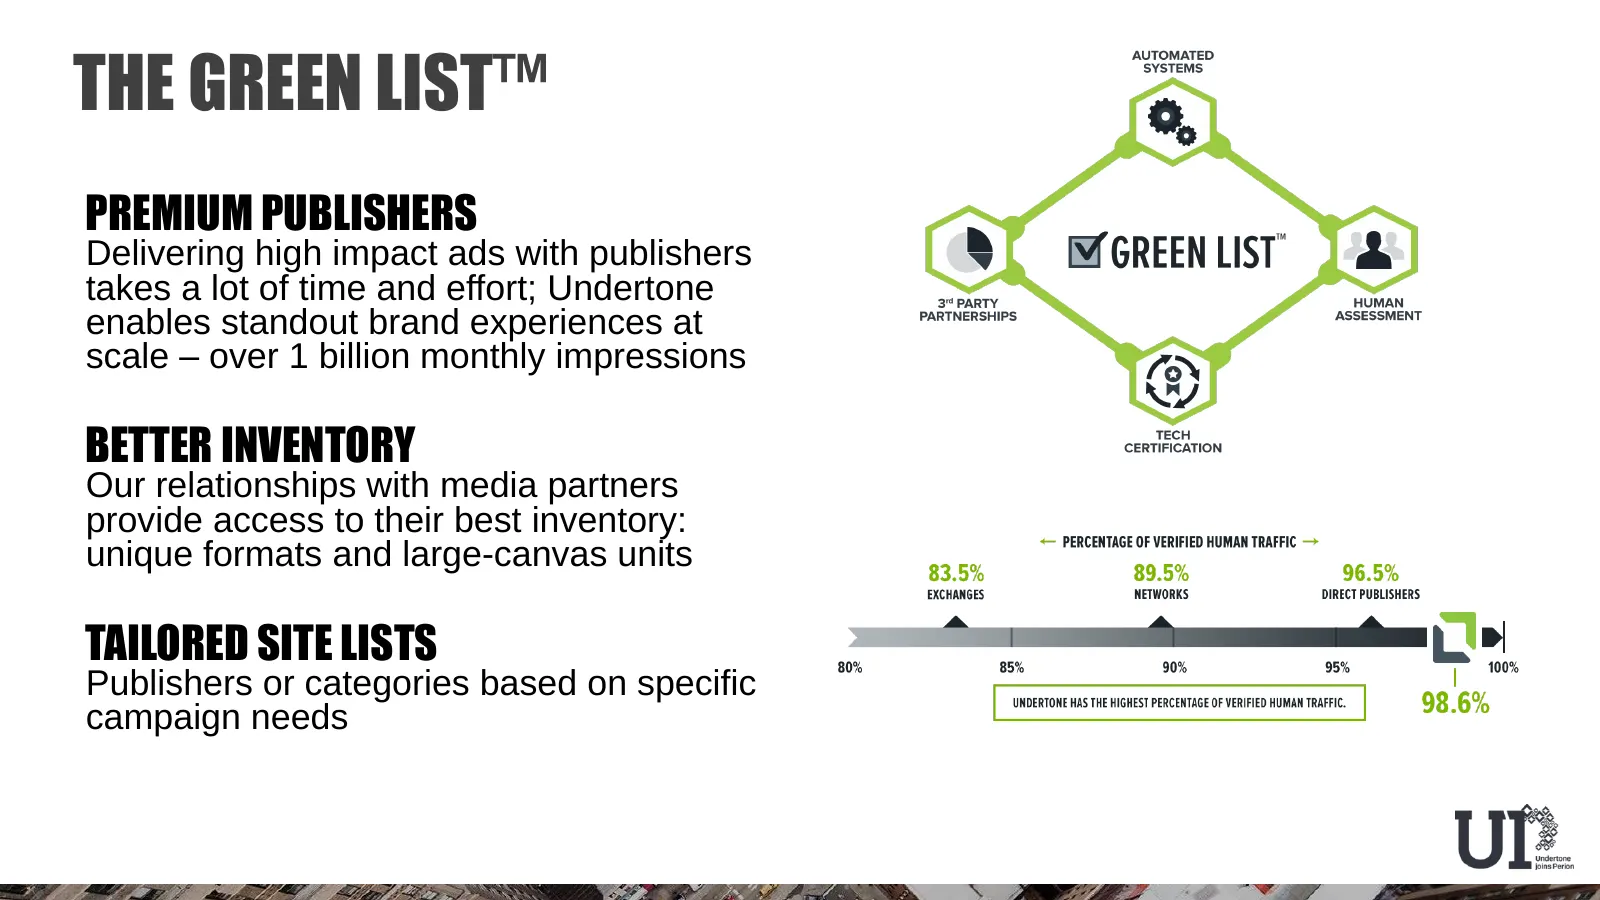
THE GREEN LIST™ PREMIUM PUBLISHERS Delivering high impact ads with publishers takes a lot of time and effort; Undertone enables standout brand experiences at scale – over 1 billion monthly impressions BETTER INVENTORY Our relationships with media partners provide access to their best inventory: uniq
Slide 41: High-quality inventory
HIGH-QUALITY INVENTORY HEARST, Forbes Oe ms: TODAY. BONNIER FOX PANDORA | boston.com The wechiget Cans The Washington S DIGITAL Post __lhe Street | @ AccuWeather @CBS — cafemom Holliigod ~ NY Ebe AMI New Hork Times sé NBC GANNETT Timeout digitalfirst
Slide 42: Superior innovation and technology
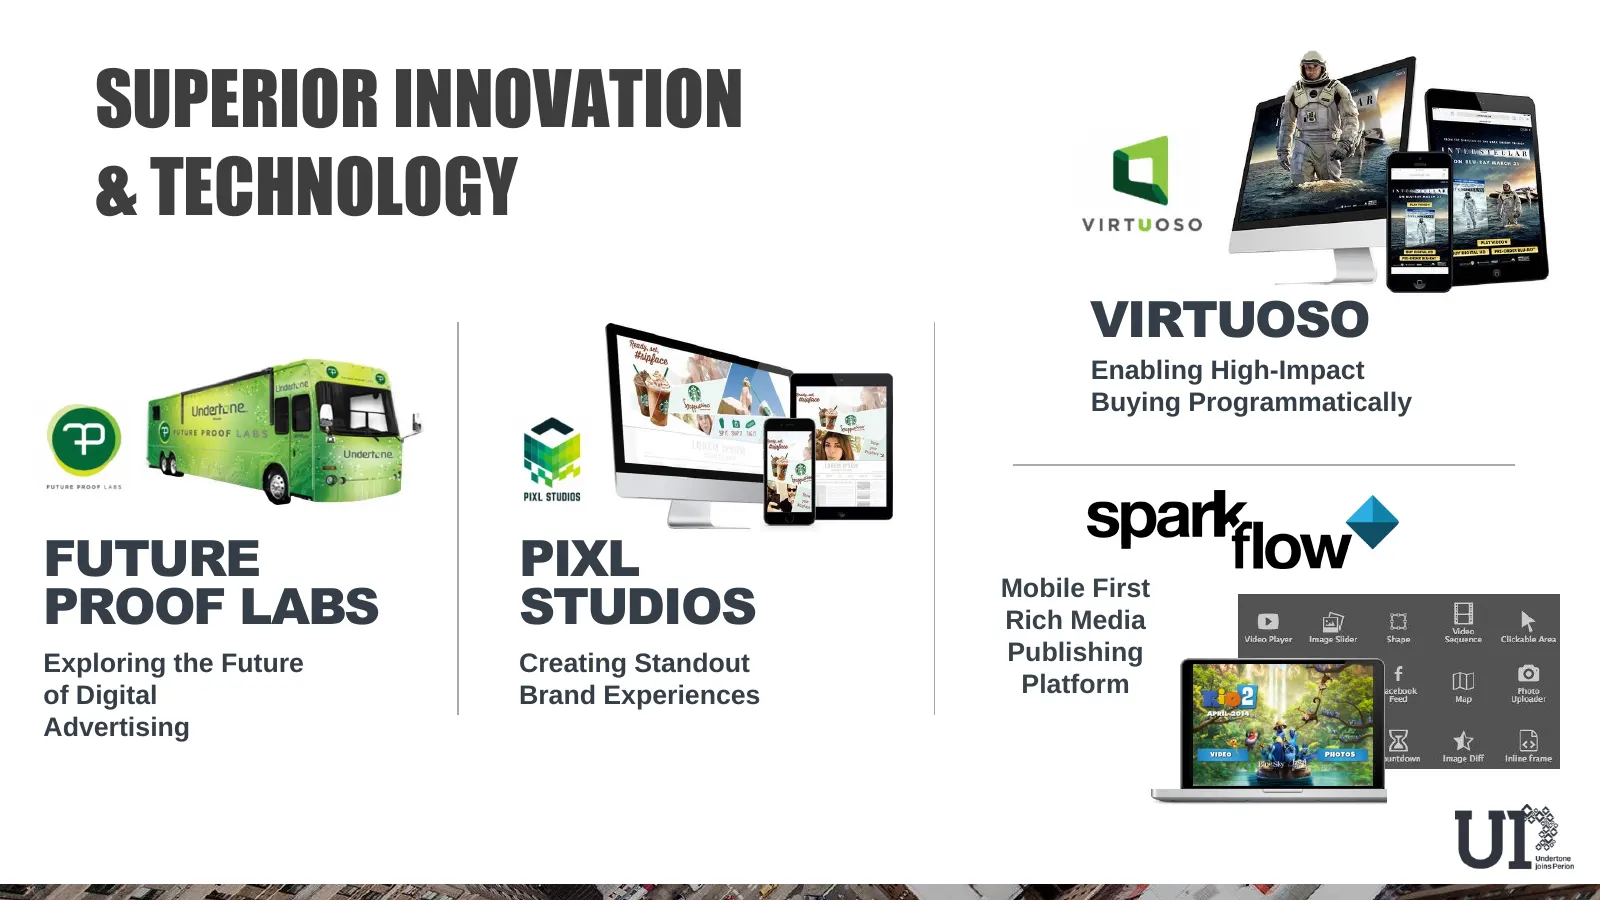
SUPERIOR INNOVATION & TECHNOLOGY VIRTUOSO Enabling High-Impact Buying Programmatically FUTURE PIXL PROOF LABS STUDIOS Mobile First Rich Media Exploring the Future Creating Standout Publishing of Digital Brand Experiences Platform Advertising
Slide 43: Growmobile
& growmobile ur. 3 ee MS as ge OLE“ ig FD PU th a A Sd fa — he >» See ff 2ZZn! Ep
Slide 44: The mobile marketing universe is crowded
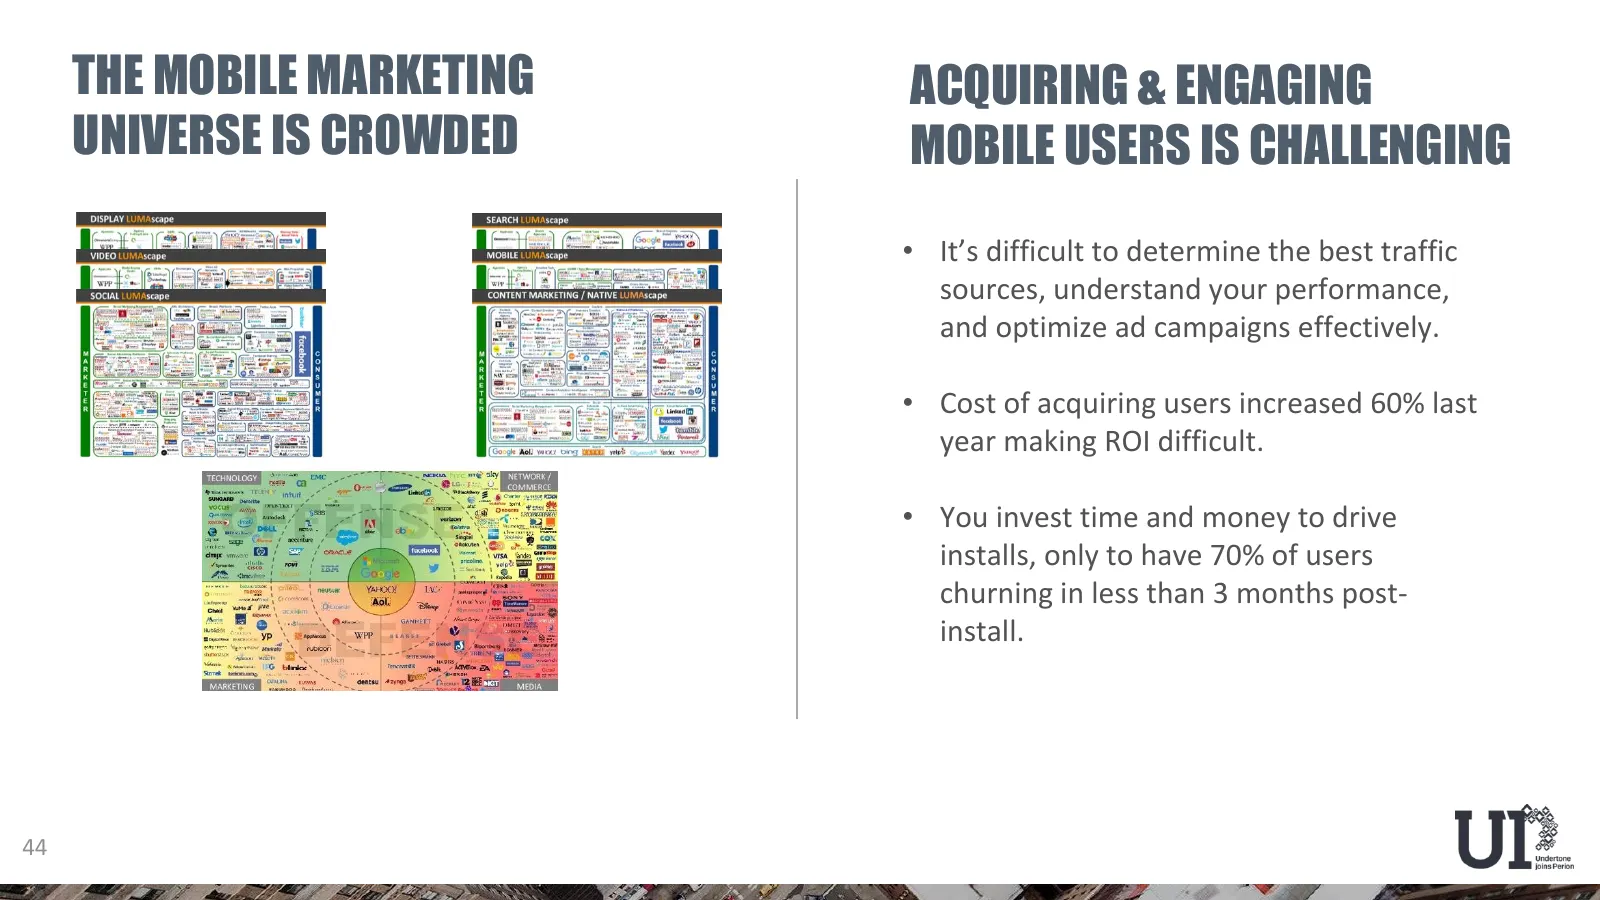
THE MOBILE MARKETING ACQUIRING & ENGAGING UNIVERSE IS CROWDED MOBILE USERS IS CHALLENGING • It’s difficult to determine the best traffic sources, understand your performance, and optimize ad campaigns effectively. • Cost of acquiring users increased 60% last year making ROI difficult. • You invest t
Slide 45: Our unique solution
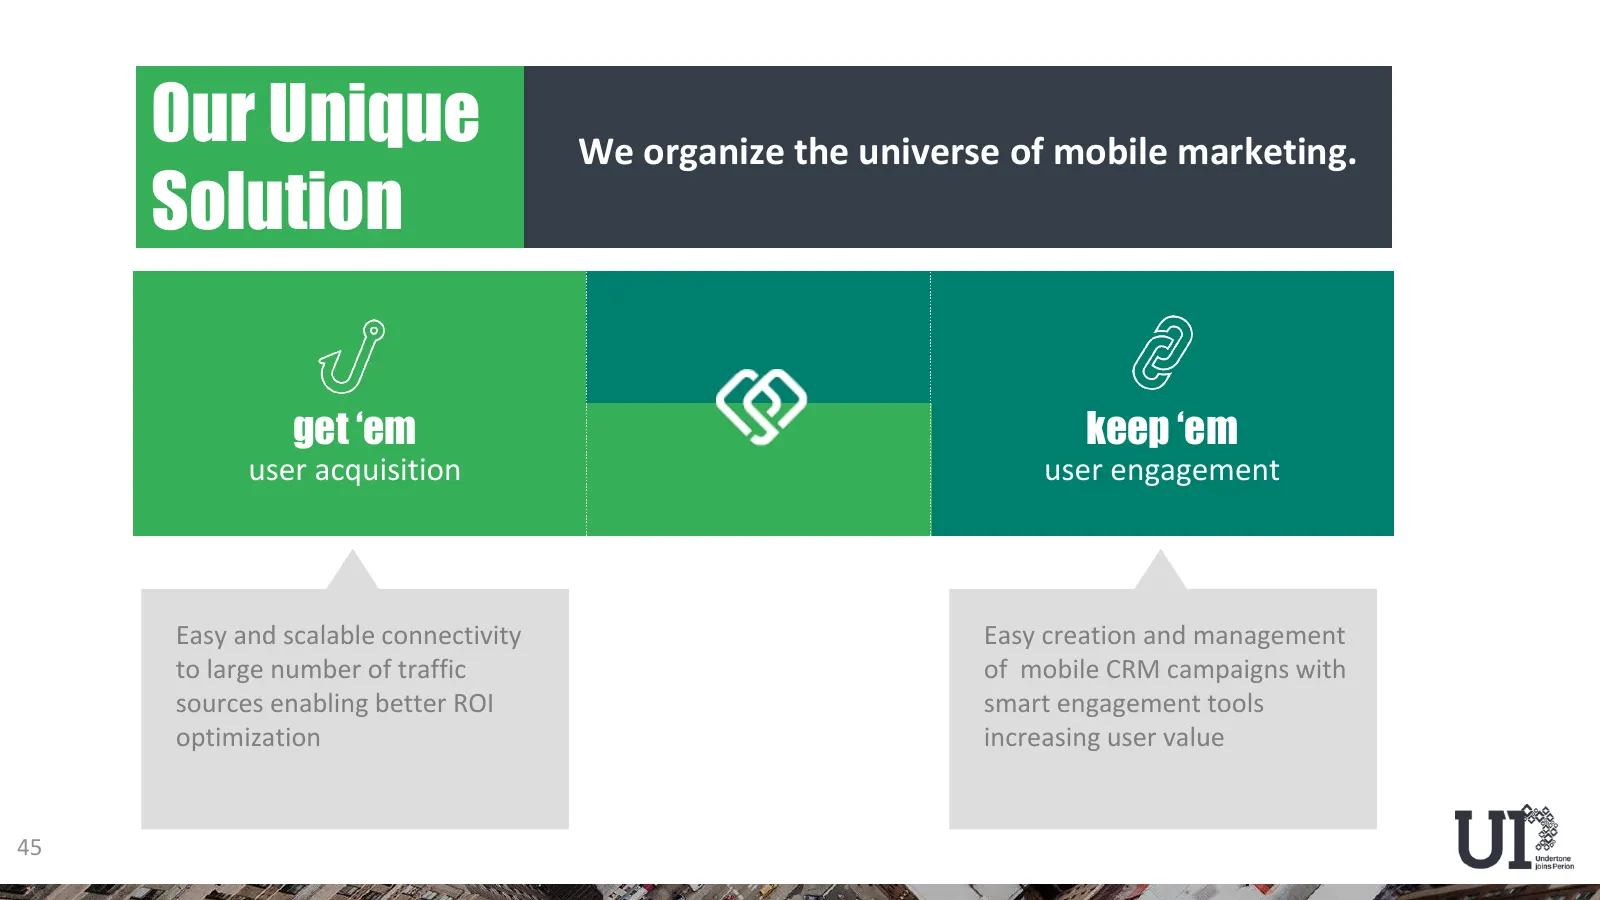
Our Unique We organize the universe of mobile marketing. Solution get ‘em keep ‘em user acquisition user engagement Easy and scalable connectivity Easy creation and management to large number of traffic of mobile CRM campaigns with sources enabling better ROI smart engagement tools optimization incr
Slide 46: Unmatched flexibility on a single platform
WITH UNMATCHED FLEXIBILITY ON A SINGLE PLATFORM self-serve fully-managed the first do-it-yourself, cross- rely on our expert account or team to manage and optimize network mobile advertising platform in the industry your campaigns for you 46
Slide 47: Get 'em: user acquisition
get ‘em user acquisition 47
Slide 48: The challenge with acquiring users
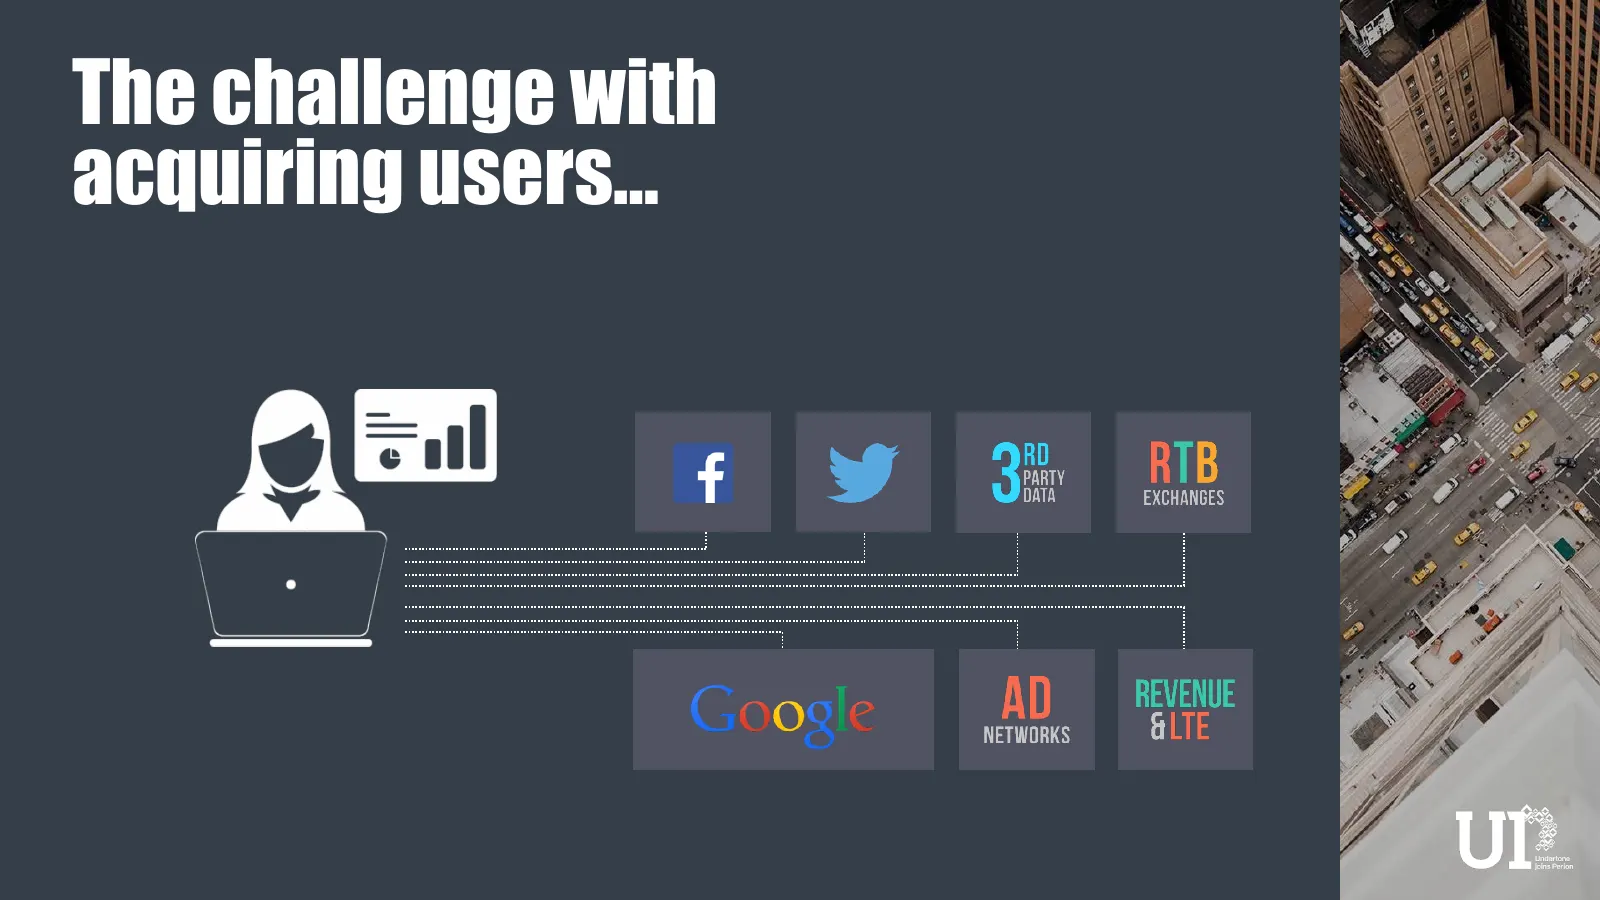
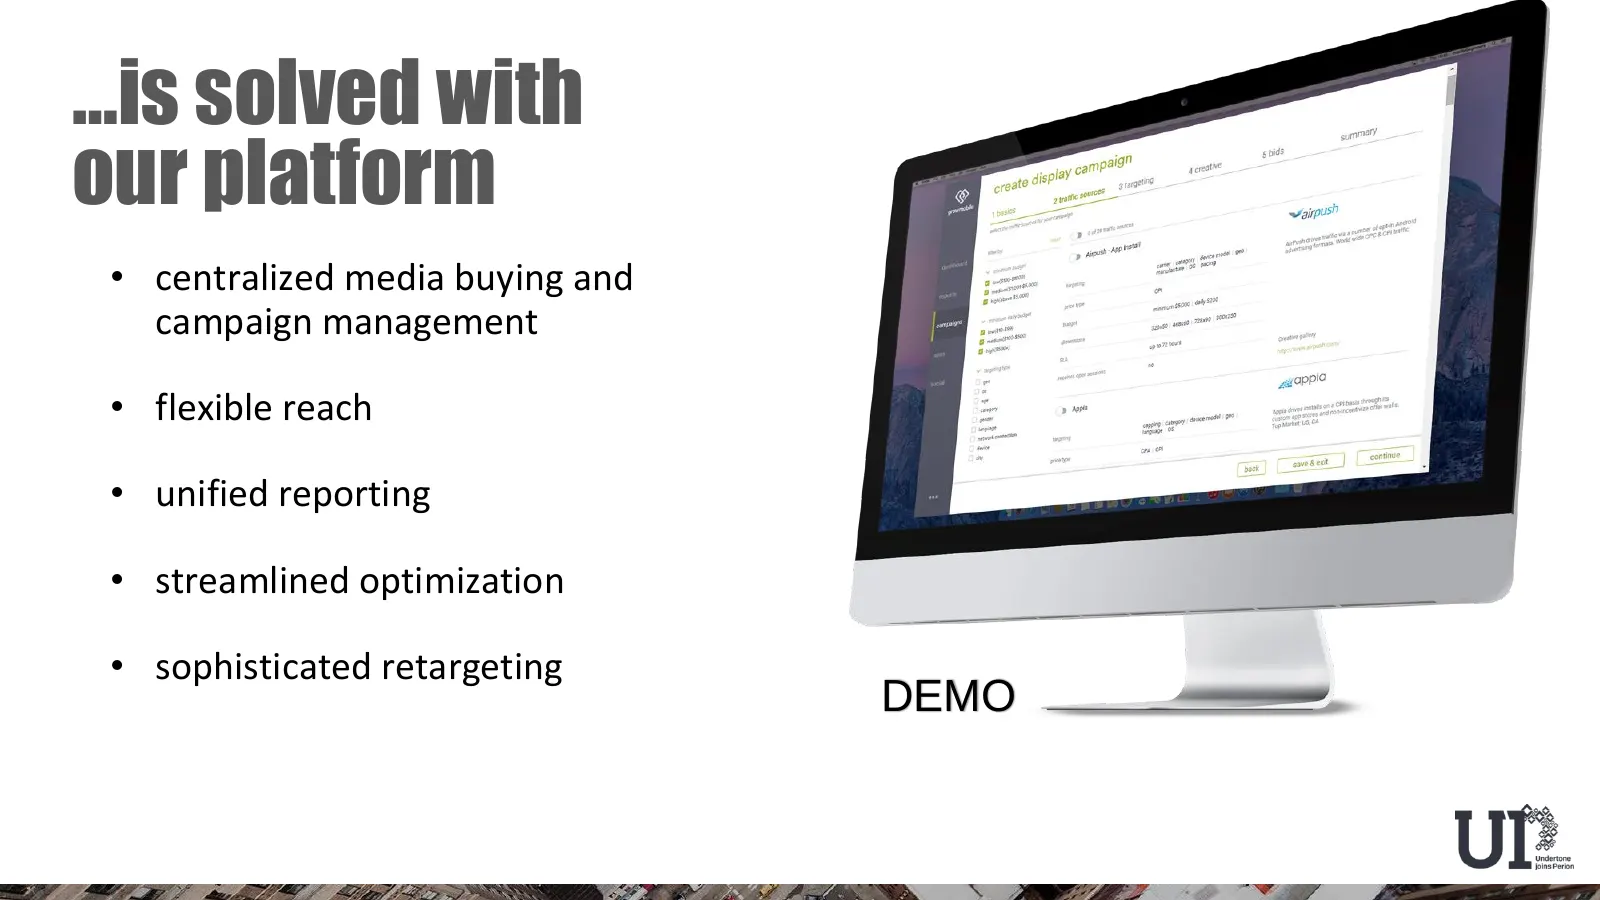
The challenge with acquiring users…
Slide 49: Is solved with our platform
…is solved with our platform • centralized media buying and campaign management • flexible reach • unified reporting • streamlined optimization • sophisticated retargeting DEMO
Slide 50: Keep 'em: user engagement
keep ‘em user engagement 50
Slide 51: Engaging mobile users is challenging
ENGAGING MOBILE USERS IS CHALLENGING marketers invest time and money to drive installs, only to have your users quickly churn out of their app
Slide 52: Our platform solves this challenge
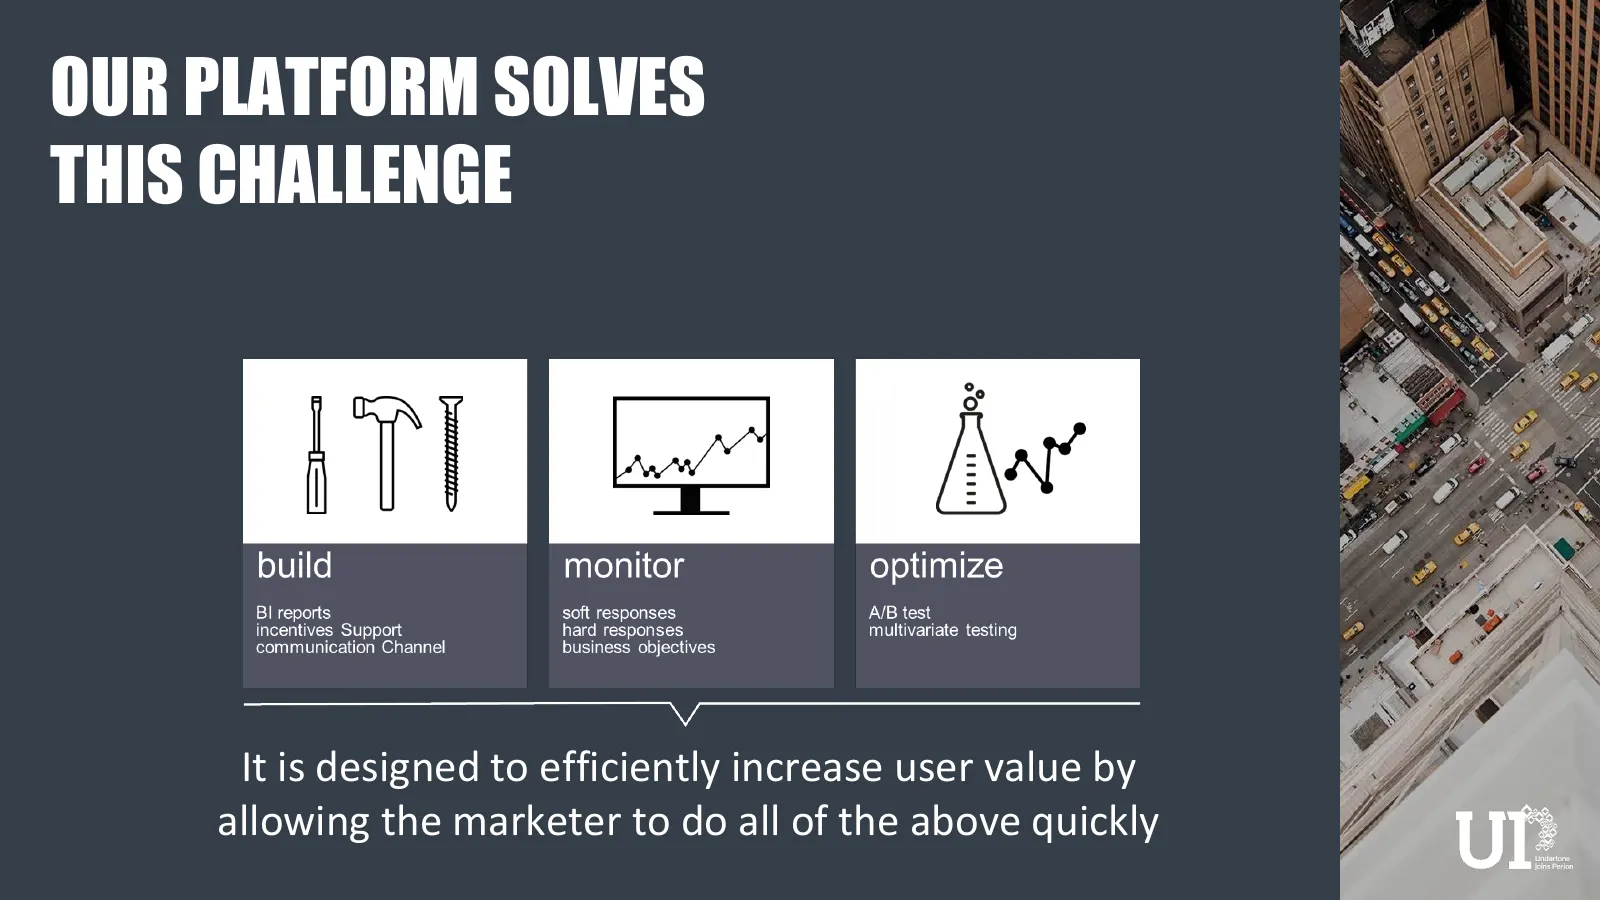
OUR PLATFORM SOLVES THIS CHALLENGE It is designed to efficiently increase user value by allowing the marketer to do all of the above quickly
Slide 53: Ask our clients
But don’t take our word for it – ask our clients…
Slide 54: And partners
…and partners and many more…
Slide 55: Customer testimonials
CUSTOMER TESTIMONIALS “with growmobile, we've been able to scale our ad spends and provide a very strong ROI month over month.” Tim Hsu, User Acquisition “we chose MakeMeReach because their software is among the most cutting-edge in the market. With MMR our KPI objectives were taken into account and
Slide 56: Together our platform is unmatched
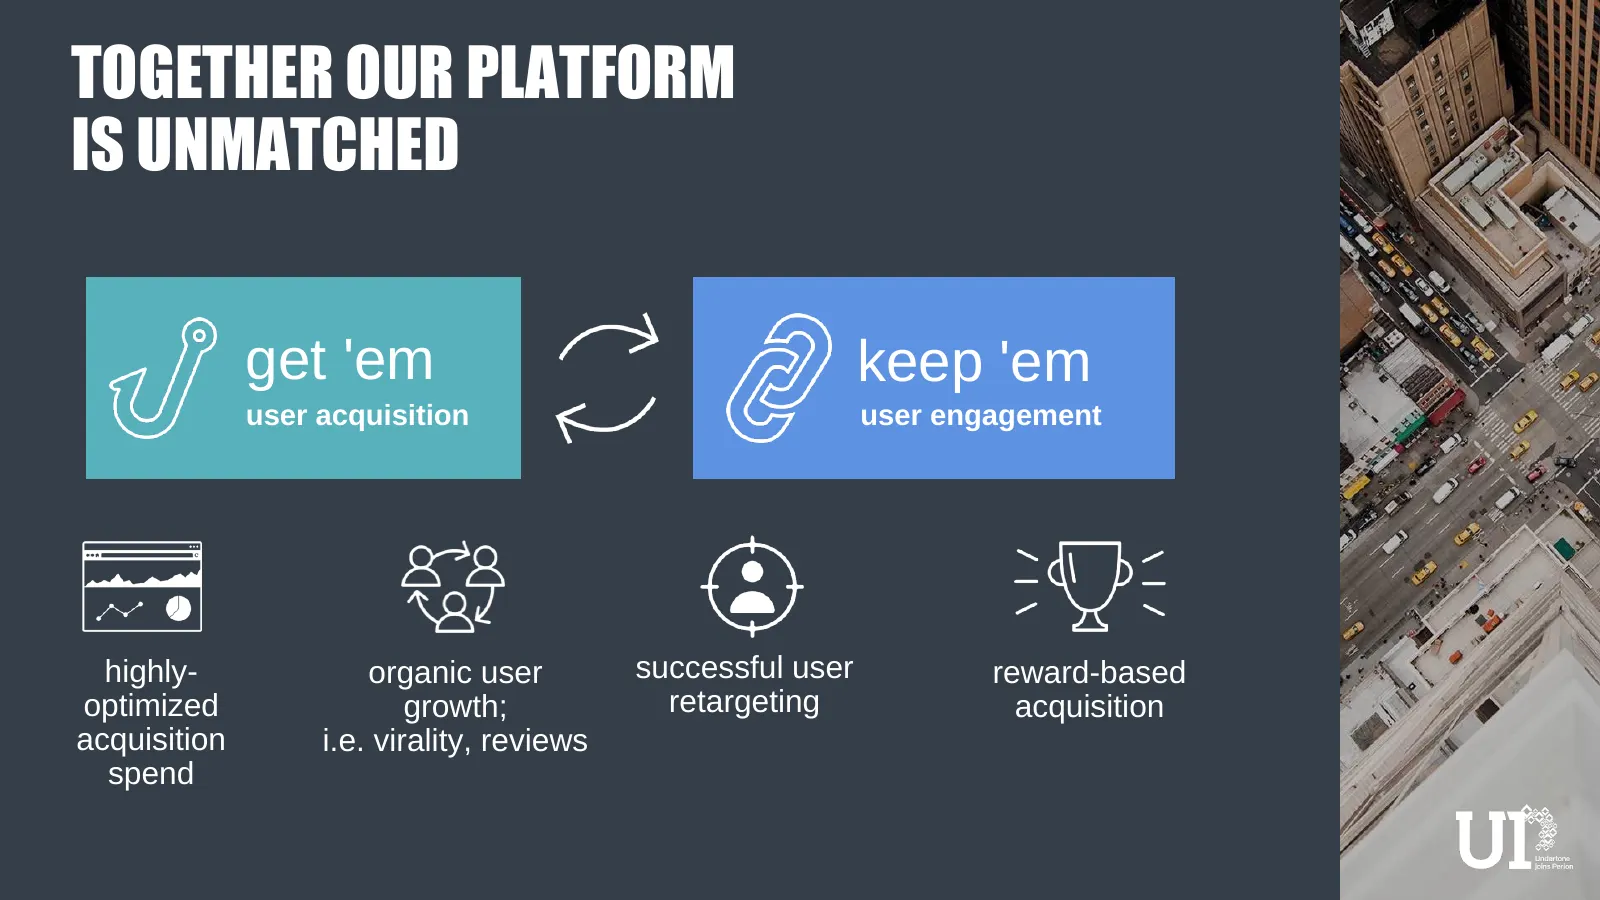
TOGETHER OUR PLATFORM IS UNMATCHED get 'em keep 'em user acquisition user engagement highly- organic user successful user reward-based optimized growth; retargeting acquisition acquisition i.e. virality, reviews spend
Slide 57: Financial Information
FINANCIAL INFORMATION 57 ce ee a la Oa“ Ske
Slide 58: Updating guidance
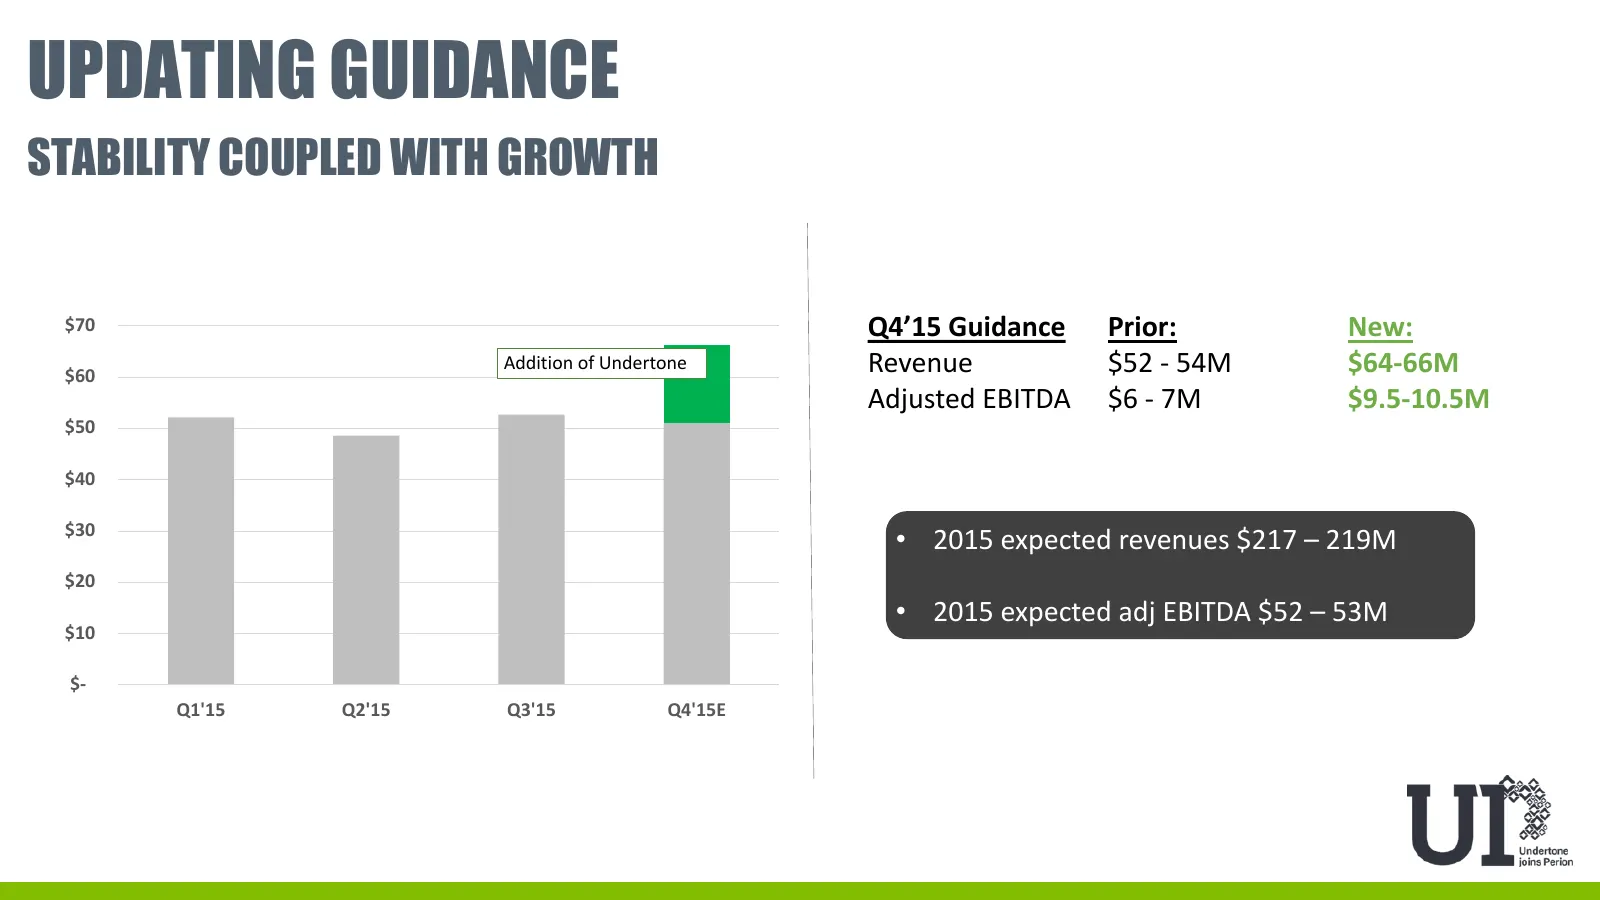
UPDATING GUIDANCE STABILITY COUPLED WITH GROWTH $70 Q4’15 Guidance Prior: New: $60 Addition of Undertone Revenue $52 - 54M $64-66M Adjusted EBITDA $6 - 7M $9.5-10.5M $50 $40 $30 • 2015 expected revenues $217 – 219M $20 • 2015 expected adj EBITDA $52 – 53M $10 $- Q1'15 Q2'15 Q3'15 Q4'15E
Slide 59: Newly diversified revenues, strong growth trajectory
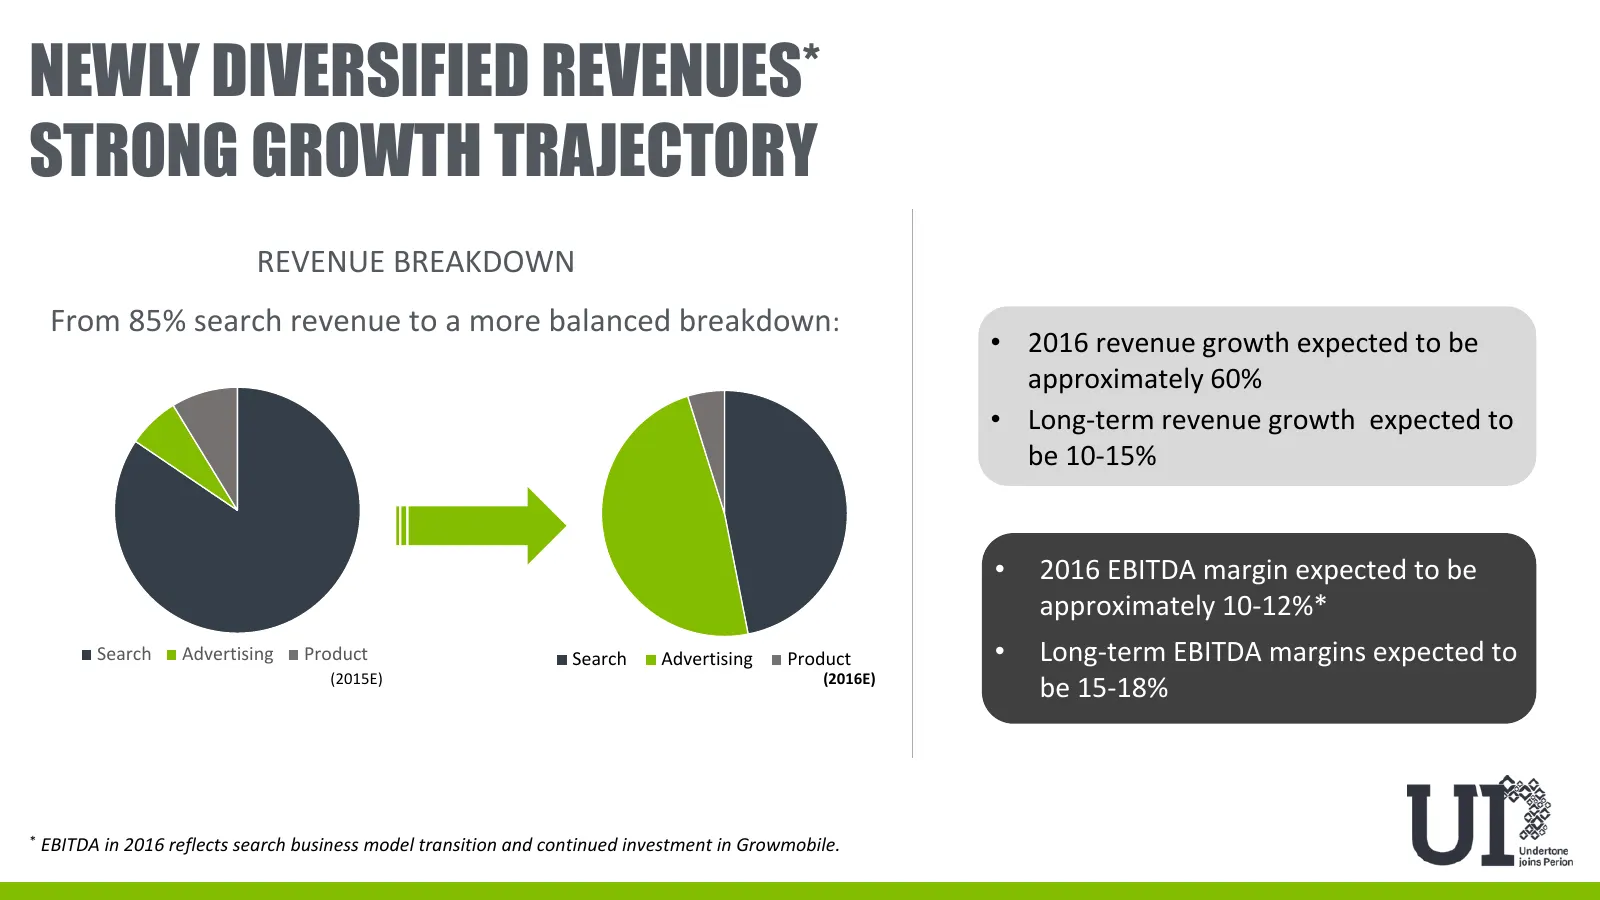
NEWLY DIVERSIFIED REVENUES* STRONG GROWTH TRAJECTORY REVENUE BREAKDOWN From 85% search revenue to a more balanced breakdown: • 2016 revenue growth expected to be approximately 60% • Long-term revenue growth expected to be 10-15% • 2016 EBITDA margin expected to be approximately 10-12%* Search Advert
Slide 60: Revenue breakdown
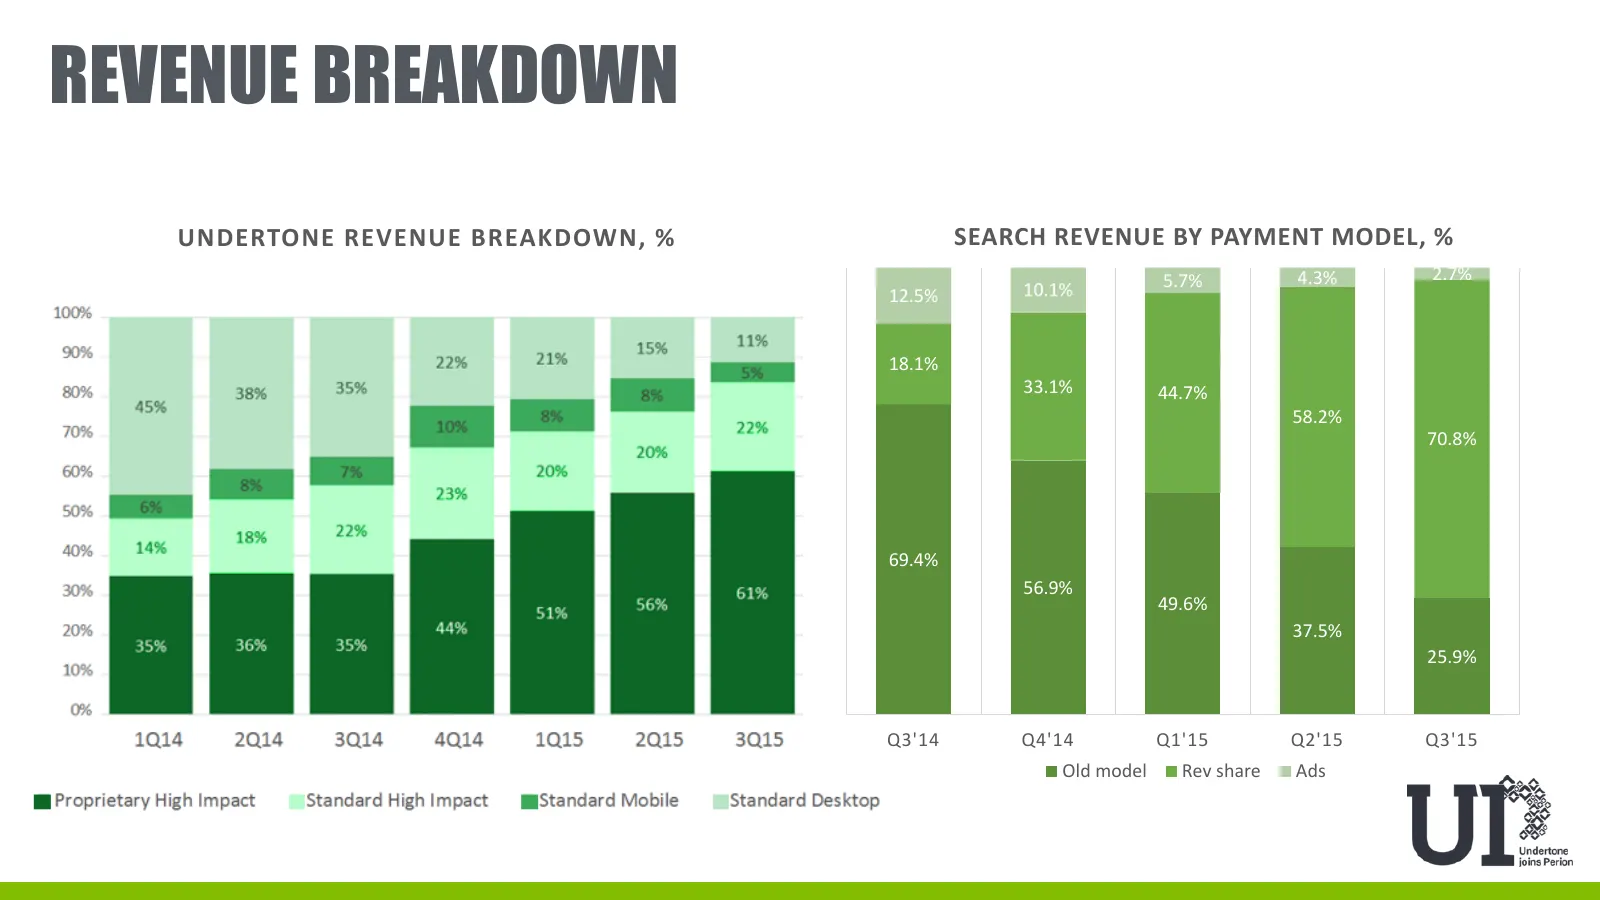
REVENUE BREAKDOWN UNDERTONE REVENUE BREAKDOWN, % SEARCH REVENUE BY PAYMENT MODEL, % 5.7% 4.3% 2.7% 12.5% 10.1% 18.1% 33.1% 44.7% 58.2% 70.8% 69.4% 56.9% 49.6% 37.5% 25.9% Q3'14 Q4'14 Q1'15 Q2'15 Q3'15 Old model Rev share Ads
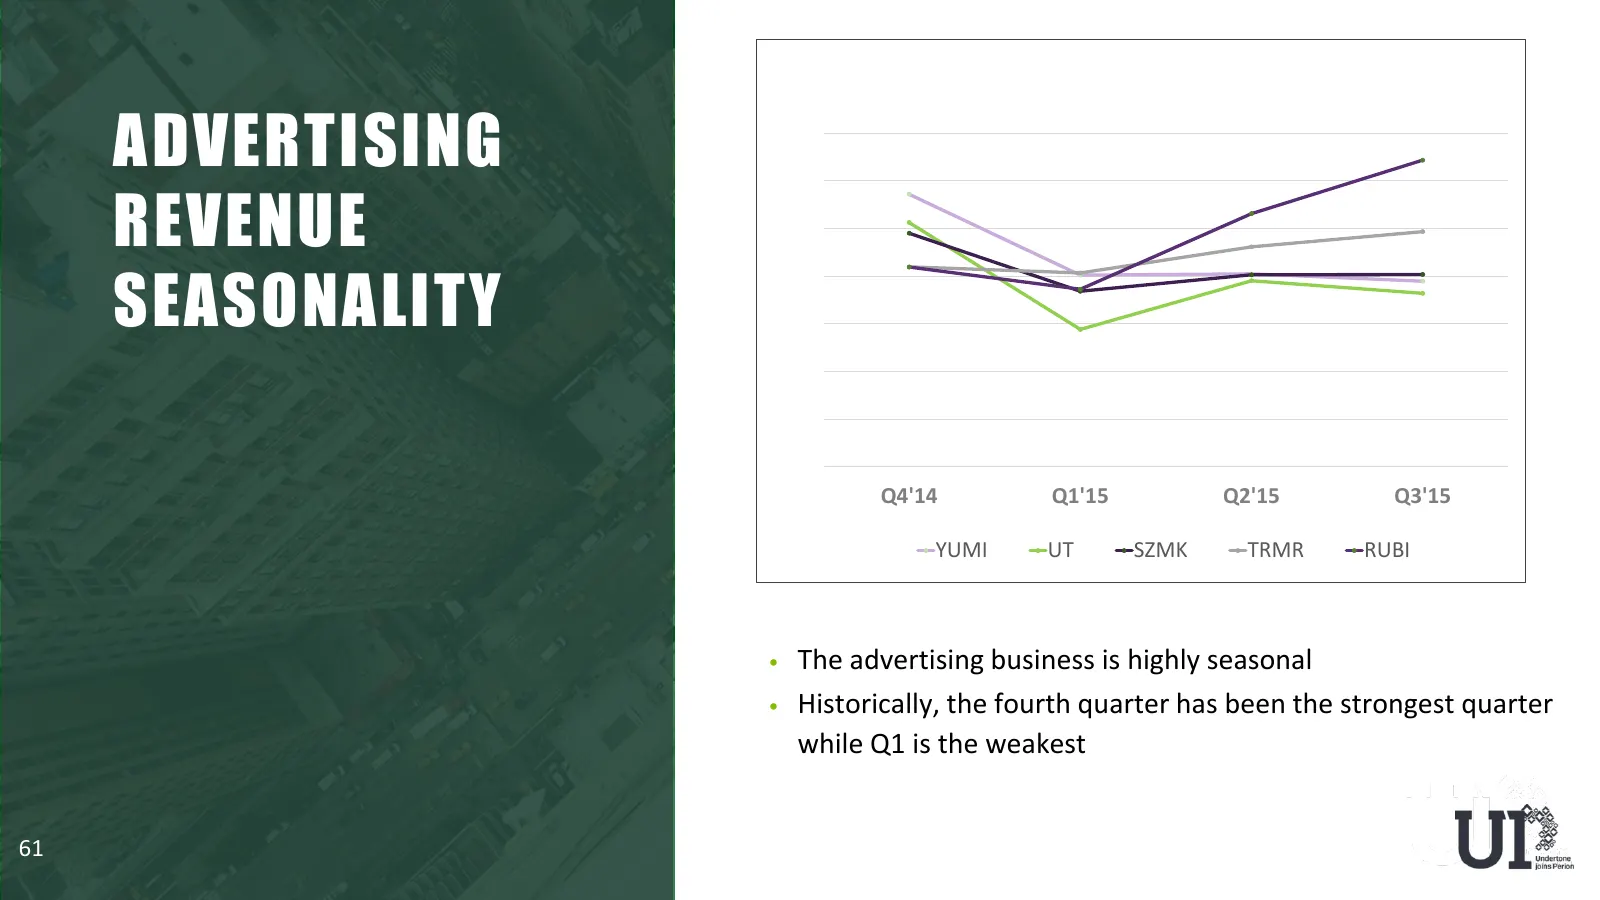
Slide 61: Advertising revenue seasonality
ADVERTISING REVENUE SEASONALITY Q4'14 Q1'15 Q2'15 Q3'15 YUMI UT SZMK TRMR RUBI • The advertising business is highly seasonal • Historically, the fourth quarter has been the strongest quarter while Q1 is the weakest 61
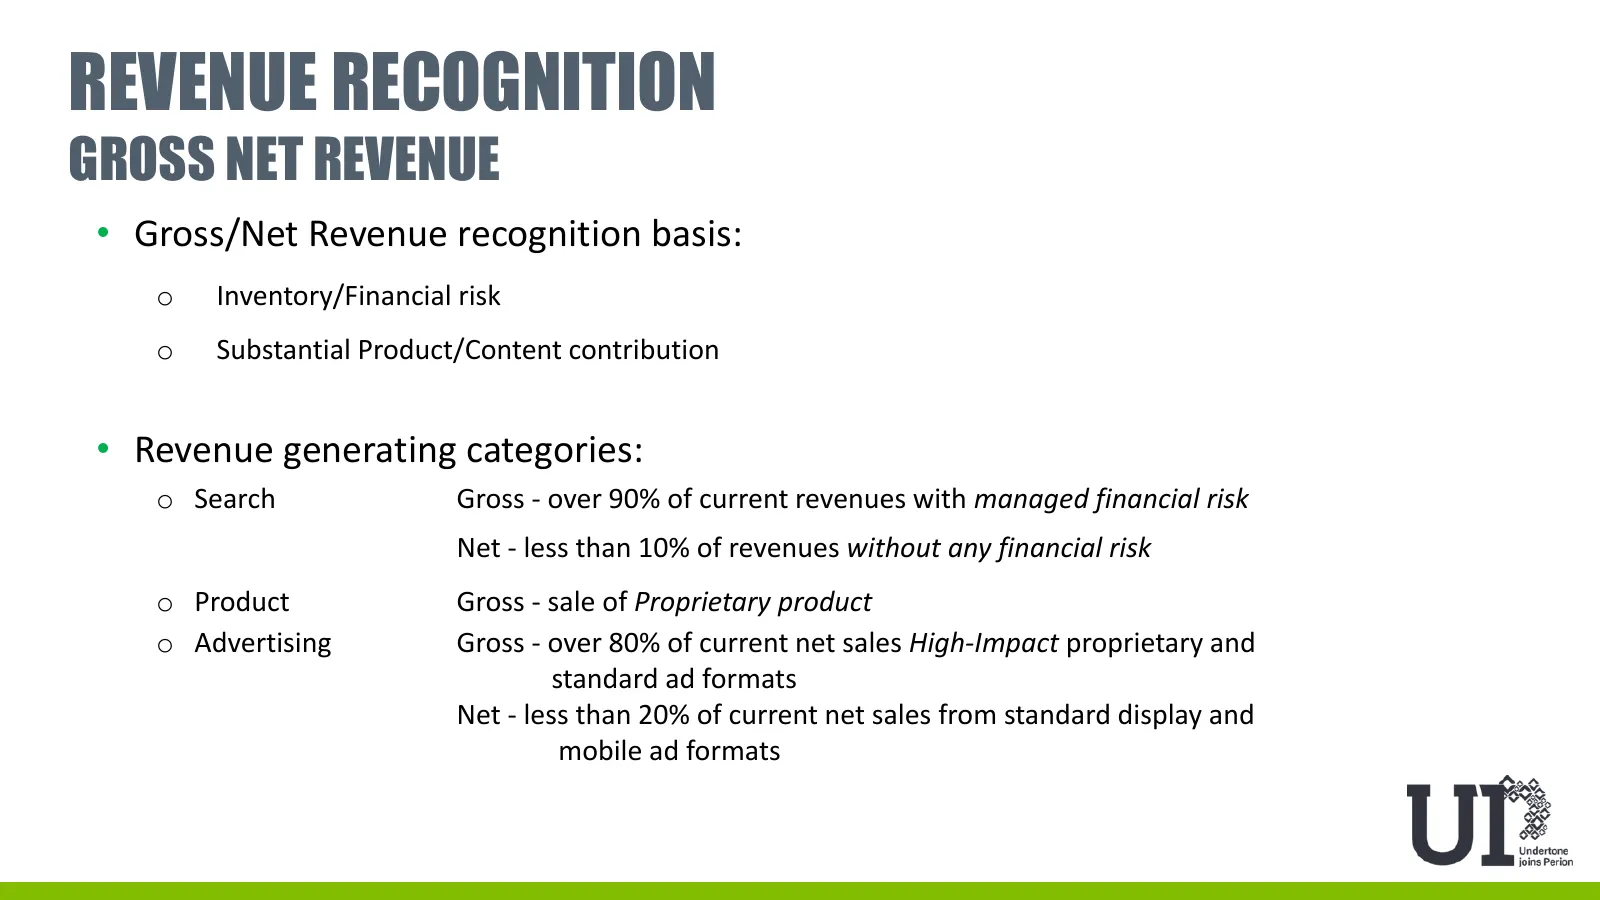
Slide 62: Revenue recognition
REVENUE RECOGNITION GROSS NET REVENUE • Gross/Net Revenue recognition basis: o Inventory/Financial risk o Substantial Product/Content contribution • Revenue generating categories: o Search Gross - over 90% of current revenues with managed financial risk Net - less than 10% of revenues without any fi
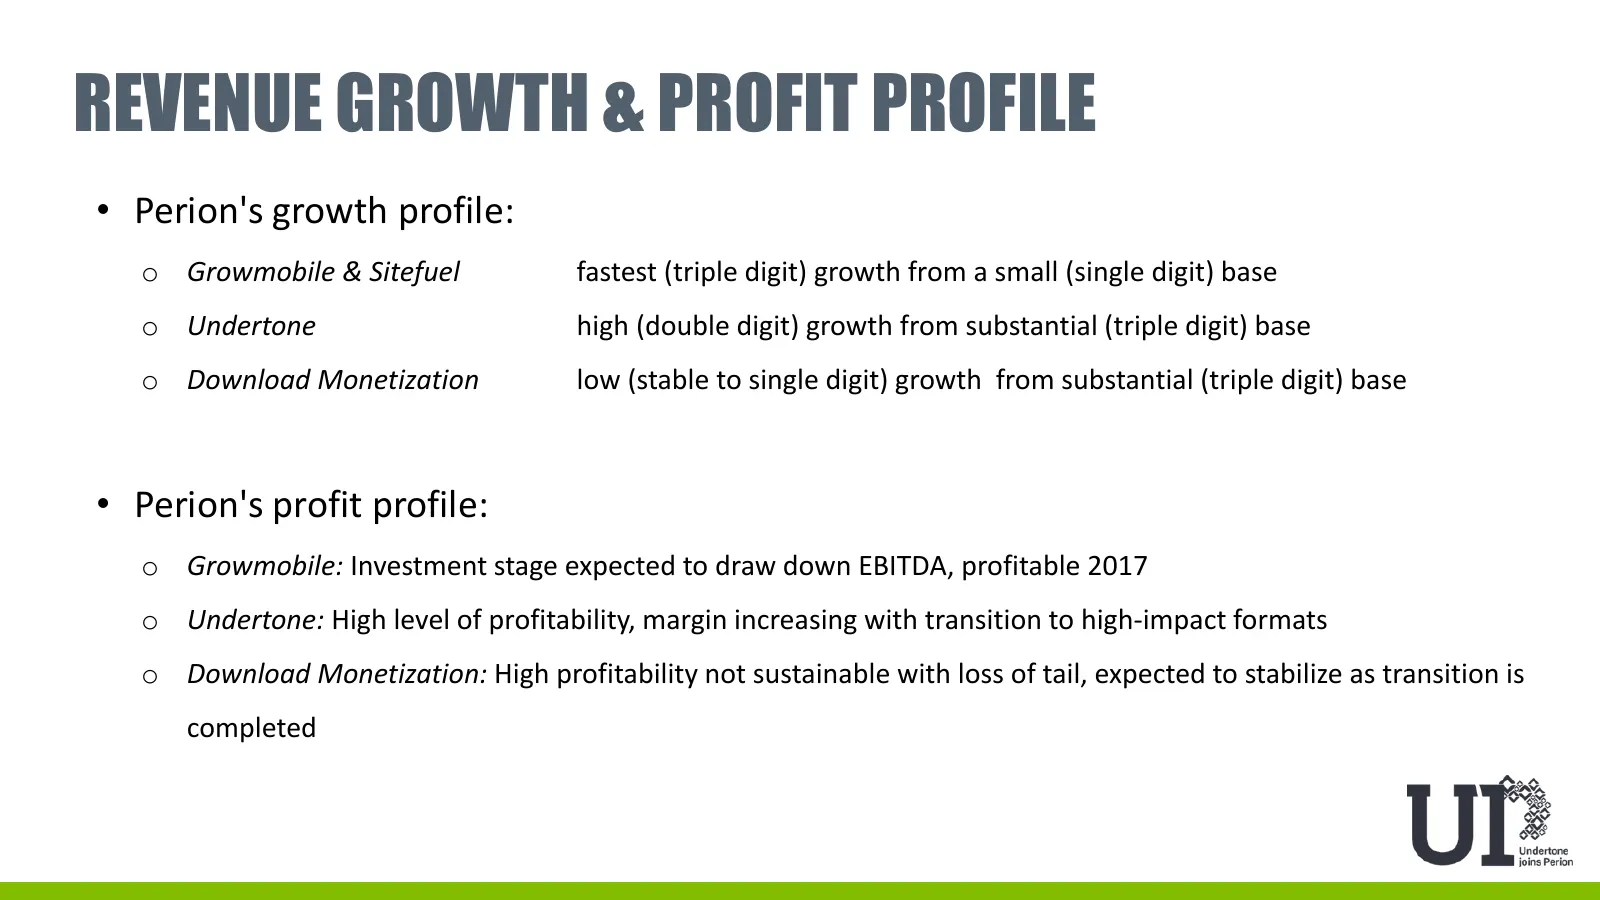
Slide 63: Revenue growth and profit profile
REVENUE GROWTH & PROFIT PROFILE • Perion's growth profile: o Growmobile & Sitefuel fastest (triple digit) growth from a small (single digit) base o Undertone high (double digit) growth from substantial (triple digit) base o Download Monetization low (stable to single digit) growth from substantial (
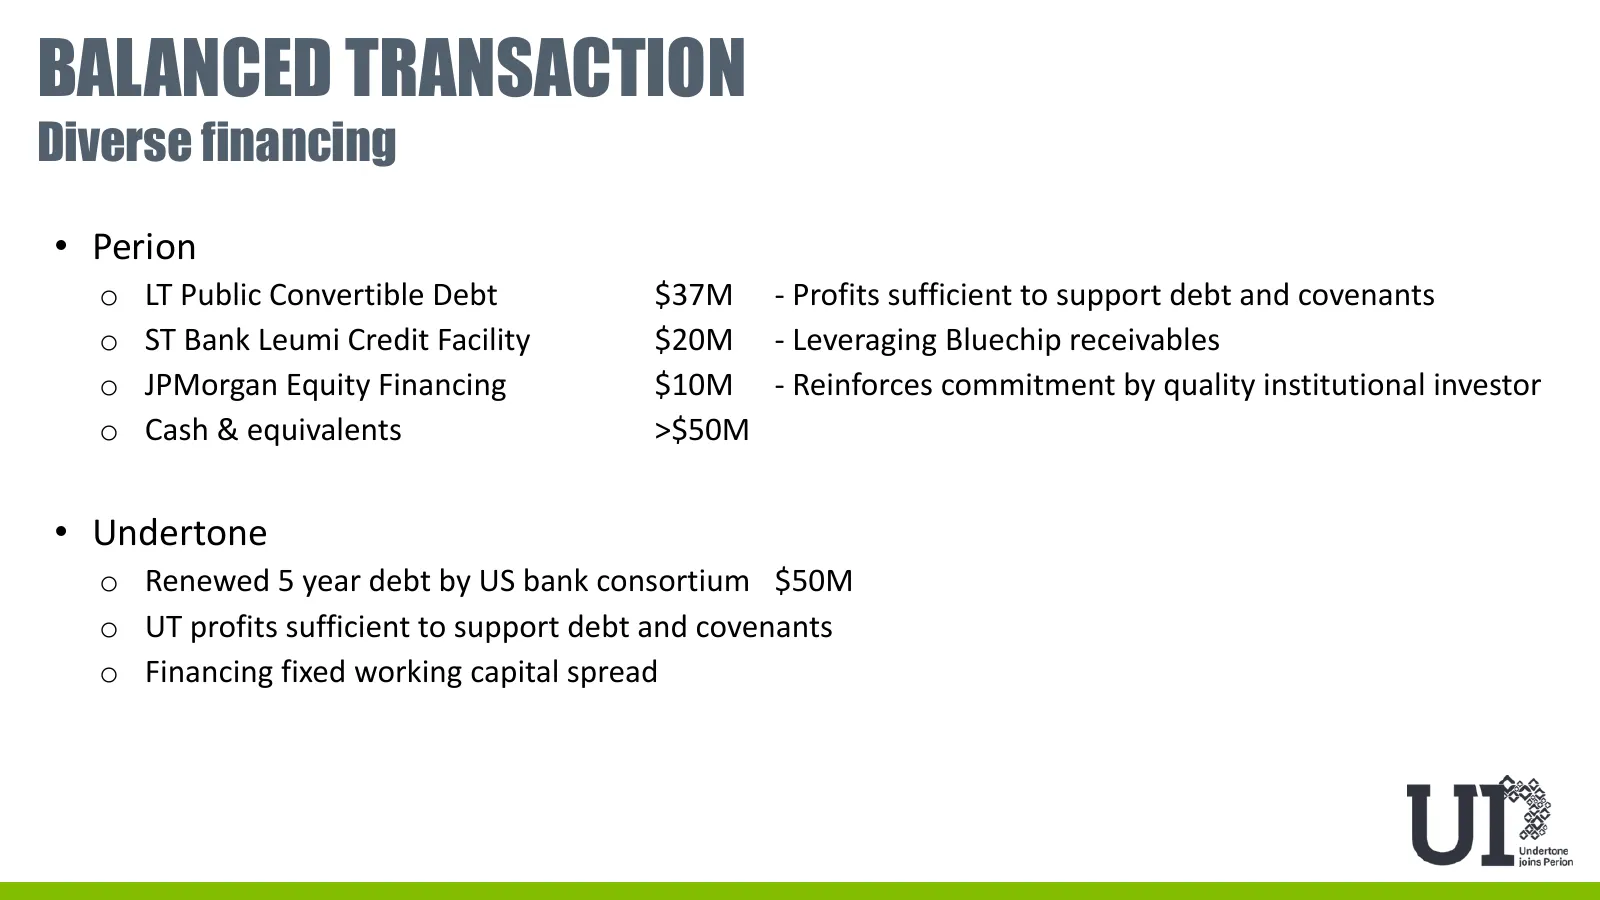
Slide 64: Balanced transaction
BALANCED TRANSACTION Diverse financing • Perion o LT Public Convertible Debt $37M - Profits sufficient to support debt and covenants o ST Bank Leumi Credit Facility $20M - Leveraging Bluechip receivables o JPMorgan Equity Financing $10M - Reinforces commitment by quality institutional investor o Cas
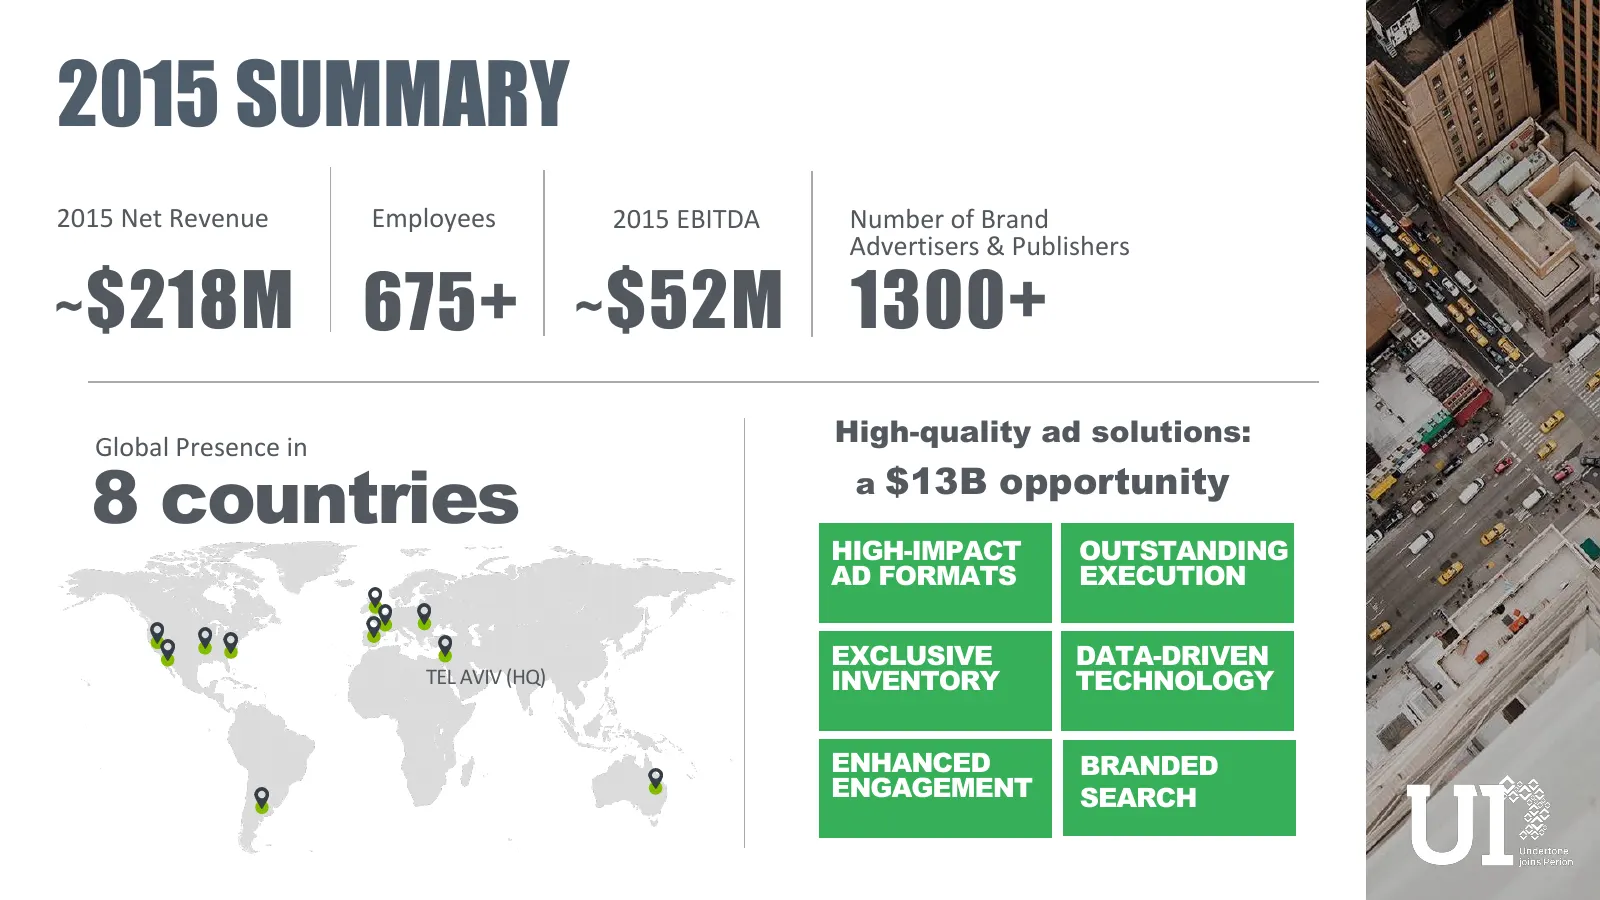
Slide 65: 2015 Summary
2015 SUMMARY 2015 Net Revenue Employees 2015 EBITDA Number of Brand Advertisers & Publishers ~ $218M 675+ ~ $52M 1300+ Global Presence in High-quality ad solutions: 8 countries a $13B opportunity HIGH-IMPACT OUTSTANDING AD FORMATS EXECUTION EXCLUSIVE DATA-DRIVEN TEL AVIV (HQ) INVENTORY TECHNOLOGY EN
Source: Internet Archive copy of perion.com
More decks from Perion Network Ltd
 Q2 2026 Earnings Presentation43 slides · Aug 10, 2026
 Investor Presentation (August 2026)83 slides · August 2026
 Investor Presentation (June 2026)80 slides · Jun 29, 2026
 Q1 2026 Earnings Presentation39 slides · May 20, 2026
 Q4 2025 Earnings Presentation54 slides · Feb 18, 2026
 Q3 2025 Earnings Presentation40 slides · Nov 12, 2025