Heartland Financial USA — Q1 2022 Earnings Presentation
44 slides from Heartland Financial USA's earnings presentation, May 9, 2022
Slide 1: 1st Quarter 2022 Financials
1st Quarter 2022 Financials Please replace this revised investor presentation to update certain Q1 2022 financial information issued April 25, 2022 at 4:00 PM ET. Please refer to Form 8-K/A furnished on May 9, 2022 for additional information.
Slide 2: Safe Harbor
2 Safe Harbor Within the charts and tables presented, certain segments, columns and rows may not sum to totals shown due to rounding. This investor presentation (including any information incorporated herein by reference) contains, and future oral and written statements of HTLF and its management ma
Slide 3: Corporate Profile
3 Corporate Profile
Slide 4: Company Overview – Fiscal 1Q 2022 Financial Highlights
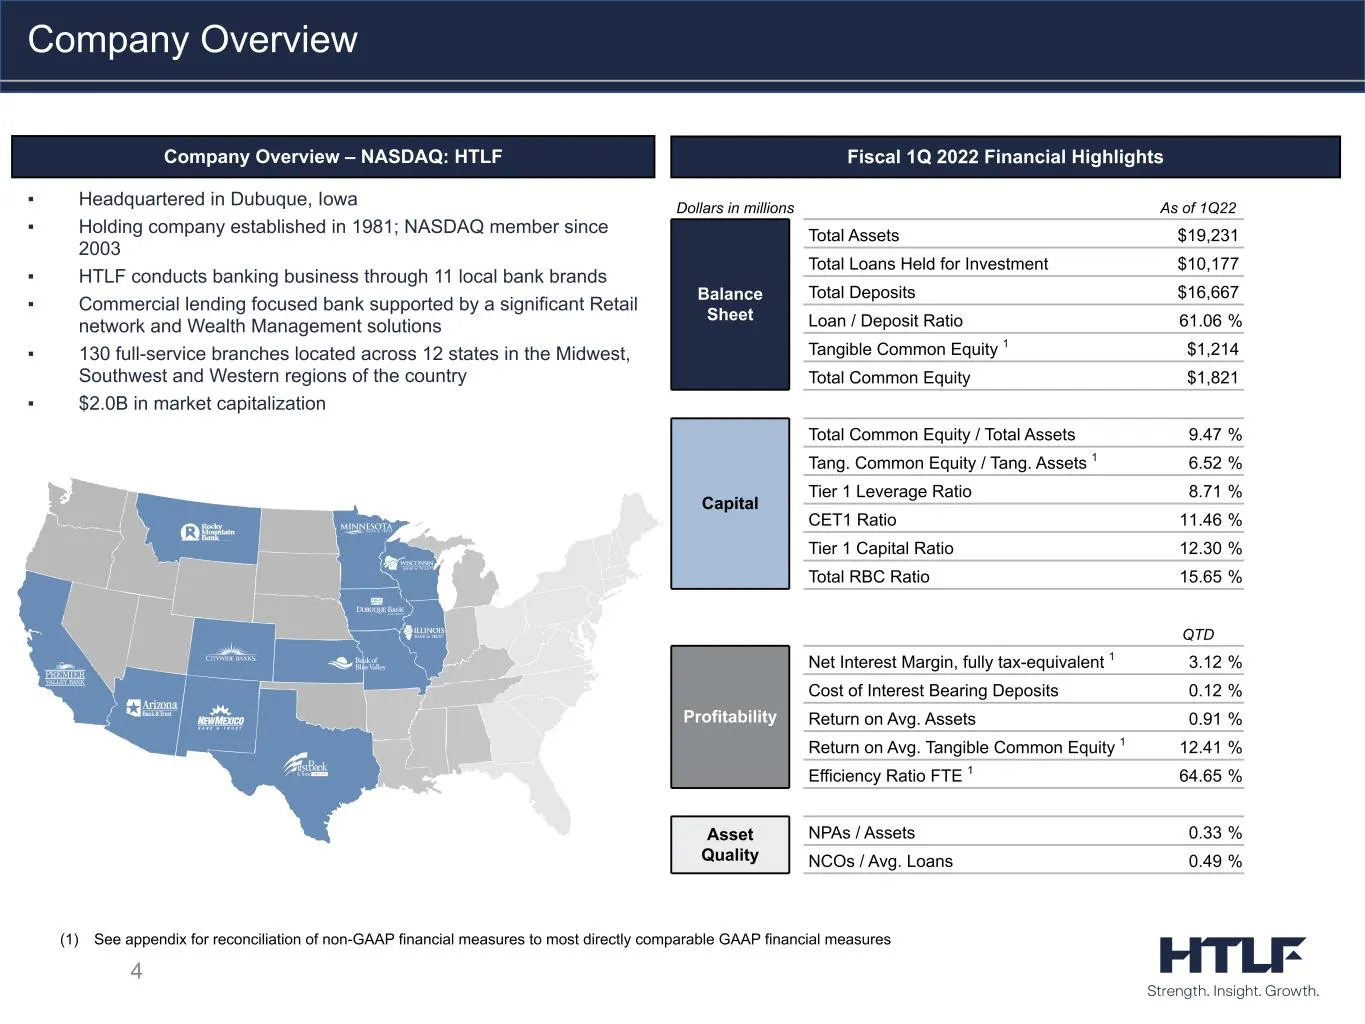
4 Company Overview – NASDAQ: HTLF Fiscal 1Q 2022 Financial Highlights ▪ Headquartered in Dubuque, Iowa ▪ Holding company established in 1981; NASDAQ member since 2003 ▪ HTLF conducts banking business through 11 local bank brands ▪ Commercial lending focused bank supported by a significant Retail net
Slide 5: Strength. Insight. Growth.
5 Strength. Insight. Growth. ▪ It’s what we bring to our customers, communities, employees and shareholders ▪ Strong corporate leadership and innovative thinking have uniquely positioned us ▪ Our business model and diverse geographic footprint reduce risk and drive organic growth ▪ Complemented by s
Slide 6: Commercial-focused local banking with the scale to compete at any level
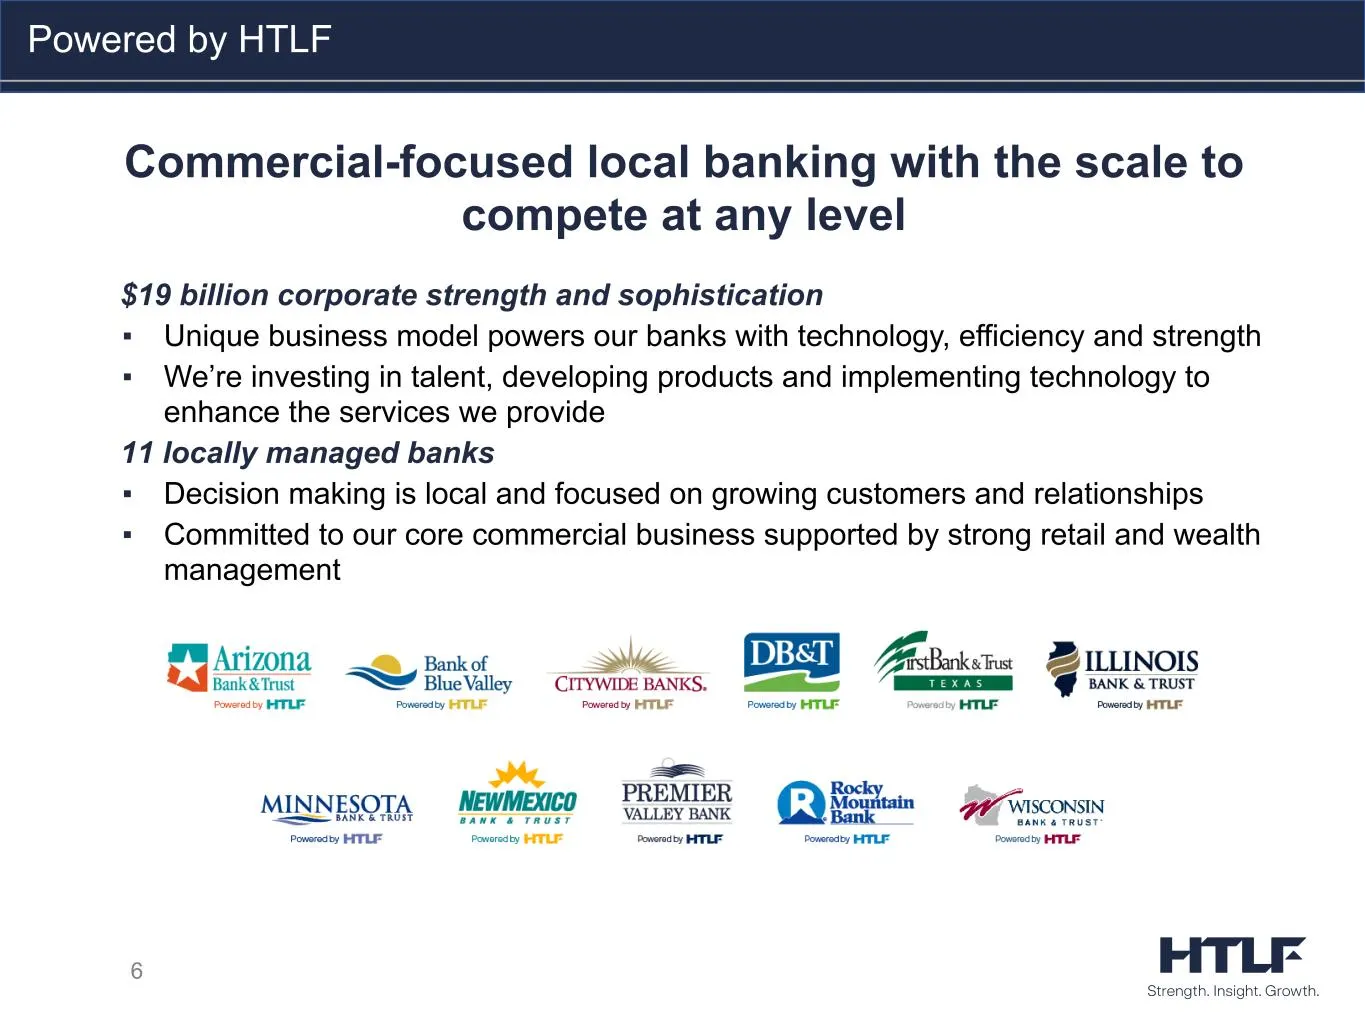
6 Commercial-focused local banking with the scale to compete at any level $19 billion corporate strength and sophistication ▪ Unique business model powers our banks with technology, efficiency and strength ▪ We’re investing in talent, developing products and implementing technology to enhance the se
Slide 7: Geographic Footprint
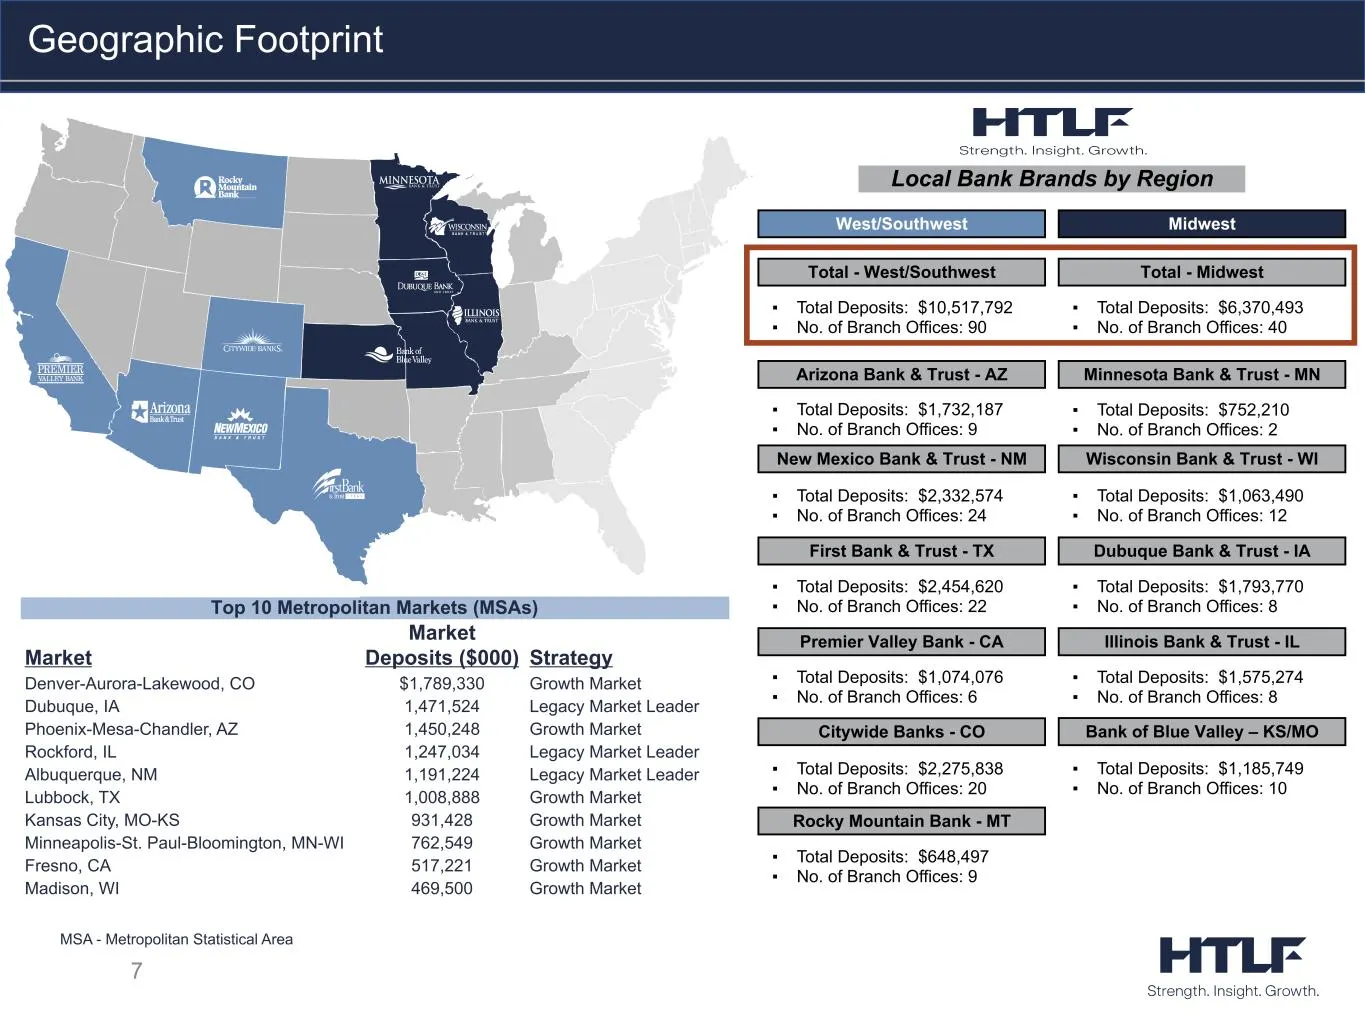
7 Geographic Footprint Local Bank Brands by Region Bank of Blue Valley – KS/MO Illinois Bank & Trust - IL Total - Midwest Midwest ▪ Total Deposits: $1,575,274 ▪ No. of Branch Offices: 8 ▪ Total Deposits: $1,185,749 ▪ No. of Branch Offices: 10 Rocky Mountain Bank - MT Citywide Banks - CO Premier Vall
Slide 8: HTLF Excellence Recognition
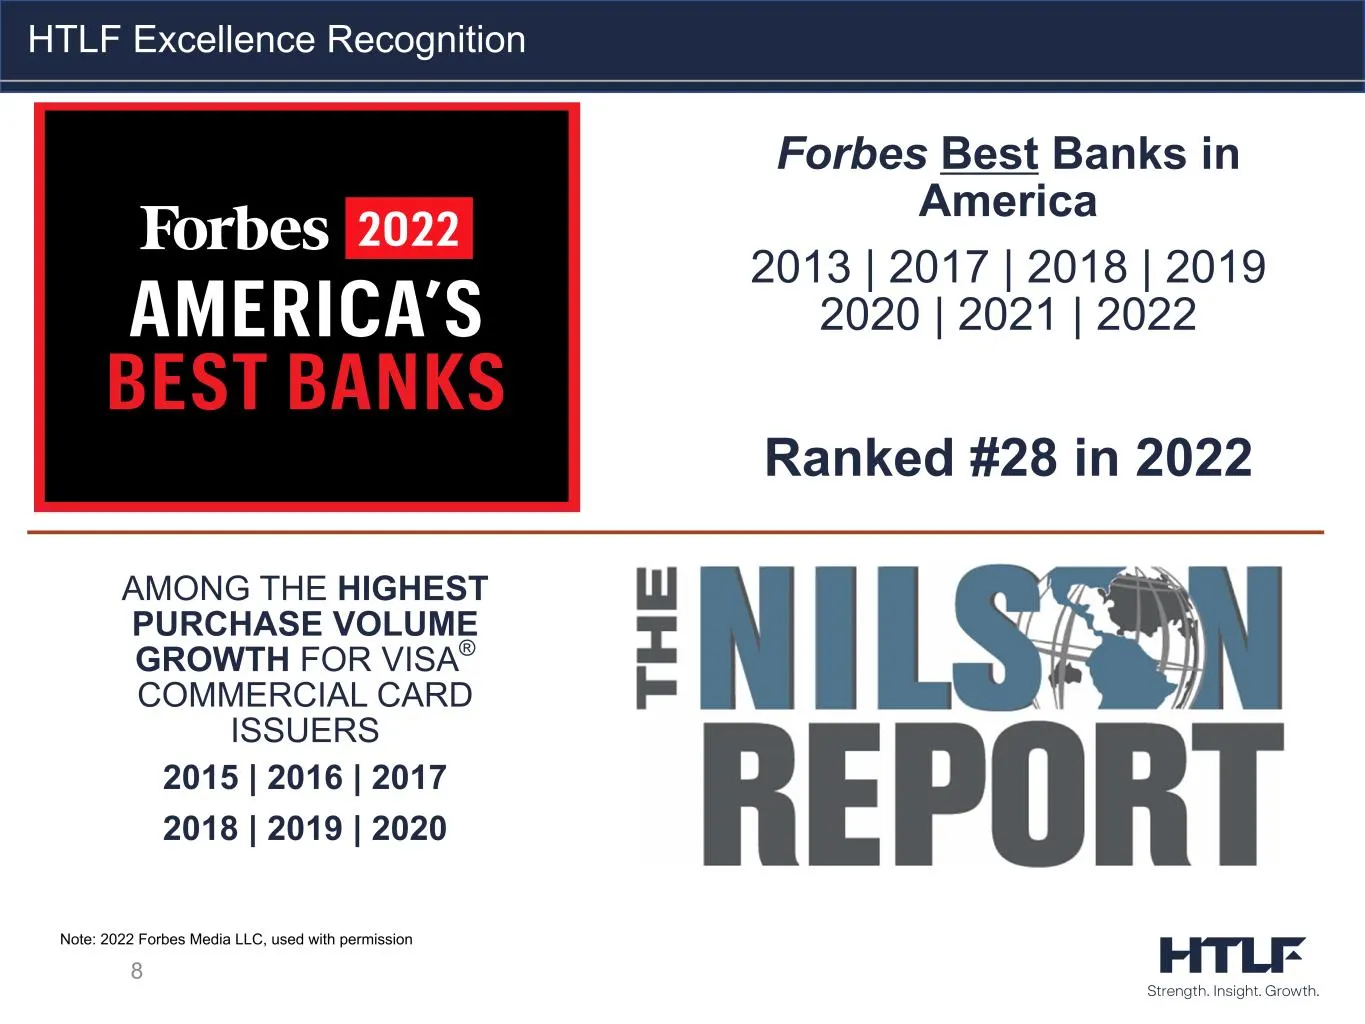
8 HTLF Excellence Recognition Note: 2022 Forbes Media LLC, used with permission AMONG THE HIGHEST PURCHASE VOLUME GROWTH FOR VISA® COMMERCIAL CARD ISSUERS 2015 | 2016 | 2017 2018 | 2019 | 2020 Forbes Best Banks in America 2013 | 2017 | 2018 | 2019 2020 | 2021 | 2022 Ranked #28 in 2022
Slide 9: A Steadfast Commitment to Growth
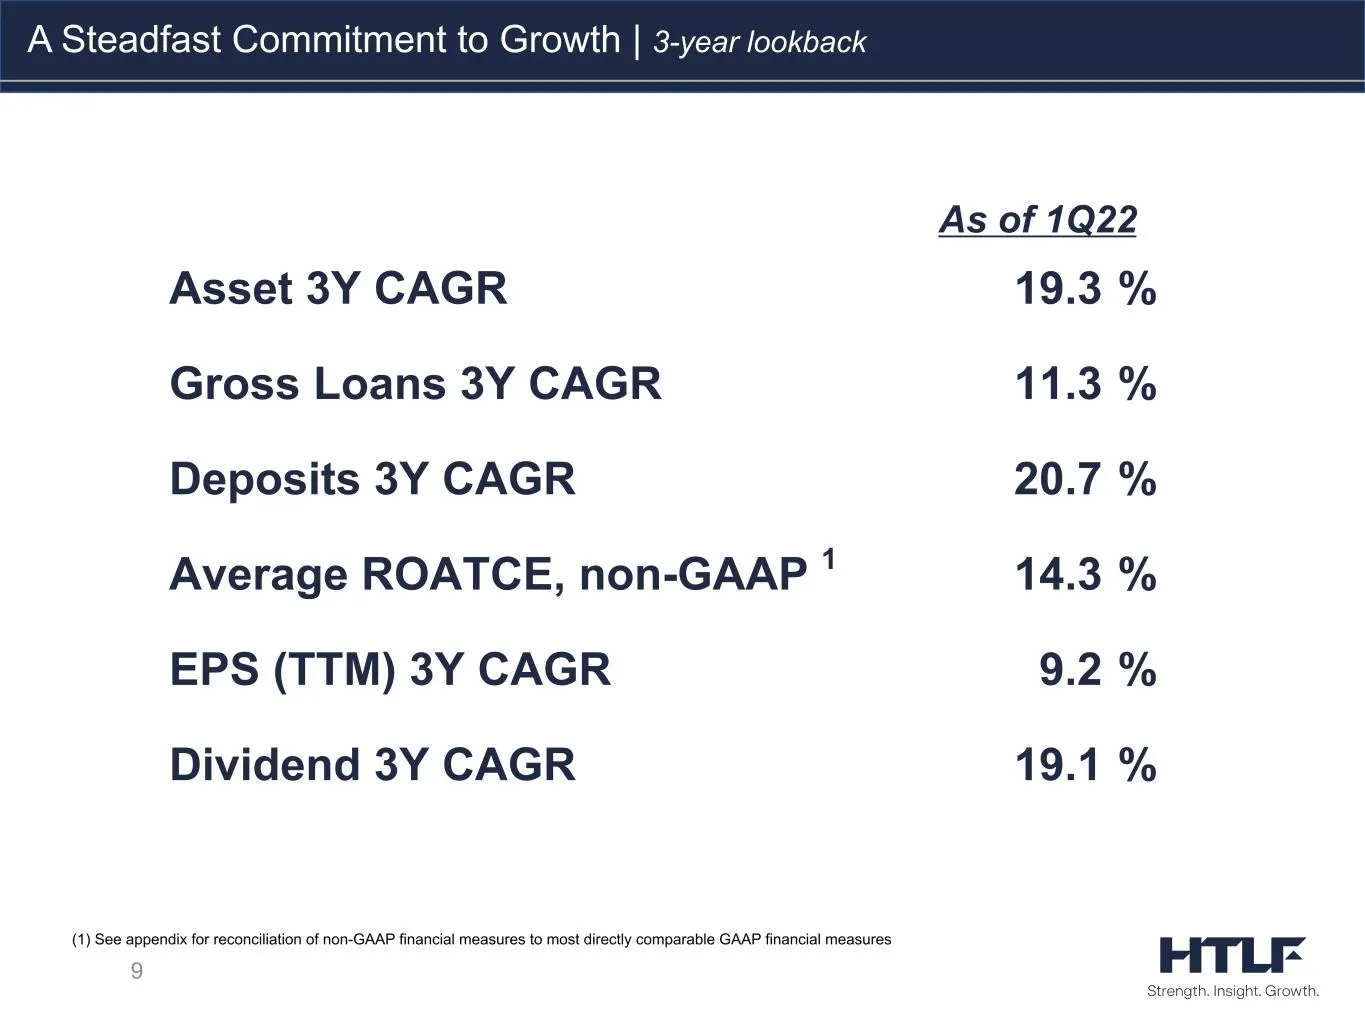
9 A Steadfast Commitment to Growth | 3-year lookback (1) See appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures As of 1Q22 Asset 3Y CAGR 19.3 % Gross Loans 3Y CAGR 11.3 % Deposits 3Y CAGR 20.7 % Average ROATCE, non-GAAP 1 14.3 % EPS (TTM) 3
Slide 10: Strategic Focus
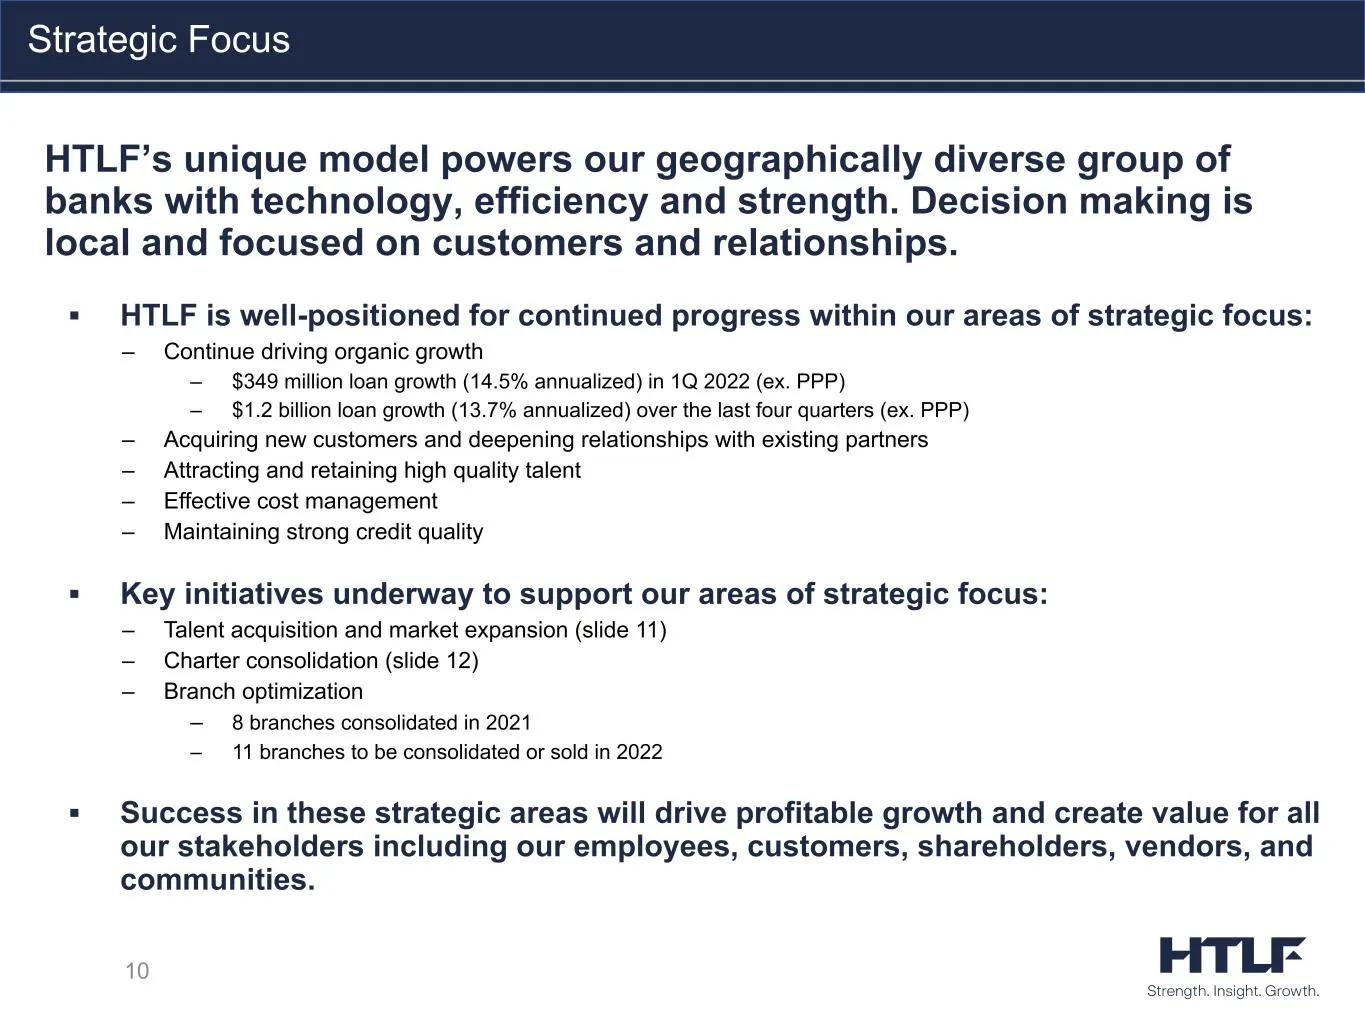
10 Strategic Focus HTLF’s unique model powers our geographically diverse group of banks with technology, efficiency and strength. Decision making is local and focused on customers and relationships. ▪ HTLF is well-positioned for continued progress within our areas of strategic focus: – Continue driv
Slide 11: Market Expansion
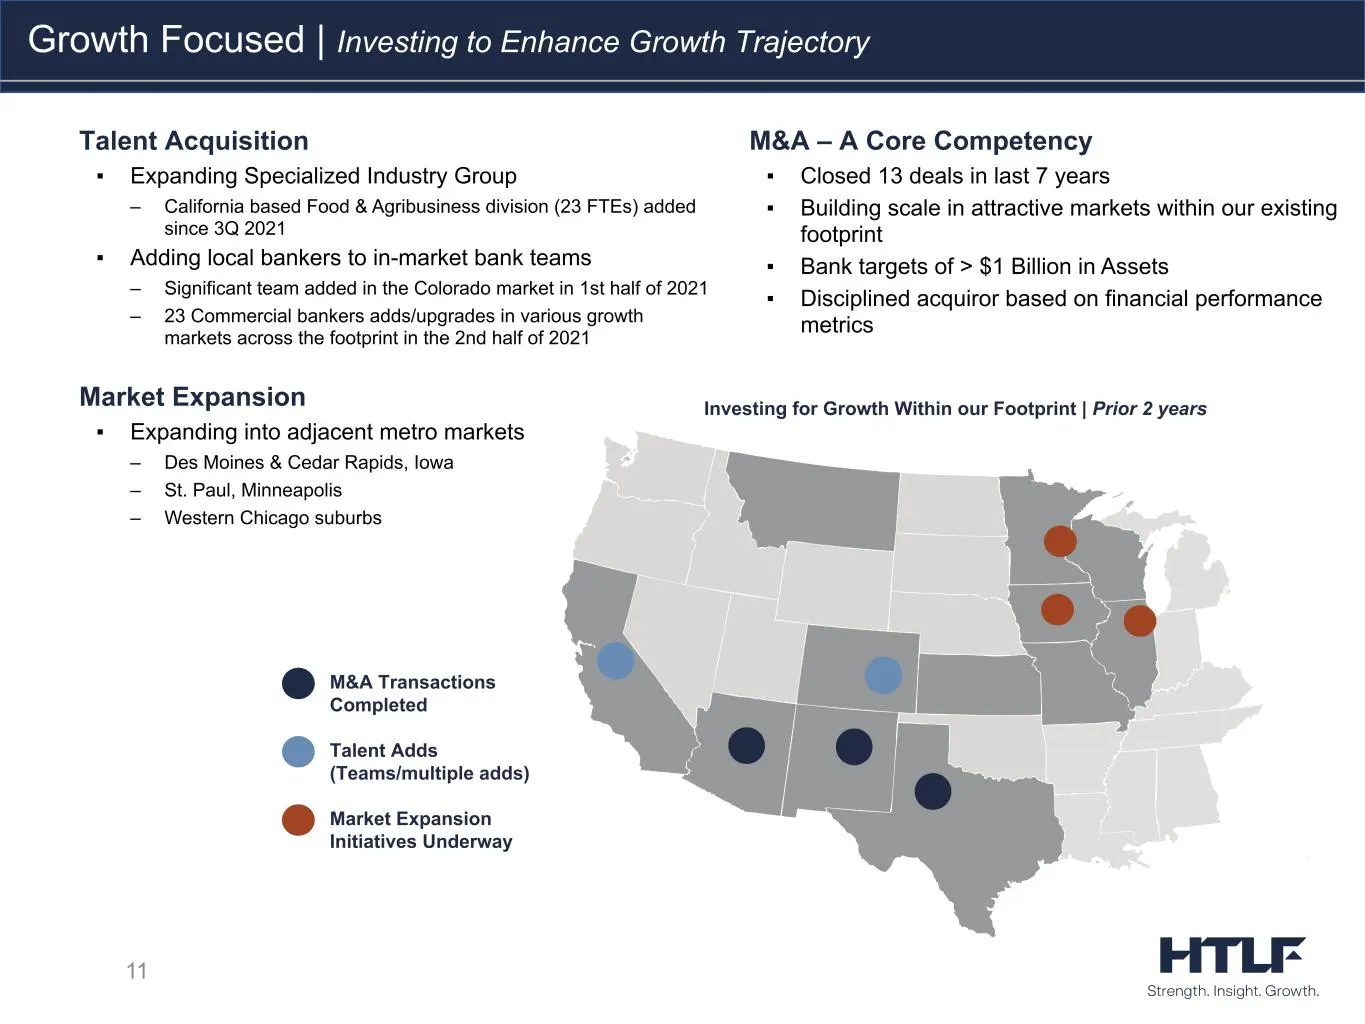
Market Expansion ▪ Expanding into adjacent metro markets – Des Moines & Cedar Rapids, Iowa – St. Paul, Minneapolis – Western Chicago suburbs 11 Growth Focused | Investing to Enhance Growth Trajectory M&A Transactions Completed Talent Adds (Teams/multiple adds) M&A – A Core Competency ▪ Closed 13 dea
Slide 12: Bank Charter Consolidation Initiative
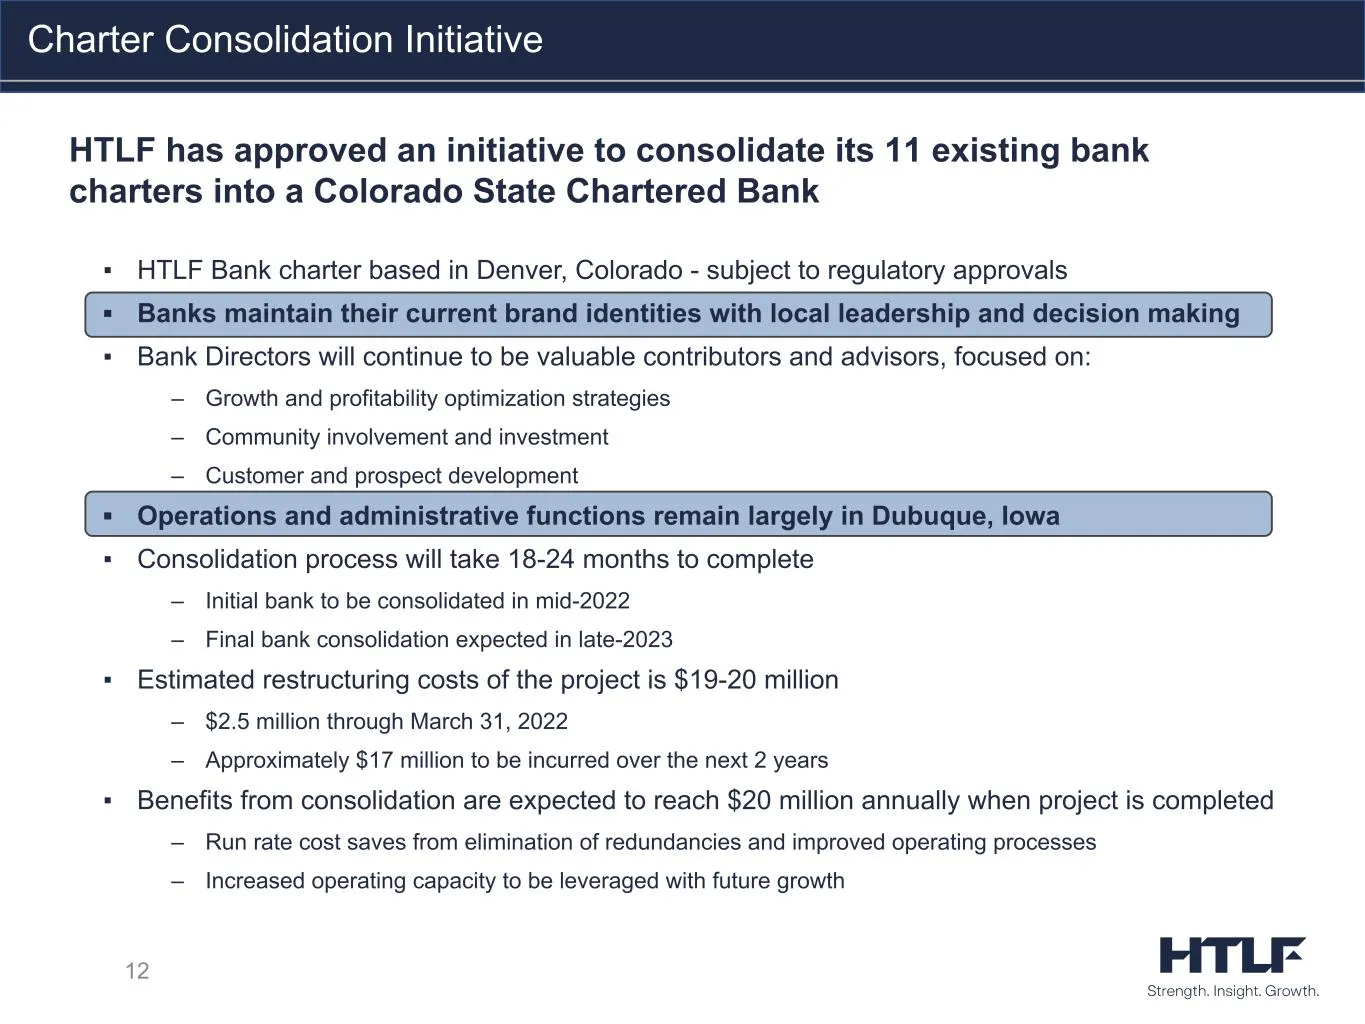
12 HTLF has approved an initiative to consolidate its 11 existing bank charters into a Colorado State Chartered Bank ▪ HTLF Bank charter based in Denver, Colorado - subject to regulatory approvals ▪ Banks maintain their current brand identities with local leadership and decision making ▪ Bank Direct
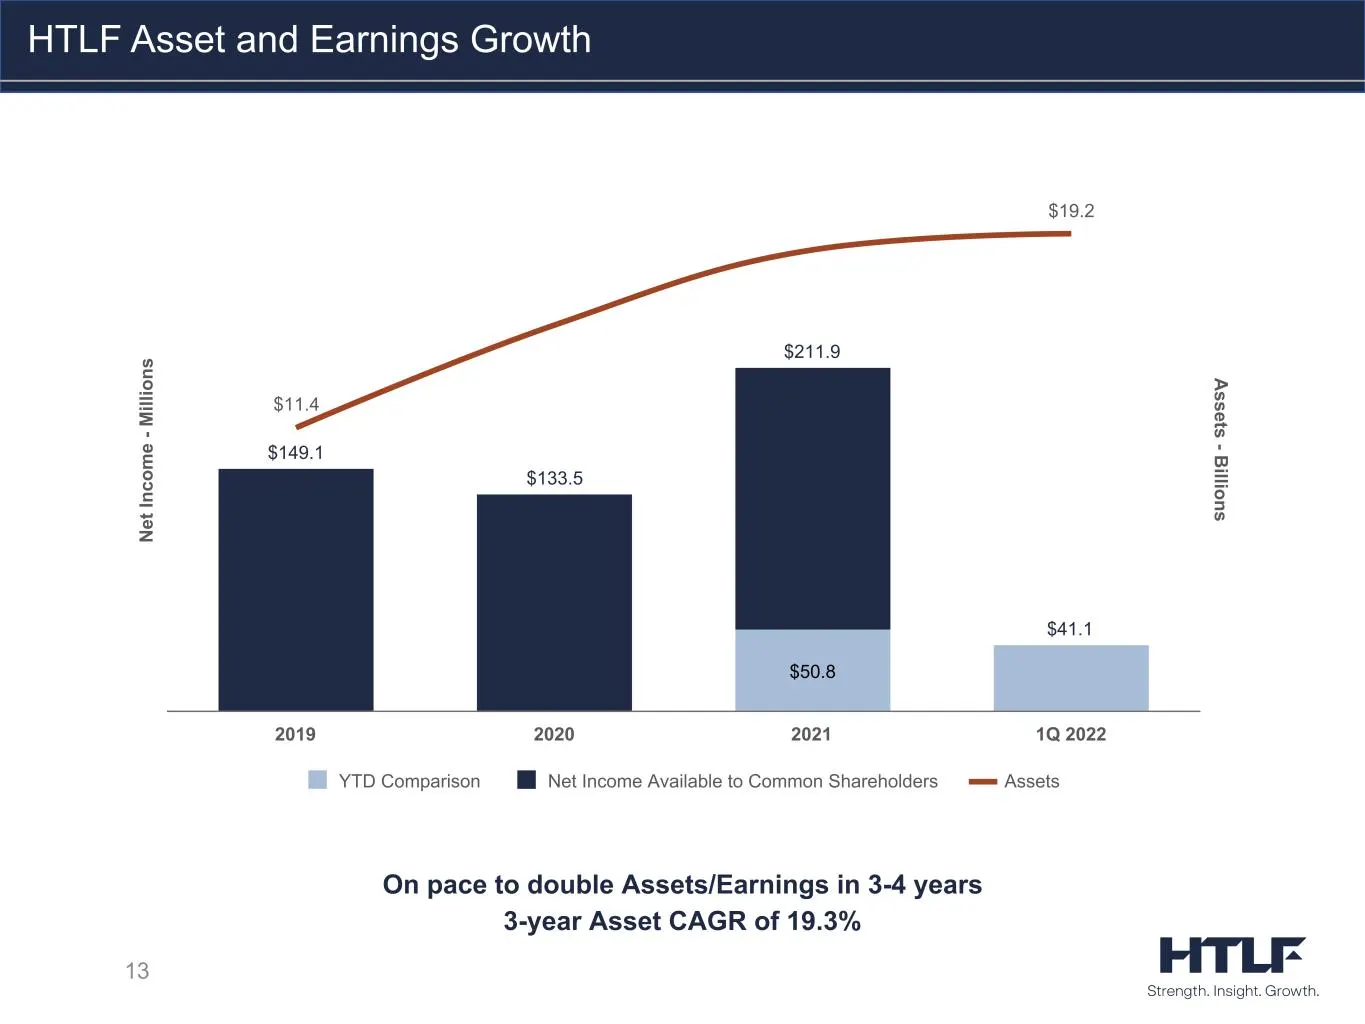
Slide 13: HTLF Asset and Earnings Growth
13 HTLF Asset and Earnings Growth On pace to double Assets/Earnings in 3-4 years 3-year Asset CAGR of 19.3% N et In co m e - M ill io ns A ssets - B illions $149.1 $133.5 $211.9 $41.1 $50.8 $11.4 $19.2 YTD Comparison Net Income Available to Common Shareholders Assets 2019 2020 2021 1Q 2022
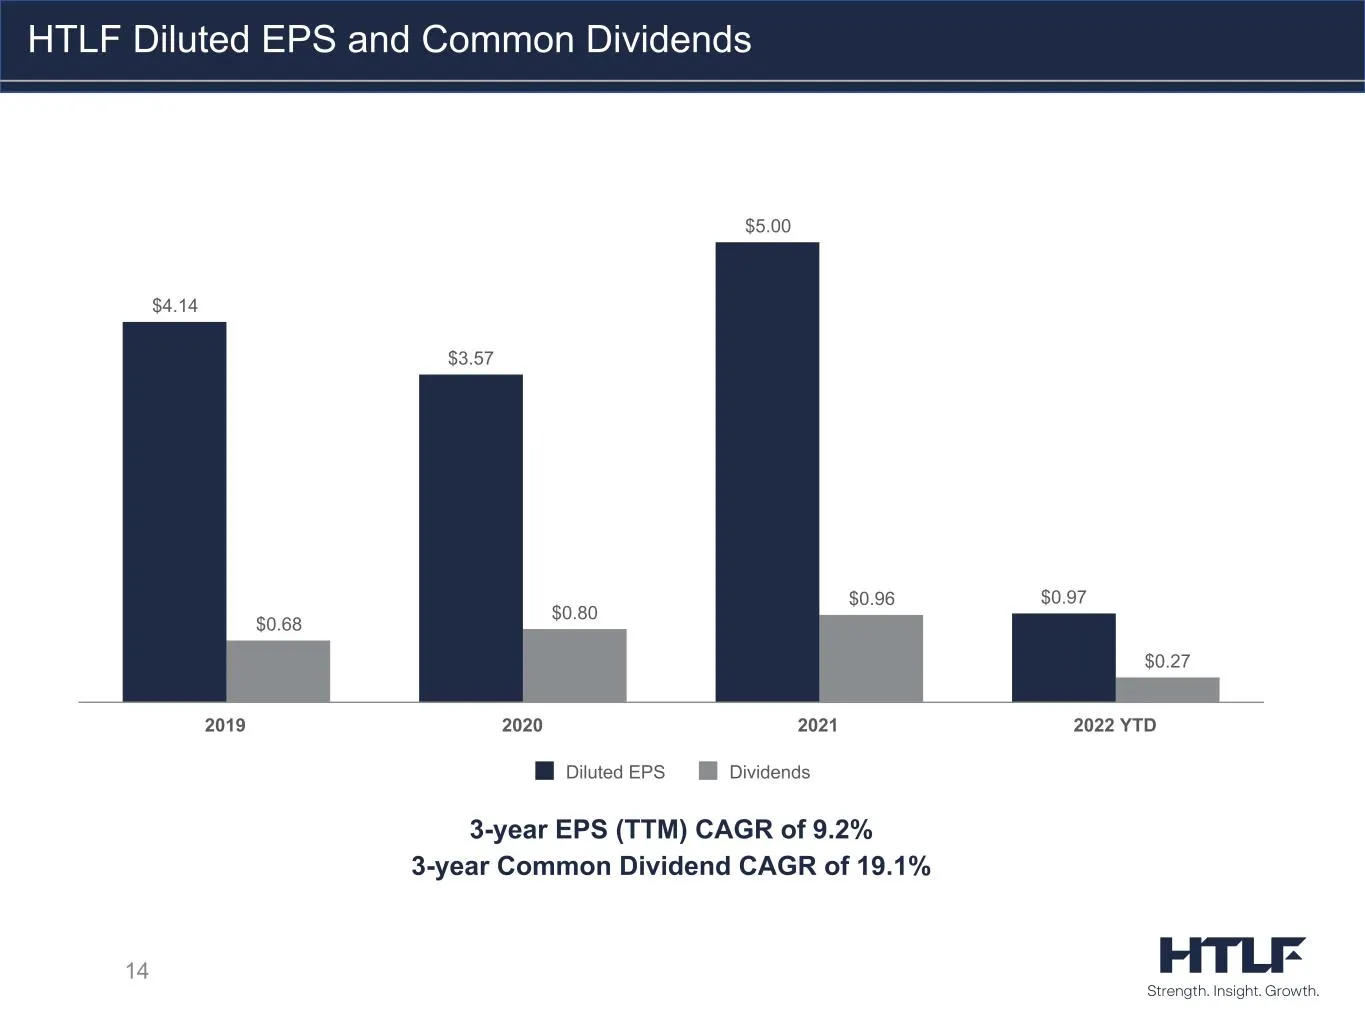
Slide 14: HTLF Diluted EPS and Common Dividends
14 HTLF Diluted EPS and Common Dividends 3-year EPS (TTM) CAGR of 9.2% 3-year Common Dividend CAGR of 19.1% $4.14 $3.57 $5.00 $0.97 $0.68 $0.80 $0.96 $0.27 Diluted EPS Dividends 2019 2020 2021 2022 YTD
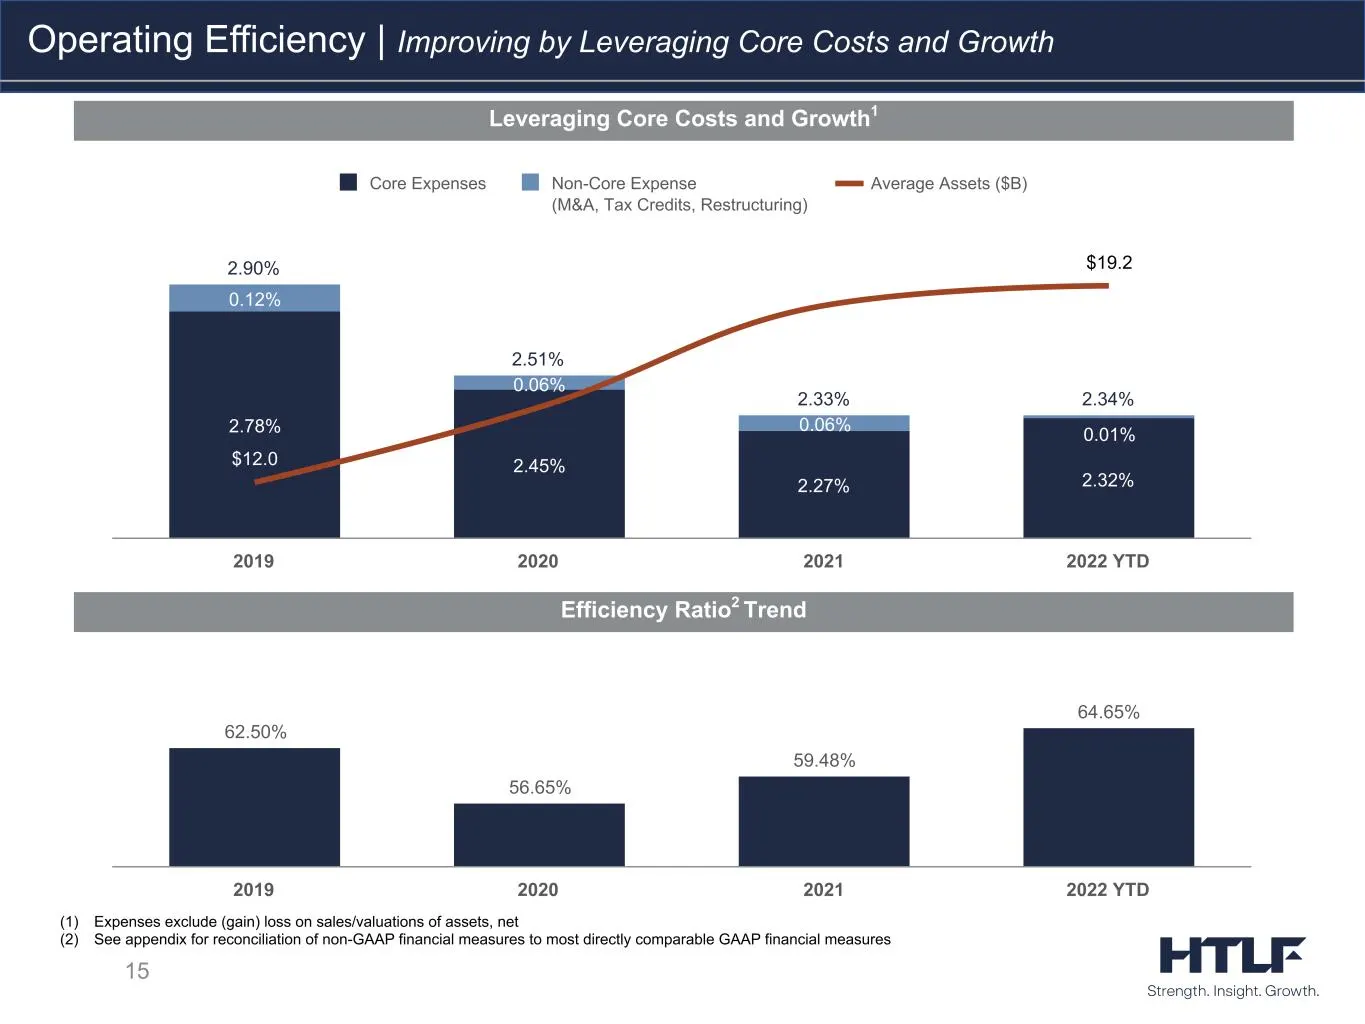
Slide 15: Operating Efficiency | Efficiency Ratio Trend
15 Efficiency Ratio2 Trend Operating Efficiency | Improving by Leveraging Core Costs and Growth Leveraging Core Costs and Growth1 (1) Expenses exclude (gain) loss on sales/valuations of assets, net (2) See appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP fi
Slide 16: Financial Summary
16 Financial Summary
Slide 17: Summary Balance Sheet Items
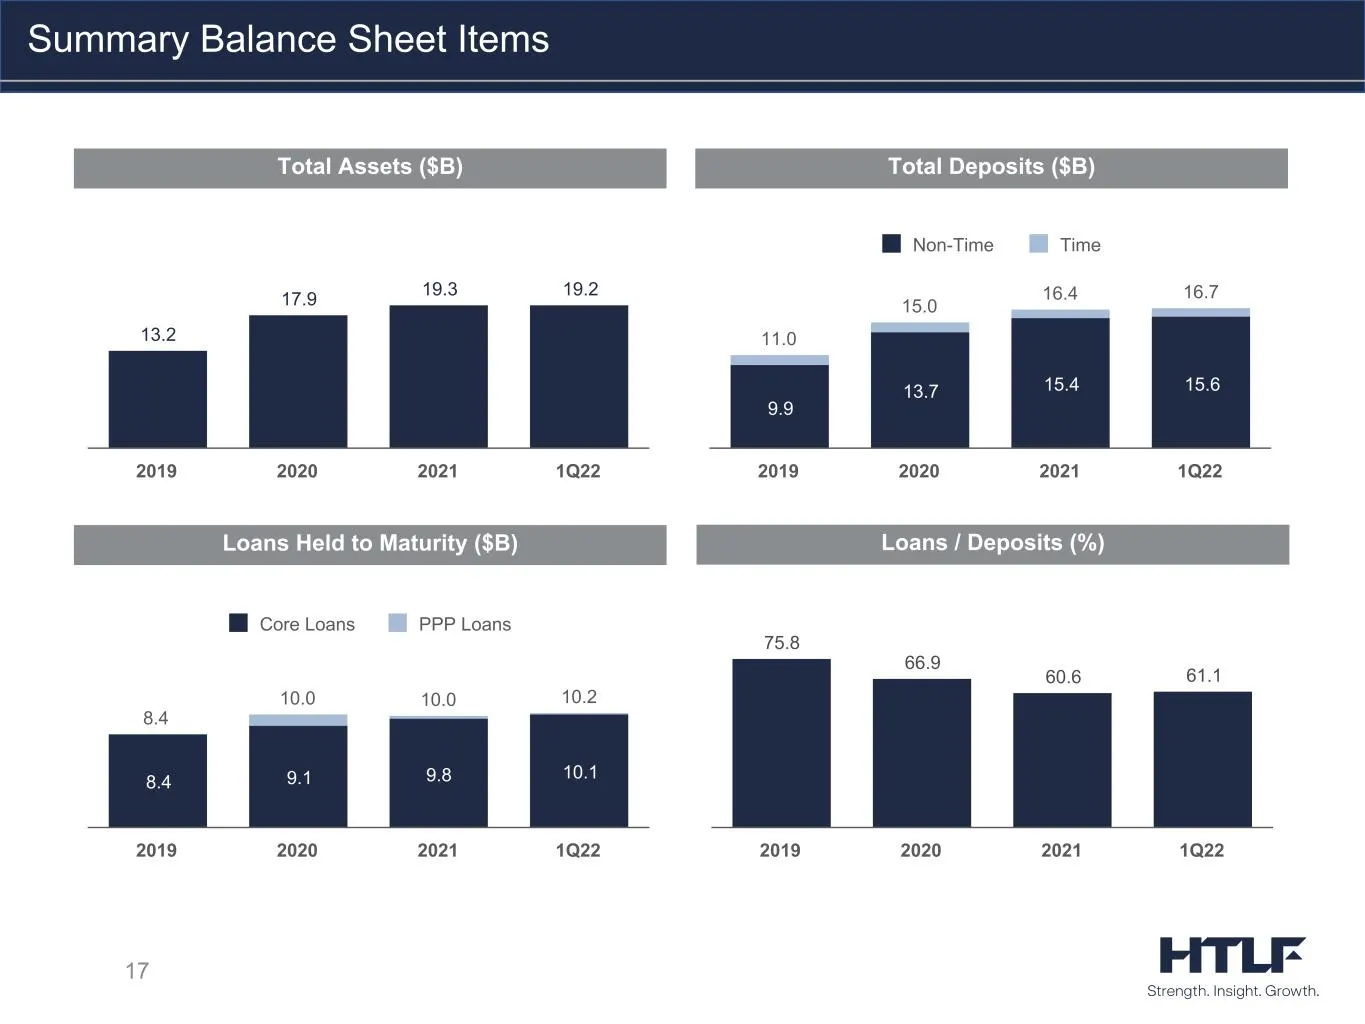
17 Total Assets ($B) Total Deposits ($B) Loans Held to Maturity ($B) Loans / Deposits (%) Summary Balance Sheet Items 13.2 17.9 19.3 19.2 2019 2020 2021 1Q22 11.0 15.0 16.4 16.7 9.9 13.7 15.4 15.6 Non-Time Time 2019 2020 2021 1Q22 8.4 10.0 10.0 10.2 8.4 9.1 9.8 10.1 Core Loans PPP Loans 2019 2020 20
Slide 18: Summary Profitability Items
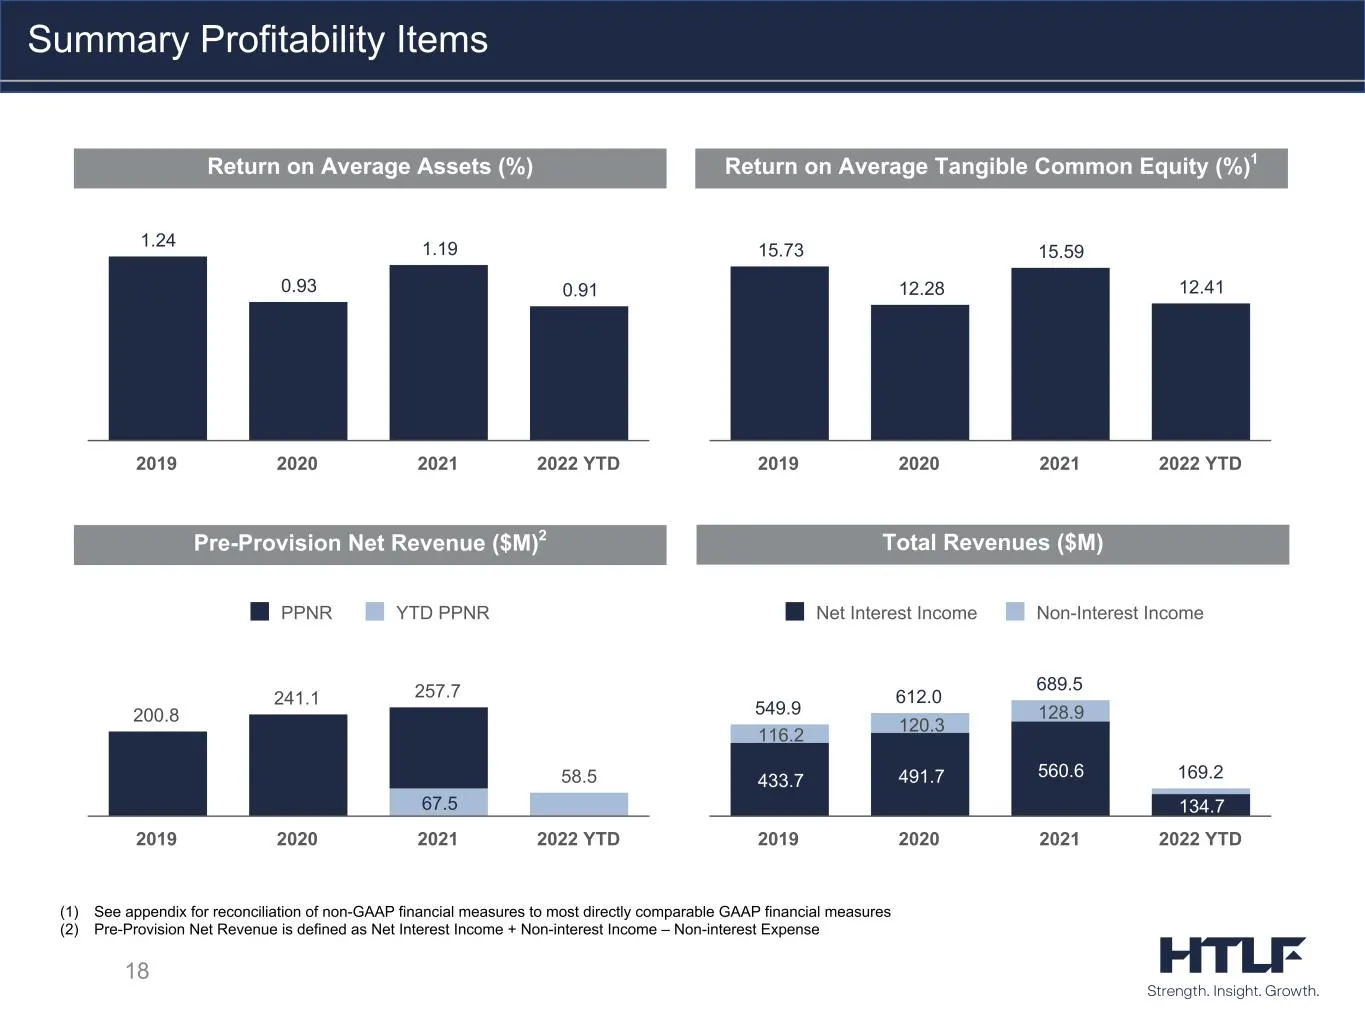
18 Summary Profitability Items (1) See appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures (2) Pre-Provision Net Revenue is defined as Net Interest Income + Non-interest Income – Non-interest Expense Return on Average Assets (%) Return on Av
Slide 19: Net Interest Margin Breakdown
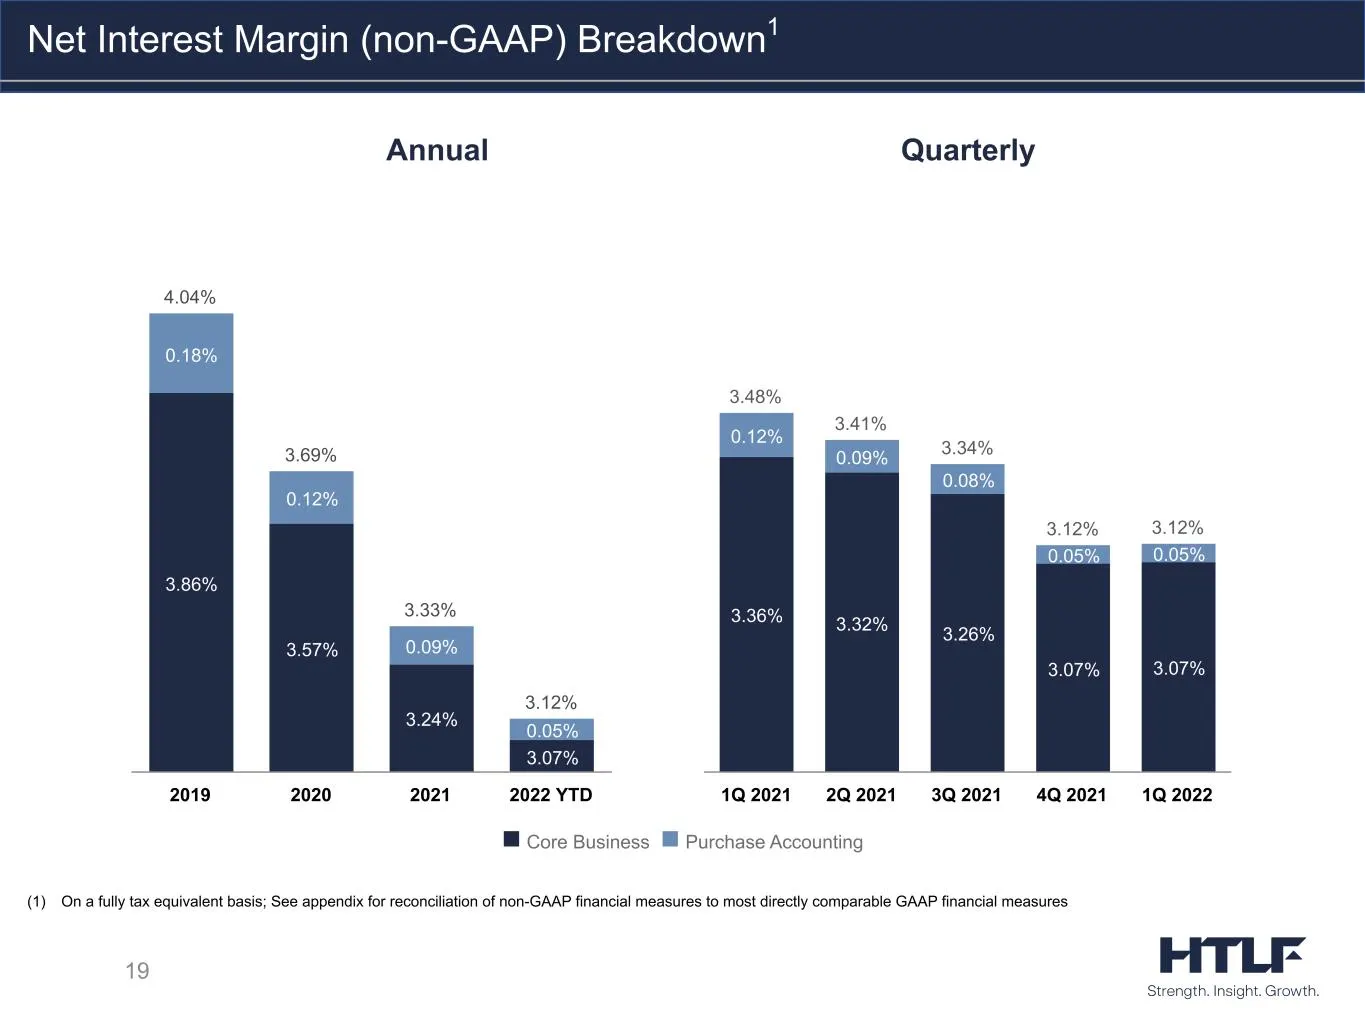
19 Net Interest Margin (non-GAAP) Breakdown1 QuarterlyAnnual (1) On a fully tax equivalent basis; See appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures 4.04% 3.69% 3.33% 3.12% 3.86% 3.57% 3.24% 3.07% 0.18% 0.12% 0.09% 0.05% 2019 2020 2021
Slide 20: Non-Interest Income Breakdown
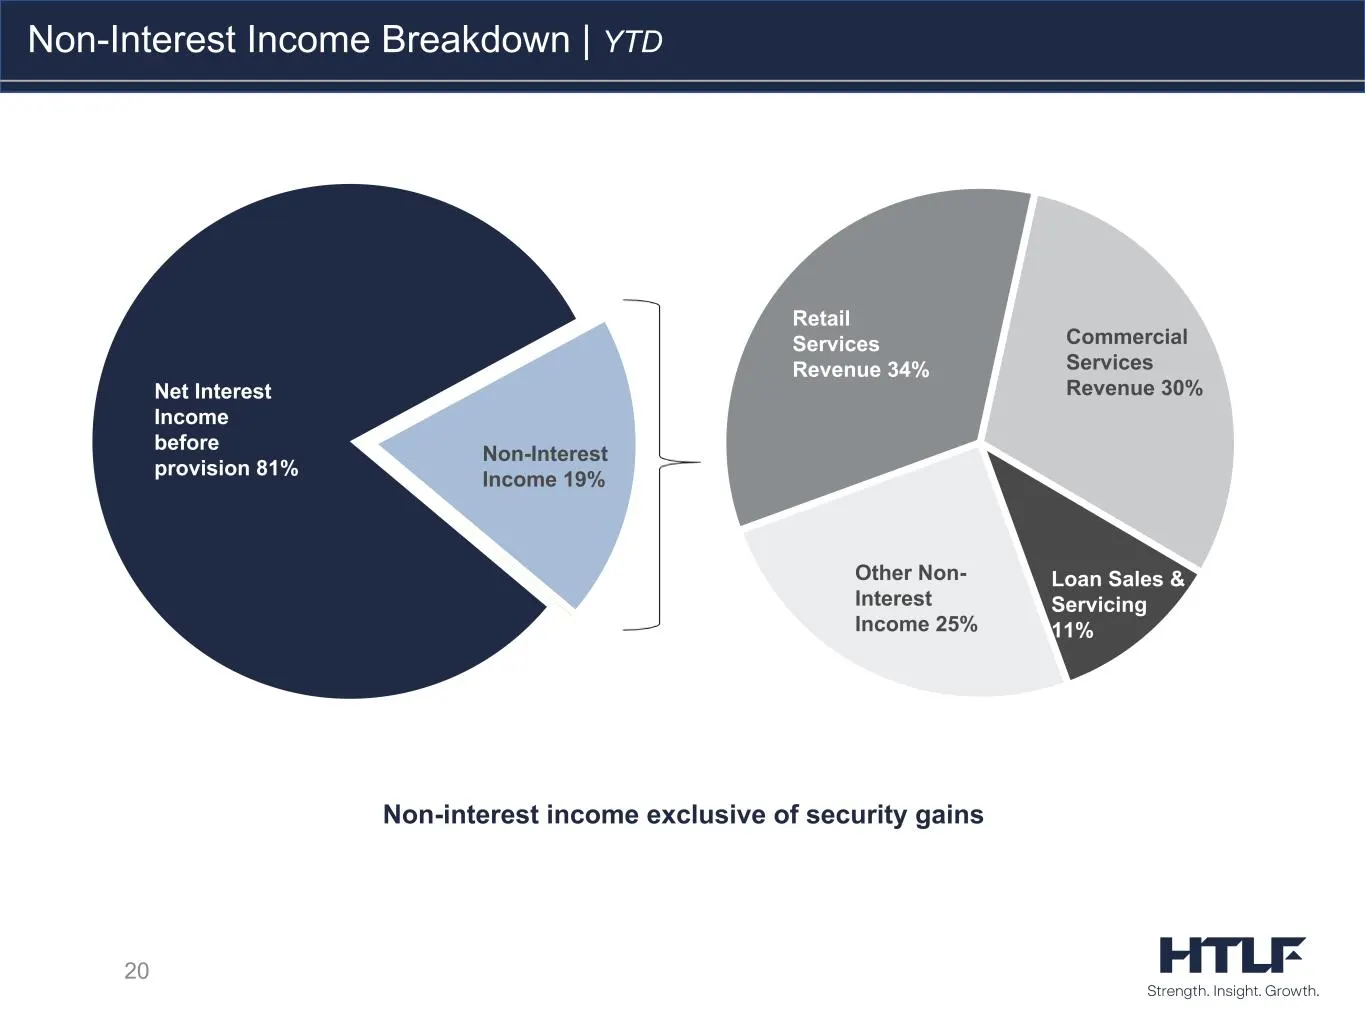
20 Non-interest income exclusive of security gains Non-Interest Income Breakdown | YTD Net Interest Income before provision 81% Non-Interest Income 19% Retail Services Revenue 34% Commercial Services Revenue 30% Loan Sales & Servicing 11% Other Non- Interest Income 25%
Slide 21: Commercial Services Revenue Trends
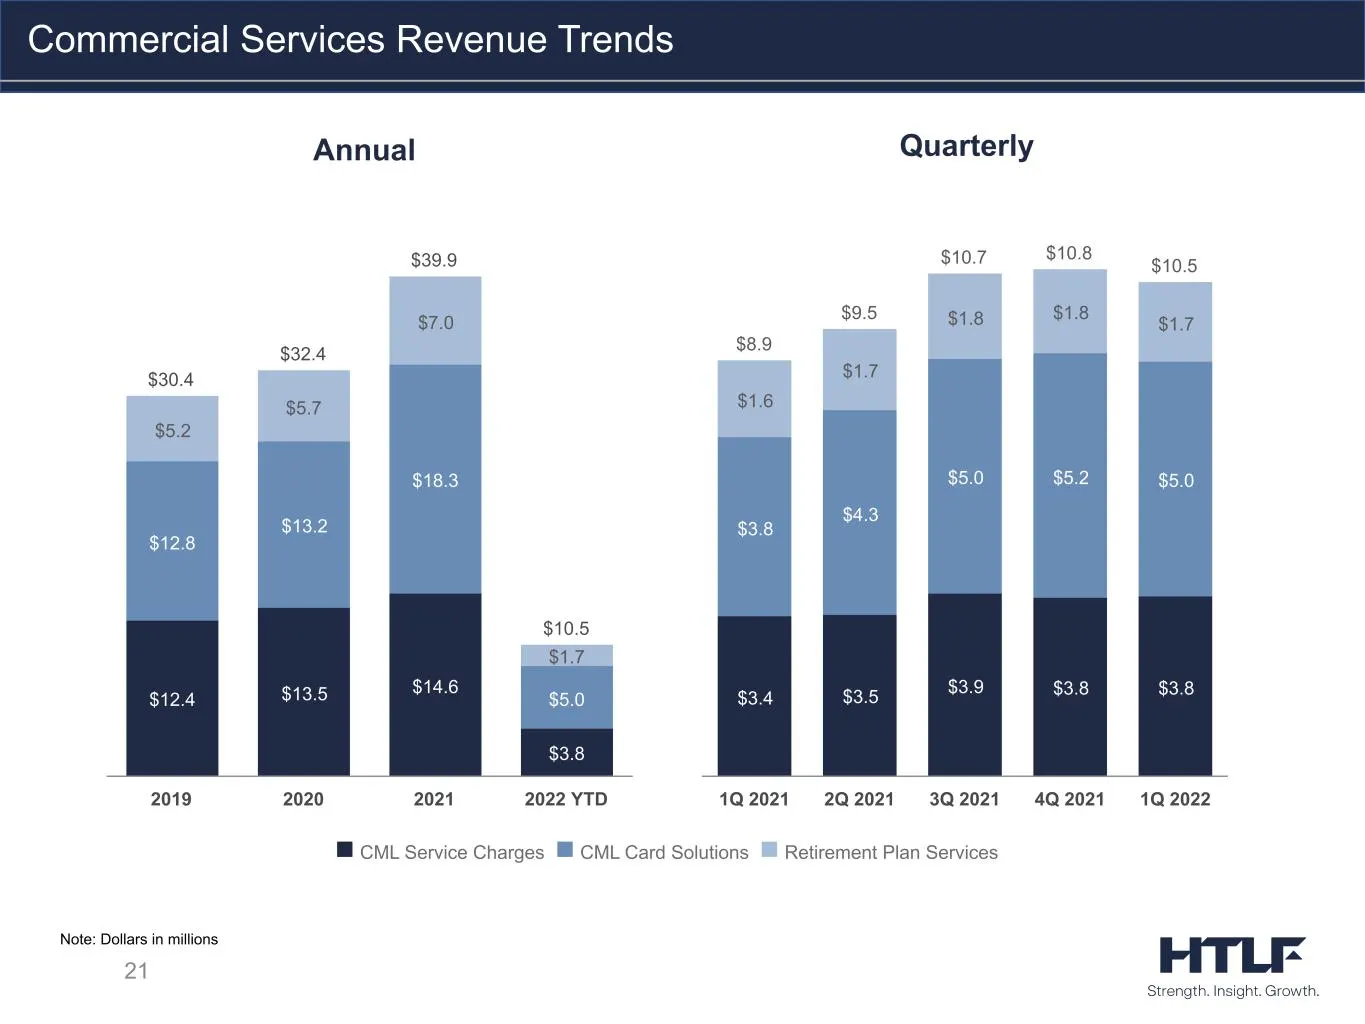
21 Commercial Services Revenue Trends Note: Dollars in millions QuarterlyAnnual $30.4 $32.4 $39.9 $10.5 $12.4 $13.5 $14.6 $3.8 $12.8 $13.2 $18.3 $5.0 $5.2 $5.7 $7.0 $1.7 2019 2020 2021 2022 YTD $8.9 $9.5 $10.7 $10.8 $10.5 $3.4 $3.5 $3.9 $3.8 $3.8 $3.8 $4.3 $5.0 $5.2 $5.0 $1.6 $1.7 $1.8 $1.8 $1.7 1Q
Slide 22: Consumer Services Revenue Trends
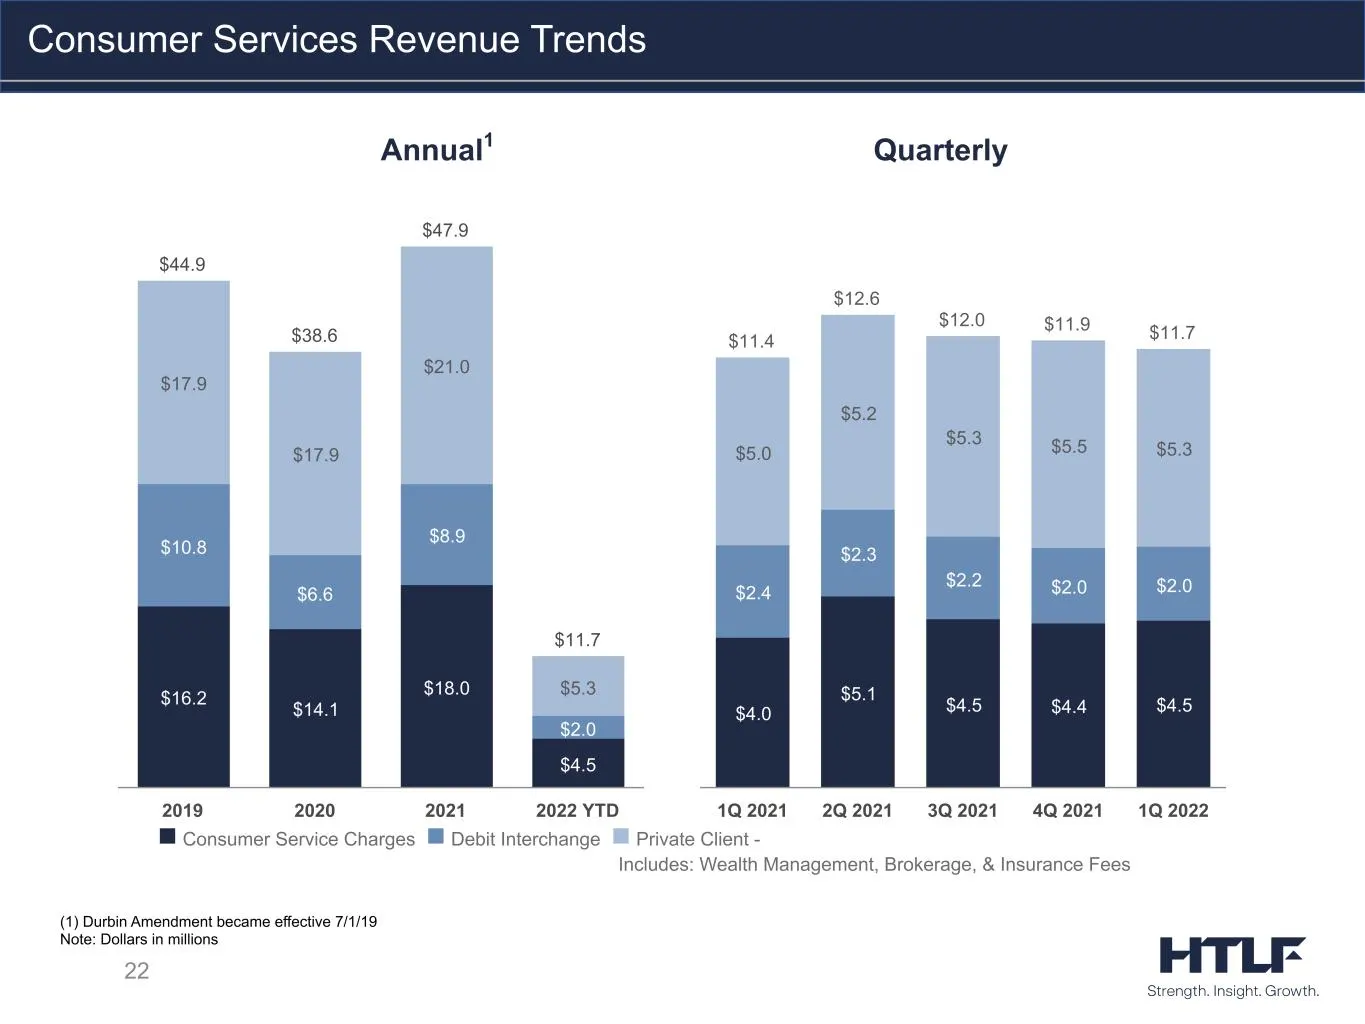
22 Consumer Services Revenue Trends (1) Durbin Amendment became effective 7/1/19 Note: Dollars in millions QuarterlyAnnual1 $44.9 $38.6 $47.9 $11.7 $16.2 $14.1 $18.0 $4.5 $10.8 $6.6 $8.9 $2.0 $17.9 $17.9 $21.0 $5.3 2019 2020 2021 2022 YTD $11.4 $12.6 $12.0 $11.9 $11.7 $4.0 $5.1 $4.5 $4.4 $4.5 $2.4 $
Slide 23: Consolidated Capital Ratios
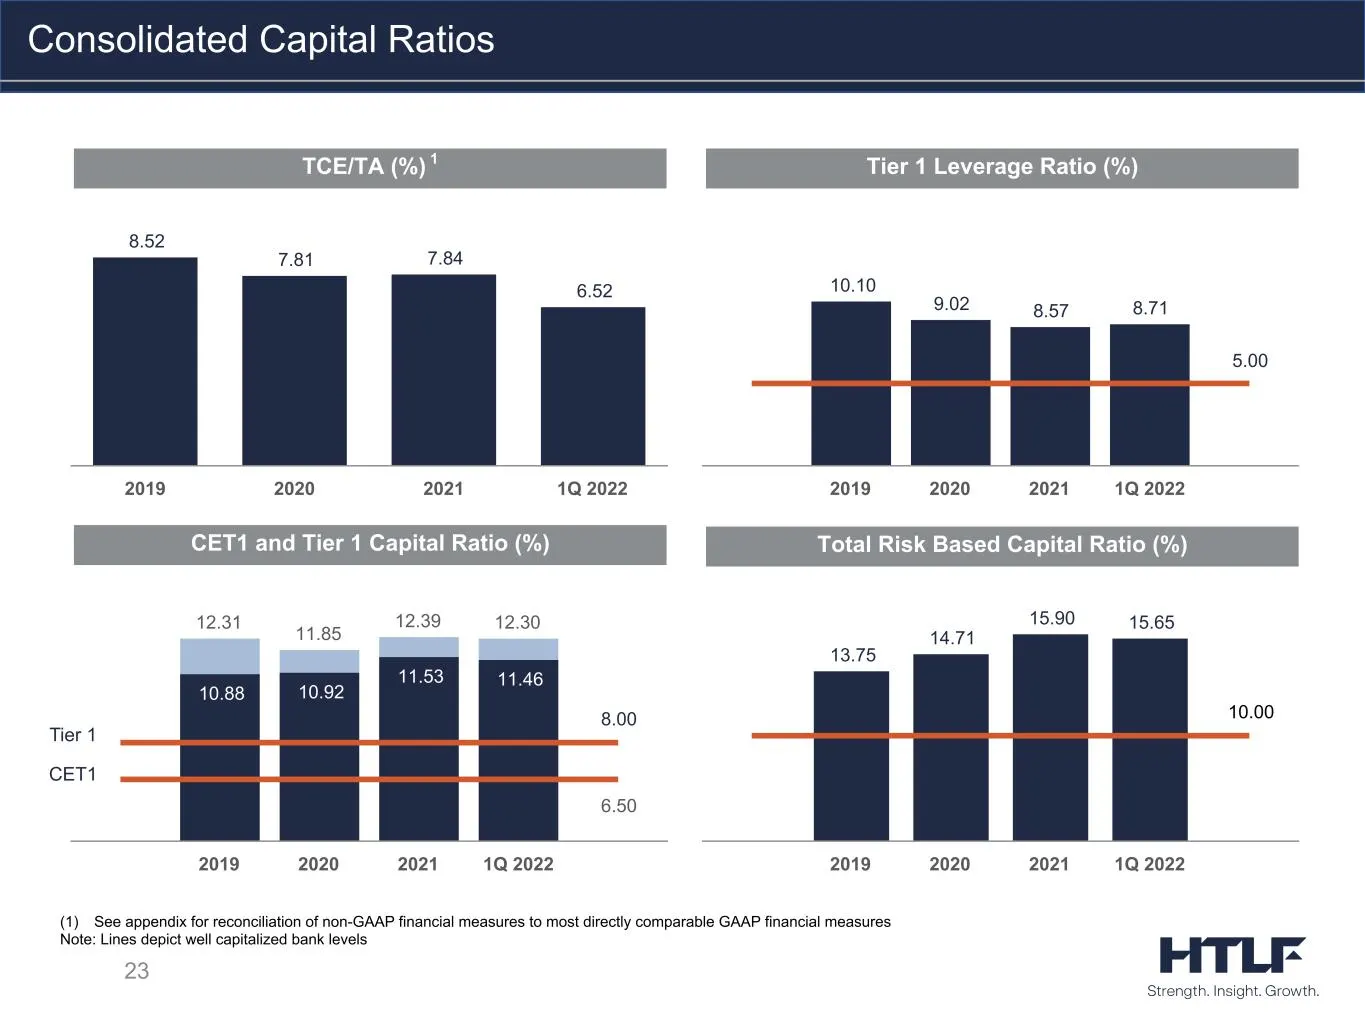
23 Consolidated Capital Ratios (1) See appendix for reconciliation of non-GAAP financial measures to most directly comparable GAAP financial measures Note: Lines depict well capitalized bank levels TCE/TA (%) 1 Tier 1 Leverage Ratio (%) CET1 and Tier 1 Capital Ratio (%) Total Risk Based Capital Rati
Slide 24: Loan Portfolio and Asset Quality
24 Loan Portfolio and Asset Quality
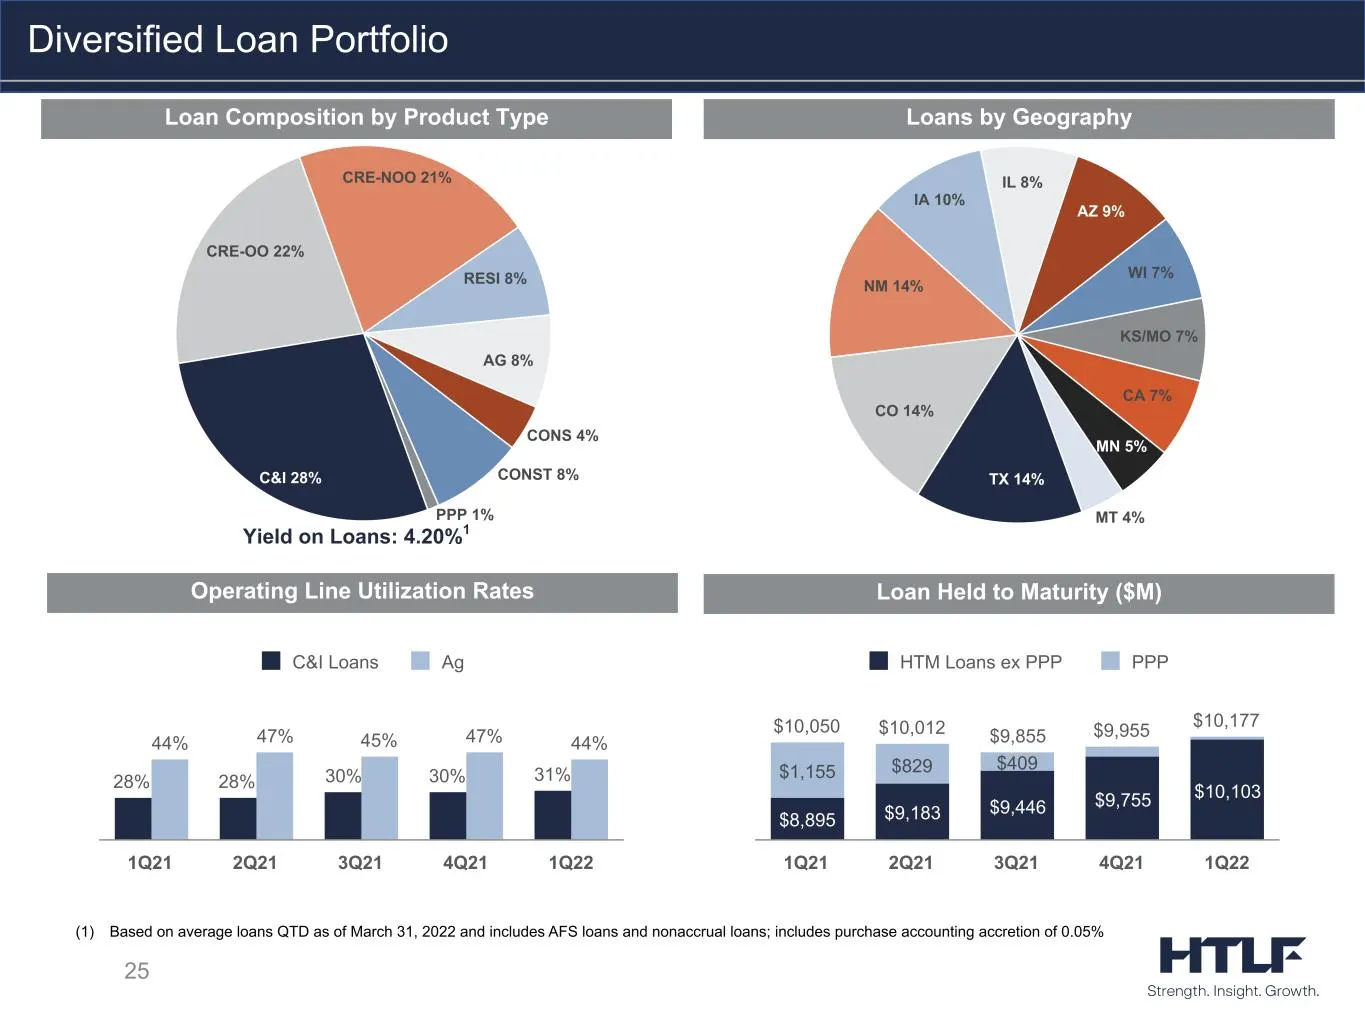
Slide 25: Diversified Loan Portfolio
25 Loan Composition by Product Type Loans by Geography Loan Held to Maturity ($M) Diversified Loan Portfolio (1) Based on average loans QTD as of March 31, 2022 and includes AFS loans and nonaccrual loans; includes purchase accounting accretion of 0.05% Operating Line Utilization Rates C&I 28% CRE-O
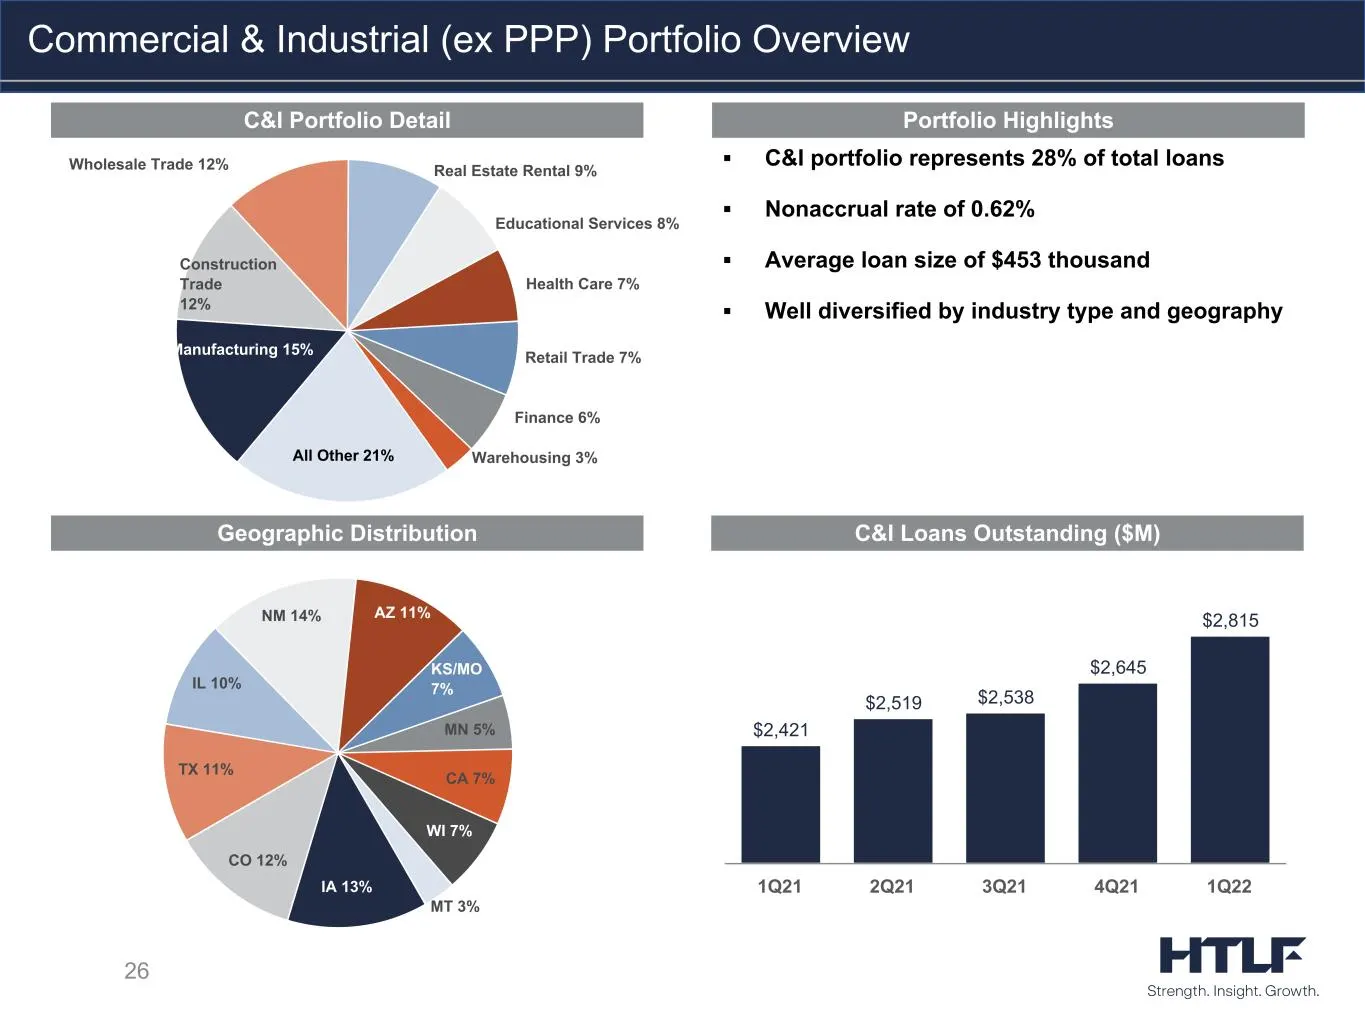
Slide 26: Commercial & Industrial Portfolio Overview
26 Manufacturing 15% Construction Trade 12% Wholesale Trade 12% Real Estate Rental 9% Educational Services 8% Health Care 7% Retail Trade 7% Finance 6% Warehousing 3%All Other 21% ▪ C&I portfolio represents 28% of total loans ▪ Nonaccrual rate of 0.62% ▪ Average loan size of $453 thousand ▪ Well div
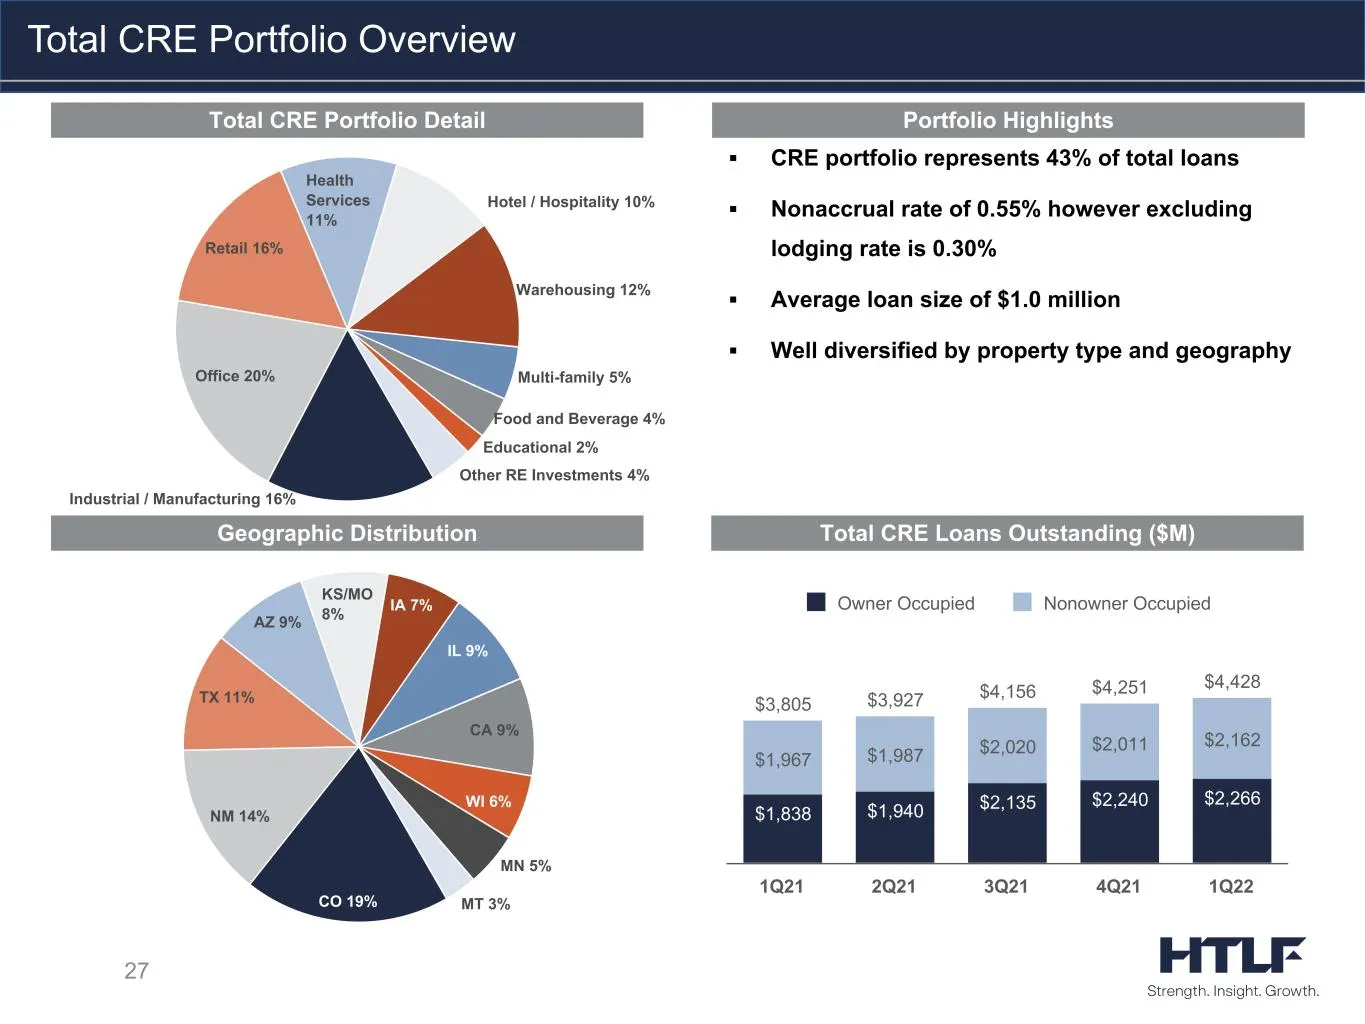
Slide 27: Total CRE Portfolio Overview
27 Industrial / Manufacturing 16% Office 20% Retail 16% Health Services 11% Hotel / Hospitality 10% Warehousing 12% Multi-family 5% Food and Beverage 4% Educational 2% Other RE Investments 4% ▪ CRE portfolio represents 43% of total loans ▪ Nonaccrual rate of 0.55% however excluding lodging rate is 0
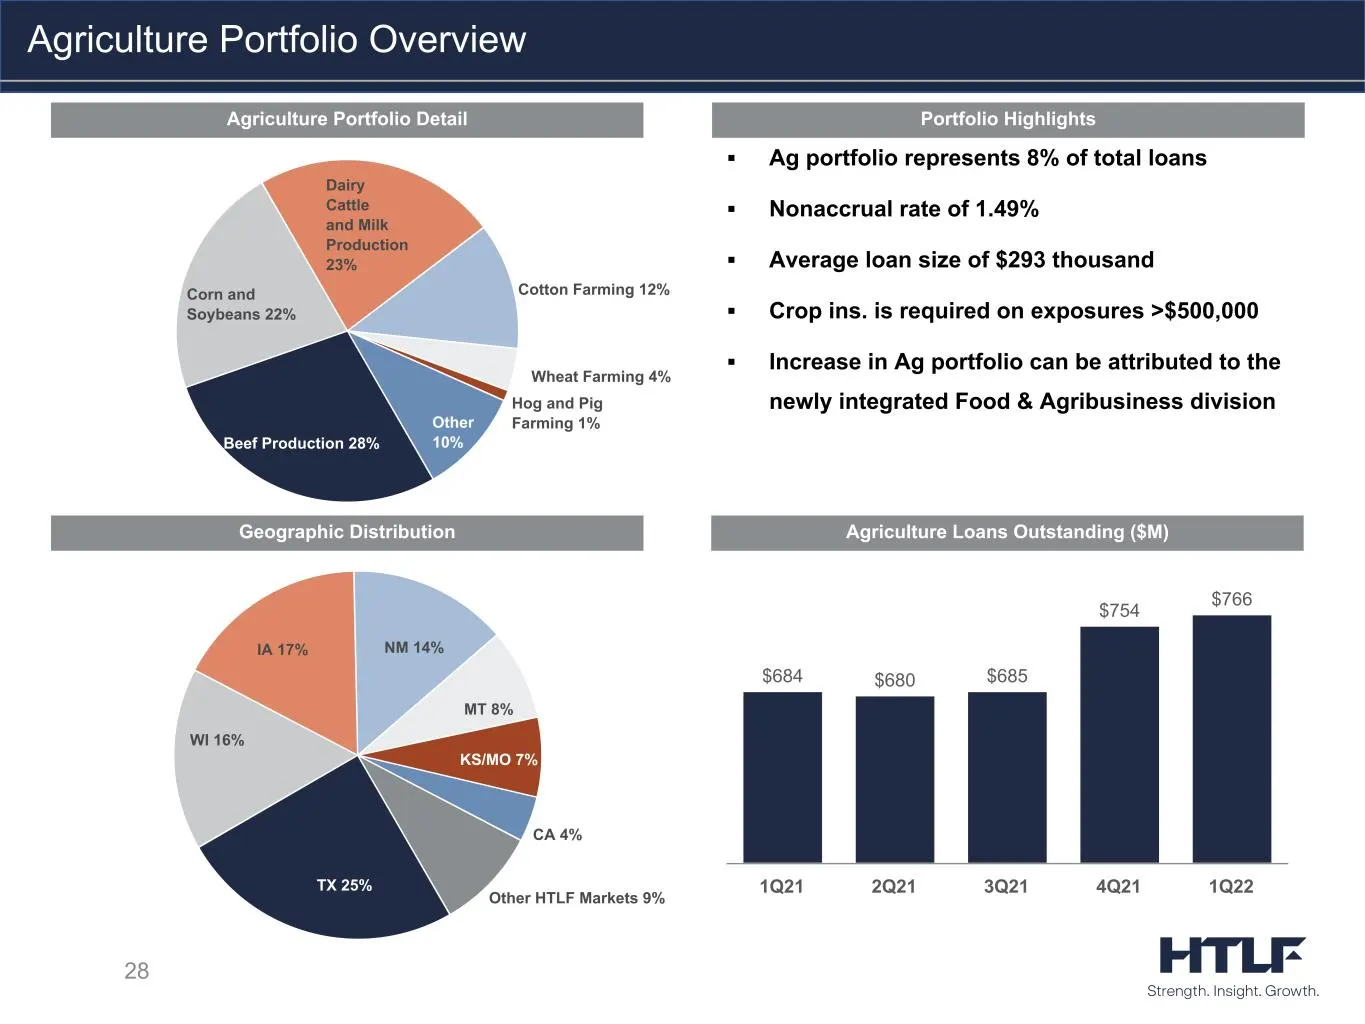
Slide 28: Agriculture Portfolio Overview
28 ▪ Ag portfolio represents 8% of total loans ▪ Nonaccrual rate of 1.49% ▪ Average loan size of $293 thousand ▪ Crop ins. is required on exposures >$500,000 ▪ Increase in Ag portfolio can be attributed to the newly integrated Food & Agribusiness division Agriculture Portfolio Overview Portfolio Hig
Slide 29: Construction Portfolio Overview
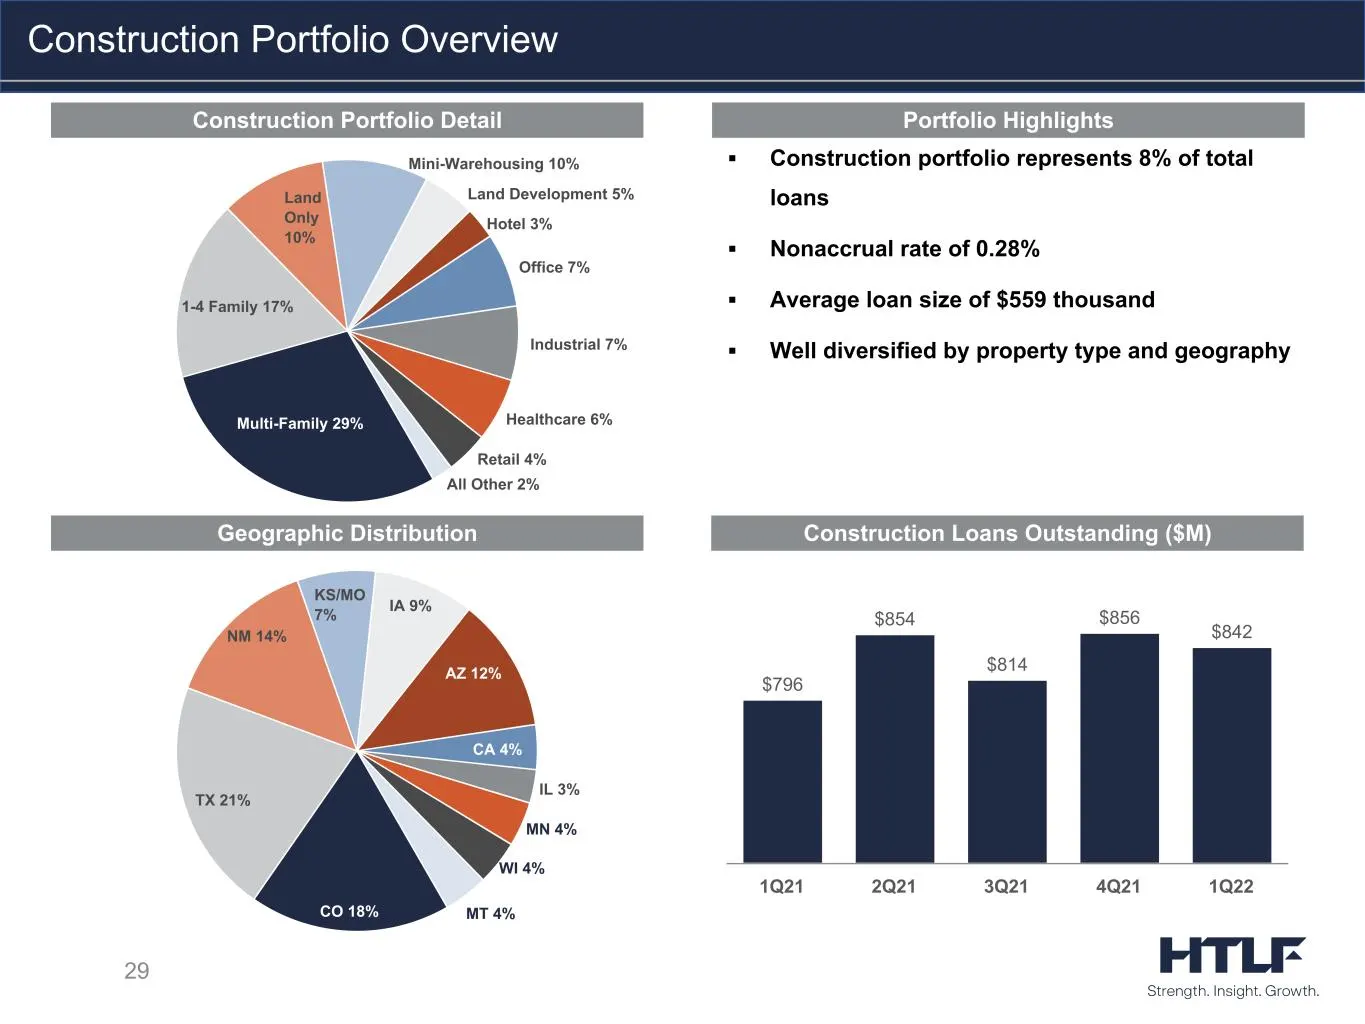
29 Multi-Family 29% 1-4 Family 17% Land Only 10% Mini-Warehousing 10% Land Development 5% Hotel 3% Office 7% Industrial 7% Healthcare 6% Retail 4% All Other 2% Portfolio HighlightsConstruction Portfolio Detail ▪ Construction portfolio represents 8% of total loans ▪ Nonaccrual rate of 0.28% ▪ Average
Slide 30: Allowance for Credit Related Losses
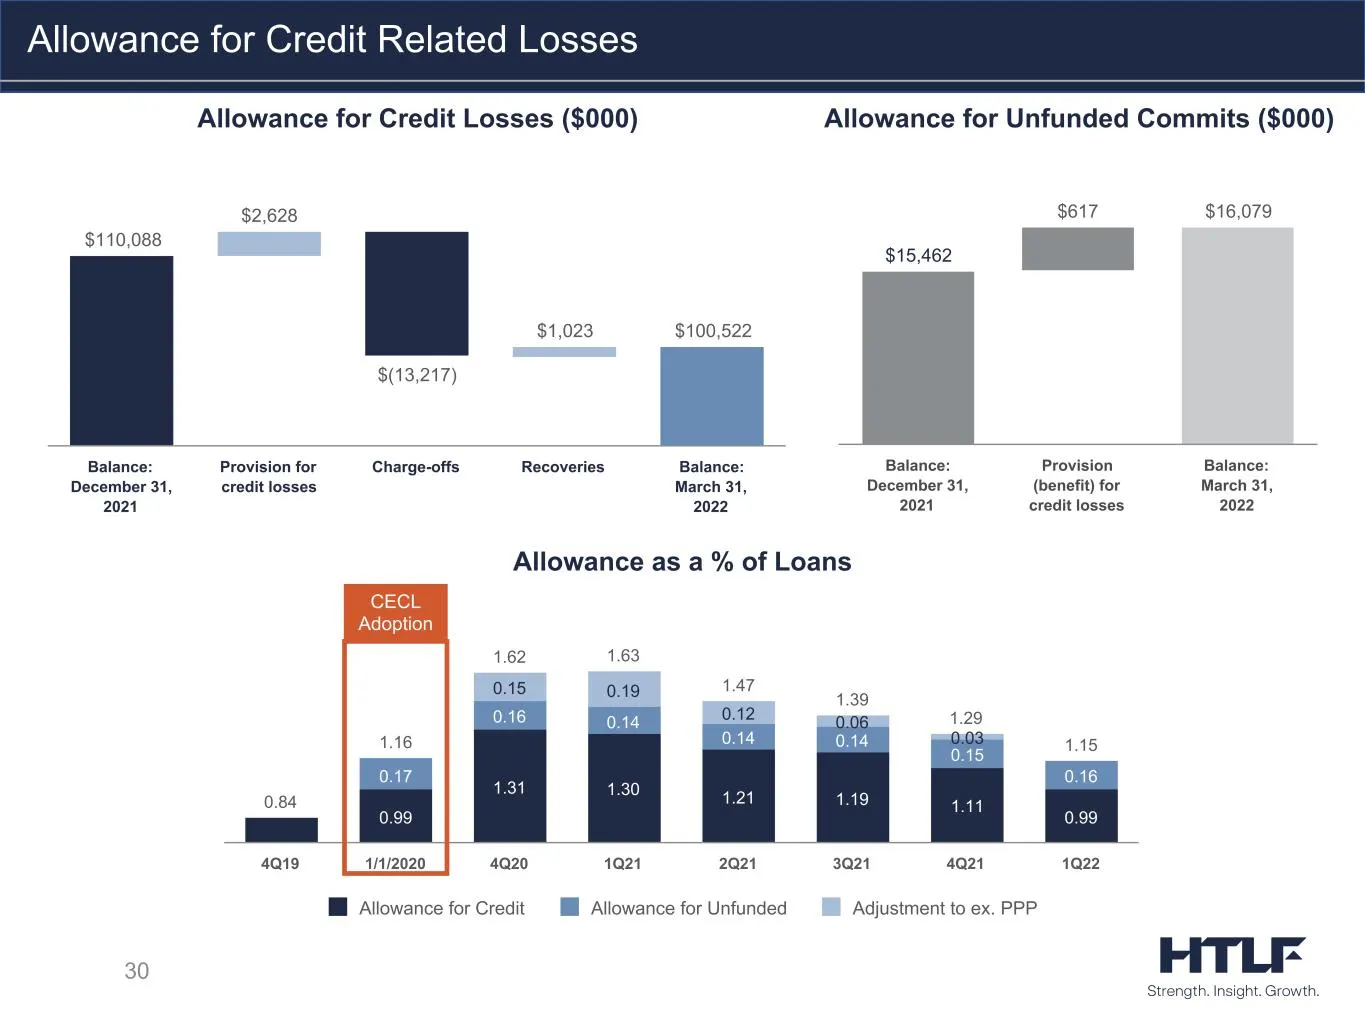
30 0.84 1.16 1.62 1.63 1.47 1.39 1.29 1.15 0.99 1.31 1.30 1.21 1.19 1.11 0.99 0.17 0.16 0.14 0.14 0.14 0.15 0.16 0.15 0.19 0.12 0.06 0.03 Allowance for Credit Allowance for Unfunded Adjustment to ex. PPP 4Q19 1/1/2020 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 $15,462 $617 $16,079 Balance: December 31, 2021 Prov
Slide 31: Summary Asset Quality
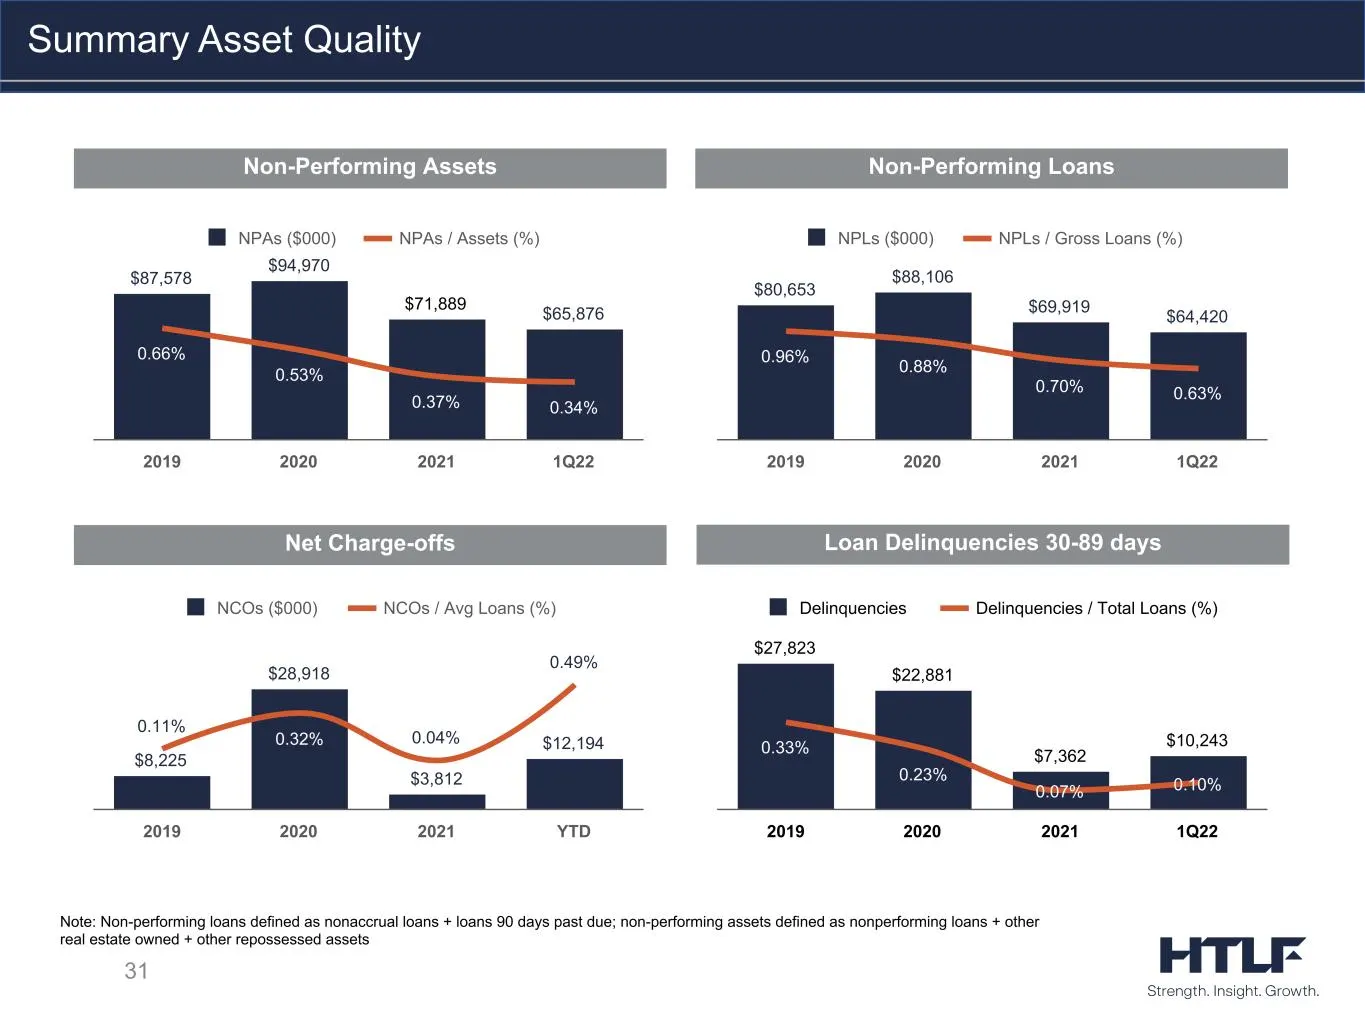
31 Summary Asset Quality Note: Non-performing loans defined as nonaccrual loans + loans 90 days past due; non-performing assets defined as nonperforming loans + other real estate owned + other repossessed assets Non-Performing Assets Non-Performing Loans Net Charge-offs Loan Delinquencies 30-89 days
Slide 32: Liquidity, Investments, Funding and Capital
32 Liquidity, Investments, Funding and Capital
Slide 33: Deposit Composition
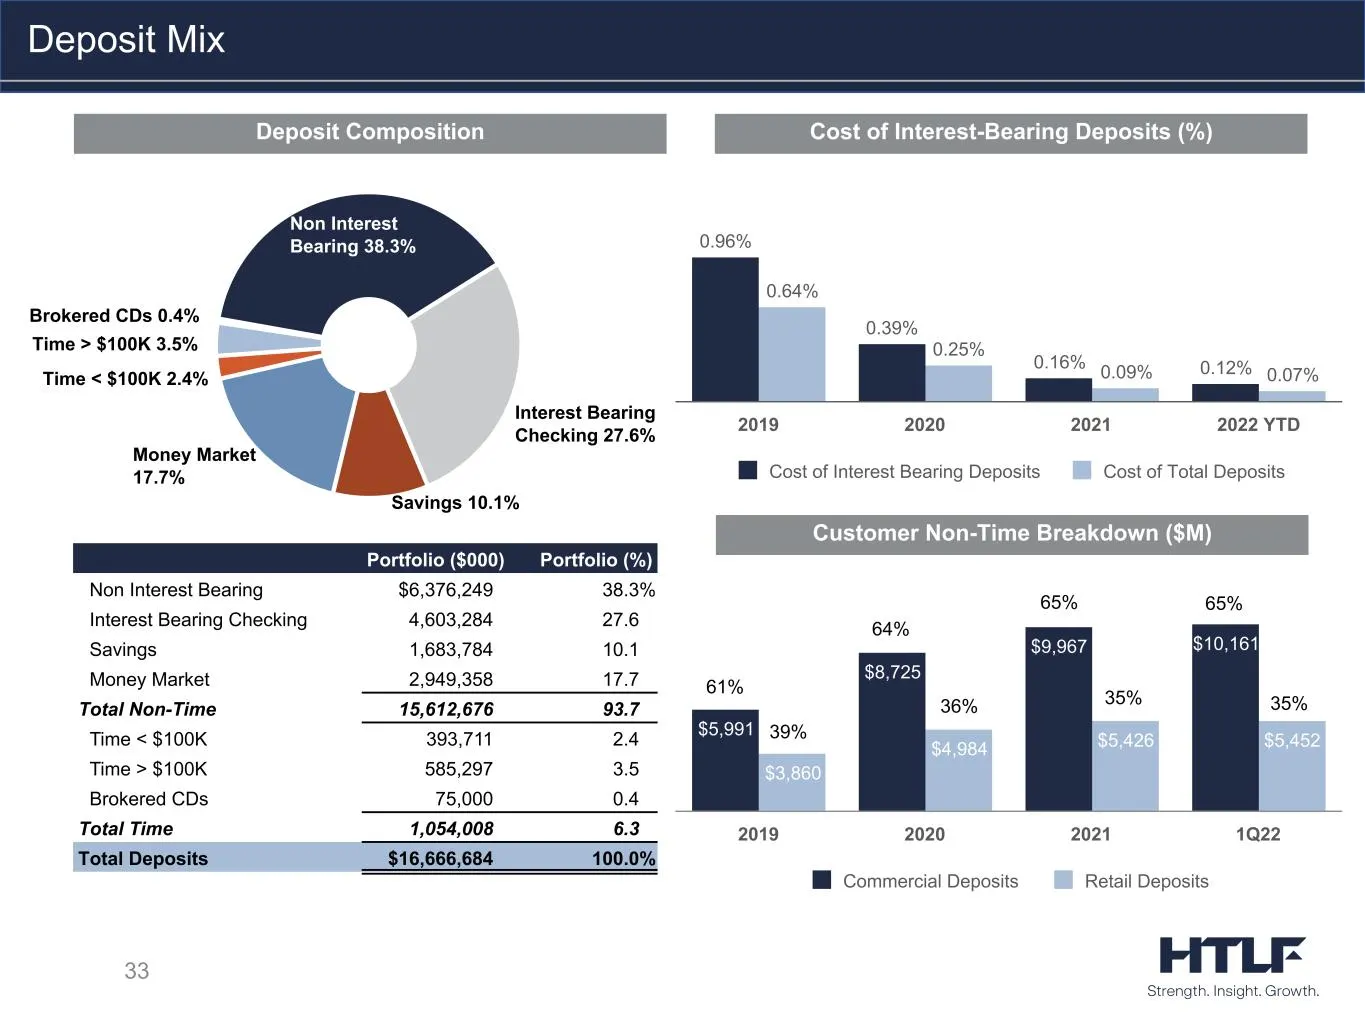
33 $5,991 $8,725 $9,967 $10,161 $3,860 $4,984 $5,426 $5,452 Commercial Deposits Retail Deposits 2019 2020 2021 1Q22 Deposit Composition Cost of Interest-Bearing Deposits (%) Customer Non-Time Breakdown ($M) Deposit Mix Non Interest Bearing 38.3% Interest Bearing Checking 27.6% Savings 10.1% Money Ma
Slide 34: High Performing Securities Portfolio
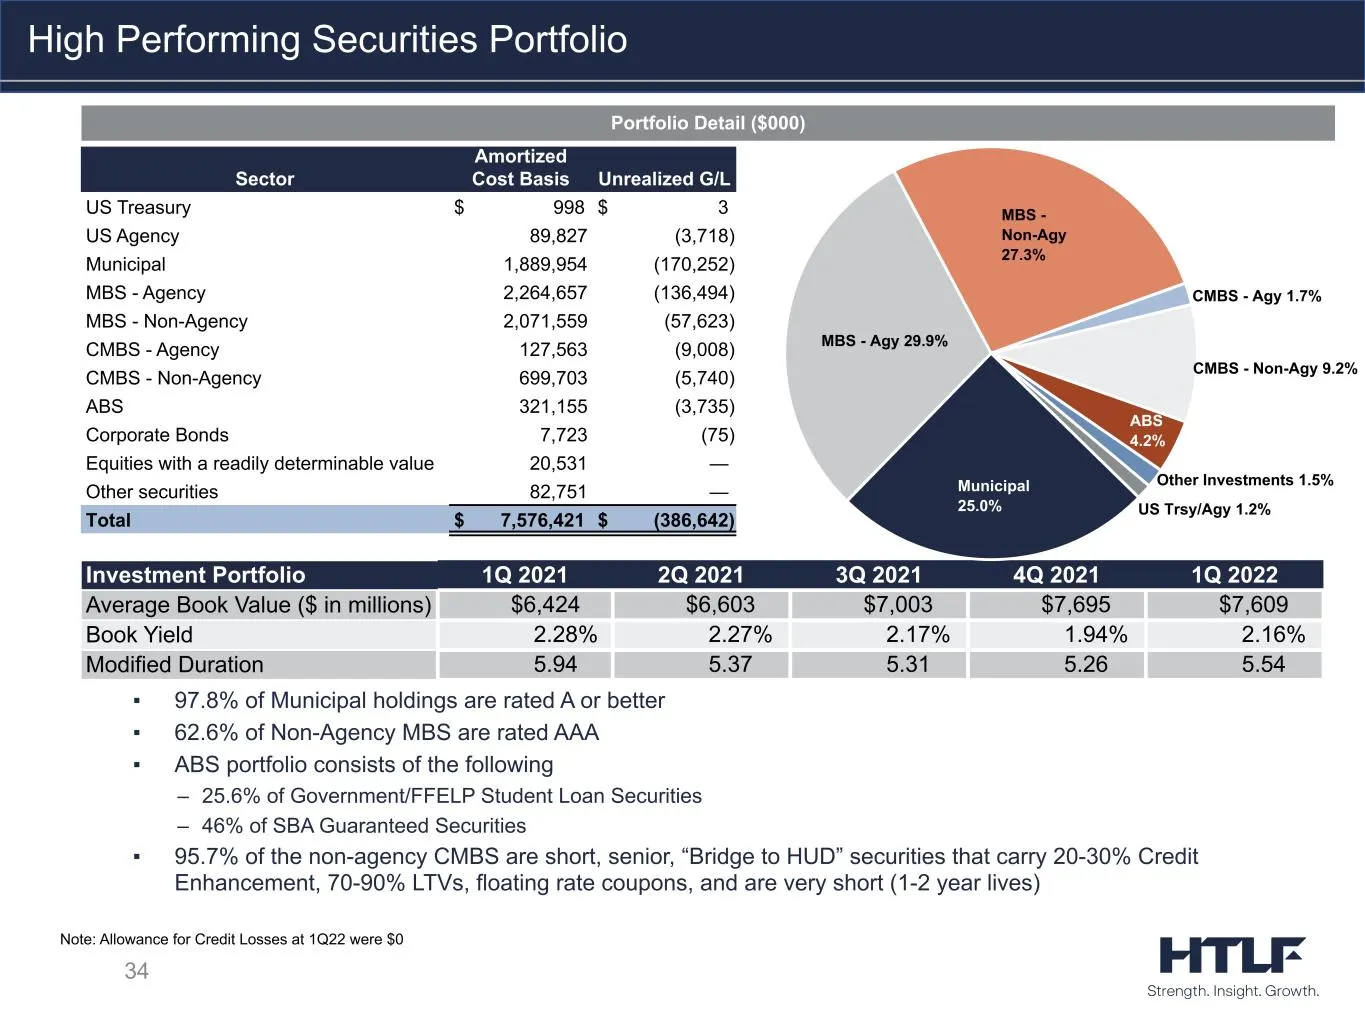
34 ▪ 97.8% of Municipal holdings are rated A or better ▪ 62.6% of Non-Agency MBS are rated AAA ▪ ABS portfolio consists of the following – 25.6% of Government/FFELP Student Loan Securities – 46% of SBA Guaranteed Securities ▪ 95.7% of the non-agency CMBS are short, senior, “Bridge to HUD” securities
Slide 35: Conservative Liquidity Profile
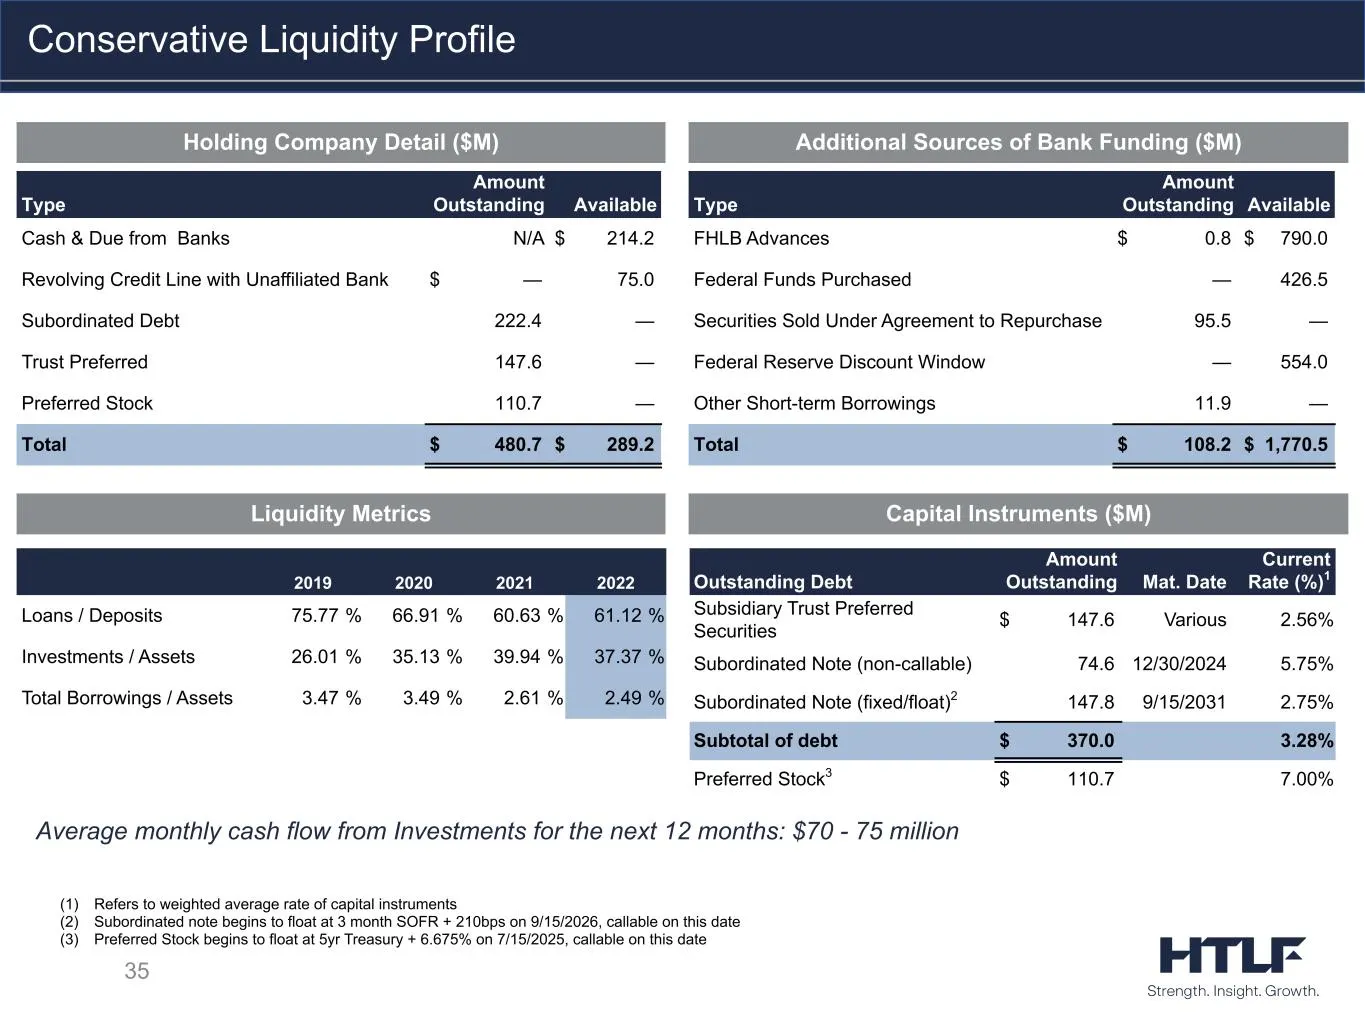
35 Average monthly cash flow from Investments for the next 12 months: $70 - 75 million Capital Instruments ($M) Conservative Liquidity Profile Liquidity Metrics (1) Refers to weighted average rate of capital instruments (2) Subordinated note begins to float at 3 month SOFR + 210bps on 9/15/2026, cal
Slide 36: Integrating ESG Across the Organization
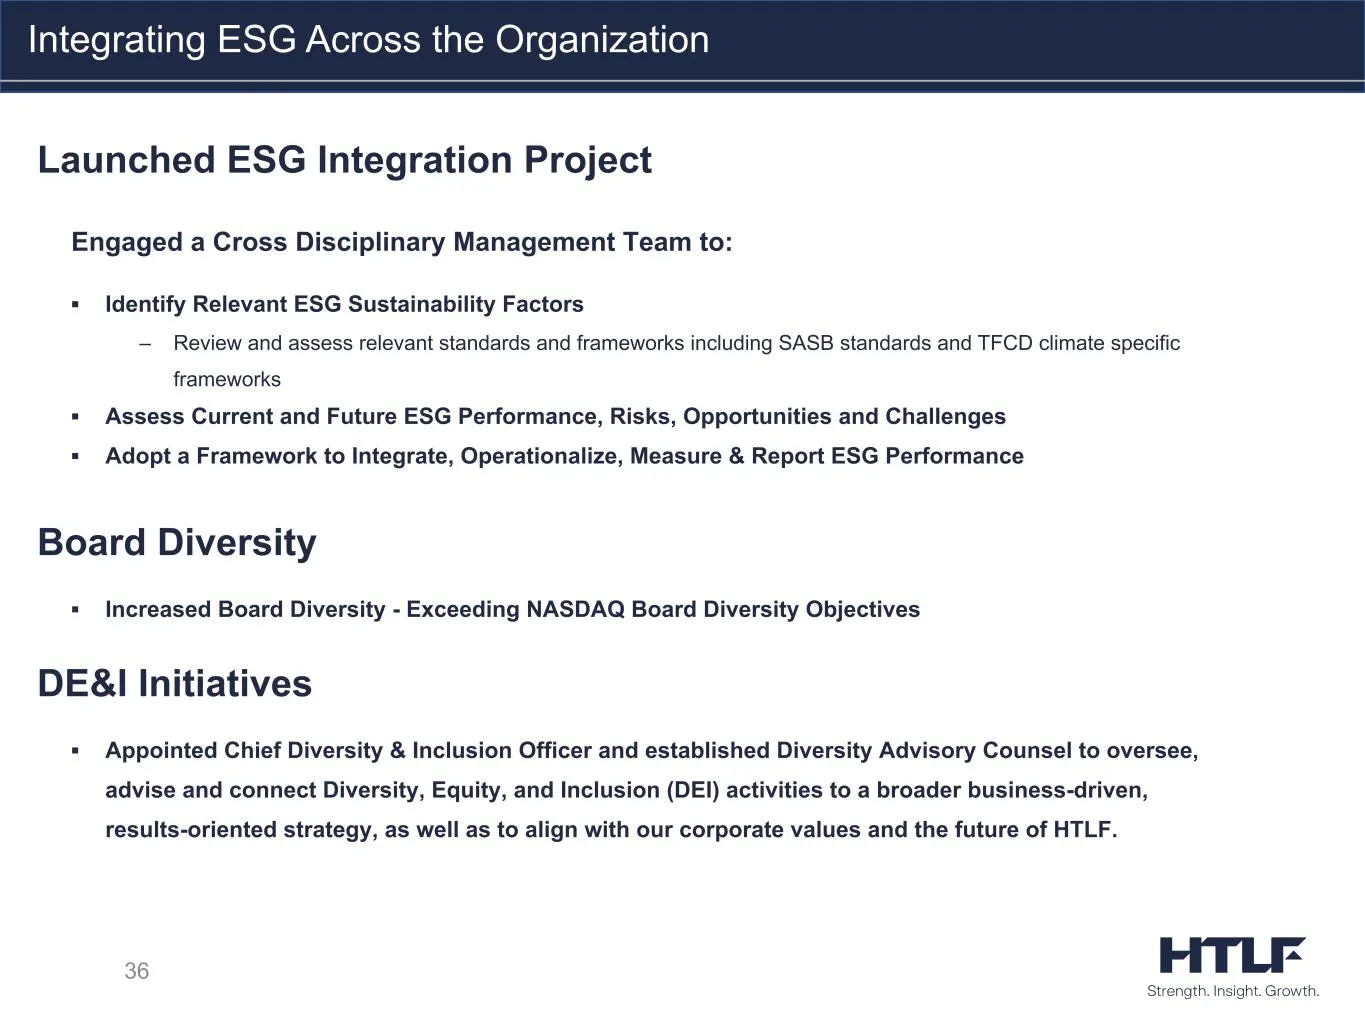
36 Integrating ESG Across the Organization Launched ESG Integration Project Engaged a Cross Disciplinary Management Team to: ▪ Identify Relevant ESG Sustainability Factors – Review and assess relevant standards and frameworks including SASB standards and TFCD climate specific frameworks ▪ Assess Cur
Slide 37: HTLF Investor Summary
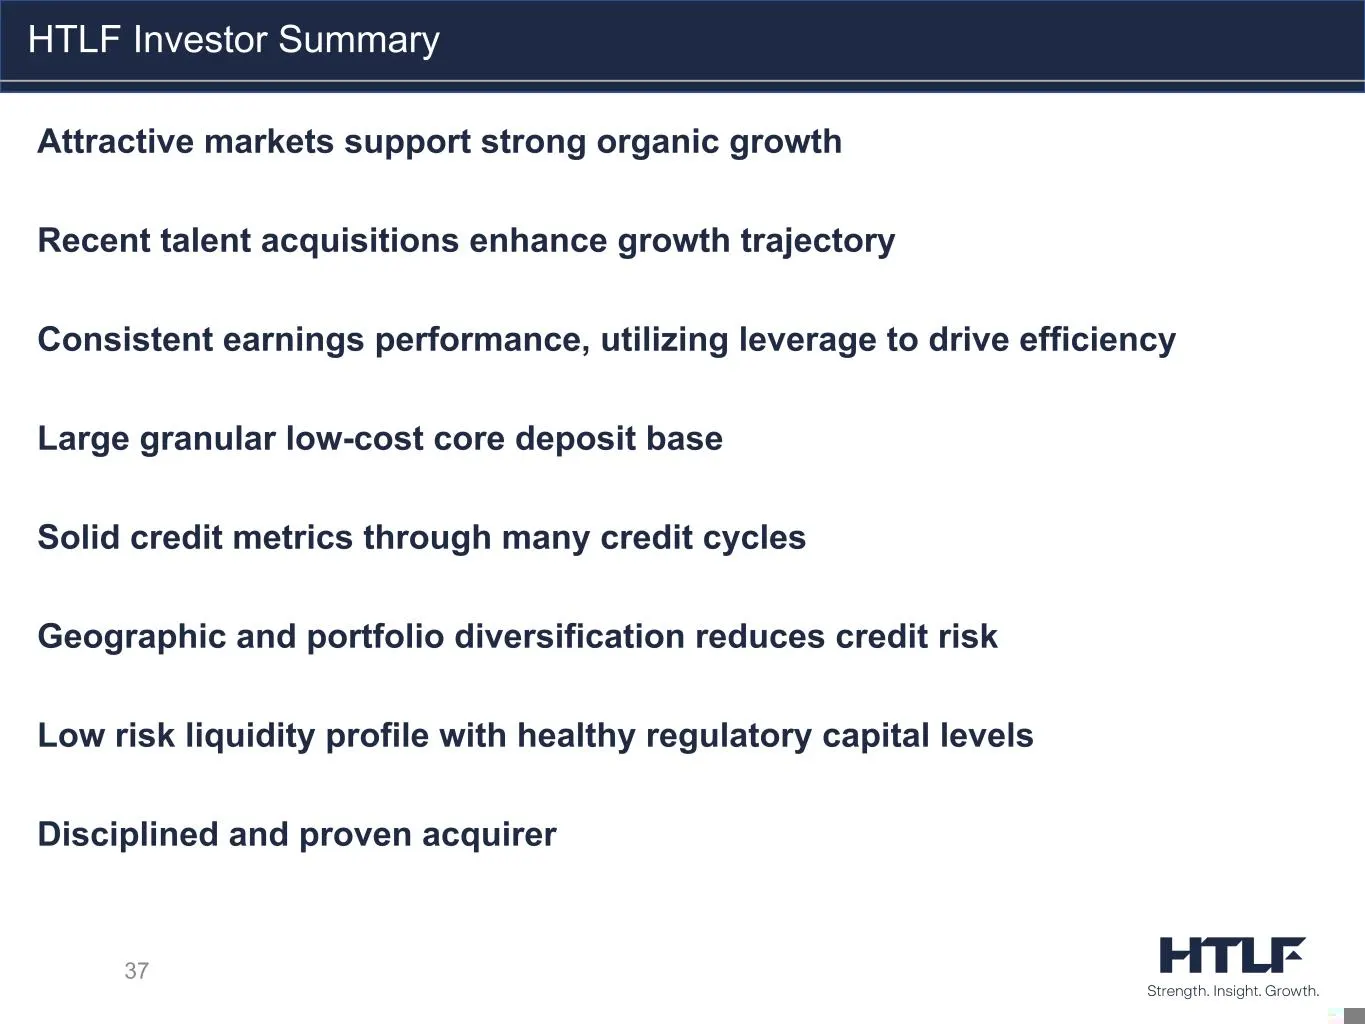
37 HTLF Investor Summary Attractive markets support strong organic growth Recent talent acquisitions enhance growth trajectory Consistent earnings performance, utilizing leverage to drive efficiency Large granular low-cost core deposit base Solid credit metrics through many credit cycles Geographic
Slide 38: Contact Information
Contact Informatio HTLF 38 Strength. Insight. Growth
Slide 39: Appendix
39 Appendix
Slide 40: Non-GAAP Measure Definitions
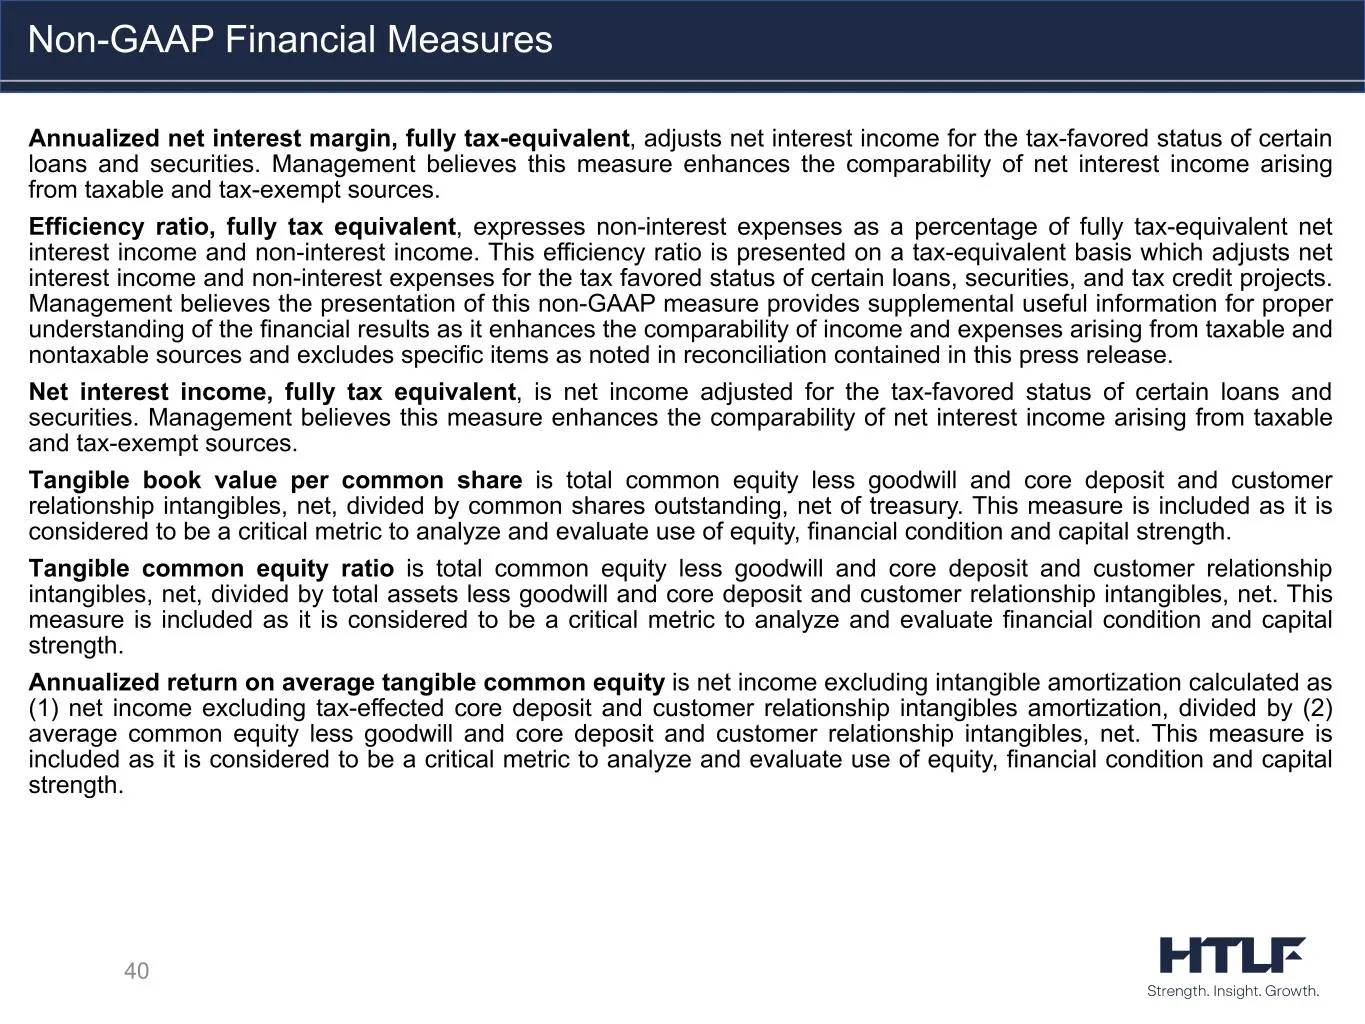
40 Annualized net interest margin, fully tax-equivalent, adjusts net interest income for the tax-favored status of certain loans and securities. Management believes this measure enhances the comparability of net interest income arising from taxable and tax-exempt sources. Efficiency ratio, fully tax
Slide 41: Non-GAAP Reconciliations
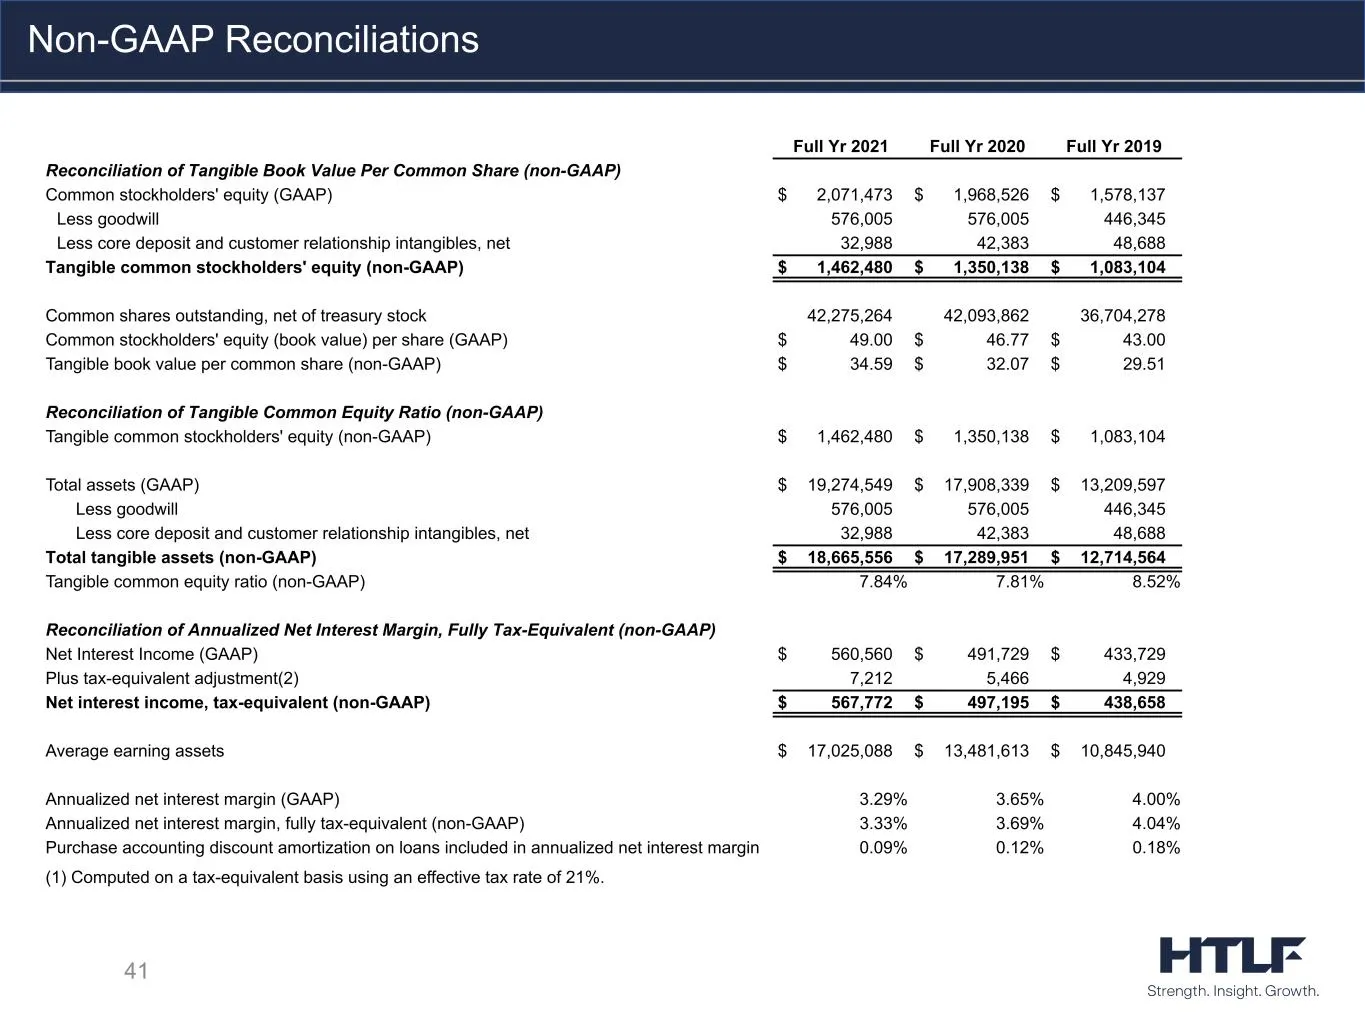
41 Non-GAAP Reconciliations Full Yr 2021 Full Yr 2020 Full Yr 2019 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common stockholders' equity (GAAP) $ 2,071,473 $ 1,968,526 $ 1,578,137 Less goodwill 576,005 576,005 446,345 Less core deposit and customer relationship intangibles, n
Slide 42: Non-GAAP Reconciliations (cont.)
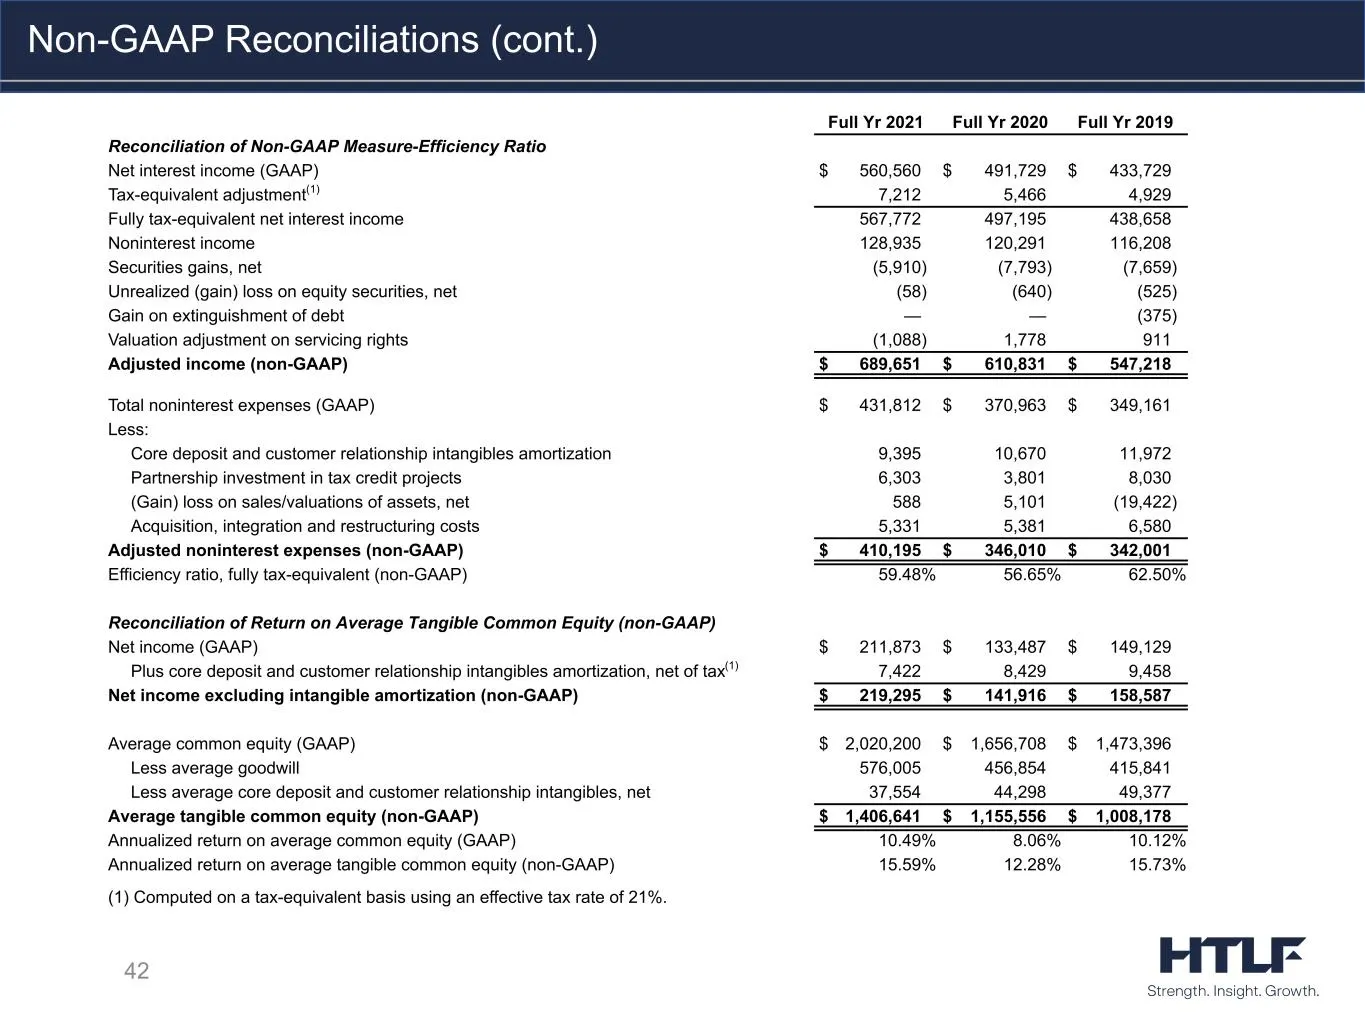
42 Non-GAAP Reconciliations (cont.) Full Yr 2021 Full Yr 2020 Full Yr 2019 Reconciliation of Non-GAAP Measure-Efficiency Ratio Net interest income (GAAP) $ 560,560 $ 491,729 $ 433,729 Tax-equivalent adjustment(1) 7,212 5,466 4,929 Fully tax-equivalent net interest income 567,772 497,195 438,658 Noni
Slide 43: Non-GAAP Reconciliations (cont.)
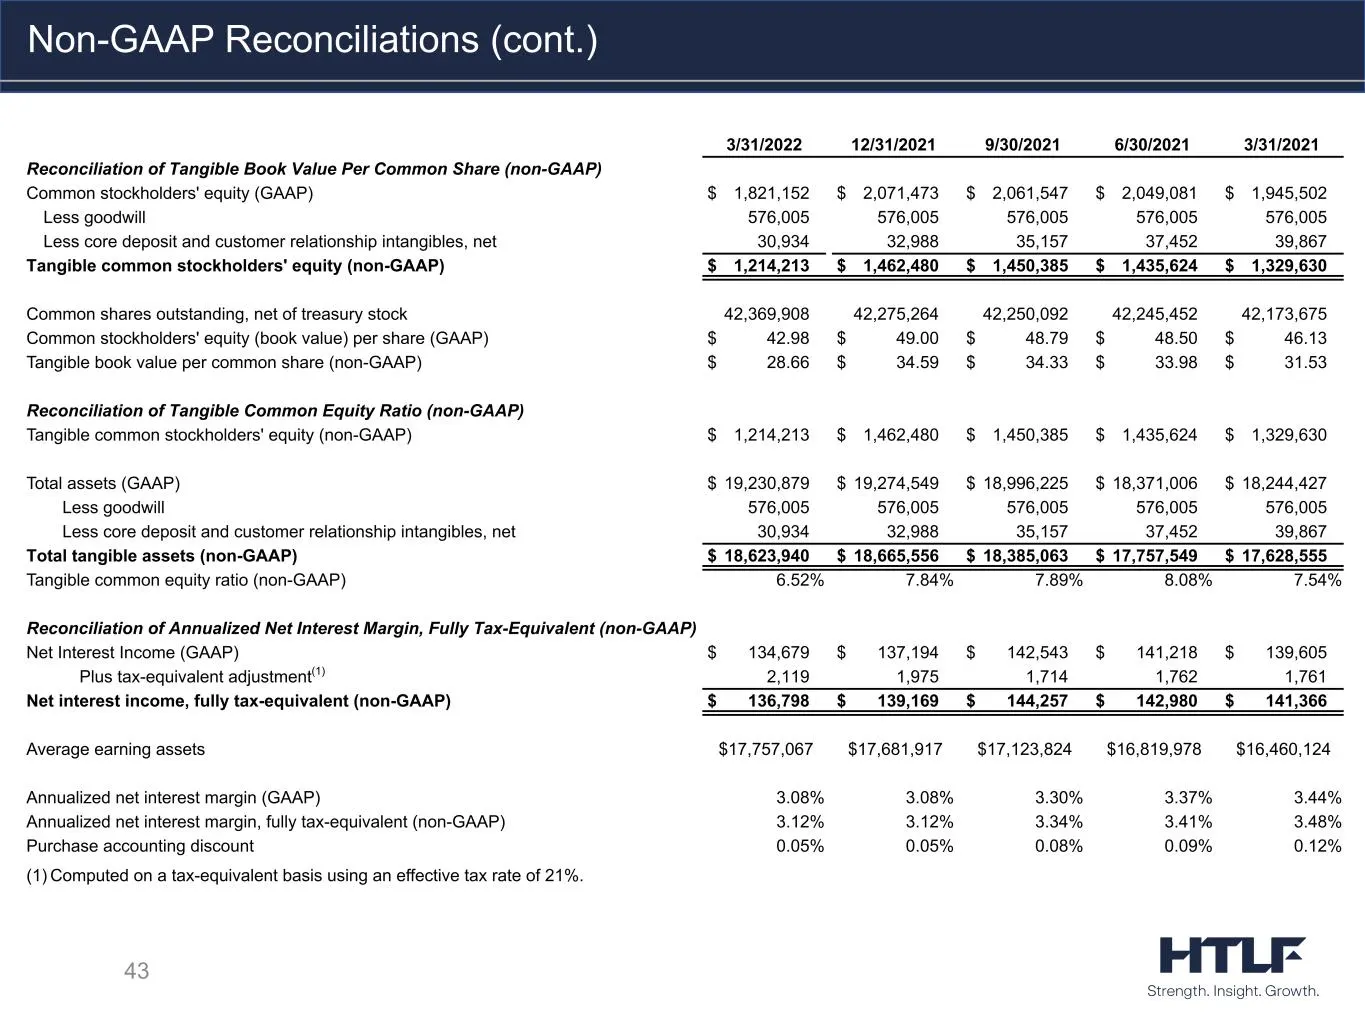
43 Non-GAAP Reconciliations (cont.) 3/31/2022 12/31/2021 9/30/2021 6/30/2021 3/31/2021 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common stockholders' equity (GAAP) $ 1,821,152 $ 2,071,473 $ 2,061,547 $ 2,049,081 $ 1,945,502 Less goodwill 576,005 576,005 576,005 576,005 576,00
Slide 44: Non-GAAP Reconciliations (cont.)
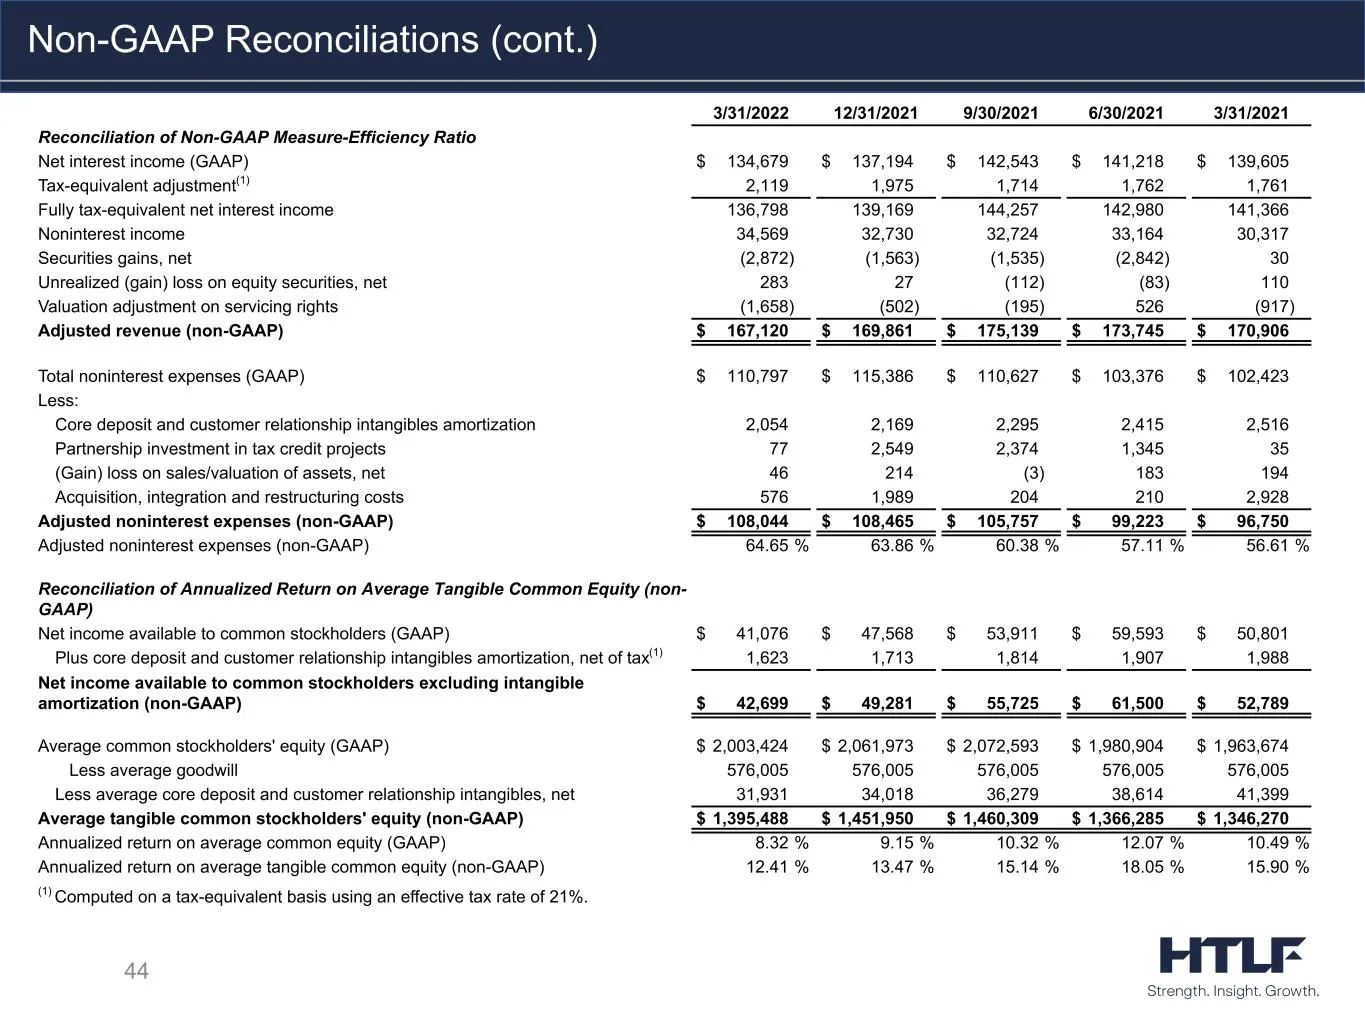
44 Non-GAAP Reconciliations (cont.) 3/31/2022 12/31/2021 9/30/2021 6/30/2021 3/31/2021 Reconciliation of Non-GAAP Measure-Efficiency Ratio Net interest income (GAAP) $ 134,679 $ 137,194 $ 142,543 $ 141,218 $ 139,605 Tax-equivalent adjustment(1) 2,119 1,975 1,714 1,762 1,761 Fully tax-equivalent net
Source: SEC EDGAR · 8-K/A filed May 9, 2022
More decks from Heartland Financial USA Inc
 Merger or Acquisition (July 2024)6 slides · Jul 31, 2024
 Merger or Acquisition (May 2024)6 slides · May 2, 2024
 Merger or Acquisition (May 2024)27 slides · May 2, 2024
 Q4 2023 Earnings Presentation54 slides · Feb 13, 2024
 Q4 2023 Earnings Presentation35 slides · Jan 29, 2024
 Q3 2023 Earnings Presentation55 slides · Nov 15, 2023