Heartland Financial USA — Q3 2023 Earnings Presentation
55 slides from Heartland Financial USA's earnings presentation, Nov 15, 2023
Slide 1: 3rd Quarter 2023 Financial Data
3rd Quarter 2023 Financial Data
Slide 2: Safe Harbor
2 Safe Harbor Within the charts and tables presented, certain segments, columns and rows may not sum to totals shown due to rounding. This investor presentation (including any information incorporated herein by reference) and future oral and written statements of HTLF and its management, may contain
Slide 3: Table of Contents
3 Table of Contents HTLF Overview 4 HTLF Transformation 5-7 HTLF Strategic Focus 8-17 Financial Summary 18-40 Mission & Vision 41-44 Non-GAAP Reconciliations 45-55
Slide 4: HTLF Overview
> $20 Billion Asset Regional Bank > Headquartered in Denver - Operations Centered in Dubuque > 11 Distinct Banking Brands with Local Leadership > Consolidated Suite of Products and Services > Commercial & Small Business Focus Across Footprint > Consumer & Wealth Management Adjacent Businesses
Slide 5: HTLF's Transformation
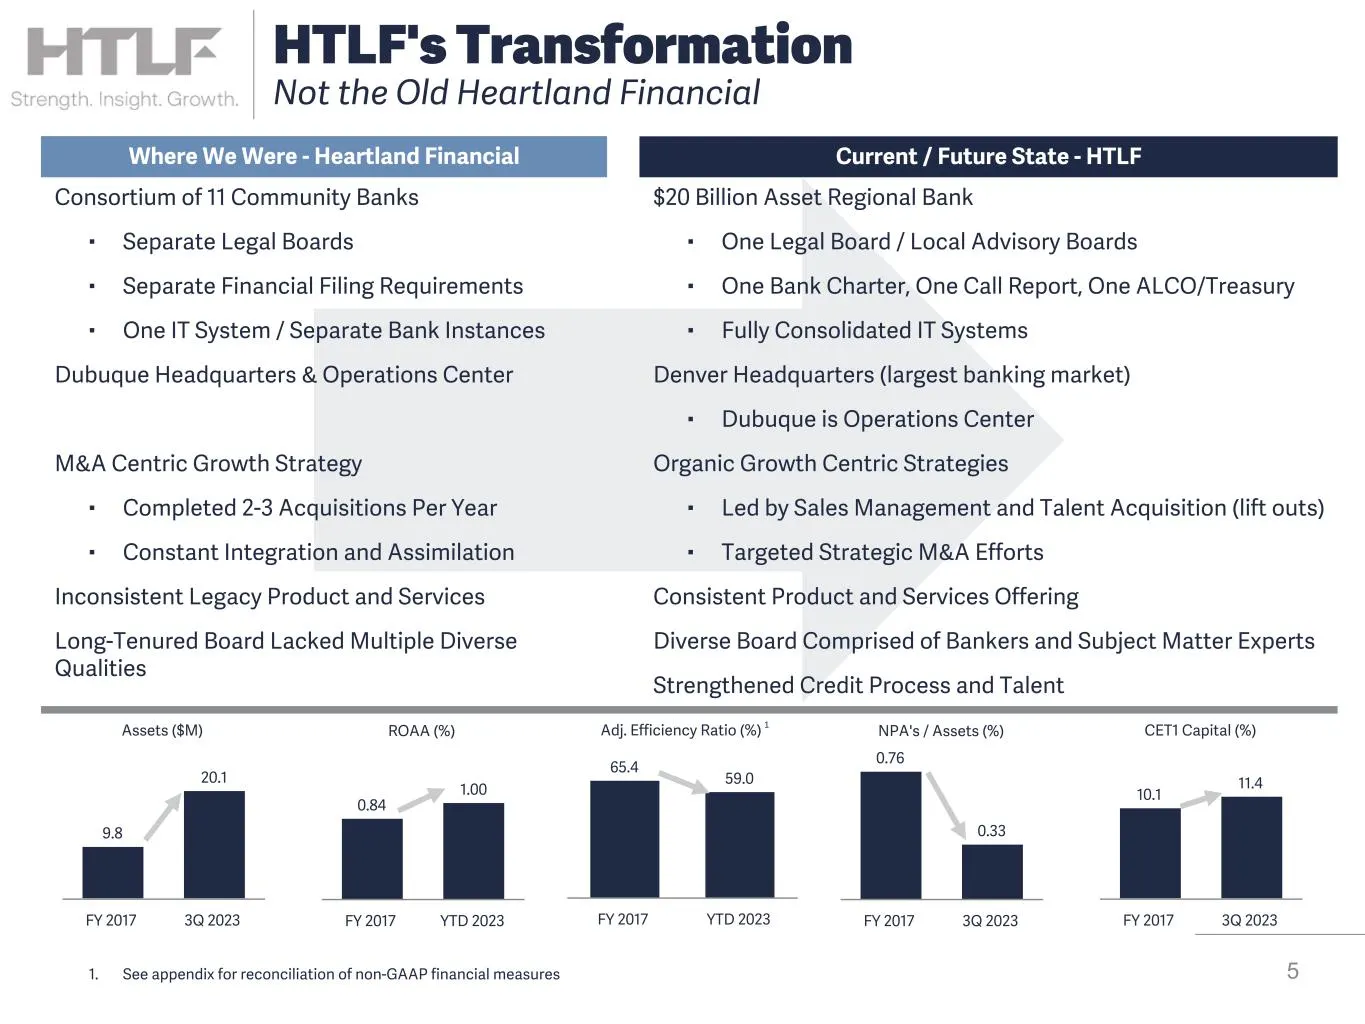
5 HTLF's Transformation Not the Old Heartland Financial Where We Were - Heartland Financial Current / Future State - HTLF $20 Billion Asset Regional Bank ▪ One Legal Board / Local Advisory Boards ▪ One Bank Charter, One Call Report, One ALCO/Treasury ▪ Fully Consolidated IT Systems Denver Headquarte
Slide 6: Charter consolidation and positioning HTLF for the future
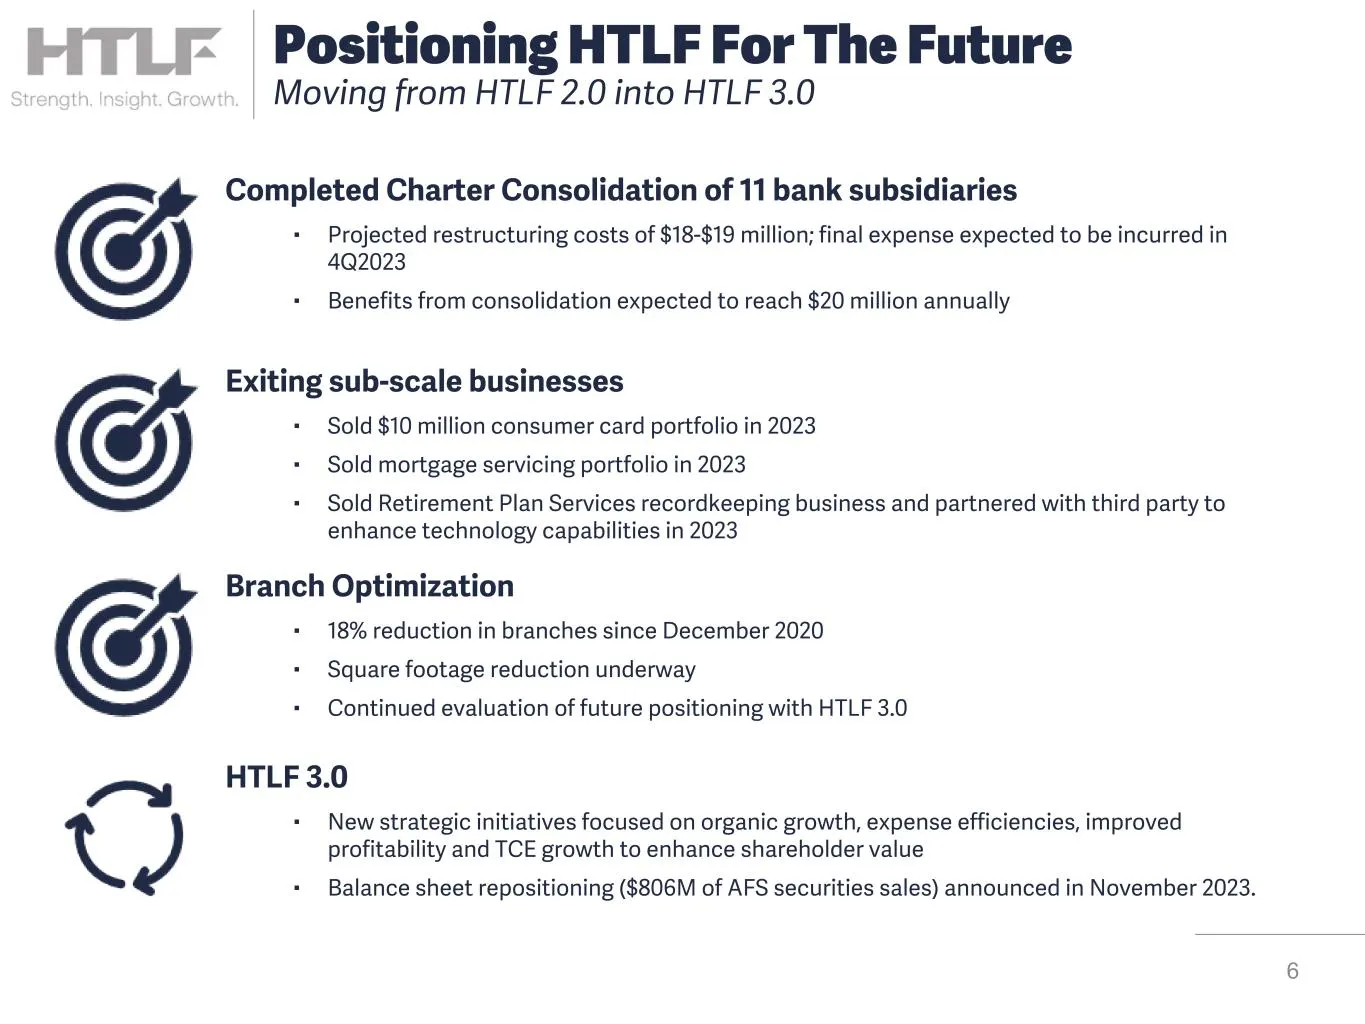
6 Completed Charter Consolidation of 11 bank subsidiaries ▪ Projected restructuring costs of $18-$19 million; final expense expected to be incurred in 4Q2023 ▪ Benefits from consolidation expected to reach $20 million annually Exiting sub-scale businesses ▪ Sold $10 million consumer card portfolio i
Slide 7: Strategic Balance Sheet Reposition
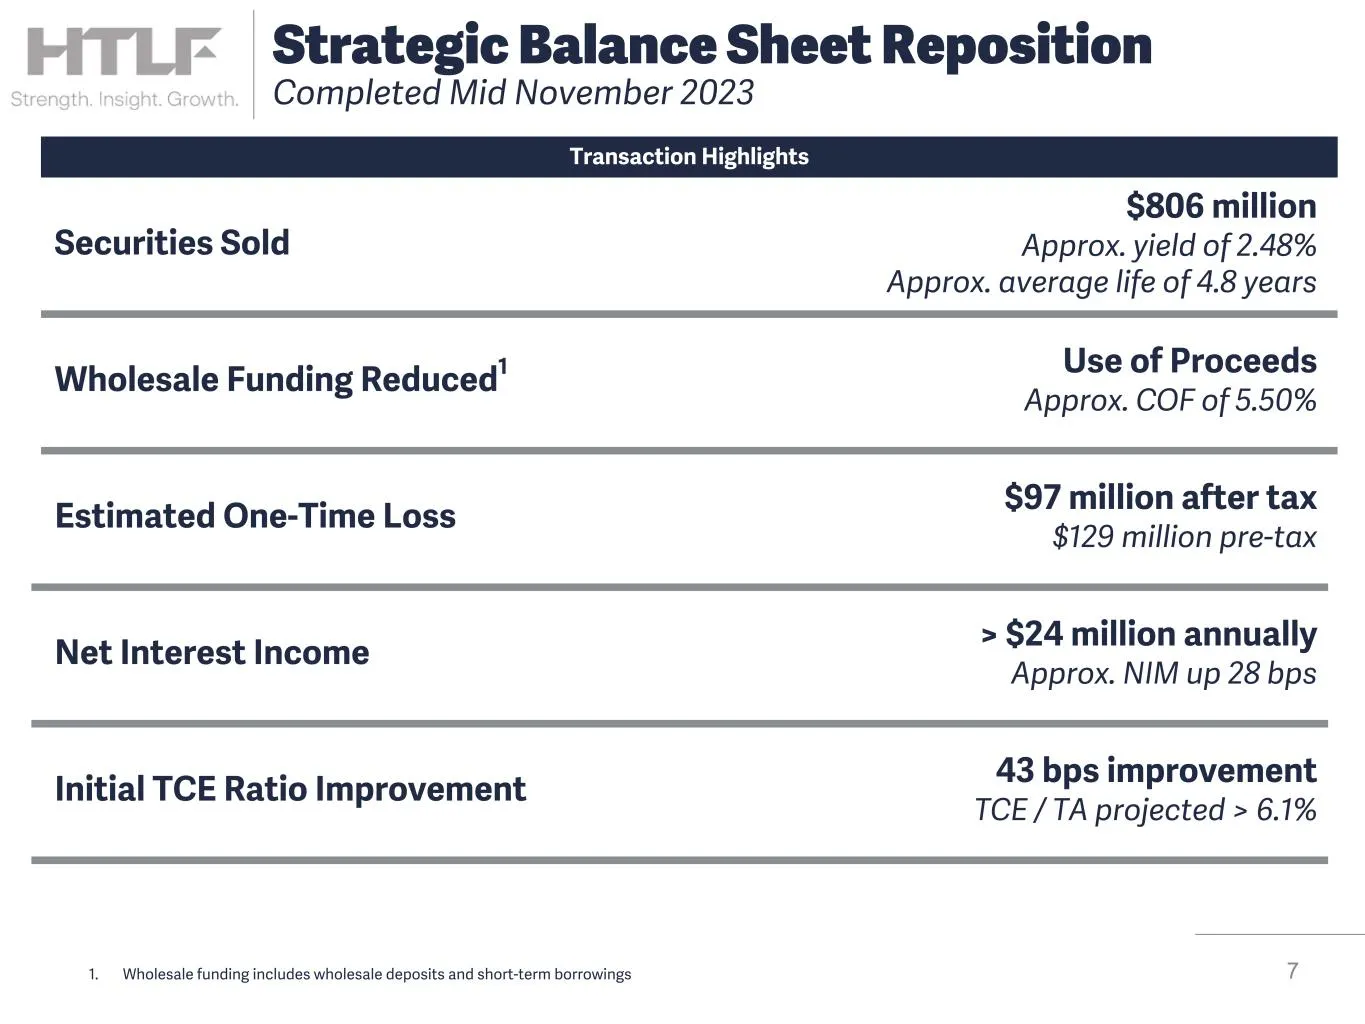
7 Strategic Balance Sheet Reposition Completed Mid November 2023 Securities Sold $806 million Approx. yield of 2.48% Approx. average life of 4.8 years Wholesale Funding Reduced1 Use of Proceeds Approx. COF of 5.50% Estimated One-Time Loss $97 million after tax $129 million pre-tax Net Interest Incom
Slide 8: Strategic Focus
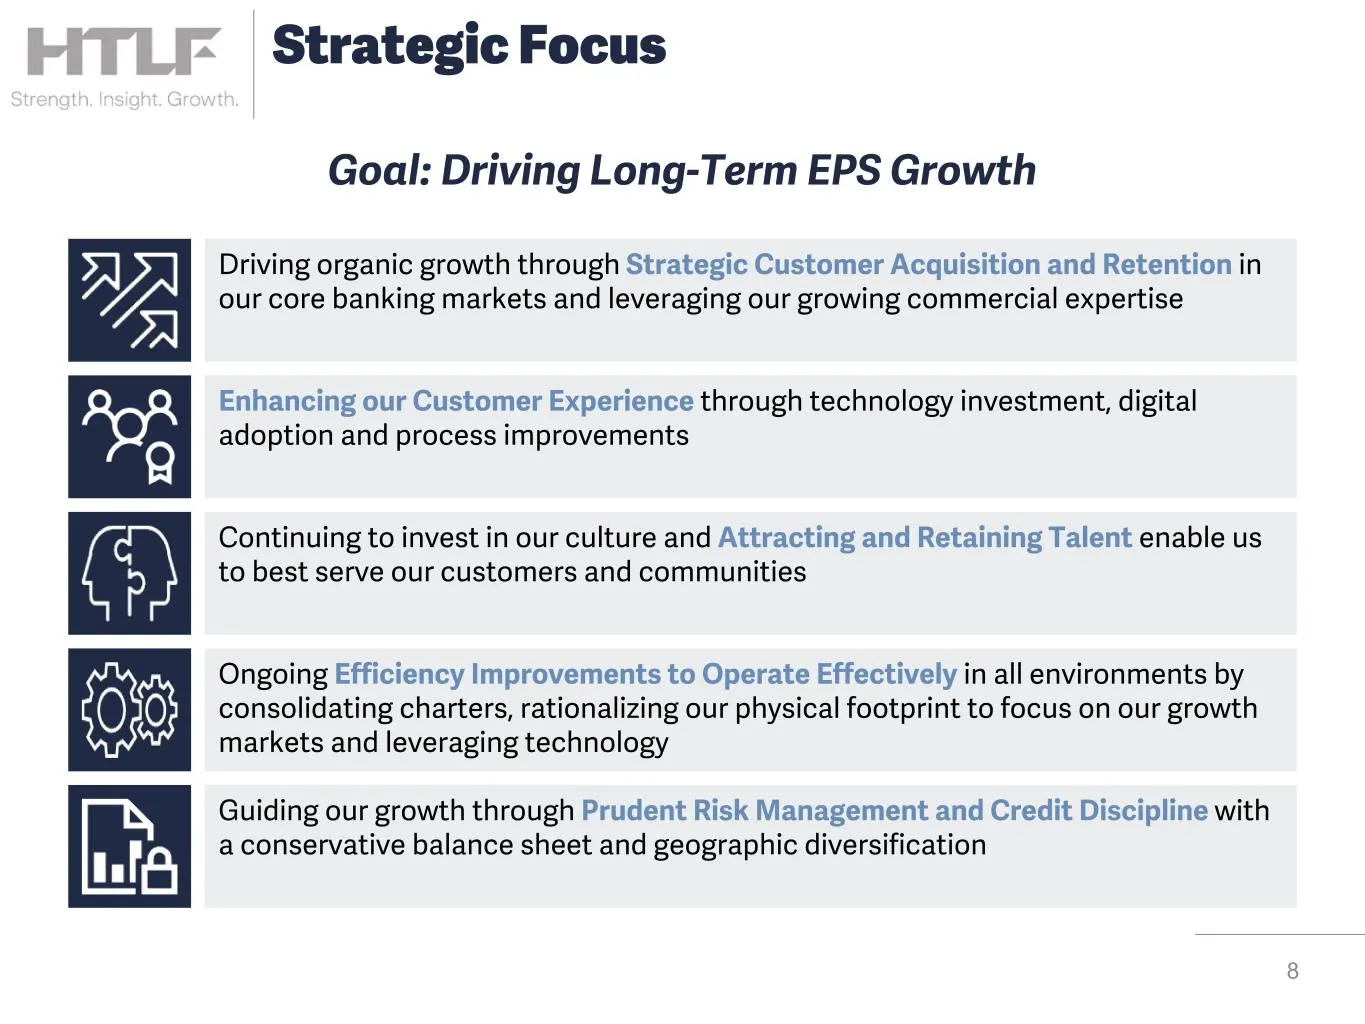
Driving organic growth through Strategic Customer Acquisition and Retention in our core banking markets and leveraging our growing commercial expertise 8 Strategic Focus Enhancing our Customer Experience through technology investment, digital adoption and process improvements Ongoing Efficiency Impr
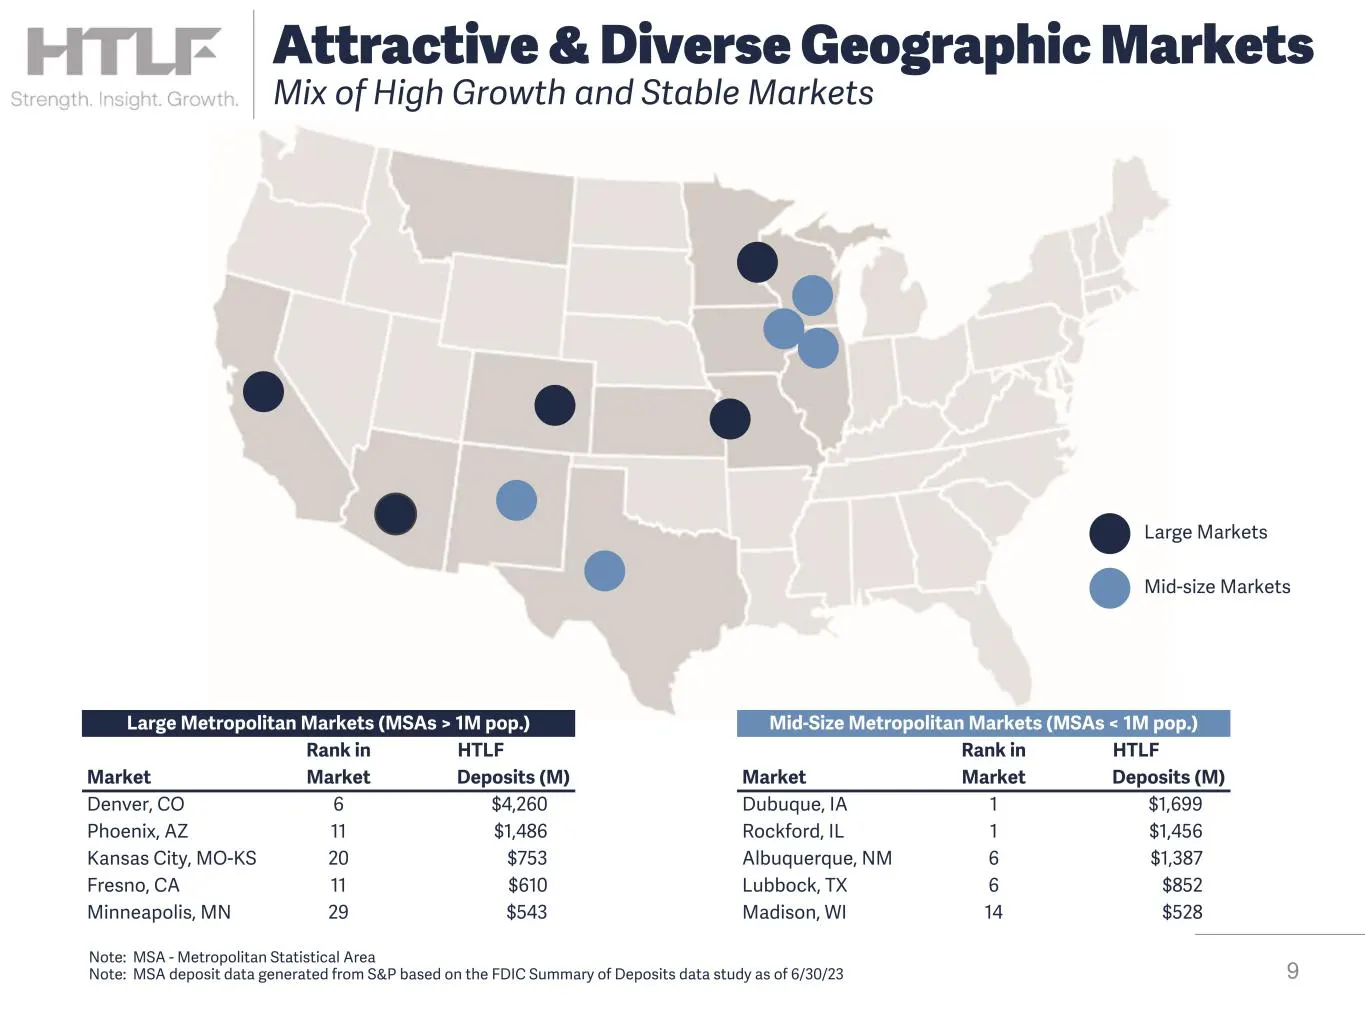
Slide 9: Attractive & Diverse Geographic Markets
Note: MSA - Metropolitan Statistical Area Note: MSA deposit data generated from S&P based on the FDIC Summary of Deposits data study as of 6/30/23 Large Metropolitan Markets (MSAs > 1M pop.) Rank in HTLF Market Market Deposits (M) Denver, CO 6 $4,260 Phoenix, AZ 11 $1,486 Kansas City, MO-KS 20 $753
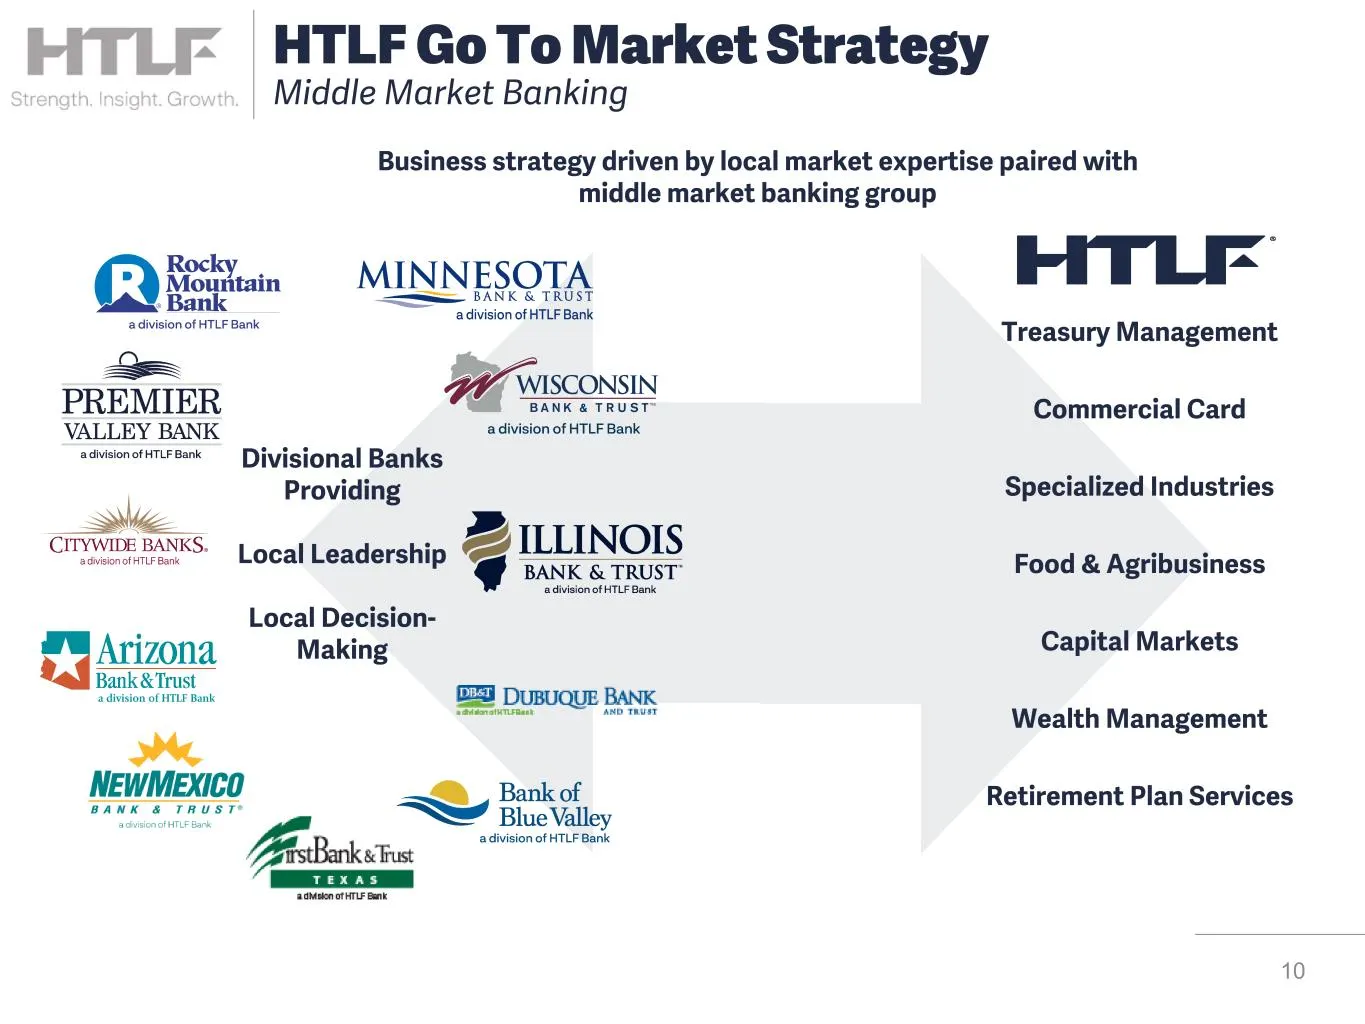
Slide 10: HTLF Go To Market Strategy
10 Business strategy driven by local market expertise paired with middle market banking group Treasury Management Commercial Card Specialized Industries Food & Agribusiness Capital Markets Wealth Management Retirement Plan Services HTLF Go To Market Strategy Middle Market Banking Divisional Banks Pr
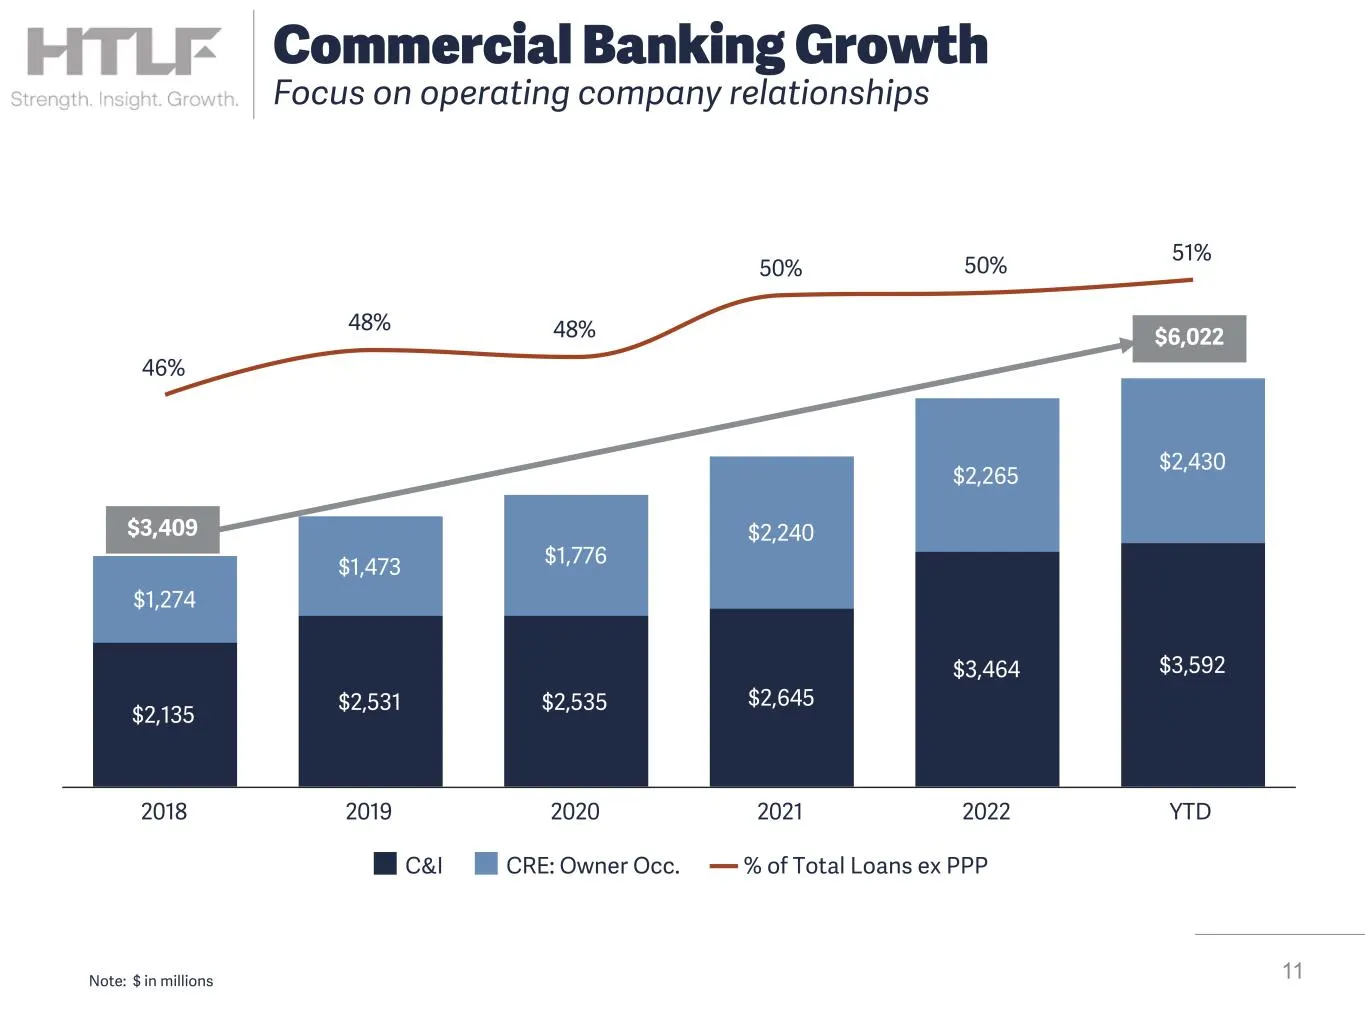
Slide 11: Commercial Banking Growth
$2,135 $2,531 $2,535 $2,645 $3,464 $3,592 $1,274 $1,473 $1,776 $2,240 $2,265 $2,430 46% 48% 48% 50% 50% 51% C&I CRE: Owner Occ. % of Total Loans ex PPP 2018 2019 2020 2021 2022 YTD 11Note: $ in millions Commercial Banking Growth Focus on operating company relationships $6,022 $3,409
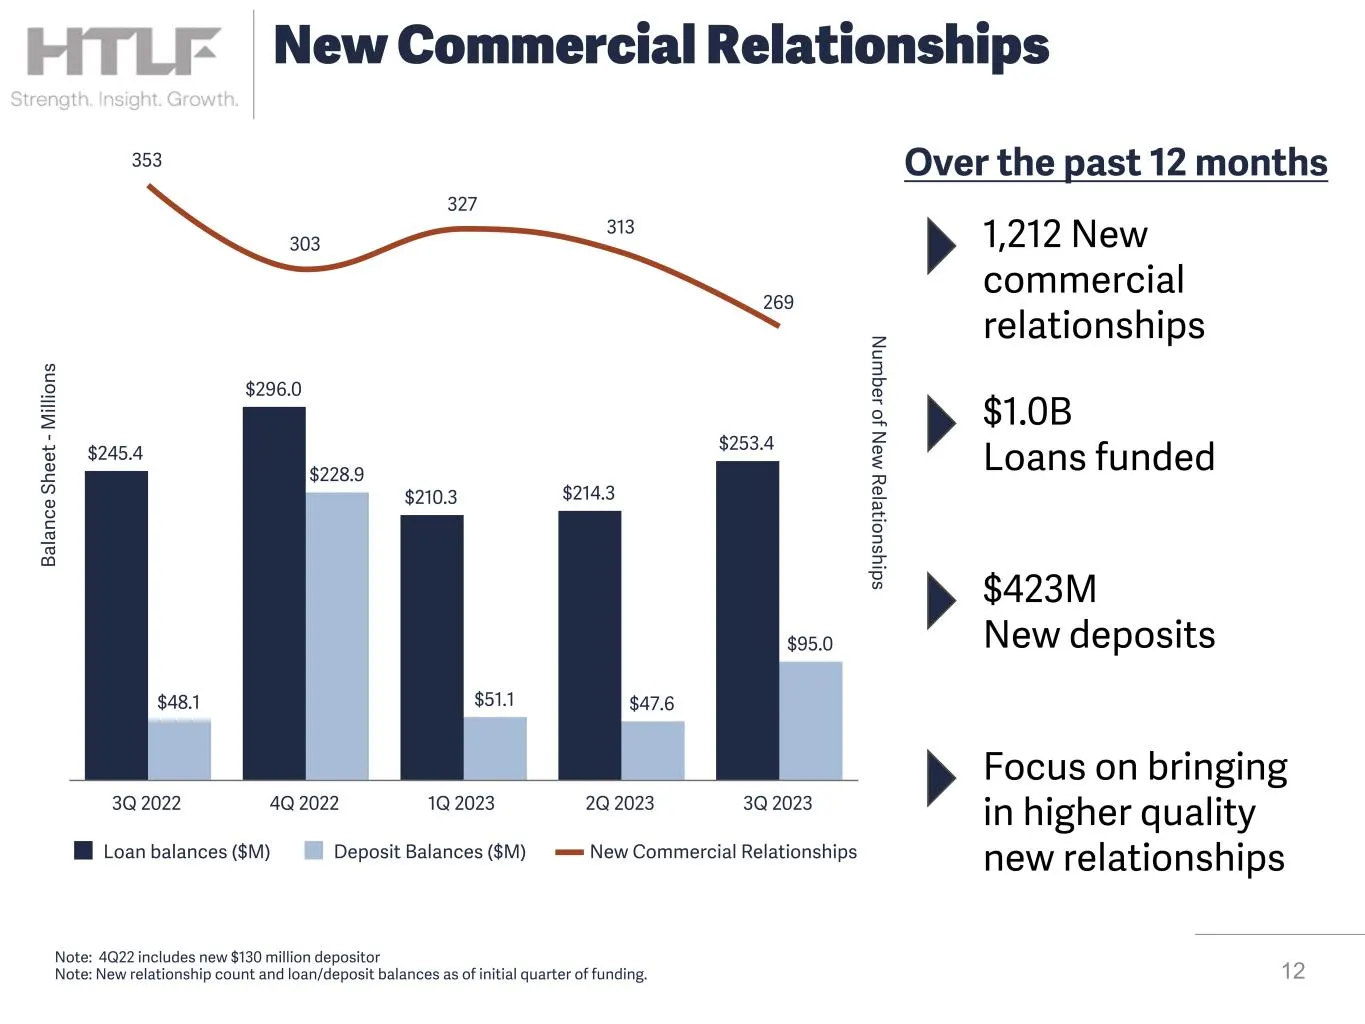
Slide 12: New Commercial Relationships
12 New Commercial Relationships B al an ce S he et - M ill io ns N um ber of N ew R elationships $245.4 $296.0 $210.3 $214.3 $253.4 $48.1 $228.9 $51.1 $47.6 $95.0 353 303 327 313 269 Loan balances ($M) Deposit Balances ($M) New Commercial Relationships 3Q 2022 4Q 2022 1Q 2023 2Q 2023 3Q 2023 1,212 N
Slide 13: Improving Customer Experiences
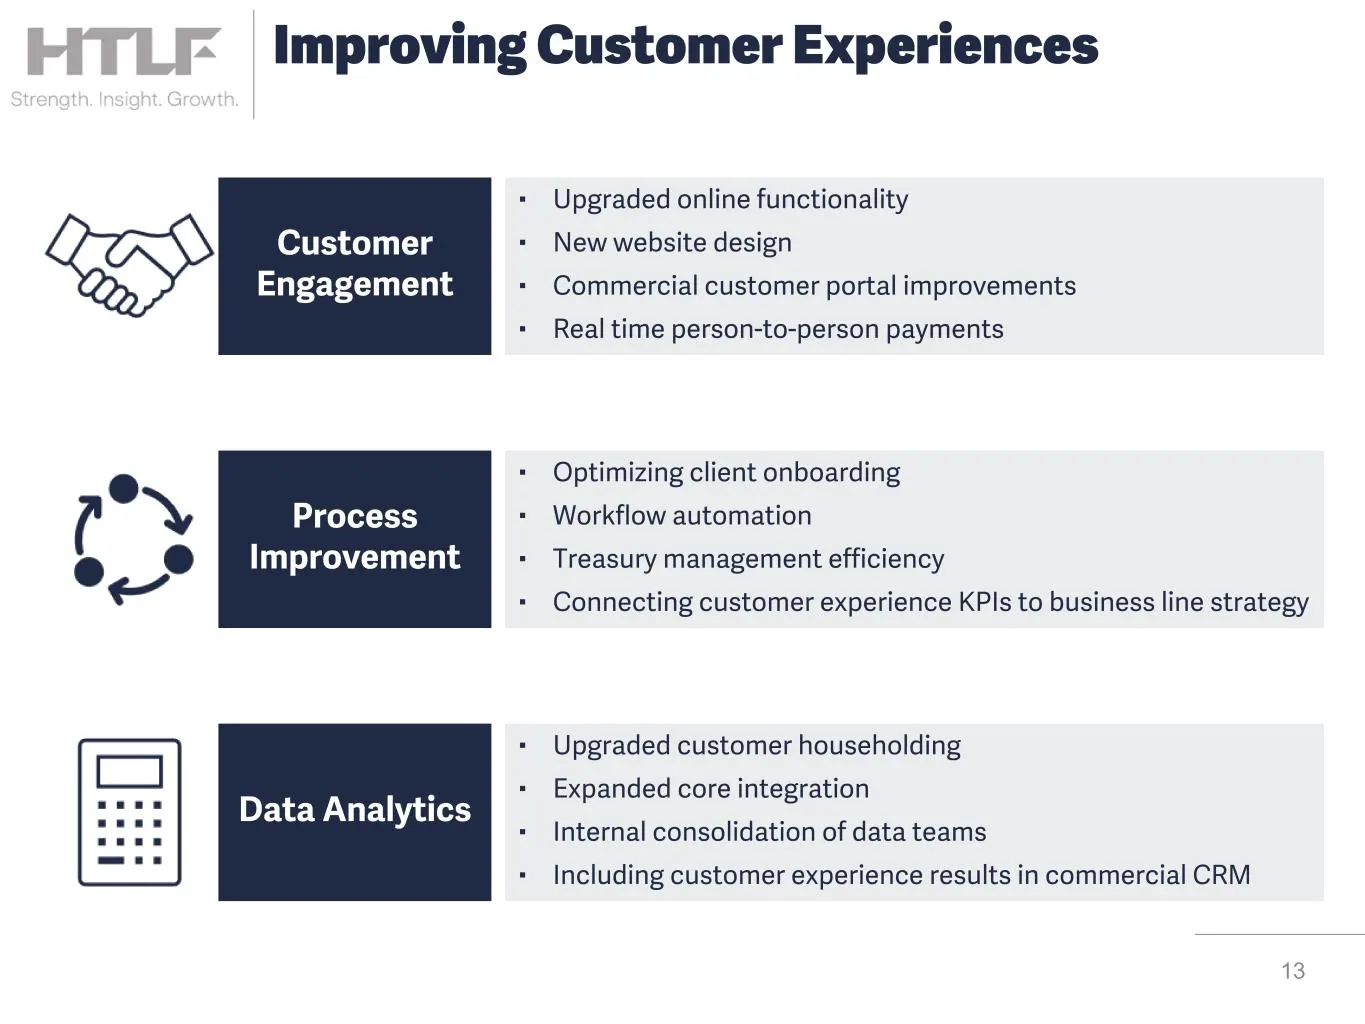
13 Improving Customer Experiences Customer Engagement Process Improvement Data Analytics ▪ Upgraded online functionality ▪ New website design ▪ Commercial customer portal improvements ▪ Real time person-to-person payments ▪ Optimizing client onboarding ▪ Workflow automation ▪ Treasury management eff
Slide 14: Focus on Credit Discipline
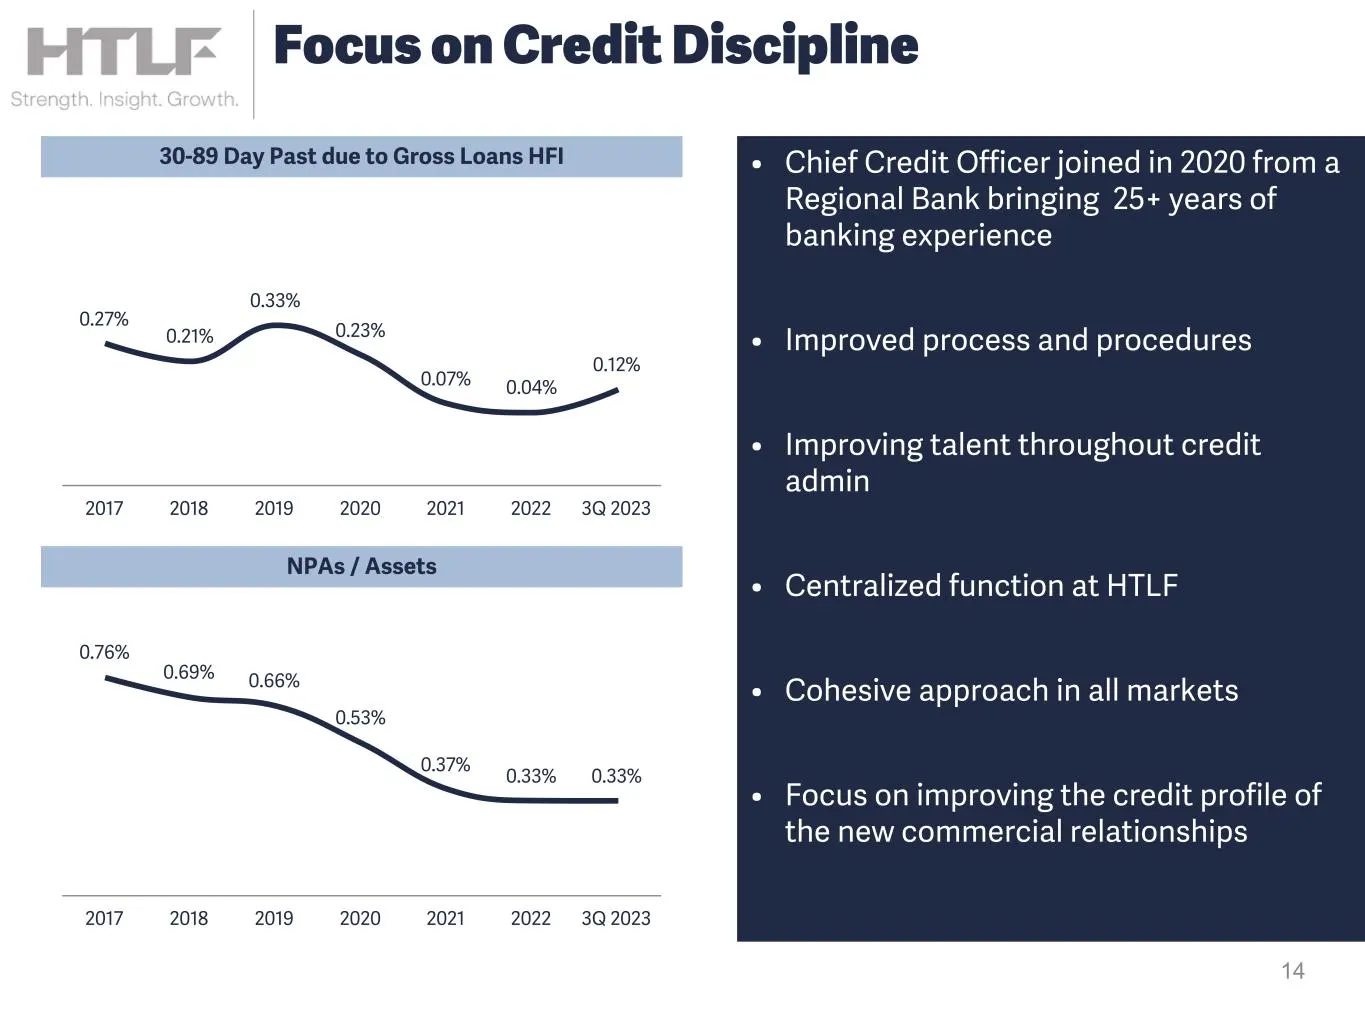
14 Focus on Credit Discipline • Chief Credit Officer joined in 2020 from a Regional Bank bringing 25+ years of banking experience • Improved process and procedures • Improving talent throughout credit admin • Centralized function at HTLF • Cohesive approach in all markets • Focus on improving the cr
Slide 15: Improving Quality of Capital Base
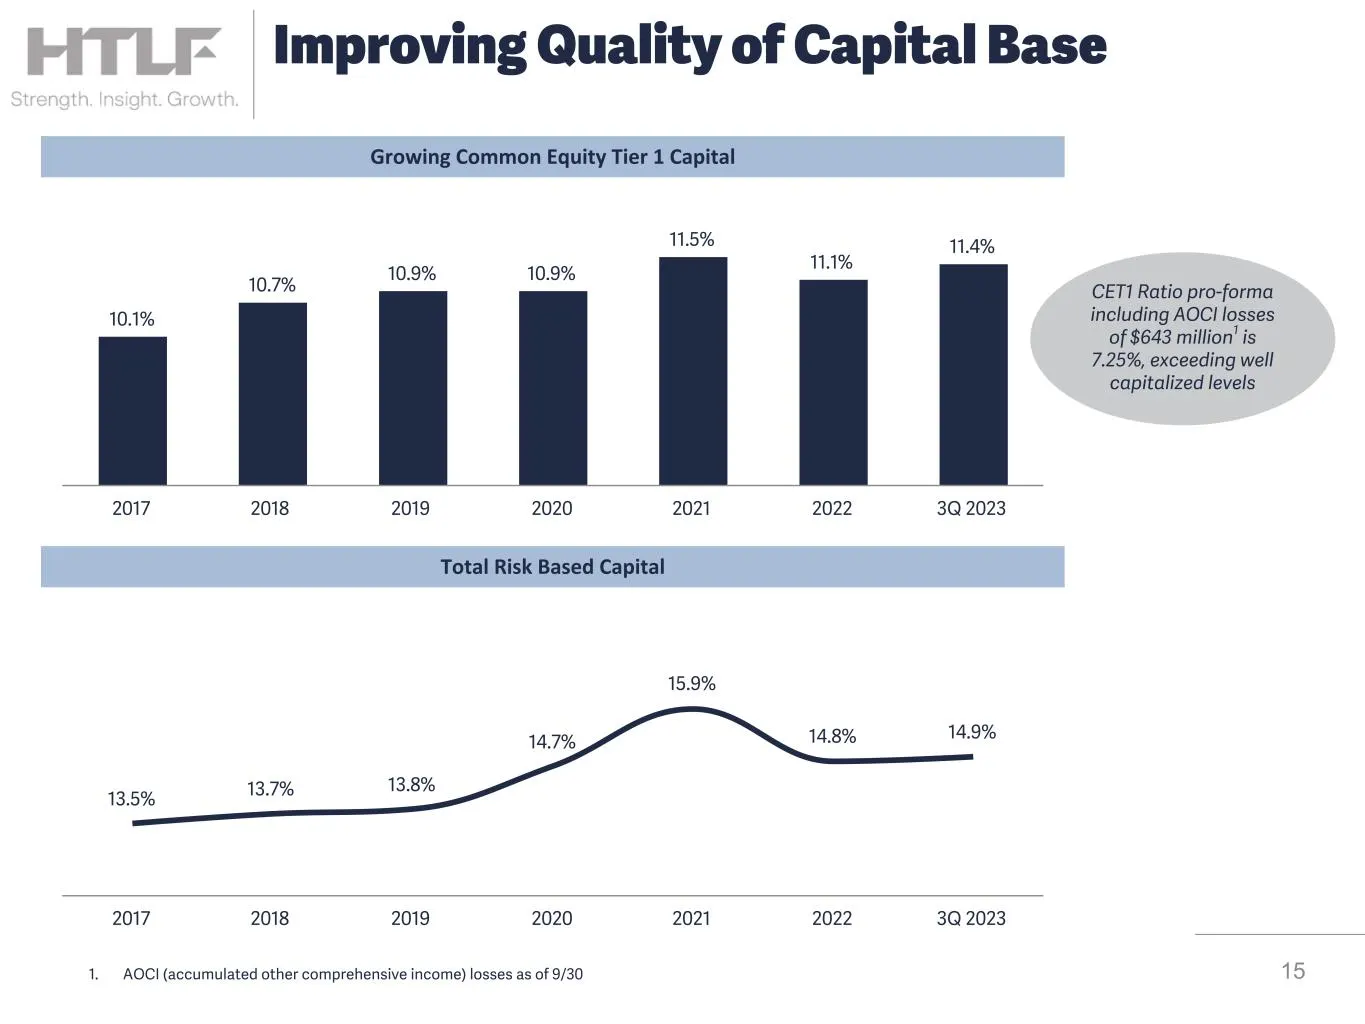
15 Improving Quality of Capital Base Growing Common Equity Tier 1 Capital Total Risk Based Capital 10.1% 10.7% 10.9% 10.9% 11.5% 11.1% 11.4% 2017 2018 2019 2020 2021 2022 3Q 2023 13.5% 13.7% 13.8% 14.7% 15.9% 14.8% 14.9% 2017 2018 2019 2020 2021 2022 3Q 2023 1. AOCI (accumulated other comprehensive
Slide 16: Commitment to Deliver Long Term Growth
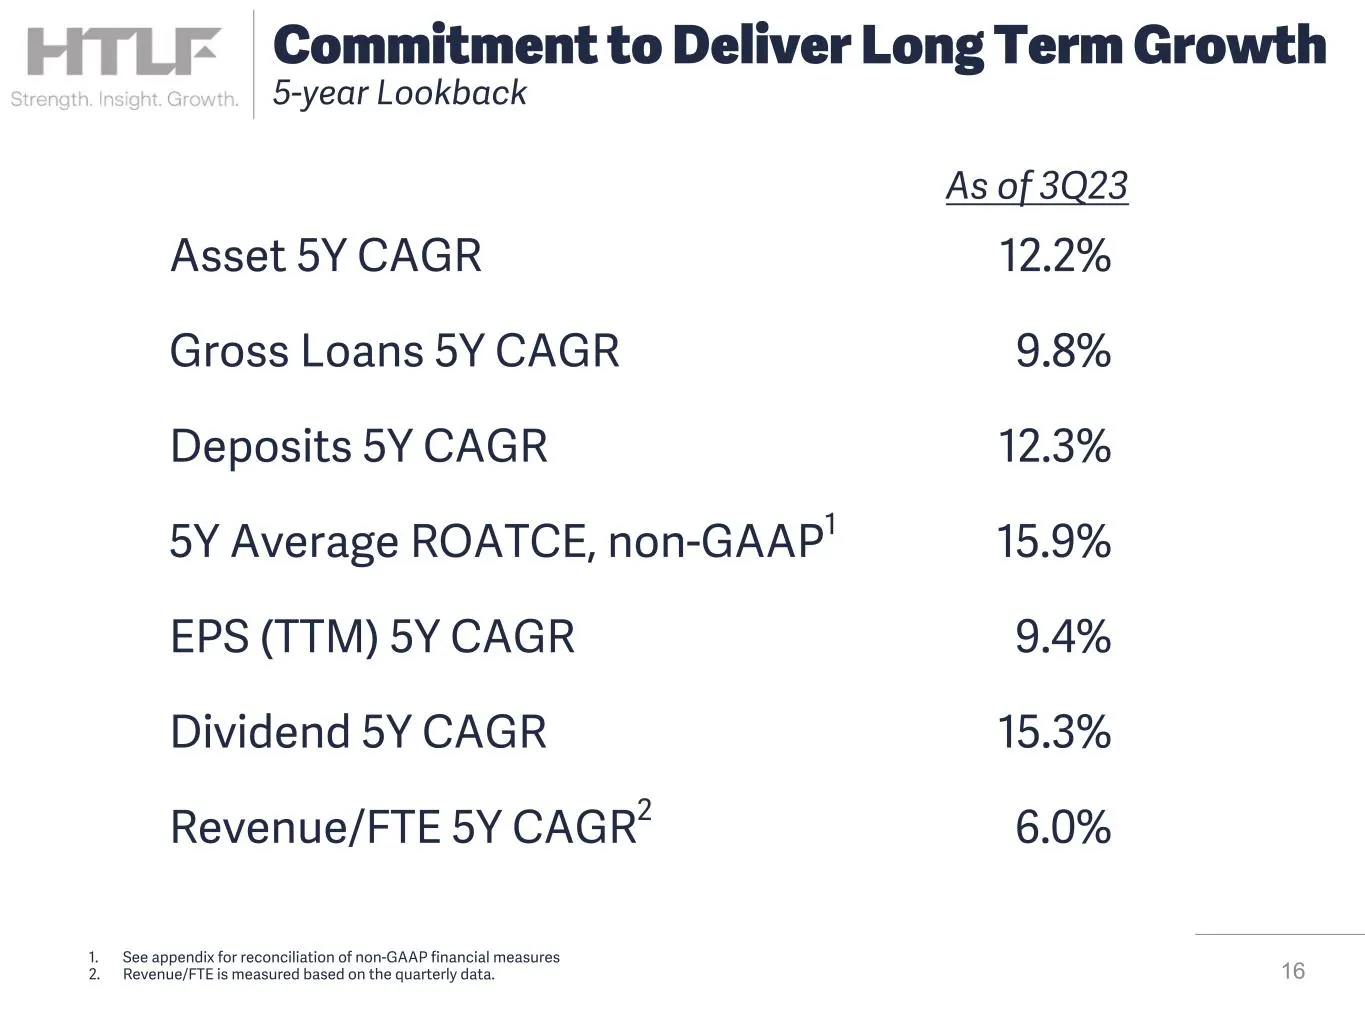
As of 3Q23 Asset 5Y CAGR 12.2 % Gross Loans 5Y CAGR 9.8 % Deposits 5Y CAGR 12.3 % 5Y Average ROATCE, non-GAAP1 15.9 % EPS (TTM) 5Y CAGR 9.4 % Dividend 5Y CAGR 15.3 % Revenue/FTE 5Y CAGR2 6.0 % 16 Commitment to Deliver Long Term Growth 5-year Lookback 1. See appendix for reconciliation of non-GAAP fi
Slide 17: HTLF Investment Thesis
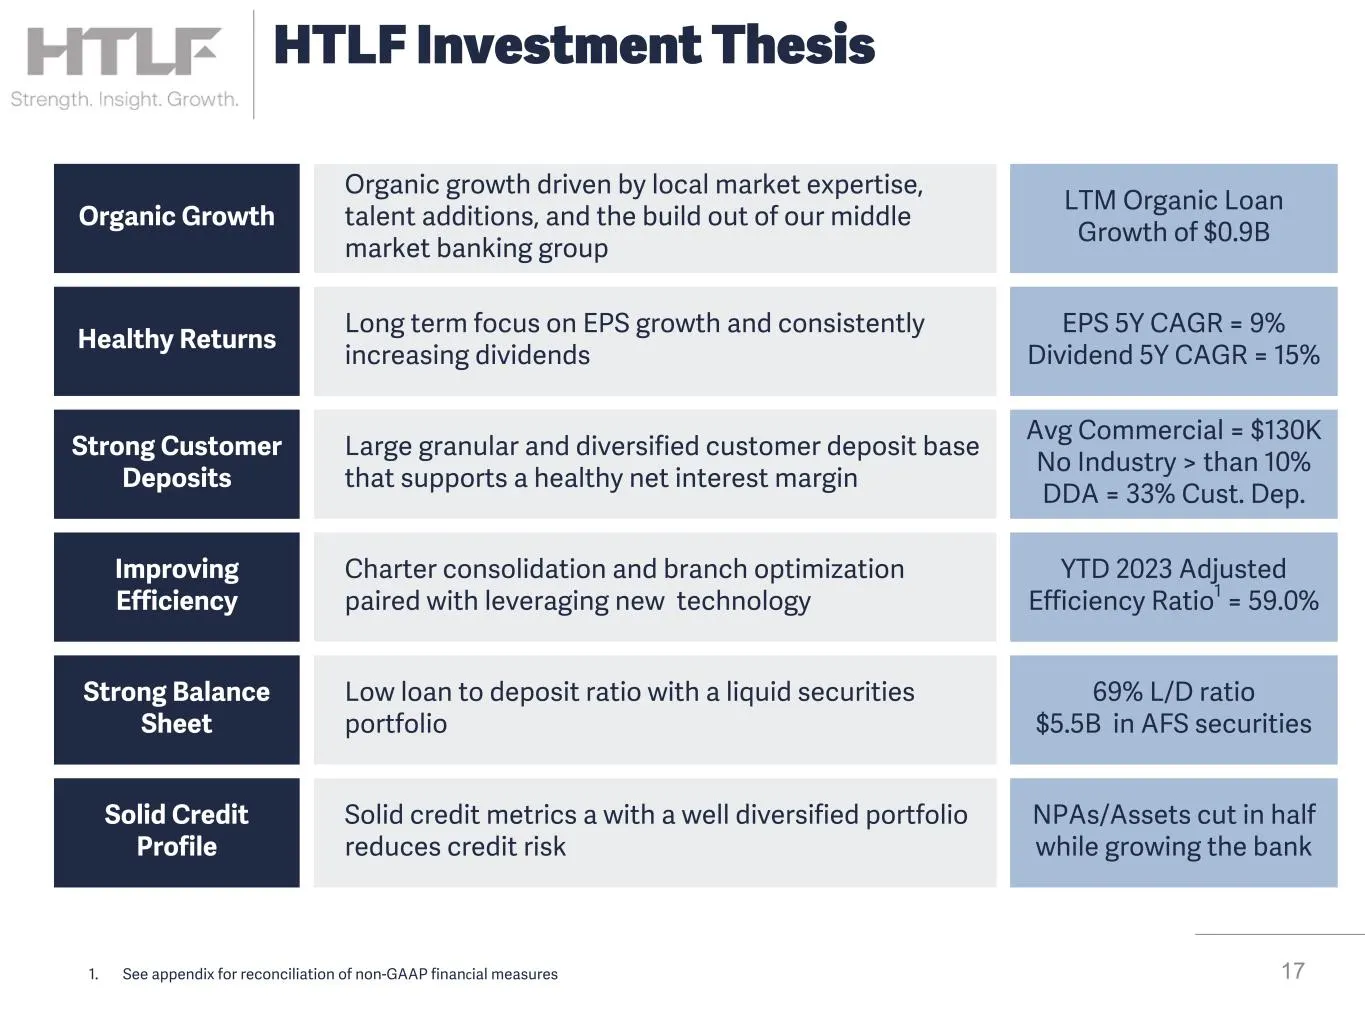
17 HTLF Investment Thesis 1. See appendix for reconciliation of non-GAAP financial measures Organic Growth Healthy Returns Strong Customer Deposits Improving Efficiency Organic growth driven by local market expertise, talent additions, and the build out of our middle market banking group Large granu
Slide 18: Financial Summary
Financial Summary 18
Slide 19: Fiscal 3Q 2023 Financial Highlights
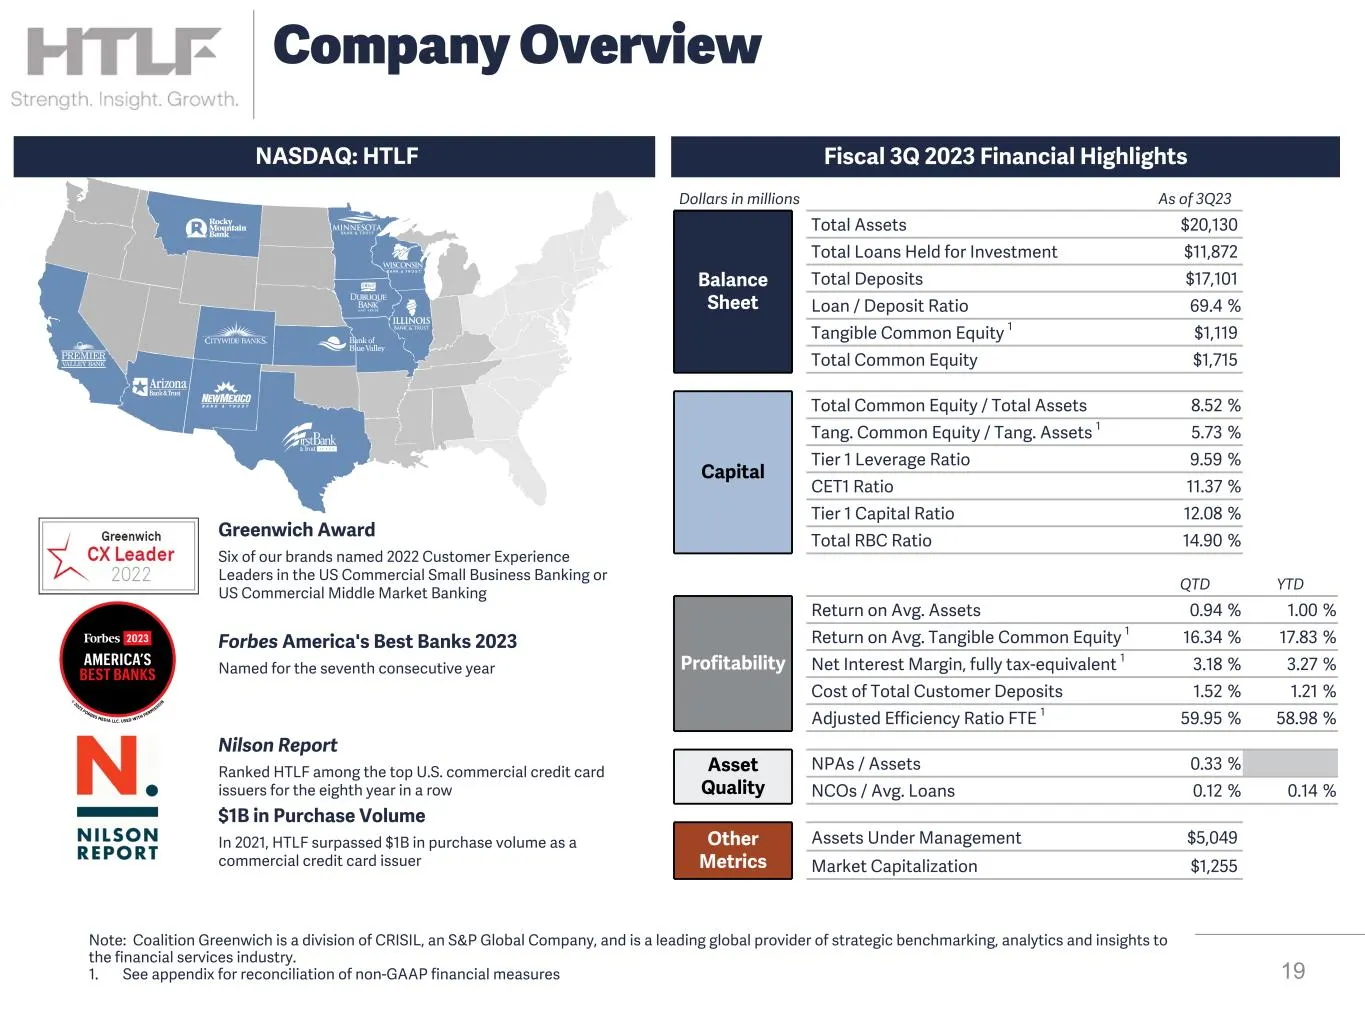
NASDAQ: HTLF Fiscal 3Q 2023 Financial Highlights Dollars in millions As of 3Q23 Balance Sheet Total Assets $20,130 Total Loans Held for Investment $11,872 Total Deposits $17,101 Loan / Deposit Ratio 69.4 % Tangible Common Equity 1 $1,119 Total Common Equity $1,715 Capital Total Common Equity / Total
Slide 20: 3Q 2023 Highlights
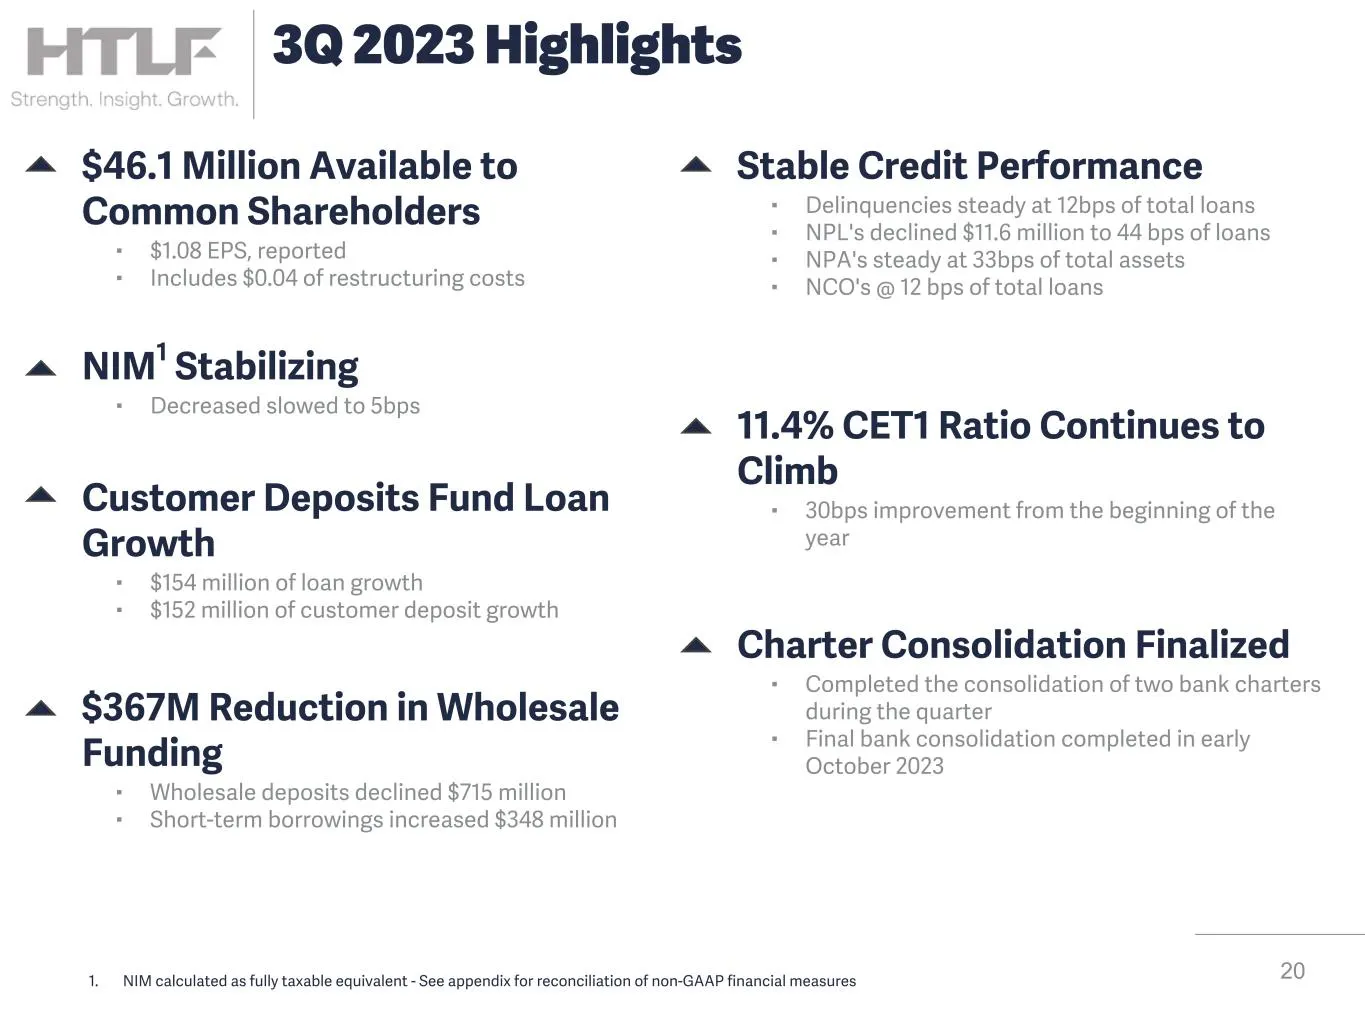
20 3Q 2023 Highlights 11.4% CET1 Ratio Continues to Climb ▪ 30bps improvement from the beginning of the year $46.1 Million Available to Common Shareholders ▪ $1.08 EPS, reported ▪ Includes $0.04 of restructuring costs Customer Deposits Fund Loan Growth ▪ $154 million of loan growth ▪ $152 million of
Slide 21: Increasing Dividends to Shareholders
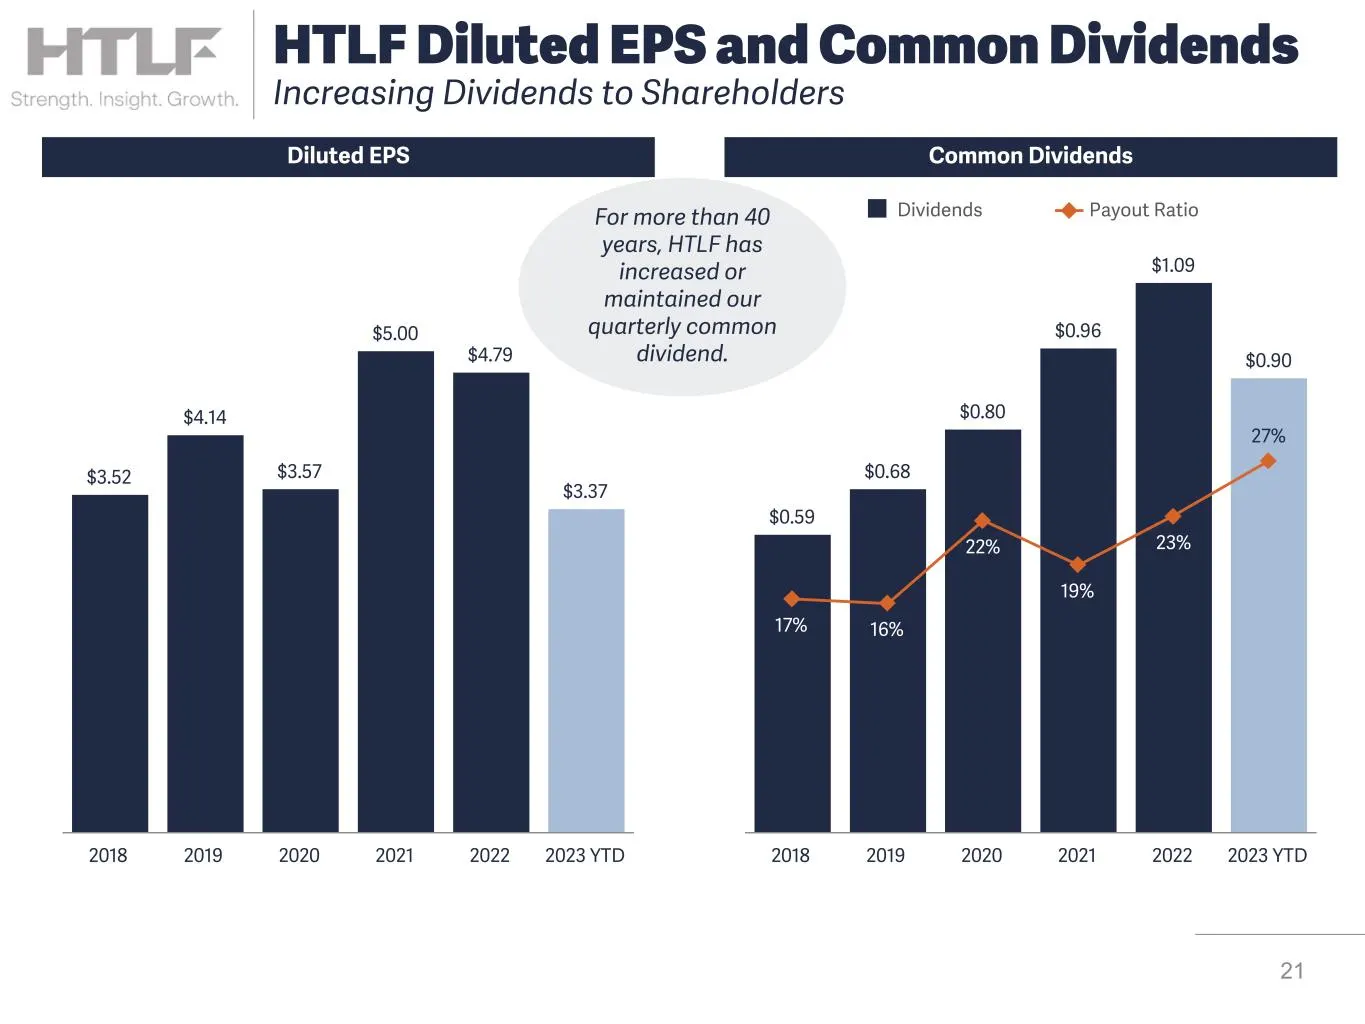
$0.59 $0.68 $0.80 $0.96 $1.09 $0.90 17% 16% 22% 19% 23% 27% Dividends Payout Ratio 2018 2019 2020 2021 2022 2023 YTD $3.52 $4.14 $3.57 $5.00 $4.79 $3.37 2018 2019 2020 2021 2022 2023 YTD 21 HTLF Diluted EPS and Common Dividends Increasing Dividends to Shareholders Diluted EPS Common Dividends For mo
Slide 22: Profitability Summary
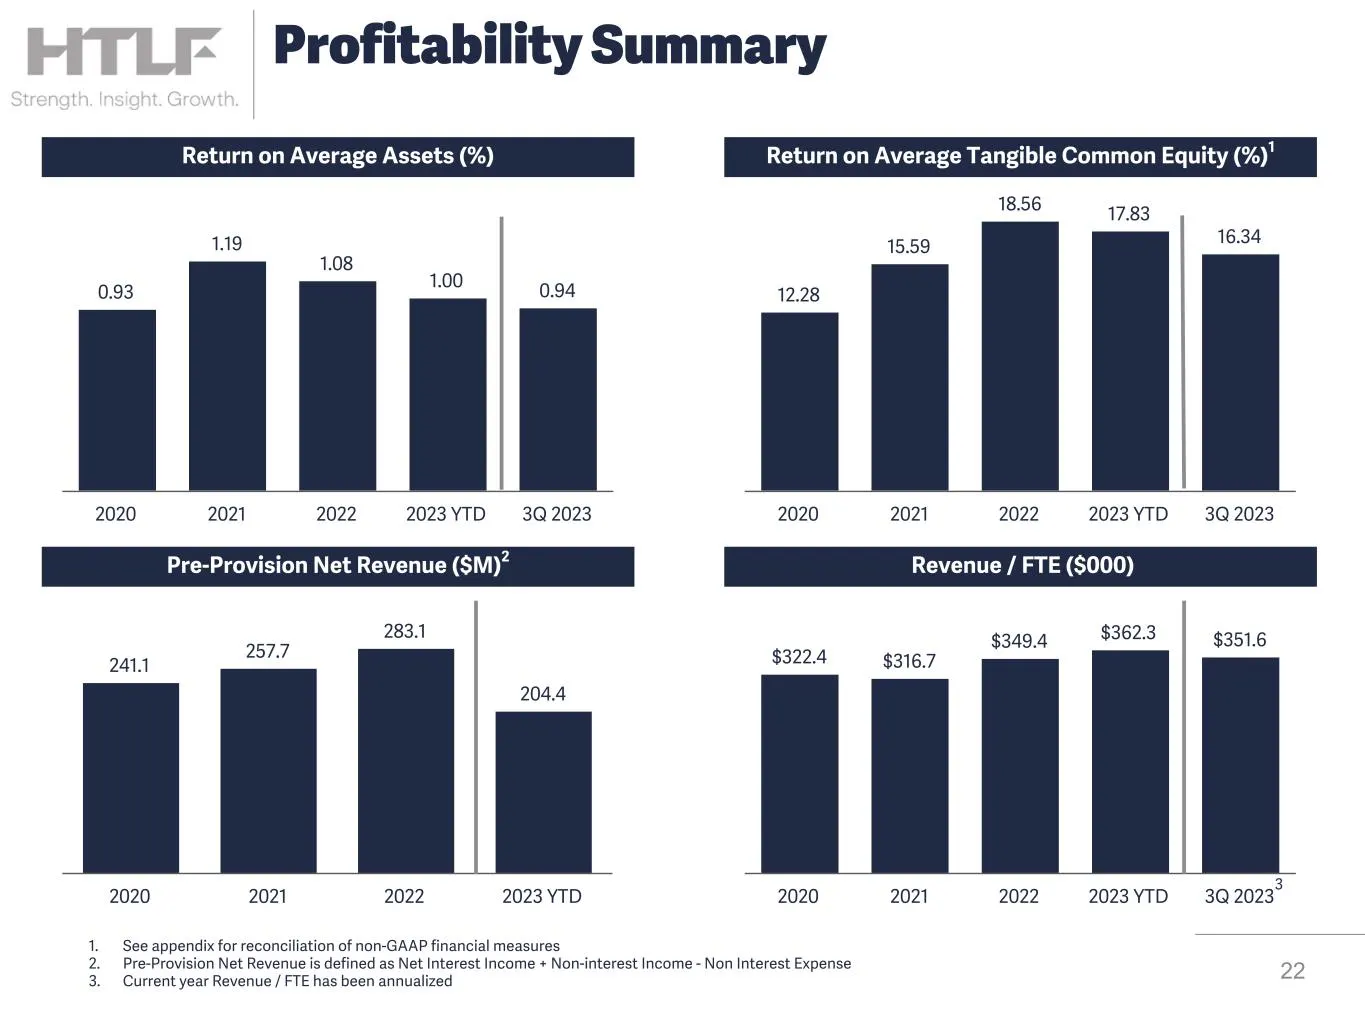
Return on Average Assets (%) Return on Average Tangible Common Equity (%)1 Pre-Provision Net Revenue ($M)2 Revenue / FTE ($000) 0.93 1.19 1.08 1.00 0.94 2020 2021 2022 2023 YTD 3Q 2023 $322.4 $316.7 $349.4 $362.3 $351.6 2020 2021 2022 2023 YTD 3Q 2023 241.1 257.7 283.1 204.4 2020 2021 2022 2023 YTD
Slide 23: Net Interest Margin Breakdown
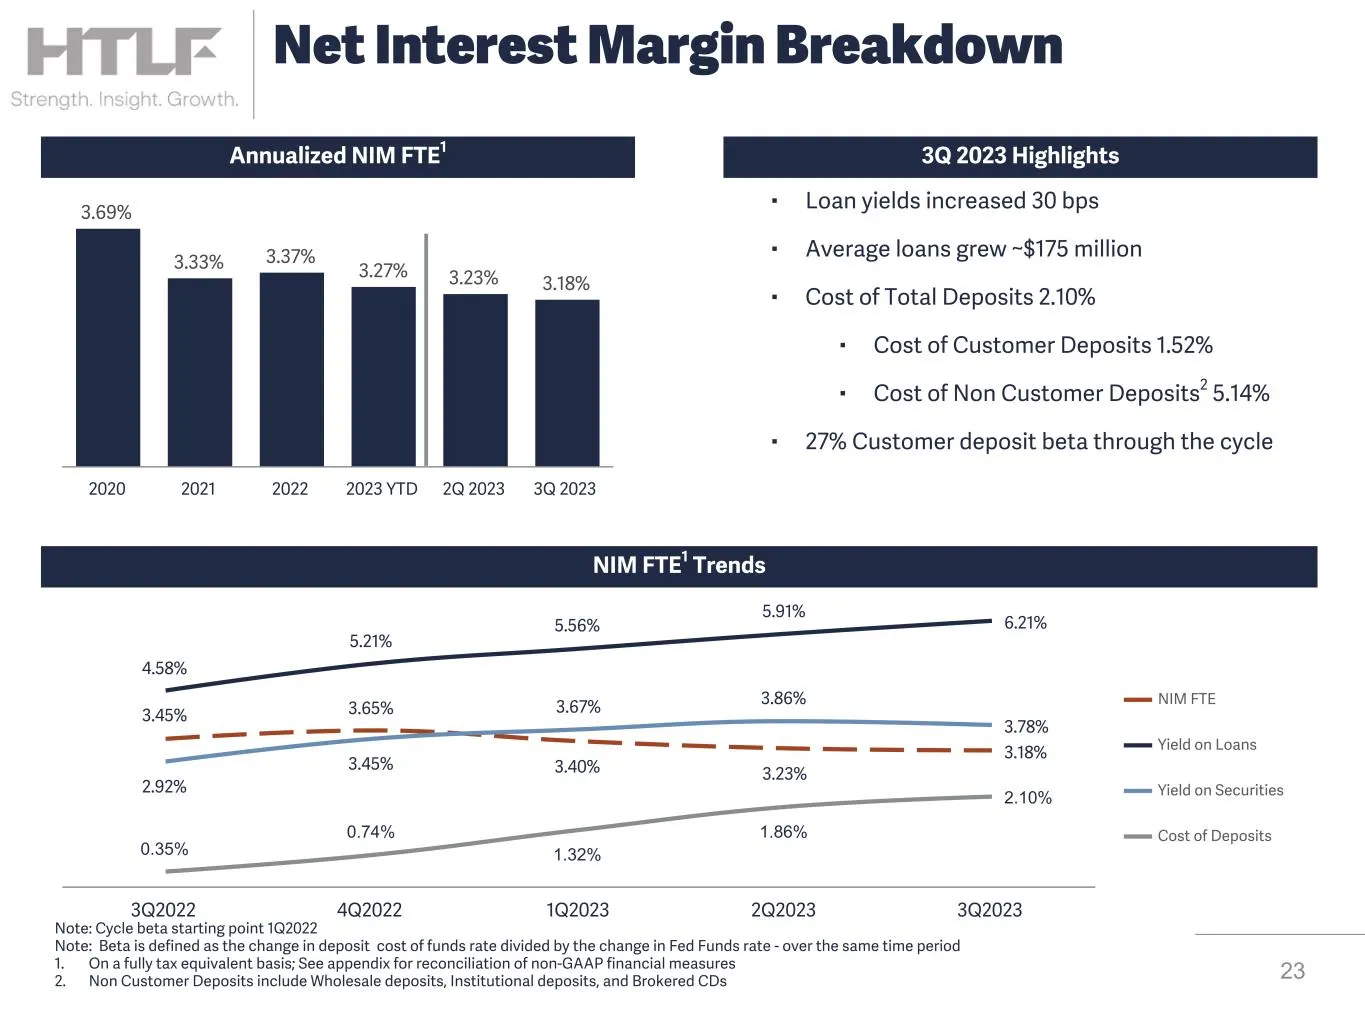
3.69% 3.33% 3.37% 3.27% 3.23% 3.18% 2020 2021 2022 2023 YTD 2Q 2023 3Q 2023 23 Net Interest Margin Breakdown NIM FTE1 Trends Annualized NIM FTE1 3.45% 3.65% 3.40% 3.23% 3.18% 4.58% 5.21% 5.56% 5.91% 6.21% 2.92% 3.45% 3.67% 3.86% 3.78% 0.35% 0.74% 1.32% 1.86% 2.10% NIM FTE Yield on Loans Yield on Sec
Slide 24: 3Q2023 Cost of Funds & Betas
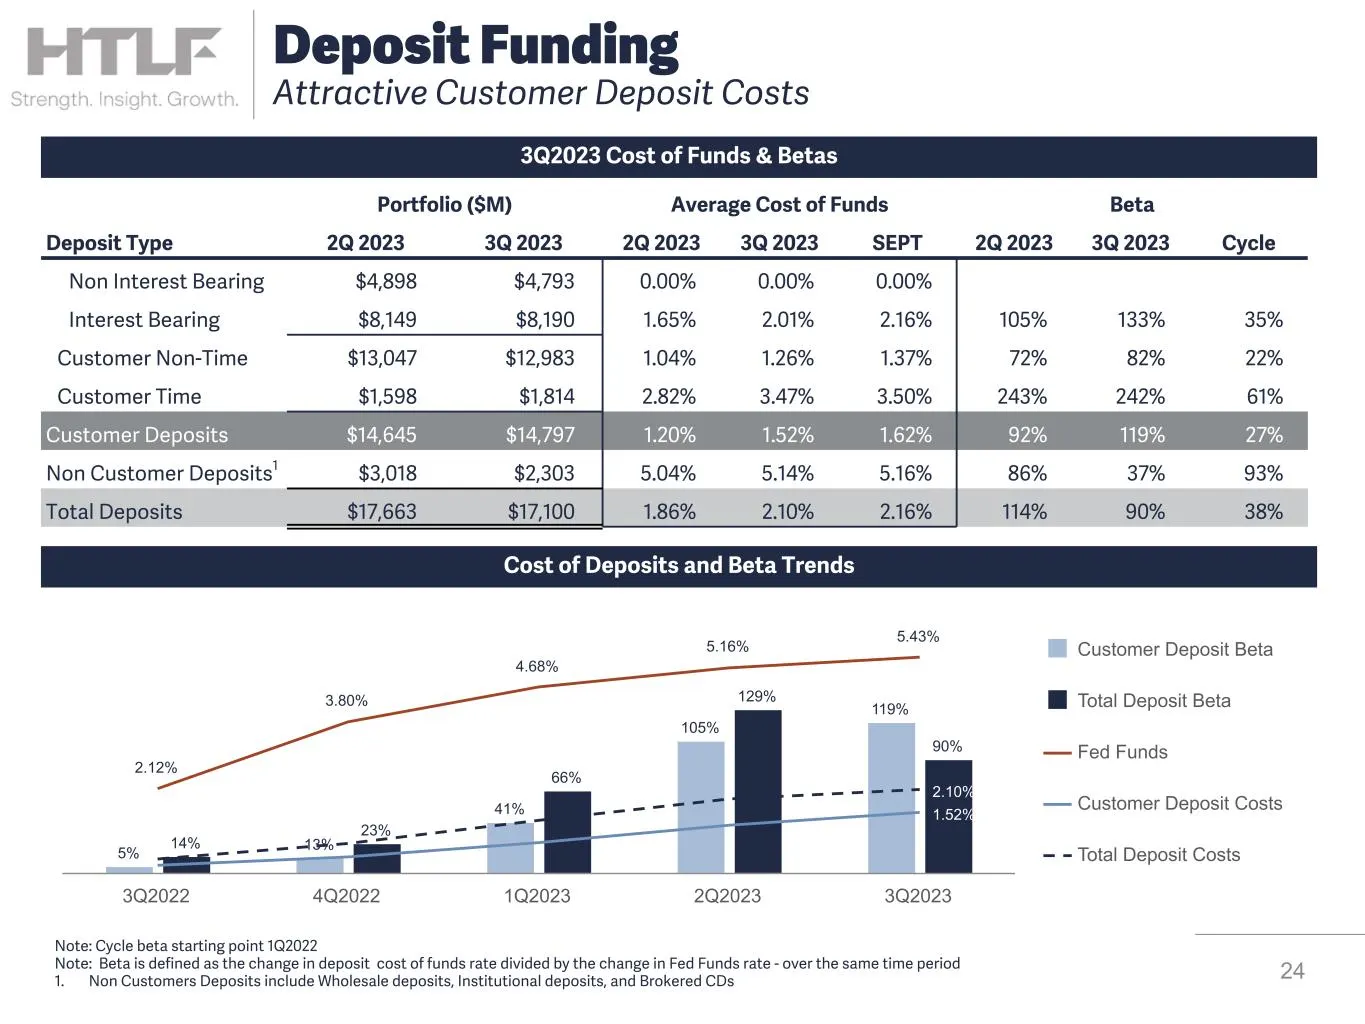
3Q2023 Cost of Funds & Betas 24 Deposit Funding Attractive Customer Deposit Costs Portfolio ($M) Average Cost of Funds Beta Deposit Type 2Q 2023 3Q 2023 2Q 2023 3Q 2023 SEPT 2Q 2023 3Q 2023 Cycle Non Interest Bearing $4,898 $4,793 0.00 % 0.00 % 0.00 % Interest Bearing $8,149 $8,190 1.65 % 2.01 % 2.1
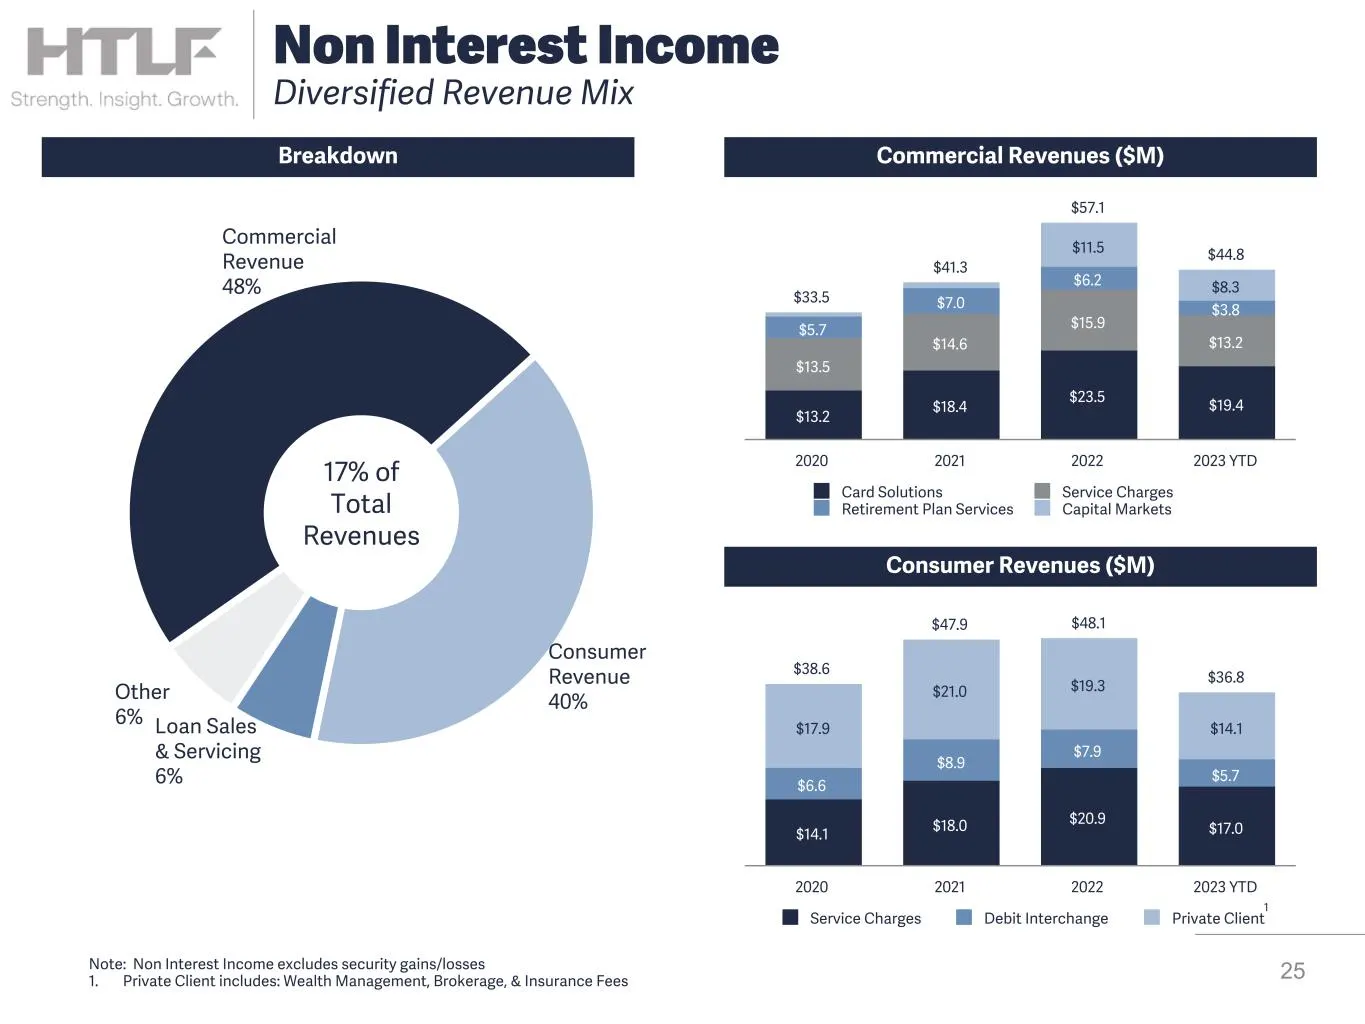
Slide 25: Non Interest Income - Diversified Revenue Mix
Commercial Revenue 48% Consumer Revenue 40% Loan Sales & Servicing 6% Other 6% 25 Non Interest Income Diversified Revenue Mix $33.5 $41.3 $57.1 $44.8 $13.2 $18.4 $23.5 $19.4 $13.5 $14.6 $15.9 $13.2 $5.7 $7.0 $6.2 $3.8 $11.5 $8.3 Card Solutions Service Charges Retirement Plan Services Capital Markets
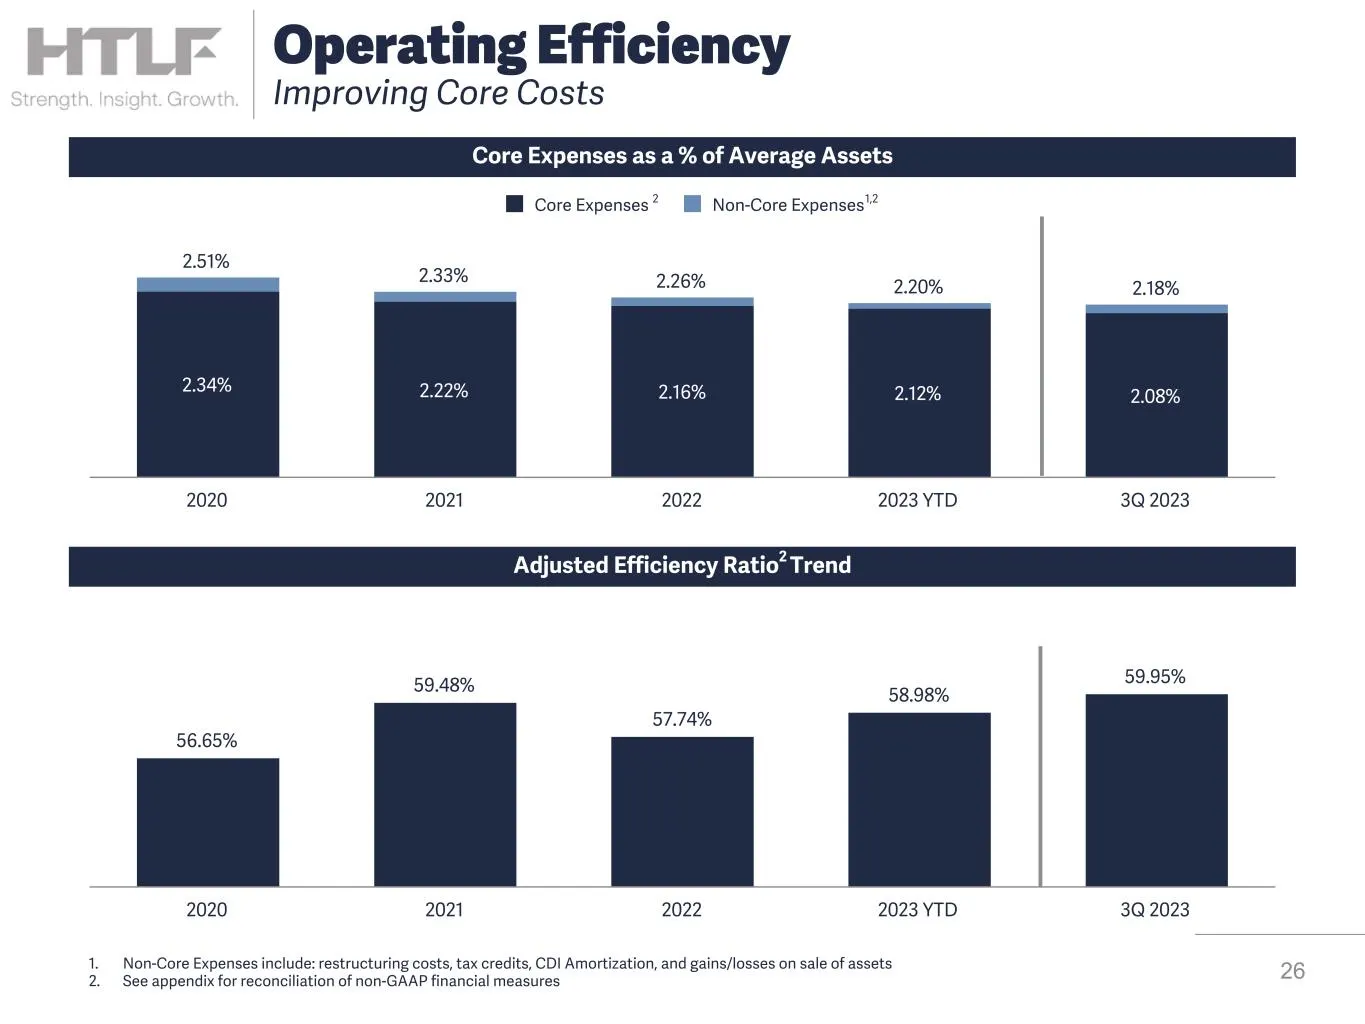
Slide 26: Operating Efficiency
2.51% 2.33% 2.26% 2.20% 2.18% 2.34% 2.22% 2.16% 2.12% 2.08% Core Expenses Non-Core Expenses 2020 2021 2022 2023 YTD 3Q 2023 56.65% 59.48% 57.74% 58.98% 59.95% 2020 2021 2022 2023 YTD 3Q 2023 1. Non-Core Expenses include: restructuring costs, tax credits, CDI Amortization, and gains/losses on sale of
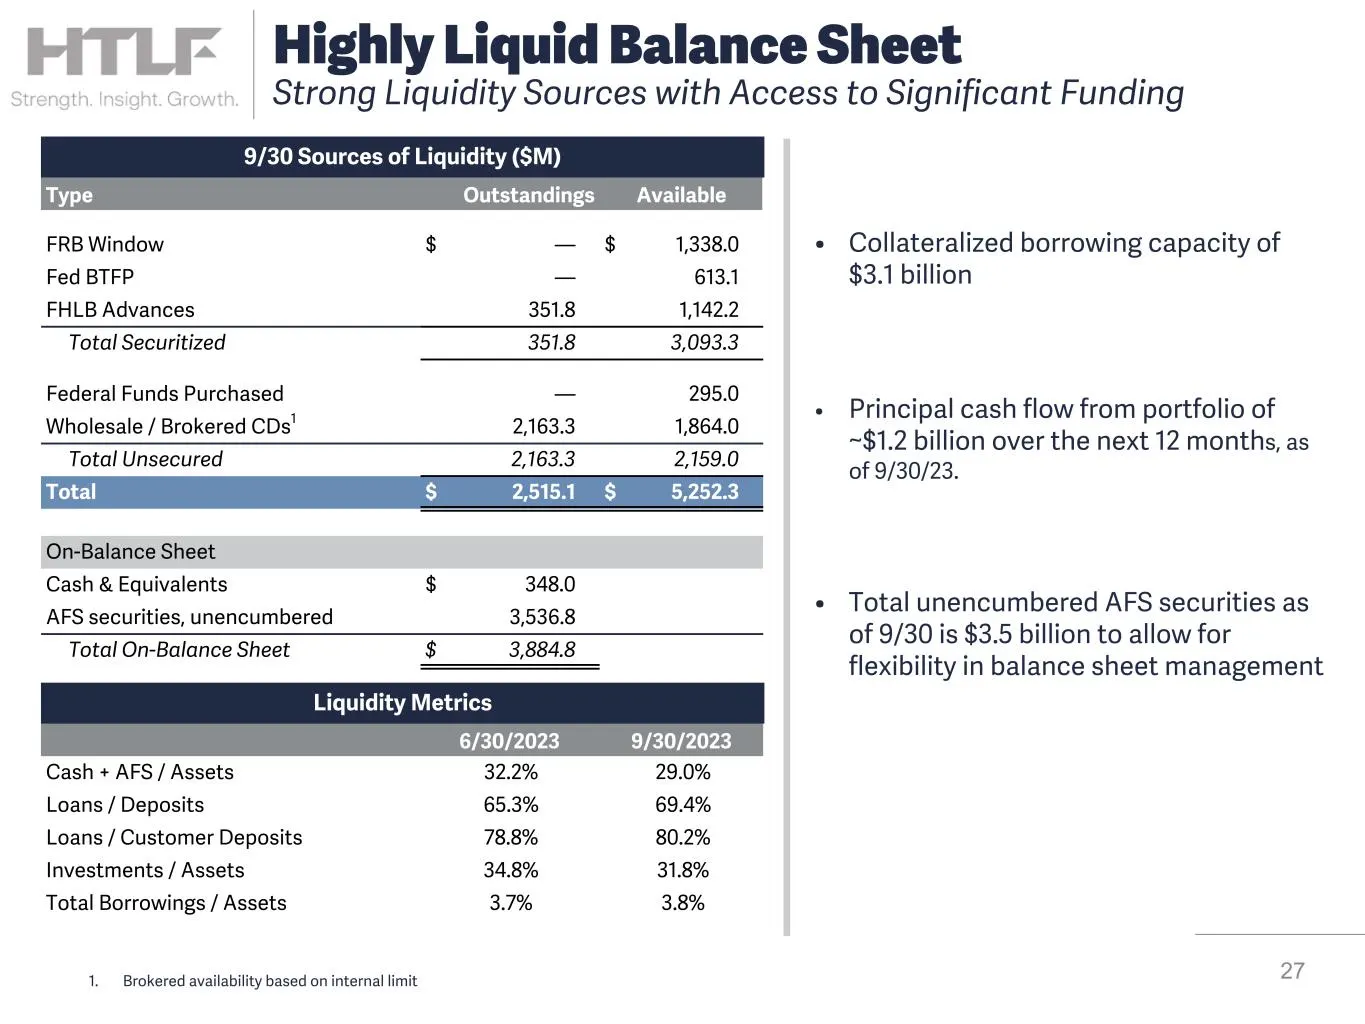
Slide 27: Highly Liquid Balance Sheet
• Collateralized borrowing capacity of $3.1 billion • Principal cash flow from portfolio of ~$1.2 billion over the next 12 months, as of 9/30/23. • Total unencumbered AFS securities as of 9/30 is $3.5 billion to allow for flexibility in balance sheet management 27 9/30 Sources of Liquidity ($M) High
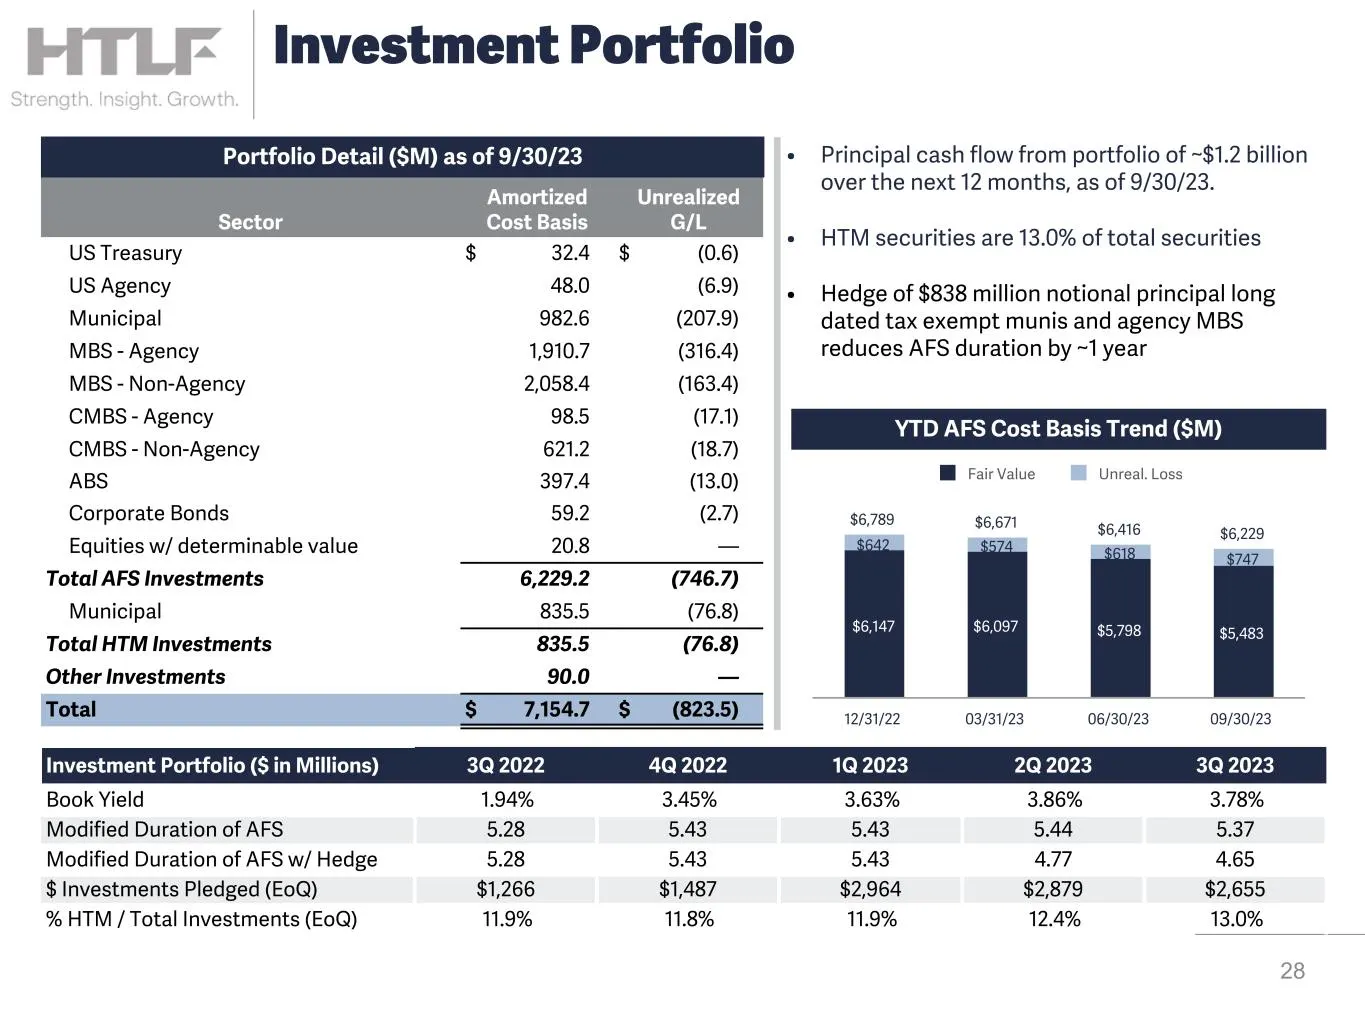
Slide 28: Investment Portfolio
Sector Amortized Cost Basis Unrealized G/L US Treasury $ 32.4 $ (0.6) US Agency 48.0 (6.9) Municipal 982.6 (207.9) MBS - Agency 1,910.7 (316.4) MBS - Non-Agency 2,058.4 (163.4) CMBS - Agency 98.5 (17.1) CMBS - Non-Agency 621.2 (18.7) ABS 397.4 (13.0) Corporate Bonds 59.2 (2.7) Equities w/ determinab
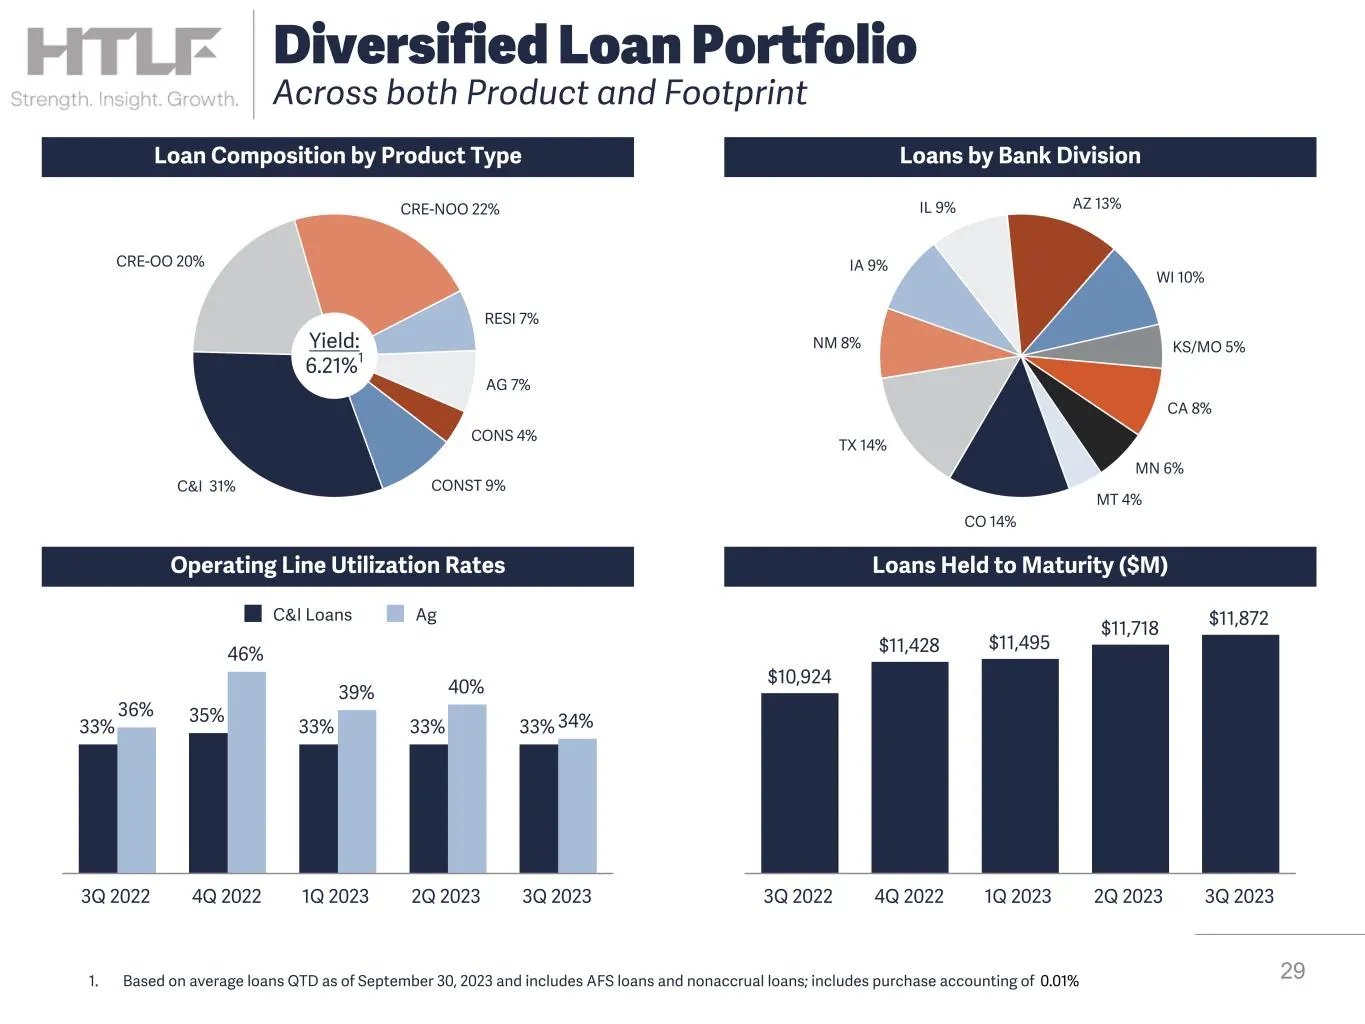
Slide 29: Diversified Loan Portfolio Across both Product and Footprint
Loan Composition by Product Type Loans by Bank Division Loans Held to Maturity ($M)Operating Line Utilization Rates C&I 31% CRE-OO 20% CRE-NOO 22% RESI 7% AG 7% CONS 4% CONST 9% Yield: 6.21%1 CO 14% TX 14% NM 8% IA 9% IL 9% AZ 13% WI 10% KS/MO 5% CA 8% MN 6% MT 4% 33% 35% 33% 33% 33% 36% 46% 39% 40%
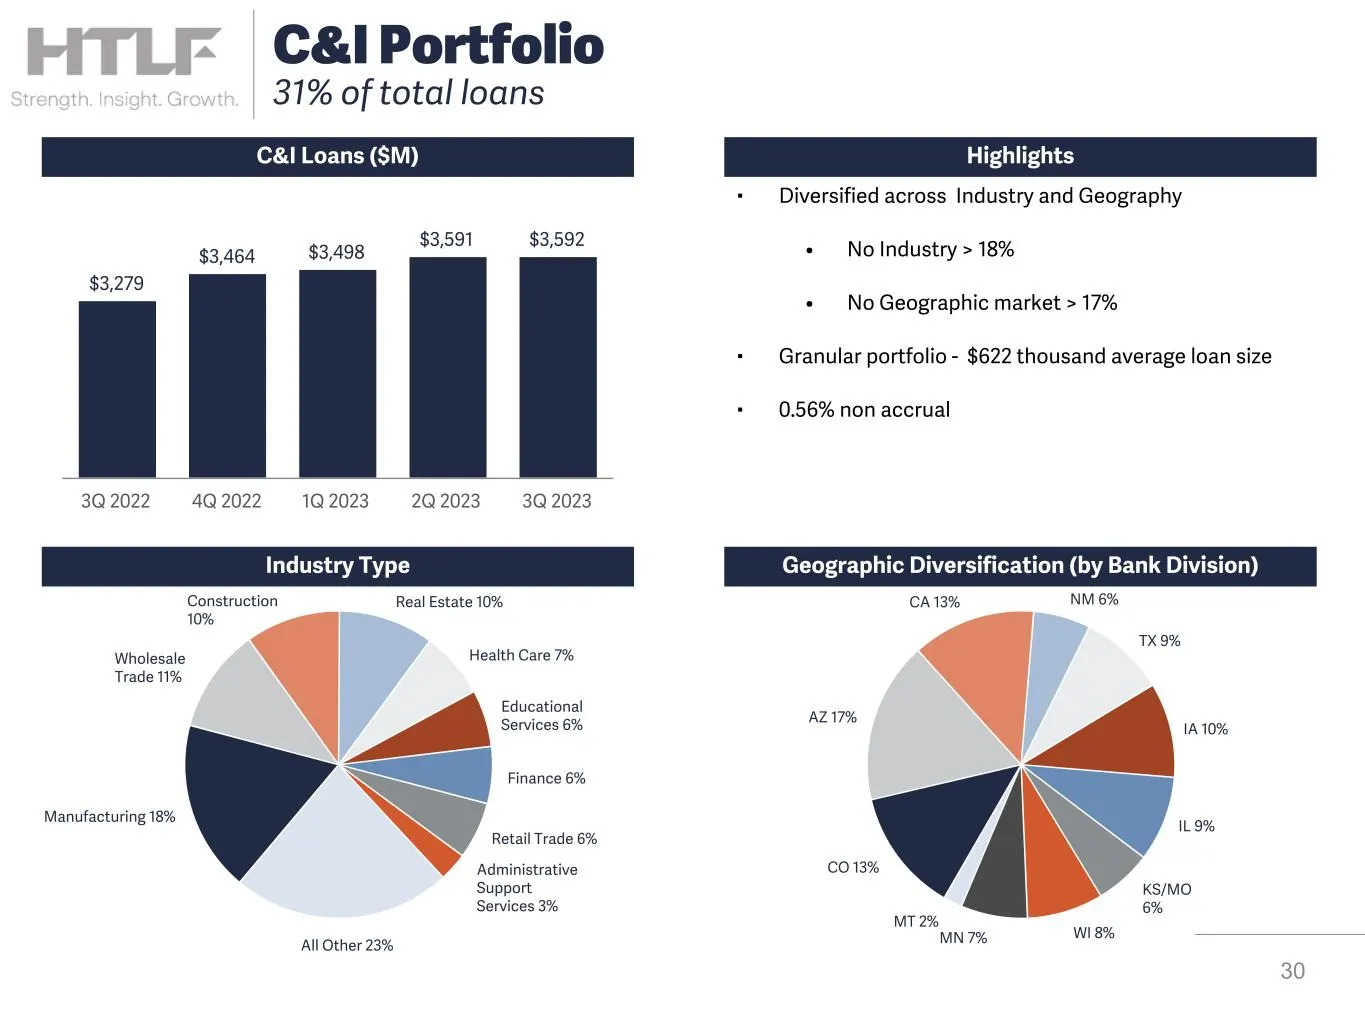
Slide 30: C&I Portfolio
Manufacturing 18% Wholesale Trade 11% Construction 10% Real Estate 10% Health Care 7% Educational Services 6% Finance 6% Retail Trade 6% Administrative Support Services 3% All Other 23% ▪ Diversified across Industry and Geography • No Industry > 18% • No Geographic market > 17% ▪ Granular portfolio
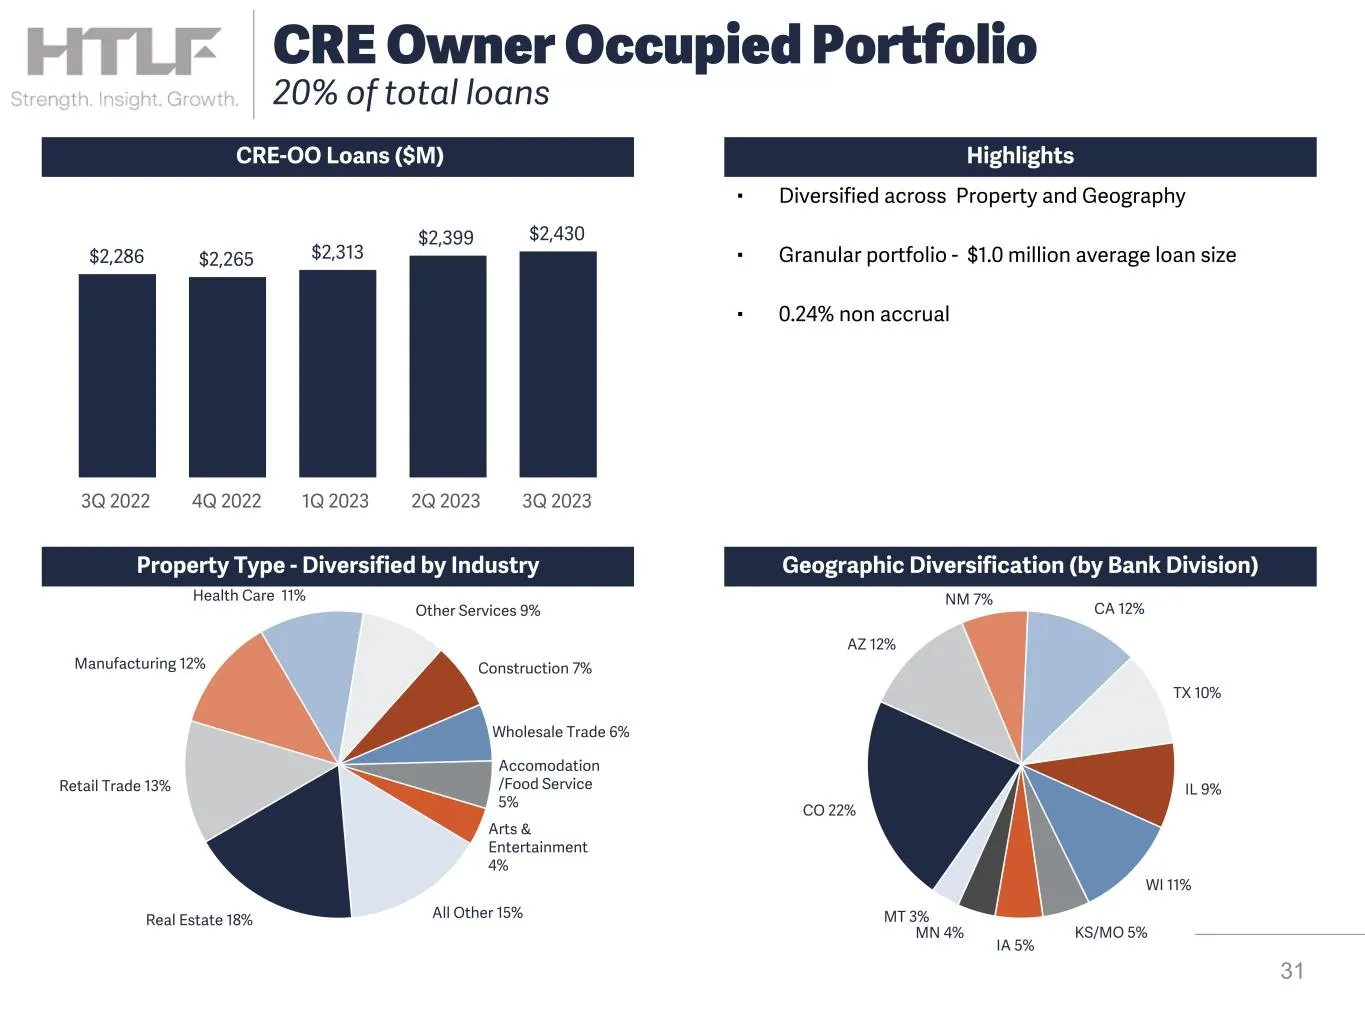
Slide 31: CRE Owner Occupied Portfolio
CO 22% AZ 12% NM 7% CA 12% TX 10% IL 9% WI 11% KS/MO 5% IA 5% MN 4% MT 3%Real Estate 18% Retail Trade 13% Manufacturing 12% Health Care 11% Other Services 9% Construction 7% Wholesale Trade 6% Accomodation /Food Service 5% Arts & Entertainment 4% All Other 15% ▪ Diversified across Property and Geogr
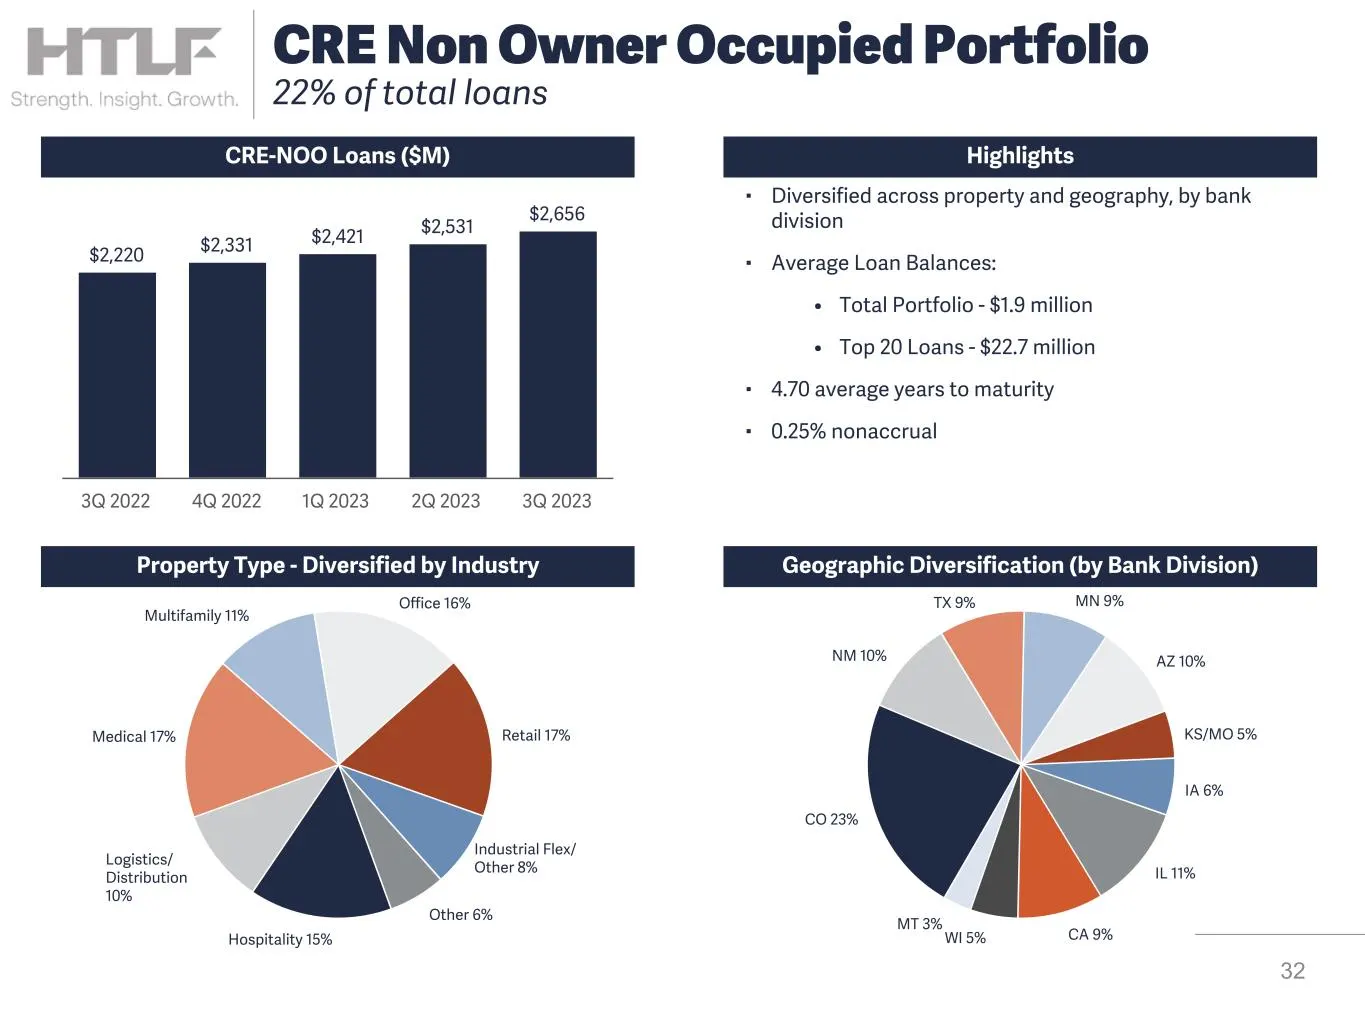
Slide 32: CRE Non Owner Occupied Portfolio
Highlights Hospitality 15% Logistics/ Distribution 10% Medical 17% Multifamily 11% Office 16% Retail 17% Industrial Flex/ Other 8% Other 6% CO 23% NM 10% TX 9% MN 9% AZ 10% KS/MO 5% IA 6% IL 11% CA 9%WI 5% MT 3% ▪ Diversified across property and geography, by bank division ▪ Average Loan Balances: •
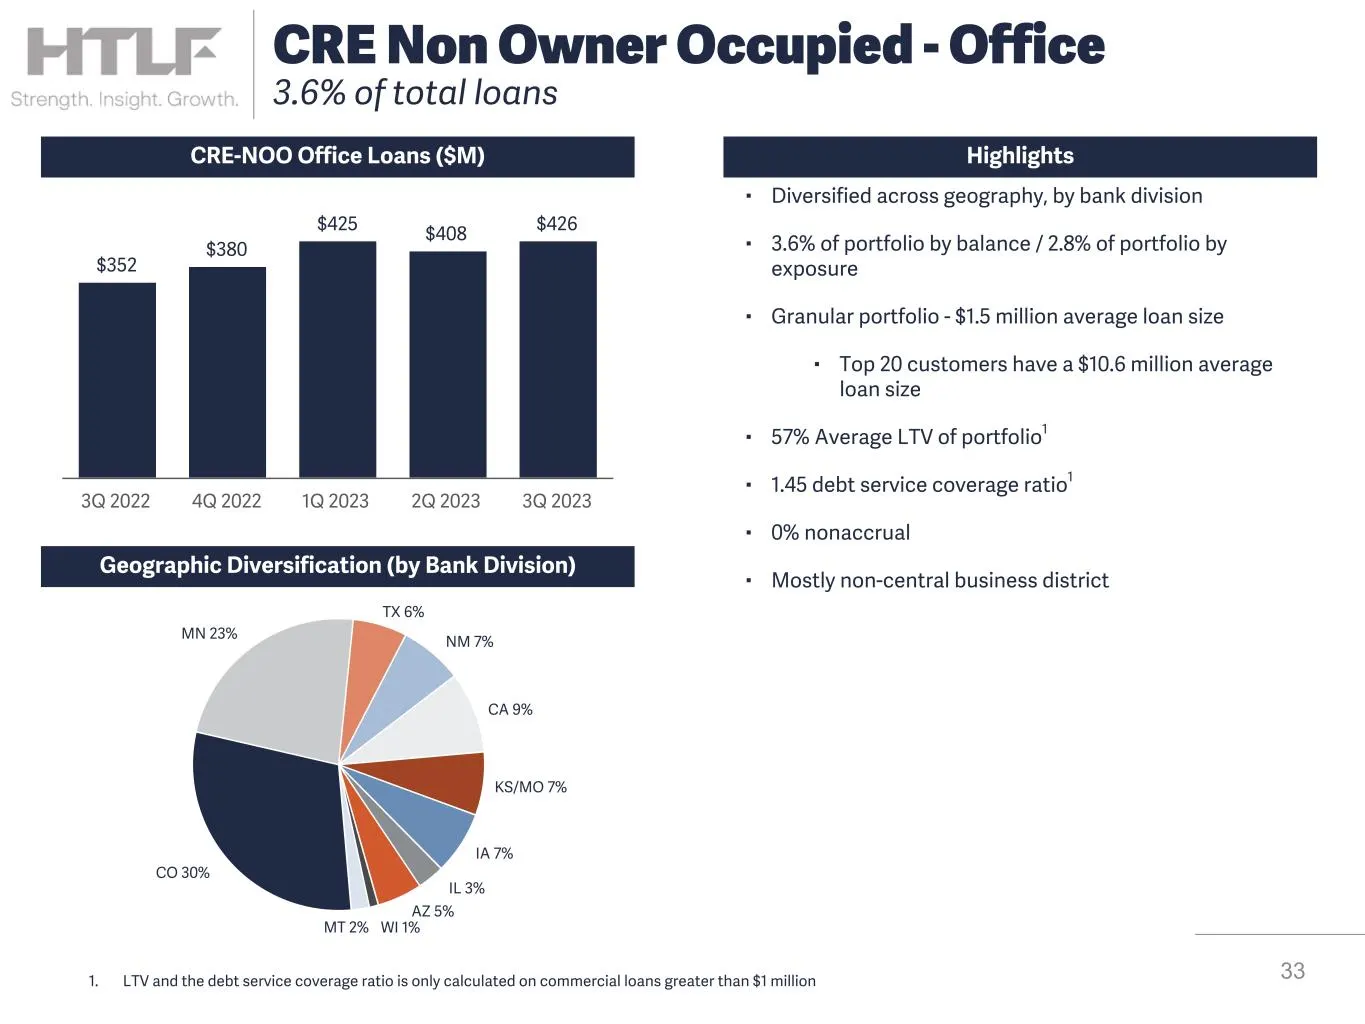
Slide 33: CRE Non Owner Occupied - Office
CRE-NOO Office Loans ($M) Geographic Diversification (by Bank Division) $352 $380 $425 $408 $426 3Q 2022 4Q 2022 1Q 2023 2Q 2023 3Q 2023 33 CRE Non Owner Occupied - Office 3.6% of total loans Highlights 1. LTV and the debt service coverage ratio is only calculated on commercial loans greater than $1
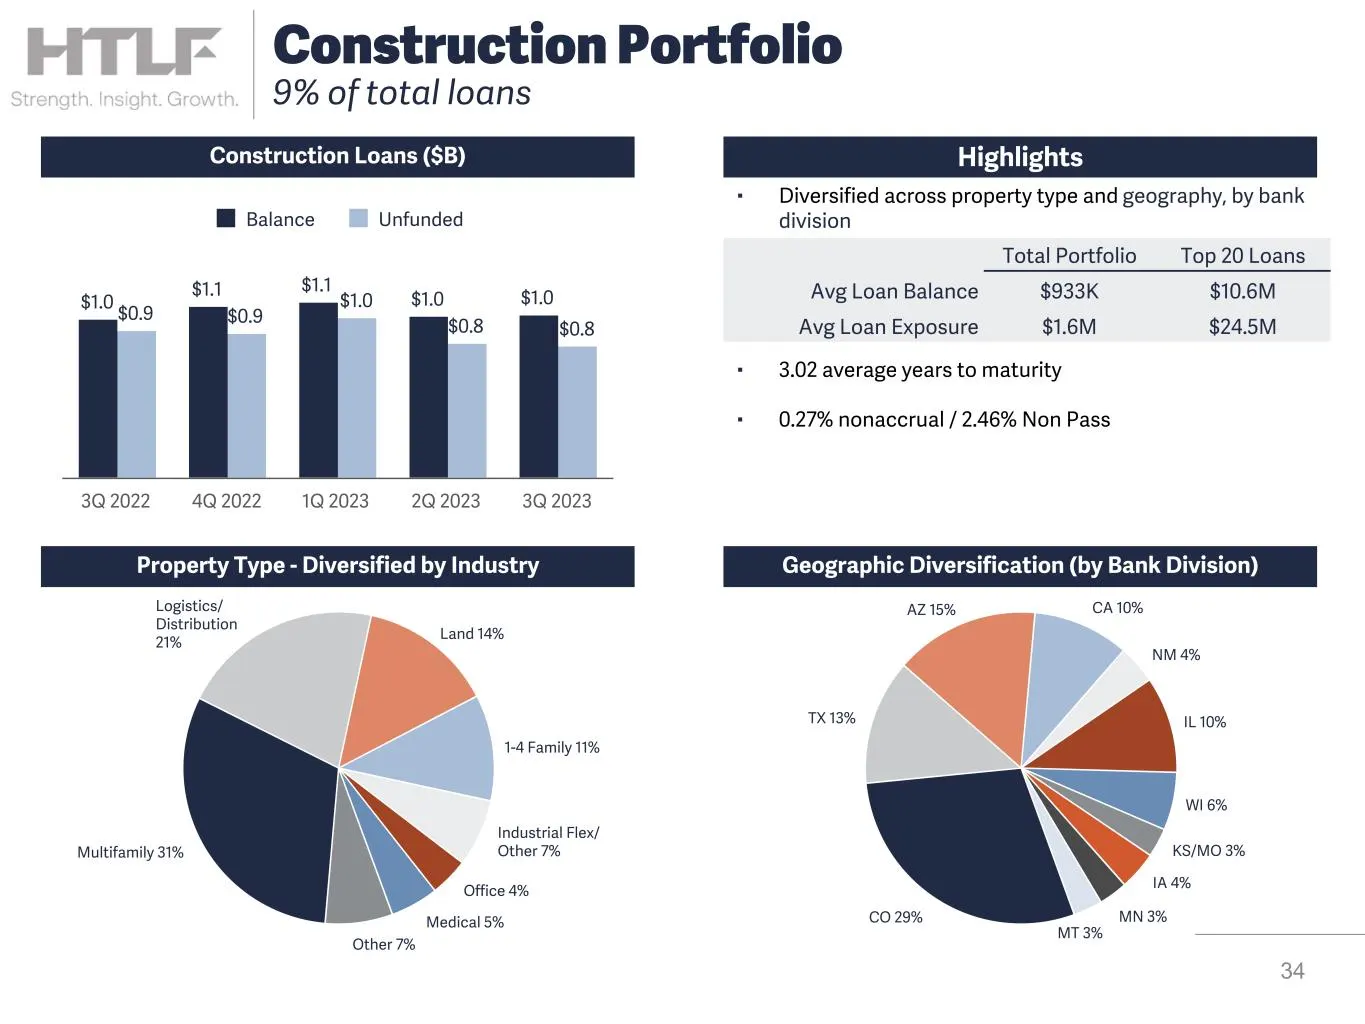
Slide 34: Construction Portfolio
34 Construction Portfolio 9% of total loans CO 29% TX 13% AZ 15% CA 10% NM 4% IL 10% WI 6% KS/MO 3% IA 4% MN 3% MT 3% Multifamily 31% Logistics/ Distribution 21% Land 14% 1-4 Family 11% Industrial Flex/ Other 7% Office 4% Medical 5% Other 7% ▪ Diversified across property type and geography, by bank
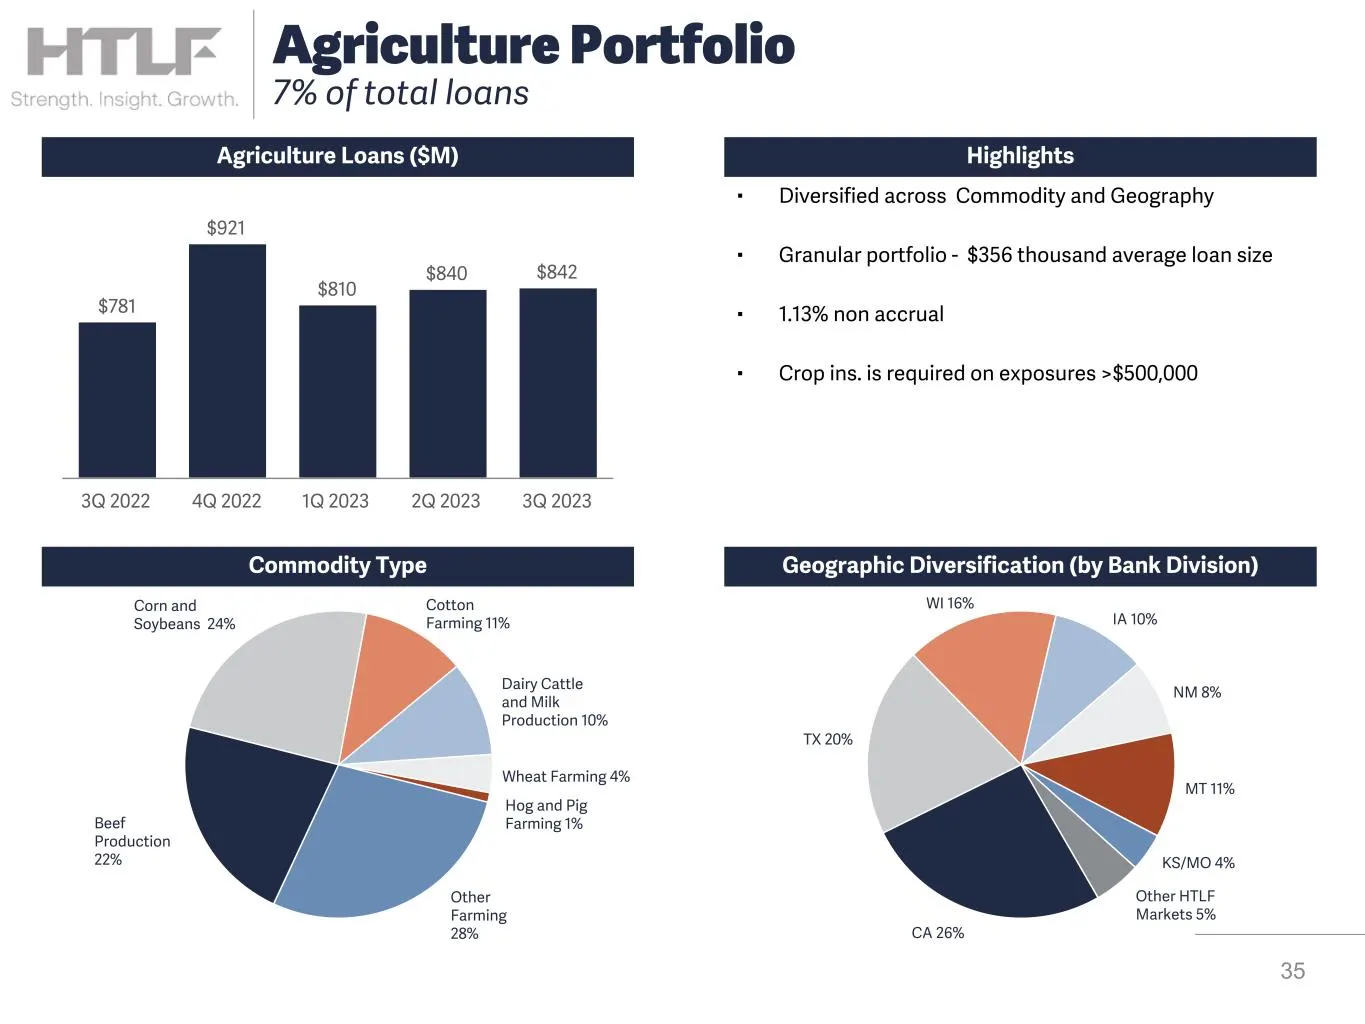
Slide 35: Agriculture Portfolio
CA 26% TX 20% WI 16% IA 10% NM 8% MT 11% KS/MO 4% Other HTLF Markets 5% ▪ Diversified across Commodity and Geography ▪ Granular portfolio - $356 thousand average loan size ▪ 1.13% non accrual ▪ Crop ins. is required on exposures >$500,000 Highlights Geographic Diversification (by Bank Division) Beef
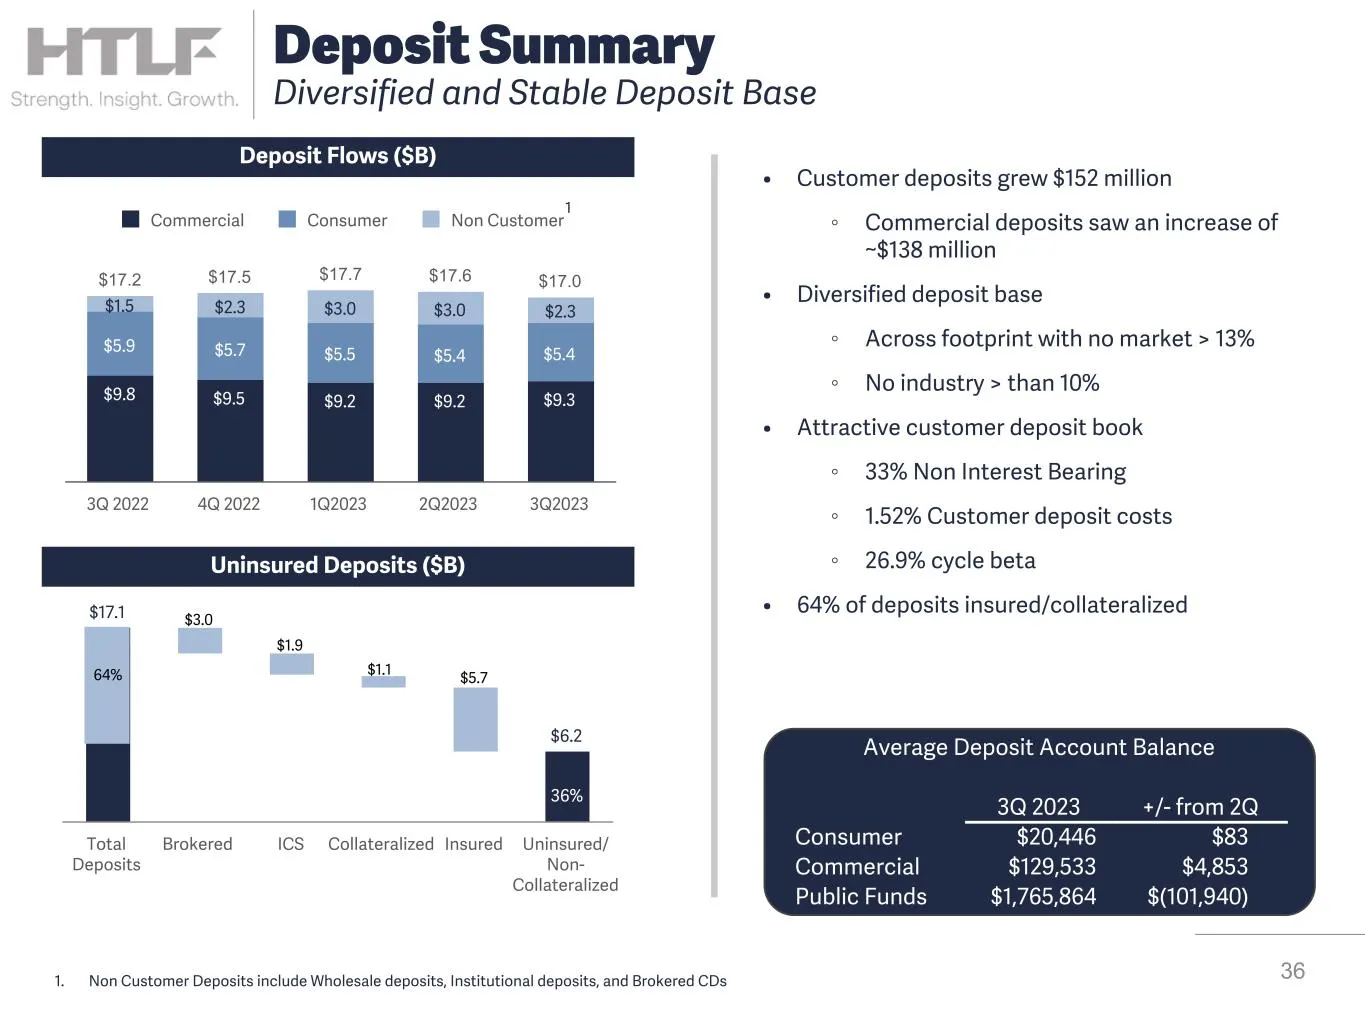
Slide 36: Diversified and Stable Deposit Base
Deposit Flows ($B) 36 Deposit Summary Diversified and Stable Deposit Base Uninsured Deposits ($B) $17.1 $6.2 36% Total Deposits Brokered ICS Collateralized Insured Uninsured/ Non- Collateralized $3.0 64% $1.9 $1.1 $5.7 $17.2 $17.5 $17.7 $17.6 $17.0 $9.8 $9.5 $9.2 $9.2 $9.3 $5.9 $5.7 $5.5 $5.4 $5.4 $
Slide 37: Deposit Diversification
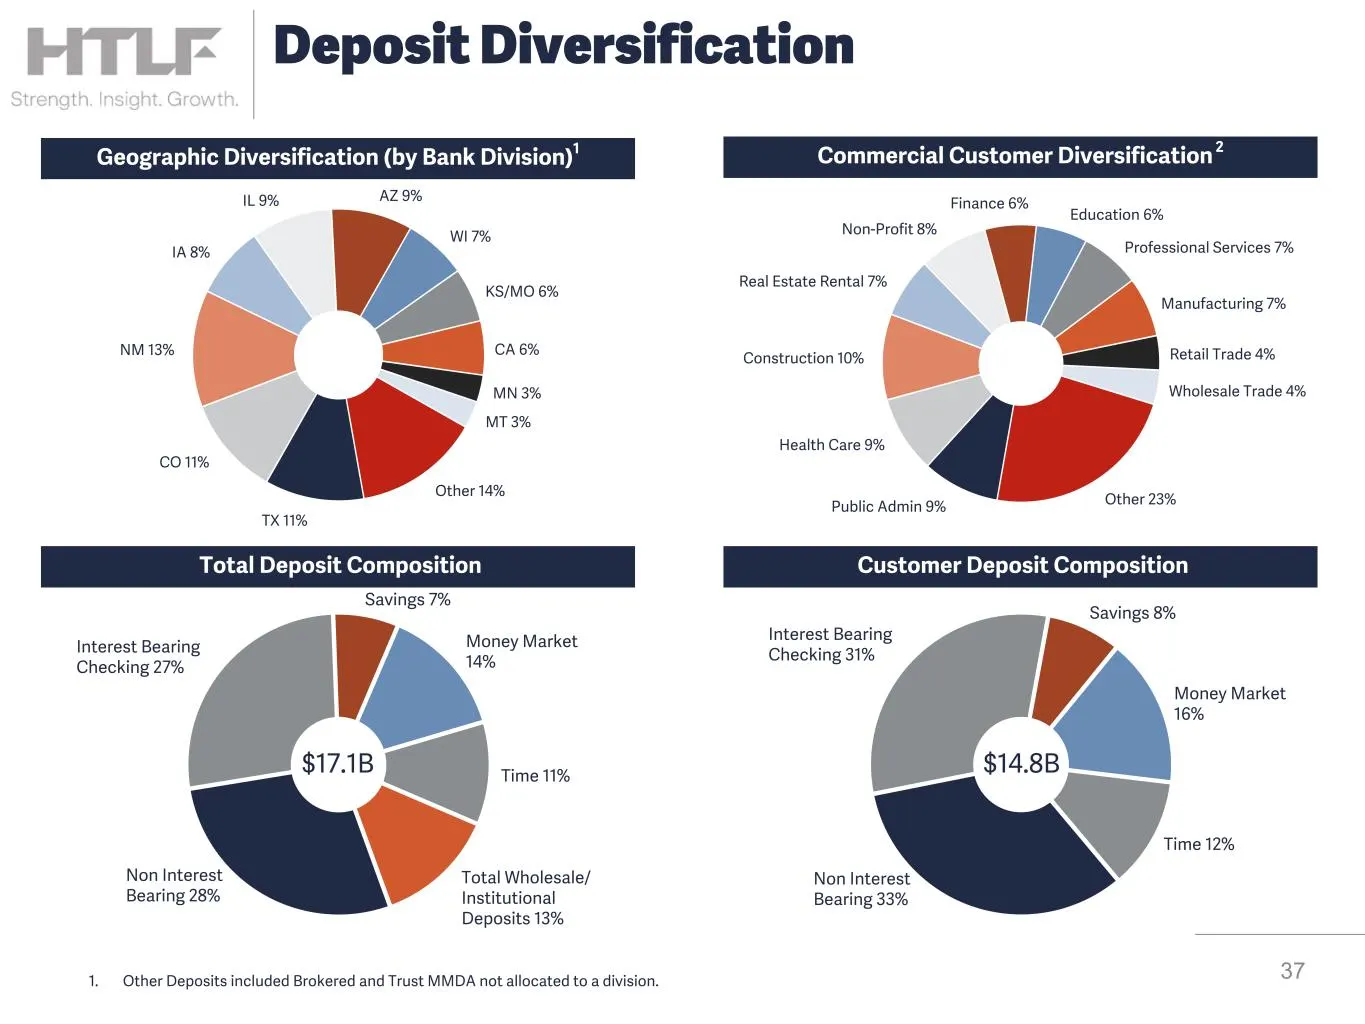
Non Interest Bearing 28% Interest Bearing Checking 27% Savings 7% Money Market 14% Time 11% Total Wholesale/ Institutional Deposits 13% Geographic Diversification (by Bank Division)1 Commercial Customer Diversification 2 37 Deposit Diversification Total Deposit Composition Public Admin 9% Health Car
Slide 38: Consolidated Capital Ratios Exceeding Well Capitalized Levels
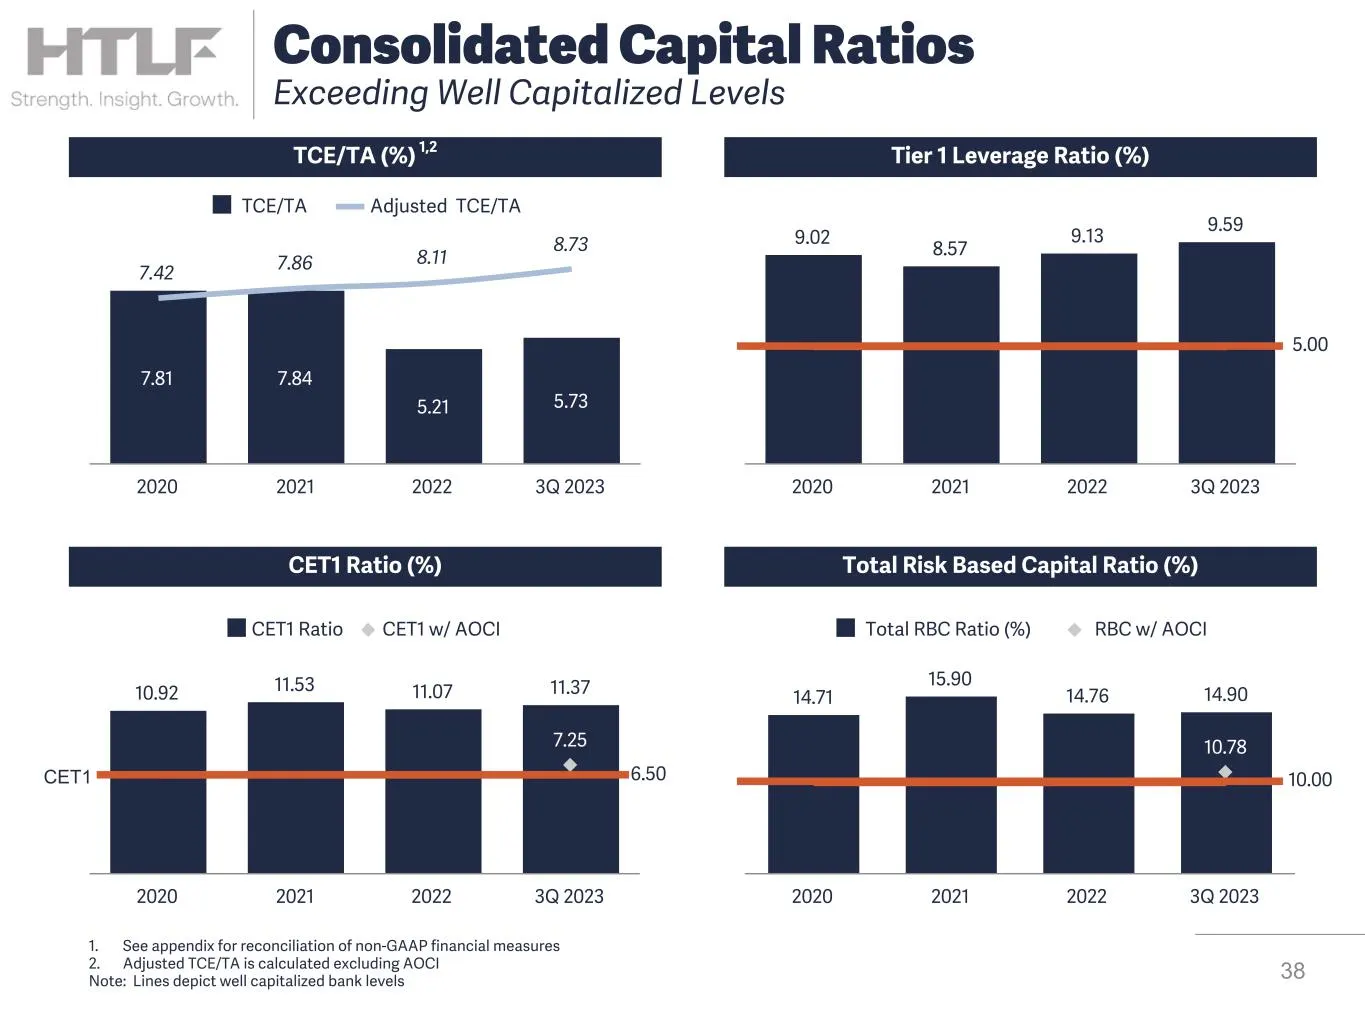
10.92 11.53 11.07 11.37 7.25 CET1 Ratio CET1 w/ AOCI 2020 2021 2022 3Q 2023 CET1 6.50 TCE/TA (%) 1,2 Tier 1 Leverage Ratio (%) CET1 Ratio (%) Total Risk Based Capital Ratio (%) 7.81 7.84 5.21 5.73 7.42 7.86 8.11 8.73 TCE/TA Adjusted TCE/TA 2020 2021 2022 3Q 2023 9.02 8.57 9.13 9.59 5.00 2020 2021 20
Slide 39: Summary Asset Quality
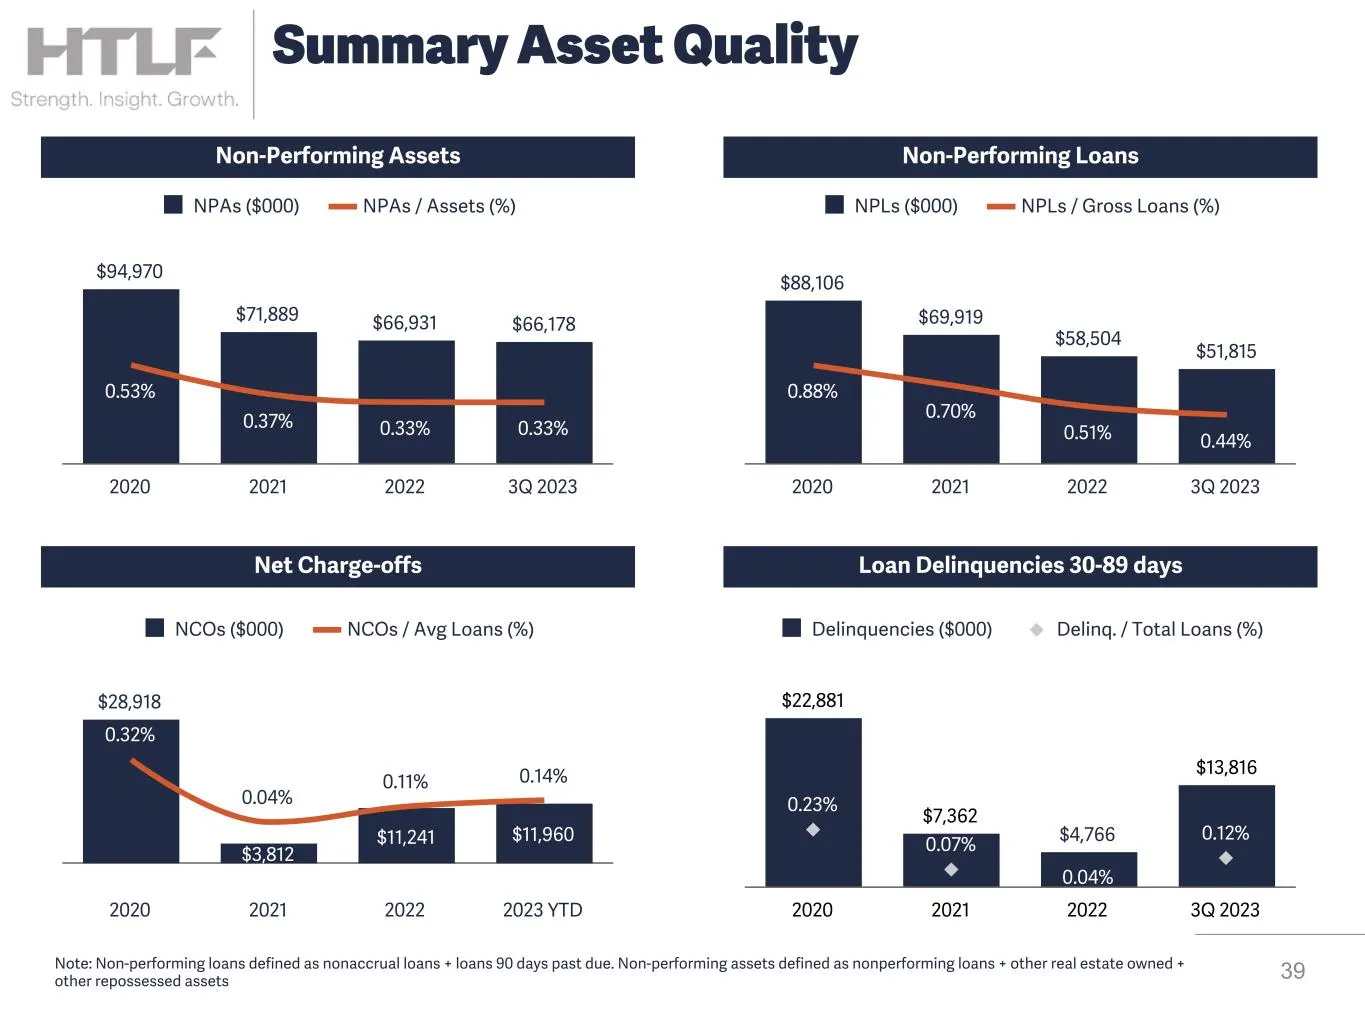
$22,881 $7,362 $4,766 $13,816 0.23% 0.07% 0.04% 0.12% Delinquencies ($000) Delinq. / Total Loans (%) 2020 2021 2022 3Q 2023 Non-Performing Assets Non-Performing Loans Net Charge-offs Loan Delinquencies 30-89 days $94,970 $71,889 $66,931 $66,178 0.53% 0.37% 0.33% 0.33% NPAs ($000) NPAs / Assets (%) 2
Slide 40: Allowance for Credit Related Losses
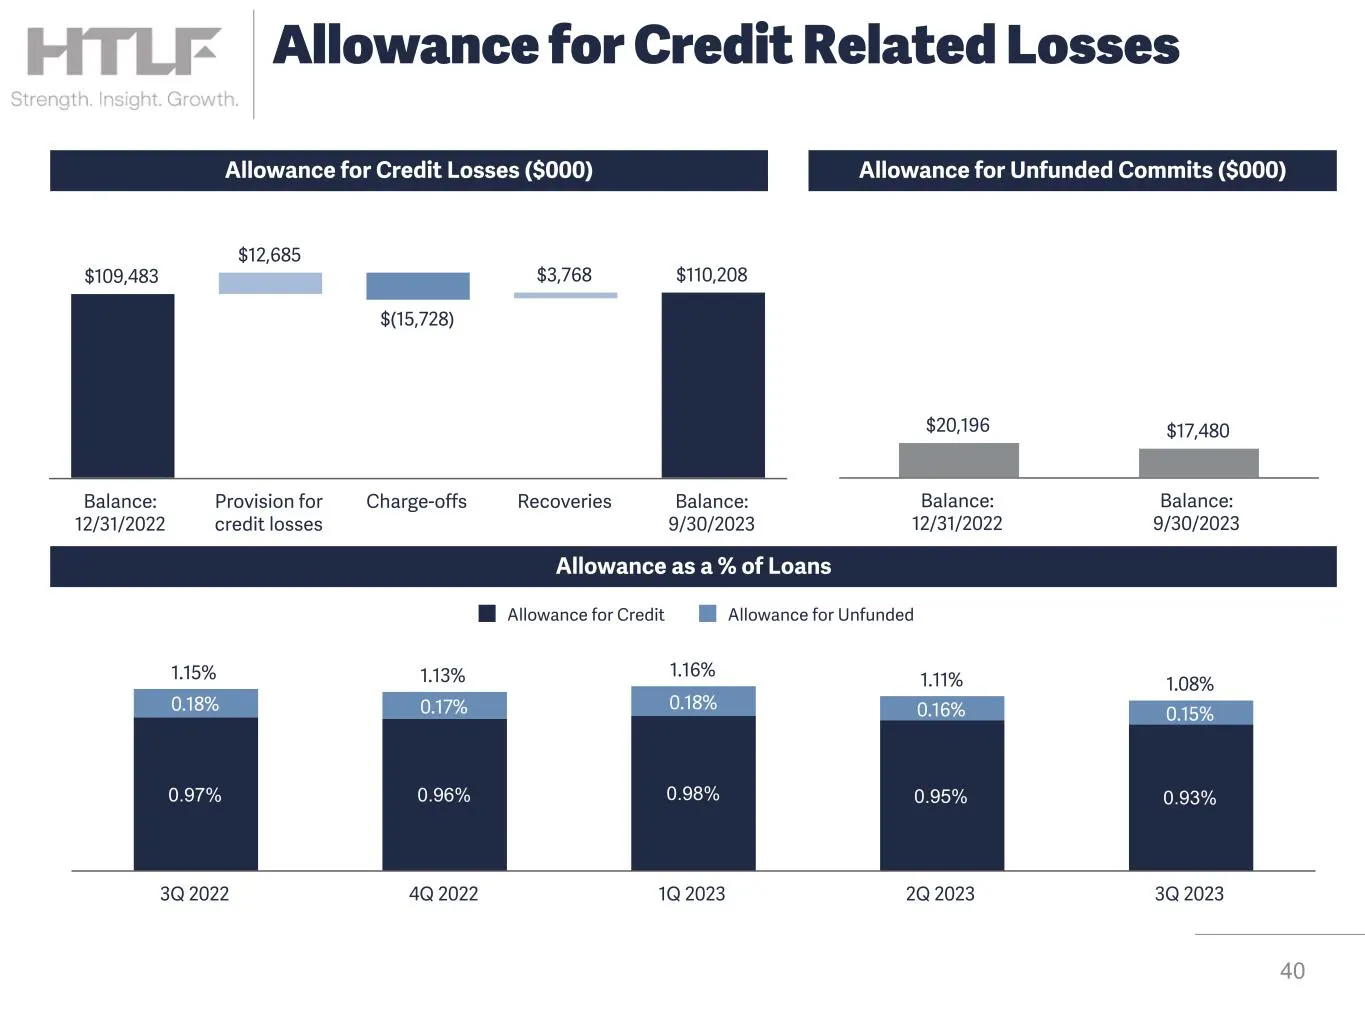
1.15% 1.13% 1.16% 1.11% 1.08% 0.97% 0.96% 0.98% 0.95% 0.93% 0.18% 0.17% 0.18% 0.16% 0.15% Allowance for Credit Allowance for Unfunded 3Q 2022 4Q 2022 1Q 2023 2Q 2023 3Q 2023 $20,196 $17,480 Balance: 12/31/2022 Balance: 9/30/2023 Allowance as a % of Loans Allowance for Credit Losses ($000) Allowance
Slide 41: Mission, Vision and Values
41 Integrity Community Accountability Excellence Always do the right thing - be honest and open Engage your community and your team - support one another and unlock the potential around you Own the opportunity and the outcome - keep your promises, follow through and follow up Exceed expectations - e
Slide 42: ESG Highlights
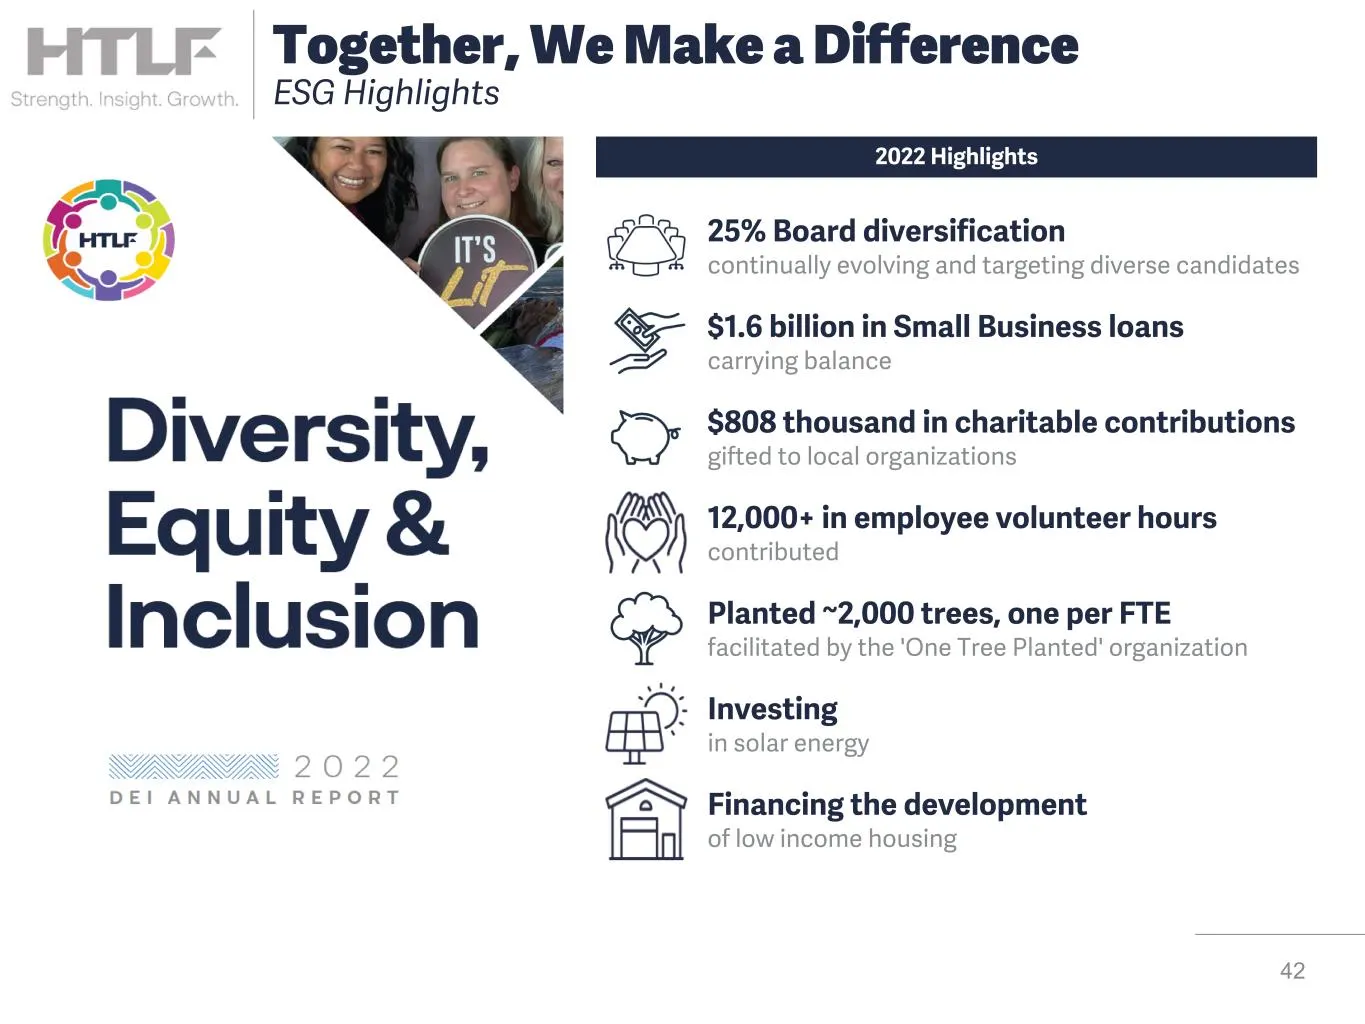
42 2022 Highlights 25% Board diversification continually evolving and targeting diverse candidates $808 thousand in charitable contributions gifted to local organizations $1.6 billion in Small Business loans carrying balance Planted ~2,000 trees, one per FTE facilitated by the 'One Tree Planted' org
Slide 43: Contact Information
HITLE Contact Information FTLF FHTLF 563.587.4164 MFlood@htif.com Strength. Bruce K. Lee Strength. Bryan R. McKeag Insight President and CEO Insight EVP, Chief Financial Officer Growth. 563.587.4176 office Growth. 5635871904 office 419,3511274 cell 920,284,0732 cell BLee@htlf.com BMcKeag@htlf.com St
Slide 44: Together We Are HTLF
i Bank of Py Atizona Qy Bake os she Pes Barksis ILLINOIS aes aciisonotirreunx CITYWIDE BANKS, elise ee Es Rocky MINNESOTA Sota PREMIER GQ fieeeeain WISCONSIN SS eemavnrom -NEWMEXICO ire nank Bank ___ BANK & TRUST" TAC 2 amen emereTrerl scent HT Bank acleen tiie + Together We Are

Slide 45: Non-GAAP Reconciliations
45 Non-GAAP Reconciliations
Slide 46: Non-GAAP measure definitions
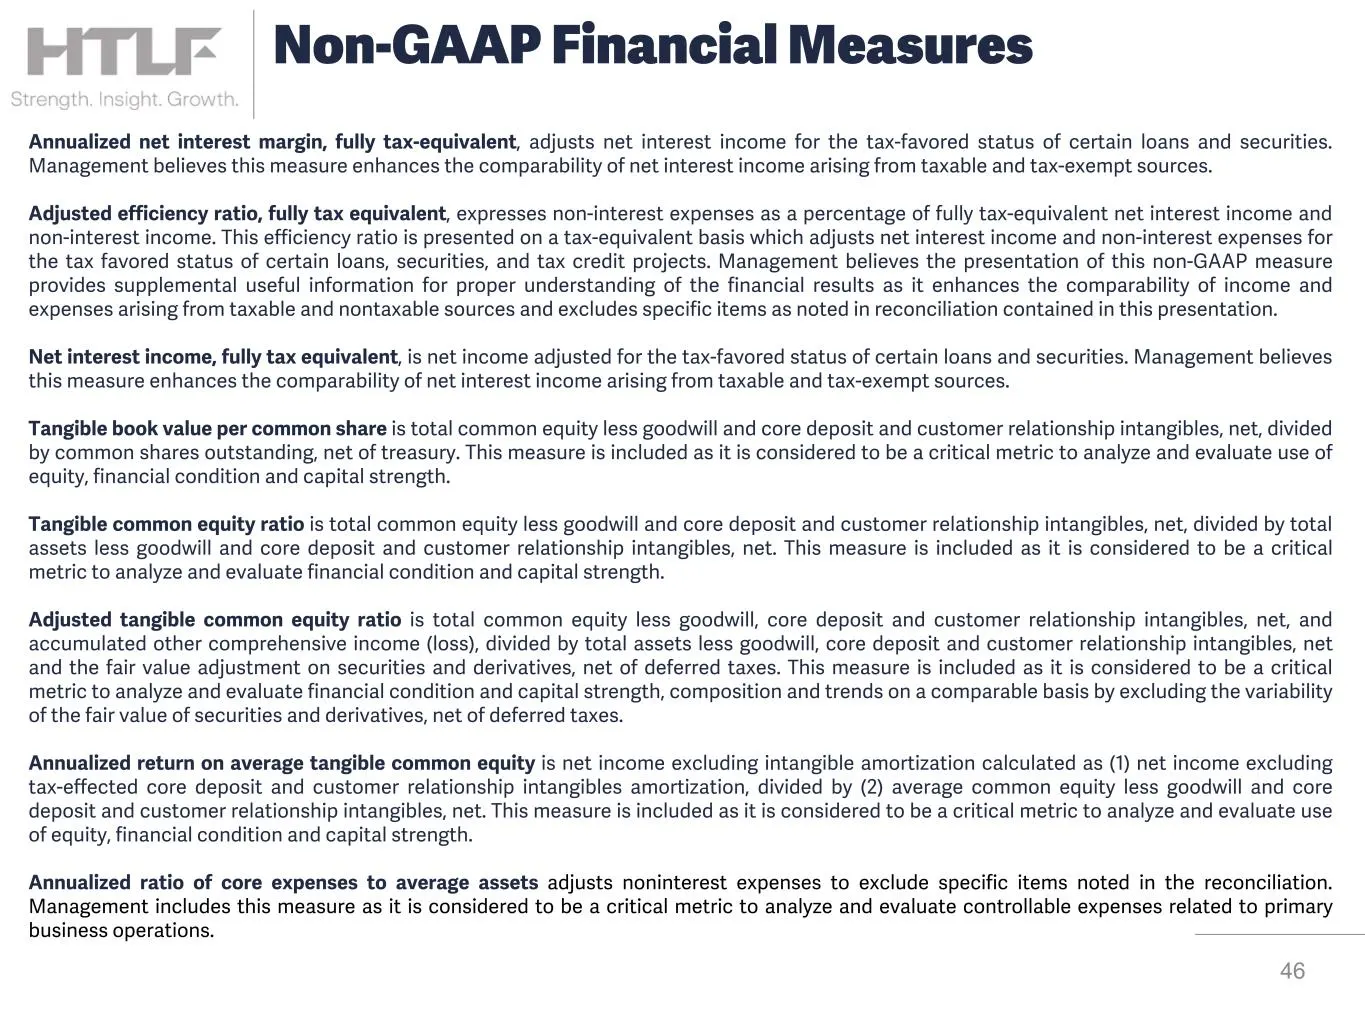
Annualized net interest margin, fully tax-equivalent, adjusts net interest income for the tax-favored status of certain loans and securities. Management believes this measure enhances the comparability of net interest income arising from taxable and tax-exempt sources. Adjusted efficiency ratio, ful
Slide 47: Reconciliation of Tangible Book Value and Tangible Common Equity Ratio
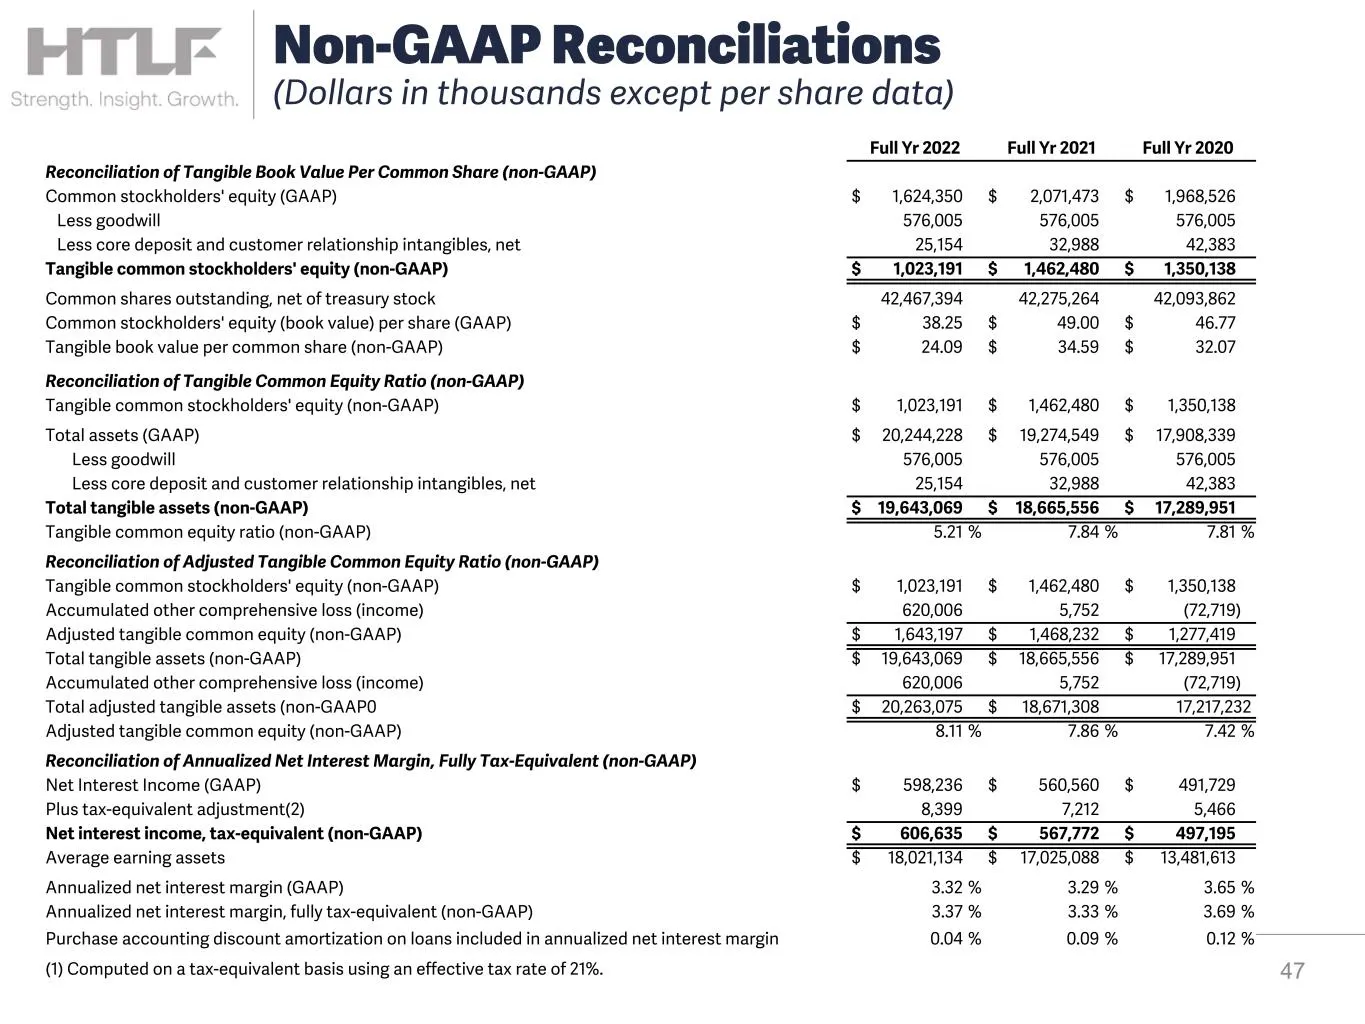
Full Yr 2022 Full Yr 2021 Full Yr 2020 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common stockholders' equity (GAAP) $ 1,624,350 $ 2,071,473 $ 1,968,526 Less goodwill 576,005 576,005 576,005 Less core deposit and customer relationship intangibles, net 25,154 32,988 42,383 Tang
Slide 48: Reconciliation of Adjusted Efficiency Ratio
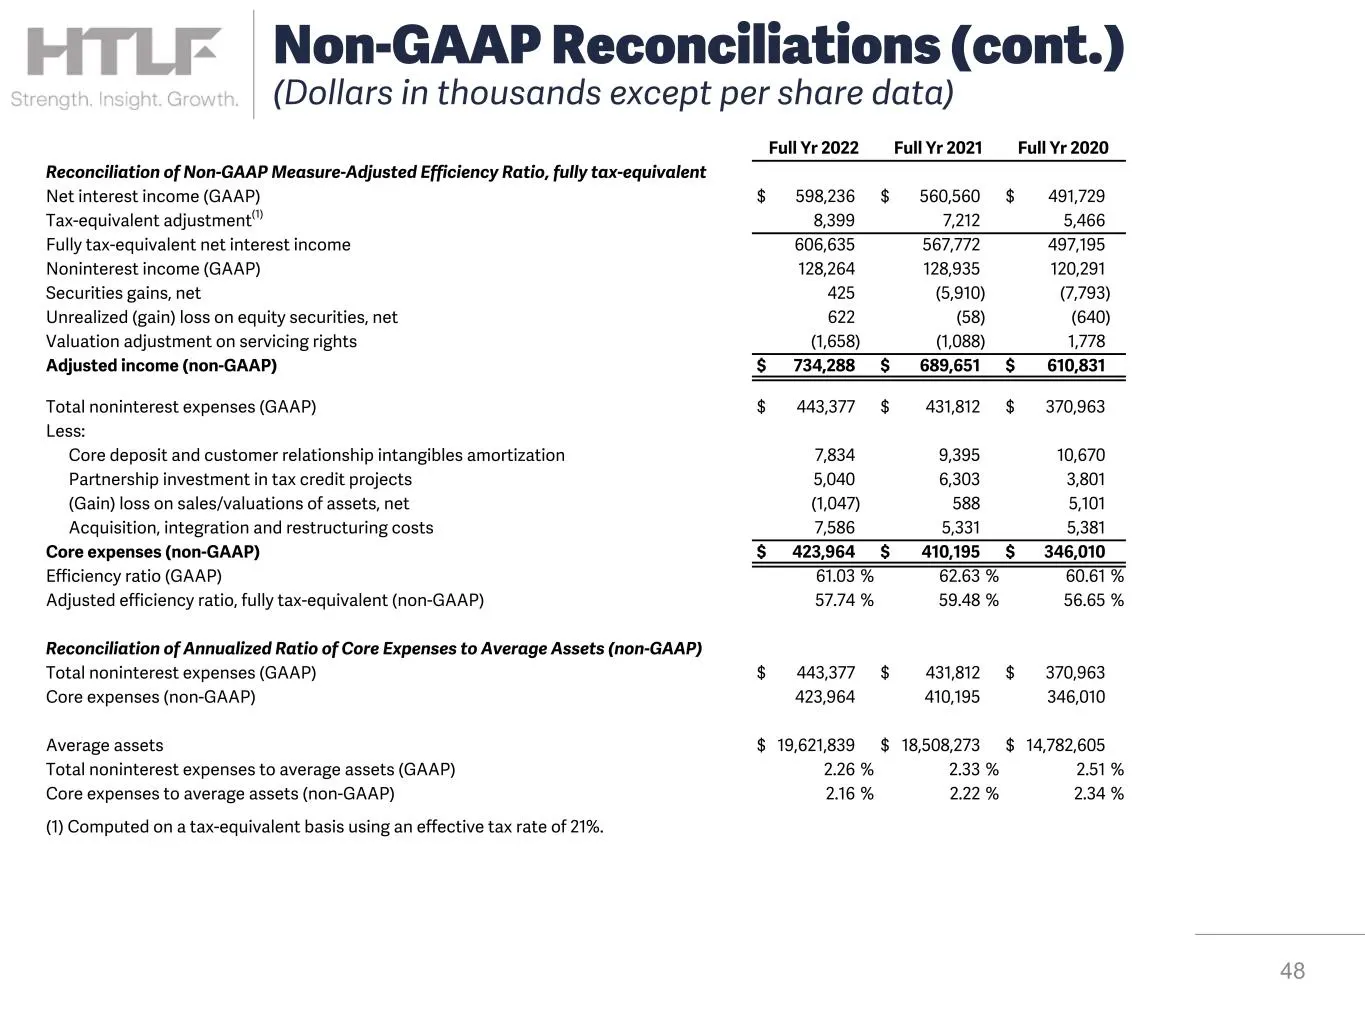
Full Yr 2022 Full Yr 2021 Full Yr 2020 Reconciliation of Non-GAAP Measure-Adjusted Efficiency Ratio, fully tax-equivalent Net interest income (GAAP) $ 598,236 $ 560,560 $ 491,729 Tax-equivalent adjustment(1) 8,399 7,212 5,466 Fully tax-equivalent net interest income 606,635 567,772 497,195 Nonintere
Slide 49: Non-GAAP Reconciliations (cont.)
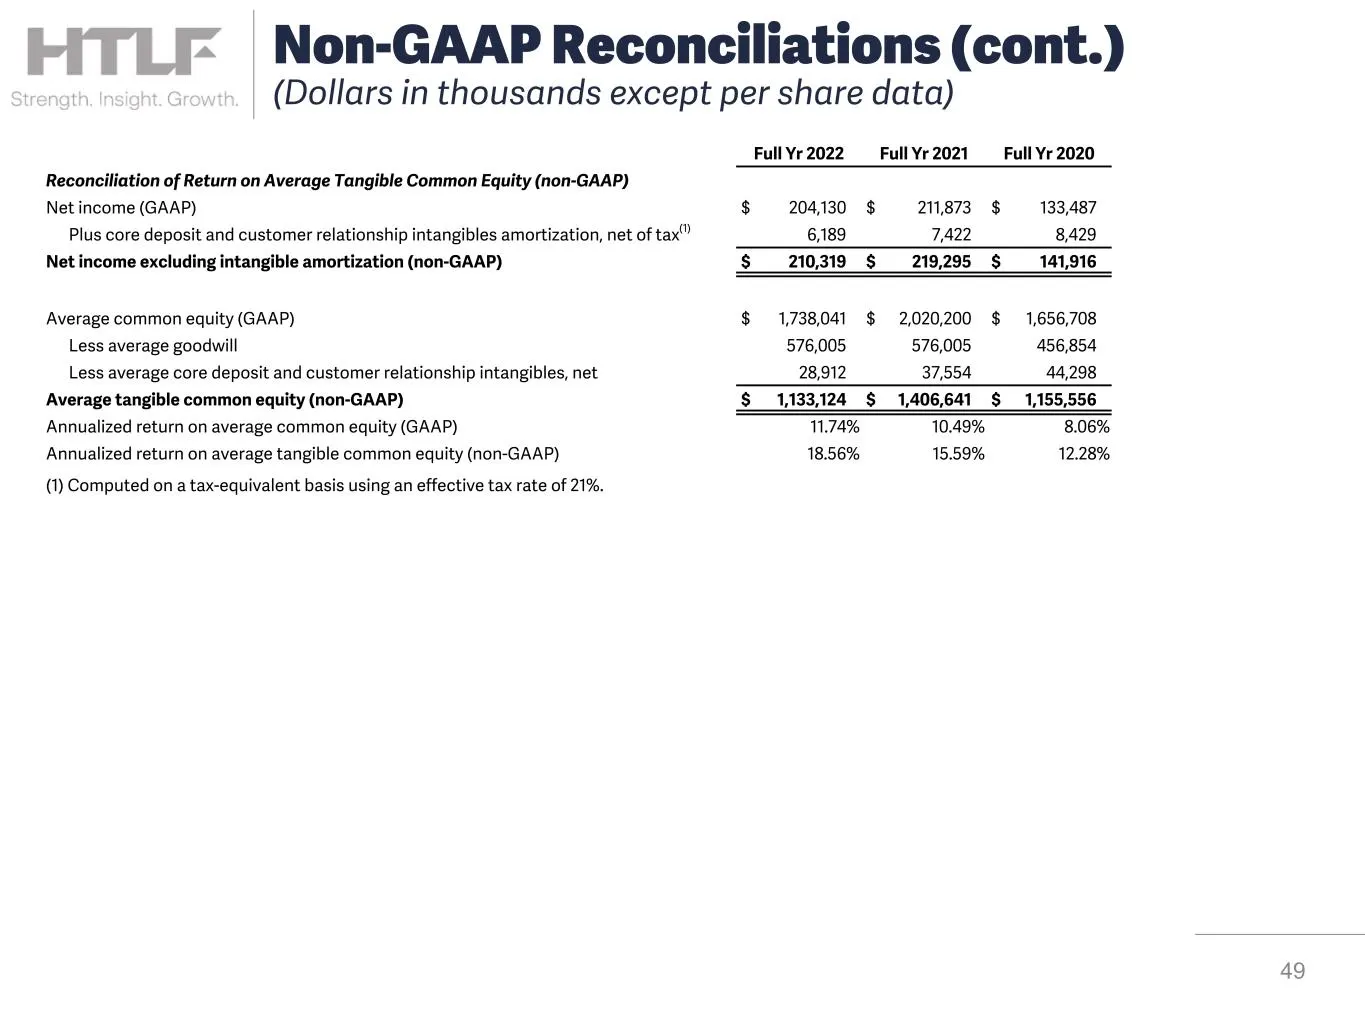
Non-GAAP Reconciliations (cont.) (Dollars in thousands except per share data) Full Yr 2022 Full Yr 2021 Full Yr 2020 Reconciliation of Return on Average Tangible Common Equity (non-GAAP) Net income (GAAP) $ 204,130 $ 211,873 $ 133,487 Plus core deposit and customer relationship intangibles amortizat
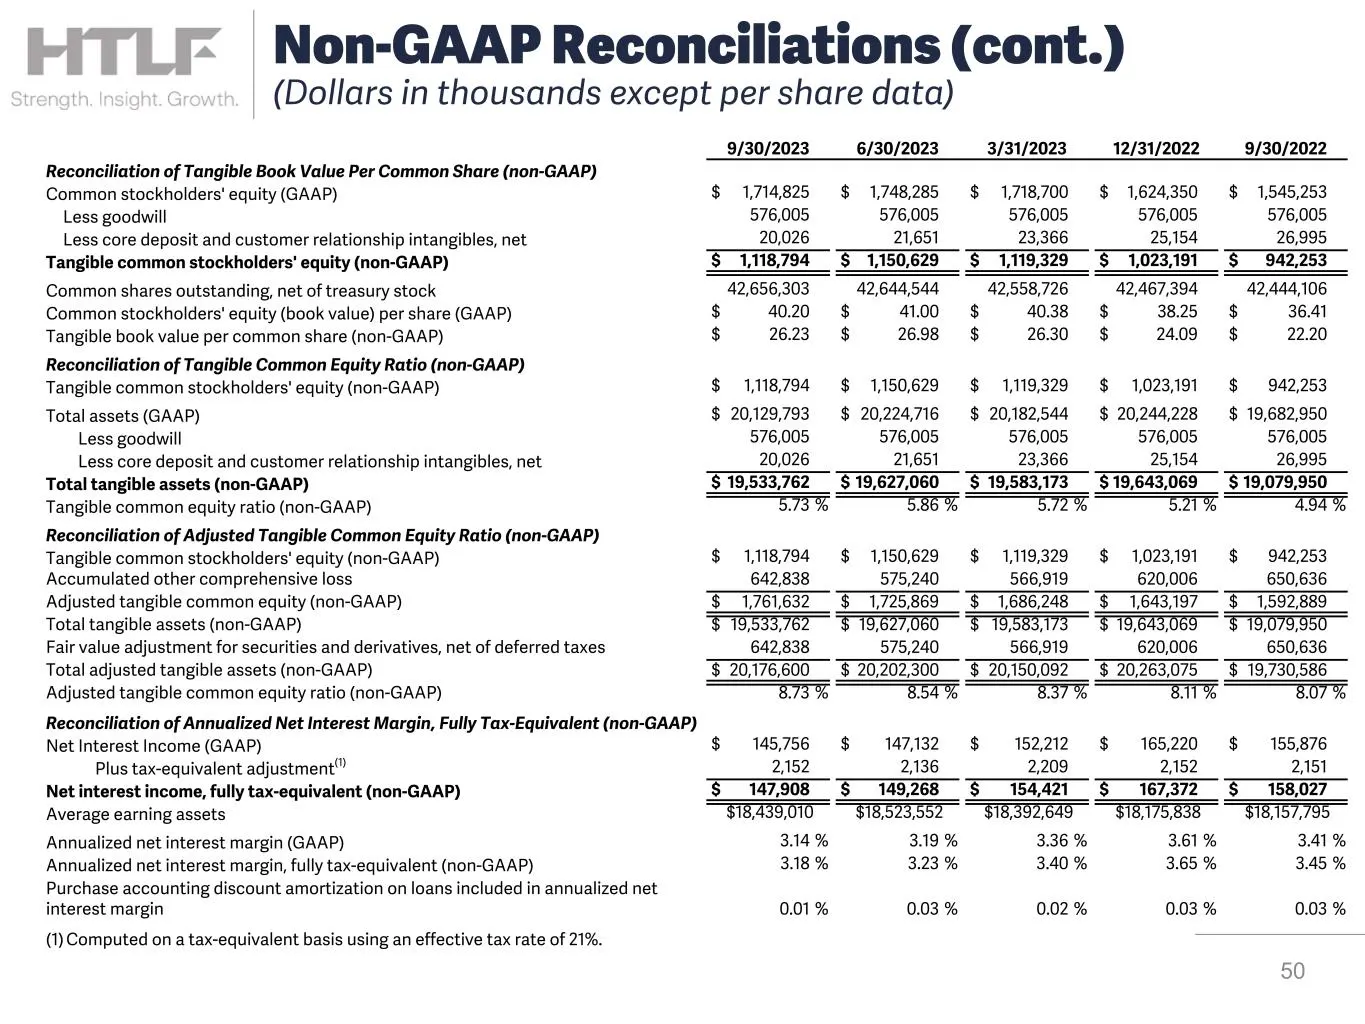
Slide 50: Reconciliation of Tangible Book Value Per Common Share
9/30/2023 6/30/2023 3/31/2023 12/31/2022 9/30/2022 Reconciliation of Tangible Book Value Per Common Share (non-GAAP) Common stockholders' equity (GAAP) $ 1,714,825 $ 1,748,285 $ 1,718,700 $ 1,624,350 $ 1,545,253 Less goodwill 576,005 576,005 576,005 576,005 576,005 Less core deposit and customer rel
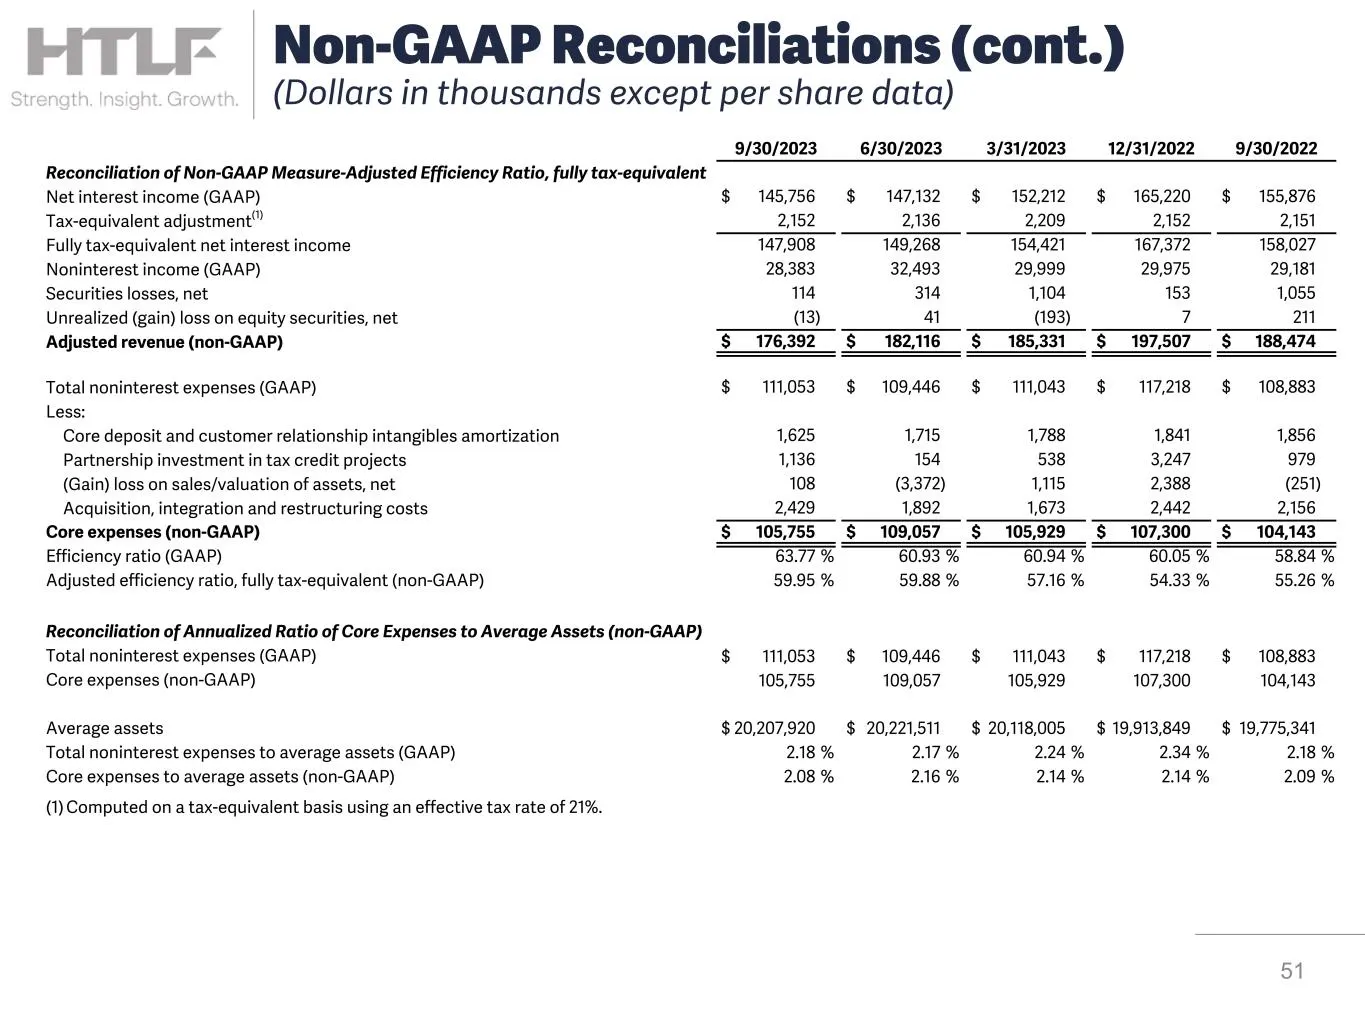
Slide 51: Reconciliation of Adjusted Efficiency Ratio, fully tax-equivalent
9/30/2023 6/30/2023 3/31/2023 12/31/2022 9/30/2022 Reconciliation of Non-GAAP Measure-Adjusted Efficiency Ratio, fully tax-equivalent Net interest income (GAAP) $ 145,756 $ 147,132 $ 152,212 $ 165,220 $ 155,876 Tax-equivalent adjustment(1) 2,152 2,136 2,209 2,152 2,151 Fully tax-equivalent net inter
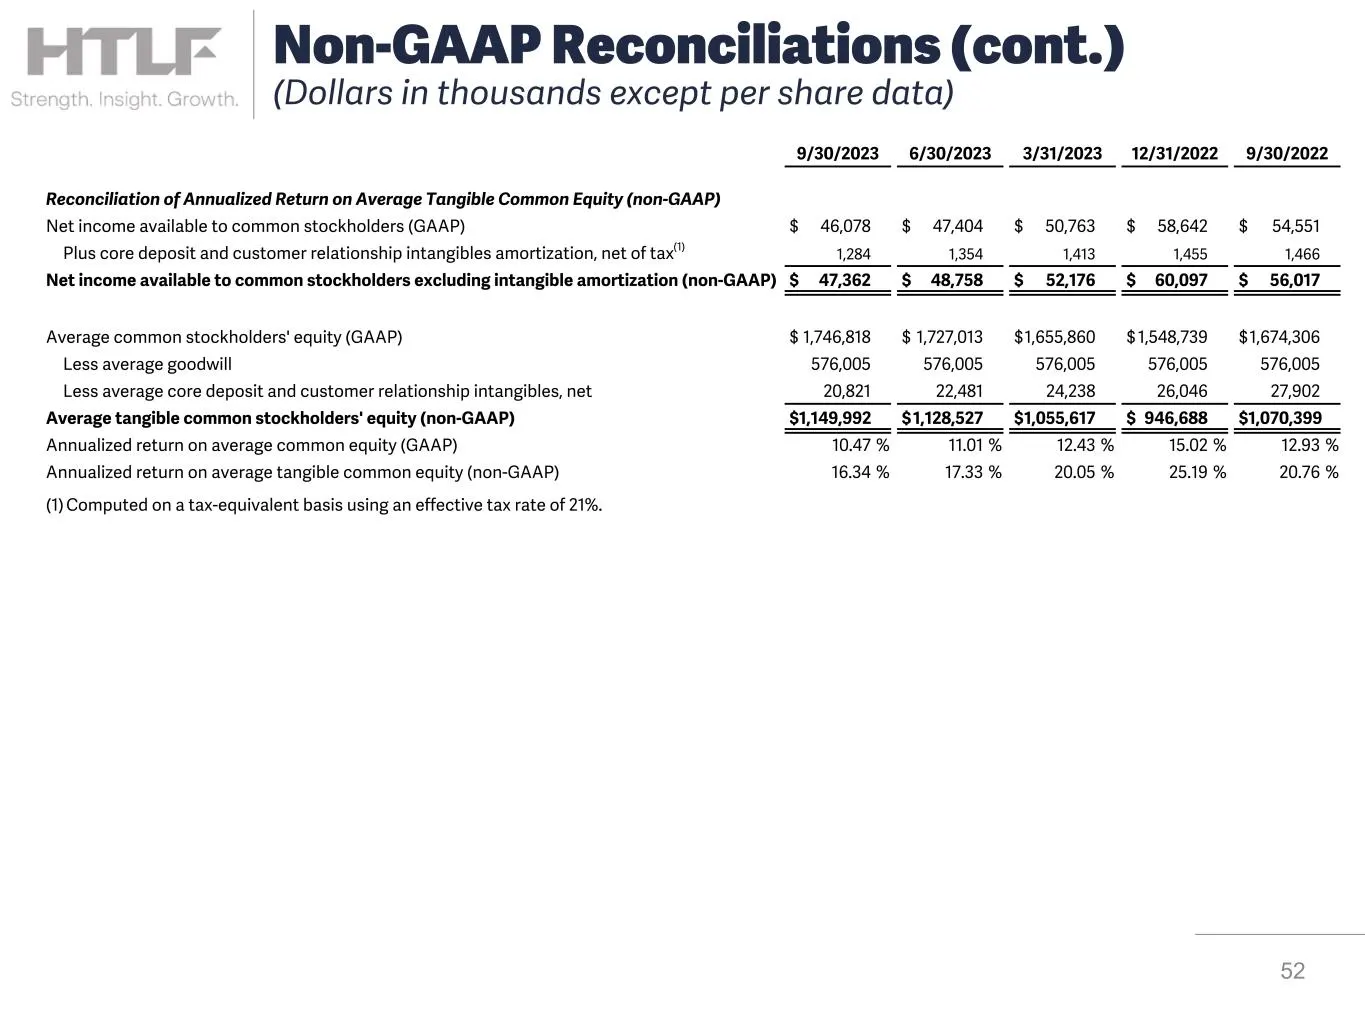
Slide 52: Reconciliation of Annualized Return on Average Tangible Common Equity
52 9/30/2023 6/30/2023 3/31/2023 12/31/2022 9/30/2022 Reconciliation of Annualized Return on Average Tangible Common Equity (non-GAAP) Net income available to common stockholders (GAAP) $ 46,078 $ 47,404 $ 50,763 $ 58,642 $ 54,551 Plus core deposit and customer relationship intangibles amortization,
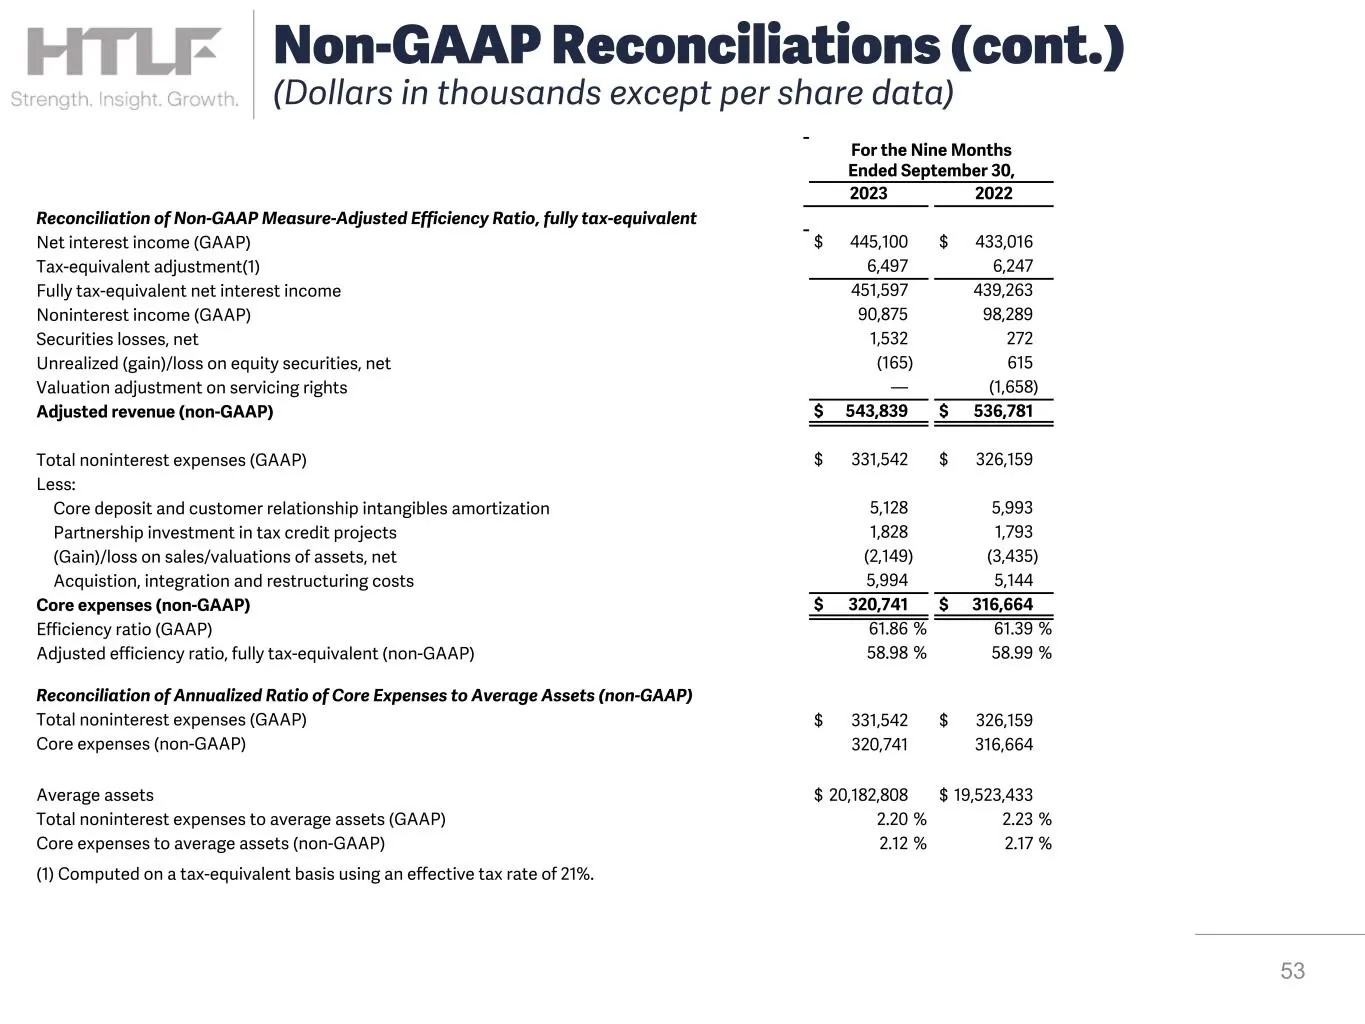
Slide 53: Reconciliation of Adjusted Efficiency Ratio, Nine Months Ended September 30
For the Nine Months Ended September 30, 2023 2022 Reconciliation of Non-GAAP Measure-Adjusted Efficiency Ratio, fully tax-equivalent Net interest income (GAAP) $ 445,100 $ 433,016 Tax-equivalent adjustment(1) 6,497 6,247 Fully tax-equivalent net interest income 451,597 439,263 Noninterest income (GA
Slide 54: Reconciliation of Return on Average Tangible Common Equity, Nine Months
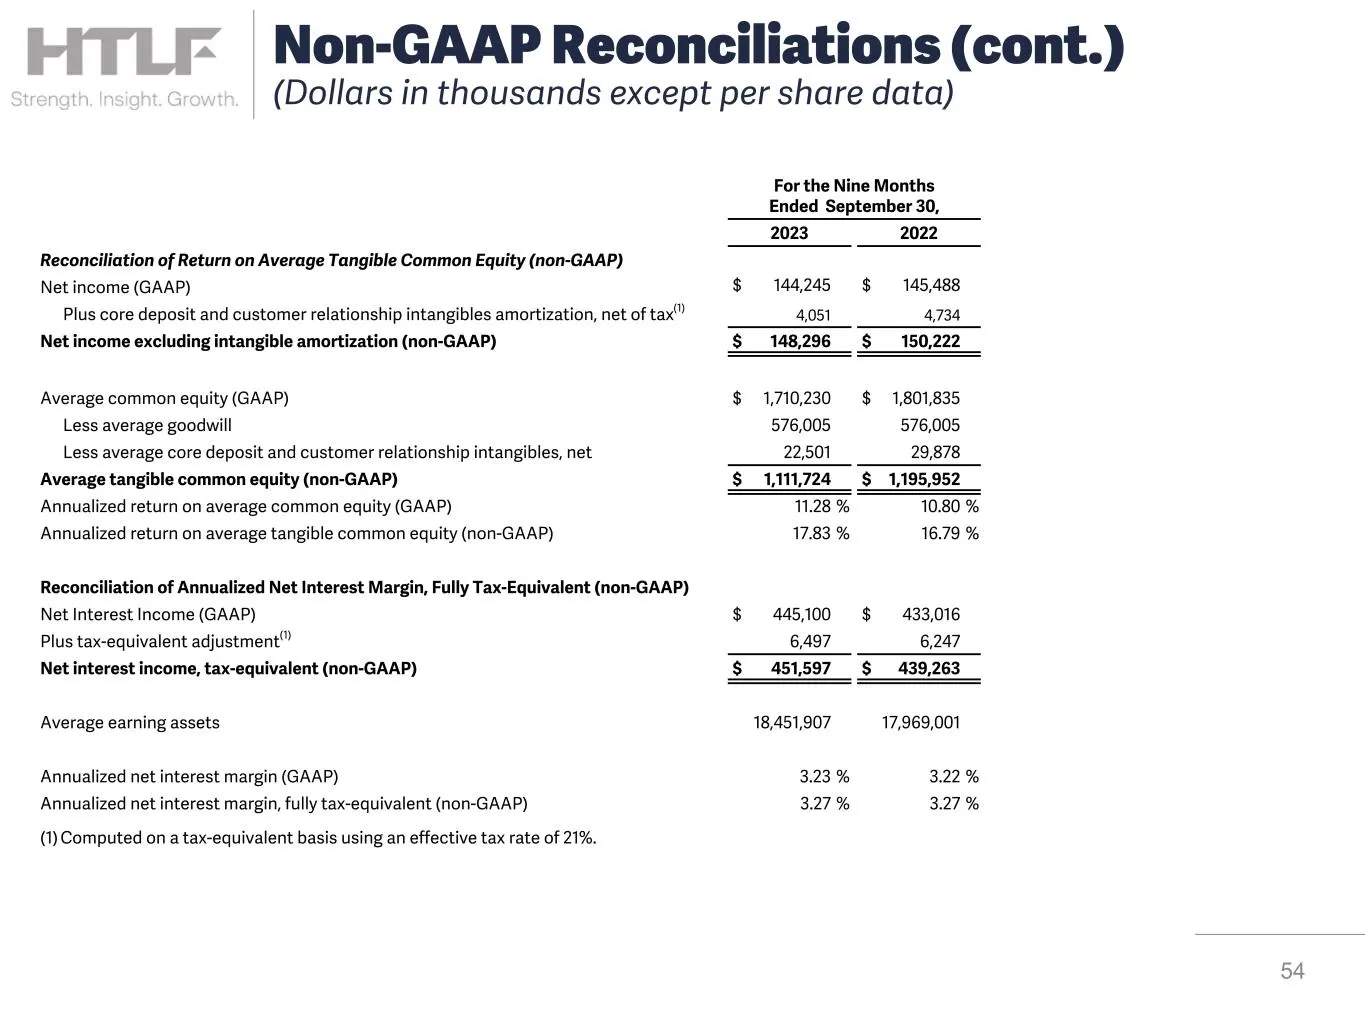
54 For the Nine Months Ended September 30, 2023 2022 Reconciliation of Return on Average Tangible Common Equity (non-GAAP) Net income (GAAP) $ 144,245 $ 145,488 Plus core deposit and customer relationship intangibles amortization, net of tax(1) 4,051 4,734 Net income excluding intangible amortizatio
Slide 55: Together We Are HTLF
i Bank of Py Atizona Qy Bake os she Pes Barksis ILLINOIS aes aciisonotirreunx CITYWIDE BANKS, elise ee Es Rocky MINNESOTA Sota PREMIER GQ fieeeeain WISCONSIN SS eemavnrom -NEWMEXICO ire nank Bank ___ BANK & TRUST" TAC 2 amen emereTrerl scent HT Bank acleen tiie + Together We Are
Source: SEC EDGAR · 8-K filed Nov 15, 2023
More decks from Heartland Financial USA Inc
 Merger or Acquisition (July 2024)6 slides · Jul 31, 2024
 Merger or Acquisition (May 2024)6 slides · May 2, 2024
 Merger or Acquisition (May 2024)27 slides · May 2, 2024
 Q4 2023 Earnings Presentation54 slides · Feb 13, 2024
 Q4 2023 Earnings Presentation35 slides · Jan 29, 2024
 Q3 2023 Earnings Presentation35 slides · Oct 30, 2023